


Running Head: CASE STUDY ELEVEN
1
Case Study 11: Roche Holding AG: Funding the Genentech Acquisition
Liberty University
BUSI 692
CASE STUDY ELEVEN
2
1. What is going on at Roche?
Roche Holding has been making an offer for the acquiring of the remaining shares for
Genentech in 2008. It is recommitting with the discount offers with the need to sell 1 year to
the 30 year of the bonds for the different currencies (Bruner et al., 2018). It is seen that the
condition of the market has been showing the increased unemployment rates with the
benchmark that yields the declining in the rates of borrowing. The bond offering process
includes the hire investment bankers for helping in providing the assistance, where Roche has
been working on hiring the 7 banks with 3 for the US dollar deal and forum for the euro and
the pound deals (Reed et al., 2019).
2. What are the business and financing “…”
There have been risks related to the intense decline in the equity or the credit markets in the
time of 45 percent (Harris & Dudley, 2018). Hence, one need to get the loan from the banks
which is difficult and so there are banks which have been bankrupt and then there are
problems related to the global depression with finance getting hard. It is also tough to
improve the economy for the multiple government which is lowering the interest rate and the
investment in the financial institutions. With this, there have been companies working on the
facing of the downgrade credit rating with the increased debt that is leading to the higher
payment interests that could directly affect the deal. For this, the business risks could be
Genentech willingness for the shares selling and handling the reduced offers (Chen et al.,
2019).
3. Do you believe the bond issuance will “…”
Yes, I firmly believe that on the bond rating which is mainly through the financial strength.
The focus is on the emission of the new debt which are raising the interest. Hence, there are
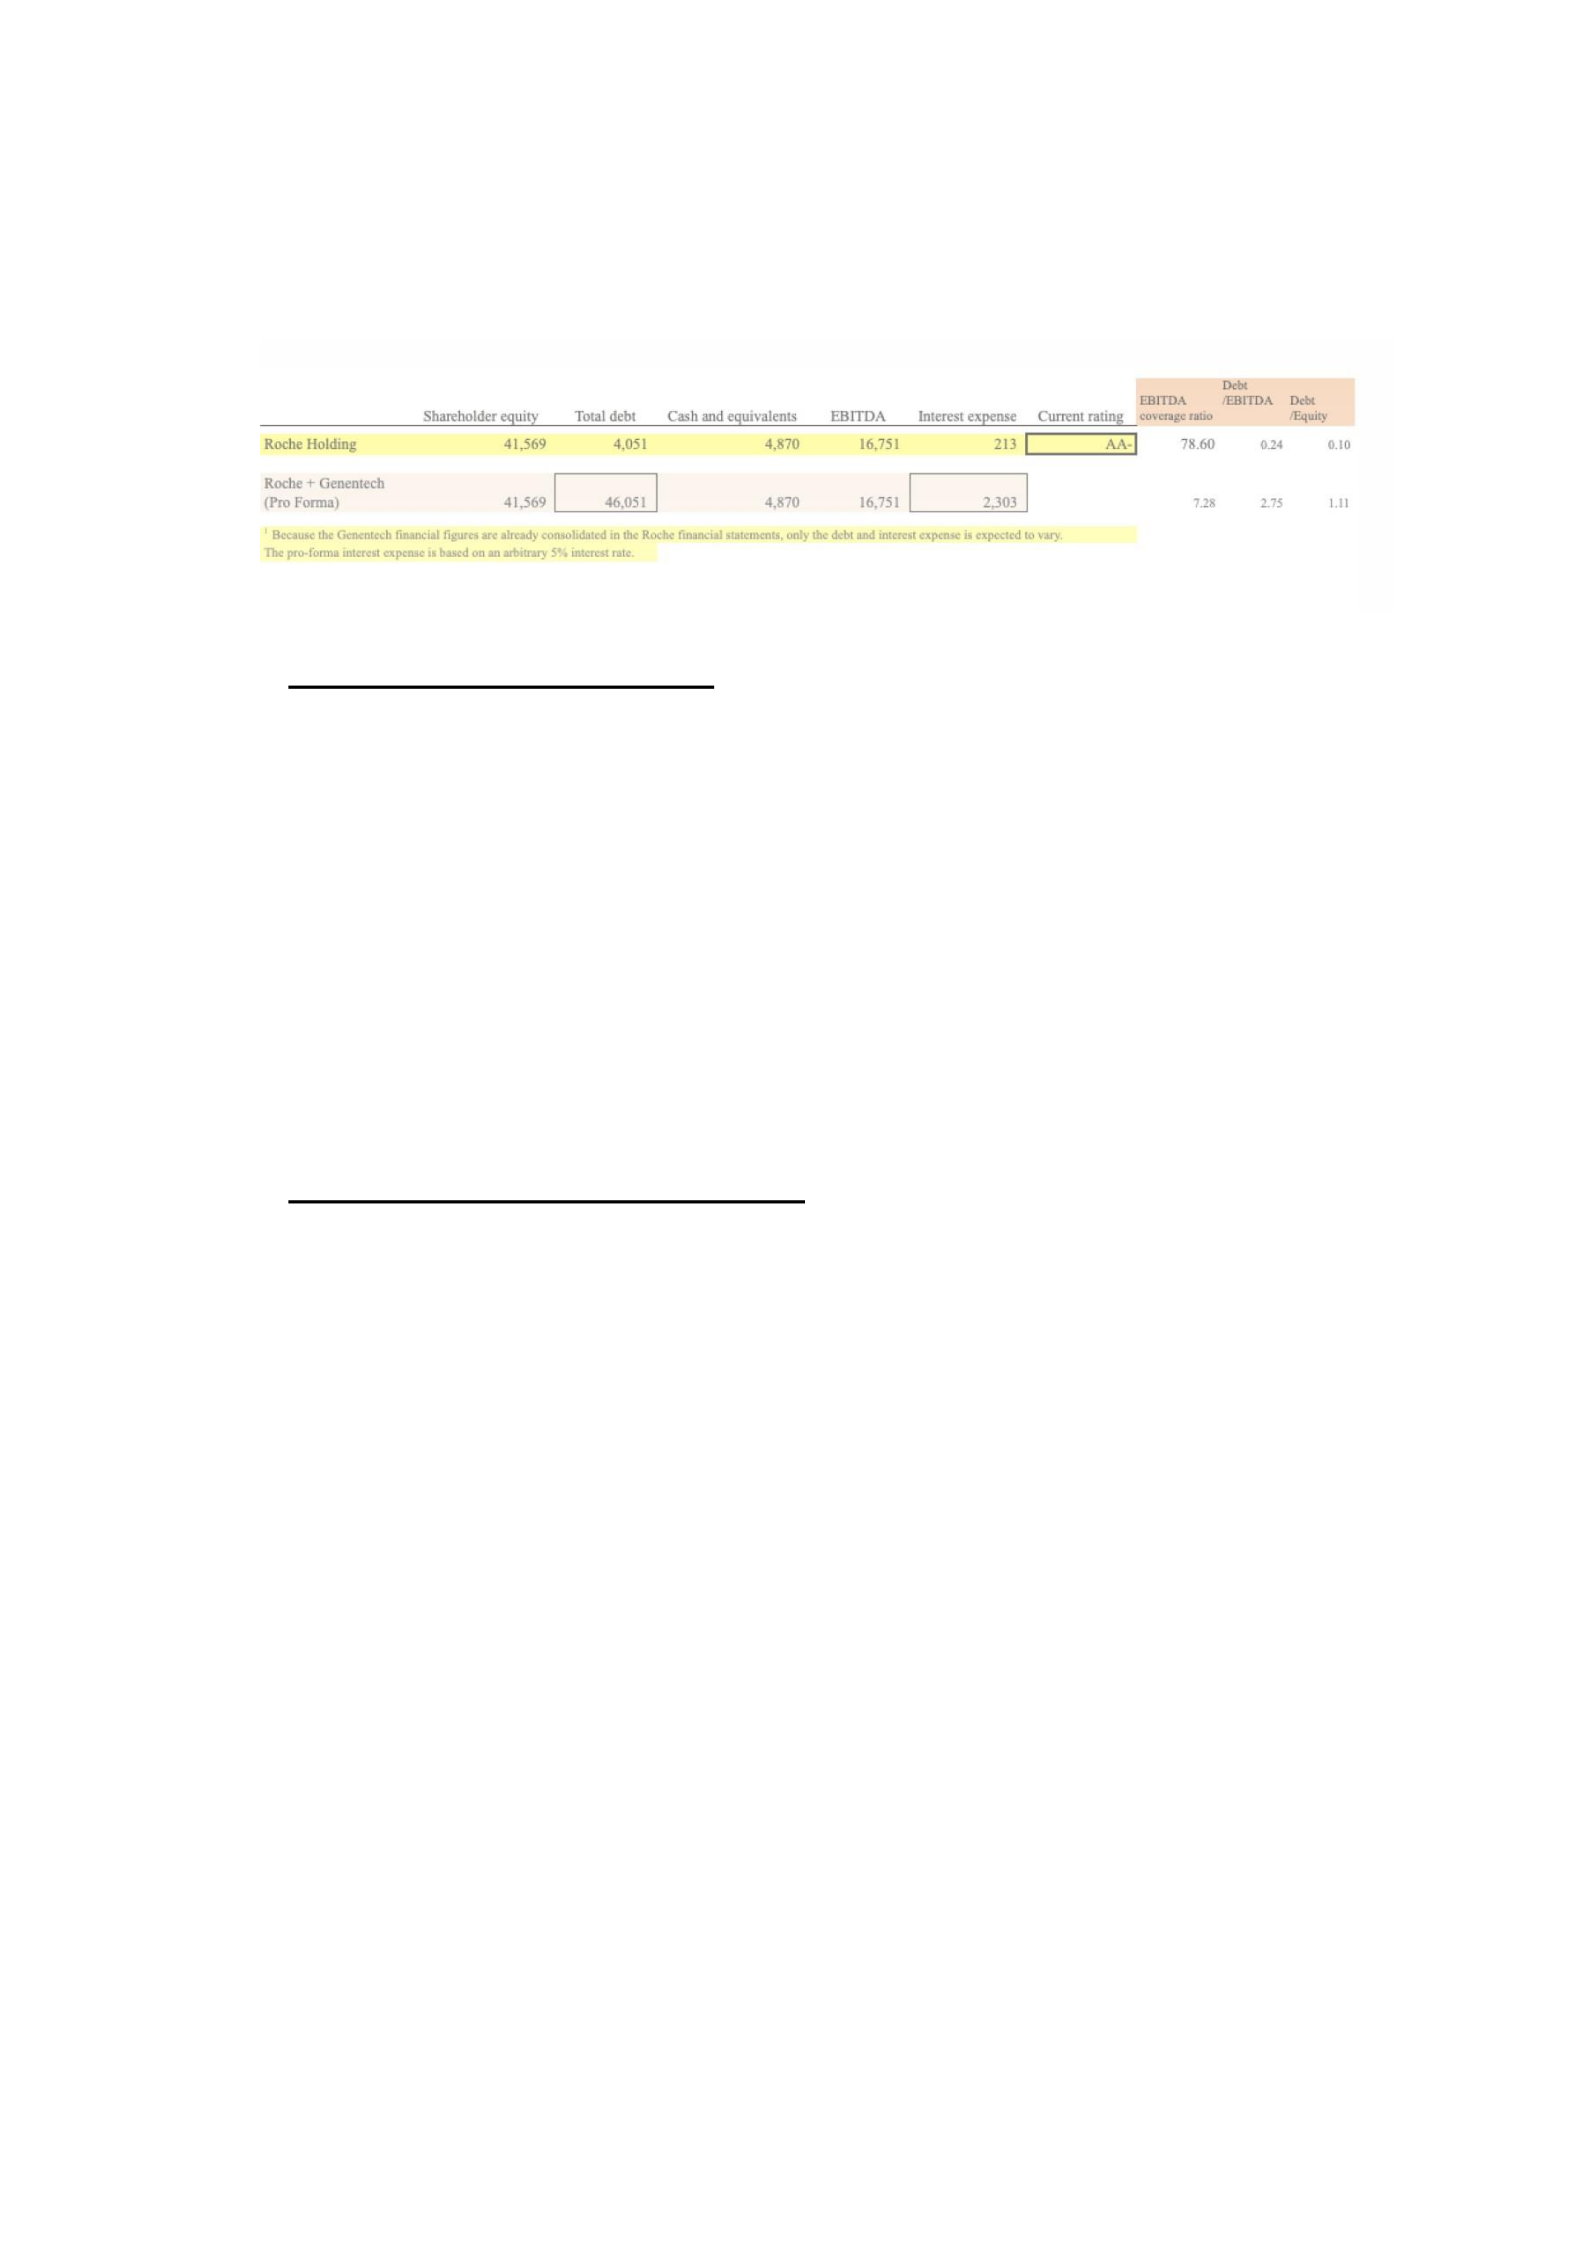
expenses of the debt which are making the rating go down from AA to A. Hence, as per the
analysis of Exhibit 12 there are acquisitions of Genentech with increased total debt of the
CASE STUDY ELEVEN
3
interest expense that highlights on the reduced liquidity and the company facing the problems
of the leverage for the debt factors.
4. How do we assess the impact of “…”
For this, the focus is on the credit rating of Roche which includes the stability as it is using
9.7% of the debt in the capital structure. There have been other credit rating agencies that are
working like S&P with Moody Rate of Roche that includes the AA and Aa1 rating. The
company has been showing the stronger capacity for meeting the different requirements and
the commitment with the rise of the financial standards. This is the urgency case in the banks
for providing the easy debts for the firms which are under AA and Aa1.
5. How do we estimate the risk premium “…”
As per the standards, it is seen that there are different financial solutions for Genentech that
needs a proper management of the company. Apart from this, there is a need to consider about
the rise of the financing issues related to the trading of the bonds which are approximately
$32 billion. The increase in the portion of the debt includes the increase of the risks that are
associated to the value of the debt. Not only this, the costs tend to increase with the debt ratio
and so the expectation is that it will lead to the lowering of the EBITDA and the coverage
ratios for the company from 78.6 to 7.3x. There are bonds with the higher maturity period
and have a higher risks default structure. Here, the investors will also be demanding for the
higher returns with the premium on the bonds (Kim et al., 2017). It includes the maturity
period and the greater time of more than 5 years. Hence, the coupon rates are for the bonds
CASE STUDY ELEVEN
4
with the maturity period of 10 years and 30 years which will be as high when there are
investors working on the demands with more premium and return due to the risks.
6. What are the prevailing spreads for non-Roche “…”
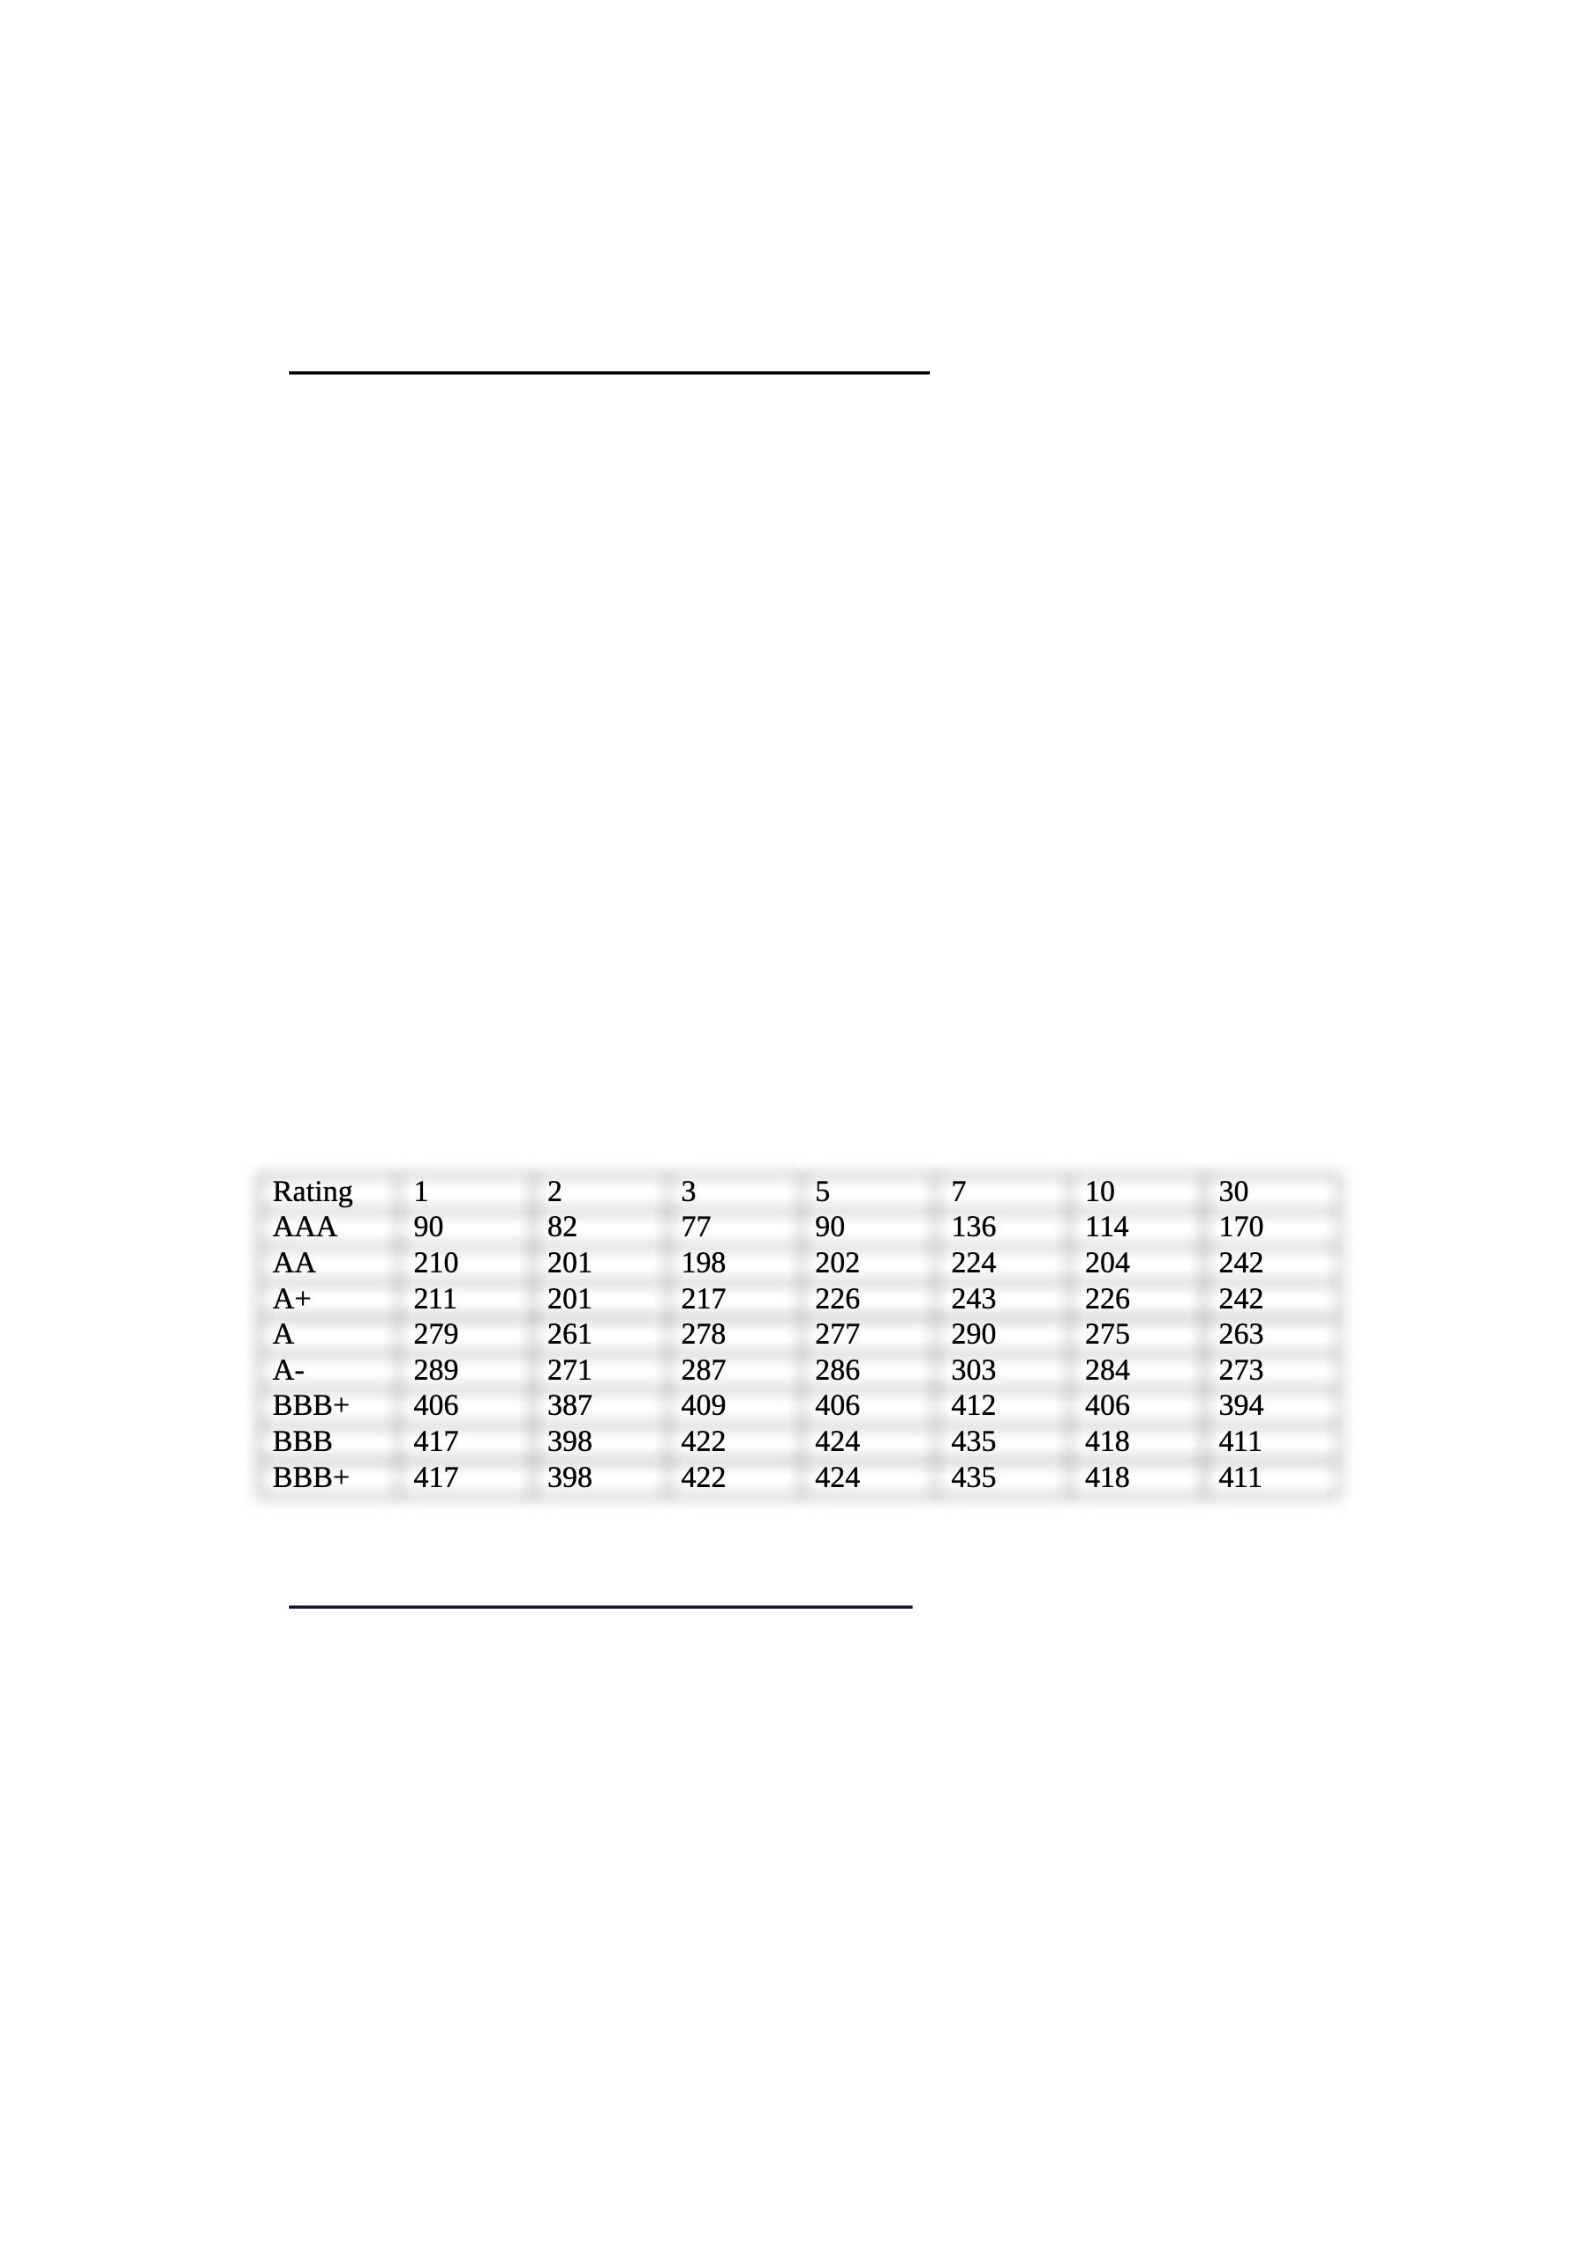
The focus is on the spread for the non-Roche bonds which are under Exhibit 6.
a. Here, there are yield for the return where the bond needs to offer for the investment
worth. Here, the spread includes the differences for the yields with handling the debt
instruments.
b. There are spreads which are same to the investor yield for the Roche bonds. This is
because there is a yield spread that gives the idea to the investor about how they need
to invest for the particular yield.
c. The spreads is from extra government treasury bill.
d. The spread is for the non-Roche goods with the benchmarks that needs to be
compared with the non-Roche financials (Bruner et al., 2018).
7. What is your specific recommendation for the “…”
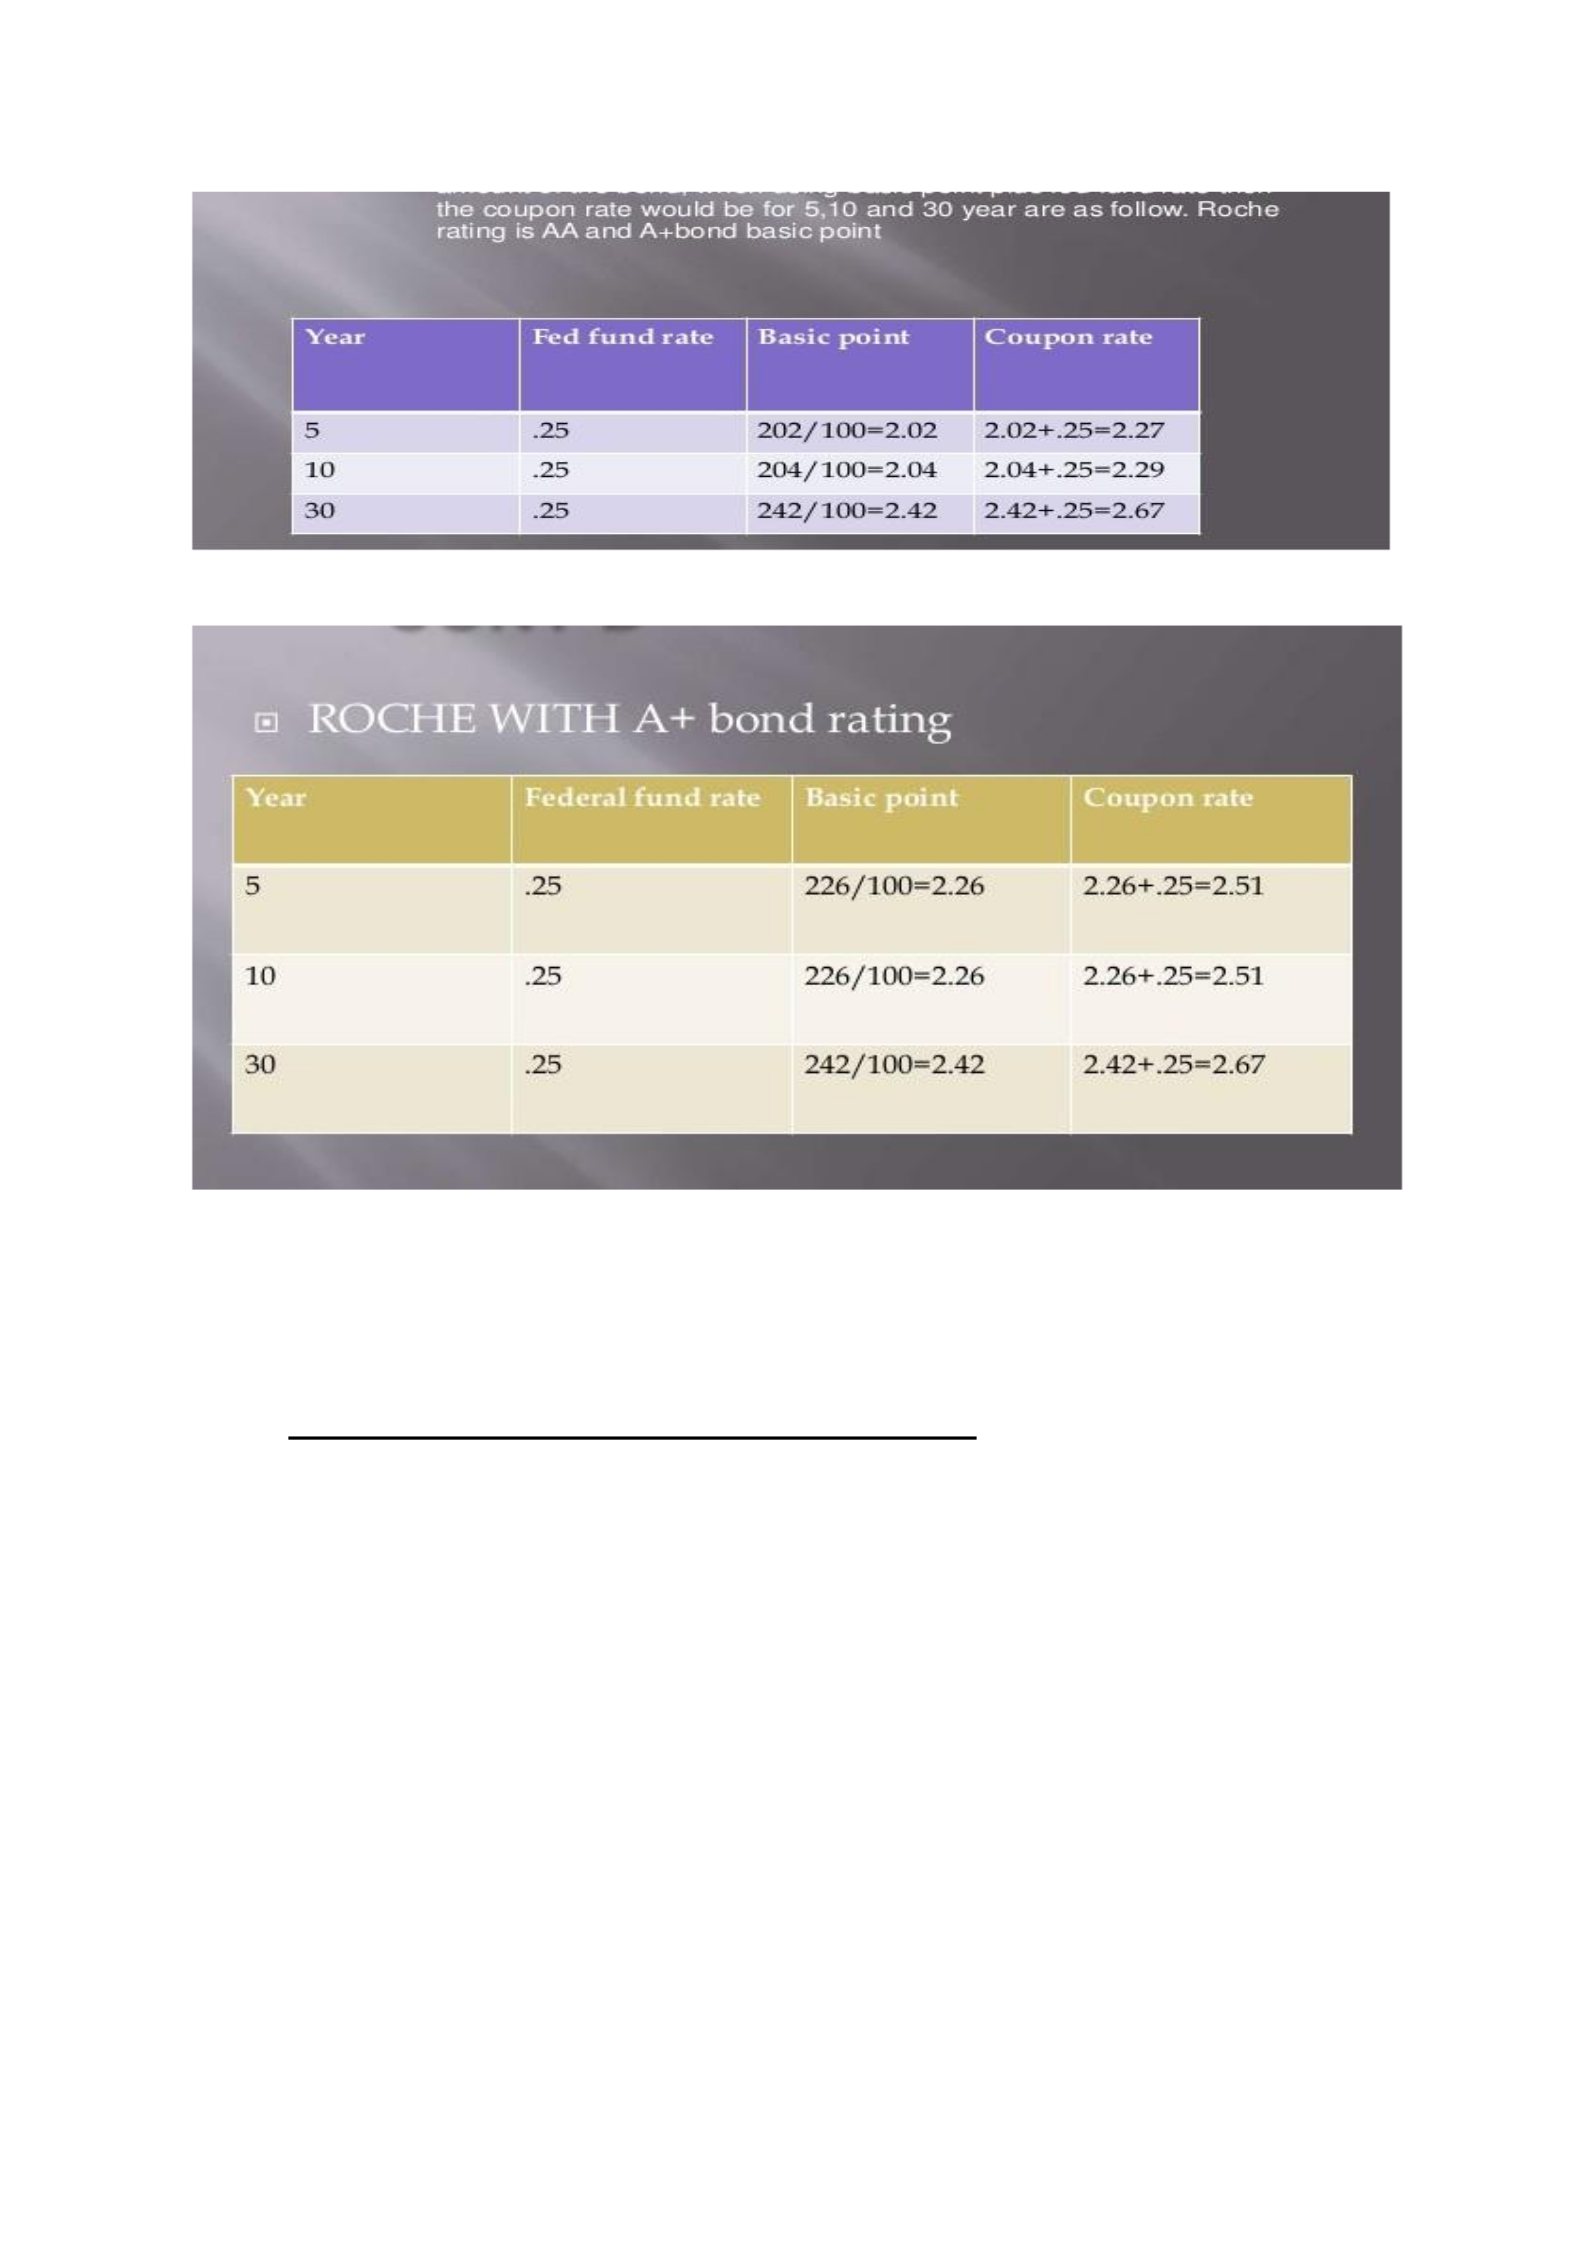
There have been coupon rates which are set for handling the interest amount which is being
paid for the year. Hence, this is based on the bond value with the coupon rate that is for the
computing of the amount bond payment. This is through basis points and the fund rates that
are used. Hence, they would be rating under AA and A+ bond basic.
CASE STUDY ELEVEN
5
Hence, the higher rate of the coupon is the better return on the bond with the lower maturity
which is better.
8. What would your coupon rate recommendation be “…”
1 Euro=1.18 usd
coupon rate for 7 years will be 224 basis points in USD. Hence, 224/1.18=189.83
Hence, the coupon rate is 189.83/100=1.8983

CASE STUDY ELEVEN
6
References
Bruner, R. F., Eades, K., & Schill, M. (2018). Case Studies in Finance (8th Edition). New
York, NY: McGraw-Hill Education.
Chen, L., Choi, K. J., & Lee, J. Y. (2019). The Effect of rating dispersion on purchase of
experience goods based on the Korean Movie Box Office Data. Asia Marketing
Journal, 21(1), 1-21.
Harris, C., & Dudney, D. (2018). Securitization, trade credit and the nature of
goods. Journal of Accounting & Finance (2158-3625), 18(2).
Kim, K., Mithas, S., & Kimbrough, M. (2017). Information technology investments and
firm risk across industries: Evidence from the bond market. Mis Quarterly, 41(4),
1347-1367.
Reed, P., Cort, T., & Yonavjak, L. (2019). Data-driven green bond ratings as a market
catalyst. The Journal of Investing, 28(2), 66-76.

