


Dealing with risk and uncertainty in project appraisal
During this course, we have dealt with information as if the cash flows from decisions are known
with certainty. The cash flows used to calculate NPV have been supplied to you without any
reference to how accurate they are or whether they are only estimates from a range of values.
Information about this is needed, because in real life the future is never known for certain and we
are interested in the range of outcomes which could occur, not just the best estimate of what
might happen. Investment decisions are particularly susceptible to risk and uncertainty, because
the cash inflows from an investment can take place over many years or even decades. The
number of years these cash flows will last; how large these cash flows will be; and whether they
will even take place at all are all uncertainties.
This section looks at risk and uncertainty in more detail, and how it can be taken into account
during project appraisal. This section begins with a discussion on the difference between risk and
uncertainty, and typical attitudes which people have towards risk and uncertainty. We discuss
some simple ways to adjust the discount rate and payback period to take risk into account. We
explain how combining cash flows with their probabilities of occurring can be used to provide
information about the expected values for the outcomes of projects. Finally the value of further
information when making decisions is defined.
At the end of this section you should:
be able to discuss the technical definitions of risk and uncertainty, and the range of
attitudes which can be taken towards them
be able to demonstrate some simple adjustments to NPV analysis to deal with risk
know how to calculate probability-weighted cash flows, and explain why this approach is
effective when risk is present in NPV analysis
be able to apply probabilities to future outcomes, and explain why this is an alternative to
an increased discount rate
be able to explain the meaning of value of information.
Risk and uncertainty
The terms ‘risk’ and ‘uncertainty’ tend be used interchangeably in normal language; however,
they have different technical meanings, set out by Knight (2012). Take a situation where there
are several possible future outcomes. We cannot say which will occur, but if we can assign
probabilities to the likelihood of each possible outcome occurring, we have a situation of risk.
(These probabilities can be determined by reference to the relative frequency of outcomes that
happened in the past. Alternatively they may be estimated from market research or using the
expertise and experience of the staff involved in a project.) If we cannot assign probabilities to
the likelihood of each possible outcome occurring, we have a situation of uncertainty.
Note that, technically, risk and uncertainty do not necessarily have negative connotations. They
simply mean that future outcomes are not known with certainty. Where they are present, it means
that cash flows could be better or worse than their estimated values. However in everyday use,
risk and uncertainty are typically used to mean outcomes which are worse than a level previously
predicted, so be aware of this difference.
You may notice that despite the definitions above, there is still a grey area between risk and
uncertainty. While we may always be able to estimate probabilities of certain outcomes

occurring, the degree to which these probabilities are accurately known is also subject to
uncertainty. For example, if I am rolling a die or tossing a coin, I know exactly the probabilities
that the possible outcomes have. However, a situation where you know the probabilities for
certain is unlikely in business situations.
A manager trying to forecast demand for a new product may be able to estimate the probability
of achieving sales of £500,000, £1,000,000 and £1,500,000 as 20%, 50% and 30%, respectively,
based on past sales for similar products. However the probabilities themselves are not known
with certainty. The amount of uncertainty will vary depending on the situation, so there will be
varying amounts of uncertainty about the risks faced! In practice, you would have to use your
judgement to decide whether probabilities can be estimated accurately enough for risk analysis to
be worthwhile, or whether the project should be treated as having uncertain outcomes without
probabilities attached to them.
Attitudes towards risk
In this course, we have taken the attitude that decision-makers are risk neutral. This means that
they select the option which produces the greatest NPV, regardless of how risky the option is. If
the same decision was taken many times, selecting the option with the greatest expected value
each time would produce the highest value in the long run. However, many decisions taken in
business are one-off decisions, not decisions which are repeated many times.
In this context, other attitudes towards risk are often taken. People can be risk averse, meaning
that they avoid risk. The technical definition of a risk-averse decision-maker is someone who
will sacrifice higher expected value in order to avoid risk. Note that this definition is different
from the common definition of simply avoiding risk where it is present. Here is an example to
demonstrate what this means.
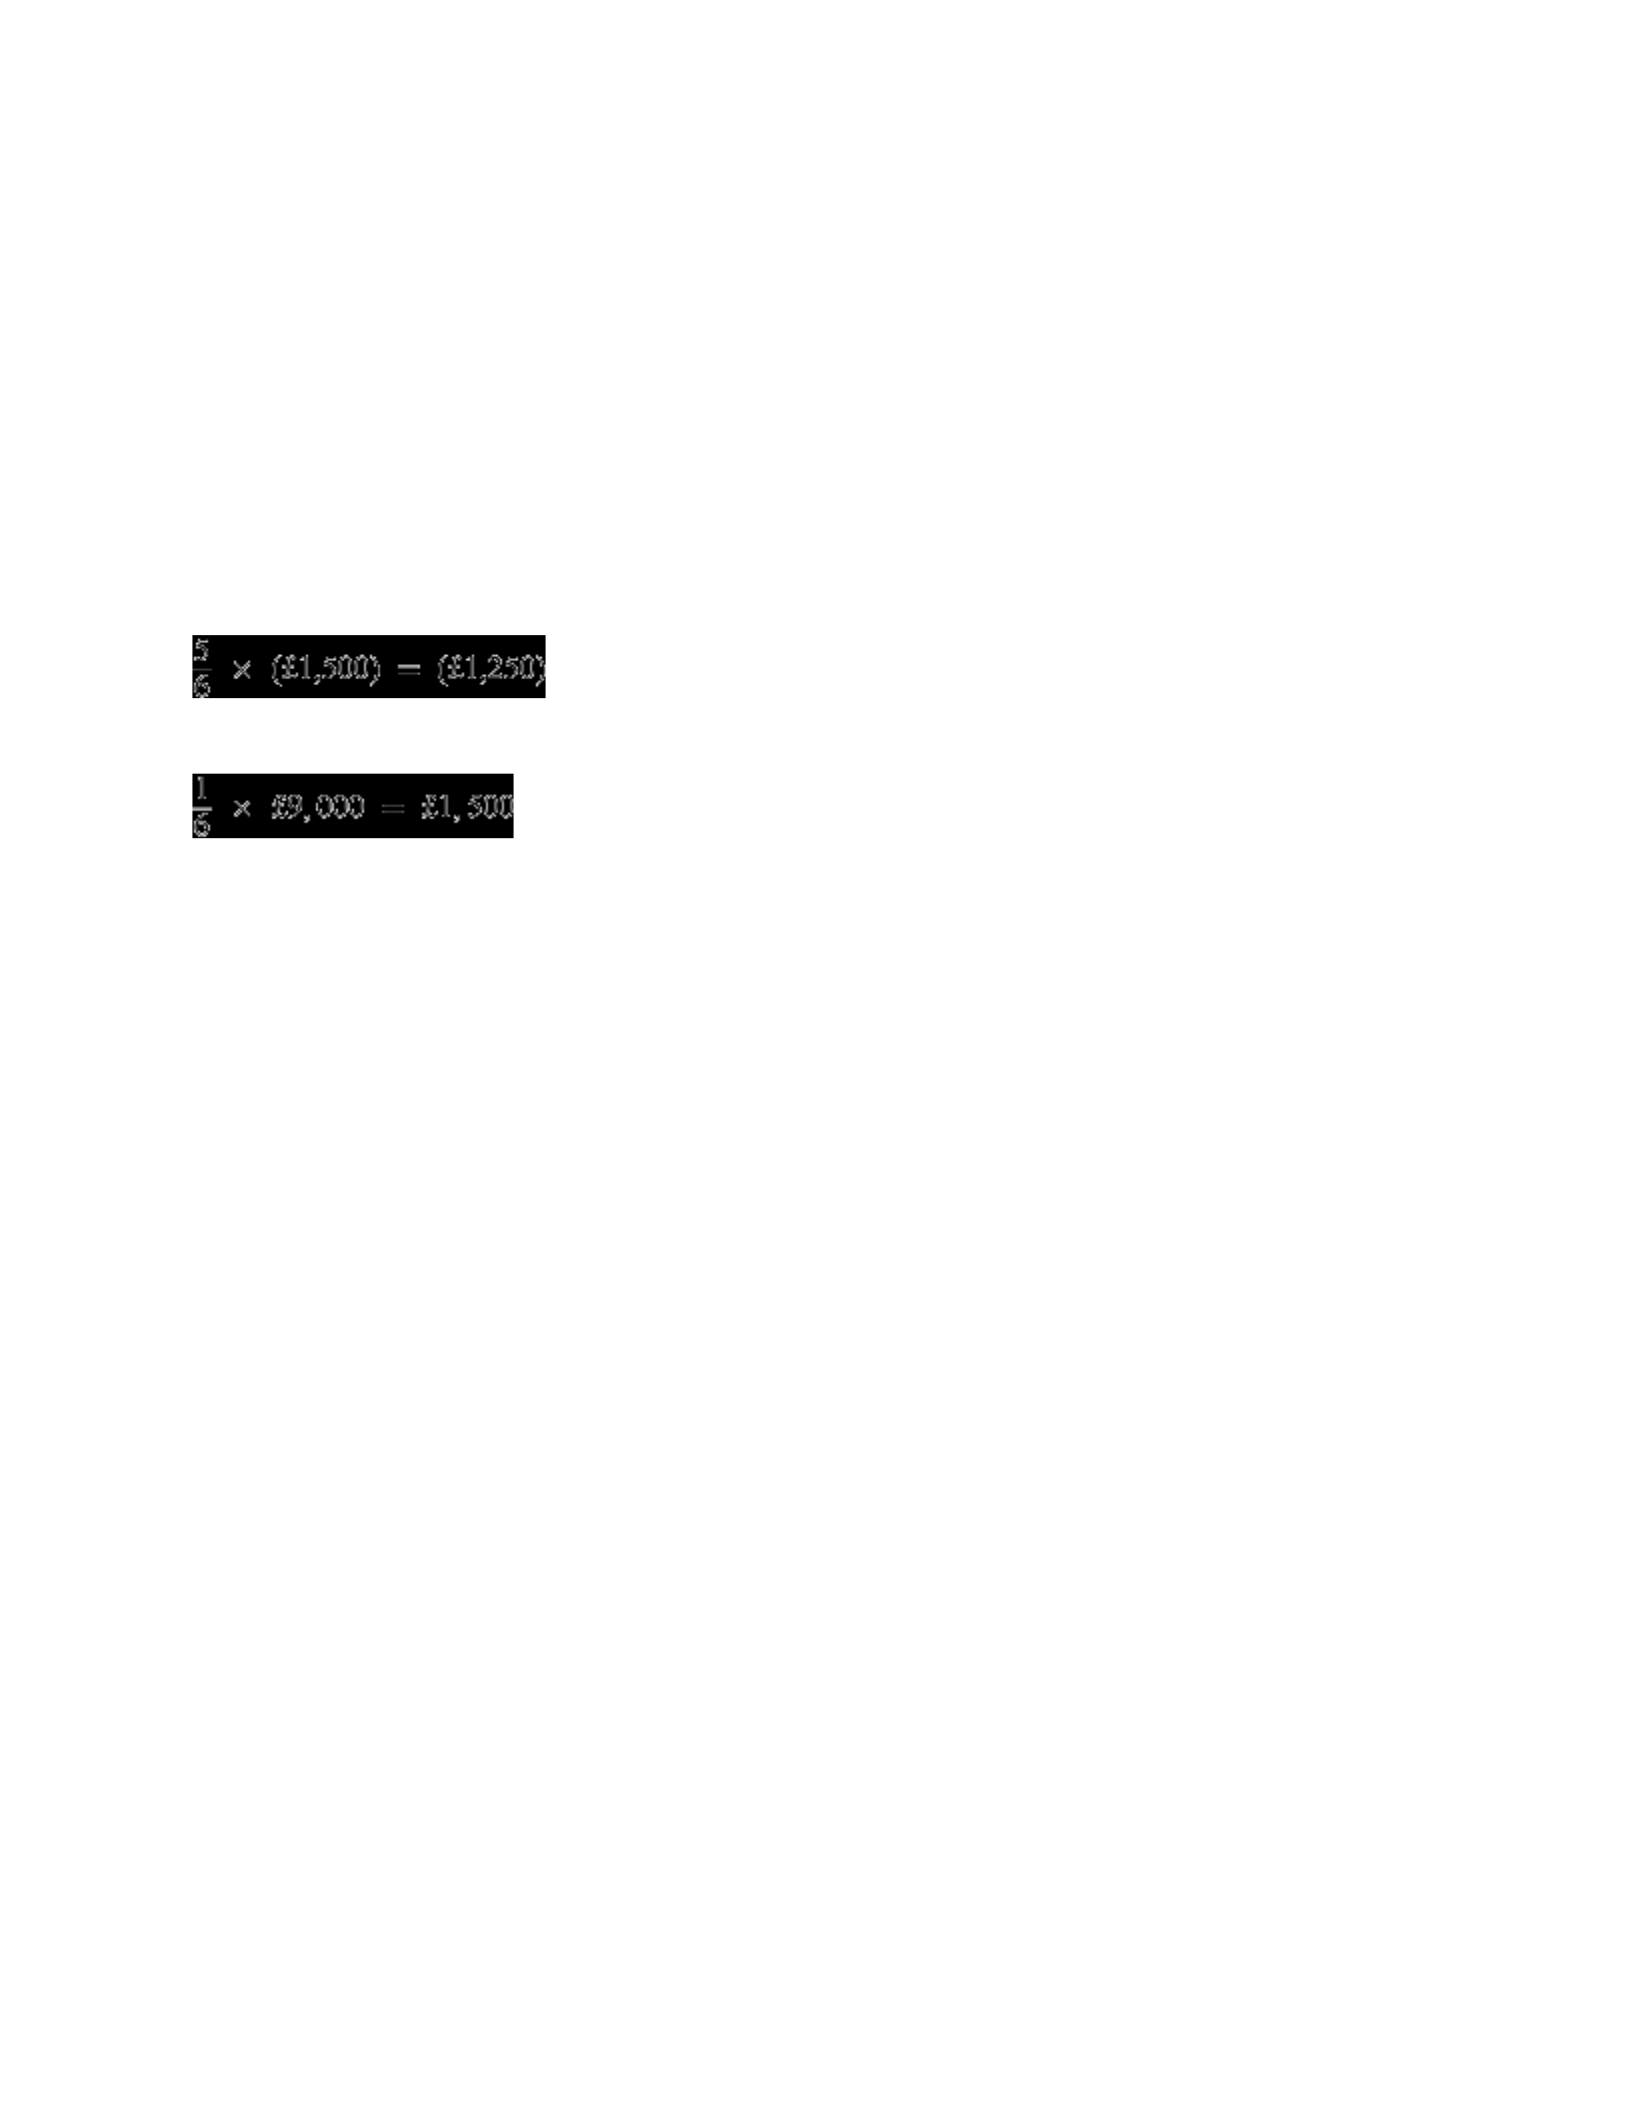
Imagine you are offered a bet: you win £9,000 if you roll a six on a die, but you pay £1,500 if
you roll any other number. Would you take the bet? The expected value of the bet is in your
favour:
So the expected value = (£1,250) + £1,500 = £250
A risk-neutral person would accept the bet, since it has a positive expected payoff: the average
gain on the bet is £250 per time. However many people would refuse such a bet, and demonstrate
that they are risk averse in this case. A risk-averse attitude is common in many people, and in
business decision-makers to some extent. People often prefer to stick with what they have – for
example, a profitable and low risk business, rather than risk losing this for the (better than
average) chance of making more money or expanding the business successfully.
It is also possible to be risk seeking, meaning unsurprisingly that people seek out risk in order to
get better returns. The technical definition of a risk-seeking decision-maker is someone who will
sacrifice higher expected value in order to take on risk. Note that this is different from the
common definition of someone who is simply willing to take risks: a risk-neutral decision-maker
will also do this when the expected value is in their favour.

Someone who was risk neutral would now reject the bet, because the expected value is negative
and the bet will lose money on average. However a risk-seeking individual would still take the
bet despite the expected value being negative, because taking the bet increases the risk they are
exposed to.
Obviously, risk-seeking individuals in this definition are unusual. Most people will accept some
risk in return for a greater average return, and people vary in how much reward they require for
additional risk. However, few people will take on more risk at the same time as making the
expected value worse on average – being ‘risk-taking’ is usually meant as a relative term. Almost
everyone is risk-averse to some extent, and how ‘risk-taking’ someone is, is a measure of how
close to being risk-neutral they are.
The layman definitions fit in better with how most people use these terms (and also how they are
used throughout this course). Risk-seeking people are simply people more likely to take on risk
than risk-averse people. For example, risk-seeking investors would be more likely to invest in
stocks, attracted by the higher potential returns on offer, while risk-averse investors may invest
in bonds and gilts, which have little risk attached to them but have lower expected returns.
By investing in riskier investments such as stocks, risk-seeking investors are actually increasing
their expected return not decreasing it, because the long-term average return of stocks is
historically higher than bonds. So these risk-seeking investors are really just risk-neutral
investors (in the technical sense of the term) who are taking the option with the highest expected
value and are not deterred by the higher overall risk.

Note that the technical and common definitions of risk-averse investors tend to be more similar.
For example, in declining to invest in stocks, investors are both avoiding risk (the common
definition), and also reducing their expected return in order to do so (the technical definition).
Simple adjustments to deal with increased risk
Dealing with risk can be relatively simple: the techniques below are quick ways to incorporate
some understanding of the risk of a project into the project appraisal. While they are not the most
sophisticated methods available, they benefit from being easy to understand and implement, and
are certainly better than making no adjustment for risk. The following subsections discuss how
the discount rate and payback period can be adjusted, and clarify that the discount rate does not
need to be adjusted for cash flows which occur further in the future, if the discount rate is used
appropriately to calculate a discount factor for each year.
Risk and the discount rate
Remember that in Section 3, you saw that the reasoning behind the discount rate is that it
represents the return that would be demanded by investors in order to invest in a project. The
higher the risk of a project, the higher the return that would be demanded to invest in that project.
A higher rate compensates an investor for the possibility that the future cash flows are not
actually received. A higher risk means that future cash flows are less certain, so where the risk of
a project is higher, a higher discount rate should be used.
So, the most basic way to adjust the discount rate for increased risk is to discount future cash
flows by an appropriate amount. Throughout most of this course, the discount rate has been
supplied to you as the cost of capital or the required return. Using the cost of capital is acceptable

if a project has the same risk as the on-going operations in an organisation. However, if the
project has a risk different from the normal operations in an organisation, a different discount
rate should be used to reflect this. Section 3 discussed how the CAPM can be used to estimate
the risk of a project by using the beta of companies which undertake similar projects or operate
in the same industry as a comparison.
Risk and the payback period
A similar way to adjust for risk is to shorten the length of the payback period, a technique known
as adjusted payback period. A shortened payback period means that a project must pay back the
initial investment more quickly in order to be acceptable. However it is still not recommended,
as it still has all the issues of the payback period that make it only somewhat useful as a heuristic.
NPV is the superior method of dealing with risk: if the discount rate is calculated correctly then
cash flows further into the future will be given less weight due to higher discounting, but they
will still be given some weight, rather than being ignored if they are after the payback period.
The same method of decreasing the acceptable payback period can also be used with the
discounted payback period. This is an improvement on the payback period but still has most of
the same problems. Also note that, whether you use the standard payback period or an adjusted
one, and standard or discounted payback, the decision rule about whether to accept a project is
still arbitrary. How many years is an acceptable payback time? There is no right answer since the
payback rule does not consistently produce the best decision. Increasing the discount rate to deal
with higher risk is a blunt instrument, but if risk is accounted for properly in setting a discount
rate, then the decision rule is still clear: accept any project where NPV is greater than zero.

Risk and time delay
People sometimes think that if cash flows occur further into the future, they are riskier so should
be discounted at a higher rate. This is incorrect: the discount rate is already applied and
compounded each year, so cash flows further into the future are discounted at a higher rate in
proportion to the amount of time you have to wait until they occur. If risk is constant over time
(e.g. the same discount rate is applied for each additional year), then the discount rate already
takes into account the increased risk with greater time into the future.
Using probability and future cash flows to deal with risk
One way to deal with risk is by using estimated cash flows in NPV analysis that take into
account the range of outcomes that could occur in the future. In fact, this has already been done
implicitly when talking about cash flows in earlier sections: it is rare that the values of future
cash flows that will occur are known precisely.
Estimated cash flows using the probability of different values of the cash flows allows NPV
analysis to take into account the possibility that actual cash flows are better or worse than
expected. This also allows adjustment for when there is a chance that cash flows may not occur
at all (i.e. they may have zero value). An extension of this technique is to assign probabilities to
different possible future scenarios and calculate the expected NPV for each scenario. The
probability of each scenario can then be used to calculate an overall probability-weighted NPV.
This probability-weighted NPV is used to decide whether the project should go ahead.
Estimating future cash flows

In this course, future cash flows have been presented to you as if they are concrete predictions of
what will occur. However, this is not strictly what they are. The cash flows used when
calculating NPV are the best estimates of future cash flows. The cash flows do not represent the
best case scenario and the purpose of the discount rate is not to reflect the risk that the best case
scenario may not occur.
The best estimate of a cash flow should be an unbiased estimate. This means that the actual
outcome may be higher or lower than the estimate, however on average the errors in estimates
should balance each other out. Another name for an unbiased estimate is the expected value,
which was mentioned earlier in this section.
The discount rates reflect the risk that the best estimate of a cash flow could be wrong, and a
higher risk means that the actual value could be further from the estimate than a cash flow with
lower risk will be different from its estimate. At the extreme, an estimate which will definitely
occur has no risk attached to it, since there will be no difference between the estimated cash flow
and the actual cash flow (and it would be discounted at the risk-free rate).
It follows that you should avoid estimating best-case cash flows and then using a higher discount
rate to try to adjust for the fact that the best-case estimate may not occur. The cash flows used
should be a fair estimate of what is expected to happen, which is neither optimistic nor
pessimistic.
Calculating probability-weighted cash flows instead of increasing the discount rate
As mentioned above, it is tempting to try to estimate the increase of the discount rate rather than
try to estimate the probability of certain outcomes occurring. However this practice should be
avoided if possible (it is sometimes known as adding a fudge factor, obviously not a term of
approval!). Ideally, major sources of risk that stem from one unknown outcome should be dealt
with separately and then the remaining cash flows discounted at a lower discount rate.
For example, imagine that the project in Activity 8 also carries a risk that the project will not be
approved by regulators, and consequently no sales will be made. If the project was originally
going to be discounted at 10%, the company may now feel the project’s extra risk means it
should be discounted at 15%. However a better approach is to estimate the probability of the
undesirable outcome occurring. Table 20 shows the situation where there is a 20% probability of
the project not being approved, and if it does go ahead, the likely revenue figures are in the same
proportion as before.
Estimating probabilities for scenarios instead of increasing the discount rate
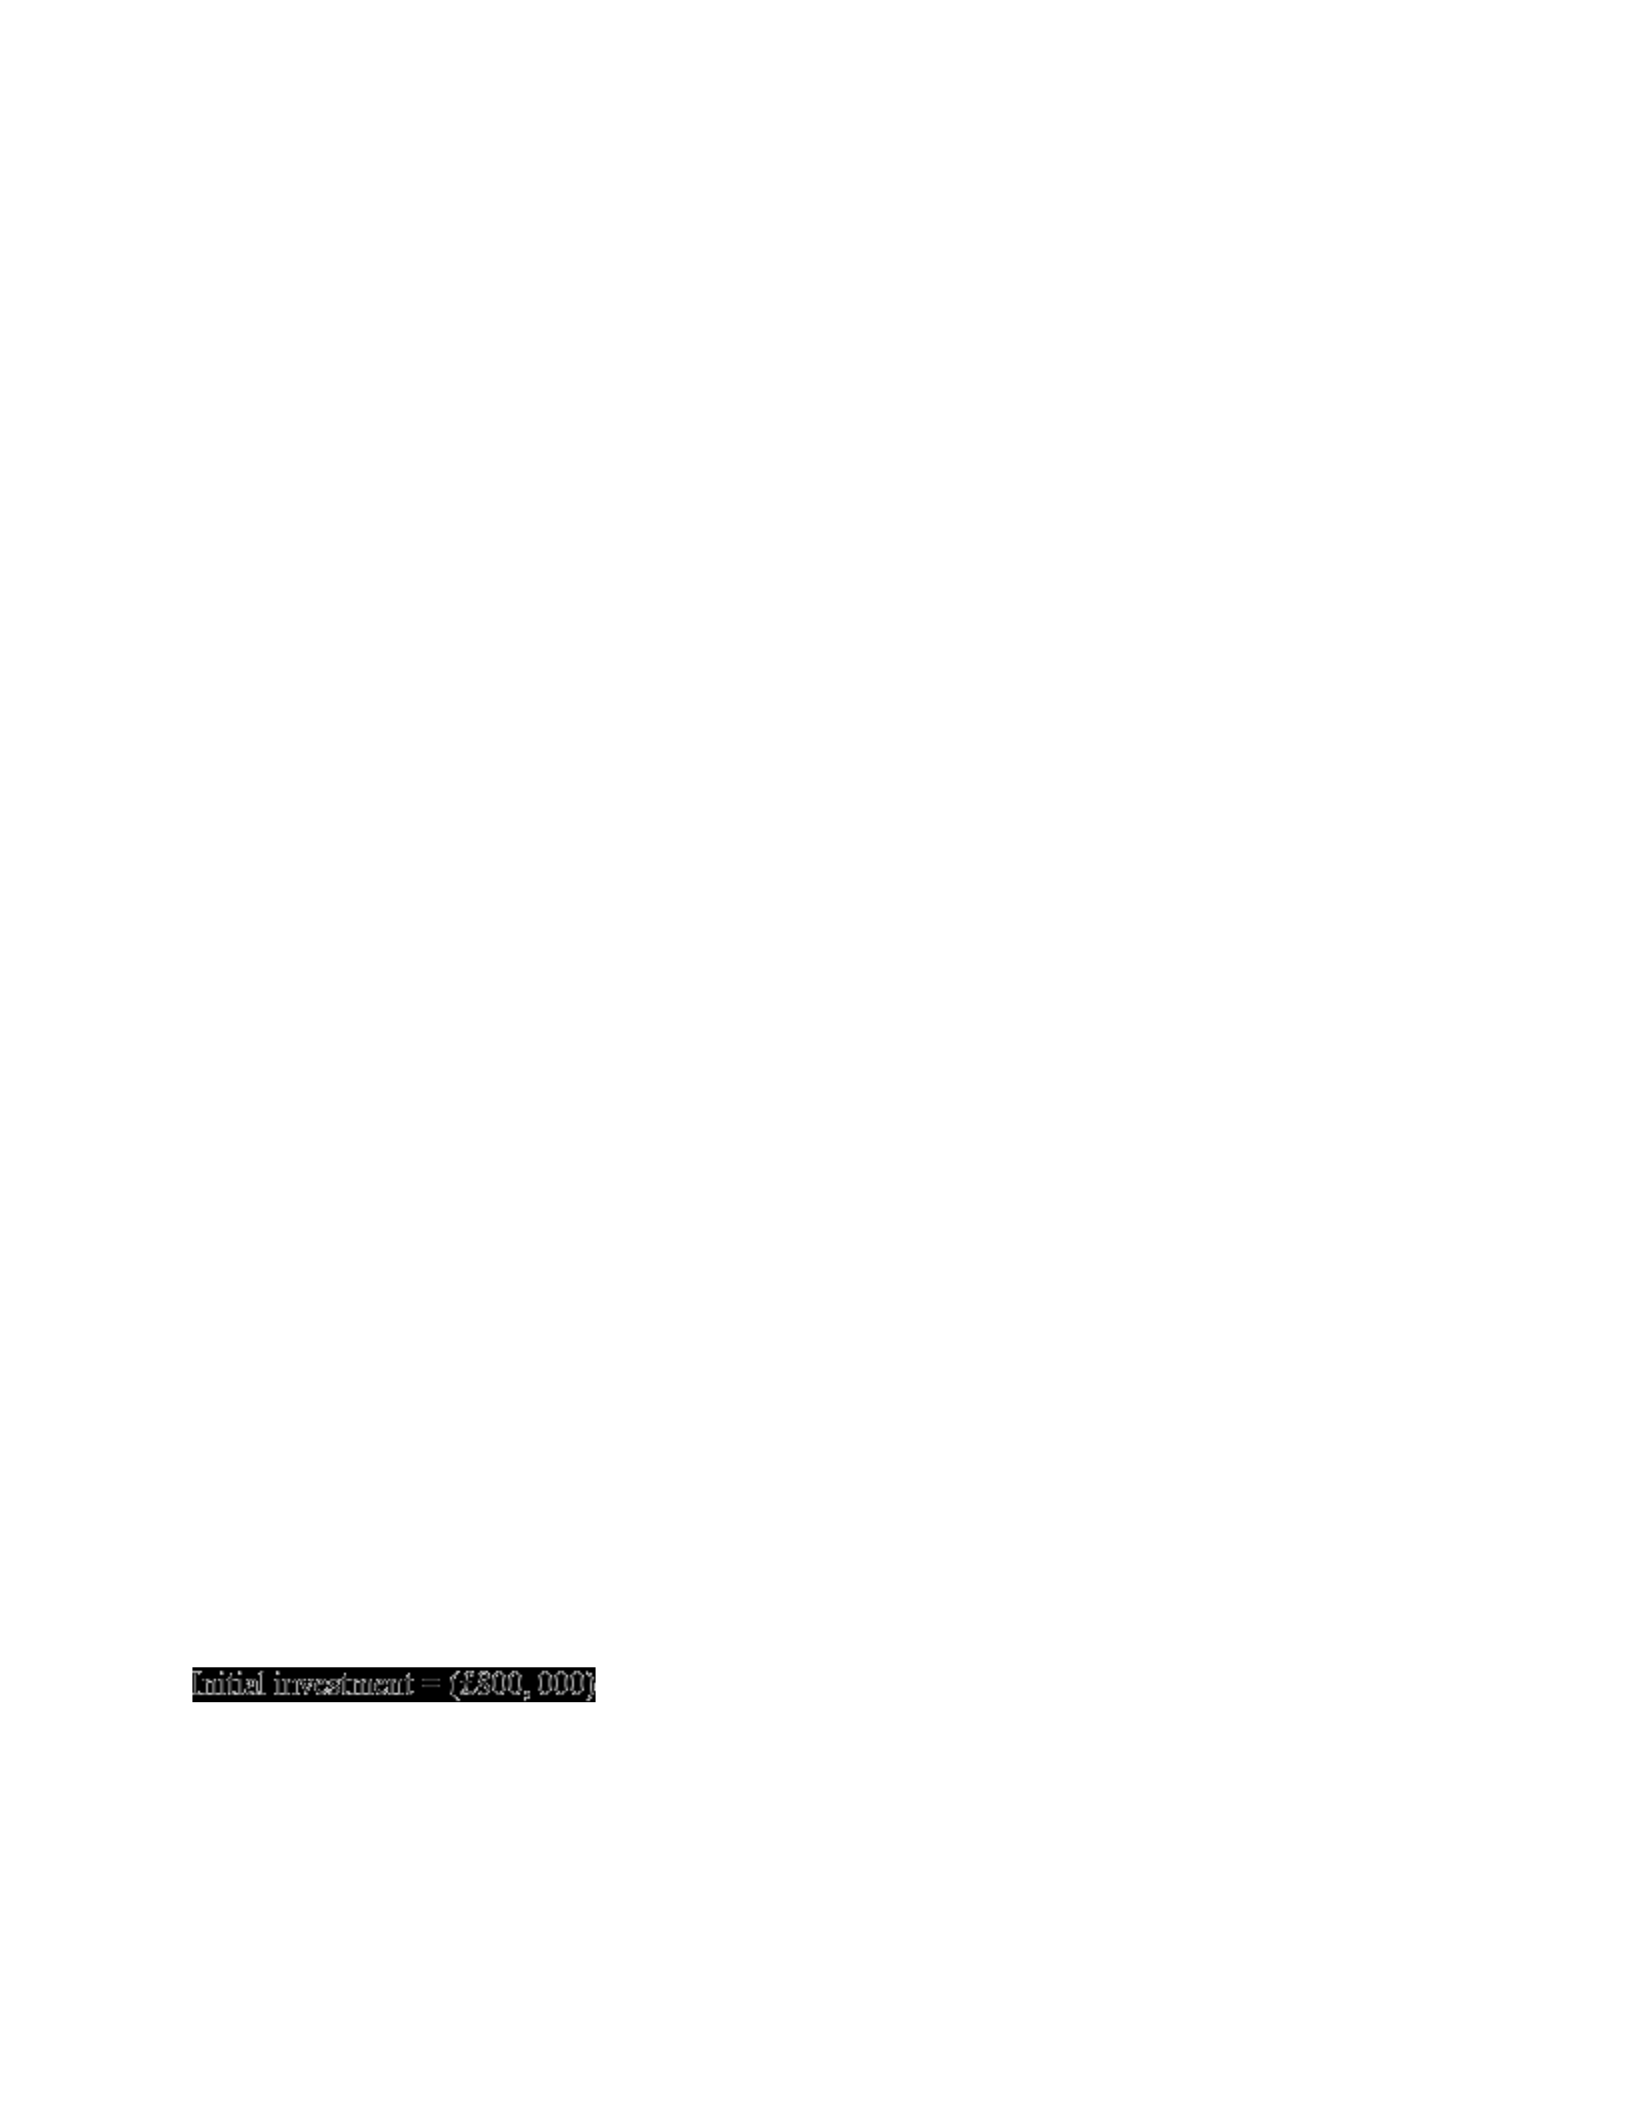
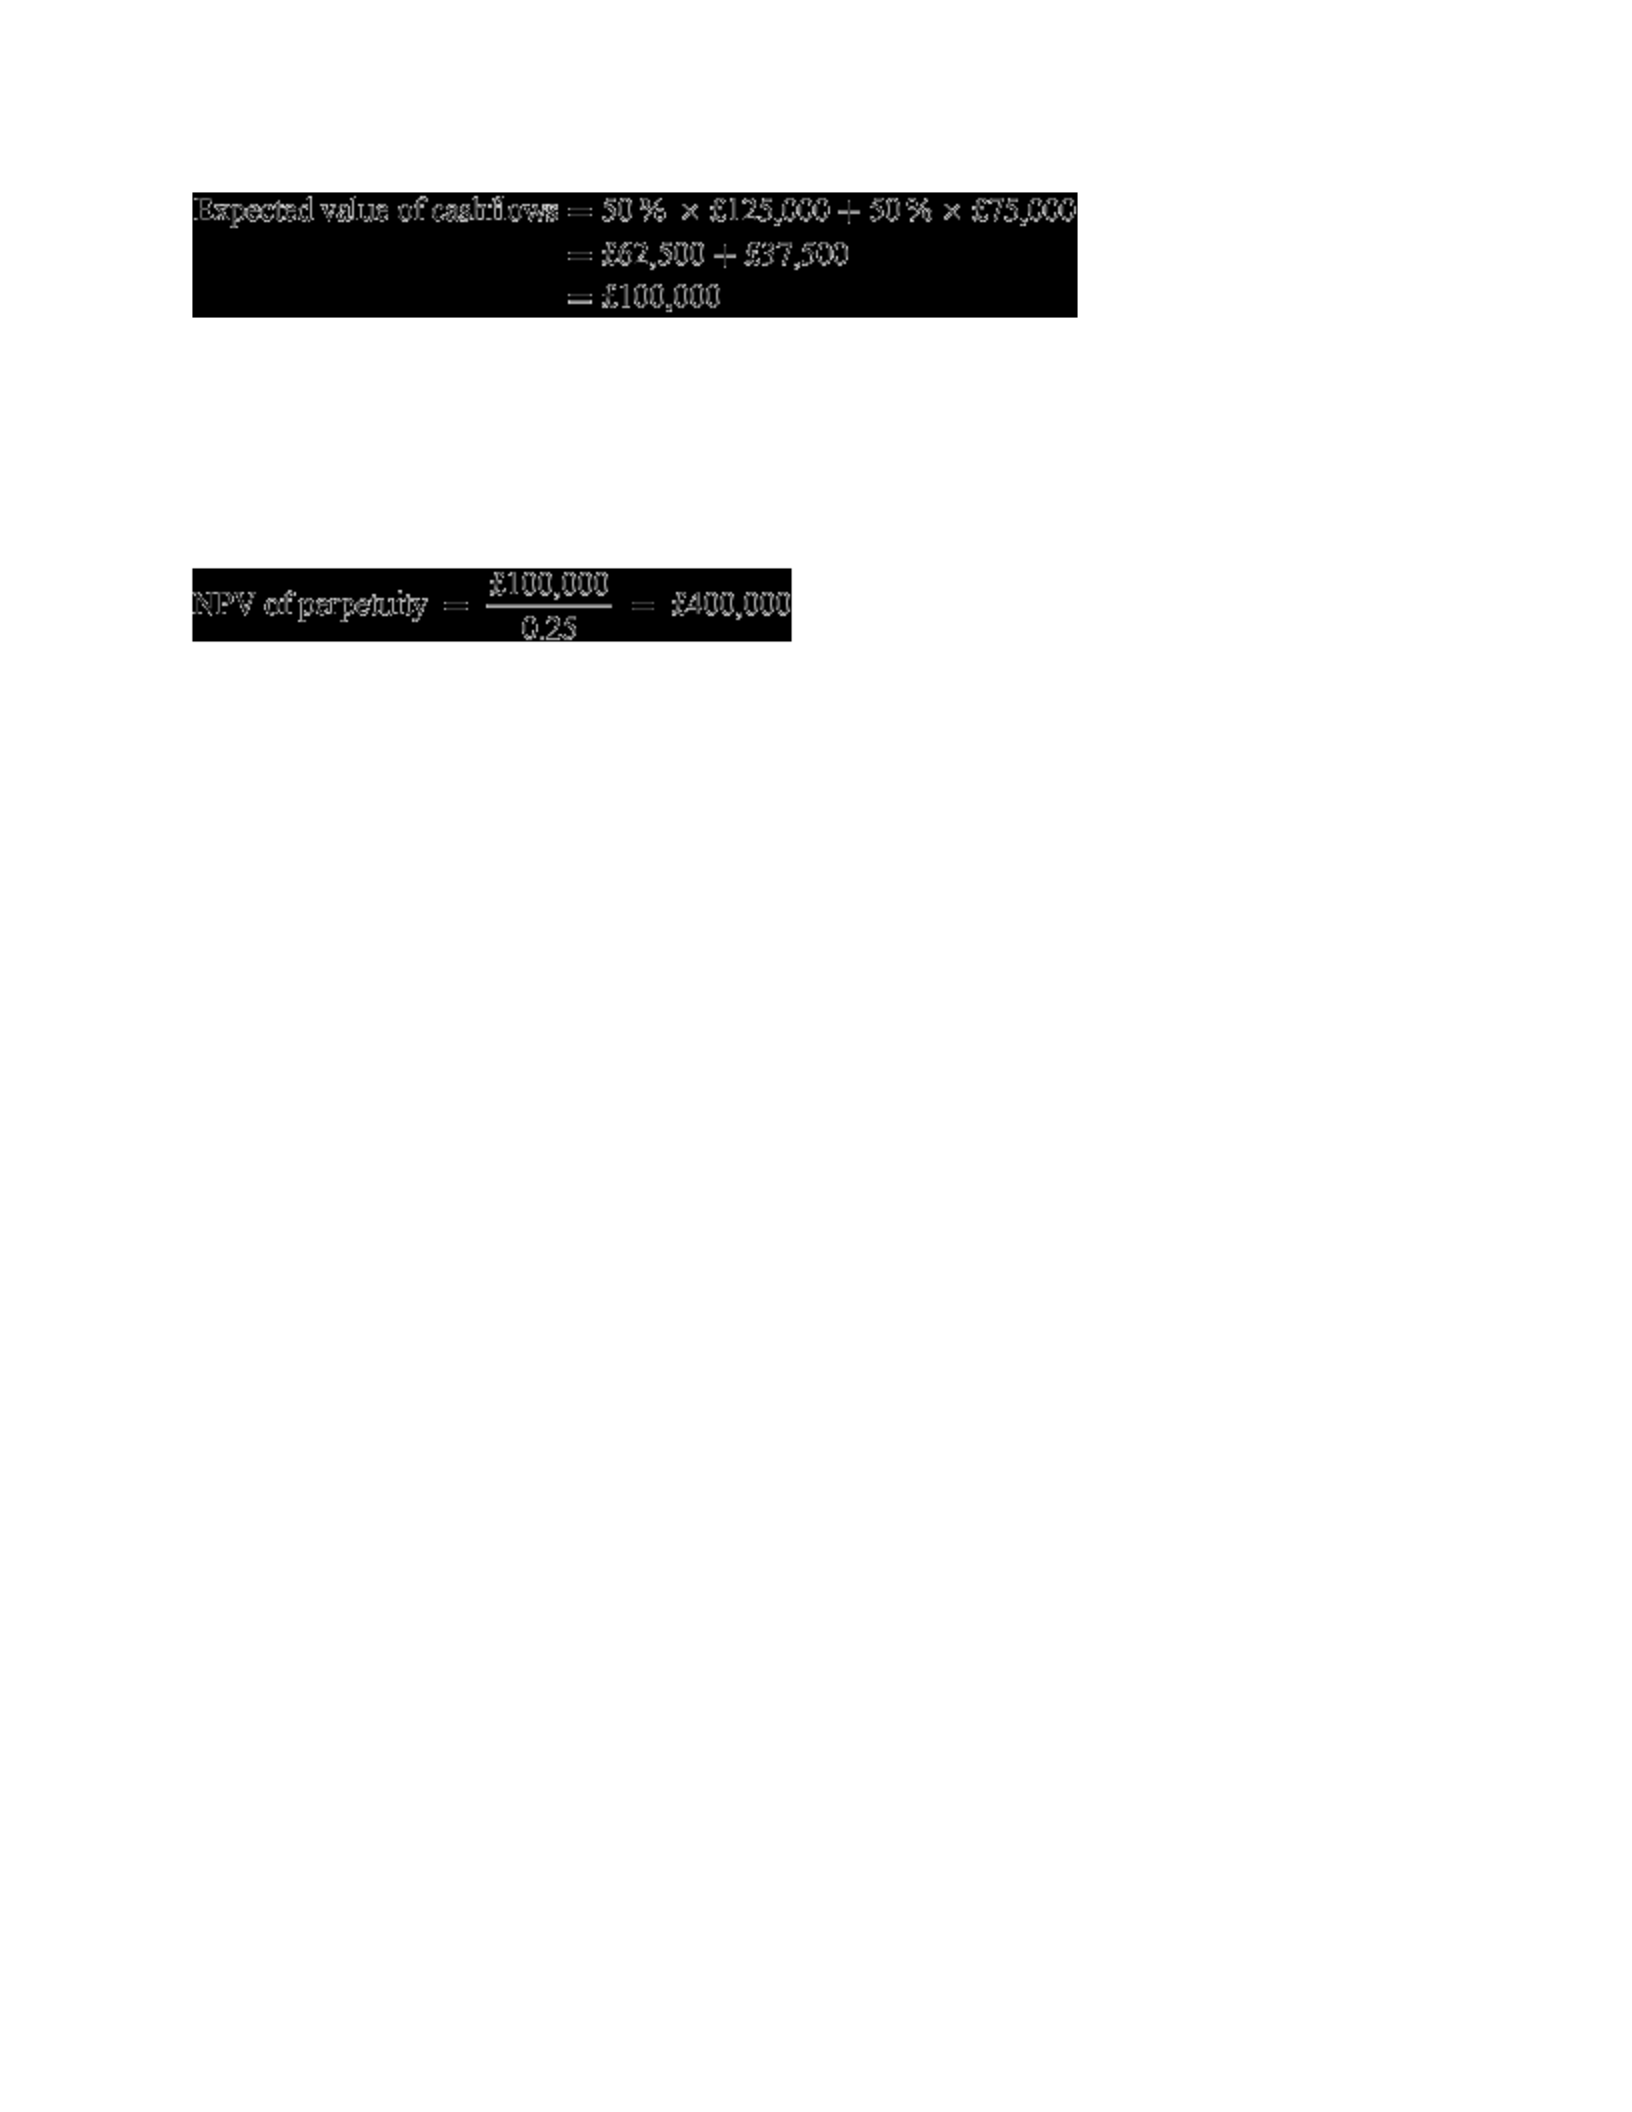
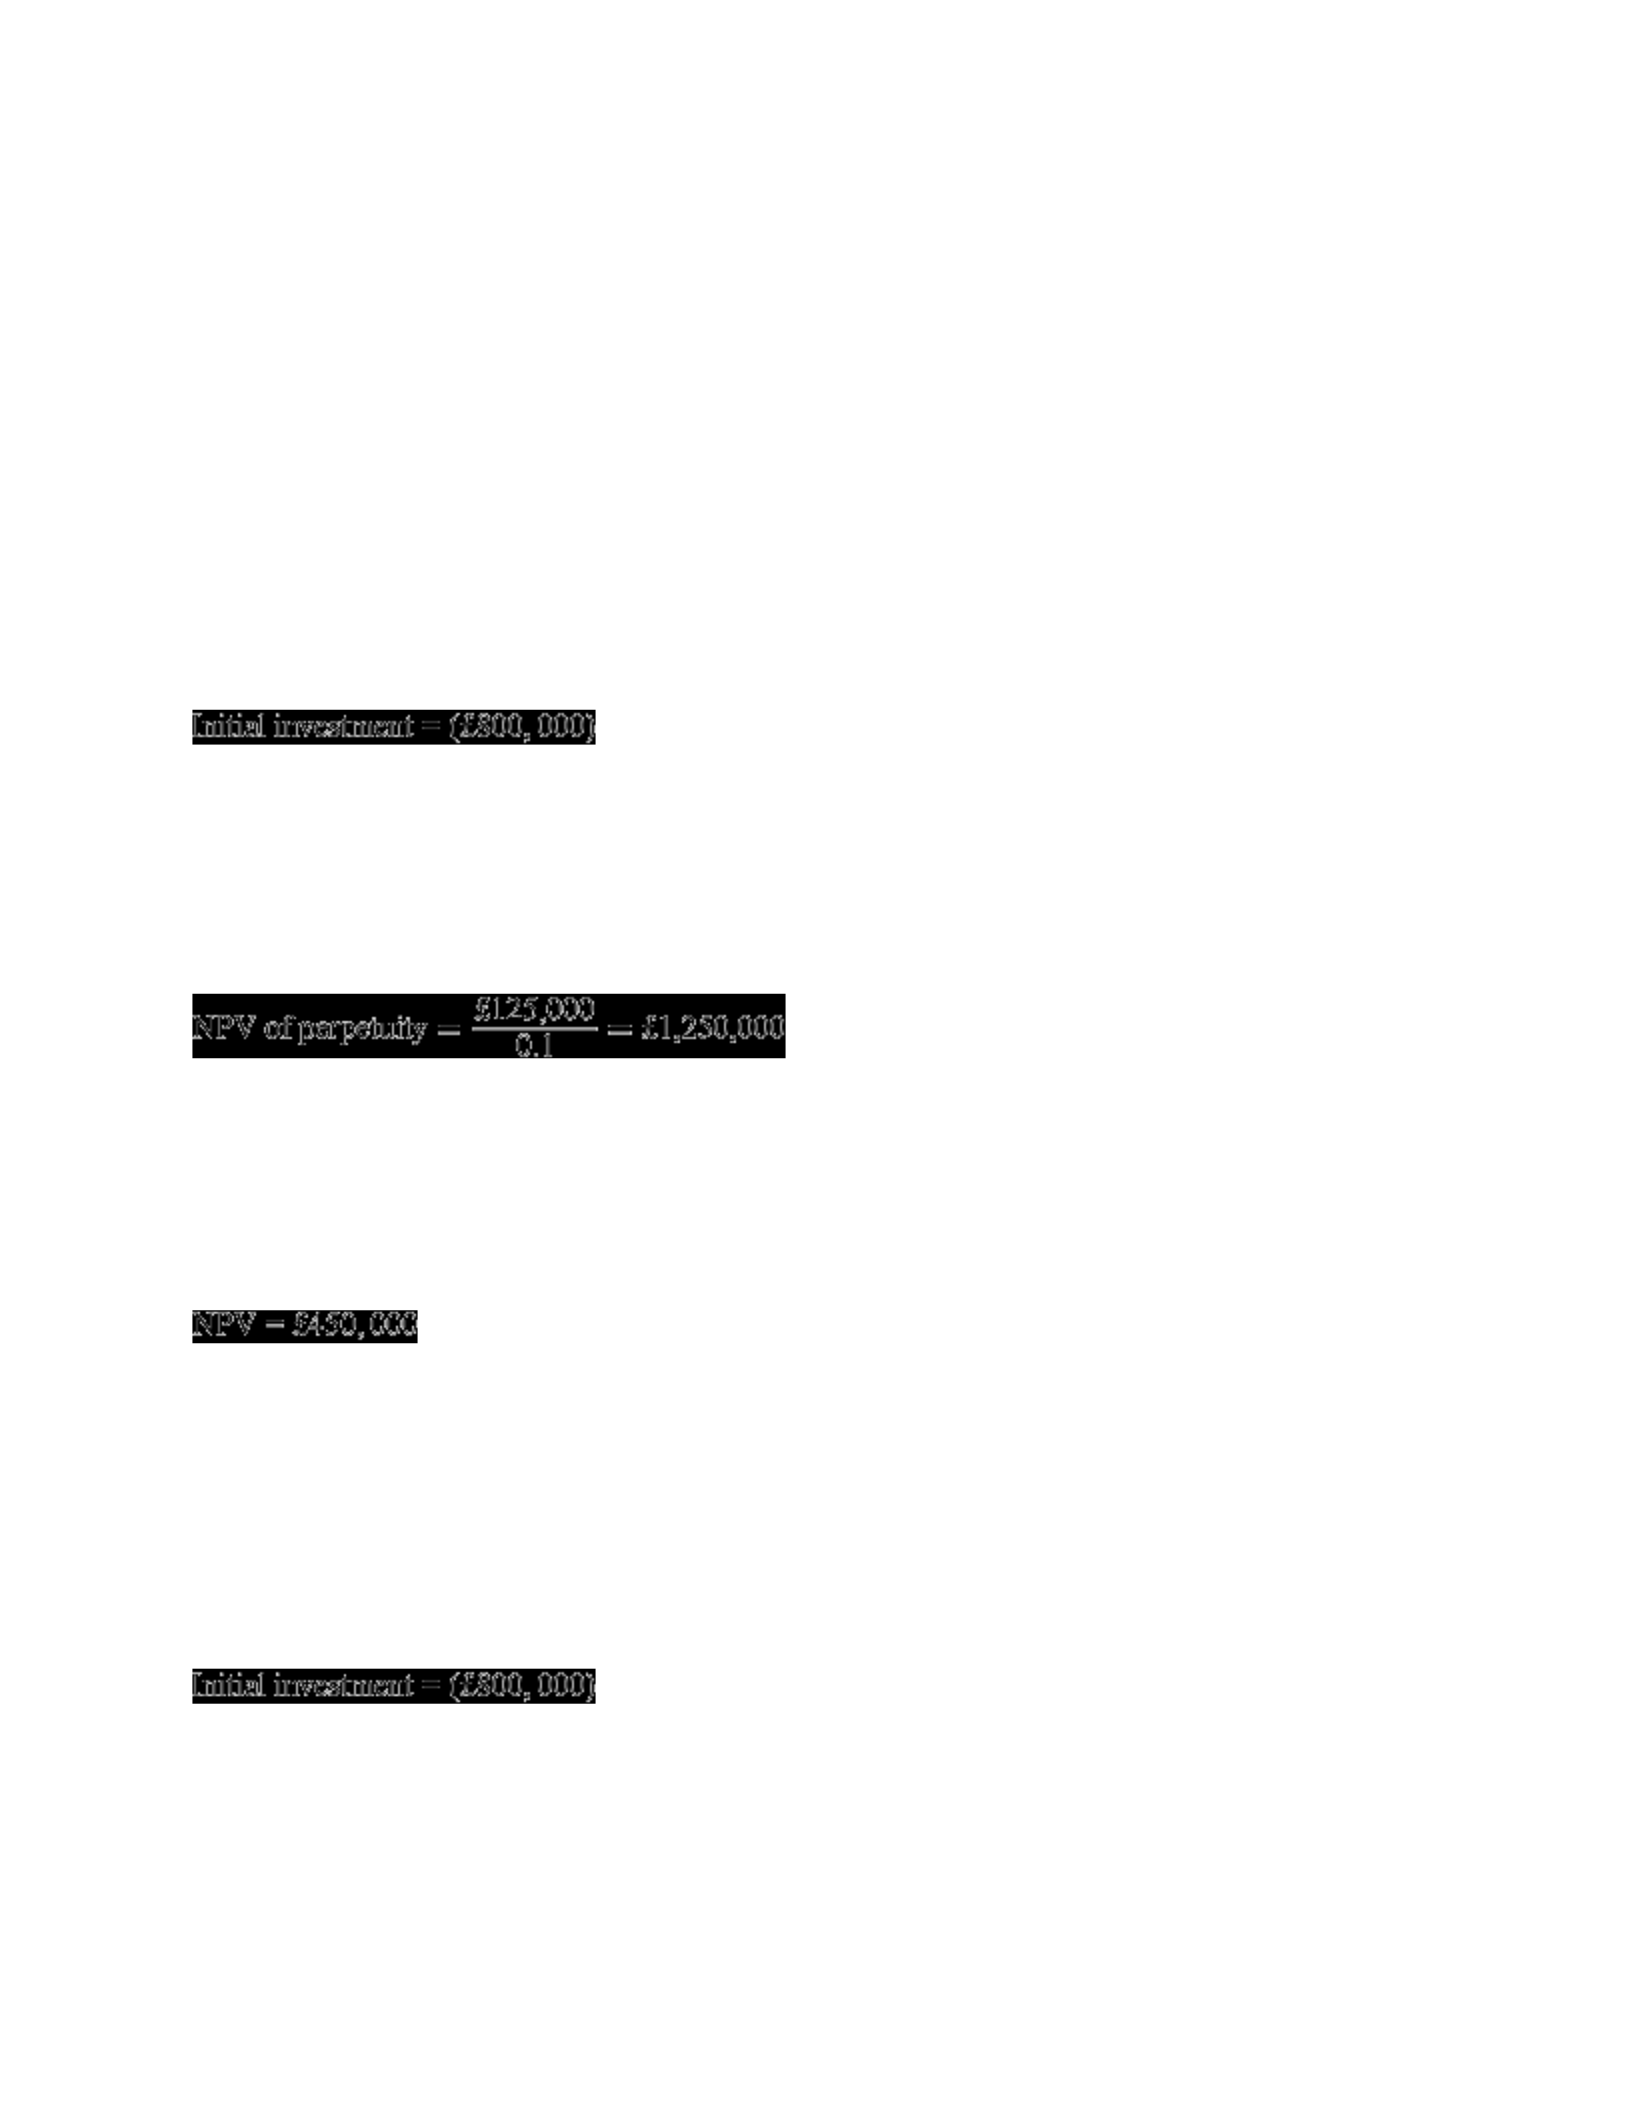
Here is a similar scenario. Say a project requires an £800,000 investment to develop a new
product. If the market demand for the product is good, an expected income of £125,000 per year
in perpetuity will be generated. However, if demand is poor the income in perpetuity will only be
£75,000. The company estimate good demand at only 50% likelihood, so uses a discount rate of
25% rather than their cost of capital of 10% (which is the standard return for selling established
products in their industry). Discounted cash flow calculations show that the project is not
worthwhile:
Equation 11
Equation 11
Equation 12
Equation 12
Equation 13
So the NPV of the project equals (£400,000), and the project is clearly not worth pursuing.
However, this is using the discount rate to account for the uncertainty in the success of the
project, not the uncertainty of the project once it is established. To look at it another way, the
company justified using a large discount in the first year because the demand is unknown.
However, after the outcome of the first year is known, will the level of additional risk be as high
for the second and subsequent years?
The answer is probably no: after the first year, whether the product is successful or unsuccessful,
cash flows in the second year and onwards will continue to be high or low, depending on the
outcome of the first year. So a further discount of 25% for income in the second year, third year,
etc. is not warranted. (Obviously this is a simplification, since cash flows from a new product are
unlikely to be constant each year.)
If we could resolve the uncertainty about the success of the product, we could avoid using this
fudge factor in the discount rate. The company thinks that if it carried out some market research
before investing in the project, it would be able to determine whether demand for the product
would be good or poor. This market research would cost £25,000 and take place just before
paying out the £800,000 investment.
The two scenarios can now be looked at separately. Since the market research removes the risk
of how well the product is received, the discount rate for the normal selling of products in this
industry can be used, rather than for launching products.
Good demand
Equation 14
Equation 14
Equation 15
Equation 15
Equation 16
Equation 16
Poor demand
Equation 17
Equation 17
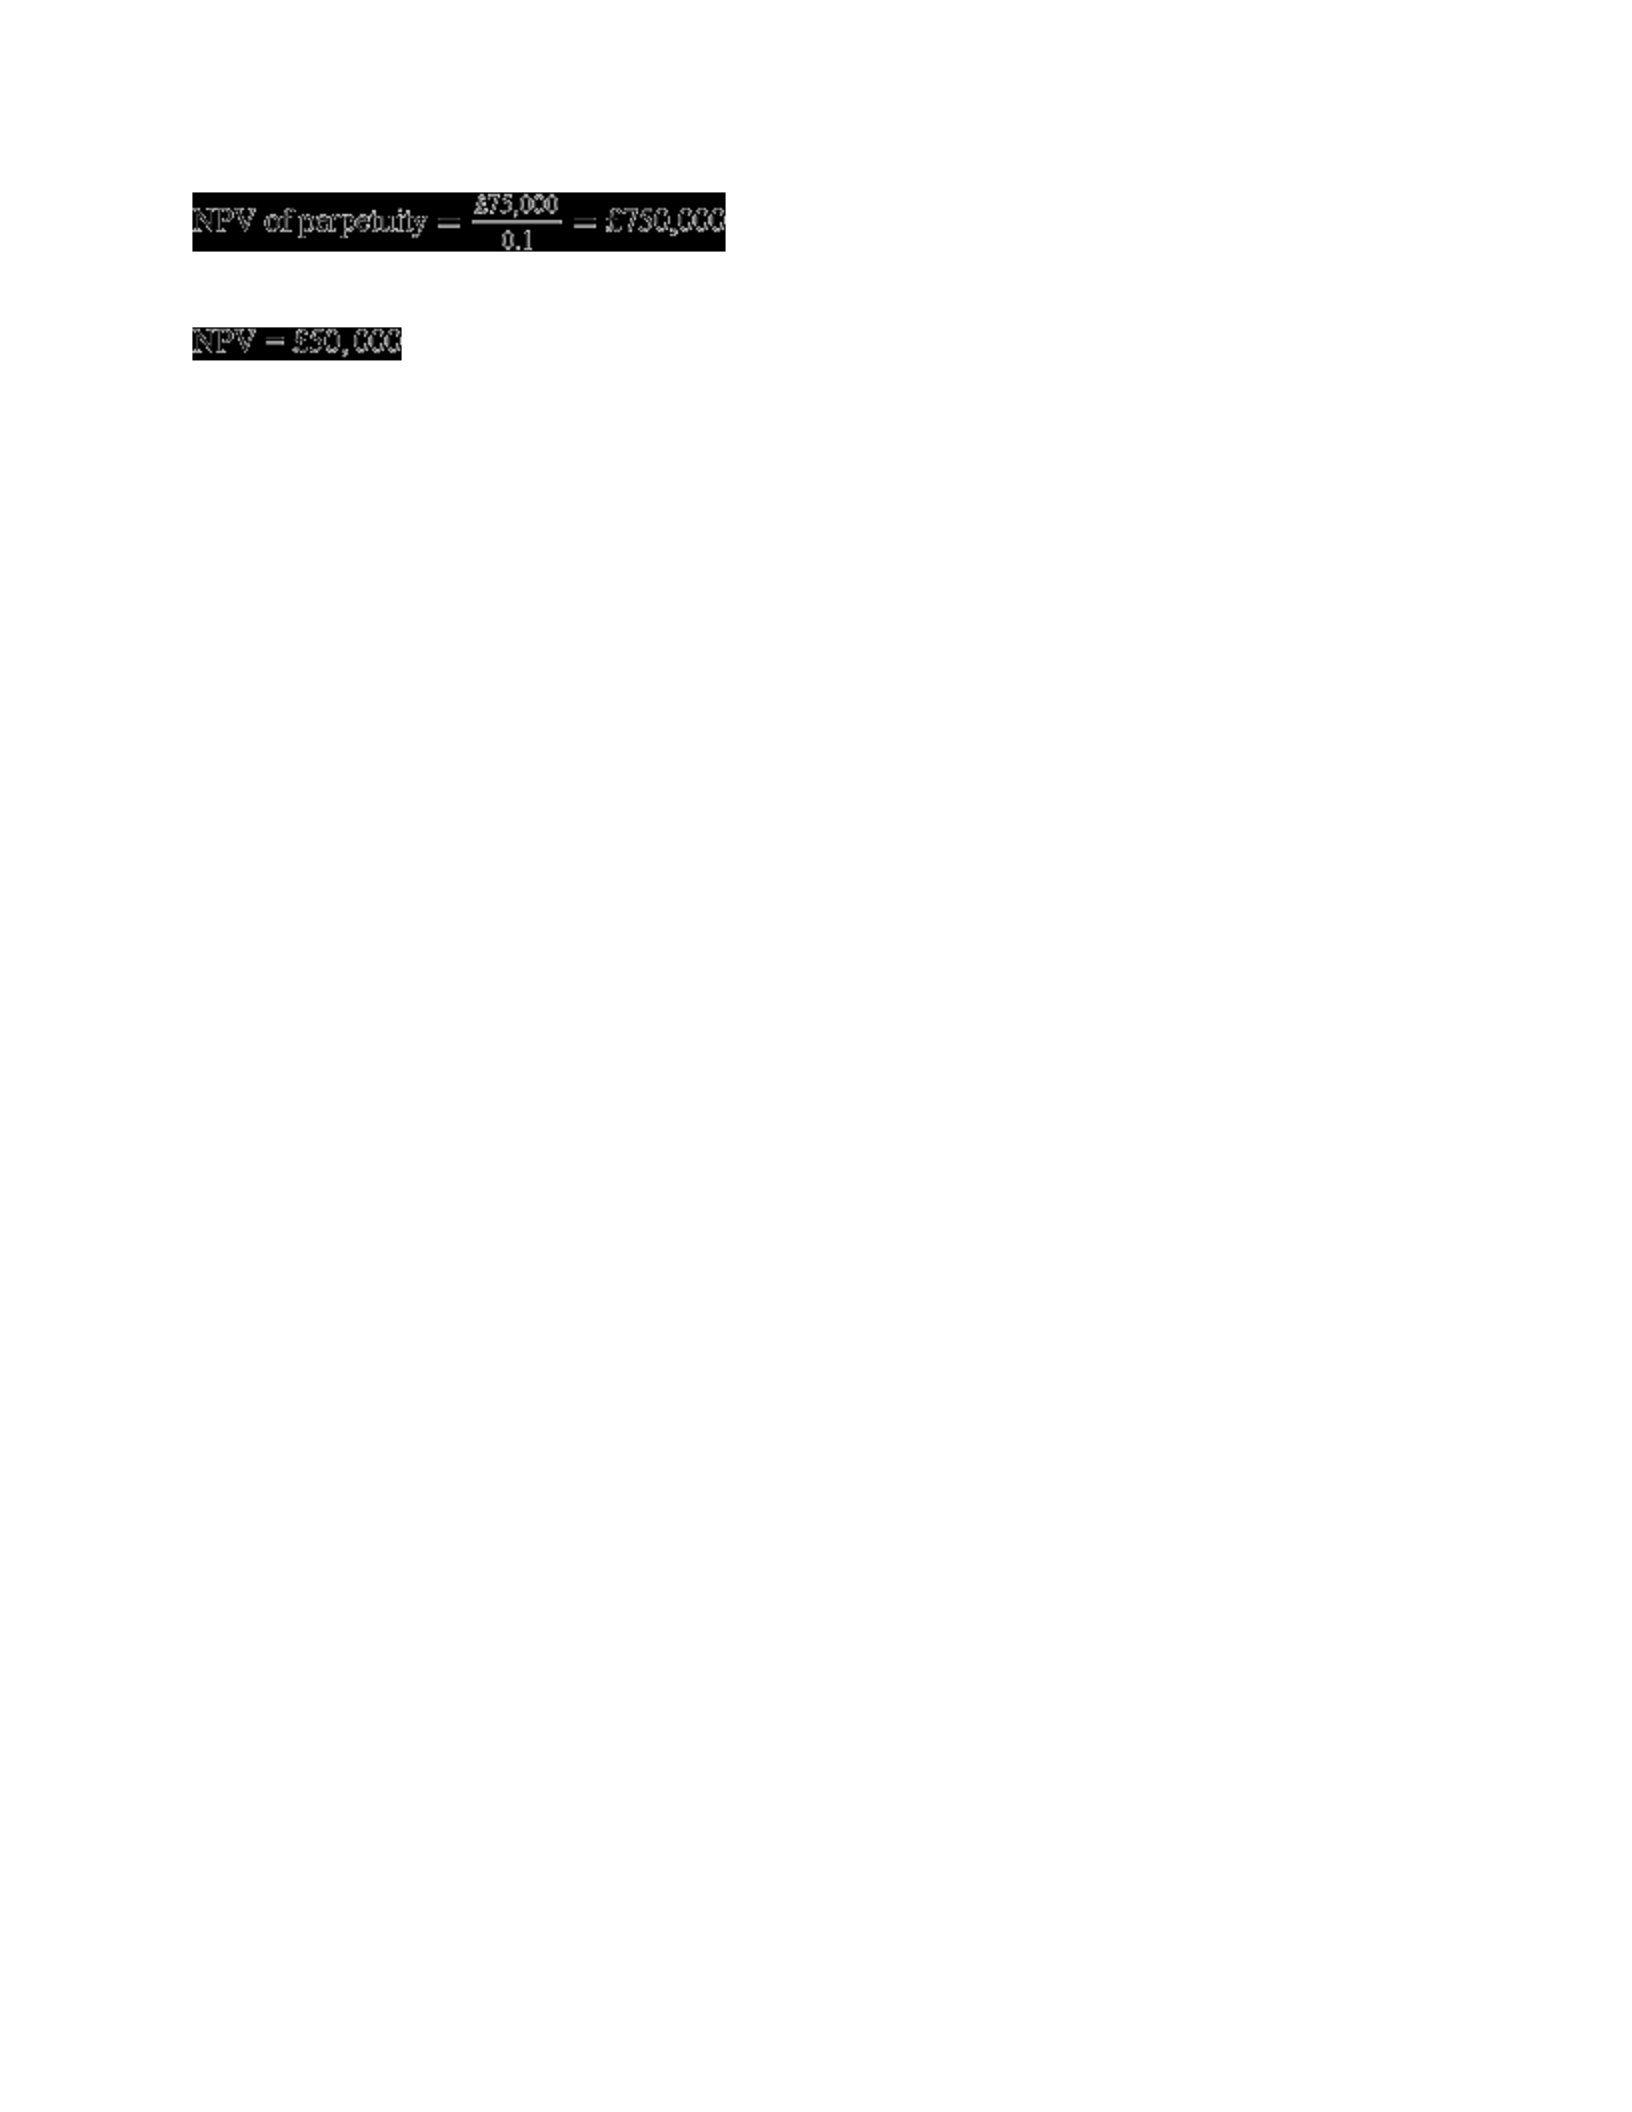
Equation 19
So the project is actually worth undertaking if there is good demand, but not if there is poor
demand. If the company knew in advance there was poor demand, it would not actually invest in
the project, whereas with good demand the project has an NPV of £450,000 and would be
invested in.
However, a company may be reluctant to invest in the project while there is risk about the levels
of demand, in case there was poor demand and the project generated negative NPV. So it would
want to carry out the market research to remove this risk.
In this scenario, the company can find out whether there would be good demand by spending an
additional £25,000 on market research, before having to decide whether to go ahead with the
£800,000 investment. So, the decision to make now is whether to go ahead with the market
research! To do this, we calculate the expected NPVs of the project with and without paying for
market research first.
Once the market research is completed, the company will know whether demand will be good or
poor, and will invest or not depending on this knowledge. The probability-weighted NPV of the
project can be calculated, taking into account that the company will have to pay for the market
research to make its decision about investment.
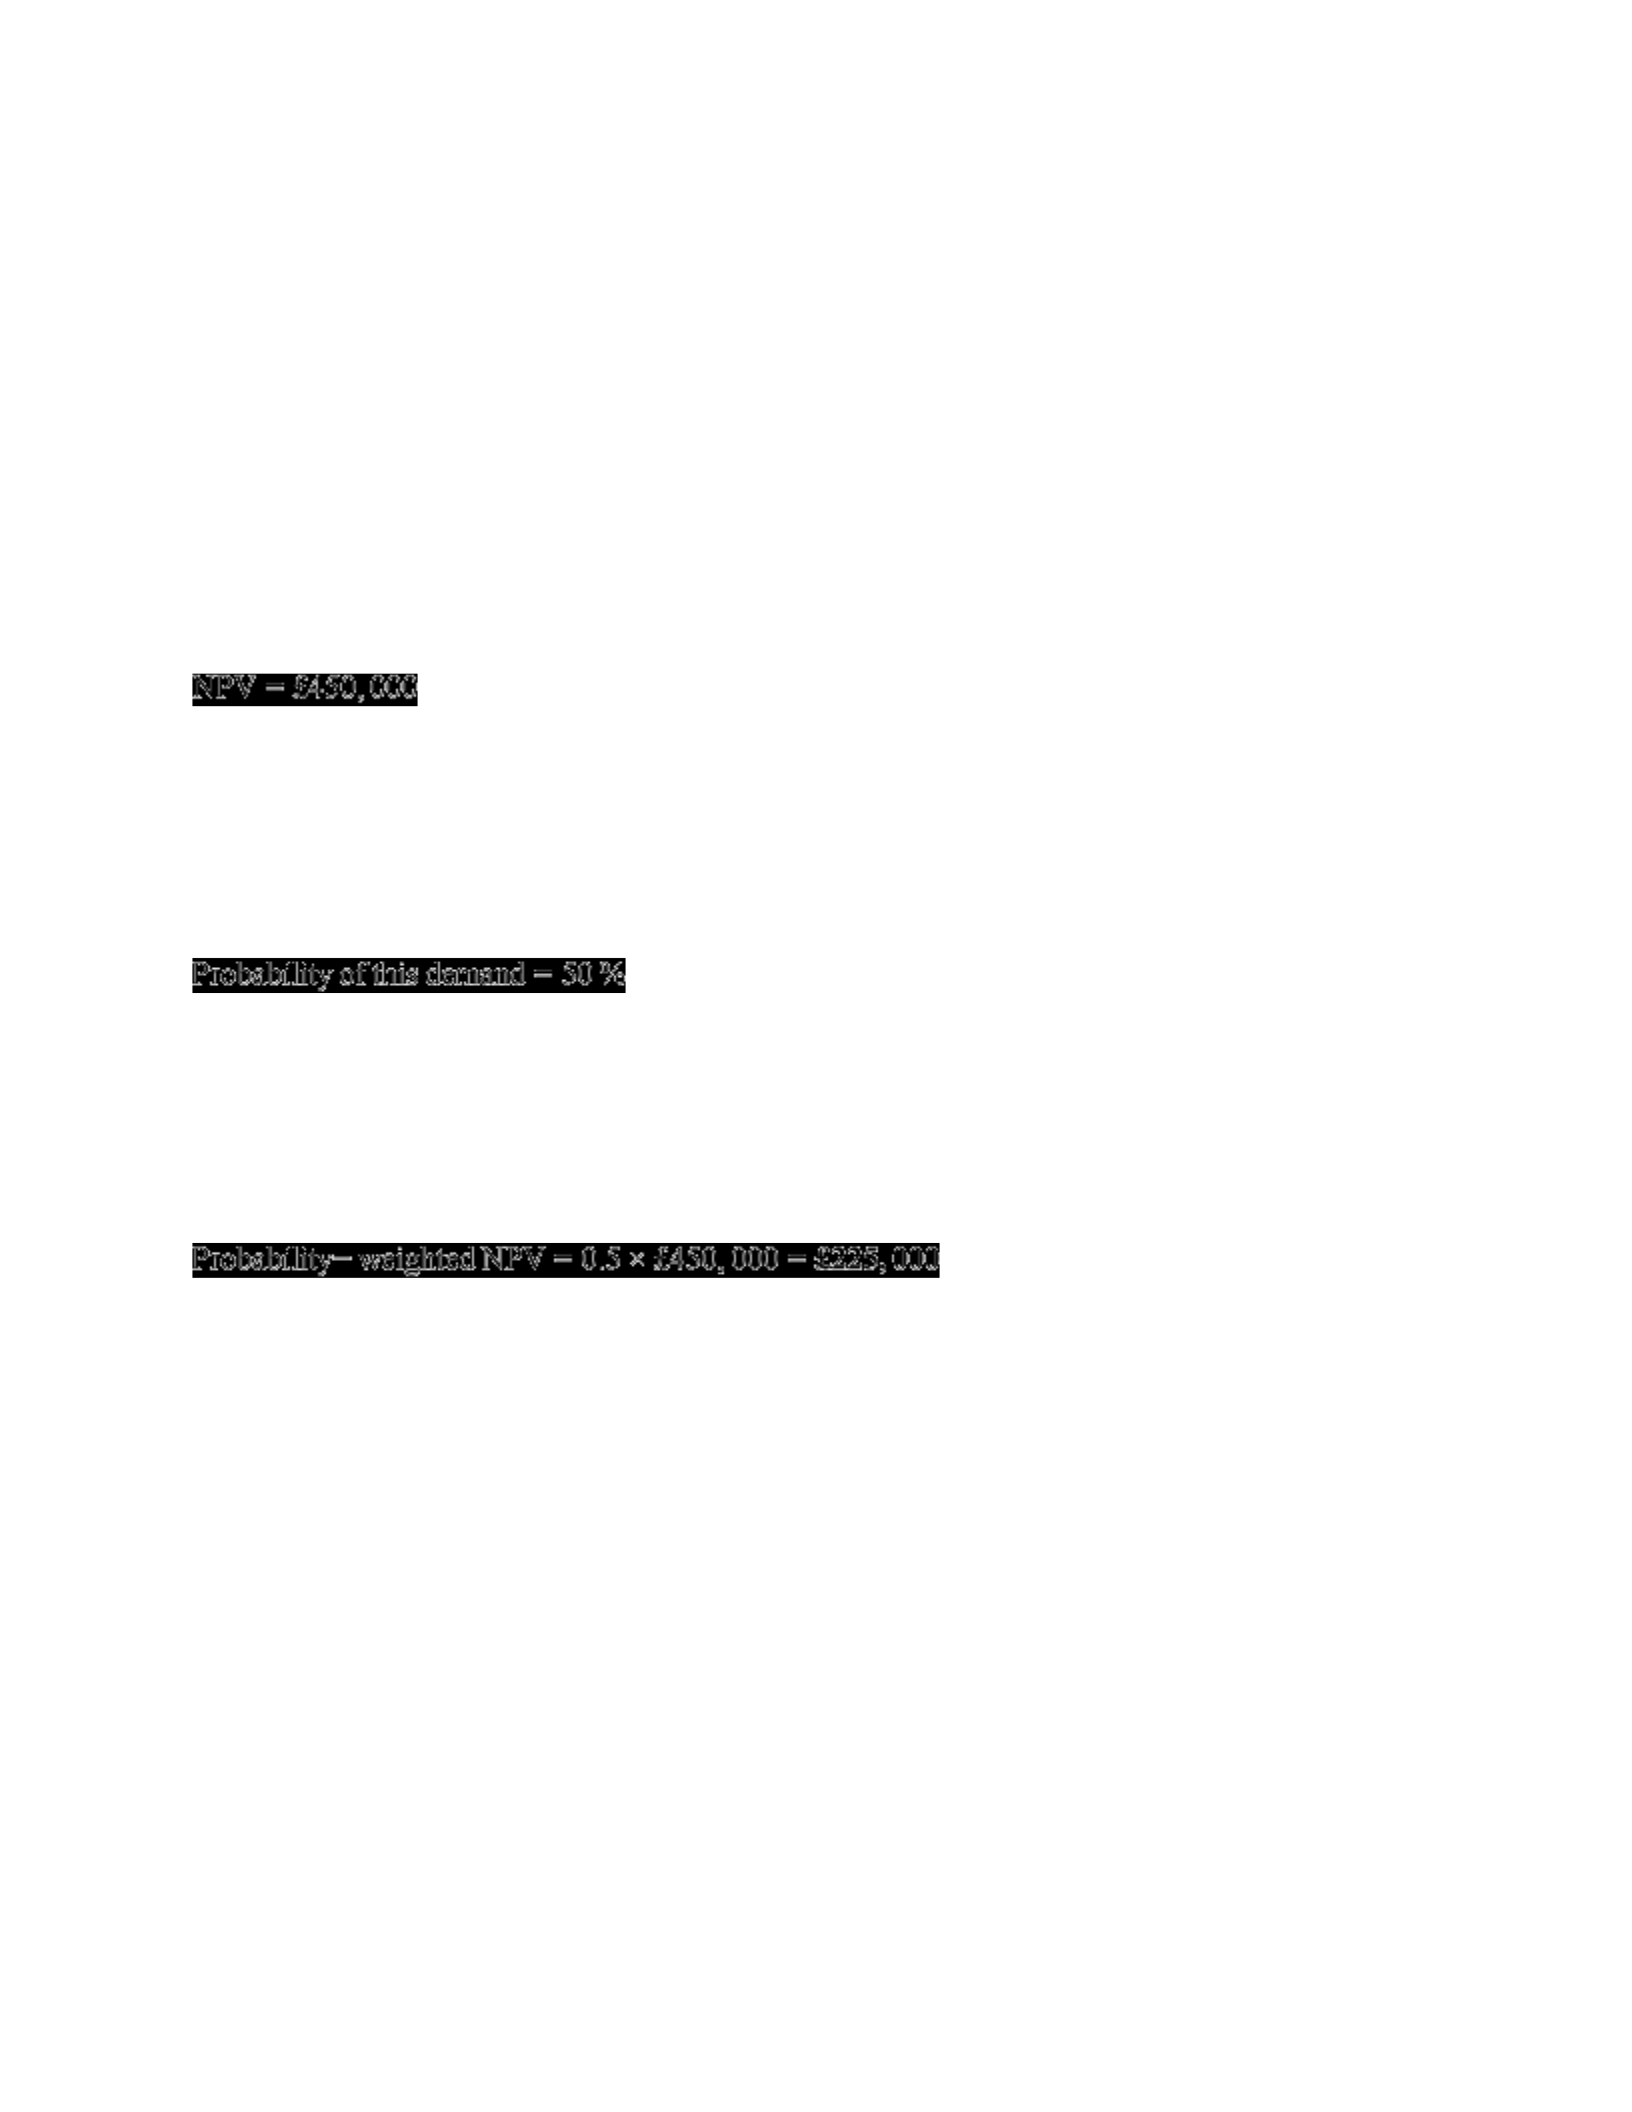
The probability-weighted NPV of the project is found by multiplying the NPV in each case by its
estimated probability, and deducting the cost of the market research. The probabilities of good
demand and poor demand have already been estimated as 50% for each by the company.
Good demand
Project goes ahead.
Equation 20
Equation 20
Equation 21
Equation 21
Equation 22

