


CONTENT, DFD, ETHICS 2
The Denmark Corporation sells computer equipment to businesses.
IT division Prints monthly statements
1. Sends monthly statements to the AR department
AR (Accounts Receivable) Clerk 2. Mails statements to customers
Customers Mail payments to Denmark Corporation
AR clerk Batches checks
1. Sends checks to cashier to update record
2. Enters payments into the computer
AR Master Data 3. Updated to record the payments
1. Create a table of entities and activities
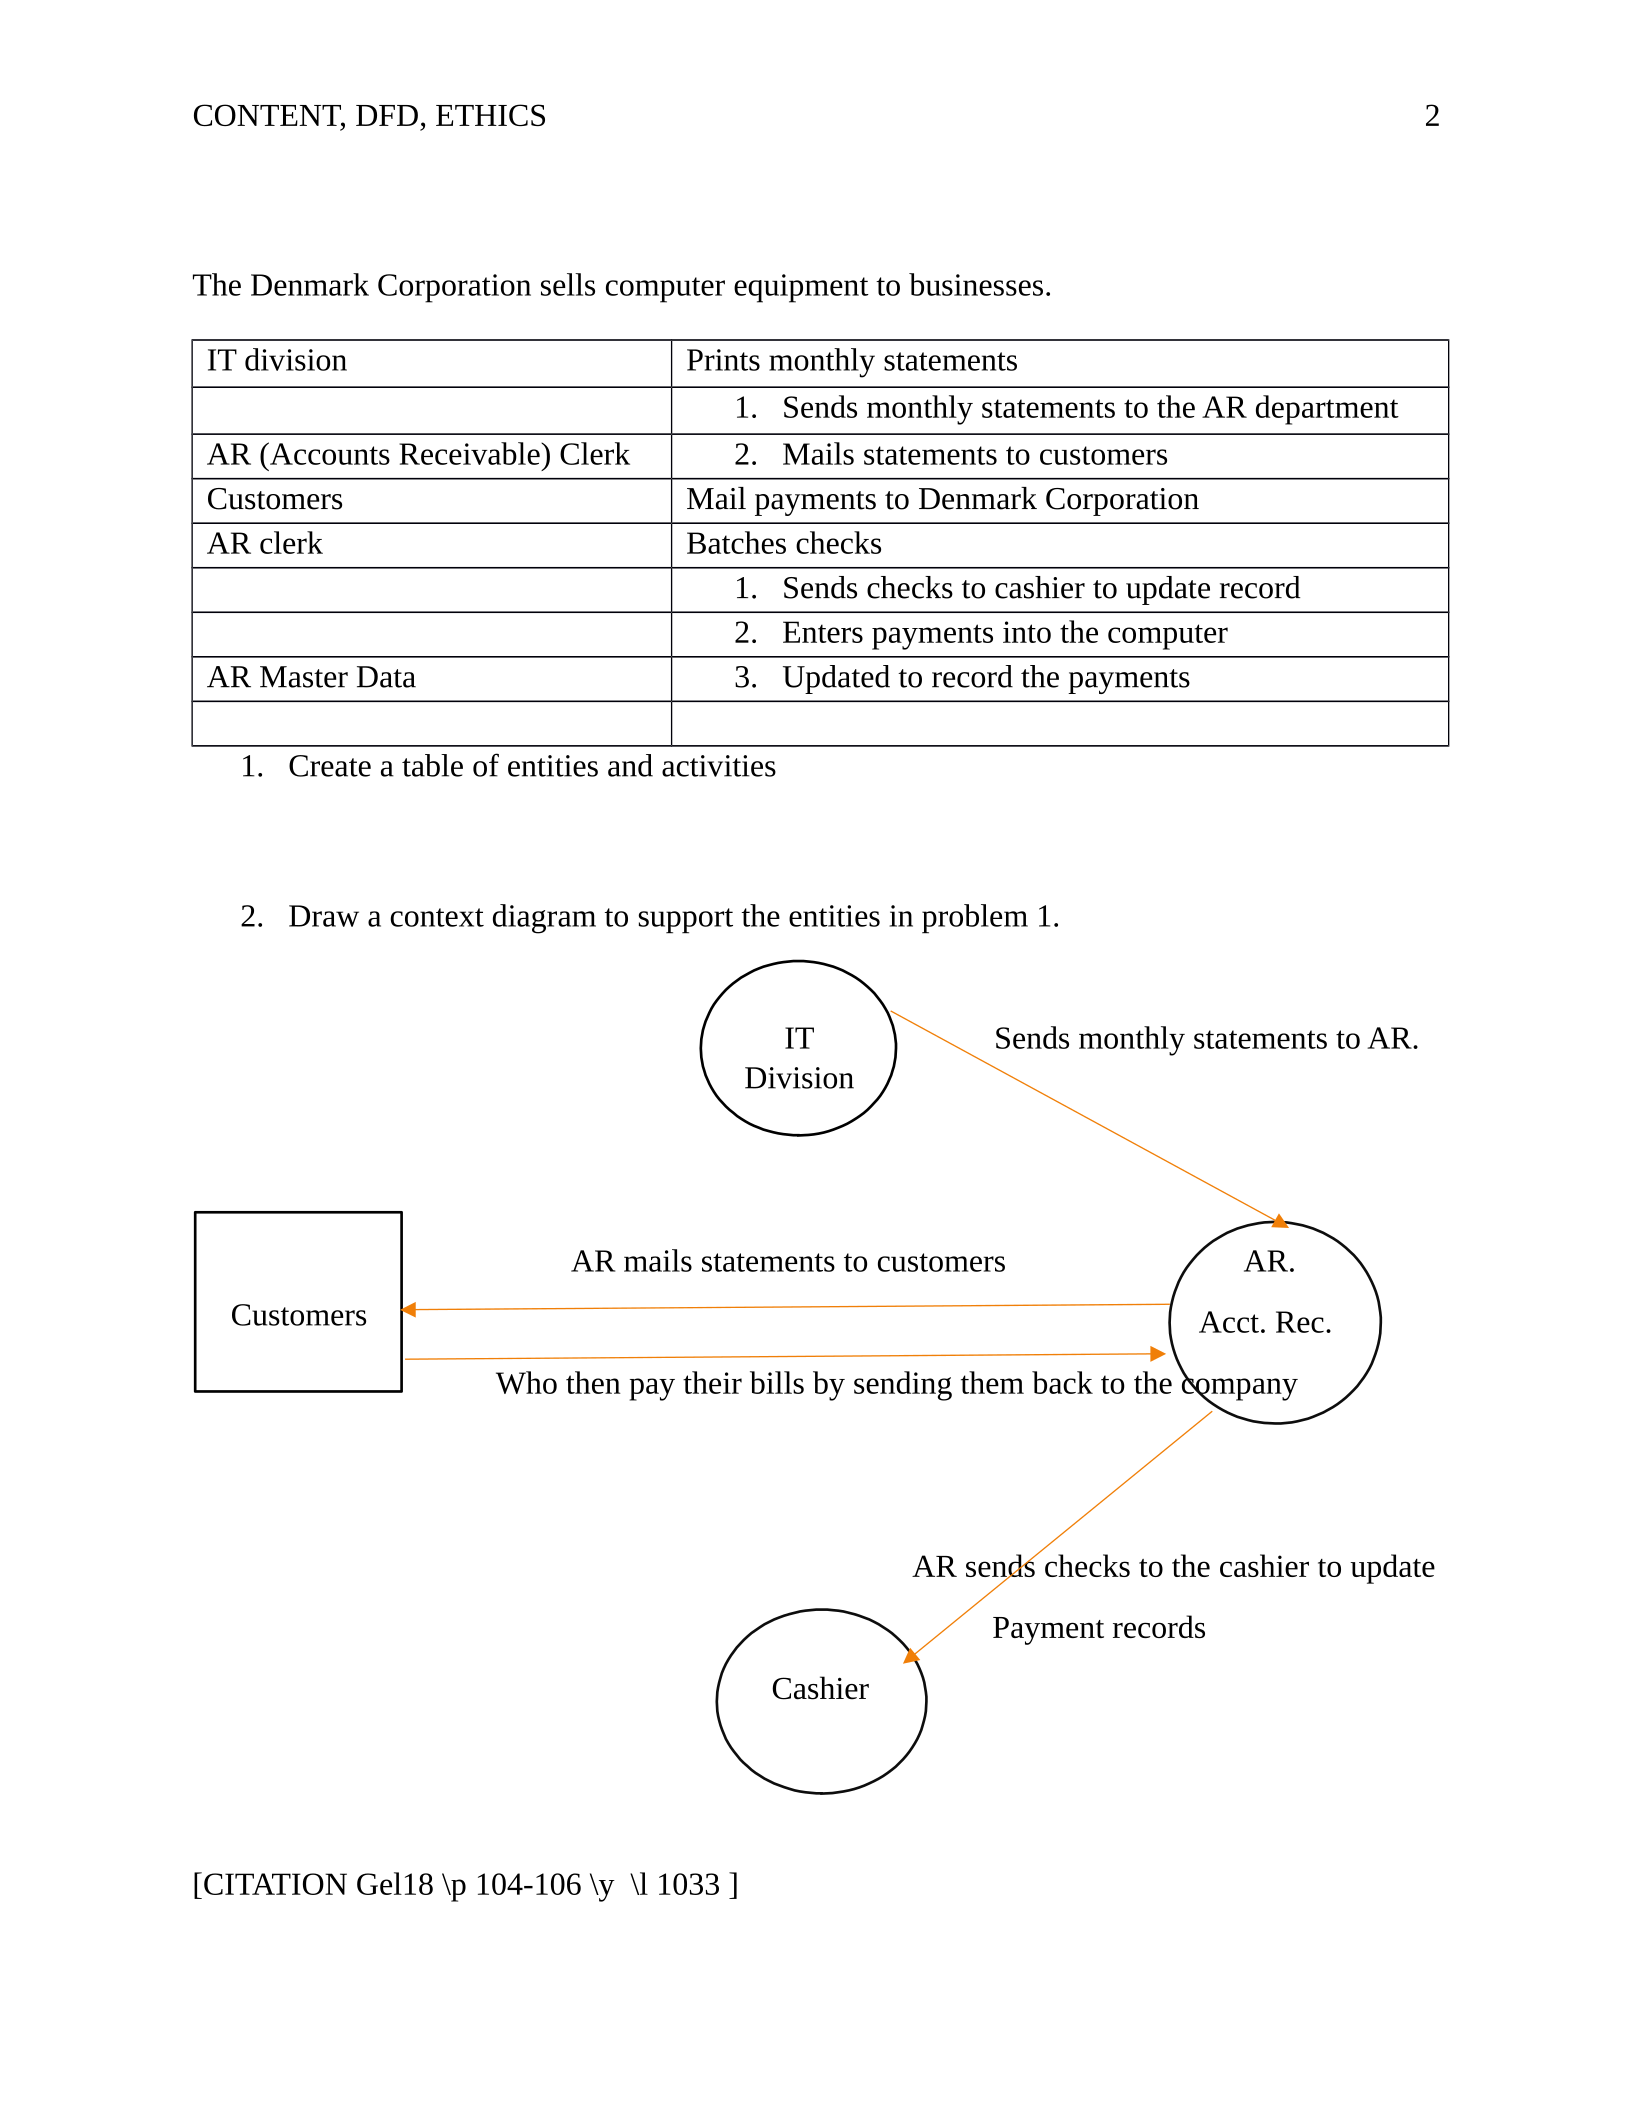
2. Draw a context diagram to support the entities in problem 1.
IT Sends monthly statements to AR.
Division
AR mails statements to customers AR.
Acct. Rec.
Who then pay their bills by sending them back to the company
AR sends checks to the cashier to update
Payment records
Cashier
[CITATION Gel18 \p 104-106 \y \l 1033 ]
Customers
CONTENT, DFD, ETHICS 3
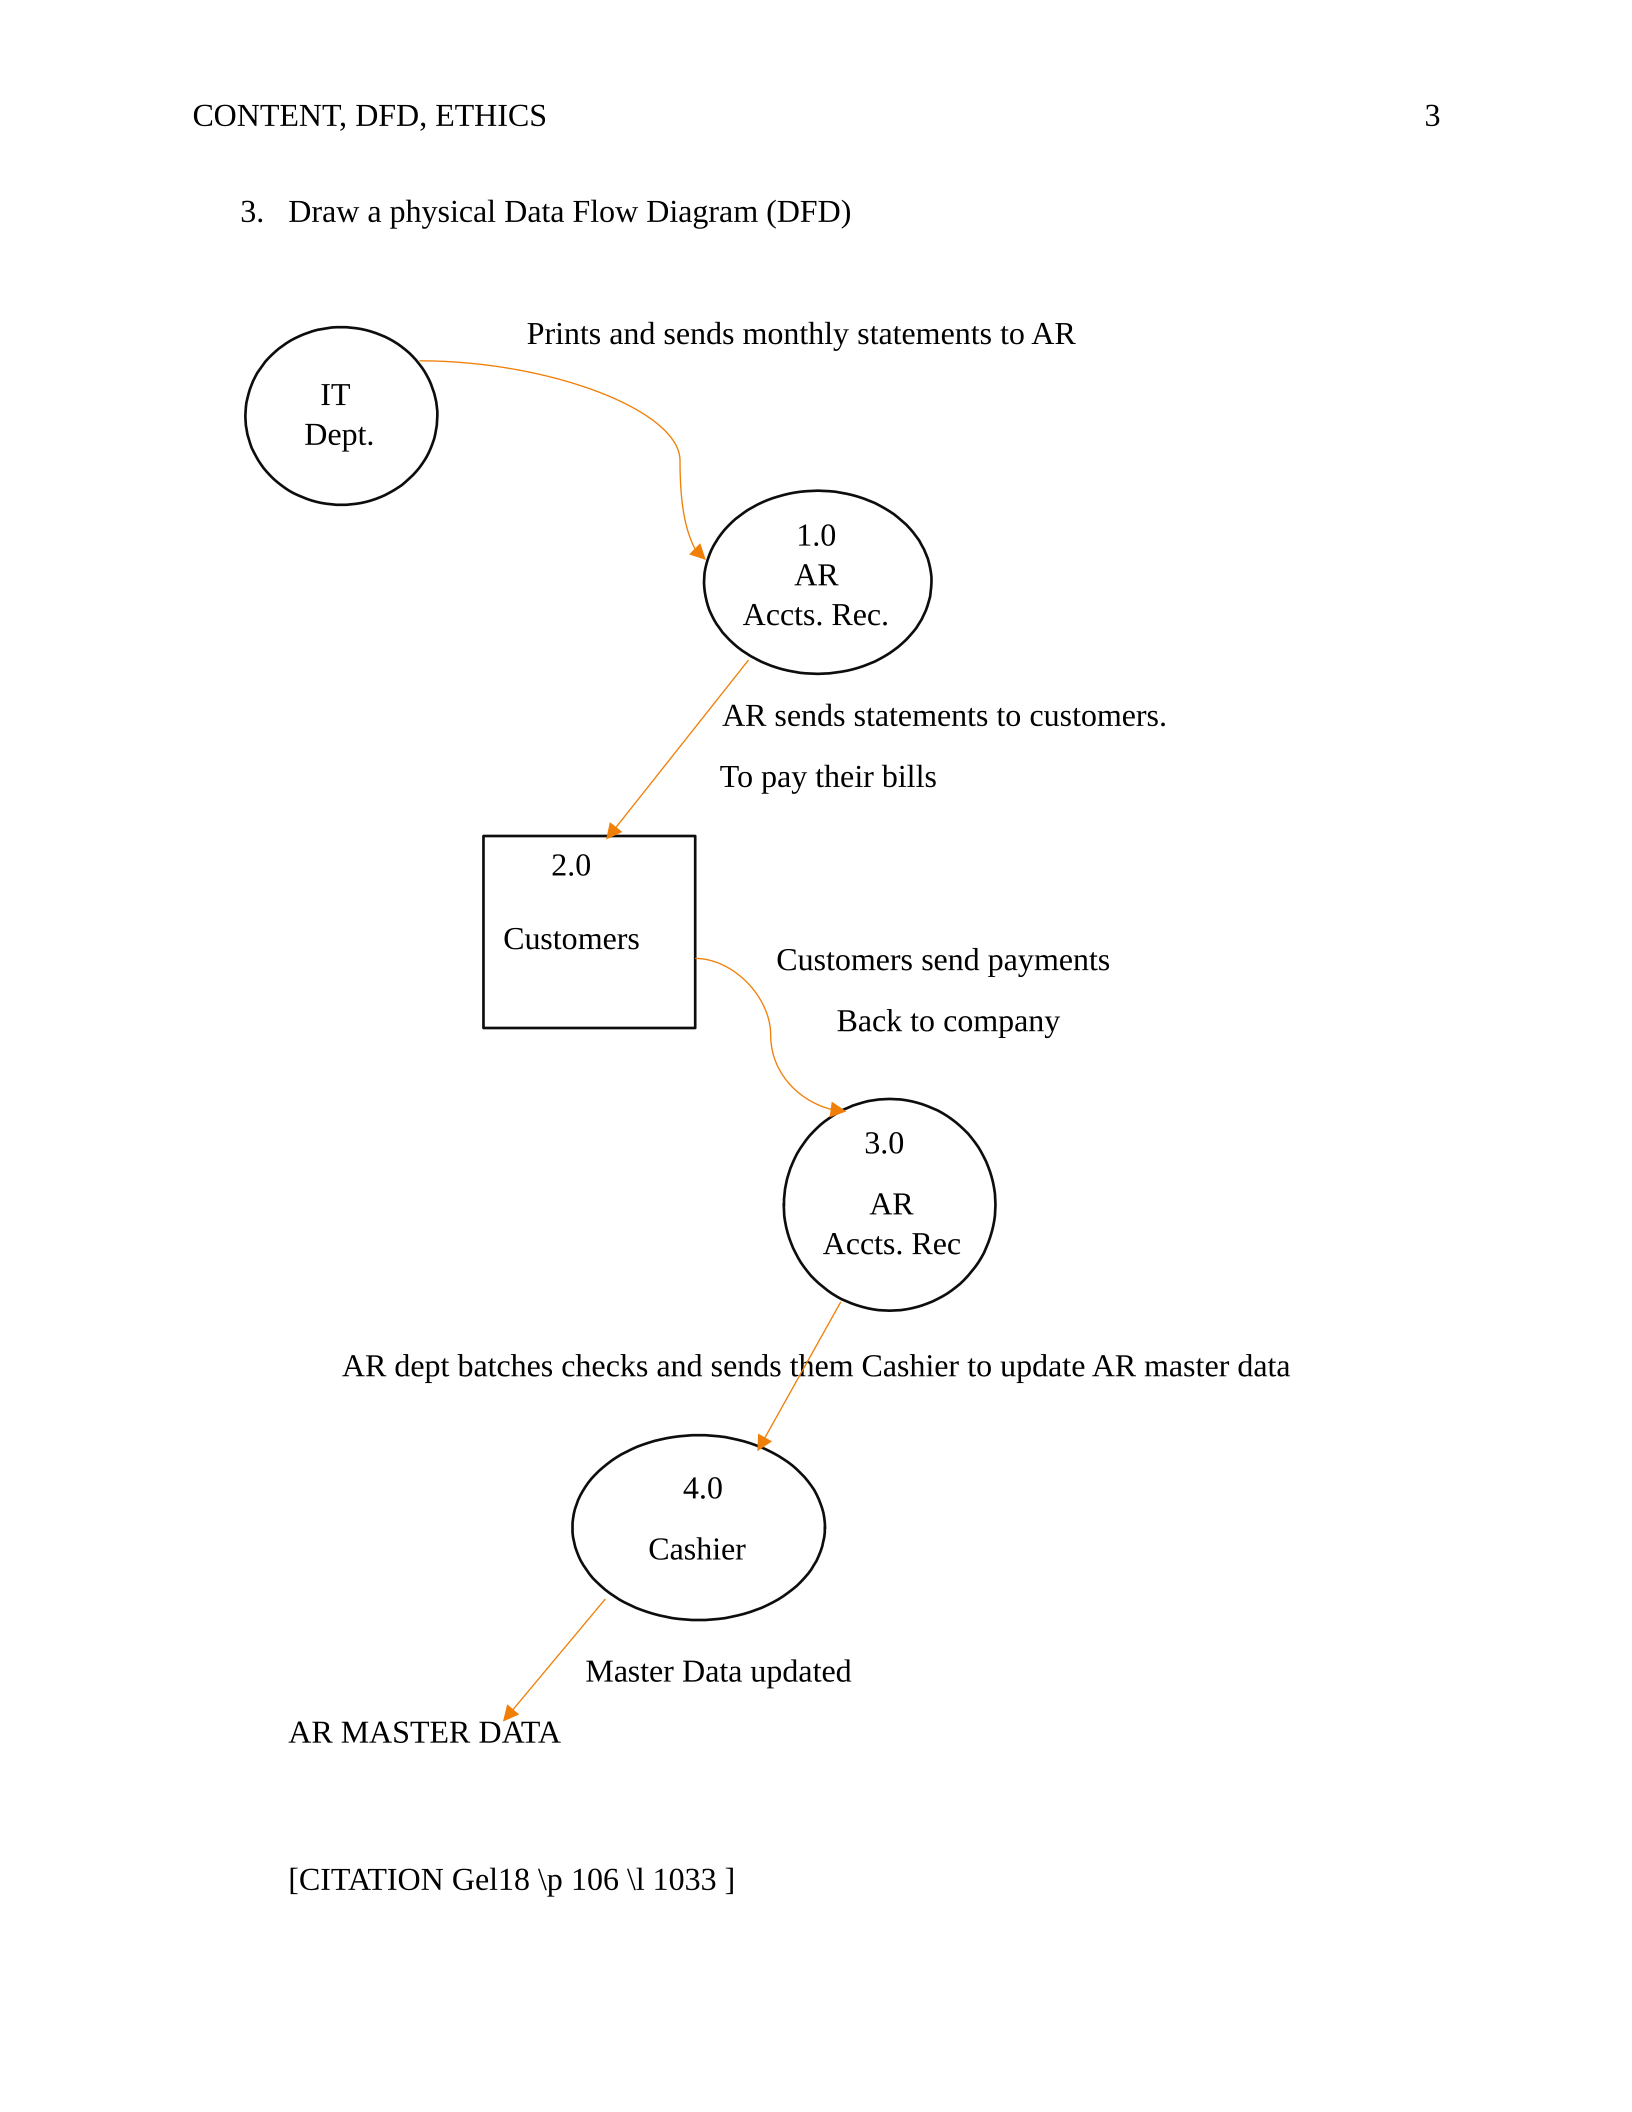
3. Draw a physical Data Flow Diagram (DFD)
Prints and sends monthly statements to AR
IT
Dept.
1.0
AR
Accts. Rec.
AR sends statements to customers.
To pay their bills
Customers send payments
Back to company
3.0
AR
Accts. Rec
AR dept batches checks and sends them Cashier to update AR master data
4.0
Cashier
Master Data updated
AR MASTER DATA
[CITATION Gel18 \p 106 \l 1033 ]
2.0
Customers
CONTENT, DFD, ETHICS 4
Problem 4
“PCAOB Audit Standard No. 5 (AS5) paragraph 37 and Statement on Auditing Standard Section
319 (AU 319), paragraph 75 suggests that management, business process owners, and auditors
prepare and analyze systems documentation to understand the flow of transactions through a
process and to identify and assess the effectiveness of the design of internal controls. However,
organizations, internal audit departments, and public accounting firms have developed their own
methods for documenting systems. Therefore, I am not going to learn to prepare systems
documentation until I know exactly what technique I will need to use in my job.” Do you agree?
Objective: Discuss fully. Please include in your discussion how mapping business processes
helps in analyzing the auditing process of understanding your client’s business. Please include
references and opinion should cover at least two paragraphs.
The statement referenced above is not something new employees in an organization
should follow. Businesses today are very competitive, and if there is no visual way to see how
the different areas work together to operate, it could be challenging to understand how
transactions flow from one department to another. This is one reason why mapping the processes
in a business is essential. Accountants can see the company's financial portion to know the
business's financial standing. Still, other departments need to understand how things worked
together to achieve that financial standing. In PCAOB Audit Standard No. 5, paragraph 34, it
says one of the objectives an auditor needs to achieve is to “Understand the flow of transactions
related to the relevant assertions, including how these transactions are initiated, authorized,
processed, and recorded.” [CITATION Aud22 \l 1033 ]. The Statement on Auditing Standard
CONTENT, DFD, ETHICS 5
Section 319, paragraph 75 also states in part that; “auditors should consider the use of
flowcharts, questionnaires, or decision tables……” [ CITATION PCA22 \l 1033 ]
This can be accomplished by mapping business processes which assist in identifying
clear views into the workflows of a business and could also help to identify problems that may
be happening [ CITATION Unk20 \l 1033 ]. Process mapping is described on this website and in
the textbook, Accounting Information Systems, using symbols to create flowcharts illustrating
how different processes are completed [ CITATION Gel18 \l 1033 ]. Mapping business
processes can be simple as creating a context diagram such as the one on page two of this
assignment for a small business processing sales to a complicated business process that
illustrates many department workflows in large corporations. Using flowcharts can enable people
to review them to identify what is working for the organization or what could be detrimental to
achieving financial stability.
CONTENT, DFD, ETHICS 6
Problem 5
The Resource Grocery sales process
Entities Line Activity/Process
Customers/Shoppers 1 Shoppers unload their groceries
Sales clerk 1 Process sales to receive payment
2 Enters the sale in a cash register
2 Places money in the cash register
3 Gives the cash and register tape to the cashier.
Cashier 4 Reconciles cash register tape to money collected to
ensure all funds are accounted for
Diagram of the table above
1.0
Sales clerk
Enters sales
into cash register
2.0
Sales Clerk
Places cash in
register
3.0
Cashier
Receives cash & tape to
Reconcile all at the end
of the day
[ CITATION Gel18 \l 1033 ]
Shoppers
unload
groceries
CONTENT, DFD, ETHICS 7
References
Gelinas, U., Dull, R., Wheeler, P., & Hill, M. (2018). Accounting Information Systems. Boston:
Cengage Learning.
PCAOB. (2022, November 19). AU Section 319.
https://pcaobus.org/oversight/standards/archived-standards/details/AU319
PCAOB. (2022, November 19). Auditing Standard No. 5.
https://pcaobus.org/oversight/standards/archived-standards/pre-reorganized-auditing-
standards-interpretations/details/Auditing_Standard_5
Unknown. (2020, November 10). What is Business Process Mapping?
https://www.ontask.io/resources/blog/what-is-business-process-mapping/
Powered by TCPDF (www.tcpdf.org)

