


1
Marketing Plan: Final Plan Assignment
Breana Picchiottino
School of Business, Liberty University Online
BUS 330: Principles of Marketing
Professor Lexi Henegar
June 30, 2025
Table of Contents 1. Executive Summary
The phrase “Mobile First, Digital Everything” was uttered by CEO of JPMorgan Chase
Jamie Dimon at the start of his career with the firm in 2006 (ICMR India, n.d.). Almost two
decades later, the firm is leading the way in mobile and digital advancements with the
introduction of the first ever mobile cash deposit system for mobile app users. This
revolutionary technology will bring enhanced security features through serial tracking and serve
as a valuable asset for expanding in underreached market groups. Product promotion and
distribution will be carried out by taking advantage of the firm's significant domestic and global
presence as well as their existing advanced mobile platforms. User adoption rates and
operational savings are substantial, surpassing over a billion dollars within the next five years,
which articulates the substantial benefits of this service announcement. JPMorgan’s initiative in
this space will deliver heightened security and convenience while simultaneously helping those
who are historically underbanked and saving the firm exponentially.
2. Company Description
JPMorgan Chase was established in 1799 originally functioning as New York City’s first
ever water company and utilizing the name The Manhattan Company (JPMorgan Chase & Co.,
2024d). Originally chartered by New York’s state legislature, the company was allowed to

2
employ spare capital for banking purposes. Shortly after, founders Alexander Hamilton and
Aaron Burr were able to get The Bank of the Manhattan Company operational. By 1868,
numerous predecessors of the firm had been established through the National Bank Act, which
was passed in 1863, including Drexel, Harjes & Co., the earliest predecessor based in Paris,
France. In 1871, J. Pierpoint Morgan merged with Anthony Drexel to form Drexel, Morgan & Co.
which would lead the way as a private merchant bank headquartered in New York and
specializing in railroad investments. The firm would receive its new name J.P. Morgan & Co. in
1895. Following the world’s post-war era, the 1950s were marked by a consolidation of financial
institutions which included the firm's acquisition of four heritage firms in New York City. The
start of the new century brought about another name change as the firm acquired The Chase
Manhattan Corporation in 2000 and adopted the name J.P. Morgan Chase & Co. After merging
with Bank One in 2004, the periods in the name were removed resulting in the current title of
JPMorgan Chase & Co. Upon the acquisition of Bank One, Jamie Dimon was appointed CEO of
the firm in 2006 and still holds the position to this day (JPMorgan Chase & Co., 2024e). The firm
has continued their expansions by establishing their presence in 48 states with the addition of a
branch in North Dakota in 2021 and acquiring First Republic Bank in 2023 (JPMorgan Chase &
Co., 2024d).
JPMorgan Chase has three recognized business segments which include Consumer &
Community Banking (“CCB”), Commercial & Investment Banking (“CIB”), and Asset & Wealth
Management (“AWM”) (JPMorgan Chase & Co., 2024c). Their consumer business falls into CCB
while wholesale business is under CIB and AWM. Examining their consumer business, CCB
reaches consumers and small businesses through bank branches, ATMs, online banking and
telephone banking. These different outreach methods entail a variety of different departments

3
including Banking & Wealth Management, Home Lending, Card Services, and Auto. Across all
four of these different departments the services offered include deposits, payments, cash and
investment management, mortgage origination, home equity loans, credit cards, and auto loans
and leases. Continuing on to wholesale business, CIB has two distinct departments, Banking &
Payments, and Markets & Securities. This segment caters mainly to corporate and institutional
clients providing services such as investment banking, lending, and financing as well as risk
assessment, market-making, and Securities Services. Lastly, AWM includes both Asset
Management and Global Private Bank. The department of Asset
Management provides investment management to a broad range of clients by providing
solutions regarding fixed incomes, equity, and money-market funds. The Global Private Bank is
reserved for high net worth clients and assists them with retirement and estate planning, as
well as brokerage accounts and additional deposit and investment management.
With such expansion and detailed services, JPMorgan Chase has been consistently
recognized for its monumental influence in the financial world. In 2024, Fortune ranked the firm
5th on its list of the World’s Most Admired Companies for the second consecutive year
(JPMorgan Chase & Co., 2024b). Additionally, Times Magazine listed JPMorgan Chase as one of
their 100 Most Influential Companies in 2023. That same year was also big for the firm globally
as they were recognized once again by Fortune on their list of companies changing the world.
Recognition has also been awarded for the firm’s internal structures as LinkedIn placed the
company on their top employers list in 2023 and highlighted the potential for career growth.

4
3. Strategic Focus and Plan
To examine the strategy of JPMorgan Chase, three specific areas will be explored
indepth. These sectors include the mission of the firm, their financial and nonfinancial goals,
and the core competencies and sustainable competitive advantages that are held by the firm.
Mission
The firm's mission is detailed through five main pillars, their purpose, vision, values,
principles, and promises. JPMorgan Chase is united behind their purpose statement to “Make
Dreams Possible, for everyone, everywhere, everyday” (Dimon, 2023). This purpose statement
communicates the impact that the firm aspires to provide. This pursuit is upheld by their
company vision which lays out the ambition that the firm holds themselves to. The vision
statement states, “We aim to be the most respected financial services firm in the world, serving
corporations and individuals (Dimon, 2023). In order to abide by their vision statement and
achieve their designated purpose, JPMorgan Chase has established five guiding values that are
to unite the mindsets of its employees. These values include service, heart, courage, excellence,
and curiosity. In addition to these key values, the firm also employs four main business
principles that guide how they work. JPMorgan Chase strives for exceptional client service,
operational excellence, a commitment to integrity, fairness, and responsibility, and a great team
and winning culture. Lastly, the firm makes four promises to its clients, employees,
communities, and shareholders which include powering economic growth, uplifting
communities, championing opportunity and enterprise, and being a great place to work.
Goals
Looking onward to 2025, JPMorgan Chase has established the following growth drivers: ●
Nonfinancial Goals for 2025 (JPMorgan Chase & Co., 2025)
1. To achieve growth in the auto lease department.
2. To see an increase in capital markets activity.

5
3. To invest in furthered business growth regarding onboarding more bankers and
advisors as well as the establishment of more branches.
4. To invest more into technological products and services.
5. To further technological business and volume growth through the establishment
of public clouds and data centers.
6. To continue driving and increasing demand for card products.
7. To enhance customer engagement.
● Goal Recommendations for the Firm:
1. To prioritize the customer experience by re-evaluating current fees and service
charges for consumer products by the end of the third quarter in 2025.
2. To streamline and expand online account openings to enhance efficiency and
convenience by 20% for consumers by 2026.
3. To establish 1,000 Card Service Departments in branches to assist clients more
effectively with credit card inquiries and issues by 2028.
● Financial Goals (JPMorgan Chase & Co., 2025)
1. To achieve a Return on Tangible Common Equity of 17% for 2025.
2. To achieve a Net Interest Income excluding markets of $90 billion for 2025 3.
To achieve a Net Interest Income including markets of $94.5 billion for
2025.
4. To operate accordingly with an expense outlook of $95 billion for 2025.
Core Competency and Sustainable Competitive Advantage
The core competencies regarding JPMorgan Chase reflect their unique desires to (1)
establish exceptional client franchises with a consumer centric focus while being the easiest to

6
do business with and (2) providing long-term shareholder value while being a complete, global,
diversified, and at scale entity (JPMorgan Chase & Co., 2025).
Relating these core competencies to the sustainable competitive advantages that are
held by the firm, JPMorgan Chase has unmatched consumer centric data metrics that are
enhanced by their dedication to expansion. One goal the firm has established is to “Be the Bank
for All” (Aquino, 2024). This goal has led the firm to announce their anticipated expansion into
25 different markets with the addition of 400 new branches, cementing their presence as the
largest financial institution with locations in 48 out of the 50 states (“What Makes JPMorgan”
2023).
Such vast size and growth pursuits are not easily rivaled by competing financial institutions.
JPMorgan Chase is recognized as the number one institution for U.S. retail deposits, the top
issuer of U.S. credit cards, and the primary bank for businesses (JPMorgan Chase & Co., 2025).
Continuously, their pursuit of providing long-term value to their shareholders is demonstrated
through their financial records and continual growth. Revenue in 2024 topped $173 billion and
represented the firm's 9th year of consecutive growth. The ten-year growth for the firm is
double that of its peers including Bank of America, Citigroup, Goldman Sachs, Morgan Stanley,
and Wells Fargo. The firm continues to present itself as the top manager of investments globally
holding client assets of $5.9 trillion in active portfolios (JPMorgan Chase & Co., 2024c). This
client base and financial revenue is unmatched by other financial firms who do not possess such
size and capital.

7
4. Situational Analysis
A situational analysis for JPMorgan Chase will be conducted through the presentation of
a SWOT (strengths, weaknesses, opportunities, and threats) analysis complete with
commentary. Additionally, a deeper exploration will be provided of the firm’s industry,
competitors, company, and client base.
SWOT Analysis ● Strengths
1. Diversified Business Model: Three distinct business segments (JPMorgan Chase
& Co., 2024c) allow for varied revenue sources which maximize profits and
mitigates risks and reliance on a sole sector (Kitov, 2023).
2. Strong Global Presence: Profound domestic and international networks and
operations allow for enhanced market penetration and customer accessibility
(Kitov, 2023).
3. Robust Financial Performance: Consistent financial stability, as proven by
financial metrics that surpass industry averages, reflects high profitability and
asset management (Kitov, 2023).
4. Resilient Capital Position: Maintains a strong capital base that demonstrates
acute ability to withstand financial stressors (JPMorgan Chase & Co., 2024c).
● Weaknesses
1. Regulatory Risks: Heavy regulation oversight may lead to legal challenges and
compliance costs and requires a significant allotment of resources and personnel
to ensure compliance (Kitov, 2023).
2. Operational Risks: Substantial reliance on operating systems and those of third
parties raises the risk of delays, financial losses, and confidentiality breaches
(JPMorgan Chase & Co., 2024c).

8
3. Strategic Risks: Poor managerial decisions regarding business and marketing
strategies may lead to financial decline. Increasing competition and climate
change concerns pose additional strategic risks for management (JPMorgan
Chase & Co., 2024c).
4. People Risks: Intense competition regarding attainment of qualified personnel
coupled with technological advancements as well as changes to immigration and
travel policies may impede talent acquisition and retention which hinders
performance (JPMorgan Chase & Co., 2024c).
● Opportunities
1. Global Expansion: Due to the strong financial position possessed by the firm,
they are well equipped to further explore expansion opportunities into emerging
markets and continue diversifying their revenue streams (Kitov, 2023).
2. Strategic Acquisitions: A growth strategy often utilized by the firm,
wellcoordinated mergers and acquisitions increase market presence and expand
the firm’s client base (JPMorgan Chase & Co., 2024c).
3. Technological Advancement: Increasing investments into digital solutions that
bolster operating systems and collaborating with financial tech companies
provide an excellent opportunity for the firm to enhance digital banking services
(Kitov,
2023).
● Threats
1. Regulatory Changes: The ever-changing regulations that govern the finance
industry pose a significant threat to the firm if they fail to be vigilant in
monitoring and adapting to changes (Kitov, 2023).

9
2. Economic Uncertainty: Adverse economic and market events as well as
uncertainty in the U.S. and global economies can negatively affect the firm's
profitability and asset quality (JPMorgan Chase & Co., 2024c).
3. Intensifying Competition: As the finance industry continues to evolve,
competition has continued to increase significantly and may impact the firm’s
pricing strategies as well as their market share (JPMorgan Chase & Co., 2024c).
Favorable internal factors for the company include its diversified business model,
which compiles three distinct segments: Consumer and Community Banking,
Commercial and
Investment Banking, and Asset and Wealth Management (JPMorgan Chase & Co., 2024c).
Additionally, the firm holds a large global market presence with branches located in 48 states
and employees stationed in 66 countries. A strong workforce and global presence allows the
firm to turn out impressive financial metrics such as their Return on Assets (ROA) which
surpasses the industry-average at 1.5% (Kitov, 2023). Furthermore, their capital positioning,
which measures the firm’s financial strength, sits at Tier 1 with a data metric of 16.8 indicating
strong financial health and stability (JPMorgan Chase & Co., 2025a).
Examining favorable external opportunities, the firm is well-positioned to expand their
operations globally which would help establish a “more balanced and resilient revenue stream”
(Kitov, 2023, pg. 4). Such expansion would allow the firm to diversify the economic market
cycles they participate in thus reducing reliance on a single sector and mitigating the risks
caused by the potential economic decline of specific regions. Continuing to pursue strategic
acquisitions, such as the one recently completed with First Republic Bank in May of 2023, allows
for the potential of increased revenue (JPMorgan Chase & Co., 2024c). Acquiring First Republic

10
increased the firm’s average deposits, which led to an increase in net interest income, and
decreased noninterest expenses proving the benefits of such strategies. Lastly, investing into the
digital sector to enhance client’s mobile banking experience will prepare the firm well to handle
the increase of technology. Choosing to jump on the opportunity to collaborate with financial
tech companies (fintech) has the potential to create new revenue streams while simultaneously
streamlining operating systems and customer experiences (Kitov, 2023).
JPMorgan Chase outlines their top risk factors in yearly reports and U.S. Security
Exchange Commission filings which detail the weaknesses of the firm. There are four specific
risks of utmost importance which include: Regulatory, Operational, Strategic, and People
(JPMorgan Chase & Co., 2024c). Ensuring that banking and finance regulations are met, limiting
reliance on operating systems, implementing strategic business and marketing plans, and
working to attract and retain highly-qualified employees are all potential action steps the firm
must consider to combat these weaknesses and avoid adverse effects.
External threats facing the firm include regulatory changes, economic uncertainty, and
intensifying competition. Frequent regulatory changes may lead to an increase in compliance
violations if not adapted to which result in steep fines and lengthy legal battles while economic
disruptions caused by geopolitical events and trade tensions harm profitability (Kitov, 2023).
Competition, especially from digital-only banks and fintech disruptors, continues to increase and
jeopardize the firm’s market share.
Industry Analysis: Trends in Investing and Banking
JPMorgan Chase & Co. operates in the financial industry conducting business both in
banking and investing. This section will review two current industry trends in both sectors as
well as one major factor that is impacting the finance industry as a whole.
Investing. The first rising trend in investing is regarding the sustainability of finance

11
(Marr, 2023). Consumers are expecting that financial companies prioritize sustainability and
Environmental, Social, and Governance (ESG) factors. As such, the investing sector has seen an
uptick of support for investments in green initiatives like renewable energy and recycling. In
addition to this green financing, other alternatives include social impact investing as well as
leveraging ESG commitments to attract socially conscious investors (Suardana, 2024).
The second trend in investing is digital and crypto currencies (Marr, 2023). The inquiry
into utilizing central bank digital currencies (CRDCs) has grown to over 130 countries. This sector
is still fairly unexplored so it is anticipated that with its current growth, additional governance
and regulations will begin to populate. Additionally, Bitcoin has been making a comeback in the
crypto currency market. After recovery from its crash in 2021, the company has been garnishing
the attention of innovators and investors which has fostered the crypto currency trend.
Banking. The first current trend in banking is cyber-security and fraud detection (Marr,
2023). As the complexity of cyber threats increases, the need for advanced counter strategies
becomes stronger. An estimated $215 billion was spent by companies on security and risk
management in 2024 which represents a 14.3% increase from the year prior. Cyber-security
threats have also inspired banks to begin investing in multi-factor authentication, blockchain,
and other security measures to ensure the protection of client and firm data (Suardana, 2024).
Specifically, the use of blockchain banking, which employs distributed ledger technology that
aids in transaction authentication, has received growing popularity in the banking sector (Marr,
2023). Examining a specific case study, JPMorgan implemented its own blockchain system called
the interbank information network (IIN) which increased transactional efficiency and elevated
the firm’s industry standing (Liu, 2024). Such examples speak to the efficiency of currently
trending technology.

12
The second banking trend is that of the customer experience (Marr, 2023). Technological
advancements continue to innovate this area of banking as each customer’s journey is analyzed
to increase satisfaction and reduce inconveniences. Banks are beginning to prioritize
omnichannel approaches that include user-friendly interfaces while working to deliver
personalized experiences that achieve customer engagement (Suardana, 2024). Technology
such as Virtual Reality (VR) aids in the pursuit of interactive and personalized experiences that
engage the clientele (Marr, 2023). Outside of technology, however, customers are also
preferring seamless transitions between all platforms such as mobile apps and online websites,
but also ATMs and physical branches as well (Suardana, 2024).
Finance Industry. It is important to recognize one of the largest impacting factors to the
finance industry currently which is the rise of AI and fintech (Marr, 2023). Generative AI utilizes
chatbots that have been implemented on banking mobile apps and websites by numerous
industry leaders. Firms have begun utilizing AI algorithms to obtain a deeper understanding of
their client base (Ranjan, 2025). As AI continues to advance, it is likely that personalized
financial plans as well as investment strategies will be generated and tailor made based on
customer profiles (Marr, 2023). Fintech innovations include peer-to-peer lending, digital
payments, and robo-advising which have challenged traditional banks by increasing
personalization and convenience for clients (Suardana, 2024). Again examining a specific case
study, JPMorgan Chase has responded to this challenge by launching its own digital payment
platform known as Chase Pay (Liu, 2024). Additionally, as fintech increases so does the
opportunity for collaboration between traditional firms and fintech startups (Suardana, 2024).
JPMorgan Chase has been able to integrate cutting-edge technology by engaging in such
collaborations which has increased customer engagement and satisfaction (Liu, 2024). Proven

13
success by JPMorgan Chase highlights the appropriate strategies available to the finance
industry as they navigate the changes brought about by AI and fintech.
Competitor Analysis: The Financial Services Industry
The top competitors of JPMorgan Chase that will be examined in this analysis are some
of the leading players in the financial services industry. They include Bank of America, Citigroup,
and Wells Fargo (Liu & Wang, 2024). When conducting a baseline comparison based on four
main data metrics-Return on Equity (ROE), Return on Assets (ROA), Net Interest Margin (NIM),
and Return on Invested Capital (ROIC)-JPMorgan Chase outperforms its main banking
competitors Bank of America and Wells Fargo. This provides a significant advantage to the firm
in corporate management, reinvestment capabilities, and generating value. Additionally, low
data metrics for the two competitors highlight weaknesses in their quest to oust JPMorgan
Chase as the industry leader. However, when compared to Citigroup, JPMorgan Chase lags by
numerous percentage points in both ROA and NIM indicating that Citigroup has advantages in
efficiency and interest rate management (Kitov, 2023).
Wells Fargo does hold an advantage over JPMorgan Chase in regard to its Price-
toEarnings ratio (P/E) leading by more than two points indicating that the market is more
favorable towards Wells Fargo in terms of growth and profitability (Liu & Wang, 2024). Bank of
America ranks third in this metric again providing limited competition to JPMorgan Chase.
Comparison of the firm’s debt ratios and asset turnover rates indicate a fairly level playing field
among Bank of America, JPMorgan Chase, and Wells Fargo meaning that operational leverage
and asset utilization efficiency are similar. However, Wells Fargo falls significantly behind in
terms of Net Profit Margin leggings by over ten percentage points from the top competitors.
Although Bank of America is second to JPMorgan Chase in this data metric, the difference is less
than half a percentage point suggesting a potential point of advantage for Bank of America.

14
When examining the long-term, the ten-year growth for the firm is double that of its peers
including Bank of America, Citigroup, and Wells Fargo (JPMorgan Chase & Co., 2025b). This
competitor analysis confidently places JPMorgan Chase above most other financial service
leaders yet showcases potential areas of improvement due to the advantages held by
competitors.
Company Analysis
Completing a company analysis of JPMorgan Chase will include a detailed dive into the
firm’s (1) leadership, (2) supply network, and (3) recent financial performance.
Leadership. The leadership at JPMorgan Chase is dispersed across their board of
directors which currently consists of twelve members with chairman and chief executive officer
being Jaime Dimon (JPMorgan Chase & Co., n.d.c). Seven out of the twelve members have been
elected to the board in the past five years suggesting a recent leadership restructuring. The
board is responsible for management of the firm on behalf of its stockholders and works either
directly or through the use of committees (JPMorgan Chase & Co., n.d.a). There are nine
different committees that board members work through, five of which are principal standing
committees which include, Audit, Compensation & Management Development, Public
Responsibility, and Risk committees. Additionally, the firm has one stock committee and board-
level executive committee as well as two specific purpose committees which include Markets
compliance and Omnibus committees. Each different committee works to ensure that
operations both towards clients and employees are working effectively and ensuring satisfaction
and safety.
Supply Network. The process of building JPMorgan Chase’s supply chain has taken place
over the course of the past thirty years (JPMorgan Chase & Co., n.d.d). The firm has a
commitment to ensuring that its supply chain is strong, diversified, and inclusive. They operate a

15
Global Supplier Diversity program which works to enable the growth of business within their
supply chain network. Continuously, the firm has launched their Corporate Alliance for
Supporter Capital which helps small and underrepresented businesses qualify to serve
corporations. To ensure that sustainability is achieved through the products and services they
purchase, the firm has implemented a supply ESG program to ensure purchases are more
environmentally conscious JPMorgan Chase & Co., n.d.e). Accountability is present throughout
the company and its supplies to ensure that there are no ethicality issues and that sustainable
practices are being lived out. While JPMorgan Chase does not disclose an exact list of their
supplies, they do conduct a program known as their Gold Suppliers which elevates the status of
preferred suppliers that have delivered outstanding performance to the firm (JPMorgan Chase &
Co., n.d.b). This program helps the companies grow in their business with the firm and acts as a
strategic stepping-stone to long-term success with JPMorgan Chase.
Financial Performance. Recent financial performance of the firm positions it well to
accomplish targeted financial goals for 2025. In regard to Return on Tangible Equity (ROTCE), the
firm surpassed the 2025 goal of 17% by achieving a ROTCE of 22% for 2024 (JPMorgan Chase &
Co., 2025a). Due to markets Net Interest Income (NII) increasing from one billion to four and
half billion in 2025 due to lower funding costs, the firm is also well positioned to achieve their
stated firmwide NII of 94.5 billion (JPMorgan Chase & Co., 2025b). An unchanged expense
outlook of 95 billion for the firm indicates that it is well-equipped to achieve its stated
nonfinancial goals including those relating to technological investments, marketing, volume, and
revenue growth. The firm has dedicated a technology expense budget of 18 billion for 2025
suggesting that growth and convenience in online account openings will be improved. In fact,
the firm employs over forty thousand engineers with coding assistants that have 100 AI

16
solutions in production. Additionally, the firm ranks number one in U.S. credit card issuers
(JPMorgan Chase & Co., 2025), implying a significant market advantage and incentive to achieve
goals relating to streamlining their Card Services Departments. Lastly, as competition increases
JPMorgan may need to reevaluate their prices for offered products and services (JPMorgan
Chase & Co., 2024c), however, 2024 data still lists them as number one in U.S. retail deposits
(JPMorgan Chase & Co., 2025c). Examining their financial data metrics as well as their budgeted
expenses, JPMorgan Chase is well-equipped to meet and even surpass their 2025 growth
drivers.
Customer Analysis
When conducting a customer analysis of JPMorgan Chase, it is imperative to clarify that
the firm does not publish or disclose any information regarding their customers demographics.
This is due to the stringent privacy regulations that financial institutions are held to. However,
the firm's private research institute has published studies that highlight recent trends in certain
demographics and sectors. Consequently, this analysis will expound on the statutory limitations
that the firm is held to as well as the only published studies that provide limited analysis of
financial consumers.
Legal Limitations. Passed in 1999, the Gramm-Leach-Bliley Act (GLBA) is the leading
privacy protection act that influences data sharing throughout the finance industry (Walrath,
2017). This law requires that financial institutions provide privacy notices to all their clients to
communicate how their private information is shared with affiliated third parties. Furthermore,
firms are required to protect the security and confidentiality of customer information and
ensure that the integrity of the information is not compromised through threats, hazards, or
unauthorized users (Federal Deposit Insurance Corporation, 2022). Certainly, JPMorgan Chase
collects client information as it is required to provide products and perform services for clients,

17
however, the information collected is for internal use only and only available to employees to
perform their jobs. Examining the privacy policy published on the company’s website, it is well-
established that the sharing of client information is done solely for business purposes including
everyday transactions and marketing (Chase, 2025). Continuously, the GLBA requires that
consumers are given the opportunity to opt-out of certain information sharing (Federal Deposit
Insurance Corporation, 2022), and the website highlights how clients are able to opt-out of
information sharing with affiliates of the firm (Chase, 2025). Considering the current regulations
in place and the firm’s own privacy policy, JPMorgan Chase is legally unable to disclose through
any of its published reports or filings the personal information of its client base, such as age,
race, gender, or income.
JPMorgan Chase Institute Findings. The JPMorgan Chase Institute conducts research on
financial topics and general market trends and publishes its findings to the public on the firm's
website. The study reviewed in this analysis will highlight demographic changes in retail
investors. Although the data provided in this report was self-identified and provided to the
institute by a third party (JPMorgan Chase & Co., 2023b), the information still provides helpful
insight into the customer base that the firm is likely servicing. Three key findings regarding the
age, gender, and race of retail investors were reviewed throughout the report (JPMorgan Chase
& Co., 2023b). Regarding the age of investors, growth among the younger generation has
greatly expanded and the monthly shares being invested by individuals under forty has tripled
over the past decade and is surpassing those aged forty and above. Although men and women
both saw an increase in investments, the data was slightly high for men showing an association
with peaks in market volatility and surges and that men lead women in overall investment
activity. Lastly, examining race, Black and Hispanic individual’s investment percentages have

18
been increasing relative to those of White individuals and actually surpassed White and Asian
percentages in 2023. Investment expansion has been more prominent within Black and Hispanic
communities as well. Considering that the firm services 82 million consumers through their
banking segment, 900,000 of which walk daily in branches (JPMorgan Chase & Co., 2024a), this
study barely scratched the surface of understanding the firm's vast client base. However, the
presence of such institutions and studies allow for the pursuit of deeper knowledge in a heavily
confidential and regulated area.
5. Market-Product Focus
This sector will explore JPMorgan’s marketing and product objectives for the next five
years while highlighting the target markets, points of difference, and positioning of their newly
innovated mobile cash deposit system.
Marketing and Product Objectives
Approximately 3.6 billion individuals utilize online banking with 91% claiming it as one of
their top priorities (Elad, 2025). In fact, 77% of all banking transactions are completed entirely
online. With the expansion of mobile banking, it raises the question of how innovation may
continue to flourish. Reports have indicated that financial institutions must pursue rapid
innovation in order to distinguish their mobile platforms and remain competitive (Daughtery,
2025). Considering that 34% of people will switch banks due to better mobile and online
banking options, the possibilities to gain a competitive edge are plentiful (Stacker, 2024). With
such statistics in mind, JPMorgan Chase has worked to design the world’s first mobile cash
deposit system that aims to enhance security and better reach the unbanked and underbanked
communities. The firm aims to engage at .25% of their active user base in utilizing the system
within the first year of its launch and holds an acquisition goal of 5% market penetration within
the underbanked and unbanked market groups across the next three to five years. The goal is

19
that 70% of individuals will become repeat users after a year of the product's creation,
establishing a growing and loyal client base for the service. The following three sections will
highlight the current markets and expansion process.
Current Markets. Mobile check depositing systems have been around since mobile and
online banking took off, with all of JPMorgan’s top competitors such as Bank of America,
Citibank, and Wells Fargo offering the service through their respective mobile banking channels
(Zhen, 2025). Over 60% of financial institutions have credited the inclusion of remote deposit
systems for significantly transforming their online banking platforms (Worldmetrics, 2025).
More than half of financial firms estimate that remote deposits will completely replace in-
person deposits within the next decade with almost 100% of banking executives viewing it as a
crucial part of future banking strategies. Although mobile check deposit certainly is a popular
and growing use of online banking, other resources that appeal to consumers are 24/7 access,
monetary transfers between accounts, and online bill pay (Self Financial, 2024).
New Product. To capitalize on the growth of remote deposits, JPMorgan Chase has been
working to innovate and expand mobile deposits to include cash in addition to checks. Such a
system would utilize the serial numbers printed on the cash to ensure deposit and additionally
track what cash has been previously deposited. This innovation aims to not only provide
additional convenience for its users and enhance security measures due to additional tracking
but also find high levels of appeal among individuals who are unbanked or underbanked. In
regard to security measures, serialized tracking has been proven to aid in fraud prevention
(NetSuite, n.d.).
Due to the uniqueness of the number, it is difficult for counterfeiters to produce fake bills that
could overcome the detailed and precise tracking system. Additionally, such tracking enhances

20
traceability by keeping a complete history of the bill and its whereabouts. In reference to the
expansion into unreached groups, those who are reported as being part of the unbanked and
underbanked communities are more likely to entertain mobile banking and payment methods
than full bank users (Federal Reserve Board, 2016). Considering that individuals who are
underbanked rely more heavily on the use of their mobile device due to the potential lack of
other internet access points, they were reported to be 40% more likely to use mobile banking
(Electronic Transaction Association, 2022). Of those individuals who have no bank, two-thirds
were classified as households that rely entirely on cash only (Federal Deposit Insurance
Corporation, 2024). This data collection would suggest a high probability of success in servicing
these underserved communities.
New Markets. Although remote deposit technology has existed previously, the creation
of a mobile cash deposit system would lead the firm into an entirely new branch of the market
that has yet to be explored. JPMorgan Chase would lead the way in increasing innovations
within the online banking world. About 65% of financial institutions have been aiming to expand
remote systems to include other financial documents and ID scans (Worldmetrics, 2025),
however, none have focused their approaches on solely cash. Fortunately, serial tracking
systems for cash do exist including utilizing transaction identifiers for each bill and then scanning
the bill to connect the serial number and transaction identifier (World Intellectual Property
Organization, 2005). A separate system tracks serial numbers and compares them to those of
counterfeit bills which are kept in a separate log and aids in validating currency and identifying
individuals who attempt to use them (Google Patents, 2010). Applying these systems into their
mobile innovation would catapult the firm ahead of its competitors. Furthermore, unbanked
and underbanked communities represent a substantial market that is largely untapped by

21
financial firms (Electronic Transactions Association, 2022). Financially underserved markets were
reported to make up $1.3 trillion in wages which highlights the massive economic value that
such communities hold. There exists a considerable incentive for the firm to find services that
will cater to such groups as they work to broaden their expansion.
Target Markets
The target market for JPMorgan Chase’s mobile cash deposit system will include their
already expansive platform of digital users as well as those who are part of unbanked or
underbanked communities and those who may have concerns regarding safety and security.
Considering that the firm already reported 67 million active users across their digital platforms
in 2023 (JPMorgan Chase & Co., 2024), they are well positioned to introduce a new service
offered to their existing client base. When recognizing the unbanked community, which
represents 4.5% of the US, it is important to note that while a small percentage their economic
potential is promising (Goodstein, 2024). Roughly 3.5 million individuals without banks rely
solely on cash with the vast majority of these people being Hispanic. Continuing with a closer
look at the demographics most unbanked, data shows White and Black people trailing
Hispanics. An examination of education shows individuals with college degrees barely
surpassing those without a high school diploma in terms of being unbanked and relying solely
on cash. Income again displays a high amount of variation with top numbers belonging to
individuals who make fifty thousand or more annually while second place are those making
between fifteen and thirty thousand. When considering the underbanked community, 19
million individuals are in question as over 14% of US households are underbanked and reliant
on nonbank products (Federal
Deposit Insurance Corporation, 2024). Such significant amounts of variation and volume present
in the data suggest that the firm’s creation of this system would bring in a broad range of

22
consumers. Lastly, 35% of individuals have expressed security and fraud concerns through
online banking platforms (Self Financial, 2024). Over 54% of individuals report being the victim
of fraud through online platforms which correlates with the heightened level of concern. If the
firm focuses on marketing the enhanced security delivered through the serialized tracking
system it may appeal well to the groups who have concerns about fraud and security.
Points of Difference
The points of difference, or what distinguishes JPMorgan’s mobile cash deposit system
from its competitors, are detailed below.
First-of-its-Kind. All competing firms have advanced online banking platforms and
mobile deposit systems fit for check acceptance (Zhen, 2025), however, none have one that
specializes in remote cash deposits making this technology unique amongst competitors.
Convenience Without In-Person Visit. Rather than having to visit an ATM or physical
branch to make a cash deposit, this system provides convenience for the consumer in a manner
yet to be attempted by opposing financial institutions by expanding the services available to
them through online platforms which is something highly sought after by consumers (Self
Financial,
2024).
Robust Anti-Fraud Detection. Although all financial institutions remain vigilant to detect
and prevent fraud, a serial tracking system that would work specifically with cash transactions
has yet to be implemented within banks. Providing a system that boosts tracking and
traceability (NetSuit, n.d.), would bolster anti-fraud detection for cash transactions.
Financial Inclusion for Cash-Reliant Communities. Cash-depent individuals who are
grouped into unbanked and underbanked communities are notoriously underserved by financial
institutions (Goodstein, 2024). Expanding the mobile banking options available to those

23
individuals who rely on cash would provide a prime advantage to the firm as it takes the lead in
expanding into unreached markets.
Positioning
The future of cash banking is mobile as JPMorgan Chase' s invention brings increasing
innovation to the online banking world. Enabling users to deposit cash anywhere without
needing to visit a branch or ATM without compromising their safety and security bolsters
consumer confidence and convenient services. The firm’s approach would utilize similar
technological innovation that is currently emerging within financial institutions but expand its
use to cash further enabling them to increase financial access in underserved markets. All
characteristics combined strive to achieve a positioning with clients where they embrace a
digitized future that still prioritizes security and service.
6. Marketing Program
A marketing plan for JPMorgan Chase’s new mobile cash deposit system will be detailed
below utilizing the four elements of a marketing mix - Product, Price, Promotion, and Place.
Product Strategy
This section expounds on the offered product and its unique attributes while
simultaneously providing information on how it will be packaged towards consumers.
Product Line. While the launch of JPMorgan Chase's new mobile cash deposit system
will be stand-alone, it will complement their other pre-existing mobile app features which
include Zelle, ChaseQuickDeposit, and ChaseQuickPay (Chase, n.d.).
Unique Product Qualities. A mobile cash deposit system will be the first of its kind across
all financial institutions providing a unique service to Chase clients as the firm leads the way in
technological innovations. Additionally, the heightened security features delivered through the

24
product's serial tracking system will provide enhanced safeguards in cash handling, an area
more prone to money laundering and fraud (Blockworks, 2024).
Packaging. The packaging for this service will present the system to the consumer
through the Chase Mobile App and its existing delivery methods for their alternative online
features. A goal for the firm is to ensure that the Chase Mobile App, which is currently available
for download on IOS and Android devices, maintains a seamless, familiar, and integrated design
across all different platforms and features (JPMorgan Chase and Co., 2023a). With this goal in
mind, the product will be incorporated into the app’s dashboard which is designed to be
naturally intuitive and user-friendly, even offering onboarding and tutorials to educate
consumers on how to utilize different features.
Price Strategy
This mobile cash depositing system will be a complimentary service provided through
the Chase Mobile App to all current and future Chase clients. Such a pricing strategy mimics
other competing financial institutions where mobile deposits are a standard feature for account
holders (Martin, 2024.). Chase is able to provide such cutting-edge technology for free to its
client base while still reaping benefits for two main reasons. First, increased amounts of
technological investments have effectively discouraged in-person branch visits which have
disproportionately decreased the firm’s infrastructure costs (D3 Harvard, n.d.-a). Second, Chase
attracts an increased client base through convenient, technology-advanced banking systems.
This increase in clients results in elevated levels of money being held and invested as well as the
creation of additional revenue opportunities from credit cards and loans.

25
Promotion Strategy
The promotion strategy for the firm's mobile cash deposit system will feature an
integrated and cross-channel approach that utilizes social media, education, physical and
technological advertisements, and mobile advertisements.
Social Media. Chase has found success employing social media to advertise their new
product and services offerings, remaining active on platforms such as Instagram, Twitter, and
LinkedIn (Everything PR, 2024). Such an approach helps the firm reach younger audiences such
as Gen-Z by leveraging social media influencers and establishing brand ambassadors that work
to generate popularity and media attention around new products. Marketing this new mobile
cash deposit service will follow along similar lines including the use of paid social media
campaigns that are designed to be targeted towards specific demographics. To target select
individuals, the firm occupies different channels including Instagram stories, sponsored LinkedIn
posts, and Facebook ads. Additionally, the utilization of cinemas, videos, TV advertisements and
radios will be employed. Whether it be superbowl ads (Retail Dive, 2016), or featured films (We
Are Chase, 2021), harnessing the power of film and television has worked wonders to reach new
audiences and will be implemented in promotion of this new product.
Education. JPMorgan Chase prides itself on maintaining its reputation as a trusted
financial firm. To accomplish this, the firm leverages educational content that enables both
clients and non-clients alike to grow in financial literacy. Doing this not only helps promote the
services offered by the firm, but also grows engagement and trust with the consumer base
(Everything PR, 2024). Chase already operates different blogs such as their Chase Slate Edge
blog that provides personal finance and credit card information to the public. The addition of
this new product will begin to be incorporated in newly published blogs. Furthermore, the firm

26
also publishes educational videos that offer guidance on how to navigate their offered services
and manage one’s personal finances. The inclusion of these videos, highlighting the new mobile
cash deposit system-how to use it and the benefits from using it-will simplify a potentially
complex concept and expand its reach to a broadened audience.
Physical and Technological Advertisements. Engaging with a cross-channel approach of
in-branch and technological advertisements will broaden the scope of promotion for the new
service. Regarding in-branch promotions, the firm uses detailed display advertisements that are
routinely changed out to reflect new products or services (Everything PR, 2024). Chase’s
branches, which total over 4,800, are an integral part of their product and service promotions
(Your Business Model, n.d.). The branches play such a crucial role in part due to the personnel
that are working within. Teller’s current roles are to encourage and assist clients in the adoption
of digital banking (D3 Harvard, n.d.-b). Prompting and educating consumers on the new mobile
cash depositing system, especially when the client has come in to complete a cash transaction,
will be an effective promotion tool that associates of the firm will directly assist with. In addition
to these physical methods of advertisements, Chase will also exercise the use of emails, website
updates, and in-app notifications to draw awareness to the new service (Everything PR, 2024).
Mobile Advertisements. JPMorgan currently takes advantage of their internal app data
collection and analytic systems to cater in-app advertisements to specific target groups
(Everything PR, 2024). Engaging with these valuable data metrics enables the firm to produce
advertisements that are in line with the roll-out of new services yet still personalized to the
consumer based on their information, patterns, and app usage. Analyzing current app users and
seeing which clients would most benefit from utilizing the new mobile cash deposit system will

27
be a critical part of the promotion process as the firm wields the power of mobile
advertisements to enhance customer engagement and conversion rates.
Place (Distribution) Strategy
The mobile cash deposit system will be accessible through the Chase Mobile App which
is available for download from the app store on both IOS and Android devices (JPMorgan Chase
& Co., 2023a). Additionally, there will be published tutorial videos online at Chase.com that will
educate consumers on accessing and using the system. All physical branches will also enable
distribution of the product through education and promotion. Lastly, should a client need
assistance accessing or engaging with the system the firm employs chatbots and advanced
AIcustomer service systems that assist in providing exceptional customer service across all
platforms (Everything PR, 2024).
7. Financial Data and Projections
Past Sales Revenue
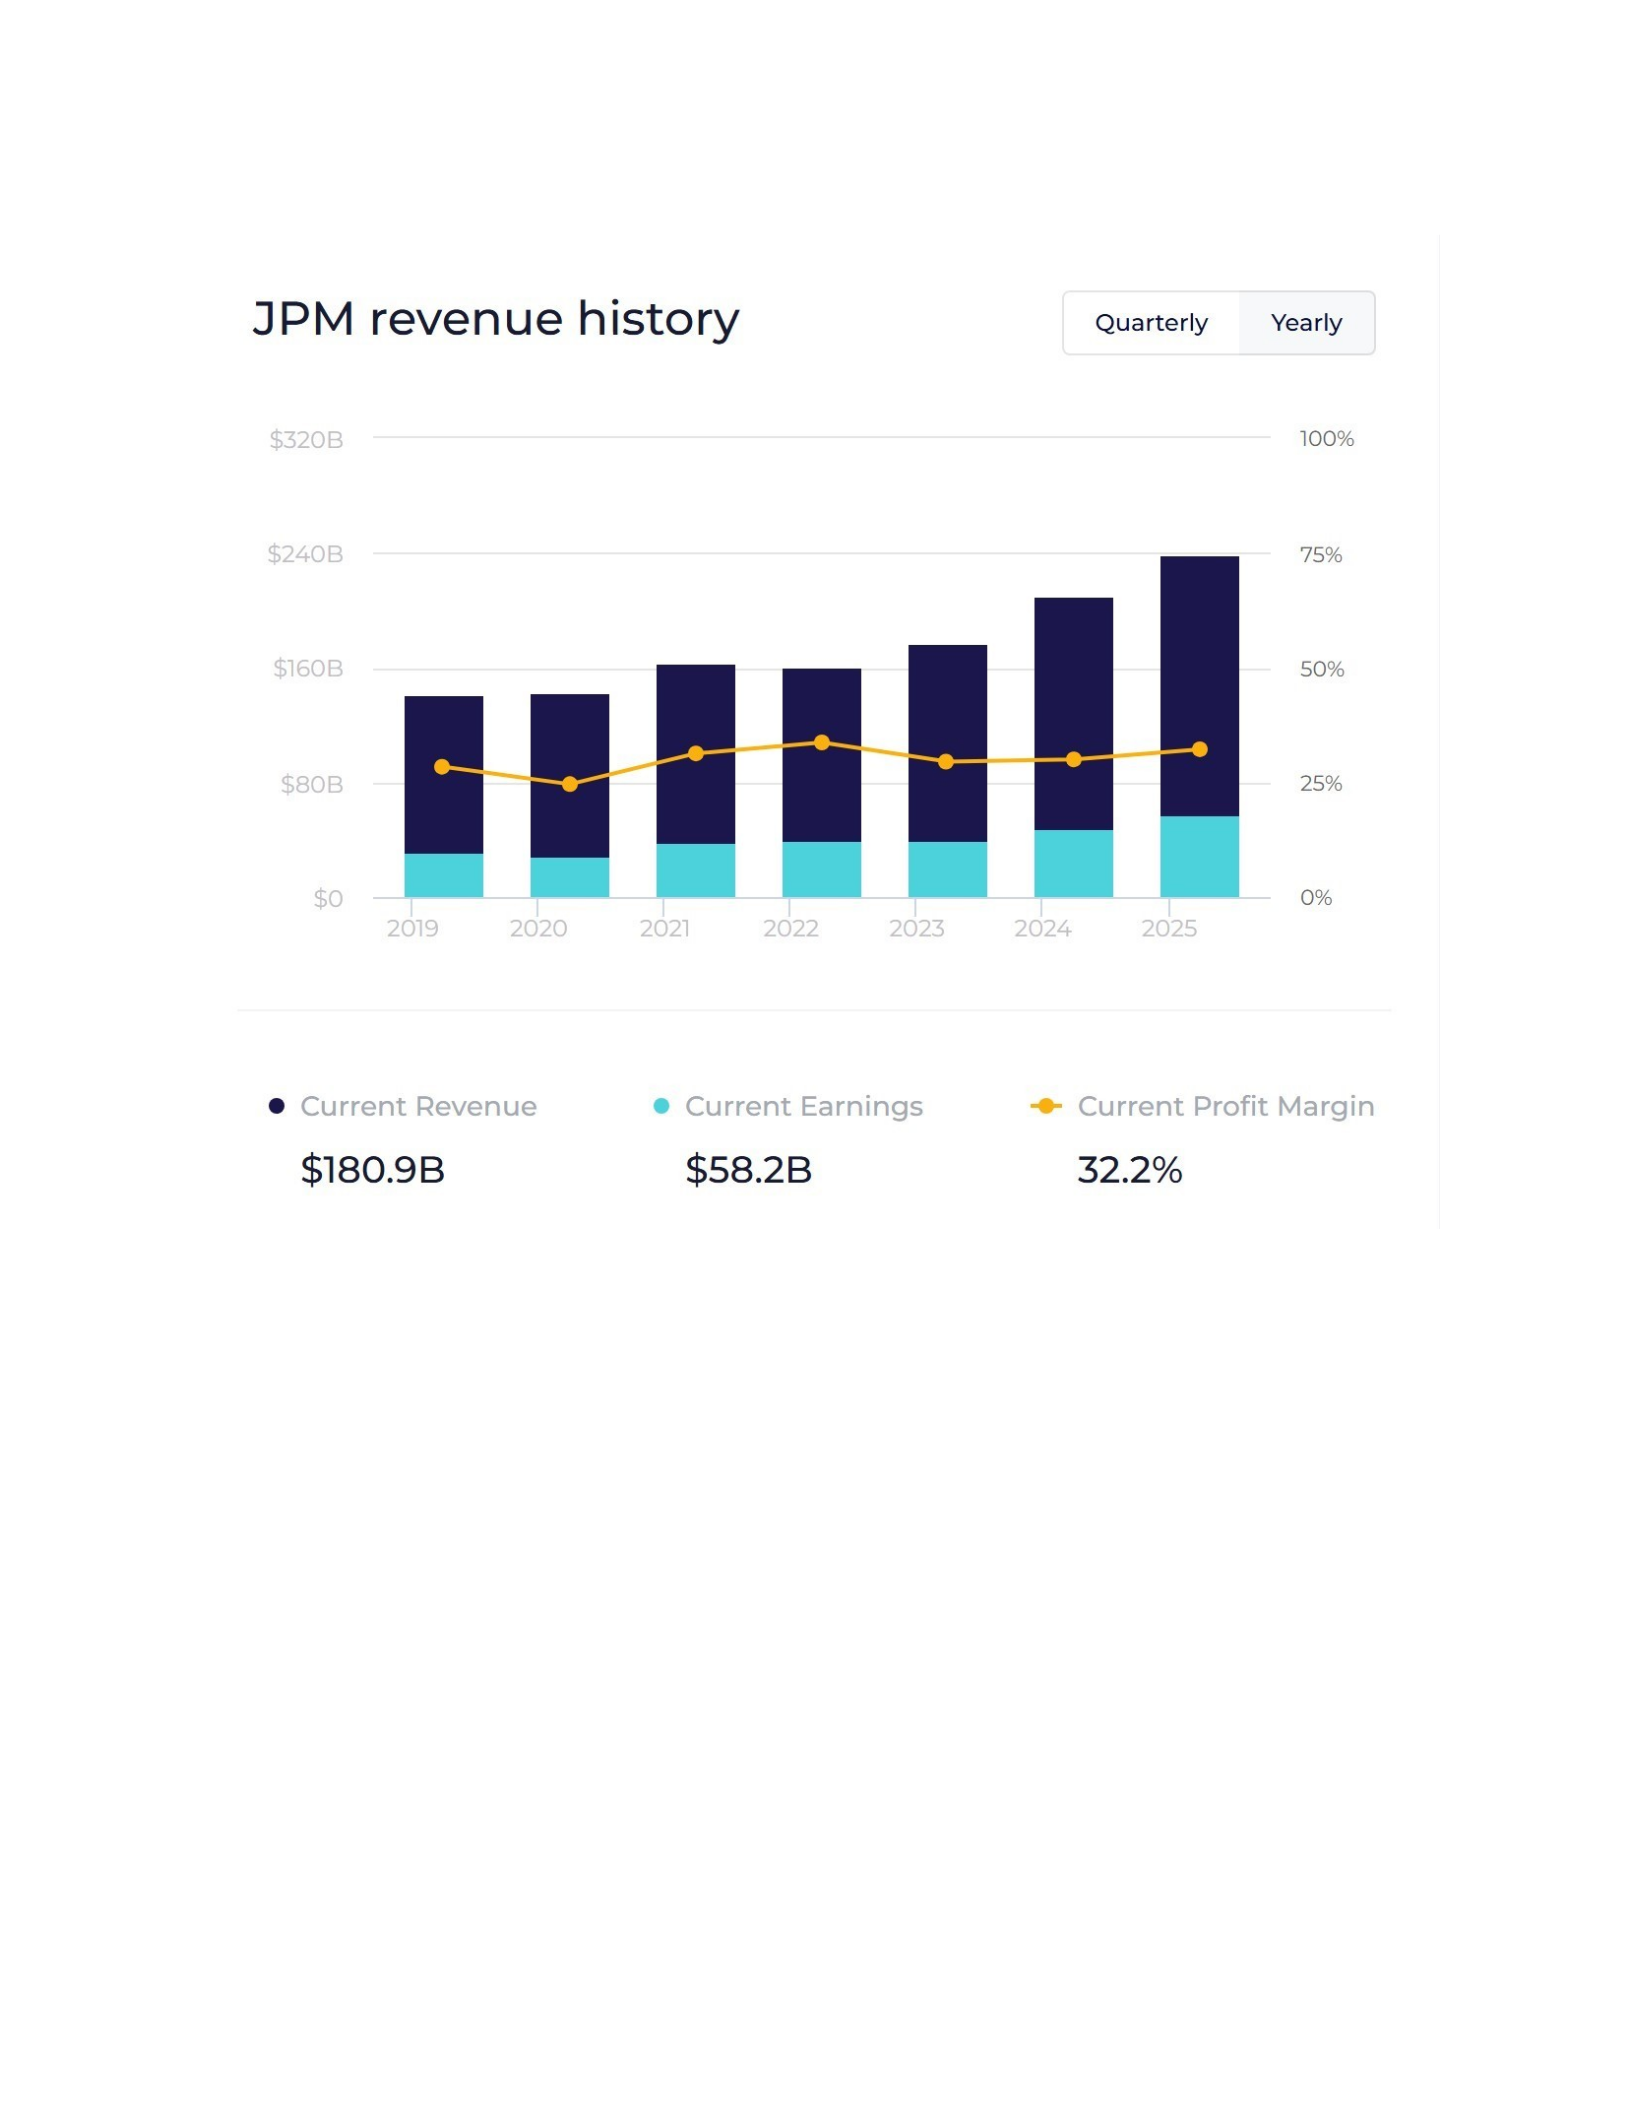
With the exception of 2022, revenue for JPMorgan Chase has steadily increased with
larger growth reported in the current year. Sales revenue as well as profit margin and earnings
for the past six years are displayed in Figure 1 (WallStreetZen, n.d.).
28
Figure 1. Revenue History for JPMorgan Chase
Five Year Projections
Taking into consideration that there is no service charge for the mobile cash deposit
system the following five year projections will be split into two separate categories that
examines user adoption rates and operational savings. The numbers regarding adoption rate are
based on the current amount of active app users which is 67 million (JPMorgan Chase & Co.,
2024) and the targeted level of engagement which was listed in Product Objectives as .25%. In
reference to operational savings the math is calculated based on a study that examined the
costs of in-person deposits compared to mobile deposits. The study concluded that the average
29
deposit costs $4.25 while that same deposit done on a mobile device only costs $0.10-a savings
of $4.15 per deposit (Stewart, 2013). The data is presented in the following two charts.
Updated User Adoption Chart (Based on 67M Users)
Year % of Total Mobile Users Number of Users (67M base) YoY Growth
Rate
1 0.25% 167,500 —
2 0.60% 402,000 +140%
3 1.20% 804,000 +100%
4 2.00% 1,340,000 +67%
5 3.20% 2,144,000 +60%
Updated Operational Savings Chart
Assuming 10 deposits per user per month, 120 deposits per user per year, and $4.15 saved per
deposit
Year Users Deposits/User/Yr Total Deposits Savings/Deposit Total Savings
1 167,500 120 20,100,000 $4.15 $83,415,000
2 402,000 120 48,240,000 $4.15 $200,196,000
3 804,000 120 96,480,000 $4.15 $400,392,000
4 1,340,000 120 160,800,000 $4.15 $667,320,000
5 2,144,000 120 257,280,000 $4.15 $1,068,312,000
References
Aquino, S. (2024). Inside Chase’s Efforts To Embrace Accessibility And “Be The
Bank For Everyone.” Forbes.
https://www.forbes.com/sites/stevenaquino/2024/08/21/inside-chases-efforts-
toembrace-accessibility-and-be-the-bank-for-everyone/

30
Blockworks. (2024). Treasury says cash still primary tool for money laundering.
https://blockworks.co/news/treasury-cash-still-primary-tool-money-laundering
Chase. (2025). U.S. consumer privacy notice. JPMorgan Chase & Co.
https://www.chase.com/digital/resources/privacy-security/privacy/
consumerprivacy-notice
Chase. (n.d.). Chase mobile app named #1 in J.D. Power wealth management
mobile app satisfaction study. https://media.chase.com/news/chase-mobile-
appnamed-number1
Credit Rape. (n.d.). JPMorgan Chase: Driving innovation in personal and business
finance. https://www.creditrape.com/jpmorgan-chase-drivinginnovation-in-
personal-and-business-finance
D3 Harvard. (n.d.-a). Digital innovation in online & mobile banking at J.P. Morgan
Chase. https://d3.harvard.edu/platform-digit/submission/digitalinnovation-in-
online-mobile-banking-at-j-p-morgan-chase
D3 Harvard. (n.d.-b). East vs. West: Can JPMorgan Chase protect its lunch from
the fintech startups of the world?
https://d3.harvard.edu/platform-rctom/submission/east-vs-west-can-
jpmorganchase-protect-its-lunch-from-the-fintech-startups-of-the-world
Daugherty, G. (2025). Survey: Bank and credit card apps and websites struggle to
stand out. Investopedia. www.investopedia.com/survey-bank-and-credit-
cardapps-and-websites-struggle-to-stand-out-11745988
Dimon, J. (2023). Letter to shareholders from Jamie Dimon, annual report 2022.
JPMorgan Chase & Co.
https://reports.jpmorganchase.com/investor-relations/2022/ar-ceo-letters.htm
Elad, B. (2025). Online banking usage statistics 2025: Adoption, user insights, etc.
CoinLaw. coinlaw.io/online-banking-usage-statistics/
Electronic Transactions Association. (2022). Serving the underserved.
electran.org/news/serving-the-underserved/?utm_source
Everything PR. (2024). Five digital marketing strategies JPMorgan Chase does
well to stay ahead in 2025. https://everything-pr.com/five-digital-
marketingstrategies-jpmorgan-chase-does-well-to-stay-ahead-in-2025
Federal Deposit Insurance Corporation. (2022). Privacy Act issues under
GrammLeach-Bliley. U.S. Department of the Treasury.

31
https://www.fdic.gov/affordablemortgage-lending-center/privacy-act-issues-
under-gramm-leachbliley:contentReference[oaicite:2]{index=2}
Federal Deposit Insurance Corporation. (2024). FDIC survey finds 96 percent of
U.S. households were banked in 2023.
fdic.gov/news/press-releases/2024/fdicsurvey-finds-96-percent-us-households-
were-banked-2023
Federal Reserve Board. (2016). Consumers and mobile financial services 2016:
Accessing financial services.
federalreserve.gov/econresdata/mobile-devices/2016-accessing-
financialservices.htm
Goodstein, R. (2024). A closer look at the unbanked: Cash-only households versus
those that use prepaid cards or nonbank payment apps. Federal Deposit
Insurance Corporation. fdic.gov/consumer-research/closer-look-unbanked-
cashonly-households-versus-those-use-prepaid-cards-or
Google Patents. (2010). US7724938B2: System and method for processing
financial transactions. patents.google.com/patent/US7724938B2/en
ICMR India. (n.d.). JPMorgan Chase: Creating next-gen banking.
https://www.icmrindia.org/casestudies/catalogue/Business%20Strategy/
jpmorganchase-creating-next-gen-banking-excerpts.htm
JPMorgan Chase & Co. (n.d.a). Board of Directors and Board Committees.
JPMorgan Chase. Retrieved June 7, 2025, from
https://www.jpmorganchase.com/about/governance/committees
JPMorgan Chase & Co. (n.d.b). Gold suppliers. JPMorgan Chase. Retrieved June
7, 2025, from https://www.jpmorganchase.com/about/suppliers/gold-suppliers
JPMorgan Chase & Co. (n.d.c). Leadership. JPMorgan Chase. Retrieved June 7,
2025, from https://www.jpmorganchase.com/about/leadership
JPMorgan Chase & Co. (n.d.d). Supplier diversity. JPMorgan Chase. Retrieved
June 7, 2025, from
https://www.jpmorganchase.com/about/suppliers/supplierdiversity

32
JPMorgan Chase & Co. (n.d.e). Supplier sustainability. JPMorgan Chase. Retrieved
June 7, 2025, from https://www.jpmorganchase.com/about/suppliers/supplier-
sustainability
JPMorgan Chase & Co. (2023a). Investing on mobile devices made easy.
https://www.jpmorgan.com/technology/technology-blog/investing-on-
mobiledevices-made-easy
JPMorgan Chase & Co. (2023b). The changing demographics of retail investors.
https://www.jpmorganchase.com/institute/all-topics/financial-health-
wealthcreation/the-changing-demographics-of-retail-investors
JPMorgan Chase & Co. (2024a). Annual Report 2023: CEO Letter by Marianne
Lake. https://reports.jpmorganchase.com/investor-relations/2023/ar-ceo-
lettermarianne-lake.htm
JPMorgan Chase & Co. (2024b). Awards and recognition.
https://www.jpmorganchase.com/about/awards-and-recognition
JPMorgan Chase & Co. (2024c). FORM 10-K Annual report pursuant to Section 13
or 15(d) of the Securities Exchange Act of 1934. U.S. Securities and Exchange
Commission.
https://www.sec.gov/ix?doc=/Archives/edgar/data/0000019617/000001961725
00 0270/jpm-20241231.htm
JPMorgan Chase & Co. (2024d). History of our firm.
https://www.jpmorganchase.com/about/our-history
JPMorgan Chase & Co. (2024e) Jamie Dimon.
https://www.jpmorganchase.com/about/leadership/jamie-dimon
JPMorgan Chase & Co. (2025a). 2024 Annual report.
https://www.jpmorganchase.com/content/dam/jpmc/jpmorgan-chase-
and-co/ investor-relations/documents/annualreport-2024.pdf
JPMorgan Chase & Co. (2025b). Financial highlights 2024.
https://www.jpmorganchase.com/content/dam/jpmc/jpmorgan-chase-and-co/
investor-relations/documents/financial-highlights-2024.pdf

33
JPMorgan Chase & Co. (2025c). Firm Overview.
https://www.jpmorganchase.com/content/dam/jpmc/jpmorgan-chase-and-co/
investor-relations/documents/events/2025/jpmc-2025-investor-day/firmovervie
w.pdf
JPMorgan Chase & Co. (2025d). Management's discussion and analysis of
financial condition and results of operations (2024).
https://www.jpmorganchase.com/content/dam/jpmc/jpmorgan-chase-and-co/
investor-relations/documents/managements-discussion-analysis-2024.pdf
Kitov, I. (2023). An in-depth analysis of JP Morgan Chase & Co. Highlights in
Business, Economics and Management, 24, 2269–2275.
https://www.researchgate.net/publication/383374744_An_Indepth_Analysis_of
_JP_Morgan_Chase_Co
Liu, J., & Wang, X. (2024). Financial analysis of JPMorgan Chase in Harvard
analytical framework. Highlights in Business, Economics and Management, 40,
170–175. https://doi.org/10.54097/krhyvr61
Liu, X. (2024). FINTECH DISRUPTION IN TRADITIONAL BANKING: OPPORTUNITIES
AND CHALLENGES FOR FINANCIAL INSTITUTIONS
[J]. Trends in Social Sciences and Humanities Research, 2(8).
http://upubscience.com/upload/20241017142802.pdf
Marr, B. (2023). The biggest banking and financial services trends for 2024.
Forbes. https://www.forbes.com/sites/bernardmarr/2023/12/11/the-
biggestbanking-and-financial-services-trends-for-2024/
NetSuite. (n.d.). How serialized inventory tracking improves operations.
netsuite.com/portal/resource/articles/inventory-management/serializedtracking.
shtml?utm_source
Ranjan, R. (2025). Behavioural Finance in Banking and Management: A Study on
the Trends and Challenges in the Banking Industry. Asian Journal of Economics,

34
Business and Accounting, 25(1), 374-386.
https://www.researchgate.net/profile/Ritesh-Ranjan-24/publication/
388302764_Behavioural_Finance_in_Banking_and_Management_A_Study_on_t
he_Trends_and_Challenges_in_the_Banking_Industry/links/
67922c8152b58d39f24954e5/Behavioural-Finance-in-Banking-and-
Management-
A-Study-on-the-Trends-and-Challenges-in-the-Banking-Industry.pdf
Retail Dive. (2016). Chase Super Bowl ad promotes mobile services to millions.
https://www.retaildive.com/ex/mobilecommercedaily/chase-super-bowl-
adpromotes-mobile-services-to-millions
Self Financial. (2024). Digital banking statistics. self.inc/info/digital-
bankingstatistics/?utm_source
Stacker. (2024). Inside the mind of today’s bank customer: Consumer survey
insights. stacker.com/stories/personal-finance/inside-mind-todays-bank-
customerconsumer-survey-insights
Stewart, J. (2013). Mobile check capture is saving banks big bucks, but how big? Digital
Transactions. https://www.digitaltransactions.net/mobile-check-capture-is-
savingbanks-big-bucks-but-how-big/
Suardana, I. G. P. (2024). Evolving Banking Sectors: A Literature Review on
Current Trends and Challenges. Bata Ilyas Educational Management Review,
4(2), 67-76. https://ojs.stieamkop.ac.id/index.php/biemr/article/view/2223/1463
TechTarget. (2024). JPMorgan Chase technology goal: Innovation with cost
control. https://www.techtarget.com/searchcio/feature/JPMorgan-
Chasetechnology-goal-Innovation-with-cost-control
WallStreetZen. (n.d.). JPMorgan Chase & Co (JPM) revenue.
https://www.wallstreetzen.com/stocks/us/nyse/jpm/revenue
Walrath, D. (2017). Privacy and information disclosure: An economic analysis of
the Gramm-Leach-Bliley Act. Policy Perspectives, 24, Article 17602.
https://doi.org/10.4079/pp.v24i0.17602:contentReference[oaicite:2]{index=2}

35
We Are Chase. (2021). Chase launches campaign in the UK.
https://www.chase.co.uk/gb/en/media/chase-campaign-launch
What makes JPMorgan (JPM) a compelling buy among big banks. (2023).
Nasdaq. https://www.nasdaq.com/articles/what-makes-jpmorgan-jpm-
acompelling-buy-among-big-banks
World Intellectual Property Organization (WIPO). (2005). WO2005017842A1: A
method and system for processing financial transactions.
patents.google.com/patent/WO2005017842A1/en
Worldmetrics. (2025). Remote deposit capture statistics: Market data report
2025. worldmetrics.org/remote-deposit-capture-statistics/?utm_source
Your Business Model. (n.d.). JP Morgan Chase marketing mix (4Ps).
https://canvasbusinessmodel.com/products/jp-morgan-chase-marketing-mix
Zhen, S. (2025). What are mobile check deposit limits? Know before you bank.
MyBankTracker. mybanktracker.com/news/comparing-mobile-check-
depositlimits

