


Test of Assumptions/Diagnostics Tests on Influence of skills development on employee
performance
BUSI 240-Organizational Behavior 1
Liberty University
2022
Test of Assumptions/Diagnostics Tests
This section presents the results from the diagnostic tests conducted. The section discusses results
from test for linearity, normality, heteroskedasticity, model specification test and, test for
multicollinearity. The tests were conducted so as to provide appropriate analysis, meaningful
and robust conclusions. Williams, Grajales and Dason (2013) conducted a study on assumptions of
multiple regressions; correction of misconceptions and concluded that carefully considering the
reasonableness of the assumptions in the context of a particular dataset and analysis is an important
prerequisite to drawing of trustworthy conclusions from data.
Test for Heteroskedasticity
In the study, to test for the assumption of constant variance, Breusch Pagan test was used. Chi-
statistic was 0.83 and the p-value of 0.3619, implying that the data was not heteroskesdastic. The
test statistics for the model is shown in Table 4.22. The P-value reported in Table 4.20 is greater
than 0.05. This means that the Chi statistic is less than its critical values at five per cent level of
significance. Therefore, the null hypothesis assumed by the Breusch Pagan test that the error term
is homoskedastic could not be rejected at five per cent level of significance. Therefore, the usual t-
tests can be used to test the significance of all the coefficients in all the models. Pedace (2013)
explained that hetereskedasticity occurs when the variance of the error term changes in response to
a change in the value(s) of the independent variable(s). Table 4.22 shows the results from the test
for heteroskedasticity.
Test for Heteroskedasticity
Model Chi statistic P value
Model 3.9 0.83 0.3619
Model Specification Test
The study adopted Ramsey specification test to test whether the models used were correctly
specified. The test has a null hypothesis of correct specification. The test statistics for estimated the
model equation 3.9 is reported in Table 4.23. The test results has a p-value of 0.2551, which
reported for regression model is greater than 0.05. This means that the F statistic is less than
their critical value at five per cent level of significance. Therefore, the null hypothesis assumed
by the Ramsey Specification test that the model is well specified could not be rejected at five
per cent level of significance. Frost (2017) argued that the simplest model that creates random
residual is a great contender for being reasonably precise and unbiased.
Specification Test
Model F statistic P value
Model 3.9 1.37 0.2551
Test for Multicollinearity
Existence of multicollinearity was measured using Variance Inflation Factor (VIF). The study
result found VIF of 1.17, implying presence of low multicollinearity which cannot affect the
stability and consistency of the study results. As a rule of the thumb, a VIF of less than five is
considered an acceptable level of multicollinearity. This concurs with the views of Pedace (2013)
who argues that if the correlation coefficient between explanatory variables is less than 0.5,
multicollinearity problems is said to be tolerable. Table 4.23 reports the VIF values for the model
estimated. It shows that the level of multicollinearity could be tolerated and the findings
interpreted.
Multicollinearity Test
Model VIF
Model 3.9 1.17
Test for Linearity
The study considered testing whether the variables were linearly related. The correlation analysis
was used and the test had a null hypothesis of no linear association. The test statistics for linear
associations between the variables and their significance is shown in Table 4.25. Table 4.25
shows that p-values for the correlation coefficients are less than 0.05. Therefore, calculated test
statistic is greater than the tabulated at five per cent level of significance. Thus, the null hypothesis
that the correlation coefficients are equal to zero is rejected at five percent level of significance.
The correlation coefficients for all the explanatory variables are positive. Therefore, employee
performance in the PSI in Kenya and the explanatory variables commove in the same direction.
Hence, positive regression coefficients are expected between employee performance and the
explanatory variable.
Test for Linearity
Reference Variable:
Employee Performance
Correlation
Coefficient P value
Employee engagement 0.257 0.002
Training 0.177 0.031
Talent acquisition 0.195 0.018
Knowledge management 0.308 0.000
Skills Development 0.306 0.000
Normality Test
The normality test was conducted. Composites were created using simple means of each domain to
test whether the variables were normally distributed and Shapiro Wilk test for normality was used.
Ghasemi and Zahediasi (2012) noted that some researchers recommend the Shapiro-Wilk Test as
the best choice for testing the normality of the data since it has high power. As per the central limit
theorem normality, should be assumed for observation greater than 30. Skewness should be within
the range of ±2 and Kurtosis values should be within range of ±7.
Normality Test
Variable Z statistic P value
Employee engagement 1.738 0.041
Training 5.000 0.000
Talent acquisition 5.030 0.000
Knowledge management 2.873 0.002
Skills Development 3.001 0.001
Employee performance 1.135 0.128
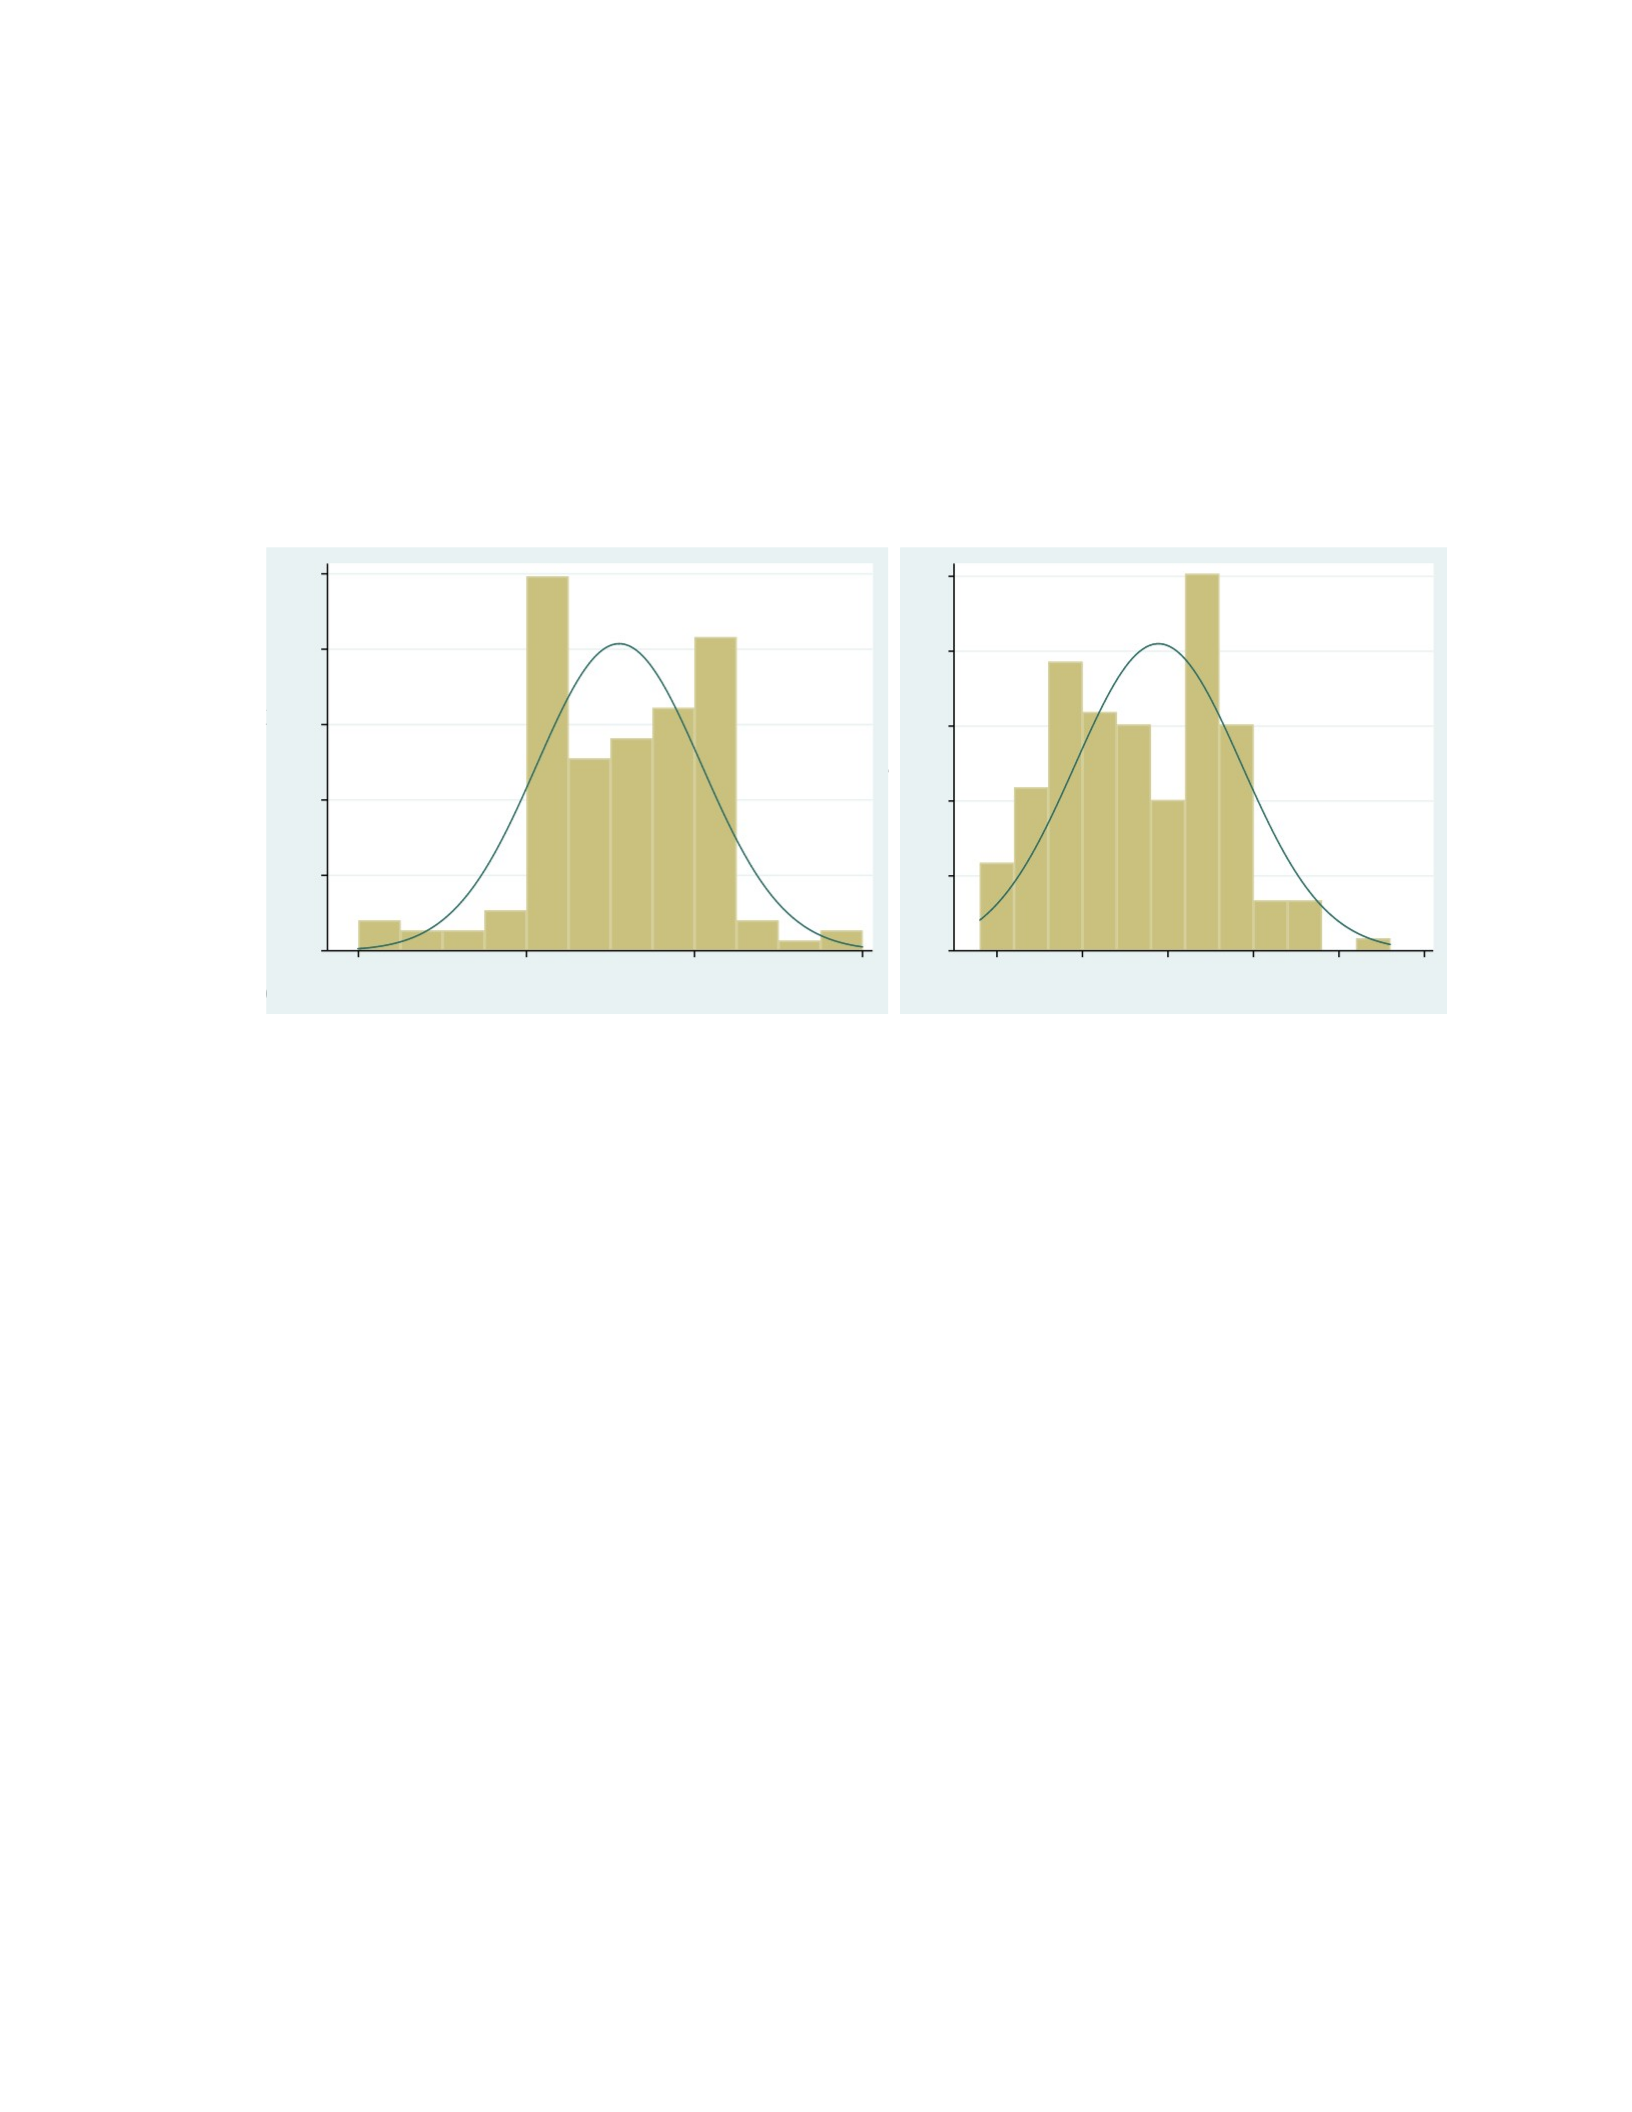
The histograms in Figure 4.13 show visual depiction of the normal distribution of employee
engagement and employee performance. In a regression analysis the predictor variable should be
normally distributed. Williams et al., (2013) in their study on assumptions of multiple regressions
and correcting misconception argues that normality violation in a study can degrade estimator
efficiency.
Inferential Statistics
This section presents the empirical evidence of the study as per the study objectives and the results
showing that the data is equally distributed. Both qualitative and quantitative data were gathered.
The data has been analysed, and the findings /the results from each of the study objectives have
been presented. The study findings have been corroborated with the works of other researchers to
help support the outcome.
Correlation Coefficient Analysis
The correlation coefficient analysis was used in the study to identify sign, the strength and direction
of the relationship between the variables. The study variables considered were employee
engagement, training, talent acquisition, knowledge management, skills development and employee
performance. shows the results of the correlation analysis of all the study variables at 1 per cent
level of significance.
The results of the analysis presented in Table 4.26 show that there is a weak positive correlation
between employee engagement and employee performance with a correlation coefficient of 0.2567.
The study results concurs with the study results by Mansoor and Hassan (2016) who carried out a
study to establish the factors affecting employee engagement in Maldives, and found weak positive
relationship between employee engagement and communication with a correlation coefficient of
0.322. The researchers also found the correlation coefficient between job role and employee
engagement to be 0.197. They also found team work and employee engagement to have a strong
positive correlation coefficient of 0.64 while learning and development had a coefficient of 0.181.
2.
5
3 3.
5
4 4.
5
5
e
p
1 2 3 4
ee
Density
.4.6 .8
1
Density
.4.6 .8
1

The results presented in Table shows that there is a weak positive correlation between training and
employee performance with a correlation coefficient of 0.1767. The study results concurs with that
of Shaheen et al., (2013) who carried out a study on employees training, mediation employee
performance and found weak but positive correlation between training and employee performance
with r = 0.18, F=43.378, P-value of 0.001. The results by the researchers implied that 0.18 that
there exists a weak positive correlation between training and employee performance. Gidey (2016)
also found weak but positive relationship between training and employee performance with
correlation coefficient of 0.309 and p-value of 0.01.
The study results summarized in Table 4.26 show that there is a weak positive correlation between
talent acquisition and employee performance with a correlation coefficient of 0.1946. The results
concurs with that of Mokaya et al., (2013) who carried out a study to establish the effects of
recruitment practices on employee performance in Co-operative Bank in Kenya. The researchers
found a weaker positive correlation between recruitment and employee performance at r =0.317
and p-value of 0.05. The results presented show that there is a relationship between talent
acquisition and employee performance.
The study results in Table show that there is a weak positive correlation between knowledge
management and employee performance with a correlation coefficient of 0.3079. The results
concurs with that of Tajali, Farahani and Baharvand (2014) who conducted a study to establish the
relationship between knowledge management and employee performance and innovation in
Kuwait. The researchers found a weak positive correlation between knowledge management and
employee performance, with the correlation coefficient of 0.277 and a p-value of 0.007, showing
that the relationship was statistically significant at 1 per cent level of significance. Based on the
results of the current study, there exists a relationship between knowledge management and
employee performance.
The study results given in Table show that there is a weak positive correlation between skills
development and employee performance with a correlation coefficient of 0.3058. The study results
concurs with that of Pradeep and Dinakar (2016) who carried out a study on employee perception
on skills development program at IT companies in Bangalore. They found that there exist a weak

but positive relationship between skills development and employee productivity, with a correlation
coefficient of 0.309 and p-value of 0.01.
Result of Correlation Analysis for HC practices and Employee Performance.
Variable EP EE Training TA KM SD
Employee Pearson 1.000
performance
Correlation
Sig.(2-tailed)
Employee Pearson 0.256** 1.000
engagement
Correlation
Sig.(2-tailed) 0.000
Training
Pearson 0.176** -0.207 1.000
Correlation
Sig.(2-tailed) 0.000
Talent
Acquisition. Pearson 0.194** -0.088 0.177 1.000
Correlation
Knowledge Sig.(2-tailed) 0.000
Management
Pearson 0.307** 0.230 0.055 0.393 1.0000
Correlation
Skills
Development. Sig.(2-tailed) .000
Pearson 0.305** 0.195 0.006 0.564 0.394 1.0000
Correlation
Sig.2-tailed) .000
** Statistically significant at 1 per cent

The Regression Results of the Effect of HC practices on employee performance
The study adopted multiple linear regression models in the analysis. In the study, performance was
regressed against five variables, employee engagement, training, talent acquisition, knowledge
management and skills development. The results show the sign, magnitude of the relationship and
the statistical significance. For the statistical significance, the P-values were interpreted where: less
than 0.01 is at 1% level of significance.
(i) Employee Engagement and Employee Performance
The regression results presented in Table 4.27, shows that there is a positive and statistically
significant relationship between employee engagement and employee performance with the
regression coefficient of 0.232, t-value 2.79 and p-value of 0.006. According to the result, the
coefficient of employee engagement is statistically significant at 1% level of significance. The
magnitude of the coefficient of employee engagement is 0.232. The result implies that, ceteris
paribus, one unit change in the score of employee engagement leads to 0.232 units change in the
score of employee performance. The study results concur with the findings of Anitha (2014) who
conducted a study on determinants of employee engagement and their impact on employee
performance. The author found that employee engagement had a significant impact on employee
performance at R2 =0.597. The results of the current study, therefore, show that there is a
statistically significant relationship between employee engagement and employee performance.
(ii) Training and Employee Performance
The regression result presented in Table 4.27shows that there is a statistically significant positive
relationship between training and employee performance with the regression coefficient of 1.112, t-
value of 2.63 and p-value of 0.010. The estimation results imply that the coefficient of training is
statistically significant at 1 per cent level of significance. The magnitude of the coefficient of
training is 1.112, which implies that, ceteris paribus, a one unit change in the score of training
leads to 1.112 units change in the score of employee performance. The results presented concurs
with that of Ravi, Nishthat, Amit, Ram and Alok (2013) who conducted a study on human capital
investment and employee performance and, found that that a unit increases in training is linked to
a 2.14 unit increase in an employee performance. The estimation results, therefore, show that there

is a statistically significant relationship between training and employee performance.
(iii) Talent Acquisition and Employee Performance
The regression results presented in Table shows that there is a positive relationship between talent
acquisition and employee performance. The estimated coefficient of the variable is 0.038 with a t-
value of 1.05 and a p-value of 0.294. The results show that the coefficient of talent acquisition is
not statistically significant. The magnitude of the coefficient of talent acquisition is 0.038; this
implies that, ceteris paribus, a one unit change in the score of talent acquisition leads to 0.038 units
change in the score of employee performance in the PSI. The study results concurs with that of
Lyra (2014) who conducted a study to establish the effect of talent management on organizational
performance of companies listed in Nairobi Securities Exchange in Kenya. The researcher found a
regression results of talent attraction and organizational performance with R squared at 0.076, and
Adjusted R squared of 0.070, an indication that talent there was a positive relationship between
talent acquisition and organizational performance. In conclusion, there is no statistically significant
relationship between talent acquisition and employee performance.
(iv) Knowledge management and Employee Performance
The regression results presented in Table shows that there is a positive and statistically significant
relationship between knowledge management and employee performance. According to the
estimation results, the regression coefficient of the variables 0.140, with a t- value of 2.31 and a p-
value of 0.022. The coefficient of knowledge management is statistically significant at 5 per cent
level of significance. The magnitude of the coefficient of knowledge management of 0.140, implies
that, ceteris paribus, a one unit change in the score of knowledge management leads to 0.140 units
change in the score of employee performance. The study results concurs with that of Kohansal,
Alimoradi and Bohloul (2013) who examined the impact of knowledge sharing on employee
performance. The researchers found that 0.250 unit increase in employee performance is attributed
to knowledge.

(v) Skills Development and Employee Performance
The regression result presented in Table shows that there is positive and statistically significant
relationship between skills development and employee performance with the regression coefficient
of the skills development variables was 0.065. It also had a t-value of 2.03 and a p-value of
0.044. The results show that the coefficient of this variable is statistically significant at 5 per cent
level of significance. The magnitude of the coefficient of skills development is 0.065. This implies
that, ceteris paribus, a one unit change in the score of skills development leads to 0.065 units
change in the score of employee performance. The study results concurs with that of Pradeep and
Dinakar (2016) who found that there exists a statistically significant relationship between skills
development and employee productivity. The estimation results presented, therefore, show that
there is a statistically significant relationship between skills development and employee
performance.
(vi) Employee Performance in the Private Security Industry in Kenya
The results in Table 4.27 show that the estimated model had R -squared of 0.2050 and adjusted R-
squared of 0.1762. This means that the components of human capital jointly explain 21 per cent of
the variations in employee performance in PSI. The F-statistic is 7.12 with a P-value of 0.0000,
which implies that human capital practices (employee engagement, training knowledge
management, skills development and talent acquisition) are jointly significant in explaining
variations in employee performance at 1 per cent level of significance. The result can be expressed
in a model as indicated:
Y 1.741 0.232 X 1 1.112 X 2 0.038 X 3 0.140 X 4 0.065 X 5
Anyango, and Aila (2017) conducted a study on employee voice and job satisfaction among
security guards. The researchers found a stable model with R Squared of 0.258 and Adjusted R
squared of 0.252. Choi, Florian and Miller (2016) and Lakens (2013), in their study argued that
there is no minimum level of R-Squared in the regression analysis since the cross-sectional analysis
is based on observed values for a given variable at one point in time.
The beta coefficients in the regression results in Table were used to identify and rank the key
drivers. The higher the beta coefficient the more a key driver a variable is. Based on this criterion,
the independent variables were ranked as follows in terms of explaining performance of employees
in the PSI in Kenya. The study results show that training is the key driver since it is ranked the
first, followed by employee engagement, knowledge management, skills development and lastly,
talent acquisition. This means that firms in PSI should provide quality and adequate training a
priority, then ensure that their workers are engaged. This result is consistent with the explanation
by Cucina, Walmsley, Gast, Martin and Patrick (2011) who argued that the study of key driver
analysis is an analysis that attempts to identify a set of survey items called drivers that have the
greatest impact on a specified organizational outcome.Table Regression results of influence of HC
practices on employee performance
Regression Analysis Test Statistic P-value
Observations (143)
Adjusted R-squared 0.1762
R-squared 0.2050
F-statistic (5, 138) 7.12*** 0.0000
ANOVA
Beta Coefficient
F=4.37
Coefficients
0.0000
t-statistic P-value
Employee engagement 0.232*** 2.79 0.006
Training 1.112*** 2.63 0.010
Talent acquisition 0.038 1.05 0.294
Knowledge management 0.140** 2.31 0.022
Skills development 0.065** 2.03 0.044
Constant
Key:
1.741*** 5.90 0.000
** Statistically significant at 5 per cent
*** Statistically significant at 1 per cent.

The result can be expressed in a model as indicated:
Y 1.741 0.232 X 1 1.112 X 2 0.038 X 3 0.140 X 4 0.065 X 5
The Overall Analysis of Variance
The one way ANOVA was used to test the significance of the overall model at 95% level of
confidence. The relationship between the two variables is considered statistically significant, when
the F-critical is less than F-calculated. This concurs with the recommendations of Cooper and
Schindler (2014). Garson (2012) explained that to interpret ANOVA one needs to check if the P-
value is less than or equal to the significance level, then reject the null hypothesis.
The study results presented in Table 4.28 shows the ANOVA results for human capital practices.
The statistics presented shows that F-statistic is 4.37, df(18,124) and the Prob>F is 0.0000. This
implies that the coefficient of joint determination is statistically significant at 1% level of
significance. This means the study independent variables jointly determines employee
performance, and that the influence is statistically significant. Basing the confidence level at 95%,
the analysis indicates that high reliability of the results was obtained in all the variables, implying
that the means were statistically different from zero.
The F-critical value at df(18,124) was 1.69 while the F-calculated reported in Table 4.28 was 4.37.
This shows that F-calculated is greater than the F-critical, hence there is a positive and statistically
significant linear relationship between human capital practices and employee performance. In addition,
the p-value was 0.0000, which is less than the significance level of 0.05. The study findings are
consistent with that of Mutindi, Namusonge and Obwogi (2013) who estimated the effect of strategic
management drivers on the performance of hotel industry in Kenyan Coast and found ANOVA result of
F=2.162 and p-value 0.008, implying a statistically significant relationship at 1 % level of significance.
The study result summarized in Table 4.28 gives the ANOVA results for employee engagement
and employee performance. The ANOVA result shows that F-statistic is 1.81 and the Prob>F is
0.1480, implying that the coefficient of employee engagement is statistically significant and
different from zero at 5% level of significance. The study results concurs with that of Preko and

Adjetey (2013) who carried out a study on the concept of employee loyalty and engagement on
performance of sales executives in Commercial Banks in Ghana. The researchers found a
statistically significant impact of employee engagement and performance with an ANOVA of F-
statistic=37.492, df(1,48) and P-value of 0.000. Based on the estimation results of the current study,
employee engagement has a statistically significant influence on employee performance.
The study result given in Table also provides the ANOVA results for training and employee
performance. The ANOVA result shows that F-statistic is 2.23 and the Prob>F is 0.0692. The
results imply that the coefficient of training is statistically significant, and different from zero at
10% level of significance. The study results concur with that of Iqbal, Ahmad and Javad (2014)
who did a study to establish the impact of training on employee performance. The study found
ANOVA result of p-value 0.000 and F-statistic of 556.177. In respect to the current study, the
ANOVA results show that training has a statistically significant relationship with employee
performance.
The study results summarized given in Table gives the ANOVA results for talent acquisition and
employee performance. The ANOVA result shows that F-statistic is 3.51 and the Prob>F is 0.0094,
implying that the coefficient of talent acquisition is statistically significant and different from zero
at 1% level of significance. The study results concurs with that of Lyra (2014) who also found the
ANOVA results of talent acquisition and organizational performance at F-statistic=13.101 and P-
value 0.000, implying that there was a significant relationship between talent attraction and
organizational performance at 1% level of significance. It follows that, therefore, that talent
acquisition has a statistically significant influence on employee performance in PSI in Kenya.
The study result summarized in Table provides the ANOVA results for knowledge management
and employee performance. The ANOVA result shows that F-statistic is 0.67and the Prob>F is
0.6134. This implies that the coefficient of knowledge management is statistically significant and
different from zero at 1% level of significance. The study results concurs with that of Kohansal,
Alimoradi and Bohloul (2013) in their study examined the impact of knowledge sharing on
employee performance. They found an ANOVA of df(1,211),
F-statistic=70.332 and Sig = 0.0000. The study, therefore, established that there exists a significant
relationship between knowledge management and employee performance.
The estimation results presented in Table 4.28 gives the ANOVA results for skills development and
employee performance. The ANOVA result shows that F-statistic is 8.10 and the Prob>F is
0.0.0001, implying that the coefficient of skills development is statistically significant and different
from zero at 1% level of significance. Pradeep and Dinakar (2016) found ANOVA results for skills
development and employee productivity at F-statistic =33.988 and Prob>F is
0.000. It follows in respect of the current study that there is a statistically significance
relationship between skills development and employee performance.
Overall ANOVA Result of joint HC practices and employee performance
Source SS df MS
F
Prob>F
Model 17.402546 18 0.9668080 4.37 0.0000
Employee engagement 1.2037185
3
0.4012395 1.81 0.1480
Training 1.9758136
4
0.4939534 2.23 0.0692
Talent acquisition 3.1071823
4
0.7767955 3.51 0.0094
Knowledge management 0.5934293
4
0.1483573 0.67 0.6134
Skills development 5.3749865
3
1.7916622 8.10 0.0001
Residual 27.422629 124 0.22115024
Y
β
0
β1 X 1β 2 X 2
β
3 X 3
β
4 X 4
β
5 X 5
ε
The study results presented in Table shows the goodness of fit and model summary of the influence
of human capital practices on employee performance. The model shows, R-squared at 0.3882 and
adjusted R2 at 0.2994, F-statistic of 4.37, and p-value of 0.0000. This implies that the model
explains 38.82% of changes in employee performance in the PSI. The results also show that there is
a statistically significant relationship between the study independent variables and dependent
variable at 1% level of significance, with a p-value of 0.0000.

The results concur with that of Mutindi, et al., (2013) who sought to establish the effect of strategic
management drivers on the performance. The authors found a goodness of fit analysis of R-squared
at 0.511 and Adjusted R squared of 0.316. The study results also concurs with that of Odhong et
al.,(2014) who in their study sought to establish the effect of human capital management drivers on
organizational performance in the banking industry and found Adjusted R2 of 20.92%, implying
that, ceteris paribus, 20.92% change in organizational performance can be explained by the
human capital management drivers studied. Based on the results, the
model: Y
β
0
β1 X 1β 2 X 2
β
3 X 3
β
4 X 4
β
5 X 5
ε
explains the goodness of fit with
F=4.37, p-value = 0.0000, and R squared = 0.3882. Table 4.29 indicates the overall
model summary.
Table 4.29: Overall Goodness of fit analysis/model summary
Model SS df MS
F
Prob>F R2Adj. R2
Regression 17.40254 18 0.96680 4.37 0.0000 0.3882 0.2994
Residual 27.42262 124 0.22211
Total 44.82517 142 0.31567
Beta Coefficients (t-test)
The results in Table 4.30 shows that β coefficient of the constant is 2.521, Standard Error (SE)
=0.329, t=7.65, and p-value = 0.000. The β coefficient was computed to determine the
degree of change in the outcome variable, for every one unit of change in the predictor
variable. The t- test was used to determine whether the coefficient is significantly
different from zero. The explanatory variables assessed were: employee engagement,
training, talent acquisition, knowledge management, and skills development. The
results were as presented in the sections that follow.
(vii) Employee engagement and employee performance
The results summarized in Table 4.30 shows that the unstandardised β coefficient of
employee engagement is 0.209, SE of 0.086, t-value =2.42, p-value=0.017 and
standardised β coefficient
is 0.205. The β coefficient of employee engagement is positive, implying that, holding
other things constant, for every one unit increase in employee engagement, employee
performance will increase by 0.209. The t-value is statistically different from zero and
has a p-value of 0.017. This shows the beta coefficient of employee engagement is
statistically significant at 5 per cent level of significance.
The results concur with that of Cheche, Muathe and Maina (2017) who conducted a study
on employee engagement, organizational commitment and performance of selected

corporations in Kenya. The researchers found a beta coefficient of employee engagement to
be 0.64 with a corresponding p-value of 0.000. This implied that a unit change in employee
engagement resulted in 0.64 unit change in performance. The results presented, therefore,
shows that the relationship between employee engagement and employee performance is
statistically significant.
(viii) Training and employee performance
The result given in Table shows that the unstandardised β coefficient of training is 0.108,
SE of 0.054, t-value =1.99, p-value=0.048 and standardised β coefficient is 0.158. The β
coefficient of training is positive, implying that for every one unit increase in training,
employee performance will increase by 0.108 units. The t-value is statistically different
from zero with a p-value of 0.048. This implied that the beta coefficient of training is
statistically significant at 5 per cent level of significance.
The study results concurs with Abeba, Mesele and Lemessa(2015) who studied the impact
of training and development on employee performance and effectiveness, in Addis Ababa.
They found that the β coefficient from the general linear models unadjusted score of
training was β=0.46(0.28, 0.63) while employee performance was 0.49(0.39, 0.60) and the
adjusted models of the β value for training was 0.25(0.11, 0.39) while employee
performance scores were 0.42(0.32, 0.53). The study results presented in Table 4.29,
therefore, shows that the relationship between training and employee performance is
statistically significant.
(ix) Talent acquisition and employee performance
The results in Table shows that the unstandardised β coefficient of talent acquisition is
0.015, SE of 0.042, t-value =0.36, p-value=0.718 and standardised β coefficient is 0.036.
The β coefficient of talent acquisition is positive, implying that for every one unit increase
in talent acquisition, employee performance will increase by 0.042. The p-value is 0.718
implying that the beta coefficient of talent acquisition is not statistically significant.
The study result concurs with that of Mokaya, et al., (2013) who found beta coefficient of

recruitment sources, with unstandardised value of 0.911, SE=0.238, standadised beta =
0.408, t-value of 3.835 and p-value = 0.000. This implies that the coefficient of the variable
was statistically significant at 1 per cent level of significance. The current study, therefore,
reveal that there is a positive relationship between talent acquisition and employee
performance, but not statistically significant.
(x) Knowledge management and employee performance
The results in Table shows that the unstandardised β coefficient of knowledge
management is 0.113, SE of 0.062, t-value =1.81, p-value=0.072 and standardised β
coefficient is 0.162. The β coefficient of knowledge management is positive, implying that
for every one unite increase in knowledge management, employee performance will
increase by 0.113 units. The coefficient of the variable had a p-value of 0.072, which shows
that the beta coefficient of knowledge management is statistically significant at 10 per cent
level of significance.
The results concur with that of Muhoya (2016) who conducted a study to establish the
influence of knowledge management practices on performance of selected Global Audit
Firms in Kenya. The researcher who found the beta coefficient of knowledge sharing at β
=0.486, with standard error of 0.159 and p-value of 0.004 and knowledge sharing at β
=0532, standard error of 0.197 and p-value of 0.005.
(xi) Skills development and employee performance
The estimation results presented in Table shows that the unstandardised β coefficient of
skills development is 0.146, SE of 0.084, t-value =1.74, p-value=0.085 and standardised β
coefficient is 0.172. The β coefficient of skills development is positive, implying that for
every one unit increase in skill development, employee performance will increase by 0.146
units. The p-value of 0.085 shows the beta coefficient of skills development is statistically
significant at 10 per cent level of significance.
The study results concurs with that of Pradeep and Dinakar (2016) who in their study on
employee perception on skills development programs at IT companies in Bangalore, found
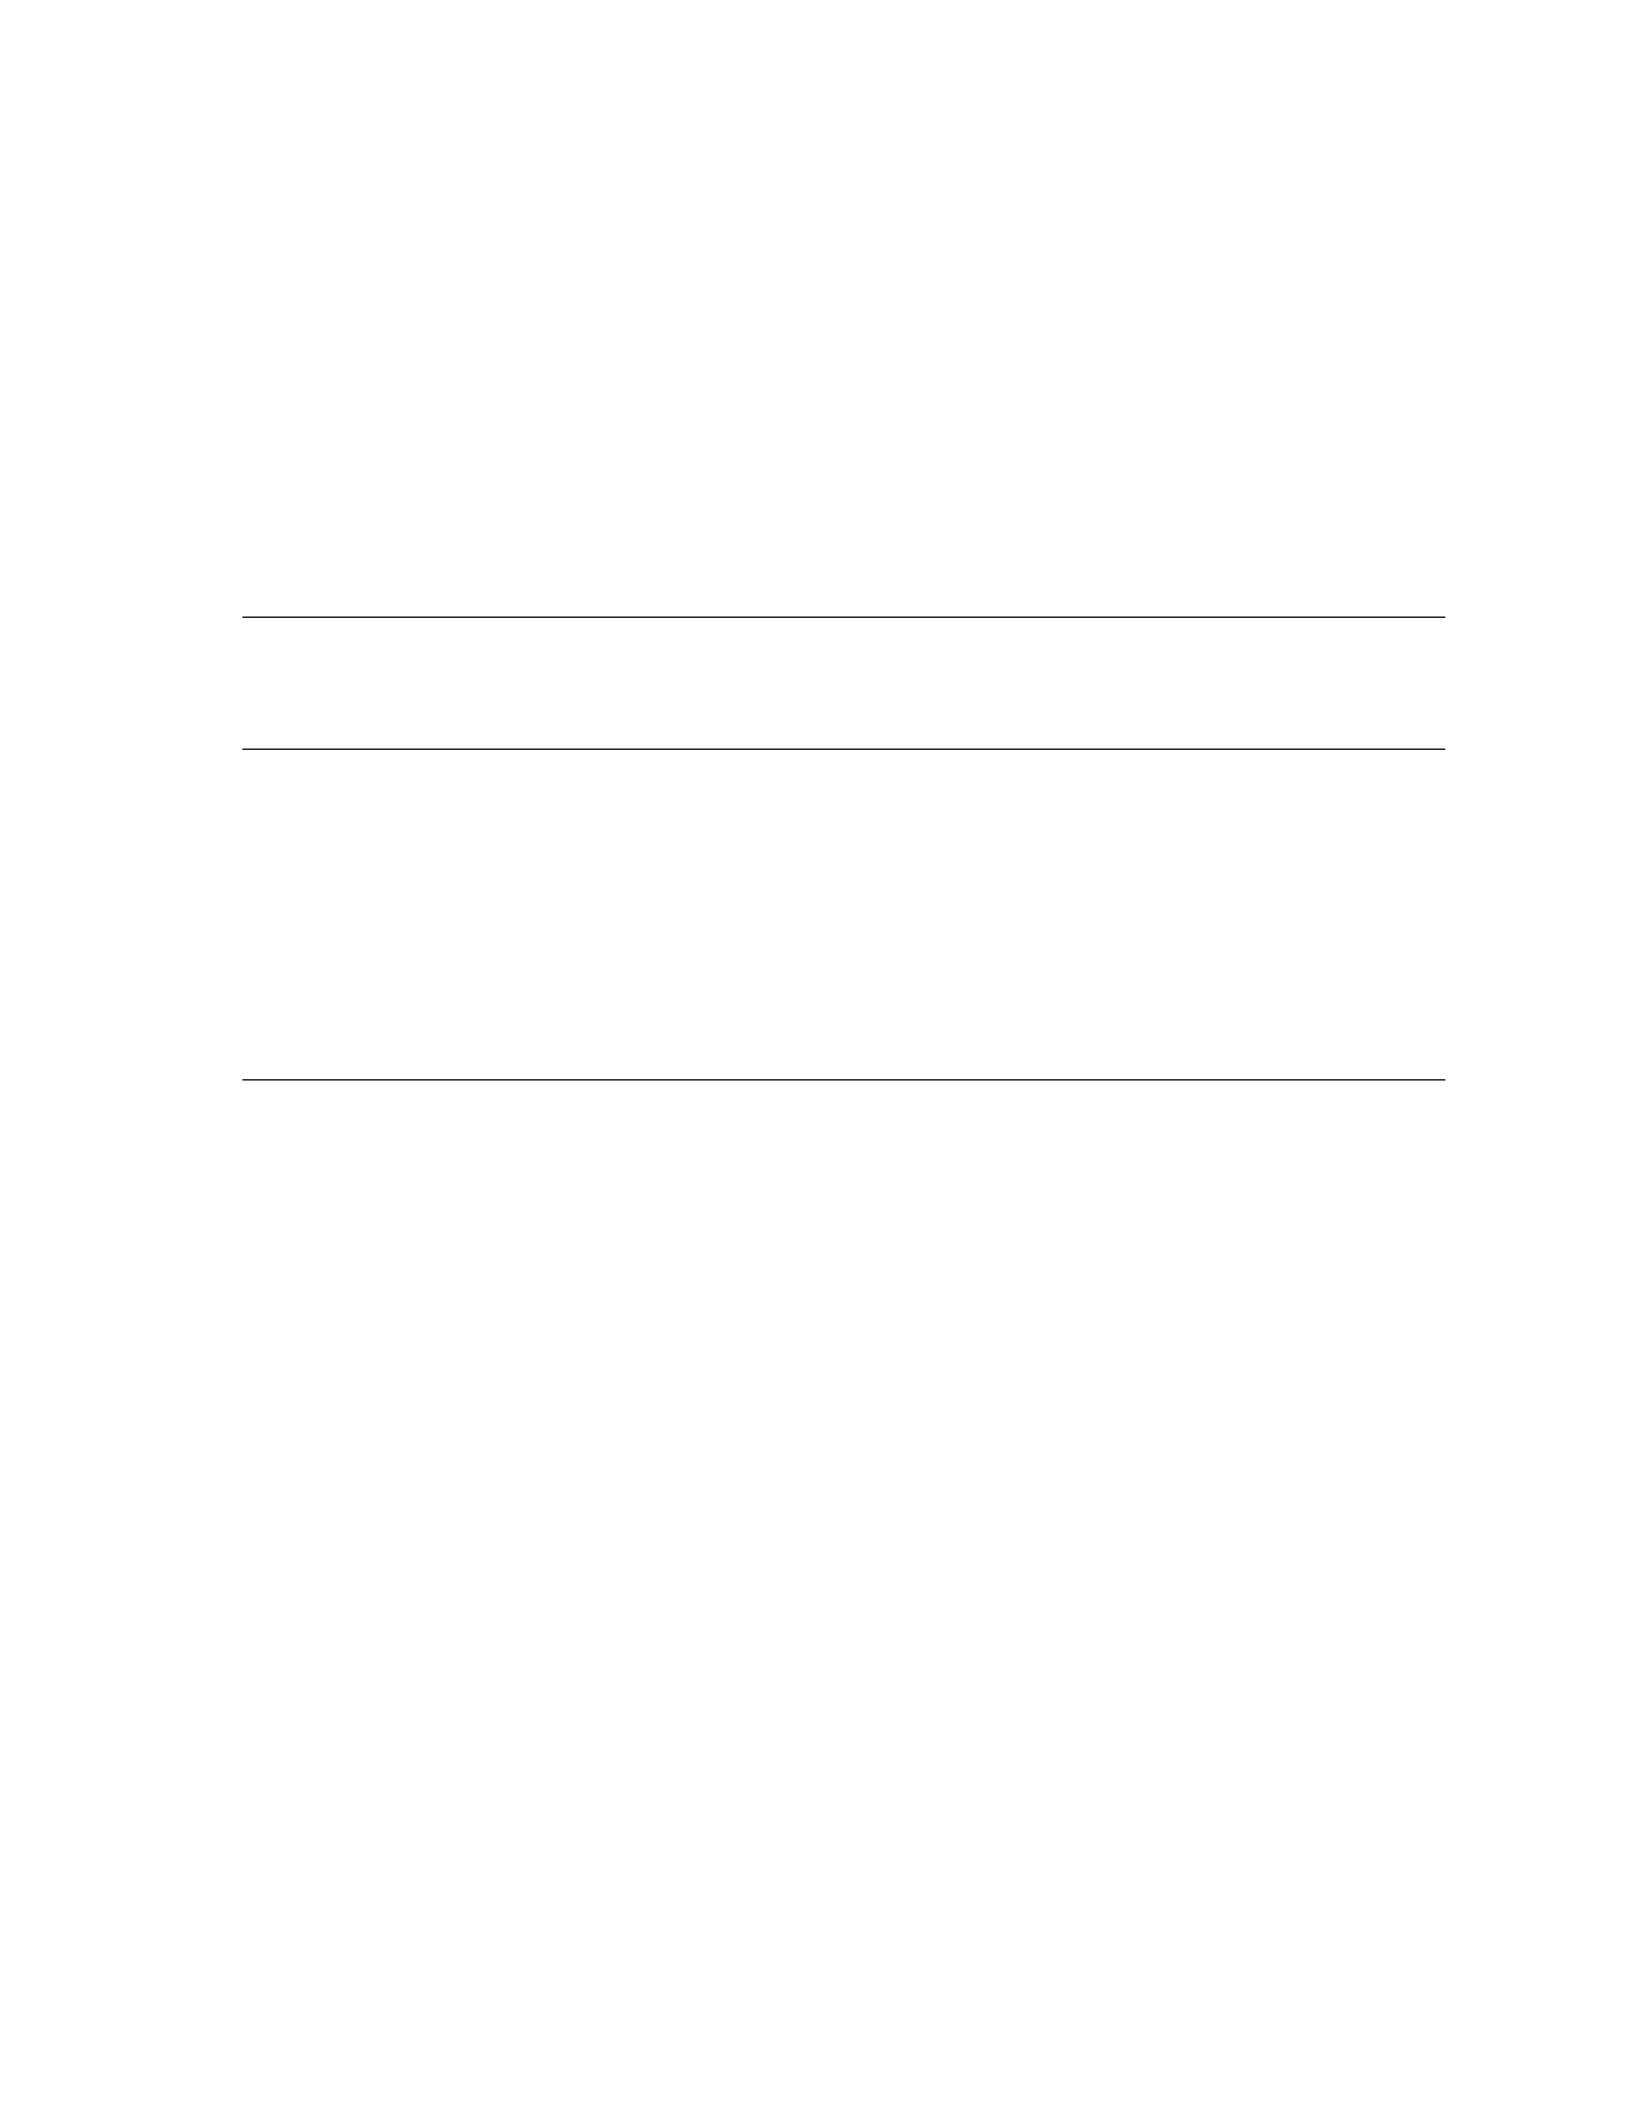
unstandardised β coefficient of 0.604, SE=0.82 and standardized β coefficient of 0.59, t-
value 7.373 and p-value =0.000. Employee productivity had unstandardised β coefficient of
0.608, SE=0.104 and standardised β coefficient 0.507, t=5.83 and p-value =0.000. Thus, the
current study finds the relationship between skills development and employee performance
to be statistically significant.
Beta Coefficient
Employee Performance Unstandardized
β coefficient
Standardised
coefficient Beta
Standard
Error
T
P-
value
Employee engagement 0.2090121 0.2057967 0.086431 2.42 0.017
Training 0.1085757 0.1584712 0.0544261 1.99 0.048
Talent acquisition 0.153222 0.366298 0.0423083 0.36 0.718
Knowledge management 0.1130426 0.1619094 0.623641 1.81 0.072
Skills development 0.146341 0.1723198 0.0843463 1.74 0.085
Constant 2.521922 0.3296239 7.65 0.000
Hypothesis Testing
This section presents the test of the various study hypotheses. The findings are thematically
presented based on the objectives. The study tested the null hypothesis. Lakens (2013)
stated that null hypothesis is often a good and sometimes extremely accurate
approximation. The explanatory variables under study were employee engagement,
training, talent acquisition, knowledge management and skills development.
Test of Hypothesis One
The first objective of the study sought to determine the effect of employee engagement on
performance of employees in the PSI in Kenya. To this end, the following null hypothesis
was tested.
H01: Employee engagement has no effect on performance of employees in the
private security industry in Kenya
that the coefficient of employee engagement was 0.232 with a t statistic of 2.79 and a

corresponding P value of 0.006. Since the p-value is less than 0.05, the calculated t is greater
than the critical at five per cent level of significance. Therefore, at 1 per cent level of
significance, the null hypothesis was rejected implying that employee engagement has a
statistically significant effect on performance of employees in the private security industry in
Kenya. The magnitude of the coefficient of employee engagement is 0.232. This implies that,
ceteris paribus, one unit change in the score of employee engagement leads to 0.232 units
change in the score of employee performance. Otieno et al., (2015) found that there is
statistically significant relationship between employee engagement and performance.
Test of Hypothesis Two
The second objective of the study sought to examine the effect of training on performance of
employees in the PSI in Kenya. To this end, the following null hypothesis was tested.
H02:Training has no effect on performance of employees in the private
security industry in Kenya the coefficient of training was 1.112 with a t-
statistic of 2.63 and a corresponding P value of 0.010. Since the p-value is
less than 0.05 the calculated t is greater
Than the critical value at five per cent level of significance. Therefore, at five per cent level
of significance the null hypothesis was rejected implying that training has a significant
positive effect on employee performance in the private security industry in Kenya. The
magnitude of the coefficient training is 1.112. This implies that a one unit change in the
score of training leads to 1.112 units change in the score of employee performance. Ravi et
al., (2013) found a significant positive impact of training on employee performance. The
study results revealed that a unit increase in training is linked to a 2.114 per cent increase in
an employee performance. Iqbal, et al., (2014) found that the correlation analysis shows
significant positive relationship between training and employee performance at P-value =
0.000 and r = 0.889.
Test of Hypothesis Three

The third objective of the study sought to establish the effect of talent acquisition on
performance of employees in the PSI in Kenya. To this end, the following null hypothesis
was tested.
H03: Talent acquisition has no effect on performance of employees in the
private security industry in Kenya.
The estimation result presented in Table shows that the coefficient of talent acquisition
was 0.038 with a t-statistic of 1.05 and a corresponding P value of 0.294. Since the p-value
is greater than 0.294, implying that the coefficient of talent acquisition is not statistically
significant. Therefore, the null hypothesis was not rejected implying that talent acquisition
has no significant effect on performance of employees in the PSI in Kenya.
The magnitude of the coefficient of talent acquisition is 0.038. This implies that a one unit
change in the score of talent acquisition leads to 0.038 units change in the score of
employee performance. Lyra (2014) found that the correlation coefficient of talent
attraction was 0.275 with a p-value of 0.000, indicating a significant positive correlation
between talent attraction and organizational performance.
Test of Hypothesis Four
The fourth objective of the study was to determine the effect of knowledge management on
employee performance in PSI in Kenya. To this end the following null hypothesis was
tested.
H04: Knowledge management has no effect on performance of employees in
the private security industry in Kenya.
Table 4.26 shows that the coefficient of knowledge management was 0.140 with a t-statistic
of
2.31 and a corresponding P-value of 0.022. Since the p-value is less than 0.05, the
calculated t- statistic is greater than the critical at five per cent level of significance.
Therefore, at five per cent level of significance the null hypothesis was rejected
implying that knowledge management has an effect on performance of employees in
the PSI in Kenya.

The magnitude of the coefficient of knowledge management is 0.140. This implies that
a one unit change in the score of knowledge management leads to 0.140 units change in
the score of employee performance. Rasula, Vuksic and Stemberger (2012) found a
statistically significant relationship between knowledge management and
organizational performance with a t-statistic of 11.67, coefficient 0.94, and an R-
squared of 89 per cent.
Test of Hypothesis Five
The fifth objective of the study sought to examine the effect of skills development on
employee performance in the PSI in Kenya. To this end, the following null hypothesis was
tested.
H05: Skills development has no effect on performance of employees in the
private security industry in Kenya.
The estimation results presented in Table 4.26 shows that the coefficient of skills
development was 0.065 with a t statistic of 2.03 and a corresponding P value of 0.044.
Since the p-value is less than 0.05, the calculated t is greater than the critical at five per cent
level of significance. Therefore, at five per cent level of significance, the null hypothesis
was rejected implying that skill development has an effect on performance of employees in
the private security industry in Kenya.
The magnitude of the coefficient of skills development is 0.065. This implies that, ceteris
paribus, a one unit change in the score of skills development leads to 0.065 units change in
the score of employee performance. Pradeep and Dinakar (2016) found that there exists
statistically significant impact of skills development programs on employee productivity,
with R-squared = 0.357. The estimation results for the current study confirm that skills
development has a statistically significant effect on employee performance at 5 per cent
level of significance.

