


BUSI 223 - CAPITAL ASSET PRICING MODEL (CAPM) AND
PORTFOLIO OPTIMIZATION
PROBLEMATIC QUESTIONS AND SOLUTIONS
QUESTION 1: CAPITAL ASSET PRICING MODEL (CAPM)
A stock has a beta of 1.2, the risk-free rate is 3%, and the expected market return is 10%.
Calculate the expected return of the stock using the CAPM.
Solution:
Step 1: Recall the CAPM formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝐸(𝑅𝑚)−𝑅𝑓)
Step 2: Substitute the given values:
𝑅𝑓=3% =0.03
𝛽𝑖= 1.2
𝐸(𝑅𝑚)=10%= 0.10
Step 3: Calculate the expected return:
𝐸(𝑅𝑖)=0.03+1.2(0.10−0.03)
=0.03+1.2(0.07)
=0.03+0.084
=0.114
Therefore, the expected return of the stock is 11.4%.
QUESTION 2: PORTFOLIO OPTIMIZATION
An investor is considering two stocks, A and B, with the following characteristics:
Stock
Expected Return
Standard Deviation
A
12%
20%
B
8%
15%
The correlation coefficient between the two stocks is 0.3. Find the optimal portfolio weights that
minimize the portfolio risk.
Solution:
Step 1: Recall the formula for portfolio variance:
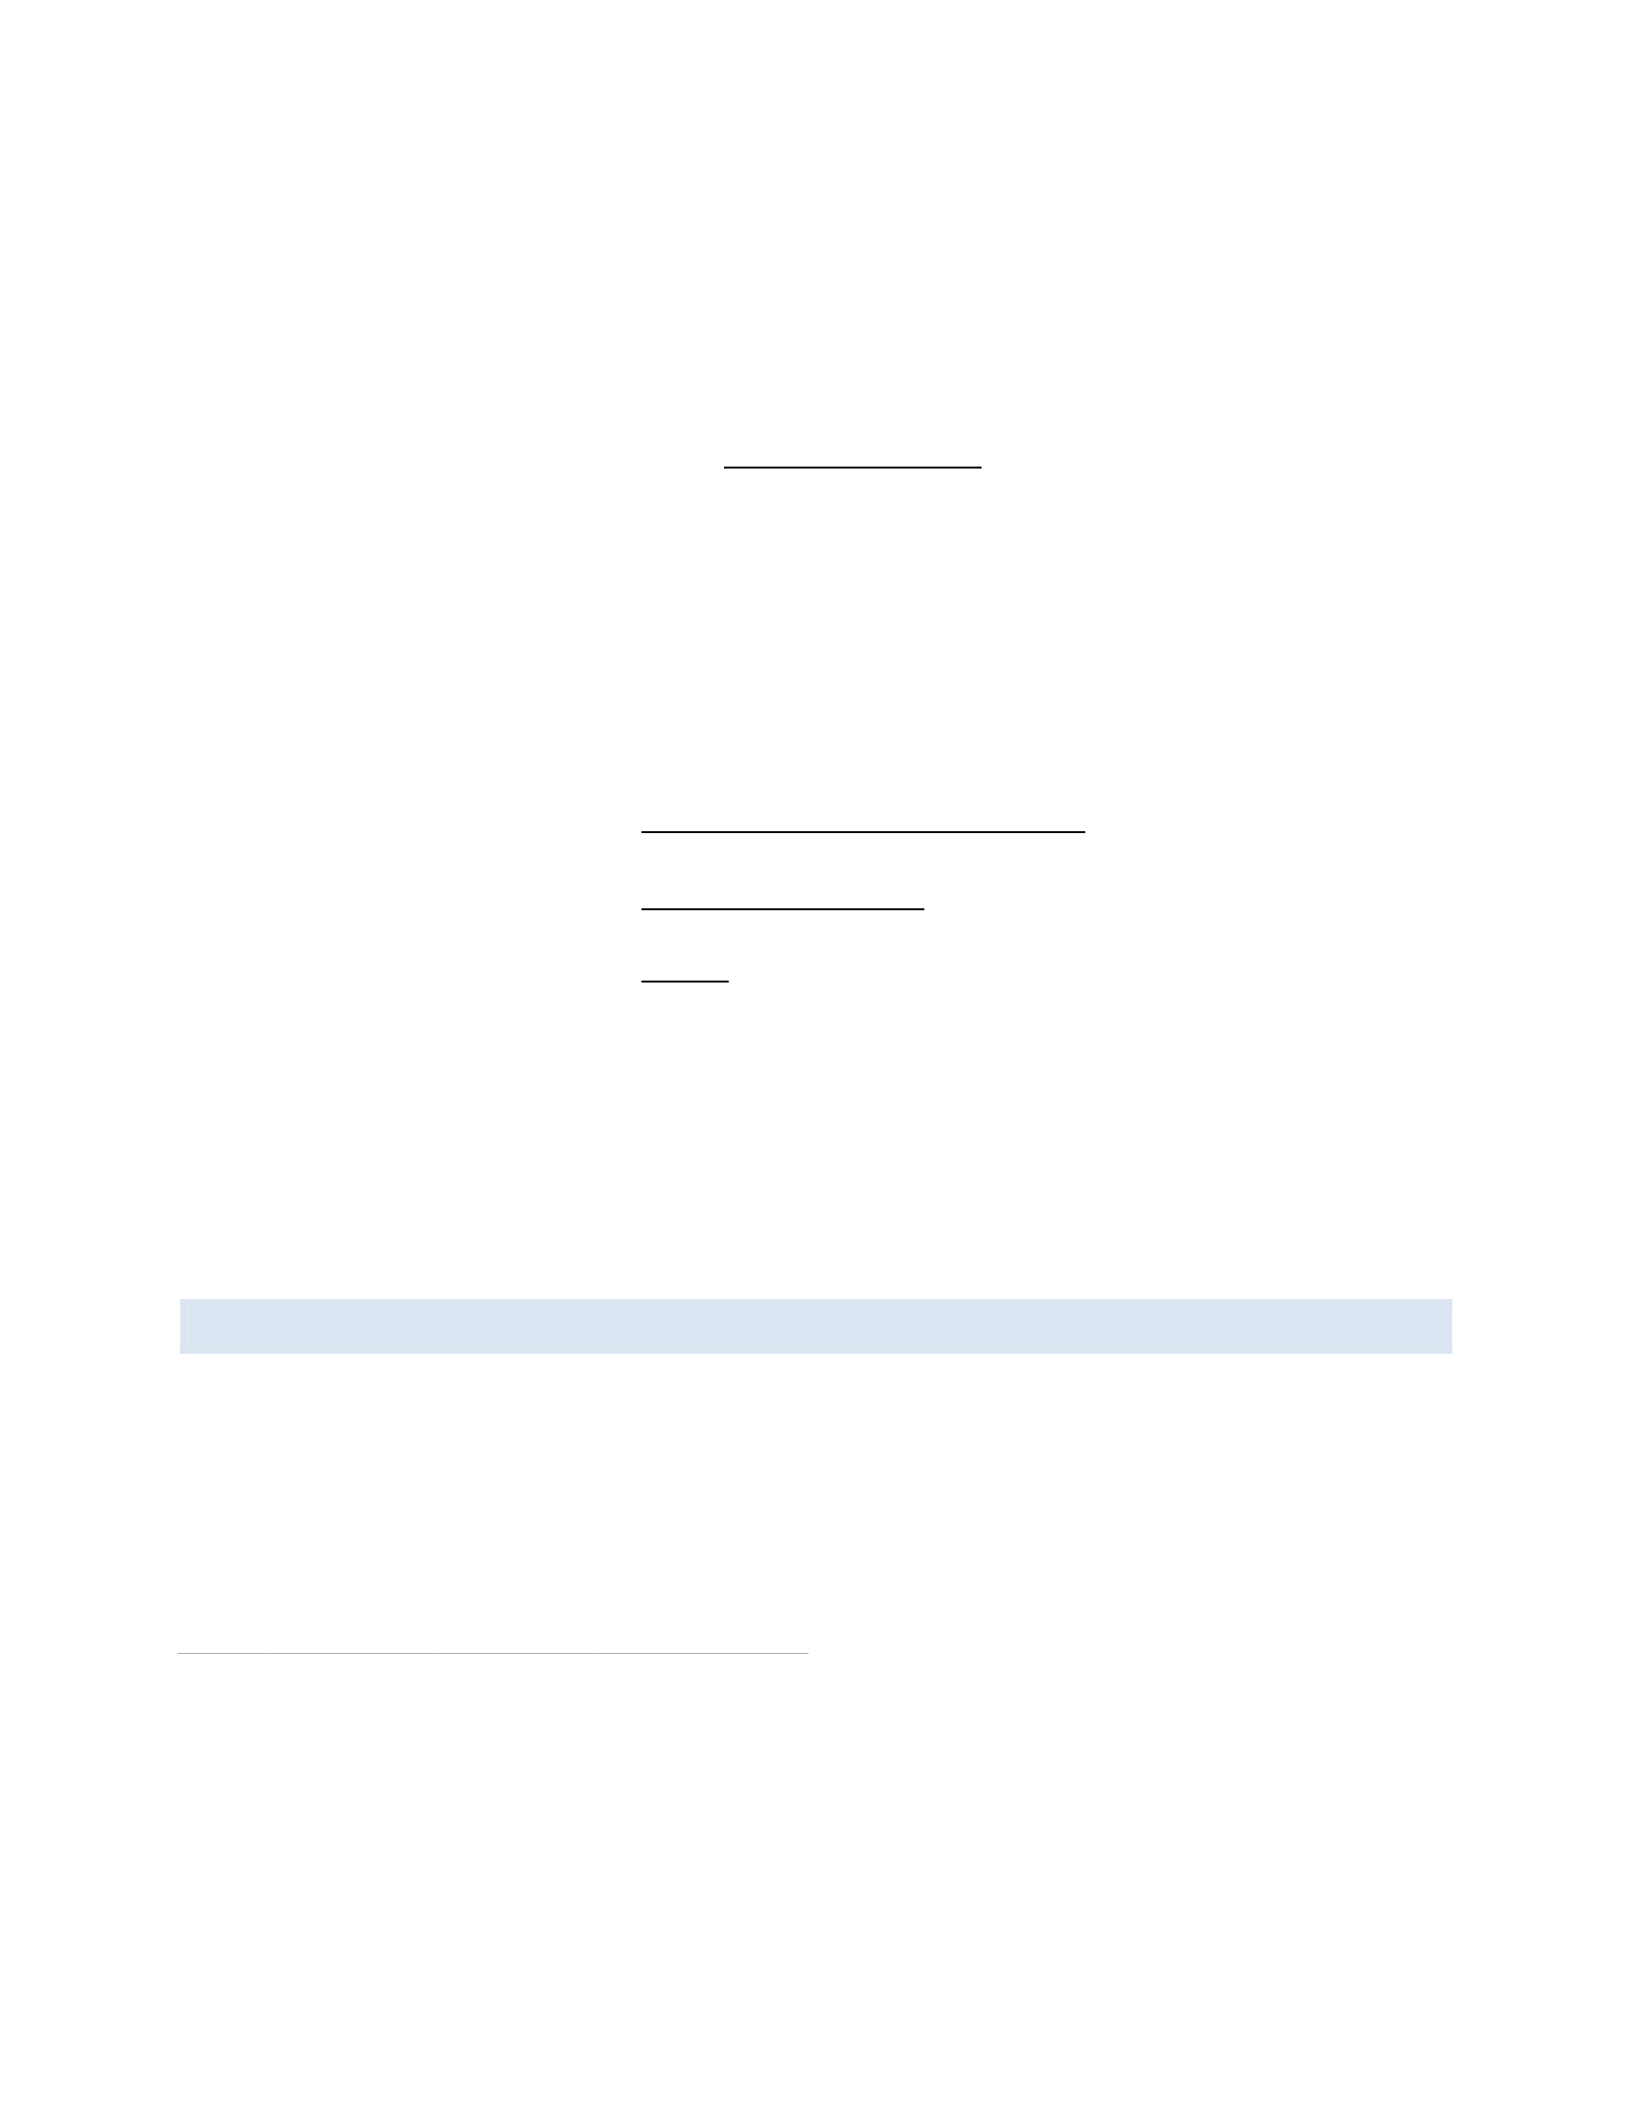
𝜎𝑝
2=𝑤𝐴
2𝜎𝐴
2+𝑤𝐵
2𝜎𝐵
2+2𝑤𝐴𝑤𝐵𝜌𝐴𝐵𝜎𝐴𝜎𝐵
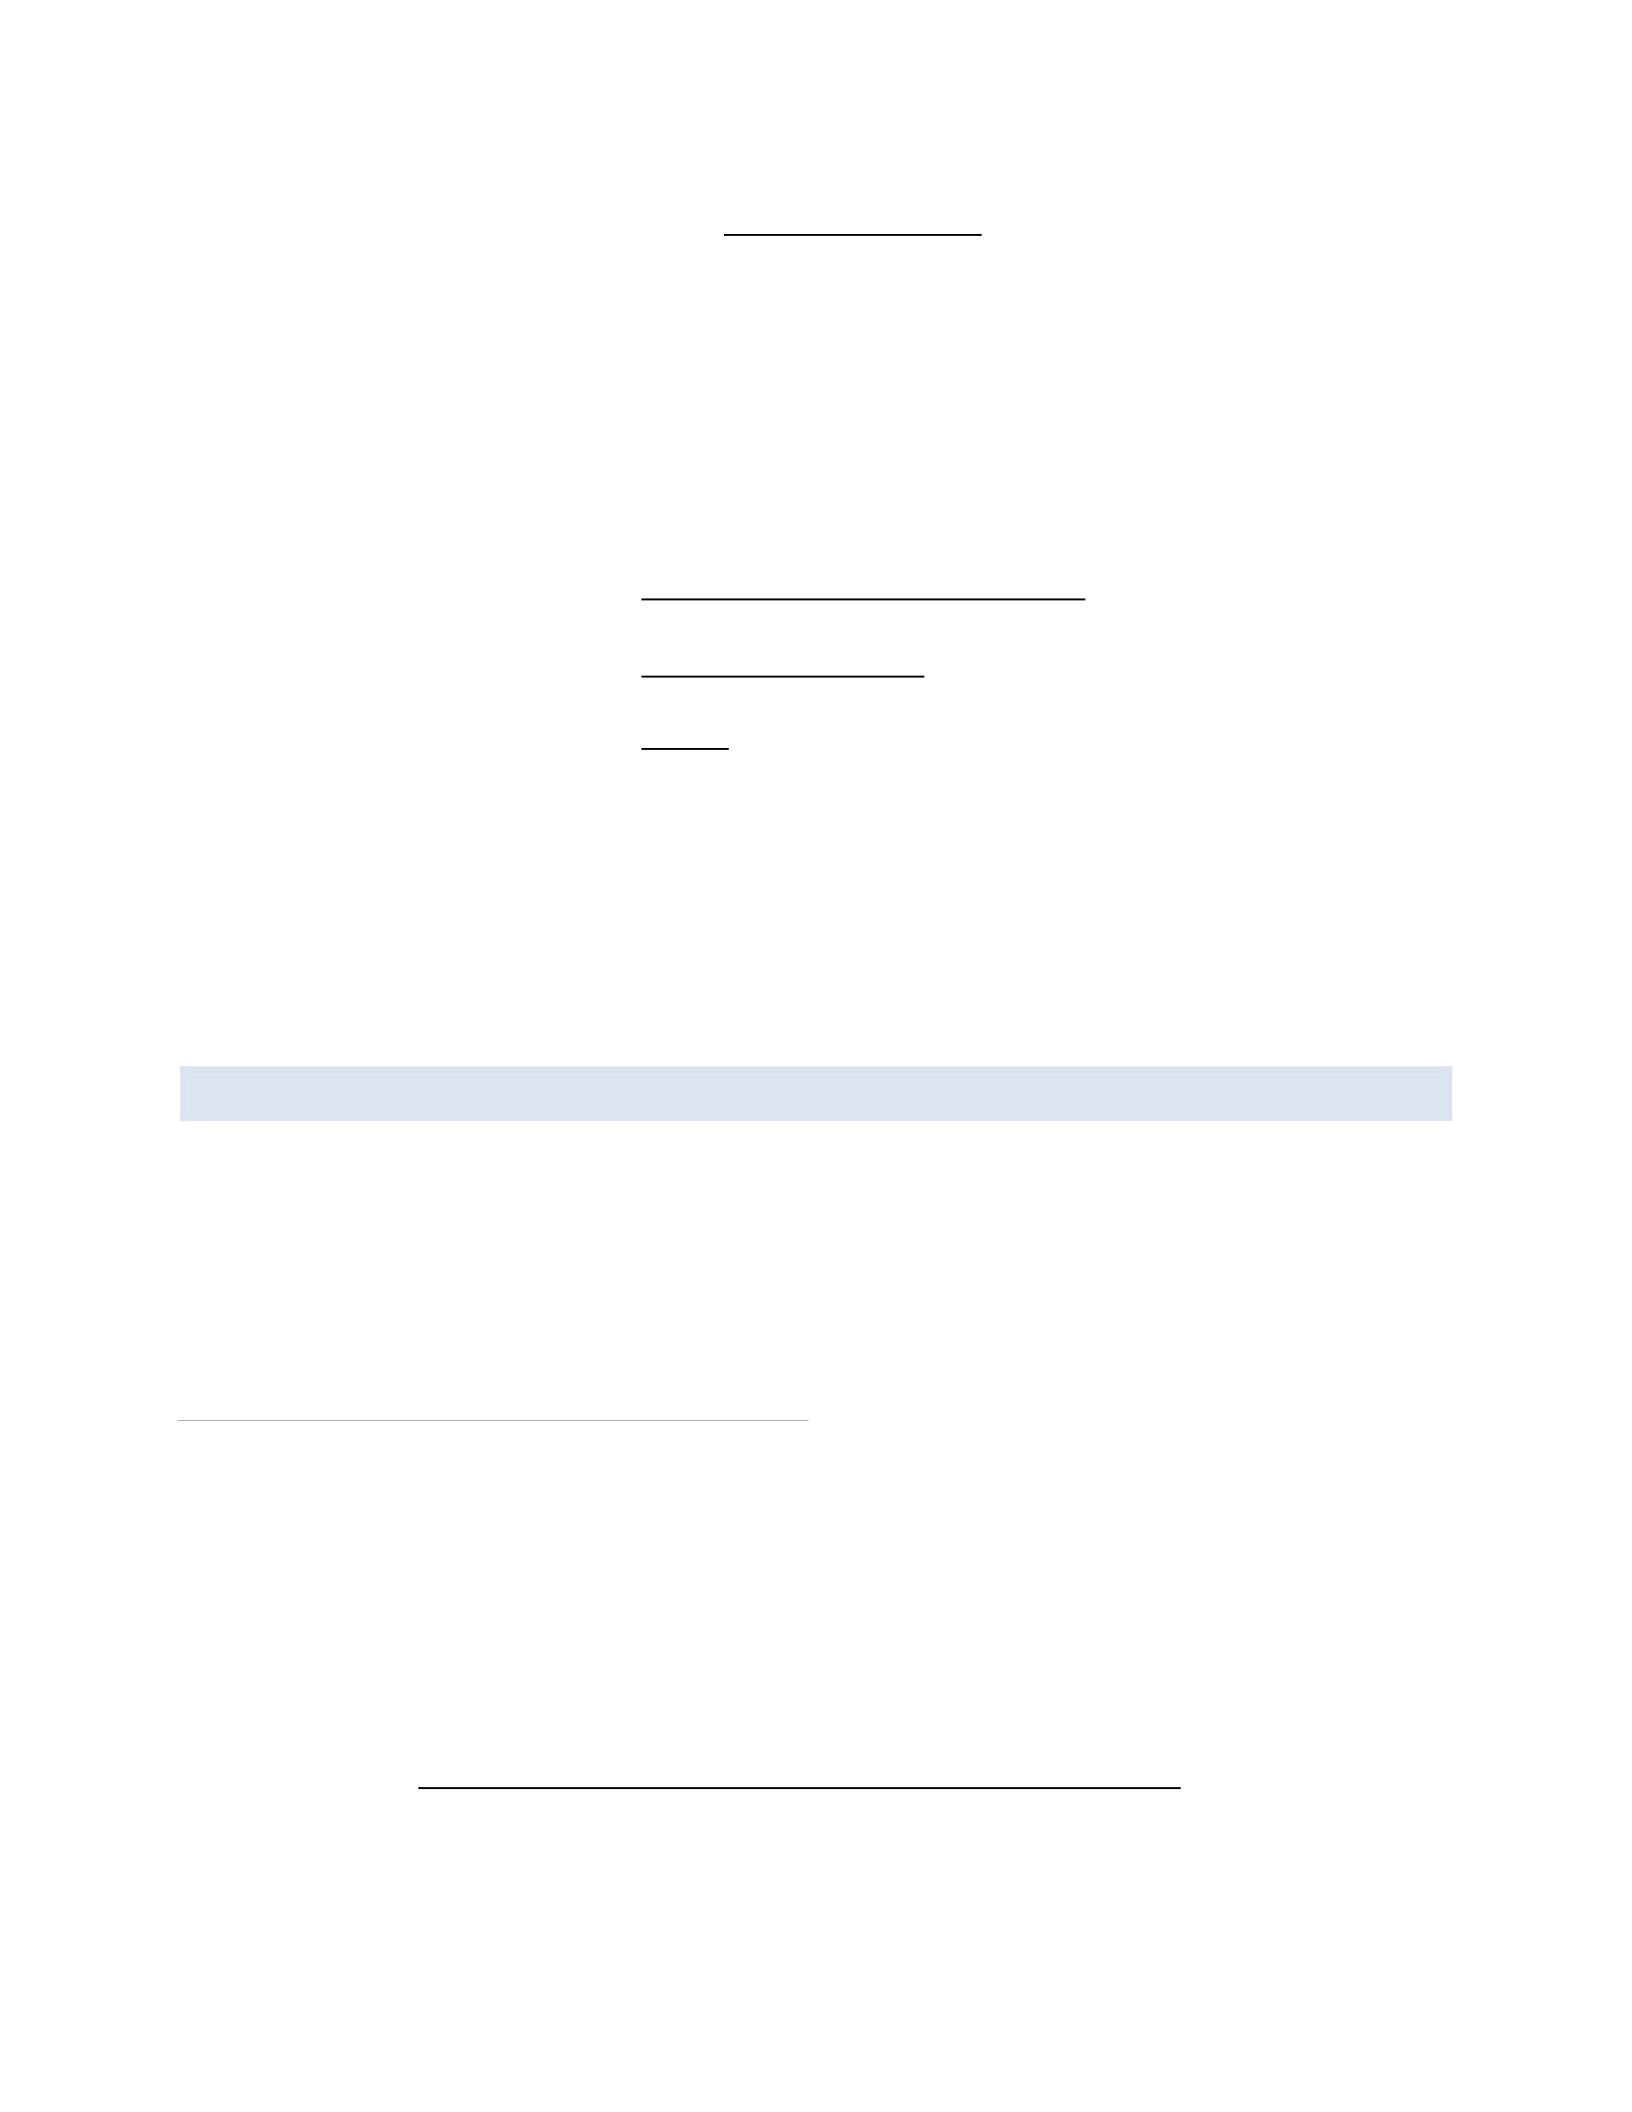
Step 2: To minimize risk, we need to find the weights that minimize the portfolio variance. The
formula for the optimal weight of stock A is:
𝑤𝐴=𝜎𝐵
2−𝜌𝐴𝐵𝜎𝐴𝜎𝐵
𝜎𝐴
2+𝜎𝐵
2−2𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 3: Substitute the given values:
𝜎𝐴=20%= 0.20
𝜎𝐵=15% =0.15
𝜌𝐴𝐵 = 0.3
Step 4: Calculate the optimal weight of stock A:
𝑤𝐴=0.152−0.3(0.20)(0.15)
0.202+0.152−2(0.3)(0.20)(0.15)
=0.0225−0.009
0.04+0.0225−0.018
=0.0135
0.0445
≈0.3034
Step 5: Calculate the weight of stock B:
𝑤𝐵= 1−𝑤𝐴=1−0.3034 =0.6966
Therefore, the optimal portfolio weights to minimize risk are approximately 30.34% in stock A
and 69.66% in stock B.
QUESTION 3: DURATION AND CONVEXITY
A 5-year bond with a face value of $1,000 and a 6% annual coupon rate is currently priced at
$1,050. The yield to maturity is 5%. Calculate the bond’s duration and convexity.
Solution:
Step 1: Calculate the bond’s cash flows and present values:
Year
Cash Flow
PV Factor
Present Value
1
$60
0.9524
$57.14
2
$60
0.9070
$54.42
3
$60
0.8638
$51.83
4
$60
0.8227
$49.36
5
$1,060
0.7835
$830.51
Step 2: Calculate the Macaulay Duration:
𝐷 =1×57.14+2×54.42+3×51.83+4×49.36+5×830.51
1050 =4.52
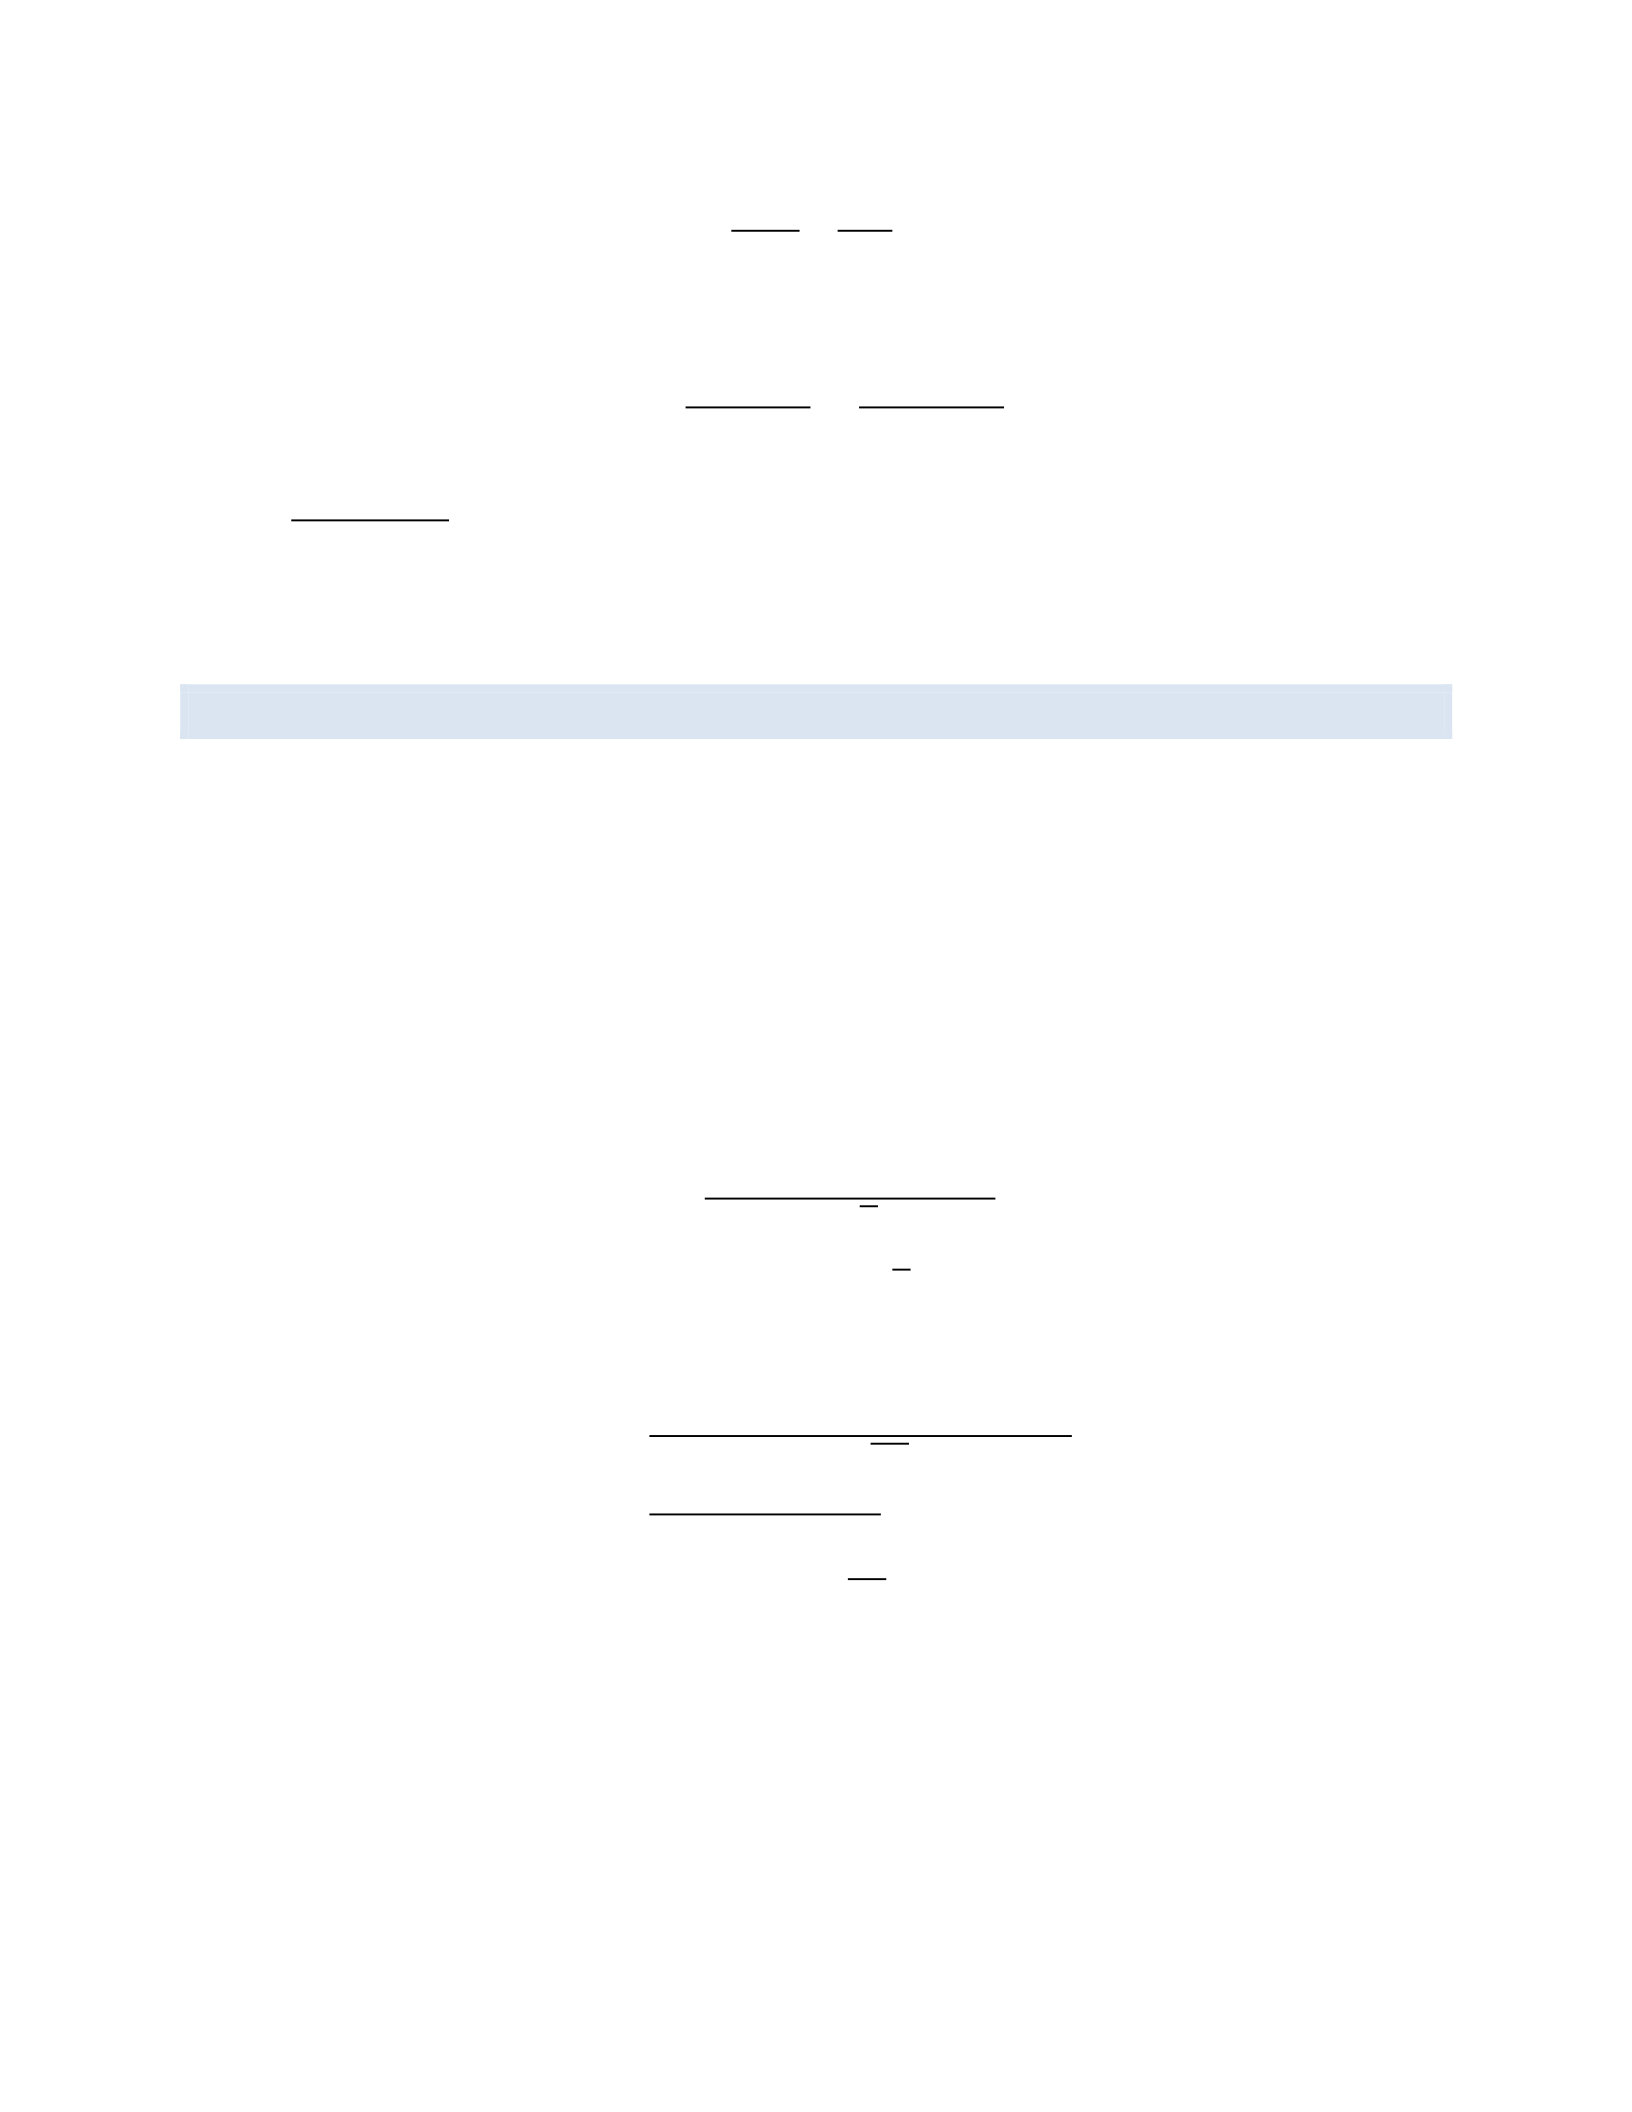
Step 3: Calculate the Modified Duration:
𝑀𝐷 =𝐷
1+𝑦 =4.52
1.05= 4.30
Step 4: Calculate the Convexity:
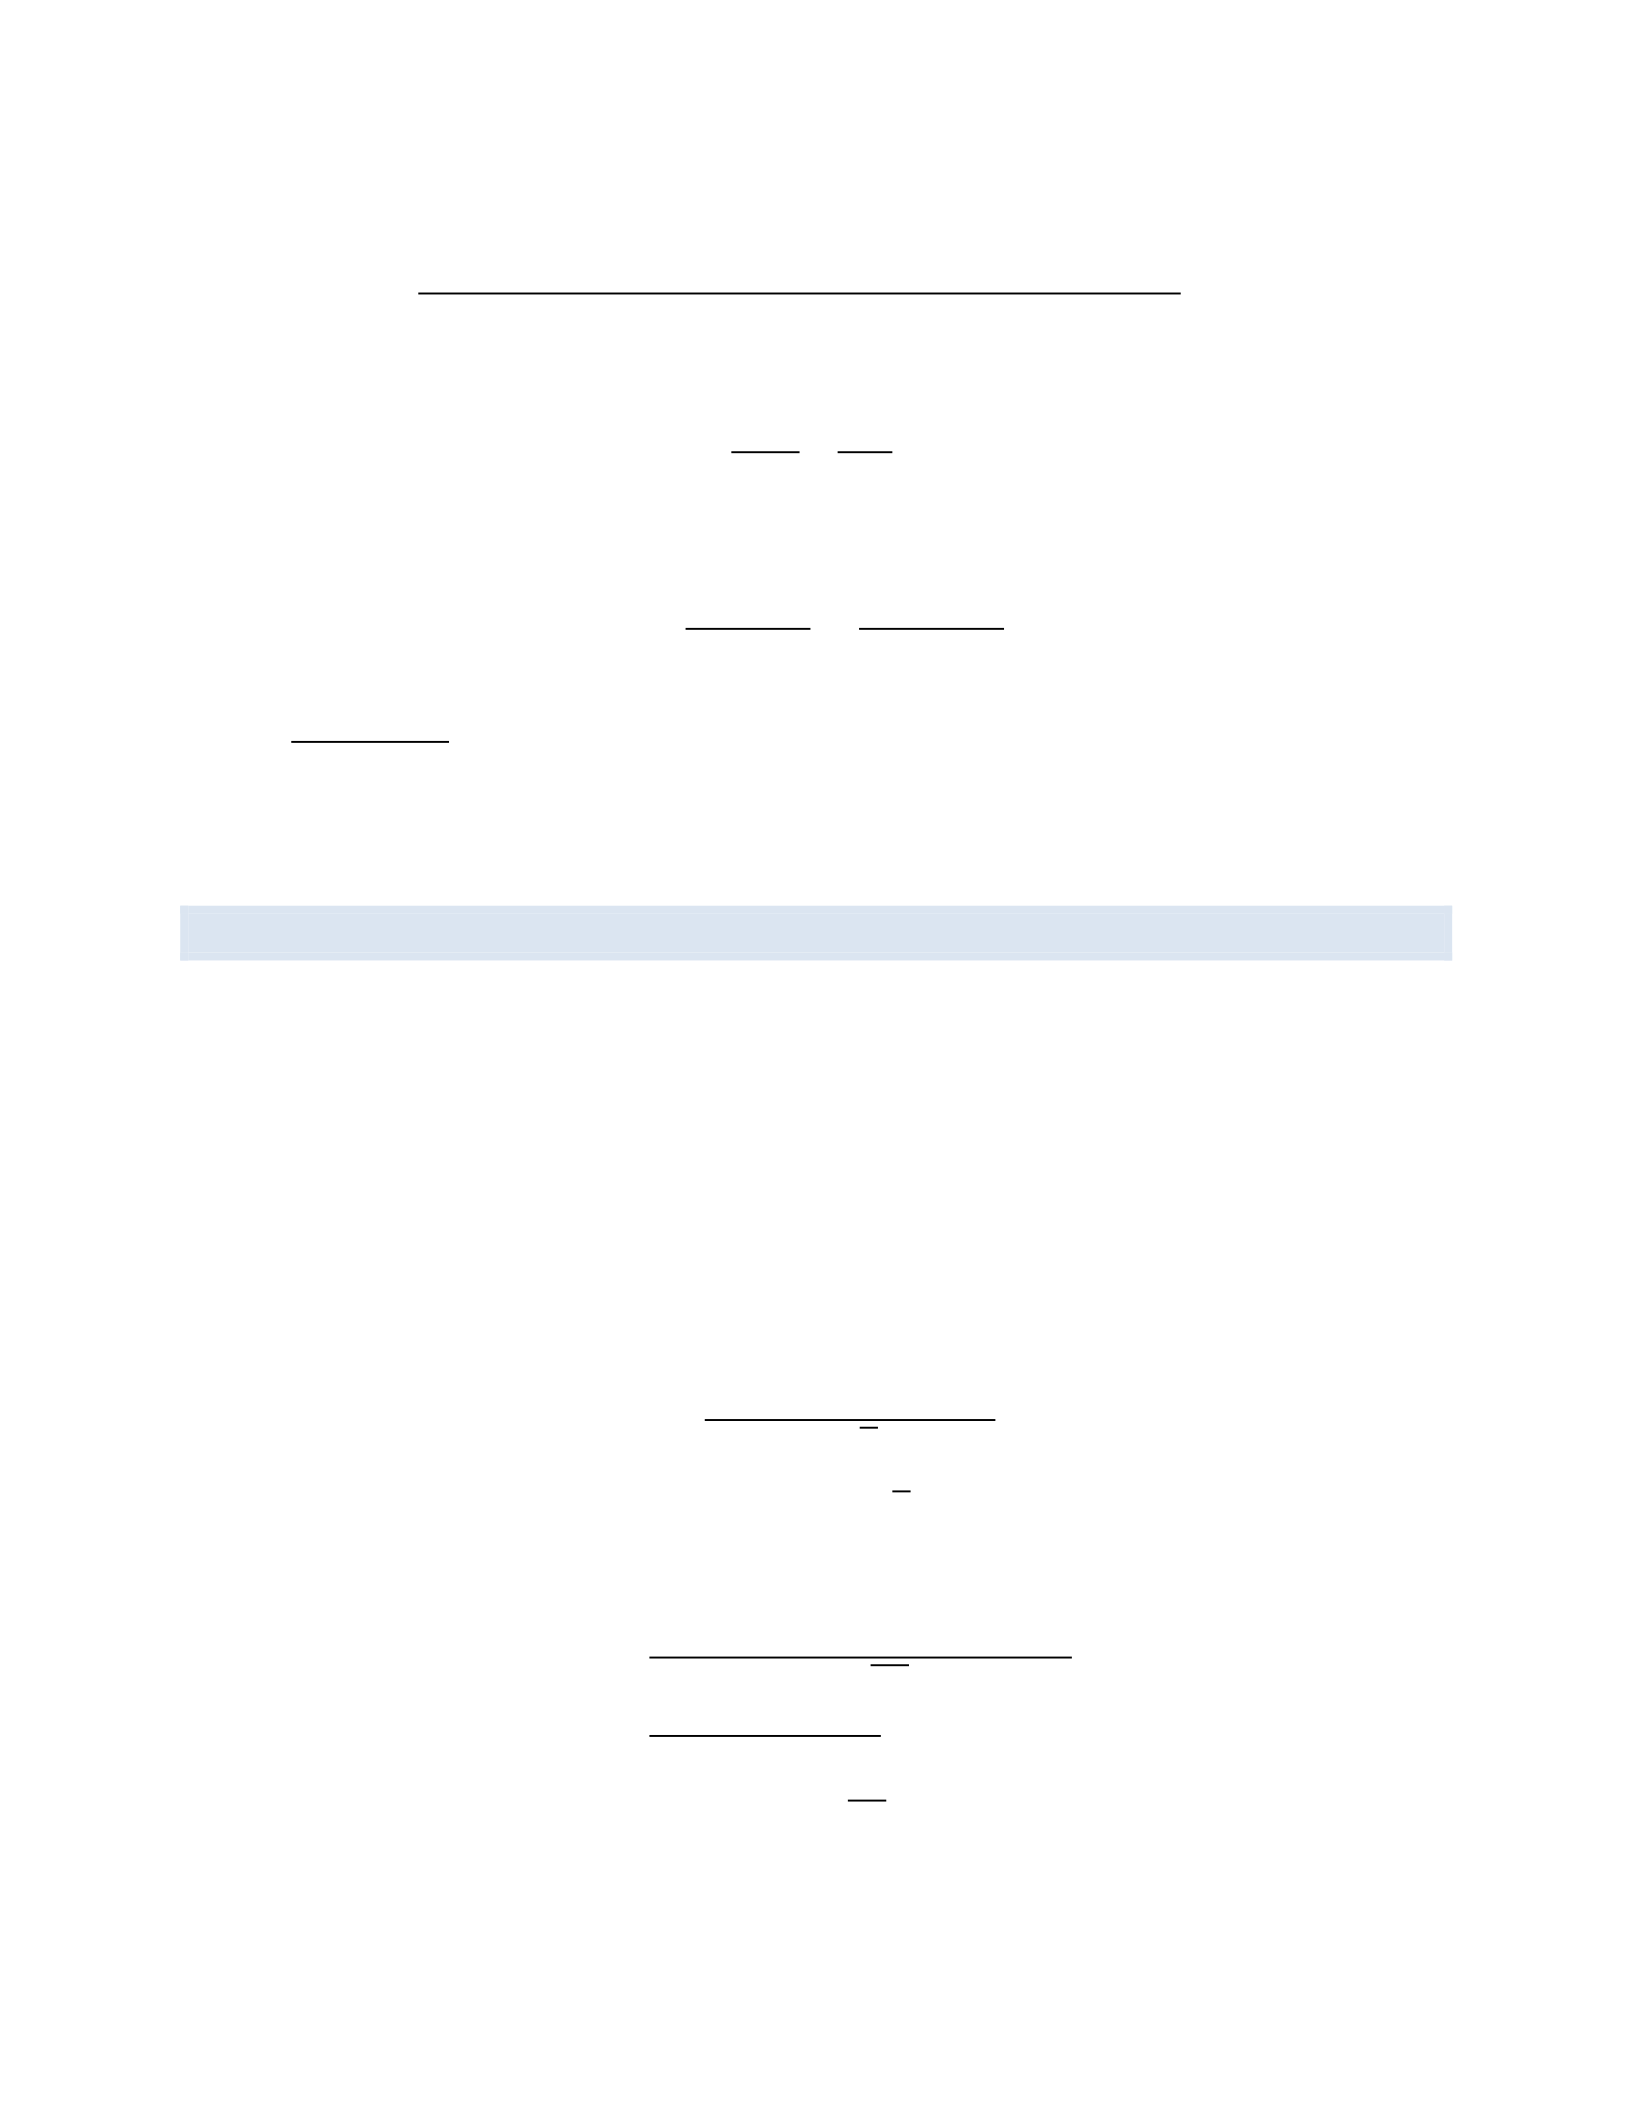
𝐶 = 1
𝑃(1+𝑦)2∑𝑡(𝑡+1)𝐶𝐹𝑡
(1+𝑦)𝑡
𝑛
𝑡=1
𝐶 = 1
1050(1.05)2(2×57.14+6×54.42+12×51.83+20×49.36+30×830.51)=22.89
Therefore, the bond’s duration is 4.52 years (Macaulay) or 4.30 years (Modified), and its
convexity is 22.89.
QUESTION 4: BLACK-SCHOLES OPTION PRICING MODEL
Using the Black-Scholes model, calculate the price of a European call option with the following
parameters: - Current stock price (S) = $50 - Strike price (K) = $52 - Time to expiration (T) = 6
months (0.5 years) - Risk-free rate (r) = 5% per annum - Stock volatility (σ) = 30% per annum
Solution:
Step 1: Recall the Black-Scholes formula for a call option:
𝐶 =𝑆𝑁(𝑑1)−𝐾𝑒−𝑟𝑇𝑁(𝑑2)
Where:
𝑑1=ln(𝑆/𝐾)+(𝑟+𝜎2/2)𝑇
𝜎√𝑇
𝑑2=𝑑1−𝜎√𝑇
Step 2: Calculate d1 and d2:
𝑑1=ln(50/52)+(0.05+0.32/2)(0.5)
0.3√0.5
=−0.0392+0.0475
0.2121 =0.0391
𝑑2=0.0391−0.3√0.5= −0.1730
Step 3: Find N(d1) and N(d2) using a standard normal distribution table or calculator:
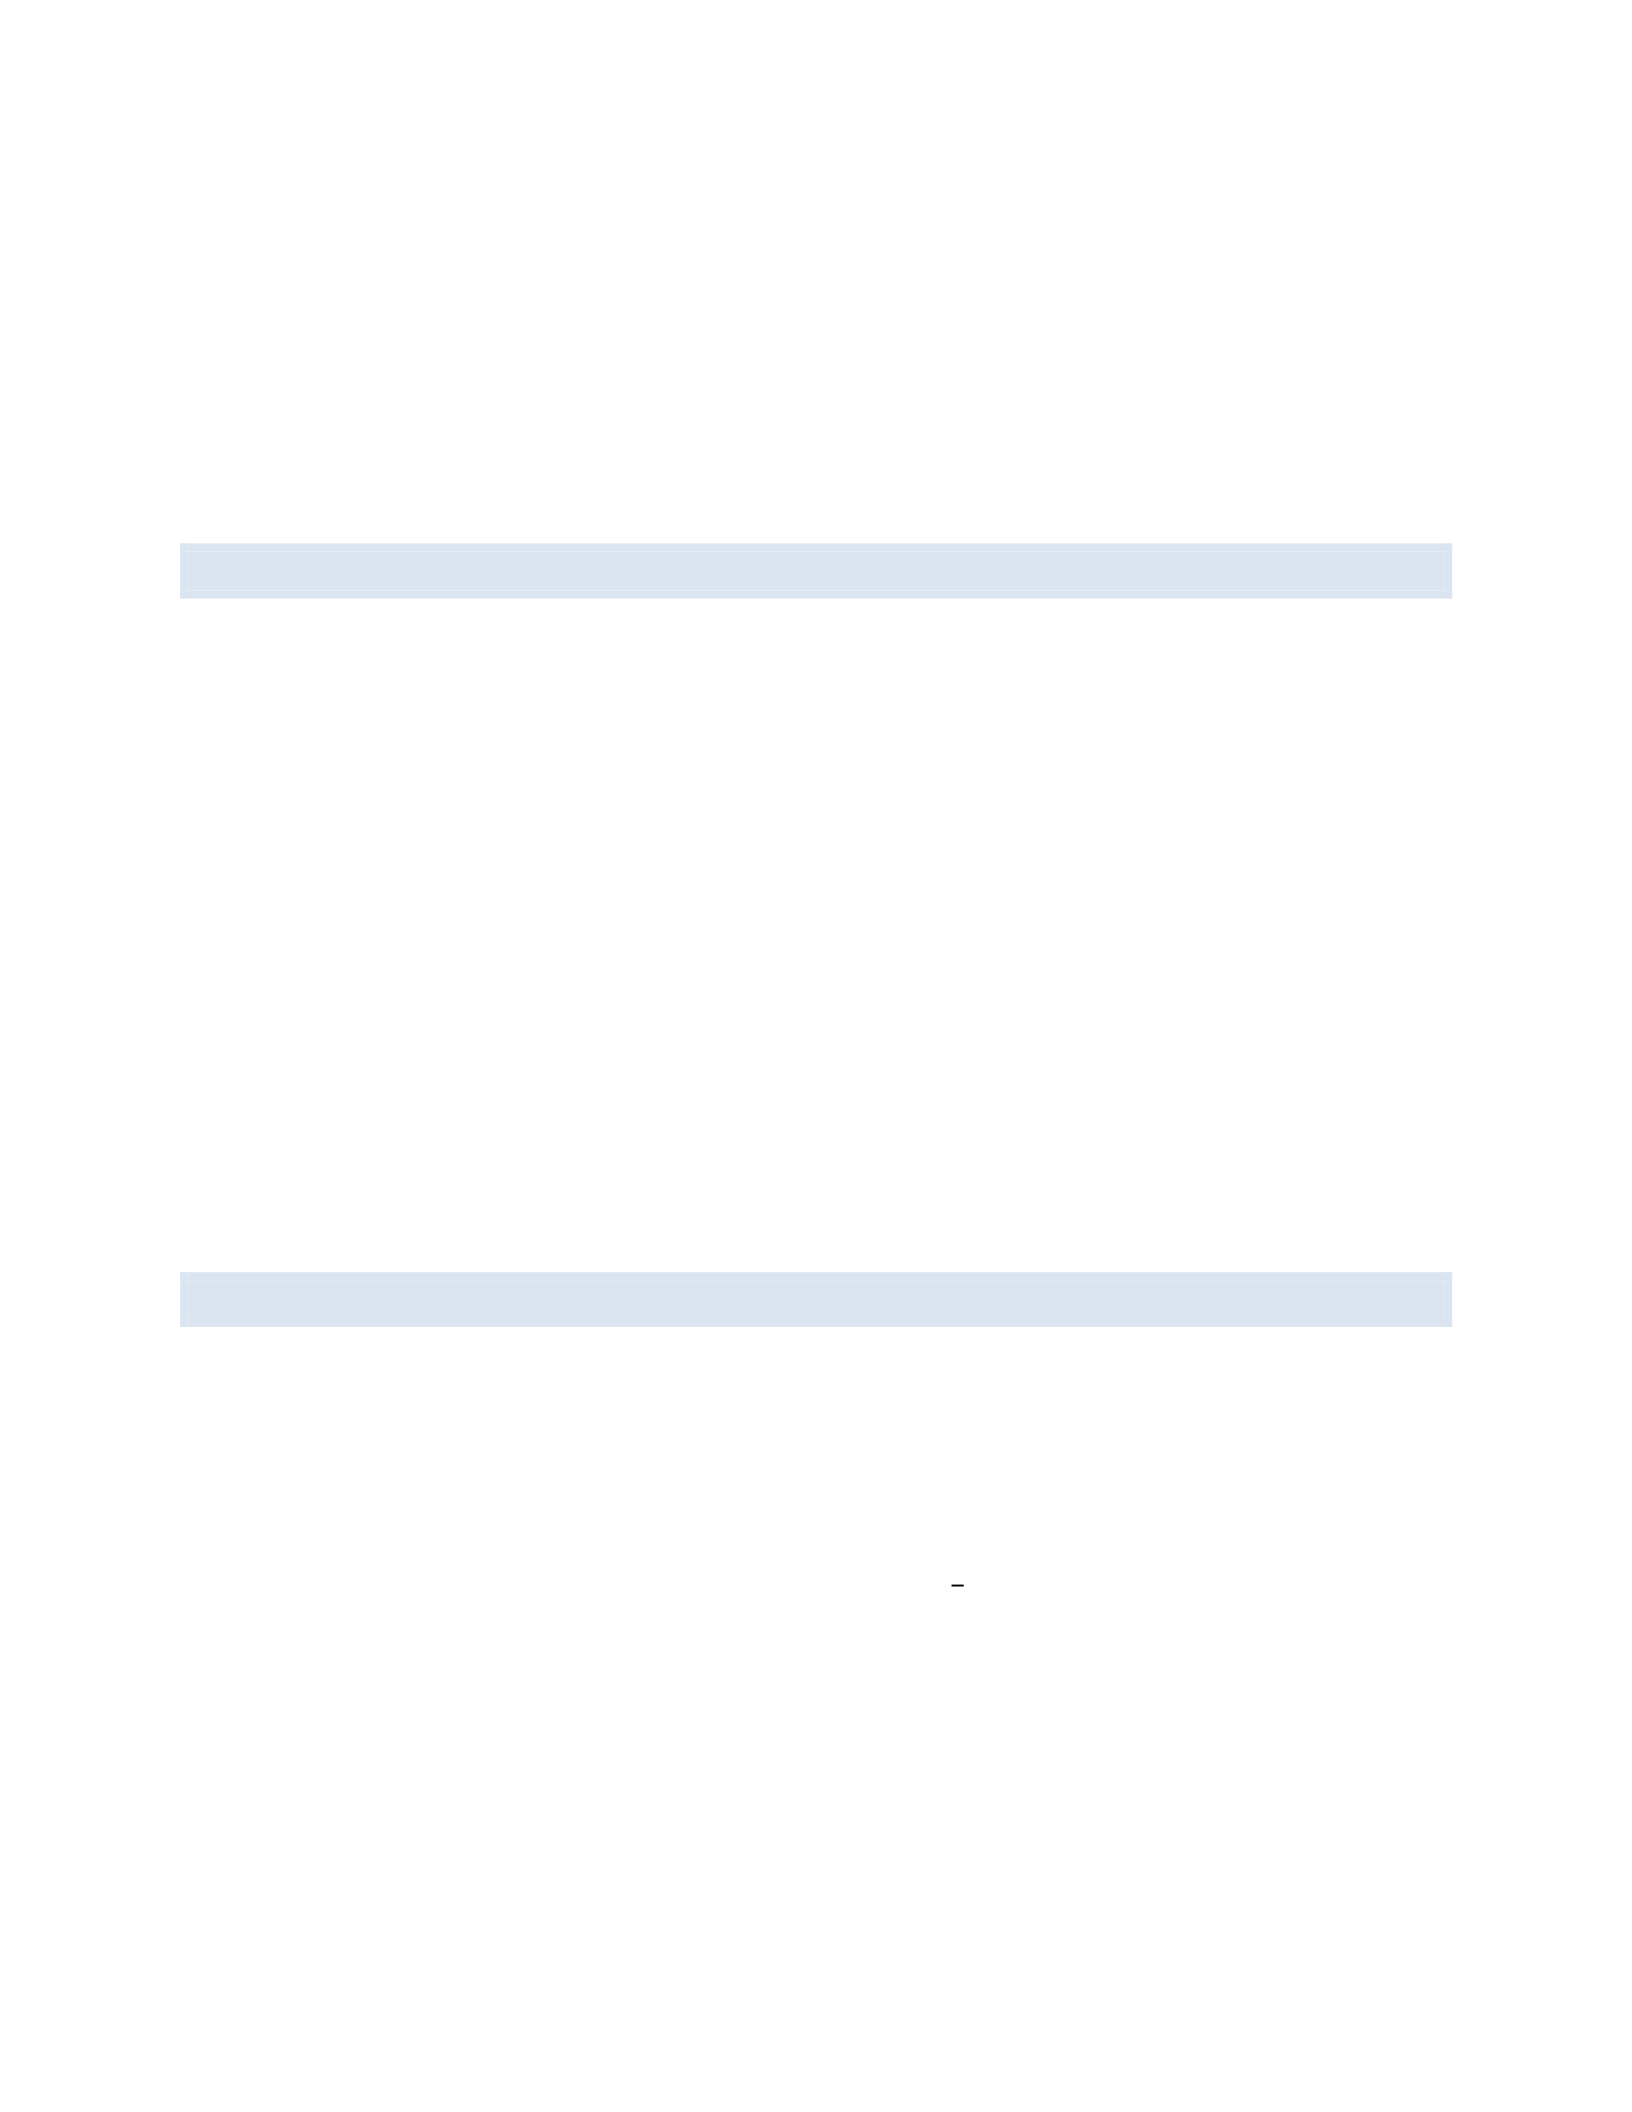
𝑁(𝑑1)=𝑁(0.0391)=0.5156
𝑁(𝑑2)=𝑁(−0.1730)= 0.4313
Step 4: Calculate the option price:
𝐶 =50×0.5156−52𝑒−0.05×0.5 ×0.4313
=25.78−22.17
=3.61
Therefore, the price of the European call option is $3.61.
QUESTION 5: ARBITRAGE PRICING THEORY (APT)
Consider a three-factor APT model with the following information: - Risk-free rate: 3% - Factor
risk premiums: λ1 = 4%, λ2 = 3%, λ3 = 2% - Stock A has factor sensitivities: β1 = 1.2, β2 = 0.8,
β3 = -0.5
Calculate the expected return of Stock A according to the APT model.
Solution:
Step 1: Recall the APT formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖1𝜆1+𝛽𝑖2𝜆2+𝛽𝑖3𝜆3
Step 2: Substitute the given values:
𝐸(𝑅𝐴)= 0.03+1.2(0.04)+0.8(0.03)+(−0.5)(0.02)
=0.03+0.048+0.024−0.01
=0.092
Therefore, the expected return of Stock A according to the APT model is 9.2%.
QUESTION 6: VALUE AT RISK (VAR)
A portfolio has a current value of $10 million and a daily volatility of 1.5%. Assuming normally
distributed returns, calculate the 1-day 99% VaR for this portfolio.
Solution:
Step 1: Recall the VaR formula for normally distributed returns:
𝑉𝑎𝑅 =𝑃×𝜎×𝑍𝛼×√𝑡
Where: - P is the portfolio value - σ is the daily volatility - Zα is the Z-score for the desired
confidence level - t is the time horizon in days
Step 2: Identify the given values:
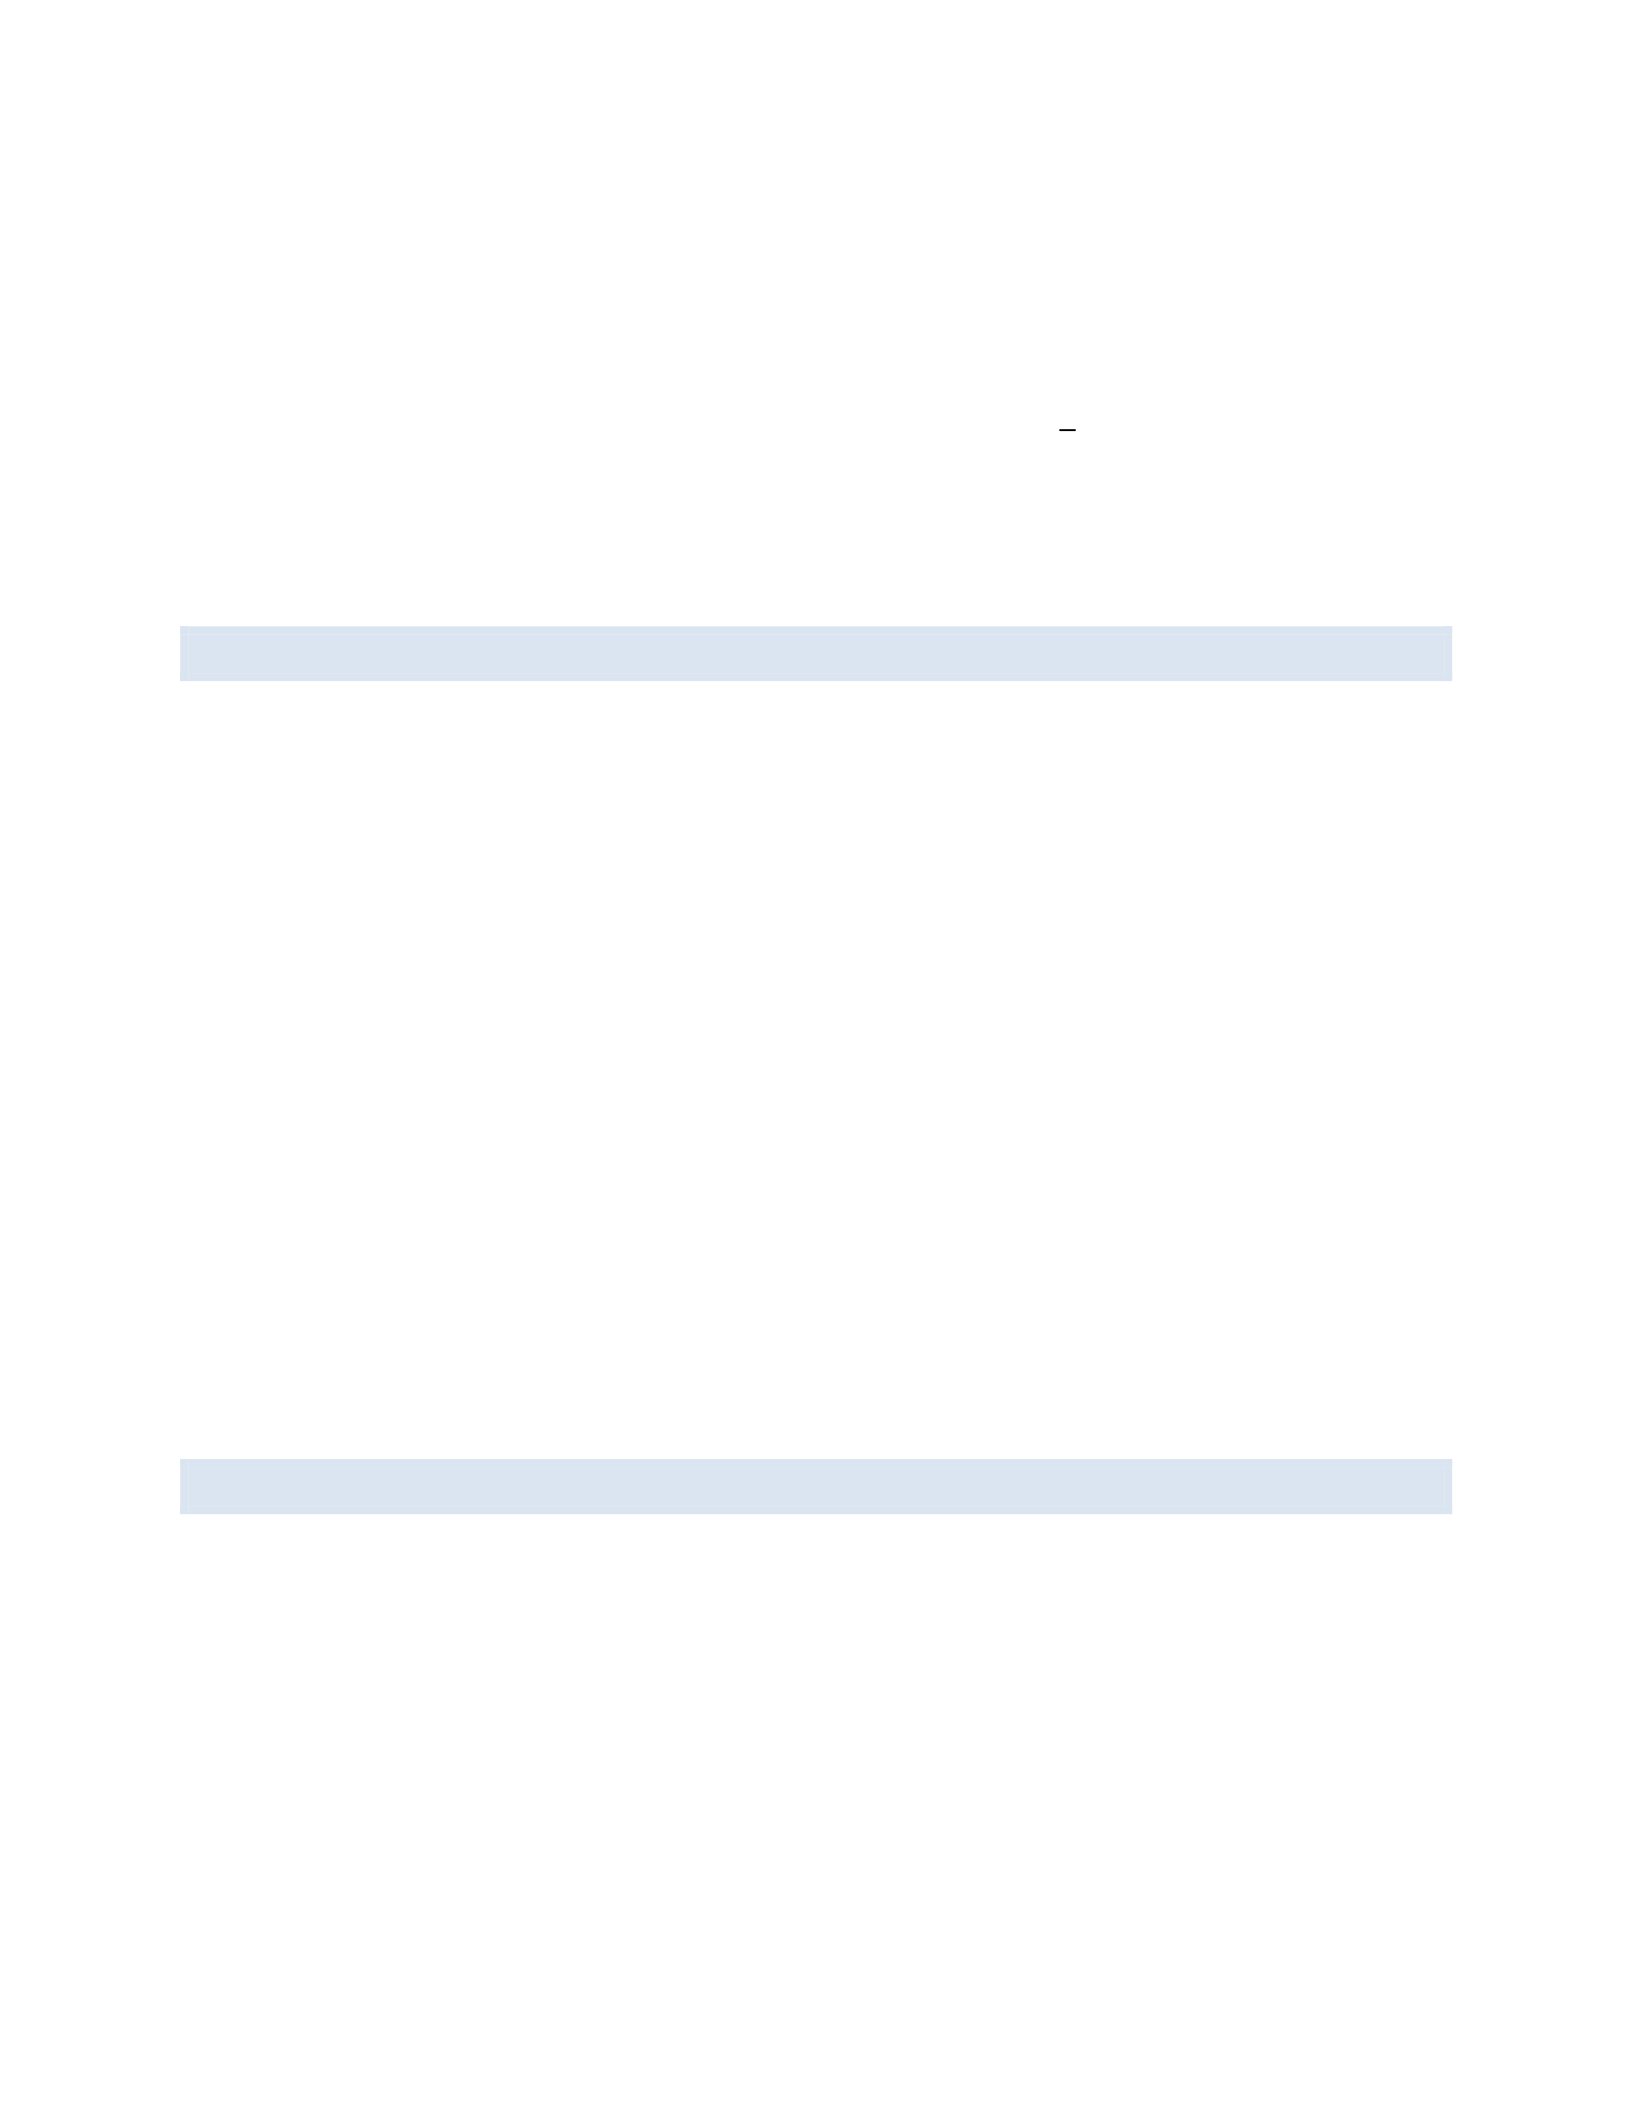
𝑃 =$10,000,000
𝜎 =1.5% =0.015
𝑍99%= 2.33(𝑓𝑟𝑜𝑚𝑠𝑡𝑎𝑛𝑑𝑎𝑟𝑑𝑛𝑜𝑟𝑚𝑎𝑙𝑑𝑖𝑠𝑡𝑟𝑖𝑏𝑢𝑡𝑖𝑜𝑛𝑡𝑎𝑏𝑙𝑒)
𝑡 =1 day
Step 3: Calculate the VaR:
𝑉𝑎𝑅 =10,000,000×0.015×2.33×√1
=349,500
Therefore, the 1-day 99% VaR for this portfolio is $349,500. This means there is a 1% chance
that the portfolio will lose more than $349,500 in one day.
QUESTION 7: FAMA-FRENCH THREE-FACTOR MODEL
A stock has the following factor exposures: - Market factor (MKT) beta: 1.2 - Size factor (SMB)
beta: 0.5 - Value factor (HML) beta: -0.3
The risk-free rate is 2%, and the factor risk premiums are: - Market risk premium: 6% - SMB
premium: 3% - HML premium: 4%
Calculate the expected return of the stock using the Fama-French Three-Factor Model.
Solution:
Step 1: Recall the Fama-French Three-Factor Model formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝑅𝑚−𝑅𝑓)+𝑠𝑖(𝑆𝑀𝐵)+ℎ𝑖(𝐻𝑀𝐿)
Step 2: Substitute the given values:
𝐸(𝑅𝑖)=0.02+1.2(0.06)+0.5(0.03)+(−0.3)(0.04)
=0.02+0.072+0.015−0.012
=0.095
Therefore, the expected return of the stock according to the Fama-French Three-Factor Model
is 9.5%.
QUESTION 8: SHARPE RATIO AND INFORMATION RATIO
A portfolio manager achieved an average annual return of 12% over the past 5 years, with a
standard deviation of 18%. The risk-free rate during this period was 3%, and the benchmark
index returned 9% with a standard deviation of 15%. Calculate:
a) The Sharpe ratio of the portfolio b) The Information ratio of the portfolio
Solution:
a) Sharpe Ratio
Step 1: Recall the Sharpe ratio formula:
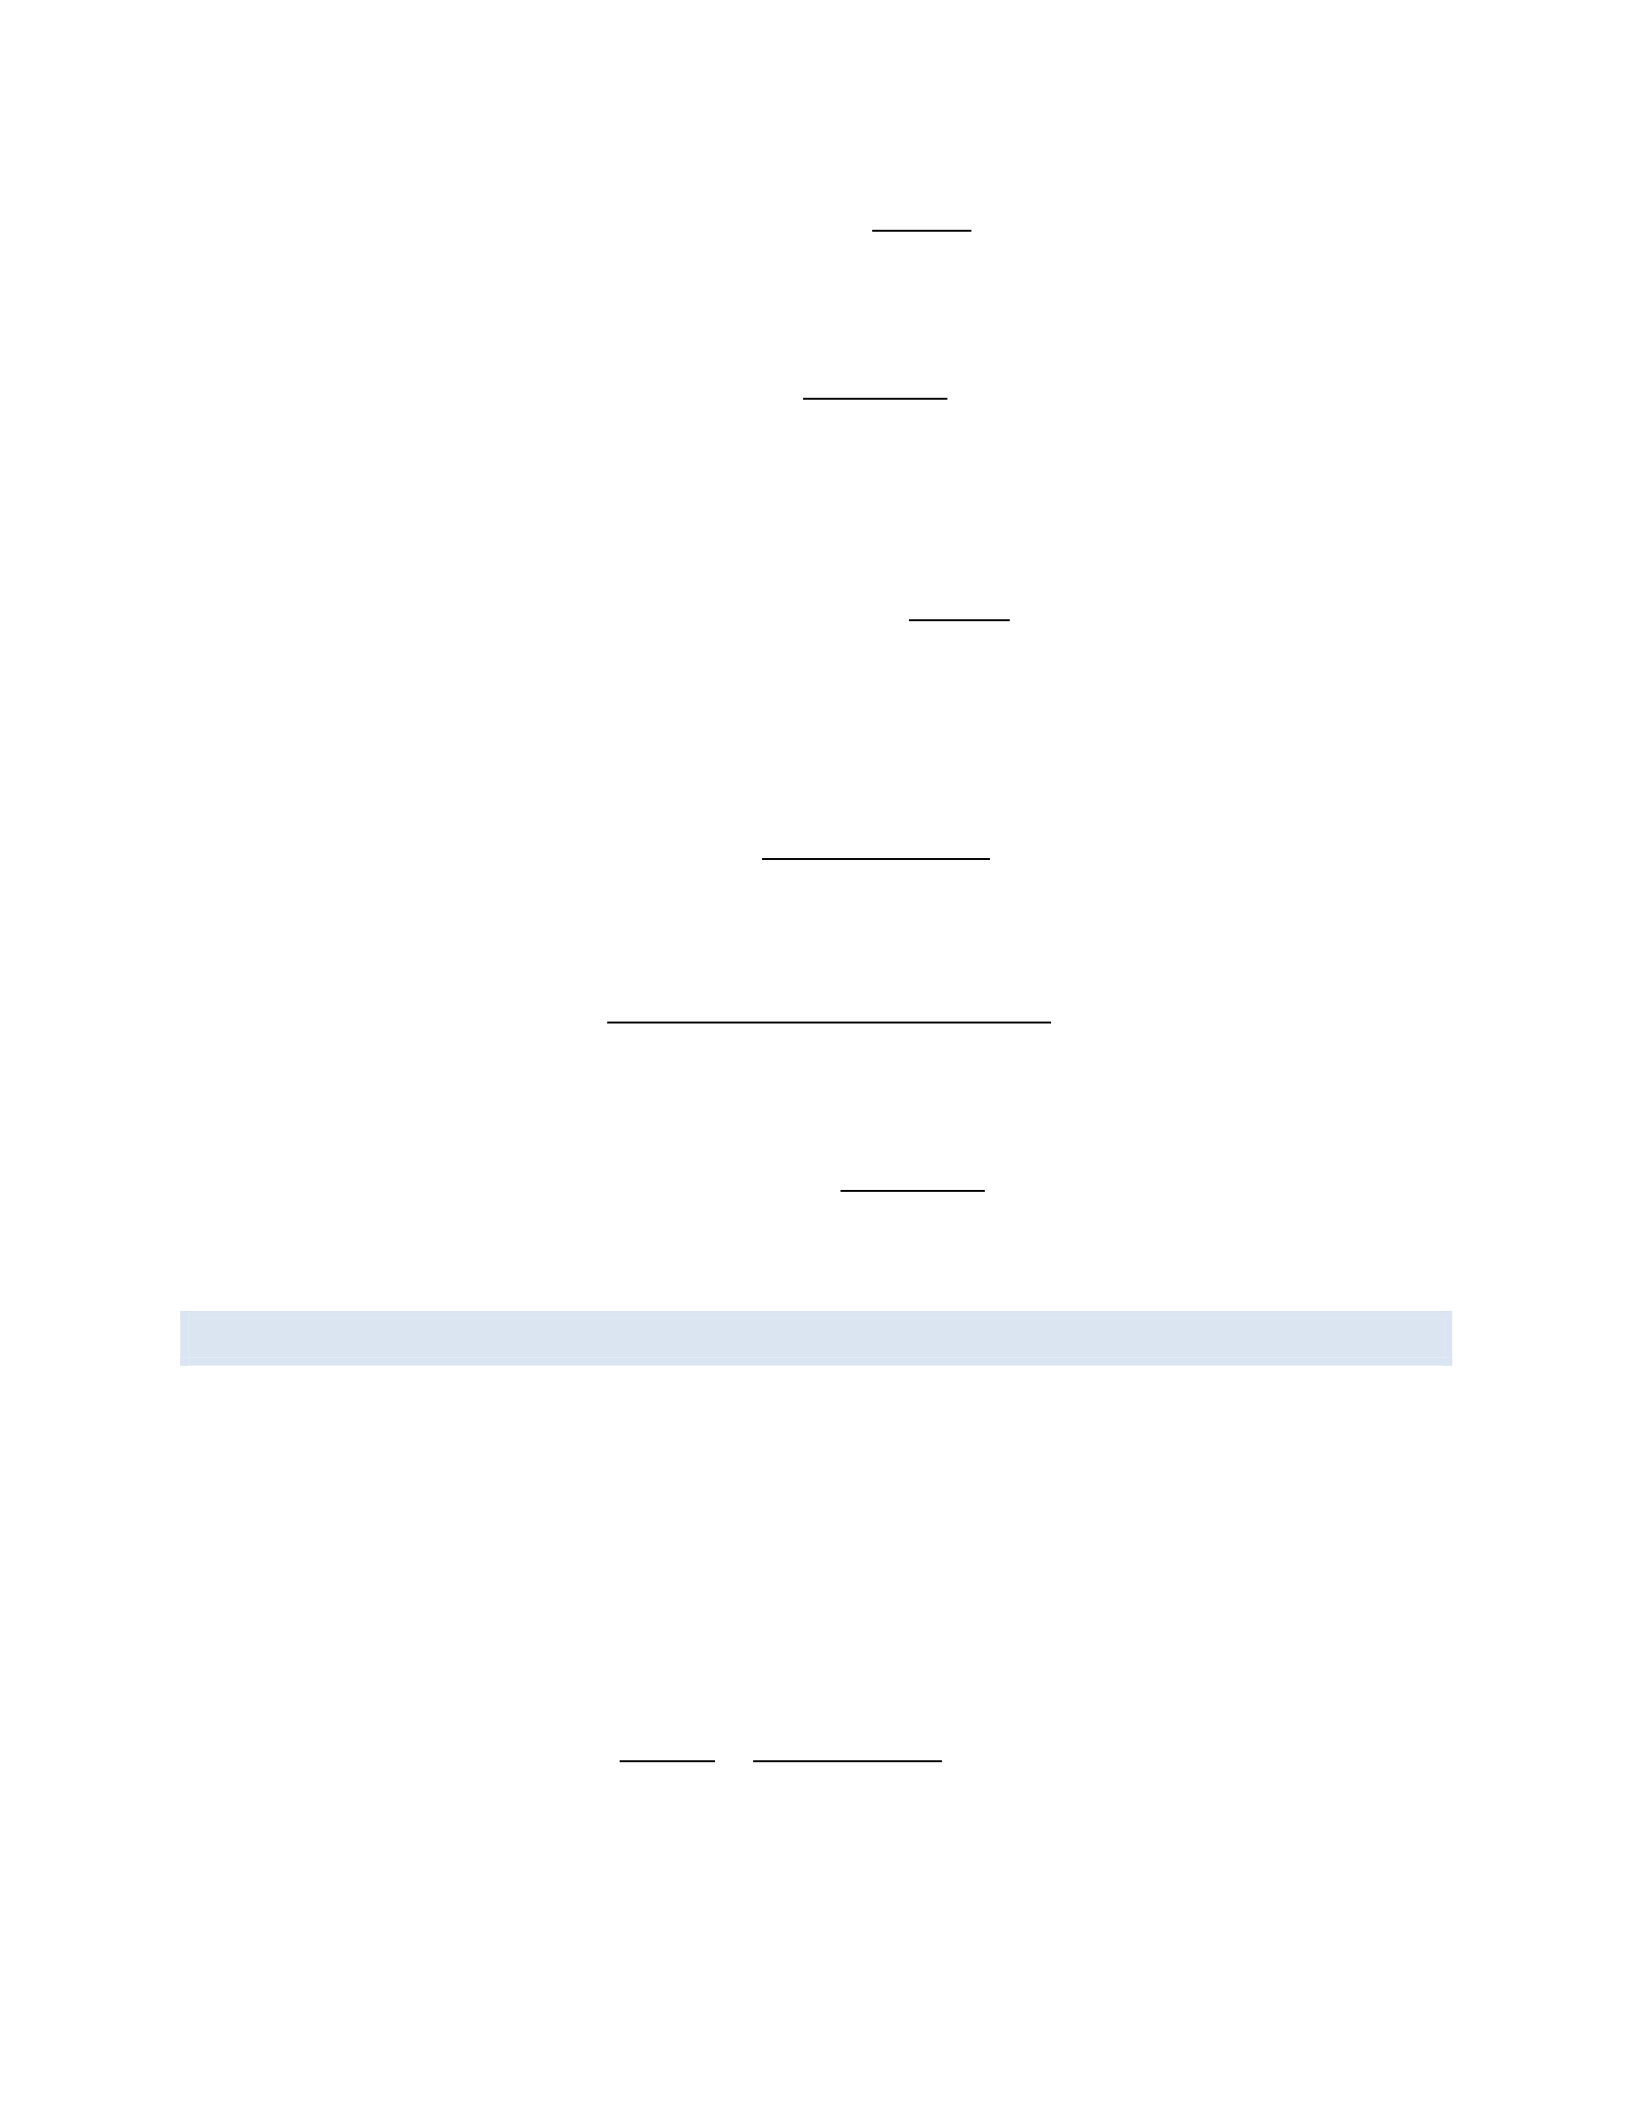
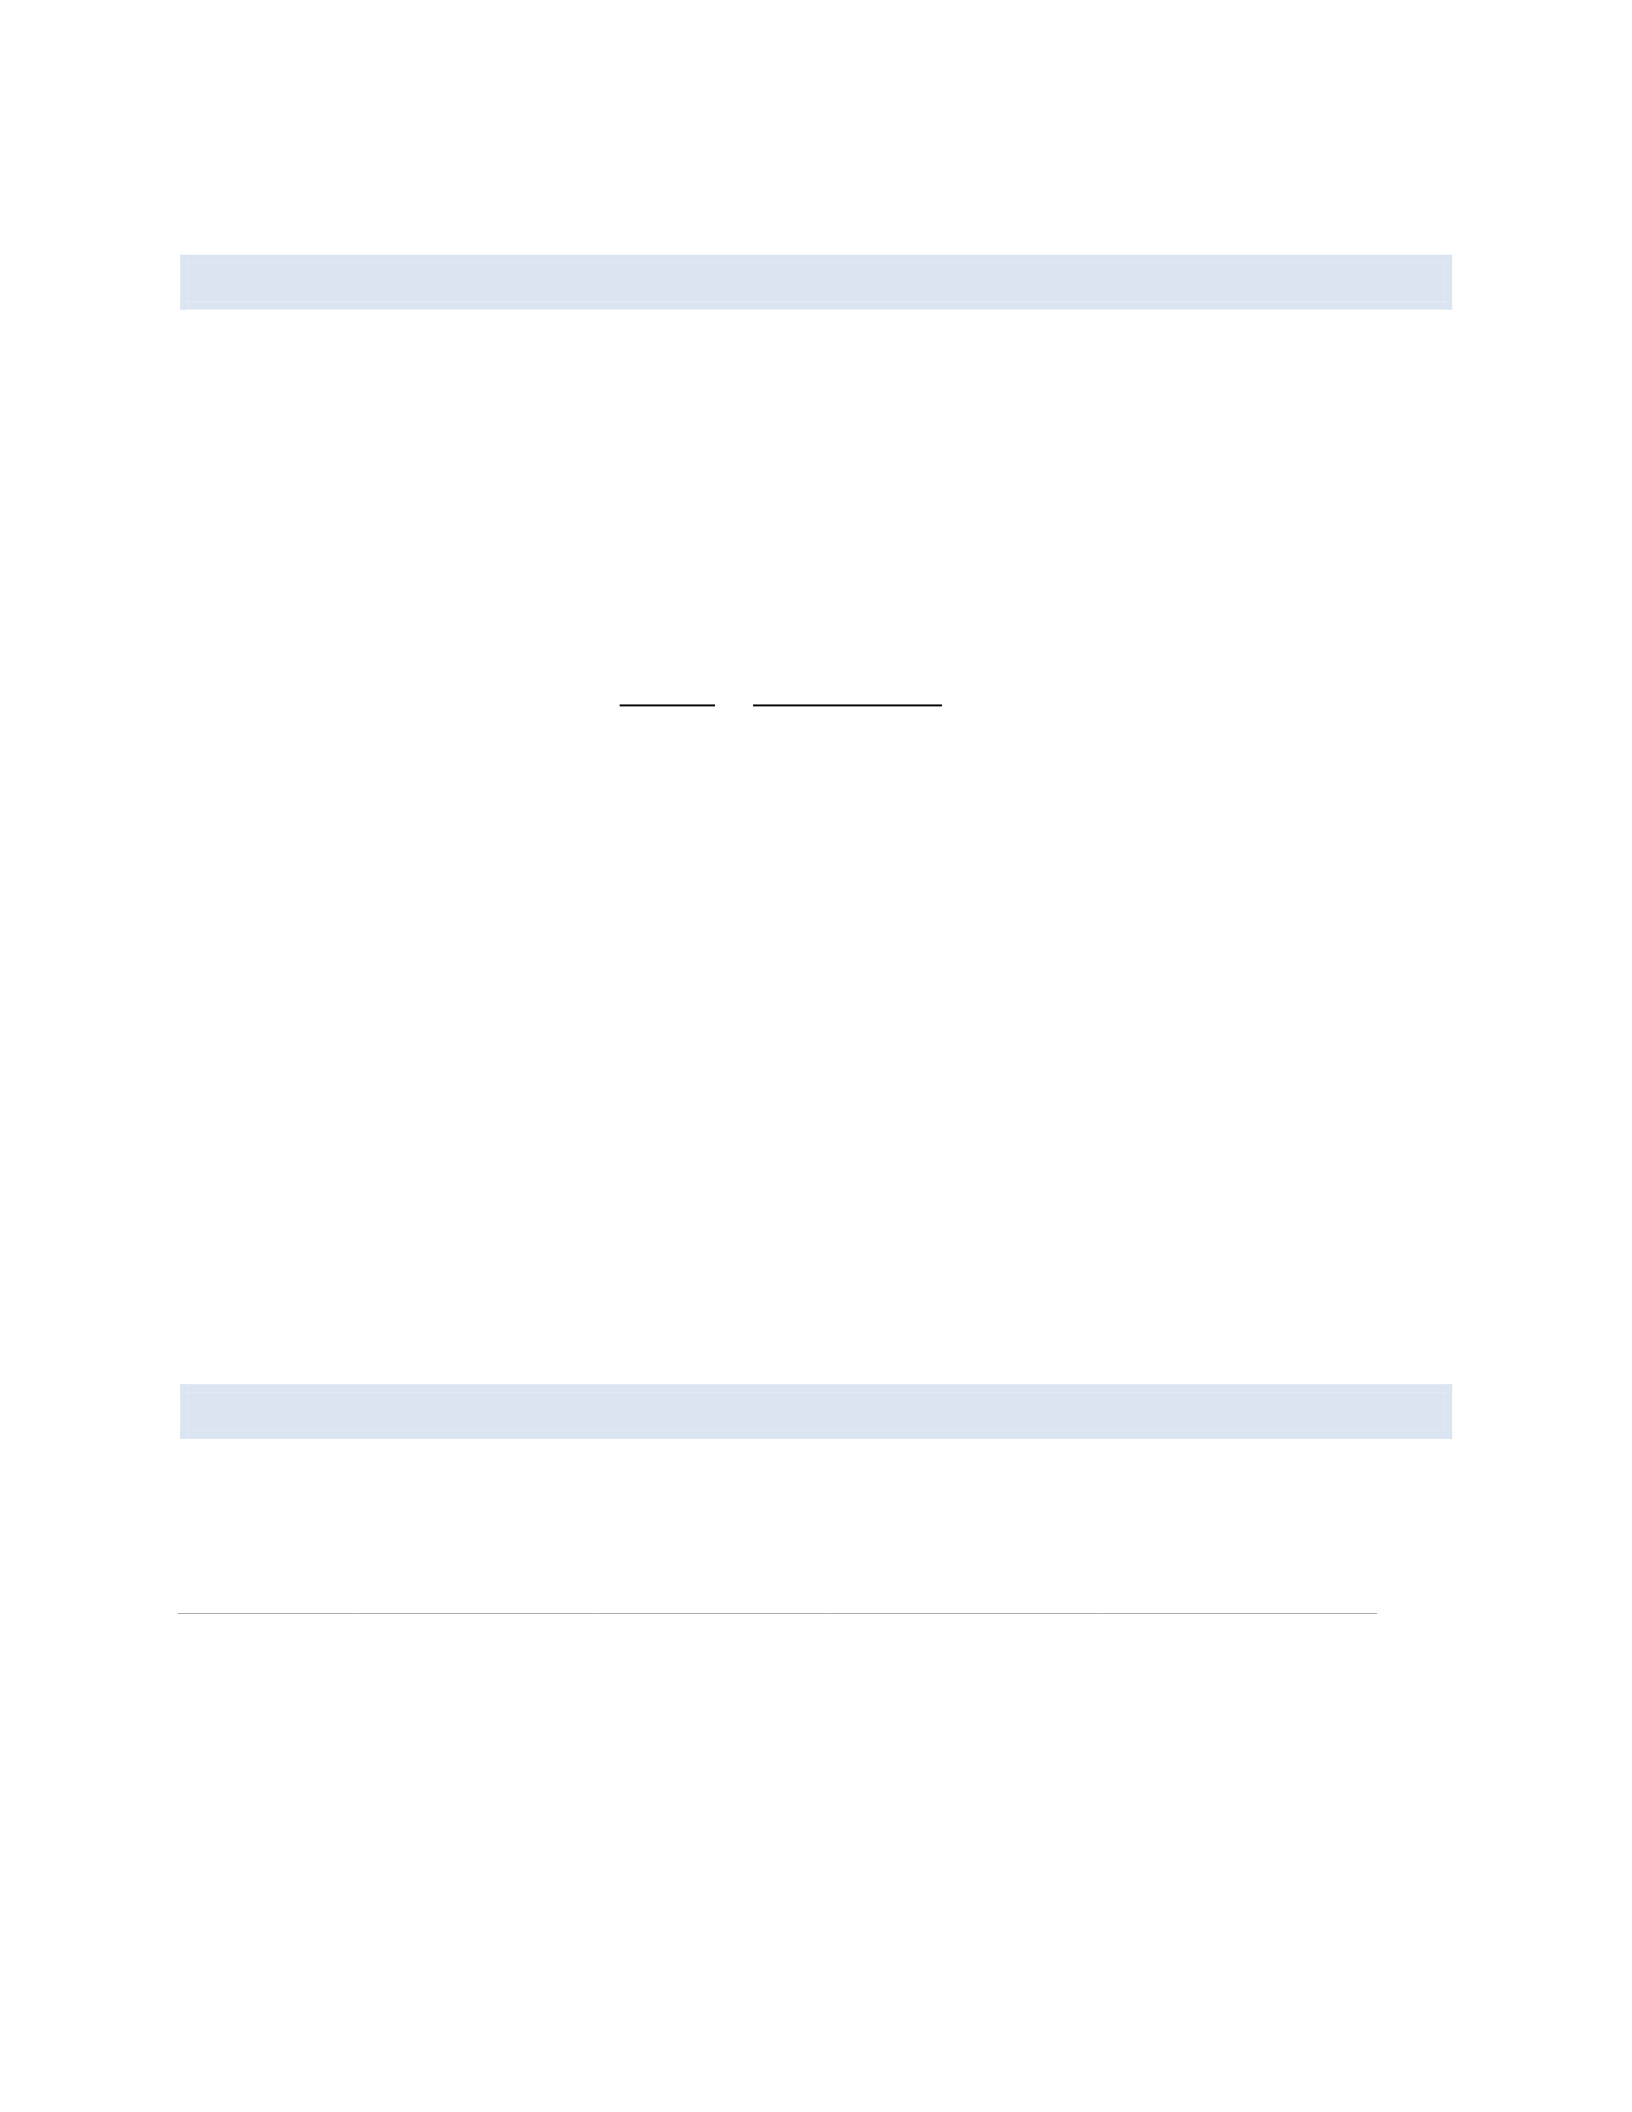
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑓
𝜎𝑝
Step 2: Substitute the given values:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 0.12−0.03
0.18 =0.50
b) Information Ratio
Step 1: Recall the Information ratio formula:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑏
𝜎𝑝−𝑏
Where σp-b is the standard deviation of the difference between portfolio returns and benchmark
returns (tracking error).
Step 2: Calculate the tracking error:
𝜎𝑝−𝑏 =√𝜎𝑝
2+𝜎𝑏
2−2𝜌𝜎𝑝𝜎𝑏
Assuming a correlation of 0.8 between the portfolio and benchmark:
𝜎𝑝−𝑏 =√0.182+0.152−2(0.8)(0.18)(0.15)=0.11
Step 3: Calculate the Information ratio:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 =0.12−0.09
0.11 =0.27
Therefore, the Sharpe ratio of the portfolio is 0.50, and the Information ratio is 0.27.
QUESTION 9: BINOMIAL OPTION PRICING MODEL (CONTINUED)
Consider a European call option with the following characteristics: - Current stock price (S0) =
$100 - Strike price (K) = $105 - Time to expiration (T) = 3 months (0.25 years) - Risk-free rate (r)
= 4% per annum - Up factor (u) = 1.1 - Down factor (d) = 0.9
Using a one-step binomial model, calculate the price of this call option.
Solution:
Step 1: Calculate the risk-neutral probability (p):
𝑝 = 𝑒𝑟𝑇 −𝑑
𝑢−𝑑 =𝑒0.04×0.25 −0.9
1.1−0.9 =0.5498
Step 2: Calculate the possible stock prices at expiration:
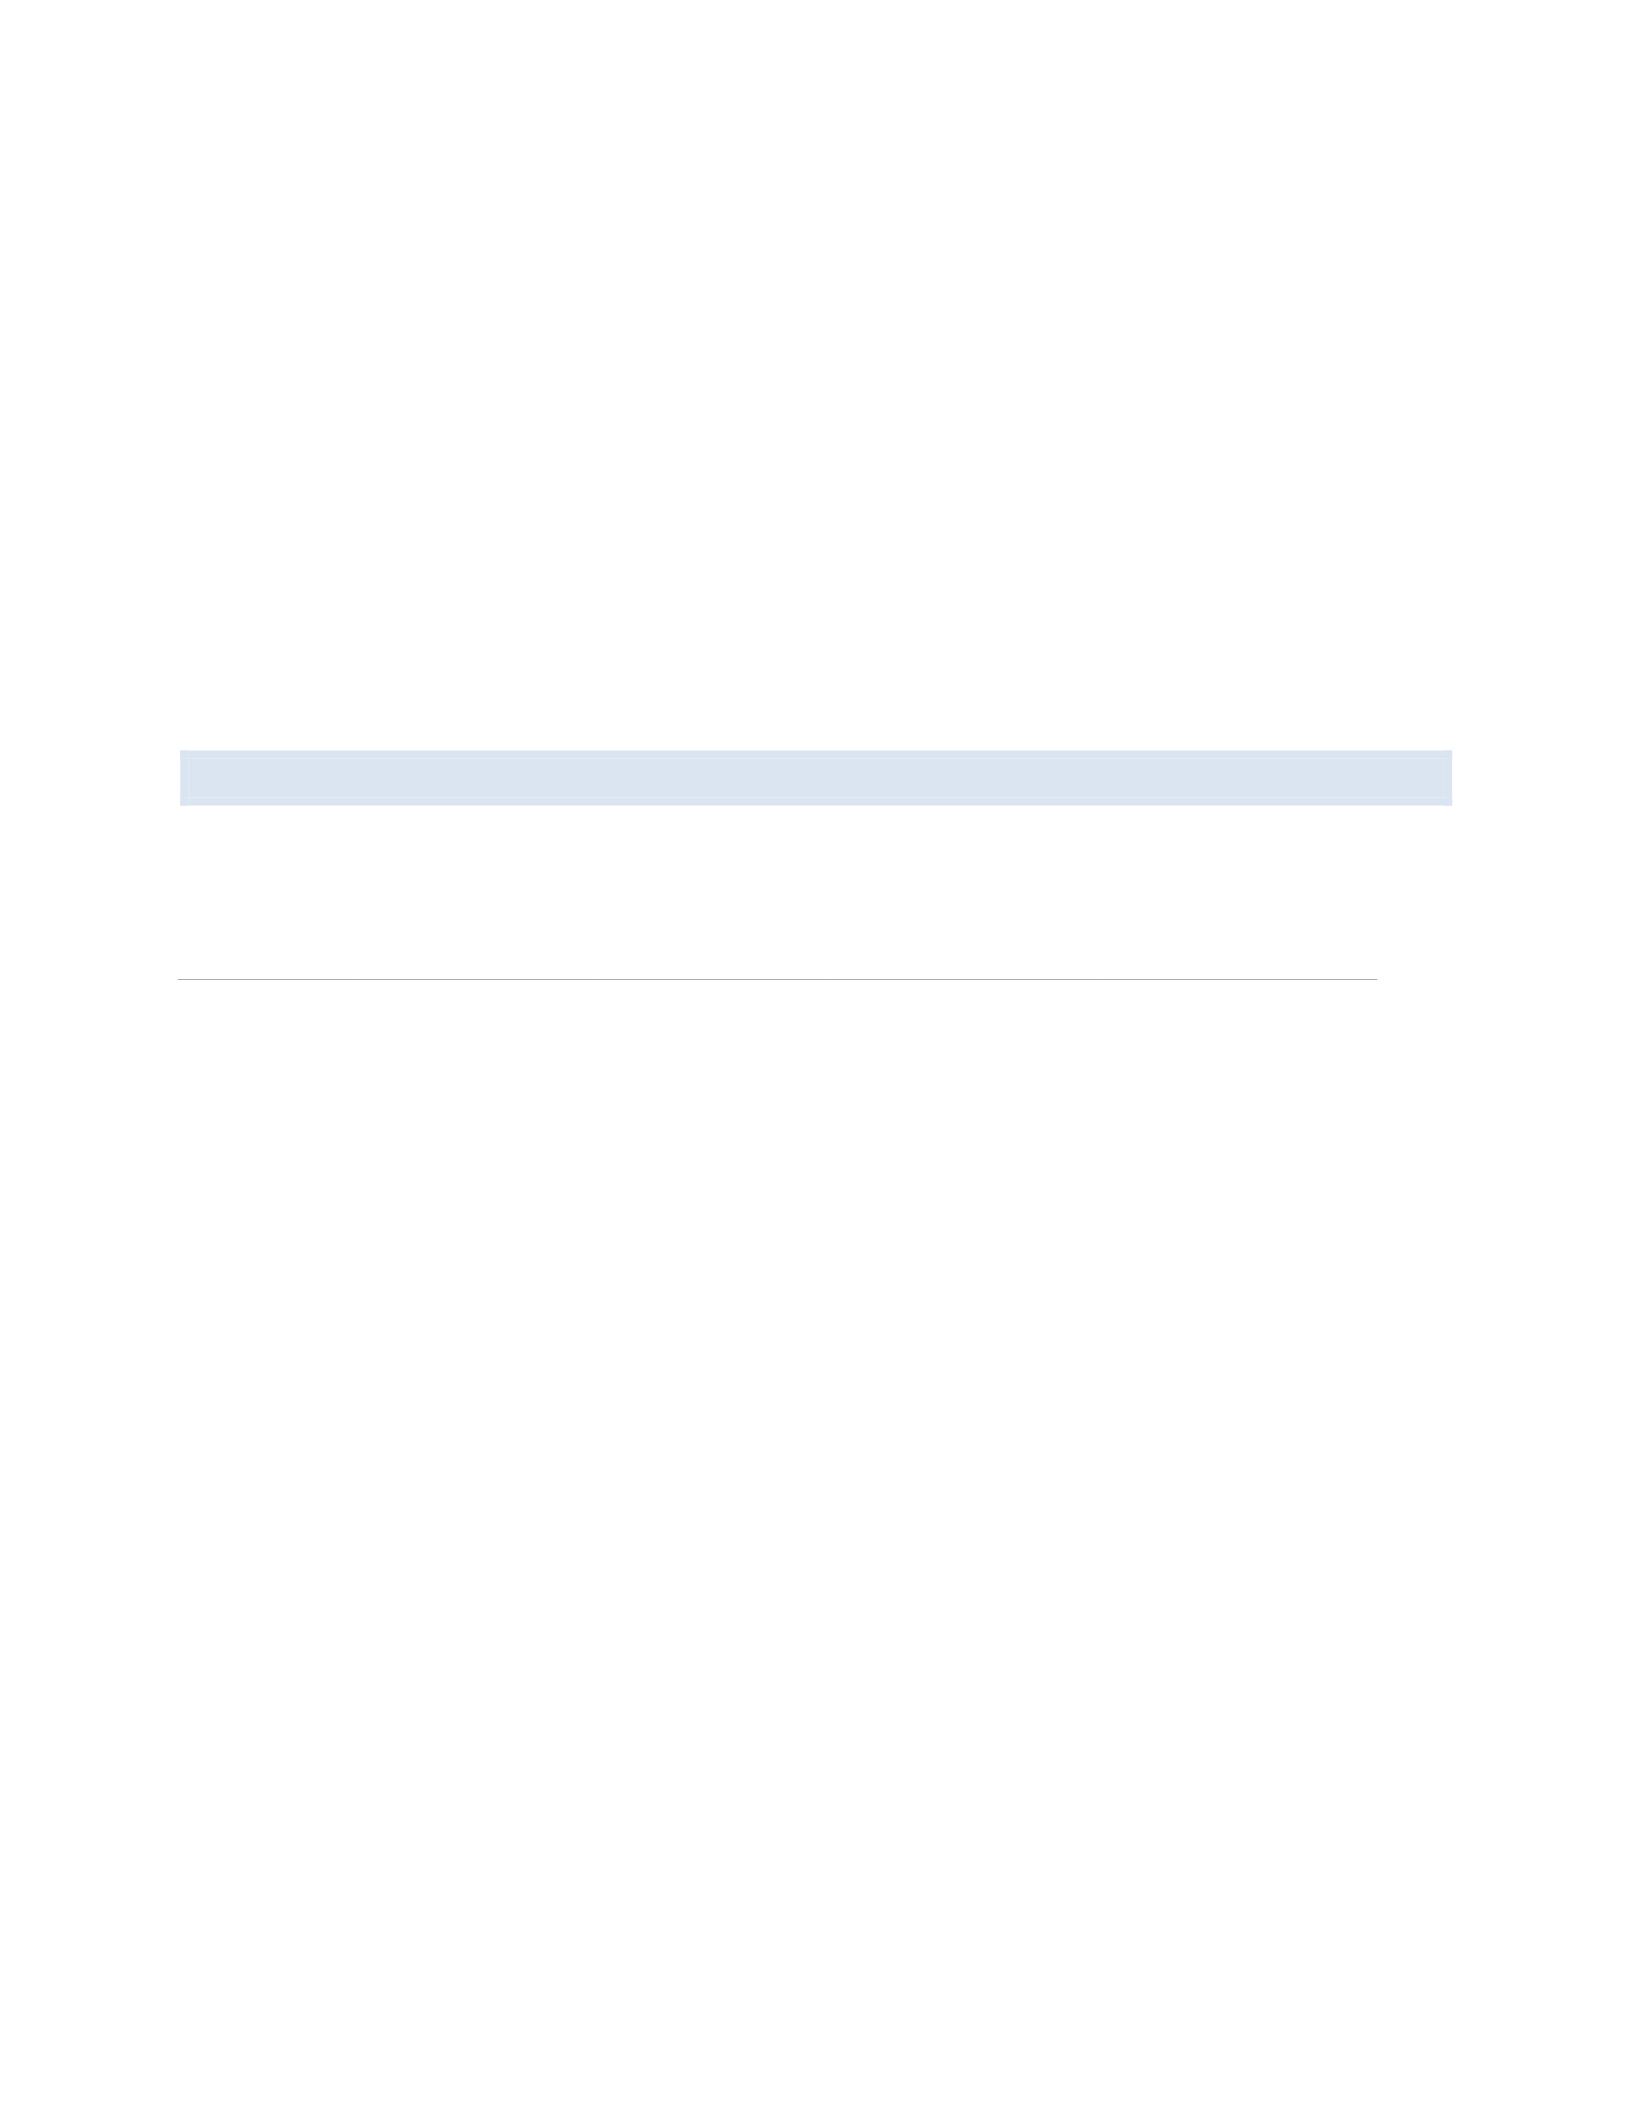
𝑆𝑢= 𝑆0×𝑢 = 100×1.1= $110
𝑆𝑑= 𝑆0×𝑑 = 100×0.9= $90
Step 3: Calculate the option payoffs at expiration:
𝐶𝑢=max(𝑆𝑢−𝐾,0)=max(110−105,0)=$5
𝐶𝑑=max(𝑆𝑑−𝐾,0)= max(90−105,0)=$0
Step 4: Calculate the option price using the risk-neutral valuation formula:
𝐶0=𝑒−𝑟𝑇[𝑝𝐶𝑢+(1−𝑝)𝐶𝑑]
=𝑒−0.04×0.25[0.5498×5+(1−0.5498)×0]
=0.9900×2.7490
=$2.72
Therefore, the price of the European call option using a one-step binomial model is $2.72.
QUESTION 10: PORTFOLIO PERFORMANCE ATTRIBUTION
An equity portfolio manager reported the following sector allocations and returns for the year,
along with the benchmark index data:
Sector
Portfolio Weight
Portfolio Return
Benchmark Weight
Benchmark Return
Technology
35%
12%
30%
10%
Healthcare
25%
8%
20%
7%
Financials
20%
6%
25%
5%
Consumer
15%
4%
15%
3%
Utilities
5%
2%
10%
1%
Perform a performance attribution analysis to determine the sources of the portfolio’s excess
return, breaking it down into allocation effect and selection effect.
Solution:
Step 1: Calculate the total portfolio and benchmark returns:
Portfolio return: (0.35 × 12%) + (0.25 × 8%) + (0.20 × 6%) + (0.15 × 4%) + (0.05 × 2%) = 8.50%
Benchmark return: (0.30 × 10%) + (0.20 × 7%) + (0.25 × 5%) + (0.15 × 3%) + (0.10 × 1%) =
6.40%
Excess return = 8.50% - 6.40% = 2.10%
Step 2: Calculate allocation effect for each sector: Allocation Effect = (Portfolio Weight -
Benchmark Weight) × (Benchmark Sector Return - Benchmark Total Return)
Technology: (35% - 30%) × (10% - 6.40%) = 0.18% Healthcare: (25% - 20%) × (7% - 6.40%) =
0.03% Financials: (20% - 25%) × (5% - 6.40%) = 0.07% Consumer: (15% - 15%) × (3% -
6.40%) = 0.00% Utilities: (5% - 10%) × (1% - 6.40%) = 0.27%

Total Allocation Effect = 0.18% + 0.03% + 0.07% + 0.00% + 0.27% = 0.55%
Step 3: Calculate selection effect for each sector: Selection Effect = Benchmark Weight ×
(Portfolio Sector Return - Benchmark Sector Return)
Technology: 30% × (12% - 10%) = 0.60% Healthcare: 20% × (8% - 7%) = 0.20% Financials:
25% × (6% - 5%) = 0.25% Consumer: 15% × (4% - 3%) = 0.15% Utilities: 10% × (2% - 1%) =
0.10%
Total Selection Effect = 0.60% + 0.20% + 0.25% + 0.15% + 0.10% = 1.30%
Step 4: Calculate interaction effect (optional): Interaction Effect = (Portfolio Weight - Benchmark
Weight) × (Portfolio Sector Return - Benchmark Sector Return)
Technology: (35% - 30%) × (12% - 10%) = 0.10% Healthcare: (25% - 20%) × (8% - 7%) =
0.05% Financials: (20% - 25%) × (6% - 5%) = -0.05% Consumer: (15% - 15%) × (4% - 3%) =
0.00% Utilities: (5% - 10%) × (2% - 1%) = -0.05%
Total Interaction Effect = 0.10% + 0.05% - 0.05% + 0.00% - 0.05% = 0.05%
Step 5: Summarize the attribution analysis:
Excess Return = 2.10% Allocation Effect = 0.55% Selection Effect = 1.30% Interaction Effect =
0.05% Total Attribution = 0.55% + 1.30% + 0.05% = 1.90%
The difference between the excess return (2.10%) and the total attribution (1.90%) is due to
rounding effects.
In conclusion, the portfolio’s outperformance can be attributed to: 1. Allocation Effect: 0.55%
(26.2% of excess return) 2. Selection Effect: 1.30% (61.9% of excess return) 3. Interaction
Effect: 0.05% (2.4% of excess return)
The selection effect was the primary driver of the portfolio’s excess return, indicating that the
manager’s stock selection within sectors contributed most to the outperformance.
A stock has a beta of 1.2, the risk-free rate is 3%, and the expected market return is 10%.
Calculate the expected return of the stock using the CAPM.
Solution:
Step 1: Recall the CAPM formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝐸(𝑅𝑚)−𝑅𝑓)
Step 2: Substitute the given values:
𝑅𝑓=3% =0.03
𝛽𝑖= 1.2
𝐸(𝑅𝑚)=10%= 0.10
Step 3: Calculate the expected return:
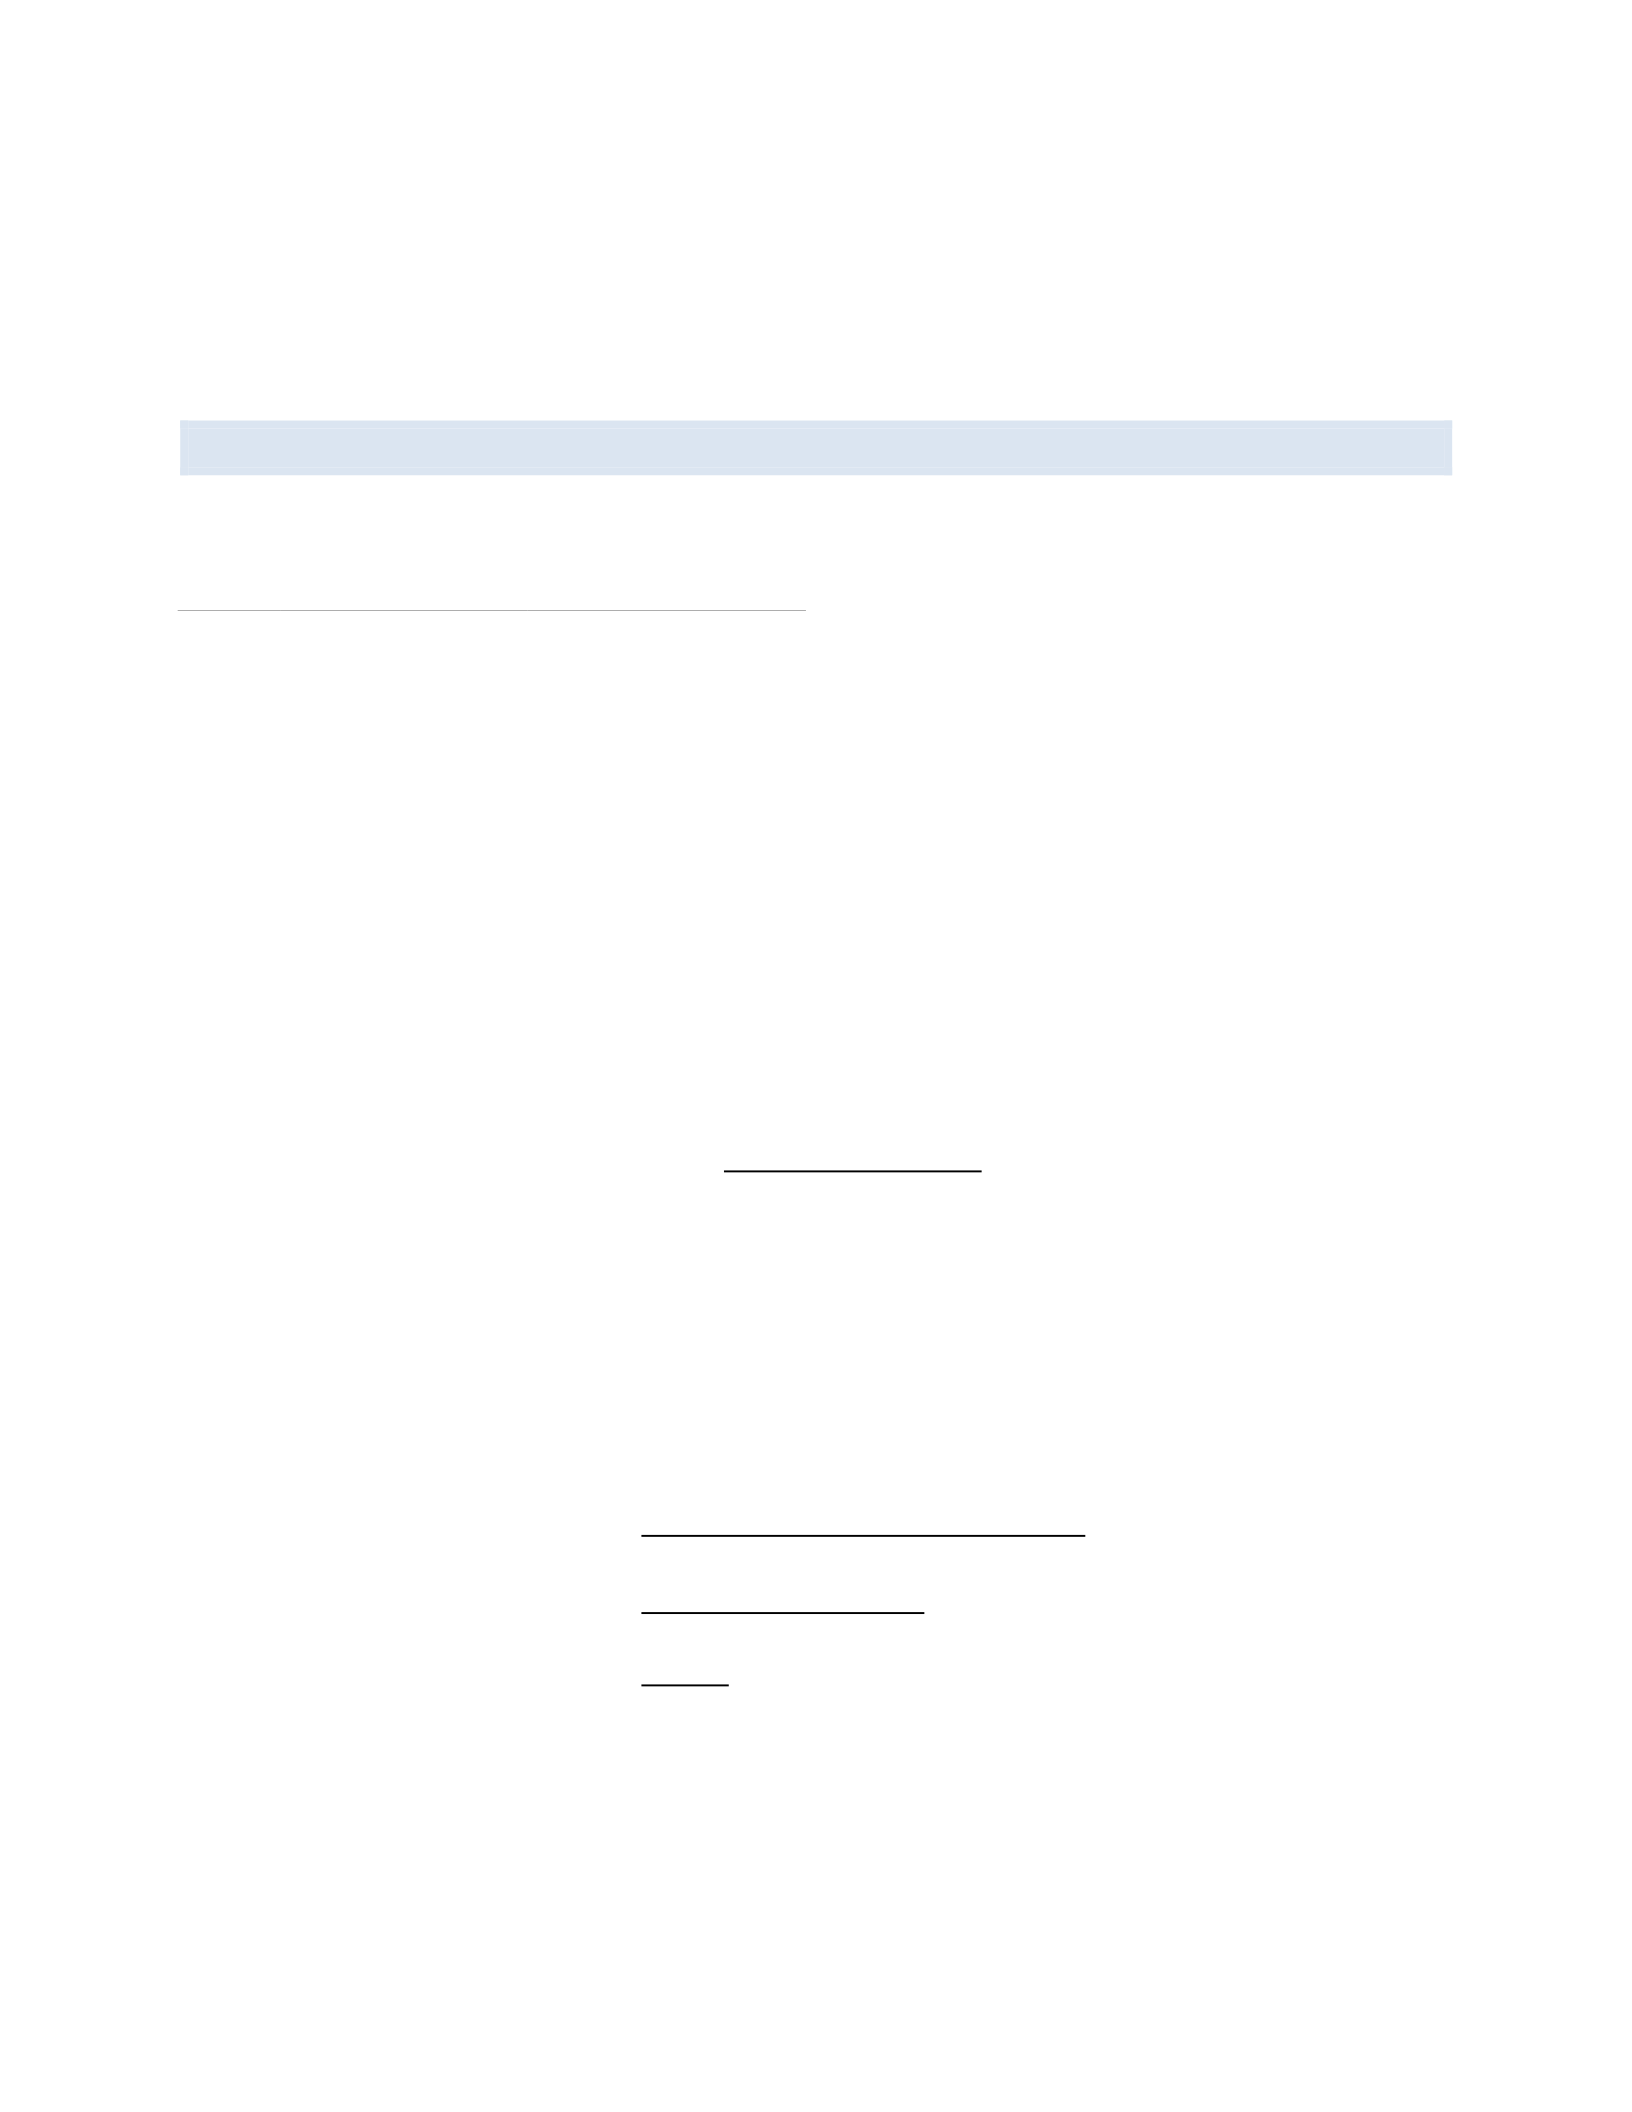
𝐸(𝑅𝑖)=0.03+1.2(0.10−0.03)
=0.03+1.2(0.07)
=0.03+0.084
=0.114
Therefore, the expected return of the stock is 11.4%.
QUESTION 2: PORTFOLIO OPTIMIZATION
An investor is considering two stocks, A and B, with the following characteristics:
Stock
Expected Return
Standard Deviation
A
12%
20%
B
8%
15%
The correlation coefficient between the two stocks is 0.3. Find the optimal portfolio weights that
minimize the portfolio risk.
Solution:
Step 1: Recall the formula for portfolio variance:
𝜎𝑝
2=𝑤𝐴
2𝜎𝐴
2+𝑤𝐵
2𝜎𝐵
2+2𝑤𝐴𝑤𝐵𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 2: To minimize risk, we need to find the weights that minimize the portfolio variance. The
formula for the optimal weight of stock A is:
𝑤𝐴=𝜎𝐵
2−𝜌𝐴𝐵𝜎𝐴𝜎𝐵
𝜎𝐴
2+𝜎𝐵
2−2𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 3: Substitute the given values:
𝜎𝐴=20%= 0.20
𝜎𝐵=15% =0.15
𝜌𝐴𝐵 = 0.3
Step 4: Calculate the optimal weight of stock A:
𝑤𝐴=0.152−0.3(0.20)(0.15)
0.202+0.152−2(0.3)(0.20)(0.15)
=0.0225−0.009
0.04+0.0225−0.018
=0.0135
0.0445
≈0.3034
Step 5: Calculate the weight of stock B:
𝑤𝐵= 1−𝑤𝐴=1−0.3034 =0.6966
Therefore, the optimal portfolio weights to minimize risk are approximately 30.34% in stock A
and 69.66% in stock B.
QUESTION 3: DURATION AND CONVEXITY
A 5-year bond with a face value of $1,000 and a 6% annual coupon rate is currently priced at
$1,050. The yield to maturity is 5%. Calculate the bond’s duration and convexity.
Solution:
Step 1: Calculate the bond’s cash flows and present values:
Year
Cash Flow
PV Factor
Present Value
1
$60
0.9524
$57.14
2
$60
0.9070
$54.42
3
$60
0.8638
$51.83
4
$60
0.8227
$49.36
5
$1,060
0.7835
$830.51
Step 2: Calculate the Macaulay Duration:
𝐷 =1×57.14+2×54.42+3×51.83+4×49.36+5×830.51
1050 =4.52
Step 3: Calculate the Modified Duration:
𝑀𝐷 =𝐷
1+𝑦 =4.52
1.05= 4.30
Step 4: Calculate the Convexity:
𝐶 = 1
𝑃(1+𝑦)2∑𝑡(𝑡+1)𝐶𝐹𝑡
(1+𝑦)𝑡
𝑛
𝑡=1
𝐶 = 1
1050(1.05)2(2×57.14+6×54.42+12×51.83+20×49.36+30×830.51)=22.89
Therefore, the bond’s duration is 4.52 years (Macaulay) or 4.30 years (Modified), and its
convexity is 22.89.
QUESTION 4: BLACK-SCHOLES OPTION PRICING MODEL
Using the Black-Scholes model, calculate the price of a European call option with the following
parameters: - Current stock price (S) = $50 - Strike price (K) = $52 - Time to expiration (T) = 6
months (0.5 years) - Risk-free rate (r) = 5% per annum - Stock volatility (σ) = 30% per annum
Solution:
Step 1: Recall the Black-Scholes formula for a call option:
𝐶 =𝑆𝑁(𝑑1)−𝐾𝑒−𝑟𝑇𝑁(𝑑2)
Where:
𝑑1=ln(𝑆/𝐾)+(𝑟+𝜎2/2)𝑇
𝜎√𝑇
𝑑2=𝑑1−𝜎√𝑇
Step 2: Calculate d1 and d2:
𝑑1=ln(50/52)+(0.05+0.32/2)(0.5)
0.3√0.5
=−0.0392+0.0475
0.2121 =0.0391
𝑑2=0.0391−0.3√0.5= −0.1730
Step 3: Find N(d1) and N(d2) using a standard normal distribution table or calculator:
𝑁(𝑑1)=𝑁(0.0391)=0.5156
𝑁(𝑑2)=𝑁(−0.1730)= 0.4313
Step 4: Calculate the option price:
𝐶 =50×0.5156−52𝑒−0.05×0.5 ×0.4313
=25.78−22.17
=3.61
Therefore, the price of the European call option is $3.61.
QUESTION 5: ARBITRAGE PRICING THEORY (APT)
Consider a three-factor APT model with the following information: - Risk-free rate: 3% - Factor
risk premiums: λ1 = 4%, λ2 = 3%, λ3 = 2% - Stock A has factor sensitivities: β1 = 1.2, β2 = 0.8,
β3 = -0.5
Calculate the expected return of Stock A according to the APT model.
Solution:
Step 1: Recall the APT formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖1𝜆1+𝛽𝑖2𝜆2+𝛽𝑖3𝜆3
Step 2: Substitute the given values:
𝐸(𝑅𝐴)= 0.03+1.2(0.04)+0.8(0.03)+(−0.5)(0.02)
=0.03+0.048+0.024−0.01
=0.092
Therefore, the expected return of Stock A according to the APT model is 9.2%.
QUESTION 6: VALUE AT RISK (VAR)
A portfolio has a current value of $10 million and a daily volatility of 1.5%. Assuming normally
distributed returns, calculate the 1-day 99% VaR for this portfolio.
Solution:
Step 1: Recall the VaR formula for normally distributed returns:
𝑉𝑎𝑅 =𝑃×𝜎×𝑍𝛼×√𝑡
Where: - P is the portfolio value - σ is the daily volatility - Zα is the Z-score for the desired
confidence level - t is the time horizon in days
Step 2: Identify the given values:
𝑃 =$10,000,000
𝜎 =1.5% =0.015
𝑍99%= 2.33(𝑓𝑟𝑜𝑚𝑠𝑡𝑎𝑛𝑑𝑎𝑟𝑑𝑛𝑜𝑟𝑚𝑎𝑙𝑑𝑖𝑠𝑡𝑟𝑖𝑏𝑢𝑡𝑖𝑜𝑛𝑡𝑎𝑏𝑙𝑒)
𝑡 =1 day
Step 3: Calculate the VaR:
𝑉𝑎𝑅 =10,000,000×0.015×2.33×√1
=349,500
Therefore, the 1-day 99% VaR for this portfolio is $349,500. This means there is a 1% chance
that the portfolio will lose more than $349,500 in one day.
QUESTION 7: FAMA-FRENCH THREE-FACTOR MODEL
A stock has the following factor exposures: - Market factor (MKT) beta: 1.2 - Size factor (SMB)
beta: 0.5 - Value factor (HML) beta: -0.3
The risk-free rate is 2%, and the factor risk premiums are: - Market risk premium: 6% - SMB
premium: 3% - HML premium: 4%
Calculate the expected return of the stock using the Fama-French Three-Factor Model.
Solution:
Step 1: Recall the Fama-French Three-Factor Model formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝑅𝑚−𝑅𝑓)+𝑠𝑖(𝑆𝑀𝐵)+ℎ𝑖(𝐻𝑀𝐿)
Step 2: Substitute the given values:
𝐸(𝑅𝑖)=0.02+1.2(0.06)+0.5(0.03)+(−0.3)(0.04)
=0.02+0.072+0.015−0.012
=0.095
Therefore, the expected return of the stock according to the Fama-French Three-Factor Model
is 9.5%.
QUESTION 8: SHARPE RATIO AND INFORMATION RATIO
A portfolio manager achieved an average annual return of 12% over the past 5 years, with a
standard deviation of 18%. The risk-free rate during this period was 3%, and the benchmark
index returned 9% with a standard deviation of 15%. Calculate:
a) The Sharpe ratio of the portfolio b) The Information ratio of the portfolio
Solution:
a) Sharpe Ratio
Step 1: Recall the Sharpe ratio formula:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑓
𝜎𝑝
Step 2: Substitute the given values:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 0.12−0.03
0.18 =0.50
b) Information Ratio
Step 1: Recall the Information ratio formula:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑏
𝜎𝑝−𝑏
Where σp-b is the standard deviation of the difference between portfolio returns and benchmark
returns (tracking error).
Step 2: Calculate the tracking error:
𝜎𝑝−𝑏 =√𝜎𝑝
2+𝜎𝑏
2−2𝜌𝜎𝑝𝜎𝑏
Assuming a correlation of 0.8 between the portfolio and benchmark:
𝜎𝑝−𝑏 =√0.182+0.152−2(0.8)(0.18)(0.15)=0.11
Step 3: Calculate the Information ratio:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 =0.12−0.09
0.11 =0.27
Therefore, the Sharpe ratio of the portfolio is 0.50, and the Information ratio is 0.27.
QUESTION 9: BINOMIAL OPTION PRICING MODEL (CONTINUED)
Consider a European call option with the following characteristics: - Current stock price (S0) =
$100 - Strike price (K) = $105 - Time to expiration (T) = 3 months (0.25 years) - Risk-free rate (r)
= 4% per annum - Up factor (u) = 1.1 - Down factor (d) = 0.9
Using a one-step binomial model, calculate the price of this call option.
Solution:
Step 1: Calculate the risk-neutral probability (p):
𝑝 = 𝑒𝑟𝑇 −𝑑
𝑢−𝑑 =𝑒0.04×0.25 −0.9
1.1−0.9 =0.5498
Step 2: Calculate the possible stock prices at expiration:
𝑆𝑢= 𝑆0×𝑢 = 100×1.1= $110
𝑆𝑑= 𝑆0×𝑑 = 100×0.9= $90
Step 3: Calculate the option payoffs at expiration:
𝐶𝑢=max(𝑆𝑢−𝐾,0)=max(110−105,0)=$5
𝐶𝑑=max(𝑆𝑑−𝐾,0)= max(90−105,0)=$0
Step 4: Calculate the option price using the risk-neutral valuation formula:
𝐶0=𝑒−𝑟𝑇[𝑝𝐶𝑢+(1−𝑝)𝐶𝑑]
=𝑒−0.04×0.25[0.5498×5+(1−0.5498)×0]
=0.9900×2.7490
=$2.72
Therefore, the price of the European call option using a one-step binomial model is $2.72.
QUESTION 10: PORTFOLIO PERFORMANCE ATTRIBUTION
An equity portfolio manager reported the following sector allocations and returns for the year,
along with the benchmark index data:
Sector
Portfolio Weight
Portfolio Return
Benchmark Weight
Benchmark Return
Technology
35%
12%
30%
10%
Healthcare
25%
8%
20%
7%
Financials
20%
6%
25%
5%
Consumer
15%
4%
15%
3%
Utilities
5%
2%
10%
1%

Perform a performance attribution analysis to determine the sources of the portfolio’s excess
return, breaking it down into allocation effect and selection effect.
Solution:
Step 1: Calculate the total portfolio and benchmark returns:
Portfolio return: (0.35 × 12%) + (0.25 × 8%) + (0.20 × 6%) + (0.15 × 4%) + (0.05 × 2%) = 8.50%
Benchmark return: (0.30 × 10%) + (0.20 × 7%) + (0.25 × 5%) + (0.15 × 3%) + (0.10 × 1%) =
6.40%
Excess return = 8.50% - 6.40% = 2.10%
Step 2: Calculate allocation effect for each sector: Allocation Effect = (Portfolio Weight -
Benchmark Weight) × (Benchmark Sector Return - Benchmark Total Return)
Technology: (35% - 30%) × (10% - 6.40%) = 0.18% Healthcare: (25% - 20%) × (7% - 6.40%) =
0.03% Financials: (20% - 25%) × (5% - 6.40%) = 0.07% Consumer: (15% - 15%) × (3% -
6.40%) = 0.00% Utilities: (5% - 10%) × (1% - 6.40%) = 0.27%
Total Allocation Effect = 0.18% + 0.03% + 0.07% + 0.00% + 0.27% = 0.55%
Step 3: Calculate selection effect for each sector: Selection Effect = Benchmark Weight ×
(Portfolio Sector Return - Benchmark Sector Return)
Technology: 30% × (12% - 10%) = 0.60% Healthcare: 20% × (8% - 7%) = 0.20% Financials:
25% × (6% - 5%) = 0.25% Consumer: 15% × (4% - 3%) = 0.15% Utilities: 10% × (2% - 1%) =
0.10%
Total Selection Effect = 0.60% + 0.20% + 0.25% + 0.15% + 0.10% = 1.30%
Step 4: Calculate interaction effect (optional): Interaction Effect = (Portfolio Weight - Benchmark
Weight) × (Portfolio Sector Return - Benchmark Sector Return)
Technology: (35% - 30%) × (12% - 10%) = 0.10% Healthcare: (25% - 20%) × (8% - 7%) =
0.05% Financials: (20% - 25%) × (6% - 5%) = -0.05% Consumer: (15% - 15%) × (4% - 3%) =
0.00% Utilities: (5% - 10%) × (2% - 1%) = -0.05%
Total Interaction Effect = 0.10% + 0.05% - 0.05% + 0.00% - 0.05% = 0.05%
Step 5: Summarize the attribution analysis:
Excess Return = 2.10% Allocation Effect = 0.55% Selection Effect = 1.30% Interaction Effect =
0.05% Total Attribution = 0.55% + 1.30% + 0.05% = 1.90%
The difference between the excess return (2.10%) and the total attribution (1.90%) is due to
rounding effects.
In conclusion, the portfolio’s outperformance can be attributed to: 1. Allocation Effect: 0.55%
(26.2% of excess return) 2. Selection Effect: 1.30% (61.9% of excess return) 3. Interaction
Effect: 0.05% (2.4% of excess return)
The selection effect was the primary driver of the portfolio’s excess return, indicating that the
manager’s stock selection within sectors contributed most to the outperformance.
A stock has a beta of 1.2, the risk-free rate is 3%, and the expected market return is 10%.
Calculate the expected return of the stock using the CAPM.
Solution:
Step 1: Recall the CAPM formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝐸(𝑅𝑚)−𝑅𝑓)
Step 2: Substitute the given values:
𝑅𝑓=3% =0.03
𝛽𝑖= 1.2
𝐸(𝑅𝑚)=10%= 0.10
Step 3: Calculate the expected return:
𝐸(𝑅𝑖)=0.03+1.2(0.10−0.03)
=0.03+1.2(0.07)
=0.03+0.084
=0.114
Therefore, the expected return of the stock is 11.4%.
QUESTION 2: PORTFOLIO OPTIMIZATION
An investor is considering two stocks, A and B, with the following characteristics:
Stock
Expected Return
Standard Deviation
A
12%
20%
B
8%
15%
The correlation coefficient between the two stocks is 0.3. Find the optimal portfolio weights that
minimize the portfolio risk.
Solution:
Step 1: Recall the formula for portfolio variance:
𝜎𝑝
2=𝑤𝐴
2𝜎𝐴
2+𝑤𝐵
2𝜎𝐵
2+2𝑤𝐴𝑤𝐵𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 2: To minimize risk, we need to find the weights that minimize the portfolio variance. The
formula for the optimal weight of stock A is:
𝑤𝐴=𝜎𝐵
2−𝜌𝐴𝐵𝜎𝐴𝜎𝐵
𝜎𝐴
2+𝜎𝐵
2−2𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 3: Substitute the given values:
𝜎𝐴=20%= 0.20
𝜎𝐵=15% =0.15
𝜌𝐴𝐵 = 0.3
Step 4: Calculate the optimal weight of stock A:
𝑤𝐴=0.152−0.3(0.20)(0.15)
0.202+0.152−2(0.3)(0.20)(0.15)
=0.0225−0.009
0.04+0.0225−0.018
=0.0135
0.0445
≈0.3034
Step 5: Calculate the weight of stock B:
𝑤𝐵= 1−𝑤𝐴=1−0.3034 =0.6966
Therefore, the optimal portfolio weights to minimize risk are approximately 30.34% in stock A
and 69.66% in stock B.
QUESTION 3: DURATION AND CONVEXITY
A 5-year bond with a face value of $1,000 and a 6% annual coupon rate is currently priced at
$1,050. The yield to maturity is 5%. Calculate the bond’s duration and convexity.
Solution:
Step 1: Calculate the bond’s cash flows and present values:
Year
Cash Flow
PV Factor
Present Value
1
$60
0.9524
$57.14
2
$60
0.9070
$54.42
3
$60
0.8638
$51.83
4
$60
0.8227
$49.36
5
$1,060
0.7835
$830.51
Step 2: Calculate the Macaulay Duration:
𝐷 =1×57.14+2×54.42+3×51.83+4×49.36+5×830.51
1050 =4.52
Step 3: Calculate the Modified Duration:
𝑀𝐷 =𝐷
1+𝑦 =4.52
1.05= 4.30
Step 4: Calculate the Convexity:
𝐶 = 1
𝑃(1+𝑦)2∑𝑡(𝑡+1)𝐶𝐹𝑡
(1+𝑦)𝑡
𝑛
𝑡=1
𝐶 = 1
1050(1.05)2(2×57.14+6×54.42+12×51.83+20×49.36+30×830.51)=22.89
Therefore, the bond’s duration is 4.52 years (Macaulay) or 4.30 years (Modified), and its
convexity is 22.89.
QUESTION 4: BLACK-SCHOLES OPTION PRICING MODEL
Using the Black-Scholes model, calculate the price of a European call option with the following
parameters: - Current stock price (S) = $50 - Strike price (K) = $52 - Time to expiration (T) = 6
months (0.5 years) - Risk-free rate (r) = 5% per annum - Stock volatility (σ) = 30% per annum
Solution:
Step 1: Recall the Black-Scholes formula for a call option:
𝐶 =𝑆𝑁(𝑑1)−𝐾𝑒−𝑟𝑇𝑁(𝑑2)
Where:
𝑑1=ln(𝑆/𝐾)+(𝑟+𝜎2/2)𝑇
𝜎√𝑇
𝑑2=𝑑1−𝜎√𝑇
Step 2: Calculate d1 and d2:
𝑑1=ln(50/52)+(0.05+0.32/2)(0.5)
0.3√0.5
=−0.0392+0.0475
0.2121 =0.0391
𝑑2=0.0391−0.3√0.5= −0.1730
Step 3: Find N(d1) and N(d2) using a standard normal distribution table or calculator:
𝑁(𝑑1)=𝑁(0.0391)=0.5156
𝑁(𝑑2)=𝑁(−0.1730)= 0.4313
Step 4: Calculate the option price:
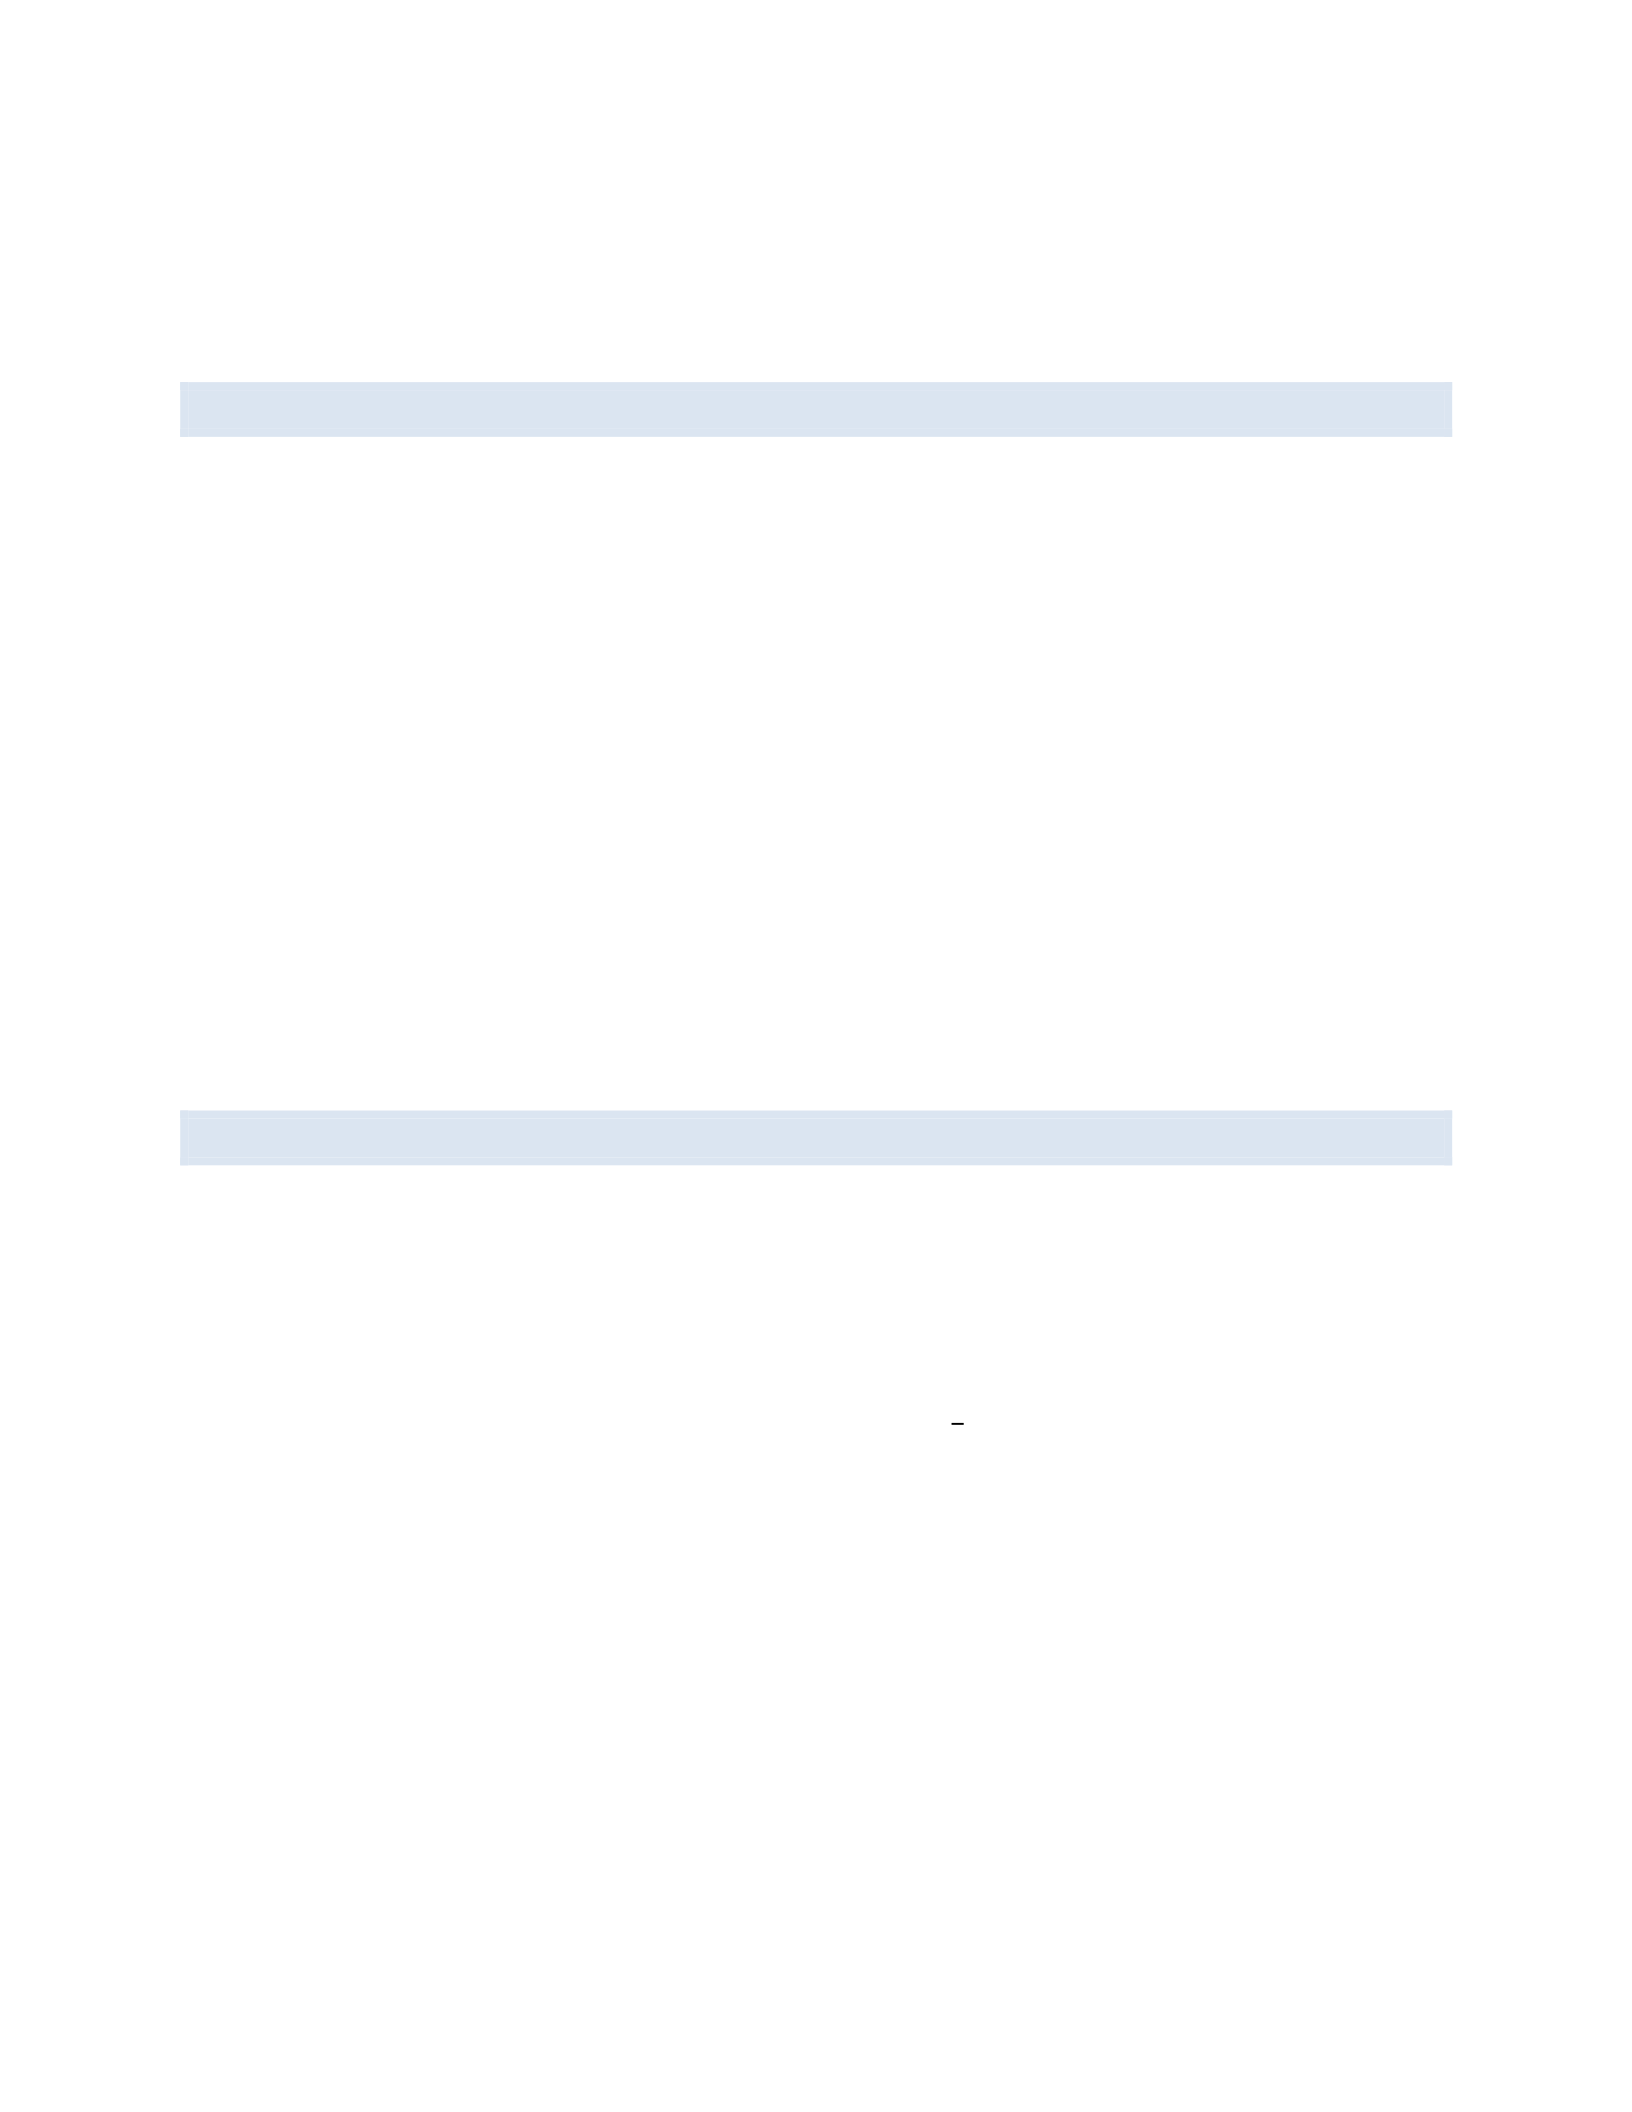
𝐶 =50×0.5156−52𝑒−0.05×0.5 ×0.4313
=25.78−22.17
=3.61
Therefore, the price of the European call option is $3.61.
QUESTION 5: ARBITRAGE PRICING THEORY (APT)
Consider a three-factor APT model with the following information: - Risk-free rate: 3% - Factor
risk premiums: λ1 = 4%, λ2 = 3%, λ3 = 2% - Stock A has factor sensitivities: β1 = 1.2, β2 = 0.8,
β3 = -0.5
Calculate the expected return of Stock A according to the APT model.
Solution:
Step 1: Recall the APT formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖1𝜆1+𝛽𝑖2𝜆2+𝛽𝑖3𝜆3
Step 2: Substitute the given values:
𝐸(𝑅𝐴)= 0.03+1.2(0.04)+0.8(0.03)+(−0.5)(0.02)
=0.03+0.048+0.024−0.01
=0.092
Therefore, the expected return of Stock A according to the APT model is 9.2%.
QUESTION 6: VALUE AT RISK (VAR)
A portfolio has a current value of $10 million and a daily volatility of 1.5%. Assuming normally
distributed returns, calculate the 1-day 99% VaR for this portfolio.
Solution:
Step 1: Recall the VaR formula for normally distributed returns:
𝑉𝑎𝑅 =𝑃×𝜎×𝑍𝛼×√𝑡
Where: - P is the portfolio value - σ is the daily volatility - Zα is the Z-score for the desired
confidence level - t is the time horizon in days
Step 2: Identify the given values:
𝑃 =$10,000,000
𝜎 =1.5% =0.015
𝑍99%= 2.33(𝑓𝑟𝑜𝑚𝑠𝑡𝑎𝑛𝑑𝑎𝑟𝑑𝑛𝑜𝑟𝑚𝑎𝑙𝑑𝑖𝑠𝑡𝑟𝑖𝑏𝑢𝑡𝑖𝑜𝑛𝑡𝑎𝑏𝑙𝑒)
𝑡 =1 day
Step 3: Calculate the VaR:
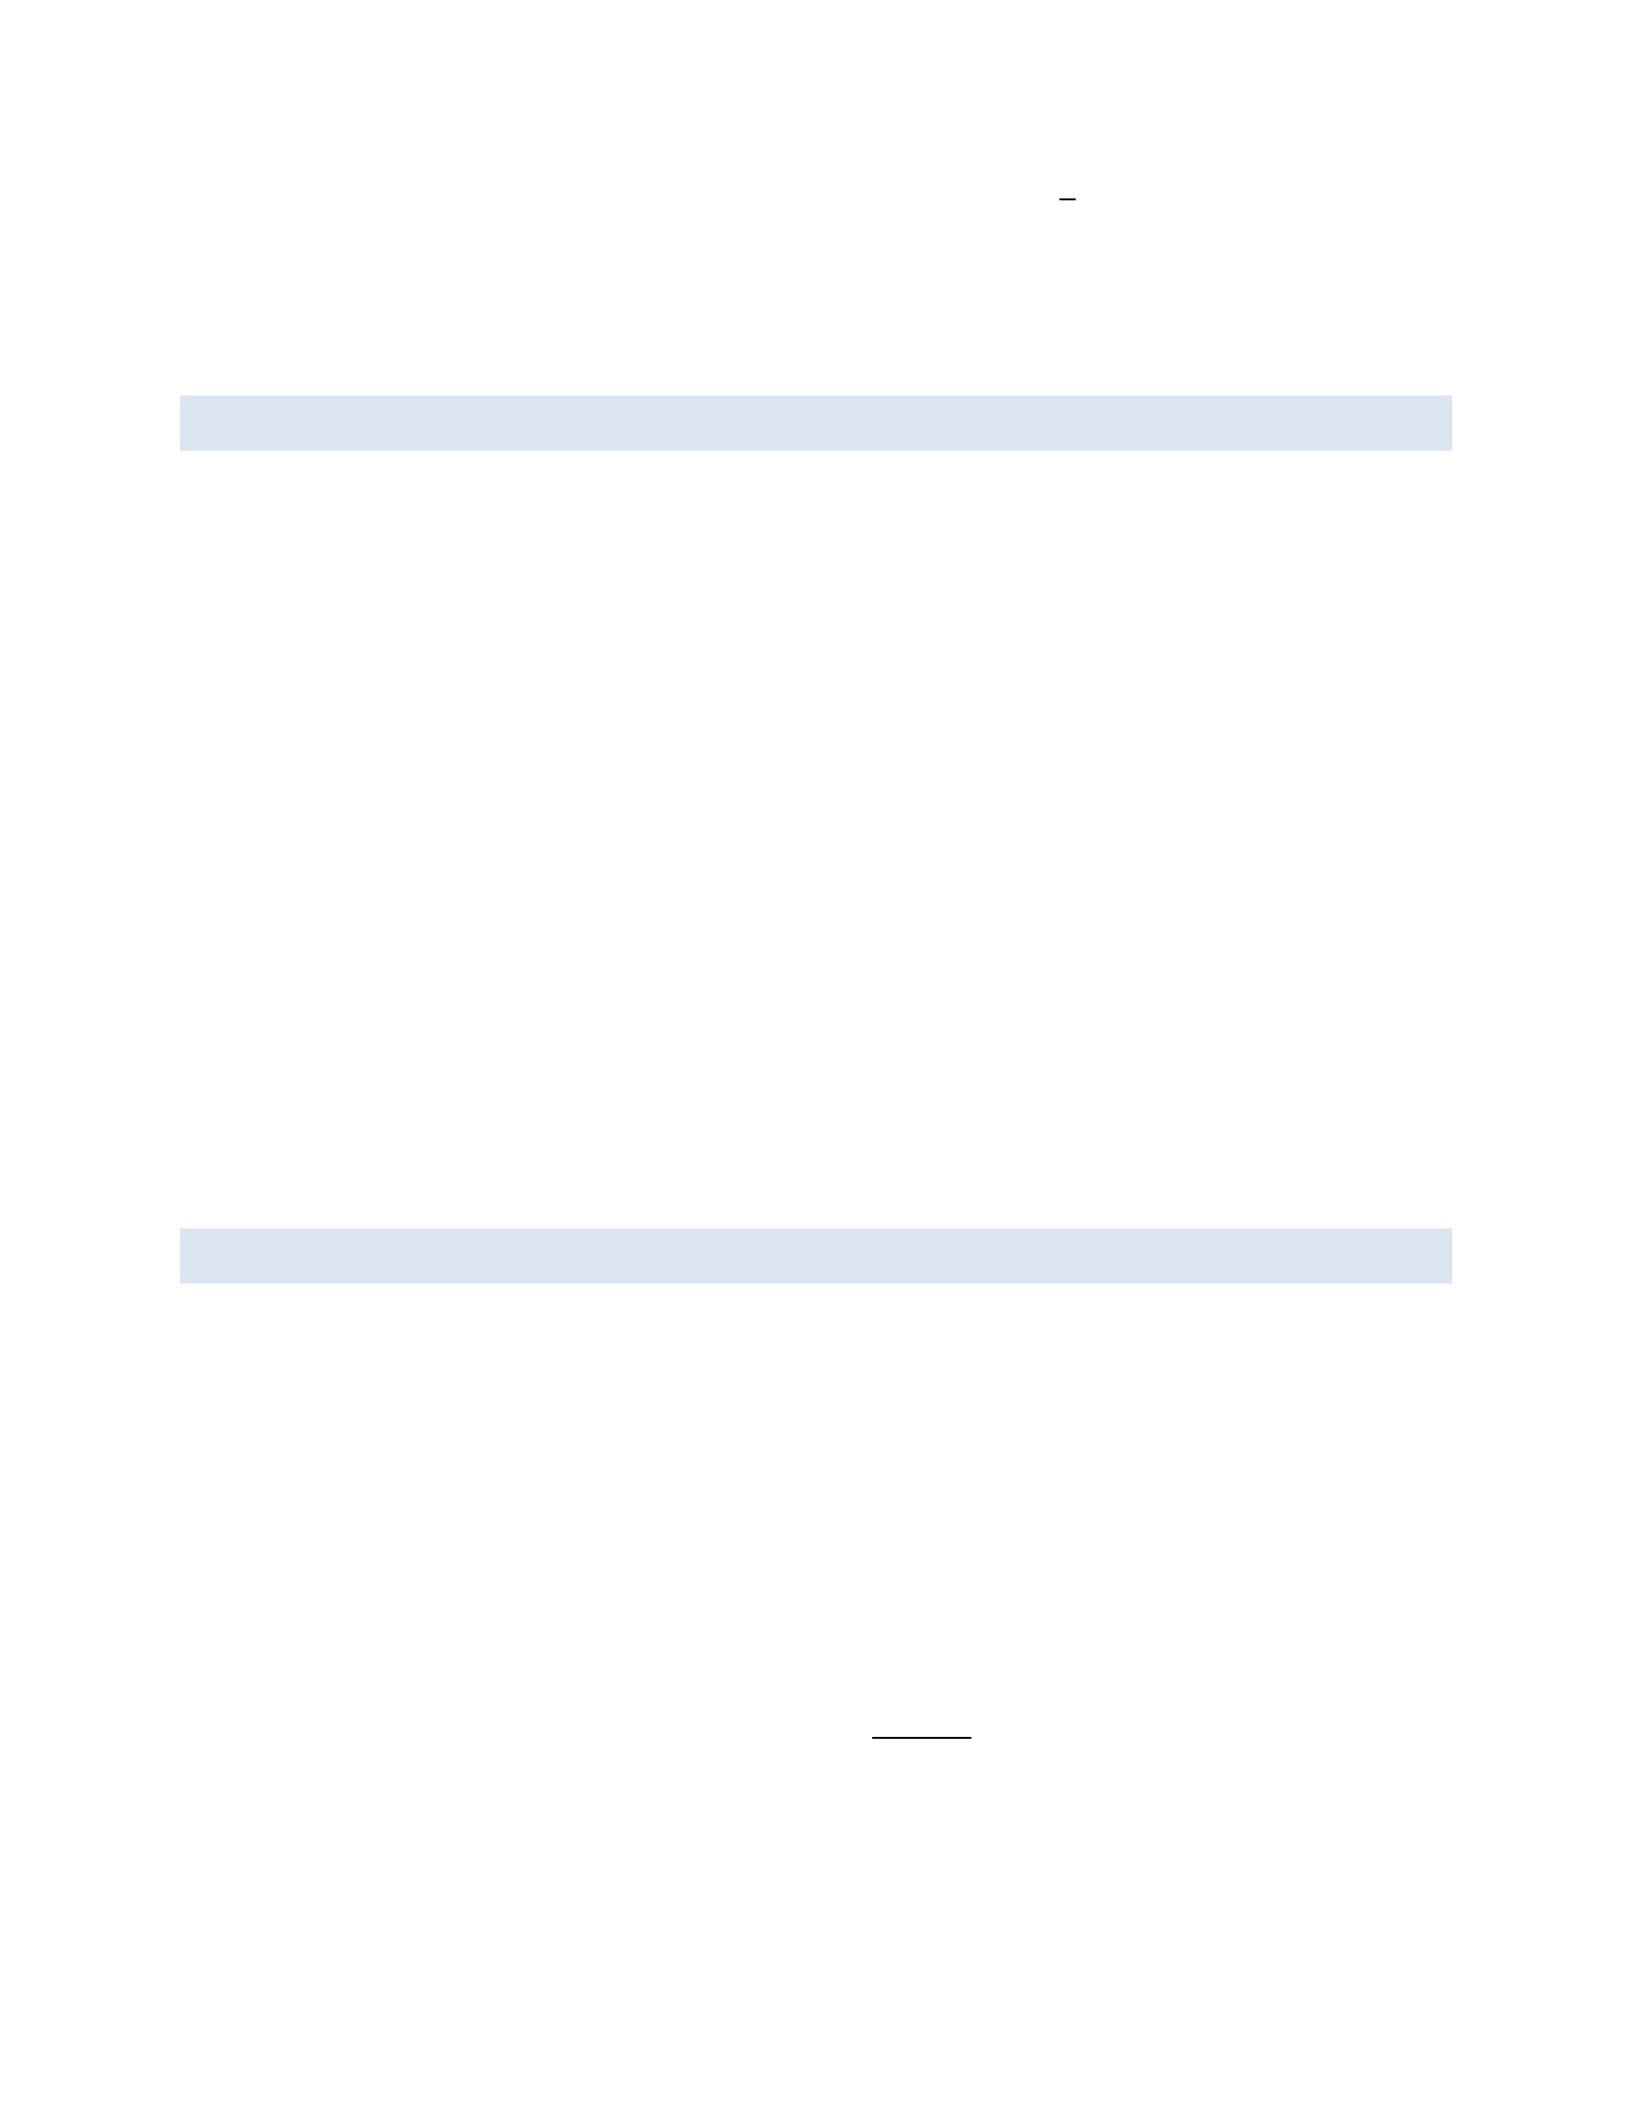
𝑉𝑎𝑅 =10,000,000×0.015×2.33×√1
=349,500
Therefore, the 1-day 99% VaR for this portfolio is $349,500. This means there is a 1% chance
that the portfolio will lose more than $349,500 in one day.
QUESTION 7: FAMA-FRENCH THREE-FACTOR MODEL
A stock has the following factor exposures: - Market factor (MKT) beta: 1.2 - Size factor (SMB)
beta: 0.5 - Value factor (HML) beta: -0.3
The risk-free rate is 2%, and the factor risk premiums are: - Market risk premium: 6% - SMB
premium: 3% - HML premium: 4%
Calculate the expected return of the stock using the Fama-French Three-Factor Model.
Solution:
Step 1: Recall the Fama-French Three-Factor Model formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝑅𝑚−𝑅𝑓)+𝑠𝑖(𝑆𝑀𝐵)+ℎ𝑖(𝐻𝑀𝐿)
Step 2: Substitute the given values:
𝐸(𝑅𝑖)=0.02+1.2(0.06)+0.5(0.03)+(−0.3)(0.04)
=0.02+0.072+0.015−0.012
=0.095
Therefore, the expected return of the stock according to the Fama-French Three-Factor Model
is 9.5%.
QUESTION 8: SHARPE RATIO AND INFORMATION RATIO
A portfolio manager achieved an average annual return of 12% over the past 5 years, with a
standard deviation of 18%. The risk-free rate during this period was 3%, and the benchmark
index returned 9% with a standard deviation of 15%. Calculate:
a) The Sharpe ratio of the portfolio b) The Information ratio of the portfolio
Solution:
a) Sharpe Ratio
Step 1: Recall the Sharpe ratio formula:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑓
𝜎𝑝
Step 2: Substitute the given values:
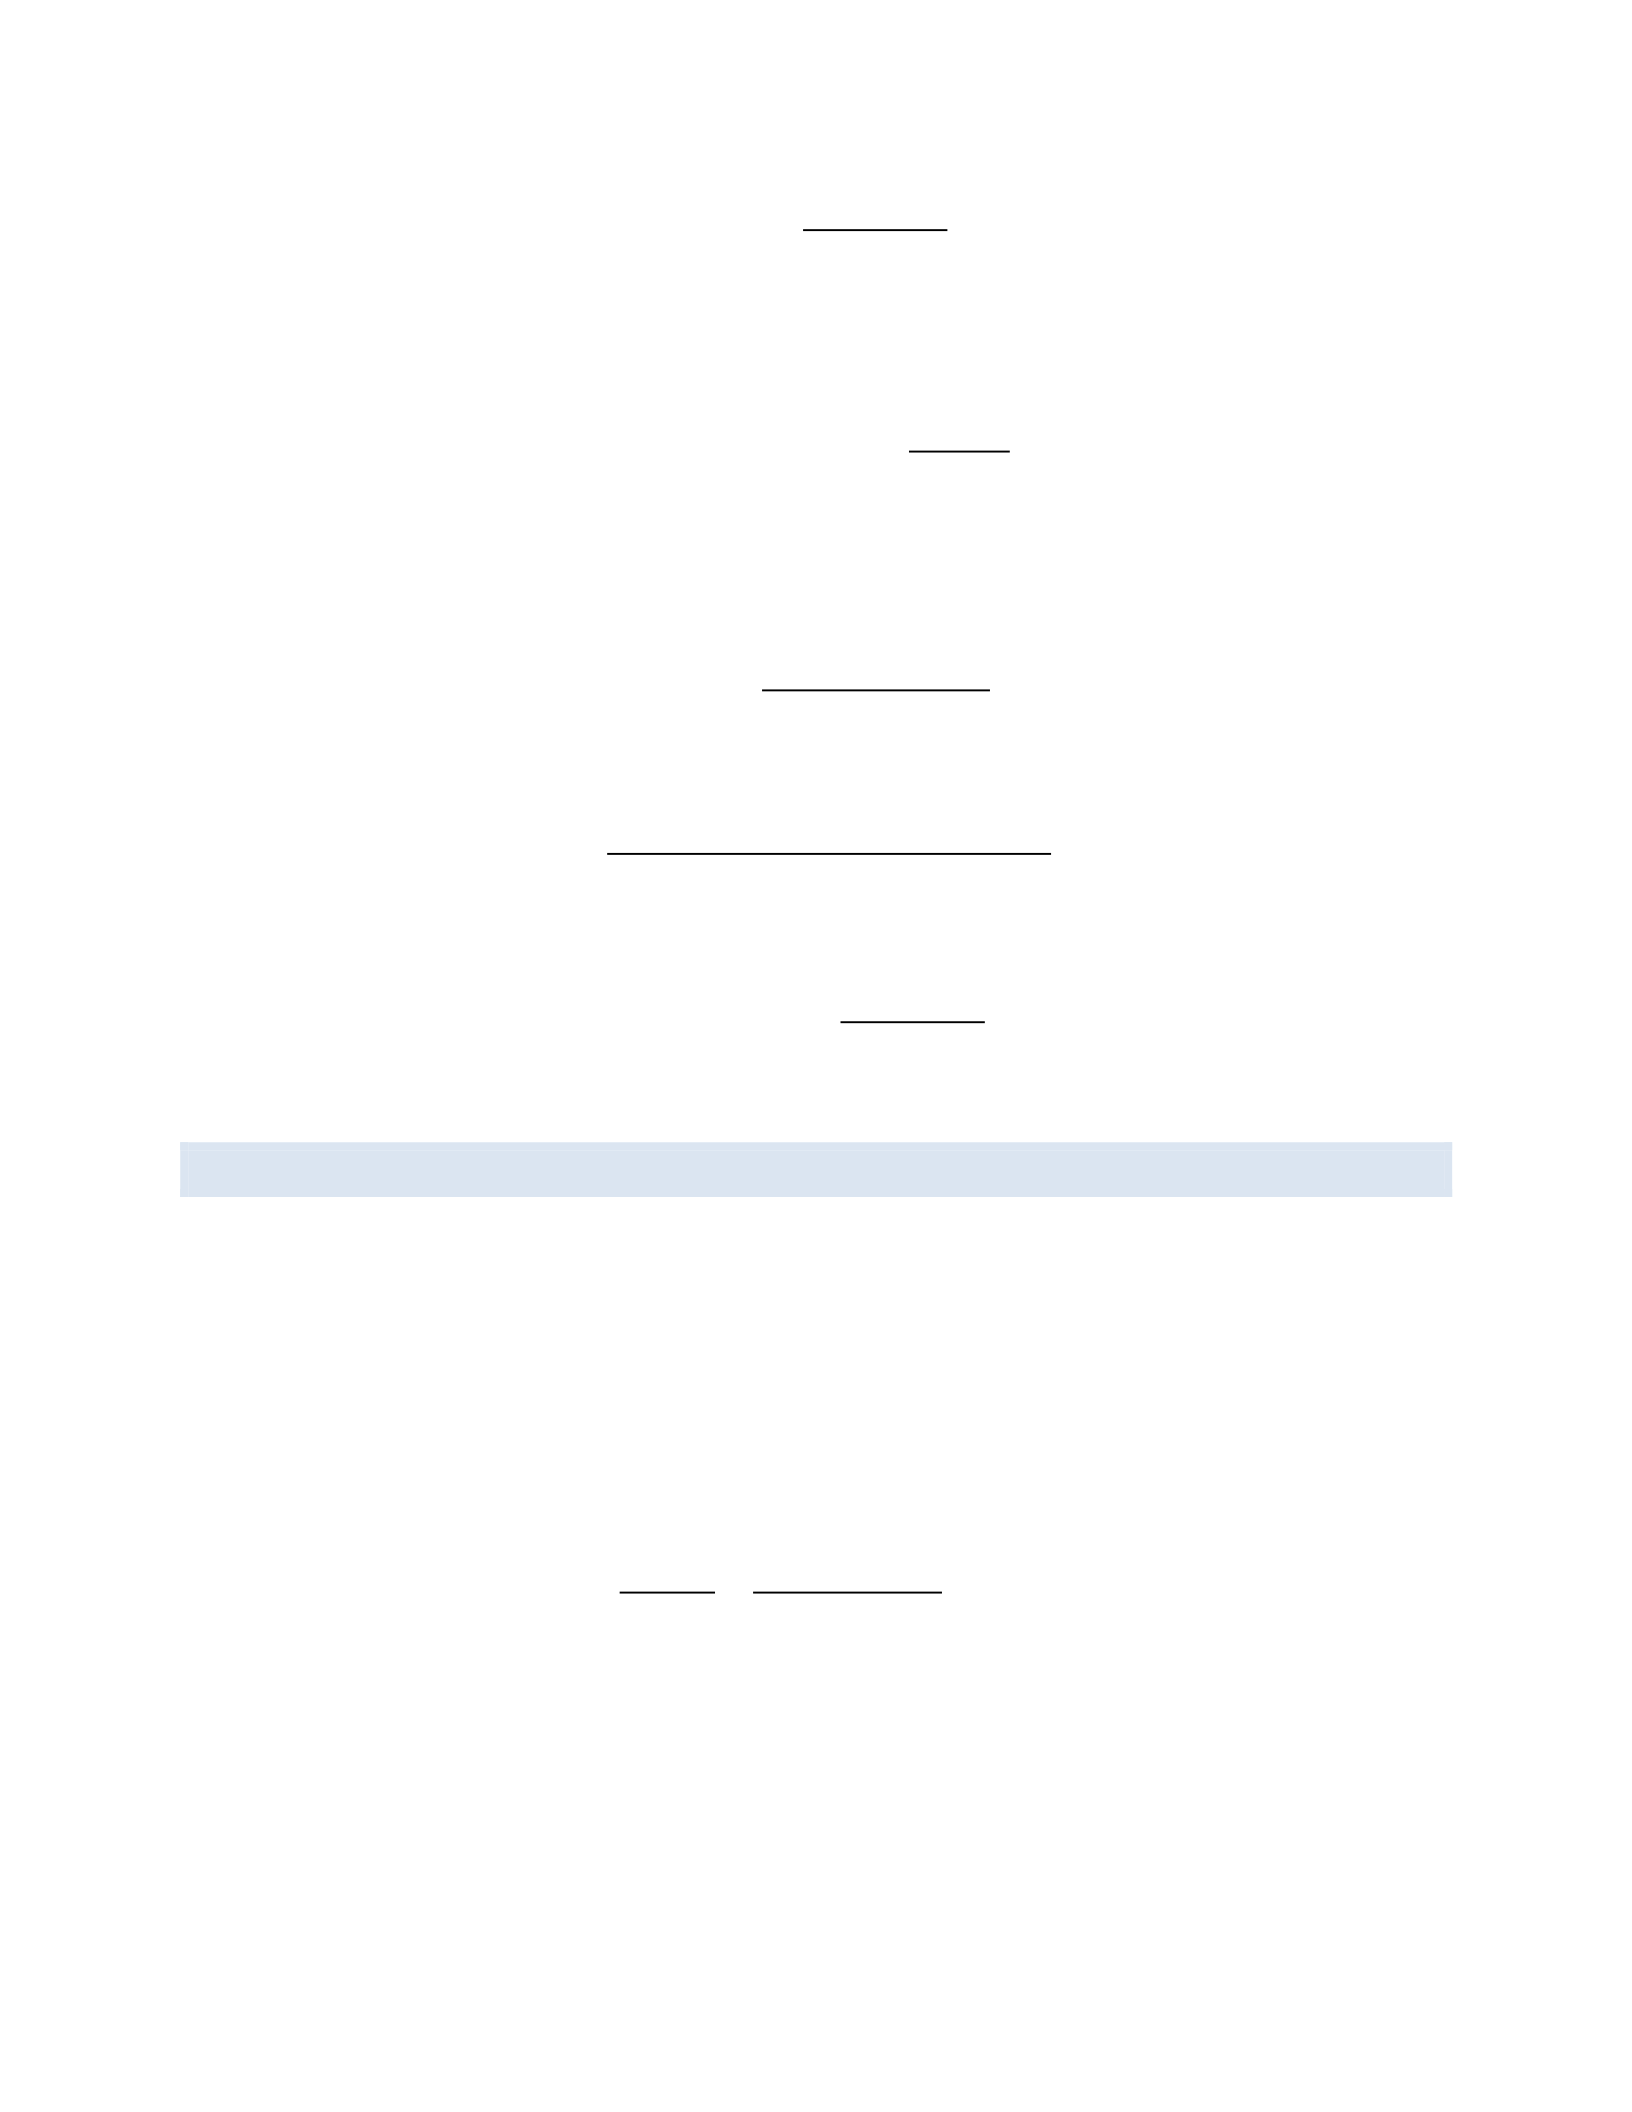
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 0.12−0.03
0.18 =0.50
b) Information Ratio
Step 1: Recall the Information ratio formula:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑏
𝜎𝑝−𝑏
Where σp-b is the standard deviation of the difference between portfolio returns and benchmark
returns (tracking error).
Step 2: Calculate the tracking error:
𝜎𝑝−𝑏 =√𝜎𝑝
2+𝜎𝑏
2−2𝜌𝜎𝑝𝜎𝑏
Assuming a correlation of 0.8 between the portfolio and benchmark:
𝜎𝑝−𝑏 =√0.182+0.152−2(0.8)(0.18)(0.15)=0.11
Step 3: Calculate the Information ratio:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 =0.12−0.09
0.11 =0.27
Therefore, the Sharpe ratio of the portfolio is 0.50, and the Information ratio is 0.27.
QUESTION 9: BINOMIAL OPTION PRICING MODEL (CONTINUED)
Consider a European call option with the following characteristics: - Current stock price (S0) =
$100 - Strike price (K) = $105 - Time to expiration (T) = 3 months (0.25 years) - Risk-free rate (r)
= 4% per annum - Up factor (u) = 1.1 - Down factor (d) = 0.9
Using a one-step binomial model, calculate the price of this call option.
Solution:
Step 1: Calculate the risk-neutral probability (p):
𝑝 = 𝑒𝑟𝑇 −𝑑
𝑢−𝑑 =𝑒0.04×0.25 −0.9
1.1−0.9 =0.5498
Step 2: Calculate the possible stock prices at expiration:
𝑆𝑢= 𝑆0×𝑢 = 100×1.1= $110
𝑆𝑑= 𝑆0×𝑑 = 100×0.9= $90
Step 3: Calculate the option payoffs at expiration:
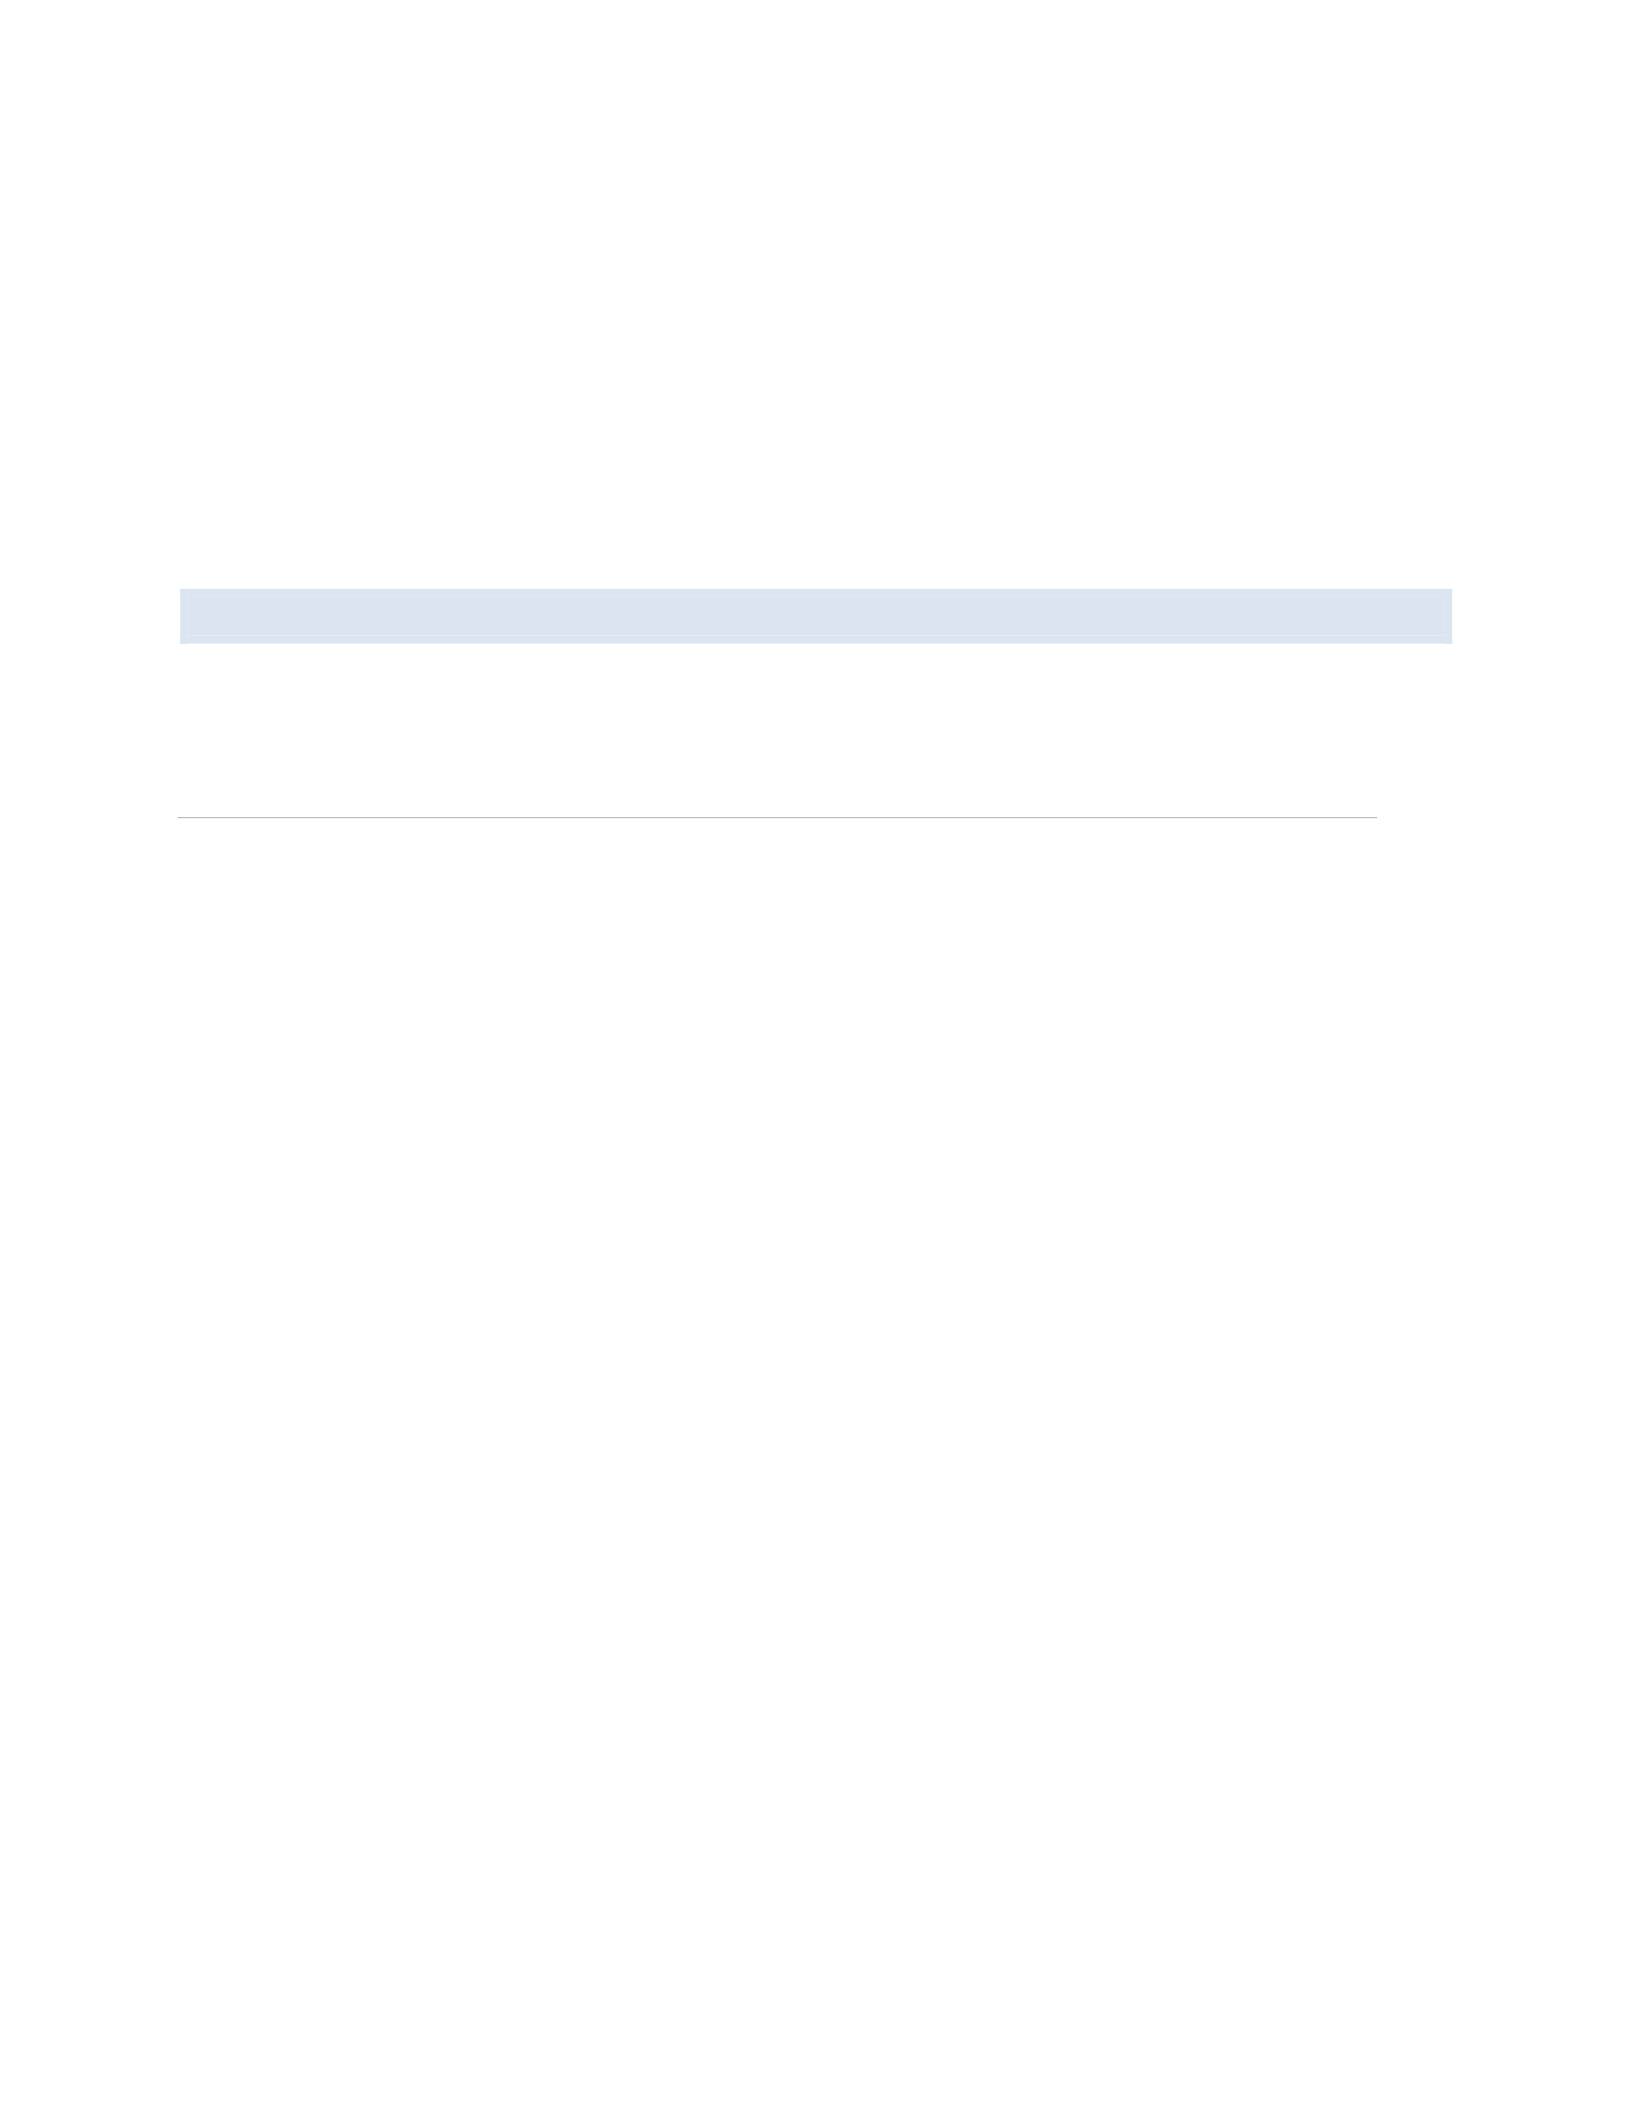
𝐶𝑢=max(𝑆𝑢−𝐾,0)=max(110−105,0)=$5
𝐶𝑑=max(𝑆𝑑−𝐾,0)= max(90−105,0)=$0
Step 4: Calculate the option price using the risk-neutral valuation formula:
𝐶0=𝑒−𝑟𝑇[𝑝𝐶𝑢+(1−𝑝)𝐶𝑑]
=𝑒−0.04×0.25[0.5498×5+(1−0.5498)×0]
=0.9900×2.7490
=$2.72
Therefore, the price of the European call option using a one-step binomial model is $2.72.
QUESTION 10: PORTFOLIO PERFORMANCE ATTRIBUTION
An equity portfolio manager reported the following sector allocations and returns for the year,
along with the benchmark index data:
Sector
Portfolio Weight
Portfolio Return
Benchmark Weight
Benchmark Return
Technology
35%
12%
30%
10%
Healthcare
25%
8%
20%
7%
Financials
20%
6%
25%
5%
Consumer
15%
4%
15%
3%
Utilities
5%
2%
10%
1%
Perform a performance attribution analysis to determine the sources of the portfolio’s excess
return, breaking it down into allocation effect and selection effect.
Solution:
Step 1: Calculate the total portfolio and benchmark returns:
Portfolio return: (0.35 × 12%) + (0.25 × 8%) + (0.20 × 6%) + (0.15 × 4%) + (0.05 × 2%) = 8.50%
Benchmark return: (0.30 × 10%) + (0.20 × 7%) + (0.25 × 5%) + (0.15 × 3%) + (0.10 × 1%) =
6.40%
Excess return = 8.50% - 6.40% = 2.10%
Step 2: Calculate allocation effect for each sector: Allocation Effect = (Portfolio Weight -
Benchmark Weight) × (Benchmark Sector Return - Benchmark Total Return)
Technology: (35% - 30%) × (10% - 6.40%) = 0.18% Healthcare: (25% - 20%) × (7% - 6.40%) =
0.03% Financials: (20% - 25%) × (5% - 6.40%) = 0.07% Consumer: (15% - 15%) × (3% -
6.40%) = 0.00% Utilities: (5% - 10%) × (1% - 6.40%) = 0.27%
Total Allocation Effect = 0.18% + 0.03% + 0.07% + 0.00% + 0.27% = 0.55%
Step 3: Calculate selection effect for each sector: Selection Effect = Benchmark Weight ×
(Portfolio Sector Return - Benchmark Sector Return)

Technology: 30% × (12% - 10%) = 0.60% Healthcare: 20% × (8% - 7%) = 0.20% Financials:
25% × (6% - 5%) = 0.25% Consumer: 15% × (4% - 3%) = 0.15% Utilities: 10% × (2% - 1%) =
0.10%
Total Selection Effect = 0.60% + 0.20% + 0.25% + 0.15% + 0.10% = 1.30%
Step 4: Calculate interaction effect (optional): Interaction Effect = (Portfolio Weight - Benchmark
Weight) × (Portfolio Sector Return - Benchmark Sector Return)
Technology: (35% - 30%) × (12% - 10%) = 0.10% Healthcare: (25% - 20%) × (8% - 7%) =
0.05% Financials: (20% - 25%) × (6% - 5%) = -0.05% Consumer: (15% - 15%) × (4% - 3%) =
0.00% Utilities: (5% - 10%) × (2% - 1%) = -0.05%
Total Interaction Effect = 0.10% + 0.05% - 0.05% + 0.00% - 0.05% = 0.05%
Step 5: Summarize the attribution analysis:
Excess Return = 2.10% Allocation Effect = 0.55% Selection Effect = 1.30% Interaction Effect =
0.05% Total Attribution = 0.55% + 1.30% + 0.05% = 1.90%
The difference between the excess return (2.10%) and the total attribution (1.90%) is due to
rounding effects.
In conclusion, the portfolio’s outperformance can be attributed to: 1. Allocation Effect: 0.55%
(26.2% of excess return) 2. Selection Effect: 1.30% (61.9% of excess return) 3. Interaction
Effect: 0.05% (2.4% of excess return)
The selection effect was the primary driver of the portfolio’s excess return, indicating that the
manager’s stock selection within sectors contributed most to the outperformance.
A stock has a beta of 1.2, the risk-free rate is 3%, and the expected market return is 10%.
Calculate the expected return of the stock using the CAPM.
Solution:
Step 1: Recall the CAPM formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝐸(𝑅𝑚)−𝑅𝑓)
Step 2: Substitute the given values:
𝑅𝑓=3% =0.03
𝛽𝑖= 1.2
𝐸(𝑅𝑚)=10%= 0.10
Step 3: Calculate the expected return:
𝐸(𝑅𝑖)=0.03+1.2(0.10−0.03)
=0.03+1.2(0.07)
=0.03+0.084
=0.114
Therefore, the expected return of the stock is 11.4%.
QUESTION 2: PORTFOLIO OPTIMIZATION
An investor is considering two stocks, A and B, with the following characteristics:
Stock
Expected Return
Standard Deviation
A
12%
20%
B
8%
15%
The correlation coefficient between the two stocks is 0.3. Find the optimal portfolio weights that
minimize the portfolio risk.
Solution:
Step 1: Recall the formula for portfolio variance:
𝜎𝑝
2=𝑤𝐴
2𝜎𝐴
2+𝑤𝐵
2𝜎𝐵
2+2𝑤𝐴𝑤𝐵𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 2: To minimize risk, we need to find the weights that minimize the portfolio variance. The
formula for the optimal weight of stock A is:
𝑤𝐴=𝜎𝐵
2−𝜌𝐴𝐵𝜎𝐴𝜎𝐵
𝜎𝐴
2+𝜎𝐵
2−2𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 3: Substitute the given values:
𝜎𝐴=20%= 0.20
𝜎𝐵=15% =0.15
𝜌𝐴𝐵 = 0.3
Step 4: Calculate the optimal weight of stock A:
𝑤𝐴=0.152−0.3(0.20)(0.15)
0.202+0.152−2(0.3)(0.20)(0.15)
=0.0225−0.009
0.04+0.0225−0.018
=0.0135
0.0445
≈0.3034
Step 5: Calculate the weight of stock B:
𝑤𝐵= 1−𝑤𝐴=1−0.3034 =0.6966
Therefore, the optimal portfolio weights to minimize risk are approximately 30.34% in stock A
and 69.66% in stock B.
QUESTION 3: DURATION AND CONVEXITY
A 5-year bond with a face value of $1,000 and a 6% annual coupon rate is currently priced at
$1,050. The yield to maturity is 5%. Calculate the bond’s duration and convexity.
Solution:
Step 1: Calculate the bond’s cash flows and present values:
Year
Cash Flow
PV Factor
Present Value
1
$60
0.9524
$57.14
2
$60
0.9070
$54.42
3
$60
0.8638
$51.83
4
$60
0.8227
$49.36
5
$1,060
0.7835
$830.51
Step 2: Calculate the Macaulay Duration:
𝐷 =1×57.14+2×54.42+3×51.83+4×49.36+5×830.51
1050 =4.52
Step 3: Calculate the Modified Duration:
𝑀𝐷 =𝐷
1+𝑦 =4.52
1.05= 4.30
Step 4: Calculate the Convexity:
𝐶 = 1
𝑃(1+𝑦)2∑𝑡(𝑡+1)𝐶𝐹𝑡
(1+𝑦)𝑡
𝑛
𝑡=1
𝐶 = 1
1050(1.05)2(2×57.14+6×54.42+12×51.83+20×49.36+30×830.51)=22.89
Therefore, the bond’s duration is 4.52 years (Macaulay) or 4.30 years (Modified), and its
convexity is 22.89.
QUESTION 4: BLACK-SCHOLES OPTION PRICING MODEL
Using the Black-Scholes model, calculate the price of a European call option with the following
parameters: - Current stock price (S) = $50 - Strike price (K) = $52 - Time to expiration (T) = 6
months (0.5 years) - Risk-free rate (r) = 5% per annum - Stock volatility (σ) = 30% per annum
Solution:
Step 1: Recall the Black-Scholes formula for a call option:
𝐶 =𝑆𝑁(𝑑1)−𝐾𝑒−𝑟𝑇𝑁(𝑑2)
Where:
𝑑1=ln(𝑆/𝐾)+(𝑟+𝜎2/2)𝑇
𝜎√𝑇
𝑑2=𝑑1−𝜎√𝑇
Step 2: Calculate d1 and d2:
𝑑1=ln(50/52)+(0.05+0.32/2)(0.5)
0.3√0.5
=−0.0392+0.0475
0.2121 =0.0391
𝑑2=0.0391−0.3√0.5= −0.1730
Step 3: Find N(d1) and N(d2) using a standard normal distribution table or calculator:
𝑁(𝑑1)=𝑁(0.0391)=0.5156
𝑁(𝑑2)=𝑁(−0.1730)= 0.4313
Step 4: Calculate the option price:
𝐶 =50×0.5156−52𝑒−0.05×0.5 ×0.4313
=25.78−22.17
=3.61
Therefore, the price of the European call option is $3.61.
QUESTION 5: ARBITRAGE PRICING THEORY (APT)
Consider a three-factor APT model with the following information: - Risk-free rate: 3% - Factor
risk premiums: λ1 = 4%, λ2 = 3%, λ3 = 2% - Stock A has factor sensitivities: β1 = 1.2, β2 = 0.8,
β3 = -0.5
Calculate the expected return of Stock A according to the APT model.
Solution:
Step 1: Recall the APT formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖1𝜆1+𝛽𝑖2𝜆2+𝛽𝑖3𝜆3
Step 2: Substitute the given values:
𝐸(𝑅𝐴)= 0.03+1.2(0.04)+0.8(0.03)+(−0.5)(0.02)
=0.03+0.048+0.024−0.01
=0.092
Therefore, the expected return of Stock A according to the APT model is 9.2%.
QUESTION 6: VALUE AT RISK (VAR)
A portfolio has a current value of $10 million and a daily volatility of 1.5%. Assuming normally
distributed returns, calculate the 1-day 99% VaR for this portfolio.
Solution:
Step 1: Recall the VaR formula for normally distributed returns:
𝑉𝑎𝑅 =𝑃×𝜎×𝑍𝛼×√𝑡
Where: - P is the portfolio value - σ is the daily volatility - Zα is the Z-score for the desired
confidence level - t is the time horizon in days
Step 2: Identify the given values:
𝑃 =$10,000,000
𝜎 =1.5% =0.015
𝑍99%= 2.33(𝑓𝑟𝑜𝑚𝑠𝑡𝑎𝑛𝑑𝑎𝑟𝑑𝑛𝑜𝑟𝑚𝑎𝑙𝑑𝑖𝑠𝑡𝑟𝑖𝑏𝑢𝑡𝑖𝑜𝑛𝑡𝑎𝑏𝑙𝑒)
𝑡 =1 day
Step 3: Calculate the VaR:
𝑉𝑎𝑅 =10,000,000×0.015×2.33×√1
=349,500
Therefore, the 1-day 99% VaR for this portfolio is $349,500. This means there is a 1% chance
that the portfolio will lose more than $349,500 in one day.
QUESTION 7: FAMA-FRENCH THREE-FACTOR MODEL
A stock has the following factor exposures: - Market factor (MKT) beta: 1.2 - Size factor (SMB)
beta: 0.5 - Value factor (HML) beta: -0.3
The risk-free rate is 2%, and the factor risk premiums are: - Market risk premium: 6% - SMB
premium: 3% - HML premium: 4%
Calculate the expected return of the stock using the Fama-French Three-Factor Model.
Solution:
Step 1: Recall the Fama-French Three-Factor Model formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝑅𝑚−𝑅𝑓)+𝑠𝑖(𝑆𝑀𝐵)+ℎ𝑖(𝐻𝑀𝐿)
Step 2: Substitute the given values:
𝐸(𝑅𝑖)=0.02+1.2(0.06)+0.5(0.03)+(−0.3)(0.04)
=0.02+0.072+0.015−0.012
=0.095
Therefore, the expected return of the stock according to the Fama-French Three-Factor Model
is 9.5%.
QUESTION 8: SHARPE RATIO AND INFORMATION RATIO
A portfolio manager achieved an average annual return of 12% over the past 5 years, with a
standard deviation of 18%. The risk-free rate during this period was 3%, and the benchmark
index returned 9% with a standard deviation of 15%. Calculate:
a) The Sharpe ratio of the portfolio b) The Information ratio of the portfolio
Solution:
a) Sharpe Ratio
Step 1: Recall the Sharpe ratio formula:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑓
𝜎𝑝
Step 2: Substitute the given values:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 0.12−0.03
0.18 =0.50
b) Information Ratio
Step 1: Recall the Information ratio formula:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑏
𝜎𝑝−𝑏
Where σp-b is the standard deviation of the difference between portfolio returns and benchmark
returns (tracking error).
Step 2: Calculate the tracking error:
𝜎𝑝−𝑏 =√𝜎𝑝
2+𝜎𝑏
2−2𝜌𝜎𝑝𝜎𝑏
Assuming a correlation of 0.8 between the portfolio and benchmark:
𝜎𝑝−𝑏 =√0.182+0.152−2(0.8)(0.18)(0.15)=0.11
Step 3: Calculate the Information ratio:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 =0.12−0.09
0.11 =0.27
Therefore, the Sharpe ratio of the portfolio is 0.50, and the Information ratio is 0.27.
QUESTION 9: BINOMIAL OPTION PRICING MODEL (CONTINUED)
Consider a European call option with the following characteristics: - Current stock price (S0) =
$100 - Strike price (K) = $105 - Time to expiration (T) = 3 months (0.25 years) - Risk-free rate (r)
= 4% per annum - Up factor (u) = 1.1 - Down factor (d) = 0.9
Using a one-step binomial model, calculate the price of this call option.
Solution:
Step 1: Calculate the risk-neutral probability (p):
𝑝 = 𝑒𝑟𝑇 −𝑑
𝑢−𝑑 =𝑒0.04×0.25 −0.9
1.1−0.9 =0.5498
Step 2: Calculate the possible stock prices at expiration:
𝑆𝑢= 𝑆0×𝑢 = 100×1.1= $110
𝑆𝑑= 𝑆0×𝑑 = 100×0.9= $90
Step 3: Calculate the option payoffs at expiration:
𝐶𝑢=max(𝑆𝑢−𝐾,0)=max(110−105,0)=$5
𝐶𝑑=max(𝑆𝑑−𝐾,0)= max(90−105,0)=$0
Step 4: Calculate the option price using the risk-neutral valuation formula:
𝐶0=𝑒−𝑟𝑇[𝑝𝐶𝑢+(1−𝑝)𝐶𝑑]
=𝑒−0.04×0.25[0.5498×5+(1−0.5498)×0]
=0.9900×2.7490
=$2.72
Therefore, the price of the European call option using a one-step binomial model is $2.72.
QUESTION 10: PORTFOLIO PERFORMANCE ATTRIBUTION
An equity portfolio manager reported the following sector allocations and returns for the year,
along with the benchmark index data:
Sector
Portfolio Weight
Portfolio Return
Benchmark Weight
Benchmark Return
Technology
35%
12%
30%
10%
Healthcare
25%
8%
20%
7%
Financials
20%
6%
25%
5%
Consumer
15%
4%
15%
3%
Utilities
5%
2%
10%
1%
Perform a performance attribution analysis to determine the sources of the portfolio’s excess
return, breaking it down into allocation effect and selection effect.
Solution:

Step 1: Calculate the total portfolio and benchmark returns:
Portfolio return: (0.35 × 12%) + (0.25 × 8%) + (0.20 × 6%) + (0.15 × 4%) + (0.05 × 2%) = 8.50%
Benchmark return: (0.30 × 10%) + (0.20 × 7%) + (0.25 × 5%) + (0.15 × 3%) + (0.10 × 1%) =
6.40%
Excess return = 8.50% - 6.40% = 2.10%
Step 2: Calculate allocation effect for each sector: Allocation Effect = (Portfolio Weight -
Benchmark Weight) × (Benchmark Sector Return - Benchmark Total Return)
Technology: (35% - 30%) × (10% - 6.40%) = 0.18% Healthcare: (25% - 20%) × (7% - 6.40%) =
0.03% Financials: (20% - 25%) × (5% - 6.40%) = 0.07% Consumer: (15% - 15%) × (3% -
6.40%) = 0.00% Utilities: (5% - 10%) × (1% - 6.40%) = 0.27%
Total Allocation Effect = 0.18% + 0.03% + 0.07% + 0.00% + 0.27% = 0.55%
Step 3: Calculate selection effect for each sector: Selection Effect = Benchmark Weight ×
(Portfolio Sector Return - Benchmark Sector Return)
Technology: 30% × (12% - 10%) = 0.60% Healthcare: 20% × (8% - 7%) = 0.20% Financials:
25% × (6% - 5%) = 0.25% Consumer: 15% × (4% - 3%) = 0.15% Utilities: 10% × (2% - 1%) =
0.10%
Total Selection Effect = 0.60% + 0.20% + 0.25% + 0.15% + 0.10% = 1.30%
Step 4: Calculate interaction effect (optional): Interaction Effect = (Portfolio Weight - Benchmark
Weight) × (Portfolio Sector Return - Benchmark Sector Return)
Technology: (35% - 30%) × (12% - 10%) = 0.10% Healthcare: (25% - 20%) × (8% - 7%) =
0.05% Financials: (20% - 25%) × (6% - 5%) = -0.05% Consumer: (15% - 15%) × (4% - 3%) =
0.00% Utilities: (5% - 10%) × (2% - 1%) = -0.05%
Total Interaction Effect = 0.10% + 0.05% - 0.05% + 0.00% - 0.05% = 0.05%
Step 5: Summarize the attribution analysis:
Excess Return = 2.10% Allocation Effect = 0.55% Selection Effect = 1.30% Interaction Effect =
0.05% Total Attribution = 0.55% + 1.30% + 0.05% = 1.90%
The difference between the excess return (2.10%) and the total attribution (1.90%) is due to
rounding effects.
In conclusion, the portfolio’s outperformance can be attributed to: 1. Allocation Effect: 0.55%
(26.2% of excess return) 2. Selection Effect: 1.30% (61.9% of excess return) 3. Interaction
Effect: 0.05% (2.4% of excess return)
The selection effect was the primary driver of the portfolio’s excess return, indicating that the
manager’s stock selection within sectors contributed most to the outperformance.
A stock has a beta of 1.2, the risk-free rate is 3%, and the expected market return is 10%.
Calculate the expected return of the stock using the CAPM.
Solution:
Step 1: Recall the CAPM formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝐸(𝑅𝑚)−𝑅𝑓)
Step 2: Substitute the given values:
𝑅𝑓=3% =0.03
𝛽𝑖= 1.2
𝐸(𝑅𝑚)=10%= 0.10
Step 3: Calculate the expected return:
𝐸(𝑅𝑖)=0.03+1.2(0.10−0.03)
=0.03+1.2(0.07)
=0.03+0.084
=0.114
Therefore, the expected return of the stock is 11.4%.
QUESTION 2: PORTFOLIO OPTIMIZATION
An investor is considering two stocks, A and B, with the following characteristics:
Stock
Expected Return
Standard Deviation
A
12%
20%
B
8%
15%
The correlation coefficient between the two stocks is 0.3. Find the optimal portfolio weights that
minimize the portfolio risk.
Solution:
Step 1: Recall the formula for portfolio variance:
𝜎𝑝
2=𝑤𝐴
2𝜎𝐴
2+𝑤𝐵
2𝜎𝐵
2+2𝑤𝐴𝑤𝐵𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 2: To minimize risk, we need to find the weights that minimize the portfolio variance. The
formula for the optimal weight of stock A is:
𝑤𝐴=𝜎𝐵
2−𝜌𝐴𝐵𝜎𝐴𝜎𝐵
𝜎𝐴
2+𝜎𝐵
2−2𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 3: Substitute the given values:
𝜎𝐴=20%= 0.20
𝜎𝐵=15% =0.15
𝜌𝐴𝐵 = 0.3
Step 4: Calculate the optimal weight of stock A:
𝑤𝐴=0.152−0.3(0.20)(0.15)
0.202+0.152−2(0.3)(0.20)(0.15)
=0.0225−0.009
0.04+0.0225−0.018
=0.0135
0.0445
≈0.3034
Step 5: Calculate the weight of stock B:
𝑤𝐵= 1−𝑤𝐴=1−0.3034 =0.6966
Therefore, the optimal portfolio weights to minimize risk are approximately 30.34% in stock A
and 69.66% in stock B.
QUESTION 3: DURATION AND CONVEXITY
A 5-year bond with a face value of $1,000 and a 6% annual coupon rate is currently priced at
$1,050. The yield to maturity is 5%. Calculate the bond’s duration and convexity.
Solution:
Step 1: Calculate the bond’s cash flows and present values:
Year
Cash Flow
PV Factor
Present Value
1
$60
0.9524
$57.14
2
$60
0.9070
$54.42
3
$60
0.8638
$51.83
4
$60
0.8227
$49.36
5
$1,060
0.7835
$830.51
Step 2: Calculate the Macaulay Duration:
𝐷 =1×57.14+2×54.42+3×51.83+4×49.36+5×830.51
1050 =4.52
Step 3: Calculate the Modified Duration:
𝑀𝐷 =𝐷
1+𝑦 =4.52
1.05= 4.30
Step 4: Calculate the Convexity:
𝐶 = 1
𝑃(1+𝑦)2∑𝑡(𝑡+1)𝐶𝐹𝑡
(1+𝑦)𝑡
𝑛
𝑡=1
𝐶 = 1
1050(1.05)2(2×57.14+6×54.42+12×51.83+20×49.36+30×830.51)=22.89
Therefore, the bond’s duration is 4.52 years (Macaulay) or 4.30 years (Modified), and its
convexity is 22.89.
QUESTION 4: BLACK-SCHOLES OPTION PRICING MODEL
Using the Black-Scholes model, calculate the price of a European call option with the following
parameters: - Current stock price (S) = $50 - Strike price (K) = $52 - Time to expiration (T) = 6
months (0.5 years) - Risk-free rate (r) = 5% per annum - Stock volatility (σ) = 30% per annum
Solution:
Step 1: Recall the Black-Scholes formula for a call option:
𝐶 =𝑆𝑁(𝑑1)−𝐾𝑒−𝑟𝑇𝑁(𝑑2)
Where:
𝑑1=ln(𝑆/𝐾)+(𝑟+𝜎2/2)𝑇
𝜎√𝑇
𝑑2=𝑑1−𝜎√𝑇
Step 2: Calculate d1 and d2:
𝑑1=ln(50/52)+(0.05+0.32/2)(0.5)
0.3√0.5
=−0.0392+0.0475
0.2121 =0.0391
𝑑2=0.0391−0.3√0.5= −0.1730
Step 3: Find N(d1) and N(d2) using a standard normal distribution table or calculator:
𝑁(𝑑1)=𝑁(0.0391)=0.5156
𝑁(𝑑2)=𝑁(−0.1730)= 0.4313
Step 4: Calculate the option price:
𝐶 =50×0.5156−52𝑒−0.05×0.5 ×0.4313
=25.78−22.17
=3.61
Therefore, the price of the European call option is $3.61.
QUESTION 5: ARBITRAGE PRICING THEORY (APT)
Consider a three-factor APT model with the following information: - Risk-free rate: 3% - Factor
risk premiums: λ1 = 4%, λ2 = 3%, λ3 = 2% - Stock A has factor sensitivities: β1 = 1.2, β2 = 0.8,
β3 = -0.5
Calculate the expected return of Stock A according to the APT model.
Solution:
Step 1: Recall the APT formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖1𝜆1+𝛽𝑖2𝜆2+𝛽𝑖3𝜆3
Step 2: Substitute the given values:
𝐸(𝑅𝐴)= 0.03+1.2(0.04)+0.8(0.03)+(−0.5)(0.02)
=0.03+0.048+0.024−0.01
=0.092
Therefore, the expected return of Stock A according to the APT model is 9.2%.
QUESTION 6: VALUE AT RISK (VAR)
A portfolio has a current value of $10 million and a daily volatility of 1.5%. Assuming normally
distributed returns, calculate the 1-day 99% VaR for this portfolio.
Solution:
Step 1: Recall the VaR formula for normally distributed returns:
𝑉𝑎𝑅 =𝑃×𝜎×𝑍𝛼×√𝑡
Where: - P is the portfolio value - σ is the daily volatility - Zα is the Z-score for the desired
confidence level - t is the time horizon in days
Step 2: Identify the given values:
𝑃 =$10,000,000
𝜎 =1.5% =0.015
𝑍99%= 2.33(𝑓𝑟𝑜𝑚𝑠𝑡𝑎𝑛𝑑𝑎𝑟𝑑𝑛𝑜𝑟𝑚𝑎𝑙𝑑𝑖𝑠𝑡𝑟𝑖𝑏𝑢𝑡𝑖𝑜𝑛𝑡𝑎𝑏𝑙𝑒)
𝑡 =1 day
Step 3: Calculate the VaR:
𝑉𝑎𝑅 =10,000,000×0.015×2.33×√1
=349,500
Therefore, the 1-day 99% VaR for this portfolio is $349,500. This means there is a 1% chance
that the portfolio will lose more than $349,500 in one day.
QUESTION 7: FAMA-FRENCH THREE-FACTOR MODEL
A stock has the following factor exposures: - Market factor (MKT) beta: 1.2 - Size factor (SMB)
beta: 0.5 - Value factor (HML) beta: -0.3
The risk-free rate is 2%, and the factor risk premiums are: - Market risk premium: 6% - SMB
premium: 3% - HML premium: 4%
Calculate the expected return of the stock using the Fama-French Three-Factor Model.
Solution:
Step 1: Recall the Fama-French Three-Factor Model formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝑅𝑚−𝑅𝑓)+𝑠𝑖(𝑆𝑀𝐵)+ℎ𝑖(𝐻𝑀𝐿)
Step 2: Substitute the given values:
𝐸(𝑅𝑖)=0.02+1.2(0.06)+0.5(0.03)+(−0.3)(0.04)
=0.02+0.072+0.015−0.012
=0.095
Therefore, the expected return of the stock according to the Fama-French Three-Factor Model
is 9.5%.
QUESTION 8: SHARPE RATIO AND INFORMATION RATIO
A portfolio manager achieved an average annual return of 12% over the past 5 years, with a
standard deviation of 18%. The risk-free rate during this period was 3%, and the benchmark
index returned 9% with a standard deviation of 15%. Calculate:
a) The Sharpe ratio of the portfolio b) The Information ratio of the portfolio
Solution:
a) Sharpe Ratio
Step 1: Recall the Sharpe ratio formula:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑓
𝜎𝑝
Step 2: Substitute the given values:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 0.12−0.03
0.18 =0.50
b) Information Ratio
Step 1: Recall the Information ratio formula:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑏
𝜎𝑝−𝑏
Where σp-b is the standard deviation of the difference between portfolio returns and benchmark
returns (tracking error).
Step 2: Calculate the tracking error:
𝜎𝑝−𝑏 =√𝜎𝑝
2+𝜎𝑏
2−2𝜌𝜎𝑝𝜎𝑏
Assuming a correlation of 0.8 between the portfolio and benchmark:
𝜎𝑝−𝑏 =√0.182+0.152−2(0.8)(0.18)(0.15)=0.11
Step 3: Calculate the Information ratio:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 =0.12−0.09
0.11 =0.27
Therefore, the Sharpe ratio of the portfolio is 0.50, and the Information ratio is 0.27.
QUESTION 9: BINOMIAL OPTION PRICING MODEL (CONTINUED)
Consider a European call option with the following characteristics: - Current stock price (S0) =
$100 - Strike price (K) = $105 - Time to expiration (T) = 3 months (0.25 years) - Risk-free rate (r)
= 4% per annum - Up factor (u) = 1.1 - Down factor (d) = 0.9
Using a one-step binomial model, calculate the price of this call option.
Solution:
Step 1: Calculate the risk-neutral probability (p):
𝑝 = 𝑒𝑟𝑇 −𝑑
𝑢−𝑑 =𝑒0.04×0.25 −0.9
1.1−0.9 =0.5498
Step 2: Calculate the possible stock prices at expiration:
𝑆𝑢= 𝑆0×𝑢 = 100×1.1= $110
𝑆𝑑= 𝑆0×𝑑 = 100×0.9= $90
Step 3: Calculate the option payoffs at expiration:
𝐶𝑢=max(𝑆𝑢−𝐾,0)=max(110−105,0)=$5
𝐶𝑑=max(𝑆𝑑−𝐾,0)= max(90−105,0)=$0
Step 4: Calculate the option price using the risk-neutral valuation formula:
𝐶0=𝑒−𝑟𝑇[𝑝𝐶𝑢+(1−𝑝)𝐶𝑑]
=𝑒−0.04×0.25[0.5498×5+(1−0.5498)×0]
=0.9900×2.7490
=$2.72
Therefore, the price of the European call option using a one-step binomial model is $2.72.
QUESTION 10: PORTFOLIO PERFORMANCE ATTRIBUTION
An equity portfolio manager reported the following sector allocations and returns for the year,
along with the benchmark index data:
Sector
Portfolio Weight
Portfolio Return
Benchmark Weight
Benchmark Return
Technology
35%
12%
30%
10%
Healthcare
25%
8%
20%
7%
Financials
20%
6%
25%
5%
Consumer
15%
4%
15%
3%
Utilities
5%
2%
10%
1%
Perform a performance attribution analysis to determine the sources of the portfolio’s excess
return, breaking it down into allocation effect and selection effect.
Solution:
Step 1: Calculate the total portfolio and benchmark returns:
Portfolio return: (0.35 × 12%) + (0.25 × 8%) + (0.20 × 6%) + (0.15 × 4%) + (0.05 × 2%) = 8.50%
Benchmark return: (0.30 × 10%) + (0.20 × 7%) + (0.25 × 5%) + (0.15 × 3%) + (0.10 × 1%) =
6.40%
Excess return = 8.50% - 6.40% = 2.10%
Step 2: Calculate allocation effect for each sector: Allocation Effect = (Portfolio Weight -
Benchmark Weight) × (Benchmark Sector Return - Benchmark Total Return)
Technology: (35% - 30%) × (10% - 6.40%) = 0.18% Healthcare: (25% - 20%) × (7% - 6.40%) =
0.03% Financials: (20% - 25%) × (5% - 6.40%) = 0.07% Consumer: (15% - 15%) × (3% -
6.40%) = 0.00% Utilities: (5% - 10%) × (1% - 6.40%) = 0.27%
Total Allocation Effect = 0.18% + 0.03% + 0.07% + 0.00% + 0.27% = 0.55%
Step 3: Calculate selection effect for each sector: Selection Effect = Benchmark Weight ×
(Portfolio Sector Return - Benchmark Sector Return)
Technology: 30% × (12% - 10%) = 0.60% Healthcare: 20% × (8% - 7%) = 0.20% Financials:
25% × (6% - 5%) = 0.25% Consumer: 15% × (4% - 3%) = 0.15% Utilities: 10% × (2% - 1%) =
0.10%
Total Selection Effect = 0.60% + 0.20% + 0.25% + 0.15% + 0.10% = 1.30%
Step 4: Calculate interaction effect (optional): Interaction Effect = (Portfolio Weight - Benchmark
Weight) × (Portfolio Sector Return - Benchmark Sector Return)
Technology: (35% - 30%) × (12% - 10%) = 0.10% Healthcare: (25% - 20%) × (8% - 7%) =
0.05% Financials: (20% - 25%) × (6% - 5%) = -0.05% Consumer: (15% - 15%) × (4% - 3%) =
0.00% Utilities: (5% - 10%) × (2% - 1%) = -0.05%
Total Interaction Effect = 0.10% + 0.05% - 0.05% + 0.00% - 0.05% = 0.05%
Step 5: Summarize the attribution analysis:
Excess Return = 2.10% Allocation Effect = 0.55% Selection Effect = 1.30% Interaction Effect =
0.05% Total Attribution = 0.55% + 1.30% + 0.05% = 1.90%
The difference between the excess return (2.10%) and the total attribution (1.90%) is due to
rounding effects.
In conclusion, the portfolio’s outperformance can be attributed to: 1. Allocation Effect: 0.55%
(26.2% of excess return) 2. Selection Effect: 1.30% (61.9% of excess return) 3. Interaction
Effect: 0.05% (2.4% of excess return)
The selection effect was the primary driver of the portfolio’s excess return, indicating that the
manager’s stock selection within sectors contributed most to the outperformance.
A stock has a beta of 1.2, the risk-free rate is 3%, and the expected market return is 10%.
Calculate the expected return of the stock using the CAPM.
Solution:
Step 1: Recall the CAPM formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝐸(𝑅𝑚)−𝑅𝑓)
Step 2: Substitute the given values:
𝑅𝑓=3% =0.03
𝛽𝑖= 1.2
𝐸(𝑅𝑚)=10%= 0.10
Step 3: Calculate the expected return:
𝐸(𝑅𝑖)=0.03+1.2(0.10−0.03)
=0.03+1.2(0.07)
=0.03+0.084
=0.114
Therefore, the expected return of the stock is 11.4%.
QUESTION 2: PORTFOLIO OPTIMIZATION
An investor is considering two stocks, A and B, with the following characteristics:
Stock
Expected Return
Standard Deviation
A
12%
20%
B
8%
15%
The correlation coefficient between the two stocks is 0.3. Find the optimal portfolio weights that
minimize the portfolio risk.
Solution:
Step 1: Recall the formula for portfolio variance:
𝜎𝑝
2=𝑤𝐴
2𝜎𝐴
2+𝑤𝐵
2𝜎𝐵
2+2𝑤𝐴𝑤𝐵𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 2: To minimize risk, we need to find the weights that minimize the portfolio variance. The
formula for the optimal weight of stock A is:
𝑤𝐴=𝜎𝐵
2−𝜌𝐴𝐵𝜎𝐴𝜎𝐵
𝜎𝐴
2+𝜎𝐵
2−2𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 3: Substitute the given values:
𝜎𝐴=20%= 0.20
𝜎𝐵=15% =0.15
𝜌𝐴𝐵 = 0.3
Step 4: Calculate the optimal weight of stock A:
𝑤𝐴=0.152−0.3(0.20)(0.15)
0.202+0.152−2(0.3)(0.20)(0.15)
=0.0225−0.009
0.04+0.0225−0.018
=0.0135
0.0445
≈0.3034
Step 5: Calculate the weight of stock B:
𝑤𝐵= 1−𝑤𝐴=1−0.3034 =0.6966
Therefore, the optimal portfolio weights to minimize risk are approximately 30.34% in stock A
and 69.66% in stock B.
QUESTION 3: DURATION AND CONVEXITY
A 5-year bond with a face value of $1,000 and a 6% annual coupon rate is currently priced at
$1,050. The yield to maturity is 5%. Calculate the bond’s duration and convexity.
Solution:
Step 1: Calculate the bond’s cash flows and present values:
Year
Cash Flow
PV Factor
Present Value
1
$60
0.9524
$57.14
2
$60
0.9070
$54.42
3
$60
0.8638
$51.83
4
$60
0.8227
$49.36
5
$1,060
0.7835
$830.51
Step 2: Calculate the Macaulay Duration:
𝐷 =1×57.14+2×54.42+3×51.83+4×49.36+5×830.51
1050 =4.52
Step 3: Calculate the Modified Duration:
𝑀𝐷 =𝐷
1+𝑦 =4.52
1.05= 4.30
Step 4: Calculate the Convexity:
𝐶 = 1
𝑃(1+𝑦)2∑𝑡(𝑡+1)𝐶𝐹𝑡
(1+𝑦)𝑡
𝑛
𝑡=1
𝐶 = 1
1050(1.05)2(2×57.14+6×54.42+12×51.83+20×49.36+30×830.51)=22.89
Therefore, the bond’s duration is 4.52 years (Macaulay) or 4.30 years (Modified), and its
convexity is 22.89.
QUESTION 4: BLACK-SCHOLES OPTION PRICING MODEL
Using the Black-Scholes model, calculate the price of a European call option with the following
parameters: - Current stock price (S) = $50 - Strike price (K) = $52 - Time to expiration (T) = 6
months (0.5 years) - Risk-free rate (r) = 5% per annum - Stock volatility (σ) = 30% per annum
Solution:
Step 1: Recall the Black-Scholes formula for a call option:
𝐶 =𝑆𝑁(𝑑1)−𝐾𝑒−𝑟𝑇𝑁(𝑑2)
Where:
𝑑1=ln(𝑆/𝐾)+(𝑟+𝜎2/2)𝑇
𝜎√𝑇
𝑑2=𝑑1−𝜎√𝑇
Step 2: Calculate d1 and d2:
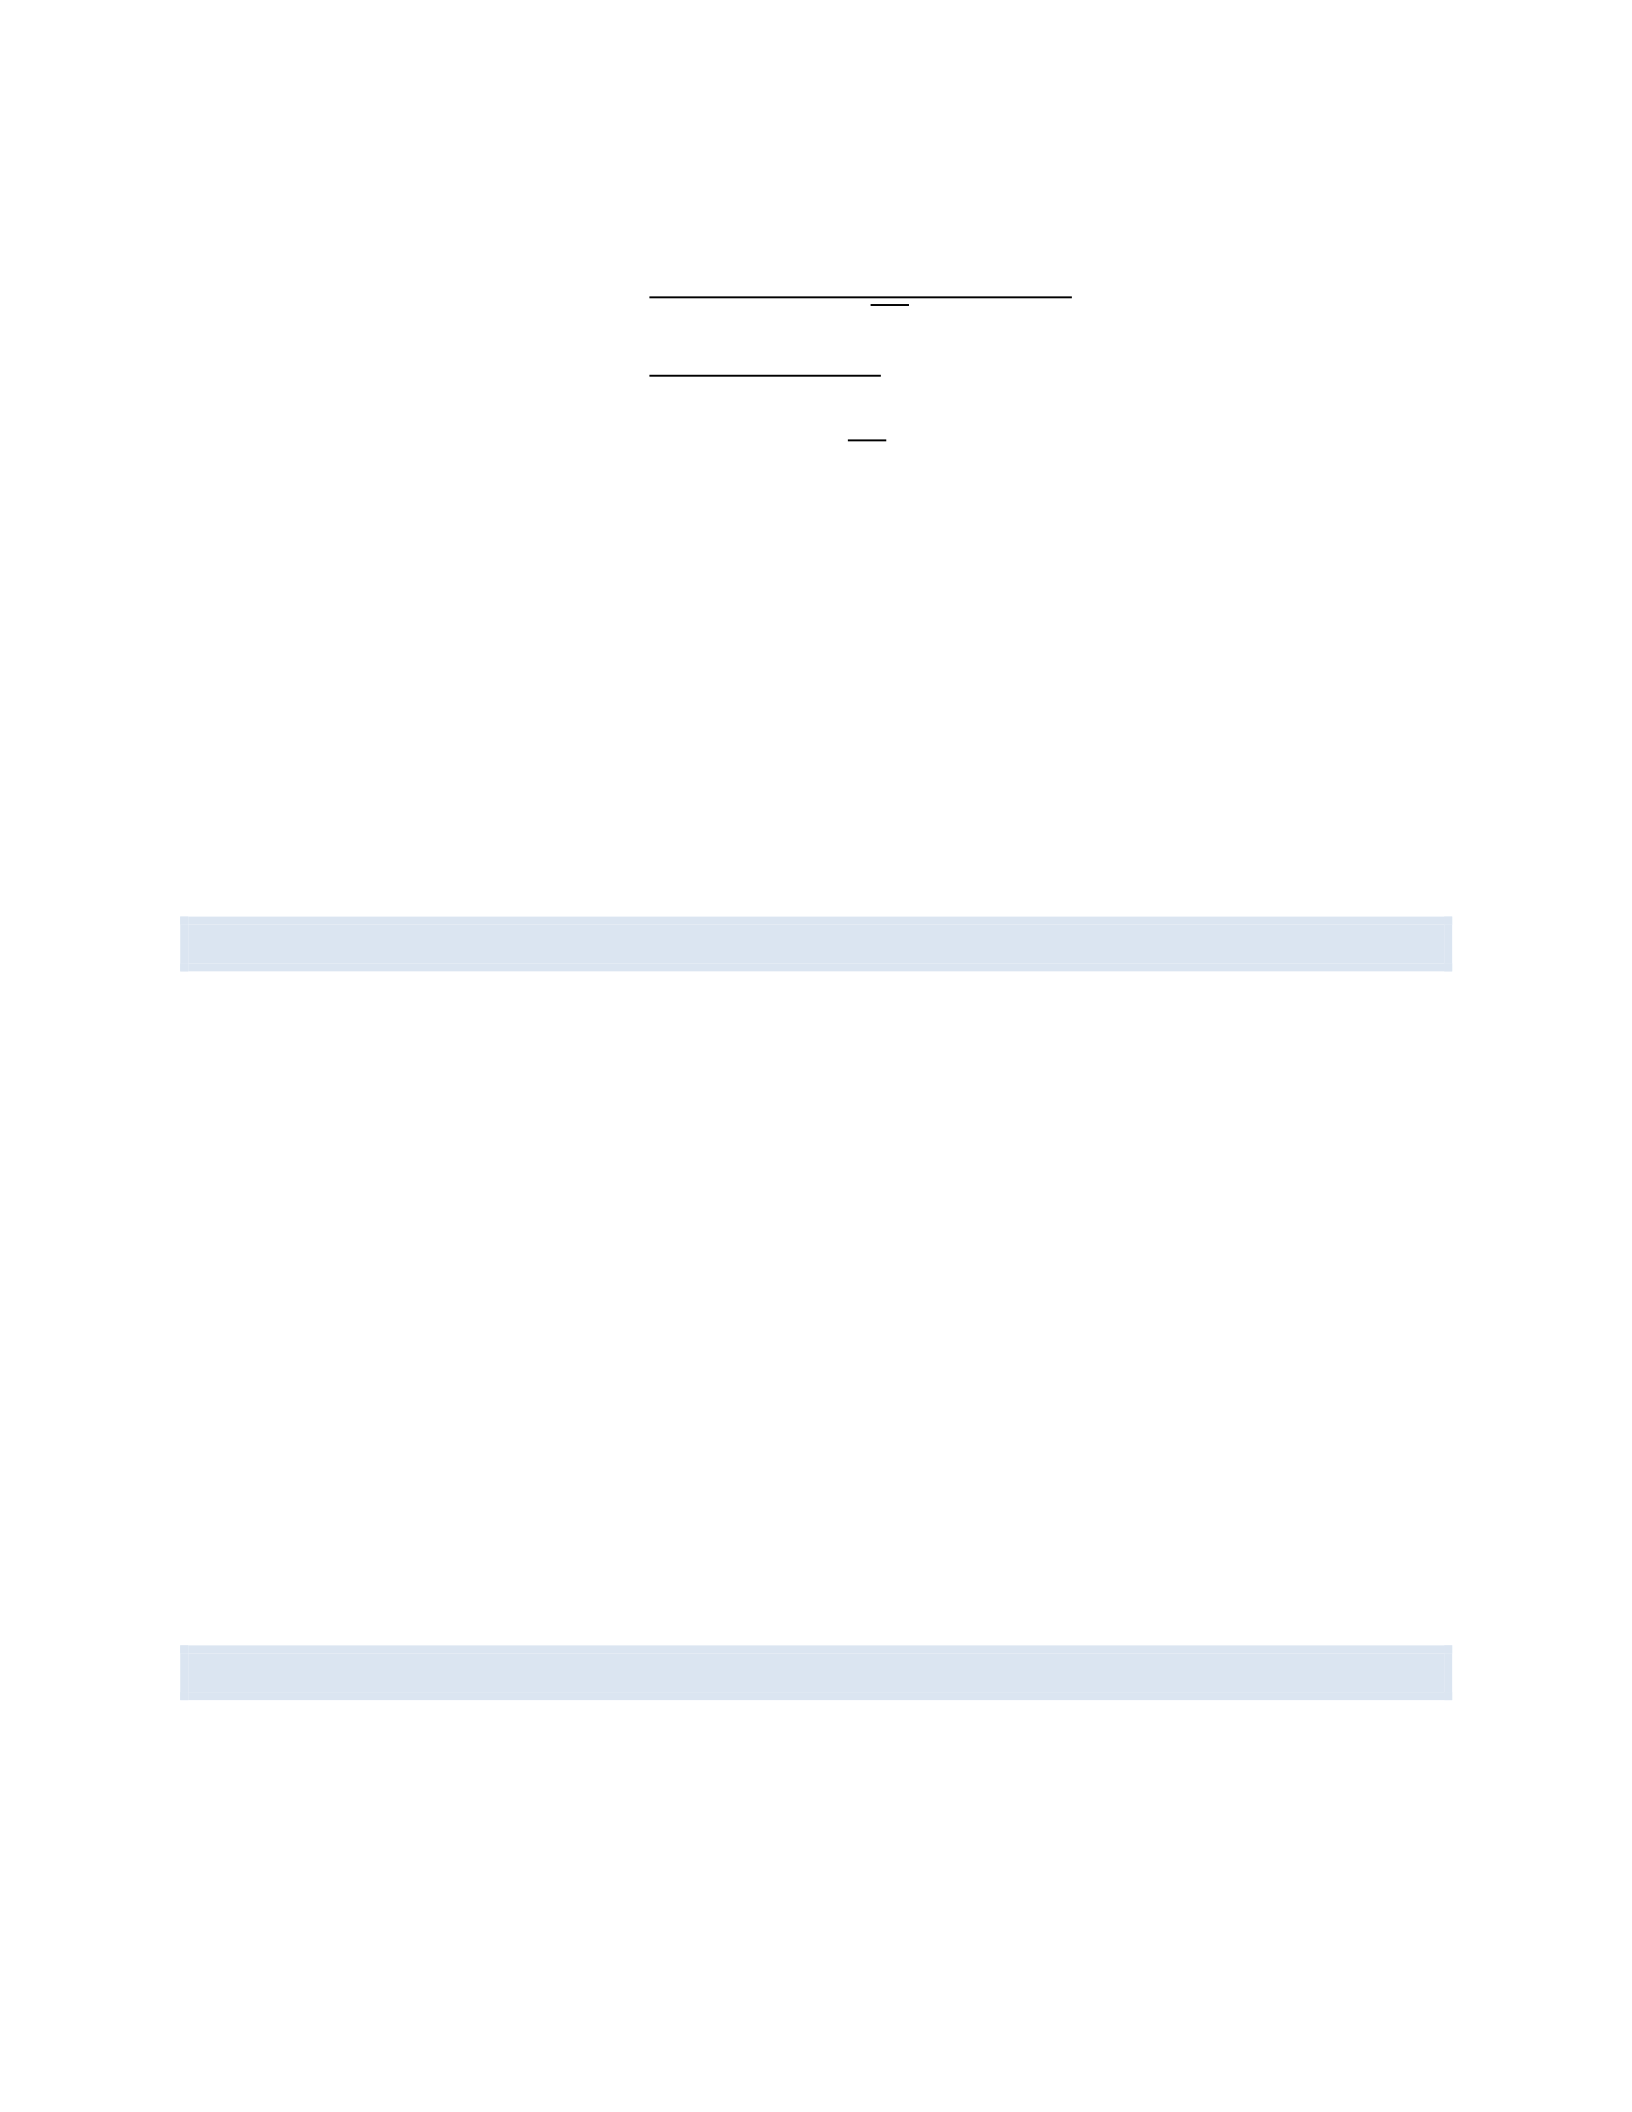
𝑑1=ln(50/52)+(0.05+0.32/2)(0.5)
0.3√0.5
=−0.0392+0.0475
0.2121 =0.0391
𝑑2=0.0391−0.3√0.5= −0.1730
Step 3: Find N(d1) and N(d2) using a standard normal distribution table or calculator:
𝑁(𝑑1)=𝑁(0.0391)=0.5156
𝑁(𝑑2)=𝑁(−0.1730)= 0.4313
Step 4: Calculate the option price:
𝐶 =50×0.5156−52𝑒−0.05×0.5 ×0.4313
=25.78−22.17
=3.61
Therefore, the price of the European call option is $3.61.
QUESTION 5: ARBITRAGE PRICING THEORY (APT)
Consider a three-factor APT model with the following information: - Risk-free rate: 3% - Factor
risk premiums: λ1 = 4%, λ2 = 3%, λ3 = 2% - Stock A has factor sensitivities: β1 = 1.2, β2 = 0.8,
β3 = -0.5
Calculate the expected return of Stock A according to the APT model.
Solution:
Step 1: Recall the APT formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖1𝜆1+𝛽𝑖2𝜆2+𝛽𝑖3𝜆3
Step 2: Substitute the given values:
𝐸(𝑅𝐴)= 0.03+1.2(0.04)+0.8(0.03)+(−0.5)(0.02)
=0.03+0.048+0.024−0.01
=0.092
Therefore, the expected return of Stock A according to the APT model is 9.2%.
QUESTION 6: VALUE AT RISK (VAR)
A portfolio has a current value of $10 million and a daily volatility of 1.5%. Assuming normally
distributed returns, calculate the 1-day 99% VaR for this portfolio.
Solution:
Step 1: Recall the VaR formula for normally distributed returns:
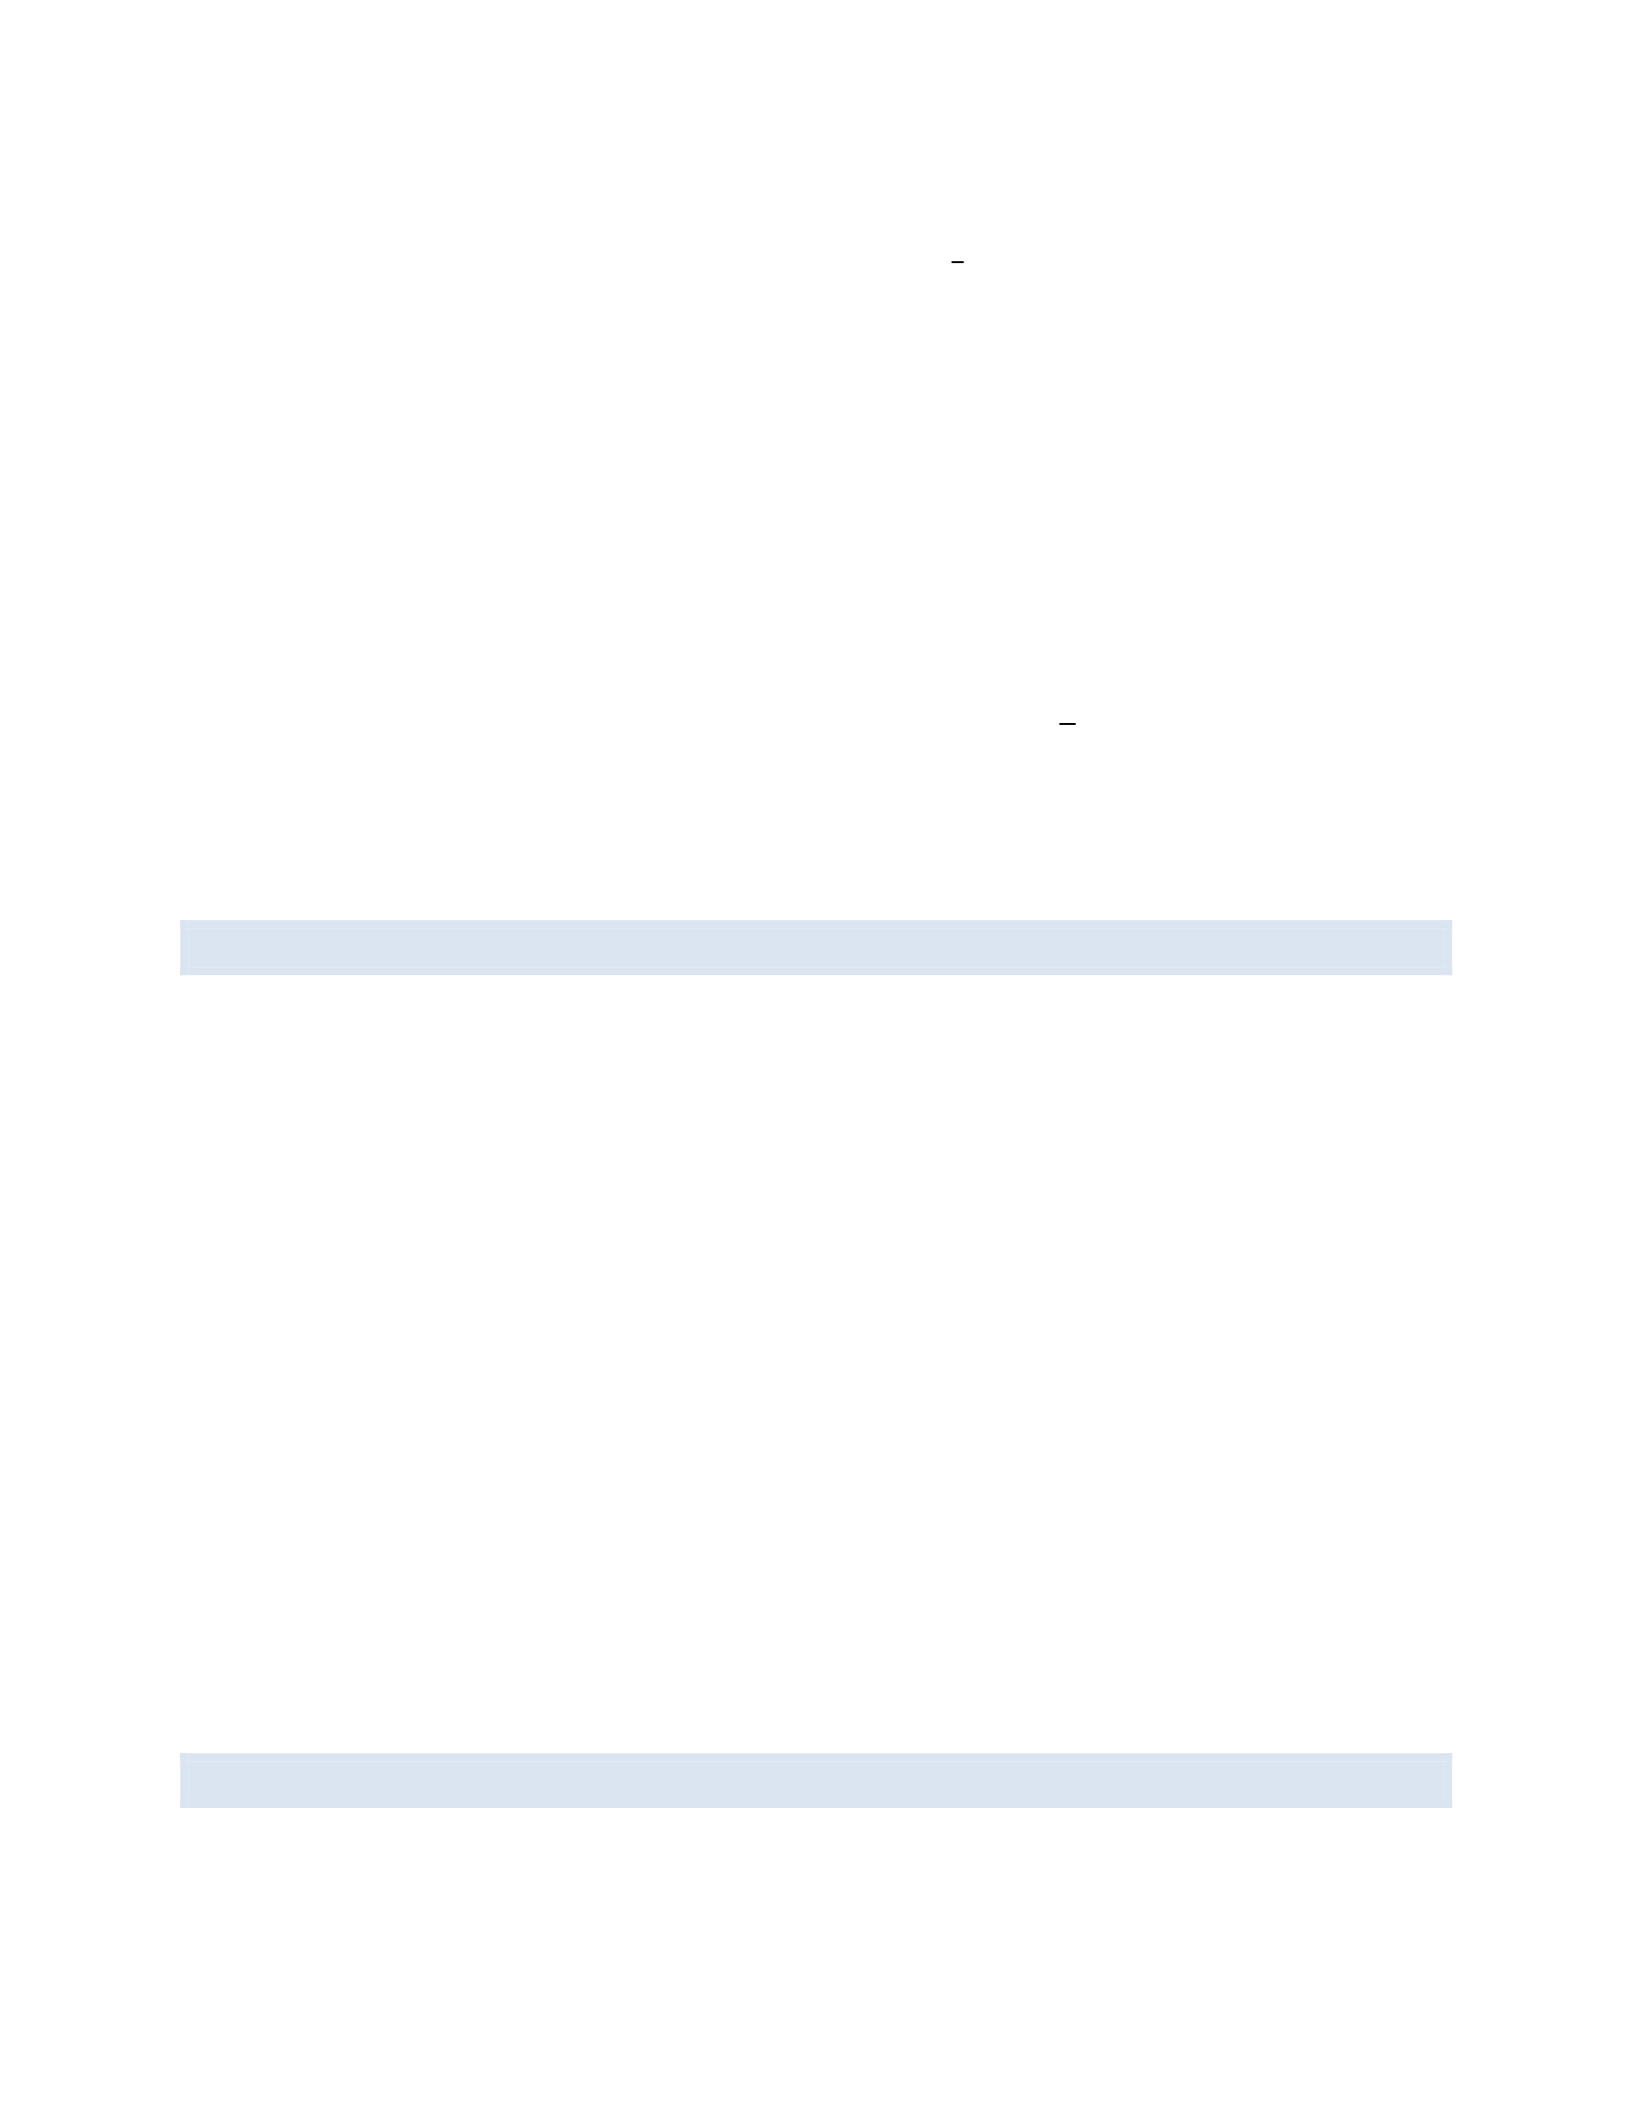
𝑉𝑎𝑅 =𝑃×𝜎×𝑍𝛼×√𝑡
Where: - P is the portfolio value - σ is the daily volatility - Zα is the Z-score for the desired
confidence level - t is the time horizon in days
Step 2: Identify the given values:
𝑃 =$10,000,000
𝜎 =1.5% =0.015
𝑍99%= 2.33(𝑓𝑟𝑜𝑚𝑠𝑡𝑎𝑛𝑑𝑎𝑟𝑑𝑛𝑜𝑟𝑚𝑎𝑙𝑑𝑖𝑠𝑡𝑟𝑖𝑏𝑢𝑡𝑖𝑜𝑛𝑡𝑎𝑏𝑙𝑒)
𝑡 =1 day
Step 3: Calculate the VaR:
𝑉𝑎𝑅 =10,000,000×0.015×2.33×√1
=349,500
Therefore, the 1-day 99% VaR for this portfolio is $349,500. This means there is a 1% chance
that the portfolio will lose more than $349,500 in one day.
QUESTION 7: FAMA-FRENCH THREE-FACTOR MODEL
A stock has the following factor exposures: - Market factor (MKT) beta: 1.2 - Size factor (SMB)
beta: 0.5 - Value factor (HML) beta: -0.3
The risk-free rate is 2%, and the factor risk premiums are: - Market risk premium: 6% - SMB
premium: 3% - HML premium: 4%
Calculate the expected return of the stock using the Fama-French Three-Factor Model.
Solution:
Step 1: Recall the Fama-French Three-Factor Model formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝑅𝑚−𝑅𝑓)+𝑠𝑖(𝑆𝑀𝐵)+ℎ𝑖(𝐻𝑀𝐿)
Step 2: Substitute the given values:
𝐸(𝑅𝑖)=0.02+1.2(0.06)+0.5(0.03)+(−0.3)(0.04)
=0.02+0.072+0.015−0.012
=0.095
Therefore, the expected return of the stock according to the Fama-French Three-Factor Model
is 9.5%.
QUESTION 8: SHARPE RATIO AND INFORMATION RATIO
A portfolio manager achieved an average annual return of 12% over the past 5 years, with a
standard deviation of 18%. The risk-free rate during this period was 3%, and the benchmark
index returned 9% with a standard deviation of 15%. Calculate:
a) The Sharpe ratio of the portfolio b) The Information ratio of the portfolio
Solution:
a) Sharpe Ratio
Step 1: Recall the Sharpe ratio formula:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑓
𝜎𝑝
Step 2: Substitute the given values:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 0.12−0.03
0.18 =0.50
b) Information Ratio
Step 1: Recall the Information ratio formula:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑏
𝜎𝑝−𝑏
Where σp-b is the standard deviation of the difference between portfolio returns and benchmark
returns (tracking error).
Step 2: Calculate the tracking error:
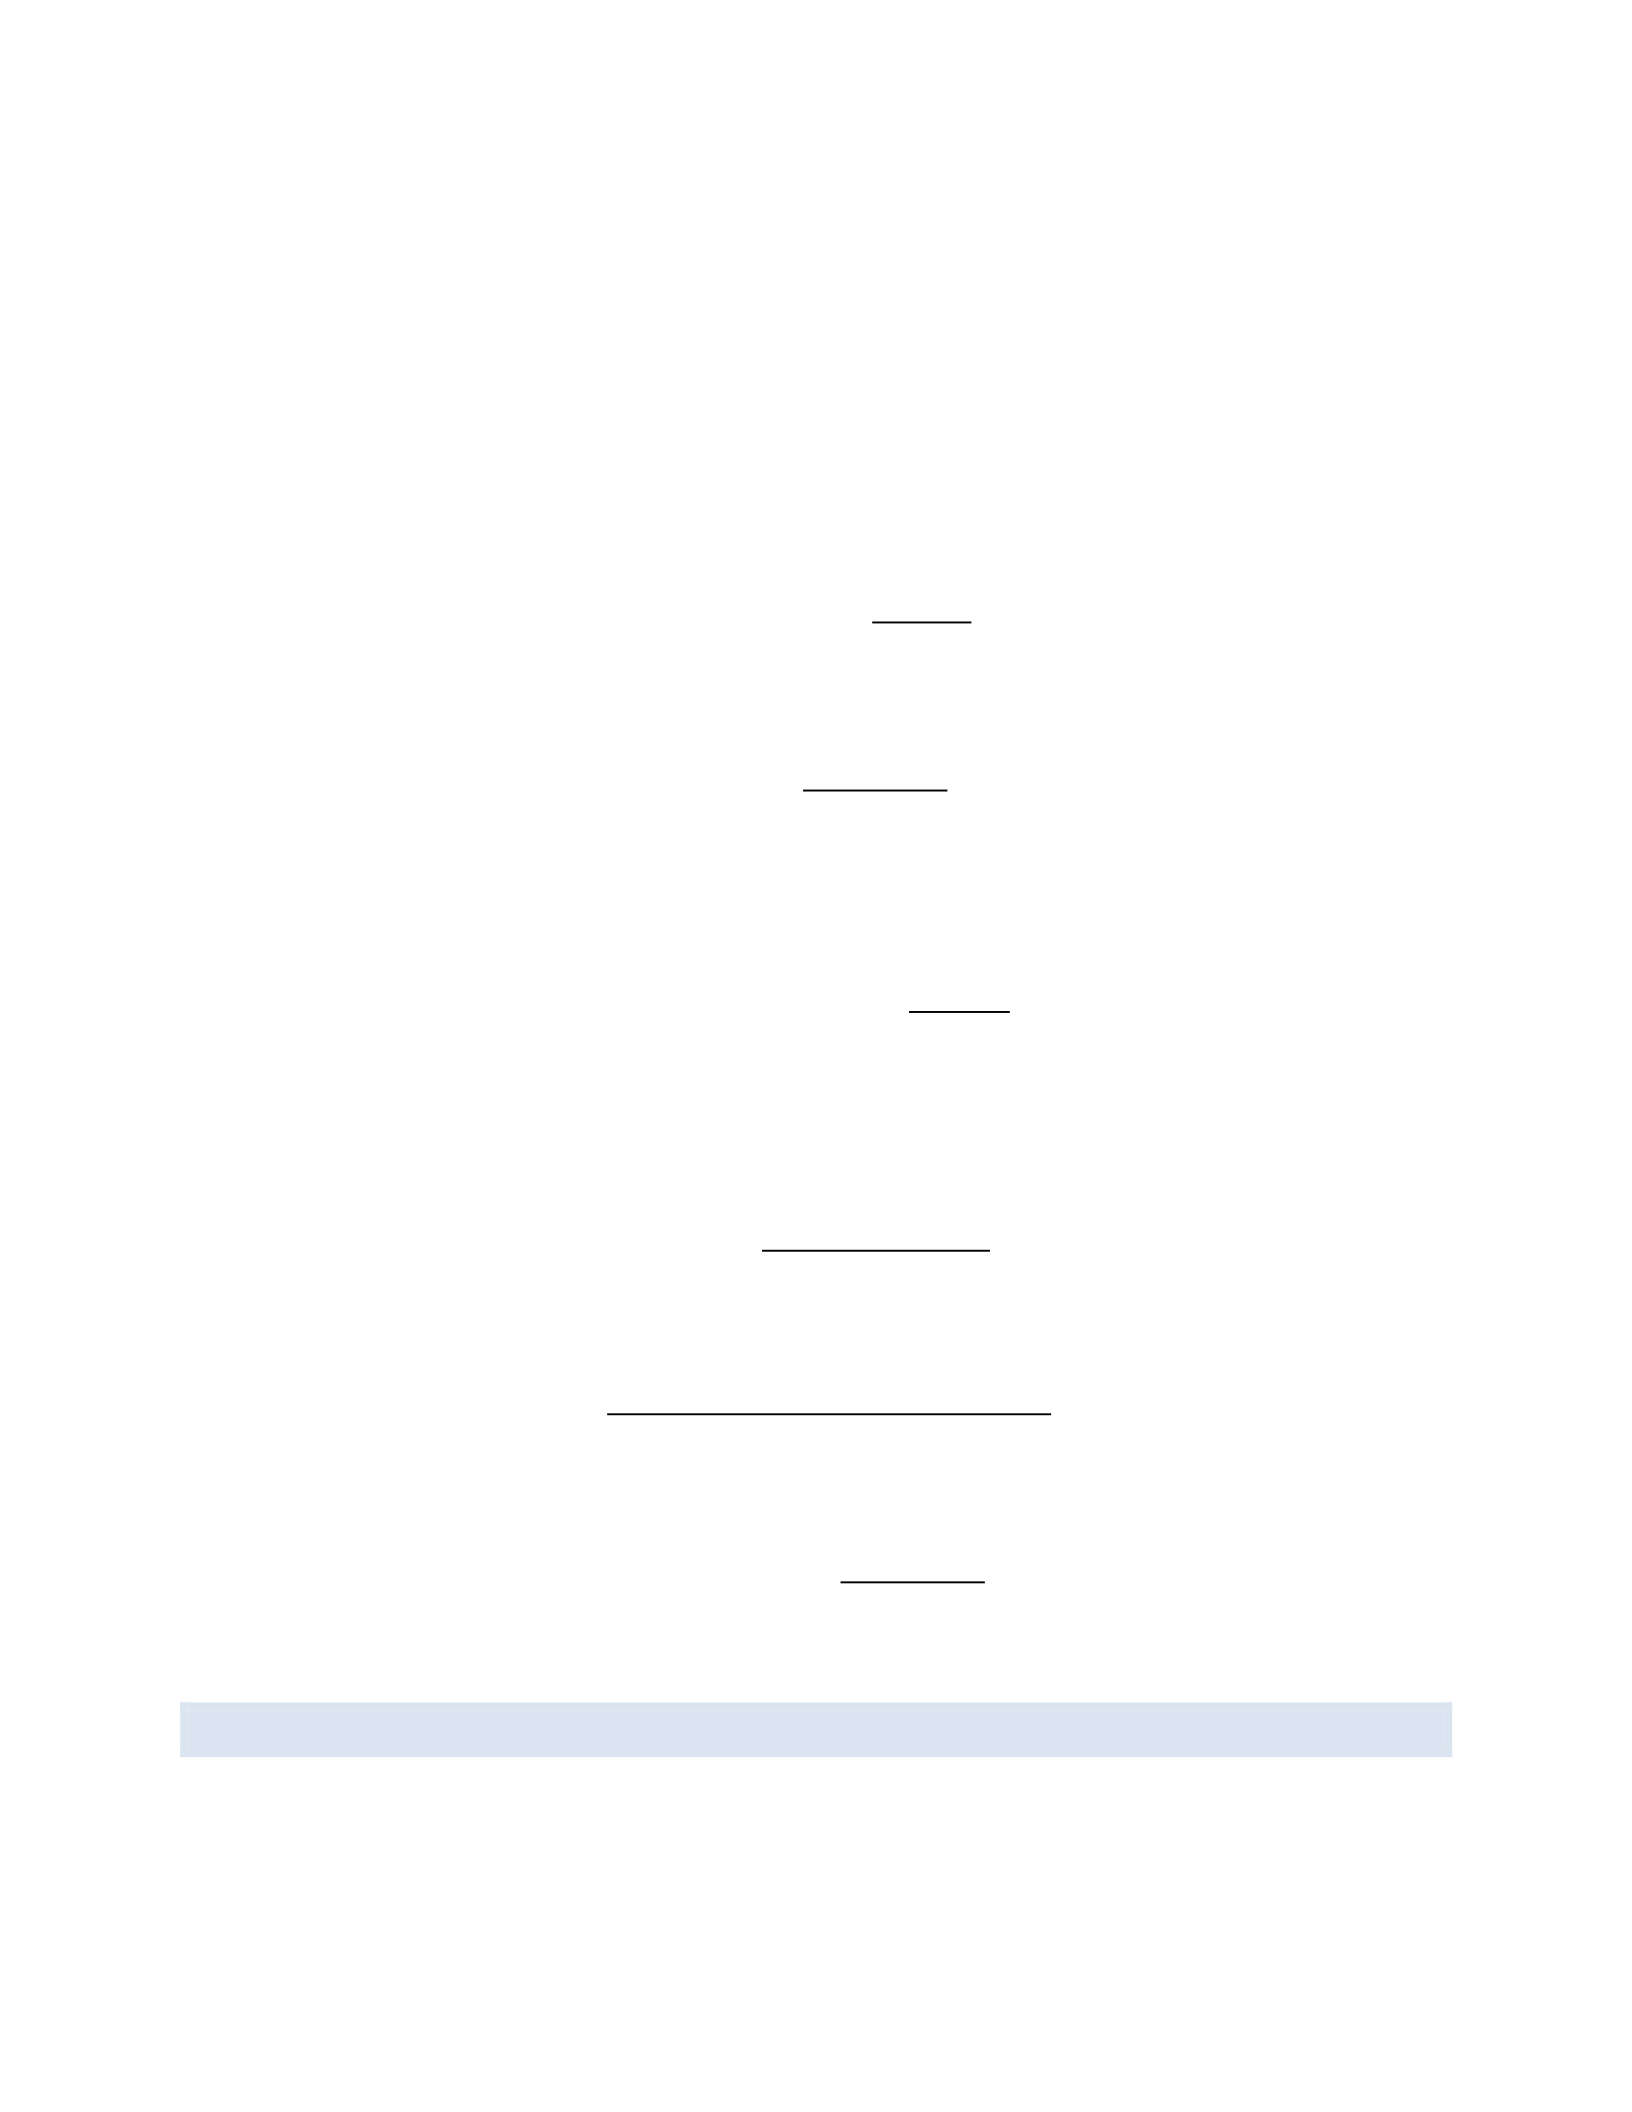
𝜎𝑝−𝑏 =√𝜎𝑝
2+𝜎𝑏
2−2𝜌𝜎𝑝𝜎𝑏
Assuming a correlation of 0.8 between the portfolio and benchmark:
𝜎𝑝−𝑏 =√0.182+0.152−2(0.8)(0.18)(0.15)=0.11
Step 3: Calculate the Information ratio:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 =0.12−0.09
0.11 =0.27
Therefore, the Sharpe ratio of the portfolio is 0.50, and the Information ratio is 0.27.
QUESTION 9: BINOMIAL OPTION PRICING MODEL (CONTINUED)
Consider a European call option with the following characteristics: - Current stock price (S0) =
$100 - Strike price (K) = $105 - Time to expiration (T) = 3 months (0.25 years) - Risk-free rate (r)
= 4% per annum - Up factor (u) = 1.1 - Down factor (d) = 0.9
Using a one-step binomial model, calculate the price of this call option.
Solution:
Step 1: Calculate the risk-neutral probability (p):
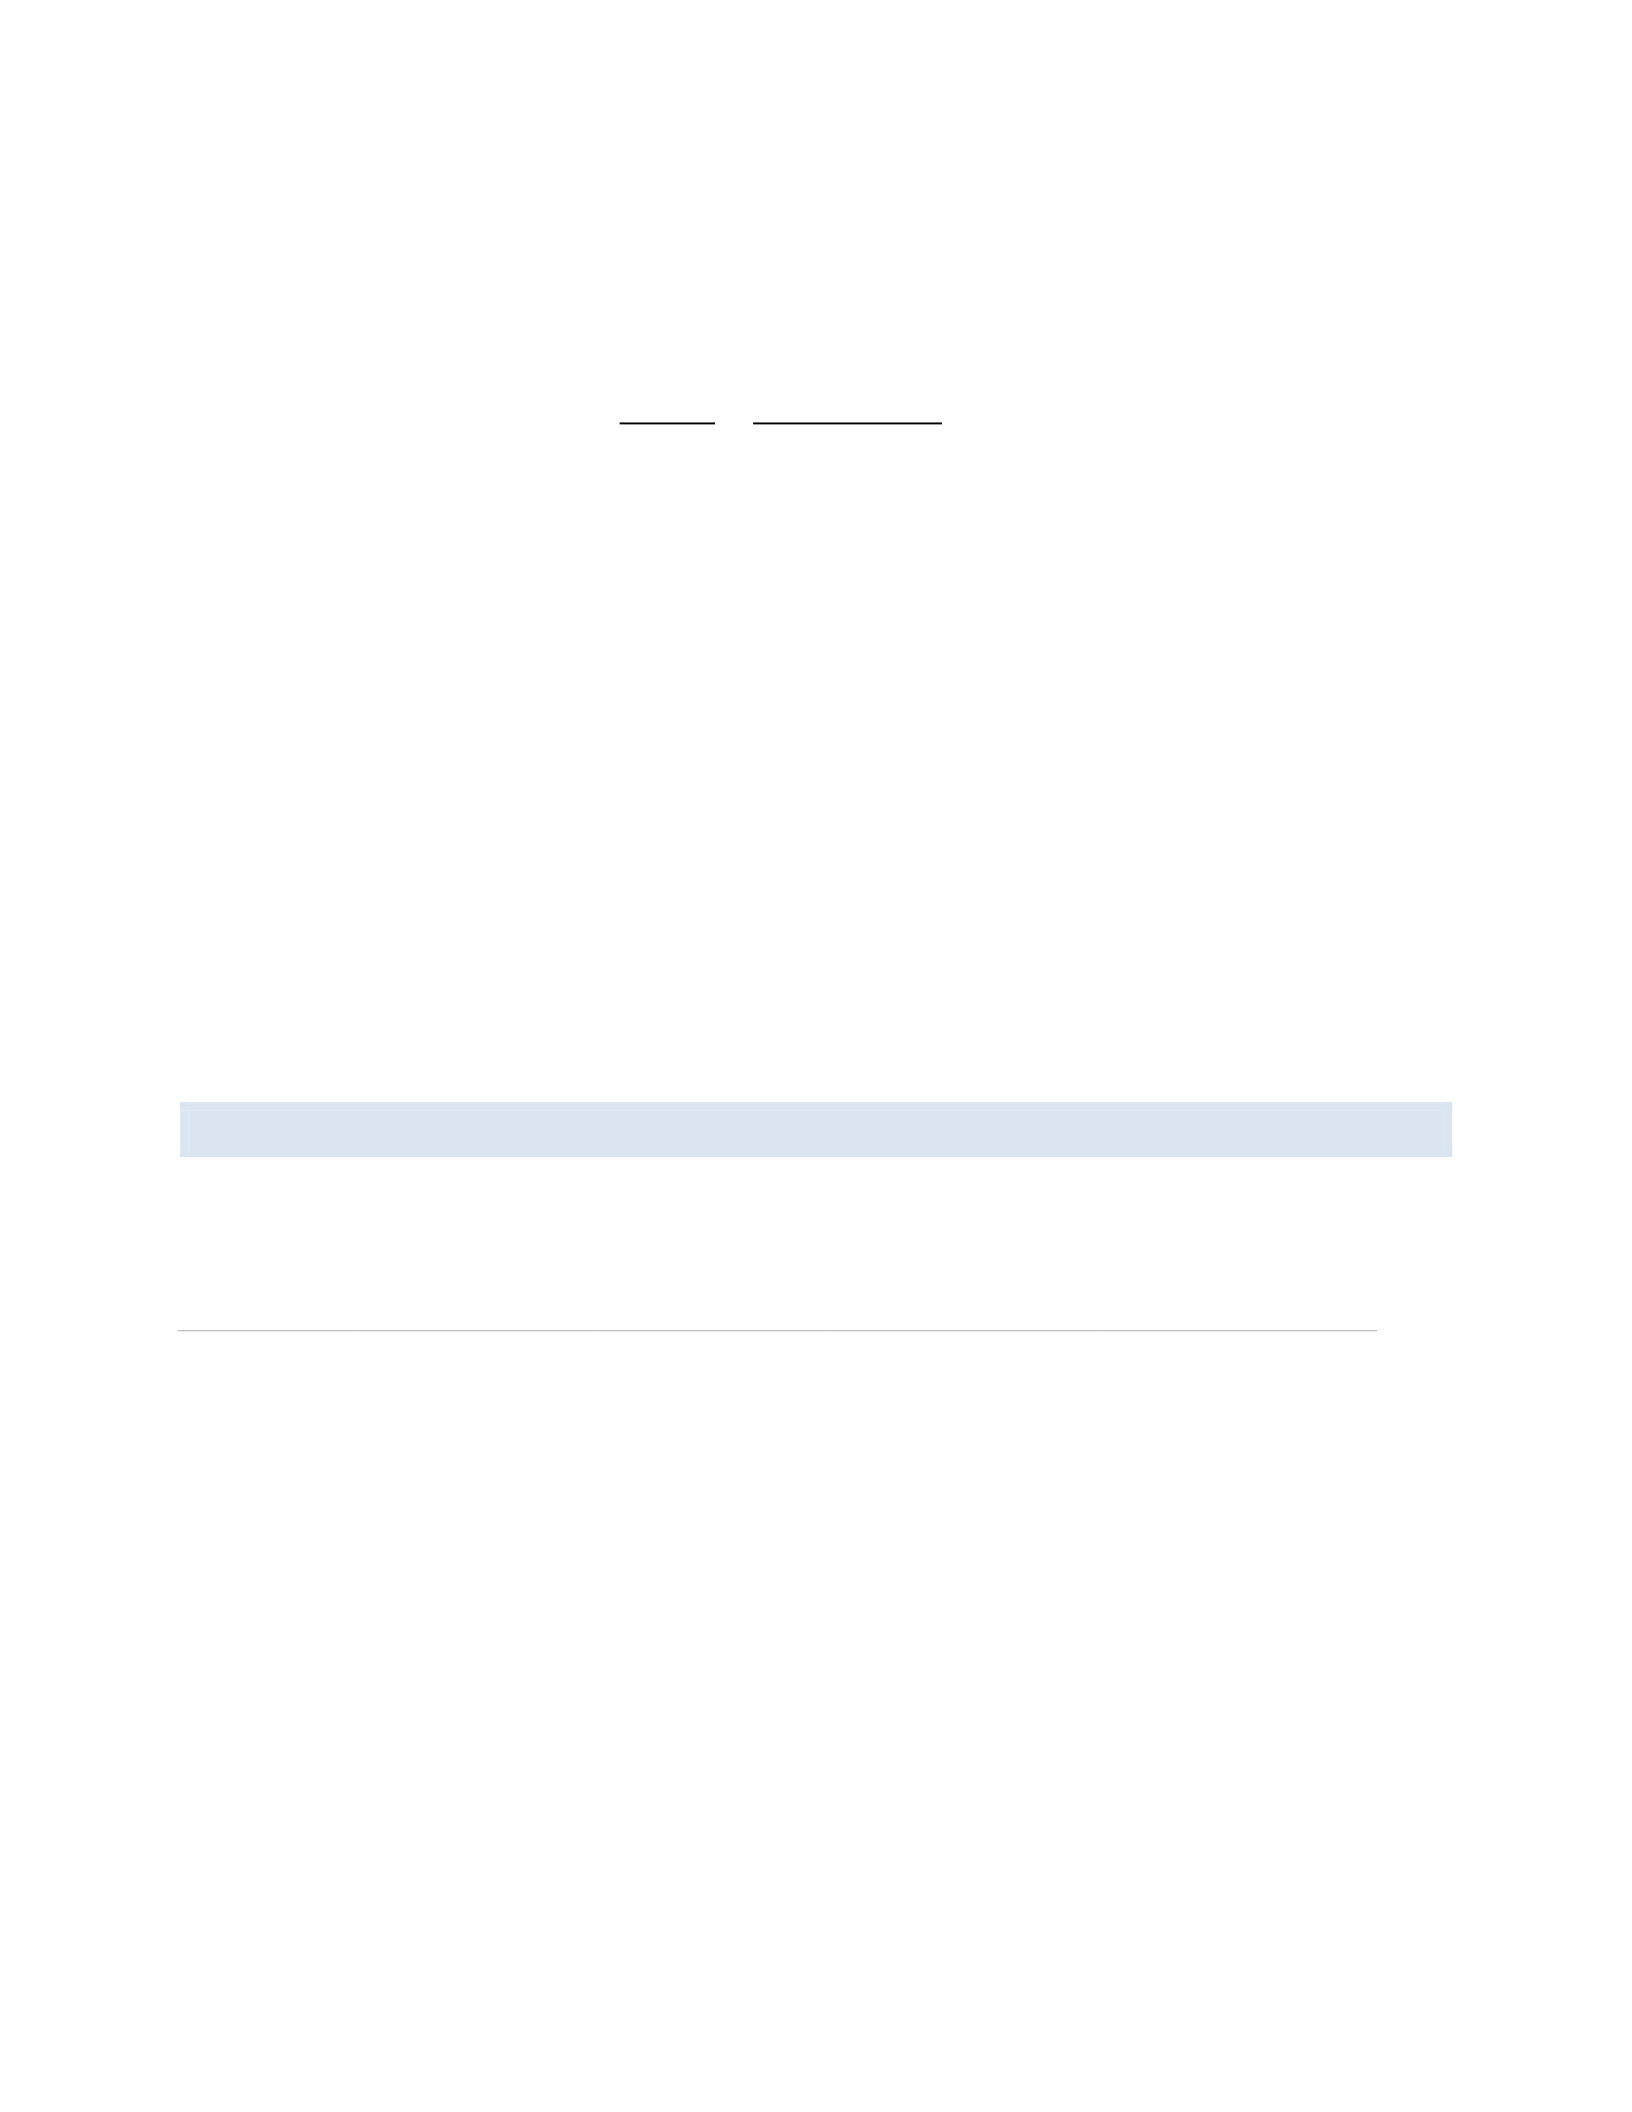
𝑝 = 𝑒𝑟𝑇 −𝑑
𝑢−𝑑 =𝑒0.04×0.25 −0.9
1.1−0.9 =0.5498
Step 2: Calculate the possible stock prices at expiration:
𝑆𝑢= 𝑆0×𝑢 = 100×1.1= $110
𝑆𝑑= 𝑆0×𝑑 = 100×0.9= $90
Step 3: Calculate the option payoffs at expiration:
𝐶𝑢=max(𝑆𝑢−𝐾,0)=max(110−105,0)=$5
𝐶𝑑=max(𝑆𝑑−𝐾,0)= max(90−105,0)=$0
Step 4: Calculate the option price using the risk-neutral valuation formula:
𝐶0=𝑒−𝑟𝑇[𝑝𝐶𝑢+(1−𝑝)𝐶𝑑]
=𝑒−0.04×0.25[0.5498×5+(1−0.5498)×0]
=0.9900×2.7490
=$2.72
Therefore, the price of the European call option using a one-step binomial model is $2.72.
QUESTION 10: PORTFOLIO PERFORMANCE ATTRIBUTION
An equity portfolio manager reported the following sector allocations and returns for the year,
along with the benchmark index data:
Sector
Portfolio Weight
Portfolio Return
Benchmark Weight
Benchmark Return
Technology
35%
12%
30%
10%
Healthcare
25%
8%
20%
7%
Financials
20%
6%
25%
5%
Consumer
15%
4%
15%
3%
Utilities
5%
2%
10%
1%
Perform a performance attribution analysis to determine the sources of the portfolio’s excess
return, breaking it down into allocation effect and selection effect.
Solution:
Step 1: Calculate the total portfolio and benchmark returns:
Portfolio return: (0.35 × 12%) + (0.25 × 8%) + (0.20 × 6%) + (0.15 × 4%) + (0.05 × 2%) = 8.50%

Benchmark return: (0.30 × 10%) + (0.20 × 7%) + (0.25 × 5%) + (0.15 × 3%) + (0.10 × 1%) =
6.40%
Excess return = 8.50% - 6.40% = 2.10%
Step 2: Calculate allocation effect for each sector: Allocation Effect = (Portfolio Weight -
Benchmark Weight) × (Benchmark Sector Return - Benchmark Total Return)
Technology: (35% - 30%) × (10% - 6.40%) = 0.18% Healthcare: (25% - 20%) × (7% - 6.40%) =
0.03% Financials: (20% - 25%) × (5% - 6.40%) = 0.07% Consumer: (15% - 15%) × (3% -
6.40%) = 0.00% Utilities: (5% - 10%) × (1% - 6.40%) = 0.27%
Total Allocation Effect = 0.18% + 0.03% + 0.07% + 0.00% + 0.27% = 0.55%
Step 3: Calculate selection effect for each sector: Selection Effect = Benchmark Weight ×
(Portfolio Sector Return - Benchmark Sector Return)
Technology: 30% × (12% - 10%) = 0.60% Healthcare: 20% × (8% - 7%) = 0.20% Financials:
25% × (6% - 5%) = 0.25% Consumer: 15% × (4% - 3%) = 0.15% Utilities: 10% × (2% - 1%) =
0.10%
Total Selection Effect = 0.60% + 0.20% + 0.25% + 0.15% + 0.10% = 1.30%
Step 4: Calculate interaction effect (optional): Interaction Effect = (Portfolio Weight - Benchmark
Weight) × (Portfolio Sector Return - Benchmark Sector Return)
Technology: (35% - 30%) × (12% - 10%) = 0.10% Healthcare: (25% - 20%) × (8% - 7%) =
0.05% Financials: (20% - 25%) × (6% - 5%) = -0.05% Consumer: (15% - 15%) × (4% - 3%) =
0.00% Utilities: (5% - 10%) × (2% - 1%) = -0.05%
Total Interaction Effect = 0.10% + 0.05% - 0.05% + 0.00% - 0.05% = 0.05%
Step 5: Summarize the attribution analysis:
Excess Return = 2.10% Allocation Effect = 0.55% Selection Effect = 1.30% Interaction Effect =
0.05% Total Attribution = 0.55% + 1.30% + 0.05% = 1.90%
The difference between the excess return (2.10%) and the total attribution (1.90%) is due to
rounding effects.
In conclusion, the portfolio’s outperformance can be attributed to: 1. Allocation Effect: 0.55%
(26.2% of excess return) 2. Selection Effect: 1.30% (61.9% of excess return) 3. Interaction
Effect: 0.05% (2.4% of excess return)
The selection effect was the primary driver of the portfolio’s excess return, indicating that the
manager’s stock selection within sectors contributed most to the outperformance.
A stock has a beta of 1.2, the risk-free rate is 3%, and the expected market return is 10%.
Calculate the expected return of the stock using the CAPM.
Solution:
Step 1: Recall the CAPM formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝐸(𝑅𝑚)−𝑅𝑓)
Step 2: Substitute the given values:
𝑅𝑓=3% =0.03
𝛽𝑖= 1.2
𝐸(𝑅𝑚)=10%= 0.10
Step 3: Calculate the expected return:
𝐸(𝑅𝑖)=0.03+1.2(0.10−0.03)
=0.03+1.2(0.07)
=0.03+0.084
=0.114
Therefore, the expected return of the stock is 11.4%.
QUESTION 2: PORTFOLIO OPTIMIZATION
An investor is considering two stocks, A and B, with the following characteristics:
Stock
Expected Return
Standard Deviation
A
12%
20%
B
8%
15%
The correlation coefficient between the two stocks is 0.3. Find the optimal portfolio weights that
minimize the portfolio risk.
Solution:
Step 1: Recall the formula for portfolio variance:
𝜎𝑝
2=𝑤𝐴
2𝜎𝐴
2+𝑤𝐵
2𝜎𝐵
2+2𝑤𝐴𝑤𝐵𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 2: To minimize risk, we need to find the weights that minimize the portfolio variance. The
formula for the optimal weight of stock A is:
𝑤𝐴=𝜎𝐵
2−𝜌𝐴𝐵𝜎𝐴𝜎𝐵
𝜎𝐴
2+𝜎𝐵
2−2𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 3: Substitute the given values:
𝜎𝐴=20%= 0.20
𝜎𝐵=15% =0.15
𝜌𝐴𝐵 = 0.3
Step 4: Calculate the optimal weight of stock A:
𝑤𝐴=0.152−0.3(0.20)(0.15)
0.202+0.152−2(0.3)(0.20)(0.15)
=0.0225−0.009
0.04+0.0225−0.018
=0.0135
0.0445
≈0.3034
Step 5: Calculate the weight of stock B:
𝑤𝐵= 1−𝑤𝐴=1−0.3034 =0.6966
Therefore, the optimal portfolio weights to minimize risk are approximately 30.34% in stock A
and 69.66% in stock B.
QUESTION 3: DURATION AND CONVEXITY
A 5-year bond with a face value of $1,000 and a 6% annual coupon rate is currently priced at
$1,050. The yield to maturity is 5%. Calculate the bond’s duration and convexity.
Solution:
Step 1: Calculate the bond’s cash flows and present values:
Year
Cash Flow
PV Factor
Present Value
1
$60
0.9524
$57.14
2
$60
0.9070
$54.42
3
$60
0.8638
$51.83
4
$60
0.8227
$49.36
5
$1,060
0.7835
$830.51
Step 2: Calculate the Macaulay Duration:
𝐷 =1×57.14+2×54.42+3×51.83+4×49.36+5×830.51
1050 =4.52
Step 3: Calculate the Modified Duration:
𝑀𝐷 =𝐷
1+𝑦 =4.52
1.05= 4.30
Step 4: Calculate the Convexity:
𝐶 = 1
𝑃(1+𝑦)2∑𝑡(𝑡+1)𝐶𝐹𝑡
(1+𝑦)𝑡
𝑛
𝑡=1
𝐶 = 1
1050(1.05)2(2×57.14+6×54.42+12×51.83+20×49.36+30×830.51)=22.89
Therefore, the bond’s duration is 4.52 years (Macaulay) or 4.30 years (Modified), and its
convexity is 22.89.
QUESTION 4: BLACK-SCHOLES OPTION PRICING MODEL
Using the Black-Scholes model, calculate the price of a European call option with the following
parameters: - Current stock price (S) = $50 - Strike price (K) = $52 - Time to expiration (T) = 6
months (0.5 years) - Risk-free rate (r) = 5% per annum - Stock volatility (σ) = 30% per annum
Solution:
Step 1: Recall the Black-Scholes formula for a call option:
𝐶 =𝑆𝑁(𝑑1)−𝐾𝑒−𝑟𝑇𝑁(𝑑2)
Where:
𝑑1=ln(𝑆/𝐾)+(𝑟+𝜎2/2)𝑇
𝜎√𝑇
𝑑2=𝑑1−𝜎√𝑇
Step 2: Calculate d1 and d2:
𝑑1=ln(50/52)+(0.05+0.32/2)(0.5)
0.3√0.5
=−0.0392+0.0475
0.2121 =0.0391
𝑑2=0.0391−0.3√0.5= −0.1730
Step 3: Find N(d1) and N(d2) using a standard normal distribution table or calculator:
𝑁(𝑑1)=𝑁(0.0391)=0.5156
𝑁(𝑑2)=𝑁(−0.1730)= 0.4313
Step 4: Calculate the option price:
𝐶 =50×0.5156−52𝑒−0.05×0.5 ×0.4313
=25.78−22.17
=3.61
Therefore, the price of the European call option is $3.61.
QUESTION 5: ARBITRAGE PRICING THEORY (APT)
Consider a three-factor APT model with the following information: - Risk-free rate: 3% - Factor
risk premiums: λ1 = 4%, λ2 = 3%, λ3 = 2% - Stock A has factor sensitivities: β1 = 1.2, β2 = 0.8,
β3 = -0.5
Calculate the expected return of Stock A according to the APT model.
Solution:
Step 1: Recall the APT formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖1𝜆1+𝛽𝑖2𝜆2+𝛽𝑖3𝜆3
Step 2: Substitute the given values:
𝐸(𝑅𝐴)= 0.03+1.2(0.04)+0.8(0.03)+(−0.5)(0.02)
=0.03+0.048+0.024−0.01
=0.092
Therefore, the expected return of Stock A according to the APT model is 9.2%.
QUESTION 6: VALUE AT RISK (VAR)
A portfolio has a current value of $10 million and a daily volatility of 1.5%. Assuming normally
distributed returns, calculate the 1-day 99% VaR for this portfolio.
Solution:
Step 1: Recall the VaR formula for normally distributed returns:
𝑉𝑎𝑅 =𝑃×𝜎×𝑍𝛼×√𝑡
Where: - P is the portfolio value - σ is the daily volatility - Zα is the Z-score for the desired
confidence level - t is the time horizon in days
Step 2: Identify the given values:
𝑃 =$10,000,000
𝜎 =1.5% =0.015
𝑍99%= 2.33(𝑓𝑟𝑜𝑚𝑠𝑡𝑎𝑛𝑑𝑎𝑟𝑑𝑛𝑜𝑟𝑚𝑎𝑙𝑑𝑖𝑠𝑡𝑟𝑖𝑏𝑢𝑡𝑖𝑜𝑛𝑡𝑎𝑏𝑙𝑒)
𝑡 =1 day
Step 3: Calculate the VaR:
𝑉𝑎𝑅 =10,000,000×0.015×2.33×√1
=349,500
Therefore, the 1-day 99% VaR for this portfolio is $349,500. This means there is a 1% chance
that the portfolio will lose more than $349,500 in one day.
QUESTION 7: FAMA-FRENCH THREE-FACTOR MODEL
A stock has the following factor exposures: - Market factor (MKT) beta: 1.2 - Size factor (SMB)
beta: 0.5 - Value factor (HML) beta: -0.3
The risk-free rate is 2%, and the factor risk premiums are: - Market risk premium: 6% - SMB
premium: 3% - HML premium: 4%
Calculate the expected return of the stock using the Fama-French Three-Factor Model.
Solution:
Step 1: Recall the Fama-French Three-Factor Model formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝑅𝑚−𝑅𝑓)+𝑠𝑖(𝑆𝑀𝐵)+ℎ𝑖(𝐻𝑀𝐿)
Step 2: Substitute the given values:
𝐸(𝑅𝑖)=0.02+1.2(0.06)+0.5(0.03)+(−0.3)(0.04)
=0.02+0.072+0.015−0.012
=0.095
Therefore, the expected return of the stock according to the Fama-French Three-Factor Model
is 9.5%.
QUESTION 8: SHARPE RATIO AND INFORMATION RATIO
A portfolio manager achieved an average annual return of 12% over the past 5 years, with a
standard deviation of 18%. The risk-free rate during this period was 3%, and the benchmark
index returned 9% with a standard deviation of 15%. Calculate:
a) The Sharpe ratio of the portfolio b) The Information ratio of the portfolio
Solution:
a) Sharpe Ratio
Step 1: Recall the Sharpe ratio formula:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑓
𝜎𝑝
Step 2: Substitute the given values:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 0.12−0.03
0.18 =0.50
b) Information Ratio
Step 1: Recall the Information ratio formula:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑏
𝜎𝑝−𝑏
Where σp-b is the standard deviation of the difference between portfolio returns and benchmark
returns (tracking error).
Step 2: Calculate the tracking error:
𝜎𝑝−𝑏 =√𝜎𝑝
2+𝜎𝑏
2−2𝜌𝜎𝑝𝜎𝑏
Assuming a correlation of 0.8 between the portfolio and benchmark:
𝜎𝑝−𝑏 =√0.182+0.152−2(0.8)(0.18)(0.15)=0.11
Step 3: Calculate the Information ratio:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 =0.12−0.09
0.11 =0.27
Therefore, the Sharpe ratio of the portfolio is 0.50, and the Information ratio is 0.27.
QUESTION 9: BINOMIAL OPTION PRICING MODEL (CONTINUED)
Consider a European call option with the following characteristics: - Current stock price (S0) =
$100 - Strike price (K) = $105 - Time to expiration (T) = 3 months (0.25 years) - Risk-free rate (r)
= 4% per annum - Up factor (u) = 1.1 - Down factor (d) = 0.9
Using a one-step binomial model, calculate the price of this call option.
Solution:
Step 1: Calculate the risk-neutral probability (p):
𝑝 = 𝑒𝑟𝑇 −𝑑
𝑢−𝑑 =𝑒0.04×0.25 −0.9
1.1−0.9 =0.5498
Step 2: Calculate the possible stock prices at expiration:
𝑆𝑢= 𝑆0×𝑢 = 100×1.1= $110
𝑆𝑑= 𝑆0×𝑑 = 100×0.9= $90
Step 3: Calculate the option payoffs at expiration:
𝐶𝑢=max(𝑆𝑢−𝐾,0)=max(110−105,0)=$5
𝐶𝑑=max(𝑆𝑑−𝐾,0)= max(90−105,0)=$0
Step 4: Calculate the option price using the risk-neutral valuation formula:
𝐶0=𝑒−𝑟𝑇[𝑝𝐶𝑢+(1−𝑝)𝐶𝑑]
=𝑒−0.04×0.25[0.5498×5+(1−0.5498)×0]
=0.9900×2.7490
=$2.72
Therefore, the price of the European call option using a one-step binomial model is $2.72.
QUESTION 10: PORTFOLIO PERFORMANCE ATTRIBUTION
An equity portfolio manager reported the following sector allocations and returns for the year,
along with the benchmark index data:
Sector
Portfolio Weight
Portfolio Return
Benchmark Weight
Benchmark Return
Technology
35%
12%
30%
10%
Healthcare
25%
8%
20%
7%
Financials
20%
6%
25%
5%
Consumer
15%
4%
15%
3%
Utilities
5%
2%
10%
1%
Perform a performance attribution analysis to determine the sources of the portfolio’s excess
return, breaking it down into allocation effect and selection effect.
Solution:
Step 1: Calculate the total portfolio and benchmark returns:
Portfolio return: (0.35 × 12%) + (0.25 × 8%) + (0.20 × 6%) + (0.15 × 4%) + (0.05 × 2%) = 8.50%
Benchmark return: (0.30 × 10%) + (0.20 × 7%) + (0.25 × 5%) + (0.15 × 3%) + (0.10 × 1%) =
6.40%
Excess return = 8.50% - 6.40% = 2.10%
Step 2: Calculate allocation effect for each sector: Allocation Effect = (Portfolio Weight -
Benchmark Weight) × (Benchmark Sector Return - Benchmark Total Return)
Technology: (35% - 30%) × (10% - 6.40%) = 0.18% Healthcare: (25% - 20%) × (7% - 6.40%) =
0.03% Financials: (20% - 25%) × (5% - 6.40%) = 0.07% Consumer: (15% - 15%) × (3% -
6.40%) = 0.00% Utilities: (5% - 10%) × (1% - 6.40%) = 0.27%
Total Allocation Effect = 0.18% + 0.03% + 0.07% + 0.00% + 0.27% = 0.55%
Step 3: Calculate selection effect for each sector: Selection Effect = Benchmark Weight ×
(Portfolio Sector Return - Benchmark Sector Return)
Technology: 30% × (12% - 10%) = 0.60% Healthcare: 20% × (8% - 7%) = 0.20% Financials:
25% × (6% - 5%) = 0.25% Consumer: 15% × (4% - 3%) = 0.15% Utilities: 10% × (2% - 1%) =
0.10%
Total Selection Effect = 0.60% + 0.20% + 0.25% + 0.15% + 0.10% = 1.30%
Step 4: Calculate interaction effect (optional): Interaction Effect = (Portfolio Weight - Benchmark
Weight) × (Portfolio Sector Return - Benchmark Sector Return)
Technology: (35% - 30%) × (12% - 10%) = 0.10% Healthcare: (25% - 20%) × (8% - 7%) =
0.05% Financials: (20% - 25%) × (6% - 5%) = -0.05% Consumer: (15% - 15%) × (4% - 3%) =
0.00% Utilities: (5% - 10%) × (2% - 1%) = -0.05%
Total Interaction Effect = 0.10% + 0.05% - 0.05% + 0.00% - 0.05% = 0.05%
Step 5: Summarize the attribution analysis:
Excess Return = 2.10% Allocation Effect = 0.55% Selection Effect = 1.30% Interaction Effect =
0.05% Total Attribution = 0.55% + 1.30% + 0.05% = 1.90%
The difference between the excess return (2.10%) and the total attribution (1.90%) is due to
rounding effects.
In conclusion, the portfolio’s outperformance can be attributed to: 1. Allocation Effect: 0.55%
(26.2% of excess return) 2. Selection Effect: 1.30% (61.9% of excess return) 3. Interaction
Effect: 0.05% (2.4% of excess return)
The selection effect was the primary driver of the portfolio’s excess return, indicating that the
manager’s stock selection within sectors contributed most to the outperformance.
A stock has a beta of 1.2, the risk-free rate is 3%, and the expected market return is 10%.
Calculate the expected return of the stock using the CAPM.
Solution:
Step 1: Recall the CAPM formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝐸(𝑅𝑚)−𝑅𝑓)
Step 2: Substitute the given values:
𝑅𝑓=3% =0.03
𝛽𝑖= 1.2
𝐸(𝑅𝑚)=10%= 0.10
Step 3: Calculate the expected return:
𝐸(𝑅𝑖)=0.03+1.2(0.10−0.03)
=0.03+1.2(0.07)
=0.03+0.084
=0.114
Therefore, the expected return of the stock is 11.4%.
QUESTION 2: PORTFOLIO OPTIMIZATION
An investor is considering two stocks, A and B, with the following characteristics:
Stock
Expected Return
Standard Deviation
A
12%
20%
B
8%
15%
The correlation coefficient between the two stocks is 0.3. Find the optimal portfolio weights that
minimize the portfolio risk.
Solution:
Step 1: Recall the formula for portfolio variance:
𝜎𝑝
2=𝑤𝐴
2𝜎𝐴
2+𝑤𝐵
2𝜎𝐵
2+2𝑤𝐴𝑤𝐵𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 2: To minimize risk, we need to find the weights that minimize the portfolio variance. The
formula for the optimal weight of stock A is:
𝑤𝐴=𝜎𝐵
2−𝜌𝐴𝐵𝜎𝐴𝜎𝐵
𝜎𝐴
2+𝜎𝐵
2−2𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 3: Substitute the given values:
𝜎𝐴=20%= 0.20
𝜎𝐵=15% =0.15
𝜌𝐴𝐵 = 0.3
Step 4: Calculate the optimal weight of stock A:
𝑤𝐴=0.152−0.3(0.20)(0.15)
0.202+0.152−2(0.3)(0.20)(0.15)
=0.0225−0.009
0.04+0.0225−0.018
=0.0135
0.0445
≈0.3034
Step 5: Calculate the weight of stock B:
𝑤𝐵= 1−𝑤𝐴=1−0.3034 =0.6966
Therefore, the optimal portfolio weights to minimize risk are approximately 30.34% in stock A
and 69.66% in stock B.
QUESTION 3: DURATION AND CONVEXITY
A 5-year bond with a face value of $1,000 and a 6% annual coupon rate is currently priced at
$1,050. The yield to maturity is 5%. Calculate the bond’s duration and convexity.
Solution:
Step 1: Calculate the bond’s cash flows and present values:
Year
Cash Flow
PV Factor
Present Value
1
$60
0.9524
$57.14
2
$60
0.9070
$54.42
Year
Cash Flow
PV Factor
Present Value
3
$60
0.8638
$51.83
4
$60
0.8227
$49.36
5
$1,060
0.7835
$830.51
Step 2: Calculate the Macaulay Duration:
𝐷 =1×57.14+2×54.42+3×51.83+4×49.36+5×830.51
1050 =4.52
Step 3: Calculate the Modified Duration:
𝑀𝐷 =𝐷
1+𝑦 =4.52
1.05= 4.30
Step 4: Calculate the Convexity:
𝐶 = 1
𝑃(1+𝑦)2∑𝑡(𝑡+1)𝐶𝐹𝑡
(1+𝑦)𝑡
𝑛
𝑡=1
𝐶 = 1
1050(1.05)2(2×57.14+6×54.42+12×51.83+20×49.36+30×830.51)=22.89
Therefore, the bond’s duration is 4.52 years (Macaulay) or 4.30 years (Modified), and its
convexity is 22.89.
QUESTION 4: BLACK-SCHOLES OPTION PRICING MODEL
Using the Black-Scholes model, calculate the price of a European call option with the following
parameters: - Current stock price (S) = $50 - Strike price (K) = $52 - Time to expiration (T) = 6
months (0.5 years) - Risk-free rate (r) = 5% per annum - Stock volatility (σ) = 30% per annum
Solution:
Step 1: Recall the Black-Scholes formula for a call option:
𝐶 =𝑆𝑁(𝑑1)−𝐾𝑒−𝑟𝑇𝑁(𝑑2)
Where:
𝑑1=ln(𝑆/𝐾)+(𝑟+𝜎2/2)𝑇
𝜎√𝑇
𝑑2=𝑑1−𝜎√𝑇
Step 2: Calculate d1 and d2:
𝑑1=ln(50/52)+(0.05+0.32/2)(0.5)
0.3√0.5
=−0.0392+0.0475
0.2121 =0.0391
𝑑2=0.0391−0.3√0.5= −0.1730
Step 3: Find N(d1) and N(d2) using a standard normal distribution table or calculator:
𝑁(𝑑1)=𝑁(0.0391)=0.5156
𝑁(𝑑2)=𝑁(−0.1730)= 0.4313
Step 4: Calculate the option price:
𝐶 =50×0.5156−52𝑒−0.05×0.5 ×0.4313
=25.78−22.17
=3.61
Therefore, the price of the European call option is $3.61.
QUESTION 5: ARBITRAGE PRICING THEORY (APT)
Consider a three-factor APT model with the following information: - Risk-free rate: 3% - Factor
risk premiums: λ1 = 4%, λ2 = 3%, λ3 = 2% - Stock A has factor sensitivities: β1 = 1.2, β2 = 0.8,
β3 = -0.5
Calculate the expected return of Stock A according to the APT model.
Solution:
Step 1: Recall the APT formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖1𝜆1+𝛽𝑖2𝜆2+𝛽𝑖3𝜆3
Step 2: Substitute the given values:
𝐸(𝑅𝐴)= 0.03+1.2(0.04)+0.8(0.03)+(−0.5)(0.02)
=0.03+0.048+0.024−0.01
=0.092
Therefore, the expected return of Stock A according to the APT model is 9.2%.
QUESTION 6: VALUE AT RISK (VAR)
A portfolio has a current value of $10 million and a daily volatility of 1.5%. Assuming normally
distributed returns, calculate the 1-day 99% VaR for this portfolio.
Solution:
Step 1: Recall the VaR formula for normally distributed returns:
𝑉𝑎𝑅 =𝑃×𝜎×𝑍𝛼×√𝑡
Where: - P is the portfolio value - σ is the daily volatility - Zα is the Z-score for the desired
confidence level - t is the time horizon in days
Step 2: Identify the given values:
𝑃 =$10,000,000
𝜎 =1.5% =0.015
𝑍99%= 2.33(𝑓𝑟𝑜𝑚𝑠𝑡𝑎𝑛𝑑𝑎𝑟𝑑𝑛𝑜𝑟𝑚𝑎𝑙𝑑𝑖𝑠𝑡𝑟𝑖𝑏𝑢𝑡𝑖𝑜𝑛𝑡𝑎𝑏𝑙𝑒)
𝑡 =1 day
Step 3: Calculate the VaR:
𝑉𝑎𝑅 =10,000,000×0.015×2.33×√1
=349,500
Therefore, the 1-day 99% VaR for this portfolio is $349,500. This means there is a 1% chance
that the portfolio will lose more than $349,500 in one day.
QUESTION 7: FAMA-FRENCH THREE-FACTOR MODEL
A stock has the following factor exposures: - Market factor (MKT) beta: 1.2 - Size factor (SMB)
beta: 0.5 - Value factor (HML) beta: -0.3
The risk-free rate is 2%, and the factor risk premiums are: - Market risk premium: 6% - SMB
premium: 3% - HML premium: 4%
Calculate the expected return of the stock using the Fama-French Three-Factor Model.
Solution:
Step 1: Recall the Fama-French Three-Factor Model formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝑅𝑚−𝑅𝑓)+𝑠𝑖(𝑆𝑀𝐵)+ℎ𝑖(𝐻𝑀𝐿)
Step 2: Substitute the given values:
𝐸(𝑅𝑖)=0.02+1.2(0.06)+0.5(0.03)+(−0.3)(0.04)
=0.02+0.072+0.015−0.012
=0.095
Therefore, the expected return of the stock according to the Fama-French Three-Factor Model
is 9.5%.
QUESTION 8: SHARPE RATIO AND INFORMATION RATIO
A portfolio manager achieved an average annual return of 12% over the past 5 years, with a
standard deviation of 18%. The risk-free rate during this period was 3%, and the benchmark
index returned 9% with a standard deviation of 15%. Calculate:
a) The Sharpe ratio of the portfolio b) The Information ratio of the portfolio
Solution:
a) Sharpe Ratio
Step 1: Recall the Sharpe ratio formula:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑓
𝜎𝑝
Step 2: Substitute the given values:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 0.12−0.03
0.18 =0.50
b) Information Ratio
Step 1: Recall the Information ratio formula:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑏
𝜎𝑝−𝑏
Where σp-b is the standard deviation of the difference between portfolio returns and benchmark
returns (tracking error).
Step 2: Calculate the tracking error:
𝜎𝑝−𝑏 =√𝜎𝑝
2+𝜎𝑏
2−2𝜌𝜎𝑝𝜎𝑏
Assuming a correlation of 0.8 between the portfolio and benchmark:
𝜎𝑝−𝑏 =√0.182+0.152−2(0.8)(0.18)(0.15)=0.11
Step 3: Calculate the Information ratio:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 =0.12−0.09
0.11 =0.27
Therefore, the Sharpe ratio of the portfolio is 0.50, and the Information ratio is 0.27.
QUESTION 9: BINOMIAL OPTION PRICING MODEL (CONTINUED)
Consider a European call option with the following characteristics: - Current stock price (S0) =
$100 - Strike price (K) = $105 - Time to expiration (T) = 3 months (0.25 years) - Risk-free rate (r)
= 4% per annum - Up factor (u) = 1.1 - Down factor (d) = 0.9
Using a one-step binomial model, calculate the price of this call option.
Solution:
Step 1: Calculate the risk-neutral probability (p):
𝑝 = 𝑒𝑟𝑇 −𝑑
𝑢−𝑑 =𝑒0.04×0.25 −0.9
1.1−0.9 =0.5498
Step 2: Calculate the possible stock prices at expiration:
𝑆𝑢= 𝑆0×𝑢 = 100×1.1= $110
𝑆𝑑= 𝑆0×𝑑 = 100×0.9= $90
Step 3: Calculate the option payoffs at expiration:
𝐶𝑢=max(𝑆𝑢−𝐾,0)=max(110−105,0)=$5
𝐶𝑑=max(𝑆𝑑−𝐾,0)= max(90−105,0)=$0
Step 4: Calculate the option price using the risk-neutral valuation formula:
𝐶0=𝑒−𝑟𝑇[𝑝𝐶𝑢+(1−𝑝)𝐶𝑑]
=𝑒−0.04×0.25[0.5498×5+(1−0.5498)×0]
=0.9900×2.7490
=$2.72
Therefore, the price of the European call option using a one-step binomial model is $2.72.
QUESTION 10: PORTFOLIO PERFORMANCE ATTRIBUTION
An equity portfolio manager reported the following sector allocations and returns for the year,
along with the benchmark index data:
Sector
Portfolio Weight
Portfolio Return
Benchmark Weight
Benchmark Return
Technology
35%
12%
30%
10%
Healthcare
25%
8%
20%
7%
Financials
20%
6%
25%
5%
Consumer
15%
4%
15%
3%
Utilities
5%
2%
10%
1%
Perform a performance attribution analysis to determine the sources of the portfolio’s excess
return, breaking it down into allocation effect and selection effect.
Solution:
Step 1: Calculate the total portfolio and benchmark returns:
Portfolio return: (0.35 × 12%) + (0.25 × 8%) + (0.20 × 6%) + (0.15 × 4%) + (0.05 × 2%) = 8.50%
Benchmark return: (0.30 × 10%) + (0.20 × 7%) + (0.25 × 5%) + (0.15 × 3%) + (0.10 × 1%) =
6.40%
Excess return = 8.50% - 6.40% = 2.10%

Step 2: Calculate allocation effect for each sector: Allocation Effect = (Portfolio Weight -
Benchmark Weight) × (Benchmark Sector Return - Benchmark Total Return)
Technology: (35% - 30%) × (10% - 6.40%) = 0.18% Healthcare: (25% - 20%) × (7% - 6.40%) =
0.03% Financials: (20% - 25%) × (5% - 6.40%) = 0.07% Consumer: (15% - 15%) × (3% -
6.40%) = 0.00% Utilities: (5% - 10%) × (1% - 6.40%) = 0.27%
Total Allocation Effect = 0.18% + 0.03% + 0.07% + 0.00% + 0.27% = 0.55%
Step 3: Calculate selection effect for each sector: Selection Effect = Benchmark Weight ×
(Portfolio Sector Return - Benchmark Sector Return)
Technology: 30% × (12% - 10%) = 0.60% Healthcare: 20% × (8% - 7%) = 0.20% Financials:
25% × (6% - 5%) = 0.25% Consumer: 15% × (4% - 3%) = 0.15% Utilities: 10% × (2% - 1%) =
0.10%
Total Selection Effect = 0.60% + 0.20% + 0.25% + 0.15% + 0.10% = 1.30%
Step 4: Calculate interaction effect (optional): Interaction Effect = (Portfolio Weight - Benchmark
Weight) × (Portfolio Sector Return - Benchmark Sector Return)
Technology: (35% - 30%) × (12% - 10%) = 0.10% Healthcare: (25% - 20%) × (8% - 7%) =
0.05% Financials: (20% - 25%) × (6% - 5%) = -0.05% Consumer: (15% - 15%) × (4% - 3%) =
0.00% Utilities: (5% - 10%) × (2% - 1%) = -0.05%
Total Interaction Effect = 0.10% + 0.05% - 0.05% + 0.00% - 0.05% = 0.05%
Step 5: Summarize the attribution analysis:
Excess Return = 2.10% Allocation Effect = 0.55% Selection Effect = 1.30% Interaction Effect =
0.05% Total Attribution = 0.55% + 1.30% + 0.05% = 1.90%
The difference between the excess return (2.10%) and the total attribution (1.90%) is due to
rounding effects.
In conclusion, the portfolio’s outperformance can be attributed to: 1. Allocation Effect: 0.55%
(26.2% of excess return) 2. Selection Effect: 1.30% (61.9% of excess return) 3. Interaction
Effect: 0.05% (2.4% of excess return)
The selection effect was the primary driver of the portfolio’s excess return, indicating that the
manager’s stock selection within sectors contributed most to the outperformance.
A stock has a beta of 1.2, the risk-free rate is 3%, and the expected market return is 10%.
Calculate the expected return of the stock using the CAPM.
Solution:
Step 1: Recall the CAPM formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝐸(𝑅𝑚)−𝑅𝑓)
Step 2: Substitute the given values:
𝑅𝑓=3% =0.03
𝛽𝑖= 1.2
𝐸(𝑅𝑚)=10%= 0.10
Step 3: Calculate the expected return:
𝐸(𝑅𝑖)=0.03+1.2(0.10−0.03)
=0.03+1.2(0.07)
=0.03+0.084
=0.114
Therefore, the expected return of the stock is 11.4%.
QUESTION 2: PORTFOLIO OPTIMIZATION
An investor is considering two stocks, A and B, with the following characteristics:
Stock
Expected Return
Standard Deviation
A
12%
20%
B
8%
15%
The correlation coefficient between the two stocks is 0.3. Find the optimal portfolio weights that
minimize the portfolio risk.
Solution:
Step 1: Recall the formula for portfolio variance:
𝜎𝑝
2=𝑤𝐴
2𝜎𝐴
2+𝑤𝐵
2𝜎𝐵
2+2𝑤𝐴𝑤𝐵𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 2: To minimize risk, we need to find the weights that minimize the portfolio variance. The
formula for the optimal weight of stock A is:
𝑤𝐴=𝜎𝐵
2−𝜌𝐴𝐵𝜎𝐴𝜎𝐵
𝜎𝐴
2+𝜎𝐵
2−2𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 3: Substitute the given values:
𝜎𝐴=20%= 0.20
𝜎𝐵=15% =0.15
𝜌𝐴𝐵 = 0.3
Step 4: Calculate the optimal weight of stock A:
𝑤𝐴=0.152−0.3(0.20)(0.15)
0.202+0.152−2(0.3)(0.20)(0.15)
=0.0225−0.009
0.04+0.0225−0.018
=0.0135
0.0445
≈0.3034
Step 5: Calculate the weight of stock B:
𝑤𝐵= 1−𝑤𝐴=1−0.3034 =0.6966
Therefore, the optimal portfolio weights to minimize risk are approximately 30.34% in stock A
and 69.66% in stock B.
QUESTION 3: DURATION AND CONVEXITY
A 5-year bond with a face value of $1,000 and a 6% annual coupon rate is currently priced at
$1,050. The yield to maturity is 5%. Calculate the bond’s duration and convexity.
Solution:
Step 1: Calculate the bond’s cash flows and present values:
Year
Cash Flow
PV Factor
Present Value
1
$60
0.9524
$57.14
2
$60
0.9070
$54.42
3
$60
0.8638
$51.83
4
$60
0.8227
$49.36
5
$1,060
0.7835
$830.51
Step 2: Calculate the Macaulay Duration:
𝐷 =1×57.14+2×54.42+3×51.83+4×49.36+5×830.51
1050 =4.52
Step 3: Calculate the Modified Duration:
𝑀𝐷 =𝐷
1+𝑦 =4.52
1.05= 4.30
Step 4: Calculate the Convexity:
𝐶 = 1
𝑃(1+𝑦)2∑𝑡(𝑡+1)𝐶𝐹𝑡
(1+𝑦)𝑡
𝑛
𝑡=1
𝐶 = 1
1050(1.05)2(2×57.14+6×54.42+12×51.83+20×49.36+30×830.51)=22.89
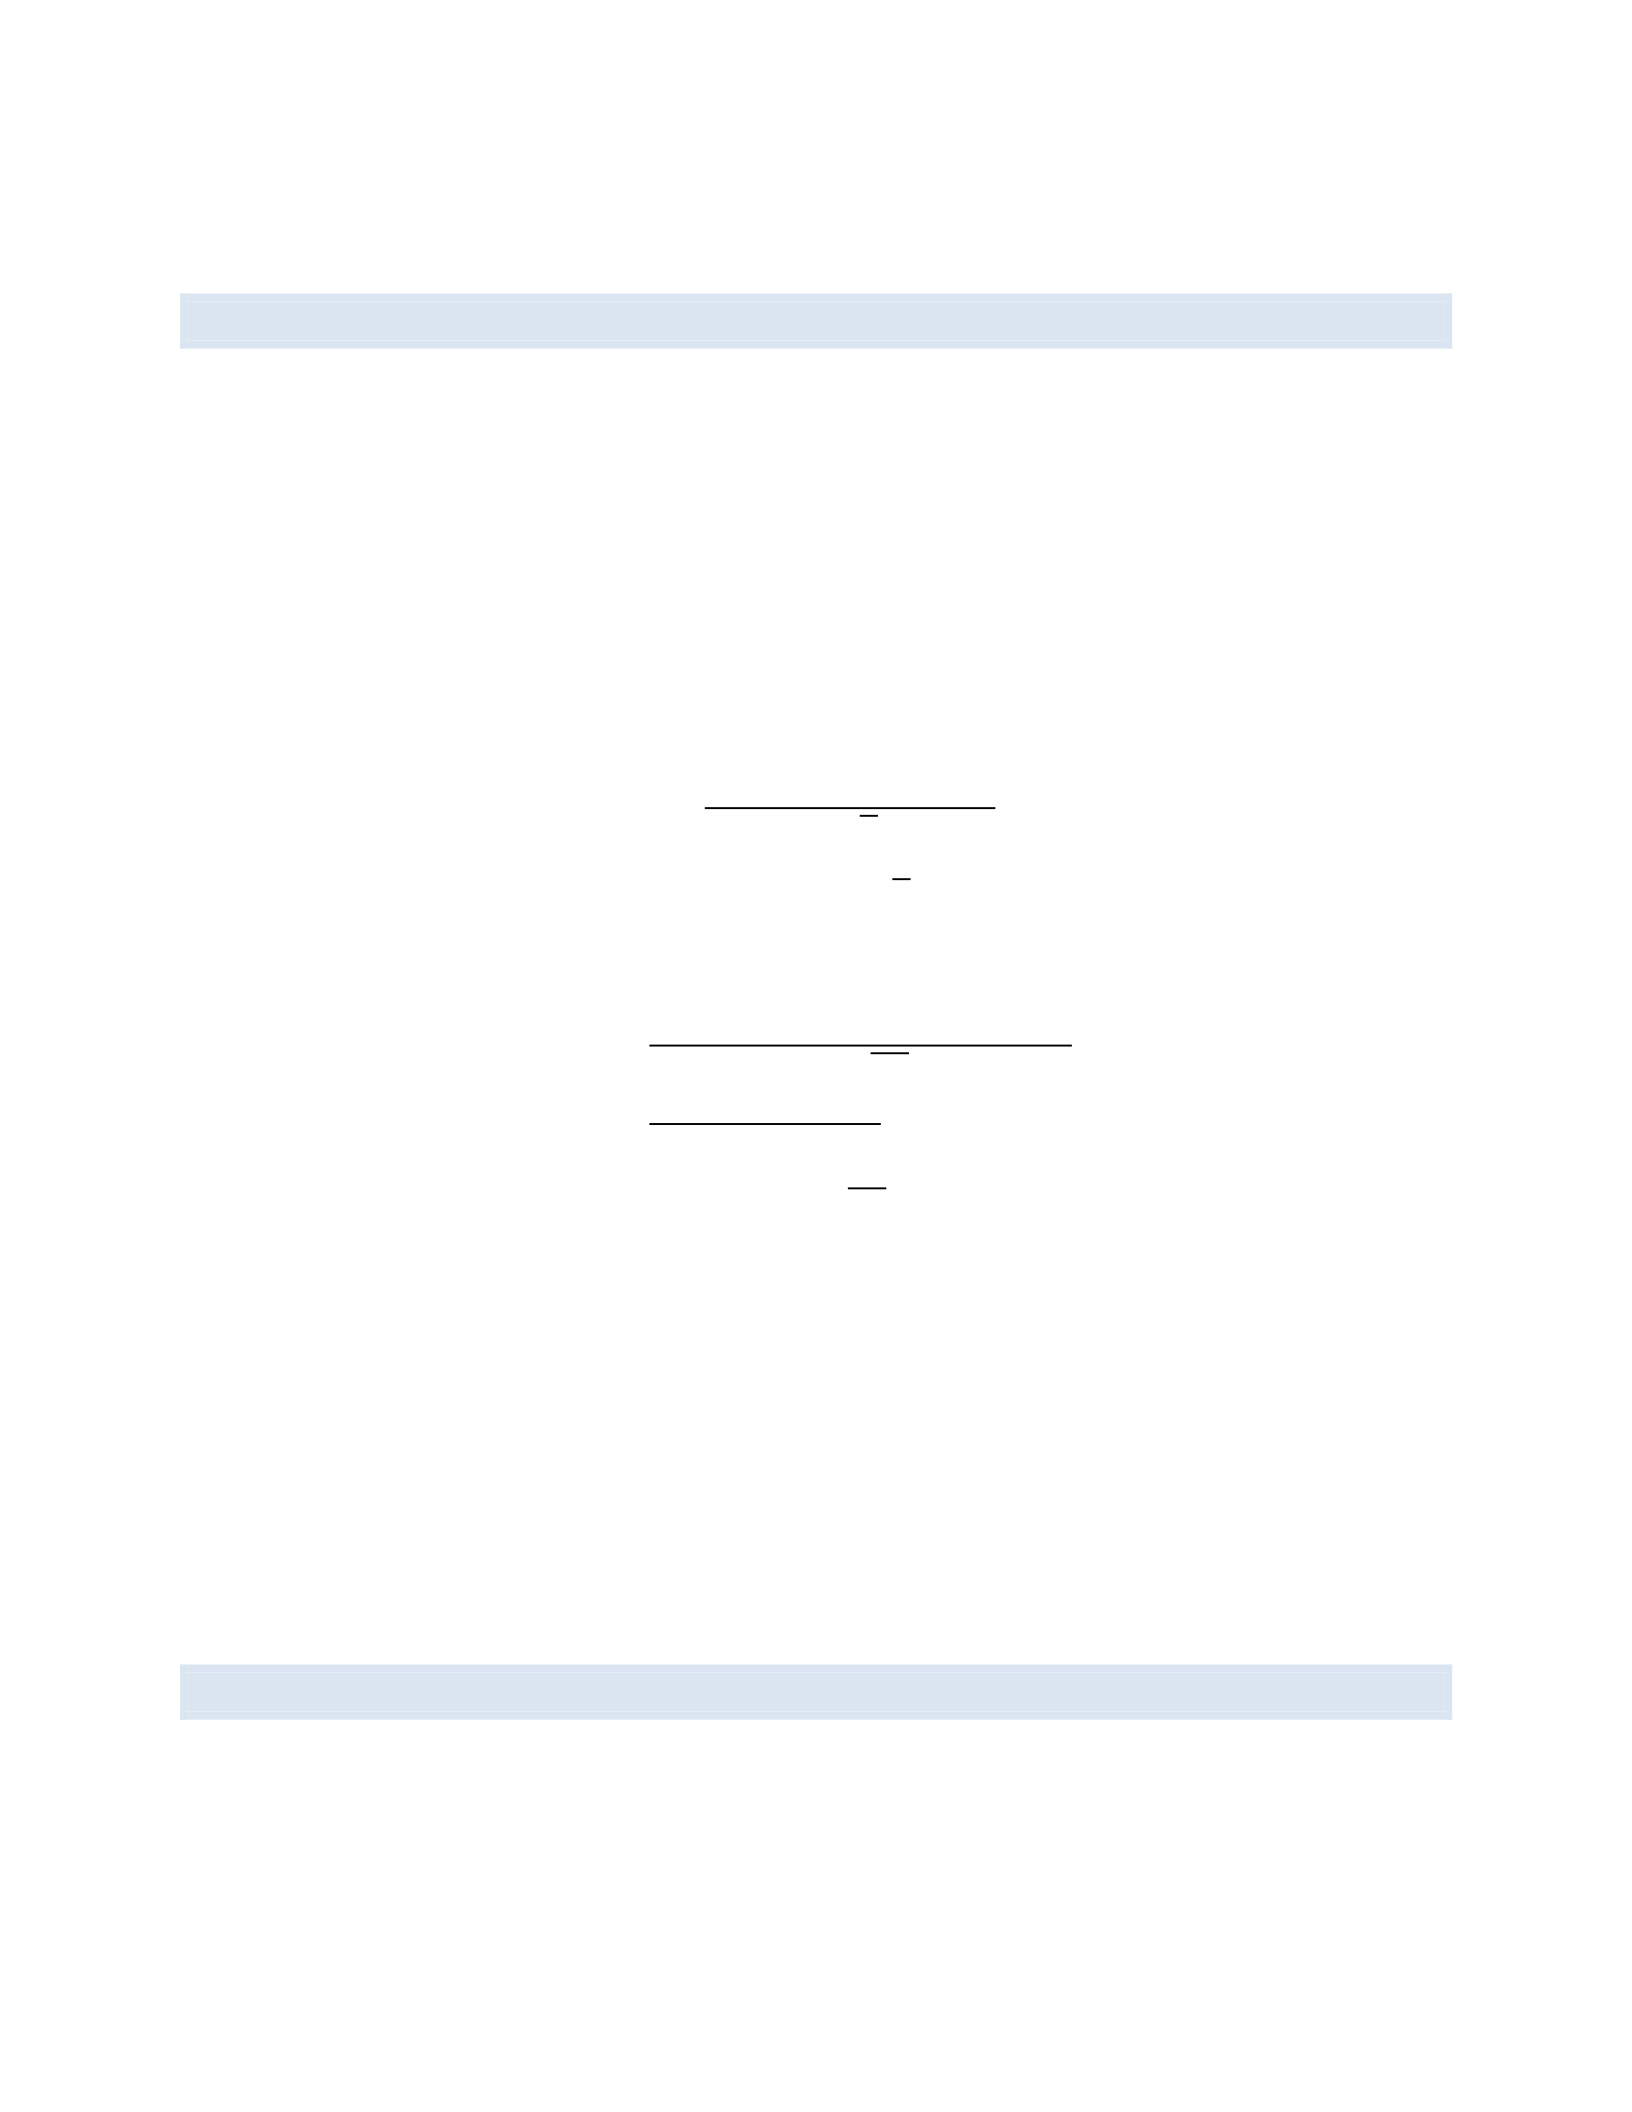
Therefore, the bond’s duration is 4.52 years (Macaulay) or 4.30 years (Modified), and its
convexity is 22.89.
QUESTION 4: BLACK-SCHOLES OPTION PRICING MODEL
Using the Black-Scholes model, calculate the price of a European call option with the following
parameters: - Current stock price (S) = $50 - Strike price (K) = $52 - Time to expiration (T) = 6
months (0.5 years) - Risk-free rate (r) = 5% per annum - Stock volatility (σ) = 30% per annum
Solution:
Step 1: Recall the Black-Scholes formula for a call option:
𝐶 =𝑆𝑁(𝑑1)−𝐾𝑒−𝑟𝑇𝑁(𝑑2)
Where:
𝑑1=ln(𝑆/𝐾)+(𝑟+𝜎2/2)𝑇
𝜎√𝑇
𝑑2=𝑑1−𝜎√𝑇
Step 2: Calculate d1 and d2:
𝑑1=ln(50/52)+(0.05+0.32/2)(0.5)
0.3√0.5
=−0.0392+0.0475
0.2121 =0.0391
𝑑2=0.0391−0.3√0.5= −0.1730
Step 3: Find N(d1) and N(d2) using a standard normal distribution table or calculator:
𝑁(𝑑1)=𝑁(0.0391)=0.5156
𝑁(𝑑2)=𝑁(−0.1730)= 0.4313
Step 4: Calculate the option price:
𝐶 =50×0.5156−52𝑒−0.05×0.5 ×0.4313
=25.78−22.17
=3.61
Therefore, the price of the European call option is $3.61.
QUESTION 5: ARBITRAGE PRICING THEORY (APT)
Consider a three-factor APT model with the following information: - Risk-free rate: 3% - Factor
risk premiums: λ1 = 4%, λ2 = 3%, λ3 = 2% - Stock A has factor sensitivities: β1 = 1.2, β2 = 0.8,
β3 = -0.5
Calculate the expected return of Stock A according to the APT model.
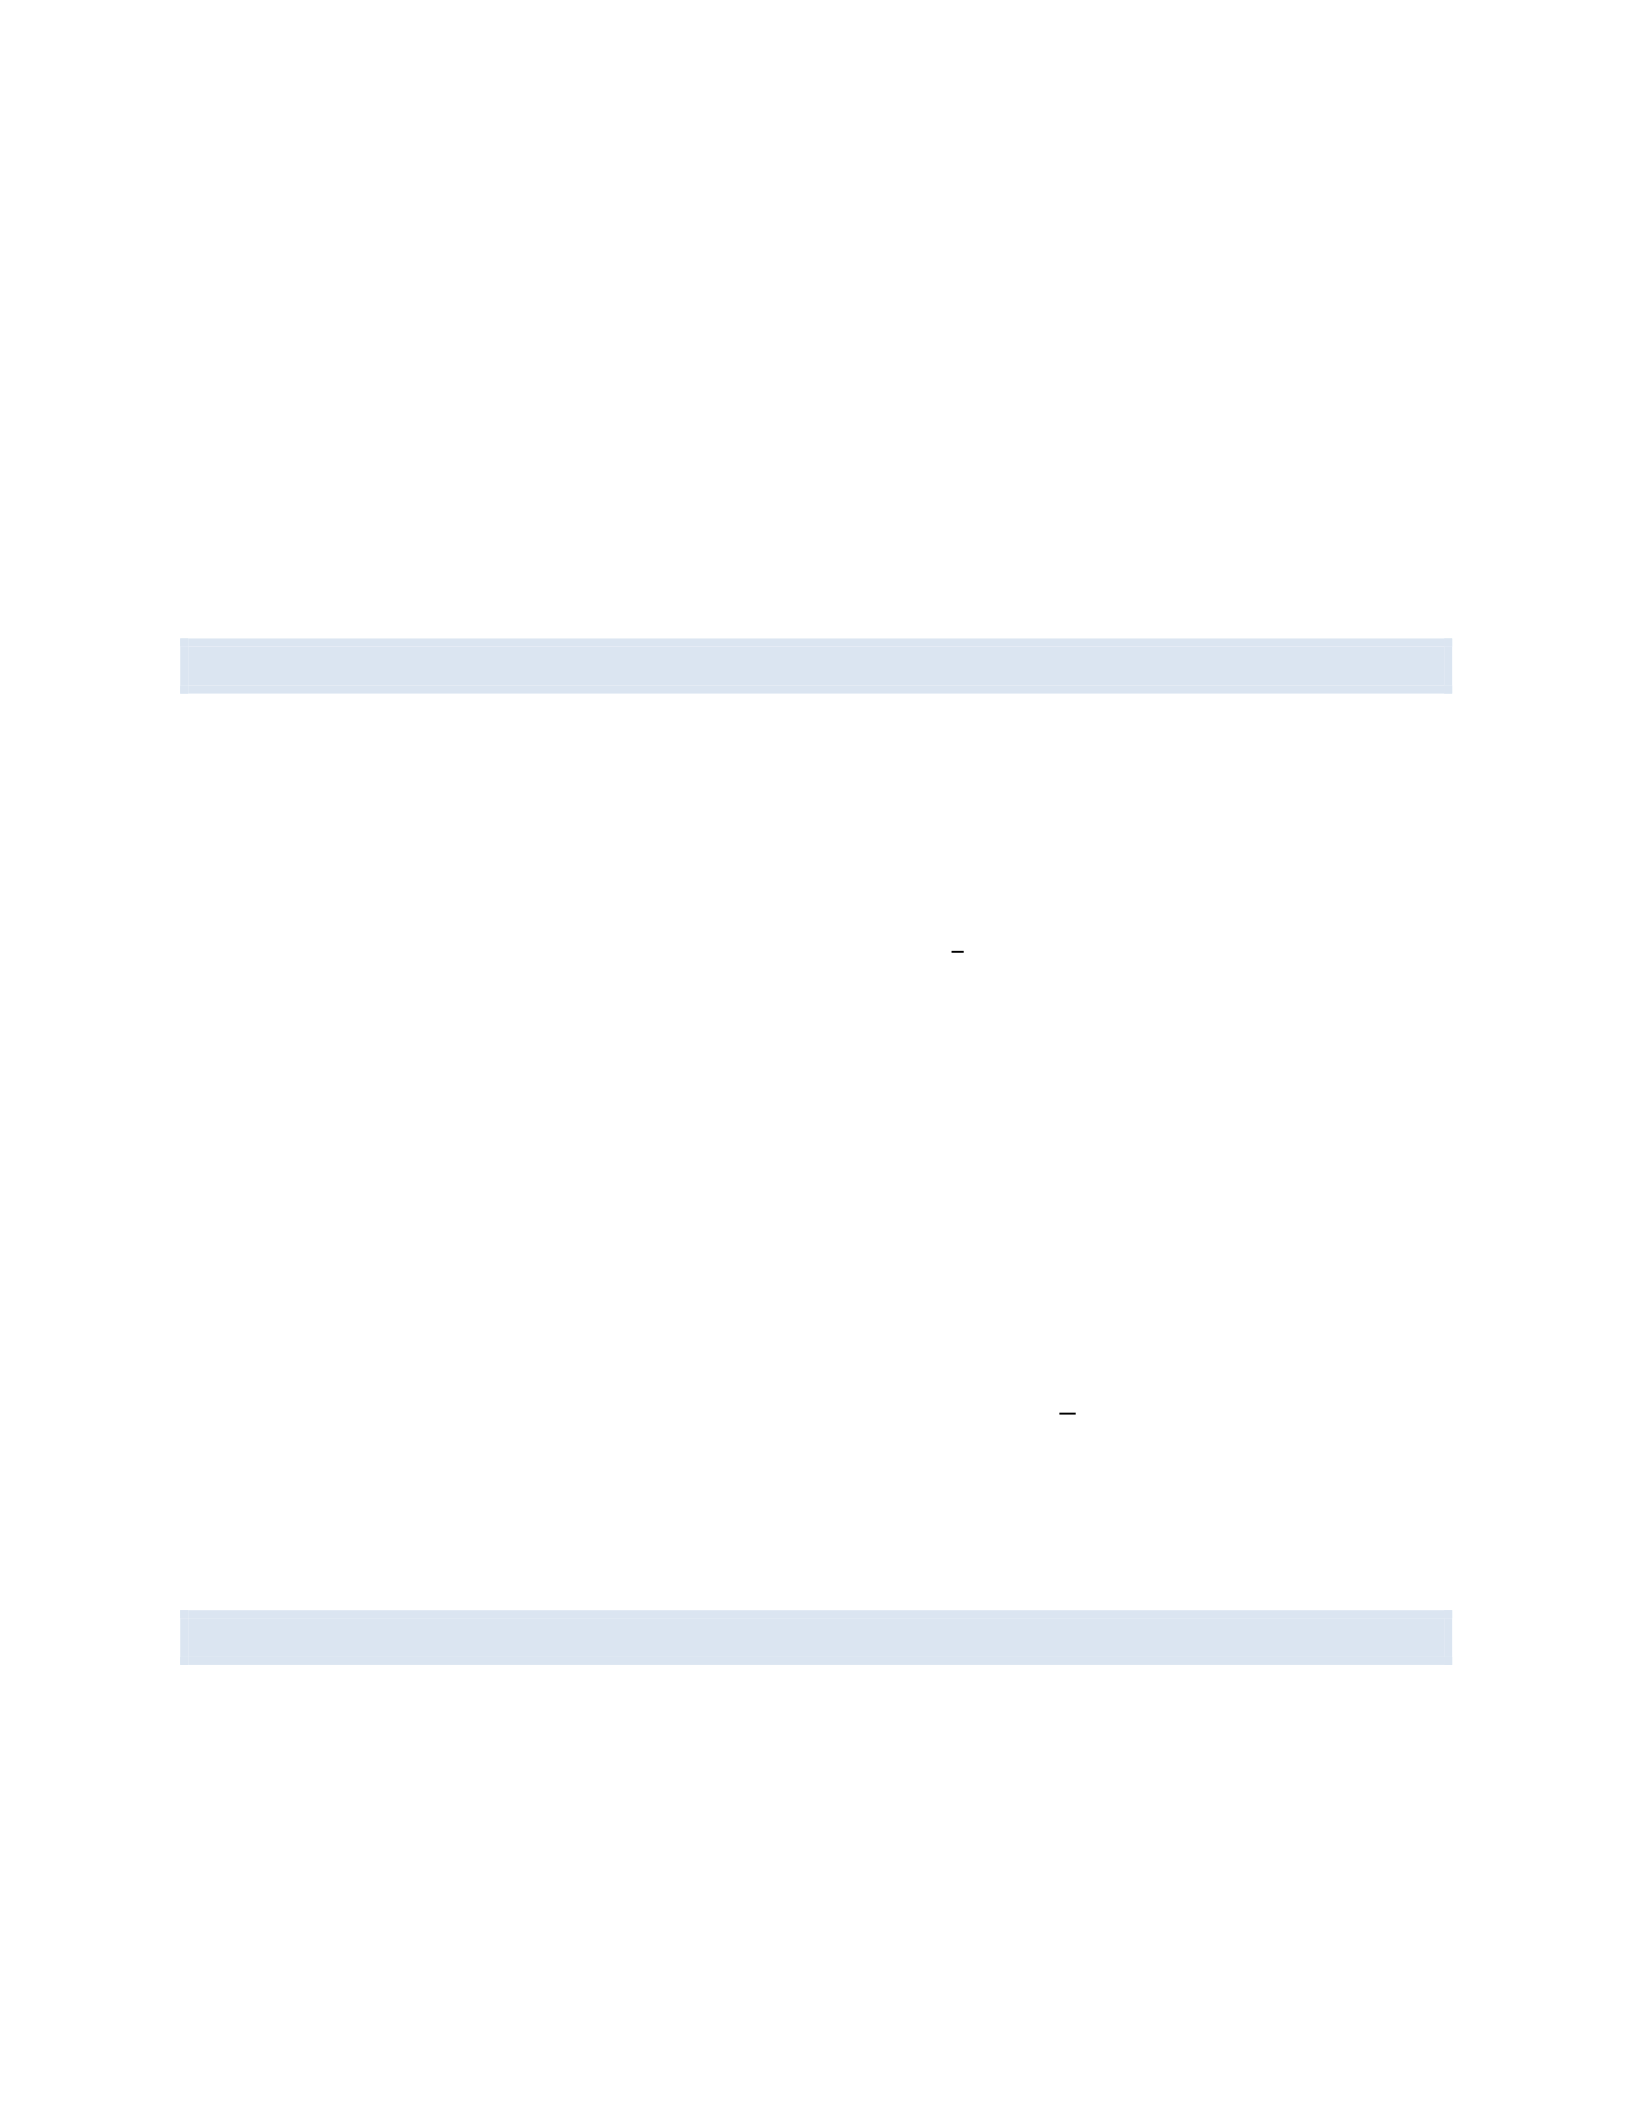
Solution:
Step 1: Recall the APT formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖1𝜆1+𝛽𝑖2𝜆2+𝛽𝑖3𝜆3
Step 2: Substitute the given values:
𝐸(𝑅𝐴)= 0.03+1.2(0.04)+0.8(0.03)+(−0.5)(0.02)
=0.03+0.048+0.024−0.01
=0.092
Therefore, the expected return of Stock A according to the APT model is 9.2%.
QUESTION 6: VALUE AT RISK (VAR)
A portfolio has a current value of $10 million and a daily volatility of 1.5%. Assuming normally
distributed returns, calculate the 1-day 99% VaR for this portfolio.
Solution:
Step 1: Recall the VaR formula for normally distributed returns:
𝑉𝑎𝑅 =𝑃×𝜎×𝑍𝛼×√𝑡
Where: - P is the portfolio value - σ is the daily volatility - Zα is the Z-score for the desired
confidence level - t is the time horizon in days
Step 2: Identify the given values:
𝑃 =$10,000,000
𝜎 =1.5% =0.015
𝑍99%= 2.33(𝑓𝑟𝑜𝑚𝑠𝑡𝑎𝑛𝑑𝑎𝑟𝑑𝑛𝑜𝑟𝑚𝑎𝑙𝑑𝑖𝑠𝑡𝑟𝑖𝑏𝑢𝑡𝑖𝑜𝑛𝑡𝑎𝑏𝑙𝑒)
𝑡 =1 day
Step 3: Calculate the VaR:
𝑉𝑎𝑅 =10,000,000×0.015×2.33×√1
=349,500
Therefore, the 1-day 99% VaR for this portfolio is $349,500. This means there is a 1% chance
that the portfolio will lose more than $349,500 in one day.
QUESTION 7: FAMA-FRENCH THREE-FACTOR MODEL
A stock has the following factor exposures: - Market factor (MKT) beta: 1.2 - Size factor (SMB)
beta: 0.5 - Value factor (HML) beta: -0.3
The risk-free rate is 2%, and the factor risk premiums are: - Market risk premium: 6% - SMB
premium: 3% - HML premium: 4%
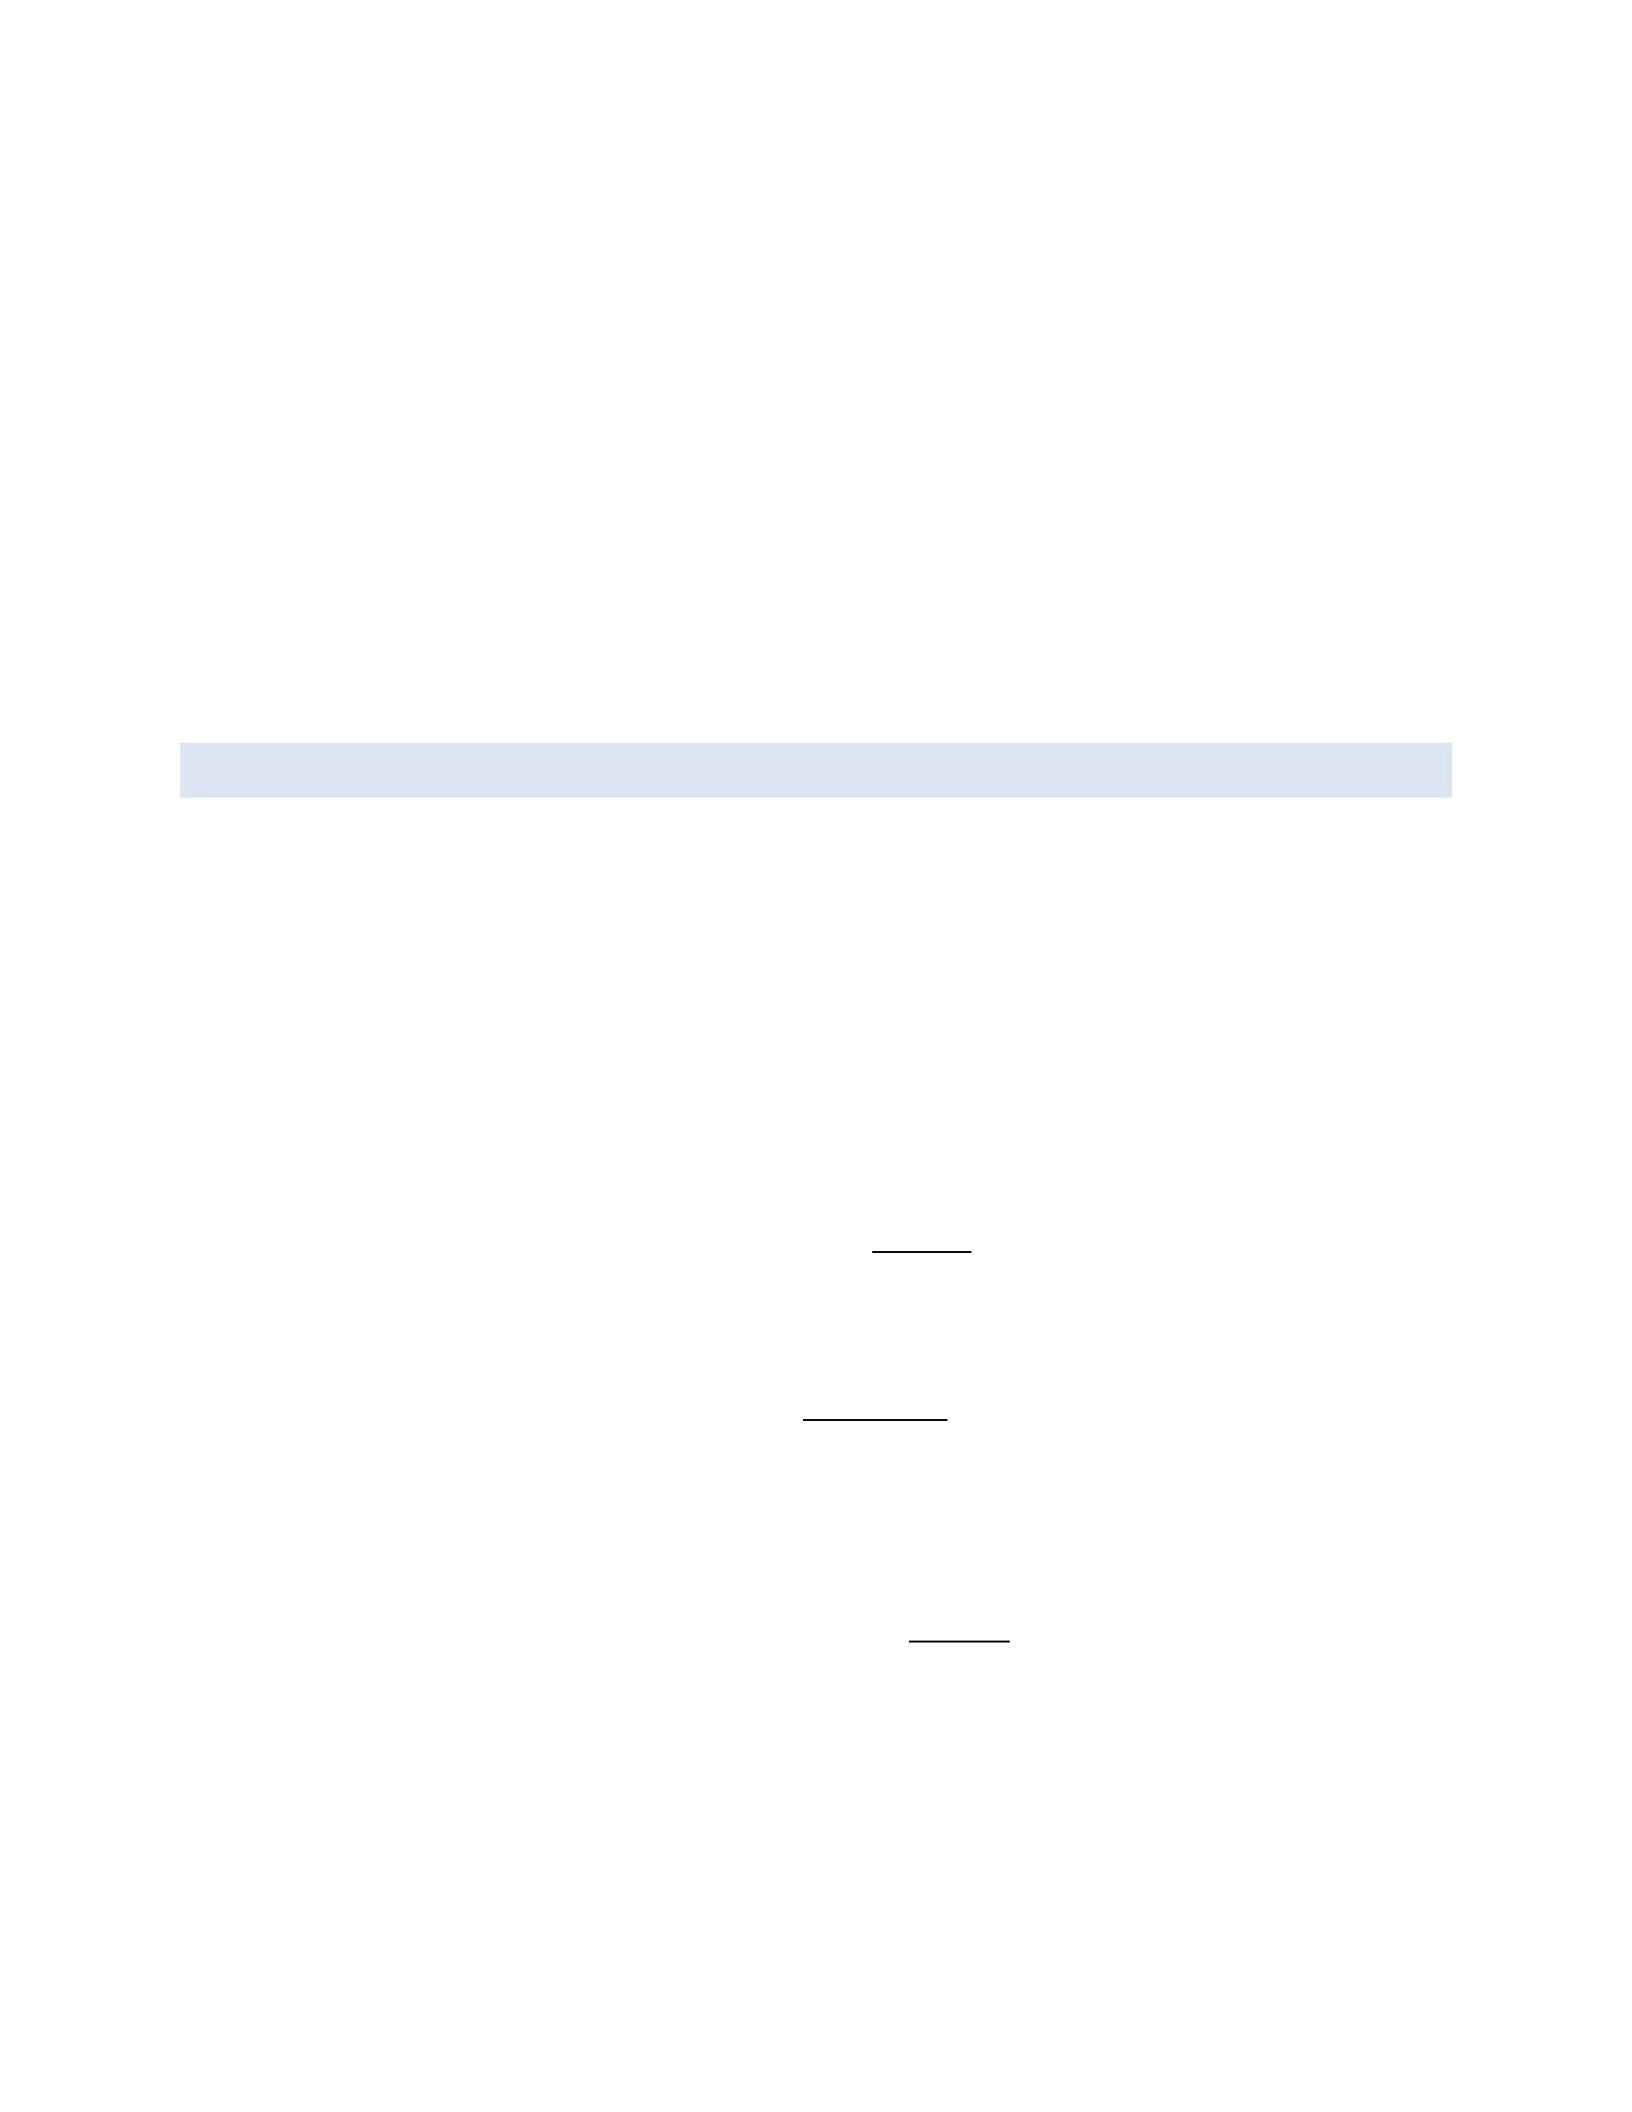
Calculate the expected return of the stock using the Fama-French Three-Factor Model.
Solution:
Step 1: Recall the Fama-French Three-Factor Model formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝑅𝑚−𝑅𝑓)+𝑠𝑖(𝑆𝑀𝐵)+ℎ𝑖(𝐻𝑀𝐿)
Step 2: Substitute the given values:
𝐸(𝑅𝑖)=0.02+1.2(0.06)+0.5(0.03)+(−0.3)(0.04)
=0.02+0.072+0.015−0.012
=0.095
Therefore, the expected return of the stock according to the Fama-French Three-Factor Model
is 9.5%.
QUESTION 8: SHARPE RATIO AND INFORMATION RATIO
A portfolio manager achieved an average annual return of 12% over the past 5 years, with a
standard deviation of 18%. The risk-free rate during this period was 3%, and the benchmark
index returned 9% with a standard deviation of 15%. Calculate:
a) The Sharpe ratio of the portfolio b) The Information ratio of the portfolio
Solution:
a) Sharpe Ratio
Step 1: Recall the Sharpe ratio formula:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑓
𝜎𝑝
Step 2: Substitute the given values:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 0.12−0.03
0.18 =0.50
b) Information Ratio
Step 1: Recall the Information ratio formula:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑏
𝜎𝑝−𝑏
Where σp-b is the standard deviation of the difference between portfolio returns and benchmark
returns (tracking error).
Step 2: Calculate the tracking error:
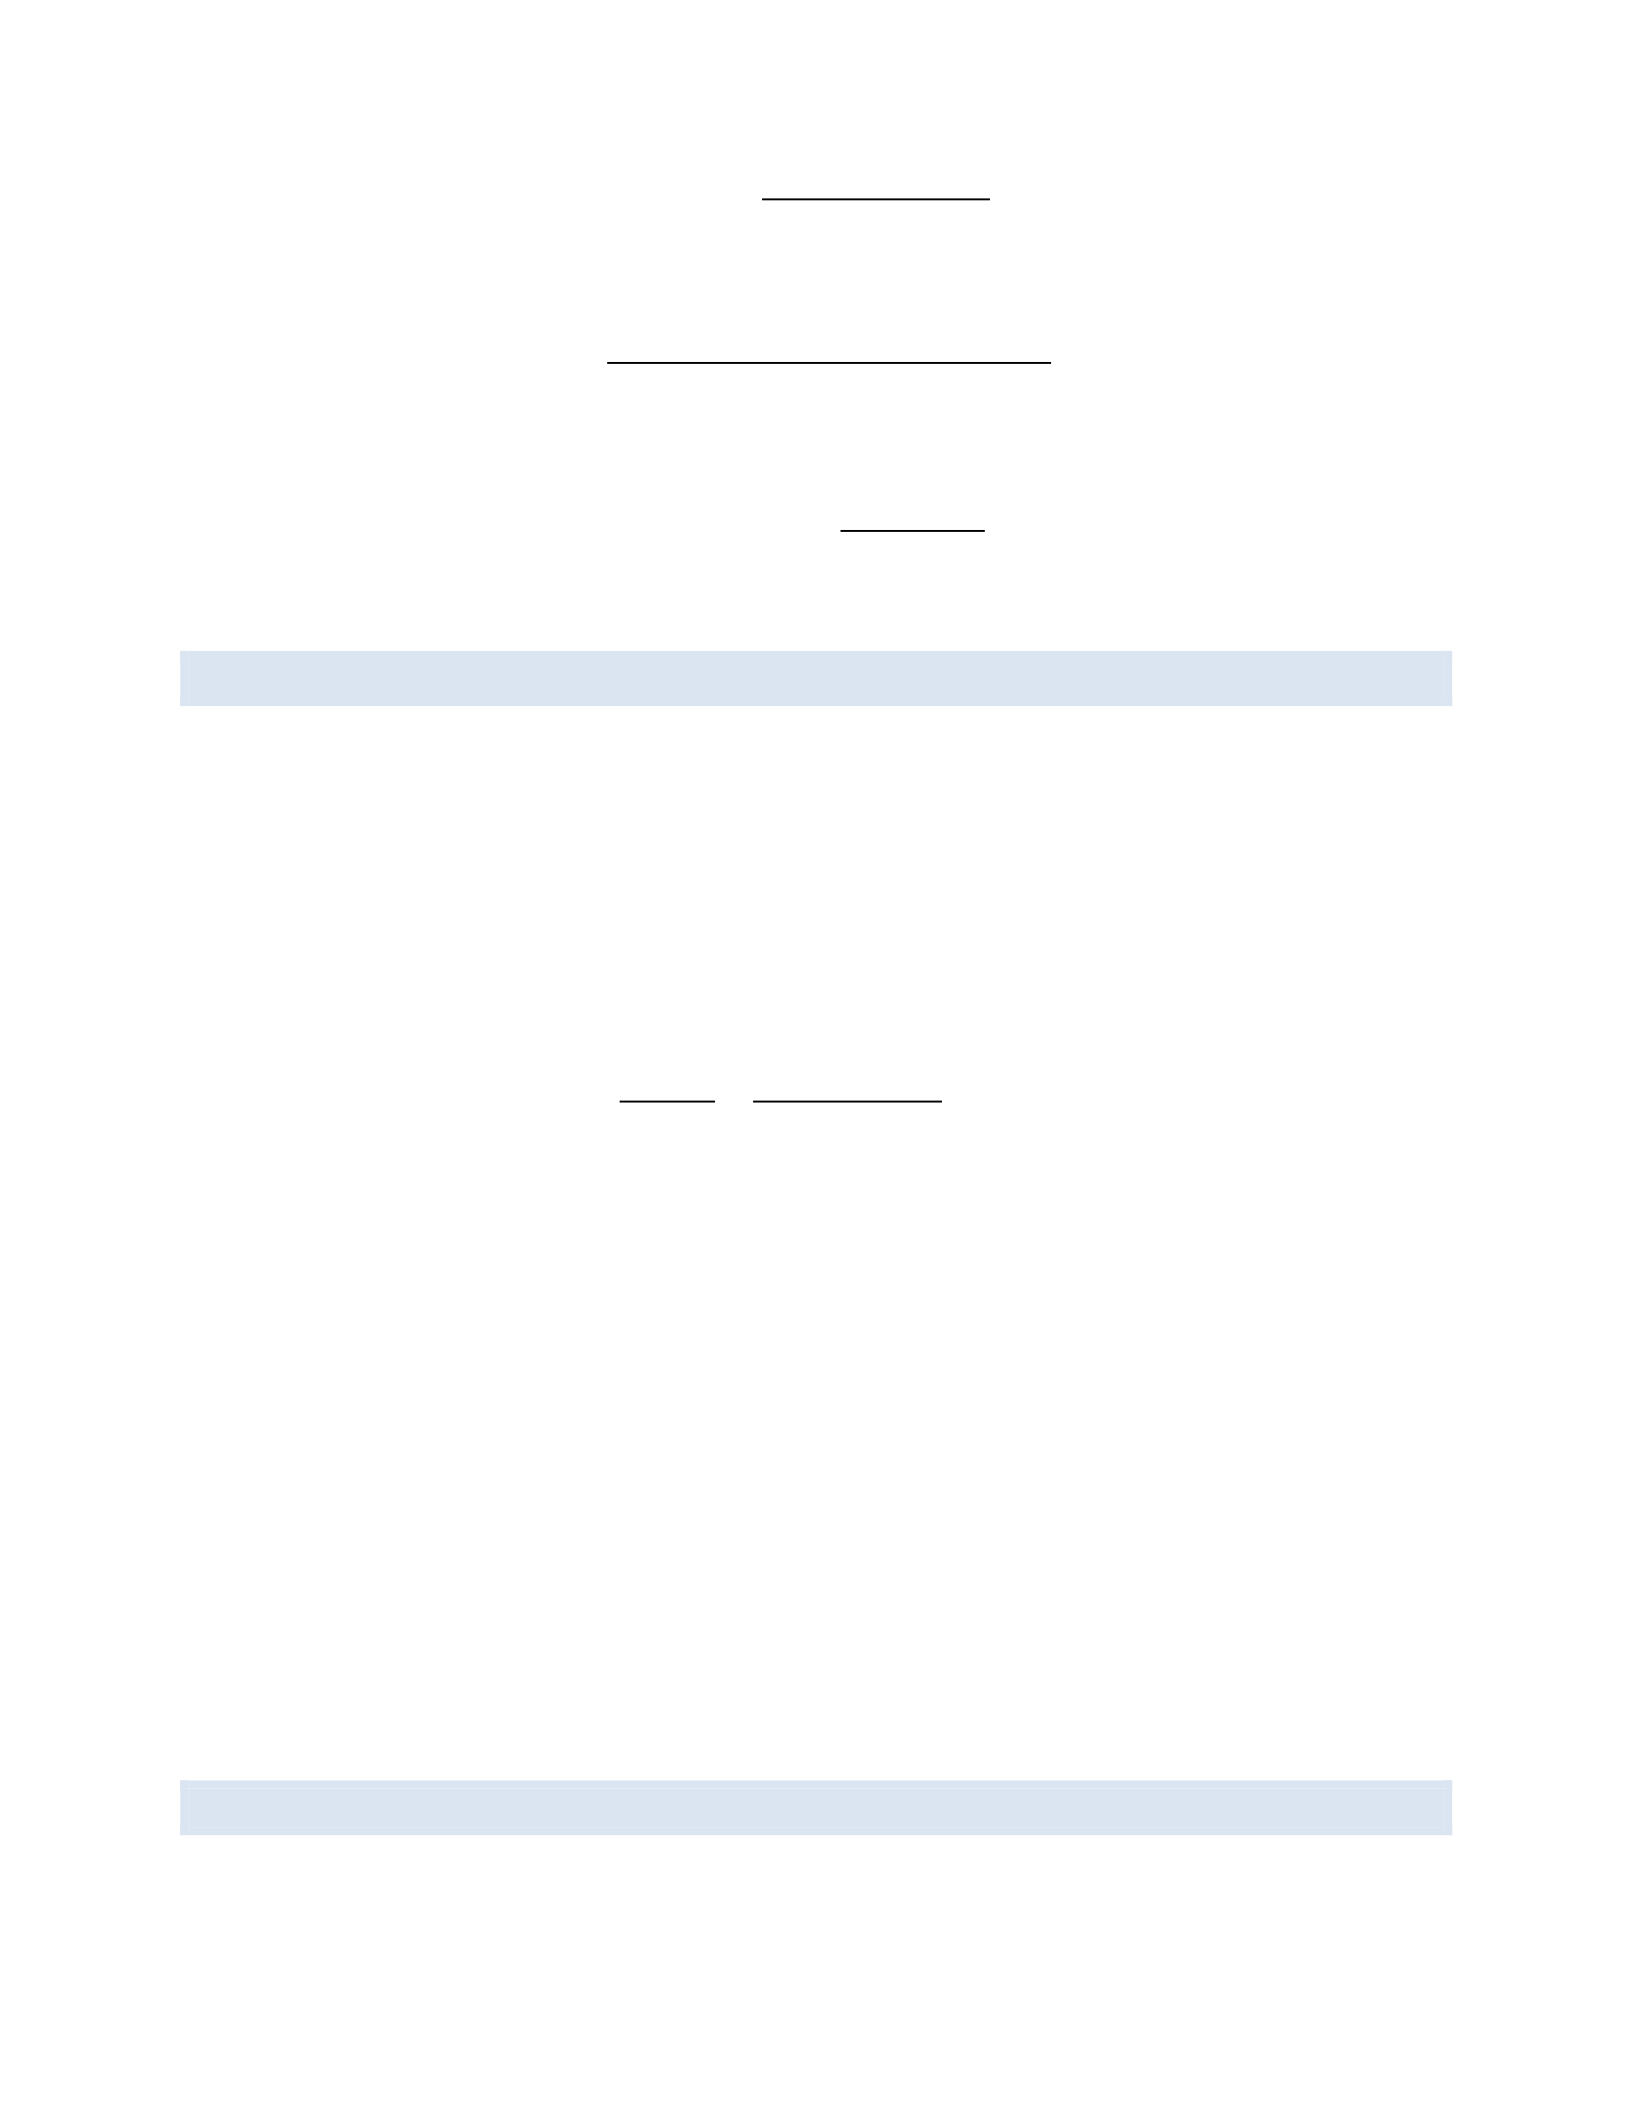
𝜎𝑝−𝑏 =√𝜎𝑝
2+𝜎𝑏
2−2𝜌𝜎𝑝𝜎𝑏
Assuming a correlation of 0.8 between the portfolio and benchmark:
𝜎𝑝−𝑏 =√0.182+0.152−2(0.8)(0.18)(0.15)=0.11
Step 3: Calculate the Information ratio:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 =0.12−0.09
0.11 =0.27
Therefore, the Sharpe ratio of the portfolio is 0.50, and the Information ratio is 0.27.
QUESTION 9: BINOMIAL OPTION PRICING MODEL (CONTINUED)
Consider a European call option with the following characteristics: - Current stock price (S0) =
$100 - Strike price (K) = $105 - Time to expiration (T) = 3 months (0.25 years) - Risk-free rate (r)
= 4% per annum - Up factor (u) = 1.1 - Down factor (d) = 0.9
Using a one-step binomial model, calculate the price of this call option.
Solution:
Step 1: Calculate the risk-neutral probability (p):
𝑝 = 𝑒𝑟𝑇 −𝑑
𝑢−𝑑 =𝑒0.04×0.25 −0.9
1.1−0.9 =0.5498
Step 2: Calculate the possible stock prices at expiration:
𝑆𝑢= 𝑆0×𝑢 = 100×1.1= $110
𝑆𝑑= 𝑆0×𝑑 = 100×0.9= $90
Step 3: Calculate the option payoffs at expiration:
𝐶𝑢=max(𝑆𝑢−𝐾,0)=max(110−105,0)=$5
𝐶𝑑=max(𝑆𝑑−𝐾,0)= max(90−105,0)=$0
Step 4: Calculate the option price using the risk-neutral valuation formula:
𝐶0=𝑒−𝑟𝑇[𝑝𝐶𝑢+(1−𝑝)𝐶𝑑]
=𝑒−0.04×0.25[0.5498×5+(1−0.5498)×0]
=0.9900×2.7490
=$2.72
Therefore, the price of the European call option using a one-step binomial model is $2.72.
QUESTION 10: PORTFOLIO PERFORMANCE ATTRIBUTION
An equity portfolio manager reported the following sector allocations and returns for the year,
along with the benchmark index data:
Sector
Portfolio Weight
Portfolio Return
Benchmark Weight
Benchmark Return
Technology
35%
12%
30%
10%
Healthcare
25%
8%
20%
7%
Financials
20%
6%
25%
5%
Consumer
15%
4%
15%
3%
Utilities
5%
2%
10%
1%
Perform a performance attribution analysis to determine the sources of the portfolio’s excess
return, breaking it down into allocation effect and selection effect.
Solution:
Step 1: Calculate the total portfolio and benchmark returns:
Portfolio return: (0.35 × 12%) + (0.25 × 8%) + (0.20 × 6%) + (0.15 × 4%) + (0.05 × 2%) = 8.50%
Benchmark return: (0.30 × 10%) + (0.20 × 7%) + (0.25 × 5%) + (0.15 × 3%) + (0.10 × 1%) =
6.40%
Excess return = 8.50% - 6.40% = 2.10%
Step 2: Calculate allocation effect for each sector: Allocation Effect = (Portfolio Weight -
Benchmark Weight) × (Benchmark Sector Return - Benchmark Total Return)
Technology: (35% - 30%) × (10% - 6.40%) = 0.18% Healthcare: (25% - 20%) × (7% - 6.40%) =
0.03% Financials: (20% - 25%) × (5% - 6.40%) = 0.07% Consumer: (15% - 15%) × (3% -
6.40%) = 0.00% Utilities: (5% - 10%) × (1% - 6.40%) = 0.27%
Total Allocation Effect = 0.18% + 0.03% + 0.07% + 0.00% + 0.27% = 0.55%
Step 3: Calculate selection effect for each sector: Selection Effect = Benchmark Weight ×
(Portfolio Sector Return - Benchmark Sector Return)
Technology: 30% × (12% - 10%) = 0.60% Healthcare: 20% × (8% - 7%) = 0.20% Financials:
25% × (6% - 5%) = 0.25% Consumer: 15% × (4% - 3%) = 0.15% Utilities: 10% × (2% - 1%) =
0.10%
Total Selection Effect = 0.60% + 0.20% + 0.25% + 0.15% + 0.10% = 1.30%
Step 4: Calculate interaction effect (optional): Interaction Effect = (Portfolio Weight - Benchmark
Weight) × (Portfolio Sector Return - Benchmark Sector Return)
Technology: (35% - 30%) × (12% - 10%) = 0.10% Healthcare: (25% - 20%) × (8% - 7%) =
0.05% Financials: (20% - 25%) × (6% - 5%) = -0.05% Consumer: (15% - 15%) × (4% - 3%) =
0.00% Utilities: (5% - 10%) × (2% - 1%) = -0.05%
Total Interaction Effect = 0.10% + 0.05% - 0.05% + 0.00% - 0.05% = 0.05%
Step 5: Summarize the attribution analysis:
Excess Return = 2.10% Allocation Effect = 0.55% Selection Effect = 1.30% Interaction Effect =
0.05% Total Attribution = 0.55% + 1.30% + 0.05% = 1.90%
The difference between the excess return (2.10%) and the total attribution (1.90%) is due to
rounding effects.
In conclusion, the portfolio’s outperformance can be attributed to: 1. Allocation Effect: 0.55%
(26.2% of excess return) 2. Selection Effect: 1.30% (61.9% of excess return) 3. Interaction
Effect: 0.05% (2.4% of excess return)
The selection effect was the primary driver of the portfolio’s excess return, indicating that the
manager’s stock selection within sectors contributed most to the outperformance.
A stock has a beta of 1.2, the risk-free rate is 3%, and the expected market return is 10%.
Calculate the expected return of the stock using the CAPM.
Solution:
Step 1: Recall the CAPM formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝐸(𝑅𝑚)−𝑅𝑓)
Step 2: Substitute the given values:
𝑅𝑓=3% =0.03
𝛽𝑖= 1.2
𝐸(𝑅𝑚)=10%= 0.10
Step 3: Calculate the expected return:
𝐸(𝑅𝑖)=0.03+1.2(0.10−0.03)
=0.03+1.2(0.07)
=0.03+0.084
=0.114
Therefore, the expected return of the stock is 11.4%.
QUESTION 2: PORTFOLIO OPTIMIZATION
An investor is considering two stocks, A and B, with the following characteristics:
Stock
Expected Return
Standard Deviation
A
12%
20%
B
8%
15%
The correlation coefficient between the two stocks is 0.3. Find the optimal portfolio weights that
minimize the portfolio risk.
Solution:
Step 1: Recall the formula for portfolio variance:
𝜎𝑝
2=𝑤𝐴
2𝜎𝐴
2+𝑤𝐵
2𝜎𝐵
2+2𝑤𝐴𝑤𝐵𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 2: To minimize risk, we need to find the weights that minimize the portfolio variance. The
formula for the optimal weight of stock A is:
𝑤𝐴=𝜎𝐵
2−𝜌𝐴𝐵𝜎𝐴𝜎𝐵
𝜎𝐴
2+𝜎𝐵
2−2𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 3: Substitute the given values:
𝜎𝐴=20%= 0.20
𝜎𝐵=15% =0.15
𝜌𝐴𝐵 = 0.3
Step 4: Calculate the optimal weight of stock A:
𝑤𝐴=0.152−0.3(0.20)(0.15)
0.202+0.152−2(0.3)(0.20)(0.15)
=0.0225−0.009
0.04+0.0225−0.018
=0.0135
0.0445
≈0.3034
Step 5: Calculate the weight of stock B:
𝑤𝐵= 1−𝑤𝐴=1−0.3034 =0.6966
Therefore, the optimal portfolio weights to minimize risk are approximately 30.34% in stock A
and 69.66% in stock B.
QUESTION 3: DURATION AND CONVEXITY
A 5-year bond with a face value of $1,000 and a 6% annual coupon rate is currently priced at
$1,050. The yield to maturity is 5%. Calculate the bond’s duration and convexity.
Solution:
Step 1: Calculate the bond’s cash flows and present values:
Year
Cash Flow
PV Factor
Present Value
1
$60
0.9524
$57.14
2
$60
0.9070
$54.42
Year
Cash Flow
PV Factor
Present Value
3
$60
0.8638
$51.83
4
$60
0.8227
$49.36
5
$1,060
0.7835
$830.51
Step 2: Calculate the Macaulay Duration:
𝐷 =1×57.14+2×54.42+3×51.83+4×49.36+5×830.51
1050 =4.52
Step 3: Calculate the Modified Duration:
𝑀𝐷 =𝐷
1+𝑦 =4.52
1.05= 4.30
Step 4: Calculate the Convexity:
𝐶 = 1
𝑃(1+𝑦)2∑𝑡(𝑡+1)𝐶𝐹𝑡
(1+𝑦)𝑡
𝑛
𝑡=1
𝐶 = 1
1050(1.05)2(2×57.14+6×54.42+12×51.83+20×49.36+30×830.51)=22.89
Therefore, the bond’s duration is 4.52 years (Macaulay) or 4.30 years (Modified), and its
convexity is 22.89.
QUESTION 4: BLACK-SCHOLES OPTION PRICING MODEL
Using the Black-Scholes model, calculate the price of a European call option with the following
parameters: - Current stock price (S) = $50 - Strike price (K) = $52 - Time to expiration (T) = 6
months (0.5 years) - Risk-free rate (r) = 5% per annum - Stock volatility (σ) = 30% per annum
Solution:
Step 1: Recall the Black-Scholes formula for a call option:
𝐶 =𝑆𝑁(𝑑1)−𝐾𝑒−𝑟𝑇𝑁(𝑑2)
Where:
𝑑1=ln(𝑆/𝐾)+(𝑟+𝜎2/2)𝑇
𝜎√𝑇
𝑑2=𝑑1−𝜎√𝑇
Step 2: Calculate d1 and d2:
𝑑1=ln(50/52)+(0.05+0.32/2)(0.5)
0.3√0.5
=−0.0392+0.0475
0.2121 =0.0391
𝑑2=0.0391−0.3√0.5= −0.1730
Step 3: Find N(d1) and N(d2) using a standard normal distribution table or calculator:
𝑁(𝑑1)=𝑁(0.0391)=0.5156
𝑁(𝑑2)=𝑁(−0.1730)= 0.4313
Step 4: Calculate the option price:
𝐶 =50×0.5156−52𝑒−0.05×0.5 ×0.4313
=25.78−22.17
=3.61
Therefore, the price of the European call option is $3.61.
QUESTION 5: ARBITRAGE PRICING THEORY (APT)
Consider a three-factor APT model with the following information: - Risk-free rate: 3% - Factor
risk premiums: λ1 = 4%, λ2 = 3%, λ3 = 2% - Stock A has factor sensitivities: β1 = 1.2, β2 = 0.8,
β3 = -0.5
Calculate the expected return of Stock A according to the APT model.
Solution:
Step 1: Recall the APT formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖1𝜆1+𝛽𝑖2𝜆2+𝛽𝑖3𝜆3
Step 2: Substitute the given values:
𝐸(𝑅𝐴)= 0.03+1.2(0.04)+0.8(0.03)+(−0.5)(0.02)
=0.03+0.048+0.024−0.01
=0.092
Therefore, the expected return of Stock A according to the APT model is 9.2%.
QUESTION 6: VALUE AT RISK (VAR)
A portfolio has a current value of $10 million and a daily volatility of 1.5%. Assuming normally
distributed returns, calculate the 1-day 99% VaR for this portfolio.
Solution:
Step 1: Recall the VaR formula for normally distributed returns:
𝑉𝑎𝑅 =𝑃×𝜎×𝑍𝛼×√𝑡
Where: - P is the portfolio value - σ is the daily volatility - Zα is the Z-score for the desired
confidence level - t is the time horizon in days
Step 2: Identify the given values:
𝑃 =$10,000,000
𝜎 =1.5% =0.015
𝑍99%= 2.33(𝑓𝑟𝑜𝑚𝑠𝑡𝑎𝑛𝑑𝑎𝑟𝑑𝑛𝑜𝑟𝑚𝑎𝑙𝑑𝑖𝑠𝑡𝑟𝑖𝑏𝑢𝑡𝑖𝑜𝑛𝑡𝑎𝑏𝑙𝑒)
𝑡 =1 day
Step 3: Calculate the VaR:
𝑉𝑎𝑅 =10,000,000×0.015×2.33×√1
=349,500
Therefore, the 1-day 99% VaR for this portfolio is $349,500. This means there is a 1% chance
that the portfolio will lose more than $349,500 in one day.
QUESTION 7: FAMA-FRENCH THREE-FACTOR MODEL
A stock has the following factor exposures: - Market factor (MKT) beta: 1.2 - Size factor (SMB)
beta: 0.5 - Value factor (HML) beta: -0.3
The risk-free rate is 2%, and the factor risk premiums are: - Market risk premium: 6% - SMB
premium: 3% - HML premium: 4%
Calculate the expected return of the stock using the Fama-French Three-Factor Model.
Solution:
Step 1: Recall the Fama-French Three-Factor Model formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝑅𝑚−𝑅𝑓)+𝑠𝑖(𝑆𝑀𝐵)+ℎ𝑖(𝐻𝑀𝐿)
Step 2: Substitute the given values:
𝐸(𝑅𝑖)=0.02+1.2(0.06)+0.5(0.03)+(−0.3)(0.04)
=0.02+0.072+0.015−0.012
=0.095
Therefore, the expected return of the stock according to the Fama-French Three-Factor Model
is 9.5%.
QUESTION 8: SHARPE RATIO AND INFORMATION RATIO
A portfolio manager achieved an average annual return of 12% over the past 5 years, with a
standard deviation of 18%. The risk-free rate during this period was 3%, and the benchmark
index returned 9% with a standard deviation of 15%. Calculate:
a) The Sharpe ratio of the portfolio b) The Information ratio of the portfolio
Solution:
a) Sharpe Ratio
Step 1: Recall the Sharpe ratio formula:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑓
𝜎𝑝
Step 2: Substitute the given values:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 0.12−0.03
0.18 =0.50
b) Information Ratio
Step 1: Recall the Information ratio formula:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑏
𝜎𝑝−𝑏
Where σp-b is the standard deviation of the difference between portfolio returns and benchmark
returns (tracking error).
Step 2: Calculate the tracking error:
𝜎𝑝−𝑏 =√𝜎𝑝
2+𝜎𝑏
2−2𝜌𝜎𝑝𝜎𝑏
Assuming a correlation of 0.8 between the portfolio and benchmark:
𝜎𝑝−𝑏 =√0.182+0.152−2(0.8)(0.18)(0.15)=0.11
Step 3: Calculate the Information ratio:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 =0.12−0.09
0.11 =0.27
Therefore, the Sharpe ratio of the portfolio is 0.50, and the Information ratio is 0.27.
QUESTION 9: BINOMIAL OPTION PRICING MODEL (CONTINUED)
Consider a European call option with the following characteristics: - Current stock price (S0) =
$100 - Strike price (K) = $105 - Time to expiration (T) = 3 months (0.25 years) - Risk-free rate (r)
= 4% per annum - Up factor (u) = 1.1 - Down factor (d) = 0.9
Using a one-step binomial model, calculate the price of this call option.
Solution:
Step 1: Calculate the risk-neutral probability (p):
𝑝 = 𝑒𝑟𝑇 −𝑑
𝑢−𝑑 =𝑒0.04×0.25 −0.9
1.1−0.9 =0.5498
Step 2: Calculate the possible stock prices at expiration:
𝑆𝑢= 𝑆0×𝑢 = 100×1.1= $110
𝑆𝑑= 𝑆0×𝑑 = 100×0.9= $90
Step 3: Calculate the option payoffs at expiration:
𝐶𝑢=max(𝑆𝑢−𝐾,0)=max(110−105,0)=$5
𝐶𝑑=max(𝑆𝑑−𝐾,0)= max(90−105,0)=$0
Step 4: Calculate the option price using the risk-neutral valuation formula:
𝐶0=𝑒−𝑟𝑇[𝑝𝐶𝑢+(1−𝑝)𝐶𝑑]
=𝑒−0.04×0.25[0.5498×5+(1−0.5498)×0]
=0.9900×2.7490
=$2.72
Therefore, the price of the European call option using a one-step binomial model is $2.72.
QUESTION 10: PORTFOLIO PERFORMANCE ATTRIBUTION
An equity portfolio manager reported the following sector allocations and returns for the year,
along with the benchmark index data:
Sector
Portfolio Weight
Portfolio Return
Benchmark Weight
Benchmark Return
Technology
35%
12%
30%
10%
Healthcare
25%
8%
20%
7%
Financials
20%
6%
25%
5%
Consumer
15%
4%
15%
3%
Utilities
5%
2%
10%
1%
Perform a performance attribution analysis to determine the sources of the portfolio’s excess
return, breaking it down into allocation effect and selection effect.
Solution:
Step 1: Calculate the total portfolio and benchmark returns:
Portfolio return: (0.35 × 12%) + (0.25 × 8%) + (0.20 × 6%) + (0.15 × 4%) + (0.05 × 2%) = 8.50%
Benchmark return: (0.30 × 10%) + (0.20 × 7%) + (0.25 × 5%) + (0.15 × 3%) + (0.10 × 1%) =
6.40%
Excess return = 8.50% - 6.40% = 2.10%

Step 2: Calculate allocation effect for each sector: Allocation Effect = (Portfolio Weight -
Benchmark Weight) × (Benchmark Sector Return - Benchmark Total Return)
Technology: (35% - 30%) × (10% - 6.40%) = 0.18% Healthcare: (25% - 20%) × (7% - 6.40%) =
0.03% Financials: (20% - 25%) × (5% - 6.40%) = 0.07% Consumer: (15% - 15%) × (3% -
6.40%) = 0.00% Utilities: (5% - 10%) × (1% - 6.40%) = 0.27%
Total Allocation Effect = 0.18% + 0.03% + 0.07% + 0.00% + 0.27% = 0.55%
Step 3: Calculate selection effect for each sector: Selection Effect = Benchmark Weight ×
(Portfolio Sector Return - Benchmark Sector Return)
Technology: 30% × (12% - 10%) = 0.60% Healthcare: 20% × (8% - 7%) = 0.20% Financials:
25% × (6% - 5%) = 0.25% Consumer: 15% × (4% - 3%) = 0.15% Utilities: 10% × (2% - 1%) =
0.10%
Total Selection Effect = 0.60% + 0.20% + 0.25% + 0.15% + 0.10% = 1.30%
Step 4: Calculate interaction effect (optional): Interaction Effect = (Portfolio Weight - Benchmark
Weight) × (Portfolio Sector Return - Benchmark Sector Return)
Technology: (35% - 30%) × (12% - 10%) = 0.10% Healthcare: (25% - 20%) × (8% - 7%) =
0.05% Financials: (20% - 25%) × (6% - 5%) = -0.05% Consumer: (15% - 15%) × (4% - 3%) =
0.00% Utilities: (5% - 10%) × (2% - 1%) = -0.05%
Total Interaction Effect = 0.10% + 0.05% - 0.05% + 0.00% - 0.05% = 0.05%
Step 5: Summarize the attribution analysis:
Excess Return = 2.10% Allocation Effect = 0.55% Selection Effect = 1.30% Interaction Effect =
0.05% Total Attribution = 0.55% + 1.30% + 0.05% = 1.90%
The difference between the excess return (2.10%) and the total attribution (1.90%) is due to
rounding effects.
In conclusion, the portfolio’s outperformance can be attributed to: 1. Allocation Effect: 0.55%
(26.2% of excess return) 2. Selection Effect: 1.30% (61.9% of excess return) 3. Interaction
Effect: 0.05% (2.4% of excess return)
The selection effect was the primary driver of the portfolio’s excess return, indicating that the
manager’s stock selection within sectors contributed most to the outperformance.
A stock has a beta of 1.2, the risk-free rate is 3%, and the expected market return is 10%.
Calculate the expected return of the stock using the CAPM.
Solution:
Step 1: Recall the CAPM formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝐸(𝑅𝑚)−𝑅𝑓)
Step 2: Substitute the given values:
𝑅𝑓=3% =0.03
𝛽𝑖= 1.2
𝐸(𝑅𝑚)=10%= 0.10
Step 3: Calculate the expected return:
𝐸(𝑅𝑖)=0.03+1.2(0.10−0.03)
=0.03+1.2(0.07)
=0.03+0.084
=0.114
Therefore, the expected return of the stock is 11.4%.
QUESTION 2: PORTFOLIO OPTIMIZATION
An investor is considering two stocks, A and B, with the following characteristics:
Stock
Expected Return
Standard Deviation
A
12%
20%
B
8%
15%
The correlation coefficient between the two stocks is 0.3. Find the optimal portfolio weights that
minimize the portfolio risk.
Solution:
Step 1: Recall the formula for portfolio variance:
𝜎𝑝
2=𝑤𝐴
2𝜎𝐴
2+𝑤𝐵
2𝜎𝐵
2+2𝑤𝐴𝑤𝐵𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 2: To minimize risk, we need to find the weights that minimize the portfolio variance. The
formula for the optimal weight of stock A is:
𝑤𝐴=𝜎𝐵
2−𝜌𝐴𝐵𝜎𝐴𝜎𝐵
𝜎𝐴
2+𝜎𝐵
2−2𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 3: Substitute the given values:
𝜎𝐴=20%= 0.20
𝜎𝐵=15% =0.15
𝜌𝐴𝐵 = 0.3
Step 4: Calculate the optimal weight of stock A:
𝑤𝐴=0.152−0.3(0.20)(0.15)
0.202+0.152−2(0.3)(0.20)(0.15)
=0.0225−0.009
0.04+0.0225−0.018
=0.0135
0.0445
≈0.3034
Step 5: Calculate the weight of stock B:
𝑤𝐵= 1−𝑤𝐴=1−0.3034 =0.6966
Therefore, the optimal portfolio weights to minimize risk are approximately 30.34% in stock A
and 69.66% in stock B.
QUESTION 3: DURATION AND CONVEXITY
A 5-year bond with a face value of $1,000 and a 6% annual coupon rate is currently priced at
$1,050. The yield to maturity is 5%. Calculate the bond’s duration and convexity.
Solution:
Step 1: Calculate the bond’s cash flows and present values:
Year
Cash Flow
PV Factor
Present Value
1
$60
0.9524
$57.14
2
$60
0.9070
$54.42
3
$60
0.8638
$51.83
4
$60
0.8227
$49.36
5
$1,060
0.7835
$830.51
Step 2: Calculate the Macaulay Duration:
𝐷 =1×57.14+2×54.42+3×51.83+4×49.36+5×830.51
1050 =4.52
Step 3: Calculate the Modified Duration:
𝑀𝐷 =𝐷
1+𝑦 =4.52
1.05= 4.30
Step 4: Calculate the Convexity:
𝐶 = 1
𝑃(1+𝑦)2∑𝑡(𝑡+1)𝐶𝐹𝑡
(1+𝑦)𝑡
𝑛
𝑡=1
𝐶 = 1
1050(1.05)2(2×57.14+6×54.42+12×51.83+20×49.36+30×830.51)=22.89
Therefore, the bond’s duration is 4.52 years (Macaulay) or 4.30 years (Modified), and its
convexity is 22.89.
QUESTION 4: BLACK-SCHOLES OPTION PRICING MODEL
Using the Black-Scholes model, calculate the price of a European call option with the following
parameters: - Current stock price (S) = $50 - Strike price (K) = $52 - Time to expiration (T) = 6
months (0.5 years) - Risk-free rate (r) = 5% per annum - Stock volatility (σ) = 30% per annum
Solution:
Step 1: Recall the Black-Scholes formula for a call option:
𝐶 =𝑆𝑁(𝑑1)−𝐾𝑒−𝑟𝑇𝑁(𝑑2)
Where:
𝑑1=ln(𝑆/𝐾)+(𝑟+𝜎2/2)𝑇
𝜎√𝑇
𝑑2=𝑑1−𝜎√𝑇
Step 2: Calculate d1 and d2:
𝑑1=ln(50/52)+(0.05+0.32/2)(0.5)
0.3√0.5
=−0.0392+0.0475
0.2121 =0.0391
𝑑2=0.0391−0.3√0.5= −0.1730
Step 3: Find N(d1) and N(d2) using a standard normal distribution table or calculator:
𝑁(𝑑1)=𝑁(0.0391)=0.5156
𝑁(𝑑2)=𝑁(−0.1730)= 0.4313
Step 4: Calculate the option price:
𝐶 =50×0.5156−52𝑒−0.05×0.5 ×0.4313
=25.78−22.17
=3.61
Therefore, the price of the European call option is $3.61.
QUESTION 5: ARBITRAGE PRICING THEORY (APT)
Consider a three-factor APT model with the following information: - Risk-free rate: 3% - Factor
risk premiums: λ1 = 4%, λ2 = 3%, λ3 = 2% - Stock A has factor sensitivities: β1 = 1.2, β2 = 0.8,
β3 = -0.5
Calculate the expected return of Stock A according to the APT model.
Solution:
Step 1: Recall the APT formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖1𝜆1+𝛽𝑖2𝜆2+𝛽𝑖3𝜆3
Step 2: Substitute the given values:
𝐸(𝑅𝐴)= 0.03+1.2(0.04)+0.8(0.03)+(−0.5)(0.02)
=0.03+0.048+0.024−0.01
=0.092
Therefore, the expected return of Stock A according to the APT model is 9.2%.
QUESTION 6: VALUE AT RISK (VAR)
A portfolio has a current value of $10 million and a daily volatility of 1.5%. Assuming normally
distributed returns, calculate the 1-day 99% VaR for this portfolio.
Solution:
Step 1: Recall the VaR formula for normally distributed returns:
𝑉𝑎𝑅 =𝑃×𝜎×𝑍𝛼×√𝑡
Where: - P is the portfolio value - σ is the daily volatility - Zα is the Z-score for the desired
confidence level - t is the time horizon in days
Step 2: Identify the given values:
𝑃 =$10,000,000
𝜎 =1.5% =0.015
𝑍99%= 2.33(𝑓𝑟𝑜𝑚𝑠𝑡𝑎𝑛𝑑𝑎𝑟𝑑𝑛𝑜𝑟𝑚𝑎𝑙𝑑𝑖𝑠𝑡𝑟𝑖𝑏𝑢𝑡𝑖𝑜𝑛𝑡𝑎𝑏𝑙𝑒)
𝑡 =1 day
Step 3: Calculate the VaR:
𝑉𝑎𝑅 =10,000,000×0.015×2.33×√1
=349,500
Therefore, the 1-day 99% VaR for this portfolio is $349,500. This means there is a 1% chance
that the portfolio will lose more than $349,500 in one day.
QUESTION 7: FAMA-FRENCH THREE-FACTOR MODEL
A stock has the following factor exposures: - Market factor (MKT) beta: 1.2 - Size factor (SMB)
beta: 0.5 - Value factor (HML) beta: -0.3
The risk-free rate is 2%, and the factor risk premiums are: - Market risk premium: 6% - SMB
premium: 3% - HML premium: 4%
Calculate the expected return of the stock using the Fama-French Three-Factor Model.
Solution:
Step 1: Recall the Fama-French Three-Factor Model formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝑅𝑚−𝑅𝑓)+𝑠𝑖(𝑆𝑀𝐵)+ℎ𝑖(𝐻𝑀𝐿)
Step 2: Substitute the given values:
𝐸(𝑅𝑖)=0.02+1.2(0.06)+0.5(0.03)+(−0.3)(0.04)
=0.02+0.072+0.015−0.012
=0.095
Therefore, the expected return of the stock according to the Fama-French Three-Factor Model
is 9.5%.
QUESTION 8: SHARPE RATIO AND INFORMATION RATIO
A portfolio manager achieved an average annual return of 12% over the past 5 years, with a
standard deviation of 18%. The risk-free rate during this period was 3%, and the benchmark
index returned 9% with a standard deviation of 15%. Calculate:
a) The Sharpe ratio of the portfolio b) The Information ratio of the portfolio
Solution:
a) Sharpe Ratio
Step 1: Recall the Sharpe ratio formula:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑓
𝜎𝑝
Step 2: Substitute the given values:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 0.12−0.03
0.18 =0.50
b) Information Ratio
Step 1: Recall the Information ratio formula:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑏
𝜎𝑝−𝑏
Where σp-b is the standard deviation of the difference between portfolio returns and benchmark
returns (tracking error).
Step 2: Calculate the tracking error:
𝜎𝑝−𝑏 =√𝜎𝑝
2+𝜎𝑏
2−2𝜌𝜎𝑝𝜎𝑏
Assuming a correlation of 0.8 between the portfolio and benchmark:
𝜎𝑝−𝑏 =√0.182+0.152−2(0.8)(0.18)(0.15)=0.11
Step 3: Calculate the Information ratio:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 =0.12−0.09
0.11 =0.27
Therefore, the Sharpe ratio of the portfolio is 0.50, and the Information ratio is 0.27.
QUESTION 9: BINOMIAL OPTION PRICING MODEL (CONTINUED)
Consider a European call option with the following characteristics: - Current stock price (S0) =
$100 - Strike price (K) = $105 - Time to expiration (T) = 3 months (0.25 years) - Risk-free rate (r)
= 4% per annum - Up factor (u) = 1.1 - Down factor (d) = 0.9
Using a one-step binomial model, calculate the price of this call option.
Solution:
Step 1: Calculate the risk-neutral probability (p):
𝑝 = 𝑒𝑟𝑇 −𝑑
𝑢−𝑑 =𝑒0.04×0.25 −0.9
1.1−0.9 =0.5498
Step 2: Calculate the possible stock prices at expiration:
𝑆𝑢= 𝑆0×𝑢 = 100×1.1= $110
𝑆𝑑= 𝑆0×𝑑 = 100×0.9= $90
Step 3: Calculate the option payoffs at expiration:
𝐶𝑢=max(𝑆𝑢−𝐾,0)=max(110−105,0)=$5
𝐶𝑑=max(𝑆𝑑−𝐾,0)= max(90−105,0)=$0
Step 4: Calculate the option price using the risk-neutral valuation formula:
𝐶0=𝑒−𝑟𝑇[𝑝𝐶𝑢+(1−𝑝)𝐶𝑑]
=𝑒−0.04×0.25[0.5498×5+(1−0.5498)×0]
=0.9900×2.7490
=$2.72
Therefore, the price of the European call option using a one-step binomial model is $2.72.
QUESTION 10: PORTFOLIO PERFORMANCE ATTRIBUTION
An equity portfolio manager reported the following sector allocations and returns for the year,
along with the benchmark index data:
Sector
Portfolio Weight
Portfolio Return
Benchmark Weight
Benchmark Return
Technology
35%
12%
30%
10%
Healthcare
25%
8%
20%
7%
Financials
20%
6%
25%
5%
Consumer
15%
4%
15%
3%
Utilities
5%
2%
10%
1%
Perform a performance attribution analysis to determine the sources of the portfolio’s excess
return, breaking it down into allocation effect and selection effect.
Solution:
Step 1: Calculate the total portfolio and benchmark returns:
Portfolio return: (0.35 × 12%) + (0.25 × 8%) + (0.20 × 6%) + (0.15 × 4%) + (0.05 × 2%) = 8.50%
Benchmark return: (0.30 × 10%) + (0.20 × 7%) + (0.25 × 5%) + (0.15 × 3%) + (0.10 × 1%) =
6.40%
Excess return = 8.50% - 6.40% = 2.10%
Step 2: Calculate allocation effect for each sector: Allocation Effect = (Portfolio Weight -
Benchmark Weight) × (Benchmark Sector Return - Benchmark Total Return)
Technology: (35% - 30%) × (10% - 6.40%) = 0.18% Healthcare: (25% - 20%) × (7% - 6.40%) =
0.03% Financials: (20% - 25%) × (5% - 6.40%) = 0.07% Consumer: (15% - 15%) × (3% -
6.40%) = 0.00% Utilities: (5% - 10%) × (1% - 6.40%) = 0.27%
Total Allocation Effect = 0.18% + 0.03% + 0.07% + 0.00% + 0.27% = 0.55%
Step 3: Calculate selection effect for each sector: Selection Effect = Benchmark Weight ×
(Portfolio Sector Return - Benchmark Sector Return)
Technology: 30% × (12% - 10%) = 0.60% Healthcare: 20% × (8% - 7%) = 0.20% Financials:
25% × (6% - 5%) = 0.25% Consumer: 15% × (4% - 3%) = 0.15% Utilities: 10% × (2% - 1%) =
0.10%
Total Selection Effect = 0.60% + 0.20% + 0.25% + 0.15% + 0.10% = 1.30%
Step 4: Calculate interaction effect (optional): Interaction Effect = (Portfolio Weight - Benchmark
Weight) × (Portfolio Sector Return - Benchmark Sector Return)
Technology: (35% - 30%) × (12% - 10%) = 0.10% Healthcare: (25% - 20%) × (8% - 7%) =
0.05% Financials: (20% - 25%) × (6% - 5%) = -0.05% Consumer: (15% - 15%) × (4% - 3%) =
0.00% Utilities: (5% - 10%) × (2% - 1%) = -0.05%
Total Interaction Effect = 0.10% + 0.05% - 0.05% + 0.00% - 0.05% = 0.05%
Step 5: Summarize the attribution analysis:
Excess Return = 2.10% Allocation Effect = 0.55% Selection Effect = 1.30% Interaction Effect =
0.05% Total Attribution = 0.55% + 1.30% + 0.05% = 1.90%
The difference between the excess return (2.10%) and the total attribution (1.90%) is due to
rounding effects.
In conclusion, the portfolio’s outperformance can be attributed to: 1. Allocation Effect: 0.55%
(26.2% of excess return) 2. Selection Effect: 1.30% (61.9% of excess return) 3. Interaction
Effect: 0.05% (2.4% of excess return)
The selection effect was the primary driver of the portfolio’s excess return, indicating that the
manager’s stock selection within sectors contributed most to the outperformance.
A stock has a beta of 1.2, the risk-free rate is 3%, and the expected market return is 10%.
Calculate the expected return of the stock using the CAPM.
Solution:
Step 1: Recall the CAPM formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝐸(𝑅𝑚)−𝑅𝑓)
Step 2: Substitute the given values:
𝑅𝑓=3% =0.03
𝛽𝑖= 1.2
𝐸(𝑅𝑚)=10%= 0.10
Step 3: Calculate the expected return:
𝐸(𝑅𝑖)=0.03+1.2(0.10−0.03)
=0.03+1.2(0.07)
=0.03+0.084
=0.114
Therefore, the expected return of the stock is 11.4%.
QUESTION 2: PORTFOLIO OPTIMIZATION
An investor is considering two stocks, A and B, with the following characteristics:
Stock
Expected Return
Standard Deviation
A
12%
20%
B
8%
15%
The correlation coefficient between the two stocks is 0.3. Find the optimal portfolio weights that
minimize the portfolio risk.
Solution:
Step 1: Recall the formula for portfolio variance:
𝜎𝑝
2=𝑤𝐴
2𝜎𝐴
2+𝑤𝐵
2𝜎𝐵
2+2𝑤𝐴𝑤𝐵𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 2: To minimize risk, we need to find the weights that minimize the portfolio variance. The
formula for the optimal weight of stock A is:
𝑤𝐴=𝜎𝐵
2−𝜌𝐴𝐵𝜎𝐴𝜎𝐵
𝜎𝐴
2+𝜎𝐵
2−2𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 3: Substitute the given values:
𝜎𝐴=20%= 0.20
𝜎𝐵=15% =0.15
𝜌𝐴𝐵 = 0.3
Step 4: Calculate the optimal weight of stock A:
𝑤𝐴=0.152−0.3(0.20)(0.15)
0.202+0.152−2(0.3)(0.20)(0.15)
=0.0225−0.009
0.04+0.0225−0.018
=0.0135
0.0445
≈0.3034
Step 5: Calculate the weight of stock B:
𝑤𝐵= 1−𝑤𝐴=1−0.3034 =0.6966
Therefore, the optimal portfolio weights to minimize risk are approximately 30.34% in stock A
and 69.66% in stock B.
QUESTION 3: DURATION AND CONVEXITY
A 5-year bond with a face value of $1,000 and a 6% annual coupon rate is currently priced at
$1,050. The yield to maturity is 5%. Calculate the bond’s duration and convexity.
Solution:
Step 1: Calculate the bond’s cash flows and present values:
Year
Cash Flow
PV Factor
Present Value
1
$60
0.9524
$57.14
2
$60
0.9070
$54.42
Year
Cash Flow
PV Factor
Present Value
3
$60
0.8638
$51.83
4
$60
0.8227
$49.36
5
$1,060
0.7835
$830.51
Step 2: Calculate the Macaulay Duration:
𝐷 =1×57.14+2×54.42+3×51.83+4×49.36+5×830.51
1050 =4.52
Step 3: Calculate the Modified Duration:
𝑀𝐷 =𝐷
1+𝑦 =4.52
1.05= 4.30
Step 4: Calculate the Convexity:
𝐶 = 1
𝑃(1+𝑦)2∑𝑡(𝑡+1)𝐶𝐹𝑡
(1+𝑦)𝑡
𝑛
𝑡=1
𝐶 = 1
1050(1.05)2(2×57.14+6×54.42+12×51.83+20×49.36+30×830.51)=22.89
Therefore, the bond’s duration is 4.52 years (Macaulay) or 4.30 years (Modified), and its
convexity is 22.89.
QUESTION 4: BLACK-SCHOLES OPTION PRICING MODEL
Using the Black-Scholes model, calculate the price of a European call option with the following
parameters: - Current stock price (S) = $50 - Strike price (K) = $52 - Time to expiration (T) = 6
months (0.5 years) - Risk-free rate (r) = 5% per annum - Stock volatility (σ) = 30% per annum
Solution:
Step 1: Recall the Black-Scholes formula for a call option:
𝐶 =𝑆𝑁(𝑑1)−𝐾𝑒−𝑟𝑇𝑁(𝑑2)
Where:
𝑑1=ln(𝑆/𝐾)+(𝑟+𝜎2/2)𝑇
𝜎√𝑇
𝑑2=𝑑1−𝜎√𝑇
Step 2: Calculate d1 and d2:
𝑑1=ln(50/52)+(0.05+0.32/2)(0.5)
0.3√0.5
=−0.0392+0.0475
0.2121 =0.0391
𝑑2=0.0391−0.3√0.5= −0.1730
Step 3: Find N(d1) and N(d2) using a standard normal distribution table or calculator:
𝑁(𝑑1)=𝑁(0.0391)=0.5156
𝑁(𝑑2)=𝑁(−0.1730)= 0.4313
Step 4: Calculate the option price:
𝐶 =50×0.5156−52𝑒−0.05×0.5 ×0.4313
=25.78−22.17
=3.61
Therefore, the price of the European call option is $3.61.
QUESTION 5: ARBITRAGE PRICING THEORY (APT)
Consider a three-factor APT model with the following information: - Risk-free rate: 3% - Factor
risk premiums: λ1 = 4%, λ2 = 3%, λ3 = 2% - Stock A has factor sensitivities: β1 = 1.2, β2 = 0.8,
β3 = -0.5
Calculate the expected return of Stock A according to the APT model.
Solution:
Step 1: Recall the APT formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖1𝜆1+𝛽𝑖2𝜆2+𝛽𝑖3𝜆3
Step 2: Substitute the given values:
𝐸(𝑅𝐴)= 0.03+1.2(0.04)+0.8(0.03)+(−0.5)(0.02)
=0.03+0.048+0.024−0.01
=0.092
Therefore, the expected return of Stock A according to the APT model is 9.2%.
QUESTION 6: VALUE AT RISK (VAR)
A portfolio has a current value of $10 million and a daily volatility of 1.5%. Assuming normally
distributed returns, calculate the 1-day 99% VaR for this portfolio.
Solution:
Step 1: Recall the VaR formula for normally distributed returns:
𝑉𝑎𝑅 =𝑃×𝜎×𝑍𝛼×√𝑡
Where: - P is the portfolio value - σ is the daily volatility - Zα is the Z-score for the desired
confidence level - t is the time horizon in days
Step 2: Identify the given values:
𝑃 =$10,000,000
𝜎 =1.5% =0.015
𝑍99%= 2.33(𝑓𝑟𝑜𝑚𝑠𝑡𝑎𝑛𝑑𝑎𝑟𝑑𝑛𝑜𝑟𝑚𝑎𝑙𝑑𝑖𝑠𝑡𝑟𝑖𝑏𝑢𝑡𝑖𝑜𝑛𝑡𝑎𝑏𝑙𝑒)
𝑡 =1 day
Step 3: Calculate the VaR:
𝑉𝑎𝑅 =10,000,000×0.015×2.33×√1
=349,500
Therefore, the 1-day 99% VaR for this portfolio is $349,500. This means there is a 1% chance
that the portfolio will lose more than $349,500 in one day.
QUESTION 7: FAMA-FRENCH THREE-FACTOR MODEL
A stock has the following factor exposures: - Market factor (MKT) beta: 1.2 - Size factor (SMB)
beta: 0.5 - Value factor (HML) beta: -0.3
The risk-free rate is 2%, and the factor risk premiums are: - Market risk premium: 6% - SMB
premium: 3% - HML premium: 4%
Calculate the expected return of the stock using the Fama-French Three-Factor Model.
Solution:
Step 1: Recall the Fama-French Three-Factor Model formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝑅𝑚−𝑅𝑓)+𝑠𝑖(𝑆𝑀𝐵)+ℎ𝑖(𝐻𝑀𝐿)
Step 2: Substitute the given values:
𝐸(𝑅𝑖)=0.02+1.2(0.06)+0.5(0.03)+(−0.3)(0.04)
=0.02+0.072+0.015−0.012
=0.095
Therefore, the expected return of the stock according to the Fama-French Three-Factor Model
is 9.5%.
QUESTION 8: SHARPE RATIO AND INFORMATION RATIO
A portfolio manager achieved an average annual return of 12% over the past 5 years, with a
standard deviation of 18%. The risk-free rate during this period was 3%, and the benchmark
index returned 9% with a standard deviation of 15%. Calculate:
a) The Sharpe ratio of the portfolio b) The Information ratio of the portfolio
Solution:
a) Sharpe Ratio
Step 1: Recall the Sharpe ratio formula:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑓
𝜎𝑝
Step 2: Substitute the given values:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 0.12−0.03
0.18 =0.50
b) Information Ratio
Step 1: Recall the Information ratio formula:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑏
𝜎𝑝−𝑏
Where σp-b is the standard deviation of the difference between portfolio returns and benchmark
returns (tracking error).
Step 2: Calculate the tracking error:
𝜎𝑝−𝑏 =√𝜎𝑝
2+𝜎𝑏
2−2𝜌𝜎𝑝𝜎𝑏
Assuming a correlation of 0.8 between the portfolio and benchmark:
𝜎𝑝−𝑏 =√0.182+0.152−2(0.8)(0.18)(0.15)=0.11
Step 3: Calculate the Information ratio:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 =0.12−0.09
0.11 =0.27
Therefore, the Sharpe ratio of the portfolio is 0.50, and the Information ratio is 0.27.
QUESTION 9: BINOMIAL OPTION PRICING MODEL (CONTINUED)
Consider a European call option with the following characteristics: - Current stock price (S0) =
$100 - Strike price (K) = $105 - Time to expiration (T) = 3 months (0.25 years) - Risk-free rate (r)
= 4% per annum - Up factor (u) = 1.1 - Down factor (d) = 0.9
Using a one-step binomial model, calculate the price of this call option.
Solution:
Step 1: Calculate the risk-neutral probability (p):
𝑝 = 𝑒𝑟𝑇 −𝑑
𝑢−𝑑 =𝑒0.04×0.25 −0.9
1.1−0.9 =0.5498
Step 2: Calculate the possible stock prices at expiration:
𝑆𝑢= 𝑆0×𝑢 = 100×1.1= $110
𝑆𝑑= 𝑆0×𝑑 = 100×0.9= $90
Step 3: Calculate the option payoffs at expiration:
𝐶𝑢=max(𝑆𝑢−𝐾,0)=max(110−105,0)=$5
𝐶𝑑=max(𝑆𝑑−𝐾,0)= max(90−105,0)=$0
Step 4: Calculate the option price using the risk-neutral valuation formula:
𝐶0=𝑒−𝑟𝑇[𝑝𝐶𝑢+(1−𝑝)𝐶𝑑]
=𝑒−0.04×0.25[0.5498×5+(1−0.5498)×0]
=0.9900×2.7490
=$2.72
Therefore, the price of the European call option using a one-step binomial model is $2.72.
QUESTION 10: PORTFOLIO PERFORMANCE ATTRIBUTION
An equity portfolio manager reported the following sector allocations and returns for the year,
along with the benchmark index data:
Sector
Portfolio Weight
Portfolio Return
Benchmark Weight
Benchmark Return
Technology
35%
12%
30%
10%
Healthcare
25%
8%
20%
7%
Financials
20%
6%
25%
5%
Consumer
15%
4%
15%
3%
Utilities
5%
2%
10%
1%
Perform a performance attribution analysis to determine the sources of the portfolio’s excess
return, breaking it down into allocation effect and selection effect.
Solution:
Step 1: Calculate the total portfolio and benchmark returns:
Portfolio return: (0.35 × 12%) + (0.25 × 8%) + (0.20 × 6%) + (0.15 × 4%) + (0.05 × 2%) = 8.50%
Benchmark return: (0.30 × 10%) + (0.20 × 7%) + (0.25 × 5%) + (0.15 × 3%) + (0.10 × 1%) =
6.40%
Excess return = 8.50% - 6.40% = 2.10%

Step 2: Calculate allocation effect for each sector: Allocation Effect = (Portfolio Weight -
Benchmark Weight) × (Benchmark Sector Return - Benchmark Total Return)
Technology: (35% - 30%) × (10% - 6.40%) = 0.18% Healthcare: (25% - 20%) × (7% - 6.40%) =
0.03% Financials: (20% - 25%) × (5% - 6.40%) = 0.07% Consumer: (15% - 15%) × (3% -
6.40%) = 0.00% Utilities: (5% - 10%) × (1% - 6.40%) = 0.27%
Total Allocation Effect = 0.18% + 0.03% + 0.07% + 0.00% + 0.27% = 0.55%
Step 3: Calculate selection effect for each sector: Selection Effect = Benchmark Weight ×
(Portfolio Sector Return - Benchmark Sector Return)
Technology: 30% × (12% - 10%) = 0.60% Healthcare: 20% × (8% - 7%) = 0.20% Financials:
25% × (6% - 5%) = 0.25% Consumer: 15% × (4% - 3%) = 0.15% Utilities: 10% × (2% - 1%) =
0.10%
Total Selection Effect = 0.60% + 0.20% + 0.25% + 0.15% + 0.10% = 1.30%
Step 4: Calculate interaction effect (optional): Interaction Effect = (Portfolio Weight - Benchmark
Weight) × (Portfolio Sector Return - Benchmark Sector Return)
Technology: (35% - 30%) × (12% - 10%) = 0.10% Healthcare: (25% - 20%) × (8% - 7%) =
0.05% Financials: (20% - 25%) × (6% - 5%) = -0.05% Consumer: (15% - 15%) × (4% - 3%) =
0.00% Utilities: (5% - 10%) × (2% - 1%) = -0.05%
Total Interaction Effect = 0.10% + 0.05% - 0.05% + 0.00% - 0.05% = 0.05%
Step 5: Summarize the attribution analysis:
Excess Return = 2.10% Allocation Effect = 0.55% Selection Effect = 1.30% Interaction Effect =
0.05% Total Attribution = 0.55% + 1.30% + 0.05% = 1.90%
The difference between the excess return (2.10%) and the total attribution (1.90%) is due to
rounding effects.
In conclusion, the portfolio’s outperformance can be attributed to: 1. Allocation Effect: 0.55%
(26.2% of excess return) 2. Selection Effect: 1.30% (61.9% of excess return) 3. Interaction
Effect: 0.05% (2.4% of excess return)
The selection effect was the primary driver of the portfolio’s excess return, indicating that the
manager’s stock selection within sectors contributed most to the outperformance.
A stock has a beta of 1.2, the risk-free rate is 3%, and the expected market return is 10%.
Calculate the expected return of the stock using the CAPM.
Solution:
Step 1: Recall the CAPM formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝐸(𝑅𝑚)−𝑅𝑓)
Step 2: Substitute the given values:
𝑅𝑓=3% =0.03
𝛽𝑖= 1.2
𝐸(𝑅𝑚)=10%= 0.10
Step 3: Calculate the expected return:
𝐸(𝑅𝑖)=0.03+1.2(0.10−0.03)
=0.03+1.2(0.07)
=0.03+0.084
=0.114
Therefore, the expected return of the stock is 11.4%.
QUESTION 2: PORTFOLIO OPTIMIZATION
An investor is considering two stocks, A and B, with the following characteristics:
Stock
Expected Return
Standard Deviation
A
12%
20%
B
8%
15%
The correlation coefficient between the two stocks is 0.3. Find the optimal portfolio weights that
minimize the portfolio risk.
Solution:
Step 1: Recall the formula for portfolio variance:
𝜎𝑝
2=𝑤𝐴
2𝜎𝐴
2+𝑤𝐵
2𝜎𝐵
2+2𝑤𝐴𝑤𝐵𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 2: To minimize risk, we need to find the weights that minimize the portfolio variance. The
formula for the optimal weight of stock A is:
𝑤𝐴=𝜎𝐵
2−𝜌𝐴𝐵𝜎𝐴𝜎𝐵
𝜎𝐴
2+𝜎𝐵
2−2𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 3: Substitute the given values:
𝜎𝐴=20%= 0.20
𝜎𝐵=15% =0.15
𝜌𝐴𝐵 = 0.3
Step 4: Calculate the optimal weight of stock A:
𝑤𝐴=0.152−0.3(0.20)(0.15)
0.202+0.152−2(0.3)(0.20)(0.15)
=0.0225−0.009
0.04+0.0225−0.018
=0.0135
0.0445
≈0.3034
Step 5: Calculate the weight of stock B:
𝑤𝐵= 1−𝑤𝐴=1−0.3034 =0.6966
Therefore, the optimal portfolio weights to minimize risk are approximately 30.34% in stock A
and 69.66% in stock B.
QUESTION 3: DURATION AND CONVEXITY
A 5-year bond with a face value of $1,000 and a 6% annual coupon rate is currently priced at
$1,050. The yield to maturity is 5%. Calculate the bond’s duration and convexity.
Solution:
Step 1: Calculate the bond’s cash flows and present values:
Year
Cash Flow
PV Factor
Present Value
1
$60
0.9524
$57.14
2
$60
0.9070
$54.42
3
$60
0.8638
$51.83
4
$60
0.8227
$49.36
5
$1,060
0.7835
$830.51
Step 2: Calculate the Macaulay Duration:
𝐷 =1×57.14+2×54.42+3×51.83+4×49.36+5×830.51
1050 =4.52
Step 3: Calculate the Modified Duration:
𝑀𝐷 =𝐷
1+𝑦 =4.52
1.05= 4.30
Step 4: Calculate the Convexity:
𝐶 = 1
𝑃(1+𝑦)2∑𝑡(𝑡+1)𝐶𝐹𝑡
(1+𝑦)𝑡
𝑛
𝑡=1
𝐶 = 1
1050(1.05)2(2×57.14+6×54.42+12×51.83+20×49.36+30×830.51)=22.89
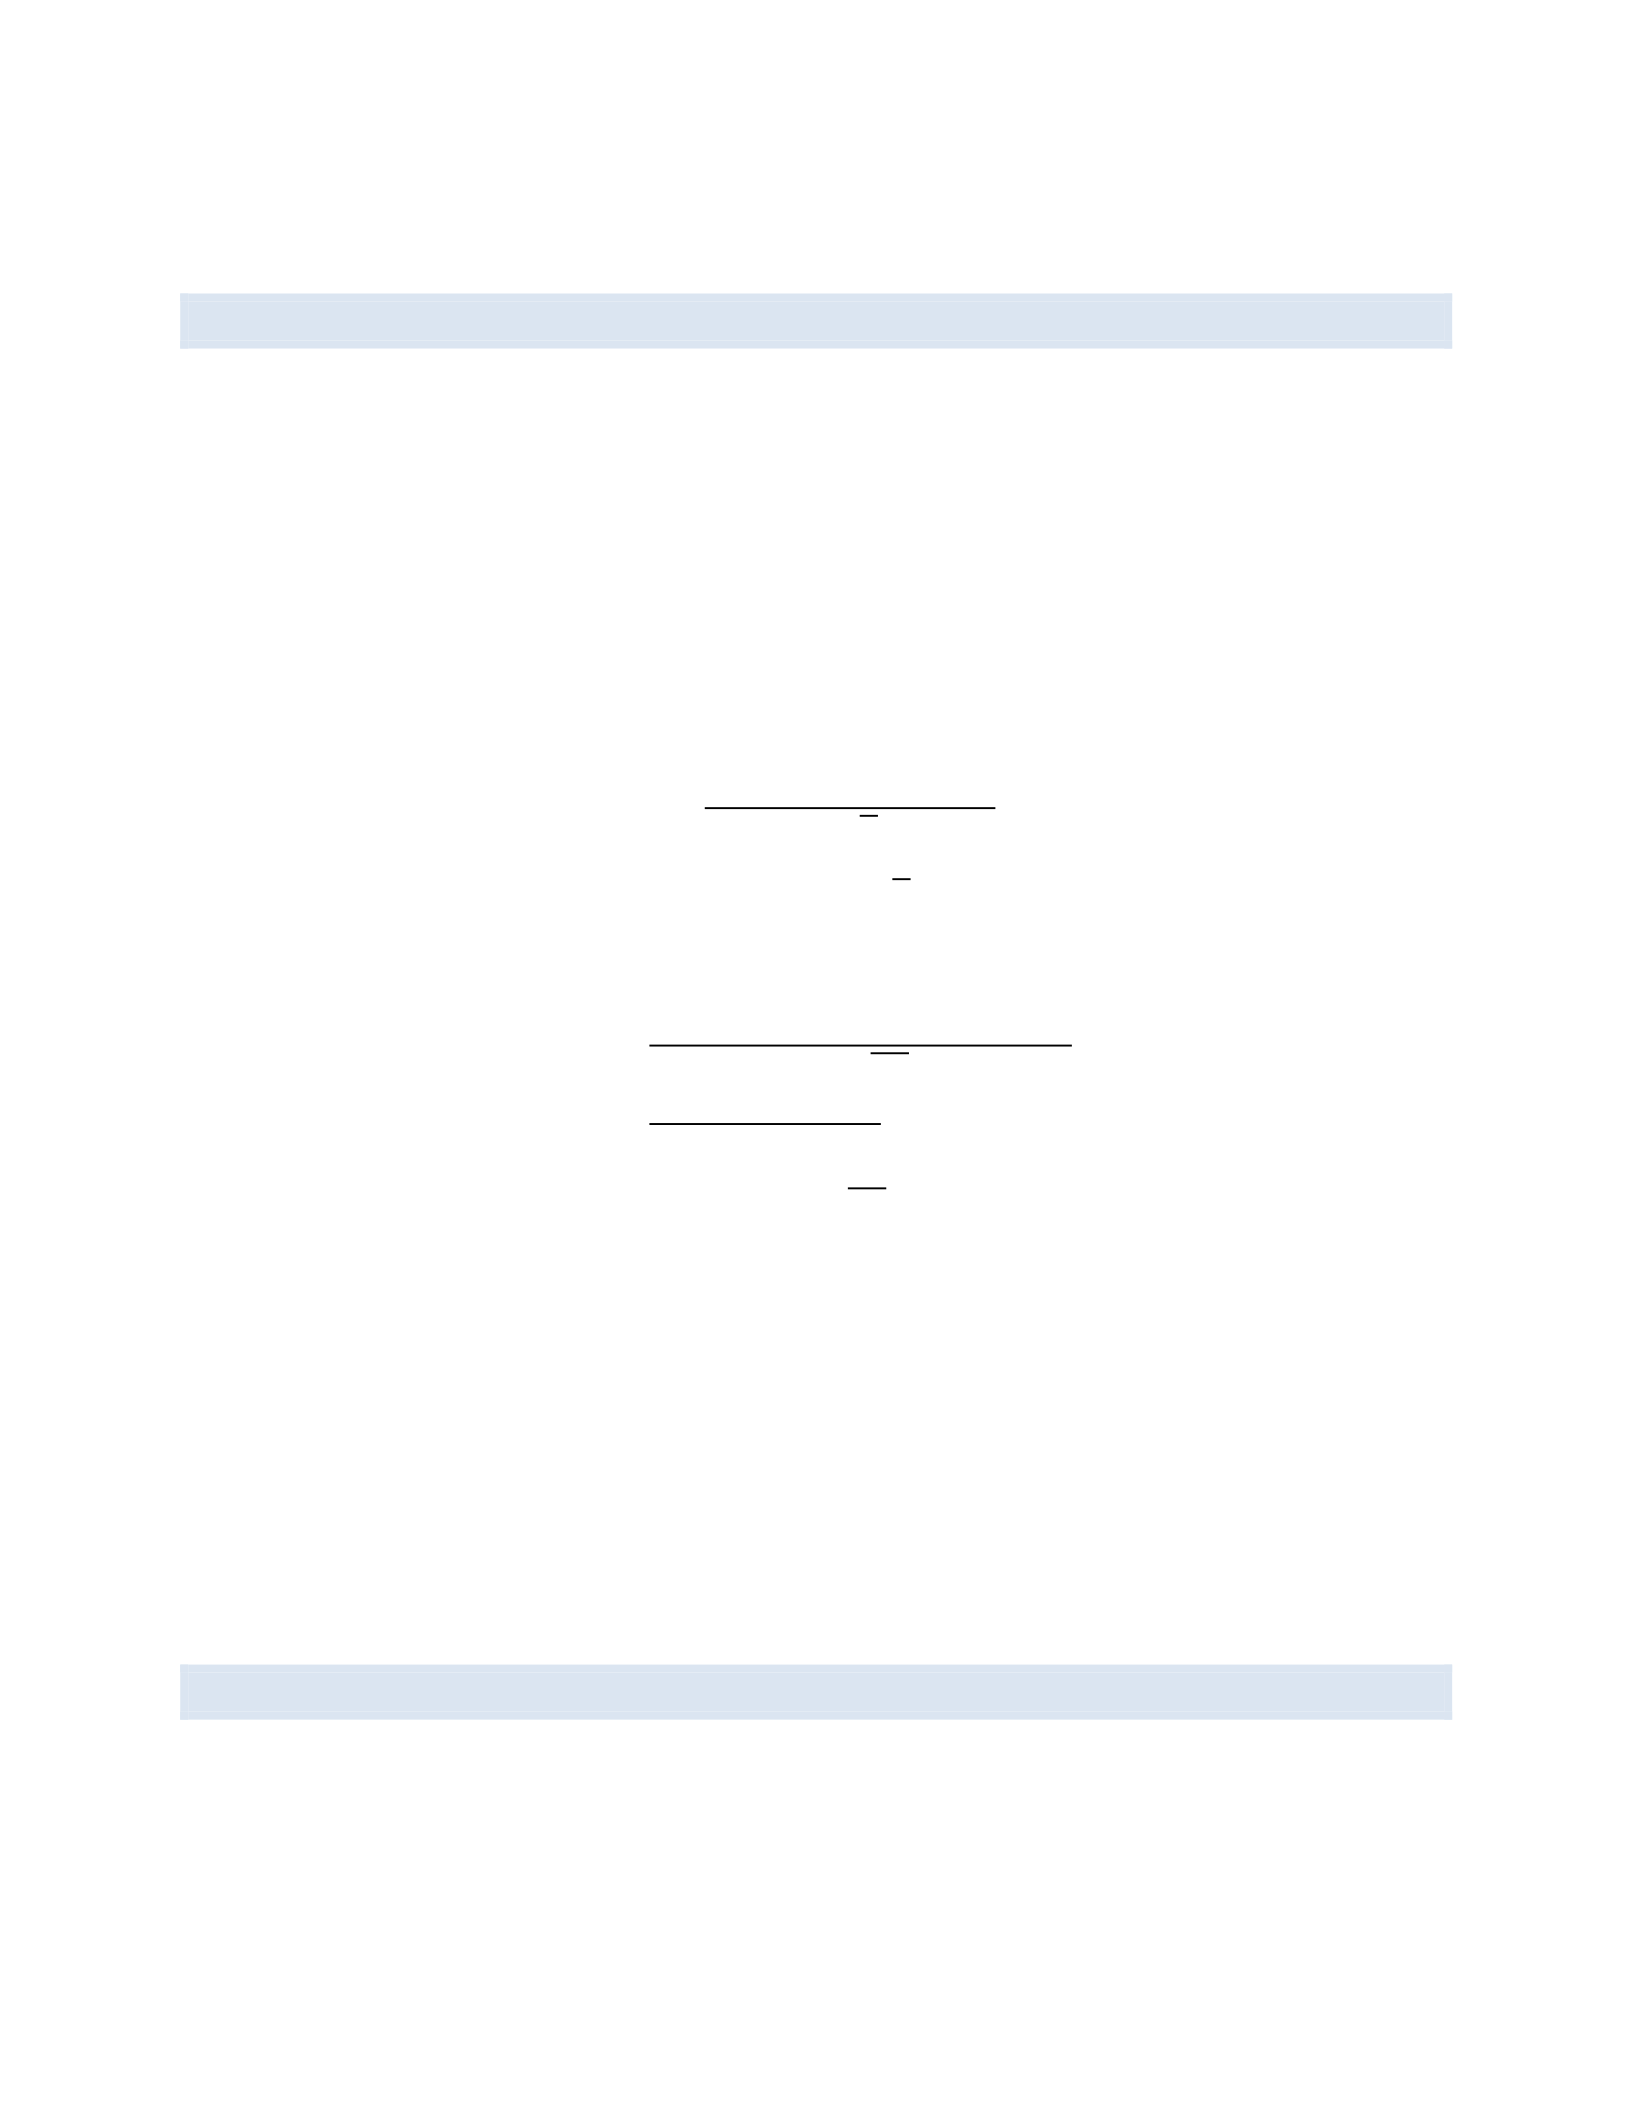
Therefore, the bond’s duration is 4.52 years (Macaulay) or 4.30 years (Modified), and its
convexity is 22.89.
QUESTION 4: BLACK-SCHOLES OPTION PRICING MODEL
Using the Black-Scholes model, calculate the price of a European call option with the following
parameters: - Current stock price (S) = $50 - Strike price (K) = $52 - Time to expiration (T) = 6
months (0.5 years) - Risk-free rate (r) = 5% per annum - Stock volatility (σ) = 30% per annum
Solution:
Step 1: Recall the Black-Scholes formula for a call option:
𝐶 =𝑆𝑁(𝑑1)−𝐾𝑒−𝑟𝑇𝑁(𝑑2)
Where:
𝑑1=ln(𝑆/𝐾)+(𝑟+𝜎2/2)𝑇
𝜎√𝑇
𝑑2=𝑑1−𝜎√𝑇
Step 2: Calculate d1 and d2:
𝑑1=ln(50/52)+(0.05+0.32/2)(0.5)
0.3√0.5
=−0.0392+0.0475
0.2121 =0.0391
𝑑2=0.0391−0.3√0.5= −0.1730
Step 3: Find N(d1) and N(d2) using a standard normal distribution table or calculator:
𝑁(𝑑1)=𝑁(0.0391)=0.5156
𝑁(𝑑2)=𝑁(−0.1730)= 0.4313
Step 4: Calculate the option price:
𝐶 =50×0.5156−52𝑒−0.05×0.5 ×0.4313
=25.78−22.17
=3.61
Therefore, the price of the European call option is $3.61.
QUESTION 5: ARBITRAGE PRICING THEORY (APT)
Consider a three-factor APT model with the following information: - Risk-free rate: 3% - Factor
risk premiums: λ1 = 4%, λ2 = 3%, λ3 = 2% - Stock A has factor sensitivities: β1 = 1.2, β2 = 0.8,
β3 = -0.5
Calculate the expected return of Stock A according to the APT model.
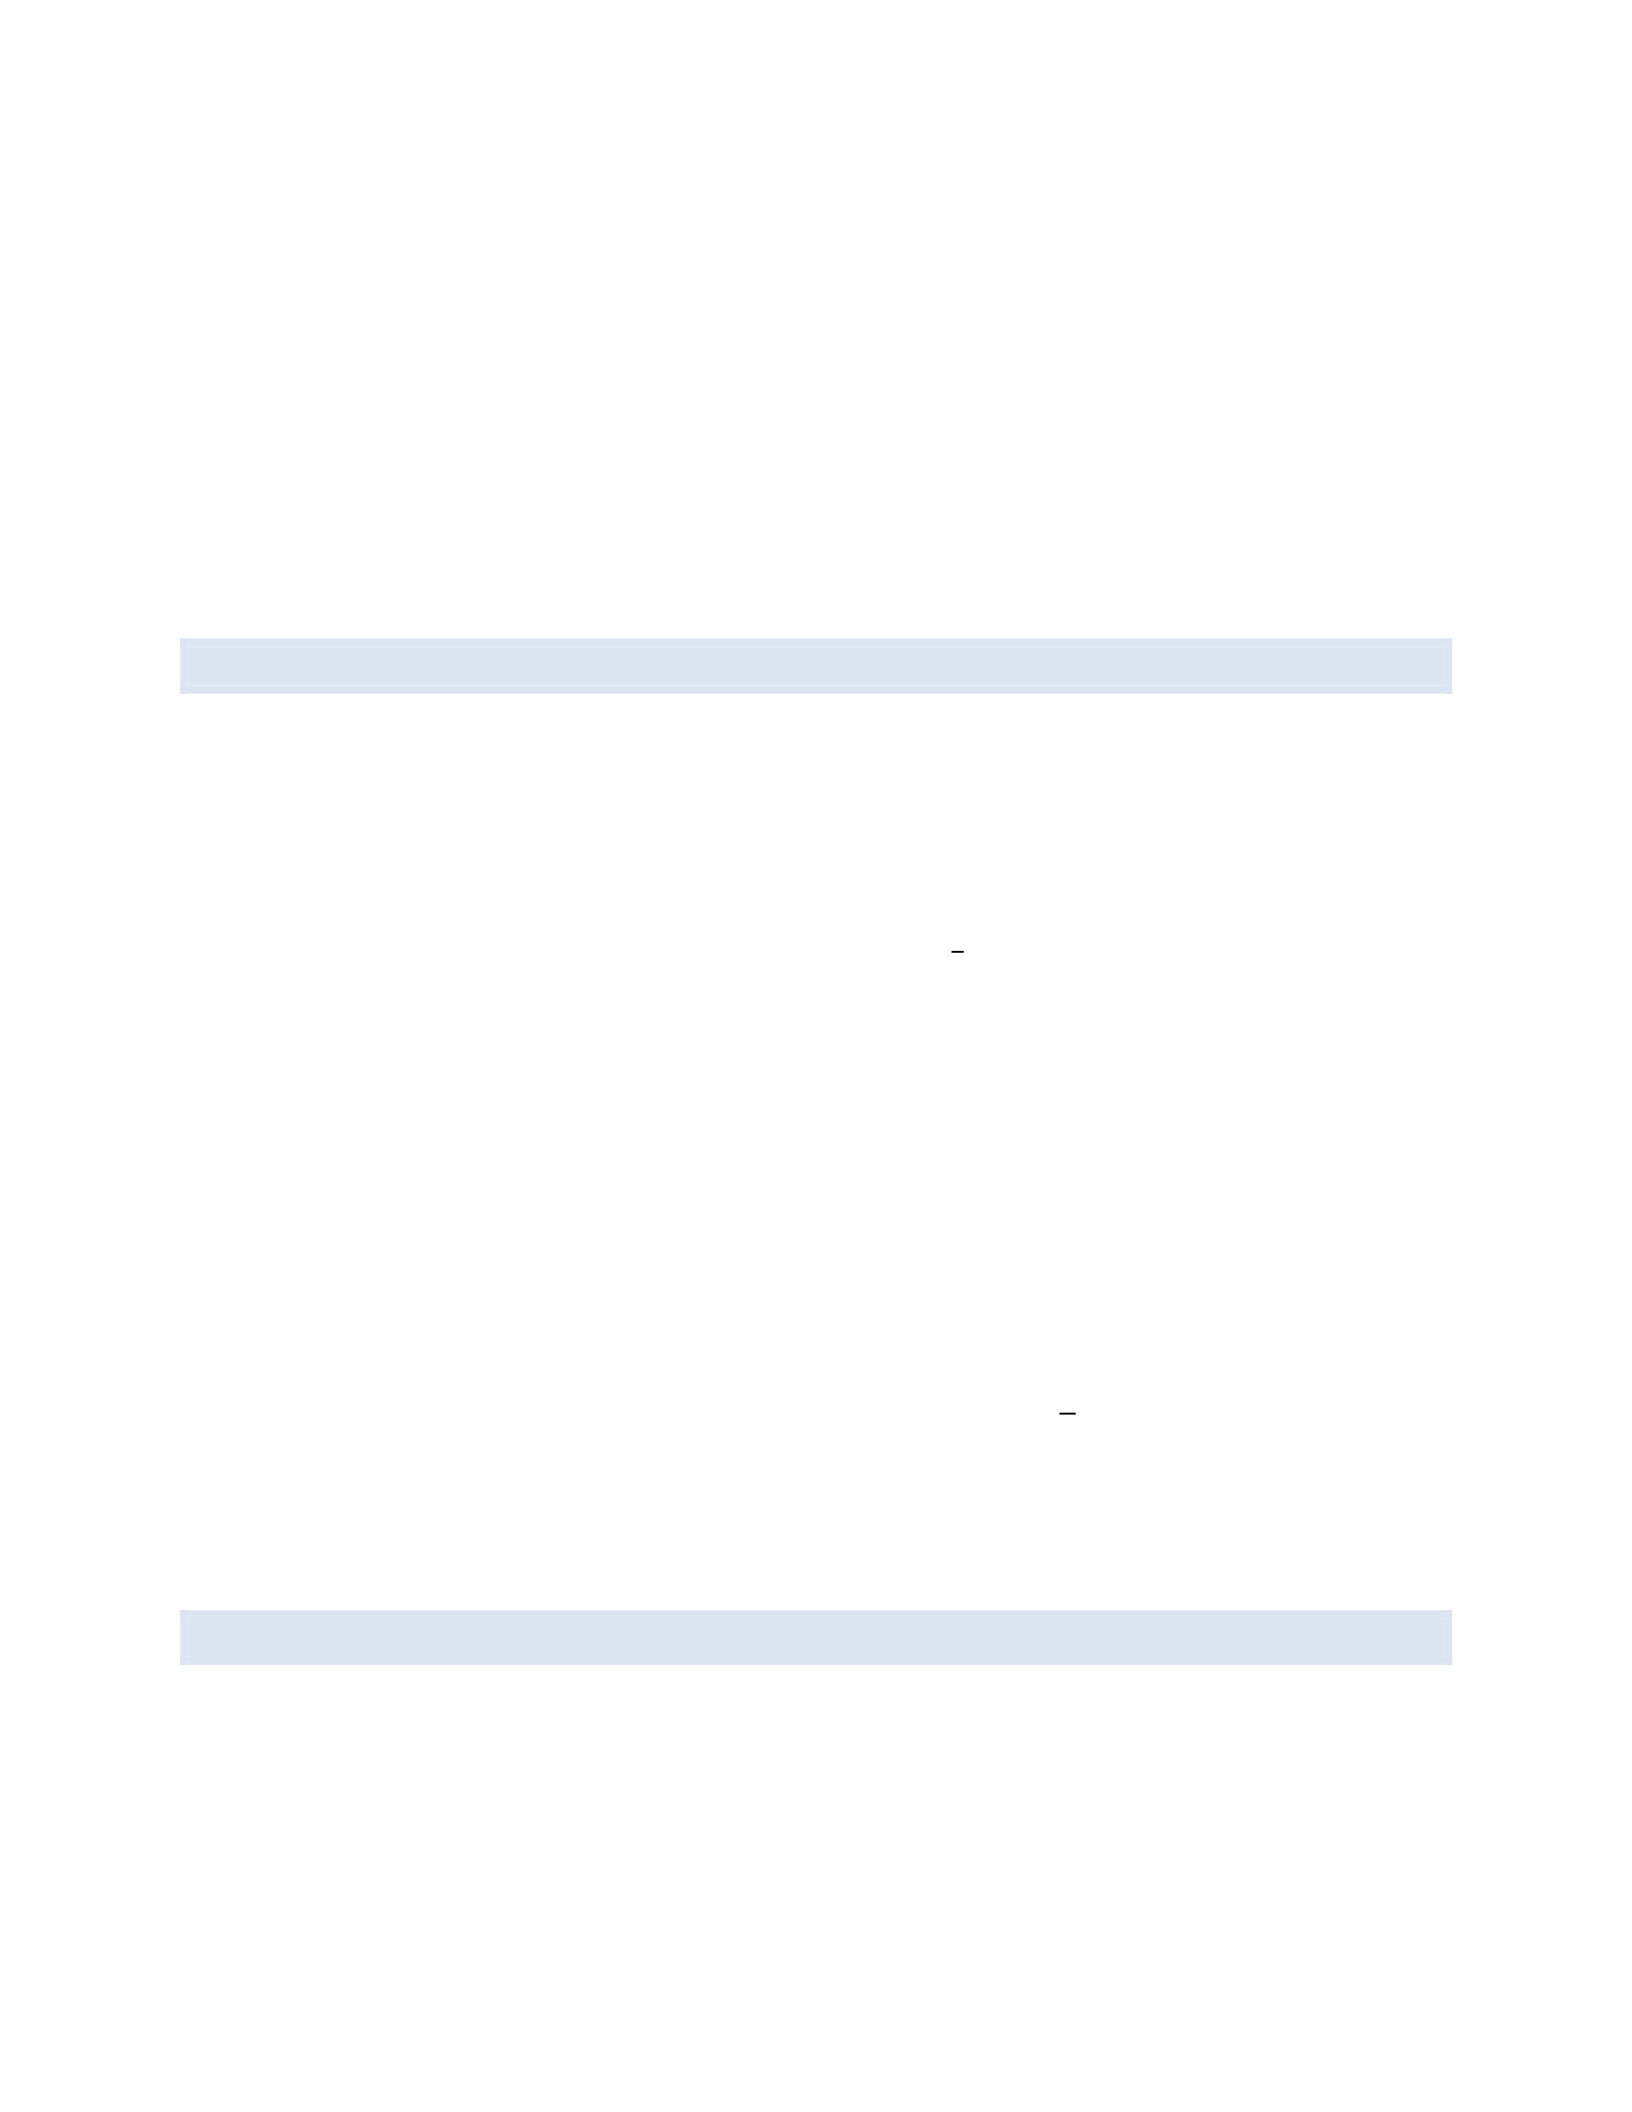
Solution:
Step 1: Recall the APT formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖1𝜆1+𝛽𝑖2𝜆2+𝛽𝑖3𝜆3
Step 2: Substitute the given values:
𝐸(𝑅𝐴)= 0.03+1.2(0.04)+0.8(0.03)+(−0.5)(0.02)
=0.03+0.048+0.024−0.01
=0.092
Therefore, the expected return of Stock A according to the APT model is 9.2%.
QUESTION 6: VALUE AT RISK (VAR)
A portfolio has a current value of $10 million and a daily volatility of 1.5%. Assuming normally
distributed returns, calculate the 1-day 99% VaR for this portfolio.
Solution:
Step 1: Recall the VaR formula for normally distributed returns:
𝑉𝑎𝑅 =𝑃×𝜎×𝑍𝛼×√𝑡
Where: - P is the portfolio value - σ is the daily volatility - Zα is the Z-score for the desired
confidence level - t is the time horizon in days
Step 2: Identify the given values:
𝑃 =$10,000,000
𝜎 =1.5% =0.015
𝑍99%= 2.33(𝑓𝑟𝑜𝑚𝑠𝑡𝑎𝑛𝑑𝑎𝑟𝑑𝑛𝑜𝑟𝑚𝑎𝑙𝑑𝑖𝑠𝑡𝑟𝑖𝑏𝑢𝑡𝑖𝑜𝑛𝑡𝑎𝑏𝑙𝑒)
𝑡 =1 day
Step 3: Calculate the VaR:
𝑉𝑎𝑅 =10,000,000×0.015×2.33×√1
=349,500
Therefore, the 1-day 99% VaR for this portfolio is $349,500. This means there is a 1% chance
that the portfolio will lose more than $349,500 in one day.
QUESTION 7: FAMA-FRENCH THREE-FACTOR MODEL
A stock has the following factor exposures: - Market factor (MKT) beta: 1.2 - Size factor (SMB)
beta: 0.5 - Value factor (HML) beta: -0.3
The risk-free rate is 2%, and the factor risk premiums are: - Market risk premium: 6% - SMB
premium: 3% - HML premium: 4%
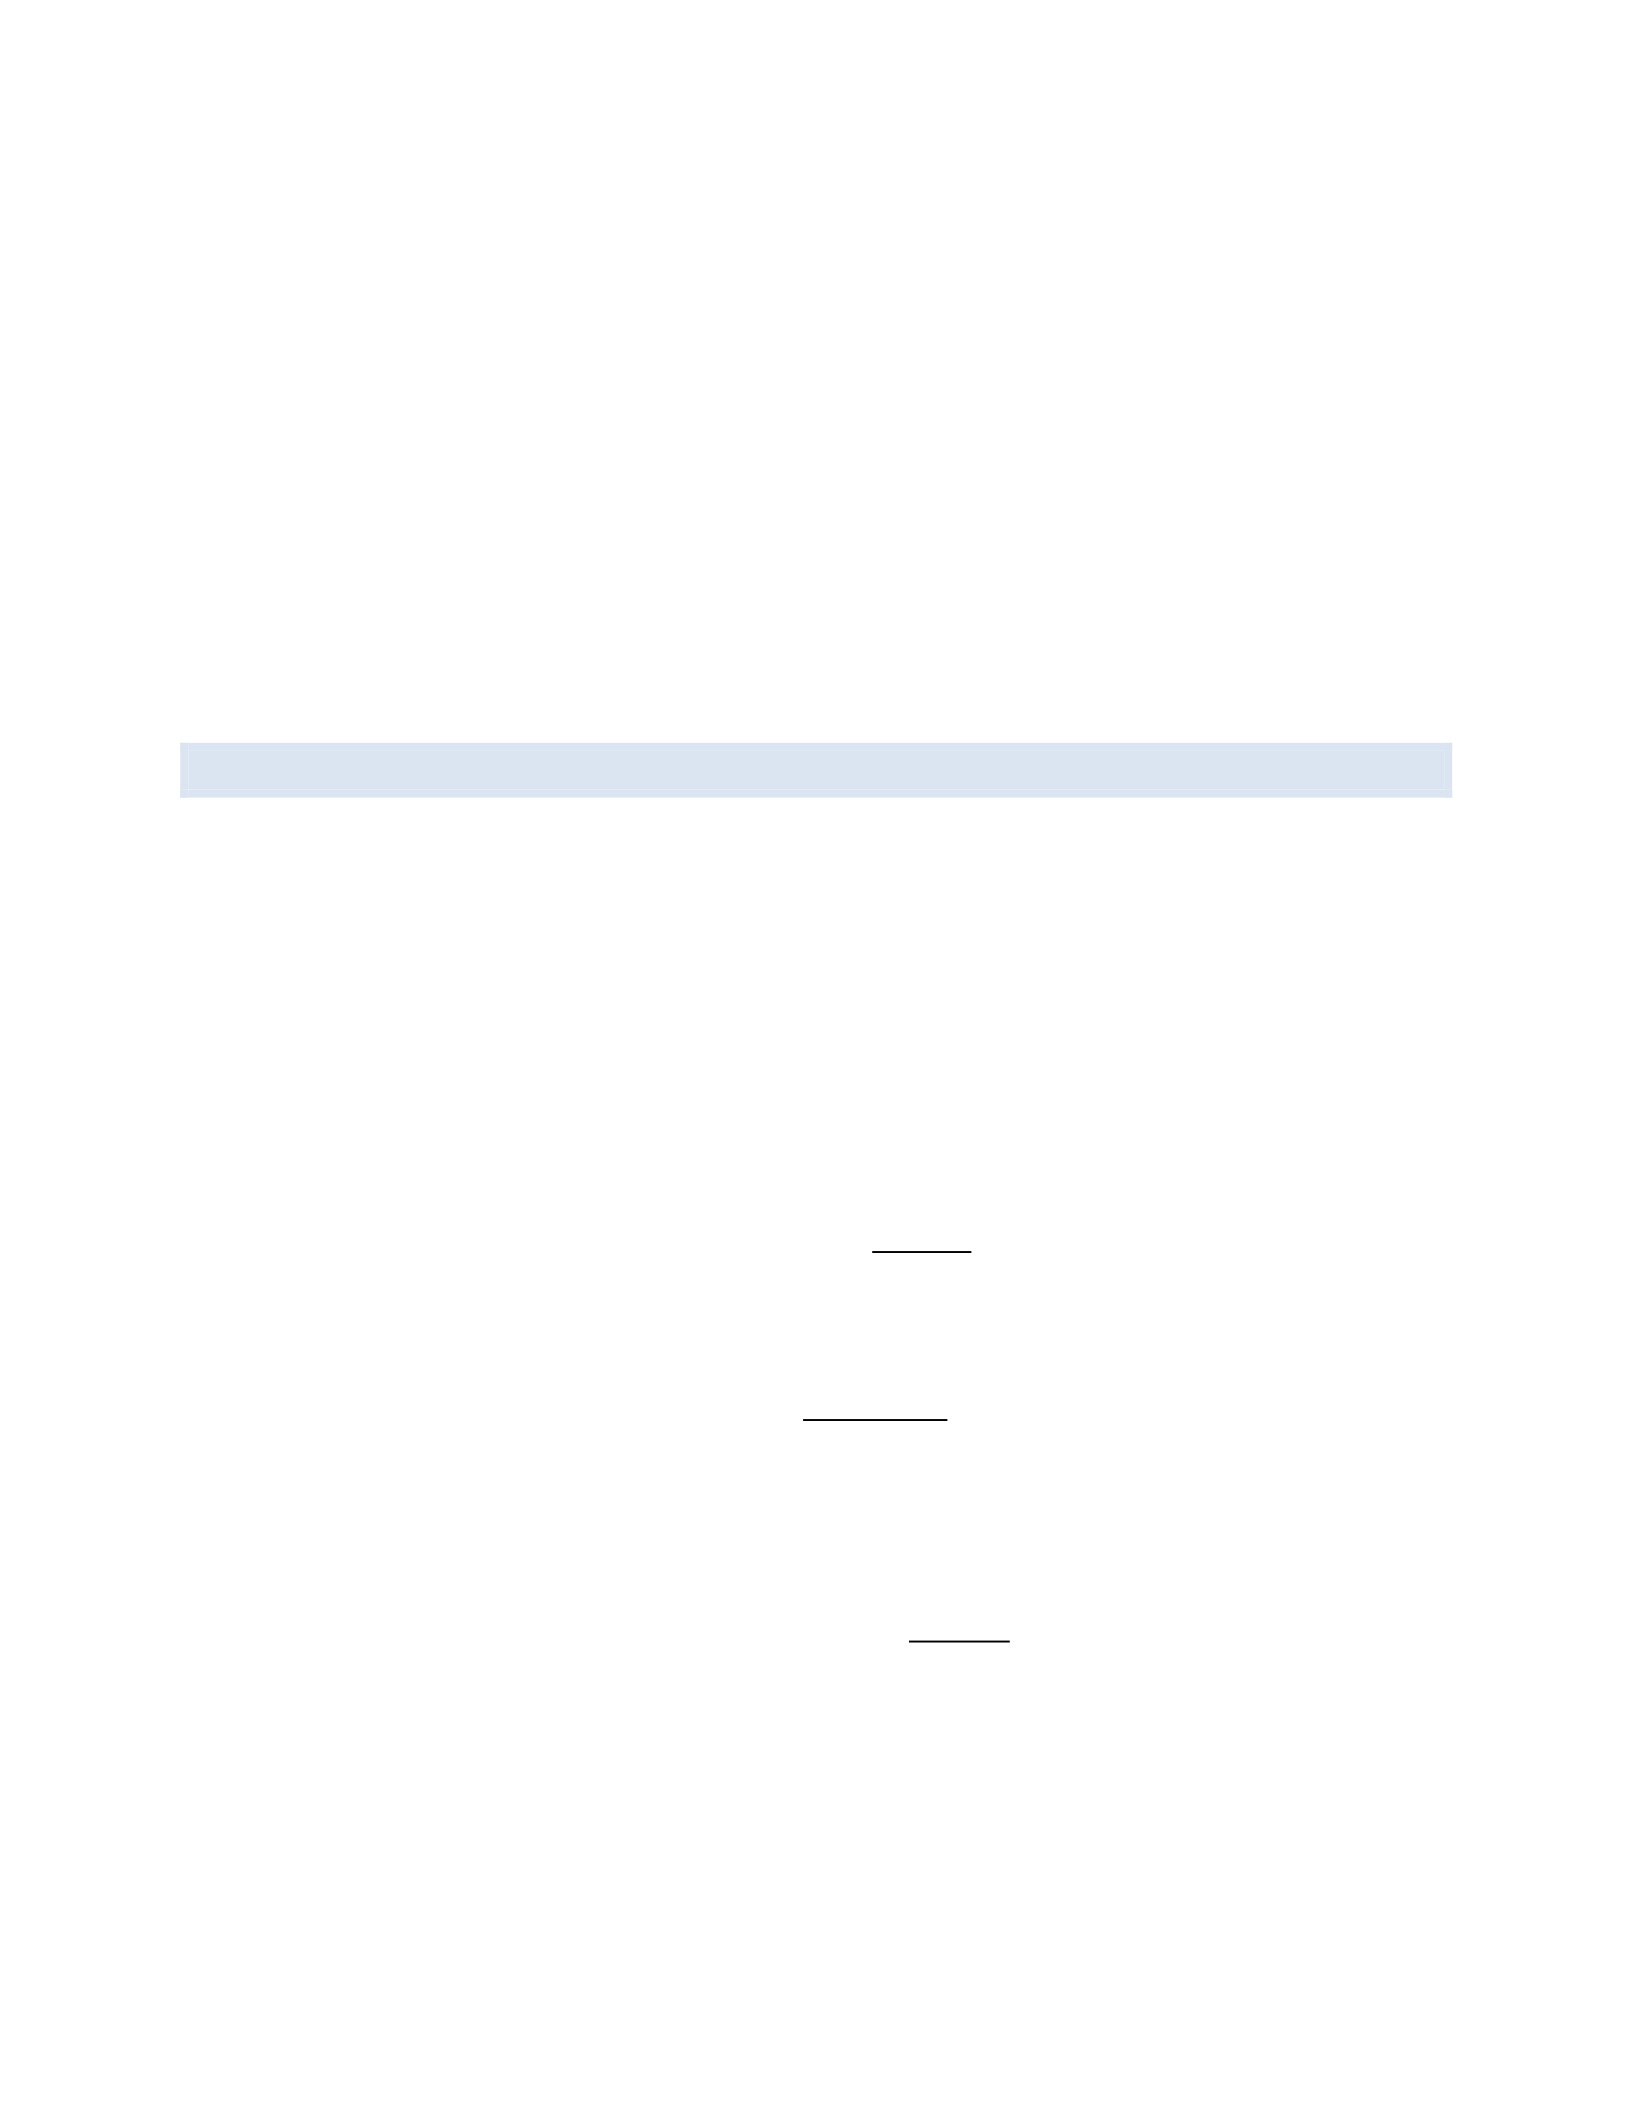
Calculate the expected return of the stock using the Fama-French Three-Factor Model.
Solution:
Step 1: Recall the Fama-French Three-Factor Model formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝑅𝑚−𝑅𝑓)+𝑠𝑖(𝑆𝑀𝐵)+ℎ𝑖(𝐻𝑀𝐿)
Step 2: Substitute the given values:
𝐸(𝑅𝑖)=0.02+1.2(0.06)+0.5(0.03)+(−0.3)(0.04)
=0.02+0.072+0.015−0.012
=0.095
Therefore, the expected return of the stock according to the Fama-French Three-Factor Model
is 9.5%.
QUESTION 8: SHARPE RATIO AND INFORMATION RATIO
A portfolio manager achieved an average annual return of 12% over the past 5 years, with a
standard deviation of 18%. The risk-free rate during this period was 3%, and the benchmark
index returned 9% with a standard deviation of 15%. Calculate:
a) The Sharpe ratio of the portfolio b) The Information ratio of the portfolio
Solution:
a) Sharpe Ratio
Step 1: Recall the Sharpe ratio formula:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑓
𝜎𝑝
Step 2: Substitute the given values:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 0.12−0.03
0.18 =0.50
b) Information Ratio
Step 1: Recall the Information ratio formula:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑏
𝜎𝑝−𝑏
Where σp-b is the standard deviation of the difference between portfolio returns and benchmark
returns (tracking error).
Step 2: Calculate the tracking error:
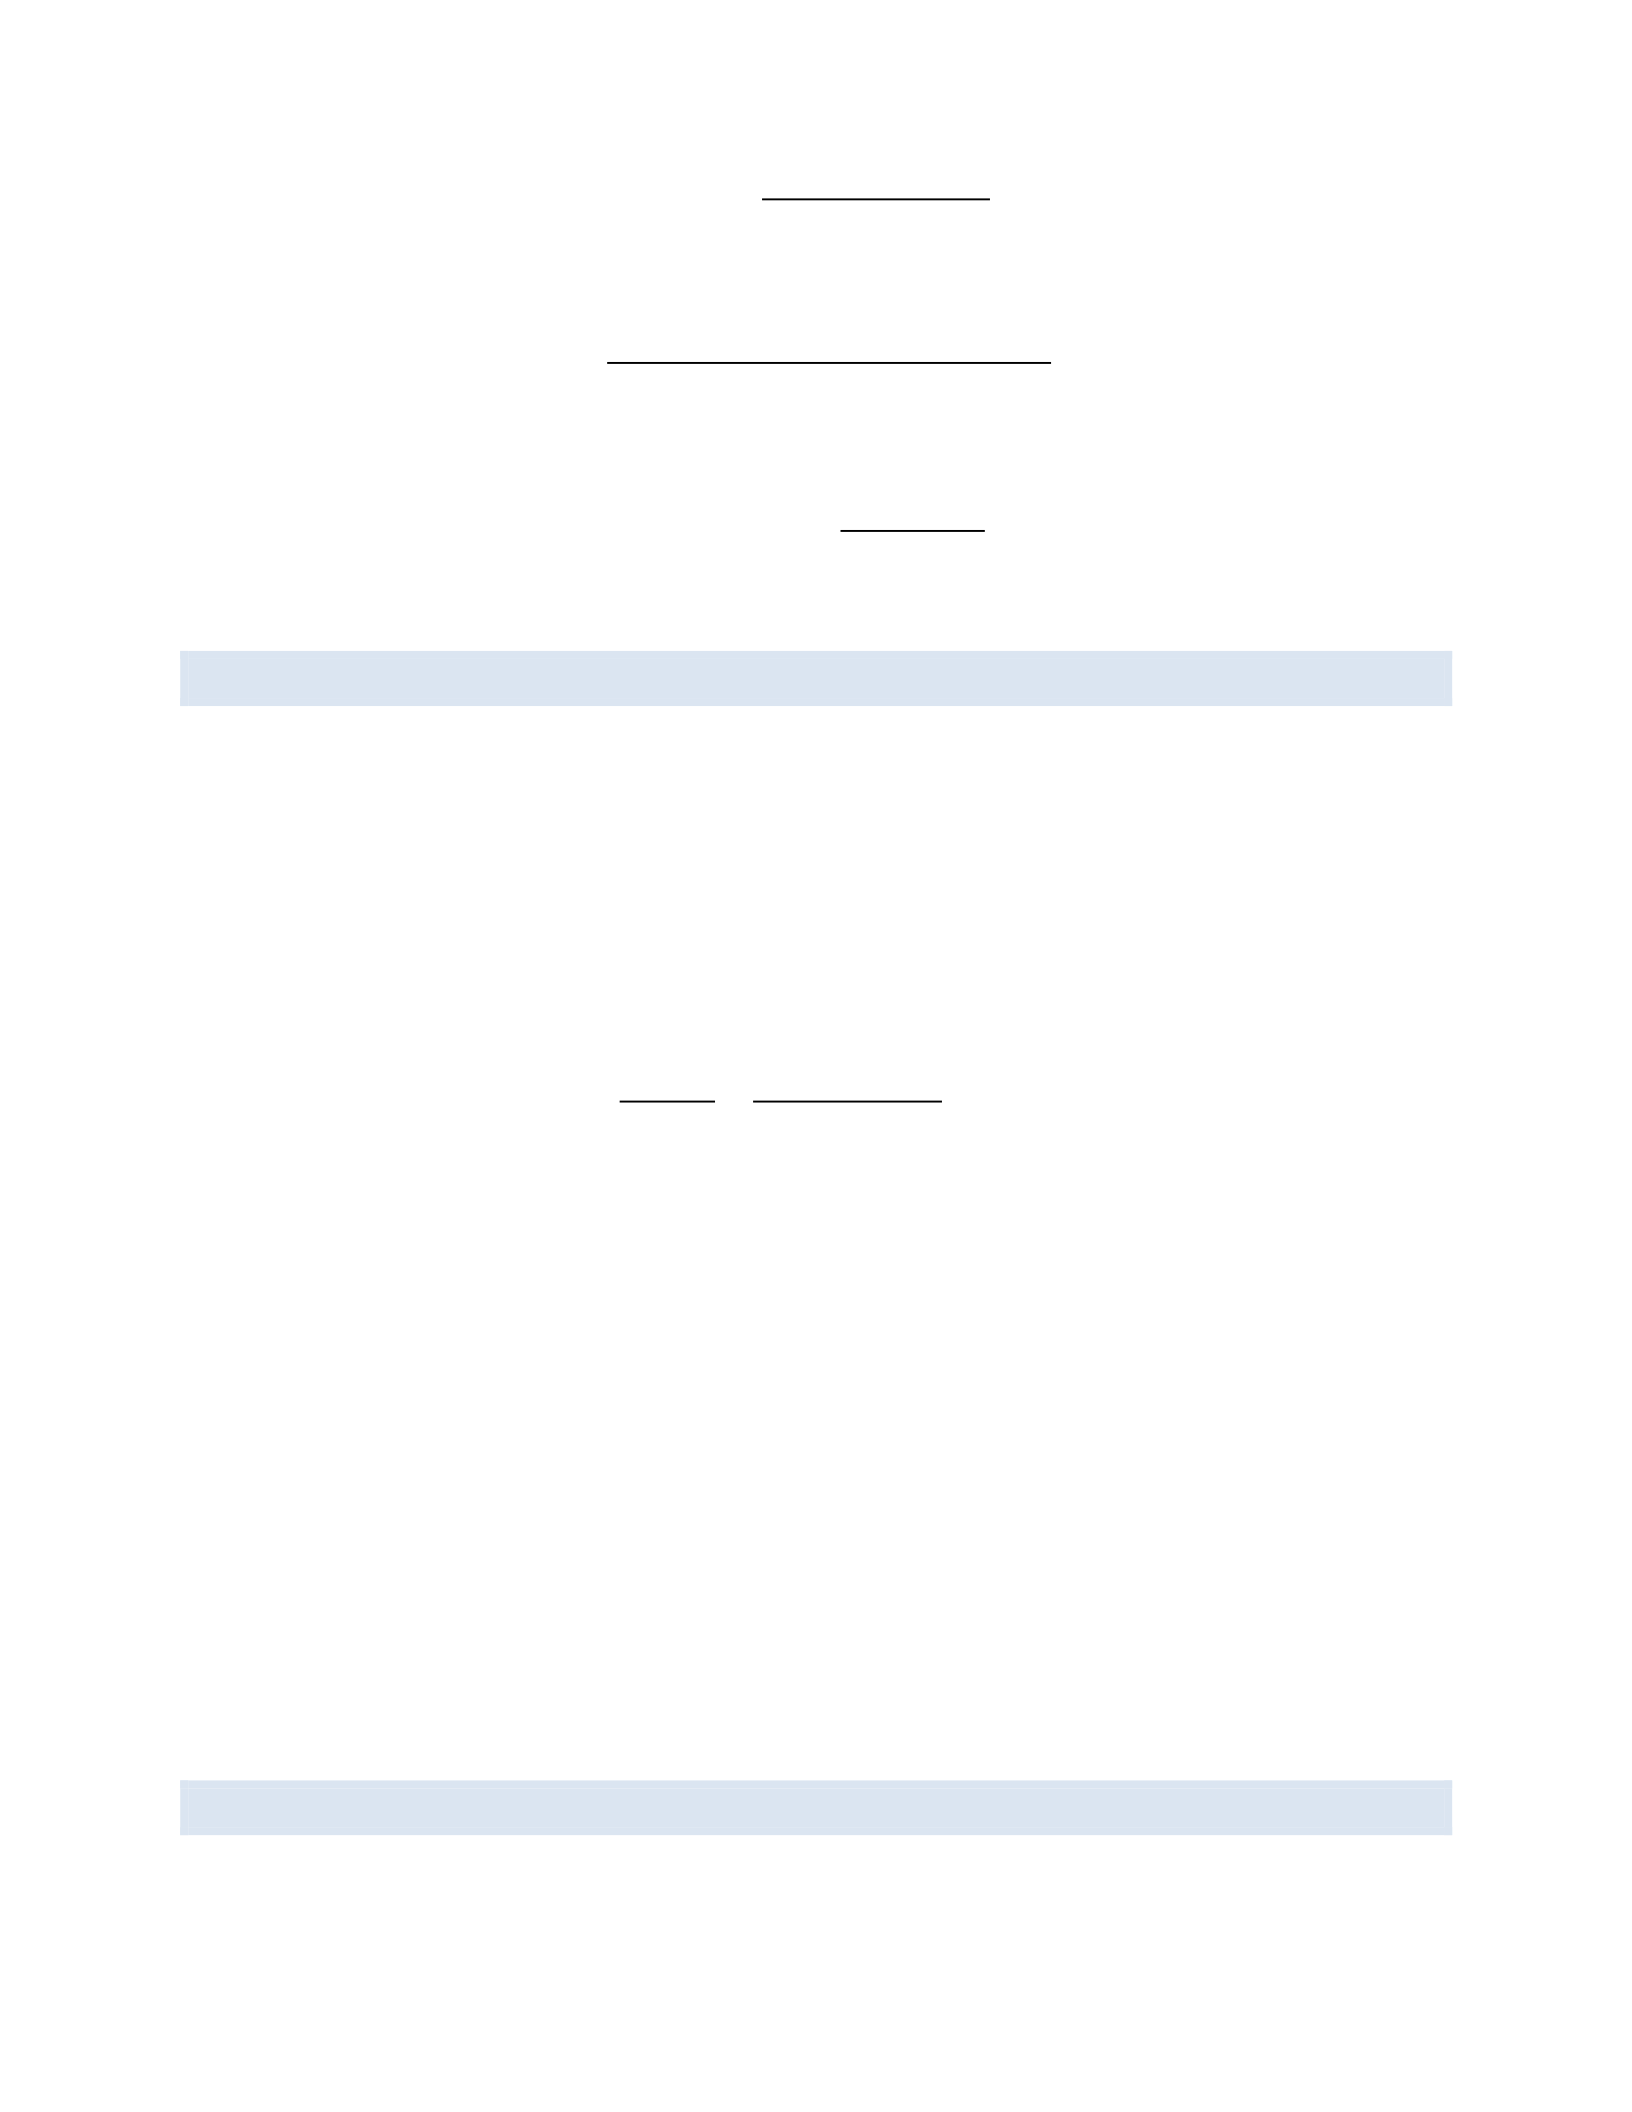
𝜎𝑝−𝑏 =√𝜎𝑝
2+𝜎𝑏
2−2𝜌𝜎𝑝𝜎𝑏
Assuming a correlation of 0.8 between the portfolio and benchmark:
𝜎𝑝−𝑏 =√0.182+0.152−2(0.8)(0.18)(0.15)=0.11
Step 3: Calculate the Information ratio:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 =0.12−0.09
0.11 =0.27
Therefore, the Sharpe ratio of the portfolio is 0.50, and the Information ratio is 0.27.
QUESTION 9: BINOMIAL OPTION PRICING MODEL (CONTINUED)
Consider a European call option with the following characteristics: - Current stock price (S0) =
$100 - Strike price (K) = $105 - Time to expiration (T) = 3 months (0.25 years) - Risk-free rate (r)
= 4% per annum - Up factor (u) = 1.1 - Down factor (d) = 0.9
Using a one-step binomial model, calculate the price of this call option.
Solution:
Step 1: Calculate the risk-neutral probability (p):
𝑝 = 𝑒𝑟𝑇 −𝑑
𝑢−𝑑 =𝑒0.04×0.25 −0.9
1.1−0.9 =0.5498
Step 2: Calculate the possible stock prices at expiration:
𝑆𝑢= 𝑆0×𝑢 = 100×1.1= $110
𝑆𝑑= 𝑆0×𝑑 = 100×0.9= $90
Step 3: Calculate the option payoffs at expiration:
𝐶𝑢=max(𝑆𝑢−𝐾,0)=max(110−105,0)=$5
𝐶𝑑=max(𝑆𝑑−𝐾,0)= max(90−105,0)=$0
Step 4: Calculate the option price using the risk-neutral valuation formula:
𝐶0=𝑒−𝑟𝑇[𝑝𝐶𝑢+(1−𝑝)𝐶𝑑]
=𝑒−0.04×0.25[0.5498×5+(1−0.5498)×0]
=0.9900×2.7490
=$2.72
Therefore, the price of the European call option using a one-step binomial model is $2.72.
QUESTION 10: PORTFOLIO PERFORMANCE ATTRIBUTION
An equity portfolio manager reported the following sector allocations and returns for the year,
along with the benchmark index data:
Sector
Portfolio Weight
Portfolio Return
Benchmark Weight
Benchmark Return
Technology
35%
12%
30%
10%
Healthcare
25%
8%
20%
7%
Financials
20%
6%
25%
5%
Consumer
15%
4%
15%
3%
Utilities
5%
2%
10%
1%
Perform a performance attribution analysis to determine the sources of the portfolio’s excess
return, breaking it down into allocation effect and selection effect.
Solution:
Step 1: Calculate the total portfolio and benchmark returns:
Portfolio return: (0.35 × 12%) + (0.25 × 8%) + (0.20 × 6%) + (0.15 × 4%) + (0.05 × 2%) = 8.50%
Benchmark return: (0.30 × 10%) + (0.20 × 7%) + (0.25 × 5%) + (0.15 × 3%) + (0.10 × 1%) =
6.40%
Excess return = 8.50% - 6.40% = 2.10%
Step 2: Calculate allocation effect for each sector: Allocation Effect = (Portfolio Weight -
Benchmark Weight) × (Benchmark Sector Return - Benchmark Total Return)
Technology: (35% - 30%) × (10% - 6.40%) = 0.18% Healthcare: (25% - 20%) × (7% - 6.40%) =
0.03% Financials: (20% - 25%) × (5% - 6.40%) = 0.07% Consumer: (15% - 15%) × (3% -
6.40%) = 0.00% Utilities: (5% - 10%) × (1% - 6.40%) = 0.27%
Total Allocation Effect = 0.18% + 0.03% + 0.07% + 0.00% + 0.27% = 0.55%
Step 3: Calculate selection effect for each sector: Selection Effect = Benchmark Weight ×
(Portfolio Sector Return - Benchmark Sector Return)
Technology: 30% × (12% - 10%) = 0.60% Healthcare: 20% × (8% - 7%) = 0.20% Financials:
25% × (6% - 5%) = 0.25% Consumer: 15% × (4% - 3%) = 0.15% Utilities: 10% × (2% - 1%) =
0.10%
Total Selection Effect = 0.60% + 0.20% + 0.25% + 0.15% + 0.10% = 1.30%
Step 4: Calculate interaction effect (optional): Interaction Effect = (Portfolio Weight - Benchmark
Weight) × (Portfolio Sector Return - Benchmark Sector Return)
Technology: (35% - 30%) × (12% - 10%) = 0.10% Healthcare: (25% - 20%) × (8% - 7%) =
0.05% Financials: (20% - 25%) × (6% - 5%) = -0.05% Consumer: (15% - 15%) × (4% - 3%) =
0.00% Utilities: (5% - 10%) × (2% - 1%) = -0.05%
Total Interaction Effect = 0.10% + 0.05% - 0.05% + 0.00% - 0.05% = 0.05%
Step 5: Summarize the attribution analysis:
Excess Return = 2.10% Allocation Effect = 0.55% Selection Effect = 1.30% Interaction Effect =
0.05% Total Attribution = 0.55% + 1.30% + 0.05% = 1.90%
The difference between the excess return (2.10%) and the total attribution (1.90%) is due to
rounding effects.
In conclusion, the portfolio’s outperformance can be attributed to: 1. Allocation Effect: 0.55%
(26.2% of excess return) 2. Selection Effect: 1.30% (61.9% of excess return) 3. Interaction
Effect: 0.05% (2.4% of excess return)
The selection effect was the primary driver of the portfolio’s excess return, indicating that the
manager’s stock selection within sectors contributed most to the outperformance.
A stock has a beta of 1.2, the risk-free rate is 3%, and the expected market return is 10%.
Calculate the expected return of the stock using the CAPM.
Solution:
Step 1: Recall the CAPM formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝐸(𝑅𝑚)−𝑅𝑓)
Step 2: Substitute the given values:
𝑅𝑓=3% =0.03
𝛽𝑖= 1.2
𝐸(𝑅𝑚)=10%= 0.10
Step 3: Calculate the expected return:
𝐸(𝑅𝑖)=0.03+1.2(0.10−0.03)
=0.03+1.2(0.07)
=0.03+0.084
=0.114
Therefore, the expected return of the stock is 11.4%.
QUESTION 2: PORTFOLIO OPTIMIZATION
An investor is considering two stocks, A and B, with the following characteristics:
Stock
Expected Return
Standard Deviation
A
12%
20%
B
8%
15%
The correlation coefficient between the two stocks is 0.3. Find the optimal portfolio weights that
minimize the portfolio risk.
Solution:
Step 1: Recall the formula for portfolio variance:
𝜎𝑝
2=𝑤𝐴
2𝜎𝐴
2+𝑤𝐵
2𝜎𝐵
2+2𝑤𝐴𝑤𝐵𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 2: To minimize risk, we need to find the weights that minimize the portfolio variance. The
formula for the optimal weight of stock A is:
𝑤𝐴=𝜎𝐵
2−𝜌𝐴𝐵𝜎𝐴𝜎𝐵
𝜎𝐴
2+𝜎𝐵
2−2𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 3: Substitute the given values:
𝜎𝐴=20%= 0.20
𝜎𝐵=15% =0.15
𝜌𝐴𝐵 = 0.3
Step 4: Calculate the optimal weight of stock A:
𝑤𝐴=0.152−0.3(0.20)(0.15)
0.202+0.152−2(0.3)(0.20)(0.15)
=0.0225−0.009
0.04+0.0225−0.018
=0.0135
0.0445
≈0.3034
Step 5: Calculate the weight of stock B:
𝑤𝐵= 1−𝑤𝐴=1−0.3034 =0.6966
Therefore, the optimal portfolio weights to minimize risk are approximately 30.34% in stock A
and 69.66% in stock B.
QUESTION 3: DURATION AND CONVEXITY
A 5-year bond with a face value of $1,000 and a 6% annual coupon rate is currently priced at
$1,050. The yield to maturity is 5%. Calculate the bond’s duration and convexity.
Solution:
Step 1: Calculate the bond’s cash flows and present values:
Year
Cash Flow
PV Factor
Present Value
1
$60
0.9524
$57.14
2
$60
0.9070
$54.42
Year
Cash Flow
PV Factor
Present Value
3
$60
0.8638
$51.83
4
$60
0.8227
$49.36
5
$1,060
0.7835
$830.51
Step 2: Calculate the Macaulay Duration:
𝐷 =1×57.14+2×54.42+3×51.83+4×49.36+5×830.51
1050 =4.52
Step 3: Calculate the Modified Duration:
𝑀𝐷 =𝐷
1+𝑦 =4.52
1.05= 4.30
Step 4: Calculate the Convexity:
𝐶 = 1
𝑃(1+𝑦)2∑𝑡(𝑡+1)𝐶𝐹𝑡
(1+𝑦)𝑡
𝑛
𝑡=1
𝐶 = 1
1050(1.05)2(2×57.14+6×54.42+12×51.83+20×49.36+30×830.51)=22.89
Therefore, the bond’s duration is 4.52 years (Macaulay) or 4.30 years (Modified), and its
convexity is 22.89.
QUESTION 4: BLACK-SCHOLES OPTION PRICING MODEL
Using the Black-Scholes model, calculate the price of a European call option with the following
parameters: - Current stock price (S) = $50 - Strike price (K) = $52 - Time to expiration (T) = 6
months (0.5 years) - Risk-free rate (r) = 5% per annum - Stock volatility (σ) = 30% per annum
Solution:
Step 1: Recall the Black-Scholes formula for a call option:
𝐶 =𝑆𝑁(𝑑1)−𝐾𝑒−𝑟𝑇𝑁(𝑑2)
Where:
𝑑1=ln(𝑆/𝐾)+(𝑟+𝜎2/2)𝑇
𝜎√𝑇
𝑑2=𝑑1−𝜎√𝑇
Step 2: Calculate d1 and d2:
𝑑1=ln(50/52)+(0.05+0.32/2)(0.5)
0.3√0.5
=−0.0392+0.0475
0.2121 =0.0391
𝑑2=0.0391−0.3√0.5= −0.1730
Step 3: Find N(d1) and N(d2) using a standard normal distribution table or calculator:
𝑁(𝑑1)=𝑁(0.0391)=0.5156
𝑁(𝑑2)=𝑁(−0.1730)= 0.4313
Step 4: Calculate the option price:
𝐶 =50×0.5156−52𝑒−0.05×0.5 ×0.4313
=25.78−22.17
=3.61
Therefore, the price of the European call option is $3.61.
QUESTION 5: ARBITRAGE PRICING THEORY (APT)
Consider a three-factor APT model with the following information: - Risk-free rate: 3% - Factor
risk premiums: λ1 = 4%, λ2 = 3%, λ3 = 2% - Stock A has factor sensitivities: β1 = 1.2, β2 = 0.8,
β3 = -0.5
Calculate the expected return of Stock A according to the APT model.
Solution:
Step 1: Recall the APT formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖1𝜆1+𝛽𝑖2𝜆2+𝛽𝑖3𝜆3
Step 2: Substitute the given values:
𝐸(𝑅𝐴)= 0.03+1.2(0.04)+0.8(0.03)+(−0.5)(0.02)
=0.03+0.048+0.024−0.01
=0.092
Therefore, the expected return of Stock A according to the APT model is 9.2%.
QUESTION 6: VALUE AT RISK (VAR)
A portfolio has a current value of $10 million and a daily volatility of 1.5%. Assuming normally
distributed returns, calculate the 1-day 99% VaR for this portfolio.
Solution:
Step 1: Recall the VaR formula for normally distributed returns:
𝑉𝑎𝑅 =𝑃×𝜎×𝑍𝛼×√𝑡
Where: - P is the portfolio value - σ is the daily volatility - Zα is the Z-score for the desired
confidence level - t is the time horizon in days
Step 2: Identify the given values:
𝑃 =$10,000,000
𝜎 =1.5% =0.015
𝑍99%= 2.33(𝑓𝑟𝑜𝑚𝑠𝑡𝑎𝑛𝑑𝑎𝑟𝑑𝑛𝑜𝑟𝑚𝑎𝑙𝑑𝑖𝑠𝑡𝑟𝑖𝑏𝑢𝑡𝑖𝑜𝑛𝑡𝑎𝑏𝑙𝑒)
𝑡 =1 day
Step 3: Calculate the VaR:
𝑉𝑎𝑅 =10,000,000×0.015×2.33×√1
=349,500
Therefore, the 1-day 99% VaR for this portfolio is $349,500. This means there is a 1% chance
that the portfolio will lose more than $349,500 in one day.
QUESTION 7: FAMA-FRENCH THREE-FACTOR MODEL
A stock has the following factor exposures: - Market factor (MKT) beta: 1.2 - Size factor (SMB)
beta: 0.5 - Value factor (HML) beta: -0.3
The risk-free rate is 2%, and the factor risk premiums are: - Market risk premium: 6% - SMB
premium: 3% - HML premium: 4%
Calculate the expected return of the stock using the Fama-French Three-Factor Model.
Solution:
Step 1: Recall the Fama-French Three-Factor Model formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝑅𝑚−𝑅𝑓)+𝑠𝑖(𝑆𝑀𝐵)+ℎ𝑖(𝐻𝑀𝐿)
Step 2: Substitute the given values:
𝐸(𝑅𝑖)=0.02+1.2(0.06)+0.5(0.03)+(−0.3)(0.04)
=0.02+0.072+0.015−0.012
=0.095
Therefore, the expected return of the stock according to the Fama-French Three-Factor Model
is 9.5%.
QUESTION 8: SHARPE RATIO AND INFORMATION RATIO
A portfolio manager achieved an average annual return of 12% over the past 5 years, with a
standard deviation of 18%. The risk-free rate during this period was 3%, and the benchmark
index returned 9% with a standard deviation of 15%. Calculate:
a) The Sharpe ratio of the portfolio b) The Information ratio of the portfolio
Solution:
a) Sharpe Ratio
Step 1: Recall the Sharpe ratio formula:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑓
𝜎𝑝
Step 2: Substitute the given values:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 0.12−0.03
0.18 =0.50
b) Information Ratio
Step 1: Recall the Information ratio formula:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑏
𝜎𝑝−𝑏
Where σp-b is the standard deviation of the difference between portfolio returns and benchmark
returns (tracking error).
Step 2: Calculate the tracking error:
𝜎𝑝−𝑏 =√𝜎𝑝
2+𝜎𝑏
2−2𝜌𝜎𝑝𝜎𝑏
Assuming a correlation of 0.8 between the portfolio and benchmark:
𝜎𝑝−𝑏 =√0.182+0.152−2(0.8)(0.18)(0.15)=0.11
Step 3: Calculate the Information ratio:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 =0.12−0.09
0.11 =0.27
Therefore, the Sharpe ratio of the portfolio is 0.50, and the Information ratio is 0.27.
QUESTION 9: BINOMIAL OPTION PRICING MODEL (CONTINUED)
Consider a European call option with the following characteristics: - Current stock price (S0) =
$100 - Strike price (K) = $105 - Time to expiration (T) = 3 months (0.25 years) - Risk-free rate (r)
= 4% per annum - Up factor (u) = 1.1 - Down factor (d) = 0.9
Using a one-step binomial model, calculate the price of this call option.
Solution:
Step 1: Calculate the risk-neutral probability (p):
𝑝 = 𝑒𝑟𝑇 −𝑑
𝑢−𝑑 =𝑒0.04×0.25 −0.9
1.1−0.9 =0.5498
Step 2: Calculate the possible stock prices at expiration:
𝑆𝑢= 𝑆0×𝑢 = 100×1.1= $110
𝑆𝑑= 𝑆0×𝑑 = 100×0.9= $90
Step 3: Calculate the option payoffs at expiration:
𝐶𝑢=max(𝑆𝑢−𝐾,0)=max(110−105,0)=$5
𝐶𝑑=max(𝑆𝑑−𝐾,0)= max(90−105,0)=$0
Step 4: Calculate the option price using the risk-neutral valuation formula:
𝐶0=𝑒−𝑟𝑇[𝑝𝐶𝑢+(1−𝑝)𝐶𝑑]
=𝑒−0.04×0.25[0.5498×5+(1−0.5498)×0]
=0.9900×2.7490
=$2.72
Therefore, the price of the European call option using a one-step binomial model is $2.72.
QUESTION 10: PORTFOLIO PERFORMANCE ATTRIBUTION
An equity portfolio manager reported the following sector allocations and returns for the year,
along with the benchmark index data:
Sector
Portfolio Weight
Portfolio Return
Benchmark Weight
Benchmark Return
Technology
35%
12%
30%
10%
Healthcare
25%
8%
20%
7%
Financials
20%
6%
25%
5%
Consumer
15%
4%
15%
3%
Utilities
5%
2%
10%
1%
Perform a performance attribution analysis to determine the sources of the portfolio’s excess
return, breaking it down into allocation effect and selection effect.
Solution:
Step 1: Calculate the total portfolio and benchmark returns:
Portfolio return: (0.35 × 12%) + (0.25 × 8%) + (0.20 × 6%) + (0.15 × 4%) + (0.05 × 2%) = 8.50%
Benchmark return: (0.30 × 10%) + (0.20 × 7%) + (0.25 × 5%) + (0.15 × 3%) + (0.10 × 1%) =
6.40%
Excess return = 8.50% - 6.40% = 2.10%

Step 2: Calculate allocation effect for each sector: Allocation Effect = (Portfolio Weight -
Benchmark Weight) × (Benchmark Sector Return - Benchmark Total Return)
Technology: (35% - 30%) × (10% - 6.40%) = 0.18% Healthcare: (25% - 20%) × (7% - 6.40%) =
0.03% Financials: (20% - 25%) × (5% - 6.40%) = 0.07% Consumer: (15% - 15%) × (3% -
6.40%) = 0.00% Utilities: (5% - 10%) × (1% - 6.40%) = 0.27%
Total Allocation Effect = 0.18% + 0.03% + 0.07% + 0.00% + 0.27% = 0.55%
Step 3: Calculate selection effect for each sector: Selection Effect = Benchmark Weight ×
(Portfolio Sector Return - Benchmark Sector Return)
Technology: 30% × (12% - 10%) = 0.60% Healthcare: 20% × (8% - 7%) = 0.20% Financials:
25% × (6% - 5%) = 0.25% Consumer: 15% × (4% - 3%) = 0.15% Utilities: 10% × (2% - 1%) =
0.10%
Total Selection Effect = 0.60% + 0.20% + 0.25% + 0.15% + 0.10% = 1.30%
Step 4: Calculate interaction effect (optional): Interaction Effect = (Portfolio Weight - Benchmark
Weight) × (Portfolio Sector Return - Benchmark Sector Return)
Technology: (35% - 30%) × (12% - 10%) = 0.10% Healthcare: (25% - 20%) × (8% - 7%) =
0.05% Financials: (20% - 25%) × (6% - 5%) = -0.05% Consumer: (15% - 15%) × (4% - 3%) =
0.00% Utilities: (5% - 10%) × (2% - 1%) = -0.05%
Total Interaction Effect = 0.10% + 0.05% - 0.05% + 0.00% - 0.05% = 0.05%
Step 5: Summarize the attribution analysis:
Excess Return = 2.10% Allocation Effect = 0.55% Selection Effect = 1.30% Interaction Effect =
0.05% Total Attribution = 0.55% + 1.30% + 0.05% = 1.90%
The difference between the excess return (2.10%) and the total attribution (1.90%) is due to
rounding effects.
In conclusion, the portfolio’s outperformance can be attributed to: 1. Allocation Effect: 0.55%
(26.2% of excess return) 2. Selection Effect: 1.30% (61.9% of excess return) 3. Interaction
Effect: 0.05% (2.4% of excess return)
The selection effect was the primary driver of the portfolio’s excess return, indicating that the
manager’s stock selection within sectors contributed most to the outperformance.
A stock has a beta of 1.2, the risk-free rate is 3%, and the expected market return is 10%.
Calculate the expected return of the stock using the CAPM.
Solution:
Step 1: Recall the CAPM formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝐸(𝑅𝑚)−𝑅𝑓)
Step 2: Substitute the given values:
𝑅𝑓=3% =0.03
𝛽𝑖= 1.2
𝐸(𝑅𝑚)=10%= 0.10
Step 3: Calculate the expected return:
𝐸(𝑅𝑖)=0.03+1.2(0.10−0.03)
=0.03+1.2(0.07)
=0.03+0.084
=0.114
Therefore, the expected return of the stock is 11.4%.
QUESTION 2: PORTFOLIO OPTIMIZATION
An investor is considering two stocks, A and B, with the following characteristics:
Stock
Expected Return
Standard Deviation
A
12%
20%
B
8%
15%
The correlation coefficient between the two stocks is 0.3. Find the optimal portfolio weights that
minimize the portfolio risk.
Solution:
Step 1: Recall the formula for portfolio variance:
𝜎𝑝
2=𝑤𝐴
2𝜎𝐴
2+𝑤𝐵
2𝜎𝐵
2+2𝑤𝐴𝑤𝐵𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 2: To minimize risk, we need to find the weights that minimize the portfolio variance. The
formula for the optimal weight of stock A is:
𝑤𝐴=𝜎𝐵
2−𝜌𝐴𝐵𝜎𝐴𝜎𝐵
𝜎𝐴
2+𝜎𝐵
2−2𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 3: Substitute the given values:
𝜎𝐴=20%= 0.20
𝜎𝐵=15% =0.15
𝜌𝐴𝐵 = 0.3
Step 4: Calculate the optimal weight of stock A:
𝑤𝐴=0.152−0.3(0.20)(0.15)
0.202+0.152−2(0.3)(0.20)(0.15)
=0.0225−0.009
0.04+0.0225−0.018
=0.0135
0.0445
≈0.3034
Step 5: Calculate the weight of stock B:
𝑤𝐵= 1−𝑤𝐴=1−0.3034 =0.6966
Therefore, the optimal portfolio weights to minimize risk are approximately 30.34% in stock A
and 69.66% in stock B.
QUESTION 3: DURATION AND CONVEXITY
A 5-year bond with a face value of $1,000 and a 6% annual coupon rate is currently priced at
$1,050. The yield to maturity is 5%. Calculate the bond’s duration and convexity.
Solution:
Step 1: Calculate the bond’s cash flows and present values:
Year
Cash Flow
PV Factor
Present Value
1
$60
0.9524
$57.14
2
$60
0.9070
$54.42
3
$60
0.8638
$51.83
4
$60
0.8227
$49.36
5
$1,060
0.7835
$830.51
Step 2: Calculate the Macaulay Duration:
𝐷 =1×57.14+2×54.42+3×51.83+4×49.36+5×830.51
1050 =4.52
Step 3: Calculate the Modified Duration:
𝑀𝐷 =𝐷
1+𝑦 =4.52
1.05= 4.30
Step 4: Calculate the Convexity:
𝐶 = 1
𝑃(1+𝑦)2∑𝑡(𝑡+1)𝐶𝐹𝑡
(1+𝑦)𝑡
𝑛
𝑡=1
𝐶 = 1
1050(1.05)2(2×57.14+6×54.42+12×51.83+20×49.36+30×830.51)=22.89
Therefore, the bond’s duration is 4.52 years (Macaulay) or 4.30 years (Modified), and its
convexity is 22.89.
QUESTION 4: BLACK-SCHOLES OPTION PRICING MODEL
Using the Black-Scholes model, calculate the price of a European call option with the following
parameters: - Current stock price (S) = $50 - Strike price (K) = $52 - Time to expiration (T) = 6
months (0.5 years) - Risk-free rate (r) = 5% per annum - Stock volatility (σ) = 30% per annum
Solution:
Step 1: Recall the Black-Scholes formula for a call option:
𝐶 =𝑆𝑁(𝑑1)−𝐾𝑒−𝑟𝑇𝑁(𝑑2)
Where:
𝑑1=ln(𝑆/𝐾)+(𝑟+𝜎2/2)𝑇
𝜎√𝑇
𝑑2=𝑑1−𝜎√𝑇
Step 2: Calculate d1 and d2:
𝑑1=ln(50/52)+(0.05+0.32/2)(0.5)
0.3√0.5
=−0.0392+0.0475
0.2121 =0.0391
𝑑2=0.0391−0.3√0.5= −0.1730
Step 3: Find N(d1) and N(d2) using a standard normal distribution table or calculator:
𝑁(𝑑1)=𝑁(0.0391)=0.5156
𝑁(𝑑2)=𝑁(−0.1730)= 0.4313
Step 4: Calculate the option price:
𝐶 =50×0.5156−52𝑒−0.05×0.5 ×0.4313
=25.78−22.17
=3.61
Therefore, the price of the European call option is $3.61.
QUESTION 5: ARBITRAGE PRICING THEORY (APT)
Consider a three-factor APT model with the following information: - Risk-free rate: 3% - Factor
risk premiums: λ1 = 4%, λ2 = 3%, λ3 = 2% - Stock A has factor sensitivities: β1 = 1.2, β2 = 0.8,
β3 = -0.5
Calculate the expected return of Stock A according to the APT model.
Solution:
Step 1: Recall the APT formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖1𝜆1+𝛽𝑖2𝜆2+𝛽𝑖3𝜆3
Step 2: Substitute the given values:
𝐸(𝑅𝐴)= 0.03+1.2(0.04)+0.8(0.03)+(−0.5)(0.02)
=0.03+0.048+0.024−0.01
=0.092
Therefore, the expected return of Stock A according to the APT model is 9.2%.
QUESTION 6: VALUE AT RISK (VAR)
A portfolio has a current value of $10 million and a daily volatility of 1.5%. Assuming normally
distributed returns, calculate the 1-day 99% VaR for this portfolio.
Solution:
Step 1: Recall the VaR formula for normally distributed returns:
𝑉𝑎𝑅 =𝑃×𝜎×𝑍𝛼×√𝑡
Where: - P is the portfolio value - σ is the daily volatility - Zα is the Z-score for the desired
confidence level - t is the time horizon in days
Step 2: Identify the given values:
𝑃 =$10,000,000
𝜎 =1.5% =0.015
𝑍99%= 2.33(𝑓𝑟𝑜𝑚𝑠𝑡𝑎𝑛𝑑𝑎𝑟𝑑𝑛𝑜𝑟𝑚𝑎𝑙𝑑𝑖𝑠𝑡𝑟𝑖𝑏𝑢𝑡𝑖𝑜𝑛𝑡𝑎𝑏𝑙𝑒)
𝑡 =1 day
Step 3: Calculate the VaR:
𝑉𝑎𝑅 =10,000,000×0.015×2.33×√1
=349,500
Therefore, the 1-day 99% VaR for this portfolio is $349,500. This means there is a 1% chance
that the portfolio will lose more than $349,500 in one day.
QUESTION 7: FAMA-FRENCH THREE-FACTOR MODEL
A stock has the following factor exposures: - Market factor (MKT) beta: 1.2 - Size factor (SMB)
beta: 0.5 - Value factor (HML) beta: -0.3
The risk-free rate is 2%, and the factor risk premiums are: - Market risk premium: 6% - SMB
premium: 3% - HML premium: 4%
Calculate the expected return of the stock using the Fama-French Three-Factor Model.
Solution:
Step 1: Recall the Fama-French Three-Factor Model formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝑅𝑚−𝑅𝑓)+𝑠𝑖(𝑆𝑀𝐵)+ℎ𝑖(𝐻𝑀𝐿)
Step 2: Substitute the given values:
𝐸(𝑅𝑖)=0.02+1.2(0.06)+0.5(0.03)+(−0.3)(0.04)
=0.02+0.072+0.015−0.012
=0.095
Therefore, the expected return of the stock according to the Fama-French Three-Factor Model
is 9.5%.
QUESTION 8: SHARPE RATIO AND INFORMATION RATIO
A portfolio manager achieved an average annual return of 12% over the past 5 years, with a
standard deviation of 18%. The risk-free rate during this period was 3%, and the benchmark
index returned 9% with a standard deviation of 15%. Calculate:
a) The Sharpe ratio of the portfolio b) The Information ratio of the portfolio
Solution:
a) Sharpe Ratio
Step 1: Recall the Sharpe ratio formula:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑓
𝜎𝑝
Step 2: Substitute the given values:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 0.12−0.03
0.18 =0.50
b) Information Ratio
Step 1: Recall the Information ratio formula:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑏
𝜎𝑝−𝑏
Where σp-b is the standard deviation of the difference between portfolio returns and benchmark
returns (tracking error).
Step 2: Calculate the tracking error:
𝜎𝑝−𝑏 =√𝜎𝑝
2+𝜎𝑏
2−2𝜌𝜎𝑝𝜎𝑏
Assuming a correlation of 0.8 between the portfolio and benchmark:
𝜎𝑝−𝑏 =√0.182+0.152−2(0.8)(0.18)(0.15)=0.11
Step 3: Calculate the Information ratio:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 =0.12−0.09
0.11 =0.27
Therefore, the Sharpe ratio of the portfolio is 0.50, and the Information ratio is 0.27.
QUESTION 9: BINOMIAL OPTION PRICING MODEL (CONTINUED)
Consider a European call option with the following characteristics: - Current stock price (S0) =
$100 - Strike price (K) = $105 - Time to expiration (T) = 3 months (0.25 years) - Risk-free rate (r)
= 4% per annum - Up factor (u) = 1.1 - Down factor (d) = 0.9
Using a one-step binomial model, calculate the price of this call option.
Solution:
Step 1: Calculate the risk-neutral probability (p):
𝑝 = 𝑒𝑟𝑇 −𝑑
𝑢−𝑑 =𝑒0.04×0.25 −0.9
1.1−0.9 =0.5498
Step 2: Calculate the possible stock prices at expiration:
𝑆𝑢= 𝑆0×𝑢 = 100×1.1= $110
𝑆𝑑= 𝑆0×𝑑 = 100×0.9= $90
Step 3: Calculate the option payoffs at expiration:
𝐶𝑢=max(𝑆𝑢−𝐾,0)=max(110−105,0)=$5
𝐶𝑑=max(𝑆𝑑−𝐾,0)= max(90−105,0)=$0
Step 4: Calculate the option price using the risk-neutral valuation formula:
𝐶0=𝑒−𝑟𝑇[𝑝𝐶𝑢+(1−𝑝)𝐶𝑑]
=𝑒−0.04×0.25[0.5498×5+(1−0.5498)×0]
=0.9900×2.7490
=$2.72
Therefore, the price of the European call option using a one-step binomial model is $2.72.
QUESTION 10: PORTFOLIO PERFORMANCE ATTRIBUTION
An equity portfolio manager reported the following sector allocations and returns for the year,
along with the benchmark index data:
Sector
Portfolio Weight
Portfolio Return
Benchmark Weight
Benchmark Return
Technology
35%
12%
30%
10%
Healthcare
25%
8%
20%
7%
Financials
20%
6%
25%
5%
Consumer
15%
4%
15%
3%
Utilities
5%
2%
10%
1%
Perform a performance attribution analysis to determine the sources of the portfolio’s excess
return, breaking it down into allocation effect and selection effect.
Solution:
Step 1: Calculate the total portfolio and benchmark returns:
Portfolio return: (0.35 × 12%) + (0.25 × 8%) + (0.20 × 6%) + (0.15 × 4%) + (0.05 × 2%) = 8.50%
Benchmark return: (0.30 × 10%) + (0.20 × 7%) + (0.25 × 5%) + (0.15 × 3%) + (0.10 × 1%) =
6.40%
Excess return = 8.50% - 6.40% = 2.10%
Step 2: Calculate allocation effect for each sector: Allocation Effect = (Portfolio Weight -
Benchmark Weight) × (Benchmark Sector Return - Benchmark Total Return)
Technology: (35% - 30%) × (10% - 6.40%) = 0.18% Healthcare: (25% - 20%) × (7% - 6.40%) =
0.03% Financials: (20% - 25%) × (5% - 6.40%) = 0.07% Consumer: (15% - 15%) × (3% -
6.40%) = 0.00% Utilities: (5% - 10%) × (1% - 6.40%) = 0.27%
Total Allocation Effect = 0.18% + 0.03% + 0.07% + 0.00% + 0.27% = 0.55%
Step 3: Calculate selection effect for each sector: Selection Effect = Benchmark Weight ×
(Portfolio Sector Return - Benchmark Sector Return)
Technology: 30% × (12% - 10%) = 0.60% Healthcare: 20% × (8% - 7%) = 0.20% Financials:
25% × (6% - 5%) = 0.25% Consumer: 15% × (4% - 3%) = 0.15% Utilities: 10% × (2% - 1%) =
0.10%
Total Selection Effect = 0.60% + 0.20% + 0.25% + 0.15% + 0.10% = 1.30%
Step 4: Calculate interaction effect (optional): Interaction Effect = (Portfolio Weight - Benchmark
Weight) × (Portfolio Sector Return - Benchmark Sector Return)
Technology: (35% - 30%) × (12% - 10%) = 0.10% Healthcare: (25% - 20%) × (8% - 7%) =
0.05% Financials: (20% - 25%) × (6% - 5%) = -0.05% Consumer: (15% - 15%) × (4% - 3%) =
0.00% Utilities: (5% - 10%) × (2% - 1%) = -0.05%
Total Interaction Effect = 0.10% + 0.05% - 0.05% + 0.00% - 0.05% = 0.05%
Step 5: Summarize the attribution analysis:
Excess Return = 2.10% Allocation Effect = 0.55% Selection Effect = 1.30% Interaction Effect =
0.05% Total Attribution = 0.55% + 1.30% + 0.05% = 1.90%
The difference between the excess return (2.10%) and the total attribution (1.90%) is due to
rounding effects.
In conclusion, the portfolio’s outperformance can be attributed to: 1. Allocation Effect: 0.55%
(26.2% of excess return) 2. Selection Effect: 1.30% (61.9% of excess return) 3. Interaction
Effect: 0.05% (2.4% of excess return)
The selection effect was the primary driver of the portfolio’s excess return, indicating that the
manager’s stock selection within sectors contributed most to the outperformance.
A stock has a beta of 1.2, the risk-free rate is 3%, and the expected market return is 10%.
Calculate the expected return of the stock using the CAPM.
Solution:
Step 1: Recall the CAPM formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝐸(𝑅𝑚)−𝑅𝑓)
Step 2: Substitute the given values:
𝑅𝑓=3% =0.03
𝛽𝑖= 1.2
𝐸(𝑅𝑚)=10%= 0.10
Step 3: Calculate the expected return:
𝐸(𝑅𝑖)=0.03+1.2(0.10−0.03)
=0.03+1.2(0.07)
=0.03+0.084
=0.114
Therefore, the expected return of the stock is 11.4%.
QUESTION 2: PORTFOLIO OPTIMIZATION
An investor is considering two stocks, A and B, with the following characteristics:
Stock
Expected Return
Standard Deviation
A
12%
20%
B
8%
15%
The correlation coefficient between the two stocks is 0.3. Find the optimal portfolio weights that
minimize the portfolio risk.
Solution:
Step 1: Recall the formula for portfolio variance:
𝜎𝑝
2=𝑤𝐴
2𝜎𝐴
2+𝑤𝐵
2𝜎𝐵
2+2𝑤𝐴𝑤𝐵𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 2: To minimize risk, we need to find the weights that minimize the portfolio variance. The
formula for the optimal weight of stock A is:
𝑤𝐴=𝜎𝐵
2−𝜌𝐴𝐵𝜎𝐴𝜎𝐵
𝜎𝐴
2+𝜎𝐵
2−2𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 3: Substitute the given values:
𝜎𝐴=20%= 0.20
𝜎𝐵=15% =0.15
𝜌𝐴𝐵 = 0.3
Step 4: Calculate the optimal weight of stock A:
𝑤𝐴=0.152−0.3(0.20)(0.15)
0.202+0.152−2(0.3)(0.20)(0.15)
=0.0225−0.009
0.04+0.0225−0.018
=0.0135
0.0445
≈0.3034
Step 5: Calculate the weight of stock B:
𝑤𝐵= 1−𝑤𝐴=1−0.3034 =0.6966
Therefore, the optimal portfolio weights to minimize risk are approximately 30.34% in stock A
and 69.66% in stock B.
QUESTION 3: DURATION AND CONVEXITY
A 5-year bond with a face value of $1,000 and a 6% annual coupon rate is currently priced at
$1,050. The yield to maturity is 5%. Calculate the bond’s duration and convexity.
Solution:
Step 1: Calculate the bond’s cash flows and present values:
Year
Cash Flow
PV Factor
Present Value
1
$60
0.9524
$57.14
2
$60
0.9070
$54.42
Year
Cash Flow
PV Factor
Present Value
3
$60
0.8638
$51.83
4
$60
0.8227
$49.36
5
$1,060
0.7835
$830.51
Step 2: Calculate the Macaulay Duration:
𝐷 =1×57.14+2×54.42+3×51.83+4×49.36+5×830.51
1050 =4.52
Step 3: Calculate the Modified Duration:
𝑀𝐷 =𝐷
1+𝑦 =4.52
1.05= 4.30
Step 4: Calculate the Convexity:
𝐶 = 1
𝑃(1+𝑦)2∑𝑡(𝑡+1)𝐶𝐹𝑡
(1+𝑦)𝑡
𝑛
𝑡=1
𝐶 = 1
1050(1.05)2(2×57.14+6×54.42+12×51.83+20×49.36+30×830.51)=22.89
Therefore, the bond’s duration is 4.52 years (Macaulay) or 4.30 years (Modified), and its
convexity is 22.89.
QUESTION 4: BLACK-SCHOLES OPTION PRICING MODEL
Using the Black-Scholes model, calculate the price of a European call option with the following
parameters: - Current stock price (S) = $50 - Strike price (K) = $52 - Time to expiration (T) = 6
months (0.5 years) - Risk-free rate (r) = 5% per annum - Stock volatility (σ) = 30% per annum
Solution:
Step 1: Recall the Black-Scholes formula for a call option:
𝐶 =𝑆𝑁(𝑑1)−𝐾𝑒−𝑟𝑇𝑁(𝑑2)
Where:
𝑑1=ln(𝑆/𝐾)+(𝑟+𝜎2/2)𝑇
𝜎√𝑇
𝑑2=𝑑1−𝜎√𝑇
Step 2: Calculate d1 and d2:
𝑑1=ln(50/52)+(0.05+0.32/2)(0.5)
0.3√0.5
=−0.0392+0.0475
0.2121 =0.0391
𝑑2=0.0391−0.3√0.5= −0.1730
Step 3: Find N(d1) and N(d2) using a standard normal distribution table or calculator:
𝑁(𝑑1)=𝑁(0.0391)=0.5156
𝑁(𝑑2)=𝑁(−0.1730)= 0.4313
Step 4: Calculate the option price:
𝐶 =50×0.5156−52𝑒−0.05×0.5 ×0.4313
=25.78−22.17
=3.61
Therefore, the price of the European call option is $3.61.
QUESTION 5: ARBITRAGE PRICING THEORY (APT)
Consider a three-factor APT model with the following information: - Risk-free rate: 3% - Factor
risk premiums: λ1 = 4%, λ2 = 3%, λ3 = 2% - Stock A has factor sensitivities: β1 = 1.2, β2 = 0.8,
β3 = -0.5
Calculate the expected return of Stock A according to the APT model.
Solution:
Step 1: Recall the APT formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖1𝜆1+𝛽𝑖2𝜆2+𝛽𝑖3𝜆3
Step 2: Substitute the given values:
𝐸(𝑅𝐴)= 0.03+1.2(0.04)+0.8(0.03)+(−0.5)(0.02)
=0.03+0.048+0.024−0.01
=0.092
Therefore, the expected return of Stock A according to the APT model is 9.2%.
QUESTION 6: VALUE AT RISK (VAR)
A portfolio has a current value of $10 million and a daily volatility of 1.5%. Assuming normally
distributed returns, calculate the 1-day 99% VaR for this portfolio.
Solution:
Step 1: Recall the VaR formula for normally distributed returns:
𝑉𝑎𝑅 =𝑃×𝜎×𝑍𝛼×√𝑡
Where: - P is the portfolio value - σ is the daily volatility - Zα is the Z-score for the desired
confidence level - t is the time horizon in days
Step 2: Identify the given values:
𝑃 =$10,000,000
𝜎 =1.5% =0.015
𝑍99%= 2.33(𝑓𝑟𝑜𝑚𝑠𝑡𝑎𝑛𝑑𝑎𝑟𝑑𝑛𝑜𝑟𝑚𝑎𝑙𝑑𝑖𝑠𝑡𝑟𝑖𝑏𝑢𝑡𝑖𝑜𝑛𝑡𝑎𝑏𝑙𝑒)
𝑡 =1 day
Step 3: Calculate the VaR:
𝑉𝑎𝑅 =10,000,000×0.015×2.33×√1
=349,500
Therefore, the 1-day 99% VaR for this portfolio is $349,500. This means there is a 1% chance
that the portfolio will lose more than $349,500 in one day.
QUESTION 7: FAMA-FRENCH THREE-FACTOR MODEL
A stock has the following factor exposures: - Market factor (MKT) beta: 1.2 - Size factor (SMB)
beta: 0.5 - Value factor (HML) beta: -0.3
The risk-free rate is 2%, and the factor risk premiums are: - Market risk premium: 6% - SMB
premium: 3% - HML premium: 4%
Calculate the expected return of the stock using the Fama-French Three-Factor Model.
Solution:
Step 1: Recall the Fama-French Three-Factor Model formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝑅𝑚−𝑅𝑓)+𝑠𝑖(𝑆𝑀𝐵)+ℎ𝑖(𝐻𝑀𝐿)
Step 2: Substitute the given values:
𝐸(𝑅𝑖)=0.02+1.2(0.06)+0.5(0.03)+(−0.3)(0.04)
=0.02+0.072+0.015−0.012
=0.095
Therefore, the expected return of the stock according to the Fama-French Three-Factor Model
is 9.5%.
QUESTION 8: SHARPE RATIO AND INFORMATION RATIO
A portfolio manager achieved an average annual return of 12% over the past 5 years, with a
standard deviation of 18%. The risk-free rate during this period was 3%, and the benchmark
index returned 9% with a standard deviation of 15%. Calculate:
a) The Sharpe ratio of the portfolio b) The Information ratio of the portfolio
Solution:
a) Sharpe Ratio
Step 1: Recall the Sharpe ratio formula:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑓
𝜎𝑝
Step 2: Substitute the given values:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 0.12−0.03
0.18 =0.50
b) Information Ratio
Step 1: Recall the Information ratio formula:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑏
𝜎𝑝−𝑏
Where σp-b is the standard deviation of the difference between portfolio returns and benchmark
returns (tracking error).
Step 2: Calculate the tracking error:
𝜎𝑝−𝑏 =√𝜎𝑝
2+𝜎𝑏
2−2𝜌𝜎𝑝𝜎𝑏
Assuming a correlation of 0.8 between the portfolio and benchmark:
𝜎𝑝−𝑏 =√0.182+0.152−2(0.8)(0.18)(0.15)=0.11
Step 3: Calculate the Information ratio:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 =0.12−0.09
0.11 =0.27
Therefore, the Sharpe ratio of the portfolio is 0.50, and the Information ratio is 0.27.
QUESTION 9: BINOMIAL OPTION PRICING MODEL (CONTINUED)
Consider a European call option with the following characteristics: - Current stock price (S0) =
$100 - Strike price (K) = $105 - Time to expiration (T) = 3 months (0.25 years) - Risk-free rate (r)
= 4% per annum - Up factor (u) = 1.1 - Down factor (d) = 0.9
Using a one-step binomial model, calculate the price of this call option.
Solution:
Step 1: Calculate the risk-neutral probability (p):
𝑝 = 𝑒𝑟𝑇 −𝑑
𝑢−𝑑 =𝑒0.04×0.25 −0.9
1.1−0.9 =0.5498
Step 2: Calculate the possible stock prices at expiration:
𝑆𝑢= 𝑆0×𝑢 = 100×1.1= $110
𝑆𝑑= 𝑆0×𝑑 = 100×0.9= $90
Step 3: Calculate the option payoffs at expiration:
𝐶𝑢=max(𝑆𝑢−𝐾,0)=max(110−105,0)=$5
𝐶𝑑=max(𝑆𝑑−𝐾,0)= max(90−105,0)=$0
Step 4: Calculate the option price using the risk-neutral valuation formula:
𝐶0=𝑒−𝑟𝑇[𝑝𝐶𝑢+(1−𝑝)𝐶𝑑]
=𝑒−0.04×0.25[0.5498×5+(1−0.5498)×0]
=0.9900×2.7490
=$2.72
Therefore, the price of the European call option using a one-step binomial model is $2.72.
QUESTION 10: PORTFOLIO PERFORMANCE ATTRIBUTION
An equity portfolio manager reported the following sector allocations and returns for the year,
along with the benchmark index data:
Sector
Portfolio Weight
Portfolio Return
Benchmark Weight
Benchmark Return
Technology
35%
12%
30%
10%
Healthcare
25%
8%
20%
7%
Financials
20%
6%
25%
5%
Consumer
15%
4%
15%
3%
Utilities
5%
2%
10%
1%
Perform a performance attribution analysis to determine the sources of the portfolio’s excess
return, breaking it down into allocation effect and selection effect.
Solution:
Step 1: Calculate the total portfolio and benchmark returns:
Portfolio return: (0.35 × 12%) + (0.25 × 8%) + (0.20 × 6%) + (0.15 × 4%) + (0.05 × 2%) = 8.50%
Benchmark return: (0.30 × 10%) + (0.20 × 7%) + (0.25 × 5%) + (0.15 × 3%) + (0.10 × 1%) =
6.40%
Excess return = 8.50% - 6.40% = 2.10%

Step 2: Calculate allocation effect for each sector: Allocation Effect = (Portfolio Weight -
Benchmark Weight) × (Benchmark Sector Return - Benchmark Total Return)
Technology: (35% - 30%) × (10% - 6.40%) = 0.18% Healthcare: (25% - 20%) × (7% - 6.40%) =
0.03% Financials: (20% - 25%) × (5% - 6.40%) = 0.07% Consumer: (15% - 15%) × (3% -
6.40%) = 0.00% Utilities: (5% - 10%) × (1% - 6.40%) = 0.27%
Total Allocation Effect = 0.18% + 0.03% + 0.07% + 0.00% + 0.27% = 0.55%
Step 3: Calculate selection effect for each sector: Selection Effect = Benchmark Weight ×
(Portfolio Sector Return - Benchmark Sector Return)
Technology: 30% × (12% - 10%) = 0.60% Healthcare: 20% × (8% - 7%) = 0.20% Financials:
25% × (6% - 5%) = 0.25% Consumer: 15% × (4% - 3%) = 0.15% Utilities: 10% × (2% - 1%) =
0.10%
Total Selection Effect = 0.60% + 0.20% + 0.25% + 0.15% + 0.10% = 1.30%
Step 4: Calculate interaction effect (optional): Interaction Effect = (Portfolio Weight - Benchmark
Weight) × (Portfolio Sector Return - Benchmark Sector Return)
Technology: (35% - 30%) × (12% - 10%) = 0.10% Healthcare: (25% - 20%) × (8% - 7%) =
0.05% Financials: (20% - 25%) × (6% - 5%) = -0.05% Consumer: (15% - 15%) × (4% - 3%) =
0.00% Utilities: (5% - 10%) × (2% - 1%) = -0.05%
Total Interaction Effect = 0.10% + 0.05% - 0.05% + 0.00% - 0.05% = 0.05%
Step 5: Summarize the attribution analysis:
Excess Return = 2.10% Allocation Effect = 0.55% Selection Effect = 1.30% Interaction Effect =
0.05% Total Attribution = 0.55% + 1.30% + 0.05% = 1.90%
The difference between the excess return (2.10%) and the total attribution (1.90%) is due to
rounding effects.
In conclusion, the portfolio’s outperformance can be attributed to: 1. Allocation Effect: 0.55%
(26.2% of excess return) 2. Selection Effect: 1.30% (61.9% of excess return) 3. Interaction
Effect: 0.05% (2.4% of excess return)
The selection effect was the primary driver of the portfolio’s excess return, indicating that the
manager’s stock selection within sectors contributed most to the outperformance.
A stock has a beta of 1.2, the risk-free rate is 3%, and the expected market return is 10%.
Calculate the expected return of the stock using the CAPM.
Solution:
Step 1: Recall the CAPM formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝐸(𝑅𝑚)−𝑅𝑓)
Step 2: Substitute the given values:
𝑅𝑓=3% =0.03
𝛽𝑖= 1.2
𝐸(𝑅𝑚)=10%= 0.10
Step 3: Calculate the expected return:
𝐸(𝑅𝑖)=0.03+1.2(0.10−0.03)
=0.03+1.2(0.07)
=0.03+0.084
=0.114
Therefore, the expected return of the stock is 11.4%.
QUESTION 2: PORTFOLIO OPTIMIZATION
An investor is considering two stocks, A and B, with the following characteristics:
Stock
Expected Return
Standard Deviation
A
12%
20%
B
8%
15%
The correlation coefficient between the two stocks is 0.3. Find the optimal portfolio weights that
minimize the portfolio risk.
Solution:
Step 1: Recall the formula for portfolio variance:
𝜎𝑝
2=𝑤𝐴
2𝜎𝐴
2+𝑤𝐵
2𝜎𝐵
2+2𝑤𝐴𝑤𝐵𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 2: To minimize risk, we need to find the weights that minimize the portfolio variance. The
formula for the optimal weight of stock A is:
𝑤𝐴=𝜎𝐵
2−𝜌𝐴𝐵𝜎𝐴𝜎𝐵
𝜎𝐴
2+𝜎𝐵
2−2𝜌𝐴𝐵𝜎𝐴𝜎𝐵
Step 3: Substitute the given values:
𝜎𝐴=20%= 0.20
𝜎𝐵=15% =0.15
𝜌𝐴𝐵 = 0.3
Step 4: Calculate the optimal weight of stock A:
𝑤𝐴=0.152−0.3(0.20)(0.15)
0.202+0.152−2(0.3)(0.20)(0.15)
=0.0225−0.009
0.04+0.0225−0.018
=0.0135
0.0445
≈0.3034
Step 5: Calculate the weight of stock B:
𝑤𝐵= 1−𝑤𝐴=1−0.3034 =0.6966
Therefore, the optimal portfolio weights to minimize risk are approximately 30.34% in stock A
and 69.66% in stock B.
QUESTION 3: DURATION AND CONVEXITY
A 5-year bond with a face value of $1,000 and a 6% annual coupon rate is currently priced at
$1,050. The yield to maturity is 5%. Calculate the bond’s duration and convexity.
Solution:
Step 1: Calculate the bond’s cash flows and present values:
Year
Cash Flow
PV Factor
Present Value
1
$60
0.9524
$57.14
2
$60
0.9070
$54.42
3
$60
0.8638
$51.83
4
$60
0.8227
$49.36
5
$1,060
0.7835
$830.51
Step 2: Calculate the Macaulay Duration:
𝐷 =1×57.14+2×54.42+3×51.83+4×49.36+5×830.51
1050 =4.52
Step 3: Calculate the Modified Duration:
𝑀𝐷 =𝐷
1+𝑦 =4.52
1.05= 4.30
Step 4: Calculate the Convexity:
𝐶 = 1
𝑃(1+𝑦)2∑𝑡(𝑡+1)𝐶𝐹𝑡
(1+𝑦)𝑡
𝑛
𝑡=1
𝐶 = 1
1050(1.05)2(2×57.14+6×54.42+12×51.83+20×49.36+30×830.51)=22.89
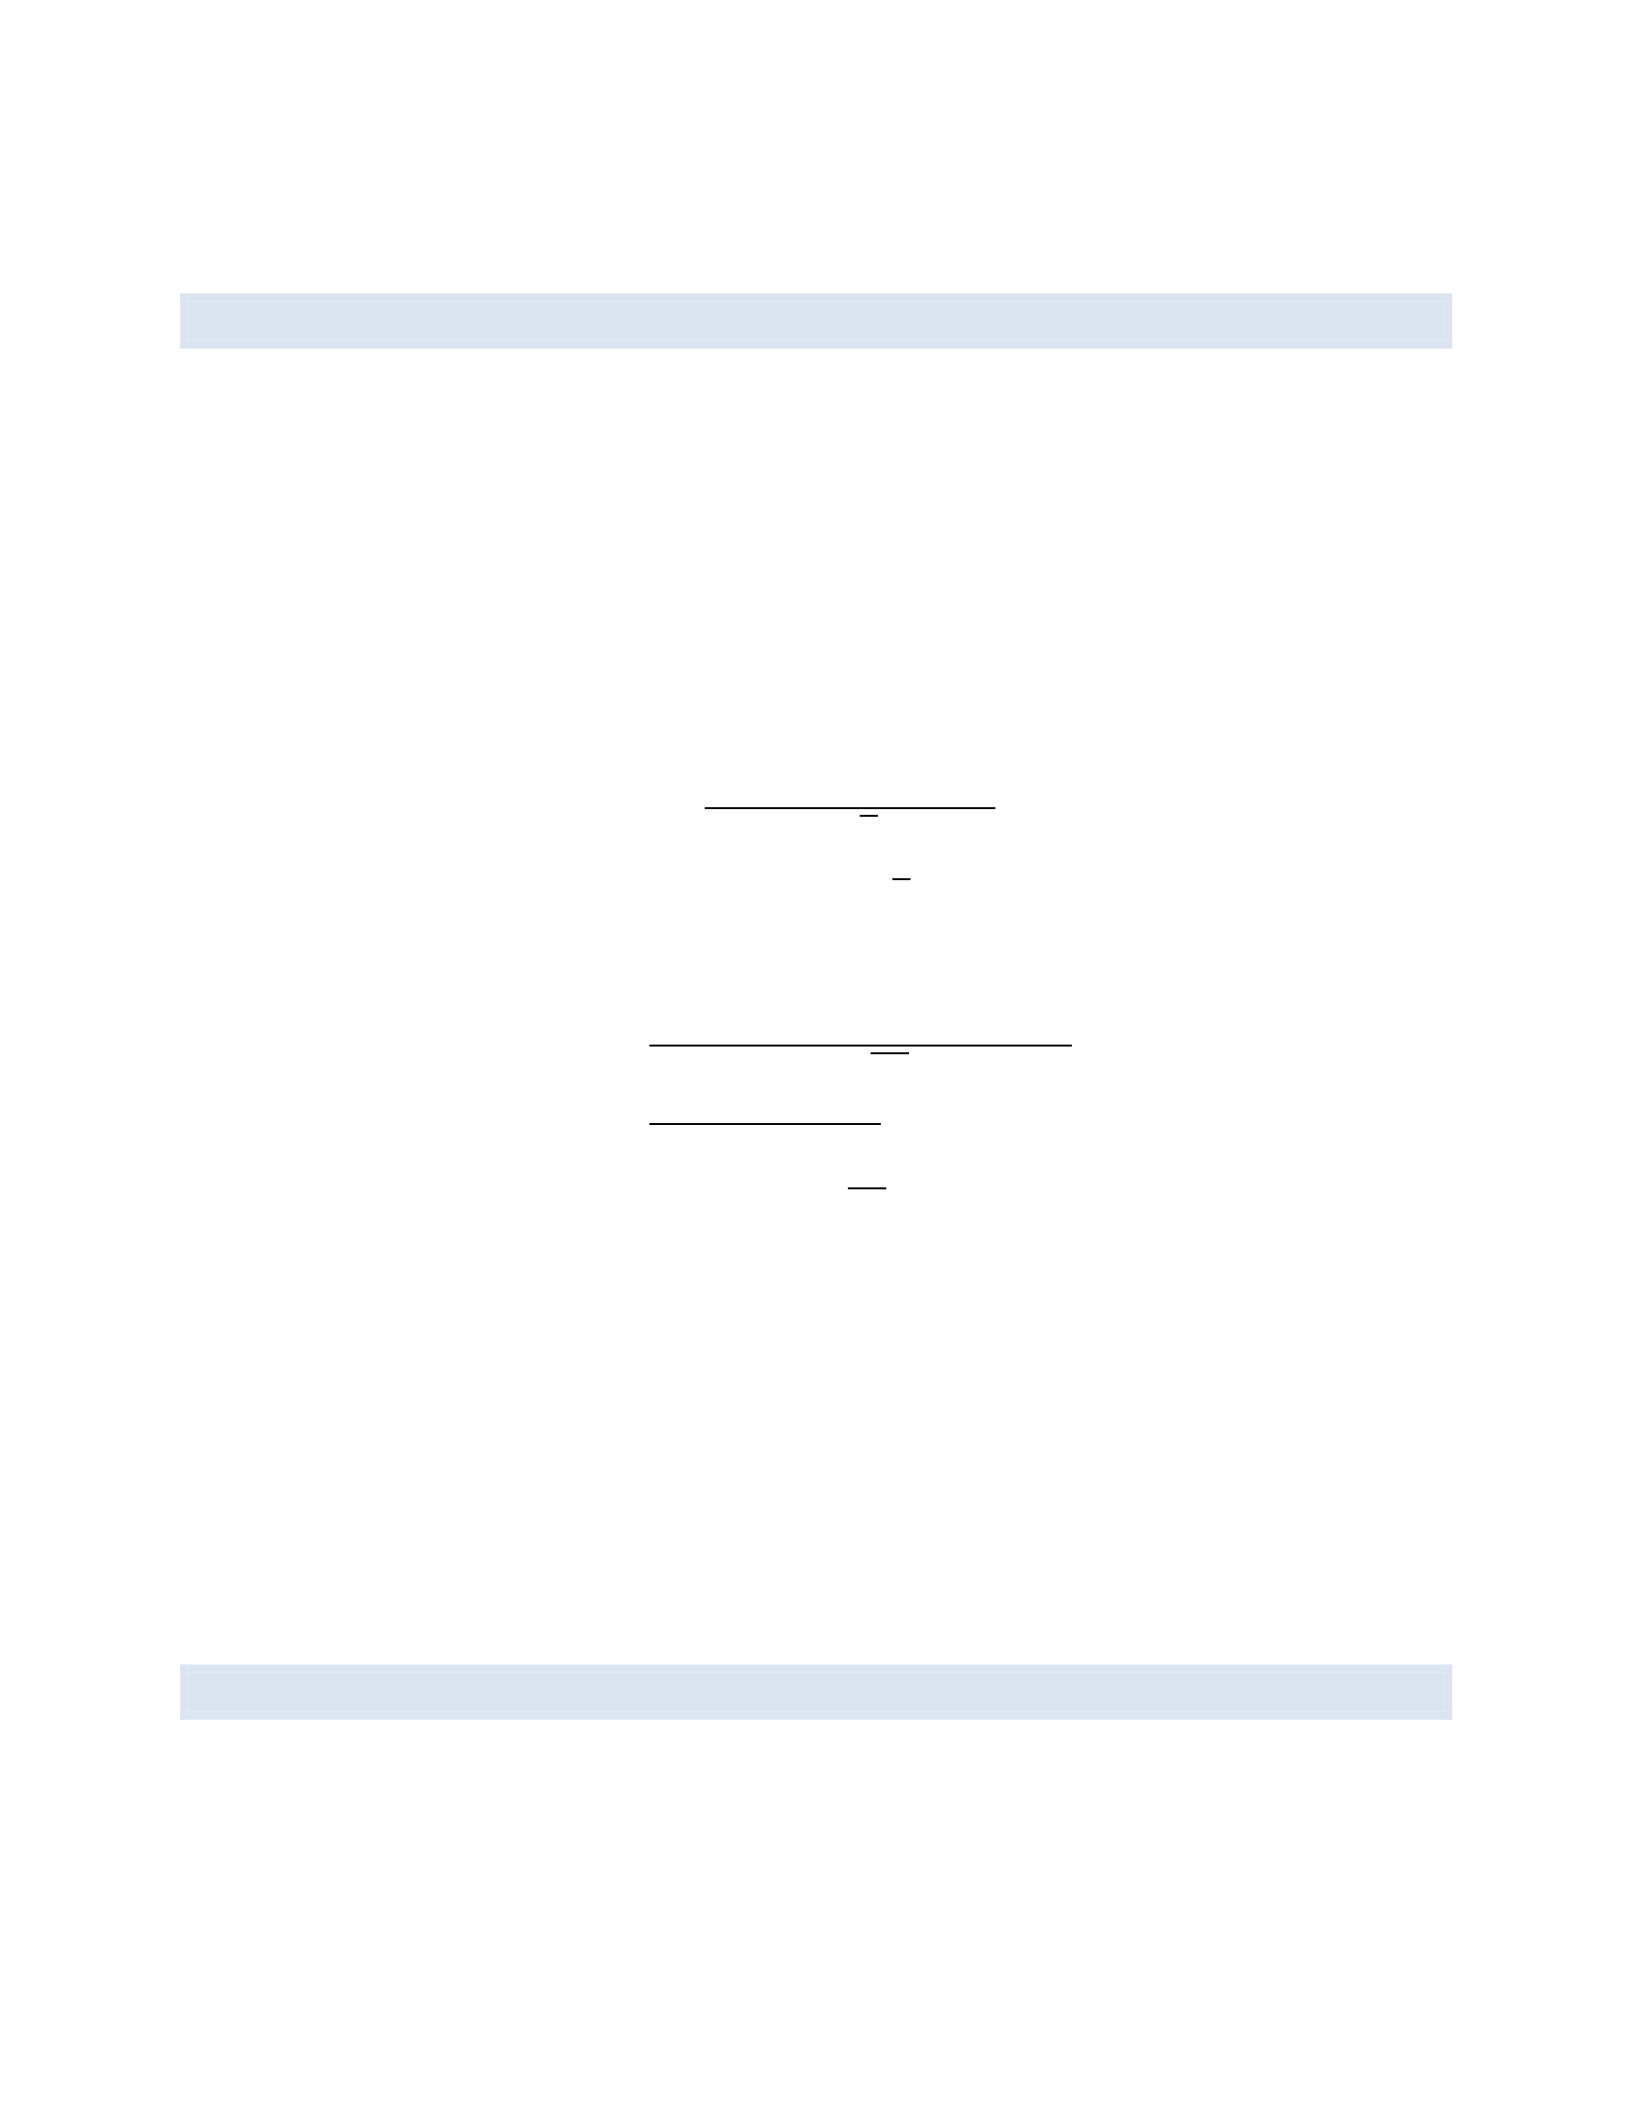
Therefore, the bond’s duration is 4.52 years (Macaulay) or 4.30 years (Modified), and its
convexity is 22.89.
QUESTION 4: BLACK-SCHOLES OPTION PRICING MODEL
Using the Black-Scholes model, calculate the price of a European call option with the following
parameters: - Current stock price (S) = $50 - Strike price (K) = $52 - Time to expiration (T) = 6
months (0.5 years) - Risk-free rate (r) = 5% per annum - Stock volatility (σ) = 30% per annum
Solution:
Step 1: Recall the Black-Scholes formula for a call option:
𝐶 =𝑆𝑁(𝑑1)−𝐾𝑒−𝑟𝑇𝑁(𝑑2)
Where:
𝑑1=ln(𝑆/𝐾)+(𝑟+𝜎2/2)𝑇
𝜎√𝑇
𝑑2=𝑑1−𝜎√𝑇
Step 2: Calculate d1 and d2:
𝑑1=ln(50/52)+(0.05+0.32/2)(0.5)
0.3√0.5
=−0.0392+0.0475
0.2121 =0.0391
𝑑2=0.0391−0.3√0.5= −0.1730
Step 3: Find N(d1) and N(d2) using a standard normal distribution table or calculator:
𝑁(𝑑1)=𝑁(0.0391)=0.5156
𝑁(𝑑2)=𝑁(−0.1730)= 0.4313
Step 4: Calculate the option price:
𝐶 =50×0.5156−52𝑒−0.05×0.5 ×0.4313
=25.78−22.17
=3.61
Therefore, the price of the European call option is $3.61.
QUESTION 5: ARBITRAGE PRICING THEORY (APT)
Consider a three-factor APT model with the following information: - Risk-free rate: 3% - Factor
risk premiums: λ1 = 4%, λ2 = 3%, λ3 = 2% - Stock A has factor sensitivities: β1 = 1.2, β2 = 0.8,
β3 = -0.5
Calculate the expected return of Stock A according to the APT model.
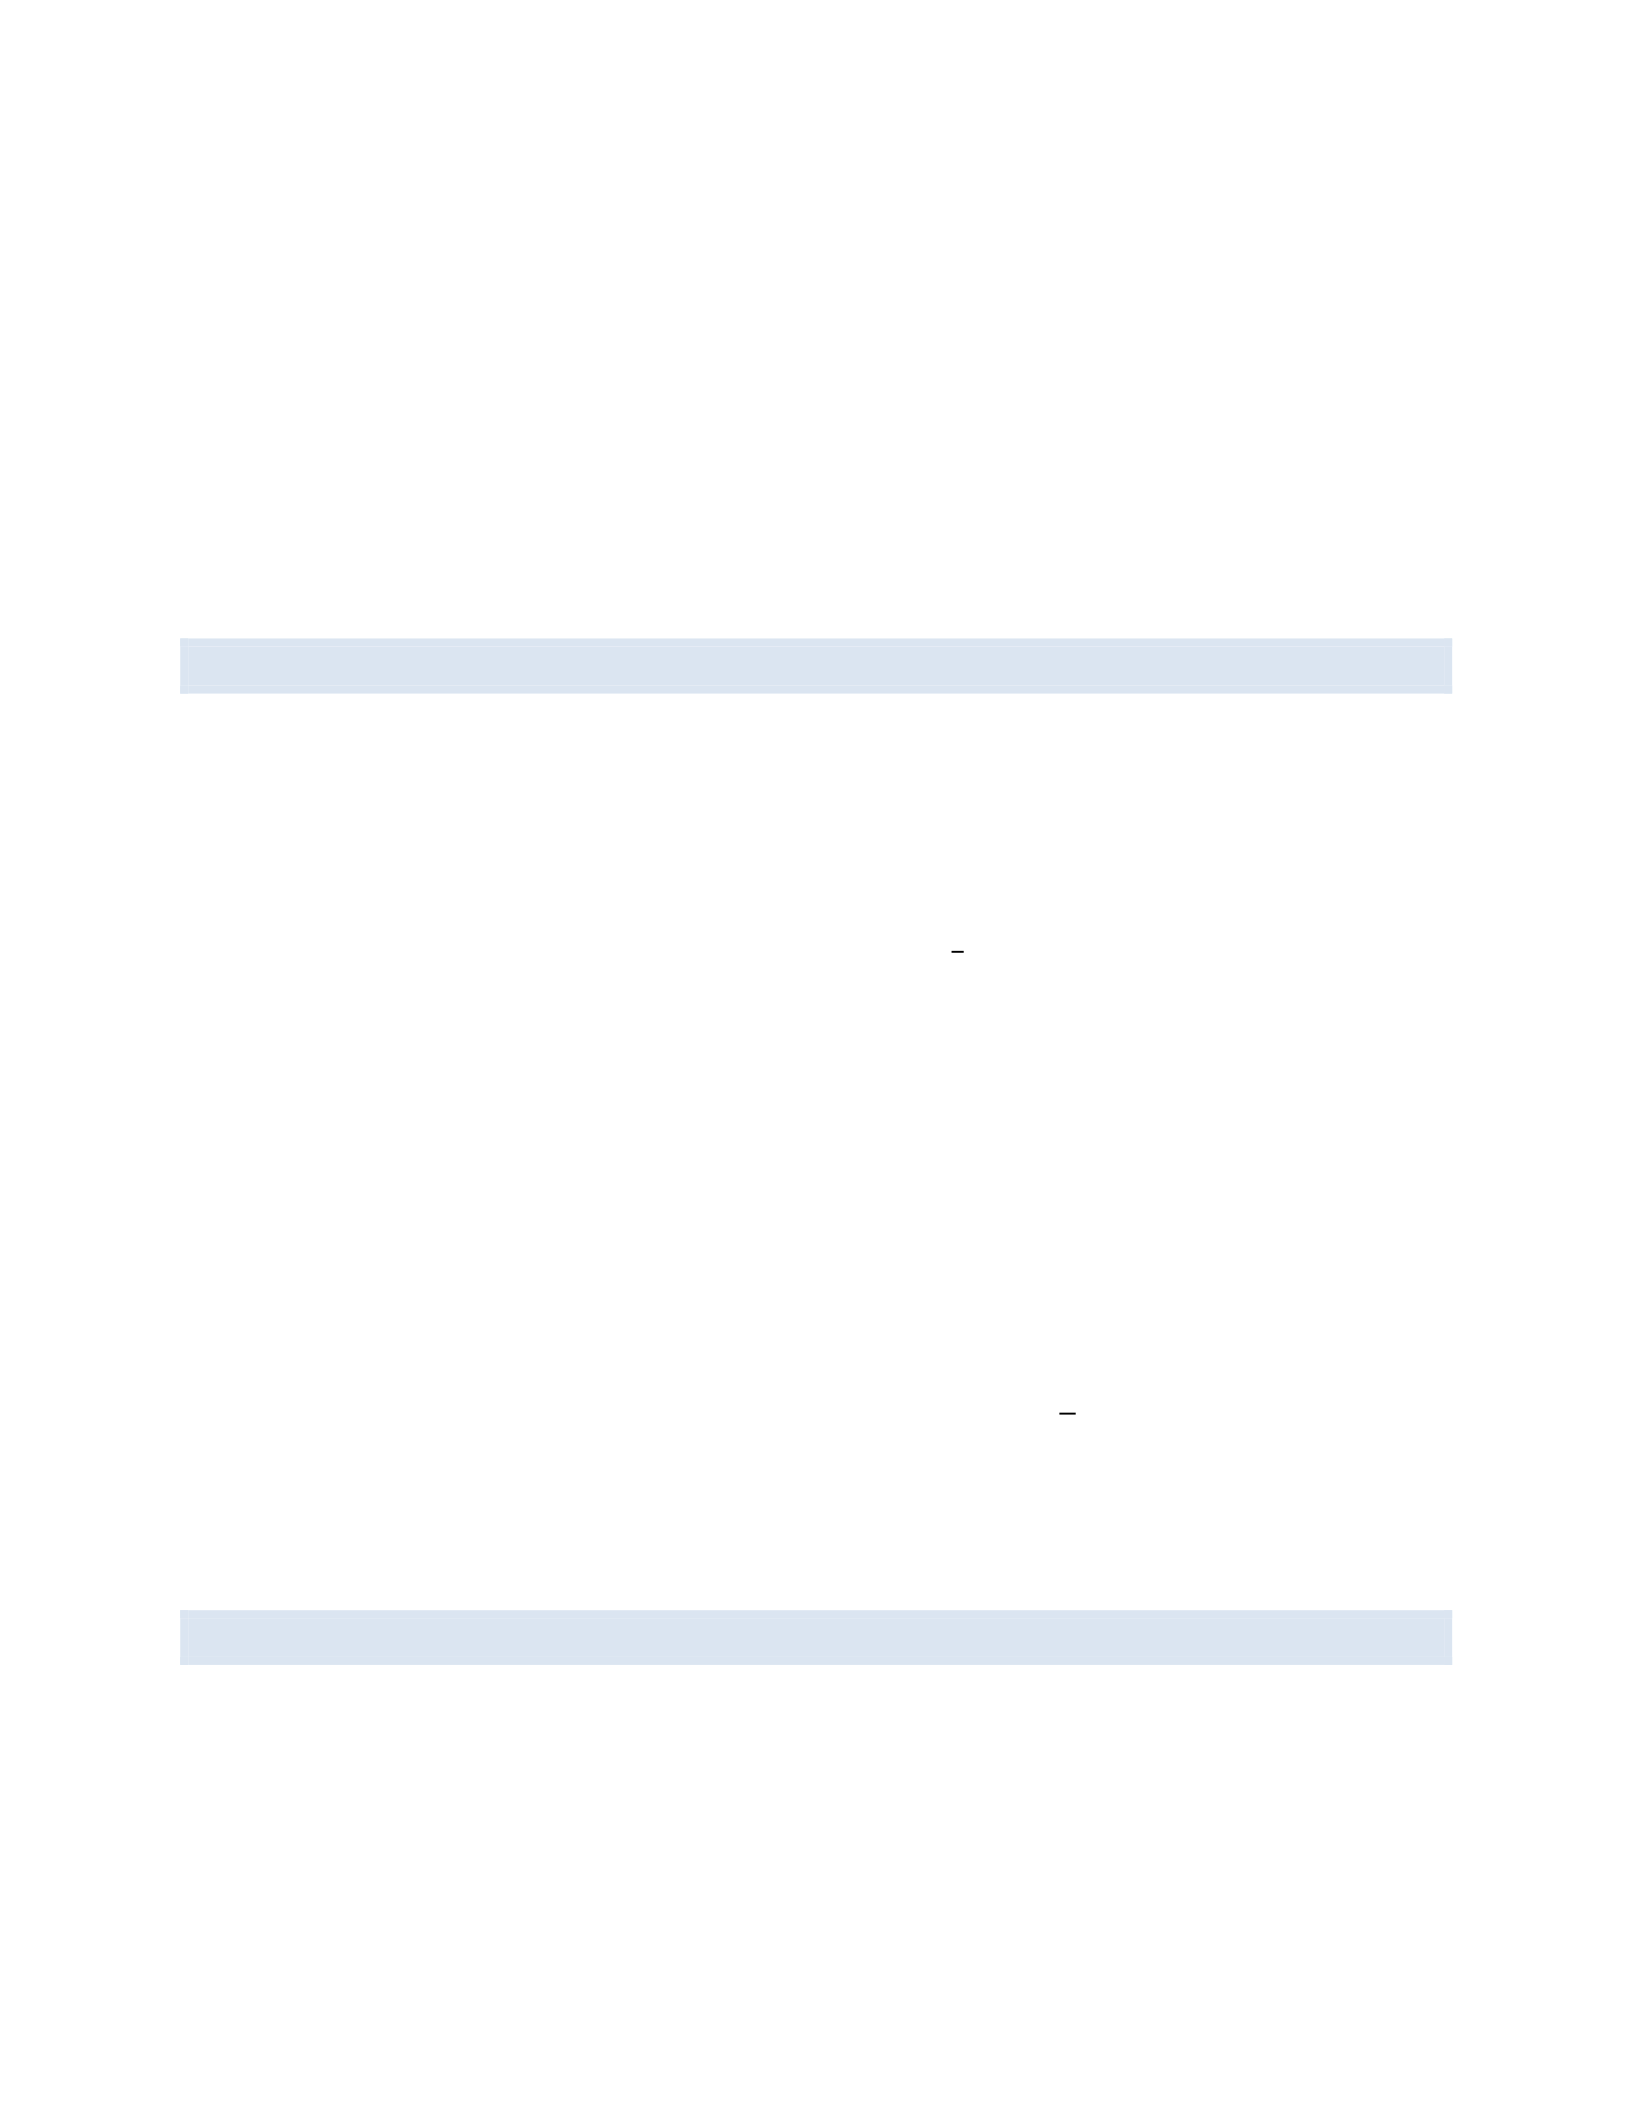
Solution:
Step 1: Recall the APT formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖1𝜆1+𝛽𝑖2𝜆2+𝛽𝑖3𝜆3
Step 2: Substitute the given values:
𝐸(𝑅𝐴)= 0.03+1.2(0.04)+0.8(0.03)+(−0.5)(0.02)
=0.03+0.048+0.024−0.01
=0.092
Therefore, the expected return of Stock A according to the APT model is 9.2%.
QUESTION 6: VALUE AT RISK (VAR)
A portfolio has a current value of $10 million and a daily volatility of 1.5%. Assuming normally
distributed returns, calculate the 1-day 99% VaR for this portfolio.
Solution:
Step 1: Recall the VaR formula for normally distributed returns:
𝑉𝑎𝑅 =𝑃×𝜎×𝑍𝛼×√𝑡
Where: - P is the portfolio value - σ is the daily volatility - Zα is the Z-score for the desired
confidence level - t is the time horizon in days
Step 2: Identify the given values:
𝑃 =$10,000,000
𝜎 =1.5% =0.015
𝑍99%= 2.33(𝑓𝑟𝑜𝑚𝑠𝑡𝑎𝑛𝑑𝑎𝑟𝑑𝑛𝑜𝑟𝑚𝑎𝑙𝑑𝑖𝑠𝑡𝑟𝑖𝑏𝑢𝑡𝑖𝑜𝑛𝑡𝑎𝑏𝑙𝑒)
𝑡 =1 day
Step 3: Calculate the VaR:
𝑉𝑎𝑅 =10,000,000×0.015×2.33×√1
=349,500
Therefore, the 1-day 99% VaR for this portfolio is $349,500. This means there is a 1% chance
that the portfolio will lose more than $349,500 in one day.
QUESTION 7: FAMA-FRENCH THREE-FACTOR MODEL
A stock has the following factor exposures: - Market factor (MKT) beta: 1.2 - Size factor (SMB)
beta: 0.5 - Value factor (HML) beta: -0.3
The risk-free rate is 2%, and the factor risk premiums are: - Market risk premium: 6% - SMB
premium: 3% - HML premium: 4%
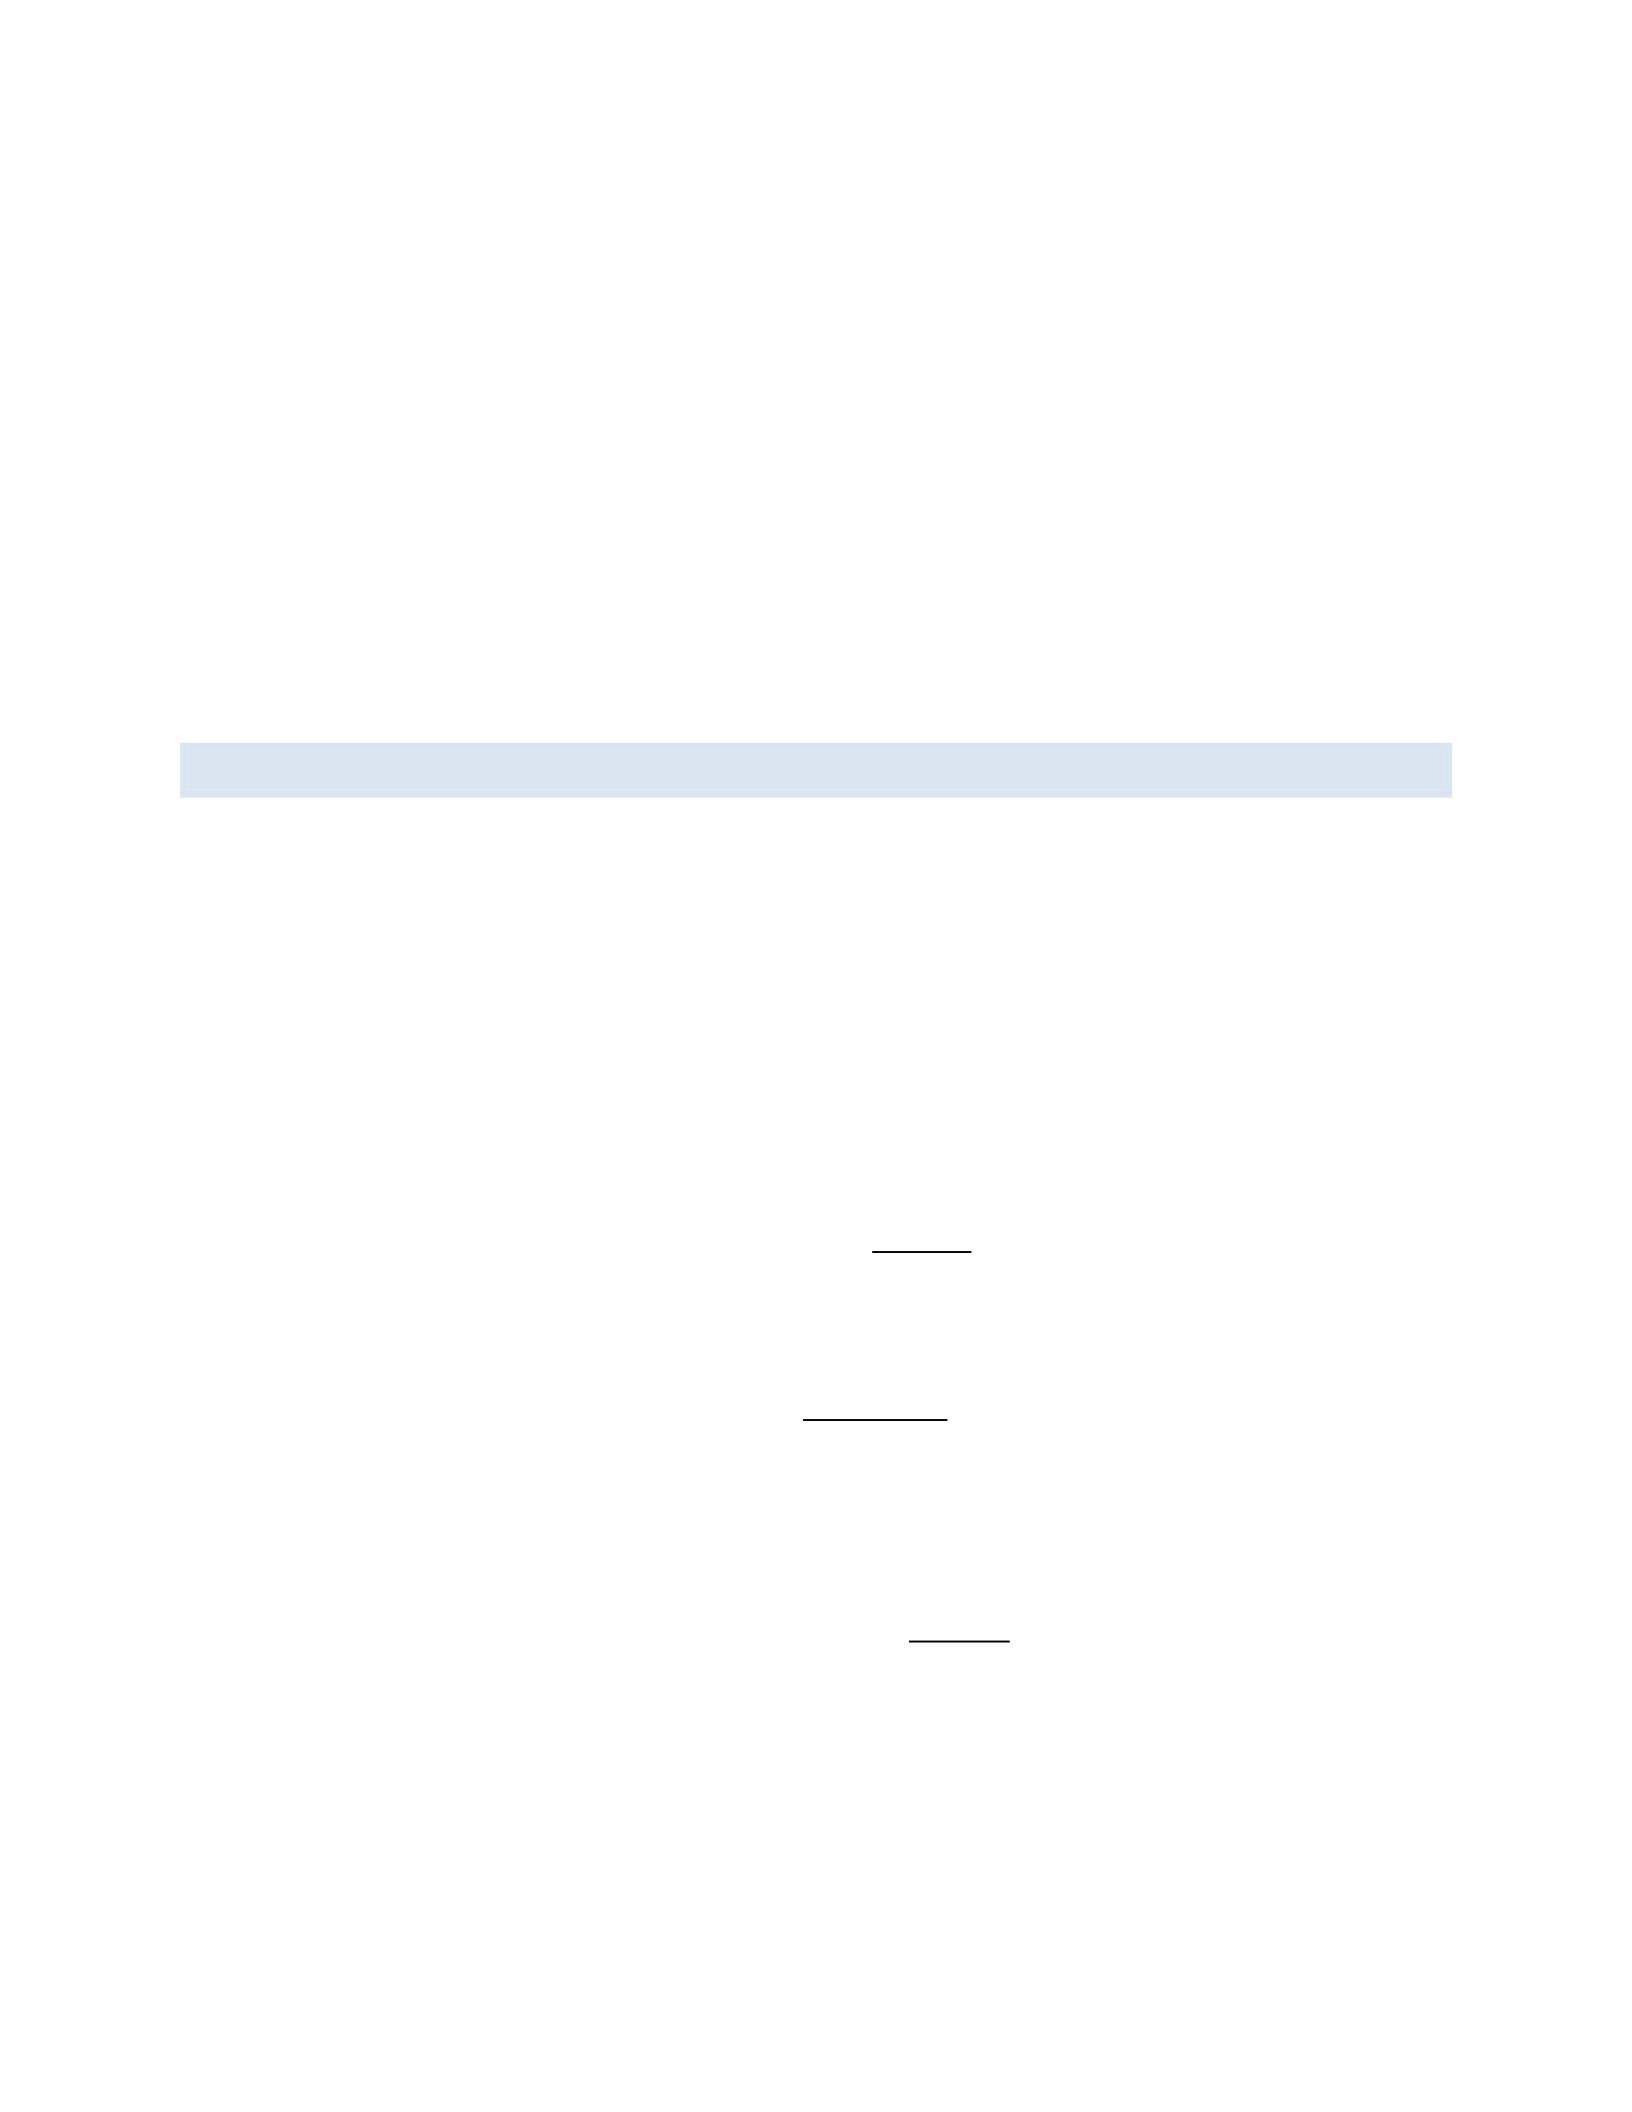
Calculate the expected return of the stock using the Fama-French Three-Factor Model.
Solution:
Step 1: Recall the Fama-French Three-Factor Model formula:
𝐸(𝑅𝑖)=𝑅𝑓+𝛽𝑖(𝑅𝑚−𝑅𝑓)+𝑠𝑖(𝑆𝑀𝐵)+ℎ𝑖(𝐻𝑀𝐿)
Step 2: Substitute the given values:
𝐸(𝑅𝑖)=0.02+1.2(0.06)+0.5(0.03)+(−0.3)(0.04)
=0.02+0.072+0.015−0.012
=0.095
Therefore, the expected return of the stock according to the Fama-French Three-Factor Model
is 9.5%.
QUESTION 8: SHARPE RATIO AND INFORMATION RATIO
A portfolio manager achieved an average annual return of 12% over the past 5 years, with a
standard deviation of 18%. The risk-free rate during this period was 3%, and the benchmark
index returned 9% with a standard deviation of 15%. Calculate:
a) The Sharpe ratio of the portfolio b) The Information ratio of the portfolio
Solution:
a) Sharpe Ratio
Step 1: Recall the Sharpe ratio formula:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑓
𝜎𝑝
Step 2: Substitute the given values:
𝑆ℎ𝑎𝑟𝑝𝑒 𝑅𝑎𝑡𝑖𝑜 = 0.12−0.03
0.18 =0.50
b) Information Ratio
Step 1: Recall the Information ratio formula:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 = 𝑅𝑝−𝑅𝑏
𝜎𝑝−𝑏
Where σp-b is the standard deviation of the difference between portfolio returns and benchmark
returns (tracking error).
Step 2: Calculate the tracking error:
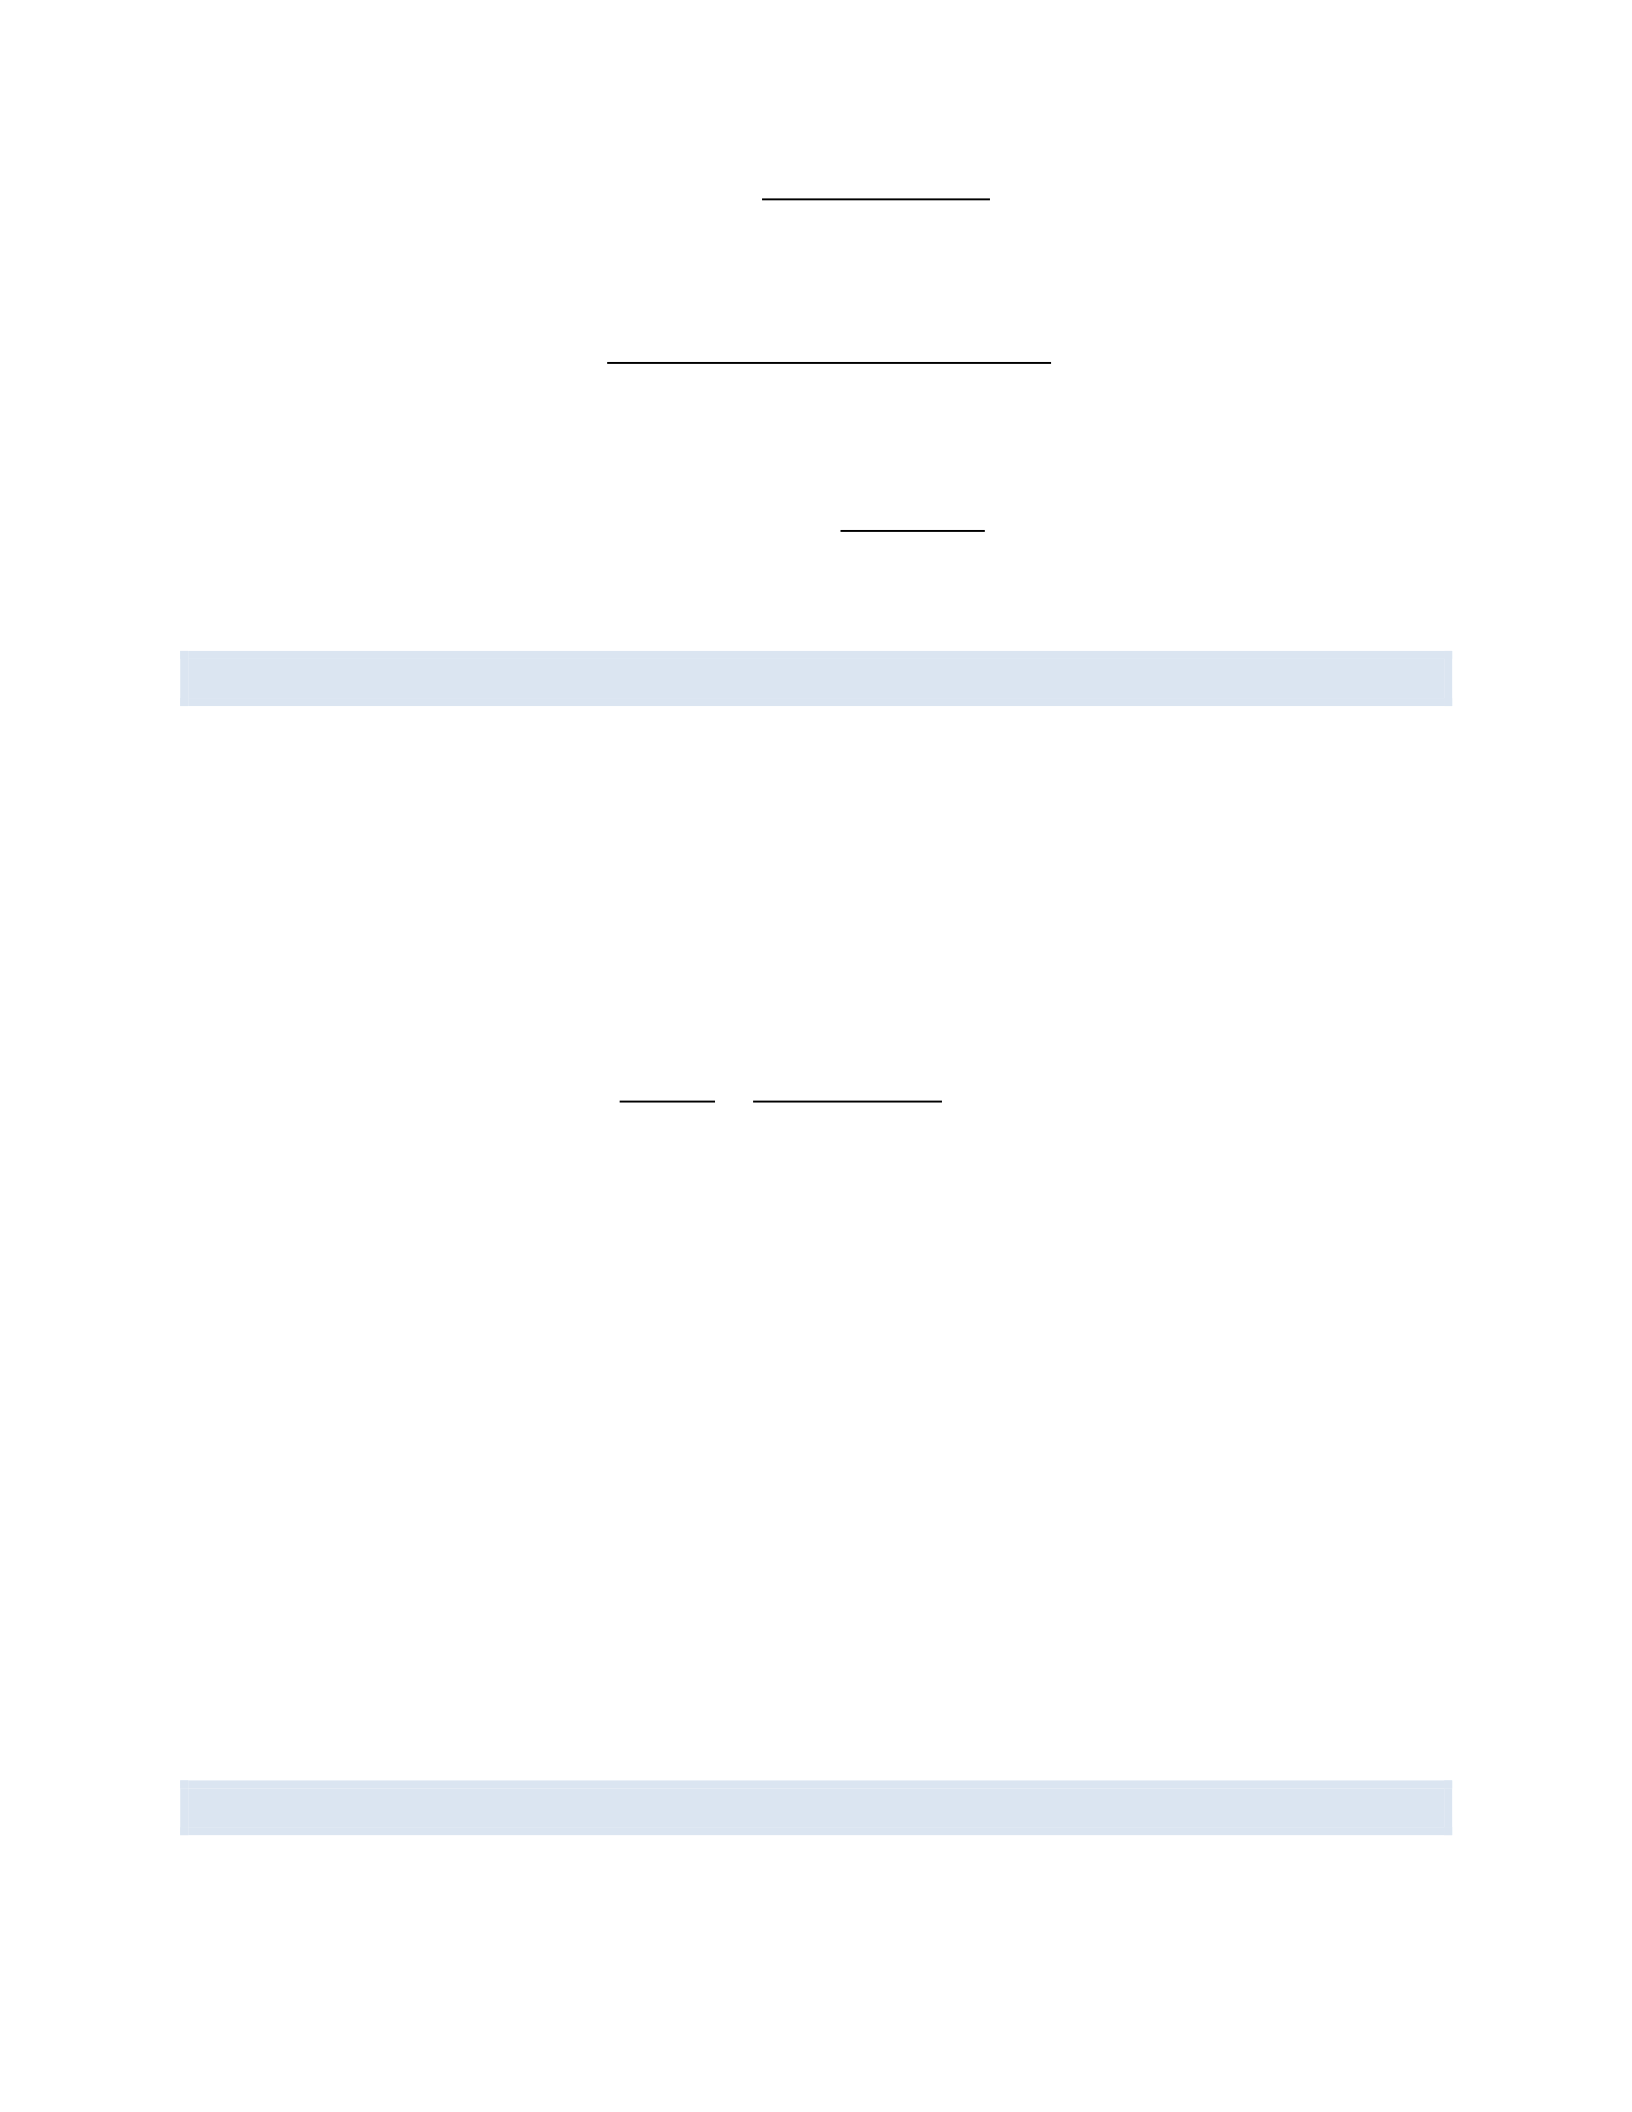
𝜎𝑝−𝑏 =√𝜎𝑝
2+𝜎𝑏
2−2𝜌𝜎𝑝𝜎𝑏
Assuming a correlation of 0.8 between the portfolio and benchmark:
𝜎𝑝−𝑏 =√0.182+0.152−2(0.8)(0.18)(0.15)=0.11
Step 3: Calculate the Information ratio:
𝐼𝑛𝑓𝑜𝑟𝑚𝑎𝑡𝑖𝑜𝑛 𝑅𝑎𝑡𝑖𝑜 =0.12−0.09
0.11 =0.27
Therefore, the Sharpe ratio of the portfolio is 0.50, and the Information ratio is 0.27.
QUESTION 9: BINOMIAL OPTION PRICING MODEL (CONTINUED)
Consider a European call option with the following characteristics: - Current stock price (S0) =
$100 - Strike price (K) = $105 - Time to expiration (T) = 3 months (0.25 years) - Risk-free rate (r)
= 4% per annum - Up factor (u) = 1.1 - Down factor (d) = 0.9
Using a one-step binomial model, calculate the price of this call option.
Solution:
Step 1: Calculate the risk-neutral probability (p):
𝑝 = 𝑒𝑟𝑇 −𝑑
𝑢−𝑑 =𝑒0.04×0.25 −0.9
1.1−0.9 =0.5498
Step 2: Calculate the possible stock prices at expiration:
𝑆𝑢= 𝑆0×𝑢 = 100×1.1= $110
𝑆𝑑= 𝑆0×𝑑 = 100×0.9= $90
Step 3: Calculate the option payoffs at expiration:
𝐶𝑢=max(𝑆𝑢−𝐾,0)=max(110−105,0)=$5
𝐶𝑑=max(𝑆𝑑−𝐾,0)= max(90−105,0)=$0
Step 4: Calculate the option price using the risk-neutral valuation formula:
𝐶0=𝑒−𝑟𝑇[𝑝𝐶𝑢+(1−𝑝)𝐶𝑑]
=𝑒−0.04×0.25[0.5498×5+(1−0.5498)×0]
=0.9900×2.7490
=$2.72
Therefore, the price of the European call option using a one-step binomial model is $2.72.
QUESTION 10: PORTFOLIO PERFORMANCE ATTRIBUTION
An equity portfolio manager reported the following sector allocations and returns for the year,
along with the benchmark index data:
Sector
Portfolio Weight
Portfolio Return
Benchmark Weight
Benchmark Return
Technology
35%
12%
30%
10%
Healthcare
25%
8%
20%
7%
Financials
20%
6%
25%
5%
Consumer
15%
4%
15%
3%
Utilities
5%
2%
10%
1%
Perform a performance attribution analysis to determine the sources of the portfolio’s excess
return, breaking it down into allocation effect and selection effect.
Solution:
Step 1: Calculate the total portfolio and benchmark returns:
Portfolio return: (0.35 × 12%) + (0.25 × 8%) + (0.20 × 6%) + (0.15 × 4%) + (0.05 × 2%) = 8.50%
Benchmark return: (0.30 × 10%) + (0.20 × 7%) + (0.25 × 5%) + (0.15 × 3%) + (0.10 × 1%) =
6.40%
Excess return = 8.50% - 6.40% = 2.10%
Step 2: Calculate allocation effect for each sector: Allocation Effect = (Portfolio Weight -
Benchmark Weight) × (Benchmark Sector Return - Benchmark Total Return)
Technology: (35% - 30%) × (10% - 6.40%) = 0.18% Healthcare: (25% - 20%) × (7% - 6.40%) =
0.03% Financials: (20% - 25%) × (5% - 6.40%) = 0.07% Consumer: (15% - 15%) × (3% -
6.40%) = 0.00% Utilities: (5% - 10%) × (1% - 6.40%) = 0.27%
Total Allocation Effect = 0.18% + 0.03% + 0.07% + 0.00% + 0.27% = 0.55%
Step 3: Calculate selection effect for each sector: Selection Effect = Benchmark Weight ×
(Portfolio Sector Return - Benchmark Sector Return)
Technology: 30% × (12% - 10%) = 0.60% Healthcare: 20% × (8% - 7%) = 0.20% Financials:
25% × (6% - 5%) = 0.25% Consumer: 15% × (4% - 3%) = 0.15% Utilities: 10% × (2% - 1%) =
0.10%
Total Selection Effect = 0.60% + 0.20% + 0.25% + 0.15% + 0.10% = 1.30%
Step 4: Calculate interaction effect (optional): Interaction Effect = (Portfolio Weight - Benchmark
Weight) × (Portfolio Sector Return - Benchmark Sector Return)
Technology: (35% - 30%) × (12% - 10%) = 0.10% Healthcare: (25% - 20%) × (8% - 7%) =
0.05% Financials: (20% - 25%) × (6% - 5%) = -0.05% Consumer: (15% - 15%) × (4% - 3%) =
0.00% Utilities: (5% - 10%) × (2% - 1%) = -0.05%

Total Interaction Effect = 0.10% + 0.05% - 0.05% + 0.00% - 0.05% = 0.05%
Step 5: Summarize the attribution analysis:
Excess Return = 2.10% Allocation Effect = 0.55% Selection Effect = 1.30% Interaction Effect =
0.05% Total Attribution = 0.55% + 1.30% + 0.05% = 1.90%
The difference between the excess return (2.10%) and the total attribution (1.90%) is due to
rounding effects.
In conclusion, the portfolio’s outperformance can be attributed to: 1. Allocation Effect: 0.55%
(26.2% of excess return) 2. Selection Effect: 1.30% (61.9% of excess return) 3. Interaction
Effect: 0.05% (2.4% of excess return)
The selection effect was the primary driver of the portfolio’s excess return, indicating that the
manager’s stock selection within sectors contributed most to the outperformance.

