INDIVIDUAL LEARNING PROJECT: FRAUD DETECTION USING FINANCIAL
STATEMENTS ASSIGNMENT 1
Acct 654- Fraud Examination
Individual Learning Project: Fraud Detection Using Financial Statements Assignment
Mahogany Reyes
Liberty University
April 22, 2024

Individual Learning Project: Fraud Detection Using Financial Statements
Assignment 2
Author Note:
Mahogany Reyes
I have no known conflict of interest to disclose.
Correspondence concerning this article should be addressed to Mahogany Reyes. Email:
mnreyes3@liberty.edu

Individual Learning Project: Fraud Detection Using Financial Statements
Assignment 3
Abstract
Abstract: Many businesses struggle with financial statement fraud, which is an
uncommon but significant issue. It results from the willful omission or misrepresentation of
important financial facts. These issues are found using methods such as vertical analysis,
horizontal analysis, and liquidity ratios. In this study, three cases are given. Case Study 1: Short
Cases at Chipmunk Company Among these cases are Short Case 7: Tool Co. and Ch. 13 Short
Case 9: ABCED Technologies (Albrecht, W. S., et al, 2019)
Each of these instances includes an overview of relevant information, an explanation of
the various financial statement fraud detection techniques used to solve the case, an assessment
of any potential red flags or fraud within the organization, and a detailed analysis and
investigation of the findings. A biblical application discussing pertinent Scripture references and
a conclusion summarizing the research findings from each section will mark the study's
conclusion.<

Individual Learning Project: Fraud Detection Using Financial Statements
Assignment 4
Fraud Detection- Using Financial Statements
Despite being rare, financial statement fraud is a significant problem that companies must
be ready for. Financial statement fraud has several elements or signs.<As shown by Albizri et al.
(2019), some components or indicators of financial statement fraud include the following:
1. 1. Material financial records, supporting documentation, or business events that have
been falsified, altered, or manipulated.<
2. Willful and major misrepresentations of events, transactions, accounts, or other important
information that is used to produce financial statements.
3. The willful misapplication, deliberate misinterpretation, and improper application of
GAAP, as well as the rules, guidelines, and techniques about measuring, identifying, and
disclosing economic events and commercial transactions.
4. Willful failure to disclose information about accounting standards, principles, practices,
and related financial data, or the presentation of insufficient disclosures (p. 207).
Financial statements can be used to detect fraud in some ways. First and foremost, it's
critical to have a thorough understanding of the business, its finances, and its sector. With this
information, one can assess the current changes by contrasting the company's financial
statements with its historical financial statements. To detect fraud, comparing the company to its
industry is also beneficial. Severe or incomprehensible changes in financials are a sign of fraud.
Analysis, particularly vertical and horizontal analysis, is another method for spotting fraud. This
is a simple method for identifying fraud. Finally, because financial ratios highlight anomalies,
using them to assess the company's financial accounts is also beneficial.<
Case Study 1: Chipmunk Company

Individual Learning Project: Fraud Detection Using Financial Statements
Assignment 5
In this instance, I have been retained by Chipmunk Company to investigate if the
financial accounts from 2016 and 2017 that have been submitted include any fraud. The
company has sent me the inventory balance as of January 1, 2016, which was $11,427,937, in
addition to the financial documents. Using liquidity ratios to solve this issue, which demonstrates
the "company's ability to meet its short-term obligations," is the best method to ascertain whether
fraud is present. (Page 11 of Bunker et al., 2019). The sales/receivables ratio, the quick ratio, the
current ratio, the number of days in the accounts receivable (A/R) ratio, and the inventory
turnover ratio are among the ratios that are employed. Each of these ratios will provide
information about whether fraud is occurring. Lastly, I'll analyze the data and compare it to the
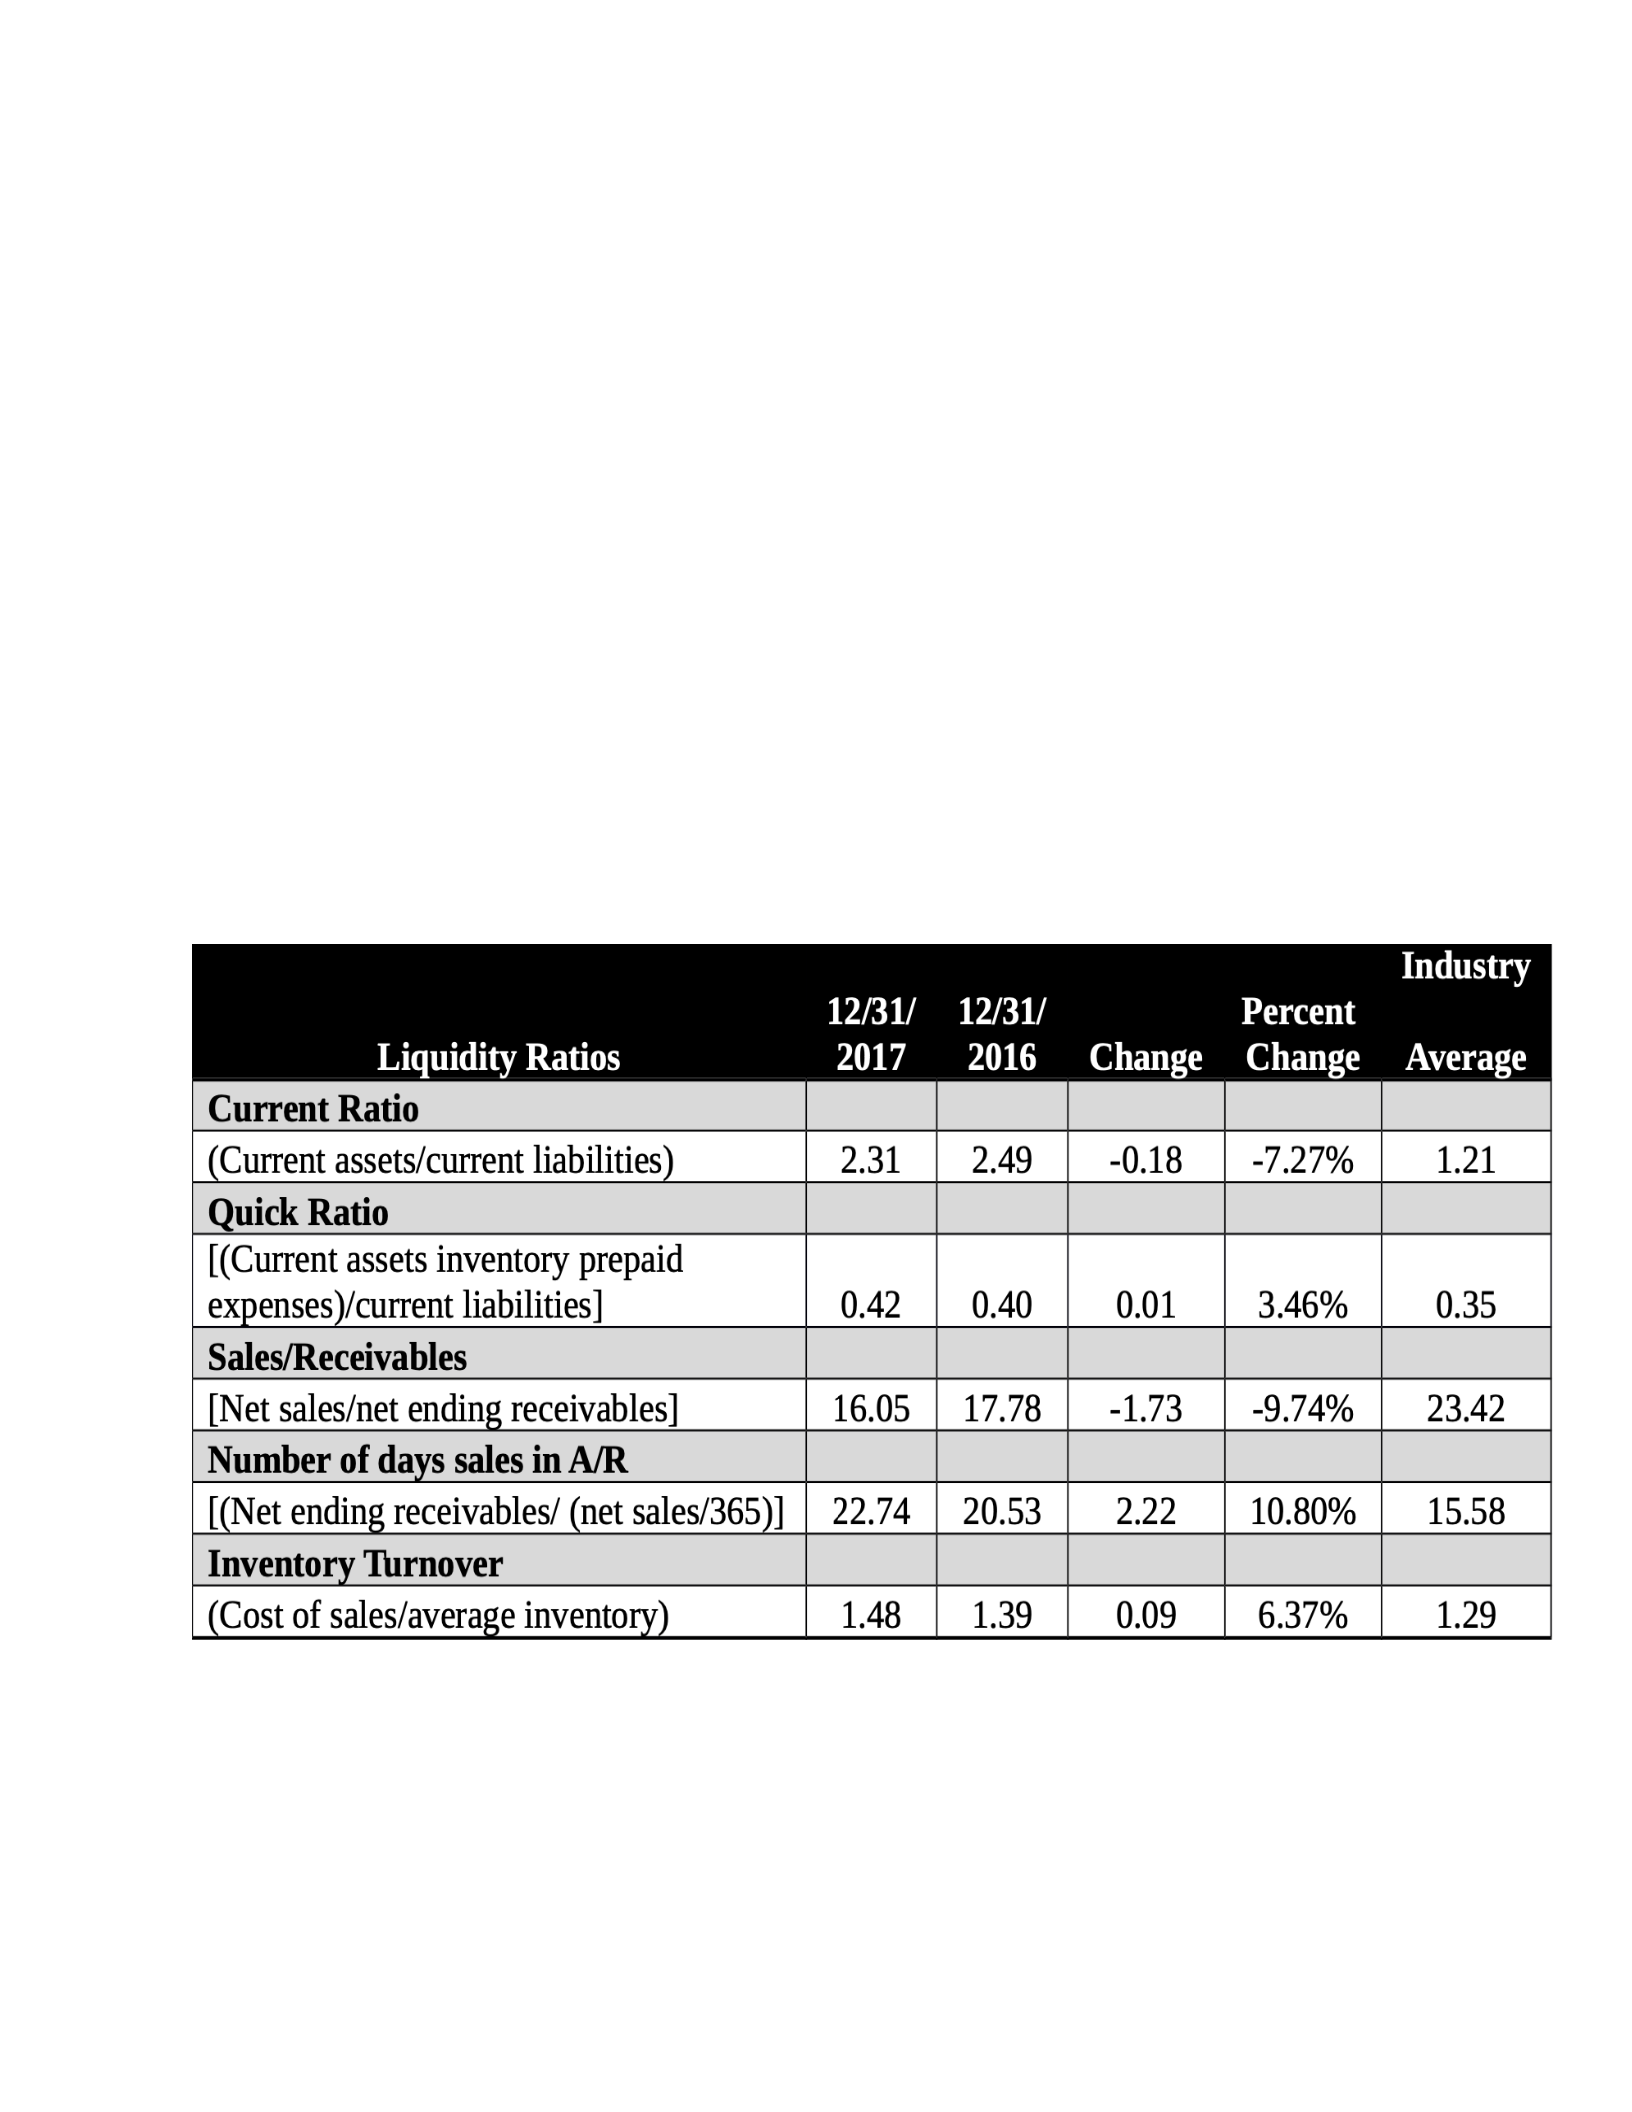
industry average before displaying the shift in ratios.<
The current ratio is the initial ratio that is used. The current ratio indicates if the business
can pay its short-term debt in less than a year. Divide current assets by current liabilities to get
this ratio. In 2017, $16,516,127 and $7,149,557 were the current assets and liabilities,
respectively. As a result, the 2017 current ratio was 2.31. In 2016, $14,753,281 was the current
asset and $5,921,882 was the current liability. As a result, 2.49 is the current ratio. These figures
surpass the 1.21 industry average by a substantial margin. A greater current ratio can be
advantageous, but a current ratio that is too high may be a sign that a company is not managing
its short-term assets well. This is, in my opinion, the situation at hand.<
The quick ratio is the second ratio. The ability of a business to satisfy short-term
obligations for liquid assets is gauged by this ratio. It also shows the short-term liquidity position
of a corporation. The quick ratio can be calculated by dividing the total current assets (less
inventories and prepayments) by the current liabilities. In the case of 2017, $16,516,127 would
be divided by $7,149,557 after deducting $13,524,349 and $17,720. This comes to 0.42. To get

Individual Learning Project: Fraud Detection Using Financial Statements
Assignment 6
$14,753,281 for 2016, deduct $12,356,400 and $15,826. The total would then be divided by
$5,921,882. In 2016, the quick ratio was 0.40. These figures show that the company can satisfy
its short-term obligations and are quite close to the industry average.<
The sales/receivables ratio is the third ratio. This ratio, which shows how well accounts
receivable are collected during a period, is computed by dividing net sales by net ending
receivables. The ratio for 2017 was 16.05, with net sales of $26,419,090 and net ending
receivables of $1,646,046. Net ending receivables were $1,285,593 and net sales were $22,861,
320 in 2016. In 2016, this ratio came to 17.78. All two figures are far below the industry average.
This suggests that there is little turnover, and that Chipmunk Company is ineffective in its
collections. To ascertain whether fraud is occurring, this area needs to be examined more
thoroughly.<
The number of days sales in accounts receivable represents the fourth ratio. This ratio
demonstrates how well a business collects the money or receivables that it issues to clients on
time. Net ending receivables should be divided by the figure obtained by dividing net sales by
365 to compute this calculation. In 2017, net sales were $26,419,090 and net ending receivables
were $1,646,046). This divides to 22.74. In 2016, net sales were $22,861,320, while net ending
receivables were $1,258,593. This adds up to 20.53. These figures are above the industry norm
once more. The money is not being retrieved by Chipmunk Company quickly enough.<
Divide the cost of sales by the average inventory turnover to arrive at the final ratio,
which is the inventory turnover ratio. In 2017, the cost of sales came to $19,133,229. The
average inventory turnover was $13,524,349; the total was totaled up to $12,356,400, which was
then split by two. For 2017, the inventory turnover is 1.48. The cost of sales in 2016 was
$16,530,114. The total divided by two of the average inventory turnovers was $12,356,400 and
Individual Learning Project: Fraud Detection Using Financial Statements
Assignment 7
$11,427,937. In 2016, the inventory turnover was 1.39. These figures surpass the mean for the
industry. This could potentially be a place of fraud.<
Two ratios may indicate fraud: the inventory ratio and the sales/receivables ratio. While
the inventory turnover ratio is higher than the industry average, the sales receivables ratio is
significantly lower. As previously mentioned, I think that both areas need to be thoroughly
examined by the investigative team or the corporate auditors because the significant difference in
the data could be a sign that fraud is taking place. These two ratios raise warning signs that need
to be carefully investigated rather than disregarded. Table 1 below is a graphic depiction of the
ratios for Chipmunk Company for the years ending in 2017 and 2016, along with the change and
percentage change between each ratio and the industry average of each ratio.
.
Individual Learning Project: Fraud Detection Using Financial Statements
Assignment 8
Short Case 7: Tool Co.
Tool Co. is a medium-sized company that buys certain materials, like plastic or copper, to make
Cooper wiring. Although they are housed in a single structure, it has four primary sections. The
office space makes up 3%. The areas of production make up 57%. 15% is made up of the
shipping and receiving area. Lastly, 25% of the inventory is held in storage spaces for both
finished goods and raw materials. This building has a total square footage of 500,000. I have
been asked to ascertain whether fraud or fraud symptoms are present based on this information
and the financials that have been presented. To do this, Due to the ease of understanding
percentages, vertical analysis—which compares data inside a financial statement from period to
period—is quite helpful in detecting fraud. (Albrecht et al., 2019, p. 183). Fraud is easy to locate
with this method.
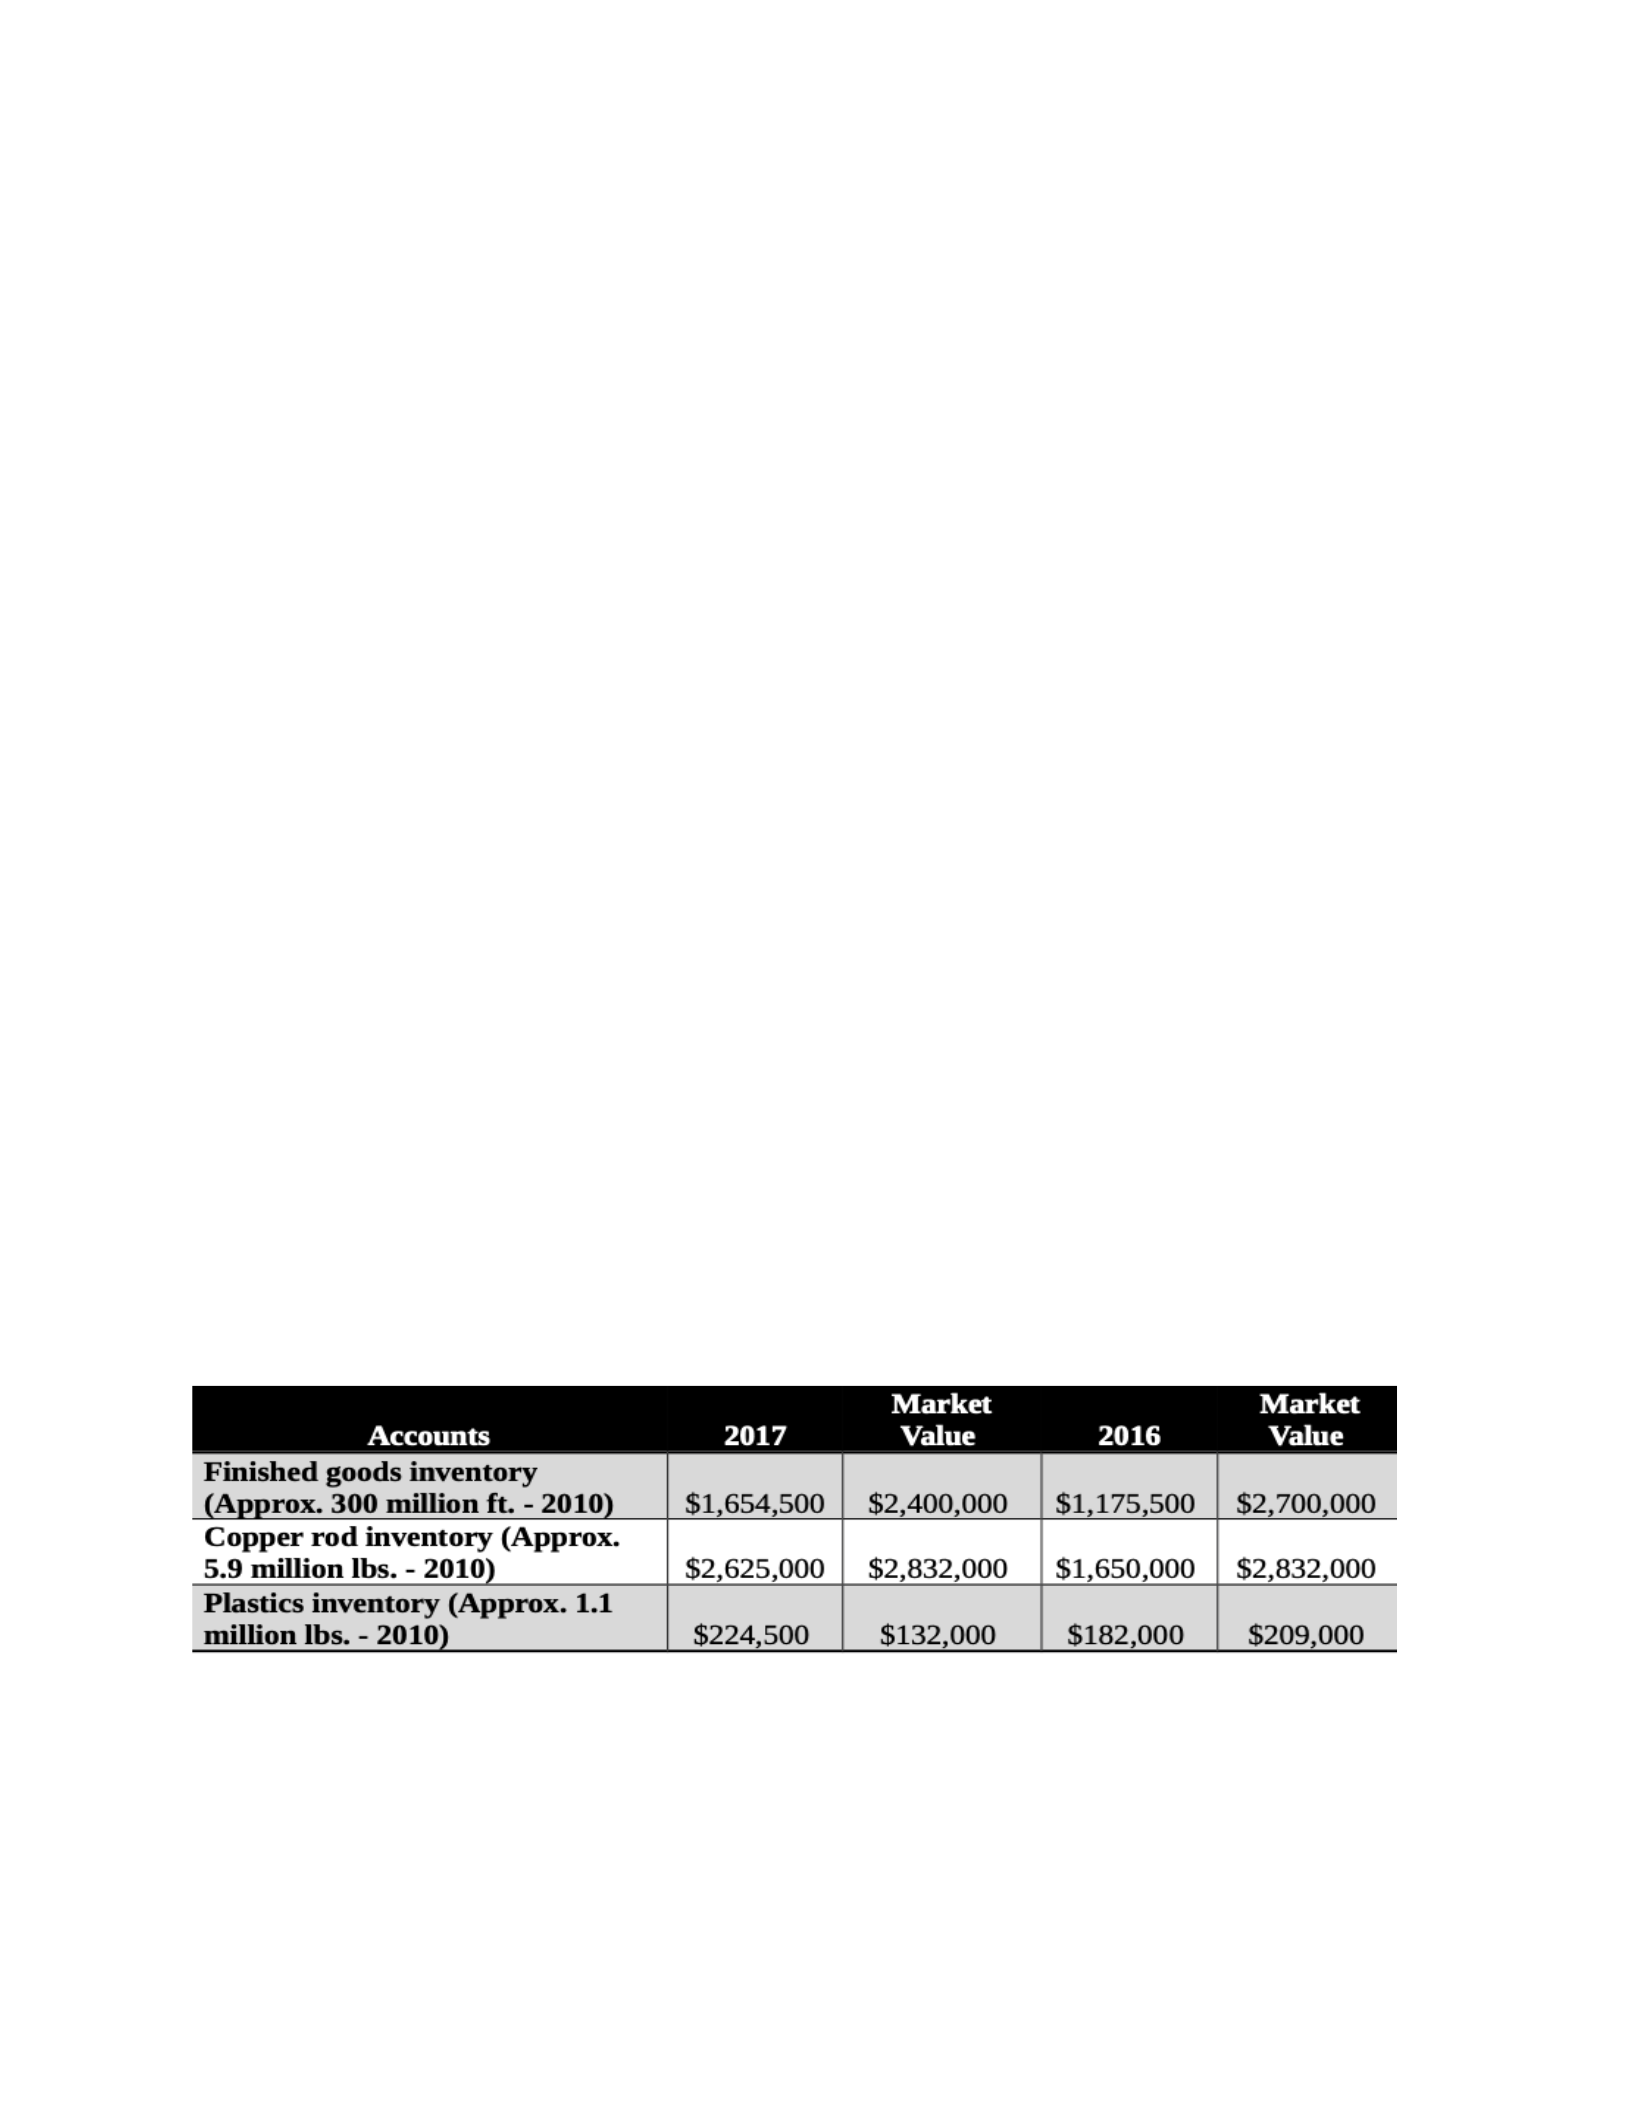
Before beginning the vertical analysis, it is important to clarify how I would search Tool Co.'s
financial accounts for any warning signs. One method of doing this is by examining the market
value of the inventories. I consider the market value of the 2010s as well as the inventories from
2016 and 2017. The purpose of this comparison is to determine whether the values from 2016
and 2017 differ from the stated levels, which could point to fraud.<
I multiply the approximate value provided in each account by the market price of each product to
obtain the numbers for the market value shown in the above table. In 2017 and 2016, the market

Individual Learning Project: Fraud Detection Using Financial Statements
Assignment 9
price per foot for insulated wire was $0.008 and $0.009, respectively. The market value of these
figures is equal to 300 million times that amount. In both 2016 and 2017, the market price of
copper rods per pound was $0.480. The market value is obtained by multiplying this value by 5.9
million. Lastly, the market price per pound for plastics was $0.120 in 2017 compared to $0.190
in 2016. The market value is obtained by multiplying these figures by 1.1 million pounds once
more.<
To find out if there are any red flags of fraud, utilize the information in the table above. I think
the preceding table has several warning signs. There are significant differences in some accounts
between the market prices from 2017 and 2016 and the real values from the same years. In 2017,
there was about a $750,000 discrepancy between the market value and the finished goods
inventory. In comparison to its market value, Tool Co.'s actual finished goods inventory is
$745,500 lower. The same problem affected the business in 2016. An even greater discrepancy of
$1,524,500 exists. I would investigate these accounts more thoroughly. Compared to the finished
goods inventory, the variance in the copper rod inventory is less significant. The 2017 variation
is $207,000, which is strange because it is much smaller than the variance in the preceding
accounts ($1,182,000 in 2016). There may be more research done on this sharp rise. The plastics
inventory account is the last section in Table 4. This account's true value exceeded its market
value in 2017; however, its actual value fell short of the market value in 2016. In 2017, Tool Co.
had a $92,500 advantage above its market value. Tool Co. was $27,000 undervalued in 2016
concerning its market value. The big disparity in amounts, particularly when they changed from
a significantly lower to a significantly greater actual value, may also cause this account to raise
red lights, 2017 has the potential for fraud.
Individual Learning Project: Fraud Detection Using Financial Statements
Assignment 10
In this scenario, performing the vertical analysis is the second step. As mentioned before, vertical
analysis is a very helpful technique for spotting fraud. It greatly facilitates the process of looking
for fraud in the income statement and balance sheet and helps to clarify the investigation's
findings. There is an exact formula that needs to be applied to compute the vertical analysis. It is
necessary to split the overall sales amount by the individual account items from the financials,
such as the Plastics Inventory. To obtain a percentage, this figure needs to be multiplied by 100.
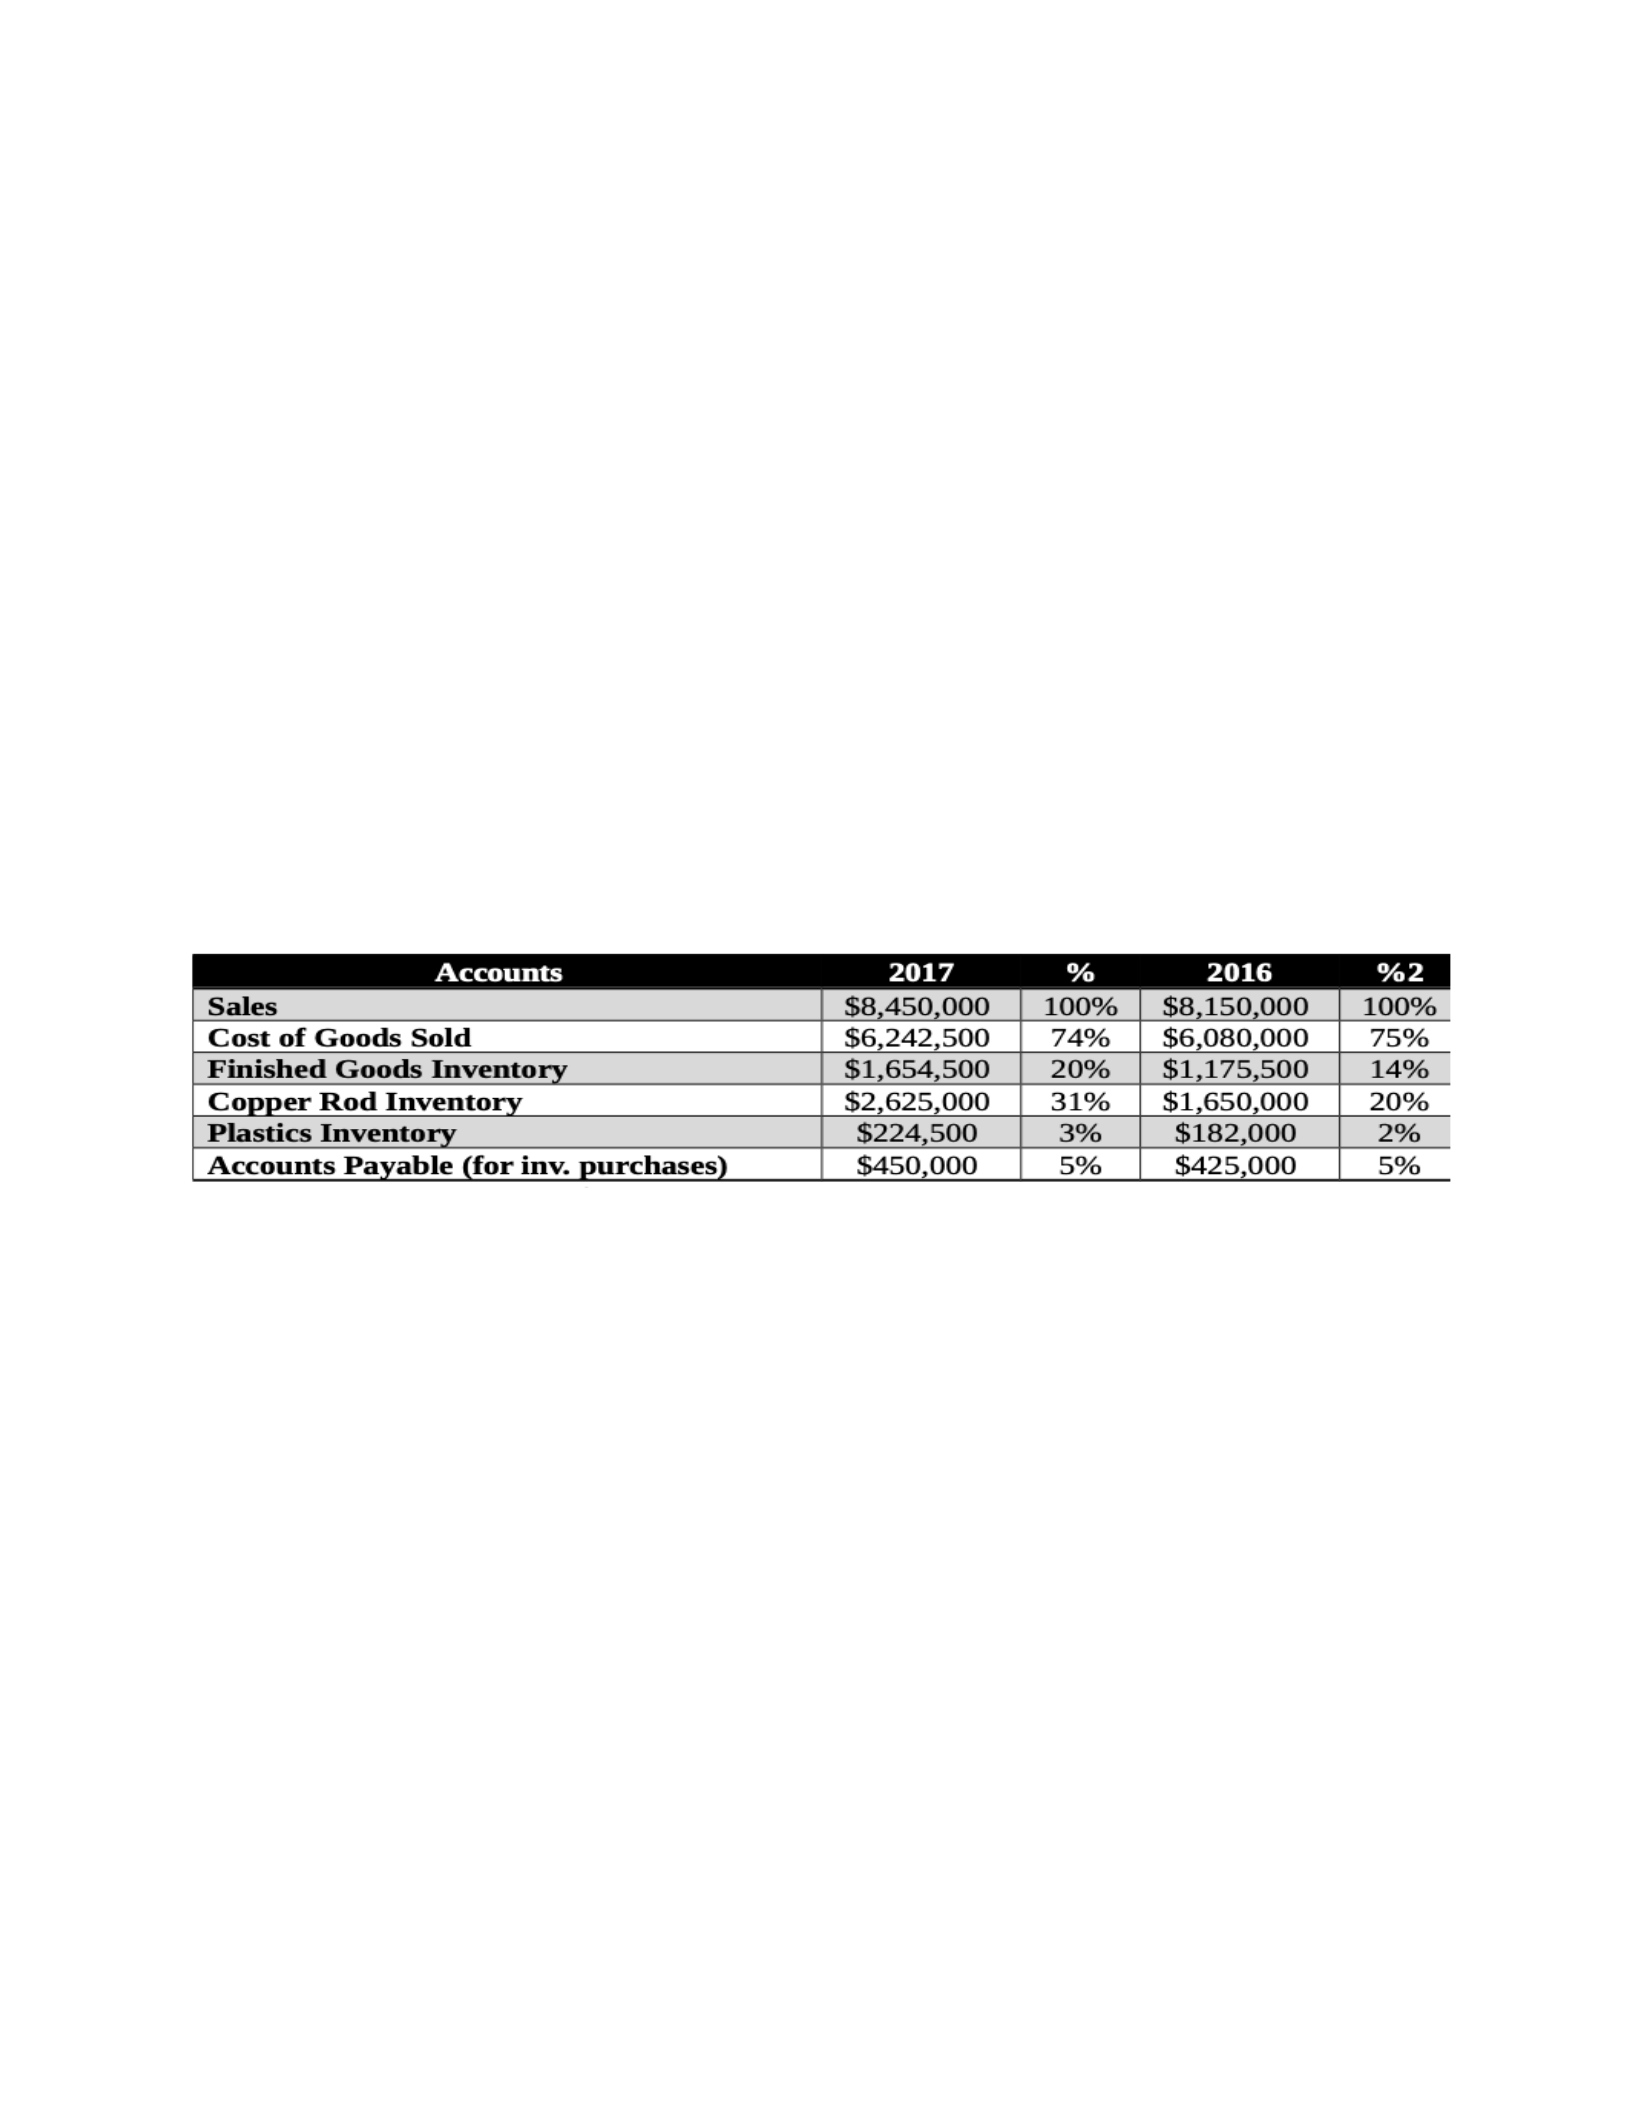
To finish this vertical study, Tool Co. has also given me other information.<I have received data
from Tool Co. regarding sales and cost of products sold for the years 2016 and 2017. Sales in
2016 came to $8,150,000. The sales rose to $8,450,000 in 2017. In 2016, the cost of products
sold was $6,080,000. In 2017, this amount grew to $6,242,000.
The vertical analysis is shown graphically in the table above. While completed goods inventory
climbed by 6% and copper rod inventory by 10%, the account items cost of goods sold, plastics
inventory, and accounts payable stayed the same in both years. The absence of a growth in
accounts payable is the table's main cause for concern. Given the rise in inventories, there ought
to have been a rise in this item, but there wasn't. This warrants additional investigation since it
may indicate possible fraud.<
Ch. 13 Short Case 9: ABCED Technologies
Case Description

Individual Learning Project: Fraud Detection Using Financial Statements
Assignment 11
ABCDE Technologies, Inc. is a PC card designer and manufacturer. Their primary market
is original equipment manufacturers (OEMs) who work in providing industrial and commercial
applications. This field has quite a bit of competition, with many competitors facing financial
difficulty in 2017. This scenario requires that the existing red flags be found along with any
possible scenarios causing these red flags. Lastly, the type of financial statement fraud at the root
of these red flags must be determined. ABCED Technologies is a software development
company that specializes in creating custom software solutions for businesses. The company was
founded five years ago by a group of computer science graduates who had a passion for creating
innovative and user-friendly software (Albrecht, W. S., et al, 2019).
ABCED Technologies has quickly built a reputation for delivering high-quality software
products that meet the specific needs of their clients. They have worked with a wide range of
businesses, from small startups to large corporations, and have developed software solutions for
various industries including healthcare, finance, and e-commerce. One of ABCED Technologies'
recent projects involved developing a custom customer relationship management (CRM) system
for a large retail chain. The CRM system was designed to help the company manage its customer
interactions more efficiently and effectively. The software included features such as customer
data management, sales tracking, and automated marketing campaigns. The project was
completed on time and within budget, and the retail chain was extremely satisfied with the final
product. They reported a significant increase in sales and customer satisfaction after
implementing the new CRM system. ABCED Technologies continues to thrive in the competitive
software development industry, thanks to their innovative solutions and commitment to customer
satisfaction. They are constantly pushing the boundaries of technology and looking for new ways
to help businesses improve their operations through custom software solutions.

Individual Learning Project: Fraud Detection Using Financial Statements
Assignment 12
Detection Methods & Techniques Used
There are a variety of detection methods and techniques that ABCED Technologies could use to
address their cybersecurity concerns. Some potential options include:
1. Intrusion Detection Systems (IDS): Implementing IDS can help ABCED Technologies detect
any unauthorized access or malicious activities on their network. IDS monitors network traffic
and alerts IT staff when suspicious behavior is detected (Tactical Provenance Analysis for
Endpoint Detection and Response Systems, 2020).
2. Security Information and Event Management (SIEM): SIEM tools can help ABCED
Technologies collect, analyze, and correlate security data from various sources to identify and
respond to security incidents. SIEM can provide real-time visibility into potential threats and
help streamline the incident response process (Tactical Provenance Analysis for Endpoint
Detection and Response Systems, 2020).
3. Endpoint Detection and Response (EDR): EDR solutions can help ABCED Technologies
monitor endpoint devices for signs of malicious activity and quickly respond to any security
incidents. EDR tools can provide valuable insights into the security posture of individual devices
and help identify and remediate threats (Tactical Provenance Analysis for Endpoint Detection
and Response Systems, 2020).
4. Security Awareness Training: Educating employees about cybersecurity best practices and
how to recognize potential threats can help ABCED Technologies create a culture of security
within the organization. Regular security awareness training can help prevent phishing attacks,
social engineering scams, and other common cybersecurity threats (Barracuda, 2023).
5. Vulnerability Scanning: Conducting regular vulnerability scans can help ABCED
Technologies identify and remediate security vulnerabilities in their systems and applications.

Individual Learning Project: Fraud Detection Using Financial Statements
Assignment 13
Vulnerability scanning can help proactively address potential security risks and prevent cyber-
attacks (Barracuda, 2023).
By implementing a combination of these detection methods and techniques, ABCED
Technologies can enhance its cybersecurity defenses and better protect its sensitive data and
systems from cyber threats.
Biblical Application
The vertical analysis is shown graphically in the table above. The cost of the account items<
I think two verses from the Bible relate to the subjects covered in this instance. The book of
Leviticus is the source of the first allusion. Leviticus 19:35–36 states, "When determining length,
weight, or quantity, do not use dishonest standards." Make use of an honest ephah, an honest
him, and honest scales and weights. You were taken out of Egypt by me, the Lord your God
((Leviticus 19:35-36 (NIV), n.d.) We must be honest in how we do business. In all facets of our
company, God asks us to take accurate measurements. Financial statements are included in this.
Financial information should never be knowingly misrepresented or left out to improve the
appearance of our company.<To achieve our objectives in the best possible way, we must be
sincere and diligent. We ought to use caution in handling the duty that has been placed upon us.
Our moral fiber should not be compromised by unlawful or unethical actions such as fraud.
The book of Ecclesiastes contains the second scripture reference that, in my opinion, is pertinent.
"Whatever your hand finds to do, do it with all you might, for there is neither working nor
planning, knowledge nor wisdom in the realm of the dead, where you are going," says
Ecclesiastes 9:10.<(Ecclesiastes 9:10 (NIV), n.d.). Whichever job we have, we are expected to
give it everything we have—that is, to give it our all. Our work should be done with diligence

Individual Learning Project: Fraud Detection Using Financial Statements
Assignment 14
and dedication. God anticipates this from us. Scripture makes numerous references to the idea
that being lazy will neither lead to success nor bring respect to God. Several texts also stress the
value of exerting oneself in one's work. We ought never to take a half-measure. We ought to put
our all into all we undertake. The Lord wants us to succeed, so let's try our best. Furthermore, He
is reflected in both our job and work ethic.<To respect Him in all we do, we should be mindful of
how we act and make sure that it reflects Him in a true and exalting way.
Conclusion
In conclusion, financial statement fraud is a very important issue that needs to be managed as
effectively as possible, even though it might not be the most prevalent kind of fraud. Fraud has
several signs or components. These signs are usually deliberate falsifications or omissions of
financial or financial-related information. These false statements or omissions can be found in a
variety of ways. Financial ratios and analysis are among the most often used methods, which also
happen to be the methods applied in the examples. Techniques for detecting financial statement
fraud include the use of liquidity ratios, vertical analysis, and horizontal analysis.
These methods are all very helpful in identifying and locating fraudulent activity. Although these
techniques do make it simpler to identify fraud in financial accounts, the process is still not
straightforward. As with most things in life, it will require work. We are called, as the biblical
application demonstrates, to labor in this life and to work as hard and as fully as possible. Instead
of being careless with our work, we ought to be industrious and hardworking. With the financial
information that is provided to us, we should exercise caution as well. We must exercise caution
to avoid inadvertently engaging in unlawful or unethical activities, like fraud. This is the source
of honor and grandeur.
Individual Learning Project: Fraud Detection Using Financial Statements
Assignment 15
Reference
Alborzi, A., Appelbaum, D. & Rizzuto, N. (2019). Evaluation of financial statements
fraud Detection research: a multi-disciplinary analysis. International Journal of Disclosure and
Governance, 16(4), 206-241. https://doi-org.ezproxy.liberty.edu/10.1057/s41310-019-00067-9
Albrecht, W. S., Albrecht, C. O., Albrecht, C. C. & Zemelman, M. F. (2019). Fraud
Examination (6th ed.). Cengage Learning, Inc.
Barracuda. (2023, October 26).<Security Awareness training. Barracuda
Networks.<https://www.barracuda.com/products/email-protection/security-awareness-training
Bunker, R. B., Cagle, C. & Harris, D. (2019). A Liquidity Ratio Analysis of Lean vs. Not-
Lean Operations. Management Accounting Quarterly, 20(2), 10-16. https://www-proquest-
com.ezproxy.liberty.edu/docview/2276832395/fulltextPDF/B3F23D73D3A3483CPQ/1?
accounted=12085
Ecclesiastes 9:10 (NIV). (n.d.). Bible Gateway.<https://www.biblegateway.com/passage/?
search=Ecclesiastes%209%3A10&version=NIV
Gregoria, M., Horvat, D. M. & Gregoria, M. (2018). PERFORMANCE ANALYSIS
AND MARKET POSITIONING OF LEADING PHARMACEUTICAL COMPANIES IN THE
REPUBLIC OF CROATIA. Business Excellence, 12(2), 123-138.
https://doi.org/10.22589/pi-be/2018.12.2.123
Leviticus 19:35-36 (NIV). (n.d.). Bible
Gateway.<https://www.biblegateway.com/passage/?search=Leviticus%2019%3A35-
36&version=NIV