


REVENUE RECOGNITION
1
INDIVIDUAL RESEARCH PROJECT REVENUE RECOGNITION
Abstract
Revenue recognition is one of the main factors in determining the financial performance of a
company. In the late 1990s and early 2000s, it was like the wild west for revenue recognition,
this led directly to the dot com bubble that peaked in 2000. Due to the market crash, in 2001, the
two major standards bodies agreed to get rid of the discrepancies between the Generally
Accepted Accounting Principles (GAAP) in the United States and the International Financial
Reporting Standards (IFRS). We will discuss the history of revenue recognition, compare it to
GAAP and IFRS, how it fits into the current conceptual framework, and suggest an appropriate
course of action all while keeping in mind how it fits into a Christian worldview.
Keywords: GAAP, IFRS, revenue, revenue recognition

REVENUE RECOGNITION
2
Revenue Recognition GAAP verse IFRS
After the dot com bubble burst and the revelation of the widespread fraud that took place,
the FASB and the IASB set out to eliminate the differences between the Generally Acceptable
Accounting Principles (GAAP) and the International Financial Reporting Standards (IFRS). It
has been a longer road than first anticipated but strides have been made recently. We will discuss
the history of revenue recognition, current GAAP, and how it compares to the IFRS standards,
suggest changes and problem areas, analyze the conceptual framework, suggest a course of
action that the two bodies should adopt, and provide a biblical application to revenue
recognition.
Historical Development of Revenue Recognition
There is a long history of accounting that dates to around 300 BC. In Iran, tokens were
used in the bookkeeping practice. By 1494, double-entry bookkeeping was created, birthing the
modern way of accounting. As time passed and civilization grew and advanced a need for
advancing in accounting grew as well. In 1929, the stock market crashed causing the Great
Depression, because of this the Securities Act of 1933 and the Securities Exchange Act of 1934
were passed. The passage of these acts resulted in Generally Accepted Accounting Principles
(GAAP) being established. The goal of the GAAP is to create a uniform and consistent
presentation of public companies’ financial statements to ensure investors and regulators can
comprehend the information provided. GAAP makes companies more accountable as now they
have a requirement to submit complete and honest financials. GAAP is a set of standards set by
the Financial Accounting Standards Board (FASB) in the United States that are rules-based.
While GAAP is the US principles, International Financial Reporting Standards (IFRS) is the
worldwide principles that 144 countries follow.

REVENUE RECOGNITION
3
In 1973, the International Accounting Standards Committee was established and
published the International Accounting Standards, by 2001 the International Accounting
Standards Board (IASB) replaced them and issues the IFRS. In 2002, FASB and IASB looked to
eliminate the differences in the two standards with the Norwalk Agreement. The two standards
remain separate due to a few differences in methodology, for example, IFRS does not allow
LIFO but GAAP does.
The American Accounting Association Committee on Realization recommended in 1964
that revenue must be capable of measurement and verified by external market transactions, and
the event must have occurred (Schroeder et al., p 148, 2019). From the late 1990s to the early
2000s companies played games with their revenue recognition to manipulate their earnings to
show greater profits. Revenue recognition has received updated principles over the last few
years. The IASB passed the core principle of IFRS 15 in May of 2014, while FASB passed
Accounting Standards Update (ASU) 2020-05, an update of ASU No. 2014-06 and ASU No.
2016-02, on June 3, 2020.
Current GAAP
The current GAAP standard for revenue recognition is FASB ASC 606 Revenue
Recognition. According to research from Lee et al. (2020), “For many businesses, the impact of
ASC 606 has been minimal; however, for the franchising industry, the impact of the new rules is
sweeping.” ASC 606 has a 5-step model, the five steps are identifying the contract with a
customer, identifying the performance obligations in the contract, determining the transaction
price, allocating the transaction price, and recognizing revenue when or as the entity satisfies a
performance obligation.

REVENUE RECOGNITION
4
Step 1 Identify The Contract With The Customer
Step 1 of the model is identifying the contract with the customer, to have a contract with
a customer it needs to be between two or more parties, there needs to be an enforceable right and
obligation, and there must be a written, verbal, or implied arrangement. To recognize revenue
from a contract you must ensure there are approvals from all parties involved, rights and
payment terms, and must have commercial substance.
Step 2 Identify The Performance Obligations In The Contract
Step 2 of the model is identifying the performance obligations in the contract; this step
describes how distinct performance obligations in the contract must be handled and can be
straightforward or have more than one obligation in a contract. In my experience, my former
company could sell a machine to a customer and that would be considered a straightforward
contract, if they added a sale of a warranty or service to that contract that all another layer and
another obligation. This would create two distinct obligations, selling the machine and selling the
warranty or service.
Step 3 Determine The Transaction Price
Step 3 of the model is determining the transaction price; a company should consider the
following when determining the sales price: Variable consideration; Constraining estimates of
variable consideration; the existence of significant financing component; noncash consideration;
consideration payable to the customer. Variable consideration is the amount that can change due
to discounts, rebates, refunds, and credits. Companies can use the expected amount, weighted
amount, or the amount most likely to collect. Constraining estimates of variable consideration
are used if the company has reasonable assurance that they will be entitled to the amount billed.

REVENUE RECOGNITION
5
For the existence of a significant financing component, if the contract involves a significant
financing component, the company must account for the time value of money. For noncash
consideration, the company should generally recognize revenue based on the fair value of what is
received. Finally, for the consideration payable to the customer, considerations, like discounts,
coupons, and free samples, serve to reduce the revenue recognized.
Step 4 Allocate The Transaction Price
Step 4 of the model is allocating the transaction price, if the contract has more than one
performance obligation then the transaction price needs to allocate each performance obligation
based on their stand-alone selling price. According to FASB ASC 606 (2014), a stand-alone
selling price is “the price at which an entity would sell a promised good or service separately to a
customer."
Step 5 Recognize Revenue When Or As The Entity Satisfies A Performance Obligation
Step 5 of the model is recognizing revenue when or as the entity satisfies a performance
obligation. Changing control is the deciding factor to determine if obligations have been
satisfied, to achieve a change of control the good or service is in the control of the customer. For
the customer to take complete control the customer has the legal title of the asset, has physical
possession of the asset, and the customer has accepted the asset.
There have been updates to ASC 606, the ASU 2016-08 update is to clarify reporting the
revenue gross versus net. If the entity is providing the service to the customer the revenue will be
recognized on a gross basis, if the entity uses a third party then the revenue is recognized as net
revenue. ASU 2016-10 updates the identification of performance obligations and licenses. The
update amends identifying performance obligations, shipping and handling activities, when a

REVENUE RECOGNITION
6
promise represents an obligation, licensing implementation guidance, sale and usage-based
royalties, and renewals of licenses that provide the use of IP.
Compare and Contrast U.S. GAAP and IFRS With Respect to Revenue Recognition
The Norwalk Agreement had the goal of making existing standards and ensuring
compatibility with future standards. Unfortunately, compatibility has been more difficult to
achieve than IFRS and IASB initially thought, but the revenue recognition project has been
considered a success. While strides have been made to get the two sets of standards uniform
there are still differences between GAAP and IFRS.
The differences between the two standards are as follows the GAAP policy on shipping
and handling activities simplifies the accounting of revenue and also accelerates the recognition
compared to the IFRS standards; the measurement for noncash considerations IFRS does not
have a specific guideline, while GAPP considers the date by the contract inception; IFRS does
not have a sales tax transaction price policy election, while GAAP excludes the price for all taxes
from measurement; Under IFRS an impairment loss is reversed while in GAAP it is prohibited;
For GAAP, a company should not recognize revenue of intellectual property until the beginning
of the renewal period, under IFRS an entity needs to choose between when the renewal is agreed
or when it starts.
While the list of differences may seem long, FASB announced an amendment to the
FASB, FASB ASU 2014-09, “Revenue from Contracts with Customers,” that created FASB ASC
Topic 606. When FASB issued the amendment the IASB issued IFRS No. 15, “Revenue from
Contracts with Customers” which makes the similarities make the two standers very close to
being uniform. Both GAAP and IFRS standards apply the standard in a five-step process, the

REVENUE RECOGNITION
7
process is to create and identify the customer, identify the performance obligations, set the sale
price, allocate the set sales price, and recognize the revenue when the obligation is satisfied.
The similarities extend beyond revenue recognition, both standards use the statement of
cash flows, the income statement, and the balance sheet. They both have the same guidelines for
cash and cash equivalent. They both use an accrued-based approach to financial statement
preparation and recognize revenue when it is realized.
The United States does not use the IFRS standards due to the Securities and Exchange
Commission (SEC) does not support the standards. The SEC believes that GAAP offers a better
framework and that IFRS is too flexible and leaves things open to interpretation, this is because
GAAP is rules-based whereas IFRS is principle-based. GAAP requires companies to adhere to
rules when completing their financial statements, while IFRS only requires that the financial
statements of a company be understandable, readable, comparable, and relevant to current
financial transactions. IRFS has an advantage over GAAP due to its broad guidelines that can be
practical for a variety of circumstances.
Suggested Changes or Problem Areas
The Committee of Sponsoring Organizations of the Treadway Commission has found that
revenues and expenditures have accounted for over half of the financial statement frauds
(Albrecht, et al., 2019). Year-over-year analytics would help catch fraud before it became a
multiyear issue. You would be able to compare the nonfinancial data in the company, ratios, and
the competition, but only if there are uniform standards to compare.
During our research, it was noted that there are still some outstanding issues that need to
be addressed before the revenue recognition can be uniform between GAAP and IFRS. With this

REVENUE RECOGNITION
8
process already taking over 20 years and multiple updates, amendments, and changes the goal of
global uniform standards may be another decade away. To help the two standard-setting bodies
implement and identify issues the FASB and the IASB established the Joint Transition Resource
Group (TRG).
According to Schroeder et al. (2019), the purpose of the TRG is to “solicit, analyze, and
discuss stakeholder issues arising from implementation of the new guidance, to inform the FASB
and IASB about those implementation issues, which will help the boards determine what, if any,
action will be needed to address those issues,” and finally to “provide a forum for stakeholders to
learn about the new guidance from others involved with implementation.”
The TRG addressed nearly 40 implementation issues and has helped the FASB and the
IASB whether additional action needs to be taken. An example of the issues the TRG found
which resulted in the publication of ASU 2016-08, 2016-10, and 2016-12. As reported in earlier
paragraphs ASU 2016-08 is the Principal Versus Agent Considerations (Reporting Revenue
Gross Versus Net), ASU 2016-10 is the Principal Versus Agent Considerations (Reporting
Revenue Gross Versus Net), and ASU 2016-12 is Narrow-Scope Improvements and Practical
Expedients. Without the help of the TRG, the two standards would be even farther away from
being uniform. The TRG also found that numerous issues were found during the implementation
of AASB 15 and that the effective date originally proposed would not be met (Davern et al.,
2019).
FASB ASC 606 has been met with criticisms with a letter to the chairman of the Financial
Accounting Standards Board, Senator Carl Levin (D-MI). From the textbook, Schroeder et al.
(2019) stated, “the potential for abuses in financial reporting from the more principles-based
revenue recognition standard issued by FASB... that the new revenue reporting standard appears

REVENUE RECOGNITION
9
to have weakened US GAAP and may open the door to greater revenue-recognition abuses.”
This could be a problem for the FASB could face in the future if the warnings are not addressed.
Analyze the Conceptual Framework
In 2010, the IASB and the FASB issued a joint project to develop an improved,
converged conceptual framework for financial accounting and reporting. After the issuance in
2010, there have been updated and some concepts have been superseded, as it is important to
update standards and concepts as needed. According to Schroeder et al. (2019), the initial and
joint Conceptual Framework Project (CFP) resulted in the issuance of eight Statements of
Financial Accounting Concepts (SFACs)
No. 1: “Objectives of Financial Reporting by Business Enterprises” (superseded);
No. 2: “Qualitative Characteristics of Accounting Information” (superseded);
No. 3: “Elements of Financial Statements of Business Enterprises” (superseded);
No. 4: “Objectives of Financial Reporting by Nonbusiness Organizations” (because the
focus of this text is financial accounting, SFAC No. 4 will not be discussed here);
No. 5: “Recognition and Measurement in Financial Statements of Business Enterprises”;
No. 6: “Elements of Financial Statements” (SFAC No. 6 replaced SFAC No. 3);
No. 7: “Using Cash Flow Information and Present Value in Accounting Measurements”;
and
No. 8: Conceptual Framework for Financial Reporting (Chapters 1 and 3), which replaces
SFAC No. 1 and SFAC No. 2 and marks the completion of the first phase of the new joint
CFP.
REVENUE RECOGNITION
10
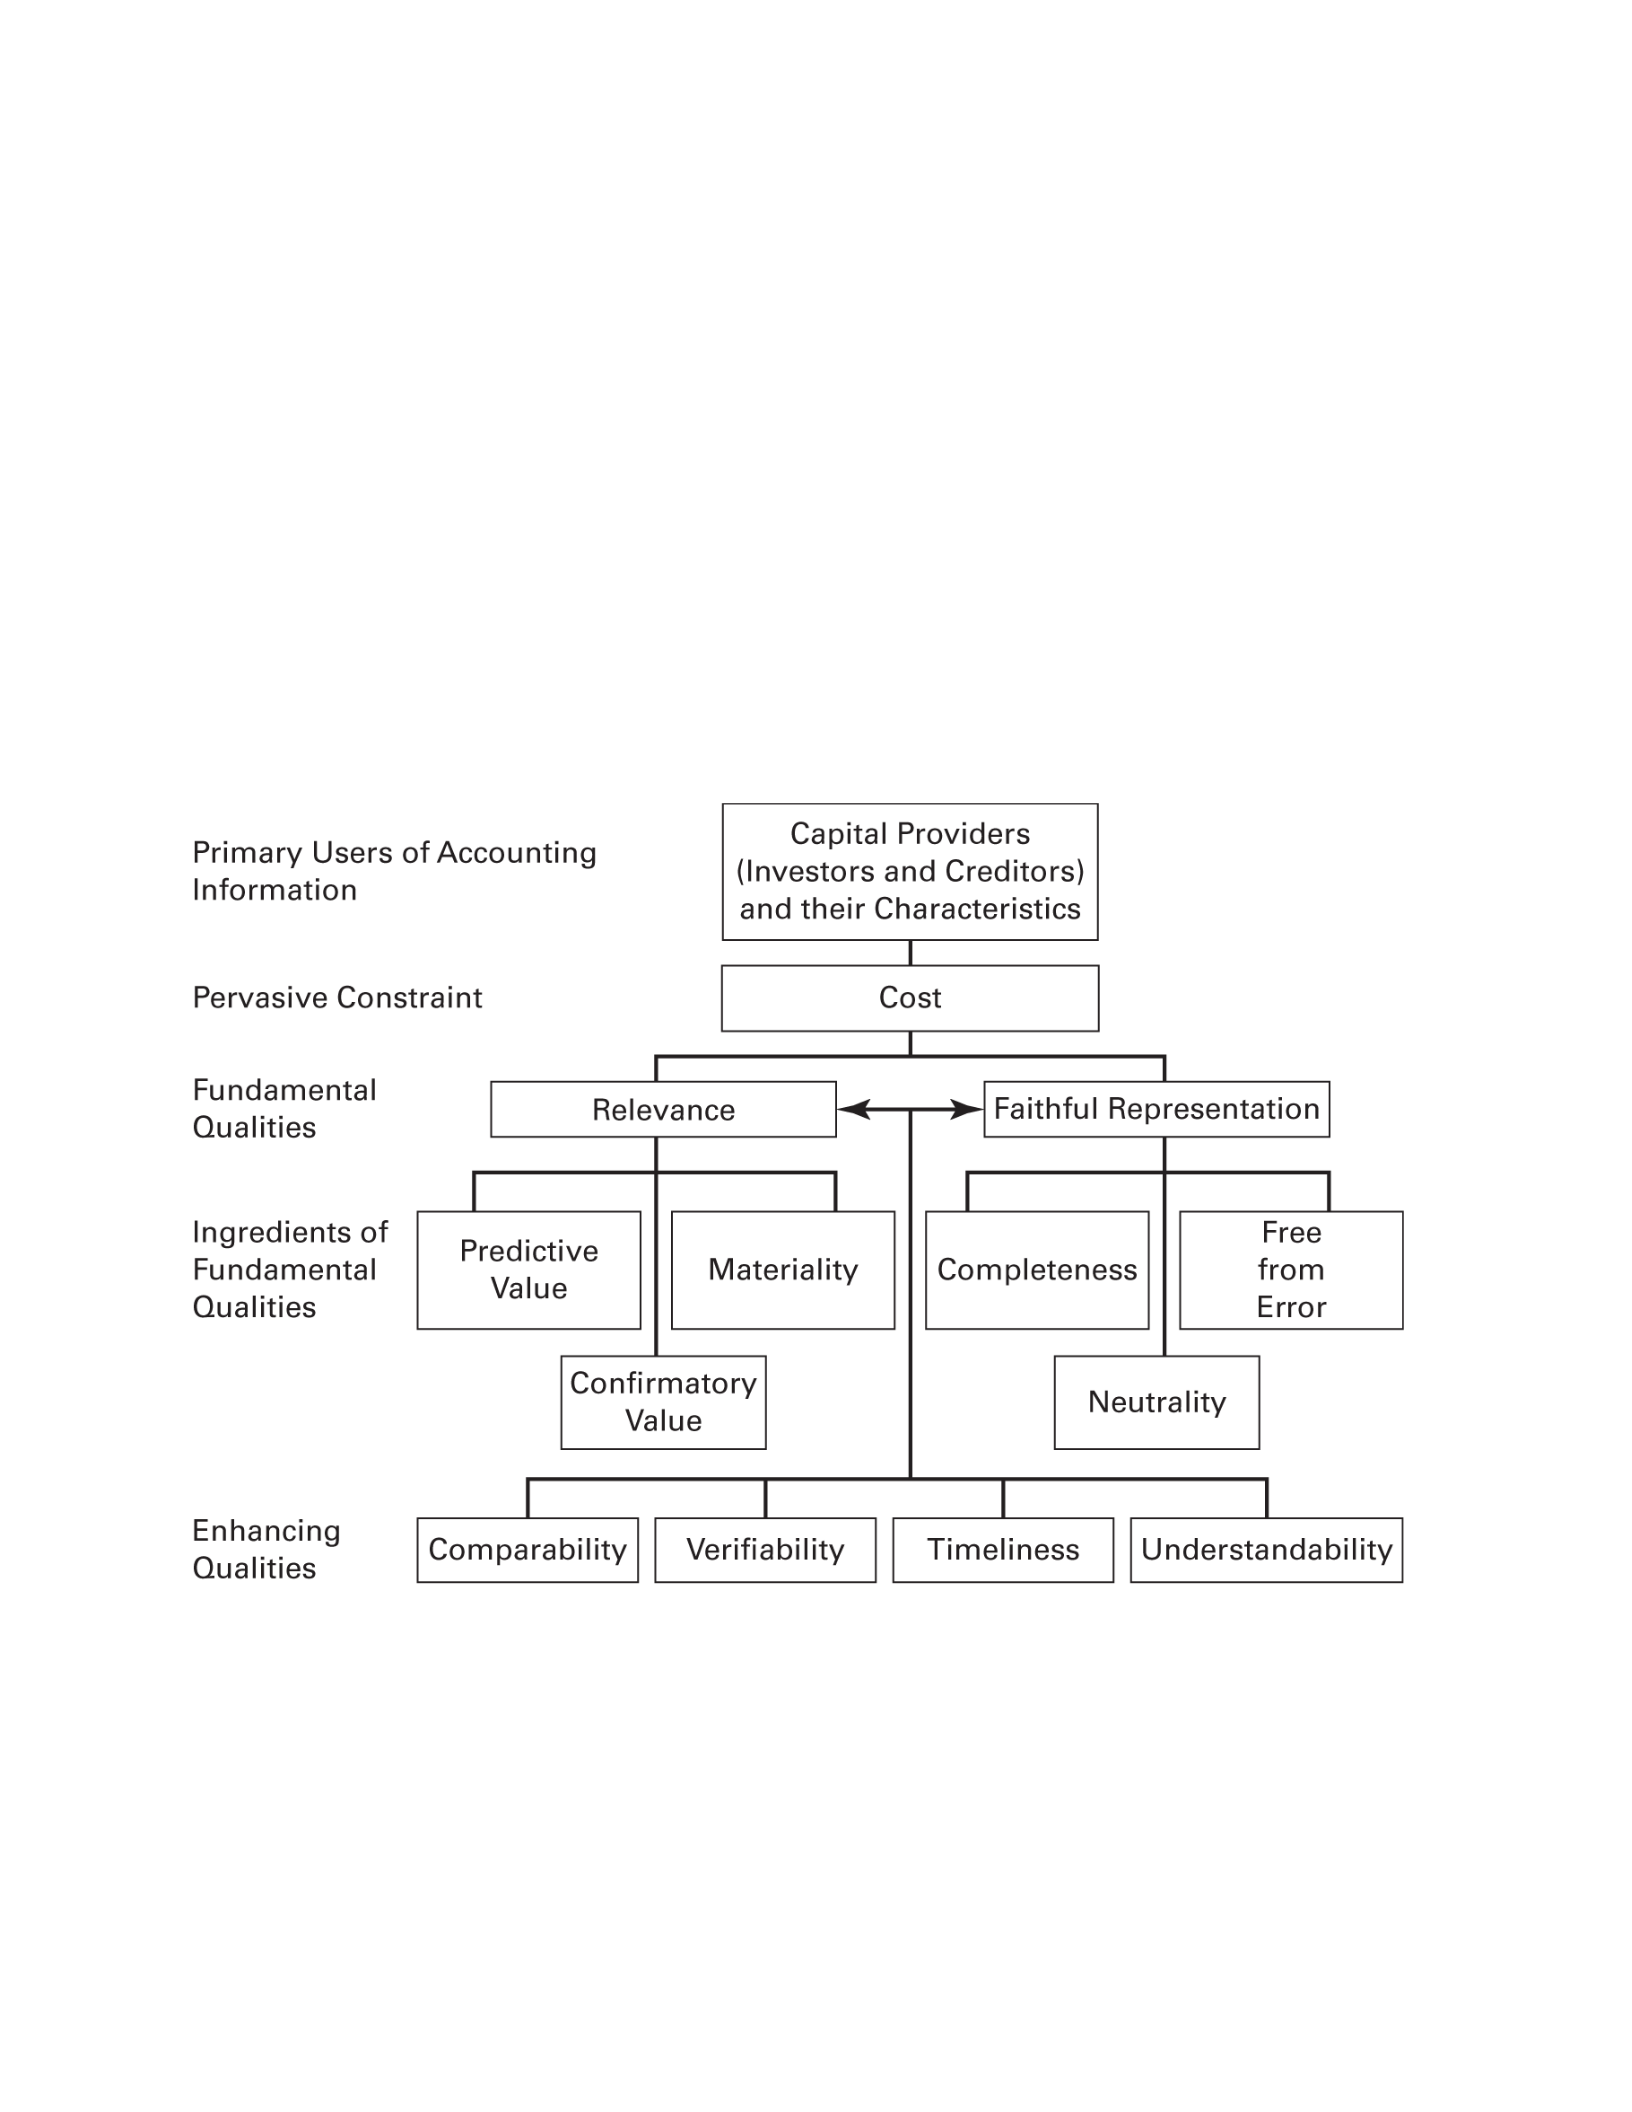
SFAC No. 8 discusses the Qualitative characteristics that help better distinguish the more useful
information from the less useful. According to FASB (2018) Statement of Financial Accounting
Concepts No. 8 The characteristics shown below “identify the types of information that are likely
to be most useful to the existing and potential investors, lenders, and other creditors for making
decisions about the reporting entity on the basis of information in its financial report.” It is
important to know the hierarchy of the qualitative characteristics of accounting information and
how it relates to the topic of revenue recognition. Below, Schroeder et al. (2019) provided the
hierarchy of the qualitative characteristics of accounting information
According to research from Myers et al. (2022) “that revenue recognition accounting standards
that restrict managerial discretion resulted in improved faithful representation but reduced
relevance.” For revenue recognition to be considered faithful representation it needs to be
complete, free from error, and neutral. Revenue recognition satisfies this definition with the five-

REVENUE RECOGNITION
11
step process of revenue recognition discussed earlier in the writing. To have relevance, the
information presented needs to have predictive value, be material, and have confirmatory value.
As discussed in the similarities of GAAP and IFRS, the predictive value in the information will
be that each standard requires the reporting of the statement of cash flows, this statement can
ensure that the company can continue its operations. For revenue recognition, the predictive
value of the revenue can use the current year’s revenue to help predict future years. Confirmatory
value in revenue would be the use of the current year’s revenue to confirm past predictions and
adjust where needed for future year’s predictions.
Enhancing Qualitative Characteristics
The need for comparability in the financial statements is vital, making the two standards
uniform will ensure such information is available to the public. To be verified means that
different knowledgeable and independent people can reach a consensus, and having uniform
standards will ensure that knowledgeable people can use and verify the information presented to
them no matter where they are globally. GAAP requires the information to be presented to the
users in a timely manner to ensure that the information is there to help fulfill their decision-
making needs. And finally, understandability, understandability allows users to easily understand
the information presented to them.
Courses of Action
Uniformity between GAAP and IFRS is necessary and needed. With the internet and the
rise of global businesses, the world is getting smaller and having fewer boundaries than before.
Revenue being the most important piece of information in the financial statement, it is
imperative that there is a complete and detailed worldwide standard on how to recognize

REVENUE RECOGNITION
12
revenue. The FASB, IASB, and TRG needs to continue working together to bridge the gap
between the two standards.
The TRG needs to continue its work with GAAP and IFRS to solicit, analyze, and discuss
stakeholder issues arising from the implementation of the new guidance, and build upon the
success they have already been having. Entities need to adopt the changes in the standards in a
timely manner to ensure they can provide feedback to FASB, IASB, and the TRG. With more
feedback the greater the chances to make a well-rounded standard that can be used globally. The
FASB has passed nine standards updates in 2021 and four in 2022, the FASB needs to continue
making updates to help clarify and to move closer to the IFRS standards. While the IFRS
updated five standards in 2022 to help better align the two sets of standards. The updates that
occurred were not pertaining to revenue recognition, but it shows a continued effort to bring the
standards closer together.
Biblical Application
Without revenue the business cannot exist, it is the heart of the business and provides life
to other parts of the business. Since it is the lifeblood of the business it is important to protect it
against fraud and abuse. With pressures to keep up with the market, competing companies, and
shareholders’ expectations, fraudulent revenue recognition is a hot-buttoned issue that can be
utilized by some bad actors in the organization. The Bible speaks about integrity throughout,
proverbs 16:11 says “A just balance and scales are the LORD's; all the weights in the bag are his
work" If you apply Proverbs 16:11 to today’s businesses you can see the connection to revenue
recognition, an inflated revenue will throw the scales off.

REVENUE RECOGNITION
13
Recognizing revenue before the five steps of revenue recognition is complete may help
the company in the short term, but in the long term, it will hurt the company. In my experience,
the company will always be playing catch-up and waiting for the one big month to right the ship.
Companies should keep in mind Proverbs 13:11, “Dishonest money dwindles away, but whoever
gathers money little by little makes it grow.”
The Bible repeatedly shares that honesty and integrity should always be your priority, this
is highlighted in Proverbs 19:1 “Better is the poor who walks in his integrity than one who
is perverse in his lips, and is a fool”. Be honorable and trustworthy in business and in your
personal life as the two blends together at points of your life, and always remember Proverbs
12:22 “The LORD detests lying lips, but he delights in people who are trustworthy.”
REVENUE RECOGNITION
14
References
Davern, M., Gyles, N., Potter, B., & Yang, V. (2019). Implementing AASB 15 revenue from
contracts with customers: The preparer perspective. Accounting Research Journal, 32(1),
50-67. https://doi.org/10.1108/ARJ-03-2018-0055
ESV. (2016). Proverbs (ESV). Bible Gateway. Retrieved November 20, 2022, from
https://www.biblegateway.com/
FASB Accounting Standards Codification®. (2014). https://asc.fasb.org/1943274/2147479930
FASB. (2018, August). Statement of Financial Accounting Concepts No. 8 As Amended.
https://fasb.org/Page/ShowPdf?
path=Concepts+Statement+8+Chapter+3+As+Amended.pdf&title=CONCEPTS+STATE
MENT+NO.
+8%E2%80%94CONCEPTUAL+FRAMEWORK+FOR+FINANCIAL+REPORTING
%E2%80%94CHAPTER+3%2C+QUALITATIVE+CHARACTERISTICS+OF+USEFU
L+FINANCIAL+INFORMATION+%28AS+AMENDED
%29&acceptedDisclaimer=true&Submit=
Lee, D. A., Sage, D. W., & Shipe, K. B. (2020). ASC 606 and its impact on the franchise
industry. Franchise Law Journal, 40(2), 273-291.
Myers, L. A., Schmardebeck, R., Seidel, T. A., & Stuart, M. D. (2022). The impact of managerial
discretion in revenue recognition: A reexamination. Contemporary Accounting
Research, 39(3), 2130-2174. https://doi.org/10.1111/1911-3846.12775
Schroeder, R. G., Clark, M. W., & Cathey, J. M. (2019). Financial Accounting Theory and
Analysis: Text and Cases (13th ed.). Wiley Global Education US.
https://mbsdirect.vitalsource.com/books/9781119577713

REVENUE RECOGNITION
15

