


REBECCA JONES ACCT 612
TAX RESEARCH PROBLEM: CHECKPOINT ASSIGNMENT INSTRUCTIONS
1. Use Thomson Reuters Checkpoint to answer the following questions:
a. What does section 199a of the 2018 tax law give to business owners?
It gives any taxpayer, other than a corporation, a deduction for any taxable year
an amount equal to the lesser of the combined qualified business income amount
of the taxpayer or an amount equal to 20% of the excess (if any) of the taxable
income of the taxpayer for the taxable year, over the net capital gain.
b. Define Qualified Business Income (QBI). Why is this important?
Qualified business income (QBI) is defined as the net amount of qualified items
of income, gain, deduction, and loss with respect to a qualified trade or business
allowed in determining taxable income for the tax year. QBI is used to measure
business income.
c. What are the threshold amounts that may constrain?
In 2018, $315,000 for married filing jointly and $157,500 for all other taxpayers.
d. How do W2 wages constrain?
The amount determined is 50% of the W-2 wages with respect to qualified trade
or business or the sum of 25 % of the W-2 wages with respect to the qualified
trade or business, plus 2.5 percent of the unadjusted basis immediately after
acquisition of all qualified properties.
e. What types of organizations qualify for this relief?
Owners of sole proprietorships, partnerships, S corporations and some trusts
and estates are qualified for this relief.
2. Use the RIA Checkpoint Citator 2nd to evaluate the 2002 Gwendolyn A Ewing Tax Court
Case.
a. What is its citation and what tax issues does the case address?
Gwendolyn A. Ewing, 118 TC 494, ¶118.31 TCR (5/31/2002).
Mrs. Ewing filed a Form 8857, Request for Innocent Spout Relief, requesting
“equitable relief” for a portion of the amount of the unpaid tax liability
shown on the 1995 joint return filed by Mrs. Ewing and her husband.
b. What is the case’s direct judicial history?
The case was overruled by legislation: Billings, David Bruce, 127 TC 7,
¶127.2 TCR (7/25/2006).
Page 1 of 6
REBECCA JONES ACCT 612
It was reversed: Ewing, Gwendolyn A. v. Com., 97 AFTR 2d 2006-1224, 439
F3d 1009 (CA9, 2/28/2006)
Same case or ruling: Ewing, Gwendolyn A., 122 TC 32, ¶122.2 TCR
(1/28/2004)
c. Where is the case annotated in the United States Tax Reporter?
ANN ¶60,155.04(5) Authority to review IRS’s determination
ANN ¶60,155.01(5) Procedure
ANN ¶60,155.04 (10) Abuse of discretion
d. The Robert Haag case cites the 2002 Ewing case at 94 A.F. T. R. 2nd 2004-6667.
What is the Haag case’s treatment of the Ewing case?
It cited it favorably.
3. Find the Supreme Court Case involving Corn Products Refining Company (not the one in
which rehearing was denied).
a. What is the citation of the case?
CORN PRODUCTS REFINING CO. v COM., 47 AFTR 1789, 350 US 46, 76
S Ct 20, 100 L Ed 29, 55-2 USTC ¶9746, 1955-2 CB 512, (US, 11/7/1955)
b. How many Supreme Court cases cite the Corn Products case?
There are 9 Supreme Court cases cited.
c. Find the related Supreme Court case involving Arkansas Best. What is the
secondary source cited by the court in the opinion?
Bittker, Federal Taxation of Income, Estates and Gifts ¶ 51.10.3 is the
secondary source.
d. Use the citator to examine cases that have cited Arkansas Best. Does the case
appear to have been reversed or overturned?
The case is upheld with a majority cited favorably. The case ruling remains
valid as it was never reversed or overturned.
e. Using the related information links to the FCC, what is the current application of
Arkansas Best and Corn Products?
The current application of Arkansas Best and Corn Products case have
reduced the number of application because the tax law was changed via FCC
regulations then by FCC code.
Page 2 of 6
REBECCA JONES ACCT 612
4. Use RIA Checkpoint Citator 2nd to evaluate Deluxe Check Printers Inc., 15 c1, Ct. 175.
a. Which tax years were in question in the case? How was the case treated upon
appeal? What is the citation of the court of appeals case?
The tax years in question is 1976, 1977, and 1978. Upon appeal, the judgment
was reversed as to liability and affirm as to the interest payment.
The citation of the appeal case is 64 AFTR 2d 89-5327, 885 F2d 848, 89-2
USTC P 9545
b. Which doctrine is the basis for part B of the Court of Federal Claims decision?
Where is this doctrine discussed in the FTC?
The doctrine is Doctrine of Variance. It is discussed in FTC at T-6802 & T-
6802.1.
c. Which cases and rulings distinguish themselves from the Deluxe Check Printers
Court of Federal Claims case?
The cases distinguished is BCS Financial Corp v. U.S., 78 AFTR 2d 96-5766,
930 F Supp 1279 (DC IL, 7/3/1996) and Sierra Pacific resources and Subs. V.
U.S., 90 AFTR 2d 2002-7511, 56 Fed Cl 376 (Ct Fed Cl, 11/21/2002).
d. How many cases were cited by the Deluxe Check Printers decision? (Hint: Check
Citing NOT cited). Does this number of cases seem logical?
The number is 21 to 23 depending on if you leave off cases with the same
names.
5. Use the RIA Citator to evaluate 59 A. F. T. R. 2nd 87-392.
a. What is the name of the case and what are its parallel citations?
The name of the case is McCARTHY, ET AL. v. U.S. (IRS) with parallel
citations of 807 F2d 1306 and 87-1 USTC P 9101.
b. In which circuit court was this case heard?
US Court of Appeals, 6th Circuit
c. What are the two main issues in the case?
Amortization of broadcast rights and amortization of certain fees incurred in
acquiring a business.
Page 3 of 6
REBECCA JONES ACCT 612
d. For the professional fees discussed in the case, which two categories were
considered? What did the court decide with respect to each?
The two fees discussed are the legal fees associated with the loan to purchase
the Yankees and the fees incurred to organize the partnership that owned the
Yankees.
The court decided that the partnership organization costs are considered
part of the basis of the Yankees and must be capitalized.
e. Have any other cases cited McCarthy? Does it modify any previous cases?
McCarthy has not been cited in any other case. The case modified its
previous judicial history – the District Court case on the same issue 56 AFTR
2d 85-5612 and 56 AFTR 2d 98-6237.
f. Use the FTC related information button and discuss whether this holding would
be true for a transaction today?
P.L. 108-356L Law Sec 866 Extension of Amortization of Intangible to
Sports Franchises which opens the door for amortization of broadcast rights
for sports franchises.
6. What is the subject of each of the following revenue rulings? Tip: You can use the main
search bar on the database homepage to find these.
a. Rev Ruling 2015-20 – Fringe benefits – noncommercial flight valuation
b. Rev Ruling 2014-32 – Certain fringe benefits – qualified transportation
fringe – use of smartcards and debit cards
c. Rev Ruling 77-438 – Military personnel; scholastic programs
d. Rev Ruling 2005-52 – Employee expense reimbursements – accountable
plans – substantiation; return of excess – tool allowances
7. Use Checkpoint Citations to answer the following questions:
a. What are the thesaurus alternatives for “like-kind”?
1031, “like kind”, likeclass, likekind
b. On the search screen, expand the FTC by clicking on the + before the title. What
subheadings are listed?
Analysis (FTC), Checklists and client letters
Page 4 of 6
REBECCA JONES ACCT 612
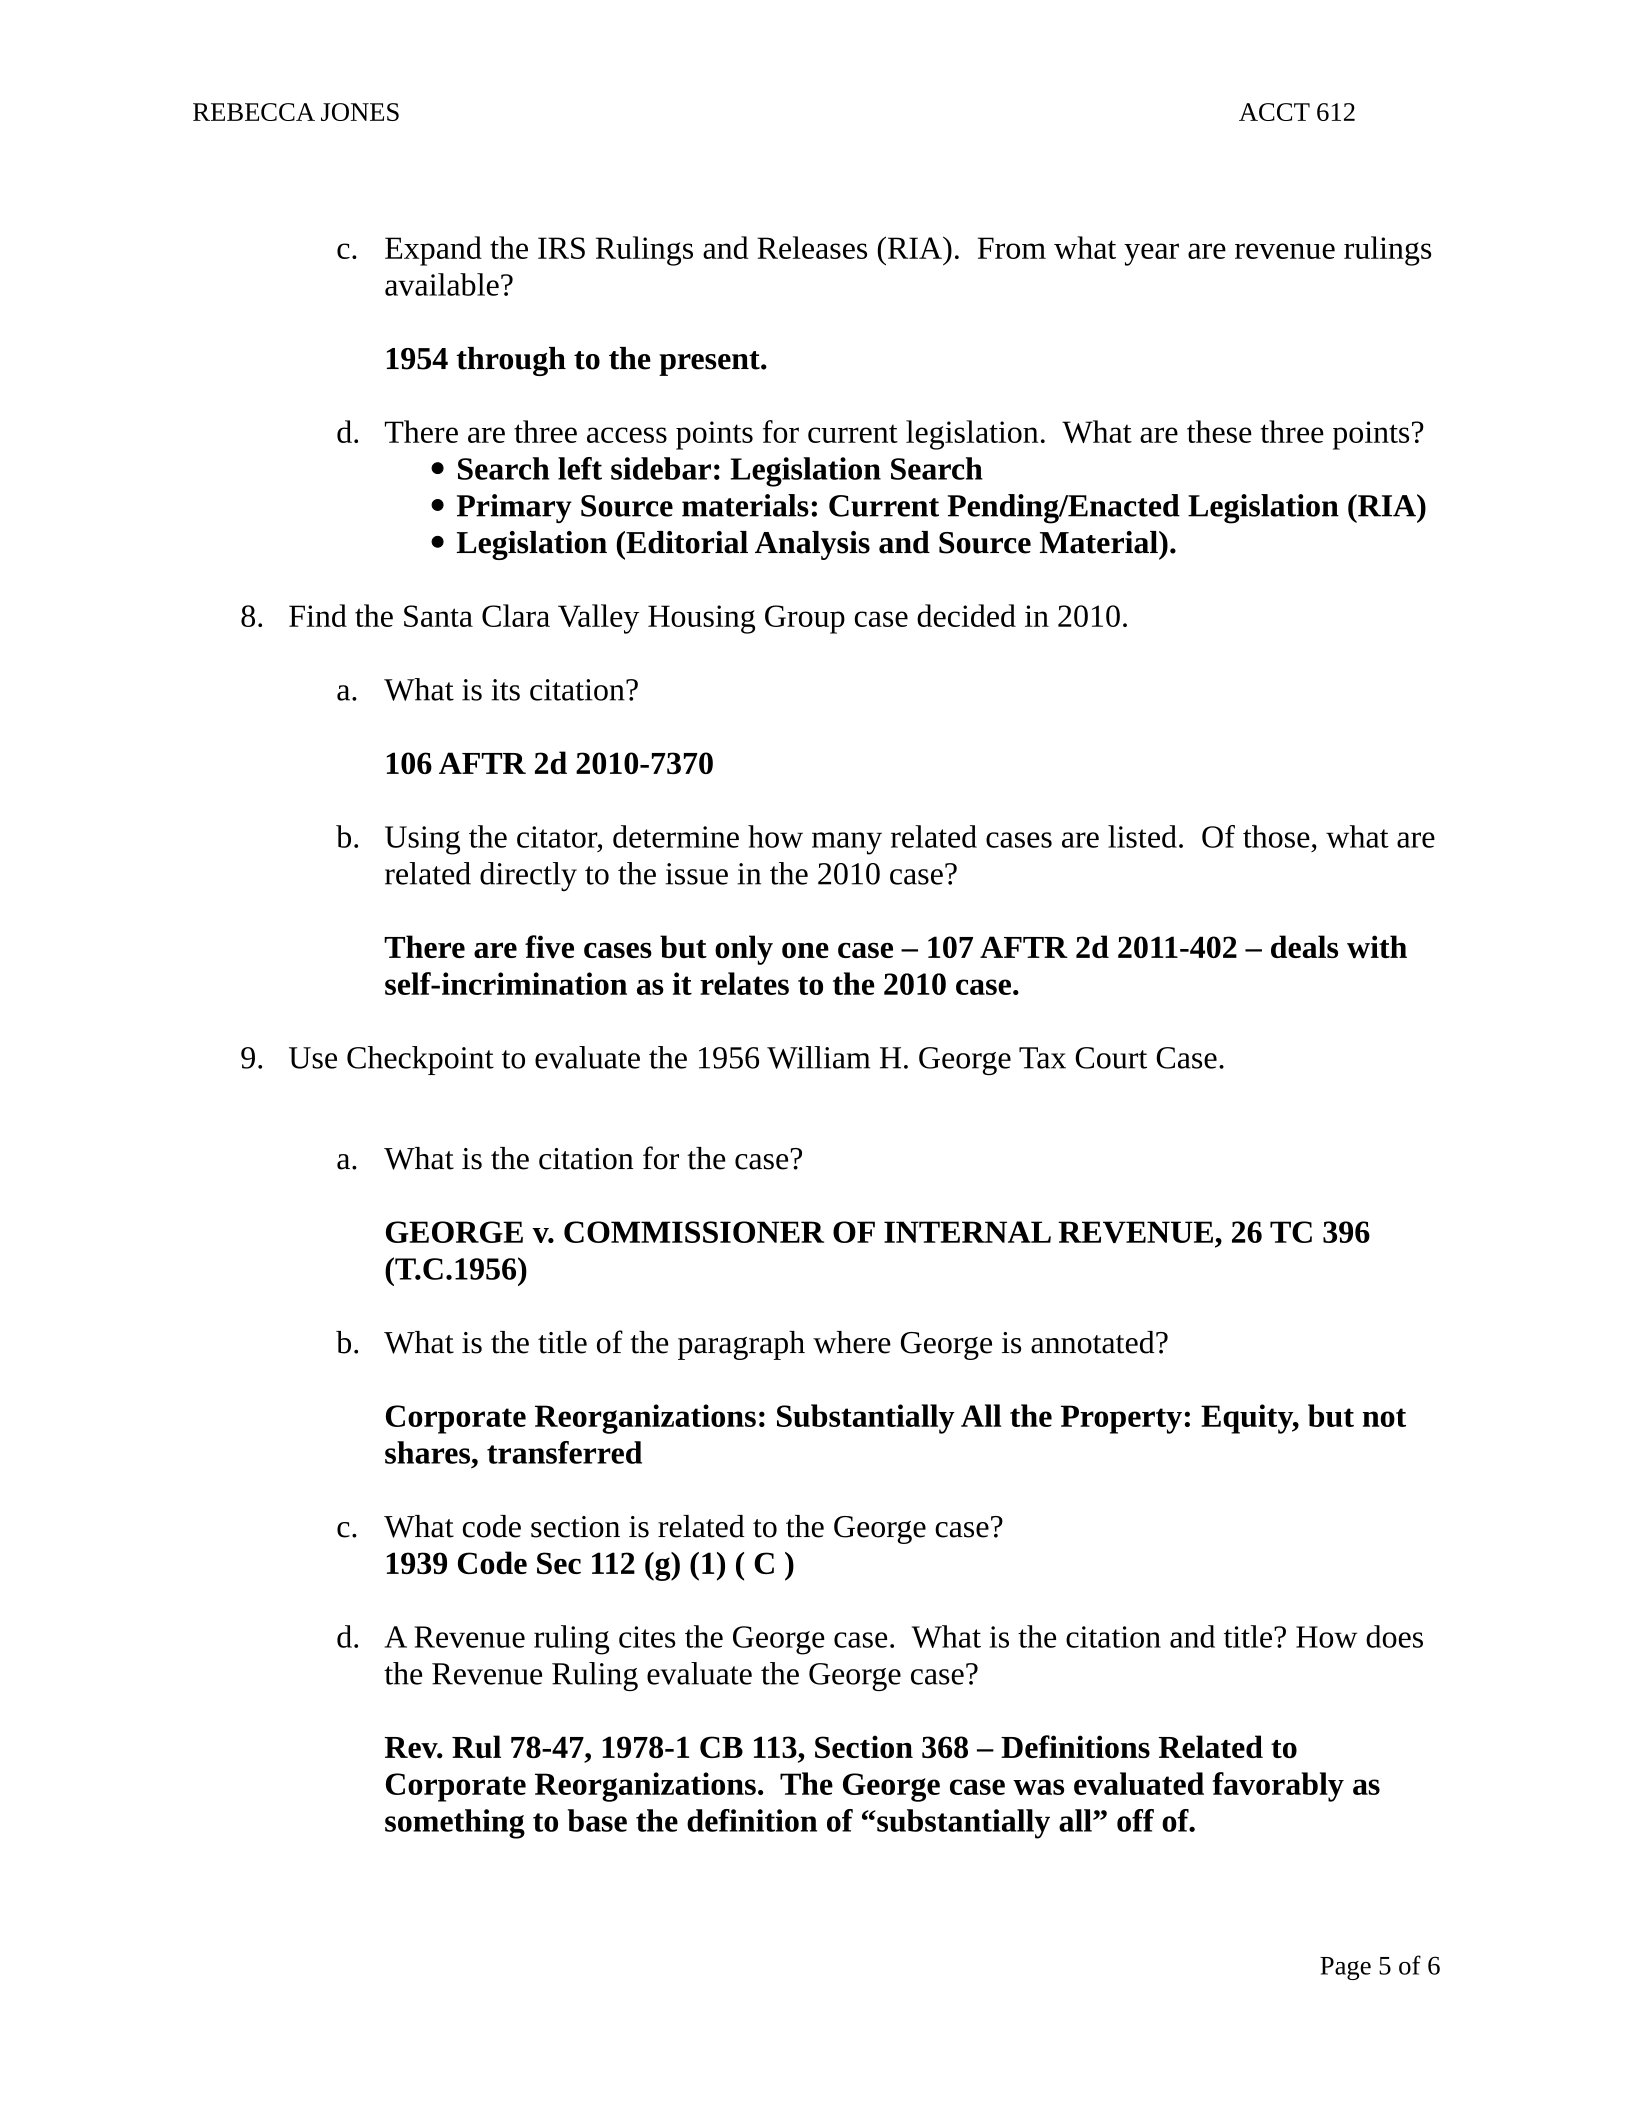
c. Expand the IRS Rulings and Releases (RIA). From what year are revenue rulings
available?
1954 through to the present.
d. There are three access points for current legislation. What are these three points?
Search left sidebar: Legislation Search
Primary Source materials: Current Pending/Enacted Legislation (RIA)
Legislation (Editorial Analysis and Source Material).
8. Find the Santa Clara Valley Housing Group case decided in 2010.
a. What is its citation?
106 AFTR 2d 2010-7370
b. Using the citator, determine how many related cases are listed. Of those, what are
related directly to the issue in the 2010 case?
There are five cases but only one case – 107 AFTR 2d 2011-402 – deals with
self-incrimination as it relates to the 2010 case.
9. Use Checkpoint to evaluate the 1956 William H. George Tax Court Case.
a. What is the citation for the case?
GEORGE v. COMMISSIONER OF INTERNAL REVENUE, 26 TC 396
(T.C.1956)
b. What is the title of the paragraph where George is annotated?
Corporate Reorganizations: Substantially All the Property: Equity, but not
shares, transferred
c. What code section is related to the George case?
1939 Code Sec 112 (g) (1) ( C )
d. A Revenue ruling cites the George case. What is the citation and title? How does
the Revenue Ruling evaluate the George case?
Rev. Rul 78-47, 1978-1 CB 113, Section 368 – Definitions Related to
Corporate Reorganizations. The George case was evaluated favorably as
something to base the definition of “substantially all” off of.
Page 5 of 6
REBECCA JONES ACCT 612
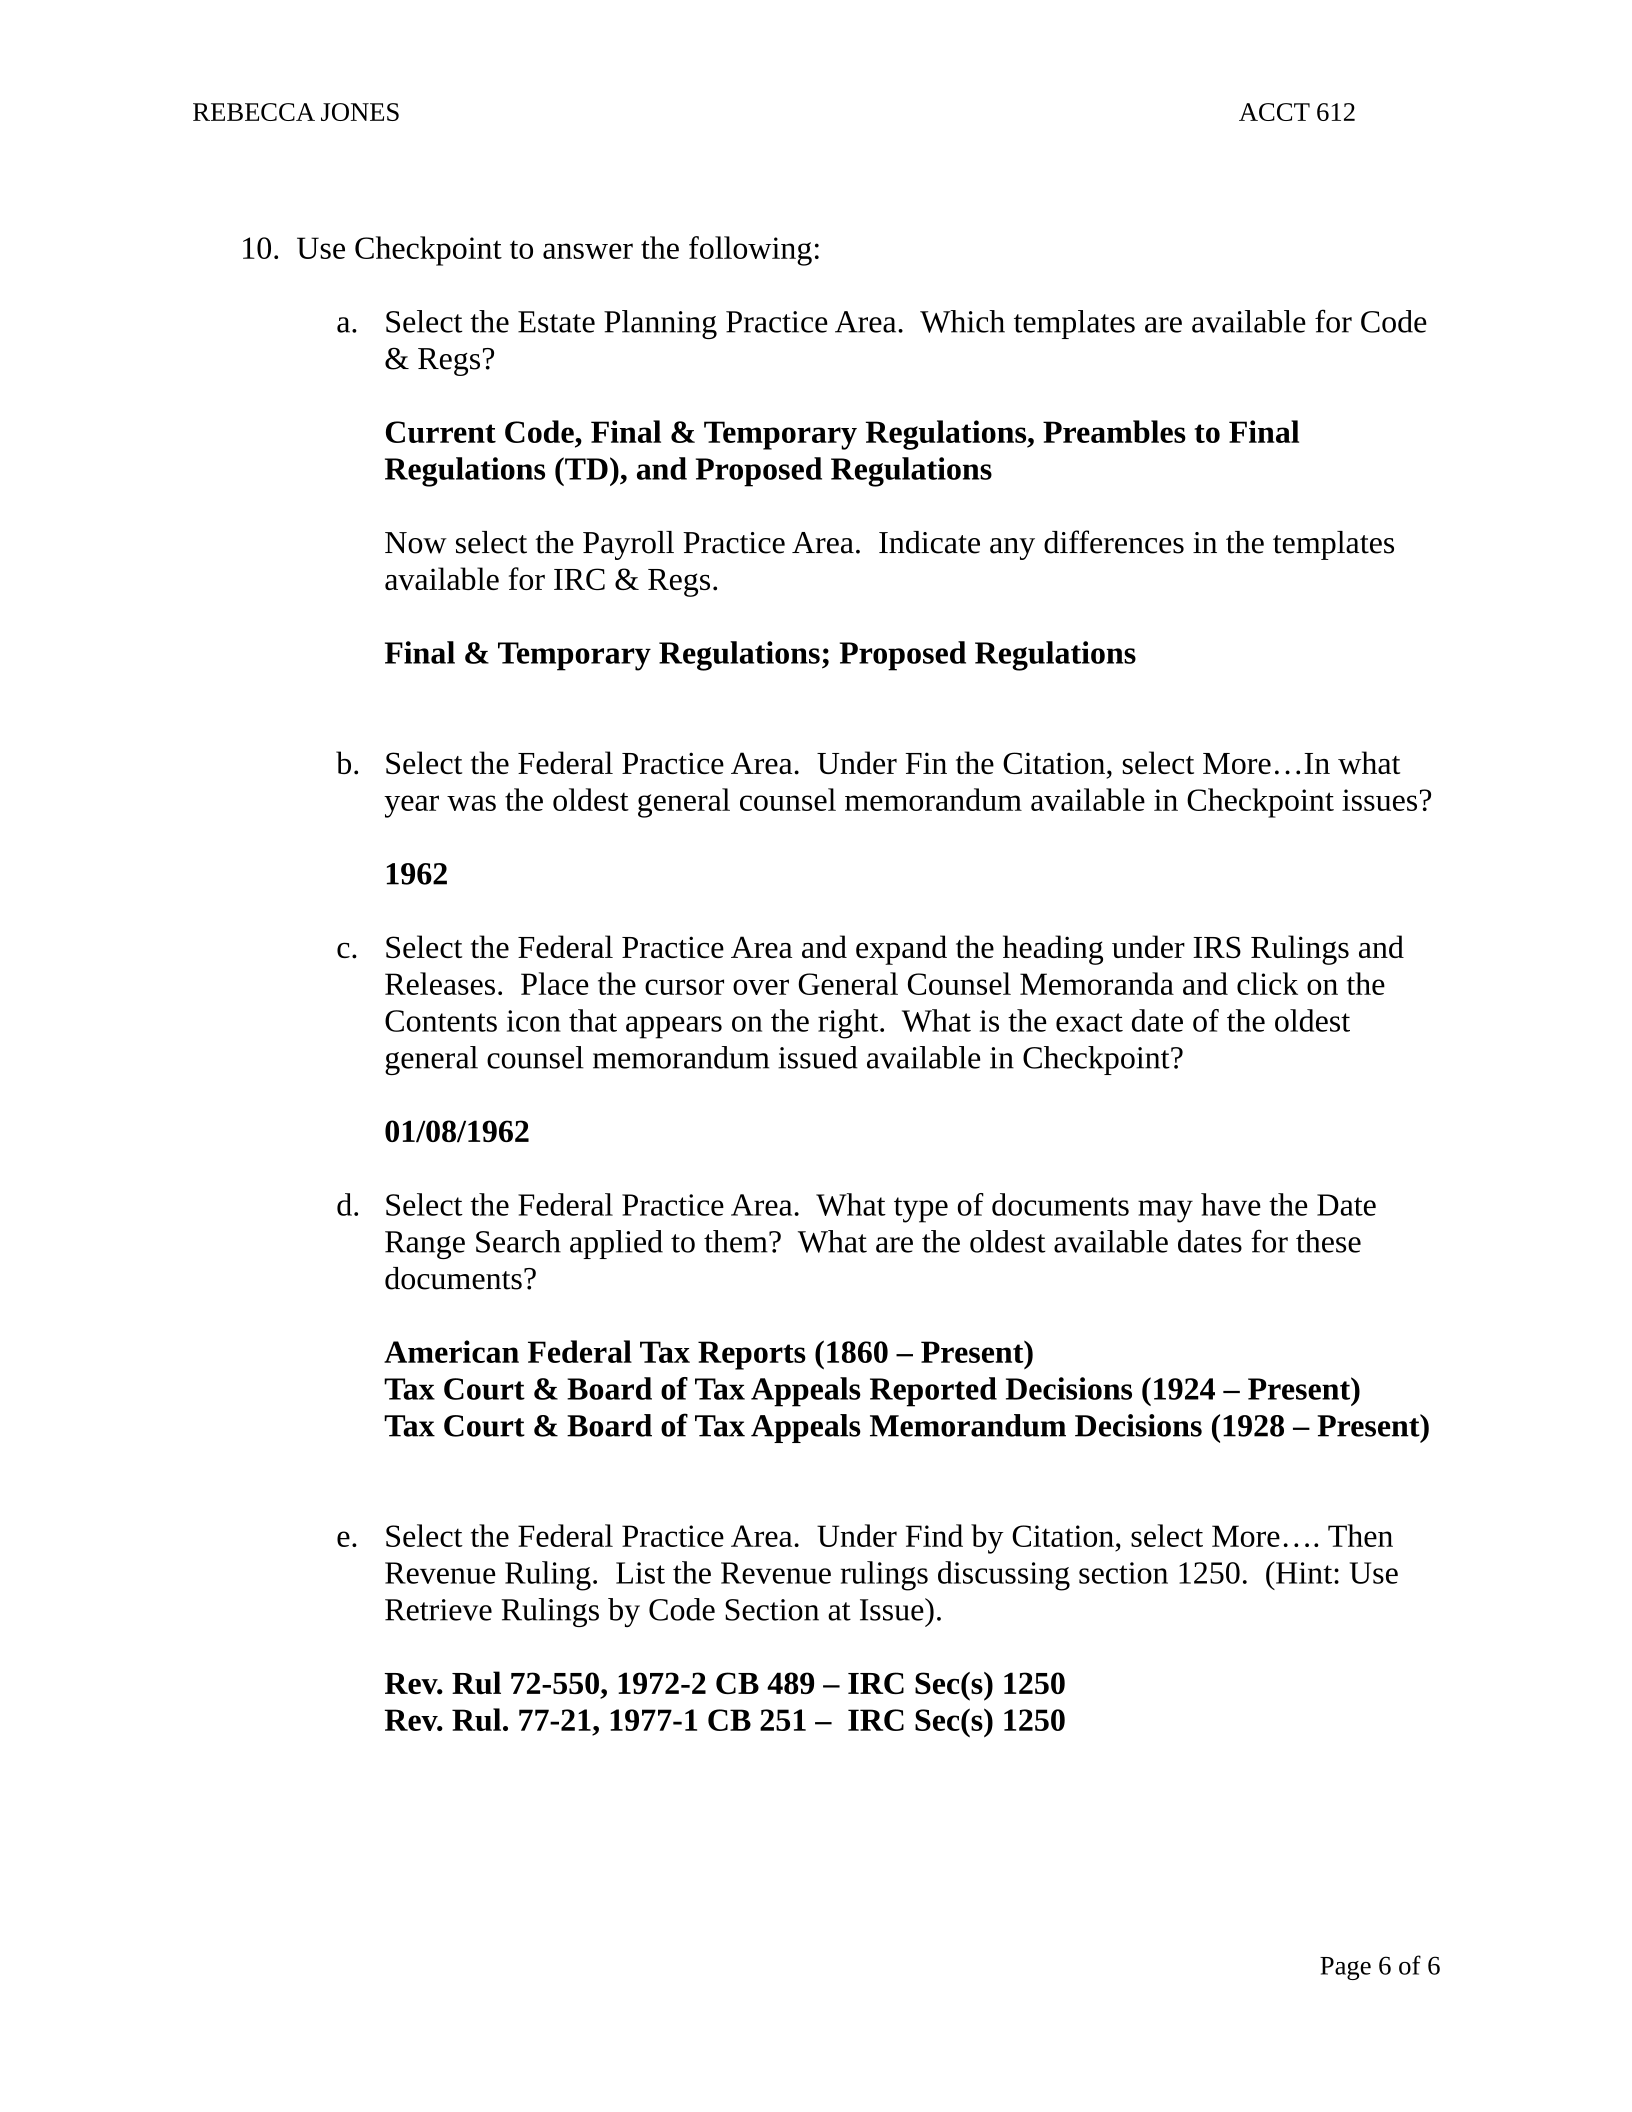
10. Use Checkpoint to answer the following:
a. Select the Estate Planning Practice Area. Which templates are available for Code
& Regs?
Current Code, Final & Temporary Regulations, Preambles to Final
Regulations (TD), and Proposed Regulations
Now select the Payroll Practice Area. Indicate any differences in the templates
available for IRC & Regs.
Final & Temporary Regulations; Proposed Regulations
b. Select the Federal Practice Area. Under Fin the Citation, select More…In what
year was the oldest general counsel memorandum available in Checkpoint issues?
1962
c. Select the Federal Practice Area and expand the heading under IRS Rulings and
Releases. Place the cursor over General Counsel Memoranda and click on the
Contents icon that appears on the right. What is the exact date of the oldest
general counsel memorandum issued available in Checkpoint?
01/08/1962
d. Select the Federal Practice Area. What type of documents may have the Date
Range Search applied to them? What are the oldest available dates for these
documents?
American Federal Tax Reports (1860 – Present)
Tax Court & Board of Tax Appeals Reported Decisions (1924 – Present)
Tax Court & Board of Tax Appeals Memorandum Decisions (1928 – Present)
e. Select the Federal Practice Area. Under Find by Citation, select More…. Then
Revenue Ruling. List the Revenue rulings discussing section 1250. (Hint: Use
Retrieve Rulings by Code Section at Issue).
Rev. Rul 72-550, 1972-2 CB 489 – IRC Sec(s) 1250
Rev. Rul. 77-21, 1977-1 CB 251 – IRC Sec(s) 1250
Page 6 of 6
Powered by TCPDF (www.tcpdf.org)

