


ACCT 531 - ACCOUNTING
INFORMATION SYSTEMS - Fair
Value Measurement
Question Bank - Set 5
Liberty University
Question 1
Question
A company holds an investment in a start-up company which operates in a
highly volatile industry. The start-up company’s financial statements indicate a
fair value of the investment of $500,000. However, the company’s management is
uncertain about the start-up’s future performance and market conditions. As a
result, they believe that a range of possible fair values exists, with a conservative
estimate at $450,000 and an optimistic estimate at $550,000. Calculate the fair
value measurement for the investment using the three-level hierarchy provided
by IFRS 13.
Solution
To calculate the fair value measurement using the three-level hierarchy provided
by IFRS 13, we need to determine at which level of the hierarchy the fair value
falls.
Step 1: Level 1 input is quoted prices in active markets for identical assets
or liabilities that the entity can access at the measurement date.
Since the start-up company operates in a highly volatile industry, there are
no active markets for identical investments. Therefore, the fair value does not
fall within Level 1.
Step 2: Level 2 input is inputs, other than quoted prices included in Level
1, that are observable for the asset or liability, either directly or indirectly.
Since the fair value of $500,000 is based on the start-up company’s financial
statements, which are observable inputs, the fair value does not fall within Level
2.

Step 3: Level 3 input is unobservable inputs for the asset or liability.
Given that the company’s management has provided a range of possible fair
values based on their own estimates (from $450,000 to $550,000), this falls
under unobservable inputs. Therefore, the fair value of $500,000 falls within
Level 3 of the hierarchy.
The fair value measurement for the investment in the start-up company is
at Level 3 of the hierarchy, as it is based on unobservable inputs provided by
the company’s management.
Question 2
Question
A company holds an investment in a privately held company and measures the
fair value of the investment using Level 3 inputs. The fair value measurement
includes significant unobservable inputs that require estimation and judgement.
Discuss the challenges faced by the company in determining the fair value of
this investment.
Solution
To determine the fair value of an investment using Level 3 inputs with significant
unobservable inputs, the company faces several challenges. Here are the key
challenges faced by the company:
Step 1: Lack of Market Data The lack of active markets for the invest-
ment can make it difficult to obtain relevant and reliable market-based data to
determine the fair value. In the absence of observable market prices, the com-
pany must rely on its own assumptions and estimates, increasing the subjectivity
of the fair value measurement.
Step 2: Complexity of Models Using Level 3 inputs often involves us-
ing complex valuation models to estimate the fair value. These models may
require expertise in financial modeling and valuation techniques, as well as a
deep understanding of the underlying asset and industry dynamics. Inaccurate
or inappropriate models can lead to misstated fair values.
Step 3: Estimation Uncertainty Significant unobservable inputs intro-
duce uncertainty into the fair value measurement. The company must make
reasonable assumptions and estimates based on the best information available,
but these estimates may be subject to bias or error. The company needs to
carefully document and disclose these uncertainties in its financial statements.
Step 4: Judgement and Subjectivity Determining the fair value of an
investment with Level 3 inputs requires judgement and subjectivity on the part
of the company’s management. Different individuals may have different opinions
on the fair value, leading to a range of possible outcomes. Management’s bias
or incentives can also influence the fair value measurement.
2
Step 5: Risk of Manipulation The subjective nature of fair value mea-
surement using Level 3 inputs can create opportunities for manipulation or bias
in financial reporting. Companies may be tempted to use aggressive assump-
tions to inflate the fair value of investments, leading to misleading financial
statements.
In conclusion, companies face various challenges when measuring the fair
value of investments using Level 3 inputs with significant unobservable inputs.
It is crucial for companies to exercise caution, transparency, and diligence in the
fair value measurement process to ensure the accuracy and reliability of their
financial statements.
Question 3
Question
A company holds an investment in a financial asset classified as a level 3 fair
value measurement. At the end of the reporting period, the fair value of the
investment has decreased from 135,000to120,000. The company’s policy is to
recognize unrealized gains and losses in other comprehensive income. Prepare
the journal entry to record the change in fair value of the investment.
Solution
To record the change in fair value of the investment, we need to determine the
unrealized loss and recognize it in other comprehensive income.
Step 1: Calculate the unrealized loss:
Unrealized loss = Fair value at the end −Fair value at the beginning
Unrealized loss = $120,000 −$135,000 = −$15,000
Step 2: Prepare the journal entry:
Other comprehensive income →
$
15,000
Investment in financial asset →
$
15,000
Therefore, the journal entry to record the change in fair value of the invest-
ment is:
Other comprehensive income $15,000
Investment in financial asset $15,000
Question 4
Question
A company holds an investment in a financial asset that is classified as a Level 3
fair value measurement. The fair value of the investment at the beginning of the
3
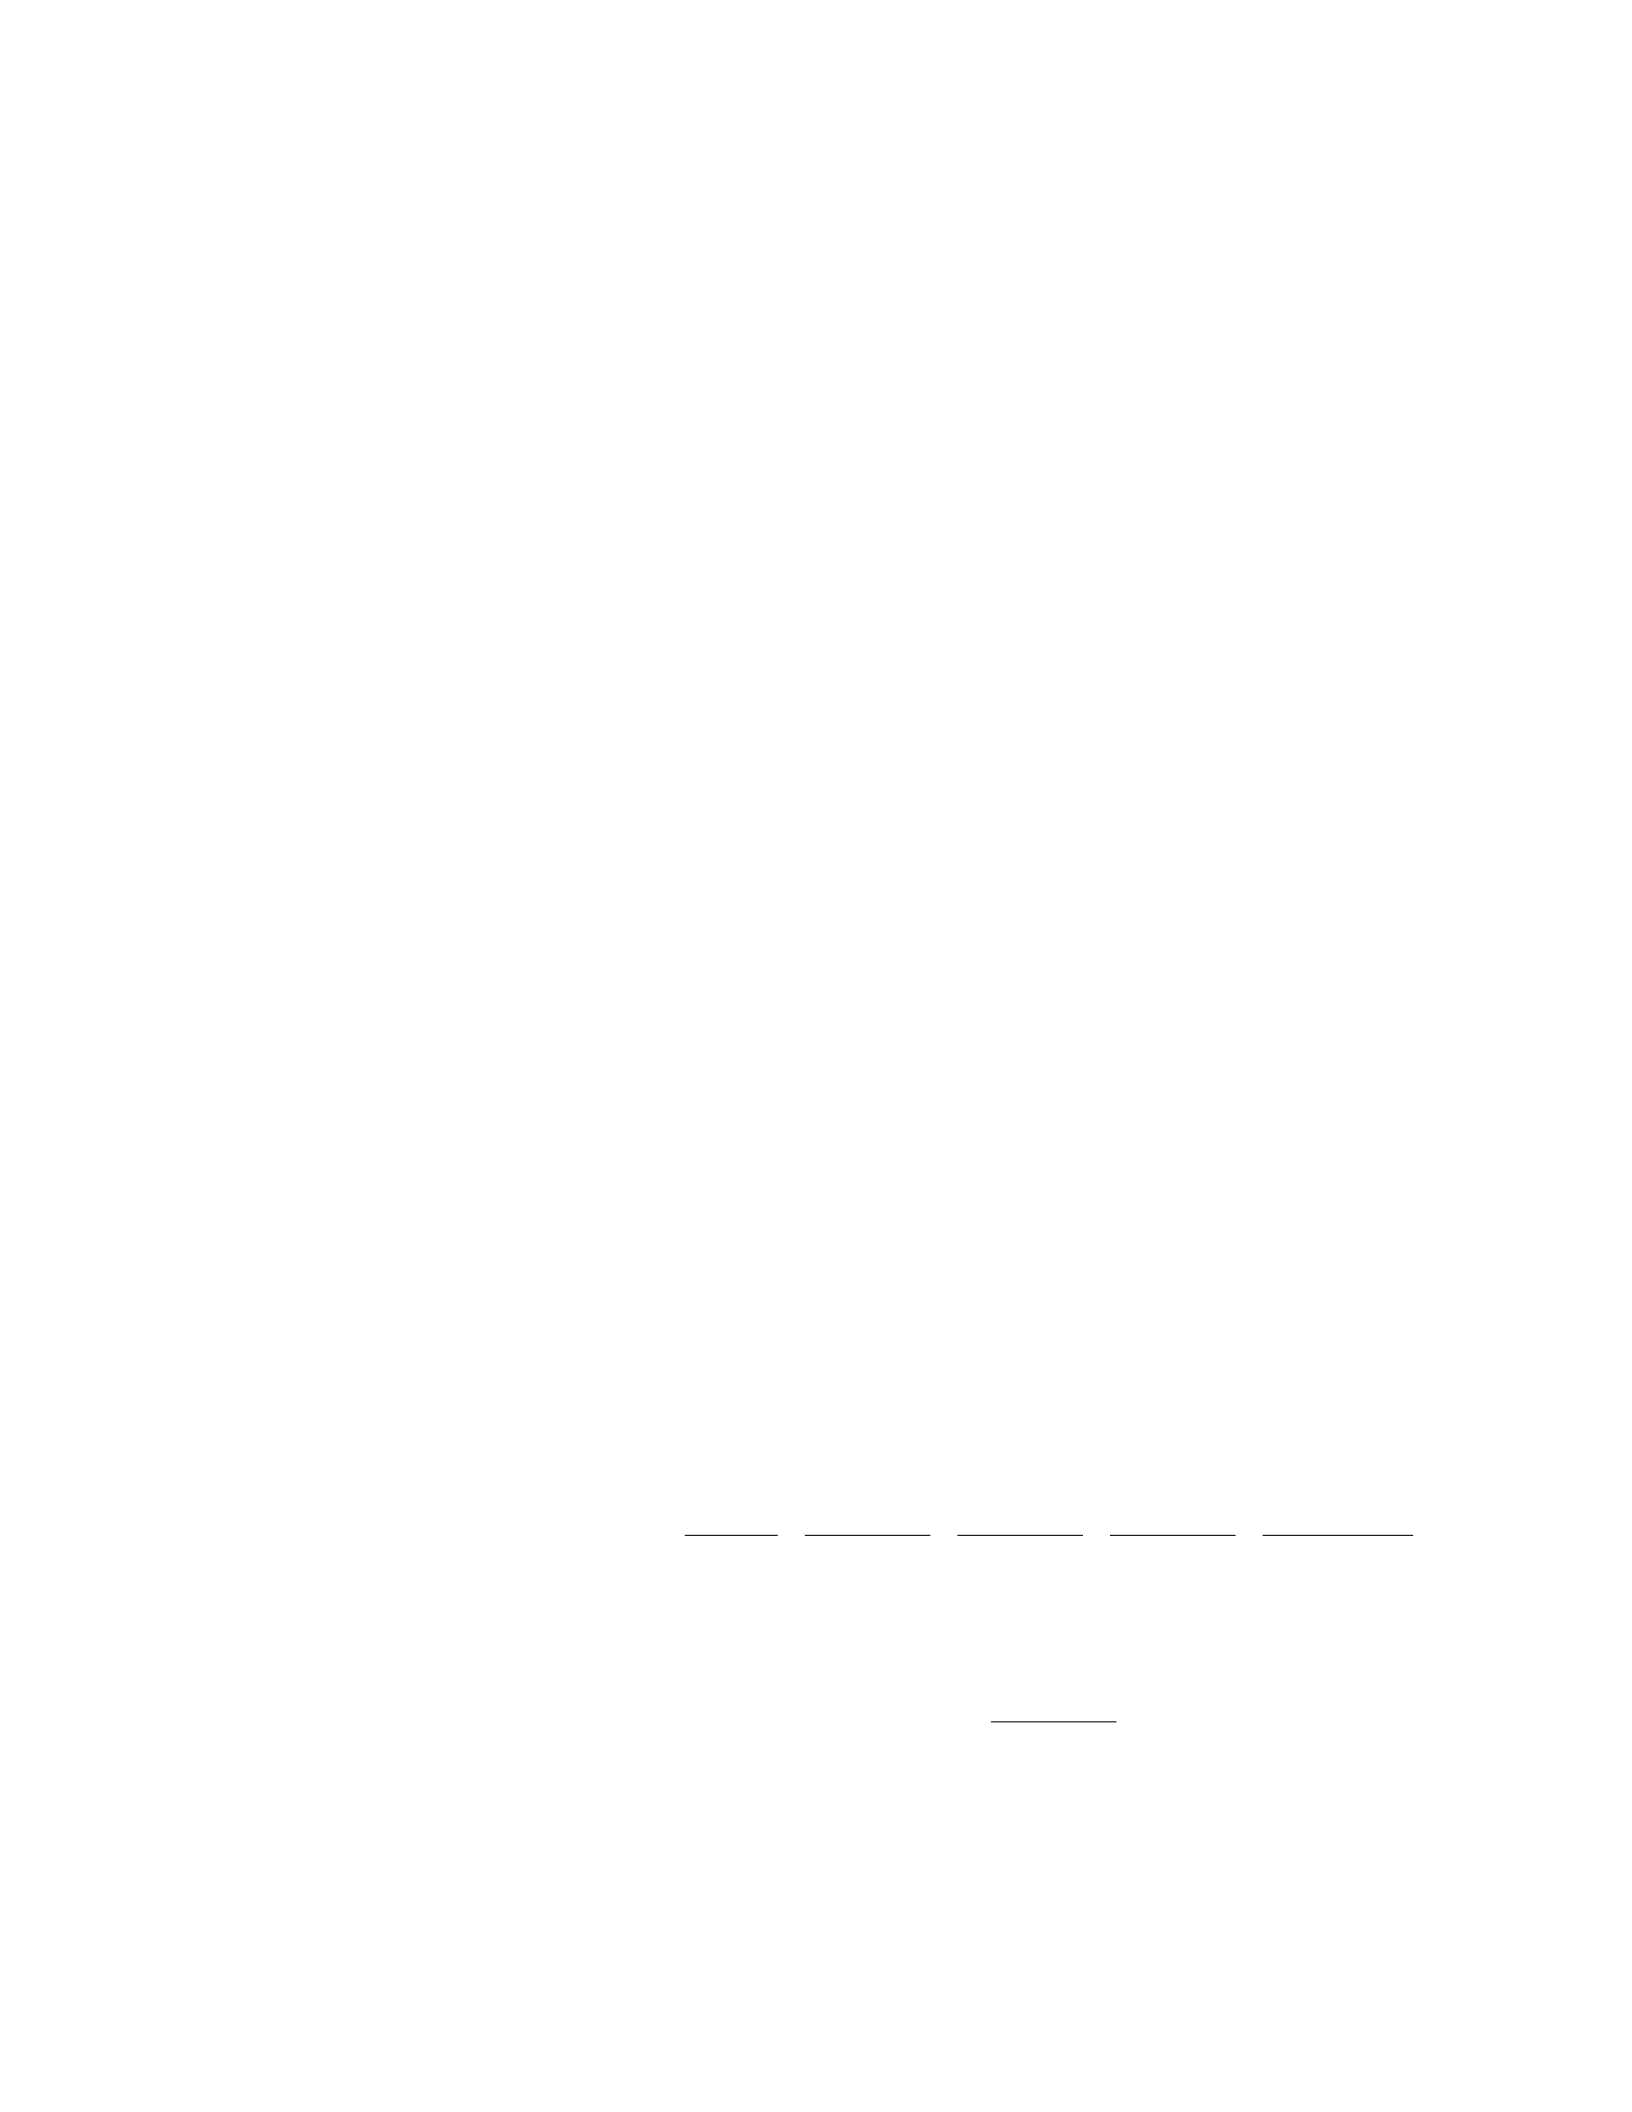
year was 10,000.Duringtheyear, therewereobservablechangesinmarketconditionsthatrequiredanadjustmenttothef airvalueof theinvestment.T hecompany′smanagementestimatedthefairvalueoftheinvestmenttobe8,500
at the end of the year.
Assuming this investment is the only Level 3 fair value measurement the
company holds, calculate the unrealized gain or loss that the company should
recognize in its financial statements at the end of the year.
Solution
Step 1: Calculate the Unrealized Gain/Loss To calculate the unrealized gain or
loss, we compare the fair value of the investment at the end of the year to its
fair value at the beginning of the year.
Given: Fair value of investment at the beginning of the year = 10,000F airvalueof investmentattheendof theyear =8,500
The unrealized gain or loss is calculated as: Unrealized Gain/Loss = Fair
value at end of year - Fair value at beginning of year
Substitute the given values: Unrealized Gain/Loss = 8,500−10,000 Unreal-
ized Gain/Loss = -1,500
Therefore, the company should recognize an unrealized loss of 1,500initsfinancialstatementsattheendoftheyear.
Question 5
Question
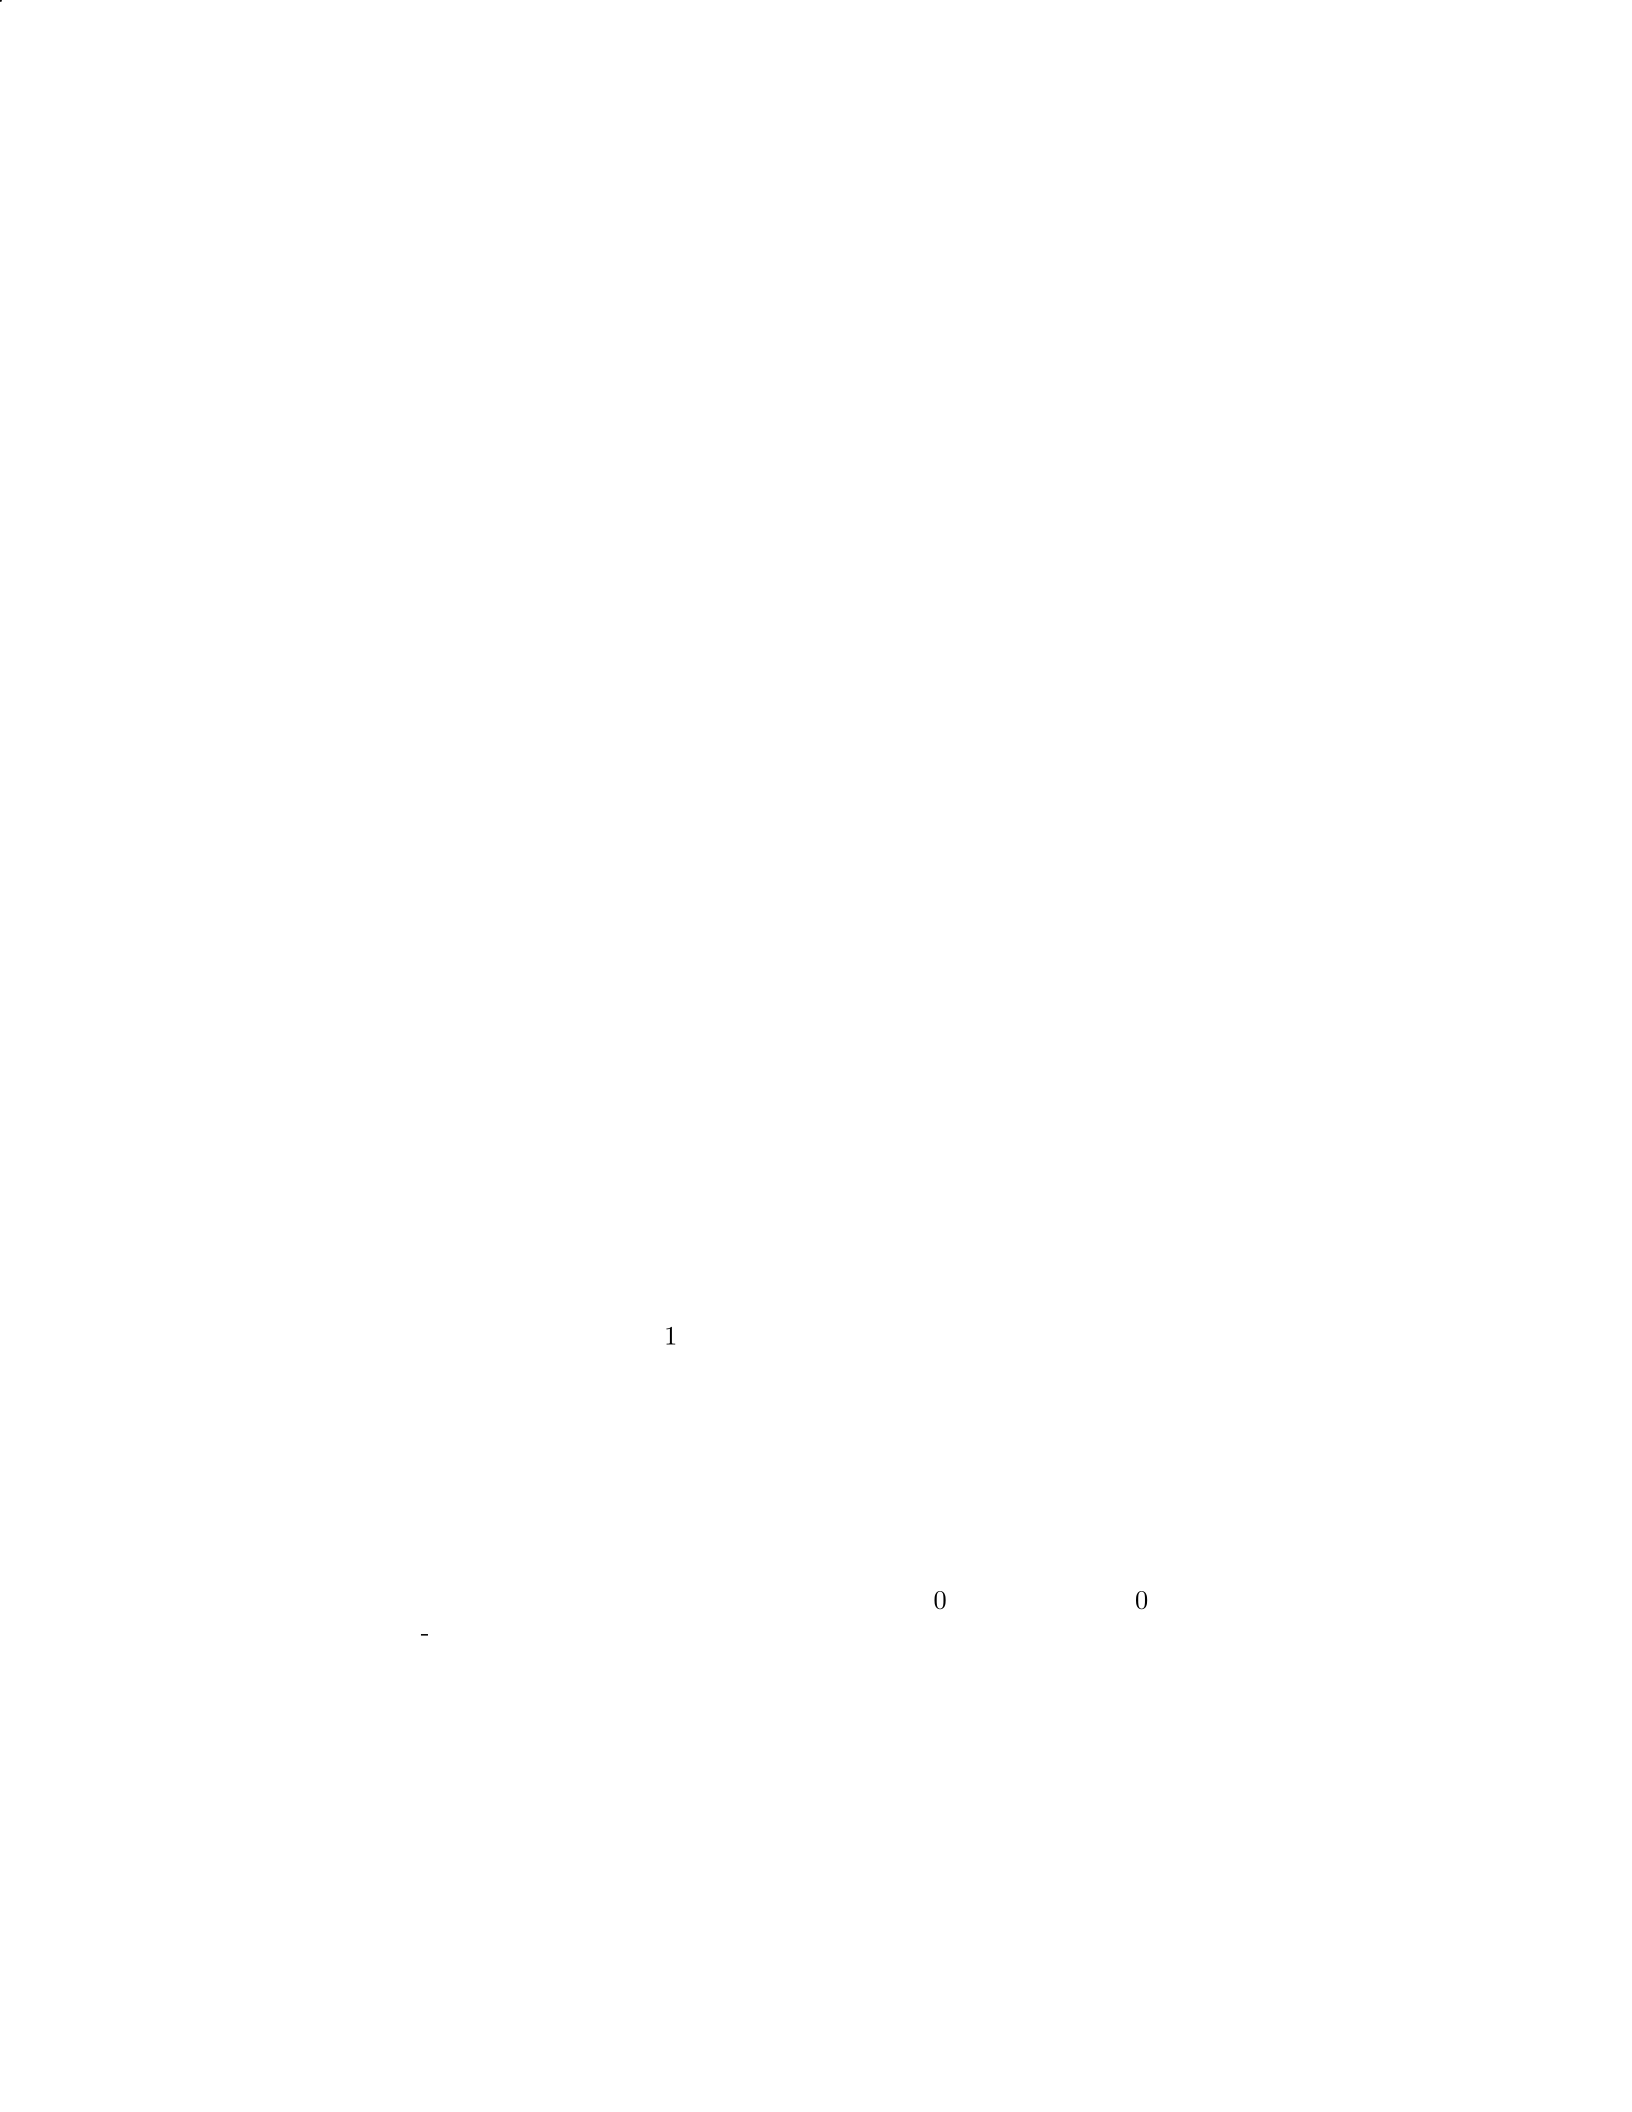
A company holds an investment in a bond with a face value of 10,000thatpaysanannualcouponrateof5
Solution
Step 1: Calculate the annual coupon payment. The annual coupon payment is
calculated as 5
Coupon Payment = 0.05 ×10,000 = 500
Step 2: Determine the present value of the bond’s cash flows. The present
value of the bond’s cash flows consists of the present value of the coupon pay-
ments and the present value of the face value received at maturity. Since the
bond is trading at a yield of 4
The present value of the annual coupon payments can be calculated using
the formula for the present value of an ordinary annuity:
PV of Coupon Payments = 500
1+0.04+500
(1 + 0.04)2+500
(1 + 0.04)3+500
(1 + 0.04)4+500 + 10,000
(1 + 0.04)5
Step 3: Calculate the fair value of the bond. The fair value of the bond is
the sum of the present value of the coupon payments and the present value of
the face value:
Fair Value = PV of Coupon Payments + 10,000
(1 + 0.04)5
Now, perform the calculations to find the fair value of the bond.
4
Question 6
Question
A company owns an investment in equity securities classified as available-for-
sale. The fair value of the investment at the end of the reporting period
is 8,500.T hecompanyinitiallypurchasedtheinvestmentf or7,000. During the
year, the fair value of the investment experienced a decrease of 500.
Calculate the unrealized holding gain/loss that would be reported in other
comprehensive income.
Solution
To calculate the unrealized holding gain/loss, we need to compare the current
fair value of the investment with the initial cost of the investment.
Unrealized Holding Gain/Loss = Fair Value at Reporting Date −Initial Cost
Step 1: Calculate the Unrealized Holding Gain/Loss
Unrealized Holding Gain/Loss = $8,500 −$7,000
= $1,500
However, we need to adjust for the decrease in fair value that occurred during
the year.
Step 2: Adjust for the Decrease in Fair Value
Adjusted Unrealized Holding Gain/Loss = $1,500 −$500
= $1,000
Therefore, the unrealized holding gain/loss that would be reported in other
comprehensive income is
$
1,000.
Question 7
Question
A company is trying to determine the fair value of a financial instrument that
is not actively traded in the market. The company has gathered the following
information: - Expected cash flows: Year 1 =
$
500, Year 2 =
$
700, Year 3 =
$
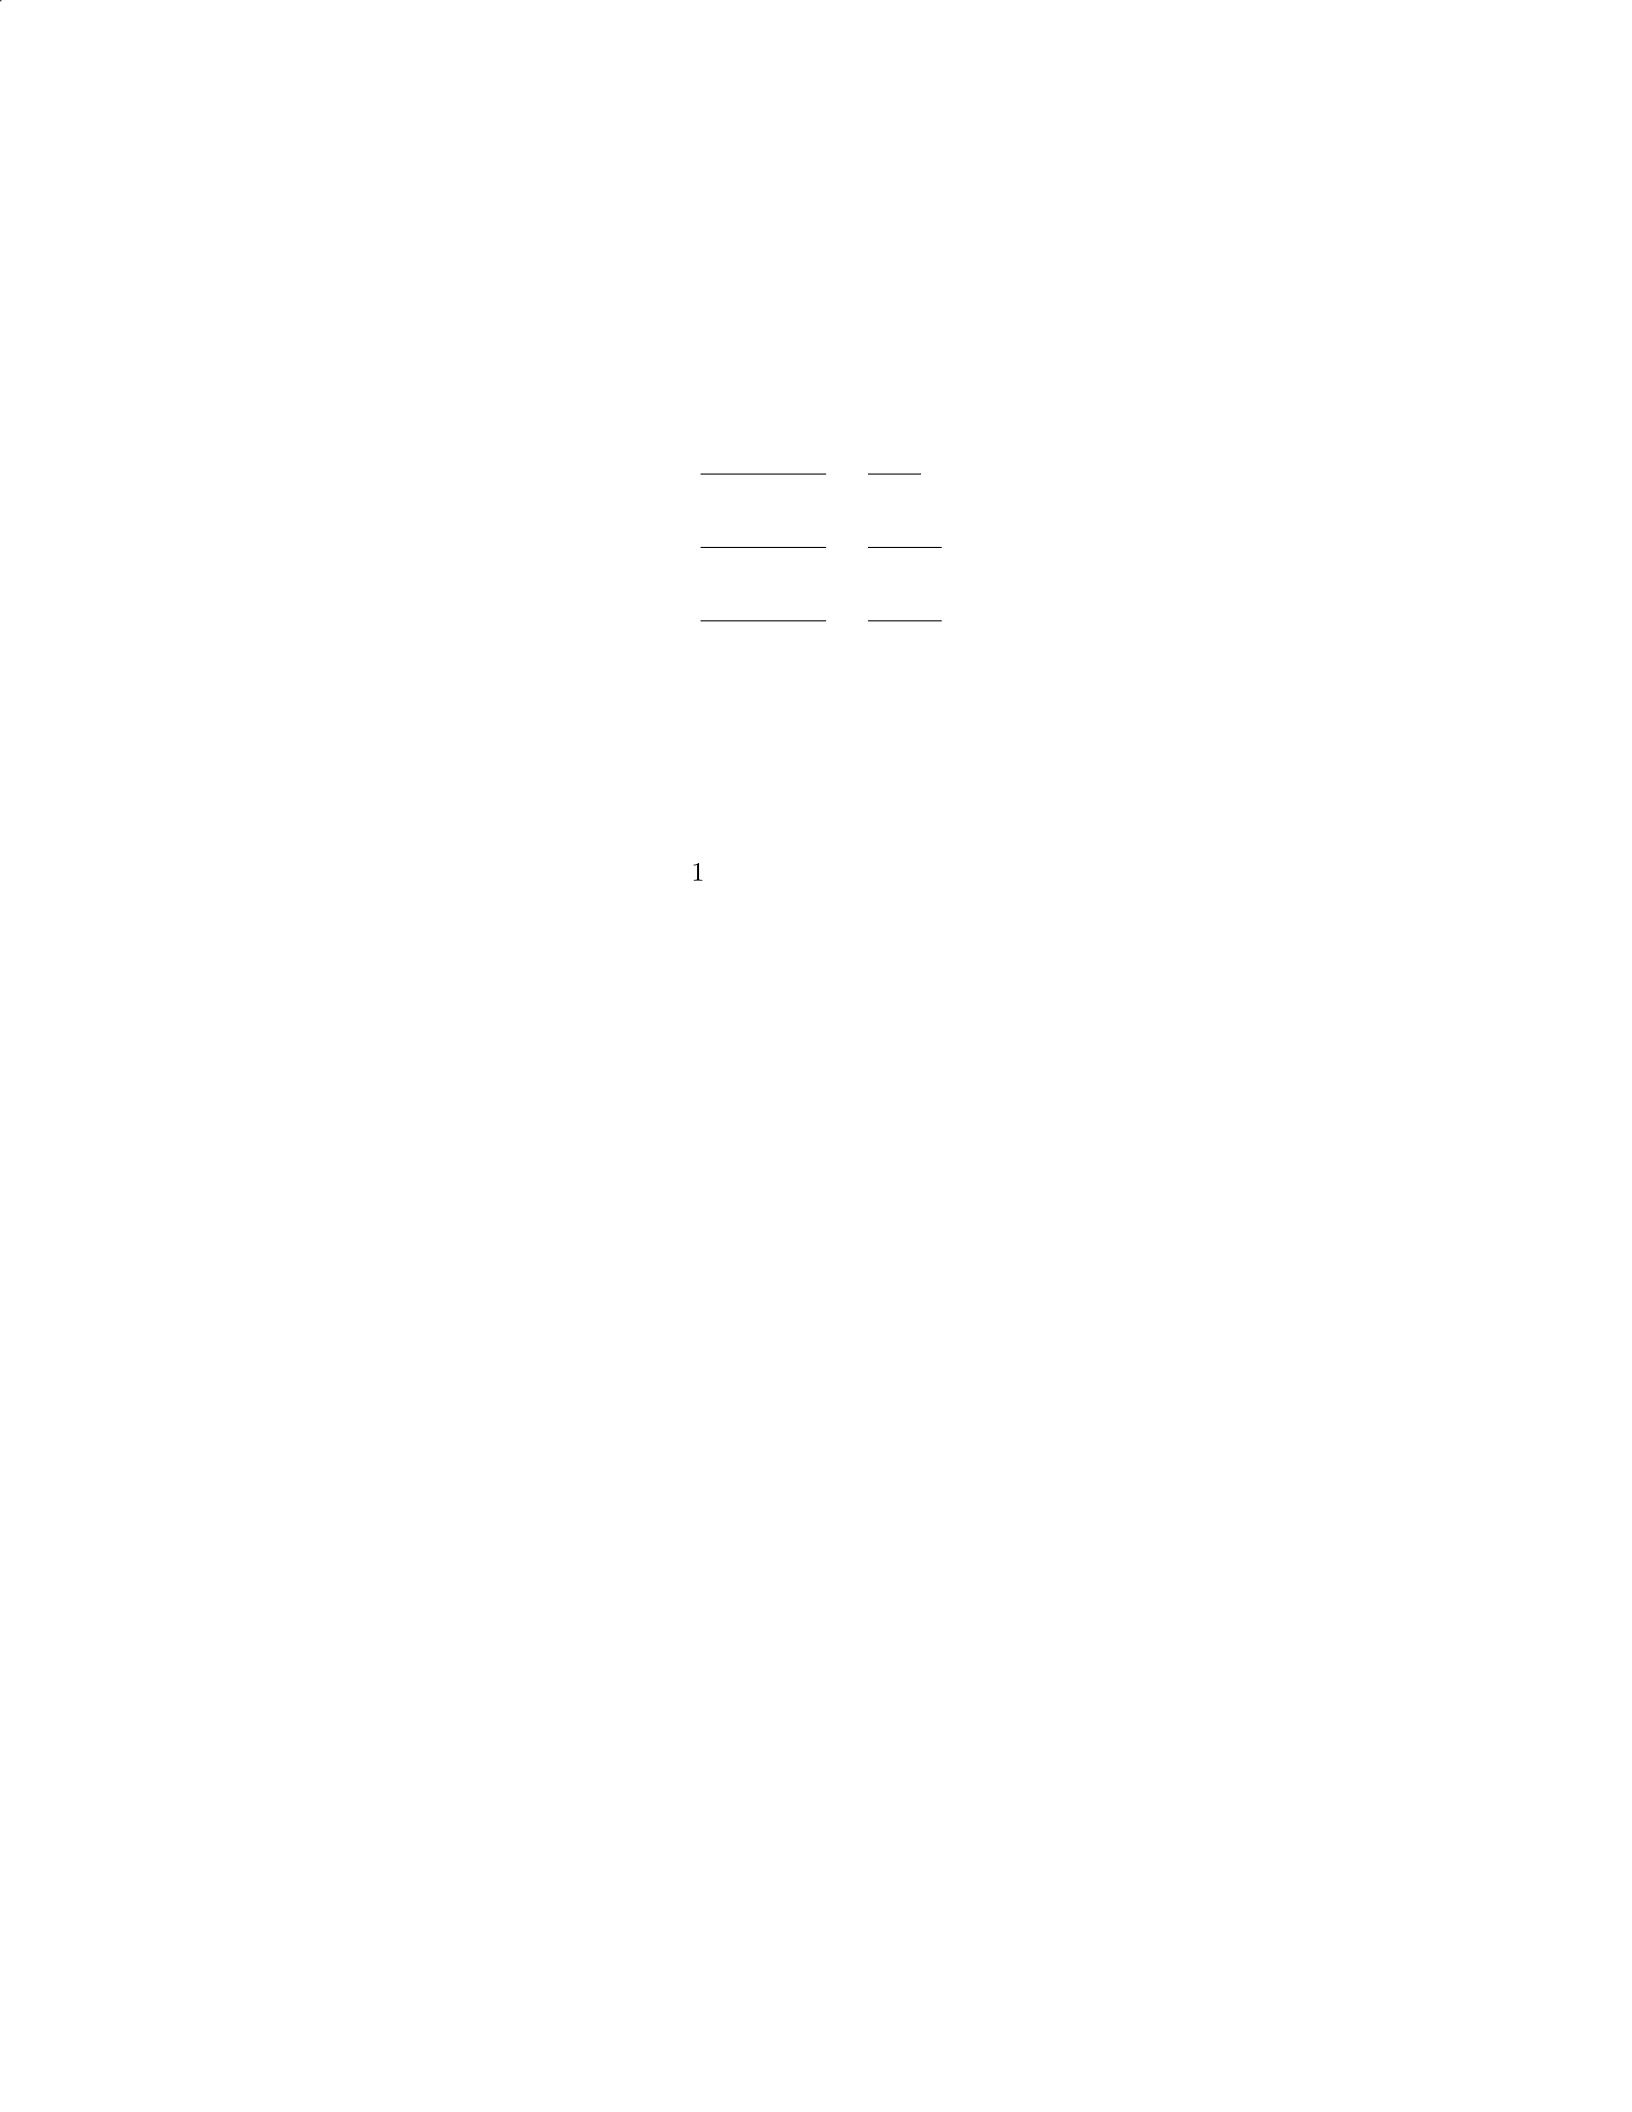
900 - Discount rate = 5Using the present value technique, calculate the fair
value of the financial instrument.
5
Solution
Step 1: Calculate the present value of each cash flow.
PVYear 1 =$500
(1 + 0.05)1=$500
1.05 ≈$476.19
PVYear 2 =$700
(1 + 0.05)2=$700
1.1025 ≈$635.51
PVYear 3 =$900
(1 + 0.05)3=$900
1.1576 ≈$777.23
Step 2: Calculate the fair value of the financial instrument by summing up
the present values of all cash flows.
Fair Value = PVYear 1 +PVYear 2 +PVYear 3 ≈$476.19+$635.51+$777.23 ≈$1888.93
Therefore, the fair value of the financial instrument using the present value
technique is approximately
$
1888.93.
Question 8
Question
A company holds an investment in a financial asset classified as a Level 3 fair
value measurement. At the end of the reporting period, the fair value of the
investment is $150,000, but there is significant uncertainty and lack of reliable
external observable data to support this valuation. The company’s management
is considering applying a weighted average cost method instead of fair value
measurement to value the investment.
Should the company’s management apply the weighted average cost method
instead of fair value measurement in this case? Justify your answer.
Solution
To determine whether the company’s management should apply the weighted
average cost method instead of fair value measurement, we need to consider the
guidance provided in the fair value measurement standard.
Step 1: Understand the fair value measurement framework Ac-
cording to the fair value measurement standard (e.g., IFRS 13 or ASC 820), fair
value is defined as the price that would be received to sell an asset or paid to
transfer a liability in an orderly transaction between market participants at the
measurement date. The standard establishes a three-level hierarchy for inputs
used in measuring fair value: - Level 1 inputs are quoted prices in active markets
for identical assets or liabilities. - Level 2 inputs are observable market data
other than Level 1 inputs. - Level 3 inputs are unobservable inputs.
6

Step 2: Consider the characteristics of Level 3 inputs Level 3 inputs
are unobservable and are used when there is significant uncertainty and lack of
reliable external observable data.
Step 3: Should the weighted average cost method be used? In this
case, the investment is classified as a Level 3 fair value measurement, indicating
the use of unobservable inputs due to significant uncertainty and lack of reliable
external observable data. If the company switches to the weighted average cost
method, it may deviate from the fair value measurement principle and possibly
understate or overstate the investment value.
Step 4: Justification Given the characteristics of the investment being
classified as a Level 3 fair value measurement with significant uncertainty and
lack of reliable external observable data, deviating from fair value measurement
to the weighted average cost method may not accurately reflect the current
market value of the investment. Therefore, the company’s management should
not apply the weighted average cost method in this case to ensure the investment
is fairly valued based on the principles of the fair value measurement standard.
Question 9
Question
A company recently acquired a piece of land for development purposes. The
company determined that the fair value of the land was $500,000 at the ac-
quisition date. Over the next six months, the fair value of the land increased
to $550,000. However, due to market conditions, the fair value dropped to
$480,000 by the end of the year.
Calculate the gain or loss on fair value measurement that the company should
recognize in its financial statements at the end of the year.
Solution
Step 1: Calculate the gain or loss on fair value measurement based on the
information given.
The gain or loss on fair value measurement is calculated as the difference
between the fair value at the end of the reporting period and the fair value at
the acquisition date.
Gain/Loss = Fair value at the end of the reporting period−Fair value at the acquisition date
Step 2: Substitute the values into the formula.
Gain/Loss = $480,000 −$500,000
Gain/Loss = −$20,000
7
Step 3: Analyze the result.
The negative value indicates a loss on fair value measurement. Therefore,
the company should recognize a loss of $20,000 in its financial statements at
the end of the year.
Question 10
Question
Company XYZ holds an investment in a privately held company. The fair
value of the investment needs to be determined for financial reporting purposes.
Company XYZ has gathered the following information about the privately held
company:
- Revenue for the year: 500,000 −Netincomefortheyear :70,000 - Total
assets: 600,000 −T otalliabilities :200,000 - Market capitalization of a similar
publicly traded company: 2,000,000
Using this information, determine the fair value of Company XYZ’s invest-
ment in the privately held company.
Solution
To determine the fair value of Company XYZ’s investment in the privately
held company, we can use the market approach, specifically the guideline public
company method. This method compares the financial metrics of a similar
publicly traded company to estimate the fair value of the private company.
Step 1: Calculate the price-to-earnings (P/E) ratio of the publicly
traded company
P/E ratio =Market capitalization
Net income =
2,000,000 70,000 = 28.57
Step 2: Calculate the estimated value of the privately held com-
pany
Using the P/E ratio calculated in Step 1, we can estimate the value of the
privately held company:
Estimated value =P/E ratio ×N et income = 28.57×
70,000 = 2,000,000
Step 3: Adjust the estimated value for the privately held company
Since the privately held company may have different risk factors or growth
prospects compared to the publicly traded company, we need to make adjust-
ments. For example, if the privately held company is riskier, we may apply a
discount to the estimated value.
Step 4: Determine the fair value of Company XYZ’s investment
8

After making appropriate adjustments, the final estimate represents the fair
value of Company XYZ’s investment in the privately held company.
Question 11
Question
Company XYZ holds a financial asset that is measured at fair value through
other comprehensive income (FVOCI). At the end of the reporting period, the
fair value of the asset is 1,200,000.However, duetotheuncertaintiesinthemarket, thereisasignif icantdecreaseincreditriskoftheasset.T hisdecreaseincreditriskisnotreflectedinthemarketprice.Asaresult, thecompanydecidestoreclassifythefinancialassetfromF V OCItofairvaluethroughprofitorloss(FVTPL).Howshouldthischangeinaccountingtreatmentberecognizedinthef inancialstatementsofCompanyXY Z?
Solution
To reclassify the financial asset from FVOCI to FVTPL, Company XYZ will
need to consider the impact on the financial statements. The change in account-
ing treatment is recognized as follows:
Step 1: Calculate the fair value adjustment for the financial asset due to
the decrease in credit risk.
The fair value adjustment is calculated as the difference between the new
fair value of the asset under FVTPL and the old fair value under FVOCI. In this
case, the fair value under FVTPL is 1,200,000.Let′sassumetheoldf airvalueunderF V OCIwas1,500,000.
Therefore, the fair value adjustment is:
F air V alue Adjustment =F air V alue (FVTPL)−F air V alue (F V OCI) =
1,200,000 - 1,500,000 = −300,000
Step 2: Record the fair value adjustment in the statement of profit or loss.
The fair value adjustment of 300,000shouldberecognizedasalossinthestatementofprof itorloss.T hislossrepresentsthedecreaseincreditriskthatwasnotref lectedinthemarketpriceof theasset.
Step 3: Reclassify the financial asset on the statement of financial position.
The financial asset should be reclassified from FVOCI to FVTPL on the
statement of financial position. The asset will now be presented at its fair value
of 1,200,000, withanysubsequentchangesinf airvaluerecordedinprofitorloss.
In summary, the change in accounting treatment from FVOCI to FVTPL
for the financial asset should be recognized by recording a fair value adjustment
as a loss in the statement of profit or loss and reclassifying the asset on the
statement of financial position.
Question 12
Question
A company holds a financial asset that is classified as a Level 3 fair value mea-
surement. The fair value of the asset increased by 10
9

Solution
Step 1: Implications on Financial Statements When the fair value of a
Level 3 financial asset increases, the company will recognize a gain in its in-
come statement. This gain affects the company’s net income and can lead to
an increase in reported profits, which may positively impact the perception of
the company’s financial performance by investors and stakeholders. Addition-
ally, the increase in fair value will also impact the company’s balance sheet by
increasing the value of the financial asset held, leading to an increase in total
assets and potentially improving key financial ratios such as return on assets.
Step 2: Challenges of Measuring Level 3 Fair Value Assets Level
3 assets are those whose fair value cannot be directly observed in the market
and require significant management judgment and estimation. Therefore, there
are several challenges associated with measuring the fair value of Level 3 as-
sets, including: - Lack of market data: Limited market activity or absence of
comparable transactions can make it difficult to determine the fair value ac-
curately. - Subjectivity in assumptions: The valuation of Level 3 assets often
involves making subjective assumptions about future cash flows, discount rates,
and other relevant factors, leading to potential bias in the reported fair value. -
Sensitivity to changes: Level 3 assets are typically more sensitive to changes in
assumptions and market conditions, which can result in significant fluctuations
in fair value and impact financial statements unpredictably. - Audit scrutiny:
Given the inherent subjectivity and complexity of valuing Level 3 assets, au-
ditors may need to exercise greater scrutiny over the methodologies used and
inputs applied, leading to additional time and cost in the audit process.
In conclusion, while an increase in the fair value of Level 3 assets can
have positive effects on a company’s financial statements, the challenges as-
sociated with measuring and valuing such assets highlight the importance of
transparency, disclosure, and robust internal controls in fair value measurement
processes.
Question 13
Question
A company holds an investment in a privately held company that is classified as
a Level 3 fair value asset. The fair value of the investment is determined using
a discounted cash flow model. The company uses unobservable inputs such as
projected revenue growth rates, discount rates, and terminal values to estimate
the fair value of the investment.
Discuss the challenges and potential issues that could arise in fair value
measurement for this investment.
10
Solution
To determine the fair value of an investment in a privately held company using
a discounted cash flow model with unobservable inputs, several challenges and
potential issues may arise. These challenges can impact the accuracy and reli-
ability of the fair value measurement. Some of the key challenges are outlined
below:
Step 1: Lack of market data
Valuing privately held companies involves the use of assumptions and es-
timates since market data may not be readily available.
The absence of comparable market transactions can make it difficult to
validate the assumptions used in the discounted cash flow model.
Step 2: Unobservable inputs
Unobservable inputs like projected revenue growth rates and discount rates
may heavily influence the fair value estimate.
The subjective nature of these inputs can lead to biases and errors in the
valuation process.
Step 3: Complexity of the model
The discounted cash flow model used to estimate the fair value of the
investment may be complex with multiple variables and assumptions.
Errors in estimating any of the inputs can have a significant impact on
the final fair value calculation.
Step 4: Sensitivity to changes
The fair value estimate is sensitive to changes in key assumptions such as
revenue growth rates and discount rates.
Small variations in these inputs can lead to substantial fluctuations in the
final fair value measurement.
Step 5: Management bias
There is a risk of management bias in selecting assumptions that may
result in a higher or lower fair value estimate.
Objectivity is crucial to ensure that fair value measurements are free from
bias and reflect economic reality accurately.
It is important for companies to be transparent about the methodologies and
assumptions used in fair value measurements, as well as to regularly reassess and
validate these inputs to enhance the reliability of the fair value estimates.
11

Question 14
Question
A company owns an investment property which is measured at fair value. At the
end of the fiscal year, the fair value of the property has decreased compared to
the previous period. Explain how the company should account for this change
in fair value.
Solution
To account for a decrease in fair value of an investment property, the company
should follow the guidelines outlined in the fair value measurement standard.
Below are the steps the company should take:
Step 1: Determine the reason for the decrease in fair value. It could be due
to changes in market conditions, property location, or potential obsolescence.
Step 2: Assess whether the decrease in fair value is temporary or perma-
nent. This distinction is important as the accounting treatment differs for each
scenario.
Step 3: If the decrease in fair value is considered temporary, no adjustment
is necessary to the carrying amount of the investment property.
Step 4: If the decrease in fair value is considered permanent, the company
should recognize an impairment loss in its financial statements.
Step 5: Calculate the impairment loss by comparing the carrying amount of
the investment property with its recoverable amount. The recoverable amount
is the higher of the property’s fair value less costs to sell and its value in use.
Step 6: Recognize the impairment loss in the income statement as an ex-
pense. The carrying amount of the investment property should be reduced by
the impairment loss amount.
Step 7: Make appropriate disclosures in the financial statements regarding
the impairment loss and its impact on the company’s financial position.
By following these steps, the company can properly account for a decrease
in fair value of its investment property and reflect this change in its financial
statements.
Question 15
Question
Company XYZ holds an investment in a startup that is not publicly traded.
The fair value of the investment needs to be assessed for financial reporting
purposes. Provide three specific techniques that can be used to determine the
fair value of this non-publicly traded investment.
12

Solution
To determine the fair value of a non-publicly traded investment, several tech-
niques can be used. Here are three specific techniques:
Step 1: Market Approach One technique is to use the market approach,
which involves comparing the investment to similar investments that are publicly
traded. This can be done by looking at comparable companies in the same
industry or sector and using their market prices to estimate the fair value of the
investment.
Step 2: Income Approach Another technique is the income approach,
which involves estimating the future cash flows that the investment is expected
to generate and discounting them back to present value. This method relies on
the premise that the fair value of an investment is based on the present value
of its expected future cash flows.
Step 3: Cost Approach The third technique is the cost approach, which
involves determining the cost to replace the investment or reproduce its benefits.
This method may involve assessing the cost of acquiring or developing a similar
investment in the current market environment.
These three techniques – market approach, income approach, and cost ap-
proach – provide different perspectives for determining the fair value of a non-
publicly traded investment.
It is important to note that the choice of technique will depend on various
factors such as the nature of the investment, availability of information, and the
specific circumstances surrounding the investment.
Question 16
Question
A company is required to measure the fair value of its investments in designated
equity securities. The fair value of these investments is determined using Level
3 inputs. Explain what Level 3 inputs are and provide examples.
Solution
Step 1: Level 3 inputs are unobservable inputs that are used in fair value mea-
surements. These inputs are based on the best information available, considering
the assumptions that market participants would make. Level 3 inputs are used
when observable market data is not available.
Step 2: Examples of Level 3 inputs include: - Company-specific data, such
as financial projections and internal valuations - Discounted cash flow models
that require significant judgment and estimation - Option pricing models where
inputs are based on unobservable data - Inputs based on recent transactions
involving similar assets but with adjustments to reflect differences
Step 3: In the case of the company measuring the fair value of its invest-
ments in designated equity securities using Level 3 inputs, it implies that the
13

fair value is determined using significant judgment and estimation due to the
lack of observable market data. This could involve using internal models and
assumptions to arrive at a reasonable estimate of the investments’ fair value,
considering factors such as market conditions, industry trends, and the specific
characteristics of the investments.
Question 17
Question
Company XYZ holds an investment in a private company that is accounted for
at fair value through profit or loss. The fair value of the private company’s
investment was determined using unobservable inputs such as discounted cash
flow analysis and comparable company analysis.
Explain the key considerations and challenges in measuring the fair value of
this investment using Level 3 inputs according to the fair value hierarchy.
Solution
To measure the fair value of an investment using Level 3 inputs (unobservable
inputs), several key considerations and challenges arise.
Step 1: Existence of Unobservable Inputs - Level 3 inputs are not
readily observable in the market and require significant judgment and estimation
in determining fair value. - In this case, the discounted cash flow analysis and
comparable company analysis are considered unobservable inputs as they involve
subjective estimates and assumptions.
Step 2: Reliability and Credibility of Inputs - The reliability and cred-
ibility of unobservable inputs are crucial when measuring fair value. - There is a
risk of bias or manipulation in estimating inputs like cash flows or selecting com-
parable companies, which could lead to a misrepresentation of the investment’s
fair value.
Step 3: Sensitivity to Assumptions - Level 3 measurements are highly
sensitive to changes in assumptions and estimates. - Small variations in discount
rates, growth projections, or selection of comparable companies can result in
significant fluctuations in the fair value of the investment.
Step 4: Transparency and Disclosures - Due to the subjectivity involved
in Level 3 measurements, it is important to provide transparent disclosures
about the valuation techniques, key assumptions, and uncertainties. - This
helps stakeholders understand the basis for the fair value measurement and
assess the reliability of the reported figures.
Step 5: Independent Verification - Given the complexity and subjectiv-
ity of Level 3 inputs, obtaining an independent valuation from a qualified third
party can enhance the credibility of the fair value measurement. - Indepen-
dent verification provides assurance to stakeholders that the fair value has been
determined objectively and in accordance with established valuation principles.
14

In conclusion, measuring the fair value of an investment using Level 3 inputs
poses challenges related to the reliability of unobservable inputs, sensitivity to
assumptions, transparency in reporting, and the need for independent verifica-
tion. It is essential for companies to exercise prudence and diligence in ensuring
the accuracy and integrity of fair value measurements for Level 3 assets.
Question 18
Question
Company XYZ holds an investment in a publicly traded stock. At the end of the
reporting period, the fair value of the stock is 172.50pershare.However, thecompany′smanagementbelievesthatduetorecentmarketevents, thef airvalueshouldbeadjustedto165.80
per share. If Company XYZ uses a Level 1 fair value measurement hierarchy,
determine the implications of this adjustment on the company’s financial state-
ments.
Solution
1. Since the fair value adjustment pertains to a Level 1 fair value measurement
hierarchy, it implies that the fair value adjustment should be recognized in the
income statement.
2. The fair value adjustment on the investment in the publicly traded stock
will result in a decrease in the fair value of the asset.
3. The decrease in the fair value of the investment will lead to a loss being
recognized in the income statement for the reporting period.
4. The loss from the fair value adjustment will decrease the net income of
Company XYZ for the reporting period.
5. The decrease in net income may impact the company’s profitability ratios
and financial performance indicators.
6. Additionally, the fair value adjustment will also impact the company’s
balance sheet, specifically the carrying amount of the investment in the publicly
traded stock.
7. The adjusted fair value of the investment in the stock will be reported
on the balance sheet as a lower carrying amount, reflecting the decrease in fair
value.
8. The fair value adjustment will be disclosed in the notes to the financial
statements, providing transparency to stakeholders regarding the change in fair
value and its impact on the financial position and performance of Company
XYZ.
Overall, the adjustment of the fair value of the investment in the publicly
traded stock to 165.80persharewillresultinalossbeingrecognizedintheincomestatement, impactingthecompany′sfinancialstatementsandfinancialmetrics.
15

Question 19
Question
A company holds an investment in a financial asset classified as Level 3 fair
value measurement. At the end of the reporting period, the fair value of the
investment decreased significantly compared to its carrying amount. Explain
how this decrease in fair value impacts the company’s financial statements and
provide examples of the disclosures required under IFRS 13 for Level 3 fair value
measurements.
Solution
Step 1: When the fair value of a Level 3 financial asset decreases significantly, it
will result in an impairment loss on the investment. This impairment loss needs
to be recognized in the company’s income statement as a separate line item to
reflect the decrease in value.
Step 2: The impairment loss will also impact the carrying amount of the
financial asset on the balance sheet. The carrying amount will be reduced to
the new fair value after recognizing the impairment loss.
Step 3: Under IFRS 13, for Level 3 fair value measurements, the following
disclosures are required: - A description of the valuation technique(s) used to
determine fair value. - The significant unobservable inputs used in the valuation.
- A quantitative sensitivity analysis showing how changes in unobservable inputs
would impact fair value. - The amounts of any transfers between Level 1, Level
2, and Level 3 fair value measurements. - For recurring fair value measurements,
the amount of any unrealized gains or losses recognized in profit or loss. - For
nonrecurring fair value measurements (such as impairment losses), the reasons
for the measurement.
Overall, a decrease in fair value for a Level 3 financial asset will lead to
recognition of an impairment loss in the income statement, a reduction in the
carrying amount on the balance sheet, and additional disclosures in the financial
statements to provide transparency and understanding to users.
Question 20
Question
A company holds an investment property at fair value and reports changes in fair
value in profit or loss. During the current year, the fair value of the investment
property increased by 15%. However, the company later found out that there
was an error in the valuation model used to determine the fair value, which
resulted in an overstatement of the fair value by 10%. How should the company
correct this error in its financial statements?
16

Solution
1. Calculate the Corrected Fair Value: Given that the fair value of the
investment property increased by 15% but was overstated by 10%, the corrected
fair value is obtained by adjusting the reported fair value. Let the original fair
value be F V . The overstated fair value is 1.10F V , and the actual fair value
increase is 1.15F V . Hence, the corrected fair value is 1.15F V −0.10F V =
1.05F V .
2. Recognize Correction of Error in Financial Statements: The
correction of the error in the valuation model should be treated retrospectively in
the financial statements. The overstatement of the fair value should be reversed
and adjusted for in the current year’s financial statements as an error correction.
3. Adjust the Financial Statements: To correct the error in the financial
statements: - Decrease the investment property value by 10% to reflect the
corrected fair value. - Reverse the impact of the overstatement in the profit or
loss for the current year.
4. Disclosures in the Financial Statements: The company should dis-
close the nature of the error, the impact on the financial statements, and the
corrections made in the notes to the financial statements. These disclosures
ensure transparency and clarity for users of the financial statements.
Therefore, the company should correct the error in the fair value measure-
ment by adjusting the reported fair value downwards by 10% to reflect the
corrected fair value in the financial statements.
Question 21
Question
Company X holds an investment in a private equity fund. At the end of the
reporting period, Company X needs to determine the fair value of this invest-
ment. Describe the steps the company should follow to measure the fair value
of this investment according to the Fair Value Measurement standard.
Solution
To measure the fair value of the investment in the private equity fund, Company
X should follow the steps outlined in the Fair Value Measurement standard.
These steps are as follows:
Step 1: Identify the Asset or Liability
In this case, the asset to be measured is the investment in the private equity
fund.
Step 2: Determine the Principal (or Most Advantageous) Market
Company X needs to determine whether there is an active market for the
private equity fund’s interest and the principal market on which the asset would
be exchanged. If there is an active market, the fair value is the quoted market
price. If not, move on to the next step.
17

Step 3: Consider Market Conditions
If there is no active market, Company X needs to consider market conditions
and the specific circumstances of the investment to determine the fair value.
Step 4: Use Valuation Techniques
In the absence of an active market, Company X should use valuation tech-
niques such as discounted cash flow analysis, comparable company analysis, or
precedent transactions to estimate the fair value of the investment.
Step 5: Verify the Assumptions
Company X should verify the key assumptions used in the valuation tech-
niques and make adjustments if necessary.
Step 6: Apply Discounts or Premiums
Depending on the specific characteristics of the private equity fund, discounts
or premiums may need to be applied to the valuation to reflect illiquidity, lack
of control, or other factors.
Step 7: Document the Fair Value Measurement
Lastly, Company X should thoroughly document the fair value measurement
process, including the techniques used, key assumptions made, discounts or
premiums applied, and any other relevant information.
By following these steps outlined in the Fair Value Measurement standard,
Company X can accurately determine the fair value of its investment in the
private equity fund.
Question 22
Question
A company holds a financial asset that is measured at fair value through profit or
loss. The fair value of the asset at the beginning of the year was 10,000.Duringtheyear, thefairvalueincreasedto12,000.
At the end of the year, the fair value decreased to 11,000.T hecompanyreceived800
in dividends related to the financial asset during the year. Calculate the gain
or loss recognized in profit or loss for the year.
Solution
Step 1: Calculate the gain or loss when the fair value increased from 10,000to12,000.
Gain in value = New fair value −Initial fair value
Gain in value = $12,000 −$10,000 = $2,000
Step 2: Calculate the gain or loss when the fair value decreased from 12,000to11,000.
Loss in value = Initial fair value −End fair value
Loss in value = $12,000 −$11,000 = $1,000
Step 3: Calculate the net gain or loss for the year.
Net gain or loss = Gain in value −Loss in value + Dividends
18
Net gain or loss = $2,000 −$1,000 + $800 = $1,800
Therefore, the gain recognized in profit or loss for the year is 1,800.
Question 23
Question
A company holds an investment in a financial instrument classified as Level 2 un-
der the fair value hierarchy. At the end of the reporting period, the market price
of the financial instrument is 60pershare.T hecompany′sinternalestimateofthefairvalueis58
per share. If the inputs used to determine the fair value of the financial instru-
ment are observable in the market, what factors should the company consider
in determining the fair value measurement?
Solution
1. Step 1: Understand Fair Value Measurement
Fair value measurement is the process of determining the price that would
be received to sell an asset or paid to transfer a liability in an orderly
transaction between market participants at the measurement date.
2. Step 2: Consider Factors in Fair Value Measurement
When determining the fair value measurement of a financial instrument,
the company should consider the following factors:
The nature and characteristics of the financial instrument.
The condition and location of the financial markets where the finan-
cial instrument is traded.
The availability and reliability of inputs used in the valuation process.
The level of comparability between the company’s estimate and ob-
servable market prices.
The degree of judgment involved in the valuation process.
The risk and uncertainty associated with the financial instrument.
3. Step 3: Apply to the Given Scenario
In the given scenario, since the inputs used to determine the fair value of
the financial instrument are observable in the market, the company should
carefully consider the factors mentioned above. This includes assessing
the reliability of the observable market prices, evaluating the nature of
the financial instrument, and considering any risks or uncertainties that
may affect the valuation.
19
Question 24
Question
Assume a company holds an investment in a highly volatile stock. The fair
value of the stock at the end of the year is
$
150 per share. The company’s
management believes that the fair value calculation is inappropriate due to the
high volatility of the stock price. As a result, they are considering using a
valuation model that takes into account the expected cash flows associated with
the stock. If the expected cash flows for the stock are estimated to be
$
10 per
share for the next 5 years, with no residual value at the end of the 5 years, what
should be the fair value of the stock according to this valuation model? The
discount rate is 8%.
Solution
Step 1: Calculate the present value of the expected cash flows using the dis-
counted cash flow (DCF) method. The formula for calculating the present value
of a series of cash flows is:
P V =CF1
(1 + r)1+CF2
(1 + r)2+... +CFn
(1 + r)n
Where: - PV = Present Value - CF = Cash Flow - r = Discount Rate - n =
Number of periods
In this case, the cash flows are
$
10 per share for the next 5 years, and the
discount rate is 8%.
P V =10
(1 + 0.08)1+10
(1 + 0.08)2+10
(1 + 0.08)3+10
(1 + 0.08)4+10
(1 + 0.08)5
P V =10
1.08 +10
1.1664 +10
1.2597 +10
1.3605 +10
1.4693
P V ≈9.26 + 8.57 + 7.94 + 7.35 + 6.79
P V ≈39.91
Step 2: Calculate the fair value of the stock. Since there is no residual value
at the end of the 5 years, the fair value is equal to the present value of the
expected cash flows.
Therefore, the fair value of the stock according to this valuation model is
approximately
$
39.91 per share.
20
Question 25
Question
A company purchased a piece of land for
$
500,000 in 2010. Due to an increase in
demand and development in the area, the fair value of the land was determined
to be
$
800,000 at the end of 2015. In 2017, the company decided to sell the land,
and the fair value was determined to be
$
750,000. Calculate the gain or loss on
the sale of the land, assuming the company uses fair value as its measurement
basis for non-financial assets.
Solution
Step 1: Calculate the carrying amount of the land in 2017. The carrying amount
of the land is the original cost plus any subsequent adjustments to fair value.
Carrying amount in 2017 = Cost + (Fair value at end of 2015 - Cost) =
$
500,000
+ (
$
800,000 -
$
500,000) =
$
500,000 +
$
300,000 =
$
800,000
Step 2: Determine the gain or loss on the sale.
If fair value at the time of sale is greater than the carrying amount, it is
a gain.
If fair value at the time of sale is less than the carrying amount, it is a
loss.
In this case, the fair value at the time of sale is
$
750,000, which is less than
the carrying amount of
$
800,000.
Step 3: Calculate the loss on the sale. Loss on sale = Carrying amount -
Fair value at time of sale =
$
800,000 -
$
750,000 =
$
50,000
Therefore, the company will incur a loss of
$
50,000 on the sale of the land.
Question 26
Question
Company XYZ holds an investment property that it plans to sell in the future.
The property is currently valued at 900,000basedonitsfairvalue.Duringtheyear, theproperty′svalueincreasedby10
Solution
Step 1: Calculate the increase in value of the investment property. Let the
current fair value of the investment property be Vcurrent = $900,000. The
increase in value is given as 10
Increase in value = 10% ×$900,000 = $90,000
21

Step 2: Determine the new fair value of the investment property. The new
fair value will be the current value plus the increase in value:
Vnew =Vcurrent + Increase in value = $900,000 + $90,000 = $990,000
Therefore, the new fair value of the investment property after the 10
Question 27
Question
On December 31, 20X7, Company A purchased an investment in Company B for
350,000.T hefairvalueof theinvestmentatDecember31,20X8, wasassessedtobe380,000.
Company A intends to hold the investment for the long term. Prepare the nec-
essary journal entry to record the fair value adjustment and explain how the
fair value measurement affects the financial statements.
Solution
Step 1: Calculate the fair value adjustment: The fair value adjustment is equal
to the difference between the fair value of the investment at December 31, 20X8,
and the initial cost of the investment. Fair value adjustment = 380,000−350,000
= 30,000
Step 2: Prepare the journal entry: The journal entry to record the fair value
adjustment is as follows:
Investment in Company B30,000
Fair Value Adjustment30,000
Step 3: Explain how the fair value measurement affects the financial state-
ments: - The fair value adjustment entry increases the Investment in Company B
account by 30,000.−T heF airV alueAdjustmentaccountisusedtocapturechangesinthefairvalueof theinvestment.−
T hefairvalueadjustmentaffectstheincomestatementasitrepresentseitheragainorlossontheinvestment.−
T hefairvalueadjustmentalsoaf fectsthebalancesheetasitchangesthecarryingamountof theinvestment.−
Overall, thef airvaluemeasurementprovidesmorerelevantinformationaboutthevalueof theinvestmentcomparedtohistoricalcost, asitreflectscurrentmarketconditions.
Question 28
Question
ABC Company is required to determine the fair value of an investment prop-
erty as of December 31, 2021. The property is a commercial building that
is currently being rented out to a tenant. ABC Company obtained the fol-
lowing information regarding the property: - The property was purchased for
1,500,000onJanuary1,2020.−T hepropertyhasaremainingusef ullifeof50years.−
Comparablepropertiesintheareaaresellingforanaveragepriceof1,750,000. - The
22
tenant is locked into a long-term lease with below-market rent. Using the cost
approach, income approach, and market approach, calculate the fair value of
the investment property as of December 31, 2021.
Solution
Step 1: Cost Approach
The cost approach determines the fair value of an asset by considering the
cost to replace or reproduce the asset.
Since the property was purchased for 1,500,000, wecanusethisasthebasisforthecostapproachvaluation.AsofDecember31,2021, thepropertyhasbeenownedfor2years.
Using straight-line depreciation, the annual depreciation would be 1,500,000
50 =30,000.
Accumulated depreciation as of December 31, 2021: 30,000 ×2 =60,000.
Property value using the cost approach: 1,500,000 −60,000 =1,440,000.
Step 2: Income Approach
The income approach values an asset based on the present value of the
future cash flows it is expected to generate.
Given that the tenant is paying below-market rent, the current rental
income may not be reflective of the property’s true value.
Adjustments must be made to estimate the potential rental income the
property could generate.
Once the potential rental income is determined, it can be discounted back
to present value using an appropriate discount rate.
Step 3: Market Approach
The market approach values an asset based on comparable market trans-
actions.
Since comparable properties in the area are selling for an average price of
1,750,000, thisprovidesabenchmarkforassessingthefairvalueoftheinvestmentproperty.
Question 29
Question
A company owns an investment property that is measured at fair value through
profit or loss. At the end of the fiscal year, the fair value of the property is as-
sessed at 3,500,000.Duringtheyear, thecompanyreceivedrentalincomeof200,000
from the property. Additionally, the property had appreciated by 5
23
Solution
Step 1: Calculate the initial fair value of the investment property. Let the initial
fair value be x.
Initial Fair Value = x
Step 2: Calculate the final fair value of the property after 5
Final Fair Value = 1.05x
Step 3: Calculate the gain or loss on the investment property.
Gain or Loss = Final Fair Value −Initial Fair Value −Rental Income
Gain or Loss = 1.05x−x−200,000
Step 4: Substitute the final fair value as 3,500,000 to find x.
1.05x= 3,500,000
x=3,500,000
1.05
x= 3,333,333.33
Step 5: Calculate the gain or loss on the investment property.
Gain or Loss = 1.05(3,333,333.33) −3,333,333.33 −200,000
Gain or Loss = 3,500,000 −3,333,333.33 −200,000
Gain or Loss = 33,666.67
Therefore, the gain on the investment property for the year is 33,666.67.
Question 30
Question
A company holds an investment in a private company for which there is no active
market. The fair value of the investment is estimated using an income approach
based on discounted cash flows. The following information is available: - Ex-
pected cash flows for the next five years: 10,000,12,000, 15,000,18,000, 20,000−
Discountrate : 8Calculatethefairvalueoftheinvestmentusingthediscountedcashflowmethod.
24
Solution
Step 1: Calculate the present value of the expected cash flows.
PV = 10,000
(1 + 0.08)1+12,000
(1 + 0.08)2+15,000
(1 + 0.08)3+18,000
(1 + 0.08)4+20,000
(1 + 0.08)5
PV = 10,000
1.08 +12,000
1.1664 +15,000
1.2605 +18,000
1.3605 +20,000
1.4693
PV ≈9259.26 + 10296.01 + 11904.38 + 13231.98 + 13579.81
PV ≈58171.44
Therefore, the present value of the expected cash flows is approximately
$
58,171.44.
Step 2: The fair value of the investment is determined by the present value
of the expected cash flows.
Fair Value = $58,171.44
Therefore, the fair value of the investment using the discounted cash flow
method is approximately
$
58,171.44.
Question 31
Question
A company holds an investment in a privately held company for which there
is no observable market price. The fair value of the investment is determined
using a discounted cash flow model. The key inputs to the model include the
discount rate and the projected cash flows of the investee.
Given the complexity of the investment and the uncertainty around the cash
flow projections, how should the company adjust its fair value measurement to
account for these factors?
Solution
To adjust the fair value measurement for the complexity and uncertainty asso-
ciated with the investment in the privately held company, the company should
take the following steps:
Step 1: Identify Key Assumptions
Identify the key assumptions used in the discounted cash flow model, such
as the discount rate, cash flow projections, and terminal value assump-
tions.
Step 2: Adjust Discount Rate
Increase the discount rate to reflect the higher risk and uncertainty asso-
ciated with the investment.
25
This higher discount rate compensates investors for the additional risk of
the investment.
Step 3: Scenario Analysis
Perform scenario analysis by varying the key assumptions within a rea-
sonable range to understand the impact on the fair value.
This helps in assessing the sensitivity of the fair value estimate to changes
in assumptions.
Step 4: Adjust Cash Flow Projections
Adjust the cash flow projections to account for the uncertainty and com-
plexity of the investment.
Consider the potential risks and uncertainties that could impact the in-
vestee’s performance and adjust the cash flow projections accordingly.
Step 5: Disclosure
Disclose the key assumptions, methodologies, and uncertainties in the fair
value measurement in the financial statements.
Provide transparent information to users of the financial statements about
the factors influencing the fair value measurement.
By following these steps, the company can adjust its fair value measure-
ment for the complexity and uncertainty associated with the investment in the
privately held company.
Question 32
Question
A company holds an investment property that is carried at fair value through
profit or loss. At the end of the reporting period, the fair value of the property
is reassessed and determined to be 2,500,000.
During the next reporting period, the fair value of the same property in-
creases by 10
Solution
Step 1: Calculate the increase in fair value: Given that the fair value of the
property increases by 10
Increase in Fair Value = 10% ×$2,500,000
Increase in Fair Value = 0.10 ×$2,500,000
26
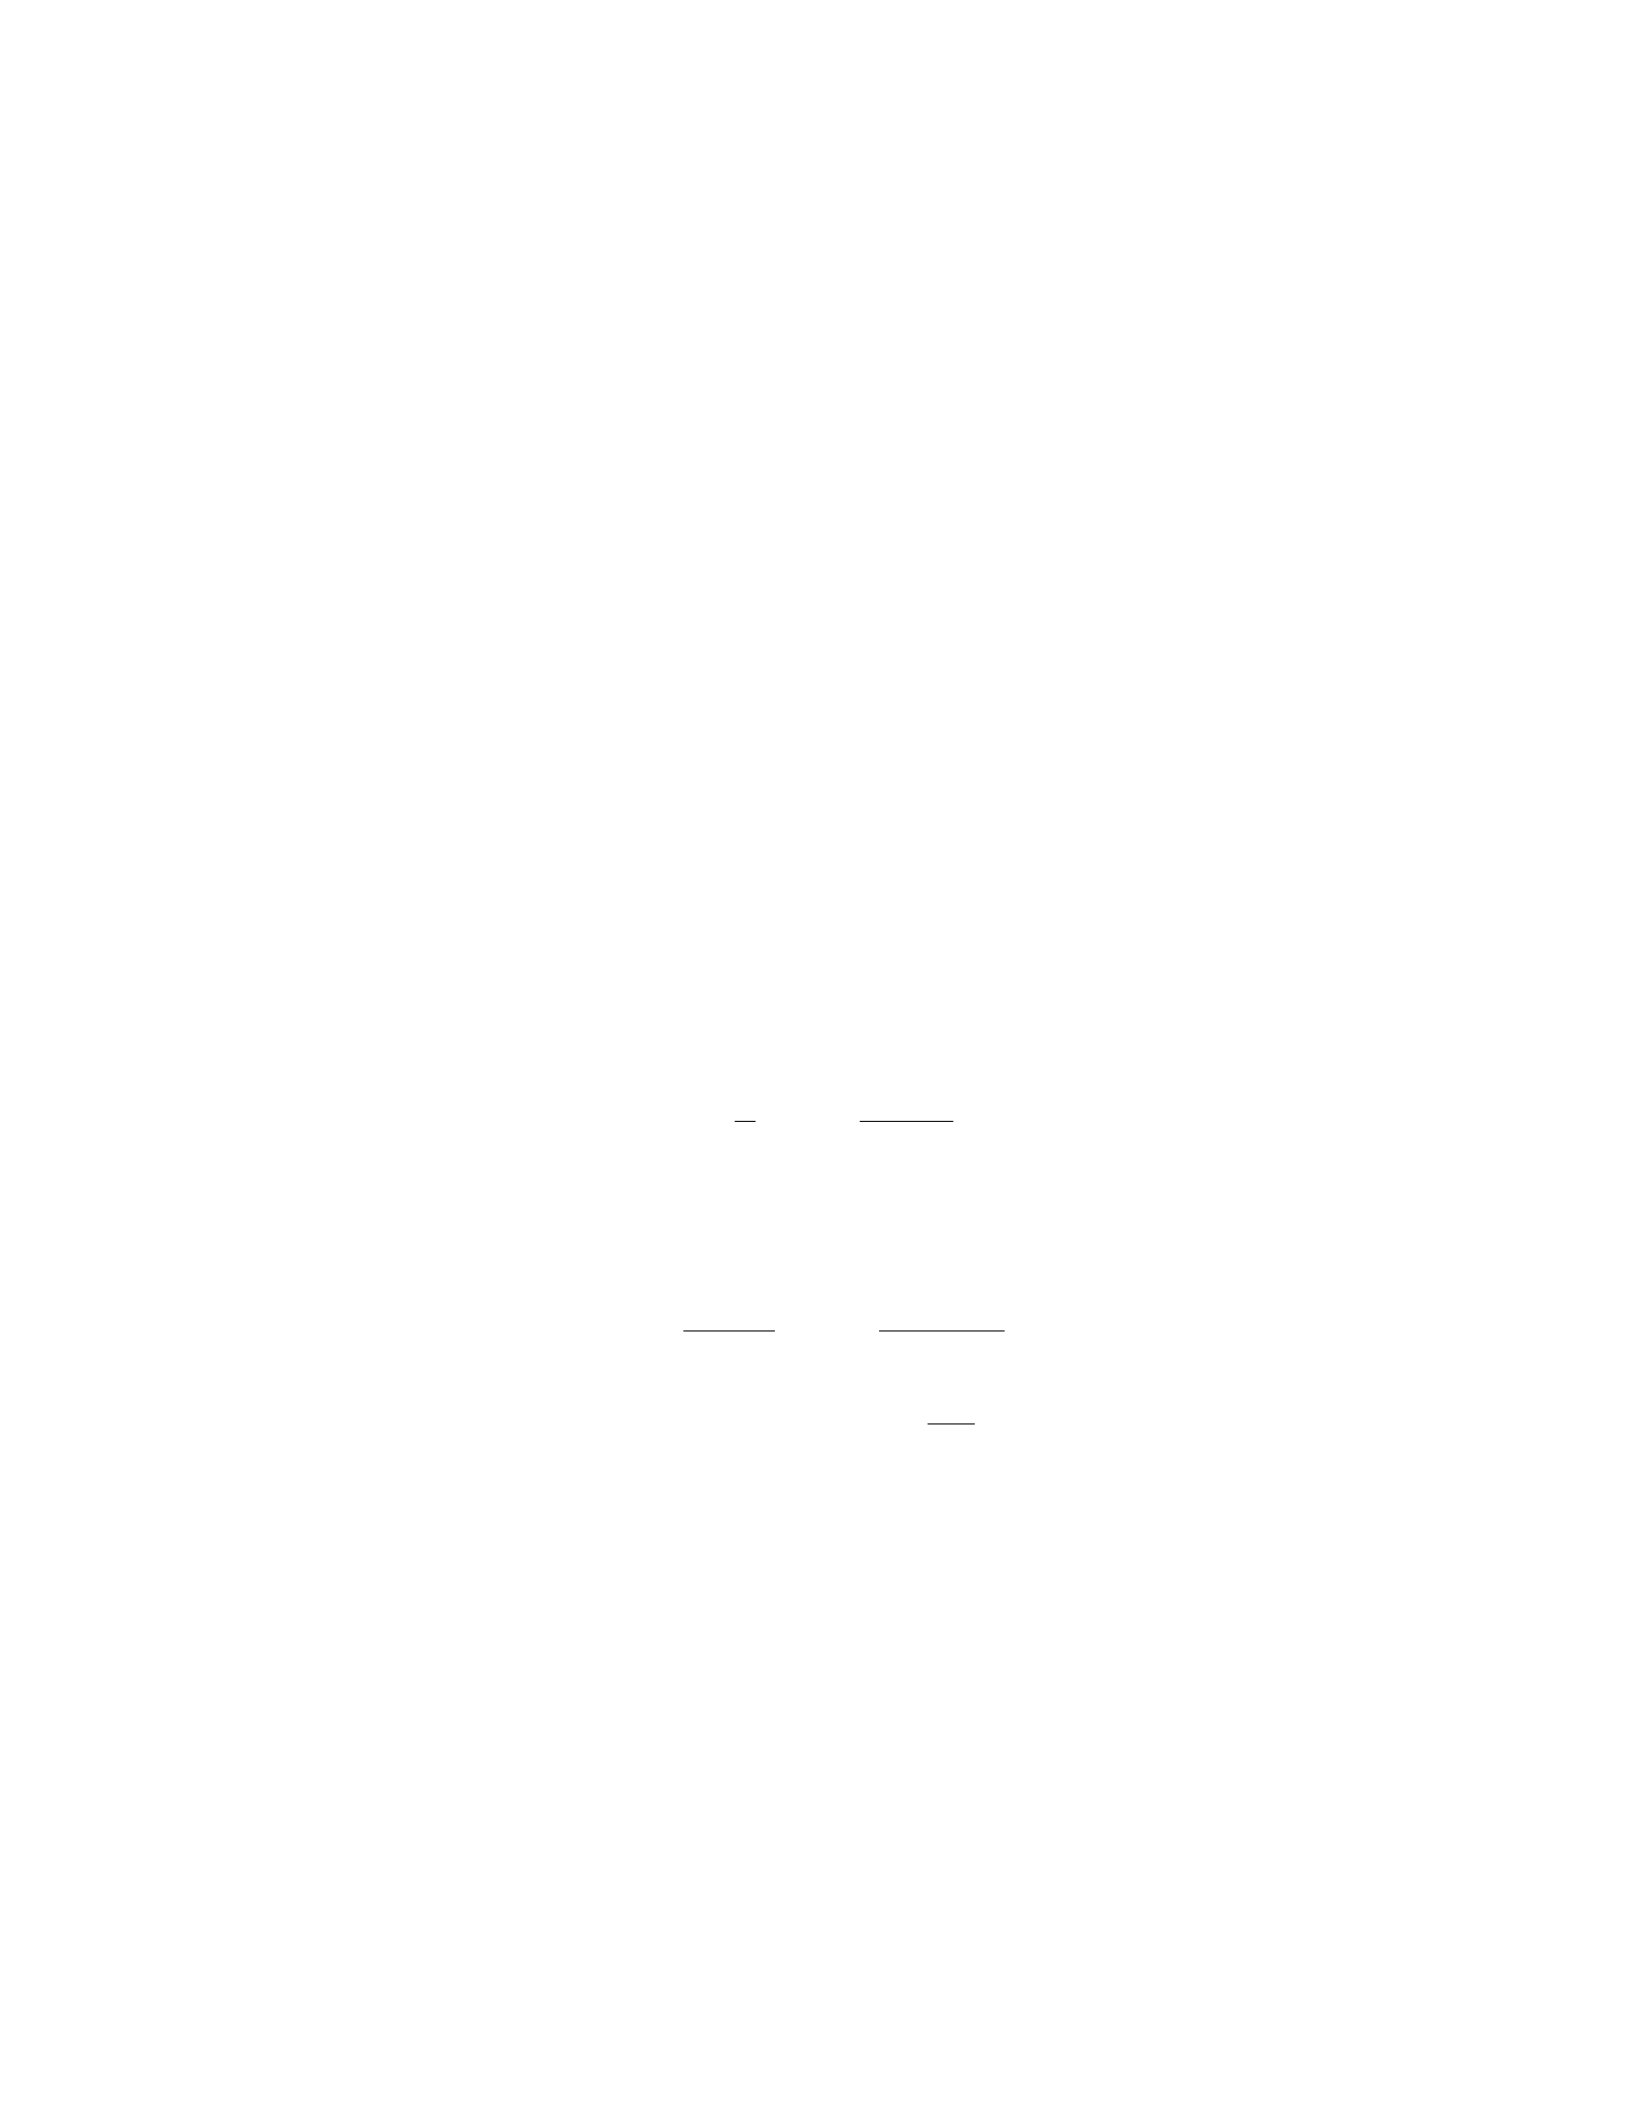
Increase in Fair Value = $250,000
Step 2: Determine the revised fair value: To find the revised fair value, we
add the increase in fair value to the original fair value:
Revised Fair Value = $2,500,000 + $250,000
Revised Fair Value = $2,750,000
Therefore, the revised fair value of the property is $2,750,000.
Question 33
Question
A company determines the fair value of its investment properties using the
income approach. The annual net rental income is estimated at $250,000 and
the discount rate is 8%. Calculate the fair value of the investment properties
using the income approach.
Solution
Step 1: Calculate the present value of the net rental income. The formula for
calculating the present value of an annuity is:
P V =C
r×1−1
(1 + r)n
Where: - P V is the present value - Cis the annual net rental income - ris the
discount rate - nis the number of years
Substitute the given values into the formula:
P V =250,000
0.08 ×1−1
(1 + 0.08)1
P V = 3,125,000 ×1−1
1.08
P V = 3,125,000 ×(1 −0.9259)
P V = 3,125,000 ×0.0741
P V = 231,187.5
Therefore, the present value of the net rental income is 231,187.5.
Step 2: Calculate the fair value of the investment properties. The fair value
of the investment properties using the income approach is equal to the present
value of the net rental income. Hence, the fair value of the investment properties
is 231,187.5.
27

Question 34
Question
A company holds an investment in a financial instrument classified as a Level 3
fair value measurement under IFRS 13. At the end of the reporting period, the
fair value of the investment is uncertain due to the illiquidity of the market. The
company’s management decides to use a valuation technique that incorporates
unobservable inputs to estimate the fair value of the investment. Discuss the key
considerations and challenges in determining the fair value of this investment.
Solution
To determine the fair value of an investment classified as a Level 3 fair value
measurement under IFRS 13, several key considerations and challenges must be
taken into account. Below are the key points to consider:
Step 1: Nature of Investment - The first consideration is understanding
the nature of the investment, including its unique characteristics, restrictions,
and legal obligations. This information will help in selecting an appropriate
valuation technique.
Step 2: Valuation Technique - Given the illiquidity of the market for
the investment, the company must use a valuation technique that incorporates
unobservable inputs. This could involve using a discounted cash flow analysis,
option pricing models, or other sophisticated valuation models.
Step 3: Unobservable Inputs - The valuation technique chosen will likely
rely on unobservable inputs, also known as Level 3 inputs, such as future cash
flows, discount rates, and volatility assumptions. Management must exercise
judgment in determining the reasonableness of these inputs.
Step 4: Market Data - The lack of readily available market data for
similar investments may make it challenging to validate the inputs used in the
valuation technique. Management may need to consider alternative data sources
or adjust existing data to reflect the specific characteristics of the investment.
Step 5: Sensitivity Analysis - Given the uncertainty surrounding the
fair value of the investment, conducting sensitivity analysis can help assess the
impact of changes in key assumptions on the final fair value estimate. This
analysis is essential for understanding the range of possible outcomes.
Step 6: Disclosures - Lastly, the company must provide detailed disclo-
sures in the financial statements regarding the fair value measurement process,
including the valuation techniques used, key assumptions, and any significant
unobservable inputs. This transparency is crucial for users of the financial
statements to understand the level of uncertainty associated with the fair value
measurement.
28
Question 35
Question
A company is valuing its investment property using the fair value model. The
property was purchased for 500,000fiveyearsagoandisnowvaluedat700,000. The
property generates annual rental income of 40,000.Ifthecompanyusesadiscountrateof8
Solution
Step 1: Calculate the present value of expected future cash flows from the
property. The present value of an annuity formula is used to calculate the
present value of the rental income.
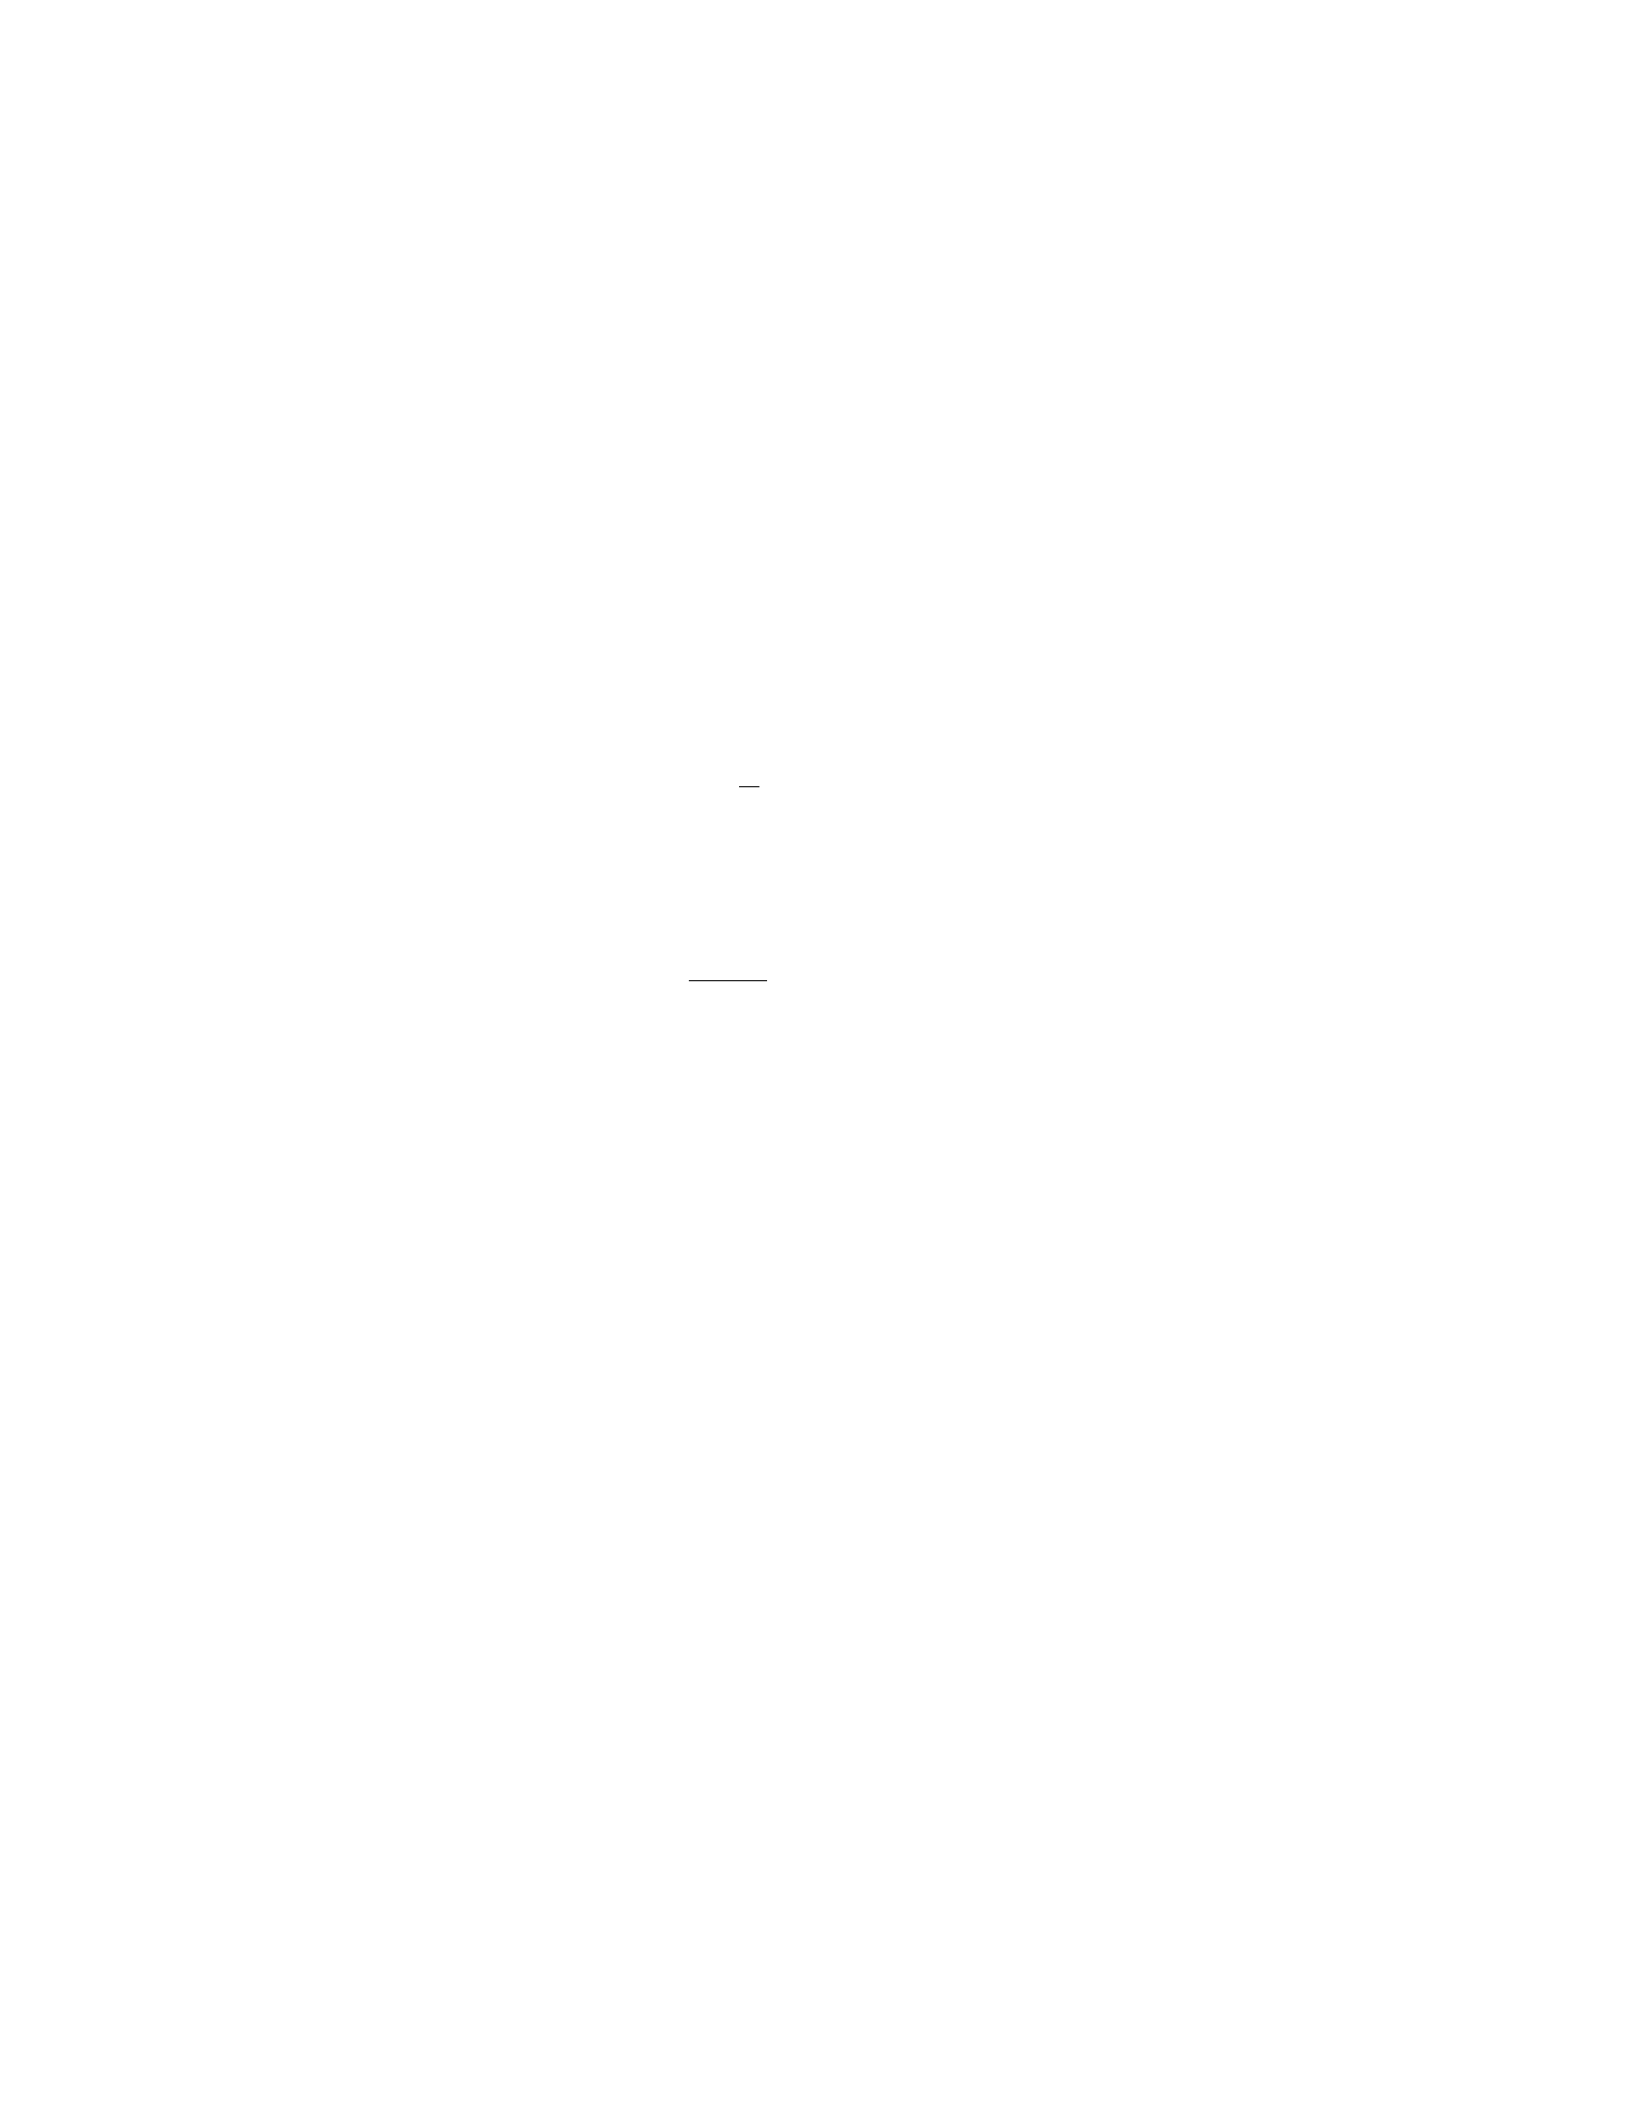
P V =R
r×(1 −(1 + r)−n)
where: - P V = present value of the rental income - R= annual rental income
(40,000) −r= discount rate (8- n= number of years (infinity in this case)
Substitute the values into the formula:
P V =40,000
0.08 ×(1 −(1 + 0.08)−∞ )
Step 2: Calculate the present value of the expected future selling price of
the property after ’n’ years. The future value formula is used to calculate this:
F V =P×(1 + r)n
where: - F V = future value of the property after ’n’ years - P= initial purchase
price of the property (500,000) −r= discount rate (8- n= number of years (5
in this case)
Substitute the values into the formula:
F V = 500,000 ×(1 + 0.08)5
Step 3: Calculate the fair value of the property by summing up the present
value of expected future cash flows and the present value of the expected future
selling price: Fair Value = PV + FV
Now, plug in the calculated values and solve for the fair value.
29
Question 6
Question
A company owns an investment in equity securities classified as available-for-
sale. The fair value of the investment at the end of the reporting period
is 8,500.T hecompanyinitiallypurchasedtheinvestmentf or7,000. During the
year, the fair value of the investment experienced a decrease of 500.
Calculate the unrealized holding gain/loss that would be reported in other
comprehensive income.
Solution
To calculate the unrealized holding gain/loss, we need to compare the current
fair value of the investment with the initial cost of the investment.
Unrealized Holding Gain/Loss = Fair Value at Reporting Date −Initial Cost
Step 1: Calculate the Unrealized Holding Gain/Loss
Unrealized Holding Gain/Loss = $8,500 −$7,000
= $1,500
However, we need to adjust for the decrease in fair value that occurred during
the year.
Step 2: Adjust for the Decrease in Fair Value
Adjusted Unrealized Holding Gain/Loss = $1,500 −$500
= $1,000
Therefore, the unrealized holding gain/loss that would be reported in other
comprehensive income is
$
1,000.
Question 7
Question
A company is trying to determine the fair value of a financial instrument that
is not actively traded in the market. The company has gathered the following
information: - Expected cash flows: Year 1 =
$
500, Year 2 =
$
700, Year 3 =
$
900 - Discount rate = 5Using the present value technique, calculate the fair
value of the financial instrument.
5
Solution
Step 1: Calculate the present value of each cash flow.
PVYear 1 =$500
(1 + 0.05)1=$500
1.05 ≈$476.19
PVYear 2 =$700
(1 + 0.05)2=$700
1.1025 ≈$635.51
PVYear 3 =$900
(1 + 0.05)3=$900
1.1576 ≈$777.23
Step 2: Calculate the fair value of the financial instrument by summing up
the present values of all cash flows.
Fair Value = PVYear 1 +PVYear 2 +PVYear 3 ≈$476.19+$635.51+$777.23 ≈$1888.93
Therefore, the fair value of the financial instrument using the present value
technique is approximately
$
1888.93.
Question 8
Question
A company holds an investment in a financial asset classified as a Level 3 fair
value measurement. At the end of the reporting period, the fair value of the
investment is $150,000, but there is significant uncertainty and lack of reliable
external observable data to support this valuation. The company’s management
is considering applying a weighted average cost method instead of fair value
measurement to value the investment.
Should the company’s management apply the weighted average cost method
instead of fair value measurement in this case? Justify your answer.
Solution
To determine whether the company’s management should apply the weighted
average cost method instead of fair value measurement, we need to consider the
guidance provided in the fair value measurement standard.
Step 1: Understand the fair value measurement framework Ac-
cording to the fair value measurement standard (e.g., IFRS 13 or ASC 820), fair
value is defined as the price that would be received to sell an asset or paid to
transfer a liability in an orderly transaction between market participants at the
measurement date. The standard establishes a three-level hierarchy for inputs
used in measuring fair value: - Level 1 inputs are quoted prices in active markets
for identical assets or liabilities. - Level 2 inputs are observable market data
other than Level 1 inputs. - Level 3 inputs are unobservable inputs.
6

Step 2: Consider the characteristics of Level 3 inputs Level 3 inputs
are unobservable and are used when there is significant uncertainty and lack of
reliable external observable data.
Step 3: Should the weighted average cost method be used? In this
case, the investment is classified as a Level 3 fair value measurement, indicating
the use of unobservable inputs due to significant uncertainty and lack of reliable
external observable data. If the company switches to the weighted average cost
method, it may deviate from the fair value measurement principle and possibly
understate or overstate the investment value.
Step 4: Justification Given the characteristics of the investment being
classified as a Level 3 fair value measurement with significant uncertainty and
lack of reliable external observable data, deviating from fair value measurement
to the weighted average cost method may not accurately reflect the current
market value of the investment. Therefore, the company’s management should
not apply the weighted average cost method in this case to ensure the investment
is fairly valued based on the principles of the fair value measurement standard.
Question 9
Question
A company recently acquired a piece of land for development purposes. The
company determined that the fair value of the land was $500,000 at the ac-
quisition date. Over the next six months, the fair value of the land increased
to $550,000. However, due to market conditions, the fair value dropped to
$480,000 by the end of the year.
Calculate the gain or loss on fair value measurement that the company should
recognize in its financial statements at the end of the year.
Solution
Step 1: Calculate the gain or loss on fair value measurement based on the
information given.
The gain or loss on fair value measurement is calculated as the difference
between the fair value at the end of the reporting period and the fair value at
the acquisition date.
Gain/Loss = Fair value at the end of the reporting period−Fair value at the acquisition date
Step 2: Substitute the values into the formula.
Gain/Loss = $480,000 −$500,000
Gain/Loss = −$20,000
7
Step 3: Analyze the result.
The negative value indicates a loss on fair value measurement. Therefore,
the company should recognize a loss of $20,000 in its financial statements at
the end of the year.
Question 10
Question
Company XYZ holds an investment in a privately held company. The fair
value of the investment needs to be determined for financial reporting purposes.
Company XYZ has gathered the following information about the privately held
company:
- Revenue for the year: 500,000 −Netincomefortheyear :70,000 - Total
assets: 600,000 −T otalliabilities :200,000 - Market capitalization of a similar
publicly traded company: 2,000,000
Using this information, determine the fair value of Company XYZ’s invest-
ment in the privately held company.
Solution
To determine the fair value of Company XYZ’s investment in the privately
held company, we can use the market approach, specifically the guideline public
company method. This method compares the financial metrics of a similar
publicly traded company to estimate the fair value of the private company.
Step 1: Calculate the price-to-earnings (P/E) ratio of the publicly
traded company
P/E ratio =Market capitalization
Net income =
2,000,000 70,000 = 28.57
Step 2: Calculate the estimated value of the privately held com-
pany
Using the P/E ratio calculated in Step 1, we can estimate the value of the
privately held company:
Estimated value =P/E ratio ×N et income = 28.57×
70,000 = 2,000,000
Step 3: Adjust the estimated value for the privately held company
Since the privately held company may have different risk factors or growth
prospects compared to the publicly traded company, we need to make adjust-
ments. For example, if the privately held company is riskier, we may apply a
discount to the estimated value.
Step 4: Determine the fair value of Company XYZ’s investment
8

After making appropriate adjustments, the final estimate represents the fair
value of Company XYZ’s investment in the privately held company.
Question 11
Question
Company XYZ holds a financial asset that is measured at fair value through
other comprehensive income (FVOCI). At the end of the reporting period, the
fair value of the asset is 1,200,000.However, duetotheuncertaintiesinthemarket, thereisasignif icantdecreaseincreditriskoftheasset.T hisdecreaseincreditriskisnotreflectedinthemarketprice.Asaresult, thecompanydecidestoreclassifythefinancialassetfromF V OCItofairvaluethroughprofitorloss(FVTPL).Howshouldthischangeinaccountingtreatmentberecognizedinthef inancialstatementsofCompanyXY Z?
Solution
To reclassify the financial asset from FVOCI to FVTPL, Company XYZ will
need to consider the impact on the financial statements. The change in account-
ing treatment is recognized as follows:
Step 1: Calculate the fair value adjustment for the financial asset due to
the decrease in credit risk.
The fair value adjustment is calculated as the difference between the new
fair value of the asset under FVTPL and the old fair value under FVOCI. In this
case, the fair value under FVTPL is 1,200,000.Let′sassumetheoldf airvalueunderF V OCIwas1,500,000.
Therefore, the fair value adjustment is:
F air V alue Adjustment =F air V alue (FVTPL)−F air V alue (F V OCI) =
1,200,000 - 1,500,000 = −300,000
Step 2: Record the fair value adjustment in the statement of profit or loss.
The fair value adjustment of 300,000shouldberecognizedasalossinthestatementofprof itorloss.T hislossrepresentsthedecreaseincreditriskthatwasnotref lectedinthemarketpriceof theasset.
Step 3: Reclassify the financial asset on the statement of financial position.
The financial asset should be reclassified from FVOCI to FVTPL on the
statement of financial position. The asset will now be presented at its fair value
of 1,200,000, withanysubsequentchangesinf airvaluerecordedinprofitorloss.
In summary, the change in accounting treatment from FVOCI to FVTPL
for the financial asset should be recognized by recording a fair value adjustment
as a loss in the statement of profit or loss and reclassifying the asset on the
statement of financial position.
Question 12
Question
A company holds a financial asset that is classified as a Level 3 fair value mea-
surement. The fair value of the asset increased by 10
9

Solution
Step 1: Implications on Financial Statements When the fair value of a
Level 3 financial asset increases, the company will recognize a gain in its in-
come statement. This gain affects the company’s net income and can lead to
an increase in reported profits, which may positively impact the perception of
the company’s financial performance by investors and stakeholders. Addition-
ally, the increase in fair value will also impact the company’s balance sheet by
increasing the value of the financial asset held, leading to an increase in total
assets and potentially improving key financial ratios such as return on assets.
Step 2: Challenges of Measuring Level 3 Fair Value Assets Level
3 assets are those whose fair value cannot be directly observed in the market
and require significant management judgment and estimation. Therefore, there
are several challenges associated with measuring the fair value of Level 3 as-
sets, including: - Lack of market data: Limited market activity or absence of
comparable transactions can make it difficult to determine the fair value ac-
curately. - Subjectivity in assumptions: The valuation of Level 3 assets often
involves making subjective assumptions about future cash flows, discount rates,
and other relevant factors, leading to potential bias in the reported fair value. -
Sensitivity to changes: Level 3 assets are typically more sensitive to changes in
assumptions and market conditions, which can result in significant fluctuations
in fair value and impact financial statements unpredictably. - Audit scrutiny:
Given the inherent subjectivity and complexity of valuing Level 3 assets, au-
ditors may need to exercise greater scrutiny over the methodologies used and
inputs applied, leading to additional time and cost in the audit process.
In conclusion, while an increase in the fair value of Level 3 assets can
have positive effects on a company’s financial statements, the challenges as-
sociated with measuring and valuing such assets highlight the importance of
transparency, disclosure, and robust internal controls in fair value measurement
processes.
Question 13
Question
A company holds an investment in a privately held company that is classified as
a Level 3 fair value asset. The fair value of the investment is determined using
a discounted cash flow model. The company uses unobservable inputs such as
projected revenue growth rates, discount rates, and terminal values to estimate
the fair value of the investment.
Discuss the challenges and potential issues that could arise in fair value
measurement for this investment.
10
Solution
To determine the fair value of an investment in a privately held company using
a discounted cash flow model with unobservable inputs, several challenges and
potential issues may arise. These challenges can impact the accuracy and reli-
ability of the fair value measurement. Some of the key challenges are outlined
below:
Step 1: Lack of market data
Valuing privately held companies involves the use of assumptions and es-
timates since market data may not be readily available.
The absence of comparable market transactions can make it difficult to
validate the assumptions used in the discounted cash flow model.
Step 2: Unobservable inputs
Unobservable inputs like projected revenue growth rates and discount rates
may heavily influence the fair value estimate.
The subjective nature of these inputs can lead to biases and errors in the
valuation process.
Step 3: Complexity of the model
The discounted cash flow model used to estimate the fair value of the
investment may be complex with multiple variables and assumptions.
Errors in estimating any of the inputs can have a significant impact on
the final fair value calculation.
Step 4: Sensitivity to changes
The fair value estimate is sensitive to changes in key assumptions such as
revenue growth rates and discount rates.
Small variations in these inputs can lead to substantial fluctuations in the
final fair value measurement.
Step 5: Management bias
There is a risk of management bias in selecting assumptions that may
result in a higher or lower fair value estimate.
Objectivity is crucial to ensure that fair value measurements are free from
bias and reflect economic reality accurately.
It is important for companies to be transparent about the methodologies and
assumptions used in fair value measurements, as well as to regularly reassess and
validate these inputs to enhance the reliability of the fair value estimates.
11

Question 14
Question
A company owns an investment property which is measured at fair value. At the
end of the fiscal year, the fair value of the property has decreased compared to
the previous period. Explain how the company should account for this change
in fair value.
Solution
To account for a decrease in fair value of an investment property, the company
should follow the guidelines outlined in the fair value measurement standard.
Below are the steps the company should take:
Step 1: Determine the reason for the decrease in fair value. It could be due
to changes in market conditions, property location, or potential obsolescence.
Step 2: Assess whether the decrease in fair value is temporary or perma-
nent. This distinction is important as the accounting treatment differs for each
scenario.
Step 3: If the decrease in fair value is considered temporary, no adjustment
is necessary to the carrying amount of the investment property.
Step 4: If the decrease in fair value is considered permanent, the company
should recognize an impairment loss in its financial statements.
Step 5: Calculate the impairment loss by comparing the carrying amount of
the investment property with its recoverable amount. The recoverable amount
is the higher of the property’s fair value less costs to sell and its value in use.
Step 6: Recognize the impairment loss in the income statement as an ex-
pense. The carrying amount of the investment property should be reduced by
the impairment loss amount.
Step 7: Make appropriate disclosures in the financial statements regarding
the impairment loss and its impact on the company’s financial position.
By following these steps, the company can properly account for a decrease
in fair value of its investment property and reflect this change in its financial
statements.
Question 15
Question
Company XYZ holds an investment in a startup that is not publicly traded.
The fair value of the investment needs to be assessed for financial reporting
purposes. Provide three specific techniques that can be used to determine the
fair value of this non-publicly traded investment.
12

Solution
To determine the fair value of a non-publicly traded investment, several tech-
niques can be used. Here are three specific techniques:
Step 1: Market Approach One technique is to use the market approach,
which involves comparing the investment to similar investments that are publicly
traded. This can be done by looking at comparable companies in the same
industry or sector and using their market prices to estimate the fair value of the
investment.
Step 2: Income Approach Another technique is the income approach,
which involves estimating the future cash flows that the investment is expected
to generate and discounting them back to present value. This method relies on
the premise that the fair value of an investment is based on the present value
of its expected future cash flows.
Step 3: Cost Approach The third technique is the cost approach, which
involves determining the cost to replace the investment or reproduce its benefits.
This method may involve assessing the cost of acquiring or developing a similar
investment in the current market environment.
These three techniques – market approach, income approach, and cost ap-
proach – provide different perspectives for determining the fair value of a non-
publicly traded investment.
It is important to note that the choice of technique will depend on various
factors such as the nature of the investment, availability of information, and the
specific circumstances surrounding the investment.
Question 16
Question
A company is required to measure the fair value of its investments in designated
equity securities. The fair value of these investments is determined using Level
3 inputs. Explain what Level 3 inputs are and provide examples.
Solution
Step 1: Level 3 inputs are unobservable inputs that are used in fair value mea-
surements. These inputs are based on the best information available, considering
the assumptions that market participants would make. Level 3 inputs are used
when observable market data is not available.
Step 2: Examples of Level 3 inputs include: - Company-specific data, such
as financial projections and internal valuations - Discounted cash flow models
that require significant judgment and estimation - Option pricing models where
inputs are based on unobservable data - Inputs based on recent transactions
involving similar assets but with adjustments to reflect differences
Step 3: In the case of the company measuring the fair value of its invest-
ments in designated equity securities using Level 3 inputs, it implies that the
13

fair value is determined using significant judgment and estimation due to the
lack of observable market data. This could involve using internal models and
assumptions to arrive at a reasonable estimate of the investments’ fair value,
considering factors such as market conditions, industry trends, and the specific
characteristics of the investments.
Question 17
Question
Company XYZ holds an investment in a private company that is accounted for
at fair value through profit or loss. The fair value of the private company’s
investment was determined using unobservable inputs such as discounted cash
flow analysis and comparable company analysis.
Explain the key considerations and challenges in measuring the fair value of
this investment using Level 3 inputs according to the fair value hierarchy.
Solution
To measure the fair value of an investment using Level 3 inputs (unobservable
inputs), several key considerations and challenges arise.
Step 1: Existence of Unobservable Inputs - Level 3 inputs are not
readily observable in the market and require significant judgment and estimation
in determining fair value. - In this case, the discounted cash flow analysis and
comparable company analysis are considered unobservable inputs as they involve
subjective estimates and assumptions.
Step 2: Reliability and Credibility of Inputs - The reliability and cred-
ibility of unobservable inputs are crucial when measuring fair value. - There is a
risk of bias or manipulation in estimating inputs like cash flows or selecting com-
parable companies, which could lead to a misrepresentation of the investment’s
fair value.
Step 3: Sensitivity to Assumptions - Level 3 measurements are highly
sensitive to changes in assumptions and estimates. - Small variations in discount
rates, growth projections, or selection of comparable companies can result in
significant fluctuations in the fair value of the investment.
Step 4: Transparency and Disclosures - Due to the subjectivity involved
in Level 3 measurements, it is important to provide transparent disclosures
about the valuation techniques, key assumptions, and uncertainties. - This
helps stakeholders understand the basis for the fair value measurement and
assess the reliability of the reported figures.
Step 5: Independent Verification - Given the complexity and subjectiv-
ity of Level 3 inputs, obtaining an independent valuation from a qualified third
party can enhance the credibility of the fair value measurement. - Indepen-
dent verification provides assurance to stakeholders that the fair value has been
determined objectively and in accordance with established valuation principles.
14

In conclusion, measuring the fair value of an investment using Level 3 inputs
poses challenges related to the reliability of unobservable inputs, sensitivity to
assumptions, transparency in reporting, and the need for independent verifica-
tion. It is essential for companies to exercise prudence and diligence in ensuring
the accuracy and integrity of fair value measurements for Level 3 assets.
Question 18
Question
Company XYZ holds an investment in a publicly traded stock. At the end of the
reporting period, the fair value of the stock is 172.50pershare.However, thecompany′smanagementbelievesthatduetorecentmarketevents, thef airvalueshouldbeadjustedto165.80
per share. If Company XYZ uses a Level 1 fair value measurement hierarchy,
determine the implications of this adjustment on the company’s financial state-
ments.
Solution
1. Since the fair value adjustment pertains to a Level 1 fair value measurement
hierarchy, it implies that the fair value adjustment should be recognized in the
income statement.
2. The fair value adjustment on the investment in the publicly traded stock
will result in a decrease in the fair value of the asset.
3. The decrease in the fair value of the investment will lead to a loss being
recognized in the income statement for the reporting period.
4. The loss from the fair value adjustment will decrease the net income of
Company XYZ for the reporting period.
5. The decrease in net income may impact the company’s profitability ratios
and financial performance indicators.
6. Additionally, the fair value adjustment will also impact the company’s
balance sheet, specifically the carrying amount of the investment in the publicly
traded stock.
7. The adjusted fair value of the investment in the stock will be reported
on the balance sheet as a lower carrying amount, reflecting the decrease in fair
value.
8. The fair value adjustment will be disclosed in the notes to the financial
statements, providing transparency to stakeholders regarding the change in fair
value and its impact on the financial position and performance of Company
XYZ.
Overall, the adjustment of the fair value of the investment in the publicly
traded stock to 165.80persharewillresultinalossbeingrecognizedintheincomestatement, impactingthecompany′sfinancialstatementsandfinancialmetrics.
15

Question 19
Question
A company holds an investment in a financial asset classified as Level 3 fair
value measurement. At the end of the reporting period, the fair value of the
investment decreased significantly compared to its carrying amount. Explain
how this decrease in fair value impacts the company’s financial statements and
provide examples of the disclosures required under IFRS 13 for Level 3 fair value
measurements.
Solution
Step 1: When the fair value of a Level 3 financial asset decreases significantly, it
will result in an impairment loss on the investment. This impairment loss needs
to be recognized in the company’s income statement as a separate line item to
reflect the decrease in value.
Step 2: The impairment loss will also impact the carrying amount of the
financial asset on the balance sheet. The carrying amount will be reduced to
the new fair value after recognizing the impairment loss.
Step 3: Under IFRS 13, for Level 3 fair value measurements, the following
disclosures are required: - A description of the valuation technique(s) used to
determine fair value. - The significant unobservable inputs used in the valuation.
- A quantitative sensitivity analysis showing how changes in unobservable inputs
would impact fair value. - The amounts of any transfers between Level 1, Level
2, and Level 3 fair value measurements. - For recurring fair value measurements,
the amount of any unrealized gains or losses recognized in profit or loss. - For
nonrecurring fair value measurements (such as impairment losses), the reasons
for the measurement.
Overall, a decrease in fair value for a Level 3 financial asset will lead to
recognition of an impairment loss in the income statement, a reduction in the
carrying amount on the balance sheet, and additional disclosures in the financial
statements to provide transparency and understanding to users.
Question 20
Question
A company holds an investment property at fair value and reports changes in fair
value in profit or loss. During the current year, the fair value of the investment
property increased by 15%. However, the company later found out that there
was an error in the valuation model used to determine the fair value, which
resulted in an overstatement of the fair value by 10%. How should the company
correct this error in its financial statements?
16

Solution
1. Calculate the Corrected Fair Value: Given that the fair value of the
investment property increased by 15% but was overstated by 10%, the corrected
fair value is obtained by adjusting the reported fair value. Let the original fair
value be F V . The overstated fair value is 1.10F V , and the actual fair value
increase is 1.15F V . Hence, the corrected fair value is 1.15F V −0.10F V =
1.05F V .
2. Recognize Correction of Error in Financial Statements: The
correction of the error in the valuation model should be treated retrospectively in
the financial statements. The overstatement of the fair value should be reversed
and adjusted for in the current year’s financial statements as an error correction.
3. Adjust the Financial Statements: To correct the error in the financial
statements: - Decrease the investment property value by 10% to reflect the
corrected fair value. - Reverse the impact of the overstatement in the profit or
loss for the current year.
4. Disclosures in the Financial Statements: The company should dis-
close the nature of the error, the impact on the financial statements, and the
corrections made in the notes to the financial statements. These disclosures
ensure transparency and clarity for users of the financial statements.
Therefore, the company should correct the error in the fair value measure-
ment by adjusting the reported fair value downwards by 10% to reflect the
corrected fair value in the financial statements.
Question 21
Question
Company X holds an investment in a private equity fund. At the end of the
reporting period, Company X needs to determine the fair value of this invest-
ment. Describe the steps the company should follow to measure the fair value
of this investment according to the Fair Value Measurement standard.
Solution
To measure the fair value of the investment in the private equity fund, Company
X should follow the steps outlined in the Fair Value Measurement standard.
These steps are as follows:
Step 1: Identify the Asset or Liability
In this case, the asset to be measured is the investment in the private equity
fund.
Step 2: Determine the Principal (or Most Advantageous) Market
Company X needs to determine whether there is an active market for the
private equity fund’s interest and the principal market on which the asset would
be exchanged. If there is an active market, the fair value is the quoted market
price. If not, move on to the next step.
17

Step 3: Consider Market Conditions
If there is no active market, Company X needs to consider market conditions
and the specific circumstances of the investment to determine the fair value.
Step 4: Use Valuation Techniques
In the absence of an active market, Company X should use valuation tech-
niques such as discounted cash flow analysis, comparable company analysis, or
precedent transactions to estimate the fair value of the investment.
Step 5: Verify the Assumptions
Company X should verify the key assumptions used in the valuation tech-
niques and make adjustments if necessary.
Step 6: Apply Discounts or Premiums
Depending on the specific characteristics of the private equity fund, discounts
or premiums may need to be applied to the valuation to reflect illiquidity, lack
of control, or other factors.
Step 7: Document the Fair Value Measurement
Lastly, Company X should thoroughly document the fair value measurement
process, including the techniques used, key assumptions made, discounts or
premiums applied, and any other relevant information.
By following these steps outlined in the Fair Value Measurement standard,
Company X can accurately determine the fair value of its investment in the
private equity fund.
Question 22
Question
A company holds a financial asset that is measured at fair value through profit or
loss. The fair value of the asset at the beginning of the year was 10,000.Duringtheyear, thefairvalueincreasedto12,000.
At the end of the year, the fair value decreased to 11,000.T hecompanyreceived800
in dividends related to the financial asset during the year. Calculate the gain
or loss recognized in profit or loss for the year.
Solution
Step 1: Calculate the gain or loss when the fair value increased from 10,000to12,000.
Gain in value = New fair value −Initial fair value
Gain in value = $12,000 −$10,000 = $2,000
Step 2: Calculate the gain or loss when the fair value decreased from 12,000to11,000.
Loss in value = Initial fair value −End fair value
Loss in value = $12,000 −$11,000 = $1,000
Step 3: Calculate the net gain or loss for the year.
Net gain or loss = Gain in value −Loss in value + Dividends
18
Net gain or loss = $2,000 −$1,000 + $800 = $1,800
Therefore, the gain recognized in profit or loss for the year is 1,800.
Question 23
Question
A company holds an investment in a financial instrument classified as Level 2 un-
der the fair value hierarchy. At the end of the reporting period, the market price
of the financial instrument is 60pershare.T hecompany′sinternalestimateofthefairvalueis58
per share. If the inputs used to determine the fair value of the financial instru-
ment are observable in the market, what factors should the company consider
in determining the fair value measurement?
Solution
1. Step 1: Understand Fair Value Measurement
Fair value measurement is the process of determining the price that would
be received to sell an asset or paid to transfer a liability in an orderly
transaction between market participants at the measurement date.
2. Step 2: Consider Factors in Fair Value Measurement
When determining the fair value measurement of a financial instrument,
the company should consider the following factors:
The nature and characteristics of the financial instrument.
The condition and location of the financial markets where the finan-
cial instrument is traded.
The availability and reliability of inputs used in the valuation process.
The level of comparability between the company’s estimate and ob-
servable market prices.
The degree of judgment involved in the valuation process.
The risk and uncertainty associated with the financial instrument.
3. Step 3: Apply to the Given Scenario
In the given scenario, since the inputs used to determine the fair value of
the financial instrument are observable in the market, the company should
carefully consider the factors mentioned above. This includes assessing
the reliability of the observable market prices, evaluating the nature of
the financial instrument, and considering any risks or uncertainties that
may affect the valuation.
19
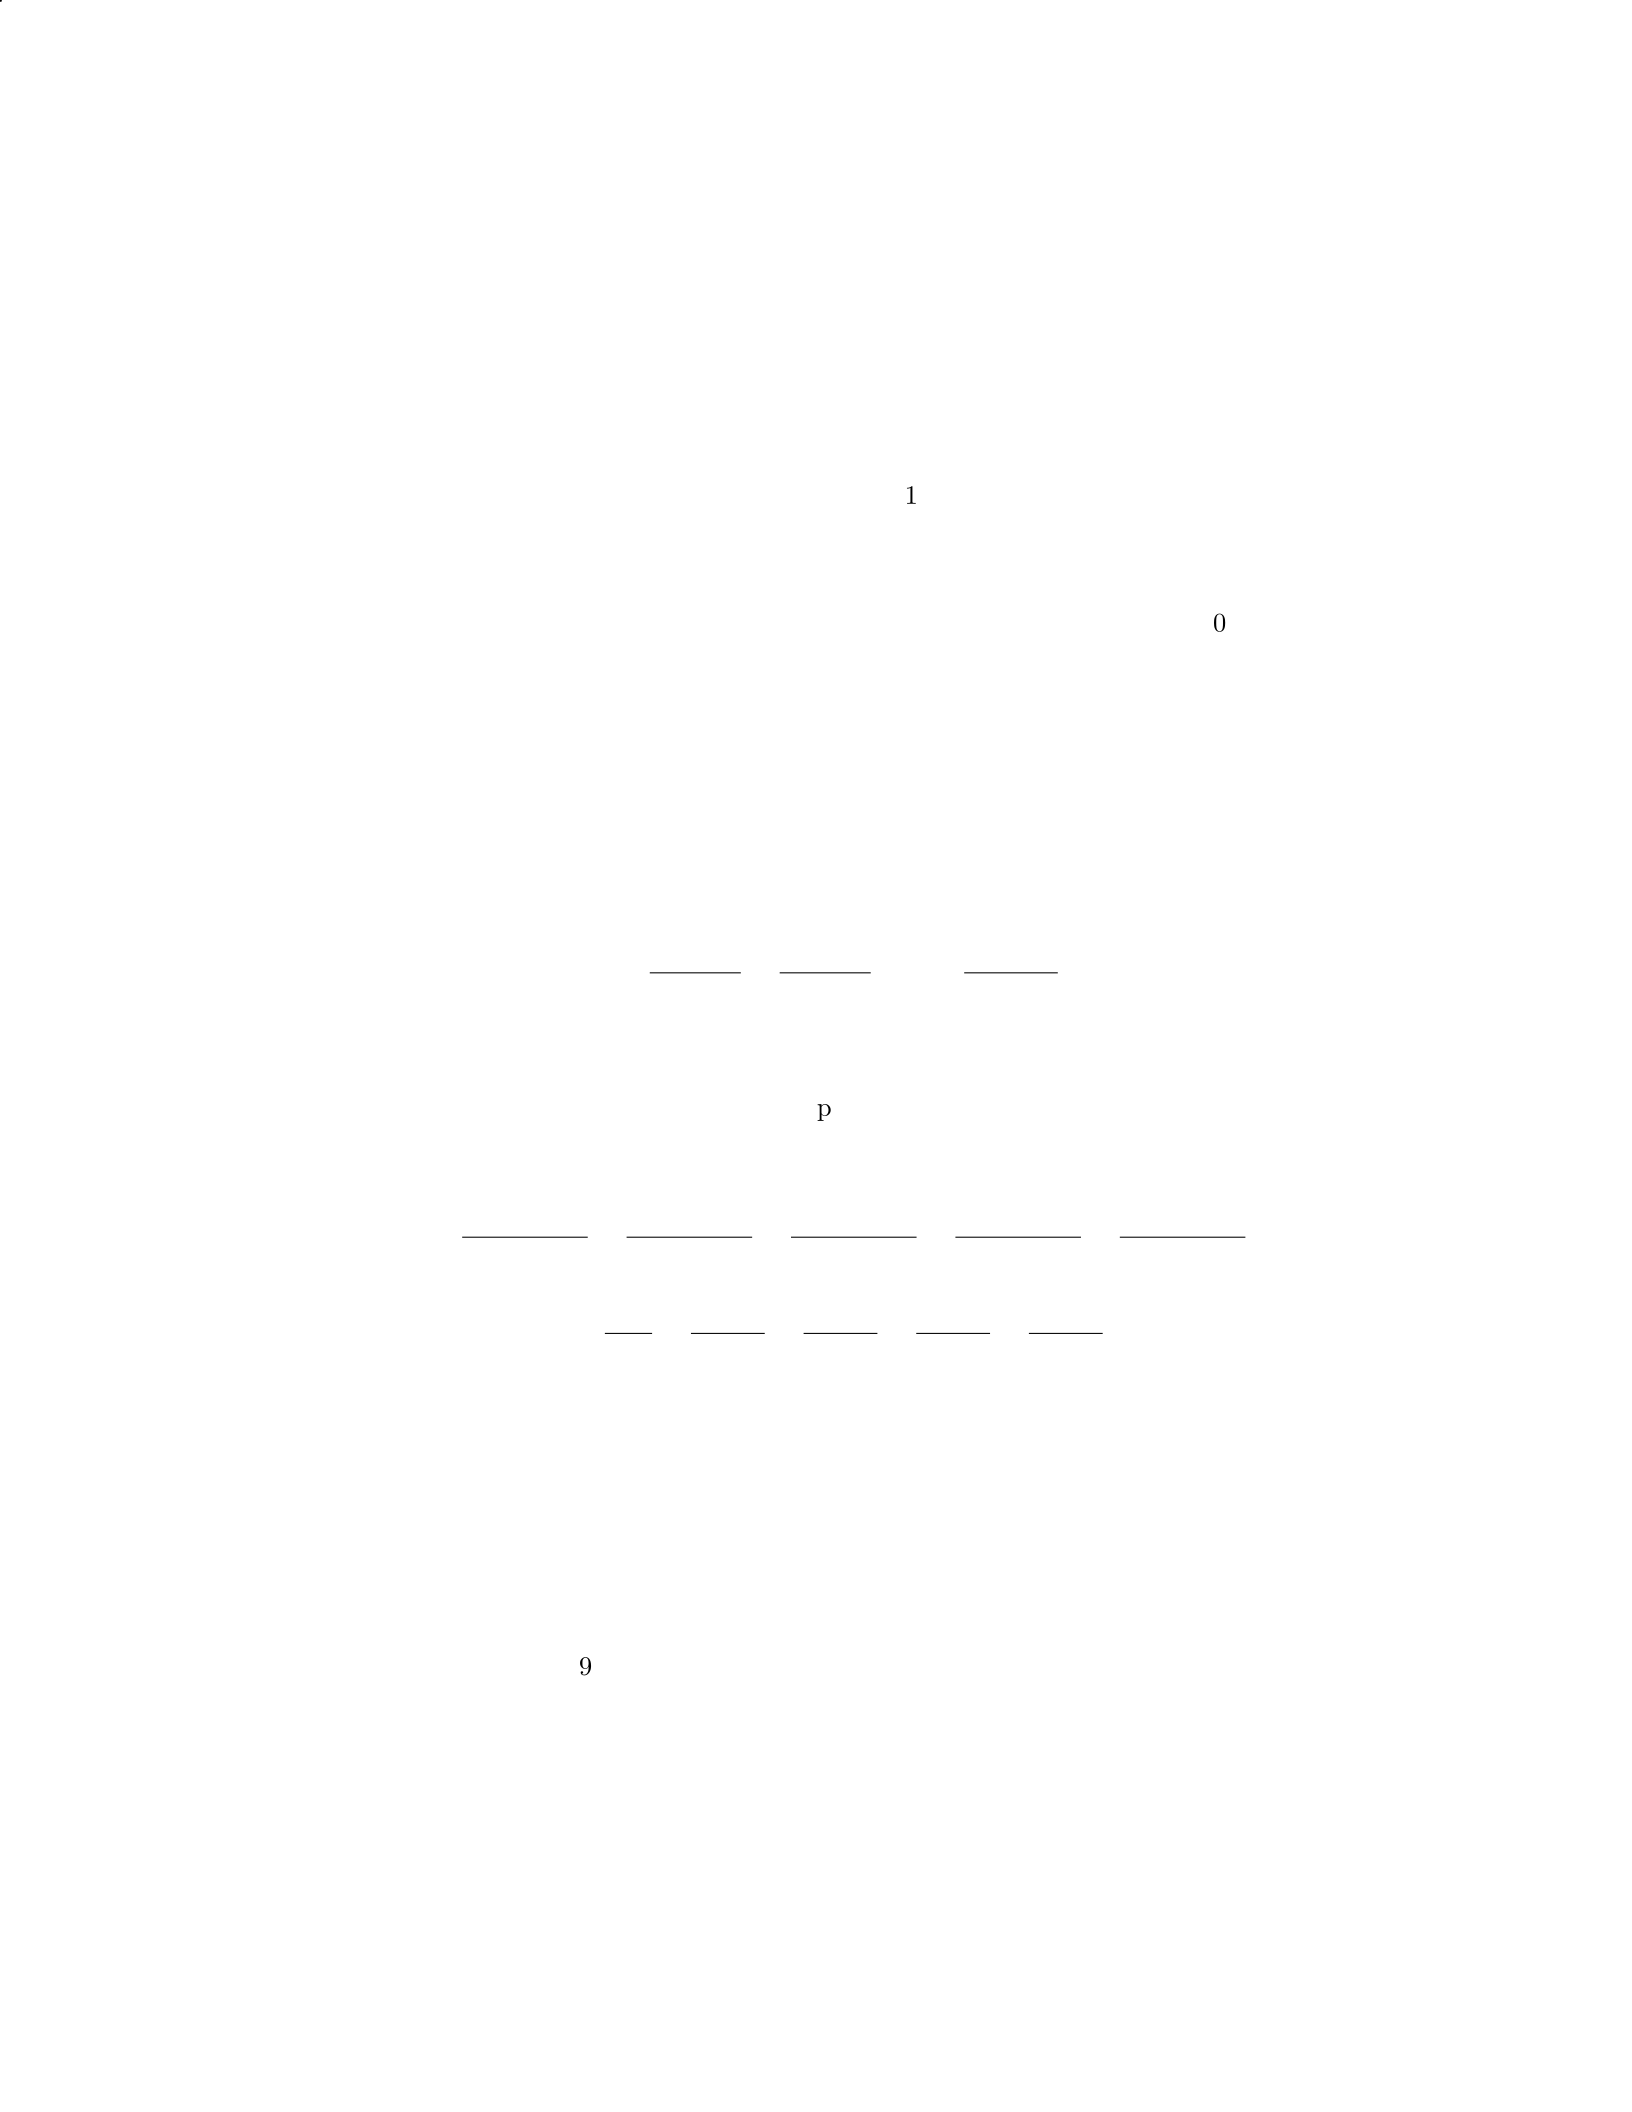
Question 24
Question
Assume a company holds an investment in a highly volatile stock. The fair
value of the stock at the end of the year is
$
150 per share. The company’s
management believes that the fair value calculation is inappropriate due to the
high volatility of the stock price. As a result, they are considering using a
valuation model that takes into account the expected cash flows associated with
the stock. If the expected cash flows for the stock are estimated to be
$
10 per
share for the next 5 years, with no residual value at the end of the 5 years, what
should be the fair value of the stock according to this valuation model? The
discount rate is 8%.
Solution
Step 1: Calculate the present value of the expected cash flows using the dis-
counted cash flow (DCF) method. The formula for calculating the present value
of a series of cash flows is:
P V =CF1
(1 + r)1+CF2
(1 + r)2+... +CFn
(1 + r)n
Where: - PV = Present Value - CF = Cash Flow - r = Discount Rate - n =
Number of periods
In this case, the cash flows are
$
10 per share for the next 5 years, and the
discount rate is 8%.
P V =10
(1 + 0.08)1+10
(1 + 0.08)2+10
(1 + 0.08)3+10
(1 + 0.08)4+10
(1 + 0.08)5
P V =10
1.08 +10
1.1664 +10
1.2597 +10
1.3605 +10
1.4693
P V ≈9.26 + 8.57 + 7.94 + 7.35 + 6.79
P V ≈39.91
Step 2: Calculate the fair value of the stock. Since there is no residual value
at the end of the 5 years, the fair value is equal to the present value of the
expected cash flows.
Therefore, the fair value of the stock according to this valuation model is
approximately
$
39.91 per share.
20
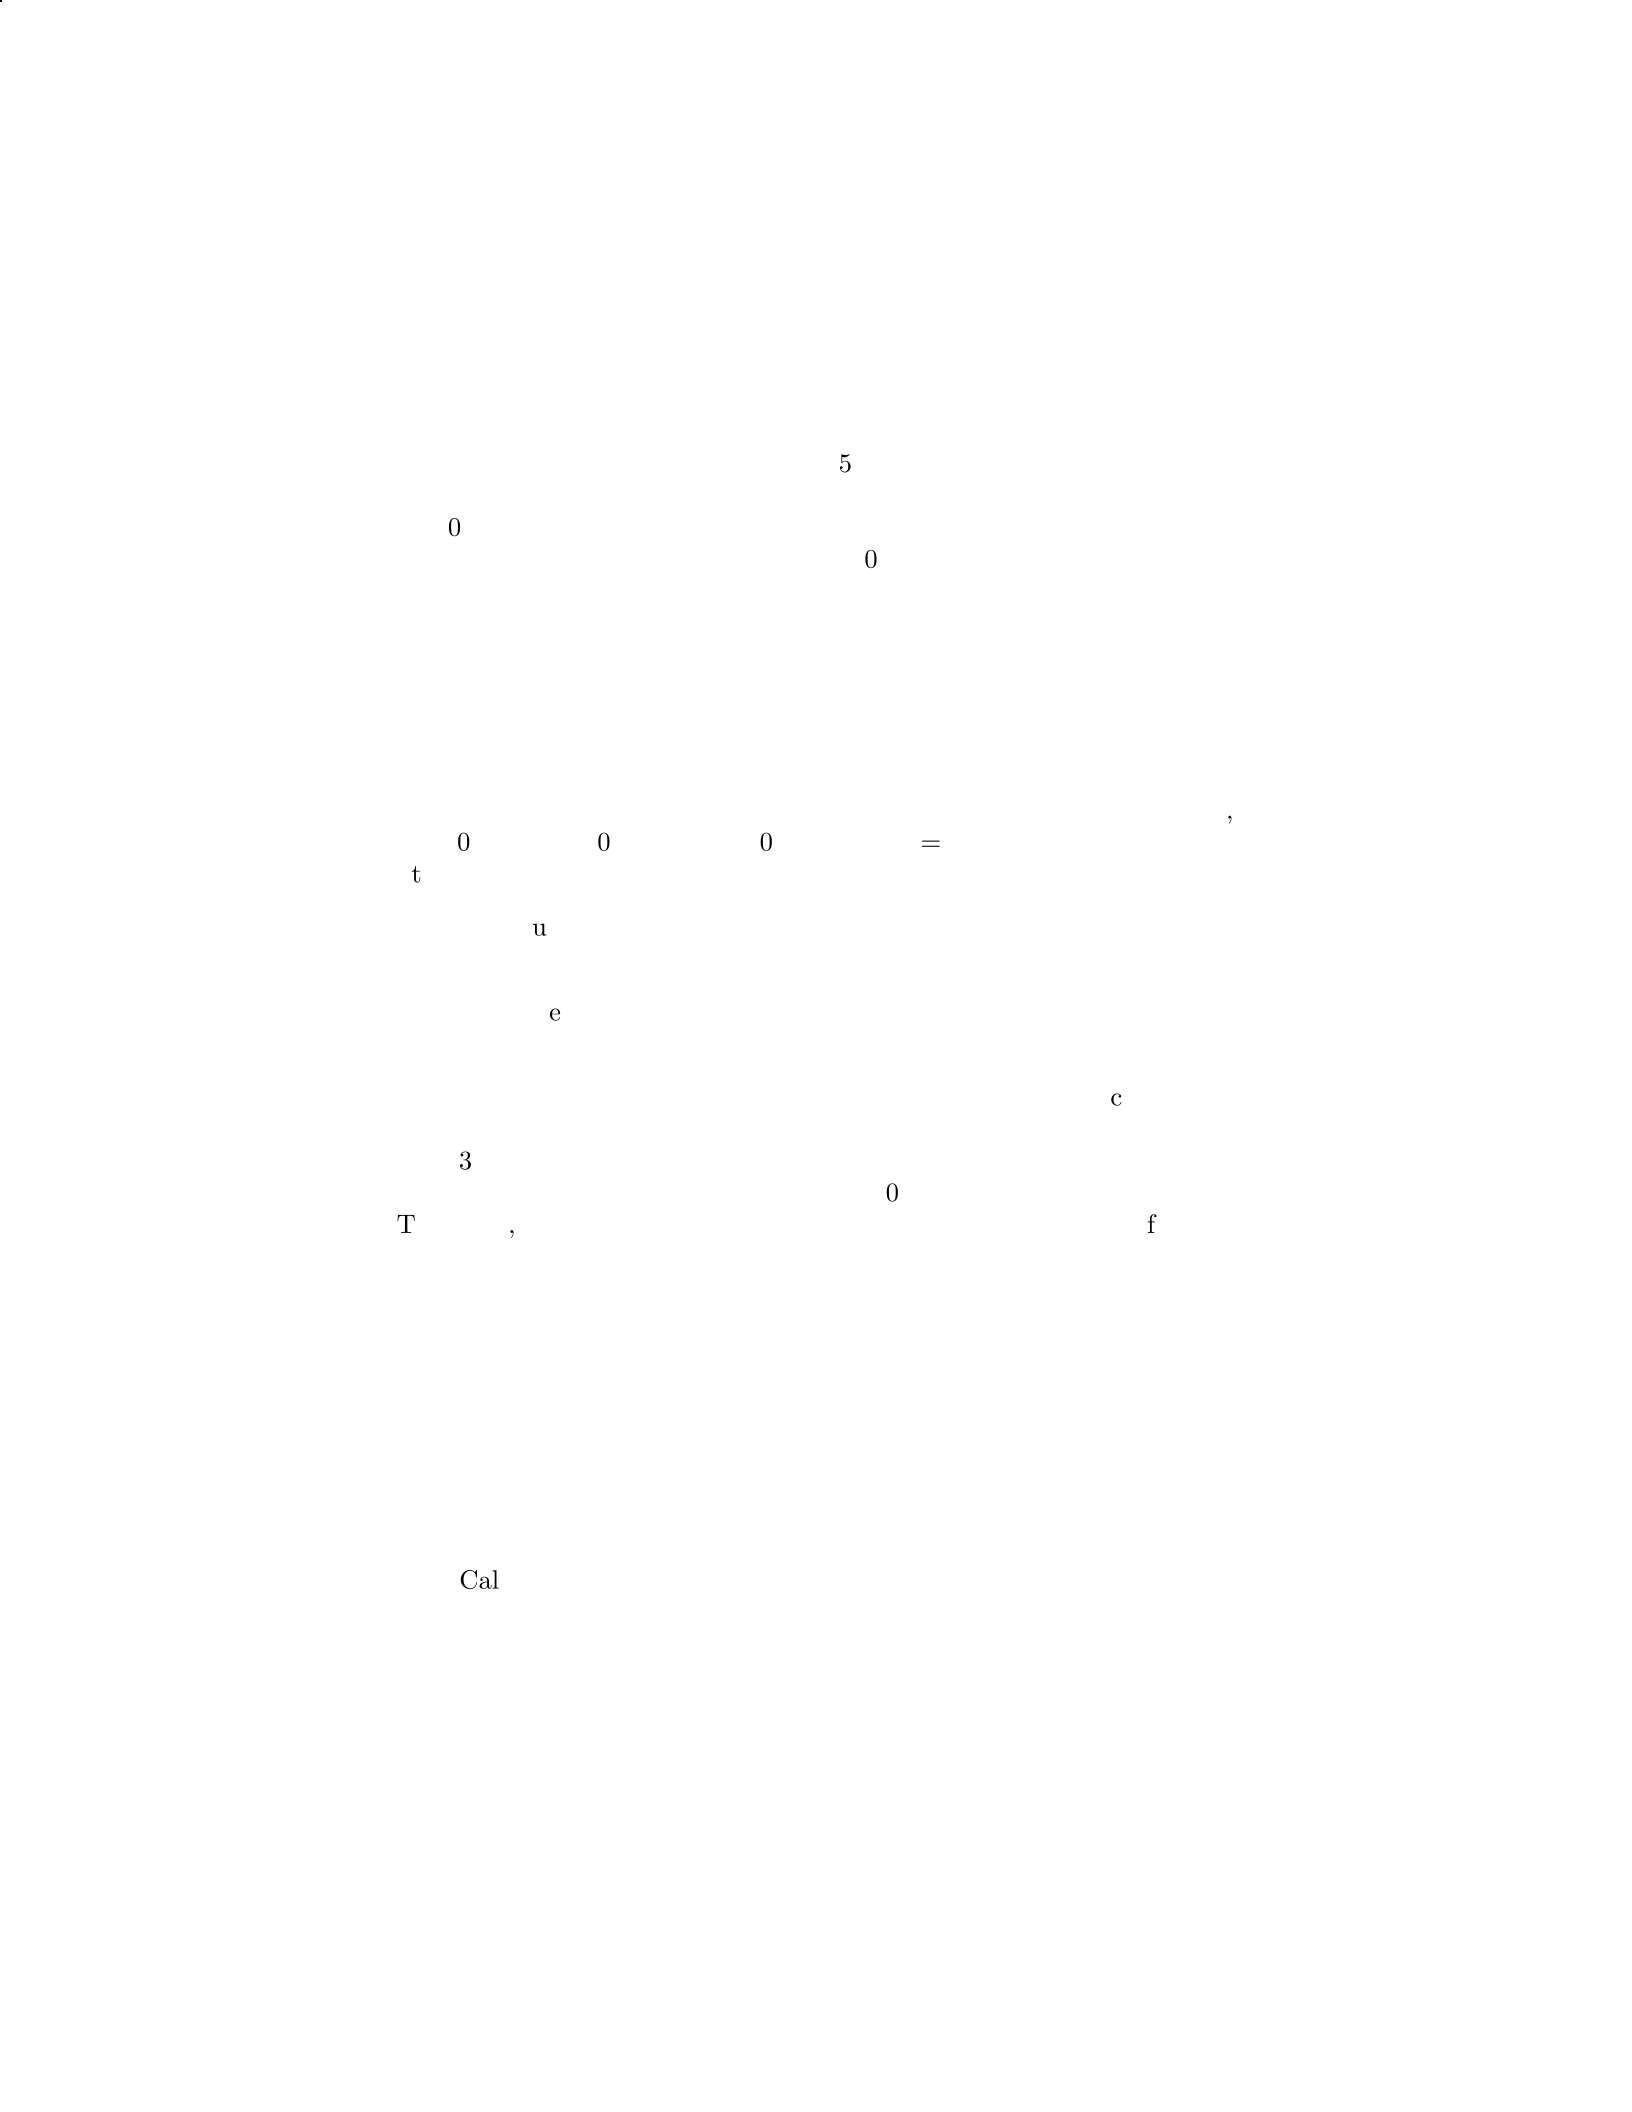
Question 25
Question
A company purchased a piece of land for
$
500,000 in 2010. Due to an increase in
demand and development in the area, the fair value of the land was determined
to be
$
800,000 at the end of 2015. In 2017, the company decided to sell the land,
and the fair value was determined to be
$
750,000. Calculate the gain or loss on
the sale of the land, assuming the company uses fair value as its measurement
basis for non-financial assets.
Solution
Step 1: Calculate the carrying amount of the land in 2017. The carrying amount
of the land is the original cost plus any subsequent adjustments to fair value.
Carrying amount in 2017 = Cost + (Fair value at end of 2015 - Cost) =
$
500,000
+ (
$
800,000 -
$
500,000) =
$
500,000 +
$
300,000 =
$
800,000
Step 2: Determine the gain or loss on the sale.
If fair value at the time of sale is greater than the carrying amount, it is
a gain.
If fair value at the time of sale is less than the carrying amount, it is a
loss.
In this case, the fair value at the time of sale is
$
750,000, which is less than
the carrying amount of
$
800,000.
Step 3: Calculate the loss on the sale. Loss on sale = Carrying amount -
Fair value at time of sale =
$
800,000 -
$
750,000 =
$
50,000
Therefore, the company will incur a loss of
$
50,000 on the sale of the land.
Question 26
Question
Company XYZ holds an investment property that it plans to sell in the future.
The property is currently valued at 900,000basedonitsfairvalue.Duringtheyear, theproperty′svalueincreasedby10
Solution
Step 1: Calculate the increase in value of the investment property. Let the
current fair value of the investment property be Vcurrent = $900,000. The
increase in value is given as 10
Increase in value = 10% ×$900,000 = $90,000
21

Step 2: Determine the new fair value of the investment property. The new
fair value will be the current value plus the increase in value:
Vnew =Vcurrent + Increase in value = $900,000 + $90,000 = $990,000
Therefore, the new fair value of the investment property after the 10
Question 27
Question
On December 31, 20X7, Company A purchased an investment in Company B for
350,000.T hefairvalueof theinvestmentatDecember31,20X8, wasassessedtobe380,000.
Company A intends to hold the investment for the long term. Prepare the nec-
essary journal entry to record the fair value adjustment and explain how the
fair value measurement affects the financial statements.
Solution
Step 1: Calculate the fair value adjustment: The fair value adjustment is equal
to the difference between the fair value of the investment at December 31, 20X8,
and the initial cost of the investment. Fair value adjustment = 380,000−350,000
= 30,000
Step 2: Prepare the journal entry: The journal entry to record the fair value
adjustment is as follows:
Investment in Company B30,000
Fair Value Adjustment30,000
Step 3: Explain how the fair value measurement affects the financial state-
ments: - The fair value adjustment entry increases the Investment in Company B
account by 30,000.−T heF airV alueAdjustmentaccountisusedtocapturechangesinthefairvalueof theinvestment.−
T hefairvalueadjustmentaffectstheincomestatementasitrepresentseitheragainorlossontheinvestment.−
T hefairvalueadjustmentalsoaf fectsthebalancesheetasitchangesthecarryingamountof theinvestment.−
Overall, thef airvaluemeasurementprovidesmorerelevantinformationaboutthevalueof theinvestmentcomparedtohistoricalcost, asitreflectscurrentmarketconditions.
Question 28
Question
ABC Company is required to determine the fair value of an investment prop-
erty as of December 31, 2021. The property is a commercial building that
is currently being rented out to a tenant. ABC Company obtained the fol-
lowing information regarding the property: - The property was purchased for
1,500,000onJanuary1,2020.−T hepropertyhasaremainingusef ullifeof50years.−
Comparablepropertiesintheareaaresellingforanaveragepriceof1,750,000. - The
22
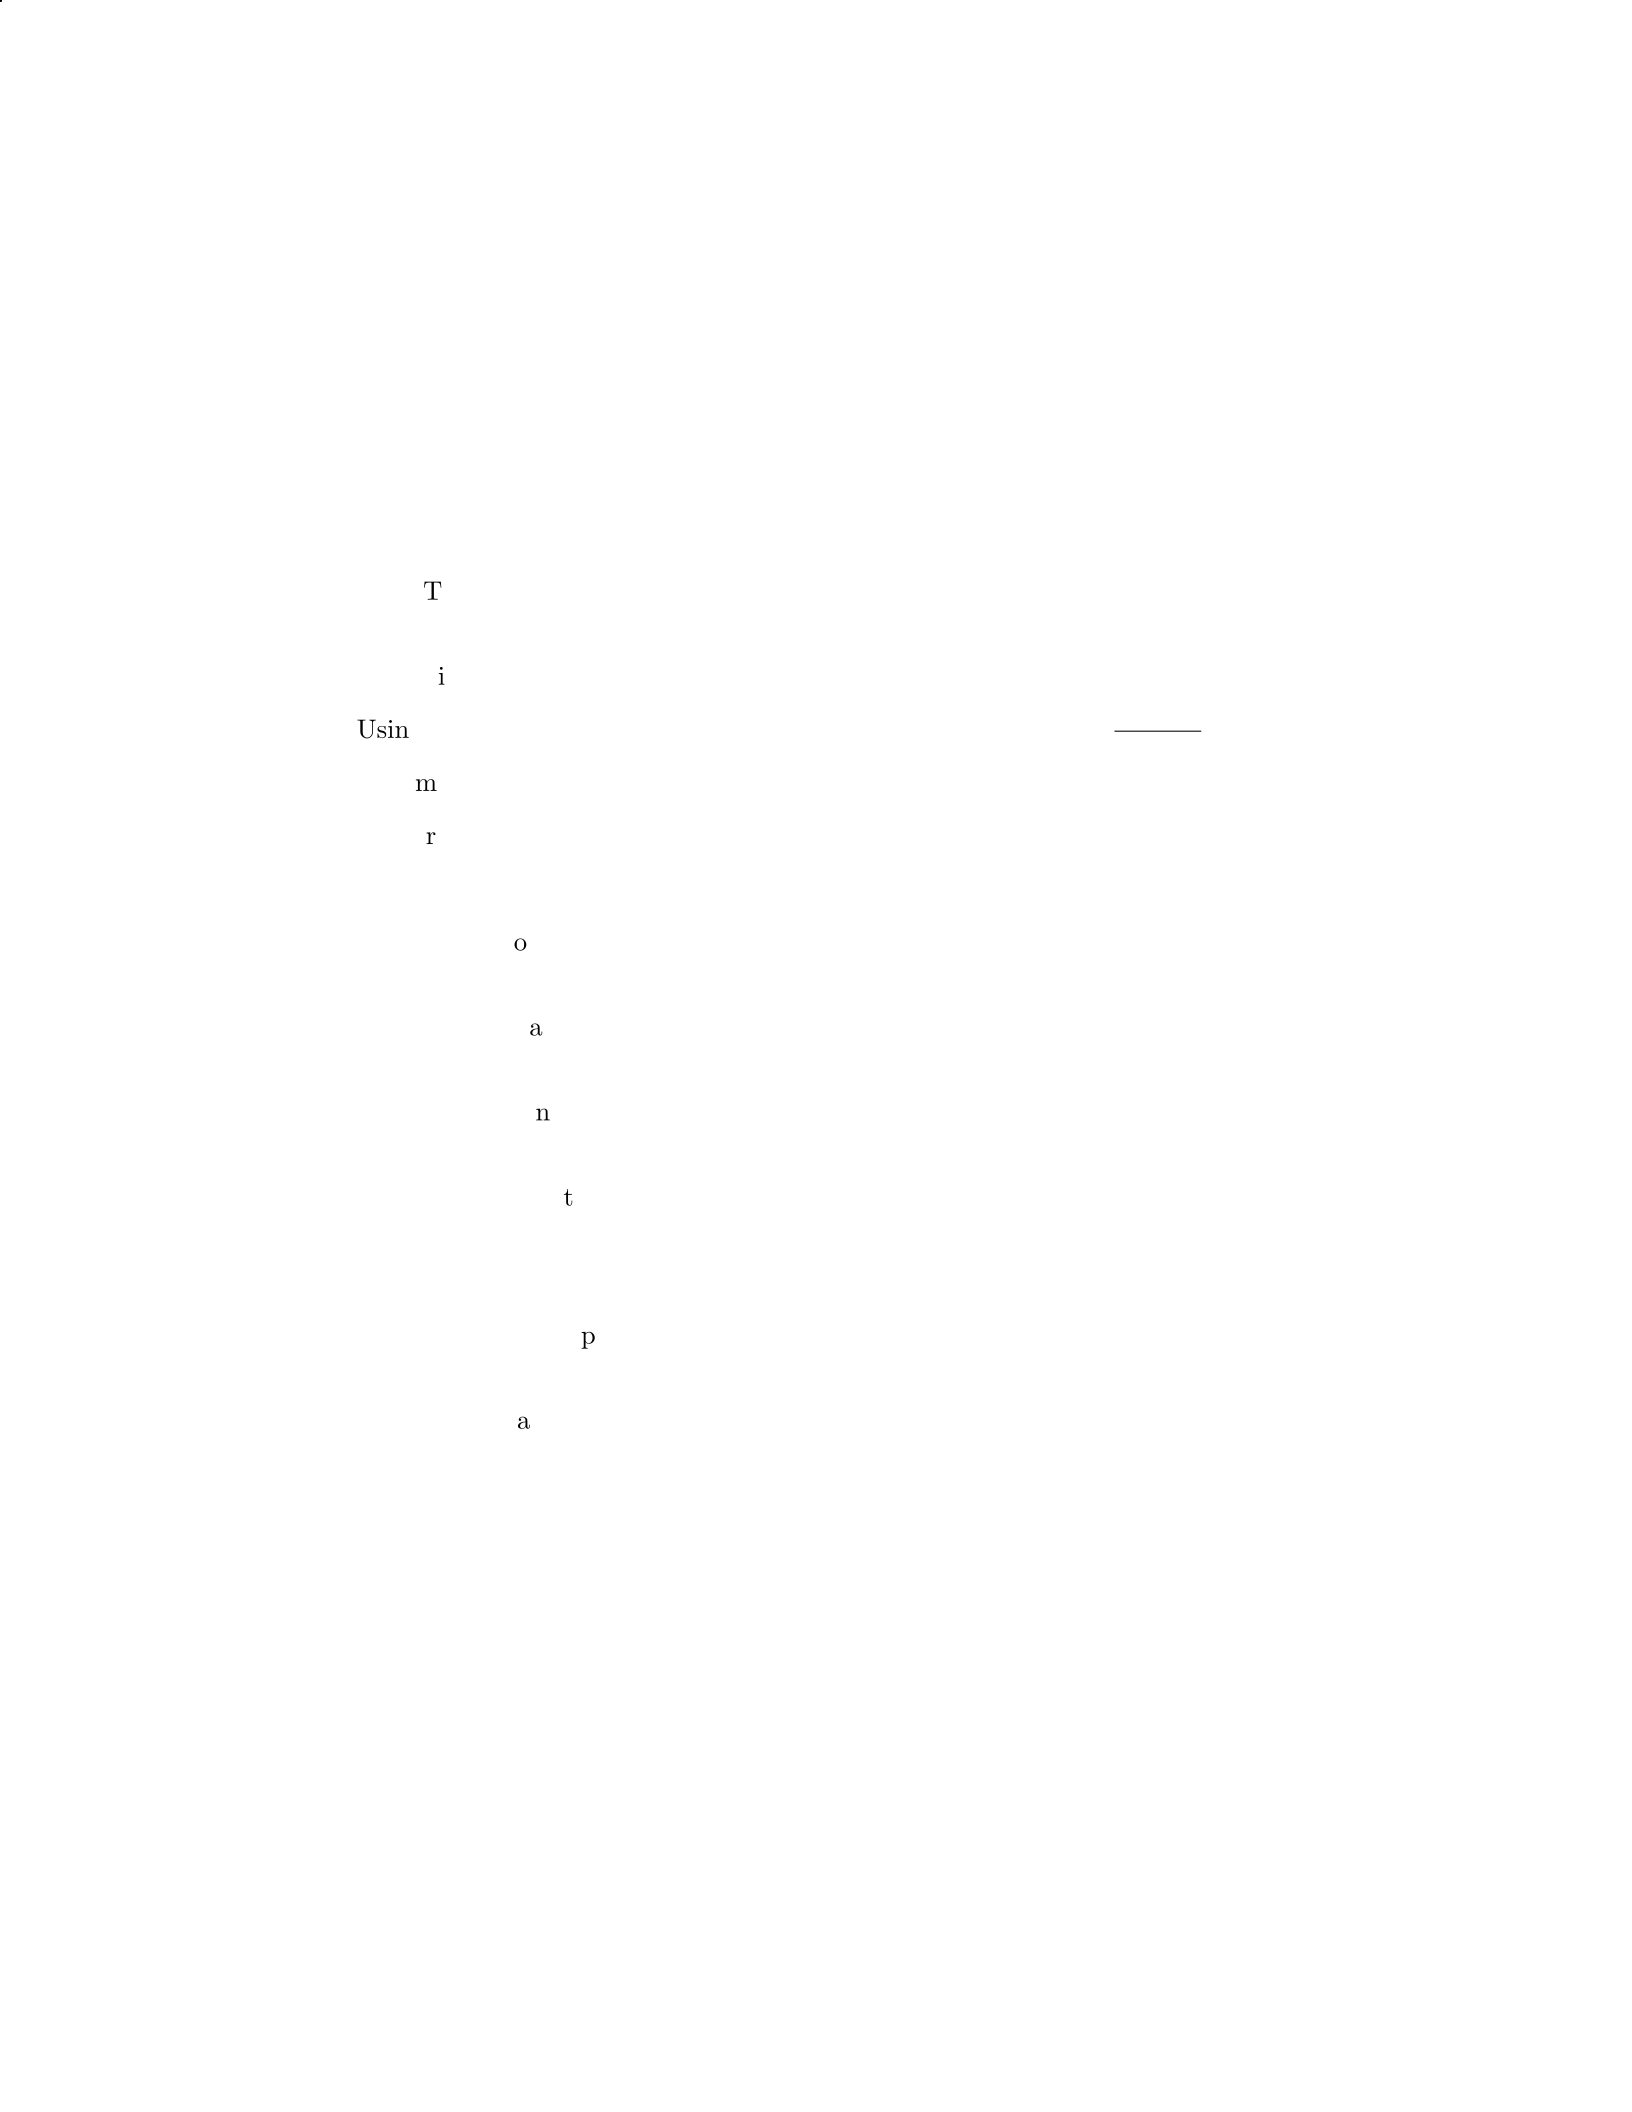
tenant is locked into a long-term lease with below-market rent. Using the cost
approach, income approach, and market approach, calculate the fair value of
the investment property as of December 31, 2021.
Solution
Step 1: Cost Approach
The cost approach determines the fair value of an asset by considering the
cost to replace or reproduce the asset.
Since the property was purchased for 1,500,000, wecanusethisasthebasisforthecostapproachvaluation.AsofDecember31,2021, thepropertyhasbeenownedfor2years.
Using straight-line depreciation, the annual depreciation would be 1,500,000
50 =30,000.
Accumulated depreciation as of December 31, 2021: 30,000 ×2 =60,000.
Property value using the cost approach: 1,500,000 −60,000 =1,440,000.
Step 2: Income Approach
The income approach values an asset based on the present value of the
future cash flows it is expected to generate.
Given that the tenant is paying below-market rent, the current rental
income may not be reflective of the property’s true value.
Adjustments must be made to estimate the potential rental income the
property could generate.
Once the potential rental income is determined, it can be discounted back
to present value using an appropriate discount rate.
Step 3: Market Approach
The market approach values an asset based on comparable market trans-
actions.
Since comparable properties in the area are selling for an average price of
1,750,000, thisprovidesabenchmarkforassessingthefairvalueoftheinvestmentproperty.
Question 29
Question
A company owns an investment property that is measured at fair value through
profit or loss. At the end of the fiscal year, the fair value of the property is as-
sessed at 3,500,000.Duringtheyear, thecompanyreceivedrentalincomeof200,000
from the property. Additionally, the property had appreciated by 5
23
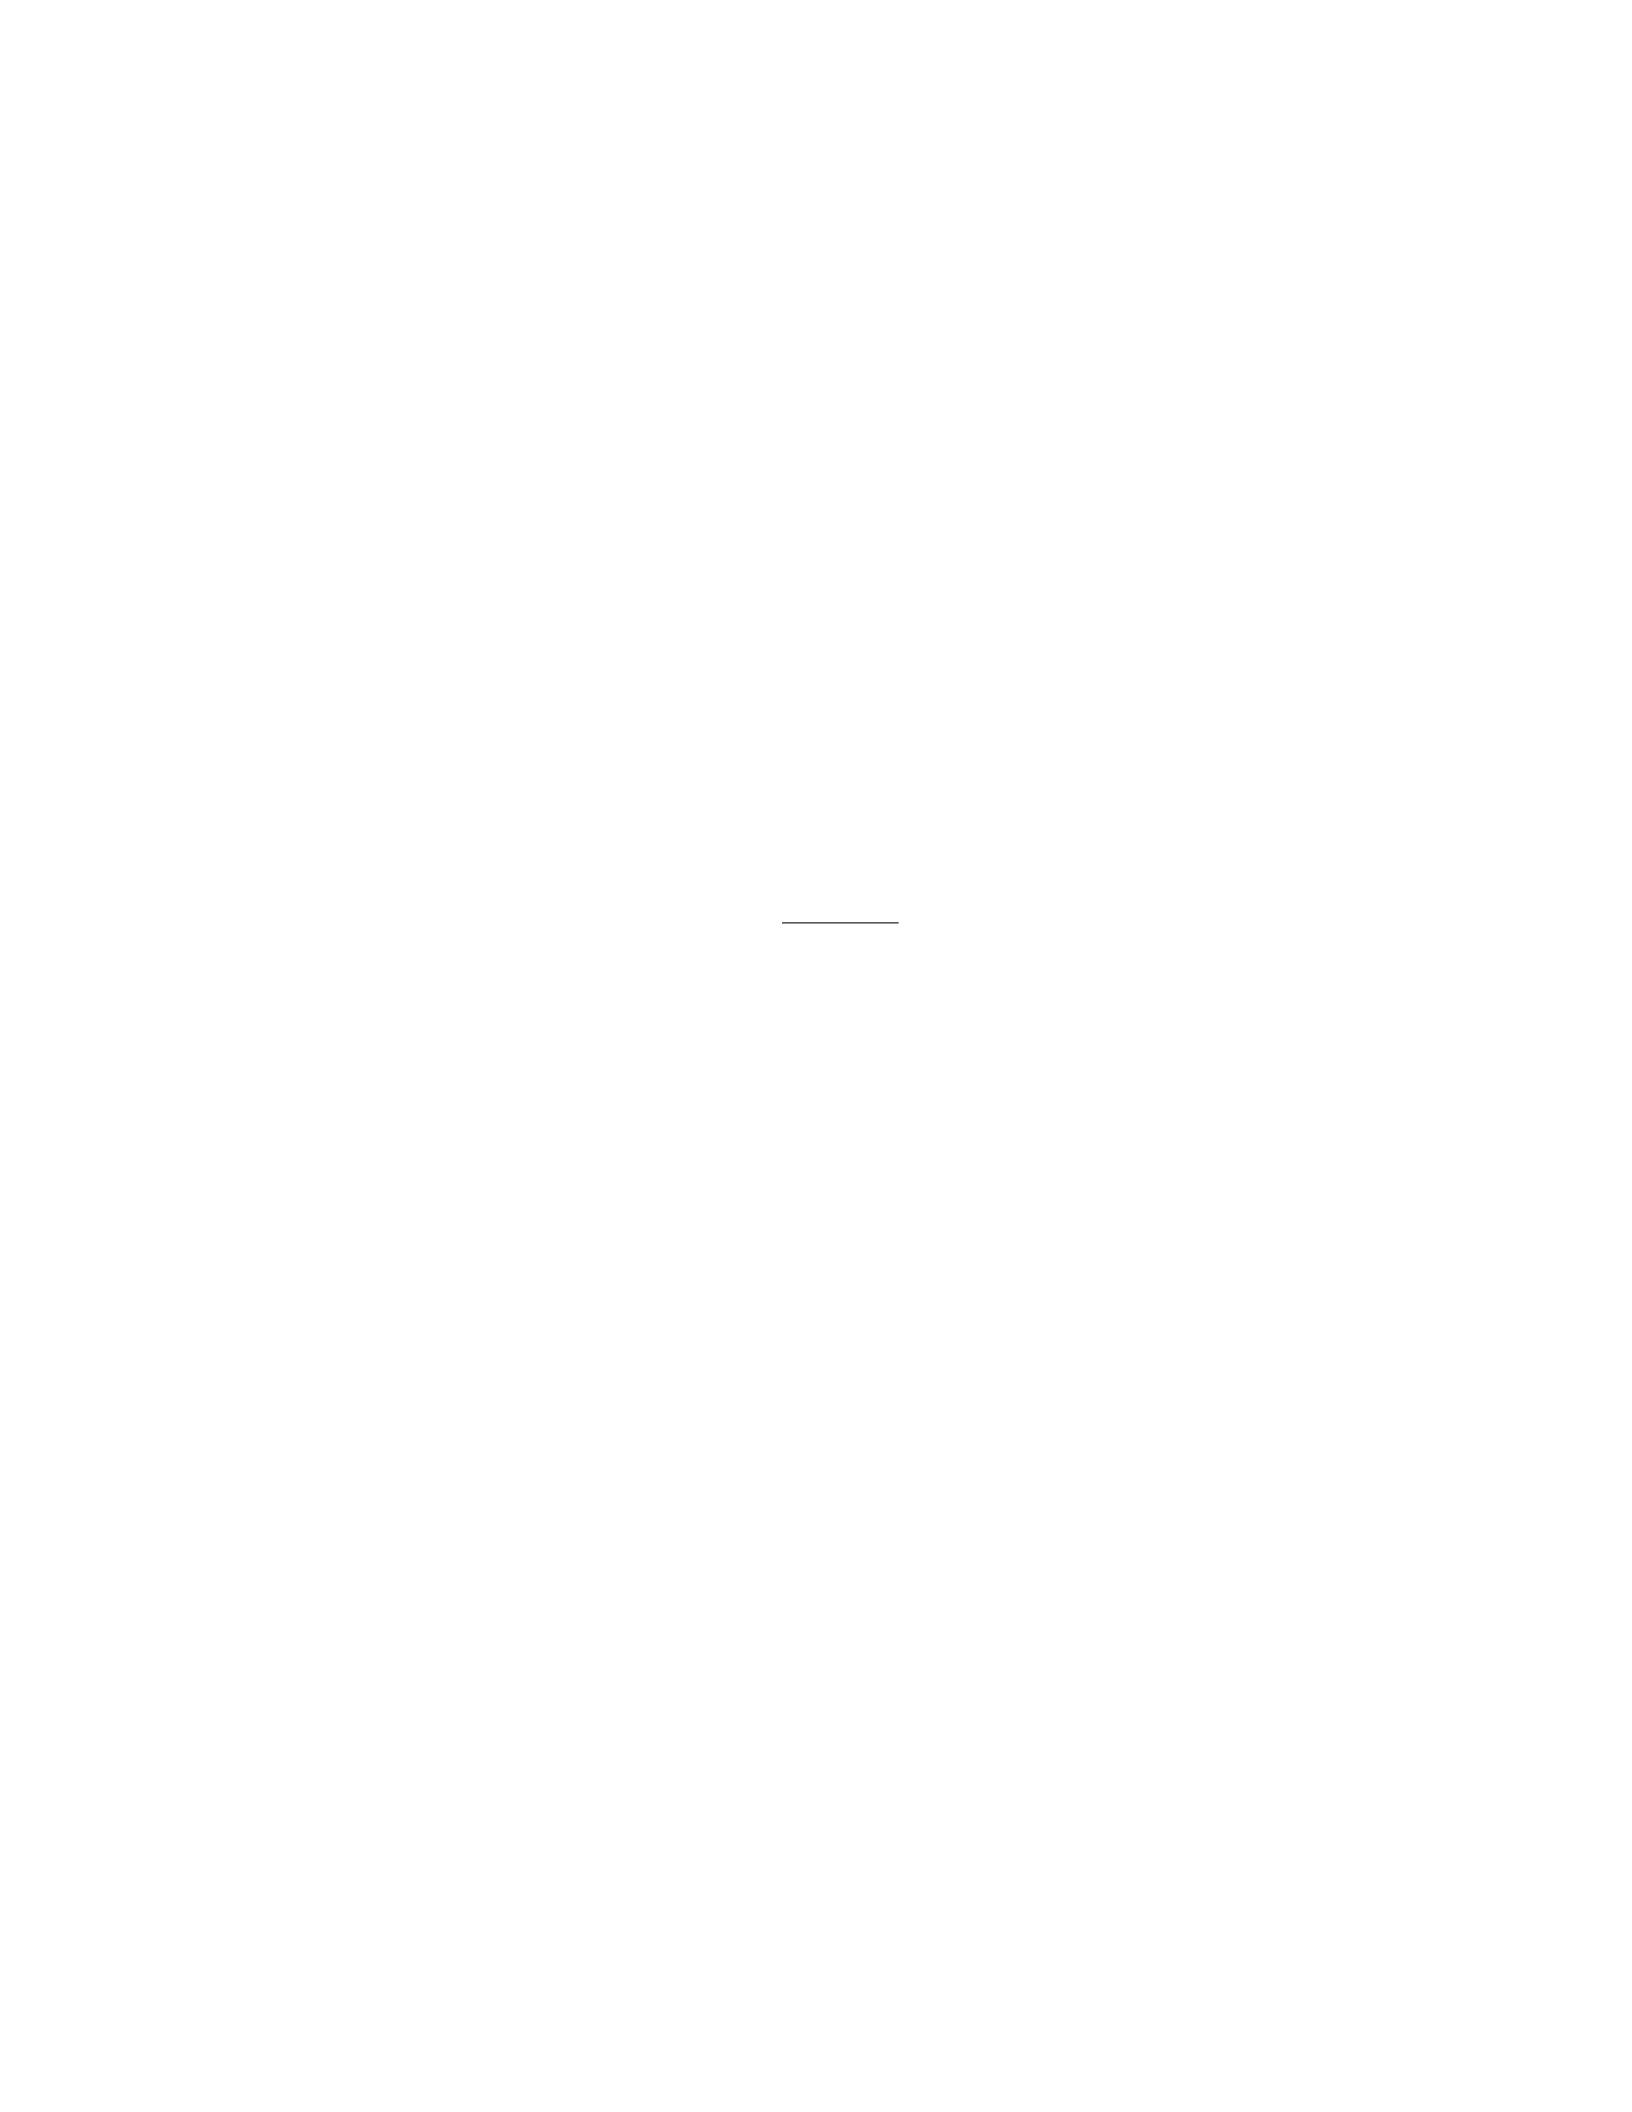
Solution
Step 1: Calculate the initial fair value of the investment property. Let the initial
fair value be x.
Initial Fair Value = x
Step 2: Calculate the final fair value of the property after 5
Final Fair Value = 1.05x
Step 3: Calculate the gain or loss on the investment property.
Gain or Loss = Final Fair Value −Initial Fair Value −Rental Income
Gain or Loss = 1.05x−x−200,000
Step 4: Substitute the final fair value as 3,500,000 to find x.
1.05x= 3,500,000
x=3,500,000
1.05
x= 3,333,333.33
Step 5: Calculate the gain or loss on the investment property.
Gain or Loss = 1.05(3,333,333.33) −3,333,333.33 −200,000
Gain or Loss = 3,500,000 −3,333,333.33 −200,000
Gain or Loss = 33,666.67
Therefore, the gain on the investment property for the year is 33,666.67.
Question 30
Question
A company holds an investment in a private company for which there is no active
market. The fair value of the investment is estimated using an income approach
based on discounted cash flows. The following information is available: - Ex-
pected cash flows for the next five years: 10,000,12,000, 15,000,18,000, 20,000−
Discountrate : 8Calculatethefairvalueoftheinvestmentusingthediscountedcashflowmethod.
24
Solution
Step 1: Calculate the present value of the expected cash flows.
PV = 10,000
(1 + 0.08)1+12,000
(1 + 0.08)2+15,000
(1 + 0.08)3+18,000
(1 + 0.08)4+20,000
(1 + 0.08)5
PV = 10,000
1.08 +12,000
1.1664 +15,000
1.2605 +18,000
1.3605 +20,000
1.4693
PV ≈9259.26 + 10296.01 + 11904.38 + 13231.98 + 13579.81
PV ≈58171.44
Therefore, the present value of the expected cash flows is approximately
$
58,171.44.
Step 2: The fair value of the investment is determined by the present value
of the expected cash flows.
Fair Value = $58,171.44
Therefore, the fair value of the investment using the discounted cash flow
method is approximately
$
58,171.44.
Question 31
Question
A company holds an investment in a privately held company for which there
is no observable market price. The fair value of the investment is determined
using a discounted cash flow model. The key inputs to the model include the
discount rate and the projected cash flows of the investee.
Given the complexity of the investment and the uncertainty around the cash
flow projections, how should the company adjust its fair value measurement to
account for these factors?
Solution
To adjust the fair value measurement for the complexity and uncertainty asso-
ciated with the investment in the privately held company, the company should
take the following steps:
Step 1: Identify Key Assumptions
Identify the key assumptions used in the discounted cash flow model, such
as the discount rate, cash flow projections, and terminal value assump-
tions.
Step 2: Adjust Discount Rate
Increase the discount rate to reflect the higher risk and uncertainty asso-
ciated with the investment.
25
This higher discount rate compensates investors for the additional risk of
the investment.
Step 3: Scenario Analysis
Perform scenario analysis by varying the key assumptions within a rea-
sonable range to understand the impact on the fair value.
This helps in assessing the sensitivity of the fair value estimate to changes
in assumptions.
Step 4: Adjust Cash Flow Projections
Adjust the cash flow projections to account for the uncertainty and com-
plexity of the investment.
Consider the potential risks and uncertainties that could impact the in-
vestee’s performance and adjust the cash flow projections accordingly.
Step 5: Disclosure
Disclose the key assumptions, methodologies, and uncertainties in the fair
value measurement in the financial statements.
Provide transparent information to users of the financial statements about
the factors influencing the fair value measurement.
By following these steps, the company can adjust its fair value measure-
ment for the complexity and uncertainty associated with the investment in the
privately held company.
Question 32
Question
A company holds an investment property that is carried at fair value through
profit or loss. At the end of the reporting period, the fair value of the property
is reassessed and determined to be 2,500,000.
During the next reporting period, the fair value of the same property in-
creases by 10
Solution
Step 1: Calculate the increase in fair value: Given that the fair value of the
property increases by 10
Increase in Fair Value = 10% ×$2,500,000
Increase in Fair Value = 0.10 ×$2,500,000
26
Increase in Fair Value = $250,000
Step 2: Determine the revised fair value: To find the revised fair value, we
add the increase in fair value to the original fair value:
Revised Fair Value = $2,500,000 + $250,000
Revised Fair Value = $2,750,000
Therefore, the revised fair value of the property is $2,750,000.
Question 33
Question
A company determines the fair value of its investment properties using the
income approach. The annual net rental income is estimated at $250,000 and
the discount rate is 8%. Calculate the fair value of the investment properties
using the income approach.
Solution
Step 1: Calculate the present value of the net rental income. The formula for
calculating the present value of an annuity is:
P V =C
r×1−1
(1 + r)n
Where: - P V is the present value - Cis the annual net rental income - ris the
discount rate - nis the number of years
Substitute the given values into the formula:
P V =250,000
0.08 ×1−1
(1 + 0.08)1
P V = 3,125,000 ×1−1
1.08
P V = 3,125,000 ×(1 −0.9259)
P V = 3,125,000 ×0.0741
P V = 231,187.5
Therefore, the present value of the net rental income is 231,187.5.
Step 2: Calculate the fair value of the investment properties. The fair value
of the investment properties using the income approach is equal to the present
value of the net rental income. Hence, the fair value of the investment properties
is 231,187.5.
27

Question 34
Question
A company holds an investment in a financial instrument classified as a Level 3
fair value measurement under IFRS 13. At the end of the reporting period, the
fair value of the investment is uncertain due to the illiquidity of the market. The
company’s management decides to use a valuation technique that incorporates
unobservable inputs to estimate the fair value of the investment. Discuss the key
considerations and challenges in determining the fair value of this investment.
Solution
To determine the fair value of an investment classified as a Level 3 fair value
measurement under IFRS 13, several key considerations and challenges must be
taken into account. Below are the key points to consider:
Step 1: Nature of Investment - The first consideration is understanding
the nature of the investment, including its unique characteristics, restrictions,
and legal obligations. This information will help in selecting an appropriate
valuation technique.
Step 2: Valuation Technique - Given the illiquidity of the market for
the investment, the company must use a valuation technique that incorporates
unobservable inputs. This could involve using a discounted cash flow analysis,
option pricing models, or other sophisticated valuation models.
Step 3: Unobservable Inputs - The valuation technique chosen will likely
rely on unobservable inputs, also known as Level 3 inputs, such as future cash
flows, discount rates, and volatility assumptions. Management must exercise
judgment in determining the reasonableness of these inputs.
Step 4: Market Data - The lack of readily available market data for
similar investments may make it challenging to validate the inputs used in the
valuation technique. Management may need to consider alternative data sources
or adjust existing data to reflect the specific characteristics of the investment.
Step 5: Sensitivity Analysis - Given the uncertainty surrounding the
fair value of the investment, conducting sensitivity analysis can help assess the
impact of changes in key assumptions on the final fair value estimate. This
analysis is essential for understanding the range of possible outcomes.
Step 6: Disclosures - Lastly, the company must provide detailed disclo-
sures in the financial statements regarding the fair value measurement process,
including the valuation techniques used, key assumptions, and any significant
unobservable inputs. This transparency is crucial for users of the financial
statements to understand the level of uncertainty associated with the fair value
measurement.
28
Question 35
Question
A company is valuing its investment property using the fair value model. The
property was purchased for 500,000fiveyearsagoandisnowvaluedat700,000. The
property generates annual rental income of 40,000.Ifthecompanyusesadiscountrateof8
Solution
Step 1: Calculate the present value of expected future cash flows from the
property. The present value of an annuity formula is used to calculate the
present value of the rental income.
P V =R
r×(1 −(1 + r)−n)
where: - P V = present value of the rental income - R= annual rental income
(40,000) −r= discount rate (8- n= number of years (infinity in this case)
Substitute the values into the formula:
P V =40,000
0.08 ×(1 −(1 + 0.08)−∞ )
Step 2: Calculate the present value of the expected future selling price of
the property after ’n’ years. The future value formula is used to calculate this:
F V =P×(1 + r)n
where: - F V = future value of the property after ’n’ years - P= initial purchase
price of the property (500,000) −r= discount rate (8- n= number of years (5
in this case)
Substitute the values into the formula:
F V = 500,000 ×(1 + 0.08)5
Step 3: Calculate the fair value of the property by summing up the present
value of expected future cash flows and the present value of the expected future
selling price: Fair Value = PV + FV
Now, plug in the calculated values and solve for the fair value.
29

