


ACCT 531 - ACCOUNTING
INFORMATION SYSTEMS - Fair
Value Measurement
Question Bank - Set 4
Liberty University
Question 1
Question
A company is valuing an investment using the fair value measurement method.
They estimate the future cash flows of the investment to be 50,000attheendofyear1,70,000
at the end of year 2, and 100,000attheendof year3.T hecompany′sdiscountrateis8
Solution
Step 1: Calculate the present value of each future cash flow. The present value
(PV) of a future cash flow can be calculated using the formula:
P V =F V
(1 + r)n
where F V is the future cash flow, ris the discount rate, and nis the number
of periods into the future the cash flow occurs.
Using the given data: For year 1:
P V1=50,000
(1 + 0.08)1=50,000
1.08 ≈46,296.30
For year 2:
P V2=70,000
(1 + 0.08)2=70,000
1.1664 ≈60,025.91
For year 3:
P V3=100,000
(1 + 0.08)3=100,000
1.2597 ≈79,355.58

Step 2: Sum the present values of all future cash flows to find the fair value
of the investment.
Fair Value = P V1+P V2+P V3
Fair Value = 46,296.30 + 60,025.91 + 79,355.58 ≈185,677.79
Therefore, the fair value of the investment using the fair value measurement
method is approximately 185,677.79.
Question 2
Question
An investment company has a financial asset that is measured at fair value
through profit or loss. At the reporting date, the fair value of the financial asset
is 5,000,000.Duringtheyear, thefairvalueofthefinancialassetincreasedto5,500,000.
Calculate the gain or loss recognized in profit or loss due to the change in fair
value.
Solution
Step 1: Calculate the gain or loss in fair value The gain or loss is calculated by
subtracting the initial fair value from the final fair value:
Gain or Loss = Final Fair Value −Initial Fair Value
Gain or Loss = 5,500,000 −5,000,000 = 500,000
Step 2: Determine the nature of the gain or loss Since the fair value of the finan-
cial asset increased from 5,000,000to5,500,000, a gain of 500,000wasrealized.Step3 :
Recognizethegaininprof itorlossT hegainof 500,000 should be recognized in profit
or loss for the period.
Question 3
Question
A company holds an investment in a real estate property classified as Level 3 in
the fair value hierarchy. The fair value of the investment at the reporting date is
750,000.Duringtheyear, thereweresignificantunobservableinputsusedtomeasurethefairvalueof theproperty.Atthebeginningoftheyear, thefairvaluewas700,000.
Calculate the unrealized gain or loss for the year related to this investment.
Solution
Step 1: Calculate the unrealized gain or loss Step 2: Use the formula: Unrealized
gain or loss = Fair value at reporting date - Fair value at beginning of the year
Step 3: Substitute the given values into the formula:
Unrealized gain or loss = $750,000 −$700,000
2
Step 4: Perform the calculation:
Unrealized gain or loss = $50,000
Therefore, the unrealized gain related to this investment for the year is
$
50,000.
Question 4
Question
Company XYZ holds an investment in equity securities that are classified as fair
value through profit or loss. At the end of the reporting period, the fair value
of the equity securities is $150,000 while the cost of investment is $120,000.
Additionally, the company incurred $5,000 in transaction costs related to the
investment. Calculate the gain or loss recognized in profit or loss for the period.
Solution
To calculate the gain or loss recognized in profit or loss, we need to consider the
fair value of the investment, the cost of investment, and any related transaction
costs.
Fair Value of the Investment = $150,000
Cost of Investment = $120,000
Transaction Costs = $5,000
Step 1: Calculate the net carrying amount of the investment. The net
carrying amount of the investment is calculated as the cost of the investment
adjusted for any transaction costs.
Net Carrying Amount = Cost of Investment + Transaction Costs
Net Carrying Amount = $120,000 + $5,000
Net Carrying Amount = $125,000
Step 2: Determine the gain or loss recognized in profit or loss. The gain or
loss recognized in profit or loss is calculated as the difference between the fair
value of the investment and the net carrying amount.
Gain/Loss = Fair Value of Investment −Net Carrying Amount
Gain/Loss = $150,000 −$125,000
Gain/Loss = $25,000
Since the fair value of the investment is higher than the net carrying amount,
the company would recognize a gain of $25,000 in profit or loss for the period.
3
Question 5
Question
A company holds an investment in a publicly traded equity security. The fair
value of the investment at the end of the reporting period is 150,000.Duringthereportingperiod, thefairvalueof theinvestmentincreasedby20,000
due to changes in market conditions. However, the company also incurred
5,000intransactioncostswhenacquiringtheinvestment.Calculatetheamountthatshouldbereportedinthecompany′sfinancialstatementsf ortheinvestment.
Solution
Step 1: Calculate the fair value change excluding transaction costs. We need to
adjust the fair value change for the transaction costs incurred by the company.
Fair value change excluding transaction costs = Fair value change−Transaction costs
Fair value change excluding transaction costs = $20,000 −$5,000
Fair value change excluding transaction costs = $15,000
Step 2: Determine the amount to be reported in the financial statements.
The amount to be reported in the financial statements is the initial cost of the
investment plus the fair value change excluding transaction costs.
Amount to be reported = Initial cost+Fair value change excluding transaction costs
Since no initial cost was provided in the question, we can assume it was equal
to the fair value at the end of the reporting period.
Amount to be reported = $150,000 + $15,000
Amount to be reported = $165,000
Therefore, the amount that should be reported in the company’s financial
statements for the investment is $165,000.
Question 6
Question
A company holds an investment in a commodity futures contract. The fair
value of the investment at the end of the reporting period is determined to be
15,000.T hecompanyneedstodecidewhethertoclassifytheinvestmentasheld−f or−
tradingorasheld−for−other−purpose.P rovidetwokeyf actorsthatthecompanyshouldconsiderwhenmakingthisclassificationdecision.
4
Solution
Step 1: One key factor that the company should consider is the company’s
intention at the time of purchase. If the company’s intention was to profit
from short-term fluctuations in market prices, then the investment should be
classified as held-for-trading. On the other hand, if the company’s intention was
to hold the investment for a longer period of time, then it should be classified
as held-for-other-purpose.
Step 2: Another key factor to consider is the frequency of transactions. If the
company frequently buys and sells similar investments, it may indicate that the
investment should be classified as held-for-trading. Conversely, if the company
rarely engages in such transactions and has a history of holding investments
for longer periods, it may be more appropriate to classify the investment as
held-for-other-purpose.
Question 7
Question
ABC Company owns an investment in a bond for which the fair value is not read-
ily determinable. The company receives annual cash flows of 4,000eachyearandattheendof year5receivesthebond′sfacevalueof 10,000.
The bond’s discount rate is 8
Solution
Step 1: Calculate the present value of the bond’s cash flows. The present value
of the annual cash flows:
P Vannuity =4000
1+0.08 +4000
(1 + 0.08)2+4000
(1 + 0.08)3+4000
(1 + 0.08)4+4000 + 10000
(1 + 0.08)5
Step 2: Simplify the expression by calculating the present values.
P Vannuity =4000
1.08 +4000
1.1664 +4000
1.2597 +4000
1.3605 +14000
1.4693
Step 3: Sum up the present values.
P Vannuity ≈3703.70 + 3428.09 + 3174.05 + 2939.12 + 9525.15 = 22770.11
Therefore, the fair value of the bond is approximately 22,770.11.
Question 8
Question
A company owns an investment in a privately held company for which there
is no active market. The financial statements of the privately held company
5
are audited, and the company intends to sell the investment in the near future.
Explain how the company should determine the fair value of this investment in
accordance with fair value measurement standards.
Solution
To determine the fair value of the investment in the privately held company,
the company should follow the fair value measurement standards as outlined in
accounting guidelines. Here are the steps the company should take:
Step 1: Identify the Level of the Fair Value Hierarchy
Level 1: If there are quoted prices in active markets for identical assets,
the fair value can be determined using these prices.
Level 2: If there are similar assets with observable inputs, the company
can use these inputs to estimate the fair value.
Level 3: If there are no observable inputs, the company will need to use
its own assumptions and valuation techniques to determine the fair value.
Step 2: Use Valuation Techniques
In this case, since there is no active market for the investment, the com-
pany would need to use valuation techniques. Common methods include
the income approach, market approach, and cost approach.
The income approach involves estimating the present value of future cash
flows expected from the investment.
The market approach involves comparing the investment to similar invest-
ments that have known market prices.
The cost approach involves estimating the cost to replace the investment.
Step 3: Disclosures
The company should provide disclosures about the fair value measurement
techniques used, the inputs and assumptions made, and the level in the
fair value hierarchy the measurements fall under.
These disclosures are important for users of the financial statements to
understand how the fair value was determined.
By following these steps and guidelines, the company can appropriately de-
termine the fair value of its investment in the privately held company.
6

Question 9
Question
Company XYZ holds a financial instrument that it measures at fair value. At
the end of the reporting period, the fair value of the financial instrument is
150,000.Duringthereportingperiod, thefollowingeventsoccurred :−Event1 :
Asimilarf inancialinstrumenthadaquotedmarketpriceof140,000. - Event 2:
Company XYZ received a valuation report indicating a fair value of 160,000f orthefinancialinstrument.−
Event3 : Asignif icanteconomiceventoccurredthatdidnothaveadirectimpactonthefinancialinstrument′svalue.
Based on the above information, discuss how each event should be consid-
ered in determining the fair value of the financial instrument at the end of the
reporting period.
Solution
To determine the fair value of a financial instrument, Company XYZ should
consider all relevant information available at the end of the reporting period.
We will discuss how each event mentioned should be considered in determining
the fair value of the financial instrument:
Step 1: Event 1: Considering that a similar financial instrument had a
quoted market price of 140,000, thiswillprovideanindicationof therangewithinwhichthefairvalueofCompanyXY Z′sfinancialinstrumentmayf all.However, itisimportanttonotethatactualtransactionsmaynotalwaysref lectfairvalueduetomarketineff icienciesorotherf actors.T herefore, thisquotedmarketpriceshouldbeusedasareferencepointratherthanthesoledeterminantoffairvalue.
Step 2: Event 2: The valuation report received by Company XYZ indicat-
ing a fair value of 160,000f orthef inancialinstrumentshouldalsobeconsidered.V aluationreportsarepreparedbyindependentexpertsandprovideadditionalinsightintothefairvalueofthef inancialinstrument.CompanyXY Zshouldevaluatethecredibilityof thevaluationreportandassesswhetherthemethodologyusedisappropriateforthespecificcharacteristicsoftheirfinancialinstrument.
Step 3: Event 3: Although a significant economic event occurred during
the reporting period that did not have a direct impact on the financial instru-
ment’s value, it is important for Company XYZ to assess whether this event
could have indirect implications on the fair value of the financial instrument.
Economic events can create volatility in financial markets, which may influence
the fair value of financial instruments.
In conclusion, Company XYZ should consider all available information, in-
cluding quoted market prices, valuation reports, and relevant economic events,
in determining the fair value of the financial instrument at the end of the re-
porting period. Each of these events provides valuable input that contributes
to a more comprehensive assessment of fair value.
Question 10
Question
Company XYZ holds an investment in a bond that it measures at fair value
through other comprehensive income. The fair value of the bond was 105,000attheendofthereportingperiod.Duringtheperiod, thebondpaidacashinterestof 3,000
which was recognized in profit or loss. Company XYZ estimated that the fair
value of the bond would have been 102,000if itwasmeasuredatfairvaluethroughprof itorloss.CalculatethegainorlossthatCompanyXY Zwouldrecognizeinothercomprehensiveincomerelatedtothebondf ortheperiod.
7
Solution
Step 1: Calculate the amount that would have been recognized in profit or loss
if the bond was measured at fair value through profit or loss.
Fair Value in profit or loss = $102,000
Fair Value in OCI = $105,000
Interest income recognized in profit or loss = $3,000
Gain or loss in profit or loss = Fair Value in profit or loss−Interest income recognized in profit or loss = $102,000−$3,000 = $99,000
Step 2: Calculate the gain or loss that would be recognized in other com-
prehensive income.
Gain or loss in OCI = Fair Value in OCI−Fair Value in profit or loss = $105,000−$102,000 = $3,000
Therefore, Company XYZ would recognize a gain of
$
3,000 in other compre-
hensive income related to the bond for the period.
Question 11
Question
Company XYZ holds an investment property that is measured at fair value. At
the end of the reporting period, the fair value of the investment property is deter-
mined to be 600,000.Duringtheyear, thepropertygeneratedrentalincomeof30,000.
The fair value hierarchy level for the investment property is Level 3.
Given this information, calculate the fair value gain or loss recognized in the
income statement for the year.
Solution
To calculate the fair value gain or loss recognized in the income statement, we
need to compare the fair value of the investment property at the end of the
reporting period with the fair value at the beginning of the period, adjusted for
any purchases or sales made during the year.
Step 1: Calculate the initial fair value of the investment property. Since
there is no information given about the initial fair value of the investment prop-
erty, we assume it to be 0atthebeginningof theyear.
Step 2: Calculate the fair value gain or loss. The fair value gain or loss can
be calculated as:
Fair value gain or loss = Fair value at the end of the period−Fair value at the beginning of the period−Net cash inflows/outflows
Substitute the given values into the formula:
Fair value gain or loss =
600,000 - 0−30,000 = 570,000
Therefore, the fair value gain recognized in the income statement for the
year is 570,000 loss .
8

Question 12
Question
A company is assessing the fair value of a financial asset using the market
approach. The asset has a Level 2 fair value hierarchy classification. The
company gathers observable market data from both identical (exact matches)
and similar assets but must adjust the data due to differences between the assets.
Explain the steps the company should take to determine the fair value of the
asset.
Solution
To determine the fair value of the financial asset using the market approach
with a Level 2 fair value hierarchy classification, the company must follow these
steps:
Step 1: Identify and select appropriate valuation techniques: The company
should select appropriate valuation techniques based on the characteristics of
the asset and the available market data. In this case, since the asset is a financial
instrument, common valuation techniques include discounted cash flow analysis,
option pricing models, and valuation multiples.
Step 2: Gather observable market data: The company should gather observ-
able market data from both identical (exact matches) and similar assets. This
data provides a basis for estimating the fair value of the asset.
Step 3: Adjust market data for differences: Since there are differences be-
tween the asset being valued and the assets in the observable market data, the
company should make adjustments to account for these differences. This may
involve adjusting pricing multiples, discount rates, or other relevant factors.
Step 4: Estimate the fair value: Using the adjusted market data and val-
uation techniques, the company should estimate the fair value of the financial
asset. This estimation should consider the current market conditions and any
relevant assumptions.
Step 5: Document the valuation process: It is essential for the company
to document the valuation process, including the data sources, assumptions,
adjustments made, and the rationale behind the final fair value estimate. This
documentation helps provide transparency and support the reliability of the fair
value measurement.
Question 13
Question
A company is assessing the fair value of its investment in a private equity fund
using the market approach. The investment recently had a change in key man-
agement personnel, leading to increased uncertainty around future cash flows.
9

How should this change in circumstances be reflected in the fair value measure-
ment of the investment?
Solution
To reflect the change in circumstances related to the key management personnel
in the fair value measurement of the investment, the company should consider
the impact of this change on the future cash flows expected from the investment.
Here are the steps to adjust the fair value measurement:
Step 1: Determine the impact of the change in key management person-
nel on future cash flows. The company should assess whether the change in
key management personnel is likely to have a positive or negative impact on the
future cash flows generated by the investment. For example, if the new manage-
ment is viewed as more capable and likely to improve the fund’s performance,
this could increase future cash flow expectations. Conversely, if the change
introduces uncertainty or risk, future cash flow expectations may decrease.
Step 2: Adjust the discount rate applied to the future cash flows. Changes
in management personnel can impact the perceived risk associated with the
investment. If the change is seen as positive and reducing risk, the discount
rate applied to the future cash flows should be adjusted downward. Conversely,
if the change increases uncertainty or risk, the discount rate should be adjusted
upward to reflect the higher required rate of return.
Step 3: Update the fair value calculation based on the revised cash flow ex-
pectations and discount rate. Using the adjusted future cash flows and discount
rate, recalculate the fair value of the investment in the private equity fund. This
updated fair value should reflect the company’s assessment of the impact of the
change in key management personnel on the investment’s value.
By following these steps, the company can appropriately reflect the change
in circumstances related to key management personnel in the fair value mea-
surement of the investment using the market approach.
Question 14
Question
Company XYZ holds an investment in a private company for which it deter-
mines the fair value using a market approach. The market approach considers
comparable transactions of similar private companies. Company XYZ identifies
three comparable companies with the following price-to-earnings (P/E) ratios:
14, 16, and 18. Assuming the private company being valued has earnings of
500,000, calculatethefairvalueof theinvestmentbasedonthisinformation.
Solution
To calculate the fair value of the investment using the market approach, we will
apply the P/E ratio of the comparable companies to the earnings of the private
10
company to estimate its fair value.
Step 1: Calculate the average P/E ratio of the comparable companies. The
average P/E ratio is calculated as:
Average P/E ratio = 14 + 16 + 18
3= 16
Step 2: Apply the average P/E ratio to the earnings of the private company
to find its fair value. The fair value of the investment is calculated as:
Fair value = Earnings ×Average P/E ratio =
500,000 ×16 =8,000,000
Therefore, the fair value of the investment in the private company using the
market approach is 8,000,000.
Question 15
Question
Company XYZ has invested in financial assets classified as Level 2 fair value
measurement. The fair value of the financial assets increased by 15
Solution
To understand how the increase in fair value will impact the financial statements
of Company XYZ, we need to consider the different components affected by this
change.
Step 1: Impact on the Statement of Financial Position (Balance
Sheet) When the fair value of financial assets increases, it leads to an unrealized
gain. This unrealized gain will impact the assets and equity sections of the
balance sheet. Specifically, the investment in financial assets will increase in
value, leading to higher total assets. Shareholders’ equity will also increase due
to the recognition of the unrealized gain as part of comprehensive income.
Step 2: Impact on the Statement of Comprehensive Income The
unrealized gain resulting from the increase in fair value of financial assets will
be recorded in the statement of comprehensive income. It will be included as
part of other comprehensive income, affecting the total comprehensive income
for the period.
Step 3: Disclosure in the Notes to the Financial Statements Com-
pany XYZ will need to disclose the fair value measurement of the financial assets
in the notes to the financial statements. This disclosure includes the valuation
techniques used, inputs to the valuation, and the impact of any changes in fair
value on the financial statements.
In conclusion, the increase in fair value of financial assets classified as Level 2
fair value measurement will result in higher asset values, increased shareholders’
11

equity, and a positive impact on the comprehensive income of Company XYZ.
It is essential for the company to provide transparent and detailed disclosures
in the financial statements to inform users of the impact of fair value changes.
Question 16
Question
A company holds an investment property which is measured at fair value through
profit or loss. The fair value of the investment property at the end of the report-
ing period is 850,000.Duringtheyear, thecompanyincurred30,000 in repair and
maintenance costs for the property. The company also received rental income of
60,000fromthepropertyduringtheyear.Determinethecarryingamountoftheinvestmentpropertyattheendofthereportingperiod, consideringtherelevantaccountingtreatmentforfairvaluemeasurement.
Solution
Step 1: Calculate the carrying amount of the investment property at the end of
the reporting period before considering any adjustments.
Carrying amount before adjustments = Fair value of the investment property
Carrying amount before adjustments =
850,000
Carrying amount before adjustments =
850,000
Step 2: Incorporate the repair and maintenance costs incurred during the
year.
Adjusted carrying amount = Carrying amount before adjustments−Repair and maintenance costs
Adjusted carrying amount =
850,000 - 30,000
Adjusted carrying amount =
820,000
Step 3: Consider the effect of rental income received during the year.
Carrying amount at the end of the reporting period = Adjusted carrying amount+Rental income
Carrying amount at the end of the reporting period =
12

820,000 + 60,000
Carrying amount at the end of the reporting period =
880,000
Therefore, the carrying amount of the investment property at the end of the
reporting period, considering the repair and maintenance costs as well as the
rental income, is 880,000.
Question 17
Question
Company X holds an investment in a privately held company. The fair value of
this investment is not readily available in the market. Company X decides to
use the income approach to determine the fair value of the investment. Provide
two key steps involved in applying the income approach to estimate the fair
value of the investment.
Solution
To estimate the fair value of the investment using the income approach, two key
steps involved are as follows:
Step 1: Determine the Expected Future Cash Flows To apply the
income approach, Company X must first estimate the future cash flows expected
to be generated by the investment. This step involves projecting the cash flows
that the investment is expected to generate over its remaining useful life. These
cash flows should be based on reasonable and supportable assumptions, taking
into account factors such as market conditions, economic trends, and the specific
characteristics of the investment. Company X may use discounted cash flow
analysis or other valuation techniques to estimate the present value of these
future cash flows.
Step 2: Determine the Discount Rate Once the expected future cash
flows have been determined, the next step is to determine an appropriate dis-
count rate to apply to these cash flows. The discount rate should reflect the
risk associated with the investment and the time value of money. Company X
may use the capital asset pricing model (CAPM) or other methods to calculate
the discount rate. By discounting the projected cash flows at the appropriate
discount rate, Company X can calculate the present value of the investment,
which represents its estimated fair value.
13
Question 18
Question
Company XYZ holds an investment in bonds classified as Level 2 in the fair value
hierarchy. The bonds have a fair value of 950,000attheendof thereportingperiod.Duringtheperiod, thebondsexperiencedacreditratingdowngrade, resultinginadecreaseof20,000
in fair value adjustment recognized in other comprehensive income. Determine
the original cost of the bonds held by Company XYZ.
Solution
Step 1: Understand the fair value adjustment in other comprehensive income.
Fair value adjustment = Fair value at end −Original cost
−20,000 = 950,000 −Original cost
Step 2: Solve for the original cost.
−20,000 = 950,000 −Original cost
Original cost = 950,000 + 20,000
Original cost = $970,000
Therefore, the original cost of the bonds held by Company XYZ is $970,000.
Question 19
Question
You are a financial analyst working for a company that holds investments in
various financial instruments. The company follows the fair value measurement
principles as per IFRS 13.
One of the financial instruments the company holds is a bond with a face
value of 100,000andastatedinterestrateof 5
Solution
Step 1: Calculate the present value of the bond using the market interest rate.
Given: Face value of the bond (F V ) = 100,000 Stated interest rate (i) =
5Market interest rate for similar bonds (r) = 6Number of periods to maturity
(n) = 5 years
First, calculate the present value of the bond using the market interest rate
formula:
P V =F V ×1−(1 + r)−n
r
Substitute the values:
P V = 100,000 ×1−(1 + 0.06)−5
0.06
14
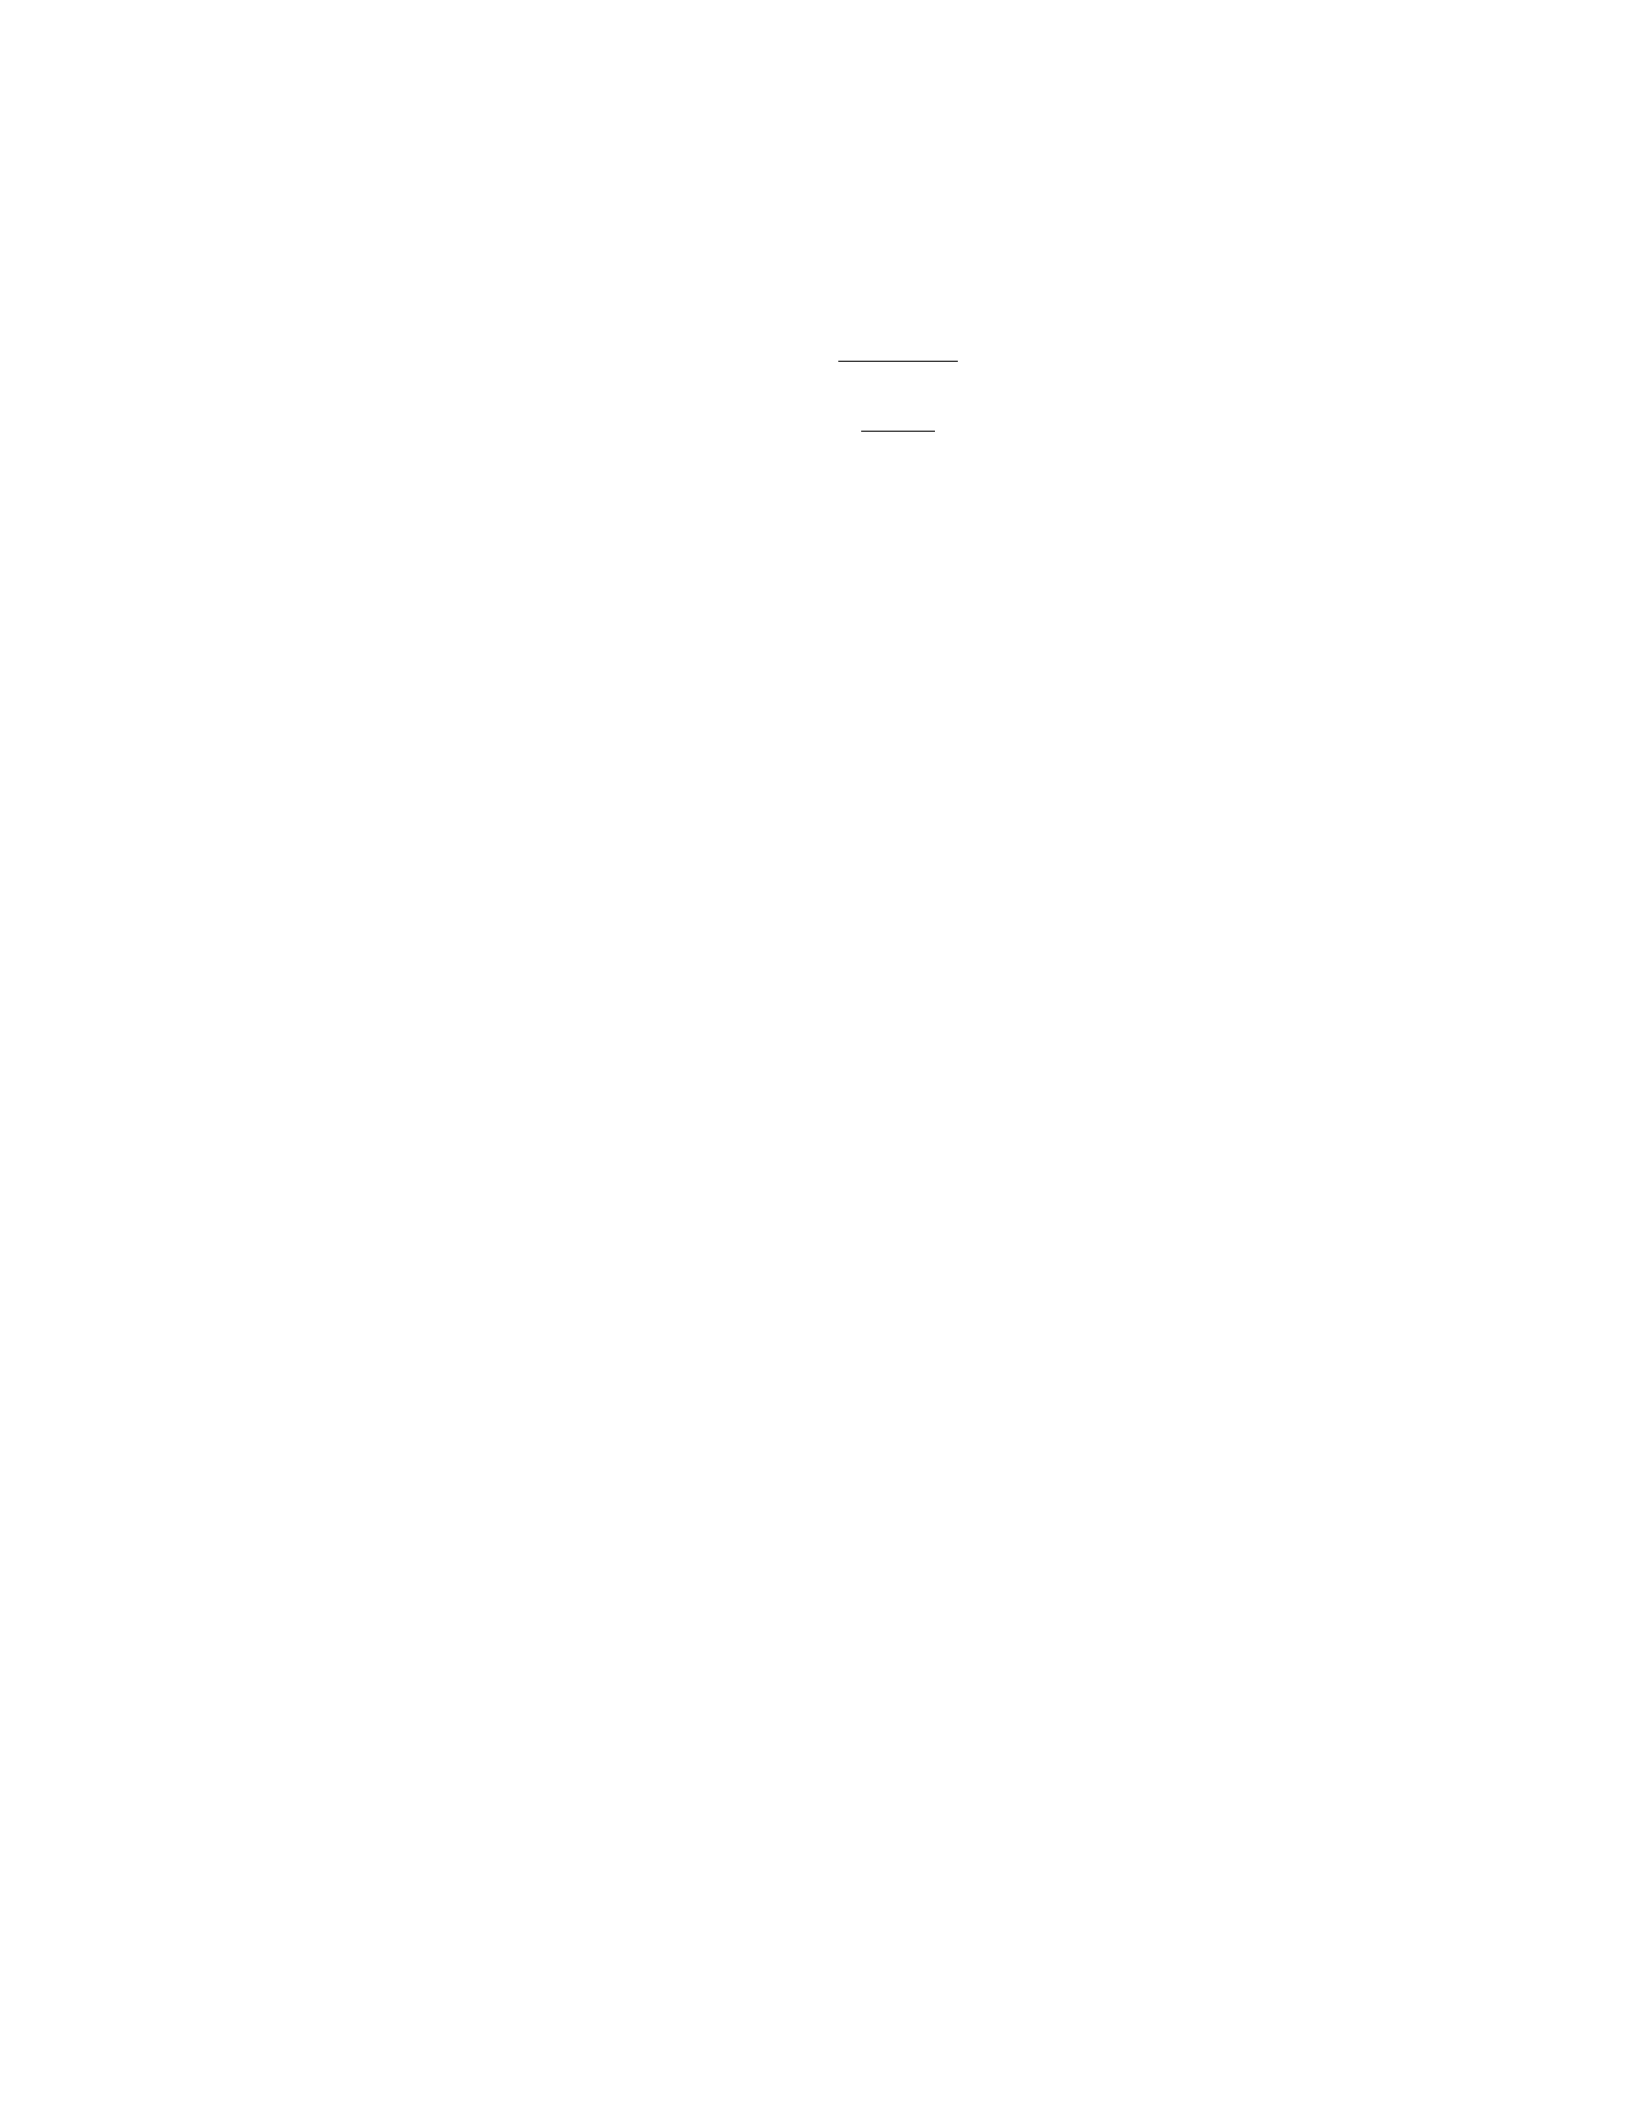
P V 100,000 ×1−0.7473
0.06
P V 100,000 ×0.2527
0.06
P V 100,000 ×4.2117
P V 421,170
Hence, the present value of the bond using the market interest rate is
421,170.
Step 2: Calculate the fair value gain or loss on the bond using Level 2 inputs.
The fair value of the bond is given as 95,000.T hefairvaluegainorlosscanbecalculatedas :
F air V alue Gain or Loss =F air V alue −P V
F air V alue Gain or Loss = 95,000 −421,170
F air V alue Gain or Loss =−326,170
Therefore, the fair value loss on the bond using Level 2 inputs is 326,170.
Question 20
Question
Company XYZ holds an investment in a privately held company where there is
no active market. The fair value of this investment is to be estimated using a val-
uation technique. Discuss the factors that should be considered in determining
the fair value of this investment.
Solution
To determine the fair value of an investment in a privately held company with no
active market, several factors need to be considered. Below are the key factors
that should be taken into account:
1. Nature of the Investment: Consider the type of investment (e.g., eq-
uity, debt) and the rights attached to it (e.g., voting rights, interest pay-
ments). Different types of investments may have different characteristics
that affect their fair value.
2. Financial Performance of the Company: Evaluate the historical and
projected financial performance of the investee company. Factors such as
revenue growth, profitability, and cash flow generation can impact the fair
value of the investment.
3. Market and Industry Conditions: Assess the conditions of the market
and industry in which the investee company operates. Changes in market
dynamics, competition, and regulatory environment can affect the fair
value of the investment.
15

4. Valuation Methodology: Select an appropriate valuation technique
based on the nature of the investee company and the availability of data.
Common valuation methods include discounted cash flow analysis, com-
parable company analysis, and precedent transactions analysis.
5. Discount Rate: Determine the appropriate discount rate to use in the
valuation. The discount rate should reflect the risks associated with the
investment, such as business risk, market risk, and liquidity risk.
6. Control Premium or Lack of Control Discount: Consider whether
the investor has control over the investee company. A control premium
may be applied if the investor has control, while a lack of control discount
may be appropriate if the investor lacks control.
7. Market Participant Assumptions: Evaluate the assumptions that
market participants would make when valuing the investment. This in-
cludes assumptions about the investee company’s future performance,
growth prospects, and risk profile.
By carefully considering these factors and conducting a thorough analysis,
an appropriate estimate of the fair value of the investment in the privately held
company can be determined.
Question 21
Question
A company has an investment in a startup company valued using the fair value
method. At the end of the reporting period, the company’s investment in the
startup has significantly increased in value. Explain how this increase in fair
value will impact the financial statements of the company.
Solution
To understand how the increase in fair value of the investment will impact the
financial statements of the company, we need to consider the different compo-
nents of the financial statements affected by fair value measurements.
Step 1: Balance Sheet - The increase in fair value of the investment will
lead to a higher valuation of the investment on the balance sheet. This increase
will be reflected in the assets section of the balance sheet. - The increase in
fair value of the investment will result in a higher total assets value on the bal-
ance sheet, which may improve the company’s financial position and potentially
increase its overall net worth.
Step 2: Income Statement - The increase in fair value of the investment
will impact the income statement through the recognition of unrealized gains.
- The increase in fair value will result in a gain which will be recognized on
the income statement. - This unrealized gain will typically be recorded in the
16

”Other Comprehensive Income” section of the income statement as it has not
been realized through a sale of the investment.
Step 3: Equity Statement - The increase in fair value of the investment
will also impact the equity statement. - The unrealized gain will be reflected in
the equity statement as part of the comprehensive income. - This will lead to
an increase in the total equity of the company.
In conclusion, the increase in fair value of the investment will lead to a higher
valuation of the investment on the balance sheet, recognition of unrealized gains
on the income statement, and an increase in total equity on the equity statement.
Question 22
Question
A company holds an investment in a financial instrument classified as a Level 3
fair value measurement. The fair value of the investment at the end of the report-
ing period is 75,000.Duringtheperiod, thecompanymadeanadjustmentof 5,000
to fair value through profit or loss. The opening balance of the investment at the
beginning of the reporting period was 65,000.Calculatetheclosingbalanceof theinvestmentattheendof thereportingperiod.
Solution
Step 1: Calculate the total gains/losses on the investment.
Total Gains/Losses = Opening Balance + Adjustment −Closing Balance
Given that the opening balance was 65,000, theadjustmentwas5,000, and the
closing balance is unknown, we can rewrite the formula as follows:
65,000 + 5,000 −Closing Balance = 0
70,000 −Closing Balance = 0
Closing Balance = 70,000
Therefore, the closing balance of the investment at the end of the reporting
period is 70,000.
Question 23
Question
A company has an investment in a security which is classified as a Level 3 asset
under fair value hierarchy. The fair value of the security has increased from
200,000 at the beginning of the year to 240,000 at the end of the year. During
the year, the company recorded a net gain of 30,000 in its income statement
related to changes in the fair value of the security. Calculate the amount of
unrealized gains recognized in other comprehensive income (OCI) for the year.
17
Solution
Step 1: Calculate the total change in fair value of the security The total change
in the fair value of the security can be calculated as:
Total Change in Fair Value = Ending Fair Value −Beginning Fair Value
Total Change in Fair Value = $240,000 −$200,000 = $40,000
Step 2: Calculate the portion of the change in fair value included in net in-
come The portion of the total change in fair value that is included in net income
can be calculated as the net gain or loss recognized in the income statement. In
this case, the net gain recognized in the income statement is
$
30,000.
Step 3: Calculate the unrealized gains recognized in OCI The unrealized
gains recognized in OCI can be calculated as the total change in fair value
minus the portion included in net income.
Unrealized Gains Recognized in OCI = Total Change in Fair Value−Portion Included in Net Income
Unrealized Gains Recognized in OCI = $40,000 −$30,000 = $10,000
Therefore, the amount of unrealized gains recognized in other comprehensive
income (OCI) for the year is
$
10,000.
Question 24
Question
A company is assessing the fair value of its investment in a private company. The
company has determined that the investment best fits within Level 3 of the fair
value hierarchy due to the absence of observable market data. The company
utilized a discounted cash flow (DCF) analysis to estimate the fair value of
the investment. The DCF model includes forecasts of future cash flows and a
discount rate that reflects the risk associated with the investment. Discuss the
challenges and limitations associated with using a DCF analysis for fair value
measurement in this context.
Solution
Step 1: Define DCF Analysis In a DCF analysis, the fair value of an invest-
ment is estimated by discounting the future cash flows generated by the invest-
ment back to the present using an appropriate discount rate. This method relies
on forecasting future cash flows and selecting an appropriate discount rate.
Step 2: Challenges with DCF Analysis 1. Forecasting: Forecasting
future cash flows can be challenging, especially for investments in private com-
panies where financial information may be limited. Errors in forecasting can
lead to significant inaccuracies in the fair value estimate.
18

2. Discount Rate Selection: Choosing the appropriate discount rate is
crucial in DCF analysis. In the absence of observable market data, determining
the risk associated with the investment can be subjective and may vary de-
pending on individual assumptions, leading to potential biases in the fair value
measurement.
3. Illiquidity Discount: Investments in private companies are often illiq-
uid, meaning they cannot be easily sold in the market. DCF analysis may not
fully account for this illiquidity risk, potentially overvaluing the investment.
4. Model Sensitivity: DCF analysis is sensitive to changes in assumptions,
such as growth rates, discount rates, and terminal values. Small changes in these
inputs can significantly impact the fair value estimate, introducing uncertainty
into the measurement.
5. Judgment and Bias: DCF analysis requires a considerable amount
of judgment in selecting assumptions and inputs. This subjectivity introduces
the risk of bias in the fair value measurement, particularly in the absence of
verifiable market data.
Overall, while DCF analysis is a commonly used method for fair value mea-
surement, it comes with inherent challenges and limitations, especially for in-
vestments in private companies within Level 3 of the fair value hierarchy. Careful
consideration of these factors is essential to producing a reliable and unbiased
fair value estimate.
Question 25
Question
Company XYZ holds an investment in a financial instrument classified as held
for trading. At the end of the reporting period, the fair value of the investment is
165,000.Duringthenextreportingperiod, thefairvalueoftheinvestmentincreasesto180,000.
Calculate the gain or loss recognized by Company XYZ in the income statement
for the next reporting period based on the fair value measurement.
Solution
To calculate the gain or loss recognized by Company XYZ in the income state-
ment for the next reporting period based on fair value measurement, we need
to compare the fair value of the investment at the end of the current reporting
period with the fair value at the end of the next reporting period. The gain or
loss recognized will be equal to the change in fair value of the investment.
Step 1: Calculate the gain/loss in fair value of the investment:
Change in Fair Value = Fair Value at the end of the next reporting period−Fair Value at the end of the current reporting period
Change in Fair Value = $180,000 −$165,000
Change in Fair Value = $15,000
19

Step 2: Determine the gain or loss recognized in the income statement:
Since the fair value of the investment increased, Company XYZ will recognize a
gain in the income statement for the next reporting period. The gain recognized
will be equal to the change in fair value:
Gain Recognized = $15,000
Therefore, Company XYZ will recognize a gain of 15,000intheincomestatementforthenextreportingperiodbasedonthefairvaluemeasurement.
Question 26
Question
A company has an investment in a private equity fund that it measures at
fair value. The fair value of the investment at the beginning of the year was
$500,000. During the year, the fair value decreased by 20%. The company
received a cash distribution of $50,000 from the investment during the year. At
the end of the year, the fair value of the investment increased by 10% from the
beginning of the year fair value. Calculate the fair value of the investment at
the end of the year.
Solution
Step 1: Calculate the fair value of the investment after the 20% decrease. Let
xbe the fair value of the investment after the 20% decrease. We can write:
x= 0.8×500,000.
Step 2: Calculate the fair value of the investment after the cash distribution.
Let ybe the fair value of the investment after the cash distribution. We can
write: y=x−50,000.
Step 3: Calculate the fair value of the investment at the end of the year after
the 10% increase from the beginning. Let zbe the fair value of the investment
at the end of the year. We can write: z= 1.1×500,000.
Step 4: Substitute the values of xand yinto the equation for z. Substitute
x= 0.8×500,000 and y=x−50,000 into the equation for z. We get: z=
1.1×(0.8×500,000 −50,000).
Step 5: Calculate the fair value of the investment at the end of the year.
Evaluate the expression for zto find the fair value of the investment at the end
of the year. z= 1.1×(0.8×500,000 −50,000) = 1.1×(400,000 −50,000) =
1.1×350,000 = 385,000.
Therefore, the fair value of the investment at the end of the year is $385,000.
20
Question 27
Question
A company has an investment in a security classified as a Level 3 asset under fair
value measurement. The fair value of the security has significantly decreased
during the year, leading to a potential impairment. The company’s management
is assessing whether an impairment loss should be recognized. Discuss the key
considerations that the company should take into account when determining
whether to recognize an impairment loss on the security.
Solution
To determine whether an impairment loss on a security classified as a Level
3 asset should be recognized, the company should consider the following key
factors:
Step 1: Review Market Indicators
Check if there have been significant adverse changes in the market, econ-
omy, or industry that could impact the fair value of the security.
Consider external factors such as interest rates, inflation rates, and geopo-
litical events that might affect the security’s value.
Step 2: Assess the Specific Security
Evaluate the specific security’s performance, financial health, and prospects
for recovery.
Consider whether there have been any changes to the security’s credit
rating or the issuer’s financial condition.
Step 3: Utilize Valuation Techniques
Use appropriate valuation techniques to estimate the fair value of the
security, considering inputs such as cash flow projections, discount rates,
and market comparables.
Compare the estimated fair value to the security’s carrying amount to
determine if there is an impairment.
Step 4: Consider Management’s Intentions
Evaluate management’s intentions regarding the holding of the security,
including any plans to sell or hold the security for the long term.
Determine if the decline in fair value is temporary or permanent based on
management’s assessment.
Step 5: Document and Disclose
21
Document the analysis performed and the rationale for recognizing or not
recognizing an impairment loss.
Ensure proper disclosure in the financial statements regarding the assess-
ment of impairment and any resulting impairment loss recognized.
By carefully considering these factors and steps, the company can make
a well-informed decision on whether to recognize an impairment loss on the
security.
Question 28
Question
A company holds an investment in a startup company, which is not traded on
any exchange. The fair value of the investment is determined using the income
approach. The following information is available: - Present value of expected fu-
ture cash flows: 150,000−Discountrate : 12−T erminalvalueafter5years :100,000
Calculate the fair value of the investment.
Solution
Step 1: Calculate the terminal value after 5 years using the formula:
Terminal value = Present value of expected future cash flows ×(1 + Discount rate)5
1 + Discount rate
Terminal value = 150,000 ×(1 + 0.12)5
1+0.12 =150,000 ×1.76234
1.12 ≈$235,851
Step 2: Calculate the fair value of the investment by summing the present
value of expected future cash flows and the terminal value:
Fair value = Present value of expected future cash flows + Terminal value
Fair value = 150,000 + 235,851 = $385,851
Therefore, the fair value of the investment in the startup company is
$
385,851.
Question 29
Question
Explain the concept of Fair Value Measurement in the context of financial re-
porting. Provide an example of an asset where fair value measurement is par-
ticularly relevant and explain why.
22

Solution
Step 1: Fair Value Measurement Fair value measurement is the process of de-
termining the value of an asset or liability based on its current market price. It
is an important concept in financial reporting, as it provides users of financial
statements with relevant and reliable information about the value of an entity’s
assets and liabilities.
Step 2: Example: Investment Property An example of an asset where fair
value measurement is particularly relevant is investment property. Investment
property is real estate that is owned for the purpose of earning rental income,
capital appreciation, or both. The fair value of investment property may fluc-
tuate over time due to changes in market conditions, demand for real estate,
economic factors, etc.
Step 3: Importance of Fair Value Measurement for Investment Property
For investment property, fair value measurement is important because it pro-
vides stakeholders with an accurate and up-to-date reflection of the property’s
value. This information is crucial for making decisions about buying, selling, or
holding onto investment properties. Additionally, fair value measurement helps
investors, lenders, and other stakeholders assess the performance and potential
risks associated with investment properties.
In conclusion, fair value measurement is a key concept in financial report-
ing that helps ensure transparency and reliability in the valuation of assets and
liabilities. For investment property, fair value measurement is particularly rel-
evant due to the dynamic nature of real estate markets and the importance of
accurate valuation for decision-making purposes.
Question 30
Question
A company has a financial asset categorized as Level 3 in the fair value hi-
erarchy. The fair value of the asset at the end of the reporting period is
137,500.Duringtheperiod, thereweresignif icantunobservableinputsinvolvedindeterminingthefairvalueof theasset.T hecompanywantstodiscloseadditionalinf ormationinthefinancialstatementsaboutthelevelsinthef airvaluehierarchy.Calculatethegainsorlossesthatthecompanywouldreportinprofitorlossfortheperiod, giventhatthefairvalueatthebeginningof theperiodwas120,000.
Solution
1. To calculate the gains or losses in profit or loss, we need to find the change in
fair value of the asset from the beginning of the period to the end of the period.
2. The change in fair value can be calculated as:
Change in Fair Value = Fair Value at the End −Fair Value at the Beginning
3. Substituting the values we have:
Change in Fair Value =
137,500 - 120,000
23

4. Calculating the change in fair value:
Change in Fair Value =
17,500
5. Therefore, the company would report a gain of 17,500inprofitorlossf ortheperiod.
Question 31
Question
Company XYZ holds an investment in a bond that is classified as a Level 2 asset
under fair value measurements. At the end of the reporting period, the fair value
of the bond is determined to be 1,500,000.Duringthenextreportingperiod, thef airvalueof thebondincreasesto1,700,000.
Determine the impact of this increase in fair value on the financial statements
of Company XYZ.
Solution
Step 1: Under fair value measurement, changes in the fair value of assets are
recognized in the income statement. The increase in fair value of the bond from
1,500,000to1,700,000 will result in a gain for Company XYZ.
Step 2: Calculate the gain by subtracting the initial fair value of the bond
from the new fair value: 1,700,000−1,500,000 = 200,000
Step 3: Recognize the gain in the income statement. The gain of 200,000willberecognizedasanon−
operatingincomeforthereportingperiod.
Step 4: The impact of the increase in fair value on the financial statements of
Company XYZ will be an increase in net income by 200,000, whichwillalsoleadtoanincreaseintotalequityonthebalancesheet.
Question 32
Question
Company XYZ holds a financial instrument that falls under Level 3 of the
fair value hierarchy. The instrument has observable inputs, including quoted
prices for similar instruments in active markets (Level 1), but also includes
unobservable inputs based on the company’s own assumptions (Level 3).
Given this information, explain how the fair value of the financial instrument
should be measured according to IFRS 13 Fair Value Measurement.
Solution
It is important to note that when a financial instrument has both observable
and unobservable inputs, the fair value should be measured using a combination
of both inputs. IFRS 13 provides guidance on how this should be done.
24

Step 1: Identify the Key Inputs First, the company needs to identify
the key inputs that drive the fair value of the financial instrument. In this
case, both the observable inputs (Level 1) and unobservable inputs (Level 3)
are important in determining the fair value.
Step 2: Weighted Average Approach The company should use a weighted
average approach to combine the observable and unobservable inputs. This in-
volves assigning weights to each input based on their relative significance in
determining the fair value.
Step 3: Consider Market Observability Since Level 1 inputs are con-
sidered more reliable due to their market observability, they should typically
have a greater influence on the final fair value calculation than Level 3 inputs.
The company should consider the extent to which each input is observable in
the market.
Step 4: Validate the Inputs The company should validate the inputs
used in the fair value measurement process to ensure they are reasonable and
appropriate. This may involve comparing the inputs to external market data
or using other valuation techniques to confirm the accuracy of the fair value
calculation.
By following these steps, Company XYZ can appropriately measure the fair
value of the financial instrument that falls under Level 3 of the fair value hier-
archy under IFRS 13.
Question 33
Question
A company holds an investment in a privately-held company that is measured at
fair value through profit or loss. The fair value of the investment at the end of the
reporting period is 1,200,000.Duringtheyear, thecompanyreceivedadividendof 50,000
from the investee. The fair value of the investment at the beginning of the re-
porting period was 1,100,000.Calculatethegainorlossrecognizedinprofitorlossfortheyear.
Solution
Step 1: Calculate the change in fair value of the investment.
Change in Fair Value = Fair Value at End −Fair Value at Beginning
Change in Fair Value =
1,200,000 - 1,100,000 =100,000
Step 2: Calculate the gain or loss recognized in profit or loss.
Gain/Loss recognized in Profit or Loss = Change in Fair Value−Dividends Received
Gain/Loss recognized in Profit or Loss =
25
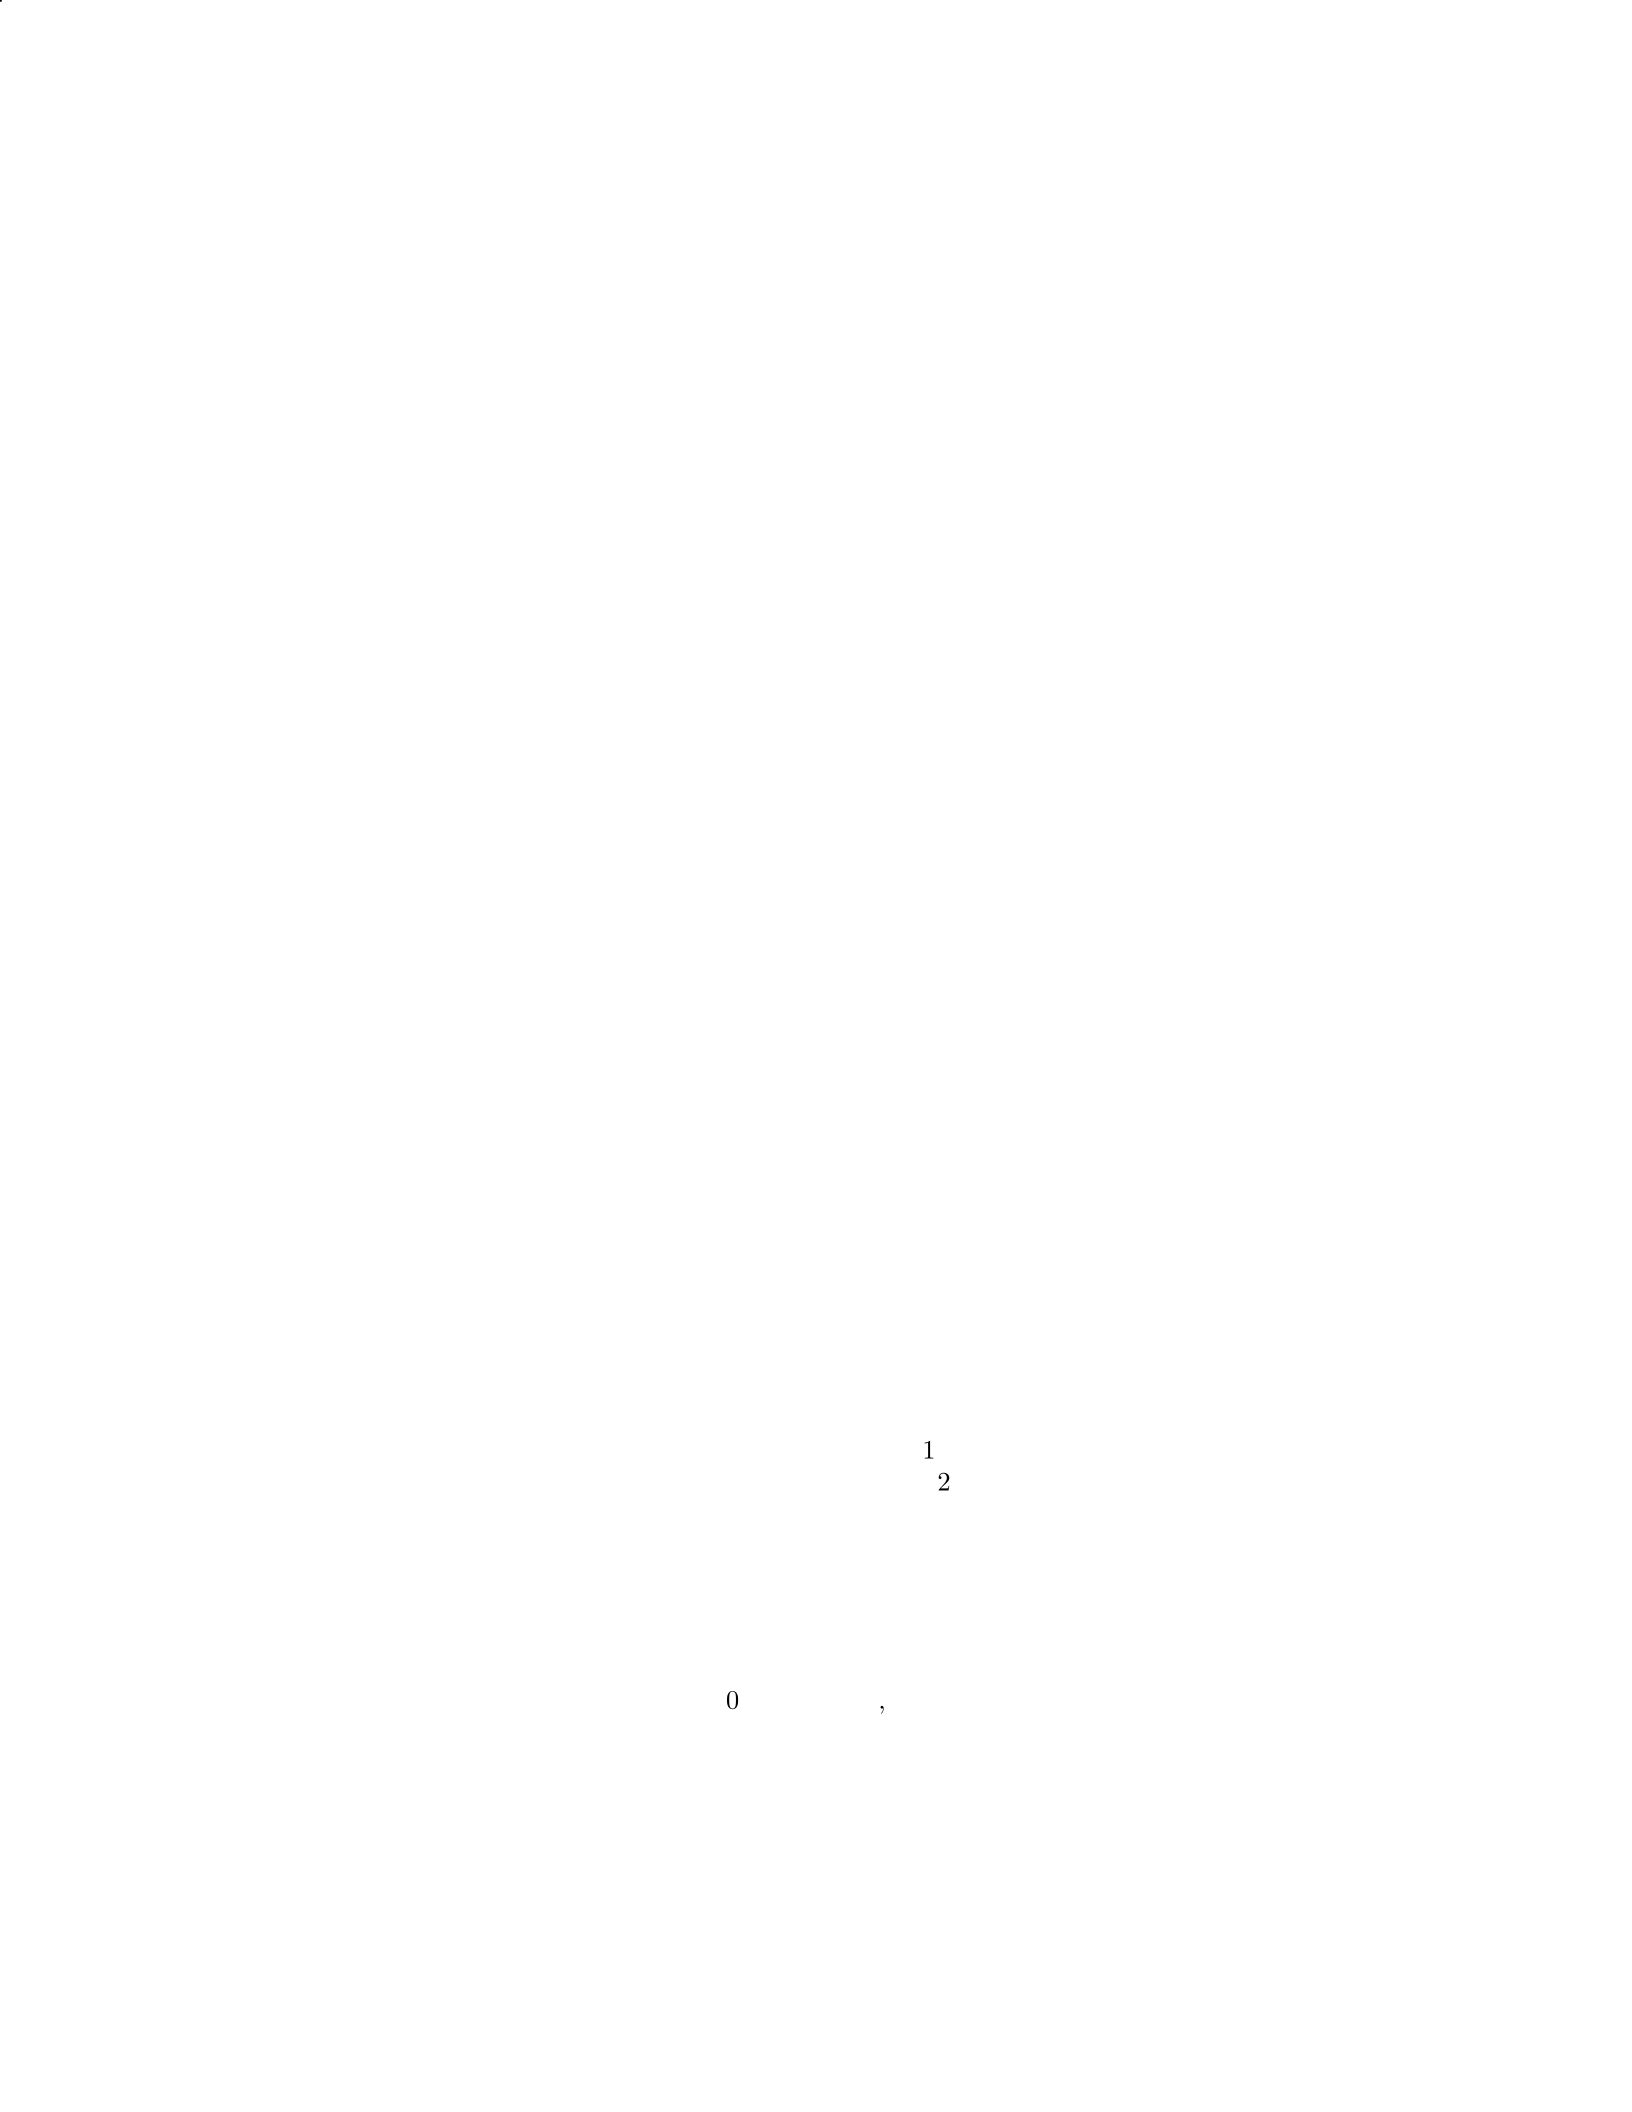
100,000 - 50,000 =50,000
Therefore, the gain recognized in profit or loss for the year is 50,000.
Question 34
Question
Company XYZ holds an investment in a foreign equity security. The fair value of
the investment was determined to be 2,500,000attheendofthereportingperiod.Duringthesubsequentreportingperiod, thefairvalueoftheinvestmentincreasedto2,700,000.
Determine the gain or loss on the investment that should be recognized in the
income statement for the subsequent reporting period.
Solution
1. The gain or loss recognized on the investment in the subsequent reporting
period is calculated by comparing the fair value at the end of the subsequent
reporting period with the fair value at the end of the previous reporting period.
2. The gain or loss is calculated as follows:
Gain or Loss = Fair Value at End of Subsequent Reporting Period−Fair Value at End of Previous Reporting Period
3. Given that the fair value of the investment at the end of the subsequent re-
porting period is 2,700,000andthef airvalueattheendof thepreviousreportingperiodwas2,500,000,
we can calculate the gain or loss:
Gain or Loss = 2,700,000 −2,500,000 = 200,000
4. Therefore, the gain on the investment that should be recognized in the
income statement for the subsequent reporting period is 200,000.
Question 35
Question
A company acquired a piece of machinery for
$
150,000. After two years, the
fair value of the machinery is estimated to be
$
120,000. If the company uses
the fair value model for measuring the machinery, how should the decrease in
fair value be accounted for in the financial statements?
Solution
1. Step 1: Recognize and record the decrease in fair value: The decrease in fair
value of the machinery from
$
150,000 to
$
120,000 should be recognized as a loss
in the financial statements. The entry to record this recognition is as follows:
Loss on Decrease in Fair Value = $30,000
26

Step 2: Sum the present values of all future cash flows to find the fair value
of the investment.
Fair Value = P V1+P V2+P V3
Fair Value = 46,296.30 + 60,025.91 + 79,355.58 ≈185,677.79
Therefore, the fair value of the investment using the fair value measurement
method is approximately 185,677.79.
Question 2
Question
An investment company has a financial asset that is measured at fair value
through profit or loss. At the reporting date, the fair value of the financial asset
is 5,000,000.Duringtheyear, thefairvalueofthef inancialassetincreasedto5,500,000.
Calculate the gain or loss recognized in profit or loss due to the change in fair
value.
Solution
Step 1: Calculate the gain or loss in fair value The gain or loss is calculated by
subtracting the initial fair value from the final fair value:
Gain or Loss = Final Fair Value −Initial Fair Value
Gain or Loss = 5,500,000 −5,000,000 = 500,000
Step 2: Determine the nature of the gain or loss Since the fair value of the finan-
cial asset increased from 5,000,000to5,500,000, a gain of 500,000wasrealized.Step3 :
Recognizethegaininprof itorlossT hegainof 500,000 should be recognized in profit
or loss for the period.
Question 3
Question
A company holds an investment in a real estate property classified as Level 3 in
the fair value hierarchy. The fair value of the investment at the reporting date is
750,000.Duringtheyear, thereweresignificantunobservableinputsusedtomeasurethefairvalueof theproperty.Atthebeginningoftheyear, thefairvaluewas700,000.
Calculate the unrealized gain or loss for the year related to this investment.
Solution
Step 1: Calculate the unrealized gain or loss Step 2: Use the formula: Unrealized
gain or loss = Fair value at reporting date - Fair value at beginning of the year
Step 3: Substitute the given values into the formula:
Unrealized gain or loss = $750,000 −$700,000
2
Step 4: Perform the calculation:
Unrealized gain or loss = $50,000
Therefore, the unrealized gain related to this investment for the year is
$
50,000.
Question 4
Question
Company XYZ holds an investment in equity securities that are classified as fair
value through profit or loss. At the end of the reporting period, the fair value
of the equity securities is $150,000 while the cost of investment is $120,000.
Additionally, the company incurred $5,000 in transaction costs related to the
investment. Calculate the gain or loss recognized in profit or loss for the period.
Solution
To calculate the gain or loss recognized in profit or loss, we need to consider the
fair value of the investment, the cost of investment, and any related transaction
costs.
Fair Value of the Investment = $150,000
Cost of Investment = $120,000
Transaction Costs = $5,000
Step 1: Calculate the net carrying amount of the investment. The net
carrying amount of the investment is calculated as the cost of the investment
adjusted for any transaction costs.
Net Carrying Amount = Cost of Investment + Transaction Costs
Net Carrying Amount = $120,000 + $5,000
Net Carrying Amount = $125,000
Step 2: Determine the gain or loss recognized in profit or loss. The gain or
loss recognized in profit or loss is calculated as the difference between the fair
value of the investment and the net carrying amount.
Gain/Loss = Fair Value of Investment −Net Carrying Amount
Gain/Loss = $150,000 −$125,000
Gain/Loss = $25,000
Since the fair value of the investment is higher than the net carrying amount,
the company would recognize a gain of $25,000 in profit or loss for the period.
3
Question 5
Question
A company holds an investment in a publicly traded equity security. The fair
value of the investment at the end of the reporting period is 150,000.Duringthereportingperiod, thefairvalueof theinvestmentincreasedby20,000
due to changes in market conditions. However, the company also incurred
5,000intransactioncostswhenacquiringtheinvestment.Calculatetheamountthatshouldbereportedinthecompany′sfinancialstatementsf ortheinvestment.
Solution
Step 1: Calculate the fair value change excluding transaction costs. We need to
adjust the fair value change for the transaction costs incurred by the company.
Fair value change excluding transaction costs = Fair value change−Transaction costs
Fair value change excluding transaction costs = $20,000 −$5,000
Fair value change excluding transaction costs = $15,000
Step 2: Determine the amount to be reported in the financial statements.
The amount to be reported in the financial statements is the initial cost of the
investment plus the fair value change excluding transaction costs.
Amount to be reported = Initial cost+Fair value change excluding transaction costs
Since no initial cost was provided in the question, we can assume it was equal
to the fair value at the end of the reporting period.
Amount to be reported = $150,000 + $15,000
Amount to be reported = $165,000
Therefore, the amount that should be reported in the company’s financial
statements for the investment is $165,000.
Question 6
Question
A company holds an investment in a commodity futures contract. The fair
value of the investment at the end of the reporting period is determined to be
15,000.T hecompanyneedstodecidewhethertoclassifytheinvestmentasheld−f or−
tradingorasheld−for−other−purpose.P rovidetwokeyf actorsthatthecompanyshouldconsiderwhenmakingthisclassificationdecision.
4
Solution
Step 1: One key factor that the company should consider is the company’s
intention at the time of purchase. If the company’s intention was to profit
from short-term fluctuations in market prices, then the investment should be
classified as held-for-trading. On the other hand, if the company’s intention was
to hold the investment for a longer period of time, then it should be classified
as held-for-other-purpose.
Step 2: Another key factor to consider is the frequency of transactions. If the
company frequently buys and sells similar investments, it may indicate that the
investment should be classified as held-for-trading. Conversely, if the company
rarely engages in such transactions and has a history of holding investments
for longer periods, it may be more appropriate to classify the investment as
held-for-other-purpose.
Question 7
Question
ABC Company owns an investment in a bond for which the fair value is not read-
ily determinable. The company receives annual cash flows of 4,000eachyearandattheendof year5receivesthebond′sfacevalueof10,000.
The bond’s discount rate is 8
Solution
Step 1: Calculate the present value of the bond’s cash flows. The present value
of the annual cash flows:
P Vannuity =4000
1+0.08 +4000
(1 + 0.08)2+4000
(1 + 0.08)3+4000
(1 + 0.08)4+4000 + 10000
(1 + 0.08)5
Step 2: Simplify the expression by calculating the present values.
P Vannuity =4000
1.08 +4000
1.1664 +4000
1.2597 +4000
1.3605 +14000
1.4693
Step 3: Sum up the present values.
P Vannuity ≈3703.70 + 3428.09 + 3174.05 + 2939.12 + 9525.15 = 22770.11
Therefore, the fair value of the bond is approximately 22,770.11.
Question 8
Question
A company owns an investment in a privately held company for which there
is no active market. The financial statements of the privately held company
5
are audited, and the company intends to sell the investment in the near future.
Explain how the company should determine the fair value of this investment in
accordance with fair value measurement standards.
Solution
To determine the fair value of the investment in the privately held company,
the company should follow the fair value measurement standards as outlined in
accounting guidelines. Here are the steps the company should take:
Step 1: Identify the Level of the Fair Value Hierarchy
Level 1: If there are quoted prices in active markets for identical assets,
the fair value can be determined using these prices.
Level 2: If there are similar assets with observable inputs, the company
can use these inputs to estimate the fair value.
Level 3: If there are no observable inputs, the company will need to use
its own assumptions and valuation techniques to determine the fair value.
Step 2: Use Valuation Techniques
In this case, since there is no active market for the investment, the com-
pany would need to use valuation techniques. Common methods include
the income approach, market approach, and cost approach.
The income approach involves estimating the present value of future cash
flows expected from the investment.
The market approach involves comparing the investment to similar invest-
ments that have known market prices.
The cost approach involves estimating the cost to replace the investment.
Step 3: Disclosures
The company should provide disclosures about the fair value measurement
techniques used, the inputs and assumptions made, and the level in the
fair value hierarchy the measurements fall under.
These disclosures are important for users of the financial statements to
understand how the fair value was determined.
By following these steps and guidelines, the company can appropriately de-
termine the fair value of its investment in the privately held company.
6

Question 9
Question
Company XYZ holds a financial instrument that it measures at fair value. At
the end of the reporting period, the fair value of the financial instrument is
150,000.Duringthereportingperiod, thefollowingeventsoccurred :−Event1 :
Asimilarf inancialinstrumenthadaquotedmarketpriceof140,000. - Event 2:
Company XYZ received a valuation report indicating a fair value of 160,000f orthefinancialinstrument.−
Event3 : Asignif icanteconomiceventoccurredthatdidnothaveadirectimpactonthefinancialinstrument′svalue.
Based on the above information, discuss how each event should be consid-
ered in determining the fair value of the financial instrument at the end of the
reporting period.
Solution
To determine the fair value of a financial instrument, Company XYZ should
consider all relevant information available at the end of the reporting period.
We will discuss how each event mentioned should be considered in determining
the fair value of the financial instrument:
Step 1: Event 1: Considering that a similar financial instrument had a
quoted market price of 140,000, thiswillprovideanindicationof therangewithinwhichthefairvalueofCompanyXY Z′sfinancialinstrumentmayf all.However, itisimportanttonotethatactualtransactionsmaynotalwaysref lectfairvalueduetomarketineff icienciesorotherf actors.T herefore, thisquotedmarketpriceshouldbeusedasareferencepointratherthanthesoledeterminantoffairvalue.
Step 2: Event 2: The valuation report received by Company XYZ indicat-
ing a fair value of 160,000f orthef inancialinstrumentshouldalsobeconsidered.V aluationreportsarepreparedbyindependentexpertsandprovideadditionalinsightintothefairvalueofthef inancialinstrument.CompanyXY Zshouldevaluatethecredibilityof thevaluationreportandassesswhetherthemethodologyusedisappropriateforthespecificcharacteristicsoftheirfinancialinstrument.
Step 3: Event 3: Although a significant economic event occurred during
the reporting period that did not have a direct impact on the financial instru-
ment’s value, it is important for Company XYZ to assess whether this event
could have indirect implications on the fair value of the financial instrument.
Economic events can create volatility in financial markets, which may influence
the fair value of financial instruments.
In conclusion, Company XYZ should consider all available information, in-
cluding quoted market prices, valuation reports, and relevant economic events,
in determining the fair value of the financial instrument at the end of the re-
porting period. Each of these events provides valuable input that contributes
to a more comprehensive assessment of fair value.
Question 10
Question
Company XYZ holds an investment in a bond that it measures at fair value
through other comprehensive income. The fair value of the bond was 105,000attheendofthereportingperiod.Duringtheperiod, thebondpaidacashinterestof3,000
which was recognized in profit or loss. Company XYZ estimated that the fair
value of the bond would have been 102,000if itwasmeasuredatfairvaluethroughprof itorloss.CalculatethegainorlossthatCompanyXY Zwouldrecognizeinothercomprehensiveincomerelatedtothebondf ortheperiod.
7
Solution
Step 1: Calculate the amount that would have been recognized in profit or loss
if the bond was measured at fair value through profit or loss.
Fair Value in profit or loss = $102,000
Fair Value in OCI = $105,000
Interest income recognized in profit or loss = $3,000
Gain or loss in profit or loss = Fair Value in profit or loss−Interest income recognized in profit or loss = $102,000−$3,000 = $99,000
Step 2: Calculate the gain or loss that would be recognized in other com-
prehensive income.
Gain or loss in OCI = Fair Value in OCI−Fair Value in profit or loss = $105,000−$102,000 = $3,000
Therefore, Company XYZ would recognize a gain of
$
3,000 in other compre-
hensive income related to the bond for the period.
Question 11
Question
Company XYZ holds an investment property that is measured at fair value. At
the end of the reporting period, the fair value of the investment property is deter-
mined to be 600,000.Duringtheyear, thepropertygeneratedrentalincomeof30,000.
The fair value hierarchy level for the investment property is Level 3.
Given this information, calculate the fair value gain or loss recognized in the
income statement for the year.
Solution
To calculate the fair value gain or loss recognized in the income statement, we
need to compare the fair value of the investment property at the end of the
reporting period with the fair value at the beginning of the period, adjusted for
any purchases or sales made during the year.
Step 1: Calculate the initial fair value of the investment property. Since
there is no information given about the initial fair value of the investment prop-
erty, we assume it to be 0atthebeginningof theyear.
Step 2: Calculate the fair value gain or loss. The fair value gain or loss can
be calculated as:
Fair value gain or loss = Fair value at the end of the period−Fair value at the beginning of the period−Net cash inflows/outflows
Substitute the given values into the formula:
Fair value gain or loss =
600,000 - 0−30,000 = 570,000
Therefore, the fair value gain recognized in the income statement for the
year is 570,000 loss .
8

Question 12
Question
A company is assessing the fair value of a financial asset using the market
approach. The asset has a Level 2 fair value hierarchy classification. The
company gathers observable market data from both identical (exact matches)
and similar assets but must adjust the data due to differences between the assets.
Explain the steps the company should take to determine the fair value of the
asset.
Solution
To determine the fair value of the financial asset using the market approach
with a Level 2 fair value hierarchy classification, the company must follow these
steps:
Step 1: Identify and select appropriate valuation techniques: The company
should select appropriate valuation techniques based on the characteristics of
the asset and the available market data. In this case, since the asset is a financial
instrument, common valuation techniques include discounted cash flow analysis,
option pricing models, and valuation multiples.
Step 2: Gather observable market data: The company should gather observ-
able market data from both identical (exact matches) and similar assets. This
data provides a basis for estimating the fair value of the asset.
Step 3: Adjust market data for differences: Since there are differences be-
tween the asset being valued and the assets in the observable market data, the
company should make adjustments to account for these differences. This may
involve adjusting pricing multiples, discount rates, or other relevant factors.
Step 4: Estimate the fair value: Using the adjusted market data and val-
uation techniques, the company should estimate the fair value of the financial
asset. This estimation should consider the current market conditions and any
relevant assumptions.
Step 5: Document the valuation process: It is essential for the company
to document the valuation process, including the data sources, assumptions,
adjustments made, and the rationale behind the final fair value estimate. This
documentation helps provide transparency and support the reliability of the fair
value measurement.
Question 13
Question
A company is assessing the fair value of its investment in a private equity fund
using the market approach. The investment recently had a change in key man-
agement personnel, leading to increased uncertainty around future cash flows.
9

How should this change in circumstances be reflected in the fair value measure-
ment of the investment?
Solution
To reflect the change in circumstances related to the key management personnel
in the fair value measurement of the investment, the company should consider
the impact of this change on the future cash flows expected from the investment.
Here are the steps to adjust the fair value measurement:
Step 1: Determine the impact of the change in key management person-
nel on future cash flows. The company should assess whether the change in
key management personnel is likely to have a positive or negative impact on the
future cash flows generated by the investment. For example, if the new manage-
ment is viewed as more capable and likely to improve the fund’s performance,
this could increase future cash flow expectations. Conversely, if the change
introduces uncertainty or risk, future cash flow expectations may decrease.
Step 2: Adjust the discount rate applied to the future cash flows. Changes
in management personnel can impact the perceived risk associated with the
investment. If the change is seen as positive and reducing risk, the discount
rate applied to the future cash flows should be adjusted downward. Conversely,
if the change increases uncertainty or risk, the discount rate should be adjusted
upward to reflect the higher required rate of return.
Step 3: Update the fair value calculation based on the revised cash flow ex-
pectations and discount rate. Using the adjusted future cash flows and discount
rate, recalculate the fair value of the investment in the private equity fund. This
updated fair value should reflect the company’s assessment of the impact of the
change in key management personnel on the investment’s value.
By following these steps, the company can appropriately reflect the change
in circumstances related to key management personnel in the fair value mea-
surement of the investment using the market approach.
Question 14
Question
Company XYZ holds an investment in a private company for which it deter-
mines the fair value using a market approach. The market approach considers
comparable transactions of similar private companies. Company XYZ identifies
three comparable companies with the following price-to-earnings (P/E) ratios:
14, 16, and 18. Assuming the private company being valued has earnings of
500,000, calculatethefairvalueof theinvestmentbasedonthisinformation.
Solution
To calculate the fair value of the investment using the market approach, we will
apply the P/E ratio of the comparable companies to the earnings of the private
10
company to estimate its fair value.
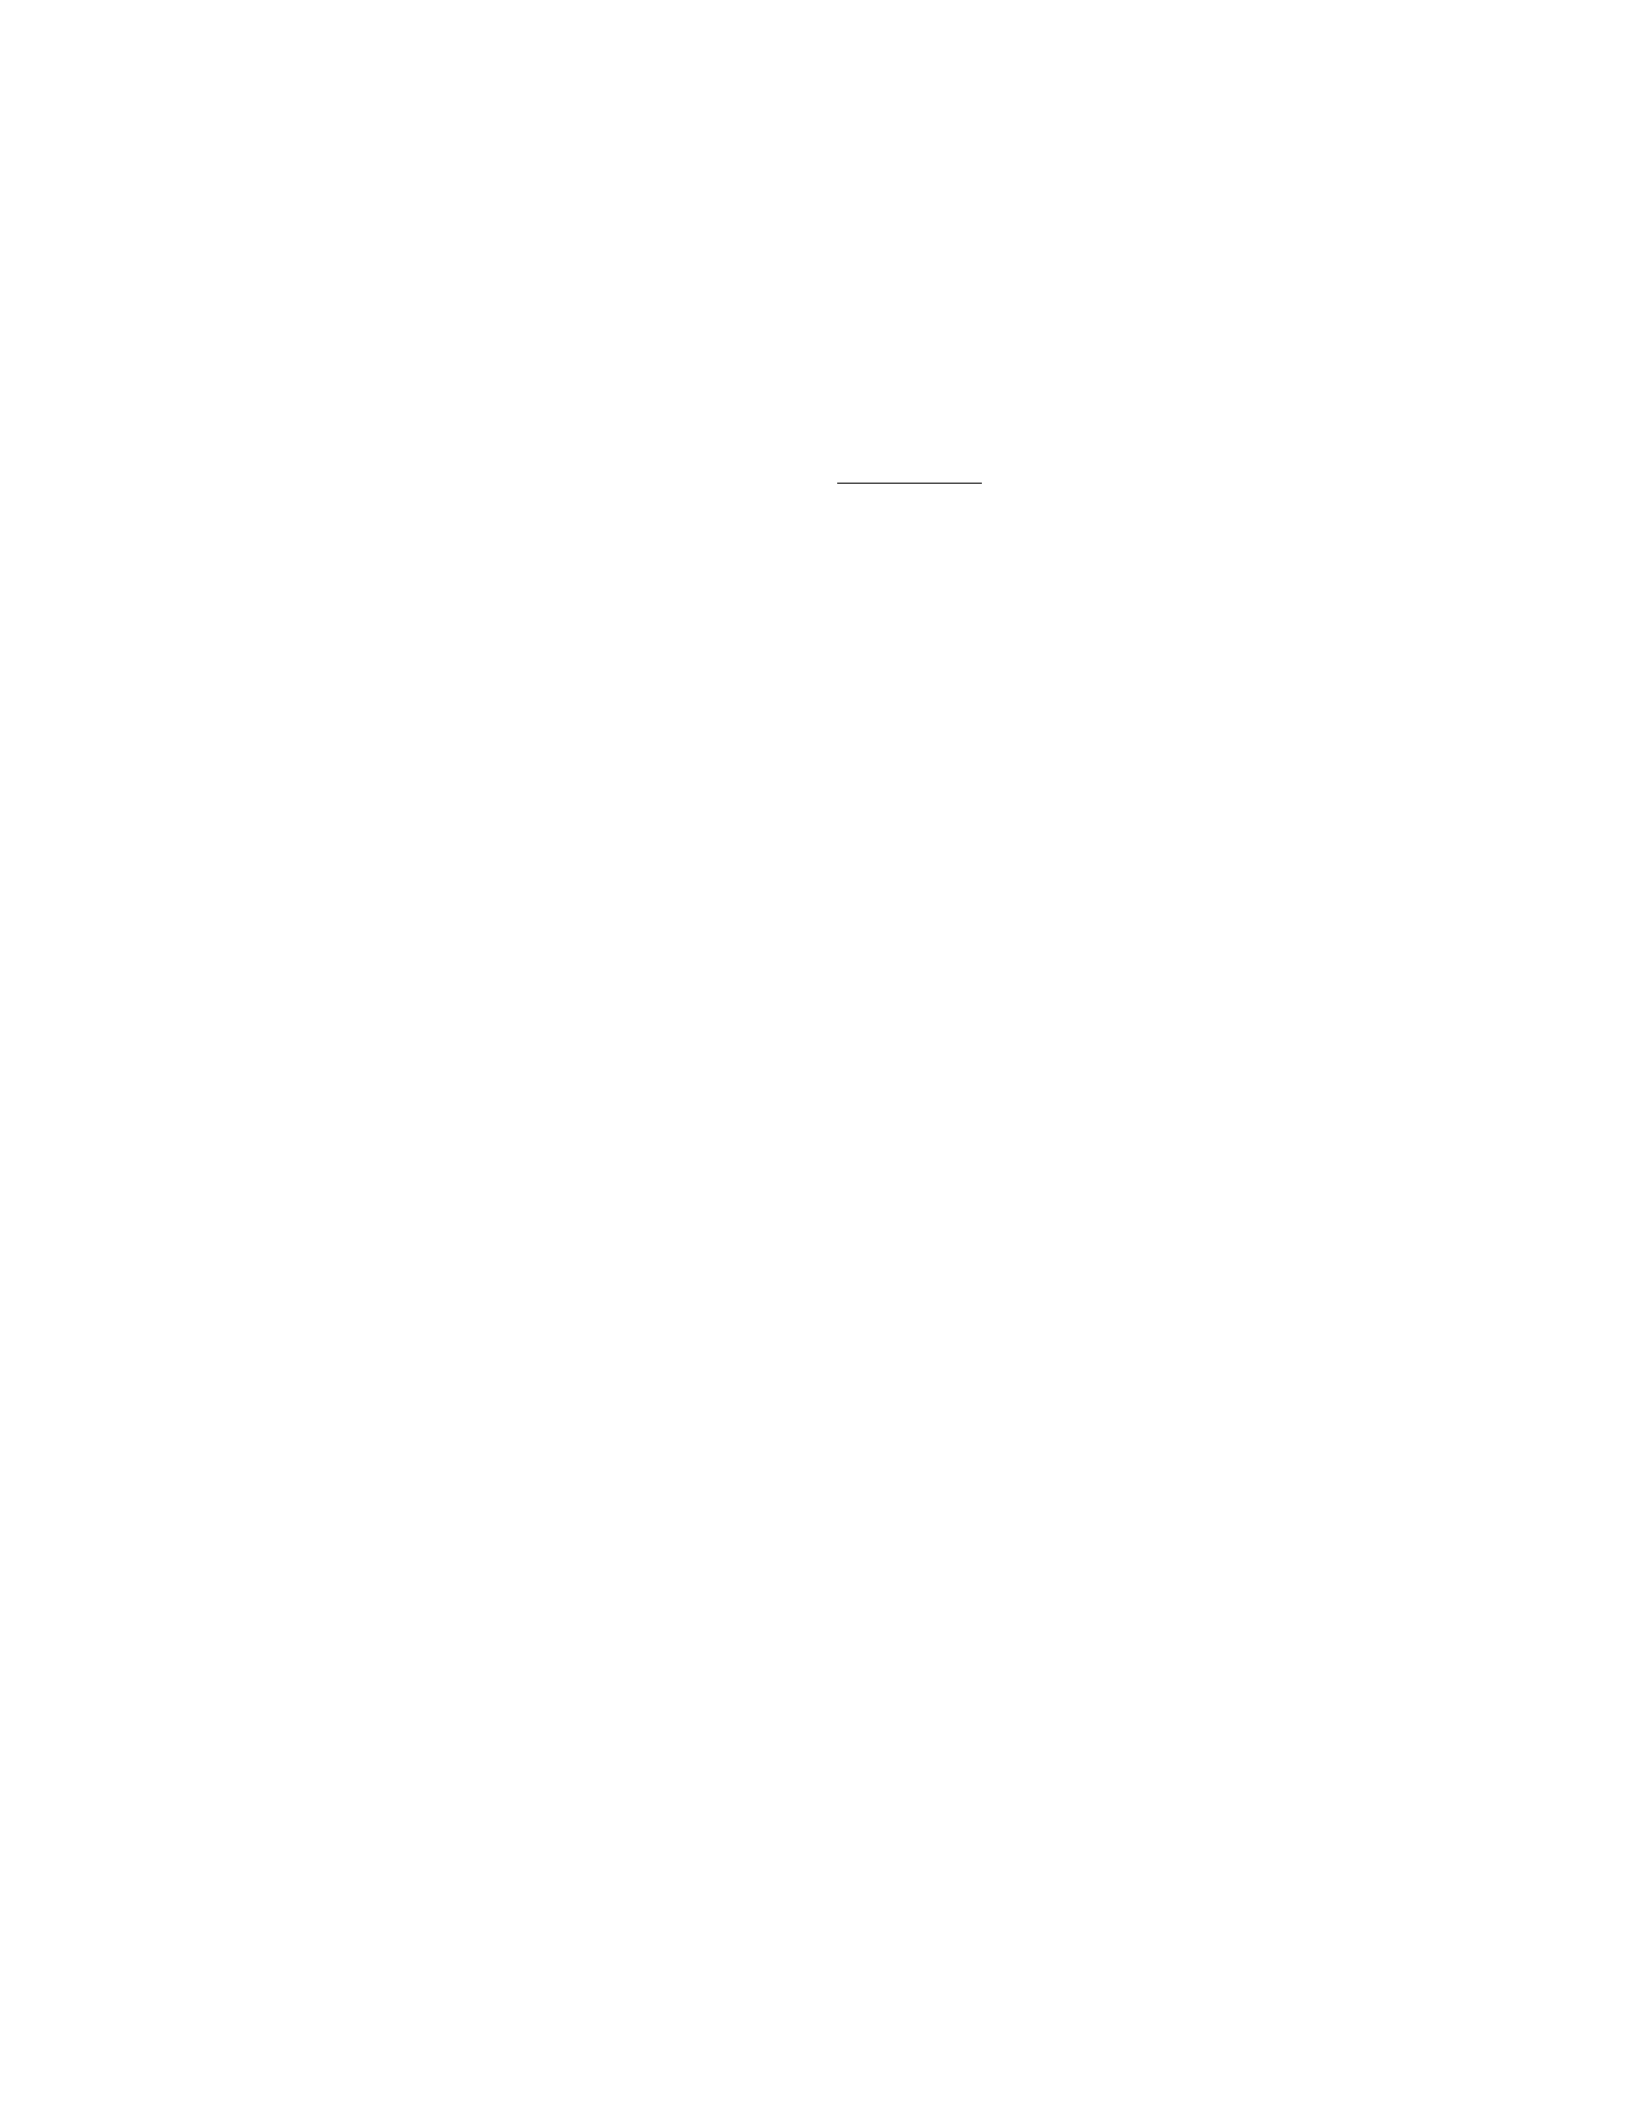
Step 1: Calculate the average P/E ratio of the comparable companies. The
average P/E ratio is calculated as:
Average P/E ratio = 14 + 16 + 18
3= 16
Step 2: Apply the average P/E ratio to the earnings of the private company
to find its fair value. The fair value of the investment is calculated as:
Fair value = Earnings ×Average P/E ratio =
500,000 ×16 =8,000,000
Therefore, the fair value of the investment in the private company using the
market approach is 8,000,000.
Question 15
Question
Company XYZ has invested in financial assets classified as Level 2 fair value
measurement. The fair value of the financial assets increased by 15
Solution
To understand how the increase in fair value will impact the financial statements
of Company XYZ, we need to consider the different components affected by this
change.
Step 1: Impact on the Statement of Financial Position (Balance
Sheet) When the fair value of financial assets increases, it leads to an unrealized
gain. This unrealized gain will impact the assets and equity sections of the
balance sheet. Specifically, the investment in financial assets will increase in
value, leading to higher total assets. Shareholders’ equity will also increase due
to the recognition of the unrealized gain as part of comprehensive income.
Step 2: Impact on the Statement of Comprehensive Income The
unrealized gain resulting from the increase in fair value of financial assets will
be recorded in the statement of comprehensive income. It will be included as
part of other comprehensive income, affecting the total comprehensive income
for the period.
Step 3: Disclosure in the Notes to the Financial Statements Com-
pany XYZ will need to disclose the fair value measurement of the financial assets
in the notes to the financial statements. This disclosure includes the valuation
techniques used, inputs to the valuation, and the impact of any changes in fair
value on the financial statements.
In conclusion, the increase in fair value of financial assets classified as Level 2
fair value measurement will result in higher asset values, increased shareholders’
11

equity, and a positive impact on the comprehensive income of Company XYZ.
It is essential for the company to provide transparent and detailed disclosures
in the financial statements to inform users of the impact of fair value changes.
Question 16
Question
A company holds an investment property which is measured at fair value through
profit or loss. The fair value of the investment property at the end of the report-
ing period is 850,000.Duringtheyear, thecompanyincurred30,000 in repair and
maintenance costs for the property. The company also received rental income of
60,000fromthepropertyduringtheyear.Determinethecarryingamountoftheinvestmentpropertyattheendofthereportingperiod, consideringtherelevantaccountingtreatmentforfairvaluemeasurement.
Solution
Step 1: Calculate the carrying amount of the investment property at the end of
the reporting period before considering any adjustments.
Carrying amount before adjustments = Fair value of the investment property
Carrying amount before adjustments =
850,000
Carrying amount before adjustments =
850,000
Step 2: Incorporate the repair and maintenance costs incurred during the
year.
Adjusted carrying amount = Carrying amount before adjustments−Repair and maintenance costs
Adjusted carrying amount =
850,000 - 30,000
Adjusted carrying amount =
820,000
Step 3: Consider the effect of rental income received during the year.
Carrying amount at the end of the reporting period = Adjusted carrying amount+Rental income
Carrying amount at the end of the reporting period =
12

820,000 + 60,000
Carrying amount at the end of the reporting period =
880,000
Therefore, the carrying amount of the investment property at the end of the
reporting period, considering the repair and maintenance costs as well as the
rental income, is 880,000.
Question 17
Question
Company X holds an investment in a privately held company. The fair value of
this investment is not readily available in the market. Company X decides to
use the income approach to determine the fair value of the investment. Provide
two key steps involved in applying the income approach to estimate the fair
value of the investment.
Solution
To estimate the fair value of the investment using the income approach, two key
steps involved are as follows:
Step 1: Determine the Expected Future Cash Flows To apply the
income approach, Company X must first estimate the future cash flows expected
to be generated by the investment. This step involves projecting the cash flows
that the investment is expected to generate over its remaining useful life. These
cash flows should be based on reasonable and supportable assumptions, taking
into account factors such as market conditions, economic trends, and the specific
characteristics of the investment. Company X may use discounted cash flow
analysis or other valuation techniques to estimate the present value of these
future cash flows.
Step 2: Determine the Discount Rate Once the expected future cash
flows have been determined, the next step is to determine an appropriate dis-
count rate to apply to these cash flows. The discount rate should reflect the
risk associated with the investment and the time value of money. Company X
may use the capital asset pricing model (CAPM) or other methods to calculate
the discount rate. By discounting the projected cash flows at the appropriate
discount rate, Company X can calculate the present value of the investment,
which represents its estimated fair value.
13
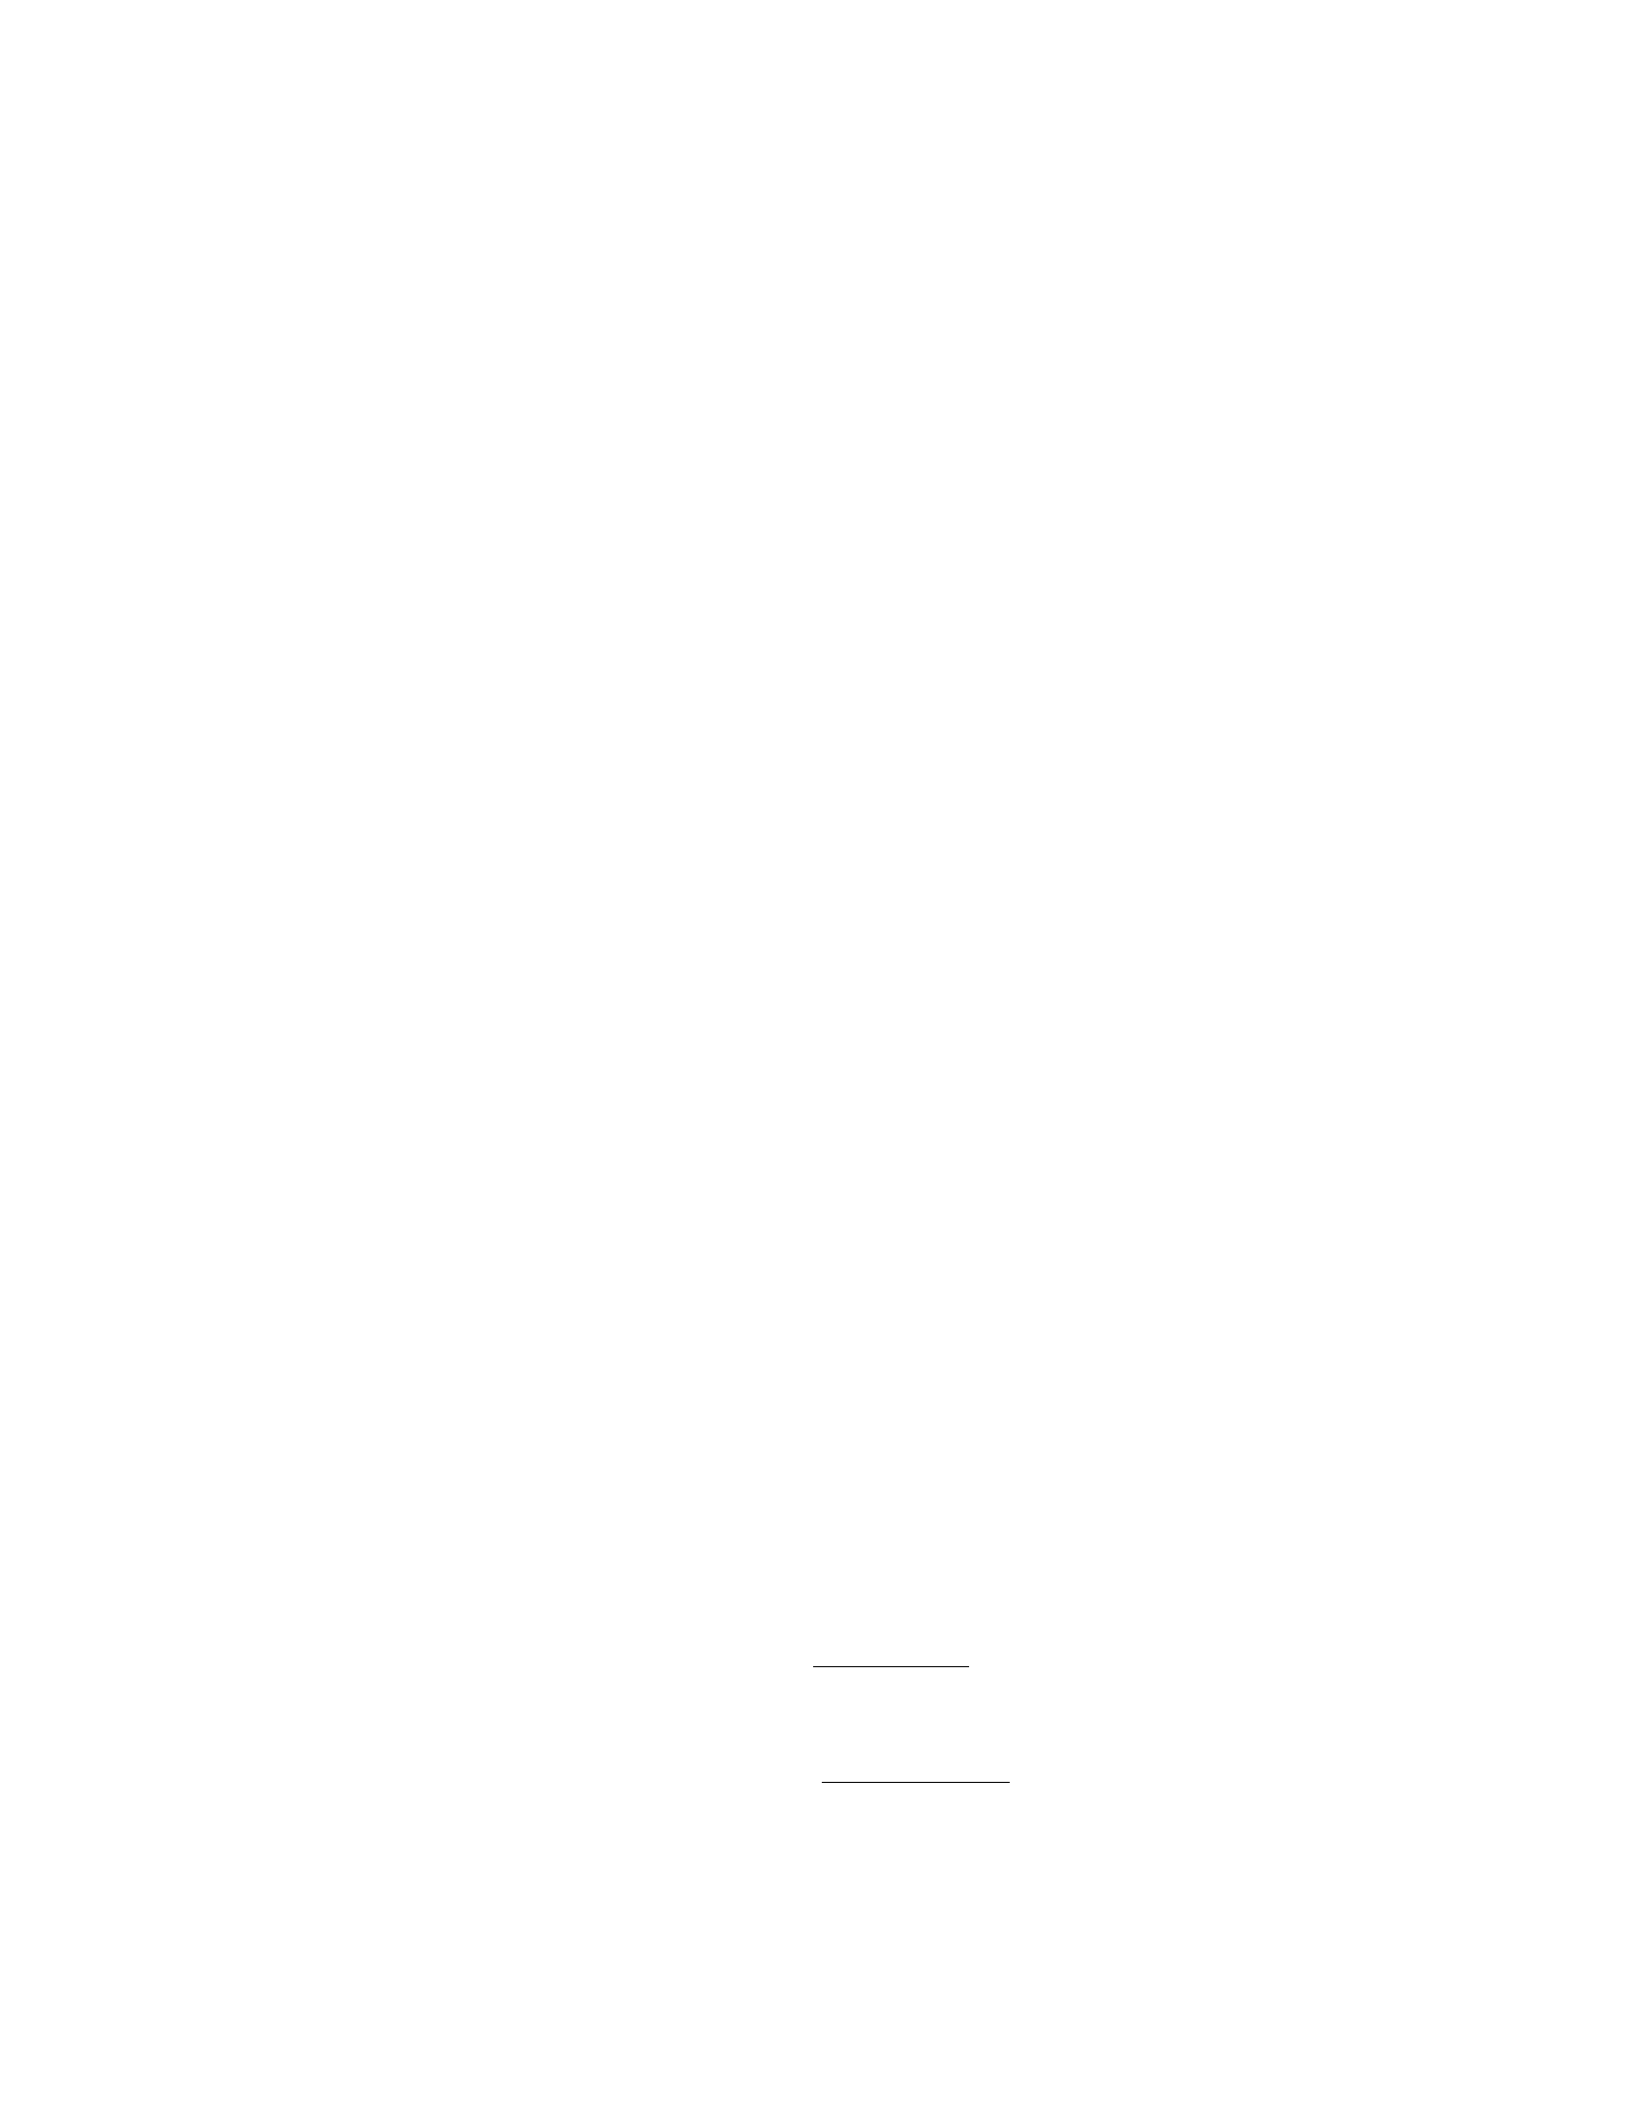
Question 18
Question
Company XYZ holds an investment in bonds classified as Level 2 in the fair value
hierarchy. The bonds have a fair value of 950,000attheendofthereportingperiod.Duringtheperiod, thebondsexperiencedacreditratingdowngrade, resultinginadecreaseof 20,000
in fair value adjustment recognized in other comprehensive income. Determine
the original cost of the bonds held by Company XYZ.
Solution
Step 1: Understand the fair value adjustment in other comprehensive income.
Fair value adjustment = Fair value at end −Original cost
−20,000 = 950,000 −Original cost
Step 2: Solve for the original cost.
−20,000 = 950,000 −Original cost
Original cost = 950,000 + 20,000
Original cost = $970,000
Therefore, the original cost of the bonds held by Company XYZ is $970,000.
Question 19
Question
You are a financial analyst working for a company that holds investments in
various financial instruments. The company follows the fair value measurement
principles as per IFRS 13.
One of the financial instruments the company holds is a bond with a face
value of 100,000andastatedinterestrateof 5
Solution
Step 1: Calculate the present value of the bond using the market interest rate.
Given: Face value of the bond (F V ) = 100,000 Stated interest rate (i) =
5Market interest rate for similar bonds (r) = 6Number of periods to maturity
(n) = 5 years
First, calculate the present value of the bond using the market interest rate
formula:
P V =F V ×1−(1 + r)−n
r
Substitute the values:
P V = 100,000 ×1−(1 + 0.06)−5
0.06
14
P V 100,000 ×1−0.7473
0.06
P V 100,000 ×0.2527
0.06
P V 100,000 ×4.2117
P V 421,170
Hence, the present value of the bond using the market interest rate is
421,170.
Step 2: Calculate the fair value gain or loss on the bond using Level 2 inputs.
The fair value of the bond is given as 95,000.T hefairvaluegainorlosscanbecalculatedas :
F air V alue Gain or Loss =F air V alue −P V
F air V alue Gain or Loss = 95,000 −421,170
F air V alue Gain or Loss =−326,170
Therefore, the fair value loss on the bond using Level 2 inputs is 326,170.
Question 20
Question
Company XYZ holds an investment in a privately held company where there is
no active market. The fair value of this investment is to be estimated using a val-
uation technique. Discuss the factors that should be considered in determining
the fair value of this investment.
Solution
To determine the fair value of an investment in a privately held company with no
active market, several factors need to be considered. Below are the key factors
that should be taken into account:
1. Nature of the Investment: Consider the type of investment (e.g., eq-
uity, debt) and the rights attached to it (e.g., voting rights, interest pay-
ments). Different types of investments may have different characteristics
that affect their fair value.
2. Financial Performance of the Company: Evaluate the historical and
projected financial performance of the investee company. Factors such as
revenue growth, profitability, and cash flow generation can impact the fair
value of the investment.
3. Market and Industry Conditions: Assess the conditions of the market
and industry in which the investee company operates. Changes in market
dynamics, competition, and regulatory environment can affect the fair
value of the investment.
15

4. Valuation Methodology: Select an appropriate valuation technique
based on the nature of the investee company and the availability of data.
Common valuation methods include discounted cash flow analysis, com-
parable company analysis, and precedent transactions analysis.
5. Discount Rate: Determine the appropriate discount rate to use in the
valuation. The discount rate should reflect the risks associated with the
investment, such as business risk, market risk, and liquidity risk.
6. Control Premium or Lack of Control Discount: Consider whether
the investor has control over the investee company. A control premium
may be applied if the investor has control, while a lack of control discount
may be appropriate if the investor lacks control.
7. Market Participant Assumptions: Evaluate the assumptions that
market participants would make when valuing the investment. This in-
cludes assumptions about the investee company’s future performance,
growth prospects, and risk profile.
By carefully considering these factors and conducting a thorough analysis,
an appropriate estimate of the fair value of the investment in the privately held
company can be determined.
Question 21
Question
A company has an investment in a startup company valued using the fair value
method. At the end of the reporting period, the company’s investment in the
startup has significantly increased in value. Explain how this increase in fair
value will impact the financial statements of the company.
Solution
To understand how the increase in fair value of the investment will impact the
financial statements of the company, we need to consider the different compo-
nents of the financial statements affected by fair value measurements.
Step 1: Balance Sheet - The increase in fair value of the investment will
lead to a higher valuation of the investment on the balance sheet. This increase
will be reflected in the assets section of the balance sheet. - The increase in
fair value of the investment will result in a higher total assets value on the bal-
ance sheet, which may improve the company’s financial position and potentially
increase its overall net worth.
Step 2: Income Statement - The increase in fair value of the investment
will impact the income statement through the recognition of unrealized gains.
- The increase in fair value will result in a gain which will be recognized on
the income statement. - This unrealized gain will typically be recorded in the
16

”Other Comprehensive Income” section of the income statement as it has not
been realized through a sale of the investment.
Step 3: Equity Statement - The increase in fair value of the investment
will also impact the equity statement. - The unrealized gain will be reflected in
the equity statement as part of the comprehensive income. - This will lead to
an increase in the total equity of the company.
In conclusion, the increase in fair value of the investment will lead to a higher
valuation of the investment on the balance sheet, recognition of unrealized gains
on the income statement, and an increase in total equity on the equity statement.
Question 22
Question
A company holds an investment in a financial instrument classified as a Level 3
fair value measurement. The fair value of the investment at the end of the report-
ing period is 75,000.Duringtheperiod, thecompanymadeanadjustmentof 5,000
to fair value through profit or loss. The opening balance of the investment at the
beginning of the reporting period was 65,000.Calculatetheclosingbalanceof theinvestmentattheendof thereportingperiod.
Solution
Step 1: Calculate the total gains/losses on the investment.
Total Gains/Losses = Opening Balance + Adjustment −Closing Balance
Given that the opening balance was 65,000, theadjustmentwas5,000, and the
closing balance is unknown, we can rewrite the formula as follows:
65,000 + 5,000 −Closing Balance = 0
70,000 −Closing Balance = 0
Closing Balance = 70,000
Therefore, the closing balance of the investment at the end of the reporting
period is 70,000.
Question 23
Question
A company has an investment in a security which is classified as a Level 3 asset
under fair value hierarchy. The fair value of the security has increased from
200,000 at the beginning of the year to 240,000 at the end of the year. During
the year, the company recorded a net gain of 30,000 in its income statement
related to changes in the fair value of the security. Calculate the amount of
unrealized gains recognized in other comprehensive income (OCI) for the year.
17
Solution
Step 1: Calculate the total change in fair value of the security The total change
in the fair value of the security can be calculated as:
Total Change in Fair Value = Ending Fair Value −Beginning Fair Value
Total Change in Fair Value = $240,000 −$200,000 = $40,000
Step 2: Calculate the portion of the change in fair value included in net in-
come The portion of the total change in fair value that is included in net income
can be calculated as the net gain or loss recognized in the income statement. In
this case, the net gain recognized in the income statement is
$
30,000.
Step 3: Calculate the unrealized gains recognized in OCI The unrealized
gains recognized in OCI can be calculated as the total change in fair value
minus the portion included in net income.
Unrealized Gains Recognized in OCI = Total Change in Fair Value−Portion Included in Net Income
Unrealized Gains Recognized in OCI = $40,000 −$30,000 = $10,000
Therefore, the amount of unrealized gains recognized in other comprehensive
income (OCI) for the year is
$
10,000.
Question 24
Question
A company is assessing the fair value of its investment in a private company. The
company has determined that the investment best fits within Level 3 of the fair
value hierarchy due to the absence of observable market data. The company
utilized a discounted cash flow (DCF) analysis to estimate the fair value of
the investment. The DCF model includes forecasts of future cash flows and a
discount rate that reflects the risk associated with the investment. Discuss the
challenges and limitations associated with using a DCF analysis for fair value
measurement in this context.
Solution
Step 1: Define DCF Analysis In a DCF analysis, the fair value of an invest-
ment is estimated by discounting the future cash flows generated by the invest-
ment back to the present using an appropriate discount rate. This method relies
on forecasting future cash flows and selecting an appropriate discount rate.
Step 2: Challenges with DCF Analysis 1. Forecasting: Forecasting
future cash flows can be challenging, especially for investments in private com-
panies where financial information may be limited. Errors in forecasting can
lead to significant inaccuracies in the fair value estimate.
18

2. Discount Rate Selection: Choosing the appropriate discount rate is
crucial in DCF analysis. In the absence of observable market data, determining
the risk associated with the investment can be subjective and may vary de-
pending on individual assumptions, leading to potential biases in the fair value
measurement.
3. Illiquidity Discount: Investments in private companies are often illiq-
uid, meaning they cannot be easily sold in the market. DCF analysis may not
fully account for this illiquidity risk, potentially overvaluing the investment.
4. Model Sensitivity: DCF analysis is sensitive to changes in assumptions,
such as growth rates, discount rates, and terminal values. Small changes in these
inputs can significantly impact the fair value estimate, introducing uncertainty
into the measurement.
5. Judgment and Bias: DCF analysis requires a considerable amount
of judgment in selecting assumptions and inputs. This subjectivity introduces
the risk of bias in the fair value measurement, particularly in the absence of
verifiable market data.
Overall, while DCF analysis is a commonly used method for fair value mea-
surement, it comes with inherent challenges and limitations, especially for in-
vestments in private companies within Level 3 of the fair value hierarchy. Careful
consideration of these factors is essential to producing a reliable and unbiased
fair value estimate.
Question 25
Question
Company XYZ holds an investment in a financial instrument classified as held
for trading. At the end of the reporting period, the fair value of the investment is
165,000.Duringthenextreportingperiod, thefairvalueoftheinvestmentincreasesto180,000.
Calculate the gain or loss recognized by Company XYZ in the income statement
for the next reporting period based on the fair value measurement.
Solution
To calculate the gain or loss recognized by Company XYZ in the income state-
ment for the next reporting period based on fair value measurement, we need
to compare the fair value of the investment at the end of the current reporting
period with the fair value at the end of the next reporting period. The gain or
loss recognized will be equal to the change in fair value of the investment.
Step 1: Calculate the gain/loss in fair value of the investment:
Change in Fair Value = Fair Value at the end of the next reporting period−Fair Value at the end of the current reporting period
Change in Fair Value = $180,000 −$165,000
Change in Fair Value = $15,000
19

Step 2: Determine the gain or loss recognized in the income statement:
Since the fair value of the investment increased, Company XYZ will recognize a
gain in the income statement for the next reporting period. The gain recognized
will be equal to the change in fair value:
Gain Recognized = $15,000
Therefore, Company XYZ will recognize a gain of 15,000intheincomestatementforthenextreportingperiodbasedonthefairvaluemeasurement.
Question 26
Question
A company has an investment in a private equity fund that it measures at
fair value. The fair value of the investment at the beginning of the year was
$500,000. During the year, the fair value decreased by 20%. The company
received a cash distribution of $50,000 from the investment during the year. At
the end of the year, the fair value of the investment increased by 10% from the
beginning of the year fair value. Calculate the fair value of the investment at
the end of the year.
Solution
Step 1: Calculate the fair value of the investment after the 20% decrease. Let
xbe the fair value of the investment after the 20% decrease. We can write:
x= 0.8×500,000.
Step 2: Calculate the fair value of the investment after the cash distribution.
Let ybe the fair value of the investment after the cash distribution. We can
write: y=x−50,000.
Step 3: Calculate the fair value of the investment at the end of the year after
the 10% increase from the beginning. Let zbe the fair value of the investment
at the end of the year. We can write: z= 1.1×500,000.
Step 4: Substitute the values of xand yinto the equation for z. Substitute
x= 0.8×500,000 and y=x−50,000 into the equation for z. We get: z=
1.1×(0.8×500,000 −50,000).
Step 5: Calculate the fair value of the investment at the end of the year.
Evaluate the expression for zto find the fair value of the investment at the end
of the year. z= 1.1×(0.8×500,000 −50,000) = 1.1×(400,000 −50,000) =
1.1×350,000 = 385,000.
Therefore, the fair value of the investment at the end of the year is $385,000.
20
Question 27
Question
A company has an investment in a security classified as a Level 3 asset under fair
value measurement. The fair value of the security has significantly decreased
during the year, leading to a potential impairment. The company’s management
is assessing whether an impairment loss should be recognized. Discuss the key
considerations that the company should take into account when determining
whether to recognize an impairment loss on the security.
Solution
To determine whether an impairment loss on a security classified as a Level
3 asset should be recognized, the company should consider the following key
factors:
Step 1: Review Market Indicators
Check if there have been significant adverse changes in the market, econ-
omy, or industry that could impact the fair value of the security.
Consider external factors such as interest rates, inflation rates, and geopo-
litical events that might affect the security’s value.
Step 2: Assess the Specific Security
Evaluate the specific security’s performance, financial health, and prospects
for recovery.
Consider whether there have been any changes to the security’s credit
rating or the issuer’s financial condition.
Step 3: Utilize Valuation Techniques
Use appropriate valuation techniques to estimate the fair value of the
security, considering inputs such as cash flow projections, discount rates,
and market comparables.
Compare the estimated fair value to the security’s carrying amount to
determine if there is an impairment.
Step 4: Consider Management’s Intentions
Evaluate management’s intentions regarding the holding of the security,
including any plans to sell or hold the security for the long term.
Determine if the decline in fair value is temporary or permanent based on
management’s assessment.
Step 5: Document and Disclose
21
Document the analysis performed and the rationale for recognizing or not
recognizing an impairment loss.
Ensure proper disclosure in the financial statements regarding the assess-
ment of impairment and any resulting impairment loss recognized.
By carefully considering these factors and steps, the company can make
a well-informed decision on whether to recognize an impairment loss on the
security.
Question 28
Question
A company holds an investment in a startup company, which is not traded on
any exchange. The fair value of the investment is determined using the income
approach. The following information is available: - Present value of expected fu-
ture cash flows: 150,000−Discountrate : 12−T erminalvalueaf ter5years :100,000
Calculate the fair value of the investment.
Solution
Step 1: Calculate the terminal value after 5 years using the formula:
Terminal value = Present value of expected future cash flows ×(1 + Discount rate)5
1 + Discount rate
Terminal value = 150,000 ×(1 + 0.12)5
1+0.12 =150,000 ×1.76234
1.12 ≈$235,851
Step 2: Calculate the fair value of the investment by summing the present
value of expected future cash flows and the terminal value:
Fair value = Present value of expected future cash flows + Terminal value
Fair value = 150,000 + 235,851 = $385,851
Therefore, the fair value of the investment in the startup company is
$
385,851.
Question 29
Question
Explain the concept of Fair Value Measurement in the context of financial re-
porting. Provide an example of an asset where fair value measurement is par-
ticularly relevant and explain why.
22

Solution
Step 1: Fair Value Measurement Fair value measurement is the process of de-
termining the value of an asset or liability based on its current market price. It
is an important concept in financial reporting, as it provides users of financial
statements with relevant and reliable information about the value of an entity’s
assets and liabilities.
Step 2: Example: Investment Property An example of an asset where fair
value measurement is particularly relevant is investment property. Investment
property is real estate that is owned for the purpose of earning rental income,
capital appreciation, or both. The fair value of investment property may fluc-
tuate over time due to changes in market conditions, demand for real estate,
economic factors, etc.
Step 3: Importance of Fair Value Measurement for Investment Property
For investment property, fair value measurement is important because it pro-
vides stakeholders with an accurate and up-to-date reflection of the property’s
value. This information is crucial for making decisions about buying, selling, or
holding onto investment properties. Additionally, fair value measurement helps
investors, lenders, and other stakeholders assess the performance and potential
risks associated with investment properties.
In conclusion, fair value measurement is a key concept in financial report-
ing that helps ensure transparency and reliability in the valuation of assets and
liabilities. For investment property, fair value measurement is particularly rel-
evant due to the dynamic nature of real estate markets and the importance of
accurate valuation for decision-making purposes.
Question 30
Question
A company has a financial asset categorized as Level 3 in the fair value hi-
erarchy. The fair value of the asset at the end of the reporting period is
137,500.Duringtheperiod, thereweresignif icantunobservableinputsinvolvedindeterminingthefairvalueof theasset.T hecompanywantstodiscloseadditionalinf ormationinthefinancialstatementsaboutthelevelsinthef airvaluehierarchy.Calculatethegainsorlossesthatthecompanywouldreportinprofitorlossfortheperiod, giventhatthefairvalueatthebeginningof theperiodwas120,000.
Solution
1. To calculate the gains or losses in profit or loss, we need to find the change in
fair value of the asset from the beginning of the period to the end of the period.
2. The change in fair value can be calculated as:
Change in Fair Value = Fair Value at the End −Fair Value at the Beginning
3. Substituting the values we have:
Change in Fair Value =
137,500 - 120,000
23

4. Calculating the change in fair value:
Change in Fair Value =
17,500
5. Therefore, the company would report a gain of 17,500inprofitorlossf ortheperiod.
Question 31
Question
Company XYZ holds an investment in a bond that is classified as a Level 2 asset
under fair value measurements. At the end of the reporting period, the fair value
of the bond is determined to be 1,500,000.Duringthenextreportingperiod, thef airvalueof thebondincreasesto1,700,000.
Determine the impact of this increase in fair value on the financial statements
of Company XYZ.
Solution
Step 1: Under fair value measurement, changes in the fair value of assets are
recognized in the income statement. The increase in fair value of the bond from
1,500,000to1,700,000 will result in a gain for Company XYZ.
Step 2: Calculate the gain by subtracting the initial fair value of the bond
from the new fair value: 1,700,000−1,500,000 = 200,000
Step 3: Recognize the gain in the income statement. The gain of 200,000willberecognizedasanon−
operatingincomeforthereportingperiod.
Step 4: The impact of the increase in fair value on the financial statements of
Company XYZ will be an increase in net income by 200,000, whichwillalsoleadtoanincreaseintotalequityonthebalancesheet.
Question 32
Question
Company XYZ holds a financial instrument that falls under Level 3 of the
fair value hierarchy. The instrument has observable inputs, including quoted
prices for similar instruments in active markets (Level 1), but also includes
unobservable inputs based on the company’s own assumptions (Level 3).
Given this information, explain how the fair value of the financial instrument
should be measured according to IFRS 13 Fair Value Measurement.
Solution
It is important to note that when a financial instrument has both observable
and unobservable inputs, the fair value should be measured using a combination
of both inputs. IFRS 13 provides guidance on how this should be done.
24

Step 1: Identify the Key Inputs First, the company needs to identify
the key inputs that drive the fair value of the financial instrument. In this
case, both the observable inputs (Level 1) and unobservable inputs (Level 3)
are important in determining the fair value.
Step 2: Weighted Average Approach The company should use a weighted
average approach to combine the observable and unobservable inputs. This in-
volves assigning weights to each input based on their relative significance in
determining the fair value.
Step 3: Consider Market Observability Since Level 1 inputs are con-
sidered more reliable due to their market observability, they should typically
have a greater influence on the final fair value calculation than Level 3 inputs.
The company should consider the extent to which each input is observable in
the market.
Step 4: Validate the Inputs The company should validate the inputs
used in the fair value measurement process to ensure they are reasonable and
appropriate. This may involve comparing the inputs to external market data
or using other valuation techniques to confirm the accuracy of the fair value
calculation.
By following these steps, Company XYZ can appropriately measure the fair
value of the financial instrument that falls under Level 3 of the fair value hier-
archy under IFRS 13.
Question 33
Question
A company holds an investment in a privately-held company that is measured at
fair value through profit or loss. The fair value of the investment at the end of the
reporting period is 1,200,000.Duringtheyear, thecompanyreceivedadividendof 50,000
from the investee. The fair value of the investment at the beginning of the re-
porting period was 1,100,000.Calculatethegainorlossrecognizedinprofitorlossfortheyear.
Solution
Step 1: Calculate the change in fair value of the investment.
Change in Fair Value = Fair Value at End −Fair Value at Beginning
Change in Fair Value =
1,200,000 - 1,100,000 =100,000
Step 2: Calculate the gain or loss recognized in profit or loss.
Gain/Loss recognized in Profit or Loss = Change in Fair Value−Dividends Received
Gain/Loss recognized in Profit or Loss =
25
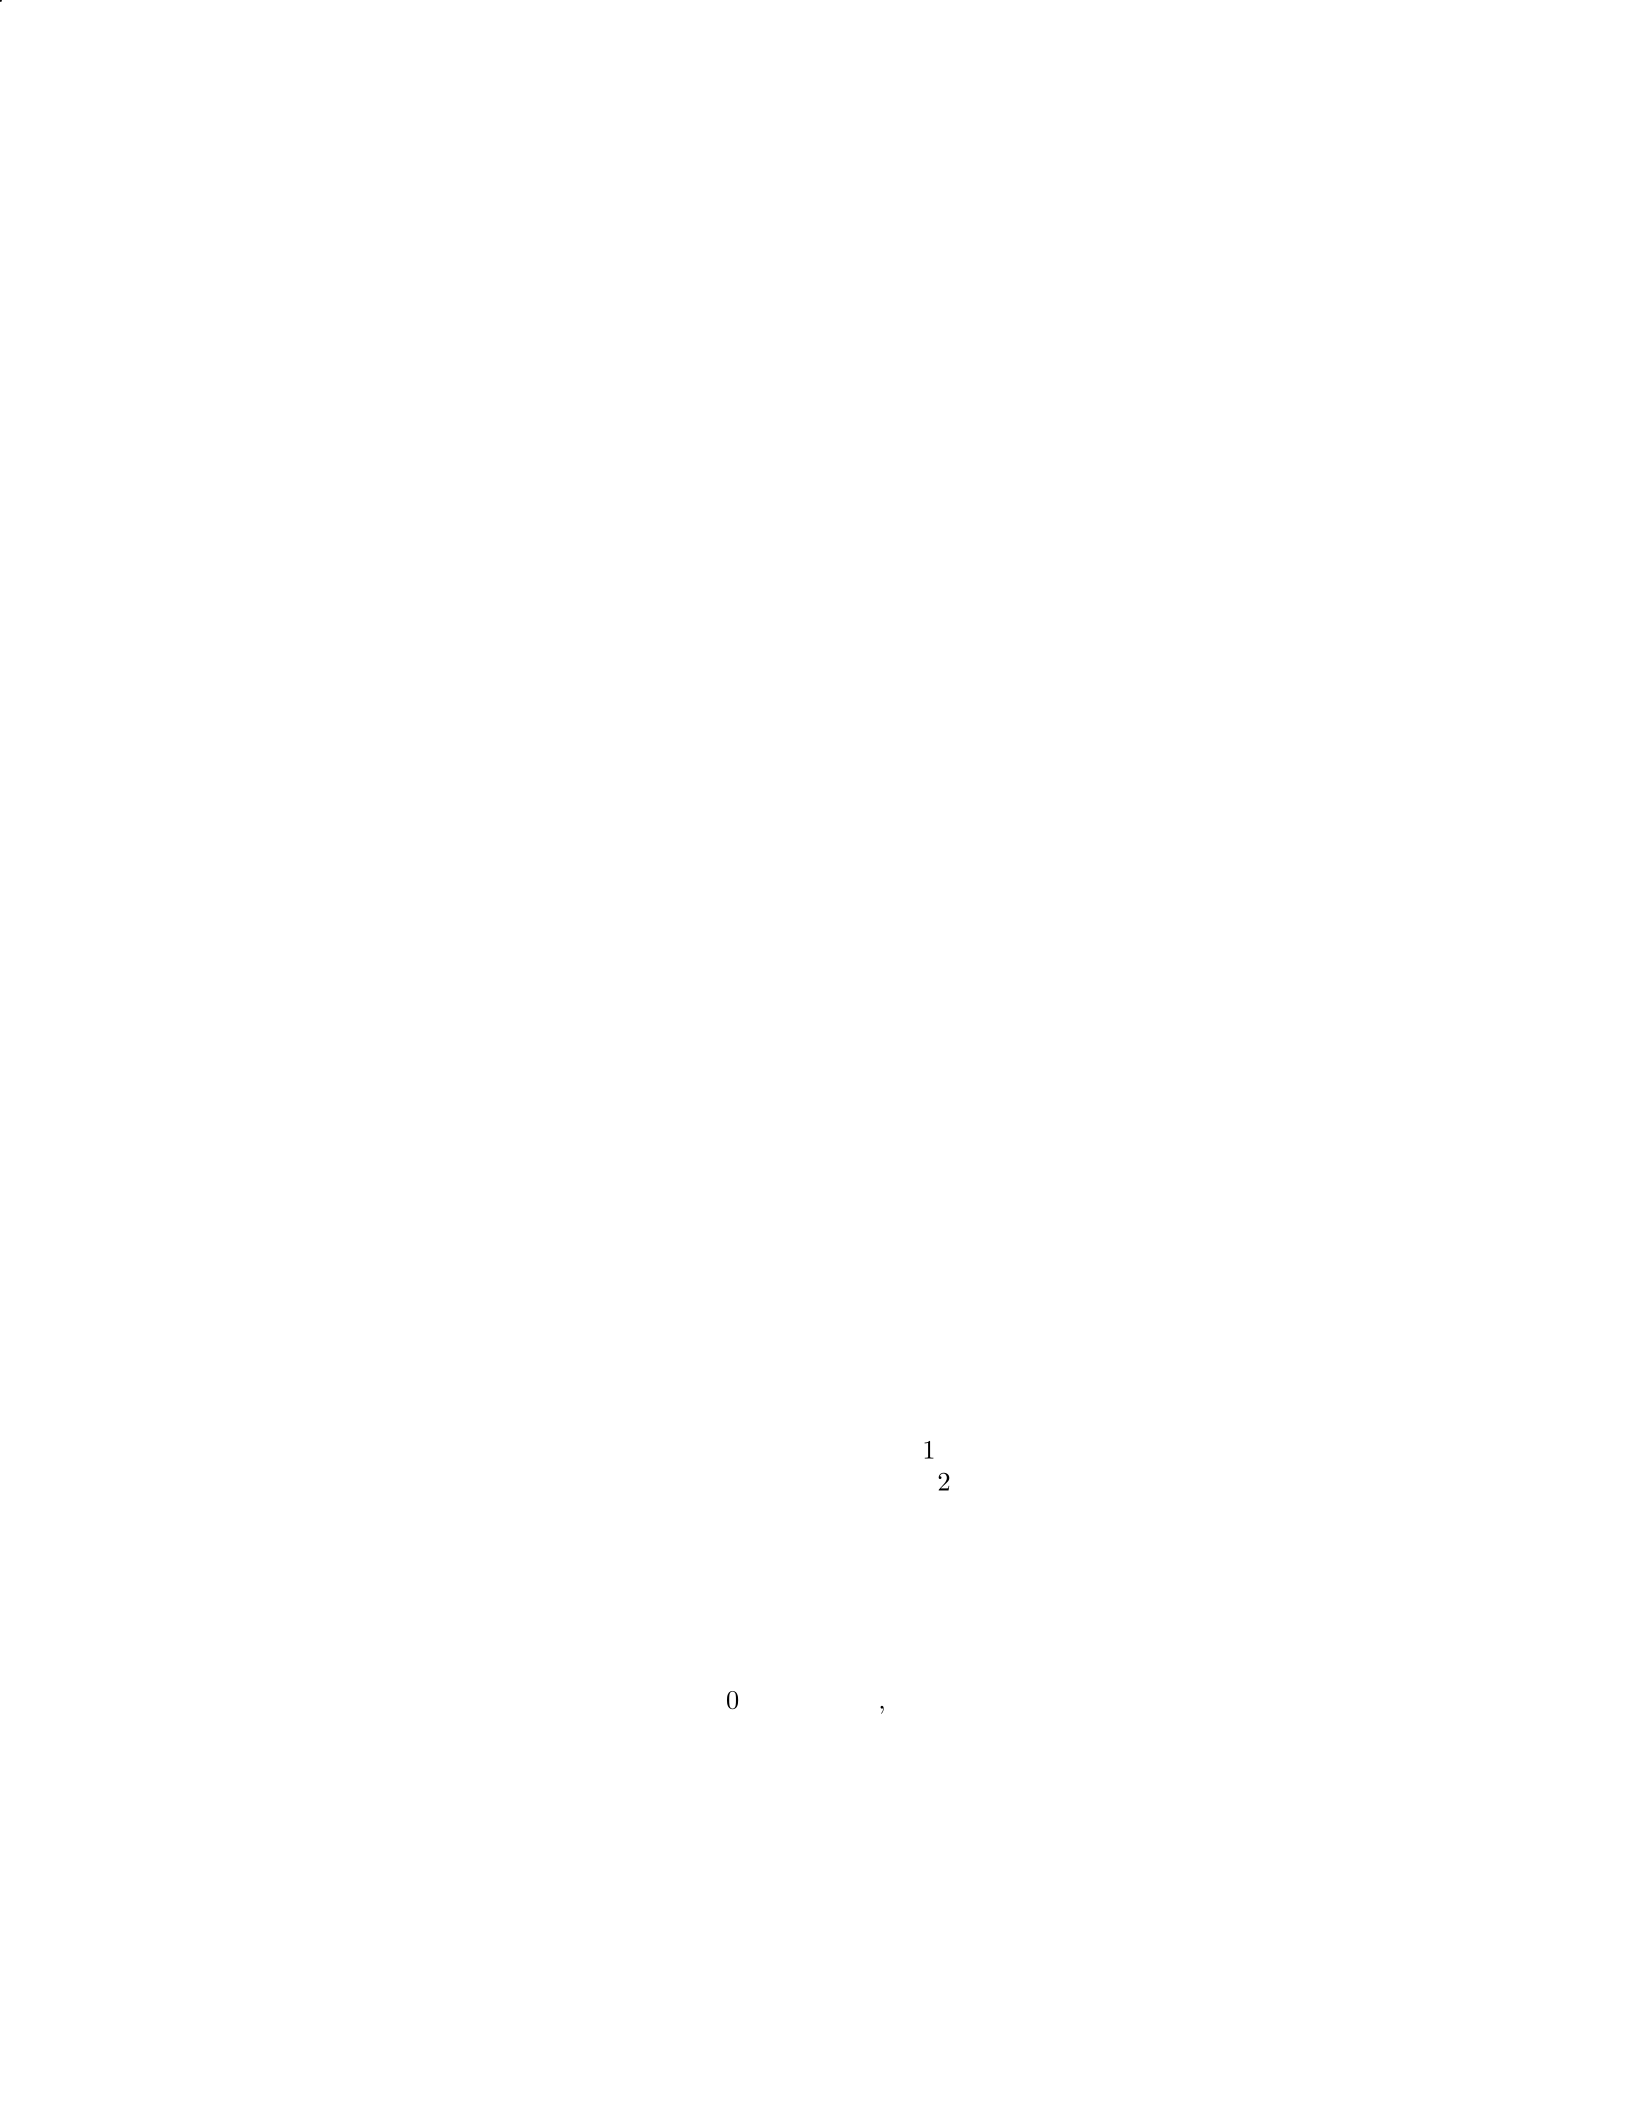
100,000 - 50,000 =50,000
Therefore, the gain recognized in profit or loss for the year is 50,000.
Question 34
Question
Company XYZ holds an investment in a foreign equity security. The fair value of
the investment was determined to be 2,500,000attheendofthereportingperiod.Duringthesubsequentreportingperiod, thefairvalueoftheinvestmentincreasedto2,700,000.
Determine the gain or loss on the investment that should be recognized in the
income statement for the subsequent reporting period.
Solution
1. The gain or loss recognized on the investment in the subsequent reporting
period is calculated by comparing the fair value at the end of the subsequent
reporting period with the fair value at the end of the previous reporting period.
2. The gain or loss is calculated as follows:
Gain or Loss = Fair Value at End of Subsequent Reporting Period−Fair Value at End of Previous Reporting Period
3. Given that the fair value of the investment at the end of the subsequent re-
porting period is 2,700,000andthef airvalueattheendof thepreviousreportingperiodwas2,500,000,
we can calculate the gain or loss:
Gain or Loss = 2,700,000 −2,500,000 = 200,000
4. Therefore, the gain on the investment that should be recognized in the
income statement for the subsequent reporting period is 200,000.
Question 35
Question
A company acquired a piece of machinery for
$
150,000. After two years, the
fair value of the machinery is estimated to be
$
120,000. If the company uses
the fair value model for measuring the machinery, how should the decrease in
fair value be accounted for in the financial statements?
Solution
1. Step 1: Recognize and record the decrease in fair value: The decrease in fair
value of the machinery from
$
150,000 to
$
120,000 should be recognized as a loss
in the financial statements. The entry to record this recognition is as follows:
Loss on Decrease in Fair Value = $30,000
26

Step 2: Sum the present values of all future cash flows to find the fair value
of the investment.
Fair Value = P V1+P V2+P V3
Fair Value = 46,296.30 + 60,025.91 + 79,355.58 ≈185,677.79
Therefore, the fair value of the investment using the fair value measurement
method is approximately 185,677.79.
Question 2
Question
An investment company has a financial asset that is measured at fair value
through profit or loss. At the reporting date, the fair value of the financial asset
is 5,000,000.Duringtheyear, thefairvalueofthef inancialassetincreasedto5,500,000.
Calculate the gain or loss recognized in profit or loss due to the change in fair
value.
Solution
Step 1: Calculate the gain or loss in fair value The gain or loss is calculated by
subtracting the initial fair value from the final fair value:
Gain or Loss = Final Fair Value −Initial Fair Value
Gain or Loss = 5,500,000 −5,000,000 = 500,000
Step 2: Determine the nature of the gain or loss Since the fair value of the finan-
cial asset increased from 5,000,000to5,500,000, a gain of 500,000wasrealized.Step3 :
Recognizethegaininprof itorlossT hegainof 500,000 should be recognized in profit
or loss for the period.
Question 3
Question
A company holds an investment in a real estate property classified as Level 3 in
the fair value hierarchy. The fair value of the investment at the reporting date is
750,000.Duringtheyear, thereweresignificantunobservableinputsusedtomeasurethefairvalueof theproperty.Atthebeginningoftheyear, thefairvaluewas700,000.
Calculate the unrealized gain or loss for the year related to this investment.
Solution
Step 1: Calculate the unrealized gain or loss Step 2: Use the formula: Unrealized
gain or loss = Fair value at reporting date - Fair value at beginning of the year
Step 3: Substitute the given values into the formula:
Unrealized gain or loss = $750,000 −$700,000
2
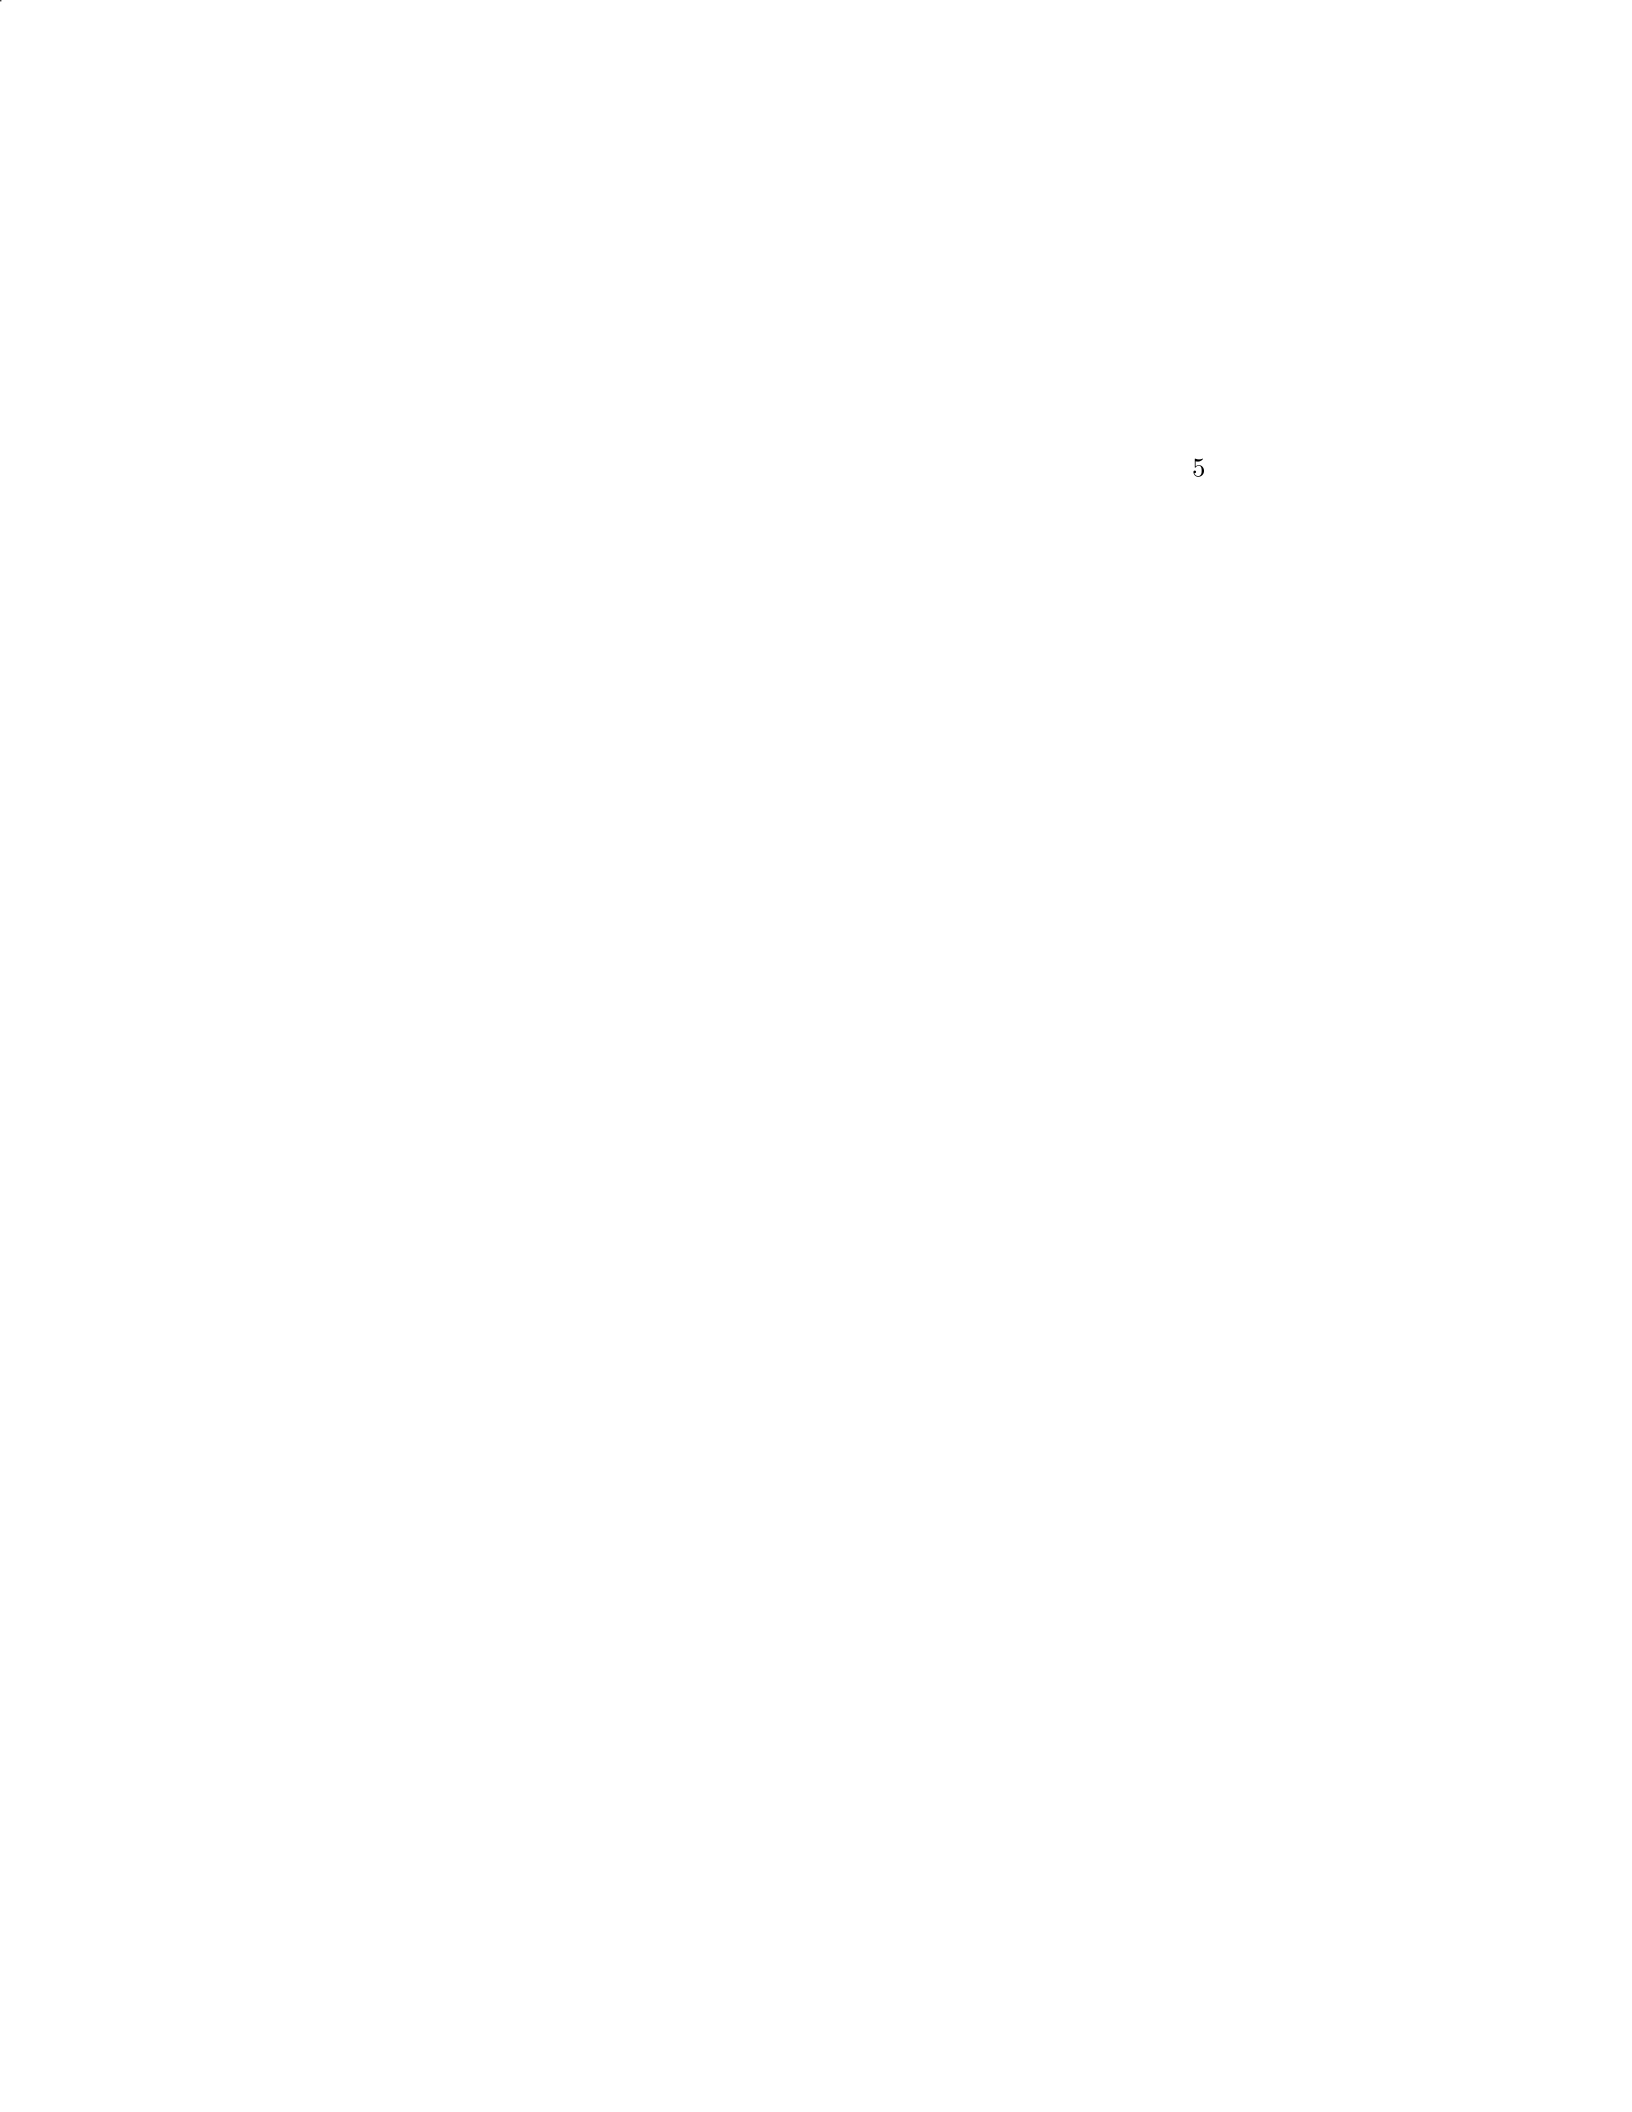
Step 4: Perform the calculation:
Unrealized gain or loss = $50,000
Therefore, the unrealized gain related to this investment for the year is
$
50,000.
Question 4
Question
Company XYZ holds an investment in equity securities that are classified as fair
value through profit or loss. At the end of the reporting period, the fair value
of the equity securities is $150,000 while the cost of investment is $120,000.
Additionally, the company incurred $5,000 in transaction costs related to the
investment. Calculate the gain or loss recognized in profit or loss for the period.
Solution
To calculate the gain or loss recognized in profit or loss, we need to consider the
fair value of the investment, the cost of investment, and any related transaction
costs.
Fair Value of the Investment = $150,000
Cost of Investment = $120,000
Transaction Costs = $5,000
Step 1: Calculate the net carrying amount of the investment. The net
carrying amount of the investment is calculated as the cost of the investment
adjusted for any transaction costs.
Net Carrying Amount = Cost of Investment + Transaction Costs
Net Carrying Amount = $120,000 + $5,000
Net Carrying Amount = $125,000
Step 2: Determine the gain or loss recognized in profit or loss. The gain or
loss recognized in profit or loss is calculated as the difference between the fair
value of the investment and the net carrying amount.
Gain/Loss = Fair Value of Investment −Net Carrying Amount
Gain/Loss = $150,000 −$125,000
Gain/Loss = $25,000
Since the fair value of the investment is higher than the net carrying amount,
the company would recognize a gain of $25,000 in profit or loss for the period.
3
Question 5
Question
A company holds an investment in a publicly traded equity security. The fair
value of the investment at the end of the reporting period is 150,000.Duringthereportingperiod, thefairvalueof theinvestmentincreasedby20,000
due to changes in market conditions. However, the company also incurred
5,000intransactioncostswhenacquiringtheinvestment.Calculatetheamountthatshouldbereportedinthecompany′sfinancialstatementsf ortheinvestment.
Solution
Step 1: Calculate the fair value change excluding transaction costs. We need to
adjust the fair value change for the transaction costs incurred by the company.
Fair value change excluding transaction costs = Fair value change−Transaction costs
Fair value change excluding transaction costs = $20,000 −$5,000
Fair value change excluding transaction costs = $15,000
Step 2: Determine the amount to be reported in the financial statements.
The amount to be reported in the financial statements is the initial cost of the
investment plus the fair value change excluding transaction costs.
Amount to be reported = Initial cost+Fair value change excluding transaction costs
Since no initial cost was provided in the question, we can assume it was equal
to the fair value at the end of the reporting period.
Amount to be reported = $150,000 + $15,000
Amount to be reported = $165,000
Therefore, the amount that should be reported in the company’s financial
statements for the investment is $165,000.
Question 6
Question
A company holds an investment in a commodity futures contract. The fair
value of the investment at the end of the reporting period is determined to be
15,000.T hecompanyneedstodecidewhethertoclassifytheinvestmentasheld−f or−
tradingorasheld−for−other−purpose.P rovidetwokeyf actorsthatthecompanyshouldconsiderwhenmakingthisclassificationdecision.
4
Solution
Step 1: One key factor that the company should consider is the company’s
intention at the time of purchase. If the company’s intention was to profit
from short-term fluctuations in market prices, then the investment should be
classified as held-for-trading. On the other hand, if the company’s intention was
to hold the investment for a longer period of time, then it should be classified
as held-for-other-purpose.
Step 2: Another key factor to consider is the frequency of transactions. If the
company frequently buys and sells similar investments, it may indicate that the
investment should be classified as held-for-trading. Conversely, if the company
rarely engages in such transactions and has a history of holding investments
for longer periods, it may be more appropriate to classify the investment as
held-for-other-purpose.
Question 7
Question
ABC Company owns an investment in a bond for which the fair value is not read-
ily determinable. The company receives annual cash flows of 4,000eachyearandattheendof year5receivesthebond′sfacevalueof10,000.
The bond’s discount rate is 8
Solution
Step 1: Calculate the present value of the bond’s cash flows. The present value
of the annual cash flows:
P Vannuity =4000
1+0.08 +4000
(1 + 0.08)2+4000
(1 + 0.08)3+4000
(1 + 0.08)4+4000 + 10000
(1 + 0.08)5
Step 2: Simplify the expression by calculating the present values.
P Vannuity =4000
1.08 +4000
1.1664 +4000
1.2597 +4000
1.3605 +14000
1.4693
Step 3: Sum up the present values.
P Vannuity ≈3703.70 + 3428.09 + 3174.05 + 2939.12 + 9525.15 = 22770.11
Therefore, the fair value of the bond is approximately 22,770.11.
Question 8
Question
A company owns an investment in a privately held company for which there
is no active market. The financial statements of the privately held company
5
are audited, and the company intends to sell the investment in the near future.
Explain how the company should determine the fair value of this investment in
accordance with fair value measurement standards.
Solution
To determine the fair value of the investment in the privately held company,
the company should follow the fair value measurement standards as outlined in
accounting guidelines. Here are the steps the company should take:
Step 1: Identify the Level of the Fair Value Hierarchy
Level 1: If there are quoted prices in active markets for identical assets,
the fair value can be determined using these prices.
Level 2: If there are similar assets with observable inputs, the company
can use these inputs to estimate the fair value.
Level 3: If there are no observable inputs, the company will need to use
its own assumptions and valuation techniques to determine the fair value.
Step 2: Use Valuation Techniques
In this case, since there is no active market for the investment, the com-
pany would need to use valuation techniques. Common methods include
the income approach, market approach, and cost approach.
The income approach involves estimating the present value of future cash
flows expected from the investment.
The market approach involves comparing the investment to similar invest-
ments that have known market prices.
The cost approach involves estimating the cost to replace the investment.
Step 3: Disclosures
The company should provide disclosures about the fair value measurement
techniques used, the inputs and assumptions made, and the level in the
fair value hierarchy the measurements fall under.
These disclosures are important for users of the financial statements to
understand how the fair value was determined.
By following these steps and guidelines, the company can appropriately de-
termine the fair value of its investment in the privately held company.
6

Question 9
Question
Company XYZ holds a financial instrument that it measures at fair value. At
the end of the reporting period, the fair value of the financial instrument is
150,000.Duringthereportingperiod, thefollowingeventsoccurred :−Event1 :
Asimilarf inancialinstrumenthadaquotedmarketpriceof140,000. - Event 2:
Company XYZ received a valuation report indicating a fair value of 160,000f orthefinancialinstrument.−
Event3 : Asignif icanteconomiceventoccurredthatdidnothaveadirectimpactonthefinancialinstrument′svalue.
Based on the above information, discuss how each event should be consid-
ered in determining the fair value of the financial instrument at the end of the
reporting period.
Solution
To determine the fair value of a financial instrument, Company XYZ should
consider all relevant information available at the end of the reporting period.
We will discuss how each event mentioned should be considered in determining
the fair value of the financial instrument:
Step 1: Event 1: Considering that a similar financial instrument had a
quoted market price of 140,000, thiswillprovideanindicationof therangewithinwhichthefairvalueofCompanyXY Z′sfinancialinstrumentmayf all.However, itisimportanttonotethatactualtransactionsmaynotalwaysref lectfairvalueduetomarketineff icienciesorotherf actors.T herefore, thisquotedmarketpriceshouldbeusedasareferencepointratherthanthesoledeterminantoffairvalue.
Step 2: Event 2: The valuation report received by Company XYZ indicat-
ing a fair value of 160,000f orthef inancialinstrumentshouldalsobeconsidered.V aluationreportsarepreparedbyindependentexpertsandprovideadditionalinsightintothefairvalueofthef inancialinstrument.CompanyXY Zshouldevaluatethecredibilityof thevaluationreportandassesswhetherthemethodologyusedisappropriateforthespecificcharacteristicsoftheirfinancialinstrument.
Step 3: Event 3: Although a significant economic event occurred during
the reporting period that did not have a direct impact on the financial instru-
ment’s value, it is important for Company XYZ to assess whether this event
could have indirect implications on the fair value of the financial instrument.
Economic events can create volatility in financial markets, which may influence
the fair value of financial instruments.
In conclusion, Company XYZ should consider all available information, in-
cluding quoted market prices, valuation reports, and relevant economic events,
in determining the fair value of the financial instrument at the end of the re-
porting period. Each of these events provides valuable input that contributes
to a more comprehensive assessment of fair value.
Question 10
Question
Company XYZ holds an investment in a bond that it measures at fair value
through other comprehensive income. The fair value of the bond was 105,000attheendofthereportingperiod.Duringtheperiod, thebondpaidacashinterestof3,000
which was recognized in profit or loss. Company XYZ estimated that the fair
value of the bond would have been 102,000if itwasmeasuredatfairvaluethroughprof itorloss.CalculatethegainorlossthatCompanyXY Zwouldrecognizeinothercomprehensiveincomerelatedtothebondf ortheperiod.
7
Solution
Step 1: Calculate the amount that would have been recognized in profit or loss
if the bond was measured at fair value through profit or loss.
Fair Value in profit or loss = $102,000
Fair Value in OCI = $105,000
Interest income recognized in profit or loss = $3,000
Gain or loss in profit or loss = Fair Value in profit or loss−Interest income recognized in profit or loss = $102,000−$3,000 = $99,000
Step 2: Calculate the gain or loss that would be recognized in other com-
prehensive income.
Gain or loss in OCI = Fair Value in OCI−Fair Value in profit or loss = $105,000−$102,000 = $3,000
Therefore, Company XYZ would recognize a gain of
$
3,000 in other compre-
hensive income related to the bond for the period.
Question 11
Question
Company XYZ holds an investment property that is measured at fair value. At
the end of the reporting period, the fair value of the investment property is deter-
mined to be 600,000.Duringtheyear, thepropertygeneratedrentalincomeof30,000.
The fair value hierarchy level for the investment property is Level 3.
Given this information, calculate the fair value gain or loss recognized in the
income statement for the year.
Solution
To calculate the fair value gain or loss recognized in the income statement, we
need to compare the fair value of the investment property at the end of the
reporting period with the fair value at the beginning of the period, adjusted for
any purchases or sales made during the year.
Step 1: Calculate the initial fair value of the investment property. Since
there is no information given about the initial fair value of the investment prop-
erty, we assume it to be 0atthebeginningof theyear.
Step 2: Calculate the fair value gain or loss. The fair value gain or loss can
be calculated as:
Fair value gain or loss = Fair value at the end of the period−Fair value at the beginning of the period−Net cash inflows/outflows
Substitute the given values into the formula:
Fair value gain or loss =
600,000 - 0−30,000 = 570,000
Therefore, the fair value gain recognized in the income statement for the
year is 570,000 loss .
8

Question 12
Question
A company is assessing the fair value of a financial asset using the market
approach. The asset has a Level 2 fair value hierarchy classification. The
company gathers observable market data from both identical (exact matches)
and similar assets but must adjust the data due to differences between the assets.
Explain the steps the company should take to determine the fair value of the
asset.
Solution
To determine the fair value of the financial asset using the market approach
with a Level 2 fair value hierarchy classification, the company must follow these
steps:
Step 1: Identify and select appropriate valuation techniques: The company
should select appropriate valuation techniques based on the characteristics of
the asset and the available market data. In this case, since the asset is a financial
instrument, common valuation techniques include discounted cash flow analysis,
option pricing models, and valuation multiples.
Step 2: Gather observable market data: The company should gather observ-
able market data from both identical (exact matches) and similar assets. This
data provides a basis for estimating the fair value of the asset.
Step 3: Adjust market data for differences: Since there are differences be-
tween the asset being valued and the assets in the observable market data, the
company should make adjustments to account for these differences. This may
involve adjusting pricing multiples, discount rates, or other relevant factors.
Step 4: Estimate the fair value: Using the adjusted market data and val-
uation techniques, the company should estimate the fair value of the financial
asset. This estimation should consider the current market conditions and any
relevant assumptions.
Step 5: Document the valuation process: It is essential for the company
to document the valuation process, including the data sources, assumptions,
adjustments made, and the rationale behind the final fair value estimate. This
documentation helps provide transparency and support the reliability of the fair
value measurement.
Question 13
Question
A company is assessing the fair value of its investment in a private equity fund
using the market approach. The investment recently had a change in key man-
agement personnel, leading to increased uncertainty around future cash flows.
9

How should this change in circumstances be reflected in the fair value measure-
ment of the investment?
Solution
To reflect the change in circumstances related to the key management personnel
in the fair value measurement of the investment, the company should consider
the impact of this change on the future cash flows expected from the investment.
Here are the steps to adjust the fair value measurement:
Step 1: Determine the impact of the change in key management person-
nel on future cash flows. The company should assess whether the change in
key management personnel is likely to have a positive or negative impact on the
future cash flows generated by the investment. For example, if the new manage-
ment is viewed as more capable and likely to improve the fund’s performance,
this could increase future cash flow expectations. Conversely, if the change
introduces uncertainty or risk, future cash flow expectations may decrease.
Step 2: Adjust the discount rate applied to the future cash flows. Changes
in management personnel can impact the perceived risk associated with the
investment. If the change is seen as positive and reducing risk, the discount
rate applied to the future cash flows should be adjusted downward. Conversely,
if the change increases uncertainty or risk, the discount rate should be adjusted
upward to reflect the higher required rate of return.
Step 3: Update the fair value calculation based on the revised cash flow ex-
pectations and discount rate. Using the adjusted future cash flows and discount
rate, recalculate the fair value of the investment in the private equity fund. This
updated fair value should reflect the company’s assessment of the impact of the
change in key management personnel on the investment’s value.
By following these steps, the company can appropriately reflect the change
in circumstances related to key management personnel in the fair value mea-
surement of the investment using the market approach.
Question 14
Question
Company XYZ holds an investment in a private company for which it deter-
mines the fair value using a market approach. The market approach considers
comparable transactions of similar private companies. Company XYZ identifies
three comparable companies with the following price-to-earnings (P/E) ratios:
14, 16, and 18. Assuming the private company being valued has earnings of
500,000, calculatethefairvalueof theinvestmentbasedonthisinformation.
Solution
To calculate the fair value of the investment using the market approach, we will
apply the P/E ratio of the comparable companies to the earnings of the private
10
company to estimate its fair value.
Step 1: Calculate the average P/E ratio of the comparable companies. The
average P/E ratio is calculated as:
Average P/E ratio = 14 + 16 + 18
3= 16
Step 2: Apply the average P/E ratio to the earnings of the private company
to find its fair value. The fair value of the investment is calculated as:
Fair value = Earnings ×Average P/E ratio =
500,000 ×16 =8,000,000
Therefore, the fair value of the investment in the private company using the
market approach is 8,000,000.
Question 15
Question
Company XYZ has invested in financial assets classified as Level 2 fair value
measurement. The fair value of the financial assets increased by 15
Solution
To understand how the increase in fair value will impact the financial statements
of Company XYZ, we need to consider the different components affected by this
change.
Step 1: Impact on the Statement of Financial Position (Balance
Sheet) When the fair value of financial assets increases, it leads to an unrealized
gain. This unrealized gain will impact the assets and equity sections of the
balance sheet. Specifically, the investment in financial assets will increase in
value, leading to higher total assets. Shareholders’ equity will also increase due
to the recognition of the unrealized gain as part of comprehensive income.
Step 2: Impact on the Statement of Comprehensive Income The
unrealized gain resulting from the increase in fair value of financial assets will
be recorded in the statement of comprehensive income. It will be included as
part of other comprehensive income, affecting the total comprehensive income
for the period.
Step 3: Disclosure in the Notes to the Financial Statements Com-
pany XYZ will need to disclose the fair value measurement of the financial assets
in the notes to the financial statements. This disclosure includes the valuation
techniques used, inputs to the valuation, and the impact of any changes in fair
value on the financial statements.
In conclusion, the increase in fair value of financial assets classified as Level 2
fair value measurement will result in higher asset values, increased shareholders’
11

equity, and a positive impact on the comprehensive income of Company XYZ.
It is essential for the company to provide transparent and detailed disclosures
in the financial statements to inform users of the impact of fair value changes.
Question 16
Question
A company holds an investment property which is measured at fair value through
profit or loss. The fair value of the investment property at the end of the report-
ing period is 850,000.Duringtheyear, thecompanyincurred30,000 in repair and
maintenance costs for the property. The company also received rental income of
60,000fromthepropertyduringtheyear.Determinethecarryingamountoftheinvestmentpropertyattheendofthereportingperiod, consideringtherelevantaccountingtreatmentforfairvaluemeasurement.
Solution
Step 1: Calculate the carrying amount of the investment property at the end of
the reporting period before considering any adjustments.
Carrying amount before adjustments = Fair value of the investment property
Carrying amount before adjustments =
850,000
Carrying amount before adjustments =
850,000
Step 2: Incorporate the repair and maintenance costs incurred during the
year.
Adjusted carrying amount = Carrying amount before adjustments−Repair and maintenance costs
Adjusted carrying amount =
850,000 - 30,000
Adjusted carrying amount =
820,000
Step 3: Consider the effect of rental income received during the year.
Carrying amount at the end of the reporting period = Adjusted carrying amount+Rental income
Carrying amount at the end of the reporting period =
12

820,000 + 60,000
Carrying amount at the end of the reporting period =
880,000
Therefore, the carrying amount of the investment property at the end of the
reporting period, considering the repair and maintenance costs as well as the
rental income, is 880,000.
Question 17
Question
Company X holds an investment in a privately held company. The fair value of
this investment is not readily available in the market. Company X decides to
use the income approach to determine the fair value of the investment. Provide
two key steps involved in applying the income approach to estimate the fair
value of the investment.
Solution
To estimate the fair value of the investment using the income approach, two key
steps involved are as follows:
Step 1: Determine the Expected Future Cash Flows To apply the
income approach, Company X must first estimate the future cash flows expected
to be generated by the investment. This step involves projecting the cash flows
that the investment is expected to generate over its remaining useful life. These
cash flows should be based on reasonable and supportable assumptions, taking
into account factors such as market conditions, economic trends, and the specific
characteristics of the investment. Company X may use discounted cash flow
analysis or other valuation techniques to estimate the present value of these
future cash flows.
Step 2: Determine the Discount Rate Once the expected future cash
flows have been determined, the next step is to determine an appropriate dis-
count rate to apply to these cash flows. The discount rate should reflect the
risk associated with the investment and the time value of money. Company X
may use the capital asset pricing model (CAPM) or other methods to calculate
the discount rate. By discounting the projected cash flows at the appropriate
discount rate, Company X can calculate the present value of the investment,
which represents its estimated fair value.
13
Question 18
Question
Company XYZ holds an investment in bonds classified as Level 2 in the fair value
hierarchy. The bonds have a fair value of 950,000attheendofthereportingperiod.Duringtheperiod, thebondsexperiencedacreditratingdowngrade, resultinginadecreaseof 20,000
in fair value adjustment recognized in other comprehensive income. Determine
the original cost of the bonds held by Company XYZ.
Solution
Step 1: Understand the fair value adjustment in other comprehensive income.
Fair value adjustment = Fair value at end −Original cost
−20,000 = 950,000 −Original cost
Step 2: Solve for the original cost.
−20,000 = 950,000 −Original cost
Original cost = 950,000 + 20,000
Original cost = $970,000
Therefore, the original cost of the bonds held by Company XYZ is $970,000.
Question 19
Question
You are a financial analyst working for a company that holds investments in
various financial instruments. The company follows the fair value measurement
principles as per IFRS 13.
One of the financial instruments the company holds is a bond with a face
value of 100,000andastatedinterestrateof 5
Solution
Step 1: Calculate the present value of the bond using the market interest rate.
Given: Face value of the bond (F V ) = 100,000 Stated interest rate (i) =
5Market interest rate for similar bonds (r) = 6Number of periods to maturity
(n) = 5 years
First, calculate the present value of the bond using the market interest rate
formula:
P V =F V ×1−(1 + r)−n
r
Substitute the values:
P V = 100,000 ×1−(1 + 0.06)−5
0.06
14
P V 100,000 ×1−0.7473
0.06
P V 100,000 ×0.2527
0.06
P V 100,000 ×4.2117
P V 421,170
Hence, the present value of the bond using the market interest rate is
421,170.
Step 2: Calculate the fair value gain or loss on the bond using Level 2 inputs.
The fair value of the bond is given as 95,000.T hefairvaluegainorlosscanbecalculatedas :
F air V alue Gain or Loss =F air V alue −P V
F air V alue Gain or Loss = 95,000 −421,170
F air V alue Gain or Loss =−326,170
Therefore, the fair value loss on the bond using Level 2 inputs is 326,170.
Question 20
Question
Company XYZ holds an investment in a privately held company where there is
no active market. The fair value of this investment is to be estimated using a val-
uation technique. Discuss the factors that should be considered in determining
the fair value of this investment.
Solution
To determine the fair value of an investment in a privately held company with no
active market, several factors need to be considered. Below are the key factors
that should be taken into account:
1. Nature of the Investment: Consider the type of investment (e.g., eq-
uity, debt) and the rights attached to it (e.g., voting rights, interest pay-
ments). Different types of investments may have different characteristics
that affect their fair value.
2. Financial Performance of the Company: Evaluate the historical and
projected financial performance of the investee company. Factors such as
revenue growth, profitability, and cash flow generation can impact the fair
value of the investment.
3. Market and Industry Conditions: Assess the conditions of the market
and industry in which the investee company operates. Changes in market
dynamics, competition, and regulatory environment can affect the fair
value of the investment.
15

4. Valuation Methodology: Select an appropriate valuation technique
based on the nature of the investee company and the availability of data.
Common valuation methods include discounted cash flow analysis, com-
parable company analysis, and precedent transactions analysis.
5. Discount Rate: Determine the appropriate discount rate to use in the
valuation. The discount rate should reflect the risks associated with the
investment, such as business risk, market risk, and liquidity risk.
6. Control Premium or Lack of Control Discount: Consider whether
the investor has control over the investee company. A control premium
may be applied if the investor has control, while a lack of control discount
may be appropriate if the investor lacks control.
7. Market Participant Assumptions: Evaluate the assumptions that
market participants would make when valuing the investment. This in-
cludes assumptions about the investee company’s future performance,
growth prospects, and risk profile.
By carefully considering these factors and conducting a thorough analysis,
an appropriate estimate of the fair value of the investment in the privately held
company can be determined.
Question 21
Question
A company has an investment in a startup company valued using the fair value
method. At the end of the reporting period, the company’s investment in the
startup has significantly increased in value. Explain how this increase in fair
value will impact the financial statements of the company.
Solution
To understand how the increase in fair value of the investment will impact the
financial statements of the company, we need to consider the different compo-
nents of the financial statements affected by fair value measurements.
Step 1: Balance Sheet - The increase in fair value of the investment will
lead to a higher valuation of the investment on the balance sheet. This increase
will be reflected in the assets section of the balance sheet. - The increase in
fair value of the investment will result in a higher total assets value on the bal-
ance sheet, which may improve the company’s financial position and potentially
increase its overall net worth.
Step 2: Income Statement - The increase in fair value of the investment
will impact the income statement through the recognition of unrealized gains.
- The increase in fair value will result in a gain which will be recognized on
the income statement. - This unrealized gain will typically be recorded in the
16

”Other Comprehensive Income” section of the income statement as it has not
been realized through a sale of the investment.
Step 3: Equity Statement - The increase in fair value of the investment
will also impact the equity statement. - The unrealized gain will be reflected in
the equity statement as part of the comprehensive income. - This will lead to
an increase in the total equity of the company.
In conclusion, the increase in fair value of the investment will lead to a higher
valuation of the investment on the balance sheet, recognition of unrealized gains
on the income statement, and an increase in total equity on the equity statement.
Question 22
Question
A company holds an investment in a financial instrument classified as a Level 3
fair value measurement. The fair value of the investment at the end of the report-
ing period is 75,000.Duringtheperiod, thecompanymadeanadjustmentof 5,000
to fair value through profit or loss. The opening balance of the investment at the
beginning of the reporting period was 65,000.Calculatetheclosingbalanceof theinvestmentattheendof thereportingperiod.
Solution
Step 1: Calculate the total gains/losses on the investment.
Total Gains/Losses = Opening Balance + Adjustment −Closing Balance
Given that the opening balance was 65,000, theadjustmentwas5,000, and the
closing balance is unknown, we can rewrite the formula as follows:
65,000 + 5,000 −Closing Balance = 0
70,000 −Closing Balance = 0
Closing Balance = 70,000
Therefore, the closing balance of the investment at the end of the reporting
period is 70,000.
Question 23
Question
A company has an investment in a security which is classified as a Level 3 asset
under fair value hierarchy. The fair value of the security has increased from
200,000 at the beginning of the year to 240,000 at the end of the year. During
the year, the company recorded a net gain of 30,000 in its income statement
related to changes in the fair value of the security. Calculate the amount of
unrealized gains recognized in other comprehensive income (OCI) for the year.
17
Solution
Step 1: Calculate the total change in fair value of the security The total change
in the fair value of the security can be calculated as:
Total Change in Fair Value = Ending Fair Value −Beginning Fair Value
Total Change in Fair Value = $240,000 −$200,000 = $40,000
Step 2: Calculate the portion of the change in fair value included in net in-
come The portion of the total change in fair value that is included in net income
can be calculated as the net gain or loss recognized in the income statement. In
this case, the net gain recognized in the income statement is
$
30,000.
Step 3: Calculate the unrealized gains recognized in OCI The unrealized
gains recognized in OCI can be calculated as the total change in fair value
minus the portion included in net income.
Unrealized Gains Recognized in OCI = Total Change in Fair Value−Portion Included in Net Income
Unrealized Gains Recognized in OCI = $40,000 −$30,000 = $10,000
Therefore, the amount of unrealized gains recognized in other comprehensive
income (OCI) for the year is
$
10,000.
Question 24
Question
A company is assessing the fair value of its investment in a private company. The
company has determined that the investment best fits within Level 3 of the fair
value hierarchy due to the absence of observable market data. The company
utilized a discounted cash flow (DCF) analysis to estimate the fair value of
the investment. The DCF model includes forecasts of future cash flows and a
discount rate that reflects the risk associated with the investment. Discuss the
challenges and limitations associated with using a DCF analysis for fair value
measurement in this context.
Solution
Step 1: Define DCF Analysis In a DCF analysis, the fair value of an invest-
ment is estimated by discounting the future cash flows generated by the invest-
ment back to the present using an appropriate discount rate. This method relies
on forecasting future cash flows and selecting an appropriate discount rate.
Step 2: Challenges with DCF Analysis 1. Forecasting: Forecasting
future cash flows can be challenging, especially for investments in private com-
panies where financial information may be limited. Errors in forecasting can
lead to significant inaccuracies in the fair value estimate.
18

2. Discount Rate Selection: Choosing the appropriate discount rate is
crucial in DCF analysis. In the absence of observable market data, determining
the risk associated with the investment can be subjective and may vary de-
pending on individual assumptions, leading to potential biases in the fair value
measurement.
3. Illiquidity Discount: Investments in private companies are often illiq-
uid, meaning they cannot be easily sold in the market. DCF analysis may not
fully account for this illiquidity risk, potentially overvaluing the investment.
4. Model Sensitivity: DCF analysis is sensitive to changes in assumptions,
such as growth rates, discount rates, and terminal values. Small changes in these
inputs can significantly impact the fair value estimate, introducing uncertainty
into the measurement.
5. Judgment and Bias: DCF analysis requires a considerable amount
of judgment in selecting assumptions and inputs. This subjectivity introduces
the risk of bias in the fair value measurement, particularly in the absence of
verifiable market data.
Overall, while DCF analysis is a commonly used method for fair value mea-
surement, it comes with inherent challenges and limitations, especially for in-
vestments in private companies within Level 3 of the fair value hierarchy. Careful
consideration of these factors is essential to producing a reliable and unbiased
fair value estimate.
Question 25
Question
Company XYZ holds an investment in a financial instrument classified as held
for trading. At the end of the reporting period, the fair value of the investment is
165,000.Duringthenextreportingperiod, thefairvalueoftheinvestmentincreasesto180,000.
Calculate the gain or loss recognized by Company XYZ in the income statement
for the next reporting period based on the fair value measurement.
Solution
To calculate the gain or loss recognized by Company XYZ in the income state-
ment for the next reporting period based on fair value measurement, we need
to compare the fair value of the investment at the end of the current reporting
period with the fair value at the end of the next reporting period. The gain or
loss recognized will be equal to the change in fair value of the investment.
Step 1: Calculate the gain/loss in fair value of the investment:
Change in Fair Value = Fair Value at the end of the next reporting period−Fair Value at the end of the current reporting period
Change in Fair Value = $180,000 −$165,000
Change in Fair Value = $15,000
19

Step 2: Determine the gain or loss recognized in the income statement:
Since the fair value of the investment increased, Company XYZ will recognize a
gain in the income statement for the next reporting period. The gain recognized
will be equal to the change in fair value:
Gain Recognized = $15,000
Therefore, Company XYZ will recognize a gain of 15,000intheincomestatementforthenextreportingperiodbasedonthefairvaluemeasurement.
Question 26
Question
A company has an investment in a private equity fund that it measures at
fair value. The fair value of the investment at the beginning of the year was
$500,000. During the year, the fair value decreased by 20%. The company
received a cash distribution of $50,000 from the investment during the year. At
the end of the year, the fair value of the investment increased by 10% from the
beginning of the year fair value. Calculate the fair value of the investment at
the end of the year.
Solution
Step 1: Calculate the fair value of the investment after the 20% decrease. Let
xbe the fair value of the investment after the 20% decrease. We can write:
x= 0.8×500,000.
Step 2: Calculate the fair value of the investment after the cash distribution.
Let ybe the fair value of the investment after the cash distribution. We can
write: y=x−50,000.
Step 3: Calculate the fair value of the investment at the end of the year after
the 10% increase from the beginning. Let zbe the fair value of the investment
at the end of the year. We can write: z= 1.1×500,000.
Step 4: Substitute the values of xand yinto the equation for z. Substitute
x= 0.8×500,000 and y=x−50,000 into the equation for z. We get: z=
1.1×(0.8×500,000 −50,000).
Step 5: Calculate the fair value of the investment at the end of the year.
Evaluate the expression for zto find the fair value of the investment at the end
of the year. z= 1.1×(0.8×500,000 −50,000) = 1.1×(400,000 −50,000) =
1.1×350,000 = 385,000.
Therefore, the fair value of the investment at the end of the year is $385,000.
20
Question 27
Question
A company has an investment in a security classified as a Level 3 asset under fair
value measurement. The fair value of the security has significantly decreased
during the year, leading to a potential impairment. The company’s management
is assessing whether an impairment loss should be recognized. Discuss the key
considerations that the company should take into account when determining
whether to recognize an impairment loss on the security.
Solution
To determine whether an impairment loss on a security classified as a Level
3 asset should be recognized, the company should consider the following key
factors:
Step 1: Review Market Indicators
Check if there have been significant adverse changes in the market, econ-
omy, or industry that could impact the fair value of the security.
Consider external factors such as interest rates, inflation rates, and geopo-
litical events that might affect the security’s value.
Step 2: Assess the Specific Security
Evaluate the specific security’s performance, financial health, and prospects
for recovery.
Consider whether there have been any changes to the security’s credit
rating or the issuer’s financial condition.
Step 3: Utilize Valuation Techniques
Use appropriate valuation techniques to estimate the fair value of the
security, considering inputs such as cash flow projections, discount rates,
and market comparables.
Compare the estimated fair value to the security’s carrying amount to
determine if there is an impairment.
Step 4: Consider Management’s Intentions
Evaluate management’s intentions regarding the holding of the security,
including any plans to sell or hold the security for the long term.
Determine if the decline in fair value is temporary or permanent based on
management’s assessment.
Step 5: Document and Disclose
21
Document the analysis performed and the rationale for recognizing or not
recognizing an impairment loss.
Ensure proper disclosure in the financial statements regarding the assess-
ment of impairment and any resulting impairment loss recognized.
By carefully considering these factors and steps, the company can make
a well-informed decision on whether to recognize an impairment loss on the
security.
Question 28
Question
A company holds an investment in a startup company, which is not traded on
any exchange. The fair value of the investment is determined using the income
approach. The following information is available: - Present value of expected fu-
ture cash flows: 150,000−Discountrate : 12−T erminalvalueaf ter5years :100,000
Calculate the fair value of the investment.
Solution
Step 1: Calculate the terminal value after 5 years using the formula:
Terminal value = Present value of expected future cash flows ×(1 + Discount rate)5
1 + Discount rate
Terminal value = 150,000 ×(1 + 0.12)5
1+0.12 =150,000 ×1.76234
1.12 ≈$235,851
Step 2: Calculate the fair value of the investment by summing the present
value of expected future cash flows and the terminal value:
Fair value = Present value of expected future cash flows + Terminal value
Fair value = 150,000 + 235,851 = $385,851
Therefore, the fair value of the investment in the startup company is
$
385,851.
Question 29
Question
Explain the concept of Fair Value Measurement in the context of financial re-
porting. Provide an example of an asset where fair value measurement is par-
ticularly relevant and explain why.
22

Solution
Step 1: Fair Value Measurement Fair value measurement is the process of de-
termining the value of an asset or liability based on its current market price. It
is an important concept in financial reporting, as it provides users of financial
statements with relevant and reliable information about the value of an entity’s
assets and liabilities.
Step 2: Example: Investment Property An example of an asset where fair
value measurement is particularly relevant is investment property. Investment
property is real estate that is owned for the purpose of earning rental income,
capital appreciation, or both. The fair value of investment property may fluc-
tuate over time due to changes in market conditions, demand for real estate,
economic factors, etc.
Step 3: Importance of Fair Value Measurement for Investment Property
For investment property, fair value measurement is important because it pro-
vides stakeholders with an accurate and up-to-date reflection of the property’s
value. This information is crucial for making decisions about buying, selling, or
holding onto investment properties. Additionally, fair value measurement helps
investors, lenders, and other stakeholders assess the performance and potential
risks associated with investment properties.
In conclusion, fair value measurement is a key concept in financial report-
ing that helps ensure transparency and reliability in the valuation of assets and
liabilities. For investment property, fair value measurement is particularly rel-
evant due to the dynamic nature of real estate markets and the importance of
accurate valuation for decision-making purposes.
Question 30
Question
A company has a financial asset categorized as Level 3 in the fair value hi-
erarchy. The fair value of the asset at the end of the reporting period is
137,500.Duringtheperiod, thereweresignif icantunobservableinputsinvolvedindeterminingthefairvalueof theasset.T hecompanywantstodiscloseadditionalinf ormationinthefinancialstatementsaboutthelevelsinthef airvaluehierarchy.Calculatethegainsorlossesthatthecompanywouldreportinprofitorlossfortheperiod, giventhatthefairvalueatthebeginningof theperiodwas120,000.
Solution
1. To calculate the gains or losses in profit or loss, we need to find the change in
fair value of the asset from the beginning of the period to the end of the period.
2. The change in fair value can be calculated as:
Change in Fair Value = Fair Value at the End −Fair Value at the Beginning
3. Substituting the values we have:
Change in Fair Value =
137,500 - 120,000
23

4. Calculating the change in fair value:
Change in Fair Value =
17,500
5. Therefore, the company would report a gain of 17,500inprofitorlossf ortheperiod.
Question 31
Question
Company XYZ holds an investment in a bond that is classified as a Level 2 asset
under fair value measurements. At the end of the reporting period, the fair value
of the bond is determined to be 1,500,000.Duringthenextreportingperiod, thef airvalueof thebondincreasesto1,700,000.
Determine the impact of this increase in fair value on the financial statements
of Company XYZ.
Solution
Step 1: Under fair value measurement, changes in the fair value of assets are
recognized in the income statement. The increase in fair value of the bond from
1,500,000to1,700,000 will result in a gain for Company XYZ.
Step 2: Calculate the gain by subtracting the initial fair value of the bond
from the new fair value: 1,700,000−1,500,000 = 200,000
Step 3: Recognize the gain in the income statement. The gain of 200,000willberecognizedasanon−
operatingincomeforthereportingperiod.
Step 4: The impact of the increase in fair value on the financial statements of
Company XYZ will be an increase in net income by 200,000, whichwillalsoleadtoanincreaseintotalequityonthebalancesheet.
Question 32
Question
Company XYZ holds a financial instrument that falls under Level 3 of the
fair value hierarchy. The instrument has observable inputs, including quoted
prices for similar instruments in active markets (Level 1), but also includes
unobservable inputs based on the company’s own assumptions (Level 3).
Given this information, explain how the fair value of the financial instrument
should be measured according to IFRS 13 Fair Value Measurement.
Solution
It is important to note that when a financial instrument has both observable
and unobservable inputs, the fair value should be measured using a combination
of both inputs. IFRS 13 provides guidance on how this should be done.
24

Step 1: Identify the Key Inputs First, the company needs to identify
the key inputs that drive the fair value of the financial instrument. In this
case, both the observable inputs (Level 1) and unobservable inputs (Level 3)
are important in determining the fair value.
Step 2: Weighted Average Approach The company should use a weighted
average approach to combine the observable and unobservable inputs. This in-
volves assigning weights to each input based on their relative significance in
determining the fair value.
Step 3: Consider Market Observability Since Level 1 inputs are con-
sidered more reliable due to their market observability, they should typically
have a greater influence on the final fair value calculation than Level 3 inputs.
The company should consider the extent to which each input is observable in
the market.
Step 4: Validate the Inputs The company should validate the inputs
used in the fair value measurement process to ensure they are reasonable and
appropriate. This may involve comparing the inputs to external market data
or using other valuation techniques to confirm the accuracy of the fair value
calculation.
By following these steps, Company XYZ can appropriately measure the fair
value of the financial instrument that falls under Level 3 of the fair value hier-
archy under IFRS 13.
Question 33
Question
A company holds an investment in a privately-held company that is measured at
fair value through profit or loss. The fair value of the investment at the end of the
reporting period is 1,200,000.Duringtheyear, thecompanyreceivedadividendof 50,000
from the investee. The fair value of the investment at the beginning of the re-
porting period was 1,100,000.Calculatethegainorlossrecognizedinprofitorlossfortheyear.
Solution
Step 1: Calculate the change in fair value of the investment.
Change in Fair Value = Fair Value at End −Fair Value at Beginning
Change in Fair Value =
1,200,000 - 1,100,000 =100,000
Step 2: Calculate the gain or loss recognized in profit or loss.
Gain/Loss recognized in Profit or Loss = Change in Fair Value−Dividends Received
Gain/Loss recognized in Profit or Loss =
25
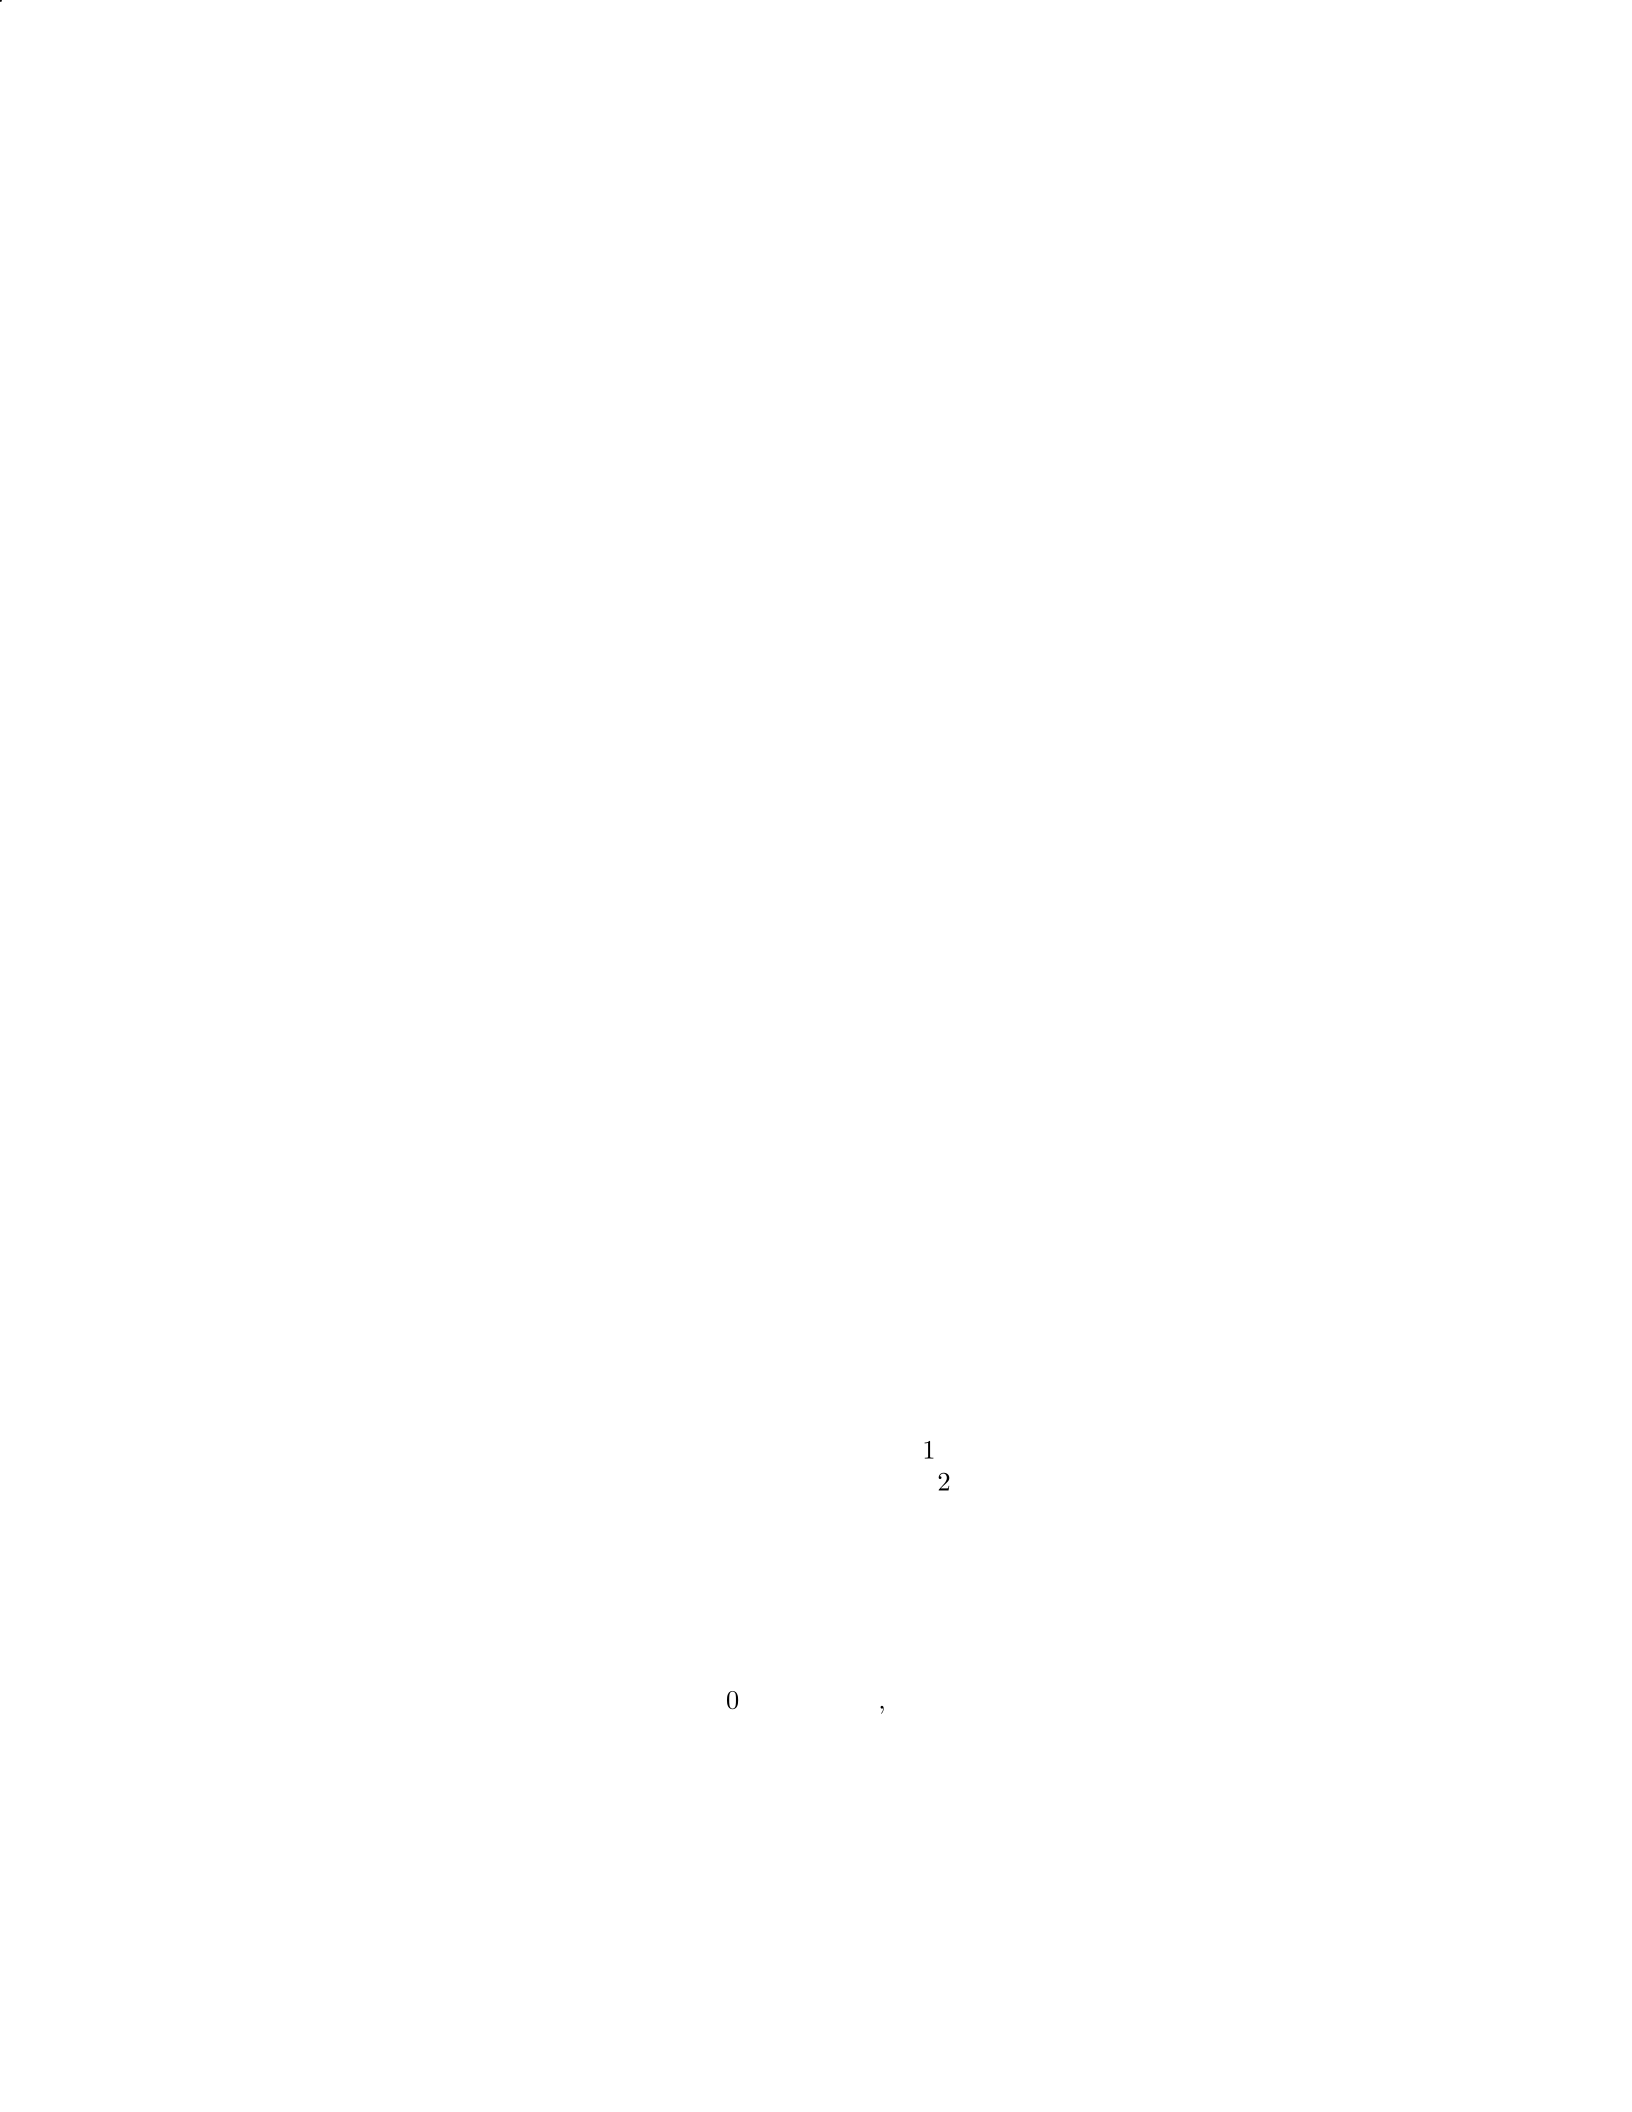
100,000 - 50,000 =50,000
Therefore, the gain recognized in profit or loss for the year is 50,000.
Question 34
Question
Company XYZ holds an investment in a foreign equity security. The fair value of
the investment was determined to be 2,500,000attheendofthereportingperiod.Duringthesubsequentreportingperiod, thefairvalueoftheinvestmentincreasedto2,700,000.
Determine the gain or loss on the investment that should be recognized in the
income statement for the subsequent reporting period.
Solution
1. The gain or loss recognized on the investment in the subsequent reporting
period is calculated by comparing the fair value at the end of the subsequent
reporting period with the fair value at the end of the previous reporting period.
2. The gain or loss is calculated as follows:
Gain or Loss = Fair Value at End of Subsequent Reporting Period−Fair Value at End of Previous Reporting Period
3. Given that the fair value of the investment at the end of the subsequent re-
porting period is 2,700,000andthef airvalueattheendof thepreviousreportingperiodwas2,500,000,
we can calculate the gain or loss:
Gain or Loss = 2,700,000 −2,500,000 = 200,000
4. Therefore, the gain on the investment that should be recognized in the
income statement for the subsequent reporting period is 200,000.
Question 35
Question
A company acquired a piece of machinery for
$
150,000. After two years, the
fair value of the machinery is estimated to be
$
120,000. If the company uses
the fair value model for measuring the machinery, how should the decrease in
fair value be accounted for in the financial statements?
Solution
1. Step 1: Recognize and record the decrease in fair value: The decrease in fair
value of the machinery from
$
150,000 to
$
120,000 should be recognized as a loss
in the financial statements. The entry to record this recognition is as follows:
Loss on Decrease in Fair Value = $30,000
26
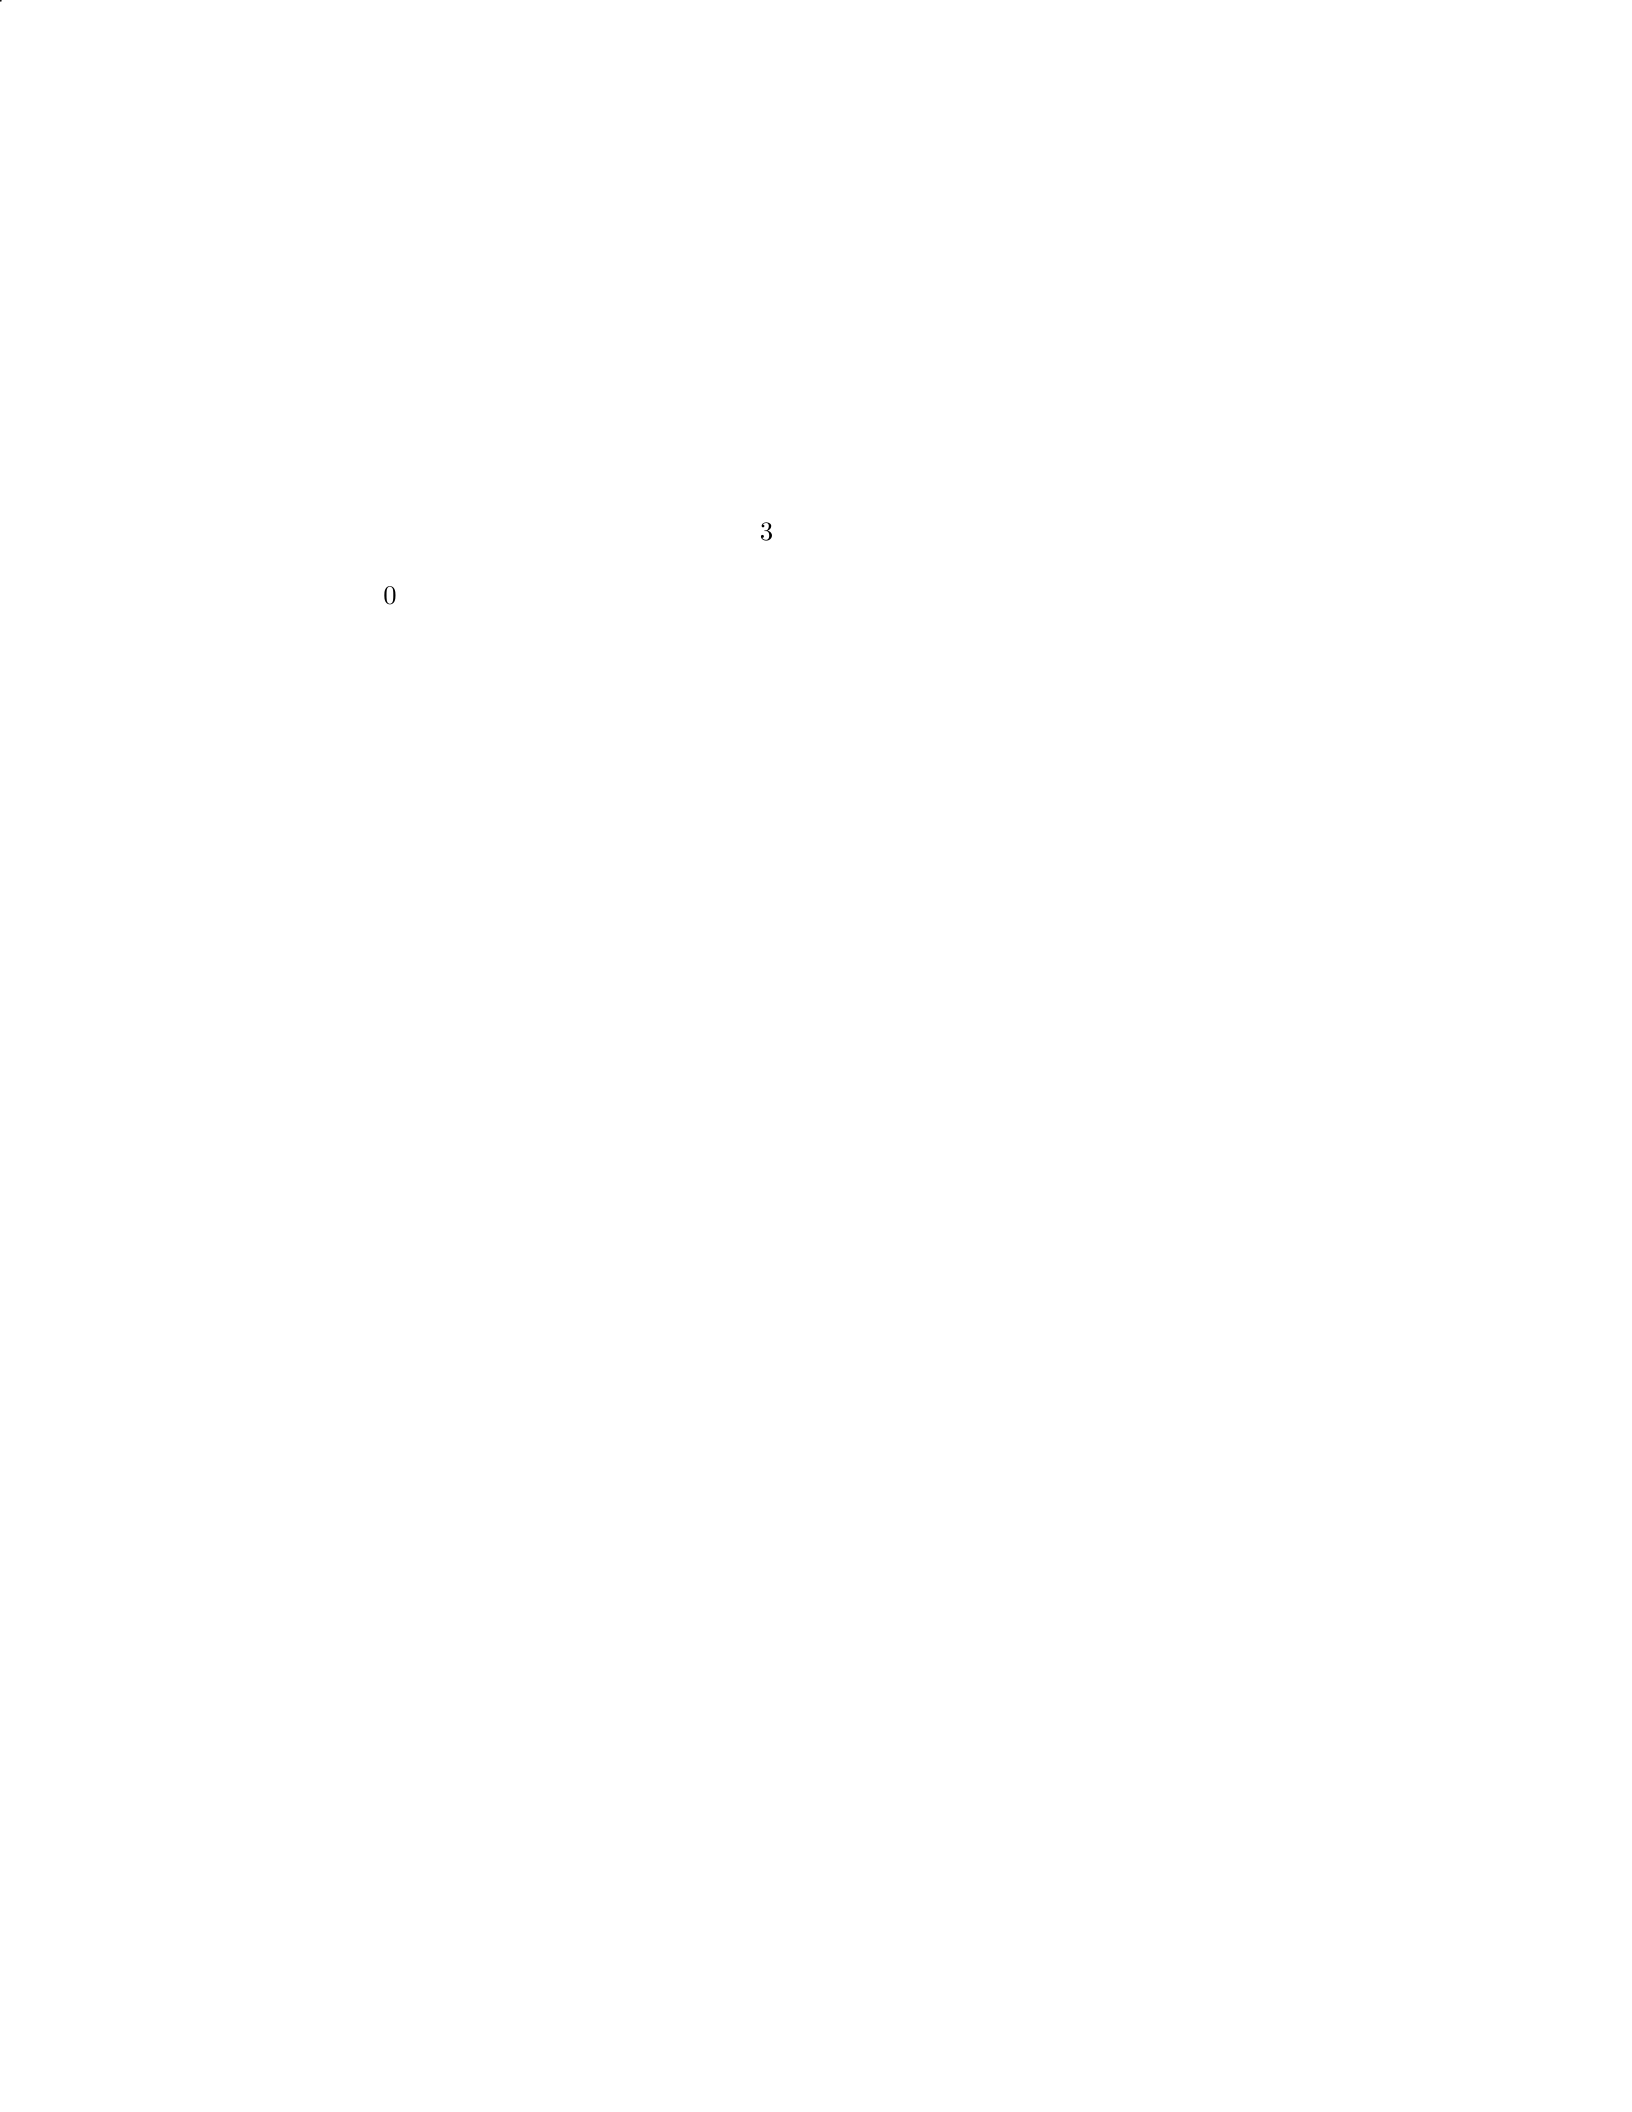
2. Step 2: Determine the journal entry: The journal entry to record the
decrease in fair value would be:
Loss on Decrease in Fair Value →Machinery : $30,000
3. Step 3: Analyze the impact on financial statements: - The income
statement would reflect a loss of
$
30,000, reducing the company’s net income.
- The balance sheet would reflect a decrease in the value of the machinery by
$
30,000, impacting the overall assets of the company. - The equity section of
the balance sheet would also be impacted by the decrease in fair value. This
treatment ensures that the financial statements accurately reflect the decrease
in fair value of the machinery.
27

