


ACCT 531 - ACCOUNTING
INFORMATION SYSTEMS - Fair
Value Measurement
Question Bank - Set 2
Liberty University
Question 1
Question
A company holds an investment in a particular stock that is classified as a
Level 3 asset. The fair value of the stock at the beginning of the period was
110pershare, withastandarddeviationof10. During the period, the stock price
increased to 120pershare.Calculatetheunrealizedgainorlossontheinvestmentusingthefairvaluemeasurementapproach.
Solution
Step 1: Calculate the fair value at the end of the period using the Level 3 val-
uation technique. Given that the fair value at the beginning of the period was
110withastandarddeviationof10, we can assume a normal distribution for the
stock price. We know that the stock price increased to 120pershareduringtheperiod.T ocalculatethef airvalueattheendoftheperiod, weneedtoconsidertheprobabilitydistribution :
Z=120−110
10 = 1 From the standard normal distribution table, the probability
of Z being less than 1 is approximately 0.8413. Therefore, the fair value at the
end of the period can be estimated as follows:
Fair value at the end of the period = 110+10×0.8413 = 110+8.413 = 118.413 per share
Step 2: Calculate the unrealized gain or loss on the investment. The unre-
alized gain or loss can be calculated as follows:
Unrealized gain or loss = Fair value at the end of the period−Fair value at the beginning of the period
Unrealized gain or loss = 118.413 −110 = 8.413 per share
Therefore, the unrealized gain on the investment using the Fair Value Mea-
surement approach is 8.413pershare.

Question 2
Question
A company has an investment in a financial asset categorized as a Level 3 fair
value measurement. The initial fair value of the investment was $75,000 and at
the end of the reporting period, the fair value increased to $85,000. During the
same period, the company recorded a net loss of $10,000 due to fluctuations in
fair value. Calculate the amount of the net loss that the company recognized in
its financial statements.
Solution
Step 1: Determine the fair value change of the investment.
The fair value change can be calculated as:
Fair Value Change = Ending Fair Value−Initial Fair Value = $85,000−$75,000 = $10,000
Step 2: Compare the fair value change with the net loss incurred.
Since the fair value change of $10,000 matches the net loss of $10,000, the entire
fair value change is recognized in the financial statements as the amount of the
net loss.
Therefore, the company recognized a net loss of $10,000 in its financial
statements due to fluctuations in fair value.
Question 3
Question
A company has an investment in a private equity fund that is classified as a Level
3 asset. The fair value of the investment increased by 10millionduringtheyear.Explainhowthisincreaseinfairvaluewillimpactthecompany′sfinancialstatementsandprovideexamplesof disclosuresthatthecompanymayneedtoincludeinitsfinancialstatementsrelatedtothisinvestment.
Solution
Step 1: The 10millionincreaseinf airvalueoftheLevel3assetwillimpactthecompany′sf inancialstatementsasfollows :
−IncomeStatement :T heincreaseinf airvaluewillresultinagainbeingrecognizedontheincomestatement.T hisgainwillbereportedaspartof thecompany′snetincomef ortheyear.−
BalanceSheet :T hef airvalueincreasewillalsoimpactthebalancesheet.T heinvestment′scarryingvaluewillbeadjustedtoreflectthenewf airvalue.T hef airvalueadjustmentwillberecordedasacomponentoftheinvestmentaccountwithinthebalancesheet.−
OtherComprehensiveIncome(OCI) : If thecompanyhaselectedthef airvalueoptionf orthisinvestment, theincreaseinf airvaluewillbypasstheincomestatementandinsteadberecordedasacomponentofOCI.
Step 2: In addition to the impact on the financial statements, the company
may need to include certain disclosures in its financial statements related to this
investment. Examples of disclosures that may be required include: - Description
of the investment: The company may need to provide information about the
nature of the investment, including the terms, conditions, and risks associated
with the investment. - Valuation methodology: The company may need to
disclose the valuation techniques and inputs used to determine the fair value
of the investment. - Sensitivity analysis: The company may need to disclose
how changes in key assumptions or inputs could impact the fair value of the
2
investment. - Level of the fair value hierarchy: The company may need to
disclose the level within the fair value hierarchy at which the investment is
classified (i.e., Level 1, Level 2, or Level 3). - Fair value measurements: The
company may need to disclose the fair value of the investment at the reporting
date and any changes in fair value during the reporting period.
These disclosures are important for users of the financial statements to un-
derstand the company’s exposure to risk and uncertainty related to the invest-
ment in the private equity fund.
Question 4
Question
A company acquired a patent for $500,000 and estimated its useful life to be 10
years. At the end of the first year, the company assessed the fair value of the
patent to be $480,000. Determine the journal entry to record the impairment
loss on the patent.
Solution
Step 1: Calculate the annual depreciation expense of the patent. Given the
patent was acquired for $500,000 and has an estimated useful life of 10 years,
the annual depreciation expense is:
Annual Depreciation Expense = $500,000
10 years = $50,000 per year
Step 2: Determine the impairment loss. The impairment loss is calculated
as the difference between the carrying value of the patent and its fair value.
Since the fair value at the end of the first year is $480,000, the carrying value
of the patent is:
Carrying Value = Original Cost −Accumulated Depreciation
Carrying Value = $500,000 −$50,000 = $450,000
Impairment Loss = Carrying Value −Fair Value = $450,000 −$480,000 =
−$30,000
Step 3: Record the journal entry to record the impairment loss on the patent.
The journal entry to record the impairment loss on the patent is:
Impairment Loss →Patent
$
30,000 →
$
30,000
Therefore, the journal entry to record the impairment loss on the patent is:
Impairment Loss $30,000Patent $30,000
3
Question 5
Question
Company XYZ holds an investment in a start-up company. The fair value of the
investment at the end of the reporting period is 50,000.Duringthenextreportingperiod, thefairvalueincreasesto60,000.
At the end of the following reporting period, the fair value decreases to 55,000.CalculatethegainorlossrecognizedineachofthereportingperiodsifCompanyXY Zusesthef airvaluethroughprof itorlossmeasurementmethod.
Solution
To calculate the gain or loss recognized in each reporting period using the fair
value through profit or loss measurement method, we need to compare the fair
value of the investment at the end of each period with the fair value recorded
in the previous period.
Step 1: Calculate the gain or loss recognized in the first reporting period.
The fair value of the investment at the end of the first reporting period is
50,000, andtherewasnof airvaluerecordedinthepreviousperiod.
Therefore, the gain or loss recognized in the first reporting period is 50,000−0
= 50,000gain.
Step 2: Calculate the gain or loss recognized in the second reporting period.
The fair value of the investment at the end of the second reporting period is
60,000, andthefairvaluerecordedinthepreviousperiodwas50,000.
Therefore, the gain or loss recognized in the second reporting period is
60,000−50,000 = 10,000gain.
Step 3: Calculate the gain or loss recognized in the third reporting period.
The fair value of the investment at the end of the third reporting period is
55,000, andthefairvaluerecordedinthepreviousperiodwas60,000.
Therefore, the gain or loss recognized in the third reporting period is 55,000−60,000
= 5,000loss.
Question 6
Question
A company holds an investment in a financial asset that is measured at fair value
through other comprehensive income (FVOCI). At the end of the reporting pe-
riod, the fair value of the investment has increased by 10,000.P rovidejournalentriestorecordthefairvalueadjustmentandexplainhowtheseentrieswouldaffectthefinancialstatements.
Solution
Step 1: To record the fair value adjustment in the investment: Let’s assume the
initial investment was 100,000.
Investment in Financial Asset(FVOCI) →Increase by
$
10,000
Other Comprehensive Income →Increase by
$
10,000
4
Journal Entry:
Account Debit
Credit
Investment in Financial Asset (FVOCI)
$10,000
Other Comprehensive Income $10,000
Step 2: Impact on Financial Statements: - The increase in the fair value
of the investment is recognized in other comprehensive income rather than the
income statement. - The investment carrying amount on the balance sheet
will reflect the higher fair value, leading to an increase in total comprehensive
income.
These entries reflect the mark-to-market accounting treatment of the invest-
ment at FVOCI.
Question 7
Question
A company holds an investment in a security that is classified as Level 3 under
the fair value hierarchy. At the end of the reporting period, the security has
a fair value of 150,000.Duringtheperiod, thecompanyrecordedalossof 20,000 in
the fair value of the security. Calculate the initial cost of the investment.
Solution
Step 1: Define the components of fair value and fair value hierarchy: - Level
1 inputs are quoted prices in active markets for identical assets or liabilities. -
Level 2 inputs are inputs other than quoted prices in active markets that are
directly or indirectly observable. - Level 3 inputs are unobservable inputs.
Step 2: Recall the fair value change formula:
Ending Fair Value = Beginning Fair Value+Additional Investments/Gains−Distributions/Losses
Step 3: Given that the security is classified as Level 3 and the fair value at
the end of the reporting period is 150,000withaf airvaluelossof20,000, we can
now calculate the initial cost of the investment:
Beginning Fair Value = Ending Fair Value−Additional Investments/Gains+Distributions/Losses
Beginning Fair Value =
150,000 - 0+20,000
5

Beginning Fair Value =
170,000
Therefore, the initial cost of the investment was 170,000.
Question 8
Question
A company is valuing an investment property using the fair value model. At the
end of the reporting period, the property has a fair value of 2,500,000.T hepropertywasinitiallyrecognizedat2,000,000,
and has accumulated depreciation of 400,000.Howshouldthecompanyaccountf orthechangeinfairvalueof theinvestmentproperty?
Solution
Step 1: Calculate the carrying amount of the investment property before the
change in fair value. The carrying amount of the investment property is calcu-
lated as the initial recognition cost minus accumulated depreciation: Carrying
amount = Initial recognition cost - Accumulated depreciation Carrying amount
= 2,000,000−400,000 Carrying amount = 1,600,000
Step 2: Determine the fair value change of the investment property. The fair
value change of the investment property is calculated as the fair value at the end
of the reporting period minus the carrying amount before the change: Fair value
change = Fair value - Carrying amount Fair value change = 2,500,000−1,600,000
Fair value change = 900,000
Step 3: Account for the fair value change in the investment property. Since
the fair value of the investment property has increased, the company recognizes
this change in fair value as a revaluation surplus in other comprehensive income
and as a revaluation reserve within equity.
Therefore, the company should recognize the fair value change of 900,000asarevaluationsurplusof900,000
in other comprehensive income and as a revaluation reserve within equity.
Question 9
Question
Assume a company has an investment in a financial asset classified as Level 3
fair value measurement. The fair value of the asset was determined using unob-
servable inputs, making it difficult to establish an accurate valuation. Discuss
the challenges the company may face in determining the fair value of this asset.
6
Solution
To determine the fair value of an asset classified as Level 3 fair value measure-
ment, a company may face several challenges due to the use of unobservable
inputs. These challenges include:
Step 1: Lack of Market Data
Because Level 3 uses unobservable inputs, there may be a lack of market
data available to compare and validate the fair value.
Without reliable market data, determining the fair value becomes subjec-
tive and may lead to potential inaccuracies.
Step 2: Subjectivity in Valuation
The use of unobservable inputs in Level 3 fair value measurement relies
heavily on management’s judgment.
Different management teams may have varying opinions on the valuation
of the asset, leading to inconsistencies and potential biases.
Step 3: Potential for Manipulation
The subjective nature of Level 3 fair value measurements can create op-
portunities for manipulation.
There is a risk that management may intentionally manipulate the fair
value of the asset to achieve certain financial reporting objectives.
Step 4: Complexity of Valuation Models
Level 3 fair value measurements often involve complex valuation models
to estimate the fair value of the asset.
These models may be difficult to understand and require specialized ex-
pertise, making it challenging to validate the accuracy of the valuation.
Step 5: Disclosure Requirements
Companies are required to disclose the significant unobservable inputs
used in Level 3 fair value measurements.
Ensuring adequate transparency in these disclosures can be challenging,
especially if the inputs are highly sensitive or proprietary.
In conclusion, determining the fair value of an asset classified as Level 3 fair
value measurement poses various challenges related to the lack of market data,
subjectivity in valuation, potential for manipulation, complexity of valuation
models, and disclosure requirements.
7

Question 10
Question
A company holds an investment in a private company for which there is no
active market. The fair value of the investment needs to be determined for the
company’s financial statements. Discuss the techniques or methods that can be
used to estimate the fair value of the investment.
Solution
To estimate the fair value of an investment in a private company where there
is no active market, various techniques or methods can be used. Here are some
commonly used methods:
Step 1: Market Approach One approach is to use the market approach,
which involves analyzing recent transactions involving similar investments in
comparable companies. This can provide a benchmark for valuing the invest-
ment in question.
Step 2: Income Approach Another method is the income approach, which
involves estimating the future cash flows expected from the investment and
discounting them back to their present value. This method often involves the
use of techniques such as discounted cash flow (DCF) analysis.
Step 3: Cost Approach The cost approach involves estimating the cost
to replace the investment or recreate it with a similar investment. This method
may be used when there is little information available about the market or
income potential of the investment.
Step 4: Option Pricing Model In some cases, an option pricing model
can be used to estimate the fair value of an investment, particularly if the
investment has option-like characteristics such as conversion rights or other
embedded options.
Step 5: Weighted Average Method The weighted average method in-
volves assigning weights to the different valuation methods based on their rele-
vance and reliability, and then calculating a weighted average fair value estimate.
Using a combination of these techniques can help provide a more accurate
estimate of the fair value of an investment in a private company. It is important
to carefully evaluate the assumptions and inputs used in each method to ensure
the final estimate is as reliable as possible.
Question 11
Question
A company holds a financial asset that is measured at fair value through profit
or loss. The fair value of the asset has increased significantly since the initial
recognition. Discuss how this increase in fair value should be accounted for
according to the fair value measurement standard.
8
Solution
To account for the increase in fair value of a financial asset that is measured at
fair value through profit or loss, we must consider the fair value measurement
standard (IFRS 13). The standard provides guidance on the measurement of
fair value and the recognition of changes in fair value in financial statements.
Step 1: Recognize the increase in fair value When the fair value of a
financial asset increases significantly, the increase should be recognized in the
income statement. This means that the company will record a gain on the asset
in the income statement, reflecting the increase in value.
Step 2: Determine the treatment of the gain The treatment of the gain
will depend on the nature of the financial asset and the company’s accounting
policies. In most cases, the gain will be recognized in the income statement as
a separate line item under revenues or gains. However, if the financial asset is
held for trading, the gain may be included in the trading income.
Step 3: Disclose the fair value measurement and gains The com-
pany must also disclose the fair value measurement of the financial asset in
the financial statements. This includes providing information on the valuation
techniques used and the inputs to those techniques. Additionally, the company
should disclose the gains recognized on the asset in the notes to the financial
statements.
In conclusion, when the fair value of a financial asset measured at fair value
through profit or loss increases significantly, the increase should be recognized
in the income statement as a gain. The treatment of the gain and the disclosure
requirements should be in accordance with the fair value measurement standard
(IFRS 13).
Question 12
Question
Company XYZ holds an investment in a publicly traded company, ABC Corp.
The fair value of this investment is determined using Level 1 inputs. At the be-
ginning of the year, the fair value of the investment was 50,000.Duringtheyear, ABCCorpreportedbetterthanexpectedfinancialresults, causingitsstockpricetorise.Attheendoftheyear, thefairvalueoftheinvestmentwasdeterminedtobe60,000.
Discuss how the change in fair value of the investment in ABC Corp should
be accounted for according to Fair Value Measurement standards.
Solution
Step 1: According to Fair Value Measurement standards, changes in fair value
should be recognized in the company’s financial statements through either profit
or loss or other comprehensive income, depending on the classification of the
investment.
Step 2: If the investment is classified as at fair value through profit or
loss (FVTPL), the change in fair value will be recognized in profit or loss in
9

the income statement. In this case, the 10,000increaseinfairvalue(60,000 -
50,000)shouldberecognizedasagaininprofitorlossinthecurrentperiod.
Step 3: If the investment is classified as available-for-sale (AFS), the change
in fair value will be recognized in other comprehensive income. The 10,000increaseinfairvaluewouldberecognizedasagaininothercomprehensiveincomewithinequity.
Step 4: It is important to note that the accounting treatment of changes in
fair value should be consistent with the initial classification of the investment
and the company’s accounting policies for fair value measurement.
Question 13
Question
A company owns an investment in a privately held company that is classified
as a Level 3 asset for fair value measurement. The fair value of the investment
is determined using a discounted cash flow model, which includes significant
unobservable inputs.
Explain the concept of fair value measurement for Level 3 assets and discuss
the challenges involved in applying this measurement approach.
Solution
Step 1: Concept of Fair Value Measurement for Level 3 Assets Level
3 assets are financial instruments or investments that are not traded in active
markets and have unobservable inputs for their fair value measurement. The fair
value of Level 3 assets is determined using valuation techniques that incorporate
significant unobservable inputs. These inputs are based on the best information
available in the circumstances and may include the company’s own data or
assumptions. Because of the lack of market activity and reliance on unobservable
inputs, Level 3 assets are considered the most difficult to value.
Step 2: Challenges in Applying Fair Value Measurement for Level
3 Assets 1. Subjectivity: The use of unobservable inputs in valuation models
introduces subjectivity into the fair value measurement process. Different val-
uation models or assumptions can result in significantly different fair values for
the same asset.
2. Reliability: The reliability of fair value measurements for Level 3 assets
can be questioned due to the subjective nature of the inputs used. This can
lead to concerns about the accuracy of reported financial information.
3. Complexity: Valuing Level 3 assets often involves complex valuation
techniques such as discounted cash flow models or option pricing models. These
models require specialized expertise and significant resources to apply effectively.
4. Verification: Since Level 3 assets have significant unobservable inputs,
there may be limited external data or benchmarks available to verify the fair
value measurements. This lack of verifiability can raise concerns about the
accuracy of the reported values.
10

5. Disclosure: Companies are required to disclose information about the
inputs and significant judgments used in the fair value measurement of Level 3
assets. However, determining which information to disclose and how to commu-
nicate the uncertainty of the measurements can be challenging.
Overall, fair value measurement for Level 3 assets presents unique challenges
due to the reliance on unobservable inputs and the complexity of valuation
techniques involved.
Question 14
Question
A company holds an investment in a privately held company that is accounted
for at fair value through profit or loss. The fair value of the investment at the
beginning of the year was $350,000. During the year, the fair value increased to
$400,000. At the end of the year, the fair value further increased to $420,000.
Given this information, calculate the fair value gain or loss recognized in the
company’s profit or loss for the year.
Solution
Step 1: Calculate the fair value gain or loss recognized in profit or loss for the
year. First, we need to determine the fair value gain or loss recognized in the
company’s profit or loss for the year. This can be calculated by comparing the
fair value at the end of the year with the fair value at the beginning of the year.
Fair Value Gain or Loss = Fair Value at End of Year−Fair Value at Beginning of Year
Step 2: Substitute the given values into the formula.
Fair Value Gain or Loss = $420,000 −$350,000
Step 3: Calculate the fair value gain or loss.
Fair Value Gain or Loss = $70,000
Therefore, the fair value gain recognized in the company’s profit or loss for
the year is $70,000.
Question 15
Question
A company is valuing a financial instrument using the fair value measurement
technique. The financial instrument has a level 3 fair value hierarchy, meaning
that significant unobservable inputs are used to determine its fair value. Explain
how the company should incorporate market participant assumptions into the
fair value measurement process.
11

Solution
Step 1: Understand Market Participant Assumptions
Market participant assumptions are used to determine the price that would be
received to sell an asset or paid to transfer a liability in an orderly transac-
tion between market participants at the measurement date. These assumptions
should reflect the perspective of market participants, not those of a specific
entity.
Step 2: Identify Market Participants
The company should identify the relevant market participants for the financial
instrument being valued. This involves understanding who the potential buyers
or sellers may be in the market for the asset or liability.
Step 3: Consider Market Participant Views
The company should consider the assumptions that market participants would
use in valuing the financial instrument. This includes factors such as risk pref-
erences, expected cash flows, and other market conditions that would impact
the fair value.
Step 4: Incorporate Market Participant Assumptions
To incorporate market participant assumptions into the fair value measure-
ment process, the company should adjust its valuation model to reflect the
assumptions that market participants would use. This may involve modifying
the discount rate, cash flow projections, or other inputs to align with market
participant views.
Step 5: Assess Consistency
The company should ensure that the market participant assumptions used are
consistent with the inputs and information available. Any discrepancies should
be carefully evaluated and resolved to arrive at a reliable fair value measure-
ment. This may involve additional disclosures about the assumptions used in
the valuation process.
Question 16
Question
A company holds an investment in a financial asset classified as fair value
through profit or loss. The fair value at the end of the reporting period is
185,000.Duringtheyear, thefairvalueincreasedby25,000, and the company rec-
ognized a gain of 15,000inprofitorlossrelatingtothisinvestment.Calculatetheinitialfairvalueof theinvestmentandthefairvaluechangerecognizedinothercomprehensiveincome.
Solution
Step 1: Let the initial fair value of the investment be x. Step 2: The fair value at
the end of the reporting period is 185,000, whichistheinitialfairvalueplusthef airvaluechange :
x+ 25,000 = 185,000
x= 185,000 −25,000
x= 160,000
12
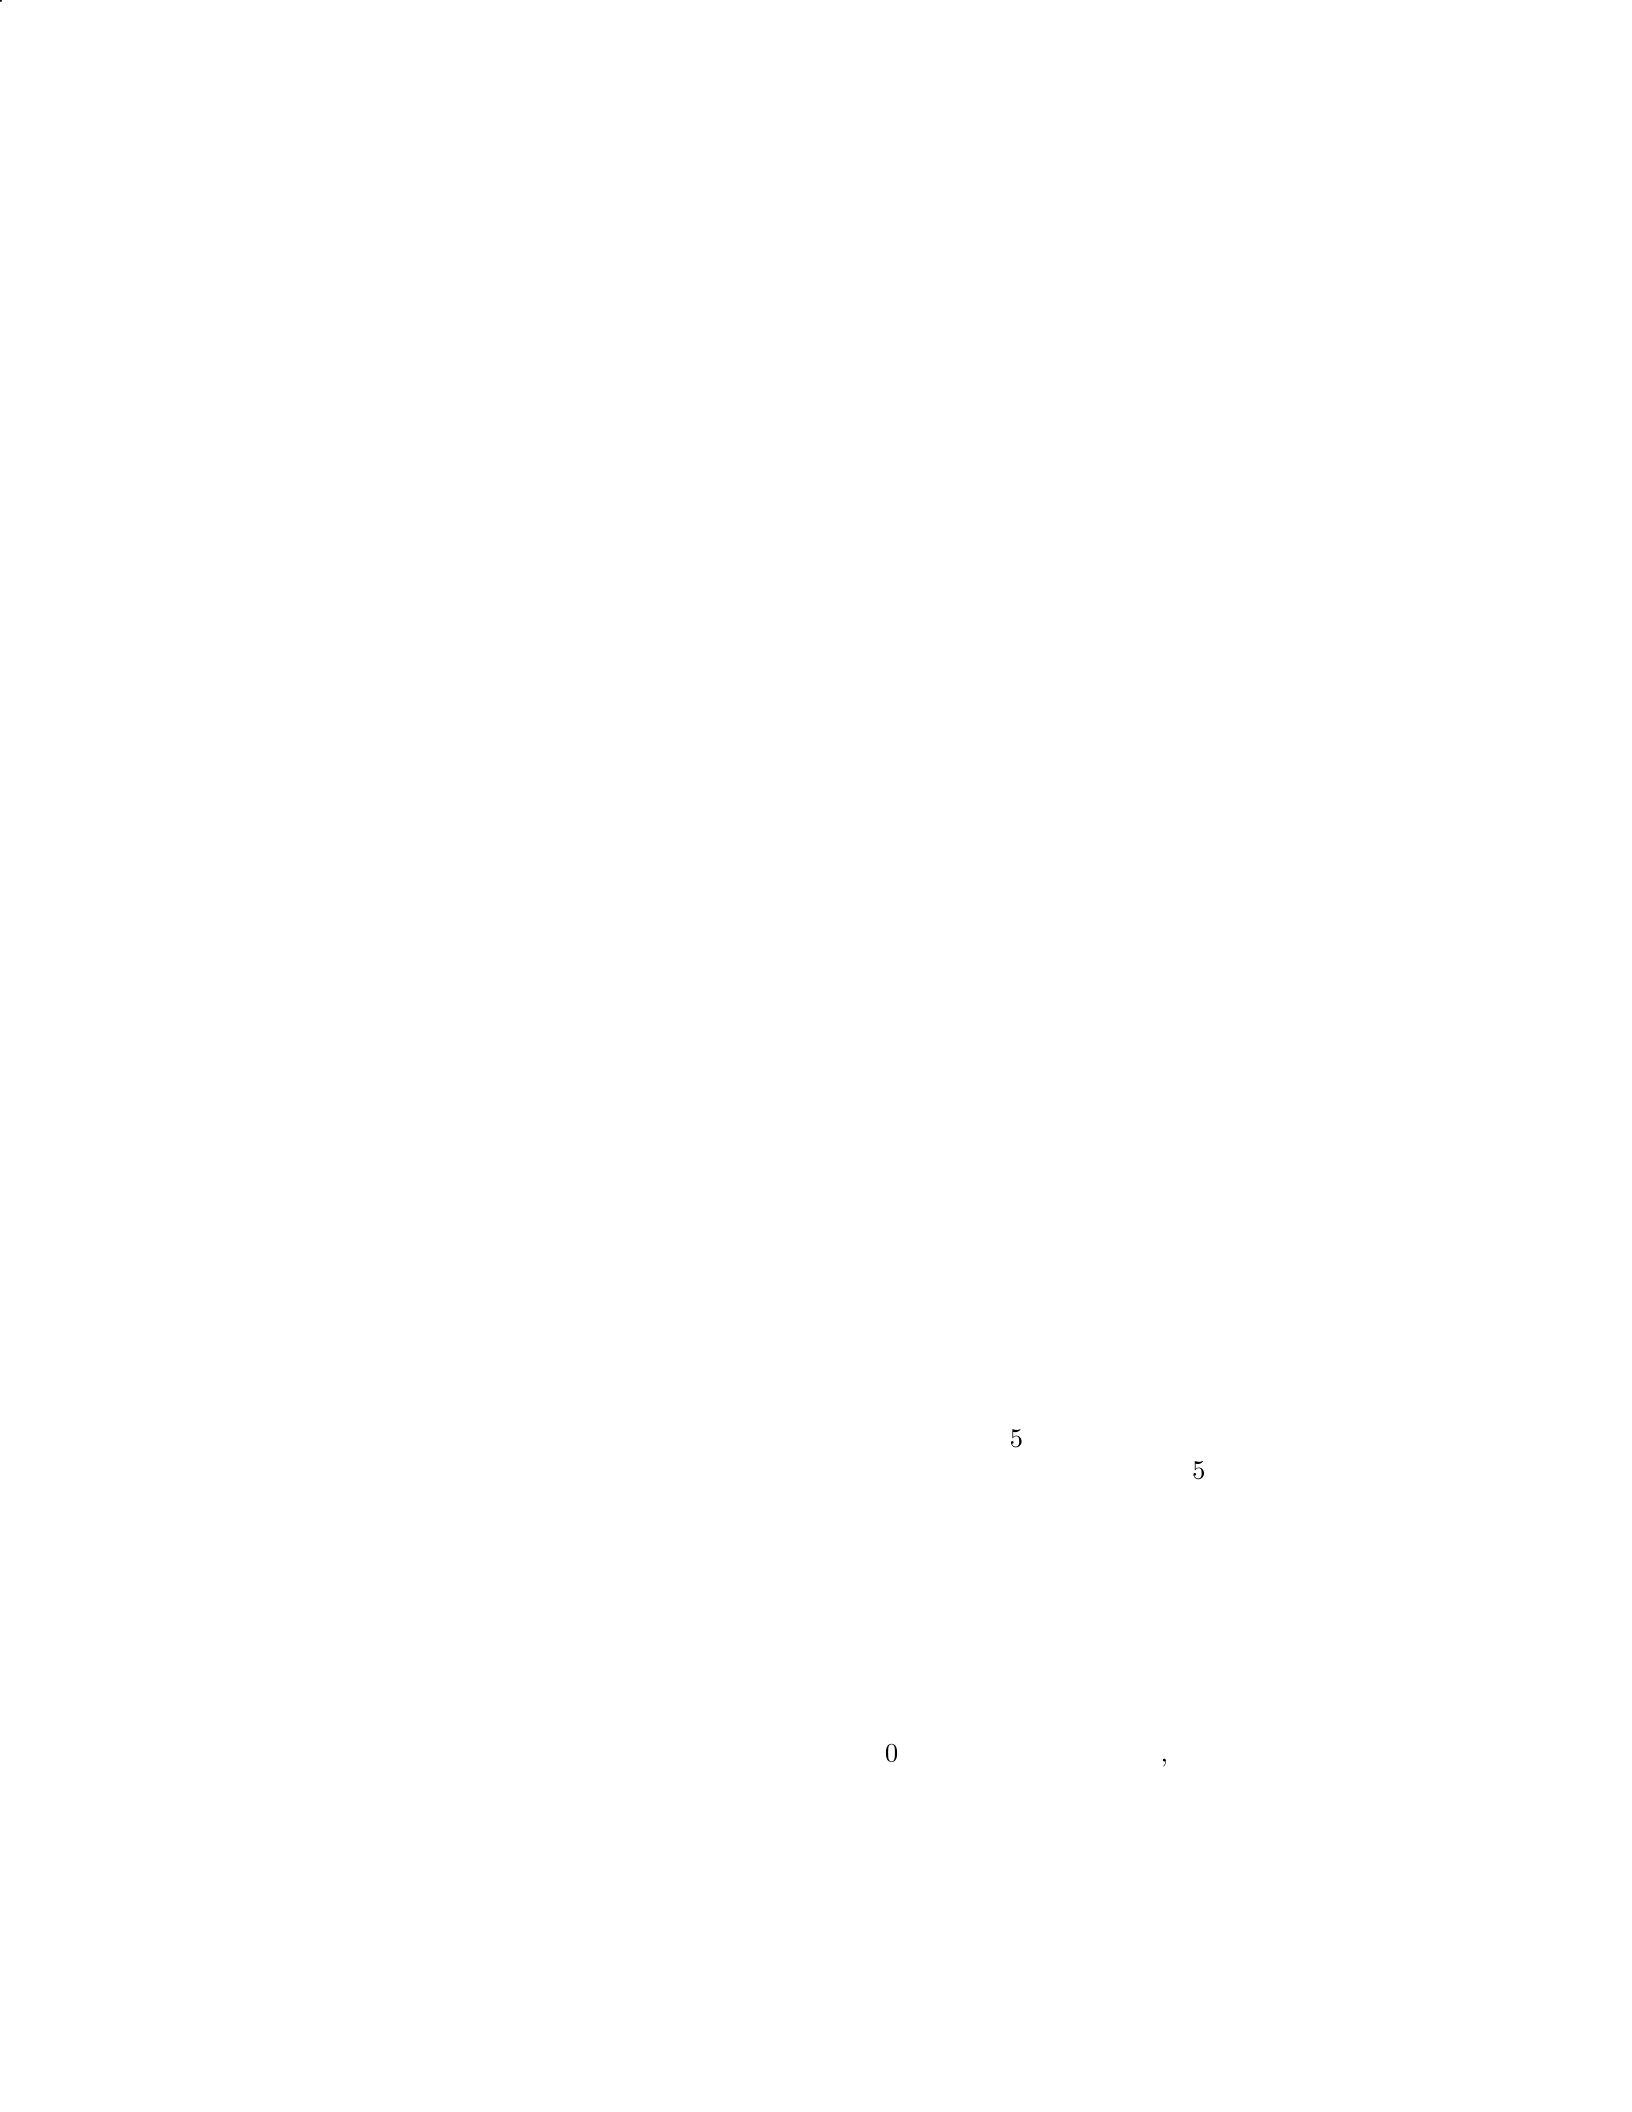
The initial fair value of the investment is 160,000.
Step 3: The gain recognized in profit or loss is 15,000, whichmeansthatthegainrecognizedinothercomprehensiveincomeisthedifference :
25,000 −15,000 = 10,000 The fair value change recognized in other compre-
hensive income is 10,000.
Question 17
Question
A company measures its financial assets at fair value through other comprehen-
sive income. On December 31, 2021, the fair value of the assets increased by
20,000.Determinetheimpactofthisincreaseonthecompany′scomprehensiveincomeandequityassumingnotaxesareapplicable.
Solution
Step 1: Understand the impact on other comprehensive income (OCI) The
increase in fair value of financial assets through OCI will result in a gain, which
is reported in OCI. This will impact the company’s comprehensive income.
Step 2: Calculate the impact on OCI The increase in fair value of 20,000willresultinagainof20,000
in OCI.
Step 3: Understand the impact on equity Since OCI is a component of equity,
the 20,000gaininOCIwillalsoincreasethecompany′sequity.
Step 4: Record the impact The journal entry to record the increase in fair
value of financial assets through OCI would be:
OCI →Gain on financial assets →+$20,000
As a result, both the comprehensive income and equity of the company will
increase by 20,000.
Question 18
Question
A company holds an investment in a startup valued at
$
500,000. Due to recent
market conditions, the fair value of the investment has decreased to
$
450,000.
The company decides to write down the value of the investment to its fair
value. Calculate the impact of this impairment loss on the company’s financial
statements.
Solution
Step 1: Determine the Impairment Loss To calculate the impairment loss, we
need to find the difference between the carrying value of the investment and its
fair value. In this case: Carrying value =
$
500,000 Fair value =
$
450,000
13
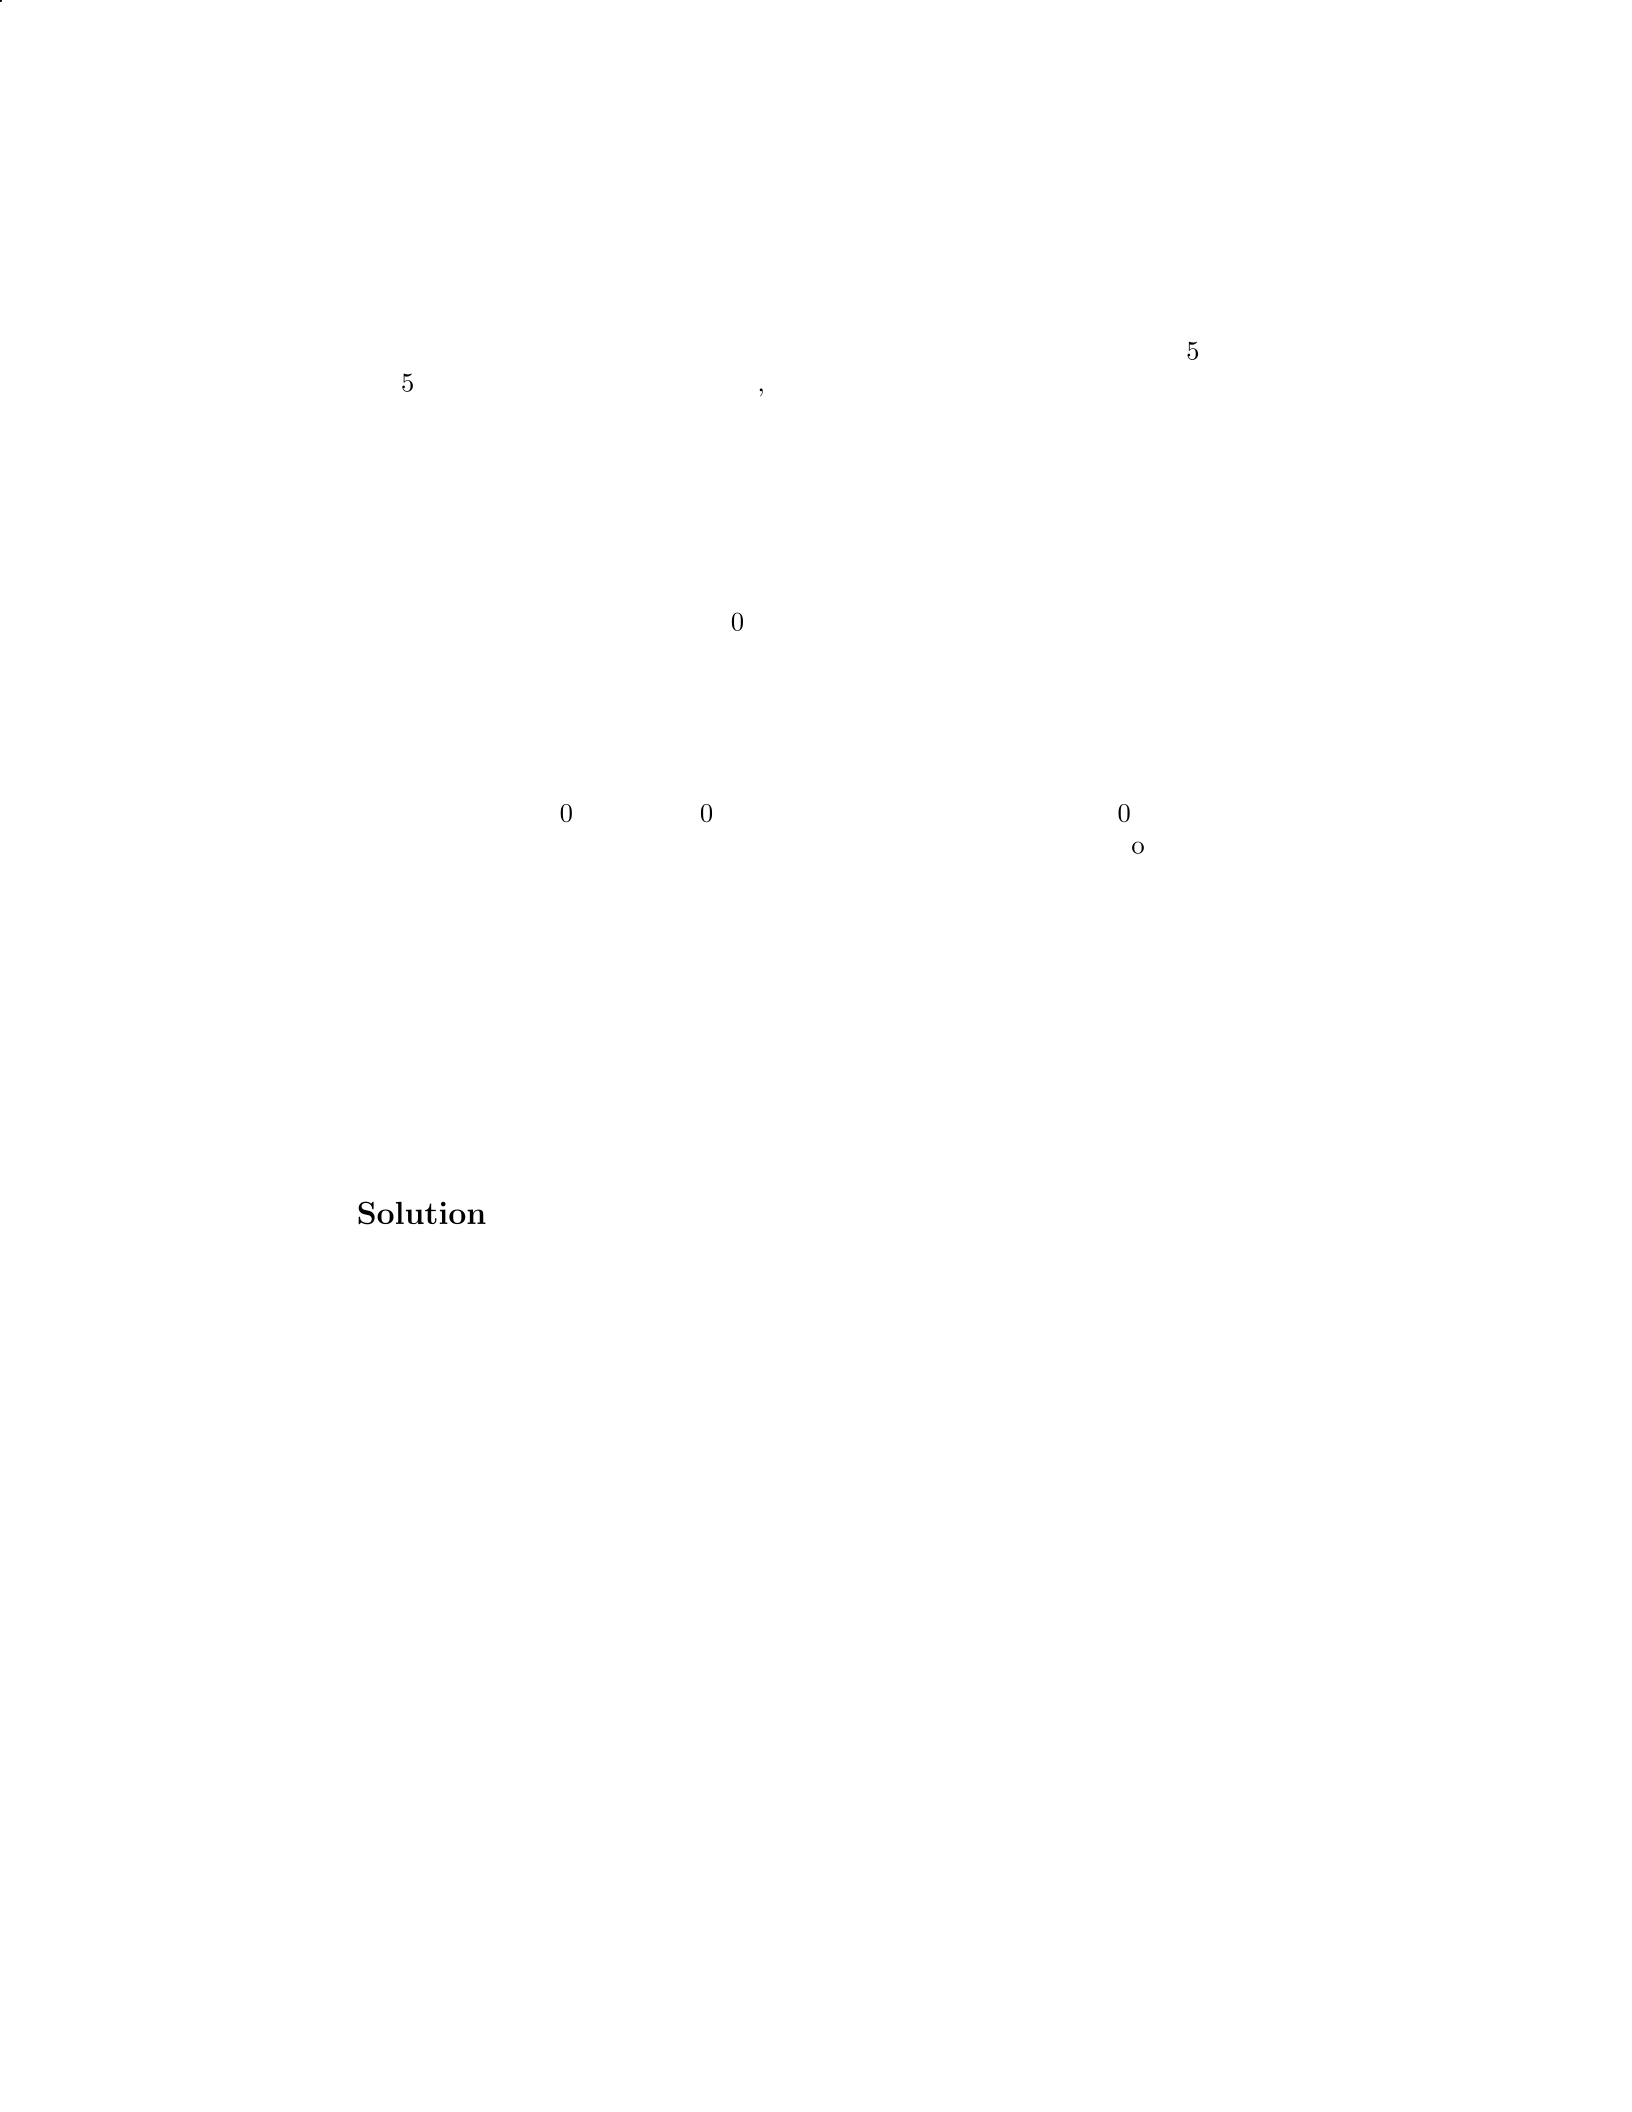
Impairment Loss = Carrying value - Fair value Impairment Loss =
$
500,000
-
$
450,000 Impairment Loss =
$
50,000
Step 2: Record the Impairment Loss The impairment loss needs to be
recorded on the company’s financial statements to reflect the decrease in the
value of the investment. The journal entry to record the impairment loss is as
follows:
Impairment Loss →Income Statement
The impairment loss of
$
50,000 will reduce the company’s net income for
the period.
Step 3: Update the Carrying Value of the Investment After recording the
impairment loss, the carrying value of the investment on the balance sheet needs
to be updated to reflect the new fair value. The revised carrying value will be:
Revised Carrying value = Carrying value - Impairment Loss Revised Carry-
ing value =
$
500,000 -
$
50,000 Revised Carrying value =
$
450,000
The revised carrying value of the investment is now
$
450,000 on the com-
pany’s balance sheet.
Question 19
Question
Company A holds an investment in Company B classified as a level 2 asset under
fair value measurement. At the end of the fiscal year, Company A estimates the
fair value of its investment in Company B to be 5,000,000.However, duetorecentmarketfluctuations, CompanyA′smanagementisconsideringreclassifyingtheinvestmentaslevel3.Discussthef actorsthatshouldbeconsideredbyCompanyAindeterminingwhethertoreclassif ytheinvestmentaslevel3underf airvaluemeasurement.
Solution
To determine whether to reclassify the investment in Company B as level 3
under fair value measurement, Company A should consider several factors.
Step 1: Company A should examine the availability and reliability of ob-
servable inputs for the fair value measurement. Level 3 assets are valued using
unobservable inputs and are considered the least reliable. If there are significant
observable inputs available, it may be more appropriate to keep the investment
classified as level 2.
Step 2: Company A should assess the impact of recent market fluctuations
on the fair value of the investment. If the recent fluctuations have caused
significant uncertainty and volatility in the fair value estimation, it may be
more appropriate to reclassify the investment as level 3 to reflect the increased
level of uncertainty.
Step 3: Company A should evaluate the level of judgment involved in the
fair value measurement. Level 3 assets require a higher degree of judgment
compared to level 2 assets. If there is a high level of subjectivity involved in
determining the fair value of the investment, it may be more appropriate to
reclassify it as level 3.
14
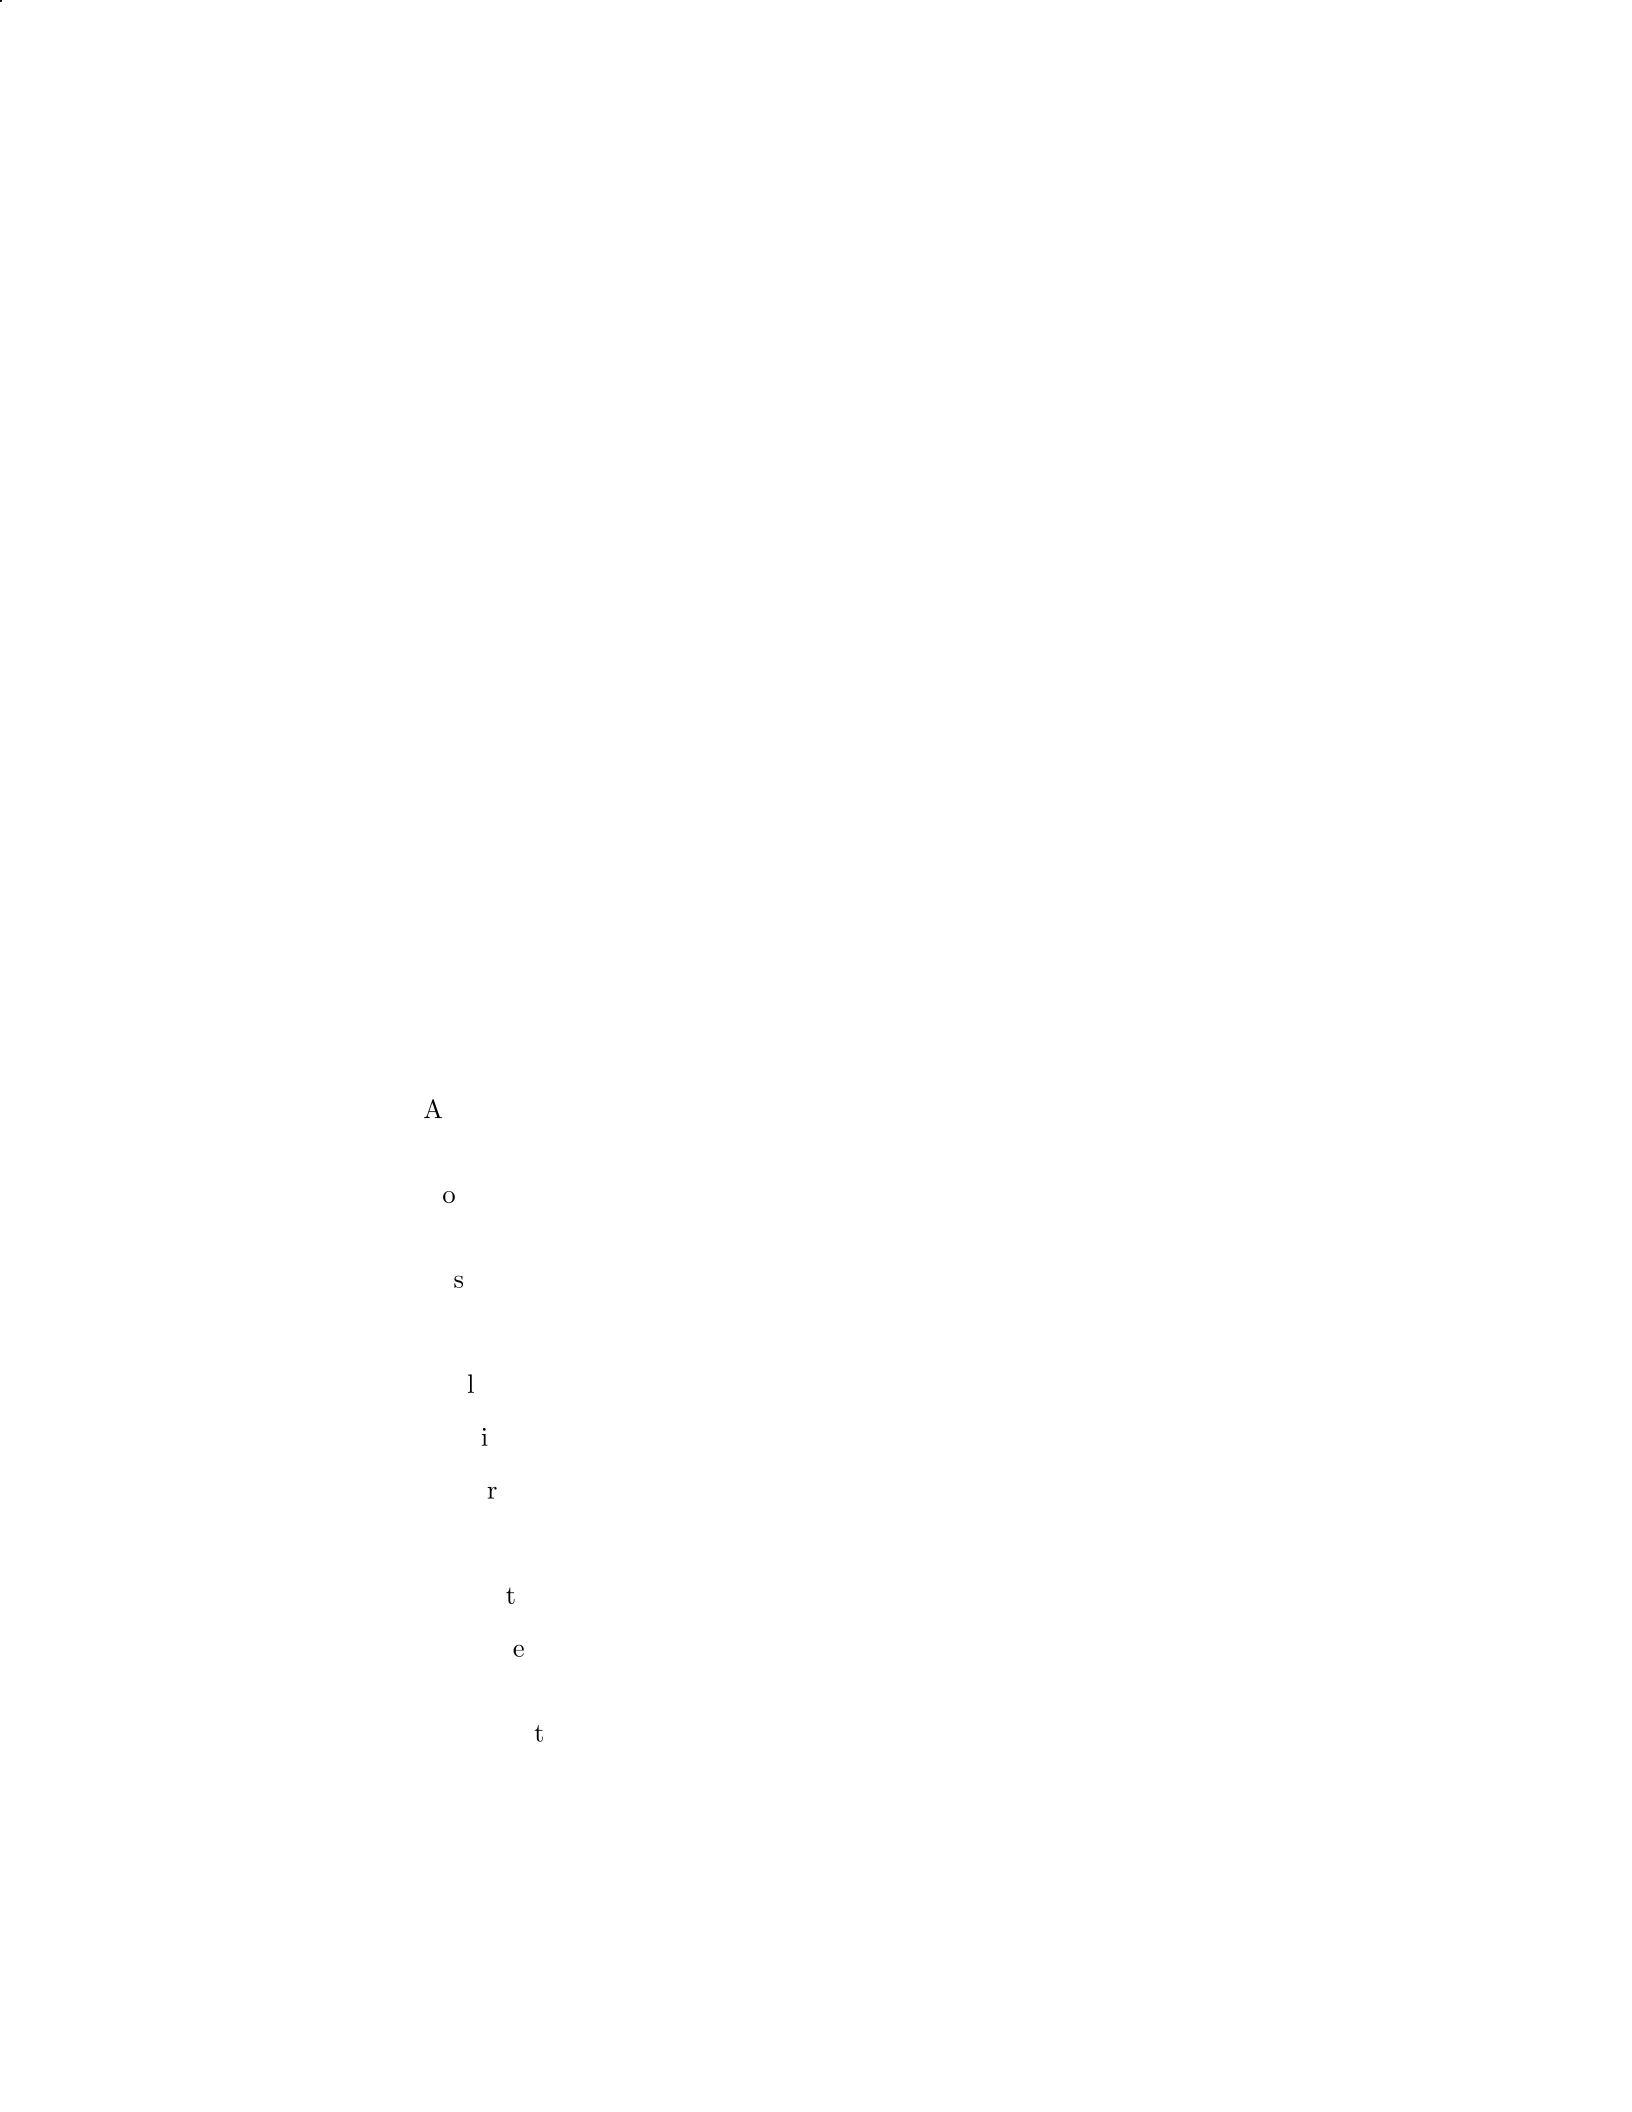
Step 4: Company A should consider the potential impact of reclassification
on financial statement users. Reclassifying the investment as level 3 may signal
increased risk and uncertainty to investors and other stakeholders. Company
A should weigh the benefits of increased transparency against the potential
negative perceptions associated with a level 3 classification.
By carefully considering these factors, Company A can make an informed
decision on whether to reclassify its investment in Company B as a level 3 asset
under fair value measurement.
Question 20
Question
You are a financial analyst tasked with determining the fair value of a particular
investment property. The property generates rental income and has a potential
for future development. Discuss the various factors and assumptions you would
consider in determining the fair value of the investment property.
Solution
To determine the fair value of the investment property, several factors and as-
sumptions need to be considered. Below are the key points to consider:
Step 1: Evaluate Property Characteristics
Analyze the location of the property: Is it in a prime area with high
demand?
Consider the size of the property and any unique features that could im-
pact its value.
Assess the condition of the property and any necessary repairs or upgrades.
Step 2: Rental Income
Evaluate the current rental income generated by the property.
Consider the stability and reliability of the rental income stream.
Factor in any potential vacancies or rent fluctuations in the future.
Step 3: Development Potential
Assess the potential for future development of the property.
Evaluate any zoning regulations or restrictions that could impact devel-
opment plans.
Consider the timeline and costs associated with development.
Step 4: Market Conditions
15
Analyze current market conditions, including supply and demand for sim-
ilar properties.
Consider trends in property values and rental rates in the area.
Take into account any external factors that could impact property values,
such as economic conditions or regulatory changes.
Step 5: Discount Rate
Determine an appropriate discount rate to calculate the present value of
future cash flows.
Consider the risk associated with the investment property and adjust the
discount rate accordingly.
By carefully evaluating these factors and making reasonable assumptions,
you can determine a fair value estimate for the investment property.
Question 21
Question
A company holds an investment in a financial instrument that is classified as a
Level 2 asset under the fair value hierarchy. The fair value of the investment was
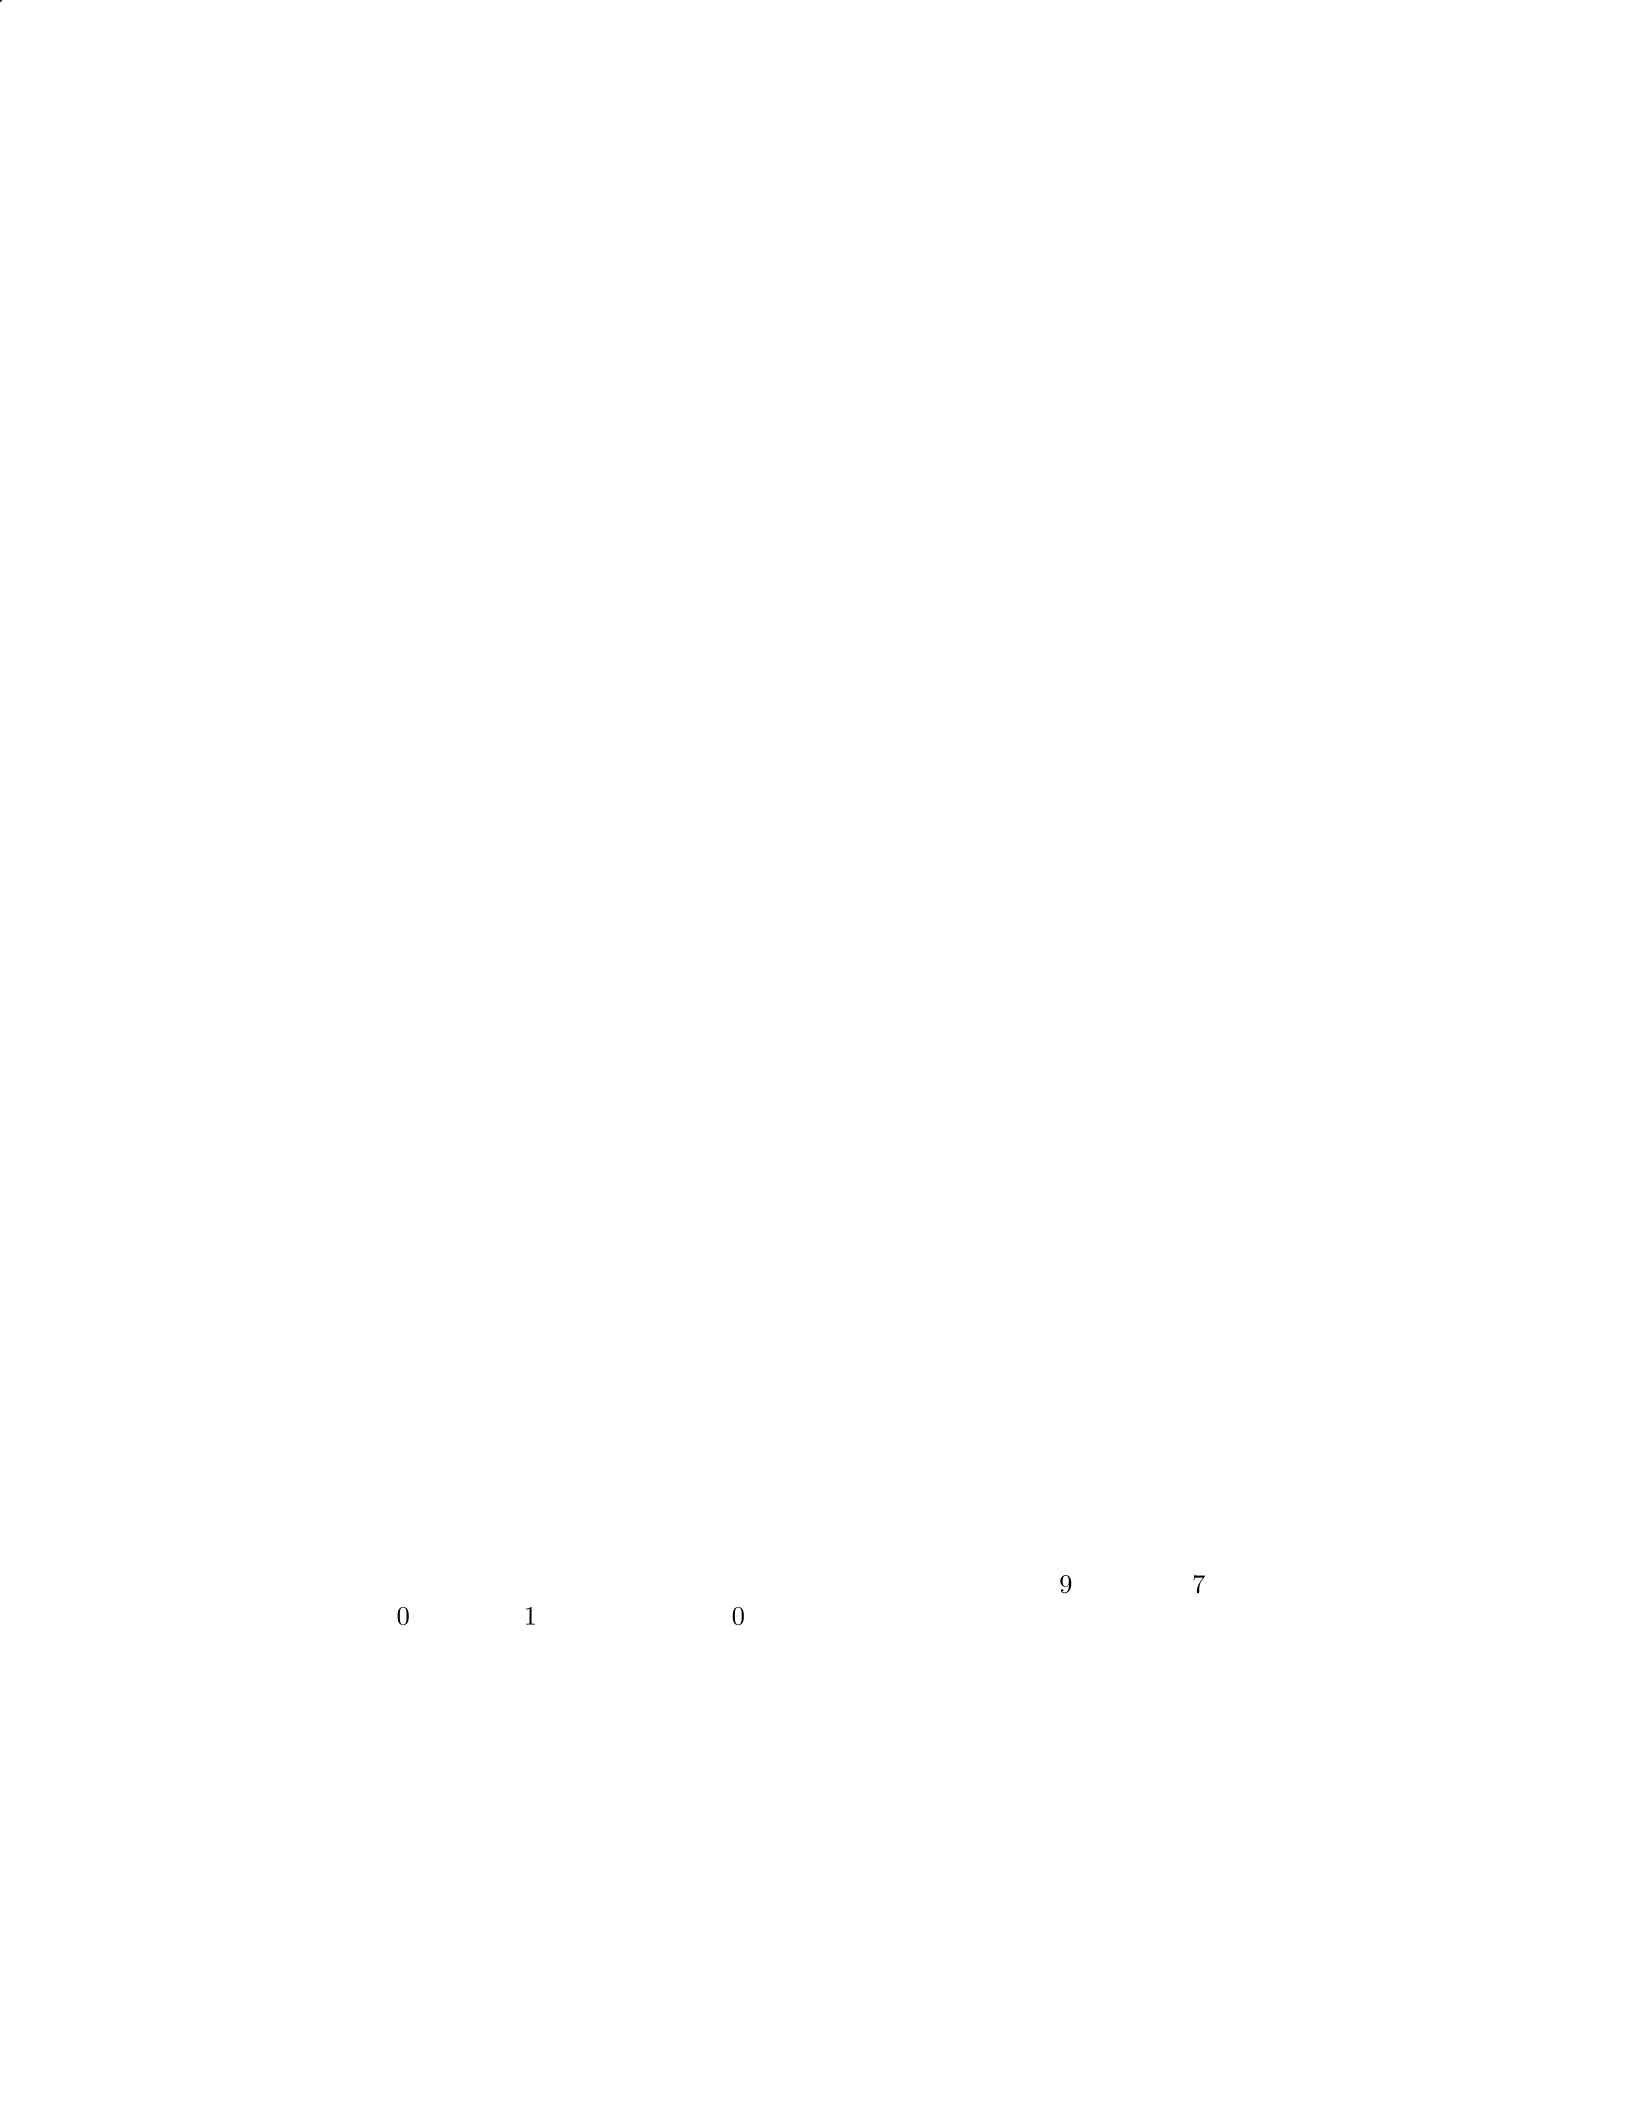
determined to be 150,000attheendofthereportingperiod.Duringtheyear, thecompanyreceivedacashdividendof3,000
and recognized a loss of 1,500infairvaluechangesontheinvestment.Calculatethecarryingamountoftheinvestmentatthebeginningofthereportingperiod.
Solution
Step 1: Calculate the total cash flows related to the investment. The total cash
flows related to the investment can be calculated by summing the cash dividend
received and the loss recognized in fair value changes: Total cash flows = Cash
dividend + Fair value loss Total cash flows = 3,000−1,500 Total cash flows =
1,500
Step 2: Use the total cash flows to adjust the fair value of the investment.
Since the total cash flows represent the net cash flows related to the investment,
we can adjust the fair value of the investment by adding the total cash flows:
Adjusted fair value = Fair value + Total cash flows Adjusted fair value =
150,000+1,500 Adjusted fair value = 151,500
Step 3: Determine the carrying amount of the investment at the beginning of
the reporting period. The carrying amount of the investment at the beginning
of the reporting period is equal to the adjusted fair value minus the total cash
flows received during the year: Carrying amount = Adjusted fair value - Total
cash flows Carrying amount = 151,500−1,500 Carrying amount = 150,000
Therefore, the carrying amount of the investment at the beginning of the
reporting period was 150,000.
16
Question 22
Question
A company holds a financial asset that is measured at fair value through profit or
loss. At the end of the reporting period, the fair value of the asset has decreased
significantly. Explain how the company should account for this decrease in fair
value.
Solution
Step 1: When the fair value of a financial asset measured at fair value through
profit or loss decreases significantly, the company should recognize the decrease
in fair value through profit or loss in the income statement.
Step 2: Determine the amount of the decrease in fair value. This is calculated
by comparing the previous fair value of the asset with its current fair value at
the end of the reporting period.
Step 3: Record the decrease in fair value as a loss in the income statement.
This loss will offset any gains or income the company may have recognized from
the asset in previous periods.
Step 4: Make the necessary journal entry to reflect the decrease in fair value.
The entry would typically involve debiting a loss account and crediting the fair
value adjustment account related to the asset.
Step 5: Ensure that the financial statements, including the income statement
and balance sheet, are updated to reflect the decrease in fair value and the
corresponding loss recognized in the income statement.
Step 6: Disclose the significant decrease in fair value and the resulting impact
on the financial statements in the notes to the financial statements or in the
management discussion and analysis section of the annual report. Investors and
stakeholders should be informed about the reasons behind the decrease in fair
value and its potential implications for the company.
Question 23
Question
A company used the market approach to estimate the fair value of an asset. The
market approach involved using comparable market transactions to estimate the
fair value of the asset. The company gathered information on several compa-
rable transactions and found the following selling prices:
$
950,000,
$
970,000,
$
990,000,
$
1,010,000, and
$
1,030,000. The company estimated the fair value
of the asset by taking the average of these selling prices. However, an analyst
noticed that one of the comparable transactions was significantly larger in size
compared to the others. Discuss whether this could affect the accuracy of the
fair value estimation based on the market approach.
17

Solution
Step 1: The Impact of Size Difference on Fair Value Estimation - The significant
difference in size between the transactions could affect the accuracy of the fair
value estimation based on the market approach. When estimating fair value
using the market approach, it is essential to select comparable transactions that
are similar to the asset being valued in all significant aspects. Size is one of the
critical factors affecting the comparability of transactions.
Step 2: Potential Issues with Size Difference - If one of the comparable
transactions significantly differs in size compared to the asset being valued, it
may not accurately reflect the fair value of the asset. Larger transactions may
involve bulk discounts, economies of scale, or other factors that do not apply
to smaller transactions. As a result, using such a transaction to estimate the
fair value could lead to an overestimation or underestimation of the asset’s true
value.
Step 3: Mitigating the Impact of Size Difference - To improve the accuracy
of fair value estimation, the company could exclude the transaction that signif-
icantly differs in size from the others. Alternatively, the company could adjust
the selling prices of comparable transactions to account for the size difference.
This adjustment could involve normalizing the prices based on the size of the
transactions or applying a size-based discount or premium to the selling prices.
Step 4: Conclusion - In conclusion, the significant difference in size between
comparable transactions could indeed affect the accuracy of fair value estimation
based on the market approach. It is essential for companies to carefully consider
the size and other relevant characteristics of comparable transactions to ensure
a more accurate estimation of fair value.
Question 24
Question
A company holds an investment in a publicly traded security classified as available-
for-sale. The fair value of the investment has significantly decreased due to
market fluctuations. Explain how the company should account for this decrease
in fair value under the fair value measurement framework.
Solution
To account for the decrease in fair value of the investment under the fair value
measurement framework, the company should follow these steps:
Step 1: Recognize the change in fair value in other comprehensive income:
The company should recognize the decrease in fair value of the investment in
other comprehensive income. This allows for the volatility in fair value to be
reflected in the financial statements without impacting net income.
Step 2: Adjust the carrying amount of the investment: The company should
adjust the carrying amount of the investment on the balance sheet to reflect the
18
new fair value. This adjustment is made by recognizing a loss on the investment
in the income statement.
Step 3: Assess the impairment of the investment: If the decrease in fair
value is significant and deemed to be other than temporary, the company should
assess whether the investment is impaired. If impairment exists, the company
should recognize an impairment loss in the income statement.
Step 4: Disclose the fair value measurement information: The company
should provide extensive disclosures about the fair value measurement of the
investment in the financial statements. This includes information about the
valuation techniques used, input factors, and sensitivity analysis.
By following these steps, the company can appropriately account for the de-
crease in fair value of the investment under the fair value measurement frame-
work.
Question 25
Question
Explain the fair value measurement hierarchy according to IFRS 13 and provide
an example for each level.
Solution
The fair value measurement hierarchy under IFRS 13 categorizes the inputs to
valuation techniques into three levels based on the observability of the inputs.
Level 1: Quoted prices (unadjusted) in active markets for identical
assets or liabilities
Example: The quoted price of a share of a public company on a stock
exchange.
Level 2: Inputs other than quoted prices included in Level 1 that
are observable for the asset or liability, either directly or indirectly
Example: Using the yield curve to discount future cash flows of a bond to
determine its fair value.
Level 3: Unobservable inputs for the asset or liability
Example: Valuing an early-stage startup company using a discounted cash
flow model where revenue projections are based on management estimates.
Question 26
Question
A company is required to determine the fair value of an investment property
it owns. The property was purchased 5 years ago for
$
500,000 and has an
19
estimated remaining useful life of 15 years. The current fair value of the property
is estimated to be
$
650,000. Using the cost approach, calculate the fair value of
the investment property.
Solution
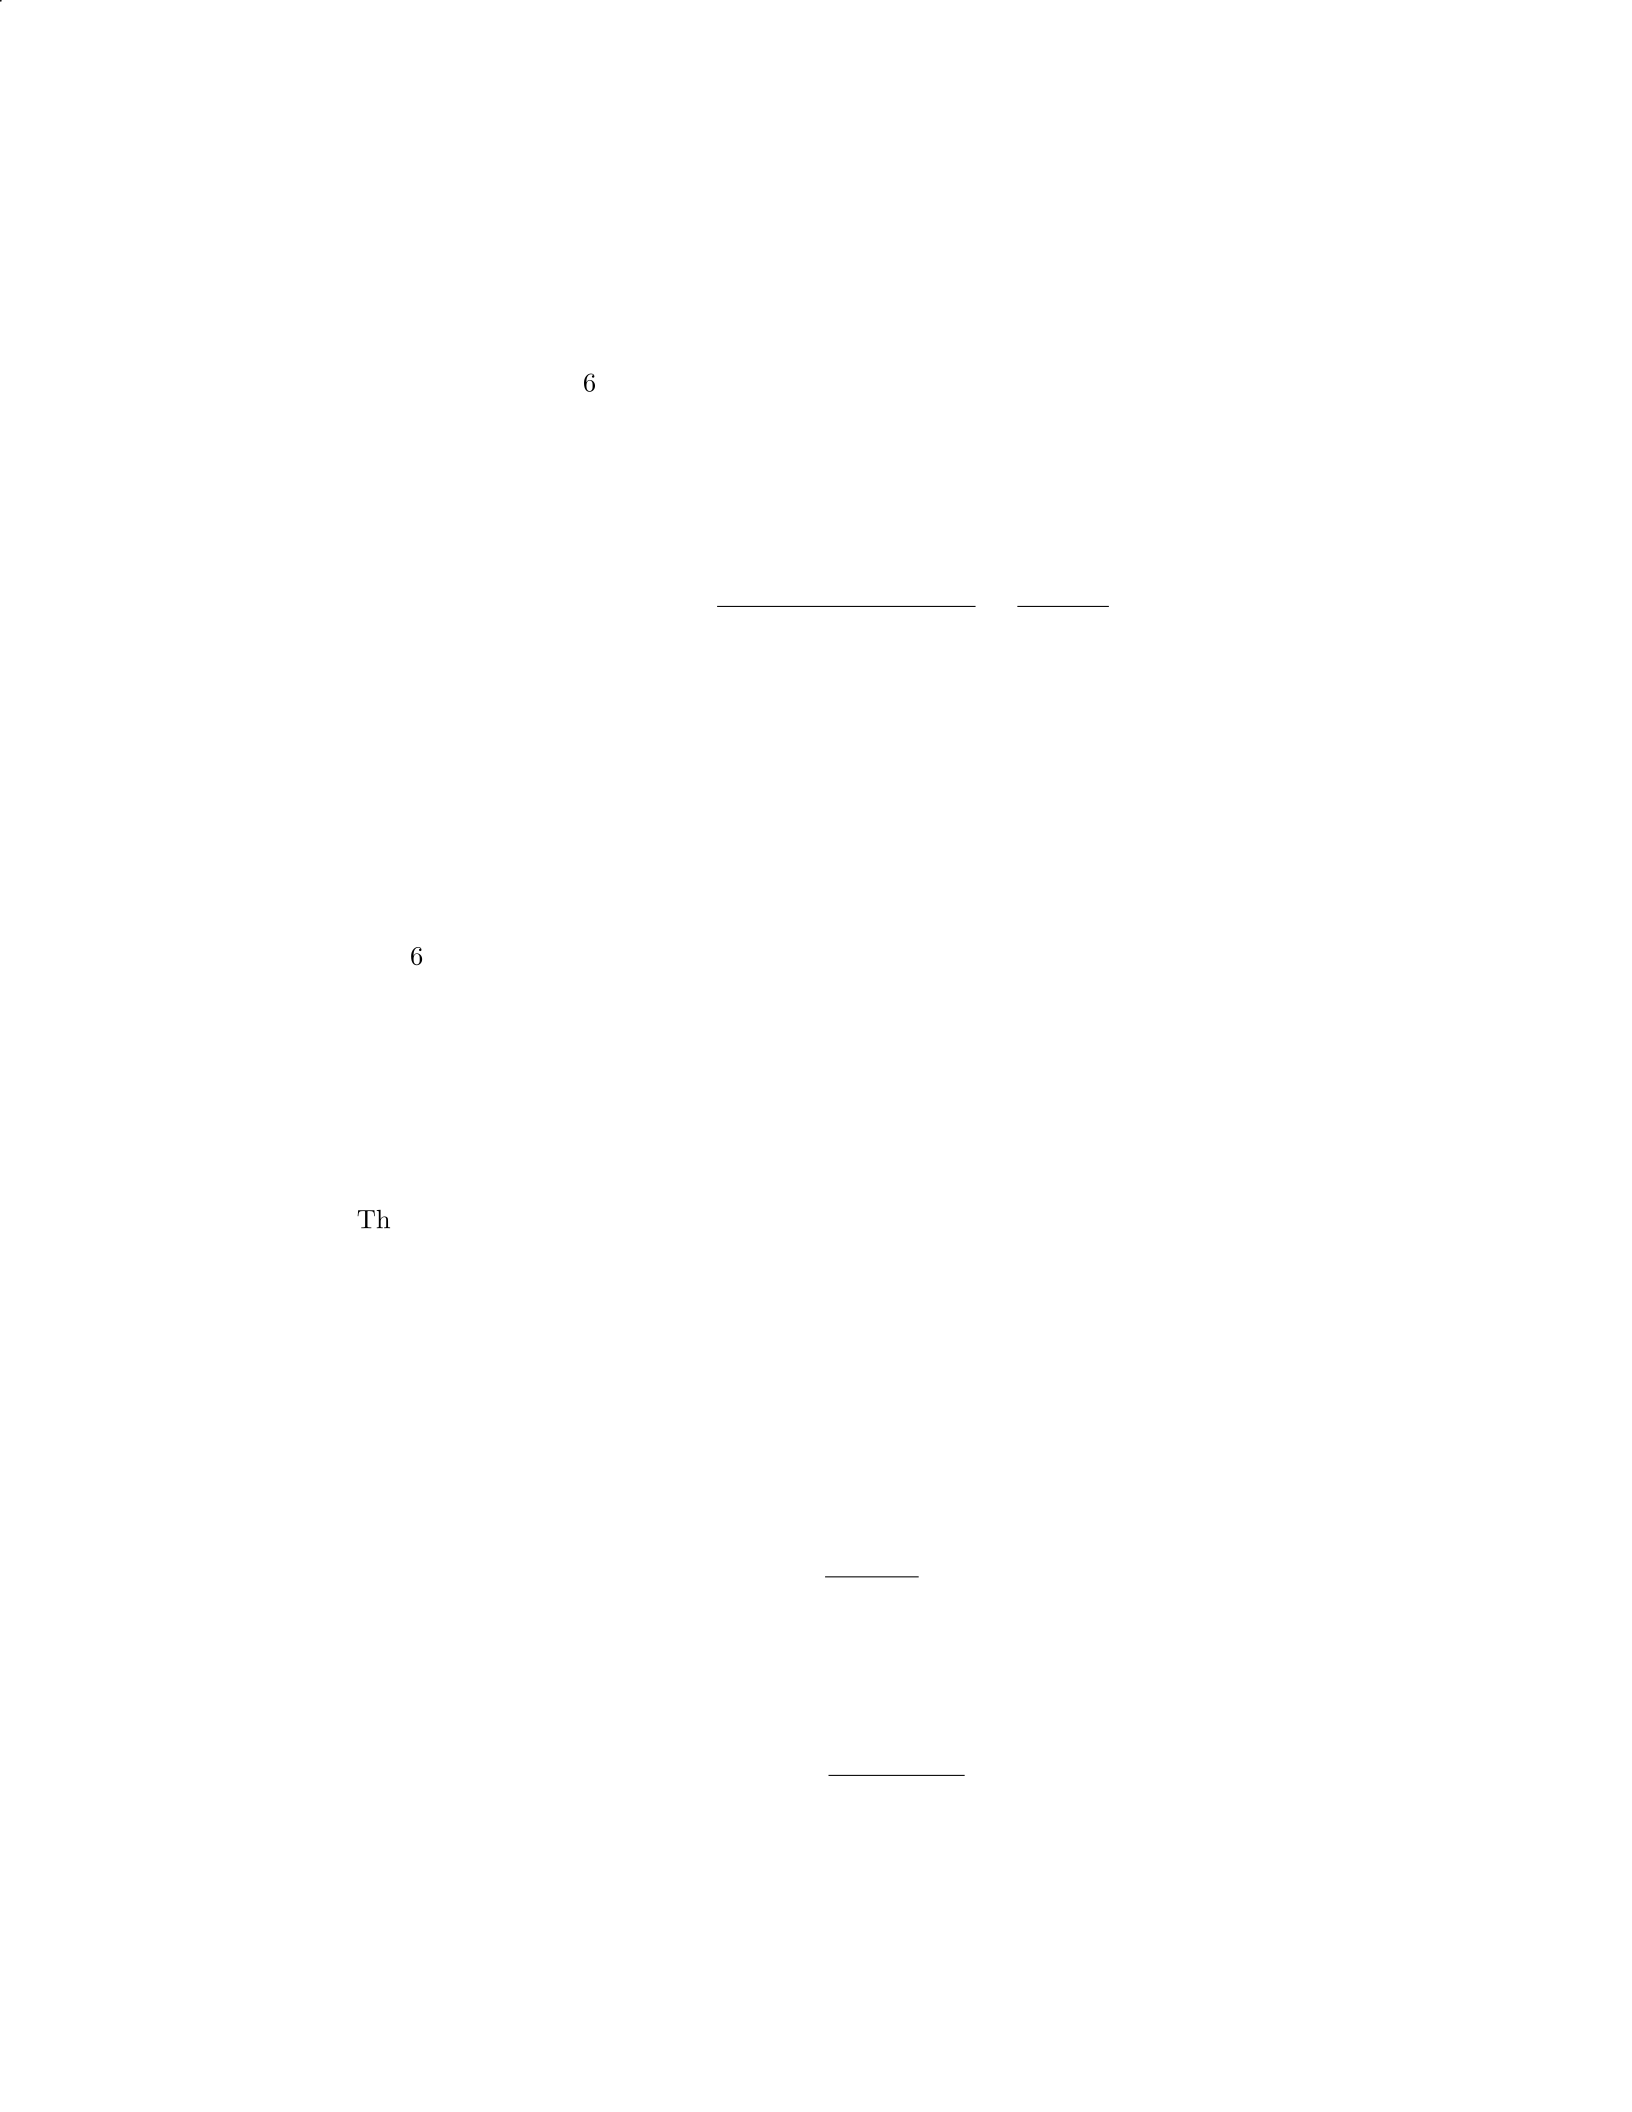
Step 1: Calculate the accumulated depreciation of the property.
Accumulated Depreciation = Cost
Remaining Useful Life =500,000
15 = 33,333.33
Step 2: Determine the book value of the property.
Book Value = Cost−Accumulated Depreciation = 500,000−33,333.33 = 466,666.67
Step 3: Using the cost approach, the fair value of the investment property
is the book value.
Fair Value = Book Value = 466,666.67
Therefore, the fair value of the investment property using the cost approach
is
$
466,666.67.
Question 27
Question
A company is assessing the fair value of an investment property. The company
estimates that the property will generate a net cash flow of 200,000peryearforthenext10years.Afterthat, thepropertyisexpectedtobesoldfor1,500,000.
The company uses a discount rate of 8
Solution
Step 1: Calculate the present value of the cash flows for the next 10 years. Step
2: Calculate the present value of the property’s sale price in 10 years. Step 3:
Add the present values calculated in Step 1 and Step 2 to find the total fair
value of the investment property.
Step 1: The present value of the annuity can be calculated using the formula
for the present value of an annuity:
P V =C×1−1
(1 + r)n∇ · r
where: - C= $200,000 (annual net cash flow) - r= 0.08 (discount rate) -
n= 10 (number of years)
Substituting the values, we get:
P V = $200,000 ×1−1
(1 + 0.08)10 ∇ · 0.08
20
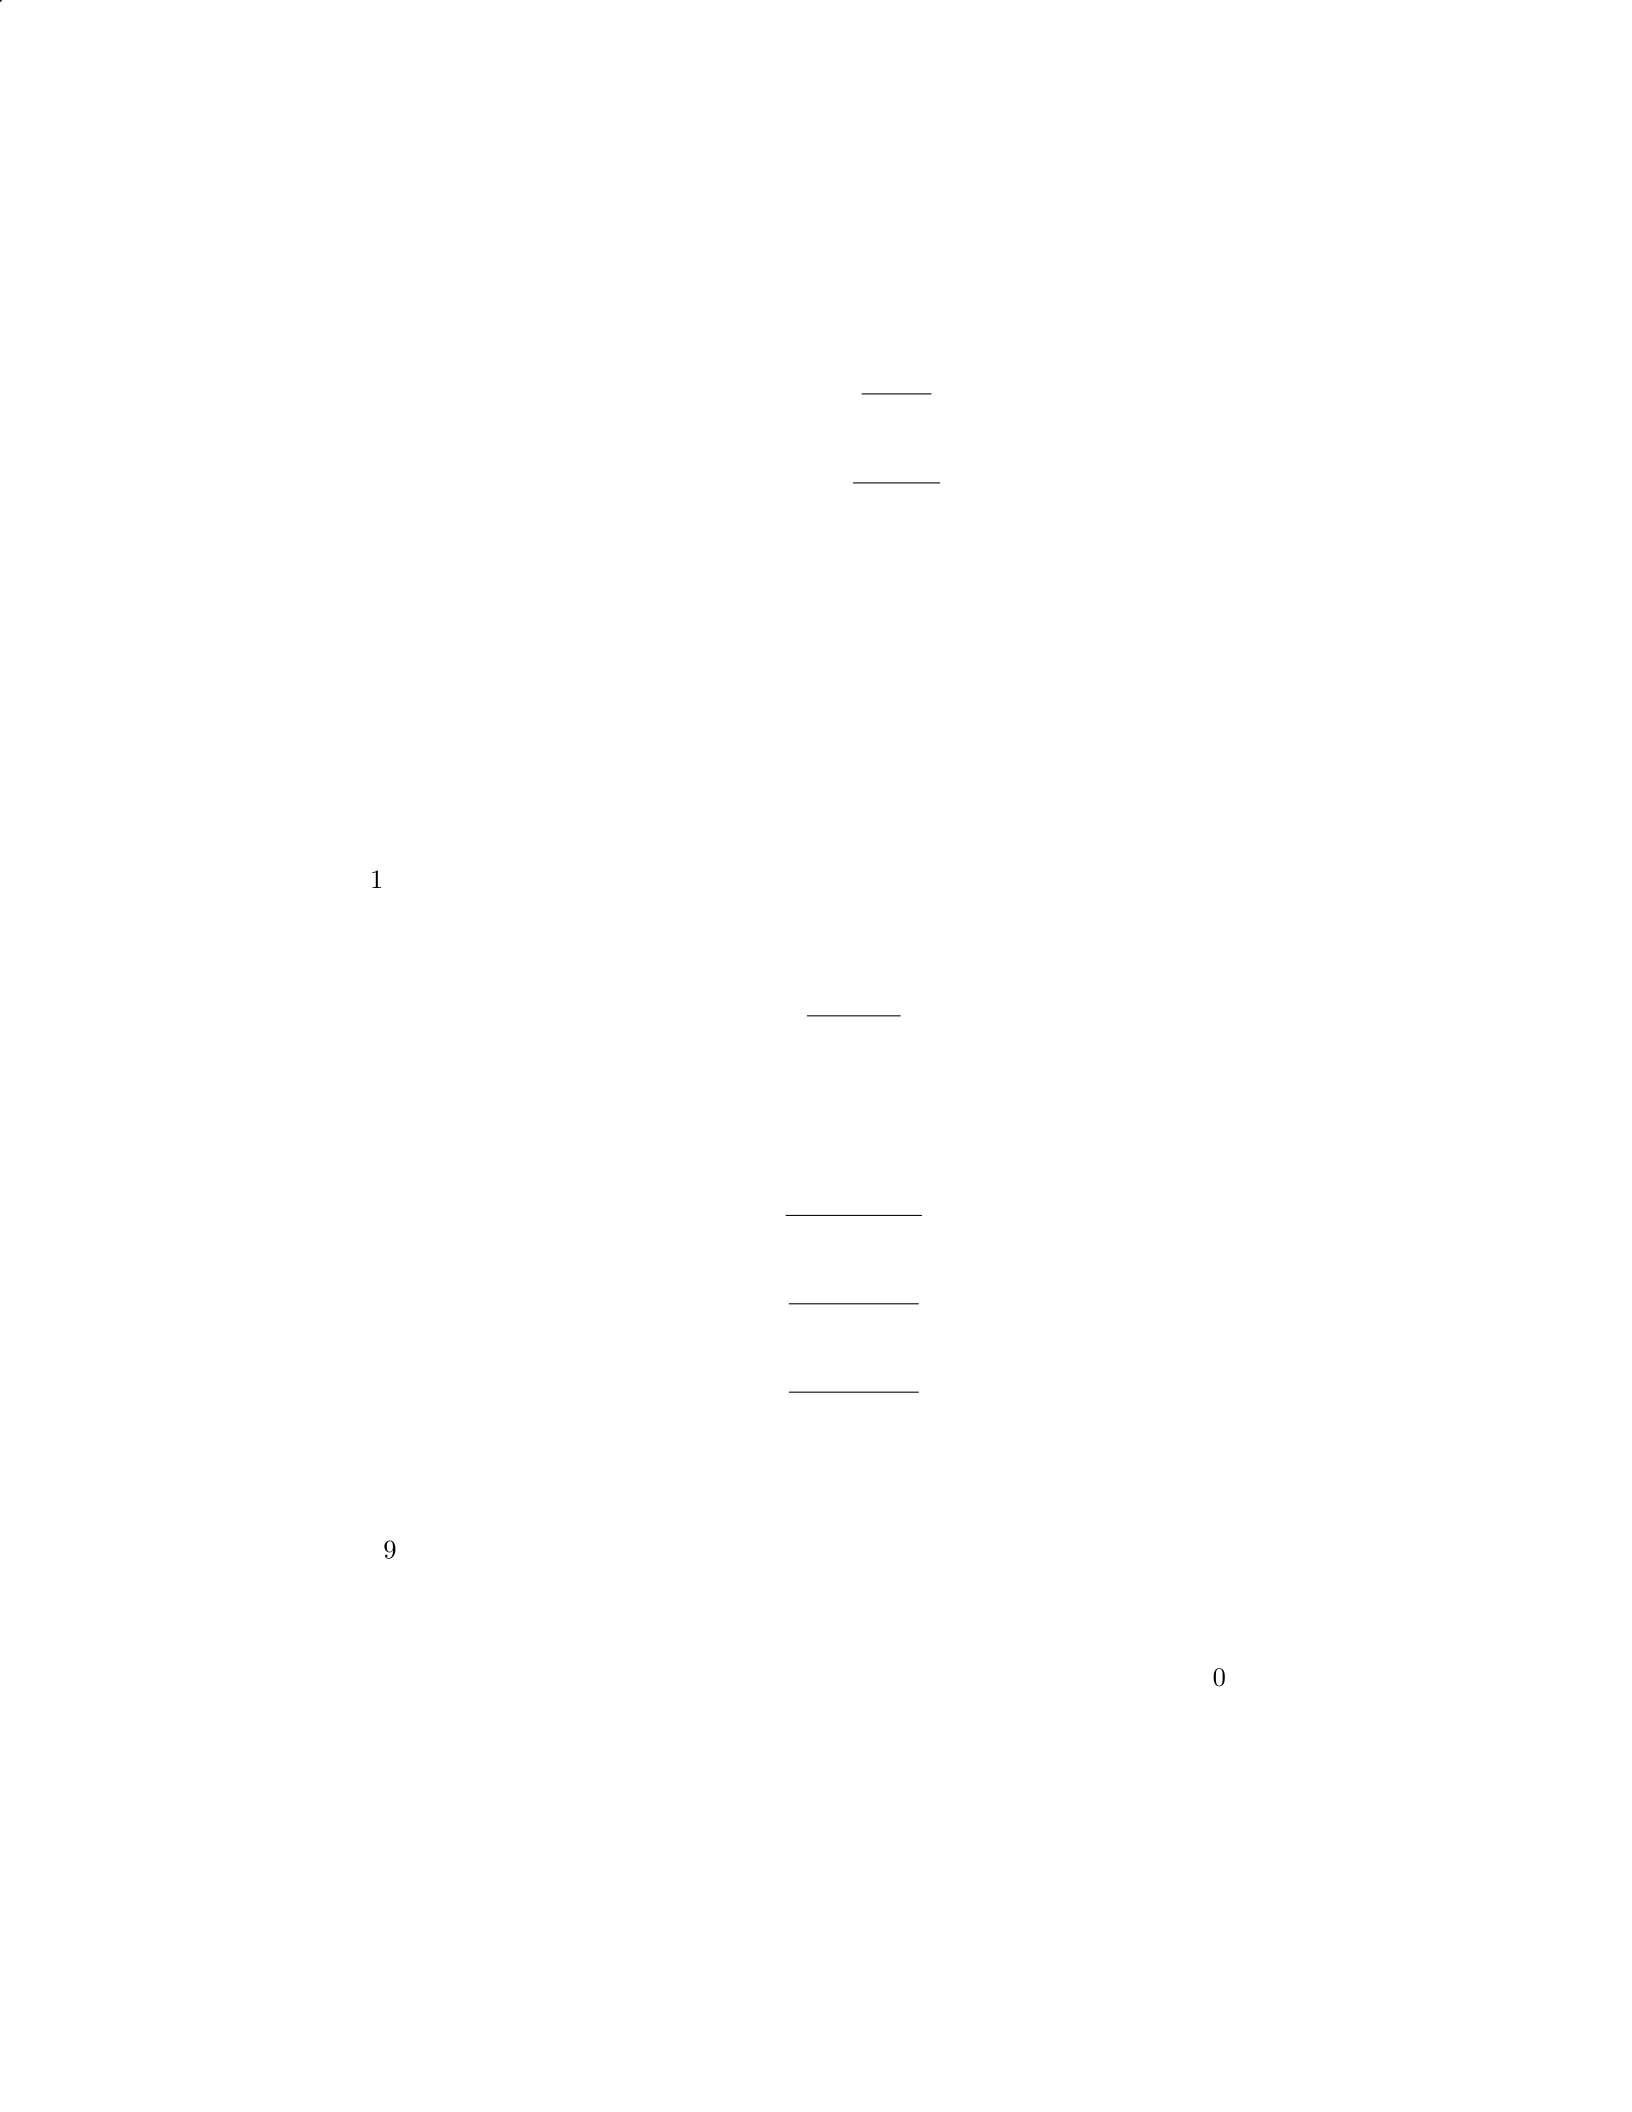
P V ≈$200,000 ×1−1
1.0810 ∇ · 0.08
P V ≈$200,000 ×1−1
2.15892∇ · 0.08
P V ≈$200,000 ×(1 −0.46319) ∇ · 0.08
P V ≈$200,000 ×0.53681∇ · 0.08
P V ≈$200,000 ×6.710125
P V ≈$1,342,025
So, the present value of the cash flows for the next 10 years is approximately
$
1,342,025.
Step 2: The present value of the property’s sale price can be calculated
using the formula for the present value of a future amount:
P V =F V
(1 + r)n
where: - F V = $1,500,000 (future sale price) - r= 0.08 (discount rate) -
n= 10 (number of years)
Substituting the values, we get:
P V =$1,500,000
(1 + 0.08)10
P V =$1,500,000
(1.08)10
P V =$1,500,000
2.15892
P V ≈$695,774
So, the present value of the property’s sale price in 10 years is approximately
$
695,774.
Step 3: The total fair value of the investment property is the sum of the
present values calculated in Step 1 and Step 2:
Total Fair Value ≈$1,342,025 + $695,774 = $2,037,799
Therefore, the fair value of the investment property is approximately
$
2,037,799.
21

Question 28
Question
Company XYZ is evaluating the fair value of an investment property they own.
The property has a current fair value of
$
800,000. After conducting a valuation,
it was determined that the property’s highest and best use is as a commercial
building. The estimated future cash flows for the property are as follows: -
Year 1:
$
40,000 - Year 2:
$
50,000 - Year 3:
$
60,000 - Year 4:
$
70,000 - Year 5:
$
80,000 If the discount rate is 8
Solution
Step 1: Calculate the present value of each future cash flow using the formula:
P V =F V
(1 + r)n
where: - F V is the future cash flow - ris the discount rate - nis the number of
years
Calculating the present value of each cash flow: - Year 1: P V =40,000
(1+0.08)1=
40,000
1.08 ≈$37,037.04 - Year 2: P V =50,000
(1+0.08)2=50,000
1.1664 ≈$42,917.85 - Year 3:
P V =60,000
(1+0.08)3=60,000
1.2597 ≈$47,605.71 - Year 4: P V =70,000
(1+0.08)4=70,000
1.3605 ≈
$51,443.89 - Year 5: P V =80,000
(1+0.08)5=80,000
1.4693 ≈$54,430.28
Step 2: Sum up the present values of all cash flows to find the fair value of
the property:
F airV alue = $37,037.04+$42,917.85+$47,605.71+$51,443.89+$54,430.28 = $233,434.77
Therefore, the fair value of the property based on the discounted cash flow
method is approximately
$
233,434.77.
Question 29
Question
A company holds an investment in a publicly traded company. The fair value of
the investment at the end of the reporting period is 625,000.T hecompanyalsoholdsasimilarinvestmentinaprivatecompany.Howshouldthecompanydeterminethefairvalueoftheinvestmentintheprivatecompany?
Solution
1. The fair value of investments in publicly traded companies can be easily de-
termined through market prices. However, determining the fair value of invest-
ments in private companies is more challenging as there is no readily available
market price.
2. The company can use various methods to determine the fair value of
the investment in the private company. One common method is the market
22
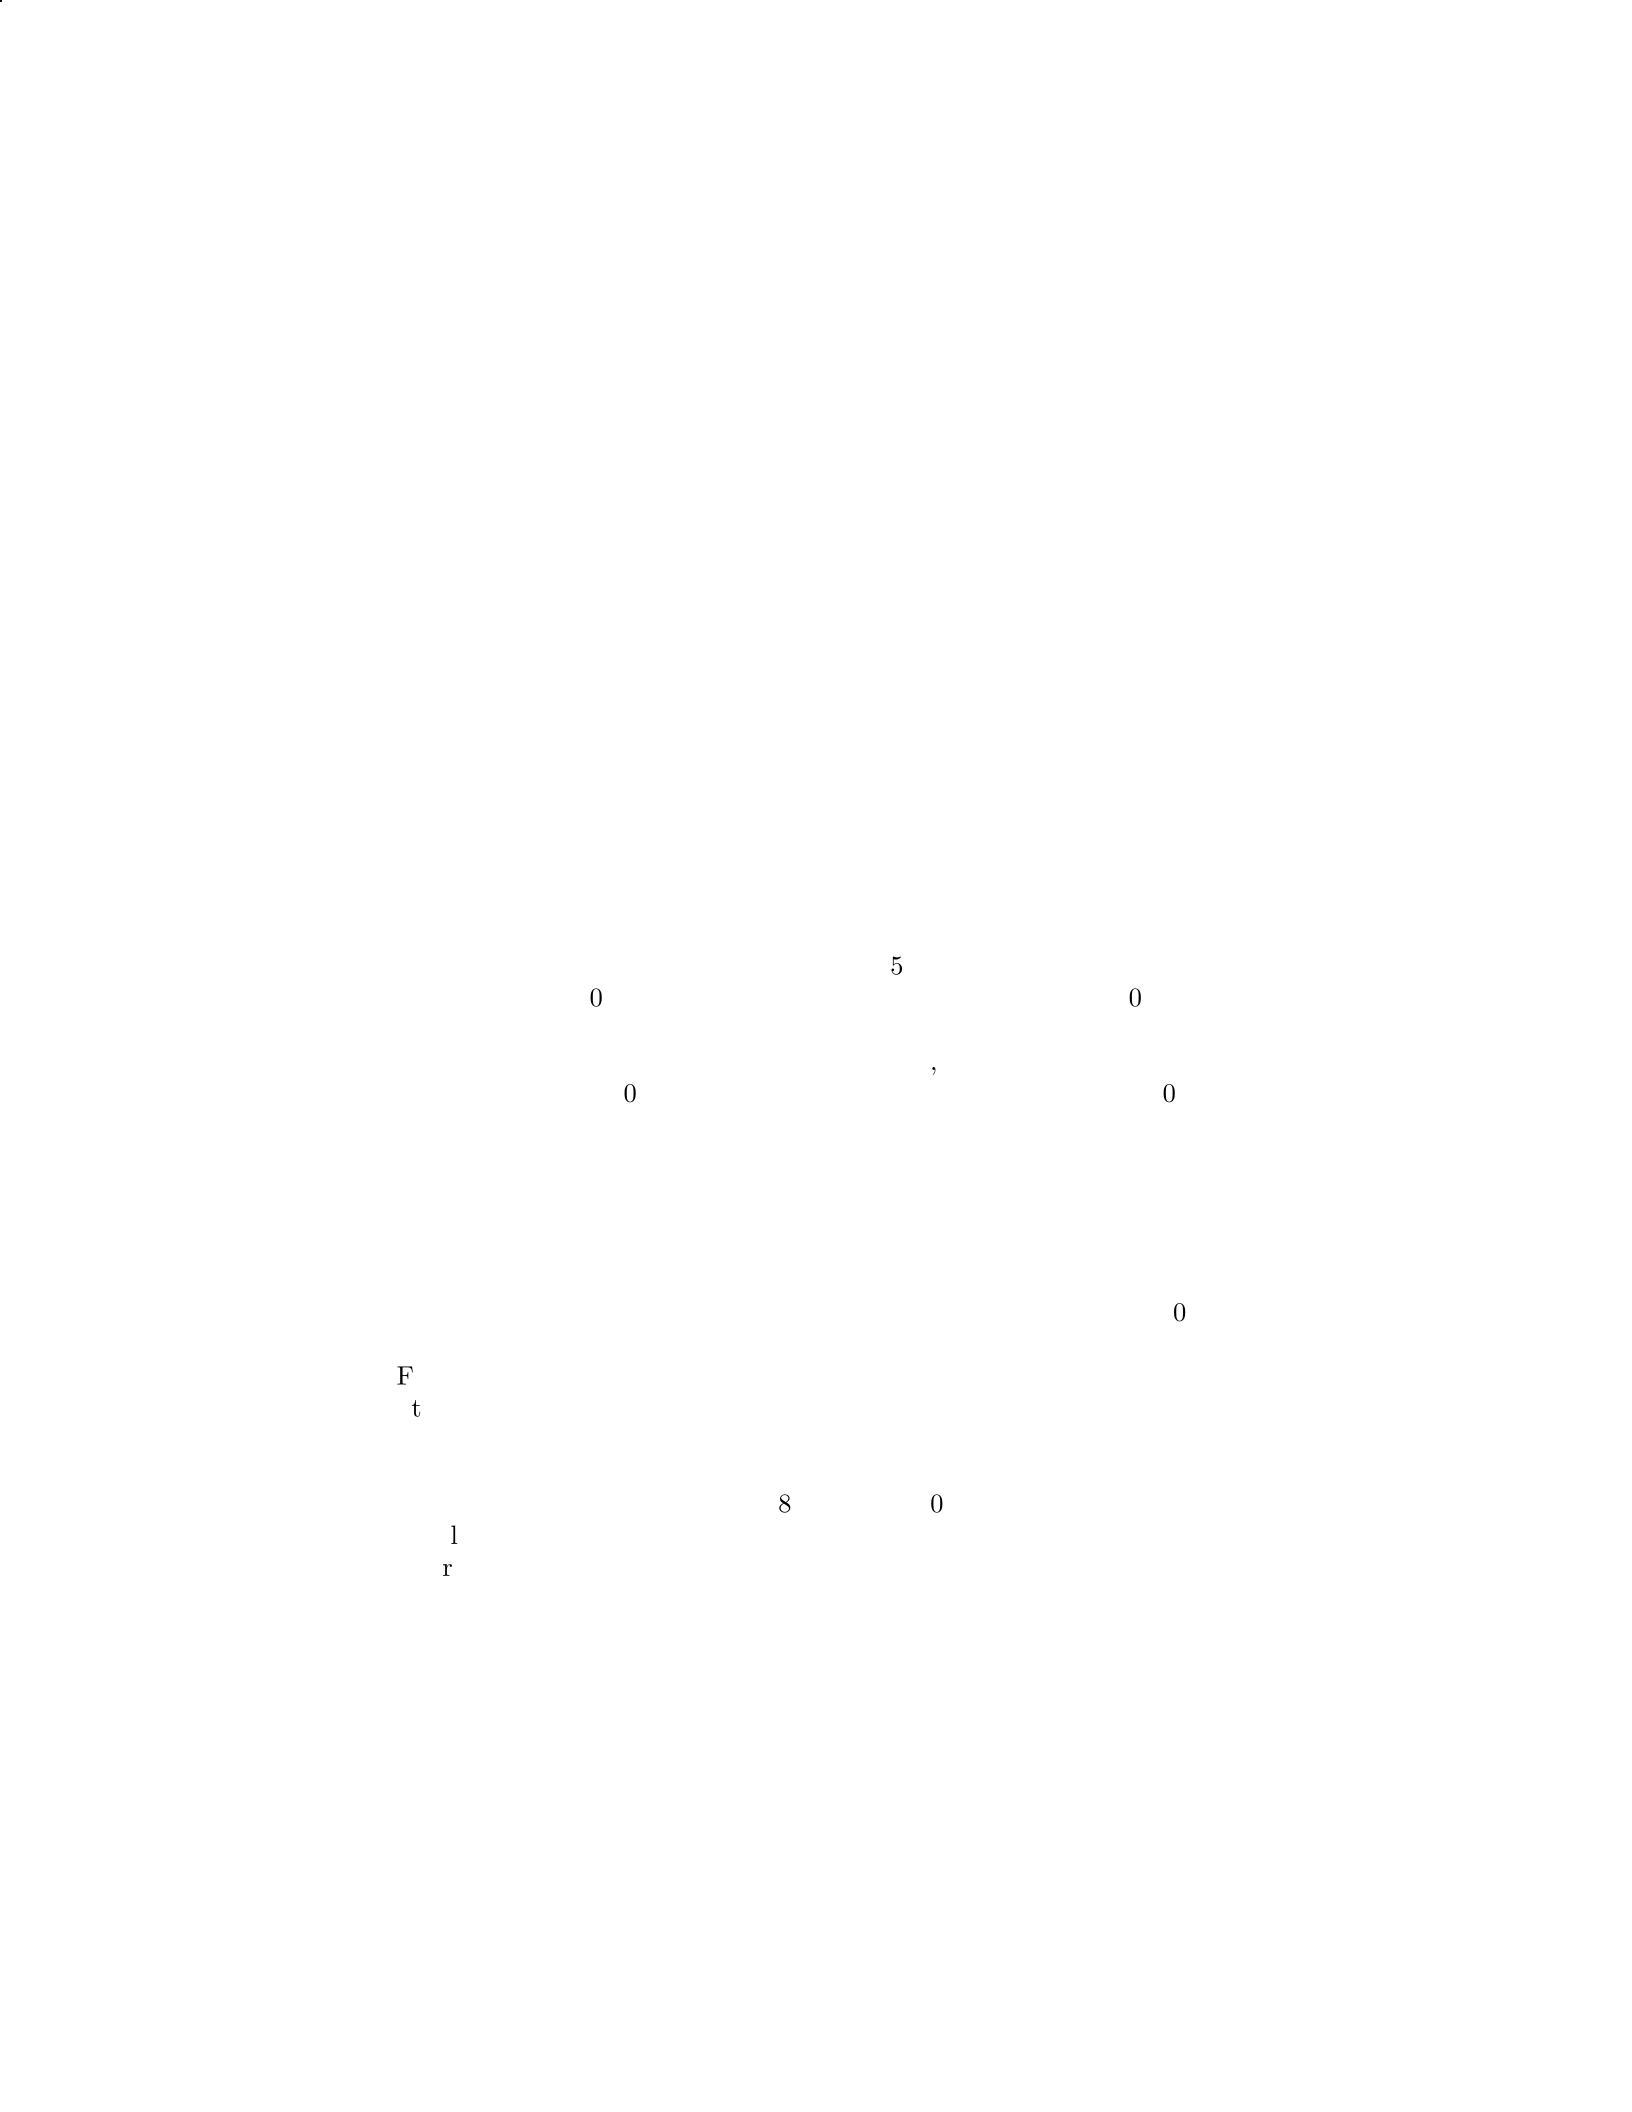
approach which involves comparing the investment in the private company to
similar publicly traded companies.
3. Another method is the income approach, which estimates the fair value
by discounting the future cash flows expected from the investment.
4. The cost approach can also be used, which values the investment based
on the cost of comparable assets.
5. Once the company selects a method for determining the fair value of the
investment in the private company, it must ensure that the valuation is based
on reliable and relevant information. The company may need to engage external
valuation experts to assist in determining the fair value.
6. The company should disclose the valuation methods used in determining
the fair value of the investment in the private company in its financial statements
to provide transparency to investors and other stakeholders.
Question 30
Question
Given below are the financial assets of XYZ Company as at December 31, 2021:
- Investment in listed equity securities:
$
500,000 - Investment in unlisted
equity securities:
$
300,000 - Investment in government bonds:
$
400,000
The fair values of these financial assets are as follows:
- Investment in listed equity securities:
$
550,000 - Investment in unlisted
equity securities:
$
280,000 - Investment in government bonds:
$
390,000
Determine the total fair value of XYZ Company’s financial assets as at De-
cember 31, 2021.
Solution
Step 1: Calculate the fair value of each type of financial asset.
For the investment in listed equity securities: Fair value =
$
550,000
For the investment in unlisted equity securities: Fair value =
$
280,000
For the investment in government bonds: Fair value =
$
390,000
Step 2: Calculate the total fair value of XYZ Company’s financial assets.
Total fair value = Fair value of listed equity securities + Fair value of unlisted
equity securities + Fair value of government bonds
Total fair value =
$
550,000 +
$
280,000 +
$
390,000
Total fair value =
$
1,220,000
Therefore, the total fair value of XYZ Company’s financial assets as at De-
cember 31, 2021 is
$
1,220,000.
23
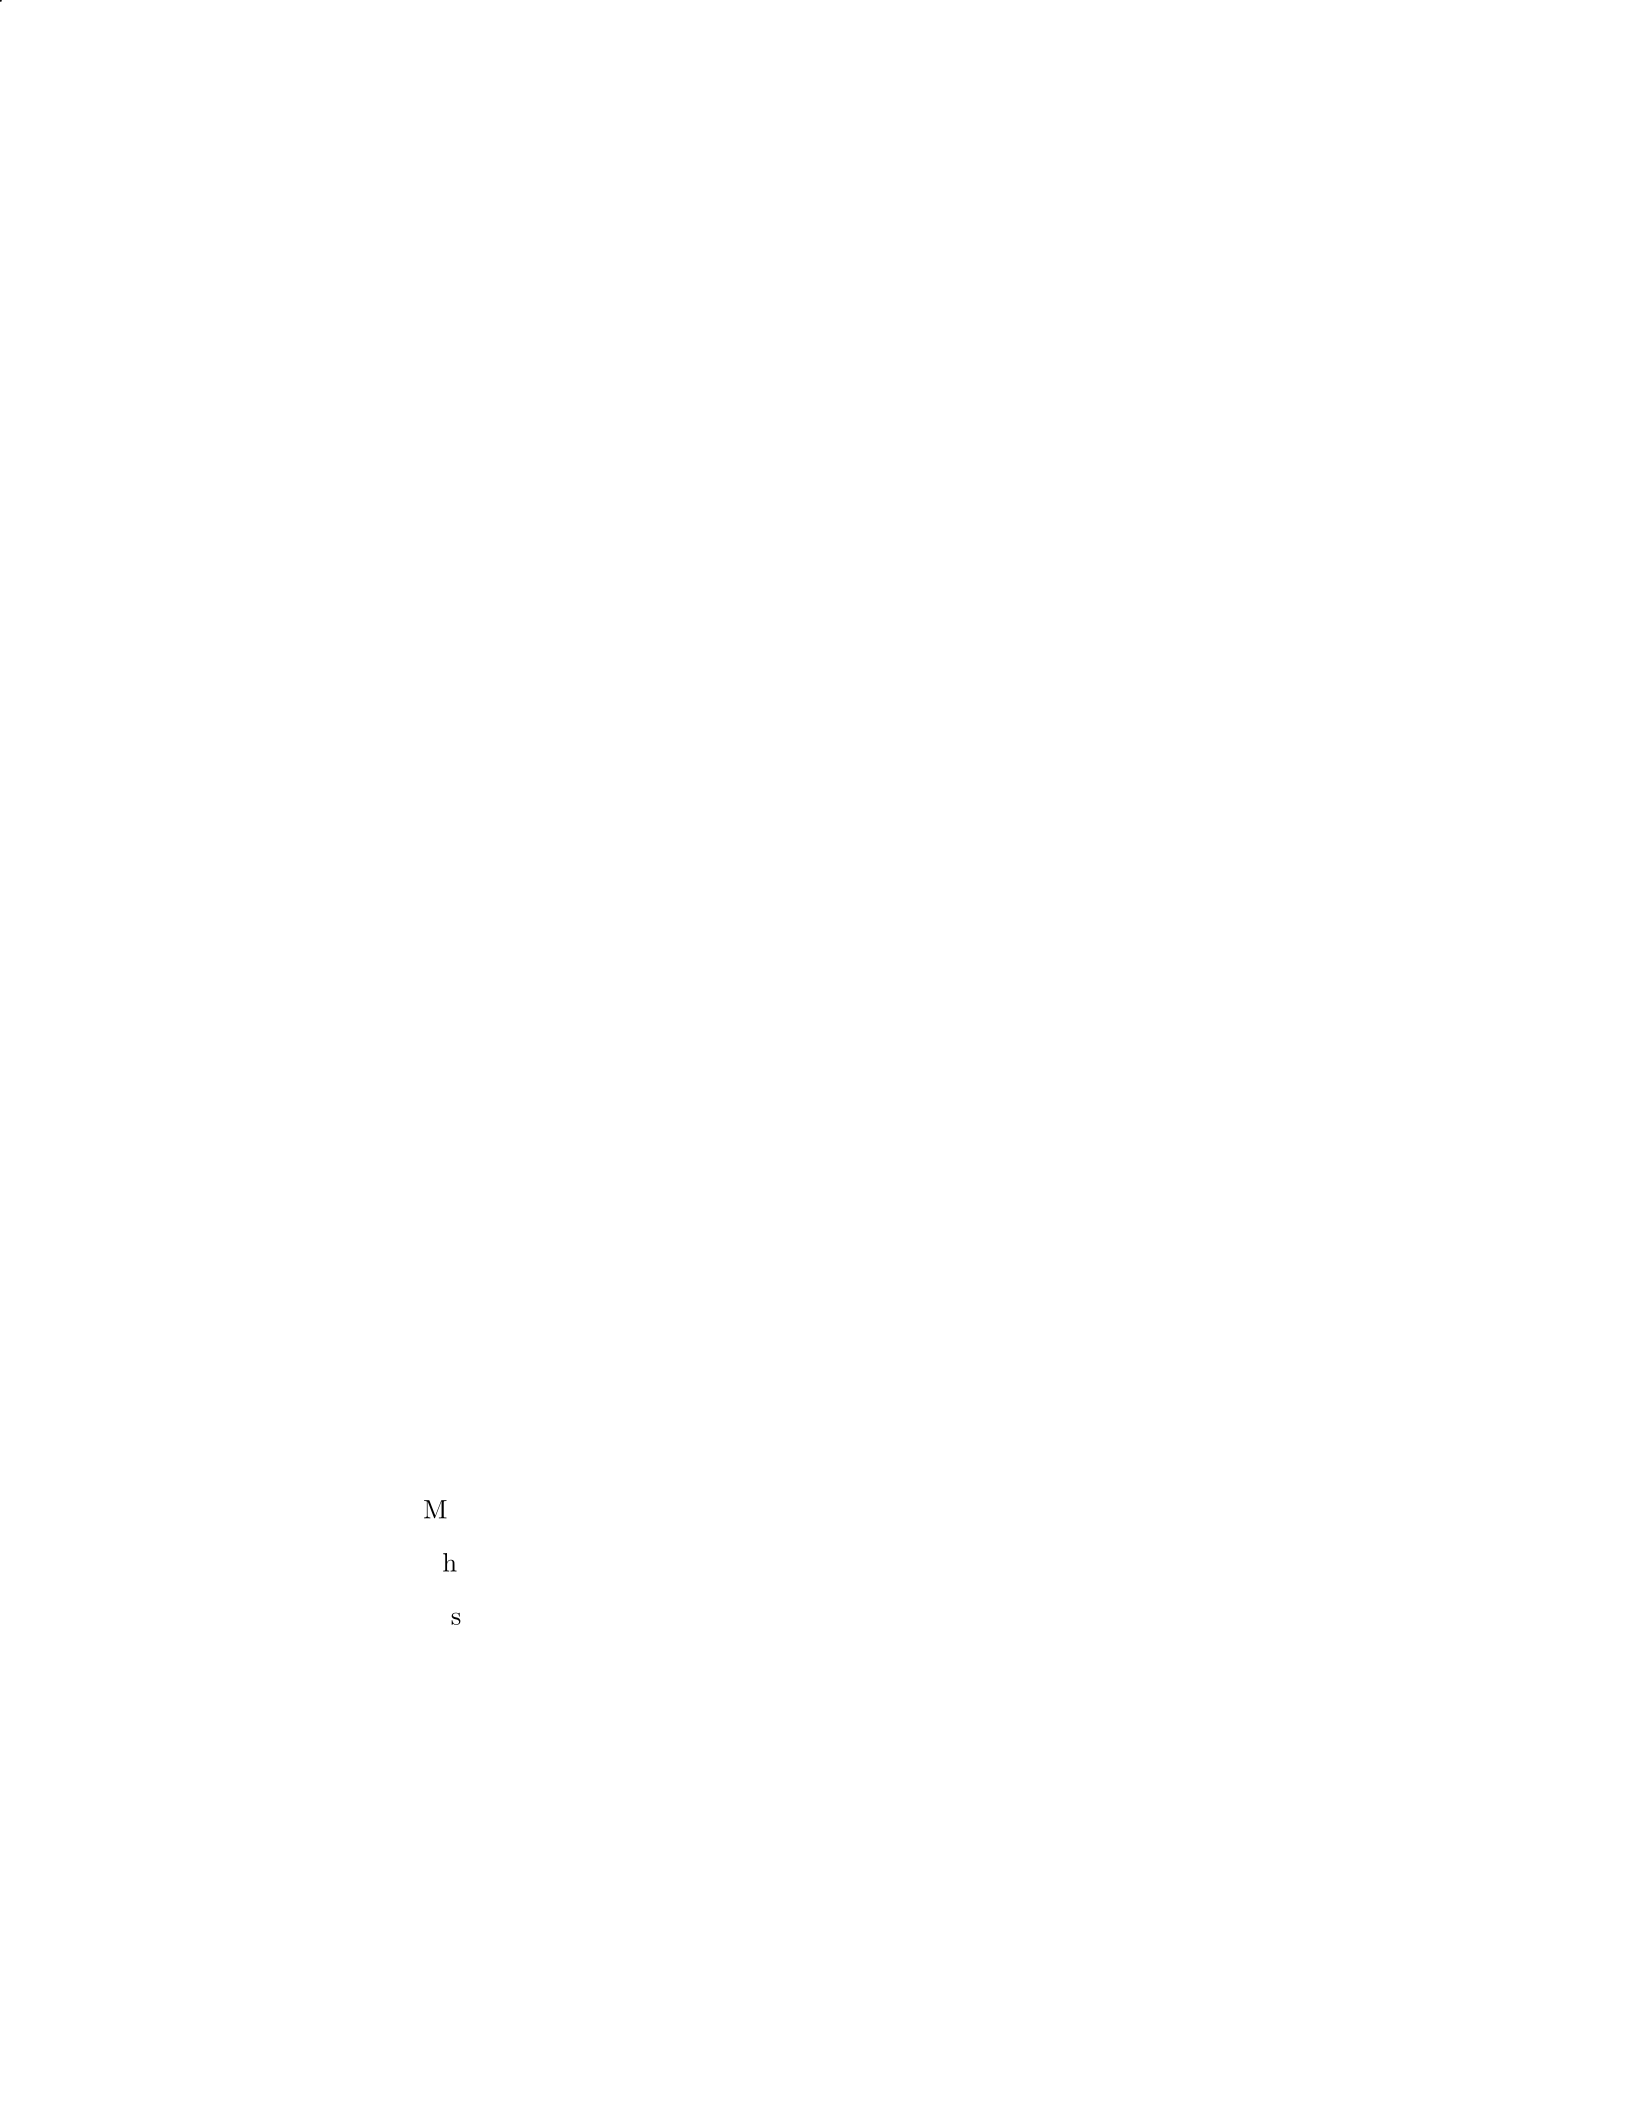
Question 31
Question
Suppose a company has an investment in a non-publicly tradable security. The
fair value of this investment is determined using Level 3 inputs. If there is a
significant decrease in the liquidity of this security, how would this impact the
fair value measurement?
Solution
Step 1: A significant decrease in liquidity of the security may result in an increase
in the risk associated with the investment. This increased risk can impact the
fair value measurement using Level 3 inputs.
Step 2: The decrease in liquidity may make it more challenging for the
company to determine a reliable fair value for the security, as there may be
limited market activity or observable transactions to use as benchmarks.
Step 3: As a result, the company may need to adjust its assumptions and
estimates when calculating the fair value of the investment. This could involve
revising discount rates, adjusting expected future cash flows, or incorporating
additional risk premiums.
Step 4: The increased uncertainty and subjectivity in determining the fair
value of the security may lead to a wider range of possible fair values. This
could result in a larger fair value measurement range or increased volatility in
the fair value estimate.
Step 5: Overall, a significant decrease in the liquidity of the security can
complicate the fair value measurement process and potentially result in a less
reliable fair value estimate for the investment.
Question 32
Question
A company is required to determine the fair value of an investment property
for its financial statements. The company obtained the following information
about the property:
Market rents for similar properties in the area: $2,500 per month
The property is expected to generate rental income for the next 5 years
Discount rate: 8%
Calculate the fair value of the investment property using the income approach.
24
Solution
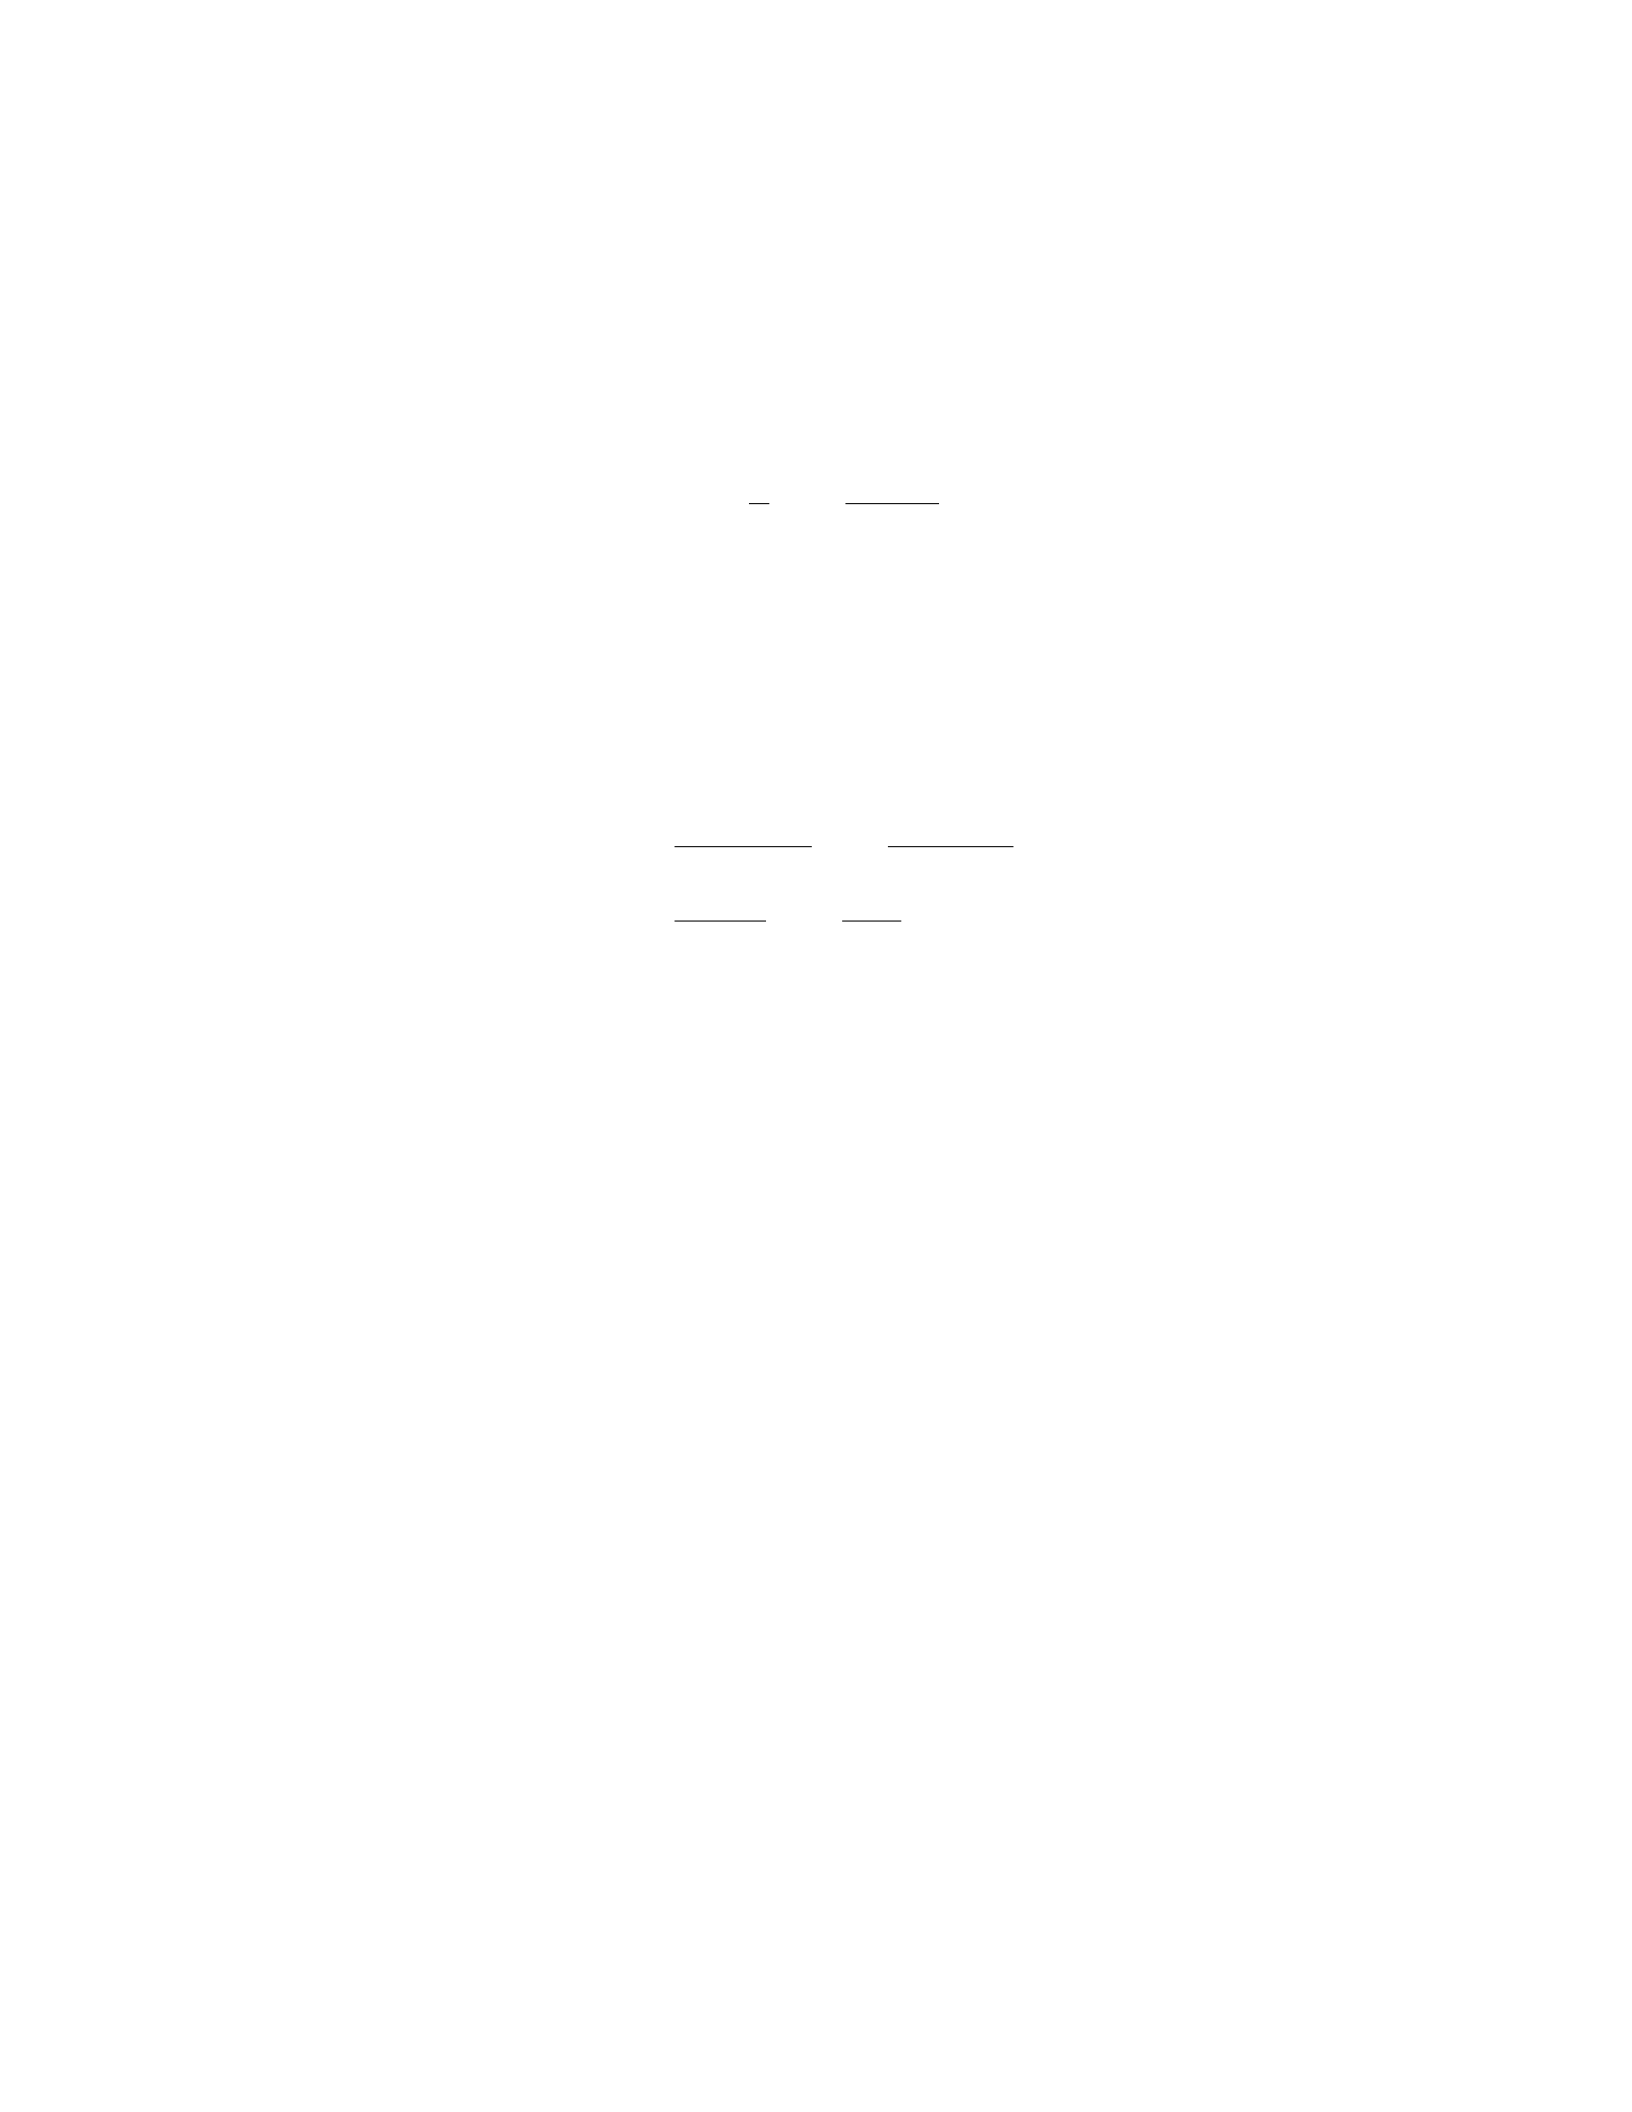
Step 1: Calculate the present value of the expected rental income over the next
5 years.
P V =R
r1−1
(1 + r)n
where:
P V = Present Value of Rental Income
R= Annual rental income = $2,500 ×12
r= Discount rate = 0.08
n= Number of years = 5
P V =$2,500 ×12
0.08 1−1
(1 + 0.08)5
P V =$30,000
0.08 1−1
1.085
P V ≈$231,145.20
Step 2: Calculate the fair value of the investment property using the present
value of the expected rental income.
Fair Value = P V
Therefore, the fair value of the investment property using the income approach
is approximately $231,145.20.
Question 33
Question
Company XYZ holds an investment in a publicly traded company where it has
significant influence. The fair value of the investment is not readily determinable
from the market, but Company XYZ believes it can estimate the fair value using
discounted cash flow analysis. Company XYZ forecasted the future cash flows
from the investment and applied a discount rate of 10
Discuss whether Company XYZ’s approach to fair value measurement is
appropriate in this scenario.
Solution
To determine whether Company XYZ’s approach to fair value measurement is
appropriate, we need to consider the requirements outlined in the accounting
standards, specifically the guidance on fair value measurement.
25

Step 1: Identify the guidance: The fair value measurement standard,
as outlined in IFRS 13 or ASC 820, requires entities to apply a market-based
approach whenever possible, which means using observable market data to es-
timate fair value when available.
Step 2: Consider the specific circumstances: In this scenario, Com-
pany XYZ does not have access to observable market data to determine the fair
value of its investment. As a result, it believes it can estimate the fair value
using discounted cash flow analysis.
Step 3: Evaluate the approach: While discounted cash flow analysis is a
common method used to estimate fair value when market data is not available, it
comes with inherent subjectivity and requires various assumptions to be made.
The accuracy of the fair value estimate is highly dependent on the cash flow
forecasts and the discount rate selected.
Step 4: Consider reasonableness: In this case, the use of discounted
cash flow analysis seems reasonable given the lack of market data. However, it
is crucial for Company XYZ to ensure that the cash flow forecasts are based on
reasonable assumptions and that the discount rate used is appropriate for the
risk associated with the investment.
Step 5: Conclusion: Based on the information provided, Company XYZ’s
approach to fair value measurement using discounted cash flow analysis appears
appropriate given the circumstances. However, Company XYZ should disclose
the significant assumptions made and the methods used in estimating the fair
value to provide transparency to users of the financial statements.
Question 34
Question
A company holds an investment property which is measured at fair value through
profit or loss. The fair value of the property at the reporting date is 3,500,000.Duringtheyear, thepropertyincreasedinvalueby15
Solution
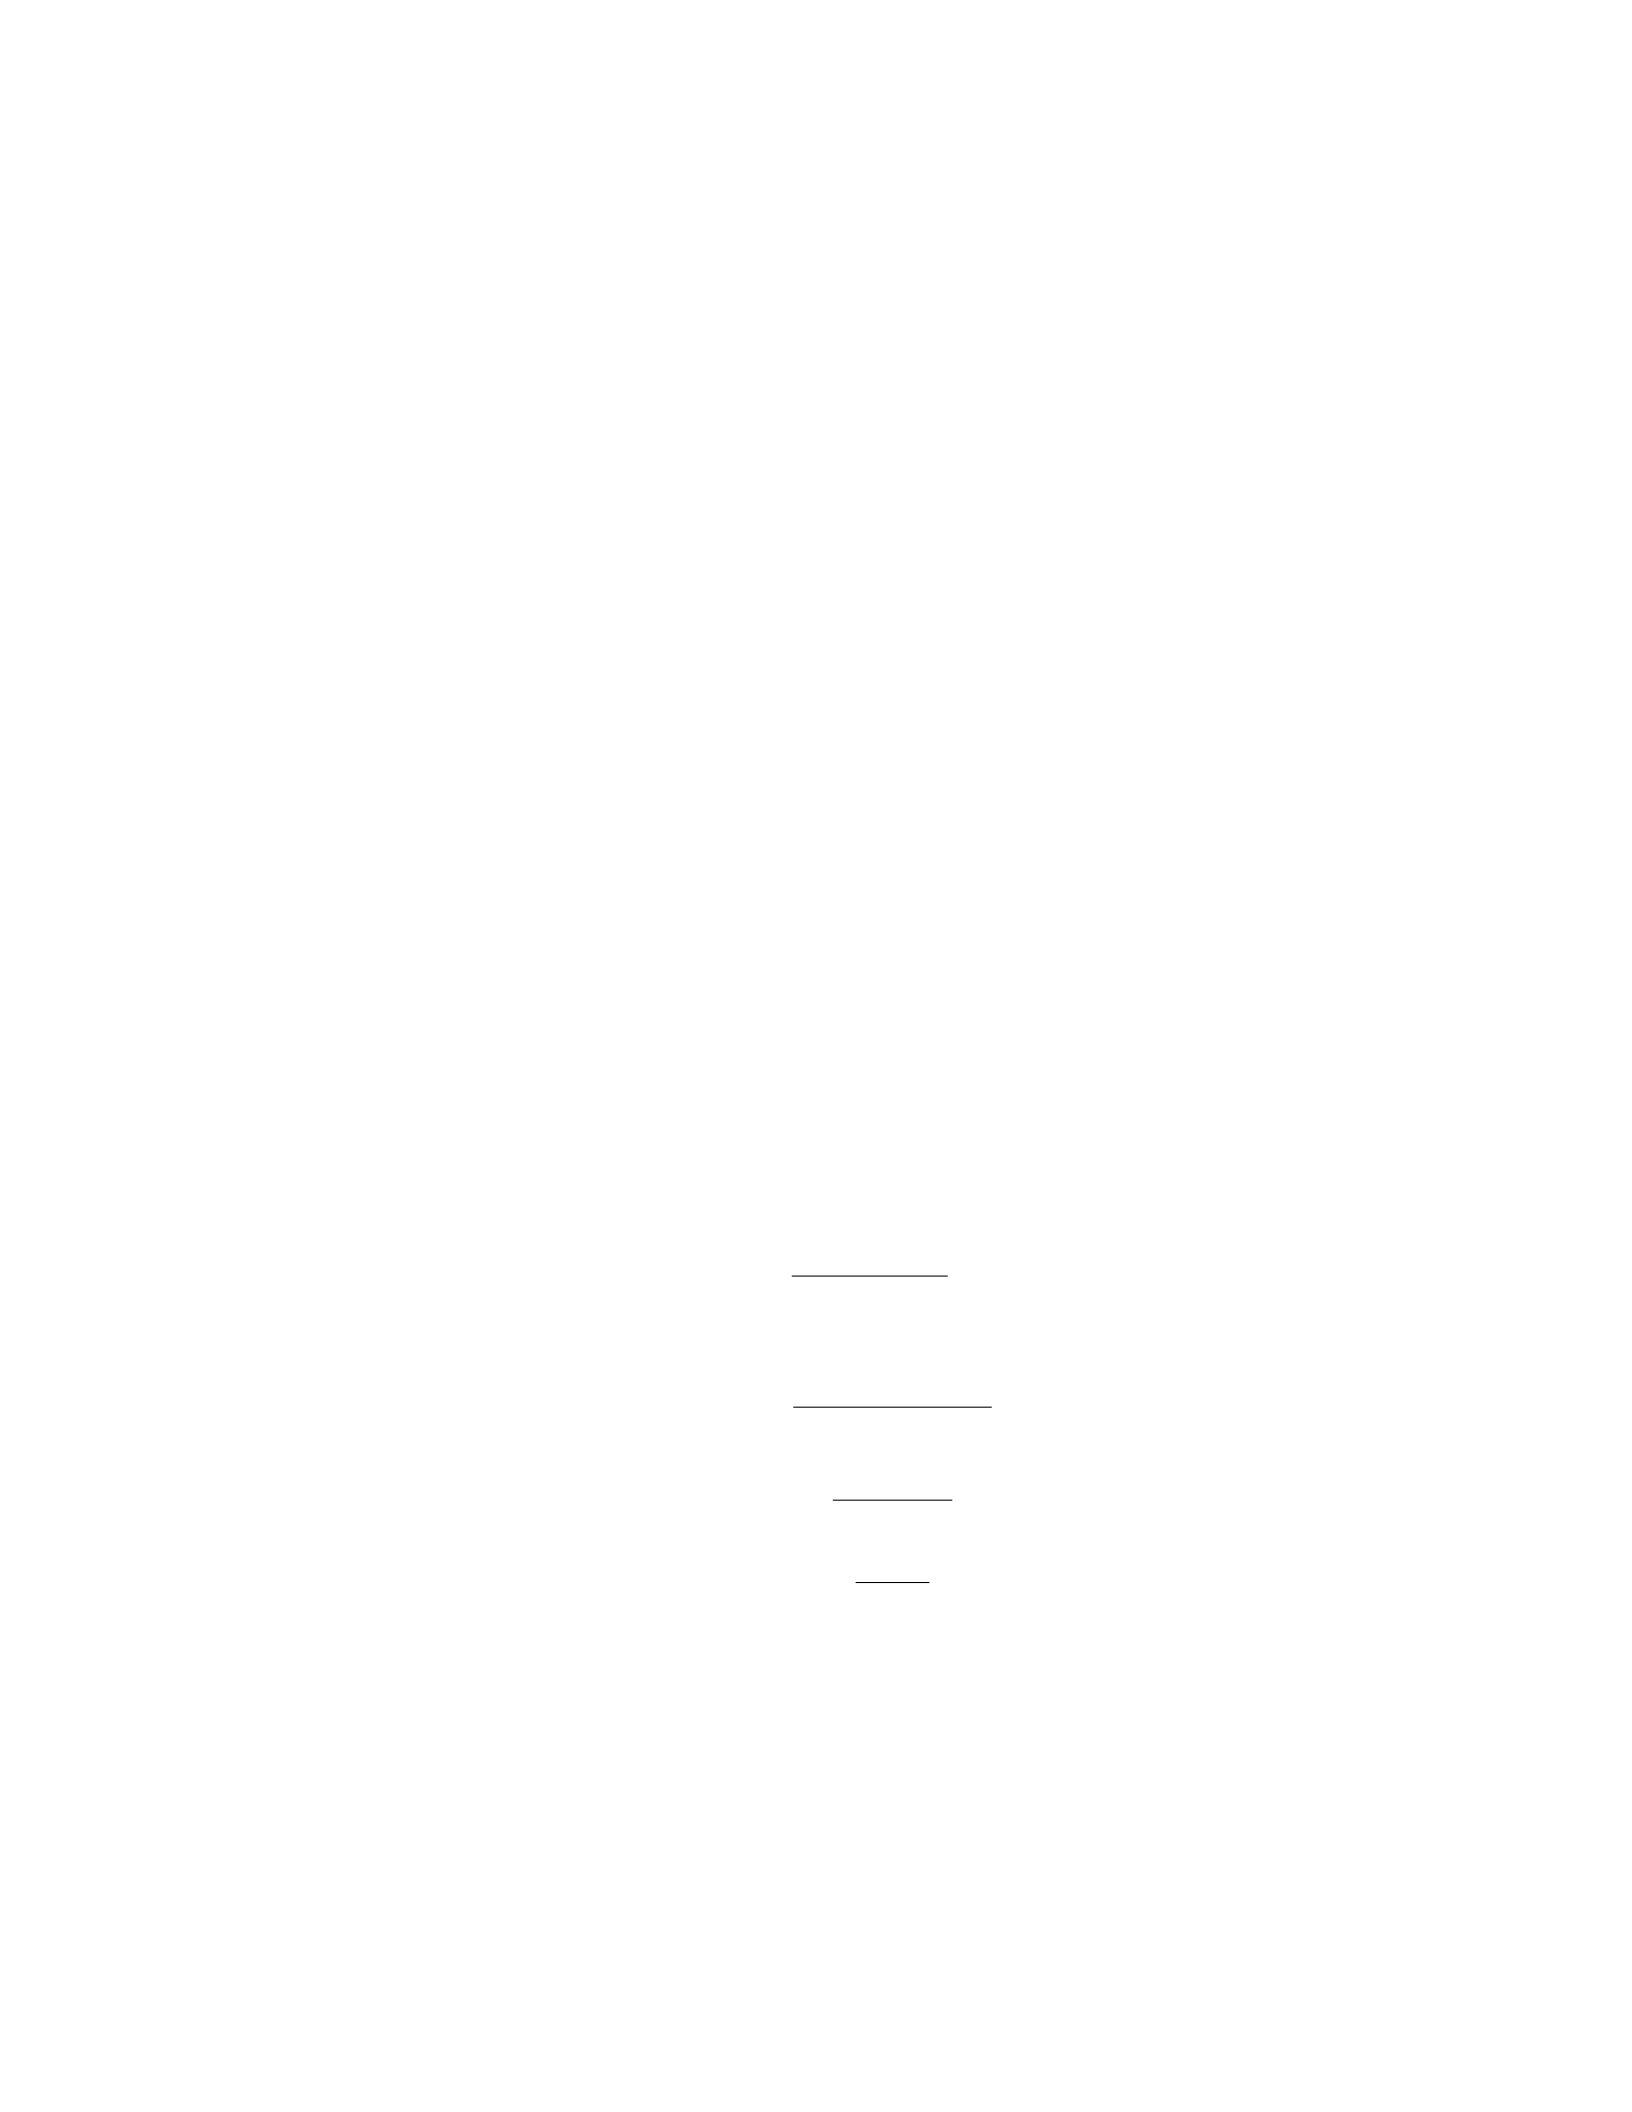
Step 1: Calculate the new fair value of the property after the 15
New Fair Value = Fair Value ×(1 + Increase Percentage)
New Fair Value =
3,500,000 ×(1 + 0.15)
New Fair Value =
3,500,000 ×1.15
New Fair Value =
4,025,000
26
Step 2: Determine the unrealized gain or loss.
Unrealized Gain or Loss = New Fair Value −Fair Value
Unrealized Gain or Loss =
4,025,000 - 3,500,000
Unrealized Gain or Loss =
525,000
Therefore, the new fair value of the property after the 15
Question 35
Question
A company holds an investment in a financial asset classified as available-
for-sale. The fair value of the asset at the end of the reporting period is
450,000.Duetotheuncertainfuturemarketconditions, thecompany′smanagementdecidedtoapplyadiscountrateof8
Solution
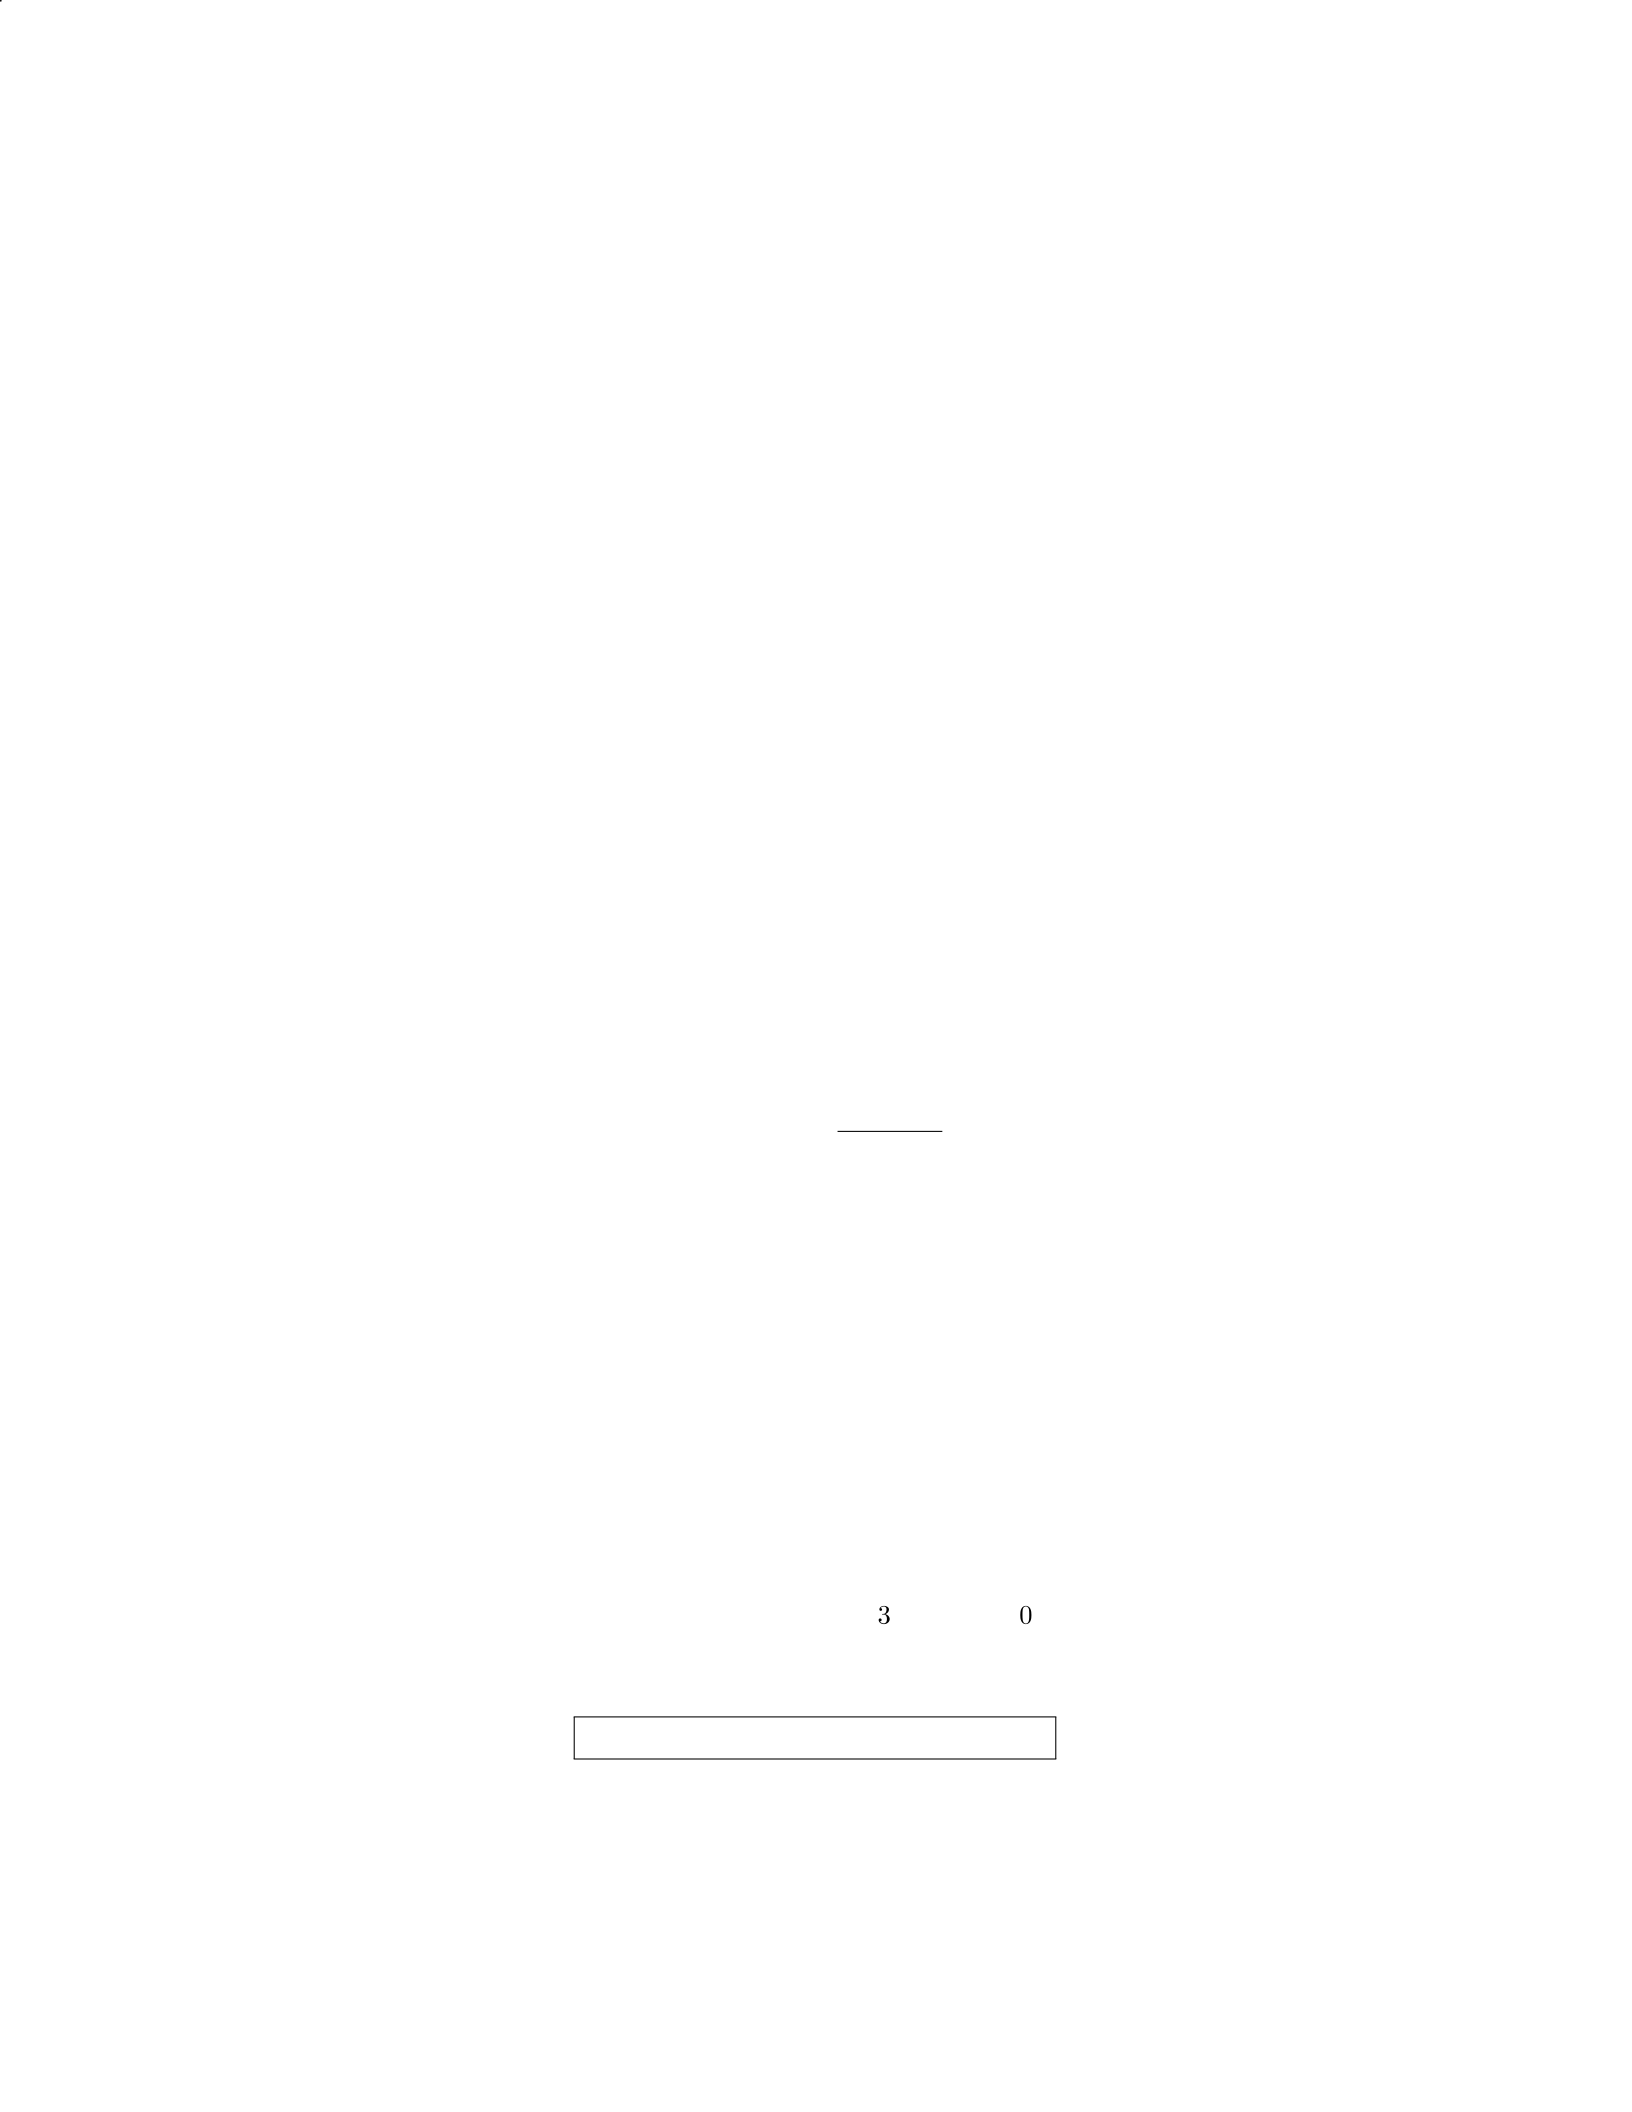
Step 1: Calculate the present value of the expected future cash flows. Let’s
denote: - Pas the present value of the asset - Cas the expected annual cash
flows (50,000)−rasthediscountrate(8−nasthenumberofyears(10)
The present value Pcan be calculated using the formula for the present
value of an annuity:
P=C×1−(1 + r)−n
r
Substitute the values into the formula:
P= 50000 ×1−(1 + 0.08)−10
0.08
P= 50000 ×1−0.4632
0.08
P= 50000 ×0.5368
0.08
P= 50000 ×6.71
P= 335,500
Therefore, the present value of the expected future cash flows is 335,500.
27

Question 2
Question
A company has an investment in a financial asset categorized as a Level 3 fair
value measurement. The initial fair value of the investment was $75,000 and at
the end of the reporting period, the fair value increased to $85,000. During the
same period, the company recorded a net loss of $10,000 due to fluctuations in
fair value. Calculate the amount of the net loss that the company recognized in
its financial statements.
Solution
Step 1: Determine the fair value change of the investment.
The fair value change can be calculated as:
Fair Value Change = Ending Fair Value−Initial Fair Value = $85,000−$75,000 = $10,000
Step 2: Compare the fair value change with the net loss incurred.
Since the fair value change of $10,000 matches the net loss of $10,000, the entire
fair value change is recognized in the financial statements as the amount of the
net loss.
Therefore, the company recognized a net loss of $10,000 in its financial
statements due to fluctuations in fair value.
Question 3
Question
A company has an investment in a private equity fund that is classified as a Level
3 asset. The fair value of the investment increased by 10millionduringtheyear.Explainhowthisincreaseinfairvaluewillimpactthecompany′sfinancialstatementsandprovideexamplesof disclosuresthatthecompanymayneedtoincludeinitsfinancialstatementsrelatedtothisinvestment.
Solution
Step 1: The 10millionincreaseinf airvalueoftheLevel3assetwillimpactthecompany′sf inancialstatementsasfollows :
−IncomeStatement :T heincreaseinf airvaluewillresultinagainbeingrecognizedontheincomestatement.T hisgainwillbereportedaspartof thecompany′snetincomef ortheyear.−
BalanceSheet :T hef airvalueincreasewillalsoimpactthebalancesheet.T heinvestment′scarryingvaluewillbeadjustedtoreflectthenewf airvalue.T hef airvalueadjustmentwillberecordedasacomponentoftheinvestmentaccountwithinthebalancesheet.−
OtherComprehensiveIncome(OCI) : Ifthecompanyhaselectedthefairvalueoptionforthisinvestment, theincreaseinfairvaluewillbypasstheincomestatementandinsteadberecordedasacomponentofOCI.
Step 2: In addition to the impact on the financial statements, the company
may need to include certain disclosures in its financial statements related to this
investment. Examples of disclosures that may be required include: - Description
of the investment: The company may need to provide information about the
nature of the investment, including the terms, conditions, and risks associated
with the investment. - Valuation methodology: The company may need to
disclose the valuation techniques and inputs used to determine the fair value
of the investment. - Sensitivity analysis: The company may need to disclose
how changes in key assumptions or inputs could impact the fair value of the
2
investment. - Level of the fair value hierarchy: The company may need to
disclose the level within the fair value hierarchy at which the investment is
classified (i.e., Level 1, Level 2, or Level 3). - Fair value measurements: The
company may need to disclose the fair value of the investment at the reporting
date and any changes in fair value during the reporting period.
These disclosures are important for users of the financial statements to un-
derstand the company’s exposure to risk and uncertainty related to the invest-
ment in the private equity fund.
Question 4
Question
A company acquired a patent for $500,000 and estimated its useful life to be 10
years. At the end of the first year, the company assessed the fair value of the
patent to be $480,000. Determine the journal entry to record the impairment
loss on the patent.
Solution
Step 1: Calculate the annual depreciation expense of the patent. Given the
patent was acquired for $500,000 and has an estimated useful life of 10 years,
the annual depreciation expense is:
Annual Depreciation Expense = $500,000
10 years = $50,000 per year
Step 2: Determine the impairment loss. The impairment loss is calculated
as the difference between the carrying value of the patent and its fair value.
Since the fair value at the end of the first year is $480,000, the carrying value
of the patent is:
Carrying Value = Original Cost −Accumulated Depreciation
Carrying Value = $500,000 −$50,000 = $450,000
Impairment Loss = Carrying Value −Fair Value = $450,000 −$480,000 =
−$30,000
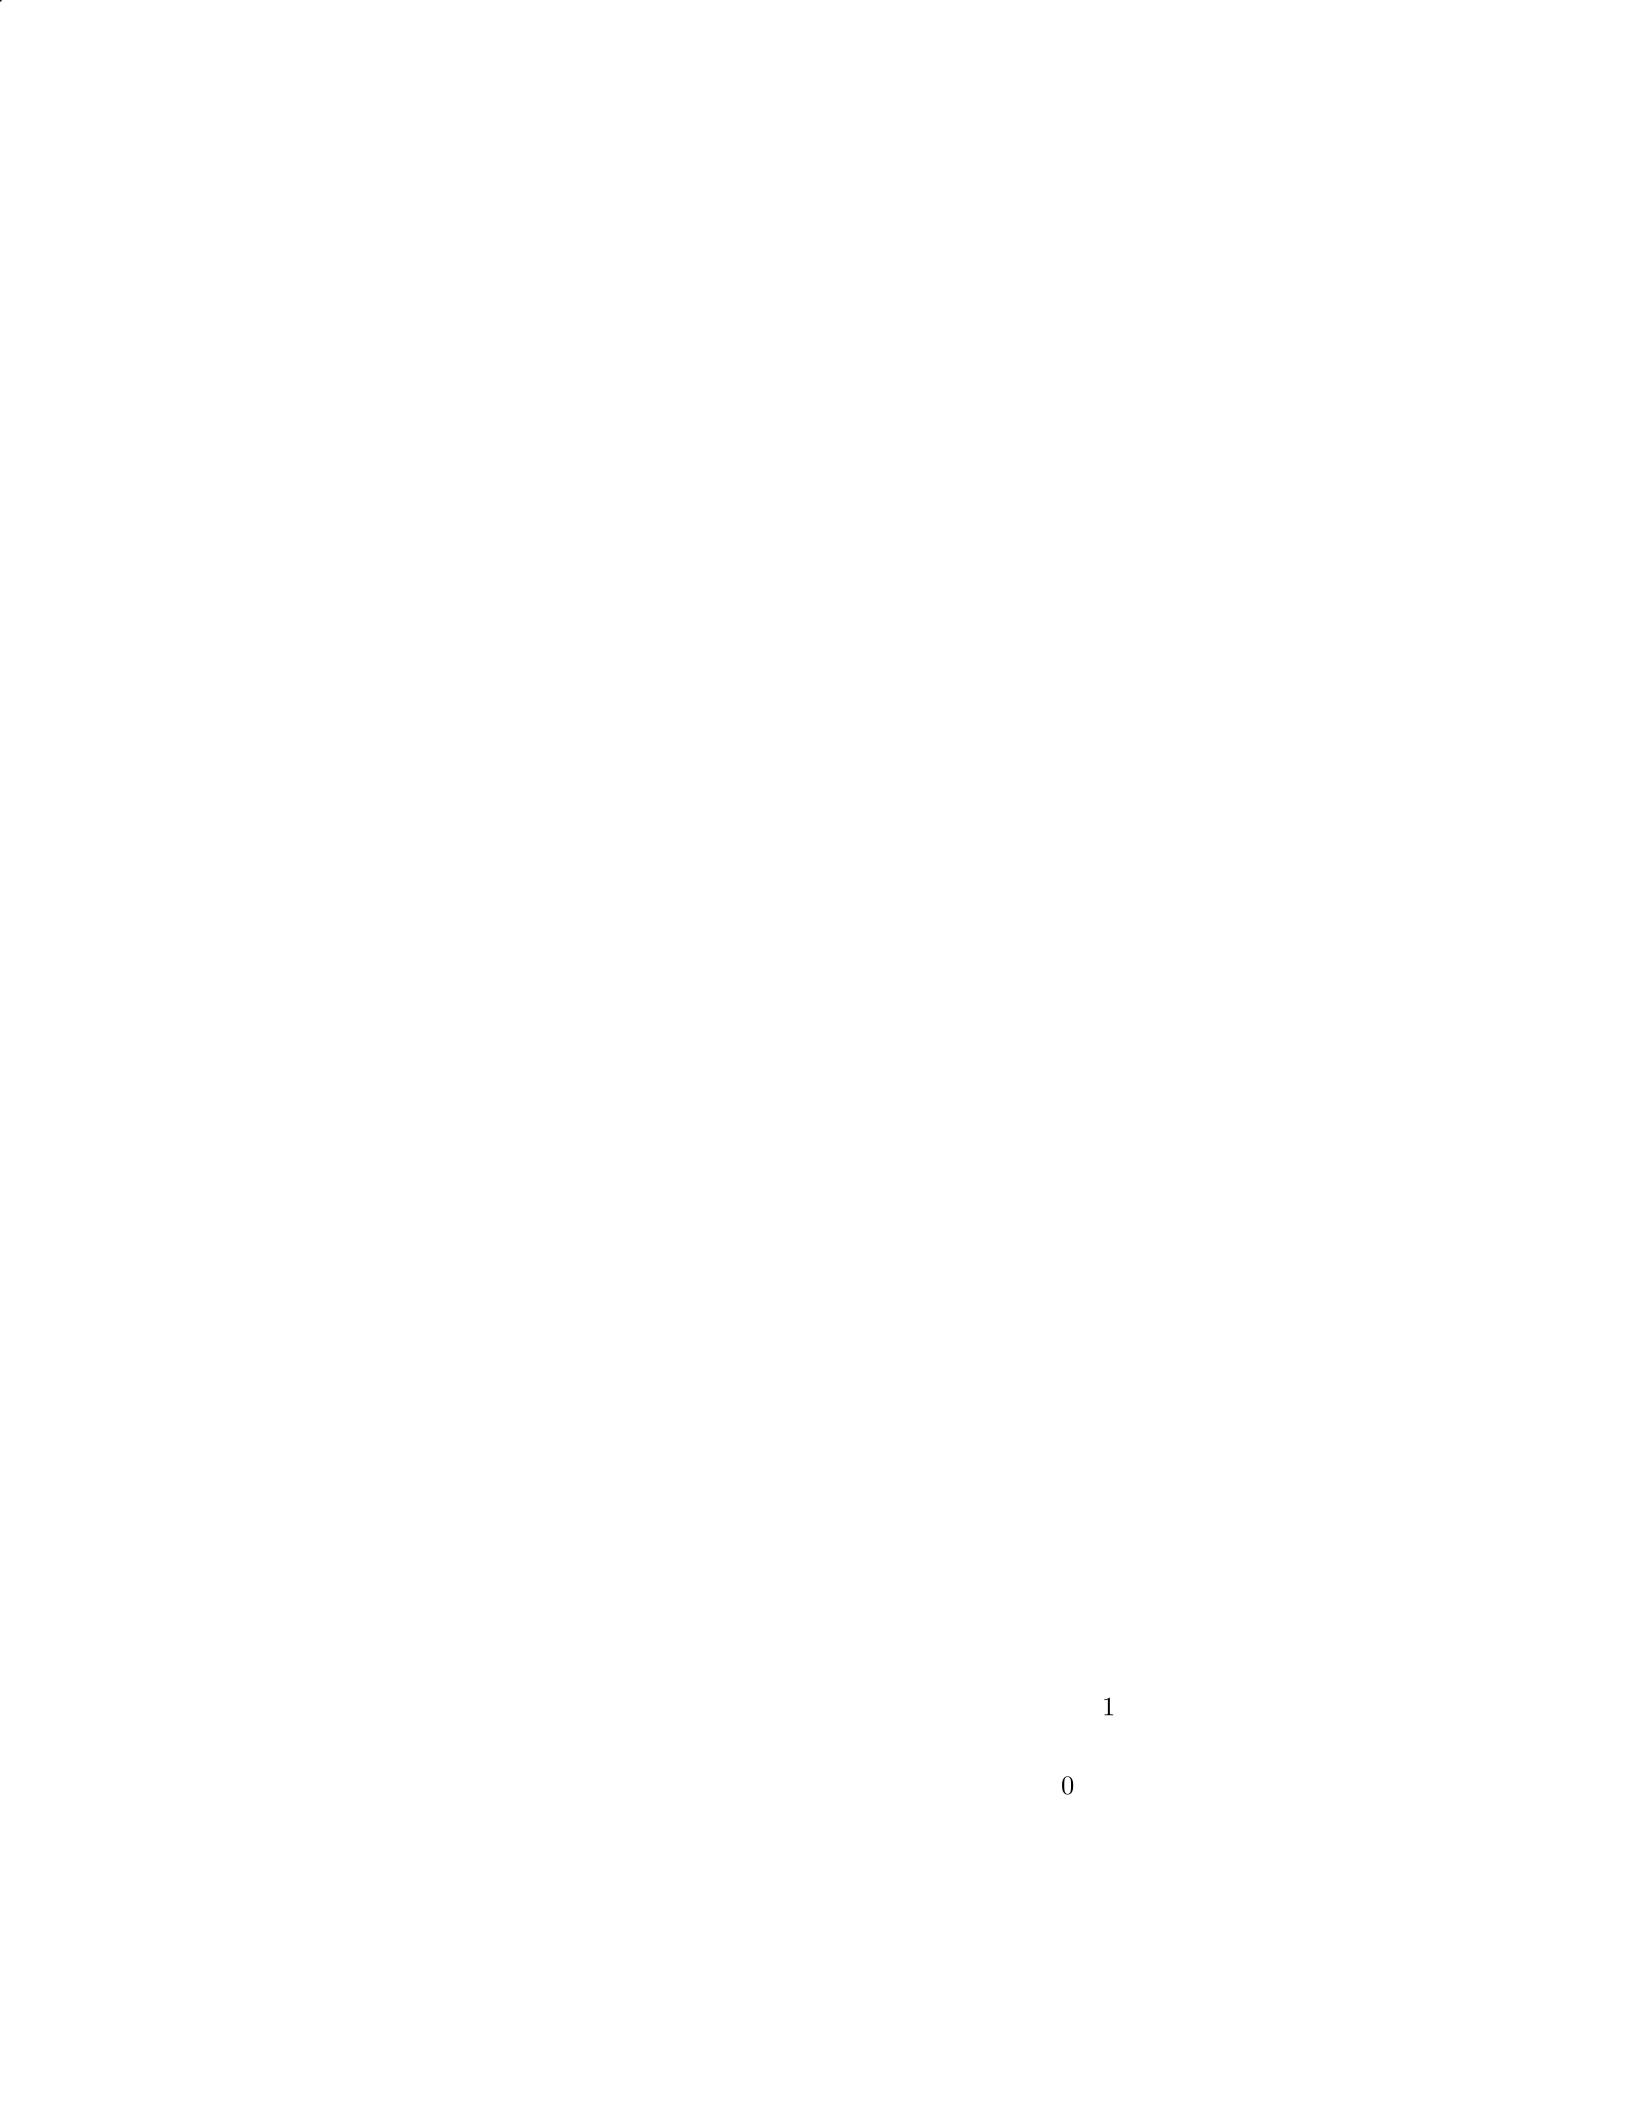
Step 3: Record the journal entry to record the impairment loss on the patent.
The journal entry to record the impairment loss on the patent is:
Impairment Loss →Patent
$
30,000 →
$
30,000
Therefore, the journal entry to record the impairment loss on the patent is:
Impairment Loss $30,000Patent $30,000
3
Question 5
Question
Company XYZ holds an investment in a start-up company. The fair value of the
investment at the end of the reporting period is 50,000.Duringthenextreportingperiod, thefairvalueincreasesto60,000.
At the end of the following reporting period, the fair value decreases to 55,000.CalculatethegainorlossrecognizedineachofthereportingperiodsifCompanyXY Zusesthefairvaluethroughprofitorlossmeasurementmethod.
Solution
To calculate the gain or loss recognized in each reporting period using the fair
value through profit or loss measurement method, we need to compare the fair
value of the investment at the end of each period with the fair value recorded
in the previous period.
Step 1: Calculate the gain or loss recognized in the first reporting period.
The fair value of the investment at the end of the first reporting period is
50,000, andtherewasnof airvaluerecordedinthepreviousperiod.
Therefore, the gain or loss recognized in the first reporting period is 50,000−0
= 50,000gain.
Step 2: Calculate the gain or loss recognized in the second reporting period.
The fair value of the investment at the end of the second reporting period is
60,000, andthefairvaluerecordedinthepreviousperiodwas50,000.
Therefore, the gain or loss recognized in the second reporting period is
60,000−50,000 = 10,000gain.
Step 3: Calculate the gain or loss recognized in the third reporting period.
The fair value of the investment at the end of the third reporting period is
55,000, andthefairvaluerecordedinthepreviousperiodwas60,000.
Therefore, the gain or loss recognized in the third reporting period is 55,000−60,000
= 5,000loss.
Question 6
Question
A company holds an investment in a financial asset that is measured at fair value
through other comprehensive income (FVOCI). At the end of the reporting pe-
riod, the fair value of the investment has increased by 10,000.P rovidejournalentriestorecordthefairvalueadjustmentandexplainhowtheseentrieswouldaff ectthefinancialstatements.
Solution
Step 1: To record the fair value adjustment in the investment: Let’s assume the
initial investment was 100,000.
Investment in Financial Asset(FVOCI) →Increase by
$
10,000
Other Comprehensive Income →Increase by
$
10,000
4
Journal Entry:
Account Debit
Credit
Investment in Financial Asset (FVOCI)
$10,000
Other Comprehensive Income $10,000
Step 2: Impact on Financial Statements: - The increase in the fair value
of the investment is recognized in other comprehensive income rather than the
income statement. - The investment carrying amount on the balance sheet
will reflect the higher fair value, leading to an increase in total comprehensive
income.
These entries reflect the mark-to-market accounting treatment of the invest-
ment at FVOCI.
Question 7
Question
A company holds an investment in a security that is classified as Level 3 under
the fair value hierarchy. At the end of the reporting period, the security has
a fair value of 150,000.Duringtheperiod, thecompanyrecordedalossof 20,000 in
the fair value of the security. Calculate the initial cost of the investment.
Solution
Step 1: Define the components of fair value and fair value hierarchy: - Level
1 inputs are quoted prices in active markets for identical assets or liabilities. -
Level 2 inputs are inputs other than quoted prices in active markets that are
directly or indirectly observable. - Level 3 inputs are unobservable inputs.
Step 2: Recall the fair value change formula:
Ending Fair Value = Beginning Fair Value+Additional Investments/Gains−Distributions/Losses
Step 3: Given that the security is classified as Level 3 and the fair value at
the end of the reporting period is 150,000withaf airvaluelossof20,000, we can
now calculate the initial cost of the investment:
Beginning Fair Value = Ending Fair Value−Additional Investments/Gains+Distributions/Losses
Beginning Fair Value =
150,000 - 0+20,000
5

Beginning Fair Value =
170,000
Therefore, the initial cost of the investment was 170,000.
Question 8
Question
A company is valuing an investment property using the fair value model. At the
end of the reporting period, the property has a fair value of 2,500,000.T hepropertywasinitiallyrecognizedat2,000,000,
and has accumulated depreciation of 400,000.Howshouldthecompanyaccountf orthechangeinfairvalueof theinvestmentproperty?
Solution
Step 1: Calculate the carrying amount of the investment property before the
change in fair value. The carrying amount of the investment property is calcu-
lated as the initial recognition cost minus accumulated depreciation: Carrying
amount = Initial recognition cost - Accumulated depreciation Carrying amount
= 2,000,000−400,000 Carrying amount = 1,600,000
Step 2: Determine the fair value change of the investment property. The fair
value change of the investment property is calculated as the fair value at the end
of the reporting period minus the carrying amount before the change: Fair value
change = Fair value - Carrying amount Fair value change = 2,500,000−1,600,000
Fair value change = 900,000
Step 3: Account for the fair value change in the investment property. Since
the fair value of the investment property has increased, the company recognizes
this change in fair value as a revaluation surplus in other comprehensive income
and as a revaluation reserve within equity.
Therefore, the company should recognize the fair value change of 900,000asarevaluationsurplusof900,000
in other comprehensive income and as a revaluation reserve within equity.
Question 9
Question
Assume a company has an investment in a financial asset classified as Level 3
fair value measurement. The fair value of the asset was determined using unob-
servable inputs, making it difficult to establish an accurate valuation. Discuss
the challenges the company may face in determining the fair value of this asset.
6
Solution
To determine the fair value of an asset classified as Level 3 fair value measure-
ment, a company may face several challenges due to the use of unobservable
inputs. These challenges include:
Step 1: Lack of Market Data
Because Level 3 uses unobservable inputs, there may be a lack of market
data available to compare and validate the fair value.
Without reliable market data, determining the fair value becomes subjec-
tive and may lead to potential inaccuracies.
Step 2: Subjectivity in Valuation
The use of unobservable inputs in Level 3 fair value measurement relies
heavily on management’s judgment.
Different management teams may have varying opinions on the valuation
of the asset, leading to inconsistencies and potential biases.
Step 3: Potential for Manipulation
The subjective nature of Level 3 fair value measurements can create op-
portunities for manipulation.
There is a risk that management may intentionally manipulate the fair
value of the asset to achieve certain financial reporting objectives.
Step 4: Complexity of Valuation Models
Level 3 fair value measurements often involve complex valuation models
to estimate the fair value of the asset.
These models may be difficult to understand and require specialized ex-
pertise, making it challenging to validate the accuracy of the valuation.
Step 5: Disclosure Requirements
Companies are required to disclose the significant unobservable inputs
used in Level 3 fair value measurements.
Ensuring adequate transparency in these disclosures can be challenging,
especially if the inputs are highly sensitive or proprietary.
In conclusion, determining the fair value of an asset classified as Level 3 fair
value measurement poses various challenges related to the lack of market data,
subjectivity in valuation, potential for manipulation, complexity of valuation
models, and disclosure requirements.
7

Question 10
Question
A company holds an investment in a private company for which there is no
active market. The fair value of the investment needs to be determined for the
company’s financial statements. Discuss the techniques or methods that can be
used to estimate the fair value of the investment.
Solution
To estimate the fair value of an investment in a private company where there
is no active market, various techniques or methods can be used. Here are some
commonly used methods:
Step 1: Market Approach One approach is to use the market approach,
which involves analyzing recent transactions involving similar investments in
comparable companies. This can provide a benchmark for valuing the invest-
ment in question.
Step 2: Income Approach Another method is the income approach, which
involves estimating the future cash flows expected from the investment and
discounting them back to their present value. This method often involves the
use of techniques such as discounted cash flow (DCF) analysis.
Step 3: Cost Approach The cost approach involves estimating the cost
to replace the investment or recreate it with a similar investment. This method
may be used when there is little information available about the market or
income potential of the investment.
Step 4: Option Pricing Model In some cases, an option pricing model
can be used to estimate the fair value of an investment, particularly if the
investment has option-like characteristics such as conversion rights or other
embedded options.
Step 5: Weighted Average Method The weighted average method in-
volves assigning weights to the different valuation methods based on their rele-
vance and reliability, and then calculating a weighted average fair value estimate.
Using a combination of these techniques can help provide a more accurate
estimate of the fair value of an investment in a private company. It is important
to carefully evaluate the assumptions and inputs used in each method to ensure
the final estimate is as reliable as possible.
Question 11
Question
A company holds a financial asset that is measured at fair value through profit
or loss. The fair value of the asset has increased significantly since the initial
recognition. Discuss how this increase in fair value should be accounted for
according to the fair value measurement standard.
8
Solution
To account for the increase in fair value of a financial asset that is measured at
fair value through profit or loss, we must consider the fair value measurement
standard (IFRS 13). The standard provides guidance on the measurement of
fair value and the recognition of changes in fair value in financial statements.
Step 1: Recognize the increase in fair value When the fair value of a
financial asset increases significantly, the increase should be recognized in the
income statement. This means that the company will record a gain on the asset
in the income statement, reflecting the increase in value.
Step 2: Determine the treatment of the gain The treatment of the gain
will depend on the nature of the financial asset and the company’s accounting
policies. In most cases, the gain will be recognized in the income statement as
a separate line item under revenues or gains. However, if the financial asset is
held for trading, the gain may be included in the trading income.
Step 3: Disclose the fair value measurement and gains The com-
pany must also disclose the fair value measurement of the financial asset in
the financial statements. This includes providing information on the valuation
techniques used and the inputs to those techniques. Additionally, the company
should disclose the gains recognized on the asset in the notes to the financial
statements.
In conclusion, when the fair value of a financial asset measured at fair value
through profit or loss increases significantly, the increase should be recognized
in the income statement as a gain. The treatment of the gain and the disclosure
requirements should be in accordance with the fair value measurement standard
(IFRS 13).
Question 12
Question
Company XYZ holds an investment in a publicly traded company, ABC Corp.
The fair value of this investment is determined using Level 1 inputs. At the be-
ginning of the year, the fair value of the investment was 50,000.Duringtheyear, ABCCorpreportedbetterthanexpectedfinancialresults, causingitsstockpricetorise.Attheendoftheyear, thefairvalueoftheinvestmentwasdeterminedtobe60,000.
Discuss how the change in fair value of the investment in ABC Corp should
be accounted for according to Fair Value Measurement standards.
Solution
Step 1: According to Fair Value Measurement standards, changes in fair value
should be recognized in the company’s financial statements through either profit
or loss or other comprehensive income, depending on the classification of the
investment.
Step 2: If the investment is classified as at fair value through profit or
loss (FVTPL), the change in fair value will be recognized in profit or loss in
9

the income statement. In this case, the 10,000increaseinf airvalue(60,000 -
50,000)shouldberecognizedasagaininprofitorlossinthecurrentperiod.
Step 3: If the investment is classified as available-for-sale (AFS), the change
in fair value will be recognized in other comprehensive income. The 10,000increaseinfairvaluewouldberecognizedasagaininothercomprehensiveincomewithinequity.
Step 4: It is important to note that the accounting treatment of changes in
fair value should be consistent with the initial classification of the investment
and the company’s accounting policies for fair value measurement.
Question 13
Question
A company owns an investment in a privately held company that is classified
as a Level 3 asset for fair value measurement. The fair value of the investment
is determined using a discounted cash flow model, which includes significant
unobservable inputs.
Explain the concept of fair value measurement for Level 3 assets and discuss
the challenges involved in applying this measurement approach.
Solution
Step 1: Concept of Fair Value Measurement for Level 3 Assets Level
3 assets are financial instruments or investments that are not traded in active
markets and have unobservable inputs for their fair value measurement. The fair
value of Level 3 assets is determined using valuation techniques that incorporate
significant unobservable inputs. These inputs are based on the best information
available in the circumstances and may include the company’s own data or
assumptions. Because of the lack of market activity and reliance on unobservable
inputs, Level 3 assets are considered the most difficult to value.
Step 2: Challenges in Applying Fair Value Measurement for Level
3 Assets 1. Subjectivity: The use of unobservable inputs in valuation models
introduces subjectivity into the fair value measurement process. Different val-
uation models or assumptions can result in significantly different fair values for
the same asset.
2. Reliability: The reliability of fair value measurements for Level 3 assets
can be questioned due to the subjective nature of the inputs used. This can
lead to concerns about the accuracy of reported financial information.
3. Complexity: Valuing Level 3 assets often involves complex valuation
techniques such as discounted cash flow models or option pricing models. These
models require specialized expertise and significant resources to apply effectively.
4. Verification: Since Level 3 assets have significant unobservable inputs,
there may be limited external data or benchmarks available to verify the fair
value measurements. This lack of verifiability can raise concerns about the
accuracy of the reported values.
10

5. Disclosure: Companies are required to disclose information about the
inputs and significant judgments used in the fair value measurement of Level 3
assets. However, determining which information to disclose and how to commu-
nicate the uncertainty of the measurements can be challenging.
Overall, fair value measurement for Level 3 assets presents unique challenges
due to the reliance on unobservable inputs and the complexity of valuation
techniques involved.
Question 14
Question
A company holds an investment in a privately held company that is accounted
for at fair value through profit or loss. The fair value of the investment at the
beginning of the year was $350,000. During the year, the fair value increased to
$400,000. At the end of the year, the fair value further increased to $420,000.
Given this information, calculate the fair value gain or loss recognized in the
company’s profit or loss for the year.
Solution
Step 1: Calculate the fair value gain or loss recognized in profit or loss for the
year. First, we need to determine the fair value gain or loss recognized in the
company’s profit or loss for the year. This can be calculated by comparing the
fair value at the end of the year with the fair value at the beginning of the year.
Fair Value Gain or Loss = Fair Value at End of Year−Fair Value at Beginning of Year
Step 2: Substitute the given values into the formula.
Fair Value Gain or Loss = $420,000 −$350,000
Step 3: Calculate the fair value gain or loss.
Fair Value Gain or Loss = $70,000
Therefore, the fair value gain recognized in the company’s profit or loss for
the year is $70,000.
Question 15
Question
A company is valuing a financial instrument using the fair value measurement
technique. The financial instrument has a level 3 fair value hierarchy, meaning
that significant unobservable inputs are used to determine its fair value. Explain
how the company should incorporate market participant assumptions into the
fair value measurement process.
11

Solution
Step 1: Understand Market Participant Assumptions
Market participant assumptions are used to determine the price that would be
received to sell an asset or paid to transfer a liability in an orderly transac-
tion between market participants at the measurement date. These assumptions
should reflect the perspective of market participants, not those of a specific
entity.
Step 2: Identify Market Participants
The company should identify the relevant market participants for the financial
instrument being valued. This involves understanding who the potential buyers
or sellers may be in the market for the asset or liability.
Step 3: Consider Market Participant Views
The company should consider the assumptions that market participants would
use in valuing the financial instrument. This includes factors such as risk pref-
erences, expected cash flows, and other market conditions that would impact
the fair value.
Step 4: Incorporate Market Participant Assumptions
To incorporate market participant assumptions into the fair value measure-
ment process, the company should adjust its valuation model to reflect the
assumptions that market participants would use. This may involve modifying
the discount rate, cash flow projections, or other inputs to align with market
participant views.
Step 5: Assess Consistency
The company should ensure that the market participant assumptions used are
consistent with the inputs and information available. Any discrepancies should
be carefully evaluated and resolved to arrive at a reliable fair value measure-
ment. This may involve additional disclosures about the assumptions used in
the valuation process.
Question 16
Question
A company holds an investment in a financial asset classified as fair value
through profit or loss. The fair value at the end of the reporting period is
185,000.Duringtheyear, thefairvalueincreasedby25,000, and the company rec-
ognized a gain of 15,000inprofitorlossrelatingtothisinvestment.Calculatetheinitialfairvalueof theinvestmentandthefairvaluechangerecognizedinothercomprehensiveincome.
Solution
Step 1: Let the initial fair value of the investment be x. Step 2: The fair value at
the end of the reporting period is 185,000, whichistheinitialfairvalueplusthef airvaluechange :
x+ 25,000 = 185,000
x= 185,000 −25,000
x= 160,000
12
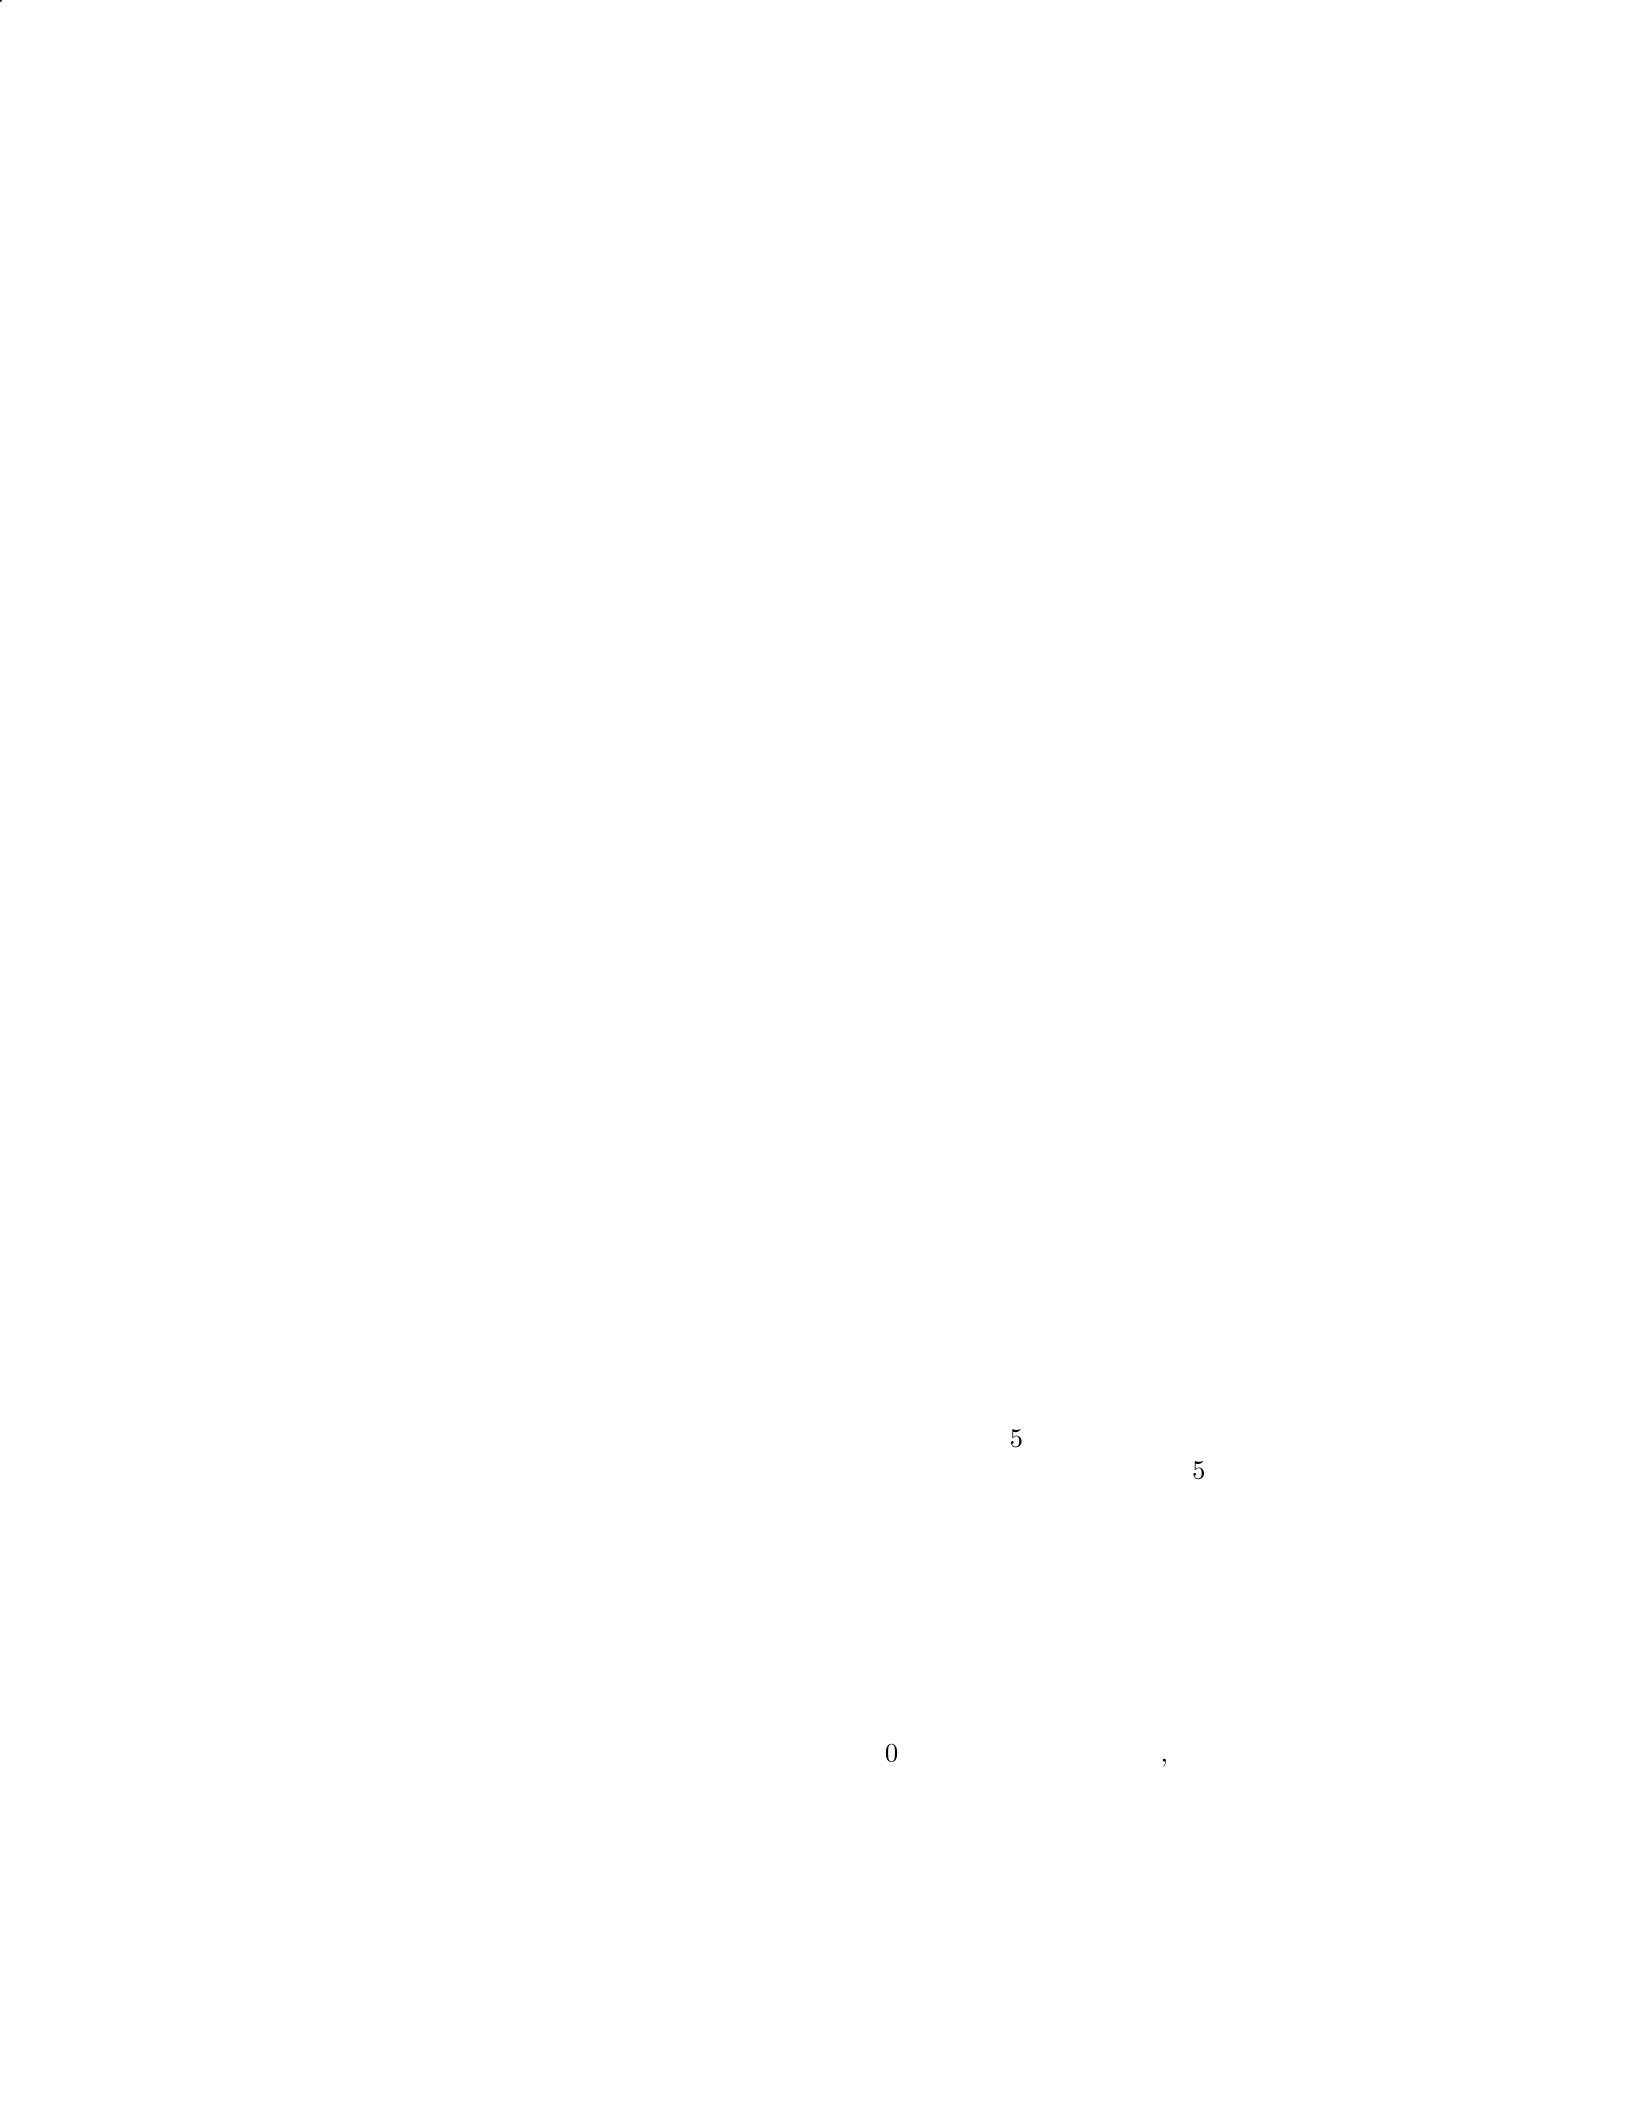
The initial fair value of the investment is 160,000.
Step 3: The gain recognized in profit or loss is 15,000, whichmeansthatthegainrecognizedinothercomprehensiveincomeisthedifference :
25,000 −15,000 = 10,000 The fair value change recognized in other compre-
hensive income is 10,000.
Question 17
Question
A company measures its financial assets at fair value through other comprehen-
sive income. On December 31, 2021, the fair value of the assets increased by
20,000.Determinetheimpactofthisincreaseonthecompany′scomprehensiveincomeandequityassumingnotaxesareapplicable.
Solution
Step 1: Understand the impact on other comprehensive income (OCI) The
increase in fair value of financial assets through OCI will result in a gain, which
is reported in OCI. This will impact the company’s comprehensive income.
Step 2: Calculate the impact on OCI The increase in fair value of 20,000willresultinagainof20,000
in OCI.
Step 3: Understand the impact on equity Since OCI is a component of equity,
the 20,000gaininOCIwillalsoincreasethecompany′sequity.
Step 4: Record the impact The journal entry to record the increase in fair
value of financial assets through OCI would be:
OCI →Gain on financial assets →+$20,000
As a result, both the comprehensive income and equity of the company will
increase by 20,000.
Question 18
Question
A company holds an investment in a startup valued at
$
500,000. Due to recent
market conditions, the fair value of the investment has decreased to
$
450,000.
The company decides to write down the value of the investment to its fair
value. Calculate the impact of this impairment loss on the company’s financial
statements.
Solution
Step 1: Determine the Impairment Loss To calculate the impairment loss, we
need to find the difference between the carrying value of the investment and its
fair value. In this case: Carrying value =
$
500,000 Fair value =
$
450,000
13
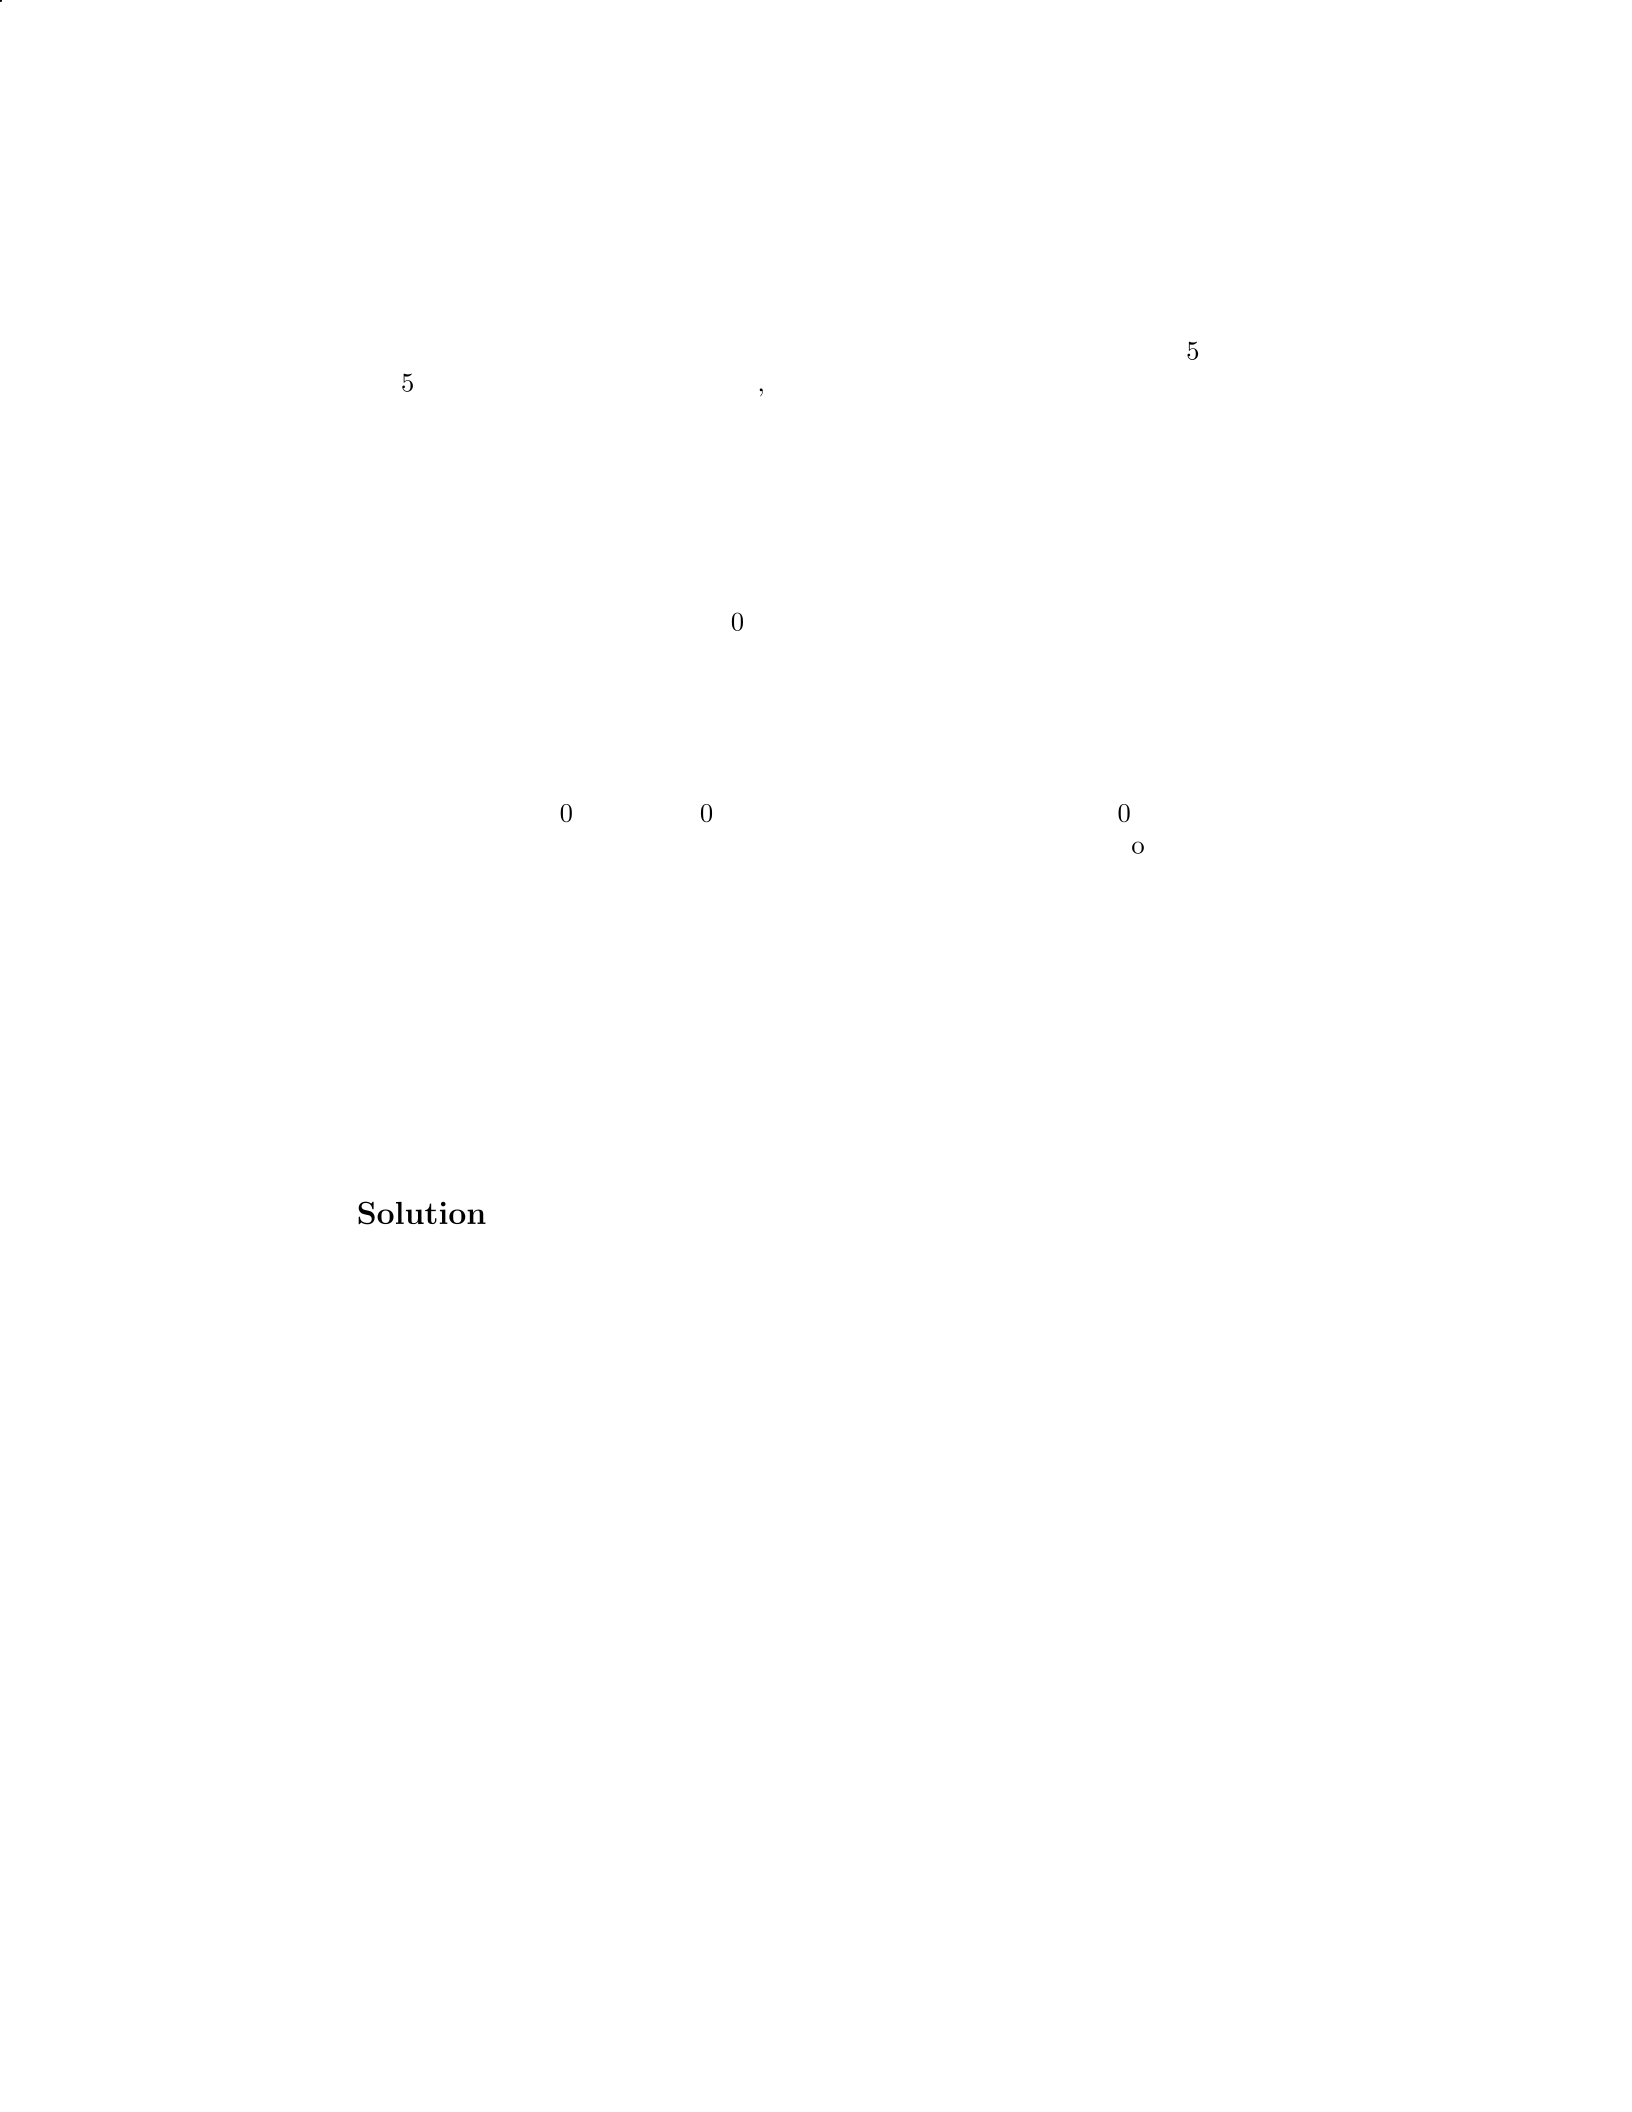
Impairment Loss = Carrying value - Fair value Impairment Loss =
$
500,000
-
$
450,000 Impairment Loss =
$
50,000
Step 2: Record the Impairment Loss The impairment loss needs to be
recorded on the company’s financial statements to reflect the decrease in the
value of the investment. The journal entry to record the impairment loss is as
follows:
Impairment Loss →Income Statement
The impairment loss of
$
50,000 will reduce the company’s net income for
the period.
Step 3: Update the Carrying Value of the Investment After recording the
impairment loss, the carrying value of the investment on the balance sheet needs
to be updated to reflect the new fair value. The revised carrying value will be:
Revised Carrying value = Carrying value - Impairment Loss Revised Carry-
ing value =
$
500,000 -
$
50,000 Revised Carrying value =
$
450,000
The revised carrying value of the investment is now
$
450,000 on the com-
pany’s balance sheet.
Question 19
Question
Company A holds an investment in Company B classified as a level 2 asset under
fair value measurement. At the end of the fiscal year, Company A estimates the
fair value of its investment in Company B to be 5,000,000.However, duetorecentmarketfluctuations, CompanyA′smanagementisconsideringreclassifyingtheinvestmentaslevel3.Discussthef actorsthatshouldbeconsideredbyCompanyAindeterminingwhethertoreclassif ytheinvestmentaslevel3underf airvaluemeasurement.
Solution
To determine whether to reclassify the investment in Company B as level 3
under fair value measurement, Company A should consider several factors.
Step 1: Company A should examine the availability and reliability of ob-
servable inputs for the fair value measurement. Level 3 assets are valued using
unobservable inputs and are considered the least reliable. If there are significant
observable inputs available, it may be more appropriate to keep the investment
classified as level 2.
Step 2: Company A should assess the impact of recent market fluctuations
on the fair value of the investment. If the recent fluctuations have caused
significant uncertainty and volatility in the fair value estimation, it may be
more appropriate to reclassify the investment as level 3 to reflect the increased
level of uncertainty.
Step 3: Company A should evaluate the level of judgment involved in the
fair value measurement. Level 3 assets require a higher degree of judgment
compared to level 2 assets. If there is a high level of subjectivity involved in
determining the fair value of the investment, it may be more appropriate to
reclassify it as level 3.
14
Step 4: Company A should consider the potential impact of reclassification
on financial statement users. Reclassifying the investment as level 3 may signal
increased risk and uncertainty to investors and other stakeholders. Company
A should weigh the benefits of increased transparency against the potential
negative perceptions associated with a level 3 classification.
By carefully considering these factors, Company A can make an informed
decision on whether to reclassify its investment in Company B as a level 3 asset
under fair value measurement.
Question 20
Question
You are a financial analyst tasked with determining the fair value of a particular
investment property. The property generates rental income and has a potential
for future development. Discuss the various factors and assumptions you would
consider in determining the fair value of the investment property.
Solution
To determine the fair value of the investment property, several factors and as-
sumptions need to be considered. Below are the key points to consider:
Step 1: Evaluate Property Characteristics
Analyze the location of the property: Is it in a prime area with high
demand?
Consider the size of the property and any unique features that could im-
pact its value.
Assess the condition of the property and any necessary repairs or upgrades.
Step 2: Rental Income
Evaluate the current rental income generated by the property.
Consider the stability and reliability of the rental income stream.
Factor in any potential vacancies or rent fluctuations in the future.
Step 3: Development Potential
Assess the potential for future development of the property.
Evaluate any zoning regulations or restrictions that could impact devel-
opment plans.
Consider the timeline and costs associated with development.
Step 4: Market Conditions
15
Analyze current market conditions, including supply and demand for sim-
ilar properties.
Consider trends in property values and rental rates in the area.
Take into account any external factors that could impact property values,
such as economic conditions or regulatory changes.
Step 5: Discount Rate
Determine an appropriate discount rate to calculate the present value of
future cash flows.
Consider the risk associated with the investment property and adjust the
discount rate accordingly.
By carefully evaluating these factors and making reasonable assumptions,
you can determine a fair value estimate for the investment property.
Question 21
Question
A company holds an investment in a financial instrument that is classified as a
Level 2 asset under the fair value hierarchy. The fair value of the investment was
determined to be 150,000attheendofthereportingperiod.Duringtheyear, thecompanyreceivedacashdividendof3,000
and recognized a loss of 1,500infairvaluechangesontheinvestment.Calculatethecarryingamountoftheinvestmentatthebeginningofthereportingperiod.
Solution
Step 1: Calculate the total cash flows related to the investment. The total cash
flows related to the investment can be calculated by summing the cash dividend
received and the loss recognized in fair value changes: Total cash flows = Cash
dividend + Fair value loss Total cash flows = 3,000−1,500 Total cash flows =
1,500
Step 2: Use the total cash flows to adjust the fair value of the investment.
Since the total cash flows represent the net cash flows related to the investment,
we can adjust the fair value of the investment by adding the total cash flows:
Adjusted fair value = Fair value + Total cash flows Adjusted fair value =
150,000+1,500 Adjusted fair value = 151,500
Step 3: Determine the carrying amount of the investment at the beginning of
the reporting period. The carrying amount of the investment at the beginning
of the reporting period is equal to the adjusted fair value minus the total cash
flows received during the year: Carrying amount = Adjusted fair value - Total
cash flows Carrying amount = 151,500−1,500 Carrying amount = 150,000
Therefore, the carrying amount of the investment at the beginning of the
reporting period was 150,000.
16
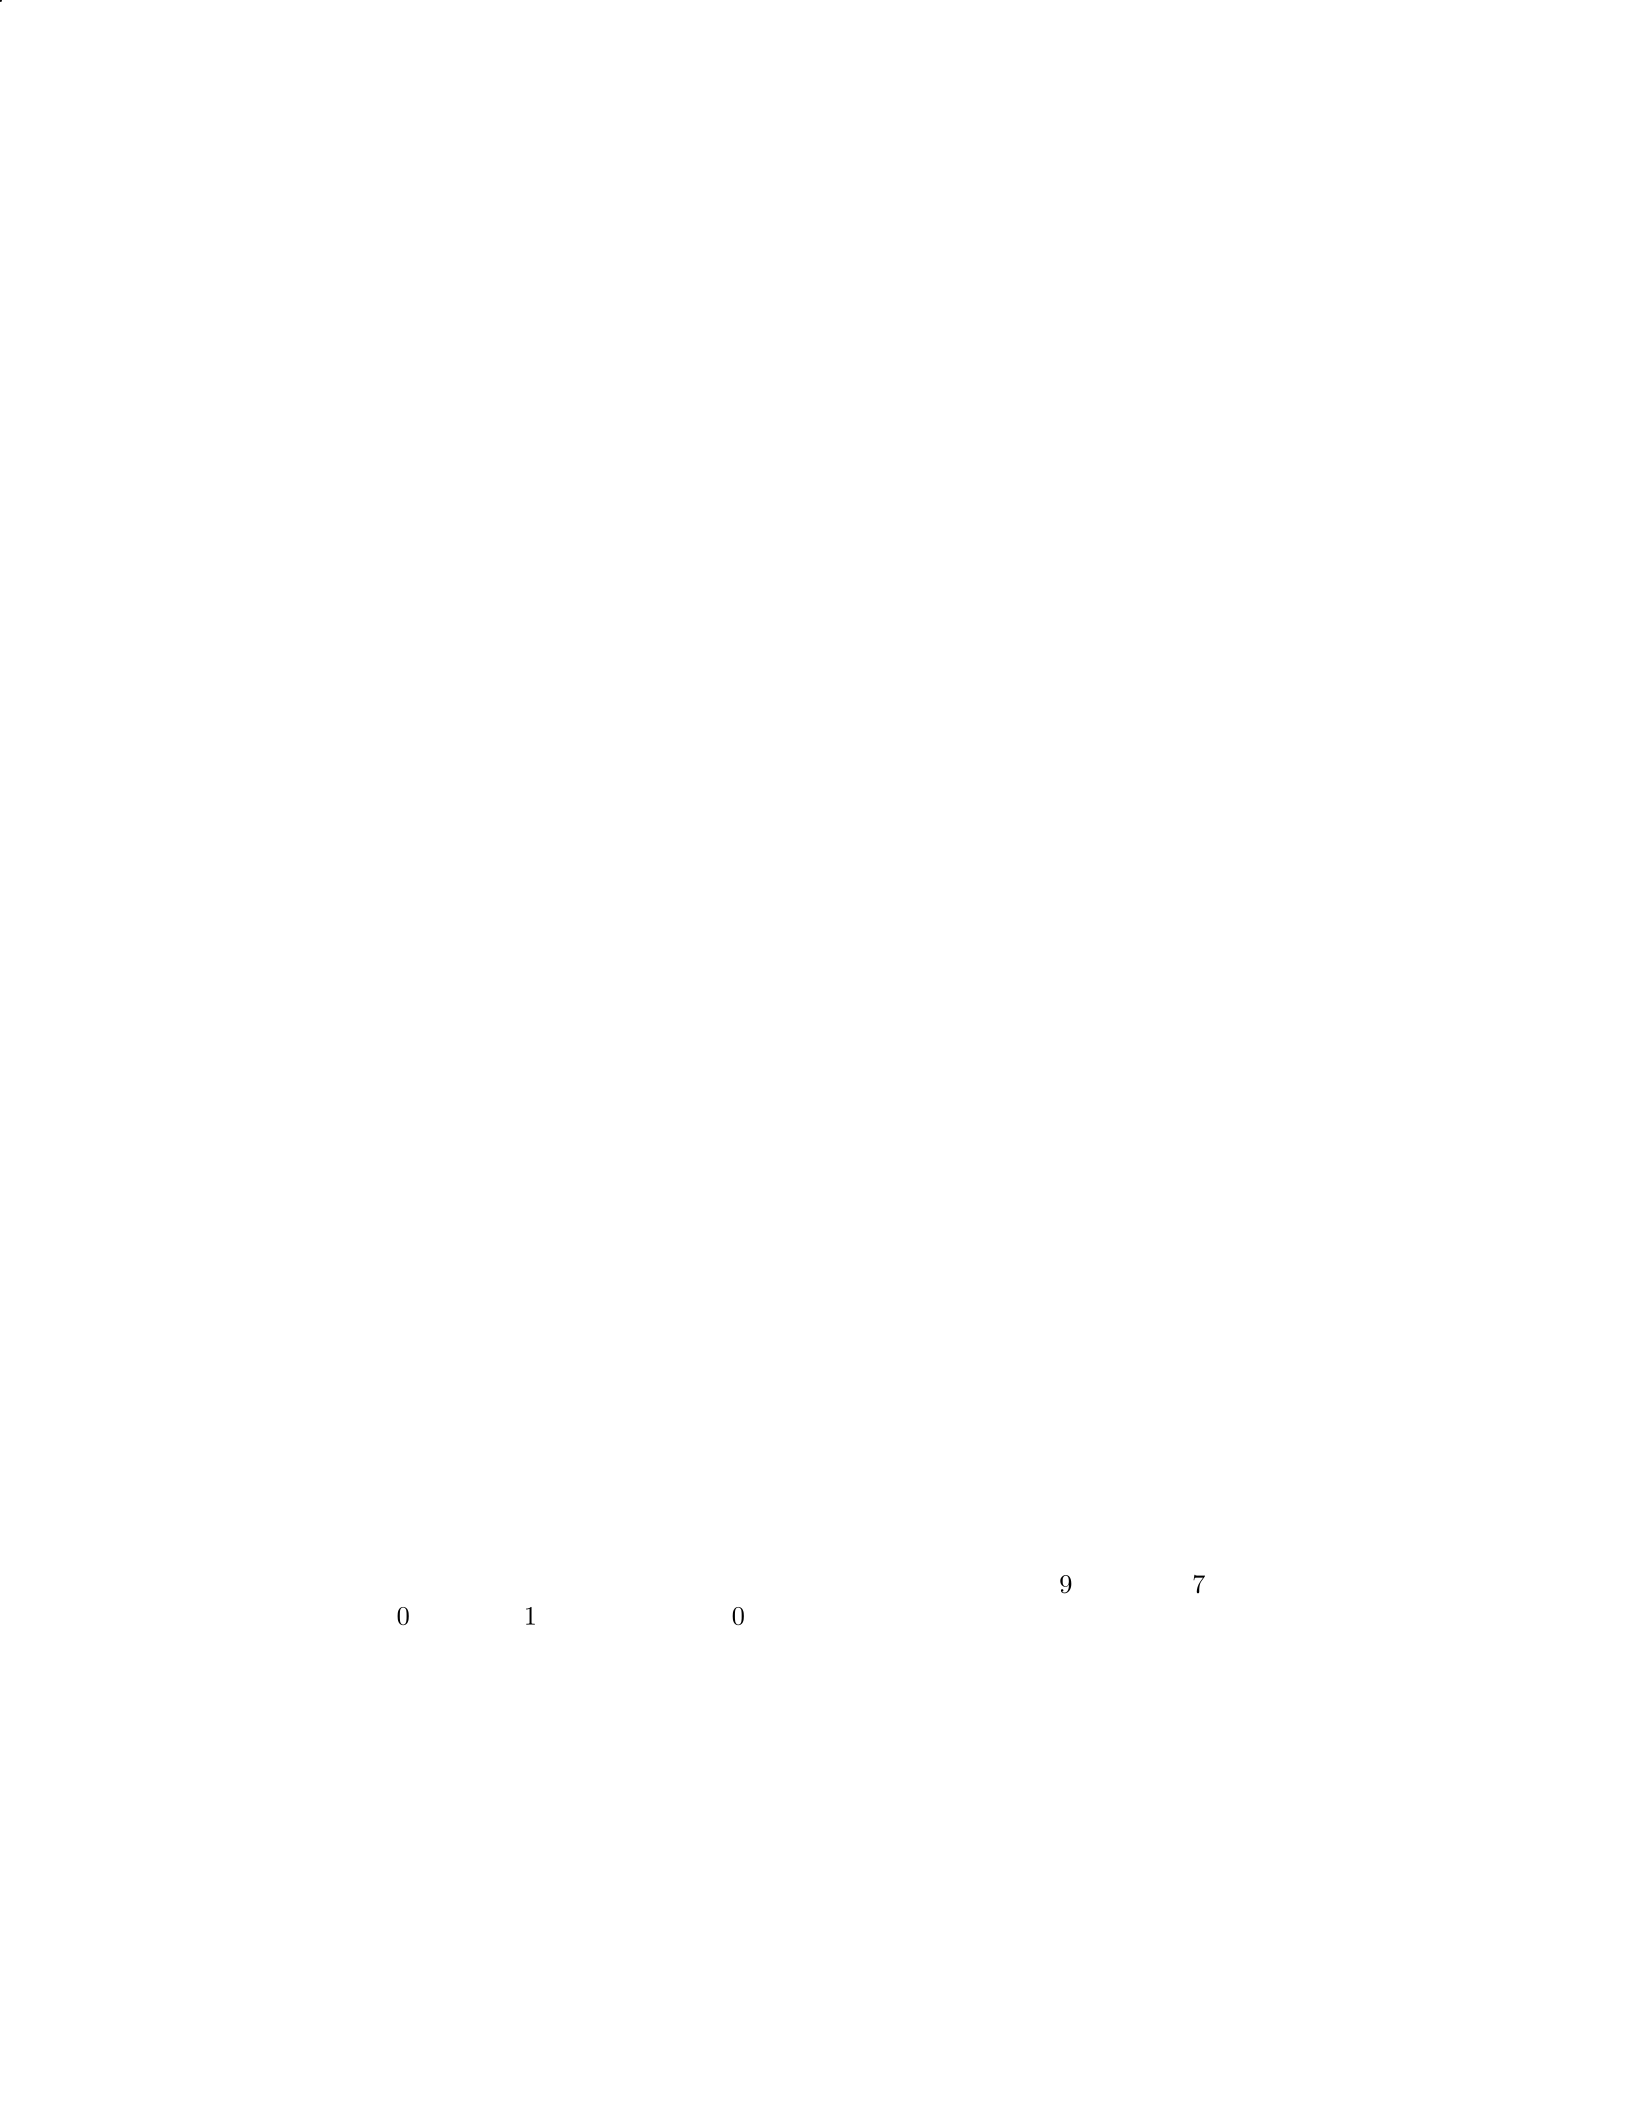
Question 22
Question
A company holds a financial asset that is measured at fair value through profit or
loss. At the end of the reporting period, the fair value of the asset has decreased
significantly. Explain how the company should account for this decrease in fair
value.
Solution
Step 1: When the fair value of a financial asset measured at fair value through
profit or loss decreases significantly, the company should recognize the decrease
in fair value through profit or loss in the income statement.
Step 2: Determine the amount of the decrease in fair value. This is calculated
by comparing the previous fair value of the asset with its current fair value at
the end of the reporting period.
Step 3: Record the decrease in fair value as a loss in the income statement.
This loss will offset any gains or income the company may have recognized from
the asset in previous periods.
Step 4: Make the necessary journal entry to reflect the decrease in fair value.
The entry would typically involve debiting a loss account and crediting the fair
value adjustment account related to the asset.
Step 5: Ensure that the financial statements, including the income statement
and balance sheet, are updated to reflect the decrease in fair value and the
corresponding loss recognized in the income statement.
Step 6: Disclose the significant decrease in fair value and the resulting impact
on the financial statements in the notes to the financial statements or in the
management discussion and analysis section of the annual report. Investors and
stakeholders should be informed about the reasons behind the decrease in fair
value and its potential implications for the company.
Question 23
Question
A company used the market approach to estimate the fair value of an asset. The
market approach involved using comparable market transactions to estimate the
fair value of the asset. The company gathered information on several compa-
rable transactions and found the following selling prices:
$
950,000,
$
970,000,
$
990,000,
$
1,010,000, and
$
1,030,000. The company estimated the fair value
of the asset by taking the average of these selling prices. However, an analyst
noticed that one of the comparable transactions was significantly larger in size
compared to the others. Discuss whether this could affect the accuracy of the
fair value estimation based on the market approach.
17

Solution
Step 1: The Impact of Size Difference on Fair Value Estimation - The significant
difference in size between the transactions could affect the accuracy of the fair
value estimation based on the market approach. When estimating fair value
using the market approach, it is essential to select comparable transactions that
are similar to the asset being valued in all significant aspects. Size is one of the
critical factors affecting the comparability of transactions.
Step 2: Potential Issues with Size Difference - If one of the comparable
transactions significantly differs in size compared to the asset being valued, it
may not accurately reflect the fair value of the asset. Larger transactions may
involve bulk discounts, economies of scale, or other factors that do not apply
to smaller transactions. As a result, using such a transaction to estimate the
fair value could lead to an overestimation or underestimation of the asset’s true
value.
Step 3: Mitigating the Impact of Size Difference - To improve the accuracy
of fair value estimation, the company could exclude the transaction that signif-
icantly differs in size from the others. Alternatively, the company could adjust
the selling prices of comparable transactions to account for the size difference.
This adjustment could involve normalizing the prices based on the size of the
transactions or applying a size-based discount or premium to the selling prices.
Step 4: Conclusion - In conclusion, the significant difference in size between
comparable transactions could indeed affect the accuracy of fair value estimation
based on the market approach. It is essential for companies to carefully consider
the size and other relevant characteristics of comparable transactions to ensure
a more accurate estimation of fair value.
Question 24
Question
A company holds an investment in a publicly traded security classified as available-
for-sale. The fair value of the investment has significantly decreased due to
market fluctuations. Explain how the company should account for this decrease
in fair value under the fair value measurement framework.
Solution
To account for the decrease in fair value of the investment under the fair value
measurement framework, the company should follow these steps:
Step 1: Recognize the change in fair value in other comprehensive income:
The company should recognize the decrease in fair value of the investment in
other comprehensive income. This allows for the volatility in fair value to be
reflected in the financial statements without impacting net income.
Step 2: Adjust the carrying amount of the investment: The company should
adjust the carrying amount of the investment on the balance sheet to reflect the
18
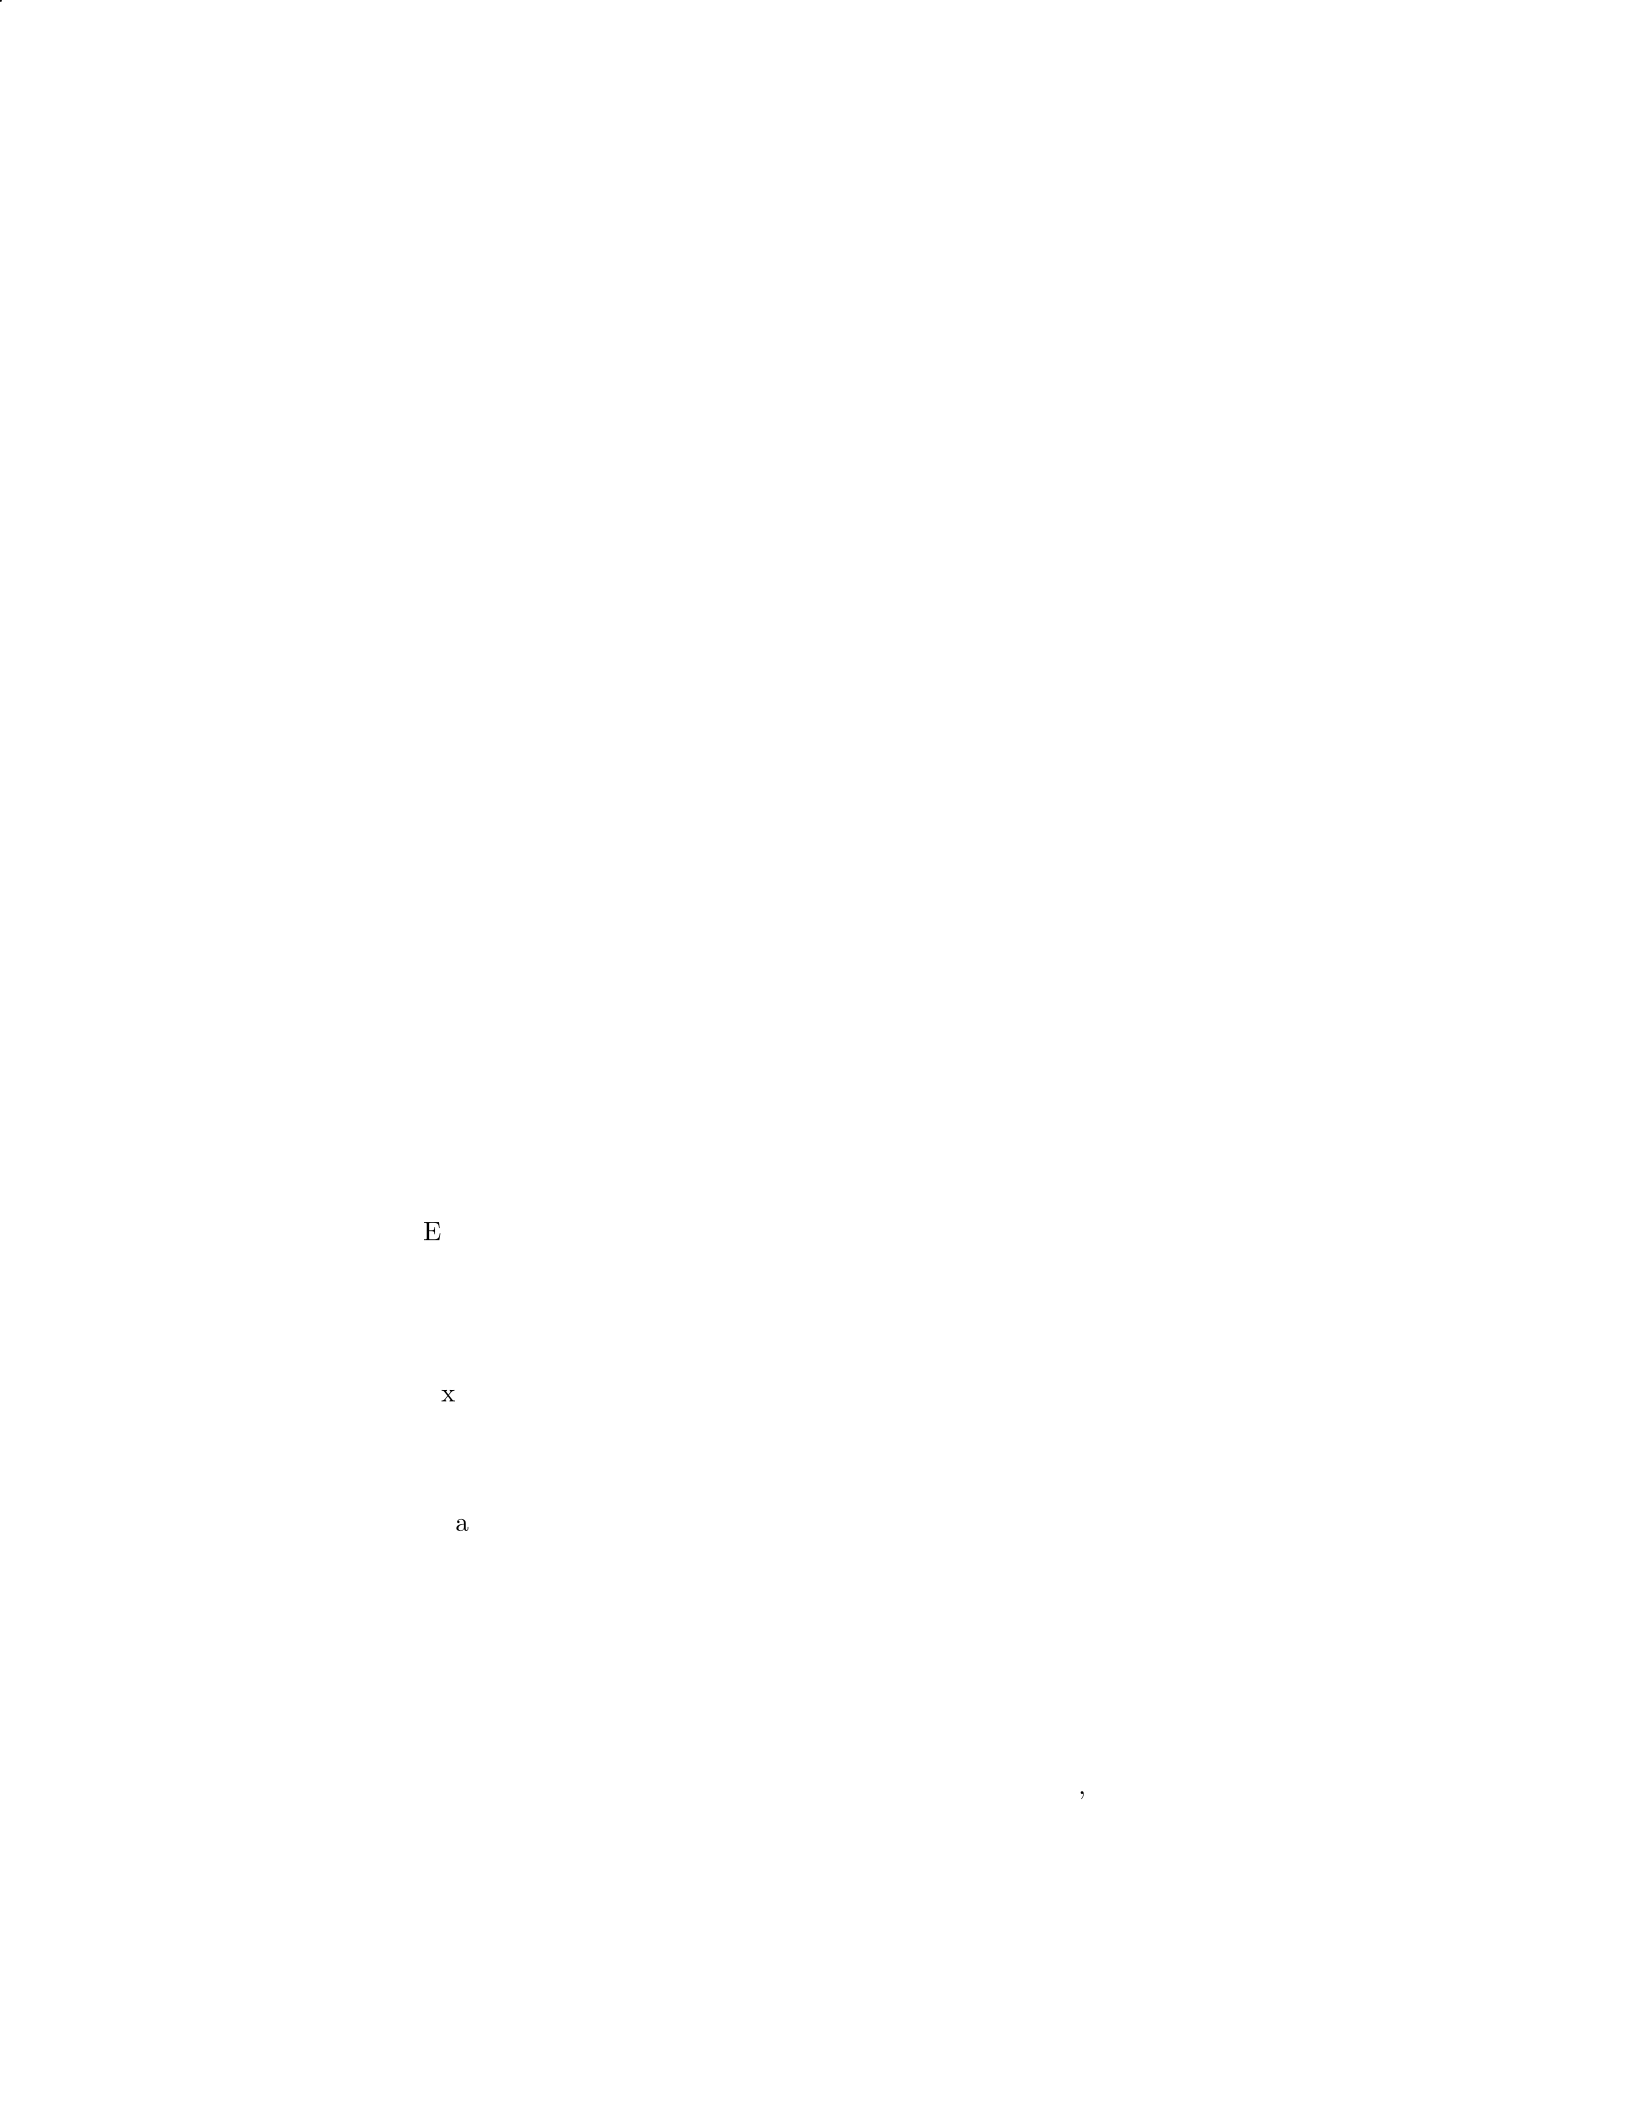
new fair value. This adjustment is made by recognizing a loss on the investment
in the income statement.
Step 3: Assess the impairment of the investment: If the decrease in fair
value is significant and deemed to be other than temporary, the company should
assess whether the investment is impaired. If impairment exists, the company
should recognize an impairment loss in the income statement.
Step 4: Disclose the fair value measurement information: The company
should provide extensive disclosures about the fair value measurement of the
investment in the financial statements. This includes information about the
valuation techniques used, input factors, and sensitivity analysis.
By following these steps, the company can appropriately account for the de-
crease in fair value of the investment under the fair value measurement frame-
work.
Question 25
Question
Explain the fair value measurement hierarchy according to IFRS 13 and provide
an example for each level.
Solution
The fair value measurement hierarchy under IFRS 13 categorizes the inputs to
valuation techniques into three levels based on the observability of the inputs.
Level 1: Quoted prices (unadjusted) in active markets for identical
assets or liabilities
Example: The quoted price of a share of a public company on a stock
exchange.
Level 2: Inputs other than quoted prices included in Level 1 that
are observable for the asset or liability, either directly or indirectly
Example: Using the yield curve to discount future cash flows of a bond to
determine its fair value.
Level 3: Unobservable inputs for the asset or liability
Example: Valuing an early-stage startup company using a discounted cash
flow model where revenue projections are based on management estimates.
Question 26
Question
A company is required to determine the fair value of an investment property
it owns. The property was purchased 5 years ago for
$
500,000 and has an
19
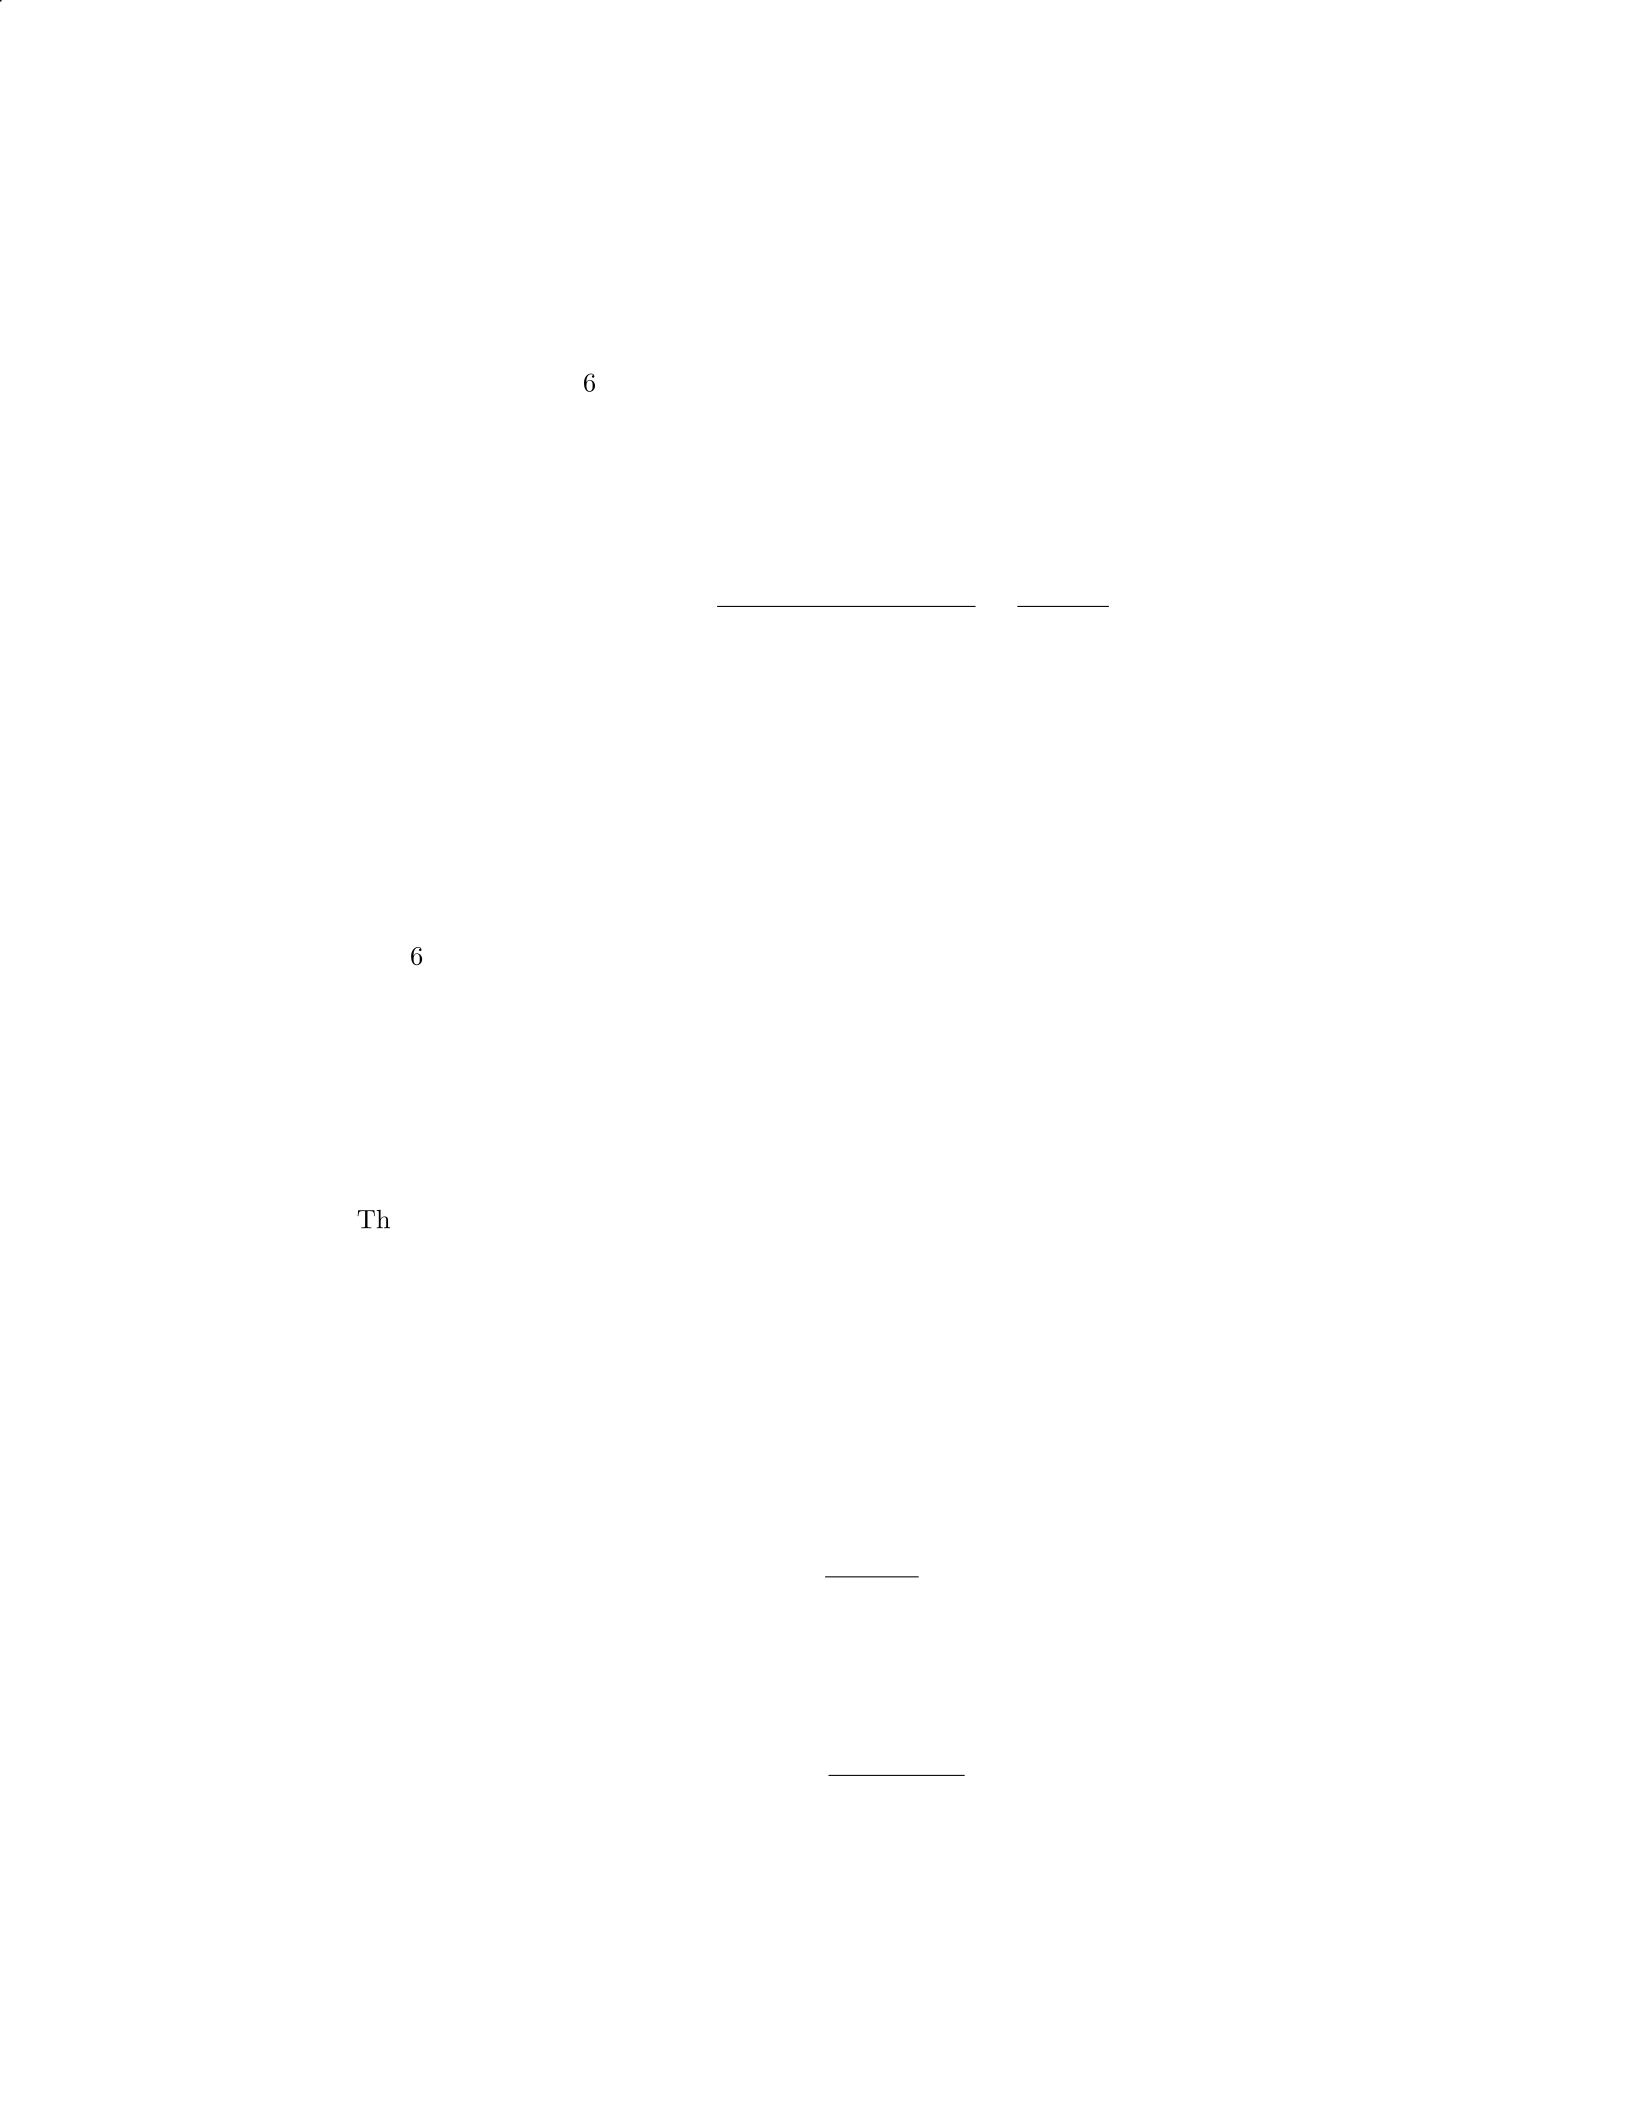
estimated remaining useful life of 15 years. The current fair value of the property
is estimated to be
$
650,000. Using the cost approach, calculate the fair value of
the investment property.
Solution
Step 1: Calculate the accumulated depreciation of the property.
Accumulated Depreciation = Cost
Remaining Useful Life =500,000
15 = 33,333.33
Step 2: Determine the book value of the property.
Book Value = Cost−Accumulated Depreciation = 500,000−33,333.33 = 466,666.67
Step 3: Using the cost approach, the fair value of the investment property
is the book value.
Fair Value = Book Value = 466,666.67
Therefore, the fair value of the investment property using the cost approach
is
$
466,666.67.
Question 27
Question
A company is assessing the fair value of an investment property. The company
estimates that the property will generate a net cash flow of 200,000peryearforthenext10years.Afterthat, thepropertyisexpectedtobesoldfor1,500,000.
The company uses a discount rate of 8
Solution
Step 1: Calculate the present value of the cash flows for the next 10 years. Step
2: Calculate the present value of the property’s sale price in 10 years. Step 3:
Add the present values calculated in Step 1 and Step 2 to find the total fair
value of the investment property.
Step 1: The present value of the annuity can be calculated using the formula
for the present value of an annuity:
P V =C×1−1
(1 + r)n∇ · r
where: - C= $200,000 (annual net cash flow) - r= 0.08 (discount rate) -
n= 10 (number of years)
Substituting the values, we get:
P V = $200,000 ×1−1
(1 + 0.08)10 ∇ · 0.08
20
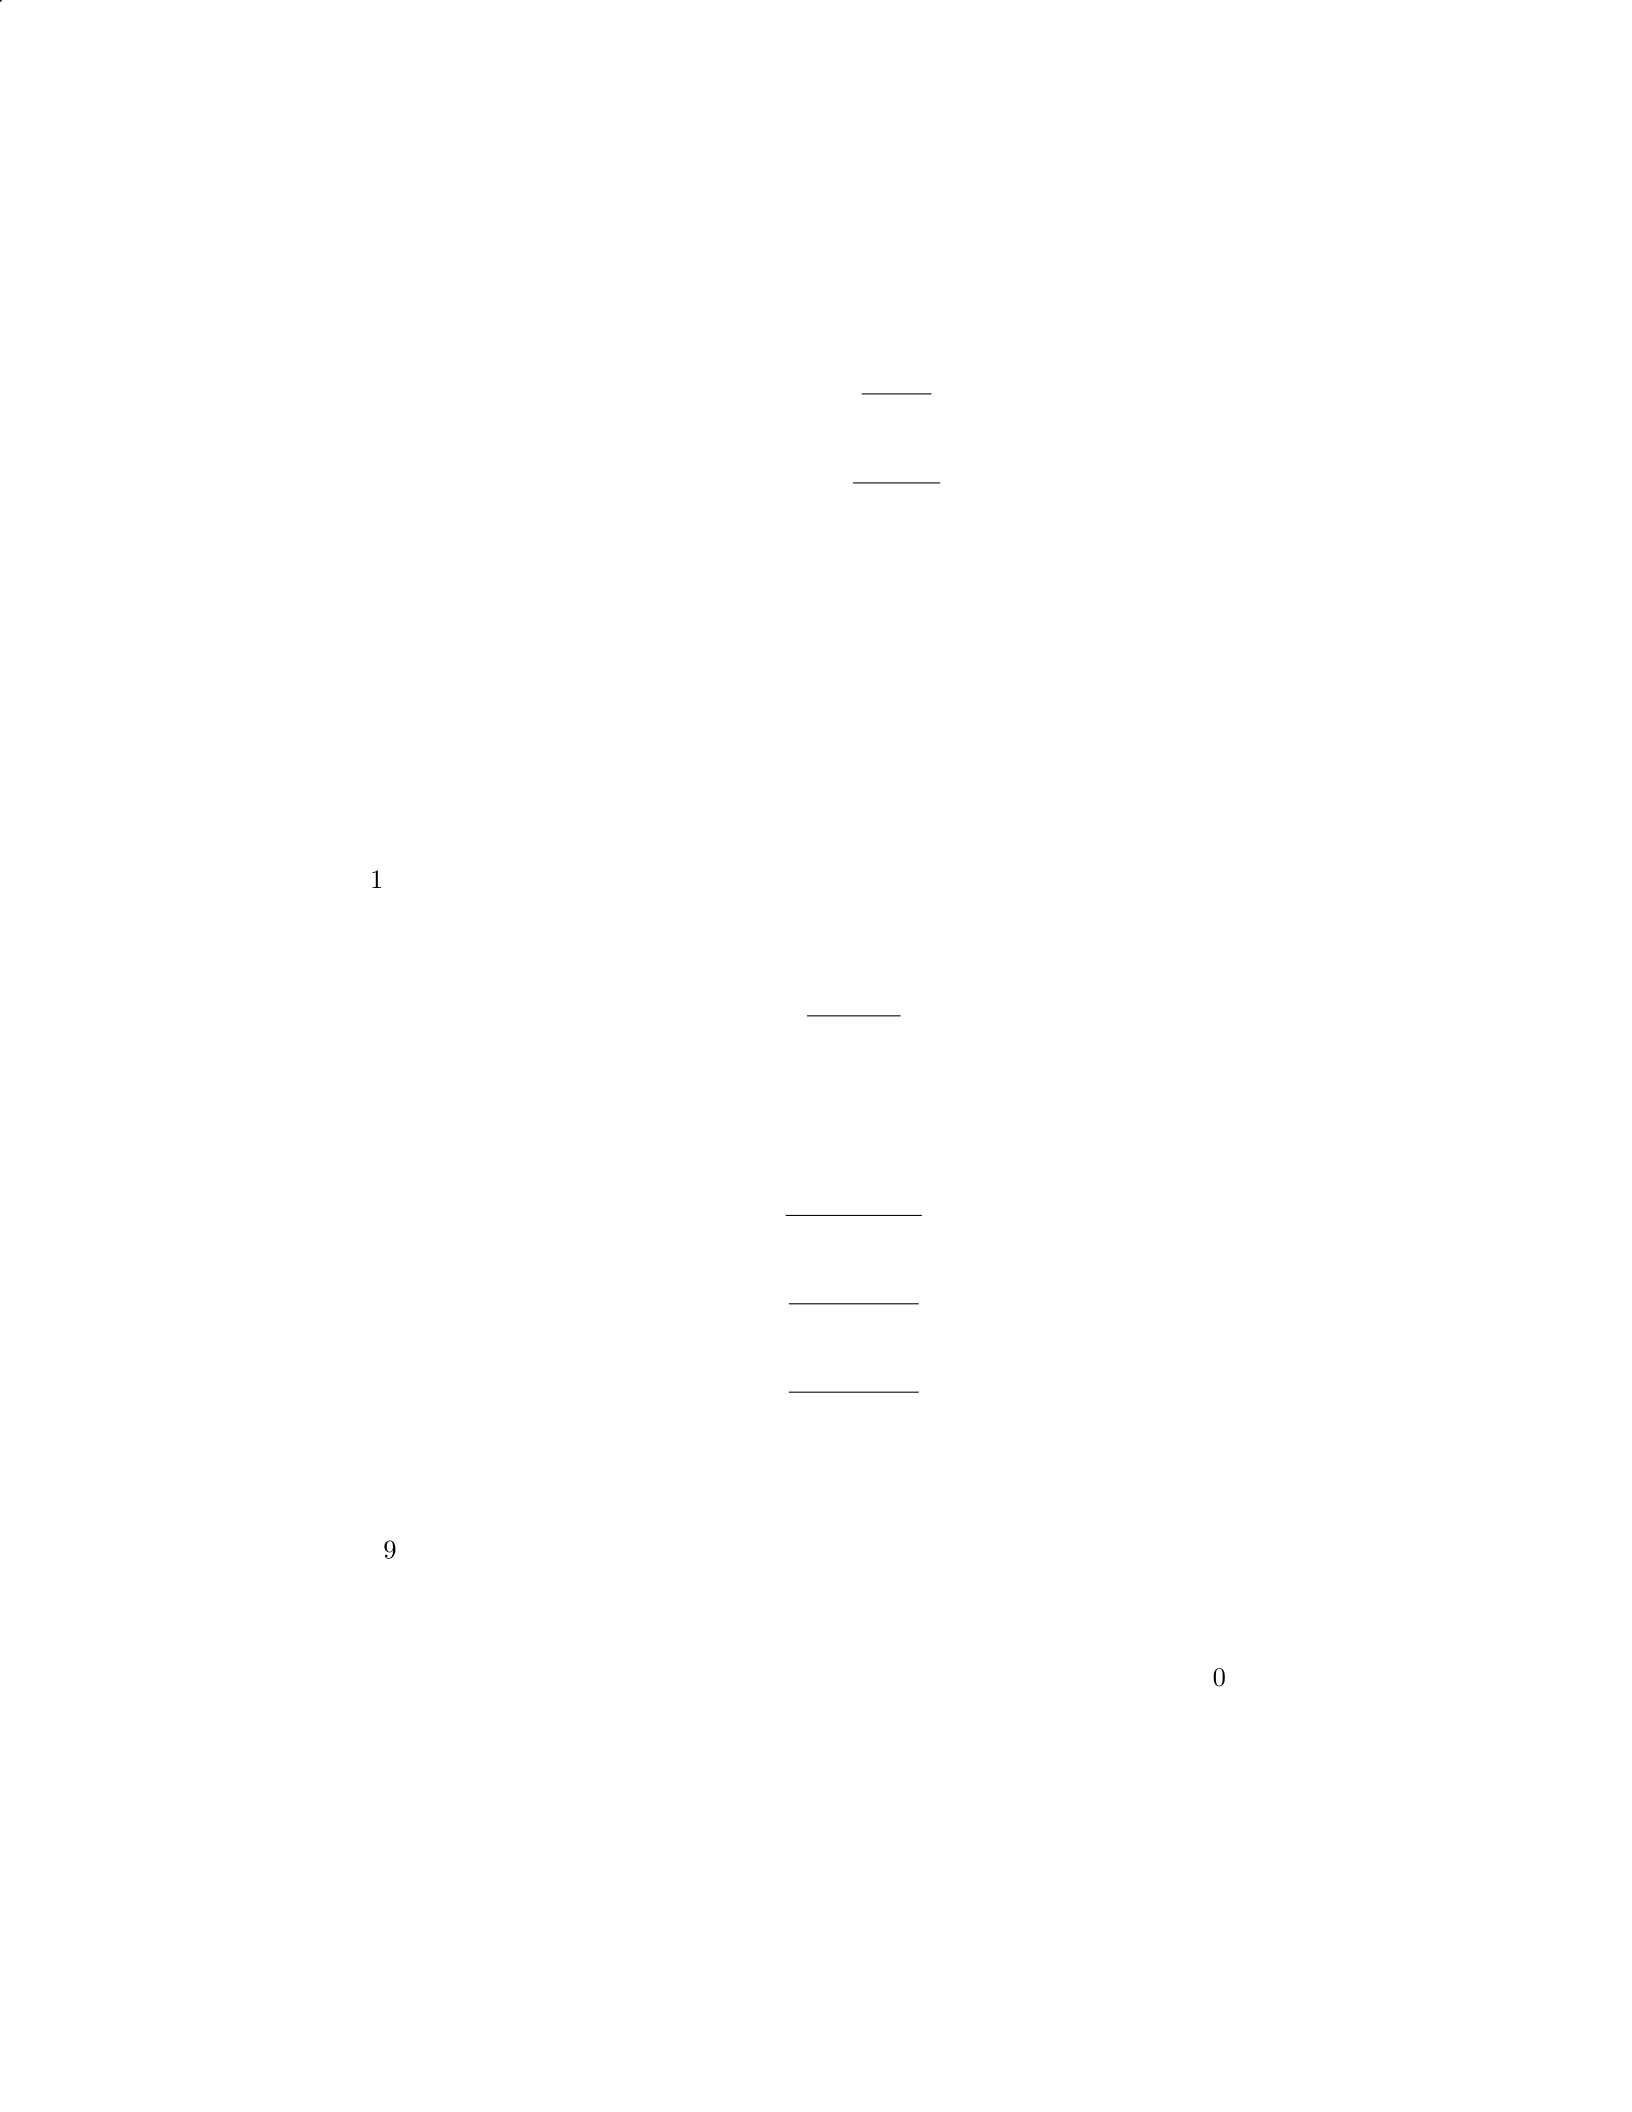
P V ≈$200,000 ×1−1
1.0810 ∇ · 0.08
P V ≈$200,000 ×1−1
2.15892∇ · 0.08
P V ≈$200,000 ×(1 −0.46319) ∇ · 0.08
P V ≈$200,000 ×0.53681∇ · 0.08
P V ≈$200,000 ×6.710125
P V ≈$1,342,025
So, the present value of the cash flows for the next 10 years is approximately
$
1,342,025.
Step 2: The present value of the property’s sale price can be calculated
using the formula for the present value of a future amount:
P V =F V
(1 + r)n
where: - F V = $1,500,000 (future sale price) - r= 0.08 (discount rate) -
n= 10 (number of years)
Substituting the values, we get:
P V =$1,500,000
(1 + 0.08)10
P V =$1,500,000
(1.08)10
P V =$1,500,000
2.15892
P V ≈$695,774
So, the present value of the property’s sale price in 10 years is approximately
$
695,774.
Step 3: The total fair value of the investment property is the sum of the
present values calculated in Step 1 and Step 2:
Total Fair Value ≈$1,342,025 + $695,774 = $2,037,799
Therefore, the fair value of the investment property is approximately
$
2,037,799.
21
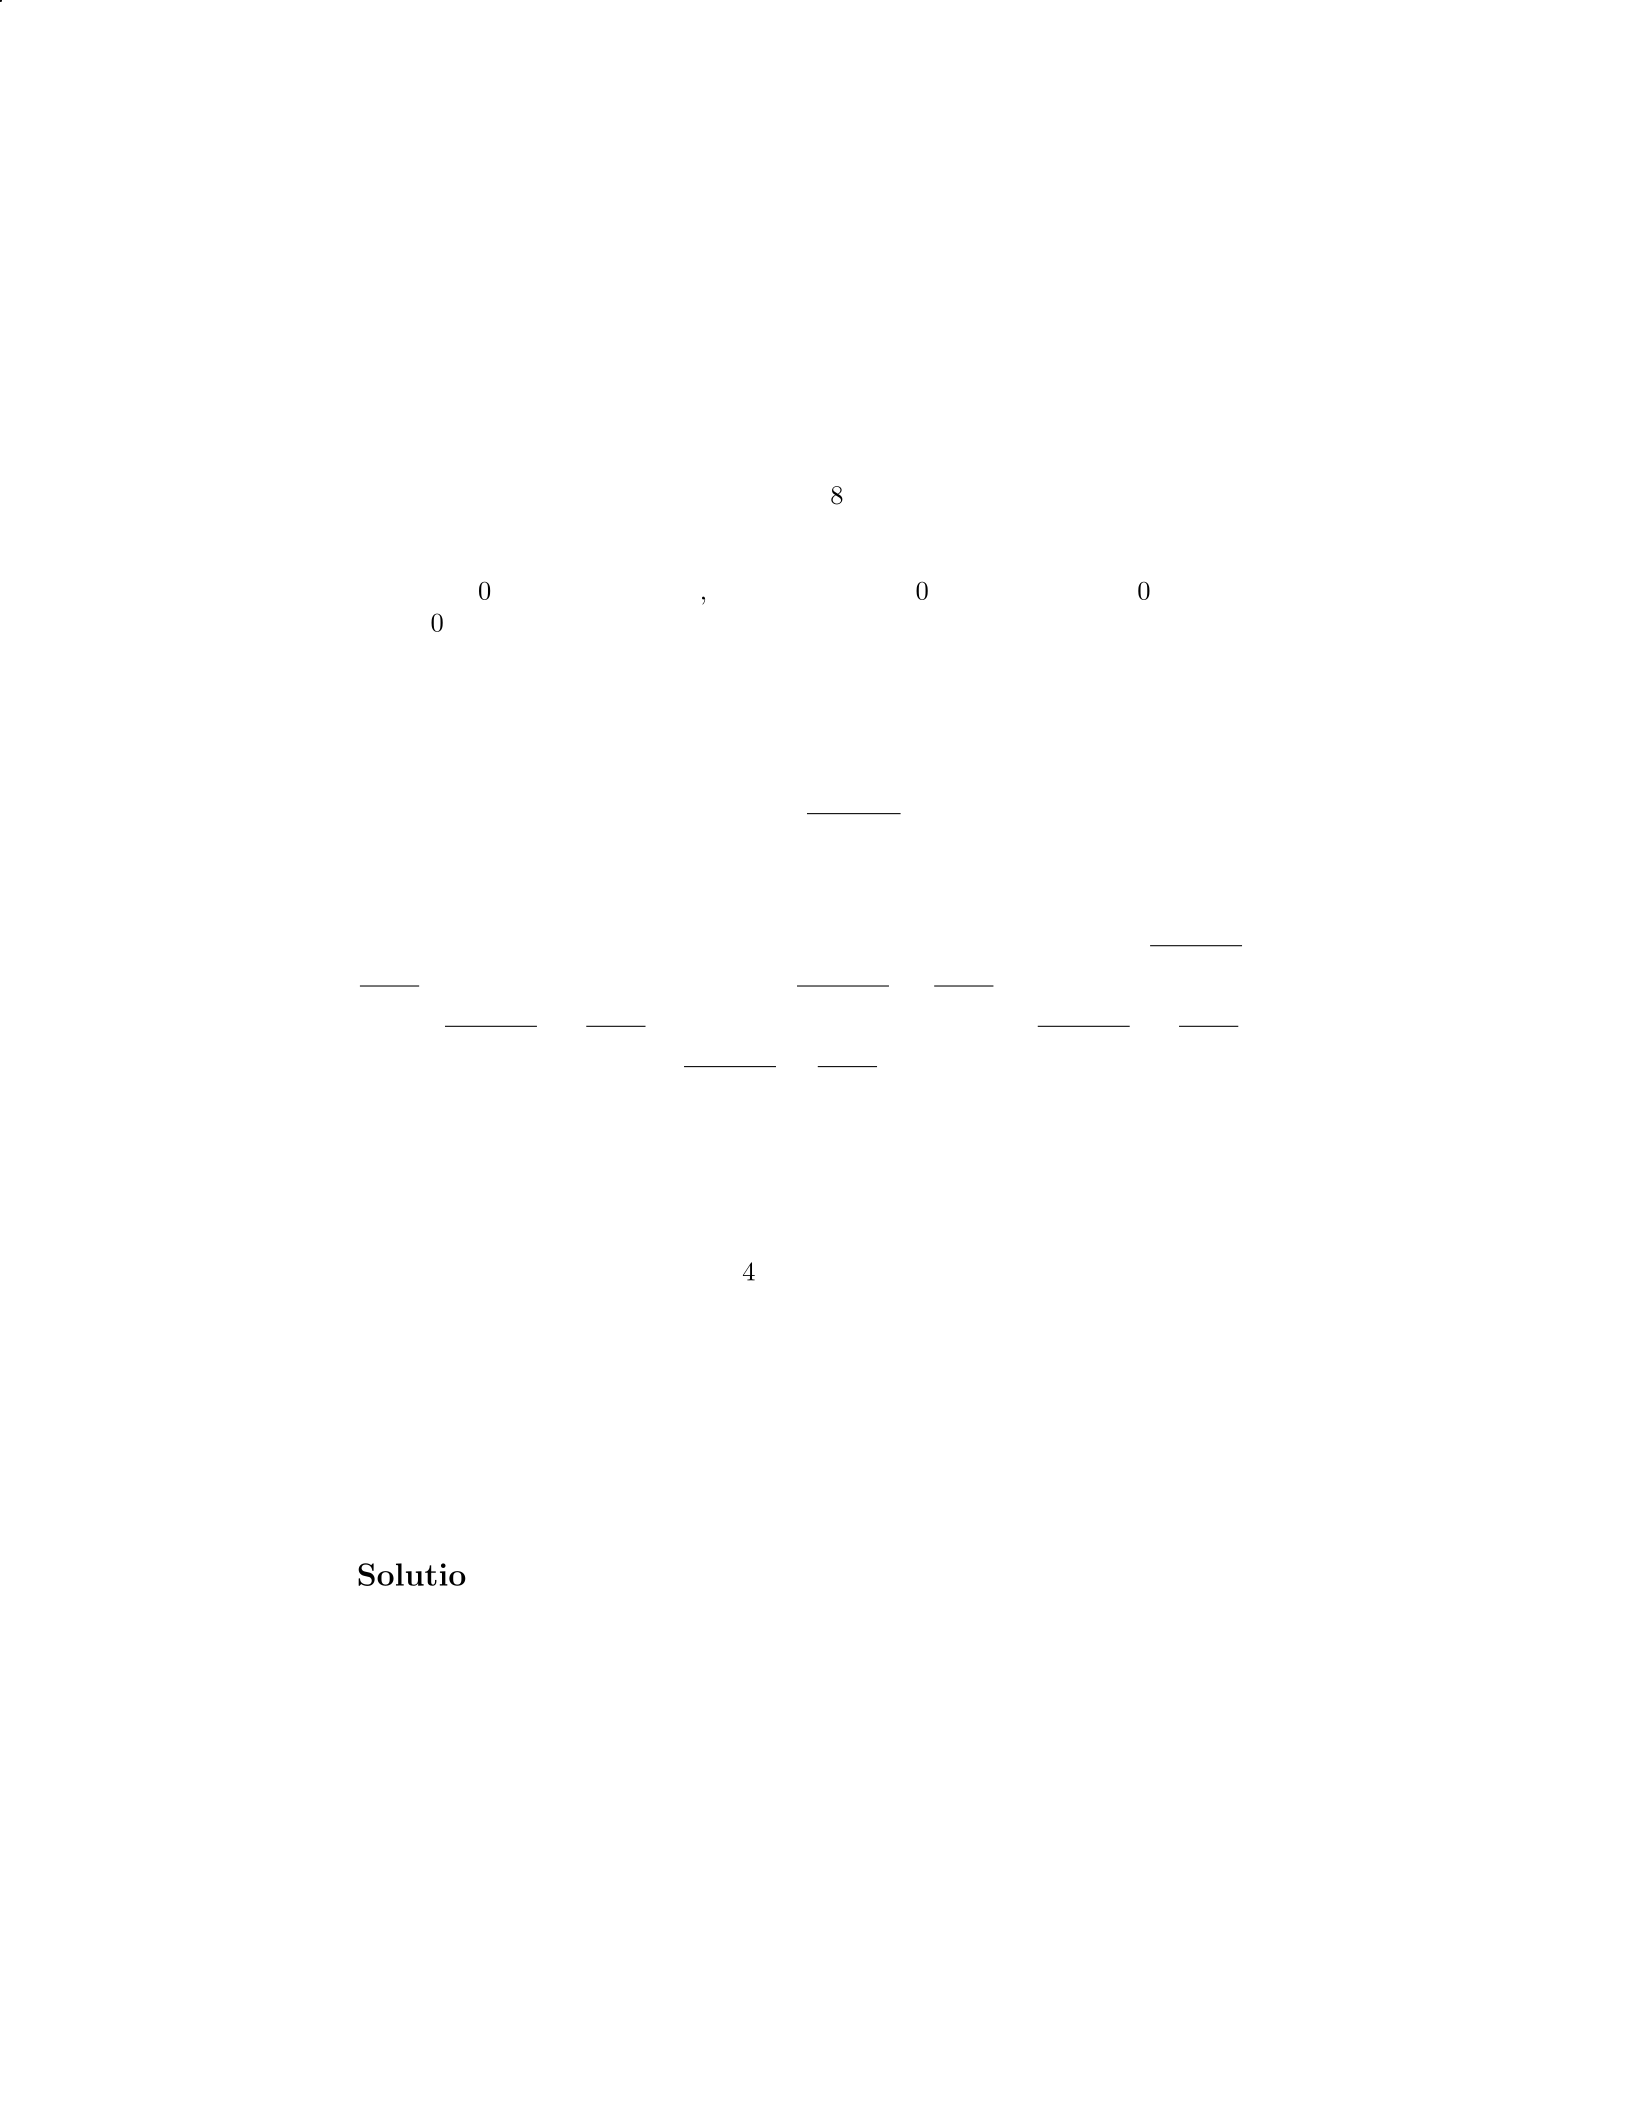
Question 28
Question
Company XYZ is evaluating the fair value of an investment property they own.
The property has a current fair value of
$
800,000. After conducting a valuation,
it was determined that the property’s highest and best use is as a commercial
building. The estimated future cash flows for the property are as follows: -
Year 1:
$
40,000 - Year 2:
$
50,000 - Year 3:
$
60,000 - Year 4:
$
70,000 - Year 5:
$
80,000 If the discount rate is 8
Solution
Step 1: Calculate the present value of each future cash flow using the formula:
P V =F V
(1 + r)n
where: - F V is the future cash flow - ris the discount rate - nis the number of
years
Calculating the present value of each cash flow: - Year 1: P V =40,000
(1+0.08)1=
40,000
1.08 ≈$37,037.04 - Year 2: P V =50,000
(1+0.08)2=50,000
1.1664 ≈$42,917.85 - Year 3:
P V =60,000
(1+0.08)3=60,000
1.2597 ≈$47,605.71 - Year 4: P V =70,000
(1+0.08)4=70,000
1.3605 ≈
$51,443.89 - Year 5: P V =80,000
(1+0.08)5=80,000
1.4693 ≈$54,430.28
Step 2: Sum up the present values of all cash flows to find the fair value of
the property:
F airV alue = $37,037.04+$42,917.85+$47,605.71+$51,443.89+$54,430.28 = $233,434.77
Therefore, the fair value of the property based on the discounted cash flow
method is approximately
$
233,434.77.
Question 29
Question
A company holds an investment in a publicly traded company. The fair value of
the investment at the end of the reporting period is 625,000.T hecompanyalsoholdsasimilarinvestmentinaprivatecompany.Howshouldthecompanydeterminethefairvalueoftheinvestmentintheprivatecompany?
Solution
1. The fair value of investments in publicly traded companies can be easily de-
termined through market prices. However, determining the fair value of invest-
ments in private companies is more challenging as there is no readily available
market price.
2. The company can use various methods to determine the fair value of
the investment in the private company. One common method is the market
22
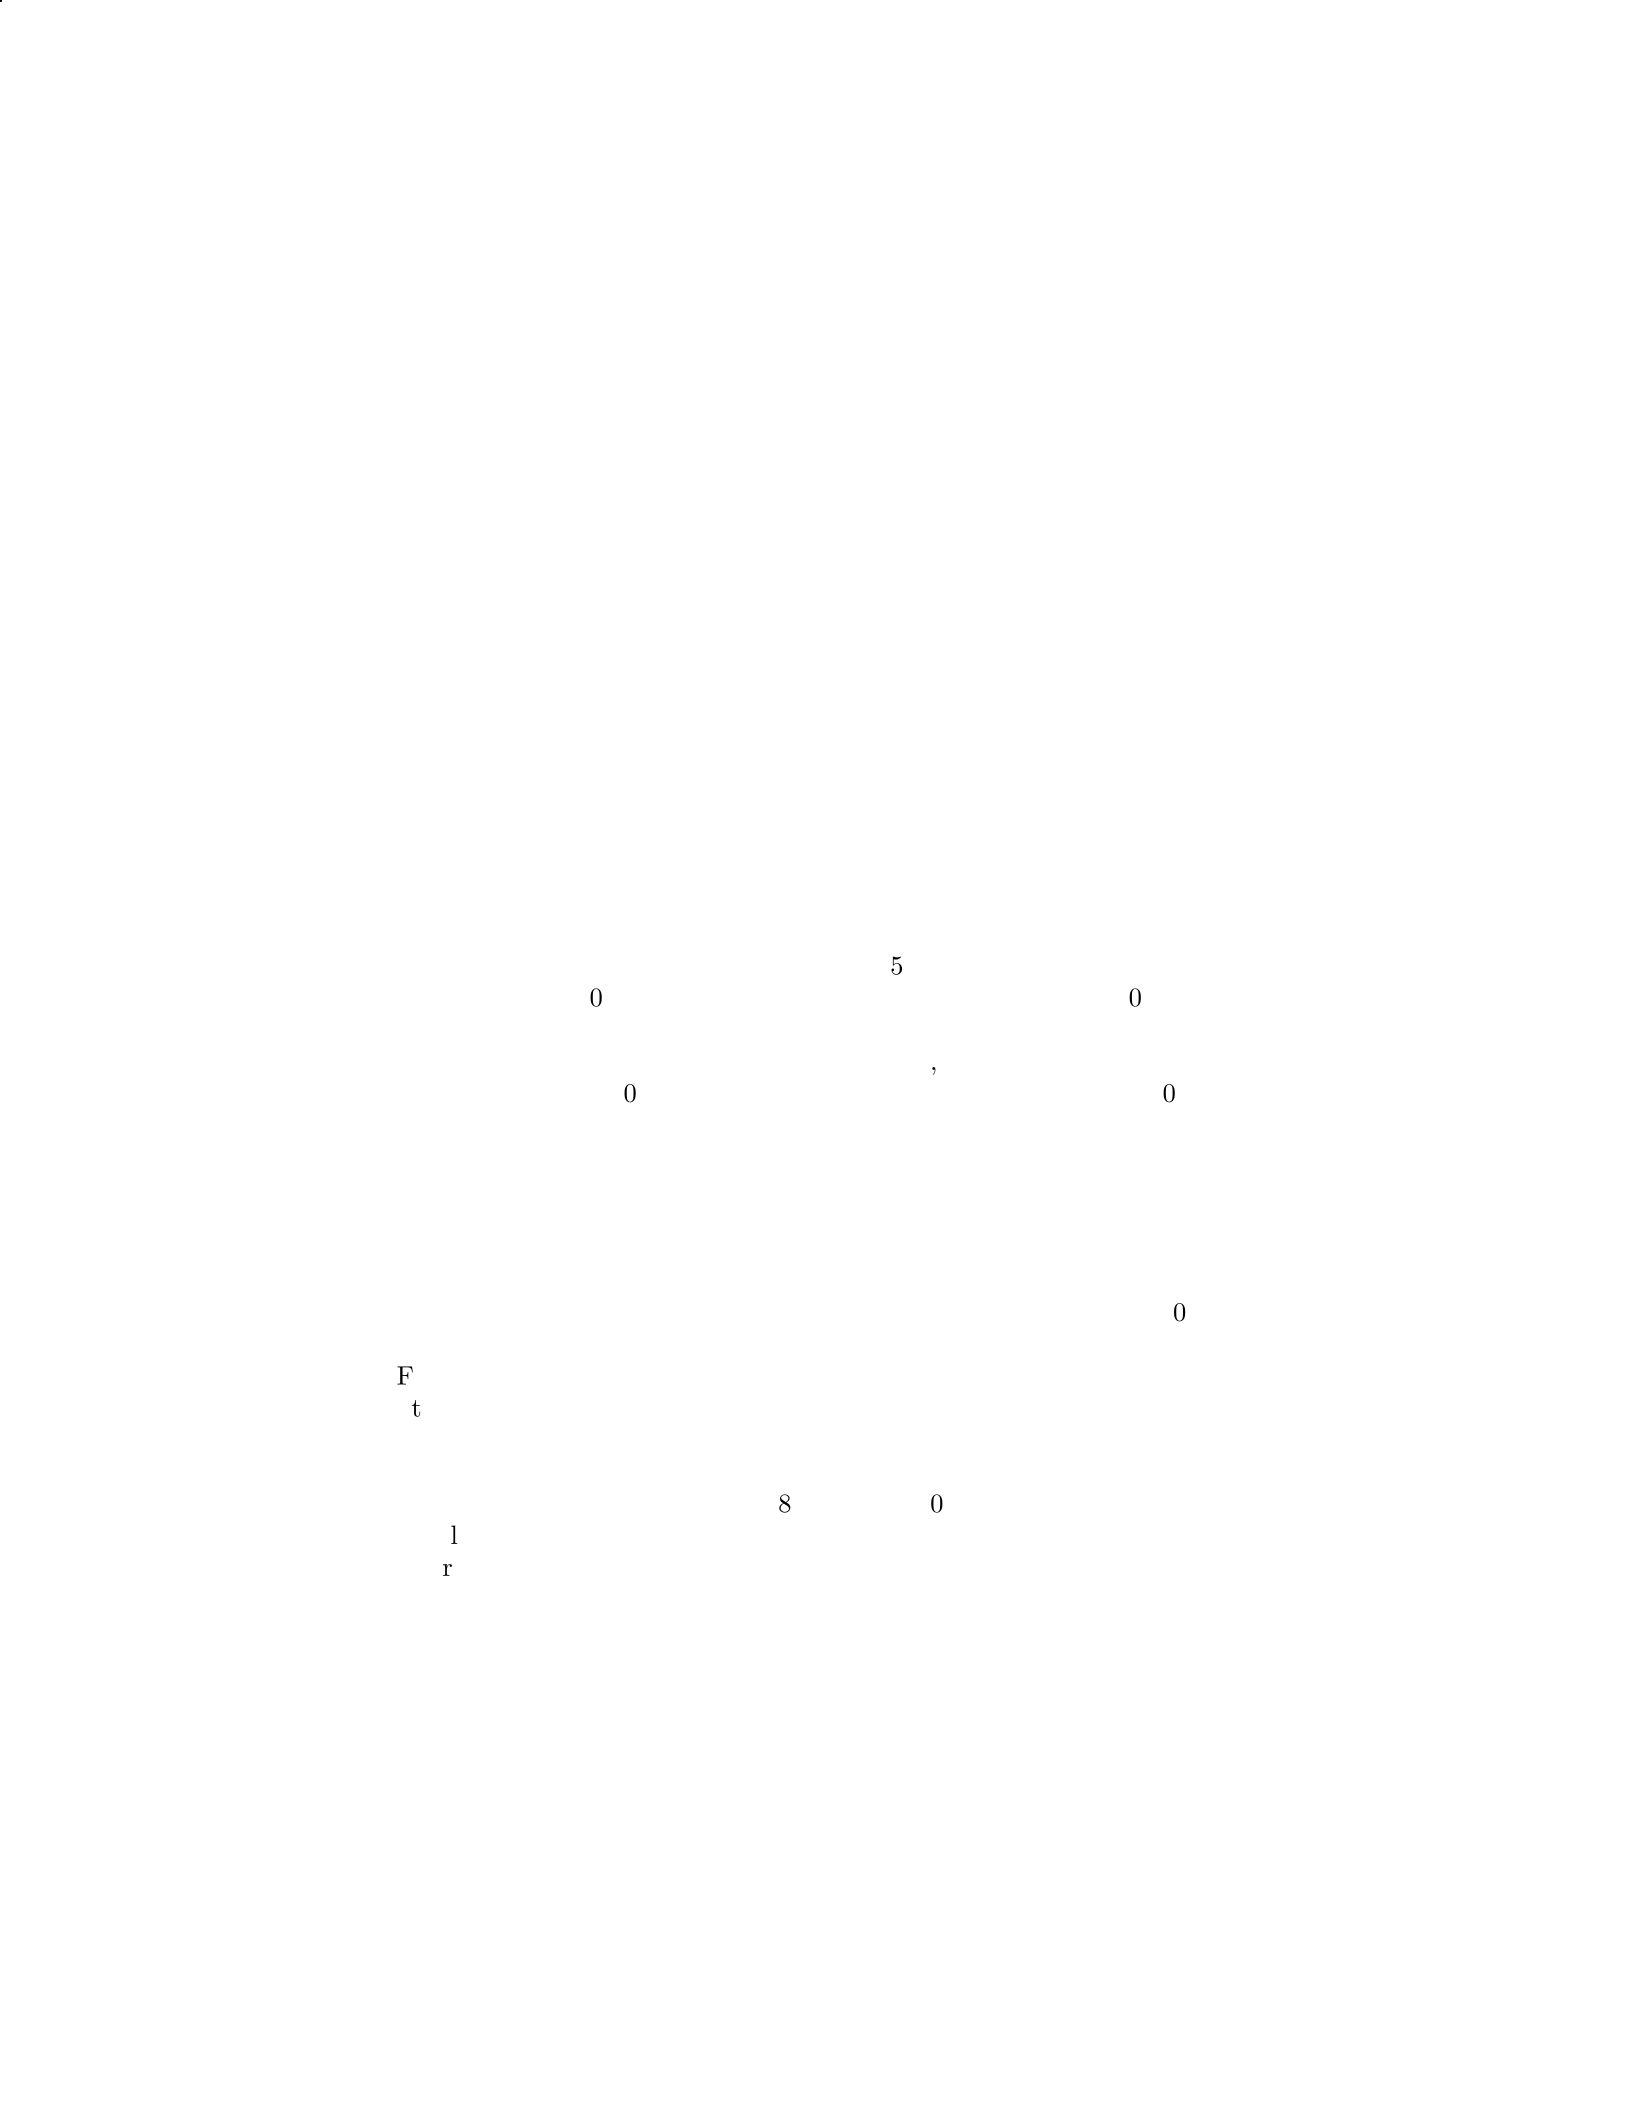
approach which involves comparing the investment in the private company to
similar publicly traded companies.
3. Another method is the income approach, which estimates the fair value
by discounting the future cash flows expected from the investment.
4. The cost approach can also be used, which values the investment based
on the cost of comparable assets.
5. Once the company selects a method for determining the fair value of the
investment in the private company, it must ensure that the valuation is based
on reliable and relevant information. The company may need to engage external
valuation experts to assist in determining the fair value.
6. The company should disclose the valuation methods used in determining
the fair value of the investment in the private company in its financial statements
to provide transparency to investors and other stakeholders.
Question 30
Question
Given below are the financial assets of XYZ Company as at December 31, 2021:
- Investment in listed equity securities:
$
500,000 - Investment in unlisted
equity securities:
$
300,000 - Investment in government bonds:
$
400,000
The fair values of these financial assets are as follows:
- Investment in listed equity securities:
$
550,000 - Investment in unlisted
equity securities:
$
280,000 - Investment in government bonds:
$
390,000
Determine the total fair value of XYZ Company’s financial assets as at De-
cember 31, 2021.
Solution
Step 1: Calculate the fair value of each type of financial asset.
For the investment in listed equity securities: Fair value =
$
550,000
For the investment in unlisted equity securities: Fair value =
$
280,000
For the investment in government bonds: Fair value =
$
390,000
Step 2: Calculate the total fair value of XYZ Company’s financial assets.
Total fair value = Fair value of listed equity securities + Fair value of unlisted
equity securities + Fair value of government bonds
Total fair value =
$
550,000 +
$
280,000 +
$
390,000
Total fair value =
$
1,220,000
Therefore, the total fair value of XYZ Company’s financial assets as at De-
cember 31, 2021 is
$
1,220,000.
23
Question 31
Question
Suppose a company has an investment in a non-publicly tradable security. The
fair value of this investment is determined using Level 3 inputs. If there is a
significant decrease in the liquidity of this security, how would this impact the
fair value measurement?
Solution
Step 1: A significant decrease in liquidity of the security may result in an increase
in the risk associated with the investment. This increased risk can impact the
fair value measurement using Level 3 inputs.
Step 2: The decrease in liquidity may make it more challenging for the
company to determine a reliable fair value for the security, as there may be
limited market activity or observable transactions to use as benchmarks.
Step 3: As a result, the company may need to adjust its assumptions and
estimates when calculating the fair value of the investment. This could involve
revising discount rates, adjusting expected future cash flows, or incorporating
additional risk premiums.
Step 4: The increased uncertainty and subjectivity in determining the fair
value of the security may lead to a wider range of possible fair values. This
could result in a larger fair value measurement range or increased volatility in
the fair value estimate.
Step 5: Overall, a significant decrease in the liquidity of the security can
complicate the fair value measurement process and potentially result in a less
reliable fair value estimate for the investment.
Question 32
Question
A company is required to determine the fair value of an investment property
for its financial statements. The company obtained the following information
about the property:
Market rents for similar properties in the area: $2,500 per month
The property is expected to generate rental income for the next 5 years
Discount rate: 8%
Calculate the fair value of the investment property using the income approach.
24
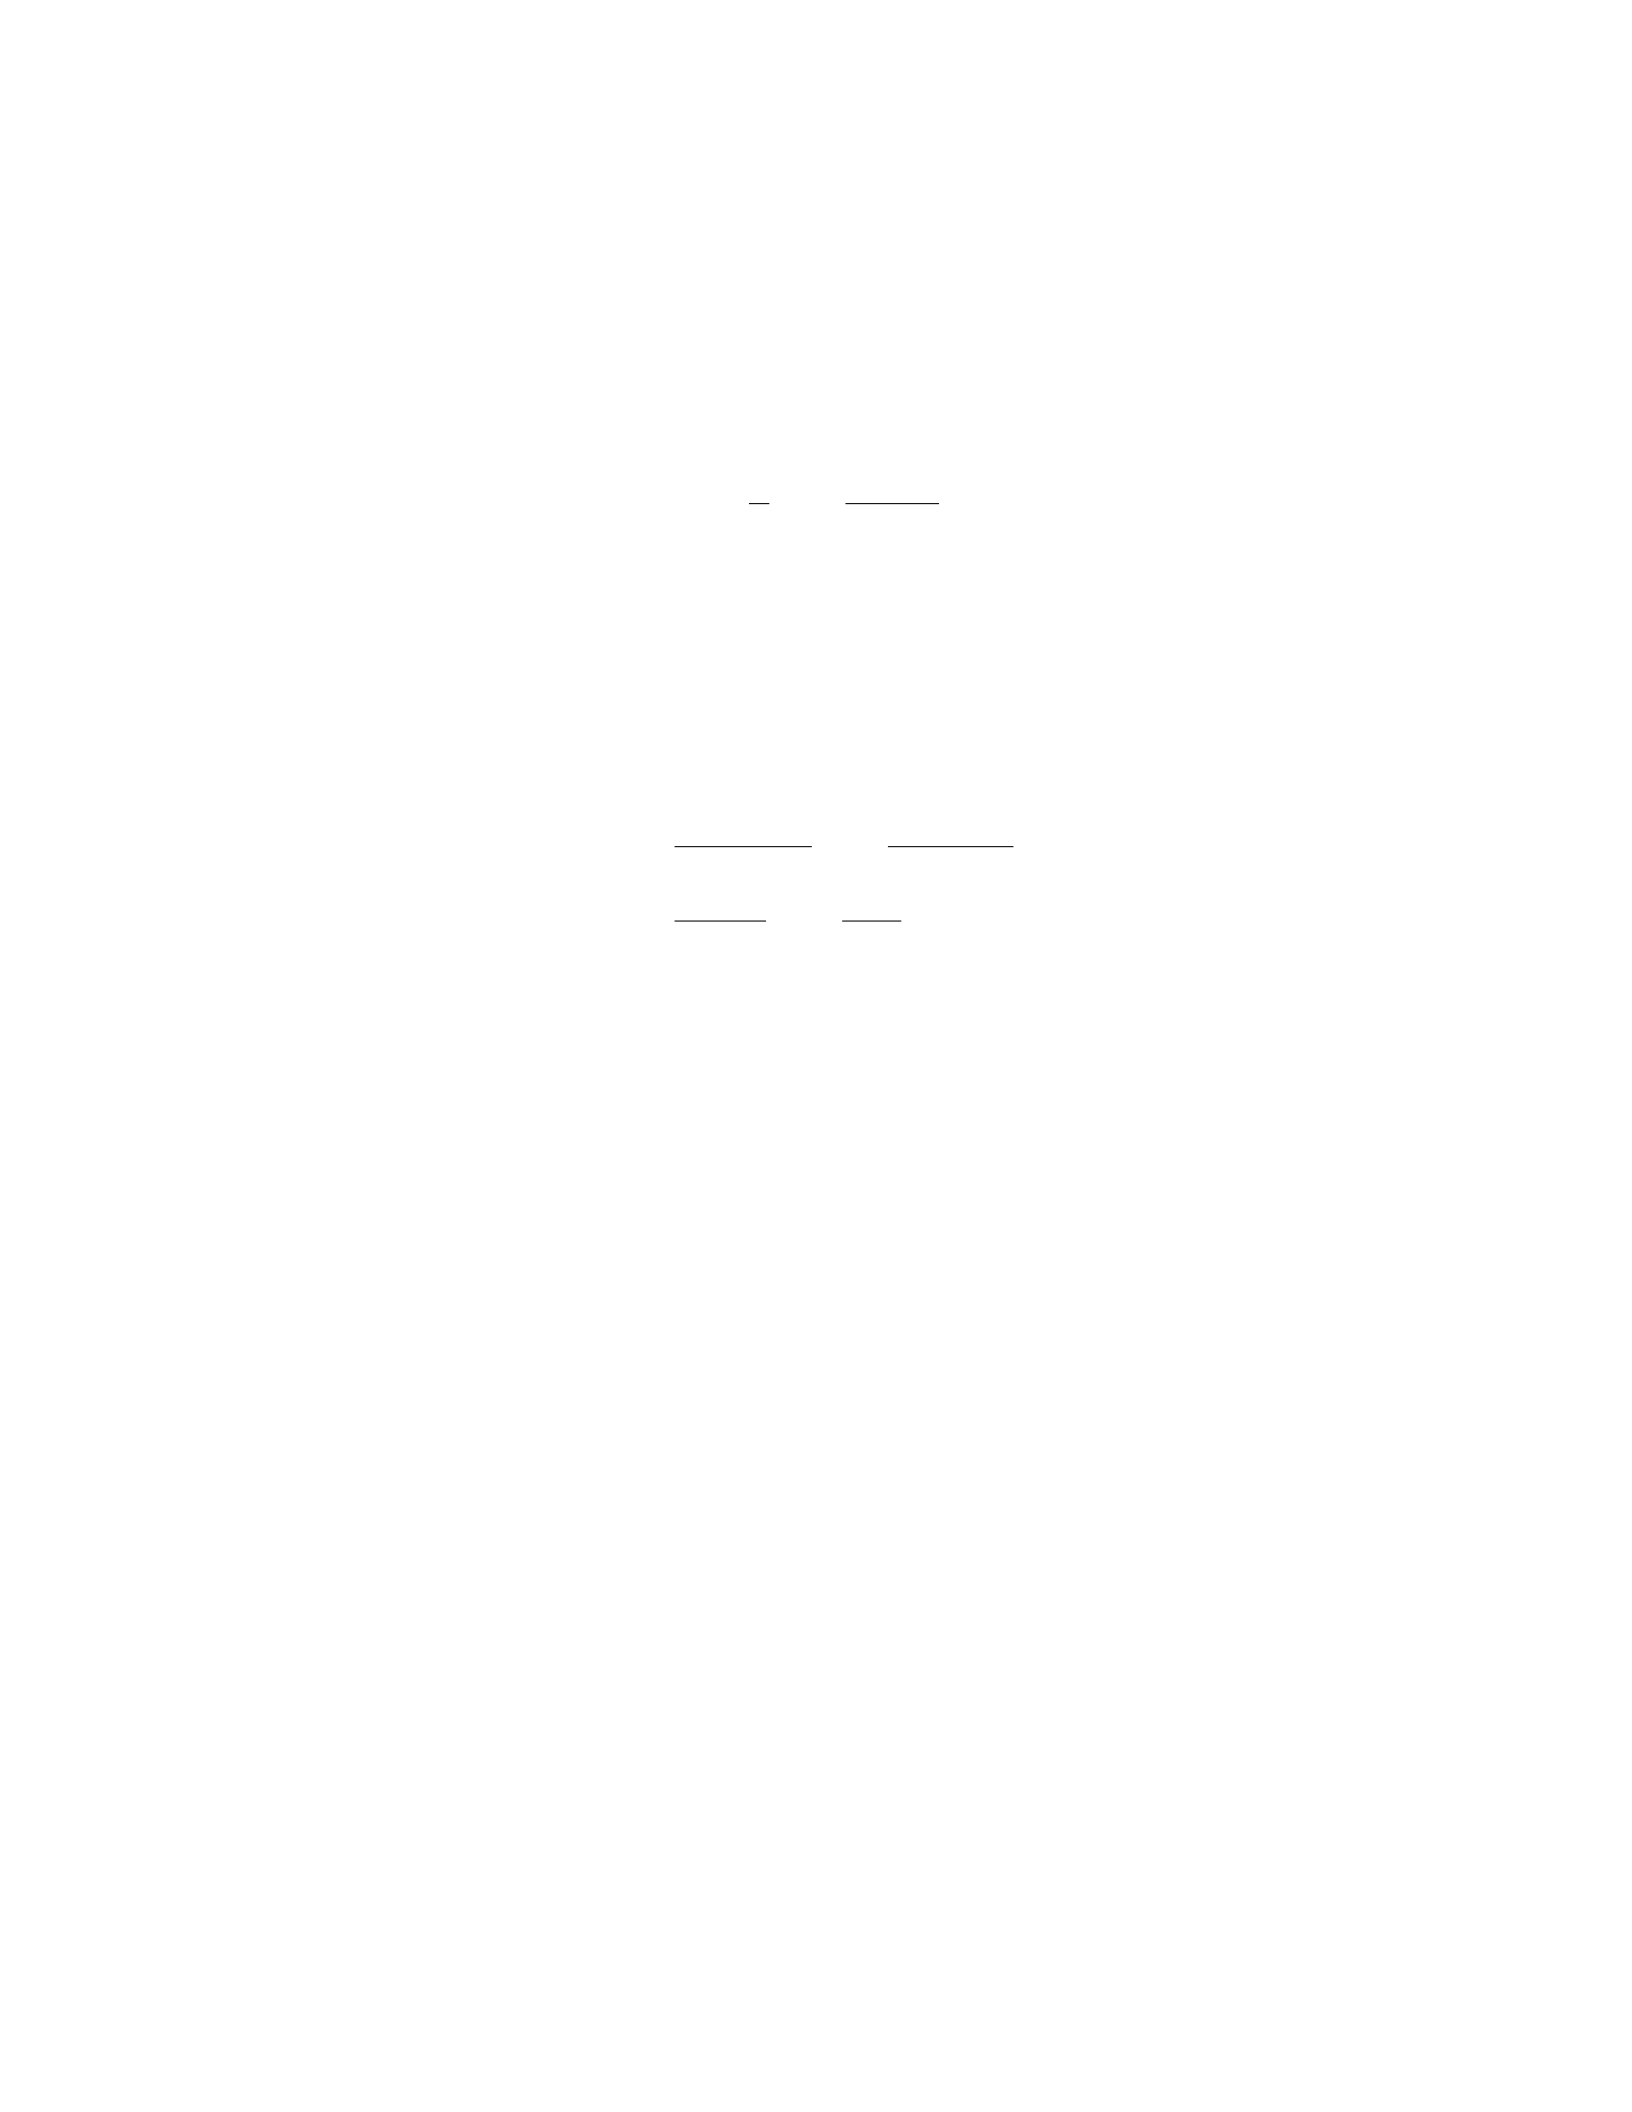
Solution
Step 1: Calculate the present value of the expected rental income over the next
5 years.
P V =R
r1−1
(1 + r)n
where:
P V = Present Value of Rental Income
R= Annual rental income = $2,500 ×12
r= Discount rate = 0.08
n= Number of years = 5
P V =$2,500 ×12
0.08 1−1
(1 + 0.08)5
P V =$30,000
0.08 1−1
1.085
P V ≈$231,145.20
Step 2: Calculate the fair value of the investment property using the present
value of the expected rental income.
Fair Value = P V
Therefore, the fair value of the investment property using the income approach
is approximately $231,145.20.
Question 33
Question
Company XYZ holds an investment in a publicly traded company where it has
significant influence. The fair value of the investment is not readily determinable
from the market, but Company XYZ believes it can estimate the fair value using
discounted cash flow analysis. Company XYZ forecasted the future cash flows
from the investment and applied a discount rate of 10
Discuss whether Company XYZ’s approach to fair value measurement is
appropriate in this scenario.
Solution
To determine whether Company XYZ’s approach to fair value measurement is
appropriate, we need to consider the requirements outlined in the accounting
standards, specifically the guidance on fair value measurement.
25

Step 1: Identify the guidance: The fair value measurement standard,
as outlined in IFRS 13 or ASC 820, requires entities to apply a market-based
approach whenever possible, which means using observable market data to es-
timate fair value when available.
Step 2: Consider the specific circumstances: In this scenario, Com-
pany XYZ does not have access to observable market data to determine the fair
value of its investment. As a result, it believes it can estimate the fair value
using discounted cash flow analysis.
Step 3: Evaluate the approach: While discounted cash flow analysis is a
common method used to estimate fair value when market data is not available, it
comes with inherent subjectivity and requires various assumptions to be made.
The accuracy of the fair value estimate is highly dependent on the cash flow
forecasts and the discount rate selected.
Step 4: Consider reasonableness: In this case, the use of discounted
cash flow analysis seems reasonable given the lack of market data. However, it
is crucial for Company XYZ to ensure that the cash flow forecasts are based on
reasonable assumptions and that the discount rate used is appropriate for the
risk associated with the investment.
Step 5: Conclusion: Based on the information provided, Company XYZ’s
approach to fair value measurement using discounted cash flow analysis appears
appropriate given the circumstances. However, Company XYZ should disclose
the significant assumptions made and the methods used in estimating the fair
value to provide transparency to users of the financial statements.
Question 34
Question
A company holds an investment property which is measured at fair value through
profit or loss. The fair value of the property at the reporting date is 3,500,000.Duringtheyear, thepropertyincreasedinvalueby15
Solution
Step 1: Calculate the new fair value of the property after the 15
New Fair Value = Fair Value ×(1 + Increase Percentage)
New Fair Value =
3,500,000 ×(1 + 0.15)
New Fair Value =
3,500,000 ×1.15
New Fair Value =
4,025,000
26
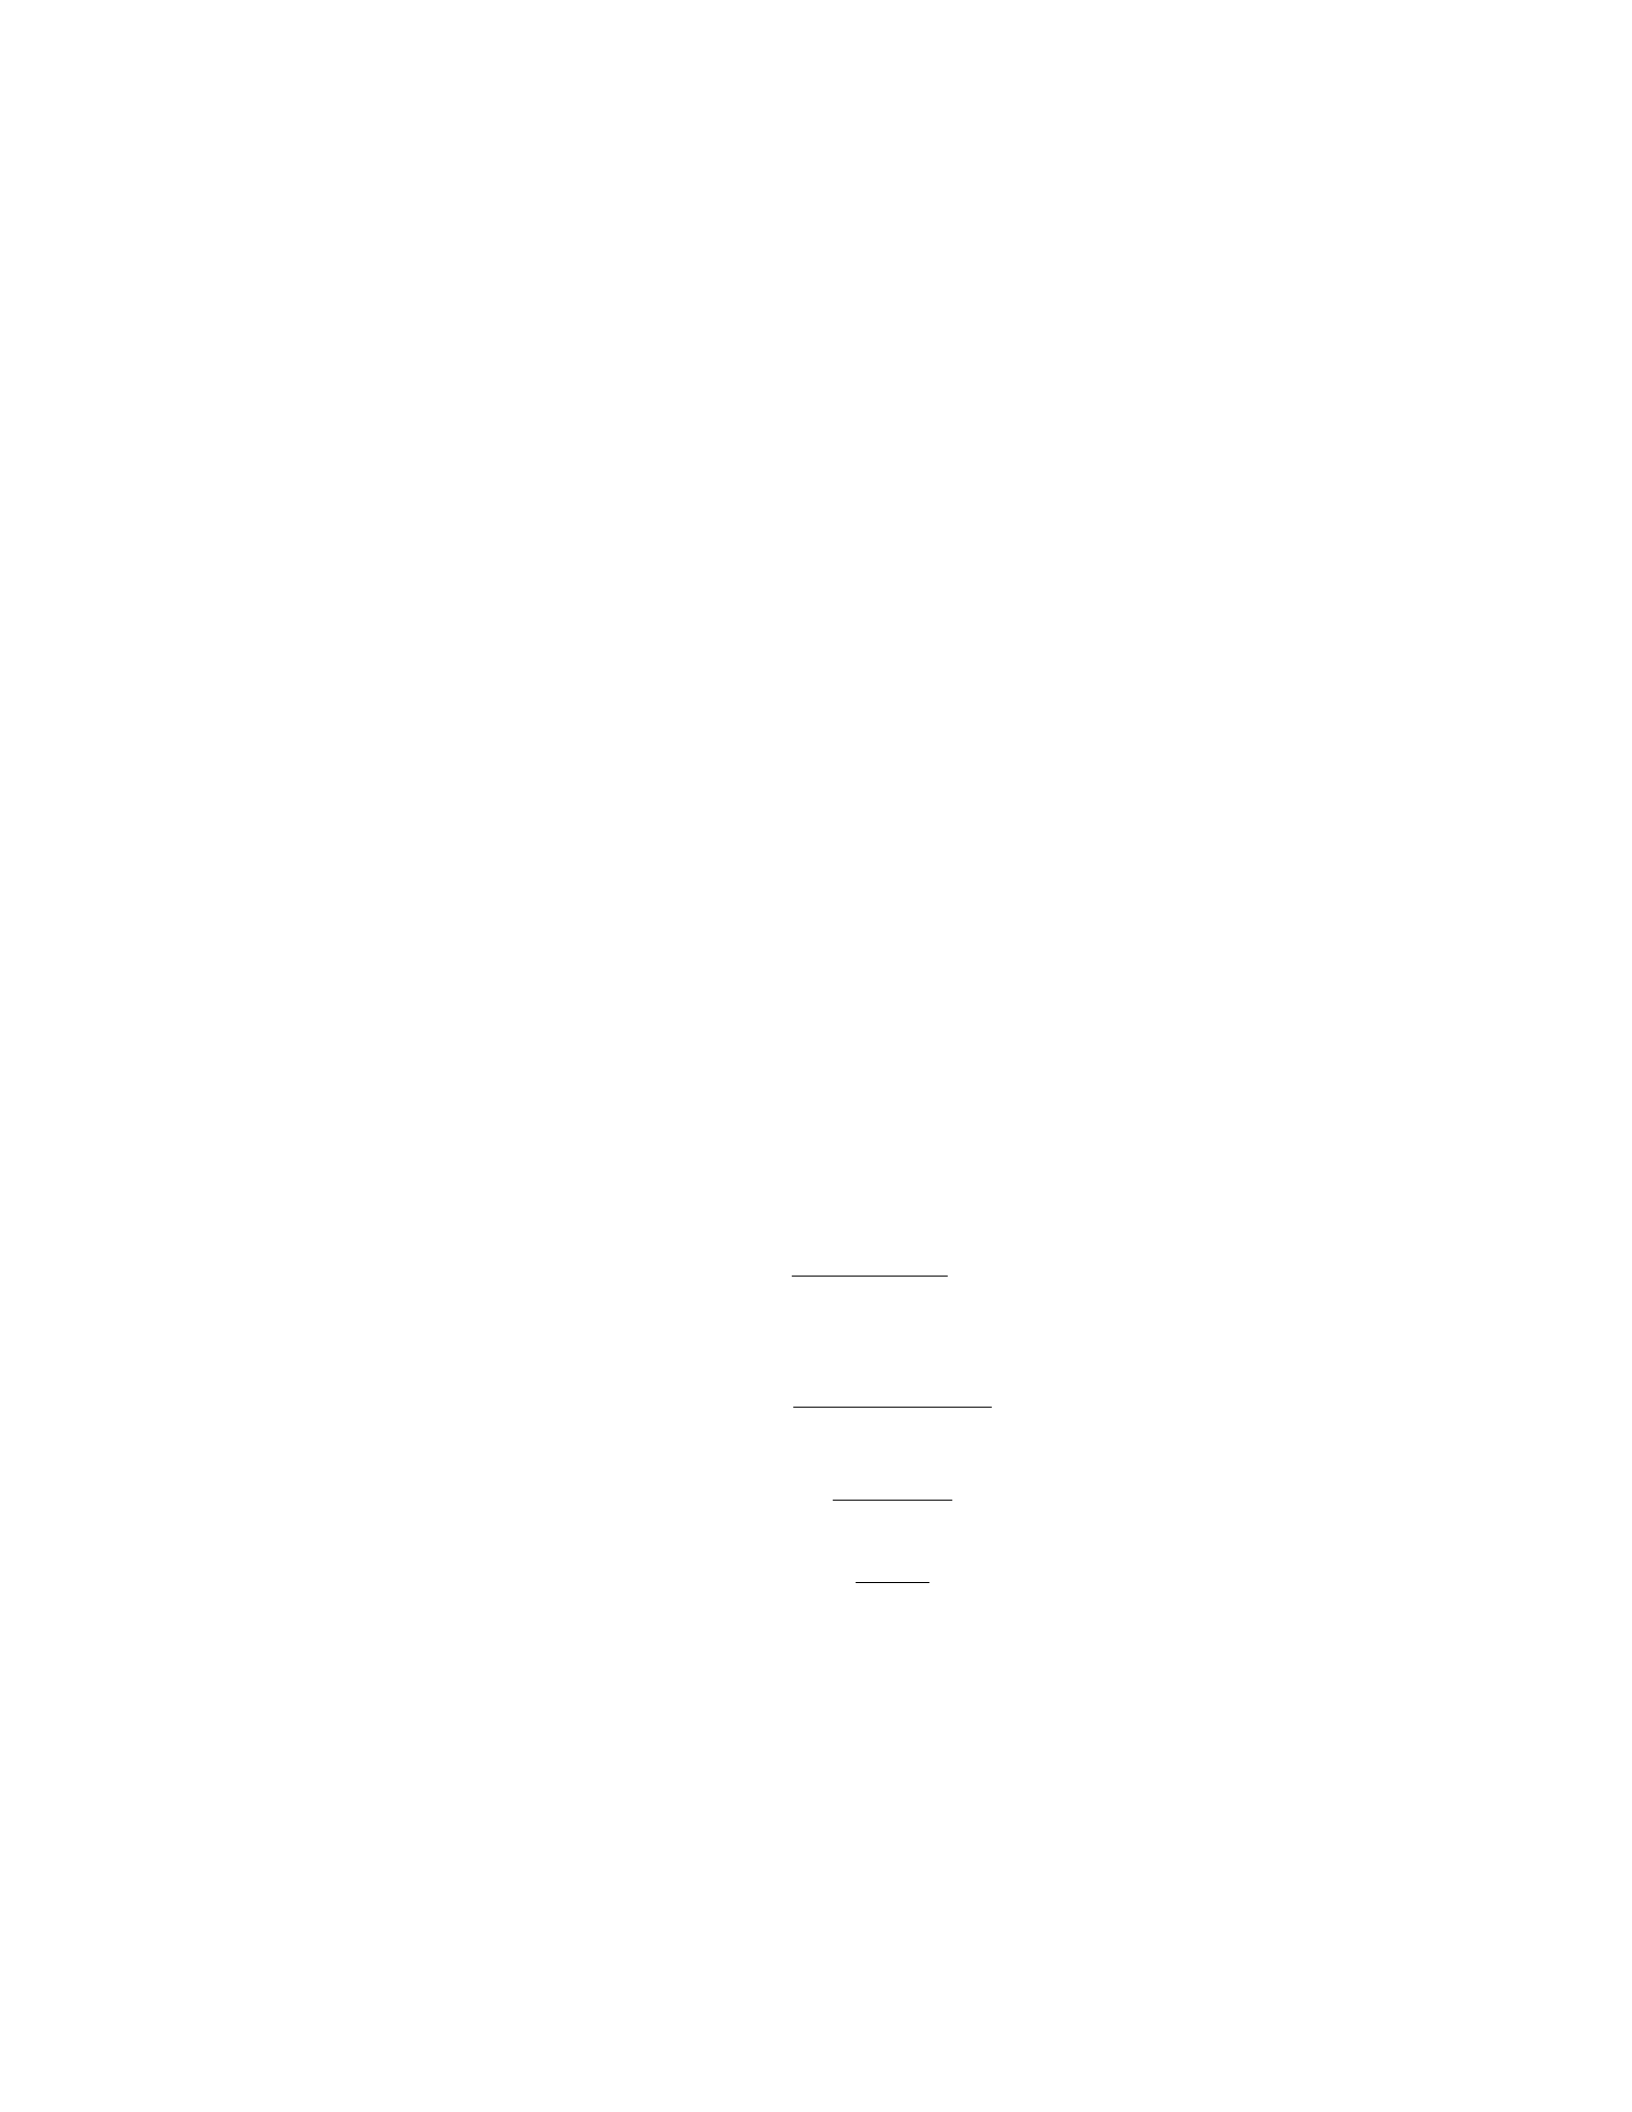
Step 2: Determine the unrealized gain or loss.
Unrealized Gain or Loss = New Fair Value −Fair Value
Unrealized Gain or Loss =
4,025,000 - 3,500,000
Unrealized Gain or Loss =
525,000
Therefore, the new fair value of the property after the 15
Question 35
Question
A company holds an investment in a financial asset classified as available-
for-sale. The fair value of the asset at the end of the reporting period is
450,000.Duetotheuncertainfuturemarketconditions, thecompany′smanagementdecidedtoapplyadiscountrateof8
Solution
Step 1: Calculate the present value of the expected future cash flows. Let’s
denote: - Pas the present value of the asset - Cas the expected annual cash
flows (50,000)−rasthediscountrate(8−nasthenumberofyears(10)
The present value Pcan be calculated using the formula for the present
value of an annuity:
P=C×1−(1 + r)−n
r
Substitute the values into the formula:
P= 50000 ×1−(1 + 0.08)−10
0.08
P= 50000 ×1−0.4632
0.08
P= 50000 ×0.5368
0.08
P= 50000 ×6.71
P= 335,500
Therefore, the present value of the expected future cash flows is 335,500.
27

Step 2: Adjust the present value for the discount rate to determine the fair
value. The fair value F V can be calculated as:
F V =P/(1 + r)n
Substitute the values:
F V = 335,500/(1 + 0.08)10
F V = 335,500/(1.08)10
F V = 335,500/2.1589
F V ≈155,572.02
Therefore, based on the management’s assessment, the fair value of the asset
would be approximately 155,572.02.
28

