


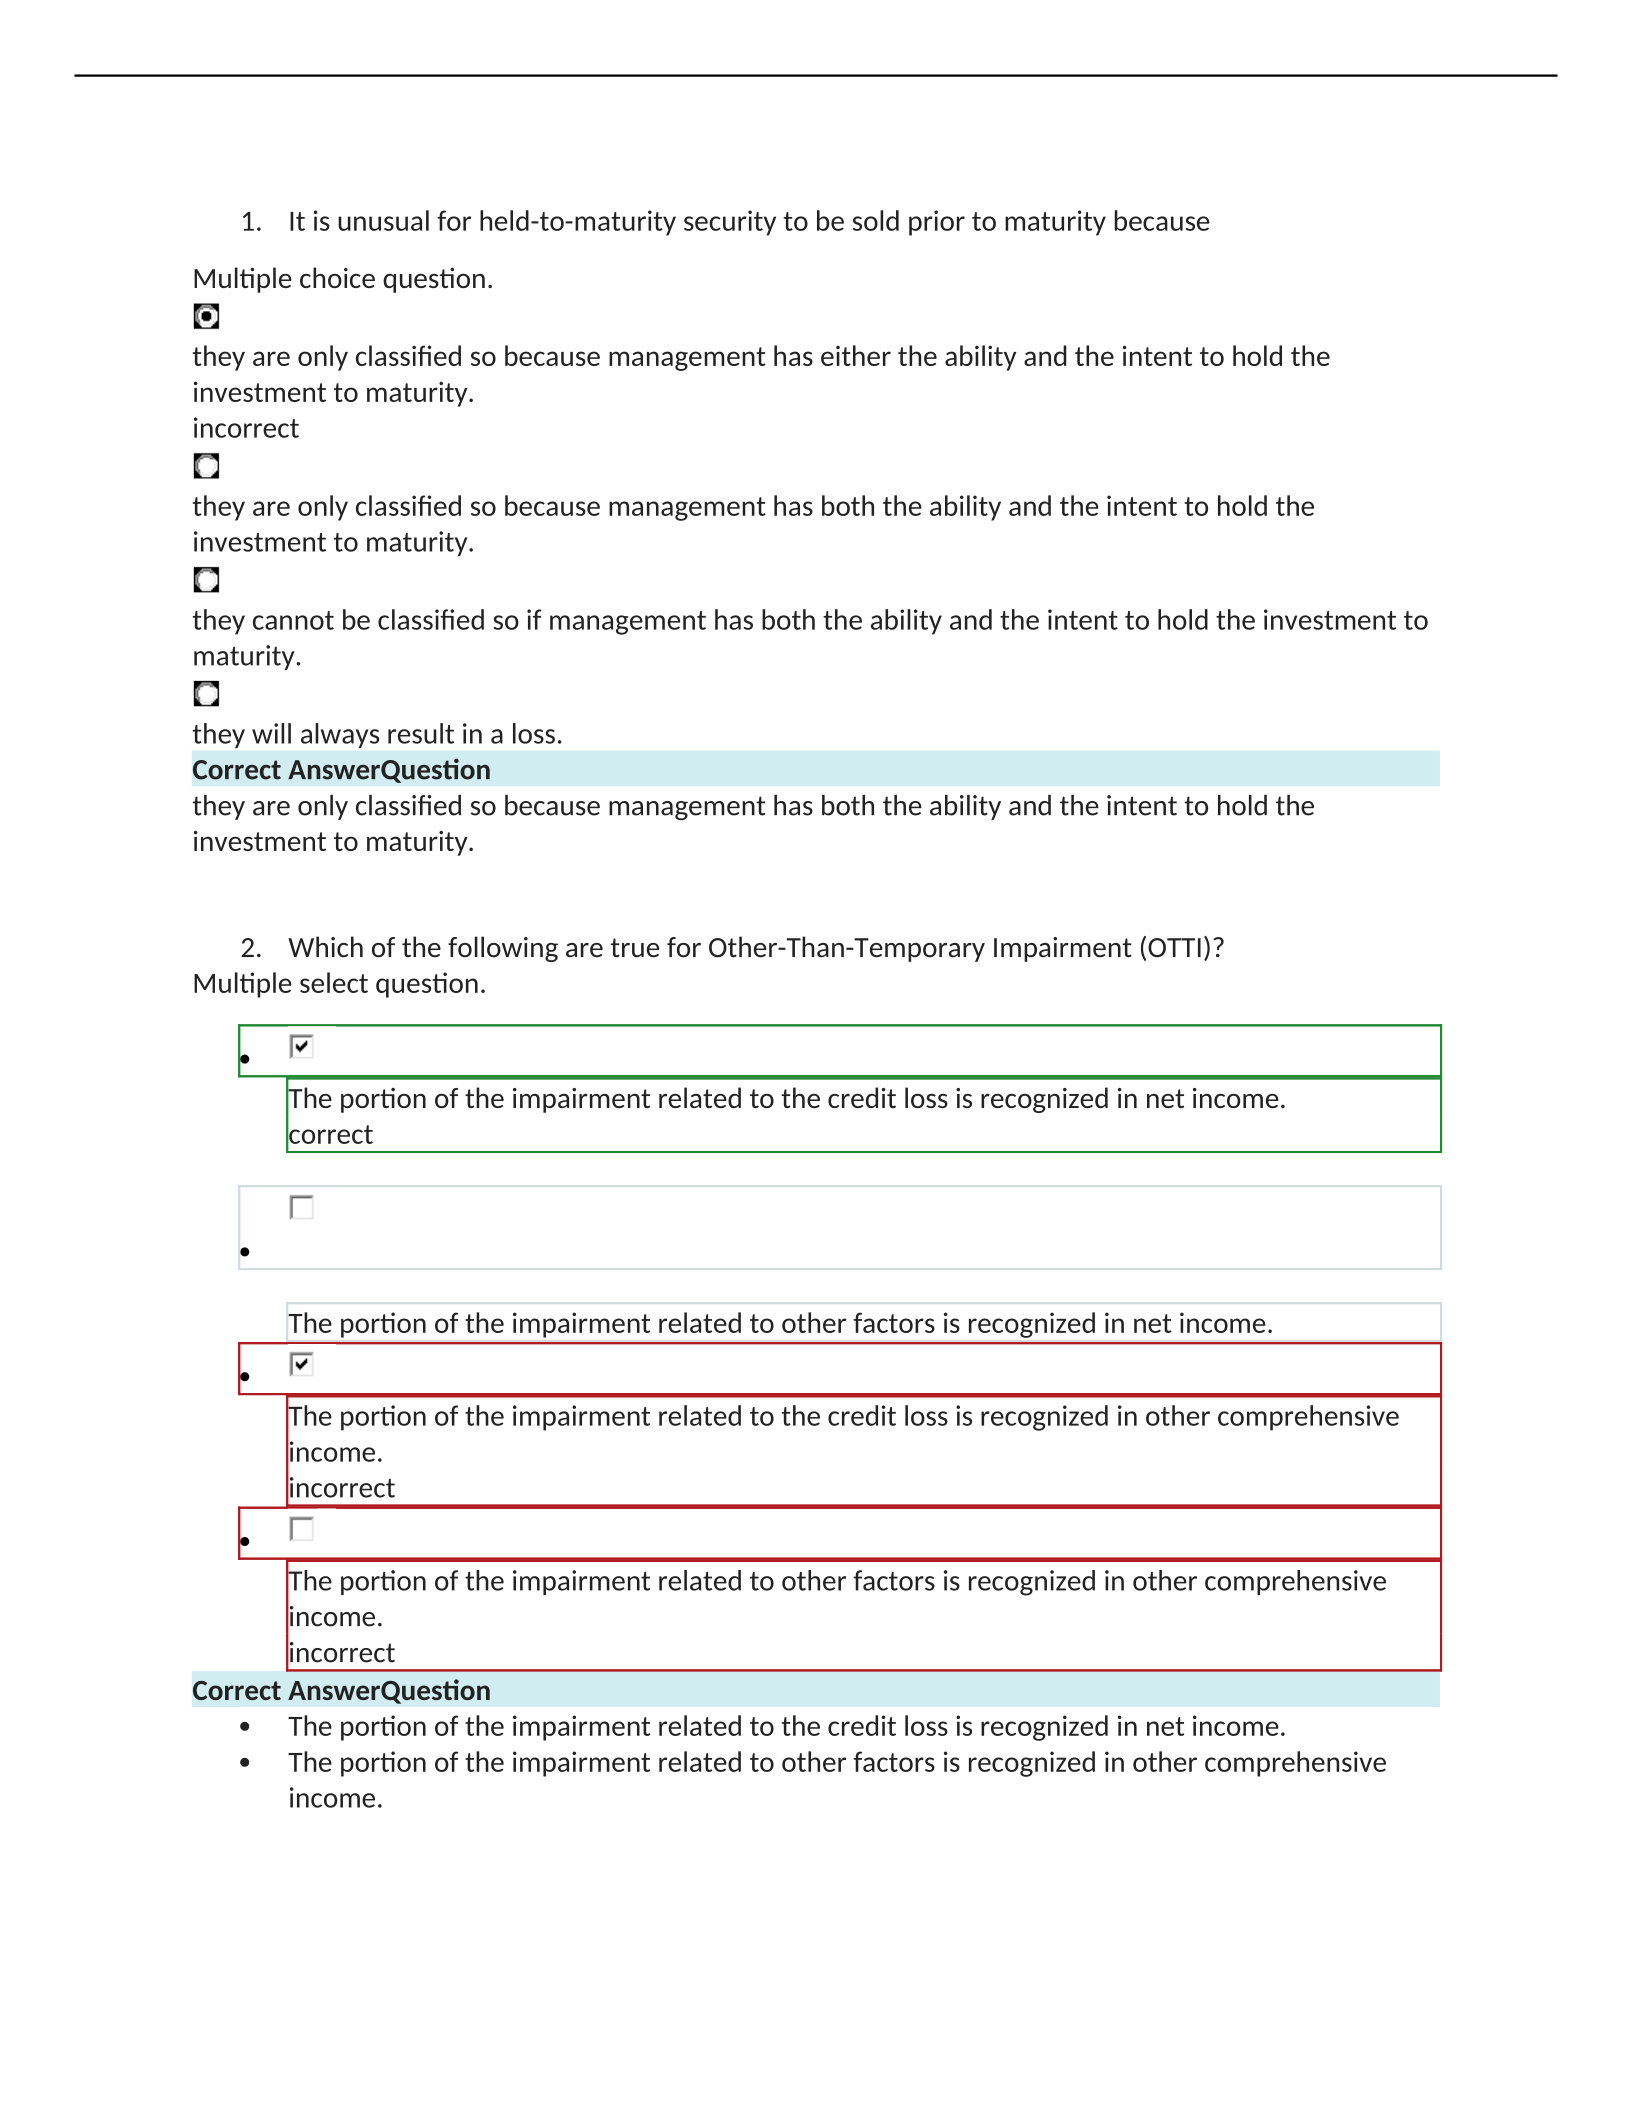
1. It is unusual for held-to-maturity security to be sold prior to maturity because
Multiple choice question.
they are only classified so because management has either the ability and the intent to hold the
investment to maturity.
incorrect
they are only classified so because management has both the ability and the intent to hold the
investment to maturity.
they cannot be classified so if management has both the ability and the intent to hold the investment to
maturity.
they will always result in a loss.
Correct AnswerQuestion
they are only classified so because management has both the ability and the intent to hold the
investment to maturity.
2. Which of the following are true for Other-Than-Temporary Impairment (OTTI)?
Multiple select question.
The portion of the impairment related to the credit loss is recognized in net income.
correct
The portion of the impairment related to other factors is recognized in net income.
The portion of the impairment related to the credit loss is recognized in other comprehensive
income.
incorrect
The portion of the impairment related to other factors is recognized in other comprehensive
income.
incorrect
Correct AnswerQuestion
The portion of the impairment related to the credit loss is recognized in net income.
The portion of the impairment related to other factors is recognized in other comprehensive
income.
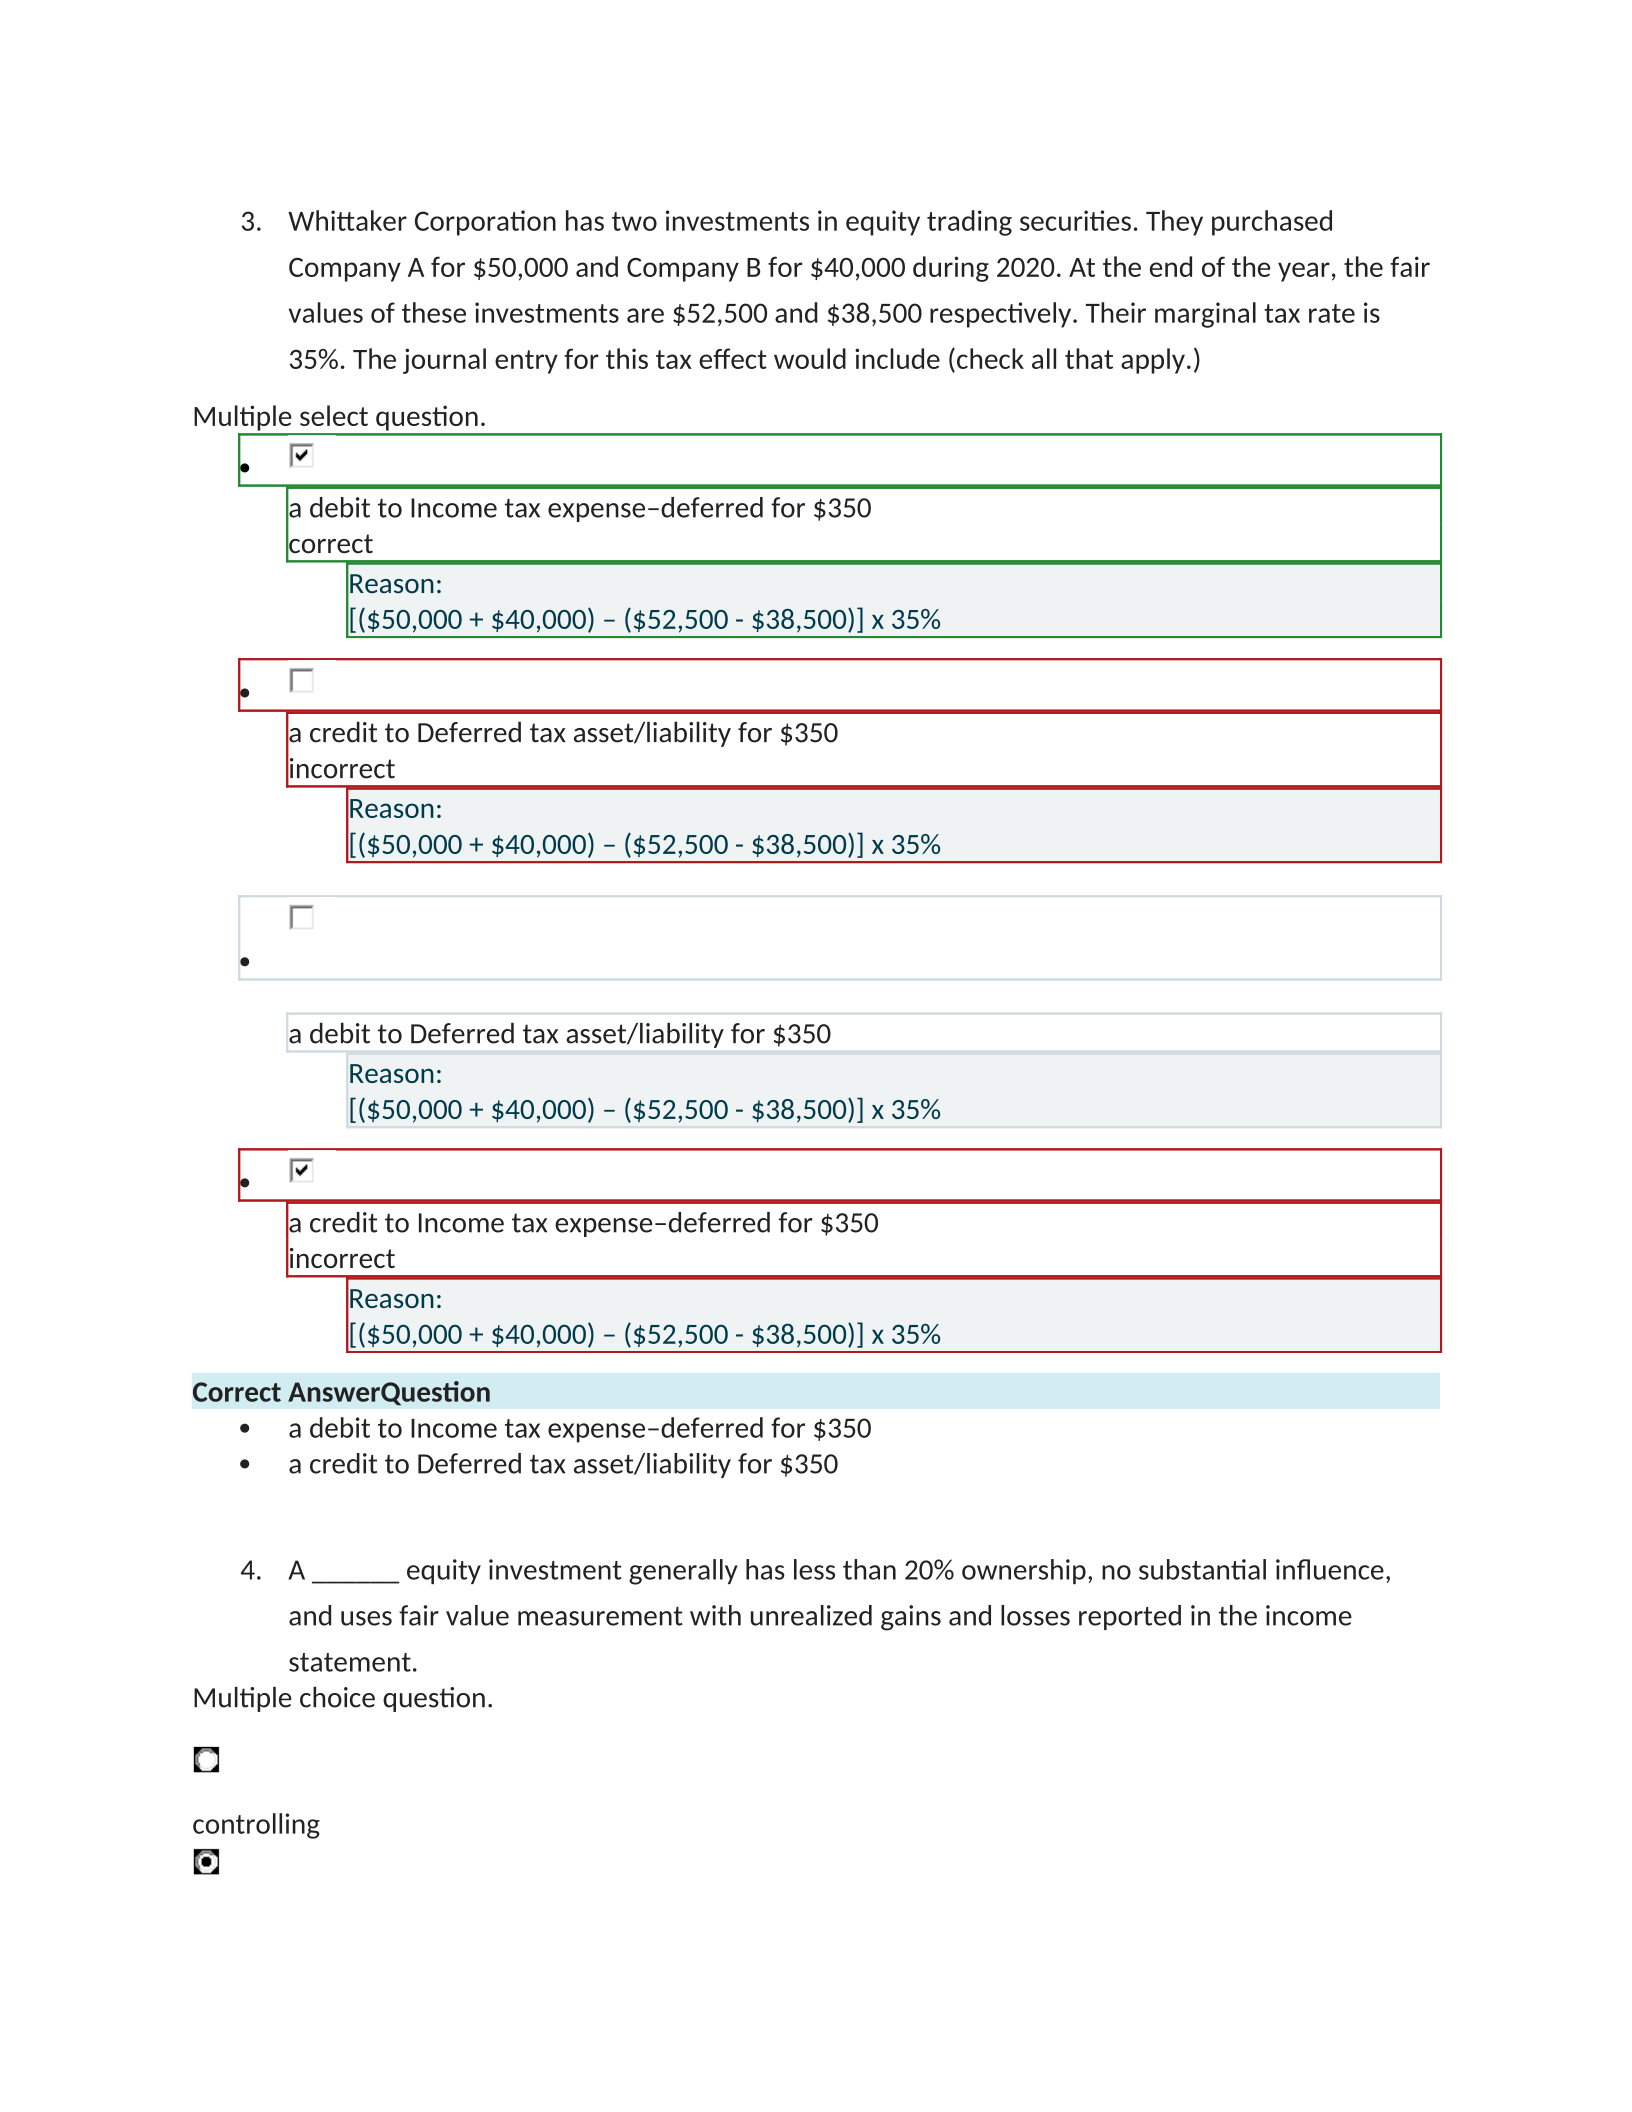
3. Whittaker Corporation has two investments in equity trading securities. They purchased
Company A for $50,000 and Company B for $40,000 during 2020. At the end of the year, the fair
values of these investments are $52,500 and $38,500 respectively. Their marginal tax rate is
35%. The journal entry for this tax effect would include (check all that apply.)
Multiple select question.
a debit to Income tax expense–deferred for $350
correct
Reason:
[($50,000 + $40,000) – ($52,500 - $38,500)] x 35%
a credit to Deferred tax asset/liability for $350
incorrect
Reason:
[($50,000 + $40,000) – ($52,500 - $38,500)] x 35%
a debit to Deferred tax asset/liability for $350
Reason:
[($50,000 + $40,000) – ($52,500 - $38,500)] x 35%
a credit to Income tax expense–deferred for $350
incorrect
Reason:
[($50,000 + $40,000) – ($52,500 - $38,500)] x 35%
Correct AnswerQuestion
a debit to Income tax expense–deferred for $350
a credit to Deferred tax asset/liability for $350
4. A ______ equity investment generally has less than 20% ownership, no substantial influence,
and uses fair value measurement with unrealized gains and losses reported in the income
statement.
Multiple choice question.
controlling
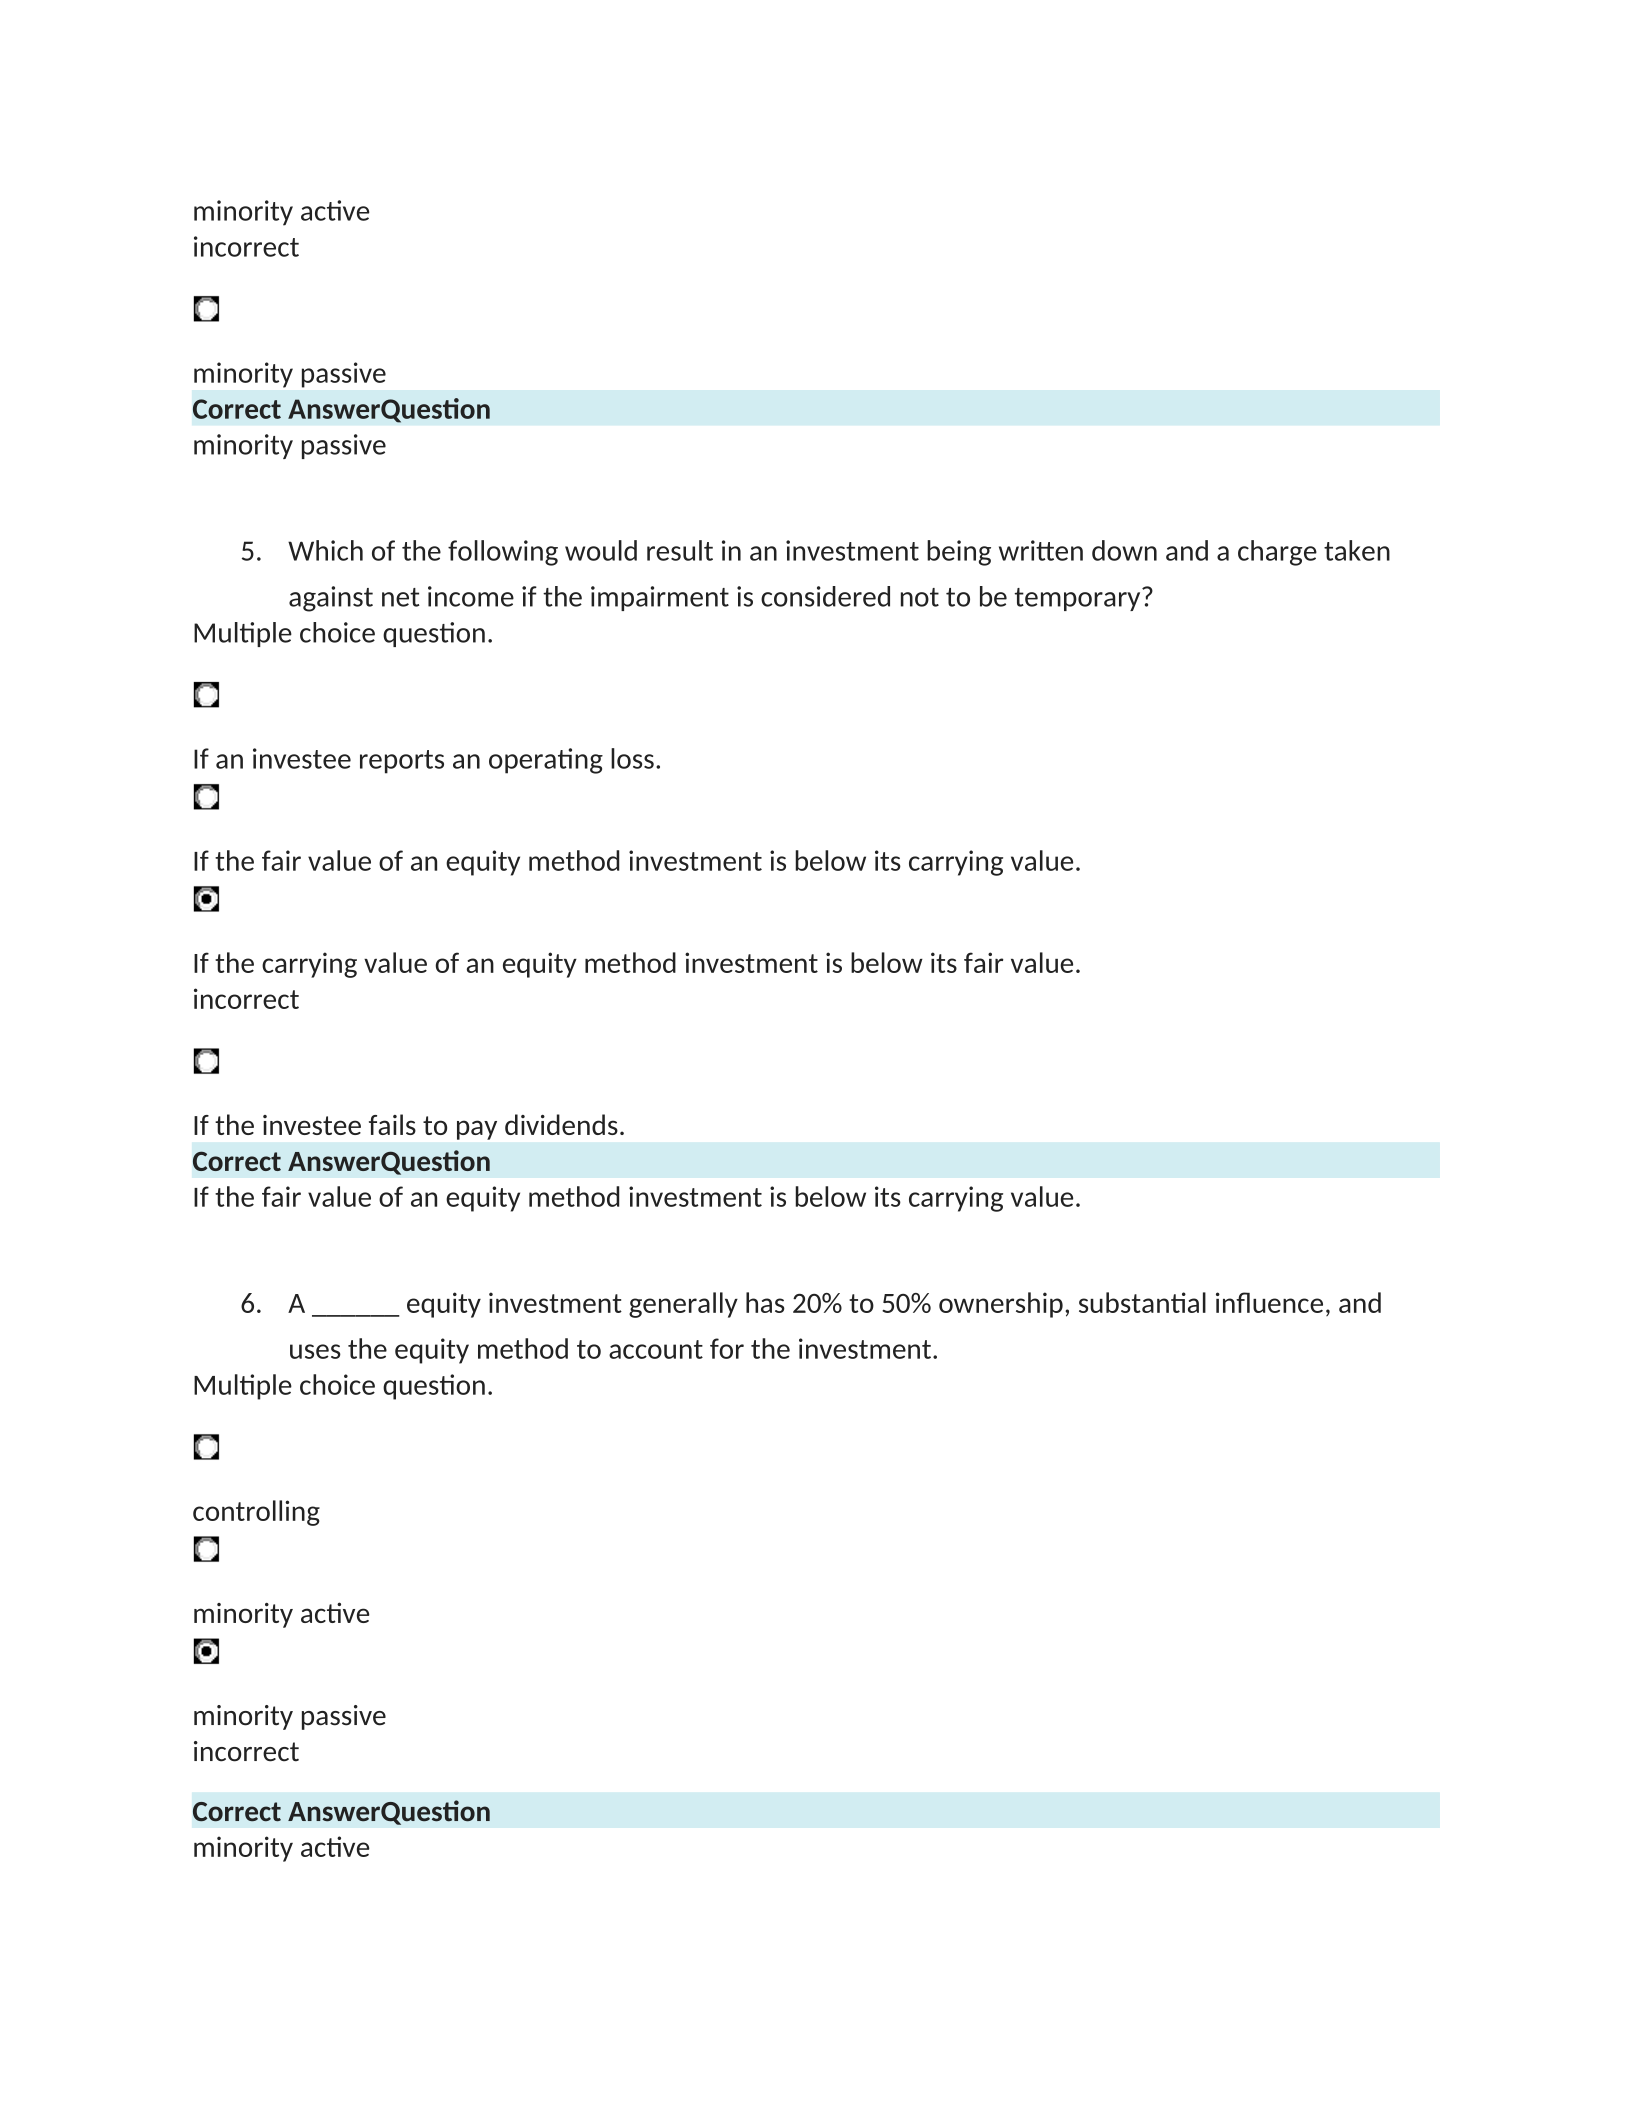
minority active
incorrect
minority passive
Correct AnswerQuestion
minority passive
5. Which of the following would result in an investment being written down and a charge taken
against net income if the impairment is considered not to be temporary?
Multiple choice question.
If an investee reports an operating loss.
If the fair value of an equity method investment is below its carrying value.
If the carrying value of an equity method investment is below its fair value.
incorrect
If the investee fails to pay dividends.
Correct AnswerQuestion
If the fair value of an equity method investment is below its carrying value.
6. A ______ equity investment generally has 20% to 50% ownership, substantial influence, and
uses the equity method to account for the investment.
Multiple choice question.
controlling
minority active
minority passive
incorrect
Correct AnswerQuestion
minority active
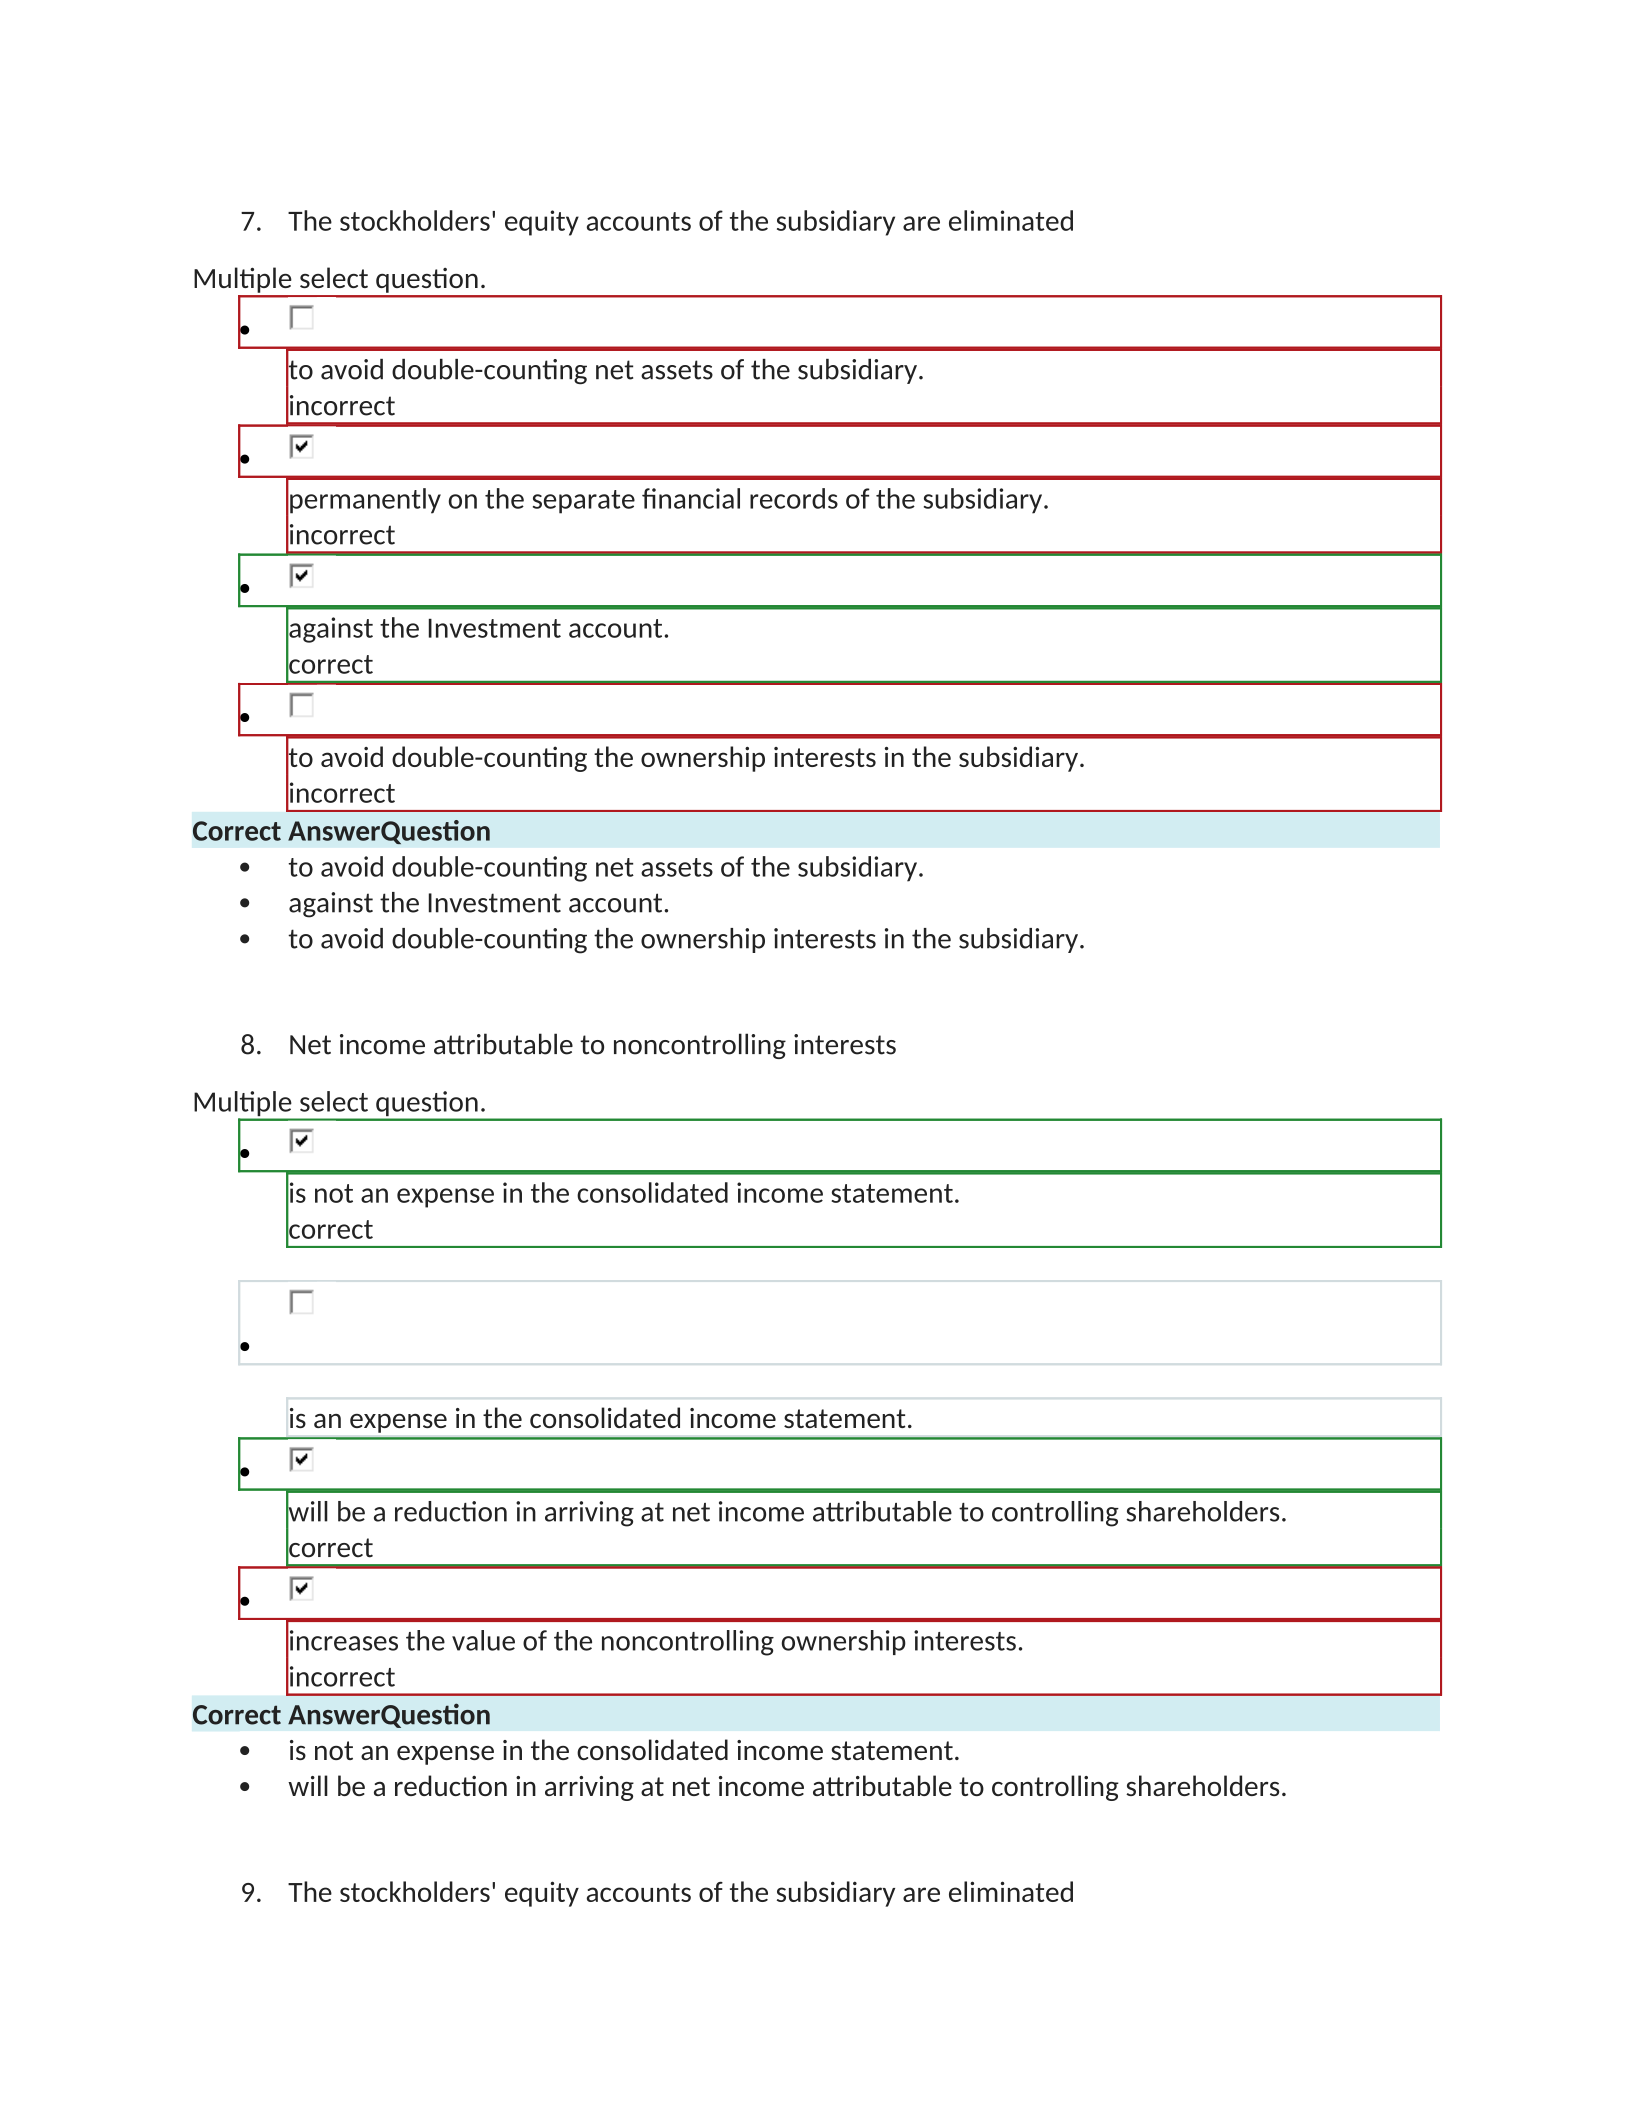
7. The stockholders' equity accounts of the subsidiary are eliminated
Multiple select question.
to avoid double-counting net assets of the subsidiary.
incorrect
permanently on the separate financial records of the subsidiary.
incorrect
against the Investment account.
correct
to avoid double-counting the ownership interests in the subsidiary.
incorrect
Correct AnswerQuestion
to avoid double-counting net assets of the subsidiary.
against the Investment account.
to avoid double-counting the ownership interests in the subsidiary.
8. Net income attributable to noncontrolling interests
Multiple select question.
is not an expense in the consolidated income statement.
correct
is an expense in the consolidated income statement.
will be a reduction in arriving at net income attributable to controlling shareholders.
correct
increases the value of the noncontrolling ownership interests.
incorrect
Correct AnswerQuestion
is not an expense in the consolidated income statement.
will be a reduction in arriving at net income attributable to controlling shareholders.
9. The stockholders' equity accounts of the subsidiary are eliminated
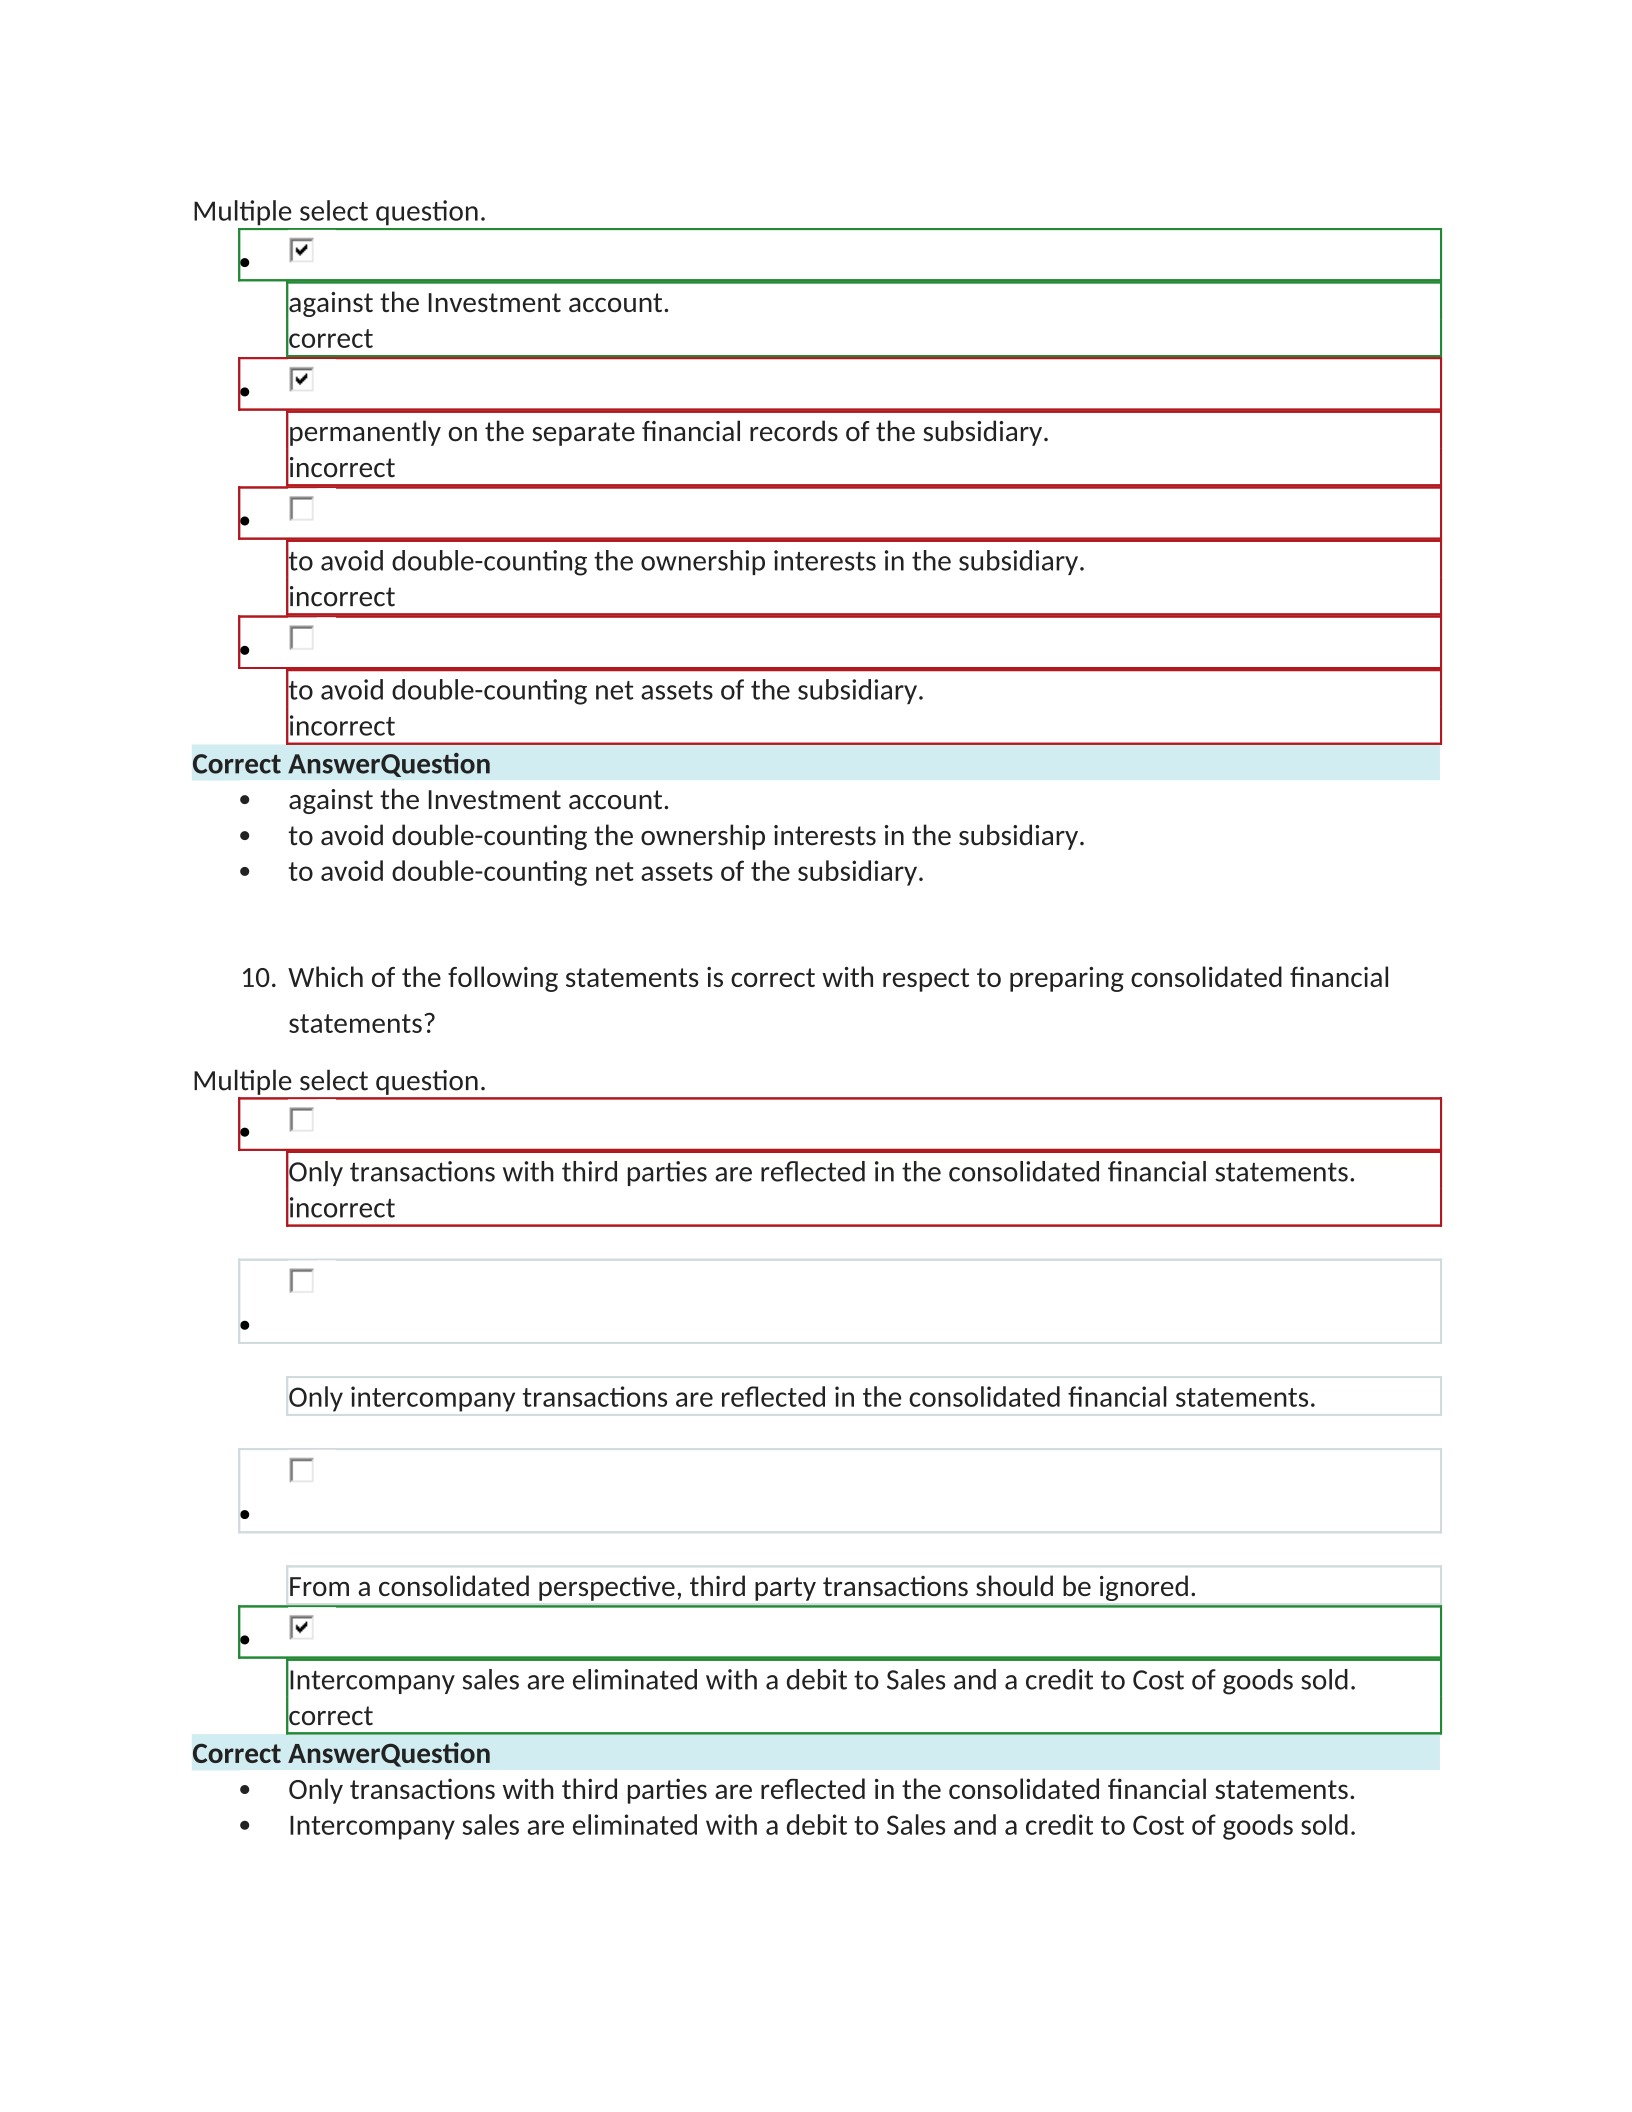
Multiple select question.
against the Investment account.
correct
permanently on the separate financial records of the subsidiary.
incorrect
to avoid double-counting the ownership interests in the subsidiary.
incorrect
to avoid double-counting net assets of the subsidiary.
incorrect
Correct AnswerQuestion
against the Investment account.
to avoid double-counting the ownership interests in the subsidiary.
to avoid double-counting net assets of the subsidiary.
10. Which of the following statements is correct with respect to preparing consolidated financial
statements?
Multiple select question.
Only transactions with third parties are reflected in the consolidated financial statements.
incorrect
Only intercompany transactions are reflected in the consolidated financial statements.
From a consolidated perspective, third party transactions should be ignored.
Intercompany sales are eliminated with a debit to Sales and a credit to Cost of goods sold.
correct
Correct AnswerQuestion
Only transactions with third parties are reflected in the consolidated financial statements.
Intercompany sales are eliminated with a debit to Sales and a credit to Cost of goods sold.

