


Instruction: Shade the letter of the correct answer. Erasures are not allowed.
1. What is the primary objective in verifying prepaid expenses?
a. Verify that payments were made through company
bank accounts Not the main audit goal
b. Ensure the payments are recorded as assets until
consumed or expired
The core objective is proper deferral and recognition in the correct period
c. Confirm prepayments directly with suppliers
Confirmation is only one possible procedure
d. Ensure that all prepayments are classified as
current assets
Not all prepayments are current assets (some can be noncurrent)
2. The greatest risk of overstatement in prepaid expenses occurs when:
a. Services are received but not yet paid for c.
Payments are made after services are received
This would understate liabilities, not Timing is
normal, not inherently risky for overstate assets.
overstatement.
b. d. Expenses are paid on the due date each month
Timing is normal, not inherently risky for Recording
fictitious benefits overstates overstatement. assets.
3. Which procedure would provide the most reliable evidence of existence for a prepaid rent balance?
a. Inspect proof of payment c.
Review the lease contract
Contract shows agreement, not necessarily
Payment doesn’t prove the benefit still current asset existence.
exists.
b. Perform analytical procedures d.
Confirm the balance with the landlord
Analytics are less persuasive. External confirmation is more reliable than internal documents.
4. If a client records travel advances to employees as prepaid expenses but does not require liquidation of
unused amounts, which risk arises?
a. Understatement of liabilities c.
Overstatement of assets
Not relevant here Advances not cleared could be personal use,
inflating assets.
b. Overstatement of revenues d.
Understatement of expenses
Not relevant here Could also happen, but the more direct risk is
overstated assets.
5. If the auditor notes that certain prepayments are non-refundable, what is the implication for audit testing?
Payments are made in advance for
services never
received
a. The amortization schedule must still reflect the
expiration of benefits.
Even non-refundable prepayments must be amortized over the period of benefit.
b. They should be excluded from valuation testing. -
Valuation testing is necessary.
c. They should be tested for rights and obligations
only. - Other assertions like valuation still apply. d.
Choices A and B are correct.
6. If a prepaid expense relates to a contract that has been terminated early, the unamortized balance
should:
a. Remain in assets until the end of original term
Would overstate assets.
b. Be written off to expense immediately
No future benefit exists; asset must be expensed.
c. Be transferred to accounts receivable Not
collectible unless refund due.
d. Both B and C are correct
7. During substantive testing of prepayments, an auditor finds that a large prepayment is recorded for a
supplier that has since gone bankrupt. This primarily raises concern about:
a. Rights and Obligations c. Completeness
The right to receive goods or services still exists Completeness is unrelated; the legally, but
recoverability is doubtful transaction is already recorded
b. Valuation d. Cut-off
If the supplier is bankrupt, the prepayment may no l Cut-off is not in question; the iss be
recoverable, creating a valuation issue collectibility/value
8. When a company prepays an expense to avoid a price increase, the auditor’s main concern is:
a. Classification c. Cut-off
Need to ensure classification between current
and noncurrent if benefit extends beyond 12
months
b. Rights and obligations d.
Completeness
9. Which of the following would provide the most persuasive evidence about the valuation of prepaid
expenses?
a. Analytical procedures comparing prepayments to
prior periods.
Analytical review helps identify unusual trends, but does not directly confirm valuation.
b. Recalculation of the amortization schedule
prepared by the client.
Recalculation is useful for recorded amounts but won’t detect unrecorded prepayments;
contracts still need to be inspected.
c. Inspection of supplier contracts and invoices to
determine coverage periods.
Inspection of contracts and invoices provides direct, reliable evidence about the timing and
extent of the prepaid benefit.
d. Inquiry of the accounting staff on their expense
allocation policy. Inquiry alone is weak evidence—
needs corroboration.
10. The most effective substantive procedure to verify the rights assertion for prepaid rent is to:
a. Inspect the lease agreement. c. Recalculate rent
amortization. The lease agreement is the primary
evidence Valuation
of the entity’s right to occupy the property for a
prepaid period.
b. Send a confirmation to the landlord. d.
Compare to prior year balances.
Existence Analytical review
11. An auditor notes a significant prepaid expense recorded in December but relating entirely to the next
year. What is the most appropriate substantive response?
a. Confirm the
payment
with the
bank
c.
Bank confirmation proves payment occurred but does not address misclassification
The expense should be reclassified as
a prepayment and not charged to the
current year’s expenses
b. Test the cut-off of accounts receivable d. Review
internal audit reports Accounts receivable cut-off is
unrelated to Reviewing internal audit reports is
prepayments indirect and not a substantive
adjustment
12. An entity sells gift cards and records them as deferred revenue until redemption. Which audit risk is most
likely if historical redemption patterns are not reviewed?
a. Overstatement of expenses. c. Understatement of
liabilities. Expenses are not affected by gift card
Understatement would occur if too little breakage
directly. deferred revenue is recorded, which is
not the case here.
b. Overstatement of liabilities. d. None of
the choices
Propose reclassification to current
assets and adjust
expenses
If old, unused gift card balances are never
adjusted for breakage, deferred revenue
remains overstated.
13. Which procedure provides the most reliable evidence about the existence and valuation of deferred
revenue?
a. Reviewing board minutes for discussions on future
projects.
Board minutes may indicate intentions but do not directly confirm balances.
b. Sending confirmations to vendors regarding
payment terms Vendor confirmations are
unrelated to deferred revenue.
c. Performing a ratio analysis comparing deferred
revenue to total revenue. Ratio analysis may flag
anomalies but doesn’t directly confirm amounts.
d. Tracing customer cash receipts to the deferred
revenue ledger and examining related contracts
Tracing receipts to the ledger and verifying
contracts ensures the amounts represent
unearned revenue and are valued correctly.
14. Which assertion is most directly tested when the auditor verifies that revenue recognized from deferrals
is matched with the delivery of goods or services?
a. Cut-off c. Completeness
The focus is on proper timing—ensuring that Completeness is about ensuring all deferred
revenue is recognized only in the liabilities are recorded, not when they’re correct
period reversed
b. Rights and Obligations d. Existence
Rights and obligations is about whether the Existence ensures the liability existed at entity
has the obligation to perform year-end, but the timing of release is a cut-off matter
15. An auditor inspects contracts to determine whether performance obligations have been met before
recognizing revenue. This primarily addresses:
a. Completeness
Completeness ensures all
liabilities are recorded; this is
about timing
c. Rights and Obligations
Rights involve ownership or entitlement, not
period recognition
b. Accuracy
Accuracy involves correct measurement, not
timing
d. Cut-off
Checking contract terms against
recognition timing ensures revenue is
recognized in the correct period (cutoff)
16. Which situation poses the highest risk of misstating deferred revenue?
a. A consulting firm recognizes revenue strictly
based on hours worked
Recognition by hours worked is closer to completion-based, not deferred
b. A manufacturer bills customers only upon delivery
of goods Billing after delivery reduces deferral risk
c. A retail store sells gift cards redeemable for
products at a later date
Gift cards are classic deferred revenue; the risk is improper recognition before redemption
d. A service company receives payments only after
service completion No prepayment means no
deferral risk
17. Which of the following is least likely to be a substantive procedure for auditing deferred income?
a. Reconciling deferred income schedules to the
general ledger.
This is a substantive analytical or recalculation procedure — you’re directly verifying the accuracy
of recorded amounts.
b. Examining contracts to determine performance
obligations.
This is a substantive test of details, confirming the correct timing and amount of revenue
recognition based on contractual terms.
c. Reviewing internal control flowcharts.
Reviewing internal control flowcharts is a control test, not a substantive procedure.
d. Testing cut-off of cash receipts at year-end.
This is a substantive cut-off test, ensuring that cash receipts and related revenue or deferred
revenue are recorded in the proper period.
ALL OTHER ELSE ARE SUBSTANTIVE PROCEDURES
18. An auditor notes that the client has recorded deferred revenue for non-refundable deposits received for
events that will never take place. What is the most likely misstatement?
a. Revenue is understated c.
Deferred revenue is understated
Since the events won’t occur and deposits are
It’s the opposite — deferred revenue is
non-refundable, the liability should be
overstated because the liability
should
derecognized and revenue recognized.
no longer exist.
Leaving it as deferred revenue understates revenue.
b. Liabilities are understated d. Expenses
are overstated
In this case, liabilities are actually overstated, This issue has nothing to do with not
understated. The client is holding onto a expenses. There is no evidence that deferred revenue
balance that should have costs were recorded incorrectly; the been removed.
misstatement lies entirely in the revenue and liability accounts
19. A deferred income balance that significantly decreases despite stable advance sales is likely due to:
a. Recording errors in accounts receivable
c. Premature revenue recognition.
Accounts receivable is unrelated to deferred If advance sales are stable but deferred income
unless there’s a misclassification income is falling, the most logical cause is between receivables
and deferred revenue. that revenue is being recognized before the However, in this scenario, sales
are stable and related obligation is fulfilled — reducing the there’s no indication of misclassification
— the deferred income balance prematurely.
key issue is timing of recognition, not receivable
balances.
b. Understatement of expenses d.
Overstatement of liabilities
Expenses don’t directly affect deferred
income because deferred income is a
liability. Even if expenses are understated,
deferred revenue would not drop unless
related to revenue recognition errors.
A drop in deferred income without sales change
often means revenue is being recognized too
early.
20. Which of the following would be most appropriate if the auditor suspects unearned revenue was
recognized?
a. Extend cut-off testing around year-end c. Confirm receivables with customers
EXISTENCE
Cut-off testing determines if revenue was recorded in
the correct period
b. Recalculate depreciation expense d. Review petty cash vouchers
VALUATION NOT RELEVANT
21. An auditor notes that deferred subscription revenue increased significantly compared to last year. Which
of the following is the most likely risk?
a. Cut-off errors in expense recognition
Expense recognition is unrelated to deferred
revenue
c. Overstatement of liabilities
A sharp increase could indicate that
revenue that should have been
recognized was incorrectly deferred,
overstating liabilities.
b. Premature recognition of revenue
Premature revenue recognition would decrease
deferred revenue, not increase it
d. Understatement of liabilities
The balance increased, so
understatement is unlikely
22. Which of the following would most likely indicate an overstatement of deferred income?
a. Revenue is recognized before goods are delivered
This would cause understatement of deferred income, not overstatement
b. Customer payments are received after the period-end
Post-year-end receipts affect the next period, not current deferral balances
c. Cash receipts are posted to the wrong customer account
Posting errors affect customer account accuracy, not necessarily total deferred income
d. Revenue from completed sales is recorded as deferred
If completed sales are recorded as deferred, liabilities are overstated
23. When auditing internally generated intangible assets, which is the most appropriate substantive
procedure to determine whether recognition criteria under PAS 38 are met?
a. Review subsequent period cash flows for evidence of economic benefits
Recognition requires probable future economic benefits; reviewing post-balance sheet cash
flows can provide evidence
b. Inspect physical documentation of the intangible asset
Intangibles have no physical form, so inspection of physical documentation is limited to support
but not recognition criteria
c. Confirm existence with third parties
External confirmation rarely applies unless related to licensing agreements
d. Recalculate amortization expense for the year
Recalculation tests accuracy, not recognition criteria
24. An auditor is verifying the capitalization of development costs. Which substantive procedure is least likely
to be performed:
a. Assess whether costs relate to the research phase
Distinguishing research from development is a key audit step
b. Perform physical inspection of the developed product
Physical inspection has limited relevance to intangible asset recognition
c. Review project feasibility studies
Feasibility is essential to determine capitalization
d. Trace costs to supporting invoices and payroll records Tracing costs is vital for valuation and
completeness
25. In testing impairment of goodwill, the most relevant substantive procedure is:
a. Compare carrying amount with recoverable amount
Goodwill impairment testing involves comparing carrying and recoverable amounts
b. Inspect physical conditions of goodwill Goodwill has no physical form
c. Confirm balances with suppliers
Supplier confirmations are irrelevant
d. All of the above
26. I. Reviewing project feasibility studies helps determine whether development costs meet capitalization
criteria.
Feasibility is a key recognition condition under PAS 38
II. Confirmation with third parties is rarely used in auditing intangible assets.
Most intangible assets are verified through internal and legal documents rather than external
confirmations
III. Disclosure testing for intangible assets includes verifying that useful lives, amortization methods,
and carrying amounts are properly presented in the notes These are specific PAS 38 disclosure
requirements
a. Only statements I and II are true c. All statements are true
b. Only statement II and III are true d. All statements are false
27. When auditing trademarks, the auditor should first verify?
a. Whether it generates royalties c. Whether it is registered and enforceable Royalties are
evidence of benefits but Registration and enforceability establish legal secondary to legal
ownership which is critical to recognition.
b. Whether it is pledged as collateral d. Both A and C are correct
Collateral status is part of disclosure, not initial
verification
28. Which evidence is most persuasive when verifying the existence of a patent?
a. Confirmation from the company’s marketing department Internal confirmation is less reliable
b. Patent registration certificate from the government Official registration directly proves legal
existence
c. Review of related expense accounts
Expenses do not confirm existence
d. Discussions with management Oral evidence is weakest
29. Testing for unrecorded customer lists obtained through acquisition is aimed at:
a. Completeness assertion c. Existence assertion – applies after items Ensures all acquired
intangible assets are are recorded recorded
b. Rights and obligations assertion - ownership d. Valuation assertion –
measurement
30. All of the following are false, except:
a. Reviewing insurance policies is a common substantive procedure for intangible assets.
Insurance coverage is uncommon for intangibles and not a primary audit step
b.
This
directly
addresses the valuation of goodwill
c. Goodwill can be tested for impairment only when there is an indicator of impairment.
Under PFRS 3, goodwill must be tested annually for impairment, even without indicators
d. Intangible assets acquired in a business combination should be recorded at cost, not fair value.
PFRS 3 requires initial recognition at fair value on acquisition date
31. If the auditor discovers that development costs were capitalized without meeting recognition criteria, the
likely audit adjustment is:
a. Remove accumulated impairment
Impairment adjustment is irrelevant
c. Increase amortization expense
Amortization does not fix recognition
errors
b. Increase asset balance
Increasing asset balance worsens misstatement
d. Reclassify as research expense
Costs failing criteria must be expensed
32. I. Goodwill should be amortized over its useful life.
Under PFRS 3, goodwill is not amortized; it is tested annually for impairment
Testing impairment of goodwill by comparing carrying amount with recoverable amount is a
substantive
procedure.
II. Reviewing industry amortization practices is sufficient audit evidence to support the client’s useful
life estimates.
Industry practices can be a reference, but specific contractual/legal terms and expected benefits
must be considered.
III. The auditor can confirm the existence of a software license by reviewing its installation in the client’s
computers.
Installation does not prove legal rights; contracts and licenses must be reviewed
a. Only statements I is true c. All statements are true
b. Only statement III is true d. All statements are false
33. To verify that internally developed software meets capitalization criteria, the auditor should:
a. Compare amortization with industry norms c. Confirm development costs with customers
Industry amortization norms are not Customers don’t confirm development costs authoritative
b. Review time records and project milestones d. All of the choices are correct Documentation of
work and milestones supports capitalization per PAS 38
34. Which is least likely a substantive procedure for accrued expenses?
a. Reconciling accrual schedules to the general c. Inspecting subsequent payments
ledger
b. Observing the preparation of the payroll register d. Reviewing unpaid vendor Observing payroll
preparation is a control test, not statements substantive
A, C, D – All directly test completeness, accuracy, or existence.
35. An auditor discovers that accrued utilities are based on estimates. The best substantive test is to?
a. Review budgeted expense reports c. Inspect physical utility meters
Budgets are not reliable proof Physical meter inspection is operational,
not financial
b. Confirm amounts with the utility company d. Compare estimates to subsequent bills
Confirmations are rare for utilities and may Subsequent invoices validate the not be timely
reasonableness of accruals
36. Which is most effective for verifying completeness of accrued payroll?
a. Comparing gross pay rates to industry averages
Industry averages are analytical, not completeness checks
b. Recalculating vacation accruals
Vacation accrual recalculation is accuracy, not completeness
c. Reviewing timecards for the last payroll period
Timecards reveal hours worked but unpaid at year-end
d. Inspecting employee personnel files
Personnel files confirm employment but not completeness of accrual
37. All statements are true, except:
a. Subsequent cash disbursement testing helps identify unrecorded liabilities . Payments after
year-end can reveal obligations existing at year-end.
b. Reviewing contracts for ongoing services tests completeness of accruals. Ensures all
obligations under contracts are recorded.
c. Testing subsequent disbursements helps detect overstated liabilities It mainly detects
unrecorded or understated liabilities.
d. Bank cut-off statements are useful in detecting unrecorded loan liabilities. They reveal
borrowings near year-end.
38. An auditor notes several invoices dated before year-end but recorded afterward. This most directly
indicates?
a. Violation of cutoff c. Understatement of expenses
Liability recorded in wrong period Possible effects, but main issue is cutoff
b. Overstatement of liabilities d. Overstatement of revenue Possible effects, but
main issue is cutoff Not revenue-related
39. I. A debt agreement is internal evidence for interest accruals.
False - It’s an external document from a lender, not internal.
II. Subsequent events review can uncover accruals that were omitted at year-end.
True - Epecially for expenses discovered after the reporting period
III. Examining utility bills received after year-end can identify accrued expenses. Bills
cover usage before year-end
a. Only statements I and II are true c. All statements are true
b. Only statement II and III are true d. All statements are false
40. Which assertion is tested when the auditor inspects legal expense accruals for ongoing litigation?
a. Accuracy
Accuracy deals with the recorded amount, not
whether the obligation exists
c. Existence assertion
Existence ensures the liability is real
but legal cases are obligations
b. Rights and obligations assertion
Legal accruals involve the company’s
obligation to settle, relating to rights and
obligations
d. Cut-off assertion
Cutoff deals with period recognition, not
legal responsibility
41. When auditors perform a review of legal expense accounts and related correspondence from the client’s
lawyers, this procedure can help identify whether there are contingent liabilities or pending lawsuits that
require accrual at year-end.
True - Legal fees often indicate ongoing cases that must be accrued if probable and measurable.
A reconciliation between the accrued liabilities account and the trial balance ensures that all liabilities
have been recorded in the financial statements.
False, It ensures internal agreement, but doesn’t prove completeness of external obligations.
a. First statement is true. c. All statements are true
b. Second statement is true. d. All statements are false
42. Which is the best audit evidence to verify accrued interest payable on a long-term note:
a. Review of board minutes approving the loan
Approves loan but doesn’t confirm amount payable
b. Analytical comparison of interest expense to prior year – analytical This directly addresses the
valuation of goodwill
c. Inspection of loan amortization schedule prepared by client - Internal document
d. Bank confirmation of outstanding loan balance and terms
Direct third-party confirmation of loan balance and terms for accurate interest calculation
43. In searching for unrecorded liabilities, the auditor examines the January cash disbursements journal.
Which disbursements would be most relevant to this procedure?
a. Payments for goods ordered in December but received in January. No liability exists until goods
are received
b. Payments for goods received in December but invoiced in January.
Goods received before year-end create liabilities that should be recorded even if invoiced after
year-end
c. Payments for goods ordered and received in January.
Occurs entirely after year-end; not relevant to prior period
d. Payments for December payroll processed on January 15. Payroll cutoff is separate from trade
payables search
44. I. If the accounts payable ledger agrees with the general ledger control account, the auditor can
conclude that
all liabilities have been recorded.
False - Agreement between ledgers only ensures internal consistency; unrecorded liabilities could
still exist.
II. Once an auditor obtains a listing of accrued liabilities from the client, no further testing is necessary
because the listing itself is considered sufficient audit evidence.
False – A client-prepared list is internal evidence and must be corroborated with external documents
or other substantive procedures.
III. Accruals for utilities can be verified solely by reviewing the client’s budget, since budgets reflect
expected usage.
False - Budgets are estimates; actual bills and meter readings provide more reliable evidence.
a. Only statements I is true c. All statements are true
b. Only statement III is true d.
45. Which procedure tests existence of accrued property taxes:
All statements are false
a. Reviewing budget allocations c.
Internal estimates, not proof
Direct third-party evidence proving the
liability exists
b. Comparing current year to prior year d. Reconciling tax expense ledger
Inspecting government tax assessment
notices
Analytical, doesn’t confirm existence Checks internal records, not existence
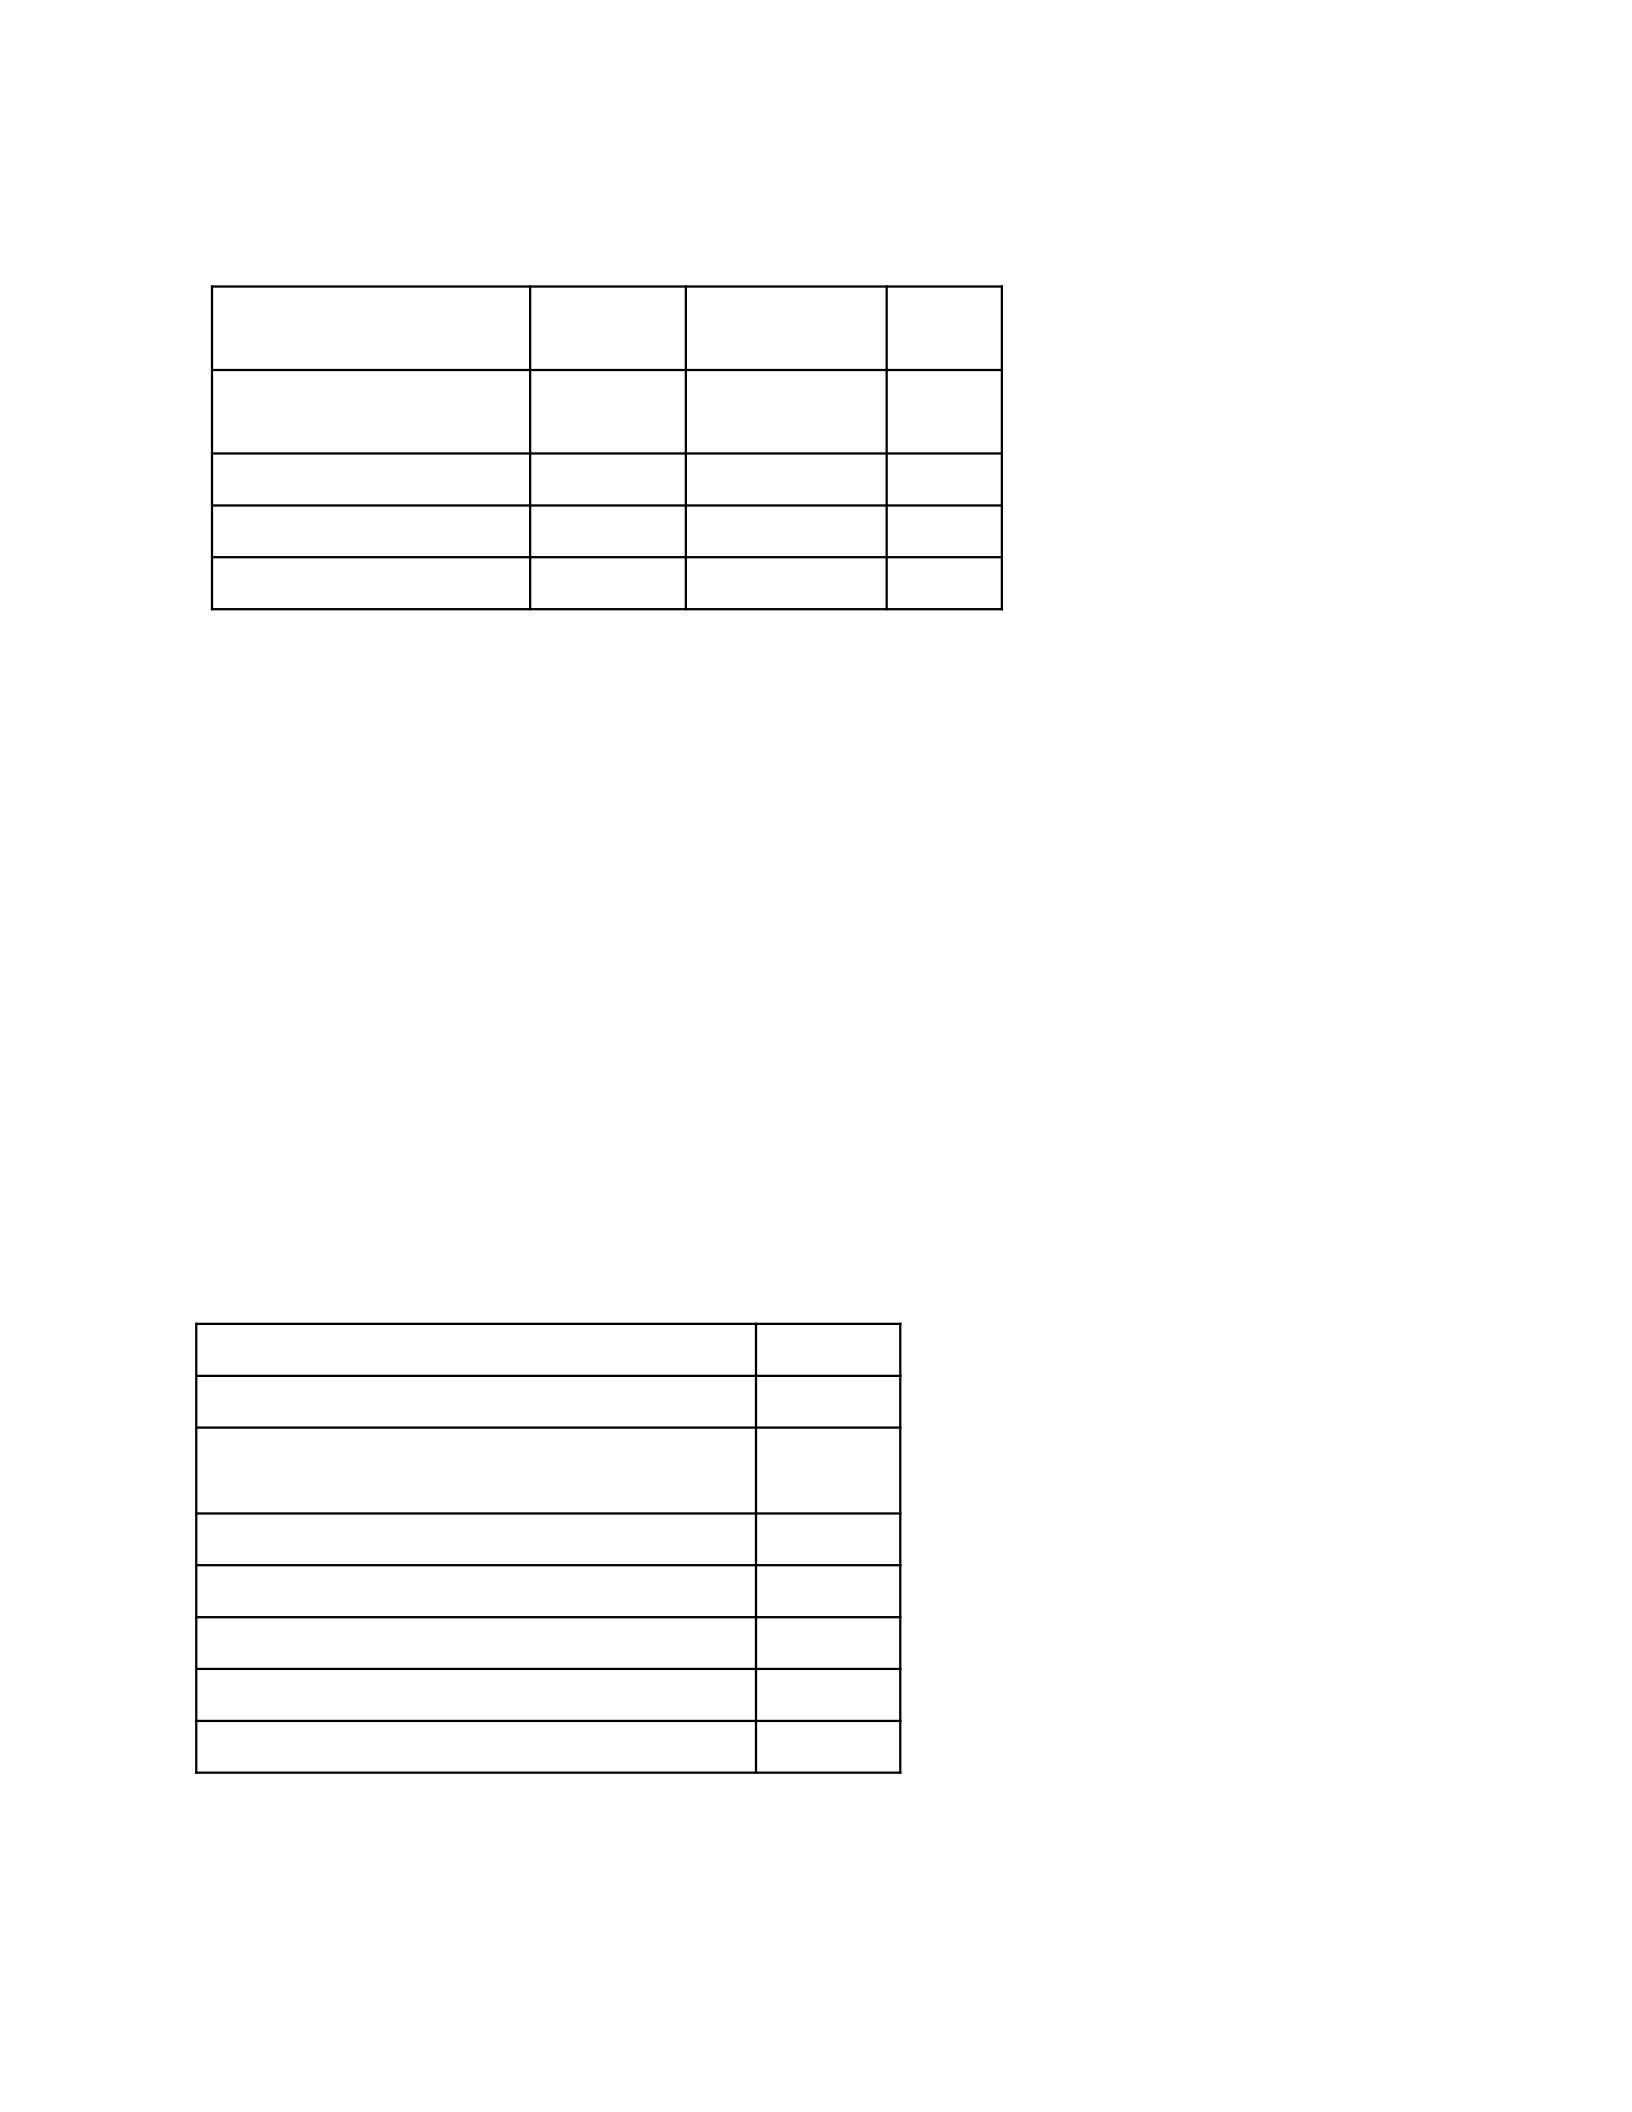
Problem Solving: Please refer to the problem below for questions 46 – 50.
I. GTG Company presented the following intangible assets in its December 31, 2024 statement of financial
position:
Description Amount Useful
Life/Contract
Legal
Life
Patent P 500,000 16 years 14
years
Computer Software 255,000 8 years -
Franchise 465,000 10 years -
Other Intangible Assets 124,220 10 years -
Additional information relative to Intangible Assets follow:
a. Litigation expense amounting to P16,200 was incurred in the company’s attempt to file a trade
name (GTG Corp). The amount was included in the Other Intangible Assets account and was
amortized accordingly.
b. Litigation expense of P16,500 was incurred in filing for trade name (GTG Company) on June 26,
2024, and shall be amortized over a 10-year period. Amount was recorded to other intangible
asset account.
c. Franchise was signed on January 1, 2024 to operate as franchisee of GGT Company for an
initial franchise fee of P400,000. Upon signing, 25% was paid and remaining balance shall be
paid in 5 annual installments beginning January 1, 2025, with 12% implicit rate. The continuing
franchise fee was agreed to be 3% of GTG’s monthly gross revenue and shall be payable
annually. GTG started its operations on 4/3/24 and as generated a total of P900,000 gross
revenue from franchise as of 12/31/24.
46. What is the total amortization expense to be recognized in 2024?
47. How much is the total intangible assets to be reported in the balance sheet as at year-end?
II. Review Search Corporation’s trial balance showed the following amounts as at year-end:
Account Name Amount
Cash P 258,000
Prepaid Expenses (Vehicle Insurance for 5
years)
440,300
Input VAT 12,150
Other Non-current Assets 1,250,600
Current Liabilities 235,125
Non-current Liabilities 653,200
Equity 1,072,725
The following transactions were unaccounted as at audit date:
● Life insurance premium for CEO amounting to P65,000 paid on 9/12/24.
● Business permit amounting to P28,500, paid on May 25, 2024.
● Vehicle insurance was paid on March 10, 2024.

48. How much of the total assets are prepaid?
49. How much of the prepayments should be recognized as expense in the current year?
50. How much is the prepaid portion of the CEO’s life insurance?

