


C213 2017 Lowest Scoring Questions on the Assessments
Order of assets listed on the balance sheet
Assets are listed in the order of liquidity. Liquidity is the amount of time it would usually
take to covert an asset into cash. Obviously, cash would be listed first, followed by
marketable investments (a company can quickly convert a short-term investment into
cash). Accounts receivable would be listed next followed by inventory, and long-term
investments, fixed assets, and intangibles.
Current assets are listed before long-term assets.
Current liabilities are listed before long-term liabilities, but there is no specific order they are
listed in outside of current and long-term.
There is also no specific order equity accounts are listed on the balance sheet; although,
typically you will see paid-in-capital followed by retained earnings followed by accumulated
other comprehensive income, and lastly, treasury stock.
Difference between a manufacturing company and a service
company
Describe the difference between a manufacturing environment and a service
environment.”
Period Costs Product Costs
Service Co. Selling Costs Direct Labor
Administrative Costs Service Overhead
Manufacturing Co Selling Costs Direct Labor
Administrative Costs Manufacturing Overhead
Direct Materials (inventory
The only difference is - a manufacturing company has direct materials (inventory).
Evaluating a historical income statement to project a future income
statement
Projected growth for 2017 = 10% increase over 2016 sales.
Step 1: Convert the income statement into a common-sized income statement.
Step 2: Multiply 2016 sales by 1.10 (10% growth) to get the forecasted 2017 sales.
Then multiply the projected 2017 sales by the percentages from step 1.
Project income statement for 2017
Step 1 Step 2
2016 2017
Sales 100,000 100% X 10% growth 110,000
COGS 60,000 60% 110,000 X 60% 66,000
Gross profit 40,000 40% 110,000 X 40% 44,000
Selling expenses 10,000 10% 110,000 X 10% 11,000
General and admin exp. 20,000 20% 110,000 X 20% 22,000
Net income 10,000 10% 110,000 X 10% 11,000
Now, what would you do if you were given the 2017 sales figure and you need to
calculate the 2016 sales figure based off the 10% growth for 2017?
Calculation for 2016: 110,000 / 1.10 = 100,000
Role of the U. S. Securities and Exchange Commission (SEC) in
financial reporting.
Regulates the U.S. Stock exchanges.
Seeks to create a fair information environment in which investors can buy and sell
stocks.
Congress created the first securities act in 1933 and the second securities act in
1934 in response to the stock market crash of 1929.
The Securities Act of 1933 requires most companies planning to issue new debt or
stock securities to the public to submit a registration statement to the public for
approval.
The Securities Act of 1934 requires a public company to file detailed periodic reports
including audited financial statements (form 10-K is the annual report; Form 10-Q is
the quarterly report).
Granted the legal authority to establish accounting standards. Currently the SEC
accepts the pronouncements set by FASB.
The SEC can suspend trading of a company’s stock, and if hearings show that the
issue failed to comply with the securities laws, the SEC can de-list the security.
Congress strengthened the SEC through the enactment of Sarbanes-Oxley (SOX),
which was enacted after the massive frauds that occurred in the late 1990s and
the early 2000s.
Compare and Contrast Traditional Costing to Activity-Based Costing
(ABC).
ABC is a more accurate product costing system than traditional product costing
systems.
ABC requires more time and expense to administer than do traditional costing
systems.
Companies with diverse products involving substantially different production
processes, an ABC system yields better cost data and better management
decisions.
Describe how basic cost behavior patterns change as sales
volumes change.
Fixed costs (FC) are fixed in total, but as sales volume increases, the per unit
FC decreases.
Variable costs (VC) are fixed per unit, but as sales volume increases, total VC
increases.
Stewart Manufacturing produces and sells die cast race cars. VC for each die cast
car is $3 and total FC are $300,000
VC per unit Total VC FC per unit Total FC
Stewart sells 1,000 units 3.00 3,000 300 300,000
Stewart sells 2,000 units 3.00 6,000 150 300,000
Stewart sells 5,000 units 3.00 15,000 60 300,000
As sales increase: Total Variable costs increase
Per Unit Variable costs remains the same
Total Fixed Costs remains the same
Per Unit Fixed Costs decrease
Analyze a statement of cash flows to identify operating, investing, and
financing activities.
Operating Activities: All categories that are on the income statement, and all
current assets and liabilities. i.e. sales (cash received
from customers); cost of goods sold (cash paid for
inventory); operating expenses (cash paid for rent);
Investing Activities: Balance sheet accounts: Long-term assets. i.e. property,
plant, and equipment; investments i.e. cash paid for
equipment, cash paid for investments (stock, loans)
Financing Activities: Balance sheet accounts i.e. Long-term liabilities and equity
accounts i.e. mortgage payable; common stock and
additional-paid-in capital (cash received from
stockholders); retained earnings (cash paid for dividends)
Explain Accrual Accounting
Revenue recognition
In order for revenue to be recognized in an accrual system, two criterial must
be met:
1. The promised work must be done before the revenue is recognized.
2. Cash collection must be reasonable assured before revenue is recognized.
Expense recognition
1. Expenses are matched to the revenue that is generated from the expense.
Direct matching, as with cost of goods sold (COGS)
2. However, some expenses are extremely difficult to match with specific revenue,
and are more aligned to a specific time period.
Systematic allocation, as with deprecation
3. Moreover, some expenses are difficult to match with specific revenue or specific
time periods.
Immediate recognition, as with advertising
Define common terms and concepts used in management accounting.
Variable Costs: A cost that changes directly with changes in the level of
sales or production.
Examples are direct materials costs and sales commission.
Fixed Costs: A cost that doesn't change based on changes in the level
of sales or production. Examples are building rent and
executive salaries.E
Product Costs: A cost incurred as part of the production process.
These costs are first reported as an asset (inventory) and then
as an expense (cost of goods sold) when the product is sold.E
Period Costs: A cost incurred outside the factory or production facility.
These costs are reported as an expense in the period in which
they are incurred.
Direct Materials:The cost of the primary raw materials used in production. In
producing French fries, the direct materials cost is the cost of
the potatoes.E
Indirect Materials: Materials that are necessary to a manufacturing or service
business but are not directly included in or are not a significant
part of the actual product.
Direct Labor: The cost of the wages of the workers who are assembling the
direct materials into the finished product. In producing an
automobile, the direct labor cost is the compensation cost of the
auto workers on the assembly line.E
Indirect Labor: Labor that is necessary to a manufacturing or service business
but is not directly related to the actual production of the product.
Manufacturing Overhead: All factory costs that are not direct materials or direct labor.
Examples are factory supervisor salaries, factory building
depreciation, and miscellaneous indirect materials such as glue
or screws.
Direct Costs: The costs that are created by a particular product or segment
that is being analyzed. If a product or segment is dropped, the
direct costs created by that product or segment will disappear.E
Indirect Costs: The costs that are assigned to a particular product or segment
but that are not actually caused by that product or segment. If a
product or segment is dropped, the indirect costs assigned to
that product or segment will remain.
Differential Costs: A future cost that can be changed by a decision made now. An
example is monthly rent for an apartment.E
Sunk Costs: A past cost that cannot be changed by any decision made now.
An example would be last month’s paid rent.
Out-of-Pocket Costs: Costs that involve the outlay of cash or the use of some other
asset (like equipment).E
Opportunity Costs: The benefits not received because of actions NOT taken. For
example, the opportunity cost of going to a basketball game is the
increased points that you could have received on the next day’s
accounting exam if you had spent that time studying.
Calculate the cost of a product
Product costs = Direct labor + Direct Materials + Factory Overhead
Factory overhead = Indirect labor + Indirect materials + “Factory expenses”
September Costs
Direct labor $20,000
Direct materials 25,000
Indirect labor 5,000
Indirect materials 3,000
Depreciation 2,000
Factory rent 7,000
Factory depreciation 8,000
Rent 5,000
Total Costs $75,000
Can you calculate the product costs for September?
Factory overhead = 5,000 + 3,000 + 7,000 + 8,000 = 23,000
Total product costs = 20,000 + 25,000 + 23,000 = 68,000
Total non-product costs = 2,000 + 5,000 = 7,000
How did you do?
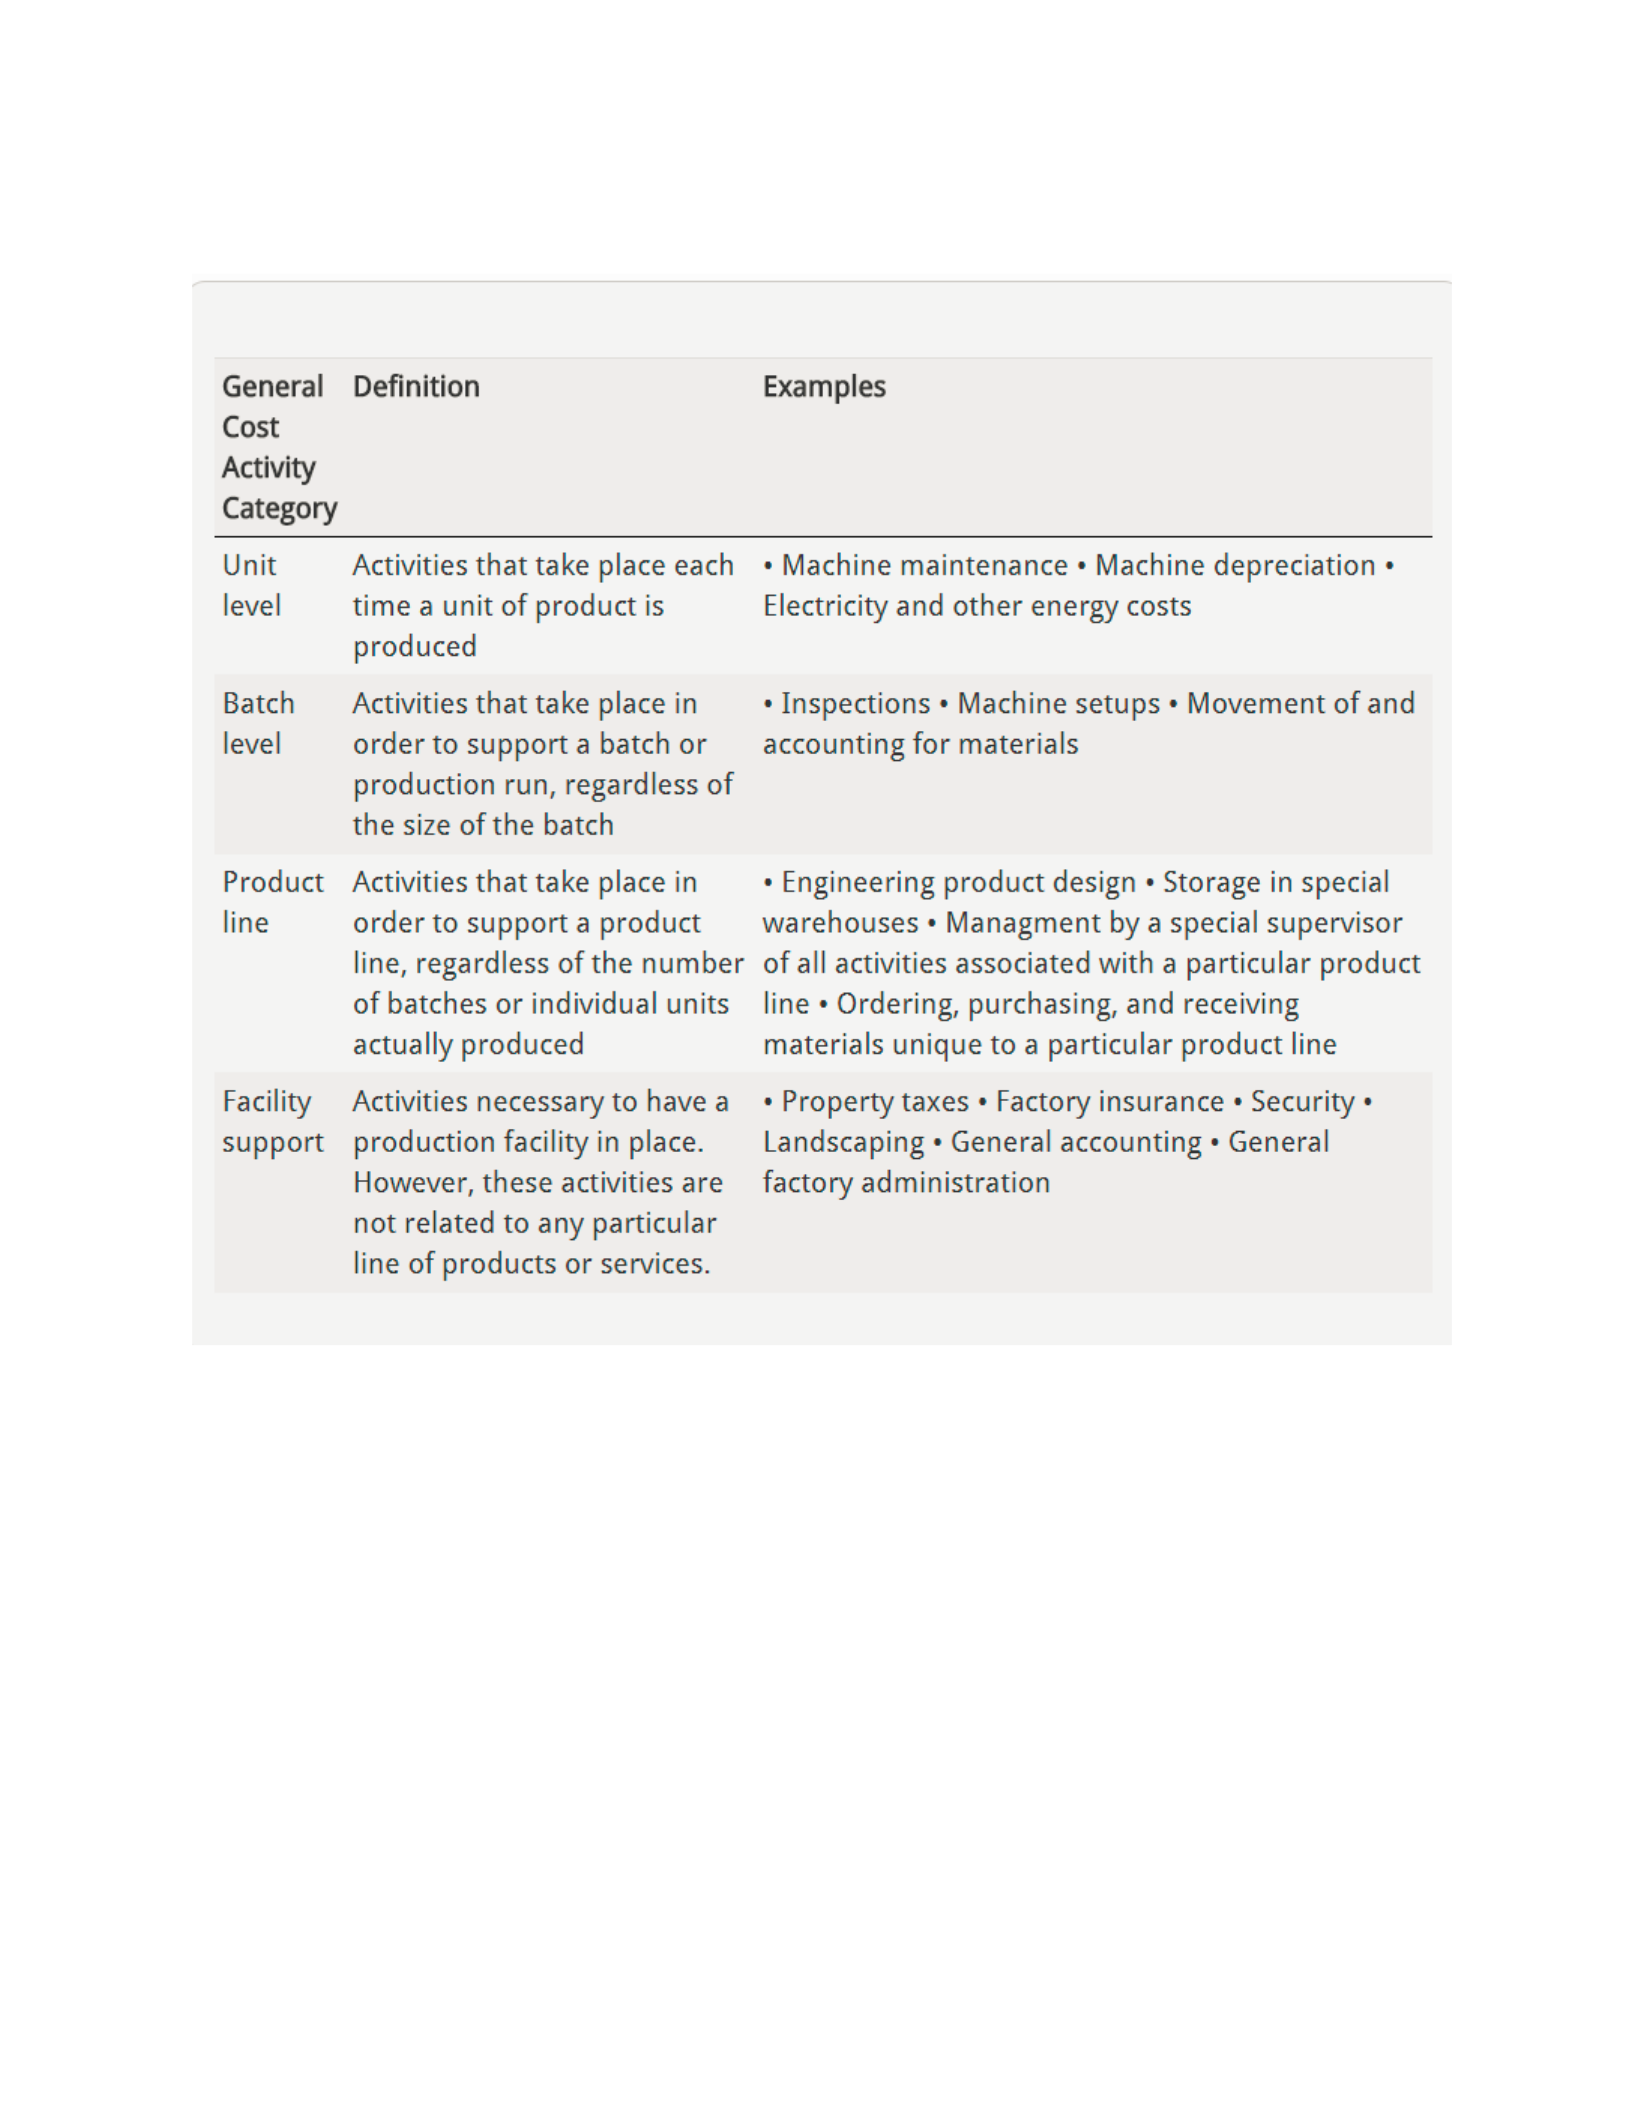
Identify overhead cost activities

