


INTRODUCTION impact on Merger and Acquisition
This study was designed as a research project that purposely examines the complex
subject of organizational culture and the potential impact on Merger and Acquisition (M&A)
transactions. The study examines post-merger integration to understand why M&A
transactions succeed or fail and whether culture drives these results. Although the study
targets acquisitions under $5 billion in the travel and travel services sector, the findings might
be helpful to all M&A deals since the underlying principles are commonly shared. Most
importantly, this study asks whether the challenges of integrating cultures during M&A
activity exist in a measurable, predictable, and actionable format to reduce failure rates.
The objective of the dissertation was to investigate the underlying reasons for mergers
and examine the impact of organizational culture on the success or failure of these
transactions. Mergers are driven by diverse factors, including the pursuit of synergies, market
expansion, scale economies, vertical integration, business diversification, access to new
technology or intellectual property, and the desire for financial gains (Gaughan, 2010). These
motivations can differ across industries and companies, and the specific drivers behind
mergers depend on factors such as market dynamics and strategic goals.
This study has significant implications for evidence-based management practices in
M&A decision-making, emphasizing the need for executives to use empirical evidence rather
than hubris. My personal experience, which includes more than 20 M&A transactions,
provides a practical foundation for this research. While most of my M&A deals were
successful, some resulted in job losses and employee departures due to cultural integration
challenges. Throughout this dissertation, the word employee means Full Time Equivalent
(FTE) workers and Independent Contractors (IC); as in the travel industry, these terms are
interchangeable when discussing staff. Thus, this research is not only driven by academic
curiosity but also by practical considerations based on experience.

Problem Addressed
We do not know enough about organizational cultural integration after a merger.
According to Christensen et al. (2011), most (between 70 and 90 percent) of M&A
transactions are deemed failures, yet companies spend more than $2 trillion on acquisitions
yearly. Christensen and his colleagues (2011) argue that executives can dramatically increase
their odds of success if they understand how to select targets, how much to pay, and whether
and how to integrate them. M&A failure has far-reaching effects beyond shareholder return as
once-solid growing companies can end up disenfranchised and underperforming while
countless careers may end up destroyed.
It is worth noting that the specific failure rate can vary depending on factors such as
public versus private transactions, industry, time period, and the definition of failure used in
different studies. Therefore, it is essential to approach this statistic cautiously and consider the
context. The definition of success in public M&A focuses on share price, regulatory
compliance, shareholder approval, and market reaction, while private M&A success is
typically evaluated based on stakeholder interests and desired financial or strategic outcomes.
Research Question
The research question is, "Are effects of organizational culture on post-merger
integration identifiable during merger and acquisition cultural due diligence?" The primary
domain of the research focused on identifying and measuring the organizational culture of
each party within an M&A transaction. Once the organizational culture was identified and
compared between each side, the types of cultures most frequently associated with M&A
success or failure emerged. Every M&A transaction sets concrete integration goals for the
first years after the transaction closes. The research focused on post-transaction integration
and resulting perceptions of outcomes. Success is most commonly measured in financial
terms, such as synergies (cost-cutting by removing redundancy), revenue growth due to new

products and services offered by merging the two companies, or profitability growth due to
operational efficiency gains of the newly-formed combined company.
Objective and Aims
The first objective focused on the post-merger integration performance of 50 travel
and travel services M&A transactions of varying sizes (public and private) with a total
transaction cost, defined as the total expenses incurred when buying a company, of less than
$5 billion. As private companies are not required to disclose their financial information
publicly, measuring their performance can be challenging. In such cases, an alternative
approach is to gauge the perceptions of integration managers regarding the intended
outcomes. This approach can be beneficial in situations where financial data may not be
readily available or other factors, such as cultural integration and employee satisfaction that
are difficult to quantify, are critical to the success of the merger or acquisition.
By relying on the perceptions of key business leaders, the researcher obtained valuable
insights into the effectiveness of their M&A strategies. While using perceptions as an
integration performance measure may not be as precise as financial data, it still provided
valuable insights into the success of M&A transactions. Subsequent employee retention and
satisfaction measures of human resources performance were also vital to understanding
integration performance.
The second objective, concurrent with the first, was to compare the organizational
cultures of both the acquiring and acquired companies. Cameron and Quinn's (2011)
Organizational Culture Assessment Instrument (OCAI) provided a basis to begin research. A
core component of the OCAI quantifies the current state of the firms' culture and the preferred
state those surveyed want to see the culture become. This preferred state may be a crucial
indicator of the challenges two firms may uncover while integrating post-merger. For
example, it should be reasonable to assume that if an acquired company shows a preferred

culture desire closer to the acquiring firm than their current state, all other factors being equal,
that M&A integration may prove effective and lead to a more successful transaction.
The third objective of the research was to conduct qualitative interviews of three
employees directly involved in the transaction from each firm involved in the proceedings of
the top and bottom three M&A performances.
Through surveys, interviews, and other feedback mechanisms, research analysts can
gather data on factors such as communication, cultural fit, and leadership, which can provide
a more nuanced view of the integration process. The primary goal of this research was to
develop a model that could effectively gauge the influence of organizational culture on
postmerger integration. By analyzing the pre- and post-merger organizational cultures of each
party involved, the study aimed to identify and evaluate the impact of culture on integration.
This information would enable key decision-makers, including the Boards of Directors,
investors, and top executives, to make more knowledgeable choices, potentially leading to a
higher rate of success in M&A deals.
Methods for Achieving Stated Aims
The research examined 50 M&A transactions at least three years post-merger in the
travel and travel services sector. Each of the 50 transactions involved a distinct acquiring
entity, although some were subsidiaries of the same parent holding company. The target M&A
transaction size was $20 million to $5 billion, with the acquiring entity headquartered in the
United States. The rationale for the sample criteria is that M&A transactions under $5 billion
in the travel and travel services sector appear to have little known research on integration
success causality. The research first examined the results of 50 post-M&A transactions
integration actual post-closing performance versus the goals for post-merger years one, two,
and three using a survey of employees directly involved in the integration. The second phase,
running concurrently with the first phase, asked the 50 acquired and acquiring companies to
each have five employees purposely chosen by human resources (HR) to take the OCAI. The

employees were all employed prior to the transaction close and are still employed post-close.
The OCAI distinguishes four distinct culture types (Clan, Adhocracy, Market, or Hierarchy),
resulting in 16 possible combinations between the two parties in the M&A transaction. The
next phase used statistical analyses to estimate the strength of the relationships between
culture types and integration performance. The final stage identified the top three and bottom
three M&A performances and interviewed three employees who completed the OCAI from
each side of the M&A transaction (36 total interviews) to further understand the qualitative
impact of culture type on M&A integration performance. The dependability of the survey,
OCAI, and interview responses rely on individuals accurately recalling integration
performance and current/preferred cultures during the transaction, which spans at least three
years in the past.
Significance of the Research
Identifying the influence of culture types on M&A integration outcomes may lead to
significant alterations in the conduct of M&A due diligence or even the prevention of
transactions. The result can directly impact M&A success, saving billions of dollars while
improving employee retention and job satisfaction.
Research studies exist on the impact of hubris, defined as the characteristic of
excessive confidence or arrogance, which leads a person to believe they may do no wrong in
M&A transactions. Managerial optimism accompanies nearly all M&A deals, yet the hubris
factor often drives up the price paid for the company. Manager optimism and hubris may
hypothetically create even greater pressure for the existence of misreporting activities. The
relationship between CEO hubris and premiums is further strengthened when board vigilance
is lacking, the board has a high proportion of inside directors, and the CEO is also the board
chair. On average, losses in acquiring firms' shareholder wealth following an acquisition, and
the greater the CEO hubris and acquisition premiums, the greater the shareholder losses.

Thus, CEO hubris has substantial practical consequences and has potentially great theoretical
significance to observers of strategic behavior (Hayward & Hambrick, 1997).
For more than 20 years, an intensive debate has ensued about acquirers' motivations in
M&A. This result is likely due to early empirical results showing that acquirers' cumulative
abnormal returns (CAR) around the announcement date are, at best, equal to zero or even
negative (Jensen & Ruback, 1983). CAR is a metric that measures the abnormal excess
returns of a company's stock during a specified period surrounding a significant event, aiding
in evaluating market reactions and performance implications. Caution must be exercised so
that the post-closing growth rates are not skewed depending on whether redundancy and staff
reductions occur on the acquirer versus the acquiree side.
This research aimed to mitigate the dynamics of hubris in M&A transactions.
Mitigating hubris may be accomplished by utilizing data-driven research to examine
organizational culture through cultural due diligence and the impact of different combinations
of cultures during M&A due diligence activity. By addressing organizational culture during
due diligence, well before the acquisition takes place, it might be possible to counter the
hubris influence on the transaction by presenting data-driven research as to the realistic
success or failure of the transaction at the proposed closing price.
The hope is that this research adds to evidence-based practice, which is a disciplined
approach to decision-making and action, the hallmark of which is attention to evidence
quality and the use of the best available evidence. Its goals are to improve the results of
professional decisions and increase the use of practices that lead to desired outcomes while
eliminating dysfunctional practices (Rousseau & Gunia, 2016).
Chapter Overview
Chapter 2 presents the relevant literature, including organization culture, M&A, due
diligence, and the research that has thus far examined the intersection of culture and M&A.
Chapter 3 explains the methodology used for the investigation of the research question,

including sample population, data collection, and analysis tools. Chapter 4 focuses on the
mixed-methods research data from the integration surveys, OCAI results, and staff interviews.
Chapter 5 discusses the data integration and results and the conclusion of the dissertation
findings.

CHAPTER 2: LITERATURE REVIEW
Extensive qualitative literature exists on organizational culture, so as a starting point
for the literature review, broadly cited articles on culture and its impact on organizations
served as the backbone. From there, the literature delved into organizational culture and the
subsequent effect on M&A transactions. The broad search terms used were organizational
culture, corporate culture, mergers and acquisitions, M&A, organizational fit, cultural fit,
M&A failure, organizational culture & M&A, and OCAI.
Quantitative data appears to be nascent in measuring organizational culture
postmerger; however, some widely revered articles exist (Datta, 1991). Though few in
quantity, these quantitative articles provide a solid statistical base for the research foundation
on postmerger integration related to organizational culture fit. Quantitative research followed
the same guidelines for discovering qualitative literature in search engines. However, in
addition to the search terms for qualitative articles, search terms used for the quantitative
literature consisted of M&A integration, integration costs, culture and integration, M&A
financial performance, organizational fit and cost, and culture cost.
Figure 1 shows a fishbone diagram of the significant search categories for the
comprehensive literature review.
Figure 1
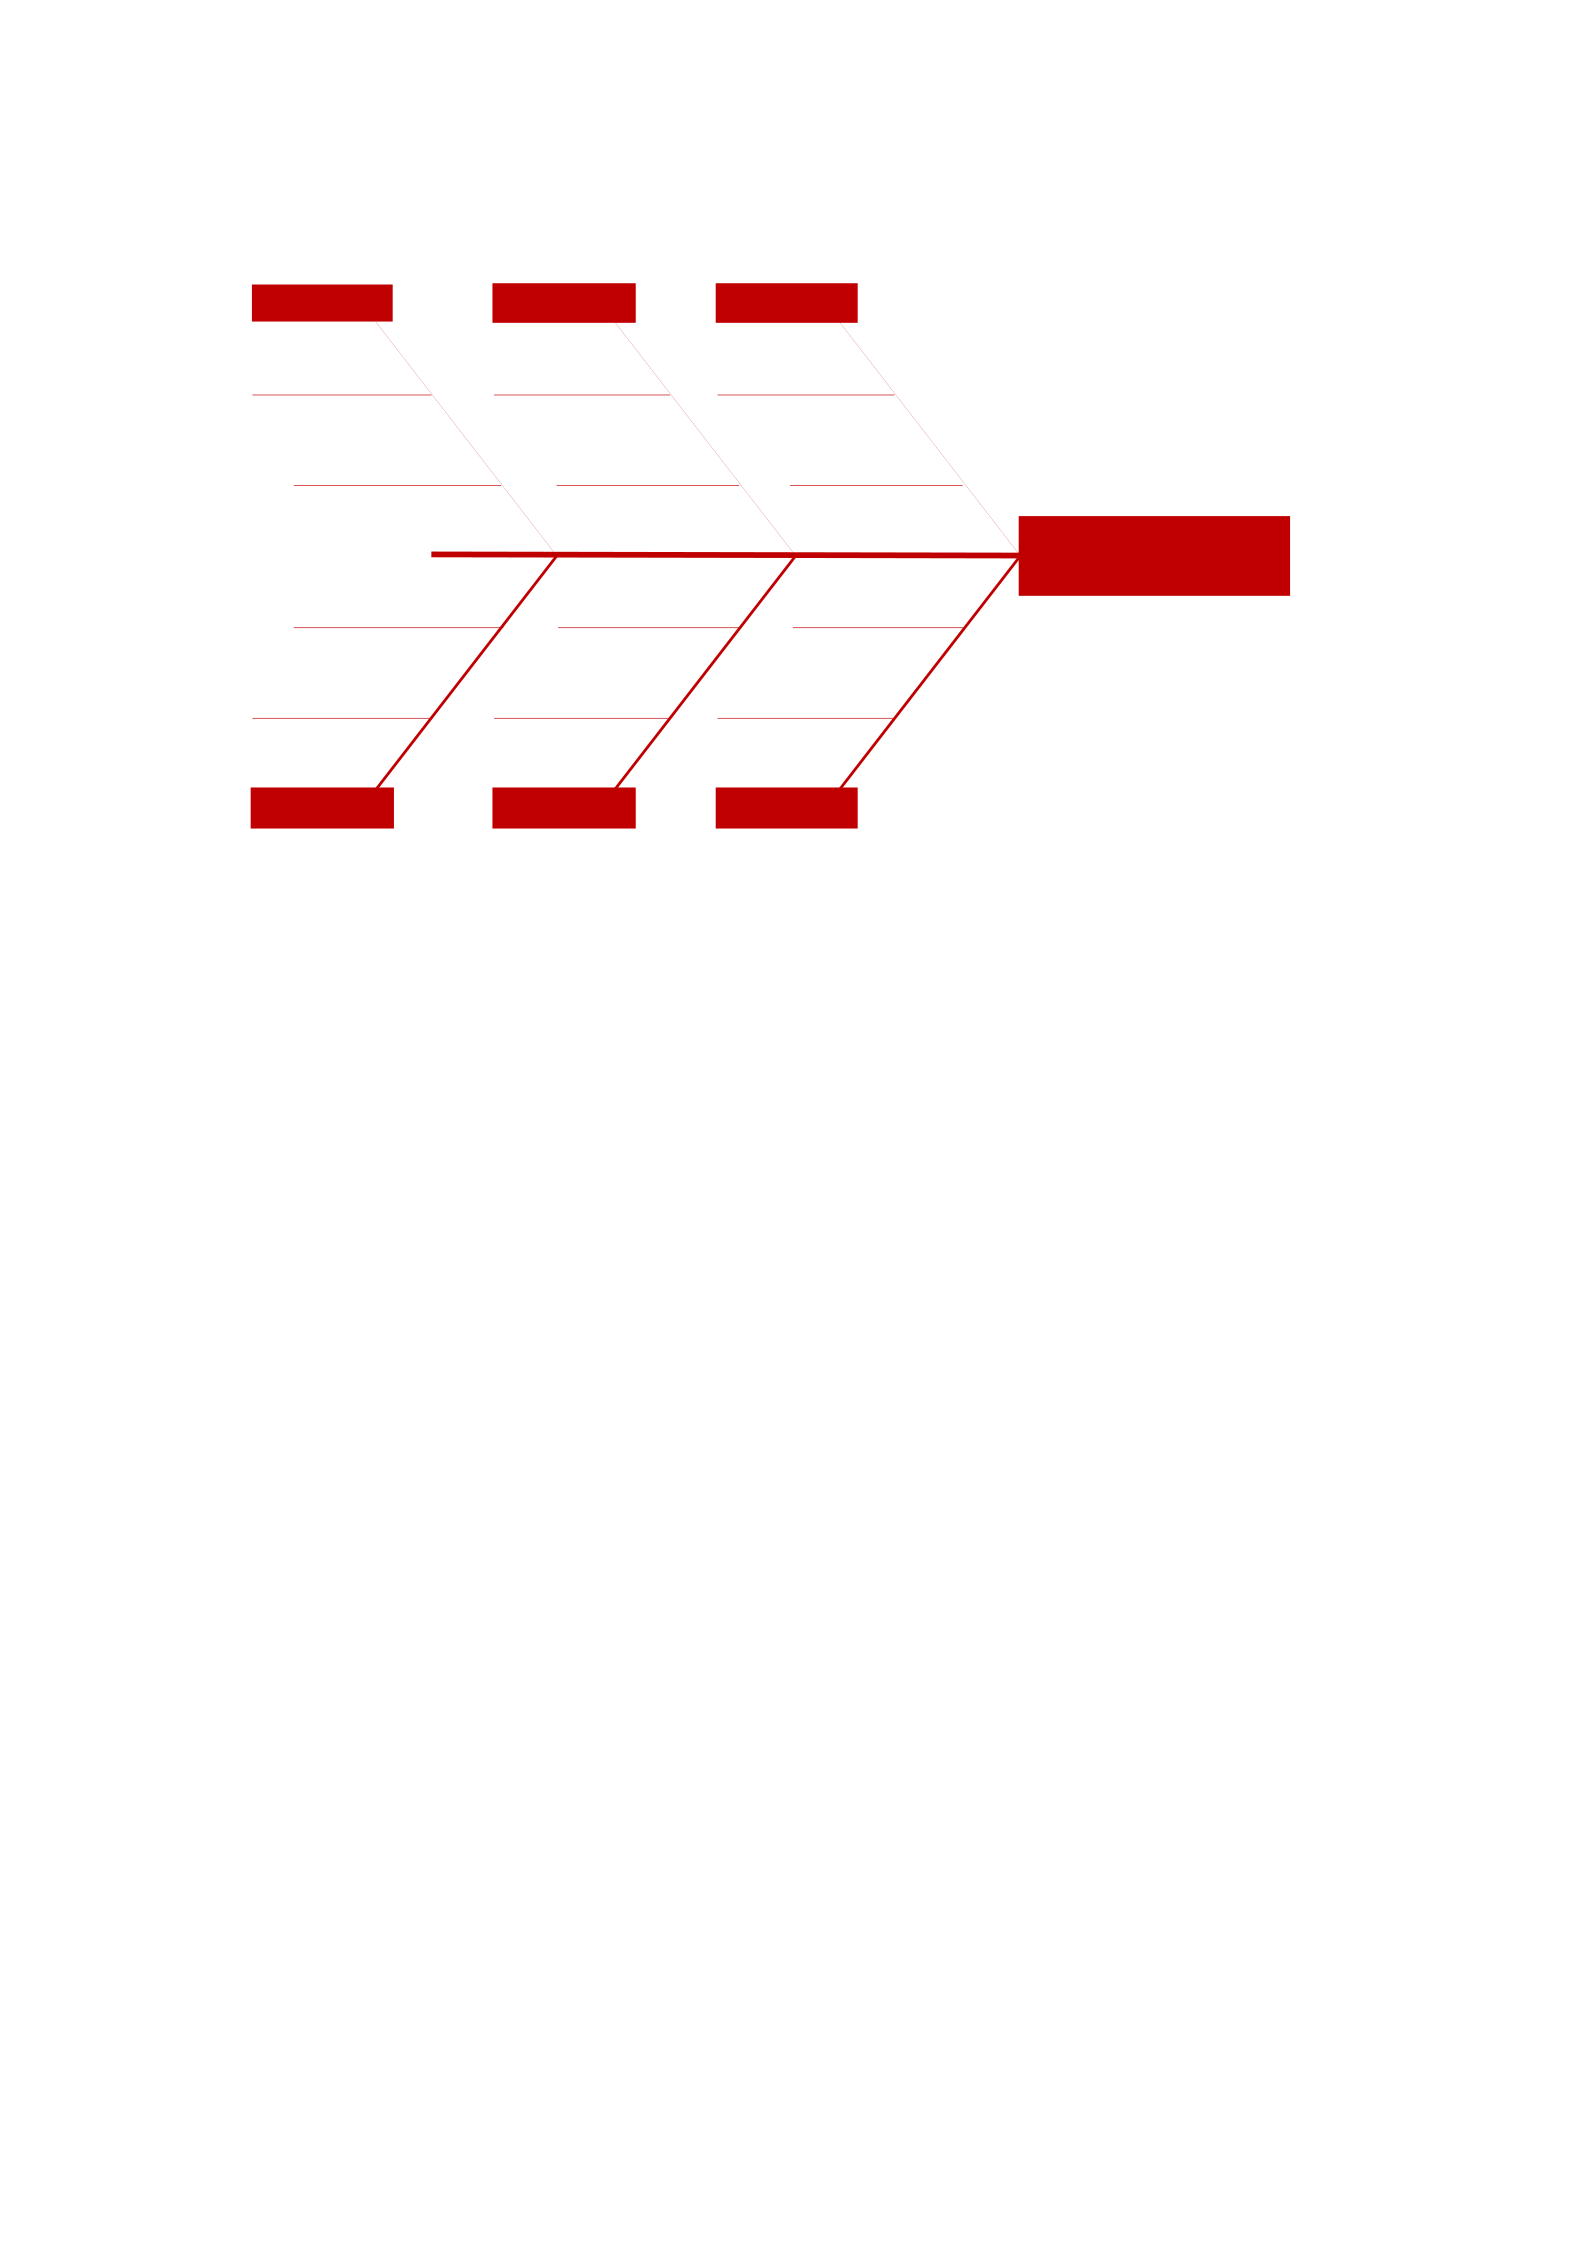
Major Research Categories of Literature
Major Categories of Literature
This dissertation aimed first to measure and describe cultural matches and mismatches
and their relationship to post-merger success and second to determine if any organizational
cultural patterns could be helpful in M&A integration and success. A substantial question of
any M&A transaction consideration could be, "Does the financial data exist to justify this
transaction regarding cultural integration"? I ask, "Why is culture often dismissed or not even
considered by seasoned executives during M&A decision-making when most if not all, have
experienced noteworthy challenges and immovable obstacles created while trying to integrate
cultures?" A plausible explanation for this anomaly is that culture is difficult to measure in a
precise format that carries any financial formulas. Thus, they are often removed or not
considered in the financial decision-making of M&A activity.
Organizational Culture
The field of organizational culture is very mature. Many top academics, academic
practitioners, and practitioners were noted for their work, such as Cameron and Quinn (2011),
Schein (1983), Kotter and Heskett (1992), Johnson (2016), and Cummings and Worley
(2014). They have all led the research and practical application within organizations.
O
C
Organizational
Culture and
M&A
E &ng the E of
O &onal Culture on
P -M Integr &on
M&A I
O
F D Diligence OCAI
M&A Failure
and Success
Integration
Cost
Measurement
Measuring
Organizational
Culture
M&A Financial
Measurement
Tools
Integration and
Culture
Organizational
Fit
Measurement
Due Diligence
and M&A
Performance
OCAI and M&A
Organizational
Fit and M&A Due Diligence
& Culture
OCAI Use
Cases

Jaques and Relations (1951) first introduced the concept of culture in the
organizational context. The leading theory utilized was organizational culture theory, which
stresses that culture is a set of values an organization or group has. An organization does not
have a culture; it is a culture, and a unique shared meaning system is core to understanding
how challenging the integration of disparate cultures is post-M&A.
For Schein and Schein (2017), the only thing of fundamental importance is that
leaders create and manage culture: “If you do not manage culture, it manages you, and you
may not even be aware of the extent to which this is happening” (p. 11). Thus, when applying
this assertation that a leader must manage culture, it may be possible to start the initial
research phase by identifying if the firm's management attends to its culture or is even aware
of the actual culture.
Dauber (2012) reveals three significant reasons for the inconsistent findings in M&A
research. First, most scholars refer to integration as an umbrella term for different and
distinctive acculturation strategies (e.g., integration, assimilation, separation,
marginalization). Second, some studies mix various levels of analysis concerning cultural
constructs (e.g., national vs. organizational culture). Finally, multiple definitions of M&A
success manifest in a plethora of measurement techniques.
Organizational analyses that indicate separate boxes for culture and strategy make
a fundamental conceptual error. Strategy is an integral part of the culture (Schein & Schein,
2017). A famous quotation from the late business management expert Drucker (1959) is,
"Culture eats strategy for breakfast" (p. 28). Strategy is a critical element of any M&A
decision and implementing that strategy is at the core of the post-merger integration of the
two companies. However, it was interesting to research why culture might play a lesser role in
M&A or integration strategy; Schein (1983) clarifies that this is a fundamental error. This
study begins with the well-established theoretical and practical observation that cultural
differences matter in M&A (Stahl & Voigt, 2008). The focus is to unravel how they affect the

due diligence process and how to manage them more effectively. The research's underlying
goal is to understand what it takes to manage the integration of cultures more effectively and
how it can be identified, measured, and ultimately quantified (so that it can be used before the
actual merger).
The study utilizes research on organizational culture to suggest that it can play a
significant and actionable role in identifying culture during M&A due diligence. This
understanding can be valuable for the acquiring entity in assessing the potential success rate
of post-transaction integration. M&A integrations can take years, and I want to examine if
culture plays an influential role at different periods in that timeline. Additional questions to be
considered include:
•Can culture be meaningfully measured in M&A contexts?
•Can the two companies categorize organizational cultures in terms of fit?
•Can financial measures be assigned based on their degree of cultural fit, and
do different integration strategies matter?
Subsequently, it is possible that large firms that make acquisitions are the firms that signal
they have exhausted internal growth opportunities so that firm value drops due to that signal
rather than because of the purchase, as described by Moeller et al. (2003). Moeller et al.
(2003) make several compelling arguments for why M&A failure rates are perceived so
negatively as the statement that large transactions skew the results, and some firms are
already in trouble from a growth standpoint, so they enter M&A activity to grow when there
is no growth, just a combination of revenue. A rapidly growing firm acquired by a sizable
stagnant firm suggests that a dynamic and potentially toxic integration of cultures may be
forthcoming.
Unrealized productivity expectations are often precipitated because some mergers
bring out the worst in the respective organizations' cultures, making it difficult to marshal

their strengths effectively (Walker, 1998). However, does the word merger have any meaning
in business? The reality is that no matter what is communicated to the markets, employees,
and media outlets, there is no such thing as a merger. This is because one entity, seen as the
winner, dominates, and when winning and losing exist, then basic primal survival instinct
takes over, and "the worst" in any organization moves to the forefront. In practice, mergers of
equals are infrequent. It is uncommon that combined entities benefit from two different CEOs
agreeing to give up authority.
One outcome may be that the very essence of what makes a company a valuable M&A
target is its culture. Its characteristics are so strong that it garners respect, profits, and esprit
de corps that separate the entity from the competition. However, this extraordinarily
successful organizational culture may prove the most difficult to integrate post-M&A
transactions (Kotter & Heskett, 1992). Some exceptionally large M&A acquirers buy an entity
and leave it alone to function as it did pre-transaction; an example is AIG’s purchase of
American General in May 2001 (Cunningham & Greenberg, 2013). The strategy used by AIG
and similar strategies used by other firms to acquire entities but allow for autonomous control
proved interesting, due to financial success, in the impact on organizational culture post-
transaction compared to other firms the new parent company assimilated.
Challenging the widely held belief that strong corporate cultures always create
excellent business performance (Kotter & Heskett, 1992) shows that while many shared
values and institutionalized practices can promote good performances in some instances,
those same values, widely shared and rigid, can undermine an organization's ability to adapt
to change. They also show that even contextually or strategically appropriate cultures that fit a
firm's strategy and business context will not promote excellent performance over extended
periods unless they facilitate adopting strategies and practices that continuously respond to
changing markets and new competitive environments. In the context of an M&A process,
robust, widely shared, and rigid cultures may provide an essential constraint to M&A success.

As Datta (1991) mentions, from the viewpoint of academic researchers, the findings
highlight the importance of taking a broader perspective in their study of acquisition
performance. There is a definite need to go beyond relatedness and synergistic benefits,
recognizing that the expression two plus two equals five does not happen automatically. With
the body of research findings linking strategic fit and performance being largely inconclusive,
future research should also focus on issues related to post-acquisition implementation (Datta,
1991). Leading with culture may be among the few sources of sustainable competitive
advantage left to companies today. Successful leaders will stop regarding culture with
frustration and instead use it as a fundamental management tool (Groysberg et al., 2018).
With such extensive research on organizational culture, expecting an apparatus to measure
culture seems reasonable. Not so. Scholars examining corporate culture tend to split on
measuring culture most effectively. Those following the Schein (1983) corporate culture
model tend to focus on qualitative research, whereas others focus on quantitative analysis.
Nevertheless, extensive measurement tools exist, as shown by Taras et al. (2009), who
identified 121 instruments for quantifying culture.
Schein and Schein (2017), widely considered leading experts on organizational
culture, do not believe that culture is measurable and quantifiable; alternatively, one could
reject any attempt to measure culture and choose to use qualitative approaches such as
observation, interviewing, or projective metaphors. Culture theory is the core postulation used
to examine culture, and the most widely used organizational culture framework is that of
Schein and Shein (2017). In this model, culture exists on three levels:
•Artifacts. Artifacts are challenging to measure but are easily observed. They deal with
organizational attributes that can be observed, felt, and heard as people enter a culture.
•Values. This level deals with the espoused goals, ideals, norms, standards, and moral
principles and is usually the level that is generally measured through survey
questionnaires.

•Underlying Assumptions. This level deals with phenomena that remain unexplained
when insiders are asked about the values of the organizational culture. Information is
gathered at this level by observing behavior to gather underlying assumptions because
they are sometimes taken for granted and not recognized. According to Schein &
Schein (2017), the essence of organizational culture lies at this level.
Denison et al. (2014) reviewed survey instruments to diagnose organizational cultures by
assessing those values and behavioral norms most related to organizational effectiveness.
They found many troubling trends and remaining gaps in the types of reliability and validity
evidence that support these instruments, underscoring the need for additional methodological
research. These trends include inadequate test-retest reliability, limited convergent and
discriminant validity, lack of consistency across different cultural dimensions, and insufficient
validation across diverse organizational contexts and populations. This literature review
revealed varying perspectives on the measurement of organizational culture, with proponents
(Ashkanasy et al. 2000; Cameron & Quinn, 2011; Denison et al., 2003) arguing for the
validity and utility of measurement instruments, while critics (Schein, 1983) raised concerns
about the complexity and comprehensiveness of capturing organizational culture through
measurement. Additionally, O'Reilly III et al. (1991) presented a person-organization fit
approach highlighting the importance of aligning individual and organizational cultures.
These diverse viewpoints reflect the ongoing debates and challenges within organizational
culture measurement.
M&A
As Chakrabarti et al. (2009) state, the cultural disparity between two merging partners
is among the usual suspects blamed for ruining M&A. Moreover, practitioners admit that
culture plays a crucial role in determining the long-term success of an M&A deal;
nevertheless, there are few rigorous studies examining the effect of cultural differences on the
performance of M&A, which makes it difficult to ascertain whether the culture clashes that

we read about in the business press are systematic, widespread phenomena, or pertain to the
handful of mega-deals that capture media attention. Stories about post-merger culture clashes
are general, but anticipating such challenges could prompt better due diligence and lead
acquiring firms to set a higher standard for expected synergies before completing deals
involving culturally distant targets.
Companies spend over $2 trillion on acquisitions yearly (Christensen et al., 2011).
Nevertheless, study after study puts the failure rate of mergers and acquisitions somewhere
between 70-90%. Many researchers have tried to explain those abysmal statistics, usually by
analyzing the attributes of deals that worked and those that did not. A robust theory that
identifies the causes of those successes and failures is lacking. Christensen and colleagues
(2011) propose this: Many executives incorrectly match candidates to the deal's strategic
purpose, failing to distinguish between arrangements that could improve current operations
and those that could dramatically transform its growth prospects. As a result, companies often
pay the wrong price and integrate the acquisition incorrectly. Although Christensen et al.
(2011) primarily examined M&A transactions in public companies, it is essential to note that
this focus may not accurately reflect the outcomes of M&A transactions in private companies.
As demonstrated in this dissertation research, M&A success rates in private companies are
perceived to be considerably higher than the aforementioned failure rate of public company
M&A transactions, potentially leading to a vastly different interpretation of overall M&A
success rates.
However, a counter to Christensen et al.’s (2011) research is that many private equity
executives state they never paid too much for a company; instead, they bought the wrong
company. The wrong company might be defined by culture, meaning the acquired company
did not fit within the construct of the acquiring entity. Additionally, significant debate exists
regarding the definition of M&A failure or success. Personal experience suggests that M&A
failure and success are measured by the goals laid out to the board of directors for approval of

the M&A transaction, which this dissertation examines in the M&A performance survey
results. These goals are tied to financial performance with key measurables such as improved
EBITDA, synergies (e.g., staff reduction), integration timelines, customer retention rates, and
office closures. A conclusion to the analysis could explain how, historically, culture is the one
variable that is the hardest to identify and yet appears to be the root cause of achieving the
aforementioned goals; if cultures seamlessly integrate, financial objectives are typically met,
and if cultures clash, nearly every plan suffers (Lodorfos & Boateng, 2006).
Berdyaev and Bamford (1992) stated that we are in a substantial historical period that
occurs every 200 or 300 years when people no longer understand the world. The past is
insufficient to explain the future, as Cameron and Quinn (2011) indicate. This challenge
becomes particularly relevant to 2021, and the impact of COVID-19 underscores how
difficult it is to understand the world in its current state. Is it reasonable to assume that the
financial implications of COVID-19 and the subsequent reshaping of the business
environment will drive unprecedented M&A activity resulting in a wealth of new data on
M&A activity and the driving factors affecting the decisions on completing the transactions?
The perceived extraordinary failure rate of M&A transactions and the lack of robust theory
presents a dynamic challenge for organizations and analysts. What is the driver of M&A
failure and, more curious, why is there a lack of theory? M&A failure is measurable in
financial terms. If the driver of the financial performance is identifiable, this implies that
research could help existing ideas become more robust theories and subsequently useful for
organizations preparing for M&A activity.
When evaluating M&A performance, return on assets (ROA) and return on equity
(ROE) are the performance indicators that often serve as DVs for the model, and risk,
indebtedness, structure, and dividends indicators are standard IVs. The type of merger may
also provide insight into the transaction's success or failure and examine the subsequent levers
that culture may play in each kind of merger (Reed et al., 1995).

The interest in emerging markets has increased significantly over the last decade,
evidenced by the emerging markets share of global foreign direct investment, inflows and
outflows, as well as cross-border acquisitions (inbound and outbound) having gone up from
24.98% to 36.96% and 14.79% to 27.78%, respectively, during the period 2005-2010, with a
corresponding diminution in the share of developed markets (WIR, 2011). Developed market
firms acquiring emerging market firms show a 50% chance of value creation. On the other
hand, acquisitions by emerging market firms of targets from developed markets typically
erode value, which could be affected by current fluctuation. This may result from the
limited/lack of experience among emerging market firms in cross-border acquisitions
(Narayan & Thenmozhi, 2014).
The geographic impact on organizational culture cannot be underestimated for its
potential implications for M&A success. Geographic culture is both cross-border and within
countries. For example, medical supplies and drugs distributor Cardinal Health announced on
March 12, 2021, on their internal website, that it had signed a definitive agreement to sell its
Cordis business to private equity firm Hellman & Friedman for approximately $1 billion.
Cardinal, in 2015, bought the cardiovascular device manufacturer from Johnson & Johnson
for $1.9 billion but was dogged in subsequent years by integration problems. Could the
impact of geographic culture have derailed this integration, with Cardinal Health being a
midwestern US company and Cordis originally from Miami?
Some estimates are that 70% or more of mergers fail to deliver their intended benefits
and destroy economic value. A meta-analysis of 93 published studies in peer-reviewed
journals that covered more than 200,000 mergers of all types and sizes showed that, on
average, the adverse effects of a merger on shareholder value become evident less than a
month after a merger is announced and persist thereafter (Pfeffer & Sutton, 2006). More
importantly, results indicate that unknown variables may explain significant variance in

postacquisition performance, suggesting the need for additional theory development and
changes to M&A research methods (King et al., 2004).
A clear delineation of M&A due diligence is drawn when analyzing the research of
Pfeffer and Sutton (2006). If the negative effect on shareholder value exists within 30 days of
the merger's announcement, after adjusting for market change, clear indicators of these
challenges were identifiable during due diligence. The acquiring companies analysts'
challenge in doing due diligence is asking the right questions to uncover the information of
the valuation algorithms. However, the due diligence teams, often shielded from this
information as the individuals wanting the transition to close, can creatively hide information
that may harm the transaction closing success.
M&A Theory is a vast field of research, encompassing a wide range of topics related
to these transactions' strategy, financing, and governance. One influential reference in the field
is Sirower (1997). Sirower (1997) critically analyzes companies' common mistakes in
pursuing M&A transactions, such as overestimating potential synergies and underestimating
integration challenges and argues that firms must clearly understand their strategic objectives
and capabilities and have a disciplined approach to assessing potential targets and executing
the integration process.
Integration
Strong culture may be the most difficult to integrate after the close of the M&A
transaction. Employees intuitively resist change, a core human behavior trait possibly
attributed to corporate survival instinct, more commonly referred to as the instinct theory of
motivation (Cofer & Appley, 1964). Suppose a strong culture produces the exemplary
financial performance of a firm. In that case, that culture will resist change during integration
as the fear of losing the edge over competitors may exist. For example, variable compensation
plans often drive culture within a firm, and research is nascent on M&A performance and the
implications caused by changing sales compensation plans. Many macro variables may affect

M&A success, such as transaction size, firm headcount, geographic location, geopolitical
influence, industry sector, brand, ownership, and firm age.
M&A indicators of the actual cost of proper integration are lacking, and the
challenges, pitfalls, and brick walls generated by the distinct cultures merged or absorbed.
One of the walls most often attributed to M&A failure is created by the founder of an
acquired entity. Founder syndrome, introduced by Block and Rosenberg (2002), refers to the
influential powers and privileges the founder exercises or attributes of the founder. The use of
the word syndrome further suggests unhealthy organizational situations in which founders are
more heavy-handed and indifferent about how the imbalance of their control over
organizations comes into play during integration as the very culture a founder created is now
changing, and that lone individual may be the single most serious obstacle to post M&A
integration success.
That lone individual may be the most material obstacle to post-M&A integration
success. Founder syndrome is most evident in private equity (PE) led transactions where the
PE firm focuses on growth to drive a change in control in five to seven years. Initial research
of one PE fund has shown 73 changes in control transactions over five years, with only one
founder making it to the close of the transaction. The other founders either quit, were
terminated by the Board of Directors, or their employment agreement was not renewed.
However, Tarba et al. (2019) posit that high cultural differences between firms
involved in mergers may lead to exceptional organizational success. They suggest that the
extent of cultural differences moderates the relationship between the effectiveness of
postacquisition approaches and overall organizational performance. Their research explicitly
amplifies the positive impact of the post-acquisition approach's effectiveness when the
merged entities have more significant cultural differences. This finding suggests that
organizations should not necessarily view cultural differences as an obstacle to successful
mergers but rather as an opportunity to leverage differences in organizational culture to drive

greater success. By recognizing and leveraging these differences, organizations may create a
more dynamic and innovative organizational culture that can drive exceptional performance
following a merger.
A prevalent theory that impacts culture is the theory of disruptive innovation
(Christensen et al., 2015). Though difficult to describe and often misapplied, the theory of
disruptive innovation is still a key indicator of potential M&A activity. Firms classified as
disruptors routinely achieve high financial market valuations and are often targets of M&A,
initial public offering (IPO), or special purpose acquisition company (SPAC).
Integration theory is a practical consideration for M&A activity, which was first
applied to international business in the 1980s and 1990s as scholars sought to explain the
complexities of coordinating multinational firms' operations across different countries and
regions (Dunning & Lundan, 2008). The theory draws on insights from organizational theory,
economics, and sociology to explain the factors influencing the extent and form of
multinational firms' integration. Dunning and Lundan (2008) tested integration theory's
prediction that the degree of control and influence a multinational firm has over its foreign
subsidiaries by the level of transaction-specific assets and the degree of cultural distance
between the parent firm and the subsidiary. The study supports the theory and highlights the
importance of considering economic and cultural factors in multinational firms' strategic
decisions about integration.
Organizational Fit
Challenging the widely held belief that dominant corporate cultures create excellent
business performance, Kotter and Heskett (1992) show that while many shared values and
institutionalized practices can promote good performances in some instances, those cultures
can also be characterized by arrogance, inward focus, and bureaucracy features that
undermine an organization's ability to adapt to change. They also show that even contextually
or strategically appropriate cultures (ones that fit a firm’s strategy and business context) will

not promote excellent performance over long periods unless they facilitate the adoption of
strategies and practices that continuously respond to changing markets and new competitive
environments (Kotter & Heskett, 1992).
According to Weber and Schweiger (1992), while cultural conflict often plays a
prominent role in producing merger failure, it is often neglected when the benefits of a
potential merger are examined by introducing a laboratory paradigm for studying
organizational culture. This paradigm captures several critical elements of the phenomenon in
the experiments, allowing subjects in firms to develop a culture and merge two firms. As
expected, performance decreased following the merging of two laboratory firms. Also,
subjects overestimate the performance of the merged firm and attribute the decrease in
performance to members of the other firm rather than to situational difficulties created by
conflicting cultures (Weber & Camerer, 2003).
Due Diligence
As Ravenscraft and Scherer (1989) proclaim, we know that pre-merger, acquired
companies exhibited exceptional profitability, particularly when they were smaller in size.
Following the merger, the profitability of acquired entities declined except among pooling-
ofinterest merger partners of roughly equal pre-merger magnitude. The decline was more
extensive than expected, and this result and the high divestiture rate for acquired entities point
toward control loss explaining the profit drop. The pooling of interests accounting can
favorably skew reported earnings and is no longer an acceptable form of acquisition
accounting under U.S. Generally Accepted Accounting Principles (GAAP).
Ravenscroft and Scherer (1989) do not appear to address that; as a result, highly
profitable developed small companies are often in this position due to reduced salaries,
benefits, and overall company infrastructure. When a large company purchases a small
company, they often bring salaries, benefits, and infrastructure online with their own, which
can dramatically impact financial performance, potentially turning the acquired entity

unprofitable. This result may have a devastating impact on the two cultures and slow or
completely derail integration efforts.
A business rule not attributable to any single executive states: "Move fast, and if you
are correct eighty percent of the time, it is acceptable." Moving fast may work for most
business decisions but not for M&A transactions, as it is unfathomable that any executive
would enter an M&A transaction saying that a 20% success rate is acceptable. So, what drives
M&A activity knowing the failure rates? Ego, financial gain, or the volume of scale? M&A
activity is cyclical by nature, and COVID-19 has created an activity cycle that may be
unequaled regarding the importance of transactions. The essential motives for these deals are
target economic weakness, financial constraints, and adverse economy-wide shocks (Masulis
& Simsir, 2018).
Research from Moeller et al. (2005) states that acquiring firm shareholders at the time
of acquisition announcements lost 12 cents per dollar spent on acquisitions for a total loss of
$240 billion from 1998 through 2001. In contrast, they lost $7 billion in the 1980s, or 1.6
cents per dollar. The figures from 1998 to 2001 are noteworthy because of a few acquisitions
with negative synergy gains by firms with extremely high valuations. Without these
acquisitions, the wealth of the acquiring firm shareholders would have increased. Firms that
make these acquisitions with significant dollar losses perform poorly afterward.
Moeller (2005)'s argument that a few substantial M&A transactions have skewed the
overall M&A activities performance is solid and quantifiable. Nevertheless, the challenge is
often uncovering data from private transactions where financial results are not public
information or small transactions made by large companies due to the immaterial size of the
transaction as a portion of the overall firm's public valuation. Within the long‐term and
dynamic nature of the M&A process, Teerikangas and Very (2006) argue that instead of
studying the simple performance impact of cultural differences in M&A, we should consider
how cultural differences impact the M&A process and its outcome.

Additionally, consideration for Agency theory should exist when evaluating M&A
performance (Eisenhardt, 1989). Agency theory is concerned with resolving two problems
that can occur in agency relationships. The first is the agency problem that arises when (a) the
desires or goals of the principal and agent conflict and (b) it is difficult or expensive for the
principal to verify what the agent is doing. The second is the problem of risk sharing when the
principal and agent have different attitudes toward risk. The problem is that the principal and
the agent may prefer different actions because of the various risk preferences.
The risk aversion or risk tolerance differences can also drive equally distributive
challenges to integration. No one has studied the frequency of due diligence or the
consideration of agency theory by the acquiring firm's CEO when evaluating the go/no-go
decision to greenlight an acquisition.
CEO hubris is an additional factor in M&A performance (Park et al., 2018). The
unknown is the percentage of M&A transactions that occur due to hubris, not the broader firm
stakeholders' or shareholders' best interests. The hubris hypothesis advanced to explain
corporate takeovers from individual decision-makers in bidding firms. Hubris can explain
why bids, even when a valuation is above the current market price, represent a positive
valuation error: bidding firms infected by hubris pay too much for their targets. The empirical
evidence in mergers and tender offers reconsidered in the hubris context argued that the
evidence supports the hubris hypothesis as it helps other explanations such as taxes, synergy,
and inefficient target management (Roll, 1986). Roll (1986) argues that the hubris hypothesis
drives M&A activity equally or even more significantly than other guiding reasons for the
transaction's approval. This lone argument suggests a blatant lack of control, fiduciary
responsibility, and accountability of the firm's board of directors entering an M&A deal. A
board of directors needs to function as a check and balance for the CEO of a firm, and Roll
(1986) argued that they are more responsible for a failed merger than the CEO, who operated
on hubris and not evidence-based management to drive forward the consolidation.

Research has shown that CEO hubris can harm a company's performance and reputation. On
average, losses in acquiring firms' shareholder wealth following an acquisition, and the
greater the CEO hubris and acquisition premiums, the greater the shareholder losses. Thus,
CEO hubris has substantial practical consequences and potentially great theoretical
significance to observers of strategic behavior (Mathew & Hambrick, 1997).
Weber and Camerer (2003) suggested that the likelihood of cultural conflict and
coordination failures is underestimated, which explains why firms enter so many doomed
mergers. Weber and Camerer (2003) clearly show how CEO hubris theory comes into play as
overconfidence and the belief that the CEO can manage anything or anyone fails to
understand the potential cultural conflict and ensuing integration challenges. Hayward and
Hambrick (1997) show that, on average, losses occured in acquiring firms' shareholder wealth
following an acquisition, and the greater the CEO hubris and acquisition premiums, the
greater the shareholder losses. Thus, CEO hubris has substantial practical consequences and
has potentially great theoretical significance to observers of strategic behavior.
This dissertation examines two other theories for their relevance to M&A: Friedman
(1970) and Shareholder Theory and Freeman et al. (2010)’s countering Stakeholder Theory. Is
it evident that shareholder theory drives M&A transactions, yet stakeholder theory may
determine the success of the activity post-integration. It is a plausible assertion that
COVID19, and the low cost of capital, have acted as catalysts for a merger wave that emerged
in 2020. This merger wave, introduced by Duchin and Schmidt (2013), is present within the
context of the COVID-19 pandemic. The shareholder value theory may serve as a
fundamental justification for this merger wave. Nonetheless, existing literature proposes that
CEO hubris may also underlie this trend, with executives justifying their actions as value
creation for shareholders.
As some literature suggests, stakeholder theory could prove to be at the core of failed
M&A activity highlighted by Freeman (2015). Do stakeholders influence an organization's

culture? If the primary stakeholders are the employees who do not feel the M&A transaction
is in their best interests, the resulting culture may prove combative and resist integration for
distinct reasons. Due to the mature nature of both Shareholder and Stakeholder theories and
the volumes of literature on this topic, the arguments can be more than adequately researched
and incorporated into the dissertation results.
In the traditional view of the firm, the shareholder view, shareholders and the firm
have a binding financial obligation to put their needs first to increase value for them.
However, stakeholder theory argues that other parties are involved, including governmental
bodies, political groups, trade associations, unions, communities, financiers, suppliers,
employees, and customers. Sometimes competitors are counted as stakeholders; their status is
derived from their capacity to affect the firm and its other stakeholders (Freeman, 2015).
Under shareholder theory, the firm's goal is to maximize shareholder returns outlined by
Friedman (2020). If the firm aims to maximize shareholder returns, it is necessary to quantify
the disruption to stakeholders during the integration. Shareholder returns drive decisions to
create synergies post-acquisition, which, simply put, is headcount, vendor, and systems
reduction.
Due diligence teams determine a company's valuation with volumes of formulas and
key performance indicators. Those financial data points accompanied by a firm's desire to
advance the transaction often drive the recommendation to the board of directors to close an
M&A transaction. The hidden costs of M&A activity are a fruitful area to research, especially
considering the embryonic state of academic literature in this area. In contrast, there appear to
be volumes of untested practitioner literature.
OCAI
Using a tool such as OCAI, it is plausible that organizational culture is identifiable
during M&A due diligence and overlaid with geographic location, size, business sector,
financial performance, and employee turnover. Despite fledgling research in this area of

externally measuring culture during M&A activity, it is explored during research as a potential
catalyst to assisting due diligence gathering in a non-disruptive fashion.
The OCAI, designed and validated by Cameron and Quinn (2011), assesses
organizational culture by scoring six aspects: dominant characteristics, organizational
leadership, management of employees, organization glue, strategic emphases, and criteria of
success. Respondents allocate 100 points across four statements for each aspect, indicating the
most fitting statement with the highest points. This scoring method reveals the current culture
profile, also referred to as present culture, and identifies the desired direction of change. The
deliberate design of the scoring process encourages respondents to make choices within the
Competing Values Framework, reflecting the reality that trade-offs are necessary. There are
two dimensions where people make choices: internal and external focus and the second
dimension is the structure from flexible to stable. The two dimensions result in a quadrant
configuration, which the authors identify as four types of culture: Clan, Adhocracy, Market,
and Hierarchy. A description of each is provided:
•Clan. Values cohesion, participation, communication, a personal place, like a
family; mentoring, nuturing, tight social networks
•Adhocracy. Dynamic, entrepreneurial; people take risks, values innovation,
adaptability, growth, cutting edge services of products
•Hierarchy. Favors structure and control, coordination and effciency, stability is
important, timeline, smooth processes
•Market. Results-oriented, getting the job done; values competition and
acheivement, customer-driven, acheivement (Cameron & Quinn, 2011, p. 39).
As additional variables, the survey's intentional brevity validity does not
enhance its effectiveness. CFA supported a four-factor structure of the OCAI

for both ideal and current organizational culture perspectives (Heritage et al.,
2014)
Many previous studies have touched on aspects of merger failure, though none
conclusively document the causal effect of cultural conflict. Most studies demonstrate the
success or failure of mergers without directly addressing cultural differences (Ravenscraft &
Scherer, 1989). One might conclude that the lack of studies addressing cultural differences is
the challenge of measuring and comparing the differences between the two cultures. Using
tools such as the OCAI may provide a basis to begin this research in a quantifiable fashion.
Do these four types of culture serve as a high-level indicator of M&A success or
failure when paired? The four types of organizational cultures may possess a key to unlocking
the challenge of quantifying culture during M&A due diligence, specifically when the OCAI
preferred state is a driver of research. However, this tool may fall short in measuring culture
during M&A due diligence so that an organization can predict the differences in cultures and
the time, cost, and effort needed to merge those cultures posttransaction.
A vital component of the OCAI determines the firm's current and preferred culture.
This preferred state may be a crucial indicator of the challenges two firms may uncover while
integrating cultures post-close. Is it reasonable to assume that if an acquired company
expresses a preferred culture that reflects the acquiring firm's current culture, then that M&A
integration may prove highly effective and lead to a successful transaction? The
dissertation research aimed to determine the feasibility of pinpointing an organization's
culture using the OCAI. Then, overlaying post-merger integration data can create a procedure
that may be used during M&A due diligence to estimate the actual integration success
probability. If successful, the process could be worth billions of dollars by making M&A
transactions identify a more realistic outcome of appraising post-merger integration success.

Knowledge Contribution
Four core theories supported the dissertation research. The first is Organizational
Culture Theory (Jaques, 2013), defined as the underlying beliefs, assumptions, values, and
ways of interacting and contributing to an organization's unique social and psychological
environment. The second theory is Agency Theory (Jensen & Meckling, 1976), which is a
principle used to explain and resolve issues in the relationship between business principals
and their agents. Most commonly, that relationship is between shareholders, as principals, and
company executives, as agents. Agency Theory is directly applied to this dissertation's
research because the travel and travel services industry is over 60% independent contractors.
Applying agency theory to independent contractors within a larger organization allows
examining contractual dynamics, conflicts of interest, and organizational culture impact. In
the travel industry, independent contractors act as their own independent businesses under the
umbrella of a parent organization for shared services support and financial buying power
while maintaining the autonomy to leave the parent organization without notice. The third
theory is Integration Theory which postulates that successful integration requires a clear
understanding of the differences between the acquiring and acquired companies and the
ability to manage those differences effectively (Cartwright & Cooper, 1993). The fourth
theory is M&A Theory which emphasizes that successful integration requires careful planning
and execution, relying on leadership, communication, due diligence, and employee
engagement (Penrose & Penrose, 2009).
CHAPTER 3: METHODOLOGY
The research question is, "Are effects of organizational culture on post-merger
integration identifiable during merger and acquisition due diligence?" The research to answer

this question required a mixed-methods approach based on retrospective examination of
closed M&A transactions. The qualitative research design explored employee insights
through interviews on organizational culture, explicitly examining culture during and after
M&A transactions. The quantitative research design examined the measurable statistics
describing organizational culture, M&A post-integration performance, and estimated the
relationships between culture and performance that impact success and failure as viewed by
the Board of Directors, shareholders, senior managers, and the employee base.
Organizational Culture Research
The OCAI portion of the dissertation research, which ran concurrently with the M&A
performance survey, consisted of organizational culture research. The dissertation
organizational culture framework identifies and measures culture, and the method chosen as
the measurement tool is the OCAI. The OCAI provides a framework in that the test can be
administered quickly and efficiently while measuring the current culture state within an
organization and the preferred state. This preferred state provided insight into the desired
outcome of an M&A integration if the acquired entity had a desired preferred state closer to
the acquiring firm than its current state. To simplify, if a company being acquired saw the
acquiring firm's culture as more desirable than its own, then resistance to integration within
the new organization may not occur and instead be met with acceptance. Thus, the integration
costs may be lower than anticipated, potentially making the transaction successful. The
OCAI is classified as a survey instrument, and the intent was to use this tool within both
organizations in the M&A transaction. Employees from multiple levels within each company
were asked to take the OCAI, as each level may show different perceptions of their current
and preferred states of culture at the time of transaction close. The next phase of the research
was the interview portion, which interviewed a subset of the OCAI respondents to glean
further insight into the organization's culture. After completing the OCAI surveys and
interviews, I identified the company's culture within an M&A context. When placed into a

merger plan with the statistics of the M&A integration, that mechanism should shed light on
the impact of culture on integration.
The seven dimensions of organizational culture (i.e., attention to detail, outcome
orientation, people orientation, team orientation, aggressiveness, stability, and innovation and
risk taking) described by Robbins et al. (2014, p. 97) provided me with a roadmap for coding
considerations while evaluating interviews to explore the multifaceted dynamic of the
organization’s culture. Additionally, the seven dimensions informed the construction of the
interview questions.
M&A Integration
The M&A integration survey phase of the research, which ran concurrently with the
OCAI phase, covered M&A integration performance, specifically post-transaction integration.
To gain insight into why firms fail to meet their pre-transaction goals, organizations often
conduct a statistical analysis of their performance following a successful transaction
integration.The framework for the quantitative portion consisted of reviews looking at firms,
at least three years post-M&A transaction, to review their performance in terms of integration.
50 M&A transactions required an in-depth review of integration performance to produce a
predictable pattern of success or failure. Only firms that completed the OCAI were eligible
for quantitative research, with employees from each side of the transaction at the time of
close participating in all phases of the study.
Additional considerations of the impact of theories on the dissertation research may be
considered in future research, such as the theory of structuration, defined as a social theory of
the creation and reproduction of social systems based on the analysis of structure and agents,
without giving primacy to either. As Giddens (1979) suggests, the essential recursiveness of
social life, as constituted in social practices, is both the medium and outcome of the
reproduction of practices. Structure enters simultaneously into the constitution of the agent
and social practices and exists in the generating moments of this constitution.

When observing organizational culture, the instances where structure defines and
drives culture formation and curation within the institution are easily spotted. Nonetheless,
the agency’s influence on the individual is equally important but much harder to identify as
the individual’s use of resources to fulfill potential is not as evident. So again, holism
provides the most logical method to explain the facts about the institution, especially
economic performance. However, when entering an M&A transaction, those holistic
explanations are incomplete without understanding the individualism that drives participation
within an institution's culture and, more predominantly, the willingness to accept and
integrate with another culture as part of the M&A integration.
In some ways, the OCAI indirectly addresses structuration theory in that the
assessment tool equally measures culture in its current and preferred states. One could
conclude that the agency is the preferred state driven by individualism, and the structure is the
current holistic state. The institution's facts are far easier to explain in holistic terms when
looking at the current state of the organization's culture and financial performance. So, the
facts are holistic, as no company performance is based upon a preferred state. A
complementary argument is that no organizational culture can exist without the individualism
of the employees, and it is leadership that then brings the individuals into the whole for a
holistic path toward institutional performance. A fascinating research topic would include
using a holistic view of institutional performance facts while factoring in the underlying
individual desires of organizational culture when calculating M&A transaction valuation.
Using this structure could dramatically impact M&A decision-making during the due
diligence phase and prove the linchpin to understating M&A failures and how to avoid those
for future transactions.
Research Design and Methods
This dissertation relies on assessing an organizational culture; the method used is the
OCAI (Cameron and Quinn, 2011). The OCAI is the framework's base, and it is then coupled

with an M&A integration survey and interviews of participants from acquired and acquired
companies and surveys regarding performance data.
The literature review showed that additional research is needed and called for
frequently on organizational culture and its impact on M&A integration. Additionally, the
mixed-methods research’s focus was amplified due to the nature of qualitative research
required to identify and classify organizational culture and the quantitative analysis needed to
understand culture's fiscal impact on M&A integration. By overlaying the quantitative data of
the integration with the OCAI data from the qualitative research and regression analysis, the
process can show how certain cultures on both sides of the transaction can positively impact
post-transaction integration.
The interviews sought employee perceptions on essential components of culture. As
Schein (1983) describes, there is a culture founder within any acquired company. This person
is often a company founder but not always, especially in older companies or ones with
longtenured C-suite executives. This culture founder has tremendous ownership of the entity's
culture and will fiercely defend and protect that culture during the M&A process. In addition,
when these culture founders remain active post-acquisition, they are often principally the
channel for successful M&A integration. The interview questions specifically addressed the
role of the founder in the subject acquisitions.
The next component is culture curators, first introduced by Franz Boas and outlined
by Stocking Jr (1966). These individuals are the ones that keep a culture alive for generations
of employees. Curators do not create a culture, but they ensure it stays alive. Sometimes,
curators can be defensive of their current culture but often hold the secret to integrating
change and becoming the most important asset post-transaction. They know how to sell a
culture evolution to employees. I directly identified the curators and their influence on culture
from the interview analysis.

External culture is another component (Hatch & Schultz, 1997). This dynamic is the
culture that those outside the organization perceive, often the linchpin to recruiting new hires.
If internal and external cultures do not match, it will result in high turnover.
The final component is internal culture. Internal culture is precisely as it sounds in that
it is the culture within the organization, conceptualized in terms of the degree of internal fit
(cohesion and consistency) and external fit (linkages to strategy and the environment)
featured by Arogyaswamy and Byles (1987). Nevertheless, here lies the billion-dollar miss
during due diligence. What is the company's internal culture being acquired, and is that
culture what most employees want as their culture? The transaction may fail if the culture of
each side of an M&A transaction is not identified, evaluated, categorized, and modeled during
due diligence.
The proposition is that culture and the difference in two companies' cultures drive
M&A success or failure, yet those cultures can be pinpointed and quantified. Thus, a
mixedmethods approach is the foundation for exploring the qualitative analysis of
organizational behavior driving the quantitative measurement of culture, producing
predictable and measurable processes to calculate M&A culture integration to drive evidence-
based management decisions.
Given the importance of researching cultural impact prior to the M&A, the research
question was slightly modified to read: “Are effects of organizational culture on post-merger
integration identifiable during merger and acquisition cultural due diligence?” Supporting this
were four hypotheses. I developed these hypotheses from the literature.
Hypotheses
•H1. The differences between the cultures of the acquiring and acquired
companies are related to financial outcomes measured three years after the
M&A.

The hypothesis that cultural differences between acquiring and acquired companies are
associated with financial outcomes three years post-M&A is a crucial area of investigation in
M&A. Researchers have conducted limited research to explore the impact of culture on M&A
success, which has revealed several challenges arising from cultural differences, including
communication breakdowns, difficulty achieving synergies, and resistance to change. Such
challenges can impede financial performance during the post-M&A period, leading to
suboptimal outcomes. As Kale et al. (2000) mentioned, empirical studies have provided
evidence that cultural integration can help mitigate adverse effects on financial outcomes
resulting from cultural differences.
•H2. The differences between the cultures of the acquiring and acquired
companies are related to cultural outcomes measured three years after the
M&A.
The hypothesis that cultural differences between acquiring and acquired companies are
related to cultural outcomes three years post-M&A is an important area of investigation in
M&A. Culture is a vital component of organizational behavior, and changes in culture during
M&A activity can significantly impact the long-term success of the merged entity. Cultural
outcomes such as employee satisfaction, commitment, and retention are critical to integrating
acquired firms and subsequent success. Cultural differences can lead to adverse cultural
outcomes such as mistrust, resentment, and decreased employee morale. In contrast,
successful cultural integration can enhance outcomes and foster positive cultural changes.
•(H3). There are culture combinations that successfully integrate and result in
successful M&A outcomes.
The hypothesis that certain culture combinations can lead to successful integration and
positive outcomes in M&A activity is a unique area of research in M&A. Combining different
cultures during M&A activity can pose significant challenges to the success of the merged

entity. However, certain cultural combinations may result in successful integration and
positive outcomes. Further research is needed to identify these cultural combinations and
understand how they promote success. Identifying successful culture combinations would be
valuable in guiding companies in selecting potential partners and developing strategies for
cultural integration.
•(H4). The acquiring company's OCAI current state closely matches the
acquired company’s preferred state and produces a successful M&A outcome.
The hypothesis that a close match between the acquiring company's current
organizational culture and the acquired company's preferred culture leads to a
successful M&A outcome is an exciting area of research in the field of M&A.
Cultural integration is a complex process that requires careful management to
ensure the long-term success of the merged entity. A close match between the
acquiring company's current culture and the acquired company's preferred
culture may or may not facilitate the integration process and promote positive
outcomes. For example, a shared culture can help to overcome communication
breakdowns and resistance to change, which are common challenges in M&A
activity.
Study Design
I considered mixed-methods research superior for this dissertation because it combines
quantitative and qualitative research methods to provide a more comprehensive and complete
understanding of a research problem. Several studies support the superiority of mixedmethods
research in a dissertation. For example, a study by Creswell and Clark (2017) found that
mixed-methods research can provide a richer understanding of a research problem,
particularly when exploring complex phenomena. By combining quantitative and qualitative

data, analysts can capture the breadth and depth of the research problem, resulting in a more
comprehensive understanding of the studied phenomenon.
Triangulation is an essential aspect of mixed-methods research that can improve the
credibility and rigor of the research findings. Johnson et al. (2007), found that triangulation
can help to overcome the limitations of using only one research method, such as limited
sample size or partial data. By using multiple methods to explore the research problem,
investigators can validate their findings and increase confidence in the conclusions drawn.
Mixed-methods research allows for flexibility in data collection and analysis, which can
be particularly useful in a dissertation where the research problem may evolve. Johnson and
Onwuegbuzie (2004) found mixed-methods research adapted to unexpected findings or
changes in the research problem. This flexibility can help researchers to adjust their approach
to data collection and analysis as needed, resulting in a more comprehensive and complete
understanding of the research problem.
Mixed-methods research can be beneficial for addressing complex research questions that
require both quantitative and qualitative data to answer. Creswell and Clark (2017) found that
mixed-methods research is used to explore the complexities of a research problem,
particularly when exploring social phenomena. Using quantitative and qualitative data,
researchers can explore the research problem from multiple perspectives, resulting in a more
nuanced understanding of the phenomenon.
These studies suggest that mixed-methods research is superior because it can provide a
more comprehensive and complete understanding of the research problem. By combining
quantitative and qualitative methods, mixed-methods research can capture the breadth and
depth of the research problem, validate findings, adapt to unexpected changes, and explore
complex phenomena.
I determined that a mixed-methods approach is most suitable for thoroughly evaluating
the effects of organizational culture on post-merger integration in the dissertation.
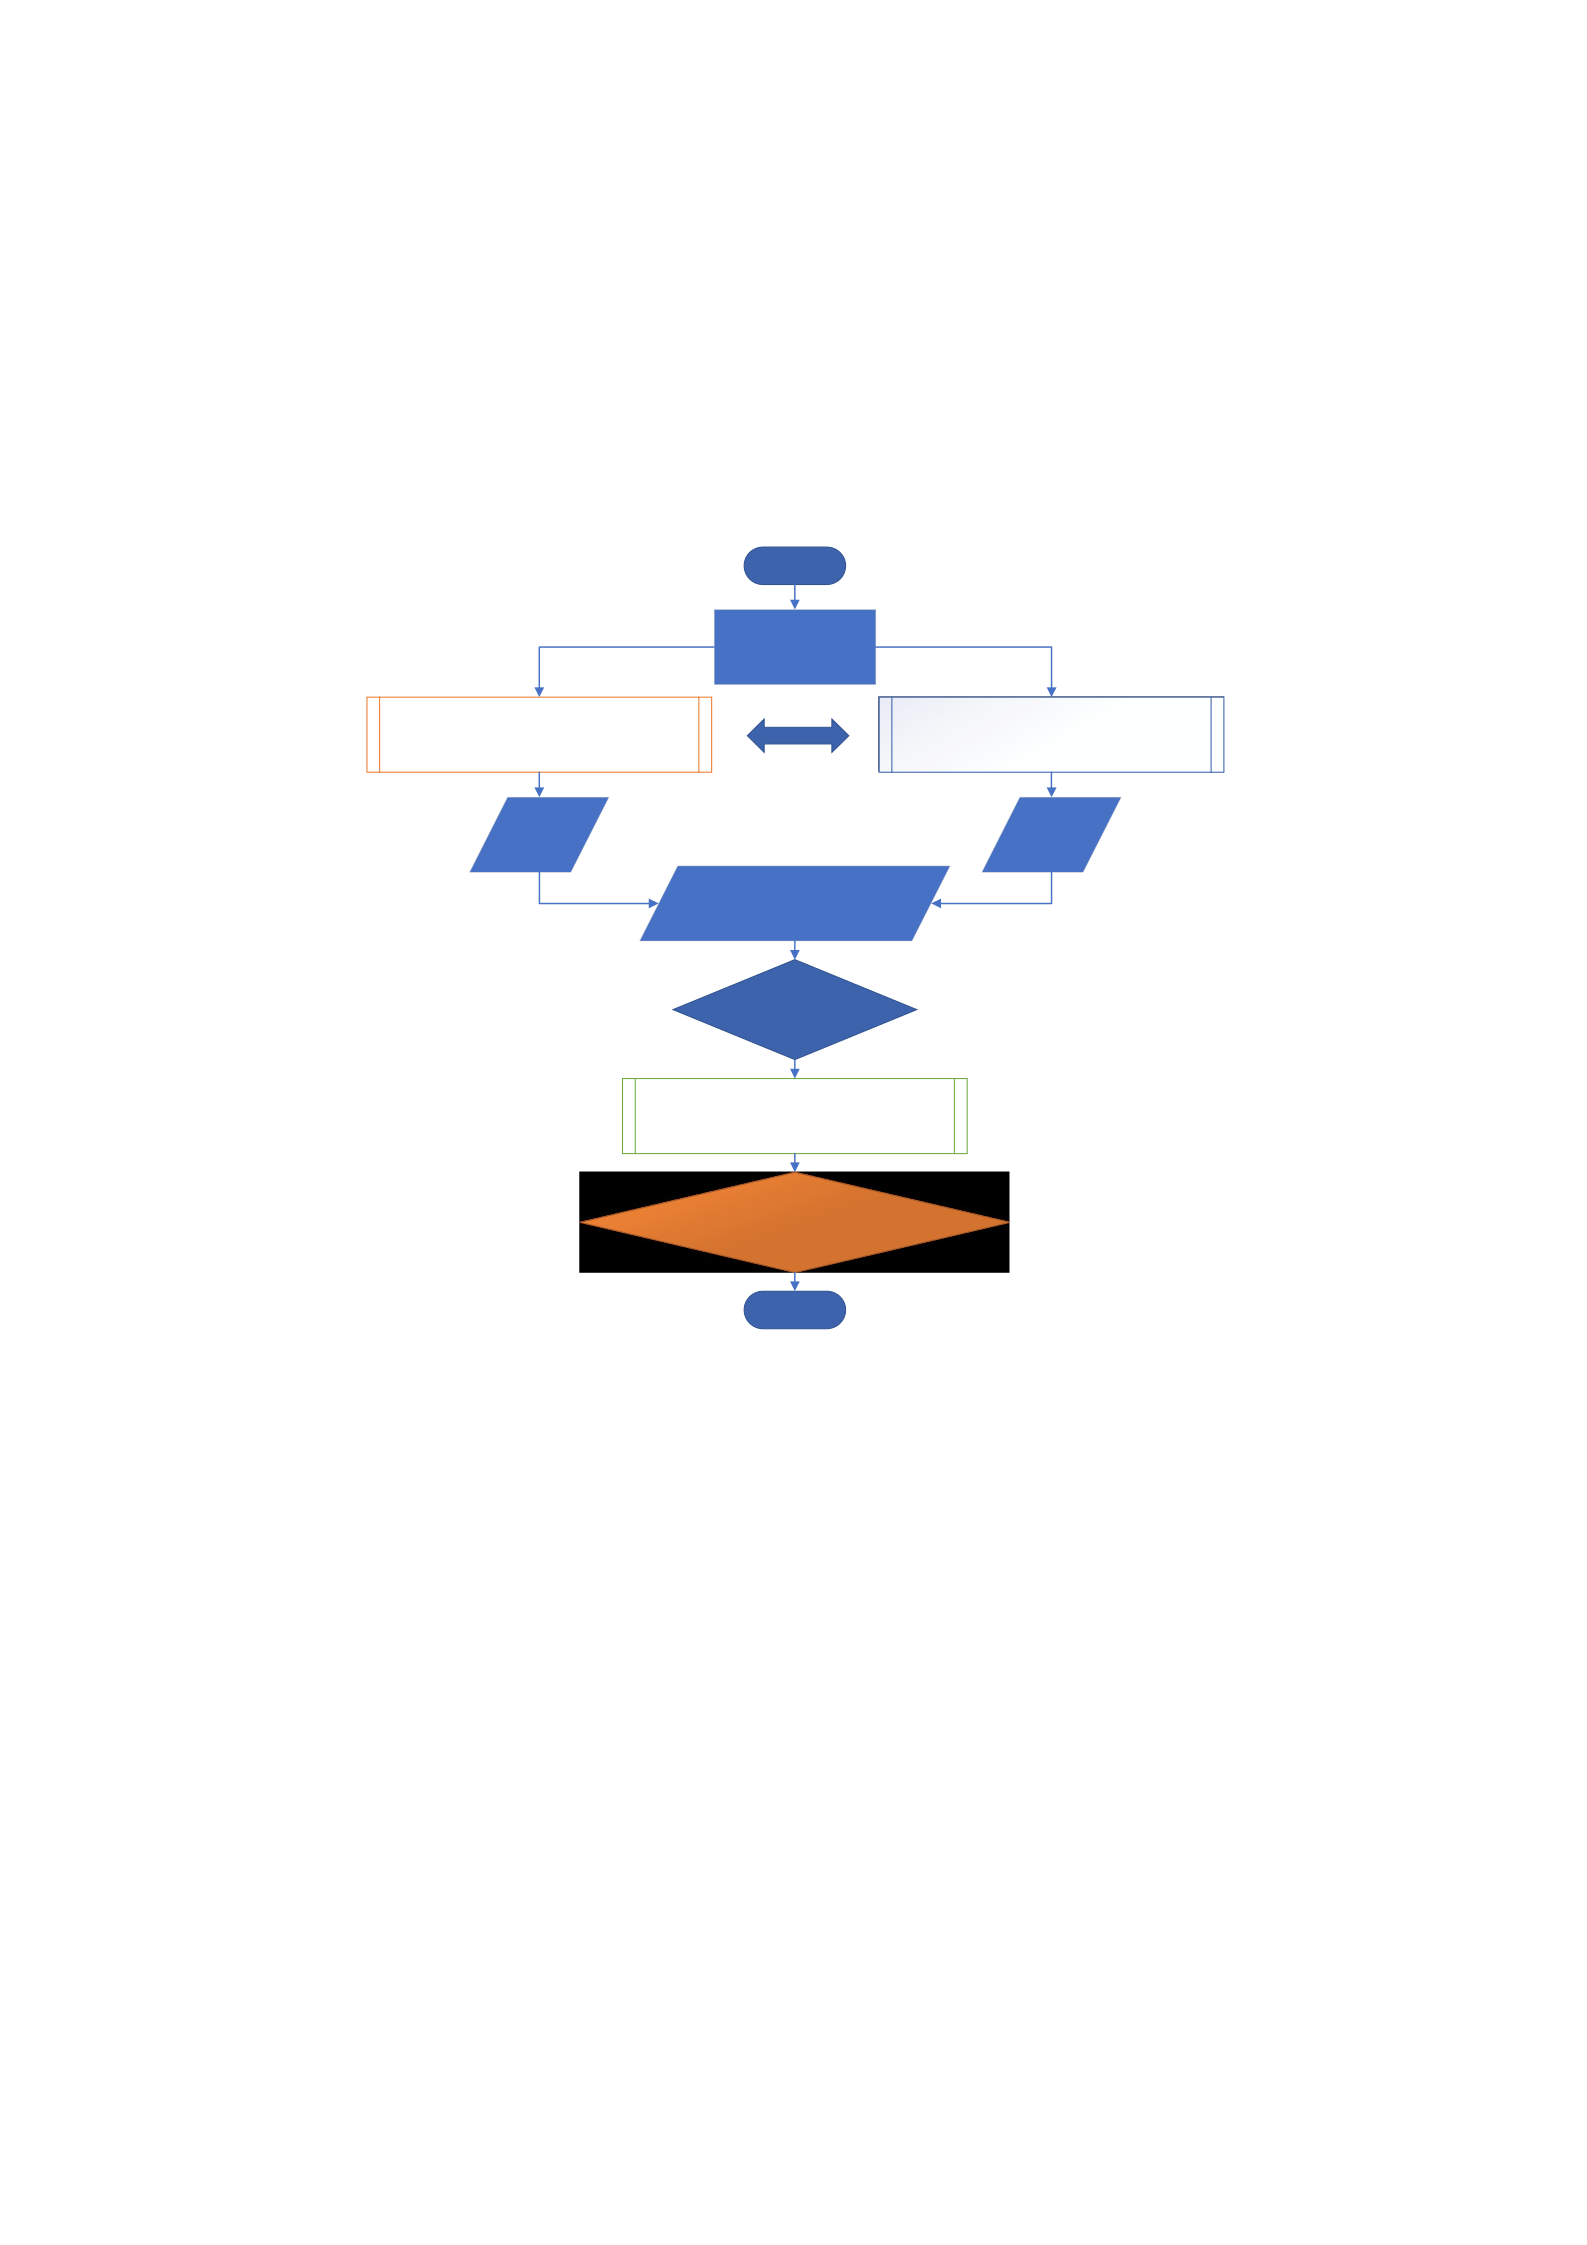
Quantitative surveys and data collocation proceeded with the OCAI and in-person interviews
of those involved in each M&A transaction. Figure 2 shows the research design and process
in a high-level flowchart.
Figure 2
Research Design and Process
Study Population and Sampling
The research examined 50 M&A transactions 3-5 years post-merger in the travel and
travel services industry. The target M&A transaction size was $20 million to $5 billion, with
the acquiring entity headquartered in the United States. The companies selected were from
my network and references from that network. This selection of companies was a purposeful
sample. After collecting an informed consent from each participant (Appendix A), I examined
the results of 50 post-M&A transaction integration performances versus the stated and
recorded goals for years one, two, and three. The second phase of the research asked the
50 acquired and acquiring companies to have five employees take the OCAI.
Start
End
M&A Transactions 50
$5B<
3- years post close
M&A performance survey
Interviews
Survey
results
OCAI
results
OCAI
Statistical analyses to
estimate relationships
Top/Bottom three
performances identified
Patterns
Concurrent

Data Collection Methods and Instruments
The data collection consisted of three stages. The first stage analyzed the performance
of 50 post-M&A transactions for the first three years of integration and compared it to the
predetermined goals using a performance integration survey. The second stage, conducted
simultaneously with the first stage, required acquiring and acquired companies to have five
employees complete the OCAI. In the third stage, I interviewed 36 employees who were
identified in the top three and bottom three M&A performances. The PI selected three
employees who had completed the OCAI and had at least three years of tenure from each side
of the six M&A transactions for interviews. I coded the interview transcripts and extracted
themes from the interviews.
Performance Integration Survey: Two senior-level employees from the acquiring
entity directly involved with the M&A transaction were asked to take the M&A performance
integration survey with a time commitment of fewer than two hours. They were asked
questions regarding their perceptions of the goals and performance for the three years post-
M&A. These data were collected using Likert scales (Appendix B).
OCAI Survey: I collected qualitative assessments of the organizational culture of
employees involved in the M&A transaction at any level using the OCAI instrument. I
engaged the HR department in the discussion, so they helped choose the employees for the
OCAI. HR also served as the co-sponsor for all communication (e-mail) to the employees
about the study, the employee's willingness to participate, and if the employee agreed.
Employees trusted the confidentiality of HR, and this direct involvement assisted with the
research, so the employees understood that their participation was voluntary and confidential.
The reference to the OCAI protocol is in Appendix C.
Statistical analysis: The average score of all parties taking the integration survey and
the OCAI constituted the categorization of each organization involved in the M&A

undertaking. The top and bottom three survey scores were flagged for examination and
discussion.
Interviews: Post-merger qualitative interviews of three employees with at least three
years of tenure from each side of the M&A transaction were conducted using an interview
guide (Appendix D). Each participant was only interviewed once and the time commitment
was 90 minutes. After determining the top and bottom three M&A performances, I involved
the HR departments in facilitating interview communication with the employees.
Data Analysis Methods
The quantitative methods used several statistical tests to estimate relationships
between OCAI and survey scores. These included correlation, regression, and t-test analysis.
Statistical analysis determined the significance and magnitude of relationships between
culture type and integration performance. The qualitative analysis explored the integration
capability of the acquiring firm and the subsequent impact on the transaction integration
versus only considering the organizational culture influence by using thematic analysis.
Thematic analysis is a qualitative research method that involves identifying,
analyzing, and interpreting patterns or themes within data. The thematic analysis enables
researchers to explore diverse perspectives of participants and identify patterns or themes
within the data. This perspective is vital in enabling analysts to understand the research topic
comprehensively. According to Braun and Clarke (2006), patterns are essential in qualitative
research, enabling researchers to categorize data and provide a structured presentation of the
research findings. The richness of data collected from interviews is retained and also provides
data that is deeply rooted in the participant’s experience, and it allows investigators to present
data in participants' own words and capture the nuances of their experiences. Thematic
analysis provides a rigorous approach to data analysis, enabling analysts to demonstrate the
reliability and validity of their findings. This rigor is paramount in dissertation research, as it
enhances the credibility of the research findings (Nowell et al., 2017).

The analysis used the Gioia Methodology (Gioia et al., 2013) to analyze interview
data collected from participants who have experienced M&A integration. The Gioia
Methodology is a qualitative data analysis technique that focuses on identifying and
interpreting themes and patterns in data. The Gioia methodology comprises six stages, which
include: 1) defining the research question, 2) selecting an appropriate sample, 3) collecting
data, 4) coding the data, 5) generating themes, and 6) interpreting the findings. The study
analyzed 37 interview transcripts to identify first-order codes and sub-themes related to M&A
integration success.
Researchers identify themes in qualitative research by rigorously analyzing the data
and organizing recurring patterns or concepts into meaningful categories. It is common for
sub-themes to share a similar rubric as other sub-themes within a more prominent theme,
mainly if they are related to different contextual aspects of the same overarching
phenomenon. This result can occur when a particular theme encompasses multiple
dimensions or facets that require further elaboration and differentiation.
The PI must clearly articulate the specific context in which each sub-theme exists and
provide detailed examples or evidence to support their interpretations, as it is requisite for the
success and credibility of the research. This investigation requires a deep understanding of the
data and a nuanced approach to analysis, considering the complexity and richness of the
studied phenomena. Ultimately, the goal of qualitative research is to uncover the underlying
meanings and experiences of the participants, and careful attention to the organization and
presentation of themes is expository to achieving this aim.
Qualitative interviews with employees directly involved in M&A transactions
provided valuable insights into the complex and multifaceted nature of M&A success or
failure. Shrivastava (1986) noted that M&A success depends not only on a thorough analysis
of quantitative data but also on understanding the subjective interpretations and meanings that
the actors involved attach to the process and outcome of the transaction.

Interviewee quotes offered detailed descriptions of the cultural, social, and
psychological factors that influenced M&A outcomes, including the role of organizational
culture fit, founder influence, employee engagement, and understanding of the acquired
company's business. By including quotes in qualitative analyses, I provide a more nuanced
understanding of the dynamics in M&A transactions and inform future research and practice.
Interviews with employees were beneficial for understanding the impact of organizational
culture fit, founder influence, employee engagement, and other factors on M&A success or
failure. Interviewees offered first-hand accounts of how these factors influenced their
experience during the integration process, which can help acquirers to anticipate challenges
and develop effective strategies for managing the integration. The PI ensured that quotes were
not taken out of context or misinterpreted and sought to consider interviewees' and analysts'
perspectives and biases.
Despite these challenges, qualitative interviews with employees produced rich and
nuanced data that can be difficult to obtain through other methods. By carefully analyzing
interviewee quotes and triangulating data from multiple sources, I comprehensively
understood the factors contributing to M&A success or failure and offered practical
recommendations for improving the integration process.
Ethical Considerations and Human Subjects Issues
Once a target company was determined and agreed to participate in the research study,
their HR department served as the co-sponsor for all communication (e-mail) to the
employees about the study, the employee's willingness, and if the employee agreed to
participate. The subject's only requirement for the OCAI was that they must have been
employed at the company before the M&A transaction close. For the interviews, each unique
subject must have had three years of employment with the company involved in the research
and be employed at the time of transaction close.

The OCAI is a self-administered assessment the subjects took on their own, and the
electronic data is stored securely. The interviews were conducted outside the workplace via
Zoom and followed the IRB data security requirements. All participants received a signed
document containing their personal information and assessment to ensure confidentiality and
privacy. Additionally, the interview responses were not disclosed to anyone outside of the
research team to maintain the confidentiality of the participants. All information was coded,
with a master list kept on a secure network. All data, including any personally identifiable
information, is stored in a password-protected and encrypted file on the PI's
passwordprotected computer. No one has access to the data except the PI.
CHAPTER 4: RESULTS
Overview
This dissertation investigated the impact of organizational culture on M&A integration
utilizing a mixed-methods approach that combined quantitative and qualitative data collection
and analysis techniques. This chapter presents the findings from this comprehensive research
methodology, providing an improved understanding of organizational culture and its impact
on M&A transactions.
A range of factors can influence research outcomes, affecting the accuracy and reliability
of the findings. In the context of this study, three potential factors may have impacted the
research outcomes: social desirability, gender, and COVID-19. The study attempted to
address these factors by employing various strategies and methods to mitigate their impact.
An additional concern arises regarding potential errors in recollection when retrospectively
assessing the actual and preferred organizational culture at the time of transaction closing,
particularly when the period exceeds three years. The reliance on retrospective perspectives
from respondents may have contributed to the observed consistency in current and preferred
outcomes and the results obtained from the integration results survey.

Social desirability, which refers to the tendency of individuals to respond in a manner that
portrays themselves favorably or aligns with societal expectations, warranted careful
consideration in the context of the present research. The industry under examination was one
with which I was intimately familiar, and many respondents were personally acquainted with
or were aware of the individual conducting the inquiries. As such, there was a heightened risk
of social desirability bias potentially influencing participants' responses, which could
ultimately impact the validity and reliability of the study findings.
Social desirability bias is a well-known phenomenon in research methodology that can
significantly impact the validity of study findings. Paulhus and Reid (1991) define social
desirability bias as "the tendency to respond in a manner that will be viewed favorably by
others" (p 49). In other words, research study participants may provide socially acceptable or
desirable responses rather than their actual beliefs or behaviors. This bias can occur for
various reasons, such as a desire to please the researcher, a fear of being judged or
stigmatized, or a belief that specific responses are more socially acceptable than others. To
minimize the impact of social desirability bias, I used a variety of strategies, such as
emphasizing the anonymity of the data and using indirect questioning techniques.
Gender can also play a role in the perception of M&A integration. During the employee
interviews, I observed anecdotal evidence indicating significant differences in the perception
of M&A activities between men and women. Research suggests that people may have
different perceptions and experiences during M&A integration due to their gendered
experiences and perspectives. For example, Greckhamer et al. (2008) found that women who
were part of the acquiring firm in M&A deals tended to have more negative perceptions of the
integration process than men. This result was due to several factors, including differences in
communication styles and networks and the potential for gendered power dynamics to
influence decision-making during the integration process.

I demonstrated a commitment to mitigating gender bias. I recruited participants from both
genders to ensure representative samples, employing gender-inclusive language throughout
the research materials and maintaining awareness of their biases. By implementing these
practices, I aimed to contribute to a more equitable and inclusive research landscape that
acknowledges all individuals' diverse experiences and needs, regardless of gender identity.
The COVID-19 pandemic was a major global event affecting various industries and
business transactions, specifically M&A. In this regard, it is crucial to explore the potential
impact of the pandemic on the perception of M&A transactions.
I sought to understand the participants' perceptions regarding the M&A process
comprehensively. The findings revealed that in all of the top three and bottom three M&A
transactions, participants commented on the notable impact of the COVID-19 pandemic on
their perception of the M&A process. The participants in these transactions passionately
believed that the acquired company would have collapsed during the pandemic lockdown if
the M&A transaction had not occurred before the pandemic.
These findings suggest that the pandemic may have influenced the perception of M&A
transactions, particularly in terms of the potential value of these deals in mitigating the
economic impact of the pandemic on companies. The perception that the M&A transactions
helped to prevent the collapse of the acquired companies during the pandemic lockdown
underscores the perceived importance of these deals in maintaining the viability of businesses
in the face of economic disruptions caused by the pandemic.
Mixed-Methods Data Analysis
The research examined 50 M&A transactions in the travel and travel services industries.
All 50 were private transactions, with just one non-private transaction, a private company
acquiring a United Kingdom-based public company and taking it private. To maintain
confidentiality in private M&A activity, I assigned a corresponding number to each
transaction referenced in the dissertation, and the transactions were not referred to by

company name. I invited employees from both sides to participate in the OCAI study, with
five employees selected from each acquiring and acquired company. I contacted 612
employees and received participation from 487, resulting in an 80% participation rate.
While conducting the OCAI study, I administered a Qualtrics survey to assess the
perceived success of the M&A to two members of the post-merger integration team for each
of the 50 M&A transactions. I reached out to 123 respondents, of which 100 agreed to
participate in achieving the goal of two respondents from each transaction, resulting in a
participation rate of 81%. After completing the Qualtrics survey and the OCAI study, the
research results identified the top and bottom three performing M&A transactions using an
average score of the 5-point Likert scale questions used in the survey. I then conducted
oneon-one interviews with six employees from these six transactions, resulting in 36
interviews. I contacted 44 employees and interviewed 36 respondents from the acquiring and
acquired companies, resulting in a response rate of 82%. Subsequently, I conducted a 37th
interview with a fund manager from a major PE firm. The fund manager had extensive M&A
experience involving more than 100 transactions. Furthermore, the firm, specializing in travel
industry transactions, independently funded seven of the 50 transactions examined.
Survey Results
In this study, I assessed the effectiveness of M&A integration using survey data.
Specifically, I administered the survey to senior integration team members from acquiring and
acquired companies in 50 different M&A transactions. 11 questions for each of the three years
of integration post M&A close date were asked, for a total of 33 questions per survey.
The results of the M&A survey provide valuable insights into the success of
organizational integration and financial performance following mergers and acquisitions. The
survey data revealed various trends, including cultural integration, financial synergy, revenue
growth, and operational gains. The survey results also shed light on the impact of M&A on
employee turnover, brand, policies and procedures, and performance management. This
analysis examined the survey results in detail, grouped into integration, financial and cultural
sets, and an overall assessment of acquisition performance. Subsequently, I utilized Q11 as a
success assessment and employed all 11 questions to examine the entire survey. Table 1
shows the survey questions alongside combined results, with confidence intervals and
average survey scores by question by year. The complete results are detailed in
Appendix E.
Table 1
Combined Average Survey Results by Year
Survey Questions Year 1 Year 2 Year 3 Avg
Q1: To what extent did the
two organizational cultures
integrate?
4.02 (3.83-4.21) 3.95 (3.76-4.14) 4.03 (3.85-4.21) 4.00
Q2: To what extent did you
achieve the acquisition
financial synergy goals?
4.03 (3.84-4.22) 3.91 (3.72-4.10) 3.98 (3.80-4.16) 3.97
Q3: To what extent did
revenues increase due to new
products or services?
3.74 (3.56-3.92) 3.80 (3.62-3.98) 3.90 (3.72-4.08) 3.81
Q4: To what extent did
profitability grow due to
operational gains?
4.05 (3.87-4.23) 4.12 (3.93-4.31) 4.03 (3.85-4.21) 4.07
Q5: To what extent was
employee turnover
impacted?
4.11 (3.93-4.29) 4.16 (3.98-4.34) 4.03 (3.85-4.21) 4.10
Q6: To what extent was your
brand positively influenced?
4.38 (4.20-4.56) 4.26 (4.07-4.45) 4.22 (4.04-4.40) 4.29
Q7: To what extent were
policies and procedures
improved?
3.95 (3.77-4.13) 4.10 (3.92-4.28) 4.14 (3.96-4.32) 4.06
Q8: To what extent were
your mission and values
changed?
4.00 (3.82-4.18) 4.05 (3.87-4.23) 4.08 (3.90-4.26) 4.04
Q9: To what extent was your
performance management
affected?
3.56 (3.38-3.74) 3.72 (3.54-3.90) 3.77 (3.59-3.95) 3.68
Q10: To what extent do
you think the purchase 3.95 (3.77-4.13) 4.03 (3.85-4.21) 4.01 (3.83-4.19) 4.00 price was
fair?
Q11: At the end-of-year
mark, what is your overall
assessment of the extent of
acquisition success?
4.11 (3.93-4.29) 4.18 (4.00-4.36) 4.14 (3.96-4.32) 4.14
The data set for each question showed an approximately normal distribution of the
M&A survey results. The data set showed a slight positive skewness. I calculated the
confidence intervals for year 1 (M = 3.99, SD = 0.19), year 2 (M = 4.03, SD = 0.05), and year
3 (M = 4.03, SD = 0.06). There is no significant difference across years based on the
observation of overlapping confidence intervals in each year's results. Hence, the researcher
pooled the data from the three years into a single dataset for the rest of the analysis.
To obtain a comprehensive representation of the integration beyond solely relying on
Q11 and the overall perception of success, I utilized all 11 questions to determine the
top/bottom three survey scores. According to the average integration survey results across the
50 transactions, three transactions (#9, #21, and #42) were the top performers with the highest
average survey score, while three other transactions (#4, #13, and #27) exhibited the lowest
performance determined by the lowest average survey score. Notably, the survey scores for
these transactions were uniquely distributed compared to the average of all 50 transactions.
These findings served as the basis for selecting companies used in the qualitative interviews
of employees.
Figure 3 provides a histogram that illustrates the normal distribution of the average
survey scores obtained by the participants for each of the 50 M&A transactions. The
horizontal axis of the histogram represents the average score for each transaction, while the
vertical axis represents the frequency of responses. The histogram helps to provide a visual
representation of the distribution of the total scores obtained, which allowed me to identify
patterns and trends in the data. The histogram shows the top three surveys in green, and the
bottom three in red, clearly delineating how those scores differ from the other 46.
Figure 3
Survey Histogram
Overall, the Qualtrics survey analysis results underscored the all-encompassing role of
organizational culture, communication, leadership, and employee engagement in successful
M&A integration. By doing so, organizations can promote successful M&A integration and
maximize the benefits of these strategic business transactions.
OCAI Results
In this dissertation, analyzing the OCAI involved interpreting the scores obtained in
each quadrant (i.e., Clan, Adhocracy, Market, Hierarchy) to determine an organization's
0 1 2 1
16
27
3
0
5
10
15
20
25
30
2 2.5 3 3.5 4 4.5 5
Frequency
Average Survey Scores
M&A Integration Survey

dominant culture type and alignment with its goals and objectives. It is important to note that
the OCAI defined dominant culture as the one quadrant that scored the highest, unlike later
where I describe quadrants with statistically dominant cultures. I analyzed the data collected
from the OCAI assessment and examined the cultural attributes associated with each
quadrant. I aimed to identify patterns and differences among the quadrants by conducting
statistical analyses of the responses. The OCAI assesses six dimensions of organizational
culture, including dominant characteristics, organizational leadership, management of
employees, organization glue, strategic emphases, and success criteria.
The OCAI captures an organization's current and preferred states by comparing the
scores of the four quadrants. The current state is the organization's current culture, while the
preferred state is the culture the organization aspires to have. By assessing an organization's
current and preferred culture, the OCAI provides a framework for understanding the
organization's strengths and weaknesses and helps identify areas for improvement. For
example, if an organization scores high in the Clan quadrant, it may value teamwork,
collaboration, and employee empowerment. A potential weakness of clan culture is its
resistance to change, which can hinder adaptability and responsiveness to external market
forces and technological advancements. Conversely, high scores in the Hierarchy quadrant
may indicate a more formal and structured culture prioritizing efficiency and control while
lacking a sense of community.
This study first used the average OCAI scores for all 50 M&A transactions to compare
the average acquiring and average acquired companies' current and preferred organizational
culture states. Later, this study considered the individual scores for each of the 50 acquisition
pairs in more detail. The results of the OCAI, shown in Appendix F, provide insight into the
current and preferred organizational culture of the acquiring and acquired companies in the
context of an acquisition.

Descriptive Statistics
The OCAI scores can provide valuable retrospective perceptions into the
organizational culture of both the acquiring and acquired companies in the context of an
M&A transaction. The current state of the acquired companies had a Clan-oriented culture
with the highest average score of 29.05, indicating a focus on collaboration and teamwork.
The Adhocracy culture type, the next highest current culture, scored 27.01, which suggests a
center on innovation and creativity. The Market culture type, with a score of 22.76, implies a
concentration on competition and achieving results. The Hierarchy culture type, with the
lowest average score of 21.19 for the current state, indicates a focal point on rules,
procedures, and formal authority.
On the other hand, the acquiring companies’ current state is more Hierarchy-oriented,
with an average score of 27.76. This result suggests a focus on structure, control, and stability.
The Market culture type, with a score of 25.88, implies a center on achieving results and
customer satisfaction. The Adhocracy culture type, with a score of 23.94, suggests a hub on
innovation and adaptability. The Clan culture type, the lowest current culture with a score of
22.42, indicates a focal point on teamwork and collaboration.
The preferred state of the acquired company is very similar to the current state and
shows a preference at the time of the transaction for a Clan-oriented culture, with an average
score of 28.06, followed by Adhocracy (27.01), Market (23.10), and Hierarchy (21.83).
Meanwhile, the acquiring company had a preferred state similar to the current one at the time
of the transaction. The preferred state for the average acquiring company is
Hierarchyoriented, with an average score of 28.42, followed by Market (25.59), Adhocracy
(23.54), and Clan (22.45).
Overall, the results suggest that there may be some cultural differences between the
acquiring and acquired companies, with the acquired company more likely to have a
Clanoriented culture while the acquiring company is more likely to have a Hierarchy-oriented
culture. The preferred state results indicate that the acquired company would like to maintain
a Clan-oriented culture, while the acquiring company would like to shift towards an even
more Hierarchy-oriented culture.
Reliability Testing
To demonstrate reliability, Table 2 shows Cronbach's Alpha for each section.
Cronbach's alpha, established by Cronbach (1951), is a widely used measure of internal
consistency reliability in research, especially in psychology, education, and social sciences. It
assesses the extent to which a set of items or questions in a survey or test measures a single
construct or dimension (Bland & Altman, 1997).
Table 2
Average OCAI Scores with Cronbach's Alpha
Acquired Acquiring Acquired Acquiring
Company Current Company
Current
Company
Preferred
Company
Preferred
Clan 29.05 22.42 28.06 22.53
Adhocracy 27.01 23.94 27.01 23.61
Market 22.76 25.88 23.10 25.50
Hierarchy 21.19 27.76 21.83 28.36
Cronbach's alpha
0.71 0.60 0.76 0.66
Acceptable Questionable Acceptable Questionable
Cronbach's alpha ranges from 0 to 1, with higher values indicating more internal
consistency reliability. Generally, as stated by Cronbach (1951), values above 0.70 are
considered acceptable for research purposes, although the specific value may depend on the
context and purpose of the study. For the acquired company in its current state, Cronbach's
alpha of 0.71 is acceptable and indicates that the OCAI scores for Clan, Adhocracy, Market,
and Hierarchy measure the same construct of organizational culture with sufficient reliability.

Similarly, the acquired company's preferred state has a higher Cronbach's alpha of 0.76,
indicating even greater internal consistency among the OCAI scores.
However, Cronbach's alpha values for the acquiring company are somewhat lower,
with a value of 0.60 for the current state and 0.66 for the preferred state. These lower values
may suggest that the OCAI scores for the acquiring company are less dependable, possibly
due to differences in the organizational culture or other factors; alternatively, it could be that
the acquiring companies have less dominant cultures. It is important to note that Cronbach's
alpha is just one measure of reliability and should be considered alongside other factors when
interpreting the OCAI results. Appendix E includes the full OCAI results.
Correlation Analysis for Survey Outcome Variables
Correlation analysis, used to explore the relationship between different variables, is
fundamental to this study. This type of analysis can help identify patterns and trends in the
data and provide insights into the factors that may impact the research question. The survey
correlation coefficients are relatively high and indicate a strong positive relationship between
the survey variables. Considering the context of the survey and the variables measured, it is
paramount to consider the correlation's strength. The results in Table 4 demonstrate that each
transaction rated the aspects of integration, financial, cultural, and overall similarly. In other
words, each transaction either broadly succeeded or failed rather than potentially succeeding
in only one aspect and failing in another.
It is also salient to note that while correlation measures the strength of the relationship
between two variables, it does not necessarily imply causality. In other words, just because
two variables are strongly correlated does not mean that one variable is causing the other
variable to change. Further analysis and consideration of the context and potential
confounding variables may need to determine causal relationships.
Table 3
Qualtrics Survey Correlation
INTEGRATION FINANCIAL CULTURAL OVERALL SUCCESS TOTAL
SURVEY
Q1 Q2-Q4
Q5-Q9
Q10-Q11
Q11
Q1-Q11
Q1 1.00
Q2-Q4 0.93 1.00
Q5-Q9 0.86 0.90 1.00
Q10-Q11 0.77 0.81 0.79 1.00
Q11 0.74 0.73 0.70 0.95 1.00
Q1-Q11 0.93 0.97 0.97 0.88 0.80 1.00
Note. All correlations are significant at p<0.05.
Combined Results
Next, I looked at the culture combination types for the 50 M&A transactions using the
current state of the culture. The most frequent culture combination observed was the
acquisition of companies with a Clan culture type by companies with a Hierarchy culture
type, with 21 such transactions (42%). The second most frequent culture combination is the
acquisition of companies with a Clan culture type by companies with a Market culture type,
with six transactions. Only 10 of the 16 possible combinations were present in the research.
The average gap between the two scores for each cultural type was estimated using the
absolute value of the differences. When comparing the acquired and acquiring companies,
these differences ranged from 6.10 for the Hierarchy/Market culture combination to 26.01 for
the Hierarchy/Clan culture combination, indicating significant variation in the alignment of
culture types between acquiring and acquired companies.

When examining the average survey scores, the Adhocracy/Clan culture types had the
highest score across all combinations. The Hierarchy/Hierarchy, culture type combination,
had the lowest score across all combinations; however, this only represented one transaction.
The data suggest that acquired companies with a Clan culture type are most likely to
be acquired by companies with a Hierarchy culture type and that there is a significant gap
between the cultural types of acquiring and acquired companies. These findings have
implications for companies engaging in M&A and highlight the importance of cultural due
diligence in such transactions. Tables 4-6 show the culture combination types for the 50
M&A transactions using the current state of the culture.
Table 4
OCAI Frequency
Acquiring
Acquired Clan Adhocracy Market Hierarchy Totals
Clan 4 4 6 21 35
Adhocracy 1 2 3 6 12
Market 0 0 0 2 2
Hierarchy 0 0 0 1 1
Totals 5 6 9 30 50
Table 5
OCAI Gaps
Acquiring
Acquired Clan Adhocracy Market Hierarchy
Clan 9.80 20.30 26.94 26.01
Adhocracy 8.80 18.40 14.63 21.02
Market . . . 6.10
Hierarchy . . . 24.40
Table 6
Survey Average with OCAI Combina
Acquiring tions
Acquired Clan Adhocracy Market Hierarchy
Clan 3.93 4.33 3.98 4.09
Adhocracy 3.59 4.32 3.91 3.85
Market . . . 4.20
Hierarchy . . . 2.45
Quantitative Analysis Summary
The quantitative sections presented a statistical analysis of the M&A Integration
surveys and the OCAI results. These analyses aimed to evaluate the validity and reliability of
these instruments and determine whether they are suitable for the research analysis in the next
chapter. Results of the analysis have indicated that both the M&A Integration surveys and the
OCAI are statistically significant and valid instruments for use. The M&A Integration surveys
exhibited internal consistency, indicating that the questions in the survey were measuring the
same underlying construct. Additionally, the surveys demonstrated construct validity, as the
questions could differentiate between different types of M&A integration.
Similarly, the OCAI results also showed internal consistency and construct validity
levels. The survey distinguished between different types of organizational culture, and the
results were consistent with theoretical expectations. A post hoc quantitative analysis
produced an emerging concept of the impact of a dominant culture on the integration survey
results. To investigate this concept, I created a measure to determine the dominance of the
company's OCAI scores. A company's OCAI scores indicate the predominance of one of the
four quadrants of its culture. For example, a company scoring 25-25-25-25 on the four
measures would indicate an ambivalent culture without particular dominance. However, if a
company scores 90-5-5-0, it would indicate a strongly dominant Clan culture.
A suitable measure for this dominance would be a Chi-Squared assessment, calculated
as the sum of squared distances from each score to the default score of 25. The measure can
be named “Culture Dominance”. I computed the Chi-Squared score for 50 acquiring and 50
acquired firms to determine their Culture Dominance. Only five firms in each group had
statistically significant numbers, while most firms were not significant, indicating they were
more ambivalent about their culture.

The results of simple regressions of Acquiring Culture Dominance and Acquired
Culture Dominance as IVs against the survey results as DVs are noteworthy, as shown in
Appendix G. Acquired Culture Dominance is significantly positive for M&A success
(Q10Q11). In contrast, Acquiring Culture Dominance is significantly negative for M&A
success (Q10-Q11). Therefore, buying a company with a dominant culture seems to be a good
decision, but fitting an acquisition into a dominant culture is challenging. This challenge may
arise from the rigidity that a statistically dominant culture may exude within an acquiring
company, making an M&A integration even more challenging.
Overall, the statistical analysis of these instruments has demonstrated that they
provide valid and reliable measures of the constructs studied. The post hoc analysis revealed
that M&A success is positively associated with the level of "Hi-Dominance" for the acquired
company and negatively associated with the level of "Hi-Dominance" for the acquiring
company. As a result, I can utilize the data, especially the “Culture Dominance” concept.
Qualitative Data Analysis
This section reports on the 37 semi-structured interviews with individuals (e.g.,
permanent staff and ICs) having experience with the top and bottom three performing
integrations of the 50 M&A transactions examined in this dissertation. The interviews were
recorded and transcribed verbatim for thematic analysis to identify and categorize patterns
and themes that emerged from the qualitative data, providing a deeper understanding of the
impact of organizational culture on M&A integration.
For this study's interviews, I utilized NVivo, a commonly used software program in
qualitative research, to aid in organizing and analyzing the data collected during interviews.
Using NVivo, I code and categorize data collected during interviews to identify emerging
themes and patterns. The software enables researchers to create a coding scheme to help
organize the data and facilitate analysis. This coding scheme can compare data across
multiple interviews to identify similarities and differences in participant responses (Jackson &

Bazeley, 2019). By identifying themes and codes, NVivo allows analysts to organize and
interpret large amounts of data systematically. This process ensures that the research findings
are grounded in the interview data, leading to more accurate and reliable results.
Furthermore, investigators can use NVivo to visualize and map the connections
between themes and codes, helping them identify relationships and patterns they may have
previously overlooked. This result can lead to a deeper understanding of the research topic
and provide new insights into the experiences and perspectives of the research participants.
The software's data exploration and visualization tools aid users in identifying patterns
and drawing accurate conclusions. NVivo supports transparent documentation of the research
process, including coding decisions, annotations, and memos, promoting transparency and
reproducibility. Furthermore, its collaboration features facilitate peer debriefing and inter-
rater reliability checks, ensuring a rigorous research process. Leveraging NVivo's capabilities
can significantly improve the accuracy and reliability of research findings by enabling
efficient data management, robust analysis, and collaborative approaches.
In summary, using NVivo for analyzing research interviews was essential in
organizing and analyzing data collected during the interview process. It allowed for a
systematic approach to identifying and analyzing themes and codes, leading to more accurate
and reliable research findings and providing a way to capture valuable insights into the
experiences and perspectives of the research participants.
Interview Codes and Themes
This dissertation explores five themes that emerged from interviews with employees
involved in the top and bottom three performing M&A transactions. The first theme is
Organizational Culture Fit, which includes sub-themes such as Cultural Differences, Open
and Frequent Communication, Leadership Vision, and Employee Involvement. The second
theme is Founder Influence, which encompasses sub-themes such as Founders' Vision and
Values, Founder Involvement and Support, Founders' Influence on Culture, and Founder's
Legacy. The third theme is Employee Engagement, which involves sub-themes such as Clear,
Concise, Timely Information, Leadership, Culture, and Empowerment. The fourth theme is
Understanding the Acquired Companies Business, which includes sub-themes such as
Financial Due Diligence, Integration Planning, and Cross-Functional Teams. The final theme
is Independent Contractors, which encompasses sub-themes such as Cultural Due Diligence,
Correspondence, Legal, and Financial Issues.
I used multiple quotes from qualitative interviews with employees directly involved in
six specific M&A transactions to formulate the themes. I subjected the transactions to more
comprehensive scrutiny based on their integration survey scores. Numerical codes were
assigned to all M&A transactions to ensure confidentiality. The interviews provided valuable
insights into these themes and their impact on M&A success, highlighting the importance of
considering organizational culture, founder influence, employee engagement, business
understanding, and independent contractors in the M&A process. I coded a total of 37
interviews using 26 unique codes. Those codes were grouped into 20 subthemes and then
classified into five distinct themes. A series of three to six sub-themes supported each theme.
The five themes, sub-themes, and codes are as follows, shown in Table 7.
Table 7 Themes, Sub-Themes, & Codes
Theme Sub-themes First-order codes
Organizational
Culture Fit
Cultural Differences, Open and
Frequent Communication, Leadership
Vision, Employee Involvement
Organizational culture impact, founder
culture, family culture, multiple cultures,
culture integration
Founder Influence Founders' Vision and Values, Founder
Involvement and Support, Founders'
Influence on Culture, Founder's Legacy
Key stakeholders, team, family, model,
organization, strategy
Employee
Engagement
Clear, Concise, Timely Information,
Leadership, Culture, Empowerment
Unhappy people, right people, talented
people, short-term people, meeting people
Understanding the
Acquired Companies
Business
Financial Due Diligence, Integration
Planning, Cross-Functional Teams
Family business, house business, vibrant
businesses, existing business, a separate
business
Independent
Contractors
Cultural Due Diligence,
Correspondence, Legal and Financial
Issues
Outside contractors, contractors'
customers, contractors' model, infinite
contractors, business model

Organizational Culture Fit
The interview analysis revealed a theme of organizational culture fit on M&A
integration success. The results showed that the organizational culture fit was crucial in
determining the success or failure of M&A integration.
A poignant quote from one of the bottom three scoring M&A transactions was, "In the
end, organizational culture played a massive role. I think that became the new culture in the
combined entities; it also played the hardest part in the combination, in the sense that multiple
cultures are involved" (Transaction #13, Interviewee 1, Transcript 001). This quote highlights
organizational culture fit and its role in the success or failure of M&A transactions. The
presence of multiple cultures heavily influenced the new culture that emerged after the
combination, making the integration process more complex in this particular case, as
suggested by the organizational culture fit. Therefore, organizations pursuing M&A
transactions may consider prioritizing organizational culture fit as a critical factor in the
success or failure of the deal.
The following sub-themes emerged from analyzing the first-level codes, as shown in
Table 8. Table 8 further explains the definitions of the quotes and subthemes, with
transactions highlighted in green representing one of the top three M&A survey scores and
the ones in orange representing one of the bottom three scoring transactions. The quotes in the
tables illustrate the difficulties encountered in high and low-scoring transactions. Highscoring
mergers actively demonstrate the ability to identify and address challenges before the closure
of the transaction, ensuring effective resolution. Conversely, the low-scoring transactions
neglected to address the challenges revealed during the interviews. This trend persisted
throughout the thematic analysis conducted on the interviews.
Table 8
Organizational Culture Fit Sub-Themes & Quotes
Sub-themes Description Quotes
Cultural Differences Differences in culture
between employees and
management
“We knew they were not going to be
a cultural fit” (Transaction #9,
Interviewee 2, Transcript 102)
Open and Frequent
Communication
Importance of clear and
regular communication
“Communication is probably the
biggest thing that did not work well”
(Transaction #4, Interviewee 28,
Transcript 528)
Leadership Vision The importance of a clear
vision for the company
“I was not bought into his vision,
but I was not afraid,” Transaction
#9, Interviewee 27, Transcript 114)
Employee Involvement Encouraging employees to
participate in decision-
making
“We just brought him as an
employee to continue expanding the
business” (Transaction #4,
Interviewee 22, Transcript 607)
Founder Influence
The interview coding revealed a recurring theme of founder influence on M&A
integration success. Regardless of whether they remained with the company or exited at the
time of close, the findings revealed that the founder of the acquired company significantly
influences the integration process and can have either a positive or negative impact on the
outcome. Research studies have identified various factors influencing M&A integration
success, including leadership, communication, culture, and employee engagement. However,
the role of the founder of the acquired company in the integration process has not received
much attention in previous research studies (Jemison & Sitkin, 1986).
The quote by Interviewee 24, a high-scoring transaction, illustrates the potential
negative impact of a founder's influence on the success or failure of M&As: "And let me be
crystal clear. I do not care what you have to say. We bought your business. If you leave
tomorrow, fine" (Transaction #9, Transcript 117). However, this transaction identified this
issue and moved the founder into a role that kept both sides moving forward. The interviewee
felt this happened because the founder conflicted with the acquirer during integration. The

quote suggests a lack of respect and disregard for the acquired company's culture and people,
which can lead to employee disengagement, low morale, and, ultimately, M&A failure.
However, this transaction succeeded because the other critical themes integrated positively
during the post-close process.
Entrepreneurs frequently influence an organization's ethos and principles, and their
exit may trigger material repercussions for the company. The aforementioned quote implies
that the acquiring firm might have disregarded the significance of the founder's impact and
the possible ramifications of estranging them and their team. Therefore, acquirers must try to
recognize the founder's influence and the importance of maintaining a positive relationship
with them and their team. Acquirers should prioritize open communication, mutual respect,
and collaboration to ensure successful integration and avoid potential pitfalls that can lead to
M&A failure.
Interviewee 6, who was part of a highly successful M&A transaction, highlights the
potential negative impact of a founder's influence on the success or failure of an M&A: "In
some ways, the founder was focused on only his ideas, and nobody else could have good
ideas, and in and the main part is that he oversold his actual background. So, he thought he
was an operations expert, and he was not. Thus, that was the crux of the issue" (Transaction
#9, Transcript 523). Notably, this quote highlights a challenge for integration. However, the
acquiring entity took proactive measures to mitigate this challenge by implementing
corrective actions. These actions aimed to minimize the founder's influence on integration and
business decisions while retaining the individual as a staff member to ensure continuity. The
quote suggests that the founder's rigid adherence to their ideas and overselling of their
background can lead to issues during the integration process, but with proper integration
guidance, the challenges of the founder can be overcome by understanding how to involve
them in the business. Understanding the motivations of a founder for engaging in an M&A
deal is crucial in determining their involvement in the new businesses post-transaction.

Founders may pursue M&A to achieve strategic objectives, such as market expansion or
accessing new technologies, or for financial gains. If their motivations align with staying
involved, founders can contribute their industry knowledge, expertise, and relationships to the
new businesses in advisory or decision-making roles. However, some founders may prefer to
step away after the deal due to exhaustion or a desire for change. In such cases, they may exit
the new businesses entirely, allowing the acquiring company's management to take the lead.
Ultimately, founders' involvement in the new businesses post-M&A depends on their
motivations and negotiated terms, with communication and alignment of goals being critical
factors in determining their level of engagement.
Founders often have a strong vision for their company and are passionate about their
ideas. However, as the previous quote highlights, their inflexibility and unwillingness to
consider other perspectives can lead to a lack of innovation and slow decision-making.
Moreover, if the founder oversells their abilities or expertise, this can result in unrealistic
expectations and ultimately hinder the integration process. Hence, acquirers may evaluate the
impact of the founder on the organization's decision-making process, in addition to their
proficiency and compatibility with the acquirer's objectives and principles. To facilitate
successful integration and avoid potential setbacks that may culminate in an M&A failure,
acquirers could prioritize fostering open communication, collaboration, and innovation.
Interviewee 11, from a low-scoring transaction, highlights the potential positive
impact of a founder's influence on the success or failure of M&A: "We found each other
because both of the ways we did business were exactly the same, and both of our goals for the
endgame were exactly the same, and I think that is a lot of it is why it worked out so well"
(Transaction #27, Transcript 226). This quote captures interest as it reveals that the
transaction did not fare well from the integration team's perspective. The primary reason for
this quote was the shielding of an employee who held a front-line operations role from the
financial results. This lack of communication contributed to the overall dissatisfaction and
challenges experienced during the integration process. The quote suggests that when the
acquirer and the target company have similar ways of doing business and shared goals, the
integration process can be smoother and lead to a successful outcome. Contrarily, an
employee in one of the least successful M&As gave this quote, which suggests a
counterintuitive possibility that companies are not always a good match. The founder's
influence in M&A can impact the integration process's success or failure. In this case, the
quote suggests that the alignment of goals and approaches to business between the acquirer
and the target company facilitated a successful integration. When founders have a shared
vision and approach to doing business, this can lead to a more seamless integration process
and ultimately contribute to the success of the merger or acquisition.
Acquirers may assess the financial and operational aspects of the target company and
the cultural fit and alignment of values and goals between the acquirer and the target
company. By prioritizing these factors, acquirers can increase the likelihood of successful
integration and avoid potential pitfalls that can lead to M&A failure.
The following sub-themes emerged from analyzing the first-level codes, as
shown in Table 9. Table 9 further explains the definitions of the quotes and subthemes, with
transactions highlighted in green representing one of the top three M&A survey scores and
the ones in orange representing one of the bottom three scoring transactions.
Table 9
Founder Influence Sub-Themes & Quotes
Sub-themes Description Quotes
Founders'
Vision and
Values
The original vision and
values of the company's
founders
“I was not bought into his vision” (Transaction
#4, Interviewee 26, Transcript 101)
Founder
Involvement
and Support
The role of the founder in
supporting the company
“But typically, if you keep the founder
involved in the day-to-day, it is a loss for
everyone” (Transaction #42, Interviewee 13,
Transcript 741)
Founders'
Influence on
Culture
The impact of the
founders on the company's
culture
“The founder is still there, and in some ways,
he was a tyrant” (Transaction #9, Interviewee
6, Transcript 523)
Founder's
Legacy
The lasting impact of the
founders on the company
“The founder's mission was to sell the
organization” (Transaction #27, Interviewee
31, Transcript 549)
The results of the interviews provided valuable insights into the role of the founder in
M&A integration success. Despite two quotes from high-scoring mergers indicating concerns
regarding the founder's role, the acquiring company deliberately retained the founder during
the transition period. This decision was motivated by factors beyond solely keeping
employees satisfied. The findings indicate that the founder's vision, values, involvement,
support, influence on culture, and legacy can all impact the integration process. Therefore, it
is all-encompassing for acquiring companies to understand the founder's role in the acquired
company and to develop strategies to address any challenges that may arise.
Employee Engagement
The analysis of the interview data revealed a recurring theme of employee
engagement in M&A integration success. The results indicated that employee engagement
could affect the integration process and lead to positive or negative outcomes. The research
identified employee engagement as a key factor in M&A integration success. Engaged
employees are more likely to be motivated, productive, and committed to the integration
process, which can lead to positive outcomes. On the other hand, disengaged employees are

more likely to resist change, lack motivation, and be unproductive, leading to integration
failure (Saks, 2006).
Interviewee 9, from one of the highest-scoring transactions, sheds light on the impact
of M&A on employee engagement, even within high-performing integrations, which can
affect the success or failure of the integration process: "They felt like they were losing
control. They felt that as though their job got a bit marginalized." (Transaction #42, Transcript
118). In many M&A scenarios, the realization of synergies can lead to employees feeling a
loss of control over their jobs. However, effectively managing this challenge through open
communication and transparency can help mitigate the negative impact. By keeping
employees informed and involved throughout the process, organizations can foster a sense of
control and alleviate concerns related to job security and uncertainty. The quote suggests that
employees in the target company may feel a loss of control and marginalization of their role
during the integration process, which can decrease employee engagement.
Employee engagement is an emotionally charged factor in the success of M&A,
impacting employee productivity, morale, and organizational commitment. Employees feeling
disengaged can lead to decreased productivity, increased turnover, and resistance to change.
This result can ultimately affect the overall success of the integration process. Interviewee 9
stresses the significance of considering employee engagement during the integration process.
When acquirers prioritize employee engagement and ensure that employees feel valued and
involved in the integration process, it can lead to smoother integration and ultimately
contribute to the success of the merger or acquisition.
The following sub-themes emerged from analyzing the first-level codes, as shown in
Table 10. Table 10 further explains the definitions of the quotes and subthemes, with
transactions highlighted in green representing one of the top three M&A survey scores and
the ones in orange representing one of the bottom three scoring transactions.
Table 10
Employee Engagement Sub-Themes & Quotes
Sub-themes Description Quotes
Clear,
Concise,
Timely
Information
The importance of
providing accurate and
timely information
“As much as they could. They were
forthcoming with the information”
(Transaction #4, Interviewee 28, Transcript
528)
Leadership The role of leadership
in guiding the
company
“They were no longer part of the leadership.
They were gone after the acquisition”
(Transaction #27, Interviewee 31, Transcript
549”)
Culture The shared values and
beliefs that shape the
company's behavior
“We looked at it that we were a sports team
with family values” (Transaction #27,
Interviewee 11, Transcript 226)
Empowerment Encouraging
employees to take
ownership of their
work
“Each organization claims ownership of their
own culture” (Transaction #4, Interviewee
28, Transcript 528)
The quote from interviewee 28 in Table 10 may initially appear counter-intuitive.
However, upon considering the geographic aspect, it becomes evident that the culture of a
foreign company played a significant role. The lack of sharing of the challenges experienced
during the integration process became apparent, highlighting the impact of cultural
differences on effective communication and collaboration. The results of this analysis provide
valuable insights into the role of employee engagement in M&A integration success. The
findings indicate that effective communication, leadership, culture, and empowerment are
keystone factors that impact employee engagement during the integration process, but this
does not necessarily translate into the success of the integration. Acquiring companies may,
therefore, carefully consider these factors and develop strategies to address any challenges.
Understanding the Acquired Company’s Business
The interview revealed a recurring theme of understanding the acquired company's
business on M&A integration success. The results indicated that understanding the acquired
company's business can powerfully impact the integration process and lead to positive or

negative outcomes. Understanding the acquired company's business has been identified as an
unexamined factor in M&A integration success. Acquiring companies may deeply understand
the acquired company's business model, products, services, customers, suppliers, and
operations to ensure a smooth integration process. Failure to understand the acquired
company's business can lead to integration challenges, such as culture clashes, operational
inefficiencies, and customer dissatisfaction.
Interviewee 14, one of the highest-scoring transactions, clarifies the importance of
understanding the acquired company's business and operations: "I got rid of all the things I
did not like doing, and I make more money than I ever did owning the whole thing."
(Transaction #21, Transcript 702). The quote suggests that by understanding the acquired
company's business, the acquirer can identify the areas that may not be profitable or aligned
with their goals and streamline the operations to improve profitability. Understanding the
acquired company's business is important for the success of M&A as it enables the acquirer to
make informed decisions on the integration process. The acquirer can identify the areas of the
acquired company's business that are core to its operations and those that may not align with
its goals. The acquirer can improve profitability, reduce costs, and increase efficiency by
streamlining the operations.
Interviewee 14 highlights the importance of understanding the acquired company's
business and the potential benefits of streamlining the operations. When the acquirer
understands the acquired company's business, they can identify areas that are not profitable
and make informed decisions on what to keep, what to eliminate, and what to improve.
Interviewee 14 emphasizes the importance of understanding the acquired company's business
and the potential positive benefits of streamlining the operation. Acquirers could prioritize
understanding the acquired company's business to make informed decisions in the integration
process, which can contribute to the success of the merger or acquisition.
The following sub-themes emerged from analyzing the first-level codes, as shown in
Table 11. Table 11 further explains the definitions of the quotes and subthemes, with
transactions highlighted in green representing one of the top three M&A survey scores and
the ones in orange representing one of the bottom three scoring transactions.
Table 11
Understanding the Acquired Company’s Business Sub-Themes & Quotes
Sub-Themes Description Quotes
Financial
Due
Diligence
The process of
evaluating a
company's financial
information
“Failures are the ones that you just did bad due
diligence, and you thought you bought an apple,
and you bought a lemon” (Transaction PE,
Interviewee 37, Transcript 618)
The planning “A successful integration is that we were already
Integration process for accustomed to taking care of customers with
Planning integrating two independent contractors” (Transaction # 4,
companies Interviewee 22, Transcript 607)
Cross-
Functional
Teams
Teams composed of
members from
different functional
areas
“The company allowing me still to play the role of
leader of the team” (Transaction #21, Interviewee
29, Transcript 229)
The quote from interviewee 22 in Table 11 provided insights into previous M&A
transactions conducted by the company, which helped shed light on potential reasons for the
challenges faced in the current transaction that involved no independent contractors. By
referencing past experiences, Interviewee 22 offered valuable context and understanding of
why issues may have arisen in this transaction. The analysis of this theme provides valuable
insights into the role of understanding the acquired company's business in M&A integration
success. The findings indicate that due diligence, including cultural due diligence, integration
planning, and cross-functional teams, are factors that impact understanding the acquired
company's business during integration. Acquiring companies should, therefore, carefully
consider these factors and develop strategies to address any challenges that may arise.

Independent Contractors
The analysis of the interview data revealed a recurring theme of understanding
acquiring companies with large numbers of independent contractors on M&A integration
success. The results indicated that understanding the role of independent contractors can
impact the integration process and lead to positive or negative outcomes. More than 60% of
the travel and travel services industry comprises independent contractors, highlighting this
sector's significance in integrating with an acquired company.
Independent contractors are essential in the travel industry because they provide
flexibility and cost savings to businesses. They offer specialized skills and knowledge that
businesses may not have in-house, allowing businesses to fill specific needs and provide
better client services. Hiring independent contractors as needed has proven to be a
costeffective strategy for businesses. This result allows companies to circumvent the expenses
of hiring full-time staff when their services are not required. By hiring independent
contractors, businesses can ensure they have access to the specialized skills and knowledge
they require without incurring additional overhead costs. Furthermore, independent
contractors in the travel industry often have a deep understanding of local cultures and
customs, and they can provide personalized experiences for clients that may not be available
through traditional travel agencies. Their flexibility and expertise make them a vital and
valuable component of the travel industry. Independent contractors are typically not included
in the acquiring company's workforce and are not subject to the same policies, procedures,
and benefits as regular employees. Contractors can create challenges during integration, as
independent contractors may have different expectations and requirements than employees.
Failure to understand the role of independent contractors in the acquired company's
operations can lead to integration challenges, such as legal and financial issues, and may
negatively impact the overall integration process.
From a low-scoring transaction, one participant said, "Certain questions are being
asked, made me paranoid over the years, like any time anybody asked things when they start
filling out surveys. I get extremely nervous that something is changing" (Transaction #4,
Interviewee 28, Transcript 528). This quote from an independent contractor in the acquired
company highlights the importance of communication and transparency during the integration
process. The independent contractor, an extremely high performer, left the acquired company
implying the new acquirer would not treat him like before the merger. The quote suggests that
independent contractors may feel uncertain about their future with the company and their role
in the integration process.
To ensure the acquisition’s success, acquirers may communicate openly with all
employees, including independent contractors, to clarify expectations and address concerns.
Communication can help to build trust and engagement among employees, which is crucial
for the success of the integration process. Interviewee 28 underscores the importance of clear
and transparent communication during M&A transactions, especially with the acquired
company. By addressing the concerns of independent contractors and other employees from
the acquired company, acquirers can improve employee engagement and increase the
likelihood of success in the integration process.
The following sub-themes emerged from analyzing the first-level codes, as shown in
Table 12. Table 12 further explains the definitions of the quotes and subthemes, with
transactions highlighted in green representing one of the top three M&A survey scores and
the ones in orange representing one of the bottom three scoring transactions.
Table 12
Independent Contractors Sub-Themes & Quotes
Sub-themes Description Quotes
Cultural Due
Diligence
The process of
evaluating a
company's cultural
information
“We knew they were not going to be a cultural
fit. But we were going to get a return on
investment” (Transaction #21, Interviewee 14,
Transcript 702)
Correspondence Written
communication
between companies
“They have to overachieve on communication
and call out the areas of sensitivity that might
cause conflict” (Transaction # 42, Interviewee
9, Transcript 156)
Legal and
Financial Issues
The legal and
financial aspects of a
business transaction
“This is some legal obligation. We could not
disclose something” (Transaction #4,
Interviewee 22, Transcript 607)
The results of this theme provide valuable insights into the role of understanding
acquiring companies with large numbers of independent contractors in M&A integration
success. The findings indicate that due diligence, communication, and legal and financial
issues are factors that impact the understanding of acquiring companies with large numbers of
independent contractors during the integration process. Acquiring companies may, therefore,
carefully consider these factors and develop strategies to address any challenges. Mini-Case
Studies
In this section, I present mini-case studies focusing on the three highest-performing
and three lowest-performing M&A transactions. These rankings were determined based on
the average scores obtained from integration surveys. I incorporated qualitative data from
structured interviews for the six selected transactions to supplement the quantitative findings.
These mini-case studies present a synopsis of each transaction, offering valuable insights and
establishing a fundamental basis for future considerations in the field of M&A. The inclusion
of interview data contributes significantly to the richness and depth of the analysis, enabling a
more holistic understanding of the factors that contribute to success or failure in M&A
activities. Consequently, this research contributes to the existing knowledge base and lays the
groundwork for enhancing future M&A practices and strategies.

High Performing Transactions, Case 9
This transaction involved acquiring a statistically dominant "clan" organization by a
statistically dominant "adhocracy" organization. This transaction holds significance due to the
presence of a dominant OCAI culture type on each side, which is unique in that of the 50
M&A transactions studied, only three presented a dominant culture purchased by a dominant
culture (Appendix F). The strong alignment between these apparently complementary factors
was evident through insights gathered from the six interviews conducted with staff members.
The founder played a pivotal role in ensuring consistency among the staff. The new owners
demonstrated their support for the founder, as highlighted in the following quote: “They came
in with an approach of, we want to be founder friendly. We want to learn" (Transaction #9,
Interviewee 6, Transcript 117). The interviews indicated high employee engagement, with
staff members feeling involved and their opinions valued. The acquiring company invested
time in understanding the acquired company's business, and this understanding translated into
the overall integration process. The acquiring company's emphasis on retaining the founder
and engaging the staff was critical in retaining the numerous independent contractors
involved in this transaction.
High Performing Transactions, Case 21
This transaction involved acquiring a statistically dominant "clan" organization by a
statistically dominant "adhocracy" organization, yet two of those were among the three
highest performers. This combination resulted in seamless integration, as evidenced by
insights from the six interviews with staff members. The founder played a patriarchal role in
ensuring calm among the staff. The new owners demonstrated their support for the founder, as
highlighted in the following quote from a founder: "It was good because I was allowed to
keep actively involved with all the accounts and with the independent contractors directly,
and my role did not change" (Transaction #21, Interviewee 29, Transcript 229).

The interviews indicated high employee engagement, with staff members feeling
essential to the newly formed combined entity. The acquiring company invested time in
understanding the acquired company's business, and this understanding translated into the
overall integration process. The acquiring company's emphasis on involving the founder and
engaging the staff was critical in retaining the independent contractors involved in this
transaction. The founder of transaction 21 highlighted this vital step the acquiring company
demonstrated that significantly assisted with the merger's success: “We did a management
contract so that we could both feel each other out and see if this would be a good fit. It gave
the company that acquired me, plus myself, time to get to know each other.”
High Performing Transactions, Case 42
This transaction involved acquiring a "clan" organization by a "clan" organization.
This transaction holds significance due to the same OCAI culture type on each side. This
combination resulted in complete alignment, as evidenced by insights from the six interviews
with staff members. The founder was pivotal to the staff in ensuring a smooth transition to the
new company. The new owners demonstrated their support for the transitioning founder. The
interviews indicated high employee engagement, with staff members supporting the open and
frequent communication between the acquiring company and the founder. Interviewee 9
emphasizes the known challenges with communication addressed before the transaction close
to ensure successful communication: “They had to overachieve on communication and set out
the areas of sensitivity and the things that might cause conflict, post-close” (Transaction 42,
Transcript 156). The acquiring company invested time in understanding the acquired
company's business, and this understanding translated into perceived success. The acquiring
company's emphasis on the companies' similarities and engaging the staff was critical in
retaining the high number of independent contractors. This quote exemplifies the cultural
similarities and the impact on success: "In one way, their culture was very similar because of
all the independent contractors" (Transaction #42, Interviewee 13, Transcript 741).

Low Performing Transactions, Case 4
This case involved the acquisition of a "clan" culture by another "clan" culture.
Despite sharing the same OCAI culture type, this transaction holds significance as one of the
lowest-scoring M&A transactions, challenging the assumption that similar cultures always
lead to success. The interviews suggested an unwarranted payout issue influencing the
departure of the founder at the close, suggesting a potential contributing factor to the lessthan-
favorable outcome. The acquired company, headquartered in France, and the acquiring
company, based in the USA, faced significant geographic and language differences, resulting
in minimal employee engagement and a limited understanding of each company's business.
Additionally, due to the nature of business practices in France, no independent
contractors were involved in the transaction. Despite sharing the same OCAI culture type, the
notable disparities between the two companies suggested that the transaction faced inherent
challenges and was predisposed to failure from its inception. The challenges outlined by a
large PE fund manager: "There is domestic versus international you have to deal with, I mean,
so there it is. It is hard" (Transaction LLR, Interviewee 37, Transcript 618).
Low Performing Transactions, Case 13
Case 13 featured a unique dynamic where another "hierarchy" culture acquired a
"hierarchy" culture. Despite sharing the same OCAI culture type, this transaction holds
significant meaning as one of the lowest-scoring M&A transactions, necessitating a deeper
exploration of hierarchical cultures. Out of the 50 M&A transactions examined in the study,
only two (Appendix F) involved an acquired company exhibiting a hierarchical culture.
The acquired company was headquartered in the USA, while the acquiring company
was based in French-speaking Canada, leading to significant geographic and language
differences. Consequently, there was minimal employee engagement and a limited
understanding of each company's business. Moreover, due to differences in business
practices, only a few independent contractors were involved in the transaction. Despite

sharing the same OCAI culture type, the notable disparities between the two companies
indicated inherent challenges and a predisposition to failure from the outset.
An executive from the acquiring company, experienced in numerous M&A
transactions, made a striking statement regarding founder challenges and their exit during the
purchase: "Founder owners often forget that they have sold their business, and they want to
continue running the business as they have. So I think the challenge is overcoming that from a
cultural perspective. Buying into the new culture would be super helpful. Do not often get
that, though unfortunate" (Transaction #13, Interviewee 1, Transcript 0011).
Low Performing Transactions, Case 27
Case 27 featured a distinct scenario where a "hierarchy" culture acquired another
"hierarchy" culture. Despite sharing the same OCAI culture type, this transaction holds
significant meaning due to the pairing of hierarchical cultures, which was rare within the
context of the 50 transactions reviewed in this study. It is noteworthy that this is only the
second instance out of 50 transactions where both cultures were hierarchical, yet they ended
up in the bottom three.
Once again, this transaction occurred internationally, with an American company
acquiring a UK-based entity with significant operations in Africa. The acquiring company
assumed it had a thorough understanding of the acquired company's business, only to realize
after the transaction that its assumptions were incorrect. Adding to the complexity, the
founder remained with the transaction but assumed a considerably diminished role, causing
dissatisfaction among the founder and impacting the underlying culture.
Employee engagement was non-existent, and only a few independent contractors
remained, the rest primarily leaving within the first six months after the transaction closed.
The following quote exemplifies the challenges faced by the transaction: "The acquiring
company came in, and was so arrogant saying; we are who we are, the clients will come
because of our logo and our name, and we no longer will need you" (Transaction #27,
Interviewee 31, Transcript 549). This quote, though isolated, highlights the potential struggles
encountered during the transaction, emphasizing the acquiring company's arrogance and its
dismissive approach towards the acquired company's value and employees.
Compendium
Table 13 highlights the core themes identified in previous sections and elucidates the
five fundamental themes, showcasing their thematic disparities. Notably, distinct variations
emerge when comparing the more successful cases to the less successful ones. These
disparities underscore the evident differences between the two groups and further contribute
to the overall analysis of the research.
Table 13
Mini-Case Comparison
Theme Case 9 Case 21 Case 42 Case 4 Case 13 Case 27
Culture Fit Informal Formal Informal
over 10 years
Not
considered Problematic Problematic
Founder
Influence
Actively
Involved
Actively
Involved
Served as a
bridge Left at close Left at close Problematic
Employee
Engagement High Very high High Little Very little None
Understandi
ng Acquired
Business
Completely Great
synergy Completely Little None
Assumptions
were
incorrect
Independent
Contractors
Many with
high retention
Some with
high
retention
Majority
with high
retention
None
(France)
Some and
most left
Some and
most left
Significant critical differences between the high and low-performing transactions were
readily apparent. Firstly, all the top-performing transactions retained the founder, whereas
only one of the low performers chose to retain the founder, albeit in a reduced emeritus role.
The high performers exhibited a solid commitment to high employee engagement, while the
acquiring company demonstrated a proactive approach to understanding the business they
were acquiring. Conversely, the low performers exhibited contrasting behaviors in these
aspects.

Furthermore, an intriguing observation is that all three of the lowest-performing
transactions involved the acquired company headquartered in a different country (remember
that the sample design required all acquiring companies to be US-based). This observation
raises the need for additional research on cross-border M&A transactions, even within the
context of small or mid-sized companies. Such investigations would shed further light on
these types of transactions' complexities and unique challenges.
Integration of Quantitative and Qualitative Data
Integrating quantitative and qualitative data is a fundamental approach to conducting
research that has become increasingly popular in recent years. This approach acknowledges
that different data types can provide unique insights into research questions and that
combining multiple data sources can provide a complete picture (Fetters et al., 2013).
The quantitative results show that the acquired companies, as a whole, had higher
average OCAI scores in Clan and Adhocracy cultures than in Market and Hierarchy cultures
in current and preferred states. On the other hand, the acquiring companies had higher
average OCAI scores in Hierarchy culture than in Clan, Adhocracy, and Market cultures in
both current and preferred states.
The integration survey's range of scores suggests that for the 50 transactions, the
overall integration process went well. However, there is room for improvement in some areas.
For instance, the low score in the Results survey dealt with performance management, which
might indicate challenges in addressing the sub-themes related to employee engagement,
understanding of the acquired company's business, and independent contractors. Though not
identified in the interviews, it may suggest that M&A integration teams often do not achieve
the results senior management set forth, and their perception is one of substandard
performance. The highest performing area had to do with brand perception, which appears
logical in that the combined forces of the M&A transaction equate to a larger, more powerful

company and the associated brand. These areas require more attention to ensure a successful
integration process because this may also secure a high brand perception.
The results of the analysis indicate that there is a possibility of cultural dominance in
the acquisition process, particularly in cases where companies with Clan and Hierarchy
cultures are involved. Companies must address potential cultural fit issues during integration
because these two cultures accounted for most of the 50 transactions analyzed. Failure to do
so may hinder the successful integration of the two companies. Therefore, companies may
need to proactively address cultural differences, specifically if cultural dominance exists, and
align their cultures to ensure a smooth and practical integration process. The need to address
culture was apparent in most employee interviews, even among companies with the same
culture type. Based on this observation, we can infer that one hierarchical culture is not
identical to another. Despite sharing a common culture type, there are likely unique
characteristics, practices, and dynamics within each hierarchical culture that distinguish them.
However, quantitative data alone cannot completely understand the complexities of
organizational culture and its impact on M&A success. This fact is where the qualitative
interviews became invaluable. By conducting in-depth interviews with key stakeholders, it
was possible to gain a more nuanced understanding of the cultural factors and how they
manifested themselves in the M&A process. By combining quantitative data analysis and
qualitative interviews, I aimed to conduct a more comprehensive assessment of the
postulation about the dominant OCAI culture. Integrating both methods allowed for a holistic
exploration of the research topic, providing numerical insights from quantitative analysis and
contextual understanding from interviews. This approach aimed to enhance the validity and
depth of the research findings by capturing statistical patterns and individuals' experiences,
perspectives, and narratives.
Overall, integrating quantitative and qualitative methods proved to be a powerful
approach to examining the impact of organizational culture on M&A outcomes. By

leveraging the strengths of each method, it was possible to gain a more robust understanding
of the complex interplay between culture and M&A success.
Data Interpretation
This dissertation examined the integration of quantitative and qualitative data in the
context of organizational culture and M&A integration. The research topic is relevant given
the perceived high failure rates of M&A, often attributed to organizational culture first
researched by Cartwright and Cooper (1993). By examining both data types, I aimed to
comprehensively interpret and understand the challenges and opportunities associated with
M&A integration and identify strategies to help organizations overcome cultural barriers and
achieve successful integration. The present study utilized a subset of M&A Integration survey
transactions to test the formulated hypotheses. This subset specifically focused on examining
the performance of a selected group of transactions. The top three performers were included
to represent instances of higher-scoring mergers. On the other hand, the bottom three
performers were chosen to represent instances of lower-scoring mergers.
By examining these distinct subsets of transactions, the study aimed to gain insights
into the factors influencing M&A success. The selection of these particular transactions
allowed for a more focused analysis of the extreme ends of the performance spectrum. This
approach aimed to identify any discernible patterns or differences between the high-scoring
and low-scoring mergers discussed in the mini-case section of the paper, contributing to a
deeper understanding of the integration process.
The observed OCAI differences between the acquired and acquiring companies
indicate the existence of distinct cultural orientations between the two entities. Specifically,
the acquired companies exhibit a stronger inclination towards Clan and Adhocracy cultures in
their current and preferred states, while the acquiring companies exhibit a stronger inclination
towards Market and Hierarchy cultures in their current states. This discovery was a broad
trend across both subsets of transactions. This trend persists in the acquiring companies'

preferred state, where their preference for Market and Hierarchy cultures remains, while the
acquired companies maintain their preference for Clan and Adhocracy cultures. Since the
OCAI results indicated a similar pattern, the qualitative analysis identified five key themes
that impact the integration process: organizational culture fit, founder influence, employee
engagement, understanding of the acquired company's business, and independent contractors.
To understand the significance of these results versus the top and bottom three
performances outlined in the Qualtrics survey, the PI compared the OCAI scores of the top
and bottom three performances with the overall average OCAI scores of the acquired and
acquiring companies in the 50 M&A transactions. Figure 4 highlights the OCAI culture
differences between the top and bottom three merger integration performances. The OCAI
scores provide insights into the organizational culture of companies involved in M&A
transactions, shown in Table 14, and their potential for success or failure. However, it is
central to note that culture is just one of many factors that can influence the success of M&A
transactions, and other factors, such as financial performance, strategic fit, and integration
planning, are also central for analysis.
Figure 4
OCAI AVG Scores Top/Bottom 3
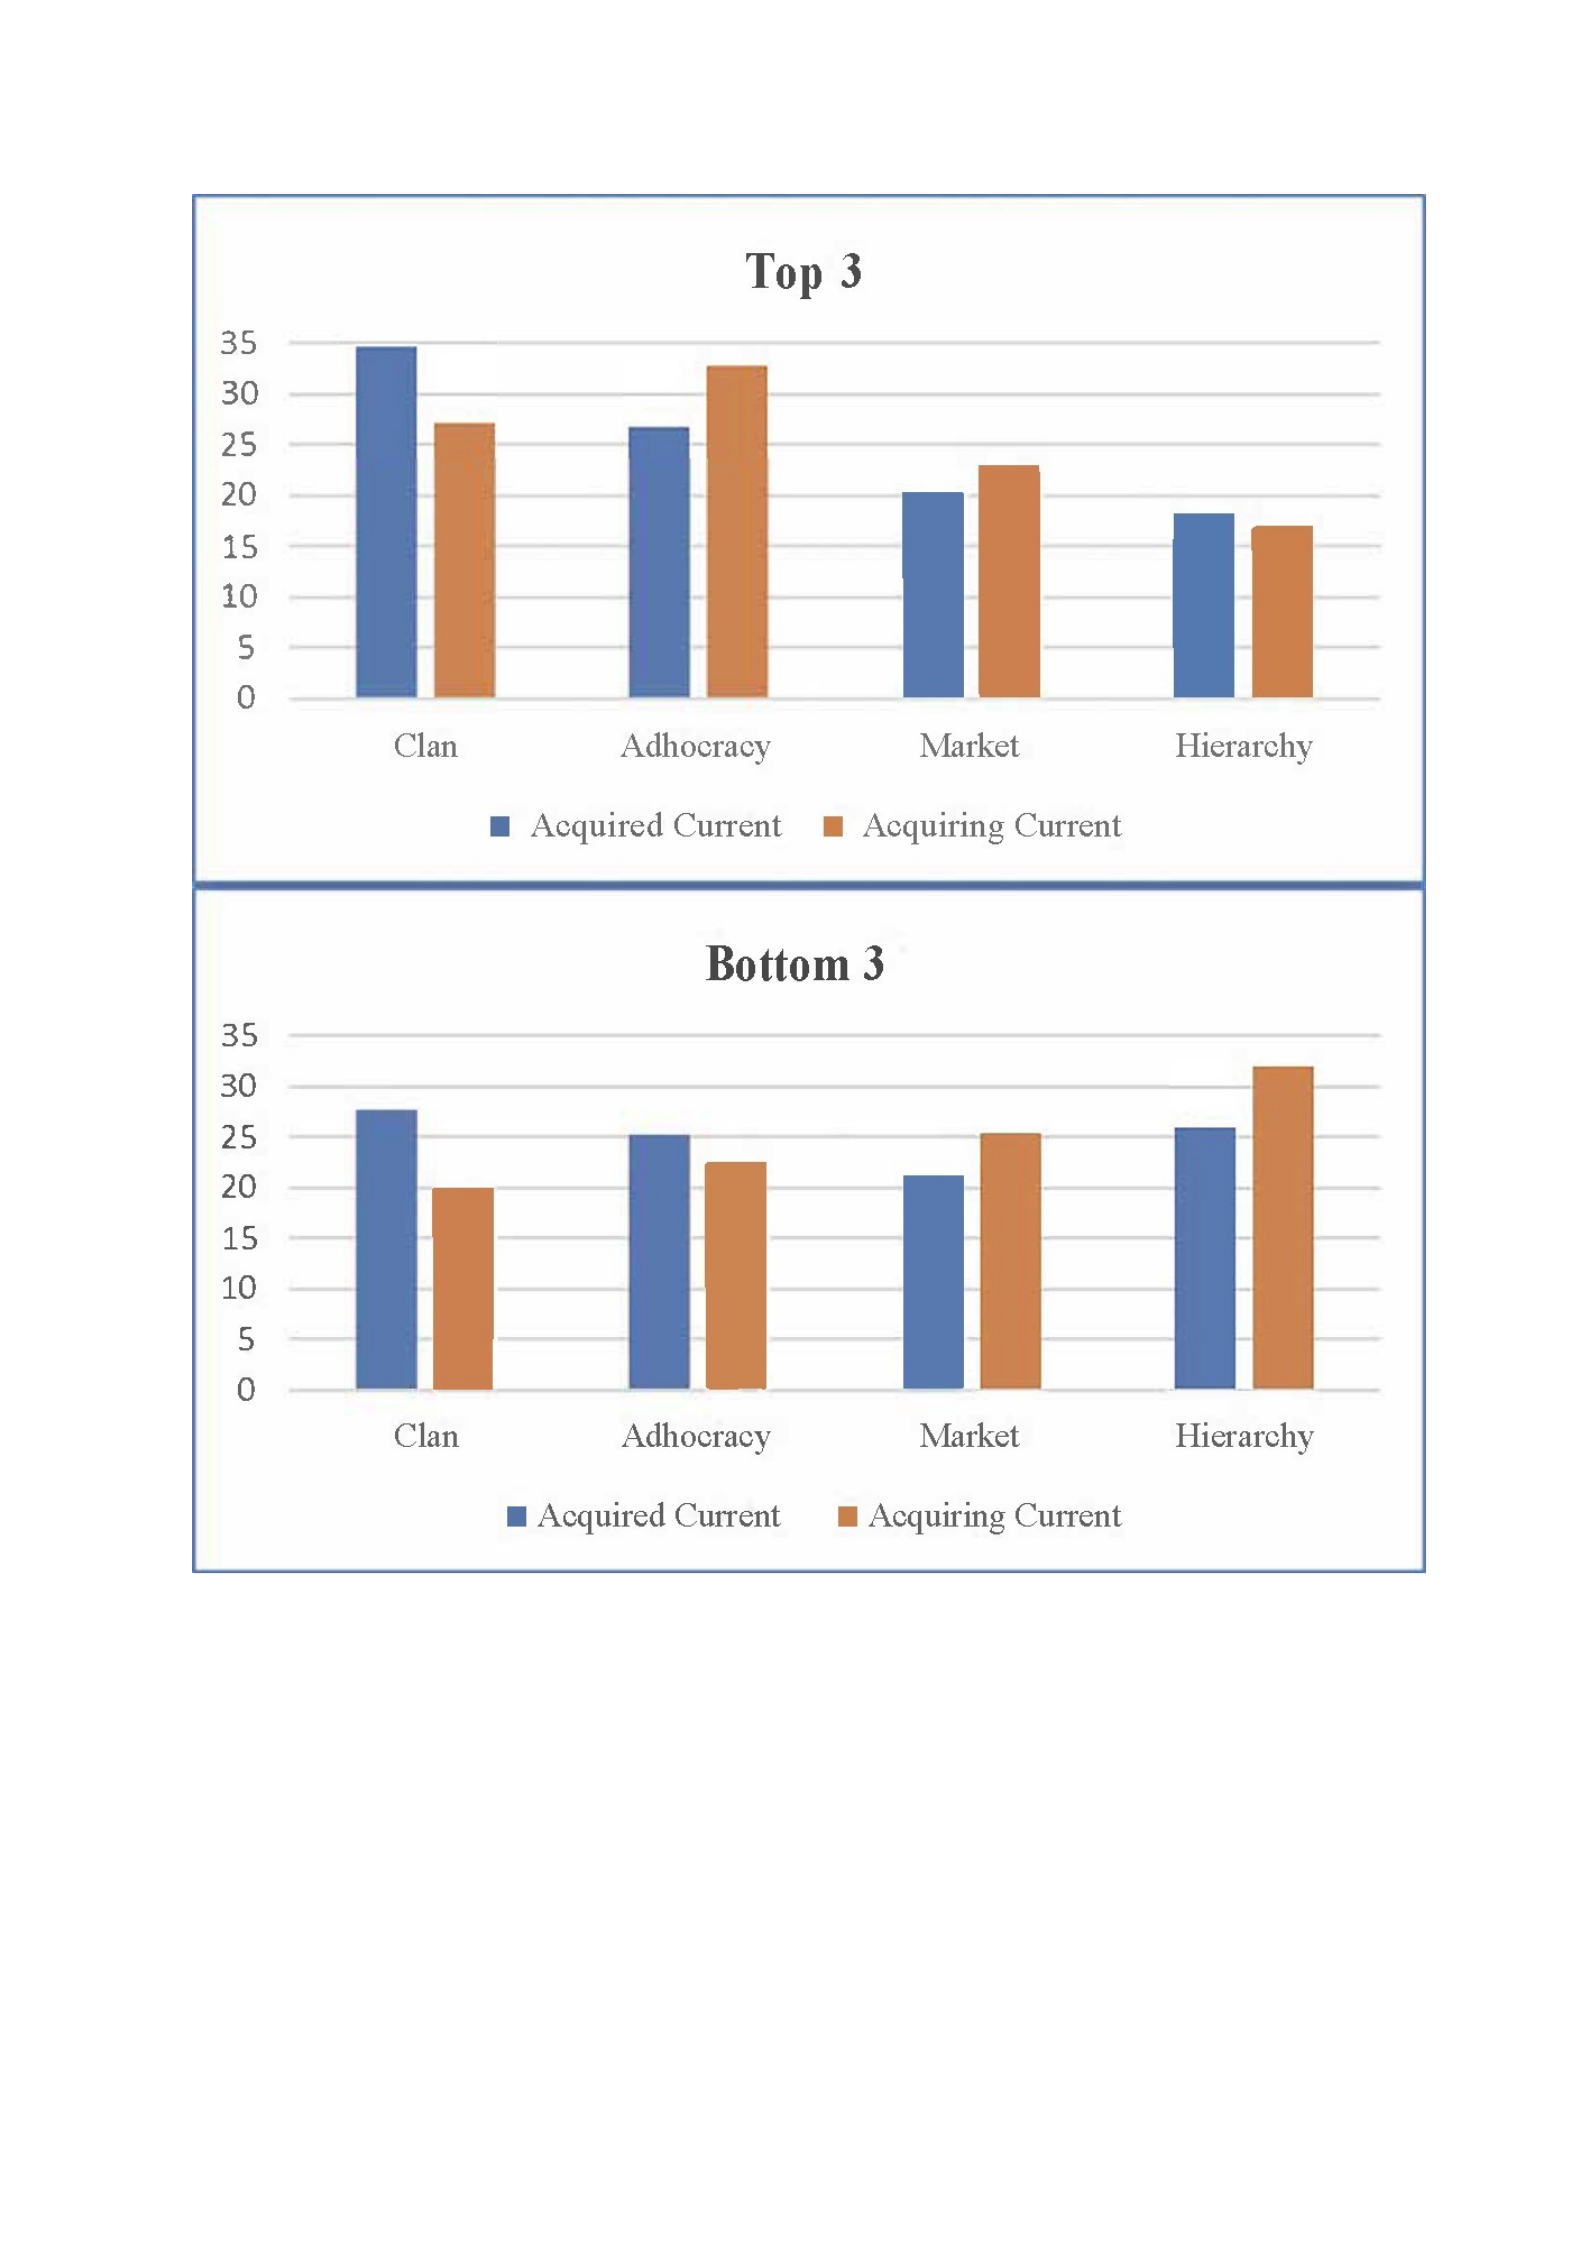
Table 14
Summary of OCAI Scores for M&A Transactions
Acquiring Company Acquired Company
Current State
Clan: 22.42 Adhocracy:
23.94
Clan: 29.05
Adhocracy: 27.01
Market: 25.88 Market: 22.76
Hierarchy: 27.76 Hierarchy: 21.19
Preferred State
Clan: 22.45 Adhocracy:
23.54
Clan: 28.06
Adhocracy: 27.01
Market: 25.59 Market: 23.10
Hierarchy: 28.42 Hierarchy: 21.83
Top Three Performances
Current State
(Survey Avg: 4.69)
Clan: 27.20
Adhocracy: 32.87
Market: 22.93
Clan: 34.60
Adhocracy: 26.80
Market: 20.27
Hierarchy: 17.00 Hierarchy: 18.33
Bottom Three Performances
Current State
(Survey Avg: 2.65)
Clan: 19.93
Adhocracy: 22.60
Market: 25.47
Clan: 27.67
Adhocracy: 25.20
Market: 21.27
Hierarchy: 32.00 Hierarchy: 25.87
This chapter adds to the existing literature on organizational culture and M&A
integration by presenting a more thorough understanding of the topic for organizations
undergoing integration. Through the combination of quantitative and qualitative data, this
research provides insights into how organizations can identify and address cultural differences
to achieve successful integration by aligning their cultures. The results emphasize the
significance of addressing cultural disparities during the integration process, as these
differences can create considerable obstacles to a positive outcome.
CHAPTER 5: DISCUSSION AND CONCLUSION

Summary of Research Findings
The present research assessed the effectiveness of M&A integration through
quantitative and qualitative data analysis. The study aimed to provide a comprehensive
framework that could serve as a foundation for M&A transactions, ultimately leading to a
higher integration success rate. The significance of the study is rooted in the potential benefits
it may yield in terms of substantial cost savings and enhanced career opportunities.
By modifying the thought process and methodology behind M&A transaction
decisions and integration processes, companies can reap material benefits that could prove
instrumental in advancing their business goals. The research findings can contribute to the
field of M&A integration by establishing an evidence-based understanding of the main
drivers of integration success and failure and providing valuable insights to guide the
decision-making process for future M&A transactions.
An anonymous executive responsible for over 80 M&A transactions said, "With an
unlimited budget, I can make any acquisition integration successful. However, my teams are
given a budget to reduce redundancies, which is met with extreme resistance as first, I need to
integrate the cultures. That cost would most likely sink the financials I presented to get
funding for the acquisition in the first place."
Quantitative
The mixed-methods study first collected quantitative information through 100 M&A
integration surveys and 487 employee OCAI assessments to understand the post-close
integration success and identify organizational cultures from both sides of 50 transactions.
The survey and OCAI results were validated and presented no significant anomalies in the
quality of the responses.
The study's findings revealed promising results that could contribute to future research
and business practices. Firstly, the top and bottom three transactions regarding average survey
scores were easily identified. Respondents' scores across the 11 questions over three years of

integration clearly showed the top and bottom performers. The qualitative analysis explored
why the transactions were considered successes or failures.
The quantitative research suggests that the founder's effect may have important
implications, as discussed in the interview analysis. I asked each of the 50 transactions if the
founder remained after the close date. Of the 50 transactions, 23 had a founder who stayed
with the newly merged company, which produced an average survey score of 4.11. Contrarily,
the 27 transactions where the founder was not employed post-transaction close produced an
average score of 3.94, as shown in Appendix H. In this case, the p-value of 0.17 is greater
than the typical significance level of 0.05. Therefore, insufficient evidence exists to conclude
that there is an effect of the founder on important implications.
I asked each interviewee if the founder remained or left at the time of the transaction
close. A noteworthy observation is that the founder did not remain with the acquiring
company in the three transactions with the lowest integration survey scores. Conversely, the
founder chose to stay on board in the three transactions with the highest scores. However, it is
reasonable to assume that the lowest-scoring transactions may have had additional underlying
issues, and the acquiring company may not have intended to retain the founder. In contrast,
the highest-scoring survey suggests that the founder held significant value for the company
involved in the transaction, leading the acquiring company to ensure continuity by retaining
the founder. However, in one high-performing transaction interview, the respondent noted that
the founder should not stay involved in the day-to-day business.
The study suggests that performance management perception is an area of concern. I
conclude that M&A integration teams are frequently reprimanded and blamed for integration
performance, even in highly successful transactions. Moreover, the study suggests that a
negative undertone toward performance management may be inherent in human nature and
unrelated to integration success.

The study also indicates that brand strength perception is another area of performance
perception. Respondents felt the brand became more robust due to the merger, which is highly
plausible. Through M&A, a larger, more powerful company equates to brand perceptions, as
outlined in Lee et al. (2011).
The OCAI study produced unexpected results, suggesting that most acquired
companies rank the Clan culture as their dominant current and preferred culture state. In
contrast, the acquiring company showed a majority Hierarchy culture in both the current and
preferred culture state. The results suggest potential areas for future research, such as
investigating the culture before an M&A transaction is announced versus the culture at the
transaction close versus three years post-close. The study suggests that retrospective human
perception might lead acquired companies’ employees to perceive themselves as a Clan
culture, as they are now the smaller entity being acquired by the larger company. Conversely,
the more prominent company employees perceive themselves as a Hierarchical entity because
they are the powerful entity absorbing the M&A target company.
Further analysis of the OCAI could assist companies in preparing for a merger. If
acquiring companies know that acquired companies tend to pull together and see themselves
as a Clan culture, integration teams can make decisions to address this and avoid challenges
and delays due to cultural conflict. Similarly, the company being acquired can understand that
the acquirer has most employees seeing themselves as a Hierarchy, and preparations
implemented to work with this type of culture. Therefore, the OCAI could prove vital in
assisting M&A integrations before and after the transaction close date.
Qualitative
The qualitative research centered on employee interviews. I conducted 37 interviews
and used NVivo to analyze the data. The analysis identified five distinct themes, each with
three to four sub-themes.

The first central theme explored in this study is the concept of Organizational Culture
Fit, centered on comprehending the cultural dynamics of an acquired company concerning its
existing culture. The results from the OCAI revealed a clear preference among the majority of
the acquired companies for the Clan culture, followed by Adhocracy. Conversely, the
acquiring company favored a Hierarchical structure, with a market culture as the second most
preferred. This lack of alignment between the two companies' cultural preferences is often the
root cause of adversarial relationships that emerge during M&A transactions. However, the
top three performing transactions broke this pattern, with the acquiring companies having
either Adhocracy or Clan cultures. This anomaly suggests an avenue for future research. The
lowest three transactions also involved cross-cultural fit and organizational culture fit. This
added layer of complexity is also an area of future research and has practical implications.
The interviews reinforced this theme of cultural fit, as the respondents felt fitting in
together was crucial to success. The notion of fit should not be limited to being the same but
viewed from a complementary perspective. It is worth investigating how complementary
factors contribute to the overall fit between companies involved in mergers and acquisitions
rather than solely focusing on similarity or sameness. By examining the complementary
aspects of fit, researchers can obtain a more comprehensive understanding of the relationship
between companies and their potential for value creation and integration. Therefore, future
research should prioritize the study of organizational cultures well before any M&A activity,
during the transaction itself, and in the post-transaction phase to ascertain how the perceived
cultures of the companies involved converge or diverge due to the merger announcement.
This study proposes that gaining an in-depth understanding of the cultural differences
between merging organizations can mitigate the issue of cultural fit, resulting in more
seamless integration. Evidence-based data may assist M&A teams in carrying out more
informed and efficient integrations.

This study's second theme explored the founders' role in the integration process,
specifically in the context of M&A transactions. The study's interviews provide valuable
insights into the impact of founder influence, including the phenomenon known as "founder's
syndrome," where the founder wields disproportionate power, particularly in M&A
transactions. Respondents frequently cite founder influence as a principal factor in failed and
successful M&A transactions, with successful integration hinging on the founder's ability to
integrate with the new company and lead their employees.
Given the potential importance of founder influence in M&A success, assessing the
founder's willingness to become part of the new combined entity is crucial, particularly if they
continue their employment with the acquiring company. Unlike rank-and-file employees,
whose involvement in due diligence is limited, founders are front and center and subjected to
complex and fact-based analysis. Such analysis of the founder can yield meaningful and
actionable information for the acquiring company to utilize upon transaction close, potentially
as the missing link in cultural due diligence.
The third theme under investigation is Employee Engagement, which focuses on
employee involvement in the integration process. While it may seem intuitive that any
company involved in an M&A transaction would prioritize employee engagement, interviews
revealed a widespread feeling among employees of exclusion from the communication
process and that leadership failed to incorporate their input into the future direction.
This sense of being marginalized and unheard is a serious concern, as employees on
both sides of the transaction feel a sense of ownership in their respective companies, and the
new combined entity might consider this when communicating the mission and vision for the
future. Retaining key employees is an underlying factor in M&A integration, as anecdotal
evidence suggests that top performers may be the first to leave, with competitors viewing a
merger as an opportunity to poach high-value human assets. The interviews of the

lowerscoring transactions uncovered that this loss of talent could negatively impact M&A
success.
The fourth theme of this study is Understanding the Acquired Companies, which
explored due diligence, integration planning, and cross-functional teams involved in the
integration process. The employee interviews revealed that many M&A transactions are
conducted without a deep understanding of the purchased company. The transaction often
relies solely on creating a larger entity with more customers and increased sales without
considering the specifics of the acquired company.
One interviewee from a high-scoring transaction stated, "They do not understand what
we do" (Transaction 9, Interviewee 17, Transcript 257). Several other interviewees echoed
this sentiment, indicating that employees feel frustration because they perceive that their
company's unique strengths and operations are not adequately considered during the M&A
process. The significance of this appearing even with employees from high-performing
M&As is an opportunity to lead to higher performance. This lack of understanding is not only
a perception issue, but it can have consequences for the success of the integration process.
Furthermore, the interviews revealed that many M&A integrations take much longer
than anticipated, with some exceeding 10 years, when nearly all M&A integrations have goals
of three years maximum for full integration. This result suggests that a lack of understanding
of the acquired company can lead to lengthy delays in the integration process, resulting in a
loss of productivity and revenue for both companies involved. Schweiger and Denisi (1991)
found that cultural compatibility between the acquiring and target companies was essential for
successful M&A integration. They emphasized the need for acquiring companies to identify
cultural differences and develop strategies to manage them during the integration process
(Schweiger & Denisi, 1991).
Companies conducting M&A transactions may prioritize thoroughly understanding the
acquired company in light of these findings. This merger plan could include a detailed

analysis of the company's organizational structure, operational processes, and unique
strengths. Gaining a comprehensive understanding of the company can streamline the
integration process and extraordinarily increase the chances of success.
At the heart of the fifth and final theme lies the challenges of integrating independent
contractors in M&A transactions, specifically within the travel and travel services industry.
Unlike other industries, independent contractors hold substantial power as their clients are
fiercely loyal and will follow them to any company. Therefore, it is surprising to note that
many M&A transactions fail to adequately consider how to integrate these contractors into the
new entity, even though 60% of the acquiring entity comprises independent contractors.
The integration process for independent contractors poses unique challenges that
require a clear, concise, and visionary integration plan to streamline the process. However, if
a company only focuses on its full-time equivalent staff, it would mean that only a minority
percentage of employees are considered in the integration plan. Consequently, many
independent contractors leave during a merger because they have no ties to the new combined
company, which presents a massive pitfall for the acquirer. Moreover, the independent
contractors working for the acquiring entity may feel threatened by the addition of the
acquired company and choose to leave. The travel and travel services industry often
overlooks the importance of prioritizing independent contractors in a comprehensive
integration plan, which could negatively impact integration success.
To address this issue, companies engaging in M&A transactions might prioritize the
development of a thorough and effective integration plan that accounts for the unique
challenges of integrating independent contractors. Streamlining the integration process
obviously increases the chances of success. Failure to do so could result in considerable
challenges for the new entity and hinder the overall success of the M&A transaction.
The five identified themes and sub-themes offer a comprehensive framework for
understanding the challenges of integrating acquired companies and independent contractors.

The findings suggest that the success of M&A transactions is contingent upon a clear and
concise visionary integration plan that includes due diligence, cross-functional teams, and a
thorough understanding of the acquired company. Moreover, the integration plan could
prioritize independent contractors and consider their distinct challenges that frequently go
unnoticed in the travel and travel services industry.
Managers and organizations may consider this study's findings and develop effective
integration strategies that address the organizational culture, including the unique challenges
of independent contractors. By doing so, they can streamline the integration process and
positively increase the chances of success. A comprehensive integration plan will ensure that
everyone involved in the integration process has a beneficial experience.
It is crucial to emphasize that effective integration requires more than technical
expertise. Organizations may consider the integration process's human element, such as the
emotions and motivations of the employees involved, to ensure the integration process is
successful. This process requires strong leadership skills, effective communication, and a
culture that supports the integration process. By prioritizing these aspects of the integration
process, organizations can ensure that the integration is successful and that the new entity can
achieve its strategic objectives.
Interpretation of the Results
To integrate the quantitative and qualitative results for this dissertation, I begin by
comparing the results from both methods. The study found that M&A integration teams are
frequently reprimanded and blamed for integration performance, even in highly successful
transactions, suggesting that performance management perception is an area of concern.
Although the interviews did not directly reveal it, respondents from the integration survey
perceived that the merger strengthened the brand. However, there was indirect evidence about
being grateful for the acquisition during COVID-19 and the acquired company’s survival.

The OCAI study produced intriguing results, suggesting that most acquired
companies rank the Clan culture as their dominant current and preferred culture state,
whereas the acquiring company showed a majority Hierarchy culture in both the current and
preferred culture state. The interviews revealed that the lack of a thoughtful and prepared
integration between the two companies' cultures is often the root cause of adversarial
relationships that emerge during M&A transactions. The interviews uncovered that all M&A
integrations have similar challenges, but the ones that acknowledge, prepare, and implement
strategies to overcome these challenges are the ones that had higher perceived success.
Moreover, it is crucial to compare the scores with the organization's strategic
objectives to identify any cultural misalignment hindering progress toward achieving its
goals. Based on the results, an organization can develop a comprehensive action plan to
strengthen its current culture, align it with its goals, or transition to a new culture that better
supports its vision.
Interpreting the OCAI results requires deeply understanding of the organization's
values and operating context. It is all-important to analyze the results holistically to
understand the organization's culture and determine effective ways to enhance it.
I can integrate the quantitative and qualitative results by analyzing the similarities and
differences in the findings from both methods. For instance, both methods indicate that
alignment between merging organizations is essential for successful M&A integration. The
OCAI study shows that most acquired companies rank the Clan culture as their dominant
current and preferred culture state, while the acquiring company showed a majority Hierarchy
culture in both the current and preferred culture state. Similarly, the qualitative research on
Organizational Culture Fit found that respondents felt fitting in together was crucial to
success. This finding supports the recommendation that future research prioritizes the study
of organizational cultures well before any M&A activity, during the transaction itself, and in

the post-transaction phase to ascertain how the perceived cultures of the companies involved
converge or diverge due to the merger announcement.
Considering how due diligence teams can effectively analyze and compare
quantitative and qualitative findings when integrating two merging companies is integral.
This process may aim to identify similarities and differences between the companies and
propose recommendations to improve the M&A process and ensure successful integration.
A mixed-methods due diligence concept could be employed to achieve this result.
This approach would provide a new and fact-based approach for companies considering
M&A activity to address integral factors such as market valuation, integration timelines, and
founder influence. Due diligence teams could follow the same model used in this research by
conducting surveys, assessing culture with tools such as the OCAI, conducting employee
interviews, and combining the data allowing more meaningful and actionable decisions.
Applying mixed methods to M&A due diligence extends beyond traditional academic
research processes. By combining academic research structures with practical application, a
mixed-methods due diligence approach can effectively integrate academic research processes
with practitioner expertise for a more comprehensive assessment of the M&A transaction.
Hypothesis Testing
In the context of hypothesis testing, the current study utilizes a comprehensive dataset
comprising all 50 M&A transaction cases. It is important to note that the analysis extends
beyond examining the top and bottom three transactions specifically chosen for qualitative
interviews. By including the entire sample of 50 transactions, the study ensures a more
representative and unbiased evaluation of the hypotheses. This broader scope enables a
comprehensive assessment of the relationship between cultural differences and M&A
Integration survey results across the entire spectrum of transactions. Consequently, the
findings derived from this expanded dataset provide a more comprehensive understanding of

the hypotheses under investigation, strengthening the validity and generalizability of the
study's results in the context of hypothesis testing.
When analyzing the available evidence, it is possible to encounter situations where the
qualitative and quantitative evidence supports, partially supports, or does not support the
research question or hypothesis. In cases where qualitative evidence partially supports the
research question, the qualitative data provides insights, perspectives, or explanations that
align with the research hypothesis, although it may not offer statistically solid or
generalizable conclusions. Similarly, quantitative evidence might partially support the
research question when statistical analyses or experimental results indicate some level of
association or significance but with limitations regarding sample size or methodology.
Conversely, when qualitative and quantitative evidence does not support the research
question, neither type of evidence provides substantial backing for the hypothesis. In such
instances, the researcher must critically evaluate the evidence's strengths and weaknesses,
consider alternative explanations, and explore factors contributing to the inconsistencies.
Recognizing the complexity and nuance of research findings is crucial, necessitating a
comprehensive analysis incorporating multiple types of evidence and their limitations.
Hypothesis 1
• H1. The differences between the cultures of the acquiring and acquired companies are
related to financial outcomes measured three years after the M&A.
o Result: The hypothesis is partially supported.
To analyze H1, I first examined the organizational culture and the M&A integration
survey results to explore the relationship between organizational culture and outcomes in the
context of M&A integration. The OCAI framework was applied to assess the cultural
differences within the M&A transaction pairs, while the M&A integration survey served as
the set of questions for evaluating financial outcomes. The findings do not support the
hypothesis that the differences between the acquired and acquired companies' cultures are
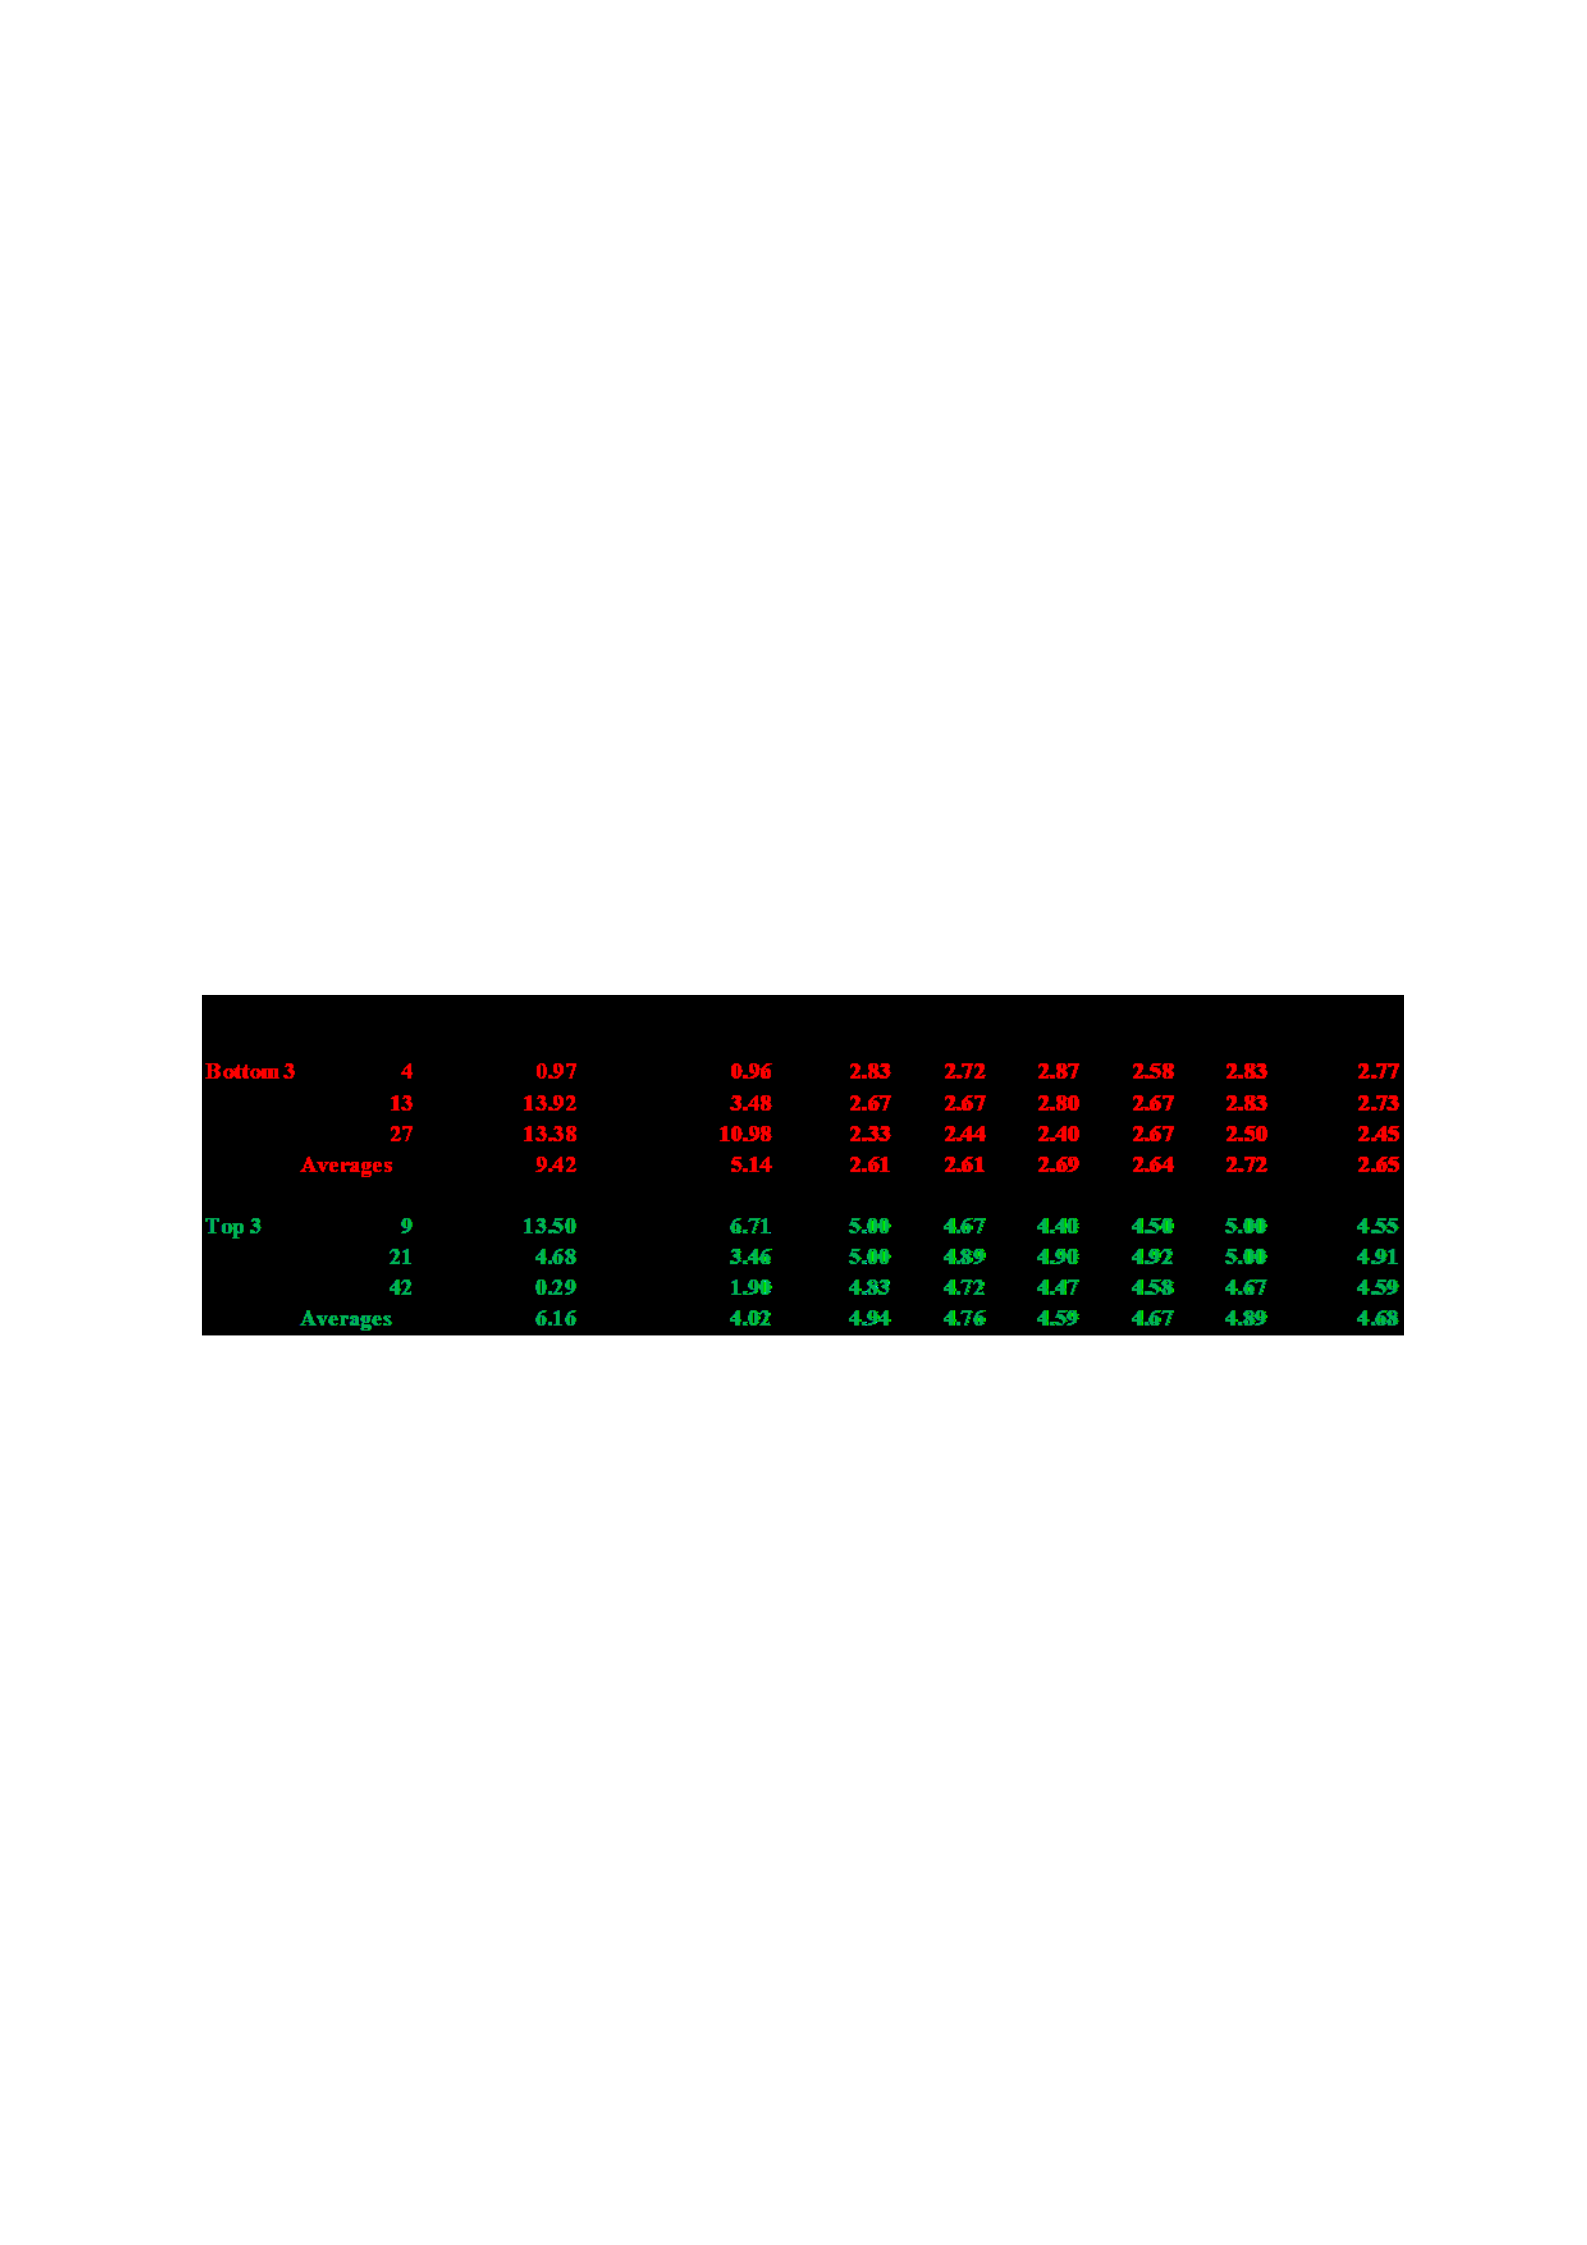
related to the financial outcomes measured three years after the M&A transaction. The
regression analysis showed no statistically significant relationship between cultural
differences and financial outcomes when using all 50 transactions.
When examining the top three and bottom three scoring M&A transactions (Table 15),
there is a lesser overall average cultural difference (6.16) in the top-performing transactions
compared with the average cultural difference (9.42) in the bottom three transactions.
Although this supports the hypothesis, a two-sample t-test reveals no significant difference
between the top three and bottom three performers (t = 0.57, p > 0.10). The small sample size
(n = 6) has little statistical power.
Table 15
Top/Bottom Three Integration Surveys with OCAI Culture Differences
I reviewed the interviews that addressed this hypothesis and provided insights outlined in the
mini-case section of the study. Specifically, this statement from a high-performing transaction
about M&A challenges and the ability to overcome those challenges when the cultures are
aligned: “There are always people and cultural challenges. There are technological
challenges. There are integration issues. There are financial, accounting, and reporting issues.
Most differences are not insurmountable. They can work through them pretty readily”
(Transaction #42, Interviewee 8, Transcript 181). This statement delves deeper into
understanding the impact of cultural fit on financial success during the post-M&A period. The
findings revealed multiple instances where interviewees explicitly stated that cultural fit was

crucial in determining the perceived financial success or lack thereof within the merger
integration period. Examples from a low-scoring transaction were: “There are struggles with
the many cultural differences. You are taking two different companies that have operated so
differently. I would say it did not work, but as a struggle, it always is the accounting and
financial side of things” (Transaction #13, Interviewee 12, Transcript 188).
The interviews provided insights into how cultural disparities between the acquiring
and acquired companies directly influenced the financial outcomes of the merged entity. With
the travel industry comprising more than 60% independent contractors, integrating those
contractors played a significant role in financial success. This quote from a low-scoring M&A
highlights a core issue of integrating contractors: “Many times from an organizational
standpoint, the resistance came from the independent advisors to change the workflow, but
also some of our employees that just did not want to commit to change” (Transaction #4,
Interviewee 26, Transcript 101). Participants highlighted the importance of aligning and
integrating organizational cultures to achieve positive financial results. The interviews shed
light on the pivotal role of cultural fit, communication, and preparation in shaping the
financial success of the integrated entity. These insights contribute to understanding the
interplay between culture and financial outcomes within the context of M&A.
In addition, the new concept of cultural dominance was tested post hoc. The post hoc
regression results supported the interview analysis that the cultures of the acquiring and
acquired companies are related to financial outcomes measured three years after the M&A.
These results are relevant for this research as they may directly impact integration success.
The variable "Cultural Dominance" showed a significant relationship, with a coefficient of
0.06 for the acquired company and -0.04 for the acquiring company (t = 2.06, p < 05). The F
value for the acquired company model (F = 4.23, p < .05) was significant, indicating that the
overall model had explanatory power. The R-squared value (0.08 for the acquired company)
indicated that the model explained a small portion of the variance in financial outcomes. It is

important to note that the observed relationships for both models are only partial, indicating
that other factors beyond culture contribute to the financial outcomes observed in the context
of the M&A transaction. Further research and analysis are necessary to explore additional
variables and their potential influence on financial outcomes.
The results highlight the complex relationship between cultural differences and
cultural dominance on financial outcomes in M&A transactions. While the acquired
company's cultural dominance demonstrates some statistical significance, the employee
interviews and mini-case studies revealed that the transaction's financial outcomes might be
strongly associated with cultural differences. The combined results underscore the need for a
nuanced and context-specific examination of the factors impacting financial performance in
M&A integration scenarios.
Hypothesis 2
• H2. The differences between the cultures of the acquiring and acquired companies are
related to cultural outcomes measured three years from the M&A.
o Result: The hypothesis is partially supported.
To analyze H2, I first examined the organizational culture and the M&A integration survey to
explore the relationship between organizational culture and cultural outcomes in the context
of M&A integration. The OCAI framework was applied to assess the cultural differences
within the M&A transaction pairs, while the M&A integration survey served as the cultural
set of questions for evaluating cultural outcomes.
The quantitative findings do not support the hypothesis that the differences between
the acquired and acquired companies' cultures are related to the cultural outcomes measured
three years after the M&A transaction. The regression analysis showed no statistically
significant relationship between cultural differences and cultural outcomes.

As in H1, the new concept of cultural dominance was tested post hoc. There was
partial support for the hypothesis that the acquired and acquired companies' cultural
dominances relate to cultural outcomes measured three years after the M&A. While H2
specifically hypothesizes cultural differences, not dominance, the discovery of cultural
dominance lends support to the qualitative interviews of employees with the top and bottom
three integration survey scores.
The variable "Cultural Dominance" showed a coefficient of 0.03 for the acquired
company and -0.05 for the acquiring company. The acquiring company (t = -2.23, p < .05)
produced a significant result while the acquired company (t = 1.08, ns) did not. The F values
for the acquiring company (F = 4.98, p < .05) were significant, while the acquired company
model was not significant. This indicated that the overall model had some explanatory power.
The R-squared values (0.09 for the acquiring company) suggest that the model explains only
a small portion of the variance in cultural outcomes.
In restating what was described in H1, when examining the top three and bottom three
scoring M&A transactions, there is less overall average cultural difference (6.16) in the
topperforming transactions compared with the average cultural difference (9.42) for the
bottom three transactions Although this suggests support for the H2, a two-sample t-test
reveals no significant difference between the top three and bottom three performers (t = 0.57,
ns). The small sample size (n = 6) lacks sufficient statistical power.
The interviews provided evidence of cultural outcomes. Surprisingly, the differences
in preferred culture were often associated with successful outcomes when examining the
top/bottom three M&A transactions, while excessive differences were linked to failures. H2
speculates that the differences between the cultures of the acquiring and acquired companies
have a significant relationship with the cultural outcomes observed three years after the
M&A. To explore this hypothesis, I reviewed the employee interviews, which uncovered five
key themes: Organizational Culture Fit, Founder Influence, Employee Engagement,

Understanding the Acquired Companies Business, and Independent Contractors.
The findings from the employee interviews support H2, indicating a clear association
between cultural differences and cultural outcomes in the post-M&A period. This quote from
an employee of a high-performing transaction clearly shows the enthusiasm due to the
cultural fit or closeness they felt: “Absolutely it just was a good (cultural) fit. I was
comfortable, and I felt I could contribute” (Transaction #21, Interviewee 29, Transcript 229).
The theme of Organizational Culture Fit emerged prominently, highlighting the importance of
aligning and integrating cultures for positive cultural outcomes. Additionally, Founder
Influence was identified as a critical factor, emphasizing the role of founders and key leaders
in shaping the cultural integration process.
Employee Engagement emerged as another influential factor, with a strong correlation
between employee engagement and favorable cultural outcomes, as shown in this quote from
one of the lowest-scoring transactions: “Where do I fit into this culture? And will I have a job,
and is my career intact? Will I lose where I want to go in my career? All those are disruptors.
I think it disrupts a lot of that. That causes nonproductivity which happened with our merger”
(Transaction #13, Interviewee 3, Transcript 153). Understanding the acquired company's
business was also crucial, as a deep understanding of the acquired company's business and its
cultural nuances played a significant role in successful cultural integration.
Lastly, the presence of independent contractors within the merged entity required special
attention to ensure their cultural alignment and engagement.
By incorporating the OCAI and the M&A integration survey, this analysis
encompassed a comprehensive examination of organizational culture and its implications for
cultural outcomes. The OCAI facilitated identifying preferred cultural factors, while the
survey provided specific insights into the cultural outcomes.
These findings underscore the complex interplay between organizational culture
outcomes in M&A transactions. Combining the OCAI results and the M&A integration

survey allowed for a multi-faceted analysis, considering the broader cultural context and the
specific types relevant to performance. This comprehensive approach enhances the validity
and depth of the findings, providing valuable insights for practitioners and researchers
involved in M&A integration efforts.
Overall, this integrated analysis of the OCAI and the M&A integration survey,
supported by the employee interviews, contributes to understanding how organizational
culture influences outcomes during M&A transactions. It emphasizes the significance of
considering cultural dynamics and the acquiring company's strength in achieving successful
cultural integration and enhancing HR performance in the context of M&A integration. The
qualitative results partially support the hypothesis that the differences between the acquired
and acquired companies' cultures are related to the cultural outcomes measured three years
after the M&A transaction.
Hypothesis 3
• H3. Culture combinations that successfully integrate result in successful M&A
outcomes.
o Result: The hypothesis is supported.
To investigate H3, I investigated the organizational culture and the M&A integration
survey results overlaid with the qualitative employee interviews. These methodologies
examine the connection between organizational culture and outcomes in the context of M&A
integration. By utilizing the OCAI framework, I assessed the culture within specific
transactions, shedding light on the prevailing organizational norms that shape the integration
process. The M&A integration survey, focusing on overall performance, provided valuable
insights into the outcomes' overall success of the outcomes.
A regression analysis was conducted using Q1, integration, as the DV, and the
combination of Q10-Q11 as the IV. There is a significant relationship (F = 70.31, p < 0.01)
between the IV and DVs when using all 50 transactions. The coefficient for Q1 was 0.66,

significant at the p < 0.01 level. The regression analysis provided includes highly correlated
survey questions. The correlation-based analysis highlights the inability to establish a causal
relationship between the variables, underscoring its importance. Specifically, it cannot be
concluded that Q1 causes the changes observed in Q10-Q11. However, the evidence
presented in this analysis supports H3. Therefore, it is advisable to approach the results
cautiously, recognizing the limitations associated with the nature of the survey questions and
the absence of causality in the observed relationships. The post hoc analysis, outside of the
hypothesis testing, yielded significant findings. It revealed the presence of a dominant culture
within certain transactions, indicating the existence of prevailing organizational norms that
influence the integration process. In this analysis, I found evidence to support the suggestion
put forth by H3 that the effective integration of culture combinations influences the success of
M&A outcomes. The focus was on examining the relationship between the strength of the
acquired and acquiring companies and the outcomes measured by Q10-Q11 from the
integration survey to support the findings of the qualitative interviews.
A regression analysis was run for the acquired company’s cultural dominance effects
on Q10-Q11 outcomes. The analysis indicated that the strong culture of the acquired company
significantly contributes to success. The acquired company’s strength coefficient was 0.08 (t
= 2.38, p = 0.02), demonstrating a statistically significant relationship. These findings provide
robust support for H3, indicating that when the acquired company has a dominant culture, it
positively influences the Q10-Q11 outcomes, leading to successful M&A outcomes. Further,
the acquiring company’s strength coefficient was -0.05, indicating a negative relationship.
However, the result as not significant and can at best show a general direction. These results
suggest that as the acquiring company’s cultural dominance increases, there may be a
negative impact on the Q11 outcomes, potentially hindering the success of M&A outcomes.
H3 suggests that culture combinations that successfully integrate lead to M&A
outcomes. The findings from the employee interviews lay the foundation for support of H3.

The interviews highlighted in the mini-case studies show the importance of effectively
managing cultural differences through proper preparation and communication to achieve
successful cultural integration.
Organizations observe positive cultural outcomes when successfully integrating
culture combinations. The interviews revealed that aligning and integrating organizational
cultures, regardless of their specific OCAI quadrants, played a significant role in achieving
successful M&A outcomes. The following quote was from a high-scoring merger: “You must
have consistent processes and procedures in the airline industry. In an airline industry
acquisition, you may have two companies with two completely different cultures, with two
different sets of processes and procedures. It could be successful if it is appropriately handled,
which our merger was” (Transaction #9, Interviewee 17, Transcript 257). This sets the stage
for how, with proper planning, any two cultures can integrate regardless of size or differing
procedures. Proper preparation involves conducting a thorough analysis of cultural
differences and anticipating potential challenges, while effective communication establishes
open channels for dialogue and fosters shared understanding. One participant said, “When
you go through the process of planning before you integrate, everything else will be easier
and faster. Now take that saved time to integrate and bring everybody together” (Transaction
#42, Interviewee 13, Transcript 741). This is a core finding; that proper preparation may
allow for almost any type of merger culture combination to succeed.
The findings suggest that culture combinations alone may not guarantee successful
M&A outcomes. However, when organizations prioritize proper preparation and
communication to address cultural disparities, they enhance the likelihood of successful
cultural integration. H3 is supported by the interview findings, highlighting the crucial role of
successful cultural integration in achieving positive M&A outcomes. The interview analysis
provides compelling evidence for the importance of the acquired company's culture in
contributing to successful M&A outcomes. Additionally, it suggests that the dominant culture

of the acquiring company may have a detrimental effect, although the statistical significance
is not as strong. These findings underscore the significance of effectively integrating cultures
during M&A processes to maximize the chances of achieving favorable outcomes.
Hypothesis 4
• H4. The acquiring company’s OCAI current state closely matches the acquired
company’s preferred state and produces successful M&A outcomes.
o Result: The hypothesis is not supported.
Based on the comprehensive analysis conducted, the hypothesis that the acquiring company's
current organizational culture closely matches the acquired company's preferred state and
leads to successful M&A outcomes is not supported. The investigation explored the
relationship between organizational culture and M&A outcomes using the OCAI results and
M&A integration survey data and then integrated with the qualitative interview analysis.
To assess the current state and preferred state of organizational culture, the OCAI
framework was employed. This framework provided a comprehensive understanding of the
culture within the acquiring and acquired companies, enabling the examination of cultural
compatibility during the integration process. By analyzing the organizational culture data, it
was possible to determine the degree of alignment or discrepancy between the acquiring
company's current and preferred cultures (Appendix I). It is worth noting that even though
two companies may exhibit the same preferred culture, the differences in those cultures may
appear significant; for example, an acquired company's preferred culture may be a Clan, but
with a score of 26 suggesting they lean slightly toward Clan. In contrast, the acquiring
company’s culture may be a Clan, with a score of 38 suggesting a dominant Clan culture.
The data analysis revealed that all three acquisitions with the lowest performance
scores had the acquiring company's current state matching the acquired company's preferred
state. However, two of the bottom three have vast cultural difference scores, so even though

they share the same organizational culture quadrant, they may not be close in actual scoring.
Future research on cross-border influence on culture may explore the impact of pairing
companies headquartered in different countries; this was the case with all three bottom
transactions, as this factor could contribute to the observed results in the bottom three
transactions. The result was similar when exploring the top three integration survey scores:
only one of the transactions had the current states matching and the cultural dominance was
wide. This finding suggests that the hypothesis is not supported, and the exact opposite
scenario may occur, whereby mergers involving similar organizational culture states,
particularly dominant culture states, could lead to integration failures. Appendix G shows
each company's preferred and current cultures.
The findings indicated that a closer alignment between the acquiring company's
current organizational culture and the acquired company's preferred state was somewhat
associated with less favorable M&A outcomes. When the two organizational cultures were
opposite, with most of the M&A transactions being a current hierarchical culture purchasing a
company with a preferred clan culture, the likelihood of achieving successful M&A outcomes
increased. These differences facilitated smoother integration processes, reduced cultural
clashes, and enhanced collaboration and coordination between entities. Such factors
contributed to the overall success of the M&A integration.
The findings from the employee interviews do not support H4, which suggests that the
acquiring company's current organizational culture state closely matches the acquired
company's preferred state, leading to successful M&A outcomes. The interviews did not
explicitly indicate a direct correlation between the similarity of organizational culture states
and the success of the M&A. One of the highest-scoring transactions clearly stated that the
two cultures did not match: “It was a test of whether our cultures did match. A short way of
saying it is that they did not match, and I think that it was a surprise, but as I understood it, it
made sense to me, and I tried to articulate why it made sense to my people” (Transaction #21,

Interviewee 14, Transcript 702).
While the OCAI framework can provide insights into cultural assessments, its
alignment with the acquired company's preferred state does not guarantee successful
outcomes. The interviews emphasized the importance of broader factors such as proper
preparation, effective communication, and cultural integration strategies in achieving
successful M&A outcomes. The cultural fit between the acquiring and acquired companies is
a complex process influenced by various elements beyond the organizational culture states.
Matching culture states is insufficient to ensure successful outcomes, as other critical factors,
such as leadership, employee engagement, and organizational alignment, also play significant
roles in the post-M&A period. It is essential to note that while the alignment of organizational
culture states played a significant role in perceived merger failure, it was not the sole
determinant of successful M&A outcomes.
In conclusion, empirical evidence did not support the hypothesis that the acquiring
company's current organizational culture closely matches the acquired company's preferred
state and contributes to successful M&A outcomes. This result could prove highly insightful
to future research on culture combinations, as instinctively, one may believe that an acquired
company could possess the desire for a new organizational culture that matches the acquiring
company’s current state and could prove to increase success. In contrast, the research did not
show this as the case, thus fueling potential additional research. The differences in
organizational cultures during the integration process can enhance the probability of
achieving desired financial outcomes. However, it is crucial to acknowledge that achieving
successful M&A outcomes involves a multifaceted process, and it is essential to consider the
differences between organizational culture states in conjunction with other critical factors to
gain a comprehensive understanding of M&A success. Further research is warranted to
explore additional variables and their interplay in the context of M&A integration.

Hypotheses Synopsis
The hypothesis testing yielded partial support for H1 and H2 due to the lack of
statistical evidence for each hypothesis but strong support from qualitative interviews. While
the statistical analysis did not establish a significant correlation between cultural differences
and success, the qualitative analysis revealed a clear link. This finding aligns with the
competing literature on organizational culture measurement in that organizational culture is
identifiable in qualitative analysis, but measuring culture statistically has varying opinions. As
outlined by O'Reilly and Chatman (1996), the presence of cultural similarities and cultural
differences within an organization can contribute to non-significant results in regression
analyses when examining their impact on organizational outcomes. When there is a high
degree of cultural similarity, limited variance in cultural variables among employees can
make it difficult to detect significant relationships with the outcomes under study. On the
other hand, other variables may interact with cultural differences, mediating or moderating
factors may play a role, measurement challenges may be faced, sample composition
limitations may occur, and contextual factors can influence cultural differences, all of which
can contribute to non-significant findings.
The observation that some transactions within the top three and bottom three groups
displayed varying degrees of cultural difference, yet achieved similar outcomes, hints at a
potential reason for the overall lack of significance in the regressions. It is plausible that
including transactions subject to both Cultural Similarity and Cultural Diversity perspectives
resulted in a cancellation of effects. For instance, if half of the transactions showed positive
outcomes due to cultural similarity while the other half showed adverse outcomes due to
cultural diversity, the overall effect would be null. This balancing effect could explain why
the regression analysis yielded non-significant results. It highlights the importance of
considering the interplay between cultural perspectives when examining the influence of
cultural differences on outcomes. While some studies may focus solely on the impact of

cultural diversity, overlooking the potential benefits of cultural similarity or vice versa could
lead to incomplete conclusions.
I attributed the lack of significant results in the Cultural Difference regressions to the
simultaneous presence of transactions subject to the Cultural Similarity and Cultural Diversity
perspectives. The observation that variations in cultural difference did not consistently align
with outcomes suggests a complex interplay between these perspectives. By acknowledging
and investigating this balancing effect, future studies can advance our understanding of how
cultural differences shape various outcomes in different contexts.
Additionally, the analysis revealed that culture combinations might not impact M&A
integration. H3 received full support as qualitative interviews demonstrated that preparation
for M&A integration, regardless of culture type, led to success. Furthermore, post hoc
analysis of the statistically dominant culture further validated the qualitative findings.
However, H4 did not receive support as neither the statistical analysis nor employee
interviews indicated any success based on the similarities between the acquiring company's
current and the acquired company’s preferred state according to the OCAI instrument.
Interestingly, the study uncovered that the acquired company did not desire a different
culture, and combining the same organizational culture types proved to be the most
challenging type of merger, particularly when integrating hierarchies.
Future research should explore the reasons behind the mixed results observed between
quantitative and qualitative approaches. Rather than categorizing the outcome as partially
supported, it is essential to delve into the potential reliability differences between the two
methods. For instance, if the survey methodology struggles to isolate cultural differences'
influence on financial performance effectively, future studies may benefit from emphasizing
the nuanced findings derived from qualitative approaches. This process could provide a more
comprehensive understanding of the research topic.

The findings suggest that successful M&A integrations necessitate careful attention to
cultural dominance, effective communication, timing, leadership, and employee engagement
practices. Additional research is needed to delve deeper into the stated hypotheses and
identify further factors contributing to successful M&A integrations. By addressing these
factors, organizations can enhance the likelihood of successful M&A integrations while
minimizing the risks and challenges involved in these complex processes.
Theoretical Frameworks
This section focuses on presenting the four core theories identified and discussed in
the literature review and aims to comprehensively comprehend these theories and illustrate
how the research undertaken aligns with and supports each theory. The literature review
serves as the foundation for identifying these core theories. By comprehensively reviewing
existing scholarly works, I identified the fundamental theories most relevant to the research
topic and objectives. These theories have been selected based on their applicability,
significance, and potential to provide a conceptual framework for the research.
The following analysis involves drawing connections, identifying patterns, and
providing evidence to demonstrate how the empirical results align with or extend the existing
theoretical frameworks. By examining the relationship between the research and the
identified theories, the dissertation highlights the theoretical contributions of the study. It
offers insights into how the factual findings validate, challenge, or expand upon the existing
theories, thereby enriching the scholarly discourse in the field. This critical analysis also
allows the reader to appreciate the significance and relevance of the research within the
broader theoretical context.
Overall, I aim to bridge the literature review and the empirical findings, establishing a
robust theoretical framework and demonstrating the research's alignment with and
contribution to the identified core theories. By explicitly outlining this relationship, I enhance

the study's overall academic rigor and validity, making a valuable contribution to the existing
body of knowledge in the field.
It is plausible that many reasons exist for merger failure, and each potential cause
could be explored thoroughly and not lay the blame on any single reason without real
evidence to support the findings and assumptions. With many theories, such as Stakeholder,
Shareholder, Agency, and CEO Hubris, a clear delineation could be drawn from each other to
understand the correlation of each to M&A success or failure.
The study supports and informs readers of previous research on cultural integration in
M&A. The study's findings are consistent with previous research that suggests that cultural
differences can be a significant obstacle to successful integration (Cartwright & Cooper,
1993; Haspeslagh & Jemison, 1991). The analysis centers on the importance of organizational
culture fit, founder influence, and employee engagement and aligns with previous theoretical
frameworks that emphasize the role of these factors in the integration process (Marks &
Mirvis, 2011; Nahavandi & Malekzadeh, 1988).
The study's use of the OCAI to assess cultural orientations is consistent with previous
research that has used this tool to evaluate organizational culture (Cameron & Quinn 2011;
Maznevski & Di Stefano, 2000). The study found that both the acquiring and acquired
companies preferred Clan and Adhocracy cultures is also in line with previous research that
has found that these cultures are associated with better organizational outcomes, such as
innovation and employee satisfaction (Cameron & Quinn, 2011; O'Reilly III et al., 1991).
However, the study's emphasis on addressing cultural differences during the integration
process aligns with a growing body of research suggesting that cultural integration should be
an active and ongoing process (Markides & Williamson, 1994). This research suggests that
successful integration requires more than simply identifying cultural differences but also
developing strategies to address these differences and create a shared organizational culture.
The underlying research theories this dissertation originally aimed to examine were

Organizational Culture Theory (OCT) and Agency Theory. Nonetheless, after careful data
analysis, two subsequent theoretical relationships emerged, Integration Theory and Mergers
and Acquisitions Theory. The following section explains all four theories and how this
dissertation's research compares, contrasts, or complements each theory.
Organizational Culture Theory
OCT is the underlying beliefs, assumptions, values, and ways of interacting that
contribute to an organization's unique social and psychological environment founded by
Jaques (1951). OCT posits that organizational culture influences the behavior, attitudes, and
performance of employees within an organization. The theory suggests that an organization's
culture is a combination of its values, beliefs, and norms, which guide the behavior of its
members. The present data is supported by OCT, in that organizational culture affects the
integration process between acquiring and acquired companies.
The qualitative analysis of the study, which included interviews with employees from
the acquired and acquiring companies, provides insight into the impact of organizational
culture on the integration process. The semi-structured interview guide uncovered five
themes: organizational culture fit, founder influence, employee engagement, understanding of
the acquired company's business, and independent contractors. The interviews' thematic
analysis helped identify multiple factors that impact the integration process. This analysis
supported OCT's proposition that organizational culture influences integration.
The three themes related to organizational culture are organizational culture fit,
founder influence, and employee engagement. Organizational culture fit emphasizes the
importance of assessing compatibility between the acquiring and acquired companies'
cultures during integration. Founder influence suggests that the values and behaviors of
founders or key leaders shape the organization's culture, while employee engagement reflects
the level of involvement and satisfaction within the organizational culture.

The self-report survey used evaluated various aspects of the integration process,
including four questions on financial performance, six questions on operational performance,
and one question on the overall integration process. The integration survey results helped to
understand the overall integration process's success or failure. The survey data provided
insights into organizational culture's impact on the merger's financial performance and
operational gains during the integration process.
OCT suggests that an organization's culture particularly impacts its performance and
success. The data provides the OCAI scores for the acquiring and acquired companies, which
analysts can use to analyze their respective organizational cultures. The OCAI scores suggest
that the acquired company in this study is more likely to have a Clan or Adhocracy-oriented
culture, while the acquiring company is more likely to have a Hierarchy-oriented culture. The
acquired company's preferred state also shows a similar pattern, emphasizing Clan and
Adhocracy more than Market or Hierarchy.
OCT informs this data by indicating that the acquiring company's culture may clash
with the acquired company's culture. Such clashes can result in cultural conflicts,
communication issues, and differences in work practices that can negatively impact M&A
outcomes. Furthermore, the data shows that the acquired company's preferred culture is more
aligned with its current culture; similarly, the acquiring company’s preferred culture is more
aligned with its current culture. This suggests that the acquiring company may try to impose
its culture on the acquired company, which can further exacerbate cultural differences.
Overall, the OCAI scores support the idea that organizational culture can play a
crucial role in the success or failure of M&A transactions. The data suggest that acquiring
companies should carefully evaluate the cultural alignment with the target company before
pursuing an M&A transaction to ensure the cultural compatibility of the two organizations.
The data support OCT's proposition that organizational culture influences acquiring and
acquiring companies' integration process. The study's qualitative and quantitative data

provided insights into the impact of organizational culture on communication, leadership, and
employee engagement during the integration process. The OCAI results supported OCT's
argument that organizational culture influences the behavior of employees. This research
highlights the importance of addressing cultural differences between the acquiring and
acquired companies during the integration process to achieve a successful outcome.
I contribute to OCT by providing pragmatic evidence to support its proposition that
organizational culture influences the integration process in M&A transactions. Moreover, I
emphasize the importance of addressing cultural differences between the acquiring and
acquired companies during the integration process to achieve a successful outcome. Doing so
provides a practical framework for managers to follow when planning and executing an
M&A transaction, incorporating the cultural differences between the two companies.
In conclusion, I add appreciable value to the OCT by providing empirical evidence to
support its proposition, highlighting the influence of organizational culture on
communication, leadership, and employee engagement during the integration process, and
emphasizing the importance of addressing cultural differences between the two companies
during the integration process to achieve a successful outcome.
Agency Theory
Agency Theory views the firm as a set of contracts among self-interested individuals.
An agency relationship is created when a person (the principal) authorizes another person (the
agent) to act on his or her behalf (Jensen & Meckling, 1976). The present research could
contribute to the Agency Theory in the context of M&A transactions. In an M&A transaction,
the acquiring company acts as an agent on its shareholders' behalf, aiming to maximize
shareholder value. However, the interests of the shareholders and the acquiring company's
management team may not always align with those of the acquired company. Similarly,
management interests and ownership of the acquired company might not align.

The findings highlight the importance of cultural integration between the acquiring
and acquired companies during the integration process, which can ultimately impact the
success of the M&A transaction. The research indicated that wider cultural differences may
determine cultural compatibility, as the highest-performing transactions had significant
differences in OCAI scores, supporting the old saying opposites attract. In contrast, the two
worst-performing transactions showed that the acquired and acquiring companies exhibited a
statistically dominant culture. By addressing cultural differences and creating an integration
plan that considers the cultural suitability between the two companies, the acquiring company
can increase the likelihood of achieving its goal of maximizing shareholder value.
Moreover, the study's emphasis on cultural fit during the integration process can
contribute to Agency Theory. A successful integration process, which addresses cultural
differences and promotes open communication and effective leadership, can help to align the
interests of the acquiring company's management team with the acquired company's
employees, ultimately benefiting both parties and improving the success of the transaction.
Agency Theory was pivotal in supporting this research as it provided a relevant
conceptual framework for analyzing the unique dynamics within the travel and travel services
industry, where more than 60% of individuals operate as independent contractors. Agency
theory provided a lens through which the complex principal-agent relationship between
independent contractors and parent organizations could be analyzed and understood. Within
the travel industry, independent contractors function as autonomous entities, acting as their
independent businesses while benefiting from the support and resources offered by the parent
organization, such as shared services support and financial buying power. Notably, the
autonomy of independent contractors to terminate their relationship with the parent
organization without prior notice added another layer of complexity to the agency
relationship. Through the application of agency theory, this dissertation shed light on the
intricate interplay of contractual arrangements, conflicts of interest, and the influence of

organizational culture on the relationship between independent contractors and their parent
organizations in the travel industry.
The research can contribute to the Agency Theory in the context of M&A transactions
by emphasizing the importance of cultural adaptability, communication, leadership, and
employee engagement during the integration process, which can ultimately align the interests
of the acquiring company's management team with those of the acquired company's
employees, benefiting both parties and improving the overall success of the transaction.
Integration Theory
Integration Theory postulates that successful integration requires a clear understanding
of the differences between the acquiring and acquired companies and the ability to manage
those differences effectively. In M&A, differences may arise due to varying organizational
structures, cultures, communication channels, power dynamics, and values. Therefore, it is
essential to identify and address these differences to achieve a successful integration by
implementing effective strategies and communication channels (Cartwright et al., 1996).
The research's support from Integration Theory is considerable because it identifies
five indispensable themes that impact the integration process: organizational culture fit,
founder influence, employee engagement, understanding of the acquired company's business,
and independent contractors. These themes align with the central tenets of Integration Theory,
which emphasize the importance of achieving a harmonious and mutually beneficial
relationship between the acquiring and acquired companies.
The findings on organizational culture highlight the importance of cultural
compatibility between two companies for successful integration. This finding aligns with
Integration Theory, which argues that integrating two companies with different cultures can
lead to momentous challenges and potentially undermine the acquisition's success. The
findings on founder influence and employee engagement also align with Integration Theory's
emphasis on creating a positive and productive working relationship between the two

companies. The study suggests that identifying and addressing the founders' roles and
interests and involving employees in the integration process can help overcome challenges
and enhance the acquisition's success. The emphasis on understanding the acquired
company's business and addressing the roles and interests of independent contractors also
aligns with Integration Theory's focus on developing a comprehensive understanding of the
acquired company's operations and stakeholders.
Altogether, the research provides valuable insights into the themes that impact the
integration process and emphasizes the importance of addressing these themes for successful
integration.
Mergers and Acquisitions Theory
M&A theory emphasizes that successful integration requires careful planning and
execution, relying on leadership, communication, due diligence, and employee engagement,
as defined by Penrose and Penrose (2009). A merger or acquisition involves the combination
of two or more companies, and it is crucial to ensure that the integration process goes
smoothly to achieve the desired outcomes. The integration process involves various factors
that can impact the success of the merger or acquisition, including communication, managing
cultural differences, employee engagement, leadership, and due diligence.
The research is supported by the existing body of M&A theory literature by providing
valuable insights into the integration process. Specifically, the research identifies five themes
that impact the integration process: organizational alignment, founder influence, employee
engagement, understanding of the acquired company's business, and independent contractors.
The data on organizational culture highlight the importance of cultural compatibility
between the acquiring and acquired companies for successful integration. The research
emphasizes that acquiring companies need to consider the cultural differences between the
two companies to achieve a smooth integration. Additionally, the study's findings on founder

influence and employee engagement highlight the importance of addressing the interests and
roles of founders and employees during the integration process.
Furthermore, the study's emphasis on understanding the acquired company's business
and addressing the roles and interests of independent contractors is consistent with the central
philosophy of M&A theory. The research highlights the significance of conducting due
diligence to understand the acquired company's operations and stakeholders to ensure a
successful integration.
Overall, the research provides helpful insights into the themes that impact the
integration process and emphasizes the importance of addressing these themes for successful
integration. By understanding the factors that affect the integration process, companies can
make informed decisions and implement effective strategies, ultimately leading to successful
M&A transactions.
Implications for Organizational Practice
Practice
M&A has gained tremendous popularity in recent decades due to globalization,
intensifying competition, technological advancements, and the desire for rapid growth and
diversification. Companies utilize M&A as a strategic tool to expand market reach, acquire
complementary resources, and leverage synergies for improved performance. Favorable
regulatory environments, available capital, and specialized expertise have further facilitated
the growth of M&A activities. Success stories and recognition of M&A as a disciplined
practice have also contributed to its rising appeal as a transformative strategy in today's
dynamic business environment.
It is a core aspect of corporate strategy that can facilitate growth, provide access to
new markets and technologies, and help companies stay competitive in the global economy.
However, M&A is not without its challenges. Integration is one of the most misunderstood

factors in ensuring the success of a merger or acquisition. Integration Theory and Mergers and
Acquisitions Theory provide frameworks to effectively understand and manage the
integration process.
The integration process can be daunting, especially when dealing with complexities of
culture, leadership, communication, and employee engagement. Integration Theory suggests
that successful integration requires a clear understanding of the differences between the
acquiring and acquired companies and the ability to manage those differences effectively. The
qualitative analysis in the study identified five themes that impact the integration process,
including organizational culture alignment, founder influence, employee engagement,
understanding of the acquired company's business, and independent contractors. By
subdividing the themes into several sub-themes, I gained a comprehensive understanding of
the integration process, which can aid in managing the differences between the two
companies effectively.
One of the challenges faced during M&A is the selection of the right CEO. The
interviews conducted for the study yielded several interesting observations from respondents.
The first was that it is hard to hire a vision from a large PE fund manager who stated that
20% of the CEOs they hire have a vision that can lead the company forward in a manner the
PE fund expects. This statement highlights the importance of selecting a CEO with a clear
vision of the company's future and who can execute it effectively.
Another relevant observation was that a company could not fake culture. This finding
offered an essential perspective because often, during the financial due diligence process, the
only culture observed is superficial and it only shows what the company to be acquired wants
to show to the new suitor. This observation underscores the importance of conducting
comprehensive cultural due diligence to identify potential cultural misalignments between the
acquiring and acquired companies.

The final observation made during the interviews was to avoid CEO hubris. Many of
the interviews uncovered that hubris from the CEO drove the transaction, even when both
parties felt it was no longer a feasible proposition to complete the transaction. This
observation highlights the importance of having a well-defined set of criteria for evaluating
the transaction's feasibility and the CEO's ability to execute the integration plan effectively.
In conclusion, the integration process is vital to the success of any M&A transaction.
Integration Theory and Mergers and Acquisitions Theory provide frameworks to effectively
manage the integration process's complexities. The observations made during the interviews
highlight the importance of selecting the right CEO, conducting comprehensive cultural due
diligence, and avoiding CEO hubris. These factors can help ensure successful integration and
a positive outcome for all parties involved.
Vision
It can be challenging to hire for corporate vision because it requires finding someone
with the necessary skills and experience who shares the same values and vision for the
company's future. The recommendation here is simple: clearly define the company's vision.
Before hiring someone who shares the vision, the institution needs to be clear on what that
vision is. Make sure the vision statement is concise, clear, and inspiring. Look for candidates
who align with the values. It is inherent to assess whether they align with company values.
Ask questions that reveal their work ethic, communication style, and critical thinking skills.
Use behavioral interview questions to help understand how a candidate has managed
situations in the past. Ask questions that reveal their ability to think strategically and align
with the company's vision. Consider cultural fit because hiring someone who does not align
with the company's culture can harm morale and productivity. Evaluate candidates for cultural
compatibility, skills, and experience. Leverage a network when finding candidates who share
the organization's vision and consider contacting a more extensive network.

Faking Culture is Hard
It is difficult to fake a genuine organizational culture for a prolonged period.
Organizational culture is the shared values, beliefs, attitudes, and behaviors that define how
people within an organization interact with one another and approach their work.
Authentic organizational culture is created through consistent actions and behaviors that align
with the stated values and beliefs of the organization. It takes time, effort, and dedication to
create a positive organizational culture that truly reflects the values and beliefs of the
organization. While it is possible to create a superficial appearance of a particular culture, it is
challenging to maintain it over time if the underlying values and behaviors do not support it.
Employees can quickly detect if an organization's stated values and behaviors do not match
the reality of their daily work experiences. Therefore, creating an authentic organizational
culture is crucial for long-term success and cannot be faked. It requires consistent action and
genuine dedication to the stated values and beliefs of the organization.
Avoiding Hubris
CEO hubris refers to a CEO's excessive self-confidence, pride, and arrogance that can
lead to risky decision-making and negative consequences for the company. CEOs with hubris
tend to overestimate their abilities, ignore constructive criticism, and make decisions based on
their beliefs and desires rather than objective data and evidence.
As mentioned in the literature review, research has shown that CEO hubris can harm a
company's performance and reputation. On average, losses in acquiring firms' shareholder
wealth following an acquisition, and the greater the CEO hubris and acquisition premiums,
the greater the shareholder losses. Thus, CEO hubris has substantial practical consequences
and potentially great theoretical significance to observers of strategic behavior (Mathew &
Hambrick, 1997).
Hubristic CEOs are more likely to engage in unethical behavior, engage in M&A that
do not benefit the company, and resist changing their strategies even in the face of declining

performance. This behavior can lead to a decline in shareholder value, damage to the
company's reputation, and even legal and regulatory repercussions. To mitigate the harmful
effects of CEO hubris, companies can adopt measures such as having a solid board of
directors that can provide oversight, establishing a culture of transparency and accountability,
and encouraging feedback and dissenting opinions from employees and stakeholders.
Additionally, CEOs can benefit from self-awareness and a willingness to seek advice and
feedback from others.
Policy
Based on the research findings, it is evident that organizations need to develop
policies aligned with the theoretical considerations discussed in this thesis to enhance the
success of the integration process. To achieve this, organizations could prioritize the
development of a cultural integration strategy that aligns with the goals and values of the
organization. This strategy may consider the benefits and drawbacks of assimilating the
acquired company's culture into the acquiring company's culture or opting for a more blended
approach. Developing this strategy might be supported by thorough research and analysis of
the cultural differences between the two organizations.
Organizations may invest in employee engagement and due diligence initiatives that
support the integration process. This investment could include training programs,
communication strategies, and leadership styles that enhance employee engagement and
support a successful integration process. The organizations could regularly evaluate and adapt
these initiatives based on feedback and the evolving needs of the integration process. By
doing so, the organization can help ensure that all employees are engaged in the process and
are committed to achieving the organization's goals.
In addition, organizations may explore using technology to support the integration
process. Virtual communication tools can enhance collaboration, communication, and
engagement during integration, making it easier for employees to work effectively and

efficiently. The organization can develop customized technology solutions that align with its
goals and values, providing an optimal environment for the integration process.
Finally, organizations could prioritize developing and promoting the concept of
cultural intelligence within the organization, as Earley and Ang (2003) outlined. Cultural
intelligence is the capability to understand, appreciate, and effectively adapt to different
cultures and ways of thinking. It involves working and relating effectively with people from
diverse cultural backgrounds and recognizing and navigating cultural differences in
communication, behavior, and values. Implementing training programs, workshops, and
mentoring programs can support the development and application of cultural intelligence
during the integration process, leading to the achievement of this result. Organizations can
enhance their employees' ability to adapt to and work effectively in culturally diverse
environments by prioritizing cultural intelligence.
In conclusion, organizations can benefit from implementing policies that align with
the theoretical considerations discussed in this study. The policies discussed can assist
organizations in developing a successful integration process aligned with their goals and
values. By doing so, organizations can improve their chances of success in M&A transactions
and create a positive outcome for all parties involved.
M&A Integration Plan
The integration process is an inherent factor in the success of any M&A transaction.
Based on the findings, organizations need to develop policies aligned with theoretical
considerations to enhance the success of the integration process. This sample M&A
integration plan outlines how organizations could develop a successful integration process.
Step 1: Develop a Cultural Integration Strategy. Organizations might prioritize the
development of a cultural integration strategy that aligns with the goals and values of the
organization. This strategy could consider the benefits and drawbacks of assimilating the
acquired company's culture into the acquiring company's culture or opting for a more blended

approach. To develop this strategy, organizations may conduct thorough research and analysis
of the cultural differences between the two organizations. To develop a cultural integration
strategy, organizations could take the following steps:
1. Conduct cultural due diligence to identify cultural differences and similarities.
2. Define the cultural values and norms of each organization.
3. Identify areas of alignment and misalignment.
4. Develop a cultural integration plan that outlines the integration approach and core
activities.
Step 2: Invest in Employee Engagement and Cultural Due Diligence Initiatives.
Organizations might invest in employee engagement and cultural due diligence initiatives that
support the integration process. This investment could include training programs,
communication strategies, and leadership styles that enhance employee engagement and
support a successful integration process. Organizations could take the following steps to
invest in employee engagement and cultural due diligence initiatives:
1. Conduct an employee engagement survey to understand the employee's attitudes and
perceptions toward the integration process.
2. Develop a communication plan that outlines the communication channels, frequency,
and essential messages.
3. Conduct training programs to enhance employees' cultural intelligence, leadership,
and communication skills.
4. Develop leadership development programs to support the integration process.
Step 3: Explore the Use of Technology to Support the Integration Process.
Organizations may explore the use of technology to support the integration process. Virtual
communication tools can enhance collaboration, communication, and engagement during
integration, making it easier for employees to work effectively and efficiently. To provide an
optimal environment for the integration process, organizations can develop customized

technology solutions that align with their goals and values. To explore the use of technology,
organizations might take the following steps:
1. Identify the key technology solutions required to support the integration process.
2. Develop a technology roadmap that outlines the technology solutions and the timeline
for implementation.
3. Conduct technology due diligence to ensure the technology solutions align with the
organization's goals and values.
4. Test the technology solutions before implementing them to ensure they meet the
organization's needs.
Step 4: Develop and Promote Cultural Intelligence within the Organization. Organizations
could prioritize developing and promoting cultural intelligence within the organization.
Implementing training programs, workshops, and mentoring programs that support the
development and application of cultural intelligence during the integration process can
achieve this result. To develop and promote cultural intelligence, organizations may take the
following steps:
1. Develop a cultural intelligence training program that enhances employees' ability to
work effectively in culturally diverse environments.
2. Conduct workshops that promote cross-cultural communication and collaboration.
3. Implement mentoring programs that pair employees from different cultural
backgrounds.
4. Develop a cultural intelligence scorecard to measure and track progress. The success
of the integration process in M&A transactions depends on implementing policies that
align with theoretical considerations. The M&A integration plan outlined above
provides a suggested framework for organizations to develop a successful integration
process aligned with their goals and values. Detailed plans will vary by organization

and M&A transaction, but this framework could prove helpful in any organization as a
baseline. By following the steps outlined in this plan, organizations can improve their
chances of success in M&A transactions and create a positive outcome for all parties
involved.
Limitations
The objective of the current study was to contribute to the existing literature on M&A
by offering valuable insights into the integration process. Nevertheless, the study's limitations
must be recognized to interpret the findings effectively.
Primarily, the study adopted a mixed-methods research design; however, the
qualitative research relied on a relatively small sample size of 37 interviews with employees
involved in only the top and bottom three scoring M&A transactions of the integration
process surveys. While this sample size is appropriate for a qualitative study, it may constrain
the generalizability of the findings. Additionally, the study's focal point on a single industry
requires caution when extending the results to other industries.
Secondarily, using self-report measures could have introduced social desirability and
response biases. Participants may have provided responses that reflect positively on
themselves or their organizations rather than genuine experiences. Therefore, the interpreter
might consider that the responses may not accurately reflect the participants' experiences.
Furthermore, it is important to consider that the qualitative research relied on
recollections of employees involved in M&A transactions at least three years before the study.
This reliance on retrospective recollection may introduce potential recall bias and limitations
in the accuracy and completeness of the information provided. Future research in this area
would benefit from a real-time longitudinal study design, allowing respondents to reflect on
their recent experiences, thus enhancing the reliability and validity of the data.
Tertiary, the study only evaluated the integration process from the perspective of the
acquiring and acquired companies, and it did not account for the viewpoint of other

stakeholders such as customers, suppliers, regulators, or individuals who have left the
organization between the transaction date and the study date. Consequently, the study's
findings may not wholly explain the integration process. It is important to note that the
OCAI results rely on respondents' recollections of current and preferred culture-related
aspects from at least three years in the past. Additionally, the input regarding the acquired
entities is limited to individuals who have remained with the combined entity for at least three
years, excluding input from individuals, especially those from the acquired entity, who have
left the organization during the intervening period.
Overall, the impact of the COVID-19 pandemic on the perception of M&A
transactions is a key area of study that warrants further investigation, given the potential
implications of these deals for the survival and sustainability of businesses during economic
uncertainty.
Finally, the study focused on five themes that impact the integration process. It is
essential to note that the study only assessed specific themes impacting the integration
process but did not encompass other equally critical factors. Therefore, researchers may
interpret the findings within the context of the themes evaluated in this study.
The present study provides valuable insights into the integration process of M&A.
However, it is crucial to consider the study's limitations when interpreting the findings. Future
research could address these limitations to provide a more comprehensive understanding of
the integration process.
Recommendations for Future Research
Based on the findings, there are several recommendations for future research to
provide a more comprehensive understanding of the integration process in M&A. Future
research could explore the impact of different cultural integration approaches on the
integration process's success. For instance, some organizations may adopt a more assimilative

approach to merge the acquired company's culture into the acquiring company's culture, while
others may prefer a more blended approach. Thus, future research might investigate the
benefits and drawbacks of these different approaches to identify the most effective approach
to cultural integration. The possibility arises that matching hierarchies may have contributed
to less successful outcomes, which could be relevant for understanding the lower success rate
observed in public companies. This result highlights an area for future research.
Subsequent studies could examine cultural dominance and how different types of
employee engagement and cultural due diligence initiatives impact the integration process.
For example, organizations could explore the impact of various training programs,
communication strategies, and leadership styles on employee engagement and overall
integration success. Researchers can explore the effectiveness of different employee
engagement initiatives and identify the most effective strategies organizations can adopt to
achieve successful integration. Further, in the ongoing study of M&A, there is a concept to
analyze data from the culture types represented by the four quadrants in the OCAI and from
each of the two dimensions. This approach offers the potential to gain additional insights and
enrich the depth of the analysis.
Another consideration could investigate the role of technology in the integration
process. Technology advancements, such as virtual communication tools, may provide new
opportunities for enhancing communication, collaboration, and engagement during the
integration process. Therefore, future research could investigate how organizations can

