


1
INTRODUCTION
The economies of GCC states depend heavily on producing and exporting fossil fuels.
They account for 34 percent of the world oil reserves and a fifth of global oil production. In
2021, GCC export of fossil fuels contributed to 60 percent of the revenues of Saudi Arabia and
80-84 percent of the U.A.E. and Qatar (IMF, 2022). Despite the openness of the GCC countries
to global trade, Western technologies, and concepts of modernization, and despite their
commitment to the UN Paris Agreement of 2015 and UN Sustainable Development Goals and
agenda, these monarchies have been slow in engaging effectively in diversifying their economies
and transitioning to green energy. Green energy is considered an industry that has the potential to
become an alternative competitive source to fossil fuels to be exported to global markets,
providing a long-term, sustainable source of revenue. Green energy transition is the process of
shifting away from fossil fuels to zero-carbon sources.
In a time series analysis of the period from 2010-2021, utilizing the frameworks of the
United Nations' SDG # 7 criteria, the Global Competitiveness Report and Green Energy Index
measurements and rankings of World Economic Forum, the Index of Economic Freedom of the
Heritage Foundation, and a case study of three GCC monarchies namely, Qatar, Saudi Arabia,
and United Arab Emirates, I attempt to identify the factors that will enable or hinder the
transition of these three monarchies to green energy and the incentives that will encourage their
political leaders to adopt policies and strategies that will enhance their transition to green
energy.

2
This study illustrates the domestic, environmental, political, economic, social, and
geopolitical instabilities these countries have and are likely to experience more profoundly if
they fail to address the drivers of these instabilities effectively and soon. The preconditions for
economic take-off, such as agriculture, were unavailable to the GCC societies because of their
hot and dry arid lands and water scarcity (IMF, 2022). Instead, these Rentier Monarchies have
built their sovereign wealth by controlling their countries' natural endowment's extraction,
production, and exporting and collecting the rents that offered these states generous economic
advantages. The political economy of the Gulf states (Often called "social contract") emerged
especially after the Arab Oil embargo of 1973-1974 combined with low production costs, liberal
trade policies for goods and services, and capital and labor (Shehabi, 2023). Without revenues
collected from taxation, they have depended mainly on revenues generated from their fossil fuel
industry.
The phenomena of "Dutch Disease" and "Protection Curse" have played paradoxical
roles for these "Rentier" states. Although the discovery of large reserves of fossil fuels in the
absence of any possibility for these countries to engage in agriculture has been vital to the
development of their economies, and although the military and intelligence security provided by
the West has helped these monarchies maintain their regional and geopolitical economic and
otherwise leadership, they have limited their economic diversification as well as political and
social growth into becoming more inclusive, democratic societies (Brookings, 2022).
So far, Qatar, Saudi Arabia, and the UAE, all rentier states, have managed, controlled,
and sustained their economic and political challenges through increased current spending to

3
accommodate social pressures, including welfare packages such as pay raises for government
employees and military personnel, and housing loan forgiveness programs. However, the ability
of these monarchies to provide jobs to their citizens in state-owned organizations, paid for by oil
rent revenues and a higher salary range than that of the privately owned companies, has limited
the opportunities for diversification into new industries (Shehabi, 2023).
More than the Rentier theory is needed to explain culturally complex societies such as
Qatar, Saudi Arabia, and the UAE. The source of their political context lies in asabiyya (group
feeling) and their nomadic way of living in a very hostile environment within a tribal framework
that emphasizes authoritarianism. Although these societies are traditional, they have successfully
developed a competitive industry, opened their economies to global markets, and developed
strategic relationships. They have adopted modernization in their cities, infrastructures,
education, architecture, and fashion while staying rooted in the characteristics of Islam and
tribalism (Morrissey, 2021).
Building an alternative industry that will augment and, in the future, provide sustainable
revenue to transition to green energy and meet their commitments to the UN Paris Agreement of
2015 and beyond, these GCC countries will need both exogenous and endogenous growth.
Exogenous economic growth will involve productivity and technological progress due to
influences or spillovers from outside the economy. The transition of these countries to a green
economy will need to allow the adoption of the skills, knowledge, and disruptive renewable
energy technologies of countries with already mature industries in the production and application
of alternative energy, such as the United States, China, and the European Union. UAE, Saudi

4
Arabia, and Qatar will need to import disruptive green energy technologies to build the
infrastructure necessary to initiate the projects to produce renewable energy, and the knowledge,
the human capacity, and the skills critical to undergo the level of industrialization needed to
build an efficient industry that will enable the diversification needed to build a sustainable,
economy.
However, obtaining the technologies and the know-how exogenously is insufficient to
create, develop, and sustain the domestic transition of fossil fuel-based energy to green energy in
the short run and the necessary efficiency in production and exporting in the long run without
endogenous economic growth (Feng, 2005). Government incentives and policies that promote
innovation, substantive investment in research and development, education, human capital, and
capacity building become the critical drivers to the success of developing an alternative industry
that will support the diversification of their economies and provide an essential source of revenue
for the government.
The rulers of these monarchies have controlled inflation, social instabilities, and religious
uprisings by pegging their currencies to the US Dollar and providing generous government
subsidies supplied by the power of generous fossil fuel revenues. In an environment where these
monarchies have absolute control over political, economic, and social affairs and where changes
are driven from top to bottom through decrees, incentives that motivate these rentier elites to
diversify and transition to green energy will be critical for a successful transition.

5
Depleting oil reserves due to maturing fields and lack of discoveries, oil price volatility,
paralleled with decreasing global demand, will weaken these GCC states' economic growth and,
therefore, their sovereign wealth. Increasing population and lack of government investments in
the private sector resulting youth unemployment and social instabilities, will shift these
monarchies' critical power impacting their regional security and global alliances; all critical
incentives for these monarchies to make the transition.
Although transitioning to green energy requires significant commitment, a profound
paradigm shift, and engagement in advancements in green technology, generation and storage of
renewable energy, and capture and storage of carbon dioxide, these countries can capitalize on
their other natural endowment, sunlight, and leverage and build on their current expertise in their
energy performance system, ability to make inexpensive energy accessible, their existing human
capacity and critical global partnerships and become a competitive source in producing and
exporting solar energy.
The findings of this study show that there seems to be a positive correlation between
Energy System Performance and SDG #7 for all countries but a negative correlation with
Transition Readiness. Also, although the trajectory of correlation between the Energy Transition
Index and UN SDG#7 is positive with an upward slope for both UAE and Qatar, and even
though Renewable Energy projects in both Saudi Arabia and the UAE are underway but, their
completion and capacity to contribute to the production of green energy needs to be accelerated.

6
To date, Qatar does not show any green energy capacity and the conditions for transition
readiness in all three countries seem to be less aligned with the UN's Sustainable Development
Goal #7 requirements, which mainly involve installed renewable energy generating capacity.
This study shows that compared to Qatar and Saudi Arabia, the United Arab Emirates has
the highest score in Transition Readiness, followed by Qatar and Saudi Arabia. The factors
enabling the transition of the UAE to green energy in advance of the other two monarchies seem
to consist mainly of UAE showing a consistent increase in both Energy Transition Index and UN
SDG#7 performance scores between 2016-2021, better structure of government that plays a
central role in implementing policies and measures for energy transition, a strong political and
institutional commitment to the United Nations' Sustainable Development Goals, higher level of
FDI (Foreign Development Investment) inflows into the UAE, and global strategic partnerships
building in preparation for exporting solar energy to the US and the EU markets. UAE also
shows higher capital investment in the private sector, which is critical in developing disruptive
new technologies and human capacity building. Furthermore, contrary to Saudi Arabia and
Qatar, the UAE shows a higher level of foreign direct investment and economic freedom.
On the other hand, Qatar has the highest score in System Performance, which consists of
economic development and growth, environmental sustainability, and Energy security and
access, followed by Saudi Arabia. The country shows a high correlation between Transition
readiness and UN SDG#7, Capital Investment, Human Capital, FDI inflows, Political

7
Commitment, Economic Freedom, and Development; however, it does not show any installed
capacity to produce green energy.
While Qatar and the UAE show increases in both ETI and SDG#7 scores for the period
between 2016-2021, Saudi Arabia shows a decrease for the same period. Even though Saudi
Arabia demonstrates to have the highest correlation between ETI (Energy Transition Index) and
competitiveness and a high correlation between Transition Readiness and human capital, because
competitiveness does not consider the transition to green energy, the correlation cannot be
interpreted as a causal effect suggesting that there is no endogeneity problem. Saudi Arabia also
shows an inverse correlation between ETI, Energy System Performance, and SDG#7, Transition
Readiness, Foreign Direct Investment, Political Commitment, and a very low correlation
between FDI inflow and Economic Development. Saudi Arabia’s substantial decrease in foreign
direct investments might result from the presence of a robust, competitive fossil fuel industry,
Saudi Aramco, and geopolitical commitment to the fossil-fuel industry.
Saudi Arabia experienced a substantial decrease in its Foreign Direct Investment inflows,
from $39.5 billion in 2008 hitting a low of just $1.4 billion in 2017 and $19.3 billion in 2021
(This investment was primarily due to a $12.4 billion Aramco deal to sell a minority stake) and
$7.9 billion in 2022 (IMF, 2021). Although the country's economy has recovered some of its
losses, the amount needed to pursue Crown Prince Mohammed Bin Salman's vision of 2030
initiatives and fund the transformation to green energy is far below what is needed.

8
Saudi government initiatives lack the institutional commitment to UN SDG#7.
Furthermore, to increase the level of FDI within the country, it has further restricted economic
freedom through government initiatives that will exclude international companies from
government contracts unless they set up their regional headquarters in Saudi Arabia, forcing
them to move away from the UAE. Even though all three countries show that they have made
substantive advances in building renewable energy projects during 2020, 2021, and 2022, and
although the total renewable energy projects initiated by Saudi Arabia is more significant than
that of the UAE (16120 MW and 14808 MW), the level of total renewable and solar energy
capacity, as well as the renewables share of electricity for the UAE, is higher than that of Saudi
Arabia and Qatar between 2010 and 2023. Qatar does not show any Renewable energy capacity
within the same period.
The center of the transition of the GCC economies to green economies lies in the
dichotomy that the way to break from the hydrocarbons depends on the revenues generated from
the hydrocarbons. The features that characterize the GCC states' energy transition and net-zero
targets center around the ongoing consumption, production, and exportation of hydrocarbons
with carbon capture mechanisms, as evident in Saudi Arabia’s cornerstone of its decarbonization,
carbon reduction and recycling solutions. Hydrocarbons are low emissions when CCE (Carbon
Capture Economy) mechanisms such as decarbonization, carbon reduction, and recycling
solutions are applied (Shehabi, 2023). The CCE framework produces hydrocarbons and new
energy sources that are clean hydrogen and heavy industries that are difficult to electrify using

9
CCUS (carbon Capture, Utilization, and Storage) technology which is currently infeasible
(Shehabi, 2023).
Because hydrogen does not emit GHG when burned, clean (blue or green) hydrogen
represents substantial diversification and exporting opportunities and another pathway for Qatar,
Saudi Arabia, and the UAE to mitigate climate change with an export market potential of $400-
$700 billion. Emissions can be reduced in two ways: application of CCS/CCUS technologies.
Saudi Arabia plans to be a leading green hydrogen exporter with a mega project (NEOM) of
$500 billion (Middle East Institute, 2023). As such, the transition of these economies is a long-
term, gradual process. The process needs a holistic, transdisciplinary approach involving the
strategies to achieve sustainable, green economies.
As the World Economic Forum (2019) recognizes, more competitive economies are
better positioned to transition to low-carbon economies. They have greater innovative
capabilities to come up with breakthrough green technologies. Furthermore, knowledge-based
societies with well-equipped human capital and better-developed infrastructure are more likely to
adopt green economies. However, although political and socio-economic factors and natural
endowments are critical, successful energy transition will only be possible through supporting
government policies.
This research also shows that economic freedom is more important than competitiveness
for green energy transition readiness to succeed. From the perspective of policy, in a society
where political, economic, and social changes are driven from top to bottom, Policies are usually

10
driven through decrees from the monarchy. UAE's 2031 vision outlining the country's path as an
economic destination, prosperity, social well-being, and human capital development has been the
personal ambition and vision of Sheikh Mohammed Bin Rashid al Maktoum, the ruler of Dubai
(Shehabi, 2023). Becoming the pioneer in the Gulf region in building a competitive and
sustainable model for a green economy and a global hub plays a vital role in planning and
realizing the domestic, economic, and geopolitical partnerships it needs to develop green energy
as an alternative industry for the country.
Public Awareness and Attitudes
Public awareness and attitudes toward climate change and renewable energy are tightly
linked to sustainable energy development. In 2009, the Arab Forum for Environment and
Development (AFED, 2009) surveyed 19 Arab countries to understand the public attitudes
toward climate change issues. The AFED survey shows that 98 percent of those questioned
believed climate change, and 89 percent believed that the change is human induced. Fifty-one
percent of respondents wanted governments to address the question more effectively, and 94
percent believed their country would benefit from participating in global action to deal with
climate change. More importantly, 93 percent pledged to personally participate and take action to
reduce their contribution to the problem. The primary mechanism preferred for reducing waste
was reducing energy use. Regarding perceptions of government, less than 35 percent of people
believed that their governments are doing enough concerning climate change, with greater
disgruntlement in the Levant than in the Gulf . "The respondents to the AFED survey revealed a
clear desire for their governments to participate and cooperate proactively to solve the problem

11
of climate change; the Arab public seems ready to accept and be part of concrete national and
regional action to deal with climate change" (AFED, 2009).
Another study conducted by Ibrahim Mosly and Anas Makki in Saudi Arabia (2018) to
understand the willingness to adopt renewable energy technologies found that the main factor
that influences willingness to adopt renewable energy technologies is economic and that the most
significant sociodemographic determinant is the educational level that is critical in increasing the
level of awareness on renewable energy technologies. The study further showed that younger
people between the ages of 18-29 are more likely to be the early adopters of renewable energy
technologies, and the ones aged 30-49 are an “excellent target to change perceptions on adopting
Renewable Energy”.
Although analysis of the relationship between awareness and acceptability is rare in the
GCC countries, in his study of public awareness in Saudi Arabia, using the snowball sampling
method, Almulhim (2022) collected and analyzed online data from 310 respondents. The data
showed that 79.2 percent of the respondents were concerned about climate change and that
alternative energy might be beneficial; however, 97.2 percent stated that renewable energy would
not be adequate because of the high prices involved compared to the current energy prices.
Middle-class and low-income families could not afford the high cost of renewable energy
technology.
The study furthermore showed that climate change, renewable energy, environmental
awareness, and behavior are tightly linked to each other and the reason why only a moderate

12
number of people in Saudi Arabia were aware of the issues connected to climate change and the
solutions available to mitigate them, was because most of the respondents used the traditional
sources to obtain their information and knowledge about the environmental risks.
When asked about their country's "biggest ally," they cited Saudi Arabia (31 percent), the
UAE (28 percent), and the US (25 percent), showed that over 90 percent support the leadership
of Crown Prince Mohammed bin Salman and believe that he is taking the country on the right
path. Inside Saudi Arabia, young people are excited about the social changes - removing
conservative restrictions on gender issues, allowing women to drive and attend musical concerts
and games (Chulov, 2018), and investing in several foreign superstars, inviting them to join the
Saudi champions (Al Ittihad).
On the other hand, since reform is entirely from above, activists demanding change are
dealt with intensified societal surveillance. The success of Crown Prince’s ambitious road map to
his Vision 2030 to opportunities in new investment and growth, depends on the stability and
integration of the major partners in the region, Israel included (U.S. Dept. of State 2023).
The new world is challenging the need of the Arab youth to hang on to traditional values.
Although significant reforms are welcomed, there is a culture that favors continuity. Stability,
desire for democracy, religion, and the rise of nationalism all play an essential part. In 2022,
ASDA'A BCW Burson-Marsteller conducted interviews in 17 Arab countries and 50 cities and
had a face-to-face interview with 3400 youth aged 18-24. The study's findings show that more
than 36 percent say that the US continues to have the strongest influence over the GCC region

13
followed by Saudi Arabia (11 percent), Israel (9 percent), the United Arab Emirates (7 percent),
Iran (7 percent) and China 4 percent).
Most of them want to disengage from the US. They name the UAE the country they
would most like to live in and want their own to be like (for the 12th consecutive year), praising
the UAE for being safe, having a growing economy, and effective leadership. GCC youth are
concerned about the quality of their education (83 percent), difficulty finding a job (15 percent),
and the increased role of government in their daily life. They believe that stability is more
important than democracy (80 percent) and that having more women in the workplace will
benefit their country (90 percent) (ASDA'A BCW, 2022).
The Internet penetration in GCC countries is between 98-100 percent. The most
important social media platform used by the Arab youth are Facebook (18 percent), Instagram
(17 percent), WhatsApp (16 percent), YouTube (13 percent0, TikTok (12 percent), Snapchat (11
percent), Twitter (8 percent) and LinkedIn (4 percent). Social media, followed by TV, remains
their most important news source (ASDA'A BCW, 2022). The popularity of online social and
news platforms provides GCC countries with a great opportunity to increase social awareness
regarding climate change and the opportunities that green energy provides for a more stable
environment, alternative industries, and exciting employment opportunities for the youth of GCC
states.
My research is partly encouraged and driven by the result of these studies, providing a
rare insight into the level of awareness of the GCC societies regarding the benefits of renewable

14
energy technologies, especially that of the younger generation and their level of adopting
sustainable, green energy.

15
Chapter 1
BACKGROUND
Why Middle East is Important?
The strategic location of the Middle East was critical to the colonial powers and, until
today, continues to play a vital role in the policies of global superpowers. The Suez Canal
connects the Mediterranean Sea with the Red Sea, saving the vessels thousands of miles in their
journey between the Atlantic and the Indian Ocean, the Strait of Gibraltar waterway, called Bab
El Maghreb (the gate of the west in Arabic) that connects the Atlantic Ocean and the
Mediterranean Sea and separates Africa from Europe through Morocco and Spain have critical
economic and geopolitical significance in the region (Shaker and Childs, 2021).
Gulf of Aqaba, north of the Red Sea, with a coastline divided among Jordan, Israel,
Egypt, and Saudi Arabia, and the Arabian Gulf (Persian Gulf), the divider between Shiite Iran
and Sunni Saudi Arabia, presents another great geopolitical significance. Aqaba, a city in
Jordan, is known as the commercial hub between Asia, Africa, and the Middle East, and access
from the Arabian Gulf to international sea waterways is facilitated by the Strait of Hormuz that
connects the Arabian Gulf with the Indian Ocean and separates the countries Iran, Oman, and the
U.A.E (Shaker and Childs, 2021).

16
Geopolitically, the security of great powers has been intertwined with that of the states of
the MENA (Middle East and Africa). Both during the First and Second World Wars, struggles
between liberal and communist powers during the Cold War, and currently, between the Shiite
and Sunni political powers. The power rivalry between the U.S. and Russia has used the Middle
East as a “battleground for influence.” These power struggles, however, have facilitated eras of
discovery, development, migration, and imperialism (Shaker and Childs, 2021).
After WWI, in 1919, the American Geological Survey predicted that the U.S. oil supply
would run out in ten years, starting America’s era of oil insecurity. However, the rise of oil as a
commodity, the post-WWII age of geopolitical competition, and the current era of deregulation
and diversification have shaped the economies of the oil rich Middle Eastern countries. (Council
On Foreign Relations, 2017).
In the early 20th century, the Middle East and North Africa had 2/3rd of the world’s oil
reserves. Oil was first discovered in Iran in 1908 by Britain, in Iraq in 1927, followed by wells
discovered in Bahrain (1932), Saudi Arabia (1935), and Kuwait (1938). During WWII, in the age
of industrialization and its effect on warfare, the Allies protected oil supplies as a critical means
of their campaign. The Colonial powers controlled the oil reserve areas and the waterways that
helped the supply chain. Great Britain established an Anglo-Persian Oil company today called
BP (BP, 2022).

17
The Colonial influence dissipated by the nationalist movements in Iran, by Mohammed
Mosaddegh to nationalize AIOC (Anglo-Persian Oil Company) in 1951, and by Gamal Abdel
Nasser in Egypt to nationalize the Suez Canal in 1956. These were followed by the 1970 Libyan
nationalization projects and the 1972 Iraqi nationalization of its oil industry (IMF, World Bank,
2018).
In the decades after the end of WWII, the exploitation of the Middle East’s oil
resources and reserves and their further utilization transformed the region economically,
politically, and socially. GDP figures per capita produced by the International Monetary Fund in
2020 placed Qatar at US$50,124.39, United Arab Emirates at US$36,284.56, and Saudi Arabia
at US$22,865, all being among the world’s 15 wealthiest nations (World Bank, 2022). Although
Qatar and the U.A.E. gained their independence from Britain and nationalized most of the oil
companies in the Middle East in the 1970s, Western nations remained dependent on the Gulf
countries for their petroleum needs (IMF, World Bank, 2018).
Culture & Structural Restrictions for Climate Protection & Policies
Economic sustainability was initially linked to trade theory for resource-rich countries
dependent on the production and export of fossil fuels. It was thought to rely on exports of the
countries' endowment. However, the theory failed to provide growth in several oil-rich countries,
many of which became impoverished economies. In 2015, the UN situated "culture" as a critical
practice in its transformative development of SDGs. Conceptualizing development beyond the
limits of economic development, the UN wanted the policymakers and professionals to see how
identity, heritage, and cultural expressions can function as enablers of the SDGs.

18
Sustainability can be achieved if seen as a culture-transforming, creative development for the
entire society. Packalen (2010) considers sustainability a constant, ongoing soul-searching
process about our present and future. Water parks in the desert using groundwater, air-
conditioned floors, and excessive street lighting are common in the GCC countries. Water and
energy are highly subsidized and not priced according to economic costs. GCC countries, in
general, can meet their water demand through desalination. Groundwater has been the primary
source of irrigation, and most aquifers are severely depleted (Zaidan et al., 2019).
The culture of the GCC countries is very difficult to define but easy to see its relevance to
politics. Culture provides a critical reference for identity as a central element in social and
political life. Khaldoun talks about two observations in his social theories involving the role of
culture in political change: interaction between nomadic peoples (badawa) and those who are
sedentary (hadara), based on something cold asabiyya, cohesion. (Shaker & Childs, 2021).
As per Khaldoun, the source of political context in these communities lies in asabiyya or
"group feeling." This cohesion manifests tribalism, and because of their hostile physical
environment, to survive hardship, family units and tribes must work closely together. As a
result, developing skills as warriors is necessary for their survival. Politically, this nomadic life
emphasizes authoritarianism within the tribal framework (Shaker & Childs, 2021) where a single
authority is needed to deal with the anarchy created by the harsh environment. This
"authoritarian" power is transplanted to the kingdom that pursues and obtains absolute
monarchy.

19
According to Roberts (2023), the traditional approach to politics of the GCC countries is
rooted in tribalism and Islam, key features of sociopolitical life in the Gulf. In 1929, the
Bedouin's tribal independence and territorial autonomy ended; however, tribal identities and
religious sects remained social and cultural categories, transformed in the face of modernization,
that formed Arab governments and the Arab League. As a result, although the Bedu were
economically, legally, and politically detribalized; however, they prospered socially (Roberts,
2023).
With the discovery of oil, globalization, and a rentier economy, the fundamental,
traditional societies of the Gulf identity changed. The new era introduced rampant wealthier
states and monarchies with racially, ethnically, and religiously mixed societies. Except in Oman,
Sunni Islam is the dominant religion among the GCC nationals. All state constitutions are rooted
in Sharia law, serving as a unifying force of these states. Saudi Arabia and Qatar are the only
states that adhere to the Wahhabi school (Salafi Islam). In 1981, GCC was formalized as a group
of states with unique cultural, religious, and sociopolitical morals and history that tied them
together, founding the term Khaleeji, referring to someone from the Gulf area (Roberts, 2023).
Although moving away from fossil fuels to developing an alternative industry in
renewable energy sector is seen as a long-term and challenging path for the GCC wealthy
economies, aligning with their vision of developing diversified economies and committing to the
United Nations 2015, 2021, 2030, and 2050 targets (World Bank, 2021) can provide them with a
sustainable industry that can develop into a comparative advantage for these economies and

20
create job opportunities in the private sector and reduce unemployment for youth and create
employment opportunities for women.
Climate change laws and policies at domestic levels can be divided into the following
categories: 1) The Constitution is the supreme law defining other legislation enacted by the Al-
Shoura Council and the legislature; 2) Although the constitutions of the GCC states do not talk
about climate change; however, several MENA constitutions provide protection for the
environment to achieve sustainable development (Olawuyi, 2020).
With the Energy Sector, oil, and gas, being the largest GHG (Greenhouse Gas) emitter,
Qatar, Saudi Arabia, and the United Arab Emirates (UAE) have committed to the United Nations
SDGs (Sustainable Development Goals) through their Nationally Determined Contribution
(NDC) as part of the 2015 Paris Agreement. UAE adopted the National Climate Change Plan
2017-2050, as well as the National Adaptation Plan (NAP), and Saudi Arabia established the
Circular Carbon Economy National Program to set targets to increase the share of cleaner energy
sources and to accelerate the momentum toward climate sustainability (Gulf Cooperation
Council, 2021).
Saudi Arabia and UAE have limited potential for wind electricity generation (2.4/4.5
m/s), and Qatar has a moderate potential (5-7 m/s). On the other hand, for all three countries,
solar is the most promising source of renewable energy (Reiche, 2020).

21
Country Climate Change Visions
Qatar National Vision 2030
Qatar National Vision 2030 Agenda, adopted in July 2008, was incorporated into the
second National Development Strategy 2017-2022. Its objectives are to transform Qatar into an
advanced country capable of sustaining its development and providing a high standard of living
for its population and future generations. It addresses five challenges: 1) modernization and
preservation of traditions, 2) the needs of the current and future generations 3) uncontrolled
expansion, and 5) expatriate labor force – size and quality - and their path of development,
6) economic growth, social development, and environmental management (Qatar Office, 2008).
Qatar is committed to achieving the 2030 Agenda goals and targets, modernizing its
statistical system to provide the required indicators as adopted by the United Nations Statistical
Commission. The potential challenges facing include effective management to lead the 2030
Agenda implementation, adequate human resources needed for the agenda, availability of
statistics to produce the 230 international indicators on a timely basis, efficient communication
strategy, stakeholder involvement in implementation, and enabling legal environment (Al Nabit,
2017).
Saudi Arabia’s Green Initiative
In 2016, Saudi Vision 2030 was launched to bring Saudi Arabia closer to a low-carbon
future moving away from its reliance on oil exports and fossil fuel extraction and production.
Saudi Arabi is currently working on reducing its carbon emissions through a multidimensional

22
approach that includes energy efficiency programs, developing carbon capture technology,
increasing public transportation, and working on growing its renewable energy capacity
(Alqahtani, 2021).
Saudi Arabia’s review of the 2018 United Nations High-Level Agenda ensures Saudi
Arabia’s strong commitment to align the 2030 Agenda with the Saudi Vision 2030 focused on
building a vibrant society, a thriving economy, and an ambitious nation that shares the same
timeframe and ultimate goals with the SDGs agenda. The Forum on Sustainable Governance
Indicators (SGI) oversees Saudi Arabia’s efforts to combat climate change and works
collaboratively with government, private, and foreign government sectors (Review, 2018).
The United Arab Emirates 2030 vision
In 2017, the UAE Cabinet put SDGs at the heart of the government’s development plans at
both federal and local levels. The pillars of RAK (Ras Al Khaimah) strategic framework 2015-
2017 included building creative talents, a competitive economy, quality of life, a leading
government, and an integrated environmental and health system.
Because of the overlap between the UAE’s current national development plan (Vision
2021) and the SDGs, a comprehensive strategic plan was developed to advance both objectives,
including many governmental and non-governmental stakeholders. The pillars of Dubai Plan
2021 included a preferred place to live, work, and visit, a pivotal hub in the global economy, a
pioneering and excellent government, a city of happy, creative, and empowered people, and an

23
innovative and sustainable city. The pillars of Ajman Plan 2021 include a distinguished
government, a green economy, a vibrant community, and the best place to live.
Abu Dhabi Economic Vision 2030 is a roadmap for the UAE’s economic progress. The
vision focused on the following pillars: A large empowered private sector, a sustainable
knowledge-based economy, transparency in regulation and optimization of government
operations, highly skilled community, strong and diverse international relationships, resource
optimization, high-quality education, healthcare and infrastructure assets, comprehensive
international and domestic security while maintaining Abu Dhabi’s values, culture and heritage
with a significant and ongoing contribution to the federation of the UAE. Finally, the pillars of
the Fujairah 2040 plan (Fujairah, 2040) involved preserving natural resources, celebrating
culture and heritage, building a community of skilled and active citizens, and creating a
sustainable economy and environment.
GCC Countries & OPEC
The economy of the Middle East is very diverse, with nations ranging from hydrocarbon-
exporting rentiers to centralized and free-market economies. Energy consumption and
production are the leading producers of greenhouse gas emissions. By the mid-20th Century, the
definition of the Middle East encompassed Turkey, Cyprus, Syria, Lebanon, Iraq, Iran, Israel,
Palestine, Jordan, Egypt, Sudan, Libya, and some territories of Arabia; Saudi Arabia, Kuwait,
Yemen, Oman, Bahrain, Qatar, and United Arab Emirates (Encyclopedia Britannica, 2022). As
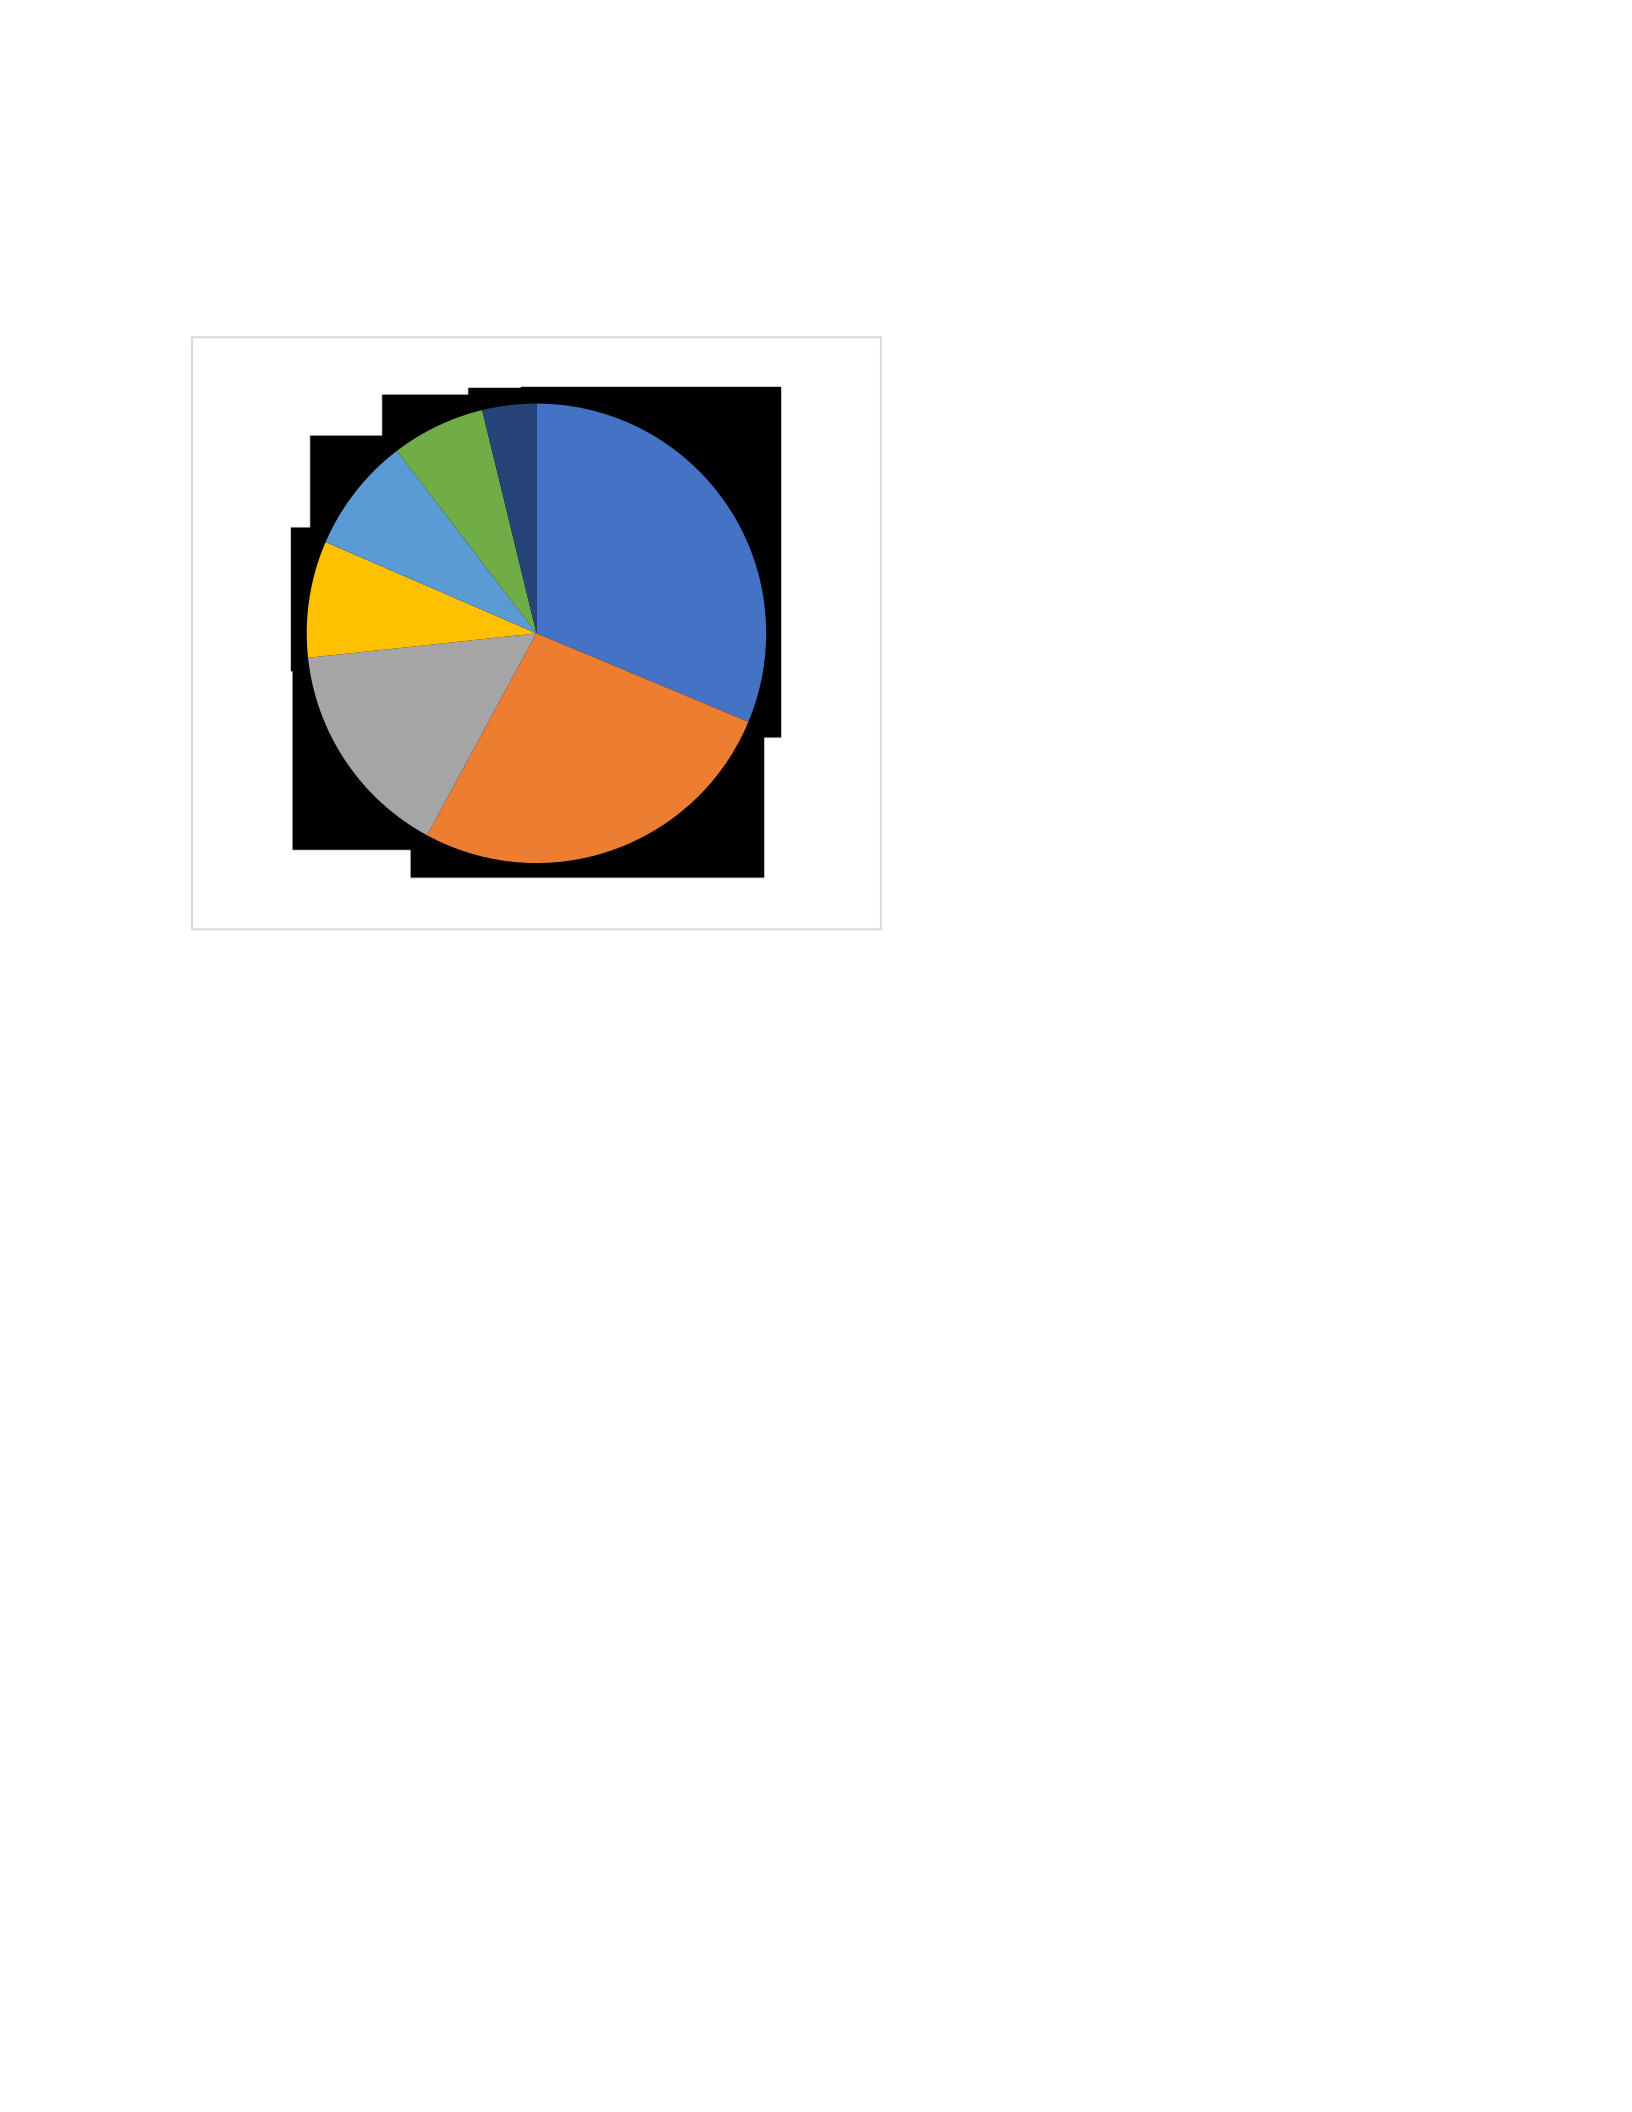
per the World Economic Forum (2022), 81 percent of the global energy mix is based on fossil
fuels, of which 31.3 percent is produced in the Middle East, followed by North American
production of 26.6 percent (BP, 2022).
24
Figure #1 Distribution of Oil Production Worldwide in 2021, By Region (BP Statistical Review, 2022)
The top 10 countries in 2020 that produced the most natural gas included: 1) Qatar, in
fifth place, with 171.3 billion m3 and a
reserve of 24.70 trillion m3 2) Saudi
Arabia, in the eighth place with 112.1
billion m3, and has a reserve of 6 trillion
m3 3) United Arab Emirates, in the ninth
place with 55.40 billion m3, and a
reserve of 5.9 trillion m3 (3.2 percent of
global reserves) (World Energy 2021).
In 1981, the GCC (Gulf Cooperation Council) countries established a political and
economic alliance to coordinate military and economic policies among the member states
(Baabood, 2023). They formed a free trade area consisting of Saudi Arabia, Kuwait, UAE,
Oman, Qatar, and Bahrain. Although these countries are different in size and population, they
are absolute or constitutional monarchies. They are rich in oil reserves, and their GDP depends
on their production and export of oil and oil-related products to global markets at competitive
prices (Duenwald, et al., 2022).
The union possesses at least 30 percent of the world's proven oil reserves and consists of
Bahrain, Kuwait, Oman, Qatar, Saudi Arabia, and the United Arab Emirates. The total export
from all GCC countries was 13.3 million barrels per day, and Saudi Arabia was the leading oil
exporting country in the region, with a projected volume of 7.2 million barrels per day (Mirzeov,
Middle
East
31%
North
America
27%
CIS
15%
Asia
Pacific
8%
Africa
8%
South and
Central
America
7%
Europe
4%

25
2020). Article 4 of the Union states that the alliance was formed to strengthen relations among
its members and promote cooperation among the countries' citizens. GCC became a Customs
Union in 2003. It promotes the economic development of member countries by eliminating visa and
customs commission, common external tariff of 5 percent for imported products from outside the Union
countries, alignment of customs and banking regulations, and elimination of non-tariff barriers for intra-
GCC movement of goods. GCC agreements typically focus on either security, a defense planning council
(Peninsula Shield Force), or economic coordination (Britannica, 2020).
The status of economic integration of these countries within the Middle East and N. Africa
(MENA) region and globally is the most advanced example of sub-regional integration. Recently, GCC
has evolved beyond free trade agreements to cross-national capital and labor movements. Following the
ratification of the Unified Economic agreement in 2003, the members signed the customs union
agreement, and in 2008, the Adoption of a Common Market. By doing so, the GCC countries have
eliminated unified external tariffs and other trade restrictions, resulting in additional trade in goods and
services among the members (Economic Integration, 2010).
For the past two generations, GCC countries have enjoyed the wealth and opportunities generated
from the production and export of oil and the security of a welfare state. The core GCC states, Saudi
Arabia, the United Arab Emirates, Kuwait, and Qatar, are called the rentier states, where most of the
country's revenue is generated from fossil fuels instead of taxation, distorting the labor markets - the
participation of the native workforce is very low, and the majority of the labor force consists of
expatriates. This raises an important question as to how sustainable these economies are. The population
of the GCC countries continue to grow; oil reserves are depleting, oil prices keep fluctuating, there is a
strong world collaboration driving the global climate agenda, and disruptive technologies and production

26
of oil in the West through Fracking drilling technology seem to lessen the demand for GCC countries' oil
(POMEPS, 2019).
Frustrated by oil price cuts by Western oil companies and the import caps of the US, which
depressed prices, in 1960, at the Baghdad Conference, OPEC, the Organization of the Petroleum
Exporting Countries, was created. OPEC's mission is to ensure price stability for exporting countries and
investors in the oil markets and a secure supply of petroleum to importing countries . Initially, the
organization's members included Iran, Iraq, Kuwait, Saudi Arabia, and Venezuela. However, currently, it
has 13 members: Algeria, Angola, Equatorial Guinea, Gabon, Iran, Iraq, Kuwait, Libya, Nigeria, the
Republic of the Congo, Saudi Arabia, the United Arab Emirates, and Venezuela. (OPEC, 2021). In 2017,
the UAE, S. Arabia, Bahrain, and other OPEC members boycotted Qatar, resulting in Qatar leaving
OPEC for good in 2018 (Gulf Business, 2018).
The OPEC crude oil price is defined by the price of the OPEC basket, which is an average of the
petroleum blend prices produced by the members (Chen, 2022). The organization's share of the world's
oil reserves in 2018 was 79.4 percent (OPEC, 2022). OPEC prices peaked in 2008 and between 2011-
2014; however, they fell sharply during the global financial crisis and in 2014. Because of supply
instability, the West (Mainly the United States) decreased its oil imports. Investors capitalized on lower
interest rates to develop new technologies such as Fracking (Hydraulic Fracturing). In 2019, before the
impact of the pandemic on oil demand, the imports from North America were reduced to below 2.5
million barrels (26 percent lower than a decade ago) (OPEC, 2021).

27
In addition to OPEC, based in Dhahran, Saudi Aramco Company, also called Saudi
Arabian Oil Company, in general, a key player in global markets and the Saudi Oil industry, was
founded by the Standard Oil Company of California (Chevron) in 1933. In May 2020, the
company became the world's largest by market cap, surpassing Apple Inc. Aramco operates the
largest single hydrocarbon network and has been the most significant contributor to global
carbon emissions since 1965 (Wikipedia, 2022). Although Aramco supports the aims of the
Paris Agreement to limit the global average temperature increase to well below 20C, the
company's profits in 2021 were more than double the previous year (Aramcolife, 2022).
GDP figures per capita produced by IMF place Qatar at US$50,124.39 per capita, United
Arab Emirates at US$36,284.56 per capita, and Saudi Arabia at US$22,865.00 per capita,
countries that are among the world's 15 wealthiest nations (World Bank, 2022). However,
despite OPEC's efforts in managing oil production and pricing for decades, these countries have
experienced severe economic and social instabilities.
Macro-Economic Instabilities
Long-term Oil Demand
Ahmed Zaki Yamani, the former Oil Minister of Saudi Arabia, once said: “The Stone Age
did not end for lack of stone, and the Oil Age will end long before the world runs out of
oil.” (The Economist, 2003). The negative impact of climate change, rising sea levels, coastal
erosion, and changing storm patterns; lack of sustainability, reduction in monarchies’
hydrocarbon revenues and macroeconomic instabilities; oil price volatility, decrease in GDP and
GDP/capital, Current Account Balance, and increase in unemployment (especially among the
28
youth); macroeconomic instabilities, the threat of the U.S. Shale oil production and decrease in
global oil demand; shifting geopolitics with the U.S., Europe, China, Iran, and Israel, and the
threat of Social instability similar to the Arab Spring (The Economist, 2008).
The following environmental, economic, social, and geopolitical challenges expose the
GCC countries’ long-term economic instability. In a world where rentier states like, Qatar,
Saudi Arabia and United Arab Emirates generate their revenues from their national endowment,
fossil fuels instead of taxation.
Despite OPEC’s efforts in managing the production and the pricing of oil, its oil prices
are affected by member countries’ unwillingness to maintain production targets, unexpected
outages, the amount and the speed of disruption, and the uncertainty of restoring output. OPEC
basket crude oil prices fluctuated during 2020 and 2021 from US$65.1 per barrel to US$17.66
and US$74.38 in December 2021 (OPEC, 2021).
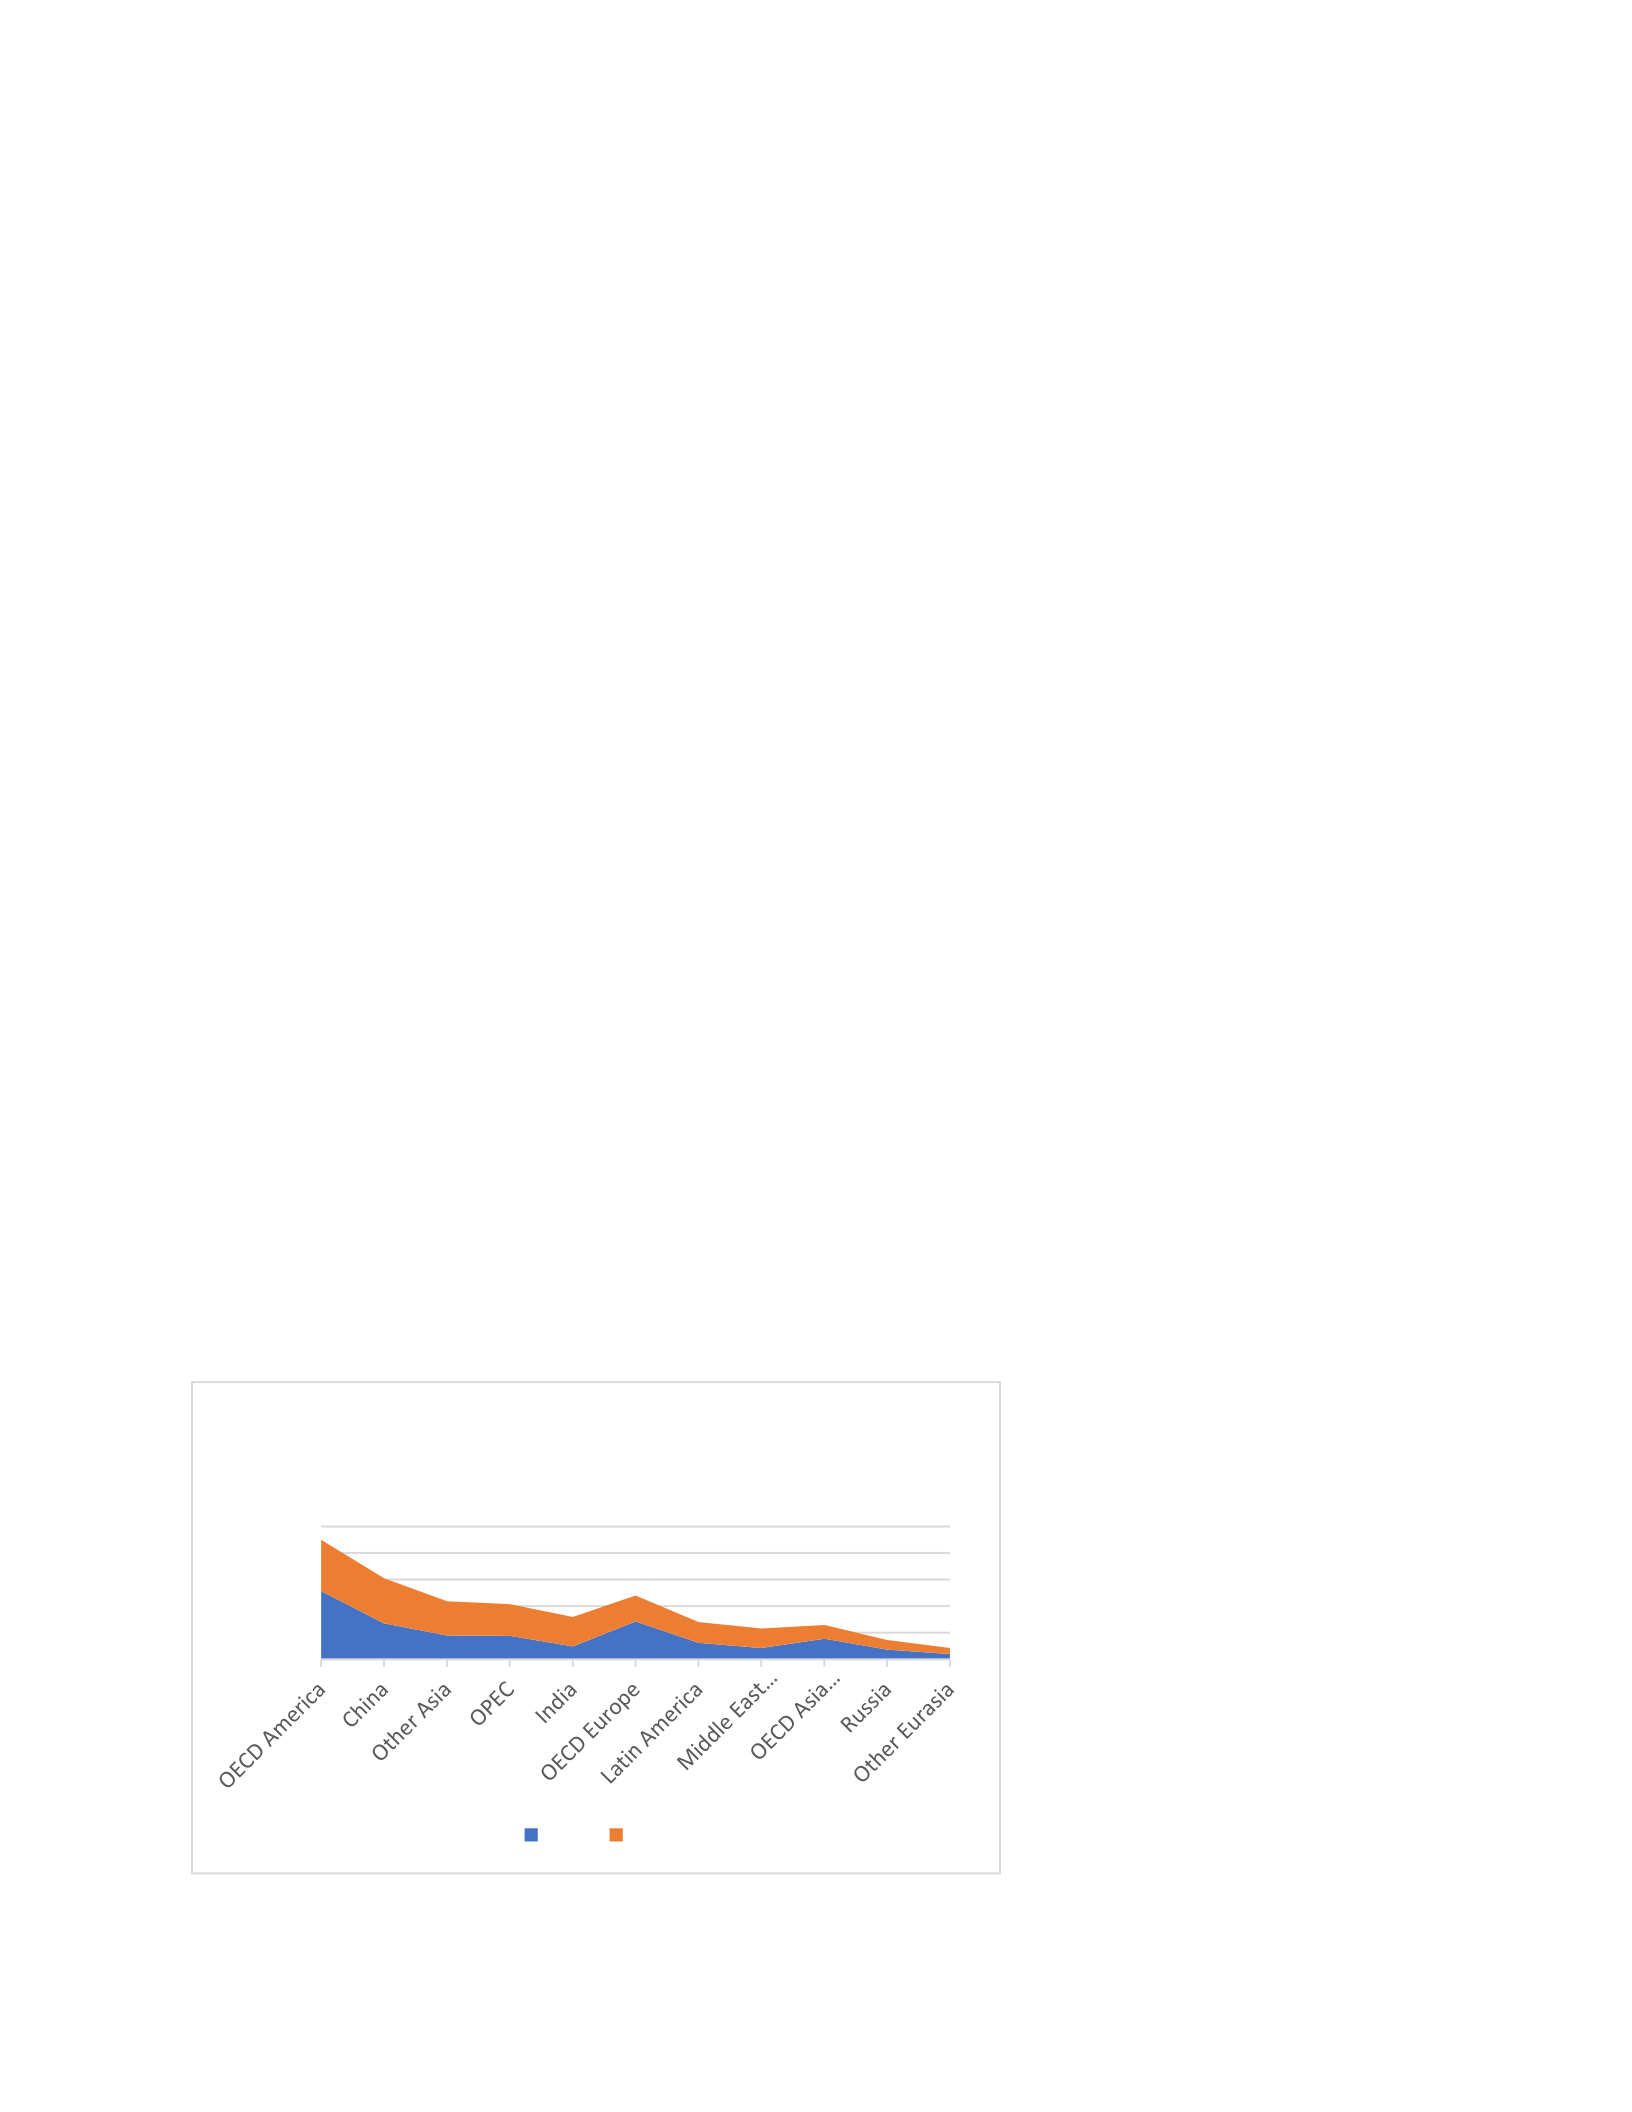
Figure #2-OPEC World Oil Demand Outlook 2045, (BP, 2021)
Figure #2 shows a decrease
of 6.4 million barrels a day for
OECD America, 4.6 million
barrels a day for OECD Europe,
and 2.7 million barrels a day for
OECD Asia Oceania compared
to 2019 levels; however, the
0.00
10.00
20.00
30.00
40.00
50.00
Global Long-term Oil Demand Outlook By
Region 2019-2045
2019 2045
29
chart also shows a total increase of 8 percent in 2045 forecast, resulting from an anticipated
increase in demand of China, Asia, OPEC, India, Latin America, Middle East and Africa.
Oil Price & Revenue Instability
The 2014-2016 70 percent reduction in oil prices was driven by the growing efficient
supply of U.S. shale oil at a marginal cost, in addition to a sharp decline in the economies of oil-
exporting countries and a decrease in growth in the economies of importing ones (World Bank,
2018).
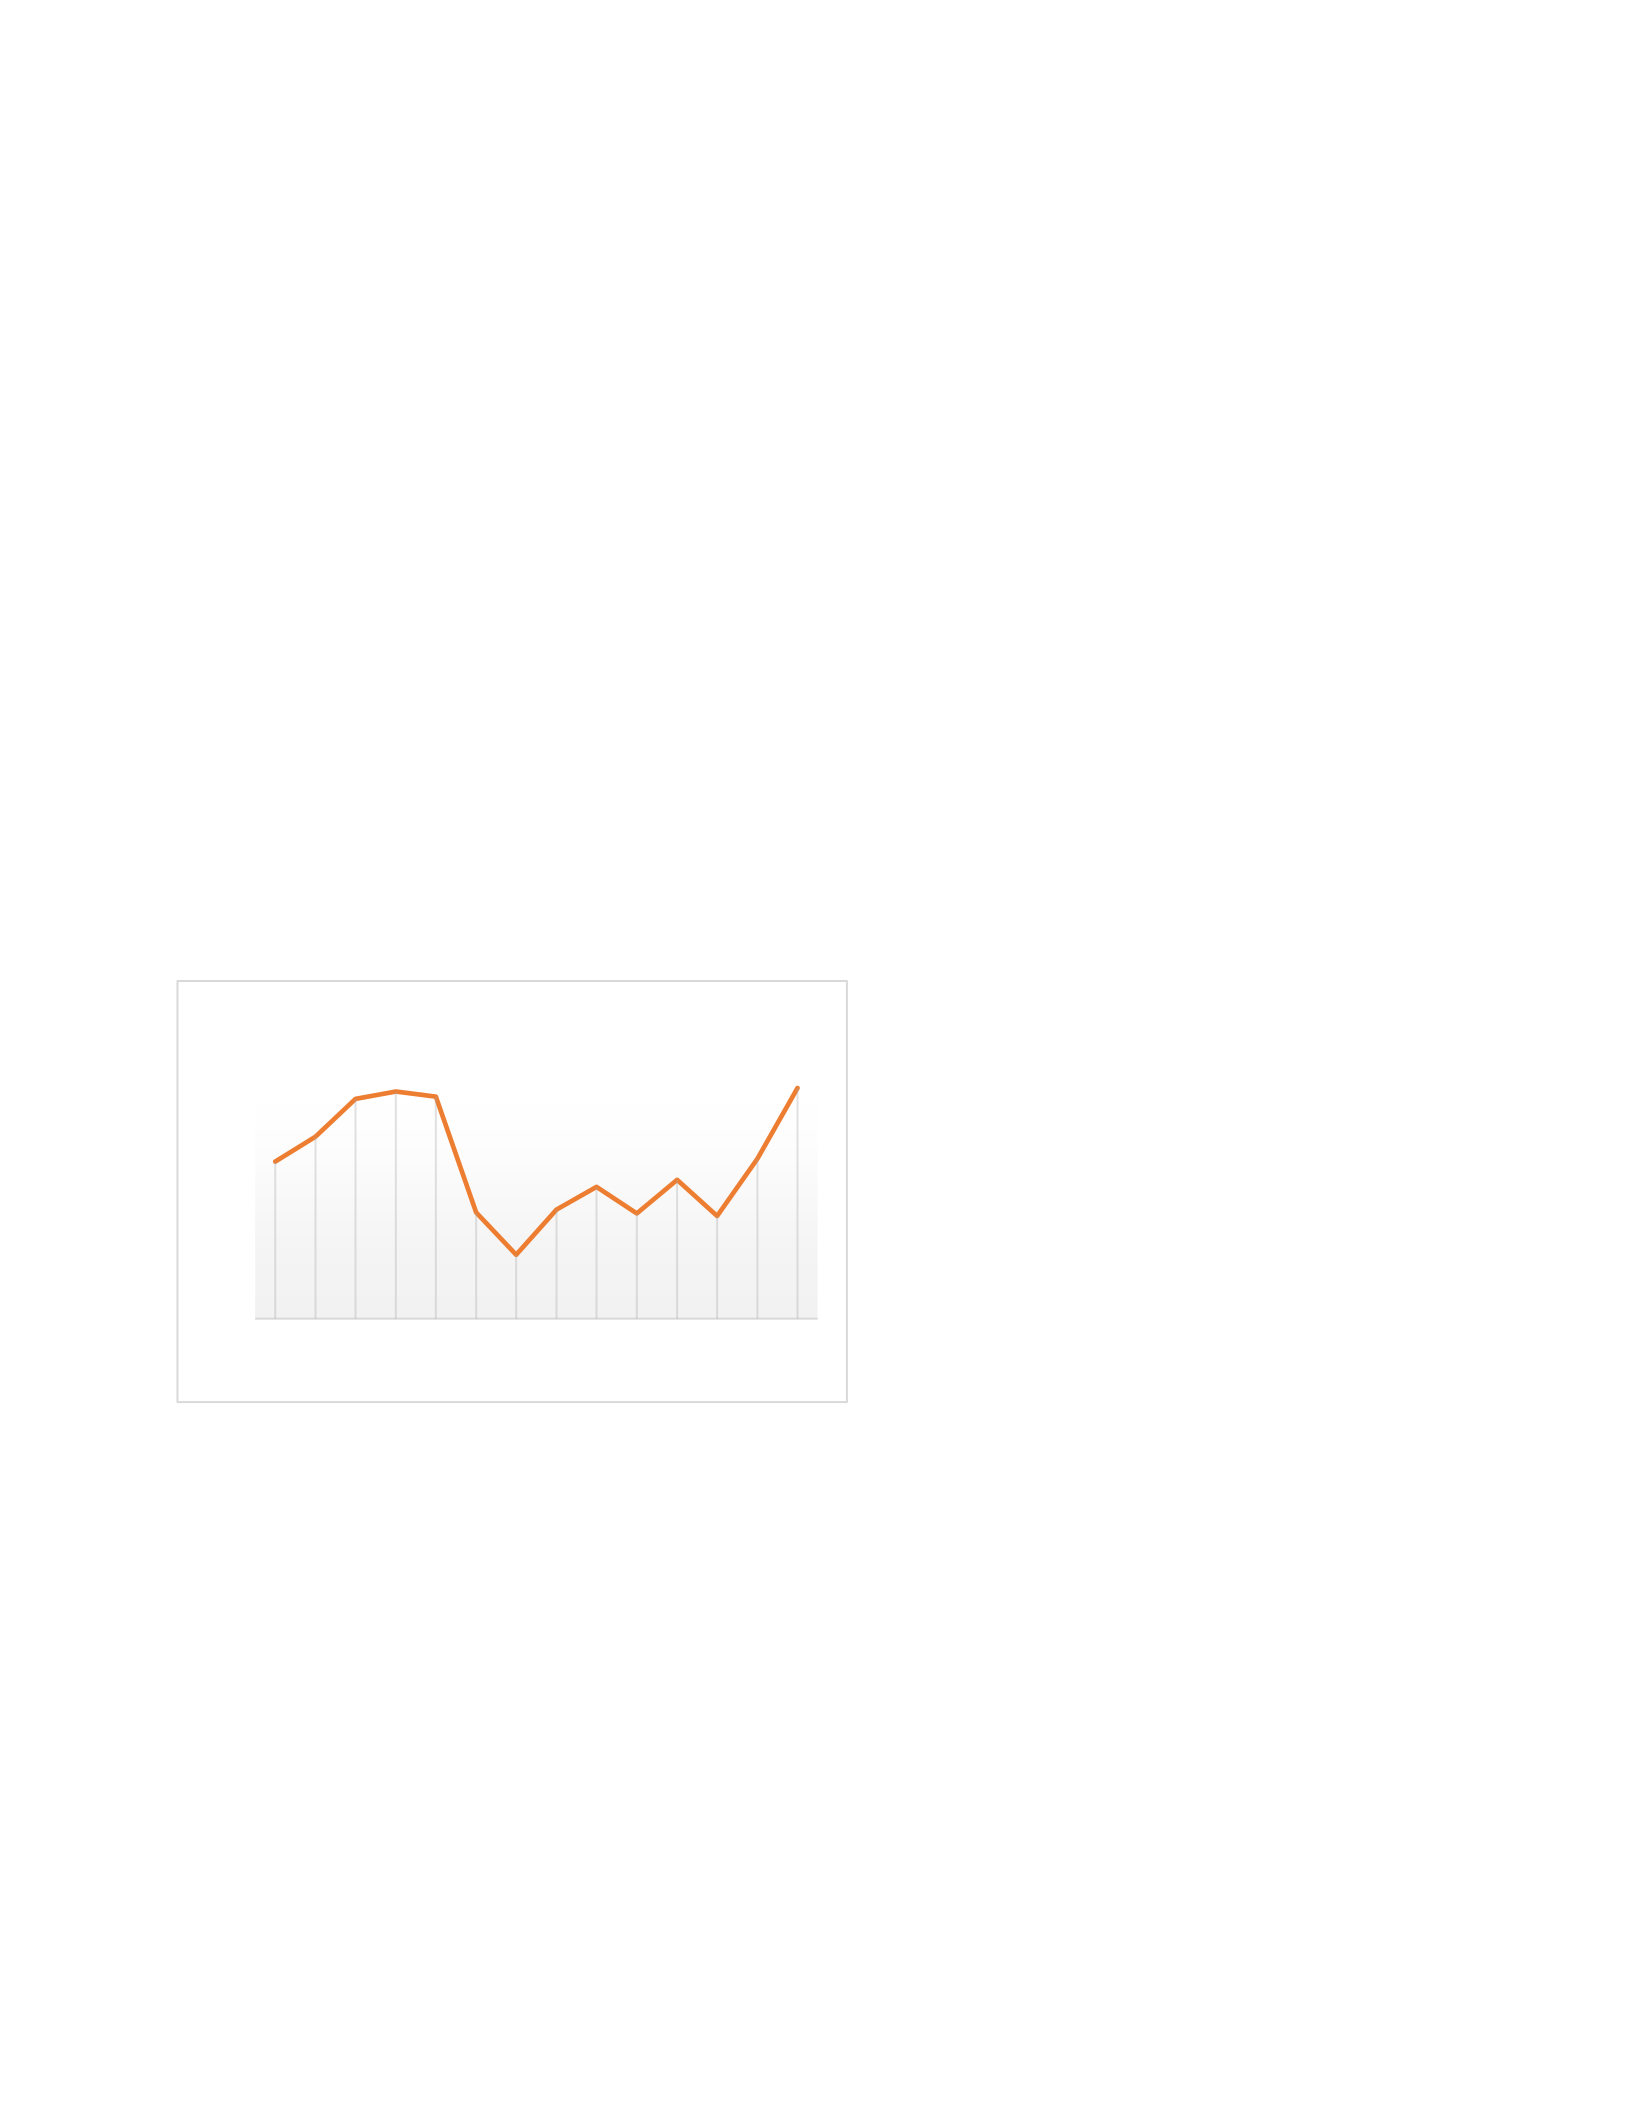
Figure #3-OPEC Basket Price Fluctuations 2009-2022 (OPEC, 2022)
Despite OPEC’s efforts to normalize
supply and manipulate the international
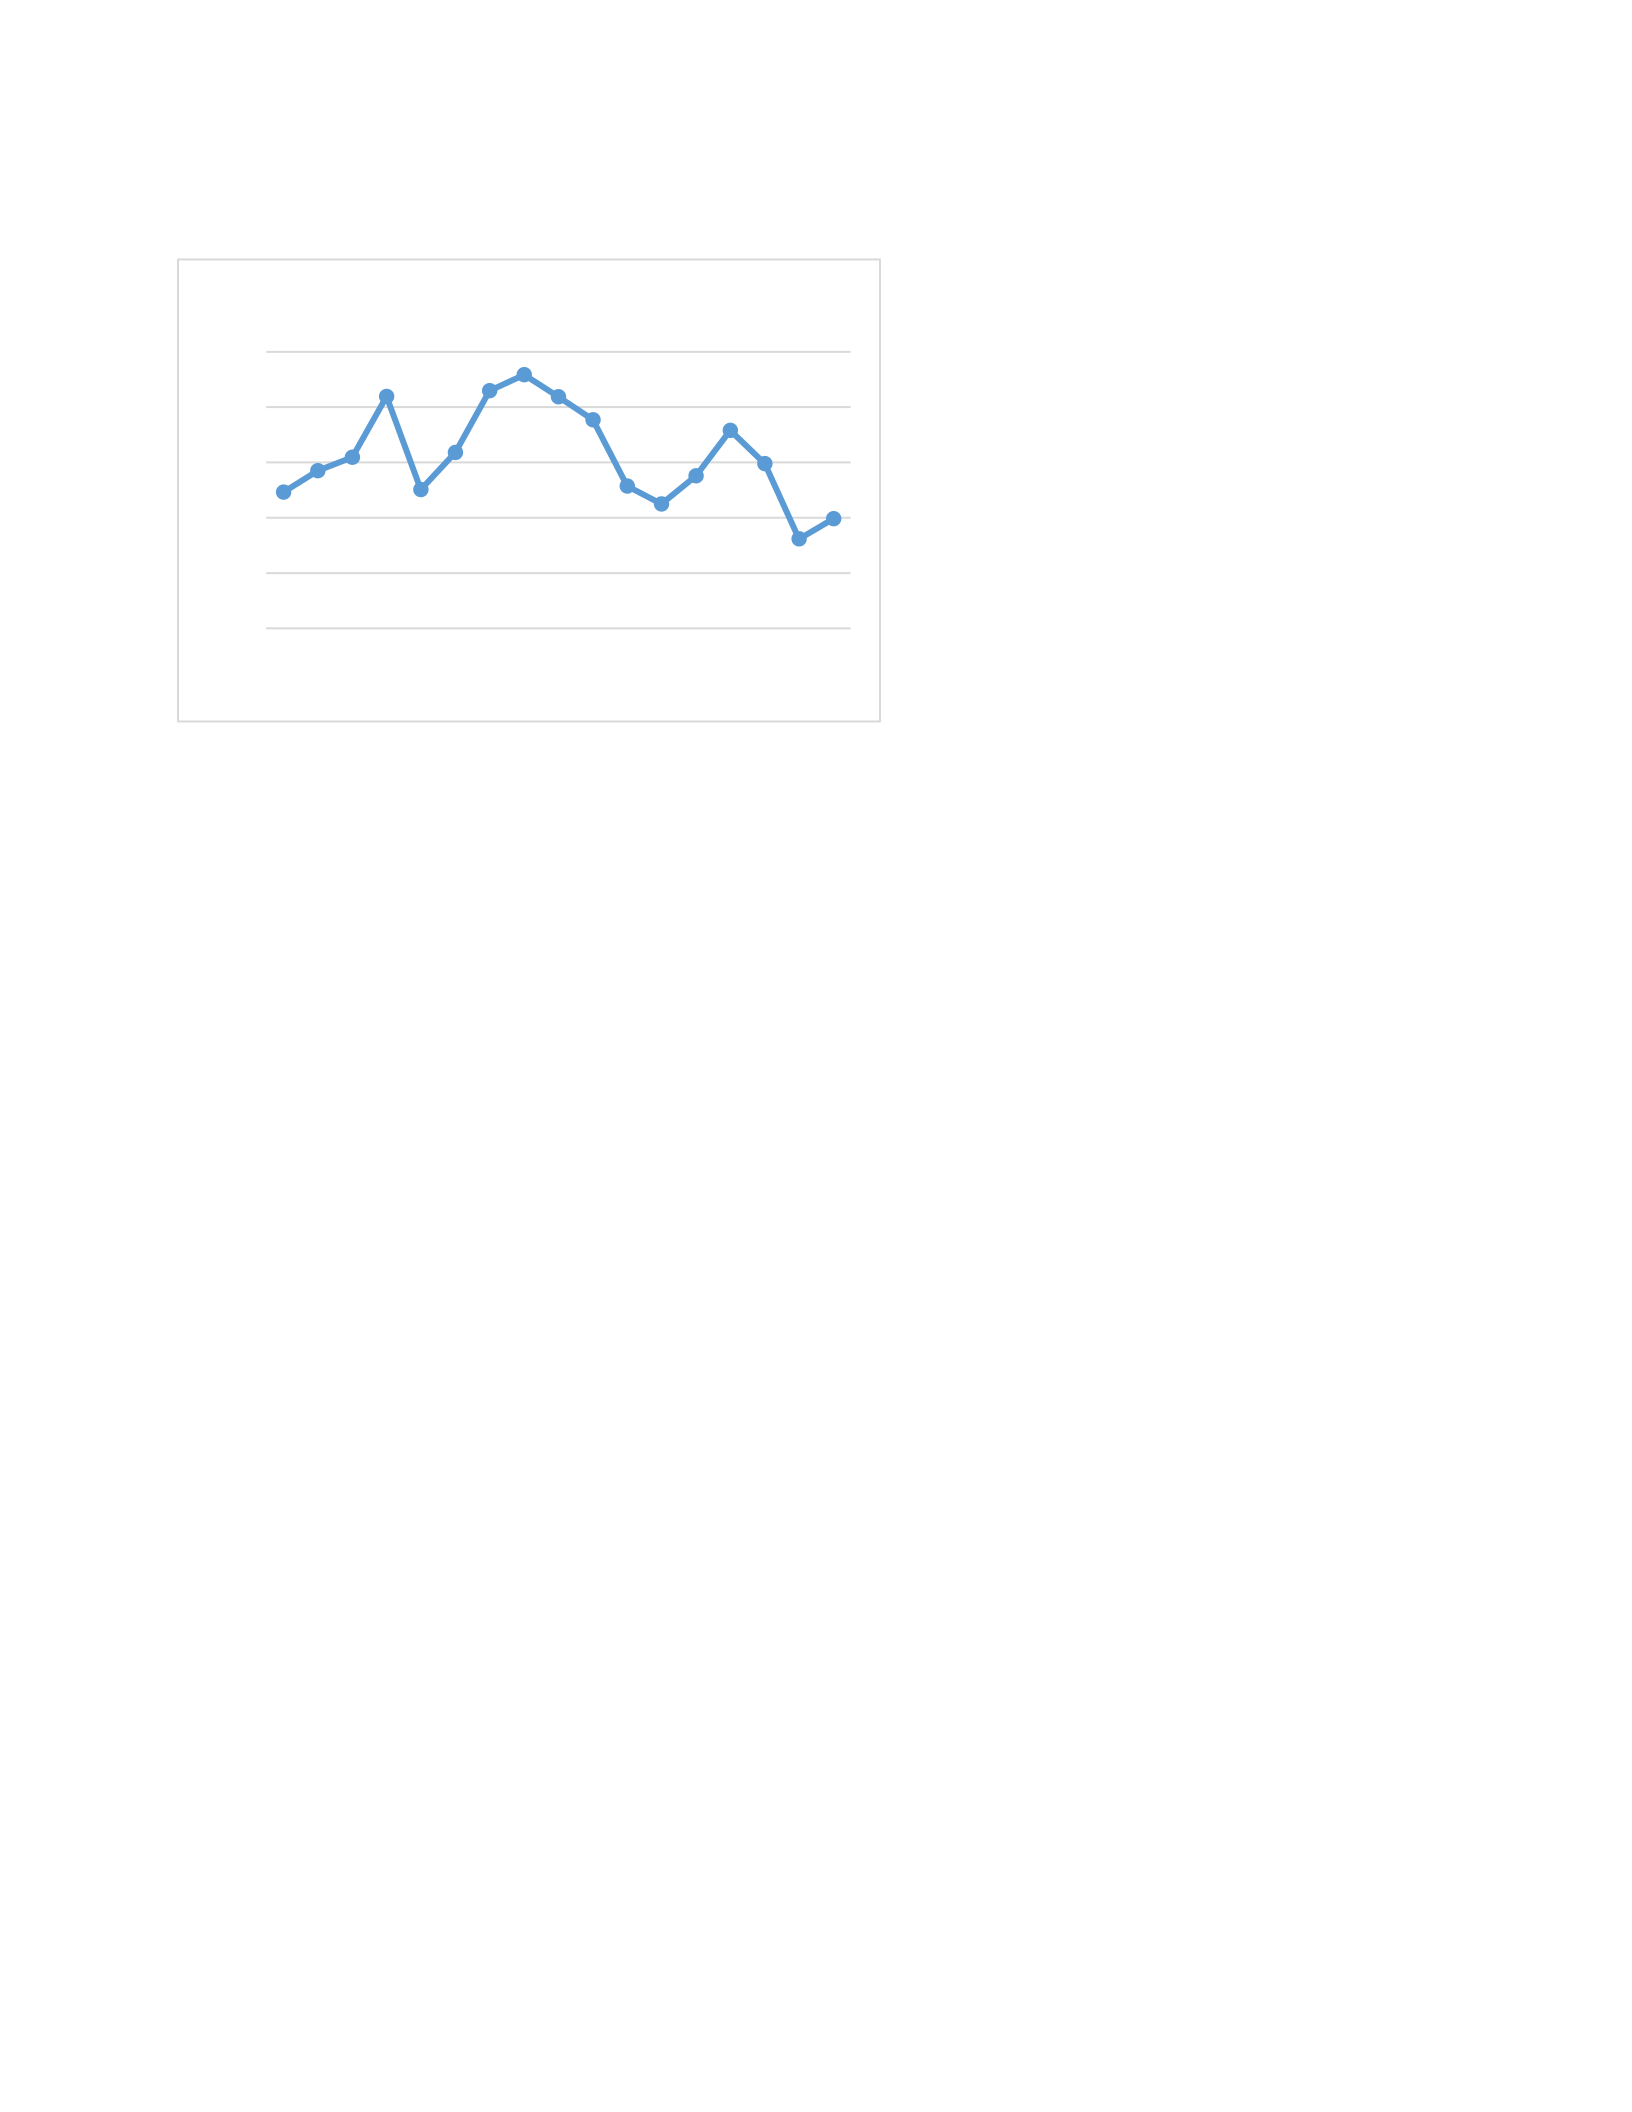
prices, oil prices keep fluctuating: Figures
#2 and #3 are based on OPEC net oil export
revenues from 2009-2019 with a forecast of
2020 and 2021 showing a sharp drop in oil
prices from 2014-2016 as well as between the years 2019 and 2021.
76.77
88.99
107.52
111.11
108.57
52
31.27
53.3
64.47
51.55
67.96
50.24
78.33
112.84
0
20
40
60
80
100
120
2009
2010
2011
2012
2013
2014
2015
2016
2017
2018
2019
2020
2021
2022
OPEC BASKET PRICES
30
Figure #4 - OPEC Net Oil Revenue in US$ billion. 2009-2022 (OPEC, 2022)
Non-diversification of the GCC
economies results in economic
vulnerability because of their reliance on
the global market. The oil price
reduction that started in 2014 shook the
economies of these countries. The
region lost 20 percent of its combined
GDP (US$340b) in 2015, resulting in budget deficits, decreased economic growth, and recession
in the Real-estate, Hospitality, and Construction sectors (Ernst & Young, 2016).
A strong world collaboration is driving the global climate agenda, and disruptive
technologies in the West are increasing oil production through fracking, reducing the demand for
GCC production. The heavy dependence of these countries on fossil fuel production and exports
creates economic instability. In the coming decades, 60 percent of the population in GCC
countries will be under the age of 30, which will put a strain on the current political structures,
with three of the six GCC nations requiring the price of oil to be at least US$100/b to enable
budget balance (IMF, 2015).
COVID-19 pandemic exposed the vulnerabilities of the GCC countries and their
economies and stressed the need for diversification and sustainability. On the other hand, the
war between Ukraine and Russia has shown that the revenue increase that the oil-producing and
492570619
839
502
636
859917837754
515450551
716
595
323397
0
200
400
600
800
1000
2005
2006
2007
2008
2009
2010
2011
2012
2013
2014
2015
2016
2017
2018
2019
2020*
2021*
OPEC net oil revenue (Billion US$)

31
exporting countries enjoyed because of the increase in the price of oil was short-lived (IMF,
2022) The high prices resulting from the shortage of supply and delivery of oil incentivized
countries outside OPEC to increase their production. By the beginning of 2023, the oil prices
remained at around $70/b Sustained production of Shale from the U.S., Canada, and Argentina
continued the market supply. An OPEC country, Venezuela increased its production and supply
in partnership with Chevron. Despite several threats, OPEC countries did not reduce their
production level, and countries under U.S. sanctions, like Iran, provided 1/5th of the global
demand at a set discount (Bordoff, 2023).
Volatile oil prices, reliance on subsidies, the problem of labor importation, high youth
unemployment, lack of investment in the private sector, and population growth are signs of
instability in the GCC countries. A study of the economic indicators for Qatar, Saudi Arabia, and
United Arab Emirates for the period between 2009-2020 (World Bank, 2022), and focusing on
the variables of instability, we observe sharp fluctuations in the values of the macroeconomic
indicators:
Qatar: 1) The GDP growth shows a decrease from 2018 (1.23 percent) to a growth of
.69 percent and -3.5 percent in 2019 and 2020, respectively. 2) GDP per capita growth indicates
a decrease from US$65,.900 .00 thousand in 2018 to US$62,000.00 and US$50,000 in 2019 and
2020 respectively. 3) The Current Account Balance shows a decrease from US$16.65 billion in
2018 to US$4.5 billion and US$ 3.6 billion in 2019 and 2020, respectively. 4) Foreign Direct
Investment (inflows) shows a decrease from US$1.070 in 2015 to minus US$2.16, US$2.81, and
US$2.43 billion in 2016, 2017 and 2018 respectively. 5) consumer price inflation percent shows
32
a decrease from 2.68 percent in 2016 to minus .67 percent and 2.54 percent in 2019 and 2020. 6)
Unemployment shows to be very low., 11 percent, .10 percent, and .14 percent in 2018.2019 and
2020, respectively (World Bank, 2022).
Table #1 Qatar Indicators of Instability
Saudi Arabia: 1) The GDP growth shows a decrease from 2018 (2.3 percent) to a
growth of .33 percent and minus 4.11 percent in 2019 and 2020 respectively 2) GDP per capita
growth indicates a decrease from .61 percent growth in 2018 to minus 1.33 percent and 5.61
percent in 2019 and 2020 respectively. 3) Current Account Balance numbers are not available in
World Bank data 4) Foreign Direct Investment (inflows) shows a decrease from US$7.4 in 2016
to US$1.4billion in 2017 and then an increase to US$4.24, US$4.56 and US$ 5.4 billion 2018,
2019 and 2020 respectively 5) consumer price inflation percent shows an increase from minus
.84 percent in 2017 to positive 2.46 percent in 2018, a decrease to minus 2.09 percent in 2019
and an increase to 3.45 percent by 2020 6) Unemployment shows to stay at around 6 percent
throughout and increases to 7.66 percent in 2020 (World Bank, 2022).
Country 2009 2010 2011 2012 2013 2014 2015 2016 1017 2018 2019 2020
QATAR
GDP Growth % 11.96 19.59 13.38 4.73 5.56 5.33 4.75 3.06 -1.50 1.23 0.69 -3.56
GDP/Capita % -2.81 6.62 3.38 -2.91 -0.79 0.08 0.40 -0.38 -4.04 -0.84 -1.10 -5.20
Curent Account NA NA 52.1 62.0 60.4 49.4 13.7 -8.2 6.4 16.7 4.2 -3.6
(BoP, current US$ Billions)
Curent Account NA NA 31.07 33.18 30.42 23.96 8.50 -5.45 3.99 9.08 2.42 -2.50
(% of GDP)
FDI/net Inflows 8.12$ 4.67$ 0.938$ 0.395$ (0.840)$ 1.040$ 1.070$ 0.773$ 0.985$ (2.186)$ (2.812)$ (2.434)$
(Current Billion US$)
Inflation/Cons. Price % -4.86 -2.43 1.14 2.32 3.22 3.35 1.81 2.68 0.39 0.26 -0.67 -2.54
Unemployment Total % 0.31 0.45 0.56 0.48 0.28 0.20 0.17 0.15 0.14 0.11 0.10 0.14
of total labor force
Unemployment Youth Total 1.20 NA 1.32 1.63 1.20 0.81 0.60 0.49 0.53 0.41 NA 0.46
% of total labor force ages 15-24
33
Table #2 S. Arabia Indicators of Instability
United Arab Emirates: 1) The GDP growth shows a decrease from 5.05 percent in
2015 to 1.19 percent 2018, 3.41 percent in 2019 and minus 6.13 percent in 2020. 2) GDP per
capita growth indicates a decrease from 1.91 percent in 2016, to 1.01 percent, minus .32 percent,
positive 1.93 percent to minus 7.27 percent in 2017, 2018, 2019 and 2020 respectively. 3)
Current Account Balance shows a decrease from US$17.55 in 2015 to US$13.20 billion in 2016,
to an increase to US$27.50 and US$41.24 billion in 2017 and 2018 respectively and a decrease
of US$37.32 and US$21.10 billion in 2019 and 2020 respectively. 4) Foreign Direct Investment
(inflows) shows an increase from US$9.60 in 2016 to US$10.35, US$10.38, US$17.87 and
US$19.88 in 2017, 2018, 2019 and 2020 respectively 5) consumer price inflation percent shows
a decrease from 4.07 percent in 2015 to 1.62 percent, 1.97 percent, 3.07 percent, minus 1.93
and minus 2.08 percent in 2016, 2017, 2018, 2019 and 2020 respectively 6) Unemployment
shows an increase from 5.30 percent in 2016 to 7.85 percent in 2017, a decrease of 7.51 percent,
7.16 percent in 2018 and 2019 and an increase to 9.01 percent in 2020 (World Bank, 2022).
SAUID ARABIA 2009 2010 2011 2012 2013 2014 2015 2016 1017 2018 2019 2020
GDP Growth % -2.06 5.04 10.00 5.41 2.70 3.65 4.11 1.67 -0.74 2.43 0.33 -4.11
GDP/Capita % -4.79 2.01 6.70 2.20 -0.37 0.75 1.48 -0.60 -2.71 0.61 -1.33 -5.61
Curent Account NA NA NA NA NA NA NA NA NA NA NA NA
(BoP, current US$ Billions)
Curent Account 4.88 12.64 23.62 22.39 18.14 9.75 -8.67 -3.70 1.52 9.15 4.82 -3.08
(% of GDP)
FDI/net Inflows 2.2 3.9 3.4 4.4 4.9 5.4 5.4 8.9 7.3 19.2 13.5 4.9
(Current Billion US$)
Inflation/Cons. Price % 5.06 5.34 5.83 2.87 3.53 2.24 1.21 2.07 -0.84 2.46 -2.09 3.45
Unemployment Total % 5.38 5.55 5.77 5.52 5.57 5.72 5.59 5.65 5.89 6.03 5.64 7.66
of total labor force
Unemployment Youth Total 29.43 29.11 29.08 28.40 29.63 30.93 29.80 25.07 28.04 28.81 22.97 28.17
% of total labor force ages 15-24
34
Table #3 United Arab Emirates Indicators of Instability
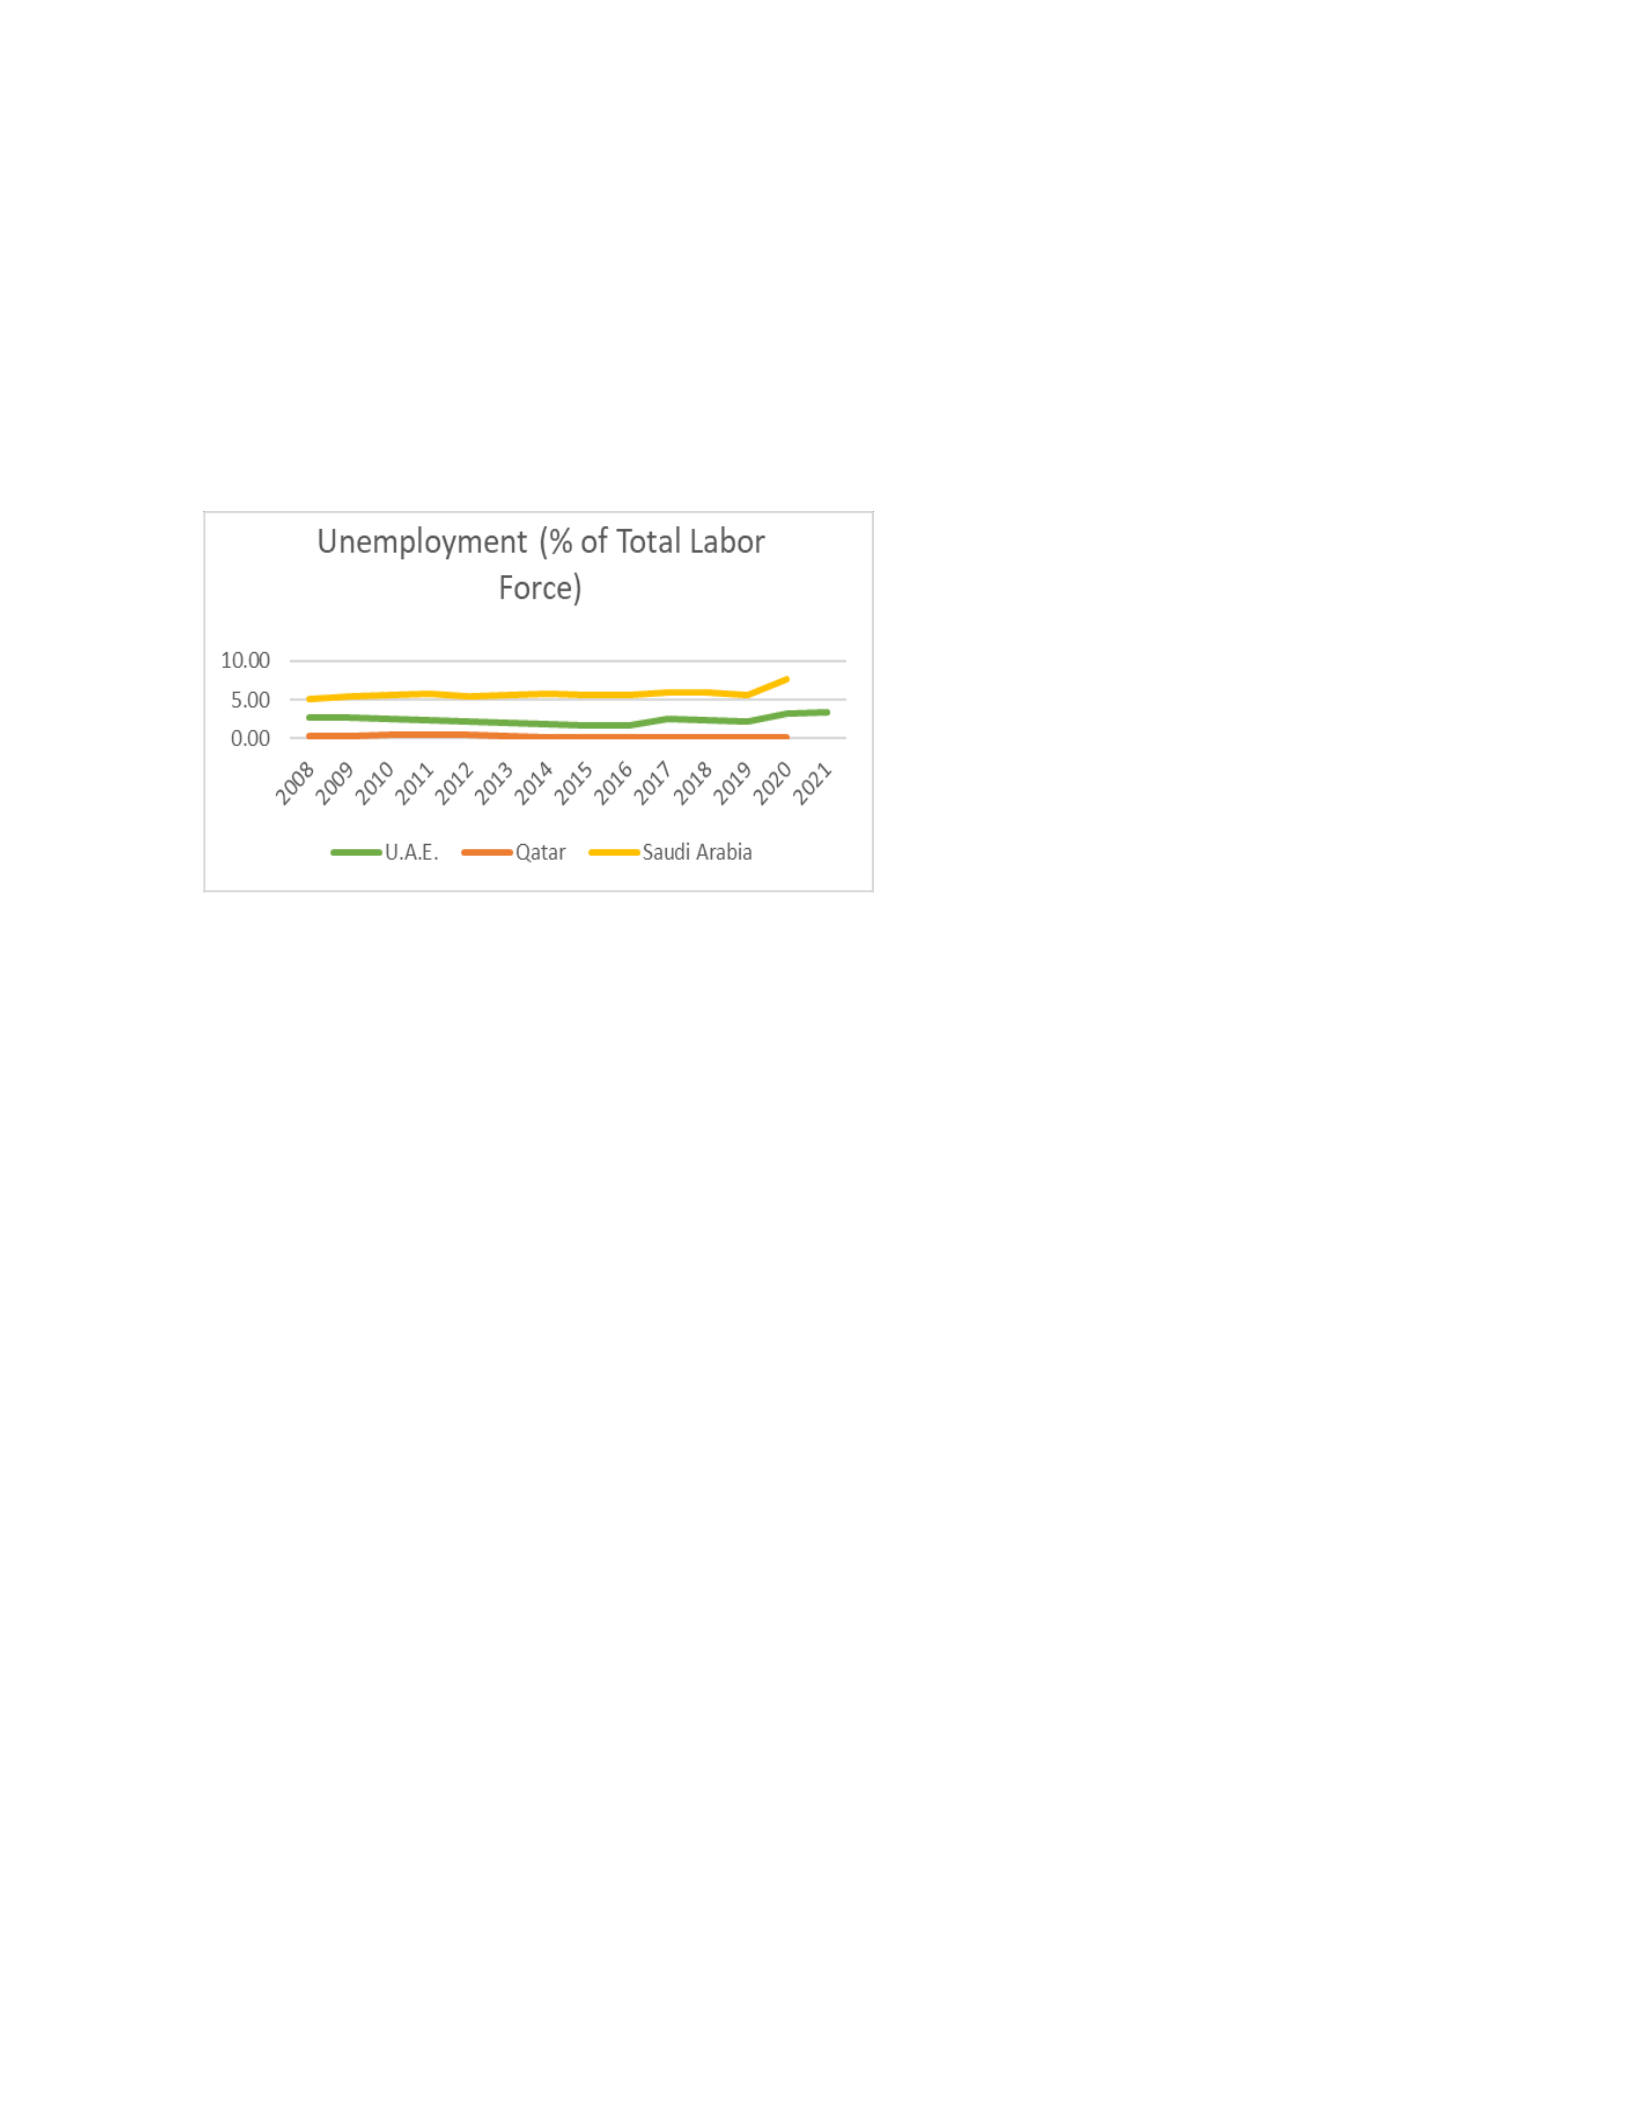
The following Figures #5, #6 & #7 Show a reduction in GDP/PC, GDP/PC percent growth, and percent
Oil Rent of GDP for all three countries between 2009-2020 (World Bank, 2020)
Figure #5 Figure #6
United Arab Emirates 2009 2010 2011 2012 2013 2014 2015 2016 1017 2018 2019 2020
GDP Growth % -5.24 1.60 6.93 4.48 5.05 4.41 5.06 2.98 2.37 1.19 3.41 -6.13
GDP/Capita % -15.15 -5.91 2.19 2.26 4.41 4.23 4.51 1.91 1.01 -0.32 1.93 -7.27
Curent Account 7.84$ 12.19$ 43.51$ 73.10$ 73.21$ 54.49$ 17.55$ 13.20$ 27.50$ 41.24$ 37.32$ 21.10$
(BoP, current US$ Billions)
Curent Account NA NA NA NA NA NA NA NA NA NA NA NA
(% of GDP)
FDI/net Inflows 1.13$ 8.79$ 7$ 9.56$ 9.76$ 11.07$ 8.55$ 9.60$ 10.35$ 10.38$ 17.87$ 19.88$
(Current Billion US$)
Inflation/Cons. Price % 1.56 0.88 0.88 0.66 1.10 2.35 4.07 1.62 1.97 3.07 -1.93 -2.08
Unemployment Total % 2.68 2.48 2.30 2.18 2.04 1.91 1.77 1.64 2.46 2.35 2.23 3.19
of total labor force
Unemployment Youth Total 7.19 7.02 6.68 6.42 6.16 5.93 5.70 5.30 7.85 7.51 7.16 9.01
% of total labor force ages 15-24
$0.00
$50,000.00
$100,000.00
2008
2009
2010
2011
2012
2013
2014
2015
2016
2017
2018
2019
2020
GDPpc (Current USD)
Qatar Saudi Arabia
United Arab Emirates
Figure #7
35
As the population of the GCC countries increases, in the absence of diversification of
industries, the unemployment among the younger generation, around 35 percent, constitutes the
majority of the unemployed who do not have new opportunities available to them to engage in.
Figure #8, Unemployment in Qatar, S. Arabia and U.A.E., 2009-2021 (World Bank, 2020)
The global economic slowdown caused by
COVID-19 pushed Brent crude prices
down from US$64.00 per barrel to a low
of $23.00 in April 2020, placing
tremendous pressure on the fiscal
positions of GCC countries (Brookings,
2021).
The inflation trend, in general, seems to be on a downward trend except for Saudi Arabia
because of the increase in the VAT rate from 5 percent to 15 percent. Despite reduced imports,
lower oil exports resulting from lower global demand because of the COVID-19 pandemic,
reduced demand from the US because of domestic Fracking success, and global high pressure to
reduce climate change footprint have weakened external balances. Delays in implementing
necessary fiscal adjustments and structural reforms could weaken fiscal sustainability and
dampen growth.
Although inflation pressures have remained contained in the GCC region, they might rise
because of global inflation (Gulf Cooperation Council, 2020).

36
The research shows no fluctuations concerning the local official currency exchange rates
because they are all pegged to the US dollar. Climate change and related global mitigation
policies present additional risks to GCC countries. The GCC region that lacks rainfall is
vulnerable to increased temperatures and sandstorms. Furthermore, global sustainable
development goals and their mitigation efforts will gradually reduce the demand for
hydrocarbons, negatively affecting these countries' fiscal and external sustainability (Gulf
Cooperation Council, 2020).
Oil prices are strongly influenced by the global economic outlook, changes in supply and
demand, and geopolitical tensions. The prices in an economy highly dependent on national
income generated from one non-renewable resource are vulnerable (Al Naimi, 2022).
Before the pandemic, the IMF had estimated that GCC countries would deplete their reserves by
2034. After reaching $70 a barrel in 2020, the price of the oil went down to its lowest level in 20
years to less than US$ 20 a barrel, creating substantial pressure on the GCC countries' fiscal
positions, averaging 9.2 percent in 2020 and 5.7 percent in 2021 (Gansbeke, 2022).
A study conducted by EIA (Energy Information Administration), GCC National
Statistical Authorities, and IMF (International Monetary Fund) (2017) involving Qatar, Saudi
Arabia, and the UAE shows that there is an 80 percent correlation between GDP in Saudi Arabia
and the oil prices and 50 percent in Qatar and the UAE (of a lesser degree because of increased
diversification in the country).
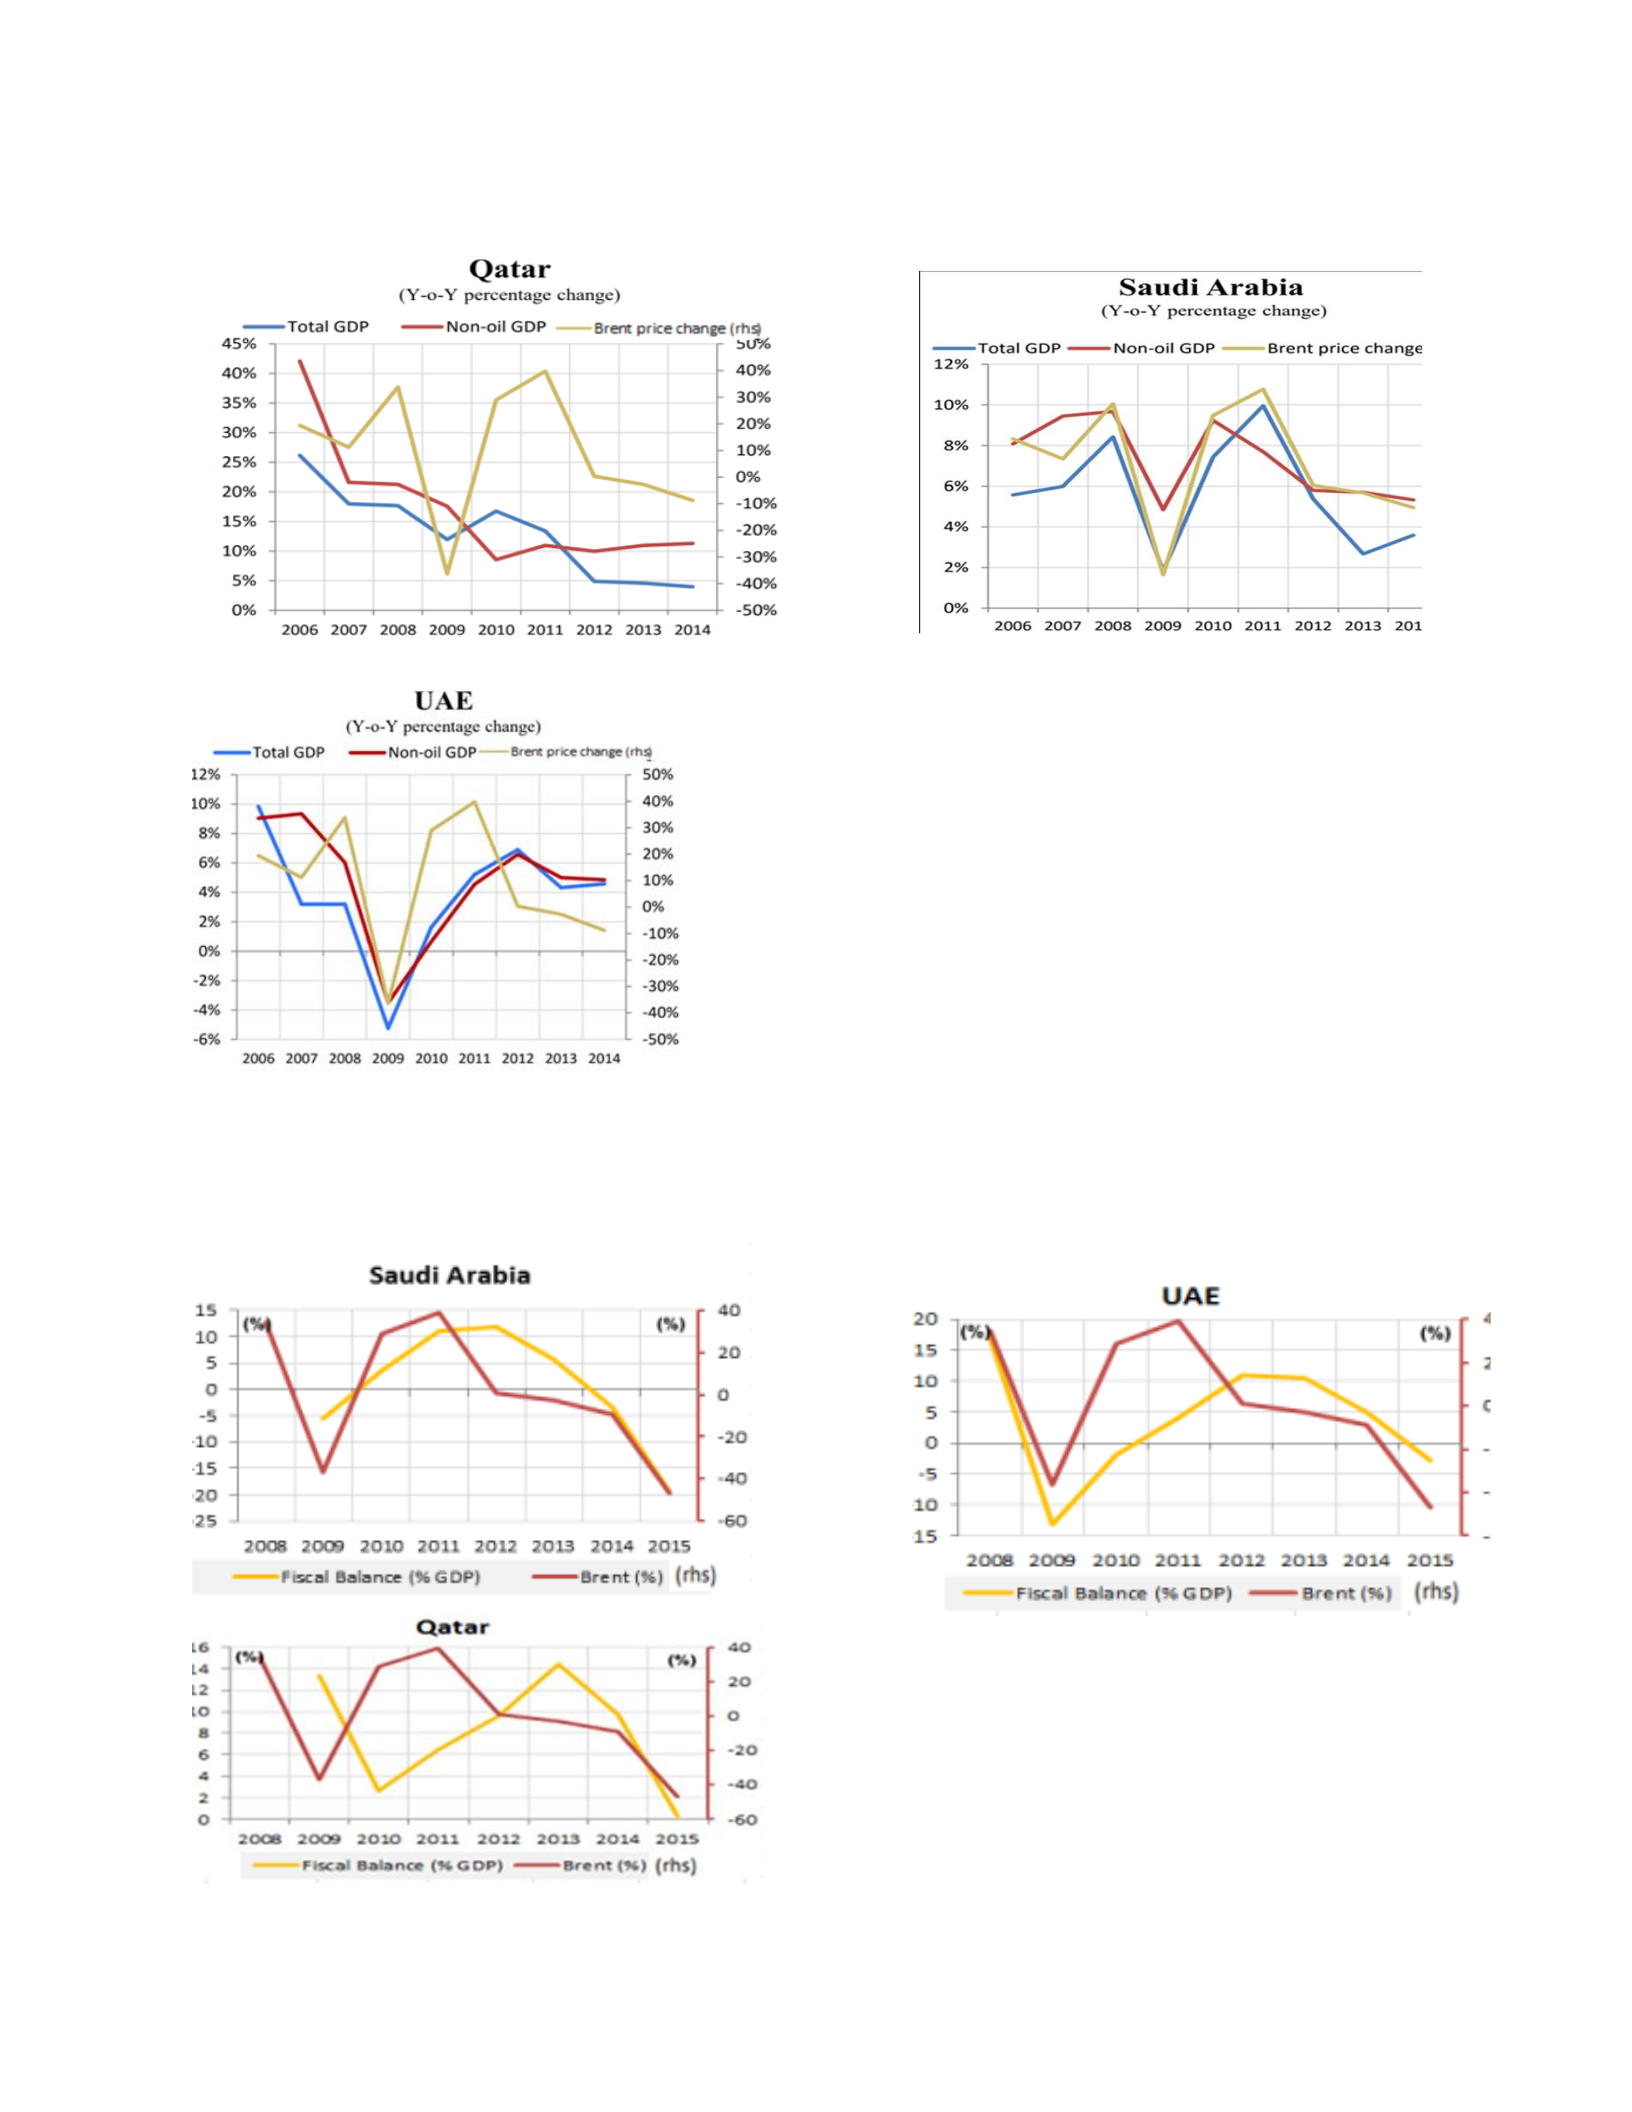
37
Figures #9, #10 & #11 - Correlation between Total GDP, Non-oil GDP & Brent Price Qatar, S. Arabia & U.A.E.
The correlation between the fiscal balance and oil
price change is 87 percent for Saudi Arabia, and 86
percent for U.A.E, and 42 percent for Qatar. Fiscal
revenues and expenditures are very much procyclical
with the oil price cycle. The correlation between the
fiscal balance and oil price change trajectories run in the
same direction as shown in
Figures # 12, #13, & #14; the lower the price of crude oil (Brent %), the lower the Fiscal Balance as a % of GDP

38
Political Instability & Security
GCC is neither a political nor a military alliance. So far, they have made the most
progress in the technocratic and apolitical areas. The ongoing conflict in Yemen, stalled talks
with Iran, the Abraham Accords with Israel, the crisis in Lebanon, and the current situation in
Ukraine have changed the economic and political landscape of the region. Although GCC
countries now look to both the West and the East for security assurances, the U.S. and Europe
remain the premier security partners.
The 2008 financial crisis, the Arab Spring uprising, and the role of Islamist groups in
political transitions in North Africa conditioned policy responses in the new Abu Dhabi (UAE)-
Riyadh (S. Arabia)-Manama (Bahrain) and Doha (Qatar) axis. The GCC states'
internationalization and interdependencies with external actors have deepened. Securing the
cooperation of the GCC states depends mainly on the United States' ability to maintain regional
security and develop effective military capability. The EU-GCC 1989 Cooperation Agreement
has created a Joint Council and Joint Cooperation Committee. Both parties cooperate on strategic
areas of mutual interest – the EU funds various regional projects, including economic
diversification, enhanced political dialogue, and cooperation. The U.S. military footprint in the
GCC countries is significant. U.S. commitment to the region includes 1) deterrence regarding the
freedom of navigation through the Middle East's waterways, including the Strait of Hormuz and
the Bab al Mandab, and any military buildups, incursions, or threats, 2) diplomacy to de-escalate
and end conflicts, and 3) Integration, building economic political and security partnerships
(White House Fact Sheets, 2022).

39
The Gulf states remain paramount security and economic partners of the U.S., even
though the level of economic partnership between the Middle East and the U.S. is at a low level
and even though the U.S. has turned its attention away from the region. The Middle East export
level to the U.S. is 48 percent of the 2008 level, and U.S. exports to the region are almost at the
same level as in 2008. After China, the EU is the second biggest trade partner of the GCC. The
EU represented 12 percent of GCC's world trade in 2020, of which 7.8 percent were imports to
the GCC region from the EU (EU, 2020).
In 2016, at COP 21 in Paris, a legally binding international treaty on climate change (the
Paris Agreement) was adopted by 196 parties and went into enforcement. The agreement
required the parties to set targets to limit global warming to below 2, preferably to 1.5 degrees
Celsius, aiming at net-zero carbon emissions by mid-century, a move that requires economic and
social transformation (Council Foreign Relations, 2022).
Although the Middle East region accounts for only 6 percent of all carbon dioxide emitted
from energy worldwide (Tieso, 2022), and although the GCC region accounts for only 2.4
percent of global greenhouse gas emissions, politically and economically, the Paris climate
discussions are of utmost importance for the GCC countries because their security and
opportunities for future economic development are dependent on the West.
GCC countries depend on the knowledge and technology from the West to produce and
manage green energy projects. The United States and the European Union, which possess
advanced green energy and management technologies, have already established strong

40
relationships with the GCC countries to provide transformational knowledge and products to
support the region's economic development. The World Bank Group has worked with the GCC
countries to promote private sector institutions through the International Finance Corporation
(IFC), which provides the financial support needed to expand the private sector's operations
(World Bank, 2022). In 2022, U.S. PACE, Partnership to Accelerate Transition to Clean Energy,
signed a key new clean energy framework and developed a strong partnership with the United
Arab Emirates (The White House, 2022).
On the other hand, the European Union is already playing a proactive role in sharing its
experience in green technology and decarbonization with GCC's local partners. In 2022, the EU
adopted a Joint Communication on a Strategic Partnership with the Gulf to provide a
comprehensive framework for green transition and sustainable energy security (GTAI, 2022).
Furthermore, in 2022, the European External Action Service created a strategic partnership with
the GCC countries, including green transition and energy security.
Despite the good intentions of GCC, their commitment to ratify the Paris Agreement, and
their national vision and economic development plans, they remain heavily dependent on
hydrocarbons. Globally, the industrial, energy, and agricultural sectors depend on fossil fuels and
generate a large portion of greenhouse gas emissions. Any action taken in this regard by the 191
countries that have committed to implementing laws to reduce carbon emissions per the
requirements of the United Nations Framework on climate change will negatively impact the
worldwide demand for the region’s production and export of fossil fuels (EU-GCC, 2016). Since

41
GCC countries’ long-term economies and security depend on the West, these countries need to
grow in industries other than the production and export of fossil fuels.
As far as Geopolitical developments are concerned, such as the US discharging its role as
“guarantor” of gulf security, heightening their security anxieties, regional realignments and
proxy conflicts that have sharpened intra-GCC sensitivities and policy divergences, and the
signing of the Abraham Accords between the United States, United Arab Emirates, and Bahrain
could ultimately create instability and weigh on investment and growth in Qatar, Saudi Arabia,
and UAE (Calabrese, 2021).
Social Instability
The trajectory of the Arab Spring was triggered not just by economic conditions but by
the nature of the governments. "Judging by economic data alone, the revolutions of the 2011
Arab Spring should have never happened. The numbers from the decades before had told a
glowing story." (World Bank, 2015). The aggregated data neglected to show nuances, wealth
distribution, social services, healthcare, and political views. The opposition's demands were met
with short-term policies that focused on cash handouts, job creation, and raising wages.
Qatar did not have an uprising, perhaps primarily because of its enormous wealth that
gives its leaders flexibility to formulate foreign and domestic policies and its international
prestige due to its growing reputation as a reliable mediator in conflict areas (Aarts et al. 2012).
The strategies to achieve green economies in GCC states like Qatar, S. Arabia, and UAE need to
happen in different stages.

42
For these countries to meet their commitments to the UN SDGs, they need to work within
the Energy Transition Readiness framework of the World Economic Forum (World Economic
Forum ETI Report, 2020). The framework provides the transition readiness enabling
dimensions: a) Capital and Investment, b) Regulation and Political Commitment, c) Institutions
and governance, d) Infrastructure and innovative business environment, e) Human Capital and
Consumer Participation, and f) Energy System Structure. This system should provide the
imperatives critical to green economies, including a) security and access, b) Environmental
sustainability, and c) Economic Development and growth.
Oil discovery has been the catalyst behind migration mobility to the GCC countries
resulting in a demographic imbalance (Aref, 2021). According to the EUI Migration Policy
Center and Gulf Research Center, in 2016, 51 percent of the GCC population are nationals, and
49 percent are expatriates. These statistics show a higher number of expatriate workers in Qatar
and UAE where nationals represent only 10.1 percent and 11.5 percent of the population
respectively. Nationals in Saudi Arabia represent 67.3 percent of the population. The expatriates
fulfill the talent and the human capacity missing in the Gulf states and they stay in GCC
countries with no pathway to citizenship under the Kafala system (the relationship between the
migrant workers and their employers), resulting in social exclusion.
After studying the economic, political, societal, and cultural nuances of the GCC states,
the variables that I think will impact the transition of these states to green economies are:
1) Diversification of Industry Sectors other than the fossil fuels; increase in non-oil revenue

43
through developing and supporting green technologies, and environmentally friendly products
2) Government private sector investment in Research and Development of sustainable, green and
renewable energies 3) Increase of the number of workers in the private sector; subsidize salaries
for the private sector to make them more attractive to the nationals 4) Build local human
capacity and the technical know-how necessary to increase domestic efficiency and comparative
advantage in the green energy industry sector 5) Build human capacity, inclusivity and increase
the number of the nationals in the workforce by training and developing both men and women
5) Develop sustainable technology curricula in the universities. Currently, the states spend 6
percent of their GDP on education; however, most graduates major in business and humanities.
In 2000, the six GCC countries announced national visions and commitments to shift
their economies from oil-based to knowledge-based economies in information, e-commerce, and
communication fields that will drive economic prosperity. During the same year, these
commitments turned into regional commitments by the GCC countries during the leaders'
summit in Manama, Bahrain (Aref, 2021). In the global arena, the United Nations and World
Economic Forum are driving the Climate Change movement, stressing that the impact of a global
temperature increase of just 1.5oC would be worse than initially thought and that the world has
until 2030 to avoid the catastrophes of climate change (UN, 2022).
The political economies of these three GCC countries that heavily rely on oil wealth have
unique political, economic, and social consequences. In addition to their lack of incentive to
diversify their economies, they are expected to provide jobs for their citizens, which results in
over-employment, subsidized by the revenues received from oil. Meanwhile, the private sector

44
customarily hires inexpensive, non-citizen workers. With the workforce increasing and their
struggle to absorb the inflow of new entrants in the labor market, these countries are looking for
nationalization policies that employ more of their nationals in the private sector (Wahab, 2019).
IMF put the public-to-private wage gap in the gulf at 30-50 percent for nationals. The
public sector workers have easier schedules, permanent employment, and salary increases that
often outpace inflation and pay raises compared to that of the private sector. In 2021, the public
sector of Qatar employed 80 percent of its nationals, Saudi Arabia employed 50 percent, and the
United Arab Emirates employed around 75 percent (The Economist, 2021). Historically, during
the first oil boom, while they were building their infrastructure, cheap foreign labor was a
comparative advantage for the GCC countries; however, as the population of these countries
grew and the new entrants in the job market increased, there is a social and political need to hire
the nationals in the private sector with higher wage expectation (Hertog, 2013).

45
Chapter 2
THEORETICAL FRAMEWORK
Implementing green energy policies globally is very complex. The Climate movement
started in the West, and the agenda has been pushed on developing countries in the East into
countries that are culturally, politically, and environmentally very complex. My research takes a
transdisciplinary look at the variables that are involved in transitioning GCC countries to green
energy, the factors that help or hinder the process, and their ecosystem, including the advantages
and the challenges that they are experiencing and will continue to experience in the future
domestically, regionally, geopolitically, economically, and socially. Qatar, Saudi Arabia, and
UAE have committed to the UN Paris Agreement (2015) to reduce the effects of climate
change.
According to Current literature, national resources can paradoxically undermine a
country’s economic, political, and human capacity growth through the following phenomena: 1)
Dutch disease, 2) Protection Curse, and 3) Rentier States.
“Dutch Disease”
Although the idea that resources might be more of an economic curse than a blessing
emerged in the early fifties and sixties, the term “Resource Curse” was first introduced in 1993
by Richard Auty to describe countries that are rich in resources but unable to grow their

46
economies and prosper as a nation. The term “Dutch disease” was first used by The Economist in
1977 describing a dichotomy in the country’s external and internal health. After the Dutch
discovered natural gas in 1959, oil exports soared, and the demand for Guilder increased, causing
it to be a stronger currency. However, the focus on gas exports resulted in increased internal
unemployment, decreased corporate investment, and an inability to compete in exporting to other
tradeable goods and services. The country went into recession with a growing gas market and a
declining export economy (The Economist, 2023).
According to Steffen Hertog (2016), distribution, with cheap energy and over-
employment of the public sector, could have been more efficient in the past. They might have
worked with newly built states with smaller populations when the level of domestic energy
consumption and global energy prices were low. Now, they have become regressive and non-
inclusive distribution tools, barriers to non-oil diversification and fiscal sustainability, and, in the
long term, the inability to grow the private sector workers (Hertog, 2016). There are, of course,
many other types of distributions like subsidized or free public services, non-salary transfers, and
preferential contracts for local businesses.
Makdisi et al. (2007) examined the drivers of growth in the MENA region and concluded
that a resource curse does exist in these countries and that a lack of human capital and effective
institutions are responsible for their low performance. In addition to Makdisi, Arezki, and Nabli
(2012) deduce that for the last forty years, resource-rich countries in MENA (Middle East and
North Africa) have experienced high volatility and low economic experience because of lack of
meaningful reforms in these countries’ institutions and governance.

47
Behbudi et al. (2010), in their study of two groups of countries highly dependent on oil-
producing and exporting industries, analyzed the relationship between human capital, natural
endowment, and economic growth. Their findings for both groups showed a negative correlation
between natural resource abundance and economic growth. On the other hand, Dreger and
Rahmani (2014) and Ncube et al. (2014) found that besides the negative link between oil
reserves and economic growth, there is a negative relation between the resource endowment and
key social development indicators, such as poverty, the rule of law and income inequality.
The ability of these monarchies to provide jobs to their citizens, paid for by oil rent
revenues, have helped create an expectation on the part of their citizens that they will receive a
job with the state-owned enterprises that pay higher salaries than the private sector. Unlike state-
owned enterprises, privately owned companies provide low-paid, low-productivity positions held
by foreigners (migrant workers). Coupled with the costly hiring process of these migrant
workers, the lack of availability of high-salaried positions with privately owned companies has
limited the opportunities for diversification into new industries.
All six GCC countries have a sharply divided labor market that costs the state a lot
because providing jobs to so many nationals at high salaries and the infrastructure necessary to
support millions of foreign workers in the private sector is costly. Because the private sector is
unable to attract educated citizens by offering them salaries compatible with state-owned
enterprises, opportunities for disruptive technologies and human capacity building are hindered.
As a result, most jobs created during periods of high growth go mostly to foreign national

48
workers who are temporary workers who are not likely to bring their experience into building
endogenous, competitive skills.
In highly specialized Gulf states, the preponderous Oligopolies provide results contrary to
the “Dutch Disease” expectations. During export booms, in addition to the domestic inflation
created because of the preceding” Dutch Disease” phenomenon (inflation, because all three GCC
countries have a pegged exchange rate with the U.S. Dollar) that results in an increase in the
value of the non-resource exports, and Busts, that render the opposite effect whereby the non-
resource exports become more competitive in international markets with the possibility of
reversing the pattern of trade (Shehabi, 2023).
In the presence of strong Oligopolies, economic efficiencies in these GCC countries are
reduced during both economic booms and downturns because these companies capture oil rents
in both market conditions as a result of having access to subsidies provided by the oil rents and
expatriate labor with lower wages than the national as well as expatriate labor exploitation, and
benefit from limited Oligopolistic regulations for pricing.
“Protection Curse”
The “Protection Curse” underpinning concept argues that abundant natural resources
stand in the way of economic and democratic development. Perceptions of regional security
allowed these leaders to take a damaging approach by creating a foreign military power in their
countries (Roberts, 2023) that created a long-term dependence of these monarchies on the West,
mainly the US, and hundreds of billions of dollars of investment in their political, military, and

49
industrial complex that provided the human resources and the equipment to deter attacks mainly
on their oil infrastructure and provide support for their domestic, regional, geopolitical,
economic and security decisions.
Since 1984, when Iran and Iraq targeted the GCC monarchies’ oil tanker fleets, these
countries struggled to defend their interests and became highly dependent on the protection and,
therefore, on the geopolitics of the West. They asked for international assistance and reflagging
of their tankers to protect their assets. From the protection of the regional partners in 1988, these
monarchies got an offer from the United States. They employed coup-proofing methods to check
the regular armed forces, the control of which was realized by the royal family members based
on loyalty rather than merit. The result was a culture of inefficiency, a centralized decision-
making machine, and bilateral partnerships based on security rather than economy (Roberts,
2023).
Gulf monarchies increasingly rely on a military dimension to drive their national identity
projects. While the US, UK, and European Union contractors have benefitted from militarization,
the process has not only been about hard power but also about strengthening rulers’ power and
fostering a bottom-up sense of national pride in all GCC countries (Ardemagni, 2019).
These military contracts are believed to have purchased political guarantees rather than the
military capabilities these countries needed. Saudi Arabia’s militarization reflects the increased
concentration of power in the hands of the monarchy to consolidate its rule. In the UAE, it means
centralization to promote the primacy of Abu Dhabi (over the other six emirates) and support the
Emiratis’ desire to exert geopolitical power. Since the rift in the GCC countries, Qatar’s
50
militarization is for defensive ambitions that give the country a sense of patriotism against Saudi
Arabia and the UAE.
Actual international security inhibits the development of the domestic military capability
of the GCC countries. The yearly military budget for Saudi Arabia is $45.6 billion, UAE $15.3,
and Qatar $4.35 (Shehabi, 2023) spent on the UK and the US to secure infrastructure and GCC
rulers’ domestic and regional power, making them heavily dependent on the geopolitics of the
West.
“Rentier States”
In the early 1930s, the discovery of oil in the GCC countries was a turning point for these
hermetic and nomadic communities. They transferred into states that have experienced
significant growth and high energy consumption. Under the process of nationalization, these
monarchies initially fixed the prices of energy products and services at a low level. GCC rentier
states provide natural resource rents to their citizens through Generous public benefits and
services, high-salaried public jobs, and access to exclusive government contracts and licenses.
These created distortions in the market, weakening the development of a competitive private
sector that might generate future growth beyond hydrocarbon. However, citizens see these
channels as a fair game to guarantee access to their fair share of the countries’ endowment
(Kabbani & Mimoune, 2021).

51
The Rentier Theory argues that oil revenues transform governments into vital economic
players with a concentration of economic power in the hands of the government. Without
revenues resulting from taxation, the state depends on revenues generated from oil to initiate
projects and programs. The government controls natural resource extraction, production, and
export and distributes the revenue generated to the public through public employment and social
programs (Beblawi, 1987). However, this concentration of political and economic power
constrains the development of state capacity (Beramendi and Rogers, 2022).
According to Adam Smith, Rents are separate income from the wages that must be
earned and are based on the ownership of assets. Later, David Ricardo defined Rents as a reward
from the ownership of a resource and, in the case of natural resources, “the income derived from
the gifts of nature.” The definition was further developed by Hossein Mahdavy (1970), who
came up with the concept of the “Rentier State” through the case of Iran to identify the effects of
nationalization on the source of the Middle East’s economic growth. He defined Rentier States as
states that receive substantial amounts of external rent regularly and external rents as rentals paid
by foreign entities to individuals or governments. Mahdavy was concerned that oil revenues
transform governments into key economic players and that without revenues resulting from
taxation, the state depends on revenues generated from oil to initiate projects and programs.
However, he did not want to disregard the rest of the economy as of secondary importance.
(Mahdavy, 1970).
The concept of "Rentier State" was later refined by Hazem El Beblawi and Giacomo
Luciani (1987) through their extensive work on developing countries heavily dependent on oil

52
production and exportation in the Arabian Gulf. A rentier state obtains a significant portion of
its fiscal revenue from producing and exporting its natural resource endowment.
The states receive income without an increase in the productivity and development of
local economies or politics, resulting in the inability of the states to tax their citizens. Only a
small percentage of the population generates the rent, and the state's government is the principal
beneficiary of the external rent. As a result, the unequal distribution of external income hurts
political liberalism and the development of the domestic economy. Economic activity is
managed mainly by the government, and the resulting economic wealth is then redistributed to
the population resulting in citizenship to become a source of economic benefit (Beblawi and
Giacomo 1987).
Today, GCC countries, including Qatar, Saudi Arabia, and the United Arab Emirates, are
rentier states. As Beblawi (1987) states, rent is the predominant income of these states. In the
absence of a productive domestic sector, most of the rent is gained externally only by a fraction
of society, mainly the government. Ross (2001) considers the behavior of these states to include
repression and modernization and natural resources like oil and gas to be an obstacle to
democratic development. Dunning (2008) posits that the dominance of oil wealth has
unavoidable political, social, and economic effects, and Rents are defined as "supernormal
profits, or the excess over the return on capital, land, and labor when these factors of production
are put to their next best use."

53
Even though the Rentier State theory has provided explanations and understanding
of the political, economic, and social dynamics of the Gulf states, several critics disagree because
of the transformation in Gulf societies after the oil crisis of 2014 when these societies aimed at
making an explicit goal to transform their economies into knowledge-based economies (Hvidt,
2015). They argue that the rentier state theory was predominant in explaining the social and
political aspects of the Gulf states since the 1971 oil crisis because of the failure of
modernization theory to explain the longevity of the family-based rulers in the Gulf. The Rentier
State theory created the perception that these kingdoms are stable because of the rents received
and the subsidies they provide to their citizens. According to Shehab (2021), the rentier state
theory failed because it was based on an outdated epistemological paradigm of modernity and
could not capture the complexities of the Gulf societies.
Furthermore, Elmessiri (2006) addresses the existing bias in the research world against
simple explanations of complex phenomena and a desire to explain these phenomena in terms of
one reference for all, "causal monism." Luciani (2021) criticizes Rentier's theories, which are
overwhelmingly used to interpret the political economy of resource-dependent countries like the
Middle East that rely heavily on oil production and export. Reliance on rent from global
resources is essential; however, it is not the only one. Mohammad Hachemaoui (2012) argues
that the effect of rent and the presence of the national endowment in the "rentier state" thesis on
the regime of these countries depends on established political institutions.

54
Michael Herb (2005) criticizes the relationship between Rentierism and regime type
(Authoritarian Petro-regime). He shows that countries endowed with fossil fuels fit the same
patterns as other countries. His findings do not support the thesis that Rentierism hurts
Democracy; however, he agrees that rentier states experience a distinctive condition that
influences development. GCC governments pursued pro-capitalistic economies and local
merchant classes. They did not witness the waves of nationalization that eliminated the old
business classes like other Arab countries like Syria, Algeria, and Egypt during the post-WII era
(Hertog, 2010). The local capacities of the GCC countries have always been limited to little
economic differentiation.
Shehab (2021), Elmessiri (2006), Luciani (2020), and Herb (2005) are true in their
criticism of the Rentier theory being a simplified way of understanding the political, economic,
and social complexities of these countries. GCC societies and their culture throughout the
Middle East are very different from one another. The motives for unrest demanding
accountability and democratic government in the existence of great wealth do not focus on
taxation alone. Taxation cannot be seen as the only motivation for democratic governance. Yes,
the GCC rentier states experience influences and development (Herb 2005); however, low
geographic endowment of the region in agriculture because of its arid land should be taken into
consideration as the primary reason for lack of early industrialization outside the fossil-fuel
sector.

55
I do agree with Beblawi (2015) in his statement that oil revenues that are not related to
enterprise and hard work, form a particular behavior and attitude on both individual and state
levels (Beblawi, 2015). Oil revenues are perceived as gift of God (Al-Khair), sudden wealth and
immediate profits. As such, the rentier mentality sees investment opportunities to be limited by
domestic trade, real-estate, and securities. Therefore, long-term developmental investments are
not attractive to the rentier. Furthermore, New Institutionalists do not see the abundance of rents
as a barrier for development, but the result of defective political institutions. Because taxation
requires real and effective penetration of society and economy, it is the engine for institutional
development. If politics are not inclusive, institutions will follow suit and extract wealth from
society for the benefit of the elites (Acemoglu and Robinson, 2013). Allocation, on the contrary,
does not foster growth and accountable government.
The “rentier state” ignores social movements based on the assumption that rent “buys
popular consent,” not understanding the motives of unrests in the presence of abundant wealth
involving demands for accountability and focusing on taxation as the only motivation for
democratic governance. The allocation of rent profits does not result in their depoliticization.
Rentier state theory is a simplified way of understanding a very complex political, economic, and
social phenomena in terms of one perspective. As Lucian (2020) himself stated, rentier state
theory alone is not enough to understand and interpret the complexities of the political
economies of the Middle Eastern countries that are heavily resource dependent, neither.
The politicians of the rentier states, the economies of which are heavily dependent on
fossil fuel, are not likely to adopt green energy if they are not furnished with incentives that

56
provide them and their families with long-term political and economic power and support the
politicians’ sovereign wealth.
Endogenous & Exogenous Economic Growth
Both Endogenous and Exogenous growth models stress the role of technological progress
to achieve sustained economic growth or, in the case of the GCC countries, a path to
diversification. Endogenous theory, the Romer model (1994), suggests that the variables to key
economic growth are activities created within a country’s economic system like knowledge,
human capital, and research and development. On the other hand, Exogenous theory, the Solow
model (1956), suggests that the key variable necessary to create and develop sustained economic
growth is born outside the country.
Whether a region or a country can achieve energy transition depends on the diverse
components and their interdependencies outside the energy sector. Within its boundaries, the
energy system includes a variety of fuel sources, extraction and conversion processes, energy
infrastructure, investors, employees, disruptors, and end users. In addition, energy is a
commodity traded outside the boundaries of a region or a country and, most of the time, it is a
key component of public policy. These countries’ BOP and monetary policies are affected by the
volatility of demand and price. Energy systems impact economic growth through development in
industries, human capacity, competitive talent, employment, and export (World Economic
Forum, 2022).

57
Economic growth refers to the increase of goods and services in an economy produced by
human capital as the main contributor to the process. Romer's (1990) Endogenous Growth theory
states that economic growth is due to internal factors and that improvements in innovation,
knowledge, and human capital lead to increased productivity, positively affecting a country's
economic outlook. Oil-fueled economic growth has benefited a minority of citizens, and most
opportunities are seen to be reserved for the elite (Mishrif, 2018). Economists who believe in the
theory emphasize the importance of the central governments providing subsidies and incentives
for the private sector that will motivate businesses to innovate through investing in research and
development. However, endogenous economic growth cannot happen without investing in
human capital through training and development, which is necessary to create new sectors in the
economy as well as new labor markets.
According to Lucas and Romer (1994) production functions are the two most popular
descriptions of the new growth theories where knowledge is endogenous to key economic
growth and technological change. Sheshinski-Romer's (1990) economic growth model focuses
on learning by doing and externalities. Romer (1994) posits that economic growth is an
endogenous outcome of an economic system, not the result of forces from outside.
Lucas (1988) further suggests that experience allows a worker to have higher productivity,
and human capital can be encouraged through education and skill-training programs. He also
states that the rate of technological change can increase due to higher investment in R&D, which
may drive a positive externality to knowledge-intensive industries; however, the protection of
intellectual property rights is important because this legal monopoly gives the incentive to carry

58
out R&D. The Sheshinski-Romer (1994) model also shows potentially increasing return to scale
from a higher level of capital investment, especially investment that has positive externalities.
Contrary to Endogenous growth, Slow-Swan's (1956) model maintains that factors
outside the country drive economic growth. The determinants of the exogenous economic
growth, as per Slow, are composed of increases in inputs (labor and capital) and technical
progress. The theory allows the determinants of economic growth to be separated into increases
in inputs (labor and capital) and technical progress. Slow-Swan's theory furthermore states that
capital is a finite entity because the resources found on the earth are limited, and since
technology is supposed to be constantly improving, the products and capital generated are more
valuable than the old capital.
Al-Iriani and Al-Shamsi's (2007) study of the relationship between FDI (Foreign Direct
Investment) inflows and economic growth in the GCC states finds a strong causal link between
FDI and GDP and vice versa. While FDI inflows promote growth, these states' GDP attracts an
inflow of direct investment. As such, the influx of FDI has great potential to realize higher
growth through positive externalities such as facilitating transition and diffusing technology and
introducing alternative management practices, organizational arrangements, and improved
entrepreneurial skills. Nevertheless, FDI externalities may have trivial effects if the links with
local businesses are weak. Thus, local governments should adopt policies to strengthen the
complementary relationship between FDIs and domestic investments.

59
Both the endogenous and exogenous models highlight the importance of technological
advances to realize economic growth. Therefore, long-term economic growth can be achieved
due to technological innovations within the economic system. More importantly, In the
endogenous model, capital may include not only physical capital but also human capital, which
synergistically accumulates, and each unit of knowledge created endogenously results in
knowledge spillovers, which allow entrepreneurs to identify and exploit opportunities (Zoltan et
al., 2008).
The real challenge in endogenous growth theory is not that the firm will under-invest in
new knowledge but how firms would balance their increasing returns with the competition. On
the other hand, if intellectual property protection becomes too strong, and all rents accrue to the
producer of knowledge, it will reduce intra-temporal knowledge spillovers and, ultimately,
innovation and growth (ACS & Sanders, 2013). Conditions staying the same, entrepreneurial
activity will be more significant where investments in new knowledge are relatively high since
start-ups will exploit spillovers from the source of knowledge production (the incumbents). In
an environment with relatively low investments in new knowledge, there will be fewer
entrepreneurial opportunities based on potential spillovers (Zolten et al., 2008).
Romer (1990) shows that economically advantageous scientific-technological advances
can be achieved through non-rival, excludable knowledge (knowledge published in books,
papers, etc...) and rival excludable knowledge through patents. Patent technology can also be

60
used to produce other goods and services separate from the production of green energy (Zoltan et
al., 2008).
The GCC countries heavily dependent on fossil-fuel economies can facilitate
technological change and develop their power technologies in green energy through establishing
knowledge transfer from countries advanced in green technologies, namely the United States and
the European Union, with close security partnerships. To fulfill their commitment to 2020, 2030,
and 2045 UN Climate Change objectives, they will need to build short-term and long-term
strategies to diversify from fossil fuel, transition to green energy, and develop an alternative
competitive industry that will augment, and in the future, provide sustainable economic growth.
To do so, GCC countries will need to experience both exogenous and endogenous economic
growth.
Exogenous economic growth will create a free economic environment to enable foreign
disruptive companies to import their products and advanced technologies in producing solar,
wind, and nuclear energy into Qatar, Saudi Arabia, and the UAE, creating a pathway for
productive partnerships with countries such as the US, EU, and China with mature markets,
technology, and production know-how of a sustainable alternative clean energy.
All three GCC states are competitive in producing and exporting fossil fuel because their
governments have provided substantive investments in the industry to build the necessary
infrastructure, critical regional and global partnerships, and human capacity. Building an
efficient production and exporting capacity of green energy, parallel to exogenous growth, Qatar,

61
Saudi Arabia, and the UAE will need endogenous economic growth driven by government
incentives and policies that promote innovation, substantive investment in research and
development, university programs that provide the academia and the critical knowledge and
experience to build the human capital and capacity that will provide local companies with the
necessary talent and skills to continue to grow rather than rely on foreign companies to drive and
control their diversified economies.
In neo-classical growth models, exogenous models argue that the economic growth rate
and differences in international productivity are also set by technological progress (Solow model,
1956). Qatar, Saudi Arabia, and the United Arab Emirates lack the green technology, knowledge,
and expertise to develop efficient local green economies. Therefore, in the initial phases of the
transition, they will be heavily dependent on importing green technologies and the know-how
through FDI (Foreign Direct Investment) inflows from China, the West, as well as Israel risking
long-term monopoly for technology and products in the long run.
Building green energy technologies and developing human capacity are key for energy
transition. All three GCC countries need to import green energy technologies through FDI
inflows paralleled with increased local government investments in R&D, the private sector to
allow the development of domestic disruptive technologies and human capacity.
What Motivates the Political Leaders to Transition to Green Energy?
The politicians of the rentier states, the economies of which are heavily dependent on
fossil fuel, are not likely to adopt green energy if they are not provided with incentives that
deliver long-term political and economic power that will not flourish the politicians' sovereign

62
wealth. So, what are the elements that motivate the rentier elites to diversify and transition to
green energy?
According to the King Abdullah University of Science and Technology Research Center
in Saudi Arabia, human-driven climate change is increasingly raising sea levels on the Red Sea
and the Arabian Gulf, running the consequent risk of salinization of soil and coastal groundwater
aquifers. Countries like Qatar and Bahrain may lose much of their coastal area to the sea. The
GCC countries' ability to adapt to resolve these problems could be better. Satellite imagery data
taken between 1993-2020 showed a significant variability and related dynamics in the Red Sea
level that was seen to rise at a rate of 3.88 mm/year, consistent with the global rate of 3.3 ± 0.5
mm/year. However, a more recent study observed a 6.40 mm/year rate in the Red Sea level from
2000 to the present (ResearchGate, 2021). Besides understanding the consequences of climate
change, the university is working on developing a basis for enhancing natural systems for
decarbonization and resilience, policy advice, international frameworks, and socio-economic
modeling, a more focused analysis of climate change and its impact both on urban and natural
systems (KAUST, 2023).
Developing a tax capacity like the Western countries to generate government revenues
and encourage green technologies and consumer behavior conflicts with the national politics of
these GCC countries (Rogers, 2016). The rulers of these countries have controlled inflation,
social instabilities, and religious uprisings for a long time through the power of their subsidies.
They have subsidized retirees, students, and the unemployed and provided their citizens with
allowances for fuel and electricity through the oil rent revenues received by the Elite. According

63
to IMF (2022), GCC countries would exhaust their $2 trillion reserves by 2034 making the
governing tools unavailable to them.
In addition to the instabilities resulting from human-driven climate change, the GCC
countries are faced with depleting oil reserves due to maturing fields and a lack of discoveries.
Depleting oil reserves means declining oil production, export, and related oil rent revenue. Since
the oil industry has been the major employer in the GCC countries, a decline in oil production
means an increase in unemployment and economic and social instabilities (IAEA, 2022). More
importantly, these monarchies have held an essential geopolitical influence because of their
competitive advantage in oil production and export. As these reserves deplete, a critical power
shift will impact both these countries' security in the region and their global alliances.
According to the World Bank (2022), the GDP growth of the GCC countries for the year
2022 was 7.3 percent. However, because of the newly generated competition from countries
with Shale technology, the shift of countries like the United States, Europe, and China towards
green energy, and reduction in global demand for fossil fuel, World Bank anticipates the GDP of
the GCC countries to be around 2.5 percent.
Depleted reserves that are estimated to run out within the next 15 years, the abundance of
Shale production capacity in the U.S. and other countries, reduced global demand for fossil fuels
resulting in price volatility, and the shifting of the highly industrialized countries to green energy
economies might be seen as a severe existential threat by the GCC leaders.

64
Building a comparative advantage in producing and exporting green energy can generate
externally derived rent for these countries and, in the meantime, create an alternative industry.
Diversification and development of clean energy technology might attract foreign direct
investments, adding another element to GDP revenues. Like the four Asian tigers that became
strong economies fueled by exports and industrialization, the GCC countries can import solar
power, wind power, and nuclear energy technologies and once they become efficient in
producing and storing clean energy, they can export globally. The European market has already
shown interest in exporting green energy from the GCC countries (EU, 2022).
Although transitioning to green energy requires significant advancements in green
technology, oil-producing and exporting countries can leverage their existing expertise in the
energy sector to invest in research and development activities to promote innovation and
advancement in the technology of solar, wind and nuclear clean energy. By doing so, they can
meet the increasing local demand for energy and, simultaneously, reduce the energy cost for the
consumers in the short run and perhaps eliminate the government subsidies for fuel and
electricity in the long run.
With a growing number of unemployed youths, men and women, a decrease in economic
growth in the GCC countries in 2023 and 2024, as predicted by the World Bank (2023), will
result in a decrease in the percentage of GDP generated from oil, resulting in less subsidies to
support social programs. Investment in the private sector, where the possibility of generating

65
disruptive green energy technologies is higher, will help create economic diversification and
increase job creation for young men and women. In the long run, this will not only reduce the
need for the government to hire workers in state-owned companies at higher wages but also
reduce the subsidies that the government usually provides to different social programs, develop
human capacity in green technologies, build a new competitive industry that provides an
alternative, sustainable revenue source for the leaders and the ability to meet their commitment
to their global agreements.
Meeting their commitment to the Paris Agreement of 2015 and the United Nations GDPs,
achieving their milestones every five years, and aligning their strategies to the Sustainable
Development Goal #7 will increase the standing of Qatar, Saudi Arabia, and the UAE in the
global markets and drive global multilateral agreements that will guarantee continued trade with
EU and the US (UAE is already in discussion with the EU to export green energy) as well as
very much needed regional and global security partnerships.
Whether public or private, long-term investment in green technology will create an
“Intra-Elite” competition among the GCC leaders and help promote fiscal development
(Beramendi, Dincecco and Rogers, 2018). GCC monarchies can become regional pioneers,
leading a sustainable, diverse economy parallel to the successful production and export of oil and
gas supporting the diversification. Green projects will give the rulers increased legitimacy from
the citizens and prestigious recognition of higher ranking in sustainable economies by
international partners.

66
Culturally, increased investment in green technology, whether public or private, will
create micro-competition among the GCC countries. Green projects will give the rulers increased
legitimacy from the citizens and prestigious recognition from regional and international partners.
Green is the fashion (ideological shift): The median age of the population in Saudi Arabia is 30
years, and 25-29 years in Qatar and UAE (World Bank, 2022). They have access to digital media
and the climate change movement emphasizing the importance of reducing carbon emissions and
environmental sustainability. Green energies can provide entrepreneurship opportunities for the
young generation and elements for self-preservation. The social changes introduced by the
current Prince Crown of S. Arabia have made him a trendy leader for the country's youth (60
percent). Developing green energy that can provide entrepreneurship opportunities for the young
generation and elements for self-preservation might help these GCC leaders become famous
leaders.
According to Al Mulali et al. (2023), global renewable energy demand has a positive
impact on economic growth, trade openness, and foreign direct investment in the GCC countries.
This, in turn, will create opportunities for green financing of the private sector. According to
IRENA (International Renewable Energy Agency, 2022), the benefits of green financing include
a potential $2 trillion boost to the GCC economies creating 1 million jobs by 2030. The role of
green bonds, sukuk (bond-like instruments; direct asset ownership interest), and loans are critical
in generating capital for sustainable projects – renewable energy, green buildings, water
management, waste management, and sustainable transport.

67
However, the transition to a green economy is a dichotomy. The revenues from fossil
fuel exports will be used to build green energy projects in all three countries: Qatar, S. Arabia,
and UAE. The transition is a long-term and gradual process for economies depending on the
production and export of fossil fuels. It poses challenges, such as the need to initiate additional
investment, balance fiscal consolidation with social spending, develop human capital and skills,
and cope with the risks of the market (IRENA, 2022).
The transition readiness and the transition period will differ for different GCC countries
depending on the reliance of the country’s GDP on the percent of oil rent, their size and
population, and other economic, political, and legal factors. It will take longer for Saudi Arabia
to transition to a green economy than the UAE and Qatar because the Kingdom’s GDP is
heavily dependent on oil rent revenues.

68
Chapter 3
METHODOLOGY
This study outlines a multicriteria analysis framework to assess a country's sustainable energy
transition readiness level, drawing from four pillars comprising a consistent set of eight evaluation
criteria: social, political/regulatory, economic, and technological. However, to make the study
comprehensive, in addition to the World Economic Forum’s Energy Transition Index, the research
measures these countries' competitiveness, economic freedom, and their performance against the
indicators, pillars, and dimensions of UN SDG#7, ETI, and GFI indices.
Definitions (United Nations)
Green Energy or renewable energy: As per the United Nations, Green energy is “energy
derived from natural sources that are replenished at a higher rate than they are consumed;
Sunlight, Wind, Nuclear, Geothermal, Hydropower, Biomass, and Wave energy.
Green Economy: is defined by the United Nations as a carbon, resource-efficient, and socially
inclusive economy where growth in employment and income is driven by public and private
investment into such economic activities, infrastructure, and assets that allow reduced carbon
emissions and pollution, enhanced energy and resource efficiency, and prevention of the loss of
biodiversity and ecosystem services.”
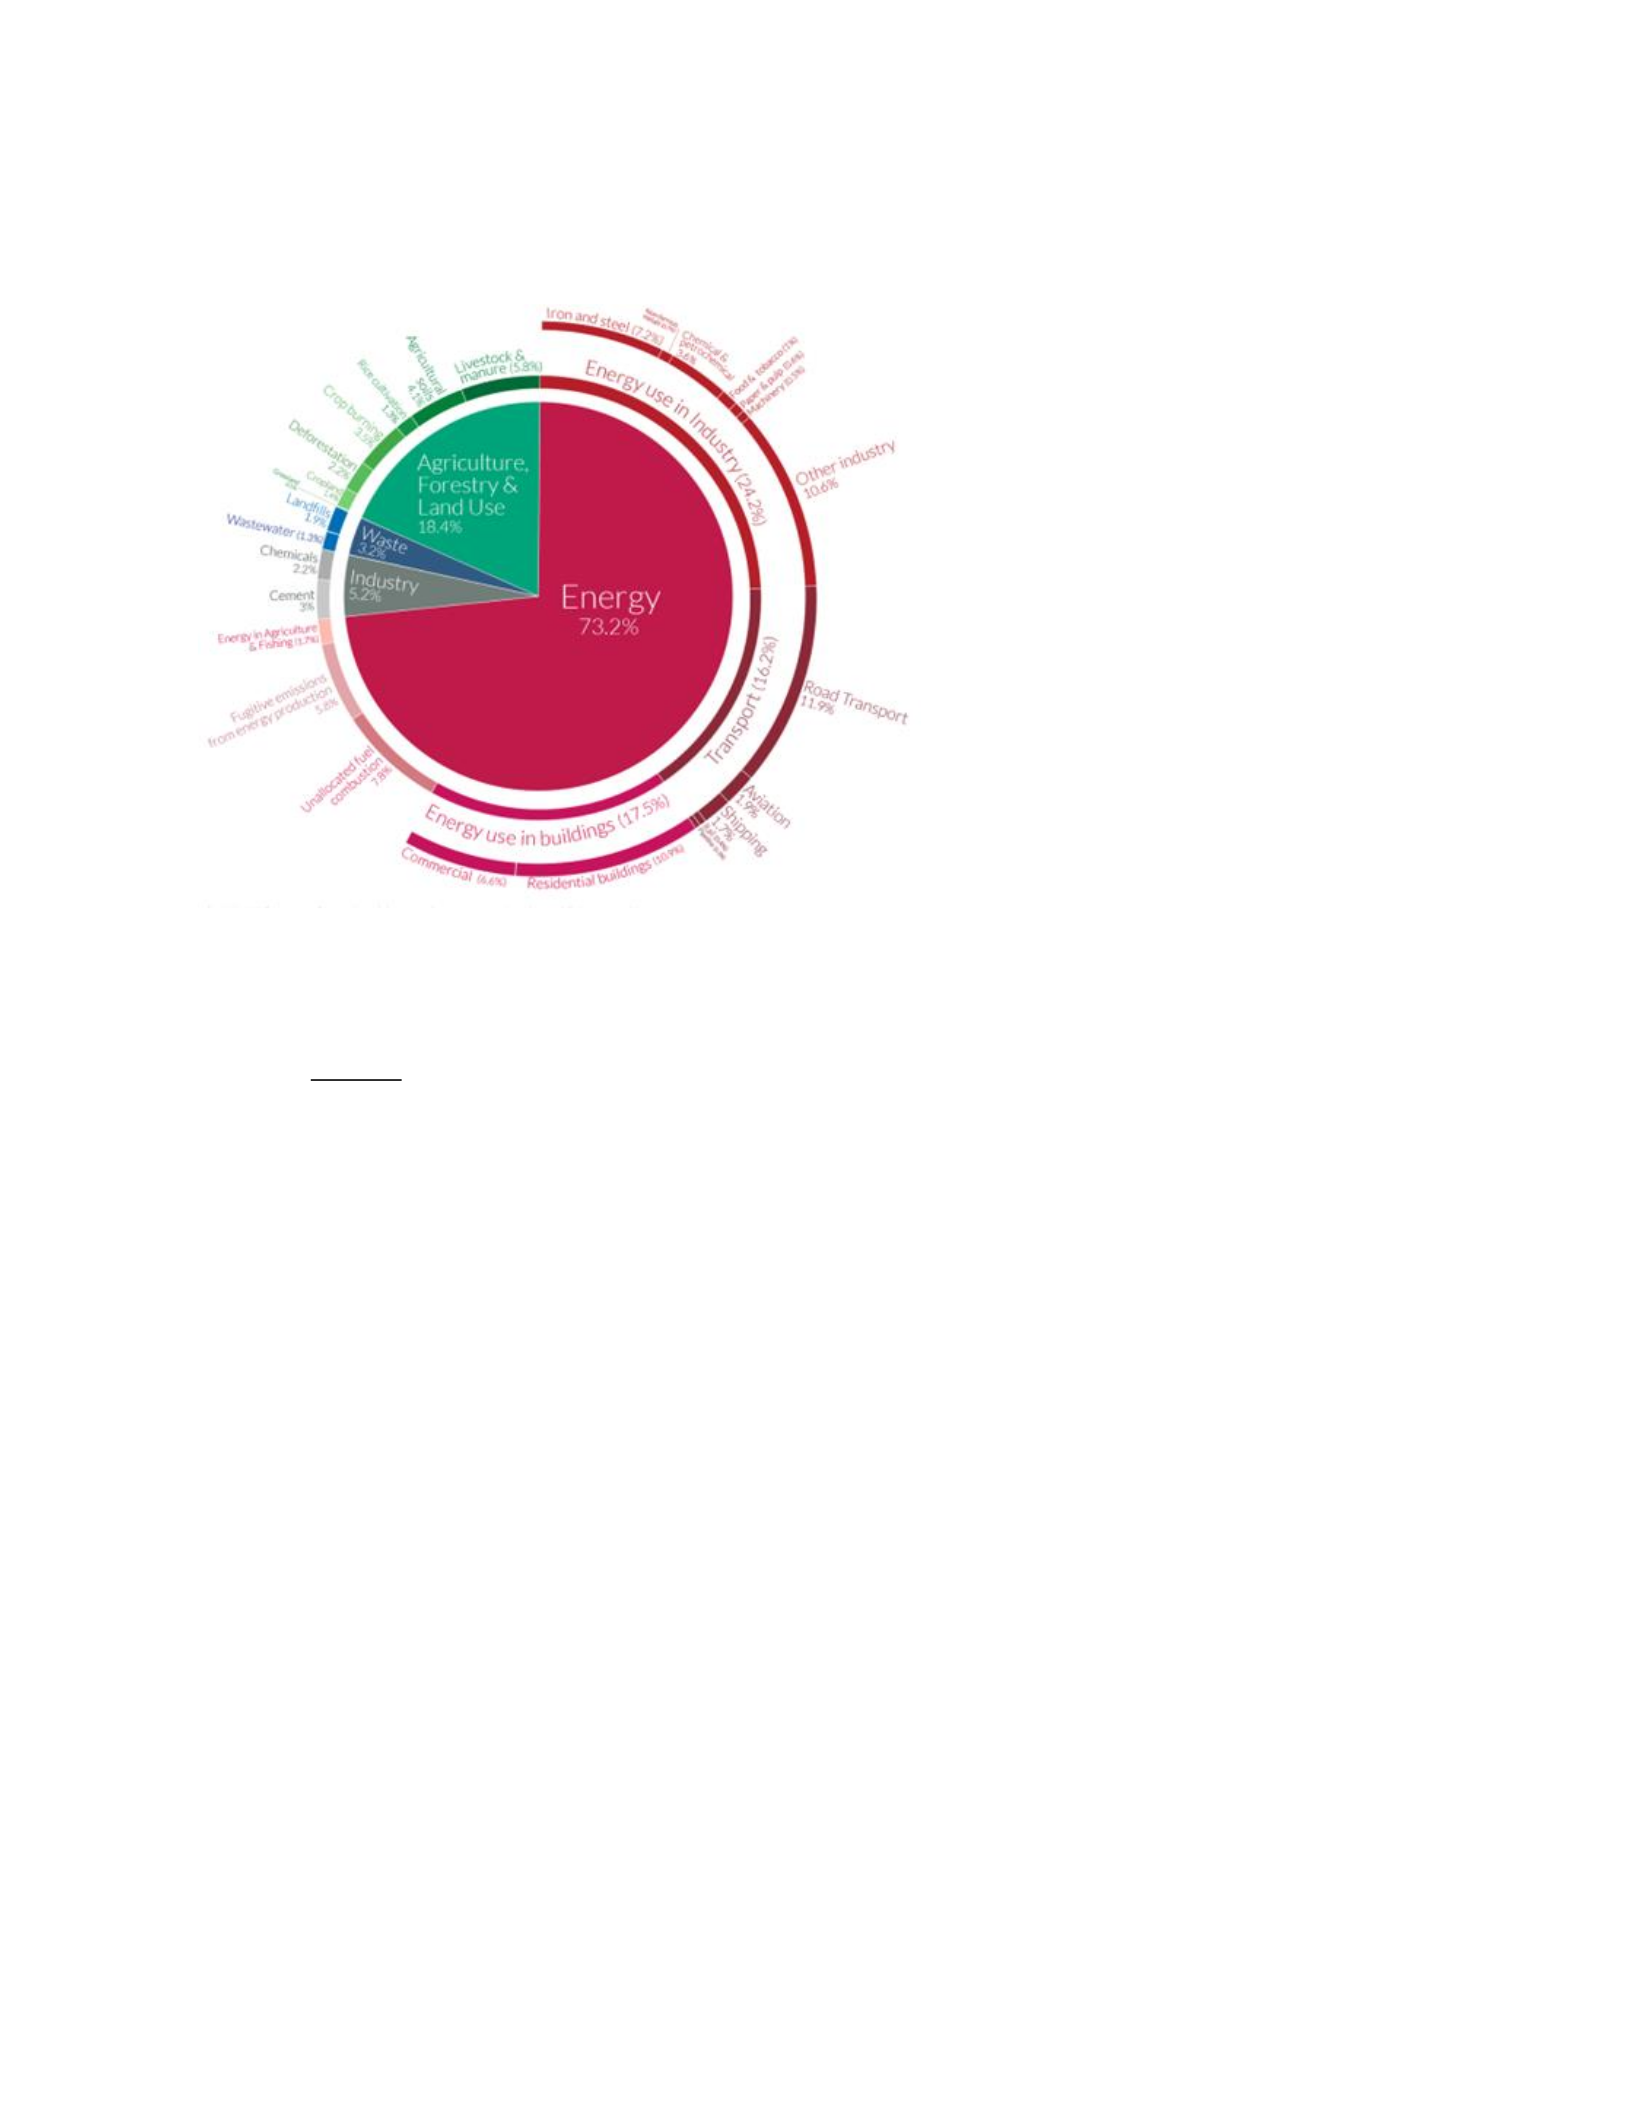
69
Energy Sector
Figure # 15 Global Greenhouse Gas Emissions by Sector, Our World Data, 2020
According to the World Resources
Institution (2020), almost three
quarters (73.2 percent) of GHG
(Greenhouse Gas) emissions come
from our energy consumption (figure
#16). Within this broad category, the
sub-categories include Transport (16.2
percent), Buildings (17.5 percent),
and industry related energy
consumption (24.2 percent) (OurWorldData, 2016). This study will focus on Renewable Energy
sector of Power: Solar Power, Onshore Wind, Offshore Wind (innovation areas), and Nuclear
Power (Not on track).
RESEARCH DESIGN
1. Model: direct control country & year fixed
This study outlines a multicriteria analysis framework to assess a country's sustainable
energy transition readiness level, drawing from four pillars—social, political/regulatory,
economic, and technological—comprising a consistent set of eight evaluation criteria. However,
to make the study a comprehensive one, in addition to the Energy Transition Index, the research

70
measures these countries competitiveness, economic freedom and their performance against the
indicators, pillars and dimension of UN SDG#7, ETI and GFI indices.
2. Qualitative Research: Case Study of 1) Qatar 2) Saudi Arabia, and 3) United Arab
Emirates
Heavily dependent on oil-producing and exporting – Qatar, Saudi Arabia, and the United
Arab Emirates. Initially, the strategy was to choose a country similar to GCC countries that, like
Kazakhstan, with an economy that is heavily dependent on oil, experiences climatic extremes
with summer temperatures reaching over 40 degrees Celsius, that has already launched its Green
Economy Plan in 2013 with a target to meet 50 percent of its energy needs from alternative and
renewable sources by 2050. However, critical differences exist in the economic and political
characteristics of GCC countries and Kazakhstan. Qatar, Saudi Arabia, and the United Arab
Emirates have high GDP/Capita (Qatar, $61,940,00; Saudi Arabia, $23,762.00; and United the
Arab Emirates, $41, 000.00, compared to Kazakhstan’s GDP/per capita of $11,500.00 (World
Bank, 2021).
Furthermore, Kazakhstan is a democratic, legal, unitary secular republic with a
presidential form of government, and its economy is dependent on coal mining. Qatar is a semi-
constitutional monarchy with the emir as the head of state and chief executive and the prime
minister as the head of the government. Saudi Arabia is a monarchy headed by the King, the
commander in chief, where the royal family dominates the political sphere, and the United Arab
Emirates is a federation of seven constituent monarchies (Republic of Kazakhstan, 2022).

71
3. Time Series Research of the Three GCC Countries: 2009-2020 Using Descriptive
Data
Since the subject of green energy and transition to green economies is a relatively new
subject, and since most of the green energy projects in these GCC countries are in the planning,
development, and construction stages, they limit evidence-based research modeling. Therefore,
my research will involve a study of the rank, score, and performance of Qatar, S. Arabia, and the
United Arab Emirates against the dimensions of the United Nations SDG#7, World Economic
Forum Competitiveness and Energy Transition Index, the Economic Freedom of the Heritage
Foundation, and MIT's (Massachusetts Institution of Technology) GFI, Green Future Index for
the last three years.
In 2015, Qatar, Saudi Arabia, and the United Arab Emirates were three of the 193 states
and the EU that signed their compliance to the Multilateral Party Agreement at the United
Nations Climate Change Conference (COP 21) in France, which was enforced in 2016. The
agreement stated that to limit global warming to 1.50C, greenhouse gas emissions must peak
before 2025 and decline 43 percent by 2030. The Paris Agreement requires economic and social
transformation based on the best available science. It also requires a review and evaluation of
the performance of the countries every five years—Climate Change and governance and
commitment to multilateral agreements.
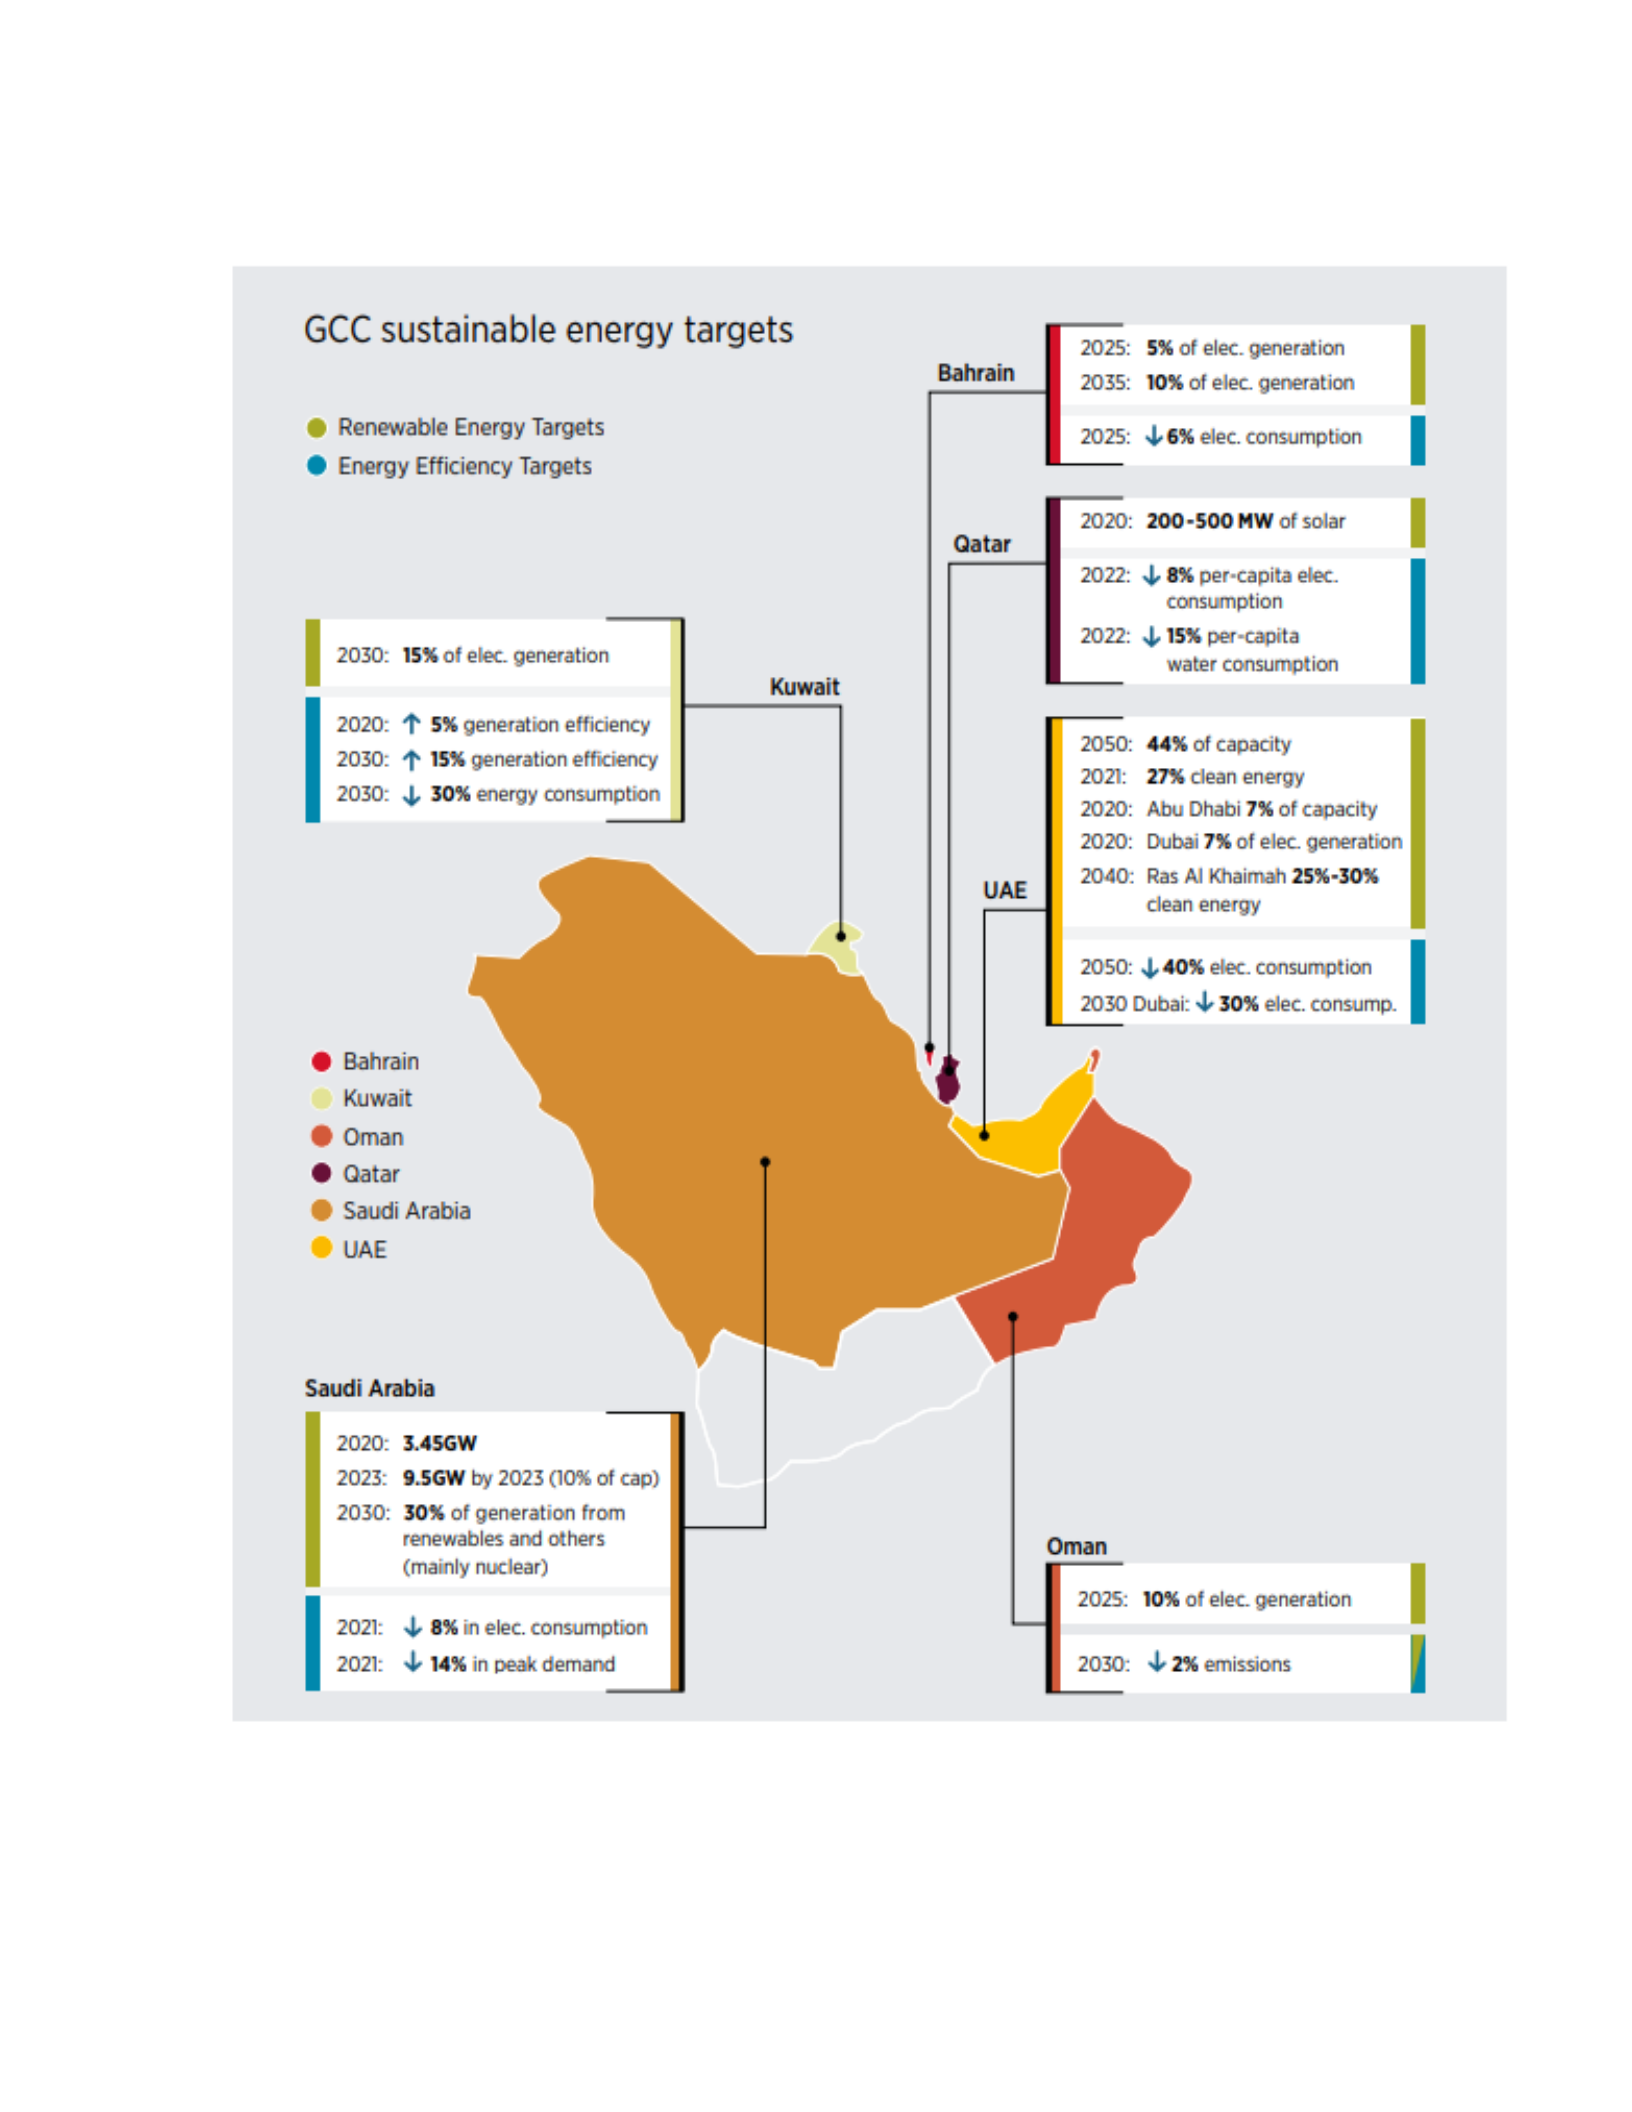
GCC
sustainable
energy
targets
5%
of
elec.
generation
OX
ct
elec
generation
@
Renewable
Energy
Targets
Lexatee
consumption
ff
©
Eneray
Efficiency
Taroets
aa
|
2022:
4
8%
per-capita
elec.
‘consumption
18%
per-capita
|
ee
‘ater
consmton
Kuwait
2020:
1
5%
generation
eticency
2030:
‘15M
generation
efficiency
2030:
J
30%
energy
consumption
2050:
44%
of
capacity
202:
27%
clean
energy
2020:
Abu
Dhabi
7%
of
capacity
2020:
Dubai
7%
of
eee.
generation
2040: Ras
Al
Khaimah
25%-50%
dean
energy
2050:
4,
40%
elec.
consumption
2030
Dubai:
30%
elec.
consump.
@
Bahrain
©
Kuwait
@
Oman
cater
©
Souci
Arabia
@
UE
Saudi
Arabia
2020:
B4SGW
2025:
9.5GW
by
2025
(10%
of
eap)
12030:
30%
of
generation
from
renewables
and
others
(mainly
nelear)
202
202
oe
waacomen
|
8%
in
elec.
consumption
tein
peak
demand
2080:
2%
emissions
1
72
Figure #17 Detailed sustainable targets of GCC countries (Irena, 2019)

73
GCC states fall in the "high category" for vulnerability to the adverse effects of climate
change: population growth, rapid urbanization, and wasteful consumption. Rising sea levels
have a severe impact on marine life, the coastline, and, as a result, the desalinization of plants,
the primary water sources. In addition, rising temperatures increase the demand for a very scarce
commodity: water. Desalinization plants are very costly to build and maintain, they use large
amounts of fuel, and using renewable energy to power them might be a viable solution to
environmental challenges (Reiche, 2020).
Furthermore, maintaining essential services in a hot and arid GCC climate has become
challenging due to rapid urbanization and economic and demographic growth. Electricity
demand is rising and may increase further because of climate change. Most electricity is used
for air conditioning and desalination processes (Zaidan et al., 2019). All these are in addition to
challenges for basic social equity, education for all, and gender equality.
Qatar’s current commitment to the Paris Agreement is to diversify the economy from
hydrocarbon to energy efficiency, clean energy and renewables, develop research and
development, education, and tourism. It also includes adaptation in water management,
infrastructure and transport, waste management, and awareness. Qatar Energy is committed to
zero routine flaring by 2030 and has signed an agreement to reduce methane emissions across the
natural gas value chain (IEA, 2022). Qatari National Vision 2030 promotes sustainable
economic development by achieving equality and social justice.
74
In October 2015, the United Arab Emirates submitted its climate action plan to the
United Nations. It was the 153rd country to pledge and the second GCC state after Oman to
submit to the United Nations its pledge to get 24 percent of energy from clean sources by 2021,
up from its 0.2 percent level of 2014. The UAE committed to reducing greenhouse gas (GHG)
emissions by 23.5 percent by 2030. In 2017, it adopted the National Climate Change Plan 2017-
2050, which sets a framework for the management of greenhouse gas (GHG) emissions,
innovative economic diversification, and climate change (United Nations, 2015).
Saudi Arabia’s Paris Agreement commitment aimed to generate 50 percent of electricity
with renewable, sustainable energy and 50 percent natural gas by 2030. Cut emissions by 278
million tons annually by 2030 and reach net zero by 2050 instead of 2060 (announced during
COP26). The Saudi Vision 2030 targets diversification and competitiveness building around
three pillars: a vibrant society, a thriving economy, and an ambitious nation. At the COP27
Climate Change global conference in Egypt, Saudi Arabia announced projects for clean
hydrogen, greening the desert, and 13 renewable energy projects generating a capacity of 11.4
gigawatts.
RESEARCH QUESTIONS
Research Question 1: Under what conditions will GCC countries transition to green energy?
Research Question 2: What are the conditions that will hinder the transition of GCC countries
to green energy?

75
CONCEPTUAL FRAMEWORKS
Substantial change is required on several levels for the energy transition to happen:
Universal access to affordable and reliable energy, increasing primary energy supply sustainable
sources, minimum levels of carbon emissions and pollutants resulting from production of energy,
reliable technologies, infrastructure, and sustainable practices for efficient energy consumption.
Complexity and scale determine the speed of energy transition (World Economic Forum, 2022).
United Nations Sustainable Development Goals
According to UNEP (United Nations Environment Program, 2010), Green Growth is an
economic development and growth that results in promoting and improving the well-being and
social equity of a society while reducing risks (UN, 2023). According to the OECD
(Organization for Economic Co-operation and Development, 2011), green growth is similar to
green economy. The Green Economy is an alternative vision for growth and development, an
economic development that includes the improvement of people’s lives that is parallel to
advancing environmental and social well-being. A critical aspect of a green economy strategy is
adopting and growing sustainable technologies (Soderholm, 2020).
This study will work within two main UN frameworks: The framework of the United
Nations Sustainable Development Goals (SDGs), and the 2030 Agenda that was adopted by
world leaders in September 2015 and came into force at a United Nations Summit on January
1st, 2016 (UN, 2016). The Goals call for action by all countries to promote prosperity while
protecting the planet. They understand that ending poverty goes parallel to building economic
growth that addresses education, health, social protection, job opportunities, and the protection of
the environment.
76
The three main areas for the current work on Green Economy are: 1) Advocacy of macro-
economic approach to sustainable economic growth through regional, sub-regional and national
forum 2) Demonstration of Green Economy approaches with a central focus on access to green
finance, technology, and investments 3) Support to countries in terms of development and
mainstreaming of macro-economic policies to support the transition to a Green Economy
(UNEP, 2022)
Although number SDG#7 of the 17 sustainable development goals of United Nations
deals directly with ensuring access to affordable, reliable, sustainable and modern energy for all,
other SDGs that are related to the topic of this study, are: Goal No. 8, Decent Work and
Economic Growth, Goal No. 9, Industry Innovation, and Infrastructure; Goal No. 10, reduced
Inequalities; Goal No. 11, Sustainable Cities and Communities, Goal 12, Sustainable
Consumption and Production; Goal 13, Climate Action; Goal No. 16, Peace Justice, and Strong
Institutions; goal No. 17, Partnerships For the Goals (UN, 2022).
Figure # 18- United Nations Sustainable Development Goal - SDG #7
The following are the indicators and the targets of the UN SDG#7:
1. Target 7.1 By 2030, ensure universal access to affordable, reliable, and modern
energy services: Indicator: 7.1.1 “Proportion of population with access to electricity.”

77
Indicator: 7.1.2 “Proportion of population with primary reliance on clean fuels and
technology.”
2. Target 7.2 By 2030, increase substantially the share of renewable energy in the global
energy mix: Indicator: 7.2.1 “Renewable energy share in the total final energy
consumption”
3. Target 7.3 By 2030, double the global rate of improvement in energy efficiency:
Indicator: 7.3.1 “Energy intensity measured in terms of primary energy and GDP.”
4. Target 7.a By 2030, enhance international cooperation to facilitate access to clean
energy research and technology, including renewable energy, energy efficiency and
advanced and cleaner fossil-fuel technology, and promote investment in energy
infrastructure and clean energy technology: Indicator: 7.4.1 “international financial
flows to developing countries in support of clean energy research and development and
renewable energy production, including in hybrid systems.”
5. Target 7.b By 2030, “Expand infrastructure and upgrade technology for supplying
modern and sustainable energy services for all in developing countries, in particular least
developed countries and small island developing States.” Indicator: 7.5.1 “Investments in
energy efficiency as a proportion of GDP and the amount of foreign direct investment in
financial transfer for infrastructure and technology to sustainable development services.”
To assess the trend, the United Nations looks at the change between the values in the initial
year and latest available value to calculate linear growth. SDG7 tracks the problem of the high
number of people globally who live without access to electricity or clean cooking solutions.
World Economic Forum Global Competitiveness Index (GCI)
World Economic Forum’s Global Competitiveness Index (GCI) is based on an aggregation of
103 individual indicators, built on data collected from international organizations and an
Executive Opinion Survey conducted by the Economic Forum. The index indicators are
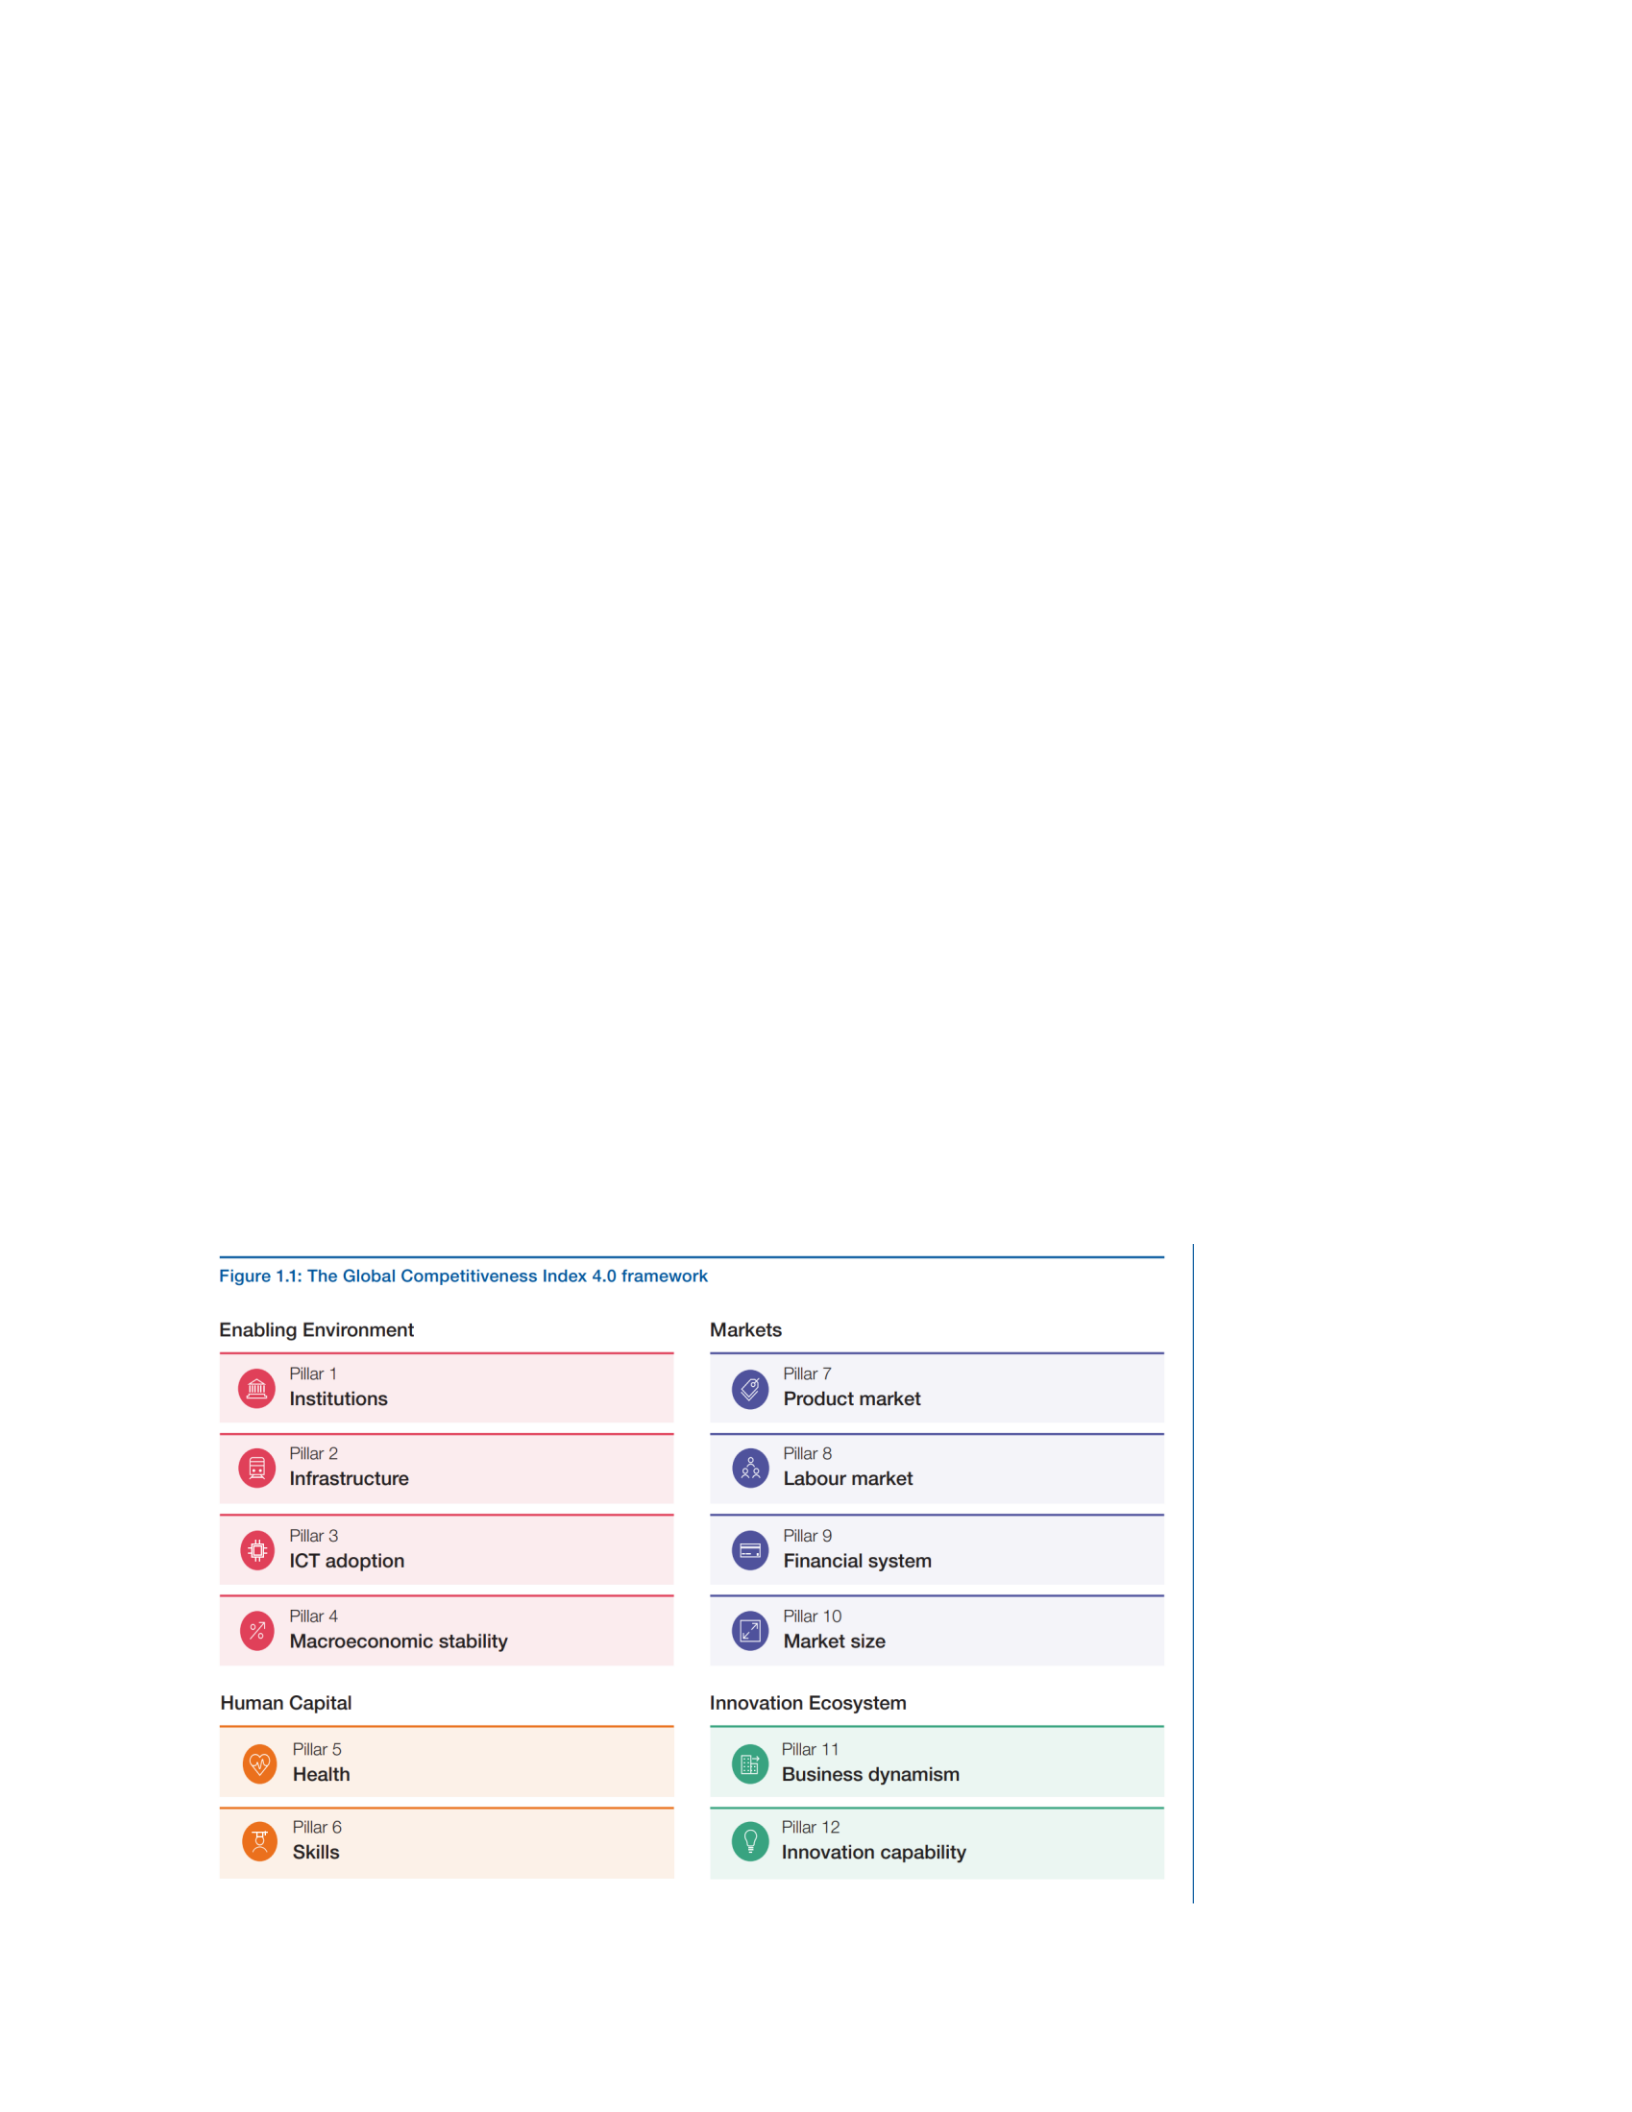
78
classified into 12 pillars: Institutions, Infrastructure, ICT Adoption, Macroeconomic Stability,
Health, Skills, Product Market, Labor market, Financial System, Market Size, Business
Dynamism, and Innovation Capability. A country’s performance involving each component of
the pillars is reported as a progress score.
The perfect score of 7 (or 100) indicates an ideal state where an issue stops being a barrier to
productivity growth (World Economic Forum, 2019). Competitiveness is a detailed map of the
factors and attributes that drive productivity growth and human development in the fourth
industrial revolution era (World Economic Forum, 2006). The report provides a detailed map of
the factors and attributes that drive productivity, growth, and human development for up to 144
countries in the era of the fourth Industrial Revolution. The following index shows the indicators
and the dimensions of the framework:
Figure # 19 - World Economic Forum Competitiveness Indicators & Dimensions
79
Anchored in growth accounting, economic literature aims to measure the drivers of total
factor productivity – the part of economic growth that is not explained by the growth in the
factors of production. The product of an aggregation of 103 individual indicators, derived from a
combination of data from international organizations and the World Economic Forum’s
Executive Opinion Survey. Detailed in its indicators that consist of 12 pillars (dimensions):
Institutions; Infrastructure; ICT adoption; Macroeconomic Stability; Health; Skills; Product
Market; Labor Market; Financial System; Market Size; Business Dynamics; Innovation
Capability
The Global Competitiveness reports, in general, cover 141 economies, accounting for 99
percent of the world’s GDP. They provide a detailed map of the factors and attributes that drove
productivity, growth, and human development in the fourth Industrial Revolution era. A
country’s performance is reported as a ‘progress score’; 100 represents an ideal state when an
issue stops constraining productivity growth. GCI allows economies to monitor progress,
emphasizing that competitiveness is not a zero-sum game between countries but is achievable for
all.
Contextual indicators and dimensions: The overall score is calculated based on the number of
participating countries, and each indicator and dimension have a total score of 100 points, 100
representing the best performance.

80
a. Enabling Environment:
• Pillar1: Institutions – Security, Social Capital, checks and Balances, Public sector
performance, Transparency, Property Rights, Corporate Governance
• Pillar 2: Infrastructure - Transport Infrastructure, Utility Infrastructure
• Pillar 3: ICT Adoption
• Pillar 4: Macroeconomic Stability.
b. Human Capital:
• Pillars5: Health
• Pillar 6: Skills – Current Workforce, Future Workforce, skills of Future Workforce,
domestic Competition, Trade Openness, Flexibility, Meritocracy and Incentivization
c. Markets:
• Pillar 7: Product market
• Pillar 8: Labor Market – Flexibility, Meritocracy & Incentivization
• Pillar 9: Financial System – Dept, Stability
• Pillar 10: Market Size
d. Innovation Ecosystem:
• Pillar 11: Business Dynamism – Administrative Requirements, Entrepreneurial culture
• Pillar 12: Innovation Capability - Interaction and Diversity, Research and Development,
Commercialization
Economic Freedom; Heritage Foundation
According to the Heritage Foundation (2021) Economic Freedom is "the fundamental right
of every human to control his or her labor and property.” In an economically free society, people
are accessible in the way they work, produce, invest, or consume, and governments allow labor,
81
goods, and capital to move freely. The ideals of economic freedom are closely associated with
societies with healthier GDP/Capita, cleaner environments, stronger human development,
prosperity, and democracy (Heritage Foundation, 2021).
The importance of economic freedom is in its ability to promote rapid growth and sustainable
social progress. According to the Heritage Organization, economic freedom has grown since
1995, globally. The global average score for Economic Freedom between 2020-2021 was 61.6.,
the highest recorded in the 27-year history of the Index. Five of the 178 economies ranked on
the Index are considered free, and an additional 92 are at least moderately free. Eighty-one
countries received below 60 and are rated "mostly unfree" or "repressed." Citizens of "free" or
"mostly free" countries enjoy incomes that are more than double the global average and more
than six times higher than in "repressed" economies. People in economically free societies live
longer and enjoy healthier lives. They have access to higher quality "social goods" such as
education, health care, and a cleaner environment (Heritage, 2021).
Economic Freedom measures the impact of liberty and free markets around the globe
(Heritage Foundation, 2023). In an economically free society, individuals can work, produce,
consume, and invest however they please. Governments allow labor, capital, and goods to move
freely and refrain from coercion on constraint of liberty beyond the extent necessary to protect
and maintain liberty itself. The measure of Economic Freedom is based on twelve quantitative
and qualitative dimensions grouped in four broad categories or pillars of economic freedom:
a. Rule of law: The dimensions are, property rights, judicial effectiveness, and government
integrity
b. Regulatory efficiency: Business freedom, labor freedom and monetary freedom
c. Government Size: Tax burden, government spending, and fiscal health

82
d. Open markets: Trade freedom, investment freedom, and financial freedom
Each of the pillars is graded on a scale of 0-100. A country’s overall score is derived by
averaging these twelve economic freedoms with equal weight being given to each. Economic
Freedom considers every component equally important to achieve economic freedom.
World Economic Forum Energy Transition Index
The World Economic Forum developed the ETI (Energy Transition Index), Figure #11, to
reflect the interdependencies of energy system transformation with the macro-economic,
political, regulatory, and social factors that determine a country’s readiness for transition. The
Index provides effective energy transition indicators and dimensions create a pathway for a
timely transition towards a more inclusive, sustainable, affordable, and secure energy system that
provides solutions to global energy-related challenges while creating value for business and
society.
The ETI, previously published as the Energy Architecture Performance Index (EAPI) by the
World Economic Forum, reflects the interdependencies of energy system transformation
involving macroeconomic, political, regulatory, and social factors that determine a country’s
readiness for transition. The framework has two parts: Current energy system
performance and enabling environment for the energy transition. System performance
provides an assessment of a county’s energy system related to its delivery in three key priorities:
1) ability to support economic development and growth, 2) universal access to a secure and
reliable energy supply, and 3) environmental sustainability across the energy value chain (World
Economic Forum, 2020).
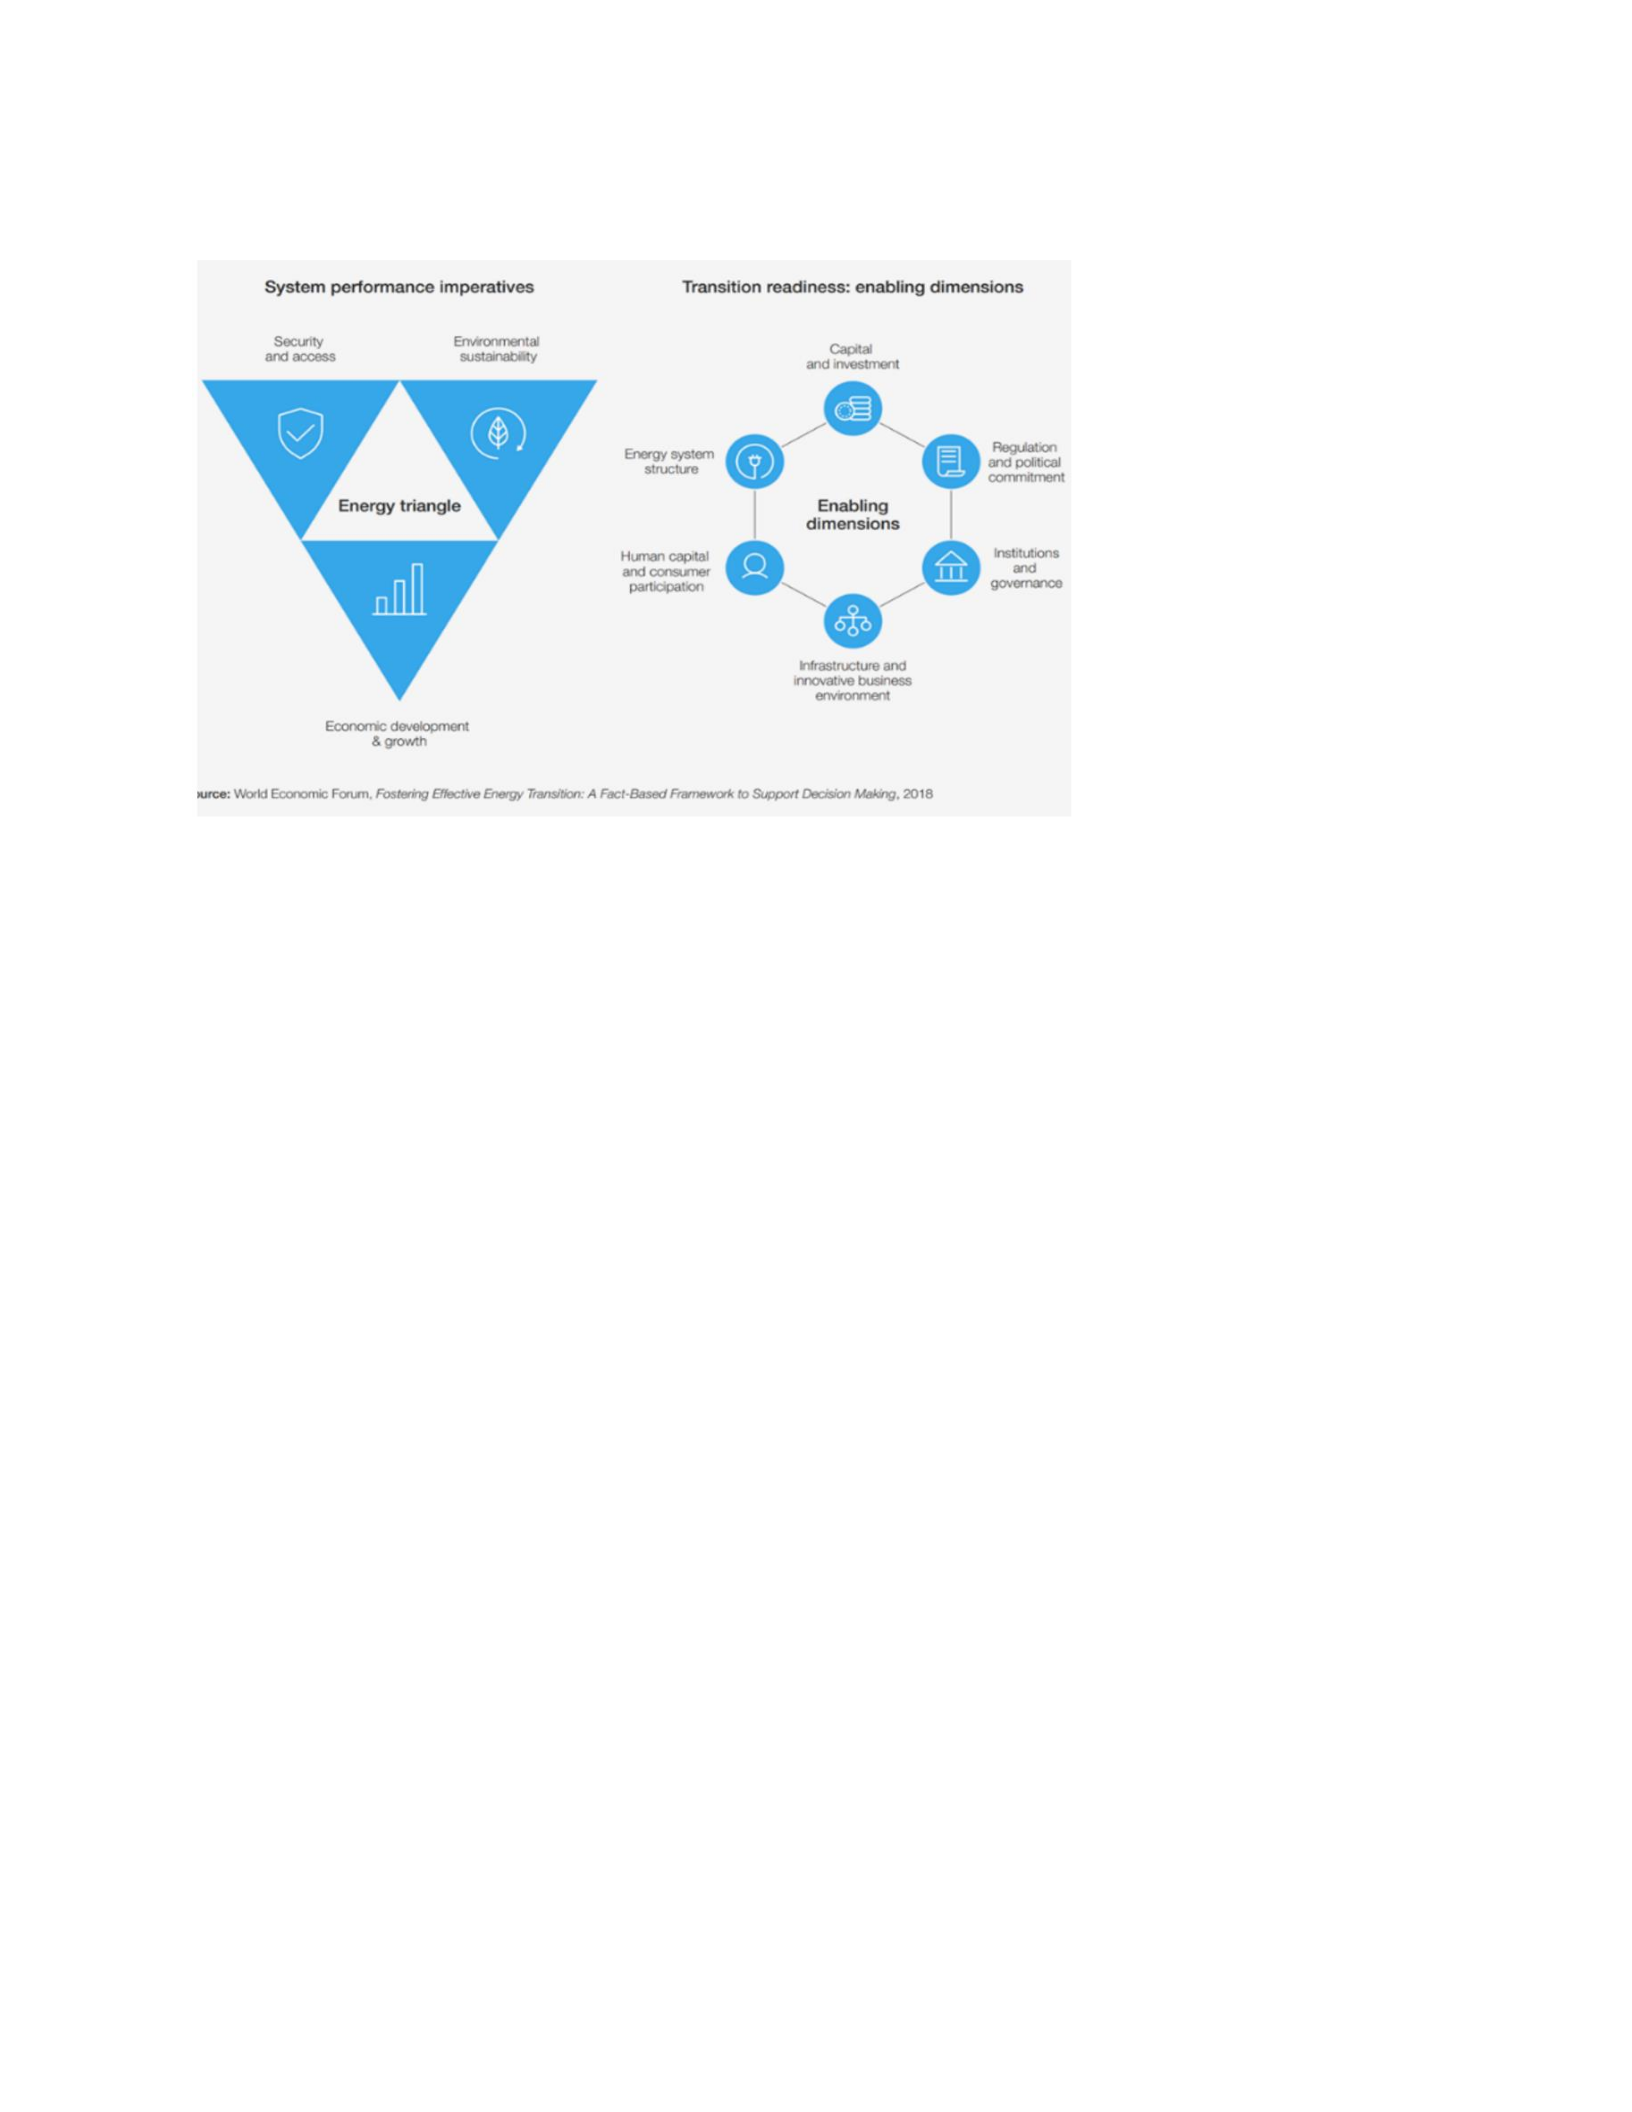
83
Figure #20 - World Economic Forum Entergy Transition Indicators
ETI tracks the
performance of energy
systems at the country
level. It incorporates
institutional,
macroeconomic,
geopolitical, and social
elements that enable the conditions for an effective transition to green energy. It comprises two
equally weighted sub-indices: Energy System Performance and Transition Readiness enabling
environment for the energy transition. System Performance: a balanced “energy triangle:” 1)
The ability to support economic development and growth 2) security, reliability, and universal
accessibility of energy 3) Environmental sustainability across the energy value chain.
The ETI report provides a data-driven framework to foster an understanding of the
performance and readiness of energy systems across countries for transition. The framework is:
Developed to reflect the interdependencies of energy system transformation with the macro-
economic, political, regulatory, and social factors that determine a country’s readiness for
transition. Energy transition is not restricted to linear shifts in fuel mix or substituting production
technologies. Rather, the social, economic, and technological systems need to co-evolve to shape
the transition.
84
a. Developed to reflect the interdependencies of energy system transformation with the macro
Economic, political, regulatory, and social factors determine a country’s readiness for transition.
Energy transition is not restricted to linear shifts in fuel mix or substituting production
technologies. Rather, the social, economic, and technological systems need to co-evolve to shape
the transition.
b. Comprehensive in its System Performance and Transition Readiness Imperatives:
Economic Development, Access to Security, Environmental Sustainability, Capital and
Investment, Regulation and Political Commitment, Institutions and Governance, Infrastructure
and Innovative Business Environment, and Human Capital Investment and Consumer
Participation. Some of the dimensions are based on factors beyond the scope of national
decision-making, such as commodity market volatility, geopolitics, international climate change
action and financial market sentiment.
ETI Indicators, Dimensions & Weights:
• System Performance
o Economic Growth & Development – 33 percent
o Energy Access Security – 33 percent
o Environmental Sustainability – 33 percent
• Transition Readiness Score
o Energy System Structure 17 percent
o Capital and Investment 17 percent
o Regulation and Political Commitment 17 percent
o Institutions and Governance 17 percent
o Infrastructure and Innovative Business Environment 17 percent
o Human Capital and Consumer Participation 17 percent
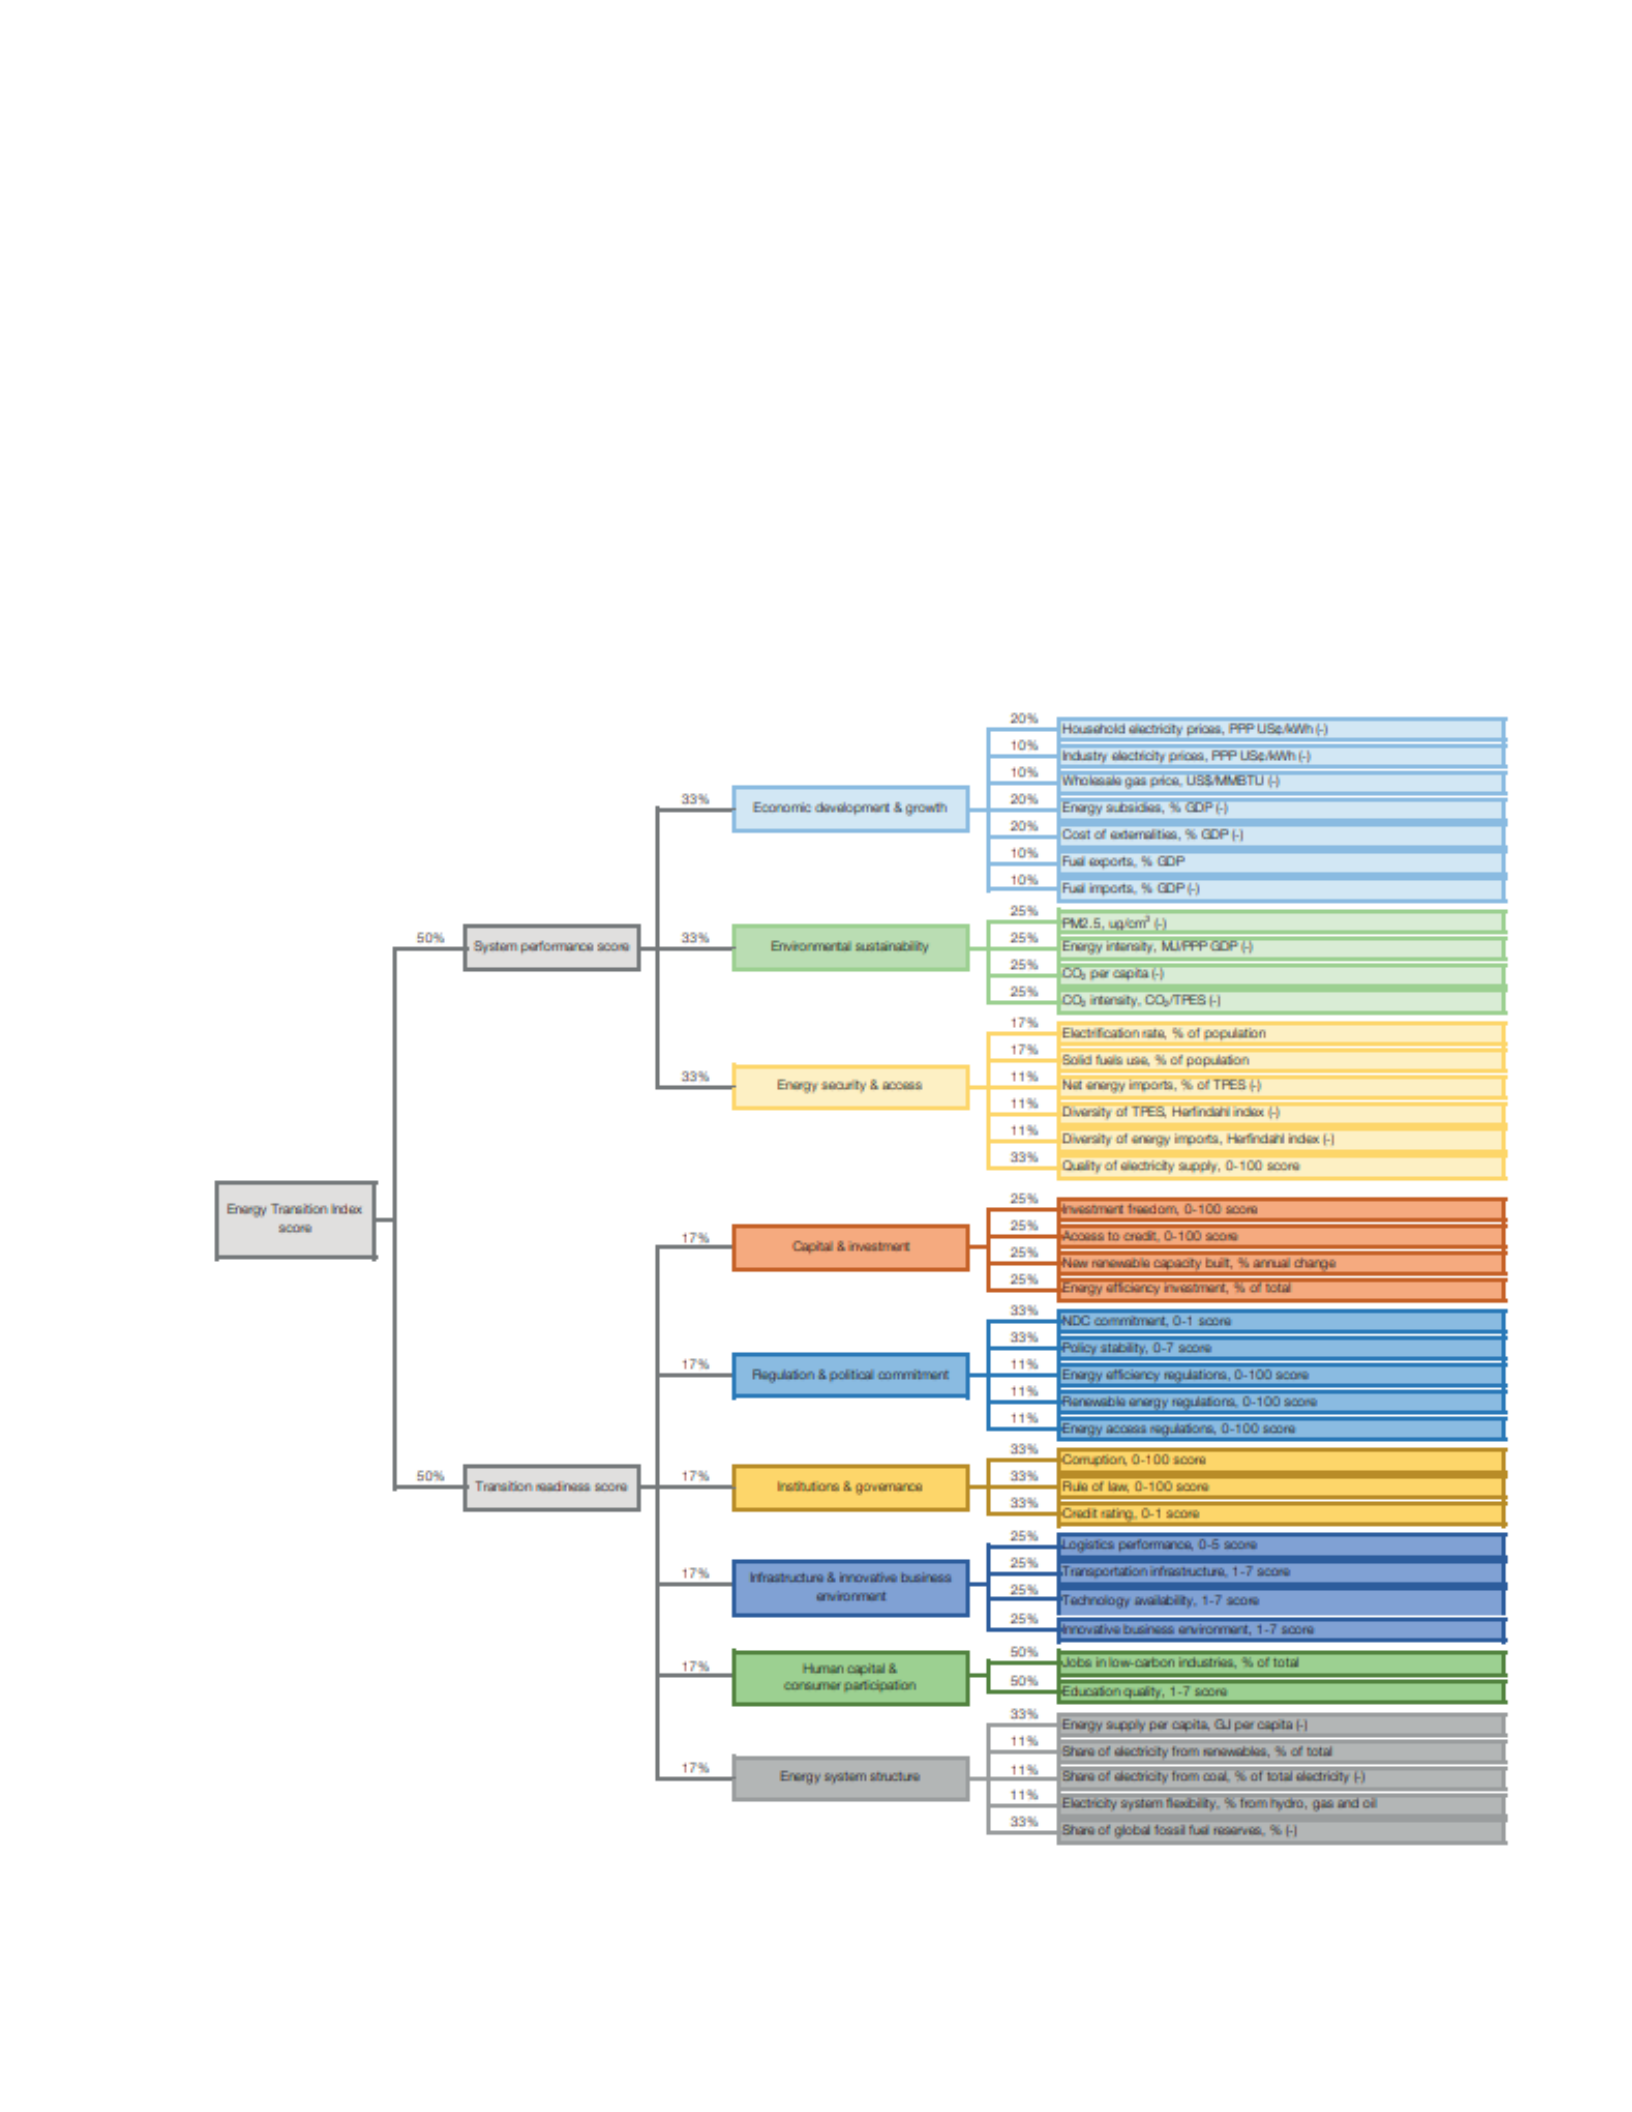
85
The above Energy Transition Index indicators and dimensions are closely related to
several UN SDGs: Goal number 7 (Affordable and clean Energy), Goal number 8 (Decent
Work & Economic Growth), Goal number 9 (Industry, Innovation and Infrastructure), Goal
number 10 (reduced inequalities), Goal number 11 (Sustainable cities and communities), Goal
number 12 (sustainable consumption and production), Goal Number 16 (Peace, Justice and
Strong Institutions), and Goal number 17 (Partnerships For the Goals).
Figure #21 - World Economic Forum Entergy Transition Score

86
MIT GFI Data Set
GFI measures the degree to which the economies of 76 countries depend on their ability
to develop a sustainable, low-carbon future. It measures the degree to which their economies
pivot toward clean energy, industry, architecture, and society through investment in renewable
innovation and green energy.
The overall rankings tab shows the performance of the examined economies relative to each
other and aggregates scores generated across the following five pillars: Carbon Emissions,
Energy Transition, Green Society, Clean Innovation, and Climate Policy. The research was
conducted through in-depth secondary research and analysis and interviews with global experts
on climate change, green energy, and technologies that will drive decarbonization.
Climate action: Scoring each country based on its climate mitigation commitment and
whether it is on track to meet its intended Paris Agreement targets. Measured from 1 (=critically
insufficient to meet targets) to 10 (=on track to meet GHG decrease levels to be compatible with
the 2 degrees goal) (Climate Action Tracker, MIT Technology Review Insight estimates).
Carbon Capture and Storage readiness – Scoring each country based on the status of its
carbon pricing initiatives: 1= no evidence of carbon taxes or carbon “markets” (emissions trading
system (ETS), 10=fully implemented carbon pricing system and ETS and all policies and
infrastructure and linked to national decarbonization plans (Carbon Pricing Dashboard by World
Bank).
Pillars of the MIT GFI measures consist of:
87
Pillar 1 Emissions Impact (15 percent) Evaluating each country’s carbon emissions and efforts
to reduce them, including the contributions from the transport, industry, and agriculture sectors
• Co2 emissions – Total Co2 emissions level, 10=lowest emissions in 2019 (Source: IEA,
EDGAR)
Pillar 2: Energy Transition – 15 percent; Evaluating each country’s utilization levels of
sustainable/renewable energy in running its economy
• Renewable Energy production growth between 2014 and 2019, 10=highest growth
(Source IEA,2022)
• Renewable Energy contribution, Renewable energy share in the total final energy
consumption, percent,2018, 10 = best performance (IEA,2022)
Nuclear energy production growth between 2015-2020, 10=highest growth (Source:
• Ember-climate)
• Nuclear energy contribution, nuclear energy share in the total electricity generation,
percent 2020, 10=best performance (Source: Ember-climate)
Pillar 3: Green Society (15 percent) Green Buildings are tangible and programmatic efforts to
positively affect social activities related to sustainability and greenhouse gas reduction, including
areas like protection of local habitats, recycling, meat and dairy consumption, and green
buildings
• Green Buildings – number of LEED-certified green buildings per million urban
population, 10 = best performance (Source: U.S. Green Building Council)
88
• Green Transport – electric passenger vehicle stock per million urban population, 2020,
10=best performance (Source: IEA, MIT Technology Review Insights estimates
Pillar 4: Clean Innovation (15 percent)- Measuring each economy’s contribution to sustainable
technology research and development, particularly related to climate change impact
• Green patents – Patents granted for environmental technology in 2016-2020, as a percent
of GDP IN 2020, 10=best performance (Source: WIPO)
• Cross-border renewables public investment – total renewables public investment received
and provided in 2016-20 as a percent of GDP in 2020, 10 = highest investment (Source:
IRENA)
• Foodtech private investment – Foodtech startups per million urban population,
10=highest investment (Source: Forward Fooding)
Pillar 5: Climate Policy (40 percent) – Evaluating state-level activities and overall policy
postures related to reducing greenhouse gases and taking the pandemic into consideration
Study and measure the Rank and Score of these countries against the:
• Dimensions of UN SDG #7 (Ensure access to affordable, reliable, sustainable, and modern
energy for all)
a) The commitment of Qatar, S. Arabia, and the UAE to their official statements at the Paris
Agreement, COP 26, and COP 27 Climate Change meetings
89
Study and measure the pillars of Global Competitiveness score (World Economic Forum) of
Qatar, S. Arabia & U.A.E. derived from a combination of the Forum’s Executive Opinion
Survey and data regarding their level of:
• Indicators: Enabling Environment, Human Capital, Markets, and Innovation Ecosystem
• Dimensions: Institutions; Infrastructure; ICT Adoption: Macroeconomic Stability;
Health; Skills; Product Market; Labor Market; financial System; Market Size; Business
Dynamism, and Innovation Capability
b) Study and measure the indicators and dimensions of the Energy Transition Index of World
Economic Forum for Qatar, S. Arabia, and U.A.E. - Developed to reflect the
interdependencies of energy system transformation with the macro-economic, political,
regulatory, and social factors that determine a country’s readiness for transition.
• Indicators: Energy System Performance and the Transition Readiness enabling
environment for the energy transition
• Dimensions: Security and access, environmental sustainability, Capital and investment,
Regulation and Political Commitment, Institutions and Governance, Infrastructure and
Innovative Business Environment, Human Capital and Consumer Participation, and
Energy System Structure
c) Study and measure the pillars of Green Future Index (MIT 2022) for all three countries to
understand the delta in their rank and score compared to 76 countries regarding their effort
in transitioning to green technology in the following indicators and dimensions: Overall
Ranking, Carbon Emissions, Energy Transition, Green Society, Clean Innovation &
Climate Policy
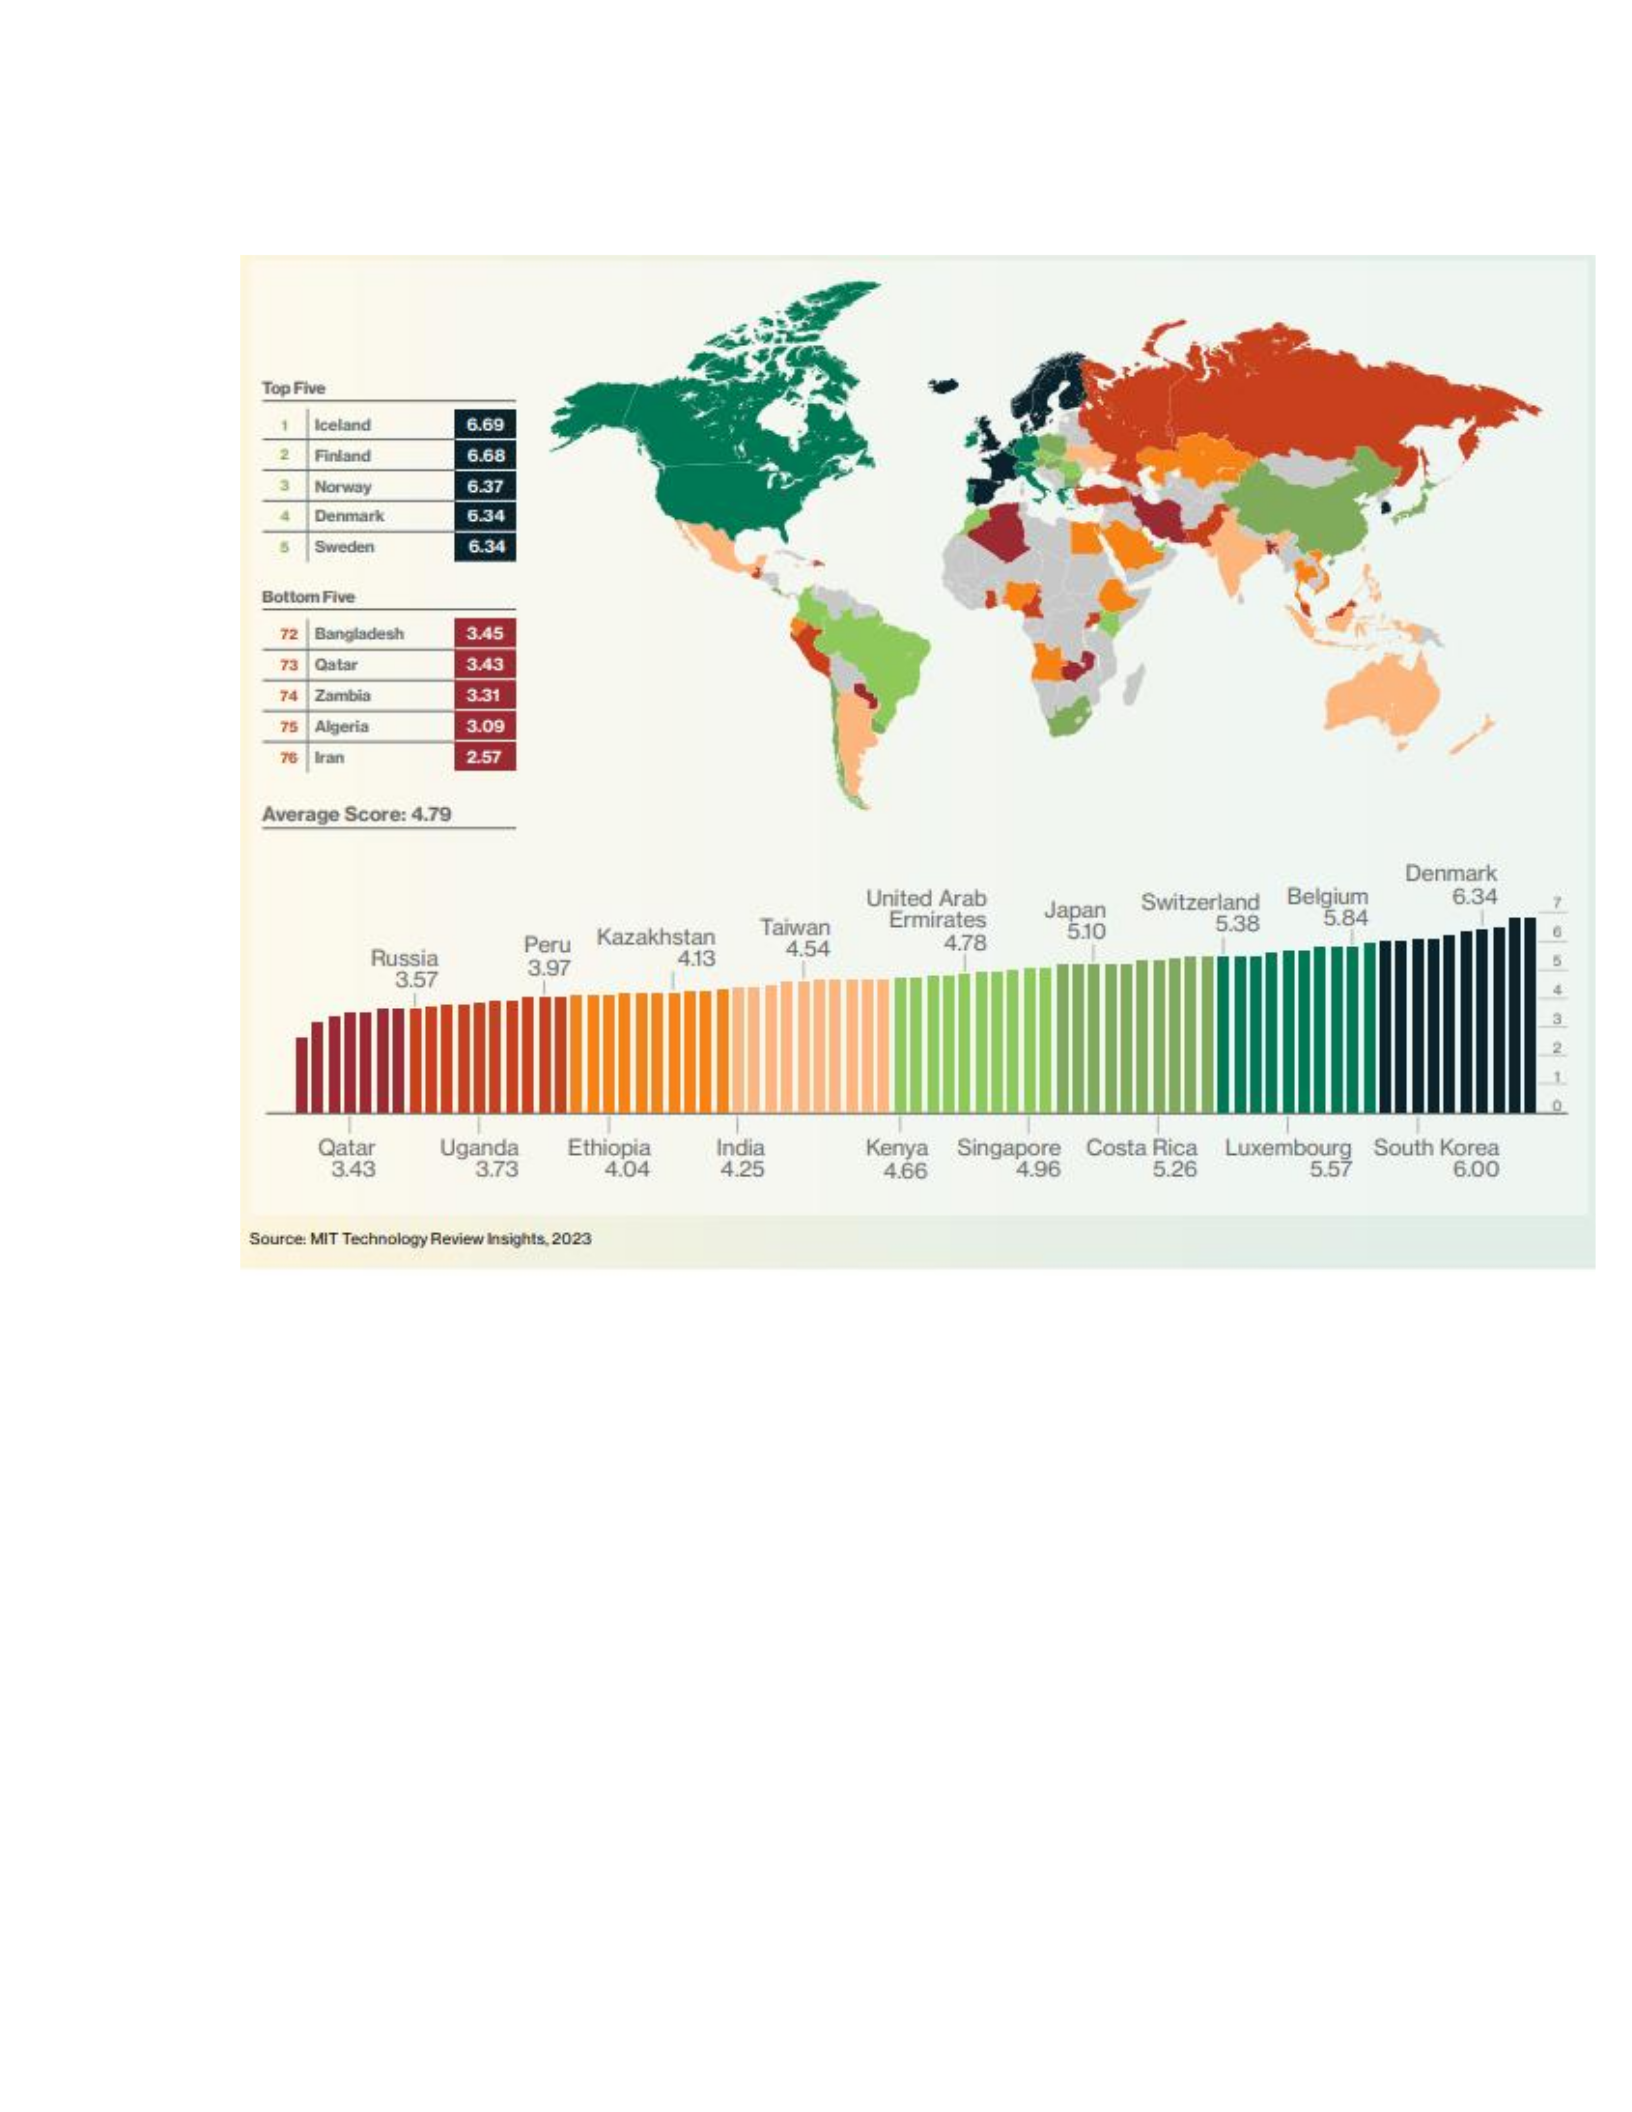
90
Figure # 22 - Green Future Index of MIT Ranking
Findings & Comparison
1) Measure the SDG#7, GCI, Economic Freedom, and ETI ranks, scores and performance
indicators and dimensions for all four indices for Qatar, S. Arabia and the U.A.E.
2) Compare them with the GFI index values for 2020, 2021 and 2022 to understand the
current perspective and Green Future Index country’ rank and score in each category
compared to the world as well as among the three GCC countries: Qatar, S. Arabia and
United Arab Emirates.

91
3) Find the level of correlations between the Dependent Variable (Transition Readiness)
with all 11 Independent Variables.
4) Provide a correlation table for the variables used in the regression
5) Provide a basic statistics table including mean, standard deviation, maximum and
minimum of each variable used in the regression
6) Run a regression on pooled data creating a dummy variable for SA and dummy variable
for U.A.E.
Analysis of Data
1) Run a regression analysis of the variables
2) Write short summaries of each model interpreting the meaning of the statistically significant
coefficients.
3) Identify the conditions that result/fail in green energy transition indicators/dimensions of all
three countries
4) Identify the country that demonstrates the conditions necessary to start transitioning
5) Identify the conditions that might help S. Arabia transition to green energy
6) Identify the conditions that will hinder S. Arabia’s transition to green energy
The variables
Dependent Variable:
• Transition Readiness
Independent Variables:
1. Capital Investment
2. Human Capital
3. Economic Freedom
4. Competitiveness
5. FDI Net Inflows
6. Institution & Government

92
7. Percent Oil Rent of GDP
8. Political Commitment
Control Variables:
1. Time Series 2010-2020
2. Countries: Qatar, S. Arabia, and United Arab Emirates
Data to be Collected
Secondary Data:
1. GDP Share by Industry Sector
2. GDP/capita Changes in Economic Activity
3. Oil percentage of GDP
4. Investments (public, private) in Green Projects
5. Patents Granted in the Field of Green Energy
6. Human Capacity
7. Government Expenditure
8. Government Oil Revenue as Share of GDP
9. Competitiveness Index Indicators & Dimensions
10. Economic Freedom Index Indicators & Dimensions
11. Energy Transition Readiness Index Indicators & Dimensions
12. United Nations SDGs
13. Energy System Performance
14. Country Macroeconomic Indicators
15. Inclusivity in Employment
16. Global/ Partnerships and Collaboration
17. OPEC prices in Global Markets
18. Country Import/Export Percent of GDP
19. Global Green Energy Transition Conferences
20. Exchange Rates
21. Number of national and Expatriate Workers
22. Subsidies

93
23. Government Expenditure
24. Policies
25. Government Investments
26. Unemployment Rate
27. Green Projects
28. Renewable Energy Capacity
29. FDI Inflows
Secondary Data Sources
1. World Economic Forum
2. World Bank
3. IMF
4. United Nations
5. IRENA
6. MIT Green Growth Index
7. International Atomic Energy Agency
8. The Heritage Foundation
9. Global Green Energy Transition Conferences
10. Gulf International
11. Peer Reviewed Research
12. Country Consulates & Embassies
13. Books related to GCC political, economic, social, and environmental issues
14. The Economist
15. IAEA
16. Statista
17. Consulate of Qatar
18. Consulate of U.A.E.
19. Consulate of Saudi Arabia
20. Claremont Graduate University Libraries
21. Gulf International

94
22. Peer Reviewed Research
23. GCC Annual Meetings
24. Peer Reviewed articles

95
Chapter 4
Correlations Between Dependent and Independent Variables &
Discussion and Analysis of Research Outcomes
96
CORRELATION
COEFFICIENTS
OF DV & IV’
CORRELATIONS
All 3
Countries
Qatar
S. Arabia
U.A.E.
Indications
ETI & SDG#7
(-0.11672)
(0.770932)
(-0.63397)
(0.881348)
a. Negative correlation coefficient of S. Arabia seems to be affecting the
correlation coefficient of all the countries combined.
b. Qatar’s has the highest ETI score of all three states. It remains below the world
average until around 2013 and very close to the world average starting towards
the end of 2019. The scores experience a negative change between 2015-2018
(Collapse of the oil price in mid-2014, the Arab Spring & Regional Boycott
against Qatar).
c. While Qatar and U.A.E. show increases in both ETI & SDG#7 scores between
2016-2021, S. Arabia shows a decrease in its ETI scores between 2016-2020
hence its negative inverse correlation with SDG#7. The relationship of these
two for S. Arabia is an inverse correlation. They change in opposing
directions perhaps, because 1) Saudi Arabia is heavily involved in CCS and
CCUS projects and hydrogen and hydrogen derivatives 2) the level of political
will does not exist the way it does with Qatar and the U.A.E.
d. U.A.E. has a high correlation. The trajectory of ETI & SDG#7 have the same
upward direction and run linear throughout 2012-2021. U.A.E.'s ETI score
runs closer to the world average in a steady way throughout the period of
2012-2021. It experiences a small dip during 2015-2018 (After the collapse of
prices in 2014). It stays above the regional average throughout 2012-2020.
U.A.E. has the highest SDG#7 score and ETI scores. Although Qatar has the
highest ETI score, U.A.E. has the highest positive change in ETI score between
2014-2022 (Qatar, +2.53, S. Arabia +5.33, and U.A.E. is +6.4)
ETI &System
Performance
(0.611787)
(0.97897)
(0.38891)
(0.51459)
a. Moderate correlation coefficient for all the three countries combined between
Energy Transition Index and System Performance (GCC countries provide
reliable, inexpensive energy available to all and have secure energy reserves).
b. Qatar Correlation between System Performance and SDG#7 is very high, and
the highest among the three countries. This is because: Qatar has the highest
score in Energy Performance– Liquid fuels supply chains are established and
well connected. The country has consistent positive change in its ETI score
between 2013-2021. Qatar’s major income, 34 percent of GDP comes from
Liquefied Natural Gas, the cleanest form of fossil fuels classified as energy
transition fuel.
c. Saudi Arabia seems to have the lowest correlation coefficient of all three
countries perhaps because it has the lowest ETI scores of all the three
countries.
d. The U.A.E. has a moderate level of correlation. Until 2019, they move in the
same direction; however, they change after 2019-2021 perhaps because of
COVID
e. ETI scores measure a country’s current energy system, but not how fast they
are transitioning. Momentum shows who is transitioning the fastest
Table #4, Analysis of Correlations
97
Energy System
performance &
SDG#7
(0.20935)
(0.69834)
(-0.398491)
(0.490815)
a. Correlation system Performance & SDG#7 for all countries combined has a
very low; however, positive correlation. Energy System Performance and
SDG#7 trajectory move together in the same direction.
b. S. Arabia System Performance and SDG#7 have a negative correlation. As S.
Arabia’s SDG#7 trajectory of score goes up, its energy system performance
score goes down. Possible explanation: S. Arabia’s 1) energy transition is not
supporting economic development and growth 2) environmental sustainability
across the value chain is lacking 3) existing energy system in S. Arabia is still
supporting the traditional energy System for Oil production & exporting.
c. Qatar has the highest correlation perhaps because it has the highest score in
Energy System Performance compared with the other two countries.
d. The U.A.E. has a moderate correlation; however, after 2019 Energy System
Performance and SDG#7 move in the opposite direction due to COVID-19
inefficiencies and reduced global demand and market prices.
e. The dimensions of System Performance are similar to that of SDG#7. As a
result, the better the System Performance, the better the commitment to SDG#7
Transition
Readiness &
SDG#7
(- 0.23129)
(0.757006)
(-0.72983)
(0.847362)
a. The negative correlation for all three countries combined might be the result of
a relatively high negative correlation between the two variables for S. Arabia
b. Qatar has a highly positive correlation between the two variables. Both
variables have linear trajectory, and they move very close to each other
c. S. Arabia has a moderately high but negative Correlation of Transition &
SDG#7 perhaps because it has the lowest mean scores for the following three
Transition Readiness Dimensions: Human Capital, Infrastructure Investment
& Business Environment, Institutions and Government, Regulation & Political
Commitment (see below graph. Around 2017, the Transition Readiness goes
down and stays down until mid-2020.
d. U.A.E. has the highest Correlation of Transition Readiness & SDG#7
correlation followed by Qatar. Transition Readiness and SDG#7 move very
closely and in the same upward direction throughout 2012-2021. U.A.E. has
both the highest SDG7& and Transition Readiness scores. U.A.E. is closer to
ensuring universal access to affordable, reliable, and modern energy services,
sustainability, and improvement of energy efficiency
e. The conditions for transition readiness in these countries are less aligned with
the requirements of the SDG#7 than the Energy System Performance
f. There is a positive correlation between Energy System Performance and
SDG#7 for all countries, but negative with Transition Readiness & SDG#7.
The better the Energy System Performance, the better SDG#7
Transition
Readiness &
Capital Investment
(0.377619)
(0.914747)
(0.410548)
(0.941474)
a. All three countries have a positive correlation between Transition readiness &
capital Investment.
b. Qatar and U.A.E. have a very high, positive correlation between the two
variables. Qatar’s Transition Readiness has an almost constant performance
throughout the period between 2012-2017; however, Capital & Investment slope
experiences a dip during the period of 2014-2016 (Arab Spring, largest oil price
declines (70 percent) due to U.S. fracking – oil production) and experiences an
increase towards the beginning of 2018 until 2021(Boycott against Qatar).
c. S. Arabia has the lowest Correlation between Transition Readiness and Capital
Investment. The trajectory of Transition Readiness and Capital & Investment
98
is very similar until the year 2017 when the level of transition readiness drops
and picks up towards the end of 2019 (the oil prices were negatively affected
due to fall in global demand). After 2020 the trajectory of TR and Capital
Investments proceed in almost a parallel fashion. It seems S. Arabia has a low
level of Capital and Investment necessary to jump start Green Energy startups
and conditions for transition readiness. Its level of capital investment related
to green energy transition readiness seems very low. It also has low investment
in clean transport to facilitate the use of electric vehicles
d. The U.A.E. has the most significant, positive, linear Transition Readiness and
Capital Investment correlation. The trajectory of both variables is positive
throughout 2012-2021. However, similar to Qatar and S. Arabia, U.A.E.
Capital investment increases sharply after 2018 (GDP drop due to low oil
prices and fiscal austerity). The U.A.E. has both the highest level of capital
investment and Transition Readiness
e. The higher the Capital Investment, the higher the transition.
Transition
Readiness &
Human Capital
(.408196)
(.878222)
(.782675)
(.904598)
a. All three countries have Transition Readiness and Human Capital correlations
that are very high. Since correlation of Transition Readiness and Capital &
Investment for all countries was also positive (0.377619), these correlations
show that both dimensions have similar weigh on determining the ET score,
and they are moving in the same linear direction
b. Qatar has a very high correlation of Transition Readiness & Human Capital.
The movement of their trajectory is very close and linear. Qatar has the
highest score in Human Capital. “Qatarization” started after 2005 after the
GCC Secretary General warned against massive presence of expatriate as a
security issue. Qatarization plays a big role in investment in human capital
that ensures knowledge transfer for future generations of Qataris. A study
(RAND) shows that for every 100 Qatari women with university
qualifications, there are only 46 Qatari men equally qualified (by age 25)
c. Saudi Arabia has a high correlation. The variables move very closely and in
the same direction; however, between 2017-2018 Human Capital takes a deep
dive and starts coming back mid 2020 (unemployment rate increased from 10
percent in 2008 to 12.8 percent in 2017 mostly female and youth
unemployment) (IMF 2018).
d. The U.A.E. Transition Readiness and Human Capital correlation is the highest
(.904598) of them all. U.A.E. has the highest score in Transition Readiness
among the three countries for the period of 2010-2021. This is part of the
“Emiritization,” the government committing to increasing the number of
nationals in private companies.
e. These correlations show that both Capital Investment and Human Capital
dimensions have similar significant weight on determining the Transition
Readiness score. The reason being that both Independent Variables are critical
to building a new disruptive technology startup necessary to start the transition
to green energy and economy
f. Human Capital seems to be very important for green Energy Transition
Readiness – Human capital in the areas of science, technology and
management leads to increases in innovation, social well-being, equality, and
increased productivity that contribute to economic growth
99
Transition
readiness &
competitiveness
(0.611962)
(-0.56077)
(0.471669)
(0.232663)
a. All three countries combined show a moderate correlation between Transition
readiness & Competitiveness
b. These figures are not very reliable because data for 2020-2021 is missing for
all three countries.
c. Qatar has a negative Transition Readiness Competitiveness correlation. Until
2018, both variables grow in the same direction and then in opposite direction
until 2021. In 2017, the level of Transition Readiness dips and it recovers early
2020 – most probably because despite Qatar’s substantial gas reserves, the
resource availability indicator is low because it lacks adequate water resources
and land area to compete in RE production. Qatar is well suited for the energy
transition due to its abundance of cleanest form of fossil fuels; natural gas but
not RE The small population and heavy industrial activity, which includes oil
and gas extraction, natural gas liquification and petrochemical production,
make Qatar one of the highest emitters of carbon dioxide (CO2) per capita.
This is in addition to the fact that Qatar uses natural gas for all water, power,
and food production.
d. S. Arabia has the highest positive correlation between Transition Readiness
and Competitiveness correlation = (0.471669) even though it is lagging in
production of Renewable Energy capacity. The competitiveness in this
category might be addressing the fact that S. Arabia has developed expertise in
carbon capture (Aramco Hawiyah plant reinjects C02 into oil reservoirs for
enhanced recovery and sequesters 800 thousand tons of Co2/year) (ibid).
Furthermore, the country aimed to address the depressed demand for
hydrocarbons by becoming a leading exporter of hydrogen (NEOM
megaproject, the futuristic city would host the world’s largest green hydrogen
production plant). The energy subsidy reforms and allowance of competition
and participation in the energy markets, enhancing energy efficiency in
buildings through certifications, supporting the clean energy in energy
intensive sectors such as desalination or petrochemicals might be the reason
why the correlation is higher than the other two countries.
e. Even though the correlation between the two variables is lower than that of S.
Arabia, U.A.E. has the most consistent, upward slope, linear score of
Transition Readiness. U.A.E. has the highest Transition Readiness score and
RE capacity of them all. Therefore, the competition values might not be
reflective of green energy
f. Even though S. Arabia’s correlation of Transition Readiness &
Competitiveness is the highest of all three countries, S. Arabia’s has the lowest
RE capacity. Therefore, competitiveness might not important in Transition
Readiness to Green Energy.
Transition
readiness &
Economic
Freedom
(0.8247947)
(0.452876)
(0.605235)
(0.785787)
a. Economic Freedom has a high correlation for all three countries combined
b. Transition Readiness and Economic Freedom correlation for Qatar has the
lowest (0.452876).
c. S. Arabia’s has the lowest scores in Economic Freedom of all three countries.
The slope for the two variables starts almost identical. However, between 2017
100
to 2020, both transition Readiness and Economic Freedom scores dip
(following oil demand and price decrease in the same period).
d. U.A.E. has the highest correlation of all three countries. Transition Readiness
scores as well as Economic Freedom scores for the period 2012-2021 are the
highest. The variables have an identical, positive linear growth except for
2020 when economic freedom dips and then catches up fast mid-2021.
e. Economic Freedom seems to be more important for Transition Readiness than
Competitiveness for all the three countries combined. The higher the
Economic Freedom, the higher the level of Green Energy Transition
Transition
Readiness & FDI
Net Inflows
(-0.39443)
(-0.83778)
(-0.90775)
(0.912468)
a. There is a low, negative correlation between the two variables for all three
countries combined. Most probably because Qatar and S. Arabia have a
negative correlation between Transition Readiness & FDI Net Inflows.
b. Qatar and Saudi Arabia have a high and negative correlation between the two
variables, the variables grow in opposite directions. The FDI inflows for both
countries show very low scores. For the transition to happen these countries
need to import technology, innovation, and green energy knowledge from
outside. The interim engine of growth and transition for S. Arabia has been
hydrogen, C02 capturing projects and oil revenue for Saudi Arabia and Liquid
Natural Gas for Qatar.
c. The U.A.E. has the highest level of FDI inflows of all three countries. Its
transition Readiness and Net Inflow FDI variables have a consistent, positive
slope that run in the same direction until 2020 (the numbers are not reliable
after 2020). The U.A.E., Transition Readiness correlation with FDI Net
Inflows is highly significant and positive. This might be because the FDI’s in
U.A.E. are related to the energy Transition Readiness. Abu Dhabi National Oil
Co., Taqa and holding company Mubadala entered a partnership to become
shareholders of renewable energy company Masdar to create a strong Clean
Energy portfolio. This partnership will launch over 23 GW of current and
renewable energy capacity. It positions Masdar as one of the largest clean
energy companies globally with ambition to grow to well over 50GW by 2030.
Today, oil exports account for only about 30 percent of the UAE economic
activity. U.A.E. operates three nuclear power reactors and is home to the
largest and lowest-cost solar plants in the world. It is the first in the region to
deploy industrial-scale carbon capture technology. The world will need gas
and oil in the interim and the U.A.E. is working on having a low-carbon oil
and gas and as such, its hydrocarbons are among the least carbon intensive in
the world (U.A.E. Embassy, 2022).
d. The higher the FDI inflows, the higher Transition Readiness
Transition
Readiness &
Institutions &
Government
(0.686791)
(-0.75143)
(-0.41573)
(0.85457)
e. Qatar has moderately high, negative Transition Readiness and Institutions &
Government correlation
f. Saudi Arabia has a negative correlation for these two variables.
g. U.A.E. has the only highly significant and positive correlation between
Transition Readiness and Institutions & Government. It was the first Gulf
state to announce a national climate strategy in 2017, and the first to link its
climate strategy with its economic development plans for which the U.A.E.
Green Agenda 2015-2030 was established. The U.A.E Council on climate
Change and Environment, established in 2016 is the committee responsible for
overseeing the implantation of the Green Agenda. To date, only the U.A.E. has
101
put forward an economy-wide strategy paving the way to achieving their net-
zero targets.
Transition
Readiness and
percent of Oil Rent
of GDP
(-0.41785)
(-0.61456)
(0.388745)
( -0.63171)
a. All three countries combined show a negative correlation. Transition
Readiness and the percent of oil rent of GDP portion are moving in opposite
directions because of decrease in global demand and the instable market
prices.
b. S. Arabia shows a positive, Transition Readiness and percent Oil Rent of GDP
correlation. Saudi Arabia has the highest percent of oil rent of its GDP and
seems to be the one with the lowest momentum transitioning to green energy.
c. The U.A.E. and Qatar show a moderate, negative Transition Readiness and
percent Oil Rent of GDP correlation.
d. Any increase in Transition Readiness seems to be resulting in the percentage
of oil rent of the GDP.
e.
Transition
Readiness &
Political
Commitment
(0.241631)
(0.49379)
(-0.04756)
(0.92776)
a. Transition Readiness and Political Commitment for all three countries
combined has a low and negative significance.
b. Qatar political commitment has a low correlation with Transition Readiness.
Although both have a linear upward growth; however, Political Commitment
starting 2017 (Boycott against Qatar of other GCC countries) experiences a
sharp decrease until mid-2019.
c. Saudi Arabia Political Commitment has a very low, negative correlation with
Transition Readiness. Mid-2016, the variables grow in opposite directions
because GDP growth is slow, inflation is high and a shift to respond to low oil
prices.
d. The U.A.E. has a very high Transition Readiness and Political Commitment
correlation coefficient = (0.92776). Both variables have a linear growth.
U.A.E. has the highest scores in Political Commitment throughout 2012-2021.
The higher the Political Commitment, the higher the Transition Readiness.

102
Findings
1. Correlation of the variables that are critical to Transition Readiness (DV):
1) Commitment to SDG#7 requirements is more important for all three countries than Energy
Transition Readiness.
• All three countries have higher scores in SDG#7 than in Transition Readiness.
• Committing to SDG#7 goals involves more transparency globally and geopolitically than
local transition readiness
2) ETI scores measure a country’s current energy system but not how fast they are transitioning
3) For all countries combined, SDG#7 has a Positive correlation with system performance but a
negative one with transition readiness. The better the system performance, the better the
SDG#7
4) The conditions for transition readiness in these countries are less aligned with the
requirements of SDG#7 than the Energy System Performance. The higher the SDG#7
number, the higher the Correlation between SDG#7 and Energy System Performance
5) There is a positive correlation between Energy System Performance and SDG#7 for all
countries but a negative with Transition Readiness and SDG#7. The better the Energy
System Performance, the better SDG#7.
6) Since the correlation between Transition Readiness and Capital and investment for all
countries is positive, these correlations show that both dimensions have similar weight in
determining the ET score and are moving in the same linear direction.
7) The correlation between Energy Systems and Transition Readiness is highly significant.
8) Economic Freedom is more important for Energy Transition than Competitiveness.
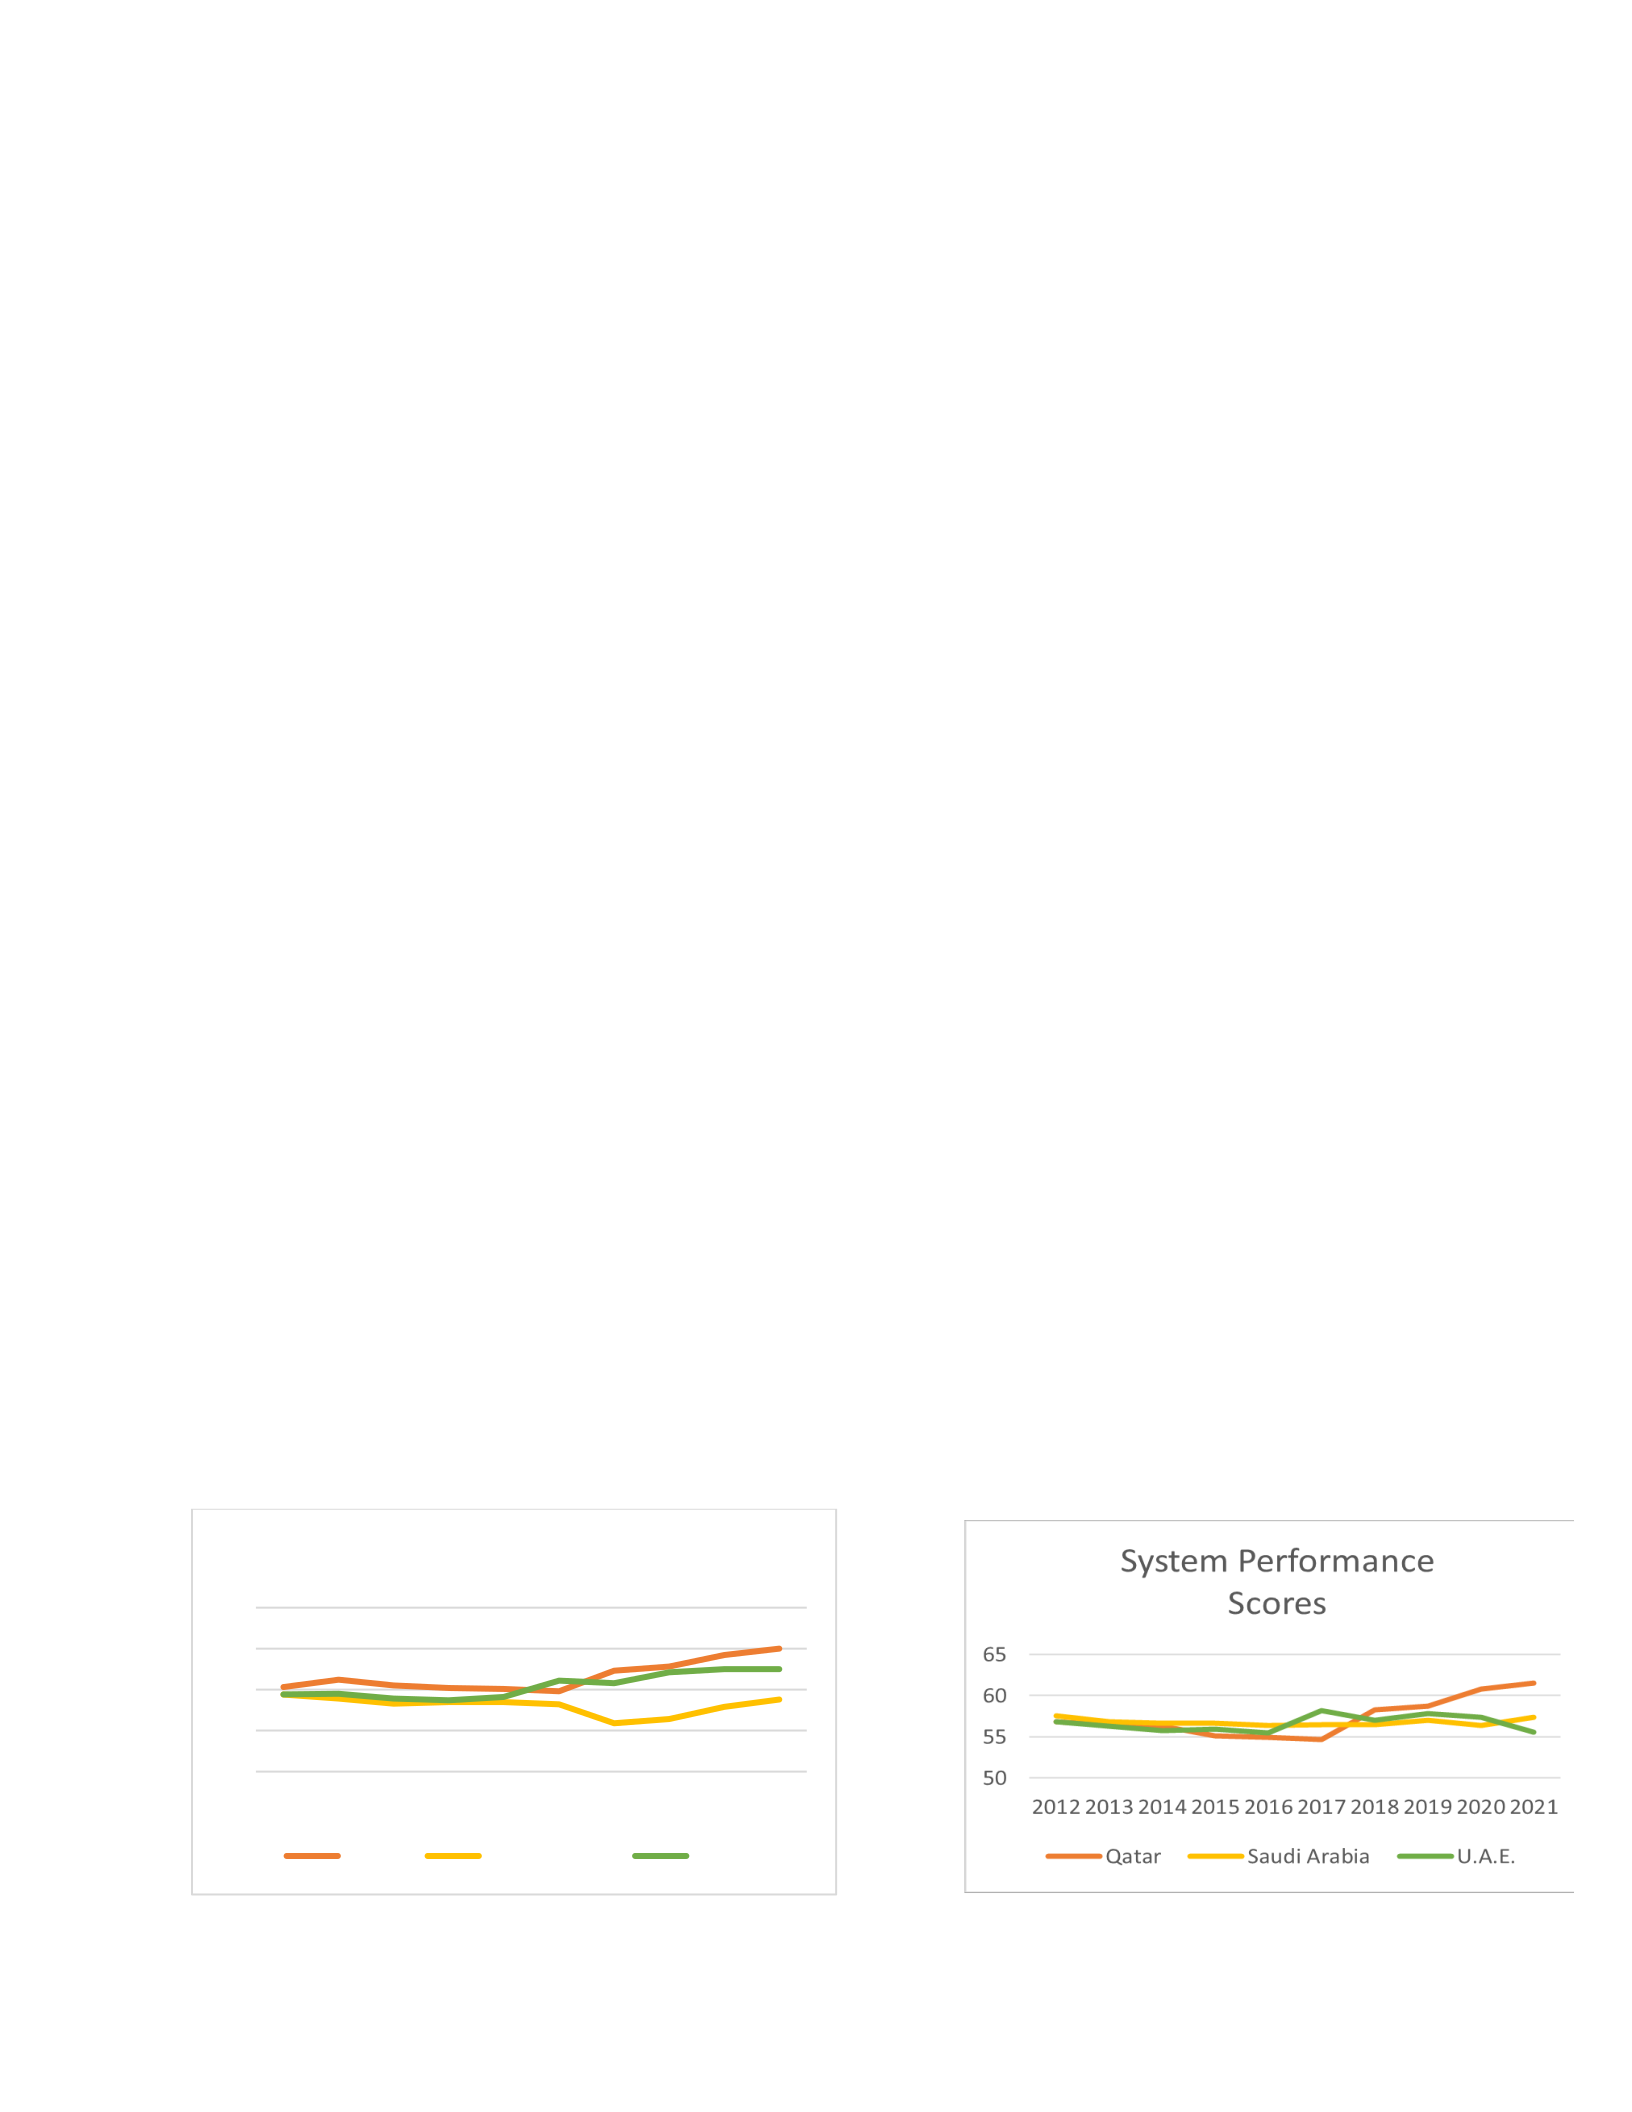
103
9) Capital Investment and Human Capital dimensions have similar significant weight in
determining the Transition Readiness score.
• They both have a very high correlation with the Transition Readiness Dependent
Variable.
• Independent Variables, Capital Investment, and Human Capital are critical to building a
new disruptive technology startup necessary to start the transition to green energy and
economy.
• The higher the capital investment in green energy, the higher the transition
10) Capital Investment, Energy Systems, Competitiveness, and percent of Oil Rent to GDP have
high collinearity
11) Human Capital and Capital Investments are very important for Transition Readiness.
12) The better the system performance, the better the SDG#7 score.
13) The lower the percent oil rent of GDP, the lower the reliance on fossil fuel revenue and
perhaps, higher the energy transition (negative correlation).
2. The Conditions that are Enabling the UAE’s Transition to Green Energy
Figure #23 – ETI Scores
45
50
55
60
65
2012 2013 2014 2015 2016 2017 2018 2019 2020 2021
ETI Score
Qatar Saudi Arabia U.A.E.
Figure #24– Energy System Performance Scores
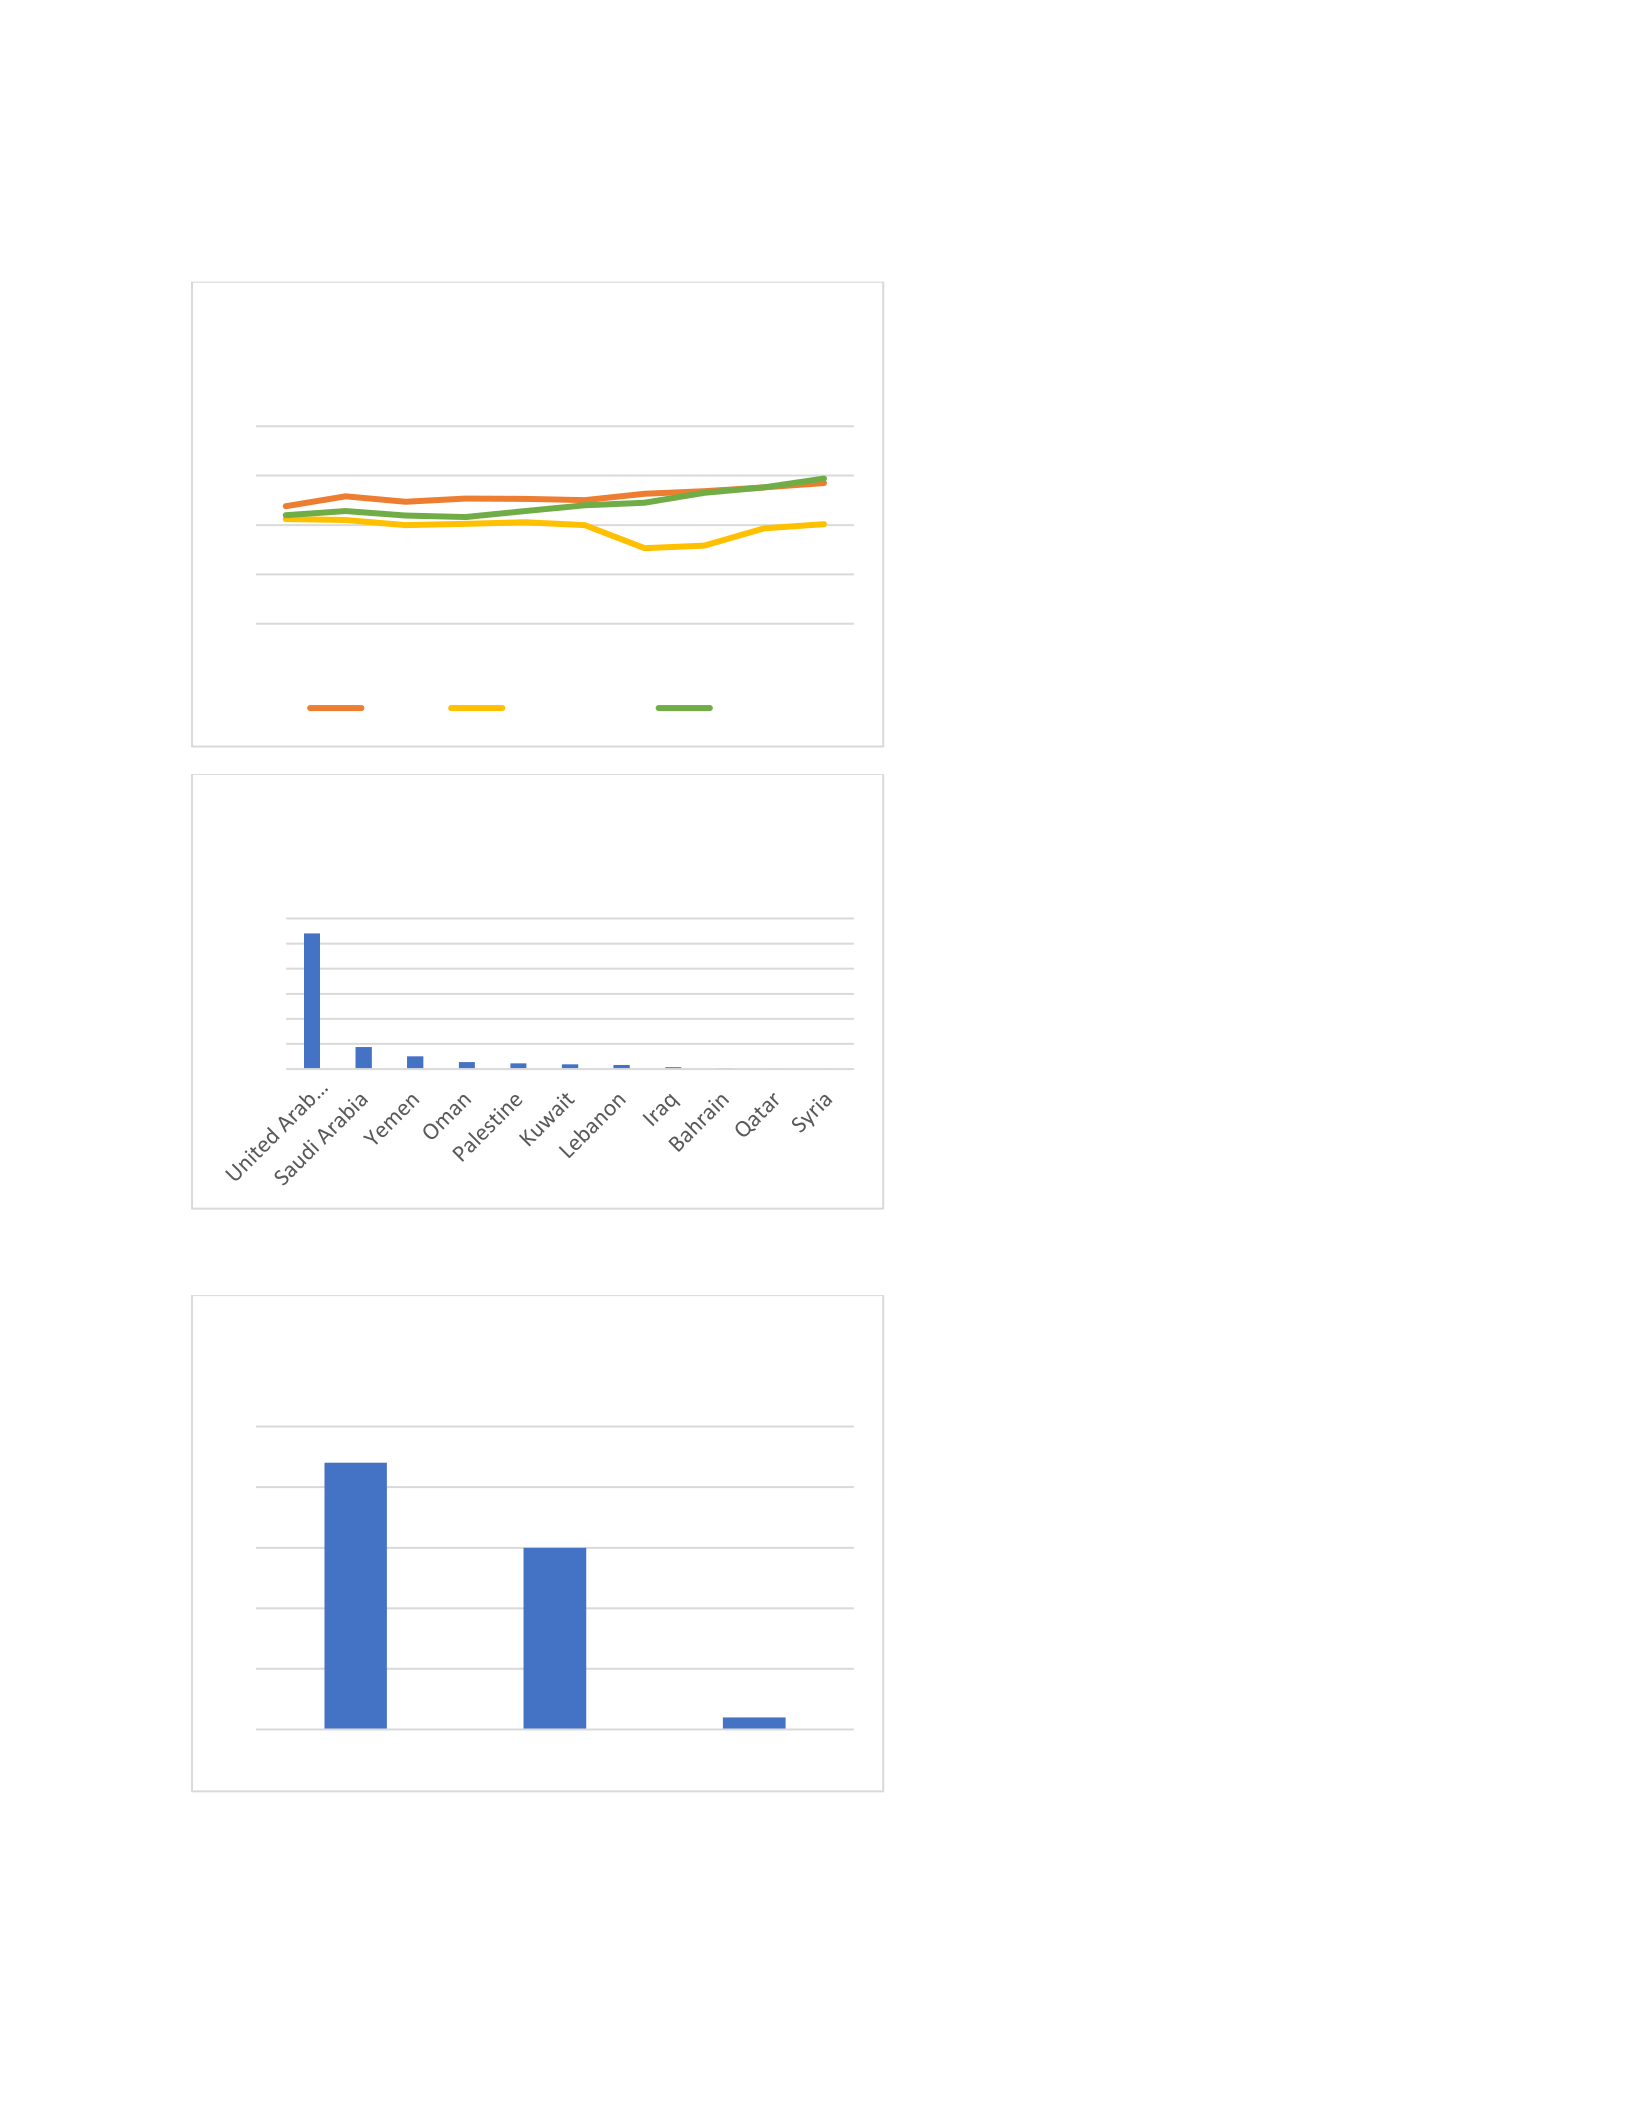
104
Figure #25 – Transition Readiness Scores
30
40
50
60
70
2012 2013 2014 2015 2016 2017 2018 2019 2020 2021
Transition Readiness
Scores
Qatar Saudi Arabia U.A.E.
0
500
1,000
1,500
2,000
2,500
3,000
Installed Capacity
Solar Energy MENA In 2021
0
5
10
15
20
25
UAE Saudi Arabia Qatar
% of Private Sector Energy Investments
2022-2026
Figure #27 – % of Private Sector Energy
Investments for all three countries
U.A.E. has a higher percentage of share
of private sector energy investments
between 2022-2026 than Qatar and
Saudi Arabia (22%)
S. Arabia has only 15% of private
sector energy investments
All three images shows that although
Qatar shows a higher score in both
overall Energy Transition Index and
Energy System Performance;
however, the UAE has the highest
transition readiness score as well as
linear, positive trajectory between
the period 2012-2021
Figure #26 – Installed RE Capacity
U.A.E. has the highest installed capacity
among the three countries
Year-to-year Renewable Energy
production growth is high; however, the
contribution of the renewable energy in
the economy is lagging for all three
countries
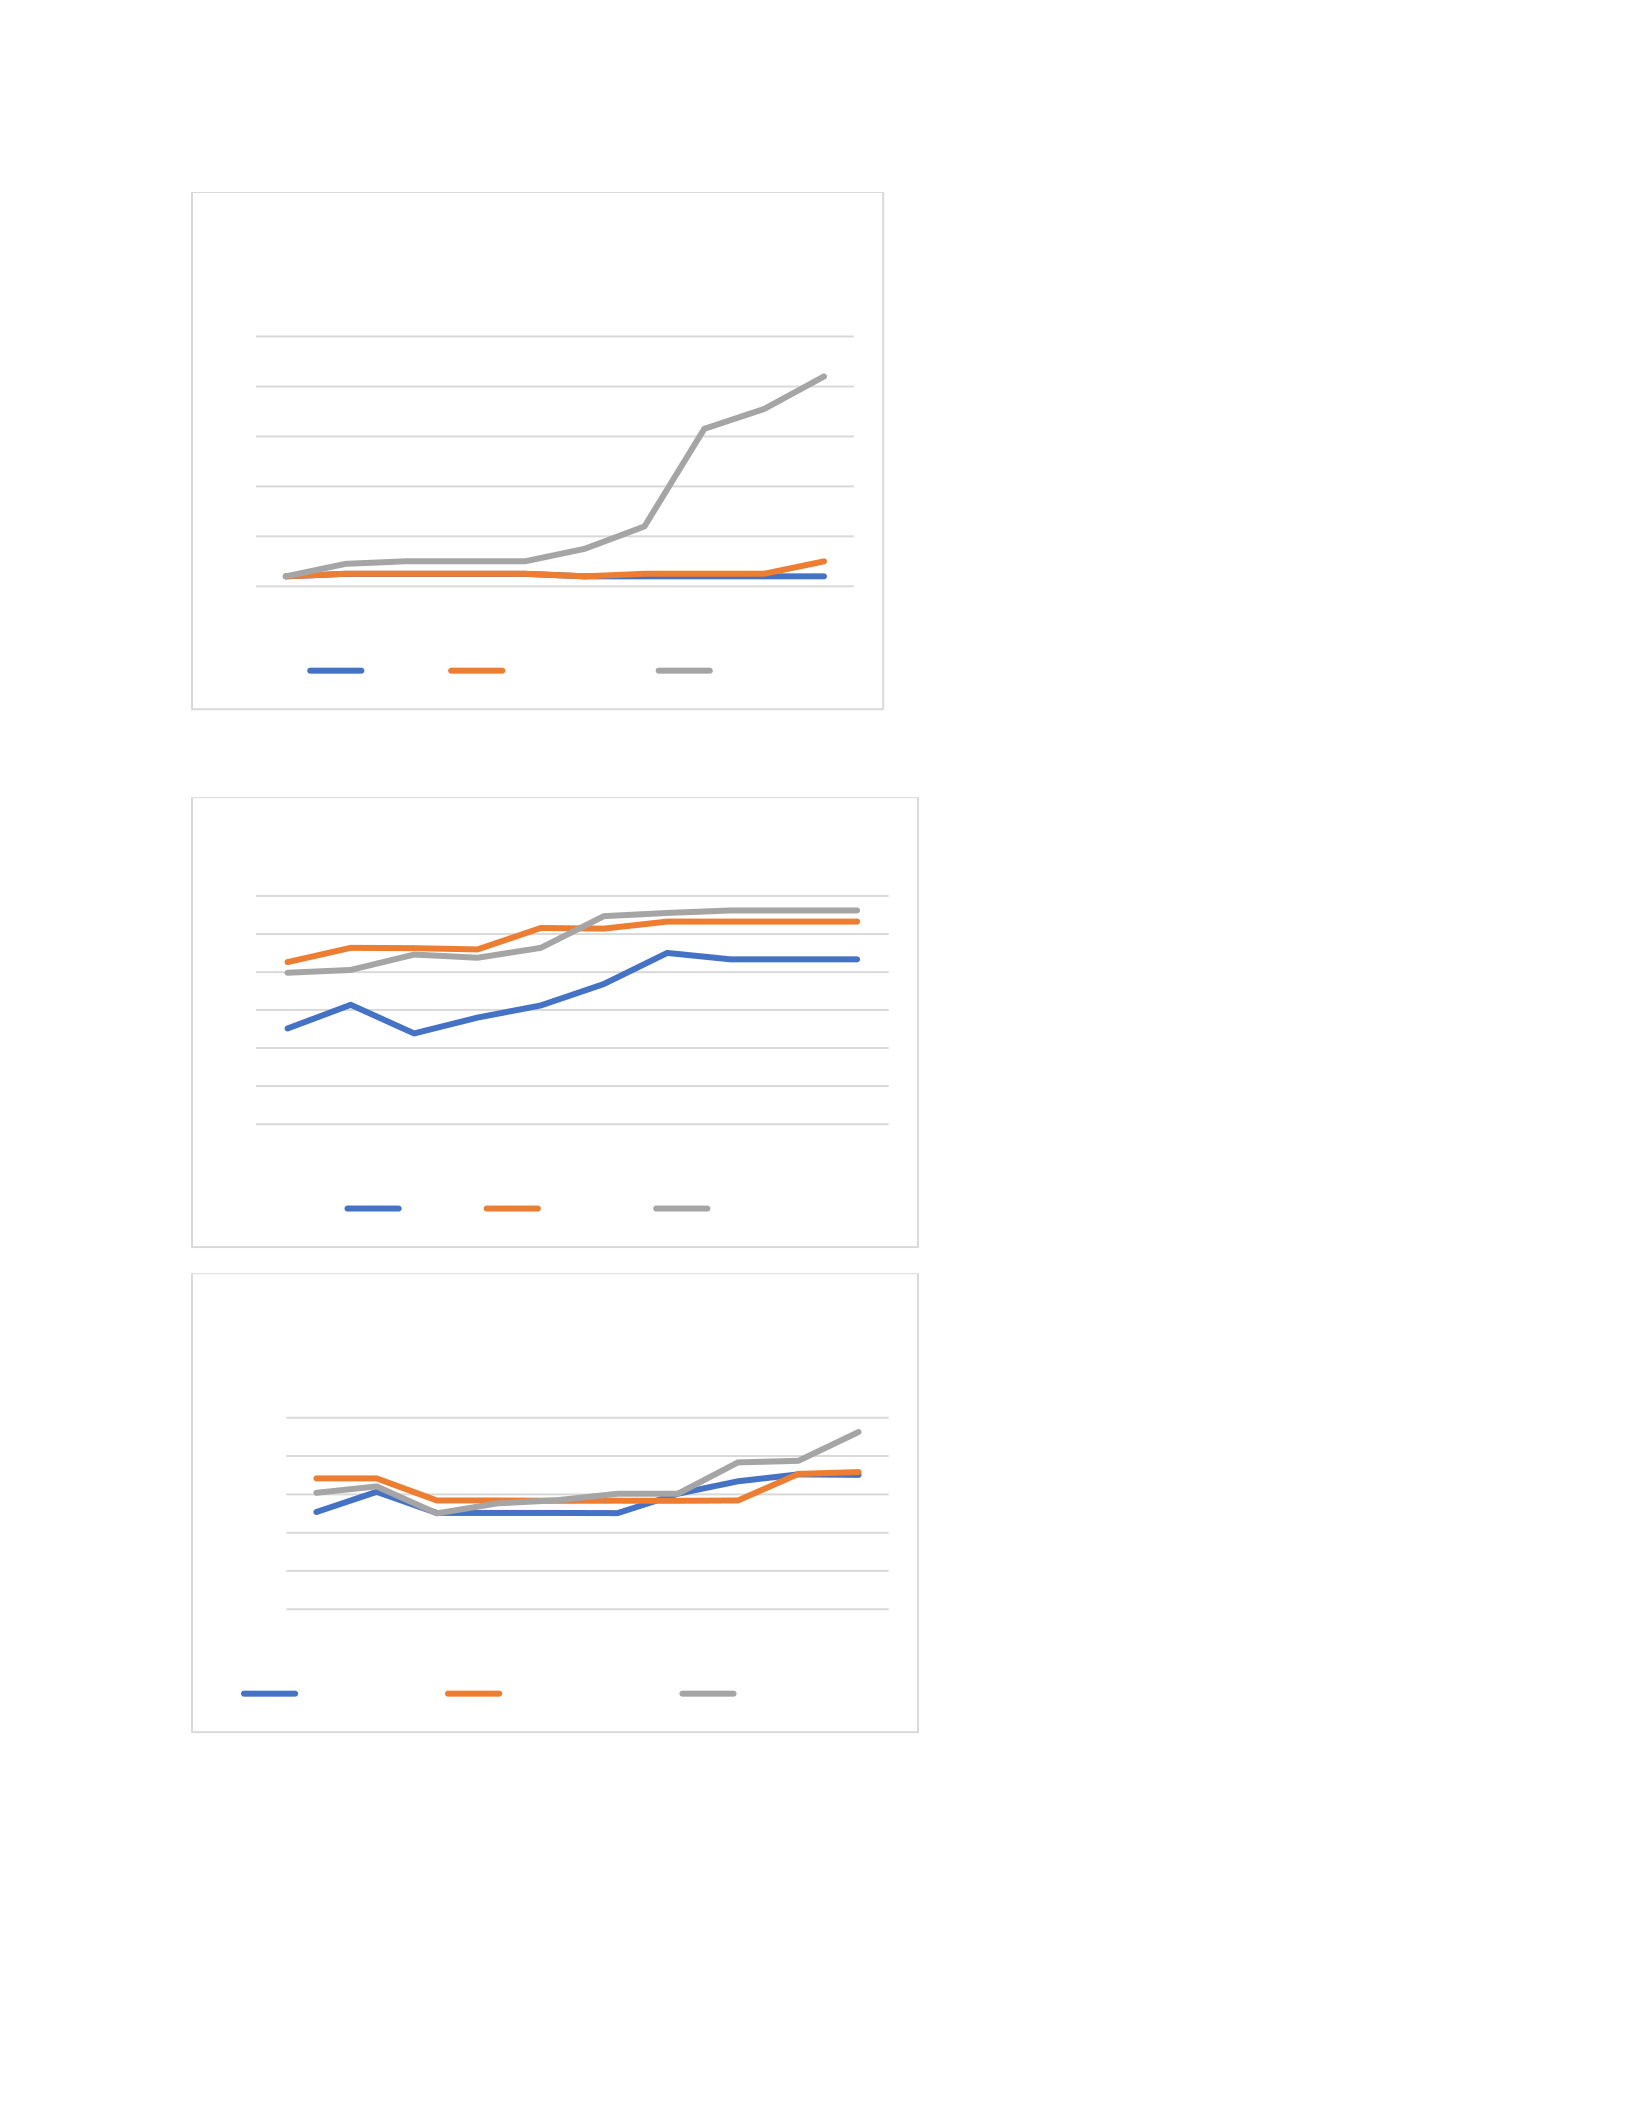
105
0
2
4
6
8
10
2012 2013 2014 2015 2016 2017 2018 2019 2020 2021
Share of Renewable Energy
Electricity Capacity %
Qatar Saudi Arabia U.A.E.
58
60
62
64
66
68
70
2012 2013 2014 2015 2016 2017 2018 2019 2020 2021
SDG#7 Scores for All three Countries
Qatar S. Arabia U.A.E.
0.00
10.00
20.00
30.00
40.00
50.00
2012 2013 2014 2015 2016 2017 2018 2019 2020 2021
Capital Investment Level- All Three
Countries
Qatar Cap Inv S. Arabia Cap Inv U.A.E. Cap Inv
Figure #28 – RE Electricity
Capacity for all three countries
U.A.E. has the highest share
of RE capacity of all the three
countries.
Figure #30 – U.A.E. Capital Investment
Level
U.A.E. has the highest level of
Capital Investment compared to
Qatar and S. Arabia
Figure #29 – U.A.E. Scores of SDG#7
2012-2021
U.A.E. has the highest SDG#7 scores
after S. Arabia and Qatar
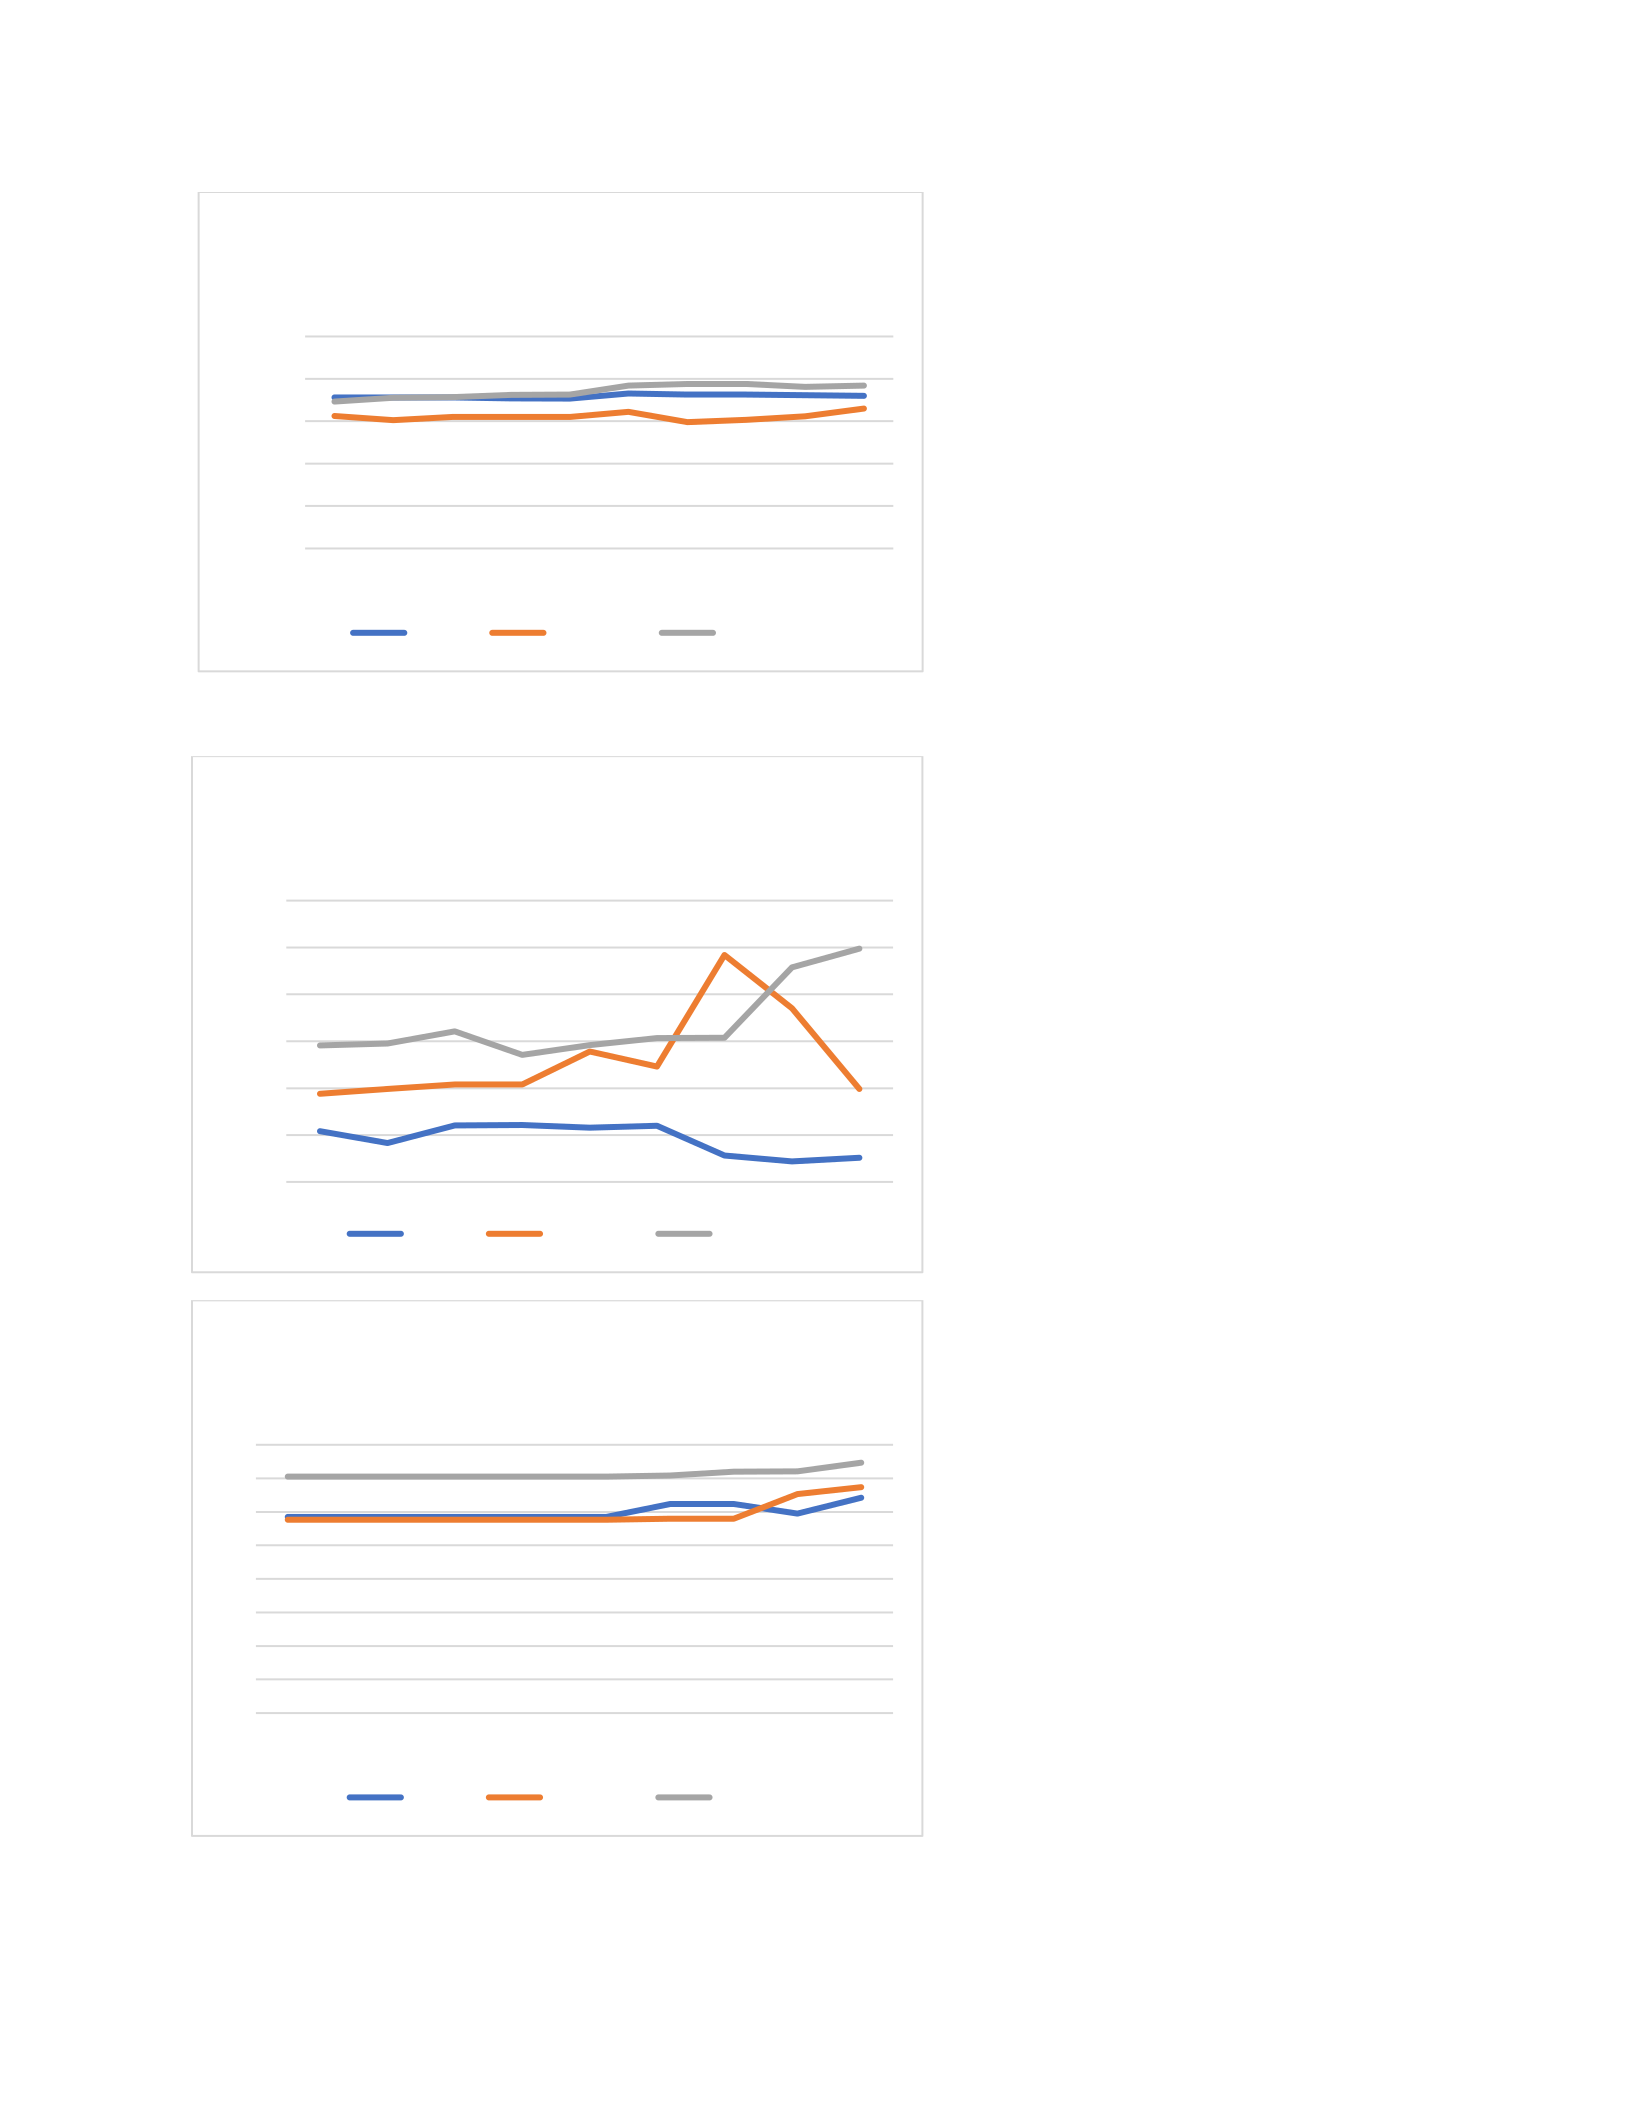
106
0.00
20.00
40.00
60.00
80.00
100.00
2012 2013 2014 2015 2016 2017 2018 2019 2020 2021
Level of Economic Freedom for All
Three Countries
Qatar S. Arabia U.A.E.
-5.00
0.00
5.00
10.00
15.00
20.00
25.00
2012 2013 2014 2015 2016 2017 2018 2019 2020
Level of FDI for
All Three Countries
Qatar S. Arabia U.A.E.
0
10
20
30
40
50
60
70
80
2012 2013 2014 2015 2016 2017 2018 2019 2020 2021
Level of Political Commitment for
All Three Countries
Qatar S. Arabia U.A.E.
Figure #31 – U.A.E. Level of
Economic Freedom
U.A.E. has the highest level of
Economic Freedom
compared to Qatar and S.
Arabia
Figure #32 – U.A.E. Level Foreign
Direct Investment
U.A.E. has the highest level of
Foreign Direct Investment
compared to Qatar and S. Arabia
Figure #33 – U.A.E. Level Political
Commitment
U.A.E. has the highest level of
Foreign Direct Investment
compared to Qatar and S. Arabia
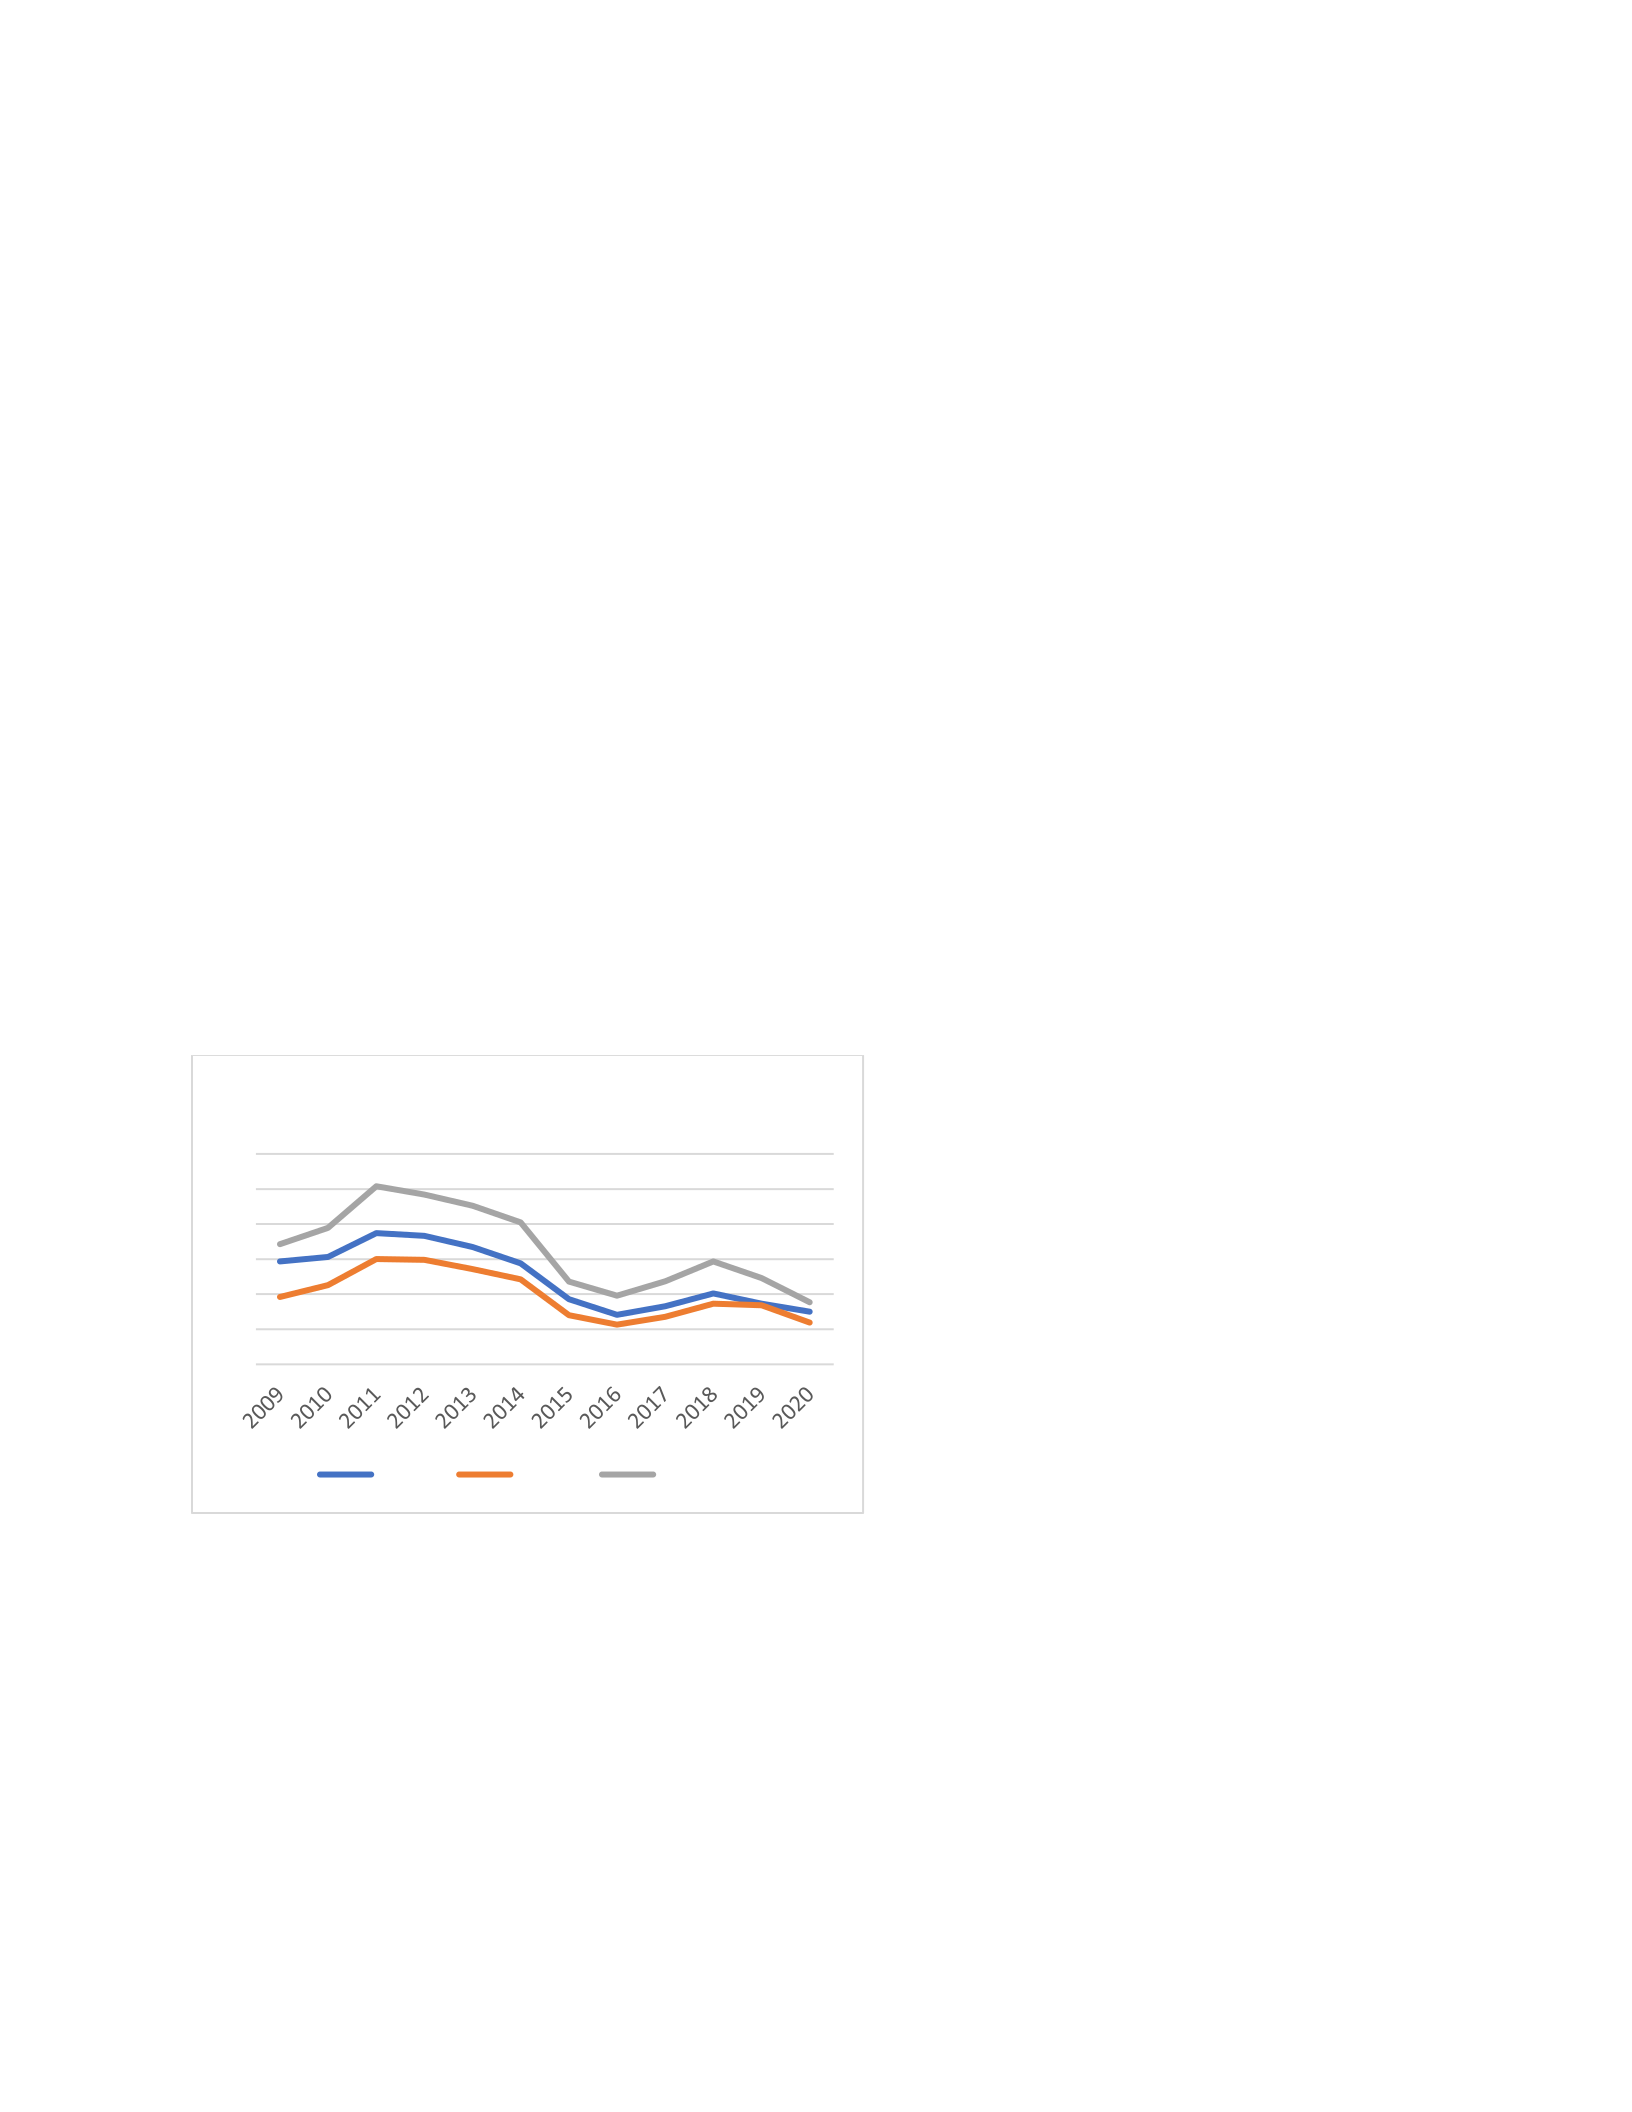
107
Furthermore, the U.A.E. has the highest correlation between Transition Readiness and:
Capital Investment, Human capital, Economic Freedom, Foreign Direct Investment, Institution &
government, and Political Commitment.
3. Incentives for the U.A.E. Politicians to Transition to Green Energy and Maintain Their Political,
Economic & Social Power:
A study conducted by EIA, GCC National Statistical Authorities and IMF (2017)
involving Qatar, Saudi Arabia, and the U.A.E. shows that there is an 80 percent correlation
between GDP in Saudi Arabia and the oil prices, 50 percent in the U.A.E. (of a lesser degree
because of increased diversification in the country), and less than 50 percent for Qatar.
0
10
20
30
40
50
60
% Oil Rent of GDP
Qatar U.A.E. S. Arabia
Figure #34 – % of Oil Rent of GDP for All Three
Countries
U.A.E. has the least % oil rent of GDP among three
countries. The decrease in global demand of fossil fuel
and increase of the RE technology and product demand
in the West will negatively impact the production and
export of domestic fossil fuel and its derivatives.
It will be beneficial for the country to diversify into
green energy technology and build a secondary
competitive industry that will create an alternative
source of revenue and maintain the political, economic,
and social stability.
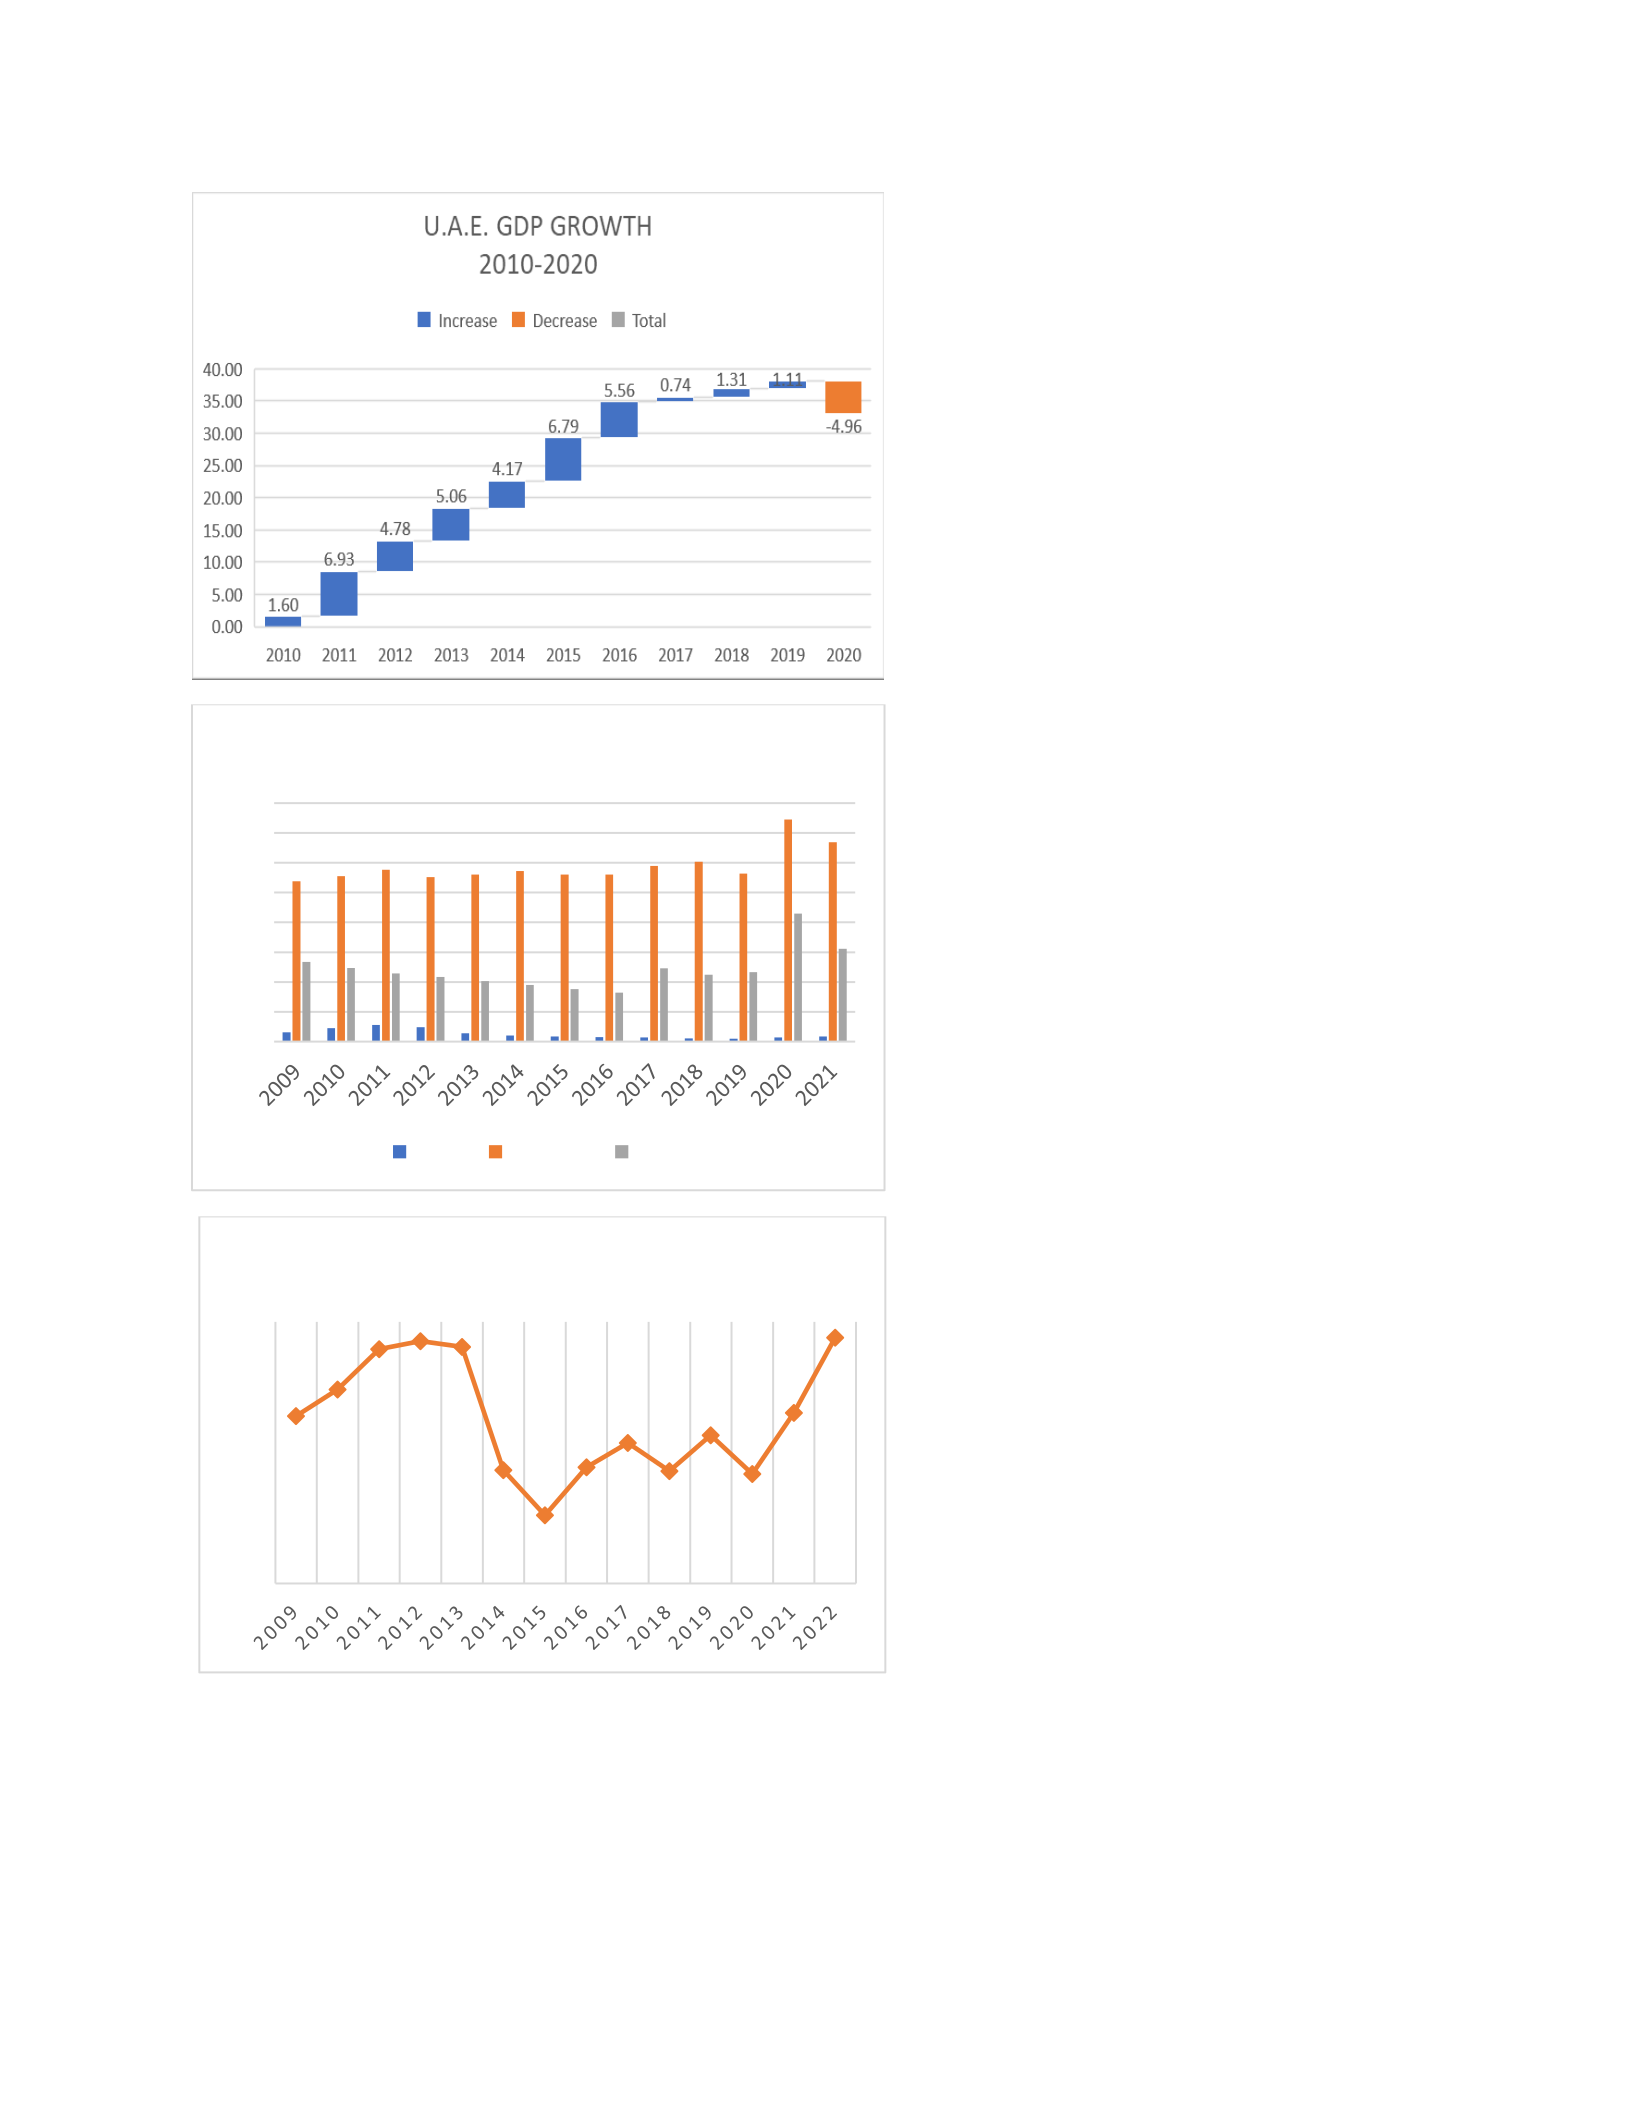
108
0.00
1.00
2.00
3.00
4.00
5.00
6.00
7.00
8.00
Unemployment Rate
Qatar S. Arabia U.A.E.
0
20
40
60
80
100
120
OPEC BASKET PRICES
Figure #37 – OPEC Basket Price Volatility
In 2020, before the Russia-Ukraine war, OPEC basket
prices were at their lowest. This was a source for
political, social, and economic instability for all three
GCC countries.
Developing a alternative competitive industry U.A.E.
leaders will avoid the economic downturn that they
experienced between 2014-2014 and 2018-2020 as a
result of OPEC price instabilities. Maintaining
Economic & Social stability is an important driver to
transition to green energy.
Figure #35 -UAE GDP Growth, 2010-2020
U.A.E. GDP reached at one of its lowest levels in
2020 right before the Russia-Ukraine crisis. The -
4.96% decrease of GDP is a serious drop in the
source of revenue of any of the GCC monarchies.
U.A.E. and other GCC countries can diversify to
producing and exporting green energy to maintain
an acceptable level of government revenue and
sovereign wealth. Saudi Arabia’s decline in GDP
in 2020 was -4/14 %.
Figure #36 – Unemployment, UAE
The UAE government has a high youth and feminine
gender unemployment rate and the inability of
providing nationals with attractive employment with
the private sector.
Transition to green energy can create opportunities to
import green technologies, support private startups
that will develop human capacity and provide new
employment opportunities for nationals in the private
sector with higher salaries. This will help the political
leaders reduce unemployment and avoid social
instabilities.
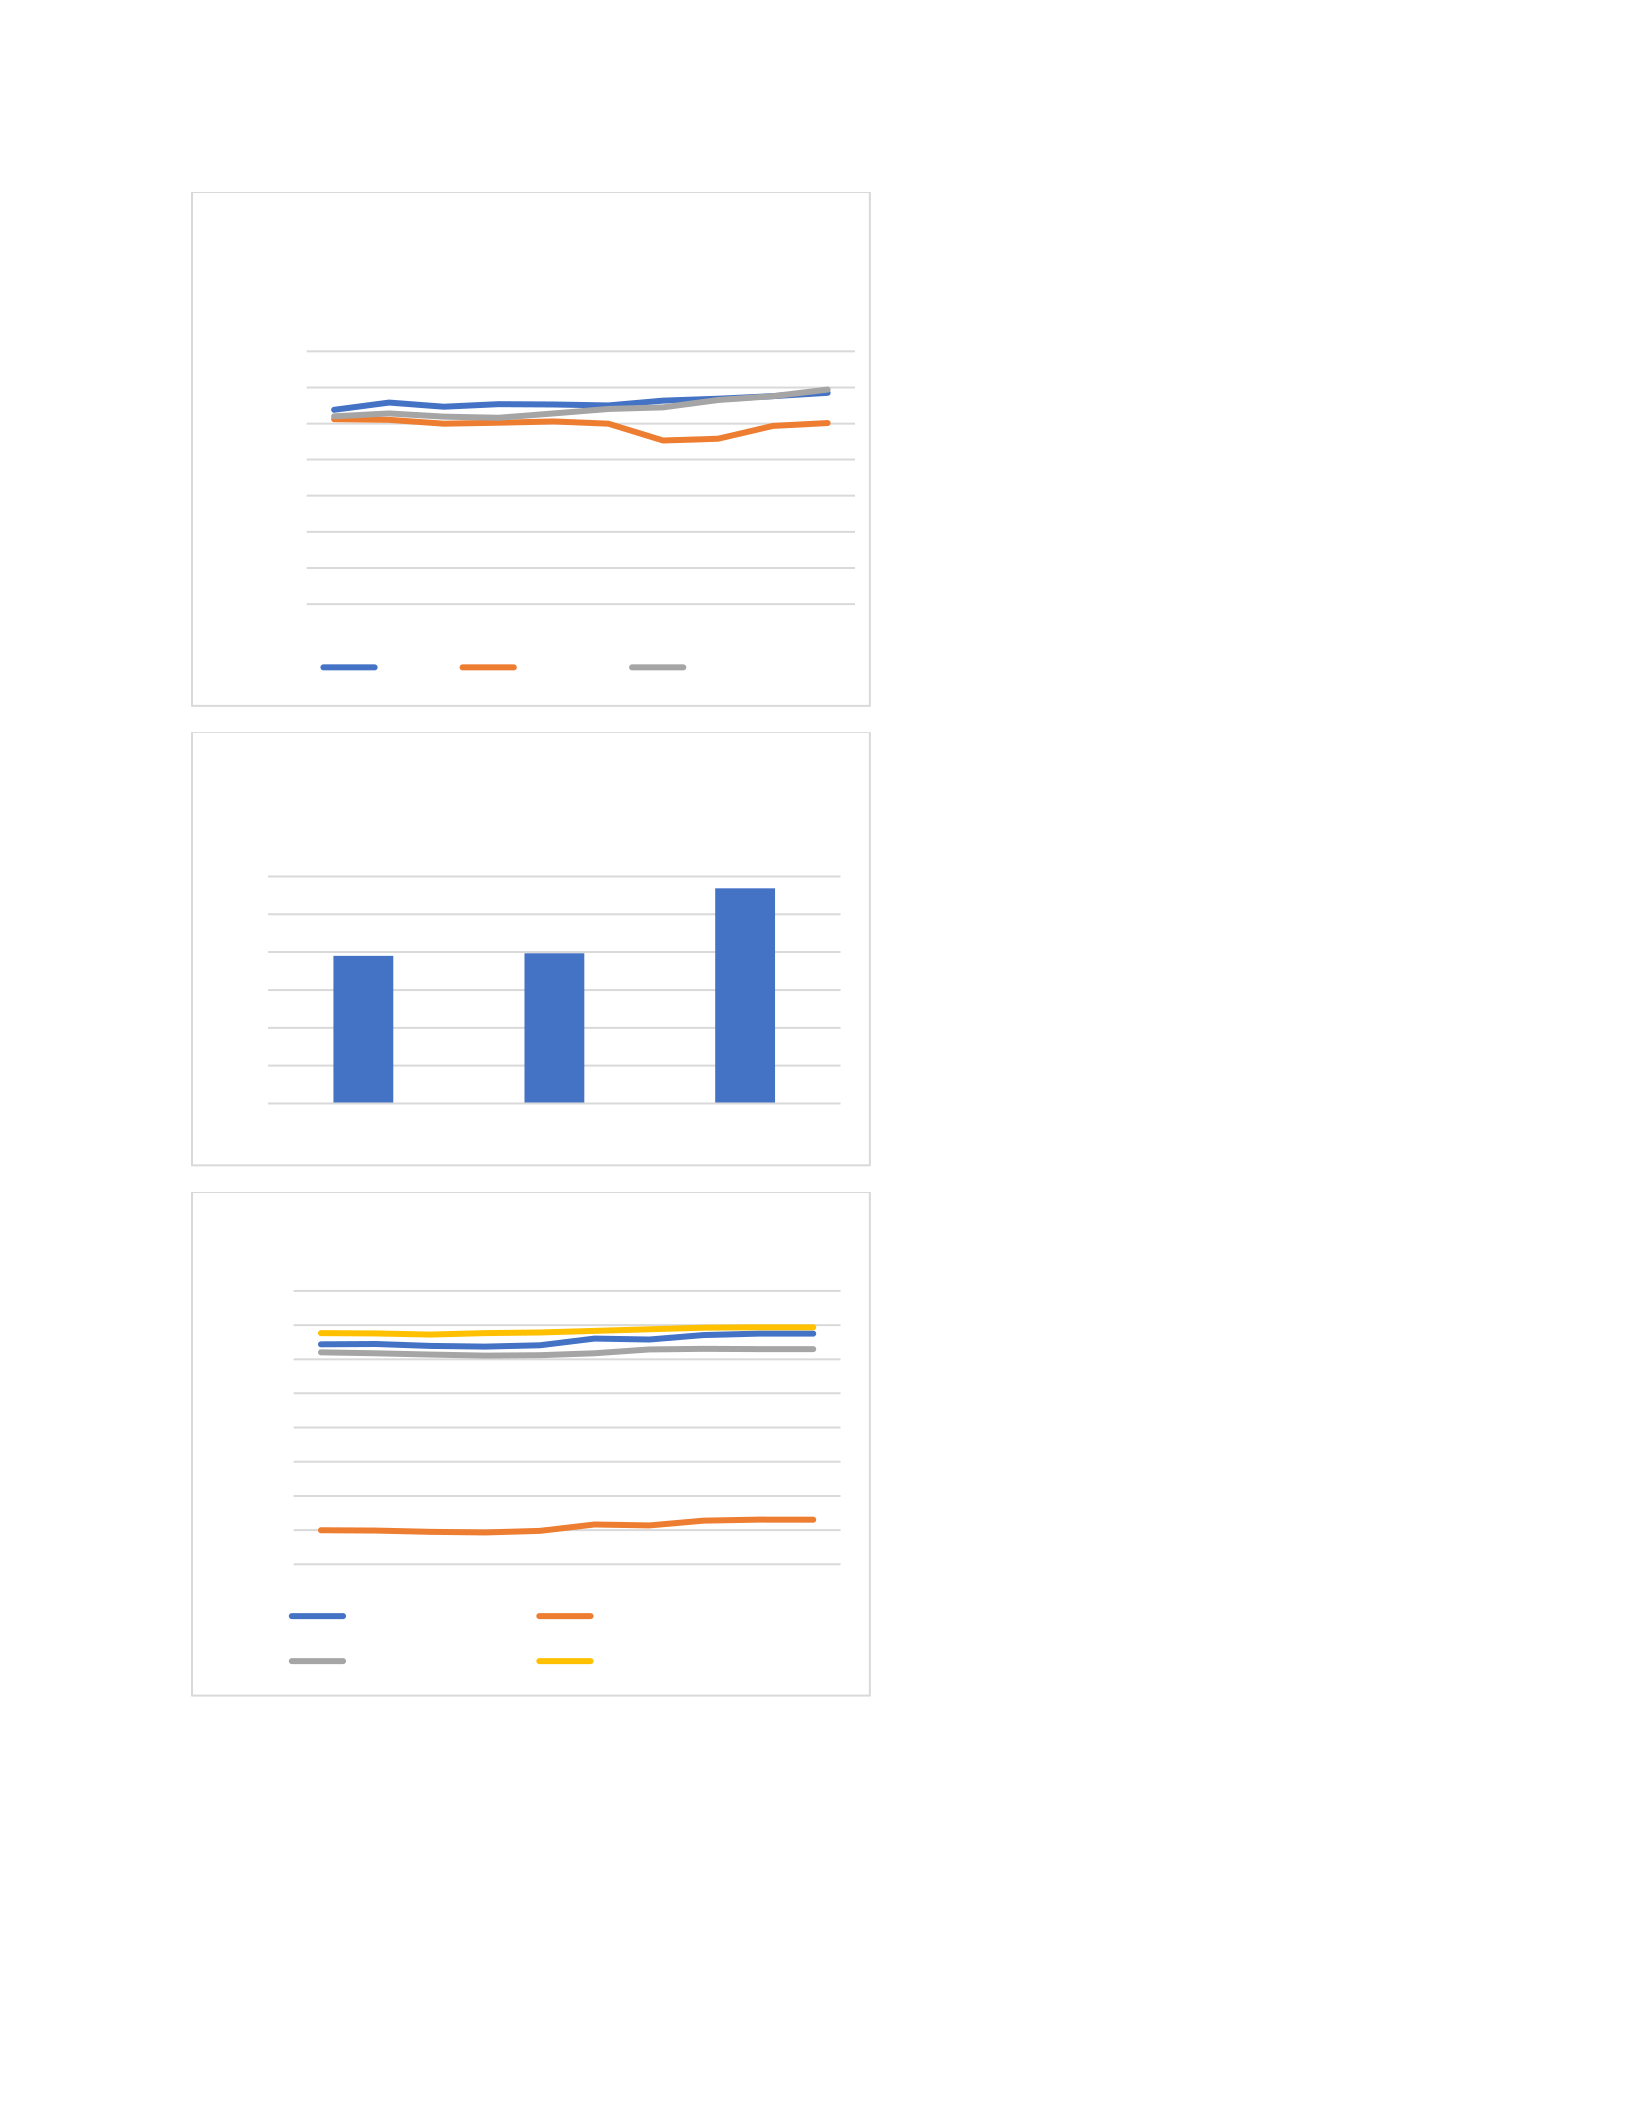
109
0.00
10.00
20.00
30.00
40.00
50.00
60.00
70.00
2012 2013 2014 2015 2016 2017 2018 2019 2020 2021
Transition Readiness Score
Qatar, S. Arabia & U.A.E.
Qatar S. Arabia U.A.E.
0
50
100
150
200
250
300
Qatar S. Arabia U.A.E.
Environmental Sustainability
Score 2012-2021
-10.00
0.00
10.00
20.00
30.00
40.00
50.00
60.00
70.00
2012 2013 2014 2015 2016 2017 2018 2019 2020 2021
U.A.E. ETI Performance
ETI Score Change Since 2012
Regional Average World Average
Figure #39 – U.A.E. Has the Highest
Environmental Sustainability
Above and beyond developing a green
energy, sustainability is a challenge for the
GCC countries. However, U.A.E. shows
that it has the highest sustainable
Environment among the three countries.
Another opportunity for the elite to
maintain leadership and a competitive edge
in the region.
Figure #40 – U.A.E. ETI Indicators Scores
U.A.E. ETI score stays at a steady positive level
from 2017-2021. It runs closer to the world
average in a steady way and stays above the
regional average. U.A.E. shows global leadership
in maintaining high scores in Energy Transition
Index.
S. Arabia has a negative ETI score change since
2012. It falls below the regional average
between 2017-2020 and performs well below the
world average compared to U.A.E. and Qatar.
.
Figure #38 – U.A.E. Transition Readiness has a
positive upward trajectory
U.A.E. Transition Readiness Score is
the highest among all three countries
and has a positive upward slope.
The U.A.E. leaders have a chance to be
the regional pioneers in developing and
exporting Renewable Energy to Asia as
well as the West.
Saudi Arabia is lagging U.A.E. and
Qatar.
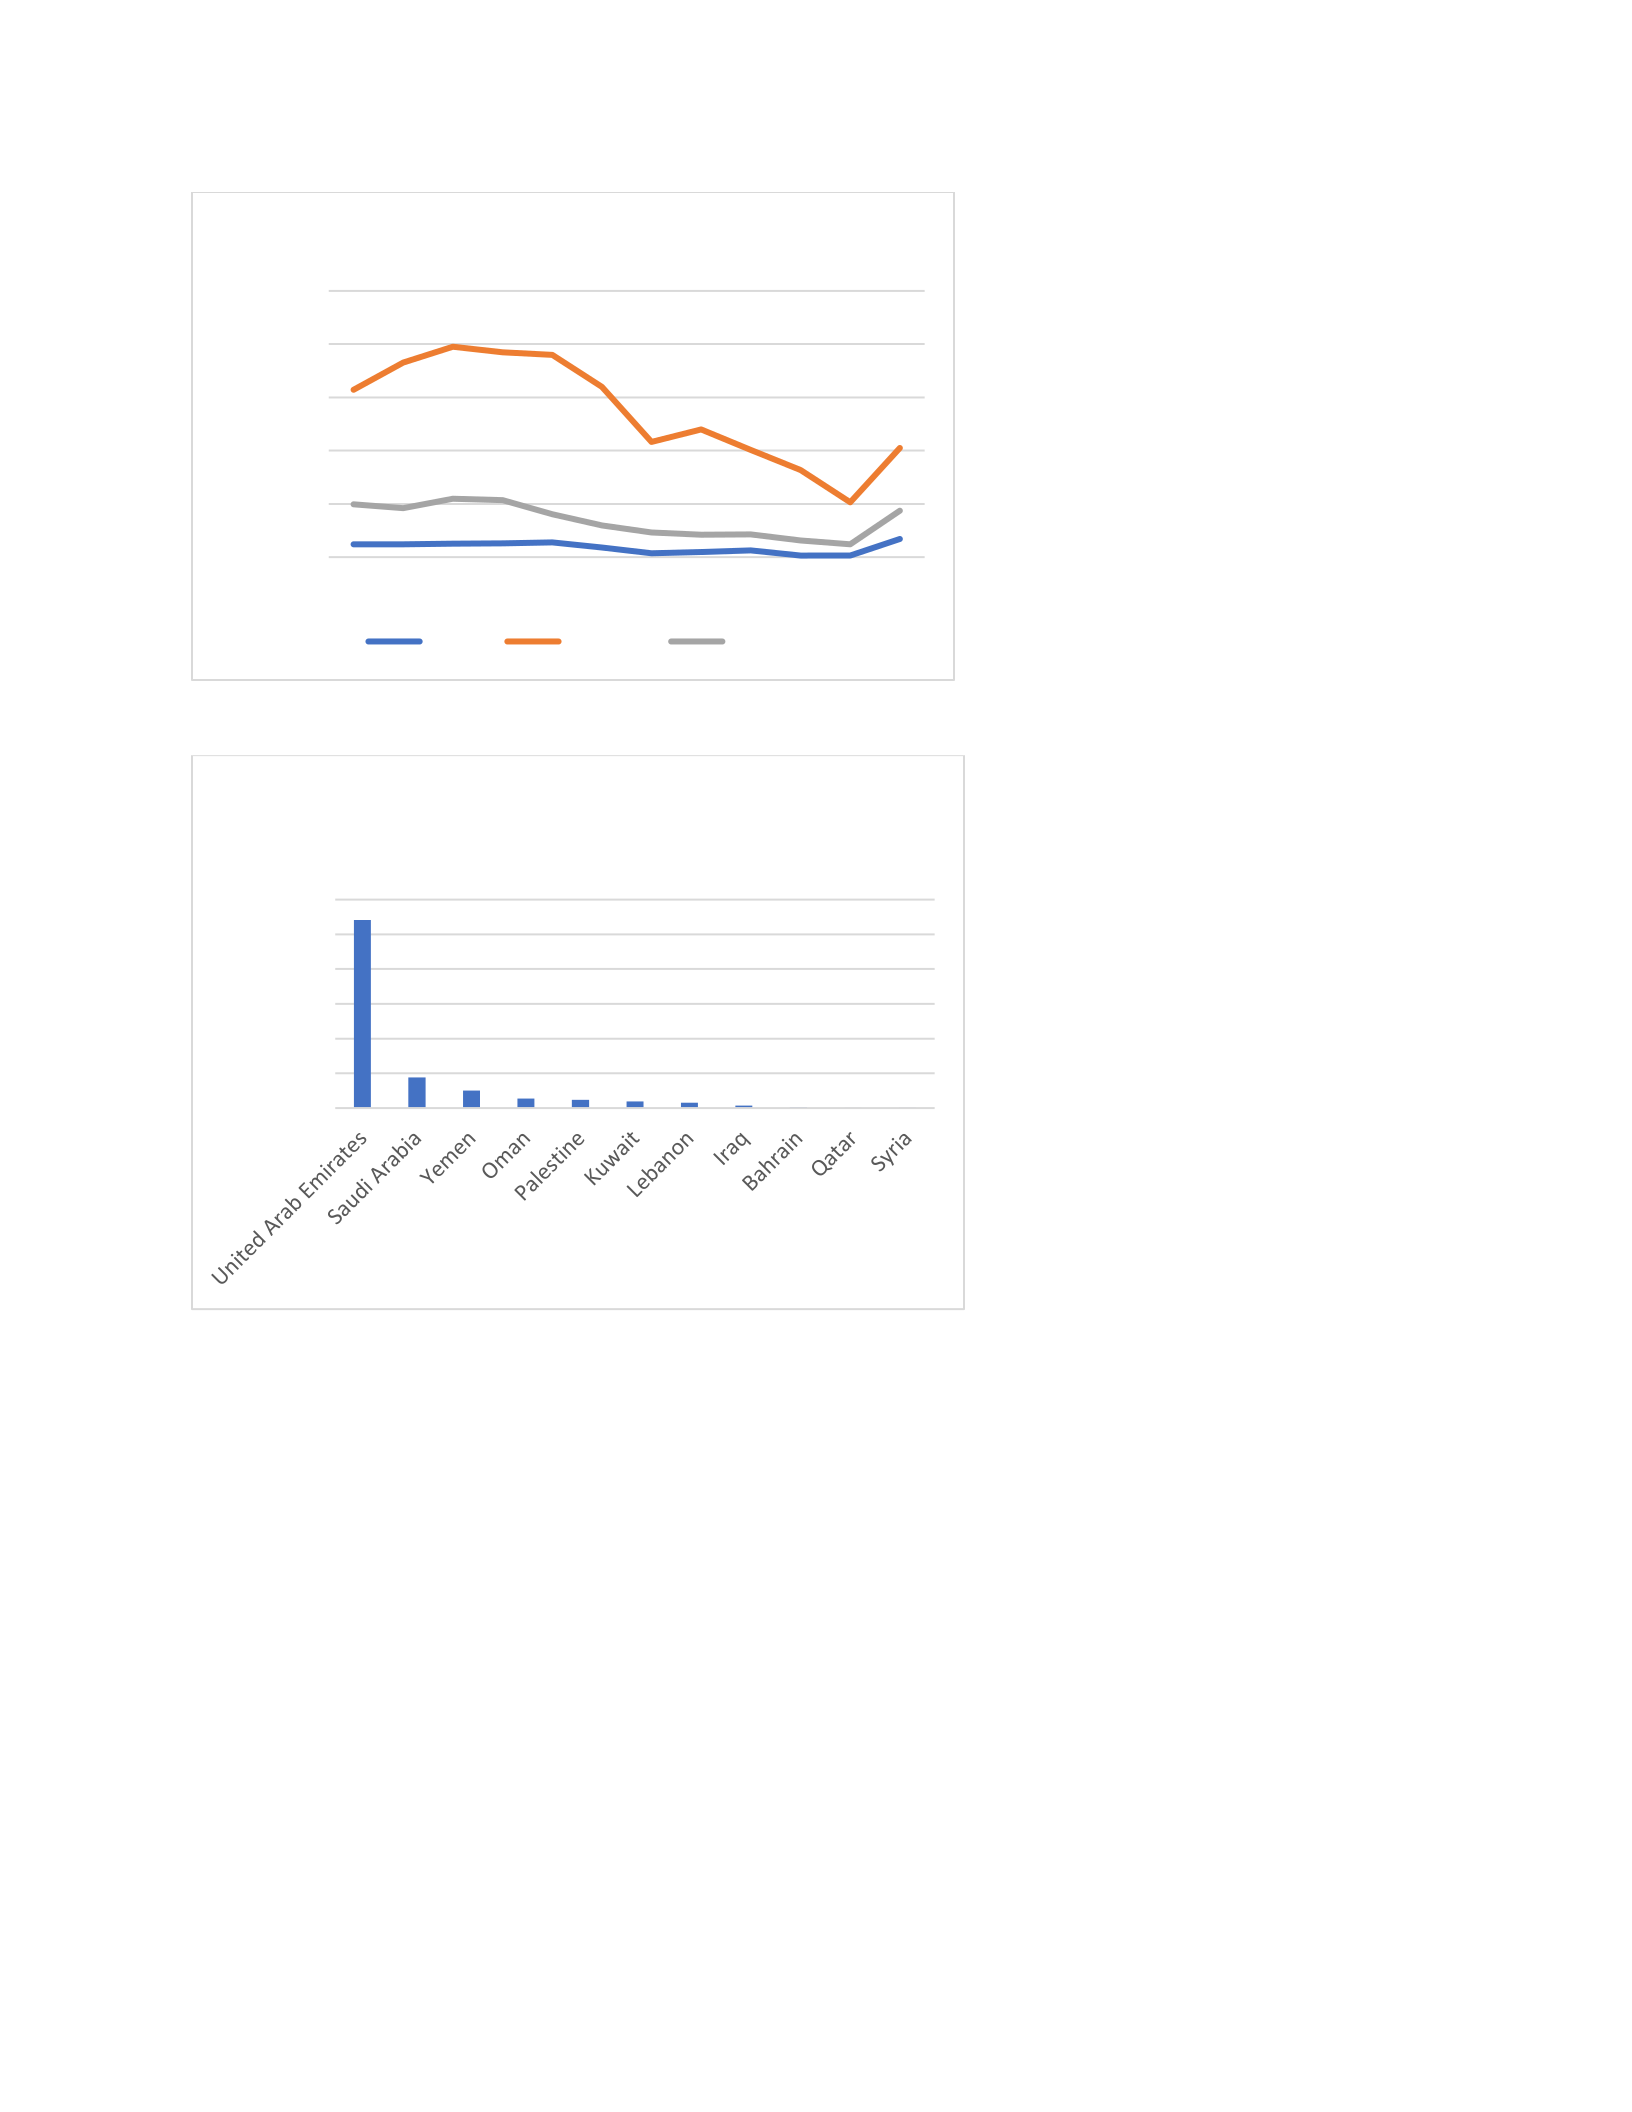
110
4. Conditions that are driving U.A.E. to be more engaged in Transition to Green Energy
In a rentier state, the higher the percentage share of Oil in a country's GDP, the higher the
leaders' commitment to that industry because of the high rent revenues received by the Elite
(Ross, 2014). The UAE is shown to have the lowest percentage of oil rent revenues of their GDP.
The UAE also shows a negative correlation between transition readiness and the percent Oil rent
share of GDP. Since the percentage of Oil rent in the GDP for these countries is an indication of
-
20,000.0
40,000.0
60,000.0
80,000.0
100,000.0
201020112012201320142015201620172018201920202021
Fossil Fuel Subsidies
Qatar S.Arabia U.A.E.
0
500
1,000
1,500
2,000
2,500
3,000
Installed Capacity
Solar Energy MENA In 2021
Figure #42 – Installed Solar Energy Capacity in
2021
U.A.E. has shown that it is the front runner
in the GCC countries capable of reaching its
commitment to climate change initiatives
and renewable energy targets (Rystad
Energy study). Currently, U.A.E. has the
highest RE capacity of all three GCC
countries.
U.A.E. leaders have a golden opportunity to
become the pioneers in developing a
competitive green energy in the region that
they can produce and export to EU, the
U.S., and other Asian countries
.
Figure 41– U.A.E. Fossil Fuel Subsidies
U.A.E. Political leaders have an
opportunity to reduce the fossil fuel
subsidies that they provide and instead,
develop and diversify their economy into
a green energy production and exporting
industry that has a great potential to
become a competitive industry.
S. Arabia has the highest fossil fuel
subsidies of them all providing political,
social, and economic stability. Leaders
will be able to provide secure,
sustainable, cheap energy to their citizens
without subsidizing the industry.

111
a strong Oil producing and exporting industry, a negative correlation between Transition
Readiness and the percentage of oil rent in GDP might be an indication of either energy
transition and/or the development of a secondary industry besides the fossil fuel industry (World
Bank, 2022).
In 2020, right before the Russian invasion of Ukraine, the UAE GDP reached its lowest level
(-4.56 percent) compared to the previous years. The decrease in the GDP growth from 6.79
percent and 5.56 percent in 2015 and 2016 to 0.74 percent,1.31 percent, and 1.11 percent in
2017, 2018, and 2019, consecutively, is a significant drop resulting in serious revenue source
cuts for the political leaders. The UAE aims to increase its total power mix to 50 percent by
2050. With 2000 MW of renewable energy being installed annually, it has become one of the
fastest-growing markets in the Middle East and North Africa. An incentive for the political
leaders with prospects of a new source of revenue (World Bank, 2020).
The primary energy sources in the UAE are natural gas (60.6 percent, crude oil (38.2
percent), and coal (1.1 percent). In 2008, the UAE started the Masdar Enterprise to develop a
program for a sustainable society using solar thermal energy, wind power carbon capture and
storage, and hydrogen technologies. About 5.7 percent of the global oil reserve is in the United
Arab Emirates, which is predicted to be depleted during the next 90 years, given that the
production remains at the same level today. The country’s elite have a crucial incentive to
develop their renewable energy technologies to provide the country with a sustainable energy
source (Reiche, 2010)

112
Energy Efficiency, Renewable Energy, and Environmental Conservation are critical to the
UAE Vision 2021 and Energy Strategy 2050. UAE is aligning with critical international
partnerships such as the International Renewable Energy Agency (IRENA), the European Union,
and the US. The UAE has signed a strategic agreement with the US for a $100 billion investment
in clean energy projects and is negotiating with the EU to export green energy to European
countries. Abu Dhabi National Energy Company has formed joint ventures with international
firms to develop renewable energy projects in the UAE. These partnerships have facilitated
foreign direct investment and the transfer of green technology and knowledge to the country
(Shehabi, 2023).
Energy security, diversification, and building a bright future for Emirati youth in the vision
of His Highness Sheikh Mohamed Bin Zayed Al Nahyan, the leader of the UAE. The country is
aligning with global efforts to combat climate change, driven by a desire to diversify energy
sources and capitalize on economic opportunities by investing in green energy reforms. The
political leaders of the country want to be the pioneers in the region with a competitive green
energy technology and industry sector that can provide sustainable energy not just to its people
but also export it to the West (the UAE is already working with the EU to develop partnerships
to export green energy to the EU in the future).
Proponents of exogenous growth theory argue that technological progress is the key
determinant of long-run economic growth and international productivity differences. The UAE
has long suffered from high youth unemployment. Transitioning to green energy allows the
youth to develop human capacity by engaging in the private sector with green technology
startups, thereby reducing youth unemployment and avoiding future social instabilities.

113
The UAE had a higher total solar and renewable energy installed projects and capacity
between 2002 and 2021 than Qatar and Saudi Arabia. In the global arena, the country is
demonstrating the ability to fulfill its commitment to climate change initiatives. Furthermore,
because green energy helps the UAE conserve its water resources - the traditional process of
power generation requires large amounts of water for cooling purposes - the country’s
investment in green technologies will promote environmental stewardship and will position the
UAE as a leader in sustainability in the region (Abu Dhabi, 2007).
This study shows that UAE is doing better in Transition Readiness because, as listed below, it
shows a range of high to very high correlation between Transition Readiness and seven of the
eight independent variables:
• Transition Readiness & SDG#7 (0.847362)
• Transition Readiness & Capital Investment (0.941474)
• Transition Readiness & Human Capital (0.904598)
• Transition Readiness & Political Commitment (0.92776)
• Transition Readiness & Institutions & Government (0.85457)
• Transition Readiness & Economic Freedom (0.785787)
• Transition Readiness & FDI inflow (0.912468)
The UAE also shows high correlation between the following indicators:
• ETI & SDG #7 (0.881348)
• ETI and Economic Freedom (0.831999)
• SDG #7 and Government Expenditure (0.776216)

114
5. The conditions that hinder Saudi Arabia’s transition to green energy
Although Saudi Arabia shows the highest correlation between Transition Readiness and
Competitiveness (0.471669) among the three countries and a moderate correlation - after that of
Qatar - between Transition Readiness and Human Capital (.782675), the country, in general
demonstrates a low level and sometimes high; however, negative correlation between Transition
Readiness and most of the independent variables:
• Transition Readiness and SDG#7 (-0.72983)
• Transition Readiness and Capital Investment (0.410548)
• Transition Readiness and Human Capital (0.782675)
• Transition Readiness and FDI net inflows ((-0.90775)
• Transition Readiness and Political Commitment (-0.04756)
• Transition Readiness and Institutions and Government (-0.41573)
• FDI inflow & Economic Development is positive but not significant (0.020296)
• SDG #7 and Government Expenditure is positive; however, low (-0.346293)
In addition, Saudi Arabia shows relatively low and sometimes negative correlation between
the following indicators:
• ETI and SDG #7 (-0.63397)
• ETI and System Performance (0.38891)
• Energy System Performance and SDG#7 (-0.398491)
Saudi Arabia has the highest positive correlation of all three countries between Transition
Readiness and percentage of Oil Rent of GDP (0.388745). This might explain why Saudi
Arabia’s correlation between Transition Readiness and Competitiveness is higher than the other
two countries (0.471669) and why Saudi Arabia’s transition to green energy is slower than that

115
of Qatar and the UAE, indicating that Saudi Arabia’s capacity for building renewable energy is
lower than that of Qatar and the UAE.
The impact of the energy transition in the hydrocarbon-producing and exporting countries
is still undermined both on the academic and policy-making levels. For the GCC rentier
countries, the transition to clean energy is perceived primarily as the means of gaining
international prestige and preserving regime legitimacy (Aminjonov, 2021). The UAE
authorities have set ambitious goals to become pioneers in innovations within the renewable
energy sector in the Gulf region. The UAE looks at diversifying and achieving sustainable
growth, believing its leaders will emerge as winners while traditional hydrocarbon exporters
unwilling to change will lose out very soon.
The transition to sustainable energy allows these GCC countries to reduce energy costs,
providing extra revenues to maintain and secure the rulers’ relationship with the citizens and the
regime’s legitimacy. The cost of shifting to renewable energy varies among the Gulf countries
according to the population size, dependence on oil rents, and effective institutions and
governance mechanisms. The UAE has a relatively smaller population, decreasing reliance on
oil rents and increasing policy reforms (Young, 2020). Therefore, the social cost of such a
transition in the UAE will be relatively low compared to that in Saudi Arabia (Goldthau and
Westphal, 2019).

116
Energy governance reforms have been critical to the UAE in expediting the transition to
green energy. Key to the success of developing renewables has been 1) Incentives provided
partially through market mechanisms and government support 2) Removal of fossil fuel
subsidies along with introducing an auction mechanism for renewable energy projects and
reducing pressure on the government budget, 3) Allowing the private sector and regular
households to adapt to the realities where energy is priced at its full economic cost (Fattouh,
2021).
In addition, the UAE government reduced subsidies, deregulated fuel prices nationwide,
and linked them to global prices. In 2015, Abu Dhabi (UAE) liberalized energy prices, surging
the electricity tariffs by 40 percent (Ministry of Energy and Industry, 2019), and developed an
auction mechanism for renewable energy projects that increased deployment of renewables in the
most cost-efficient way (Atalay, Kalfagianni, and Pattberg, 2017).
In the initial stage, successful implementation of innovative energy policies is sufficient
to add clean energy to the power consumption balance and gain international recognition;
however, significant transformation readiness needs the propagation of green energy
technologies around the country, and the involvement of the consumers as well as the private
sector as the driving force. Transitioning to green economies may also require effective
leadership and management of politics to promote cooperation and engage the regional and
global stakeholders (Zaidan et al., 2019).

117
Despite the successful pathway of the UAE in transitioning to green energy and despite
its ability to develop renewable energy capacity through several projects, the rentier mentality,
intermittent nature of the challenges of the renewables, and geopolitical implications may
prevent the UAE from appearing to be the winner in the transition. It is instrumental for the
UAE to introduce policy innovations to encourage stakeholders’ participation beyond the state
and the region, making the system sustain the potential technical and geopolitical disruptions
(Aminjonov, 2021).

118
Chapter 5
CONCLUSION
Limitations
The lack of transparency and availability of reliable data from official GCC sources was a
significant limitation in my research and data findings. Most data and publications I found
related to green energy provided by the Qatari, Saudi, or UAE governments were mainly in the
form of marketing pieces or campaigns. Furthermore, statistics collected from the World Bank
and World Economic Forum contained missing data between 2010 and 2021 that might have
impacted or limited the interpretation of my findings.
My observations involving my research subject are limited because the time series period
of my study is only ten years. The World Economic Forum started tracking the green energy
performances of countries only in 2012, and the Massachusetts Institute of Technology started
tracking the green future of countries only in 2021 - used only for discussion purposes in the
research.
Regarding the data on the current projects, the figures involving the capacity of green
energy for each project are unreliable. Finally, because of the collective nature of the societies of
the Gulf states, obtaining a deeper perspective of the insights into the psyche of the educated

119
nationals regarding climate change and the transition of their countries to green energy is
impossible.
Policy Implications
Economic motivations drive energy transitions to maximize hydrocarbon and energy
exports to protect the existing political economy. Prioritizing the export economy necessary to
keep the level of government revenue delays energy transitions. Energy transitions can safeguard
the existing production and export of hydrocarbons while generating a diversification in the
economy with the potential for revenues from a new competitive industry that can maintain the
state's role and fund socio-economic development.
In 2022, the share of renewable energy in generating power of GCC states was less than 1
percent, except for the UAE, which was 7 percent. Renewable Energy and Power efficiency are
deprioritized in most of these states to make room for hydrogen and carbon capture technology
(CCS and CCUS), all pro-export projects. Without economic, integrative energy and regulatory
policies, these countries will maintain an unsustainable environment.
Emissions during the last decade have accelerated in GCC countries, especially in the
energy and transport sectors. These are driven by low fossil fuel production costs, rising water
desalination, cooling requirements, and excessive energy consumption (both industrial and

120
household). Today, GCC has the highest per capita emissions (Qatar is the highest, followed by
the UAE and S. Arabia).
Alongside consuming and exporting hydrocarbons, carbon capturing depends on the
availability of CCS and CCUS technologies to achieve initial market penetration. Despite
significant R&D investments by Saudi Arabia and the UAE, the share of spending comprised a
low percentage of their GDP: Qatar 0.5 percent, S. Arabia 0.5 percent, and the UAE 1.45
percent. The absence of collective policies for environmental protection, decarbonization, and
CCUS (Carbon Capture, Utilization, Storage) hinders clean hydrogen development. CCUS rather
than CCS (Carbon Capture and Storage) technologies are essential.
Even though these GCC countries have a high potential to diversify and become
competitive in producing and exporting Renewable Energy, they lack the infrastructure
necessary to develop the industry. Reasons for the lack of infrastructure include technical
barriers – grid access difficulties, technology, and lack of availability of skilled workers.
Despite subsidy reforms and advancements in green energy, GCC countries' political
economies remain unchanged. The accelerated green energy projects transform these economies
from hydrocarbon to energy exporters without impacting their economies' structure and rigidity.
A significant policy gap exists regarding low-income households' access to green energy. Price
cap regulations and competition reforms are needed to have oligopolies reduce their markups.

121
The implementation of the above policies requires political will and balancing long short-
term policy objectives and trade-offs in a way that maximizes socio-economic welfare and
sustainability. Because any change in the policies of these states happens from top to bottom,
political, economic, and social regulations are driven only by royal decrees.
Conclusion
With expertise in hydrocarbons and the potential to build a competitive advantage in
renewable energy and export them to global markets, Saudi Arabia and the UAE have placed
themselves as regional leaders. My findings show that currently, the U.A.E. is the highest green
energy capacity producer among the three GCC states. MIT's combined Green Future Index
report of 2021, 2022, and 2023, which is a comparative ranking of 76 nations on their ability to
develop a sustainable, low-carbon future for their societies, shows that UAE has the highest
overall scores among the three GCC states in Green Future Index, Energy Transition, Climate
Policy, Green Society and Clean Innovation indicators.
The factors that help the UAE to be the front-runner in transitioning to green energy are
1) the political commitment of its institutions and government to their national climate strategy
initiatives of 2017, 2) the level of investment in the private sector and human capacity building,
and 3) the level of economic freedom enabling a robust Foreign Direct Investment to develop
domestic green energy technologies. Furthermore, what also helps the UAE to be the front
runner is its renewable energy capacity that is higher than both Qatar and Saudi Arabia. The
U.A.E. Al Reyadah carbon capture project launched in 2016 produces an estimated 70 kilo tons

122
annually of low-emission hydrogen. However, it is the only project of its type in operation
today.
Saudi Arabia has the highest percentage of its GDP generated by oil rents. It has the
highest level of all six GCC countries in GHG (Greenhouse gas Emissions) from the energy and
transport sectors (UN, 2018). Consequently, the country focuses more on carbon dioxide
capture, storage technology, and projects and energy carriers, including hydrogen and hydrogen
derivatives, that are being explored beyond building renewable energy capacity. Saudi initiative
involves the production of hydrocarbons and other new sources that are difficult to electrify
using CCUS technology, which currently is a technology that is not commercialized.
Furthermore, Saudi Arabia has adopted a Circular Carbon Economy (CCE) National
Program as the primary initiative for decarbonization, carbon reduction, and recycling solutions.
The country has initiated a very ambitious sustainable urban development project, NEOM, a
"living laboratory to advance energy, water, and hydrogen," a $8.5 billion, 3.5 GW project to
produce 219,000 tons of hydrogen and 1.2 million tons of ammonia yearly.
So far, the share of renewable energy in the total electricity capacity of Saudi Arabia has
been 0.20 percent compared to Qatar's .10 percent and the U.A.E. 7.00 percent (Shehabi, 2023).
Saudi Arabia seems to plan on becoming a leading green hydrogen producer. The factors that
hinder Suadi Arabia's transition to green energy involve the relation of its energy system
performance to the UN SDG#7 target that calls for reliable, sustainable, clean energy that seems

123
to be out of sync. In addition, the level of FDI inflows needed for the exogenous growth and the
political commitment of the government and its institutions to instigate policies to enable the
energy transition is progressing in opposite directions with the performance needed for the
transition. Furthermore, despite the country's financial capacity, investment in R&D, in general
and in the private sector, in particular, seems to be very low.
In the absence of diversification, the production and export of fossil fuels are critical to
the survival of the Gulf economies and countries that heavily depend on producing and exporting
fossil fuels globally. Their transition will need to happen gradually, in different phases. Because
of their excessive consumption of electrical power and reliance on meager energy prices both at
home and at the pump, these states need to engage in building green energy technologies while
focusing on Hydrogen, which can play an essential role in the future energy mix, including
fueling cars, trucks, trains, and ships, and generating electricity. This strategy will prevent prices
from going wild, resulting in the public losing interest in supporting the transition. GCC states
present a solid comparative advantage in blue Hydrogen because of their expertise in fossil fuels
and the global trade partnerships that they have established.
To meet their 2050 Climate Change targets, these rentier states can get there halfway by
gradually reducing the production and export of fossil fuel and increasing their capacity building
in solar, wind, and nuclear energy, and not just initiating ambitious projects. The other half can
be achieved by importing existing CCS and CCUS technologies and know-how to reduce the
carbon dioxide in the atmosphere, provided these technologies become fully commercialized.

124
However, the long-term strategy of the transition cannot happen without a firm
commitment from the government and the institutions. These states cannot build high-tech
infrastructure without serious science behind it. They cannot have a scientific mind without
creating the momentum for the transition that involves providing incentives to 1) strengthen
energy governance and institutions, 2) enable and encourage knowledge transfer through FDI
inflows to develop technology capacity, 3) increase investment in R&D of green energy
technologies 3) develop human capacity and train employees 4) align university curriculum with
market need for high-tech human resources 3) invest in the private sector to encourage disruptive
technologies and provide employment opportunities to the growing young population. In
addition, multi-stakeholder partnerships with international agencies will always help GCC states
leverage technical assistance and expertise to build effective programs.
Policies and regulations will be vital in paving the way for a gradual, effective transition
into green energy, and diligence with implementation will define the trajectory and the
momentum of the transition. Since any change in the political, economic, and social regulations
happens from top to bottom, the driver of these regulations and initiatives will be possible only
through royal decrees.
Future studies
Following the oil price collapse of 2014 and resulting fiscal challenges, these Gulf states
implemented various energy and tax reforms, including value-added tax and reduction of energy

125
subsidies; however, these reforms were politically debatable because they threatened the wealth
and the existing political equilibrium.
Without sustainability - a critical element in the equation of creating and developing green
energy and economies - subsidies, welfare distribution measures, unemployment among youth,
bloated public sector, energy transition efforts, and projects in Qatar, Saudi Arabia, and the UAE
will transform their economies from hydrocarbon exporters to energy exporters with the
hydrocarbon industry remaining the center of their economies—with no actual diversification.
Renewable Energy and Power efficiency are deprioritized to make room for Hydrogen
and carbon capture technology. Sustainability does not feature in GCC states' vision statements
except for Oman. Net-zero targets are part of the economic diversification as a result of the
expected future decline in global demand for fossil fuels. That is why CCE and CCUS
technologies accelerate while the transition to renewable energy is slow. There is an excellent
opportunity for future research to focus on the sustainability of these GCC states.

