


RISK AND CONSUMER UNCERTAINTY
ARIZONA STATE UNIVERSITY
IEE 454 - RISK MANAGEMENT
WEEK 4
12.1
Risk Management:
The issue of risk management is widely discussed in government administration. It is
even contained in several regulations that have been established. One of them is Government
Regulation Number 60 of 2008 concerning the Government Internal Control System (SPIP).
The regulation is related to the obligation to carry out risk management as a control of an
activity in Ministries / Institutions and Local Governments. Recently, the Ministry of
Administrative Reform and Bureaucratic Reform has issued Permenpan RB no. 5 of 2020
concerning Electronic-Based Government Systems related to Risk Management. In this
regulation, risk management must be integrated in sharing planning activities up to
implementation.
Risk management arrangements are also a parameter in the maturity level of the Goods
and Services Procurement Implementation unit as stipulated in Presidential Regulation number
16 of 2018 concerning Government Procurement of Goods and Services, whose
implementation guidelines are outlined in the Head of LKPP Regulation No. 17 of 2019
concerning the Goods / Services Procurement Work Unit (UKPBJ). These are just a few of the
many regulations related to risk management. Seeing so many risk management rules and
guidelines, making it a proper and important thing for us (State Civil Apparatus) to know.
Because, risk management is indeed very important in the implementation of an organization.
12.1.1
What Risk Management Means:
In organizing or managing something, all forms of uncertainty must always be taken
into account and must be able to be managed properly. The ability and management of
uncertainty is what is known in management science as risk management. In the process, risk
management can be included in management planning. Where planning activities perfectly
must include elements of risk in order to answer and anticipate the possibility of harming the
organization in the future.
From this description, it can be said that risk management is the process of making and

implementing decisions to increase the probability of achieving goals, and reducing the adverse
effects of an event for the organization. In addition, risk management serves to provide
oversight for the organization in achieving organizational goals and objectives.
Emmett J. Vaughan and Curtis Elliot (1978) mentioned that risk is defined as the
chance of loss, the possibility of loss, uncertainty, the dispersion of actual from expected
results, the probability of any outcome different from the expected.
Meanwhile, Herman Darmawi (2006) states that risk management is an effort to
identify, analyze, and control risks in every activity. company, with the aim of gaining higher
effectiveness and efficiency.
On the other hand, Irham Fahmi (2010) defines risk management as a field of science
that discusses how an organization or company applies measurements in mapping various
existing problems, by placing various management approaches in a comprehensive and
systematic manner. From these two theories, in general, risk management must meet the
requirements of organizational goal parameters. Risk management must also be analyzed and
risk management can be monitored and controlled. Some rules about risk management have
actually long been a necessity in the application of performance systems.
12.1.2
Risk Management Objectives:
The purpose of risk management is to ensure that a company or organization can
understand, measure, and monitor the various kinds of risks that occur and also ensure that the
policies that have been made can control the various kinds of risks that exist. In order for the
implementation to run smoothly, it is necessary to have support in preparing risk management
policies and guidelines, in accordance with the conditions of the company. The purpose of risk
management is generally used as a basis for predicting hazards or unpleasant things, which will
be faced with careful calculation and careful consideration of various information in advance,
to avoid unwanted things. Specifically, risk management aims to:
a.
Provide information about risks to decision-makers.
b.
Minimize losses from various risks that are likely to be faced.
c.
Maintain company stay alive with sustainable development.
d.
Efficient and effective risk management costs.
e.
Provide a sense of security.
f.
Gives the company the ability to control financial aspects more thoroughly.
12.2
Risk:

When we enter the business world, we must be ready to face all forms of changes,
events, and things that are full of uncertainty. This is the fundamental difference between
studying in school, which is full of theory and certainty, and entrepreneurship, which is full of
uncertainty and risk.
1. Uncertainty (Unexpected Risk)
Uncertainty always relates to circumstances that have several possible outcomes and impacts.
Uncertainty is often called the unforeseen risk of an event. Example:
a.
Weather changes that result in delivery problems.
b.
Risks that occur due to natural disasters.
c.
Risks that occur due to changes in other countries' currency exchange rates.
The characteristics of uncertainty are :
a.
Unpredictable,
b.
Difficult to plan,
c.
Sudden,
d.
Can be classified as "force majeure" (natural disaster).
2. Expected Risk
Risks are information, events, losses, or jobs that occur as a result of decisions made in
everyday life. Risks can be certain or uncertain and can be calculated qualitatively. Example of
risk:
a.
Loss due to loss of goods
b.
Decrease in revenue due to decrease in sales
c.
Burning buildings that are at risk of causing losses.
12.2.1
Business Risk Classification
1. Classification of risks in general;
a.
Pure risk; risk that causes loss and is unlikely to cause profit. Pure risk occurs by accident and
cannot be prevented. Examples: loss due to machine breakdown, loss due to power failure, loss
due to building fire.
b.
Speculative Risk; a risk taken intentionally or consciously by an entrepreneur and has two
possible outcomes, namely profit and loss. Example: buying goods using foreign currency.
2. Classify risks based on the type of impact;

a.
Systematic risk; risk that has a more complex impact than pure or speculative risk. This is
because one risk can affect other parts of the company. This risk lasts more long time.
Example: a decrease in the level of sales of a product will cause losses, but if it is a long time,
it will have a broad impact.
b.
Specific risks; risks that have a specific impact and cannot be avoided but can be minimized.
Example: selling ice cream will decrease during the rainy season. Selling umbrellas will
increase during the rainy season. This risk can be overcome by doing a combination of
businesses, namely selling umbrellas in the rainy season, and ice cream in the dry season.
12.2.2
Types of Business Risks:
The types of risks that often occur in the world of business and entrepreneurship are as
follows:
1. Company Risk
Risks that occur in the business that will have an impact on the survival or shares of the
company.
Example: A company is protested by citizens due to environmental issues, the government
issues new regulations related to the survival of the company.
2. Financial Risks
Risks that have a loss impact on the financial aspects of the company. Example: Currency
exchange risk, namely if our products are purchased with foreign currency, there is a risk of
loss due to changes in the exchange rate.
3. Liquidity Risk (Cash Availability) Risks that occur when there are bad bills from customers
which causes problems in the company's cash availability (liquidity). This can lead to interest
rate losses and difficulties in paying employee salaries.
4. Capital Risk
Risks that occur due to sales, liquidity, and financial losses that make the business capital
experience a significant decline. This must be addressed by researching and evaluating the
contributing factors.
5. Market Risk
Risks that occur due to business competition, changes in competition patterns, customer
survival, or the emergence of potential new competitors in our product market. The impact is
reduced sales turnover.
6. Operational Risk

Risk of deviation from predicted results due to imperfect implementation of decisions, system
changes, human resources, technology, productivity, innovation, processes, and product
quality.
12.2.3
Factors Causing Business Risk:
Factors that lead to the emergence of business risk are:
1. Changes that include: environmental and global, social and economic, competition, lifestyle,
market trends, technology, culture, and government regulations.
2. Strategy and planning errors.
3. Decision which not right, resulting in leading to unplanned events.
4. Inadequate preparation.
5. Personal negligence or irresponsibility.
Classification of People in Facing Business Risk Based on the way of viewing and
facing risks, each person/entrepreneur is classified as follows:
1.
Risk Avoider / Risk Free
These are people who do not like to face risks and even tend to avoid risks. According to these
people, risk is a source of problems.
2.
Risk Calculator
Is a person who dares to make decisions if the risk or impact can be calculated (calculated how
much the loss rate is).
3.
Risk Taker
A bold but speculative decision-maker who measures risk intuitively. These risk takers are
often called speculators or gamblers.
4.
Risk Manager
A person who is brave and able to make decisions based on calculating the level of risk and
uncertainty by relying on his intuition to obtain business profits.
12.2.4
How to Identify Business Risks:
How to identify risks is as follows:
1. Methods of analysis from experience and history
Use existing information and data to analyze the risks that will occur in the future. Example:
a.
Customer complaint information
b.
Product record information

c.
HR track record information (employee track record)
d.
Sales growth information
2. Observation and survey method
By doing observations and survey, will be obtained about the desired thing. Example:
a.
Observation and survey of market demand
b.
Observations and survey about customer dissatisfaction
c.
Customer lifestyle observations and surveys
d.
Observations and surveys to discover new products
3. Reference method:
The reference method is often used in finding weaknesses, opportunities, obstacles, strengths
and threats so that entrepreneurs know whether their products, strategies and quality are in line
with the market. The reference used is a strategic reference, namely the market leader or purple
product.
4. Methods from pakat or expert opinion:
We can identify risks and what might happen by asking expert opinion when making certain
decisions.
12.3
Uncertainty
The terms uncertainty and risk are often considered to be the same thing. However, the
two terms are actually different. Uncertainty refers to the notion of unexpected risk, while the
term risk itself refers to expected risk. Almost all of our activities face a lot of uncertainty in
this world. This uncertainty will eventually lead to risk. Because they always want to live
safely and securely, most people are afraid of taking risks. However, all stages of life involve
risk. Where to Even if you avoid risk, there will be other risks because risk is an inseparable
part of life. It is even said that there is no life without risk. So, thus, every day humans face
risks, both as individuals and as companies. People try to protect themselves from risk, and
business entities must also try to protect their business from risk. Risk arises because there are
conditions of uncertainty. Investments can bring profits, but they can also cause losses.
This uncertainty leads to the emergence of risk. Thus, talking about uncertainty means
talking about risk. Risk itself is the result of uncertainty. Businesses carried out by humans, of

course, will always face a number of uncertainties and risks because risks and uncertainties are
everywhere, and that is the character of a business. In investment matters, investors will always
face a number of possibilities such as the possibility of profit, loss or no loss, and also no profit
(break-even). The issue of uncertainty and risk is important in financial discussions because it
greatly affects the form of policies taken with regard to investment. So far, the efforts made by
conventional economists to deal with this uncertainty have been carried out by changing the
uncertain conditions into definite conditions in relation to returns, for example by applying
interest rates on the amount of capital that has been invested. This condition can and will
certainly lead to the loss of one of the parties.
Here we will go deeper to discuss what is uncertainty? Uncertainty is often defined as a
situation where there are several possible events and each event will lead to a different
outcome. However, the likelihood or probability of the event itself is not known quantitatively.
The word uncertainty means a doubt, and thus the definition of uncertainty in a broad sense is a
measurement where the validity and accuracy of the results are still in doubt. Thus, uncertainty
is caused by imperfect knowledge of humans. Example of Uncertainty
a.
The weather forecast says that "it may rain tomorrow morning". The word "may" indicates the
uncertainty of the weather expert due to the imperfection of his knowledge in making the
forecast.
b.
For example, you say that the election will take place in one of the following three scenarios. In
the first scenario, the election is safe; in the second scenario, there are minor riots that have no
significant impact; in the third scenario, there are riots that cause the election to fail. Then, you
make a prediction for each of these scenarios.
Pure risk is a risk that, if it occurs, causes losses alone, such as building fires, motor
vehicle accidents, floods and riots.
While speculative risk is a risk that when it occurs can cause two possibilities, namely
loss or profit.
Pure types include:
a.
Personal risk,
b.
Property risk, and
c.
Liability risk.
Static risks are risks that always exist even though there are no changes in

circumstances. While dynamic risks are risks that arise as a result of a constantly changing
situation such as changing social conditions, changing environments, changes in business risk
technology, and so on. Financial risk is any type of risk that can be measured in nominal
money, for example a vehicle accident. Meanwhile, non-financial risks are risks that cannot be
measured by monetary value, for example, someone's actions that hurt someone's heart.
According to one of the experts Leo J. Susilo, in his book entitled Risk Management
Based on ISO 31000 said that "uncertainty is a state, even if only partially, of insufficient
information about understanding or knowledge related to an event, its impact, and the
possibility of occurrence". Based on this definition, the relationship between uncertainty and
risk is explained by the definition of risk as stated in the ISO 31000 International Standard for
Risk Management. In this document, risk is defined as the effect of uncertainty on an
organization's objectives. Furthermore, Leo J. Susilo explains that risk is often referred to as
the combination of the impact of an event (including in this case a change in circumstances)
combined with the likelihood of the event occurring.
Can a Degree of Certainty be Derived from Risk Management?
Finding out how much certainty is obtained from risk management can also be related
to the probability and impact of a risk. This is as stated by Stefiany Norimarna, Program
Director of CRMS Indonesia, where more specifically said that the question is tantamount to
asking the probability of a risk will occur. Of course, if the probability of a risk occurring can
be known, decision makers become more confident about the decisions they will make. This
confidence can be said to be a level of certainty. The certainty of when a risk will occur will
increase confidence in making decisions in every business process.
Two views with different focuses emerged during the discussion. Some were of the
view that the level of certainty can be determined by using a risk measurement tool. A good
measurement of uncertainty will be very important to obtain the level of certainty. Others
argued that it is difficult to know how much certainty can be obtained from risk management as
expressed by Claire Darlington and Ian Bayne.
Antonius Alijoyo, Principal of CRMS Indonesia, is of the view that the question is
neither directly answerable nor even necessary to question. He explains that obtaining a level
of certainty depends on how much we understand a phenomenon, how far we go to find out
information about the phenomenon. In line with this opinion, Leo J. Susilo explains that in
general, uncertainty management can be done by reducing as much "known uncertainty" as

possible, while we cannot do anything about the "unknown uncertainty". Claire Darlington
also argues that the level of certainty can be known by knowing information about a
phenomenon. That way, someone will know how much effort to make to reduce the impact.
This phenomenon that can be known is called known uncertainty.
Information on how big the impact of a phenomenon is is also needed to determine
what action needs to be taken. Whether a decision is made based on risk informed or based on
risk based. Ian Dalling explains that risk informed decision making is decision making based
on information about risks that are already known, which can be in the form of experience and
expertise from a person, while risk based decision making is decision making based on
information about risks that are structured and obtained from a system. Describing these two
things, it will be very easy if you look at the conditions found in the world of medicine.
In medicine, a doctor usually makes risk-informed decisions. Simplifying what
Jacquetta Goy said, an example can be taken from someone who has a critical illness and must
be treated immediately with a surgical procedure. Surgical decisions made by the doctor are
sometimes taken quickly before the condition of the affected person does not worsen. A doctor
only looks at the symptoms shown by the patient, and based on his experience, The doctor can
immediately conclude what actions must be taken quickly. In contrast to risk-based decision
making, where this method is commonly found in an organization that implements risk
management.
There are various ways to understand a phenomenon. Among the various ways that
exist, in this case the author can only conclude that risk management is the best way at this
time to obtain certainty from an existing phenomenon. With the implementation of structured
risk management, individuals or organizations can identify, analyze, and evaluate each existing
risk, so that information is obtained to help make more certain decisions. In line with this,
Vladimir Trbojevic explains that reducing uncertainty does not necessarily directly reduce the
risk, but is a better approach in terms of prevention.
MARKET RISK AND FINANCING RISK
13.1
Definition of Market Risk:
A company experiences a condition called market risk due to changes in market
conditions and situations that cannot be controlled by a company. Market risk conditions are
sometimes referred to as risks that occur as a whole, this generally has the nature of a

phenomenon that is comprehensive and experienced by the company (Dewi, 2019). The
emergence of this market risk phenomenon is caused by market price indicators moving in a
direction that has a detrimental impact on an organization or company. For example. In a
company that has a stock portfolio in the form of securities and the shares are purchased at a
price of Rp. 1 billion. Then at a later time the price of the shares falls so that the market value
of the shares drops to Rp.800 million. Because the stock market value has decreased by Rp.200
million, the company can be said to have suffered a loss in the value of its stock portfolio. The
cause of this loss in the securities portfolio is due to a decrease in market value that moves in a
direction that is less favorable to the company.
Another example of market risk is the world economic crisis of the 1930s, while the
economic crisis in Indonesia occurred in 1997 and 1998, coup d'e' tat was an event that
occurred in the Philippines when the president, Marcos, was elected. His power was taken by
the People Power until Crazon Aquino was appointed president, then in the United States
occurred in the 2007 Subrime Mortage case, while the incident in Thailand centered on the
Central Bank of Thailand devalued Bath so that it caused a shock to the Thai economy as a
whole. And in another case occurred during the Gulf War which caused several countries in the
Middle East such as Iraq and Kuwait to experience catastrophic economic shocks and there
were various cases that had an overall impact.
13.2
Market Risk:
Market risk is a loss experienced by administrative balance sheet positions in which
there are derivative transactions in market conditions due to changes in overall market value.
The source of this risk comes from clien transaction records managed by financial institutions
or what is called the trading book and bank balance sheets or bank banking books (Darmawi,
2022).
a.
Market risk of the trading book (Traded Market Risk)
The continuous process of buying and selling financial instruments with the aim of
making profits in the market is known as the risk of investment value of losses. The bank's
actions taken deliberately from the emergence of these consequences give rise to a risky
position with the expectation of a return on the profits from the risk position it has taken.
b.
Furthermore, the banking book is very different from Traded Market Risk.
This risk naturally results from the nature of the bank's business with the customer,
namely is an agreement with the consequences of two parties. In general, the nature of the bank

has a funding structure with a short-term nature or called short funding seen in terms of credit
in general given to customers by giving a longer period of time than the customer's deposit.
The term market risk in the English dictionary is market risk, which is a risk that arises
due to a decrease in the value of an investment due to several factors that occur in the market,
causing problems in a market economy. The factors that cause market risk are four, namely:
1. Capital risk
2. Interest rate risk
3. Currency risk, and
4. Commodity risk
13.3
Forms of Market Risk:
In general, market risk is divided into two forms (Mz, 2015), namely:
1. General Market Risk:
All companies must have experienced General Market Risk, where this market risk is
caused by policies implemented by related agencies and has the potential to affect all market
business sectors. An example of this general market risk is when a central bank in a country
that has implemented a tight money policy (tight money policy), namely by means of various
instruments such as by conducting or implementing a tight money policy raising the BI Rate.
By raising the BI Rate, it will have a considerable impact on all business sectors related to
interest rate related instruments.
Such strategies are used by customers in taking out loans and also used to deposit their
money with banks. A typical example is that if the BI Rate is raised, then the bank's lending
rate will also rise, depending on the situation. Particularly in the case of banks applying income
estimation using a sliding rate. What is meant by the sliding rate calculation is the interest
charged on the calculation of the principal value of the loan as an effect carried out by a
director by paying installments of the principal loan.
2. Specific Market Risk:
Specific market risk is a risk that is only experienced specifically by one business sector or only
part of the business is affected and is not comprehensive. For example, the company PT. ABC
has been announced by an appraisal agency where the agency has a good reputation in the eyes
of the public and is respected so that it is recognized by the public. The announcement contains

that PT. ABC has poor performance and the company has a lot of debt so that the financial
statements are not actual published to the public. The news had an impact on the investment in
shares and bonds of PT. ABC immediately dropped dramatically. But the decline in investment
was not followed by other companies.
In another example in a company where a manager is involved in an extraordinary
criminal case and the case is exposed in various media. So that the public response considers
that the company is very bad or is not doing well. So that with this case, it will have an impact
on the decline in investment.
On the other hand, companies sell products that are considered to contain harmful or
haram ingredients. For example, companies that have haram foods such as those containing
lard are haram. From that statement, it is then exposed to the mass media, both ceta media and
electronic media, it will cause a drastic decrease in product sales and affect the company's sales
profit.
13.4
Market Risk Factors:
The problems posed by shifts in market prices, such as the value of assets held, are
known as market risk. In addition, changes in market prices pose a significant risk of loss both
on and off balance sheet financial statements, referred to as market risk. The four standard
market risk factors are as follows: currency risk, commodity risk, rate of return risk, and capital
risk (Corry, 2019).
1.
Interest rate risk is the risk of loss due to changes in interest rates. In banking companies, the
most dominant form of interest rate risk is the banking book, which includes: cash flow, yield
curve, basis risk and options. Judging from this statement, banks are required to be able to
manage the impact of price risk caused by trading book exposures. Categorized by its nature,
interest rate risk is called systematic risk. It is important to measure interest rate risk for a
country which is growing and can affect the financial system in the world.
2.
Exchange rate risk, a market risk phenomenon whose risk impact is influenced by movements
in gold prices and foreign exchange rates. The business will exchange foreign currency for
rupiah to manage this risk (exchange rate). In the same vein, the business controls its exposure
to foreign currencies as a result of its operating costs. Issues with bank borrowings as well as
the effect of the company's exposure may result in interest rate risk.
3.
Commodity risk, which is a market risk where it is caused by changes in the value of
commodity prices. There are factors that affect commodity risk, namely the movement of
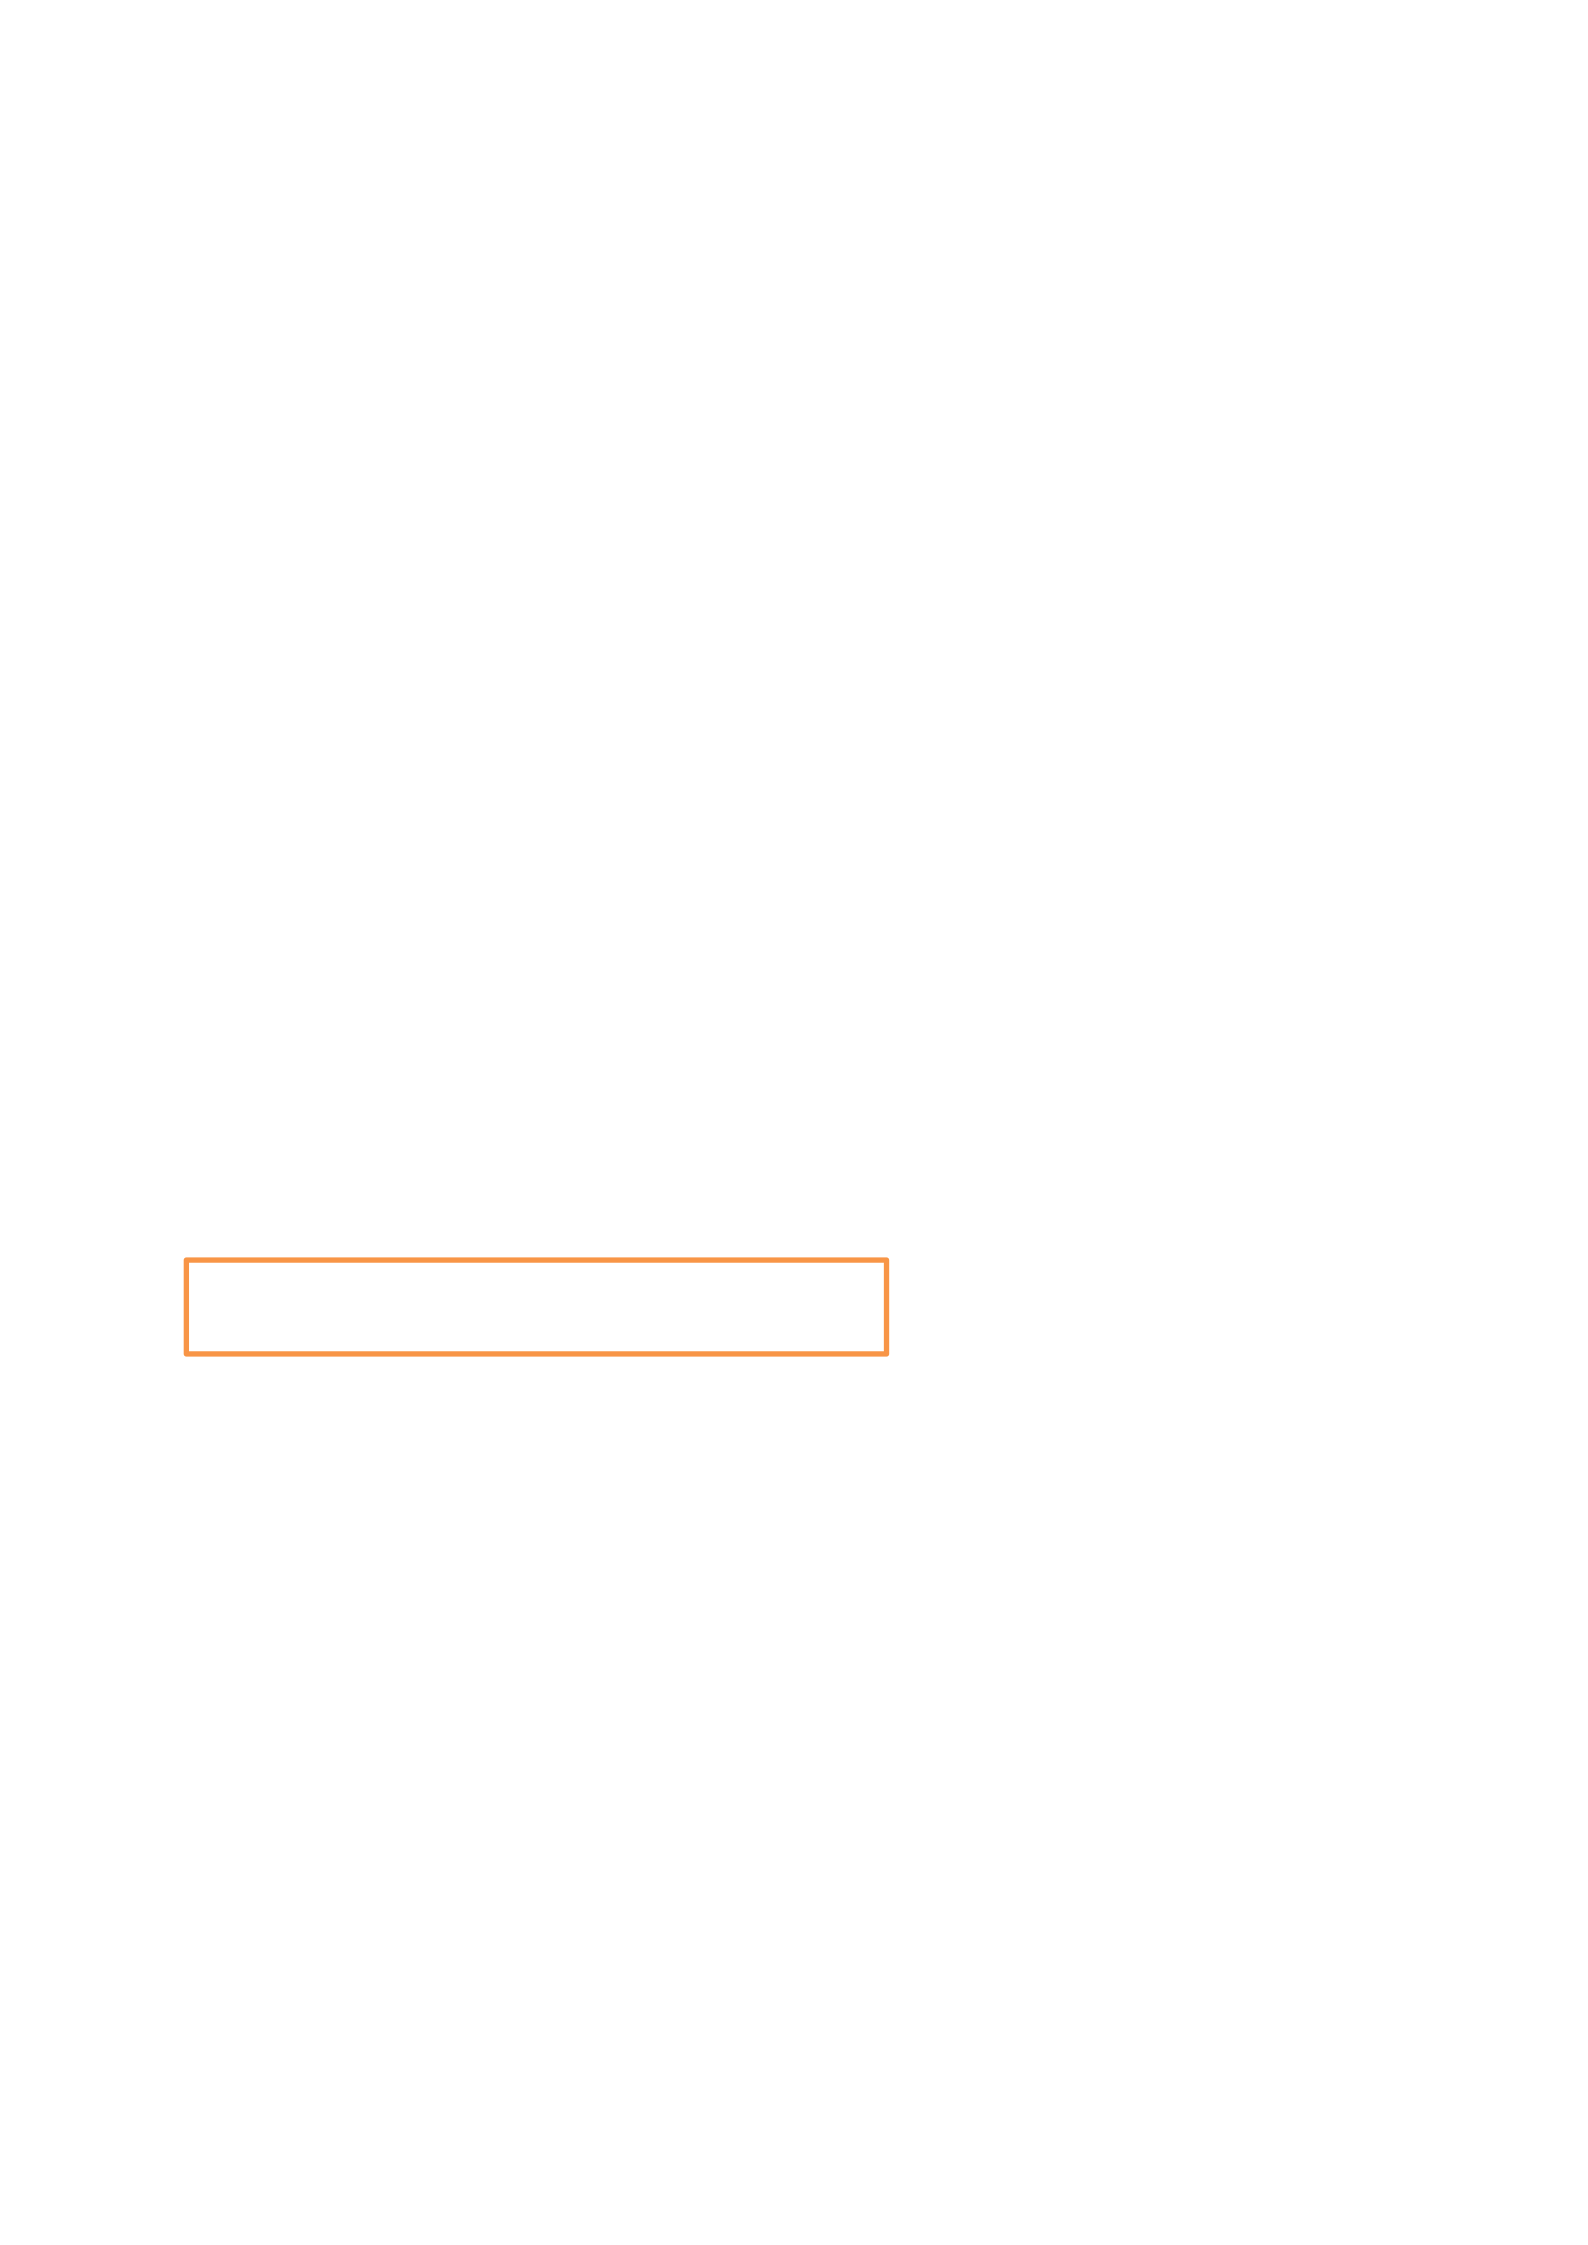
Market Risk = Sensitivity x Volatility
world oil. This commodity risk is very difficult to minimize.
4.
Equity risk, which is a type of market risk where the cause is the overall change in the value
of equity when it is in the AFS (Available For Sale) category. Sometimes investors sell
excessively in the stock market, causing equity risk to occur.
13.5
Market Ratio Identification and Measurement:
1.
Market Ratio Identification:
From several risks, there is one risk that causes other risks to emerge, namely liquidity
risk, which is part of the definition of market risk. Suppose the value of assets decreases due to
unstable market price movements. The decline in asset value has an impact on the report the
company's financial position between the asset and liability sides of the company.
It is since the basel I amendments in 1996 that market risk has been recognized and
accounted for. Business activities were categorized into two at the time of basel II which
included the trading book and the banking book. Then categorized again into the capital
adequacy ratio or CAR. The cause of market risk for Islamic banks is usually due to
fluctuations in commodity prices and physical assets.
2.
Market risk measurement:
In measuring a market risk, we can use the method of integrating the sensitivity and
volatility equation in measuring market risk as follows:
There are several things that can pose a risk to the income earned by LKS, namely those
related to the risk of rate of return, and changes in interest rates. Therefore, with some of these
rights, the LKS rate of return can use alternative tools by considering the risk as caused by
market risk when drafting Islamic financial contracts.
3.
Value at Risk (VaR) Method:
VaR is a method that uses risk calculations on how losses are distributed. This method
is in a neutral position and can be applied to various types of risk because losses The
distribution is value-free. This VaR method is used to calculate the deviation / variance value
of the distribution. Appropriate calculations used by banks are With the statement that the
smaller the percentile, the further away from the average value of the distribution, the greater

the calculated loss, banks can use percentiles, such as those with a significant level of 1%, 5%,
or even 10%.
13.6
Market Risk Control Strategy:
In controlling market risk, there is one approach. That is by using a limit system. By
using this approach, in order to keep market risk under control and at the same time
accommodate the various units needed by the business in carrying out business activities, the
bank must set limits with reference to a certain amount (Dewi, 2019).
In this provision, the limit should not be violated, but in conditions that do not allow it,
limit violations are inevitable. If a limit violation has occurred, the bank must immediately
develop an action plan to resolve the problem that has occurred. In addition, if the limit is often
violated, the bank must review the amount of the limit so that it is balanced with the
development of the bank's business needs and the market.
13.7
Financing Risk:
Risk financing is the provision of funds made by the company to recover the company
due to losses (Darmawi, 2022). Or in another sense, Risk Financing is the provision of funds
that aims to reduce the impact of losses experienced by the company financially due to
unwanted impacts experienced by the company.
Risk financing, or risk financing as it is called, deals with the ways of procuring funds
to overcome the company's financial losses. It usually consists of the following methods:
1. Risk financing transfer (transferring risk accompanied by financing)
2. Risk retention (risks that are handled by the company itself)
13.7.1
Risk financing transfer:
If a loss occurs, a risk transfer method will be carried out through risk financing and
requires funds to pay for the loss. Risk financing can be done in two ways, namely:
1.
Risk transfer to insurance companies (insurance transfer):
Risk can be transferred to an insurance company through insurance transfer. The term
"insurance" can be used to describe a method of risk management in which a business transfers
risk to an insurance company at a much lower premium than the risk of financial loss in the
event of a loss. In the future, insurance is the main goal of financial planning. With regard to
insurance, there are three schools of thought. The first school is that insurance is a cooperation

between the insured and the insurer that serves as a means of transferring risk. The next school
is that organizations do not care about this relationship and think about protection as an
inclusion strategy or component. Finally, the third school is a combination of both schools.
There are risks that can be eligible to be insured. Namely:
a. The loss is substantial, but the probability is low. For example, if a company employee has a
minor illness, there is no need for insurance, it is enough to be handled by each company.
b. Probability can be taken into account, i.e. if the premium on insurance is based on a future
forecast, but the forecast is based on estimated probabilities. Then past experience will underlie
it.
c. Massive and Homogeneous, is the main requirement that must be met by the company in order
to be insured in mass, meaning that there must be a number of transparent units for risks that
are not much different.
d. The loss that occurs is accidental, meaning that the insured must not have a plan or purpose
that has an influence on the event to be insured. In actuality, this statement is only for events
where there is no element of intent. For example, earthquakes or bad weather.
e. A certain loss, which is a loss that will be paid by the insurance company if it occurs during a
certain time in a certain place, such as an agreement to cover or compensate for losses due to
fire in a certain location, this contract applies when the incident is known when and where the
loss occurs.
2.
Risk transfer to other companies that are not insurance companies (noninsuarance):
The majority of non-insurance transfers are made by non-insurance parties, which can be
done through standard contracts or special contracts to transfer risks. (Corry, 2019).
Some of the contents of this contract relating to the transfer of responsibility for the risk
are:
a. Assets, taken from Dr. Lanita Nianta's 1994 article. Money, goods, and rights resulting from
transactions that occurred in the past and are anticipated to provide benefits in the future are
examples of assets, or economic resources, that a company owns.
b. Loss of net income, which is an event of temporarily ceasing activities due to a loss in which
one is no longer allowed to occupy one's workplace.
c. Personnel losses, quoted from (Mz, 2015) Is a loss caused by behavior that befalls personnel or
people within the company
d. Liabilities, this contract is more in favor of third parties. What is meant is the obligation that

must be fulfilled by the insured against third parties according to the provisions of the policy,
with a note if the risks guaranteed by the policy cause losses to third parties.
13.7.2
Risk Retention:
Risk tetention is a method that is often used in handling risks by being borne by the
company concerned. the company seeks the source of funds to be used. Companies in risk
coverage, namely passive or unplanned retention which can be active or planned (planned
retention) (Darmawi, 2022).
There are several reasons why companies do retention:
a. Necessity, because there is no other alternative, Necessity in bearing one's own risk, for
various reasons especially when it is not possible to transfer the risk. As is the case with
responsibility in the matter of criminal acts, and problems that are more than property. The
necessity in retention is due to the absence of insurance companies that are willing to bear the
risk.
b. Cost, If the company's risk is transferred to an insurance company, the company must pay a
premium where the premium is classified into two parts, namely:
•
Loss allowance
•
Loading which includes profit costs
c. Loss of hope
If the company has confidence in the losses and expectations that are considered lower than the
insurance estimate, then the company can save expenses in the long term, the savings are equal
to the difference between the two calculations. But if the loss-expectation is considered the
same as the insurance company, then the company will prefer the rentinor. Losses The
expectation that must be considered is if the company faces a loss that is likely to occur in the
following year will be greater than the anticipated loss with the aim of eliminating uncertainty
in the short term.
d. Opportunity Cost, is the timing of premium payments in relation to loss-related costs referred
to as opportunity cost. Consider scenarios where the premium will be less than or equal to the
loss and alternative costs. If there is a time lag between premium payment and loss payment,
the business may prefer to bear the risk itself. Alternative expenditures that would result in
greater returns on investment returns, reserve funds for loss payouts
e. Quality of service
Some employers think that an insurance company's insurance services can be better handled by

the insurance company itself or by a Service Bureau. Because the company lacks
professionalism and experience, it is doubtful that the insurance company can provide coverage
services that are superior to those provided by the insurance company.
THE ROLE OF INSURANCE AS A RISK MANAGER
14.1
Definition of Insurance:
Insurance is a means of providing economic security for the country. Insurance is a
financial arrangement that reimburses the cost of unexpected losses. Insurance involves the
transfer of potential losses to an insurance pool. The pool aggregates all potential losses and
then transfers the cost of the predicted losses back to the revealed losses. Thus, insurance
involves the transfer of loss exposure to an insurance pool, and the redistribution of losses
among the members of the pool.
Insurance is an economic activity, and an important one at that. Most authors of general
economics texts discuss insurance, usually in a separate section. In his book Wealth of Nations,
(book I, Chapter 10) Adam Smith (1776) wrote that insurance "Premiums must be sufficient to
compensate for general losses, to pay the expenses of management, and to give such profits as
may be drawn from an equal capital employed in any general trade". This is a very good
statement of how insurance premiums should be calculated.
Insurance is a contractual arrangement where one party agrees to compensate another
party for a loss. We refer to the party who agrees to pay for a loss as the insurer. We call the
party whose loss causes the insurer to make claim payments as the insured. We call insurance
payments receiving premiums. We refer to an insurance contract as a policy. We refer to the
insured's possible loss as the insured's loss exposure. we say the insured transfers loss exposure
to the insurance company by purchasing an insurance policy.
Insurance is a branch of contract law. Insurance policies, like contracts, are
arrangements that create corresponding rights and obligations for those who are parties to
them. For example, an insurance contract creates the right of the insured to collect payment
from the insurance company in the event of a covered loss. The insurer has a corresponding
obligation to pay for the loss. Insurance contracts also create other rights and obligations. The
insurer has the right to collect premiums, and those who want their coverage to continue have a
corresponding obligation to pay them. The insurer has the right to determine the rules and
conditions for participating in the insurance pool, and the insured has a corresponding

obligation to comply if they expect to collect losses. In analyzing insurance contracts, you must
remember that the rights created for one party are obligations for the other party.
Perhaps the word 'liability' is too strong a term to describe the obligations of an insured
to an insurer. Generally, an insurance company cannot legally force an insured to pay a
premium or follow its procedures, but it can cancel the insurance or reject a claim if the
premium is not paid. Similarly, the insurer cannot legally force the insured to fulfill the
conditions set out for him in the contract, but if the insured does not fulfill the conditions, the
insurer can cancel the insurance or deny the claim the loss will not be paid. As such, it seems
fair to note that insurance contracts create corresponding rights and obligations for both the
insurer and the insured.
There are four factors that build insurance premiums, namely:
a)
Actual cost of loss
b)
Insurance pool operation and maintenance costs
c)
Provision for unexpected losses, or insurance pool risk factors
d)
Income from investment.
14.2
Risk Transfer
Risk transfer is divided into two, namely:
1. Transferring risk to an insurance company
In this case the company registers itself with the insurance company. This can be done in
various forms, namely:
1)
Insurance on objects owned by the company.
2)
Life and health insurance.
2. Transferring risks to non-insurance companies
In this case, a company transfers some of the risks it will experience to another company. This
can be done in the following ways:
1)
The company transfers a certain amount of work to another party.
2)
The company moves a number of assets from monetary to tangible form
3)
Leave some items valuable company to a place that is considered safe
4)
Diversify assets.
14.3
Benefits and costs to society of the Assurance System
1.
Cost

The cost to society of operating the insurance system includes the cost of the resources
used by the system-labor, land, and capital-but excludes the cost of losses. Losses incurred due
to fraudulent attempts to collect insured proceeds are a reasonable cost attributable to the
insurance system. The cost of property insurance fraud is estimated to exceed $20 billion per
year. Health insurance fraud losses are estimated to generate larger losses than property
insurance fraud. However, some losses are less frequent or less severe because the possibility
of lower insurance premiums encourages loss prevention or loss reduction activities. For
example, because of the discounts insureds receive for hiring security guards, or installing fire
sprinklers and smoke detectors, society loses fewer of its resources to fire or theft losses.
2.
Benefits:
What benefits does society gain from the operation of the insurance system? How do these
benefits compare to the resources used? One of the greatest benefits that the insurance system
provides to society is stability within the family. Insurance prevents families from experiencing
great hardship caused by the unexpected loss of property or the premature death of the family's
income provider. Insurance allows families to continue their activities in a much more normal
way after a loss than if there was no insurance.
Insurance is also very useful for businesses. Insurance helps the planning process because
planners know property loss does not mean financial ruin, and the future of a business cannot
be destroyed by fire or death. Insurance facilitates credit transactions because creditors are
more willing to lend money if the death of the debtor does not make collection of the loan
difficult or impossible. Similarly, lenders are more willing to provide property or real estate
loans if they know a disaster cannot destroy the financial security that lies behind their loans.
An economist would place a high value on the insurance system because of its function as
an antitrust device. That is, if there is no insurance system in place, only the largest businesses
can bear losses and continue to operate. Without insurance, there would be monopolistic
tendencies in many industries. For example, the country's largest grocery store chain, Kroger,
may be able to lose one of its stores in a fire and remain in business, whereas a mom-and-pop
grocery store may have to close permanently if an uninsured fire destroys its only store.
Smaller store chains cannot sustain uninsured losses as well as larger chains. Insurance allows
smaller operators to pool their exposure to losses and thus remain competitors in an industry.
Financiers recognize that the availability of insurance tends to lower a company's cost of
capital because both creditors and investors will charge more for the use of their money if it is
exposed to risks associated with natural disasters in addition to business risks. In addition,

without insurance, companies have to keep more money in relatively unproductive near-cash
reserves to protect themselves from a rainy day. Basically, all insurance provides negative
benefits. From a participant's perspective, net present value (NVP) insurance is not the best
option. If the discipline is to save or invest, the protection needs can be managed by the
participants themselves. However, the view not to enter insurance is wrong. As an insurance
participant, you get the main benefits, such as protection, comfort and certainty that these
benefits can become the basic capital for worker productivity, even though these benefits are
not made in writing or not expressed in nominal rupiah.
Seeing that insurance is so beneficial, people are interested in enrolling in an insurance
program. Insurance is beneficial not only for oneself but also for the whole family and their
heirs who can enjoy. The benefits of insurance in general and through the types of insurance
can be explained, as follows:
1)
Benefits of Insurance in general
a.
Provides a Sense of Calm
Socio-economic conditions and the increasing demands of life can trigger stress for everyone.
A lifestyle with economic difficulties allows a person to experience the worst unwanted risks.
Risks in work and future events are difficult to predict. Insurance products can provide
protection against adverse events in the future. For example, life insurance where when the
insured person dies, the insured's family gets the sum insured according to the insurance policy.
Another example is property insurance when there is a fire or building damage can be replaced
with this insurance. So insurance can provide a sense of calm and comfort in any field of
business because all the risks that arise have been covered by insurance.
b.
Minimizing the Risk of Loss
Insurance products all have the same benefits and functions, namely minimizing the risk of
loss. Basically, insurance is a service that helps to bear losses due to an unexpected event.
c.
Savings and Investments for the Future Insurance is also useful as savings and future
investments. This is because many insurance companies now guarantee the return of
investment funds when the contract ends. This type of insurance will provide relief for
policyholders in choosing the coverage period. The coverage period usually has three options,
namely five, seven and 10 years.
d.
Manage finances well
Discipline in paying premium obligations regularly, one can manage finances well. The
obligation to set aside part of the money to pay insurance premiums.

2)
Insurance benefits according to the type, among others:
a.
Life Insurance
Life insurance is useful for people who bear financial losses due to death or total disability. For
example, a head of the family has an accident and dies, of course this affects the family's
finances. If the head of the family has insurance, the heirs can claim the insurance so that it can
help the distress of the family left behind.
b.
Health Insurance
Health insurance provides benefits such as guaranteed health or care costs when the insured or
policy holder experiences illness or accident so as to reduce medical expenses. To finance the
treatment the insurance company guarantees the availability of funds.
c.
Old Age Security Insurance
Old-age security insurance is to provide income certainty for the insurance policy holder when
he/she retires.
d.
Education insurance
Education insurance is useful to cover the cost of children's education. In this way, the burden
of parents in paying for their children's education becomes lighter when compared to people
who do not have insurance.
e.
Property Insurance
Property insurance is insurance that guarantees the insured as a result of unexpected things, for
example due to fire and natural disasters.
f.
Travel Insurance
Travel insurance is insurance that protects the insured when traveling, for example covering
medical expenses, loss of travel documents, loss of goods and several other forms of loss while
traveling.
g.
Vehicle Insurance
Vehicle insurance is insurance that protects vehicles due to damage from traffic accidents, fires
and so on.
The experience of many who have health insurance, whether government-mandated
(BPJS) or private, shows how important it is for everyone to have insurance just in case. We
don't expect anything bad to happen, but if it does, it's not too bad financially. Because there is
an imbalance where the policy owner must pay contributions regularly, but bad events are
incidental and chance. Therefore, to overcome this, the insurance company is expected to be

credible in dealing with a "bad event". This can be a good marketing instrument to attract
enthusiasts.
The nature of the agreement between insurance companies and investors should be well
considered and interpreted in a balanced manner, not allowing investors to have the
interpretation of loss. This affects the difficulty in convincing the market of the benefits of
insurance. If the insurance participant has a negative NPV, it does not mean that the insurance
company is profitable, in fact many insurance companies are bankrupt or "collapsed".
Naturally, profit is part of business. Insurance companies that manage risk in their business
Individuals or companies are also likely to have risks, such as bills that are larger than
expected.
Stakeholder trust will be lost when there is a default on insurance bills, so that the
insurance company is considered "collapsed". The loss of stake holders' trust in insurance. In
this case it is important for insurance companies to strengthen capital rules and increase
vigilance in managing the business to maintain the existence of the insurance company. To
anticipate or prevent defaults, the management of reserve funds (such as LPS) by the insurance
board is very important. Currently, with the existence of LPS, customer peace of mind for their
funds (up to 2 billion) can reduce the potential for "Rush", and can support economic stability.
14.4
Risk Classification in Insurance:
Risk classification is the process of separating into groups (classifications) potential
insureds (risks). Classification mechanisms include, but are not limited to, determining the
acceptability of insurance and the type, amount, and price of such insurance. The justification
for classification is that risks are assumed to be placed in relatively homogeneous groups, i.e.
groups where risks have similar loss probabilities. If the classification is accurate, insureds are
treated fairly (because similar insureds pay similar premiums and premiums are related to
expected losses) and insurance companies can accurately estimate expected losses.
Recently, objections have been raised to some of the results of the risk classification
process, including the unavailability of coverage, high prices, and low benefits. The objections
that have received the most publicity are objections to "redlines" in property coverage; the use
of variable pricing such as age, gender, and region in car insurance; and differences in pension
plan benefits depending on the gender of participants.
Other objections are directed at certain aspects of the risk classification process. Some
objections stem from ignorance or misinterpretation of insurer practices or the nature of
insurance. Other objections stem from reasonable attempts to investigate the theoretical basis

of risk classification. Specific objections related to risk classification include the following:
1)
The classification system arbitrarily uses some factors related to loss, but ignores others. For
example, female pensioners argue that while gender may or may not have an effect on
mortality, other factors that may also have an effect, such as smoking habits or occupational
hazards, are not taken into account in calculating pension benefits.
2)
Classification systems give rise to heterogeneous classes; in other words, risks with different
loss probabilities are grouped together. Some people argue that the use of age groups in car
insurance gives rise to heterogeneous classes because each age group contains both good and
bad drivers.
3)
The data used to determine the probability of loss for the class was inappropriate because it
was based on risks that differed in some important respects from the class in question. For
example, the teachers' group challenged the pension calculation using mortality tables that did
not have retired teachers in their experience base.
4)
Classification systems combine the effects of various classification factors in a way that does
not accurately reflect the total impact of those factors. For example, the numerical rating
system used for classification in individual life insurance generally does not reflect the fact that
the presence of more than one impairment may lead to higher (or lower) mortality rates than
would be implied by adding the effects of individual impairments.
5)
Many classification factors have no causal relationship with the loss whose probability is being
measured, but are actually surrogates or proxies for the true causal variable. In automobile
insurance, it has been suggested that the true causal variable. In car insurance, it is said that sex
is a proxy for the number of miles traveled.
6)
Most classification factors are not within the control of the risk; hence the risk has no incentive
or ability to change these factors to reduce insurance costs. This argument is made to reflect
lifestyle variables, such as smoking habits, in life insurance classification.
The following are risk classifications, namely:
1. Pure risk is a risk that always experiences a loss, meaning that the loss is a sure thing, for
example a factory fire, the company will definitely experience losses due to the fire.
2. Speculative risk, which is a risk that is speculative in nature, means that risk can bring profits
and can also bring losses. For example, a cake trader, if the buyer is crowded then it is certain
to make a profit,
However, if there are few buyers, it is likely that the trader will suffer losses because the cakes

do not last long.
3. Specialized Risks, which are risks that only affect individuals and localities. For example, theft
and unemployment.
4. Fundamental risks, which are risks that will have a very broad impact. For example, due to the
covid pandemic
19 Many companies cannot operate and eventually go bankrupt. This has an impact on the
economic balance and employees who work for the company lose their jobs. Another example
is the risk of natural disasters.
5. Individual risks are risks that can affect a person's financial activities, for example an accident
that results in temporary or permanent disability.
6. Property risk is a loss associated with ownership of property or a valuable object.
7. Liability risk, which is the risk of responsibility given to other parties due to our actions. For
example, if a person named A accidentally hits another motorcyclist, B, who is seriously
injured, then A must be responsible for B's treatment and is legally responsible.
Despite having various types of risks, not all of these risks get protection from an
insurance company. Only fundamental and pure risks can be insured, with the following
conditions:
1. Risk occurs due to unexpected or unpredictable events.
2. Risks that are borne are homogeneous and common risks.
3. The consequences of a risk can be assessed financially or valued in money.
4. There are objects that are insured or insured such as illness, loss, property and so on.
5. Objects listed in the coverage or insurance are not contrary to the public interest and applicable
rules.
6. The level of risk insured or insured is in accordance with the premium charged to the insurance
owner.

