


The Rise of Dollar Credit in Emerging Market
Economies and US Monetary Policy
Introduction
The surge of dollar credit in the emerging market economies (EMEs henceforth) has
drawn close attention from the international financial market participants and the
policymakers due to its potential role in the monetary and financial stability of the global
economy. The data from the Bank of International Settlements (BIS) shows that the
outstanding US dollar credit to non-bank borrowers in the EMEs has risen from 1.69
trillion dollar in 2008Q4 to 3.25 trillion dollar in 2015Q4. The cyclical nature of EME
dollar credit
1
could also amplify the overall credit condition in the domestic economy and
increase the vulnerability of these the EMEs in dealing with negative economic shocks.
For example, during the expansionary phase, the dollar credit floods into the EMEs, which
raises the challenge to stabilize the domestic monetary base. In the contractionary phase,
the dramatic outflow of dollar credit also creates difficulty to stabilize the exchange rate
and asset prices (Avdjiev et al., 2012). This was very evident during the ’taper tantrum’ of
2013. On the other hand, however, it has also been argued that the increasing role of dollar
credit in the EMEs may signify a more integrated global financial market and a greater
degree of risk sharing across different countries.
The growing academic interest in the literature on examining the dollar credit in the
EMEs has also coincided with the recent emphasis on the role of US monetary policy in
boosting global liquidity. Global liquidity refers to the global factor that drives cross-
border spillover in financial conditions and credit growth. Shin (2013) proposes two
phases of global liquidity after the Millennium. The first phase of global liquidity
transmission (2002-2008) is more associated in form of bank loans through global
banking system. The international bond market gradually took over the share of bank
loans in the second phase of global liquidity transmission starting in 2009. Since then, the

large scale of bond purchases as a result of of Quantitative Easing (QE) programs had led
to the portfolio re-balancing effect
2
in the international bond market. A few papers and
policy studies have provided narrative evidence (Borio, et al. 2011; McCauley, et al., 2015)
in support of the hypothesis that the abundance of global liquidity was one of the causes
of the boom of the dollar credit in the EMEs.
Although much attention has been given to the rise of dollar credit and its apparent
relationship with US monetary policy and the valuation of the US dollar, not much work
has been done to systematically disentangle the short-run and the long-run relationships
among these variables. It is perfectly plausible to think that the short-run relationship
between dollar credit in emerging markets and the stance of monetary policy in the US
may be very different from its long-run relationship. The long-run dollar credit in the
emerging market may be driven more by its long-run absorptive capacity instead of the
short-run increase in liquidity or the weakness of the US dollar. Therefore, it is very
important to decompose the overall EME dollar credit and isolate the cyclical variations
from its long-term trend, by taking into account the information on US interest rate and
the dollar valuation. In addition to estimating the short-run and the long-run correlation
between the shocks to each series, this approach will also yield us a quantitative estimate
of how big the cyclical component in dollar credit was at different points in time during
the last few years.
To examine the long-run and short-run relationship among these variables, we
propose to use a correlated multivariate unobserved component (UC hereafter) model
which is a multivariate counterpart of the correlated univariate UC model as outlined in
Morley, Nelson and Zivot (2003).
3
This model allows us to decompose the movements in
dollar credit, interest rate and dollar index
4
into a slow-moving trend component and a
cyclical component simultaneously. The slow-moving trend captures the long-run
evolution of these variables and the cyclical component captures the short-run

movements. This model allows us to not only estimate the permanent and transitory
movements, but also provides us a measure of correlation of the long-run movements and
the short-run movements among dollar credit, interest rate and dollar index.
5
For
example, if the recent narrative about the role of exceptionally low interest rate in
boosting EME dollar credit is correct, then we would observe a negative correlation
between the shock to the transitory component of dollar credit and the shock to transitory
component of the US interest rate. To take into account the zero lower bound problem
associated with the federal funds rate and the short-term interest rate in the recent time
period, we use the shadow interest rate as proposed by Wu and Xia (2016) as a proxy for
US monetary policy stance. The shadow interest rate takes into account the impact of
unconventional monetary policy on interest rate and unlike the federal funds rate, is
allowed to fall below zero.
To understand the intuition behind the structure of our model, one could think of the
credit activities in the EMEs as a form of international investment. From the investors’
perspective, the return of lending dollar in the EMEs depends on the interest rate paid
from these credit instruments. The US interest rate, the risk-free rate in the international
credit market, is a major factor in pricing the interest rates on the international bank loans
and the corporate bond yields. From the EME borrowers’ perspective, the dollar valuation
in the currency market is also critical in determining their real external debt burden,
besides the US monetary policy rate. The expectation of domestic currency appreciation
will lower the expected external debt burden in the future and vice versa. To summarize,
we can think of this three-variable dynamic system as the application of interest rate
parity in international credit activities.
We find interesting and economically meaningful results from the estimated
multivariate correlated unobserved component model. The maximum likelihood
estimates of our correlated multivariate UC model suggest that there is a strong negative
correlation between the transitory shock to dollar credit and the transitory shock to the

US interest rates. This suggests that a temporary decline in interest rate below its long-
run level is associated with an increase in dollar credit above its long-run level. We also
find a very high negative correlation between the transitory shocks to dollar credit and
the transitory shocks to the dollar index, implying an appreciation of US dollar is
associated with a decline in dollar credit in the EMEs in the short-run. These results
support the anecdotal and narrative evidence on the strong relationship between dollar
credit and the US interest rates and also between dollar credit and the strength of the US
dollar. We also find that the trend-cycle decomposition of EME dollar credit from our
multivariate correlated unobserved component model captures the recent boom and bust
behavior and compares favorably to a univariate trend-cycle decomposition benchmark.
In particular, our results suggest that the dollar credit before the taper tantrum was 10%
above its long-run trend in the emerging market economies.
The rest of the paper is structured as follows. The second section provides a literature
review about global liquidity transmission and discusses the associated monetary policy
spillover effect. The third section introduces the data used in this study and the setup of
the correlated multivariate UC model. The fourth section interprets and presents the
results from the model. The last section concludes the paper.
2.2 Literature Review
The literature on dollar credit in the EMEs is nascent. Few papers have tried to address
this issue from different perspectives. In understanding the phenomenon that dollar
credit outside the US behaves differently from the US domestic dollar credit, Borio,
McCauley and McGuire (2011) take a look at the recent behavior of international credit
and associate it with the overall credit conditions. Their descriptive analysis reveals the
fact that US dollar credit in some countries has been outgrowing the overall credit during
the credit booms. A formal analysis later on from Avdjiev, McCauley and McGuire (2012)
regresses the cross-sectional change in credit-to-GDP ratio on the change in international
credit during the credit boom phase (2002-2008) and regresses the credit growth in the
EMEs on the change in international credit during the credit bust phase (2008-2011).

Their results suggest that international credit amplifies the overall credit cycles in the
EMEs. While in these studies, the authors often use the share of international credit in the
overall credit to measure the cyclical variation of international credit, it is worthwhile to
recognize that the trend of international credit and the trend of the overall credit can be
driven by different underlying factors, therefore they do not need to share the common
trend in the numerator and denominator. For instance, the long-term trend of
international credit could be explained by the integration of international financial
market, but the long-term trend of the overall credit condition may respond more to the
domestic economic fundamentals. Thus without isolating the long-term trend from these
two credit series, it is very difficult to perform a clean analysis about the cyclical
comovement between the international credit and the overall credit condition.
Since the recent global financial crisis of 2008-2009, the outstanding US dollar credit
to the non-bank borrowers in the EMEs has roughly doubled within the past seven years.
The commentators associate this surge to US monetary policy spillover, mainly because of
the ultra low interest rates in the US. He and McCauley (2013) survey a number of studies
on the transmission of monetary policy of the major advanced economies to East Asia and
conclude that policy rates, bond yields and exchange rates are three price channels in the
transmission process. McCauley, McGuire and Suchko (2015) also link the US monetary
policy, leverage and flow into bond funds to explain the dollar credit extended to non-US
borrowers. In this paper, since our goal is to understand the behavior of the overall dollar
credit condition, regardless of the credit instruments, we focus on the two price
channels—interest rate and currency appreciation/depreciation, an analytical framework
which can be interpreted as based upon international interest rate parity theory.
6
It should be pointed out that we focus on EME dollar credit, a subject we believe to be
ideal to study the monetary policy spillover effect in global liquidity transmission. This is
because, the composition of bank loan and bond issuance depends on country-specific
contexts, for instance, the regulatory emphasis of capital control. Tighter regulation on

international banking practice could push the domestic borrowers to issue bonds
overseas and vice versa (Caballero et al., 2015). Since our goal is to understand the trend
and cycle of the dollar credit in emerging market economies, we purposely ignore the
credit breakdown based on types of financial instruments. Furthermore, we choose to
study EME dollar credit, instead of Euro, Yen or other currency credit, is because different
currency credit could be sensitive to different monetary policy rates and dollar credit
dominates other currencies in the currency breakdown of international credit (Borio, et
al., 2011). The last but not the least, we work with the dollar credit in the EMEs, because
the dollar credit outside US may respond to factors in different ways when it comes to the
EMEs compared to other advanced economies. (Borio, et al. 2011; McCauley, et al., 2015)
2.3 Data and Empirical Model
2.3.1 Data Description
Our sample period spans from the first quarter of 2000 to the last quarter of 2015. The
sample period is based on data availability. Measuring dollar credit can be a challenging
exercise. Fortunately, the Bank of International Settlements (BIS) website provides global
liquidity indicators to measure the ease of financing in global financial markets.
7
Among
various global credit aggregates, we use the US dollar credit to non-bank sector in the
EMEs in this study. This measure aggregates all the maturities of credit instruments. The
original data is measured in trillions of US dollar and we take the natural log of this series
and use the log-transformed series in the model estimation.
The second variable in our exercise is US interest rate that proxies the stance of US
monetary policy. The ideal candidate would have been the federal funds rate if there was
not a zero lower bound (ZLB) problem. The ZLB issue arises during and after the Great
Recession, as the Fed quickly lowered the federal funds rate close to zero and also
implemented the unconventional monetary policies, including large-scale purchases of

financial assets from private financial corporations. These unconventional monetary
policies helped inject more liquidity into the market than implied by the federal funds
rate, which basically had no room to be lowered further. The overall monetary policy
stance thus can not simply be captured by the variations in the federal funds rate itself.
To take this ZLB problem into account, Wu and Xia (2016) proposed to use the shadow
interest rate to provide a comprehensive measure to summarize the overall stance of
monetary policy while the federal funds rate stuck at the ZLB environment. The shadow
interest rate measure originated from the idea in Black (1995) to price the interest rate
as an option. Wu and Xia (2016) conducted an analytical approximation for the forward
rate in the Shadow Rate Term Structure Model (SRTSM), by linearizing the state-space
model representation of the three-factor SRTSM. Then they used the estimated
parameters and decomposed three unobserved factors to compute the shadow interest
rate. The likelihood ratio test could not reject the hypothesis that the parameters relating
the shadow interest rate to key macroeconomic variables under the ZLB environment are
the same as those that related the federal funds rate to those variables before the Great
Recession. Because of its intuitive appeal, Wu and Xia (2016) shadow interest rate
measure has been gaining widespread attention.
8
Because of the above mentioned reasons, we use the shadow interest rate proposed
by Wu and Xia (2016) as a proxy for the Fed’s overall monetary policy stance. The reason
we choose to use this measure in our benchmark estimation over some alternative
measures, for instance, the longer-term interest rates which suffer less from the ZLB issue,
is because the term premium in the long-term interest rates could potentially contaminate
the monetary policy stance. Nevertheless, we still perform a robustness test with 1-year
treasury bill rate, given the fact that our dollar credit measure aggregates all the credit
instruments regardless of their term to maturity. The third variable in our exercise is the
US dollar exchange rate in the global currency market. We use the broad trade-weighted
US dollar index to measure the dollar valuation in the currency market. The larger the
index, the stronger the US dollar is, or equivalently, the more US dollar appreciates, and
vice versa.
2.3.1 Empirical Model
In this paper, we use a trivariate unobserved component model to model the dynamics
in EME dollar credit (Yt), interest rate (It) and dollar index (Dt). This model is multivariate
extension of the model proposed by Morley, Nelson and Zivot (2003). To understand the
intuition behind the structure of our model, one could think of the credit activities in the
EMEs as a form of international investment. From the investors’ perspective, the return of
lending dollar in the EMEs depends on the interest rate paid from these credit
instruments. The US monetary policy rate, the risk-free rate in the international credit
market, is a major factor in pricing the interest rates on the international bank loans and
the corporate bond yields. From the EME borrowers’ perspective, the dollar valuation in
the currency market is also critical in determining their real external debt burden, besides
the US monetary policy rate. The expectation of domestic currency appreciation will lower
the expected external debt burden in the future and vice versa. To summarize, we can
think of this three-variable dynamic system as the application of interest rate parity in
international credit activities. Moreover, the interest rate parity
//www.frbatlanta.org/cqer/research/shadowrate.aspx?panel = 1
has to hold in both the short-run and the long-run market equilibrium. Therefore, the
dynamics of interest rate and exchange rate will provide useful information in explaining
the dynamics of dollar credit in the EMEs.
9
Our model takes the following form:
EME Dollar Credit:
Yt = τyt + cyt (1)
τyt = µy + τyt−1 + ηyt,ηyt ∼ iidN(0,σηy2 ) (2)
) (3)
Interest Rate:
It = τit + cit (4)
τit = µi + τit−1 + ηit,ηit ∼ iidN(0,σηi2 ) (5)
cit = φ1icit−1 + φ2icit−2 + εit,εit ∼ iidN(0,σεi2 ) (6)
Dollar Index:
Dt = τdt + cdt (7)
τdt = µd + τdt−1 + ηdt,ηdt ∼ iidN(0,σηd2 ) (8)
cdt = φ1dcdt−1 + φ2dcdt−2 + εdt,εdt ∼ iidN(0,σεd2 ) (9)
Each series is decomposed into a stochastic trend component (τjt,i = Y,IorD) and a cyclical
component (cjt,i = Y,IorD) implying an I(1) process for all the variables. The non-
stationarity of these variables are confirmed by the unit root tests where we do not reject
the null of unit root for all the variables.
10
We also do not impose the common trend
restriction, i.e., all three variables have their own trend and cycle components and these
components are allowed to have a certain degree of correlation based on the economic
intuition we will discuss later. In fact, we do test for cointegration among these three
variables and do not find evidence to support this for the sample period under study.
Secondly, we specify the dynamics of trend and cycle components. The cyclical
component in each series is assumed to follow an AR (2) process. This assumption
captures the auto correlation structures as observed in the correlogram and provides rich
dynamics in the data series to enable us to identify all the parameters under the state-
space model framework (Morley, Nelson and Zivot, 2003). The trend components are

assumed to follow a random walk process with a drift, and as mentioned above, we do not
impose a common trend among these three variables.
11
Thirdly, we assume the shocks to the trend and cycle components follow a white noise
process, but allow for non-zero cross-correlation across series. The shocks to the trend
components (ηjt,i = Y,I,orD) have a long-run effect on the trend because the trend is
assumed to follow a random walk process. The shocks to the cyclical component (εjt,i =
Y,IorD) have a short-run effect on the cycle because the cycle follows a stationary
autoregressive process with two lags. The shocks to each trend component are allowed to
be correlated across each other, so are the shocks to the cyclical components. However,
we impose the zero correlation between the shocks to the trend component and the
shocks to the cycle component within and between series. That is to say, we assume that
the shocks that generate a long-run effect are different from the shocks that generate a
short-run effect. This assumption for example, isolates the monetary policy shocks, which
often are considered neutral in the long term, from the productivity shocks, which has a
persistent effect in the real economy.
Below is the correlated multivariate unobserved component model setup based on the
previous discussion. It should be pointed out that, in the variance-covariance matrix of
the shocks to the trend and cycle, σηyηi, σηyηd, and σηiηd are the pairwise covariance of the
shocks to the trend of EME dollar credit, monetary policy rate and dollar index. σεyεi, σεyεd,
and σεiεd are the pairwise covariance of the shocks to the cycle of EME dollar credit,
monetary policy rate and dollar index. The estimates of correlation coefficients, instead
of covariances, will be reported in Table 1. We estimate the model using the classical
maximum likelihood via the Kalman filter.
12
Measurement Equation:
Variance-Covariance Matrix of the Shocks to Trend and Cycle:

2.4 Results and Interpretation
We present the results of this model in the next three subsections. In the first
subsection, we discuss the parameter estimates and also provide interpretation for the
correlation of the shocks to the trend and cycle among the three variables. In the second
subsection, we discuss the evolution of the estimated trend and cycle of each series and
examine whether the trend and cycle components capture the long-run trend and the
cyclical variation during the sample period. In the third subsection, we look at both the
long-term and short-term comovement among these three variables.
2.4.1 Dynamic Relationship among EME dollar Credit, US Interest
Rate and the Dollar Index
Table 1 provides the maximum likelihood estimates of all the parameters. The
corresponding standard errors are in the parentheses. The results suggest that the cyclical
shocks dominate the variation in the overall EME dollar credit. The standard deviation of
the shocks in the trend of EME dollar credit is 0.014
13
, smaller compared to the standard
deviation of the shocks in the cycle, 0.017. Additionally, for the shadow interest rate, the
standard deviation of the shocks in the trend is 0.274, almost twice as large as the
standard deviation of the shocks in the cycle. The results seem to suggest that variations
in slow moving component in the shadow interest rate is dominant. However, the
variations in cyclical component are also significant. For the dollar index, the standard
deviation of shocks to the trend and cycle components are 0.015 and 0.016 respectively,
implying similar importance of transitory and permanent variation in dollar index. As far
as the estimated parameters of the cyclical components are concerned, we find that the
cyclical component of all the variables are persistent implying a shock to the cycle, though
transient, persists for a while.

The correlation analysis of the shocks to the cycles among these variables suggests that
the cyclical variation among EME dollar credit, monetary policy rate and dollar credit are
strongly correlated. The correlation coefficient between the transitory shock to dollar
credit and the transitory shock to US interest rate is -0.97. The correlation coefficient
between the transitory shock to EME dollar credit and the transitory shock to dollar index
is -0.94. And the correlation coefficient between the transitory shock to US interest rate
and the the transitory shock to dollar index is 0.99. The standard errors of these estimated
parameters confirm that these correlation coefficients are significantly different from
zero.
The strong negative correlation between the transitory shock to US interest rate and
the transitory shock to dollar credit in the EMEs suggests that, a temporary decrease in
US interest rate below its long-run trend leads to a temporary increase in EME dollar
credit as it lowers the cost of borrowing. In addition to the lower cost, the transitory
decline in interest rate may also reflect temporary abundance of liquidity as witnessed
during the QE programs. The negative correlation between transitory shock to dollar
index and transitory shock to dollar credit in the EMEs is also very intuitive. An increase
in dollar index implies an appreciation of dollar index above its long-run trend and these
movements make the dollar financing activities in the EMEs less appealing temporarily.
We can motivate the strong positive correlation between the transitory shock to US
interest rate and the transitory shock to US dollar index by considering an open economy’s
short-run equilibrium model. At the initial output level and given the sticky price level in
the short-run, an increase in US money supply pushes down the US interest rate. Since the
US monetary change is temporary and does not affect the expected future exchange rate,
so to preserve interest rate parity, the exchange rate must depreciate immediately to
create the expectation that the US dollar will appreciate in the future. Therefore, in the
short run, a negative transitory shock to US monetary policy rate is predicted to associate
with a negative transitory shock to US dollar index, which is exactly what we identify in
our model estimation.
The correlation analysis of the shocks to the trends among these variables confirm our
earlier finding that these three variables do not share a common trend and hence, are not
cointegrated.
14
The correlation coefficient between the permanent shocks to EME dollar
credit and the permanent shocks to US interest rate is 0.67. The correlation coefficient
between the permanent shock to US interest rate and the permanent shocks to dollar
index is -0.68. The standard errors of these estimated parameters confirm that these
correlation coefficients are significantly different from zero. The correlation coefficient
between the permanent shock to EME dollar credit and the permanent shock to dollar
index is insignificant and low. Therefore, it is not likely that these variables share the
common trend, which supports the conjecture that we need to decompose the trend and
cycle components from the series to understand the business cycles of these variables.
The negative correlation between the permanent shock to US interest rate and the
permanent shock to dollar index seems puzzling at the first glance. However, it can be
explained using the forward looking behavior of these variables. If an unexpected
permanent increase in interest rate provide the signal that inflation is expected to go up
in future, then nominal exchange rate may respond instantaneously in response to this
Table 1: Maximum Likelihood Estimates: A Correlated Multivariate UC Model
Description
Parameter
Estimate
(Standard Error)
Log likelihood value
llv
EME dollar credit
295.8723
S.D. of permanent shocks to the EME dollar credit
σηy
0.0139
(0.0041)
S.D. of temporary shocks to the EME dollar credit
σεy
0.0168
(0.0033)
the EME dollar credit drift
µy
0.0274
(0.0025)
EME dollar credit 1st AR parameter
φ1y
1.3851
(0.1399)
EME dollar credit 2nd AR parameter
φ2y
shadow interest rate
-0.4770
(0.1251)
S.D. of permanent shocks to shadow interest rate
σηi
0.2738
(0.0312)
S.D. of temporary shocks to shadow interest rate
σεi
0.1549
(0.0327)
Shadow interest rate drift
µi
-0.0792
(0.0481)
Shadow interest rate 1st AR parameter
φ1i
1.9072
(0.0355)
Shadow interest rate 2nd AR parameter
φ2i
US dollar index
-0.9462
(0.0363)
S.D. of permanent shocks to US dollar index
σηd
0.0148
(0.0029)
S.D. of temporary shocks to US dollar index
σεd
0.0158
(0.0027)
US dollar index drift
µd
-0.0026
(0.0021)
US dollar index 1st AR parameter
φ1d
1.3585
(0.1144)
US dollar index 2nd AR parameter
φ2d
Cross-series correlations
-0.5726
(0.0980)
Correlation: Permanent dollar credit/
Permanent interest rate
ρηyηi
0.6669
(0.2118)
Correlation: Permanent dollar credit/
Permanent dollar index
ρηyηd
0.0842
(0.3396)
Correlation: Permanent interest rate/
Permanent dollar index
ρηiηd
-0.6864
(0.2532)
Correlation: Transitory dollar credit/
Transitory interest rate
ρεyεi
-0.9719
(0.1157)
Correlation: Transitory dollar credit/
Transitory dollar index
ρεyεd
-0.9406
(0.2205)
Correlation: Transitory interest rate/
Transitory dollar index
ρεiεd
0.9941
(0.0372)
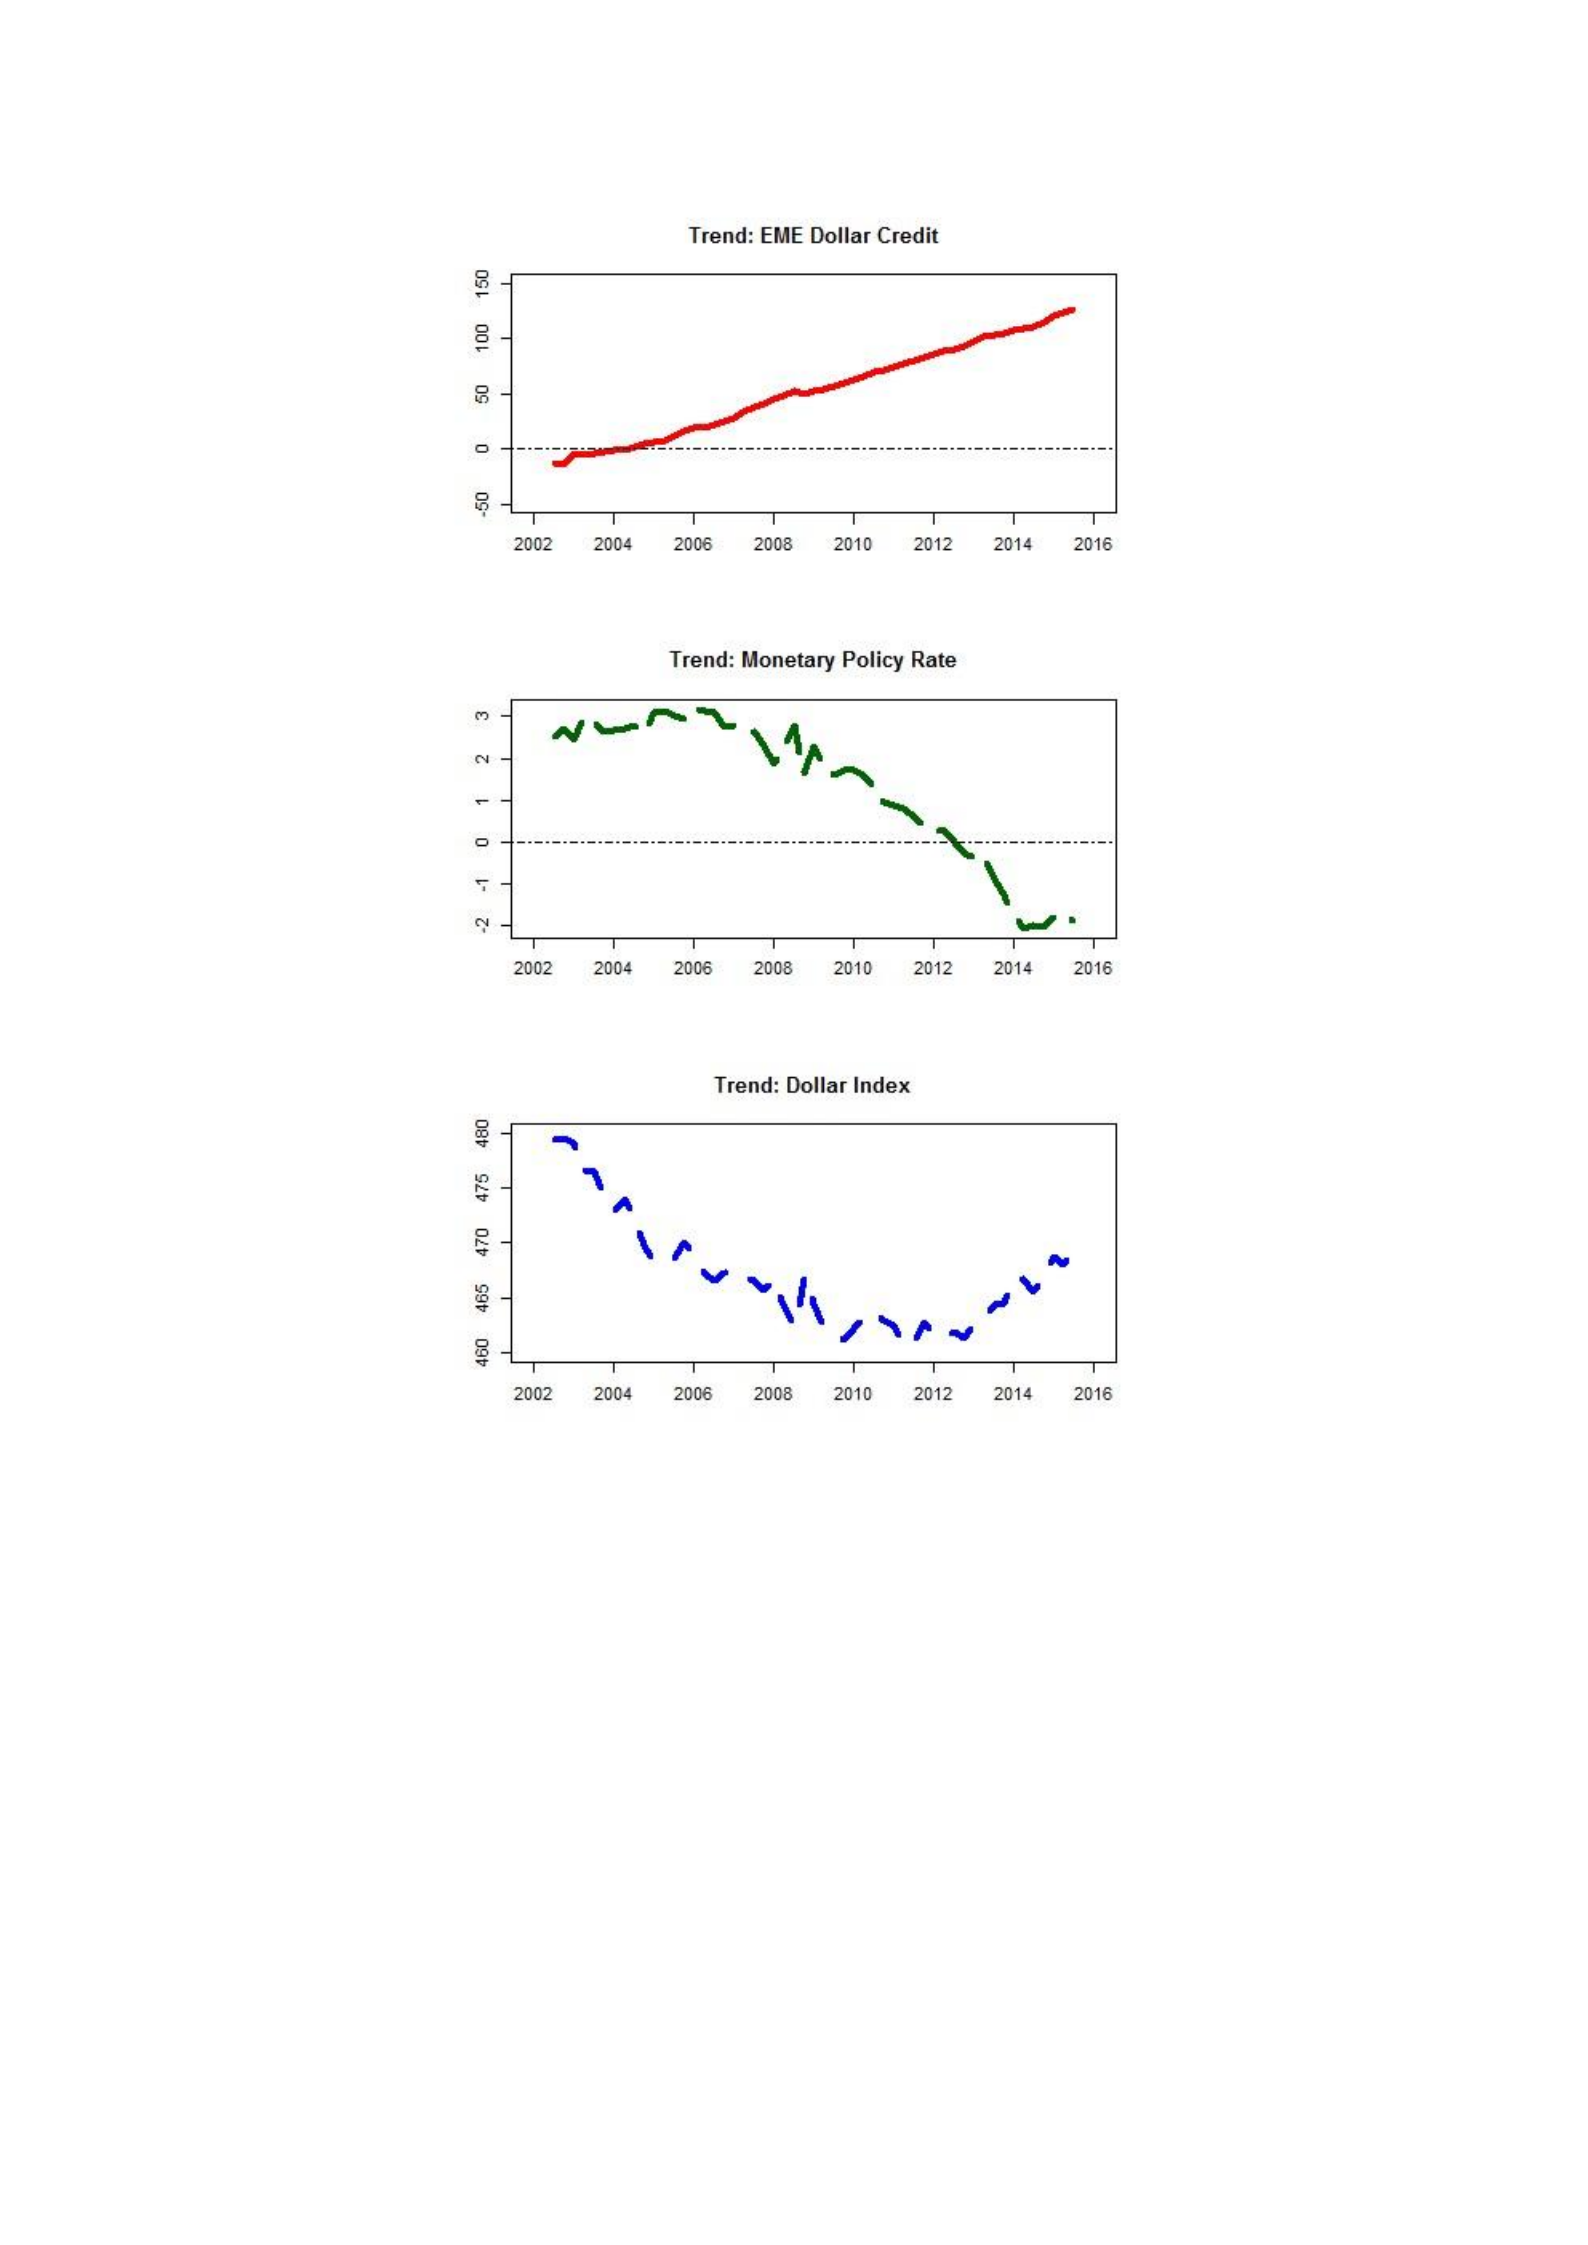
Figure 1: Trends from Correlated Multivariate Unobserved Component Model
The figures below report the trend components of EME dollar credit, shadow interest rate and
dollar index. The dollar credit in the EMEs is measured in log trillions of USD and multiplied by
100. The shadow interest rate is measured in percentage points. The log of US dollar index has
been multiplied by 100.
news about higher than expected inflation. Similarly, the forward-looking behavior can
explain the positive correlation between permanent shock to interest rate and permanent
shock to dollar credit. An unexpected permanent increase in interest rate may provide
information about higher than expected inflation, which in turn may lead to a depreciation
of the dollar as argued before. This will be associated with an unexpected permanent
increase in dollar credit in emerging market economies. Overall, the results from the
correlation analysis clearly suggests value in examining the short-run and the long-run
relationships separately. The results suggest that fundamentals seem to matter more in

the long-run, whereas the short-run boom may be associated with temporary phases of
monetary policy as well as movements in dollar index.
2.4.2 Trend-Cycle Decomposition
In this subsection, we decompose the trend and cycle of EME dollar credit, interest rate
and dollar index using the correlated multivariate unobserved component model. The
stochastic trend in the multivariate UC model captures the long-run evolution in
EME dollar credit and also reflects the effect of recent global financial crisis (Figure 2). In
the long-run, there is an increasing trend in EME dollar credit, due to the global financial
integration. There was a downward shift in the trend during the financial crisis. The effect
of this negative shock on the trend of EME dollar credit persisted for few years.
The cyclical component from our multivariate UC model captures the evolution of the
dollar credit and its dynamic relationship with US interest rate and the dollar index really
well (Figure 2). During the initial part of our sample, the dollar credit cycle was negative
implying lower than potential credit in these countries. After the collapse of Bear Stearns,
emerging market economies provided a sanctuary for the international capital, mainly
because the investor community assumed that the EMEs are decoupled from the
developed markets.In the third quarter of 2008, Lehman Brother filed bankruptcy that led
to financial panic. These events were associated with a global contraction in credit
lending, which brought the dollar credit back down to its long-term trend. During Figure
2: Trend/Cycle Decomposition from Correlated Multivariate UC Model
This figure reports the trend component and the cyclical component of EME dollar credit.
The dollar credit in the EMEs is measured in log trillions of USD and multiplied by 100. The UC
trend is the trend component of EME dollar credit decomposed using the correlated multivariate
unobserved component (UC) model. The HP trend is the trend component of EME dollar credit
decomposed using Hodrick and Prescott (HP) filter.
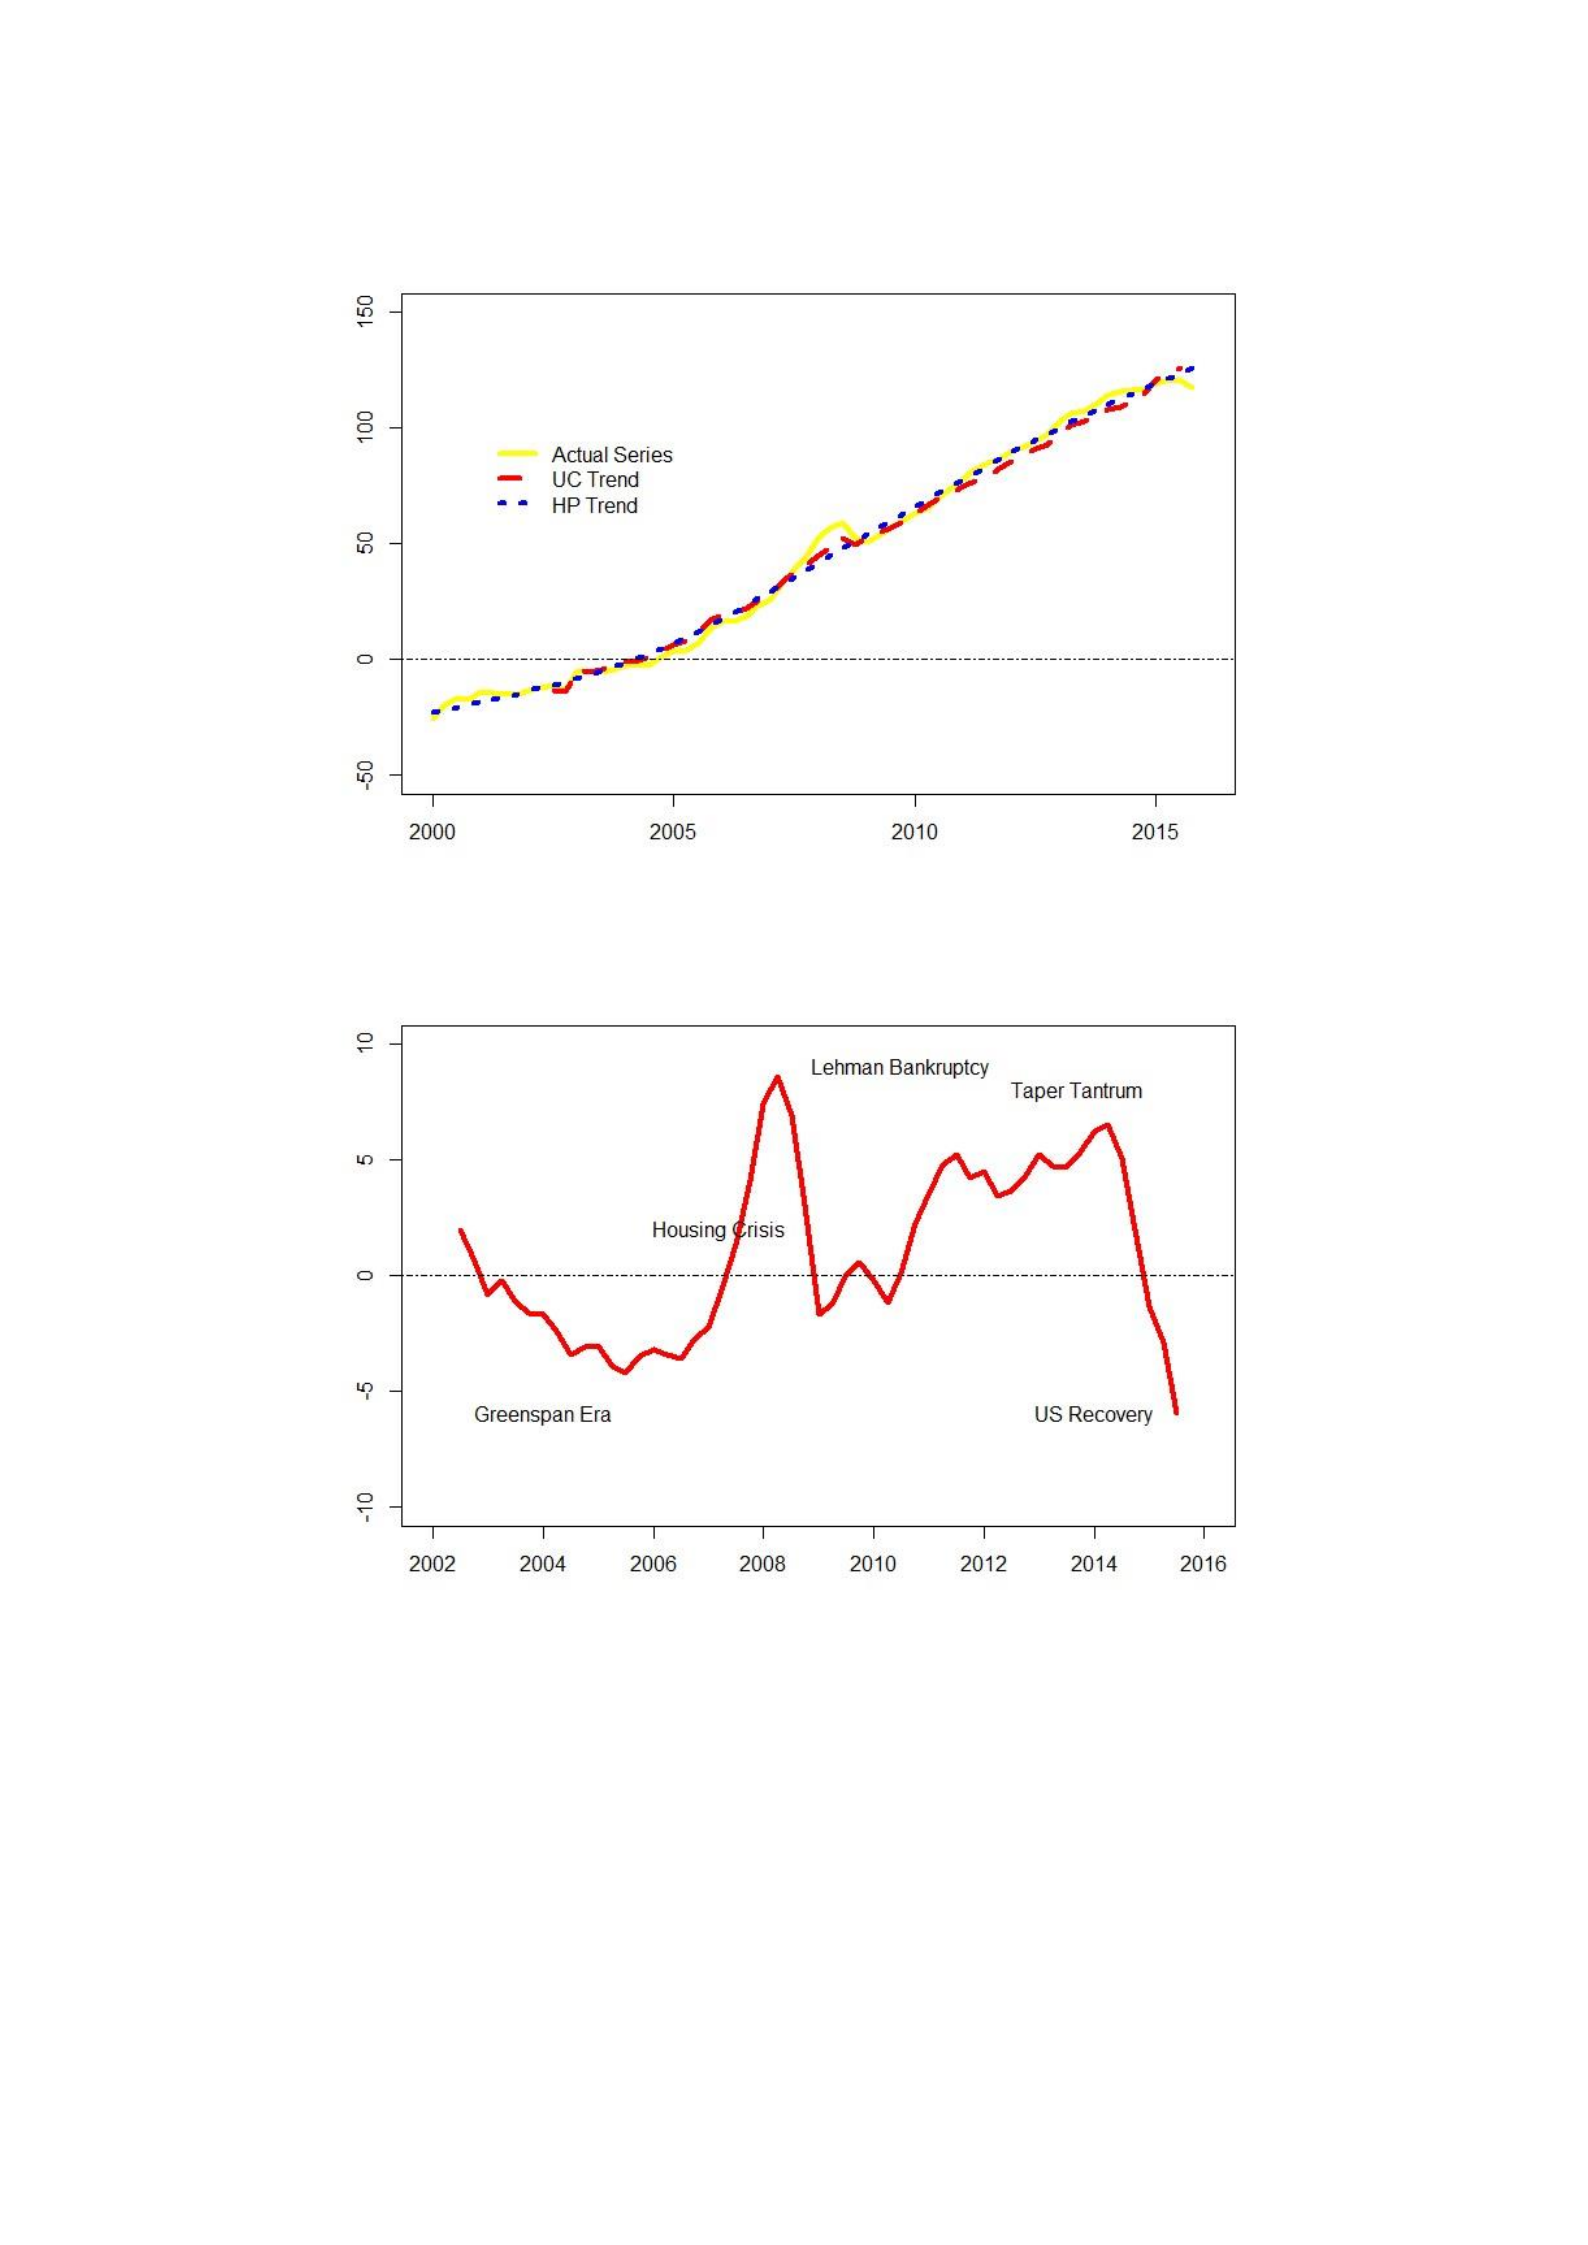
this time period, the Federal Reserve lowered the policy rate significantly and dumped
liquidity into the financial market through several runs of the QE programs. The portfolio
re-balancing effect quickly directed the investors to the credit market in the EMEs to chase
for yield. Shin (2013) denotes the year 2009 as the beginning of the second phase of global
liquidity, because of the rapid capital flow into the EMEs in the form of nonfinancial firm
bond issuance. Our cyclical component from the multivariate UC model indicates the

expansionary cycle of EME dollar credit during 2009-2014, a phenomenon widely
observed and agreed upon among the financial market observers and researchers.
Starting from 2015, the persistent recovery of US economy and the slowdown in the EMEs
overturned the dollar credit flow and created the concern about the instability of the EME
financial markets and the feedback loops between the EMEs and advanced
economies.
2.4.3 Co-movement among the Cyclical Components
The estimated cyclical components from our model are displayed in Figure 3. Both the
qualitative and quantitative measures of the cycles are consistent with intuition and they
follow the dynamics of dollar credit, interest rates and dollar index very well. We observe
that cyclical variation in dollar index is strongly negatively associated with the cyclical
variation of EME dollar credit. Before 2008 financial crisis, when dollar was relatively
strong, the overall EME dollar credit was increasing but was still below its trend,
consistent with the idea that stronger dollar works against capital inflow in the EMEs. The
correlation between the cyclical components of EME dollar credit and the dollar index
suggests that the weak dollar could potentially contribute to the surge in the credit flow
into the EMEs. When the financial crisis hit the US economy, the dollar depreciated and
the investors with dollar assets were looking for higher yields in alternative asset classes.
During this recessionary phase in the US, EME dollar credit witnessed an expansionary
period during the 2009-2014 sample period. The negative correlation between cyclical
components of EME dollar credit and the dollar index also suggests that the strong dollar
could potentially slow down the credit flow into the EMEs. Since 2015, the recovery of the
Figure 3: Cycles in the Correlated Multivariate Unobserved Component Model
This figure reports the cyclical components of the three variables EME dollar credit, shadow
interest rate and the dollar index. The dollar credit in the EMEs is measured in log trillions of
USD and multiplied by 100. The shadow interest rate is measured in percentage points. The US
dollar index is in logs and has been multiplied by 100.
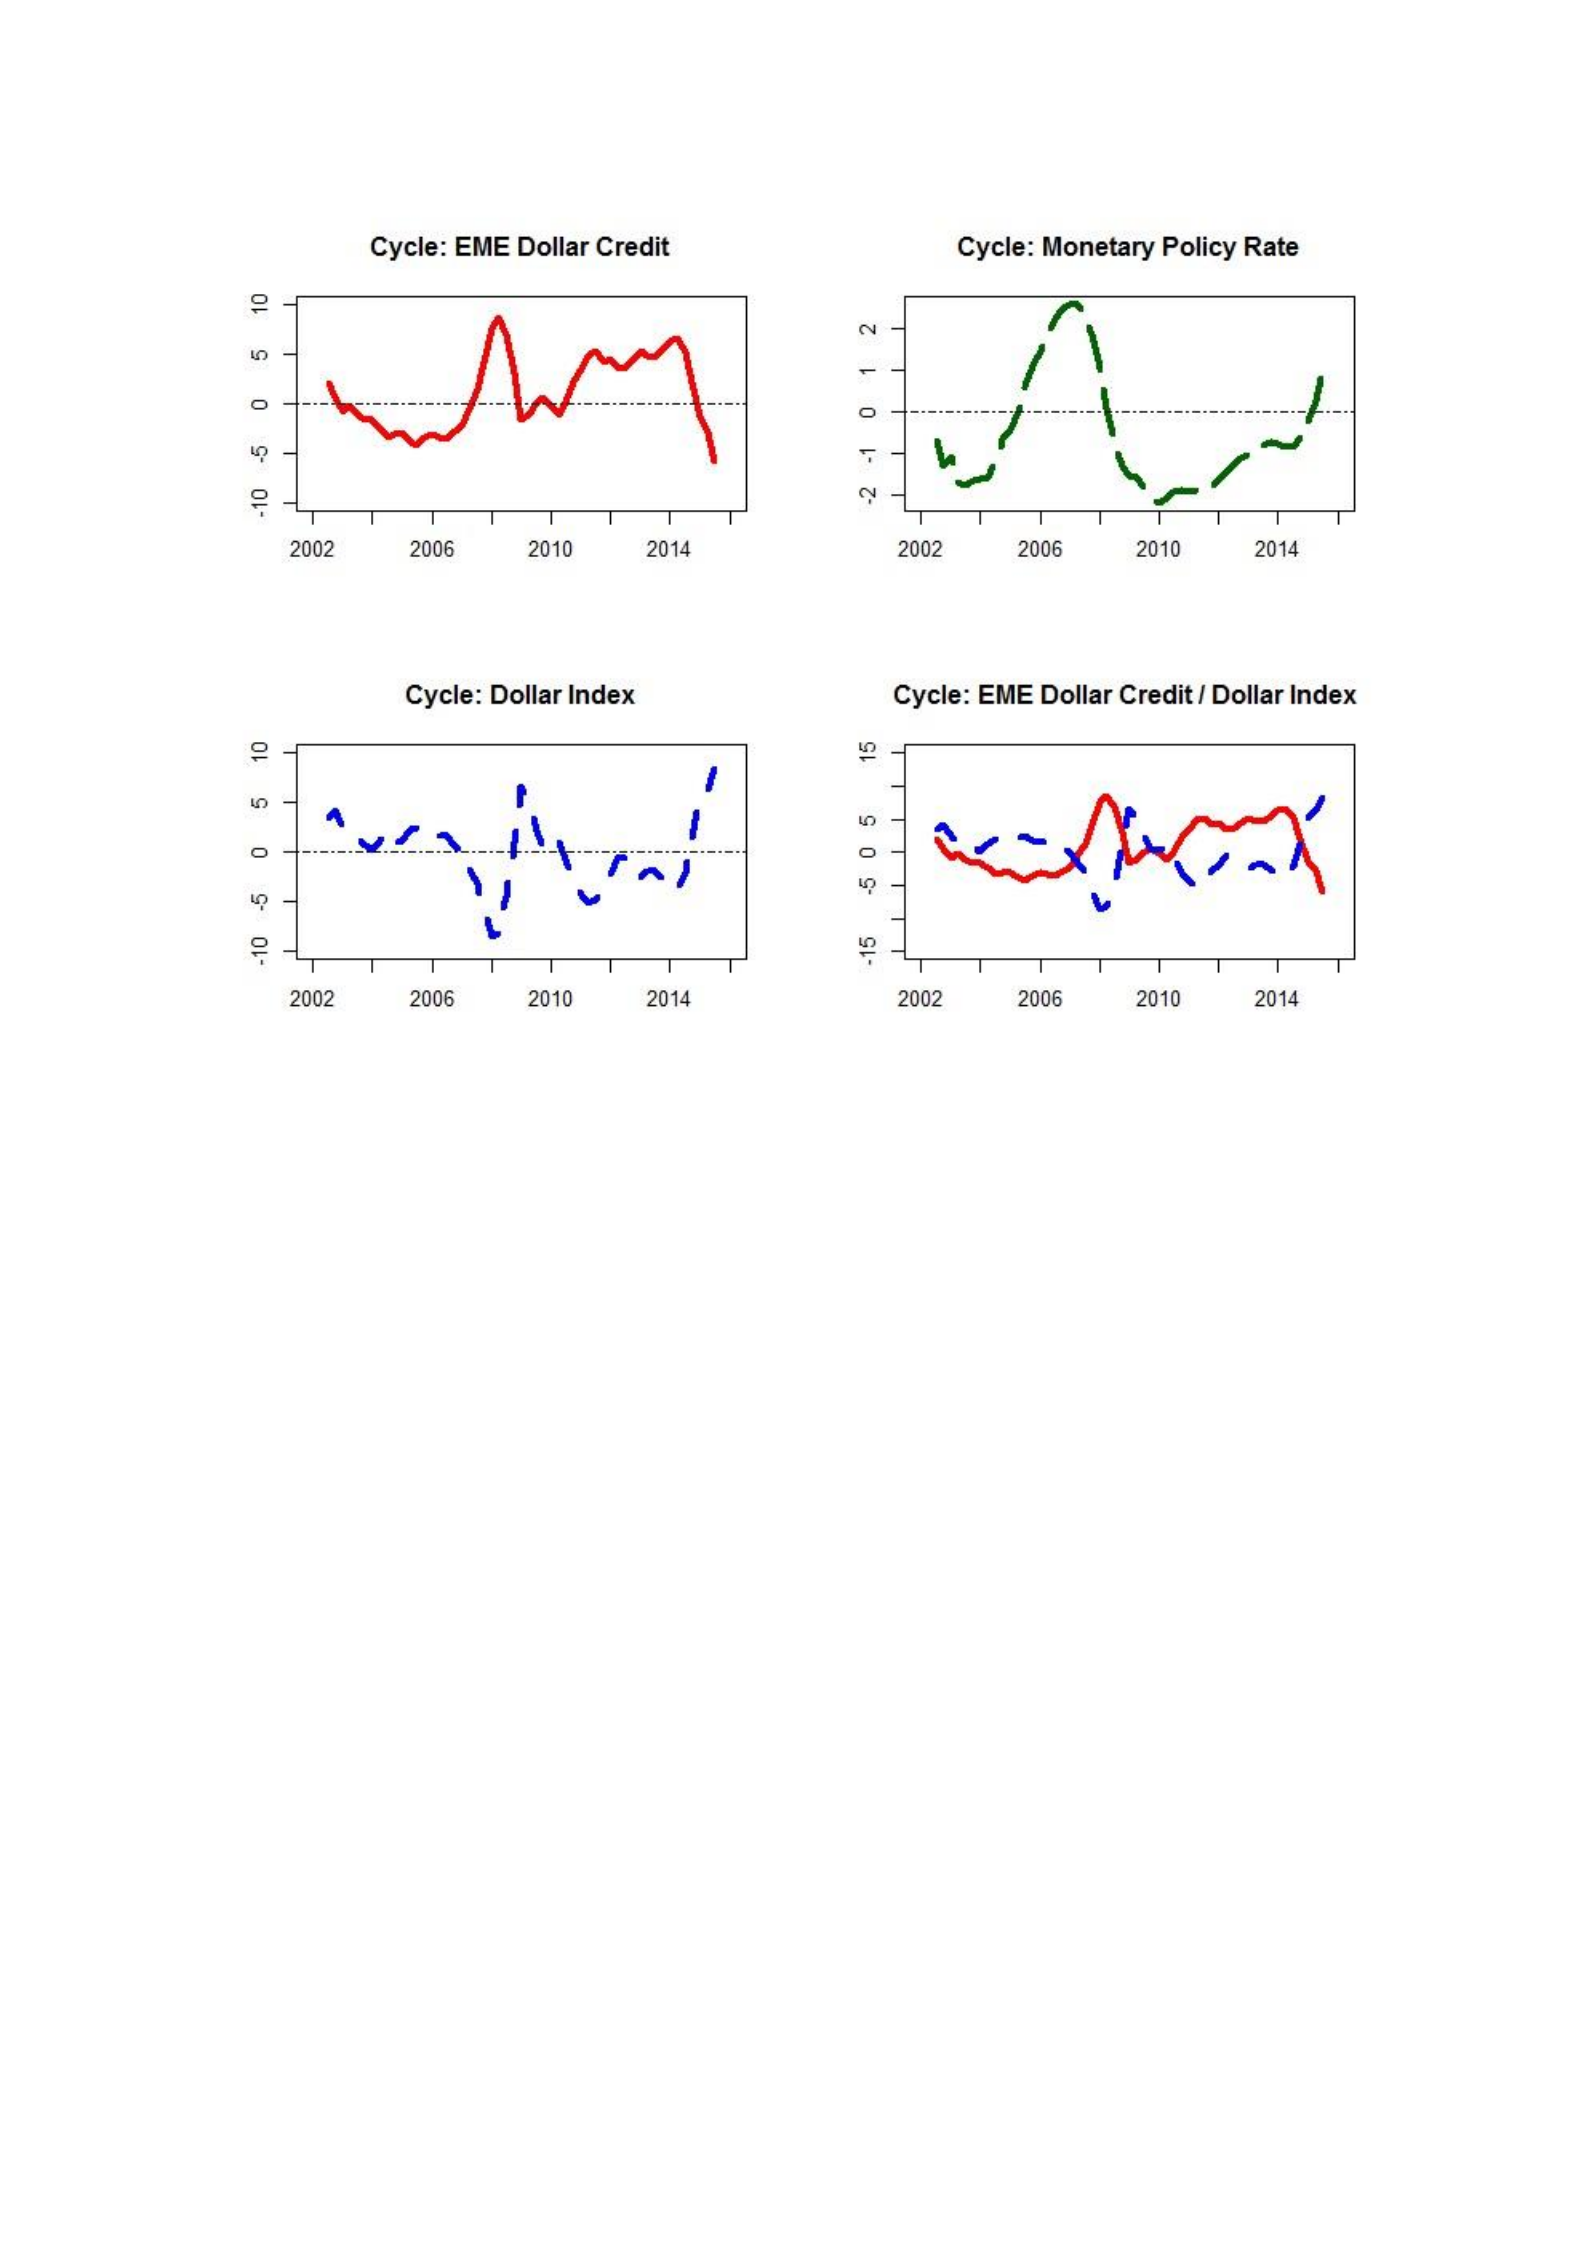
US economy has played a role in strengthening of the US dollar and as a result financial
markets started anticipating a hike in the interest rates. EME dollar credit seemed to have
entered a contractionary phase during this time period. Note that the overall EME dollar
credit could still increase due to the underlying increasing trend. The dollar index is also
relevant for the market participants to estimate the overall return when US policy rate
hits the zero-lower bound. The risk of international carry trade, a typical cyclical
investment behavior, mainly comes from the exchange rate risk under this environment.
Therefore, it is not surprising that the dollar index can provide useful information in
understanding the EME dollar credit conditions.
The plot of the cyclical component of interest rate suggests that interest rates were
slightly above its long-run trend prior to the great recession. In the earlier part of the
sample, the results suggest that the interest rate were below its trend suggesting an
accommodative stance of monetary policy. This is consistent with the arguments
proposed in the literature that has argued that the interest rates were too low in the

prefinancial crisis period (Taylor, 2007). The unconventional monetary policy tools
utilized by the Federal Reserve during the great recession led to a decline in the interest
rate below its long-run average in our model during and after the great recession. This
period was also associated with surge in dollar credit above its long-run trend as shown
in Figure 3. The plot also shows that interest rate started moving towards its long-run
trend at the beginning of 2015 and this is also associated with the decline in the cyclical
component of dollar credit.
2.5 Robustness Check
In this section, we check the robustness of our results by substituting Wu and Xia
(2016) shadow interest rate with other proxies for the stance of monetary policy. We also
compare the estimated trend-cycle from our approach with univariate trend-cycle
decomposition using different methods.
2.5.1 An Alternative Interest Rate Measure
As explained earlier, there are several possible proxies that can capture the stance of
monetary policy. We use shadow interest rate because it does not suffer from ZLB
problem, and is also not contaminated by term premium . The shorter term interest rates,
for instance, federal funds rate or three-month treasury bill rate, suffer seriously from the
ZLB issue during post-2008 sample period. While the longer term interest rates raise less
concern from this problem, they are more easy to be contaminated by the variation in the
term premium. Since our EME dollar credit measure aggregates all the credit instruments,
regardless of the term to maturity, by taking the middle ground, we use one-year Treasury
bill rate in the model to check the robustness of our result. The results from this exercise
is shown in Figure 4. The plot clearly shows the robustness of our estimation to the use of
1-year interest rate as a measure of monetary policy stance, as the estimated cycle closely
resembles the one with the shadow rate as a measure of monetary policy stance.
Figure 4: The Cyclical Component from Correlated Multivariate UC Model
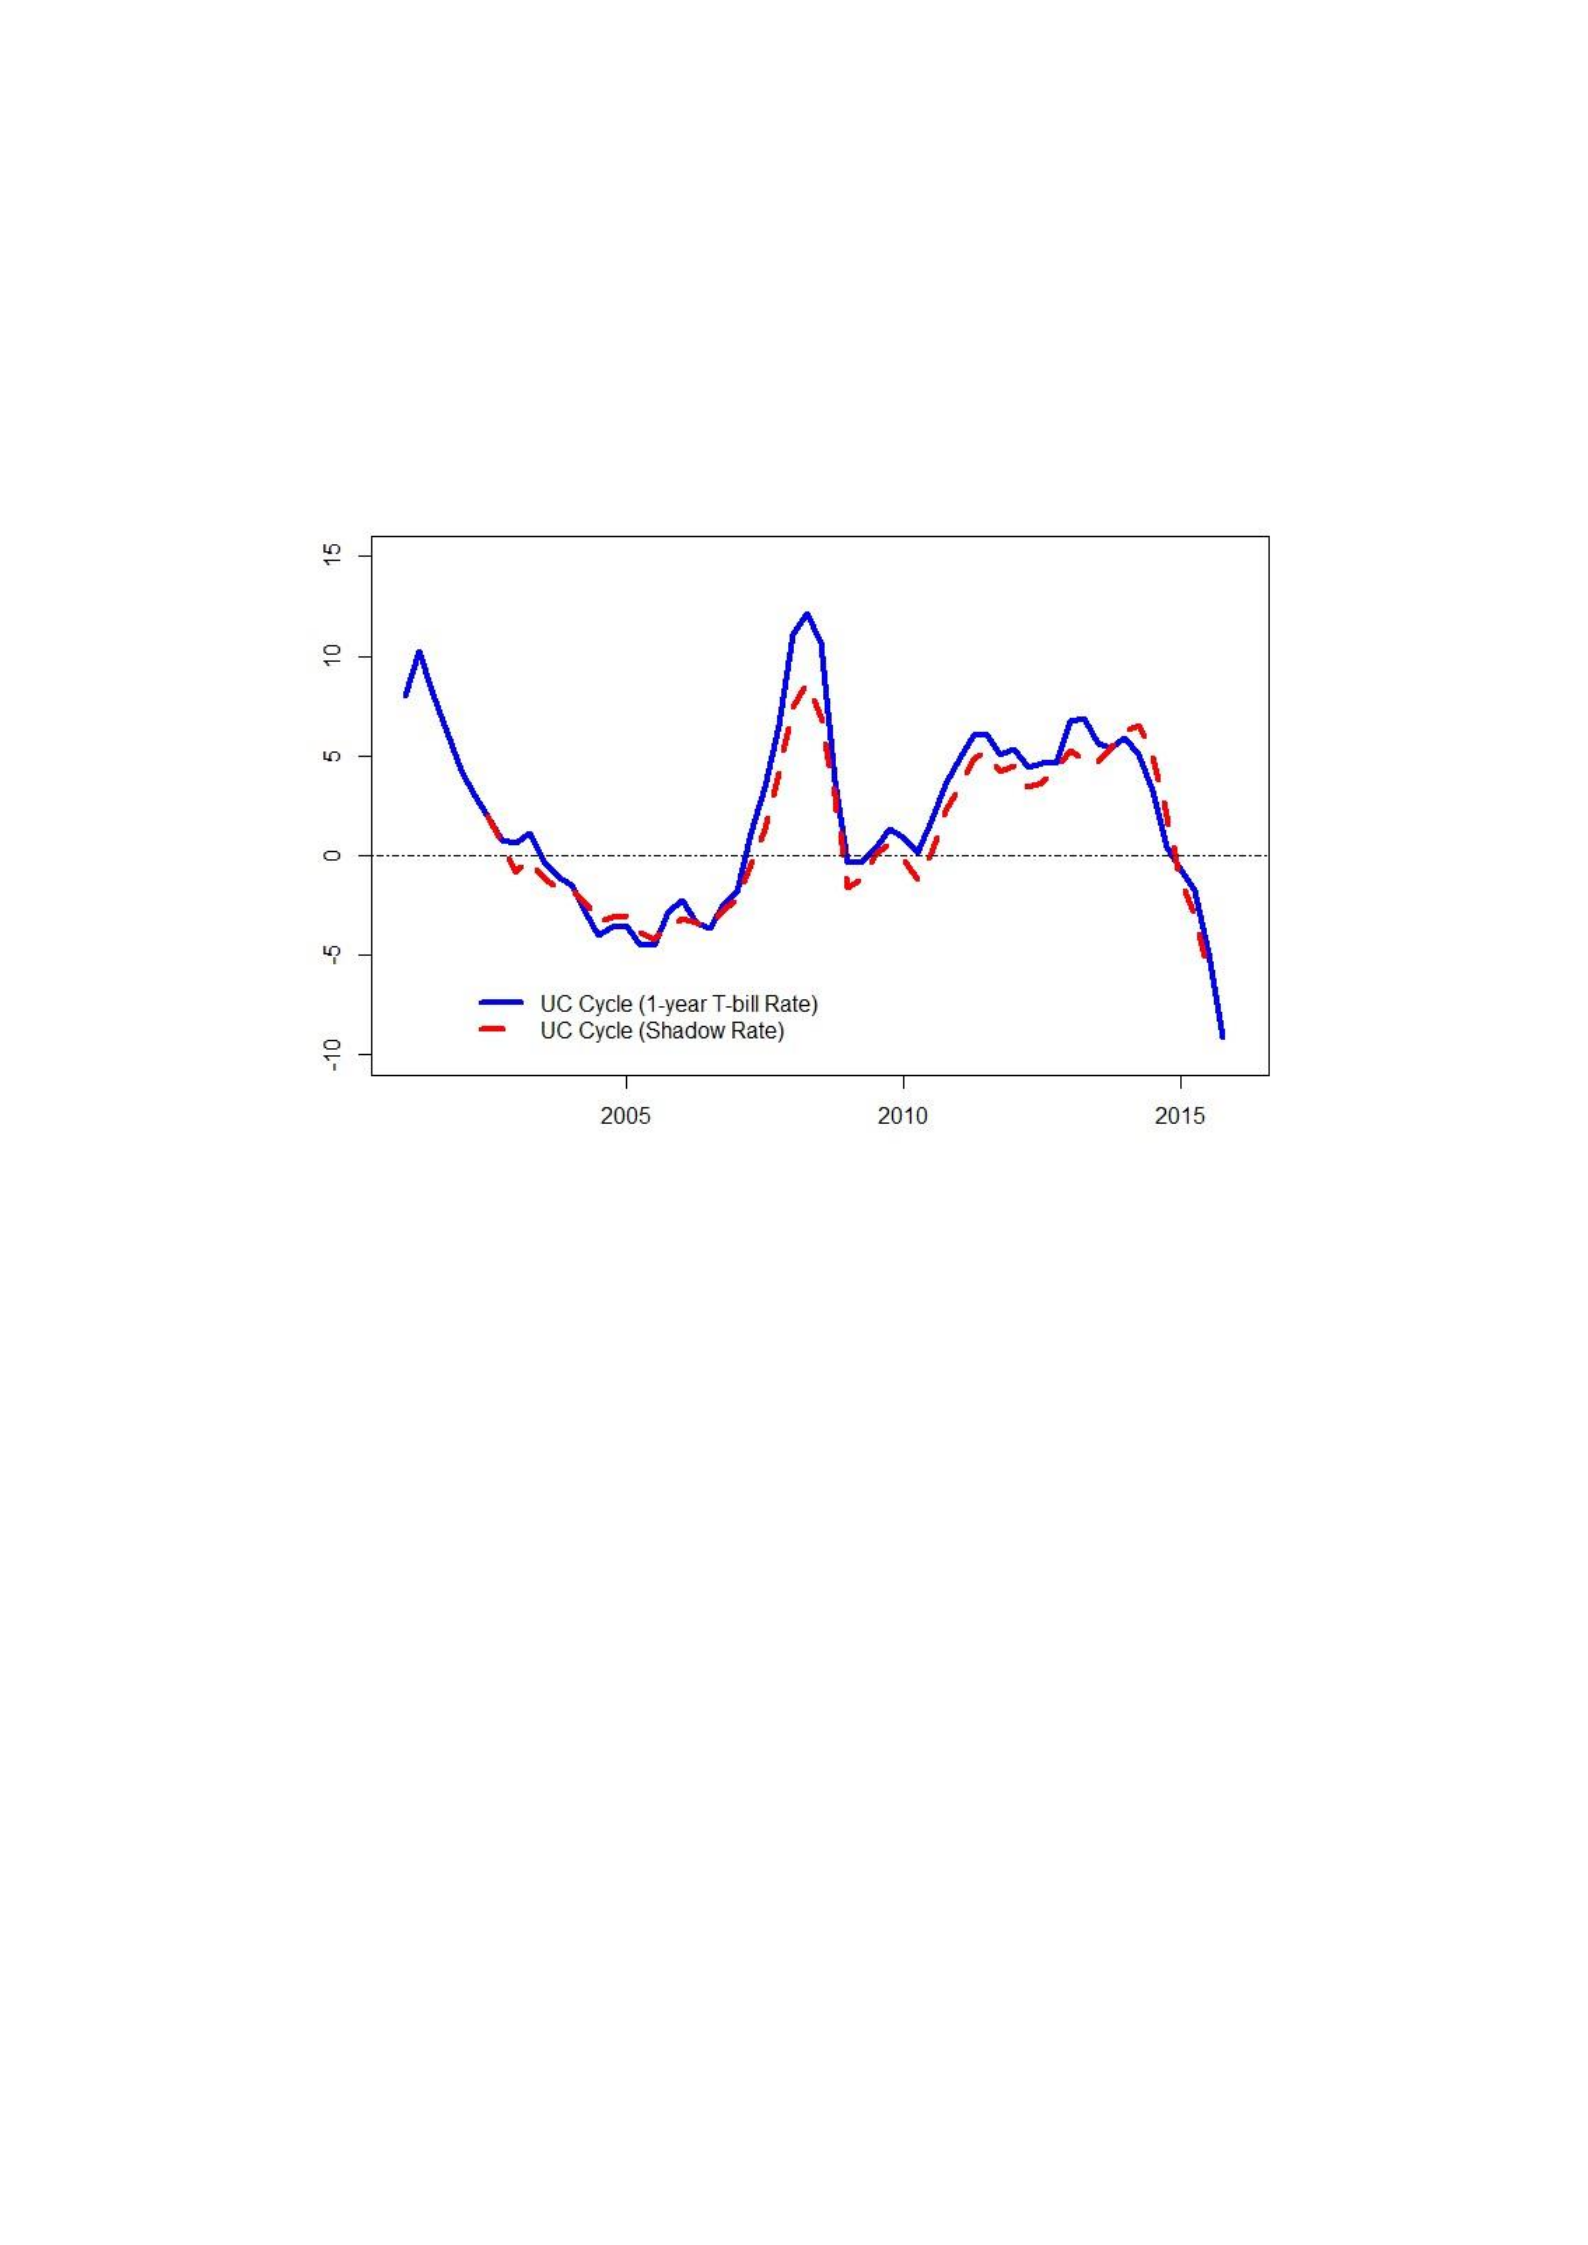
This figure reports the cyclical component of EME dollar credit. The dollar credit in the
EMEs is measured in log trillions of USD and multiplied by 100. The UC cycle (Shadow Rate) is
the cyclical component of EME dollar credit decomposed using the shadow interest rate as the
measure of US monetary policy stance in the correlated multivariate unobserved component
(UC) model. The UC cycle (1-year T-bill Rate) is the cyclical component of EME dollar credit
decomposed using the one-year treasury bill rate as the measure of US monetary policy stance in
the same UC model setup.
2.5.2 Comparison with Univariate Trend-Cycle Decomposition
In addition to the estimation of the correlation between shocks to the permanent and
transitory component, the use of multivariate model in theory should also provide us a
superior measure of trend and cycle as compared to the univariate model. To examine this
hypothesis, we also perform trend-cycle decomposition using the univariate models
(Figure 5). The univariate models include a linear trend model, a HP filter model and a
univariate UC model. The linear trend model decomposes the EME dollar credit series into
a linear-trend component and a cycle component. The HP filter method uses an algorithm
to smooth the original data series to estimate the trend component and the difference
between them is the cyclical component. The parameter value λ is set at 1600 as suggested
by Hodrick and Prescott for the quarterly data. The univariate UC model only uses the
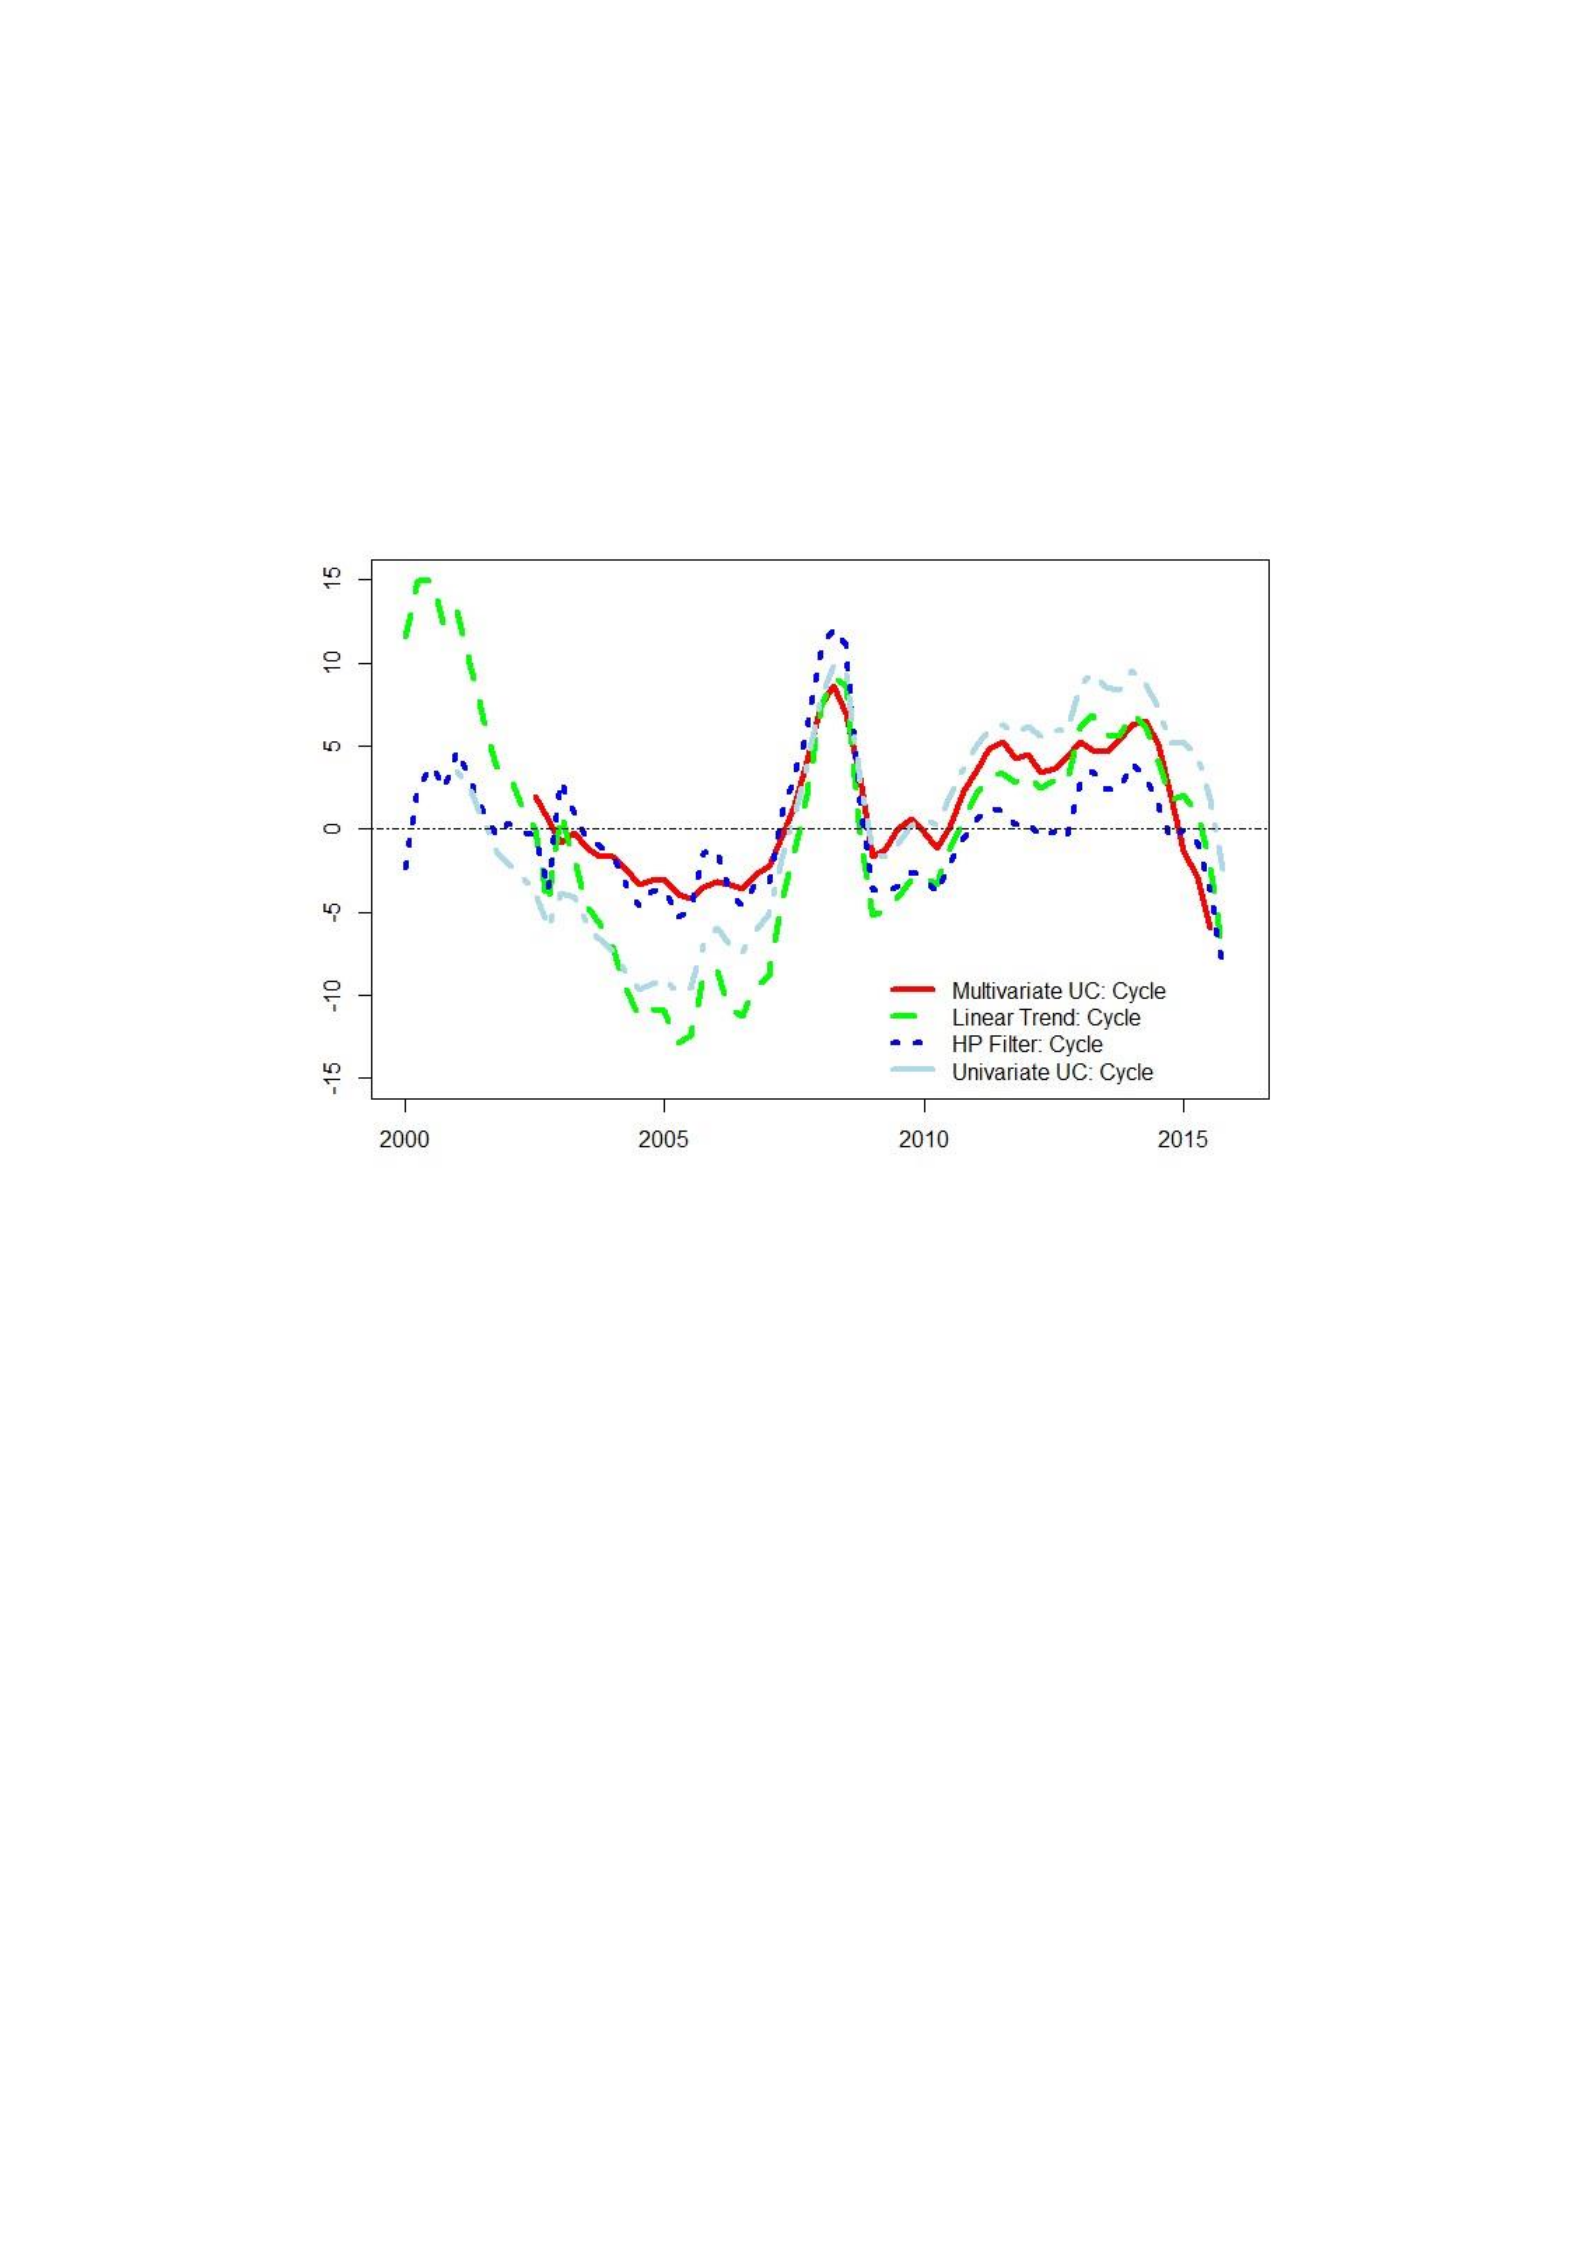
series of EME dollar credit to decompose a stochastic trend component and a cyclical
component with the same specification as in the multivariate UC model.
Figure 5: Comparing EME Dollar Credit Cycles
This figure reports cyclical components of EME dollar credit based on alternate decompositions.
The results presented above clearly demonstrates that the estimate of trend and cycles
obtained from the the multivariate UC model is better able to capture the dynamics of
these three variables. The linear trend model, assuming a constant slope in the trend
component, is not appropriate since it assumes no shock to the trend. The recent crisis is
considered as the most severe financial crisis after the Great Depression (1929-1933) and
we observe a clearly big negative shock to EME dollar credit series which the linear trend
model is unable to capture. Other univariate models, without assuming a linear trend, fail
to generate realistic trend and cycle series by ignoring the relationship between EME
dollar credit and its price channels. The HP cycle seems to mimic the counterpart from
multivariate UC model very well before the crisis but diverge afterwards. The cycle from
the univariate UC model, instead, is close to the multivariate counterpart after the crisis.
Taking into account all the historical events as mentioned in the cycle interpretation, the

outflow of dollar credit slowed down before the crisis, due to the domestic boom, but the
magnitude of the negative cycle did not seem to be as large as suggested by the univariate
UC model. The HP cycle fails to capture the credit boom since 2009, while it performed
reasonably well before the crisis. Overall, it is clear from the analysis presented above that
there is valuable pay-off in utilizing information from other variables that are useful in
explaining EME dollar credit if one is interested in extracting its permanent and transitory
component.
2.6 The Effects of US Monetary Policy Shocks
With global financial integration and dollar as international currency, US monetary
policy plays a critical role in global liquidity transmission. Both the Fed and the EME
authorities are concerned about the dynamic impact of US monetary policy changes on
the international financial system. It would be an interesting exercise, therefore, to
examine the dynamic impact of monetary policy shock on dollar credit in the EMEs using
our multivariate unobserved component model.
Figure 6 plots the impulse responses of EME dollar credit and US dollar index when
there is a transitory Fed interest rate hike. Based on our model, the cyclical variation of
the three variables are correlated through the contemporary shocks in the error terms.
Given a positive transitory shock to US monetary policy, we would expect a negative
contemporaneous transitory shock to EME dollar credit and a positive contemporaneous
transitory shock to dollar index. The effects of the transitory shock would not disappear
immediately after the current period because of the persistent nature of the cyclical
components as it depends on the lagged values. From our impulse response analysis,
Figure 6: Impact of a Transitory Increase in Interest Rate
This figure reports the impulse response functions of EME dollar credit and the dollar index to to
a temporary increase in US interest rates
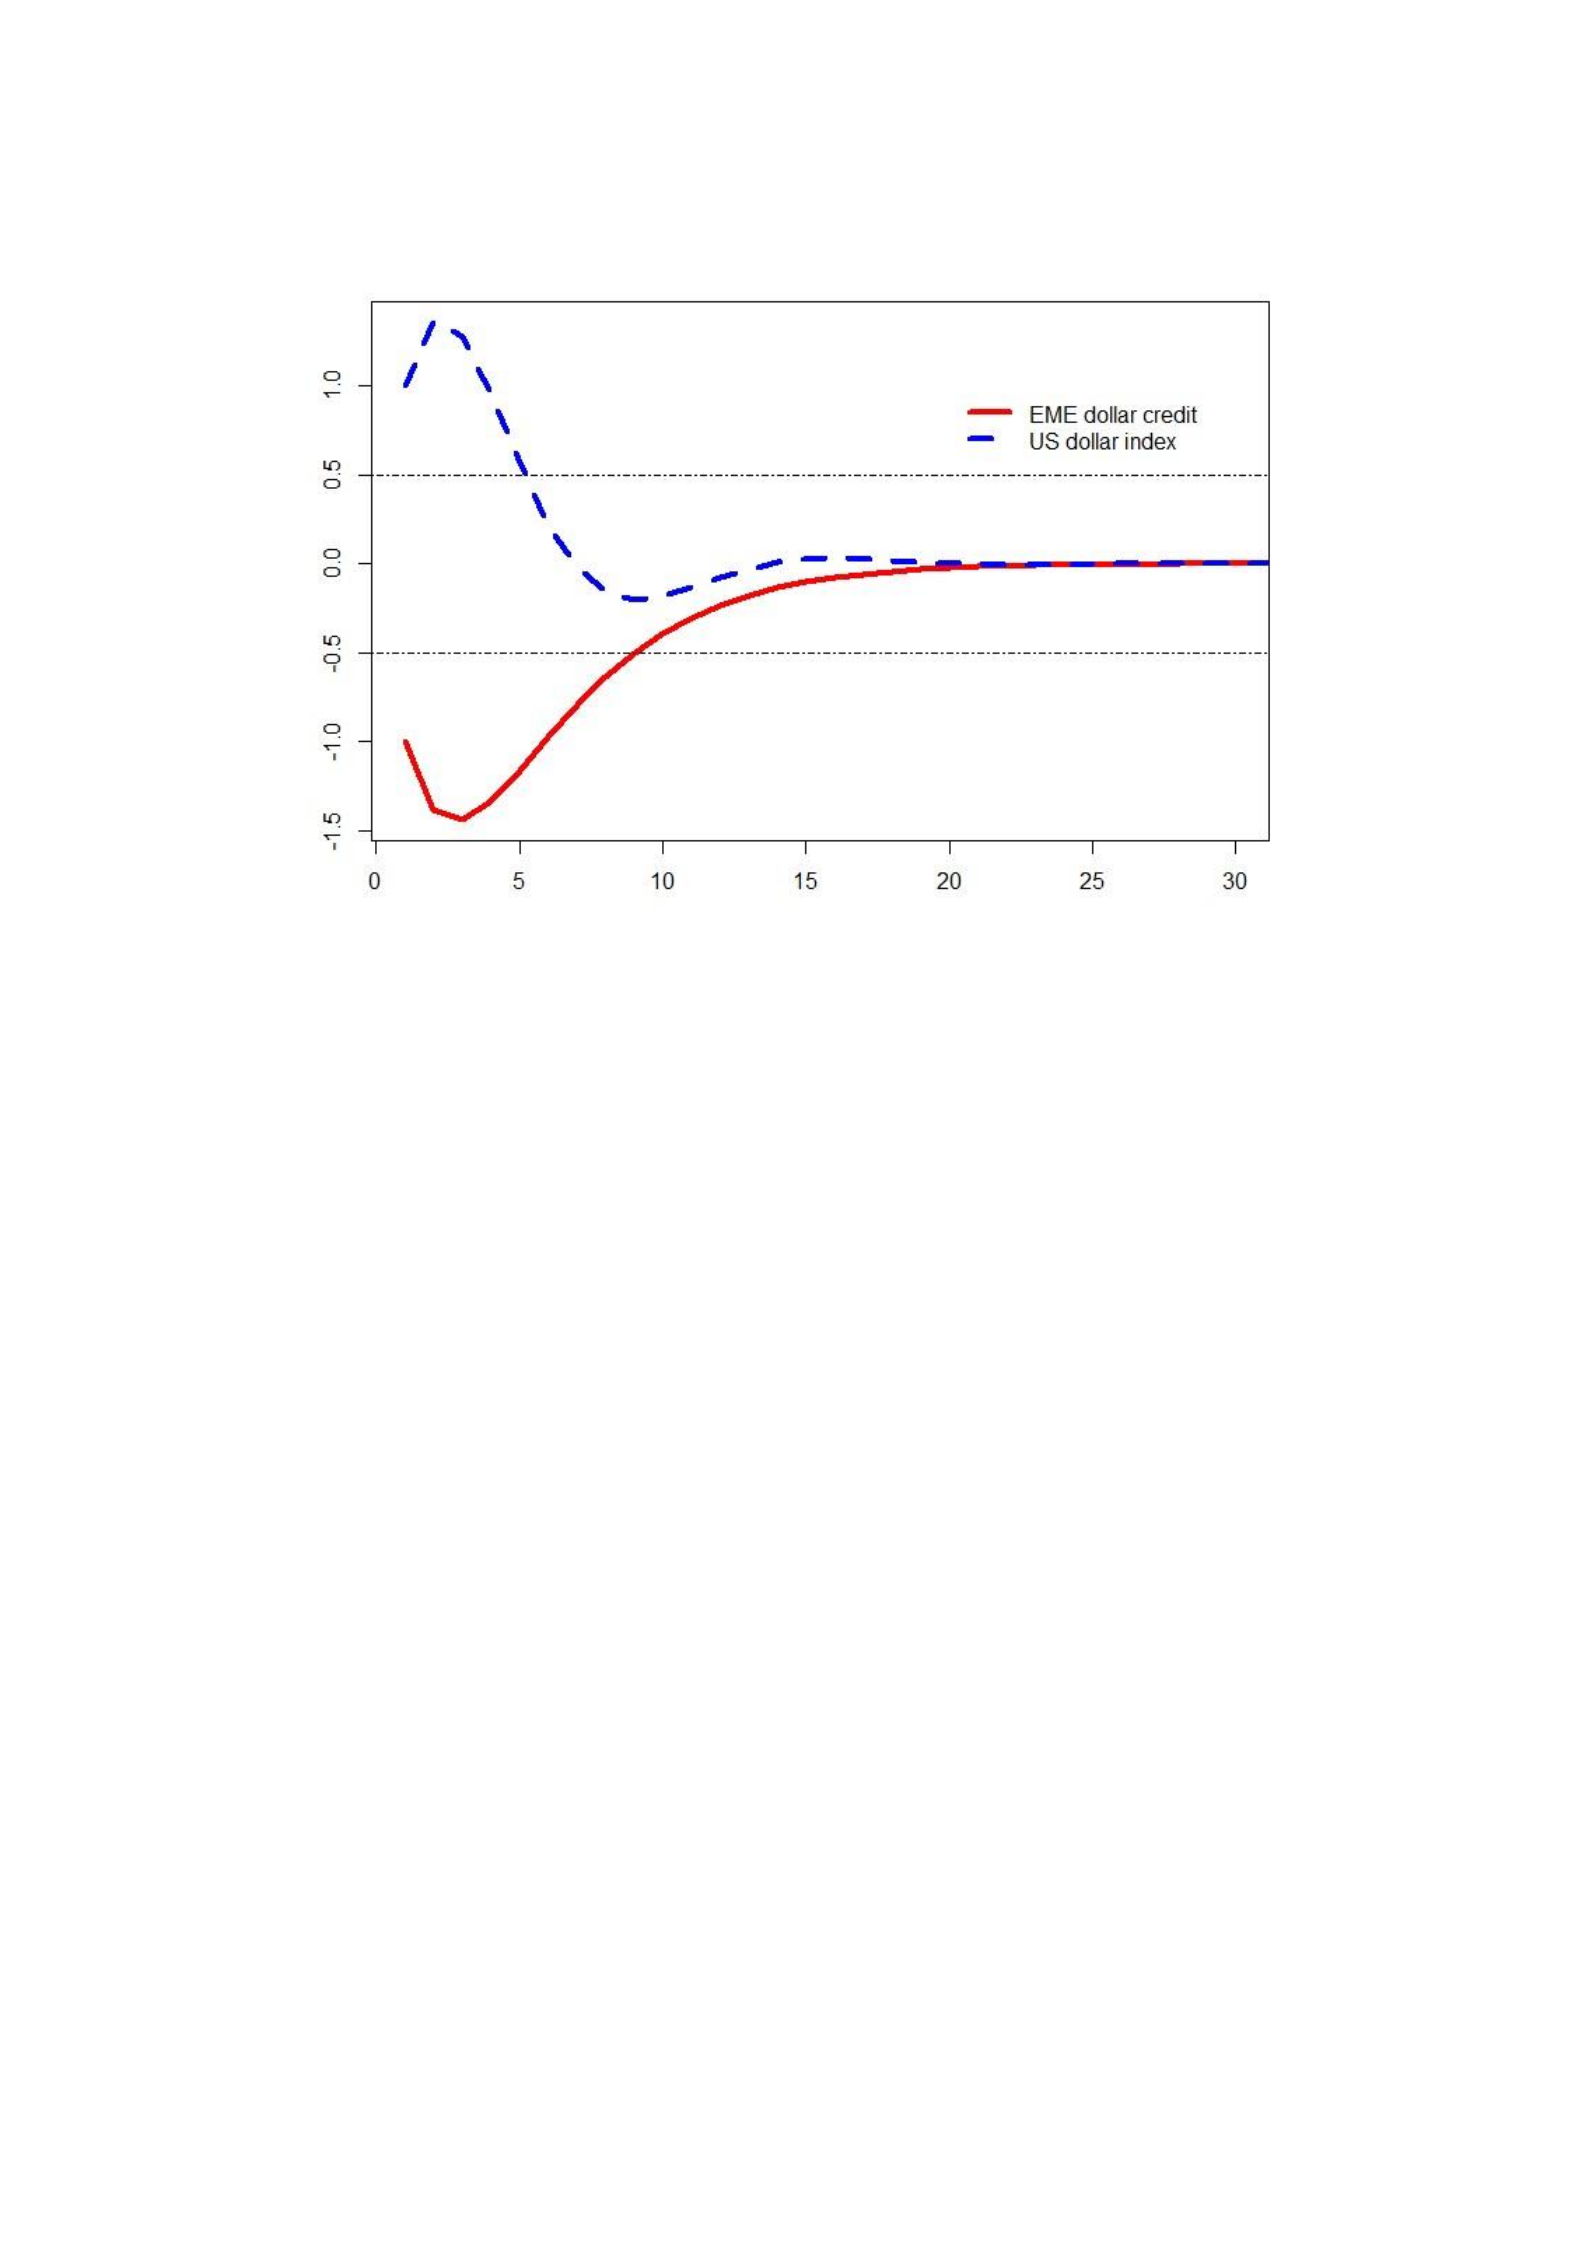
we find a hump shaped response of US dollar index and a U-shaped response of dollar
credit to a contractionary monetary policy shock. The transitory nature of the shock
suggests that these effects slowly disappear over time. The results suggest that the US
dollar index and EME dollar credit do not move to the new equilibrium immediately after
the transitory shock to US monetary policy. From policy maker perspective, the US interest
rate hike above it long-run trend would strengthen US dollar and induce dollar credit
outflow for several months. Although the effect eventually disappears, however, the
transition process may come with international financial instability. On one hand, the
process creates the challenges in the balance of payment for the EME authorities. They
need to equip with enough official reserves to manage the rapid outflow of capital and
stabilize the foreign exchange rate. On the other hand, the appreciation of US dollar and
the outflow of dollar credit leave the EME borrowers pressured to pay back the dollar-
denominated debt.
In order to be prepared for the transmission of international financial risk, in this case
through the rise in US interest rate above its trend, policy makers should adopt both
macro- and micro-prudential policies to deal with the monetary policy spillover effect.

Traditional macro-prudential policies focus on the soundness of financial corporations,
however, after 2009, non-financial firms engage heavily in the carry trade activities and
serve as surrogate financial intermediaries. The associated financial risks create new
challenges to the existing regulatory framework. For example, Hoffman (2014) provides
evidence that the very low world funding interest rates are associated with a rise in
volatile capital flows and asset market bubbles in fast-growing emerging markets.
Furthermore, although the integration of financial markets promote risk sharing in the
long run, in the short run, the external liquidity shocks and the interconnectivity of
financial markets make the international financial risk transmission easier and faster. In
other words, the global financial system may become more fragile in the short run, due to
the externalities in the market.
15
Internalizing the costs and benefits require macro-
prudential policy and international coordination.
2.7 Conclusions
In this paper, we use a correlated multivariate unobserved component model to
examine the hypothesis about the role of ultra low US interest rates in the dollar credit
boom in the emerging market economies. In doing so, we also decompose the movements
in dollar credit in emerging markets, US interest rate and the dollar index into a
permanent and transitory component. The correlations among the cyclical components
support the idea that the rise of dollar credit in the EMEs is associated with US interest
rate and the US dollar index below its long-run trend. The estimated permanent and
transitory component from our model captures the dynamic features of EME dollar credit
series and performs better than univariate benchmarks in capturing the boom and the
boost during the last few years. The strong cyclical correlations among dollar credit in the
EMEs, US interest rate and the dollar index suggest that the policymakers may need to
take into account the US monetary policy spillover effect on domestic credit conditions of

the EMEs, by observing the stance of the US monetary policy and the behavior of the US
dollar in the foreign exchange market. Macro-prudential policies and international
coordination may be justified and needed, along with micro-prudential policies, as a
consequence of global liquidity transmission and the implied international financial
instability.

Chapter 3
Corporate Overseas Debt Issuance in the
Context of Global Liquidity Transmission
3.1 Introduction
The recent surge in non-financial corporate
16
(hereafter ”corporate” ) overseas debt
issuance after 2007-2009 financial crisis has started drawing attention from
macroeconomic researchers, as it plays a critical role in the conduct of international
capital flow activities in the emerging markets. This surge in the overseas debt issuance
is also referred to as the second phase of global liquidity (Shin, 2013).The first phase
(2003-2007) of global liquidity is associated with a rapid increase in cross-border
international bank loans. The international banks lose the market share to international
bond markets in the cross-border activities substantially after the global financial crisis,
partly because of the strengthened financial system regulation. This fall in cross-border
lending by international banks was followed by a rise in the overseas debt issuance of the
non-financial corporate sector. The relative importance of corporate overseas debt
issuance can be gauged from the fact that more than half of the net ”external” financing of
emerging economies in 2012 took place through the issuance of international debt
securities (Turner, 2014).

Given its importance for the stability of the global financial system, it is important to
understand the behavior and determinants of corporate overseas debt issuance. The
purpose of this paper is to fill this gap in the literature. In particular, we want to examine
three hypotheses related to the overseas debt issuance of these corporate firms. First, is
there an evidence of price arbitrage on the part of these firms? Traditionally, a
textbookversion corporate only issues bonds overseas because of foreign currency
exposures. Think about the case when an exporting firm expects to receive a payment in
foreign currency. This firm should issue foreign currency liability to match the foreign
currency asset, in order to hedge foreign currency exposure. This behavior is considered
as a typical corporate risk management practice to help this company focus on the main
operating activities. In other words, they are not supposed to be interested in doing price
arbitrage in foreign exchange markets. Nevertheless, in recent years, many studies
suggest that corporate firms, especially large firms in emerging markets, may behave like
financial intermediaries in overseas debt issuance activities. [Black and Munro (2010),
Bruno and Shin (2015), Caballero et al (2015), Shin and Zhao (2013)]. Secondly, we also
examine whether the firms get around capital control measures enacted by the countries
and act more like a financial intermediary. This hypothesis is motivated by the recent
behavior of the firms in the emerging markets where we observe a surge in debt issuance
even in the presence of capital controls. Thirdly, we also examine the recent debate about
the transmission of the U.S monetary policy to the global financial system by examining
the link between overseas debt issuance and risk premium. To examine these hypotheses,
we utilize a recently developed database on international debt securities by the Bank of
International Settlement and perform a panel study of 32 countries for the 1993-2015
sample period.
Overall our results are consistent with the idea that non-financial firms in emerging
economies have been acting like financial intermediaries. Firstly, we find evidence in
support of price arbitrage hypothesis in case of emerging economies where we find
significant negative impact of level and volatility of exchange rate on changes in overseas
debt issuance. This implies that the corporate firms issue debt overseas in expecting that

domestic currency will appreciate against the US dollar. We also find that capital control
on bond market are positively correlated with corporate overseas debt issuance in
emerging economies whereas this relationship has opposite pattern in the advanced
economies. This difference in response to capital control across border reflects that
corporate firms in emerging markets have strong incentive to walk around capital control
to tap into international bond market, whereas corporate firms in advanced economies
typically follow the regulation to reduce cross-border financial activities. We also find
strong evidence between a measure of risk premium in the U.S. and overseas debt
issuance in emerging economies implying that overall credit conditions in the U.S. do play
a significant role. For advanced economies, however, we don’t find a significant
relationship between risk premium and debt issuance by its corporate firms implying that
the non-financial firms in the advanced economies do behave very differently than the
firms in the emerging market economies.
The remainder of this paper is structured as follows. Section 2 reviews the literature
on international debt securities. Section 3 presents our conceptual framework and
econometric methodology followed by a discussion. In section 4 and 5 we interpret and
check the robustness of the results. Section 5 concludes the paper.
3.2 Literature Review
The surge in corporate overseas debt issuance plays an important role in the second
phase of global liquidity. Turner (2014) suggests that declining in term premium in 10-
year US treasuries may have implication on greater sensitivity to global long-term interest
rates in emerging economy bond markets. McCauley et al (2014) also suggests that term
premium compression in US treasuries has significantly stimulate offshore
dollardenominated bond issuance. Shin (2013) points out, furthermore, the transmission
of financial condition across borders has taken the form of ’reaching for yield’. The
compositional shift in asset managers’ portfolios increases the demand for emerging
market corporate bonds, which leads to the decline of risk premium for these debt

securities. Meanwhile, the issuances of international debt securities explode in response
to the compression in risk premium and the declining capital cost in overseas bond
market. Chung et al (2014) identify a positive relationship between domestic money
growth and capital flow to the non-bank sector in emerging markets. Large corporates
borrow money overseas and hold short-term instruments in home country, such as
deposits and other liquid assets. This behavior essentially enables small corporates to
borrow money overseas and weakens the independence of monetary policy aiming at
domestic liquidity control. These papers describe the paths in monetary policy spillover
and the role of corporates in global liquidity transmission in the context of strict
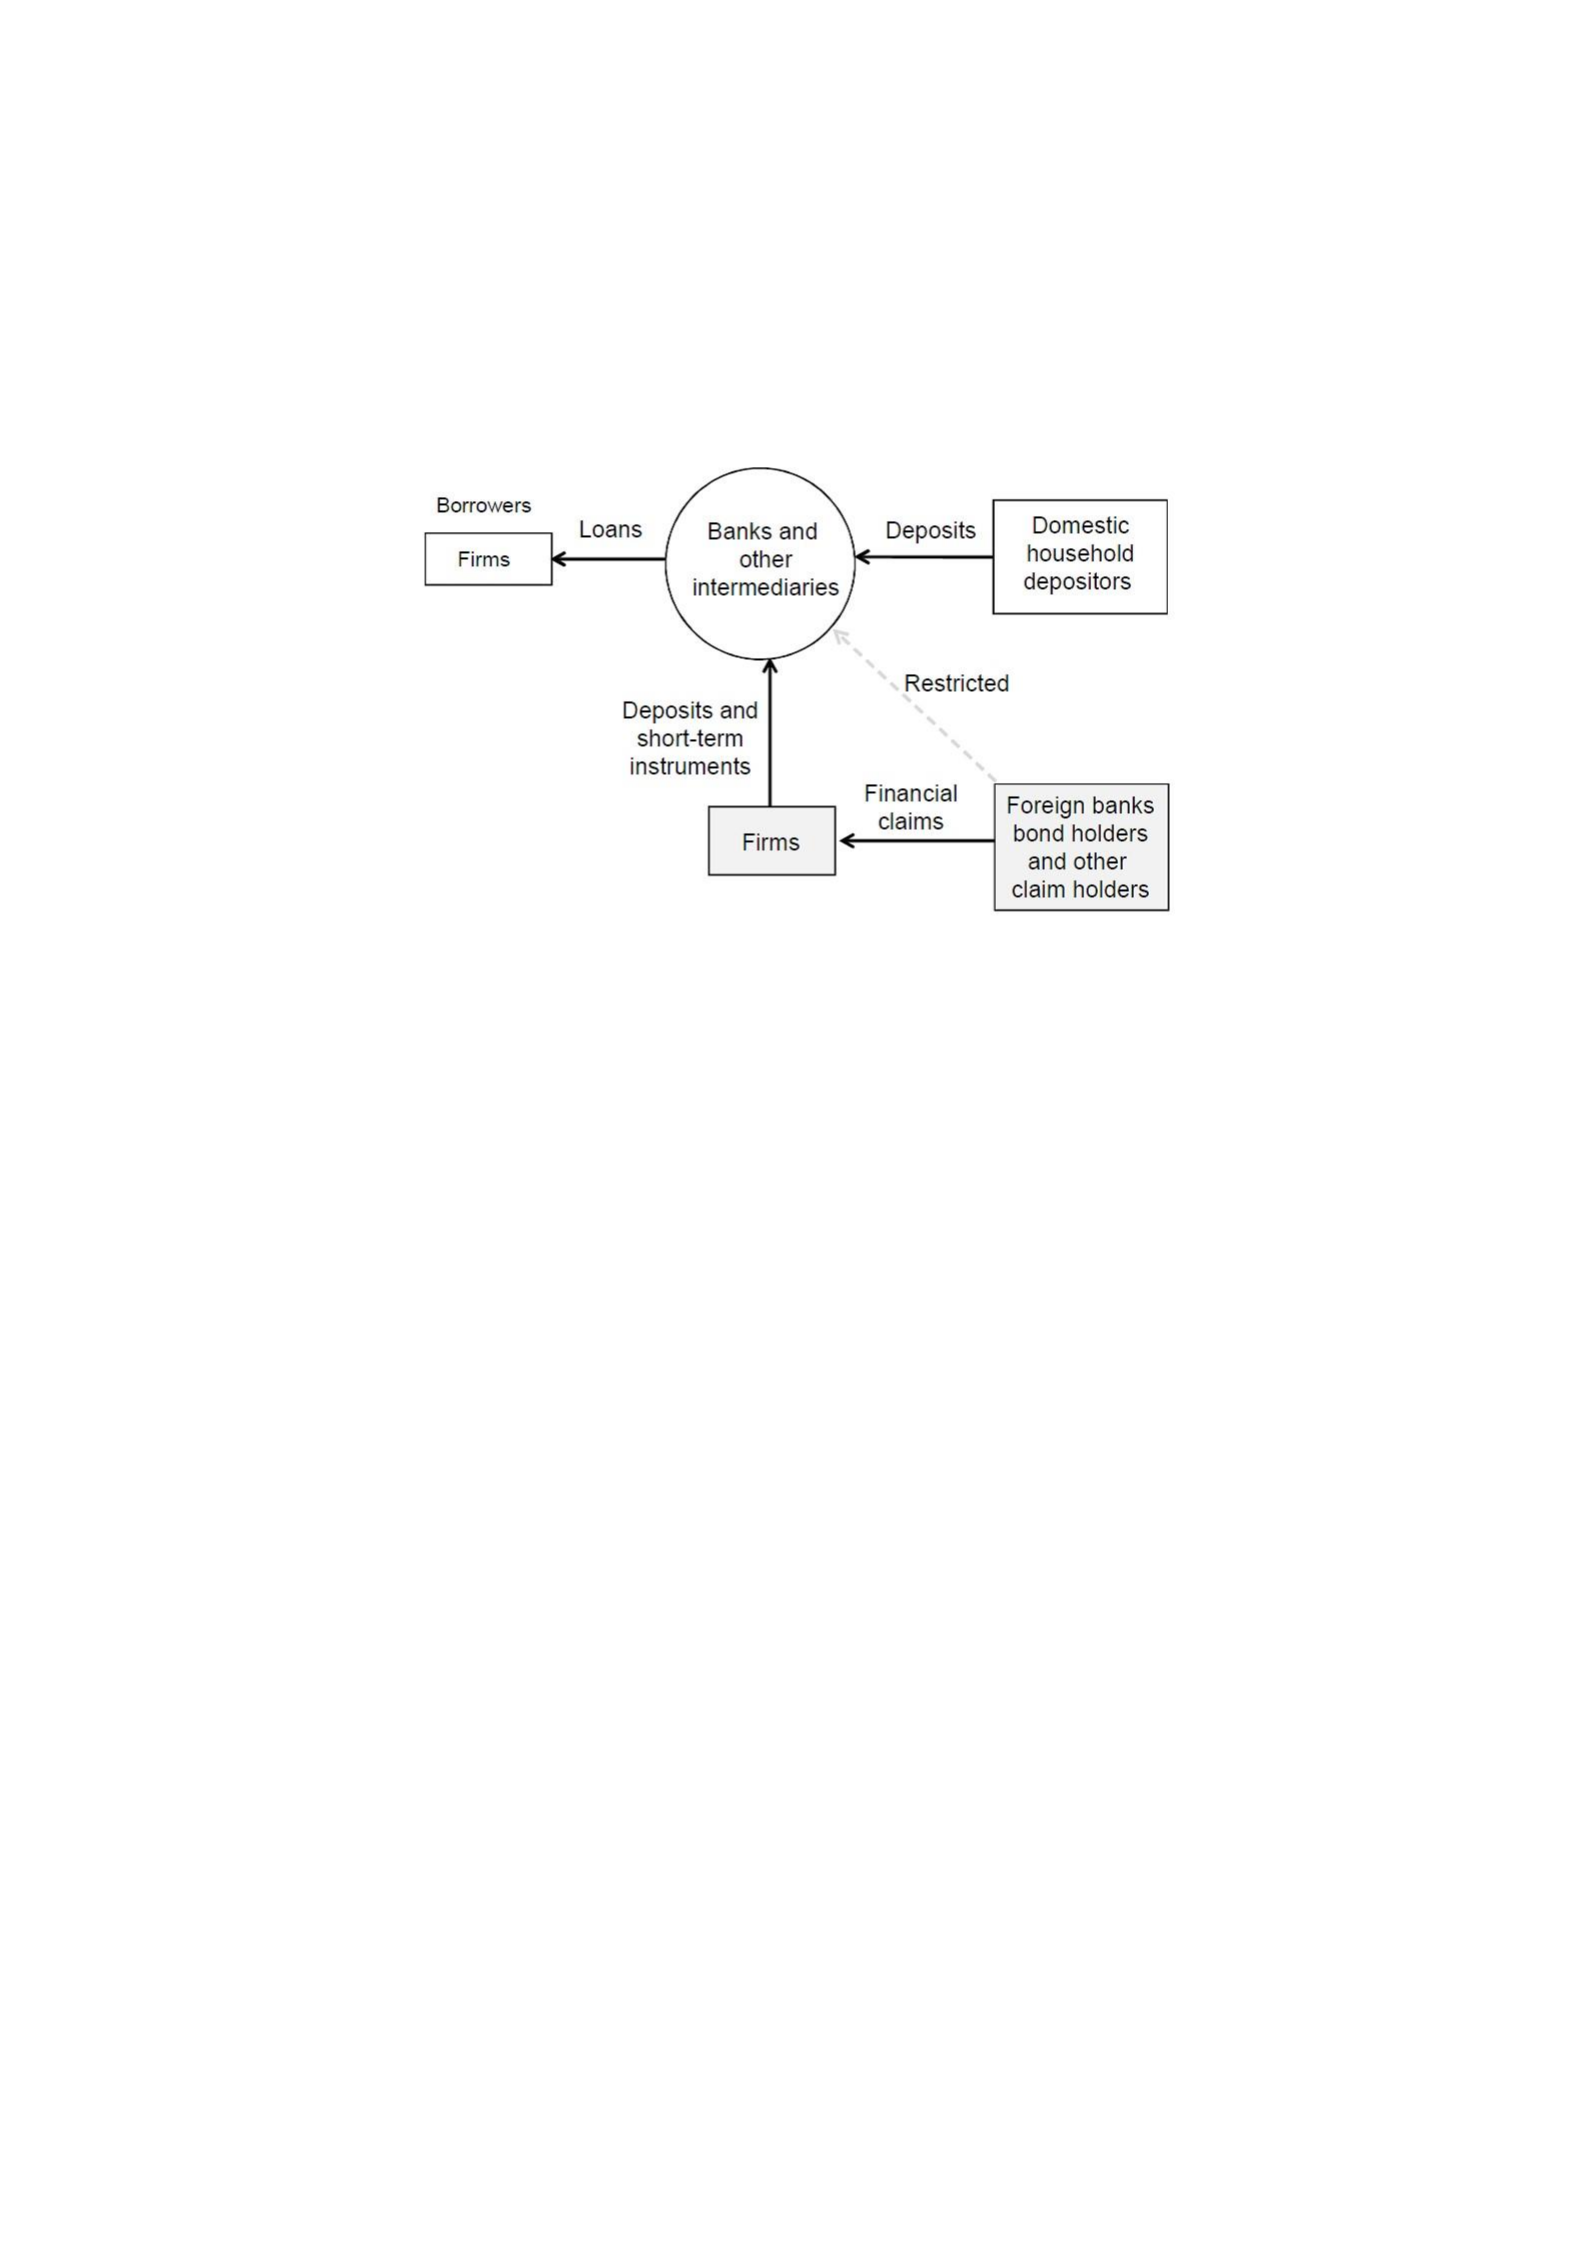
regulation imposed on international banking system. We borrow Figure 1 from Shin and
Zhao (2013) to visualize the role of corporate debt issuance in global liquidity
transmission. In the first phase of global liquidity, domestic household depositors and
international investors (mostly international banks) supply liquidity to domestic financial
system to finance the final corporate borrower production projects. However, in the
second phase of global liquidity, domestic large corporates, rise to serve as surrogate
intermediaries to facilitate liquidity transmission into domestic financial system,
presumably due to the restriction on direct lending from international banks. The large
corporates headquartered in emerging markets may use their overseas subsidiaries to
issue bonds in international financial markets and receive the proceeds through intra-
company transactions (The subsidiaries can pay for operation costs for the headquarters,
for instance). In this way, the proceeds flowing into emerging markets are treated as a
form of foreign direct investment and do not appear in the residency-based external debt
positions. This conjecture worries policy makers about the effectiveness of capital control
policies at the border and the creation of systematic risks outside traditional international
financial regulation framework.
Under this backdrop, researchers investigate the determinants of corporate debt
issuance behavior by exploiting micro evidence from firm-level overseas debt issuance
and financial accounting information. Black and Munro (2010) examines the
onshore/offshore bond issuance decision by non-government residents of five Asia-
Pacific countries. Price arbitrage is identified as the most important motivator to issue
offshore, for both financial and non-financial corporates. Market completeness and
liquidity are also estimated to drive issuance decisions, i.e. firms seeks for more complete
financial markets to issue Figure 7: Transmission of Global Liquidity across Borders
Shin and Zhao (2013)
larger-size, longer-maturity bond at a lower capital cost. Nevertheless, this study uses
residency-based international bond issuance data, which may not be able to capture the
real volume of cross-border issuance, especially given the fact that non-financial firms use
intra-company transactions to avoid capital regulation across border. As depicted by
Bruno and Shin (2015), the difference widen significantly between nationality-based and
residency-based amount of external debt outstanding: the nationality-based external debt
position reaches roughly twice as much as the residency-based measures in 2014. (Figure
2) Shin and Zhao (2013) use firm-level financial accounting information based on
consolidated balance sheet and debt issuance data to further investigate the role of
corporates as surrogate financial intermediaries. Their results also suggest that
corporates in emerging markets behave like financial intermediaries in the sense that the
correlation between financial assets and financial liabilities has a positive sign, which is
supposed to be an accounting feature for financial corporates instead of non-financial
corporates.
17
Figure 8: Corporate Overseas Debt Issuance in Emerging Markets
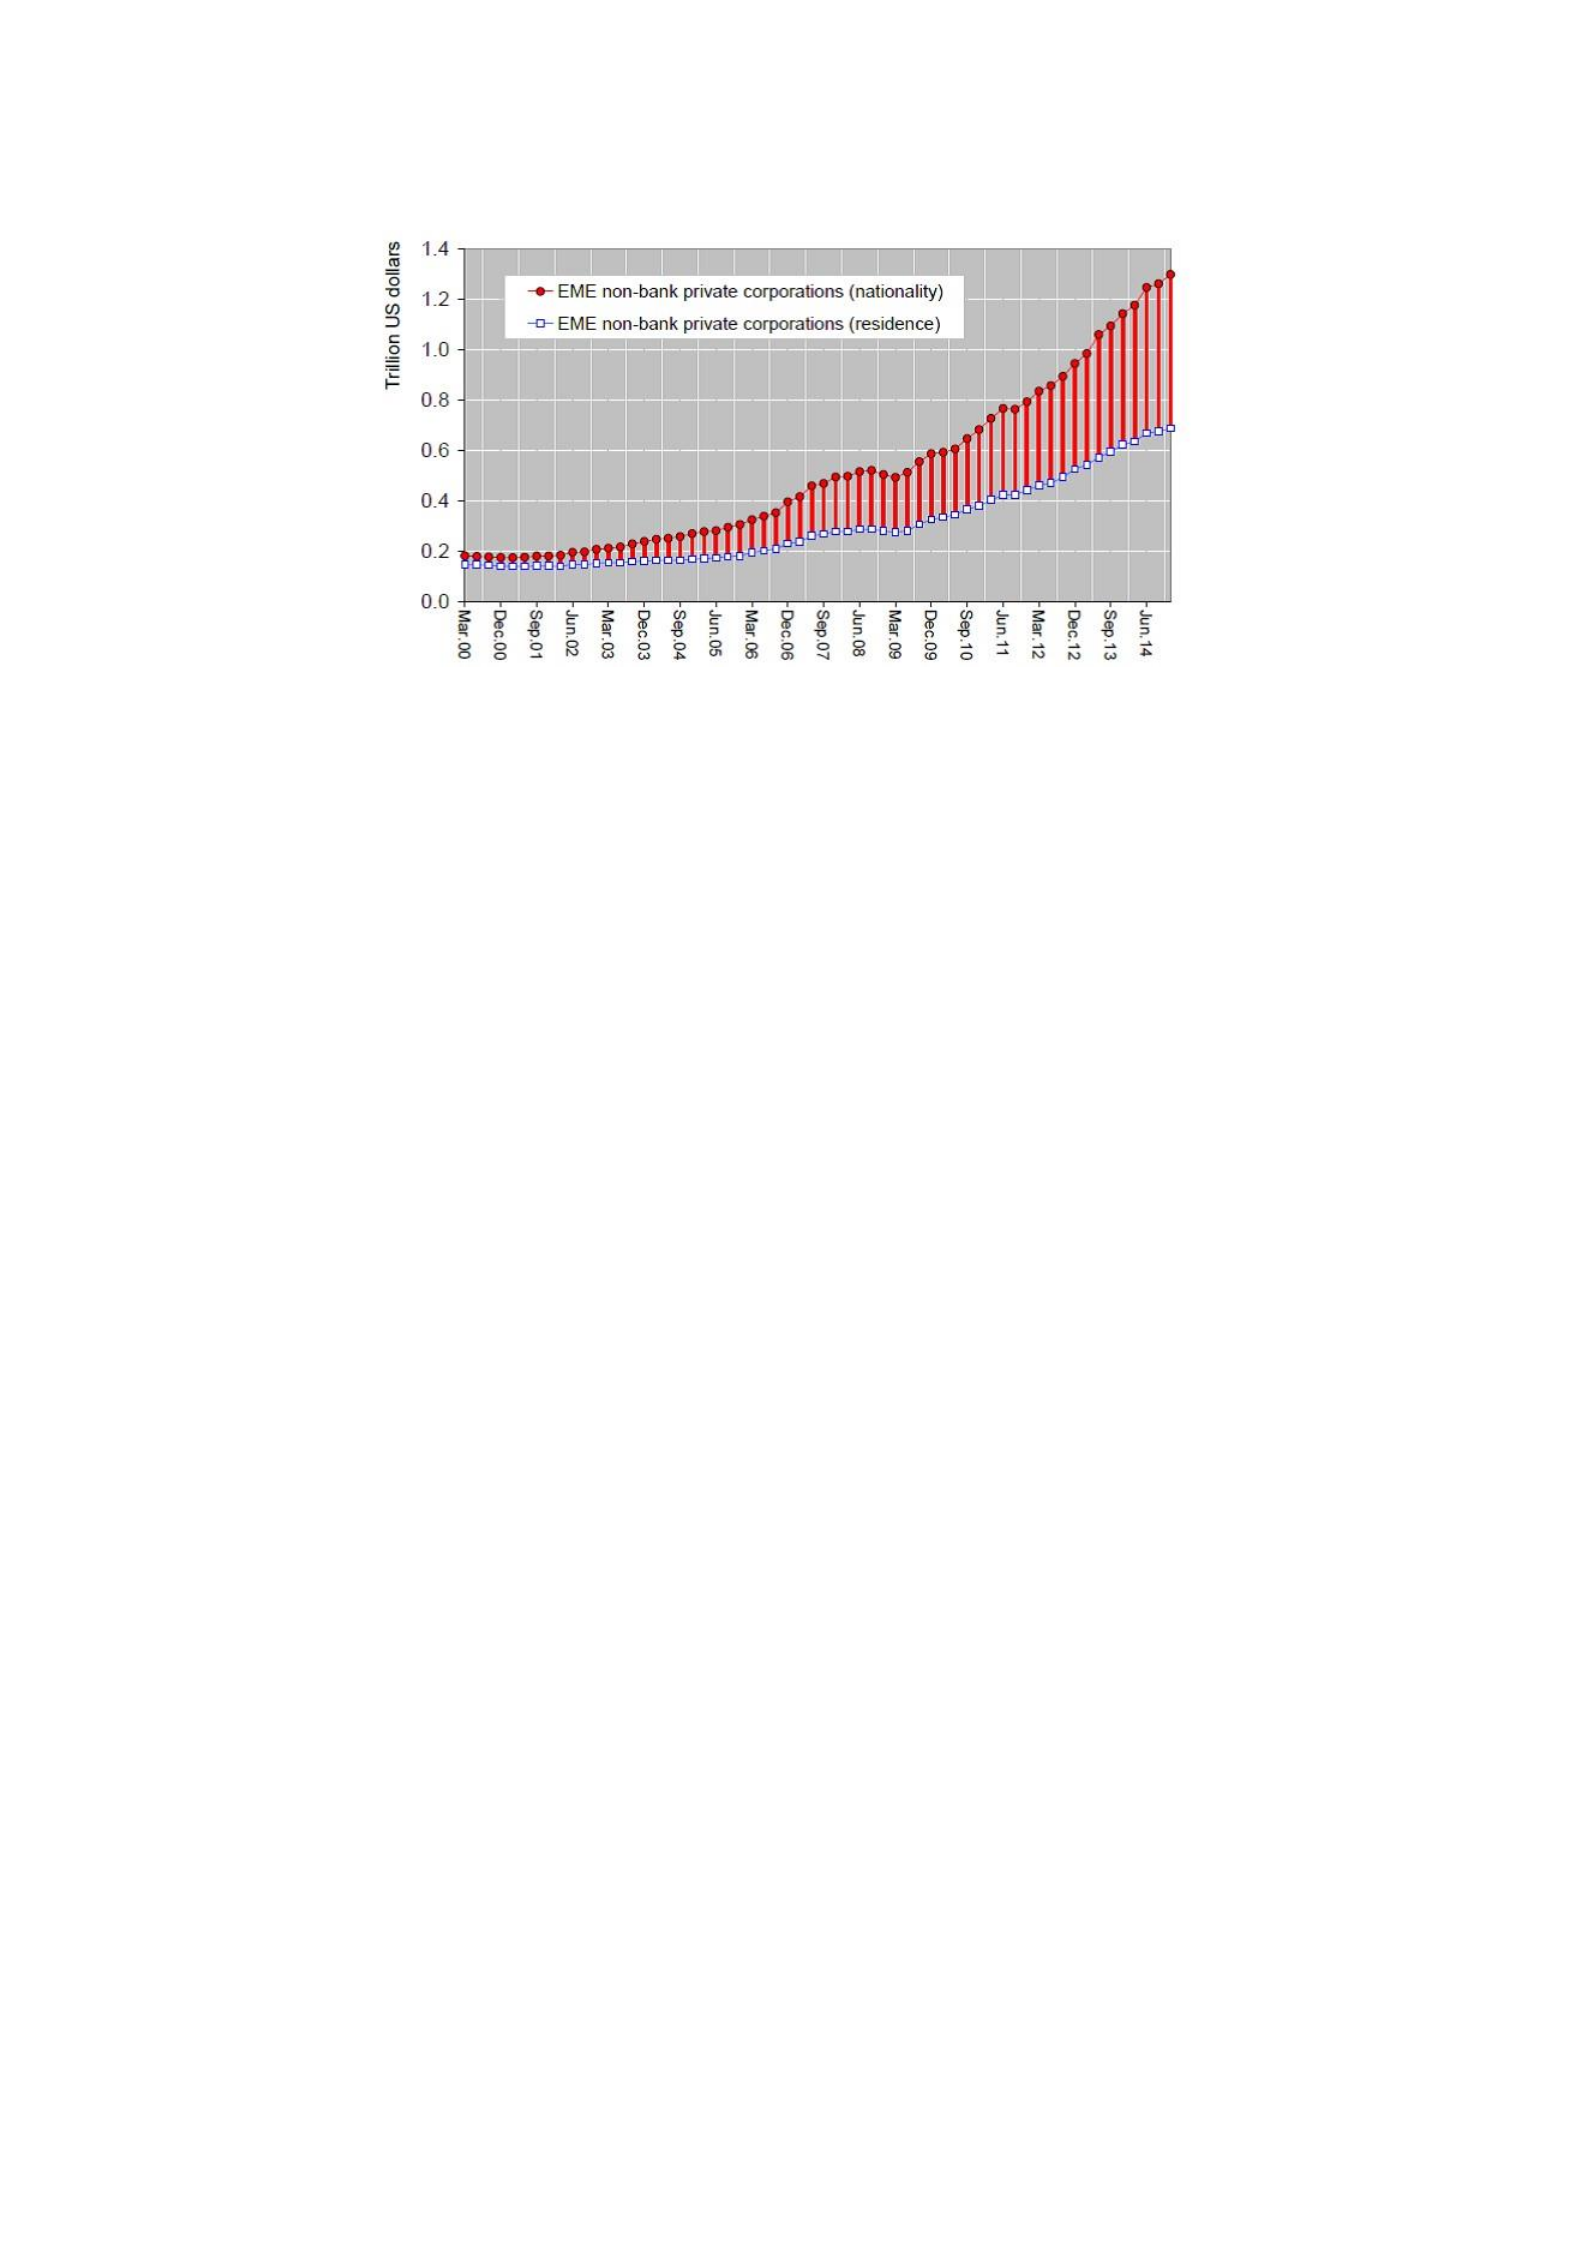
Bruno and Shin (2015)
Two recent micro studies, instead, focus on testing carry trade hypothesis. Both papers
support the positive correlation between corporate overseas debt issuance and firm cash
holding, which essentially indicates a carry trade position. Bruno and Shin (2015),
furthermore, point out this phenomenon is more prevalent for emerging market firms
during favorable carry trade periods. Caballero et al (2015) suggests that there is evidence
for carry trade activities in countries with higher levels of capital controls. In our paper,
we also find that corporate overseas debt issuance behaviors are positively correlated
with capital controls at the border, especially in emerging markets where overall capital
control levels are much higher than in advanced economies.
To summarize, the literature provides some evidence to support the idea that corporates
dramatically increase overseas debt issuance to conduct price arbitrage and serve as
surrogate financial intermediaries to facilitate capital flow across borders in emerging
markets or countries with strict capital controls. Put it differently, corporates may step
into the vacuum whereas financial sectors are blocked by international capital control
regulation. This paper, from our knowledge, is the first paper using macro nationality-
based corporate overseas debt issuance data, to tackle several hypotheses in the literature
and to explain the determinants of corporate overseas debt issuance behavior.

3.3 Empirical Models
3.3.1 Price Arbitrage VS. Risk Management
To test the hypotheses mentioned above, we build three empirical models to study the
determinants of corporate overseas debt issuance behavior. In first model, we try to test
price arbitrage hypothesis against risk management hypothesis based on the
contradictive implication in response to exchange rate variables from these two
hypotheses. If corporates behave more like price arbitragers, they will issue less debt
when domestic currency depreciates/ when the exchange rate is volatile. Whereas, if
corporates behave like what textbook suggests, they will issue more debt when domestic
currency depreciates because when domestic currency depreciates, export increases so
as the foreign currency exposure.
In order to hedge the foreign currency exposure, they should issue more debt securities.
In addition, when exchange rate is more volatile, corporates are expected to have stronger
incentive to hedge larger portion of foreign currency asset exposure. In our model, the
exchange rate is computed based on direct quote against US dollar, which means the
exchange rate number is interpreted as the amount of domestic currency one US dollar
can purchase. Therefore, an increase in the exchange rate number implies depreciation of
domestic currency.
To be explicit, if price arbitrage hypothesis dominates risk management hypothesis,
then we would expect that β1 > 0 and β2 > 0; if the other way around, then β1 < 0 and β2 <
0. Besides exchange rate and exchange rate volatility, we also control for relevant
economic fundamentals. In this case, we control for both domestic real GDP growth rate
and current account balance. In the most complete specification, we also control for
government foreign exchange market intervention, by adding the growth rate of official
reserve. This specification allows us to see the impact of exchange rate and exchange rate
volatility on corporate overseas net debt issuance while government intervention is in
place.
(10)
3.3.2 The Effectiveness of Capital Control Policies
In the second model, we are interested to study the effect of capital control on
corporate overseas debt issuance. The capital control policies imposed by governments
are designed to control for the amount of international capital flow across borders.
Therefore, if the capital control policies were effective and well-designed, we would
expect the reduction of all types of international capital flow, implying the reduction of
corporate debt issuance. If, instead, we found the effect of capital control was the rise in
corporate debt issuance, then the effectiveness of capital control policies could be in
doubt. Explicitly speaking, the capital control policies may impose a binding constraint on
financial sectors, whereas the corporates may gain comparative advantage to take the role
as financial intermediaries. As explained previously, corporates are able to use intra-
company transactions to avoid the international capital control regulation.
Thereupon, the positive sign of capital control coefficient suggests the lack of effectiveness
of capital control on corporates, whereas the negative sign indicates the effectiveness of
capital control on both financial and non-financial sectors. As you may have noticed, we
do not control both exchange rate variables and capital control variables simultaneously
in one specification. This is due to the fact that capital control policies and exchange rate
stability are strongly dependent on each other. According to international monetary policy
trilemma, if the government imposes capital control at the border, then the country will
gain the ability to stabilize the exchange rate and the independence of domestic monetary
policy. If, instead, the government is willing to let exchange rate float according to market
forces, then the capital are free to flow across borders and monetary authorities still
maintain the independence of domestic monetary policies. Hence, the bottom line is, we
are not able to identify the clean effect of capital control and exchange rate variables
separately, by putting both of them into one specification.
(11)
3.3.3 Advanced Economy Monetary Policy Spillovers: An Indirect
Test based on Corporate Risk Premium
As explained in the introduction, there may exist advanced economy monetary policy
transmission effect. In this study, we perform an indirect test based on the effect of
corporate risk premium. If β1 is negative, which suggests a decrease in risk premium will
increase corporate debt issuance, provides a piece of supportive evidence in the process
of monetary policy spillovers. We test this hypothesis by adding back all the variables in
the previous regressions and are able to show that risk premium indeed causes the rise
in corporate overseas debt issuance.
(12)
We control for both country fixed effect and year fixed effect in panel regressions in all the
model estimations. The standard errors we report in our paper are Driscoll and
Kraay (1998) robust standard errors. Driscoll and Kraay (1998) propose a nonparametric
covariance matrix estimator that produces heteroscedasticity- and
autocorrelationconsistent standard errors that are robust to general forms of spatial and
temporal dependence. Because the nonparametric technique of estimating standard
errors place no restrictions on the limiting behavior of the number of panels, the size of
cross-sectional dimension in finite sample does not constitute a constraint on feasibility.
These features make Driscoll and Kraay (1998) standard error the most suitable
candidate in our models. Our sample includes 32 countries and quarterly data
observations spanning across 1993-2015. Clearly, we have limited cross-sectional
dimensions but relatively large time series dimensions. Since our conjectures are mostly
based on the stylized fact in emerging markets, we split the sample countries into
emerging market subsample (20 countries) and advanced economy subsample (12
countries).
3.4 Data Description
Our sample includes 32 countries
18
during the period 1993Q3-2015Q1. The key
variable we are interested in, net debt issuance based on nationality of corporate issuers,
is from Bank of International Settlement (BIS) website. Luckily, we are also able to find a
dataset, just available recently, about capital control measures in various financial
markets, constructed based on IMF annual reports. This dataset allows us to disentangle
the effect of the capital control policies in each financial sector on corporate overseas debt
issuance separately. Table 2 lists all the data sources we use in this study.
Table 2: Data Sources
Variable
Data Source
Net Debt Issuance (Millions of USD)
Bank for International Settlements (BIS): http://www.bis.org
Exchange Rate (Quarterly Average)
OANDA: http://www.oanda.com
Exchange Rate Volatility
OANDA: http://www.oanda.com
GDP Growth Rate (%)
FRED: https://fredqa.stlouisfed.org; IFS: http://www.imf.org
Current Account Balance (Millions of USD)
IFS: http://www.imf.org
Foreign Reserve Growth Rate (%)
IFS: http://www.imf.org
Risk Premium (Junk Spread) (%)
FRED: https://fredqa.stlouisfed.org
Capital Control Measures (range: [0,100])
NBER: http://www.nber.org/data/international-finance/
The variables used in this paper are constructed as described below.
Net Debt Issuance: We remove the seasonality in the international debt security amount
outstanding, which are issued by non-financial corporates and categorized based on
nationality of issuers. Then first difference these series to get net debt issuance in millions
of US dollars for each country.
Exchange Rate:measured in direct quote, i.e. in domestic currency per unit of US dollar.
We take the average of the daily closing rate in the quarter to serve as quarterly average
exchange rate.
Exchange Rate Standard Deviation: The standard deviation of exchange rate within the
quarter based on the daily closing rate.
Exchange Rate Volatility: = (ExchangeRateStandardDeviation/ExchangeRate) ∗ 100. It
can be interpreted as percentage deviation from the quarterly average. This measure of
exchange rate volatility gets rid of unit of measures, therefore is comparable across
currencies.
Real GDP Growth Rate: We take log difference of seasonality-adjusted real GDP to get the
quarterly GDP growth rate.
Current Account Balance: We remove seasonality in current account balance data and
convert series to be measured in millions of US dollars.
Foreign Reserve Growth Rate: We take log difference of official reserve assets which are
measured in US dollars.
Risk Premium: We use BAA corporate bond rate minus 10-year Treasury bond rate to
measure risk premium in corporate bonds.
Capital Control Measures: We use international capital control indexes on the money
market/ bond market/ equity market/ real estate market/ foreign direct investment
separately. These measures are continuous variables ranging from 0 to 100. This variable
is only available between 1995 and 2013.
Table 3: Summary statistics
Variable
Mean
Std. Dev.
Min.
Max.
N
Net Debt Issuance (Millions of USD)
358.199
2077.493
-22934.971
23020.229
2720
Exchange Rate
356.624
1599.789
0.014
10000
2738
Exchange Rate Standard Deviation
2.82
35.909
0
1151.724
2738
Exchange Rate Volatility
1.7
1.956
0
48.979
2738
Real GDP Growth
0.88
1.816
-12.074
42.294
2637
Current Account Balance (Millions of USD)
2127.202
11555.506
-39157.066
108339.003
2603
Foreign Reserve Growth
2.743
10.293
-95.652
85.048
2815
BAA minus 10 Treasury Bond Yield
2.406
0.794
1.37
5.58
2855
Capital Control: Money Market
38.035
38.612
0
100
2432
Capital Control: Bond Market
36.397
39.083
0
100
2176
Capital Control: Real Estate Market
47.862
36.247
0
100
2432
Capital Control: Direct Investment
41.612
40.304
0
100
2432
Capital Control: Equity Market
37.87
39.116
0
100
2432
3.5 Results and Interpretation
3.5.1 Price Arbitrage Hypothesis VS. Risk Management Hypoth-
esis
Price arbitrage hypothesis implies that domestic currency depreciation and volatile
exchange rate against US dollar has a negative impact on corporate overseas net debt
issuance. Whereas, risk management hypothesis suggests that domestic currency
depreciation will stimulate export and create larger currency exposure position needed
to be hedged by issuing overseas liabilities, and the more volatile the exchange rate
against US dollar, the stronger the incentive for corporates to hedge the exposures. These
ideas implies a positive impact on overseas debt issuance from domestic currency
depreciation and exchange rate fluctuation, from the risk management perspective.
Table 4 reports the results from the first model that tests price arbitrage against risk
management hypothesis. In all specifications, as the exchange rate increases, i.e. domestic
currency depreciates, corporate overseas debt issuance will decrease; as exchange rate
becomes more volatile, the less the corporate will issue debt securities overseas. This
result is in line with price arbitrage hypothesis. The corporates issue debt overseas in
expecting that domestic currency will appreciate against US dollar. From model
specifications (1) to (4), we add real GDP growth and current account balance to control
for the economic fundamentals. Interestingly, current account balance is insignificant in
explaining corporate overseas debt issuance, which confirms the result that corporate
overseas debt issuance does not strongly associate with hedging foreign currency
receivable exposure. In the last column, by adding the growth rate of official reserve, a

proxy for government foreign exchange market intervention, we find that government
intervention stabilizes corporate debt issuance by mitigating the effect of exchange rate
volatility, while the exchange rate variables still play a significant role in explaining the
corporate overseas debt issuance behavior.
Table 5 reports the same regressions using advanced economy subsample. No
significant impacts are found for exchange rate and exchange rate volatility, which
suggests that corporates in advanced economies are not sensitive to exchange rate
variables in overseas bond issuance activities. Together with insignificant effect from
current account balance, we could not support either of the hypothesis in advanced
economies. Our conjecture is that corporates in advanced economies could issue bonds
overseas in domestic currency so that these firms are less sensitive to exchange rate
variables. Another interpretation could be, if countries fall into more flexible exchange
rate regimes, there is less opportunity to conduct price arbitrage in the foreign exchange
markets. Most emerging markets impose much stronger capital control at the border to
stabilize the exchange rate and maintain monetary policy independence. Thereupon, the
exchange rates in emerging markets may not reflect market expectation about the ’true’
exchange rate against US dollar. It will take much longer time to arbitrage away these zero-
risk opportunities because capitals need to find a way to walk around the capital control
regulation at the border. Whereas, in advanced economies, domestic financial markets are
well integrated into international financial markets and the overall capital control levels
are much lower at the border for these counties. Corporates headquartered in advanced
economies presumably on average face a smaller interest rate gap at the border, due to
financial market integration. Moreover, they do not have comparative advantage,
compared to financial corporates, to rise as financial intermediaries because of less
regulation at the border. Overall, there is no evidence to support the price arbitrage
hypothesis for the corporates in advanced economies.
To0
>d
,,,
900
>d
,,
OTO
od,
sasayjualeduisoysneys
7
69VL69VTV9OST6C9T67Z9
TSUONEAIasSq
SAKSAKSIASAASAAIJJA
POX
ICI,
SAX
SAXSAASAXASAAVAIJqpPaxl
AUN’)
(60°21)
(vo'zt)(t6'zZ)
(Test)
(6st)
exe
COOT
zee
LOOT
weve
LOC
xxv?
OES
ek
L’STGjuejysu0)
(Ze)
TEESE
(T-YUMoOLHaAIISayeIUJO
(Zs'T)(09'T)
60700'00€700'0(T-3)a.urTegjUNosdyIUeLIND
(s0'T-)(90'T-)(S6'0-)
£9°81-PE'8T-76
91-(T-Ymmorndayeeu
(98'T-)(S6'T-)(66'T-)(8E°Z-)
8SS0°0-
8S0'0-
1IS90'0-
x
18Z0'0-(T-ayeyasueyoxy
(8t'z-)(v9'2Z-)(Zz'Z-)(0Z'Z-J
1
1'Z-)
v8'ST-
LL
6T-
wLV’8T-
LEVI
-
6T'ET-(T-YAnefojaieyosueyoxg
DIUENSS]}G9q19
N2UeNSS]1
G99
N2IUENSS]}G9q}aN2UENSS]}1G9q1aN2IUENSS]}G9aqION
(s)(v)(e)(Z)
(1)
"SUONEUITJSO|[EUIpoy
Oda
lolesIo.Iopiepueys
3snqo1(g66T)Aeet[pueloosiiq‘aptsoddoayyo1paidsisayjodAyjuawaseueUulyslLisyjseatloyM
‘sAesaualeA}I
[I
e[OAS}
puea}elasueyoxajo
sJUdTYJaooy
OgGs}IpaidsisayjodAyasesjg1esdL1g'aye.lasueyoxajoasejaAeA]19}1en
bayWo1jUONeAapasejuadJodayjsepainseaulsiAye[oA
ayelasueyoxy
uoMedaidapAdua1InddINsawiopo}useAInbasia}e1as
uUeYIxXaUlaseaIOUIULAIOJaJay
|
aseyoinduesie[jopspnjoywunsadAduasin9d
IsawWopjoyUNoWwesy}y'9'1'9j0nbya.lIpsulsnpa.inseawis{a}e.1adsuUeYyoOX
|
19}.
1en
bay
IY
WMIIUENss]qapseas.1gA0}aUud}e.1OdIOOSIa[qeLiea
quapuadapay
|
AT
Ne[OAa}e1aSULYOXa
pUb|}e.1OSULYOXIUOUOT
CIT
AUILBATOIPe.UODaYUOpaseqsasayjOdAYOMy9Y}S9}0}S19[qeysiy,L,
Saxe
PSUISIEWy:sisayjodAH
UsWeseuepLysly
/ase.IGIVsdLg
Pagel,
100
>d
arts
900
>d
a6
OL0
>d
*
sasayjuareduisonsyeys
7
6V66V6E0OTTTLOTT
LO
LSuoneAtesg(¢
SIA
SAA
SAASAASIAVIJJAPOXT
ICI,
SOX
S9AS9X
SAA
SAA
VaJJqpoxty;AUNG)
(st'o)(eT'0)(T0'T-)(Z8'0-)
(hr'Z-)
G8'VLIZ'ESS'LTE-0'SLZ-
x
Z
98E-JUeIsUO)
(66'0-)
810°9-
(T-YIMoOINeALASaY
[EO
(Zr'0-)(Z¥'0-)
Z010°0-8010'0-(T-3)e29ueTegqunosoy}ueLIND
(ot'0)(70'0)(6T'0-)
096'PZPT'ZS98'8-(T-
Mong
Gy
TeaY
(62z'0-)(9Z'0-)(Sz'0-)(O¥F'0-)
66£'V-SL6'E-Z18'€-S86'S-(T-aieyasueyoxy
(19'T-)(19'T-)(9Z'T-)(EET-)(ZE'T-)
9'SST-Z'VST-8'bZ1-9
6ZT-F
OF
T-(T-
Anne
foAayeyasueyoxy
ddUPNSS]}G9(19
NeIUeNSS]}1G9qJeNeDUeNSS]3GQaq1e
NODUENSS]GeqJeNeoUeNSS]IGIQION
(s)(p)(e)(Z)()
‘SUOT]EUINSA|[eUIps}1odatates101lap.iepue}s
ysnqo1(g66T)Aeerypueloosiiq‘ayisoddoay
qi
paidsisayjodAy
UsWiaseUeULYSLIay}sealayM
‘sANesaUaIeAT
I
e[OASIpue|}elasUeYyoXaJO
SJUSTDYJa0y4}0qGS1IIpaidstsayjodAyasesjg1eadLig‘a}e.1lasueyoxajoase.1aAeA]
aL
en
bay}
Wol1UONelAapasejUuadJodayjsepainseaulsiAy]e[OA
ayelasueyoxy
uoedaidepAdua.LInddNsawopo}useAInbasia}e1ad
UeYIXaUlaseaIOUIUeAIOJa1ay
|
aseyoinduesieljopsnjoywunsadAduasind
INsawopjoyUNowesy}'a'1ajonbypa.lIpsulsnpa.inseauls{a}e.1adsuUeYoOX
yy
19}.
JeNbay
UI
UMIIUENSS]qapseas.19A0}aUd}e.1Od1OISIa[qeLiea
quapuadapay
|
Al[Ne[OAa}e1asULYOXapUb|}e1OSULYOX9UOUONedT[CUIIDAIOIPe.QUOIaYUWOpasegsasayOdAYOMy9Y}S9}0}S19[qeysiy,L,
SaTWOU0DTpsdUeApyY:sIsay
OdAP
UsWaseUL|STY
/ASe.IGIVSILIg:Ga|qeL

To summarize, the results from the first model support the conjecture that price
arbitrage incentive dominates corporates overseas debt issuance behavior in emerging
markets. This assessment is in line with the micro evidence from Black and Munro (2010),
which concludes that price arbitrage is the most important incentive for corporates to
issue bonds overseas, although the evidence for financial corporates is even more
prevalent. On the other hand, there is no such evidence found among the counterparts in
advanced economies. Shin and Zhao (2013) suggests that corporates in advanced
economies behave more like textbook-version corporates.
3.5.2 The Effectiveness of Capital Control in Emerging Markets
Typically we would expect a reduction in cross-border activities from all market
participants when facing a strengthened international regulation. This intuition implies a
negative impact of capital control on corporate debt issuance overseas. Table 6 reports
the effect of capital control on corporate debt issuance in emerging markets. Surprisingly,
we find that capital control on bond market are positively correlated with corporate
overseas debt issuance. This result suggests that corporates may exercise their
comparative advantage as surrogate financial intermediaries, while financial sectors face
strict regulation at the border. This result, together with Caballero et al (2015), illustrates
the importance of corporate overseas debt issuance as surrogate financial service in
countries where strict international capital flow regulation is in place.
Using advanced economy data in the same specifications (Table 7), we see the opposite
pattern: capital controls in financial markets are negatively correlated with corporate
overseas debt issuance. This difference in response to capital control across border
reflects that corporates in emerging markets have strong incentive to walk around capital
control to tap into international bond market, whereas corporates in advanced economies
typically follow the regulation to reduce cross-border financial activities. Especially
among our sample countries, many advanced economies have international financial
centers in their home countries or they are by themselves financial centers (e.g. Hong

Kong and Singapore). Corporates in these countries do not have strong incentive to issue
bonds overseas, when they face more strict capital control at the border.
TOO
>d
,,,
900
od
,,
QTO
od,
sasayjuatedulsonsne}s
7
COETCOETCOELOLZLC6E
TSUONPAIOSqQ
(16'0-)(S9'0)(19'0-)(Z9'T)(04'0)
(€S'T)
6L9'Z
(2Z'0)
(09'T)
(ST’€)
(€S'0)
(s3'T)(vz'z)
(912)
(zE'z)(S0'Z)
ZS00°0
~28500'0
66500'0
~1Z900'0
(0z'0-)(19'0-)(99'0-)(¢6'0-)(79'0-)
SALSAKSIASAASAAIDAJJA
PAXIL
JICIA
SO
SAASAASAAS9AWVAJJAPOXLJATUNO)
6
8ITT-2o
LSOT
0S-8'07TSZZEqWesUO)
([-2)JUeUNsSeaAUT{I9IIG:[0.19U0DeHIde7)
OTE
O(T-)IOyITeWeIeIsAeoy:[oUODeydeD
LLL
(1a)
eyseWAINDY:;o.QUoDeydey
L6L'2(T-1)e41eWpuog:joUODfeyWdeD
229
O(T-3)exIeWASUOW:[O.UODTeydeD
'8S00'0(T-e0ue[egqyUNOD2y}UaLIN)
ZEEL-SLTL-bb
ZI-10'6T-27'7T-(1-
ym
Molndayleeu
SIUENSSIG9}9
NeIUeNSS]}q9q}9
NOIUENSS]}
G00
No
IUeNSS]}qQoqJaNooueNss}}qaqieN
(s)(y)(E)(Z)
1)
‘SUOTCUINSa][eUIPs}.10da.10.1es.10.1lapilepueys}sngol(g66T
)Aeelypue][OosLiq
aouenssiyqapseas.1aA0e}e.1od.1ossulule[dxaulefo.r1e
ske[dAn1[0djo.1uosTeyWdesyITyM4S9}0}.1a
p.1OUL10}Ias
[eI
ULULIYINadseuoxa
puljo.UOI[eyde.aUOppeaM
‘UOTeIYDadsyoeauy'a}e1y
MoI
dday[ee1ey)
puesoueryleqyunosoejywaLind'a
s|eyUaWepUNJIIUIOUOIAaIOJ[O.1]U0IEM
‘SUO}eI
Dads
|[eu]isa}1enbaywuIyMessuenssngep
S¥9S19A0}9U9}e.10d.109SI9[qeLIeA}Ua
pudadapay
J
AOLAeYaqoaIUeNSsSqapseas.19aA09}e.10d.109U0]O.UOITeNdedJ0DaJJaayApNjso}jsi9[qejay,L
Saye
SUIs.1dW
7
:[0.1]U0)
[ede
j)JossauaAnIayjqey
L:99[GeL
TOO
>d
,,,
900
od
,,
QTO
od,
sasayjuatedulsonsne}s
7
LZ8TZ8TZ866Z2T
Z8Su0neAlesqg
SALSAKSIASAASAAIDAJJAPAXLJICIA
SO
SAASAASAAS9AWVAJJAPOXL]AUNO)
(so'v-)(Z8'r-)(v8'r-)(TE'E-)(SZ'7-)
ew
90TT-
eal
OLZT-
eV
B8BIT-
exi0
TOL-
wae
T'Z9TT-queysuos
(vI'T-)
LS9'L-
([-)JUeUNs9aAUIID9a.1IG:[0.19U0D[e}Ide’)
(Z€'0)
960°
T(T-ieyTeEWeareIsyesy:[oUODeydey
(Zo'e-)
we
SZr'6-(T-)eyeWAINDYJoNUODeydey
(L6T-)
*
L19°S-(T-3)1
oy
Le
Wpuog:jo.UODleydey
(6T'€-)
wee
GT'ZT-(T-3)yeyIeWAuop]:jonuogleydey
(zz'0)(Sz'0)(0¢
0)
(ZT'0-)(vE'0)
Z9S00'0L£900'079Z00'0£9£00'0-TS800'0(T-1)29ue[egiUNODDyqWA.LIND
(t¢'0)(8¢'0)(Sz'0)(¢s'0)(ZZ'0)
9L'OLTP'0ZZS'ETSE
OE8T'
ZL
(T-umoindayeed
SIUENSSIG9}9
NeIUeNSS]}q9q}9
NOIUENSS]}
G00
No
IUeNSS]}qQoqJaNooueNss}}qaqieN
(s)(y)(E)(Z)
1)
"SUOTJEUTS9[[CUIPs}OdaJales1oLiapslepueys}sngo.1(g66T
)Aee.y
puel[OosLIq'adueNssqapseastaAoa}e1Od1oosulUle[dxaulaforesAe[dAstjod
JO1QUODTeVI
ded
YIIYM}S9}0}.
19
POULSUINYIea1OWas|[eINULULOYINadseuoxa
puljo.UoOo[eydesauOppeaM
‘UOHeoyDadsyoeauy'aye.1y
Mois
ddy)[ee1ey}puessueyeqjunos9eUaLInd'a'I's]e}UaWe
pUNJIIWOUOIaIOJ[O.1]U0IaM
‘SUO}eI
ads]
[eulsej1enbayjuiyywMaouenssngqap
SB9S19A0}9U9}L.10d.1ODSI9[qeLIeAjUapUsdapay
J
IOLAeEYaqaoUeNSsTqapseas.19A09}e.10d.109U0[O.1}U0I
[EU
AeIJOWaJJaayIApNyso}jsia[qeyoy_L,
SaIWIOUOIApadueApY:[0.]U0)eEUdejJOssaUsANIaTJ
Ae
|:
ZAGeL

3.5.3 Advanced Economy Monetary Policy Transmission and an
Indirect Test Based on Risk Premium
There exists a common sense that compression in corporate risk premium originates
from expansionary monetary policy in advanced economies, among researchers and
market participants. To test monetary policy spillover effect, one of the key factors in the
spillover chain is the response of corporate overseas debt issuance from compression in
risk premium. In the third model, we test this broad hypothesis by providing some
supportive evidence from the impact of risk premium on corporate overseas debt
issuance behavior. Table 8 provides strong evidence to support that corporates issue more
bonds overseas in response to compression in risk premium in emerging market
economies.
No significant effect in advance economies (Table 9) suggests that corporates in these
countries do have different incentive in conducting cross-border activities, compared to
the emerging market counterparts. In advanced economies, domestic financial markets
are well connected in the international financial market. Compression in risk premium in
international bond market also imply compression in risk premium in domestic bond
market. Therefore, these firms have no strong incentive to go abroad to issue bonds,
whereas the corporates in emerging markets face a segregation between domestic bond
market and international bond market.
These results offer some support to the idea of advance economy monetary policy
spillover effect. Although the less integration of emerging markets in international
financial system, monetary policy in advanced economies do push international investors
to crack through border barriers to chase for yield; and meanwhile market participants in
emerging markets also try to walk around the regulation to arbitrage the return across
the borders. This phenomenon raises the concern about the relevant liquidity measures
for policy makers, even for those policy makers in countries where impose tight capital
regulation at the borders. They may also need to put an eye on the global liquidity
measure, as it helps explain anomalies in domestic liquidity supply. (Chung et al, 2014)

In the most complete regression estimation, we include all the three sets of variables
together with real economic fundamentals. The effect of exchange rate variables
disappears. This result may imply that the effect of capital control can dominate the effect
of exchange rate variables because they are strongly interdependent and it is hard to tease
apart the marginal effect if we try to regress them simultaneously in one estimation.
Without controlling for capital control policies, we found the consistent results as in
previous model specifications.
TOO
>d
,,,
S00
od
,,
QTO
od,
sasayjuaieduisonsyeys
2
9LZTE9VT697T
COST
Z6S
LOOZTSUOHeAIesq(
SOASAASAASAASAASIAWVIJJAPOXLJeI_,
SOASOKSALSAASAASAAVIJqpoxtjAUNO)
(sz'v)(7z'6)(€6'8)
(BEF)
(ES'7) (85'S)
J
6T0T
2
L6Z1
9
VIZI
wf
EVOL
..0'S66
ves
L'6ySqueysuo)
(to's)
PVL'C
(T-1)exTeWpuog:o.UODfeydey
(z¢'T-)(1é'T-)
Z0€0'0-
9LS0'0-
(T-Jareyesueupxy
(et
T-)(Zr'2Z-)(0£'Z-)
€89'9-
_LV8t-
-
26°
ST-(T-
Ae
[OAaTeyasueyoxy
(or'z)(99'T)(08'T)(Z8'T)
a
79900'0ZEF00'0
JZ¥00'0
.
7L¥00
0(T-)a0ueTegjunossyquaLIN)
(ss'T-)(Zp'T-)(os'T-)(90'T-)(¥6'0-)
€£°9Z-1Z'7ZZ-98
02-SL9T-ZS'ST-(T-YmMolngay
eeu
(11T'e-)(S9°Z-)(99°2-)(89°2Z-)(99'2-)(Fr'Z-)
ff)
69T-
WV
Tbt-
WL
CVi-
9
LUT-
WL
LET-
ox
S'6LT-(T-umnimaigysny
JIUPNSS]IQIQI]9N2IUENSS]Q9
G19
N2*uUeNSS]Q9IqQ
JPNsouenss]}qoa
qje
N2uUenss]}qoqjeNesuenss
192°d79N
(9)(s)(F)(E)(Z)
1)
"‘SUONeUINSa][eUIpeiodaJa1es10.1lapiepuejysjsngol
(8661,
)Aeerypurl[oosLiq
uintwia1dys11a}e.10d.109sa.njdesysiym
‘pjatApuogAinseal
ieaX¢
[
snulwiplatApuoqyygAqpa.nseaulsi
WINIWaIdysty
pajjolaaolidsAd
od
A1eyauOWIsy}.10ddnsojaouaplAsaWOssla1ayNeYepn[IuoIaM
‘adueNssyqapseas.iaA0e}e.10d.109
ulaseaDUTUeAGpaMoy][OjsiuMniws1dyslLulesea.oa
prey
19}.
1enbayjuiy
Maouenssiyqepjeuseas.1aA0e}e.10d.109s1a[qelieAjuapuadap
ay
L
wntwaidysiiaye1od.1osuodnpaseqiajjataAo[IdsAa1[odA1eyauUOWAWOU0Ia
padUPAPEUO}sS9a}{Ia1IPUIURSULIOJ.1ada[qeysiy
(axe
P[SUISIEW
A
)ISaTOeIIPU[UY:UOISsTUIsUeL]
ADT[OgAIeBUOW:8alqeL,
Too
>d
.,
G00
>d
.,
QTo
od,
sasayuatedulsoysneys
7
96L6V66VE66T6EDNTOZOTSUOHEAIeSq¢
SOX
SIASOASOASAASOAVIJJA
POX
IeI_
SAASOASAASAASAASAAVIIJJqpoexLyAUNO’
()(zeT-)(er
T-)
(rr
T-)(so't)(eo'T)
O£'€S6-S
OLOT-9'SENT-L'9E9TE'909
TIUeISUOD
(¥Z°0-)
CCC
C-
yaye|Wpuog:jo.1U07/eude)
(95°0-)(92'0-)
8V'0T-S06'E-
(T-)aieyasueyoxy
Ce
tort
Jr
T-)
8'9ST-S'9ST-9'9ST-(T-a)Anejojayeyasueyoxg
(ZT'0-)(Z7'0-)(8¥'0-)(T7'0-)
TE700'0-8010'0-0T
L0'0-1S600'0-(T-2)aouelegjunoss
yuan
(sr'0)(80'0)(TT'0)(Z0'0)(TT'0-)
€6'7Z29S
EBL
P
SSZ8'£659'S-(T-a)
Monga
yeeu
(sz'0)(60'0)(60'0)
(Tz'0-)(TT'0-)
(oT
'0-)
TE'868Z'ZEL9'EES7
PL-PL'BE-SP
EE-(T-YunIwelgysy
SIUENSS]IG
9739
NODUENSS]1G9(39
NOdUENSS]}q0q}9
NOIUENSS]}qo(}9NOoUeNSS]}qQoqJONooUeNSS]}qoqION
(9)(s)
(He)
(ZT)
‘SUOQPUINSA[PUIPs}odaJales1o.1iapiepuejs}snqol
(866
T
)Aeerypurl[oosLiq
wuntwasidysiieye10d.109sa.njdesysiym
‘pjatApuogAinseal]
1eaXQ
[
snulwiplatApuoqyygAqpa.nseaulsi
UINIWa1dyshypajja.1aao][dsAdT[odA1eyaUO
WY
}.10ddnsojaduapAVaWOSSIa.1ayeYepn[IuoIaM
‘BIUENSsSH
qapsess.1aA0a}e.10d.109
UlaseaOUTUPAGpaMO][OJSIWINIWd.1dysLulased.1da
prey]
1a}
enbayuIyLMadueNssn
qapjeuseas.1aA09}e.10d.
109s
la[qeLieAjuapuadap
ay,
wntuiaidysLieye1od.1osuodnpaseqiajja1aAo[IdsAd1[odAreyauUOWAWOUOIa
psdUPAPEUO}S9}I91IPUIURSULIOJ.1ada[qeysiy
(Awou0d
7
paoueApy)}sa]aIIPUlUY:UOIssIuIsuel]
ADT[OgAIeUOW:69a[GEL

3.6 Robustness Check
So far, our main results show that the compression in risk premium increases
corporate overseas debt issuance and the stronger regulation policy makers impose at the
border, the more bonds corporates issue overseas. These features seem to suggest the role
of corporates as surrogate financial intermediaries. If this interpretation is solid, by
adding the interaction between risk premium and capital control measures, we should see
the effect of this interaction term is negative in the second phase of global liquidity. The
reason is as follows. If corporates are indeed surrogate financial intermediaries, they have
stronger incentive to issue overseas when both risk premium is lower and financial
corporates face more strict capital control at the borders. Given a constant level of capital
control, the lower the corporate risk premium is, the more corporate bond issuance. Given
a constant level of risk premium, the tighter the capital control is, the less corporate bond
issuance. This is because, corporate capital cost from issuing bonds is the risk free interest
rate plus corporate risk premium. A constant level of risk premium implies a constant
level of capital cost in the bold part. Given a constant level of capital cost, the corporates
should have less incentive to serve as surrogate financial intermediaries when facing more
strict capital regulation at the borders. Therefore, the effect of the interaction term in the
second phase of global liquidity is expected to be negative if corporates indeed serve as
surrogate financial intermediaries.
We provide the robustness test results in Table 10 below. To tease apart the effect of
capital control and risk premium, we incorporate them separately in different regressions
and also split the whole sample based on the timing of the second phase of global liquidity.
The first two columns report the effect of capital control on corporate overseas debt
issuance. The effect of capital control in the 2007-2013 subsample is positive and three
times as much as the counterpart in the 1993-2006 subsample, suggesting that
strengthened international capital control policies indeed stimulate corporates to act as
financial intermediaries across borders. The middle two columns report the effect of risk
premium on corporate overseas debt issuance. Corporates were not sensitive to corporate

risk premium before 2007. However, since 2007, one percentage decrease in corporate
risk premium lead to more than 100 million US dollar more corporate bond issuance
within the following quarter. The last two columns provide further evidence to support
the corporate role as surrogate financial intermediaries in the second phase of global
liquidity. The effect of interaction term between capital control and risk premium is
insignificant before 2007, while in the second phase of global liquidity, the coefficient of
the interaction is negative and significant. Based on the intuition described in the last
paragraph, the data favor the conjecture about corporates behaving like financial
intermediaries. It is worth to point out, in the last two regressions, we control for linear
time trend instead of time fixed effect because our capital control measures are in annual
frequency. There will not exist meaningful variation in the interaction term if we control
for annual time fixed effect. Therefore, we instead use annual time trend to control for the
variation over time.
To sum up, we perform a robustness check to verify our interpretation about
corporates serving as financial intermediaries, with further evidence by exploiting
information in subsamples and allowing for the interaction between variables.
Too
>d
.,
900
>d
,,
OTO
>a,
sasayjuaredulsonsyeys
7
LSS6TLV09868Z2ZSS6T
ZSUONeAIISqQ
wed
EOSEST-
axa
ITV
*e
£0'0V
06S0000'0
6
CLSG9ZC-
(v2'S)(8Z'T)
LEET
(99'2-)(8€'0)
6LT'2-¥8Z'0
sud
ITT
9V'STS87'7
OS'ZE-TSGZ
(92'S-)(ZZ'T-)(0S°9)C)(60'0-)
(OFT)
eK
(v2'0)(SZ'E-)(66'E-)(TZ'0)
wR
(st's)(zr't)(Zz'
e)(vr'F)
+xBCS'6
one
(to'0)(¢0'z-)(So'0)
(TE'Z-J(TT'0)
(6T'Z-)
69800'0-TZ7000'0
x
1Z600'0-T0T00'0
es
(69°T-)(s9°0)
(Th'2Z-)(Z9'0)(ZT'T-)(Z9'0)
ee
ONONSOXSAAS9XS8AIIAJJAPOXI
CIA
SAA
SOXSAA
SOA
SAASOAVIJJq
PaxtyAQunNo)
Cc
88ET087
8T-S8
BZ1uesUOy
leah
(T-umnrmeigysty,(puog)jonuopeyde)
0'02Z-E€E
TI(T-untua1gysry
106
'Z(T-3)394eWpuog:jonuoDleydey
90600'0-(T-3)e2ueTeg
UNOS.
YIUAaLINY
76
'6£-079
PL0'LZ-08T
L(T-uMoin
day
ead
aoUeNSss]1qeq12
NeDUeNsspqeqjeaNeouenssy]}qaq19
NedUeNSs]1q9q1e
NeduUeNsspqeqjeaNeouensspjqeqieNn
(N(NwlE)(Z))
‘SUOTEUINSI][ePUIpe}.1ode1
31es.10.laprepuejs}sngo.i(g66
7,
)Aee
ry
pueljoosiiq
Sul|[eystwMniwaidysiipuepausyysuetsslo.uosjeyidesy}oquaymeasea.1ulo}
peyedxasleouenssiseas.1aA0e}e.10d.10daYJasneseaq
‘SaLIeIpeul1ajUleDUeUIJe}esO.LINSses[o.19}e10d.10994
YU
UMeUT]SIwNTWaidystipue
[O.QUODTE}IdedDJOULIaUOTIeIIUIBYYo
sap
YJaooayYyoustseaynesauay
|
Aypinbiy[eqo[sjooseydpuosasayyovsejsayjsepadlsoiod
sSeMUSYM‘/00Z1eyepueslojaqaouenssyqapseas.1aA0a}e10d1oduOUINIWIaIdysTIpuejo.Uuos[eydesjo}ajjaay}sapAoidayqeyay
J,
AleIpsUlilayU][eMueuUl,jayesoO.LINSsea[oyajze.10d.107)ay
|
:ssauIsnqoy:9
La[qel,

3.7 Conclusions and Policy Implication
This paper studies the determinants of corporate overseas debt issuance in 32
countries during the period 1993-2015. The results provide some macro evidence to
support the conjecture that corporates in emerging markets serve as financial
intermediaries at the border to facilitate global liquidity transmission. Corporates hold a
carry trade position, in other words, borrowing liabilities in foreign currency and holding
assets in domestic currency, during the periods when domestic currency is expected to
appreciate against US dollar and the exchange rate is less volatile. The rise in corporate
overseas debt issuance can be explained as the product of advanced economy monetary
policy spillover and capital control policies at the border. As corporate risk premium
compresses, corporates have incentive to serve as surrogate financial intermediaries
across border, especially in countries where domestic financial sector faces strict
international capital flow regulation.
Policy makers should carefully evaluate the potential side effect from international
capital control policies. Ill-designed these policies reduces the effectiveness of cross-
border capital control. Furthermore, these policies may create the systematic risk outside
the traditional framework and makes it harder for policy makers to monitor and manage
international capital flow activities. Additionally, policy makers should be aware the
international financial risk transmission through either monetary policy shocks in
advanced economies or financial risk materialization in emerging market corporates. The
last but not the least, domestic currency depreciation and volatile exchange rate against
US dollar may add uncertainty in the capacity for emerging markets corporates to borrow
and rollover the existing debt.
Chapter 4
What is Driving Debt Dollarization in

Global Economy? A Dynamic Factor
Analysis
4.1 Introduction
The takeoff of US dollar-denominated debt issuance
19
has been one of the most eye-
catching phenomena in the global financial market since the Great Recession. Many
studies suggest that loose US monetary policy may factor in the global liquidity
transmission during this period. (Chung et al., 2015) While Basel III tightened the cross-
border capital flow regulation, the border-control policy loopholes push international
capital flow towards the global bond market from the global banking system. In short, the
rapid growth of dollar debt seems to be closely related to the super-low policy rates and
quantitative easing policies from the Fed. Nevertheless, it is possible that some other
factors, such as, the fast economic growth of emerging market economies, European
Sovereign Debt Crisis and some country-specific factors, could play a critical role in
explaining the second phase of global liquidity. (Shin, 2014)
In this paper, we want to understand the relative role of these factors in explaining the
dollar-denominated debt growth in the global bond market. This research question
becomes more important nowadays in the sense that market participants and policy
makers are more aware of international liquidity transmission as a potential threat to
global financial stability. The conventional wisdom in the literature suggests that domestic
business cycle and monetary policy determine the liquidity condition within one country.
This was mainly due to lack of global financial market integration. Domestic condition was
more relevant for policy makers at that time to implement policies to offset economic
fluctuation. With global trade and financial integration, the impact of the external shocks

on domestic market has been increasing over time. It is important for market participants
and policy makers to watch the external economic environment, especially the most
influential player in global financial market - Federal Reserve System of United States (the
Fed).
20
Taper Tantrum in 2013 is a good example of the Fed’s monetary policy influence
on foreign exchange rates and asset prices. Meanwhile, regional economic integration, for
instance, the European Monetary Union (EMU), also have an impact on foreign currency
loans and deposit in domestic banking system. (Kishor and Neanidis, 2015)
This paper decomposes the movements in dollar debt in a set of 12 countries into
global, emerging market and idiosyncratic factors using a dynamic factor model. This
approach helps us in examining the relative importance of different factors in evolution of
dollar debt growth in these countries. This also helps us in examining the hypothesis of
loose US monetary policy as the primary source of the boom in dollar debt growth.
We find that the global factor accounts for most of the variations of the dollar debt
growth in these countries. The emerging market factor also plays a secondary role in
explaining the rapid growth of the outstanding dollar debt balance among emerging
market economies. The country-idiosyncratic factor, however, is not as important
compared to these external factors. The results suggest that the global financial market
integration plays an important role in the cross-border liquidity transmission. From the
time series of three decomposed factors, we find that the global factor has been
accelerating since 2009. This pattern coincides with the extremely loose monetary policy
environment in the US after Great Recession. This result further enhances the message to
the policy makers that major country monetary policy spillover effect can have a
significant impact on the cross-border capital flow of other countries. We also find that
financial market uncertainty, VIX, is highly negatively correlated with the level of global
factor implying global increase in the level of debt dollarization in case of a decline in
financial market uncertainty.

The rest of the paper are structured as follows. The second section provides a
literature review about global liquidity transmission and discusses the associated
monetary policy spillover effect. The third section introduces the data used in this study
and the setup of the dynamic factor model. The fourth section interprets and presents the
results from the model. The last section concludes the paper.
4.2 Literature Review
The recent surge in non-financial corporate (hereafter ”corporate” ) overseas debt
issuance after 2007-2009 financial crisis has started drawing attention from
macroeconomic researchers, as it plays a critical role in the conduct of international
capital flow activities in the emerging markets. This surge in the overseas debt issuance
is also referred to as the second phase of global liquidity (Shin, 2013).The first phase
(2003-2007) of global liquidity is associated with a rapid increase in cross-border
international bank loans. The international banks lose the market share to international
bond markets in the cross-border activities substantially after the global financial crisis,
partly because of the strengthened financial system regulation. This fall in cross-border
lending by international banks was followed by a rise in the overseas debt issuance of the
non-financial corporate sector. The relative importance of corporate overseas debt
issuance can be gauged from the fact that more than half of the net ”external” financing of
emerging economies in 2012 took place through the issuance of international debt
securities (Turner, 2014).
We borrow Figure 9 from Shin and Zhao (2013) to visualize the role of corporate debt
issuance in global liquidity transmission. In the first phase of global liquidity, domestic
household depositors and international investors (mostly international banks) supply
liquidity to domestic financial system to finance the final corporate borrower production
projects. However, in the second phase of global liquidity, domestic large corporates, rise
to serve as surrogate intermediaries to facilitate liquidity transmission into domestic
financial system, presumably due to the restriction on direct lending from international
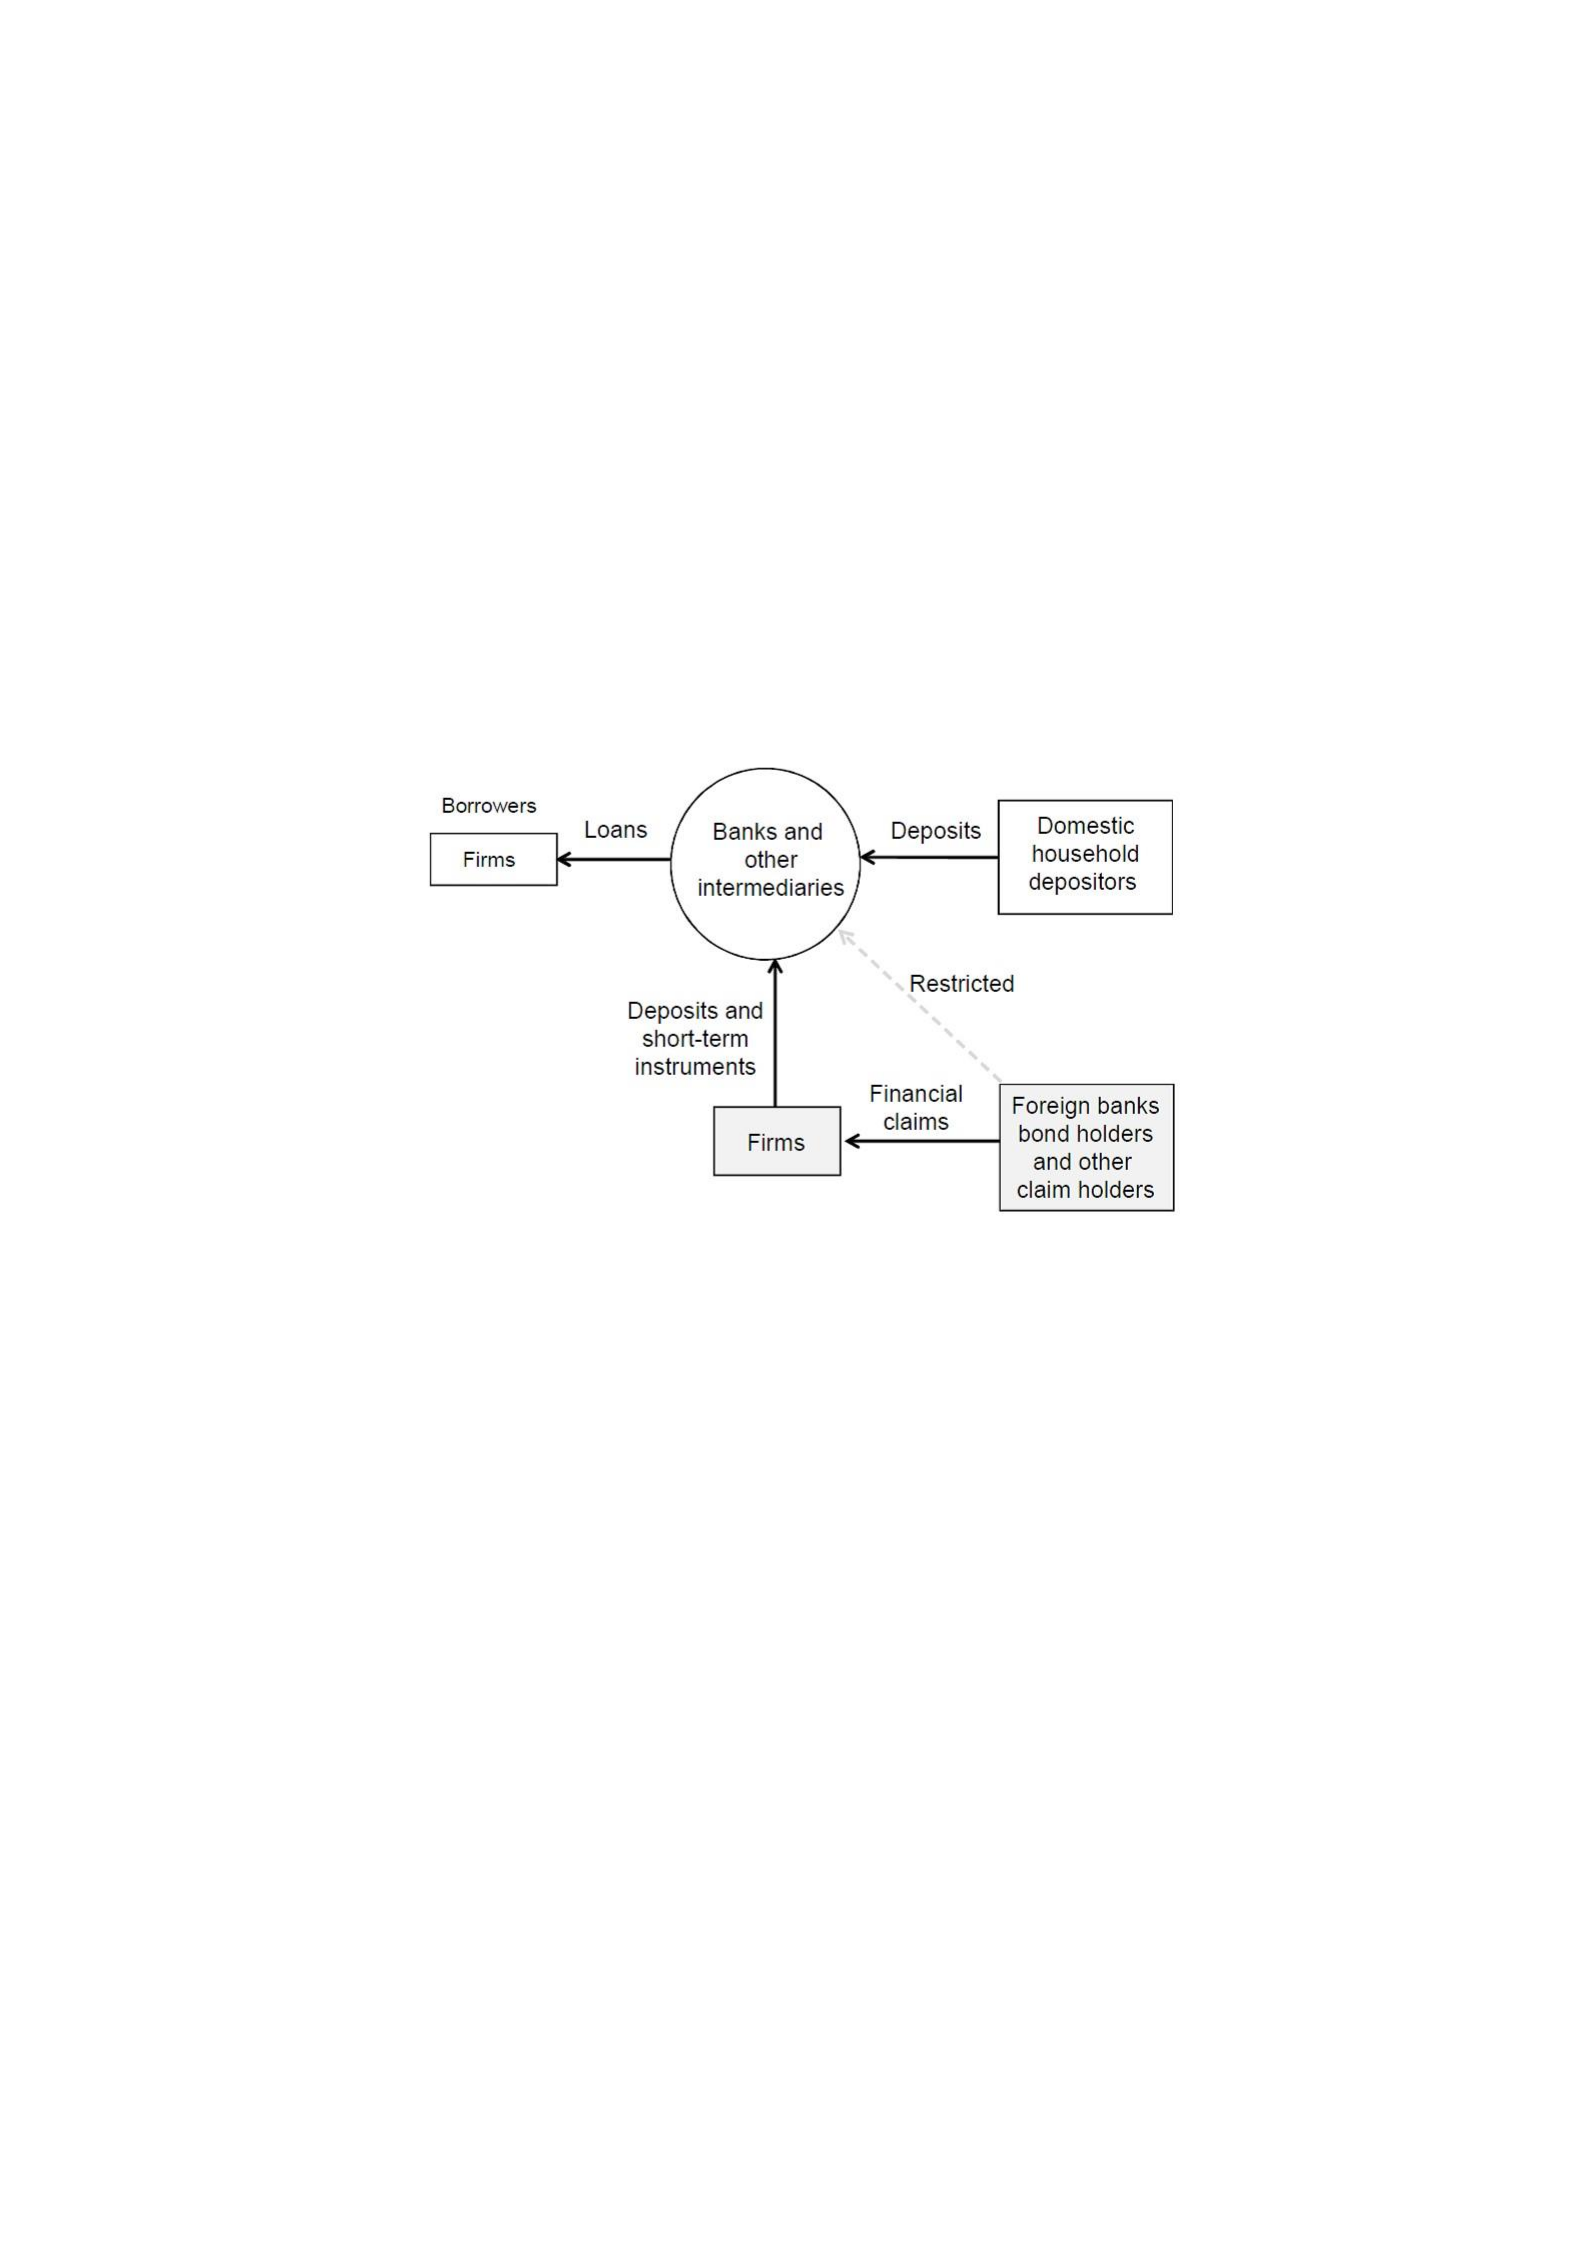
banks. The large corporates headquartered in emerging markets may use their overseas
subsidiaries to issue bonds in international financial markets and receive the proceeds
through intra-company transactions (The subsidiaries can pay for operation costs for the
headquarters, for instance). In this way, the proceeds owing into emerging markets are
treated as a form of foreign direct investment and do not appear in the residency-based
external debt positions. This conjecture worries policy makers about the effectiveness of
capital control policies at the border and the creation of systematic risks outside
traditional international financial regulation framework.
Figure 9: Transmission of Global Liquidity across Borders
Dynamic factor model has been widely used in the literature to study the relative
contribution of global, regional and country-idiosyncratic factors on international finance
issues. Kishor and Ssozi (2001) use a dynamic factor model to measure business cycle
synchronization as the proportion of structural shocks that are common across East
African Community (EAC) countries. Kishor and Neanidis (2013) use a dynamic factor
model to decompose fluctuations in financial dollarization for 24 transition economies
into a common factor, an EU factor, a non-EU factor, and country-idiosyncratic factors to
study the relative importance of the EU factor to the financial dollarization of a country.
Bhatt et. al. (2017) decomposes the observed variation in long-term sovereign bond yields
for each of 21 OECD countries into a common factor, a regional factor (EMU/non-

EMU) and an idiosyncratic country specific factor to study the impact of EMU on bond
yield convergence, using a time-varying dynamic factor model. These papers use dynamic
factor model to study the relative importance of various levels of co-movements across
countries. Therefore, we believe it is appropriate to use a dynamic factor model to answer
the question about the relative strength of the global, regional and idiosyncratic factors
on the dollar debt growth rates across 12 countries.
4.3 Data and Empirical Model
4.3.1 Data Description
We download the country-level time series data of the outstanding dollar-
denominated debt securities from Bank of International Settlement (BIS) debt security
statistics. The ultimate borrowers of these securities are non-financial corporations. The
outstanding amount of dollar debt is aggregated based upon the nationality instead of the
residency of the issuers. We take the log difference of the outstanding amount to compute
the growth rate of the dollar debt growth for each country. In this study, we pick top 12
countries with the largest dollar debt amount outstanding at the forth quarter of 2016.
There are 6 developed economies: Australia, Canada, France, Germany, United Kingdom
and United States, and 6 emerging market economies: Brazil, China, Hong Kong India,
Indonesia and Mexico. These data series start from the forth quarter of 1993 and end at
the last quarter of 2016, in total 93 quarters.
The summary statistics of the dollar debt growth rates in these countries is in Table
11. For the developed economies, the average dollar debt growth rates are around 2 to 3
percents; while for the emerging market economies, the average dollar debt growth rates
are around 5 percents during the sample period. Not surprisingly, the standard deviation
of the debt growth rates in emerging market economies are on average higher than the
developed counterparts. This distinction between the developed economy and emerging
markets suggests that there may be common movements specific to the developed
economies and the emerging market economies respectively. Therefore, in the model
below, we propose to model this feature by adding a developed market factor to capture
the co-movements among Australia, Canada, France, Germany, United Kingdom and
United States. Similarly, an emerging market factor is added in modeling the dynamics of
Brazil,
China, Hong Kong India, Indonesia and Mexico.
Table 11: Summary Statistics: The Dollar Debt Growth in 12 Countries
Statistic
N
Mean
St. Dev.
Min
Max
Australia
93
2.931
7.859
−7.309
55.701
Canada
93
2.225
2.763
−4.319
10.330
France
93
2.932
9.456
−35.292
60.661
Germany
93
3.599
13.356
−23.209
80.950
UK
93
3.211
4.685
−6.336
22.306
US
93
2.956
6.086
−12.723
22.765
Brazil
93
4.073
6.829
−7.566
33.001
China
93
7.478
10.861
−7.966
64.189
HongKong
93
4.925
15.376
−7.710
132.599
India
93
5.882
19.621
−29.570
119.760
Indonesia
93
5.175
10.770
−16.461
51.456
Mexico
93
2.929
7.332
−19.100
28.162
4.3.2 Empirical Model
Our objective is to measure the relative impact of the global/ regional/idiosyncratic
factors on the dollar debt growth. For this purpose, we construct a model where we
decompose the dollar debt growth into four factors: (i) a global factor, (ii) a developed
market factor, (iii) an emerging market factor and (iv) an individual country factor. The
global factor is common across all the 12 countries in the system, regardless of whether
the country is a developed country or an emerging market country. The developed market
factor is common across countries including Australia, Canada, France, Germany, United
Kingdom and United States, whereas the emerging market factor is common across Brazil,
China, Hong Kong India, Indonesia and Mexico. The portion of dollar debt growth that can
not be explained by the unobservable (global, developed economy, emerging market)

factors is the idiosyncratic factor that is unique to each country. All dynamic relationships
in the model are captured by modeling each of the factors as autoregressive processes.
Suppose yit ( yjt) stands for the growth rate of dollar debt for country i (j) at time period
t. We can decompose this variable into four components. The global factor (Ct) is the
common factor that estimates the impact of macroeconomic conditions in all countries on
the dollar debt growth of country i at time t. For example, if there is a common shock that
would accelerate the dollar debt growth, it would be captured by an increase in Ct.
Similarly, Dt denotes the developed market factor that captures the common movement
across the six developed economies, whereas Et denotes the emerging market factor that
captures the common movement across the six emerging market economies. The
inclusion of the regional factors absorbs the common movement within each country type,
to control for potentially higher volatility not being due to an idiosyncratic country
component. Coefficients γi, δi, γj, δj are the factor loadings on the common factor of the
developed country i, the developed market factor of the developed country i, the common
factor of the emerging country j, the emerging market factor of the emerging country j.
These factor loadings reflect the degree to which the variations in the dollar debt growth
can be explained by each of the factors. Finally, ηit (ηjt) is an idiosyncratic component,
which is unique to each country. This idiosyncratic component reflects the fluctuations in
the dollar debt growth that can be explained by the individual country characteristics.
Developed Economies
yit = γiCt + δiDt + ηit (13)
i = Australia,Canada,France,Germany,UnitedKingdom,UnitedStates (14)
Emerging Markets
yjt = γjCt + δjEt + ηjt (15)
j = Brazil,China,HongKong,India,Indonesia,Mexico (16)

Because the three factors and the idiosyncratic component are unobserved, we need
to specify a dynamic structure for their identification. To this end, we follow the dynamic
factor model of Stock and Watson (1991) and assume an AR (1) process for all four
components. They are specified as below, where the innovation terms in equations (5) -
(8), εt, υt, νt, and ekt, are mutually orthogonal across all equations and countries in the
system.
Common Factors
Ct = β1Ct−1 + εt,εt ∼ N(0,1) (17)
Dt = β2Dt−1 + υt,υt ∼ N(0,1) (18)
Et = β3Et−1 + νt,νt ∼ N(0,1) (19)
Idiosyncratic Factors
ηkt = δkηkt−1 + ekt,ekt ∼ N(0,σk2) (20)
k = i,j (21)
Further, we measure the relative contributions of each of the four factors to the dollar
debt growth in each country with variance decomposition analysis. This provides an
empirical assessment of how much of a country’s fluctuations in the dollar debt growth
are attributable to each of the three common factors and to the idiosyncratic component.
Because the global factor, the developed market factor, the emerging market factor, and
country-specific factors are by construction orthogonal to each other, it is possible to
perform variance decomposition for these components in the dynamics of dollar debt
growth based on equation (1) or (3), which can be rewritten as
var(yit) = var(γiCt) + var(δiDt) + var(ηit) (22)
var(yjt) = var(γjCt) + var(δjEt) + var(ηjt) (23)
or as
) (24)
) (25)
The last term in equation (12) and (13) represents the variance of the dollar debt
growth associated with country-specific factors. The fraction of volatility due to the
global factor would be
) (26)
which suggests that the share of each factor depends on its relative variance as well as
the relative persistence of its autoregressive parameter.
To disentangle the importance of the various factors, we can cast the dynamic factor
model given by equations (1), (3), (5)-(8) into a state-space framework. Following the
literature, we assume zero covariance across shocks to the global factor, the developed
economy factor, the emerging market factor, and the idiosyncratic factors. The preceding
state-space model is estimated using maximum likelihood via the Kalman filter. Due to the
fact that the scales of those unobserved factors cannot be uniquely identified, we assume
a unit innovation variance for all factors.
In sum, the dynamic factor model we use is well suited for studying the properties of
the fluctuations in dollar debt growth. This technique allows estimation of the evolution
of each factor over time. In this way, we can identify changes or breaks in the relationship
between the factors and dollar debt growth during the examined period of time.
Importantly, such regime shifts can be traced back to changes in policies and, thus, offer
intuitive interpretations and policy recommendations.
Measurement Equation:
Ct
yit γi
=
yjt γj
δi
0
0
φj
1
0
ηit
ηjt
Transit
ion
Equati
on:
Ct β1
Dt 0
Et = 0
ηit
0
ηjt 0
0
β2
0
0
0
0
0
β3
0
0
0
0
0
δi
0
0 Ct−1 εt
0Dt−1
υt
0Et−1 + νt
0ηit−1 eit
δj ηjt−1 ejt
Variance-Covariance Matrix of the Shocks to Factors:
σεt2
0
Q =
0
0
0
0
0
0
0
0
0
0
0
0
0
0
0
0
0
0
0
σe2jt
4.4 Results and Interpretation
In this section, we examine the evolution of the various factors and analyze their ability
to track changes in the outstanding dollar debt in our sample. We then examine the
sources of fluctuations across factors, using variance decomposition.
4.4.1 Evolution of the Global, Developed, and Emerging Market Factors
Figure 10 displays the dynamics in the outstanding dollar debt that is associated with
the global factor, the developed market factor and the emerging market factor. It is very
clear that the global factor has been increasing dramatically since 2009. Compared to the
global factor ,the changes in the regional factors are subtle. This is to say, the global factor
plays a dominant role in explaining the rapid growth of dollar debt during the post
Great Recession period.
Figure 10: Dollar Debt: Dynamic Factor Decomposition in 12 Countries
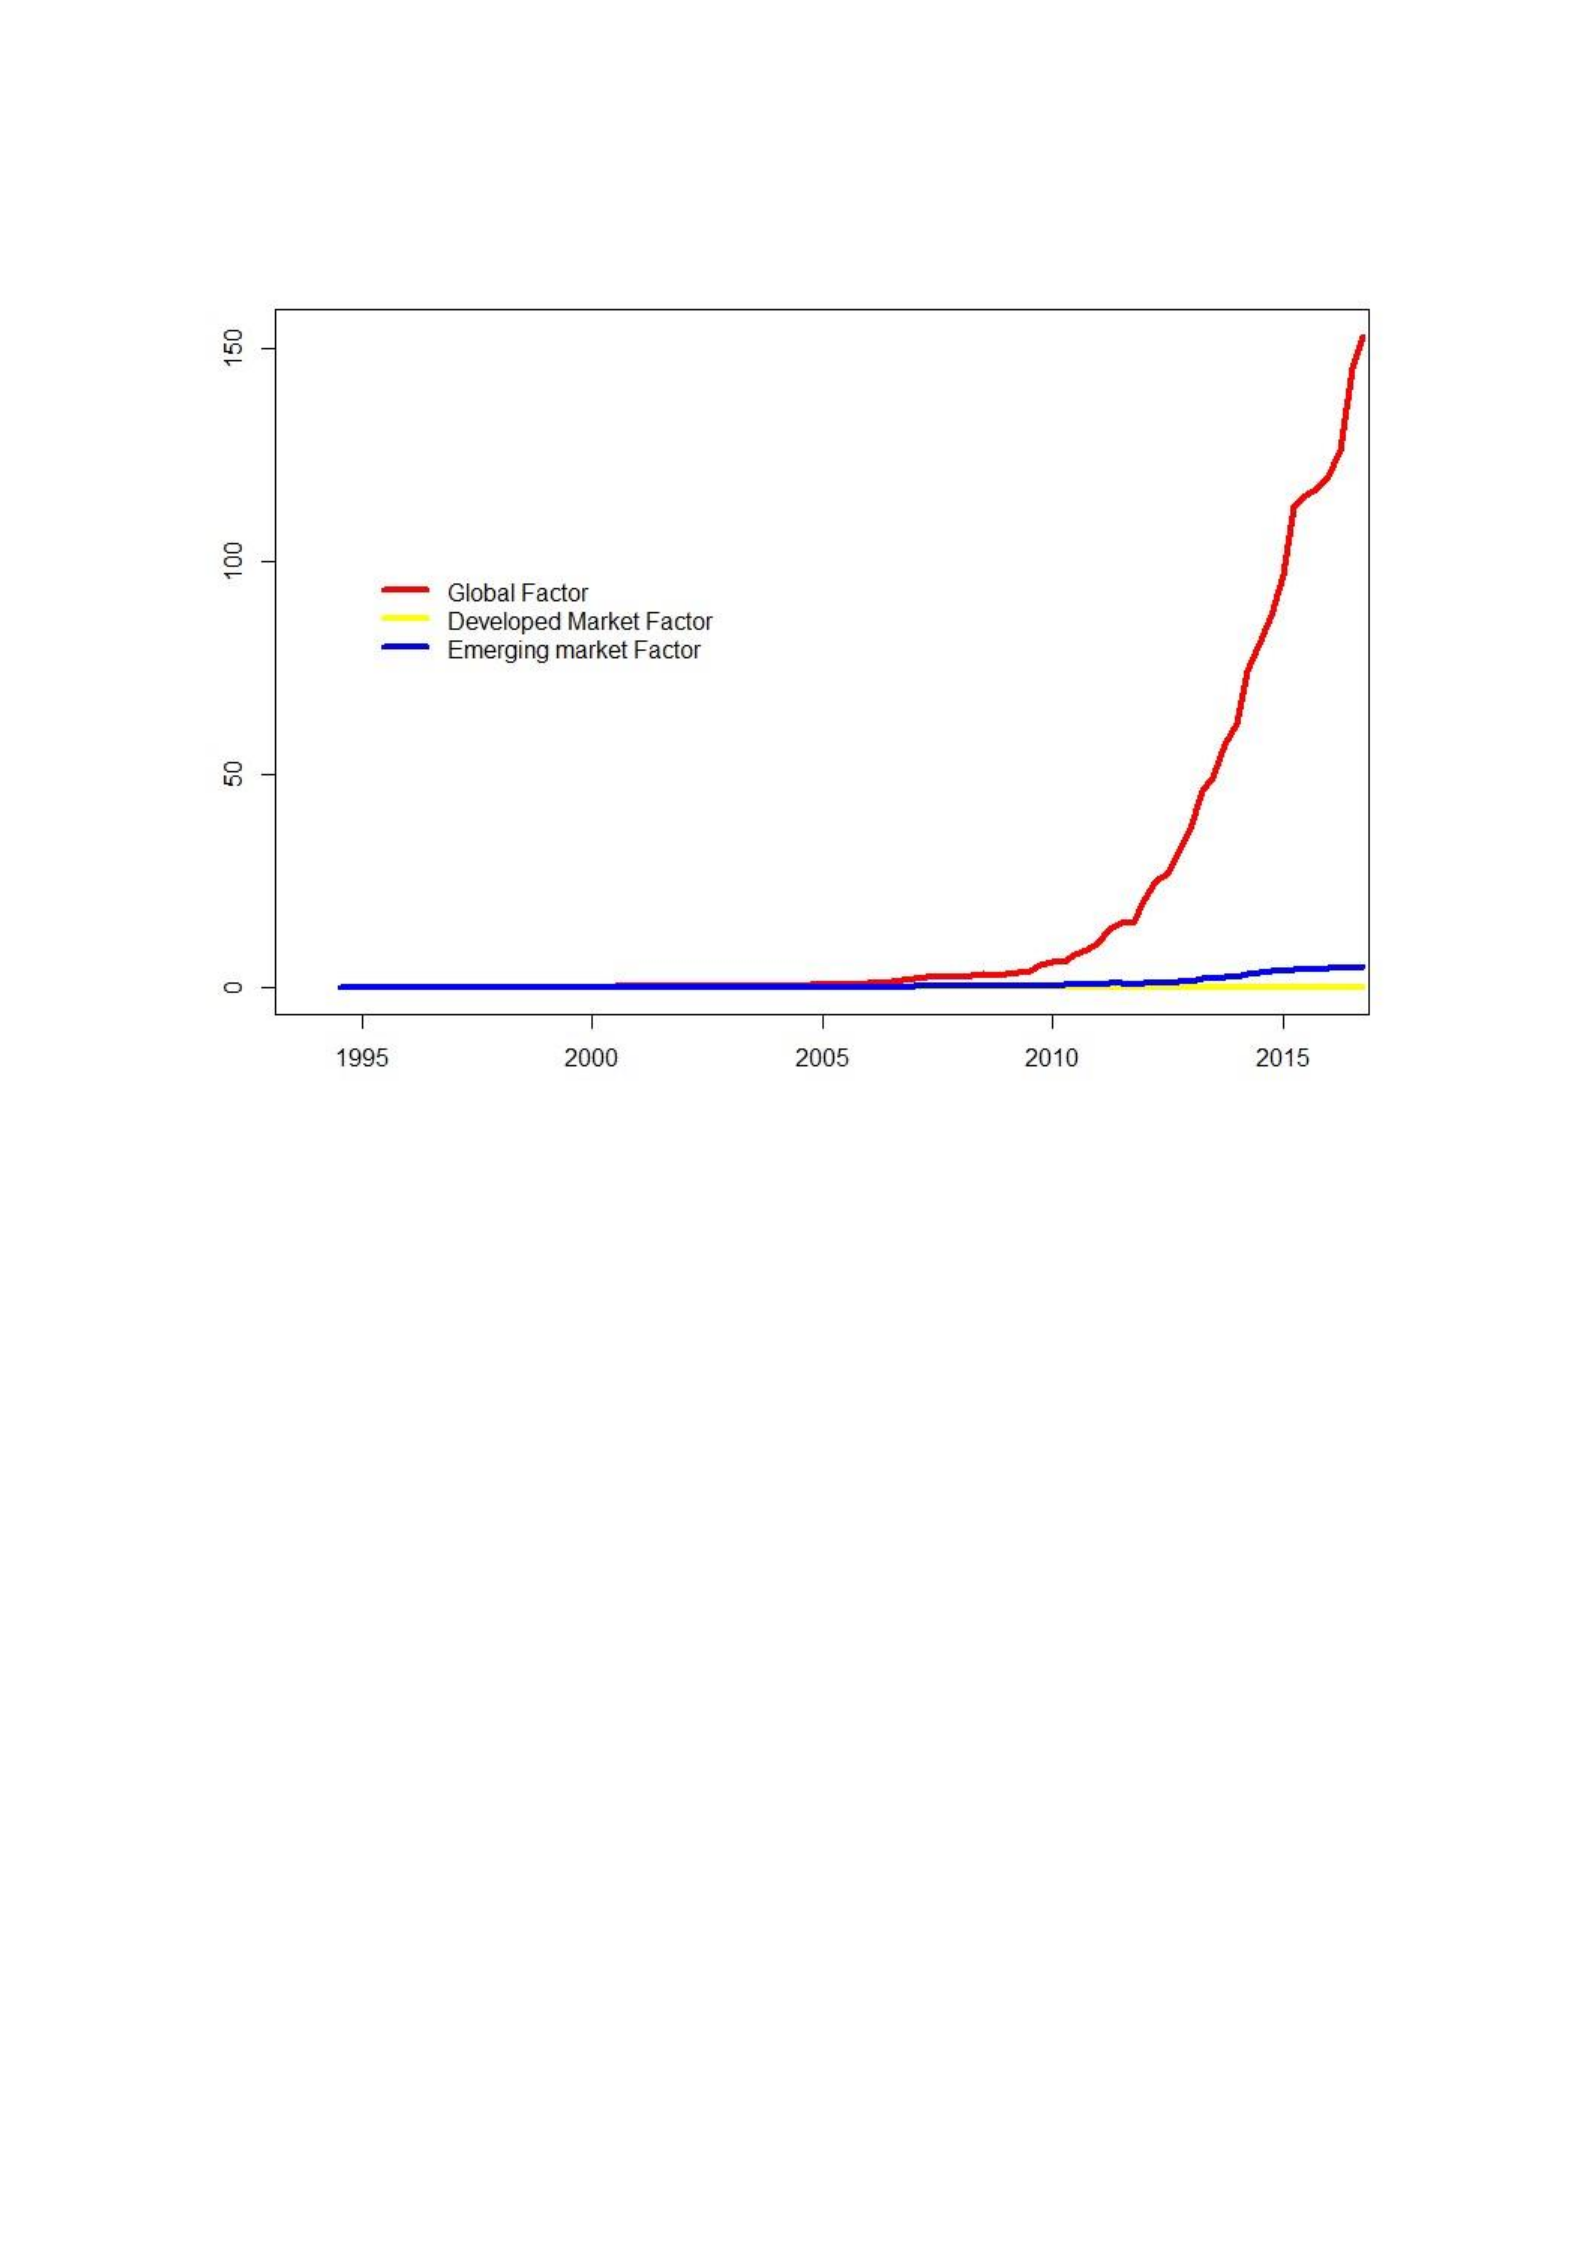
What is the underlying global factor that drives the skyrocketing outstanding dollar
debt since 2009? The Fed almost immediately lowered the federal funds rate towards zero
after the 2009 financial crisis outbreak. Quantitative easing programs further dampen the
shadow federal funds rate to the negative territory (Wu and Xia, 2016). The ultralow
interest rate environment motivates American investors to seek for higher yields outside
the US. Prior to 2009, global banking system closed the cross-border interest rate
arbitrage opportunity by operating the commercial bank business at the international
scope, i.e., taking deposit from low interest rate environment and giving loans to the
borrowers that were facing higher domestic interest rates. Since 2009, the changes to
Basel III capital framework have accentuated the cross-border regulation on the global
banks, with adverse impacts on cross-border capital flows into emerging markets through
international bank loans. At the same time, the global bond market started taking the
market share of the cross-border capital flow from global banking system, due to the
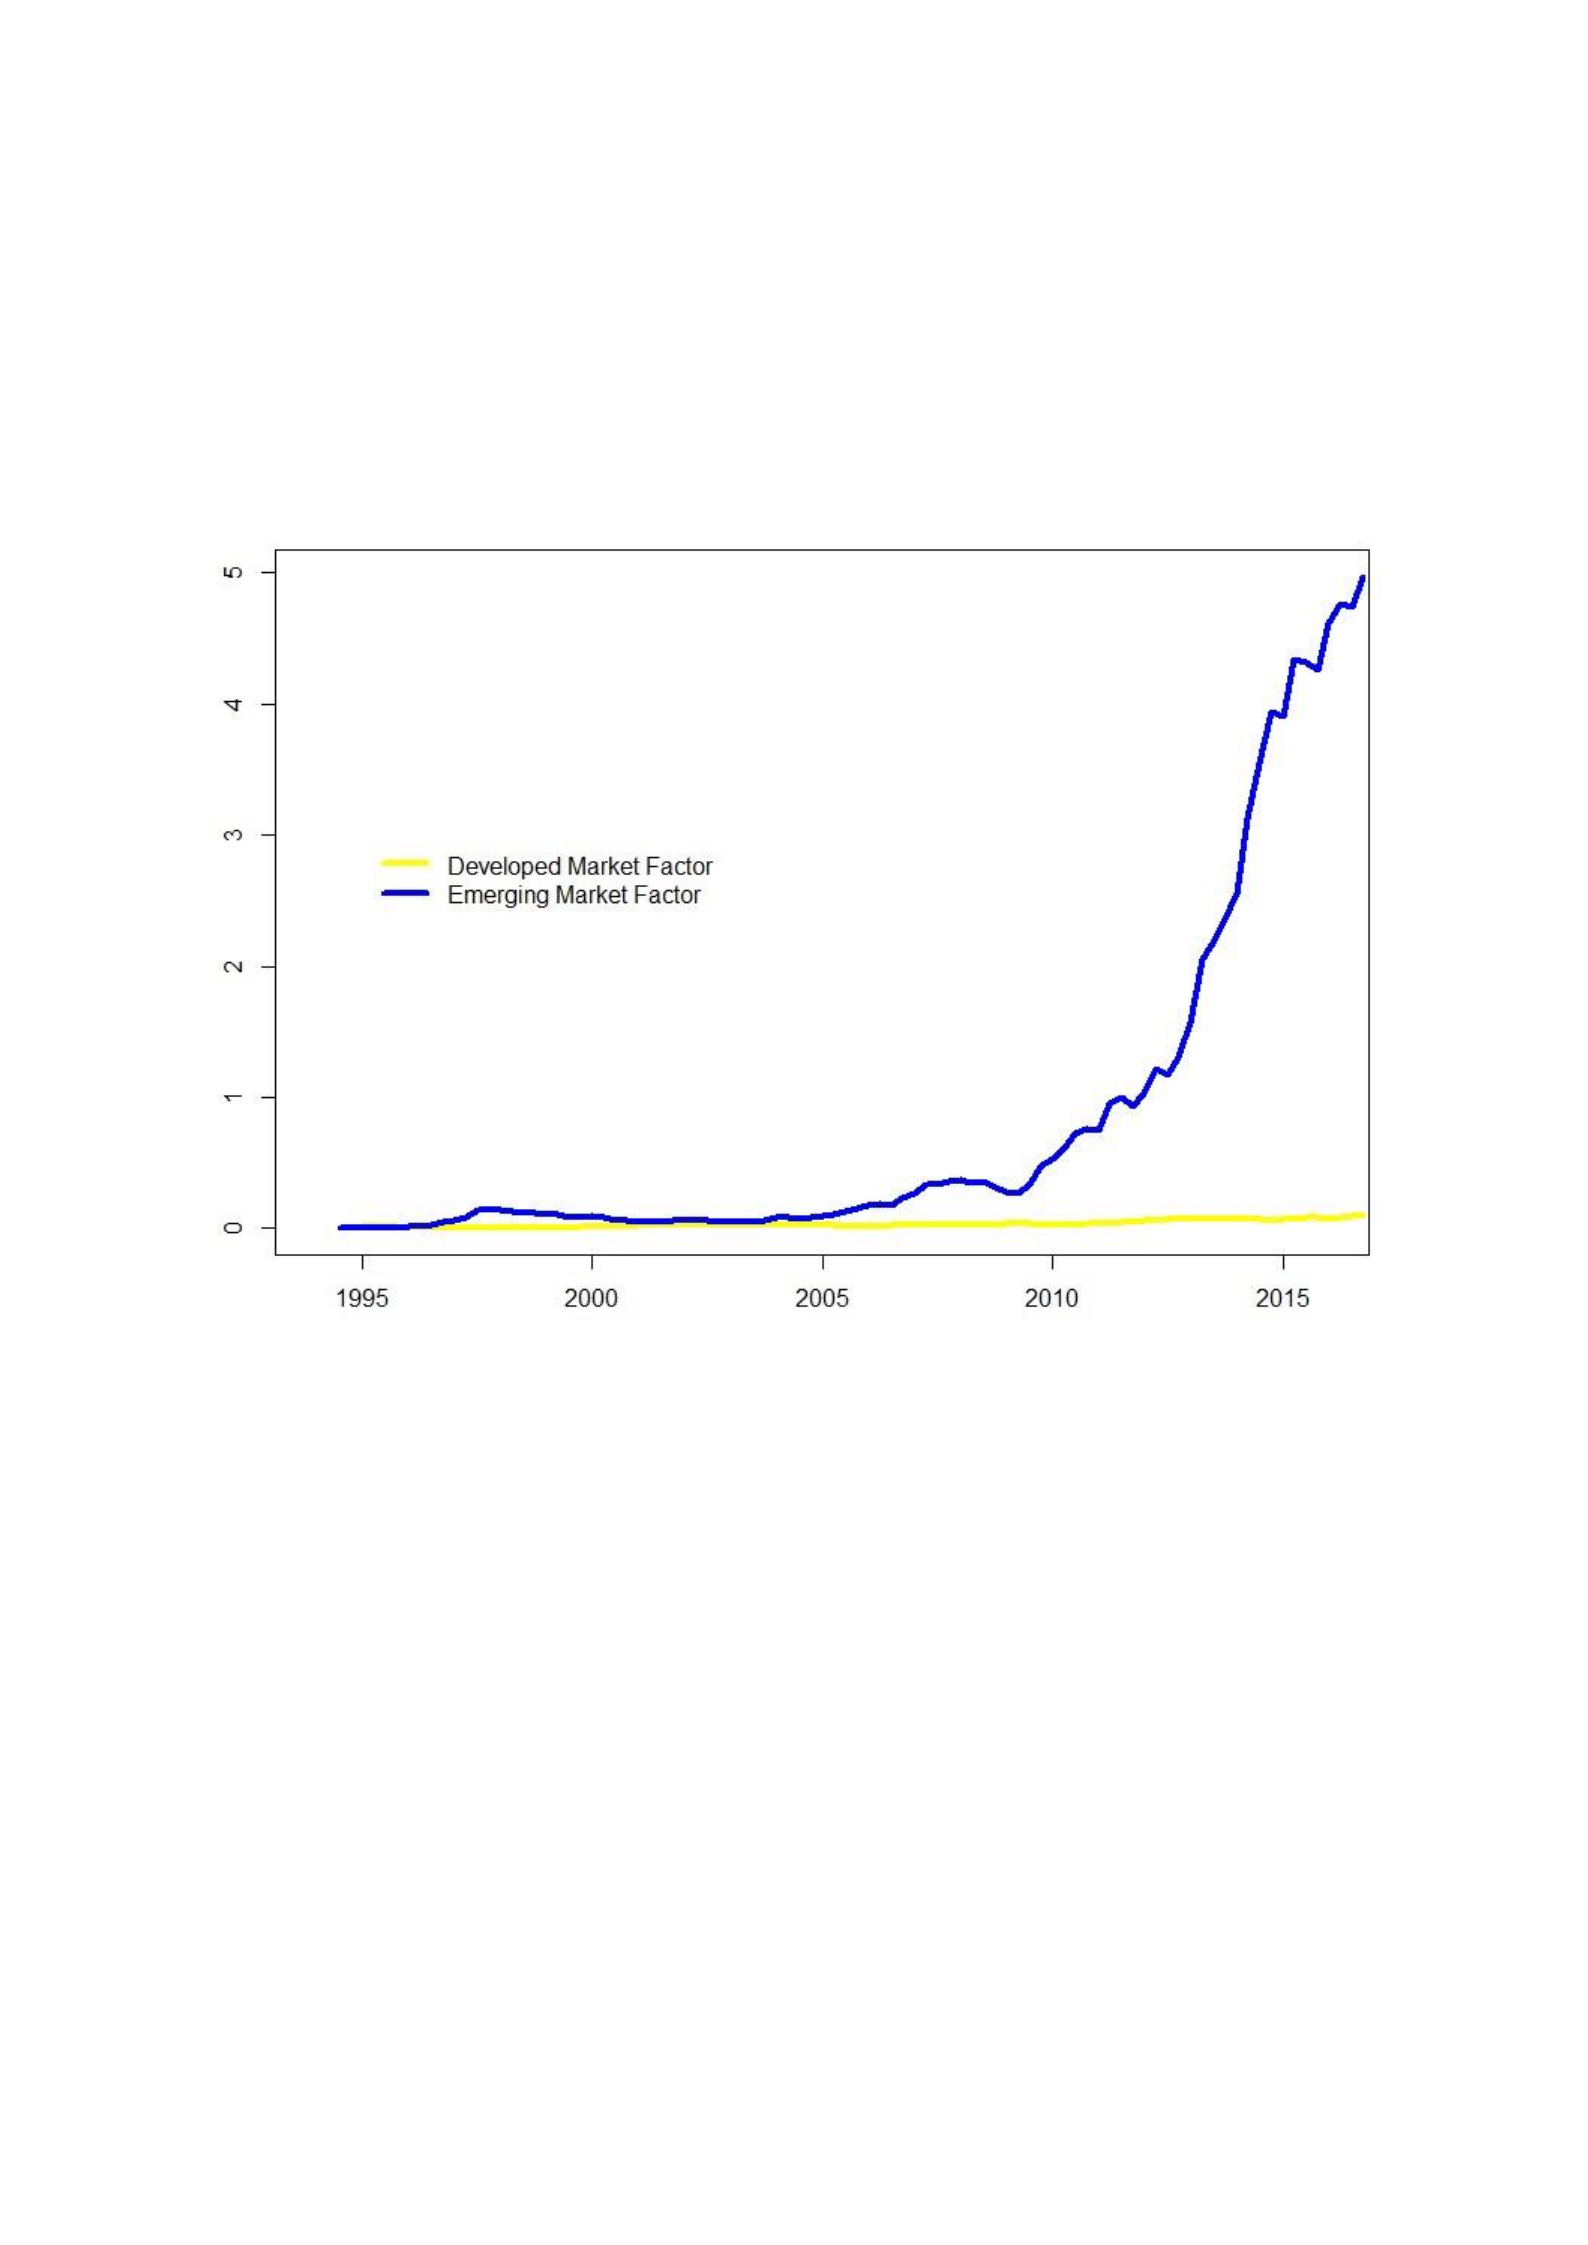
comparative advantage gained through the capital control policy loopholes. In sum, the
joint force of low interest rate environment and ill-designed cross-border banking
regulation might explain the boom of global bond market during the post crisis period.
Figure 11: Dollar Debt: Dynamic Factor Decomposition in 12 Countries
Figure 11 takes a closer look at the evolutions of the developed market factor and the
emerging market factor. Although the changes in the emerging market factor are not as
sizable, we still observe a similar pattern as from the global factor. The emerging market
factor reached the local maximum prior to 2009 financial crisis. While there was a
downturn afterwards, the dip only lasts one year followed by a take-off. Since then, the
emerging market factor appear to skyrocket throughout the rest of the sample period. The
developed market factor almost stays flat around zero throughout the whole sample
period.

What explains the difference between the emerging market factor and the developed
market factor? What is unique among the emerging markets? There are probably two
reasons. The first one is the economic growth among emerging market economies. Prior
to the crisis, there was a boom phase of global economy. The increase of dollar debt in
emerging market economy during this period captured the boom phase of credit cycle.
Since 2009, the financial crisis hit most of the developed economies, whereas the
emerging markets provide an opportunity for safety and return. The fast economic growth
among emerging markets encourage the borrowers to take advantage of global low
interest rate environment. Moreover, as the overall interested rates among the emerging
markets are higher than the counterpart among the developed economies, the borrowers
from the emerging markets have stronger incentive to issue dollar debt in the global bond
market. The second reason is the developed market is more integrated into the global
financial market; therefore the global factor probably captures the majority of the
variations among the developed countries.
4.4.2 Sources of Dollar Debt Fluctuations
We now examine the sources of fluctuations in dollar debt using variance
decomposition. As a measure of the importance of the factors for the dollar debt growth,
we present the variance shares attributable to each factor: the global factor, the developed
market factor, the emerging market factor and the country-idiosyncratic factors.
Table 12 shows the results for this variance decomposition for the dollar debt growth
rates among 12 countries during 1993-2016. In most of the countries, the global factor
explains the majority of the variations of the dollar debt growth of the country. The
regional factors, whether the developed market factor or the emerging market factor,
plays the secondary role in explaining these variations. The country-idiosyncratic factors
account for only single-digit percentages of the variations of the dollar debt growth among
most of the sample countries.
Table 12 clearly reflects the dominant impact of the global factor and the minor
influence from the country-idiosyncratic factors. This result suggests that it is the global
factor that drives the cross-border debt issuance behavior. The global low interest rate
environment creates the surge of the dollar debt around the world. This is to say,
sometimes the Fed’s monetary policy can be more important to explain a country liquidity
condition than the country domestic economic events per se. These results shed light on
the global financial stability issues. On one hand, the US monetary policy, with the
traditional objective of dual mandate, could be the source of uncertainty to stabilize the
global capital flow. If the domestic price and employment requires the Fed to behave in a
different way than that being expected from the global financial stability perspective, then
the US monetary policy might create turbulences to global economy. On the other hand,
policy makers around the world have to watch the external factors closely and maintain
enough foreign reserves to manage international financial risk in this interconnected
global economy.
There are three countries in the sample that the global factor does not play a dominant
role in explaining the dollar debt growth of that country. For Germany, 48.50 percents of
the the variations attribute to the global factor and 48.97 percents attribute to the
developed market factor. This result might be due to the critical role of Germany within
European Monetary Union. Brazil and India have less than 50 percents of variations that
can be explained by the global factor, whereas the emerging market factor becomes the
primary source of variations for these two countries. Compared to China, Hong Kong,
Indonesia and Mexico, Brazil and India are less integrated in the global financial market.
The variations of the dollar debt growth are more related to the emerging market
comovements. This result suggests that the external shocks from other emerging market
economies may have a significant impact on Brazil and India. Policy makers in these two
countries should pay attention to not only the US monetary policy shocks but also the
macroeconomic conditions among the emerging market economies.
Table 12: Factor Variance Decomposition: Dollar Debt Growth (1993-2016)
Country
Global
Developed
Emerging
Idiosyncratic
Australia
67.89%
26.14%
5.96%
Canada
78.89%
8.38%
12.73%
France
94.50%
0.11%
5.39%
Germany
48.50%
48.97%
2.53%
UK
65.42%
29.60%
4.98%
US
88.55%
4.57%
6.88%
Brazil
36.79%
61.19%
2.02%
China
82.97%
15.71%
1.32%
Hong Kong
75.64%
18.54%
5.82%
India
14.21%
84.88%
0.91%
Indonesia
60.46%
34.19%
5.35%
Mexico
85.01%
7.66%
7.34%
4.4.3 What is behind the global factor?
So far, from the dynamic factor model, we have found that it is the global factor that
accounts for most of the variations in the dollar debt growth among these countries.
Furthermore, since 2009, the global factor increases sharply. Combining these empirical
results, we believe that the global factor helps explain the rapid growth of dollar debt
during the post recession period.
Nevertheless, we still have not dived into the question what is the global factor. In the
literature, the global factor that drives cross-border spillovers in financial conditions and
credit growth is often termed as ”Global Liquidity”. The term is often used in connection
with monetary policy spillovers from advanced economies. (Shin, 2013) A few papers
suggest that, due to low US monetary policy rate, US dollar weakens against other
currencies and also the term premium decreases in the post-recession period, which is
featured with the expectation of low near term volatility, which can be measured by VIX
(CBOE Volatility Index). We build a correlation matrix to see the co-movements between
the global factor and key macro variables from the literature. (Table 13) We find that,
during 1994-2016, the global factor is moderately negatively correlated with shadow

federal funds rate, suggesting that federal funds rate is a decent indicator of global
liquidity transmission. The US monetary policy rate could be the underlying global driver
of

