


Decarbonizing the Global Cement Industry
In 2015, the United Nations introduced their 2030 agenda for Sustainable Development, which
emphasized in its 13th goal, the urgent action to combat climate change and its consequences. At the
end of the same year, global leaders came together to sign the Paris Agreement in 2016, during the
21st session of the Conference of the Parties to the United Nations Framework Convention on Climate
Change. This landmark agreement aimed to limit the rise in worldwide temperatures to below 2°C
above pre-industrial levels (IEA, 2018).
Alongside these developments, many nations established their own Nationally Determined
Contributions (NDCs), setting self-governed targets for greenhouse gas emissions reduction. Notable
examples include the US, committing to reduce emissions by 50% to pre-2005 levels by 2030, the
EU aiming for a 40% reduction in emissions below 1990 levels by 2030, and China pledging to reach
peak emissions by 2030 and achieve carbon neutrality by 2060 (IEA, 2018).
These NDCs were shaped by two significant developments in recent years. First, an increase in the
frequency and severity of extreme weather events, such as heatwaves, hurricanes, and wildfires, has
been observed globally. Notable occurrences include the devastating wildfires in Australia during
2019-2020, the record-breaking heatwave in the Pacific Northwest in June 2021, and the deadly
floods in Pakistan in 2022 (Clarke et al., 2022). Secondly, there has been increasing pressure from
investors in heavy carbon companies for more reporting on environmental footprint, and roadmaps to
lower emissions to ensure sustainability, although with limited efficacy so far (Baines & Hager, 2023).
Consequently, sustainable, and responsible investing has witnessed significant growth, incorporating
environmental, social, and governance (ESG) factors into investment decisions. In 2020, the global
market for sustainable investing reached an estimated $35.3 trillion, representing a 15% increase from
the previous year. Moreover, investors are increasingly urging companies to address climate change
and provide more information about their climate-related risks and opportunities, leading to a rising
trend of companies setting their climate targets and disclosing their progress (Deloitte, 2023).
After the Paris agreement in 2016, the Intergovernmental Panel on Climate Change (IPCC), the
foremost international authority on climate change, released several reports monitoring the progress
towards achieving the NDCs. In 2021, the IPCC released a pivotal report indicating a global lag to
reach the NDCs, stressing the necessity for countries to accelerate their efforts to realize their carbon
emissions’ reduction target (IPCC, 2021.)

As cement production is responsible for 7-8 % of carbon emissions, several countries have started to
explore ways of decarbonization for their cement industry. The global production and consumption
of cement is not uniform, with China and other Asian countries producing more than 80% (IEA,
2018). It is important to highlight that cement is a decentralized industry because it relies on locally
available raw materials, such as limestone, clay, and sand, which vary in quality and composition
from one region to another. In addition, cement production also varies widely between regions based
on infrastructure needs, urbanization levels, and availability of raw materials, among others. For
example, in China the cement production per capita in China is 1818 kilograms of cement, compared
to around 600 kg per capita globally. In the Middle East it is close to 827 kilograms of cement per
capita (IEA, 2018). This indicates that policies to decarbonize cement industry will need to be tailored
to region or country specific characteristics.
Lastly, cement is considered one of the hardest industries to decarbonize due to the fact that the biggest
portion of CO2 emissions from cement comes from chemical reactions in the production process that
are not possible to change (IEA, 2018). Cement production is a three-stage process, the first stage is
extracting the main ingredient, limestone from quarries (Busch et al., 2022). The next stage involves
mixing limestone and other additives to form a material called clinker. This is done through a chemical
reaction that results in decomposition of limestone CaCO3 into Lime (CaO) and Carbon Dioxide
CO2. This material, clinker, which constitutes on average 80% of what cement is made of, is then
mixed with other additives to form cement (ETC, 2020). This process is called calcination, and it is
where most of the CO2 emissions in the cement production comes from. This is because the chemical
reaction in this process results in the releasing of CO2, but also because to make this process happen,
there is a lot of heat required. This heat comes from burning of fossil fuels to reach temperatures
typically in the range of 1,400 to 1,500 degrees Celsius (Monteiro et al., 2017).
The other source of CO2 in the production process of cement is usually referred to as “indirect
emissions”, and this includes the CO2 emissions from the electricity used, the logistics and
transportation, among others. Indirect emissions are responsible for about 10% of the CO2 emissions
in the cement industry, while the other 90% is released by the calcination process, and the burning of
fuels (Monteiro et al., 2017). These figures are based on global averages, so it should be noted that
certain local factors can influence the ability of cement plants to reduce their carbon footprint
including the availability of different raw materials, or other alternative fuels (Busch et al., 2022).

1.2. Sustained cement demand through 2050
Cement is the primary ingredient in concrete and holds the distinction of being the second most
consumed material globally, behind water (McKinsey, 2020). Considering the ongoing trends of
urbanization and the increasing need for infrastructure, the demand for cement is projected to rise
significantly by approximately 12-20% until the year 2050 (IEA, 2018). However, the cement
industry is a significant contributor to greenhouse gas emissions, accounting for approximately 7%
of global carbon dioxide emissions. Each ton of cement production results in an equivalent of 600
kilograms of Co2 (IEA, 2018). There is a growing need for change in the cement industry as countries
across the world are scrambling to reduce their carbon footprint while shifting their focus towards
heavy industries that are heavy carbon emitters.
This in turn has put pressure on global leaders of heavy industry sectors as investors and shareholders
are in turn pushing for corporates to transition to more sustainable practices considering increased
carbon pricing policies (Rissman et al., 2020). For example, the CSI, Cement Sustainability Initiative,
which was founded in 1999 and brings together 24 major cement producers in 100 different countries,
have recently published a Low Carbon Roadmap in partnership with the International Energy Agency
(IEA) with a plan to reduce carbon emissions in line with the 2 Degrees Scenario (2DS). The 2
Degrees Scenario was developed by the International Energy Agency (IEA) to describe a future
pathway for the energy system that is consistent with limiting global warming to below 2 degrees
Celsius above pre-industrial levels, as agreed upon in the Paris Agreement. The roadmap assumes
ambitious deployment of carbon reduction technologies in the cement industry, but it also sets out an
expectation for a high level of international cooperation and policy support towards encouraging
lowcarbon cement (IEA, 2018). Other heavy industries including iron & steel, chemicals, and plastics
are also under the same pressures to decarbonize, with varying degrees of difference when it comes
to availability of substitutes. However, the one of the shared factors is the sustained demand for
cement and other heavy industry products, which makes policies and actions to reduce emissions even
more critical (Rissman et al., 2020)
1.3. The Egyptian Cement Industry’s Carbon Footprint
The cement industry is one of the oldest industries in Egypt, with the first plant established in 1927
in Cairo (Askar, 2010). Historically, the industry has been one of the drivers for economic
development and urbanization, with the first cement plants built along the Nile River to transport
cement across the country (Askar, 2010).

As per latest figures, the cement industry contributes to around 3.7% of GDP and is providing jobs
for 50,000 directly, and an estimated 200,000 indirectly (Abdou, 2017). Cement is also a major
contributor to the construction and real-estate sectors which represent close to 40% of Egypt’s
national economy. However, the cement industry also has a heavy environmental impact, with 5.3%
consumption of total energy in Egypt, and approximately 14% share of Egypt’s CO2 emissions,
which is double the global average (EBRD, 2016, p. 10)
In Egypt, the cement industry has recently received much criticism after cement companies lobbied
to allow the importing and use of coal in Egypt after the natural gas shortage in 2016 (Global Cement,
2015). Critics argued this will only add to the already heavy carbon footprint of cement production.
The Egyptian cement industry also compares unfavorably to other regions in terms of carbon
emissions. For example, the average CO2 emissions per tons of cement produced were 0.62 (620
kilograms) as of 2019, while in Egypt, the reported average was 0.75 (750 kilograms) tons of CO2
per ton of cement produced (IEA, 2018). It is important to note the actual number for Egypt might be
much higher as indicated by the ‘Getting Numbers Right’ (GNR) database (GNR, 2020).
The differences in cement footprint are due to variances in cement production capabilities and
maturity of sustainable practices across different regions (Rissman et al., 2020). Accordingly, the
transition to low-carbon cement production will vary based on the available infrastructure,
technology, and raw materials, among others (Rissman et al., 2020). Therefore, the approach to
reducing carbon emissions from cement production will need to be tailored to the specific context
of each country and region.
In particular, Egypt is highly vulnerable to climate change impacts, due to its geographical location
and socio-economic conditions. The whole region of the Middle East and North Africa (MENA) is
already experiencing the effects of climate change, such as rising temperatures, water scarcity, and
more frequent and severe weather events, including droughts and floods. Egypt’s coastal areas are at
risk from sea level rise, which could lead to flooding and erosion, damaging infrastructure, and
displacing communities. In addition, current economic conditions and limited resources make it
challenging to adapt to impacts of climate change, which was highlighted in Egypt’s latest update for
its NDCs (UNFCCC, 2023). There has been ongoing discourse on reducing greenhouse emissions in
the Egyptian economy ever since Egypt hosted COP27, the latest conference for the United Nations
Framework Convention on Climate Change, at the end of 2022. In the months leading to and after
COP27, Egypt has issued and updated its NDCs to include climate change mitigation.

In the recent June-2023 update, cement is listed at the top of the industry list that Egypt plans to
decarbonize (UNFCCC, 2023). Even though there are no clear targets in terms of CO2 emissions
reduction, there is an approach to increase efficiency and reduce dependency on fossil fuels by
incorporating more alternative fuels (refuse derived fuels). In March 2021, Egypt’s Ministry of
Environment published a mandatory decree for cement plants to substitute 10% of their energy usage
by alternative fuels (EEAA, 2022). However, these efforts will seem insufficient if we consider the
starting point: the cement industry’s carbon footprint is higher than the global average. While cement
production is responsible for around 7% of CO2 emissions, in Egypt this number is closer to 14%
(EBRD, 2016, p. 10). The higher percentage of CO2 emissions for Egypt’s cement industry mirrors
those of other developing and middle east countries with high production capacity of cement. The
global average for CO2 produced as a byproduct of cement production is 620 kilograms of CO2 per
ton of cement, while in Egypt this number is much higher – sometimes reported at more than 800
kilograms of CO2 per ton of cement (EBRD, 2016).
There are several explanations for the above figures that this study will present, but it is also important
to note that the cement industry in Egypt is a major contributor to the construction sector, which
represents 15% of GDP (Abdou, 2017), which means policy actions for reducing the cement
industry’s footprint in Egypt must consider its overall contribution to the economy. Cement plants by
design are made to accommodate different types of fuel, and this means there is an opportunity to
create a closed-loop system whereby waste is transformed into a valuable resource, driving the
transition towards a more sustainable and circular economy (Busch et al., 2022). However, the cement
industry in Egypt is facing many challenges including overcapacity, high energy costs, lack of access
to financing, and lack of supporting regulator infrastructure for a true green transition (EBRD, 2022).
This study aims to assess Egypt’s recent efforts in reducing the cement industry’s carbon footprint, as
well as provide insights for how the industry can move towards a more sustainable and efficient
future.
1.4. Problem Statement
The cement industry in Egypt is a significant contributor to the country’s economy, but it also has a
substantial environmental impact, including high levels of greenhouse gas emissions and intensive
energy usage (EBRD, 2016). To address these issues, there is a need for a green transition towards
more sustainable and environmentally friendly practices within the industry. The cement industry in

Egypt is responsible for close to 14% of the country’s emissions, and is also a heavy user of energy,
with low opportunities for exporting its products due to the logistical nature of the product. This
reason- added to the complexity of the economic challenges currently faced by the industry and in
Egypt in general such foreign currency shortage, decreasing local economic activity, among others-
means that the question of green transition in the cement industry in Egypt is much more complex
than the availability of technology for carbon reduction. Although there are several green transition
models implemented in other countries, as well as a dedicated 2016 EBRD report with a low carbon
road map for the cement industry in Egypt (EBRD, 2016); there has been slow uptake and lack of
progress in moving toward sustainable practices. This is due, historically, to several factors including
lack of regulations or policy actions promoting or mandating emissions reduction, low awareness
levels of climate change mitigation imperatives, and economic conditions that limit investments in
new technologies in addition to general heavy industry inertia. This study thus aims to understand
industry perspectives on what a potential green transition grounded in the Egyptian context will look
like, as well as the policy challenges and opportunities.
1.5. Research Aim & Questions
This study attempts to fill the literature gap in answering the complex questions about obstacles to
green transition in the cement industry and aims to contribute to the discussion on how to move
towards a cement industry with a lower environmental impact. This study also aims to explore the
interconnectedness of the cement industry with other sectors in the economy, like solid waste
management and disposal, and how these can be leveraged for the green transition.
The main research question is: How is the cement industry in Egypt working to reduce its
greenhouse gas emissions and what are the policy opportunities and challenges?
To answer this question, this study will look at several sub-questions as follows:
- What are the factors influencing cement companies in taking steps toward reducing their
environmental footprint? What are the available incentives or regulatory pressures?
- What are the available practices or technologies for cement companies in Egypt to reduce
their carbon emissions? What are the challenges facing these practices, especially in terms
of financing?

- What are the current oversight tools by regulatory agencies to monitor and support the
cement industry in reducing their environmental footprint? What are the latest trends and
challenges from a regulatory perspective?
- What policies can incentivize cement companies toward shifting to more sustainable
practices?
1.6. Thesis Outline
To answer the above research questions, this thesis is organized into six chapters, as follows:
Chapter one provides an overview of the research problem and the complexity of green transition
in the cement industry as well as the research question, and the research objectives.
Chapter two demonstrates the recent literature on green transition in the cement industry. The
literature review covers three main themes: first, an overview of the latest publications from
different international agencies and bodies that are active in pursuing sustainable practices for the
cement industry. Second, the chapter discusses recent publications and experiences from the cement
industry undergoing a green transition from comparable countries in the Global South. Finally, a
review of recent literature on the cement industry in Egypt.
Chapter three discusses the conceptual framework designed for this study, and an explanation and
reasoning for the adopted research design. The chapter details the research methods used, overview
of data analysis, and ethical considerations as well as limitations to this research.
Chapter four provides the necessary contextual policy background to the cement industry in Egypt.
The chapter first highlights the recent challenges and dynamics in wake of the economic challenges,
as well as a simplified explanation of the cement production process to highlight how green
transition technologies can help reduce carbon emissions. This chapter also presents the recent
regulatory changes in the cement industry in Egypt.
Chapter five presents the findings from the interviews conducted with cement industry experts as
well as insights from analyzing available secondary data like reports and publications. The chapter
is divided into themes that discuss recent trends in the Egyptian industry, the carbon footprint of
cement production in Egypt, current practices, and options to reduce Co2 emissions, and finally a

discussion of the low carbon roadmap available for the cement industry in Egypt and its different
challenges.
In closing, chapter six presents the conclusion and policy recommendations. This study calls for a
pragmatic, but also practical and holistic approach to reducing the cement industry’s carbon
footprint in Egypt. The study advocates for the inclusion of cement companies as key stakeholders
in circular economy solutions like recycling municipal waste. Finally, the study will highlight the
low-hanging fruits for achieving considerable CO2 reductions through specific policy
recommendations for collaborative stakeholder actions.

1. Chapter Two: Literature Review
Even though climate change has been identified as an issue since the 1980s, it is only in this last
decade that public discourse on climate change has made it into official agreements and policy
documents that are now widely spread. Today, climate change is one of the most pressing global
issues facing humanity. This is partially because Climate change is already having significant impacts
on countries around the world. Many regions are experiencing more frequent and severe weather
events, including droughts, floods, heatwaves, and storms (UNFCCC, 2022).
The leading international authority on climate change, the Intergovernmental Panel on Climate
Change (IPCC) has identified two scenarios of potential global warming: one where temperatures rise
by 1.5 degrees Celsius, and another where temperatures rise by 2 degrees Celsius above pre-industrial
levels between 2030 and 2050 (IPCC, 2018). The 1.5-degree scenario is the more ambitious target of
the Paris Agreement, signed by nearly 200 countries in 2015, which aims to limit global warming to
well below 2 degrees Celsius and pursue efforts to limit it to 1.5 degrees Celsius. The difference
between the two scenarios may seem small, but it has significant implications for the planet (IPCC,
2018).
This chapter presents the recent literature on reducing emissions in heavy industry, as well as an
overview of the body of research on decarbonisation in the cement industry, including technical
measures and policy actions. The first section demonstrates the high-profile publications by industry
groups on roadmaps to reducing carbon emissions, including a review of the academic literature that
reviews these plans. Section two reviews recent literature and best practices for reducing emissions
in the cement industry, followed by a review of prominent literature and case studies from China and
developing countries, while the final section reviews the literature from Egypt.
2.1. Climate change mitigation - reducing carbon emissions in heavy industries
There are two main approaches for addressing climate change, mitigation, and adaptation.
Mitigation involves reducing greenhouse gas emissions to lower the pace of climate change impacts
(UNFCCC, 2022). This is where different industries are expected to be modifying their energy
efficiency or operations to reduce their emissions. These include practices such as electrification of
industrial processes to reduce dependency on fossil fuels, use of hydrogen, energy efficiency, and
carbon capture, among others (Rissman et al., 2020). On the other hand, adaptation involves
preparing for and adapting to the impacts of climate change that are already happening or are
expected to occur (UNFCCC, 2022). This can include measures such as building sea walls,

developing drought-resistant crops, and improving public health systems (Ray Biswas & Rahman,
2023). The goal of adaptation is to reduce the vulnerability of individuals, communities, and
ecosystems to the impacts of climate change, and to help them cope with the changes that are
already occurring.
In the context of cement production, and heavy industries in general, all proposed green transition
options discussed usually fall under the mitigation approach, with the eventual goal of reducing the
environmental impact of the industry. This is because the demand for cement is expected to rise
until 2050, which means that, to a great extent, the discussion on decarbonisation for cement
industry refers to ways to reduce the carbon emissions resulting from the production process, or
offsetting it, but not on alternatives to cement as a building material or to explore ways to decrease
the demand (Busch et al., 2022). This is fairly similar to other heavy industrial sectors, indicated in
a McKinsey 2020 report on cement decarbonization potential, which highlights cement and steel
industries for their share of 7% and 8% of carbon emissions, respectively (McKinsey 2020).
Cement is one of the leading six heavy industries, alongside iron and steel, chemicals, aviation, and
shipping (Rissman et al., 2020). These industries are usually referred to as “hard-to-abate” in gray
literature like reports by industry associations or consulting powerhouses like Mckinsey to describe
industries that are particularly challenging to decarbonize. These industries often rely on fossil fuels
as a primary source of energy and/or their processes involve high-temperature heat or chemical
reactions that are difficult to electrify or replace with low-carbon alternatives. It is more
complicated because these industries are essential industries with no viable environment friendly
replacements so far (Deloitte, 2022).
The collective CO2 emissions of heavy industries are significant, reaching about 30% of global
CO2 emissions, and cement production alone is responsible for 7% of this amount (Rissman et al.,
2020). Addressing emissions from hard-to-abate industries is critical to achieving climate change
mitigation targets. However, decarbonizing these sectors is challenging due to their reliance on
fossil fuels and the technical difficulties of reducing emissions from high-temperature heat and
chemical processes. For example, the production of cement inherently generates carbon emissions
due to the chemical process of calcination, where limestone (calcium carbonate) is heated to
produce lime (calcium oxide), releasing carbon dioxide as a byproduct. This accounts for a
significant portion of carbon emissions in cement industry, in addition to the heat needed to make
this process happen, which is achieved by fossil fuels (Rissman et al., 2020). Nevertheless, there is

growing recognition of the need to accelerate efforts to decarbonize these sectors to achieve a
netzero emissions target, usually set at 2070 in different industry roadmaps (Rissman et al., 2020).
Another important factor that is also often referenced as an indicator of the level of difficulty for the
cement industry to reduce its carbon footprint, is the high percentage of emissions per dollar of
revenue. This statement means that the cement industry, on average, generates more carbon dioxide
emissions per unit of revenue than any other industry (McKinsey, 2020). This could mean that the
cement industry will need more financial incentives for decarbonisation since there is less room on
the balance sheets of cement companies to fund green transition solutions, when compared to other
industries like iron or oil and gas (McKinsey, 2020) This is due to several factors but mainly the
chemical reactions inherent in the production process and the energy used to facilitate the whole
process (Li et al.,2015). This figure has been used to argue that decarbonizing the industry will be
particularly challenging as reducing emissions from the cement industry will likely require
significant changes to the fundamental processes and materials used in cement production, which
could have significant economic and logistical implications (Deloitte, 2022).
In the past few years, there have been several high-profile publications that addressed the challenges
of decarbonizing hard-to-abate industries including cement. Most notably, the Energy Transition
Committee (ETC) published a comprehensive report in 2020 titled “Making Mission
Possible: Delivering a Net-Zero Economy” which sets out a roadmap for achieving a net-zero
emissions in the global economy by 2050, with a focus on decarbonizing hard-to-abate sectors like
cement, steel, and shipping. The Energy Transition Committee (ETC) is a coalition which is
composed of global leaders in the energy, industry, finance, and policy that was formed in 2015 to
drive progress towards a low-carbon future. This is one example of several roadmaps or scenarios
by industry associations or global consultants. Roadmaps to reducing carbon emissions in heavy
industries outline the strategic pathways and actions required to achieve significant decarbonization
within these sectors. These roadmaps serve as comprehensive plans that outline the necessary steps,
technologies, policy changes, and investments needed to transition heavy industries towards
lowercarbon and more sustainable practices. These roadmaps often prioritize a portfolio of
measures that can be implemented in a phased manner, considering short-term, mid-term, and long-
term goals. They may include strategies like energy efficiency improvements, fuel switching,
adoption of lowcarbon or carbon capture technologies, process optimization, and the integration of

renewable energy sources. In addition to the above example from ETC, there is also The Shell Sky
Scenario (Shell, 2022), the 2-Degree Scenario (2DS) and Beyond 2-Degree Scenario (B2DS) from
the
International Energy Agency’s (IEA) whereby different scenarios for industries to decarbonize are
presented, in compatibility with holding global average temperature to below 2 °C, which the goal
of the 2015 Paris Agreement (Rissman et al., 2020).
Within the scholarship on Energy transitions, several key studies have evaluated and provided
complimentary recommendations to these different roadmaps. Most notably, one review article in
the Applied Energy journal (2020) analyzed the different technologies and policies to decarbonize
industry, to provide an assessment of these roadmaps (Rissman et al., 2020). Decarbonization or
net-zero roadmaps is the term most often used for medium and long-term strategic plans to reduce
greenhouse gas emissions in heavy industry. They mainly identify key areas of improvement across
energy consumption, type of fuel, carbon capture potential, and other demand-factor areas. These
roadmaps are usually funded by industry associations or international organizations, and in some
cases by relevant regulatory authorities. The roadmaps are supposed to serve as an action plan on
steps that need to be taken in order to reach reduction or net-zero carbon in the specific industry.
There are several points of critique or challenges to these roadmaps, firstly, the effectiveness and
feasibility of the proposed roadmap strategies need to be carefully assessed. The implementation of
new technologies and operational improvements may face challenges in terms of scalability,
costeffectiveness, and compatibility with existing infrastructure. It is essential to thoroughly
evaluate the technical and economic viability of the proposed measures to avoid unrealistic
expectations or over-reliance on unproven solutions (Rissman et al., 2020). Additionally, roadmaps
should not overlook the potential rebound effects or unintended consequences of emission reduction
strategies. For instance, a shift to new technologies or processes may inadvertently lead to increased
resource consumption or other environmental impacts. A comprehensive assessment of the life
cycle implications and broader sustainability considerations is necessary to avoid shifting the
burden or creating new environmental problems in the pursuit of emissions reductions (Rissman et
al., 2020).
Reviews by the different scholars such as Rissman et al., (2020) and Davis et al. (2018), evaluate
the decarbonisation pathways which outlines a range of strategies to reduce CO2 emissions in
different industrial sectors. These pathways can be summarized in three different phases, from 2020

to 2035: a focus on electrification, material and energy efficiency, and circular economy. In the
following decades from 2035 to 2050, there is an expectation that carbon capture and utilization
would be economically usable, and alternative materials would start being available for industries
like steel and cement (Dowel et al., 2017). From 2050 to 2070, there is an expectation for wide
scale hydrogen use and zero-carbon hydrogen production (Bardow et al., 2017).
Several of these methods will be addressed in more detail in the next sections for their relevance to
the cement industry.
An important note to the above framework is that these roadmaps are modeled using global
averages. The actual implementation would most likely differ between developing countries and
developed countries. This is why there are constant calls in recent literature to explore the
discrepancies and the unique regional characteristics that would affect decarbonisation strategies
(Rissman et al., 2020). The most common levers of decarbonisation mentioned in the literature can
be summarized as follows. There are supply side technological interventions that would limit the
carbon emissions during the industrial process itself, in addition to the carbon capture solutions that
would remove the excess carbon (Fennell et al., 2021). Then there are demand side interventions,
which improved product longevity, more intensive product use, material efficiency, material
substitution, and demand changes driven by circular economy interventions (Napp et al., 2014).
Lastly, both demand and supply interventions are supplemented by policy actions that would either
limit or discourage emissions, increase demand for sustainably produced products through
government green procurement policies, or promote research and development (Rissman et al.,
2020).
The majority of literature on decarbonization of heavy industries place more emphasis on
supplyside interventions, which include specific technological solutions that can reduce the carbon
emissions while essentially producing the same products. More advanced technical solutions like
carbon capture and storage go a step further and present potential options for producers to keep their
operations largely unchanged while ensuring carbon capture solutions would cancel out their carbon
emissions (Bardow et al., 2017). There is uncertainty in literature on the practicality of this
approach as there are not enough evidence for its efficacy from an economical or technical
perspective (Bardow et al., 2017).
The demand-side interventions that are referenced in literature usually refer to improving material
efficiency, longevity, and the potential of re-use. This can apply to several industries including

cement, steel, concrete, plastics, among others (Monteiro et al., 2017). While such actions might not
necessarily need the same level of technological innovation as supply-side, they would need policy
actions to accelerate implementation across different stakeholders and are usually given long-term
action plans in relevant industry roadmaps (Monteiro et al., 2017). This is due to the fact that
demand for products such as cement and concrete, as an example of heavy industry, is expected to
continue rising, and changes to the use of such products would involve the need to change
regulations, behaviors and attitudes of numerous stakeholders in different regions (Miller & Moore,
2020).
The most referenced policy action is carbon pricing. It refers to a set of different policy tools that
essentially assigns some economic price for carbon emissions (Rissman et al., 2020). By putting a
price on carbon emissions, carbon pricing is expected to provide a market incentive for companies
to invest in low-carbon technologies and practices and can help accelerate the transition to a more
sustainable, low-carbon economy. Carbon pricing has been implemented in several countries and
regions around the world, including the European Union, Canada, and some US states (Rissman et
al., 2020). The most frequently mentioned concern of carbon pricing is “carbon leakage”, which
refers to the increase of greenhouse gas emissions in one country or location as result of an
emissions reduction policy action in another country (Harvey et al., 2018). This can understandably
be difficult to assess, and recent research on how to estimate this risk have provided large variance
in results (Fowlie & Reguant, 2018). However, it can point out to the importance of international
cooperation in policy actions towards reducing emissions (Rissman et al., 2020). Other notable
policy actions that are government procurement policies, data disclosure and ESG, and recycling
incentives or requirements (Rissman et al., 2020).
The literature landscape on reducing emissions in heavy industries is still relatively new, as recent
drives for decarbonisation have picked up after the 2015 Paris agreement (Rissman et al., 2020), but
there is a clear need for more research from developing countries, as the rest of the chapter will
explain. There are numerous sources for research on technological solutions for the top three
emitting heavy industry sectors: cement, iron & steel, and chemicals and plastics. Research
highlights there are historically a 30-year window between the development of new technologies
and the time it takes for an implementation on an economically scalable way (Rissman et al., 2020),
which indicates the importance of exploring how transitions will take place.

2.2. Literature on reducing emissions in the cement industry
The global demand for cement is expected to increase, especially in developing countries, fueled by
urbanization trends, low cost of cement, abundance of raw materials needed for its production, and
absence of viable substitutes (Monteiro et al., 2017). There have been numerous technical solutions
in recent literature for possible decarbonization options (Fennell et al., 2021; Habert et al., 2020;
Miller et al., 2016; Pamenter and Myers, 2021), but adopting technologies needs policy actions to
support implementation.
There are more than 35 recent studies on decarbonisation in the cement sector, and most of these
studies provide an analysis of different measures to reduce emissions, while very few analyze
policies or barriers (Busch et al., 2022). There are also several roadmaps or pathways that provide
quantitative models and are mostly from industry associations, government, or international
organizations (IEA, 2018), (GCCA, 2021), (Somers and Moya, 2020), and (McKinsey, 2020).
Though cement emissions are higher in developing countries (Rissman et al., 2020), the majority of
literature on cement decarbonization comes from developed countries. This outlines a clear need for
research on reducing emissions in cement in middle- and low-income countries (Busch et al., 2022).
These studies typically provide or evaluate different technological measures for reducing emissions,
A recent review in 2022 of the literature on reducing emissions in the cement sector summarizes the
most common approaches and provides the foundation for the conceptual framework of this study.
There are numerous measures for reducing carbon emissions in the cement industry, including
energy efficiency, alternative fuels, carbon capture and storage, among others. Most notably, there
are plenty of measures proposed for reducing emissions during the production process, but only
handful of studies addressing lifecycle assessment (Rissman et al., 2020).
While the first measure in above table, which is ‘improving energy efficiency of current cement
production process’, is not the most frequently cited, it is one of the most implemented measures
as it could be considered as a win-win situation for cement companies since such energy efficiency
gains would be economically attractive as well. It is important to note that these efficiencies are
expected to provide only 12% reduction CO2 emissions of global cement production (BEIS and
MPA, 2017; Miller et al., 2016).
It is important to note that these improvements will be voluntary in nature in the absence of policy
obligations, which essentially means that capital intensive improvements will most likely be only

applied in markets where it is economically viable. This is especially true to Middle East and China
markets where cement markets have an overcapacity.
Another commonly cited measure is ‘switching to alternative fuels’, which refers to switching to
fuels that are less carbon intensive (Fennell et al.,2021) The second largest source of carbon
emissions in the cement industry comes from fuel combustion that is required for production. This
is why there are considerable carbon emissions reductions that can be gained with switching to
alternative fuels. Alternative fuels include a variety of kinds that will differ in their availability in
each region or location. The most common alternative fuels that can be used in the cement industry
are biomass, which can contain agricultural waste, wood chips, and rice straw among others.
Refuse-derived fuels or (RDF) is also one of the most common alternative fuels and it can include
remains of municipal waste and sewage sludge. Used tires can also be used as well as other
industrial by-products like fly ash, which is a by-product of the coal industry, and slag, which is a
by-product of the steel industry.
Switching to alternative fuels is particularly attractive to policymakers and companies alike since
these fuels are more cost effective than traditional fossil fuels and can also contribute to the creation
of a circular economy and diverting waste from being buried in landfills. This is also considered a
viable option since there are relatively lower capital costs needed to adjust the production process in
the cement industry to use these different kinds of alternative fuels (Rissman et al., 2020).
However, it is important to note that this shift to alternative fuels could essentially require more
energy consumption for processing of the different kinds of fuel. Also, there is no change in the
cement production process itself, which is the largest source of the CO2 emissions in the industry.
This is why the shift to alternative fuels is expected to help reduce carbon emissions of the cement
industry by 9% only by 2050 (ETC, 2020).
There are of course several challenges to using alternative fuels in the cement industry, some of
them are related to the production process, whereby pretreatment is mostly needed for handling
different kinds of fuels, and certain adjustments in the cement plants as alternative fuels do not
provide the same energy of fossil fuels (ETC, 2020). However, the bigger challenges to using
alternative fuels comes from the degree of maturity of local infrastructure and regulatory
frameworks that make it both possible and economically logical for the different stakeholders. The
local infrastructure must support an effective and efficient waste collection network, and one that
makes landfilling waste costlier than burning it in cement plants. There are also usually challenges

with local governments, especially in developing countries where there are bureaucratic hurdles and
low social acceptance (EBRD, 2016).
Another commonly cited reduction measure is ‘reducing the clinker to cement ratio’, which refers
to reducing the percentage of limestone needed in the making of cement – which is the main source
for the high emissions in the production process. This option promises the second largest reduction
percentage of CO2 emissions compared to the alternatives in the green transition options in the
cement industry. A recent IEA report estimated it could save almost 35% of CO2 emissions
resulting from the cement industry by 2050 (IEA, 2018). There are numerous technical variations of
methods to reduce the ratio of limestone needed in the production of cement (Fransen et al., 2021).
These include blended cements which are new cement types are made by combining different
materials in the cement production process that can be mixed with limestone and deliver the same
quality but reduce CO2 emissions. Examples of these materials include fly ash, a by-product of
burning coal, slag, which is a by-product of iron and steel production. There is also a potential for
using alternative raw materials, of which calcined clay is the most common example, and it
involves using naturally occurring clays to replace limestone, which helps in reducing CO2
emissions and needs much lower energy consumption to deliver the same results (Fransen et al.,
2021).
There are several challenges to the above options including the fact that current regulatory standards
for cement use are not unified across the world, and there have been several calls for adopting
standards that are focused on the quality of cement and concrete, instead of raw material
requirements. There has been notable progress in these regulations, with India being the leading
country that adopted LCM3 followed by EU standards, but it has not yet been adopted in most of
the developing countries (Deventer et al., 2011).
Also, the challenge with alternative raw materials like clay instead of limestone is since the material
availability is not unified across the world which means adoption of this technology will vary
regionally.
Another commonly referenced measure in the literature is the use of ‘carbon capture, storage, and
utilization’ (CCSU) (Rissman et al., 2020). Carbon capture is a technology that captures carbon
dioxide (CO2) emissions from cement production process and stores them underground or reuses

them in other applications in the chemical industry. According to the recent 2018 IEA low carbon
roadmap, carbon capture has the potential of removing up to 35% of CO2 emissions by 2050 (IEA,
2018). There are more than four different technologies at varying phases of trials in the cement
industry, including calcium looping, direct separation, and chemical absorption. A 2017 study in
Romania analyzed two different scenarios for carbon capture which indicated a massive potential of
up to 90% capturing for CO2 emissions from the cement production process using calcium looping,
but at a staggering 120% of the actual cost of production (Cormos & Cormos, 2017).
It is important to note that the cost of capturing and storing CO2 from cement production is
estimated to range from around 70 USD to 160 USD per ton of CO2 (Cormos & Cormos, 2017).
This is higher than the current market price for carbon credits, which is around 40 USD to 80 USD
per ton of CO2, which can mean carbon capture is a long way for large scale deployment. This also
must take into consideration that the average cost of producing one ton of cement is around 40
USD, which can clarify how carbon capture is not going to be economically viable for most cement
plants as of today. The cost of carbon capture is expected to fall as policy interventions and R&D
efforts into practical applications take place. There are also calls for cross-sectoral collaboration
between industries that would be end users for the captured CO2 so that there is a closed economy
cycle instead of storing CO2 in underground expensive storage with no economic benefits
(Beddington et al., 2019)
On the other hand, excess heat recovery (EHR) refers to the recovery of excess or surplus heat that
is generated during the cement production process and is not needed for other purposes. This excess
heat can be used to generate additional electricity or to provide heat for other industrial processes or
for district heating. Again, there are several technical variances depending on the cement plant type
and available infrastructure but as of now, it is still not economically viable for cement companies
to opt for this option in absence of further financial support or policy conditions (ETC, 2020)
Lastly, there are several initiatives that are currently in the technical evaluation phase for alternative
cement binding materials. An example of these techniques is a method that uses carbonation of
calcium silicates, which is a process that allows cement final product to absorb CO2 during the
process. However, it is still in early testing stages, and it would not be viable to use for all uses of
cement due to technical specifications (Gartner and Sui, 2017). Another example is belite cement,
which is a mineral compound of different composition that needs lower energy than in traditional
cement process, but also in testing stages. These are only examples of alternative materials to

traditional cement that can be used in the same manufacturing process, but all of these are currently
under development and would require collaborative efforts and policy actions before they can be
commercially available (Gartner and Sui, 2017).
These measures have varying degrees of applicability, as well as being in different stages of
maturity for the technology used. There are different barriers to implementing above measures as
mentioned in the different studies. The barriers cited in studies include economic barriers,
pertaining to high setup costs or other market dynamics like lack of demand. Technology barriers
usually refer to technological immaturity of proposed solutions, or difficulty of retrofitting proposed
measures to current production sites (Benhelal et al., 2021; Miller et al., 2021). A common theme
across literature was that new technologies are estimated to take 15 to 30 years to move to maturity
and achieve high levels of market penetration (Rissman et al., 2020).
Regulatory barriers include limitations on adoption of new technologies in cement production that
could change the product specifications, which are commonly strict standards related to
longstanding construction and building codes (IEA, 2018). This is also due to cement being an
intermediary product to different end users changes to building or design standards are usually slow
to take place due to the nature of the industry and the fact that the cost of failure is bigger than the
cost of over-specification (Ida Karlsson et al., 2020). For example, there are certain changes that can
be done to reduce the co2 emissions of cement by substituting some raw materials, but these
changes mean a different way of using cement for construction; thus, posing a risk of enforcing and
technical capacity questions (Ida Karlsson et al., 2020.
In addition to technology measures and their possible implementation, there are general policy
actions that are common across literature to reduce carbon emissions in the cement industry. These
policy actions can also be found in other literature on decarbonization in heavy industries as well
(Rissman et al., 2020). Policy actions can include carbon pricing, public procurement and support to
research and development (Busch et al., 2022).
In summary, the literature provided common technological recommended measures and policy
actions for reducing carbon emissions in cement. Less focus has been on stakeholders and barriers
to these measures (Busch et al., 2022). There is also a lack of actionable plans in the studies, which
means that identification of the most suitable approaches for specific markets will be difficult

(Busch et al., 2022). Most notably, there is a no common identified policy framework for
decarbonizing heavy industries or cement as mentioned in particular by Nilsson et al., (2021).
Lastly, there were also studies that criticized the focus on developing new technologies and
processes to keep producing cement while reducing carbon emissions since it overlooks the
potential for demand-side interventions, and to tackle the bigger question of alternatives to cement
or even to the need of it (Ahman, 2018). This means that the emphasis on finding less energy
intensive ways of producing cement might mean the potential of reducing cement consumption or
substituting it with alternative building materials could be overlooked (Ahman, 2018).
2.3. Literature from China and developing countries on reducing emissions
The literature review already highlighted that the majority of research on reducing emissions in the
cement industry comes from developed countries in the global north. However, there has been
extensive research from China in the past years, as efforts to decarbonize have swept through the
industrial sector in China (Dinga and Wen, 2022). A recent review of literature on China’s cement
industry decarbonisation efforts highlighted that most studies were targeting emission reductions
but not carbon neutrality, which can be understood considering demand for cement in China
accounts for more than 50% of the world’s cement industry (Dinga and Wen, 2022). However, the
literature from China provides extensive quantitative modeling which can be helpful for replicating
studies in other countries. Overall, there is a strong emphasis on emission reduction measures that
can be identified as circular economy approaches, alternative fuel derived wastes as an example,
since the expected co-benefits from such measures would make them more cost-effective to
implement (Schneider, 2019). Identified co-benefits include recycled waste, less areas used as
landfills, and safe disposal of hazardous waste (Schneider, 2019).
There is also recent literature from India, examining the different barriers to reducing emissions in
India’s cement industry (Balsara et al., 2021). The study highlighted the importance of analyzing
barriers, citing 26 different barriers including economic and regulatory factors, technological and
capacity gaps, among others. Most notably, Balsara et al. (2021) highlighted the need for
developing countries to use analytical tools to rank policy actions that can be most effective in each
country’s specific case (Balsara et al., 2021).

Other research from developing countries included emission reduction measures that were not
targeting carbon neutrality as well, but more towards the target of low-carbon cement. This means
that no long-term research or roadmaps for net-zero cement production by 2050 were available for
developing countries. However, literature from developing countries often focus on particular
emission reduction measures that can effectively work in the country’s specific context. For
example, a recent study in Philippines highlighted the co-benefits from using sugarcane ash, a waste
byproduct of sugarcane, for use as biomass derived fuel in cement plants (Jamora et al., 2019). This
is in line with Balsara et al. (2021) approach for focusing on specific measures that can be
implemented in developing countries and will be relevant for the following discussion on Egypt.
2.4. Decarbonization of the cement industry in Egypt
Discussions on the decarbonization of cement production was not always on top of the agenda for
publications on the cement industry in Egypt. Egypt was a late adopter of the regulatory standards
that limit dust emissions and harmful pollutants from cement plants. It was only in 2010 that the
Egyptian Environmental Affairs Agency (EEAA) implemented a stricter emissions guideline with
online monitoring for cement plants (Askar, 2010). These guidelines were a long-awaited amendment
to the 1994 Egyptian environment protection law which set the limits of dust emissions and other air
pollutants for cement plants. It was only in 2010 that the EEAA updated the limits of air pollutants to
match international standards. The guidelines and current regulations do not have any reference for
CO2 emissions (Askar, 2010).
However, it should be noted that there were calls for using alternative fuels and using cement
production process as a method of eliminating hazardous waste instead of landfilling, as several
developing countries have started doing (Askar, 2010).
In 2015, there were several reports and official publications on the cement industry in Egypt and its
environmental impact. This is due to the new regulations of the cement industry that allowed the
importing and use of coal and petcoke (a high carbon by-product of oil refining) to be used as energy
instead of subsidized natural gas that was either unavailable or economically not feasible. This change
of fuel for the cement industry was expected to increase the CO2 emissions by up to 15% (EBRD,
2016). A study in 2016 conducted an environmental impact assessment for the cement industry after

the new regulations using a life-cycle assessment (LCA) methodology to evaluate the environmental
footprint of cement production in Egypt. The study found lacking monitoring and evaluation of
greenhouse gas emissions, and only automated monitoring for carbon monoxide by the Egyptian
Environmental Affairs Agency (EEAA) (Abdou, 2017).
The most notable publication on decarbonization of the cement industry came out at the end of
2016, one year after the Paris agreement and almost 2 years after Egypt allowed cement companies
to start using coal and high carbon fuels in their operations. The “Low-Carbon Roadmap for the
Egyptian Cement Industry” was published and funded by the European Bank for Reconstruction
and Development (EBRD), in partnership with the relevant Egyptian authorities including the
Egyptian Environmental Affairs Agency (EEAA), the Ministry of Trade and Industry (MTI) and the
cement companies’ association in Egypt with support from the World Business Council for
Sustainable Development (WBCSD). The study provided a roadmap for the cement industry and the
relevant stakeholders including government organizations to implement mitigation measures to
reduce the CO2 emissions increase that will happen due using coal and heavy carbon fuels. The
study estimates that without the mitigation measures, the cement industry in Egypt would be within
the top 2% of carbon emitting cement industries in the world – with up to 820 kilograms of CO2 per
ton of cement (EBRD, 2016).
It is important to note the study also provided a more ambitious roadmap, which would reduce CO2
emissions from the cement industry by 2% lower than the historical levels before switching to coal
and heavy carbon fuels – the reference year is 2014 (EBRD, 2016). The following will present the
most notable recommendations and insights of this report.
Establishing a monitoring, reporting and verification (MRV) system was one of the top
recommendations of the 2016 EBRD report, which would provide accurate and up-to-date
information on CO2 emissions in the cement industry, in line with relevant international standards
(EBRD, 2016). It is worth noting that the last update of the NDCs by Egypt in 2023 included a
commitment to establishing an MRV platform for greenhouse gas emissions but it did indicate that
it was pending funding (UNFCCC, 2023).
Other recommendations generally followed the same approaches mentioned in the above section,
including lowering the clinker ratio in cement, which essentially means using other raw materials
with different qualities than limestone. The application of this in Egypt is expected to be more
difficult as most of these materials, like fly-ash, a coal-byproduct, or pozzolana, a volcanic material,

are close to non-existent in Egypt. However, the report does indicate that several other countries
have allowed the import of such materials to reduce the environmental impact of the cement
industry and that this is an economically viable measure for companies as well (EBRD, 2016).
However, in the Egyptian context, there is another challenge to this approach, since lowering the
clinker content of cement means there will be different types of cement for different uses. To put it
mildly, the application of this in Egypt suffers from long-term resistance from authorities
responsible for construction codes, as well as from cement companies based on their historical
experience with the end-users of the cement industry – leading to most of the cement sold in Egypt
to be of the same, high clinker content type, for safety concerns in the absence of necessary training
and lack of oversight (EBRD, 2016).
The EBRD report also calls for mandating the use of alternative fuels and raw materials (AFR) in
the cement industry and providing a suitable legislative and market framework for the use of refuse
and waste derived fuels. The report included a call for new solid waste management regulatory
framework in Egypt, which did come out in 2022 (Enterprise, 2022).
Lastly, the EBRD report made recommendations to balance the licensing of new cement plants with
long-term domestic market needs. This is because the cement market is operating at a 70% capacity,
which is not sustainable economically in the long run, due to an influx in supply in the last 10 years
that has been met with a decrease in demand. This is relevant from the green transition perspective
since the cement companies will be less able to maneuver and take actions to reduce their CO2
emissions if they are in a negative economic condition. The report also made recommendations on
financial and market-based incentives and capacity building and enhanced dialogue between
stakeholders. It should be noted that no follow-up report or analysis was published (EBRD, 2016)
Based on the above, there is a clear need for more research on the potential pathways for green
transition in the cement industry in Egypt, especially from a more holistic and less technical
approach to reach a wider audience and garner relevant stakeholder engagement. The objective of
this research is to move technical discussions on the decarbonisation of the cement industry
conversation to a more holistic discussion on the available opportunities for a circular economy and
sustainable development in Egypt. This study also attempts to reveal some of the consequences of
the cement industry’s low carbon roadmap after six years of implementation, to the extent possible
within the scope of the study.

2. Chapter Three: Research Design
This chapter will present the research design of this thesis, starting with the conceptual framework,
the rationale for the choice of research methodology, research design and sampling, and the ethical
considerations and limitations.
3.1. Conceptual Framework
This section presents the conceptual framework used for this study and discuss the underlying
assumptions behind it. The framework is prepared based on the main levers of reducing emissions
in the cement industry, which were included in the previous literature review section (Busch et al.,
2022) and (Zhang et al., 2021). It is important to customize these frameworks to local and regional
contexts. This is because the challenges and opportunities of green transition can vary significantly
depending on factors such as the local regulatory framework, the availability of resources and
infrastructure, and the social and economic context. For example, the feasibility of using alternative
raw materials or fuels in cement production may be influenced by factors such as their availability,
cost, and quality in a particular region.
However, this study primarily utilizes the conceptual framework that was used in a recent
comprehensive study for green transition pathways for the cement industry in China (Zhang et al.,
2021), with adaptations to reflect the scope of this research and the local context in Egypt.
As previously discussed, the literature reviewed has presented several approaches to reducing the
environmental impact of cement. In general, there are two main approaches, one is to explore ways
to reduce the demand for cement in its current form, this could include a range of research from
studying alternative building materials to evaluating ways to reduce the demand for building
materials, for example through innovative building designs and public space sharing concepts. The
other approach focuses on the cement production process and evaluates the technological available
options to reduce the CO2 emissions from cement plants.
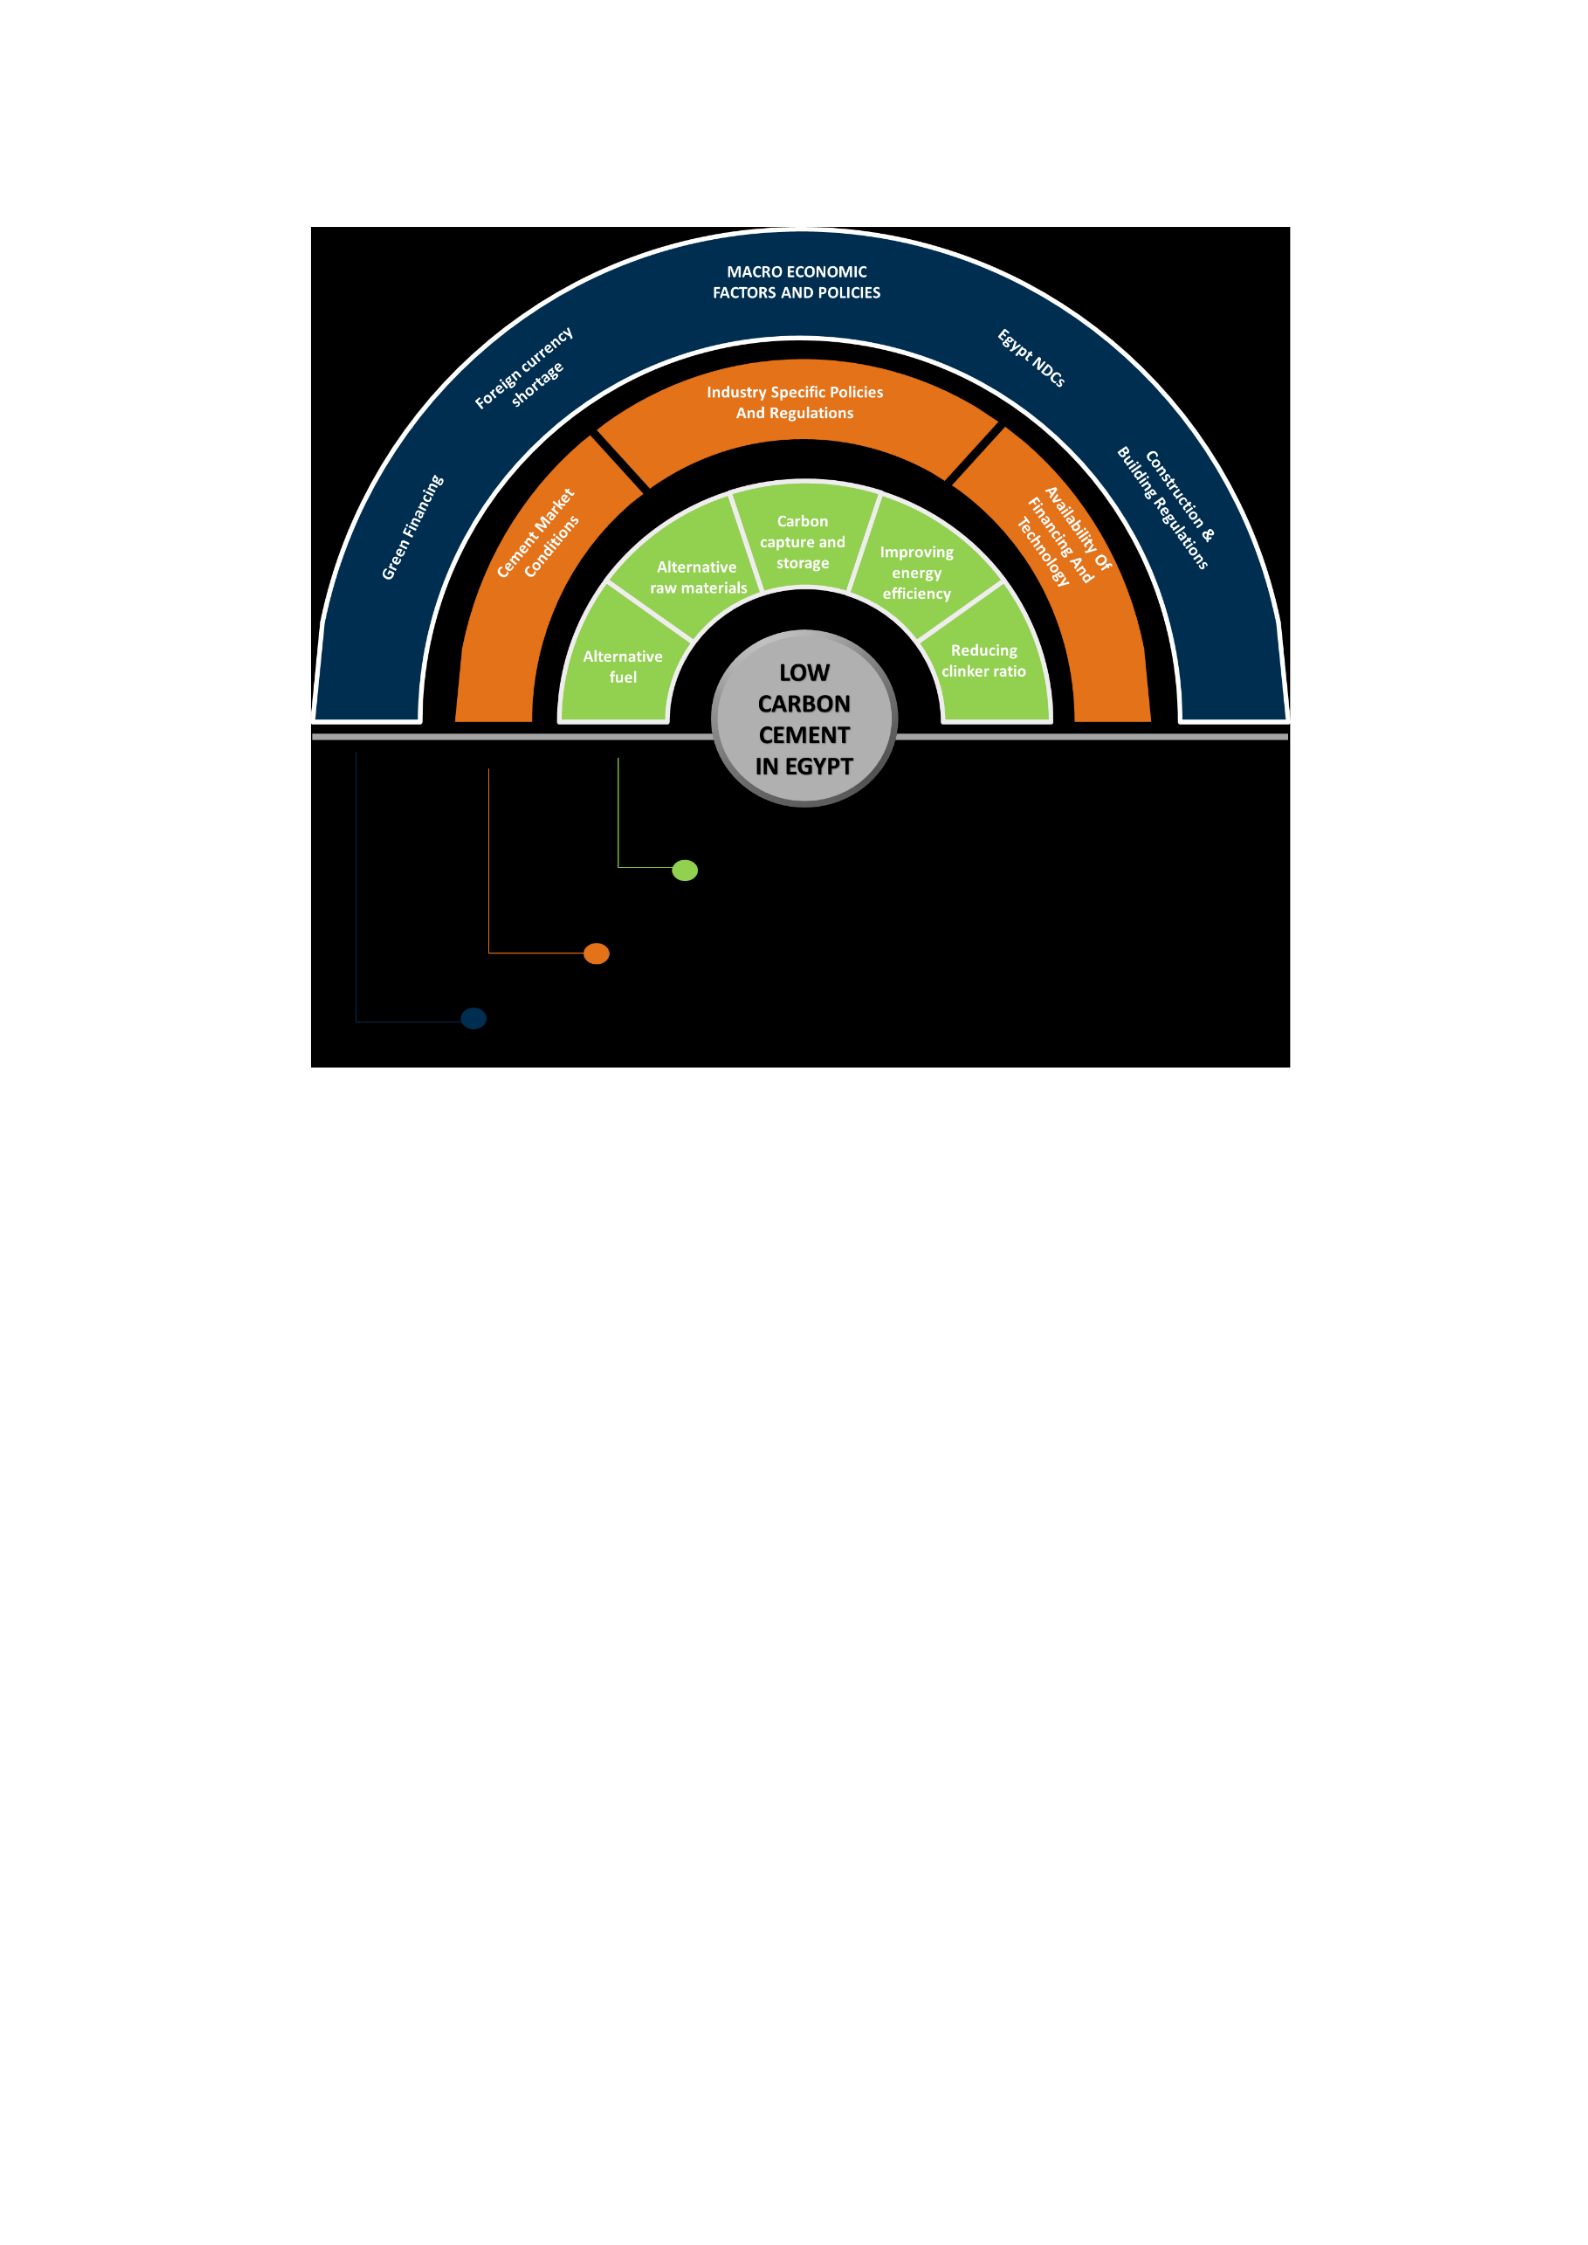
Figure 1 - Conceptual Framework, developed by author for this study
This study will use a modified version of the Net-Cement model in China (Zhang et al., 2021) to
explore the potential of the different technologies that can reduce C02 emissions in cement. As
illustrated in the diagram, the main dependent variable in this study is the production of low-carbon
cement in Egypt, and the research will attempt to identify how it could be achieved.
The study will attempt to understand and clarify the recent market conditions and regulatory
framework changes and how it affects the potential of low-carbon cement in Egypt. This will also
be accompanied with exploring how other macro or overarching factors like general economic
conditions or Egypt’s NDCs have affected the viability of the above options for reducing cement’s
carbon footprint.
3.2. Research Methodology Rationale
This study uses a qualitative approach to provide insight into the possible green transition options
for the cement industry in Egypt and its challenges. While there are several quantitative studies
from different regions on the same topic, there is a lack of qualitative research that addresses the

perspectives of industry leaders, their current practices, and plans for the green transition (Busch et
al., 2022). In addition, there is a lack of available data regarding several areas of interest in this
topic of research including accurate numbers of CO2 emissions in Egypt and the cement industry’s
share in it. Also, as presented in the literature review, there are few studies on reducing emission in
the cement industry in developing countries, and this applies for Egypt for both qualitative and
quantitative studies. For this study, a qualitative approach for understanding potential green
transition options for the cement industry in Egypt is supplemented by conducting content analysis
of relevant reports and publications to gain a comprehensive understanding. The content analysis
was done prior and after conducting the expert interviews so that focus points can be identified and
then later further explored. This approach allowed for a more in-depth exploration of the social,
economic, and environmental factors that influence the adoption of sustainable practices.
3.3. Research Design and Sampling
This research used two main methods: in-depth interviews with relevant experts, and content
analysis of relevant reports and official data. The following describes these methods used.
First, systematic content analysis addressed the gray literature available on the cement industry in
Egypt. These included industry reports from international organizations like the International
Energy Agency and the Energy Transitions Commission, and local relevant official publications
including Egypt’s NDCs, Ministry of Environment and EEAA publications, among others. A total of
40 documents were analyzed and the emerging themes helped inform the guiding questions for the
interviews, as well as triangulation of the results of the interviews by including diverse backgrounds
of participants and contrasting results with other interviews and data from content analysis. Some
documents were also identified from the interviewees and were included in the content analysis.
Second, in-depth interviews were selected as the research tool that is most suitable to collect data
from industry experts. The approach used for identifying the interviewees was non-random
sampling. To get quality in-depth insights within the scope of this study, a purposive quota sampling
technique was applied to identify potential participants. There were three different stakeholder
categories identified for this research, first were cement producers, which included senior
executives at cement companies in Egypt. The second category were either senior officials or
consultants within the regulatory and financial sphere, which included the official regulatory agency
in Egypt that supervises the cement industry, Egyptian Environment Affairs Egypt (EEAA) and the
European Bank for Reconstruction and Development (EBRD). The last category were senior

experts in the technology provision sector, to understand the current offerings available to cement
companies to support their green transition.
The interviews were conducted using a semi-structured interview guide with separate set of
questions for each category, which can be seen in Annex 1. Interviews were recorded and
transcribed and were conducted in both English and Arabic. Interview files were stored in an online
2-factor authentication drive. A total of 12 in-depth interviews conducted for this study, with the
following breakdown, all using online calls of 40-50 minutes:
- Cement producers: a total of 7 interviews with senior executives in the cement industry in
multinational and local cement companies. Local companies’ interviewees included
executives from private family-owned companies as well as EGX listed companies. This
provided a good overview of cement companies in Egypt, but no interviews were conducted
with representatives from state-owned cement companies – which represent 30% of the
market.
- Regulatory/Finance officials: a total of 3 interviews were conducted with senior
consultants in the EEAA and the EBRD.
- Technology providers’ representatives: a total of 2 interviews were conducted with
technical experts within companies offering green transition solutions to cement producers.
3.4. Data Analysis
This study used thematic analysis as the primary method to analyze the data collected through
indepth interviews and content analysis. Thematic analysis allowed for understanding the data
gathered through the 12 interviews on a more abstract level. This approach allowed me to organize
the findings into different themes including regulatory challenges, market and operational
dynamics, financing concerns, among others.
3.5. Ethical Considerations and Limitations

Ethical considerations
The relevant procedures were followed while conducting the qualitative research for this thesis. The
required IRB approval was acquired before conducting any interviews. Informed consent was
obtained from all interviewees who acknowledged understanding that no potential harm or benefit
will be gained from this research. For all interviewees, anonymity was agreed when quoting, and if
a quote had to be referenced directly, it will be verified first with them.
In terms of positionality, I have worked in the cement and mining industries for more than 10 years,
which allowed me to get high quality in-depth interviews with senior executives in the industry as
well as consultants. I have conveyed to all my participants the academic nature of this study, and
there was no competing financial interests or personal relationships that could have influenced the
results of this research.
Research Limitations
There were several limitations faced while conducting this research. First, the fieldwork and indepth
interviews conducted with cement companies did not include state-owned companies due to time
and bureaucratic concerns. It should be noted that interviews with cement experts in the private
sector indicated that state-owned companies would be facing the same concerns and challenges in
pursuing green transition options, but no further exploration was possible. This should be a future
research topic for researchers interested in the field. Second, the focus of this thesis was the supply
side of the cement industry, exploring the different pathways for cement production companies in
Egypt. While the literature review and international experience indicates a growing emphasis on the
demand side as well, such as reducing the amount of cement used in infrastructure and buildings by
using enhanced structural engineering, 3D manufacturing or printing, or alternative building
materials, these options were not explored within the context of this research. Further study is
required to explore the potential of these options in Egypt.
3. Chapter Four: Contextual Background on the Cement Industry in Egypt
This section presents an overview of the cement industry in Egypt and the most relevant historical
policy milestones, in addition to the environmental impact of the industry. This section also
provides an understanding of the current economic and market conditions for cement, which would

affect efforts to move toward more sustainable practices. The section ends with an overview of the
current regulatory framework and policies relevant to environmental impact, and an introduction to
the key stakeholders for the green transition of cement.
4.1. The cement industry in Egypt
Historically, the cement industry drew much attention in the 1990s with the state’s privatization
program that allowed multinational and private companies to buy state-owned cement plants or
establish their own (Ghoneim, 2010). This allowed the cement industry to increase its production,
and Egypt turned in a few years to be an exporter of cement, after being the second largest importer
of cement in 1993 (Ghoneim, 2010). This privatization was able to attract several long-term foreign
investments including Germany’s HeidelbergCement, France’s Vicat, Switzerland’s
LafargeHolcim, Greece’s Titan Cement and Mexico’s CEMEX, and Spain’s Cementos La Union.
Today, the cement production landscape in Egypt is mixed, with 19 companies operating 24 cement
plants. Of these 19 companies, there are five multinational companies, two state-owned, and the rest
are national or regional private entities. It is worth noting that the cement industry plants in Egypt
are fairly new, since more than 50% of the facilities have been built after 2000. This is relevant to
the green transition question since newer facilities tend to be easier to retrofit or adjust to increase
energy efficiency and solutions that reduce co2 emissions.
Another chronic issue that has plagued the Egyptian cement market is oversupply, where plants are
running at 70% capacity, and there is a yearly production quota agreement sponsored by the
Ministry of Trade as of 2021. The cement demand peaked in Egypt in 2015 at around 54 million
tons, but has dropped to close to 45 tons, production capacity has increased to 87 million tons
(Cemnet, 2021). This rise in production capacity is due to the inauguration of a state-owned 13
million ton-per-year plant in the recent years, which represents more than 20% additional supply to
an already troubled market (Reuters, 2021).
It should be noted that the cement industry has been facing several economic challenges in the past
10 years. The following sections will give an overview of the challenges relevant in the context of
the green transition.
Energy crisis: gas shortages and removal of fuel subsidies (2010-2015)
The challenges go back to the early 2010s when Egypt was faced with an extreme energy crisis that
was caused by the lack of natural gas (Hafeez et al., 2015). This lack of natural gas in turn led to

severe power shortages and blackouts across the country as the power generation plants were not
getting enough energy. This resulted in the Egyptian government redirecting a huge share of the
natural gas that was going to industrial factories, including cement, to power generation plants. This
was also coupled with the phasing out of fuel subsidies that cement companies were benefiting
from. This resulted in billions of lost revenues due to the lack of production during these early e
years (ACC, 2016).
These energy challenges continued until 2015, when it was finally resolved by allowing cement
companies to import high-intensity CO2 fuels like coal and petcoke (EBRD, 2016). Before that, the
Egyptian Environmental Affairs Agency (EEAA), one of the regulatory bodies for the cement
industry, had not allowed the import of coal due to public health concerns. In fact, during the years
prior to the decision, there were several local campaigns by environmental and human rights
activists against the importing of coal (Zayed & Sowers, 2014). The new regulations did have a
requirement for cement plants to have an action plan of how they would mitigate the increased CO2
emissions resulting from the use of coal, but it did not have obligatory guidelines of how it will
enforce these plans (EBRD, 2016). It should also be noted that this switch to using coal instead of
natural gas required a high capital investment from the cement companies, estimated to be 600
million USD at the time (ACC, 2016). The huge capital investments by cement plants in Egypt to
switch to coal in the past years can also explain the reluctance to invest in green transition
technologies, especially during worsening economic conditions.
Economic challenges and Currency Devaluation (2016-2018)
At the end of 2016, the Central Bank of Egypt (CBE) implemented a significant currency
devaluation as part of an overall economic reform plan (PWC, 2016). This resulted in the Egyptian
pound losing around 50% of its value against the US dollar. This was part of economic reforms
aiming at addressing several challenges including a decreasing foreign currency reserve and a
growing budget deficit, among others. Typically, this would have been good news for the cement
industry, and other potential exporting industries, as it meant that Egyptian exports are now more
competitive in the international market. However, the currency devaluation had a tremendous
negative effect on the cement industry since the production process was now fully dependent on
imported fuel like coal, which meant that their operating costs have suddenly exponentially risen.
Also, cement plants are dependent, for the most part, on imported spare parts and service

agreements with multinational companies, which means their operation fees have also doubled
(Ramadan, 2020). It should be noted that the 2016 currency devaluation and economic conditions
have also had their effect on cement demand in Egypt, as demand for cement started declining in
the following years (Reuters, 2018). In summary, the currency devaluation increased the operating
expenses of cement plants due to the dependency on imported fuel and spare parts, while the
resulting economic downturn meant a decrease in demand for cement in the Egyptian market.
Oversupply due to economic conditions and new state-owned plants (2018-2020)
The economic challenges from the previous years continued, and it was worsened in 2018 as the
Egyptian cement market started facing a new challenge: severe oversupply. In 2018 a new
stateowned 1.1$ billion USD cement plant was inaugurated, which broke the records for the biggest
cement plant in the world to be built at one time and one place, and the largest cement plant in
Africa (Reuters, 2018). This added production capacity worsened the oversupply crisis and several
companies made public calls claiming there are risks of closing plants or divesting, with few
suspending operations and conducting major layoffs (Ramadan, 2020). In 2018, the Egyptian
government did close off one of the historical state-owned cement plants (National Cement
Company), but one that had been idle for several years already (Reuters, 2018). This did not change
the chronic issue of oversupply but was seen as a token gesture for changing policies within the
industry.
Yet, the situation continued to get worse for cement producers, several companies started reducing
their manpower due to low utilization, and other companies shut down their plants temporarily. This
was further exacerbated when the Egyptian government enacted a new building permits system that
put a freeze on construction in Cairo and other capital cities in the governorates at the end of 2019.
As Covid-19 hit, the cement industry continued to face increasing oversupply and lower demand
problems. The majority of cement consumption is mostly for individual usage, whereby 60% on
average is domestic and only 40% is going to industrial uses like infrastructure projects including
bridges and major constructions. Individual usage refers to apartment buildings and other small
works by mid-size and individual contractors including home renovations, new buildings, among
others (Ramadan, 2020). This means that even the massive infrastructure projects and new cities
built by the public did not generate enough demand that would have compensated the decrease
caused by the economic downturn (Ramadan, 2020).

Cement’s lifeline: industry-wide production quota (2021-2023)
In the second half of 2022, and after years of calls and different media statements, mostly by
multinational cement companies, cement producers reached a unanimous agreement with support
from the Egyptian Competition Authority (ECA), in coordination with the Industrial Development
Authority (IDA) to apply a production cut of 10% across all plants, with some variations depending
on the cement plant’s capacity, and other financial specifications (Reuters, 2021). The quota was
welcomed by the industry as it provided needed assurance and stability. This production quota was
requested by the majority private and international cement producers in Egypt, after oversupplying
due to the inauguration of new state-owned plants, as well as dwindling demand due to building
restrictions and economic downturn started to have severe effects. In the years prior to the
production quota, there have been several plants that have halted operations, shutdown production
lines, or laid off staff due to economic pressures (Enterprise, 2021). The quota allowed producers to
reduce their losses and provided a degree of stability for companies to plan their operations. It
should be noted that there were also criticisms to this regulation since it meant an increase in
cement prices from an all-time low, which was justified by producers as a needed measure to remain
economically viable. However, it is important to note that the quota was set for one year only,
which limits the ability of cement companies in forecasting their sales and revenue, and thus their
capacity to make long-term capital-intensive decisions like retrofitting or installing equipment that
will support in reducing Co2 emissions.
The official reasoning for the quota system, as per official communication, was to control the
oversupply in the market and stabilize prices, while maintaining that all companies can continue
operating in an economically viable way. Companies that were able to export their excess product,
were exempted from the quota. However, it should be noted that Egypt’s cement fee on board
(FOB), which is the price used to quote for exporting, is not competitive compared to other regional
players, due to factors including high shipping costs, the higher bill of fuel and other operating costs
in Egypt, among others. Essentially, this means Egyptian cement companies do not have many
opportunities for exporting, except for neighboring markets that are accessible by trucks (EBRD,
2016).
In 2022, the production quota system for cement industries was renewed for another year, and the
move was again welcomed as there has been no major changes in demand, which is still 70% of
total production capacity (Enterprise, 2022). As of July 2023, there are reports that the quota system

will again be renewed for 2023-2024 as well, and cement companies are endorsing this renewal as
they believe is the only way to navigate the dilemma of oversupply and decreased demand
(Enterprise, 2023).
4.2. Carbon footprint of cement industry in Egypt
Historically, Egypt's cement plants were underperforming when it comes to control of air pollutants
when compared to international standards. This was due to relaxed regulation that was eventually
brought up to speed in 2010 when the Egyptian Environmental Affairs Authority (EEAA) amended
the regulations for harmful emissions from cement plants and put in place a monitoring system
(Askar et al., 2010).
According to the most recent available data, the cement industry in Egypt is estimated to be
responsible for up to 14% of Egypt’s CO2 emissions, which is double the global average (EBRD,
2016). In terms of fuel, the cement industry in Egypt uses a fuel mix of almost 95% coal and
petcoke, which are high carbon emitting fuels, and only 5% of waste and refuse derived fuels
(RDFs). It should be noted that this increase in CO2 emissions for the cement industry is largely
attributed to the allowance of using coal in 2015.
The global average for the cement industry in using waste and refuse derived fuels (RDFs) as a
source of energy is 15%, but the good available practice, which is an indication of moderate targets
that can be reached by cement plants goes up to 30% (IEA, 2018). As for the direct CO2 emissions
per ton of cement, the Egyptian cement market also compares unfavorably to the global average:
each ton of cement produced results in more than 800 kilograms of CO2 emissions, which is far
more than the global average of around 650 kilograms of C02 per ton of cement (EBRD, 2016t).
The cement industry in Egypt had a track record and reputation of contributing to air pollution since
the 1980s, and the different Egyptian governments had tried to mitigate this by opening new plants
in remote areas to reduce usage of plants in the middle of the cities like Cairo and Alexandria
(Zayed & Sowers, 2014). More recently, the cement industry in Egypt began lobbying for
introducing the use of coal as an alternative to natural gas that started to be scarce in supply in the
years following 2012 (EBRD, 2016).
The move to use coal was not without opposition, as coal is linked with adverse health effects and
increased pollution (Zayed & Sowers, 2014). In the years following 2012 and up to 2015, there was

considerable debate on the use of coal from different civil society organizations, but eventually a
regulation allowing the import of coal was enacted (Zayed & Sowers, 2014).
4.3. Regulatory framework and policies related to environmental impact of cement
industry
The cement industry in Egypt is regulated by Egyptian Environmental Affairs Agency (EEAA)
which was created in1994 to oversee companies working in the fields of cement, oil and gas, among
others (IEA, 2022). The current guidelines for the cement industry by the EEAA mainly concern the
dust emissions and air pollutants limitations and does not have mandates for CO2 emissions limits.
These guidelines have remained the same from 1994 until an amendment in 2010 decreased the
allowable limits of air pollutants from cement plants to match international standards (Askar, 2010).
In 2015, the EEAA allowed cement plants to import coal, which was previously banned, to use as
fuel in the production process after a severe energy crisis. The next update came in March 2021,
when the EEAA published new regulations for mandatory partial replacement of coal in cement
plants (EEAA, 2021). The regulations set a new quota of 10% minimum use for alternative fuels
(RDFs) as a requirement for cement plants to achieve every year to renew their licenses to import
coal – which makes up 95% of the fuel used (EBRD, 2016). These regulations constitute the
regulatory framework that governs the environmental impact of cement plants, which is still notably
missing a clear mandate for carbon emissions.
However, in the latest update of Egypt’s Nationally Determined Commitments (NDCs), the
Egyptian government issued a clear declaration to implement several measures to reduce carbon
emissions for Egyptian industries as a whole. For the cement industry, the national commitment
meant lowering the clinker value in cement to 80% conditional on meeting relevant national
standards, and implementing energy improvements (UNFCCC, 2023). In spite of these new
commitments, there are still no clear carbon pricing approaches by regulatory authorities in Egypt,
including the ones for cement. It is worth noting that recent studies have demonstrated potential
positive impact for carbon taxes on economic activity in Egypt. (Elshennawy & Willenbockel,
2021)
The NDCs also included a commitment to increase the usage of waste-to-energy by utilizing waste
in the cement industry as a fuel to replace coal, and to reach a 20% utilization rate of total collected

waste (UNFCCC, 2023). The NDCs indicated there is also a plan to improve waste collection
efficiency from 55% to 95% by 2025. This is relevant to the discussion on using alternative fuels
such as solid waste in cement, but as the following section will discuss, there are challenges to
procuring enough waste to use as fuel by the plants (UNFCCC, 2023). Lastly, it must be
highlighted that while the latest NDCs published by Egypt have certain action items for the cement
industry, there is no clear number or commitment for the percentage of reduction for CO2
emissions. The current share of CO2 emissions from cement production in Egypt is reported to be
14%, and the NDCs did not mention that number, and did not mention a target number (UNFCC,
2023).
There have also been recent policy developments for waste management. The executive regulations
for the Waste Management act of 2021 finally came out in 2022, to set guidelines for the safe
disposal of different kinds of waste and identify how it would be financed. The regulations
stipulated that relevant administrative authorities would provide a range of incentives for companies
working in the field of solid waste management and recycling including tax and financing
incentives, in coordination with the newly established Waste Management Regulatory Authority
(WMRA) (UNEP, 2020). Also, these new regulations established a timeline of two years from the
date of issuance for the New Urban Communities Authority (NUCA) to finance municipal waste
management in new cities. It is worth noting that cement plants would be the biggest buyers for
municipal waste as it can be used as alternative fuel (EBRD, 2016). However, as these rules and
regulations have just come into effect, it would be early to assess their effect.
4.4. Landscape of key stakeholders influencing a green transition
Implementation of sustainable development practices in the cement industry will require close
collaboration of different stakeholders including cement producers, official regulatory authorities in
Egypt, and relevant industry associations, among others. In addition, there are other key
stakeholders who could influence the green transition in cement that industry players will have to
collaborate with. It is thus important to understand these dynamic relationships between these
players.
First, the construction sector is one of the most important stakeholders. The Ministry of Housing,

Utilities and Urban Development, along with the relevant authorities that set and oversee the
Egyptian construction code and practices, would be the main drivers of allowing the cement
industry to reduce the clinker content in cement. This will involve capacity building and ensuring
monitoring mechanisms are in place, as well as updated labeling and technical guidelines (EBRD,
2016). Organizations responsible for architectural and structural designs will also need to be
involved, as well as construction and real-estate companies that are on the demand-side of cement
and would also facilitate the reduction of CO2 emissions if they start to incorporate sustainable
practices in design and building (EBRD, 2016).
Other important stakeholders include regional and international financing partners. There have been
a few green financing programs available for cement companies in Egypt to apply for green
financing, which would mean more favorable lending terms, and often a small percentage of grant
(EBRD, 2016). Most notable initiatives have been the Egyptian pollution abatement program
(EPAP), and the green economy financing facilities (GEFFS) by the EBRD. The range of offering
can include financing, but also technical assistance and knowledge transfer of new technologies.
This has provided few opportunities for cement companies to finance expensive upgrades that
would increase their efficiency and lower their co2 emissions (JICA, 2018)
Lastly, the most notable stakeholders of government organizations, other than the obvious EEAA,
would be the newly established Waste Management Regulatory Authority (WMRA). This authority
is mandated to regulate and improve the waste management infrastructure and can have positive
impacts if collaboration is improved with cement plants. There are several policy measures and
action points that would need to be coordinated to allow the creation of a cyclical economy for
Egypt’s waste, and ensuring cement plants have access to waste that would be used as an alternative
fuel to coal.
4. Chapter Five: Findings and Discussion
This chapter presents the main findings and results of the interviews with industry experts and
content analysis of key documents in the industry. These findings include in-depth discussions with
cement producers, green transition technology providers, and experts in the regulatory and
financing policy spaces. This chapter is divided into five different themes. The first will present new
insights from senior executives in the cement industry on the outlook of the market and the
upcoming transition. The second will provide an important comparison in the different readiness

levels for cement companies to embrace green practices. The third section will present the current
practices that are in place to reduce CO2 emissions in the cement industry in Egypt, and future
potential options. Finally, the fourth section will provide a summary of the major regulatory
framework and financing challenges to reducing carbon emissions in the cement industry.
5.1. Insights on current outlook Egyptian cement market
The cement market in Egypt has been facing a chronic oversupply problem that was exacerbated
when new state-owned plants also joined the market in2018 (Reuters, 2018). In 2021, the Egyptian
Competition Authority (ECA) stepped in to resolve the chronic dilemma by establishing a year-long
agreement with all cement producers to mandate a quota system of supply cuts in the range of 10%
to 13% (Werr, 2021). This policy change tried to stabilize the market and protect cement producers
that were on the brink of collapse. The quota system was applied in the summer of 2021, and was
renewed for one more year in 2022 to the summer of 2023. Currently, there are news reports
indicating there are requests from most cement producers to renew the production quota for two
more years, to provide more short-term visibility to the market (Enterprise, 2023). This comes after
a continuous decline in demand for cement, with 2023 in specific seeing further year-on-year 9%
decrease in demand (Enterprise, 2023).
This uncertainty has been reflected in the comments by industry experts, as one senior executive
highlighted as lack of short-term visibility of forecasted production capacity beyond one year, and
consequently of sales and revenue, can limit their ability for effective planning and budgeting:
“Yes, the cement production quota since July 2021 has greatly helped stabilize the
market, but the problem is it was a one-year agreement. Last year, the renewal of the
quota was announced only a few days before the expiration of the previous
agreement, and it was also for one-year. This year, we are in the same situation, it’s
less than one month and we have no confirmation, but we are optimistic of the
renewal. You can imagine what this means if you are trying to make long-term or
even medium-term budgeting.” (Cement executive 1, local private sector, 20-
June2023)
As mentioned above, this uncertainty makes it harder for companies to plan short or medium-term
projects. The quota agreement sponsored by the Egyptian competition authority (ECA) puts a cap

on production capacity by the cement plants, and this in turn has consequences for how much sales
they can budget for, and other operational needs. This means their revenue estimations are also
affected, and hence any plans for large-scale projects related to sustainability or reducing emissions
as well.
This has also been coupled with continued stricter regulations on building permits in Cairo and
other governorate’s capitals and main cities, which was cited by several cement executives as one of
the main reasons for declining demand and was also referenced by the CEO of the biggest
multinational cement company in Egypt in a recent public interview (Ramadan, 2020). Also, in
early 2023, the Egyptian government announced it will reduce expenditures on construction and
infrastructure projects, as part of the efforts to mitigate the foreign currency shortage, which will in
turn cause further reduction in demand for cement (Abelmoneim, 2023). These reductions are
expected to have effects on the cement industry as well. As for smaller consumers or individuals,
the decrease in demand is also caused by stricter building codes in the main cities (Ramadan, 2020).
As previously mentioned, most of the cement use is for domestic demand (60%) which means that
all these components together directly affect the core business of the industry (Ramadan, 2020).
In addition, here are also certain industry specific challenges that have negatively impacted the
market. One of these identified by my respondents are the increased operating costs coupled with
lower export opportunities as a new executive from a local private Egyptian company further
elaborates:
“There are more challenges for the cement industry, a couple of years ago there was
a national company established for the management of quarries and mines, and it
imposed significantly higher fees for the quarries we are using. Also, the current
security situation in Sudan has meant that our export options have decreased even
more.” (Cement executive 2, local private sector, 3-July-2023)
In addition to these challenges, the current foreign currency shortage also adds to the long-existing
woes of the industry, and this will be reflected in the below sections on green transition options and
their feasibility. The majority of my respondents, especially from local Egyptian private companies,
indicated that one of their biggest operating challenges is the importing of coal and other major
spare parts as the foreign currency shortage and fluctuation in rates makes it more difficult to plan.
Also, respondents indicated that the recent devaluation of the Egyptian pound has meant that
installing or retrofitting equipment for reducing carbon emissions is even more expensive as most

are imported technologies and parts. These macroeconomic challenges are one of the biggest
hinderances to reducing GHG emissions in industry, as illustrated in recent literature from other
developing countries. (Morrow et al., 2012)
5.2. Current practices to reduce Co2 emissions
Overall, the general market trend is that multinational companies have already started taking action
to reduce their carbon emissions long before any regulations or policy pressures from authorities in
Egypt. These actions or initiatives were implemented mostly due to ESG reporting requirements by
the different multinational companies’ global directives.
The interviews conducted with senior executives in different cement companies provided an
understanding of the current practices by cement producers in Egypt to reduce their carbon
emissions. A senior executive in one of the Egyptian private local cement companies provides an
explanation for this trend:
“Of course, the multinational cement companies in Egypt have already started
implementing actions towards environmental sustainability before local regulations
came into effect. This is because they have their own global ESG mandates that they
must follow. But you must also note they can finance such projects. Most local
private companies do not have such mandates and will only do these sustainable
projects when it economically makes sense and can provide either increased revenue
or decrease cost but also it can be difficult if a big investment is needed in these
market conditions.” (Cement executive 1, local private sector, 20-June-2023)
The above quote resonates with the other respondents from multinational companies, who have
confirmed they have had environmental objectives from their global management to mandate
energy efficiency and carbon emissions reduction upgrades for several years now.
However, it should be mentioned that most cement experts and consultants agree that there are at
least certain potential green transition options that all cement producers will be looking to
implement, like fuel substitution which promises savings on the import of coal if substituted by
waste derived fuels. These would include the usage of solid waste and refuse derived fuels (RDF) to
replace a portion of the imported coal that is currently the main fuel used in the industry in Egypt.
One of the senior executives in a leading private Egyptian cement producer explained how
sustainable practices can be good for business:

“To work in an environmentally sustainable way is good for two reasons, to reduce
the environmental impact, but also it is good for business. We have set our own
environmental sustainability plan for 2030 before the new regulations from the
EEAA and with more ambitious targets, this is because the first step in the green
transitions is to have operational excellence in production processes to reduce
energy consumption. If you manage to reduce the fuel you need, you automatically
reduce your CO2 emissions, but also, you reduce the need to use imported coal – this
means lower operational costs and most importantly less dependability on hardto-
find foreign currency for importing. On the same note, improving the reliability and
performance of your equipment will mean less electricity used, which will also result
in decreasing CO2 emissions. These are win-win solutions where CO2 emissions can
be reduced without the need for capex investments.” (Cement executive 2, local
private sector, 3-July-2023)
This sentiment shows that there are at least some actions that cement companies are already
considering reducing their CO2 emissions before or regardless of policy pressures. Another
producer mentioned some of the steps they have also begun to consider in the past years to establish
their own subsidiary for waste management to supply their cement plants with waste needed for
waste derived fuels.
There is a multitude of new technologies that are featured in recent literature that promise a huge
potential of reducing CO2 emissions in cement production (Busch et al., 2022), but within the
Egyptian context, the interviews with industry experts pointed to a few options only.
The most common practice that cement companies in Egypt are using to reduce their CO2
emissions is the shift to alternative fuels - fuels that are less carbon intensive than conventional
fuels. Alternative fuels are an expansive term that includes different kinds of waste from solid waste
to sludge and sewage waste. Even though the above quote mentions the push by the new EEAA
regulations for cement companies to substitute 10% of their energy by alternative fuels, the next
section will elaborate on why this might not be as effective as it is expected to be. However, the
other current major driver for cement companies to use refuse derived fuels from waste instead of
coal is indeed because of the foreign currency shortage, as supported by evidence from other
interviews. This can be considered a beneficial consequence since supporting cement plants to use
refuse derived fuels (RDFs) can deliver several benefits in addition to reducing CO2 emissions.

However, using refuse derived fuel (RFD) is not as simple as it can seem at the first instance. There
are several challenges with procuring and sourcing waste for cement companies to as can be seen in
below quote by one of the senior executives interviewed, who was also responsible for the cement
company’s subsidiary created for waste management:
“There is a huge market gap for alternative fuel in the cement industry, yes, a recent
study just before COP27 indicated a need 2.5 million tons of alternative fuel is
needed by cement plants, and to meet that target, 15 million tons of municipal waste
must be collected. The problem is that collection is very expensive, we do have tons
of garbage available, but the collection and handling is too expensive. The
shredders, and other equipment needed for the recycling process are all imported,
which means prices have skyrocketed. I was the general manager of our company’s
subsidiary for waste management, and we have been losing on an annual basis for
five years, and barely broke even in the one year.” (Cement executive 3,
multinational private sector, 5-July-2023)
The statement above provides insight into the challenges of the private sector waste management
companies, which have been suffering due to several economic and structural challenges in past
years. A recent report by Enterprise indicated that 15 waste management companies have closed
since 2013 (Enterprise, 2022). The latest version of Egypt’s NDCs have a dedicated section for
waste management initiatives, and it includes a commitment to bring up collection percentages to
95% up from 55% by 2025 and to increase the recycling and waste to energy rates (UNFCCC,
2023).
However, it seems that cement plants also face other less obvious challenges in this regard, because
in the absence of efficient solid waste management infrastructure, cement plants can find it difficult
to procure the needed waste to fulfil the quota, and it can get quite expensive as the below quote from
a senior executive in a cement production company explains.
“I wonder if there was enough market study for the waste management sector before
introducing the new EEAA regulations of mandating 10% refuse derived fuels
(RDFs)? Did they consider the required tonnes of waste that will be needed by the 24
cement plants in Egypt? Now, it is probably 7-8 plants that are using refuse derived
fuels, and if that number is expected to suddenly increase then there will be a
shortage of waste to use, and I can tell you the vendors are aware of this. We already

face price hikes when we are procuring the waste because the waste management
companies are moving their prices with coal prices because they know this is the
only other alternative in the market. This is not good for the market or the
environment. The use of refuse derived fuels in cement plants is a cumbersome
process that includes many technical challenges that must be overcome, including
how to handle the different kinds of waste in a safe way, and so on. If the price of
waste becomes close to the price of coal, the cement plants will just choose coal.”
(Cement executive 6, multinational private sector, 20-June-2023)
While this sentiment was echoed by other interviewers, it must be noted that other cement
executives indicated that the foreign currency shortage is a continuous problem so far, and one that
has been as extreme as nearly causing some plants to stop their operations due to lack of foreign
currency to import coal. Accordingly, while the challenges with using refuse derived fuels (RDFs)
are acknowledged, it is still expected to be prioritized by cement companies as it can relieve a share,
even if small, of the foreign currency shortage.
There are other practices that cement companies in Egypt have started implementing to reduce their
carbon emissions and increase their operational efficiency. Most notably, waste heat recovery
(WHR), is one of these options. Waste heat recovery is a process by which excess heat and energy
from the cement production process can be recaptured and turned into electricity that the plants can
use (Busch et al., 2022). This can provide cement plants with considerable savings on energy
consumption and subsequently provide a sizable reduction to carbon emissions. However, only a
handful of cement companies in Egypt are considering or implementing this solution. This is
because there is a huge capital investment required for the initial setup, and two different executives
have conveyed that they put their plans on hold after the most recent currency devaluation at the
end of 2022.
The below quote by a senior technical expert at one the global leading providers for cement
equipment provides contextual background for why this is the case:
“We have one of the best solutions in the market for substituting high carbon
emitting fuels like coal with a wide variety of solid waste, from sludge to tyres, and
this solution provides guaranteed cost reduction since there will be less dependance
on high-cost fuels. However, we only have one installation in Egypt’s 24 cement
plants, and while of course there is competition, we can also observe the demand for

green technology solutions in Egypt is driven only by economic viability of the
solution itself. So, if there are no policy pressures, no price put on carbon emissions,
no incentive for cutting it down either, then the cement companies will only pursue
such options if it makes sense from an economic point of view only. And currently,
the cement market in Egypt is in a dilemma due to the oversupply, the foreign
currency, and other economic conditions. (Cement technology expert 1,
multinational private sector, 20-June-2023)
The above quote summarizes the overall status that cement companies would only act based on
incentives or cost. This is consistent with other research findings that clearly indicate that for
companies to invest in green transition technologies, there are certain policy assurances that need to
be in place first (Busch et al., 2022).
5.3. Low carbon roadmap challenges: regulatory framework and financing options
The literature on reducing emissions in heavy industries, including cement, highlighted the
importance of regulatory frameworks for guiding the transition to more sustainable practices
(Rissman et al., 2020). There have been several updates to the regulatory framework that governs
the cement industry. These changes have been briefly discussed in previous sections, but this
section explains how these recent changes affect the efforts by cement companies to reduce their
carbon emissions. This section will also provide insights into the available green financing options
available to the cement companies, and the challenges that come with it.
While there has been an increase in policy pressures to the cement industry in some regions, like the
emissions trading system (ETS) that the EU set for its industries, including cement plants
(CEMBUREAU, 2020), this does not yet exist in Egypt. Currently, Egypt does not have maximum
limits for CO2 emissions for the cement industry. While the EBRD did publish a low carbon
roadmap for the Egyptian cement industry in 2016 (EBRD, 2016), this roadmap needs to be
revisited now, as indicated by the below comments from one of my respondents, a senior EBRD
regional economist who worked on the report in 2015:
Our whole baseline for the report has to be recalculated, because when we do these
types of studies, cement, steel, whatever the industry is, at least 80% of the capacity
of the market has to be represented in the modeling analysis, so considering that the
new state-owned cement plant is about 25-30 of the overall production capacity, this

means the baseline has to be redone basically. And that will change the business as
usual, the accelerated and the fast accelerated scenario,
Other thing: we did this study in 2015 with a view up to 2030, so a 15-year
projection period, now it has to be done up until 2050 and with a view of net-zero
commitment or 1.5 Paris alignment commitment. At that time the government of
Egypt had not ratified the Paris agreement, they did that later in 2016 and ratified in
2017, which means that we did not include the long-term low carbon levers or
technologies like CCUS or large-scale deployment of green hydrogen or large-scale
deployment of wind or photovoltaic into the cement industry. (EBRD Regional
Director, 1, 24-July-2023)
The above quote speaks to the importance of new research efforts to create an updated version of a
low carbon roadmap for cement industry in Egypt, which will reflect the new realities of
oversupply, but also of increased government commitments to reducing emissions.
However, this government commitment is not yet reflected in the regulations of the EEAA, as
confirmed by interviews. So far, carbon emissions are measured and governed by requiring cement
companies to provide periodical performance reports that indicate their energy usage and updates on
voluntary action plans to offset the increased CO2 emissions due to the use of coal, compared to the
base year of measuring CO2 emissions, 2014 – which is the base year used by authorities to monitor
cement companies. The below quote from a senior consultant with the EEAA explains how the
periodical reporting works and the reasoning behind the voluntary approach:
“So far there is no mandatory CO2 emissions reduction target for cement plants,
there is general guidance that pre-2014 levels, which is pre-using of coal is not
surpassed but not yearly or periodical reduction target. The industry is already in
very hard economic conditions and the demands must be realistic.” (Cement
consultant 1, 9-July-2023)
While this approach can be justified by the challenging economic conditions, it can also make
planning for a green transition more challenging. Without clear emission limits or regulations in
place, it can be difficult for cement producers to prioritize reducing their emissions during
challenging economic times. This lack of regulation may also discourage investment in cleaner
technologies and processes, as companies may not see a financial incentive to make these changes.

The current framework by the EEAA has additional flexibility for cement companies as it does not
have an interactive or automated monitoring and verification (MRV) system for CO2 emissions, as
confirmed by interviews. The initial step in greenhouse gas emissions reduction action plans
typically start with collecting quality data in place to make informed decisions.
Evidently, the absence of data can make it harder for policymakers to set clear targets and track
progress towards reducing emissions from the cement industry, which is a significant contributor to
Egypt's overall greenhouse gas emissions. Nevertheless, the new EEAA regulations mandating
cement companies to have at least 10% of their fuel mix as refuse derived fuels (RDF) has clearly
put a financial obligation on these companies. To comply, cement plants will need to install or
adjust certain equipment that would involve a huge capital investment. The regulations do not offer
a grace period, but they do indicate a financial penalty that would be applied in case of
noncompliance. A senior executive in one of the cement companies explains the process further:
“The way the regulation works is that a percentage of 10% from total fuel needs of
the cement plant is supposed to be from RDF, but there is also a penalty that can be
paid if this percentage cannot be met. The penalty is not substantial, so some local
companies prefer to pay the penalty than to do the necessary capital investments and
operational changes needed to use waste as an alternative fuel. What is even worse
is that this approach is reportedly welcomed by the authorities as well because it
means more revenue for them. While they should instead be putting more pressure to
the plants to make an action plan to start using waste as an alternative fuel to meet
the regulations. (Cement executive 3, multinational private sector, 5-July-2023)
The above approach is counter-intuitive to practices that have been referenced in different
literature that calls for holistic policy actions (Busch et al., 2022). However, there are cement
companies that are increasing the percentage of alternative fuel from waste well before the
regulations came into effect. As explained above, this is because despite the challenges
associated with using waste as an alternative fuel, it still provides the companies with an
opportunity to save some hard-to-find foreign currency which is used for importing coal. But
this is not an approach that can be sustainable in the long run, and this has been proven more
than once, as the example in the below quote.
“If there are no incentives to use waste as alternative fuels, then any company will
only use it when it makes economical and operational sense. You must understand

burning a ton of coal is not like burning a ton of waste. There are technical
difficulties that must be overcome so it must be cost effective. For example, in the
last years there was a couple of times when cement plants went back to using 100%
coal when its prices dropped in 2015 and in 2022 – because then it made sense to
just use coal, even if its imported, and not have to do the other operational and
technical workarounds necessary to use waste as alternative fuel” (Cement executive
6, multinational private sector, 22-June-2023)
Evidently, this is an example of the importance of a regulatory framework that would provide the
right mix of incentives and limitations for the cement industry that would guide the companies in
managing their carbon emissions. While the recent changes present an improvement, there are still
calls for a more holistic approach, as the challenges of utilizing waste in cement plants go beyond
regulations or mandates for the cement industry. Experts have stated that waste management in
Egypt has a chronic problem with informality and financing, and cement companies have
experienced this first-hand as confirmed by several participants. There are several companies that
have started their own subsidiary companies of waste management to guarantee a continuous flow
of waste to be used as alternative fuels in their sites, but this has been a challenging endeavor, as
discussed with a senior EEAA consultant:
“It is very good that cement companies start waste management subsidiaries
because they can increase the standard of the market, but it is not profitable. People
are confused when they hear waste management companies here are losing money,
while they are profitable business outside of Egypt. But you can easily observe this
regardless of where you live in Egypt, look at any garbage disposal place and you
will see the “scavengers” or informal garbage collectors and they take out the
plastics, the paper, and the cans and metals. As a result, when this waste stream
arrives to the waste management companies, it is devoid of any high value waste and
it is mostly organic waste that must be composted at extra cost, cost that should be
financed by the missing plastics, paper, and cans. There have been several trials to
include the informal garbage collectors in the formal system through small and
medium enterprises, but this is another topic. For now, the practical thing for cement
companies is they try to source industrial waste from big corporations, but the

municipal waste so far is challenging.” (Cement executive 3, multinational private
sector, 5-July-2023)
The above quote provides contextual understanding for the complex problems that face the green
transition options, not just in the cement industry but in Egypt. There are currently new regulations
that have yet to come into effect for waste management, which in principle promise better
collaboration and incentives, but it would be too early to assess.
The other major opportunities for cement companies to reduce their carbon emissions and their
electricity consumption- waste heat recovery (WHR) and renewable electricity generation- also face
certain regulatory and financial constraints. While both technologies offer long-term savings and
operational efficiencies, there are very few expected implementations. The below quote from a
senior executive in a multinational cement company in Egypt provides more context.
“Yes, we had two major projects for installations of waste heat recovery and solar
panels that would have provided more than 15% of the electricity needs of our
operations by renewable energy. This would have of course reduced our CO2
emissions as well. But after the last devaluation we have stopped the project because
now the payback period for the initial investment is going to be 12 years instead of 5.
You also have to understand that getting financing from banks for the cement sector
is increasingly challenging as they are aware the sector is in a tough situation.”
(Cement executive 3, multinational private sector, 5-July-2023)
Another executive shared similar remarks, adding that there are also problems in getting approvals
for such projects and that authorities are less likely to provide approvals for projects providing
renewable energy of more than 10% of industrial need for a factory because there is excess
electricity already. In the past years, Egypt has achieved a surplus in electricity production by
adding several new power stations, and this surplus has continued to grow beyond global averages
to reach approximately 30% (Al-Wali, 2022). This means logistical and operational difficulties for
the government owned electricity supplier, since maintaining production and efficiency in a market
riddled with over-supply is economically difficult. Essentially, several respondents indicated that
projects to substitute portions of their electricity usage by renewable energy solutions like solar
farms within their plants have faced difficulties in getting the required approvals. If this is added to
the increasing cost of imported materials due to currency devaluations and long-term return nature
of this products, it can be expected that few companies would opt for renewable electricity solutions

unless clear incentives start to emerge. In summary, any attempts reduce carbon emissions caused
by the high electrical energy consumption in the cement industry will currently face tough
challenges that will most likely mean they will be put on hold for the time being.
Lastly, the option of lowering clinker ratio in cement has its own regulatory dilemma since there are
various official authorities and organizations involved, with varying levels of willingness to change.
The lowering of clinker ratio in cement means there will be different types of cement intended for
different uses. The consensus is that this has not been a recommended practice in Egypt since most
likely there is a lack of attention to these differences by the end-users. The result is that regulating
authorities have been on the more conservative side and kept clinker ratios higher than global
averages. There are many technical specifications of different options that can be used to lower the
clinker ratio in cement, and thus lower the resulting the CO2 emissions, but the feedback from the
interviews and content analysis pointed to the regulatory aspect to be the most challenging, which
can be summarized in the below quote from one of the senior executives in a multinational cement
company.
“To really achieve any improvement in this, the authorities responsible for
construction code and Egyptian cement standards should have some flexibility and
explore what other countries have done in Europe, India, and other countries. We
cannot still be insisting on high clinker factor in cement. We have excellent research
facilities if there are any tests that need to be done to do this, but the problem is it
seems there is no willingness to take responsibility or make changes.” (Cement
executive 2, local private sector, 3-July-2023)
It should also be noted that there are more barriers to the option of reducing clinker factor in cement
in Egypt. In addition to the bureaucratic challenges in changing the construction code above, there
are also challenges in availability of some of the materials that can substitute clinker, and some of it
will have to be imported. Overall, this option will require extensive research and collaboration
between different stakeholders before on-ground improvements can be observed.
The green transition in the cement industry is closely linked to questions of financing and
regulatory framework. The transition to a more sustainable and low-carbon cement production
requires significant investments in new technologies and infrastructure, and financing these
investments is a key challenge. At the same time, regulatory frameworks play a crucial role in
creating the incentives and requirements for the industry to transition to more sustainable practices.

There is already sufficient literature and best practices from other countries to demonstrate that a
combination of public and private financing, along with supportive policy frameworks and
regulatory measures, can create the conditions for industries, including cement, to reduce their
environmental footprint (Miller et al., 2016). The below was the closing remark by one of the senior
executives in a leading multinational cement company in Egypt on this note:
“What incentives? We have no incentives. We seem to always insist on reinventing
the wheel. We have said a million times before in different meetings that the use of
waste in cement as fuel was successful in other countries because there is a gate-fee
to finance it. In a previous meeting I had with a plant manager in a cement factory in
Europe, my counterpart was astonished when I told him we pay to procure waste to
use as fuel, because in his plant they get paid at least 40 euro per ton to burn it. You
know, the lowest gate-fee in Europe is 28 Euro per ton, and it goes up to 90 euros in
some countries which can be a considerable stream of revenue for the plants to
finance green transition. But we have nothing like this here and even no hope for it.
We have even got to the point where we are just asking to exempt the trucks that are
carrying the waste to the cement plants from the road fees because this is a benefit to
the country that this waste is going to be disposed in safe way instead of illegal
landfilling and fires, but no success even for this simple request.” (Cement executive
2, local private sector, 3-July-2023)
While the above comments on incentives for companies to support moving to sustainable practices
can be valid, it also points to more complex questions on financing, and the different levels of
readiness across the word.
Finally, in the broader context of climate change and sustainability, it is important to note that the
challenges faced by the cement industry are part of a larger global challenge of reducing greenhouse
gas emissions and achieving climate justice. For example, Discussions of the Loss and Damage
fund at COP27 were a clear example of how the issue of climate justice is at the forefront of global
climate discussions. The below was the closing remark by one of the senior executives in a leading
local private Egyptian cement company in Egypt in response to a question on the potential of using
carbon capture and storage (CCS) for further reduction of CO2 emissions:
“Ok, let’s say we have captured CO2 and stored it underground, and then? There
isn’t any realistic way to use this CO2 so who is going to pay for this super expensive

technology? To be transparent, yes we are implementing environmental sustainable
practices but ones that are also reducing the cost for us. But let me ask you this for
the sake of argument, what is the CO2 emissions per capita for the US or China? It
is 14.8 tons and 8 tons per capita. The number for Egypt is only 2 tons per capita.
We contribute only to 0.73% of CO2 emissions globally. Why would we be expected
to pay for these reductions then? But I am still saying we are doing the sustainable
practices that do make economic sense.” (Cement executive 2, local private sector,
3-July-2023)
The quote highlights the significant disparities in CO2 emissions per capita between countries, with
Egypt having a relatively low level of emissions compared to other developed countries like the US
and China (Rissman et al., 2020). Moreover, the quote demonstrates that Egyptian industries may
perceive themselves as less responsible for acting on climate change and may expect external
financing and support to invest in low-carbon technologies and reduce their carbon footprint.
5. Chapter Six: Conclusions and Policy Recommendations
6.1. Concluding remarks
The research on carbon emissions reduction options for cement industry highlighted several options
that are currently available (Busch et al., 2022). However, there is a clear need for research that
focuses on Egypt as a developing country with its own specific characteristics, as the roadmap for
reducing emissions will differ greatly based on country specific factors (Busch et al., 2022).
The results of this study indicate that the cement industry in Egypt is facing severe chronic
challenges including oversupply, economic challenges due to foreign currency shortage, as well as
decreasing demand due to economic conditions and increased regulatory pressure. These factors
inevitably affect any potential for green transition by the cement companies. It can also be difficult
for developing countries like Egypt to implement the same incentive schemes that have supported
the green transition of industries in other countries. However, the research also implies that there are
plenty of underlying advantages to supporting certain options that would secure a sizable reduction
in Egypt’s carbon emissions (EBRD, 2016). The research indicates that the waste management
industry is an untapped potential for the green transition in Egypt, and if it is coupled with close
collaboration with the cement industry, a continuous revenue stream can be secured for companies

that operate in this sector which would add thousands of jobs to the Egyptian labor market, ensure a
reduction in CO2 emissions, and also reduce the dependability on coal which requires foreign
currency for importing. This research also highlights the importance of Egypt’s latest update to its
NDCs and how it has already helped in providing clarity on Egypt’s climate objectives. However,
there is also the need for more clarity on the objectives for the cement industry, which can have a
guidance instead of a mandating form, but this clarity will support in either securing green financing
or providing multinational companies already working in Egypt with long-term vision to support in
their investment decisions.
Lastly, mitigating the environmental impact of the cement industry in Egypt is an extremely
complex topic that can be approached from various angles. It was not possible to explore the full
potential of the green transition options within the scope of this thesis. For example, this study only
touched upon the demand-side of the equation but did not explore the different policy options that
can create the market for greener cement products from the side of construction or real-estate
companies.
6.2. Policy recommendations to support green transition in cement
Based on the findings and the analysis conducted in this research, the below section will present a
set of policy recommendations that are complimentary to the low carbon roadmap for cement
industry in Egypt. These suggestions are based on discussions with the different stakeholders
including senior executives in the cement industry, regulatory consultants, and technical experts.
1. Revisit the low carbon roadmap for the Egyptian cement industry that was prepared by
the EBRD in 2015. This roadmap was prepared prior to the inauguration of several new
cement production lines that added to the market capacity, and thus the baseline year of
2014 can no longer be a valid reference point as indicated by the expert interviews. Also,
after Egypt signed the Paris agreement and published its NDCs, there are now public
commitments that need to be translated into specific action plans, and cement is one of the
industries targeted by Egypt to reduce emissions. Hence, an updated study needs to take
place for a roadmap of the cement industry up to 2050, in accordance with the Egyptian
national climate change strategy for 2050.
2. Mandate a specific CO2 emissions reduction target for the cement industry. This should
be included as part of the country's national determined commitments (NDCs) by 2030.
Mandating a specific emissions target for cement production would serve as a clear signal to

the industry that reducing emissions is a priority for the government and would encourage
cement producers to invest in cleaner technologies and processes. The target should be set at
a level that is both ambitious and achievable, considering the technical and economic
realities of the industry. This policy recommendation would demonstrate Egypt's
commitment to transitioning to a low-carbon economy and meeting its climate goals under
the Paris Agreement. Also, this policy recommendation would help in facilitating green
financing options for both the cement companies as well as the official authorities that
would need such financing for implementing green transition solutions, monitoring and
verification systems, or technical capacity building programs.
3. Provide more on-ground procedures to support and increase the usage of refuse
derived fuels (RDFs). The recent EEAA regulations mandating the 10% minimum RDFs in
the energy used by cement plants and the newly established solid waste management
regulations have provided the fundamental framework, and the below recommendations can
provide immediate improvements:
● Revisit and possibly remove the road fees associated with the transportation of waste to
cement plants to be used as alternative fuel. Imposing road fees on waste transport is
counterintuitive to sustainability and circular economy objectives of Egypt’s NDCs, as it
disincentivizes the use of waste as a resource and encourages the landfilling of waste
instead. By removing road fees for waste transport to cement plants, policymakers can
incentivize the use of waste as an alternative fuel source, reduce greenhouse gas
emissions from waste disposal, and promote a more circular economy. This would also
help to reduce the cost of waste transport for waste management companies and other
players in the waste value chain, making it more financially viable and reducing the cost
for the end-users.
● Design and implement a collaboration framework between cement companies, the waste
management regulatory authority (WMRA), and private sector companies that are
operating across the waste value chain, from waste generators to companies working in
disposal. Such a framework can help to address some of the regulatory and logistical
challenges including sorting, separating, and can help in developing processes for

handling and transporting waste to cement plants. Also, such a framework would
promote a more circular economy by encouraging the reuse and recycling of waste
materials. Lastly, this collaboration will eventually allow the WMRA and other relevant
stakeholders to apply the “polluter pays principle” after enough data, experience and
logistical setup is done. This would allow the introduction of gate-fees, which are fees
the cement industry can collect from disposing of waste by using it as alternative fuels
instead of landfilling.
4. Expedite actions required to lower the clinker ratio in cement. This will include utilizing
partnerships and best practices in other countries that have already adopted such measures
like India and other comparable countries to modify local construction codes and standards
that are currently mandating higher clinker ratios that global requirements and causing
higher CO2 emissions as well as increased energy consumption, and in turn, higher cost of
foreign currency for the industry. While the latest NDCs did clearly state a reduction in
clinker ratio is going to happen by 2030, there is still no indication of a timeline or actual
progress yet. This will be a collaborative effort across different authorities and industries in
addition to cement producers since it will include end-users like construction and real-estate
companies, architects, and official monitoring organizations.
5. Establish a system for monitoring, reporting and verification (MRV) for measuring
carbon emissions. This system will enable the availability and accuracy of data needed for
decision making on CO2 emissions and energy usage and performance of cement plants. As
it stands today, regulatory agencies are dependent on semi-voluntary performance reports
submitted by the cement plants to measure their carbon emissions based on high-level
calculations, which have been confirmed by experts to be inaccurate. It is also recommended
to introduce a need for 3rd party verification of reported energy performance and CO2
emissions reporting by cement companies. This will ensure compliance with international
standards and a level playing field. The establishment of such a platform will also allow the
relevant authorities to explore different incentive schemes for cement companies that are
exceeding their targets, as explained in below point.

6. Implement an incentive scheme for reducing emissions that can be added to the recent
regulations that indicate a penalty for cement companies not meeting the 10% minimum
usage of refuse derived fuels (RDFs). These incentives can be provided for companies that
exceed the 10% on an upward scale up to the global average of 25%. It is recommended to
explore what incentives can be provided in an equitable and practical way, and it can range
from higher export subsidies or green public procurement agreements that favor cement
with lower carbon emissions, or certain reductions in import or quarry fees.
7. Revisit or remove current limitations of the maximum of renewable energy
substitution threshold for cement plants. The use of renewable electrical energy in the
cement industry can support CO2 reduction efforts in a cost-effective way for cement plants.
While these limits might be based on on-ground facts like excess electricity production at
the national grid level, it should be highlighted that its contradictory to Egypt’s NDCs vision
of achieving 42% of electricity to be generated from renewable sources by 2030. Along the
same lines, revisit and possibly remove the EEAA regulations stipulating that cement plants
that reach 40% thermal substation rate (which means plants reduced usage of fossil fuels by
40%) would be subject to stricter emissions guidelines.
8. Finally, the Egyptian Competition Authority (ECA) should revisit the production
quota in the cement industry in Egypt to consider extending for at least two or three
years, with the option of periodical revisions in case of market changes instead of the 1-year
renewals that have been ongoing for the past two years. The current gap between the
production capacity of cement plants in Egypt and the demand for cement is 30-35% and
there are no realistic expectations that this would be resolved within a year. This policy
change would provide better long-term planning for cement producers, allowing them to
make more informed investment decisions and protect the market from disturbances or
shortages. By providing greater stability and predictability in the industry, cement
companies would be able to plan with better visibility and implement more sustainable
practices. Additionally, the option for periodical revisions would allow for adjustments to be
made based on changing market conditions or other factors, while still maintaining a level of
stability in the industry. Lastly, when cement companies have better revenue and overall
business forecasting, it will improve their ability to secure long-term green financing for

capital investments needed for technical solutions that would reduce their carbon footprint
(Miller et al., 2016).
6.3. Implications for future research
While this research aimed to assess the decarbonization policies for the cement industry in Egypt
there are several pathways for future research that have been identified. First, the findings presented
above suggest the need to conduct technical research for the advanced methods that could reduce
CO2 emissions from cement. New technologies like carbon capture and utilization can be useful for
other industries like oil and gas but these technologies are still in early stages and would require
extensive research.
Second, this thesis explored the potential of green transition in the cement industry from a cement
production perspective and did not evaluate the potential options for reductions in cement’s
environmental footprint by changes on the end-user’s side like the construction or concrete

