


Weeks 5 & 6
Lecture 7: Risk (Uncertainty) and Return
Risk preferences:
1. Risk taker: will always take the riskier investment even with the same return
2. Risk indifferent: doesn’t care about risk if the return is equal
3. Risk adverse: will take the smallest amount of risk given the same return
How can you measure risk?
1) Probability Distributions – calculate the expected value (return) and standard deviation.
Ex.) Builtrite is considering the following two mutually exclusive projects: (one or the other, not both)
Project A:
Belief Cash Flow Prob Weighted Average
Pessimistic 40 x .20 = 8
Most likely 45 .60 27
Optimistic 50 .20 10
Expected return = 45
Project B:
Belief Cash Flow Prob Weighted Average
Pessimistic 0 x .20 = 0
Most likely 45 .60 27
Optimistic 110 .20 22
Expected return = 49
Which project should be picked? Which project has less risk? Project A has less risk
Which project has more variability (risk)? Project B is riskier
We measure variability by the standard deviation “ σ “
Standard deviation A = sqrt( ((40-45)squared*.20)+((45-45)squared*.6)+((50-45)squared*.20))= 3.16
Diversification and risk
- Total risk = diversifiable risk + nondiversifiable risk “company specific” + “market risk”
“unsystematic risk” + “systematic risk”
Lawsuits war
Strikes inflation
- By diversifying, we can reduce “company specific” risk, but not market risk.
- A particular firm’s market risk (or relevant risk) is measured by its beta.
- A beta measures the average relationship between a stock’s returns and the market’s returns.
- “average” stock has a beta = 1.0
- a firm twice as risky has a beta = 2.0
- As beta ↑, a firm’s relevant/ market risk ↑
Risk and Return Trade-off
The higher the risk, the higher the required return
CAPM: Capital Asset Pricing Model
Market return 11%
T bill rate 4%
Stock twice as risky CAPM = 4 + 2 (11-4) = 18%
Average stock CAPM = 4 + 1 (11-4) = 11%
WEEK 6
Cost of Capital
The cost to borrow long-term funds The minimum acceptable return for a new asset cost of capital
= required return
What factors influence the cost of capital? 1) economy 2) business & financial risk 3) a firm’s capital
structure (mix of debt & equity)
Four sources of long-term funds
1. Bonds (Debt) Calculate the ‘YTM’ or “cost to maturity”
Kd = cost of debt
Kd = $interest + Par-Net Proceeds Years Par + 2(Net) 3
Ex: Builtrite will sell 9% coupon, 25 year, $1000 par value bonds to raise money. The bonds will sell at
$20 discount and under-writing (flotation) costs will be $25. Builtrite’s tax rate is 40%.
What is Builtrites’ after tax cost of debt? 90 + 1000-955 Kd = 25 1000 + 2 (955) 3
ATKd =
2) Preferred Stock Kp = Cost of preferred stock
Kp = Dividend = Dp Net Proceeds Np
Builtrite will issue a $40 par value preferred stock with an 8% coupon. The stock is expected to sell at
$38. Flotation costs will be $3.50 per share.
What is Builtrite’s after tax cost of preferred stock? Kp = ATKp ?
3) Retained Earnings Opportunity cost of common stock or ‘internal equity’
Kc = Cost of retained earnings = KRE Kc = Dl + g PO Dl = Next Dividend PO = Price of common
stock G = Growth rate
Builtrite’s common stock sells for $48. Past dividend was $2.82 and the expected next dividend is $3.10.
Dividends are expected to grow at a 10% rate. What is Builtrite’s after tax cost of retained earnings?
Kc =
ATKc ?
4) New Common Stock A firm will need to sell new common stock when it uses up its retained
earnings.
Kc = Dl + g = KNC Net proceeds ‘NNC’
The CAPM can also be used to determine the cost of equity.
(Continue example #3) Flotation costs to sell common stock will be $0.50 per share and the expected
selling price of the stock is $46.75. What is the after tax cost of selling new common stock? KNC =
Weighed Average Cost of Capital
Uses of proportions of debt & equity in a firm’s capital structure to calculate the cost of capital.
WACC = Ka = Kd(%debt) + Kp(%PS) + Kc or KNC (%CS)
All investments/projects should earn a return greater than 11.81%.
Capital Budgeting
-the process of determining which fixed asset/project to purchase
- Capital budgeting involves:
1) large sums of money
2) long-term consequences
Capital Budget: calculating the initial investment, after-tax free cash flows and terminal cash flow
Reasons for capital expenditures:
1) expansion: need additional assets.
2) replacement: buy new or repair.
3) renewal: modernize an existing asset, make it more efficient.
4) compliance or regulatory: government/safety/environmental reasons.
Two types of projects:
1) independent: no competition between the projects, one doesn’t influence the other.
2) mutually exclusive: pick the ‘best’ asset or project from alternatives.
Cash Flow Diagrams:
Conventional AND Non-Conventional (look up n)
Three components to a Capital Budget:
1) Initial Investment ‘II’ or Outlay ‘IO’
2) Relevant After Tax Free Cash Flows ‘RATFCF’
3) Terminal Cash Flow ‘TCF’
1. Initial Investment ‘II’
+ new asset cost
+ shipping/installation
- old asset sale proceeds
+/- taxes on sale of old asset
+/- investment in net working capital
= Initial Investment
2. Relevant After Tax Free Cash Flows ‘RATFCF’
+ Savings/Revenue
- Cash Operating Expenses
- Depreciation/Amortization
= EBT
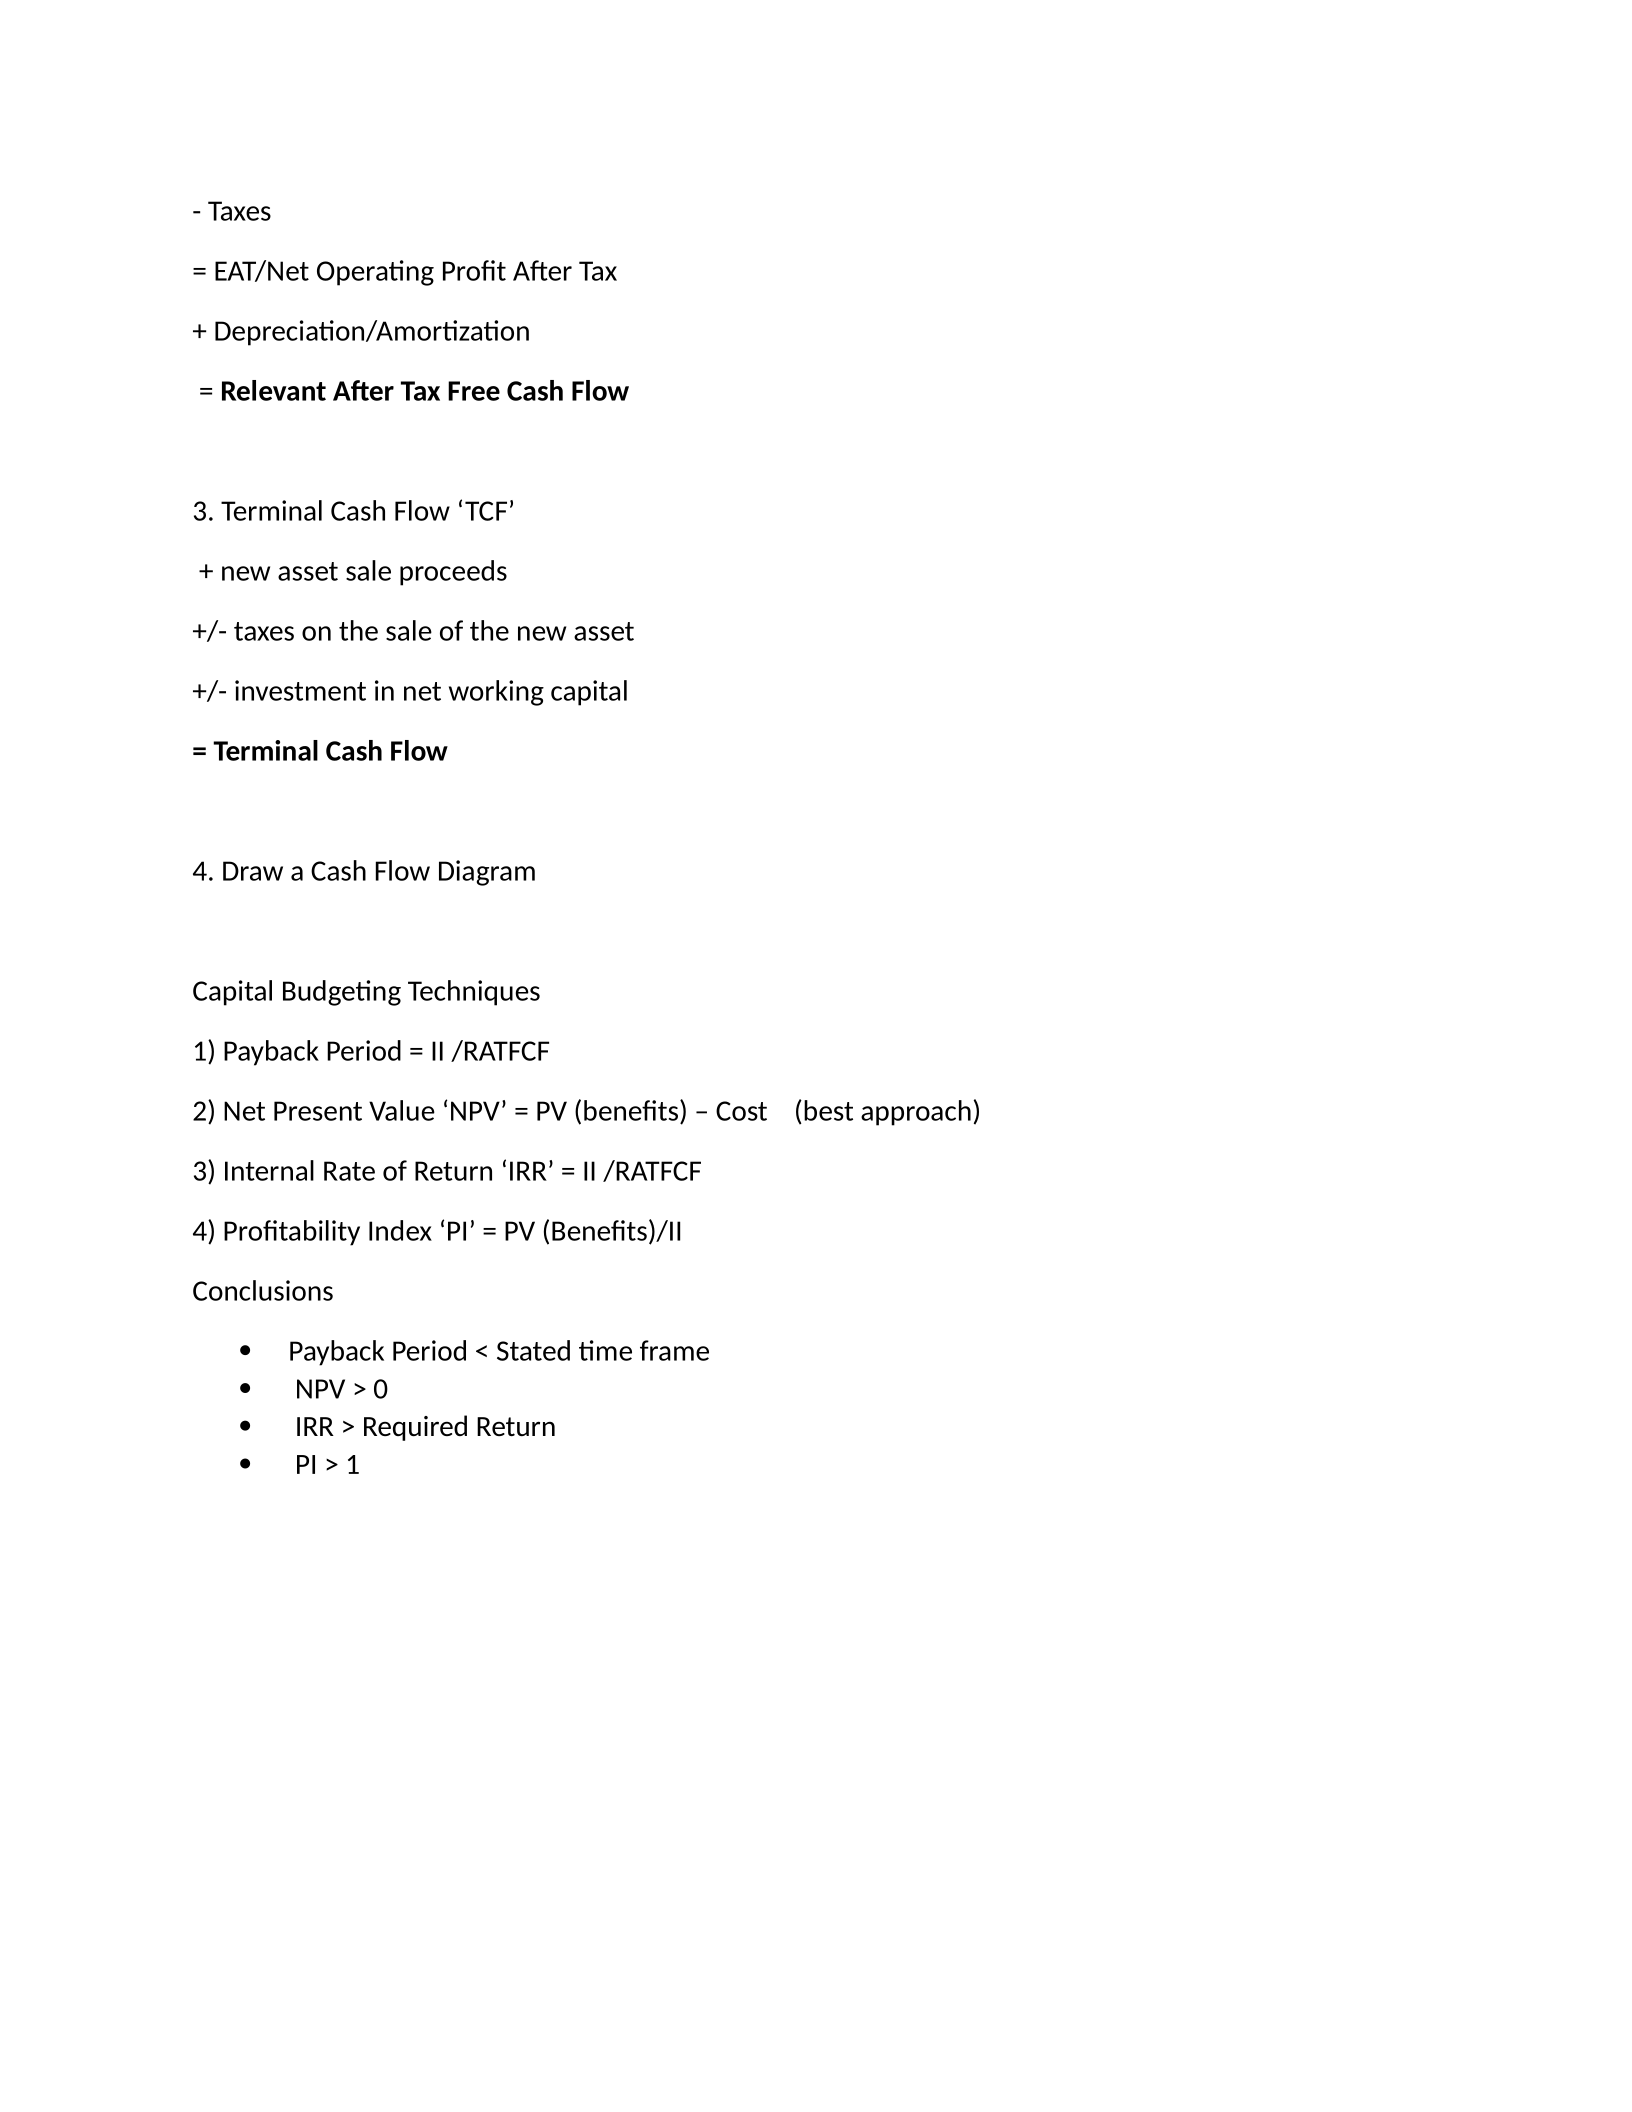
- Taxes
= EAT/Net Operating Profit After Tax
+ Depreciation/Amortization
= Relevant After Tax Free Cash Flow
3. Terminal Cash Flow ‘TCF’
+ new asset sale proceeds
+/- taxes on the sale of the new asset
+/- investment in net working capital
= Terminal Cash Flow
4. Draw a Cash Flow Diagram
Capital Budgeting Techniques
1) Payback Period = II /RATFCF
2) Net Present Value ‘NPV’ = PV (benefits) – Cost (best approach)
3) Internal Rate of Return ‘IRR’ = II /RATFCF
4) Profitability Index ‘PI’ = PV (Benefits)/II
Conclusions
Payback Period < Stated time frame
NPV > 0
IRR > Required Return
PI > 1
Powered by TCPDF (www.tcpdf.org)

