


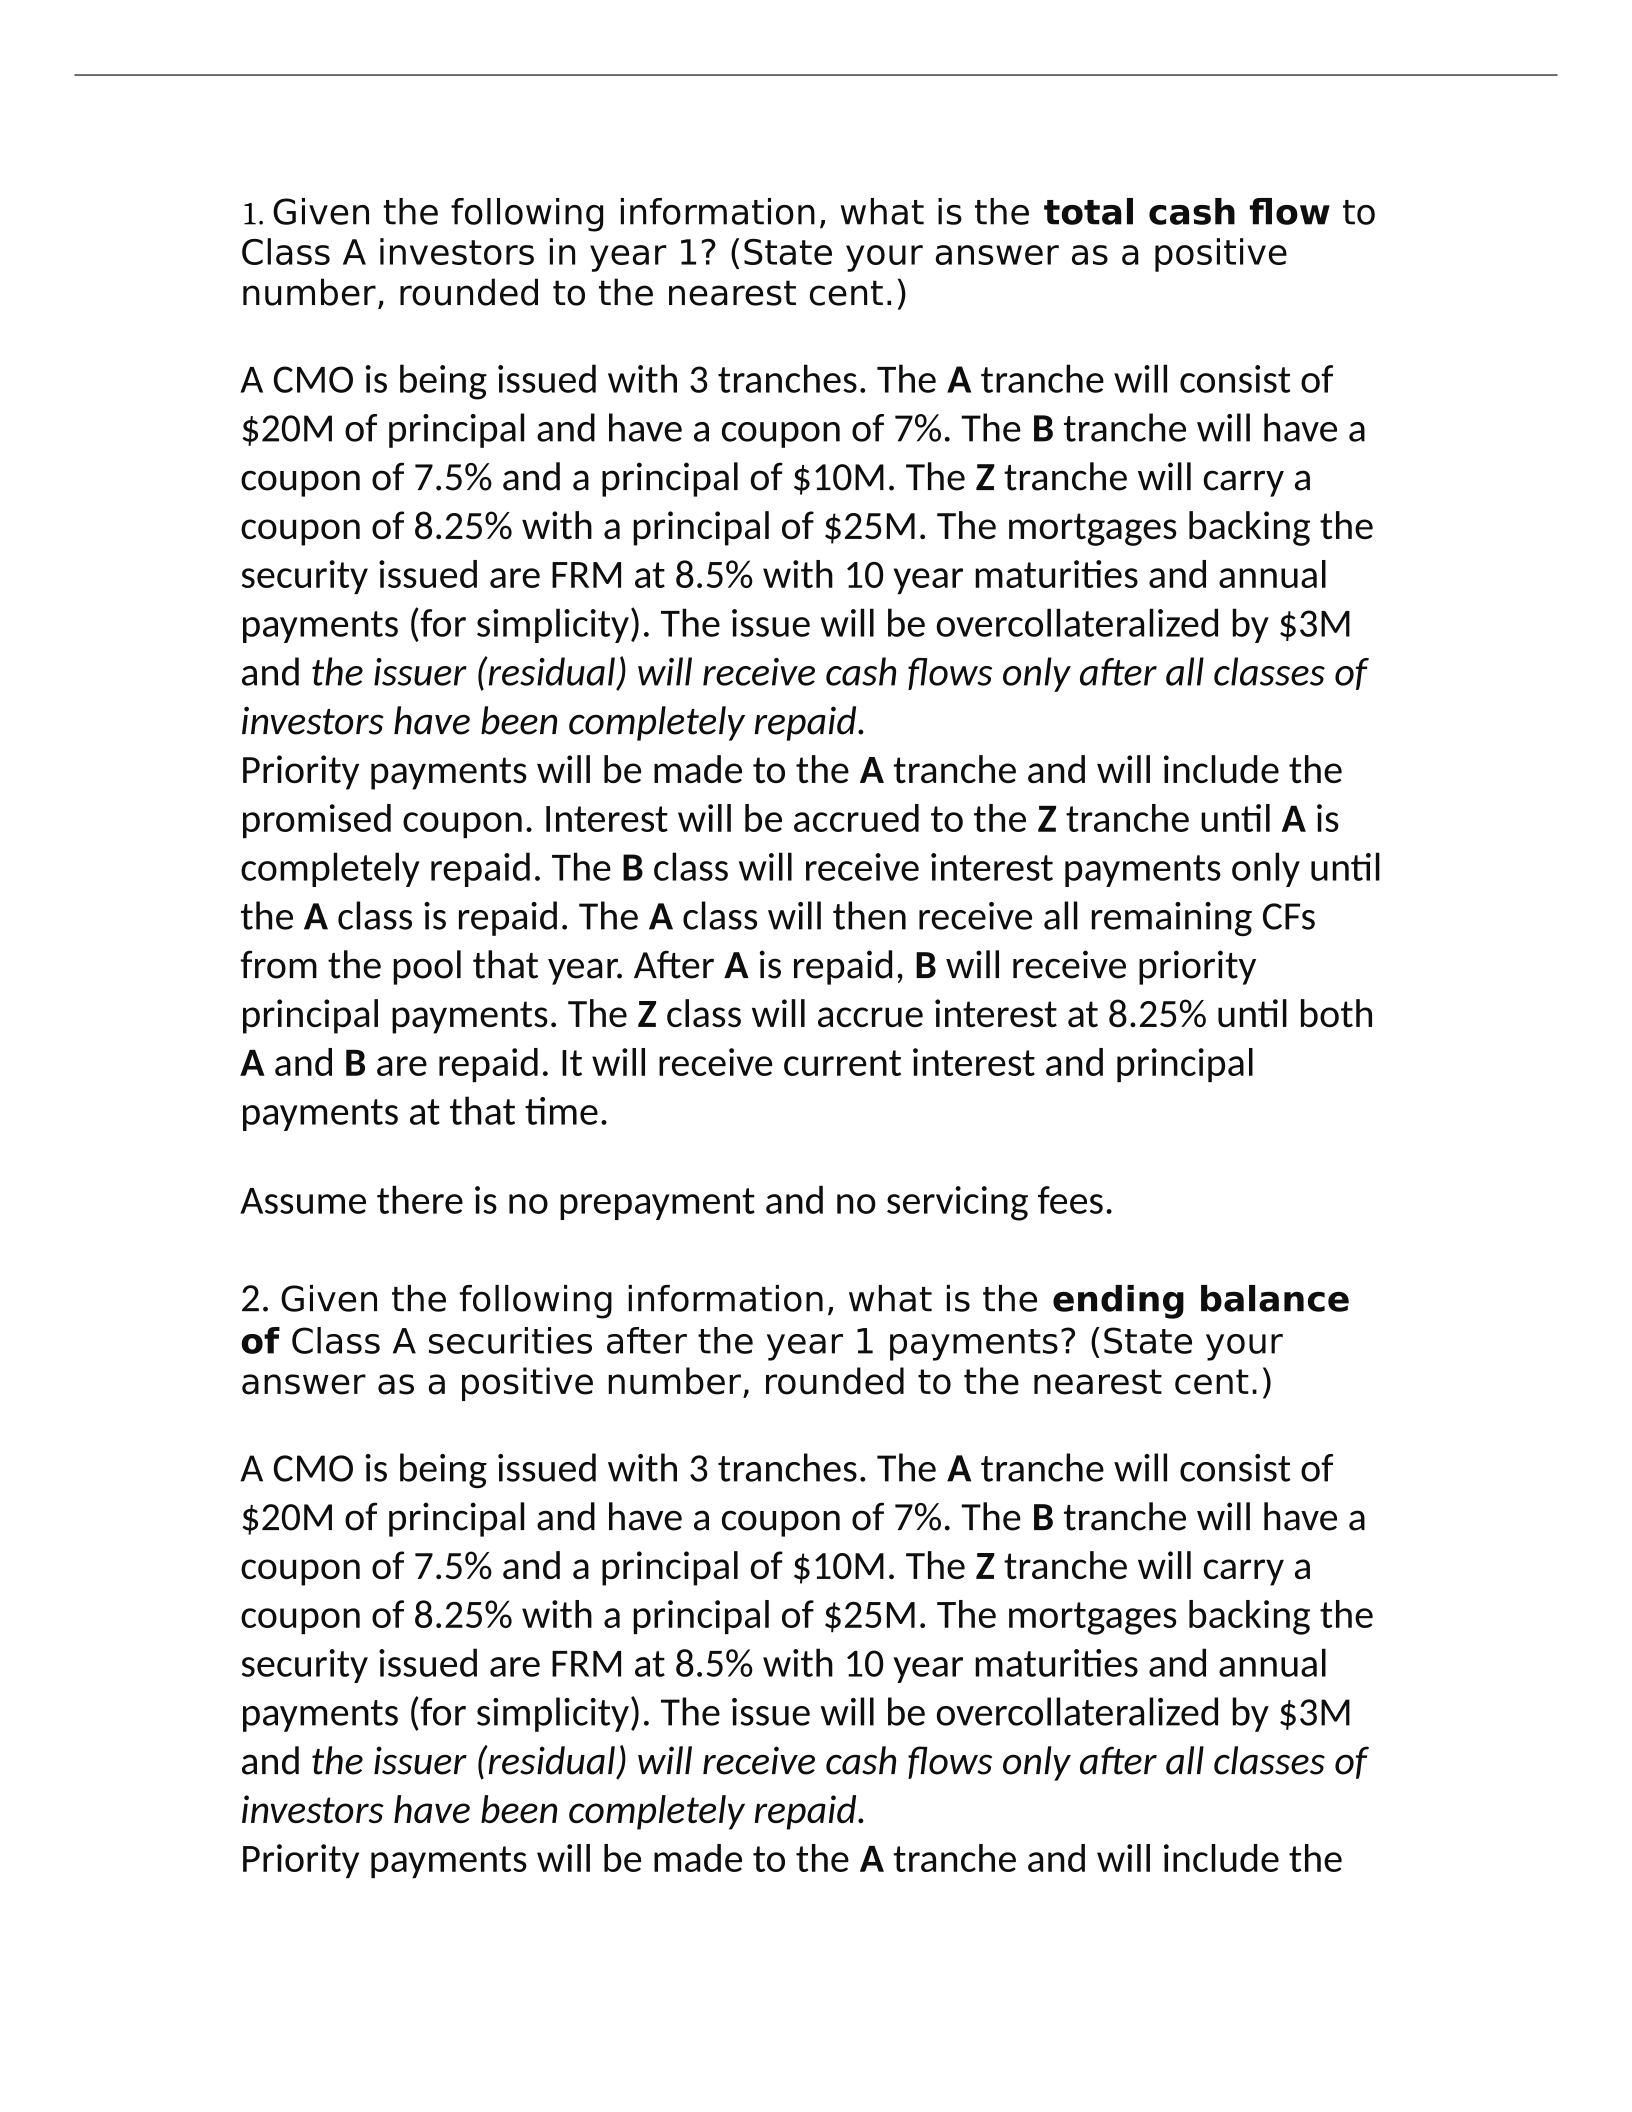
1. Given the following information, what is the total cash flow to
Class A investors in year 1? (State your answer as a positive
number, rounded to the nearest cent.)
A CMO is being issued with 3 tranches. The A tranche will consist of
$20M of principal and have a coupon of 7%. The B tranche will have a
coupon of 7.5% and a principal of $10M. The Z tranche will carry a
coupon of 8.25% with a principal of $25M. The mortgages backing the
security issued are FRM at 8.5% with 10 year maturities and annual
payments (for simplicity). The issue will be overcollateralized by $3M
and the issuer (residual) will receive cash flows only after all classes of
investors have been completely repaid.
Priority payments will be made to the A tranche and will include the
promised coupon. Interest will be accrued to the Z tranche until A is
completely repaid. The B class will receive interest payments only until
the A class is repaid. The A class will then receive all remaining CFs
from the pool that year. After A is repaid, B will receive priority
principal payments. The Z class will accrue interest at 8.25% until both
A and B are repaid. It will receive current interest and principal
payments at that time.
Assume there is no prepayment and no servicing fees.
2. Given the following information, what is the ending balance
of Class A securities after the year 1 payments? (State your
answer as a positive number, rounded to the nearest cent.)
A CMO is being issued with 3 tranches. The A tranche will consist of
$20M of principal and have a coupon of 7%. The B tranche will have a
coupon of 7.5% and a principal of $10M. The Z tranche will carry a
coupon of 8.25% with a principal of $25M. The mortgages backing the
security issued are FRM at 8.5% with 10 year maturities and annual
payments (for simplicity). The issue will be overcollateralized by $3M
and the issuer (residual) will receive cash flows only after all classes of
investors have been completely repaid.
Priority payments will be made to the A tranche and will include the
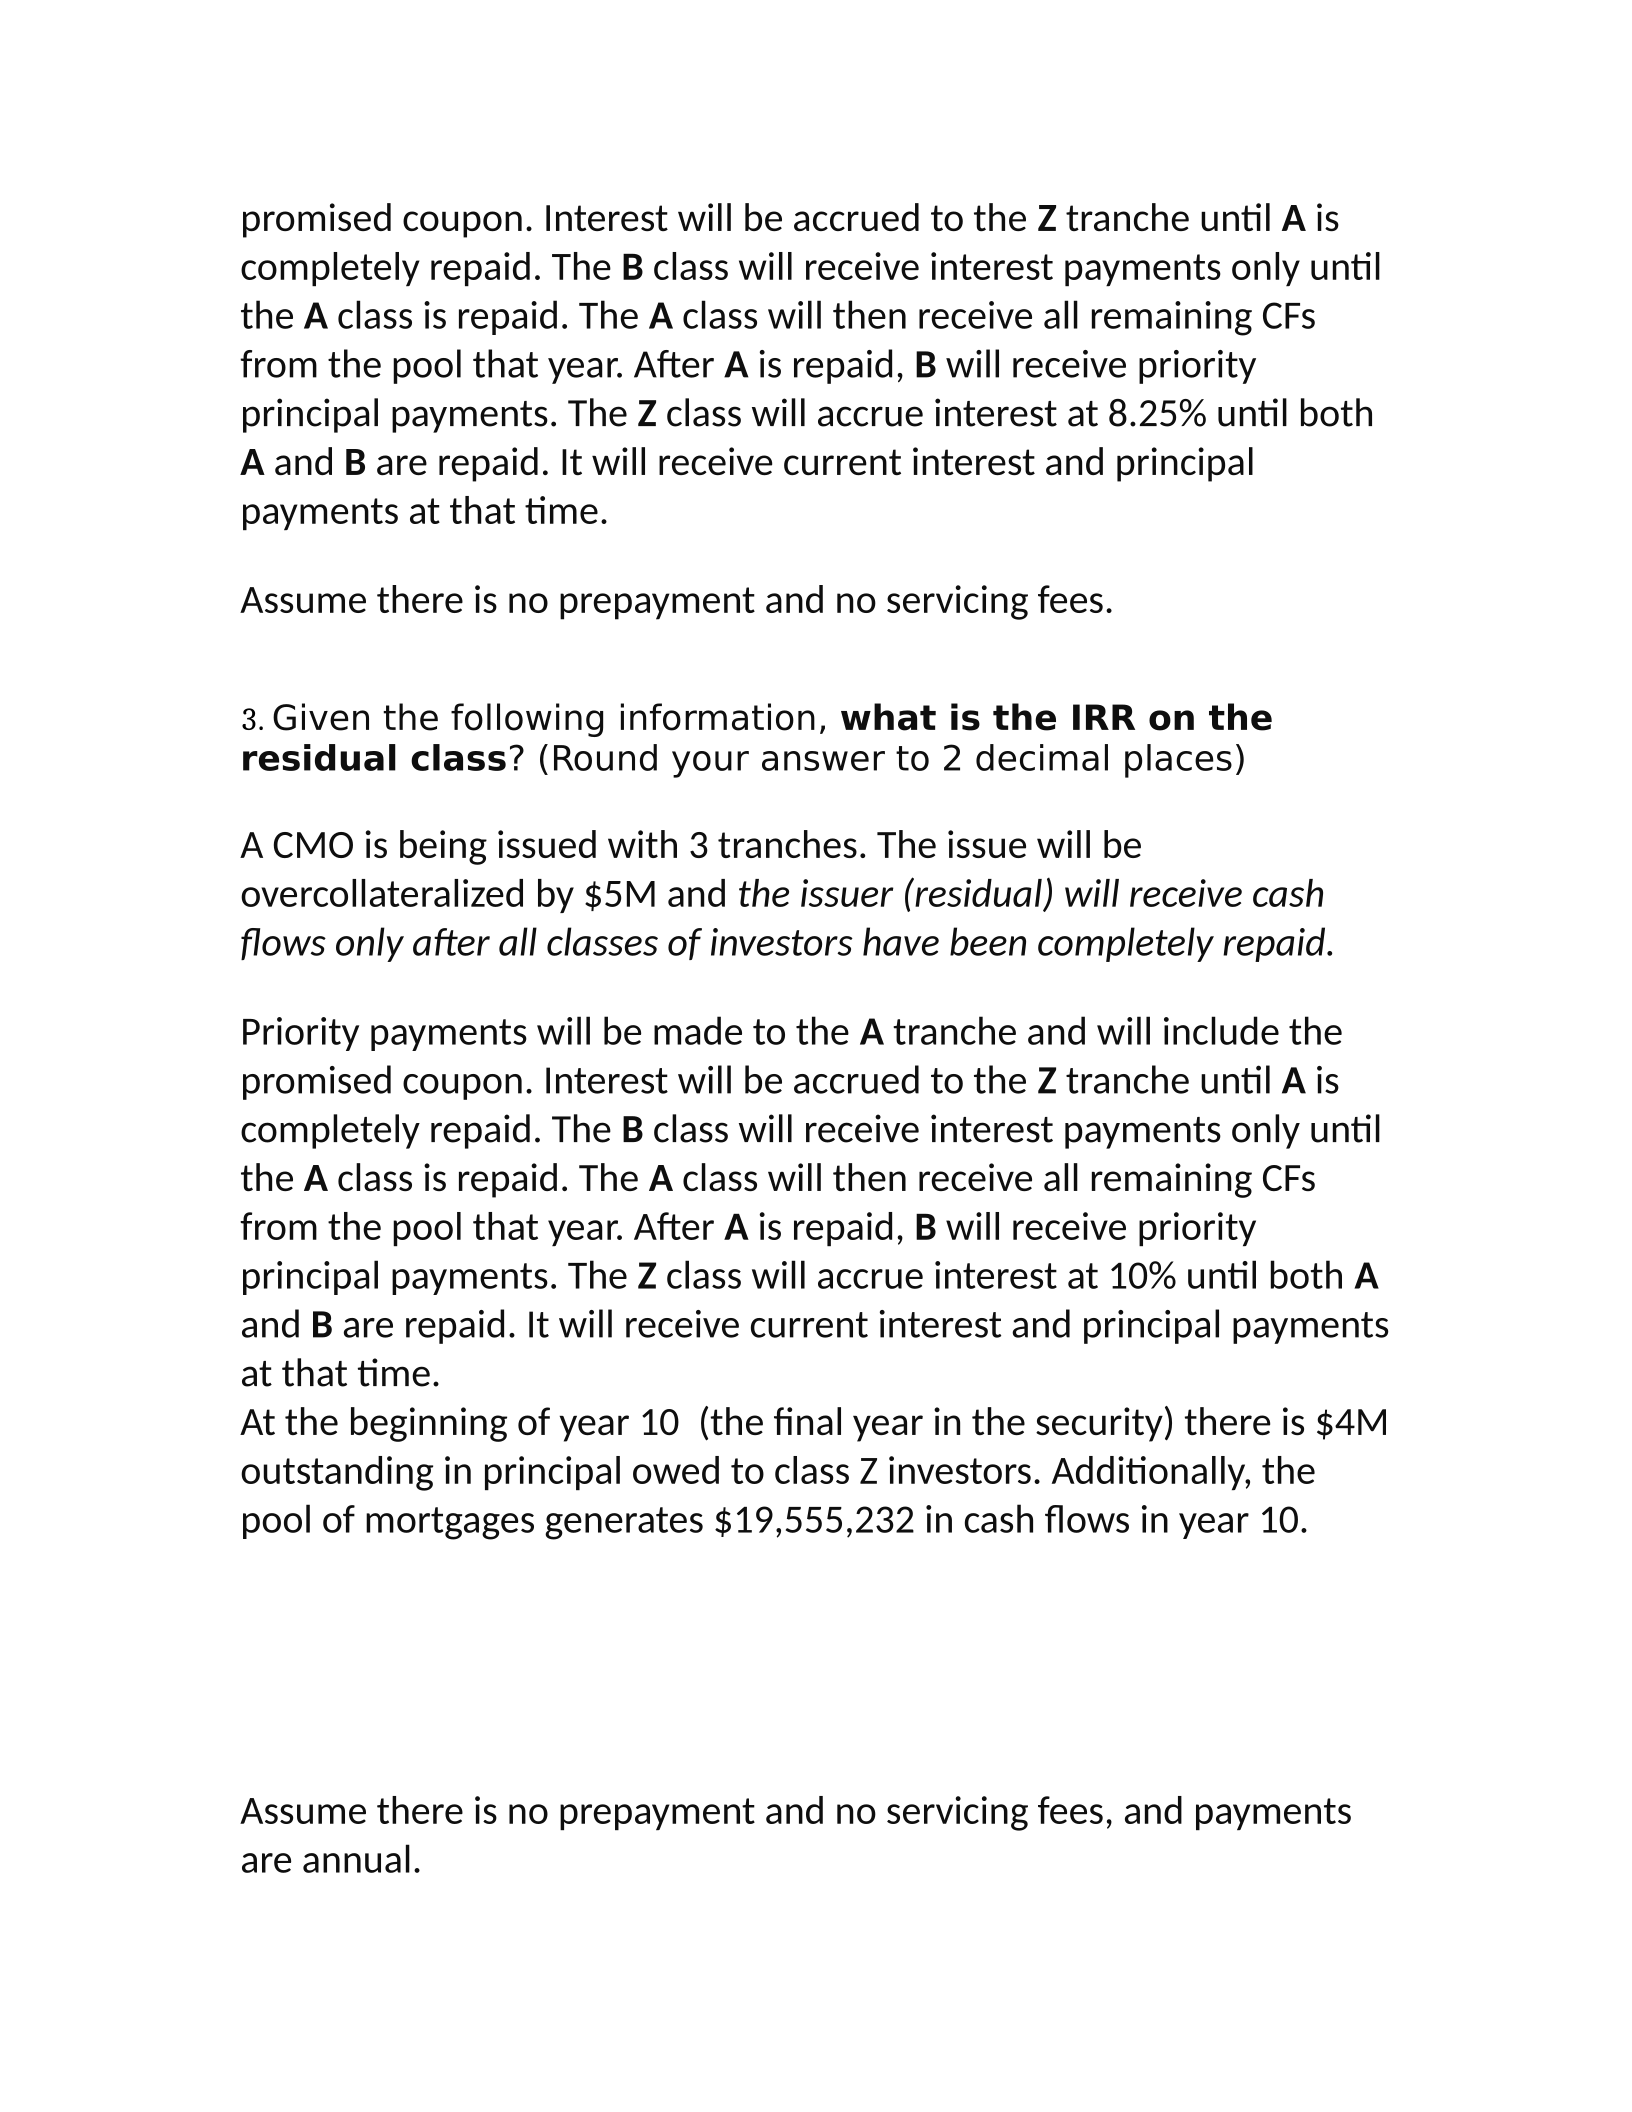
promised coupon. Interest will be accrued to the Z tranche until A is
completely repaid. The B class will receive interest payments only until
the A class is repaid. The A class will then receive all remaining CFs
from the pool that year. After A is repaid, B will receive priority
principal payments. The Z class will accrue interest at 8.25% until both
A and B are repaid. It will receive current interest and principal
payments at that time.
Assume there is no prepayment and no servicing fees.
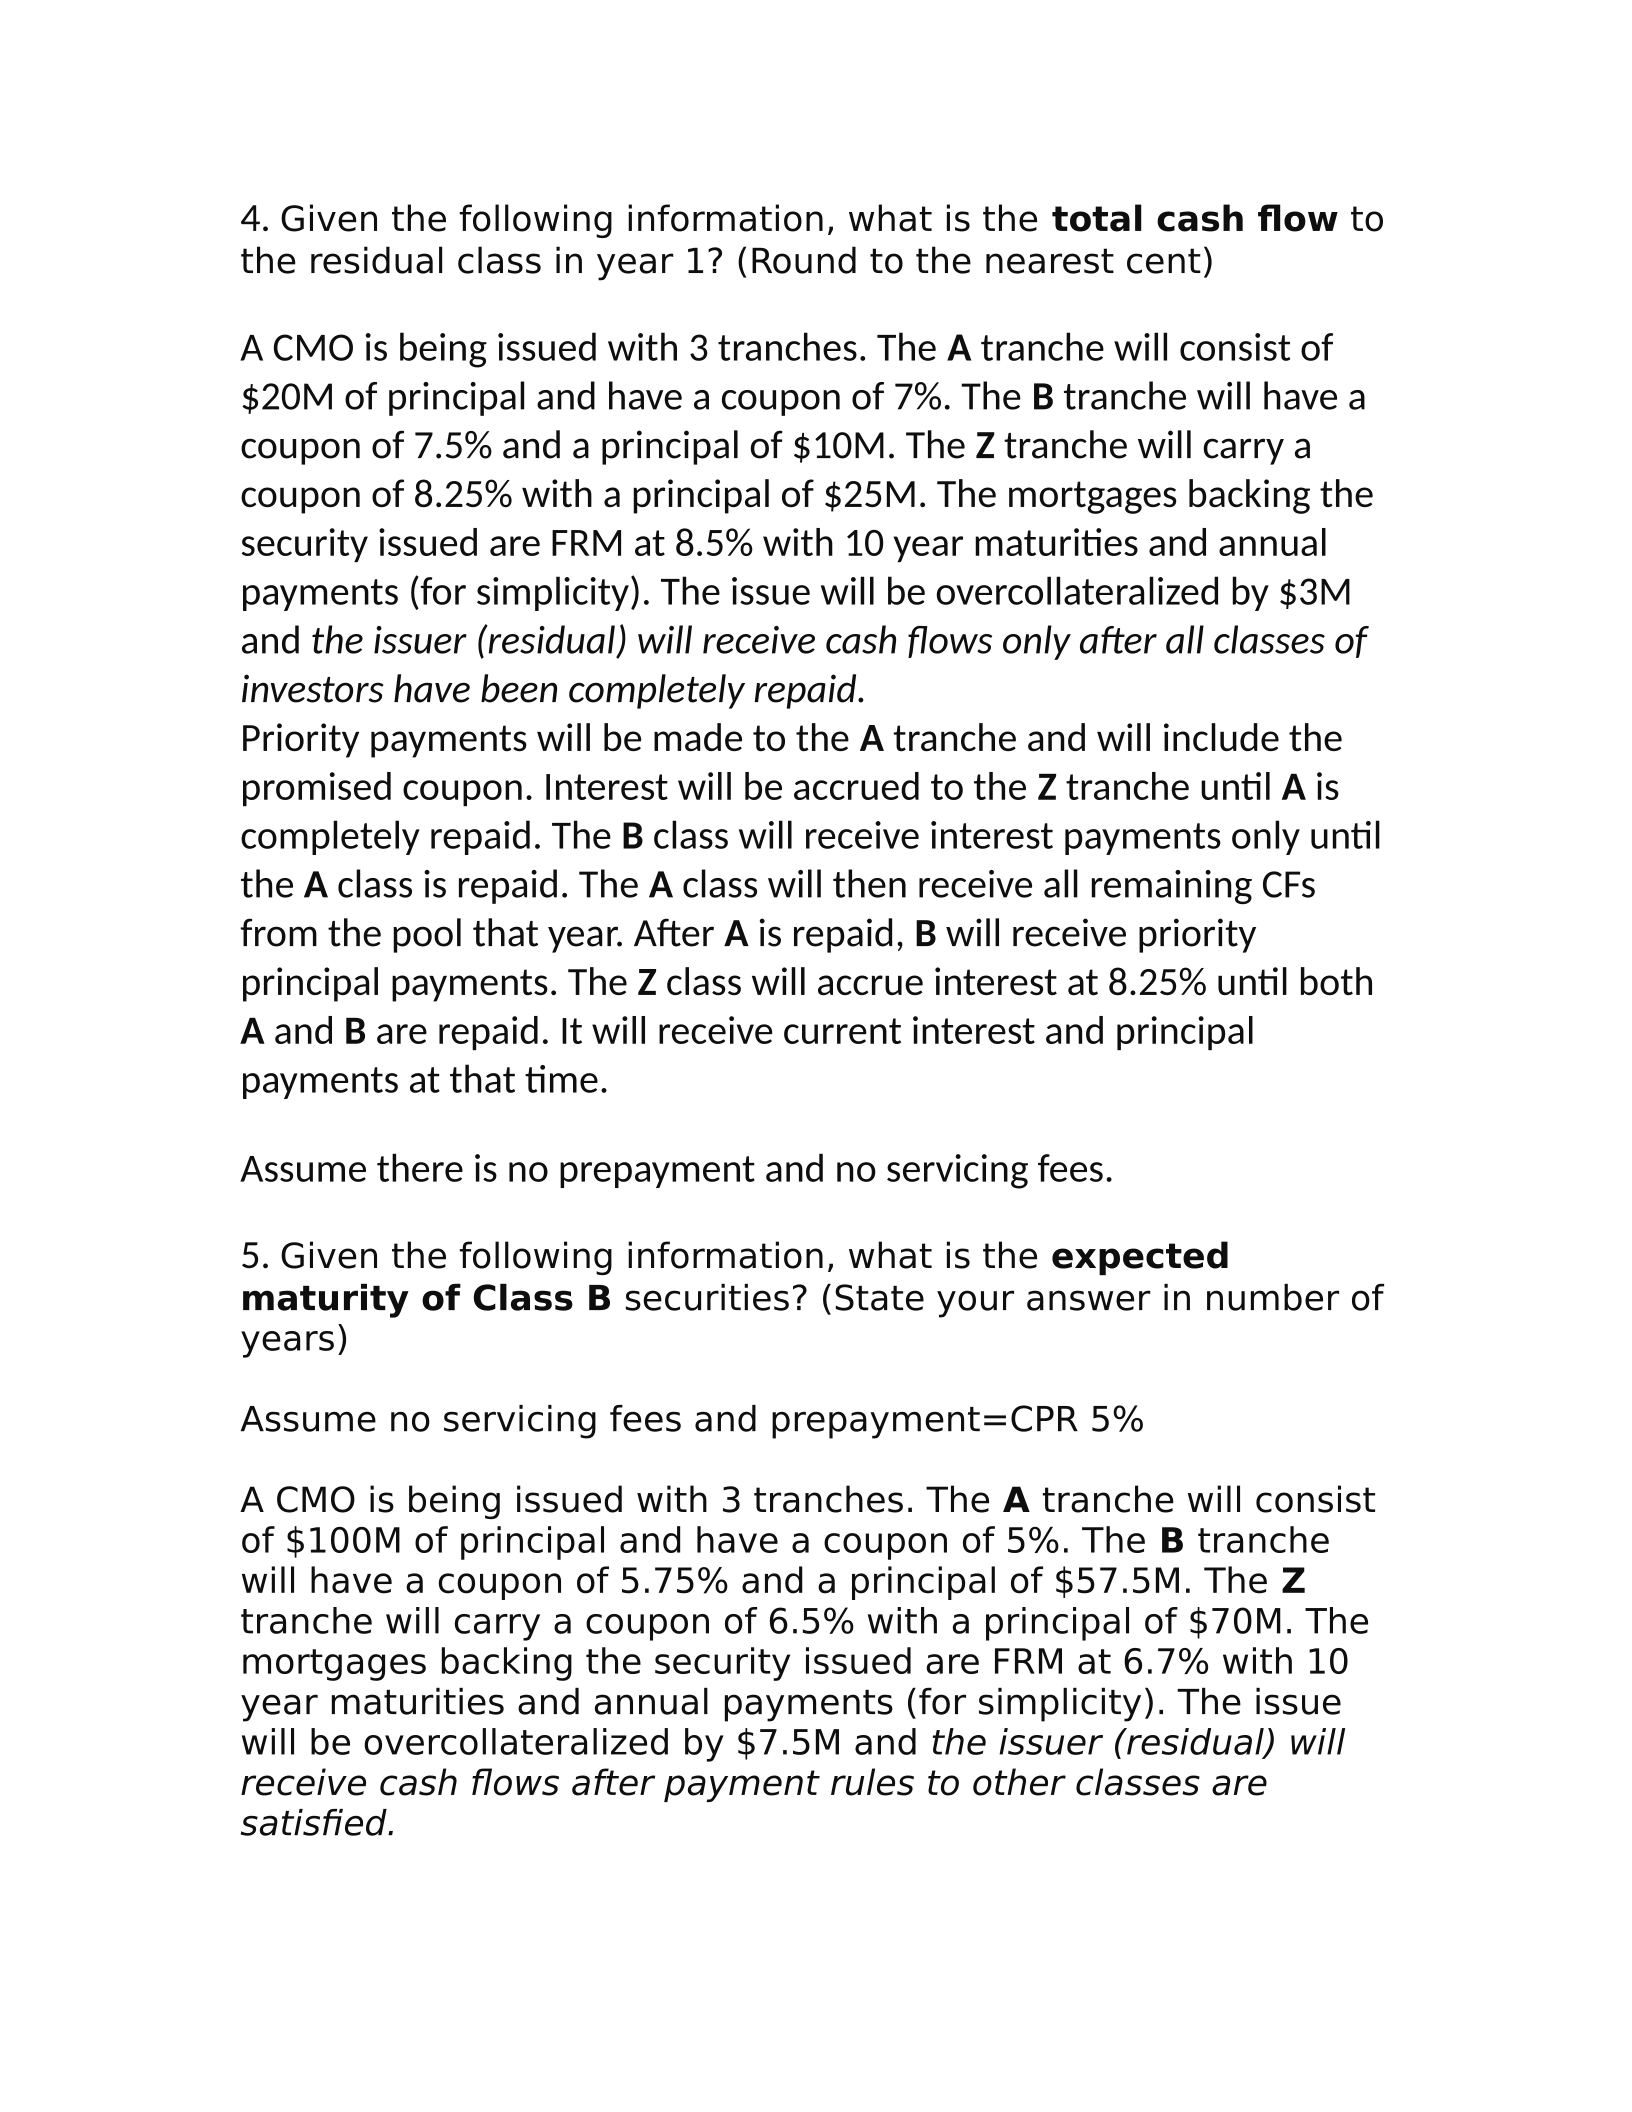
3. Given the following information, what is the IRR on the
residual class? (Round your answer to 2 decimal places)
A CMO is being issued with 3 tranches. The issue will be
overcollateralized by $5M and the issuer (residual) will receive cash
flows only after all classes of investors have been completely repaid.
Priority payments will be made to the A tranche and will include the
promised coupon. Interest will be accrued to the Z tranche until A is
completely repaid. The B class will receive interest payments only until
the A class is repaid. The A class will then receive all remaining CFs
from the pool that year. After A is repaid, B will receive priority
principal payments. The Z class will accrue interest at 10% until both A
and B are repaid. It will receive current interest and principal payments
at that time.
At the beginning of year 10 (the final year in the security) there is $4M
outstanding in principal owed to class Z investors. Additionally, the
pool of mortgages generates $19,555,232 in cash flows in year 10.
Assume there is no prepayment and no servicing fees, and payments
are annual.
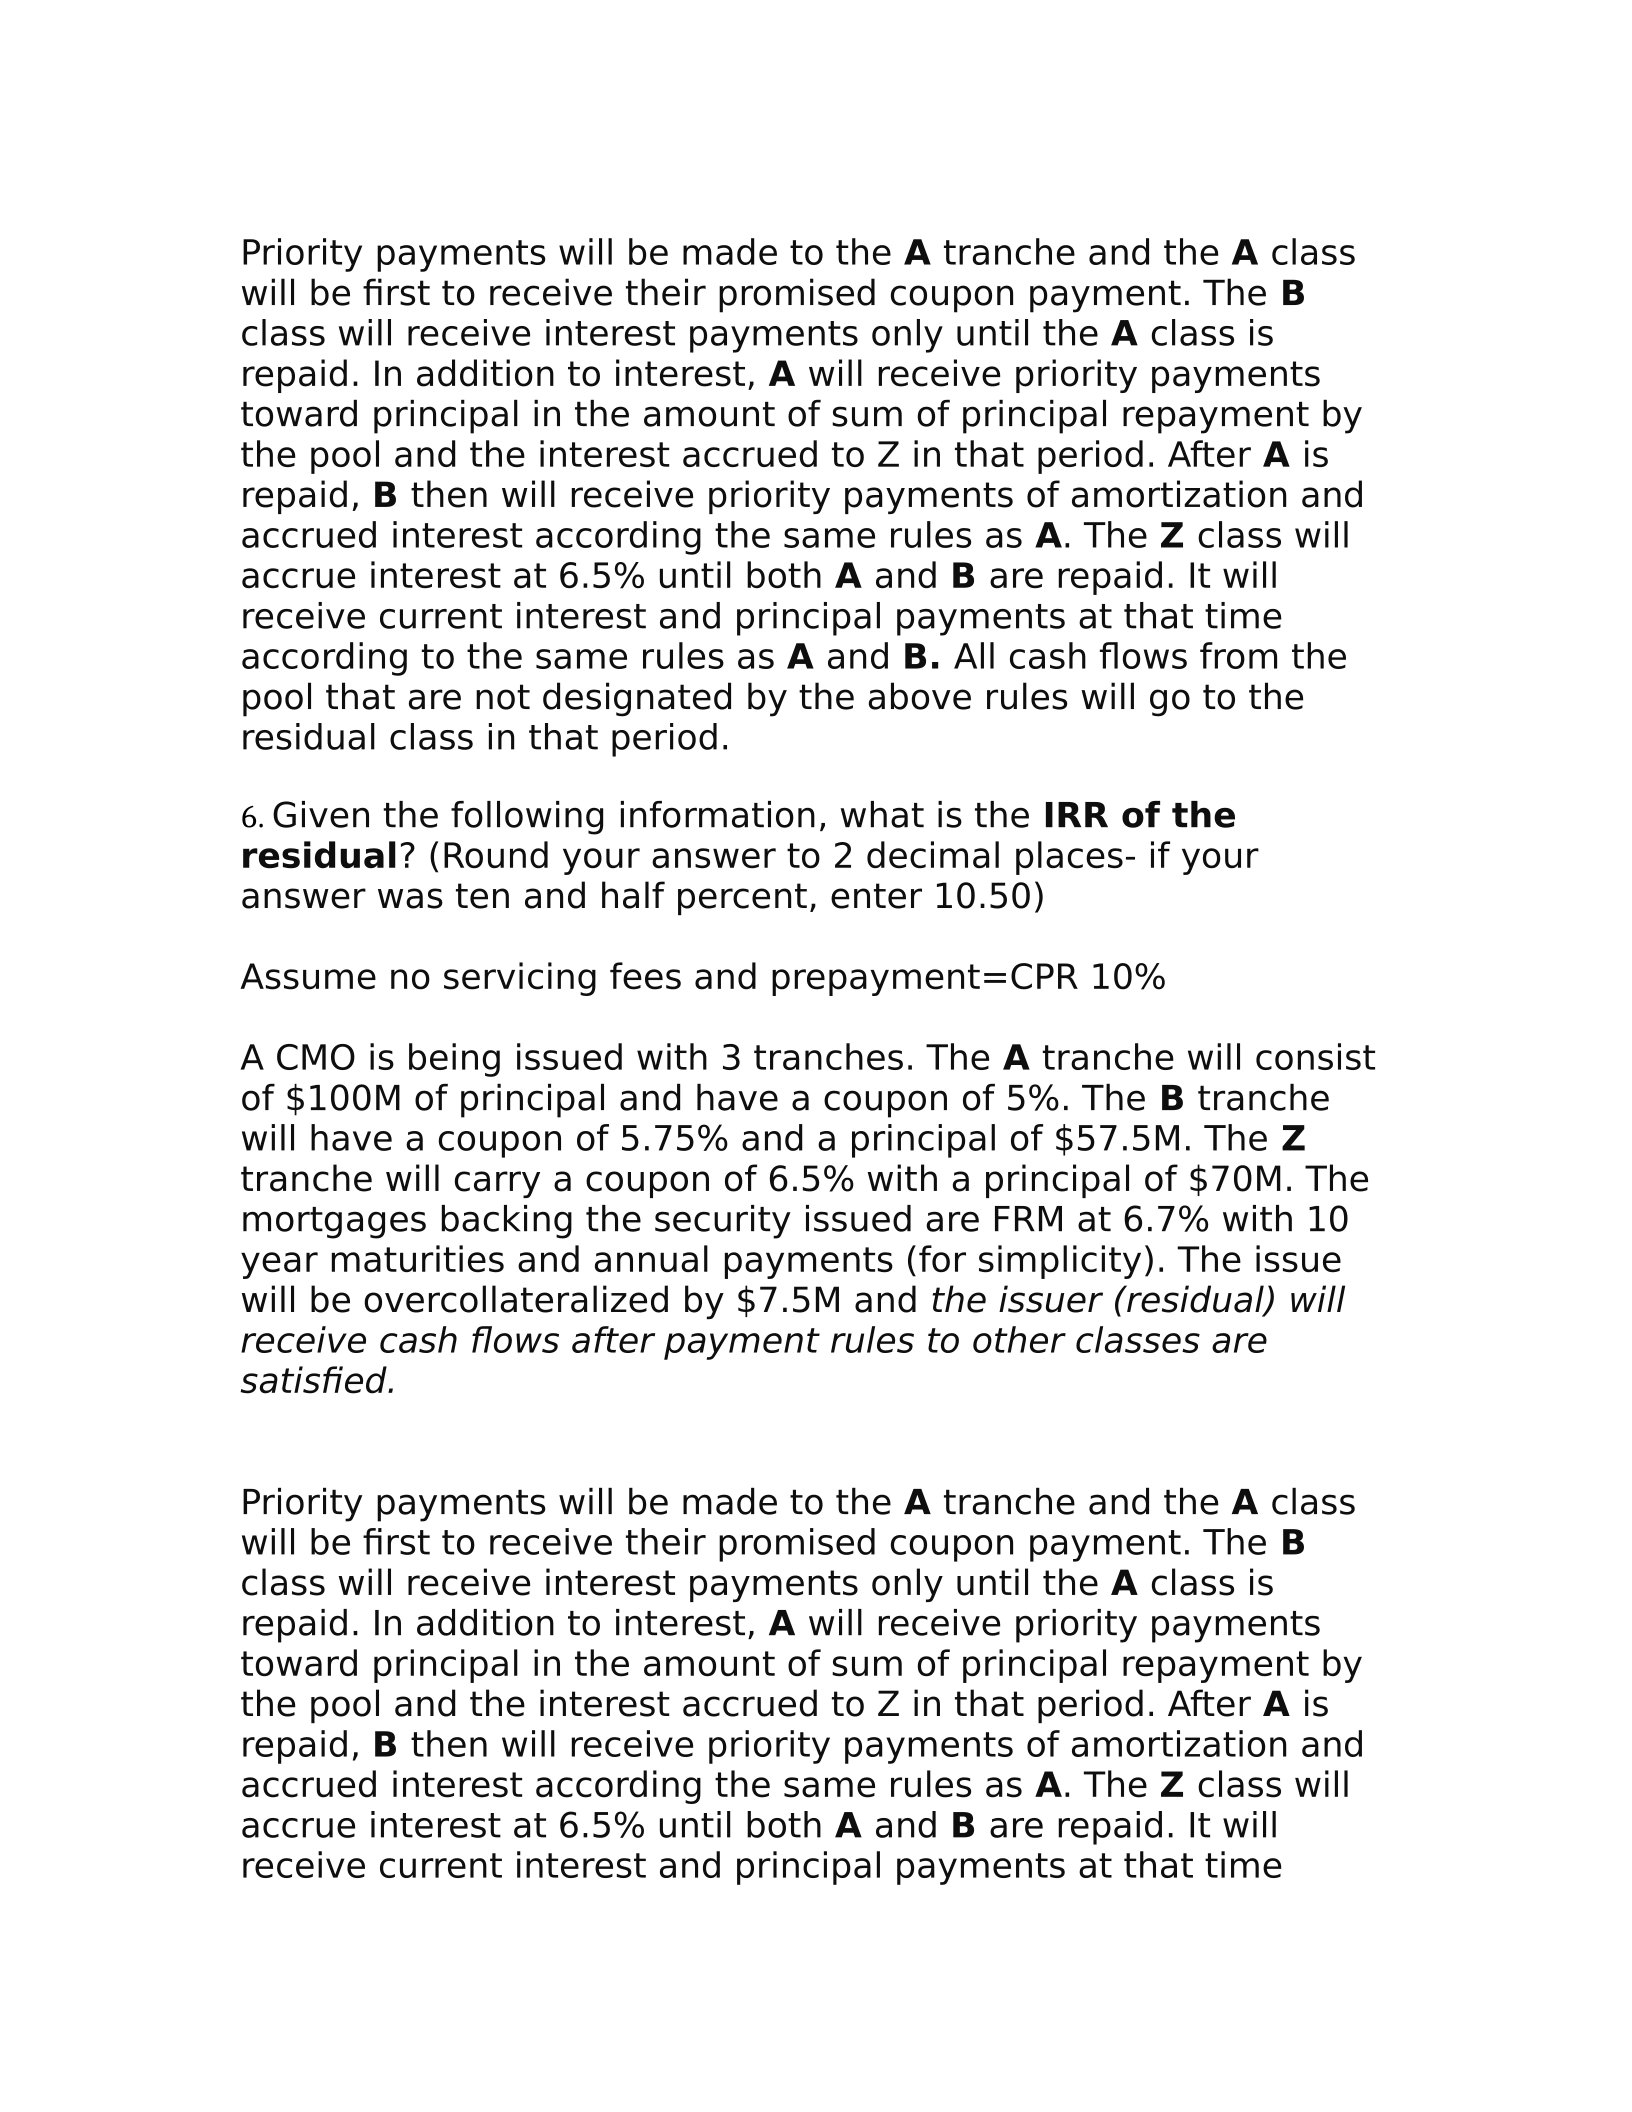
4. Given the following information, what is the total cash flow to
the residual class in year 1? (Round to the nearest cent)
A CMO is being issued with 3 tranches. The A tranche will consist of
$20M of principal and have a coupon of 7%. The B tranche will have a
coupon of 7.5% and a principal of $10M. The Z tranche will carry a
coupon of 8.25% with a principal of $25M. The mortgages backing the
security issued are FRM at 8.5% with 10 year maturities and annual
payments (for simplicity). The issue will be overcollateralized by $3M
and the issuer (residual) will receive cash flows only after all classes of
investors have been completely repaid.
Priority payments will be made to the A tranche and will include the
promised coupon. Interest will be accrued to the Z tranche until A is
completely repaid. The B class will receive interest payments only until
the A class is repaid. The A class will then receive all remaining CFs
from the pool that year. After A is repaid, B will receive priority
principal payments. The Z class will accrue interest at 8.25% until both
A and B are repaid. It will receive current interest and principal
payments at that time.
Assume there is no prepayment and no servicing fees.
5. Given the following information, what is the expected
maturity of Class B securities? (State your answer in number of
years)
Assume no servicing fees and prepayment=CPR 5%
A CMO is being issued with 3 tranches. The A tranche will consist
of $100M of principal and have a coupon of 5%. The B tranche
will have a coupon of 5.75% and a principal of $57.5M. The Z
tranche will carry a coupon of 6.5% with a principal of $70M. The
mortgages backing the security issued are FRM at 6.7% with 10
year maturities and annual payments (for simplicity). The issue
will be overcollateralized by $7.5M and the issuer (residual) will
receive cash flows after payment rules to other classes are
satisfied.
Priority payments will be made to the A tranche and the A class
will be first to receive their promised coupon payment. The B
class will receive interest payments only until the A class is
repaid. In addition to interest, A will receive priority payments
toward principal in the amount of sum of principal repayment by
the pool and the interest accrued to Z in that period. After A is
repaid, B then will receive priority payments of amortization and
accrued interest according the same rules as A. The Z class will
accrue interest at 6.5% until both A and B are repaid. It will
receive current interest and principal payments at that time
according to the same rules as A and B. All cash flows from the
pool that are not designated by the above rules will go to the
residual class in that period.
6. Given the following information, what is the IRR of the
residual? (Round your answer to 2 decimal places- if your
answer was ten and half percent, enter 10.50)
Assume no servicing fees and prepayment=CPR 10%
A CMO is being issued with 3 tranches. The A tranche will consist
of $100M of principal and have a coupon of 5%. The B tranche
will have a coupon of 5.75% and a principal of $57.5M. The Z
tranche will carry a coupon of 6.5% with a principal of $70M. The
mortgages backing the security issued are FRM at 6.7% with 10
year maturities and annual payments (for simplicity). The issue
will be overcollateralized by $7.5M and the issuer (residual) will
receive cash flows after payment rules to other classes are
satisfied.
Priority payments will be made to the A tranche and the A class
will be first to receive their promised coupon payment. The B
class will receive interest payments only until the A class is
repaid. In addition to interest, A will receive priority payments
toward principal in the amount of sum of principal repayment by
the pool and the interest accrued to Z in that period. After A is
repaid, B then will receive priority payments of amortization and
accrued interest according the same rules as A. The Z class will
accrue interest at 6.5% until both A and B are repaid. It will
receive current interest and principal payments at that time
according to the same rules as A and B. All cash flows from the
pool that are not designated by the above rules will go to the
residual class in that period.
7. What is the Macaulay duration of the following security?
(Round your answer to 2 decimal places.)
3 year bond with semiannual coupon payments
Par value $1000
4% coupon payments
5% market/discount rate
8. What is the estimated price change, as a percentage, for this
bond if the market interest rate declined by 20bp? (Round your
answer to 2 decimal places, use a negative sign for price
decrease. If your answer was a price decrease of a tenth of a
percent, enter -0.10)
(Hint, first calculate modified duration)
2 year bond with annual payments
Par value $1000
10% coupon
9% discount rate
9. If a CMO has 3 tranches, A, B, and Z (an accrual tranche), as
well as a residual class, answer the following question?
If the prepayment on a pool of mortgages increases from PSA 100
to PSA 150, what would happen to the expected maturity of the Z
class?
Increase, decrease or stay the same?
10. If a CMO has 3 tranches, A, B, and Z (an accrual tranche), as
well as a residual class, answer the following question?
If the prepayment on a pool of mortgages decreases from CPR
10% to CPR 5%, what would happen to the expected maturity of
the A class?
Increase, decrease, or stay the same?
Powered by TCPDF (www.tcpdf.org)

