


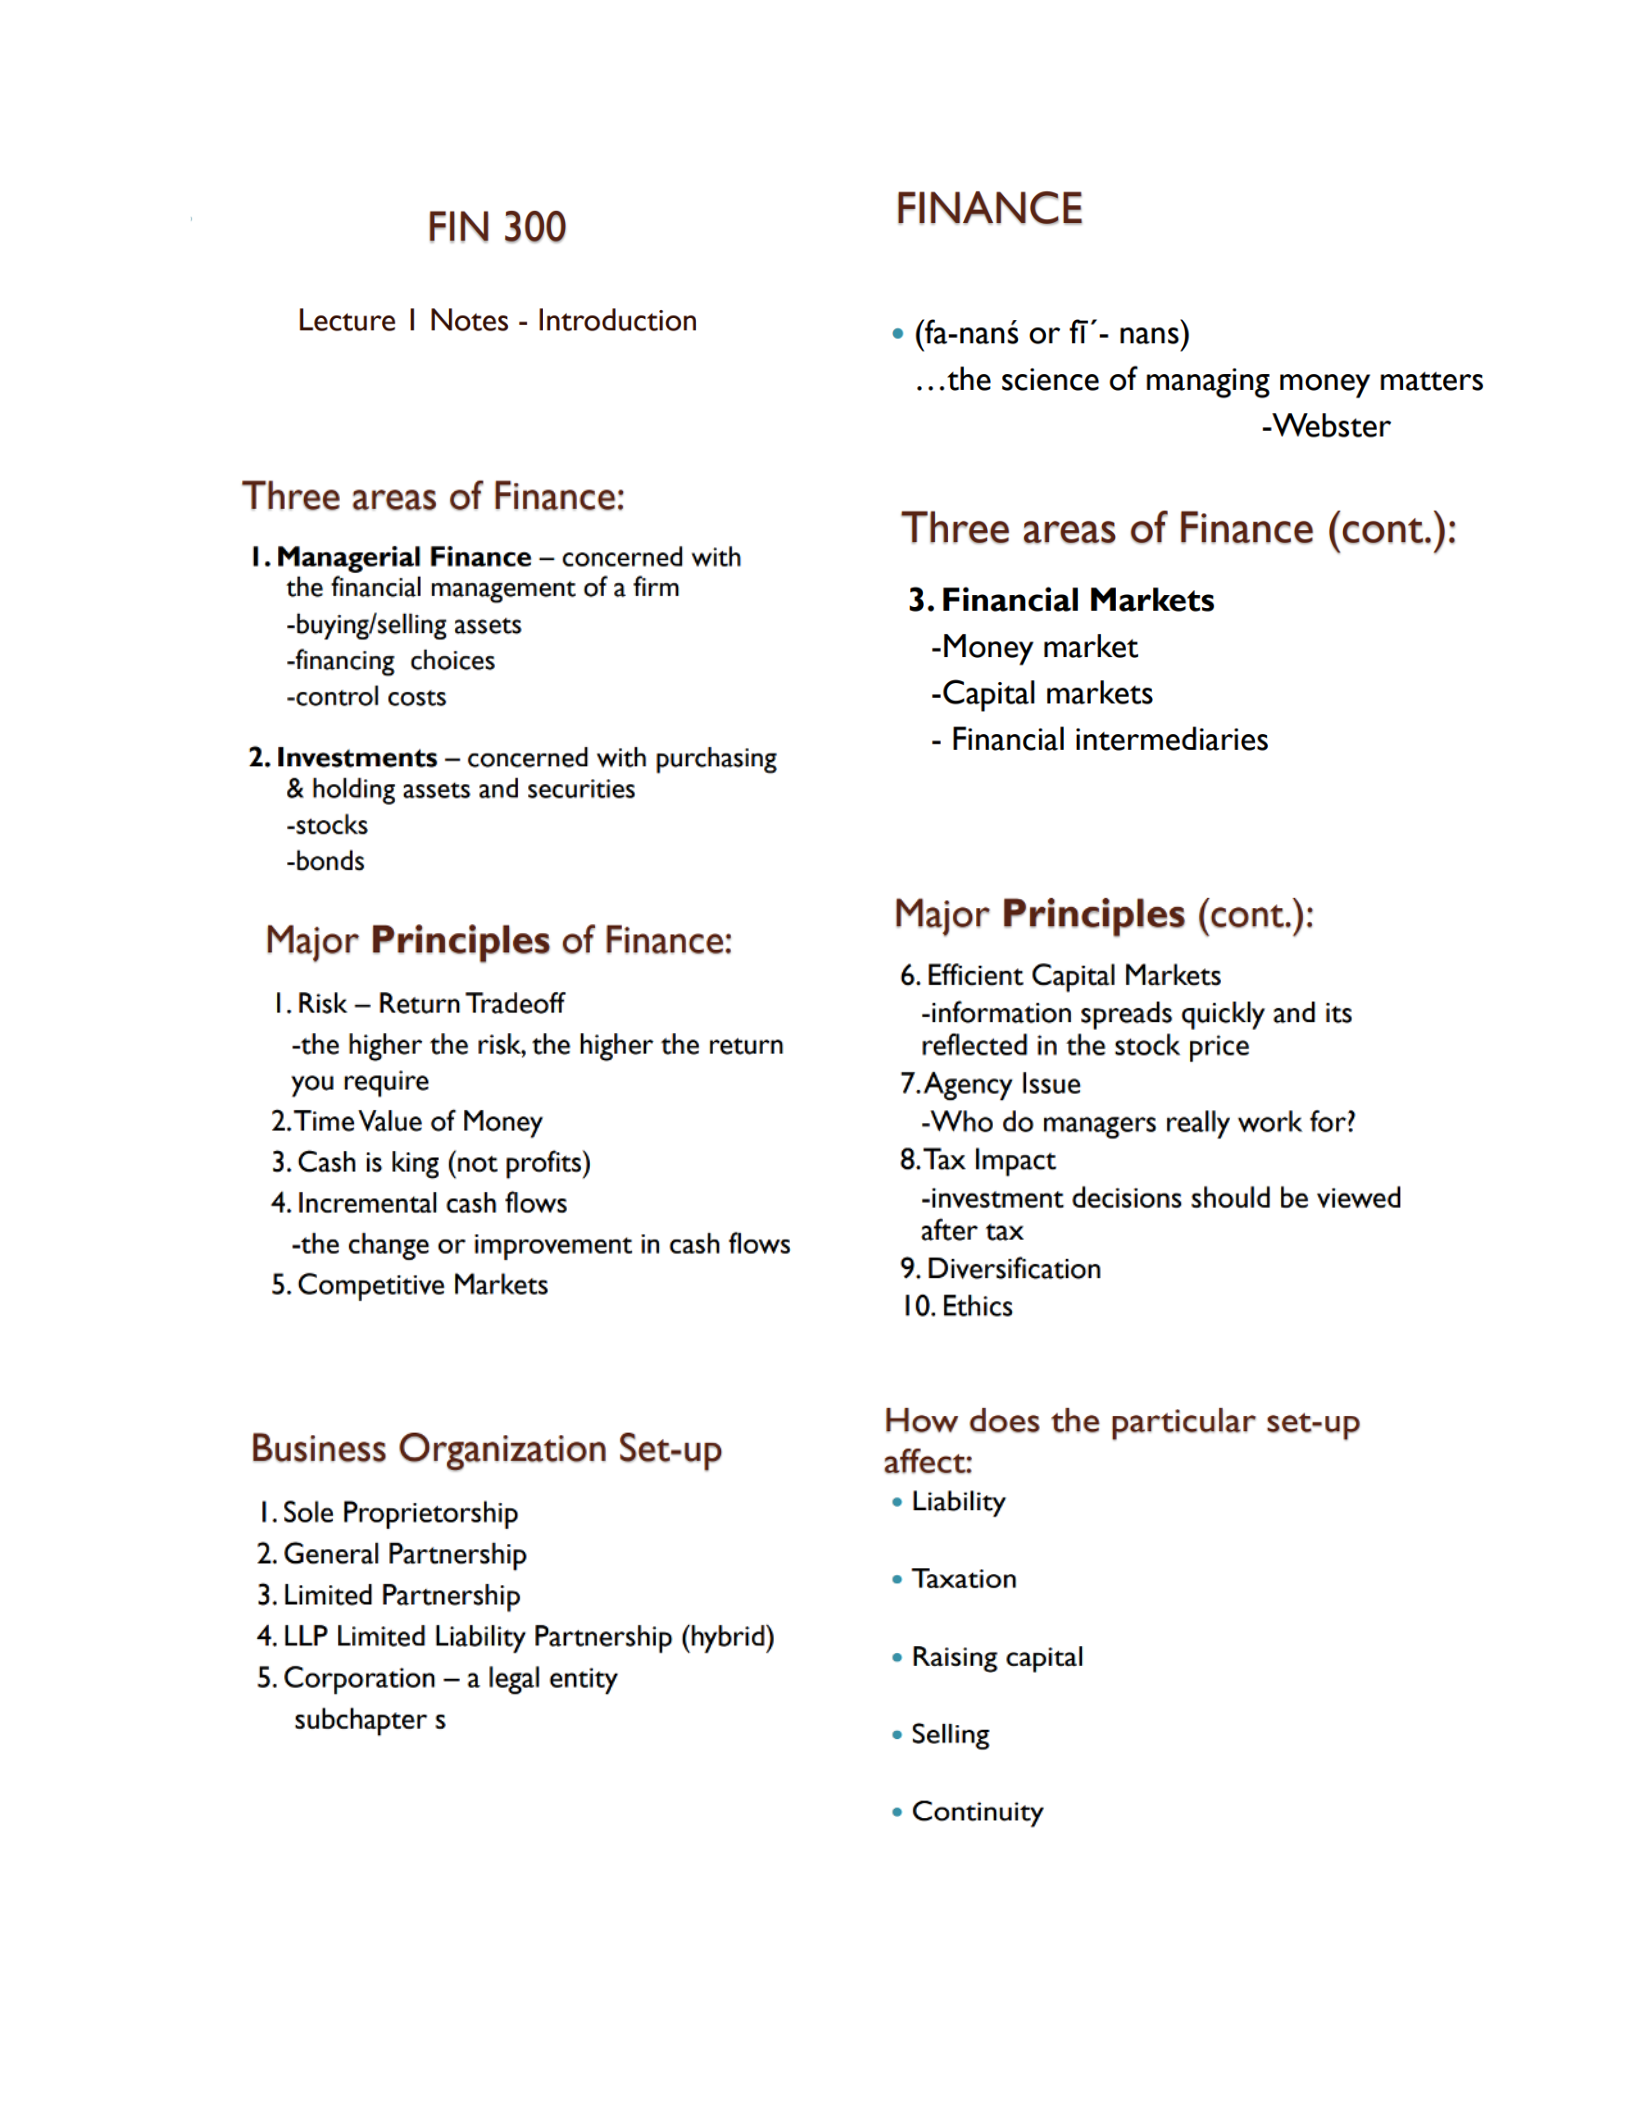
FIN
300
Lecture
|
Notes
-
Introduction
Three
areas
of
Finance:
|.
Managerial
Finance
—
concerned
with
the
financial
management
of
a
firm
-buying/selling
assets
-financing
choices
-control
costs
2.
Investments
—
concerned
with
purchasing
&
holding
assets
and
securities
-stocks
-bonds
Major
Principles
of
Finance:
|.
Risk
—
Return
Tradeoff
-the
higher
the
risk,
the
higher
the
return
you
require
2.Time
Value
of
Money
3.
Cash
is
king
(not
profits)
4.
Incremental
cash flows
-the
change
or
improvement
in
cash
flows
5.
Competitive
Markets
Business
Organization
Set-up
|.
Sole
Proprietorship
2.
General
Partnership
3.
Limited
Partnership
4,
LLP
Limited
Liability
Partnership
(hybrid)
5.
Corporation
—
a
legal
entity
subchapter
s
FINANCE
e
(fa-nans
or
ff"-
nans)
...the
science
of
managing
money
matters
-Webster
Three
areas
of
Finance
(cont.):
3.
Financial
Markets
-Money
market
-Capital
markets
-
Financial
intermediaries
Major
Principles
(cont.):
6. Efficient
Capital
Markets
-information
spreads
quickly
and
its
reflected
in
the
stock
price
7.
Agency
Issue
-Who
do
managers
really
work
for?
8.Tax
Impact
-investment
decisions
should
be
viewed
after
tax
9.
Diversification
10,
Ethics
How
does
the
particular
set-up
affect:
*
Liability
©
Taxation
©
Raising
capital
*
Selling
*
Continuity
Lecture 1 - Course Introduction
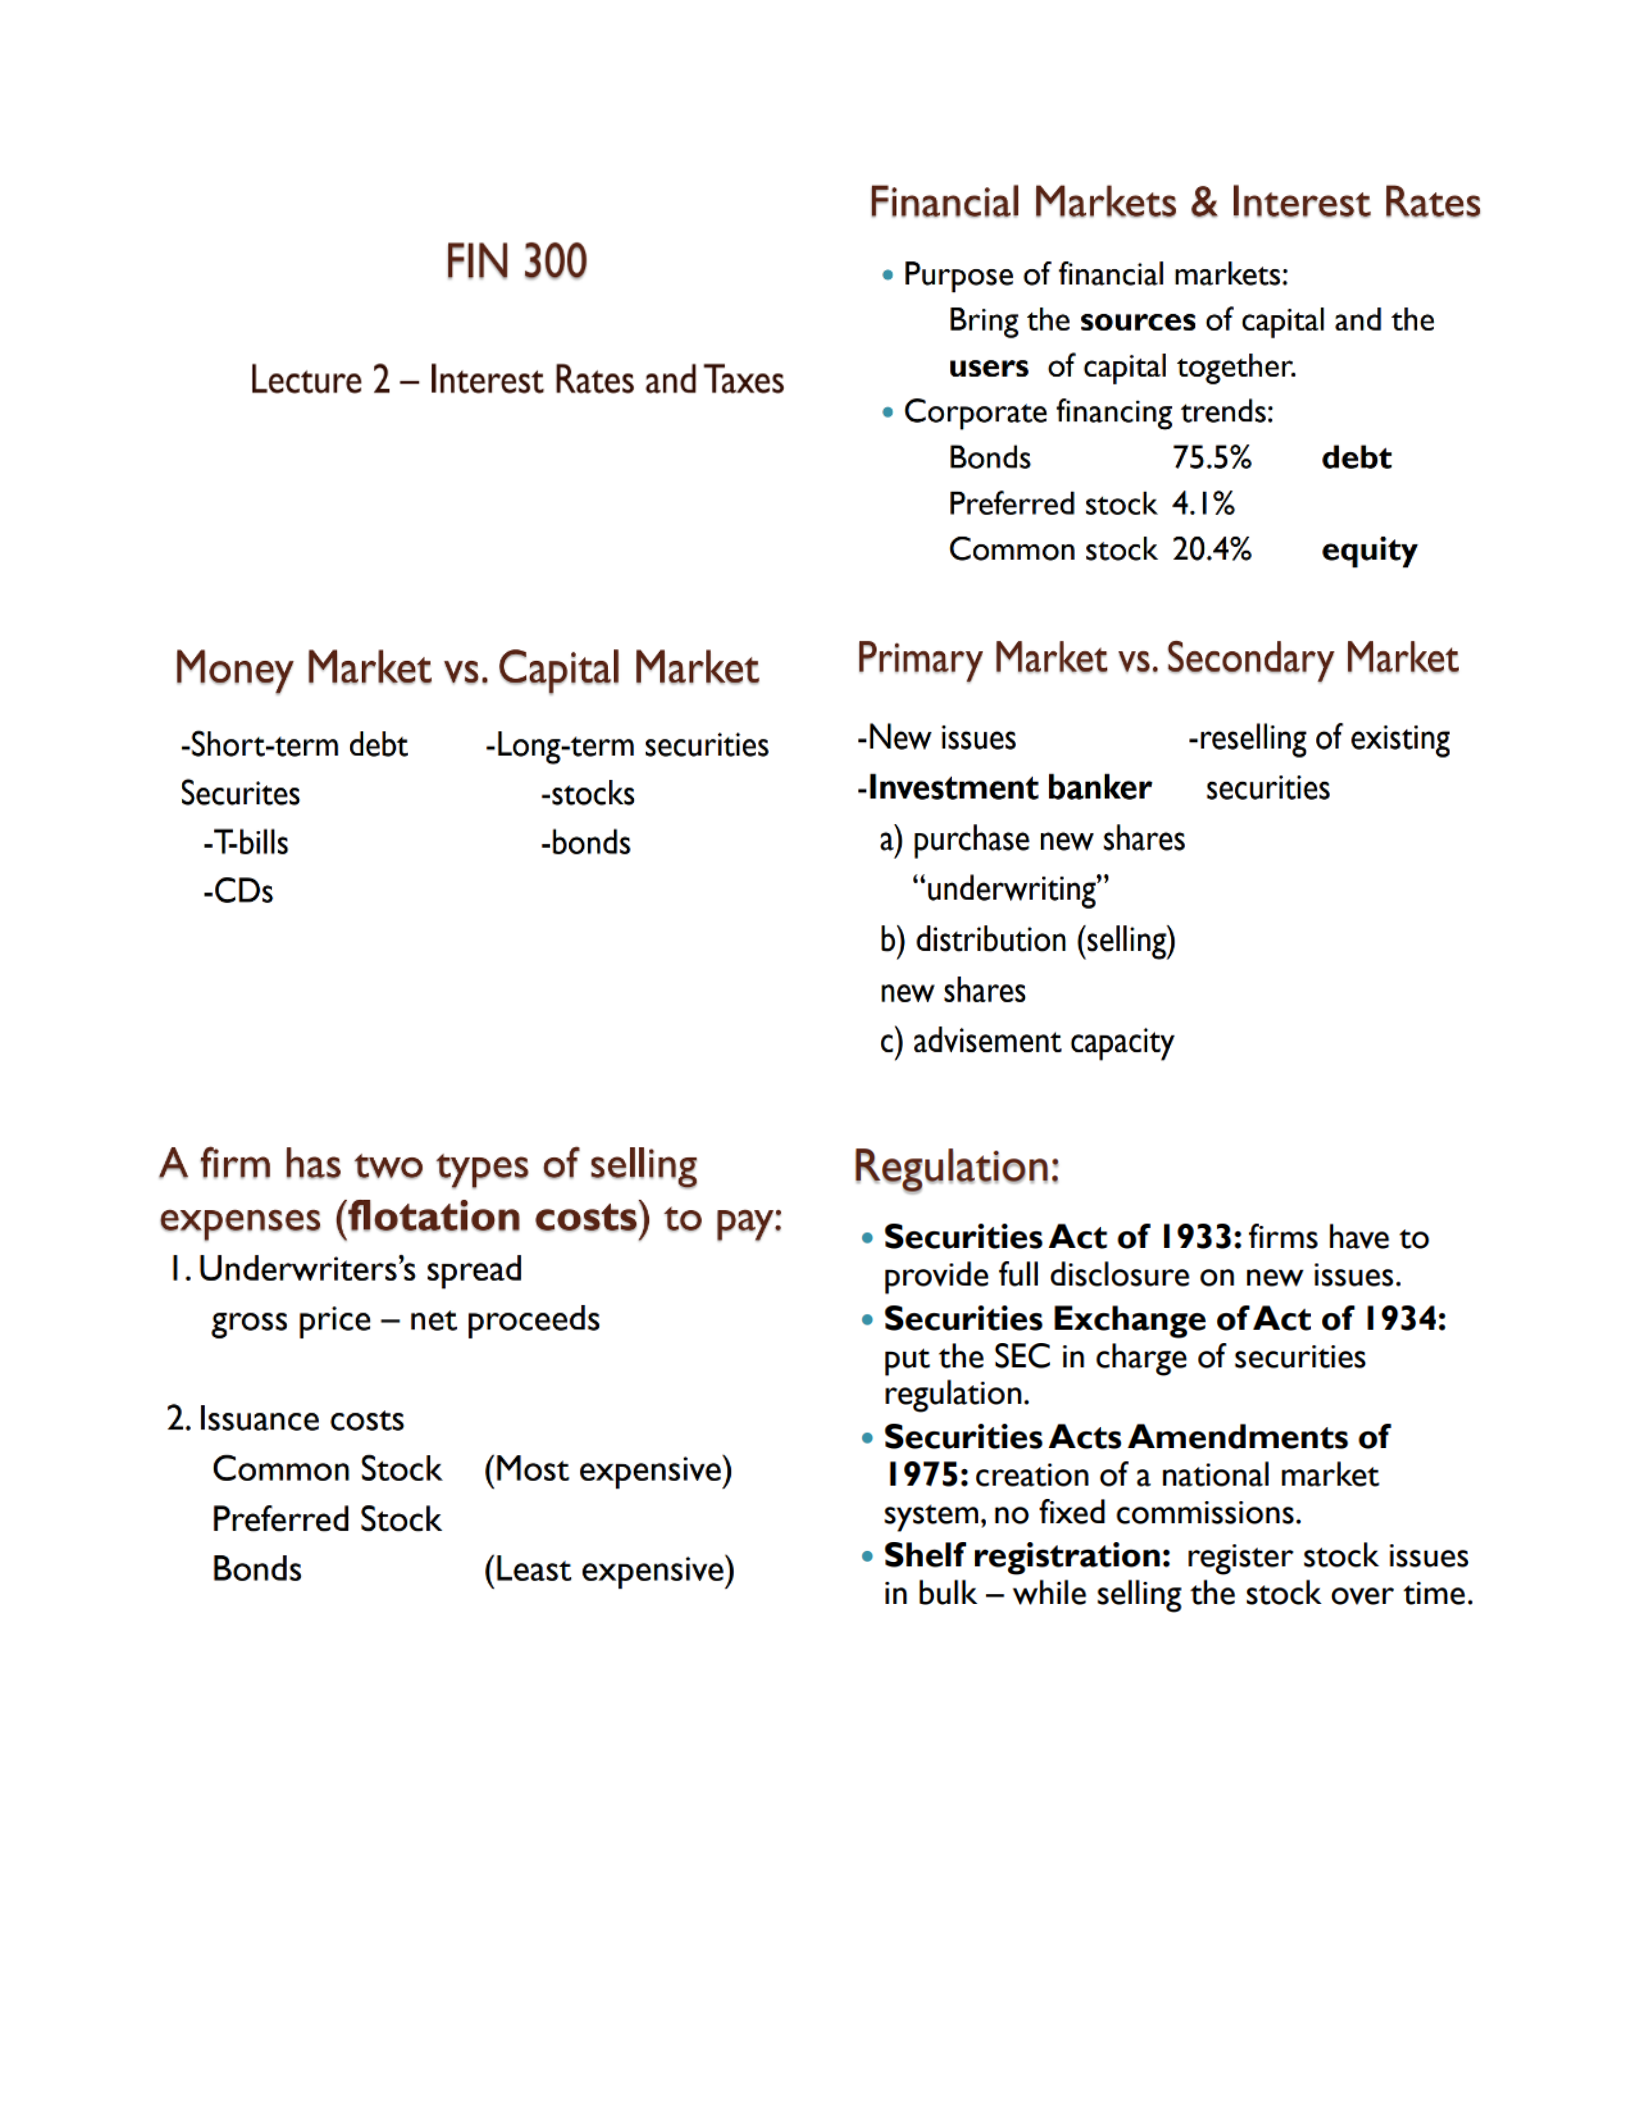
FIN
300
Lecture
2
—
Interest
Rates
and
Taxes
Money
Market
vs.
Capital
Market
-Short-term
debt
-Long-term
securities
Securites
-stocks
-Fbills
-bonds
-CDs
A
firm
has
two
types
of
selling
expenses
(flotation
costs)
to
pay:
|.
Underwriters’s
spread
gross
price
—
net
proceeds
2.
Issuance
costs
Common
Stock
(Most
expensive)
Preferred
Stock
Bonds
(Least
expensive)
Financial
Markets
&
Interest
Rates
e
Purpose
of
financial
markets:
Bring
the
sources
of
capital
and
the
users
of
capital
together.
e
Corporate
financing
trends:
Bonds
75.5%
debt
Preferred
stock
4.1%
Common
stock
20.4%
equity
Primary
Market
vs.
Secondary
Market
-reselling
of
existing
securities
-New
issues
-Investment
banker
a)
purchase
new
shares
“underwriting”
b)
distribution
(selling)
new
shares
c)
advisement
capacity
Regulation:
e
Securities
Act
of
1933:
firms
have
to
provide
full
disclosure
on
new
issues.
e
Securities
Exchange
of
Act
of
1934:
put
the
SEC
in
charge
of
securities
regulation.
e
Securities
Acts
Amendments
of
1975:
creation
of a
national
market
system,
no
fixed
commissions.
e
Shelf
registration:
register
stock
issues
in
bulk
—
while
selling
the
stock
over
time.
Lecture 2 - Interest Rates and Taxes
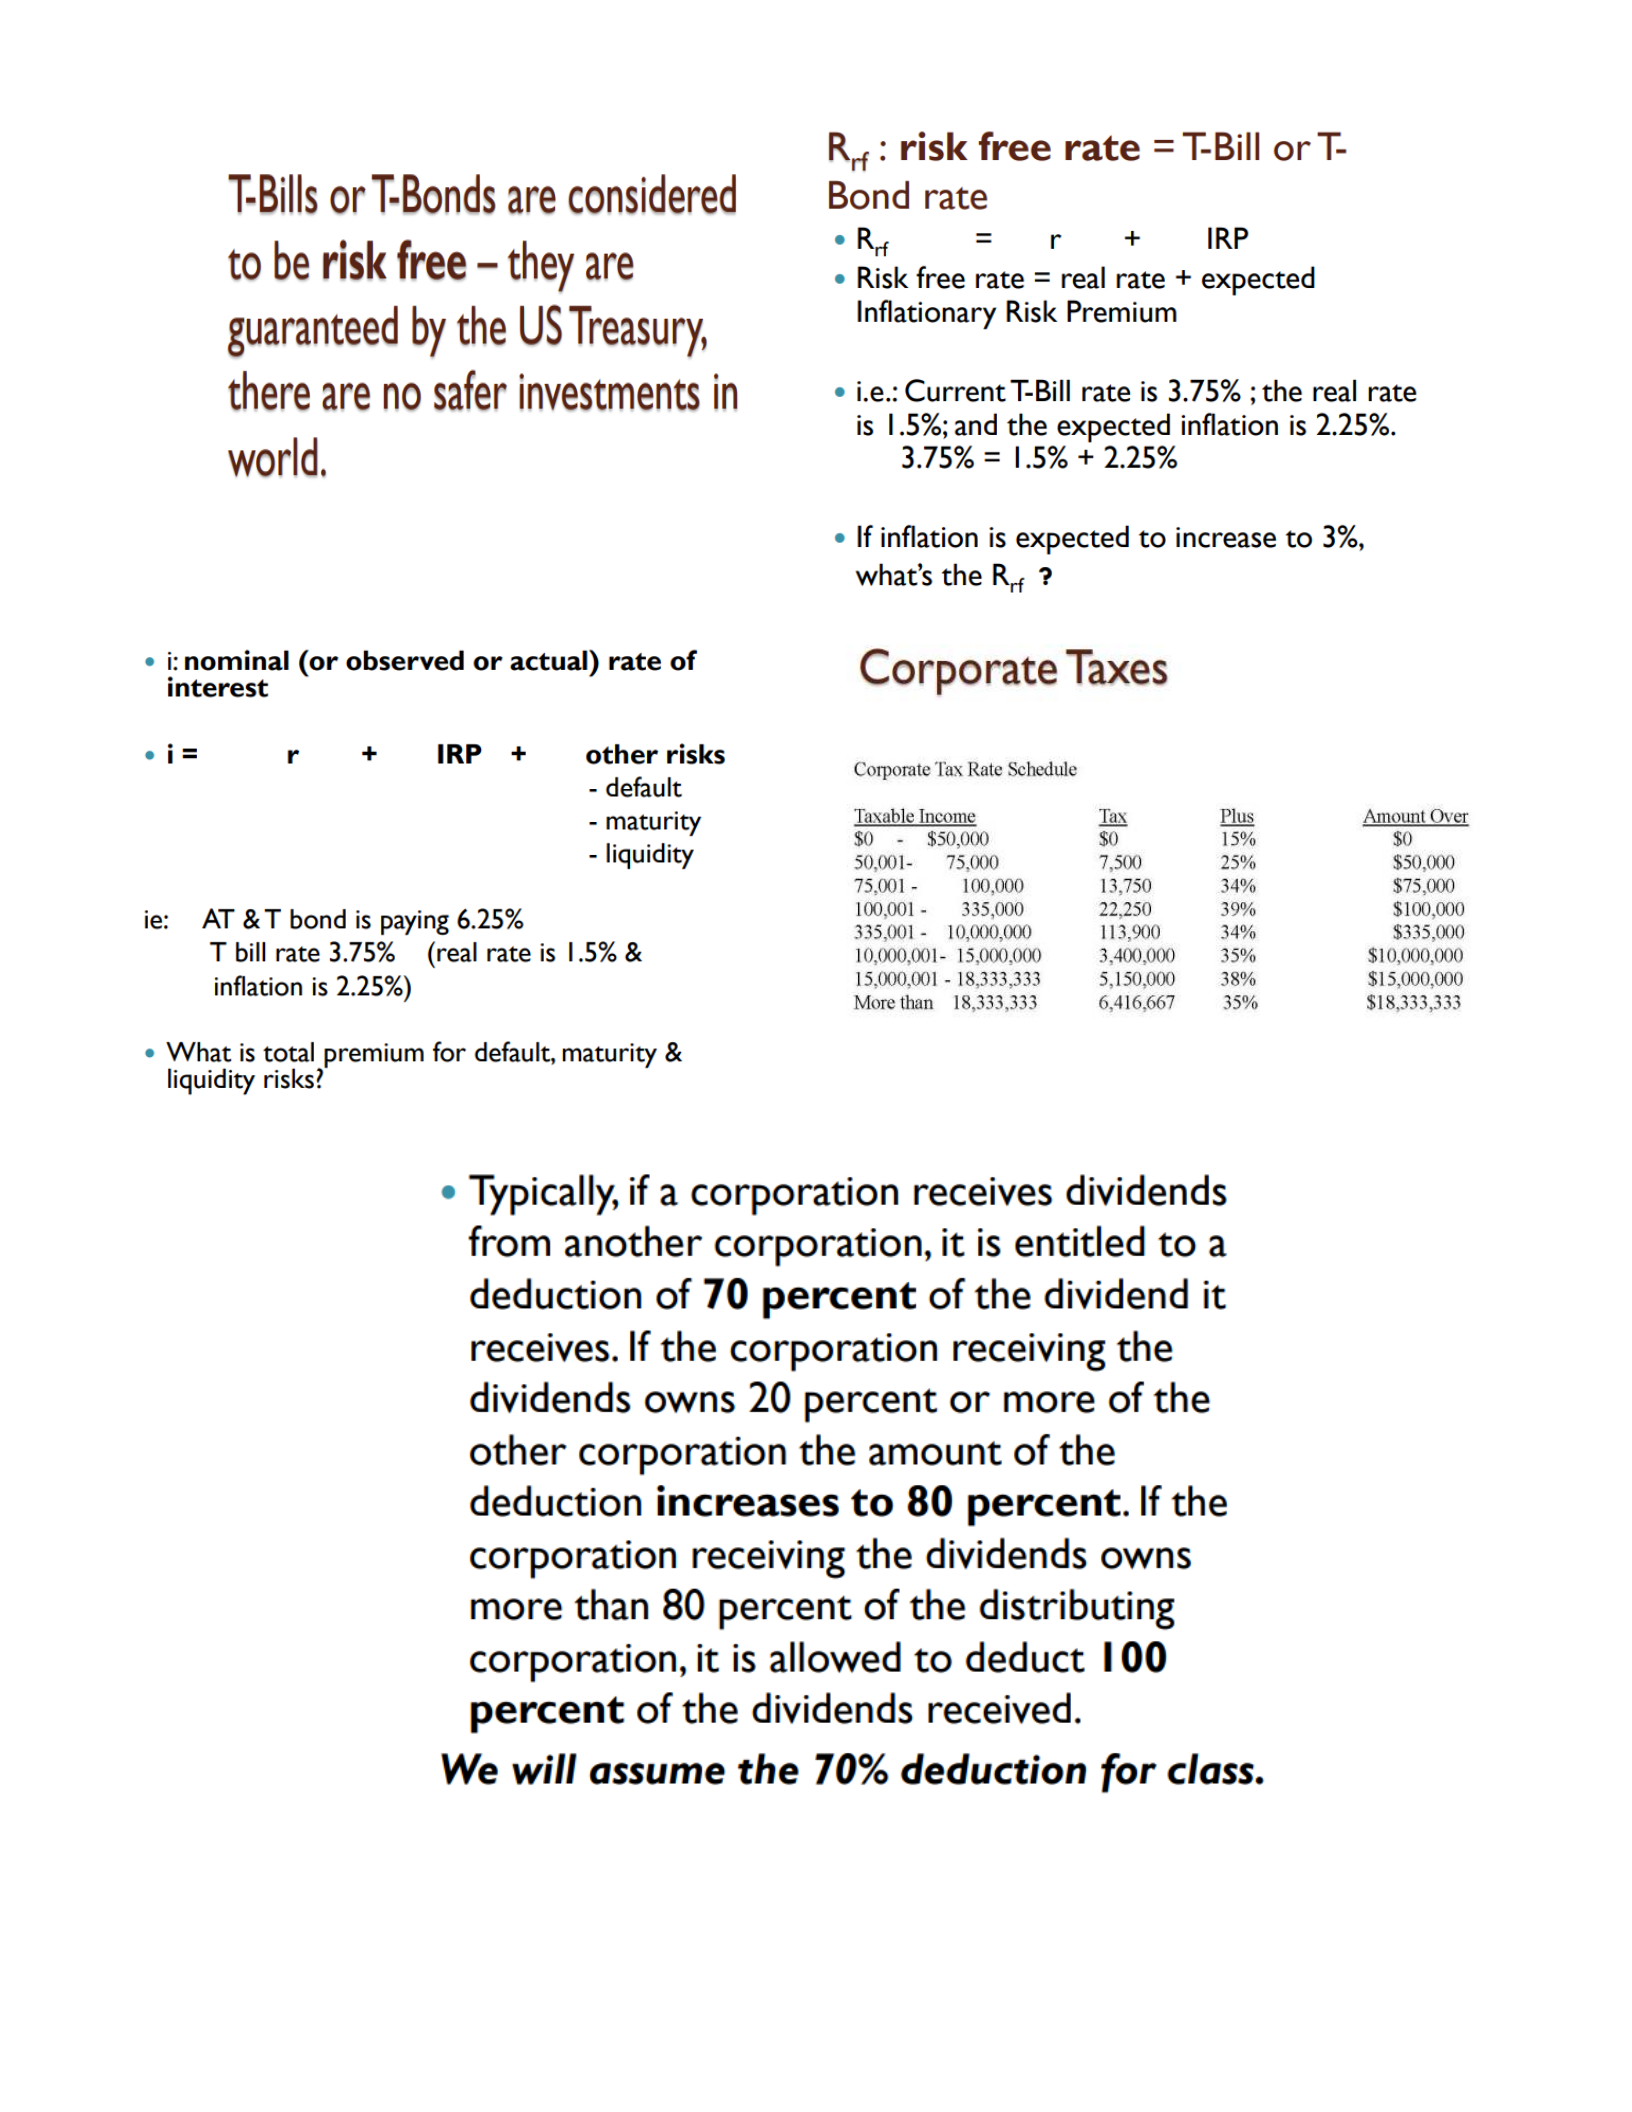
T-Bills
or
T-Bonds
are
considered
to
be
risk
free
-
they
are
guaranteed
by
the
US
Treasury,
there
are
no
safer
investments
in
world,
e
i:nominal
(or
observed
or
actual)
rate
of
interest
ei=
r
+
IRP_
+
other
risks
-
default
-
maturity
-
liquidity
ie:
AT
&T
bond
is
paying
6.25%
T
bill
rate
3.75%
(real
rate
is
1.5%
&
inflation
is
2.25%)
e
What
is
total
premium
for
default,
maturity
&
liquidity
risks?
R,:
risk
free
rate
=
T-Bill
or
T-
Bond
rate
°Ry
=
r+
IRP
e
Risk
free
rate
=
real
rate
+
expected
Inflationary
Risk
Premium
e
i.e:
Current
T-Bill
rate
is
3.75%
;
the
real
rate
is
1.5%;
and
the
expected
inflation
is
2.25%.
3.75%
=
1.5%
+
2.25%
«
If
inflation
is
expected
to
increase
to
3%,
what's
the
Ry
?
Corporate
Taxes
Corporate
Tax
Rate
Schedule
Taxable
Income
Tax
Plus
$0
-
$50,000
$0
15%
50,001-
73,000
7,500
25%
75,001
-
100,000
13,750
34%
100,001
-
335,000.
22,250
39%
335,001
-
10,000,000
113,900
34%
10,000,001-
15,000,000
3,400,000,
35%
15,000,001
-
18,333,333
5,150,000
38%
More
than
18,333,333 6,416,667
35%
©
Typically,
if
a
corporation
receives
dividends
from
another
corporation,
it
is
entitled
to
a
deduction
of
70
percent
of
the
dividend
it
receives.
If
the
corporation
receiving
the
dividends
owns
20
percent
or
more
of
the
other
corporation
the
amount
of
the
deduction
increases
to
80
percent.If
the
corporation
receiving
the
dividends
owns
more
than
80
percent
of
the
distributing
corporation,
it
is
allowed
to
deduct
100
percent
of
the
dividends
received.
We
will
assume
the
70%
deduction
for
class.
Amount
Over
$0
$50,000
$75,000
$100,000
$335,000
$10,000,000
$15,000,000
$18,333,333
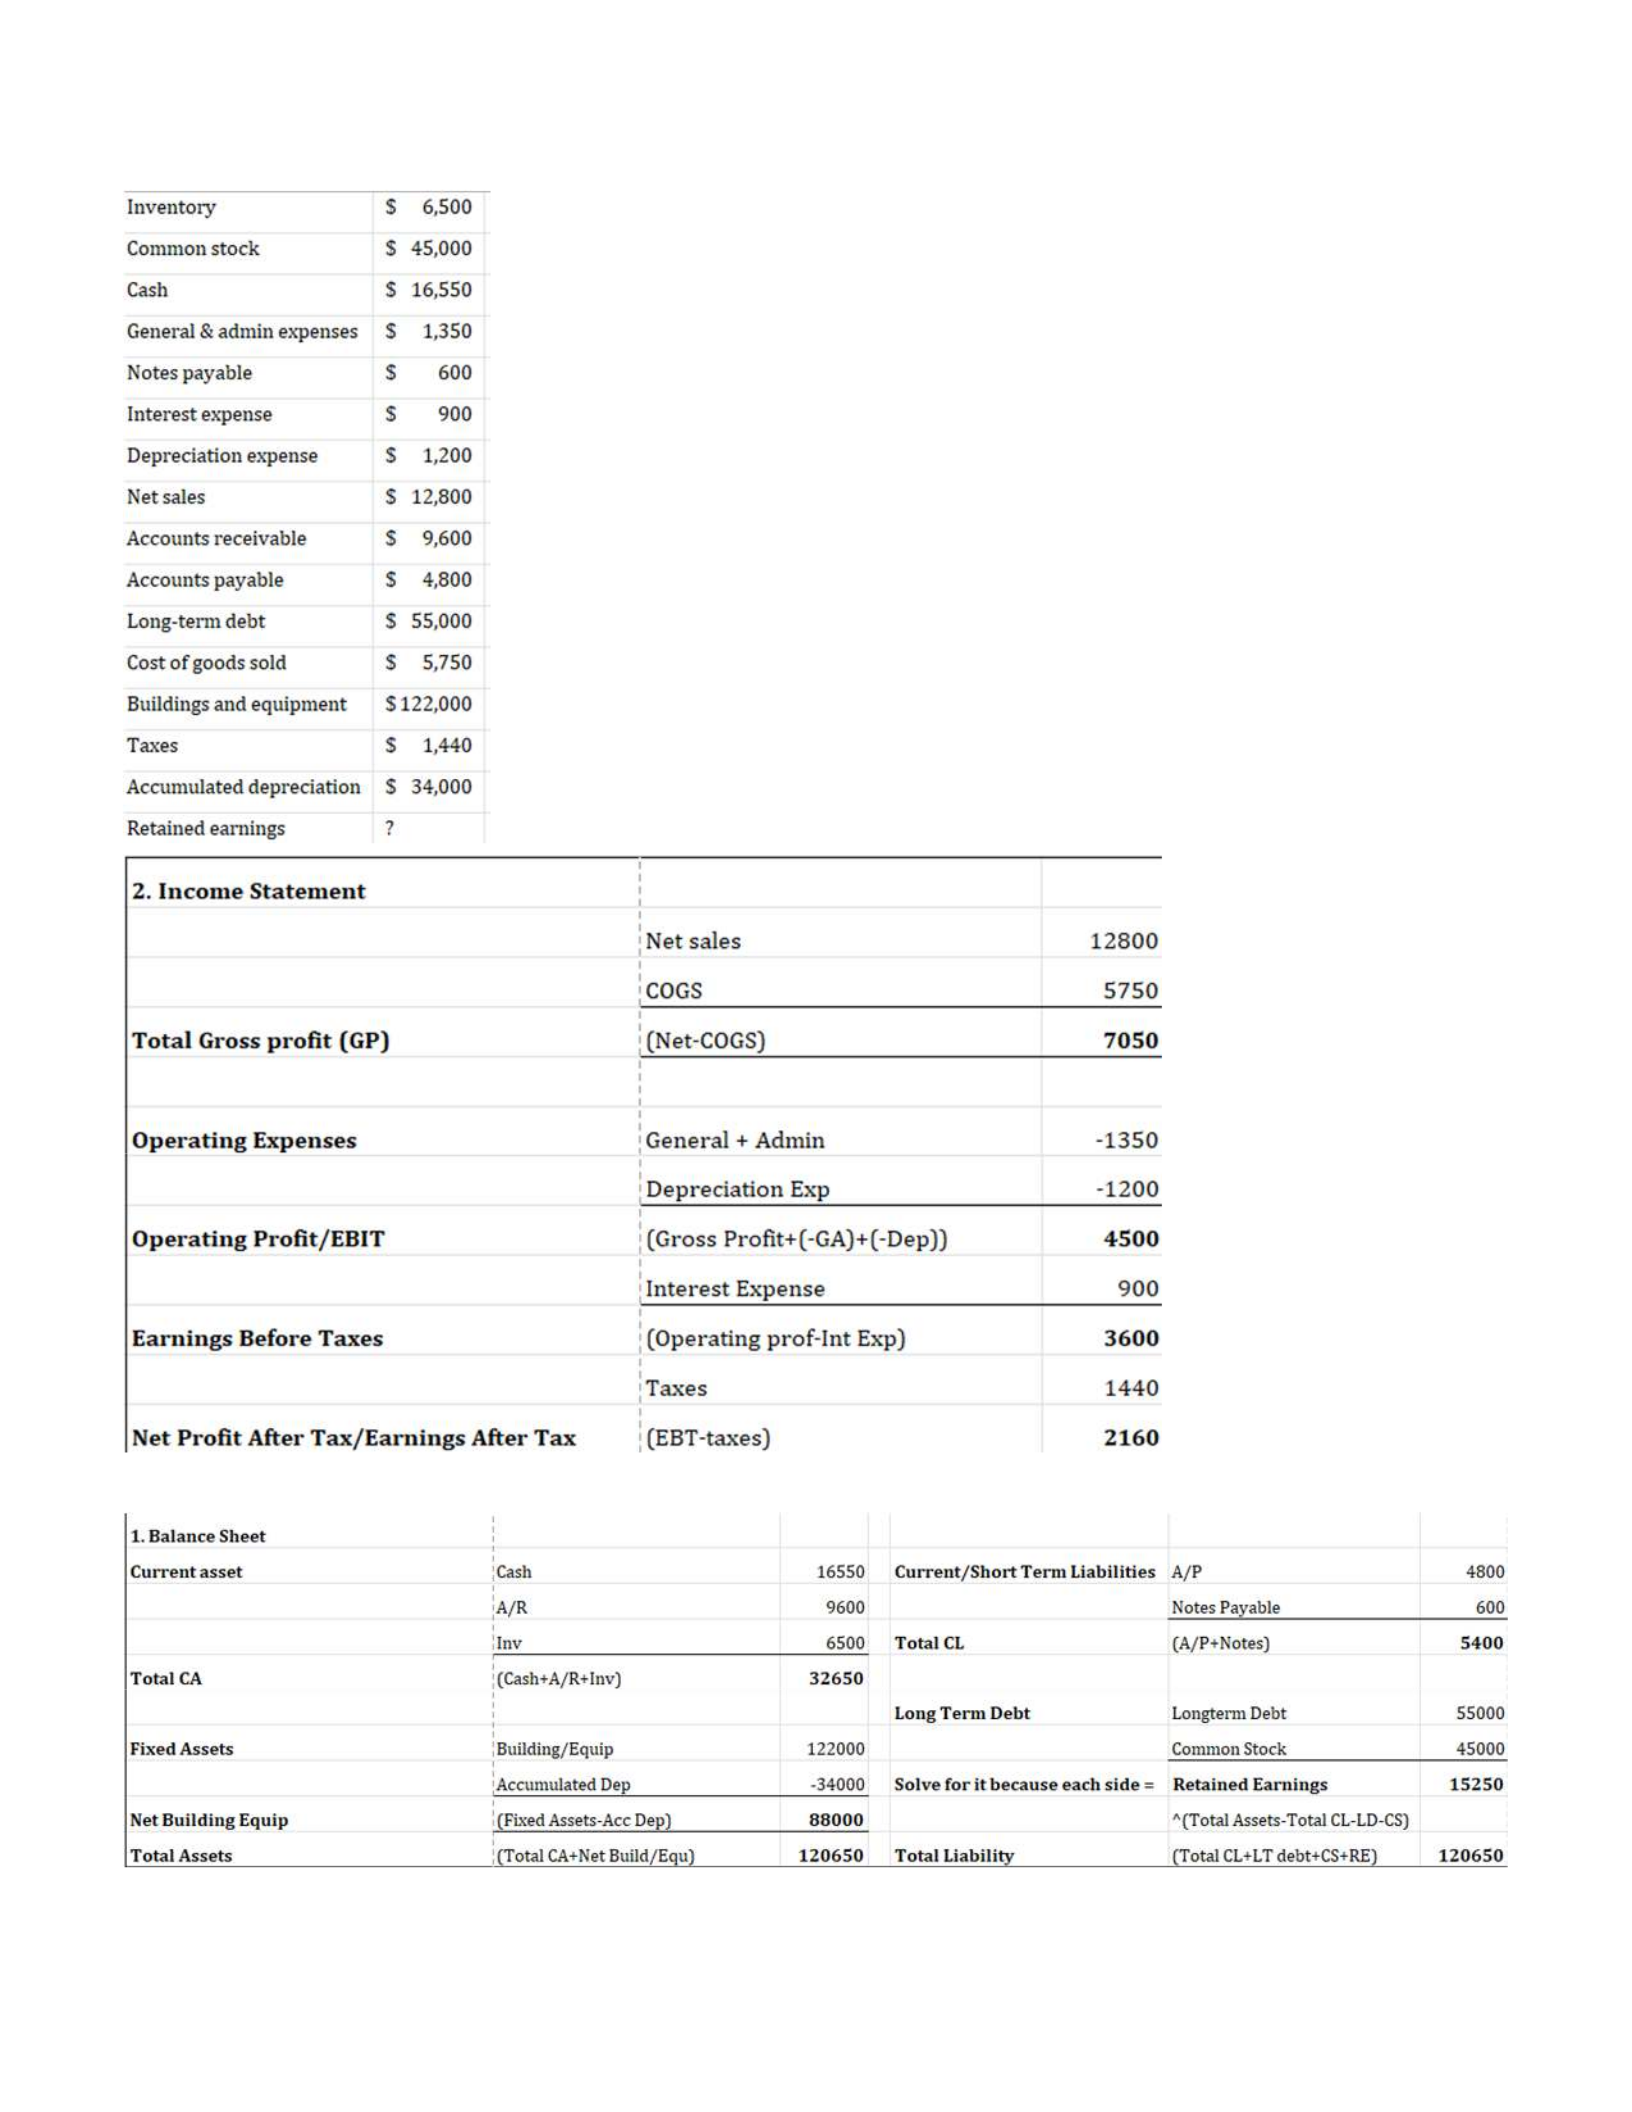
Inventory
$
6,500
Common
stock
$
45,000
Cash
$
16,550
General
&
admin
expenses
$
1,350
Notes
payable
S$
600
Interest
expense
Ss
900
Depreciation
expense
$
1,200
Net
sales
$
12,800
Accounts
receivable
$9,600
Accounts
payable
$
4,800
Long-term
debt
$
55,000
Cost
of
goods
sold
S
5,750
Buildings
and equipment
$122,000
Taxes S
1,440
Accumulated
depreciation
$
34,000
Retained
earnings
2
2.
Income
Statement
Total Gross
profit
(GP)
Operating
Expenses
Operating
Profit/EBIT
Earnings
Before
Taxes
1.
Balance
Sheet
Current
asset
Total
CA
Fixed
Assets
Net
Building
Equip
Total
Assets
Net
Profit
After
Tax/Earnings
After
Tax
Net
sales
coGs
(Net-COGS)
General
+
Admin
‘Depreciation
Exp
(Gross
Profit+(-GA)+(-Dep))
Interest
Expense
(Operating
prof-Int
Exp)
Taxes
|
(EBT-taxes)
‘Cash
16550
A/R
9600
‘Inv
6500
(Cash+A/R+Inv)
32650
\Building/Equip
122000
Accumulated
Dep
-34000
(Fixed
Assets-Acc
Dep)
88000
(Total
CA+Net
Build
/Equ)
120650
12800
5750
7050
-1350
-1200
4500
900
3600
1440
2160
Current/Short
Term
Liabilities
Total
CL
Long
Term
Debt
Solve
for
it
because
each
side
=
Total
Liability
AP
4800
Notes
Payable
600
(A/P+Notes)
5400
Longterm
Debt
55000
CommonStock
45000
Retained
Earnings
15250
‘(Total
Assets-Total
CL-LD-CS)
(Total
CL+LT
debt+CS+RE)
120650
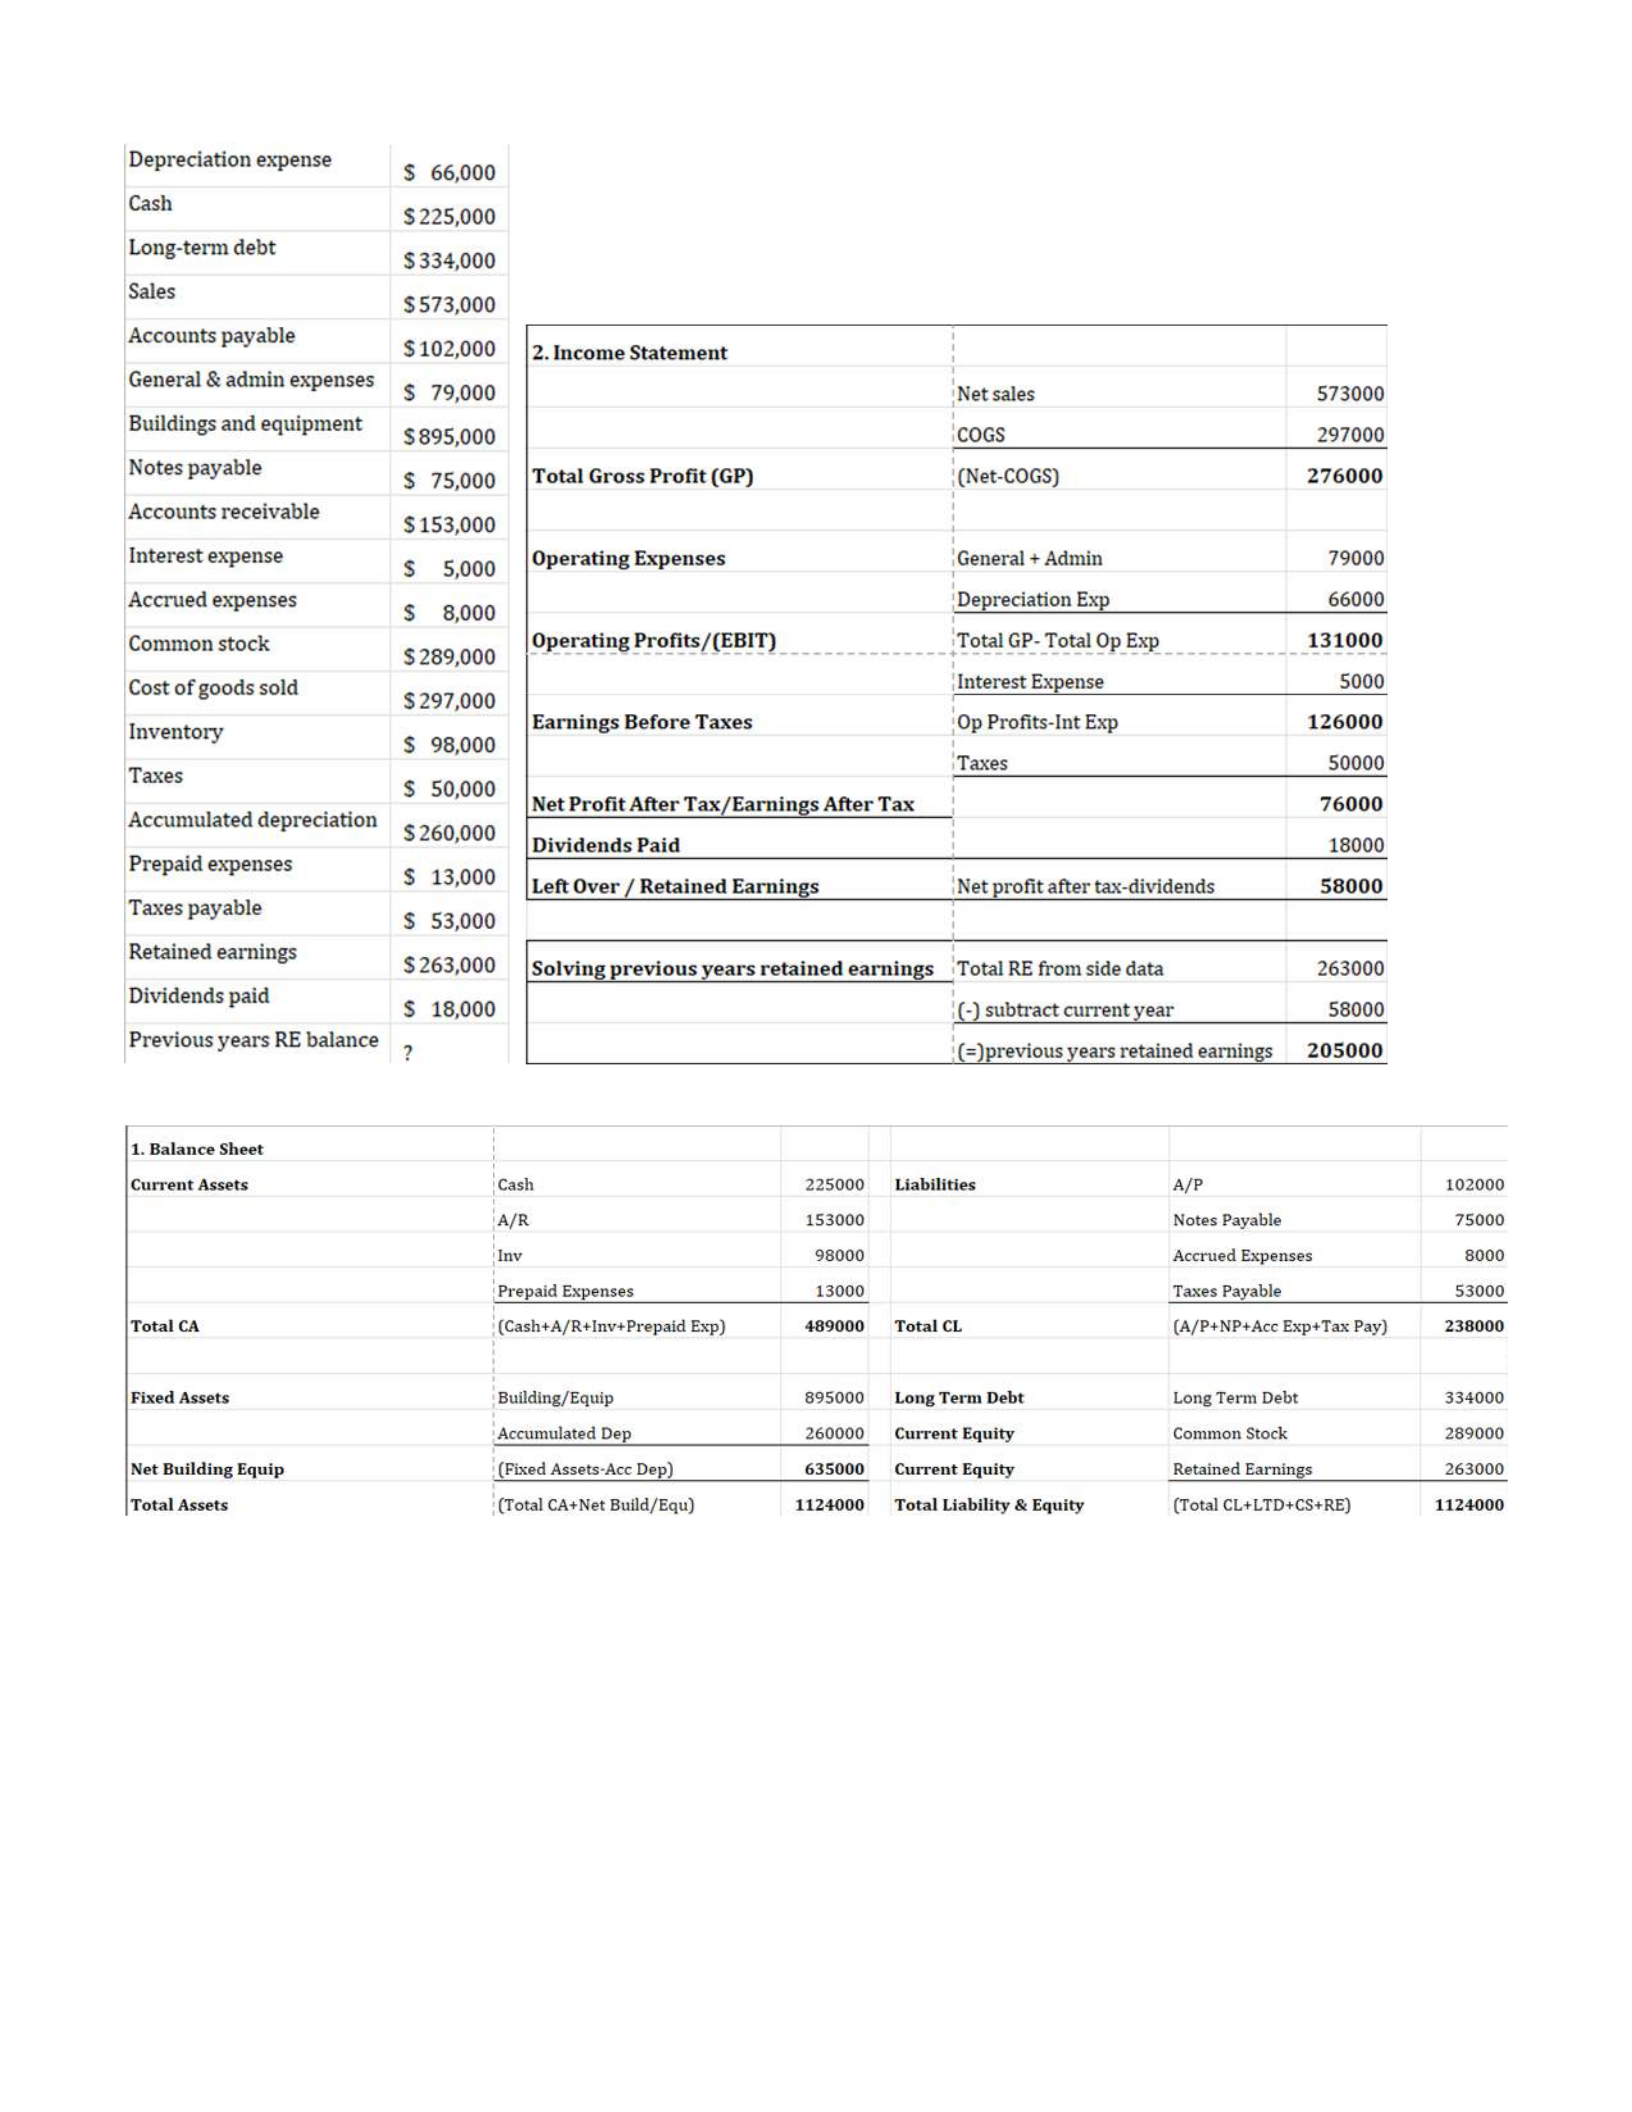
Financial Statement Problem 1 – Net Profit After Tax + Balance Sheet
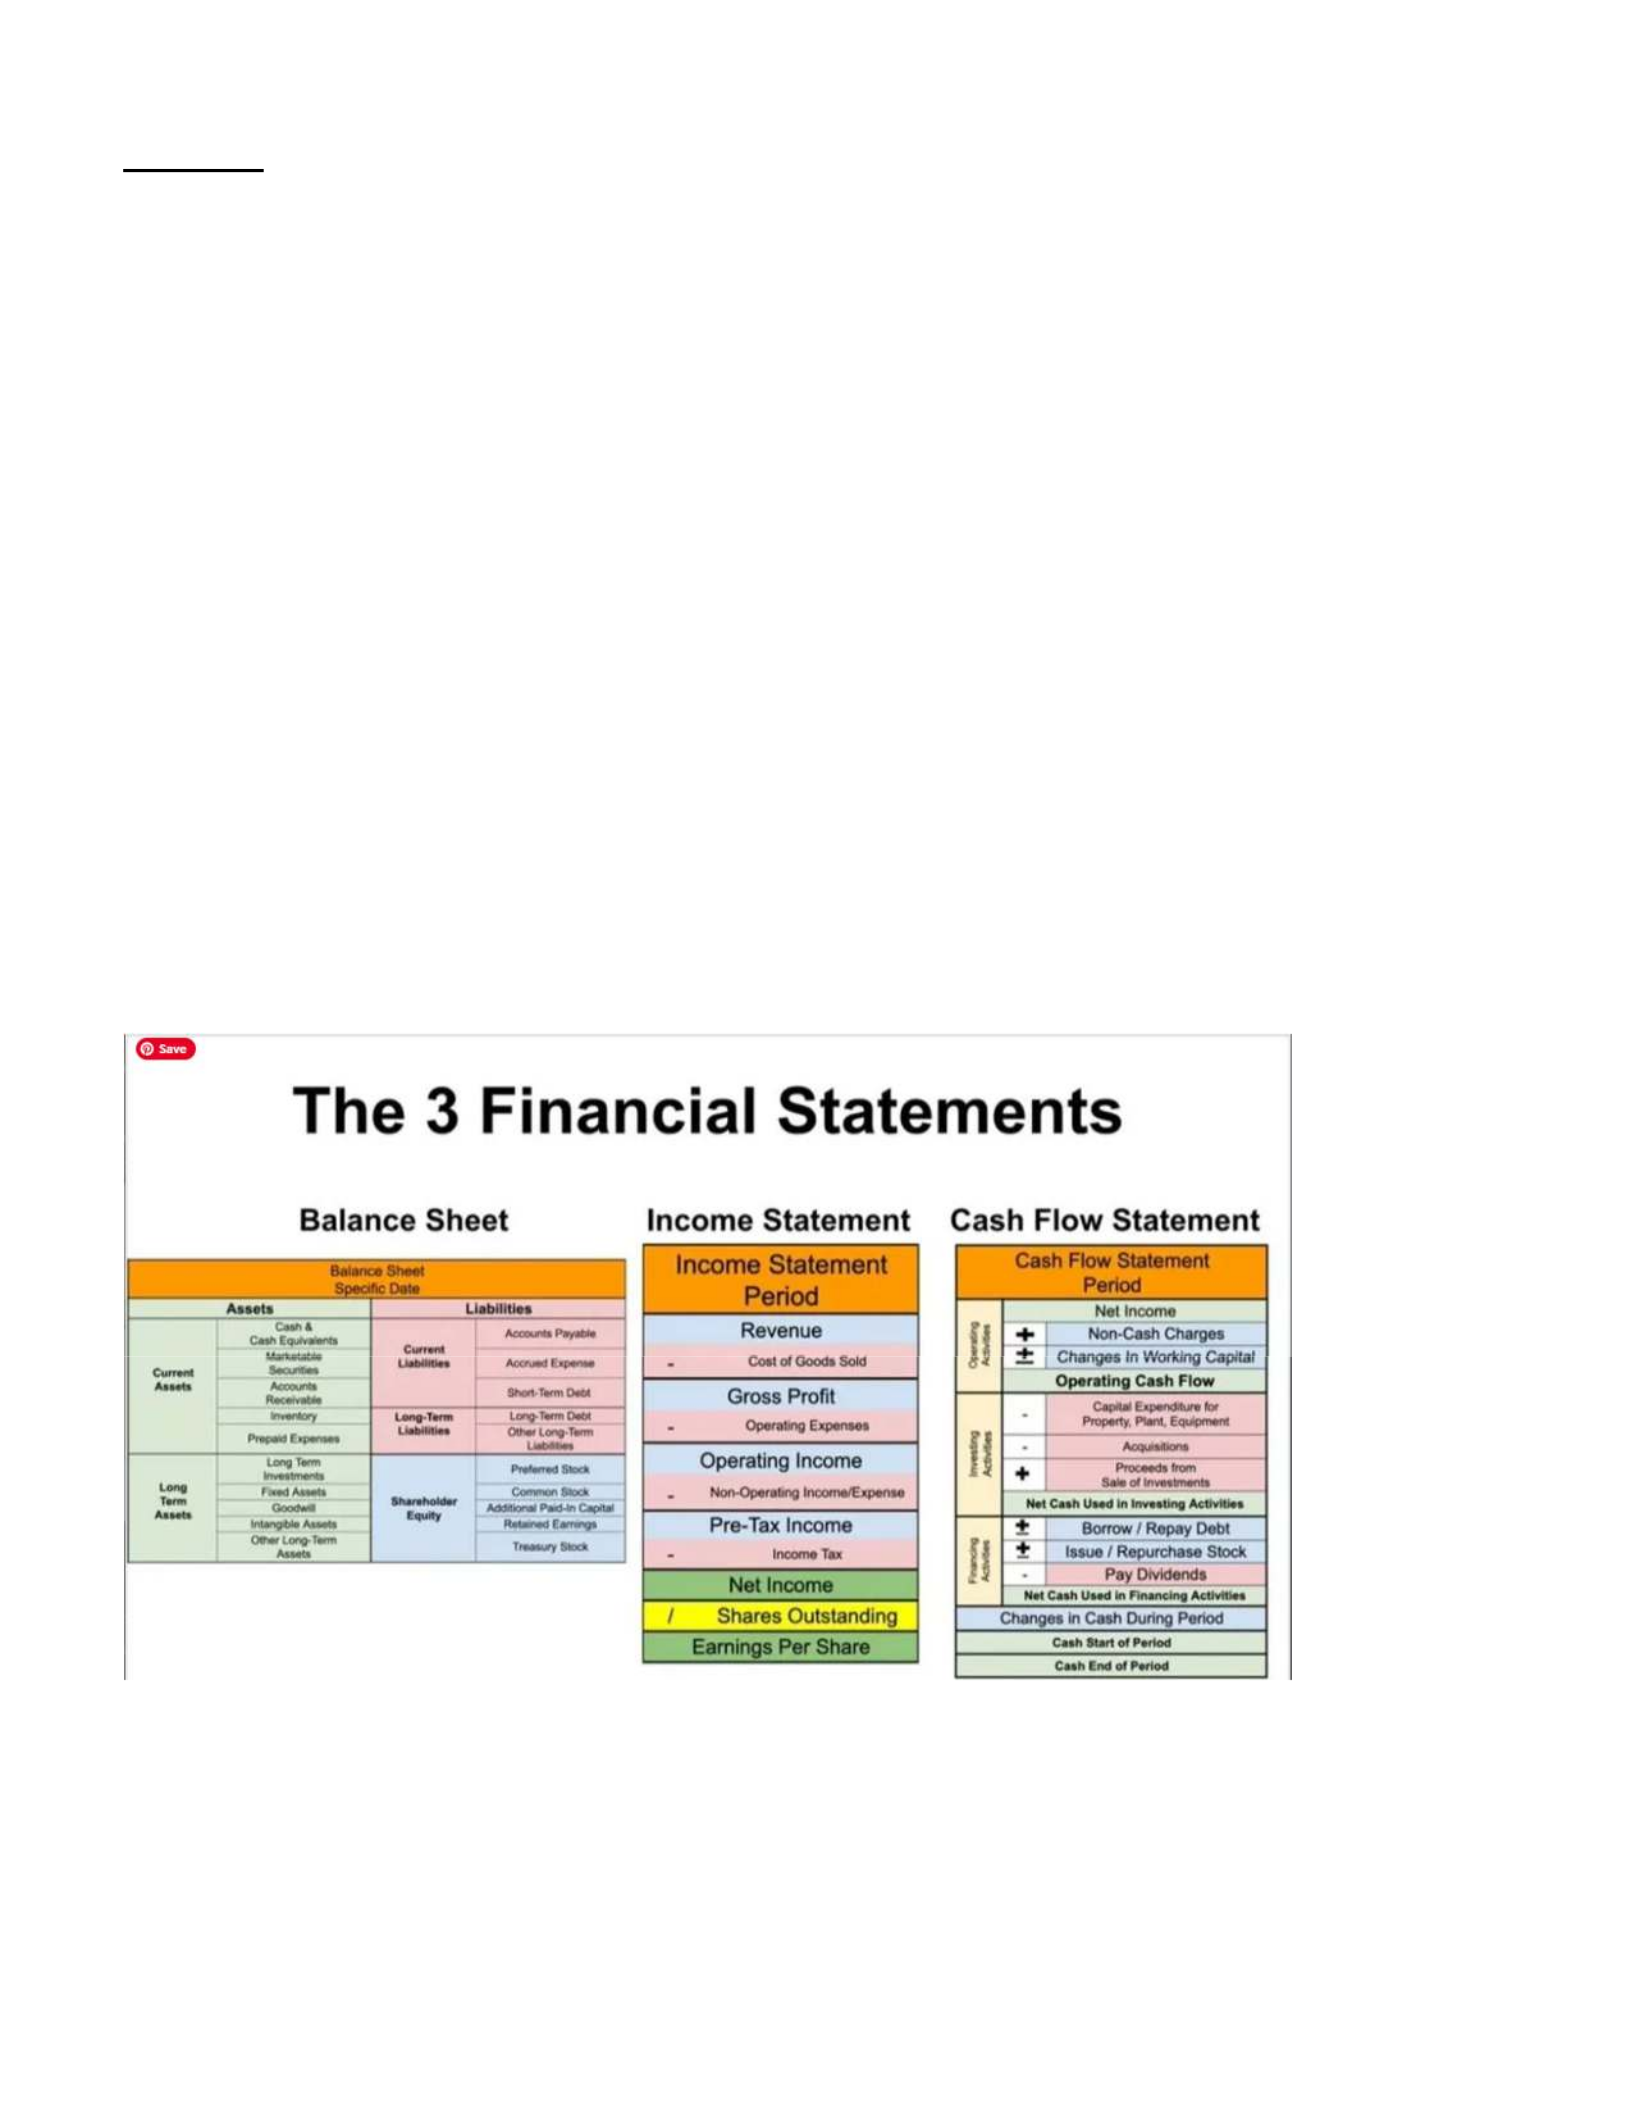
Definitions
COGS: Cost of Goods Sold
GP: Gross Profit (Sales - COGS)
OE: Operating Expenses
DEPR EXP: Depreciation Expense
OP/EBIT: Operating Profit/Earnings Before Interest and Taxes (GP - OE + DEPR EXP)
INT EXP: Interest Expense
EBT: Earnings Before Tax (OP/EBIT - Interest Expense)
DIV: Dividends
LTCG: Long-Term Capital Gain
STCL: Short-Term Capital Loss
EAT: Earnings After Tax (EBT - Tax)
PSD: Preferred Stock Dividends
EACS: Earnings Available for Common Stockholders (EAT - PSD)
CSD: Common Stock Dividends
RE: Retained Earnings
TRUE RE: True Retained Earnings (RE + Dividends not declared as dividends yet)
TRUE EAT: True Earnings After Tax (EAT + Dividends not declared as dividends yet)
Tax Problem A – Tax + Additional Stock Loss
Sales of $36,000,000
Cost of goods sold were calculated at 65% of sales
Operating expenses were $6,000,000 which included depreciation expense
Bonds with a total par value of $12,000,000 were outstanding and had a 9% coupon rate
Received $100,000 in dividends from stock owned
Paid out $600,000 in dividends to its preferred stockholders
Sold stock that it had purchased in 2018 and realized a $350,000 capital gain.
a) Calculate Builtrite’s taxable income and tax liability (assuming a 21% tax rate)
Sales: $36,000,000
- Cost of Goods Sold (COGS): $23,400,000
----------------------------------------------------
= Gross Profit (GP): $12,600,000
Operating Expenses (OE): $6,000,000 (OE + Depreciation Expense)
---------------------------------------------------------
= Operating Profit (OP/EBIT): $6,600,000
- Interest Expense (INT EXP): $1,080,000 (value of bonds * coupon)
----------------------------------------------------------
= Earnings Before Taxes (EBT): $5,520,000
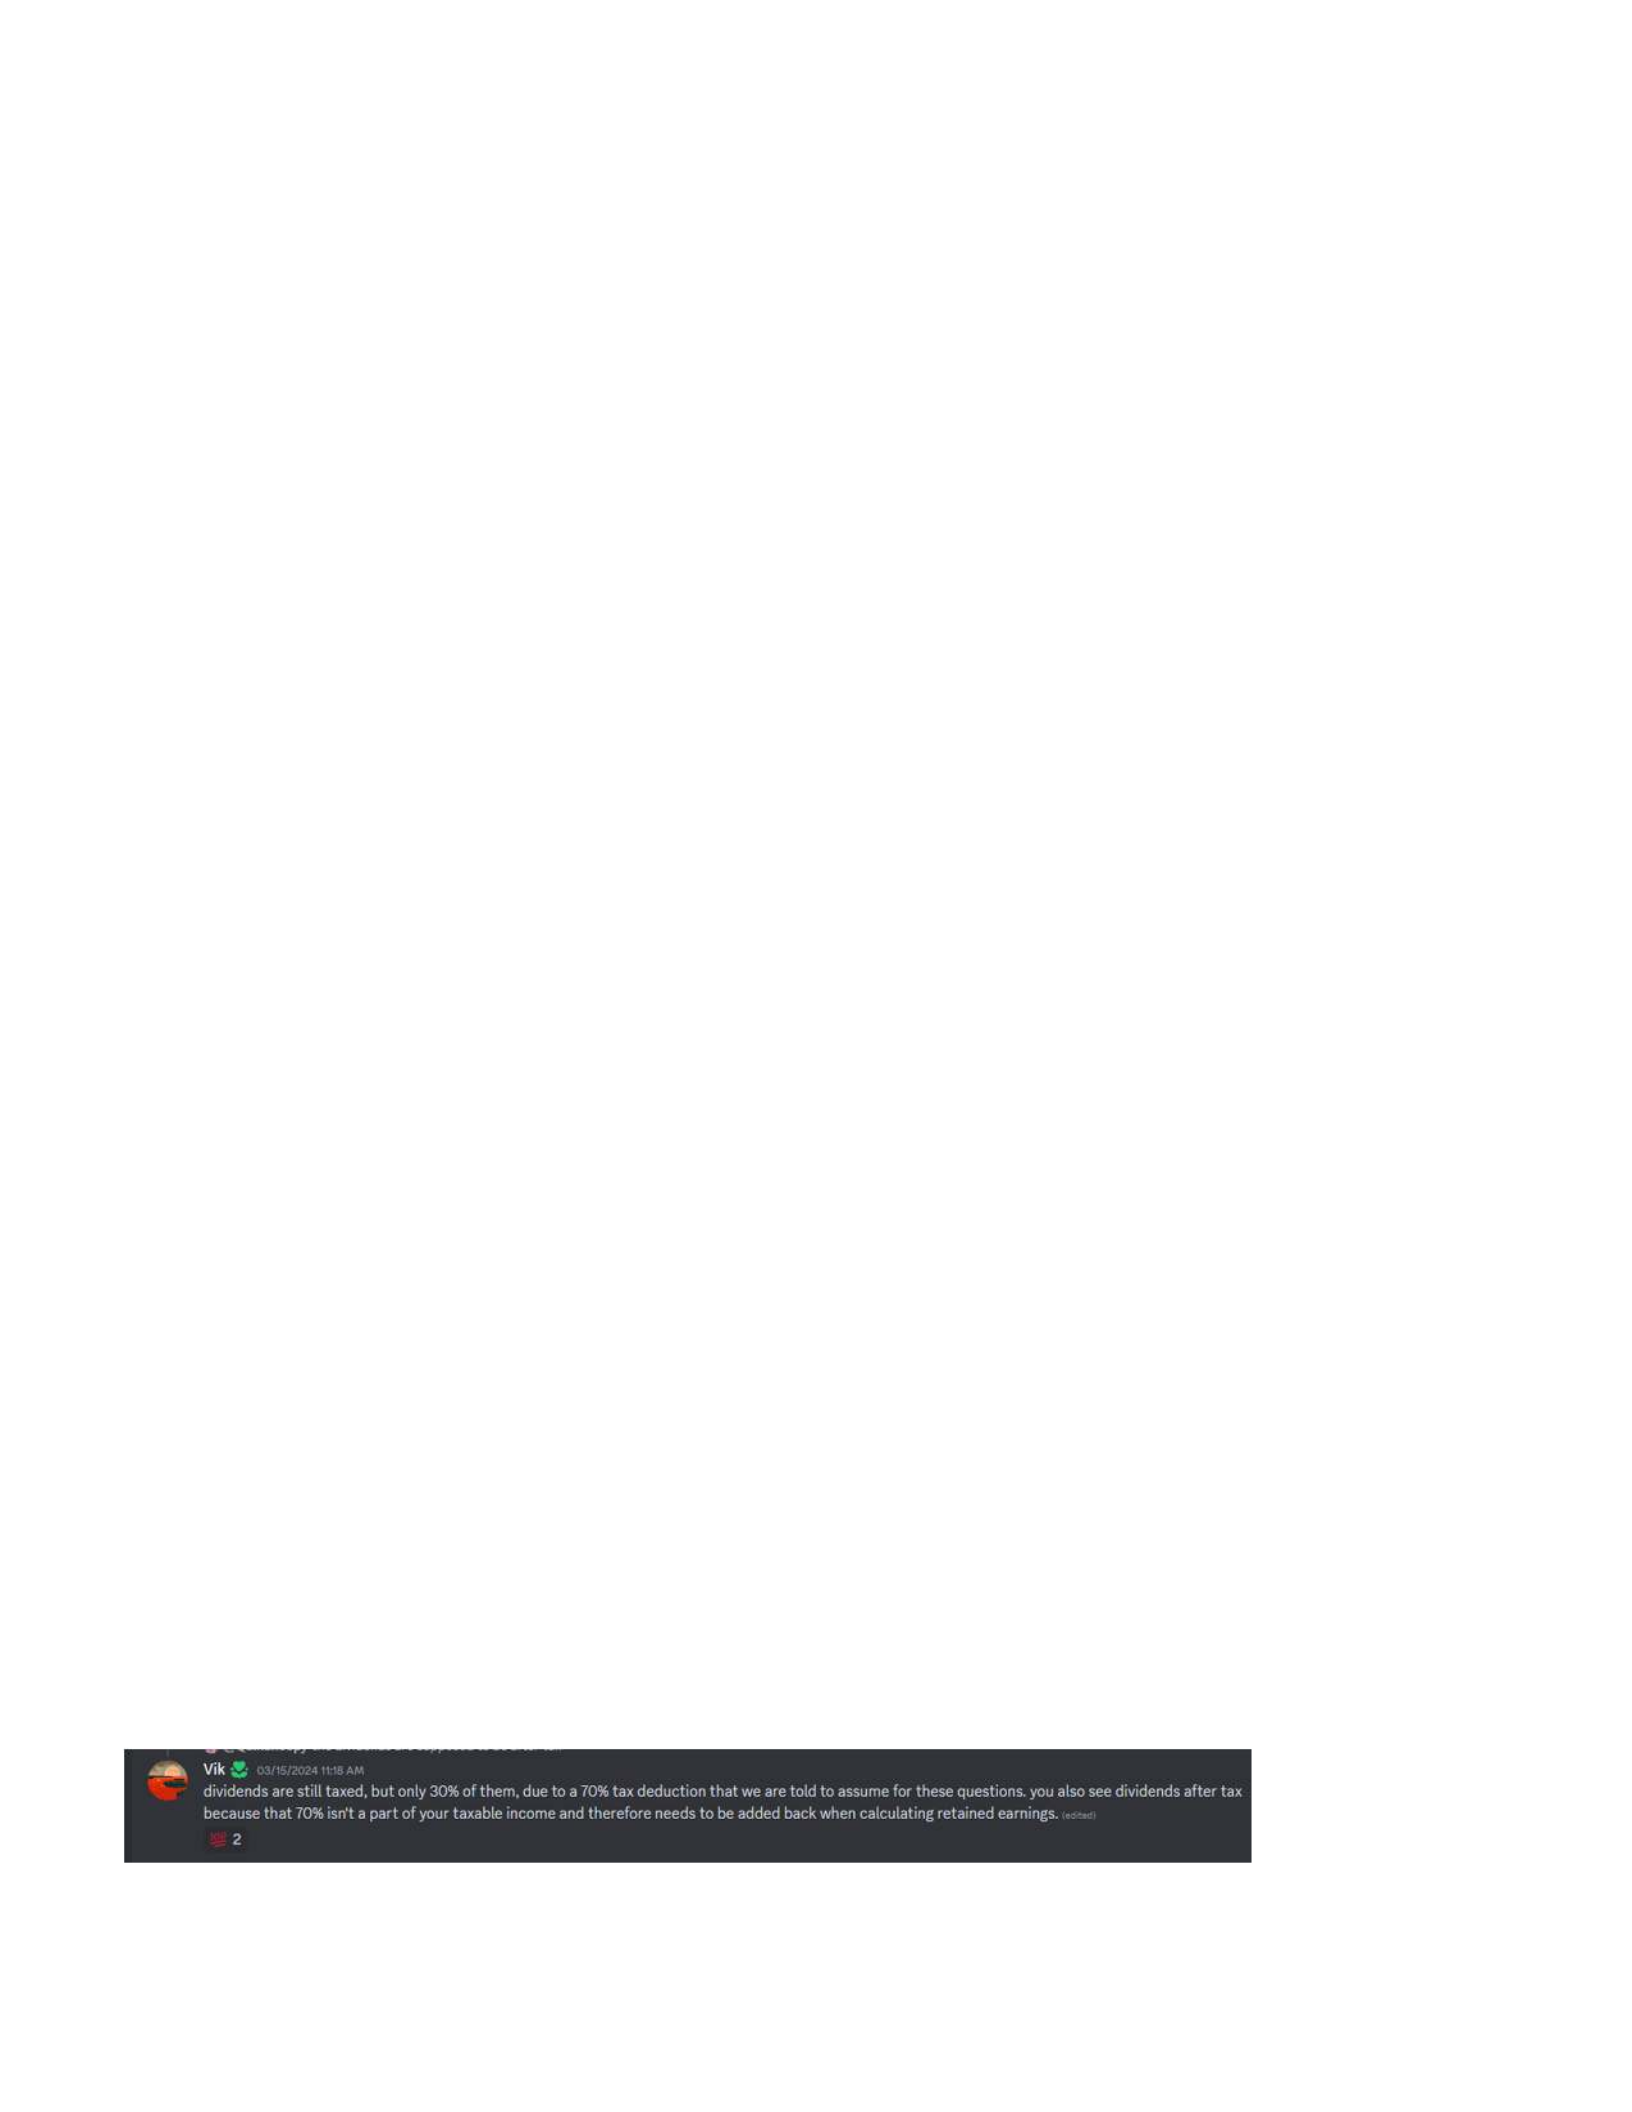
+ Dividends: $30,000 (30% of $100,000)
+ Gain on Stock: $350,000
---------------------------------------------
= Earning Before Tax (EBT) $5,900,000 (part a – taxable income)
Tax = $1,239,000 (21% of $5,900,000) (part a – tax liability)
(Preferred stock dividends are paid out of NPAT so they do not affect net profits or tax liability.) - Paid
out $600,000 in dividends to its preferred stockholders does not matter
b) If Builtrite had also sold another stock that resulted in a $400,000 capital loss, calculate Builtrite’s taxable
income. (Remember that excess capital losses can’t be written off.)
= Earnings Before Taxes (EBT): $5,520,000
+ Dividends: $30,000 (30% of $100,000)
+ Gain on Stock: $350,000
- Loss on Stock: $350,000
Earning Before Taxes (EBT): $5,550,000 (part b - new taxable income)
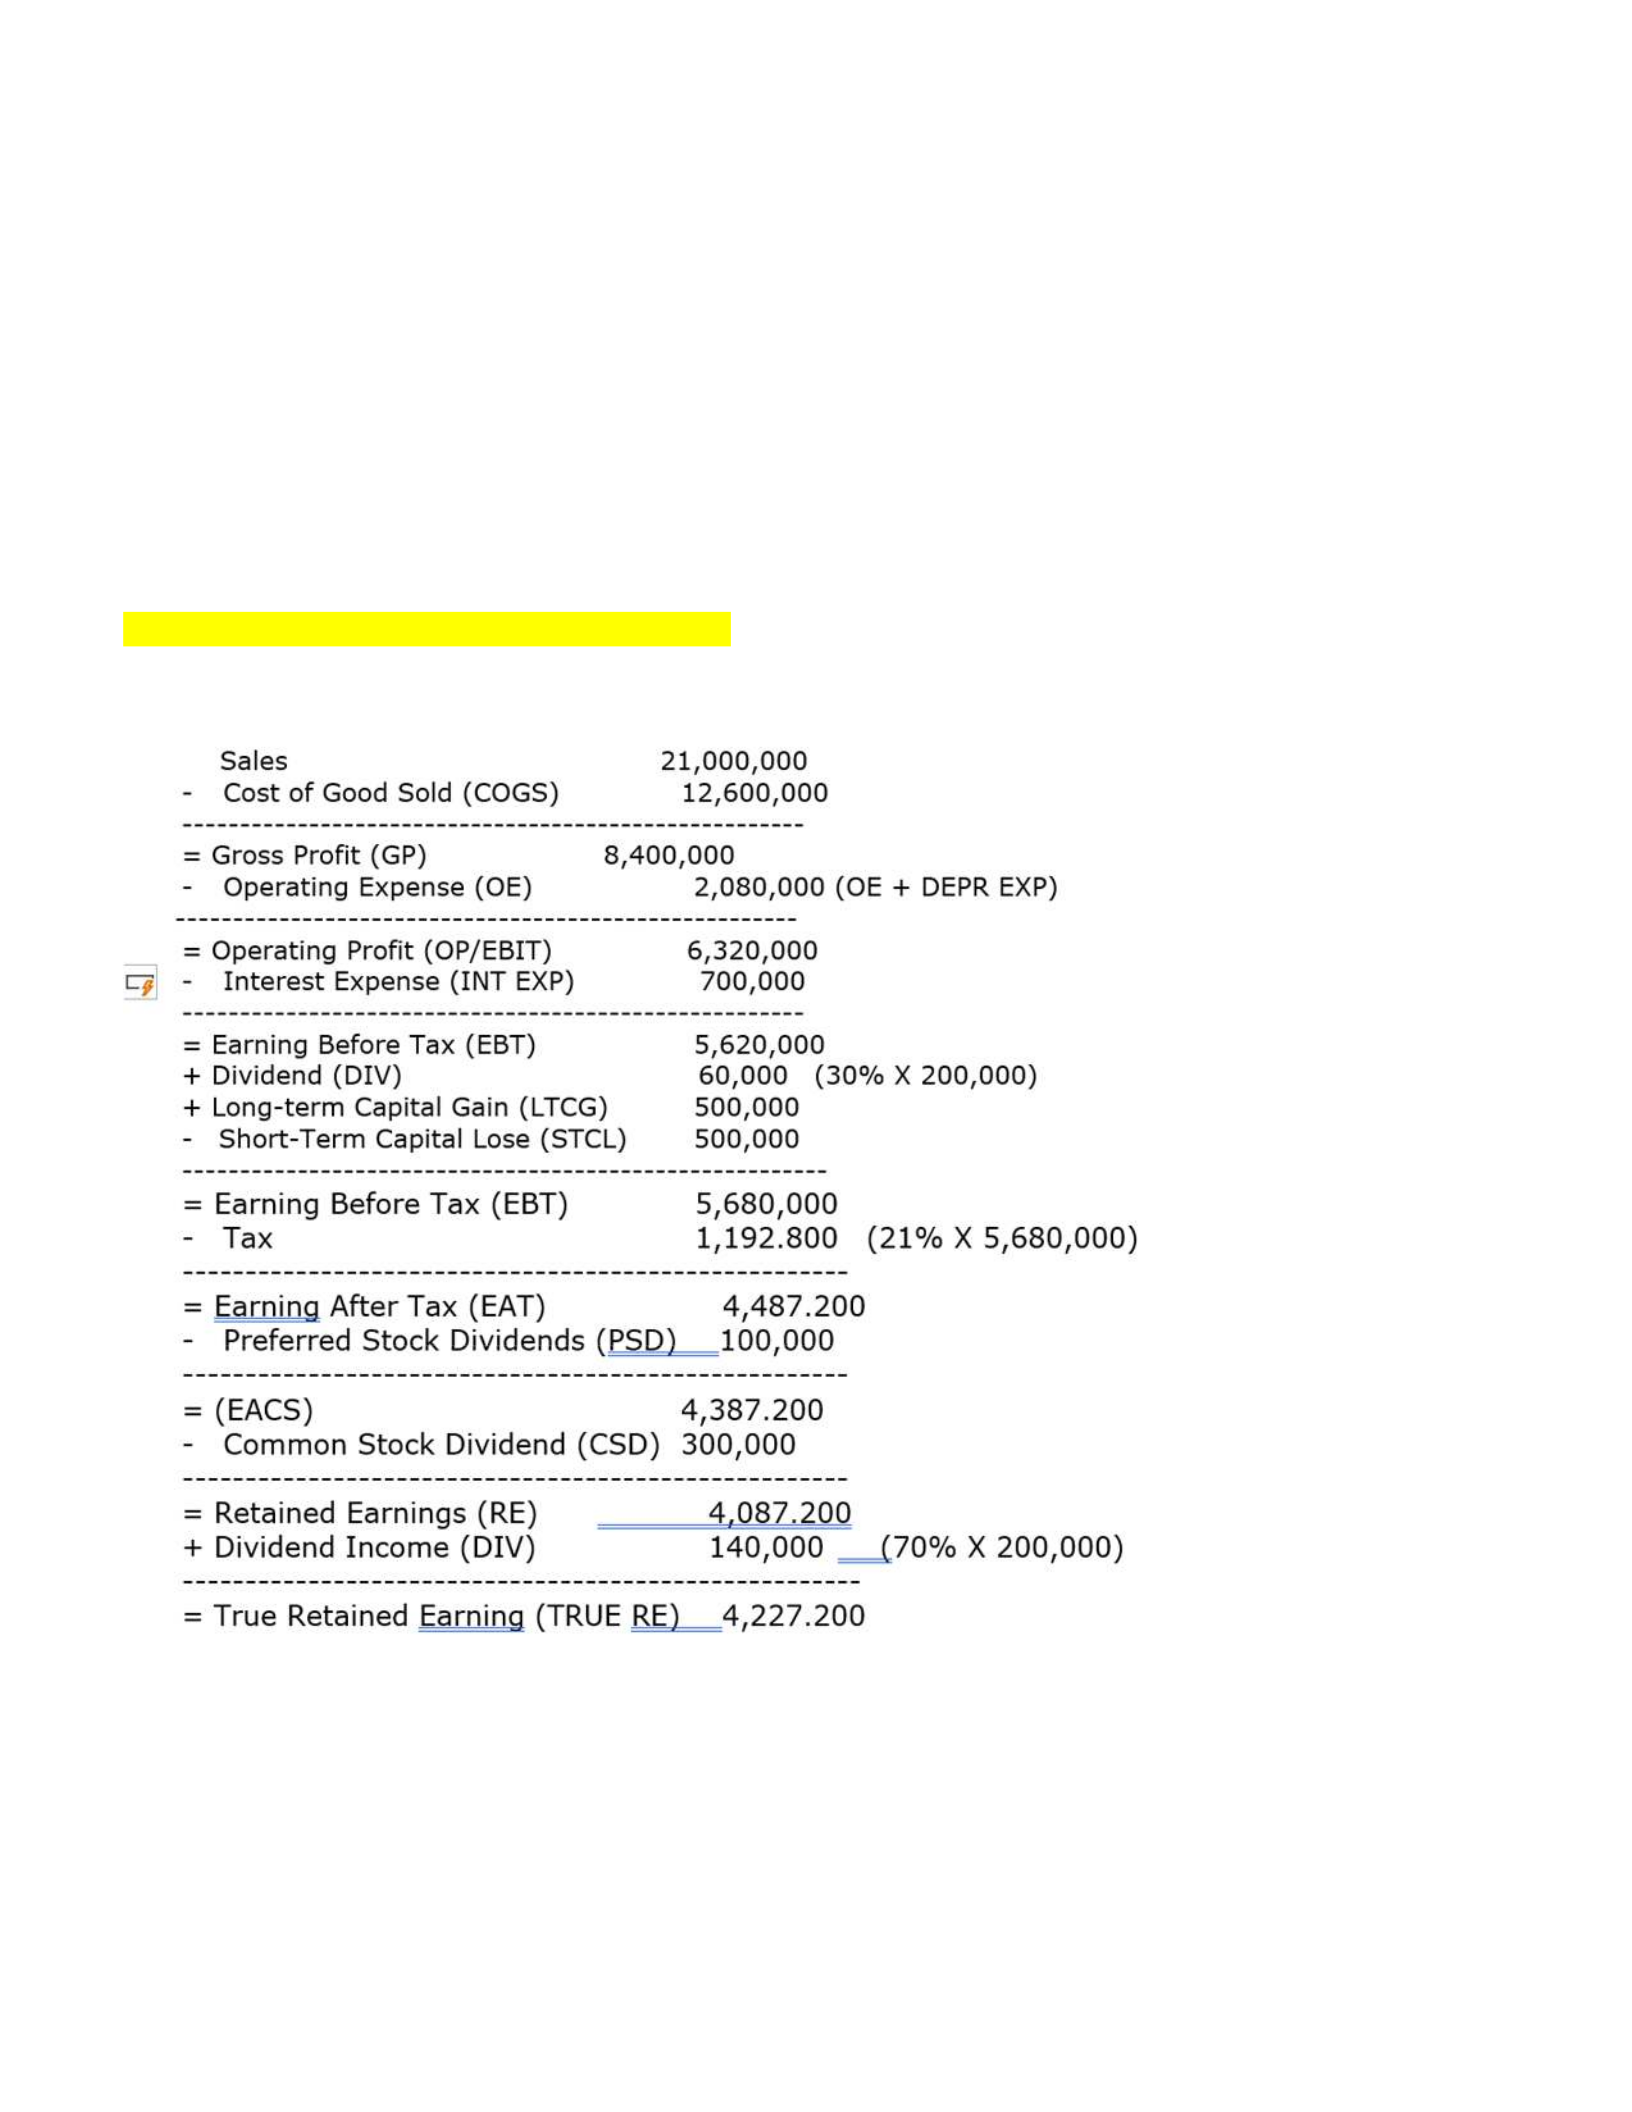
Tax Problem B – RE* + True RE
Builtrite had annual sales of $21,000,000 with the following information:
Dividend income was $200,000.
Interest expense was based on the total par value of $10,000,000 in bonds with a 7% coupon rate.
Operating expenses were $1,800,000.
Depreciation expense was an additional $280,000.
COGS were calculated at 60% of sales.
Preferred stock dividends of $100,000 were paid.
Common stock dividends of $300,000 were paid.
A long-term capital gain of $500,000 was realized.
A short-term capital loss of $600,000 was realized.
Assume a 21% federal tax rate.
What are Builtrite's retained earnings for the year?
Tax Problem C – Tax Liability + True NPAT + True EPS
Sales of $14,000,000
Cost of goods sold amounted to $6,000,000
Operating expenses (including depreciation) came to $3,500,000
Invested in one of its suppliers and received $80,000 in dividends
Interest expense from 10-year-old bonds came to $400,000.
Sold land purchased two years prior for a $1,250,000
Sold some stock for a $200,000 loss
Paid a preferred dividend of $150,000 and a common dividend of $500,000
Assume a 21% tax rate
a) What if Builtrite’s tax liability?
b) What would be the “true” net profits after tax?
c) What would be the “true” earnings per share for the common
stockholders assuming Builtrite has 1,000,000 shares of common stock?
Sales: $14,000,000
- Cost of Goods Sold (COGS): $6,000,000
----------------------------------------------------
= Gross Profit (GP): $8,000,000
Operating Expenses (OE): $3,500,000 (OE + Depreciation Expense)
---------------------------------------------------------
= Operating Profit (OP/EBIT): $4,500,000
- Interest Expense (INT EXP): $400,000
----------------------------------------------------------
= Earnings Before Taxes (EBT): $4,100,000
+ Dividends: $24,000 (30% of $80,000)
+ Gain on Sale of Land: $1,250,000
- Loss on Sale of Stock: ($200,000)
---------------------------------------------
= Earning Before Tax (EBT) $5,174,000
- Tax: $1,086.540 (21% of $5,174,000) (part a)
--------------------------------------------------------------------------------
= Earnings After Taxes (EAT): $4,087,460
+ Dividends from Investments: $56,000 (70% of $80,000)
--------------------------------------------------------------------
= True Earnings After Tax (TRUE EAT): $4,143,460 (part b)
- Preferred Stock Dividends (PSD): $150,000
------------------------------------------------------------------------
Earnings Available for Common Stockholders (EACS): $3,993,460 (Dividends + TRUE EAT)
Number of Common Stock Shares: 1,000,000
= Earnings Per Share (EPS): $3.99 (3,993,460 / 1,000,000 = 3.99346) (part c)

Tax Problem D – Taxable Income + Taxable Liability + True EPS
Sales of $4,000,000 last year
Cost of goods sold was calculated at 70% of sales
Operating expenses were $700,000 which included depreciation expenses
Bonds with a total par value of $2,000,000 were outstanding and had a 4% coupon rate
Received $150,000 in dividends from stock owned and paid out $50,000 in dividends to its preferred
stockholders. Sold stock that it had purchased in 2019 and realized a $60,000 capital gain.
a) Calculate Builtrite’s taxable income and tax liability (assume 21%).
Sales $4,000,000
- Cost of Goods Sold $2,800,000 (70% of 4,000,000)
-------------------------------------------------
= Gross Profit (GP) $1,200,000
- Operating Expense $700,000
----------------------------------------------
= Operating Profit (OP/EBIT) $500,000
- Interest Expense $80,000 (4% of 2,000,000)
------------------------------------------------
= Earnings Before Taxes (EBT) $420,000
+ Dividend (DIV) $45,000 (30% of 150,000)
+ Stock $60,000
--------------------------------------------------
= Earnings Before Taxes (EBT) $525,000
Tax $110,250 (21% of EBT $525,000) – Part A
b) What are Builtrite’s true earnings per share if Builtrite has 500,000 shares of common stock?
Earnings Before Taxes (EBT) $525,000
+Dividend (DIV) $105,000 (70% of $150,000)
--------------------------------------------------------------------------------
= Earnings Before Taxes (EBT) $630,000
- Taxes $110,250 (21% of 525,000)
-------------------------------------------------------------------------------------
= Earnings After Taxes (EAT) $519,750
- Preferred Stock Dividends (PSD) $50,000
---------------------------------------------------------------------------
= Earnings Available for Common Stockholders (EACS) $469,750
Earnings Per Share (EPS) 469,750/500,000 = 0.9395 = 0.94 – Part B

