


3
Problem Statement
Short-term financial performance to meet stakeholders’ expectations no longer
guarantees an organization’s long-term survival (Sezen & Cankaya, 2013). Proactively
sustainable organizations outperform their counterparts in terms of accounting
performance, with average annual abnormal performance 4.8% higher on a value-
weighted base, and 2.3% higher on an equally-weighted base (Eccles et al., 2014). The
general business problem was that supply chain managers in organizations are negatively
affected by stakeholder pressures for short-term profitability rather than sustainable
profitability, which results in a decrease in long-term performance for the business. The
specific business problem was that some global supply chain managers in different
industries and organizational sizes lack understanding of the relationship between
sustainable SCM, stakeholder pressure, and corporate sustainability performance.
Purpose Statement
The purpose of this quantitative correlation study was to examine the relationship
between sustainable SCM, stakeholder pressure, and corporate sustainability performance
while controlling for industry and organizational size. The first independent composite
variable was sustainable SCM, as measured by Sustainalytics dimensions of: (a) social
supply chain standards, (b) supply chain monitoring systems, and (c) green procurement.
The second independent composite variable was stakeholder pressure, as measured by
Sustainalytics dimensions of: (a) social supply chain related issues and controversies, (b)
operations and product related issues and controversies, and (c) environmental supply
chain related issues and controversies. Stakeholder pressure also took the roles of

4
moderator and mediator. The dependent variable was corporate sustainability
performance, as measured by Standard and Poor’s credit rating. The control variables
were industry and organizational size, measured by the number of employees. For this
study, I obtained secondary data on organizations located in North America, South
America, and Eurasia, identified in a Newsweek Green Rankings Global 2016 list. This
study’s implications for positive social change include the potential to provide a better
understanding of the correlates of corporate sustainability performance by organization
managers, which encourage long-term sustainable profitability that improves
environmental, social, and economic standards of living.
Nature of the Study
I chose a quantitative methodology for this study. Researchers conduct
quantitative studies to statistically confirm causal linkages among sets of accounting
information, business factors and financial success, management systems and
performance, and strategy and performance (Field, 2013; Leedy & Ormrod, 2015;
Makrakis & Kostoulas-Makrakis, 2016; Yilmaz, 2013). The quantitative method was
appropriate for this study because the purpose of the study was to statistically confirm
causal linkages among sustainable SCM, stakeholder pressure, and corporate
sustainability performance while controlling for industry and organizational size. A
qualitative method provides answers to how and why, bringing meaning and
understanding to the research question, which comes from the human judgment of
context (Kaivo-oja, 2016; Makrakis & Kostoulas-Makrakis, 2016; Yilmaz, 2013). The
qualitative method was not applicable to this study since the variables in the study were

5
numerical in nature. Mixed method studies combine qualitative and quantitative methods
to address a range of complex research questions demanding inductive and deductive
research logic in a more flexible, integrative, and holistic manner to create divergent
views and findings (Kaivo-oja, 2016; Mayoh & Onwuegbuzie, 2013; Makrakis &
Kostoulas-Makrakis, 2016; Venkatesh, Brown, & Bala, 2013). The mixed method
approach was not applicable to this study because a mixed study requires the collection of
both qualitative and quantitative data, while in this research I only sought to investigate if
causal linkages among the numerical variables could be statistically confirmed.
I selected a correlational design for this study. Researchers use correlation design
to examine the relationship between variables by characterizing the nature and magnitude
of the relationship between two quantitatively coded variables (Field, 2013; Grange,
Lewis, & Carslaw, 2016; Leedy & Ormrod, 2015). Correlation does not prove causation,
while the absence of correlation implies the absence of the existence of a causal
relationship (Field, 2013; Cohen, Cohen, West, & Aiken, 2013; Leedy & Ormrod, 2015).
The correlation design was appropriate for this study because my aim was to determine
the relationship between a set of predictor composite variables (sustainable SCM and
stakeholder pressure), a moderator and a mediator (stakeholder pressure), and a
dependent variable (corporate sustainability performance). Experimental and quasi-
experimental designs are applicable when the researcher’s aim is to assess uncontrollable
environmental events or certain conditions when randomization is not possible (Field,
2013; Leedy & Ormrod, 2015; Rideout & Gray, 2013). The experimental and quasi-

6
experimental designs were not applicable to this study because the research was focused
on identifying a predictive model.
Research Question
A research question is an issue of interest to the researcher presented in the form
of a clear statement of what the researcher wants to know (Bryman & Bell, 2015; Field,
2013). The main research question in this study was: What is the relationship between
sustainable SCM, stakeholder pressure, and corporate sustainability performance while
controlling for industry and organizational size? From the main research question, I
developed the following research sub-questions:
Research Question 1: What is the relationship between sustainable SCM and
corporate sustainability performance, while controlling for industry and organizational
size?
Research Question 2: What is the relationship between stakeholder pressure and
corporate sustainability performance, while controlling for industry and organizational
size?
Research Question 3: What is the relationship between sustainable SCM,
stakeholder pressure as a moderator, and corporate sustainability performance, while
controlling for industry and organizational size?
Research Question 4: What is the relationship between sustainable SCM,
stakeholder pressure as a mediator, and corporate sustainability performance, while
controlling for industry and organizational size?

7
Hypotheses
Hypotheses are formal statements of logical suppositions, reasonable guesses, or
educated conjectures that propose some form of relationship between one or more factors
of interest (independent variables) and an outcome (dependent) variable (Cohen et al.,
2013; Field, 2013; Leedy & Ormrod, 2015). I formulated the following hypotheses based
on the research questions posed above:
H
0
1: There is no statistically significant relationship between sustainable SCM
and corporate sustainability performance while controlling for industry and
organizational size.
H
1
1: There is a statistically significant relationship between sustainable SCM and
corporate sustainability performance while controlling for industry and organizational
size.
H
0
2: There is no statistically significant relationship between stakeholder pressure
and corporate sustainability performance while controlling for industry and
organizational size.
H
1
2: There is a statistically significant relationship between stakeholder pressure
and corporate sustainability performance while controlling for industry and
organizational size.
H
0
3: There is no statistically significant relationship between sustainable SCM,
stakeholder pressure as a moderator, and corporate sustainability performance while
controlling for industry and organizational size.

8
H
1
3: There is a statistically significant relationship between sustainable SCM,
stakeholder pressure as a moderator, and corporate sustainability performance while
controlling for industry and organizational size.
H
0
4: There is no statistically significant relationship between sustainable SCM,
stakeholder pressure as a mediator, and corporate sustainability performance while
controlling for industry and organizational size.
H
1
4: There is a statistically significant relationship between sustainable SCM,
stakeholder pressure as a mediator, and corporate sustainability performance while
controlling for industry and organizational size.
Theoretical Framework
I used resource dependence theory (RDT) as the theoretical framework for this
study. RDT has its roots in Emerson’s classic “Power-Dependence Relations” (1962)
article, and Pfeffer and Salancik’s The External Control of Organizations: A Resource
Dependence Perspective (1978). Davis and Cobb (2010) used the RDT to seek an
explanation of the behavior of an organization in terms of its context. Key constructs
underlying the theory are that resources are anything that is valuable to an organization,
and that an organization depends on others to gain access to valuable resources (Emerson,
1962; Pfeffer & Salancik, 1978). Resource dependency directions are valuable for
understanding the complexity of external dependencies, which is fundamental for supply
chains (Malatesta & Smith, 2014; Pfeffer & Salancik, 1978; Wry, Cobb, & Aldrich,
2013). RDT is a central theory in scholarly and applied understandings of the relationship
between sustainable SCM, stakeholder pressure, and corporate sustainability

9
performance. RDT lends support to the concept that organizations should proactively
engage in sustainable SCM because sustainable SCM resolves a resource dependency
problem, ameliorates stakeholder pressure, and ensures sustainable profitability.
Operational Definitions
Corporate sustainability performance: The strategies, practices, and tactics
employed by an organization with the objective of improving its relationships with the
social and natural environment (Wolf, 2014).
Credit ratings: A forward-looking opinion about credit risk such as the capacity
and willingness of an entity to meet its financial commitments as they come due
(Standard & Poor’s, 2015).
Issuer credit ratings: The forward-looking opinions concerning an obligor’s
overall creditworthiness (Standard & Poor’s, 2015).
Stakeholder pressure: The situation in which an organization is held accountable
by stakeholders for its actions and decisions regarding product design, sourcing,
production, or distribution (Parmigiani, Klassen, & Russo, 2011).
Supply chain management: The management of physical, logical, and financial
flows within the organization and supply chain (Taticchi, Tonelli, & Pasqualino, 2013).
Sustainable supply chain management: The strategic integration and achievement
of the long-term economic, social, and environmental objectives of the individual
organization and its supply chains (Carter & Rogers, 2008).

10
Sustainability: Sustainable development by meeting the needs of the present
generation without compromising the needs of the future generation (World Commission
on Environment and Development, 1987).
Assumptions, Limitations, and Delimitations
Assumptions
Assumptions are beliefs that are taken as given and are usually not subject to
empirical testing (Field, 2013; Leedy & Ormrod, 2015). My first assumption in this study
was that the archival data I collected from Sustainalytics and Standard and Poor’s (S&P)
databases had been obtained by Sustainalytics and S&P from valid and reliable sources.
Another assumption was that the data from analysis providers with substantial experience
and expertise in evaluating publicly traded organizations were based on financial
accounts, organizational documentation, databases, media reports, and stakeholder
interviews. My third assumption was that organizations I examined in the study had
reported accurate data in their corporate annual reports.
Limitations
Limitations are weaknesses of a study related to the proposed sample, data
collection environment, measurement techniques, and personal biases that may affect the
quality of the results and credibility of the conclusions (Field, 2013; Leedy & Ormrod,
2015). I identified two limitations to this study. The first limitation was that the measure
of corporate sustainability performance captured only the economic dimension of
sustainability. The second limitation of the study was that there could be a lagged effect

11
of stakeholder pressure on sustainable SCM-corporate sustainability performance
relationship, which is outside of the focus of the study.
Delimitations
Delimitations mark how far the research effort extended, into what relevant areas
the researcher did not inquire, and what the researcher never intended to do (Field, 2013;
Leedy & Ormrod, 2015). In this research, my focus was on the contribution of
sustainable SCM to an organization’s corporate sustainability performance. Thus study
was delimited to only the economic dimension of sustainability, and did not include
social and environmental dimensions of sustainability.
Significance of the Study
The purpose of this study was to examine the relationship between sustainable
SCM, stakeholder pressure, and corporate sustainability performance, while controlling
for industry and organizational size. Considering the complexity and the insufficient
theoretical development of an original approach to sustainability, the findings of this
study could be a significant contribution to academic literature related to corporate
sustainability performance. The results of the study could be of value both to business
organizations and society because corporate sustainability integrates corporate financial
performance, social performance, and environmental performance. Effective decision-
making requires the manager-researcher relationship. Thus, this study could be a
significant contribution both to business practice and to social change.

12
Contribution to Business Practice
The results of this study could be of benefit to business organizations—and
particularly to supply chains—because there is insufficient theoretical development or
empirical analysis of the integrative sustainability logic. The findings of the study could
prove critical for supply chains managers’ understandings of the relationship between
sustainable SCM, stakeholder pressure, and corporate sustainability performance. The
results of the study could be of value to practitioners considering that the primary
objective of organizations is sustainable financial performance. The outcome of the study
may assist business decision-makers to become more effective in integrating corporate
financial performance, social performance, and environmental performance as a part of a
system. Thus, the findings of the study might assist organizational leaders in the decision-
making process in pursuit of long-term business sustainability.
Implications for Social Change
The findings of this study might further challenge managerial decision makers to
rethink management approaches to corporate sustainability. The results of the study
might also help organization managers acknowledge potential benefits of deploying
sustainability in supply chains in an integrated manner, and understand how companies
contribute individually and collectively to sustainability, which incorporates people,
planet, and profit. A deep understanding of the very nature of sustainable development
could lead supply chain managers across the world to manage economic, social, and
environmental dimensions of business operations by considering the needs of the present
generation without compromising the needs of future generations. Sustainable

13
development of supply chains supports the conservation of natural resources, the
improvement of working conditions and living standards of stakeholders, and
corporations’ involvement in philanthropic activities in an integrated manner.
A Review of the Professional and Academic Literature
In this study, I attempted to extend Davis and Cobb’s (2010) RDT, which holds
that sustainable SCM and stakeholder pressure influence the strategies that organizations
employ to improve their corporate sustainability performance. The purpose of this
literature review was to identify the existing research to provide a substantial basis for
investigating the primary research question: What is the relationship between sustainable
SCM, stakeholder pressure, and corporate sustainability performance, while controlling
for industry and organizational size? I formulated the following four research sub-
questions and associated hypotheses:
Research Question 1: What is the relationship between sustainable SCM and
corporate sustainability performance, while controlling for industry and organizational
size?
H
0
1: There is no statistically significant relationship between sustainable SCM
and corporate sustainability performance while controlling for industry and
organizational size.
H
1
1: There is a statistically significant relationship between sustainable SCM and
corporate sustainability performance while controlling for industry and organizational
size.

14
Research Question 2: What is the relationship between stakeholder pressure and
corporate sustainability performance, while controlling for industry and organizational
size?
H
0
2: There is no statistically significant relationship between stakeholder pressure
and corporate sustainability performance while controlling for industry and
organizational size.
H
1
2: There is a statistically significant relationship between stakeholder pressure
and corporate sustainability performance while controlling for industry and
organizational size.
Research Question 3: What is the relationship between sustainable SCM,
stakeholder pressure as a moderator, and corporate sustainability performance, while
controlling for industry and organizational size?
H
0
3: There is no statistically significant relationship between sustainable SCM,
stakeholder pressure as a moderator, and corporate sustainability performance while
controlling for industry and organizational size.
H
1
3: There is a statistically significant relationship between sustainable SCM,
stakeholder pressure as a moderator, and corporate sustainability performance while
controlling for industry and organizational size.
Research Question 4: What is the relationship between sustainable SCM,
stakeholder pressure as a mediator, and corporate sustainability performance, while
controlling for industry and organizational size?

15
H
0
4: There is no statistically significant relationship between sustainable SCM,
stakeholder pressure as a mediator, and corporate sustainability performance while
controlling for industry and organizational size.
H
1
4: There is a statistically significant relationship between sustainable SCM,
stakeholder pressure as a mediator, and corporate sustainability performance while
controlling for industry and organizational size.
In this literature review section, I provide a synthesis of ideas and concepts from
the perspective of RDT concerning reactive and proactive approaches to sustainable
SCM, the effect of stakeholder pressure on sustainable practices, and corporate
sustainability performance. To ensure validity and credibility of the information, I
reviewed peer-reviewed journal articles that I retrieved from online journal databases
such as Emerald, ProQuest, and SAGE. The keywords I used to filter results that were
more relevant to the research topic were: supply chain management, sustainable supply
chain management, impact of sustainable SCM, stakeholder pressure, economic
sustainability, and corporate sustainability performance. The literature review included
136 peer-reviewed journal articles. One hundred and twenty-two of these 136 peer-
reviewed journal articles were published in the last 5 years, representing 90% of the total
sources used in the study.
Communities and governments around the world demand environmentally
friendly businesses, quality products and services, and organizational compliance with
regulations concerning the socio-environmental impact of the supply chain (Ding, Liu, &
Zheng, 2016; Gopalakrishnan et al., 2012; Sebastianelli, Tamimi, & Iacocca, 2015). The

16
evolutionary nature of supply chains requires continuous improvement of practices for
sustaining the business operations (Gopalakrishnan et al., 2012). More organization
managers are striving to embrace and transcend contradictions in operational and
organizational activities regardless of the challenges in the process of implementing
sustainability due to the complexity of issues, difficulties in capturing this complexity,
and continuously emerging new areas of concern (Gopalakrishnan et al., 2012;
Schaltegger & Burritt, 2014). Often organizational leaders attempt to develop creative
solutions to not only build a competitive advantage, but also to do so in harmony with the
planet and society (Elliot, 2013; Gao & Bansal, 2013). The implementation of any
sustainability agenda in supply chains requires formulation and operationalization of an
integrated approach that addresses the relevant social, economic, and environmental
issues (Hahn, Pinkse, Preuss, & Figge, 2015; Whiteman, Walker, & Perego, 2013).
Resource Dependence Theory
RDT was the basis for this study’s theoretical framework. The strong principles of
RDT present a premier framework for understanding the relationship between the
organization and the environment (Drees & Heugens, 2013; Esfahbodi, Zhang, &
Watson, 2016). Davis and Cobb (2010) claimed that there is evidence of the need for
more attention to RDT. RDT facilitates understanding of the relationship between
sustainable SCM, stakeholder pressure, and corporate sustainability performance. In this
study, I attempted to extend Davis and Cobb’s (2010) RDT, which holds that sustainable
SCM and stakeholder pressure influence the strategies that organizations employ to
improve their economic sustainability.

17
One of the fundamental assumptions of RDT is that organizations are not self-
sufficient, but rely on their environment and its resources for survival and achievement of
long-term objectives (Brettel & Voss, 2013; Kisaka & Anthony, 2014; Parastuty,
Schwarz, Breitenecker, & Harms, 2015; Pfeffer & Salancik, 1978). Organizations obtain
critical resources by looking outside their boundaries (Malatesta & Smith, 2014;
Nuruzzaman, 2015). Interdependence over needed resources produces inter-
organizational power that drives organizational behavior and buyer-supplier relationships
(Gaffney, Kedia, & Clampit, 2013; Pfeffer, 1987 as cited in Gaffney et al., 2013).
Organizations with a power advantage gain a dominant position in the network and often
exploit their power of resources, which results in a competitive advantage (Green, Toms,
& Clark, 2015; Nuruzzaman, 2015; Tachizawa & Yew Wong, 2014). Distribution of
power and the ability to influence the activities of other members of the network
influences the depth of collaboration between buyers and suppliers in networks
(Kähkönen, 2014; Tachizawa & Yew Wong, 2014). Organizations employ different
strategies to acquire needed resources that require different levels of coordination
(Malatesta & Smith, 2014).
Another fundamental assumption of RDT is that uncertainty in the internal and
external environment of the organization is responsible for the internal power distribution
within the organization and the external power distribution between organizations
(Brettel & Voss, 2013; Kisaka & Anthony, 2014; Parastuty et al., 2015; Pfeffer &
Salancik, 1978). The difficulty any organization faces creates the uncertainty and
dependence of an organization (Vecchiato, 2015). A lack of autonomy also creates the

18
dependence of the organization and the external power (Brettel & Voss, 2013; Kisaka &
Anthony, 2014; Parastuty et al., 2015; Pfeffer & Salancik, 1978).
Power relationships are intrinsic to global supply networks (Tachizawa & Yew
Wong, 2014). Competition and innovation are no longer just between single
organizations, but between supply chain networks. Supply chain systems of
interdependencies make inter-organizational relationships increasingly challenging
(Malatesta & Smith, 2014). Dependency on suppliers for critical resources directly
affects the adoption of environmentally and socially responsible practices (Hoejmose,
Grosvold, & Millington, 2013; Tachizawa & Yew Wong, 2014). Organizations’
application of RDT to supply chains is evident as organizations consistently purchase
strategically critical resources (e.g. standards, procedures, technologies, material sources,
distribution channels) and depend on contingencies in the external environment
(Malatesta & Smith, 2014; Pfeffer & Salancik, 1978; Tachizawa & Yew Wong, 2014). A
few strong principles of RDT apply to sustainable SCM. The theory’s directions are
valuable for understanding the complexity of external dependencies, which is
characteristic of supply chains, by emphasizing that every organization in the network
pursue a different strategy and objectives (Malatesta & Smith, 2014; Pfeffer & Salancik,
1978; Wry et al., 2013).
Managers use RDT to guide organizational strategy from short-term survival to
long-term organizational growth (Malatesta & Smith, 2014). RDT is highly relevant to
the study of contemporary organizations, and specifically to the study of the supply chain
relations (Tachizawa & Yew Wong, 2014). Wry et al. (2013) argued that resource

19
dependency’s unique insights on the complexity of an organization’s external
environment are the keys to unlocking its contemporary relevance. Thus, the resource
dependence perspective has the potential to become a strongly developed theoretical
perspective (Wry et al., 2013). A few researchers have already applied the insights of
RDT in the supply chain management field. Paulraj and Chen (2007) developed a
strategic supply management model based on uncertainty and concluded that the
relationship between environmental uncertainty and strategic supply management
supports the claims of RDT. Wolf (2014) applied RDT to a sustainable SCM context,
broadening the range of theories currently employed in the field. Ramanathan,
Poomkaew, and Nath (2014) conducted a holistic analysis considering a variety of
stakeholder pressures in a single framework, and extended the application of the RDT.
Esfahbodi et al. (2016) applied RDT to examine relationships between the
implementation of sustainable SCM practices and organizational performance.
Opponents of RDT argue that resource dependence key principles are near
obvious and accepted, but at the same time lacking (Malatesta & Smith, 2014).
Additionally, according to Malatesta and Smith (2014), empirical researchers largely
support the RDT’s main assumptions and principles but often report that it is difficult to
rule out alternative explanations and compare findings across studies. According to
Hillman, Withers, and Collins (2009), basic arguments of RDT and inter-organizational
relations are not sufficient on their own. Integration of RDT with other theoretical
frameworks may prove to be more productive in researching the relationship between an

20
organization and its environment. RDT has been integrated with other theoretical
perspectives in examining the phenomenon of interest (Hillman et al., 2009).
The resource-based view of the organization, stakeholder theory, real options
theory, population ecology perspective, niche theory, and institutional theory are several
concepts related to RDT (Hillman et al., 2009). The integration of the resource-based
view of the organization with RDT has enhanced organizational understanding in the area
of organizational resource endowment. RDT merged with stakeholder theory may offer
greater insights for managing dependencies (Hillman et al., 2009). The application of
RDT and real options theory may show resource dependence-reducing strategies and
approaches to reducing uncertainty. The combination of RDT with the population
ecology perspective may help to address the role of the external environment more
effectively, which in turn may help to develop a meta-theoretical perspective for
organizations (Hillman et al., 2009). The niche theory offers a combination of resources
needed for survival and insights into resource dependence relationships. Integration of
RDT with institutional theory may also offer solutions for issues concerning uncertainty
and dependency by taking into consideration the country’s institutional environment
(Hillman et al., 2009). Thus, comparing and integrating RDT with other complementary
perspectives or competing theories may guide a better understanding of environmental
interdependence and uncertainty. These identified theories are relevant to sustainable
SCM. Examining such perspectives can help identify the drivers for sustainability
initiative and provide insights on how organizations can benefit from internal and

21
external factors to develop sustainable supply chains (Varsei, Soosay, Fahimnia, &
Sarkis, 2014).
Institutional theory and population ecology are the rival theories of RDT. The
institutional theory indicates that the institutional environment can influence the
development of a structure in an organization more than the market pressures (Bradly,
2015; Fuenfschilling & Truffer, 2014; Rottig, 2016). Moreover, organizational managers
will adopt these structures if they improve the efficiency of the organization. Applying
this theory to the study would mean that the internal structure of the organization would
decide to implement sustainable SCM in the organization if it improves their efficiency.
For population ecology for organizations, Hannan and Freeman (1977) stated that
organizations exist within a population of similar organizations, and the survival of the
organization would depend on how the organization responds to their environment. Two
kinds of environment can influence the survival of the organization; external and internal.
In this study, I apply this theory on how organizations respond to the internal and external
environment concerning sustainability. The strengths of population ecology are that it
shows a holistic approach to understanding the structure of organizations, and it shows an
explanation on how organizations survive (Hannan & Freeman, 1977). However, there
are limitations of the theory as well such as having a deterministic view of human beings
(Daft, 2012). A deterministic view indicates that human beings or organizations respond
in a mechanical way to the experiences they have encountered. As such, individuals or
organizations that hold the population ecology are not proactive and are only reactive to
the situation. One of the weaknesses of the population ecology is its dependence on the

22
reaction of the organization towards what is happening in its external environment.
However, Daft (2012) explained that companies have the capability to define and
redefine their external environment. Bozeman and Moulton (2011) supported the
sentiments of Daft with the fact that organizations especially large ones have the
capability to modify the conditions of their environment.
Population ecology theory for organizations is a major rival theory of RDT
because they have similarities such that both theories acknowledge the influence of the
internal and external environment to the organization. However, population ecology
theory does not align with the purpose of this study. This study is more aligned with RDT
because at the core of the concept of sustainability is the issue of resources. Population
ecology theory focuses on the reaction of the individuals or organizations about the
situation at hand while RDT focuses on how to ensure that the organization has sufficient
resources now and in the future to ensure survival and progress.
Sustainable SCM
International business environment challenges organizations to concentrate on
SCM to gain a competitive advantage (Nuruzzaman, 2015; Shen, Olfat, Govindan,
Khodaverdi, & Diabat, 2013). General pressures of the environment on organizations
hypothesized by Pfeffer and Salancik (1978) are almost the same as they were during the
1970s (Davis & Cobb, 2010). According to the principles of RDT, resources and their
acquisition is the core of decision-making process of organizations (Davis & Cobb,
2010). The scarcity of resources pressures organizations to seek sustainable supply chain

23
strategies essential for an organization’s survival, long-term sustainability of resource
supply, and sustainable economic performance (Karimi & Rahim, 2015).
The scope of the components included in supply chain management range from
operations management, resource and distribution management, logistics and
transportation, marketing, purchasing, and information technology (Chan, Nayak, Raj,
Chong, & Manoj, 2014; Roh, Hong, & Min, 2014). All of these key inter-organizational
business processes are integrated for an effective supply chain strategy that influences
and improves the performance of the organization (Carter & Rogers, 2008; De Marchi,
Di Maria, & Micelli, 2013; Roh et al., 2014; Winter & Knemeyer, 2013). Because of the
advancement in technology of global supply chain, organization managers can benefit
from real-time data about demand and supply of products that are helpful for decision-
makers in the supply chain (O’ Rourke, 2014).
SCM is central to achieving sustainability through changing buying practices and
impacts on the natural environment as it deals with the resources needed for the
production (Glover, Champion, Daniels, & Dainty, 2014). RDT supports the notion that
the lack of strategic resources may incentivize focal organizations to establish direct links
with third parties (Nuruzzaman, 2015). Focal organization managers can use non-
governmental organization-built environmental and social databases to monitor their
lower-tier suppliers (Tachizawa & Yew Wong, 2014). The global flow of goods,
information, labor, and capital that extends from raw materials to final products provide
an excellent context to understand sustainable supply chain and to test the concept of

24
sustainability (Miller, 2013). Both supply chain and sustainability focus on system
dynamics (Beske, Land, & Seuring, 2014).
As opposed to the traditional perspective of supply chain management that
emphasizes on the economic aspect of an organization, sustainable SCM is described as
the explicit incorporation of environmental and social goals that extends the economic
dimension of the triple bottom line (Brandenburg, Govindan, Sarkis, & Seuring, 2014;
Seuring & Müller, 2008). To reflect the principles of business sustainability, organization
managers integrate social and environmental issues with core strategic issues at the
supply chain level (Gao & Bansal, 2013). The main objective of sustainable SCM is to
make the supply chain more sustainable with the end goal of producing an effective
sustainable supply chain (O’ Rourke, 2014). As such, sustainable supply chain refers to
the outcome of a specific supply chain. Sustainable SCM is also a strategic integration of
the social, environmental, and economic objectives of an organization with collaboration
within and with other organizations to develop term economic, social, and environmental
performance of the organizations and its supply chains (Seuring & Müller, 2008). Thus,
the innovative supply chain contains the components of the traditional supply chain and
also integrates sustainability issues withing the traditional areas of expertise by focusing
on the long-term survival of the organization (Carter & Easton, 2011; Taticchi et al.,
2013).
In sustainable supply chains, the environmental and social dimensions are
addressed by the members of the supply chain through corporate social responsibility
(CSR) initiatives while competitiveness is maintained through meeting the demands and

25
needs of consumers that satisfy the economic aspect of sustainability (Diabat, Kannan, &
Mathiyazhagan, 2014; Seuring & Müller, 2008). Sustainable SCM is often understood as
ensuring that supply chain practices are environmentally friendly (Diabat et al., 2014;
Govindan, Kaliyan, Kannan, & Haq, 2014). Sustainable SCM is also sometimes called
green supply chain, focusing on the environmental component of sustainability (Lee,
Klassen, Furlan, & Vinelli, 2014; Turker & Altuntas, 2014).
Technology has boosted the lean manufacturing of organizations to meet the
demands of the consumers; however, some organization managers failed to understand
more about the environment and social consequences of the production aspect of the
supply chain (O’ Rourke, 2014). A number of organization managers have pursued
sustainable practices. However, these practices should not be limited to environmental
and social responsibilities of the organization but also include the economic benefits of
sustainability for the organization (Galpin, Whittington, & Bell, 2015). At the same time,
certain organization managers applying the triple bottom line approach still tend to focus
strongly on the economic dimension (Beske & Seuring, 2014). Organizations need to
work with one another in promoting sustainable SCM practices as a way to achieve
organizational success rather than merely as a moral obligation (Alexander, Walker, &
Naim, 2014; Wang, Rodrigues, & Evans, 2015). Sustainable SCM practices should
promote to organizational success (Green et al., 2015). A strong focus of organizations on
the integration of social, economic, and environmental dimensions needed to ensure
corporate sustainability and a sustainable future (Gopalakrishnan et al., 2012; Tseng &
Chiu, 2013; Tseng et al., 2015). There is little theoretical development or empirical

26
analysis of the integrative sustainability logic while it is critical for supply chain
managers to gain an absolute understanding of the complex correlation and interplay of
factors that foster sustainability and company competitiveness (Gopalakrishnan et al.,
2012).
The adoption of sustainable SCM practices has a positive effect on three
categories of outcomes such as economic, social, and operational (Tseng et al., 2015). For
instance, sustainable packaging in organizations has resulted in a positive impact
regarding environmental, economic, and social outcomes (Bealt, Barrera, & Mansouri,
2016). The results have shown evidence that sustainable SCM practices have a positive
effect on the economic and social aspects of an organization (Albertini, 2013). Golicic
and Smith (2013) examined 77 studies published from 2000 to 2011. Golicic and Smith
used meta-analysis to determine whether specific practices of sustainability would
influence the performance of an organization. The results showed that there is a
significant positive relationship between environmental supply chain practices and the
organizational performance. This finding indicates support that sustainable SCM results
in positive firm performance. The study contributed to extending the understanding of the
relationship between environmental supply chain practices and a firm performance (Mitra
& Datta, 2014).
Given that sustainable SCM can have a positive influence on the financial
performance of an organization, sustainable SCM researchers still focus on the
environmental issues while social aspects of sustainable SCM are not examined enough
(Golicic & Smith, 2013; Wolf, 2014). Environmental factors in quantitative studies

27
mainly include the utilization of natural resources as well as emission of waste by the
organization rather than the social (consumers, suppliers, producers, stakeholders) and
financial (financial performance and economic sustainability) components of sustainable
SCM (Golicic & Smith, 2013; Seuring & Müller, 2008; Seuring, 2013). For instance,
Seuring and Müller (2008) examined 191 papers published from 1994 to 2007. Seuring
and Müller provided a conceptual framework that summarized the findings of sustainable
SCM. Two strategies included in the sustainable SCM framework were the management
of the supply chain to address risks and performance and the management of the supply
chain to address sustainability. Seuring and Müller concluded that the literature on
sustainable SCM still mostly around environmental issues. Social aspects and the
integration of the three dimensions of sustainability are still rare (Seuring & Müller,
2008). Seuring and Müller extended the review of the literature on sustainable SCM up to
308 papers by 2010 and found that only 36 papers were quantitative studies (Seuring,
2013). Seuring (2013) reviewed 36 quantitative studies published from 1990 to 2010 and
found that the social side of sustainability is usually not taken into account.
Studies on sustainable SCM are often pursued in a standalone fashion, which
means that the economic, environmental, and social aspects of the triple bottom line
attended independently without deliberating the existence of interrelationships (Gao &
Bansal, 2013; Lozano, 2015). Also, empirical studies about supply chain management
often focus on single organizations and do not examine the interrelationships of
organizations (Carter & Easton, 2011). The conflict in the supply chain management
perspectives of organizations also leads to the question on whether model-based research

28
considers the intercompany perspective and whether the perspective of the government
authorities or stakeholders other than the investors reflected in the quantitative studies of
sustainable SCM. The studies of Brandenburg et al., (2014) and Carter and Rogers (2008)
were crucial in the integration of many dimensions within the relationship of
sustainability and supply chains.
Carter and Rogers (2008) conducted a comprehensive literature review and
structured a conceptual framework with the goal of introducing sustainability within the
supply chain management. One of the objectives was to demonstrate the relationship
between environmental, social, and economic performance in the context of the supply
chain. Conceptual theory building was used as a methodology to represent sustainable
SCM. The framework of sustainable SCM was based on RDT and the resource-based
view of a firm. Carter and Rogers (2008) expanded the concept of sustainability to SCM
and suggested major facets that are prerequisites for the implementation of sustainable
SCM practices.
Brandenburg et al., (2014) conducted a content analysis of 134 studies on formal
quantitative models that address sustainability aspects in the forward supply chains.
Brandenburg et al. concluded that expanding the types of tools and factors considered in
the formal modeling efforts offer numerous possibilities and insights. Brandenburg et al.
(2014) also suggested that the sustainable SCM modeling field is on the research upswing
and significantly more modeling based research needs to be completed to fully
understand and integrate sustainable SCM into business thought and practice. Pagell and
Shevchenko (2014) identified that previous researchers have focused on the synergistic

29
and familiar while overlooking trade-offs and radical innovation. Current knowledge
about sustainable SCM is not sufficient to develop and implement an efficient and
effective sustainable SCM. Pagell and Shevchenko (2014) highlighted five main issues
compounded by measures that do not truly capture a supply chain’s impacts and
suggested to address these issues to help in the development of truly sustainable supply
chains.
Therefore, studies associated with a holistic approach of sustainable SCM that
reflect all three sustainability dimensions are relatively rare (Brandenburg et al., 2014;
Lozano, 2015; Roh et al., 2014; Seuring & Müller, 2008). The holistic approach of
sustainable SCM involves interactions between the environmental, social, and economic
dimensions in the short and long term, and also between internal and external
stakeholders (Lozano, 2015; Seuring & Müller, 2008). Lozano (2015) proposed corporate
sustainability driver model that offers a holistic perspective on how companies can be
more proactive in their effort to becoming more sustainability-oriented. In proposing the
corporate sustainability model, Lozano (2015) considered both internal and external
drivers and the drivers that connect them. Based on the review of the literature on
corporate sustainability and the empirical research, Lozano (2015) drew together a large
number of recognized drivers that affect corporate sustainability.
Overall, researchers in the initial studies regarding sustainable SCM focused on
green products and green operations management; however, these researchers did not
include the social and financial aspects of sustainable SCM. Even though these
researchers paved the way for more studies about sustainable SCM, researchers were not

30
able to inform on current developments as well as provide recommendations for future
studies. The subject of sustainability has moved from the borders of supply chain
management research to the mainstream. The increase in acceptance of sustainability has
led to a greater understanding of sustainability; however, the present knowledge about
sustainability is not sufficient in creating a truly sustainable supply chain (Pagell &
Shevchenko, 2014; Schrettle, Hinz, Scherrer-Rathje, & Friedli, 2014). Thus, when it
comes to empirical studies, there is the growing relevance that there should be multiple
perspectives on sustainability.
Sustainable SCM and Stakeholder Pressure
Increasing awareness of the need for sustainable future is prompting governments,
customers, and various stakeholders to pressure organizations to incorporate
sustainability issues into their SCM (Tseng & Hung, 2014). Stakeholder pressures or
drivers are factors that motivate leaders of organizations to adopt sustainability in supply
chain management. Within an organization, stakeholder pressure can be categorized as
either internal or external (Brindley & Oxborrow, 2014; Glover et al., 2014; Tseng &
Hung, 2014). The driving force for the adoption of sustainable practice is usually reactive
as opposed to proactive, underscoring the role of internal or external pressure in
sustainable SCM (Mathiyazhagan, Govindan, & Noorul Haq, 2014). Organizations more
visible to institutional pressure and final customers tend to adopt a proactive approach to
sustainability. Less visible organizations tend to be more reactive in implementing
sustainable practices and waiting longer to establish links with other agents in the supply
chain (Tachizawa & Yew Wong, 2014).

31
The adoption of environmental practices can stem from both internal pressures
such as an organizational strategy and external pressures (Pålsson & Kovács, 2013; Seles,
de Sousa Jabbour, Jabbour, & Dangelico, 2016). Pålsson and Kovács examined the
intention of freight transportation-intensive industries to reduce CO
2
emission. By
combining the resource-based view and stakeholder theory, Pålsson and Kovács found
that organizational strategy outweighs stakeholder pressure in determining whether an
organization intends to green its transportation. Stakeholder pressure sets the minimal
levels that elevate the performance (Pålsson & Kovács, 2013). Internal motives differ
between organizations. External drivers lead to a reduction of transportation emissions to
a predetermined point that is an actual requirement for organizations (Pålsson & Kovács,
2013).
When organizations adopt sustainable supply chain management, stakeholders are
likely to be more concerned with the environmental and social components of
sustainability while organizations are likely to focus on maintaining the economic
benefits while practicing sustainability (Diabat et al., 2014; Ramanathan et al., 2014).
Lee, Singal, and Kang (2013) examined the relationship between corporate social
responsibility and corporate financial performance. Lee et al. found that organizations in
the hospitality industry often reduce social and environmental investments when
economic conditions are unfavorable whereas they continue investments in operations
related programs.
Sustainable SCM is an important area of focus for researchers because of
stakeholders’ demands for organizations’ commitment to adopt sustainability practices

32
(Taticchi et al., 2013). Meixell and Luoma (2015) conducted a quantitative systematic
review of the stakeholder-focused sustainable SCM literature, and specifically literature
on the pressure and influence of stakeholders on sustainable SCM. Different types of
stakeholders have a different influence on corporate sustainability performance
depending on whether the sustainability issue is environmental or social. Additionally,
certain stakeholders play a larger role in social vs. environmental sustainability (Meixell
& Luoma, 2015). Corporate sustainability involves various and often conflicting demands
of a wide set of stakeholders, who tend to apply different decision logics than managers
(Hahn et al., 2015).
Internal pressures such as the need to develop risk management drive sustainable
SCM within the organization (Brindley & Oxborrow, 2014; Glover et al., 2014; Tseng &
Hung, 2014). Internal pressure to adopt sustainable SCM often originates from leaders
and managers (Brindley & Oxborrow, 2014; Glover et al., 2014; Tseng & Hung, 2014).
Reducing costs and increasing profits are also the main drivers of the implementation of
sustainable SCM (Bealt et al., 2016). Every organization has the goal of cost reduction to
increase profits (Glover et al., 2014). The incorporation of sustainability in supply chain
management is a way for an organization to cut down expenses by improving efficiency
(Brindley & Oxborrow, 2014). The need to improve quality is also one of the internal
pressures that can influence the adoption of sustainable SCM (Carter & Easton, 2011).
Such sustainable approach as the decrease of waste and pollution improves quality
(Albertini, 2013). Organizations with environmentally friendly practices produce superior
quality products (Carter & Easton, 2011). Increased pressure from investors can also lead

33
to the development of sustainable policies in organizations (Diabat et al., 2014). The
increased awareness is also related to the understanding of the raw materials of the
organizations in making the products or the services (Long, Tallontire, & Young, 2015).
The growing awareness of the original approach to sustainability, which
recognizes the three dimensions of sustainability (corporate financial performance, social
performance, and environmental performance) as a part of a system, drive organizational
leaders to proactively pursue sustainable SCM (Esfahbodi et al., 2016; Gao & Bansal,
2013; Hahn et al., 2015; Jamali, 2014). Organizational leaders recognize their roles and
responsibilities towards the environment and society not just for the present but for the
future, which foster a proactive development of initiatives to address sustainability
(Lozano, 2013; Walls & Triandis, 2014). Organizations understand their dependence
upon the long-term sustainability of their resource supply (Esfahbodi et al., 2016; Wolf,
2014). Thus, organizations gain long-term benefit from the adoption of sustainable SCM
strategies. By promoting environmental and social sustainability and proactively
engaging in the sustainable supply chain, organizations build a good citizen reputation.
The good reputation improves legitimacy and access to critical resources (Wolf, 2014).
Based on RDT, Wolf (2014) conducted a quantitative analysis of ESG data to
assess the idea that proactive sustainable practices increase organizational legitimacy.
The sample of the study included data of organizations from different industries and both
highly polluting and less polluting industries (Wolf, 2014). Wolf proposed three
competing models of the potential relationship between sustainable SCM, stakeholder
pressure, and corporate sustainability performance. The objective was to examine, which

34
of the three models best represent information on 1,621 organizations. Multiple
regression analysis was used to estimate the corporate sustainability performance impact
of the two independent constructs (sustainable SCM and stakeholder pressure) (Wolf,
2014). Corporate sustainability performance was measured by two dimensions of
sustainability, environmental and social, but did not include the economic dimension of
sustainability. Wolf found that the first model, which assumed that sustainable SCM and
stakeholder pressure have a direct and separate effect on corporate sustainability
performance, represents the data best. Based on the finding, proactive sustainable SCM
directly benefits an organization beyond reducing stakeholder pressure. Thus, proactive
sustainable SCM positively related to corporate sustainability performance (Wolf, 2014).
External pressures, such as consumers, suppliers, competitors, and governments,
influence organizations to assimilate sustainable SCM (Cantor, Blackhurst, Pan, & Crum,
2014). The external pressures that drive the assimilation of sustainable SCM are aspects
outside the internal processes of the organization but still have a significant influence on
the internal activities of the organization (Nuruzzaman, 2015). More than internal
pressures, external pressures obligate organizations to include sustainable environmental
and social practices in the supply chain management (Nuruzzaman, 2015). The findings
of empirical research supporting the benefits of green and environmentally friendly
practices in organizations further encourage stakeholders pressure (Kumar, Luthra, &
Haleem, 2013).
Legislative and regulatory policies drive organizations to deliver products and
services through environmental or sustainable practices. California Transparency in

35
Supply Chains Act is one of the examples of how regulations affect the sustainable
practices of organizations. Some countries also approved tax deductions to organizations
that are practicing environmental or sustainable practices (Fahimnia, Sarkis, Choudhary,
& Eshragh, 2015; Osmani & Zhang, 2014; Rezaee, Dehghanian, Fahimnia, & Beamon,
2015). Customers are one of the most influential external drivers that can pressure
organizations to adopt sustainable SCM (Brindley & Oxborrow, 2014; Ting, Tse, Ho,
Chung, & Pang, 2014). While the customers regularly stress small and medium-sized
companies by the demands, the stakeholders and investors manipulate the large
organizations by the demands (Beske et al., 2014; Brindley & Oxborrow, 2014; Ting et
al., 2014). Organizations must always be alert to the needs of their customers to gain
competitive advantage. Competitors of organizations also serve as an external pressure
that can drive the adoption of sustainable SCM (Beske & Seuring, 2014). The integration
of sustainable practices in organizations was formed to improve competition among
rivals in the same industry (Aguilera-Caracuel & Ortiz-Mandojana, 2013; Wolf, 2014).
The society is also an external pressure that can drive organizations to become more
conscious of environmental issues (Coombs & Holladay, 2015). Organizations are under
pressure to adopt sustainability practices to show the public that they have a sense of
social responsibility (Hsueh, 2015).
External pressures and sustainability demands often come from secondary
stakeholders, such as social activists, non-governmental organizations, and local
communities (Coombs & Holladay, 2015; Hahn et al., 2015). Helmig, Spraul, and
Ingenhoff (2016) found that secondary stakeholders influence primary stakeholders but

36
do not have a direct impact on the implementation of environmental and social practices.
The finding is in alignment with RDT. Stakeholders in relationships with low
interdependence will choose an indirectly influencing strategy (Helmig et al., 2016).
Activities and behaviors outside of an organization’s control are relationships
outside of its boundaries and part of the environment with many other organizations
and/or stakeholders. The relationships outside of an organization’s boundaries recognized
for dispersed authority and power within the environment, scarcity of critical resources,
and interconnectedness of organizations (Malatesta & Smith, 2014). RDT indicates that
organizations as open systems depend on the external environment and helps to
understand strategies that organizations employ to reduce environmental interdependence
and uncertainty (Gaffney et al., 2013; Pfeffer & Salancik, 1978). The more dependent the
organization is on external resources, the more demands the external stakeholders would
have in the control of these resources (Xia, Ma, Lu, & Yiu, 2014).
Managing various demands of suppliers is challenging for organizations (Kam-
Sing Wong, 2014). The objective of any organization is to maximize independence and
certainty especially in resources (Pfeffer & Salancik, 1978). Organizations significantly
depending on the external environment will struggle to lessen this dependence in various
manners (Pfeffer & Salancik, 1978). Often organizations engage in sustainable practices
when they fear or faced with reduced access to resources due to stakeholder pressure
(Wolf, 2014). Sustainable SCM becomes critical to organizations vulnerable to internal
and external stakeholder pressures (Wolf, 2014). Through sustainable SCM,
organizations address environmental, social, and economic aspects of their supply chains

37
to reduce stakeholder pressure (Wolf, 2014). Stakeholder pressure is often one of the
main reasons why organizations will pursue sustainable SCM (Brindley & Oxborrow,
2014; Glover et al., 2014; Tseng & Hung, 2014). Wolf (2014), upon conducting a
multiple linear regression analysis of the relationship between sustainable SCM,
stakeholder pressure, and corporate sustainability performance, found that stakeholder
pressure directly affects corporate sustainability performance.
Organizational managers may have a reason for proactively pursuing sustainable
practices other than stakeholder pressure since sustainable SCM contributes to corporate
sustainability performance but the effect can be greater when stakeholder pressure occur
(Wolf, 2014). The stakeholders’ expectations, whether they are internal or external, need
to be incorporated into the sustainable supply chain operations if the pressure is present
(Cantor et al., 2014; Wolf, 2014). The integration of stakeholder expectations into the
organizational strategy improves corporate sustainability performance (Cantor et al.,
2014; Wolf, 2014). Wolf conducted a multiple linear regression analysis of three
competing models of the potential relationship between sustainable SCM, stakeholder
pressure, and corporate sustainability performance by employing RDT. Wolf (2014)
found that the information on 1,621 organizations based on the ESG data did not support
the second model, which assumed the moderating effect of stakeholder pressure on the
sustainable SCM-corporate sustainability performance relationship. It is possible that
factors not examined in the study determined the importance of stakeholder pressure in a
sustainable SCM context (Wolf, 204). Adebambo, Abdulkadir, Mat, and Alkafaagi
(2013) also investigated the sustainable environmental manufacturing, the direct

38
influence of its drivers, and financial performance by employing a survey approach and
structural equation modeling. Adebambo et al. found that stakeholder pressure,
legislation, and perceived benefits directly influence the implementation of sustainable
environmental manufacturing practices and financial performance.
Despite the internal and external pressures to adopt sustainable SCM, there are
challenges and obstacles to the integration of sustainability and supply chain processes
(Al Zaabi, Al Dhaheri, & Diabat, 2013). The challenges of sustainable SCM
implementation are (a) cost increase, (b) change of culture, (c) operationalization of
sustainable development, (d) uncertainties among the employees and the organization,
and (e) the complexity of the issues of the organization (Alexander et al., 2015; Galpin et
al., 2015). While sustainable SCM is also supposed to reduce costs of the organization,
the integration of sustainability to supply chain processes can also be expensive to
accomplish (Zhang, Shah, Wassick, Helling, & Van Egerschot, 2014). The adoption of
sustainable SCM would require a significant capital for small to medium-sized
companies (Zhang et al., 2014).
Lack of knowledge of the organizations is also one of the most common obstacles
to the integration of sustainable SCM practices in an organization (Al Zaabi et al., 2013).
Lack of training of the employees is also an obstacle to sustainable SCM, as it leads to a
lack of environmental awareness for employees (Dashore & Sohani, 2013; Myung et al.,
2012; Sisson & Elshennawy, 2015). The lack of integration of IT system was also
identified by Dashore and Sohani (2013) as an obstacle to the implementation of
sustainable SCM practices in an organization. The integration of IT is essential for

39
information exchange processes and successful sustainable SCM (Brandenburg et al.,
2014; Dashore & Sohani, 2013). Regulations also tend to be an obstacle for the
implementation of sustainable SCM if the regulation does not facilitate the environment
needed for implementing the sustainable supply chain (Dashore & Sohani, 2013). Thus,
corporate sustainability challenges managers in organizations with complex issues full of
tensions as it requires managers to simultaneously address concerns for the environment,
social welfare, and economic prosperity (Hahn, Preuss, Pinkse, & Figge, 2014; Hahn et
al., 2015).
Many organization managers fail to recognize the potential benefits of sustainable
practices for overall organizational performance unless they yield short-term profits
(Alexander et al., 2014; Bradly, 2015). Organizations are not recognizing sustainable
SCM as beneficial to strategic objectives also due to the challenges engage in sustainable
practices only if there is pressure upon the resource dependence relationship with one or
more stakeholders (Pfeffer & Salancik, 1978; Wolf, 2014). Stakeholder pressure
determines the extent to which an organization engages in sustainable SCM. The extent
of engagement in sustainable SCM will affect corporate sustainability performance
(Wolf, 2014). Thus, stakeholder pressure mediates sustainable SCM, and in turn,
sustainable SCM shapes corporate sustainability performance (Cantor et al., 2014; Wolf,
2014).
For instance, risk management is one of the drivers of sustainable SCM within the
organization (Brindley & Oxborrow, 2014; Glover et al., 2014; Tseng & Hung, 2014).
Organizations may not recognize the benefits of risk management programs, such as

40
managing the long-term sustainability of resources by fostering innovation, unless there
is pressure from external and internal forces to develop an effective supply chain risk
mitigation strategy (Cantor et al., 2014; Lozano, 2013). Cantor et al. (2014) empirically
tested how stakeholders place pressure on organizations to engage in risk management
activities. Cantor et al. (2014) utilized a survey approach to test the nomological model
by employing structural equation modeling techniques. Stakeholders pressure on
organizations to mitigate risk, and joint planning activities with suppliers serve as a
mediating role in the model (Cantor et al., 2014; Lozano, 2013). The Cantor et al. (2014)
study is one of the first papers to test empirically how stakeholders’ pressure mediate the
relationship between sustainable SCM and corporate sustainability.
Wolf (2014) revealed that the mediating effect of stakeholder pressures on
sustainable SCM is not significant. Wolf conducted a multiple linear regression analysis
of three competing models of the potential relationship between sustainable SCM,
stakeholder pressure, and corporate sustainability performance by employing RDT. Wolf
(2014) found that the information on 1,621 organizations based on the ESG data did not
support the third model, which assumed the mediating effect of stakeholder pressure on
the sustainable SCM-corporate sustainability performance relationship. It is possible that
factors not examined in the study determined the importance of stakeholder pressure in a
sustainable SCM context (Wolf, 2014).
Stakeholder pressure has contributed to the sustainability practices and
performance of organizations (Ramanathan et al., 2014; Wolf, 2014). Ramanathan et al.
(2014) analyzed the impacts of various organizational pressures on the environmental

41
performance of manufacturing firms and found that all five analyzed pressures exert
significant influence on environmental performance. Ramanathan et al. used a structural
equation modeling techniques to consider the impact of all five pressures simultaneously.
Ramanathan et al. also provided evidence that an internal stakeholder such as marketing
department and economic pressure provide the highest influence on the environmental
and economic performance of an organization. Ramanathan et al. (2014) provided a
holistic analysis considering a variety of stakeholder pressures in a single framework and
extended the application of RDT. The theory is one of the theoretical frameworks to
understand the role of organizational pressures on the sustainability performance
(Ramanathan et al., 2014). Organizations are not self-sufficient but rely on their
environment and its resources for survival and achievement of long-term objectives.
Organizations should strive to manage the dependency on the external environment to
gain sustainable development (Pfeffer & Salancik, 1978; Ramanathan et al., 2014).
The adoption of both proactive sustainable SCM and sustainable SCM due to
stakeholder pressure is associated with positive outcomes such as improved
environmental concerns, competitive advantage, cost and risk reduction, revenue
increase, and positive effects on company image and employee motivation (Bradly, 2015;
Kumar et al., 2013). Thus, sustainable SCM and stakeholder pressure directly influence
the strategies organizations employ to enhance corporate sustainability performance
because doing so resolves elements of a resource dependence problem, ameliorates
stakeholder pressure, and ensures sustainable profitability (Wolf, 2014). The moderating
and mediating effect of stakeholder pressures on the sustainable SCM-corporate

42
sustainability performance relationship requires additional research. Research in the field
of sustainable SCM receives considerable attention. However, the research field is still
very young but is growing very fast (Taticchi et al., 2013).
Sustainable SCM and Corporate Sustainability Performance
During the 1990s, concerns about the environment and social sustainability
emerged such as global warming, climate change, and corporate social responsibility
(Govindan, Khodaverdi, & Jafarian, 2013). Well-known examples of business practices
related to substantial resource depletion have led stakeholders to apply pressure on
organizations to restrict their purchasing activities to sustainable resources not only
within their premises but also across supply chains (Govindan et al., 2013; Wolf, 2014).
Focal organizations are pressured to manage sustainability standards actively beyond
their organizational boundaries due to the reputational and economic risk (Leppelt,
Foerstl, Reuter, & Hartmann, 2013). Even though a focal organization may have little
control over its suppliers’ unsustainable behavior, stakeholders are still likely to point
responsibility to the focal organizations (Hartmann & Moeller, 2014; Tachizawa & Yew
Wong, 2014). The awareness and acceptance of society regarding the importance of
sustainability have led to a political momentum of implementing sustainable projects and
policies (Bason & Anagnostopoulos, 2015; Kolk & Lenfant, 2013; Macagno, 2013).
However, despite the rising human awareness of environmental and social aspects of
doing business, financial performance continues to be the core objective of organizations
(Bateh, Heaton, Arbogast, & Broadbent, 2013; Torugsa et al., 2013; Varsei et al., 2014;

43
Zhu et al., 2013). The most important linkage between business and society tends to stem
from economic and corporate interests (Varsei et al., 2014).
The concept of sustainability often evolves over time to reflect the changes in the
society (Bateh et al., 2013; Milne & Gray, 2013). Corporate sustainability has been
conceptualized using different theoretical approaches, mainly stakeholder pressure,
institutional theory, and the resource-based view (Milne & Gray, 2013; Montiel &
Delgado-Ceballos, 2014). The topic of sustainability had expanded in public since 1987
when the Brundtland Commission initiated by the United Nations (UN) published its
report titled Our Common Future (World Commission on Environment and
Development, 1987; McManus, 2014). Corporations gradually integrate corporate
sustainability into organizational activities (Bealt et al., 2016; Lozano, 2015).
Bansal and DesJardine (2014) and Montiel and Delgado-Ceballos (2014)
concluded that there is no single understanding of sustainability in businesses as the
interpretations range from reverse logistics to strategic sustainability. The number of
interpretations of sustainability and the broad definition makes it difficult to create
operational tools to contextualize sustainability in the macro context of businesses (Carter
& Rogers, 2008; Milne & Gray, 2013). Sustainability research is highly diverse and
unsystematic as different types of organizations face different sustainability needs (Bateh
et al., 2013). Regardless of the numerous definitions provided about sustainability, Bateh
et al. (2013) asserted that three elements such as longevity, maintenance of purposes, and
responsibility to external needs are essential in the definition of sustainability.

44
Montiel and Delgado-Ceballos (2014) reviewed the literature on corporate
sustainability from 1995 through 2013. After summarizing the different definitions,
organizational theories, and adopted measures of corporate sustainability, Montiel and
Delgado-Ceballos provided recommendations on how to advance the corporate
sustainability field. Montiel and Delgado-Ceballos concluded that the corporate
sustainability field is still evolving. Thus, sustainability is a complex process that is
multi-dimensional in nature, which makes studies about sustainability very difficult when
combined with the complex nature of supply chain management (Bradly, 2015;
Whiteman et al., 2013).
Despite fewer studies about sustainable supply chain in the early 1990s, the
researchers of initial studies have defined sustainability concept as well as its association
with supply chains that focuses on the importance and benefits of the relationship
between sustainability and supply chains (Green et al., 2015; Winter & Knemeyer, 2013).
However, the researchers of earlier studies about sustainable SCM focused more on the
environmental dimension of sustainability; lacking a perspective of integration among
different concepts (Alexander et al., 2015; Qi, Zeng, Yin, & Lin, 2013; Signori, Flint, &
Golicic, 2015). A limited number of authors have considered a holistic view of
sustainability where there are interactions between the environmental, social, and
economic dimensions (Lozano, 2015). The economic sustainability dimension emerged
as a result of the three-dimensional concept of Elkington’s (1998) Triple bottom line
(Elliot, 2013; Goyal, Rahman, & Kazmi, 2013; Ralston et al., 2014).

45
The triple bottom line concept introduced by Elkington (1998) incorporates profit,
people, and the planet and evokes the necessity to attend to all three aspects of
sustainability, which has become a framework for sustainability (Gopalakrishnan et al.,
2012; Singal, 2013). The economic dimension of the triple bottom line is the profit
portion of the triple bottom line and refers to economics-sustaining profit and competitive
advantage. The environmental aspect of the triple bottom line relates to resource
depletion. The social aspect involves an organization’s behavior in relation to employees
and community. The profit portion of the triple bottom line - economics remains a major
concern of socially responsible business (Gopalakrishnan et al., 2012; Singal, 2013;
Reefke, & Sundaram, 2017).
Bateh et al. (2013) stressed the need to shift emphasis away from a purely profit-
driven economic perspective to considering the organization as part of a system that is
currently unsustainable. The scarcity of resources, globalization, and the competitive
market along with stakeholders force supply chains to look beyond pure economic gain,
which is becoming an issue of strategic importance (Goyal et al., 2013; Seuring, 2013).
Financial performance no longer guarantees an organization’s long-term survival (Sezen
& Cankaya, 2013). Socio-environmental and economic performance relationships offer
win-win opportunities (Fahimnia et al., 2015). Organizations incorporating sustainability
will succeed, and the organizations that do not will be challenged (Green et al., 2015).
Eccles et al. (2014) investigated the effect of corporate sustainability on organizational
processes and performance and found that high sustainability organizations significantly
outperform their counterparts over the long-term, both regarding stock market as well as

46
accounting performance (Eccles et al., 2014). To have a sustainable future for all
organization, the integration of the social, economic, and environmental facets of
business operations should be explored (Dixon-Fowler, Slater, Johnson, Ellstrand &
Romi, 2013; Gopalakrishnan et al., 2012; Wan Ahmad, Rezaei, Tavasszy, & de Brito,
2016).
According to the integrative view on corporate sustainability, organizations need
to pursue all three aspects of sustainability simultaneously and embrace the tensions
between different conflicting sustainability aspects rather than dismissing them. Hahn et
al. (2015) recognized that such a strategy goes beyond the triple bottom line because it
addresses the conflicting relationships between these various aspects. Hahn et al. (2015)
developed a systematic framework that allows to identify and characterize tensions in
corporate sustainability. The integrative view on corporate sustainability is the basis of
the framework.
Integration of the three dimensions of sustainability represents a fundamental
mechanism of business sustainability (Reefke & Sundaram, 2017; Windolph, 2013). Gao
and Bansal (2013) tested the presence of instrumental and integrative logic using data of
738 organizations over 13 years and found evidence of integrative logic applied by
organizations. The sample of the study included data of organizations rated by Kinder,
Lydenberg, and Domini & Co. (KLD), Compustat, and the Center for Research in
Security Prices (CRSP). Forty-six percent of the sampled organizations were
manufacturing companies (Gao & Bansal, 2013). Gao and Bansal employed a
generalized estimating equation (GEE) to test the causal effects. Gao and Bansal

47
articulated that the integrative logic is at the foundation of sustainability, and the
instrumental logic is the facilitator. Gao and Bansal concluded that the result of the
analysis is a business model that aims to integrate business, society, and nature.
Wang and Sarkis's (2013) investigated whether organization's environmental and
social supply chain activities associated with their financial performance. Wang and
Sarkis employed multivariate regression analysis to empirically test the relationship. The
sample of the study included data of organizations from the top 500 US companies based
on Newsweek’s green ranking report, Bloomberg ESG database, and Compustat financial
database (Wang & Sarkis, 2013). Wang and Sarkis found evidence of a positive
relationship between corporate financial performance and simultaneous implementation
of both environmental and social SCM. The study is the first research to investigate the
direct relationship between organizational environmental and social practices and
financial performance. By being the first to use publically available Bloomberg ESG
database to investigate the financial performance related to individual and joint
environmental and social supply chain management activities, Wang and Sarkis made a
significant contribution to sustainability management literature (Wang & Sarkis, 2013).
Singal (2013) examined the link between sustainability and economic
performance for the hospitality industry using MSCI’s ESG database and Standard and
Poor’s credit ratings. Historical long-term issuer ratings assigned to an organization by
S&P represented the financial performance of organizations. ESG indicators represented
the environmental and social performance of organizations. Singal employed multiple
regression analysis and t-tests to evaluate the proposed relationships. One of the several

48
findings of the study is evidence supporting an integrative logic rather than an
instrumental logic for the relationship between corporate social, environmental, and
financial performance. Singal also suggested that organizations should continue to invest
in sustainability initiatives for strategic reasons even in times of low financial
performance.
Wolf (2014) employed Sustainalytics ESG database and extended existing
research by conceptualizing corporate sustainability with environmental and social
dimensions of sustainability. By applying RDT to a sustainable SCM context, Wolf
empirically assessed the relationship between sustainable SCM and corporate
sustainability performance, with that of stakeholder pressure and corporate sustainability
performance, and the effect of stakeholder pressure on the sustainable SCM and
corporate sustainability performance. Wolf provided valuable insights for managerial
decision makers by illustrating the positive relation between sustainable SCM and
corporate sustainability performance (Wolf, 2014).
A discussion of sustainability impacts on organizational performance, including
discussion of the competitive and cost-effectiveness potentials of sustainability, is one of
the most recent trends (Bateh et al., 2013; Linnenluecke & Griffiths, 2013). In existing
studies, Singal (2013), Wang and Sarkis (2013), and Wolf (2014) have examined the
combined effect of sustainability parameters on firm performance. Lee et al. (2013) and
Fujii, Iwata, Kaneko, and Managi (2013) addressed the effect of individual dimensions of
sustainability on firm performance.

49
Lee et al. (2013) examined the relationship between corporate social
responsibility and corporate financial performance by employing Pearson’s correlation
analysis. The sample of the study included data of organizations from KLD STATS,
Compustat, and U.S. Bureau of Economic Analysis. Lee et al. found that organizations in
the hospitality industry often reduce social and environmental investments when
economic conditions are unfavorable whereas they continue investments in operations
related programs. Fujii et al. (2013) examined the relationship between environmental
performance and economic performance in Japanese manufacturing firms. Fujii et al.
employed a multiple regression analysis to examine the relationship. Fujii et al. found
that there is a significant positive relationship between financial and environmental
performance due to savings on intermediate energy costs. Fujii et al. also stated that
reduction of CO
2
emissions might not improve capital productivity in the short term (Fujii
et al., 2013). Kurapatskie and Darnall (2013) extended prior research on the broader
connections between sustainable practices and financial performance. Kurapatskie and
Darnall found that while lower and higher order sustainability activities are in alignment
with organizations’ financial performance, financial benefits related to higher
sustainability activities are greater. Thus, organizations actively integrating sustainability
are more likely to reap greater financial benefits (Kurapatskie & Darnall, 2013).
The best predictors of an organization’s economic and market-based performance
are social and environmental performance (Klettner, Clarke, & Boersma, 2014). The
effects of both social and environmental performance on organizations’ economic and
market-based performance are particularly significant (Green et al., 2015; Klettner et al.,

50
2014). Positive links widely established between organizations’ sustainable and economic
performance (Klettner et al., 2014; Shamsuddoha, 2015). Investors are becoming aware
of the importance of ESG factors in the estimation of corporate value as ESG
performance indicators reflect the future cash flows (Klettner et al., 2014; Kosmanova &
Docekalova, 2013). Investors and owners of organizations employ ESG performance
indicators to evaluate the economic performance to determine whether the organization
can increase its value and provide adequate returns on their investments over a longer
period (Kosmanova & Docekalova, 2013). ESG factors are becoming the core of business
and presenting long-term consequences on a corporation’s financial performance
(Klettner et al., 2014). ESG reporting forces companies to manage environmental, social,
and economic aspects of business operations effectively to avoid the disclosure of
negative ESG performance to their stakeholders (Ioannou & Serafeim, 2016). National
governments and stock exchange authorities have promoted sustainability reporting
further by adopting laws and regulations that mandate sustainability reporting (Ioannou &
Serafeim, 2016; Milne & Gray, 2013). The regulators are also reviewing the governance
arrangements of corporations to ensure that companies maintain a healthy long-term
focused organizational culture (Ioannou & Serafeim, 2016). ESG performance leads to
higher economic performance as it provides competitive advantage (Ioannou & Serafeim,
2016).
Even though sustainability is encouraged by governments, investors, and
customers, the economics of sustainable decisions are still uncertain (Singal, 2013).
Financial costs and benefits alone cannot create the full picture of sustainability impacts

51
on organizations (Bateh et al., 2013; Milne & Gray, 2013). Often organizations lack
effective instruments and adequate knowledge to measure financial outcomes of
sustainability measures (Alexander et al., 2015; Milne & Gray, 2013; Windolph, 2013).
Thus, the dominant instrumental logic still establishes a hierarchy of financial outcomes
over sustainability concerns (Hahn et al., 2015).
Economic principles of rationality and accountability mainly govern societal
thinking and decision making (Bateh et al., 2013). Economic interests are still the main
principle in determining attitudes and policies of corporate sustainability (Gupta &
Kumar, 2013; Rahardjo, Idrus, Hadiwidjojo, & Aisjah, 2013). Economic stakeholders
such as employees, shareholders, suppliers, and customers remain very concerned about
the economic benefits as a primary consideration in providing support to the company’s
survival. Customers encourage sustainable practices, but they also do not approve price
increase if it caused by the burden of philanthropic activity (Rahardjo et al., 2013).
The long-term investments that most sustainability improvements require make
them unattractive to organizations that apply high discount rates in estimating projects’
net present values (Eccles & Serafeim, 2013). The sustainable strategy has to increase
shareholder value while at the same time has to improve the organization’s performance
on ESG dimensions. Sustainability requires trade-offs in strategic decision making so that
both the short and long term are considered (Alexander et al., 2015; Bansal &
DesJardine, 2014; Eccles et al., 2014). Often organizational managers fail to understand
trade-offs that exist between financial and ESG performance. The capital market does not
reward organizations for ESG programs that fail to enhance financial performance

52
(Eccles & Serafeim, 2013). Therefore, organizations still prioritize financial over ESG
performance.
Overall, corporate sustainability is a concept to achieve long-term economic
benefits through the integration of environmental, social, and economic criteria (Carter &
Rogers, 2008). The economic impact of corporate sustainability efforts is the main
research concern. Research propositions have been developed based on RDT, transaction
cost economics, and population ecology, all based upon a view of the industries (Al Zaabi
et al., 2013). The review of the literature from the viewpoint of RDT led to the following
conclusions: (a) organizations take a proactive approach to the sustainable supply chain
and corporate sustainability in an effort to ensure the long-term resource supply and
sustainable corporate performance, (b) organizations take reactive approach to
sustainable practices when they fear or faced with reduced access to resources due to
stakeholder pressure, (c) proactive sustainable supply chain practices contribute to
corporate sustainability performance, but the effect is greater when stakeholder pressure
occurs, and (d) stakeholder pressure determines the extent to which an organization
engages in sustainable supply chain practices. These conclusions guided this research to
address a business problem concerning the understanding and effective practice of
corporate sustainability performance. The complexity and the little theoretical
development of an original approach to sustainability suggest that findings of this study is
not an end in itself, but the next-to-last step in a scientific process that culminates in
providing information about the corporate sustainability performance (see Cohen et al.,
2013). The results of the study indicated that there is a significant positive relationship

53
between sustainable practices and financial performance. The findings of the study might
assist organizational leaders in the decision-making process in pursued of the long-term
corporate sustainability.
Transition
In Section 1, I presented an introduction and the brief background of the
sustainability agenda. Sustainability issue initiated by the rising concern regarding
resource depletion and the related decline of social well-being, which demands a strong
focus on the integration of social, environmental, and economic aspects of business
operations in supply chains is discussed. The need to understand the connection between
a firm’s financial performance and its investment in sustainability initiatives and the
complex correlation and interplay of factors that foster sustainability and company
competitiveness are highlighted in this section as well.
In this section, I also presented research questions of the study and the appropriate
methodology for addressing the research questions and for testing the hypotheses. The
main research question was what is the relationship between sustainable SCM,
stakeholder pressure, and corporate sustainability performance while controlling for
industry and organizational size? The chosen theory to seek an explanation of the
behavior of an organization in terms of its context was RDT. The chosen methodology
for this study was quantitative, as the purpose of the study was to analyze the
relationships between the constructs. Specifically, to appropriately address the aim of this
study, which is to predict the relationship between a set of predictor variables (sustainable

54
SCM and stakeholder pressure) and a dependent variable (corporate sustainability
performance), the chosen research design was correlational.
Additionally, in this section, there was also a review of the related literature to
provide context for the study. In an attempt to extend Davis and Cobb’s (2010) RDT,
which holds that sustainable SCM and stakeholder pressure influence the strategies that
organizations employ to improve their economic sustainability, the focus was on the
review of literature related to the theoretical framework and the composite variables of
the study. The several keywords used to filter the studies that are more relevant to the
research topic are: supply chain management, sustainable supply chain management,
impact of SSCM, stakeholder pressure, economic sustainability, and corporate
sustainability performance.
First, in the literature review section, there was a review of RDT and its
application within supply chains as organizations consistently purchase scarce resources
and depend on contingencies in the external environment (Pfeffer & Salancik, 1978;
Malatesta & Smith, 2014). RDT helps to shift an organizational strategy from short-term
survival to long-term organizational growth (Malatesta & Smith, 2014). RDT is a central
argument and highly relevant to the study of contemporary organizations and specifically
to the study of the supply chain relations (Tachizawa & Yew Wong, 2014). RDT
facilitates understanding of the relationship between sustainable SCM, stakeholder
pressure, and corporate sustainability performance.
Second, in the literature review section, there was a review of sustainable SCM
practices. The scarcity of resources pressures organizations to seek sustainable supply

55
chain strategies that are essential for their survival, long-term sustainability of their
resource supply, and sustainable economic performance. The increase in acceptance of
sustainability has led to a greater understanding of sustainability; however, the present
knowledge about sustainability is not sufficient in creating a truly sustainable supply
chain (Pagell & Shevchenko, 2014; Schrettle et al., 2014). Sustainable SCM is a complex
process that is multi-dimensional in nature, which makes studies about sustainable SCM
very difficult when combined with the complex nature of supply chain management
(Whiteman et al., 2013). Thus, when it comes to empirical studies, there is the growing
relevance that there should be multiple perspectives on sustainability.
Third, in the literature review section, there was a review on the role of
stakeholder pressure in sustainable SCM, including both internal and external pressure,
and its effect on corporate sustainability performance. Internal pressures encourage
organizations to take a proactive approach to the sustainable supply chain considering the
overconsumption and rising resource scarcity phenomenon to ensure the long-term
sustainability of their resource supply. External pressures are also the main reason why
organizations will pursue sustainable SCM. The driving force for the adoption of
sustainable practice is usually reactive as opposed to proactive, underscoring the role of
internal or external pressure in SSCM (Mathiyazhagan et al., 2014). Stakeholders’
demands for organizations’ commitment to adopt sustainability practices makes
sustainable SCM is an important area of focus for researchers (Taticchi et al., 2013).
Finally, in the literature review section, there was a review of the relationship
between the sustainable SCM and corporate sustainability performance. The need for the

56
holistic approach of sustainable SCM that incorporates environmental, social, and
economic facets of business operations, especially given that sustainable SCM can have a
positive influence on the financial performance of an organization, was stressed. In the
literature review section, it was also recognized that current knowledge about corporate
sustainability performance is not sufficient as there are only a few studies that focused on
the relationship between the sustainable practices and corporate sustainability
performance (Schrettle et al., 2014).
In Section 2, the selected methodology and its appropriateness for this study
elaborated. Specifically, a detailed discussion of the participants in the study, research
method and design, population and sampling, data collection instruments and techniques,
data analysis, and as well as ethical research and study validity presented. In section 3,
the findings of the study related to each of the research questions and the hypotheses
presented. Application of the findings to professional practice and implications for
change and the recommendations for further research also discussed.

57
Section 2: The Project
This section includes a review of the methodology and research design I used to
conduct the study. The section also includes a review of the study participants, population
and sampling technique, data collection instruments, and specific statistical techniques I
used to investigate the relationships in the study. Finally, this section includes a review of
my data analysis ethical research practices, and concludes with a discussion of the study’s
validity.
Purpose Statement
The purpose of this quantitative correlation study was to examine the relationship
between sustainable SCM, stakeholder pressure, and corporate sustainability performance
while controlling for industry and organizational size. The first independent composite
variable was sustainable SCM, as measured by Sustainalytics dimensions of: (a) social
supply chain standards, (b) supply chain monitoring systems, and (c) green procurement.
The second independent composite variable was stakeholder pressure, as measured by
Sustainalytics dimensions of: (a) social supply chain related issues and controversies, (b)
operations and product related issues and controversies, and (c) environmental supply
chain related issues and controversies. Stakeholder pressure also took the roles of
moderator and mediator. The dependent variable was corporate sustainability
performance, as measured by Standard and Poor’s credit rating. The control variables
were industry and organizational size, measured by the number of employees. For this
study, I obtained secondary data on organizations located in North America, South
America, and Eurasia, identified in a Newsweek Green Rankings Global 2016 list. This

58
study’s implications for positive social change include the potential to provide a better
understanding of the correlates of corporate sustainability performance by organization
managers, which encourage long-term sustainable profitability that improves
environmental, social, and economic standards of living.
Role of the Researcher
I have professional experience in a semiconductor manufacturing organization,
and I am presently studying supply chain management—specifically sustainable SCM—
in the organization. In planning a research project, it is essential for the researcher not
only to choose a feasible research problem, but also to consider the kinds of data that a
study of the problem will require, as well as reasonable means of collecting and
interpreting those data (Leedy & Ormrod, 2015). Thus, my role as researcher in this study
was to choose appropriate data needed for investigation of the particular research
problem. I collected the data pertaining to the variables of interest using convenience
sampling to select participants from archival databases hosted by Sustainalytics and
Standard & Poor’s. The Environmental, Social, and Governance (ESG) and Standard &
Poor’s (S&P) data sets with historical data have been used extensively for quantitative
analysis and effectively applied in sustainability and finance research (Singal, 2013;
Wang & Sarkis, 2013; Wolf, 2014).
However, data contains sources of bias. Outliers can bias estimates of parameters
and affect the sum of squared errors. The biased sum of squared errors will affect most
test statistics (Field, 2013). I used graphs such as histograms and boxplots to spot unusual
scores. Also, the potential sources of bias come in the form of violations of assumptions

59
relevant to statistical procedures. My main assumptions were (a) linearity, (b) normality,
(c) homogeneity of variance, and (d) independence (Green & Salkind, 2013; Hopkins &
Ferguson, 2014). A violation of the assumptions leads to an inaccurate test statistic and p-
value, and wrong conclusions such as Type I (falsely rejecting the null hypothesis) or
Type II (incorrectly failing to reject the null hypothesis) errors (Field, 2013; Green &
Salkind, 2013; Hopkins & Ferguson, 2014). The violation of assumptions is preventable
by conducting a test of statistical model assumption (Field, 2013; Green & Salkind, 2013;
Hopkins & Ferguson, 2014). I employed SPSS features that allow assessing the
assumptions of regression and the consequences of violating these assumptions.
In order to conduct ethical research, I followed the ethical principles outlined in
The Belmont Report (U.S. Department of Health & Human Services, 1979). When
conducting research using archival data, informed consent forms are unnecessary. The
data for the research are archival and available publicly and upon request. Thus, I did not
provide informed consent because this research, according to the principles of The
Belmont Report, did not adversely affect the rights and welfare of the research
participants and involved no more than minimal risk (see U.S. Department of Health &
Human Services, 2015, CFR 46.116). However, the data gathered for the study should
still be ensured by the researcher to be kept confidential or anonymous, however (Field,
2013; Ippoliti, 2015; Leedy & Ormrod, 2015; see U.S. Department of Health & Human
Services, 2015, CFR 46.116). Therefore, I was solely responsible for collecting data from
Sustainalytics and Standard & Poor’s, entering the data into a spreadsheet software, and
analyzing the data using SPSS v 21 software.

60
Participants
No primary data were collected for this study. I used archival (secondary) data
provided by Sustainalytics and S&P. These databases include data of publicly traded
worldwide organizations that are becoming increasingly sensitive to sustainability
concerns regarding environmental and social issues. Publicly traded organizations are
corporations issuing stocks traded on a stock exchange market (Hannah, 2015). Publicly
traded organizations are more likely to implement socially responsible programs and
consequently perform better in sustainability than small organizations because
sustainable practices require considerable investments that often prove challenging for
small organizations (Gopalakrishnan et al., 2012; Wang & Sarkis, 2013; Wolf, 2014).
Moreover, publicly traded organizations tend to have extensive supply chains that are
sensitive to stakeholder pressures and that are more likely to report sustainability
information (Reilly & Hynan, 2014; Wang & Sarkis, 2013). In similar studies, Singal
(2013), Wang and Sarkis (2013), and Wolf (2014) also used publicly listed worldwide
organizations as participants. Analyzing organizations in countries and industries with
less sustainability reporting would be less useful. The purpose of this study was to test the
relationship between sustainable SCM, stakeholder pressure, and corporate sustainability
performance while controlling for industry and organizational size. Thus, it was
appropriate to choose the participants for the study from a population that consists of
publicly traded global corporations engaged in sustainable SCM.
Newsweek Green Rankings 2016 Global 500 List included organizations with the
most sustainable practices. The green ranking list was comprised of the 500 largest

61
publicly traded companies globally by market capitalization, as determined by
Bloomberg as of March 4, 2015 (Newsweek, 2016). The green ranking list is the most
comprehensive rankings available on this subject; eight indicators of environmental
performance contribute to the ranking (Wang & Sarkis, 2013; Newsweek, 2016).
Blazovich, Smith, and Smith (2013) employed Newsweek’s green ranking list to examine
financial performance and risk of environmentally friendly green companies. Wang and
Sarkis (2013) obtained a sample from the top 500 U.S. companies based on Newsweek’s
green ranking to investigate the relationship between organizations’ environmental and
social supply chain activities and their financial performance. Jackson and Singh (2015)
also selected a sample from Newsweek’s green ranking to examine the financial-
environmental performance of organizations in the U.S. food and beverage supply chain.
Because the ESG and S&P’s financial data were archival, there was no need for
me to use any survey instrument. The most extensively used and validated databases for
studying corporate sustainability performance are the ESG and S&P’s financial
performance databases (Singal, 2013). The ESG archival data are available upon request
from the ESG database hosted by Sustainalytics. The financial performance data are
available publicly from the database hosted by Compustat S&P. Sustainalytics is a
research firm that specializes in ESG research and analysis assisting organizations in
global responsible investment (Sustainalytics, 2016). Sustainalytics data are less
vulnerable to social desirability bias than survey data (Wolf, 2014). S&P’s rating
services, with a 150 year history, provide high-quality market intelligence in the form of
credit ratings and research (Standard & Poor’s, 2016).

62
Wang and Sarkis (2013) employed the Bloomberg ESG database and the
Compustat financial database to investigate the relationship between organizations’
environmental and social supply chain activities and their financial performance. Singal
(2013) used data from MSCI’s ESG database and credit ratings from S&P to examine the
link between investment in sustainability initiatives and firm financial performance.
Jackson and Singh (2015) used the Compustat financial database to examine the
financial-environmental performance of organizations. Surroca, Tribo, and Zahra (2013)
utilized Sustainalytics and COMPUSTAT Global Vantage databases to investigate
stakeholder pressure on MNEs and the transfer of socially irresponsible practices to
subsidiaries. Wolf (2014) also effectively employed the Sustainalytics ESG database in
investigating the relationship between sustainable SCM, stakeholder pressure, and
corporate sustainability performance. Singal (2013) suggested that researchers should
consider using the ESG and S&P rating databases for studies in the future. Thus, I
employed the Sustainalytics ESG database and the S&P financial database to conduct this
study.
The ESG scores of organizations based on the wide range of issues related to
corporate social and environmental performance are the key source of this study’s
environmental and social data corresponding to the independent composite variables
sustainable SCM and stakeholder pressure (Gao & Bansal, 2013). The Sustainalytics
ESG database is the only dataset that presents ESG scores for a wide range of global
firms over an extensive period. Using the Sustainalytics ESG data set allowed me to
bridge this research with Wolf’s (2014) study, given that I built this study on Wolf’s

63
suggestion to test further whether corporate sustainability performance measured by the
economic dimension of sustainability is affected by sustainable SCM and stakeholder
pressure.
The long-term issuer rating assigned to a firm by S&P allow for a measurement of
the firm’s financial performance that represents the economic dimension of corporate
sustainability performance, which is the dependent variable in this study (Singal, 2013).
The credit rating of an organization is a better measure of a firm’s performance because it
is calculated based on both publicly available and non-publicly available data, and is
easily compared with the ratings of other organizations (Singal, 2013). Accounting and
market-based flow variables such as stock returns, return on assets, sales growth, and
return on equity suffer from their transitory nature in measuring the impact of sustainable
practices on financial performance (Gregory & Whittaker 2013; Singal, 2013). Before
gathering data, I gained approval from the Walden Institutional Review Board (IRB) that
performs an ethical review of proposed research to ensure proper ethical procedures and
that the research meets ethical standards (Ippoliti, 2015; Protecting Human Research
Participants, 2015; U.S. Department of Health & Human Services, 2015). The approval
number is 12-22-16-0442285.
Research Method and Design
For this research study, I used a quantitative method and non-experimental
correlational design. In this section, I discuss my selection of the design and methodology
and elaborate on the appropriateness of the selected methodology and design.

64
Research Method
I chose a quantitative methodology for this study. The three research
methodologies are quantitative, qualitative, and mixed methods, which combine both
quantitative and qualitative methods (Field, 2013; Leedy & Ormrod, 2015; Makrakis &
Kostoulas-Makrakis, 2016). While the quantitative-qualitative distinction is one of
philosophy rather than of method as any research method can provide both types of data
(Kaivo-oja, 2016; Makrakis & Kostoulas-Makrakis, 2016). The quantitative researchers
tend to support the logical positivist view of science, while qualitative researchers lean
towards the humanistic view (Bryman & Bell, 2015; Lunde, Heggen, & Strand, 2013;
Yilmaz, 2013). Methodological processes are numerous, diverse, and vulnerable to
methodological trade-offs and practical constraints (Kaivo-oja, 2016; Rosenthal, 2016).
Thus, various research questions with various levels of uncertainty require different
methods and lead to different results (Kaivo-oja, 2016; Yilmaz, 2013).
Researchers use the quantitative methodology to explain or describe a
phenomenon by using numerical information and statistical analysis; they specifically
emphasize quantification in the collection and analysis of data (Bryman & Bell, 2015;
Field, 2013; Makrakis & Kostoulas-Makrakis, 2016; Yilmaz, 2013). Quantitative method
is appropriate for the statistical confirmation of causal linkages among sets of accounting
information, business factors and financial success, management systems and
performance, and strategy and performance (Field, 2013; Makrakis & Kostoulas-
Makrakis, 2016). Wang and Sarkis (2013) effectively employed a quantitative
methodology to investigate the relationship between organizations’ environmental and

65
social supply chain activities and their financial performance. Jackson and Singh (2015)
conducted quantitative research to examine the financial-environmental performance of
organizations. Christoffersen, Frampton, and Granitz (2013) used a quantitative method
to investigate environmental sustainability’s impact on earnings. Wolf (2014) also used
the quantitative methodology to examine the relationship between sustainable SCM,
stakeholder pressure, and corporate sustainability performance.
Qualitative research would involve the exploration of human experience to
understand how people undergo and interpret phenomenon by emphasizing words rather
than quantification in the collection and analysis of data (Bryman & Bell, 2015; Field,
2013; Makrakis & Kostoulas-Makrakis, 2016; Yilmaz, 2013). A qualitative research
methodology allows the researcher an in-depth examination of the phenomenon through
non-numeric information, such as descriptions of behavior or the content of people’s
responses to interview questions (Field, 2013; Leedy & Ormrod, 2015; Makrakis &
Kostoulas-Makrakis, 2016; Yilmaz, 2013). Qualitative methodology is more suited for
answering how and why questions and for bringing meaning and understanding to the
research question, which comes from the context of human judgment (Makrakis &
Kostoulas-Makrakis, 2016; Rosenthal, 2016; Yilmaz, 2013). My research questions and
the associated hypotheses did not warrant such inquiry since the variables I examined are
numerical in nature.
A mixed methods approach also was not appropriate for this study. A mixed study
requires the collection of both qualitative and quantitative data. Researchers use it to
address a range of complex research questions demanding inductive and deductive

66
research logic in a more flexible, integrative, and holistic manner to create divergent
views and findings (Kaivo-oja, 2016; Mayoh & Onwuegbuzie, 2013; Makrakis &
Kostoulas-Makrakis, 2016; Venkatesh et al., 2013). I thus determined that the
quantitative method was the appropriate method for this study because the purpose of the
study was to analyze the relationship between the constructs-sustainable SCM,
stakeholder pressure, and corporate sustainability performance.
Research Design
A choice of research design reflects the priority given to a range of dimensions
such as expressing causal connections between variables, generalizing to larger groups,
and understanding of behaviors (Bryman & Bell, 2015). I followed a non-experimental,
correlational design for this study. Quantitative research methods are either experimental
or non-experimental (Imai, Tingley, & Yamamoto, 2013). Non-experimental research
predicts the relationship between variables and does not infer causation (Field, 2013).
Experimental designs involve the manipulation of treatments or intervention mechanisms
on one or more groups of subjects (Imai et al., 2013; Leedy & Ormrod, 2015).
Experimental and quasi-experimental designs are applicable when the research aim is to
assess uncontrollable environmental events or certain conditions when randomization is
not possible (Leedy & Ormrod, 2015; Rideout & Gray, 2013). Because I collected and
analyzed archival data, which did not involve intervention mechanisms, a non-
experimental design was appropriate for this research.
Correlation researchers examine the relationship between variables by
characterizing the nature and magnitude of the relationship between two quantitatively

67
coded variables (Cohen et al., 2013; Field, 2013). Correlation does not prove causation
while the absence of correlation implies the absence of the existence of a causal
relationship (Cohen et al., 2013; Field, 2013). The end goal of using correlational
research is to measure two or more variables and then to determine whether there are
statistically significant relationships between them (Leedy & Ormrod, 2015). The
correlation design was appropriate for this study because my aim was to predict the
relationship between the predictor constructs (sustainable SCM and stakeholder pressure)
and the dependent construct (corporate sustainability performance) and between the
predictor construct (sustainable SCM), the moderator and the mediator construct
(stakeholder pressure), and the dependent construct (corporate sustainability
performance).
Wang and Sarkis (2013) effectively used non-experimental design, specifically
multivariate regression analysis, to investigate the relationship between organizations’
environmental and social supply chain activities and their financial performance.
Christoffersen et al. (2013) used non-experimental multiple regression analysis to
investigate environmental sustainability’s impact on earnings. Mitra and Data (2014)
employed structural equation modeling analysis to examine the impact of green SCM
practices on corporate performance. Wolf (2014) also effectively employed non-
experimental design and conducted multiple linear regression analysis of the relationship
between sustainable SCM, stakeholder pressure, and corporate sustainability
performance. Similarly, I employed non-experimental, correlational design for this study.

68
Population and Sampling
The population for this study consisted of publicly listed global organizations
from different regions and a range of industries included in the Newsweek Green
Ranking 2016 Global 500 List (Newsweek, 2016). The publicly listed organizations
around the world are more likely to have extensive supply chains susceptible to resource
dependency and stakeholder pressure, incline to invest in sustainable initiatives, and tend
to have more established norms on social and environmental reporting (Mathiyazhagan et
al., 2014; Reilly & Hynan, 2014; Singal, 2013; Wang & Sarkis, 2013). Blazovich et al.
(2013) employed Newsweek’s green ranking list to examine financial performance and
risk of environmentally friendly green companies. Wang and Sarkis (2013) obtained a
sample from the top 500 US companies based on Newsweek’s green ranking to
investigate the relationship between organizations’ environmental and social supply chain
activities and their financial performance. Jackson and Singh (2015) also selected a
sample from Newsweek’s green ranking to examine the financial-environmental
performance of organizations in the US food and beverage supply chain. Because the
purpose of this study was to test the relationship between sustainable SCM, stakeholder
pressure, and corporate sustainability performance, it was appropriate to choose a sample
for the study from a population that consists of publicly listed global organizations
engaged in sustainable SCM.
Sampling is an important stage of an investigation, and often business research
involves convenience sampling to make use of the data collection opportunities that are
available (Bryman & Bell, 2015; Olsen, Orr, Bell, & Stuart, 2013). However, the

69
sampling principles employed in this study based on the concept that samples chosen
based on their appropriateness to the purpose of the research. For this study, I employed a
convenience sampling technique to collect the data. The convenience sampling, which
provides readily available and easily selected sample, was appropriate for this study
considering the research question and the needed data to fulfill the purpose of the
investigation (Field, 2013; Bryman & Bell, 2015; Leedy & Ormrod, 2015).
The convenience sampling allowed bridging this research with Wolf’s (2014)
study since this research built on Wolf’s study. Wolf also employed readily available and
easily selected sample from Sustainalytics database to examine the relationship between
sustainable SCM, stakeholder pressure, and corporate sustainability performance. Golini,
Longoni, and Cagliano (2014) employed the convenience sampling in investigating the
role of site competence on sustainability performance. Gao and Bansal (2013) examined
the integration of social and environmental aspects of business operations with corporate
financial performance. Gao and Bansal used convenience sampling in obtaining social
and environmental performance data of organizations from Kinder, Lydenberg, and
Domini & Co. (KLD) and matching financial data from Compustat and CRSP. However,
a convenience sampling is a form of non-probability sampling where some members of
the population have little or no chance of being sampled, which reduces the probability of
presenting each element of the population (Leedy & Ormrod, 2015).
In selecting the sample, availability of the organizations’ historical data was the
focal criteria to eliminate a year- specific occurrence. Changes in organizations effects
cannot be detected reliably over a short period to evaluate the true long-term benefits of

70
sustainable practices (Gao & Bansal, 2013; Wang & Sarkis, 2013). The use of historical
data increases the probability of stable findings. Three-year data period is also a
limitation for an extensive time study (Wang & Sarkis, 2013). Wang and Sarkis
investigated the relationship between sustainable SCM and corporate financial
performance. Wang and Sarkis (2013) used three-year data period in obtaining a sample
from Bloomberg ESG and Compustat databases. Singal (2013) used historical data from
1991 through 2011 from MSCI’s ESG database and S&P Compustat in investigating the
link between firm financial performance and investment in sustainability initiatives. Gao
and Bansal (2013) also obtained social and environmental performance data of
organizations from KLD, which covers a wide period. Gao and Bansal examined the
integration of social and environmental aspects of business operations with corporate
financial performance. Thus, I also used historical data in this study. Sustainalytics ESG
data set consist of historical data from 2009 through 2016 that provides ESG scores of
4500 analyzed global organizations (Sustainalytics, 2016). S&P Compustat provides
historical and current credit ratings of organizations across the world (Singal, 2013).
Since the population is heterogeneous, a larger sample is necessary (Leedy &
Ormrod, 2015; Wilson et al., 2014). In investigating the relationship between sustainable
SCM and corporate financial performance, Wang and Sarkis (2013) analyzed 411
organizations that are cross-listed in three years’ rankings in Bloomberg and Compustat
databases, which also contain all elements of the social, environmental, and financial
data. Singal (2013) analyzed 624 industry specific organizations identified through the
intersection of KLD ESG data and S&P credit ratings in examining the link between firm

71
financial performance and investment in sustainability initiatives. Wolf (2014) analyzed
the relationship between sustainable SCM, stakeholder pressure, and corporate
sustainability performance with the sample of 1,621 organizations included in the
Sustainalytics database. While the sample was limited to the availability of data from
Sustainalytics and S&P Compustat, where I collected the archival data, these databases
allowed obtaining a significant sample size (Singal, 2013; Wang & Sarkis, 2013; Wolf,
2014). If the sample size is too large, the validity threat may occur (Hopkins & Ferguson,
2014). Too large sample may cause type III error that represents statistically significant
result with no meaningful practical implication (Hopkins & Ferguson, 2014). G*Power
software was employed to determine the appropriate sample size for the study.
To compute the minimum required sample size, I used the main statistical test
along with four parameters: (a) effect size, (b) level of significance, (c) power, and (d)
number of predictors. The basis for the sample size calculation is the effect size (Field,
2013; Hopkins & Ferguson, 2014; Leedy & Ormrod, 2015). Effect size is a quantitative
reflection of the magnitude of a phenomenon, such as the relationship between
independent variables, moderators and/or mediators, and a dependent variable that can be
measured in terms of the strength of the relationship, which is used for the purpose of
addressing a question of interest (Cohen et al., 2013; Leedy & Ormrod, 2015). For effect
size, a medium effect size (0.15) was used as suggested by Cohen (1992) based on his
experience. The level of significance is 0.05. With alpha level 0.05, it is easier to reject
null hypothesis than when it is 0.01. The power is 0.80, which is appropriate in
calculations of a suitable sample size to have a high probability of obtaining a statistically

72
significant result (Field, 2013). The maximum number of predictors is six, which
includes three variables (three for both sustainable SCM composite variable and
stakeholder pressure composite variable), two control variables (industry and
organizational size), and a moderating or a mediating variable. Using the parameters
above, the computed minimum required sample size necessary to achieve a given level of
0.80 power is 98 samples. Increasing the sample size to 194 increases the power of the
statistical test to 0.99. Statistical power allows detecting an effect, to maximize the
chances that a given test will find an effect if the effect is present, or to ensure that a
negative finding is a strong ground for believing that there is no significant difference
(Field, 2013; Heyvaert & Onghena, 2014; Hopkins & Ferguson, 2014). Statistical power
increases the probability of correct conclusions about the null hypothesis (Field, 2013;
Hopkins & Ferguson, 2014). As such, I obtained data from 164 organizations for the
research. Larger samples have more power to detect effects (Field, 2013; Hopkins &
Ferguson, 2014; Wilson et al., 2014).
Ethical Research
It is important to acknowledge that a researcher takes responsibility to the people
and organizations that are the recipients of the research activities (Bryman & Bell, 2015;
Field, 2013; Leedy & Ormrod, 2015; Wilburn & Wilburn, 2013). In order to conduct
ethical research, I followed ethical principles of the Belmont Report to guide the
research. The most applicable principle of the Belmont Report to this study is risk/benefit
assessment principle to the conduct of research. Following the assessment of risks and
benefits principle, I carefully managed the gathering of systematic and comprehensive

73
information about the proposed research. Also, I ensured that the proposed research was
properly designed (see U.S. Department of Health & Human Services, 2015). In
Appendix A presented my National Institutes of Health (NIH) certificate of completion of
the Protecting Human Research Participants course. The data for the research were
archival and available publicly and upon request. According to the Global Reporting
Initiative, a non-profit organization that promotes economic, environmental, and social
sustainability and regarded as the global standard, electronic or web-based reporting is
appropriate and acceptable for reporting company information (Fernandez-Feijoo,
Romero, & Ruiz, 2014; Hahn & Kühnen, 2013; Wilburn & Wilburn, 2013). Thus, I did
not provide informed consent as this research according to the principles of The Belmont
Report did not affect adversely the rights and welfare of the research participants and
involved no more than minimal risk (see U.S. Department of Health & Human Services,
2015, CFR 46.116). However, as a researcher, I still ensured confidentiality and
anonymity of the gathered data (Ippoliti, 2015; see U.S. Department of Health & Human
Services, 2015, CFR 46.116; Wilburn & Wilburn, 2013). I obtained approval from the
Institutional Review Board (IRB), which determines the acceptability of the proposed
research in terms of institutional commitments and regulations, applicable law, and
standards of professional conduct and practice, before gathering the data (Ippoliti, 2015;
Leedy & Ormrod, 2015; U.S. Department of Health & Human Services, 2015, 45 CFR
46.107). The IRB approval number is 12-22-16-0442285.
After gaining approval from the IRB, I proceeded to access data from
Sustainalytics and S&P’s for the sustainable SCM, stakeholder pressure, and corporate

74
sustainability performance variables, as well as for the control variables of industry and
number of employees. The Statistical Package for the Social Sciences (SPSS) v.21
software was appropriate for entering data for storage and data analysis after gathering
the data. I employed combined IDs of the organizations assigned by Sustainalytics as the
reference numbers for individual identification. The data were stored in a password-
protected computer file with no paper copies of the data to maintain confidentiality. After
the completion of the study, I stored the electronic data in secure personal files in my
home office for five years and after which the data will be deleted from the USB flash
drive.
Data Collection Instruments
The data collection involves gathering data from the sample to answer the
research question (Bryman & Bell, 2015). To gather the needed data, I did not use any
survey instrument as the data were archival and were obtained from databases hosted by
Sustainalytics and S&P’s. Relying on electronic or web-based nongovernmental reporting
and/or corporate annual reports is appropriate and acceptable according to the Global
Reporting Initiative (Wilburn & Wilburn, 2013).
Wang and Sarkis (2013) employed archival data, specifically Bloomberg ESG
and Compustat financial databases, to investigate the relationship between organizations’
environmental and social supply chain activities and their financial performance. Singal
(2013) used archival data from MSCI’s ESG database and credit ratings from S&P’s to
examine the link between investment in sustainability initiatives and firm financial
performance. Jackson and Singh (2015) used Compustat financial database and

75
Newsweek’s green ranking to examine the financial-environmental performance of
organizations. Wolf (2014) also effectively employed Sustainalytics ESG database in
investigating the relationship between sustainable SCM, stakeholder pressure, and
corporate sustainability performance. While S&P’s Compustat is an archival database
containing data on corporate financial performance, there are a few ESG archival
databases providing data on corporate environmental and social performance. However,
for this research, I obtained ESG data from Sustainalytics to bridge this research with
Wolf’s (2014) study, as this study built on Wolf’s suggestion to test further whether
corporate sustainability performance measured by the economic dimension of
sustainability is affected by sustainable SCM and stakeholder pressure. Besides,
Newsweek and Bloomberg ESG data scores are based on Sustainalytics ESG database
since they are collaborating (Jackson & Singh, 2015).
The Sustainalytics ESG scores of organizations built on the wide range of issues
related to corporate social and environmental performance, which are the key sources of
this study’s environmental and social data corresponding with independent, moderating,
and mediating composite variables, sustainable SCM and stakeholder pressure (Gao &
Bansal, 2013). Sustainalytics’ analysts compile data of the organizations using various
sources including financial accounts, organizational documentation, databases, media
reports, as well as stakeholder interviews. Sustainalytics then sends the initial
compilations to the organizations for revisions, corrections, and/or changes, after which,
these changes verified again by Sustainalytics’ analysts (Sustainalytics, 2016; Wolf,
2014). The data from Sustainalytics, an independent ESG research and analysis provider

76
with substantial experience and expertise in evaluating the ESG performance of publicly
traded corporations, are not as susceptible to social desirability bias as compared to data
gathered from surveys. Thus, the data assumed to be valid and reliable (Wolf, 2014).
A long-term issuer credit rating assigned to an organization by S&P’s is the
measure of the dependent variable, corporate sustainability performance. The long-term
issuer credit rating built on the data beyond publicly available information. The issuer
credit rating is a forward-looking opinion of obligor's overall creditworthiness
considering the obligor's capacity and willingness to meet its financial commitments as
they come due (Standard & Poor’s, 2016). S&P’s has obtained information from sources
it believes to be reliable (Singal, 2013; Standard & Poor’s, 2016).
The ESG and S&P’s databases contain data necessary to test the employed theory
and the set of hypotheses, including the addition of control, moderator, and mediator
variables (Singal, 2013; Wang & Sarkis, 2013; Wolf, 2014). The raw data were archival.
The credit ratings were available publicly from S&P’s database, and ESG data were
available upon request from Sustainalytics. Overall, several researchers such as Singal
(2013), Wang & Sarkis (2013), Christoffersen et al. (2013), Gao and Bansal (2013),
Gregory and Whittaker (2013), Wolf (2014), and Jackson and Singh (2015) effectively
employed archival ESG and financial databases in quantitative analysis related to
corporate sustainability performance.
The ESG and S&P’s data measures accurately captured and defined the targeted
variables increasing the validity and reliability properties (Singal, 2013; Wang & Sarkis,
2013; Wolf, 2014). The variables were sustainable SCM (composite variable),

77
stakeholder pressure (composite variable), and corporate sustainability performance.
Each of these composite variables (sustainable SCM and stakeholder pressure) is a
characteristic in the study that has three possible values (Leedy & Ormrod, 2015). The
sustainable SCM variable was composed of three variables, which were: (a) social supply
chain standards, (b) supply chain monitoring systems, (c) and green procurement
(Sustainalytics, 2016; Wolf, 2014). The stakeholder pressure variable was composed of
three variables, which were: (a) social supply chain related issues and controversies, (b)
operations and product related issues and controversies, and (c) environmental supply
chain related issues and controversies (Sustainalytics, 2016; Wolf, 2014). The corporate
sustainability performance represented by the economic dimension of corporate
sustainability performance was measured by a long-term issuer credit rating (Goyal et al.,
2013; Singal, 2013).
In studying the relationship between one or more factors of interest and an
outcome variable, there are usually other variables such as control variables, whose
effects also significant (Cohen et al., 2013; Sebastianelli et al., 2015). In the study, I
considered industry and organizational size measured by a number of employees as
control variables. Wang and Sarkis (2013) considered industry and a size of an
organization as control variables in investigating the relationship between sustainable
SCM and corporate financial performance. Ramanathan et al. (2014) acknowledged the
effect of industry and an organizational size in examining the impact of organizational
pressures on the environmental performance of firms. Wolf (2014) employed industry
and an organizational size as control variables in examining the relationship between the

78
sustainable SCM, stakeholder pressure, and corporate sustainability performance. Powell
and Eddleston (2013) also employed organizational size and industry among other
control variables in the hierarchical regression analysis of entrepreneurial success
assessed by economic measures.
The sustainable SCM composed of: (a) social supply chain standards, (b) supply
chain monitoring systems, and (c) green procurement (Sustainalytics, 2016; Wolf, 2014).
The three sustainable SCM variables are continuous variables, which are indicators of the
respective issues (social supply chain standards, supply chain monitoring systems, and
green procurement) (Sustainalytics, 2016; Wolf, 2014). The stakeholder pressure
composed of: (a) social supply chain related issues and controversies, (b) operations and
product related issues and controversies, and (c) environmental supply chain related
issues and controversies (Sustainalytics, 2016; Wolf, 2014). The three stakeholder
pressure variables are continuous variables, which are indicators of the respective issues
and controversies (social supply chain, operations and product, and environmental supply
chain) that assess the degrees of control and the quality of preventive steps by the
organization for their respective issues (Sustainalytics, 2016; Wolf, 2014). A long-term
issuer credit rating was a measure of the economic dimension of sustainability, which is a
continuous variable. The economic dimension of sustainability represented corporate
sustainability performance.
A continuous variable offers a score and represents an unlimited number of
possible values falling along a particular continuum (Field, 2013; Leedy & Ormrod,
2015). The control variables are a continuous variable-number of employees and a

79
categorical variable-industry. A categorical variable names distinct entities (Field, 2013).
I collected the data for the control variables from corporate annual reports and
Sustainalytics. Appendix B includes information on all items and their definitions.
Data Collection Technique
For this study, I collected data from existing sources such as secondary data
gathered by Sustainalytics, S&P’s, Newsweek, and corporate annual reports.
Sustainalytics data were available upon request by visiting the company’s website.
S&P’s, Newsweek, and corporate annual reports were publicly available to access
through the Internet through their websites (Singal, 2013; Sustainalytics, 2016; Wolf,
2014).
Blazovich et al. (2013) employed Newsweek’s green ranking list to examine
financial performance and risk of environmentally friendly green companies. Wang and
Sarkis (2013) obtained a sample from the top 500 US companies based on Newsweek’s
green ranking to investigate the relationship between organizations’ environmental and
social supply chain activities and their financial performance. Wang and Sarkis (2013)
also employed Bloomberg ESG database and Compustat financial database to conduct
the study. Jackson and Singh (2015) used Compustat financial database and Newsweek’s
green ranking to examine the financial-environmental performance of organizations.
Singal (2013) used data from MSCI’s ESG database and credit ratings from S&P’s to
examine the link between investment in sustainability initiatives and firm financial
performance. Wolf (2014) also effectively employed Sustainalytics ESG database in

80
investigating the relationship between sustainable SCM, stakeholder pressure, and
corporate sustainability performance.
While S&P’s Compustat is the widely used archival database containing data on
corporate financial performance, there were a few ESG archival databases providing data
on corporate environmental and social performance. However, for this research, I
obtained ESG data from Sustainalytics to bridge this research with Wolf’s (2014) study,
as this study built on Wolf’s suggestion to test further whether corporate sustainability
performance measured by the economic dimension of sustainability is affected by
sustainable SCM and stakeholder pressure. Besides, Newsweek and Bloomberg ESG data
scores are based on Sustainalytics ESG database since they are collaborating (Jackson &
Singh, 2015).
Strand (2014) in analyzing the strategic leadership of corporate sustainability used
a combination of data that included publicly available information such as corporate
websites and corporate annual reports. Peters and Romi (2014) gathered sustainability
data of organizations from company websites and corporate annual reports. Kurapatskie
and Darnall (2013) also collected data from corporate annual reports to investigate
corporate sustainability activities associated with greater financial payoffs. Thus, I used
corporate annual reports to collect data for the control variable, which is an
organizational size measured by a number of employees.
Sustainalytics provides ESG data set for the independent composite variables, the
moderating composite variable, and the mediating composite variable (sustainable SCM
and stakeholder pressure) in the study (Sustainalytics, 2016). The preliminary step was

81
taken to gain access to ESG archival data by contacting Sustainalytics. A brief proposal
submitted for review by gatekeepers was accepted. Sustainalytics assigned a Responsible
Investment and Institutional and Relations advisor to assist in providing the data for the
study. Sustainalytics made available an example of the data. After gaining IRB approval,
which determines the acceptability of the proposed research regarding institutional
commitments and regulations, applicable law, and standards of professional conduct and
practice, I requested the data from Sustainalytics (see Ippoliti, 2015; see U.S. Department
of Health & Human Services, 2015, 45 CFR 46.107). I transferred the data into the
Statistical Package for the Social Sciences (SPSS) v.21 software for storage and data
analysis (Field, 2013; Leedy & Ormrod, 2015).
A long-term issuer credit rating of an organization (a variable representing the
economic dimension of corporate sustainability performance) gathered through publically
available S&P’s Rating Services website, which provides credit ratings of thousands of
global companies organized by industry (Singal, 2013; Standard & Poor’s, 2016; Wang
& Sarkis, 2013). The data for the control variables were archival as well. I collected the
data for the industry variable from Sustainalytics ESG dataset along with ESG data and
the number of employees from the publicly available corporate annual reports, which are
accessible through the Internet browser. The collected data for dependent and control
variables were also entered into the Statistical Package for the Social Sciences (SPSS)
v.21 software for storage and data analysis (Field, 2013; Leedy & Ormrod, 2015). Global
manufacturing organizations with the most sustainable practices were identified through
the Newsweek Green Rankings 2016 Global 500 List, which was the publicly available

82
information and accessible through the Newsweek website (Newsweek, 2015; Wang &
Sarkis, 2013).
Relying on electronic or web-based nongovernmental reporting and/or corporate
annual reports was appropriate and acceptable according to the Global Reporting
Initiative (Wilburn & Wilburn, 2013). The advantages of utilizing secondary data
services are saving time and costs of acquiring information. However, a disadvantage of
using the secondary data as the sole source of information is that the data may not meet
the specific needs of the research. In this study, despite the data being archival, it was the
most appropriate and reliable data for investigating the particular problem in the study.
The data obtained from Sustainalytics and S&P’s accurately captured and defined the
targeted variables increasing the validity and reliability properties (Singal, 2013; Wang &
Sarkis, 2013; Wolf, 2014). Collecting such specific valid data would have been beyond
the grasp of an individual researcher (Wolf, 2014).
Data Analysis
The data analysis stage incorporates several elements such as the management,
analysis, and interpretation of the data, which requires the application of statistical
techniques to the collected data to reduce the large corpus of gathered information by
producing tables or averages so the researcher can make sense of it (Bryman & Bell,
2015). The research questions and formulated hypotheses were:
Research Question 1: What is the relationship between sustainable SCM and
corporate sustainability performance, while controlling for industry and organizational
size?

83
Research Question 2: What is the relationship between stakeholder pressure and
corporate sustainability performance, while controlling for industry and organizational
size?
Research Question 3: What is the relationship between sustainable SCM,
stakeholder pressure as a moderator, and corporate sustainability performance, while
controlling for industry and organizational size?
Research Question 4: What is the relationship between sustainable SCM,
stakeholder pressure as a mediator, and corporate sustainability performance, while
controlling for industry and organizational size?
H
0
1: There is no statistically significant relationship between sustainable SCM
and corporate sustainability performance while controlling for industry and
organizational size.
H
1
1: There is a statistically significant relationship between sustainable SCM and
corporate sustainability performance while controlling for industry and organizational
size.
H
0
2: There is no statistically significant relationship between stakeholder pressure
and corporate sustainability performance while controlling for industry and
organizational size.
H
1
2: There is a statistically significant relationship between stakeholder pressure
and corporate sustainability performance while controlling for industry and
organizational size.

84
H
0
3: There is no statistically significant relationship between sustainable SCM,
stakeholder pressure as a moderator, and corporate sustainability performance while
controlling for industry and organizational size.
H
1
3: There is a statistically significant relationship between sustainable SCM,
stakeholder pressure as a moderator, and corporate sustainability performance while
controlling for industry and organizational size.
H
0
4: There is no statistically significant relationship between sustainable SCM,
stakeholder pressure as a mediator, and corporate sustainability performance while
controlling for industry and organizational size.
H
1
4: There is a statistically significant relationship between sustainable SCM,
stakeholder pressure as a mediator, and corporate sustainability performance while
controlling for industry and organizational size.
Each of these hypotheses proposes some form of relationship between the
independent composite variables, the moderating and the mediating composite variable,
and the dependent variable, where testing of the hypotheses involved building statistical
models of the phenomenon of interest (Cohen et al., 2013; Field, 2013). A researcher’s
task is to develop a statistical model based on the data that will accurately estimate how
the variables of interest are related to one another and then conduct inference-making
procedures (Cohen et al., 2013; Field, 2013; Grange et al., 2016). Many statistical
techniques are available suitable for addressing different purposes, different questions,
and particular sets of data; however, it is essential for a researcher to understand the
foundational requirements (Grange et al., 2016; Hopkins & Ferguson, 2014; Leedy &

85
Ormrod, 2015). In this study, I relied on the purpose of the research and on the types of
variables under the investigation in choosing the appropriate technique.
Nonparametric techniques designed for simple statistical analyses of problems
that include one or more variables measured on a nominal or an ordinal scale (Green &
Salkind, 2014; Leedy & Ormrod, 2015). Because research question calls for a
sophisticated analysis with underlying assumptions about the nature of the data,
parametric statistical procedures were the only viable option (Leedy & Ormrod, 2015).
The parametric statistical techniques also vary in their purpose. For instance, t-Test
techniques are applied to address research problems that involve a single sample, paired
samples, or two independent samples to compare whether statistical differences exist
between two groups. Univariate and multivariate analyses of variance techniques such as
ANOVA are designed to assess the relationship of one or more factors with a dependent
variable or with multiple dependent variables in experimental, quasi-experimental,
longitudinal, and field studies (Green & Salkind, 2014). The purpose of this study was to
determine the relationships between the constructs, rather than compare differences
between groups. Consequently, the use of analysis of variance was unlikely to produce
unbiased estimates.
Among the most sophisticated parametric statistical techniques are such analyses
as regression and structural equation modeling (SEM). SEM technique allows to examine
the correlations among a number of variables and often with different variables measured
for a single group of people at different points in time. Regression analyses allow
examining how accurately one or more variables enable predictions regarding the values

86
of another variable (Field, 2013; Leedy & Ormrod, 2015). Thus, among the many
commonly used parametric and nonparametric statistical techniques for testing
hypotheses, the most suitable technique for this study that allows to estimate unbiased
effects was a multivariable technique-multiple regression analysis concerned with the
statistical analysis of the relationships when at least three variables are involved (Field,
2013; Khademi, Jamal, Deshpande, & Londhe, 2016; Leedy & Ormrod, 2015; Silhavy,
Silhavy, & Prokopova, 2016).
Christoffersen et al. (2013) employed multiple regression analysis in investigating
the environmental sustainability’s impact on earnings. Singal (2013) used multivariate
regression analysis in examining the link between investment in sustainability initiatives
and firm financial performance. Golini et al. (2014) employed multiple linear regression
analysis in investigating the role of site competence on sustainability performance. Golini
et al. adopted three regression models, including a mediating model to measure the effect
of the variables. Wolf (2014) also used multiple regression analysis in examining the
relationship between sustainable SCM, stakeholder pressure, and corporate sustainability
performance. Wolf conducted three sets of regression analysis corresponding to three
competing research models (direct effects model, moderation model, and mediation
model). Powell and Eddleston (2013) employed hierarchical regression analysis in
studying entrepreneurial success assessed by economic measures.
Hierarchical multiple regression analysis, which I used to address all the
hypotheses, most appropriately addressed the purpose of the study and the types of data
for which the problem called (Hopkins & Ferguson, 2014; Leedy & Ormrod, 2015).

87
Regression analysis is a highly general and flexible data analytics system with the
capabilities to assist in invalidating causal alternatives, choosing between competing
theories, and disentangling multiple influences (Cohen et al., 2013; Field, 2013; Hopkins
& Ferguson, 2014; Leedy & Ormrod, 2015). The generality, capacity, and flexibility of
the regression analysis allow to use information in almost any form and to mix forms as
necessary (Cohen et al., 2013; Field, 2013; Hopkins & Ferguson, 2014). Regression
analysis applies to hypotheses generated by researchers in various disciplines, including
business, and from a variety of research areas including previous research (Cohen et al.,
2013). Multiple regression techniques appropriately address the complexity of the
relationships between sustainable SCM, stakeholder pressure, and corporate sustainability
performance. The technique allows developing statistical models to test the hypotheses,
to rule out competing explanations, and to detect relationships that may be present in the
data (Cohen et al., 2013; Hopkins & Ferguson, 2014). Multiple regression analyses allow
determining if one or more variables are statistically significant predictors of a criterion
variable (Field, 2013; Green & Salking, 2014). Linear regression techniques in
particularly have wide applicability, can be the most straightforward to implement, and
offer complex statistical procedures (Hopkins & Ferguson, 2014).
Multiple regression analysis, specifically hierarchical regression analysis, was the
appropriate statistical technique to address all four research questions and their respective
hypotheses since each of the four research questions involved determining the
relationship between the independent composite variables with the continuous variables,
the moderating and mediating composite variables with the continuous variables, and the

88
dependent continuous variable, while controlling for industry and organizational size
(Hopkins & Ferguson, 2014). Industry and organizational size are control variables.
Control variables are variables that may affect the relationship but have no major interest
in the study (Hopkins & Ferguson, 2014). Hierarchical regression analysis is an advanced
approach in which the researcher enters the predictors into the model in a specific order
based on the theoretical explanations, which allows determining the predictive power of
each variable (Field, 2013; Hopkins & Ferguson, 2014; Wilson et al., 2014). Hierarchical
regression technique commonly used to evaluate the impact of moderating, mediating,
and control variables in predictive models (Hopkins & Ferguson, 2014). Hierarchical
analysis can be used for business research topics (Hopkins & Ferguson, 2014).
To address the first and second hypotheses, I used a hierarchical multiple linear
regression analysis. The independent variables of sustainable SCM, which is a composite
variable, were: (a) social supply chain standards, (b) supply chain monitoring systems,
and (c) green procurement (Hypothesis 1). The dependent variable was a long-term issuer
credit rating, and the control variables were industry and organizational size measured by
a number of employees. The independent variables of stakeholder pressure, which is
composite variable, were: (a) social supply chain related issues and controversies, (b)
operations and product related issues and controversies, and (c) environmental supply
chain related issues and controversies (Hypothesis 2). The dependent variable was a long-
term issuer credit rating, and the control variables were industry and organizational size
measured by a number of employees.

89
To address the third hypothesis, I used a moderated multiple linear regression
analysis. The independent composite variable of hypothesis 3 was sustainable SCM,
which represented the composite assessment of sustainable SCM measured by
Sustainalytics dimensions of: (a) social supply chain standards, (b) supply chain
monitoring systems, and (c) green procurement. The moderation variable of hypothesis 3
was stakeholder pressure, which represented the composite assessment of stakeholder
pressure measured by Sustainalytics dimensions of: (a) social supply chain related issues
and controversies, (b) operations and product related issues and controversies, and (c)
environmental supply chain related issues and controversies. The dependent variable was
corporate sustainability performance measured by S&P a long-term issuer credit rating.
The control variables were industry and organizational size measured by a number of
employees.
To address the fourth hypothesis, I used mediated multiple linear regression
analysis. The independent composite variable of hypothesis 4 was sustainable SCM,
which represented the composite assessment of sustainable SCM measured by
Sustainalytics dimensions of: (a) social supply chain standards, (b) supply chain
monitoring systems, and (c) green procurement. The mediation variable of hypothesis 4
was stakeholder pressure, which represented the composite assessment of stakeholder
pressure measured by Sustainalytics dimensions of: (a) social supply chain related issues
and controversies, (b) operations and product related issues and controversies, and (c)
environmental supply chain related issues and controversies. The dependent variable was
corporate sustainability performance measured by S&P a long-term issuer credit rating.

90
The control variables were industry and organizational size measured by a number of
employees.
Multiple regression models effectively address the complexity and variety of
relationships where independent variables may be expected to influence the dependent
variable, independent variables themselves may be related, and the independent variables
may take different forms; therefore allowing to assess unique or partial relationships
(Cohen et al., 2013; Hopkins & Ferguson, 2014). According to the hypotheses 3 and 4,
the independent composite variable, stakeholder pressure, takes a form of a moderating
and a mediating variable. A moderating variable influences the nature and strength of a
correlational relationship between an independent variable and a dependent variable
(Field, 2013; Leedy & Ormrod, 2015). A mediating variable, known as an intervening
variable, comes between two other variables in a casual chain and might help explain
why a certain independent variable has the effect that it does on a dependent variable
(Field, 2013; Leedy & Ormrod, 2015). Including such factors in the study as mediators,
moderators or control variables would help improve the confidence in the results
(Hopkins & Ferguson, 2014).
I employed SPSS v.21 software to perform all statistical analysis. SPSS statistical
software package is available for use on a personal computer, extremely efficient as data
can be downloaded directly into the software package, and includes a wide variety of
statistical procedures that can handle large data sets, multiple variables, and missing data
points (Field, 2013; Leedy & Ormrod, 2015; Wilson et al., 2014). After obtaining the
data required, I transferred the data to the SPSS v.21 program. Before conducting any

91
statistical tests, filtering out entries that have missing data/responses (information not
available for a participant) on at least one variable cleans the data (Field, 2013).
Cleaning the data using this method ensured that all statistical analyses received the same
sample size without missing data. Sustainalytics and S&P extensive data sets allow
choosing a sample from organizations with no missing data. Sustainalytics ESG data set
consist of historical data from 2009 through 2016 that provides ESG scores of 4,500
analyzed global organizations (Sustainalytics, 2016). S&P’s Compustat provides
historical and current credit ratings of organizations across the world (Singal, 2013).
Based on the computation of the minimum required sample size, the minimum sample
size was 98 organizations. Taking the mean of the non-missing items for computing total
scores also was a possible option to address the missing data points (Green & Salkind,
2013).
For instance, Jackson and Singh (2015), Kam-Sing Wong (2014), Roh et al.
(2014), Shokri et al. (2016), and Tlapa, Limon, García-Alcaraz, Baez, and Sánchez
(2016) employed SPSS application to conduct a variety of statistical procedures related to
the processing large data sets, multiple variables, missing data points, statistical model
tests, assumption violation tests, and data analysis. Jackson and Singh (2015) employed
SPSS in examining the financial-environmental performance of organizations. Kam-Sing
Wong (2014) employed SPSS to examine the relationship between the innovativeness,
proactiveness, and risk-taking and new product success. Roh et al. (2014) used SPSS in
analyzing the key variables relevant to the implementation of a successful responsive

92
supply chain. In following earlier works, Shokri et al. (2016) and Tlapa et al. (2016) also
used SPSS to investigate relationships among constructs in the manufacturing sector.
In SPSS, if data collected using nonexperimental methods, independent and
dependent variables in a regression analysis are frequently called a predictor and a
criterion, which I used in the data analysis and the presentation of the findings (Green &
Salkind, 2013). Considering the nonexperimental design of the study and quantitative
nature of both independent and dependent variables certain assumptions pertaining to the
statistical analyses were applicable (Field, 2013; Green & Salkind, 2013). The violation
of assumptions, which is the source of bias, is preventable by conducting a test of
statistical model assumption (Field, 2013; Hopkins & Ferguson, 2014). SPSS features
allow assessing the assumptions of regression and the consequences of violating these
assumptions. A violation of the assumptions lead to inaccurate test statistic and p-value
and wrong conclusions such as Type I (falsely rejecting the null hypothesis) or Type II
(incorrectly failing to reject the null hypothesis) errors (Becker, Rai, Ringle, & Völckner,
2013; Field, 2013; Hopkins & Ferguson, 2014).
The statistical assumptions underlying the significance test for the multiple
correlation coefficients are:
Assumption 1: The variables are multivariatly normally distributed in the
population (Green & Salkind, 2013; Hopkins & Ferguson, 2014). According to the
assumption, normally distributed variables are ignoring the other variables at every
combination of values of the other variables (Green & Salkind, 2013). The assumption of
normality is important in small samples when constructing confidence intervals around

93
parameters of a statistical model or computing significant tests related to the parameters
(Field, 2013; Lomax & Hahs-Vaughn, 2013). I conducted a test for normality of residuals
using SPSS v.21 software to determine if the residuals appear to conform to the
assumption of being normally distributed. If the multivariate normality assumption met,
the only type of statistical relationship that can exist between the variables is a linear one.
The non-linear relationship might be present if the assumption of multivariate normality
violated (Lomax & Hahs-Vaughn, 2013).
Accordingly, it is important to assess whether non-linear relationships exist
between the predictors and the criterion. Histograms and scatterplots between the each
predictor and the criterion and as well partial regression plots were analyzed to diagnose
problems of non-linearity (Green & Salkind, 2013; Hopkins & Ferguson, 2014; Lomax &
Hahs-Vaughn, 2013). A moderate violation of the assumption may cause minimal effect,
and a severe violation may reduce the power of statistical tests (Green & Salkind, 2013;
Lomax & Hahs-Vaughn, 2013). The violation of the normality assumption requires the
elimination of outlying cases and data transformation (Field, 2013; Hopkins & Ferguson,
2014; Lomax & Hahs-Vaughn, 2013).
Assumption 2: The cases represent a random sample from the population, and the
scores on variables are independent of other scores on the same variables (Green &
Salkind, 2013; Hopkins & Ferguson, 2014). If the independence assumption violated,
ignoring the dependency of the scores on variables can lead to invalid statistical
conclusions as the F ratio is very sensitive to violation of the independence assumption in
terms of increased likelihood of Type I and/or Type II error in the F-statistic, which is

94
likely to increase with larger samples (Green & Salkind, 2013; Hopkins & Ferguson,
2014; Lomax & Hahs-Vaughn, 2013). Consequently, the F test regression analyses yield
inaccurate p-values (Green & Salkind, 2013). Thus, the violation of the independence
assumption leads to invalid confidence intervals and significant tests (Fields, 2013). The
independence assumption was assessed by conducting the Durbin-Watson statistic and by
examining residual plots (Hopkins & Ferguson, 2014; Lomax & Hahs-Vaughn, 2013). If
the assumption is not satisfied, special methods, such as generalized estimating equations
(GEE) approach for analyzing correlated response data, can be used to find the best-
fitting model and to make valid statistical inferences. The method chosen depends on the
response variable, the type of dependence, and the complexity of the problem (Field,
2013).
A confidence interval of 95% was selected, as it usually set, where a predictor
considered statistically significant if the significance value (p-value) is 0.05 or lower, and
thus is the criteria for rejecting or accepting the null hypothesis (Hopkins & Ferguson,
2014). The confidence interval is a range of values that represents the population
parameter (Field, 2013; Hopkins & Ferguson, 2014). A p-value describes the statistical
significance of the data and statistical significance provides information about whether
the relationship exists at all (Cohen et al., 2013). I investigated the beta coefficient of the
regressions (where it was applicable) to determine the strength of the predicting power of
the independent composite variables on the dependent variable (see Hopkins & Ferguson,
2014).

95
Study Validity
The most important step in a study is an assessment of validity to ensure the
integrity of the conclusions generated from the research (Bryman & Bell, 2015; Field,
2013; Hopkins & Ferguson, 2014; Yilmaz, 2013). Validity, which takes on many
different forms, is the extent to which an outcome accurately answers the research
question (Field, 2013; Neall & Tuckey, 2014; Yilmaz, 2013). Any condition that
compromises the validity of the research is known as a threat (Neall & Tuckey, 2014).
While the assessment of the validity represents a continuous, iterative, holistic, and
synergistic process, in nonexperimental quantitative research, it is especially important to
be aware of statistical conclusion validity (SCV) and external validity (Becker et al.,
2013; Bryman & Bell, 2015).
SCV, which applies to all research within quantitative methods, is the extent to
which the statistical relationship between the variables is accurate (Becker et al., 2013;
Brutus, Aguinis, & Wassmer, 2013; Neall & Tuckey, 2014). A violation of SCV occurs if
the data not subjected to adequate statistical analyses or when the researcher loses control
of Type I or Type II errors (Becker et al., 2013; Field, 2013; Leedy & Ormrod, 2015). In
nonexperimental research, violating a threat to SCV results in the overestimation or
underestimation of the relationship between variables (Becker et al., 2013; Neall &
Tuckey, 2014). The threats to SCV of the study were assumption violation of statistical
tests, low statistical power, and unreliability of the measures (Becker et al., 2013; Field,
2013; Hopkins & Ferguson, 2014; Neall & Tuckey, 2014).

96
The assumption violation of statistical tests, depending on the extent of the
violation, can lead to overestimation or underestimation of the practical and statistical
significance of an outcome (Becker et al., 2013). I tested the assumptions underlying
statistical tests to guide the choice of suitable statistical analysis for the null hypotheses
of interest. However, the testing of assumptions first to control Type I error and
subsequently testing the null hypotheses of interest may cause severe effects on Type I
and Type II error rates and a breach of SCV (Field, 2013; Leedy & Ormrod, 2015).
Whether to test assumptions and face the challenge of losing control of Type I and Type
II errors or not to test assumptions and to threaten SCV as a result of uncontrolled Type I
and Type II error rates needs to be decided by the researcher (Field, 2013; Leedy &
Ormrod, 2015). I employed SPSS to address the threats to assumption violation of
statistical tests to ensure the validity of the results and protection from undesirable
outcomes such as Type I and Type II errors (see Field, 2013; Karpinski, Kirschner, Ozer,
Mellott, & Ochwo, 2013). The violation of the normality assumption requires the
elimination of outlying cases and data transformation (Hopkins & Ferguson, 2014;
Lomax & Hahs-Vaughn, 2013). The violation of independence assumption requires
special methods, such as generalized estimating equations (GEE) approach for analyzing
correlated response data, to find the best-fitting model and to make valid statistical
inferences. The method chosen depends on the response variable, the type of dependence,
and the complexity of the problem (Field, 2013).
For instance, Jackson and Singh (2015), Kam-Sing Wong (2014), and Roh et al.,
(2014) employed SPSS application to conduct a variety of statistical procedures related to

97
the processing large data sets, multiple variables, missing data points, statistical model
tests, assumption violation tests, and data analysis. Jackson and Singh (2015) employed
SPSS to conduct the necessary tests in the process of examining the financial-
environmental performance of organizations. Kam-Sing Wong (2014) employed SPSS to
address effectively the validity and the reliability of the measurements and findings in
examining the relationship between the innovativeness, proactiveness, and risk-taking
and new product success. Roh et al. (2014) used SPSS in investigating the key variables
relevant to the implementation of a successful responsive supply chain and ensuring the
validity and reliability of the measurements. Similarly, I employed SPSS features to
ensure an accurate statistical relationship between the variables and to prevent the
violation of SCV.
Both small and large sample sizes may present threats to SCV (Becker et al.,
2013; Hopkins & Ferguson, 2014). To achieve a given level of power the sample size
must be appropriately calculated (Field, 2013; Heyvaert & Onghena, 2014; Hopkins &
Ferguson, 2014). To ensure the extent of the statistical power to which the results of an
analysis accurately reveal a statistically significant difference between the cases when a
statistical difference exists, I employed the G*Power software to determine the
appropriate sample size for the study (see Becker et al., 2013; Field, 2013; Hopkins &
Ferguson, 2014). To compute the minimum required size that the sample must have
according to planned power, I considerd the main statistical test, along with four
parameters: (a) effect size, (b) level of significance, (c) power, and (d) number of
predictors (Hopkins & Ferguson, 2014). Using the parameters above, the computed

98
minimum required sample size for a power of 0.80 was 98 samples. Increasing the
sample size to 194 increases the power of the statistical test to 0.99.
Measurement validity is an application set to test if the measures measure what
they are set out to measure (Becker et al., 2013; Bryman & Bell, 2015; Field, 2013).
Measures maintain certain levels of transparency, reliability, and validity lack of which
causes inconsistency in measurement (Hopkins & Ferguson, 2014; Venkatesh et al.,
2013). The measures used to assess key constructs may be contaminated (a measure
includes a domain outside of the construct) or deficient (part of the construct domain is
not measured) (Hopkins & Ferguson, 2014; Tlapa et al., 2016). To ensure the validity of
the constructs’ measure, this study adhered to the tested and reliable measurements
utilized in previous research. Wolf’s (2014) applied sustainable SCM and stakeholder
pressure items in the research. Wolf employed a confirmatory factor analysis using
MPlus software used to assess scale reliability and validity of the overall measurement
scheme. This study was built on Wolf’s study by considering the same constructs and the
measurement items. Jackson and Singh (2015) applied confirmatory factor analysis in
investigating the environmental-financial performance of organizations. Mitra and Datta
(2014) applied confirmatory factor analysis in examining the impact of green supply
chain management practices on organizational performance.
An issue of validity that may arise for this particular research would be for
external validity. External validity deals with the question of whether the result of a
particular study generalizable beyond the specific research context and applicable in the
real world to other similar programs and approaches (Brutus et al., 2013; Bryman & Bell,

99
2015; Kaivo-oja, 2016; Neall & Tuckey, 2014). Lack of generalizability is one of the
most pervasive methodological challenges (Kaivo-oja, 2016). Over-generalizing the
conclusions across populations, settings or contexts, and time, which would affect
population validity, ecological validity, and temporal validity will compromise overall
external validity (Becker et al., 2013). Reflection on the limitations of the data and
sample size can prevent the researcher from over-generalizing findings (Becker et al.,
2013). While I considered the target population organizations across the world and of
different organization sizes, this was limited to the list provided by the Newsweek Green
Rankings 2015 Global 500 List and the data available from Sustainalytics and Standard
& Poor’s. The available data limited to specific regions and sizes of organizations may
result in biased conclusions concerning generalizability (Becker et al., 2013; Neall &
Tuckey, 2014). Also, the availability of data may pertain only to specific types of
industries. The generalizability of the findings of this research may depend on the final
form of data collected. To partially account for external validity, I considered
organization size and industry by controlling the number of employees and the type of
industry as the measure (Cohen et al., 2013; Hopkins & Ferguson, 2014).
In investigating the relationship between sustainable SCM and corporate financial
performance, Wang and Sarkis (2013) analyzed 411 organizations that are cross-listed in
three years’ rankings in Bloomberg and Compustat databases, which also contain all
elements of the social, environmental, and financial data. Singal (2013) analyzed 624
industry specific organizations identified through the intersection of KLD ESG data and
S&P credit ratings in examining the link between firm financial performance and

100
investment in sustainability initiatives. Wolf (2014) analyzed the relationship between
sustainable SCM, stakeholder pressure, and corporate sustainability performance with the
sample of 1,621 organizations included in the Sustainalytics database. While the sample
in this study was limited to the availability of data from Sustainalytics and S&P
Compustat, where I collected the archival data, these databases allow obtaining a
significant sample size (Singal, 2013; Wang & Sarkis, 2013; Wolf, 2014). However, I
employed G*Power software to determine the appropriate sample size for the study as the
validity threat may occur if the sample size is too large (Becker et al., 2013; Hopkins &
Ferguson, 2014). Type III error (statistically significant result with no meaningful
practical implication) may occur if the sample size is too large (Hopkins & Ferguson,
2014).
Transition and Summary
In Section 2, I presented an expanded discussion of the selected research design
and methodology and elaborated their appropriateness for this study compared to the
other forms of research design and methodology. In this section, there was also a
discussion of data collection and analysis. The section included a discussion of ethical
concerns and possible validity issues as well.
The purpose of this quantitative correlational study was to examine the
relationship between sustainable SCM, stakeholder pressure, and corporate sustainability
performance, while controlling for industry and organizational size. My role in this study
was to consider the kinds of data that the study of the problem requires and reasonable

101
means of collecting and interpreting those data by conducting the ethical research without
compromising the study validity. I used the Belmont Report to guide this research.
I chose quantitative methodology and non-experimental correlational research
design for this research. The quantitative method was appropriate for this study because
the purpose of the study was to analyze the relationship between the variables. The
correlation design was appropriate for this study because the aim of this study was to
predict the relationships between a set of predictor variables (sustainable SCM and
stakeholder pressure), a moderating and a mediating variable (stakeholder pressure), and
a dependent variable (corporate sustainability performance).
The population for this study consisted of publicly traded worldwide
organizations with extensive supply chains sensitive to stakeholder pressure that are more
likely to report sustainability information. Newsweek Green Rankings 2016 Global 500
List presents a list of global organizations with the most sustainable practices. I used
G*Power software to determine the appropriate sample size for the study, which is 98
samples. The data collected from existing secondary sources such as Sustainalytics,
S&P’s, and corporate annual reports that are publicly available and upon request.
A convenience sampling technique was employed to collect data from
Sustainalytics ESG and S&P’s, databases using the Newsweek Green Rankings 2016
Global 500 List as the inclusion criteria. The ESG dataset provided the data for the
independent composite variables (sustainable SCM and stakeholder pressure) and the
moderating and mediating composite variable (stakeholder pressure). S&P’s database
provided the data for the dependent variable (corporate sustainability performance).

102
Sustainalytics database and corporate annual reports provided the data for control
variables (industry and organizational size).
I chose hierarchical multiple linear regression analysis to address all the
hypotheses, including moderated and mediated multiple linear regression as appropriate.
Multiple linear regression analysis was the appropriate technique to examine the direct
relationships proposed by the hypothesis 1 and hypothesis 2 between the independent
composite variables (sustainable SCM and stakeholder pressure) and the dependent
variable (corporate sustainability performance). Moderated and mediated multiple linear
regressions wee the appropriate techniques to examine the moderating and mediating
relationships proposed by the hypothesis 3 and hypothesis 4 between the independent
composite variable-sustainable SCM, the independent composite variable-stakeholder
pressure that took a form of the moderator and a mediator, and the dependent variable-
corporate sustainability performance. The two control variables in the statistical analysis
were industry and organizational size. Hierarchical multiple linear regression
appropriately addressed the purpose of the study and the types of data for which the
problem called. SPSS v.21 software was appropriate to perform all statistical analysis.
The assessment of the validity of the statistical analysis, which takes on many different
forms, also considered for ensuring the integrity of the conclusions generated from the
research.
In section 3, I include presentation and analysis of the findings of the study
related to each of the research questions and hypotheses. In this section I also provide a
detailed discussion on the applicability of the findings with respect to the professional

103
practice of business. Additionally, in this section I discus implications that the findings
might initiate regarding social change. My recommendations for actions and further
research I also included in this section. There I also discus reflections on the experience
within the DBA Doctoral Study process.

104
Section 3: Application to Professional Practice and Implications for Change
Introduction
The purpose of this quantitative correlation study was to examine the relationship
between sustainable SCM, stakeholder pressure, and corporate sustainability
performance, while controlling for industry and organizational size. I developed
hypotheses regarding whether significant relationships exist between sustainable SCM,
stakeholder pressure, and corporate sustainability performance while controlling for
industry an organizational size. The first independent composite variable was sustainable
SCM, and the second independent composite variable was stakeholder pressure. The
moderating composite variable was stakeholder pressure, and the mediating composite
variable was stakeholder pressure. The dependent variable was corporate sustainability
performance. The control variables were industry and organizational size.
As discussed in Section 2, I employed multiple measures possibly affecting
corporate sustainability performance, and generated four regression models. Based on the
regression results, I rejected null Hypothesis 1 stating that there is no significant
relationship between Sustainable SCM and corporate sustainability performance, and null
Hypothesis 2 stating that there is no relationship between stakeholder pressure and
corporate sustainability performance. I accepted null Hypothesis 3 stating that there is no
significant relationship between sustainable SCM, stakeholder as a moderator, and
corporate sustainability performance, and rejected null Hypothesis 4 stating that there is
no significant relationship between sustainable SCM, stakeholder pressure as a mediator,
and corporate sustainability performance.

105
Presentation of the Findings
This presentation of the findings includes the relevant descriptive statistics,
provides an evaluation of statistical assumptions, and reports inferential statistical
analyses results supported by appropriate tables and figures. The participants of the study
were publicly traded global companies from 2014 to 2016 identified in Newsweek Green
Rankings Global 2016 list. I obtained corporate ESG and industry data from
Sustainalytics, financial data from S&P Global Ratings, and data on organizational size
from corporate annual reports. The first independent composite variable was sustainable
SCM, as measured by Sustainalytics dimensions of: (a) social supply chain standards, (b)
supply chain monitoring systems, and (c) green procurement. The second independent
composite variable was stakeholder pressure, as measured by Sustainalytics dimensions
of: (a) social supply chain related issues and controversies, (b) operations and product
related issues and controversies, and (c) environmental supply chain related issues and
controversies, which also took a form of a moderator and a mediator. The dependent
variable was corporate sustainability performance, as measured by S&P credit rating. The
control variables were industry and organizational size measured by the number of
employees.
In this study, I built upon Wolf’s suggestion to further research the relationship
between sustainable SCM, stakeholder pressure, and corporate sustainability
performance. Wolf (2014) combined insights from research on both sustainable SCM and
stakeholder pressure, and found that sustainable SCM has more to offer an organization
when not implemented as a reaction to stakeholder pressure. In measuring corporate

106
sustainability performance, Wolf captured two dimensions of sustainability,
environmental and social. I designed this study to test whether corporate sustainability
performance measured by the economic dimension of sustainability is affected by
sustainable SCM and stakeholder pressure.
I employed quantitative correlational design with hierarchical multiple regression
analysis to examine the relationship between sustainable SCM, stakeholder pressure, and
corporate sustainability performance while controlling for industry and organizational
size. To test the relationships between the variables, I formulated four hypotheses:
H
0
1: There is no statistically significant relationship between sustainable SCM
and corporate sustainability performance while controlling for industry and
organizational size.
H
1
1: There is a statistically significant relationship between sustainable SCM and
corporate sustainability performance while controlling for industry and organizational
size.
H
0
2: There is no statistically significant relationship between stakeholder pressure
and corporate sustainability performance while controlling for industry and
organizational size.
H
1
2: There is a statistically significant relationship between stakeholder pressure
and corporate sustainability performance while controlling for industry and
organizational size.

107
H
0
3: There is no statistically significant relationship between sustainable SCM,
stakeholder pressure as a moderator, and corporate sustainability performance while
controlling for industry and organizational size.
H
1
3: There is a statistically significant relationship between sustainable SCM,
stakeholder pressure as a moderator, and corporate sustainability performance while
controlling for industry and organizational size.
H
0
4: There is no statistically significant relationship between sustainable SCM,
stakeholder pressure as a mediator, and corporate sustainability performance while
controlling for industry and organizational size.
H
1
4: There is a statistically significant relationship between sustainable SCM,
stakeholder pressure as a mediator, and corporate sustainability performance while
controlling for industry and organizational size.
Each of the hypotheses proposes some form of relationship. To test these
hypotheses, I generated four competing research models. The first model was a direct
effect model that represented the direct relationship between sustainable SCM and
corporate sustainability performance. The independent composite variable of Hypothesis
1 was sustainable SCM measured by Sustainalytics dimensions of: (a) social supply chain
standards, (b) supply chain monitoring systems, and (c) green procurement. The
dependent variable was corporate sustainability performance measured by S&P long-term
issuer credit rating. The control variables were industry and organizational size measured
by number of employees. To test the first model, I employed hierarchical multiple
regression analysis.

108
The second model was also a direct effect model that represented the direct
relationship between stakeholder pressure and corporate sustainability performance. The
independent composite variable of Hypothesis 2 was stakeholder pressure measured by
Sustainalytics dimensions of: (a) social supply chain related issues and controversies, (b)
operations and product related issues and controversies, and (c) environmental supply
chain related issues and controversies. The dependent variable was corporate
sustainability performance measured by the S&P long-term issuer credit rating. The
control variables were industry and organizational size measured by number of
employees. To test the second model, I used hierarchical multiple regression analysis.
The third model was a moderation model that represented the relationship
between sustainable SCM, stakeholder pressure as a moderator, and corporate
sustainability performance. The independent composite variable of Hypothesis 3 was
sustainable SCM, which represented the composite assessment of sustainable SCM
measured by Sustainalytics dimensions of: (a) social supply chain standards, (b) supply
chain monitoring systems, and (c) green procurement. The moderation composite
variable of Hypothesis 3 was stakeholder pressure, which represented the composite
assessment of stakeholder pressure measured by Sustainalytics dimensions of: (a) social
supply chain related issues and controversies, (b) operations and product related issues
and controversies, and (c) environmental supply chain related issues and controversies.
The dependent variable was corporate sustainability performance measured by S&P long-
term issuer credit rating. The control variables were industry and organizational size

109
measured by number of employees. To test the third model, I used a moderation
regression analysis.
The fourth model was a mediation model that represented the relationship
between sustainable SCM, stakeholder pressure as a mediator, and corporate
sustainability performance. The independent composite variable of Hypothesis 4 was
sustainable SCM, which represented the composite assessment of sustainable SCM
measured by Sustainalytics dimensions of: (a) social supply chain standards, (b) supply
chain monitoring systems, and (c) green procurement. The mediation composite variable
of Hypothesis 4 was stakeholder pressure, which represented the composite assessment of
stakeholder pressure measured by Sustainalytics dimensions of: (a) social supply chain
related issues and controversies, (b) operations and product related issues and
controversies, and (c) environmental supply chain related issues and controversies. The
dependent variable was corporate sustainability performance measured by S&P long-term
issuer credit rating. The control variables were industry and organizational size measured
by number of employees. To test the fourth model, I employed a mediation regression
analysis.
SPSS v.21 software was used to perform all statistical analyses. Additionally, I
employed Process Procedure for SPSS, written by Andrew F. Hayes, to test Moderation
Model 3 and Mediation Model 4. Before conducting statistical analyses, entries with
missing data were filtered out, thus ensuring that all statistical analyses received the same
sample size without missing data. Sustainalytics and S&P’s extensive data sets allowed
me to choose a sample from organizations with no missing data. The sample size

110
consisted of 164 organizations (based on the computation of the minimum required
sample size, I determined that the minimum required sample size was 98 participants).
Also, I analyzed the data for the presence of outliers by visually examining the scatter
and normal probability plots. No obvious outliers were detected in the data.
I used SPSS to assess the assumptions of regression underlying the significance
test for the multiple correlation coefficients. Preliminary analyses of whether assumptions
of multicollinearity, outliers, normality, linearity, homoscedasticity, and independence of
residuals were met indicated no obvious violations. I employed bootstrapping (2,000
samples for two direct models and 5,000 samples for the mediating model) and 95% bias-
corrected confidence intervals to gain an accurate estimate of the true population value of
correlation coefficient for each predictor. Bootstrapping 95% confidence intervals are
presented where appropriate.
Tests of Assumptions
I evaluated the assumptions of multicollinearity, outliers, normality, linearity,
homoscedasticity, and independence of residuals. Bootstrapping using 2,000 samples
enabled preventing the influence of assumption violation. The results of the tests of
assumptions described next.
The assumption of multicollinearity. The results of the collinearity diagnostics,
specifically the variance inflation factor (VIF) values, were all well below 10, and the
tolerance statistics were all well above 0.2. The average VIF was close to 1, which
confirmed that collinearity was not an issue. Also, upon analysis of the correlation
matrix, the violation of the assumption of multicollinearity was not evident as there were
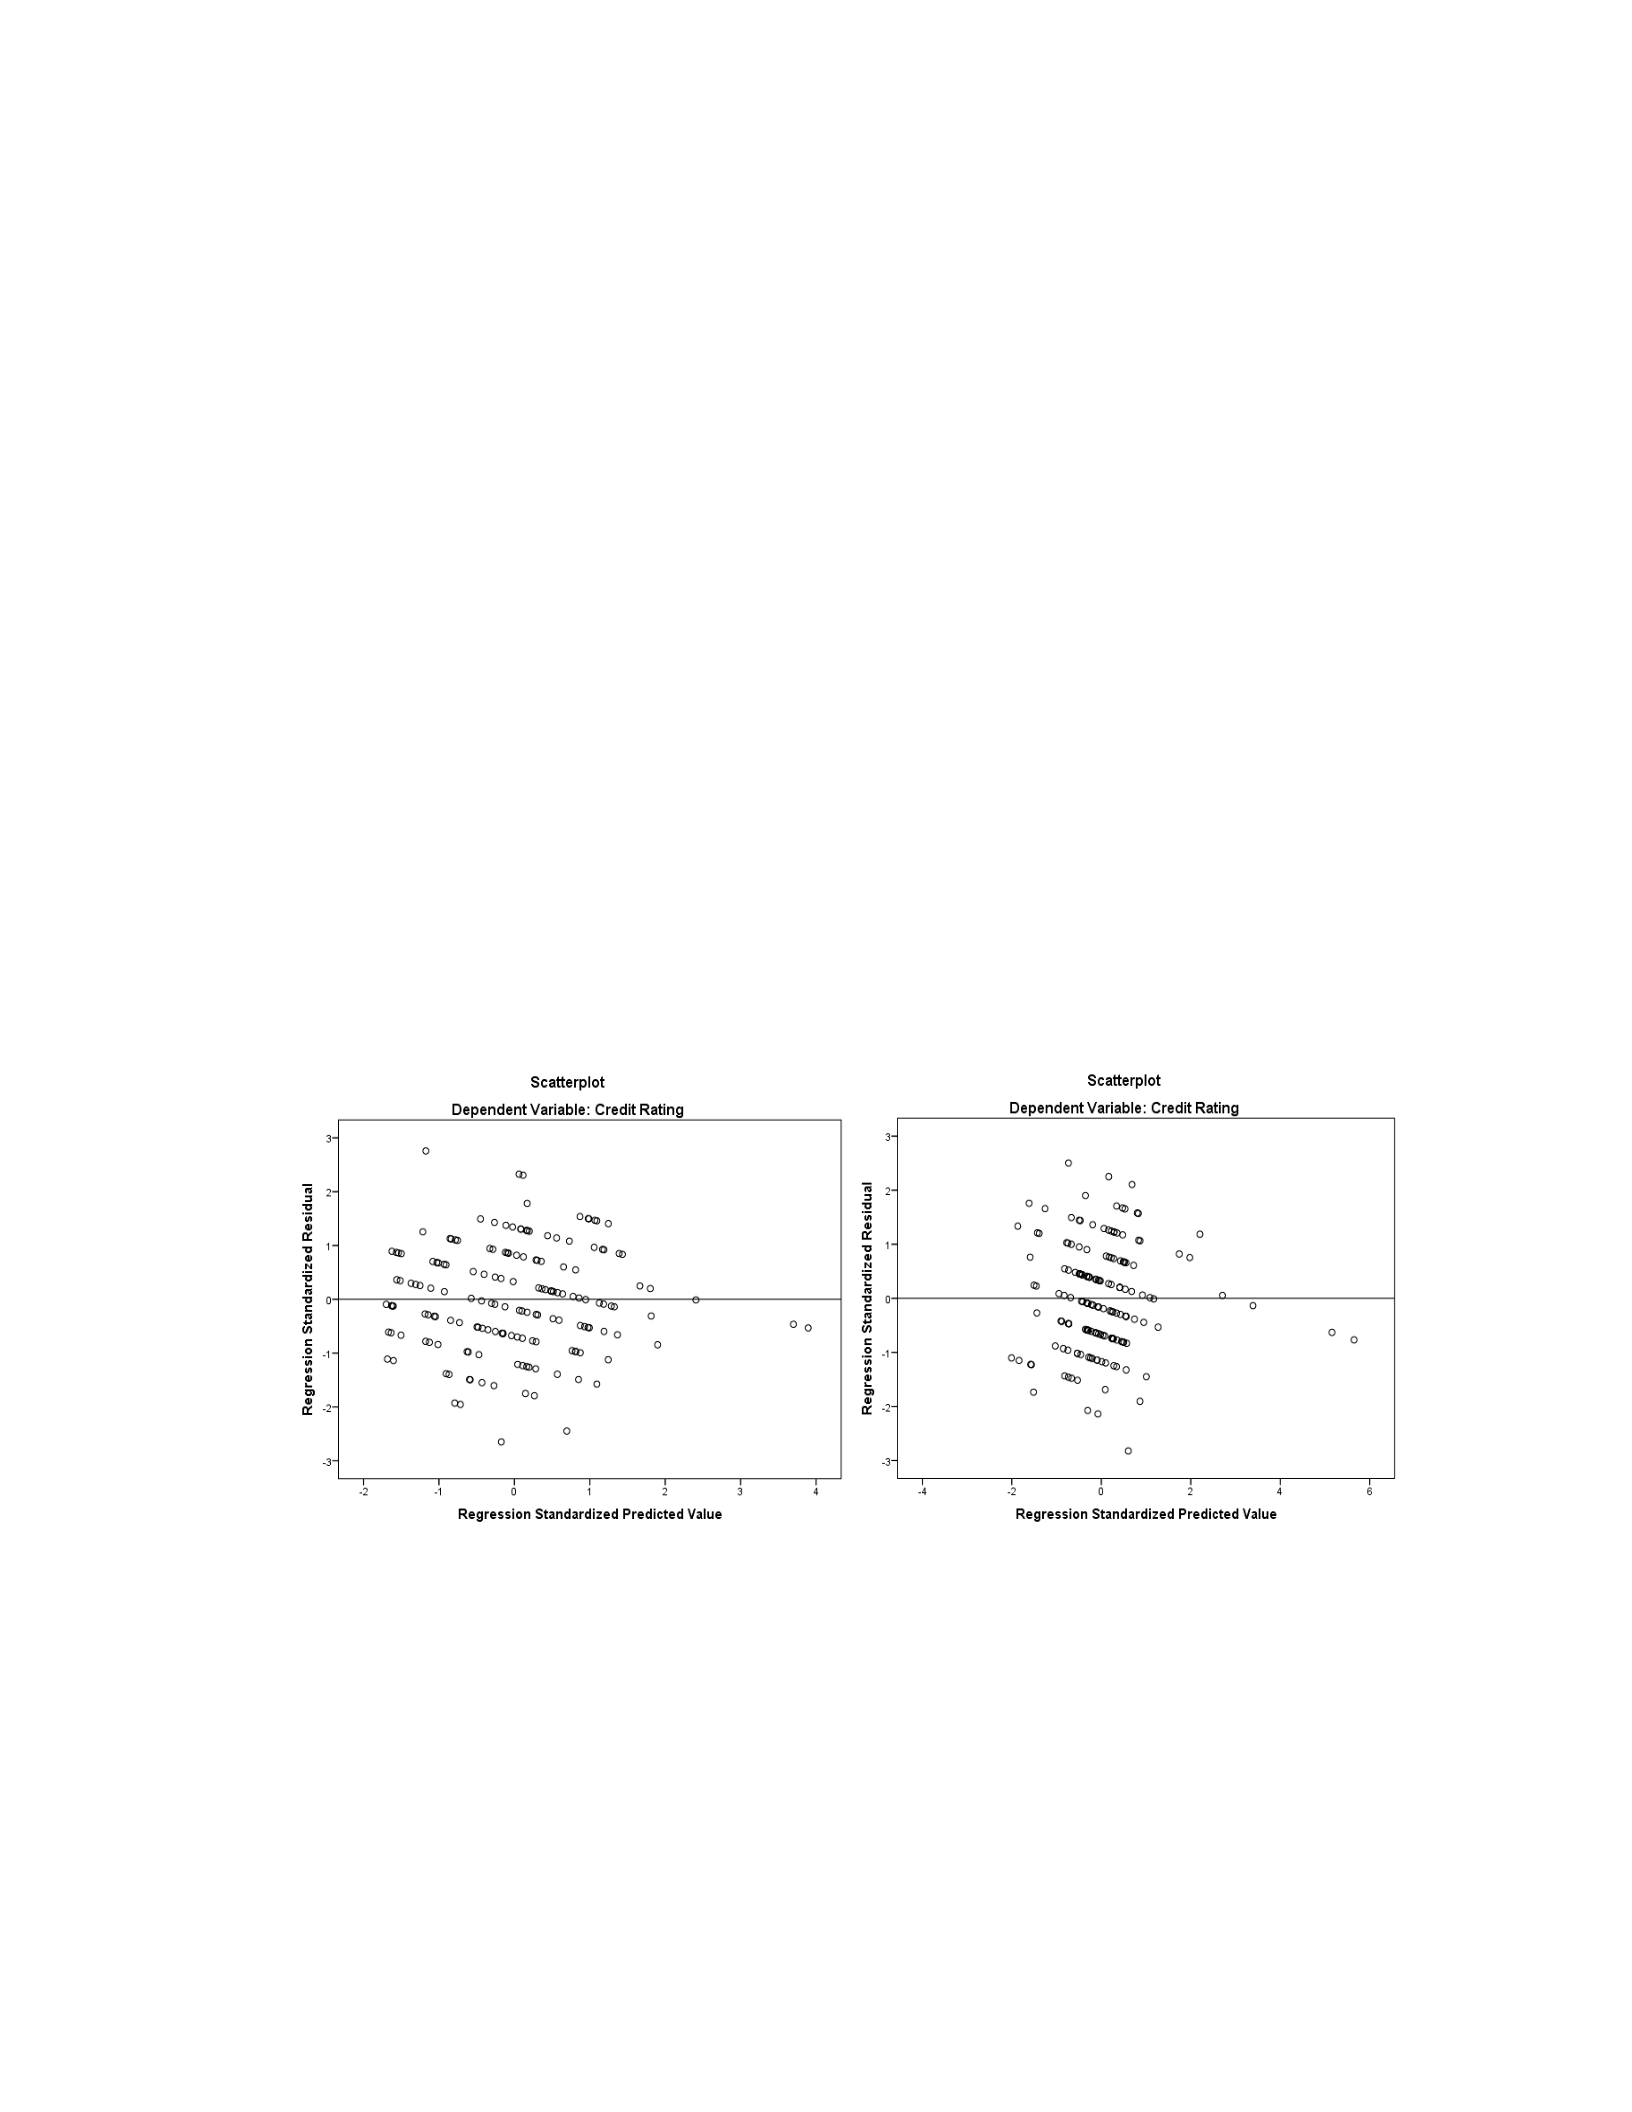
111
no substantial correlations between the predictors (r > .9). Thus, there was no collinearity
within the data.
The assumption of independence of residuals. I used a Durbin-Watson test to
assess the assumption of independent errors, specifically whether the residuals in the
models were independent. The Durbin-Watson test statistics value was very close to 2.
Therefore, there was no violation of the independence assumption.
The assumption of homoscedasticity and linearity. To evaluate the assumptions
of homoscedasticity and linearity, I visually examined the plots of standardized residuals
against standardized predicted values. The points were randomly and evenly dispersed
throughout the plot. The pattern indicated that the assumptions of linearity and
homoscedasticity had been met.
Figure 1. Plot of standardized predicted values against standardized residuals. The left
figure represents sustainable SCM, while the right figure represents stakeholder
pressure).
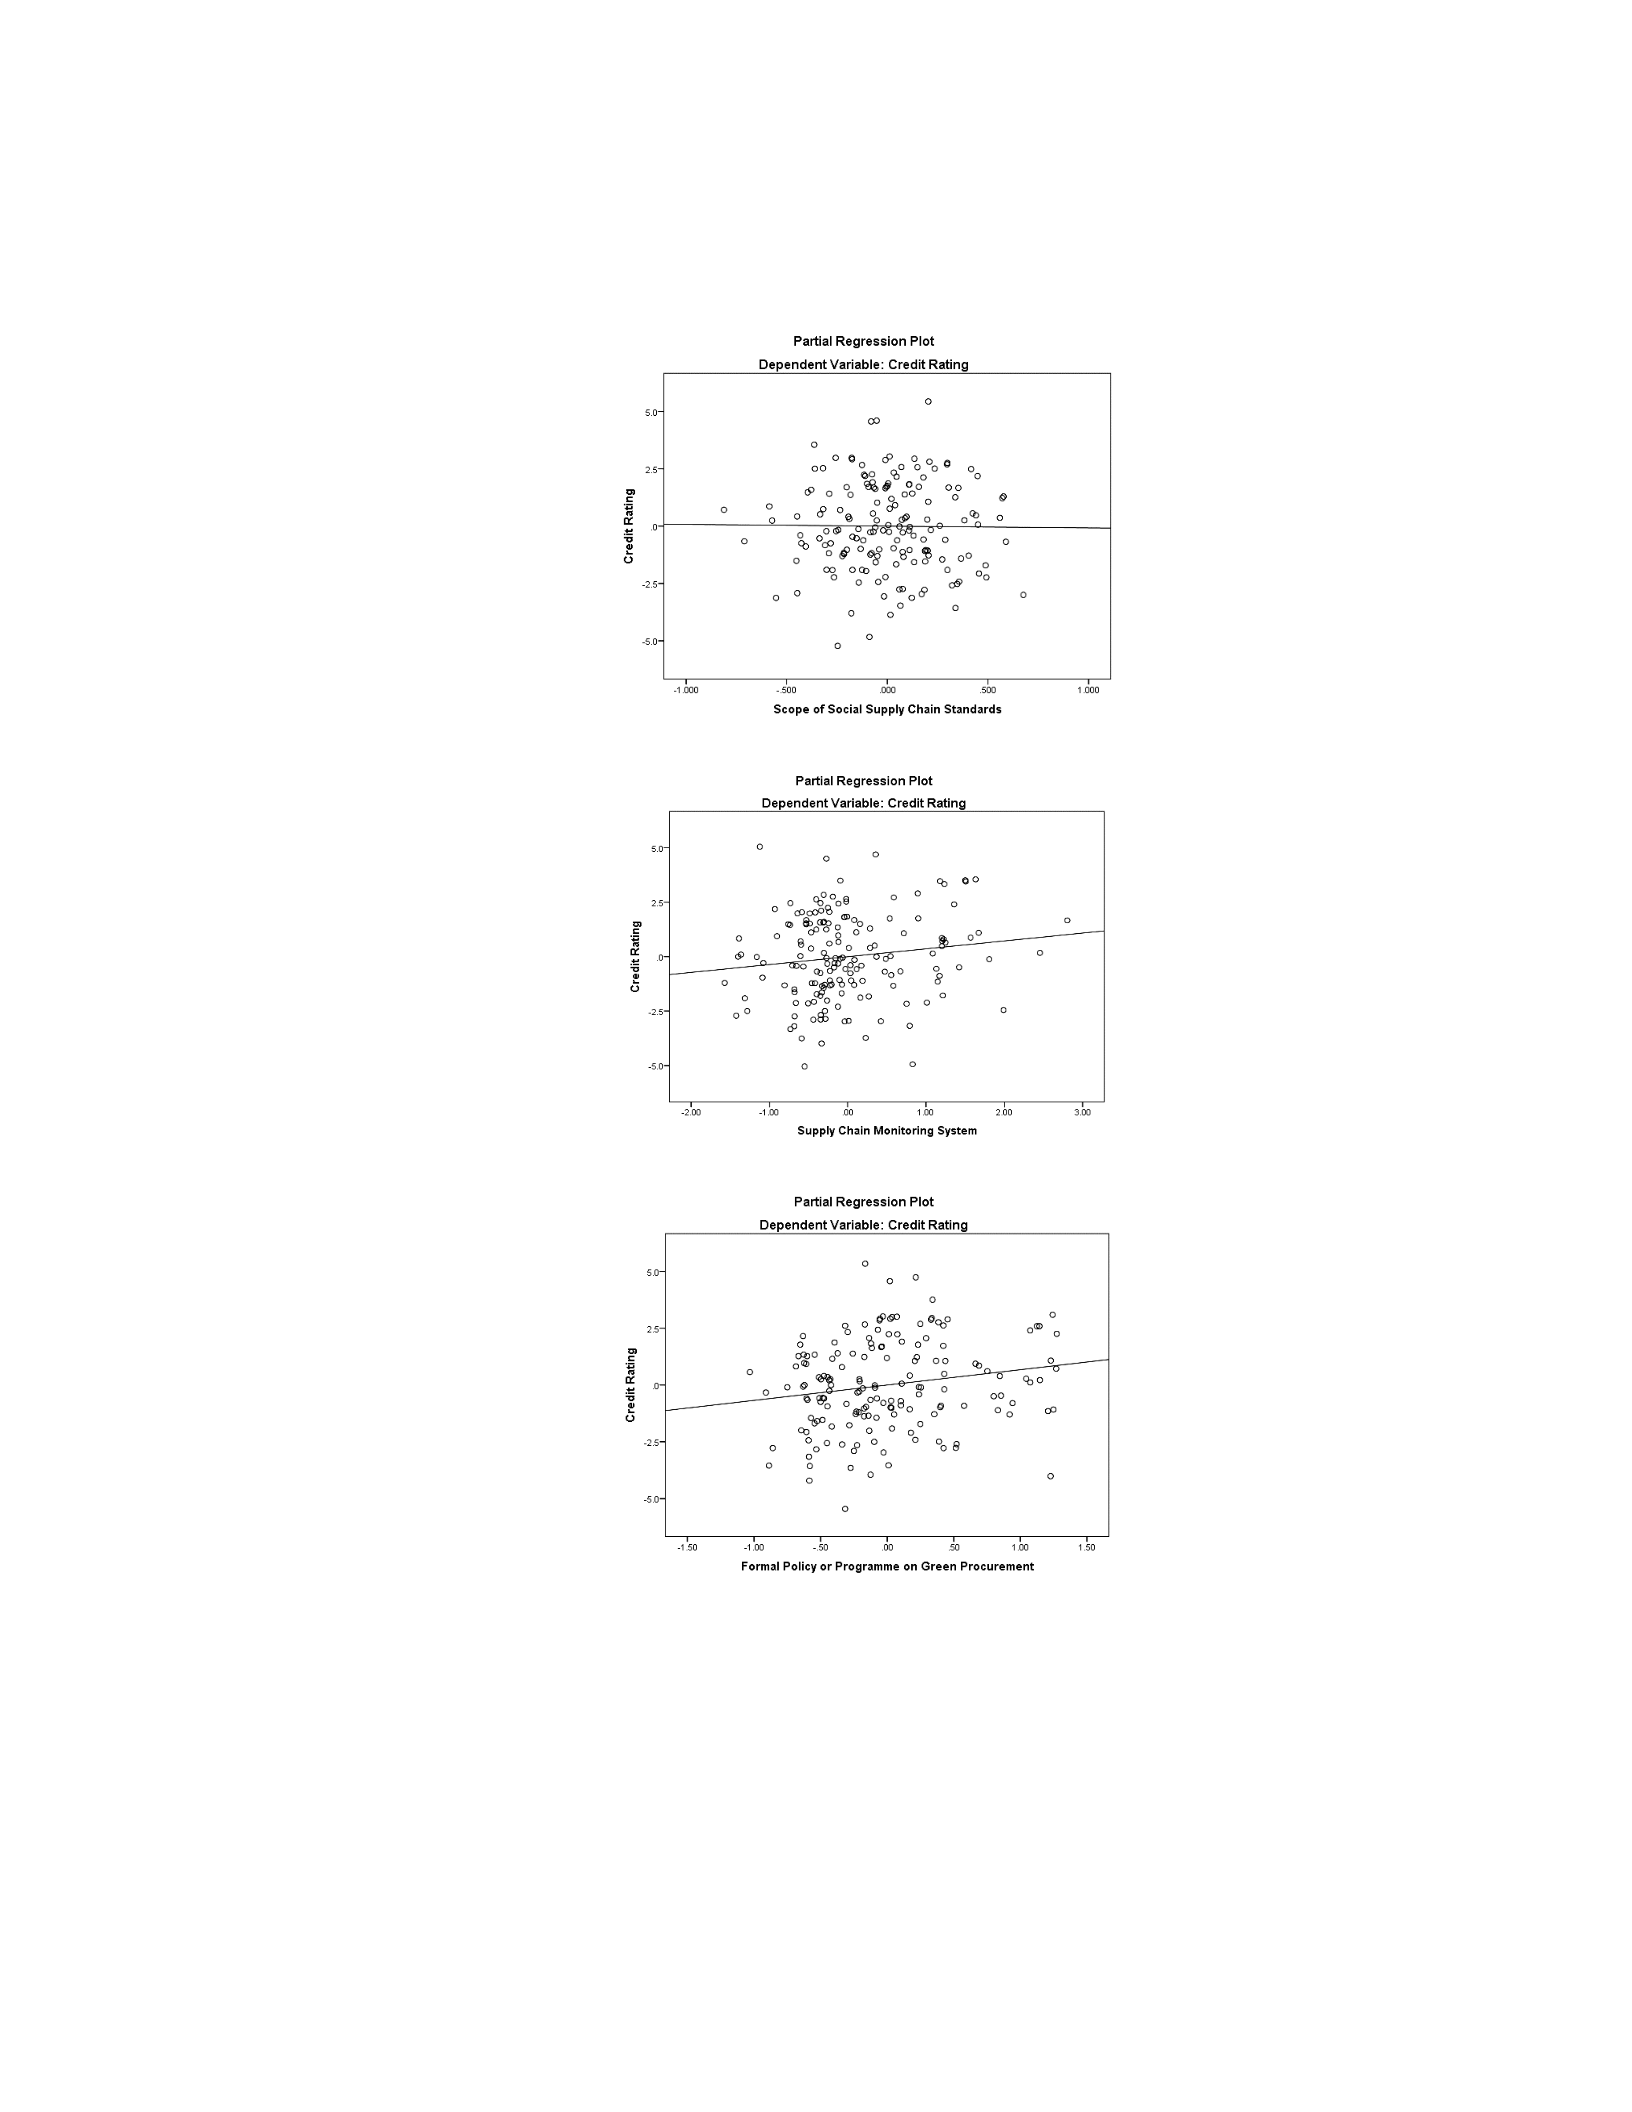
112
Figure 2. Partial plots of corporate sustainability performance (measured by credit rating)
against sustainable SCM (measured by scope of social supply chain standards, supply
chain monitoring system, and formal policy or program on green procurement).
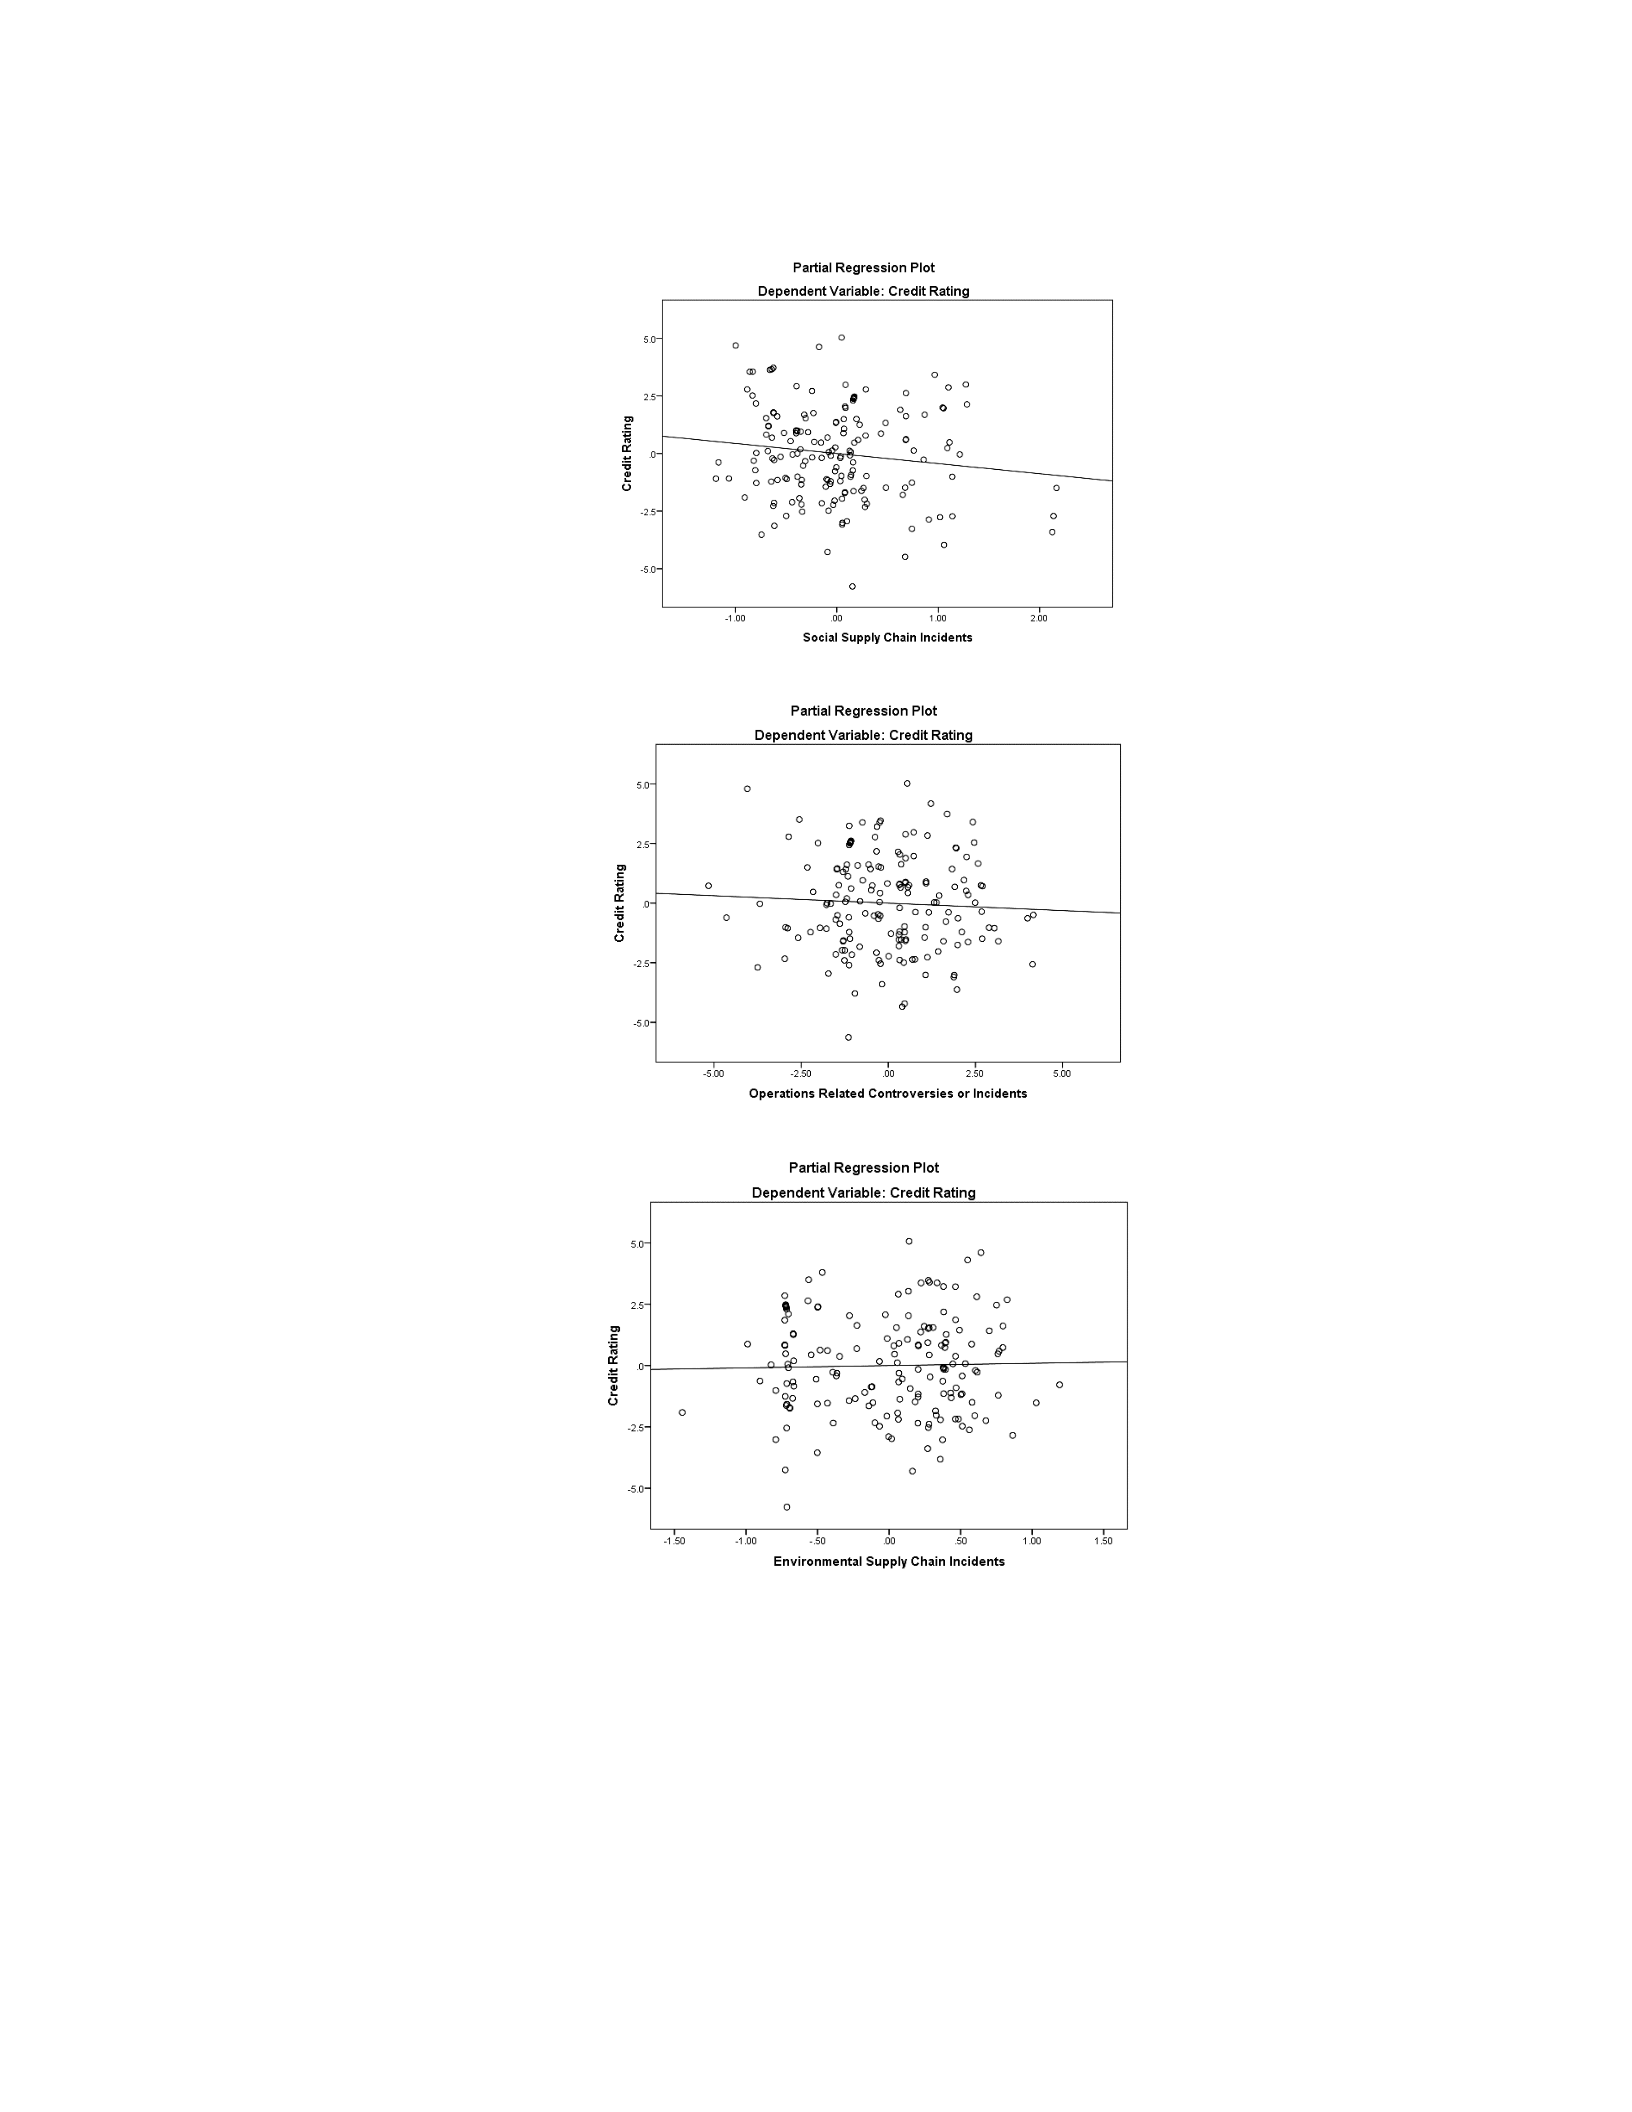
113
Figure 3. Partial plots of corporate sustainability performance (measured by credit rating)
against stakeholder pressure (measured by social supply chain related issues and
controversies, operations and product related issues and controversies, and environmental
supply chain related issues and controversies).

114
Outliers. The partial plots, which are scatterplots of the residuals of the outcome
variable and each of the predictors when both variables are regressed separately, had no
obvious outliers. In Figure 3, the partial plots indicated the strong positive relationship
between sustainable SCM and corporate sustainability performance. Sustainable SCM
was measured by (a) social supply chain standards, (b) supply chain monitoring systems,
and (c) green procurement. Corporate sustainability performance was measured by credit
rating. In Figure 4, the partial plots indicated the strong positive relationship between
stakeholder pressure and corporate sustainability performance. Stakeholder pressure was
measured by (a) social supply chain related issues and controversies, (b) operations and
product related issues and controversies, and (c) environmental supply chain related
issues and controversies. Corporate sustainability performance was measured by credit
rating.
The assumption of normality of residuals. To test the normality of residuals, I
examined the histograms and normal probability plots (P-P) of regression standardized
residual. The distribution of the data was normal. The histograms were approximately
symmetrical and bell-shaped. The normal probability plots also confirmed that the
residuals were normally distributed.
115
Figure 4. Normality histogram for variables predicting Credit Rating (sustainable SCM
as measured by scope of social supply chain standards, supply chain monitoring system,
and formal policy or program on green procurement).
Figure 5. Normality histogram for variables predicting Credit Rating (stakeholder
pressure as measured by social supply chain related issues and controversies, operations
and product related issues and controversies, and environmental supply chain related
issues and controversies).
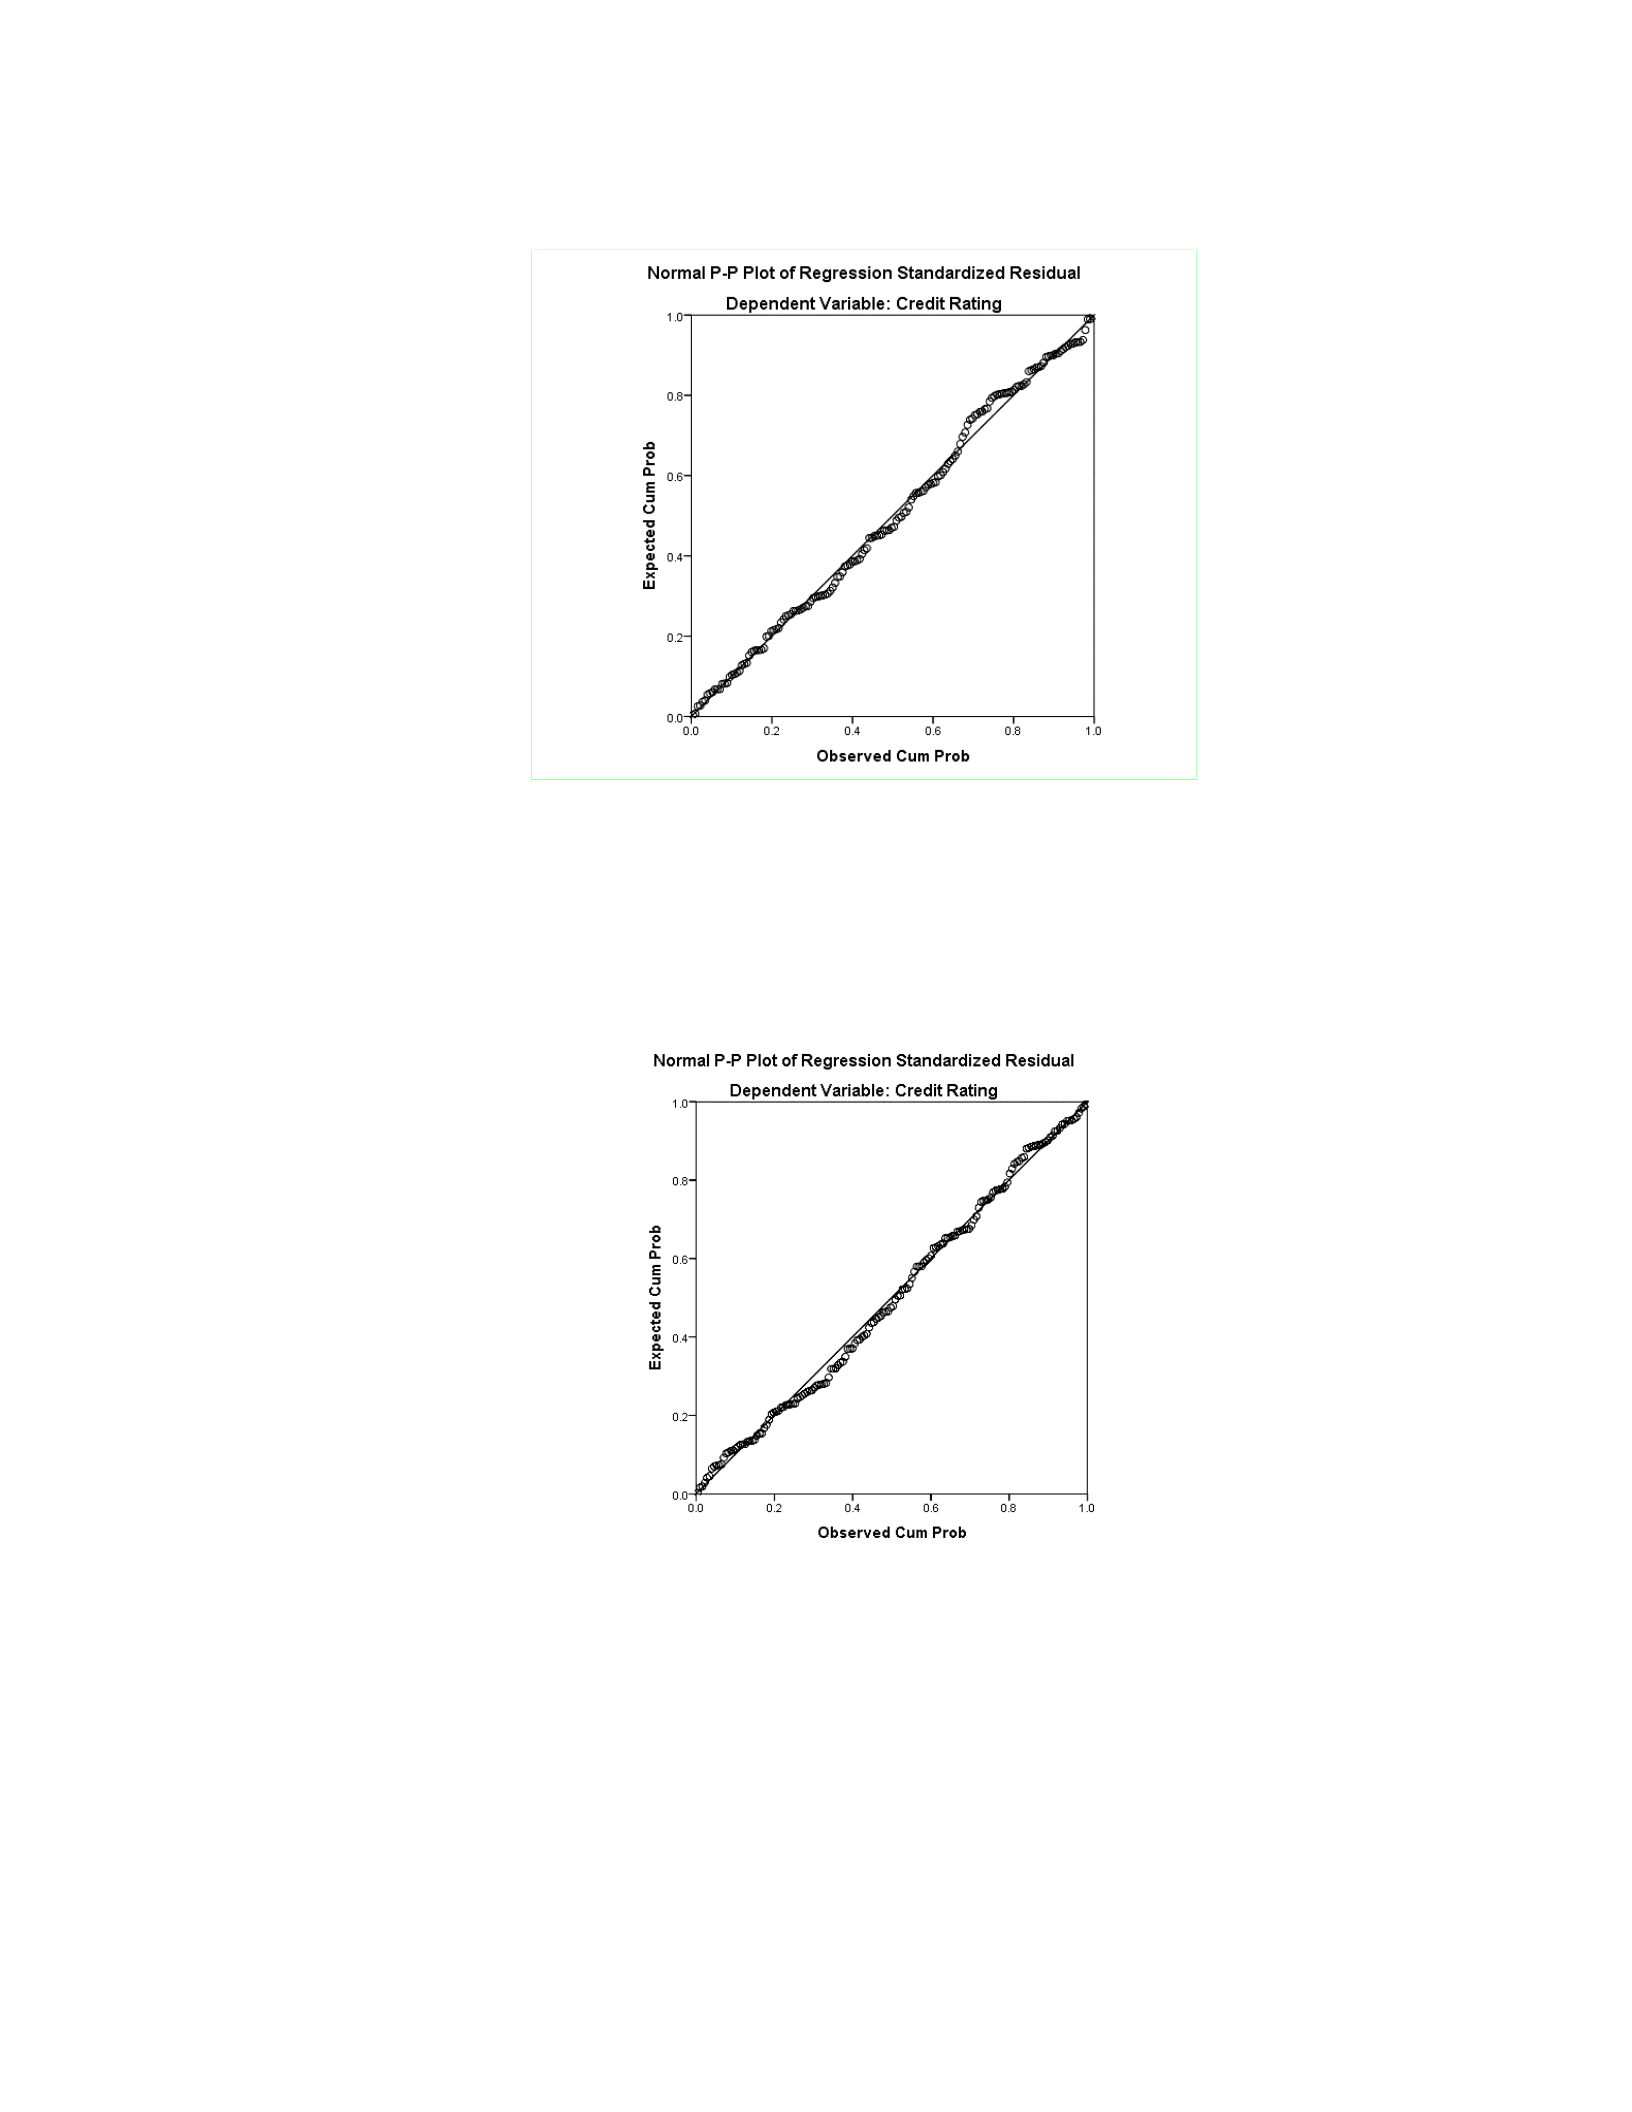
116
Figure 6. Normality P-P plot for variables predicting Credit Rating (sustainable SCM as
measured by scope of social supply chain standards, supply chain monitoring system, and
formal policy or program on green procurement).
Figure 7. Normality P-P plot for variables predicting Credit Rating (stakeholder pressure
as measured by social supply chain related issues and controversies, operations and
product related issues and controversies, and environmental supply chain related issues
and controversies).

117
Thus, preliminary analyses whether assumptions of multicollinearity, outliers,
normality, linearity, homoscedasticity, and independence of residuals were met indicated
no obvious violations or bias. Initial regression analyses also indicated that the models
could be generalized. The results of hierarchical regression analyses for the four
competing models supported by appropriate tables and figures presented next.
Direct Effect Model (Model 1)
Direct Effect Model 1 represented the Hypothesis 1.
H
0
1: There is no statistically significant relationship between sustainable SCM
and corporate sustainability performance while controlling for industry and
organizational size.
H
1
1: There is a statistically significant relationship between sustainable SCM and
corporate sustainability performance while controlling for industry and organizational
size.
Hierarchical multiple regression analysis was used to examine the efficacy of sustainable
SCM in predicting corporate sustainability performance. The independent composite
variable was sustainable SCM (as measured by Sustainalytics dimensions of: (a) social
supply chain standards, (b) supply chain monitoring systems, and (c) green procurement).
The dependent variable was corporate sustainability performance (as measured by S&P’s
credit rating). The control variables were industry and organizational size measured by
the number of employees. The null hypothesis was that sustainable SCM would not
significantly predict corporate sustainability performance, while controlling for industry
and organizational size. The alternative hypothesis was that sustainable SCM would
118
significantly predict corporate sustainability performance, while controlling for industry
and organizational size. Preliminary analyses were conducted to assess whether the
assumptions of multicollinearity, outliers, normality, linearity, homoscedasticity, and
independence of residuals were met; no serious violations were noted (Test of
Assumptions).
The descriptive statistics (Table 1) is a summary of the data. It presents the mean
(M) and standard deviations (SD) of each variable in the dataset. The number of
participants contributing to each correlation is 164 (N = 164).
Table 1
Descriptive Statistics for Direct Effect Model 1 (N = 164)
Variables M SD N
Credit rating 17.36
2.066
164
Industry 17.84
10.47
164
Organizational size 9.16
13.17
164
Scope of social supply chain standards .67
.35
164
Supply chain monitoring system 1.12
.97
164
Formal policy or programme on green
Procurement
.78
.56
164
The Direct Effect Model 1 as a whole was able to significantly predict corporate
sustainability performance, F(5, 158) = 3,981, p = .002. The R
2
[.112] value indicated that
11% of variations in corporate sustainability performance measured by credit rating is
accounted for by the linear combination of the predictor variable (sustainable SCM

119
measured by (a) social supply chain standards, (b) supply chain monitoring systems, and
(c) green procurement) and covariates (industry and organizational size). Organizational
size and Formal Policy or Programme on Green Procurement were statistically significant
with organizational size (beta=.197, p= .012) accounting for a higher contribution to the
model than Formal Policy or Programme on Green Procurement (beta=.183, p= .022).
Supply Chain Monitoring Systems (beta=.170, p=.072), Scope of Social Supply Chain
Standards (beta= -.013, p=.894), and Industry (beta= -.014, p=.852) did not provide a
statistically significant contribution to the model (Appendix C). Thus, I rejected the null
hypothesis stating that there is no statistically significant relationship between sustainable
SCM and corporate sustainability performance while controlling for industry and
organizational size.
Direct Effect Model (Model 2)
Direct Effect Model 2 represented the Hypothesis 2.
H
0
2: There is no statistically significant relationship between stakeholder pressure
and corporate sustainability performance while controlling for industry and
organizational size.
H
1
2: There is a statistically significant relationship between stakeholder pressure
and corporate sustainability performance while controlling for industry and
organizational size.
Hierarchical multiple regression analysis was used to examine the efficacy of stakeholder
pressure in predicting corporate sustainability performance. The independent composite
variable was stakeholder pressure (measured by Sustainalytics dimensions of: (a) social

120
supply chain related issues and controversies, (b) operations and product related issues
and controversies, and (c) environmental supply chain related issues and controversies).
The dependent variable was corporate sustainability performance (measured by S&P’s
credit rating). The control variables were industry and organizational size measured by
the number of employees. The null hypothesis was that stakeholder pressure would not
significantly predict corporate sustainability performance while controlling for industry
and organizational size. The alternative hypothesis was that stakeholder pressure would
significantly predict corporate sustainability performance while controlling for industry
and organizational size. Upon preliminary analyses assessing the assumptions of
multicollinearity, outliers, normality, linearity, homoscedasticity, and independence of
residuals no serious violations were noted (Test of Assumptions).
The descriptive statistics (Table 2) is a summary of the data. It presents the mean
(M) and standard deviations (SD) of each variable in the dataset. The number of
participants contributing to each correlation is 164 (N = 164).
121
Table 2
Descriptive Statistics for Direct Effect Model 2 (N = 164)
Variables M SD N
Credit rating 17.36
2.07
164
Industry 17.84
10.47
164
Organizational size 9.16
13.17
164
Social supply chain incidents 2.59
.85
164
Operations related controversies or incidents 6.46
1.87
164
Environmental supply chain incidents 2.55
.73
164
The Direct Effect Model 2 as a whole was able to significantly predict corporate
sustainability performance, F(5, 158) = 2,552 p = .030. The R
2
[.075] value indicated that
7,5% of variations in corporate sustainability performance measured by credit rating is
accounted for by the linear combination of the predictor variable (stakeholder pressure
measured by (a) social supply chain related issues and controversies, (b) operations and
product related issues and controversies, and (c) environmental supply chain related
issues and controversies) and covariates (industry and organizational size). The
organizational size was the only statistically significant contributor to the model
(beta=.227, p= .004). Environmental Supply Chain Incidents (beta=.033, p= .760),
Industry (beta=.063, p=.433), Operations Related Controversies and Incidents (beta= -
.056, p=.506), and Social Supply Chain Incidents (beta= -.179, p=.084) did not provide
statistically significant contribution to the model (Appendix D). Thus, I rejected the null
hypothesis stating that there is no statistically significant relationship between

122
stakeholder pressure and corporate sustainability performance while controlling for
industry and organizational size.
Moderation Model (Model 3)
Direct Effect Model 3 represented the Hypothesis 3.
H
0
3: There is no statistically significant relationship between sustainable SCM,
stakeholder pressure as a moderator, and corporate sustainability performance while
controlling for industry and organizational size.
H
1
3: There is a statistically significant relationship between sustainable SCM,
stakeholder pressure as a moderator, and corporate sustainability performance while
controlling for industry and organizational size.
Hierarchical moderation multiple regression analysis was used to examine the efficacy of
sustainable SCM, with stakeholder pressure as a moderator, in predicting corporate
sustainability performance. The independent composite variable was sustainable SCM (as
measured by Sustainalytics dimensions of: (a) social supply chain standards, (b) supply
chain monitoring systems, and (c) green procurement). The moderating composite
variable was stakeholder pressure (as measured by (a) social supply chain related issues
and controversies, (b) operations and product related issues and controversies, and (c)
environmental supply chain related issues and controversies). The dependent variable
was corporate sustainability performance (as measured by S&P’s credit rating). The
control variables were industry and organizational size measured by the number of
employees. The null hypothesis was that sustainable SCM, with stakeholder pressure as a
moderator, would not significantly predict corporate sustainability performance, while
123
controlling for industry and organizational size. The alternative hypothesis was that
sustainable SCM, with stakeholder pressure as a moderator, would significantly predict
corporate sustainability performance, while controlling for industry and organizational
size. Preliminary analyses were conducted to assess whether the assumptions of
multicollinearity, outliers, normality, linearity, homoscedasticity, and independence of
residuals were met; no serious violations were noted (Test of Assumptions). Model 1 of
the Process Procedure for SPSS written by Andrew F. Hayes was used to test the model.
The level of confidence for all confidence intervals in output was 95.00. The descriptive
statistics (Table 3) is a summary of the data. It presents each variable in the data set. The
number of participants contributing to each correlation is 164 (N = 164).
Table 3
Descriptive Statistics for Moderating Model 3 (N = 164)
Variables N
Credit rating (dependent variable)
164
Industry (covariate)
164
Organizational size (covariate)
164
Sustainable SCM (SSCMStr) (independent composite variable)
164
Stakeholder pressure (SPCon) (moderating composite variable)
164
The Moderation Model 3 as a whole was able to significantly predict corporate
sustainability performance. F (5, 158) = 5.54, p < .001, R
2
=.11 (Table 4). However,
interaction effect of the moderator was not significant. R
2
-chng =.0007, p-int = .669
(Table 5). Statistically significant contributors to the model were covariate -
124
organizational size (b
= .033, t(158) = 3.63, p <.001) and predictor - sustainable SCM (b
=.32, t(158) = 3.20, p = .002). The moderation variable - stakeholder pressure (b
= -. 072,
t(158) = -1.14, p = .255), interaction effect (b
= -.012, t(158) = -. 429, p = .669), and
covariate – industry (b
= .004, t(158) = .015, p = .813) did not make significant
contribution to the model (Table 6). The changed R
2
[.0007] value due to the interaction
indicated that 0 % of variations in corporate sustainability performence is accounted for
by the linear combination of the predictor (sustainable SCM), with the moderator
(stakeholder pressure) and the covariates (industry and organizational size).
Table 4
Moderation Effect Model Summary
R R-sq MSE F df1 df2 p
.33 .11 3.91 5.54 5.00 158.00 .00
Note. a. Dependent variable: Corporate sustainability performance
Table 5
R-square Increase due to the Interaction (Moderation Model)
R
2
-chng F df1 df2 P
Int_1 .00 .18 1.00 158.00 .67
Simple slops equations of the regression of corporate sustainability performance on
sustainable SCM at three levels of stakeholder pressure indicated that there is no
significant interaction of stakeholder pressure on the relationship between sustainable
SCM and corporate sustainability performance (Figure 8).
Table 6
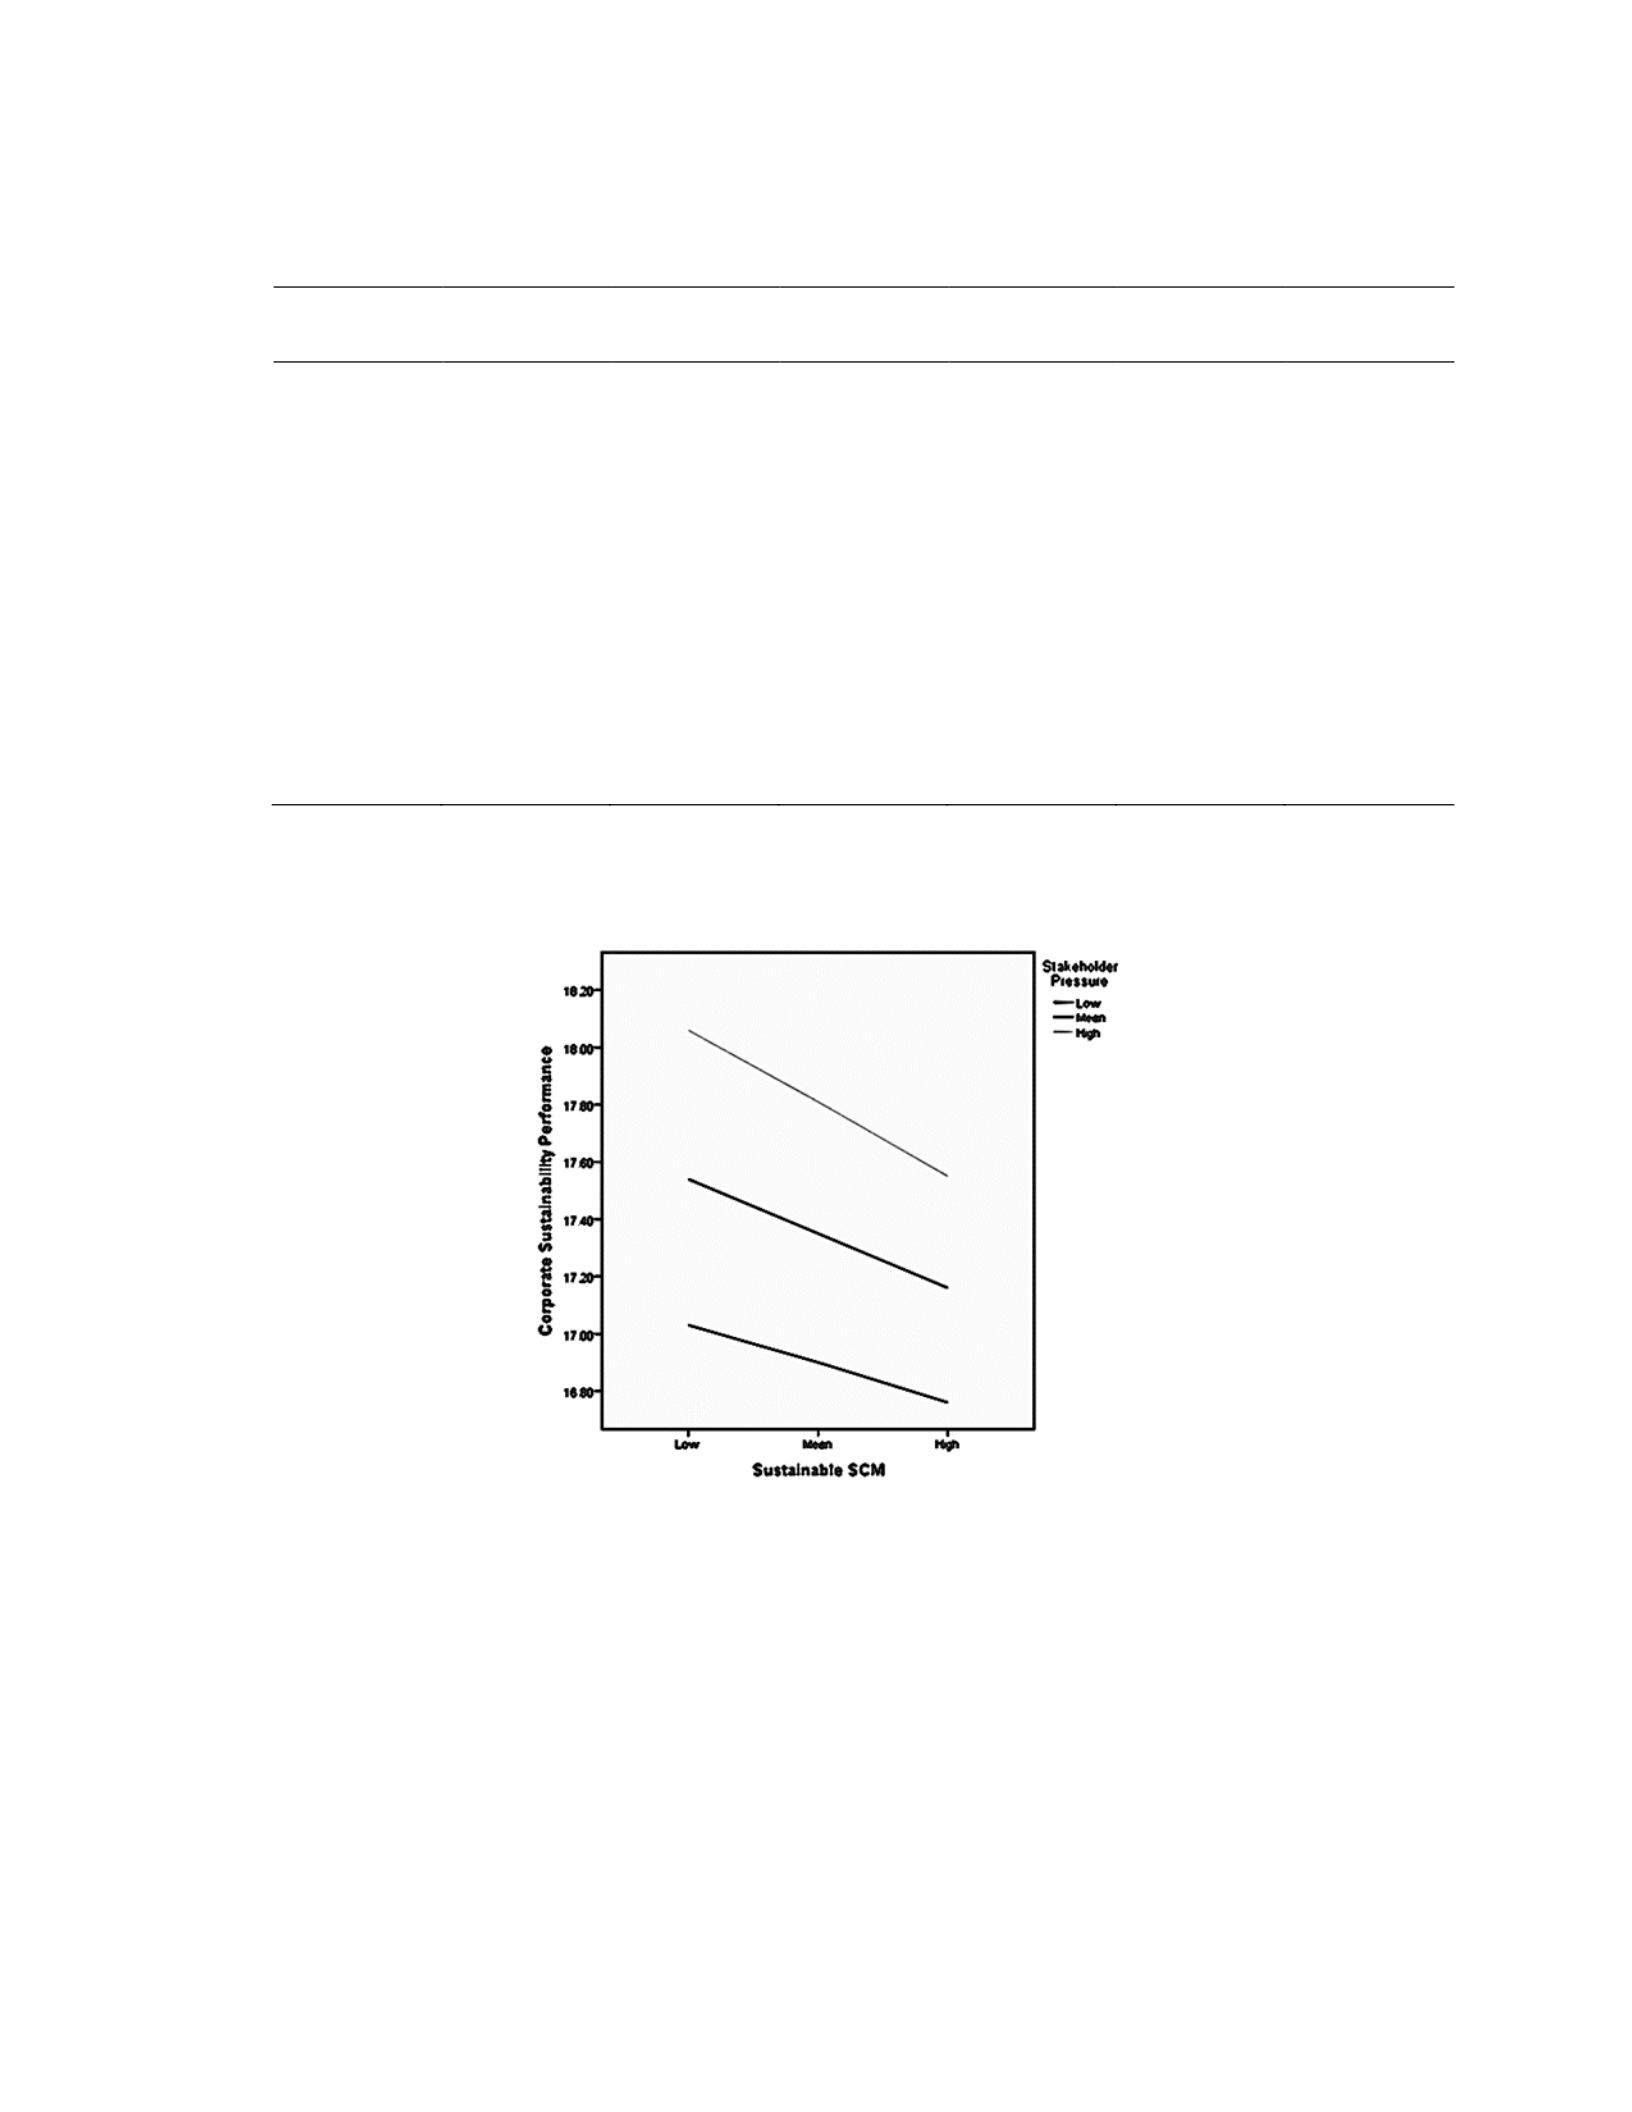
125
Coefficients of the Moderating Regression Model
Model Coff(b) se t p LLCI ULCI
constant 16.98 .31 54.97 .00 16.38 17.60
SPCon -.07 .06 -1.14 .26 -.20 .05
SSCMStr .32 .10 3.20 .00 .12 .52
Int_1 -.02 .04 -.43 .67 -.09 .06
Industry .00 .02 .24 .81 -.03 .03
Organiza .03 .01 3.63 .00 .01 .05
Note. Int_1: SSCMStr x SPCon
Figure 8. Simple slopes equations of the regression of credit rating on sustainable SCM
at three levels of stakeholder pressure.
The three levels of regressions for sustainable SCM as a predictor of corporate
sustainability performance are: (1) when stakeholder pressure is low (-2.677); (2) at the
126
mean value of stakeholder pressure (centered stakeholder pressure value is 0 as indicated
in the output); and (3) when the value of stakeholder pressure is high (2.677) (Table 7).
Table 7
Conditional Effect of Sustainable SCM on Corporate Sustainability Performance at
Values of the Moderator-Stakeholder Pressure
SPCon Effect se t p LLCI ULCI
-2.68 .36 .13 2.80 .00 .11 .62
.00 .32 .10 3.20 .00 .12 .52
2.68 .28 .15 1.86 .06 -.02 .57
Note. Values for quantitative moderators are mean and plus/minus one SD from the mean.
Values for dichotomous moderators are the two values of the moderator.
When stakeholder pressure was low, there was a statistically significant negative
relationship between sustainable SCM and corporate sustainability performance, b =
.3616, 95%CI [.106, .617], t = 2.80, p = .006. As sustainable SCM increases, corporate
sustainability performance declines (and vice versa). The contribution of the low
stakeholder pressure as a moderator to the relationship between sustainable SCM and
corporate sustainability performance was .36.
At the mean value of stakeholder pressure, there was a significant positive
relationship between sustainable SCM and corporate sustainability performance, b =
.3198, 95%CI [.123, .517], t = 3.20, p = .002. As sustainable SCM increases, corporate
sustainability performance increases (and vice versa). The contribution of the average
stakeholder pressure as a moderator to the relationship between sustainable SCM and
corporate sustainability performance was .32.

127
When stakeholder pressure is high, there is a non-significant positive relationship
between sustainable SCM and corporate sustainability performance, b = .2780, 95%CI [-
.016, .573], t = 1.86, p = .064. Thus, the higher stakeholder pressure, the lesser
moderating effect it has on the relationship between sustainable SCM and corporate
sustainability performance. Thus, I accepted the null hypothesis stating that there is no
statistically significant relationship between sustainable SCM, with stakeholder pressure
as a moderator, and corporate sustainability performance, while controlling for industry
and organizational size.
Mediation Model (Model 4)
Direct Effect Model 4 represented the Hypothesis 4.
H
0
4: There is no statistically significant relationship between sustainable SCM,
stakeholder pressure as a mediator, and corporate sustainability performance while
controlling for industry and organizational size.
H
1
4: There is a statistically significant relationship between sustainable SCM,
stakeholder pressure as a mediator, and corporate sustainability performance while
controlling for industry and organizational size.
Hierarchical mediating multiple regression analysis was used to examine the efficacy of
sustainable SCM, with stakeholder pressure as a mediator, in predicting corporate
sustainability performance. The independent composite variable was sustainable SCM (as
measured by Sustainalytics dimensions of: (a) social supply chain standards, (b) supply
chain monitoring systems, and (c) green procurement). The mediating composite variable
was stakeholder pressure (as measured by (a) social supply chain related issues and

128
controversies, (b) operations and product related issues and controversies, and (c)
environmental supply chain related issues and controversies). The dependent variable
was corporate sustainability performance (as measured by S&P’s credit rating). The
control variables were industry and organizational size measured by the number of
employees. The null hypothesis was that sustainable SCM, with stakeholder pressure as a
mediator, would not significantly predict corporate sustainability performance, while
controlling for industry and organizational size. The alternative hypothesis was that
sustainable SCM, with stakeholder pressure as a mediator, would significantly predict
corporate sustainability performance, while controlling for industry and organizational
size. Preliminary analyses were conducted to assess whether the assumptions of
multicollinearity, outliers, normality, linearity, homoscedasticity, and independence of
residuals were met; no serious violations were noted (Test of Assumptions). Model 4 of
Process Procedure for SPSS written by Andrew F. Hayes was employed to test the
Mediation Model 4. A number of bootstrap samples for bias-corrected bootstrap
confidence intervals was 5000. The level of confidence for all confidence intervals in
output was 95.00. The descriptive statistics (Table 8) is a summary of the data. It presents
each variable in the dataset. The number of participants contributing to each correlation is
164 (N = 164).
129
Table 8
Descriptive Statistics for Mediating Model 4 (N = 164)
Variables N
Credit rating (dependent variable)
164
Industry (covariate)
164
Organizational size (covariate)
164
Sustainable SCM (SSCMStr) (independent composite variable)
164
Stakeholder pressure (SPCon) (mediating composite variable)
164
Regression of stakeholder pressure from sustainable SCM. Sustainable SCM
significantly predicts stakeholder pressure while controling for industry and
orgnaizational size, F (3, 160) = 5.30, b
= -.34, t(160) = -2.37, p = .02. R
2
=.09 (Tables 9
and 10). The R
2
value indicates that the sustainable SCM explains 9% of the variance in
stakeholder pressure and the negative b indicates that the relationship is negative: as
sustainable SCM increases, stakeholder pressure declines (and vice versa). Industry made
a significant contribution to the model b
= .06, t(160) = 3.26, p = .001) while
orgnaizational size did not make significant contribution to the model (b
= .02, t(160) =
1.24, p = .22) (Tables 9 and 10).
Table 9
Mediation Effect Model Summary (Regression of Stakeholder Pressure from Sustainable
SCM)
R R-sq MSE F df1 df2 p
.30 .09 6.64 5.30 3.00 160.00 .002
Note. Outcome: SPCon
130
Table 10
Coefficients of the Mediating Regression Model (Regression of Stakeholder Pressure
from sustainable SCM)
Model Coff(b) se t p
Constant 11.17 .54 20.77 .00
SSCMStr -.34 .14 -2.37 .02
Industry .06 .02 3.26 .00
Organiza .02 .02 1.24 .22
Note. Outcome: SPCon
Direct effect. The results of the direct effect of sustainable SCM on corporate
sustainability performance when stakeholder pressure is included as a predictor while
controlling for industry and organizational size indicated that sustainable SCM
significantly predicts corporate sustainability performance with stakeholder pressure in
the model while controlling for industry and organizational size, F (4, 159) = 4.94, b
=.33, t(159) = 2.93, p = .004. R
2
=.11. Stakeholder pressure did not predict corporate
sustainability performance (b
= -. 07, t(159) = -1.16, p = .247) (Tables 11 and 12). The R
2
value indicated that the model explains 11% of the variance in corporate sustainability
performance. The positive b for sustainable SCM indicated that as sustainable SCM
increases, corporate sustainability performance increases also. The negative b for
stakeholder pressure indicates that as stakeholder pressure increases, corporate
sustainability declines (and vice versa). Covariate - organizational size made significant
contribution to the relationship (b
= .03, t(159) = 2.77, p = .006). Covariate - industry did
131
not make a significant contribution to the relationship (b
= .003, t(159) = .23, p = .821)
(Tables 11 and 12).
Table 11
Mediation Effect Model Summary (Direct Effect)
R R-sq MSE F df1 df2 p
.33 .11 3.89 4.94 4.00 159.00 .00
Note. Outcome: Credit Rating
Table 12
Coefficients of the Mediating Regression Model (Direct Effect)
Model Coff(b) se t p
constant 16.98 .79 21.45 .00
SPCon -.07 .06 -1.16 .25
SSCMStr .33 .11 2.93 .0039
Industry .00 .02 .23 .82
Organiza .03 .01 2.77 .01
Note. Outcome: Credit Rating
Total effect. The total effect is the effect of the predictor on the outcome when
the mediator is not present in the model (Field, 2013). The results of sustainable SCM on
corporate sustainability performance in isolation (total effect) indicated that when
stakeholder pressure is not in the model, sustainable SCM significantly predicts corporate
sustainability performance while controlling for industry and organizational size. F (3,
160) = 6.121, b
=.35, t(160) = 3.20, p = .002. R
2
=.103 (Tables 13 and 14). The R
2
value
indicated that the model explains 10% of the variance in corporate sustainability
132
performance. Similarly, as when the stakeholder pressure was included in the model,
sustainable SCM has a positive relationship with corporate sustainability performance.
The positive b for sustainable SCM indicated that as sustainable SCM increases,
corporate sustainability performance increases also. Covariate - organizational size made
a significant contribution to the model (b
= .03, t(160) = 2.67, p = .008). Covariate -
industry did not make significant contribution to the relationship (b
= -.0010, t(160) = -
.067, p = .947) (Tables 13 and 14) .
Table 13
Mediation Effect Model Summary (Total Effect Model)
R R-sq MSE F df1 df2 p
.32 .10 3.90 6.12 3.00 160.00 .00
Note. Outcome: Credit Rating
Table 14
Coefficients of the Mediating Regression Model (Total Effect Model)
Model Coff(b) se t p
Constant 16.19 .41 39.29 .00
SSCMStr .35 .11 3.20 .00
Industry -.00 .02 -.07 .95
Organiza .03 .01 2.70 .09
Note. Outcome: Credit Rating
Indirect effect. The results of the indirect effect analysis of the relationship
between sustainable SCM and corporate sustainability performance when stakeholder
pressure is included as a mediator while controlling for industry and organizational size
133
indicated the presence of indirect effect of stakeholder pressure as b-value falls between
bootstrapped CI [-.012, .089] (if b=0 then there is no effect). Analysis of the effect sizes
also indicated the presence of indirect effect as all of the size measures have confidence
intervals that are greater than 0 (greater than “no effect”) (Field, 2013). The size of the
indirect effect is b = .024, z = 0.97 (standard error-associated z-score), p = .329. Thus,
there is a relatively small and non-statistically significant indirect effect. I accepted the
null hypothesis stating that there is no statistically significant relationship between
sustainable SCM, with stakeholder pressure as a mediator, and corporate sustainability
performance while controlling for industry and organizational size (Tables 15 and 16).
Table 15
Indirect Effect of sustainable SCM on Corporate Sustainability Performance
Effect Boot SE BoorLLCI BootULCI
SPCon .024 .025 -.012 .089
Table 16
Normal Theory Tests for Indirect Effect (Sobel Test)
Effect se z p
.024 .024 .975 .329
Summary of the Analysis
The purpose of this study was to examine the efficacy of sustainable SCM and
stakeholder pressure in predicting corporate sustainability performance while controlling
for industry and organizational size. The participants of the study were publicly traded

134
global companies from 2014 to 2016 identified in Newsweek Green Rankings Global
2016 list. The gathered secondary data for the participants were ESG and industry data
obtained from Sustainalytics, financial data from S&P’s Global Ratings, data on
organizational size from corporate annual reports. Hierarchical multiple regression was
employed to conduct all the analyses. Preliminary analyses whether assumptions of
multicollinearity, outliers, normality, linearity, homoscedasticity, and independence of
residuals were met indicated no obvious violations. I used bootstrapping and 95% bias-
corrected confidence intervals to gain an accurate estimate of the true population value of
correlation coefficient for each predictor. To test the relationships between the variables,
four hypotheses were formulated. Each of the hypotheses proposed some form of
relationship. To test these hypotheses, four competing research models were generated.
The first model was a Direct Effect Model that represented the direct relationship
between sustainable SCM and corporate sustainability performance. The independent
variable of hypothesis 1 was a composite variable - sustainable SCM measured by
Sustainalytics dimensions of: (a) social supply chain standards, (b) supply chain
monitoring systems, and (c) green procurement. The dependent variable was corporate
sustainability performance measured by S&P a long-term issuer credit rating. The control
variables were industry and organizational size measured by a number of employees. To
test the Model1, I employed hierarchical multiple regression analysis. The Direct Effect
Model 1 as a whole was able to significantly predict corporate sustainability
performance, F(5, 158) = 3,981, p = .002. The R
2
[.11] value indicated that 11% of
variations in corporate sustainability performance measured by credit rating is accounted

135
for by the linear combination of the predictor (sustainable SCM measured by (a) social
supply chain standards, (b) supply chain monitoring systems, and (c) green procurement)
and covariates (industry and organizational size). Organizational size and Formal Policy
or Programme on Green Procurement were statistically significant with organizational
size (beta=.197, p= .012) accounting for a higher contribution to the model than Formal
Policy or Programme on Green Procurement (beta=.183, p= .022). Supply Chain
Monitoring Systems (beta=.170, p=.072), Scope of Social Supply Chain Standards (beta=
-.013, p=.894), and Industry (beta= -.014, p=.852) did not provide a statistically
significant contribution to the model. Thus, I rejected the null hypothesis stating that
there is no statistically significant relationship between sustainable SCM and corporate
sustainability performance while controlling for industry and organizational size.
The second model also was a Direct Effect Model that represented the direct
relationship between stakeholder pressure and corporate sustainability performance. The
independent variable of hypothesis 2 was a composite variable - stakeholder pressure
measured by Sustainalytics dimensions of: (a) social supply chain related issues and
controversies, (b) operations and product related issues and controversies, and (c)
environmental supply chain related issues and controversies. The dependent variable was
corporate sustainability performance measured by S&P a long-term issuer credit rating.
The control variables were industry and number of employees. To test the second model,
I employed hierarchical multiple regression analysis. The Direct Effect Model 2 as a
whole was able to significantly predict corporate sustainability performance, F(5, 158) =
2,552 p = .030. The R
2
[.075] value indicated that 7.5% of variations in corporate

136
sustainability performance measured by credit rating is accounted for by the linear
combination of the predictor (stakeholder pressure measured by (a) social supply chain
related issues and controversies, (b) operations and product related issues and
controversies, and (c) environmental supply chain related issues and controversies) and
covariates (industry and organizational size). However, organizational size was the only
statistically significant contributor to the model (beta=.227, p= .004). Environmental
Supply Chain Incidents (beta=.033, p= .760), Industry (beta=.063, p=.433), Operations
Related Controversies and Incidents (beta= -.056, p=.506), and Social Supply Chain
Incidents (beta= -.179, p=.084) did not provide statistically significant contribution to the
model. Thus, I rejected the null hypothesis stating that there is no statistically significant
relationship between stakeholder pressure and corporate sustainability performance while
controlling for industry and organizational size.
The third model was a moderation model that represented the relationship
between sustainable SCM, stakeholder as a moderator, and corporate sustainability
performance. The independent variable of hypothesis 3 was a composite variable -
sustainable SCM, which represented the composite score of sustainable SCM measured
by Sustainalytics dimensions of: (a) social supply chain standards, (b) supply chain
monitoring systems, and (c) green procurement. The moderation variable of hypothesis 3
was composite variable - stakeholder pressure, which represented the composite score of
stakeholder pressure measured by Sustainalytics dimensions of: (a) social supply chain
related issues and controversies, (b) operations and product related issues and
controversies, and (c) environmental supply chain related issues and controversies. The

137
dependent variable was corporate sustainability performance measured by S&P’s a long-
term issuer credit rating. The control variables were industry and number of employees.
To test the third model, I employed a moderation regression analysis. The Moderation
Model 3 as a whole was able to significantly predict corporate sustainability
performance. F (5, 158) = 5.54, p < .001, R
2
=.11. However, the interaction effect of the
moderator was not significant. R
2
-chng =.0007, p-int = .669. The changed R
2
[.0007]
value due to the interaction indicated that 0 % of variations in corporate sustainability
performance is accounted for by the linear combination of the predictor construct
(sustainable SCM), with moderating construct (stakeholder pressure) and covariates
(industry and organizational size). Statistically significant contributors to the model were
covariate - organizational size (b
= .033, t(158) = 3.63, p <.001) and predictor -
sustainable SCM (b
=.32, t(158) = 3.20, p = .002). The moderation variable - stakeholder
pressure (b
= -. 072, t(158) = -1.14, p = .255), interaction effect (b
= -.012, t(158) = -.
429, p = .669), and covariate – industry (b
= .004, t(158) = .015, p = .813) did not make
significant contribution to the model. Thus, I accepted the null hypothesis stating that
there is no statistically significant relationship between sustainable SCM, with
stakeholder pressure as a moderator, and corporate sustainability performance, while
controlling for industry and organizational size.
The fourth model was a mediation model that represented the relationship
between sustainable SCM, stakeholder pressure as a mediator, and corporate
sustainability performance. The independent variable of hypothesis 4 was a composite
variable - sustainable SCM, which represented the composite score of sustainable SCM

138
measured by Sustainalytics dimensions of: (a) social supply chain standards, (b) supply
chain monitoring systems, and (c) green procurement. The mediation variable of
hypothesis 4 was composite variable - stakeholder pressure, which represented the
composite score of stakeholder pressure measured by Sustainalytics dimensions of: (a)
social supply chain related issues and controversies, (b) operations and product related
issues and controversies, and (c) environmental supply chain related issues and
controversies. The dependent variable was corporate sustainability performance as
measured by S&P a long-term issuer credit rating. The control variables were industry
and number of employees. To test the fourth model, I employed a mediation regression
analysis.
The results of the effect of sustainable SCM on corporate sustainability
performance in isolation (total effect) indicated that when stakeholder pressure is not in
the model, sustainable SCM significantly predicts corporate sustainability performance
while controling for industry and organizational size. F (3, 160) = 6.121, b
=.35, t(160) =
3.20, p = .002. R
2
=.103. The R
2
value indicated that the model explains 10% of the
variance in corporate sustainability performance. Sustainabe SCM has a positive
relationship with corporate sustainability performance. Covariate - organizational size
made a significant contribution to the model (b
= .03, t(160) = 2.67, p = .008). Covariate -
industry did not make significant contribution to the relationship (b
= -.0010, t(160) = -
.067, p = .947).
The results of the direct effect of sustainable SCM on corporate sustainability
performance when stakeholder pressure included as a predictor while controlling for

139
industry and organizational size indicated that sustainable SCM significantly predicts
corporate sustainability performance with stakeholder pressure in the model while
controlling for industry and organizational size, F (4, 159) = 4.94, b
=.33, t(159) = 2.93, p
= .004. R
2
=.11. Stakeholder pressure did not predict corporate sustainability performance
(b
= -. 07, t(159) = -1.16, p = .247). The R
2
value indicated that the model explains 11%
of the variance in corporate sustainability performance. The positive b for sustainable
SCM indicates that as sustainable SCM increases, corporate sustainability performance
increases also. The negative b for stakeholder pressure indicates that as stakeholder
pressure increases, corporate sustainability declines (and vice versa). Covariate -
organizational size made significant contribution to the relationship (b
= .03, t(159) =
2.77, p = .006). Covariate - industry did not make significant contribution to the
relationship (b
= .003, t(159) = .23, p = .821).
The results of the indirect effect of sustainable SCM on corporate sustainability
performance when stakeholder pressure is included as a mediator while controlling for
industry and organizational size indicated the presence of the indirect effect of
stakeholder pressure as b-value falls between bootstrapped CI [-.012, .089]. Analysis of
the effect sizes also indicated the presence of indirect effect as all of the size measures
had confidence intervals that are greater than 0. The size of the indirect effect is b = .024,
z = 0.97 (standard error-associated z-score), p = .329. Thus, there is a relatively small and
non-statistically significant indirect effect. I accepted the null hypothesis stating that there
is no statistically significant relationship between sustainable SCM, with stakeholder

140
pressure as a mediator, and corporate sustainability performance while controlling for
industry and organizational size.
Overall, the results of all four hierarchical regression analyses indicated that all
four models were able to significantly predict corporate sustainability performance. In
Direct Effect Model 1, the most significant contributors to the corporate sustainability
performance were the organizational size and sustainable SCM. In Direct Effect Model 2,
the only significant contributor to the corporate sustainability performance was
organizational size, stakeholder pressure, however, was not a significant contributor to
the model. In Moderating Model 3, the most significant contributors to the corporate
sustainability performance were the organizational size and sustainable SCM. The
interaction effect of stakeholder pressure on the relationship between sustainable SCM
and corporate sustainability performance was not significant. In Mediating Model 4, the
most significant contributors to the corporate sustainability performance were sustainable
SCM organizational size. The indirect effect of stakeholder pressure on the relationship
between sustainable SCM and corporate sustainability performance was not significant.
Therefore, sustainable SCM and organizational size have significant effect on corporate
sustainability performance, stakeholder pressure has a direct effect on corporate
sustainability performance if the organizational size is significant, stakeholder pressure as
a moderator and a mediator is not a significant predictor of corporate sustainability
performance, and industry is also not a significant predictor of corporate sustainability
performance.

141
Findings in the Context of the Theoretical Framework
The purpose of the study was to examine the efficacy of sustainable SCM and
stakeholder pressure in predicting corporate sustainability performance while controlling
for industry and organizational size. In this study, I built upon Wolf’s suggestion for
further research. Wolf (2014) combined insights from both sustainable SCM and
stakeholder pressure and found that sustainable SCM has more to offer an organization
when not implemented as a reaction to stakeholder pressure. In measuring corporate
sustainability performance, Wolf captured two dimensions of sustainability,
environmental and social. In this research, I tested whether corporate sustainability
performance as measured by an economic dimension of sustainability is affected by
sustainable SCM and stakeholder pressure.
Overall, corporate sustainability is a concept to achieve long-term economic
benefits through the integration of environmental, social, and economic criteria (Carter &
Rogers, 2008). The economic impact of corporate sustainability efforts is the main
research concern. Research propositions have been developed based on various theories
including RDT (Al Zaabi et al., 2013). RDT is one of the theoretical frameworks to
understand the role of organizational pressures on the sustainability performance
(Ramanathan et al., 2014). Organizations are not self-sufficient but rely on their
environment and its resources for survival and achievement of long-term objectives. RDT
is a central theory in the understanding of the relationship between sustainable SCM,
stakeholder pressure, and corporate sustainability performance. RDT shows support to
the concept that organizations should proactively engage in sustainable SCM as it

142
resolves a resource dependency problem, ameliorates stakeholder pressure, and ensures
sustainable profitability.
The review of the literature from the viewpoint of RDT led to the following
conclusions: (a) organizations take a proactive approach to the sustainable supply chain
and corporate sustainability in an effort to ensure the long-term resource supply and
sustainable corporate performance, (b) organizations take reactive approach to
sustainable practices when they fear or faced with reduced access to resources due to
stakeholder pressure, (c) proactive sustainable supply chain practices contribute to
corporate sustainability performance, but the effect is greater when stakeholder pressure
occurs, and (d) stakeholder pressure determines the extent to which an organization
engages in sustainable supply chain practices. These conclusions guided me to research a
business problem concerning the understanding and effective practice of corporate
sustainability performance. The results of the study indicated that there is a significant
positive relationship between sustainable practices and financial performance. The results
of the study are in alignment with the findings of Wolf (2014) as this study built on
Wolf’s study. In the analysis, I employed the same competing models of the potential
relationship between sustainable SCM, stakeholder pressure, and corporate sustainability
performance to examine which of the four models best predict the outcome. Hierarchical
multiple regression analyses were used to estimate the corporate sustainability
performance impact of the two independent composite variable (sustainable SCM and
stakeholder pressure), with stakeholder taking moderating and mediating effect as well.

143
The direct effect of sustainable SCM on corporate sustainability
performance. The growing awareness of the original approach to sustainability, which
recognizes the three dimensions of sustainability (corporate financial performance, social
performance, and environmental performance) as a part of a system, drive organizational
leaders to proactively pursue sustainable SCM (Esfahbodi et al., 2016; Gao & Bansal,
2013; Hahn et al., 2015; Jamali, 2014). Organizational leaders recognize their roles and
responsibilities towards the environment and society not just for the present but for the
future, which foster a proactive development of initiatives to address sustainability
(Lozano, 2013; Walls & Triandis, 2014). Organizations understand their dependence
upon the long-term sustainability of their resource supply (Esfahbodi et al., 2016; Wolf,
2014). Thus, organizations gain long-term benefit from the adoption of sustainable SCM
strategies. By promoting environmental and social sustainability and proactively
engaging in the sustainable supply chain, organizations build a good citizen reputation.
The good reputation improves legitimacy and access to critical resources (Wolf, 2014).
Thus, organizations take a proactive approach to the sustainable supply chain and
corporate sustainability to ensure the long-term resource supply and sustainable corporate
performance.
This Direct Effect Model 1 represented the direct relationship between sustainable
SCM and corporate sustainability performance. The model as a whole was able to
significantly predict corporate sustainability performance. This finding is in alignment
with Wolf’s finding indicating that sustainable SCM has a direct and separate effect on
corporate sustainability performance, which also represents the data best. Based on the

144
finding, proactive sustainable SCM directly benefits an organization beyond reducing
stakeholder pressure. Thus, sustainable SCM positively related to corporate sustainability
performance and specifically to corporate financial performance.
The direct effect of stakeholder pressure on corporate sustainability
performance. Managing various demands of suppliers is challenging for organizations
(Kam-Sing Wong, 2014). The objective of any organization is to maximize independence
and certainty especially in resources (Pfeffer & Salancik, 1978). Organizations
significantly depending on the external environment will struggle to lessen this
dependence in various manners (Pfeffer & Salancik, 1978). Often organizations engage
in sustainable practices when they fear or faced with reduced access to resources due to
stakeholder pressure (Wolf, 2014). Sustainable SCM becomes critical to organizations
vulnerable to internal and external stakeholder pressures (Wolf, 2014). Through
sustainable SCM, organizations address environmental, social, and economic aspects of
business operations to reduce stakeholder pressure (Wolf, 2014). Stakeholder pressure is
often one of the main reasons why organizations will pursue sustainable SCM (Brindley
& Oxborrow, 2014; Glover et al., 2014; Tseng & Hung, 2014). Thus, organizations take a
reactive approach to sustainable practices when they fear or faced with reduced access to
resources due to stakeholder pressure.
The Direct Effect Model 2 represented the direct relationship between stakeholder
pressure and corporate sustainability performance. The model as a whole was able to
significantly predict corporate sustainability performance. This finding is also in
alignment with Wolf’s finding indicating that stakeholder pressure has a direct and

145
separate effect on corporate sustainability performance, which also represents the data
best. Thus, stakeholder pressure positively related to corporate sustainability performance
and specifically to corporate financial performance. However, the main contributor in this
model was an organizational size. Thus, the significance of the stakeholder pressure to
directly predict the corporate sustainability performance depends on the size of an
organization.
The moderating effect of stakeholder pressure. Organizational managers may
have a reason for proactively pursuing sustainable practices other than stakeholder
pressure since sustainable SCM contributes to corporate sustainability performance but
the effect can be greater when stakeholder pressure occur (Wolf, 2014). The
stakeholders’ expectations, whether they are internal or external, need to be incorporated
into the sustainable supply chain operations if the pressure is present (Cantor et al., 2014;
Wolf, 2014). The integration of stakeholder expectations into the organizational strategy
improves corporate sustainability performance (Cantor et al., 2014; Wolf, 2014). Thus,
proactive sustainable supply chain practices contribute to corporate sustainability
performance, but the effect is greater when stakeholder pressure occurs.
The Moderating Effect Model 3 represented the relationship between sustainable
SCM, with stakeholder pressure as a moderator, and corporate sustainability
performance. The results of the analysis indicated non-significant moderation effect of
stakeholder pressure on the relationship between sustainable SCM and corporate
sustainability performance. This finding is also in alignment with Wolf’s finding

146
indicating the non-significant moderating effect of stakeholder pressure on sustainable
SCM-corporate sustainability performance relationship.
The mediating effect of stakeholder pressure. Many organization managers fail
to recognize the potential benefits of sustainable practices for overall organizational
performance unless they yield short-term profits (Alexander et al., 2014; Bradly, 2015).
Organizations are not recognizing sustainable SCM as beneficial to strategic objectives
also due to the challenges engage in sustainable practices only if there is pressure upon
the resource dependence relationship with one or more stakeholders (Pfeffer & Salancik,
1978; Wolf, 2014). Stakeholder pressure determines the extent to which an organization
engages in sustainable SCM. The extent of engagement in sustainable SCM will affect
corporate sustainability performance (Wolf, 2014). Thus, stakeholder pressure mediates
sustainable SCM, and in turn, sustainable SCM shapes corporate sustainability
performance (Cantor et al., 2014; Wolf, 2014). Thus, Stakeholder pressure determines the
extent to which an organization engages in sustainable supply chain practices
The Mediating Effect Model 3 represented the relationship between sustainable
SCM, with stakeholder pressure as a mediator, and corporate sustainability performance.
The results of the analysis indicated non-significant mediation effect of the stakeholder
pressure on the relationship between sustainable SCM and corporate sustainability
performance. This finding is also in alignment with Wolf’s (2014) findings indicating
that the mediating effect of stakeholder pressures on sustainable SCM is not significant.
Overall, the findings of the study are in alignment with the results of Wolf’s
study. Wolf employed environmental and social dimensions of sustainability in

147
measuring corporate sustainability performance. In this study, I employed economic
dimension of sustainability in measuring corporate sustainability performance to test
whether corporate sustainability performance as measured by an economic dimension of
sustainability is affected by sustainable SCM and stakeholder pressure. Wolf (2014)
employed Sustainalytics ESG database and extended existing research by conceptualizing
corporate sustainability with environmental and social dimensions of sustainability. By
applying RDT to a sustainable SCM context, Wolf empirically assessed the relationship
between sustainable SCM and corporate sustainability performance, stakeholder pressure
and corporate sustainability performance, and the effect of stakeholder pressure on the
sustainable SCM and corporate sustainability performance. Wolf provided valuable
insights for managerial decision makers by illustrating the positive relation between
sustainable SCM and corporate sustainability performance (Wolf, 2014). This study
extended Wolf’s study by testing if corporate sustainability performance as measured by
an economic dimension of sustainability is affected by sustainable SCM and stakeholder
pressure. Thus, hypothesized relationships apply equally to all three dimensions of
corporate sustainability performance. Additionally, the results of the tests of the models
indicated that the models were significant in predicting the outcome.
The adoption of both proactive sustainable SCM and sustainable SCM due to
stakeholder pressure is associated with positive outcomes such as improved
environmental concerns, competitive advantage, cost and risk reduction, revenue
increase, and positive effects on company image and employee motivation (Bradly, 2015;
Kumar et al., 2013). Sustainable SCM and stakeholder pressure directly influence the

148
strategies organizations employ to enhance corporate sustainability performance because
doing so resolves elements of a resource dependence problem, ameliorates stakeholder
pressure, and ensures sustainable profitability (Wolf, 2014). The moderating and
mediating effect of stakeholder pressures on the sustainable SCM-corporate sustainability
performance relationship requires additional research. Research in the field of sustainable
SCM receives considerable attention. However, the research field is still very young but
is growing very fast (Taticchi et al., 2013).
A discussion of sustainability impacts on organizational performance, including
discussion of the competitive and cost-effectiveness potentials of sustainability, is one of
the most recent trends (Bateh et al., 2013; Linnenluecke & Griffiths, 2013). In existing
studies, Singal (2013), Wang and Sarkis (2013), and Wolf (2014) have examined the
combined effect of sustainability parameters on firm performance. Lee et al. (2013) and
Fujii, Iwata, Kaneko, and Managi (2013) addressed the effect of individual dimensions of
sustainability on firm performance. Kurapatskie and Darnall (2013) extended prior
research on the broader connections between sustainable practices and financial
performance. Kurapatskie and Darnall found that while lower and higher order
sustainability activities are in alignment with organizations’ financial performance,
financial benefits related to higher sustainability activities are greater. Thus,
organizations actively integrating sustainability are more likely to reap greater financial
benefits (Kurapatskie & Darnall, 2013).
Stakeholder pressure has contributed to the sustainability practices and
performance of organizations (Ramanathan et al., 2014; Wolf, 2014). Stakeholders

149
pressure on organizations to mitigate risk and joint planning activities with suppliers
serve as a mediating role in the model (Cantor et al., 2014; Lozano, 2013). The Cantor et
al. (2014) study is one of the first papers to test empirically how stakeholders’ pressure
mediates the relationship between sustainable SCM and corporate sustainability.
Ramanathan et al. (2014) analyzed the impacts of various organizational pressures on the
environmental performance of manufacturing firms and found that all five analyzed
pressures exert significant influence on environmental performance. Ramanathan et al.
(2014) provided a holistic analysis considering a variety of stakeholder pressures in a
single framework and extended the application of the RDT. Adebambo, Abdulkadir, Mat,
and Alkafaagi (2013) also investigated the sustainable environmental manufacturing, the
direct influence of its drivers, and financial performance by employing a survey approach
and structural equation modeling. Adebambo et al. found that stakeholder pressure,
legislation, and perceived benefits directly influence the implementation of sustainable
environmental manufacturing practices and financial performance. However, this study
findings as well Wolf’s findings did not support moderating and mediating effect of
stakeholder pressure on corporate financial performance. In the moderation model, while
the model was significant in predicting the outcome, the interaction effect of stakeholder
pressure was not significant. In the mediation model, there was small mediating effect of
stakeholder pressure but non-significant. It is possible that factors not examined in the
study determined the importance of stakeholder pressure in a sustainable SCM context
(Wolf, 2014).

150
Applications to Professional Practice
Prior research on sustainability in business often assumed that decisions on social
and environmental investments are made for instrumental reasons (Gao & Bansal, 2013).
To be able to reflect the principles of business sustainability, organizations need to
integrate social and environmental issues with core strategic issues at the supply chain
level (Gao & Bansal, 2013). The growing awareness of the original approach to
sustainability, which recognizes the three dimensions of sustainability (corporate
financial performance, social performance, and environmental performance) as a part of a
system, drive organizational leaders to proactively pursue an integrative logic to
sustainability, especially within their supply chains (Gao & Bansal, 2013). Yet, there is
little theoretical development or empirical analysis of the integrative sustainability logic
while it is critical for supply chains to gain an absolute understanding of the complex
correlation and interplay of factors that foster sustainability and company
competitiveness (Gopalakrishnan et al., 2012). The complexity and the little theoretical
development of an original approach to sustainability suggest that findings of this study is
not an end in itself, but the next-to-last step in a scientific process that culminates in
providing information about the phenomenon (Cohen et al., 2013). This study addressed
a gap in the academic literature concerning the understanding and effective practice of
corporate sustainability performance. The study, as a business research, gathered,
analyzed, interpreted, and reported information so that business decision-makers become
more effective in the desire to better understand the sustainability issue. The research
could be of value to practitioners as it attends to the primary objective of organizations

151
such as sustainable financial performance. Thus, the findings of the study might assist
organizational leaders in the decision-making process in pursued of the long-term
sustainable business, as an effective decision-making requires the manager-researcher
relationship where both the decision maker and the researcher perform their respective
roles responsibly and ethically.
Implications for Social Change
Communities and governments around the world long for environmentally
friendly businesses, quality products and services, and organizational compliance with
regulations concerning the socio-environmental impact of the supply chain
(Gopalakrishnan et al., 2012). More organizations strive to embrace and transcend
contradictions in operational and organizational activities regardless of the challenges in
the process of implementing sustainability due to the complexity of issues, difficulties in
capturing this complexity, and continuously emerging new areas of concern. The
evolutionary nature of supply chains requires continuous improvement of practices for
sustaining the business operations (Gopalakrishnan et al., 2012). Often organizational
leaders attempt to develop creative solutions to not only build a competitive advantage
but also do so in harmony with the planet and society (Elliot, 2013; Gao & Bansal, 2013).
The implementation of any sustainability agenda in supply chains requires formulation
and operationalization of an integrated approach that addresses the relevant social,
economic, and environmental issues (Whiteman, Walker, & Perego, 2013). The findings
of this study might further challenge managerial decision makers to rethink management
approaches to corporate sustainability, to acknowledge potential benefits of deploying

152
sustainability in supply chains in an integrated manner, and to understand how companies
contribute individually and collectively to the sustainability, which incorporates people,
planet, and profit (Gopalakrishnan et al., 2012). A deep understanding of the very nature
of sustainable development could lead supply chains across the world to manage
economic, social, and environmental dimensions of business operations by considering
the needs of today without compromising the needs of future generations (Gao & Bansal,
2013; WCED, 1987). Sustainable development of supply chains support the conservation
of natural resources, the improvement of working conditions and living standards of
stakeholders, and their involvement in philanthropic activities in an integrated manner.
Recommendations for Action
Many supply chain managers fail to recognize the potential benefits of sustainable
practices for overall organizational performance unless they yield short-term profits
(Alexander et al., 2014; Bradly, 2015). Organizations are not recognizing sustainable
SCM as beneficial to strategic objectives also due to the challenges engage in sustainable
practices only if there is pressure upon the resource dependence relationship with one or
more stakeholders (Pfeffer & Salancik, 1978; Wolf, 2014). Short-term financial
performance to meet stakeholders’ expectation no longer guarantees an organization’s
long-term survival (Sezen & Cankaya, 2013).
In this study, using Sustainalytics ESG data and S&P’s long-term issuer credit
ratings of 164 organizations form Newsweek 2016 Green Ranking list, I tested whether
there is a significant relationship between sustainable SCM, stakeholder pressure, and
corporate financial performance. The results of the study are in alignment with Wolf’s

153
(2014) findings indicating that sustainable SCM has more to offer an organization when
not implemented as a reaction to stakeholder pressure. While stakeholder pressure also
has a direct effect on corporate sustainability performance, the best predictors of financial
and market-based performance are the environmental and social performance of
organizations. The effect of sustainable SCM on corporate financial performance is
considerably significant than the effect of stakeholder pressure. Additionally, the analysis
of the moderating and mediating effect of stakeholder pressure on the sustainable SCM-
corporate financial performance relationship did not provide significant results. Thus,
supply chain managers may consider results of this study in the decision-making process.
To make the results of the study available for supply chain decision makers, I will offer
the study for publication in peer-reviewed academic journals and professional
organizations such global supply chain associations. The recommendations to supply
chain managers upon the result of the study are:
First, supply chain managers must strive to better understand the relationship between
sustainable SCM and stakeholder pressure to consider more appropriate strategies for
supply chain sustainability, to integrate stakeholder expectations into the design of those
strategies effectively, and to gain the long-term economic sustainability. Second, the
integration of the environmental, social and economic dimensions of business operations
should be explored by supply chain decision makers as there is a positive link between
organizations’ sustainable SCM and economic performance. Third, organizations must
strive for a higher ESG performance as ESG factors are becoming the core of business.
Investors are becoming aware of the importance of environmental, social, and

154
governance factors in the estimation of corporate value and whether the organization can
increase its value and provide adequate returns on their investments over a longer period
(Klettner et al., 2014; Kosmanova & Docekalova, 2013).
Organizations need to work with one another in promoting sustainable SCM
practices as a way to achieve organizational success rather than merely as a moral
obligation (Alexander, Walker, & Naim, 2014; Wang, Rodrigues, & Evans, 2015).
Sustainable SCM practices should promote to organizational success (Green et al., 2015).
A strong focus of organizations on the integration of the social, economic, and
environmental dimensions needed to ensure corporate sustainability and a sustainable
future (Gopalakrishnan et al., 2012; Tseng & Chiu, 2013; Tseng et al., 2015).
Recommendations for Further Research
This study had limitations that offer opportunities for future research. In this
study, I built upon Wolf’s suggestion for further research and tested whether corporate
sustainability performance as measured by an economic dimension of sustainability is
affected by sustainable SCM and stakeholder pressure. In measuring corporate
sustainability performance, Wolf captured two dimensions of sustainability,
environmental and social. In this research, I extended Wolf’s study by employing the
third economic dimension of sustainability in measuring corporate sustainability
performance. S&P long-term issuer credit rating was used as a measure of corporate
sustainability performance. Future research migh test the hypothesized relationships by
using accounting and market-based flow variables as a measure of corporate financial
performance. As in Wolf’s study, the data were cross-sectional that might have created

155
lagged effect of stakeholder pressure on the relationship between sustainable SCM and
corporate sustainability performance, which could affect the results of the analyses for
models 3 and 4. This also provides an opportunity for the additional research. Future
research might extend the research on moderating and mediating effect of stakeholder
pressure on corporate sustainability performance by using different measures and larger
sample size to test the hypothesized relationships.
Reflections
The doctoral study was another learning experience that extended my knowledge
and experience in academic research and writing. Further research of an existing study,
specifically, addressing a limitation of the existing study was a challenging process. The
help of my committee members and the extensive academic literature available through
the Walden library was very valuable. The textbooks on quantitative methodology and
especially Andy Field’s Discovering Statistics using IBM SPSS Statistics were most
helpful in conducting the data analysis. Standards & Poor’s publicly available data and
the cooperation of Sustainalytics in providing the data for the research made this study
possible.
Conclusion
Lack of understanding of the relationship between sustainable SCM, stakeholder
pressure, and corporate sustainability performance causing many supply chain managers
to fail to recognize the potential benefits of sustainable practices for overall
organizational performance unless they yield short-term benefits. This gap was a driving
force for examining the efficacy of sustainable SCM and stakeholder pressure in

156
predicting corporate sustainability performance. In this study, I built upon Wolf’s
suggestion for further research. By applying the RDT to a sustainable SCM context, Wolf
examined the relationship between sustainable SCM and corporate sustainability
performance, stakeholder pressure and corporate sustainability performance, and the
effect of stakeholder pressure on the sustainable SCM and corporate sustainability
performance. In measuring corporate sustainability performance, Wolf captured two
dimensions of sustainability, environmental and social. In this study, I tested whether
corporate sustainability performance as measured by an economic dimension of
sustainability is affected by sustainable SCM and stakeholder pressure. Wolf’s competing
models of the potential relationship between sustainable SCM, stakeholder pressure, and
corporate sustainability performance were employed to analyze which of the four models
best predict the outcome. The participants of the study were 164 global public
organizations with sustainable practices from the Newsweek 2016 Global Green Ranking
list.
Hierarchical multiple regression analyses were employed to estimate the
corporate sustainability performance impact of the independent composite variables
(sustainable SCM and stakeholder pressure), and the moderating and mediating effect of
stakeholder pressure. The results of the study indicated that there is a significant positive
relationship between sustainable practices and financial performance and between
stakeholder pressure and financial performance. The effect of sustainable SCM on
corporate financial performance is considerably significant than the effect of stakeholder
pressure. The analysis of the moderating and mediating effect of stakeholder pressure on

157
the sustainable SCM-corporate financial performance relationship did not provide
significant results. The results of the study are in alignment with the findings of Wolf
(2014) indicating that sustainable SCM and stakeholder pressure directly influence the
strategies organizations employ to enhance corporate sustainability performance. This
study extended Wolf’s study by testing if corporate sustainability performance as
measured by an economic dimension of sustainability is affected by sustainable SCM and
stakeholder pressure. Thus, hypothesized relationships apply equally to all three
dimensions of corporate sustainability performance. Additionally, the results of the tests
of the models indicated that the models were significant in predicting the outcome. Thus,
the integration of the environmental, social and economic dimensions of business
operations should be explored by supply chain decision makers as there is a positive link
between sustainable SCM and economic performance. This study had limitations that
offer opportunities for future research. Future research might further test moderating and
mediating effect of stakeholder pressure on corporate sustainability performance by using
different measures and larger sample size to test the hypothesized relationships.

158
References
Adebambo, H. O., Abdulkadir, R. I., Mat, N. K. N., & jihad Alkafaagi, A. A. (2013).
Drivers of sustainable environmental manufacturing practices and financial
performance among food and beverages companies in Malaysia. American
Journal of Economics, 3, 127-131.
doi:10.5923/j.economics.20130302.11
Aguilera-Caracuel, J., & Ortiz-de-Mandojana, N. (2013). Green innovation and financial
performance: An institutional approach. Organization and Environment, 26, 365-
385. doi:10.1177/1086026613507931
Albertini, E. (2013). Does environmental management improve financial performance? A
meta-analytical review. Organization and Environment, 26, 431-457. doi:10.1177
/1086026613510301
Alexander, A., Walker, H., & Naim, M. (2014). Decision theory in sustainable supply
chain management: A literature review. Supply Chain Management: An
International Journal, 19, 504-522. doi:10.1108/SCM-01-2014-0007
Al Zaabi, S., Al Dhaheri, N., & Diabat, A. (2013). Analysis of interaction between the
barriers for the implementation of sustainable supply chain management.
International Journal of Advances Manufacturing Technology, 68, 895-905. doi:
10.1007/s00170-013-4951-8
Bansal, P., & DesJardine, M. R. (2014). Business sustainability: It is about time.
Strategic Organization, 12, 70-78. doi:10.1177/1476127013520265
Bason, T., & Anagnostopoulos, C. (2015). Corporate social responsibility through sport:
A longitudinal study of the FTSE100 companies. Sport, Business and

159
Management: An International Journal, 5, 218-241. doi:10.1108/SBM-10-2014-
0044
Bateh, J., Heaton, C., Arbogast, G. W., & Broadbent, A. (2013). Defining sustainability
in the business setting. American Journal of Business Education, 6, 397-400.
Retrieved from http://www.cluteinstitute.com/
Bealt, J., Barrera, J. C. F., & Mansouri, S. A. (2016). Collaborative relationships between
logistics service providers and humanitarian organizations during disaster relief
operations. Journal of Humanitarian Logistics and Supply Chain Management, 6,
118-144. doi:10.1108/JHLSCM-02-2015-0008
Becker, J. M., Rai, A., Ringle, C. M., & Völckner, F. (2013). Discovering unobserved
heterogeneity in structural equation models to avert validity threats. Mis
Quarterly, 37, 665-694. Retrieved from http://misq.org/
Beske, P., & Seuring, S. (2014). Putting sustainability into supply chain management.
Supply Chain Management: An International Journal, 19, 322-331. doi:10.1108
/SCM-12-2013-0432
Beske, P., Land, A., & Seuring, S. (2014). Sustainable supply chain management
practices and dynamic capabilities in the food industry: A critical analysis of the
literature. International Journal of Production Economics, 152, 131-143. doi:10
.1016/j.ijpe.2013.12.026
Blazovich, J. L., Smith, K. T., & Smith, M. (2013). An examination of financial
performance and risk of environmentally friendly 'green' companies. Journal of

