


INTRODUCTION Sustainability was formally addressed
Sustainability was formally addressed in the General Assembly of the United
Nations in 1987 and sustainable development was officially defined in the report that
followed as the ability to “ensure that [development] meets the needs of the present
without compromising the future generations to meet their own needs” (World
Commission on Environment Development, 1987). Applying this definition to a
business context, companies are expected to not compromise their social
responsibility in their pursuit of high economic performance. According to Gherghina
and Simionescu (2015), this implies that the role of companies is to maximise its
shareholders’ wealth as well as to create value for the society. They argue that this
will result in a win-win proposition for both companies and society and thereby
develop a long term innovative strategy with many business opportunities. Many
prior research studies have proven that companies that adopted this strategy have
yielded many competitive advantages over their competitors such as increase in
market share and enhancement in reputation and brand value (Schaltegger &
Burritt, 2006), reduced operating costs and improvement in financial performance
(Adams & Zutshi, 2004) and increased sales and customer loyalty (Creyer, 1997;
Mohr & Webb, 2005).
Many companies have recognised the importance of including non-financial
information such as sustainability disclosures in their annual financial and stand-
alone sustainability reports to demonstrate their contribution to sustainability (Aras &
Crowther, 2009; Cho, Guidry, Hageman, & Patten, 2012; Higgins, Milne, &
Gramberg, 2015; Patten & Zhao, 2014). Hence, in the last few decades, the concept
of sustainability, which involves corporate social responsibility, has received
renewed attention among diverse groups such as academic researchers, company
stakeholders, government organisations and industry groups to study the
development of sustainability reporting (Byrch, Milne, Morgan, & Kearins, 2015;
Cho, Michelon, Patten, & Roberts, 2015; Higgins et al., 2015). Burritt and
Schaltegger (2010) classified this development of sustainability reporting into two
main paths: critical path and managerial path.

The critical path adopts a critical theory perspective. It consists of critical theorists
who argue that sustainability remains ambiguous and highly contestable in its
definition (Gray, 2010; Milne & Gray, 2013; Patten & Zhao, 2014), and they question
the feasibility of implementing sustainability (Aras & Crowther, 2009; Gray, 2010;
Milne & Gray, 2013). They also query the validity of sustainability disclosures
provided by companies (Atkins, Atkins, Thomson, & Maroun, 2015; Gray, 2010) and
the ability to reflect actual performance that could contribute to a sustainable society
(Atkins et al., 2015; Cho et al., 2012; Gray, 2010; Gray & Milne, 2002; Hopwood,
2009; Milne & Gray, 2013).
The managerial path recognises sustainability reporting as an important tool that
assists managers in making effective decisions. These management theorists posit
that managers can effectively apply information in sustainability disclosures to
assess deliberate actions for sustainable developments (Burritt & Schaltegger,
2010;
Hawkins, 2006; Schaltegger & Burritt, 2006; Weidinger, Fischler, & Schmidpeter,
2014). They believe that managers are driven by both external and internal
stakeholders to ensure quality sustainability measures are implemented. The
managers are thus motivated to engage in strategies that can produce good results
in sustainable development to meet stakeholders’ expectations.
Both paths suggest a need for a standardised and comprehensive reporting
framework that can effectively measure practical sustainability performance with
disclosures that are verifiable and comparable. Supporters of the critical path are
demanding that companies’ sustainability disclosures demonstrate actual
contributions to sustainable development (Atkins et al., 2015; Milne & Gray, 2013)
while proponents of the managerial path require a framework that provides guidance
in sustainability reporting to make managers’ contributions towards sustainability
evident (Deegan & Gordon, 1996; Emery, 2002; Frost, Jones, Loftus, & Laan, 2005).
However, the lack of a standardised reporting framework has resulted in
inconsistencies in the extent of sustainability disclosures, which hinder verifiability
and comparability.

In addition to the lack of a standardised reporting framework, there are other
influencing factors that have caused vast differences among companies’
sustainability reporting. Prior research studies have identified that companies with
differences in various company characteristics such as companies’ size, financial
performance and governance structure tend to differ in their sustainability reporting
(Aras & Crowther, 2008; Deegan & Gordon, 1996; Kolk, 2006; Tagesson et al.,
2009). This research addresses these problems by developing a framework that can
effectively measure and compare companies’ sustainability performance and
disclosures.
This introductory chapter introduces the background information which underpins
the importance and purpose of this study. It also explains the research questions
developed from relevant theoretical frameworks and prior studies and presents a
summary of the structure of this research.
1.1 Research Background
Discussions about sustainable development and concern over the impact of
economic and industrial development on the environment have increased
significantly since the
1970s. In the past, many considered sustainable development to be “nothing more
than an ideal” notion which could not be easily achieved (Deegan, 2013, p. 383). An
important step in raising awareness about sustainable development occurred when
it was included in the agenda at the General Assembly of the United Nations in 1987
(De Jong, Brown, & Lessidrenska, 2009; Deegan, 2013; Hussey, Kirsop, & Meissen,
2001). A report published after the assembly entitled Our Common Future provided
a definition for sustainable development. The report claimed that sustainable
development should be “a process of change in which the exploitation of resources,
the direction of investments, the orientation of technological development, and
institutional change are made consistent with future as well as present needs”
(World Commission on Environment Development, 1987, p. 9). The report also
highlighted the need for governments and companies to consider the impacts on the
economy, society and environment when making decisions and formulating policies.

It concluded with a unanimous call for nations to adopt relevant changes for a
common goal towards sustainability development.
Many companies globally have responded to this call by disclosing sustainability
information about the economic, social and environmental impact of the companies’
operations (Betianu, 2010; Deegan, 2013). Government legislation, media pressure
and public interest groups have also demanded for greater transparency in
companies’ sustainability disclosures as they expect companies to not only be
profitable but also socially and environmentally responsible.
According to Kolk (2006), the increased call for transparency about corporate
behaviour comes from two different angles, and has recently shown some overlap.
One of the angles is accountability requirements in the context of corporate
governance that have expanded from internal operating mechanisms relating to
board of directors and managers to include ethical aspects such as remuneration,
managerial and employee behaviour and complaint mechanisms. The other angle is
sustainability reporting that was originally focused primarily on the environmental
aspect, but has broadened in scope to include ethical/ social issues such as
employee and community matters. Thus, Kolk concludes that the two rather distinct
angles of transparency have shown convergence in terms of topics and also in a
broader targeted audience.
This increasing demand for sustainability disclosures from broader and diverse
groups of stakeholders has resulted in a significant increase in research studies in
sustainability and sustainability disclosures in recent decades. Cho et al. (2015)
studied the development of research studies in sustainability and examined whether
the recent studies have differed from those of the 1970s. In the initial stage,
researchers generally focused on the discussion of the definition for sustainability,
the significance of sustainability and the drivers for companies to disclose
sustainability information (Deegan, 2002; Patten, 1992). With the increased
acceptance of the notion of sustainability and the adoption of sustainability
reporting, the focus of the research shifted to the accounting aspects of
sustainability that address disclosure issues such as what, when and how to include

information on sustainability (Deegan & Gordon, 1996; Emery, 2002). In more recent
research, studies have focused on empirical evidence that examine factors affecting
sustainability reporting (Cho et al., 2015; Clarkson, Li, & Richardson, 2004; Jones,
Frost, Loftus, & Laan, 2007; Tagesson, Blank, Broberg, & Collin, 2009) and have
investigated the relationship between sustainability disclosures and practical
sustainability performance (Cho et al., 2012; Clarkson, Li, Richardson, & Vasvari,
2008; Patten & Zhao, 2014).
Despite the changes in the research focus performed by researchers across
different decades and among different geographical locations, many of these prior
studies have identified the lack of a standardised sustainability reporting framework
as a common problem (Adams & Frost, 2007; Betianu, 2010; Crawford & Williams,
2010; De Jong et al., 2009; Dingwerth & Eichinger, 2010; Gibson & O'Donovan,
2007; Gray, Javad, Power, & Sinclair, 2001; Hussey et al., 2001; Tagesson et al.,
2009) and suggested the urgent need of “innovative techniques for enhanced
sustainability accounting and stewardship” (Atkins et al., 2015). Kolk (2006, p. 1)
highlighted another common problem of sustainability reporting where companies,
especially multinational enterprises, are also challenged with more complex
situations because they are “confronted with a multitude of requests from
shareholders and other stakeholders in different markets with frequently varying
regulations and governance systems”. Without a standardised framework to guide
companies’ disclosures, companies have produced sustainability reports that differ
extensively in both the amount and nature of sustainability information and this has
hindered comparison. Furthermore, the sustainability disclosures generally do not
provide sufficient quantified information on companies’ actual performance that may
have an effective contribution towards sustainability development.
Hence, this research addresses these problems with the development of a new
scoring framework that integrates verifiable and comparable measures into a current
comprehensive sustainability reporting framework, the Global Reporting Initiative
(GRI). The new index is applied to examine the effects of companies’ size, financial
performance and governance structure on sustainability reporting.

1.2 Research Rationale
1.2.1 Disclosures not reflective of performance
The development of sustainability reporting has formed two main paths: critical path
and managerial path (Burritt & Schaltegger, 2010). While researchers from the
critical path found companies’ sustainability reporting on business activities having
no or little relevance to sustainability (Gray, 2010; Gray et al., 2001; Gray & Milne,
2002; Milne & Gray, 2013), others from the managerial path are using their
knowledge on sustainability to implement feasible business systems that drive
effective business strategies to achieve better sustainability performance (Burritt &
Schaltegger, 2010; Weidinger et al., 2014).
Gray (2010, p. 48) from the critical path explained that the “relationships and
interrelationships [of sustainability] are simply too complex” and any simple
assessment that is used to evaluate the relationship between “a single organisation
and planetary sustainability is virtually impossible”. He believed that it is not possible
to put any tangible meaning to sustainability at an organisational level as this means
ignoring the correct understanding of sustainability altogether because sustainability
is a systems-based concept that would be difficult to conceptualise at the level of
ecosystem. He questioned the ability of companies to understand this complex
concept of sustainability to produce appropriate and measurable accounts of
sustainability that are related to effective sustainable developments for society. His
views were supported by many prior researches in the critical path (Aras &
Crowther, 2009; Gray et al., 2001; Milne & Gray, 2013) .
Similar to other prior research (Cho et al., 2012; Milne & Gray, 2013), Gray (2010, p.
50) alleged that companies nowadays tend to use these reports as “linguistic
devices” to proclaim their social responsibility while diverting attention away from
actual sustainability performance. He asserted that these reports “do not constitute
genuine accounts of sustainability, but are “powerful fictions” because it is common
to assume a successful business will have to be socially and environmentally

responsible and thus there would be generally no verification to ensure that the
business is actually socially responsible. According to Gray, this consequently leads
to a decline in real sustainability performance and causes un-sustainability that
ironically contradicts the fundamental notion of sustainability.
In a recent empirical study performed by Patten and Zhao (2014) on the retail
industry in the United States, they found companies were disclosing more
information on initiative programmes and strategy than relevant performance data.
Companies with standalone sustainability reports that were assessed to be more
environmentally reputable were not genuinely good environmental performers. This
result was consistent with the findings in Cho et al. (2012) where negative
relationships were found between companies’ environmental performance and both
reputation scores and memberships in Dow Jones Sustainability Index (DJSI). Cho
et al. (2012) also found companies’ environmental performance to be negatively
related to their environmental disclosure. Similar results were yielded in prior
research (Hopwood, 2009).
This study addresses the gap identified by researchers of the critical path by
developing a scoring index that establishes the missing connection between
companies’ disclosures to their actual sustainability performance.
1.2.2 Limitations of existing reporting framework
Despite the availability of a comprehensive sustainability reporting guidelines - the
Global Reporting Initiatives (GRI) framework, the GRI framework has several
limitations. Gray (2010) claimed that the GRI framework merely includes all three
aspects (social, economic and environment) of sustainability but it still fails to
establish relationships between the demand for sustainability performance to the
reported disclosures. Milne and Gray (2013, p. 21) described the GRI framework as
“both partial and incoherent”. They argued that the GRI framework is partial as the
full range of performance indicators represent on one part the difficulty to produce
acceptable indicators and the other part which companies are reluctant to produce
as they are too demanding. They also claimed that the GRI framework is not

coherent as there is a lack of over-arching theory to guide the selection of reporting
indicators and to ensure that the selected indicators are related to one another and
capable to address the issues of concern.
Clarkson et al. (2008) classified the GRI environmental performance indicators into
hard and soft disclosure items. Hard disclosure items refer to disclosures that are
“relatively difficult for poor environmental performers to mimic” and thus these
disclosures are awarded higher scores as they represent companies’ real
commitments to sustainability (Clarkson et al., 2008, p. 313) . On the other hand,
soft disclosure items relate to information which is relatively difficult to verify with
companies’ actual efforts to protect the environment, such as companies’ vision and
environmental strategy claims, and hence they are allocated with lower scores.
Clarkson et al.’s (2008) index provides an improved measurement to evaluate
environmental disclosure because companies with genuine contributions to
environmental sustainability can be identified through the higher scores awarded by
the index. This study builds on the fundamental principles of Clarkson et al.’s (2008)
environmental index and develops a new index that also includes the social and
economic aspects of sustainability which were not covered by Clarkson et al.
1.2.3 Inconsistent empirical results
Previous researchers have attempted to establish relationships between companies’
characteristics (such as company’s size, financial performance, governance
structure and industry type) and the extent of sustainability disclosures (Deegan &
Gordon, 1996; Frost, 2007; Gray et al., 2001; Ho & Taylor, 2007; Rupley, Brown, &
Marshall, 2012; Tagesson et al., 2009; Webb, 2004).
1.2.3.1 Company size
Tagesson et al. (2009) studied listed companies in Sweden and found some
variables that have significant correlations to the extent of social and environmental
disclosures. These include the size of the company, the industry in which the
company operates, and the profitability and ownership structure of the company.

Positive relationships were found between the extent of disclosures and the
company’s size and profitability. It was also found that companies in environmentally
sensitive industries and stateowned companies engaged in greater sustainability
disclosures. Tagesson et al. (2009, p. 354) concluded that ‘industry – together with
size – was the most common variable for explaining the extent and content of social
and environmental disclosures’.
In general, larger corporations are expected to possess greater capabilities and
resources to engage in a greater extent of information disclosure. In addition, larger
companies which attract greater publicity are generally under greater scrutiny (Frost,
2007). These suggest a positive relationship between the size of a company and the
extent of its environmental disclosure. While some findings from previous research
have confirmed this suggestion (Frost, 2007; Gray et al., 2001; Ho & Taylor, 2007;
Tagesson et al., 2009), some other research have found that this relationship is only
applicable to companies operating in environmentally sensitive industries (Deegan &
Gordon, 1996). To further explore these inconsistent results, this research revisits
selected Australian listed companies in the resources industry and analyse, using all
three aspects of the GRI framework, the extent of sustainability disclosures provided
by these companies in their annual financial reports and standalone sustainability
reports.
1.2.3.2 Company financial performance
Evidence from prior studies suggests that companies with superior financial
performance tend to produce more environmental disclosure (Gray et al., 2001; Ho
& Taylor, 2007; Tagesson et al., 2009). Jones et al.’s (2007) study of Australian
companies yielded a different result when his group analysed companies’ financial
performance based on a wider range of financial indicators. Two out of nine financial
performance indicators studied by Jones et al. (cash to total assets and price to
book value) indicated negative relationships with companies’ sustainability
disclosures. In view of the conflicting results, this research seeks to explore the
relationships between companies’ sustainability disclosures and their financial
performances using financial indicators such as operating revenue, earnings before

interest and tax, return on assets, return on equity, book value per share and year-
end share price.
1.2.3.3 Company board composition
Corporate governance structure comprises the policies, rules and procedures by
which a company is directed and controlled. Recent developments in economic
theory suggest that the board of directors (BOD) is an important part of a company’s
governance structure (Fama & Jenson, 1983). The BOD of a company, which
represents the highest method of internal control of top management (Fama &
Jensen,
1983; Keasey & Wright, 1993), has a major impact on a company’s reporting
practices and procedures. Many recent studies have identified a significant
correlation between the composition of a company’s BOD and the quality of its
sustainability reporting (Michelon & Parbonetti, 2012; Post, Rahman, & Rubow,
2011; Rao, Tilt, & Lester, 2012; Rupley et al., 2012; Siregar & Bachtiar, 2010; Webb,
2004). These studies have identified that the extent of sustainability disclosures is
affected by the following aspects of BOD:
• Proportion of independent non-executive directors (Michelon & Parbonetti,
2012; Post et al., 2011; Rao et al., 2012; Rupley et al., 2012)
• Proportion of female directors (Post et al., 2011; Rao et al., 2012; Rupley et
al., 2012)
• Proportion of directors with multiple directorships (Rupley et al., 2012)
• CEO duality (i.e. company CEO acting as board chairman) (Michelon &
Parbonetti, 2012; Rupley et al., 2012)
• Ownership concentration (Rao et al., 2012)
• Board size (Rao et al., 2012; Siregar & Bachtiar, 2010)
• Existence of a sustainability committee (Michelon & Parbonetti, 2012; Rupley
et al., 2012)
While there have been many studies conducted on BOD in recent research, few
have focused on a board’s impact towards sustainability reporting. Furthermore,

they have tended to concentrate only on the environmental aspects of sustainability.
Hence, this research addresses this gap to explore the impact of the composition of
a company’s BOD on the quality of its sustainability reporting.
1.2.3.4 Company industry type
Prior studies in sustainability reporting have found that companies in
environmentally sensitive industries provide more sustainability disclosures than
those companies in other industries (Bachoo, Tan, & Wilson, 2013; Cho et al., 2015;
Dong & Burritt, 2010; Frost, 2007; Gray et al., 2001; Jones et al., 2007; Tagesson et
al., 2009). This supports the legitimacy theory which suggests that companies
operating within environmentally sensitive industries will respond to social
expectations of corporate behaviour by providing more sustainability disclosures to
legitimise their business operations. Cho et al.’s (2015) study that analysed the
development of sustainability reporting for the last five decades since 1970s have
found strong influence of legitimacy factors on sustainability disclosures over the
decades.
Governments in different countries have adopted varying degrees of mandatory
sustainability disclosure for companies across different industry types. While some
European countries such as Denmark and the Netherlands (Emery, 2002; Frost,
2007) have required all listed companies to provide mandatory environmental
reports, many countries have adopted voluntary disclosure.
In Australia, the first legal requirement for sustainability disclosure was implemented
in 1998. The Corporations Act (2001) section 299 sets out that:
(1) The directors’ report for a financial year must :
(f) if the entity’s operations are subject to any particular and significant
environmental regulation under a law of the Commonwealth or of a State or
Territory, give details of the entity’s performance in relation to environmental
regulation.

Since then, companies with operations bound by environmental regulations have
been required by the Act to provide mandatory disclosure on environmental issues
in their annual reports (Frost, 2007; Jones et al., 2007). Companies in
environmentally sensitive industries such as the resources, manufacturing and
transportation industry are affected by this legislation as the nature of their business
operations has significant impact on the environment (Deegan & Gordon, 1996;
Dong & Burritt, 2010; Wilmshurst & Frost, 2000).
Although companies in the Australian resources industry are mandated to provide
environmental disclosure, they are not obliged to report on the social and economic
aspects of sustainability. In this study, the implementation of the new GRI-based
reporting index facilitates the review of all three aspects of sustainability disclosures
(social, economic and environmental) to determine if resources companies have
placed more emphasis on environmental disclosure compared to the economic and
social aspects, which may indicate their compliance to the legal requirements. In
addition, the study reviews whether companies disclose more hard disclosure items
in each aspect of sustainability to portray themselves as effective sustainability
performers.
1.3 Research Scope
Frost (2007) explored the impact of the first legislation in 1998 on the environmental
reporting of Australian companies by studying companies in environmentally
sensitive industries which were most likely to be affected under this regulation. He
selected companies from the resources (mining, oil and gas), utilities and
infrastructure, and paper and packaging industries. Evidence from his selected
sample revealed that since the introduction of the legislation, the number of
Australian companies providing environmental disclosure has significantly
increased. However, despite this increase, Frost (2007) noted that there were large
variations in the nature of the disclosures, which suggested considerable differences
in the interpretation of the legislation and raised concerns about its practical
application.

Recent studies in sustainability reporting have shown an increasing interest in
industry-specific contexts, such as oil and gas, food and beverages, retail and water
and energy (Dong & Burritt, 2010; Guthrie, Cuganesan, & Ward, 2008; Patten &
Zhao,
2014; Stray, 2008). Consistent with Frost’s (2007) results, these studies found that
companies generally provide broad and generic sustainability disclosures which are
not useful in assessing their sustainability performance (Dong & Burritt, 2010;
Guthrie et al., 2008). Shareholders, investors and regulators have realised that
sustainability issues affect different industry sectors in different ways (Dong &
Burritt, 2010). Hence, there is an increasing demand for more industry-specific
sustainability disclosures to assist companies’ stakeholders make better business
decisions. Furthermore, companies have realised that any major environmental
damage that is caused by a single company in an industry may attract the media
attention, and effectively the whole industry has to bear the consequences. Parker
(cited in Wood & Ross, 2008, p.
6) commented that ‘environmental management and accountability become an
industry rather than a single company issue’.
Industry-based sustainability reporting is also emphasised by the Australian
Government and the GRI (Dong & Burritt, 2010). Industry bodies are encouraged by
the Australian Government to produce sector-wide reports on sustainability as
reporting benchmarks for companies within the industry. The GRI has supplied
sector supplements for selected sectors to assist companies to consider specific
performance indicators relevant to their industry types. This promotes comparability
of sustainability reports and allows monitoring and benchmarking for quality
reporting practices.
Derived from the above discussion, this research aims to measure the quality of
sustainability reporting by adopting a similar industry-specific approach and focusing
on the current leading environmentally sensitive industry in Australia – the resources
industry.

This research has chosen to focus on Australia’s resources industry for several
reasons. First, the resources industry is an important industry sector in Australia.
According to the Australian Securities Exchange’s (ASX) classification used in 2012
at the time of the data collection for this study, the resources industry includes two
sectors: Metals and Mining, and Energy and Utilities. As at December 2014, these
two sectors made up the largest industry sector in ASX, representing 60% of the
total number of listed companies. The resource industry was also the second largest
industry sector measured by market capitalisation, making up 29% of the total
market capitalisation after the financial sector (Australian Security Exchange, 2015).
Second, despite the requirement for companies operating in the resources industry
to include mandatory environmental reporting, the lack of a prescribed reporting
framework has resulted in large variations in companies’ sustainability reporting,
making comparisons and benchmarking very difficult. Third, while many prior studies
have been conducted in the Australian context, very few of them are industry-
specific. Hence, this research addresses this issue by developing a comprehensive
sustainability reporting index to promote comparability among companies’
sustainability reports, and therefore, assists to set a benchmark for good reporting
practices in the resources industry.
1.4 Research Analysis
Previous studies on sustainability reporting have traditionally focused on content
analysis whereby the quantity of words or meaning of paragraphs is used to
evaluate the extent of sustainability disclosures (Deegan & Gordon, 1996; Frost,
2007; Gibson & O'Donovan, 2007; Guthrie & Parker, 1990) . Researchers in earlier
periods have employed content analysis by codifying expressed information based
on the quantity of words, paragraphs or pages used in companies’ annual reports. It
is commonly agreed that one of the major limitations of employing this technique
based on quantity of words used is the potential error in codification, especially
when word counts do not significantly differ (Deegan & Gordon, 1996; Gibson &
O'Donovan, 2007; Guthrie & Abeysekera, 2006; Steenkamp & Northcott, 2007).
Hence, in recent decade, researchers have employed content analysis technique by
focusing on the information disclosed (Cho et al., 2015; Clarkson et al., 2008;

Clarkson, Overell, & Chapple, 2011; Comyns & Figge, 2015; Dong & Burritt, 2010;
Frost et al., 2005; Martínez‐Ferrero, Garcia‐Sanchez, & Cuadrado‐Ballesteros,
2015; Meng, Zeng, Shi, Qi, & Zhang,
2014).
Researchers have adopted different methods to analyse sustainability disclosures.
Some categorised the disclosures into the individual aspects (i.e. social, economic,
and environmental) of sustainability (Cho et al., 2015; Frost et al., 2005; Guthrie &
Parker, 1990), and others classified disclosures according to their nature and details
of information (Comyns & Figge, 2015; Guthrie & Parker, 1990; Meng et al., 2014).
Many analysed the content using a content analysis index such as the GRI
framework (Frost et al., 2005; Martínez‐Ferrero et al., 2015; Tagesson et al., 2009)
and the environmental index of Clarkson et al. (2008). In recent research, more are
focusing on measuring sustainability information in relation to its sustainability
performance (Cho et al., 2012; Galbreath, 2013; Meng et al., 2014). Despite the
various methods used in prior research studies, the lack of a standardised reporting
framework has hindered comparison of sustainability information (Burritt, 2002).
This research seeks to rectify this problem with an appropriate scoring index by
enhancing the comprehensive guidelines stipulated in the GRI social, economic and
environmental indicators with the integration of hard and soft principles from
Clarkson et al. (2008).
1.5 Research Framework
This research measures the quality of sustainability reporting in the Australian
resources industry through the use of a newly developed index based on the GRI
guidelines. This study critically reviews prior studies’ contradictory findings related to
the relationships between company size, financial performance, composition of BOD
and types of resources extracted and the extent of sustainability disclosures to
develop the research questions. This research addresses the following questions:

• To what extent do Australian listed companies in the resources industry
disclose sustainability information in their annual financial reports and
standalone sustainability reports?
• Are there any significant relationships between the extent of sustainability
disclosures (social, economic and environmental) and company
characteristics (company size, financial performance, composition of BOD
and type of resources extracted)?
This research selects the sample from companies listed on the resources industry of
the Australian Securities Exchange (ASX). This study collects data from both the
annual financial reports and standalone sustainability reports of these companies for
the period ending 2012 using stratified sampling to obtain equal representation from
the two sectors within the resources industry (i.e. Metals and mining and Energy
and utilities). Adopting similar criteria that have been used in many prior studies
(Adams, Hill, & Roberts, 1998; Dong & Burritt, 2010; Frost et al., 2005; Guthrie &
Parker, 1990;
Hackston & Milne, 1996; Ho & Taylor, 2007; Jones et al., 2007; Rao et al., 2012;
Suttipun & Stanton, 2012), this study selects the top 100 companies listed on both
the sectors of ASX resources industry based on market capitalisation. This
represents approximately 20% of the total number of listed resources companies as
at June 2012.
Findings from this study address the research questions and provide empirical
evidence to measure the quality of sustainability reporting in the listed companies of
the Australian resources industry. It identifies significant relationships between the
extent of social, economic and environmental disclosures and company size,
financial performance, composition of BOD and type of resources extracted. Market
capitalisation, total sales and total assets of companies are used as measures of a
company’s size. A wide range of financial measures such as operating revenue,
earnings before interest and tax, return on assets, return on equity, book value per
share and year-end share price. Various aspects relating to the composition of a
company’s BOD, such as the proportion of independent directors, multiple

directorships, CEO duality, proportion of women directors on board and the
existence of a sustainability committee, are also considered.
In addition, this study aims to investigate if resources companies have focused more
on environmental disclosure compared to the economic and social aspects and
reviews whether companies disclose more hard disclosure items in each aspect of
sustainability.
Figure 1.1 below illustrates the research framework that is used in this study.
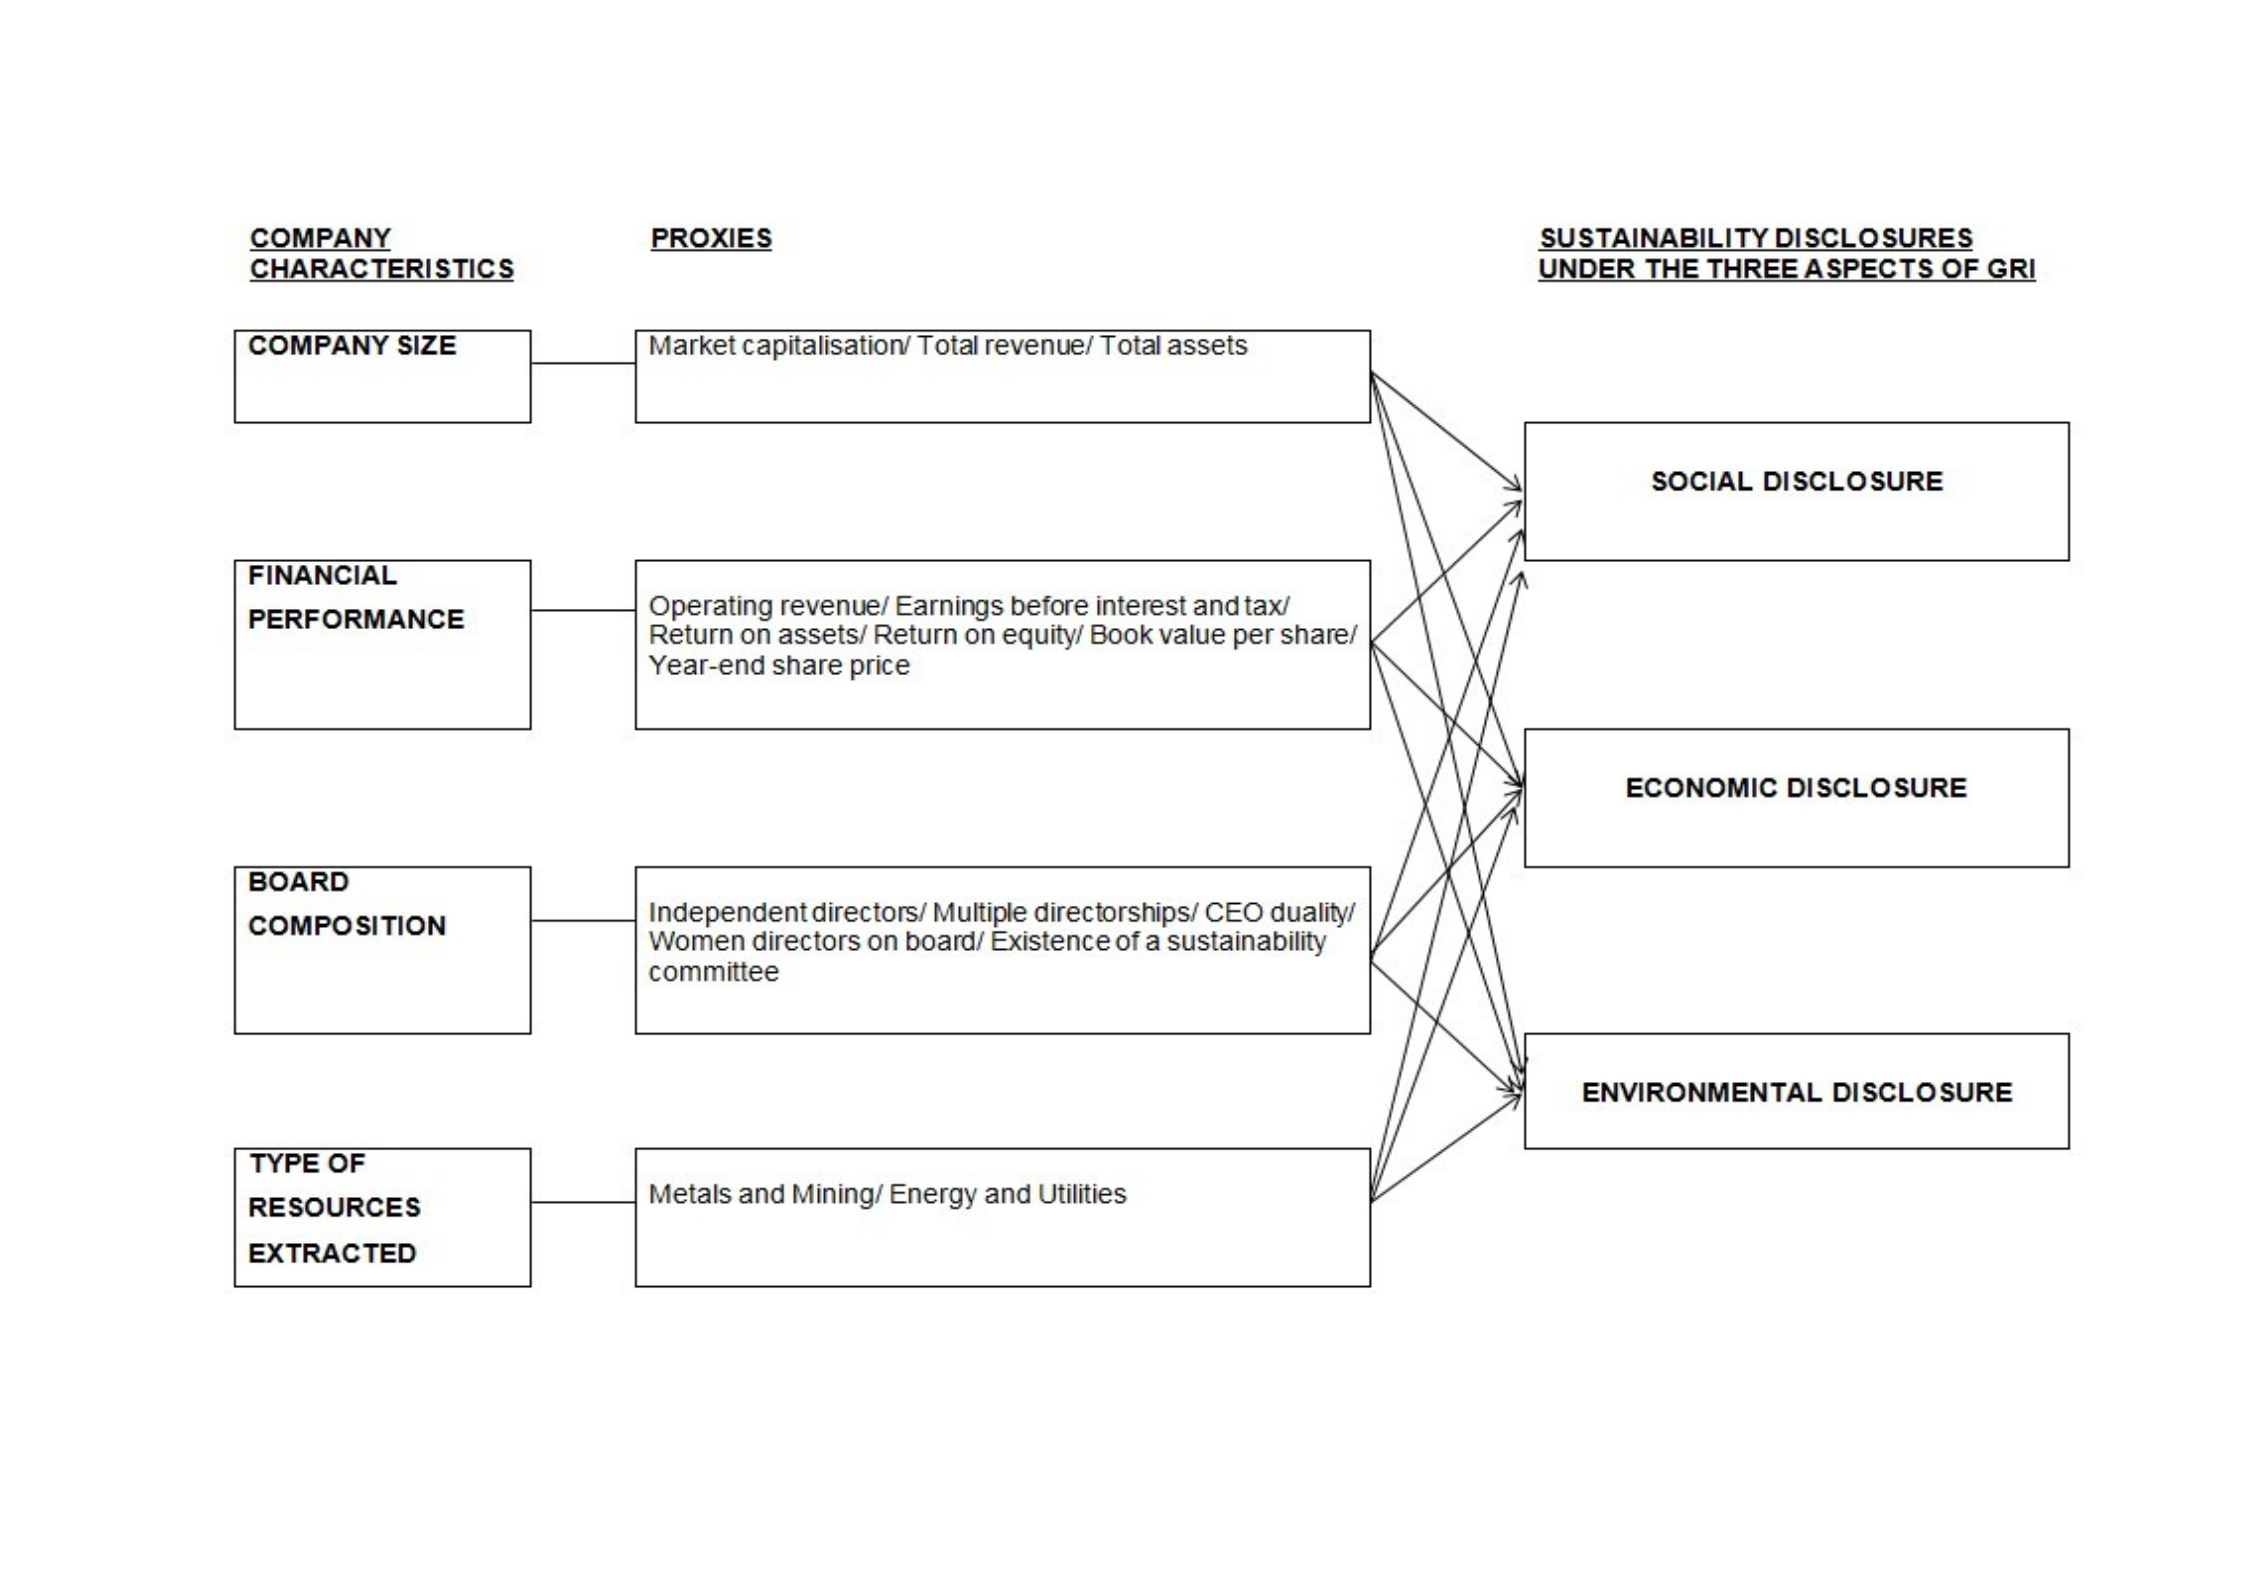

Figure 1.1 Research framework
17

1.6 Research Significance
The development of a new and comprehensive sustainability reporting index in this
research provides an improved measurement for sustainability disclosures. It
addresses the fundamental problem of a lack of a standardised sustainability
reporting index. The ability of the index to align company’s sustainability disclosure to
reflect its practical performance resolves the concern raised by critical theorists and
supports proponents from the managerial path by assisting business managers in
preparing sustainability reports that are reflective of their genuine contribution in
sustainability developments.
The results from this research have practical implications for regulators, investors
and shareholders who rely on both financial and non-financial information to
formulate policies and make business decisions. The outcomes of this industry-
specific study address the demands for industry-based sustainability information. In
addition, it promotes comparability between companies’ sustainability reports and
provides a benchmark for quality sustainability reporting.
Empirical evidence from this research enhances the understanding of the
relationships between various company characteristics (company size, financial
performance, composition of BOD and types of resources extracted) and the extent
of all the three aspects of sustainability disclosures (social, economic and
environmental). The findings from this study also contribute significantly to
companies in the Australian resources industry, which is currently the leading
Australian industry sector.
1.7 Research Organisation
This introduction chapter provides the background and rationale for this study and
establishes the significance and contributions for this research. The following chapter
critically reviews the relevant literature in sustainability and sustainability reporting.
Chapter three explains details of the theoretical framework and traces the
20

development of hypotheses. Following that, chapter four outlines the research
methodology for this study and chapter five describes the development of the new
GRI-based scoring index. Chapter six presents the results of the implementation of
the index with a pilot test and chapter seven discusses the results of the main study.
Finally, chapter 8 concludes the study by summarising the main findings and
presenting the limitations, implications and suggestions for future research.
21

CHAPTER TWO
LITERATURE REVIEW
This chapter reviews the literature related to sustainability and sustainability
reporting. It commences with an overview of the concept of sustainability followed by
an evaluation of the importance and the drivers for companies to engage in
sustainability reporting. Recent developments in sustainability reporting in global
trends are reviewed before focusing specifically on developments in Australia. The
theoretical framework for this research including the legitimacy theory and the
stakeholder theory is presented. The chapter continues with a discussion on the
Global Reporting
Initiatives (GRI) and Clarkson et al.’s (2008) framework for sustainability disclosures
before concluding with a critical review of the variables that have been identified in
prior studies that have impacted on sustainability disclosures.
2.1 Concepts of Sustainability
Some of the recent literature has treated sustainability as a relatively new issue.
However, discussions around the concept of sustainability began much earlier albeit
the term was more commonly known as corporate social responsibility (CSR) at that
stage.
The World Business Council for Sustainable Development defines CSR as “the
continuing commitment by business to behave ethically and contribute to economic
development while improving the quality of life of the workforce and their families as
well as the local community and society at large” (cited in Rankin, 2011, p. 49).
According to Rankin, this definition of CSR suggests companies’ willingness to
accept their social responsibilities, sustainability standards and codes of ethics
above legal requirements. The basis of this view is that companies adopting CSR
principles strive to achieve economic development while monitoring their operating
activities to ensure that they are not harming the society and the environment.
22

Rankin highlighted the similarities in the definition, components and measuring
scope of CSR and sustainability. He argued that since sustainability, which
comprises three aspects – economic, social and environmental -could not be
achieved without maintaining sustainability in all three aspects simultaneously,
companies that practice CSR will attain sustainability.
The report of the World Commission on Environment and Development (WCED)
provided a formal definition of sustainability as the ability to meet the needs of the
present generation without compromising the needs of the future generations (World
Commission on Environment Development, 1987). Much of the prior literature on
sustainability has adopted this definition and referred to both CSR and sustainability
as the efforts and responsibilities towards sustainable development as defined by
WCED (Deegan, 2013; Guenther, Hoppe, & Poser, 2006; Guthrie & Parker, 1990).
The Global Reporting Initiative (GRI), a non-profit organisation which developed a
comprehensive reporting framework for sustainability, defines sustainability reporting
as reporting on “how an organization contributes, or aims to contribute in the future,
to the improvement or deterioration of economic, environmental and social
conditions, developments, and trends at the local, regional or global level” (Global
Reporting Initiatives, 2013, p. 17). The GRI (2013) explains that organisations should
seek to present a broader concept of sustainability that “involves discussing the
performance of the organization in the context of the limits and demands placed on
environmental or social resources at the sector, local, regional, or global level” (p.
17). These broad definitions for sustainability and sustainability reporting are adopted
by KPMG and PricewaterhouseCoopers in their regular global survey on CSR
(KPMG, 2015; PricewaterhouseCoopers, 2014).
The roots of the concept of corporate social responsibility can be traced to the
beginning of the twentieth century when the business community began to express
concern towards its impact on society (Carroll, 1979). During the Industrial
Revolution, businesses were mainly concerned about employee issues such as
exploitation of labour and child labour (Crane, McWilliams, Matten, Moon, & Siegel,
2008). The emphasis of CSR shifted to environmental issues when the problems of
23

pollution arose, especially after the disastrous oil spill incident in Alaska in 1989
(Patten, 1992) and the discovery of the depletion of the ozone layer in 1985 by
Farman et al. (cited in Shanklin & Jones, 1995, p. 409).
Murphy (cited in Crane et al., 2008, p. 24) classified the development of the concept
of CSR into four eras: philanthropic, awareness, issue and responsiveness. He
suggested that the period up to the 1950’s was the ‘philanthropic’ era when
companies demonstrated their social responsibility by donating to charities. The
period from 1953 to 1967 was categorised as the ‘awareness’ era when
organisations recognised more
‘overall responsibility’ and contributed to community affairs. The period 1968 to 1973
was known as the ‘issue’ era when companies began ‘focusing on specific issues’
such as racial discrimination and problems of pollution. Finally, the period from 1974
to 1978 and beyond was classified as the ‘responsiveness’ era when companies
began to undertake relevant management actions to address CSR. Companies in
this era generally responded through examining corporate ethics and implementing
corporate social disclosures.
The corporate world responded to the imperatives of social responsibility in various
ways. Sethi (cited in Crane et al., 2008, p. 31) examined the different dimensions of
corporate social performance and proposed that corporate behaviour could be
termed
‘social obligation’, ‘social responsibility’ and ‘social responsiveness’. He distinguished
‘social obligation’ as the corporate response to CSR due solely to legal constraints.
According to Sethi, ‘social responsibility’ differs as it goes beyond ‘social obligation’
by bringing CSR to a level of performance that meets the prevailing social norms,
values, and expectations. The next stage in Sethi’s model is ‘social responsiveness’
and this highlights the proactive efforts of companies that take anticipatory and
preventive measures in CSR.
Both Murphy’s classification of CSR and Sethi’s analysis of corporate behaviours
reveal how the concept of CSR has developed through the decades to a level where
companies are expected to demonstrate a much higher level of social responsibility
24

towards the community. Today, the community is expecting this responsibility to
extend beyond words to actual commitments and genuine actions to benefit the
community (Heard & Bolce, 1981; Lessem, 1977).
2.2 Importance and Drivers of Sustainability
Many companies have responded to the community’s demand for sustainability
information with a proactive approach. They provide voluntary non-financial
information as they have recognised the importance for them to be socially
responsible and economically profitable in order to attain sustainability for long term
viability. Adams and Zutshi (2004, p. 31) assert that the demand for corporate social
responsibility has become “essential” for corporate “long term survival”.
Werther and Chandler (2011) identified several key reasons to explain the
importance for companies to be proactive in volunteering sustainability information.
Growing affluence has given consumers the ‘power’ to make purchasing decisions
based on preferences for companies. Improved living standards have given people
the ability to choose the brand and quality of their purchases. In general, consumers
prefer to select companies which are deemed to be more socially responsible.
Werther and Chandler also claimed that globalisation and the internet have made
information globally and readily available, resulting in companies being especially
cautious about the type of image they project to potential consumers. The increasing
power of the media, environmentalists and other activist groups are also driving
forces for sustainability reporting. There is an increasing imperative to preserve the
environment as people become more aware and concerned about the depletion of
limited resources and the damaging impact of industrialisation. These driving forces
underpin the emphasis on sustainability and have created a greater demand for
transparency in companies’ business activities (Werther & Chandler, 2011).
Prior research studies in sustainability reporting have identified that companies can
benefit in many various ways when they adopt a proactive approach in their
disclosures. Sandhu and Kapoor (2010) have compiled a list of these benefits that
include:
25

• Reduced operating costs and improvement in financial performance
(Adams & Zutshi, 2004; Bachoo et al., 2013; Porter & van der Linde, 1999)
• Enhanced reputation through establishing brand image (Adams & Zutshi,
2004)
• Increased sales and customer loyalty (Creyer, 1997; Mohr & Webb, 2005)
• Increased ability to recruit and retain employees (Adams & Zutshi, 2004)
Better access to capital (Bachoo et al., 2013)
Werther and Chandler (2011, p. 105) gave an empirical example of the benefits when
they compared the approaches taken by two petroleum companies: BP and
ExxonMobil. BP, which repositioned itself as an environmentally responsible
petroleum company, significantly outperformed ExxonMobil, which was attacked by
non-government organisations for their socially irresponsible practices leading to
consumers boycotting their products. However, Werther and Chandler highlighted
that these positive brand building efforts need genuine commitment in the actual
business operations to realise their full benefits. Werther and Chandler gave the
example of when BP was criticised for the lethal accidents at key refineries in the
United States and for the extent of its investments in alternative energy sources.
These infringements have undermined BP’s efforts and investments in building a
positive brand image.
2.3 Recent Developments in Sustainability Reporting
Recent decades have seen renewed attention on sustainability issues and reporting.
As business organisations respond to increasing concerns about social and
environmental issues by producing sustainability reports, a lack of a standardised
reporting framework and an ambiguity in interpreting the reporting requirements and
coverage have resulted in inconsistency in the extent of their disclosures. Hence, for
decades, companies have been facing persistent problems such as defining the
scope of sustainability, and deciding what to include, how to report and when to
disclose information related to sustainability (Adams & Frost, 2007; Betianu, 2010;
Crawford & Williams, 2010; De Jong et al., 2009; Dingwerth & Eichinger, 2010;
26

Emery, 2002; Gibson & O'Donovan, 2007; Gray et al., 2001; Hussey et al., 2001;
Tagesson et al., 2009).
2.3.1 Developments in academic research
A recent longitudinal study performed by Huang and Watson (2015) provided a
summary of recent developments in academic studies relating to sustainability. They
reviewed prior research studies relating to corporate social responsibility (CSR)
completed in the last decade by examining journal papers published in thirteen
prominent accounting journals. Their study adopted a broad definition of
sustainability and included journal papers where different terms such as “corporate
responsibility”, “corporate social responsibility” and “sustainability” were used. They
identified 47 papers fitting these selection criteria. They investigated the focus of
these studies and classified them into four general themes: determinants of CSR,
CSR and financial performance, consequences of CSR and CSR disclosure and
assurance.
Huang and Watson (2015) found prior research studies identified several
determinants of CSR that have significant implications on CSR. These studies found
that managers’ personal philosophy, religion and accountability can shape
companies’ CSR orientation (Parker, 2014). Besides, concerns of other stakeholders
such as clients and creditors have affected companies’ choice of management
strategy and environmental control systems (Rodrigue, Magnan, & Boulianne, 2013)
and managers’ motivation to create sustainable value for their shareholders by being
eco-efficient (Figge & Hahn, 2013). Although being eco-efficient may not have a
direct influence on a company’s financial performance, it has a mediating effect on a
company’s financial performance (Henri & Journeault, 2010). Similarly, Rodrigue et
al. (2013) have also found that being eco-efficient can improve CSR performance
through managers’ desire to outperform their competitors in being industry leaders.
While there is considerable evidence about the relationship between CSR and
financial performance (Jones, 1995; Porter & Kramer, 2007), Huang and Watson
(2015) found that results from prior studies are not conclusive about this relationship
and highlighted the study of Lys, Naughton, and Wang (2015) that investigated the
27

possibility of a “reverse causality” (Huang & Watson, 2015, p. 7). According to Lyns
et al., it is common for prior studies to assume that a positive correlation between
CSR and financial performance implies that CSR expenditures have led to
improvement in companies’ financial performance. They argued that the link between
CSR and financial performance is not casual and that this effect may have been
misinterpreted in previous literature. Consequently, Lyns et al. hypothesised the
reverse and posited that companies may undertake a CSR initiative because of their
expectation for a better future financial performance.
Huang and Watson (2015) also found many prior studies considered one of the main
consequences of CSR as the relationship between CSR performance and firm value
(Cho, Lee, & Pfeiffer, 2012; Kim, Park, & Wier, 2012; Matsumura, Prakash, &
VeraMunoz, 2014). There are, however, limited studies focusing on studying the
cost of CSR; hence, Huang and Watson suggested that future studies may consider
investigating the cost behaviour of CSR expenditures and whether there is an
opportunity cost of CSR.
Huang and Watson (2015) revealed that while studies of CSR have increased in
recent decades, there are considerable differences among the studies. Most of the
studies were relatively more shareholder oriented, and Huang and Watson
suggested that future research should address the demands of a broader group of
stakeholders. Another suggestion is that future CSR studies should consider the long
term impact of CSR information. The qualitative and non-financial nature of CSR
information has posed difficulties for credible evaluation of the CSR data, which
suggests the need for assurance services for CSR information to increase their
credibility (Junior, Best, &
Cotter, 2014; Mock, Strohm, & Swartz, 2007; SeguÍ‐Mas, Bollas‐Araya, & Polo‐
Garrido, 2015; Wong & Millington, 2014).
2.3.2 Developments in the business sector
28

Atkins et al. (2015) argued that despite the improved methods used by many
business corporations to produce sustainability reports, the current sustainability
disclosures do not satisfy the needs of companies’ broad stakeholder groups. They
found that a majority of the reports produced by companies “fail to make a strong
connection between climate change, environmental management and financial
reporting” (Atkins et al., 2015, p. 663). They advocated that unless sustainability
information becomes a driver for change, the information is yet another example of
companies merely satisfying legal requirements and image management, which
does not address the crucial problem of climate destruction. They stressed that
companies need to adopt practical business changes that can effectively reduce
climate change risks and their carbon footprints. They concluded that a traditional
accounting reporting framework that focuses only on financial information is not
effective for sustainability accounting, and that there is an urgent need for an
enhanced stewardship and improved accounting framework to address the problem.
PricewaterhouseCoopers’s (PwC) conducted a survey on a diverse mix of
institutional investors to gain a deeper understanding of whether sustainability issues
are affecting investors’ decisions related to their investment strategies and practices
(2014). They found that investors considered sustainability issues such as corporate
social responsibility and climate change as relevant when they made decisions
regarding shareholder and corporate engagement, proxy voting and investment
strategy. It is also interesting to note that the likelihood that investors consider these
sustainability issues increases with investors that manage a larger amount of assets.
More than 84% of investors participating in the survey expected that they would
continue to consider these sustainability issues in investment decisions in the next
three years.
According to the PwC survey, mitigating risk is the major driving force for investors to
consider sustainability issues when making investment decisions. Other significant
drivers include enhancing investment returns and avoiding business corporations
who demonstrate unethical conduct. Consistent with other PwC surveys, investors
expressed a high level of dissatisfaction with companies’ sustainability disclosures.
Investors were significantly more dissatisfied then satisfied in all eight sustainability
29

topics included in the survey (PricewaterhouseCoopers, 2014). Topics surveyed
include how risks and opportunities are identified and quantified in financial terms,
comparability of sustainability reporting, and relevance and implications of
sustainability risks. This recent survey has provided empirical evidence that indicates
a lack of useful sustainability information available for investors to make good
investment decisions.
2.3.3 Developments in global trends
KPMG perform regular global surveys of corporate responsibility (CR) reports on the
world’s 250 largest companies by revenue (G250) and top 100 companies (N100) of
many different countries. In the most recent survey, KPMG (2015) analysed
thousands of company annual financial reports, corporate responsibility reports and
websites. They presented the results from the survey in three parts: accounting for
carbon, quality of CR reporting among the G250, and global CR reporting trends
among the N100.
They found that there is a lack of consistency in carbon reporting from the G250,
“making it almost impossible to accurately compare one company’s carbon
performance with another” (KPMG, 2015, p. 9). 20% of these large companies in the
high carbon sectors such as mining and chemicals did not report on carbon. 47% of
the companies did not publish targets on carbon reduction. Of those that reported on
the set targets, only 35% of the companies provided reasons for their chosen targets
on carbon reduction. The average time frame set for corporate carbon reduction was
approximately 11 years, with some using the 15 year targets set by many national
governments. Among the G250, European companies are the most likely to report on
carbon, while companies in the United States and Asia Pacific countries including
China are the least likely to report.
Part two of KPMG’s report, which focused on the quality of CR reporting among the
G250, found that there was no overall improvement since 2013, except on the topic
of
30

CR trends and risks. KPMG described this as “disappointing” as the previous positive
improvement in the 2013 survey had not continued (KPMG, 2015, p. 24). KPMG
viewed this as contradicting the emphasis on the quality of CR reporting made by the
Global Reporting Initiatives (GRI) in their latest G4 version.
It was found in the survey that about 73% of N100 companies reported on CR, which
is a small rise from 71% in the 2013 survey. KPMG also found that 92% of the G250
reported on CR. Over the last four years of the survey, the percentage of G250
companies that reported on CR has fluctuated between 90% and 95%, and KPMG
concluded that this is largely due to the change in the composition of the G250 list.
The main driver for CR reporting in both N100 and G250 continues to be legislative.
The survey conducted across 45 different countries globally found the Asia Pacific to
be the leading region in CR reporting compared to the United States and European
countries. This growth has been driven by increasing mandatory and voluntary
reporting requirements in countries such as India, Taiwan and South Korea. Four
countries have emerged as having the greatest increases in country CR reporting
rates since 2013: India (+27 percentage points), South Korea (+25), Taiwan (+21)
and Norway (+17). Three out of these four countries attributed the growth to the
introduction of mandatory reporting requirements. KPMG concluded from the results
that “it is unlikely that rates of over 90 percent will be achieved in any country without
some legislative driver” (KPMG, 2015, p. 32).
With increasing demand for improvement in companies’ environmental performance
as a measurement towards their sustainability contribution, recent research studies
have focused on studying data related to companies’ carbon and gas emissions
(Chapple, Clarkson, & Gold, 2013; Clarkson et al., 2008; Clarkson et al., 2011;
Comyns & Figge, 2015; Cowan & Deegan, 2011; Guenther et al., 2006; Li, Eddie, &
Liu, 2014). Comyns and Figge (2015) conducted a longitudinal study between 1998
and 2010 on 245 sustainability reports of 45 oil and gas companies listed on the
2011 Global Fortune 500 index. They explored the quality of greenhouse gas (GHG)
information reported in companies’ sustainability disclosure by classifying the
information into ‘search’, ‘experience’, ‘credence’ and ‘mixed’.
31

‘Search’ information is information which can be easily verified by a report reader
without special expert knowledge or cost outlay. This includes information such as
location of activities and awards won that can be easily verified. The ‘search’
information is considered to be of high quality and would remain as high quality
information over time as users of this information can easily verify the data. This type
of information may even be improved over time with increased pressure from
stakeholders for more disclosures.
‘Experience’ information is information that cannot be verified immediately but which
can be verified at some future date. This includes forward looking statements or
future targets set by companies. Thus, ‘experience’ information is considered initially
to be of low quality but is expected to improve in quality as the information becomes
apparent and verifiable.
‘Credence’ information is that which cannot be verified by the report reader. This
information includes quantitative emissions information that requires expert
knowledge or significant cost outlay. The quality of this information is considered
poor and is expected to remain poor even in the longer term as it cannot be used to
drive improvement since stakeholders cannot determine its quality.
Comyns and Figge (2015) found that companies were reporting poor quality
information despite the increasing focus on the issue of climate change
internationally during the study period, and there is scientific evidence linking GHG
emissions to the climate change issue. The results from their study have indicated
that the adoption of guidelines alone does not result in better quality reporting and
that the quality of information in companies’ disclosures varied significantly. The
various types of information were also not significantly different among the three
types of information during the 12 year period of study. Comyns and Figge (2015)
concluded that more regulation is necessary to improve the quality of information in
the ‘experience’ and ‘credence’ categories. They posited that regulation may still be
required to ensure that specific information such as third party assurance is included
to improve the quality of
32

‘search’ information.
Comyns and Figge’s (2015) findings supported those obtained by Guenther et al.
(2006) which indicated that the quantitative GHG emissions data is poor and
reporting by companies in the oil and gas industry is also low compared to the
reporting benchmark (Dong & Burritt, 2010).
Recent developments in sustainability reporting have identified a strong demand
globally from both academics and stakeholders of business organisations to see an
alignment of sustainability disclosure to sustainability performance. This study
addresses this increasing demand through the development of a new reporting
framework that ensures companies’ disclosures are in line with good sustainability
performances that lead to improvements in sustainability developments.
2.4 Sustainability in the Australian Context
Sustainability reporting in Australia remains predominantly voluntary especially in
relation to social issues since mandatory reporting only applies to environmental
reporting and is confined to companies that are bound by environmental regulations.
Consequently, there has been ongoing debate as to whether sustainability reporting
should be made mandatory through legislation. Some studies have shown that
greater legal requirements have produced more sustainability disclosures (Adams &
Frost, 2007; Crawford & Williams, 2010; Frost, 2007). They claim that the extent of
sustainability disclosures will decrease under a system of voluntary disclosures as
companies can be selective about the amount, scope and nature of the information
disclosed in their reports (Crawford & Williams, 2010; Deegan & Gordon, 1996;
Deegan & Rankin, 1996; Guthrie & Parker, 1990). However, some studies advocate
retaining voluntary reporting, as they claim that mandating the reporting may result in
minimal information being disclosed purely to satisfy statutory requirements (Adams
& Frost, 2007; Ho & Taylor, 2007). This view was supported by
33

PricewaterhouseCoopers (PwC) in their reply to an inquiry by the Commonwealth
Parliamentary Joint Committee on Corporations and Financial Services (PJCCFS)
reported in June 2006 regarding corporate responsibility and reporting in Australia.
PwC claimed that “any further legislation on environmental and social matters using
the current reporting framework will only burden Australia with little value being
added to stakeholders” (Adams & Frost, 2007, p. 3; Cowan & Deegan, 2011).
2.4.1 Regulatory framework
Since 1 July 1998, companies with operations bound by environmental regulations
have been required by section 299(1)(f) of the Corporations Act (2001) to provide
mandatory reporting on environmental issues in their annual reports. Other
companies that do not fall under this jurisdiction volunteer this type of information
(Adams & Frost, 2007; Clarkson et al., 2011; Deegan & Gordon, 1996; Frost, 2007;
Jones et al., 2007).
Following the introduction of section 299(1)(f), a Practice Note (PN 68) was issued by
the Australian Securities and Investments Commission (ASIC) in November 1998 to
provide guidelines for complying with the section. Despite this, it has been criticised
for being broad-spectrum and not providing sufficient guidelines necessary for
reporting (Bubna-Litic, 2008; Burritt, 2002; Frost, 2007). Several Australian bodies
attempted to provide more guidance to their members in the early 1990s by
producing environmental reporting guidelines. These include the Australian Institute
of Company Directors, the Australian Institute of Management, the Business Council
of Australia, the Australian Manufacturing Council (Deegan & Rankin, 1996),
Minerals Council of Australia and Australia Industry Group (Frost et al., 2005).
However, Deegan and Gordon (1996, p. 192) claimed that the guidelines provided by
these Australian bodies were not useful as they “typically provide minimal guidance
in relation to disclosure policies”. As a result, the environmental reports produced by
Australian companies do not follow a standardised framework and this hinders
comparison between companies. Besides, the mandatory reports of companies are
not subject to an audit process by ASIC which Frost (2007) suggested as a possible
indication that active implementation of the act is lacking. Bubna-Litic (2008, p. 81)
34

confirmed Frost’s suggestion when she quoted from ASIC that a “hands-off”
approach is adopted to the enforcement of section 299(1)(f).
There are two primary regulatory bodies to which Australian companies are
compelled to report (Bachoo et al., 2013). First, from 1997, companies have been
required to report to the National Pollutant Inventory (NPI) of the Department of
Environment the emissions of any of 93 registered pollutants emitted in excess of the
prescribed threshold (Bachoo et al.). Second, companies whose energy usage or
greenhouse gas emissions exceed prescribed thresholds are obliged to report to the
Clean Energy Regulator (previously the Department of Climate Change) of the
Department of Environment under the jurisdiction of the National Greenhouse and
Energy Reporting Act 2007 (Bachoo et al.; Cowan & Deegan, 2011). The first
emissions reduction policy was proposed in early 2008 but was repeatedly voted
down by the Parliament in 2008, 2009 and 2010. It was finally approved in November
2011 after some significant changes that include an increase in the emissions
threshold (Li et al., 2014). According to Li et al. (2014), this new legislation has
resulted in additional economic costs and social responsibilities to companies that
are regulated under this legislation.
2.4.2 Prior research studies
Higgins et al. (2015) analysed sustainability reporting practices of Australian
business organisations over an extended period of more than twenty years. They
examined companies in Australia that produced stand-alone sustainability reports
and discovered the earliest reporting by a company in Australia began in 1995.
Higgins et al. (2015) classified the companies into early adopters or late adopters
according to the time when the companies began to produce stand-alone reports.
They examined companies’ sustainability disclosures and objectives of disclosures
and determined if they differed among companies with different characteristics such
as the level of impact to physical environment, the level of public visibility, company
size and customer base.
35

They found that sustainability reporting has “spread widely across the business
community in Australia” (Higgins et al., 2015, p. 462). Most of the early adopters
were companies in high-impact industries such as mining, utilities and energy. More
recent adopters came from low-impact industries such as legal and real estate
property companies. Two apparent patterns emerged from their study. First, the
depth of the disclosures has improved in only a small number of high-impact
industries that were associated with negative environmental impacts. Second,
sustainability reporting has spread to many low-impact industries such as the finance
and services sector where most of the recent growth has occurred.
Unlike most prior research that found companies in the high-impact industries were
disclosing more information than those in the low-impact industries due to higher
legitimacy and stakeholder pressure, Higgins et al. (2015) found no differences
between the two groups. According to Higgins et al., this suggests that sustainability
reporting “has matured, changed, and in need for further investigation” (p. 447).
However, they found that commonly, sustainability reporting is tied to companies’
strategic priorities, management of social and environmental impacts and, to some
extent, the number of government customers companies have. Two clusters of
sustainability reporters were evident. The first was consumer-oriented, later adopter,
low-impact companies with mixed levels of visibility; the second was high-impact,
early adopter companies with higher visibility. Higgins et al. suggested that the first
cluster of early adopters are likely to engage in sustainability reporting to gain
advantage through differentiating their sustainability strategies. The second cluster of
late adopters, which were more experienced, has fewer incentives for competitive
positioning, and are probably keen to show the strategic importance of legitimacy
and responsiveness.
Earlier research studies on sustainability reporting in Australia have focused on
environmental aspects of sustainability reporting (Bubna-Litic, 2008; Deegan &
Gordon, 1996; Deegan & Rankin, 1996; Frost, 2007; Frost et al., 2005; Galbreath,
2013). These prior research studies have yielded some consistent results that
include the following:
36

• There has been a general increase in environmental disclosures in recent
decades (Cowan & Deegan, 2011; Deegan & Gordon, 1996; Frost, 2007;
Frost et al., 2005; Gibson & O'Donovan, 2007).
• The driver for the increase in environmental disclosures is largely due to
regulatory requirements (Cowan & Deegan, 2011; Frost, 2007).
• There is ambiguity in the legislative requirements relating to environmental
disclosures (Burritt, 2002; Frost, 2007; Gibson & O'Donovan, 2007).
• The environmental reporting is typically self-laudatory in nature and
companies tend to disclose only good news (Deegan & Gordon, 1996;
Deegan & Rankin, 1996; Frost et al., 2005; Guthrie & Parker, 1990) and this
may be misleading to users of this information (Deegan & Rankin, 1996).
• There is a positive relationship between the extent of environmental
disclosure and the environmental sensitivity of the company’s industry type
(Deegan & Gordon, 1996; Frost, 2007).
Despite these similarities, there were inconsistent results obtained between
company’s size and the extent of environmental disclosures. Jones et al. (2007)
identified a positive correlation between the company’s size and industry type and
the extent of environmental disclosure. However, Deegan and Gordon (1996)
concluded in their study that the positive relationship only exists for companies that
operate in an environmentally sensitive industry type. Prior studies have also yielded
different results about the relationship of sustainability reporting and other company
characteristics such as companies’ financial performance and their board
composition. These inconsistent results are examined in this study.
More recent research on sustainability reporting in Australia has included other
aspects of sustainability (Bachoo et al., 2013; Frost et al., 2005; Williams,
Wilmshurst, & Clift, 2011). However, to date, few of these studies have evaluated all
three aspects (social, economic, and environmental) of sustainability in a single
study. One of the main objectives of this research is to evaluate the quality of
sustainability reporting in the Australian resources industry through an examination of
all the three aspects of sustainability.
37

2.4.3 Research studies in the resources industry
Companies operating in the Australian resources industry are required to provide
mandatory environmental disclosures in their annual reports according to the
regulation in section 299(1)(f) of the Corporations Act (2001) (Frost, 2007; Jones et
al., 2007). The resources industry, which involves exploration and extractive activities
of minerals, energy and other natural materials from the environment, is classified as
an ‘environmentally sensitive’ industry because of the nature of its operating activities
which have significant impact on the environment (Deegan & Gordon, 1996; Dong &
Burritt, 2010; Wilmshurst & Frost, 2000).
Many prior studies have identified that companies operating in an environmentally
sensitive industry tend to provide more environmental disclosures in their reports
(Deegan & Gordon, 1996; Deegan & Rankin, 1996; Frost, 2007; Patten, 1992). Many
cited the legitimacy theory as the main reason for this as companies in an
environmentally sensitive industry attempt to reduce potential political costs by
providing more information.
Wood and Ross (2008) investigated Australian financial managers’ response to
several environmental social controls (ESC) such as mandatory disclosures and their
capital investment decision processes across three industry types – extractive, food
manufacturing and heavy metals manufacturing. These industries were selected as
companies in these industries produce pollutant chemicals that are regulated for
National Pollutant Inventory (NPI) reporting. The mining companies in the extractive
industries are required to disclose environmental information and costs by the
accounting standard AASB1022 Exploration and Evaluation costs and Australian
Accounting Standard AAS 7 Accounting for the Extractive industries. While
companies in the food industry are required to provide environmental disclosure on
their usage of highly toxic chemicals, those in the metal industry must disclose
information that relate to hazardous waste and disposal.
According to Wood and Ross (2008), in Australia, there are four key ESCs that are
adopted to promote better industry environmental behaviour, namely mandatory
38

disclosure, regulation, subsidies and stakeholder opinion. They found statistically
significant differences among the three industries. These significant differences were
evident across the disclosure indicators in all four ESCs.
The extractive industry is found to have the highest level of responsiveness to all four
ESCs. Wood and Ross (2008) suggested that a probable reason for this high level of
responsiveness is that mining is highly capital intensive and relies on large
investments for site acquisitions and purchase of plant and equipment. It is also
noted that the extractive industry is under a high level of public scrutiny, resulting in
environmental issues being viewed as a crucial issue for this industry. Although
mandatory disclosure was found to have the lowest responsiveness among the 4
ESCs in this industry, it is still relatively high compared to the food and heavy metals
manufacturing industry. Wood and Ross (2008) observed that managers of the
extractive industry have indicated a higher awareness of disclosure requirements
and this is likely due to more stringent disclosure requirements for this industry.
Companies in this industry are also highly influenced by the regulatory indicators
such as site restoration, licenses and permits, and environmental fines and penalties.
Stakeholders such as investors, insurers and creditors were perceived by managers
of the extractive industry as more influential than employees and customers. A
probable reason is that this industry caters largely to the export market whose
customers are mainly from other countries and therefore less concerned with
environmental performance in Australia. In addition, companies in this industry are
mainly public listed companies that are highly influenced by investors (Wood & Ross,
2008).
Wood and Ross (2008) observed that the food manufacturing industry has, despite
its heavy usage of highly toxic chemicals, shown least concerned with site
restoration, but is highly influenced by regulatory indicators such as fines, licenses
and permits. On the other hand, the heavy metals manufacturing industry has the
lowest influence relative to the other two industries. Companies in the heavy metals
manufacturing industry have shown significant concern towards ‘hazardous waste
treatment and disposal’ and ‘future increases in compliance costs’ regulation
indicators. They have also indicated that customers and employees are the most
39

influential groups of stakeholders. The lower influence from investors may be
explained by the number of proprietary companies in the metal industry compared to
the other two industries. Mandatory disclosure is also less influential in this industry
compared to the extractive industry as the metal industry supply predominantly to
other manufacturers. Wood and Ross (2008) proposed that this has seemed to divert
public scrutiny to companies in the extractive industry. These significant differences
among the three industries have led Wood and Ross (2008) to conclude that it is
important to understand industry differences to increase the effectiveness of ESC.
Dong and Burritt (2010) conducted an industry-specific sustainability study on the
Australian oil and gas industry. A content analysis approach was applied to 25 listed
companies in the Australian Stock Exchange 300 index in 2006. They found that
companies had reported on a broad range of social and environmental issues.
However, there was a lack in both the quantity and quality of information provided.
On average, each individual company was reporting 13 sentences of information and
there was a lack of quantification of targets or outcomes. It was even lower in both
volume and quality of disclosures that relate specifically to the oil and gas industry.
While companies in the oil and gas industry were reporting on many social and
environmental disclosures, the information was about employees and the
environment, neglecting other stakeholders such as the community and consumers.
Dong and
Burritt (2010) described this reporting practice as “relatively narrow focus and
underprovides information relative to the industry guidelines” (p.116). It is suggested
that the lack of specific relevant information has undermined the credibility of
companies’ disclosures, leading to a reduction in investor confidence in their
investment decision making.
Dong and Burritt (2010) also highlighted the limited information on actual
sustainability performance which hindered readers ‘assessment of the actual
outcomes and achievements of the companies. It was very rare for companies to
provide quantitative information on outcomes and achievements in numerical terms
against their predictions. This has pointed to the fact that industry-specific indicators
40

are not integrated with effectiveness and efficiency to assess companies’ progress
against a benchmark. There was also omission of information that compares
expectations with actual performance. Dong and Burritt (2010) stressed that this
omission has failed to allow a measurable performance gap to be identified so that
appropriate action can be carried out to improve performance.
While companies in the Australian resources industry are obliged to provide
mandatory environmental disclosures, there are no specific requirements or
guidelines to promote effective sustainability reporting practice. Moreover, the
companies are not mandated for the other two aspects of sustainability disclosures –
social and economic. Prior research studies have also identified a lack of a
comprehensive and standarised reporting framework to benchmark reporting
practice in the resources industry (Dong & Burritt, 2010; Frost, 2007; Guenther et al.,
2006; Wood & Ross, 2008). This research addresses these problems encountered
by companies in the resources industry through the development of a new reporting
index based on all three aspects (social, economic and environmental) of
sustainability.
2.5 Theoretical Framework for Sustainability
This research focuses on two fundamental theoretical frameworks that underpin
sustainability and sustainability reporting: the stakeholder theory and the legitimacy
theory (Cho et al., 2015; Elijido-Ten, 2007; Michelon & Parbonetti, 2012; O'Donovan,
2002; Patten, 1992; Roberts, 1992; van Staden & Hooks, 2007; Wilmshurst & Frost,
2000). Prior empirical studies on the two theories are critically reviewed in this
chapter.
2.5.1 The stakeholder theory
2.5.1.1 Definition of stakeholders
41

Freeman and Reed (1983) recognised that the business environment had changed
and companies’ obligations were no longer limited to just stockholders who are the
holders of companies’ equity. Companies are faced with a more complex business
environment and management theories, which used to focus on companies
operating efficiently and effectively within a traditional simple and predictable
business environment, need to accommodate this shift. Hence, Freeman and Reed
asserted that companies have obligations towards wider groups “who can affect the
achievement of the firm’s objectives” (Freeman & Reed, 1983, p. 91) and proposed
the adoption of a broader definition of the term ‘stakeholder’. Consequently, Freeman
and Reed (1983, p. 91) defined the stakeholder to be “any identifiable group or
individual who can affect the achievement of an organisation’s objectives or who is
affected by the achievement of an organisation’s objectives”. This broader definition
implies that shareholders, creditors, employees, suppliers, consumers, government,
media, interest groups and the general public are considered to be the stakeholders
of a company (Freeman, 2010; Freeman & Reed, 1983). This study has chosen to
adopt this broad definition of stakeholders because it is relevant in the context of this
study that focuses on sustainability disclosures of companies under the current
business environment.
2.5.1.2 Stakeholders’ demand for sustainability disclosures
The increased attention on sustainability in recent decades has brought about an
increased demand for sustainability information by stakeholders (Crawford &
Williams, 2010; Deegan & Rankin, 1997; Ho & Taylor, 2007; O'Donovan, 2002).
Applying the broad definition of stakeholders in Freeman and Reed (1983) to the
context of sustainability reporting, companies are obliged to provide all aspects
(social, economic and environmental) of sustainability information to satisfy the
stakeholders’ demand. However, the various groups of stakeholders can have
diverse information needs (Michelon & Parbonetti, 2012). For example,
shareholders who have direct financial interest in a company’s profit distribution are
likely to focus on the economic aspects of sustainability, whereas the
environmentalist groups tend to be more concerned about the environmental
42

aspects. Furthermore, internal stakeholders, such as managers and employees of
companies, are expected to demand more information relating to the social aspects
because they can be assured of better employee welfare if they are working for
socially responsible companies (Adams & Zutshi, 2004).
Deegan and Rankin (1997) investigated the materiality of environmental information
for different groups of stakeholders who were users of company annual reports. They
found most of the stakeholders (shareholders, accounting academics,
representatives of financial institutions, organisations including Australian Council of
Trade Unions, environmental lobby groups, industry and consumer associations)
considered environmental information to be material and relevant for their business
decisions. However, stockbrokers and analysts did not consider environmental
information to be material. This is consistent with the findings of Business in
Environment (cited in Deegan & Rankin, 1997) that analysed the attitudes of 85
British investment analysts on environmental issues, concluded that “assessments
are made on rational, financial criteria. Issues considered moral or emotional are not
seen as part of the analysts remit, unless such issues have identifiable financial
consequences” (p. 566).
Freeman (2010) argues that it is inappropriate for stakeholders to perceive a
company’s social responsibility as isolated from its economic performance. Freeman
claimed that these stakeholders, who have considered corporate social responsibility
as merely an additional item to business operations when companies can afford it,
have failed to understand the complex interconnections between economic and
social forces. Freeman emphasised that it is important for companies to consider all
aspects of these forces to better predict the business world in order to be successful.
2.5.1.3 Different perspectives of the stakeholder theory
Deegan (2013) classified the stakeholder theory into two main perspectives: the
‘normative’ (ethical) and the ‘positive’ (managerial) perspective. According to
Deegan, the normative branch, which is the prescriptive view, argues that all
stakeholders, regardless of their influencing power, should be treated equally and
43

companies should be ethical and accountable to all stakeholders. Expanding on the
broad definition of stakeholders in Freeman and Reed (1983), Clarkson (1995)
divided stakeholders into primary and secondary stakeholders. Clarkson defined
primary stakeholders as those
“without whose continuing participation the corporation cannot survive as a going
concern” (p. 106) and these include stakeholder groups, such as shareholders,
customers, suppliers and employees. Secondary stakeholders are defined as those
“who influence or affect, or are influenced or affected by the corporation, but they are
not engaged in transactions with the corporation and are not essential for its
survival’” (p. 107). These include the media and special interest groups. Clarkson
asserted that corporate managers’ responsibilities go beyond satisfying
shareholders’ demand for wealth creation; they are also responsible to all other
primary stakeholders. This implies that corporate managers are required to resolve
fairly any conflicting interests among the various primary stakeholder groups
because unfair treatment towards any primary stakeholder may result in them
seeking alternatives and eventually lead to their withdrawal from the corporate’s
stakeholder system, threatening a corporation’s survival.
While Clarkson (1995) focused solely on primary stakeholders, the broader
normative perspective of the stakeholder theory posits that all stakeholders, which
include both primary and secondary, deserve a right to be provided with information
about the company that affects them (Deegan, 2013). Hence, companies are
deemed to have an obligation to provide all relevant information, including
sustainability information, to all their stakeholders.
In contrast, the positive branch seeks to explain how corporate managers are
affected by the stakeholders’ power and results in management providing more
information according to the stakeholders’ power of influence (Deegan, 2013;
Godfrey, 2010; Ullmann, 1985). While the normative branch prescribes the ethical
requirements of business management, the positive branch may in fact be more
dominant, assuming that managers are driven by individual self-interest according to
the positive accounting theory (Watts & Zimmerman, 1978).
44

Ullmann (1985) studied stakeholders’ power in relation to corporate social
responsibility and developed a three-dimensional conceptual model that consisted of
stakeholders’ power, strategic posture and economic performance. The model was
adopted to explain the correlations among social disclosure and social and economic
performance. Ullman contended that a stakeholder’s power to influence a company’s
management is positively correlated to the stakeholder’s degree of control over
resources required by a company. It is expected that a stakeholder that controls
resources that are critical to the continued viability and success of a company will
have its demand addressed, resulting in a positive relationship between stakeholder
power and social disclosure and performance (Roberts, 1992). Hence, it is often
predicted that the objectivity of sustainability reporting practice may be compromised,
especially under a voluntary disclosure system.
Critics have argued that companies may be inclined to disclose only positive
information to satisfy the information demands of stakeholders. Guthrie and Parker
(1990) compared the corporate social disclosure practices in the United States, the
United Kingdom and Australia in 1983. They found that no Australian company
provided ‘bad news’ about its activities in the aspect of environmental disclosures. A
significant proportion of companies in the United Kingdom and the United States
reported on ‘bad news’ basically at the instigation of government or accounting
profession regulations.
This is consistent with the findings from Deegan and Gordon (1996) and Deegan and
Rankin (1996). Both studied the environmental disclosure practices of Australian
corporations and obtained similar results. They concluded that the reports were
generally “self-laudatory” in nature. They noticed that firms were disclosing ‘positive’
news, but were suppressing ‘negative’ news (Deegan & Gordon, 1996). Deegan and
Gordon (1996) argued that the credibility of the environmental disclosures may be
questioned when there is a total omission of ‘negative’ news as users of the
company’s annual reports would generally expect a certain degree of potentially
harmful company activities.
45

2.5.1.4 Empirical studies of the stakeholder theory
While most literature on sustainability has assumed the importance of sustainability
information to company’s stakeholders, Deegan and Rankin (1997) provided
empirical evidence when they investigated the materiality of environmental
information to the users of company’s annual reports. They studied various groups of
company stakeholders including shareholders, stockbrokers and research analysts,
accounting academics, representatives of financial institutions, environmental lobby
groups and business associations. They analysed the stakeholders’ demand for
environmental information and the stakeholders’ perception of the importance of
environmental information compared to other social and financial information. Based
on 123 responses of their questionnaires, Deegan and Rankin concluded that all of
the stakeholders, except the stockbrokers and research analysts, indicated that
environmental information was material to them. However, the level of importance of
environmental information perceived by the stakeholders demonstrated significant
divergence, evidenced by the large statistical deviations in their study.
Roberts (1992) empirically tested the stakeholder theory using the three-dimensional
framework developed by Ullmann (1985). He selected 130 large companies that
were investigated in 1984, 1985 and 1986 by the Council on Economic Priorities,
whose studies focus on large Fortune 500 companies because these companies are
influential and generally establish trends in the social responsibility area. His results
supported Ullmann’s framework and provided strong empirical evidence that is
consistent with the stakeholder theory. The findings suggested that social
responsibility disclosures are affected by stakeholder groups such as shareholders,
government and creditors.
Elijido-Ten (2007) analysed sustainability reporting practice in Australia using the
stakeholder theory. She selected 61 Australian listed companies in the Australian
Securities Exchange (ASX) which were the top ranked companies in Australian
Conservation Foundation’s (ACF) environmental performance and adopted
Ullmann’s (1985) three-dimensional framework comprising stakeholder power,
strategic posture and economic performance to analyse the determinants of
46

corporate environmental performance. She studied the relationship between the
powers of various stakeholder groups (shareholders, creditors, government) and the
extent of environmental disclosures using the 2002 ACF environmental performance
ranking. Her findings provided empirical evidence to support the stakeholder theory.
Among the three groups of stakeholders, Elijido-Ten observed that the powers of the
shareholders and the government were significantly related to the environmental
performance. However, no significant relationship was found between the creditors’
power and the environmental performance.
2.5.2 The legitimacy theory
According to Lindblom (cited in Deegan, 2013), legitimacy exists when “an entity’s
value is congruent with the value system of the larger social system of which the
entity is a part” (p. 348). As such, Suchman (1995) defined legitimacy as “a
generalized perception or assumption that the actions of an entity are desirable,
proper, or appropriate within some socially constructed system of norms, values,
beliefs, and definitions” (p. 574). This implies that companies need to act according
to the expectations of the community (Dowling & Pfeffer, 1975; Guthrie & Parker,
1990; Patten, 1992; Wilmshurst & Frost, 2000) and are expected to carry out their
business activities within the boundaries of what the society accepts to be the norm
(Dowling & Pfeffer, 1975; Wilmshurst & Frost, 2000).
Dowling and Pfeffer (1975) posited that organisations that fail to demonstrate
business activities that are congruent with general social norms and values may
confront a threat to organisation legitimacy. Dowling and Pfeffer (1975) suggested
that legitimacy is not “defined solely by what is legal or illegal” (p. 124) and they
proposed three possible reasons for a low correlation between legality and
legitimacy. First, a legal change would require more time than a change of societal
norm and thus current legality may not be fully reflective of current societal norm.
Second, norms may at times be contradictory while legal codes are presumed to be
more consistent. Third, societies are generally more tolerant of certain behaviours
informally than accepting them legally, and this again could result in differences
47

between legality and legitimacy. Dowling and Pfeffer (1975) advocated that
organisations will take these factors into account and strive to engage in behaviours
that meet all the criteria, thereby engage in business operations that are
economically viable, legal and legitimate.
Suchman (1995) classified legitimacy in organisations into three types: pragmatic,
moral and cognitive. Suchman’s study assumed that these three types of legitimacy
adhere to general social norms and adopt practices that are acceptable to the public
at large, however, he differentiated them according to their behavioural dynamic.
Pragmatic legitimacy refers to legitimacy based on exchange or influence factors
between an organisation and its audiences. This type of legitimacy often involves a
support for an organisational policy or action because it has a direct influence on the
audience’s well-being. Unlike pragmatic legitimacy that focuses on the benefits to the
audience, moral legitimacy reflects a positive normative behaviour where an
organisation’s practice is accepted because it is deemed to be morally right.
Cognitive legitimacy, according to Suchman (1995), involves either comprehensibility
that leads to an affirmative backing of an organisation or an acceptance merely on
the basis of some “taken-for-granted cultural account” (p. 582). Cognitive legitimacy
by comprehensibility refers to a form of legitimation where an organisation’s activities
are accepted because organisations can provide plausible explanations to make its
activities predictable and meaningful. In contrast, the taken-for-granted legitimacy
refers to legitimacy that is accepted because the alternatives are impossible and
unthinkable.
2.5.2.1 Legitimacy gap
Heard and Bolce (1981) observed that the expectations of society on companies are
no longer limited to the traditional view of providing goods and services, jobs and
wealth creation. Society expects businesses to also “attend to the human,
environmental and other social consequences of business activities” (Heard & Bolce,
1981, pp. 247-248). These expectations include more stringent enactment of
48

regulations restricting business activities which affect the society, utilisation of public
opinion surveys, and increased advocacy movements and lobbying groups.
Consequently, to conform to society’s expectations on sustainability issues,
companies are required to act in a socially responsible manner and be accountable
for sustainability disclosures (Heard & Bolce, 1981).
The legitimacy theory posits that companies that deviate from the bounds of these
societal expectations may experience difficulties in obtaining the necessary
resources for their business operations, which may eventually threaten their survival
(Deegan, 2013; Deegan & Rankin, 1997). Deegan (2013) uses the term ‘legitimacy
gap’ to describe a situation where there is “a lack of correspondence between how
society believes an organisation should act and how it is perceived that the
organisation has acted” (p. 348). Deegan suggested that this can arise when a
company fails to make disclosures to show its compliance with societal expectations
or when the business activities of a company fail to satisfy the expectations of the
society. According to Sethi (cited in Deegan, 2013), there are two major sources of
legitimacy gaps: the gap may arise due to a change in societal expectations,
resulting in a legitimacy gap even when companies have continued operating in the
same manner, or when new information that was previously unknown becomes
known.
Dowling and Pfeffer (1975) suggested three strategies that organisations can adopt
to address the legitimacy gap. First, the organisation can adapt its business
operations to conform to existing definitions of legitimacy. Second, the organisation
can attempt to alter the current definition of social legitimacy through communication,
so that the definition conforms to the organisation’s existing values and practices.
Lastly, the organisation can attempt, through communication, to become identified
with values or institutions that have a very strong base of social legitimacy.
Suchman (1995) contended that the appropriateness of legitimacy strategies is
largely dependent on the nature of an organisation’s challenges. Suchman classified
organisations’ challenges for legitimation into gaining, maintaining and repairing
legitimacy. Organisations that are embarking on a new product or business operation
49

are classified as organisations that are attempting to gain legitimacy, because there
are no or fewer precedent social norms and thus a need to acquire societal
acceptance and validity. Organisations belonging to this category need a proactive
approach to build legitimacy. Organisations that are classified as maintaining
legitimacy are deemed to have an easier task than those attempting to gain or repair
legitimacy. Suchman proposed different strategies for this classification depending on
whether organisations are seeking to maintain legitimacy due to anticipated future
changes or to protect past achievements. Organisations need to focus on their ability
to recognise their audiences’ reactions in the case of emerging changes. In addition
to this, organisations attempting to protect past achieved legitimacy should avoid
unexpected events that may trigger new scrutiny. Suchman suggested that
organisations can provide explanations for the change and focus on making the
change seem “natural and inevitable” (p. 596). Organisations that are classified as
repairing legitimation are deemed to be similar to those attempting to gain legitimacy,
except that the approach for them is considered to be reactive instead of proactive.
Organisations that seek to repair legitimacy are expected to respond to any
unforseen reaction from society.
2.5.2.2 Empirical studies of the legitimacy theory
Most prior literature uses the legitimacy theory to explain actions that companies
have undertaken to regain their legitimacy when they encounter events which
threaten their legitimacy status. Companies may increase environmental disclosures
in the annual reports to legitimise their business operations to the community
(Deegan & Rankin, 1996; Patten, 1992). In contrast, O'Donovan (2002) proposed
that the legitimacy theory can be used strategically by companies to gain competitive
advantage over their competitors through adequate information disclosures.
O'Donovan (2002) adopted the classification in Suchman (1995) related to the
different challenges encountered by companies in the process of legitimation.
O’Donovan aimed to apply the legitimacy theory by investigating possible
relationships between a potential legitimacy threat from an environmental issue and
50

several related issues such as the choice of and purpose for legitimacy strategies
and the disclosures made in company annual reports. O’Donovan interviewed six
senior managers from three large Australian companies which operate in the mining
(BHP Ltd), chemical (Oric Ltd) and paper and pulp (Amcor Ltd) industries. These
companies were selected because they were the leading disclosers of environmental
information within the industry group for the year 1983 to 1997 in a study by Gibson
and O’Donovan (cited in O'Donovan, 2002, p. 353).
The results from O'Donovan (2002) supported the legitimacy theory and provided
empirical evidence that the legitimacy theory can explain managers’ decisions on
environmental disclosures in the annual reports. A strong correlation was found
between the significance of an environmental issue decisions on environmental
disclosures. An environmental issue of low significance would not be considered a
legitimacy threat and this would normally not warrant a need to use any strategies,
resulting in no disclosures. For environmental issues of medium and high
significance, companies that are seeking to maintain a high level of legitimacy and
those seeking to repair legitimacy are likely to adopt strategies to alter societal
perspectives or to conform to society’s expectations. Companies seeking to gain
legitimacy are likely to adopt a strategy to alter societal perspectives and are unlikely
to adopt strategies to conform. Hence, O’Donovan concluded that companies’
decisions on environmental disclosures and adopted strategies are made on the
basis of projecting a positive and legitimate corporate image.
Whereas O'Donovan (2002) focused on investigating companies’ reactive approach
to a potential legitimacy threat in environmental issues, van Staden and Hooks
(2007) examined companies’ proactive approach towards achieving legitimacy. Van
Staden and Hooks assessed the relationship between companies’ environmental
responsiveness and their voluntary environmental disclosures. Van Staden and
Hooks defined environmental responsiveness as “a measure of an entity’s sense of
responsibility for its environmental impact and includes the development of
strategies, policies, objectives and targets to address this responsibility” (p. 198).
Van Staden and Hooks used the 2002 environmental responsiveness ranking from
the survey results of the Centre for Business and Sustainable Development (CBSD)
51

to measure the companies’ environmental responsiveness. The CBSD has
conducted yearly survey since 1999 on New Zealand companies and the survey
does not based its information on companies’ disclosures but collects information
directly from a responsible officer of each company. The rankings awarded to
companies by the CBSD was considered to be reliable and valid by van Staden and
Hooks because they were provided by an independent external part that has
professional knowledge in environmental issues.
Van Staden and Hooks evaluated companies’ voluntary environmental disclosures
using companies’ environmental reporting in various different resources that includes
annual reports, stand-alone environmental reports and company websites. Positive
correlation was found between companies’ environmental responsiveness and
disclosures, indicating that responsive companies are taking a proactive approach to
organisational legitimacy.
Similarly, Patten (1992) study provided evidence that supported the legitimacy theory
when he found increased environmental disclosures by petroleum companies after
the Alaskan oil spill incident. He examined the annual reports of 21 listed petroleum
companies of the 1989 Fortune 500 for environmental disclosures and found a
significant increase in environmental disclosures after the disaster.
Deegan and Rankin (1996) also provided empirical evidence that supported the
legitimacy theory. They investigated the environmental disclosures of twenty
Australian companies that were successfully prosecuted by the Environmental
Protection Authorities during 1990 to 1993. They found eighteen of the selected
companies provided increased environmental information in their annual reports. The
information disclosed was predominately favourable qualitative disclosures and only
two out of the eighteen companies provided details of the prosecutions. Deegan and
Rankin (1996) suggested that the legitimacy theory could explain the increase in
environmental disclosures as it appeared that the companies felt the necessity to
legitimise their business operations through disclosing positive environmental news.
Recent research conducted by Cho et al. (2015) provided strong evidence that
legitimacy is still a significant factor affecting companies’ environmental and social
52

disclosures. They reviewed annual reports of companies from the Fortune 500
companies for the period 1977 and 2010. The results from their study indicates that
legitimacy factors continued to be important as the differences in the environmental
and social disclosure items remain largely unchanged over time.
However, the results from Wilmshurst and Frost (2000) provided limited support for
the legitimacy theory. They analysed management’s motivation for environmental
disclosures in company annual reports. While most had provided a higher level of
environmental disclosures in response to the perceived stakeholders’ demand for
sustainability information, their study failed to establish a correlation between specific
environmental issues that require legitimating and environmental disclosures that
were disclosed in the annual reports.
A longitudinal study of BHP Ltd by Guthrie and Parker (1990) also failed to confirm
the legitimacy theory’s explanation of the social disclosures in BHP Ltd’s annual
reports over 100 years to 1985. Deegan, Rankin, and Tobin (2002) re-examined BHP
Ltd’s annual reports for 15 years from 1983-1997 for social and environmental
disclosures, focusing on the impact of public concern through the media. Deegan et
al. (2002) noticed that greater media attention had increased corporate disclosures,
and annual reports were used to regain legitimacy especially when there was
adverse media opinion.
2.6 The Global Reporting Initiative (GRI) Framework
Prior research studies have found that many companies globally have been utilising
the Global Reporting Initiative (GRI) reporting framework for their sustainability
reporting, and the framework has become commonly regarded as the leading
standard for sustainability reporting (Adams & Frost, 2007; Betianu, 2010; Dingwerth
& Eichinger, 2010; Frost et al., 2005; Hussey et al., 2001; Tiong & Anantharaman,
2011). This is evident from the results of a survey conducted by KPMG on more than
2200 companies including Global Fortune 250 (G250) and the 100 largest
companies by revenue (N100) in 22 countries. KPMG found more than three-
53

quarters of the G250 and nearly 70% of the N100 used the GRI framework for their
reporting (KPMG, 2008). In a recent survey conducted by KPMG (2015), it was found
that the GRI remains the most popular voluntary reporting guideline worldwide, even
though it was noted that there has been a decline in the use of the GRI reporting
framework by the world’s largest companies.
2.6.1 Formation and development of the GRI
The roots of the GRI, which was established in 1997, can be traced to the Coalition
for Environmental Responsible Economics (CERES) and the Tellus Institute in the
United States. The idea to develop an environmental reporting framework was
pioneered by two individuals: Dr Robert Massie (CERES President) and Dr Allen
White
(Tellus Institute Acting Chief Executive). A department was formed for the ‘Global
Reporting Initiative’ project with the primary aim being to ensure that corporations are
following CERES principles for responsible environmental conduct. The department
established the guidelines for the reporting of non-financial environmental
information ("GRI's History," n.d.).
Initially, the department focused solely on environmental issues. Within a year, in
1998, a steering committee was formed and the scope of the GRI expanded to
include the triple bottom line concept (Brown, de Jong, & Lessidrenska, 2009;
Elkington, 1999) that included reporting on social, economic and environmental
issues. By 2001, the GRI was operating separately as an independent organisation
("GRI's History," n.d.).
2.6.2 The GRI framework
The GRI stipulates that sustainability reports should first identify topics and related
performance indicators that are relevant and appropriate for reporting by considering
the reporting principles of materiality, stakeholder inclusiveness, sustainability
54

context, and completeness ("Defining Report Content: The Process," n.d.). The
framework provides guidance to assist users to determine what content and issues
are reportable for sustainability. It guides users through each of the reporting
principles by defining, explaining and providing a set of tests for each individual
principle. Any information that has a significant impact on the social, economic and
environmental context or that substantially affects the stakeholders’ decisions
requires reporting under the GRI framework. Reporting organisations are expected to
identify their stakeholders and explain how their sustainability reports have
responded to their stakeholders’ interests. The framework also requires
organisations to include information on their current contributions to and future
development plans in relation to sustainability. In addition, the GRI framework
stresses the importance of completeness in the organisations’ coverage of their
sustainability disclosures.
The GRI framework aims for organisations to provide quality information in their
sustainability reports by ensuring that the disclosed information has the following
attributes: balance, comparability, accuracy, timeliness, clarity and reliability
("Reporting principles for defining quality," n.d.). The framework provides details
about how each of these attributes can be attained. It specifies that quality
information should balance favourable and unfavourable disclosures. Sustainability
disclosures are required to be presented in a way that allows comparisons within the
organisations, across periods and among other organisations. The disclosures
should also be sufficiently accurate to provide stakeholders with details to assess the
organisations’ performances and the reporting needs to be done regularly to ensure
timely information is presented with clarity to stakeholders so that they can make
informed decisions. In addition, the sustainability disclosures should be reliable,
suggesting that the information “should be gathered, recorded, compiled, analyzed,
and disclosed in a way that could be subject to examination” ("Reporting principles
for defining quality," n.d.).
Adopting the above conceptual principles, the first version of the GRI sustainability
reporting framework was launched in 2000. The framework promoted transparency
and accountability in organisations by developing comprehensive performance
55

indicators in three aspects of sustainability: social, economic and environmental.
The second version of the GRI framework, G2, was introduced in 2002 at the World
Summit on Sustainable Development in Johannesburg ("GRI's History," n.d.) and
was embraced by the United Nations Environment Program. In 2006, the GRI
launched the G3 version with more than 3000 experts that participated in the
development process. These participants consisted of multi-stakeholder groups,
which included business, civil society and labour movement groups. This evidently
demonstrated the GRI’s core approach for stakeholders’ involvement in its activities.
Subsequently, the GRI published the G3.1, an updated and completed version of
performance indicators in March 2011.
The latest version of the GRI framework, G4, was released in May 2013. The G4
version was developed with the aim of making the guidelines more user-friendly than
previous versions and emphasised that organisations should focus on reporting
issues that are material to their business and key stakeholders ("G4 Development
Process," n.d.).
This research has chosen to utilise the GRI G3.1 version framework rather than the
latest G4 version to develop the new scoring index as the G4 version had just been
released when this research commenced and subsequently has not yet been
adopted by the majority of companies. In addition, this research study is designed to
apply the newly developed index to analyse the sustainability information disclosed
in companies’ reports in 2012. Therefore, the G3.1 version is considered to be the
most recent and relevant version for this process.
2.6.3 The GRI application levels
The GRI developed three application levels (A, B or C) that reporting organisations
can use to evaluate their sustainability disclosures. The GRI listed reporting criteria
that companies can check against to determine their level of disclosures. A level A
indicates that the companies have reported on all the performance indicators in the
G3 framework and has provided explanations for the omitted indicators. Corporations
in the level A are also required to provide a statement on their management
56

approach to the indicators. A level B and C indicate that the companies have
reported on a minimum of twenty and ten performance indicators respectively.
Using the GRI application levels, companies are required to self-declare the level of
their disclosures based on their own assessments. Companies can choose to either
have a third party verification or request the GRI to confirm their self-declaration.
Companies that successfully completed a GRI application level check are awarded a
special GRI-checked icon with information about their assessment bodies.
Companies with the GRI award are also granted a statement to formally confirm that
their sustainability disclosures conform to the criteria set out by the GRI for a
particular application level. The GRI also recommends companies to engage a third
party to have their sustainability reports externally assured to increase the credibility
of the reports ("GRI Application Levels," n.d.).
2.6.4 Empirical studies on the GRI framework
Hussey et al. (2001) studied ten global companies from three industry groups
(energy and oil, consumer goods, and health care products) that have made a formal
commitment to be sustainable in their products, processes and services. The ten
global companies include British Petroleum (BP), Shell, and Sunoco in the energy
and oil industry; Procter and Gamble (P&G), 3M, DaimlerChrysler and Volvo in the
consumer goods industry; and Bristol-Myers Squibb, Johnson and Johnson, and
Baxter International in the health care products industry. They reviewed a total of 23
environmental reports of these ten companies that were published during the period
1995 through 2000 by matching the disclosures against the GRI framework. They
found that all the companies reported mainly in the environmental aspect, with very
minimal information in the economic and social aspects of the GRI framework. They
proposed that these companies focused on the environmental aspect due to
regulatory requirements; reporting on the economic and social aspects was minimal
as they were considered to be at their early stages.
57

As part of the study, Hussey et al. (2001) compared the GRI framework with other
available reporting frameworks such as the Global Environmental Management
Initiative (GEMI) and the Coalition for Environmental Responsible Economics
(CERES). It was found that the other frameworks are either too high level or too
general which make them less comprehensive compared to the GRI guidelines.
Hussey et al. thus concluded that the GRI framework appears to be the ‘best
available tool’ for sustainability reporting.
Tagesson et al. (2009) used the GRI framework to evaluate the extent of social and
environmental disclosures of 267 Swedish listed companies on the Stockholm Stock
Exchange. The empirical data for their study was collected from the companies’
annual reports and websites. Tagesson et al. divided the GRI performance indicators
into three areas: environmental, ethics and human resources. They analysed the
data using an unweighted scoring approach with a total of 22 performance indicators
categorised into environmental disclosures (8), ethics disclosures (8) and human
resources disclosures (6). Tagesson et al. examined the relationships between the
extent of the social and environmental disclosures and companies’ characteristics
(size, industry type, profitability, and ownership structure and ownership identity).
They found significant positive correlations between the extent of the disclosures and
the companies’ sizes and profitability. Corporations within the consumer goods
industry provided more disclosure about ethics while those in the raw materials
industry provided more disclosure about the environment. It was also found that
stateowned companies provided more disclosures than the privately-owned ones.
Frost et al. (2005) reviewed the sustainability reporting in Australia using the GRI G2
framework. With a total of 40 performance indicators categorised into 24 social
performance indicators (labour practice: 11, human rights: 7, society: 3 and product
responsibility: 3) and 16 environmental performance indicators, Frost et.al. assessed
25 companies from the top 500 listed on the Australian Stock Exchange (ASX) which
issued discrete sustainability reports as at September 2003. They studied the
sampled companies’ annual reports, discrete sustainability reports and their
corporation websites. Frost et al.’s study revealed the following results:
58
• There were very few sustainability disclosures in the annual reports as most
of the sampled companies had produced discrete sustainability reports.
• The overall number of disclosures using the GRI performance indicators was
generally low. The average number of indicators used in the discrete reports
was 7.24 while that used in the website was 6.28.
• There is significant variation among the companies over the range of GRI
performance indicators used.
• Not all companies use the GRI framework as a checklist for their reporting.
A more recent empirical study conducted by Tiong and Anantharaman (2011) applied
the latest GRI G3 guidelines and the GRI (2008) financial services sector
supplement to three banks in Australia. The three banks (ANZ, NAB and Westpac)
were selected as they have employed the GRI G3 framework in their sustainability
reporting. All the three selected banks’ sustainability reports were awarded a level “A”
by the GRI. Despite satisfying the highest level in the GRI framework, Tiong and
Anatharaman still identified flaws in the banks’ sustainability reports. Westpac was
found to provide information on all the 95 GRI required performance indicators; ANZ
failed to provide disclosures on 11 indicators, but had provided reasons for their
omissions; NAB, however, omitted a total of 31 indicators and failed to justify the
reasons for their omissions.
2.6.5 Limitations of the GRI framework
While the usefulness and comprehensive attributes of GRI are appreciated by most
prior research studies (Betianu, 2010; Frost, 2007; Frost et al., 2005; Hussey et al.,
2001), others have critiqued the GRI. Brown et al. (2009) highlighted the
impracticality and inconsistency between the expectations of the GRI developers and
the users. The GRI developers demand high quality sustainability reporting from
companies that adopt the GRI framework for their reporting. However, according to
Brown et al., smaller firms tend to find the GRI framework too complicated and
demanding, while larger companies find the GRI framework too standardised or
insufficiently specific.
59

This is concurred by Frost et al. (2005), who suggested that “there will always be
potential problems with the adoption of a generic set of reporting guidelines given the
diversity of the issues covered and the complex nature of corporations” (p. 90).
Furthermore, Brown et al. (2009) pointed out that the GRI framework does not
provide insight to the actual progress of an organisation towards sustainability. The
extent of the disclosures under the GRI reporting framework is also one of the major
concerns, as the sustainability reports are neither audited for their contents nor
verified against actual sustainability performance.
Dingwerth and Eichinger (2010) analysed the GRI framework and highlighted several
drawbacks regarding its actual implementation by corporations. They raised a
possibility of contradictory relationships between the GRI’s ambitious objectives and
its fundamental principles. They also questioned whether the GRI’s ambitious calls
for transparency and comparability in the sustainability disclosures are actually
feasible and achievable. Dingwerth and Eichinger described the GRI’s definition for
transparency as normatively demanding because it demands all relevant
sustainability disclosures (social, economic and environmental) that would
significantly impact the community or would substantially affect the stakeholders’
decisions. According to Dingwerth and Eichinger, this demand for transparency may
at times contradict companies’ other business targets. Using the example of
multinational companies that aim to increase their market share, Dingwerth and
Eichinger questioned whether these companies would provide all sustainability
disclosures including those which might have a negative impact on their companies
in securing market leadership.
In addition, Dingwerth and Eichinger (2010) raised the problem of comparability of
companies’ disclosures. Despite using the same GRI principles and performance
indicators, companies’ sustainability disclosures could still be substantially different.
This is because companies might have not reported on similar indicators as not all
the GRI indicators would be equally relevant to all companies. It was also highlighted
that companies might address different social and environmental issues in their
60

reports even when the same performance indicators were used. Hence, the
comparison problem is still unresolved.
Although the GRI framework awards companies on various application levels to
assist users of sustainability reports to determine companies’ level of disclosures,
these application levels are not reflective of companies’ actual sustainability
performance and contributions. The focus of the application levels is on assessing
the number of disclosures made by companies, without reference to their
sustainability performance.
To address the above limitations while at the same time enhancing the
comprehensive guidelines provided by the GRI framework, this research developed
a new GRI-based scoring index by integrating the GRI framework with the hard and
soft principles of Clarkson et al. (2008).
2.7 Clarkson, Li, Richardson and Vasvari’s (2008) Environmental Index
To date, the research on the GRI framework has tended to focus on dichotomy
studies where only the presence or absence of the GRI performance indicators is
recorded. No weighting, scoring or ranking is given to the disclosures; thus, the
nature of the disclosures is not evaluated. Clarkson et al. (2008), however,
developed a scoring scale based on the GRI G2 environmental performance
indicators with the assistance of an expert who was an original member of the GRI
Steering Committee. They categorised discretionary information of companies’
environmental disclosures into hard and soft items. Hard disclosure items refer to
items that were difficult for poor environmental performers to mimic and were
awarded higher scores as they represented companies’ real commitments in
sustainability. Lower scores were allocated for soft disclosure items such as
companies’ vision and environmental strategy claims that were considered relatively
easy for companies to mimic. Clarkson et al. developed an improved measurement
with a scoring scale to evaluate the extent of environmental disclosures, as
61

companies that displayed true contributions to environmental sustainability were
awarded higher scores to recognise the higher extent of environmental disclosure.
While most of the items in Clarkson et al.’s (2008) environmental index are scored as
either ‘1’ or ‘0’ for the existence or absence of the item, there is a section A3 in the
hard disclosure category that assesses the extent of a firm’s environmental
disclosure on specific GRI performance indicators. Disclosure items in this section
are awarded a range of scores from 0 to 6, based on performance data presented
relative to a range of indicators. A point each is awarded when the performance data
is presented and additional points are awarded when the data is presented with
information that contains details in each of the following: relative to peers or industry;
compared with previous period; compared to targets set; provided in both aggregate
and normalised form; or detailed at disaggregate level.
Clarkson et al. (2008) used their index to evaluate the environmental disclosures of
191 companies from the five most polluting industries in the United States: pulp and
paper, chemicals, oil and gas, metals and mining and utilities. They analysed the
relationship between the discretionary environmental disclosures in the media, such
as the companies’ corporate websites and discrete sustainability reports, and the
actual pollution discharge data from the United States Environmental Protection
Agency’s toxics release inventory. A positive correlation was found between
environmental performance and the level of environmental and social disclosures in
Clarkson et al.’s study. They also found that although companies with good
environmental performance were producing more disclosures than those with poor
environmental performance, the scores of good environmental performers were still
generally low, which suggested substantial improvements were required. In
particular, they found that companies whose environmental legitimacy was
threatened were making soft disclosure claims to be committed to the environment.
Clarkson et al. (2011) conducted a similar study on 51 Australian listed companies
that reported their pollutant emissions data to the National Pollutant Inventory (NPI)
in both 2001-2002 and 2005-2006. Using the index developed by Clarkson et al.
(2008)
62

, they compared the discretionary environmental disclosures in the companies’
annual reports and discrete sustainability reports to the data collected from the NPI
for these two periods. Clarkson et al. (2011) found that there was only modest
improvement between 2002 and 2006 in the companies’ environmental disclosures.
They also documented a positive relationship between the discretionary
environmental disclosures and the level of emissions. This result is contrary to those
obtained in Clarkson et al. (2008) where good performers were producing more
disclosures. The results in Clarkson et al. (2011) has raised concerns as poor
performers, as indicated in this more recent study, were also disclosing more
environmental disclosures. This, apparently, indicates the need to scrutinise
companies’ sustainability disclosures to ensure companies’ disclosures are reflective
of their true sustainability performance.
It is evident that Clarkson et al.’s (2008) environmental index enhances the GRI
environmental guidelines by distinguishing companies’ hard verifiable disclosures
from their soft disclosures, which can be easily followed by poor environmental
performers. While the hard and soft principles used in Clarkson et al.’s index allows
companies with effective environmental performance to be identified, the index is
limited by its ability to analyse only the environmental aspect of sustainability. The
primary aim of this research study is to address this gap by integrating the hard and
soft principles to include the social and economic aspects of sustainability to yield a
comprehensive GRI-based sustainability reporting framework that is capable of
identifying companies that have effective sustainability performances in all three
aspects of sustainability.
2.8 Company Characteristics Affecting Sustainability Disclosures
Prior research studies have identified a number of company characteristics such as
company size, industry type, profitability and management structure that have
significant correlations with the amount and nature of sustainability disclosures
(Frost, 2007; Gibson & O'Donovan, 2007; Gray et al., 2001; Jones et al., 2007;
Michelon &
63

Parbonetti, 2012; Post et al., 2011; Rao et al., 2012; Rupley et al., 2012; Sandhu &
Kapoor, 2010; Siregar & Bachtiar, 2010; Tagesson et al., 2009; Webb, 2004).
However, these studies have not yielded consistent results. The following factors are
likely to have contributed to these inconsistent results: they were conducted at
different time periods, they utilised different evaluation methods, they involved
different sample sizes, and they analysed companies operating in different countries.
This study has chosen to focus on investigating company characteristics that have
been identified as having a correlation with sustainability disclosures that may be
explained by the legitimacy theory and the stakeholder theory. The legitimacy theory
predicts that larger companies and those with superior financial performance tend to
engage in more sustainability disclosures. Larger companies normally attract greater
publicity and tend to be under greater scrutiny from their stakeholders. The
legitimacy theory suggests that larger companies are more likely to use media as a
tool to provide more voluntary sustainability disclosures to legitimise their business
activities. These larger companies are also expected to have more human resources
and technical knowledge to engage in more active sustainability reporting.
Theoretically, profitable companies are also relatively more exposed to political
pressure and public scrutiny; therefore, they attempt to provide more sustainability
disclosures to minimise potential political costs in the form of increased tax and
wages (Deegan, 2013). In addition, profitable companies are deemed to have the
economic capacity to produce better quality sustainability reports. Hence, this study
examines the impact of company size and financial performance on sustainability
disclosures.
The stakeholder theory stresses the importance of providing sustainability
information to companies’ different stakeholder groups (Deegan, 2013). Providing
sustainability disclosures not only assists companies to gain stakeholder support, it
also helps them to assess potential risks in their business operations and improve
their sustainability performance (Rao et al., 2012). Larger companies, which have
greater number of stakeholders and more diverse stakeholder groups, are expected
to engage in more diverse sustainability reporting to satisfy the different needs of
their stakeholders. Managers working in companies with better financial performance
64

may be expected to provide more detailed sustainability disclosures to other
stakeholder groups to show that corporate social responsibility is not compromised
for better financial performance.
According to the stakeholder theory, company has a binding fiduciary duty to value
the different stakeholders’ needs. This is in line with the recommendations of the
Australian Corporate Governance Council (ACGC) in the call for companies to be
transparent in their corporate governance structure, which involves the system of
rules, practices and processes of companies. The ACGC sets out principles and
recommendations related to corporate governance for listed companies in Australia.
The principles and recommendations are structured to promote the following eight
central principles:
• Lay solid foundations for management and oversight
• Structure the board to add value
• Act ethically and responsibly
• Safeguard integrity in corporate reporting
• Make timely and balanced disclosure
• Respect the rights of security holders
• Recognise and manage risk
• Remunerate fairly and responsibly
Using these principles, Gibson and O'Donovan (2007) established the link between
sustainability reporting and corporate governance. They explained that one of the
key principles of good governance recommended by the ACGC is to disclose the
extent of compliance with, and any departure from, best practice suggested in the
annual reports. This suggested that companies with good governance should
incorporate information about their company’s sustainable developments in their
annual reports.
Gibson and O’Donovan claimed that good governance is now closely associated with
the concept of sustainability and accountability, and corporate social responsibility
can be demonstrated by increasing annual report disclosures. Using the board
composition as an element of company governance structure (Baysinger & Bulter,
1985), this study investigates the impact of corporate governance on sustainability
disclosures through reviewing several aspects of a company’s board composition.
65

The legitimacy theory suggests that companies in environmentally sensitive
industries such as the resources industry are more likely to conform to society’s
expectations for better environmental performance and provide more sustainability
reporting (Heard & Bolce, 1981). Evidence from prior research has supported this
view and indicated that companies in environmentally sensitive industries provide
more sustainability disclosures, especially in relation to environmental aspects
(Deegan & Gordon, 1996; Deegan & Rankin, 1996; Frost, 2007; Patten, 1992).
Renewed attention to sustainability and increased regulatory obligations in relation to
environmental reporting and responsibilities have also resulted in an increased
demand for environmental disclosure by stakeholders of resources companies (Dong
& Burritt, 2010; Guenther et al., 2006; Wood & Ross, 2008). Stakeholders such as
shareholders, governments and public interest groups are interested to know about
the additional risks and potential increases in costs that may result from these
changes. The stakeholder theory suggests that these companies will likely disclose
more environmental related information to satisfy their stakeholders (Deegan &
Rankin, 1997; Elijido-Ten, 2007).
Australian resources companies have been required to provide mandatory
environmental reporting in their annual reports since July 1 1998 (Adams & Frost,
2007; Deegan & Gordon, 1996; Frost, 2007; Jones et al., 2007; Wood & Ross,
2008).
The resources industry is also governed by the extractive industry accounting
standard AASB 1022 which stipulates that environmental information such as
provision for site restoration and land rehabilitation and associated costs for
treatment of waste materials is disclosed in company annual reports (Deegan, 2013).
Furthermore, companies in the resources industry are governed by regulatory
measures which include pollution taxes and penalties for breaches of environmental
regulations monitored by the Environment Protection Authority in Australia. These
companies are involved in the exploration and extraction of minerals, oil and gas
and other natural materials, which have significant impacts on the environment and
they generally generate “a sufficient output of pollutant chemicals” (Wood & Ross,
2008, p. 7); therefore, they are subjected to high public scrutiny and strict
66

environmental regulations. This research aims to explore the impact of regulatory
compliance on the two sectors (metals and mining sector and energy and utilities
sector) within the resources companies listed in the Australian Securities Exchange.
While some studies have been conducted on sustainability reporting in the mining
and oil and gas industries, only a few of these studies have compared the two
industries. Furthermore, most of these studies have focused on the environmental
disclosures with little discussion on the social and economic aspects of sustainability.
Hence, this research investigates whether companies in the resources industry
provide relatively more environmental disclosures over the social and the economic
aspects of sustainability due to the legal obligation for mandatory environmental
reporting. In addition, this study explores whether the type of resources extracted by
companies affect the extent of sustainability disclosures. Sectors within the
resources industry are studied to determine if sustainability reporting practices differ
significantly between the metals and mining sector and the energy and utilities
sector.
The legitimacy theory and the stakeholder theory, together with prior research
studies in sustainability, have identified various company characteristics that have
impacted sustainability disclosures. This research focuses on investigating the
relationships between these company characteristics (company size, financial
performance, board composition, and industry types) and sustainability disclosures
using the newly developed scoring index.
2.9 Summary
This chapter highlights the developments in sustainability reporting practices and
performance. The discussion on the Global Reporting Initiative framework and the
Clarkson et al.’s (2008) environmental index explains the reasons and the method
that is adopted to develop a new reporting scoring index. The stakeholder theory and
the legitimacy theory lay the theoretical foundation and identify the company
characteristics that are tested in this study. The next chapter continues this literature
review in the development of the hypotheses.
67

CHAPTER THREE
HYPOTHESIS DEVELOPMENT
This chapter details the development of the hypotheses to address the research
questions in this study. The research hypotheses were established after a thorough
analysis and evaluation of the literature review relating to sustainability and
sustainability reporting. The hypotheses are tested for the existence of relationships
between the extent of sustainability disclosures in the annual reports and stand-
alone sustainability reports (the dependent variables) and the selected company
68

characteristics (the independent variables) including company size, financial
performance, board composition, and industry types, as explained in Chapter 2.
This project studies all three aspects of sustainability disclosures by investigating the
correlations between social, economic and environmental disclosures and company
characteristics. Most of the studies which have utilised the Global Reporting
Initiatives (GRI) framework have assessed the extent of sustainability disclosures
based on the number of GRI performance indicators reported. This study develops a
new GRIbased reporting index that integrates the hard and soft principles used in
Clarkson et al. (2008) into all three aspects of the GRI framework. The hypotheses
formulated are tested using the newly developed reporting index.
3.1 Company Size
Company size has been commonly considered an influencing factor in the analysis of
the extent of sustainability disclosures (Adams et al., 1998; Hackston & Milne, 1996;
Roberts, 1992). Larger companies are generally under greater public scrutiny due to
greater media exposure (Frost, 2007), which attracts greater attention from both the
general public and special interest groups (Roberts, 1992). The legitimacy theory
suggests that larger companies tend to provide more sustainability disclosures to
demonstrate their compliance to responsible corporate behaviours that are expected
by the society. In addition, larger companies have more diverse groups of
stakeholders, such as shareholders and employees, who are concerned about their
companies’ sustainable developments and who tend to demand and exert greater
pressure on companies to provide more extensive sustainability disclosures.
Furthermore, large companies are expected to have more financial and human
resources to engage in more extensive disclosures.
Many prior studies have established a positive relationship between company size
and the extent of sustainability disclosures and results were generally consistent with
samples from many different countries that include the following: Australia (Jones et
al., 2007); Denmark (Andrikopoulos & Kriklani, 2013); Japan and the United States
69

(Ho & Taylor, 2007); Netherlands, Switzerland, France, Germany and the United
Kingdom (Adams et al., 1998); New Zealand (Hackston & Milne, 1996); Sweden
(Adams et al., 1998; Tagesson et al., 2009); Indonesia (Siregar & Bachtiar, 2010);
and Thailand (Suttipun & Stanton, 2012).
Adams et al. (1998) examined 150 annual reports from six European countries
(Netherlands, Switzerland, France, Germany, Sweden and the United Kingdom) and
found that larger companies provided more sustainability disclosures in all three
categories studied – environmental, employee and ethical issues. Similar significant
results were observed across all the six different countries studied by Adams et al.
Thus, they concluded in their study that significant correlation existed between the
company size and the extent of sustainability disclosures, in spite of several
apparent differences across the European countries: culture, accounting systems,
banking and finance systems, government and legislative systems, and influences of
pressure groups.
Adams et al. (1998) also observed that there was a significant inter-relationship
between company size and company industry membership and disclosures on
environmental and employee issues. Larger companies in more sensitive industries
were found to be disclosing significantly more information about the environmental
and employee issues. However, there was no consistent effect on their disclosures
on ethical issues.
This result was consistent with Hackston and Milne (1996) study on New Zealand
companies. Hackston and Milne found a ‘size-industry’ disclosure relationship.
Roberts (cited in Hackston & Milne, 1996) classified profile industry as “those with
consumer visibility, a high level of political risk or concentrated intense competition”
(p. 87). They found that “size-disclosure relationship is much stronger for the
highprofile industry companies than for the low-profile industry companies” (p. 102).
These findings are in line with the study of Deegan and Gordon (1996) on Australian
companies which found that large companies are only disclosing more environmental
disclosures when they operate in environmentally sensitive industries.
70

Jones et al. (2007) investigated the top 100 listed companies on the Australian
Securities Exchange (ASX) in 2004 and analysed the environmental and social
information disclosed in these companies’ annual reports, sustainability reports and
corporate websites. Unlike the results found in Adams et al. (1998) where ethical
issues did not reflect the ‘size-industry’ relationship, Jones et al. found that larger
firms and resource companies are associated with significantly higher sustainability
disclosure index scores that include both environmental and social indicators.
Focusing on an environmentally sensitive industry - Australian resources - this
research investigates if a significant relationship exists between a company’s size
and the extent of sustainability disclosures. This study determines if significant
correlations exist between company size and total sustainability disclosures, as well
as between company size and each individual aspect of sustainability – social,
economic and environmental. Results from prior studies have suggested that
company size is positively associated with all three aspects of sustainability
disclosures and thus this study proposes the following hypotheses:
H1: There is a positive relationship between company size and the extent of total
sustainability disclosure provided by companies in the resources industry.
H1A: There is a positive relationship between company size and the extent of total
economic disclosure provided by companies in the resources industry.
H1B: There is a positive relationship between company size and the extent of total
environmental disclosure provided by companies in the resources industry.
H1C: There is a positive relationship between company size and the extent of total
social disclosure provided by companies in the resources industry.
Numerous variables that have been used in prior studies to proxy company size are
used in this study. These include market capitalization (Hackston & Milne, 1996; Ho
& Taylor, 2007; Jones et al., 2007), total revenue (Adams et al., 1998; Hackston &
71

Milne, 1996; Tagesson et al., 2009) and total assets (Andrikopoulos & Kriklani, 2013;
Hackston & Milne, 1996).
3.2 Company Financial Performance
Prior studies have tested company financial performance against the extent of
sustainability disclosures. Evidence has suggested that companies with greater
financial performance tend to provide more sustainable disclosures (Gray et al.,
2001; Ho & Taylor, 2007; Jones et al., 2007; Tagesson et al., 2009). Jones et al.
(2007) suggested several reasons for this positive relationship. First, companies with
better financial performance are likely to have more financial resources to devote to
voluntary sustainability disclosures. Second, these profitable companies tend to be
more effectively managed companies. Consequently, it is probable that companies
that can effectively manage financial issues are likely to be effective in their
management of other activities such as sustainability reporting. Lastly, profitable
companies, especially those in highly regulated and reputable industries such as
resource companies and banks, may be subjected to additional political cost in the
absence of adequate disclosures. Jones et al. proposed that these companies would
likely be more motivated to provide more extensive sustainability disclosures to
justify their strong financial performance.
These suggested reasons are consistent with those proposed in other prior studies.
Watts and Zimmerman (1978) indicated that demands placed on companies by
interest groups such as governments, trade unions and environmental lobby groups
might be affected by the accounting performance of the companies. Companies with
high profit records may attract political costs in the form of increased taxes,
increased wage claims or product boycott (Deegan, 2013). Thus, it is predicted that
companies may attempt to avoid these political costs by voluntarily providing both
financial and sustainability information to justify that their social responsibilities have
not been compromised while pursuing the objective of earning high profits.
72

Jones et al.’s (2007) study yielded a mixed result when they analysed company
financial performance of the top 100 listed companies in the ASX. They examined
the firms’ abnormal stock market returns and other various financial performance
indicators. They explored a total of nine financial variables: cash position to total
assets, net operating cash flow to total assets, total liabilities to total equity
(leverage), working capital to total assets, retained earnings to total assets, price to
book value, net tangible asset per share, capital expenditure to total assets and
interest cover ratio. They found strong statistical relationships between the extent of
sustainability disclosures and seven of the nine selected financial performance
indicators. Only cash position to total asset and price to book value were found to be
negatively correlated to the extent of sustainability disclosures.
Tagesson et al. (2009) conducted their study to evaluate the relationship of
companies’ disclosures in environmental, ethics and human resource disclosures
and their financial performance using return on asset (ROA) and return of equity
(ROE) as proxies for financial performance variables. Their study yielded a
significant positive relationship between company financial performance and the
extent of sustainability disclosures. In contrast, Ho and Taylor (2007) obtained a
different result when they examined the 50 largest companies from both the United
States and Japan. They discovered a negative relationship between financial
performance (leverage and liquidity) and the extent of sustainability disclosures.
Prior research has employed different proxies to determine company financial
performance. While most studies have established a positive correlation between
company financial performance and sustainability disclosures, there have been some
inconsistent results, especially when different proxies were used. This research
analyses the relationship between a company’s financial performance and its extent
of sustainability disclosures in the three aspects of sustainability (social, economic
and environmental) using various proxies such as operating revenue, earnings
before interests and taxes (EBIT), return on assets (ROA), return on equity (ROE),
book value per share and year-end share price.
73

According to the results and analysis from prior studies, it is expected that
companies in the resources industry, which is an environmentally sensitive industry,
are likely to provide a greater extent of sustainability disclosures to justify their better
financial performance to avoid potential political costs. Hence, the following
hypotheses are proposed.
H2: There is a positive relationship between company financial performance and the
extent of total disclosure provided by companies in the resources industry.
H2A: There is a positive relationship between company financial performance and
the extent of economic disclosure provided by companies in the resources
industry.
H2B: There is a positive relationship between company financial performance and
the extent of environmental disclosure provided by companies in the
resources industry.
H2C: There is a positive relationship between company financial performance and
the extent of social disclosure provided by companies in the resources
industry.
3.3 Board Composition
The role of a company’s board of directors (BOD) is to “oversee the actions and
decisions of corporate management” (Rupley et al., 2012, p. 614). The board
composition would affect how effectively the board fulfils this important role (Fama &
Jensen, 1983; Goodstein, Gautam, & Boeker, 1994; Pfeffer, 1972). Hence, it is
posited that a board composition that supports stronger board governance will result
in broader awareness and concern for companies’ stakeholders, and this situation
may lead to a higher quality of sustainability reporting (Rupley et al., 2012).
Gibson and O'Donovan (2007) also claimed that corporate governance is closely
related to sustainability reporting. This concept is in line with the Global Reporting
74

Initiative’s definition for sustainability when governance performance is included as a
component of sustainability. Previous research has also provided empirical evidence
that sustainability reporting is affected by important corporate governance attributes
such as the composition of the board of directors (BOD) of a company (Michelon &
Parbonetti, 2012; Post et al., 2011; Rao et al., 2012; Rupley et al., 2012; Siregar &
Bachtiar, 2010; Webb, 2004).
Rupley et al. (2012) studied 127 US firms across five industries (chemical, oil and
gas, electrical utilities, pharmaceutical and biotech, and food and beverage) over a
period of six years (2000-2005). They empirically tested the characteristics of
corporate governance and media in relation to voluntary environmental disclosures.
Their results suggested that companies provided more voluntary environmental
disclosures when they were exposed to greater media coverage, especially when
this was negative exposure. They also found significant positive relationships
between company voluntary environmental disclosures and several aspects of the
board composition: board independence, multiple directorships and proportion of
women directors. Similarly, Rao et al. (2012) found positive relationships between
board independence and proportion of women directors and environmental
disclosure when they examined the 2008 annual reports of the largest 100 Australian
companies listed on the Australian Securities Exchange.
While recent research has tested the relationship between environmental disclosure
and board composition, they have tended to focus only on the environmental aspect
of sustainability. This study fills this gap by extending the study to evaluate the
relationships of board composition with all three aspects of sustainability disclosures,
including the economic and social aspects. This research studies the various aspects
of board composition including the proportion of independent directors, multiple
directorships, Chief Executive Officer (CEO) duality, women directors on the board
and the existence of a sustainability committee.
3.3.1 Independent directors
75

Independent directors are directors that have no personal or professional relationship
with a company, other than being a board member. They are also often referred to as
external directors. The presence of independent directors on a board can help to
segregate the management and control tasks of a company and this is expected to
offset inside members’ opportunistic behaviours (Jensen & Meckling, 1976). In
addition, independent directors generally have stronger and extended engagement
with wider groups of stakeholders (Wang & Dewhirst, 1992) and they tend to have a
broader perspective that is likely to result in a greater exposure to reporting
requirements (Rupley et al., 2012). Hence, a higher proportion of independent
directors is expected to support stronger board governance and more sustainability
disclosures. Numerous empirical studies have found a positive correlation between
the proportion of independent directors on the board and the extent of sustainability
disclosures (Post et al., 2011; Rao et al., 2012; Rupley et al., 2012).
Michelon and Parbonetti (2012), however, did not find any direct correlation between
the proportion of independent directors and the extent of sustainability disclosures in
their study. Instead, they found a significant correlation between the proportion of
community influential board members and the extent of sustainability disclosures.
They suggested that board composition should be measured “beyond the traditional
outsider/insider dichotomy” (p. 504) and consider the individual characteristics of
directors. Baysinger and Hoskisson (cited in Michelon & Parbonetti, 2012)
recognised that independent directors are not “homogeneous in terms of specific
skills, knowledge, and expertise” (p. 485). Based on the results of Michelon and
Parbonetti’s study, independent directors of a company who were also community
influential members contributed significantly to the extent of sustainability disclosures
made by the company. Michelon and Parbonetti defined community influential
members to be nonexecutive directors who assist the company to establish
networking and reputation. Examples given in their study included retired politicians,
academics, and members of social organisations. Hillman, Cannella and Paetzold
(cited in Michelon & Parbonetti,
2012) claimed that these members provided contacts with the society and “provide
valuable non-business perspectives on proposed actions and strategies” (p. 485).
76

This study follows the results of many prior research studies which suggest that
independent directors are generally less aligned to the management’s interests;
hence, they are expected to have a tendency to focus on the needs of a wider group
of stakeholders and demand companies to provide more sustainability disclosures.
Thus, the following hypotheses are proposed.
H3(i): There is a positive relationship between the proportion of independent
directors on the board and the extent of total disclosure provided by
companies in the resources industry.
H3(i)A: There is a positive relationship between the proportion of independent
directors on the board and the extent of economic disclosure provided by
companies in the resources industry.
H3(i)B: There is a positive relationship between the proportion of independent
directors on the board and the extent of environmental disclosure provided
by companies in the resources industry.
H3(i)C: There is a positive relationship between the proportion of independent
directors on the board and the extent of social disclosure provided by
companies in the resources industry.
3.3.2 Multiple directorships
Fama and Jensen (1983) proposed that directors signal their expertise by serving on
multiple boards. Board members are likely to be exposed to more firm practices and
gain knowledge by interacting with other board members if they serve on more than
one board (Rupley et al., 2012). Rupley et al. (2012) posited that, in the context of
environmental disclosure, firms with board members serving on multiple boards
tended to have greater exposure to reporting practices of various firms and this
would result in a greater extent of disclosures. This claim was confirmed by their
findings that showed a significant positive relationship between the proportion of
multiple directorships and environmental disclosures. Lipton and Lorsch (1992),
77

however, made a cautious comment that multiple directorships could adversely affect
the corporate governance of a firm as directors were often distracted by other
organisations’ matters and this affected their performance in their monitoring roles.
While the issue of multiple directorships has been commonly explored in the area of
corporate governance, only a few studies have focused on its impact on
sustainability disclosures. This research, which focuses on Australian resources
companies, argues that resources companies with directors serving on multiple
boards are likely to have greater exposure to sustainability reporting requirements in
different industries, including those required in the resources industry. These
directors may share with other board members the knowledge and expertise of
different sustainability reporting practices and regulations from other industry types.
This is expected to provide the companies’ boards with a wider perspective on
sustainability reporting and, accordingly, enhance the willingness of the companies to
provide more disclosures in all three aspects of sustainability. Thus, the following
hypotheses are proposed:
H3(ii): There is a positive relationship between the proportion of directors with
multiple directorship and the extent of total disclosure provided by
companies in the resources industry.
H3(ii)A: There is a positive relationship between the proportion of directors with
multiple directorship and the extent of economic disclosure provided by
companies in the resources industry.
H3(ii)B: There is a positive relationship between the proportion of directors with
multiple directorship and the extent of environmental disclosure provided
by companies in the resources industry.
H3(ii)C: There is a positive relationship between the proportion of directors with
multiple directorship and the extent of social disclosure provided by
companies in the resources industry.
78

3.3.3 Chief Executive Officer (CEO) duality
Chief executive officer (CEO) duality refers to the leadership structure of a company
where the CEO also serves as the board chair. There are two competing theories
that explain the results of this organisation structure: agency theory and stewardship
theory (Mohamed Yunos, 2011). Agency theory claims that the roles are conflicting
as the board duties include the task of monitoring the CEO. However, the
stewardship theory argues that the dual position enhances the effectiveness of both
the roles by reducing the information asymmetry problem between the board and the
management, and thus facilitates timely decision making.
Forker (1992) supported the agency theory and posited that “a dominant personality
commanding a company may be detrimental to the interest of shareholders” (p. 117),
and hence under a duality arrangement, the monitoring role of the board chair may
be compromised. Adams and Ferreira (2009) mentioned that CEO duality tends to
constrain board independence since this arrangement increases the power of the
CEO over the BOD, and consequently this may reduce good corporate governance.
Fama and Jensen (1983) also explained that CEO duality could signal “the absence
of separation between decision control and decision management” (p. 314). The
consequences of a compromised monitoring role in CEO duality may result in
adverse effects on corporate governance and company disclosures.
Empirical findings on the impact of CEO duality on sustainability disclosure have not
yielded consistent results. While Gul and Leung (2004) found CEO duality to be
negatively related to voluntary corporate disclosures, Chen and Jaggi (2000) and
Cheng and Stephen (2006) did not find any relationship between these two variables
in their studies.
This research argues that the separation of the monitoring role of board chair and the
management role of CEO may avoid or reduce potential conflicting interest and
79

increase firm transparency. This enhances the corporate governance of a company
and promotes a greater extent of sustainability disclosures in all the three aspects.
Hence, this research proposes hypotheses as follows.
H3(iii): Companies in the resources industry with CEO duality provide a lesser extent
of total disclosure.
H3(iii)A: Companies in the resources industry with CEO duality provide a lesser
extent of economic disclosure.
H3(iii)B: Companies in the resources industry with CEO duality provide a lesser
extent of environmental disclosure.
H3(iii)C: Companies in the resources industry with CEO duality provide a lesser
extent of social disclosure.
3.3.4 Women directors
Adams and Ferreira (2009) raised the issue of the importance of gender diversity on a
board in their proposals for governance reform. Rao et al. (2012) have also stated that
the recognition of women directors’ contribution has continuously risen. Some of the
benefits of having women on the board have been highlighted in prior studies:
• More committed and involved; more prepared; more diligent; and creates better
atmosphere (Huse & Solberg, 2006)
• Improves decision making process; increases board effectiveness; and better
attendance and participation (Adams & Ferreira, 2009)
• Demonstrates greater responsibilities; more philanthropically driven; less
concerned with economic performance (Ibrahim & Angelidis, 1994)
• Enhances board independence (Kang, Cheng, & Gray, 2007)
• Associated with firms that are more socially responsible (Webb, 2004)
• Increases board effectiveness and shareholder value (Carter, Simkins, &
Simpson, 2003)
80

Fernandez‐Feijoo, Romero, and Ruiz‐Blanco (2014) examined the sustainability
reporting practices of the global fortune 250 (G250) and the 100 largest companies
(N100) in 22 countries using the 2008 KPMG international survey of corporate social
responsibility reporting. They found that companies with more than three women
directors on their boards provided more sustainability disclosures compared to
companies with three or less women directors on their boards. Likewise, Rupley et al.
(2012) also found that gender diversity, which was measured by the proportion of
female board members, was positively related to the extent of environmental
disclosures.
Based on the results from prior research, this study argues that companies with more
women directors on their boards are likely to improve their corporate governance
through increased board independence and accountability. Women directors are
expected to possess a greater passion for their companies’ sustainable
developments (Adams & Ferreira, 2009; Webb, 2004). Thus, several hypotheses are
proposed, as follows:
H3(iv):
There is a positive relationship between the proportion of women
directors on the board and the extent of total disclosure provided by
companies in the resources industry.
H3(iv)A:
There is a positive relationship between the proportion of women
directors on the board and the extent of economic disclosure provided by
companies in the resources industry.
H3(iv)B:
There is a positive relationship between the proportion of women
directors on the board and the extent of environmental disclosure
provided by companies in the resources industry.
H3(iv)C: There is a positive relationship between the proportion of women
directors
on the board and the extent of social disclosure provided by companies
in the resources industry.
81

3.3.5 Sustainability committee
A sustainability committee is typically in charge of reviewing the sustainability policies
and conducting internal audits of a company’s sustainability efforts in the business
operations. The existence of a sustainability committee in a company signals the
importance of sustainability issues to the company. It highlights the board’s
commitment towards the company’s sustainable developments and ensures that
designated personnel are accountable for the sustainability issues. Following this
rationale, it is expected that companies with a sustainability committee tend to
engage in more active sustainability reporting.
However, Rupley et al. (2012) and Michelon and Parbonetti (2012) did not find any
strong significant relationships between the existence of a sustainability committee
and the extent of sustainability disclosures. Michelon and Parbonetti suggested two
possibilities for the moderately significant results in their study. First, they had not
considered the age of the sustainability committee which might have an impact on
the relationship; and second, only 20.2% of the studied sample had a sustainability
committee.
As there are limited existing studies that investigate the impact of a sustainability
committee on the extent of sustainability disclosure, this study posits that the
existence of a sustainability committee in a company is likely to reinforce a
company’s dedication to its sustainable developments. It is predicted that the
sustainability committee is inclined to reflect their effective performances by providing
more sustainability disclosures in their reports. In addition, this study presumes that
members in the committee tend to possess greater knowledge and passion towards
sustainability issues. Thus, this study proposes the following hypotheses:
H3(v):
Companies in the resources industry with a sustainability committee
provide a greater extent of total disclosure.
H3(v)A: Companies in the resources industry with a sustainability committee
provide a greater extent of economic disclosure.
82

H3(v)B: Companies in the resources industry with a sustainability committee
provide a greater extent of environmental disclosure.
H3(v)C: Companies in the resources industry with a sustainability committee provide
a greater extent of social disclosure.
3.4 Resources Industry
Companies in the Australian resources industry are legally obliged to provide
mandatory environmental reporting. They are also under strong public scrutiny to
include additional voluntary sustainability disclosures. Furthermore, various benefits
such as increased sales, reduced operating costs and increased customer loyalty
have given companies incentives to be proactive in their sustainability reporting
(Adams & Zutshi, 2004; Creyer, 1997; Mohr & Webb, 2005). However, the lack of a
standardised reporting framework for these companies has yielded varying degrees
of sustainability disclosures (Dong & Burritt, 2010; Guenther et al., 2006; Perez &
Sanchez, 2009).
The resources industry in the Australian Securities Exchange (ASX) has two sectors:
metals and mining and energy and utilities. The two sectors differ in the types of
resources extracted. The metals and mining sector consists of companies involved in
mineral exploration, development and production. On the other hand, the energy
sector comprises companies that engage in the exploration and development of coal,
uranium, oil and gas, and renewable energy assets. Companies in the utilities sector
are generally involved in water, electricity and gas distribution. Both sectors belong to
the larger extractive industry and they share some similarities: they are required to
comply with the AASB 1022 accounting requirements for extractive industries; their
operating activities have significant impacts on the environment; they are subjected
to high levels of public scrutiny; and they generally need to demonstrate significant
efforts in sustainability for approval of their operating licenses.
83

However, according to Guenther et al. (2006), the two sectors do differ in other ways.
They have different professional industrial associations that produce varying
guidelines to assist in their environmental disclosures. Also, companies in the two
sectors have placed different emphasis on different environmental performance
indicators. Firms in the mining sector have tended to disclose more information in
areas such as land use and rehabilitation while companies in the oil and gas sector
have disclosed more details on transportation methods and oil spill incidents.
Furthermore, companies in the mining industry have followed the GRI guidelines
more closely than companies in the oil and gas industry, which followed the
guidelines developed by their industry associations. In their study, Guenther et al.
found that in general the mining industry reported a higher number of environmental
performance indicators compared to the oil and gas industry. They concluded that
the differences between the reporting practices in the two sectors were likely due to
varying reporting strategies and monitoring methods in the two industries.
In contrast, Bolívar (2009) yielded different results when he compared listed Spanish
companies in the utility and resources sectors. He found that the sampled companies
in the utility sector disclosed more environmental disclosure than those companies in
the resources industry. He noted that companies in the utility sector had disclosed
their company code of conduct and published contact details of the personnel in
charge of sustainability to facilitate feedback. These reporting features were not
found in the sampled companies from the resources sector. They also noticed that
companies in the resources sector had focused on reporting on environmental
revenue aspects that were closely linked to environmental grants and tax deductions
for environmental investments. While Bolivar’s study provided valuable insights into
the reporting practices in these two sectors, his findings may not be representative
due to a small sample size of nine.
Perez and Sanchez (2009) and Dong and Burritt (2010) conducted studies on the
mining sector and the oil and gas sector respectively. Both found that their sampled
companies provided broad coverage of the disclosed information, and companies in
both sectors failed to provide disclosures with quantified targets and outcomes.
Generally, they found that the companies disclosed wide-ranging information such as
84

statement of economic goals, but failed to provide meaningful disclosures relating to
specific volume and quality or comparison to standard or regional levels.
While many studies have been conducted on sustainability reporting in the mining
and oil and gas industry, only a few of these have compared the two industries.
Furthermore, most of these studies have focused on the environmental disclosures
with little discussion on the social and economic aspects of sustainability. Due to this
limited research comparing the two sectors, it is difficult to predict which sector may
be producing more sustainability disclosures. However, it is expected that there are
differences in their extent of disclosures due to different reporting practices in the two
sectors (Guenther et al., 2006). Therefore, this study proposes alternative
hypotheses as follows:
H4: There are differences in the extent of total disclosure provided by companies in
the metals and mining sector compared to those in the energy and utilities
sector.
H4A: There are differences in the extent of economic disclosure provided by
companies in the metals and mining sector compared to those in the energy
and utilities sector.
H4B: There are differences in the extent of environmental disclosure provided by
companies in the metals and mining sector compared to those in the energy
and utilities sector.
H4C: There are differences in the extent of social disclosure provided by companies
in the metals and mining sector compared to those in the energy and utilities
sector.
Figure 3.1 below sums up the selected independent variables (company
characteristics) and proxies that are used in this research. The independent
variables with the relevant proxies are statistically tested for their correlations to the
dependent variable (extent of sustainability disclosures).
85

86
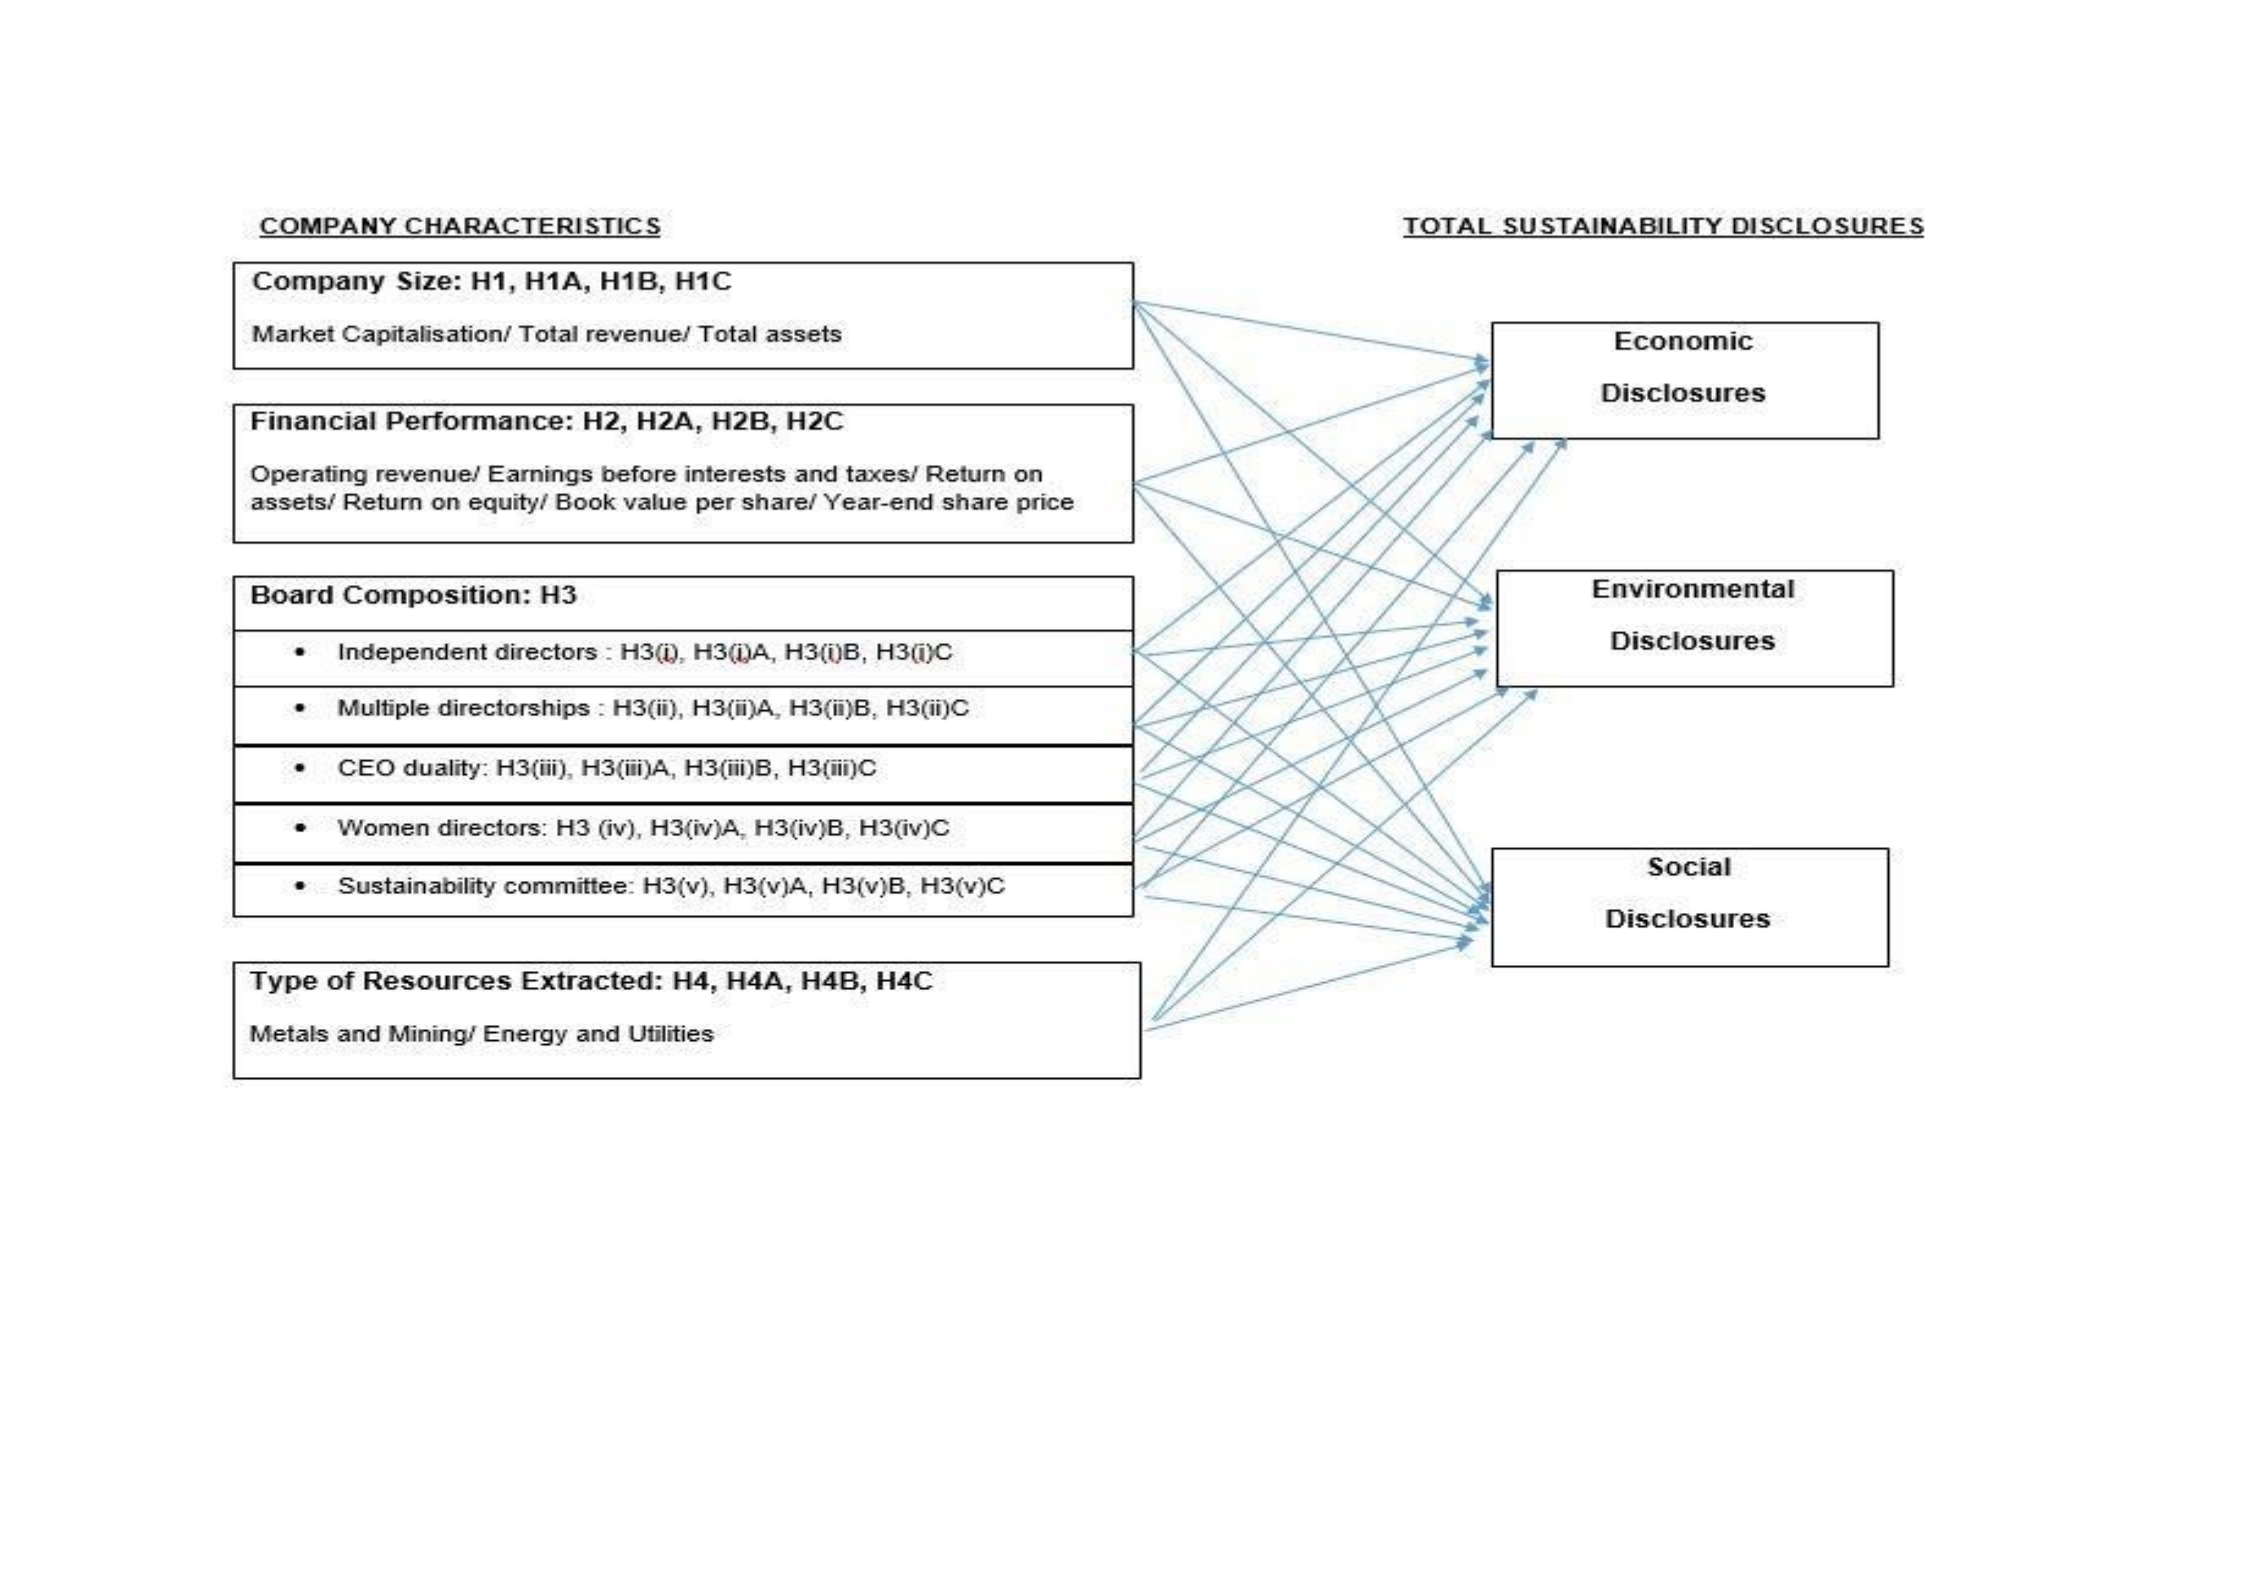
Figure 3.1 Research hypothesis framework

82

3.5 Hard and Soft Disclosure Items
Prior studies that have used the Global Reporting Initiative (GRI) framework to
analyse the extent of sustainability disclosures have tended to focus on the
evaluation of content based on the number of indicators reported. The same criterion
is used in the GRI awarding system. Organisations are graded A, B or C on their
sustainability disclosures by the GRI, according to the number of indicators reported
in their company sustainability reports. The sustainability indicators are given equal
importance by the GRI framework – no scorings are assigned to them.
This research develops a new GRI-based reporting index to measure the quality of
company sustainability reporting. It integrates the hard and soft principles of an
environmental index developed by Clarkson et al. (2008) into GRI G3 performance
indicators in all three aspects of the GRI framework. Clarkson et al. assigned higher
scores to hard environmental GRI performance indicators that were difficult for poor
environmental performers to follow. Lower scores were awarded to soft performance
indicators such as a company’s mission statement that were easily followed by poor
environmental performers. Clarkson et al.’s index facilitated an improved
measurement of a company’s environmental disclosures by awarding higher scores
for genuine contribution towards improving the environment. Similar principles are
adopted in this study to develop the scoring indexes for the social and economic
aspects of sustainability disclosures.
There were two competing predictions that Clarkson et al. (2008) put forward in their
study for testing. They claimed that the voluntary disclosure theory predicted that
companies who had performed well environmentally would disclose more hard
disclosure items to differentiate themselves from their competitors as being ‘superior’
in environmental performance. On the other hand, social-political theories, such as
the legitimacy theory and the stakeholder theory, predicted that companies would
disclose more soft disclosure items to simply satisfy their stakeholders’ desire for
information. These companies would attempt to change stakeholders’ perception
89

about their actual performance by disclosing more soft disclosure items that might be
difficult for stakeholders to verify.
Using the same environmental index that was developed by Clarkson et al. (2008),
Clarkson et al. (2008) and Clarkson et al. (2011) conducted two separate studies to
investigate the relationship between environmental performance and environmental
disclosure of companies in the United States and Australia respectively. The two
studies yielded contrasting results that were previously discussed in section 2.7 of
chapter 2. The results in Clarkson et al. (2008) supported the social-political theories
in that companies were disclosing more soft disclosure items, especially those who
had their legitimacy threatened. On the contrary, the results in Clarkson et al. (2011)
supported the voluntary disclosure theory where companies were found to be
disclosing more hard disclosure items to demonstrate their contribution towards
sustainability.
Given that the nature of soft disclosure items relates to items that require less effort
and commitment from reporting companies, it is predicted that companies in the
resources industry are likely to provide more soft disclosure items, especially in the
environmental aspects, to satisfy the mandatory reporting requirements in Australia.
This argument is in line with results obtained in prior research where the legitimacy
theory has been found to be the dominating factor, particularly in environmentally
sensitive industries (Cho et al., 2015; Clarkson et al., 2008; O'Donovan, 2002). In a
recent longitudinal study performed by Cho et al. (2015) on Fortune 500 data from
the late 1970s and 2010, they found that the relationship between legitimacy factors
and sustainability disclosures does not differ across the two time periods.
In the absence of a standardised reporting framework that stipulates specific
reporting items to be disclosed, companies tend to provide minimum, vague and
broad disclosures with little verifiability in the contents (Dong & Burritt, 2010;
Guenther et al., 2006; Guthrie et al., 2008). This ensures that they meet the required
regulations and satisfy stakeholders, without being penalised for items that are left
undisclosed. Hence, it is posited that companies in the resources industry may
90
provide more soft than hard sustainability disclosures in their reports and the
following hypothesis is suggested:
H5: Companies in the resources industry provide more soft disclosure items than hard
disclosure items.
3.6 Three Aspects of Sustainability Disclosures
This study adopts the Global Reporting Initiative’s (GRI) definition for sustainability
reporting that includes the provision of information about a company’s economic,
environmental, social and governance performance ("Sustainability reporting," n.d.).
Thus, information disclosed in all three aspects of sustainability (social,
environmental and economic) constitutes a total sustainability disclosure. Figure 3.2
below summarises the measurement for the total sustainability disclosure. The
framework in Figure 3.2 will be used in this research to measure the total
sustainability disclosure of companies in the Australian resources industry.
Figure 3.2 Measurement for total sustainability disclosure
Many prior studies have found that companies in the resources industry provide the
most sustainability disclosures (Dong & Burritt, 2010; Frost et al., 2005; Guenther et
al., 2006; Wood & Ross, 2008).
91
Economic Disclosure
E nvironmental Disclosure
Social Disclosure
TOTAL
SUSTAINABILITY
DISCLOSURE

Rikhardsson, Raj and Bang (cited in Bolívar, 2009, p. 186) found that environmentally
intensive companies reported more environmental disclosure than social disclosure.
They observed that companies in environmentally sensitive industries tend to
provide more disclosures in environmental issues such as emissions and resource
consumption.
Likewise, Yongvanich and Guthrie (2005) study of 100 top mining companies listed
on the Australian Securities Exchange yielded consistent results. They noticed that
the mining companies have focused on the environmental aspects of sustainability
reporting and their reports have “concentrated in a narrow group of reporting
elements” (p. 116). They found that companies reported approximately 40.59% of
their disclosures in the environmental aspects which concentrated on a few reporting
items such as compliance (94.12%), emissions, effluents and waste (88.24%), and
energy (58.82%).
Companies in the Australian resources industry are required to provide mandatory
environmental disclosures. Their business operations are closely related to the
environment and have massive impact on it. As such, they are subjected to high
levels of public scrutiny to ensure their compliance. On the contrary, economic and
social disclosures are generally voluntary for these companies. Hence, it is proposed
that companies in the resources industry are likely to place more emphasis on the
environmental aspect of sustainability and produce more environmental disclosures
to fulfil the legislative requirements and to satisfy their stakeholders. Consequently,
the following hypothesis is proposed:
H6: Companies in the resources industry provide more environmental disclosures
than social and economic disclosures in their sustainability disclosures.
3.7 Summary
92

This chapter has discussed the development of hypotheses that are tested to
evaluate the extent of sustainability reporting in the Australian resources industry.
These hypotheses are statistically tested in this study through the use of a newly
developed
GRI-based scoring index that enhances the current GRI framework by distinguishing
between hard and soft disclosure items. The methodology adopted for this study and
the details of the testing process are presented in the next chapter.
93

CHAPTER FOUR
METHODOLOGY
This chapter discusses the procedures and analysis that were used to measure the
extent of sustainability disclosures of companies in the Australian resources industry.
The research design and method, sample selection, data collection and analysis that
were adopted for this study are presented.
4.1 Research Design
Bryman (2016) defines a research design as “a framework for the collection and
analysis of data” (p. 40). The research is specifically designed to achieve the main
objective of measuring companies’ sustainability disclosures using an enhanced
Global Reporting Initiative (GRI) based reporting scoring index. The research design
consists of three stages: develop a new scoring index, conduct a pilot study and
undertake the main study.
The development of a new scoring index provides an improved instrument to collect
and code the data. A pilot study is conducted to assess the appropriateness of the
new instrument and to help identify any required revisions prior to the main study.
Finally, the main study is undertaken to generate more robust results using a larger
sample.
Figure 4.1 below depicts the research design framework.
94
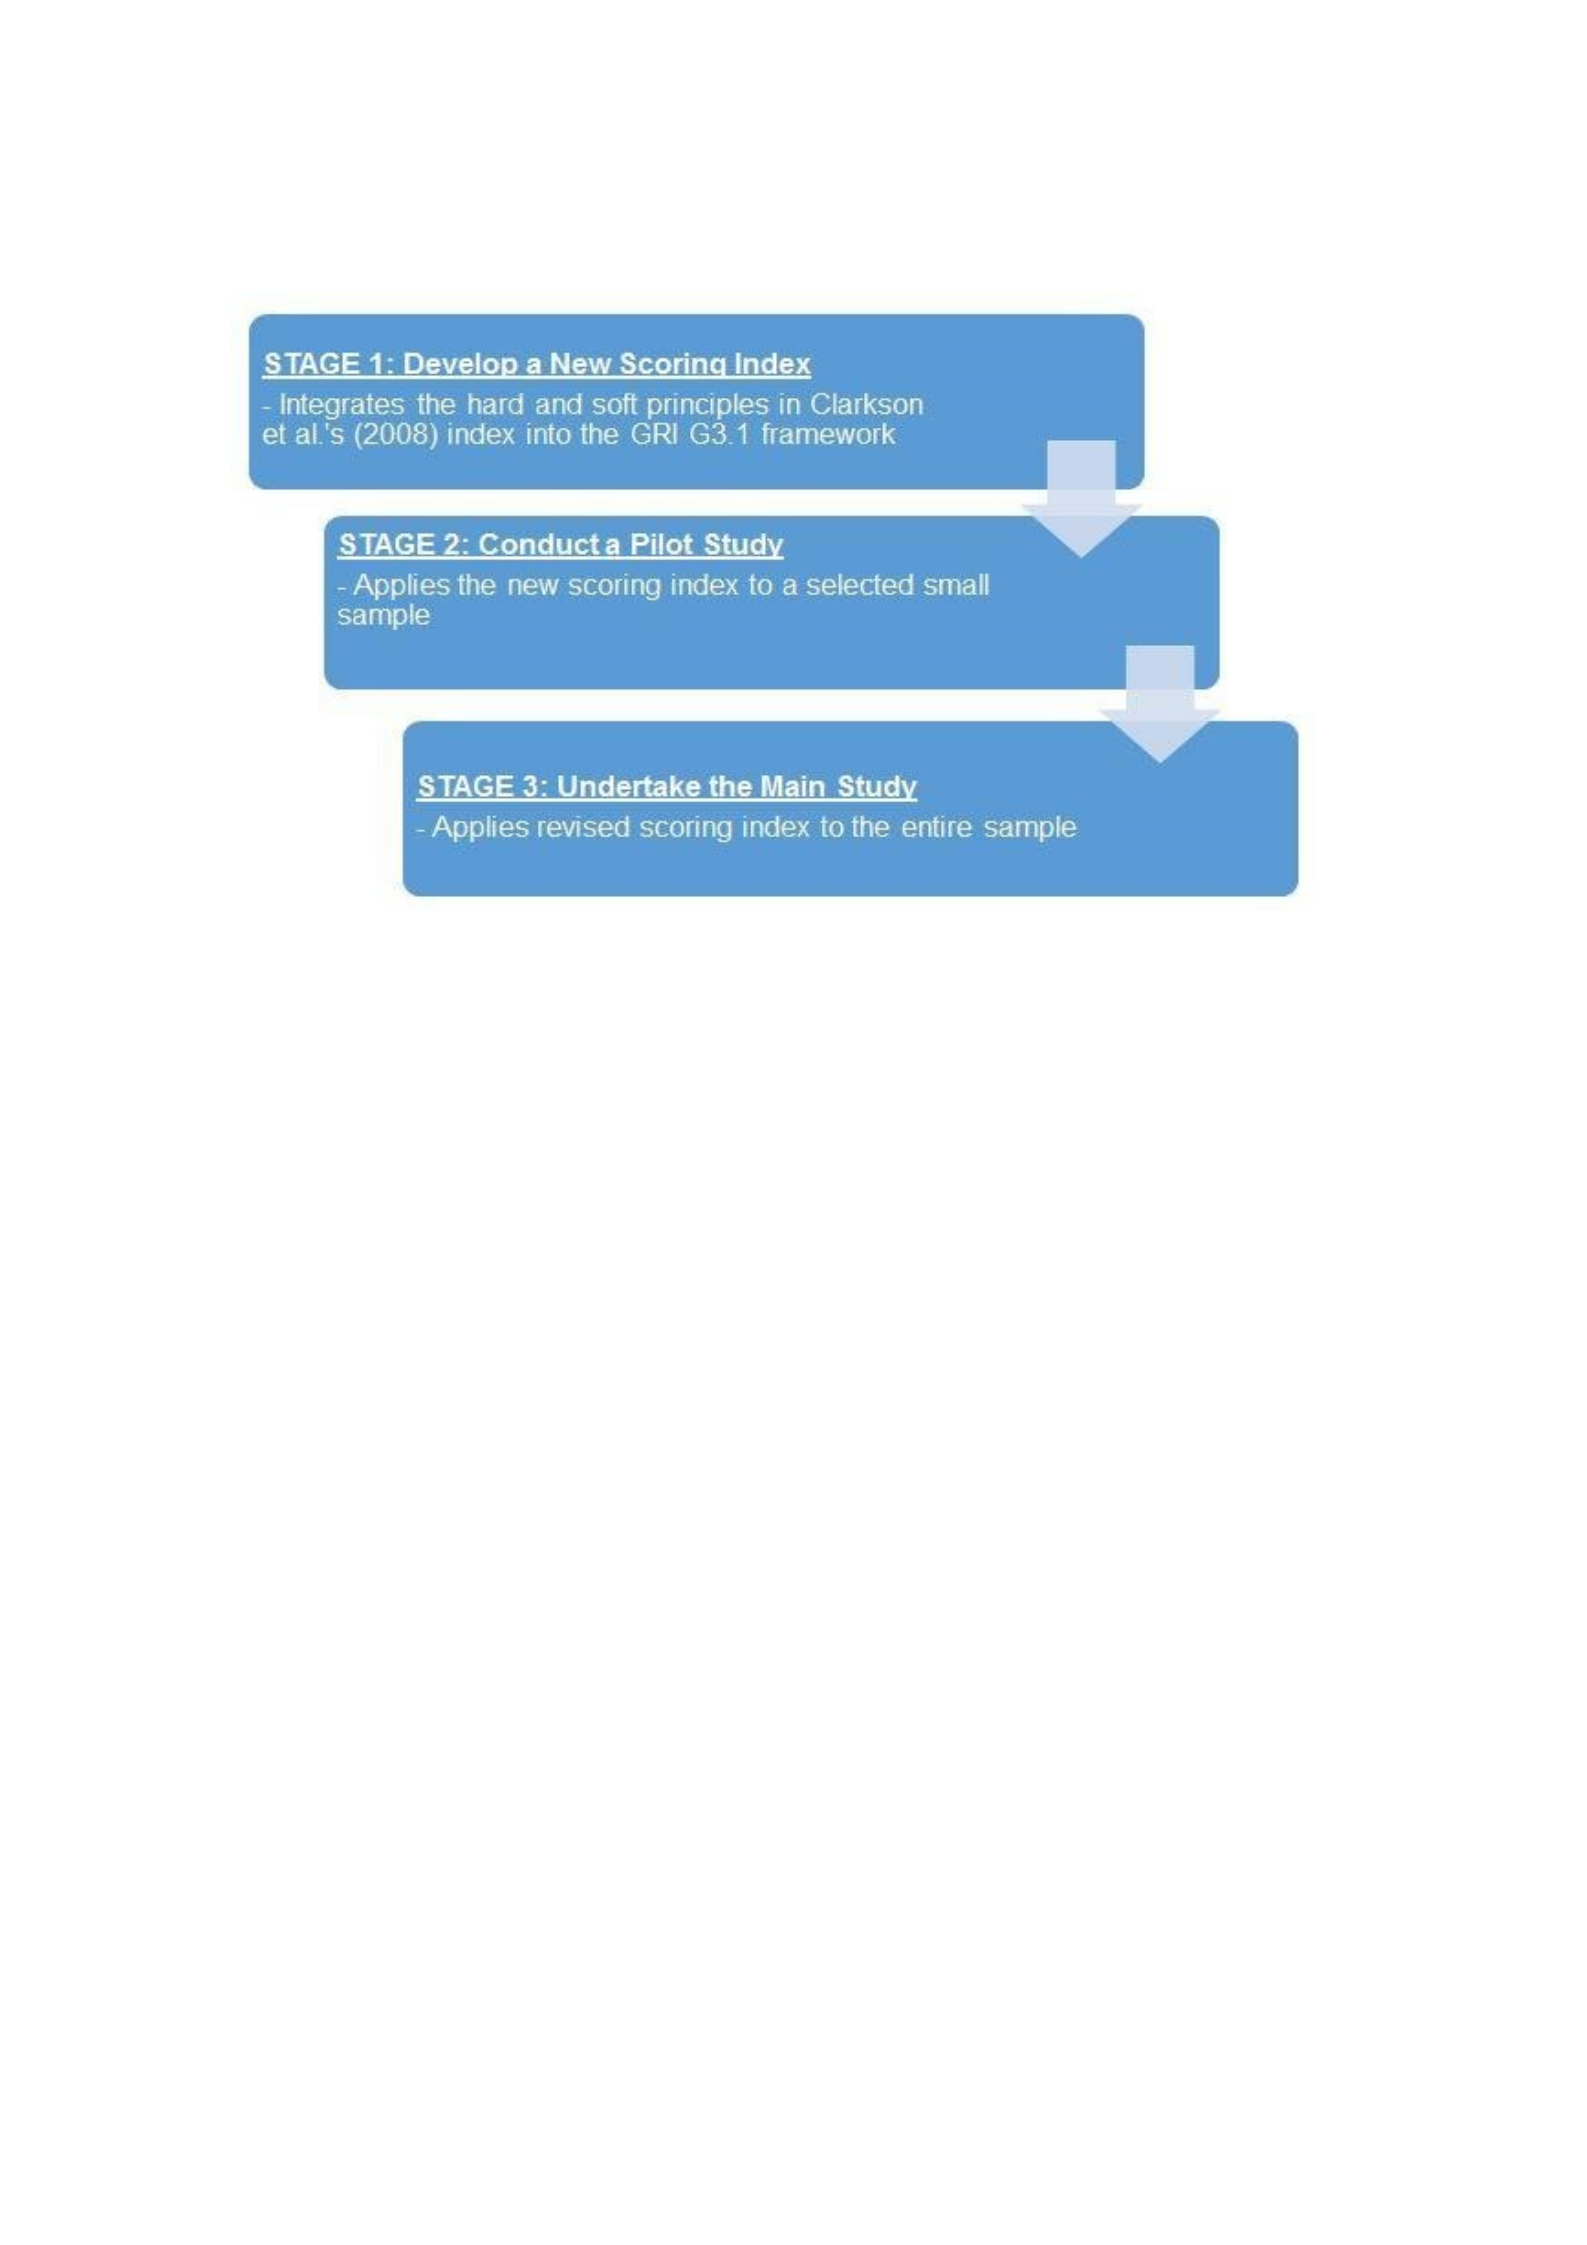
STA- I the hard and soft principles in Clarkson et al.'s (2008) index into
GRI G3.1 framework
Figure 4.1 Research design framework
4.2 Research Method
The following sub-sections cover the research methods adopted in the three different
stages of the research design.
4.2.1 Develop a new scoring index
This study addresses the problem of a lack of a standardised sustainability reporting
framework by developing a new Global Reporting Initiatives (GRI) - based scoring
index. This index integrates the fundamental principles of hard and soft disclosures
used in the environmental index of Clarkson et al. (2008) into all three aspects
(social, economic and environmental) of the GRI G3.1 version.
The G3.1 version of the GRI framework is used to develop this scoring index rather
than the latest G4 version, because the G4 version was only released in May 2013
95
and had not been adopted by many companies at the commencement of this
research.
The G3.1 version is considered to be the most relevant version for this study as it is
applied to collect data from companies’ annual reports and sustainability reports for
the period ending 2012.
The development process involves the incorporation of Clarkson et al.’s (2008)
environmental index with modifications to form the environmental aspect of the new
scoring index. The fundamental principles of the hard and soft disclosure items
underlying Clarkson et al.’s index are adopted to develop the social and economic
aspects of the new scoring index. Figure 4.2 below summarises and illustrates the
development process. A detailed account of the entire integration process is
presented in Chapter 5.
96
New GRI -Based
Sustainability Scoring Index
Modified with GRI G3.1
environmental performance
indicators
Adopt Cl arkson et al.
principles (2008)
Integrated into GRI G3.1
economic performance
indicators
Adopt principles and Integrated into GRI G3.1
social performance
indicators
Clarkson et al. (2008)
Environmental Index
Developed based on (
GRI G2 environmental
performance
indicators)
Environmental
Scoring Index
Economic Scoring
Index
Social Scoring
Index
Principles of
Hard Disclosure
Items
Soft Disclosure
Items

Figure 4.2 Development of a new GRI-based sustainability scoring index
4.2.2 Conduct a pilot study
A pilot study was conducted using the newly developed GRI-based sustainability
scoring index to evaluate companies’ sustainability disclosure. The pilot study was
designed to achieve the following objectives:
• review the validity and feasibility of the newly developed GRI-based
sustainability scoring index,
• maintain consistent scoring criteria in the application of the scoring index,
• identify necessary revisions to improve the scoring index,
• provide preliminary findings, and
• review the research design for the main study.
During the pilot study, annual and sustainability reports of selected companies were
scored using the new scoring index to test the validity and feasibility of the index. A
scoring check list was developed to record the criteria adopted in the scoring
process to ensure that consistency is maintained throughout the process. It was
crucial to identify any necessary revisions at this initial implementation stage, before
the scoring index is applied in the main study. The preliminary results from the pilot
study provided an initial overview of the extent of sustainability reporting in the
Australian resources industry. The methods, including the procedures for sample
selection and data collection, are evaluated in the process of the pilot study to
identify any modifications necessary to improve the main study. The details and the
implications of the pilot study are explained in Chapter 6.
4.2.3 Undertake the main study
Revisions to the new scoring index identified in the pilot study are implemented
before the revised version is applied to a larger sample in the main study. Data
collected in the main study is analysed using the Statistical Package for Social
97

Science (SPSS) program version 22 and is applied to test the hypotheses developed
in Chapter 3.
4.2.4 Content analysis method
The method of content analysis was applied extensively in both the pilot and the
main study. Content analysis method has been widely used to analyse the extent of
sustainability disclosures in companies’ reports (Gray, Kouhy, & Lavers, 1995;
Guthrie & Abeysekera, 2006; Guthrie & Parker, 1990; Steenkamp & Northcott, 2007).
Krippendorff (2013) defines content analysis as “a research technique for making
replicable and valid inferences from texts (or other meaningful matter) to the
contexts of their use” (p. 24). Krippendorff (2013) emphasises that content analysis,
being a research technique, is expected to be reliable and must have the ability to
yield valid results. This implies that it should result in findings that are replicable,
meaning that researchers that apply the same technique to the same data should
obtain the same results despite working at different times and under different
circumstances (Krippendorff, 2013).
Chadwick, Bahr, and Albrecht (1984) posit that “content analysis involves
systematically coding messages, or information in them, into categories, thus
allowing quantitative analysis” (p. 239). Chadwick et al. (1984) argue that one
important advantage of content analysis is that it is normally nonreactive in that no
human participants are involved in the form of an interview, a questionnaire or a lab
test. Content analysis also tends to be relatively inexpensive as the materials
involved are usually readily available. It is also the preferred method when direct
surveying or observing of the studied population is not feasible. However, drawbacks
of content analysis include the difficulty of locating information that is directly linked
to the research questions and its inability to be used to test causal relationships
between variables.
This study applies content analysis to collect data for both the pilot and the main
study by reviewing company annual financial reports and stand-alone sustainability
98

reports. Content analysis was conducted by awarding scores for sustainability
information disclosed in these reports based on the scoring criteria of the newly
developed GRIbased scoring index. The standardised scoring criteria address
potential problems that may arise from the drawbacks of using the content analysis
method by ensuring that content analysis technique can be replicated by the
researcher throughout the data collection process. The scoring criteria stipulate a set
of comprehensive guidelines to ensure consistency is maintained in the scoring
process.
According to Krippendorff (2013), the data coded may be biased if there is only a
single coder. To address this problem, this study has engaged another independent
coder with experience in using content analysis to revisit a sample of the company
reports before the pilot study was conducted. The initial results indicated that there
was a small percentage of variance (1%) in the scoring of the researcher and the
independent coder. As suggested by Krippendorff (2013), the differences were
reviewed by the researcher and the independent coder. The problem was resolved
through further discussion and clarification, resulting in the addition of more specific
guidelines to the scoring criteria for further coding work. The independent coder
applied these additional guidelines when conducting further checking and confirmed
that the scoring process was not biased with a single coder. This process is in line
with the approach suggested by Chadwick et al. (1984) whereby different coders
performed independent coding before their results are compared for reliability.
Thereafter, further coding was undertaken by a single coder who had undergone the
training process. The same coding and training practice is also adopted in other prior
studies (Adams et al., 1998; Jones et al., 2007; Yongvanich & Guthrie, 2005).
Further details relating to the specific coding guidelines and their practical
applications in the coding process is presented in section 4.4.4 of this chapter.
The data was screened and cleaned before it was analysed. The screening process
includes checking for errors and missing data. Checking for errors was done by
ensuring that the minimum and maximum values for the variables were within the
range of their possible scores. Missing variables were checked and valid values
were updated.
99

4.3 Sample
4.3.1 Selection criteria
This research has chosen to focus on the Australian resources industry for the
reasons explained in section 1.3 of Chapter 1. Many prior studies have noted that
there is still considerable scope for improvement in sustainability reporting in
Australia despite the increase in disclosures in recent years (Clarkson et al., 2011;
Dong & Burritt, 2010; Frost et al., 2005; Rao et al., 2012; Yongvanich & Guthrie,
2005). Due to the limited sustainability disclosures among Australian companies, this
study targets large companies only, as prior studies have identified that they are
representative and generally responsible for establishing corporate trends within
their industry; also, they have been found to disclose relatively more sustainability
information (Adams et al., 1998; Andrikopoulos & Kriklani, 2013; Dong & Burritt,
2010; Elijido-Ten, 2007; Guthrie & Parker, 1990; Hackston & Milne, 1996; Siregar &
Bachtiar, 2010; Tagesson et al., 2009). Hence, purposive sampling is adopted for this
study for comparability and relevance (Krippendorff, 2013).
The sample has been selected from listed companies in the resources industry in the
Australian Securities Exchange (ASX) for comparability to other prior studies and
relevance to the industry focus of this study. Listed companies are chosen as they
are normally larger in size (Yongvanich & Guthrie, 2005), are often the most visible,
and have significant influence on the economy as both large producers and
employers (Andrikopoulos & Kriklani, 2013). The industry classification of the ASX
also ensures that companies selected are operating in the resources industry as
classified by the Global Industry Classification Standard and can provide relevant
data to address the designed research questions.
There are two sectors within the resources sector of the ASX: metals and mining and
energy and utilities. This study selected large companies from both sectors of the
ASX resources industry based on market capitalisation. Many prior studies have also
100

adopted market capitalisation as their criteria for sample selection (Adams et al.,
1998; Dong & Burritt, 2010; Frost et al., 2005; Guthrie & Parker, 1990; Hackston &
Milne, 1996; Ho & Taylor, 2007; Jones et al., 2007; Rao et al., 2012; Suttipun &
Stanton, 2012).
4.3.2 Selection process
The sample for the pilot study was selected using the sector profile lists produced by
the ASX. First, the top 50 companies listed in both the metals and mining and the
energy and utilities sectors as at 30 June 2012 were identified. Companies that
have a different reporting year-end period are considered to be invalid for inclusion
as sample companies for this study. This is because the study, which focuses on a
single year of study, uses numerous year-end figures, such as market capitalisation
and other balance sheet items, in the analysis. Annual financial reports with a
different year-end date and figures will hinder comparison and result in an inaccurate
analysis.
Hence, companies with a different year-end date were eliminated.
Subsequently, the remaining companies on the top 50 list that had the same
reporting currency, Australian dollars, were selected for the pilot study. There were
23 companies from each of the two sectors that matched these selection criteria,
making a total sample size of 46 companies for the pilot study. The list of companies
and their respective market capitalisation is contained in Appendix 4-1.
A larger sample was planned for the main study. To resolve the problem caused by
different reporting currencies in companies’ annual financial statements, a common
financial database – DatAnalysis - was used. DatAnalysis is a finance database
provided by Morningstar, Inc. who is a leading provider of independent investment
research in North America, Europe, Australia and Asia. The company commenced
operation in 1984 in Chicago and has since grown into a company that has
operations in 27 countries, with more than $180 billion in assets under advisement
and management as at 31 March 2016. It provides data on approximately 525,000
investment instruments including stocks, mutual funds, and real-time market data on
101
nearly 18 million equities, indexes, futures, options and commodities (Morningstar
Inc). A total of 5 and 10 companies from the metals and mining sector and energy
and utilities sector respectively were added to the sample for the main study. This
brought the total sample for the main study to 61 as shown in Table 4.1 below.
To increase the number of sample companies for the main study, the ASX’s list of top
100 stocks for the next quarter – 30 September 2012 - was referred to. A list of the
top 100 stock list as at 30 September 2012 was produced by the ASX. A total of 72
companies (32 from the metal and mining sector and 40 from the energy and utilities
sector) that matched the selection criteria were included in the sample for the main
study. Table 4.1 below presents the entire sample selection process and the number
of companies that were selected at each of the stages. The list of sample companies
and their respective market capitalisation for the main study is contained in Appendix
4-2.
Table 4.1 Sample selection process for pilot study and main study
Stage Step Selection criteria Metals
and
Mining
Energy
and
Utilities
Total Remarks
Pilot
Study
From the ASX’s list
of top 50 stock as
at 30 June 2012 50 50 100
1
Companies without
financial year-end
date on 30 June
2012
22 17 19
Eliminated from
this study
2
Companies with
financial year-end
date on 30 June
2012 and
reporting currency
in
Australian dollars
23 23 46
Sample for pilot
study
(Appendix 4-1)
3
Companies with
financial year-end
date on 30 June
2012 and does not
reporting currency in
Australian dollars
5 10
15
Included for
main study
Main
Study
Total number of
valid sample
companies for main
study
(Step 2 and 3) 28 33 61
102
4 From the ASX’s list
of top 100 stock as
at 30 September
2012
(Step 2 to 4) 32 40 72
Included for
main study
Final sample for main study 60 73 133 (Appendix 4-2)
4.3.3 Descriptive summary
According to DatAnalysis, there were a total of 913 resources companies with a total
market capitalisation of $557,769.76 million listed in ASX as at 30 June 2012. This
made up the total population intended for this study. 46 companies (5.04% of
population) with a total market capitalisation of $79,011.23 million (14.17% of
population) were included in the pilot study. For the main study, 133 companies with a
total market capitalisation of $284,348.49 million were included. This made up 14.57%
and 50.98% of the total population based on the number of companies and total
market capitalisation respectively. Table 4.2 below provides a summary of the sample
for both the pilot and the main study. The percentages in the table indicate the
percentages of each item relative to the total population.
Table 4.2 Summary of sample for pilot study and main study
Metals and
Mining
Energy and
Utilities Total
Total number of listed companies in ASX
661
252
913
Total market capitalisation of listed
resources companies in ASX
(millions in Australia Dollars)
437,072.44
120,697.32
557,769.76
Number of companies in pilot study
23
(3.48%)
23
(9.13%)
46
(5.04%)
Total market capitalisation of companies
used in pilot study
(millions in Australia Dollars)
36,425.33
(8.33%)
42,585.90
(35.28%)
79,011.23
(14.17%)
Number of companies in main study
60
(9.08%)
73
(28.97%)
133
(14.57%)
103
Total market capitalisation of companies
used in main study
(millions in Australia Dollars)
229,451.94
(52.50%)
54,896.55
(45.48%)
284,348.49
(50.98%)
*All figures above are based on information as at 30 June 2012. Percentages displayed in brackets
indicate the percentages relative to the total population (total listed resources companies in ASX).
4.4 Data Collection
4.4.1 Data source
This study collects data from companies’ annual financial reports and stand-alone
sustainability reports. A company’s annual report is considered to be the most
important source of information about a company’s activities as it is the only
document that is sent to shareholders by all companies (Adams et al., 1998). The
information disclosed in a company’s annual reports is considered reliable because
they are a mandatory requirement under the Companies Act (Gray et al., 1995) and
listed companies in Australia are required by the ASX to have their annual reports
audited. There is also evidence that companies have consistently used annual
reports as a primary source for sustainability disclosures (Adams & Zutshi, 2004;
Brown & Deegan, 1998). In a recent KPMG survey on global trends in sustainability
reporting, it was found that approximately 56% of companies have included
sustainability information in their annual reports (KPMG, 2015). This rate has almost
tripled, compared to 20% in a similar survey in 2011. Hence, this study has chosen
to focus on the use of companies’ annual reports because of their high credibility
(Guthrie & Parker, 1989; Wilmshurst & Frost, 2000), widespread distribution,
standardised data approach over long periods of time and easy availability (Dong &
Burritt, 2010).
There are other information channels for sustainability disclosures in addition to
companies’ annual reports. Some companies prepare a separate sustainability
report and some provide sustainability information on their companies’ corporate
websites (Frost et al., 2005; Tagesson et al., 2009; van Staden & Hooks, 2007).
While the increased use of the internet has seen more companies provide
104

sustainability information on their corporate websites, information available on the
internet has the risk of information overload (Debreceny, Gray, & Rahman, 2002). It
is normally diverse in nature (Frost et al., 2005) and the information disclosed in this
category is nonregulated; thus, it is difficult to assess its credibility (Xiao, Yang, &
Chow, 2004). As this study is an exploratory attempt to utilise a newly developed
scoring index to score companies’ sustainability disclosures, disclosures on
companies’ websites are beyond the scope of this study so as to avoid the problems
of information overload and issues relating to diversity. However, sustainability
disclosures provided in companies’ standalone sustainability reports are included in
this study as companies that produced a separate sustainability report tend to
disclose more sustainability information in these reports than in their annual reports
(Frost et al., 2005; Higgins et al., 2015; van Staden & Hooks, 2007).
This study focuses on a single year of study (2012) instead of a longitudinal one as it
aims to evaluate the most recent disclosures available at the time of study. Annual
financial reports and stand-alone sustainability reports of companies in the sample
group for the year ending 30 June 2012 were downloaded from the companies’
corporate websites. Sustainability information disclosed directly on the company’s
corporate website that was not reported in companies’ formal financial reports and
sustainability reports were excluded from this research.
4.4.2 Dependent variables
The dependent variable of this research is the extent of companies’ sustainability
disclosure. This is measured by scores awarded to companies’ sustainability
information disclosed in their annual reports and sustainability reports based on the
scoring criteria of the newly developed scoring index. Adopting the scoring scale of
Clarkson et al.’s (2008) index, the new scoring index consists of two main scoring
scales, one for soft disclosure items and another for hard disclosure items.
While soft disclosure items are awarded a score of 1 for presence and 0 for absence
of the disclosure item, hard disclosure items are awarded a range of scores from 0 to
6. For hard disclosure items, a point is awarded for each of the following items:
105

(1) Performance data is presented;
(2) Performance data is presented relative to peers/rivals or industry;
(3) Performance is presented relative to previous periods (trend analysis);
(4) Performance data is presented relative to targets;
(5) Performance data is presented both in absolute and normalised form; and
(6) Performance data is presented at a disaggregated level.
According to Clarkson et al. (2008), hard disclosure items with the above details are
useful in the assessment of a company’s genuine environmental performance.
Hence, the design of Clarkson et al.’s scoring criteria was developed so that higher
points reflect better environmental performance. Accordingly, the newly developed
scoring index awards scores only to information disclosed that indicates an
improvement in sustainability performance. This is because the intended aim of this
new index is to measure actual sustainability performance rather than the extent of
sustainability disclosure. It is designed so that a higher score is meant to reflect a
company’s better sustainability performance, which can be demonstrated in the form
of achieving a set target, outperforming its peers or attaining better performance than
the industry average. As a result, non-compliance or a decline in sustainability
performance is not awarded any points. Table 4.3 below provides the details of the
scoring criteria that are applied in this study.
106
Table 4.3 Scoring criteria for hard disclosure items
Disclosures: Scoring Criteria: Scoring Method:
1. Performance data is
presented
Performance data is disclosed (in
any form or nature).
Information provided may be
presented:
• in any form or nature;
• by descriptions in words or
quantified in numeric terms; or
• in a general or specific context.
2. Performance data is
presented relative to
peers/rivals or
industry
Performance data is compared to
companies in a similar industry
or industry average.
Peers/rivals or industry-related
information is included.
Information may include:
• compliance to legislative
requirements specific to the
industry; or
• better performance compared to
peers/rivals or industry average.
3. Performance data is
presented relative to
previous periods
Performance data of previous
periods is presented.
Information that relates to improved
performance compared to previous
period.
4. Performance data is
presented relative to
targets
Performance data is reviewed
against previously set targets.
Information related to set targets is
included. Information may include:
• actual performance met or
surpassed the set targets; or
• company performed better than
their expectations.
5. Performance data is
presented both in
absolute and
normalised form
Performance data is disclosed in
raw data and also presented in
ratio or percentage.
Information is presented in both raw
and comparative data. Raw data
may be presented in absolute
numeric terms and also reflected as
a ratio or percentage of comparable
data.
6. Performance data is
presented at
disaggregate level
Performance data is presented
with breakdown.
Information may be presented
with breakdown details relative to:
Business unit; or
• Geographic segments; or
• Projects.
107
4.4.3 Independent variables
The independent variables of this study are company characteristics that include
company size, financial performance and composition of board of directors (BOD).
Table 4.4 below indicates the chosen proxies for the independent variables to
measure the respective company characteristics. These proxies were selected
based on commonly used indicators in prior studies on sustainability that were found
to be associated with sustainability disclosures as discussed in Chapter 3.
Table 4.4 Proxies used for independent variables
Independent variables
Proxies used
Company
Characteristics
Company Size
Market capitalisation
Total revenue
Total assets
Financial
Performance
Operating revenue
Earnings before interest and tax (EBIT)
Return on assets (ROA)
Return on equity (ROE)
Book value per share
Year-end share price
Board
Composition
Independent directors
Multiple directorships
Chief executive officer (CEO) duality
Women directors
Sustainability committee
While reviewing the companies’ annual financial reports during the data collection
stage, it was observed that there were differences in the companies’ reporting
currency and that they were using different formulas for the financial ratios shown in
their reports. As a result, it was inappropriate to collect data of the companies’
characteristics directly from companies’ annual financial reports. To overcome these
problems that hinder effective comparison, the data was collected via the same
database - ‘DatAnalysis’ explained in section 4.3.2.
4.4.4 Content analysis process
108

A recording score sheet was developed to record and compile the data for the
dependent variables (scores of sustainability disclosure items) and the independent
variables (company characteristics).
There are numerous advantages in using a recording score sheet to document the
scoring process, including:
(a) To ensure completeness in the data collection as it provides a comprehensive
checklist for the scoring process.
(b) To identify the scoring items and their respective maximum points to be
awarded.
(c) To consolidate the data collected with the corresponding references.
(d) To provide a distinctive classification between the hard and soft sustainability
information collected.
(e) To sort the sustainability information disclosed in the companies’ reports
according to the different aspects of sustainability - economic, environmental
and social.
(f) To facilitate the compilation of the total scores in the different categories of the
scoring index.
In the initial stage of the recording process, pages of the companies’ reports that
contained relevant sustainability disclosures scored by the index were copied. The
relevant words and paragraphs were highlighted and marked with the corresponding
index codes to record the scoring process. The respective page numbers of the
companies’ reports with the sustainability disclosures were also recorded on the
recording sheet. In cases where there were complex scoring issues, justifications for
the scores awarded were also recorded. This assisted in the compilation of a list of
scoring criteria to ensure that consistency is maintained throughout the scoring
process.
4.5 Data Analysis
109

Data collected was analysed using the Statistical Package for the Social Science
(SPSS) program version 22. A normality test was first performed on both the
dependent and independent variables using the Kolmogorov-Smirnov and
ShapiroWilk tests. The two tests compare the variables of the sample to a normally
distributed set of scores with the same mean and standard deviation (Field, 2013). If
the result of the test is significant with p-value greater than 0.05, it means that the
distribution of the tested sample tested is not significantly different from that of a
normal distribution. However, if the result indicates a p-value that is less than the
significance level of 0.05, it shows that the distribution of the tested sample does not
follow a normal distribution. It is generally considered more appropriate to use the
Shapiro-Wilk test when the sample is small (Allen, Bennett, & Heritage, 2014).
The results on both the dependent and independent variables from the
KolmogorovSmirnov and Shapiro-Wilk tests revealed that most of the variables do
not follow a normal distribution. As the normality rule is violated, non-parametric
statistical tests were applied. Non-parametric techniques are ideal and useful for
small samples and when the data do not meet the stringent assumptions of the
parametric techniques (Pallant, 2013).
Kendall’s tau-b, Mann-Whitney U, Wilcoxon signed rank and Friedman two way
ANOVA tests were the main non-parametric analyses used for the statistical tests in
the pilot study. Kendall’s tau-b coefficient is a non-parametric statistic used to
measure correlation. Kendall’s tau-b coefficient is considered more rigorous than that
in
Spearman’s rho as “it tends to provide a better estimate of the true population
correlation, and is not artificially inflated by multiple tied ranks” (Allen & Bennett,
2012, p. 279). Field (2013) also recommends that Kendall’s tau-b coefficient be used
when the data set is small with a large number of tied ranks. Hence, Kendall’s tau-b
coefficient was applied to analyse correlations between variables in this pilot study.
To increase the robustness of the statistical tests, an additional bootstrapping
process was performed with 1000 bootstrap samples with a 95% confidence interval.
Bootstrapping provides a better estimation of the properties of the sampling
110

distribution in the case where the sample lacks normality (Field, 2013). According to
Field, the results obtained from the bootstrap can confirm the robustness when the
robust confidence intervals obtained from the bootstrapping do not cross zero. In
addition, the effect size is measured using the range proposed in Cohen (1988). An
effect size measures the size of an effect, which is the strength of a relationship
between variables (Field, 2013). Cohen (1988) suggested the effect is considered
small when the calculated effect size is less than 0.2. A value between 0.2 and 0.5 is
considered a medium effect and a value greater than 0.5 is considered a large effect.
The Mann-Whitney test is used to compare two conditions between independent
samples when the assumption of normality is violated in the distribution (Field,
2013). This test is used to determine if there are significant differences between
sustainability disclosures and the following categorical company characteristics such
as:
• companies with Chief Executive Officer (CEO) duality to those that are without,
companies with a sustainability committee to those that are without, and
• companies that operate in the Metals and Mining sector to those in the Energy
and Utilities sector.
The Wilcoxon signed rank, which works with the same theoretical concept as the
Mann-Whitney test, is used with related samples. This test is used to determine if
there is any significant difference between the disclosures of hard items and soft
items.
The Friedman two way ANOVA is another non-parametric statistical test that is used
to analyse the data. It is used to ascertain if there are significant differences in the
disclosures among the three aspects of sustainability. It is also used to test for
significant differences among the four different social performance indicators within
the broader social aspect of sustainability.
These non-parametric statistical tests were applied to the data collected to yield
preliminary results of the pilot study. The preliminary results identified existing
111

correlations between the variables and answered hypotheses developed for the pilot
study.
4.6 Summary
This chapter has presented the methodology used in this study, including the
process of sample selection, data collection and data analysis. The next chapter,
Chapter 5, discusses the detailed development process of the new GRI-based
scoring index followed by Chapter 6, which presents the process and results from
the pilot study where the newly developed index is pilot-tested.
CHAPTER FIVE
DEVELOPMENT OF NEW SCORING INDEX
This study addresses the problem of a lack of a standardised sustainability reporting
framework by developing a new Global Reporting Initiatives (GRI) - based scoring
index by integrating the fundamental principles of hard and soft disclosures used in
Clarkson et al. (2008) into all three aspects (social, economic and environmental) of
the GRI G3.1 version. The index enhances the existing GRI guidelines, creates an
improved measurement for sustainability reporting, and establishes a standardised
framework to measure the quality of sustainability reporting for future research
projects.
Further to the development process described in Chapter 4 (section 4.2.1), this
chapter presents an account of how the index is developed. The new completed
scoring index is tested in a pilot study (Chapter 6) to identify any required revisions.
This chapter explains the development process in the following order:
112

1. Section 5.1 provides a summary of the GRI G3.1 framework detailing the
different parts within the framework and the respective information items that
are disclosed under each part.
2. Section 5.2 provides an overview of the environmental index used in
Clarkson et al. (2008), explaining the hard and soft disclosure principles and
the scoring criteria used in their index.
3. The first phase of the development process is covered in section 5.3. This
phase involves incorporating Part I (company’s profile disclosures) of the GRI
framework into the new scoring index.
4. Section 5.4 discusses the second phase of the development process. This
section covers the process of incorporating a new part of the GRI G3.1
framework, Part II, which involves disclosures on management approach
(DMA) of the company to the three aspects of sustainability.
5. Finally, section 5.5 explains the process of incorporating the scoring criteria
used in Clarkson et al.’s (2008) index for hard and soft disclosure items to
Part III of the GRI framework that covers the specific sustainability
performance indicators.
5.1 The GRI G3.1 Framework
The GRI G3.1 framework consists of three major parts: Part I profile disclosures;
Part II disclosures on management approach (DMA); and Part III performance
indicators. Table 5.1 below shows the structure of the GRI G3.1 framework.
Companies are expected to provide their profile information in Part I that consists of
four sections: strategy and analysis; organisational profile; report parameters; and
governance, commitments and engagement. Part II identifies the companies’
disclosures on management approach (DMA) to sustainability issues and comprises
six different sections on sustainability. These sections provide the users with
information on how the company manages these material aspects of sustainability.
113
Part III of the GRI G3.1 framework consists of reportable items known as
performance indicators which are directly related to operating information in the
various aspects of sustainability. Table 5.1 summarises the respective disclosure
items under each part of the GRI framework.
Table 5.1 The GRI G3.1 framework
Part Disclosure items:
Part I: Profile disclosures 1. Strategy and analysis
2. Organisational profile
3. Report parameters
4. Governance, commitments, and engagement
Part II: Disclosures on management
approach (DMA)
• Economic (DMA EC)
• Environmental (DMA EN)
• Social: Labour practices and decent work (DMA LA)
• Social : Human Rights (DMA HR)
• Social: Society (DMA SO)
• Social: Product responsibility (DMA PR)
Part III : Performance indicators • Economic : EC1 to EC9
• Environmental : EN1 to EN30
• Social – Labour practices and decent work: LA1 to LA14
• Social – Human Rights: HR1 to HR11
• Social – Society: SO1 to SO8
• Social – Product responsibility: PR1 to PR9
114

5.2 Clarkson, Li, Richardson and Vasvari’s (2008) Environmental Index
Clarkson, Li, Richardson and Vasvari’s (2008) environmental index focused solely on
the environmental aspect of sustainability and they categorised the GRI G2
environmental performance indicators into hard and soft disclosure items. They
classified items that are relatively difficult for poor environmental performers to mimic
as hard disclosure items. These hard disclosure items refer to information items that
a third party can verify and validate, such as quantified savings in a water
conservation project or documented expenditure of a sustainability orientated
research project. On the other hand, those items that are relatively easy for poor
environmental performers to mimic are defined as soft disclosure items. Examples of
soft items include a mission statement or a future vision about sustainability.
As shown in Figure 5.1 below, there are four sub-classifications (A1 to A4) of the
hard disclosure items. A1 focuses on a firm’s disclosures pertaining to its
governance structure and management system relating to environmental protection.
A2 measures the credibility of a firm’s environmental disclosure report, and A3
assesses the extent of a firm’s environmental disclosure on specific GRI
performance indicators. The last sub-classification in the hard disclosure items, A4,
indicates a firm’s spending on environmental aspects. While individual items in A1,
A2 and A4 are scored as either ‘1’ or ‘0’ for the existence or absence of the item,
items in A3 are allocated a range of scores from 0 to 6. A score for each disclosure
item in section A3 is allocated based on performance data presented relative to a
range of indicators. A point is awarded when performance data is presented and
more points are awarded if the data is presented with information relative to peers or
industry; relative to previous period; relative to targets; in both aggregate and
normalised form; or at disaggregate level (Clarkson et al., 2008). The details of the
scoring system are shown in Figure 5.2.
The soft disclosure items consist of three sub-classifications (A5 to A7). A5
measures a firm’s vision and strategy claims and A6 assesses a firm’s environmental
profile. The last classification, A7, scores a firm’s environmental initiatives. All the
115

individual items in A5 to A7 are scored ‘1’ or ‘0’ depending on the presence or
absence of each item.
116
*The scoring scale for each environmental performance indicator in category A3 ranges from 0 to 6. A point is awarded for each of the following items : (1)Performance data is
presented; (2) Performance data is presented relative to peers/rivals or industry; (3) Performance data is presented relative to previous periods (trend analysis); (4)
Performance data is presented relative to targets; (5) Performance data is presented both in absolute and normalised form; (6) Performance data is presented at
disaggregate level (i.e. plant, business unit, geographic segment) (Clarkson et. al, 2008, p. 313).
Figure 5.1 Clarkson, Li, Richardson and Vasvari’s (2008) environmental scoring index
A1 : Governance structure and management system (6 items, max score =6) A5 : Vision and strategy claims (6 items, max score = 6)
A2 : Credibility (10 items, max score = 10) A6 : Environmental profile (4 items, max score = 4)
A3 : Environmental performance indicators (10 items, max score = 60*) A7 : Environmental initiatives (6 items, max score = 6)
A4 : Environment al spending (3 items, max score = 3)
TOTAL HARD ITEMS = 29 TOTAL SOFT ITEMS = 16
MAX SCORES FOR HARD ITEMS = 79 MAX SCORES FOR SOFT ITEMS = 16
TOTAL MAXIMUM SCORING = 95
CLARKSON, LI, RICHARDSON AND VASVARI’s
(2008)
ENVIRONMENTAL SCORING INDEX
HARD DISCLOSURE ITEMS
I which ar relatively for poor (
p mimic)
SOFT DISCLOSURE ITEMS
I which are r eas f poor (
p )

110

5.3 Development Phase One: Incorporation of Profile Disclosures into the New
Scoring Index
The development process is divided into three phases. The first phase involves
incorporating the GRI G3.1 Part I (profile disclosure) into the new scoring index. This
incorporation process consists of several steps.
First, disclosure items in the GRI G3.1 version are matched against Clarkson et al.’s
(2008) index to identify the items that are listed in the GRI G3.1 version but not found in
Clarkson et al.’s index. Second, these unlisted items are critically evaluated to determine
the probable reasons for its exclusion from Clarkson et al.’s index. Lastly, these reasons
are examined to form the criterion to determine if the items are relevant for its inclusion
into the new scoring index. To help determine if the item will be included, the item will be
evaluated based on the value of the information disclosed, such as whether it would
assist users of this information to improve their understanding of a company’s
sustainability efforts or approaches. Items that are considered to enhance a company’s
sustainability disclosures in any of the three aspects (environmental, social and
economic) of sustainability are included.
Table 5.2 below compares the disclosure items between the GRI G3.1 Part I and
Clarkson et al.’s (2008) index. The table also presents a summary of the results after the
abovementioned steps were taken for development phrase one. This generates the list
of disclosure items to be included in the new innovative GRI-based scoring index.
Subsequently, this list of disclosure items is sorted according to the different categories,
A1 to A7, used in Clarkson et al. (2008).
119
Table 5.2 Comparison between disclosure items in the GRI G3.1 part I and Clarkson et
al.’s (2008) index
GRI G3.1 Part I:
Profile Disclosures
Incorporated in Clarkson et
al.’s (2008)
Possible
reason for
exclusion
Revision taken
for new scoring
index
1. Strategy and
Analysis
1.1 – 1.2 Category A5: Vision and strategy
claims
2. Organisational
Profile
2.1 – 2.9 Not included Proprietary
information
Not included
2.10 Category A2: Credibility
3. Report
Parameters
3.1 – 3.5 Not included Proprietary
information
Not included
3.6 – 3.8 Not included Define scope of
report
Not included
3.9 Category A1: Governance structure
and management system
3.10 – 3.11 Not included Define scope of
report
Not included
3.12 Not included Not a reportable
item in previous
GRI G2
Not included. This
item identifies the
location of
disclosure content
in the report. This
information does
not affect
sustainability
disclosure.
3.13 Category A2: Credibility
4. Governance,
Commitments,
and
Engagement
4.1 – 4.7 Category A1: Governance structure
and management system
4.8 – 4.9 Category A5: Vision and strategy
claims
4.10 Category A1: Governance structure
and management system
4.11 Category A5: Vision and strategy
claims
4.12 – 4.13 Category A2: Credibility
4.14 Not included Not a reportable
item in previous
GRI G2
Not included. This
item provides a list
of stakeholder
groups engaged by
the organisation.
This information
does not affect
sustainability
disclosure.
4.15 Not included Proprietary
information
Not included
120
4.16 – 4.17 Category A1: Governance structure
and management system
Note: Categories A1 to A4 are hard disclosure items and categories A5 to A7 are soft disclosure items.
5.4 Development Phase Two: Incorporation of Disclosures on Management
Approach (DMAs) into the New Scoring Index
Part II of the GRI G3.1 version, which consists of companies’ disclosures on
management approaches (DMA) to sustainability and was not required by the earlier G2
version, is embedded into the new scoring index. The reporting on the DMAs provides
an overview of how companies manage different aspects of their sustainability issues.
This may include disclosure on evaluation processes and results of the effectiveness of
companies’ management approaches in sustainability. As shown in Table 5.1, there are
six categories in the DMAs, namely DMA Economic (DMA EC), DMA Environmental
(DMA EN), DMA Labour practices and decent work (DMA LA), DMA Human rights (DMA
HR), DMA Society (DMA SO), and DMA Product responsibility (DMA PR).
The significance of reporting the DMAs is reflected in three ways: the addition of an
entirely new section of DMAs absent in the earlier G2 version; the need to include the
DMAs in companies’ sustainability reports to be awarded a level B or better grade by the
GRI; and the provision of detailed guidance and explanations on how each category of
the DMAs is to be reported in the latest G4 version. Hence, the reporting on the DMAs is
included into the new scoring index. This approach also concurs with one of the main
objectives of this study which is to evaluate the actual implementation of sustainability
policies through reviewing of companies’ management approach towards sustainability
issues.
All six categories in the DMAs are included in the new scoring index as they are relevant
for the analysis of the economic, environmental and social aspects of sustainability. The
reporting of DMAs is classified as soft disclosure items according to Clarkson et al.’s
(2008) definition as they relate to the internal management controls and procedures
which are difficult to verify and validate and thus are easier for poor sustainability
performers to mimic. Consistent with the scoring of soft disclosure items by Clarkson et
al., scores for this category are awarded a ‘1’ or ‘0’ respectively for the presence or
absence of the DMAs in the GRI G3.1 Part II as shown in Table 5.3 below.
121
Table 5.3 New scoring index for the category on DMAs
Category Disclosure item Min -Max
Scores
DMA EC – Disclosure on
Management Approach
Economic
Economic performance
Market presence
Indirect economic impacts
0 – 3
(3 items)
DMA EN – Disclosure on
Management Approach
Environmental
Materials
0 – 9
(9 items)
Energy
Water
Biodiversity
Emissions, effluents and waste
Products and services
Compliance
Transport
Overall
DMA LA – Disclosure on
Management Approach Labour
Employment
0 – 6
(6 items)
Labour/management relations
Occupational health and safety
Training and education
Diversity and equal opportunity
Equal remuneration for women and men
DMA HR – Disclosure on
Management Approach Human
Rights
Investment and procurement practices
0 – 9
(9 items)
Non-discrimination
Freedom of association and collective bargaining
Child labour
Prevention of forced and compulsory labour
Security practices
Indigenous rights
Assessment
Remediation
DMA SO – Disclosure on
Management Approach Society
Local communities
0 – 5
(5 items)
Corruption
Public policy
Anti-competitive behaviour
Compliance
DMA PR – Disclosure on
Management Approach Product
Responsibility
Customer health and safety
0 – 5
(5 items)
Product and service labelling
Marketing communications
Customer privacy
Compliance
Total:
0 – 37
(37 items)
122
5.5 Development Phase Three: Incorporation of Performance Indicators into the
New Scoring Index
Part III of the GRI G3.1 framework consists of specific sustainability performance
indicators that reflect company performance in the economic, environmental and social
aspects of sustainability. Within each of these three aspects of sustainability, the GRI
framework has developed specific performance indicators to assist in the preparation of
sustainability reports. Table 5.4 below indicates the performance indicators in Part III of
the GRI G3.1 framework.
Table 5.4 The GRI G3.1 part III performance indicators
Three Aspects of
Sustainability Disclosure item Performance
Indicators
Economic
Economic performance EC1 – EC4
Market presence EC5 – EC7
Indirect economic impacts EC8 – EC9
Environmental
Materials EN1 – EN2
Energy EN3 – EN7
Water EN8 – EN10
Biodiversity EN11 – EN15
Emissions, effluents and waste EN16 – EN25
Products and services EN26 – EN27
Compliance EN28
Transport EN29
Overall EN30
Social
Labour
Employment LA1-LA3, LA15
Labour/management relations LA4 – LA5
Occupational health and safety LA6 – LA9
Training and education LA10 – LA12
Diversity and equal opportunity LA13
Equal remuneration for women and men LA14
Human Rights
Investment and procurement practices HR1 – HR3
Non-discrimination HR4
Freedom of association and collective
bargaining HR5
Child labour HR6
Prevention of forced and compulsory labour HR7
Security practices HR8
Indigenous rights HR9
Assessment HR10
Remediation HR11
Society
Local communities SO1, SO9-SO10
Corruption SO2 –SO4
Public policy SO5 – SO6
Anti-competitive behaviour SO7
123
Compliance SO8
Product
Responsibility
Customer health and safety PR1 – PR2
Product and service labelling PR3 – PR5
Marketing communications PR6 – PR7
Customer privacy PR8
Compliance PR9
Clarkson et al. (2008) classified the environmental performance indicators of the GRI
framework as hard disclosure items under category A3 because they relate to data “that
firms can disclose to convince stakeholders about their environmental commitments” (p.
310). Clarkson et al. also introduced a scoring system for these hard environmental
performance indicators. These hard disclosure items are divided into two categories:
category A3 for the non-monetary environmental performance indicators and category
A4 for monetary environmental spending. While category A4 was awarded a ‘1’ or ‘0’ for
the presence or absence of the disclosure, Clarkson et al. applied special scoring criteria
to category A3. For each performance indicator in category A3, a range of scores from 0
to 6 was awarded based on how the performance data was presented relative to a range
of indicators. A point was awarded for each of the following six disclosures: peers or
industry; previous period; targets; aggregate and normalised form; and disaggregate
level.
Applying similar intention and scoring criteria used by Clarkson et al. (2008) for
performance indicators under category A3, the new developed scoring index in this study
awards scores only to information disclosed that indicates an improvement in
sustainability performance. A non-compliance or a decline in sustainability performance
will result in no points being awarded. Hence, a company’s awarded scores are
reflective of its actual sustainability performance. The scoring criteria for performance
indicators under category A3 follow the scoring for hard disclosure items. The details for
the scoring has been explained in Table 4.3 of Chapter 4.
The scoring criteria used for categories A3 and A4 respectively are adopted to develop
the new scoring index for this study. This study modifies Clarkson et al.’s (2008)
environmental index to reflect the latest GRI G3.1 version which has additional
environmental performance indicators. Furthermore, the new scoring index expands the
124
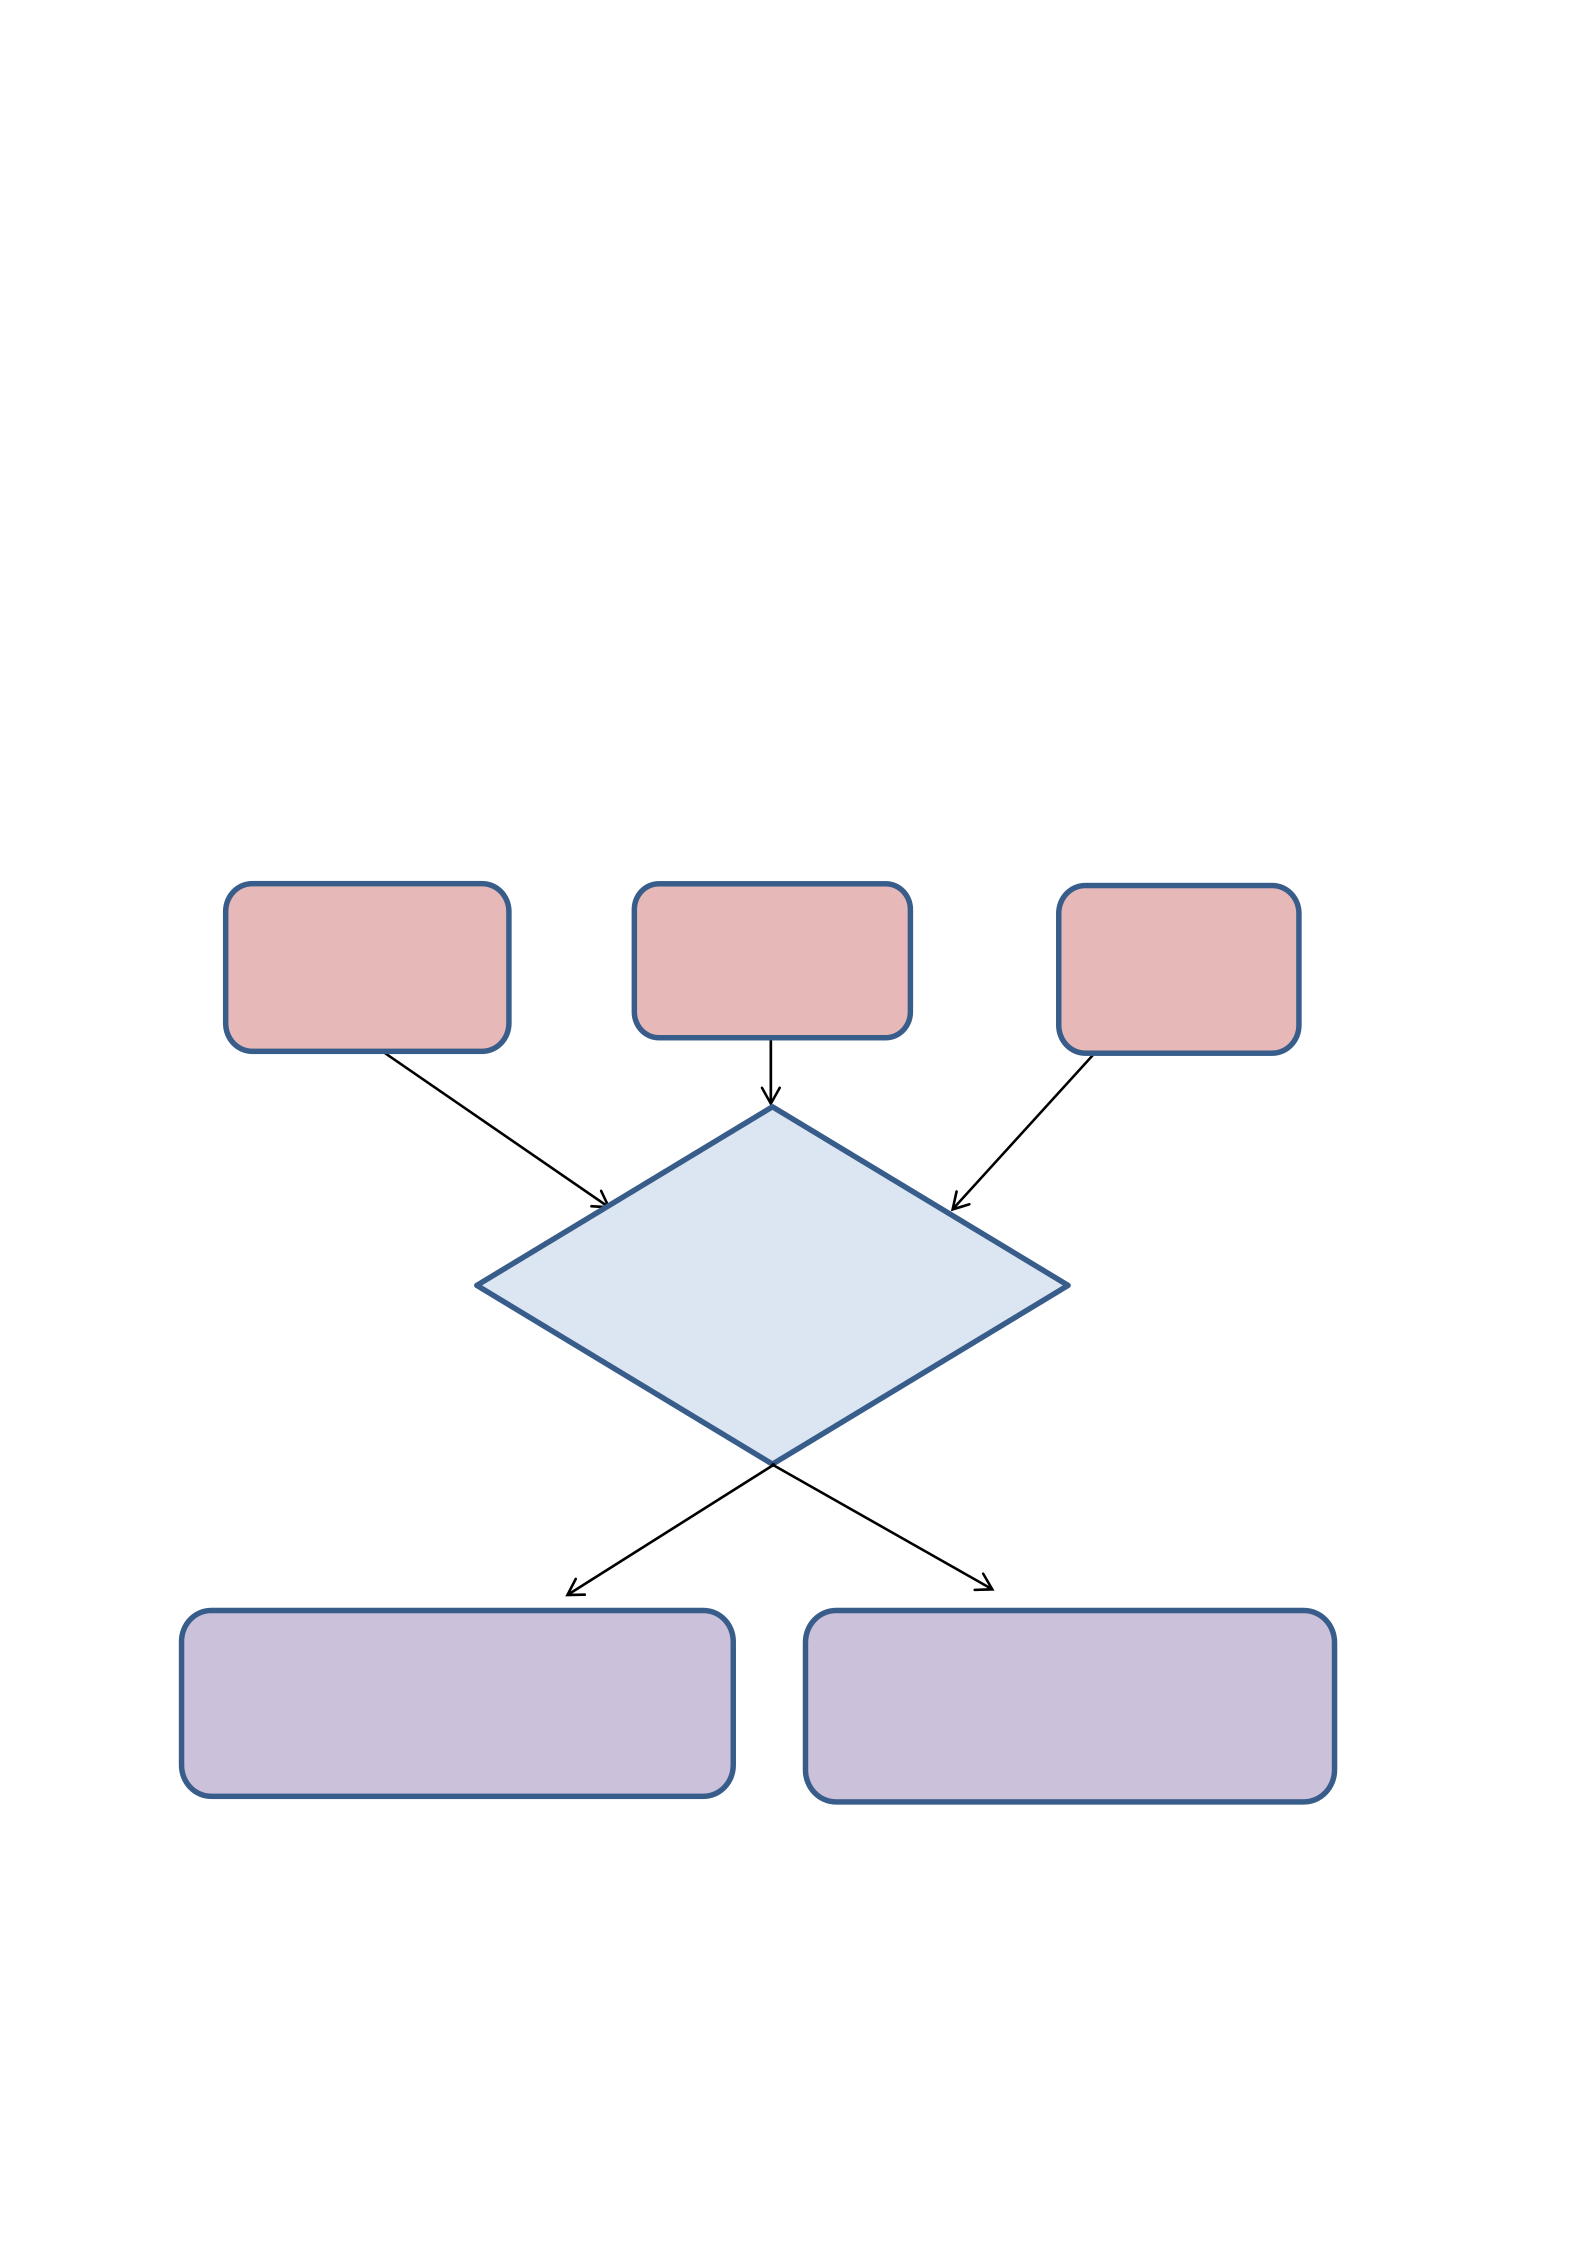
same scoring system to the economic and social performance indicators of the GRI G3.1
version, which have not been included by Clarkson et al. Figure 5.2 below depicts the
development process in phase three to yield category A3 (hard non-monetary disclosure
items) and category A4 (hard monetary disclosure items) of the new scoring index.
Figure 5.2 Flowchart for index development process phase three
125
No Yes
Economic
Performance
Indicators
Environmental
Performance
Indicators
Social
Performance
Indicators
Does the disclosure
item involve
monetary
information?
New scoring index category A3
(Sustainability Performance Index)
Scoring criteria for each item: 0 - 6
New scoring index category A 4
(Sustainability Spending )
Scoring criteria for each item: 0 - 1
5.5.1 Economic performance indicators
The economic aspect of the new scoring index was developed by adopting the economic
performance indicators of the GRI G3.1 framework. The classification method and
scoring system used in Clarkson et al. (2008) were incorporated into the new scoring
index. As shown in Figure 5.3 above, each economic performance indicator in the GRI
G3.1 framework is first classified to either category A3 or category A4 depending on
whether the disclosure item involves monetary information. Following Clarkson et al.’s
classification, those economic performance indicators that do not involve monetary
spending are classified to section A3 while those with monetary spending are classified
to section A4.
The GRI G3.1 framework consists of nine economic performance indicators (EC1 to
EC9) as displayed in Table 5.4. The two monetary performance indicators, EC1 and
EC4, are classified under category A4, and the remaining seven non-monetary economic
performance indicators are classified under category A3 of the new scoring index. The
seven non-monetary economic performance indicators were sorted into three groups
according to the nature of their disclosure items. The scoring system applicable to
category A3 is applied to each of the three groups. Each group are awarded a range of
scores from 0 to 6. Table 5.5 below presents the results after the classification process.
Table 5.5 Category A3 economic performance indicators of the new scoring index
Aspect of
sustainability
Disclosure item Performance
indicators of
the GRI G3.1
framework
Recoded for
new scoring
index
Number
of
Groups
Scores
(Min –
Max)
Economic
1. Economic performance
EC2 - EC3 A3 ECP1
3 0 – 18
2. Market presence
EC5 – EC7 A3 ECP2
3. Indirect economic
impacts
EC8 – EC9 A3 ECP3
5.5.2 Environmental performance indicators
126

Clarkson et al.’s (2008) index, which focuses solely on the environmental aspects of
sustainability, used only the environmental performance indicators in the GRI G2
framework in their index. The following steps were carried out to modify Clarkson et al.’s
index, specifically category A3 (environmental performance indicators), to develop the
environmental performance indicators for the new scoring index:
i. The GRI G3.1 framework consists of thirty environmental performance indicators
(EN1 to EC30). EN30 that relates to monetary expenditures and investments of
environmental protection is classified under category A4 (Sustainability
spending).
ii. The remaining 29 environmental performance indicators in the GRI G3.1 are
matched against the list in Clarkson et al.’s (2008) category A3.
iii. Those environmental performance indicators that are not included in Clarkson et
al.’s index are added to the new scoring index.
iv. The newly developed list of environmental performance indicators are sorted and
grouped according to the nature of their information disclosed.
v. The groups are recoded for the new scoring index.
Table 5.6 below summarises the revision and classification process to Clarkson et al.’s
(2008) category A3 on environmental performance indicators to incorporate the newer
GRI G3.1 version.
127
Table 5.6 Summary of revision to environmental performance indicators classified under Clarkson et al.’s (2008) category A3
Aspect of
sustainability
Disclosure item Performance
indicators of the
GRI G3.1
framework
Incorporated in
Clarkson et al.’s
(2008)
Revision taken for new scoring
index
Recoded for new
scoring index
Environmental
Materials EN1 – EN2 Not included Included as a new group A3 ENP1
Energy EN3 – EN7 (A3) Item 1 A3 ENP2
Water EN8 – EN10 (A3) Item 2 A3 ENP3
Biodiversity EN11 – EN15 (A3) Item 8 A3 ENP4
Emissions, effluents
and waste
EN16 – EN18
(A3) Item 3
A3 ENP5
EN19 – EN20 (A3) Item 4 A3 ENP6
EN21, EN23 (A3) Item 6 A3 ENP7
EN22 (A3) Item 5 & 7 A3 ENP8
EN24 Not included Included and placed in new code with
A3 ENP8 as it relates to waste
management that is similar to EN22
A3 ENP8
EN25 Not included Included and placed in new code with
A3 ENP7 as it relates to other
discharges that are similar to EN21
and EN23
A3 ENP7
Products and
services
EN26 – EN27 (A3) Item 9 A3 ENP9
Compliance EN28 (A3) Item 10 A3 ENP10
Transport EN29 Not included Included as a new group A3 ENP11
120


The 29 non-monetary environmental performance indicators are sorted into eleven
groups as shown in Table 5.6 above. The scoring system applicable to category A3 is
applied to each of the eleven groups and each group is awarded a range of scores
from 0 to 6.
5.5.3 Social performance indicators
The GRI G3.1 framework has four sub-categories for the social aspects of
sustainability: labour practices and decent work; human rights; society; and product
responsibility. For each of these four sub-categories, the same incorporation process
as described in section 5.5.1 is adopted to develop the social aspect of the new
scoring index. Firstly, social performance indicators that involve monetary amounts
are classified under category A4 and the non-monetary social performance indicators
are classified under category A3. Following that, the disclosure items that are
classified to categories A3 and A4 are re-classified to different groups within each
category based on the information type of its disclosure. Finally, the different scoring
systems applicable to categories A3 and A4 are also applied to each of the two
categories.
Table 5.7 below shows the results after the process.
130

131
Table 5.7 Category A3 social performance indicators of the new scoring index
Aspect of
sustainability
Disclosure item Performance
Indicators of the
GRI G3.1
framework
Recoded for
new scoring
index
Number of
Groups
Scores
(Min – Max)
Social
Labour
Practices and
Decent Work
(LA)
Employment LA1-LA3, LA15 A3 LAP1
6 0 - 36
Labour/management relations LA4 – LA5 A3 LAP2
Occupational health and safety LA6 – LA9 A3 LAP3
Training and education LA10 – LA12 A3 LAP4
Diversity and equal opportunity LA13 A3 LAP5
Equal remuneration for women and men LA14 A3 LAP6
Human Rights
(HR)
Investment and procurement practices HR1 – HR3 A3 HRP1
9 0 – 54
Non-discrimination HR4 A3 HRP2
Freedom of association and collective bargaining HR5 A3 HRP3
Child labour HR6 A3 HRP4
Prevention of forced and compulsory labour HR7 A3 HRP5
Security practices HR8 A3 HRP6
Indigenous rights HR9 A3 HRP7
Assessment HR10 A3 HRP8
Remediation HR11 A3 HRP9
Society (SO)
Local communities SO1, SO9-SO10 A3 SOP1
5 0 – 30
Corruption SO2 –SO4 A3 SOP2
Public policy SO5 – SO6 A3 SOP3
Anti-competitive behaviour SO7 A3 SOP4
Compliance SO8 A3 SOP5
Product
Responsibility
(PR)
Customer health and safety PR1 – PR2 A3 PRP1
5 0 – 30
Product and service labelling PR3 – PR5 A3 PRP2
Marketing communications PR6 – PR7 A3 PRP3
Customer privacy PR8 A3 PRP4
Compliance PR9 A3 PRP5
122

5.6 Modification to the New Scoring Index
The final phase of the development process involved the assembly of the various
incorporated parts of the scoring index. The overall incorporated scoring index is
reviewed and the following modifications are applied.
1. Disclosure items within categories A1 to A7 are reviewed. Items that were
previously restricted solely to environmental disclosure are revised to reflect all
three aspects of sustainability.
2. Common disclosure items that are repetitive are deleted.
3. The disclosure items in the scoring index are again mapped to the entire list of
disclosure items in all the three parts of the GRI G3.1 framework (Part I, Part II
and Part III) to ensure completeness. Items that could lead to duplication in the
scoring process are reviewed and deleted where required.
Table 5.8 presents a summary of the final scoring index indicating the maximum
possible scores in each category. A detailed scoring index is contained in Appendix 5-1.
133
Table 5.8 The new scoring index
Hard Disclosure Items (A1-A4)
Category Disclosure items Items
Max
Scores
A1
Governance structure and management systems
9
9
A2
Credibility
5
5
A3 Economic Performance Indicators (ECP) 3 18
Environmental Performance Indicators (ENP)
11
66
Social Performance Indicators
Labour Practices and Decent Work (LAP)
6
36
Human Resource (HRP) 9 54
Society (SOP) 5 30
Product Responsibility (PRP) 5 30
A4
Spending related to sustainability
2
2
Total Hard Disclosure 250
Soft Disclosure Items (A5-A7)
Category Disclosure items Items Max
Scores
A5
Vision and strategy claims
7
7
A6
Sustainability Initiatives
3
3
A7
Disclosure of Management Approach (DMA)
Economic
3
3
Environmental 9 9
Labour Practices and Decent work 6 6
Human Rights 9 9
Society 5 5
Product Responsibility
5
5
Total Soft Disclosure 47
Total Disclosure = 250 +47 = 297
134

5.7 Test of New Scoring Index Using a Pilot Study
The new GRI-based scoring index is tested through a pilot study described in Chapter
6. The pilot study aims to assess the feasibility of the scoring index and to identify
revisions necessary to improve the index for the main study. It also provides preliminary
findings about the extent of sustainability disclosure of listed companies in the
Australian resources industry.
135

CHAPTER SIX
PILOT STUDY
A pilot study was conducted using the newly developed GRI-based sustainability
scoring index to evaluate companies’ sustainability disclosure and to identify revisions
required to improve the scoring index. This chapter presents the design, processes and
results of the pilot study. Implications for the main research identified through the pilot
study are discussed and a summary of the revisions required to improve the main study
are presented.
6.1 Design
The pilot study was specifically designed to achieve the list of objectives discussed in
Chapter 4 section 4.2.2. Figure 6.1 below depicts the design of the pilot study with a
summary of the steps and procedures undertaken. The sample selection process was
explained in Chapter 4 section 4.3. The other processes of the pilot study are discussed
in the remaining sections of this chapter, following the sequence shown in Figure 6.1.
136
Figure 6.1 Design of the pilot study
6.2 Collection and Recording of Data
6.2.1 Data collection
The data source for the dependent variables are companies’ annual financial reports
and stand-alone sustainability reports. First, the reports of the sample companies for
the year ended 30 June 2012 were collected. Then, content analysis method was
applied on each of the companies’ reports, and the data were coded and scored
according to the scoring criteria applicable to the soft and hard disclosure items as
explained in Chapter 4 section 4.4.2. The respective scoring criteria were applied
specifically to each of the disclosure items in the different categories of the newly
137
•Selected companies with the highest market capitalisation
from the resources sector of Australian Securities Exchange
2012ASX) as at 30 June (
S Sample
•Obtained companies' annual financial reports and
sustainability reports
•Collected dependent variables (companies' sustainability
disclosures)
•Collected independent variables (companies' characteristics)
C and Recor Data
•Analysed data using a statistical analysis software SPSS
A Data
•Compiled prelimary descriptive results and consolidated
results of hypotheses tests
C Results
•Reviewed critically the implications to the main study
R Implications
•Revised research design and methods accordingly for the
main study
R R
developed scoring index. The classifications and details of these disclosure items are
contained in Appendix 5-1 as explained in Chapter 5. Finally, the data for the
independent variables were collected via the DatAnalysis database.
6.2.2 Data recording
A recording worksheet was developed to record and compile the data for the dependent
and the independent variables. Table 6.1 below presents a summary of the various
categories and sub-categories on the recording worksheet. A copy of the recording
worksheet including a detailed classification is presented in Appendix 6-1.
Table 6.1 Summary of recording worksheet
Variable Category Sub-categories
1.Company
Profile
Company Size
Market capitalisation
Total revenue
Total assets
Financial Performance
Operating revenue
Earnings before interest and tax (EBIT)
Return on assets (ROA)
Return on equity (ROE)
Book value per share
Year-end share price
Board Composition
Independent directors
Multiple directorships
Chief executive officer (CEO) duality
Women directors
Sustainability committee
2. Hard
Disclosure
Items
A1: Governance structure and
management system
A2: Credibility
A3: Performance indicators Economic Performance (ECP) Indicators
Environmental Performance (ENP) Indicators
Labour Performance (LAP) Indicators
Human Rights Performance (HRP) Indicators
Society Performance (SOP) Indicators
Product Responsibility (PRP) Indicators
A4: Spending on sustainability
related expenditures
3. Soft
Disclosure
Items
A5: Vision and strategy claims
A6: Sustainability initiatives
A7: Disclosure on Management
Approach (DMA)
Economic (DMA ECP)
Environmental (DMA ENP)
Labour (DMA LAP)
138
Human Rights (DMA HRP)
Society (DMA SOP)
Product Responsibility (DMA PRP)
As shown in Table 6.1 above, the recording worksheet comprises three variables:
company profile, hard disclosure items (A1-A4) and soft disclosure items (A5-A7). The
first variable, company profile, consists of company information that formed the
independent variables for the hypotheses testing. This includes information on
company size, financial performance and board composition. The second variable, hard
disclosure items, consists of four categories A1 to A4 that identify hard sustainability
disclosures that are relatively easier to verify. The recording sheet provides a list of
disclosure items within each category to guide the coder in the data collection process.
The third variable, soft disclosure items, has three categories, A5 to A7, which collect
data related to sustainability disclosures that are relatively more difficult to verify.
While soft disclosure items are scored based on the presence and absence of a
disclosure item, hard disclosure items are awarded a score of zero to six, depending on
whether the information disclosed is presented relative to the respective indicators as
shown and highlighted in Table 6.2 below. Table 6.2 presents an extract of the recording
worksheet used to record hard disclosure items.
Table 6.2 An extract of the recording worksheet for hard disclosure items
New
Index
Code
(A3)
Environmental
Performance
(ENP) Indicators
(Max score is 66)
Map
to GRI
G3.1
Data
Present
Relative
to Peers/
Industry
Relative
to
Previous
Period
Relative
to Targets
Absolute
and
Normalise
d form
At
Disaggregate
level
MinMax
Score
(0 -6) Ref
A summary score chart is also developed in the data recording process to compile the
total scores for each company, indicating clearly the scores awarded for the different
categories. The total score for a company is the total scores awarded to variable 2
139
(hard disclosure items) and variable 3 (soft disclosure items) in Table 6.1. A copy of the
summary score chart is contained in Appendix 6-2.
6.2.3 Data coding and scoring
The scoring process is illustrated through the use of two examples which explain how
the scoring criteria are applied in the scoring process for hard disclosure items.
Example 1, company ‘X’, disclosed the following in its report: ‘There have been no
known breaches of the tenement conditions, and no such breaches have been notified
by any Government agencies during the year ended 30 June 2012.’ This disclosure
was awarded a score of two points under the sub-category ‘A3-ENP’ (Environmental
Performance) in the item ‘A3 ENP 10’ that relates to ‘compliance’. One point was
awarded for the presence of data relating to the company’s compliance because the
company reported no breaches of any environmental legislation. Another point was
awarded for the disclosure of data in relation to the industry as the data relates to the
environmental regulations pertaining to the industry. Table 6.3 below shows an extract
of the information recorded for company ‘X’. The page number that relates to the
relevant disclosure was also recorded for further reference.
Table 6.3 Example 1: An extract of the information recorded for company ‘X’
New
Index
Code
(A3)
Environmental
Performance
(ENP) Indicators
(Max score is 66)
Map
to GRI
G3.1
Data
Present
Relative
to
Peers/
Industry
Relative
to
Previous
Period
Relative
to Targets
Absolute
and
Normalised
form
At
Disaggregate
level
Min-Max
Score
(0 -6)
Ref
A3
ENP10
Compliance EN28 1 1 2 *
*The relevant page number where the information was found was recorded in the ‘Ref’ column.
In contrast, in Example 2, company ‘Y’ was awarded a total of five points under the
same sub-category A3-ENP in the same item A3 ENP10. As well as the provision of
data to show its compliance to industry related legislation, company ‘Y’ had also
included information on environmental compliance that was awarded additional points
under the item A3 ENP10. The extra information included the following:
• compliance to the company’s target to manage its environmental risk according
to ISO 14001 Environmental Management Systems standard;
140
• compliance with the different forms of environmental risk such as biodiversity
and water; and
• compliance in various projects across different geographical locations by
providing specific project locations.
Table 6.4 below indicates how the above awarded scores were recorded.
Table 6.4 Example 2: An extract of the information recorded for company ‘Y’
New
Index
Code
(A3)
Environmental
Performance
(ENP) Indicators
(Max score is 66)
Map
to GRI
G3.1
Data
Present
Relative
to Peers/
Industry
Relative
to
Previous
Period
Relative
to
Targets
Absolute
and
Normalised
form
At
Disaggregate
level
MinMax
Score
(0 -6) Ref
A3
ENP10
Compliance EN28 1 1 1 1 1 5 *
*The relevant page number where the information was found was recorded in the ‘Ref’ column.
6.2.4 Further guidelines for data scoring
It was noted in the data scoring process that there were few recurring issues requiring
further guidelines to ensure that a consistent scoring process is maintained throughout
the study. This section provides an account of the issues encountered and discusses
the decisions made to resolve these issues and the implications to the scoring process.
6.2.4.1 Environmental performance indicators
Companies in the resources industry are generally required to submit an Environmental
Impact Assessment (EIA) to the Environmental Protection Authority (EPA) for evaluation
of their site operation plans. Companies are mandated to provide information on how
their operations may impact the environment in their EIA submission. The EPA
assesses companies’ proposals based on the appropriateness and practicability of the
projects according to the Environmental Impact Assessment (Part IV Divisions 1 and 2)
Administrative Procedures 2012. It was noted in the pilot study that companies
generally disclosed this information in their annual and sustainability reports when
141

describing the progress of their projects. However, this type of environmental disclosure
tended to focus on the feasibility of a project and the emphases were generally placed
on the cost of extracting the minerals and the potential mineral content of a site; there
was minimal or no information on the actual impact on the environment. Hence, it is
concluded that no points will be awarded to such general environmental information
that is mandated by the EIA. Only information that relates to environmental
performance indicators specified in section A3 ENP1 to ENP11 of the newly developed
reporting index are to be included for scoring.
6.2.4.2 Economic performance indicators
The data of this study is collected predominantly from companies’ annual financial
reports as companies have included sustainability disclosures in these reports (Adams
& Zutshi, 2004; Brown & Deegan, 1998; KPMG, 2015). As the fundamental purpose of
an annual financial report is to provide a company’s shareholders with information on its
financial performance during the financial period, it contains largely regulated financial
information that complies with the accounting standards and are required for reporting
by the Australian Securities and Investments Commission (ASIC). Generally, it contains
a company’s economic information such as the statement of financial position and the
statement of comprehensive income. The new scoring index has designed scoring
criteria that awards scores to reflect companies’ sustainability performance. Hence,
generic financial information that has no direct implication on sustainability or
sustainability performance is not awarded scores in the scoring process. However,
financial expenditures or losses due to climate change, or investments and financial
savings that relate to sustainability initiatives are awarded scores.
6.2.4.3 Compliance
There are four items in section A3 (performance indicators) of the scoring index that
record companies’ compliance in sustainability performance: A3 ENP10, A3 HRP9,
A3SOP5 and A3 PRP5 that relate to compliance in environment, human rights, society
and products responsibility respectively. As the scoring index is designed for a higher
score to reflect a better sustainability performance, it is contradictory if disclosures in
142

companies’ reports that relate to non-compliance in sustainability performance are
given additional points. Hence, a company is to be awarded a zero score if it reports a
noncompliance in any of the above aspects of sustainability performance. This is to
take precedence over any previous scores that may be awarded for compliance in the
same aspect. However, it should not affect the individual scores that were awarded in
the specific performance indicators.
For example, a company is given a score of three for A3 ENP10 (Compliance in
Environmental aspect) because they complied with water treatment according to set
target, industry level and improved from the previous period. However, if they were
fined for an incident of oil spillage, this disclosure is to take precedence and the score
for A3 ENP10 is thus reduced to zero. This, however, does not affect any previous
scoring under the specific performance indicator item A3 ENP3 (Water) which may
relate to disclosure of an improved usage of recycled water.
6.3 Data Analysis, Results and Discussion
6.3.1 Data analysis
A normality test was conducted using the Kolmogorov-Smirnov and Shapiro-Wilk tests
on a total of 29 variables that included both the independent and dependent variables.
The two statistical tests indicated that more than 93% of these variables violated the
normality assumption as their significance is less than 0.05. It is generally considered
more appropriate to use the Shapiro-Wilk test when the sample is small (Allen et al.,
2014). Only one variable has passed the normality test based on the Shapiro-Wilk test.
Hence, non-parametric statistical tests were applied to analyse the data. Appendix 6-3
provides the detailed results of the normality tests.
6.3.2 Overview of results
A total of 46 companies were selected to be pilot-tested. Only seven of the 46
companies (15.22%) analysed produced separate stand-alone sustainability reports.
These sustainability reports have contributed substantially to the companies’ total
143
sustainability disclosures. The seven companies with stand-alone sustainability reports
disclosed an average of 48.1% more sustainability information in their sustainability
reports than their annual financial reports.
Table 6.5 below presents an overview of the results from the pilot study. The table
shows the mean scores of companies’ total disclosure, total hard disclosure and total
soft disclosure. The mean scores are also reported as percentages of their respective
maximum scores to facilitate comparison. The results suggest that companies in the
Australian resources industry were generally providing very minimal sustainability
information in their annual reports. On average, the mean score of the total disclosure
is low (74.13) as it constitutes only 24.96% of the total maximum score of 297. Mean
scores from both the hard and soft disclosure items are also low at 22.39% and 38.62%
of their maximum scores of 250 and 47, respectively. The higher percentage in the total
soft disclosure suggests that companies were disclosing more soft than hard disclosure
items. In fact, further analysis indicates that all of the 46 companies disclosed more soft
than hard disclosure items.
Table 6.5 Overview of results from pilot study
Disclosure
Items
Range of
scores (Min
– Max)
Mean
Scores (A)
Median
Scores
Maximum
Possible
Scores (B)
Percentage of
Disclosure
= A/B
Total hard
disclosure (C)
10 – 203 55.98 48.00 250 22.39%
Total soft
disclosure (D)
3 – 45 18.15 19.00 47 38.62%
Total disclosure
(C + D)
13 - 248 74.13 68.00 297 24.96%
Note: A higher score denotes greater disclosure.
The large range of scores, shown in Table 6.5, indicates significant diversity in
companies’ disclosures on sustainability information. The results of a Friedman two way
ANOVA test indicated statistically significant differences among the percentage of
disclosure in total hard disclosure, total soft disclosure and total disclosure (Chi-
Square= 92, df=2, N=46, p<0.05). While some companies provided extensive detailed
information in a separate stand-alone sustainability report, some companies provided
144

either a short sentence or paragraph about sustainability. In cases where companies
provided such minimal information, it was usually related to a declaration of the
company’s compliance to environmental legislation. This behaviour is in line with the
results from some prior studies (Dong & Burritt, 2010; Frost, 2007; Guenther et al.,
2006; Wood & Ross, 2008) as companies operating in the Australian resources industry
are mandated to provide environmental information in their annual reports. Despite this,
the lack of a standardised reporting framework has resulted in some companies
reporting very minimal information to indicate their compliance to the legislation. This
form of reported information is, however, limited and is generally not indicative of
companies’ true sustainability performance.
6.3.3 Descriptive statistics
Descriptive statistics of various dependent variables – companies’ sustainability
disclosures - from different categories of the scoring index were obtained after an initial
exploratory analysis. Table 6.6 below summarises the results. A list of the detailed
mean disclosure scores of each individual disclosure item by category and sub-
categories are contained in Appendix 6-4.
145
Table 6.6 Descriptive statistics of companies’ sustainability disclosures
Categories in New
Scoring Index
Min Max Range Mean
(A) Median Standard
Deviation
Maximum
Possible
Scores (B)
Percentage
of
Disclosure
= A/B
A1: Governance 2 9 7 6.41 6.50 2.07 9 71.26%
A2: Credibility 0 5 5 1.74 2.00 1.76 5 34.78%
A3: Performance Indicator
A3: Economic 2 18 16 7.09 6.00 4.15 18 39.37%
A3: Environmental 0 59 59 13.78 8.00 14.33 66 20.88%
A3: Social–Labour 1 31 30 13.65 14.00 8.08 36 37.92%
A3: Social-Human Rights 0 32 32 4.09 0.50 7.43 54 7.57%
A3: Social-Society 0 22 22 3.63 3.00 4.55 30 12.10%
A3: Social-Product
Responsibility 0 29 29 4.74 1.50 6.66 30 15.80%
A4: Spending 0 2 2 0.85 1.00 0.73 2 18.26%
A5: Vision 0 7 7 5.28 7.00 2.63 7 75.47%
A6: Initiatives 0 3 3 0.54 0.00 0.96 3 18.12%
A7: Disclosure of Management Approach (DMA)
A7: Economic 1 3 2 1.72 1.00 0.83 3 57.25%
A7: Environmental 0 9 9 3.54 3.00 2.40 9 39.37%
A7: Social–Labour 1 6 5 3.33 4.00 1.55 6 55.43%
A7: Social-Human Rights 0 8 8 1.54 0.50 2.31 9 45.41%
A7: Social-Society 0 5 5 1.09 1.00 1.15 5 21.74%
A7: Social-Product
Responsibility 0 5 5 1.11 1.00 1.46 5 22.17%
Note: A higher score denotes greater disclosure. The percentage of disclosure is extracted from results in SPSS. Results may
differ due to rounding.
A Friedman two way ANOVA test was performed on the percentage of disclosure in the
17 different categories of disclosures as shown Table 6.7 above. The results indicate
significant differences among the percentage of disclosure of these categories
(ChiSquare= 405.3, df=16, N=46, p<0.05).
146

As shown in Table 6.6 above, generally, the ranges across all the different disclosure
categories were substantially large, especially for performance indicators under
category A3. 12 out of 17 of the different categories had their ranges as large as the
maximum possible scores. This was also reflected by their large standard deviation. For
some, the standard deviation was also larger than their mean and median. This
preliminary result is both interesting and critically important. The large standard
deviation has provided evidence to validate the reliability of the newly developed
scoring index as it is capable of differentiating between companies disclosing better
sustainability information and those that were not. Apparently, the large standard
deviation in the data indicates that companies were disclosing significantly different
amounts of sustainability disclosures and the scores awarded by the newly developed
scoring index have made it possible to differentiate them. Companies disclosing more
sustainability information can be easily identified by their higher scores. The next
section elaborates on the contribution of the new scoring index due to its ability to
identify the forms and nature of sustainability information that companies were
disclosing and the types of information found lacking.
This assisted companies to identify the reporting areas for improvement.
6.3.4 Disclosure items
To facilitate comparison among companies’ disclosures in the various categories of the
scoring index, the categories were ranked in descending order from the highest to the
lowest based on their percentages of disclosures. The percentage of the disclosures of
the various categories was obtained by taking their respective mean scores as a
percentage of their respective maximum scores. Table 6.7 below shows the result of the
ranking which assists in interpreting the extent of companies’ disclosures in various
categories of the new scoring index developed in this study.
147
Table 6.7 Ranking of companies’ disclosures in various categories
Rank Categories of Scoring Index Percentage of
Disclosure= A/B
1 A5: Vision 75.47%
2 A1: Governance 71.26%
3 A7: Economic 57.25%
4 A7: Social-Labour 55.43%
5 A7: Social-Human Rights 45.41%
6 A3: Economic 39.37%
7 A7: Environmental 39.37%
8 A3: Social-Labour 37.92%
9 A2: Credibility 34.78%
10 A7: Social-Product Responsibility 22.17%
11 A7: Social-Society 21.74%
12 A3: Environmental 20.88%
13 A4: Spending 18.26%
14 A6: Initiatives 18.12%
15 A3: Social-Product Responsibility 15.80%
16 A3: Social-Society 12.10%
17 A3: Social-Human Rights 7.57%
Note: 1. Ranking is based on the mean scores of each section as a percentage to their respective maximum scores.
2. Categories A1 to A4 are hard disclosure items and categories A5 to A7 are soft disclosure items.
Category A5 (Vision and strategy claim) is ranked first with 75.47%. This is followed
closely by category A1 (Governance structure and management system) with 71.26%.
It is apparent from the results shown that A5 was ranked first with the highest
percentage among the soft disclosure items. This indicates that companies disclosed
more soft disclosure items through setting vision statements and making claims of their
sustainability strategies and plans. On the other hand, category A1, which had the
highest ranking among the hard disclosure items, reveals that many companies have
148
included more information about their corporate governance structure in the reports.
This result confirms that many companies have widely embraced the Australian
Securities Exchange (ASX) recommendations, which were introduced in 2003, to
include information of their corporate governance practice in the annual reports (Gibson
& O'Donovan, 2007; Kang et al., 2007). As shown in Table 6.6, the minimum score
found in category A1 was 2. This indicates the importance of this category as all the 46
sampled companies, without exception, have included some information about
corporate governance.
The results from Table 6.7 reveal that most of the soft disclosure items (categories A5
to A7) tend to rank higher than those of the hard disclosure items (categories A1 to A4).
Detailed statistical tests were conducted using SPSS to compare companies’ total
disclosure on soft items to that on hard items. The result was used to test the
hypothesis for any statistical differences between the disclosures on soft and hard
items (section
6.4.4).
Table 6.8 below shows the ranking for the six performance indicators within category A3
(Performance indicators). They are ranked from the highest to the lowest based on the
percentage of disclosure, calculated using their mean scores as a percentage of their
respective maximum scores. The four social performance indicators Labour
Performance (LAP), Human Rights Performance (HRP), Society Performance (SOP)
and Product Responsibility Performance (PRP) are combined to yield the mean
percentage of disclosure that reflects the social aspect of sustainability.
Table 6.8 Ranking for performance indicators within category A3
Rank Aspects of
Sustainability
Performance Indicators Percentage of Disclosure
1 Economic A3: Economic 39.37%
2 Environmental A3: Environmental 20.88%
149
3 Social
A3: Social
18.35%
(Mean percentage of the four
performance indicators within the
social indicators)
Percentage of disclosure on
individual performance indicators:
A3: Social-LAP 37.92%
A3: Social-PRP 15.8%
A3: Social-SOP 12.10%
A3: Social-HRP 7.57%
Note: Ranking is based on the mean scores of each section as a percentage to their respective maximum scores.
Table 6.8 indicates that companies have disclosed the most information in the
economic aspect of sustainability, followed by the environmental aspect and the social
aspect. One unanticipated result was that the economic aspect remains in the highest
rank, despite stringent scoring criteria applied to the disclosure of economic information
in this study. Only financial information that has direct implications to sustainability has
been awarded scores in the scoring process. Examples include financial expenditures
or losses due to climate change, or investments that relate to sustainability initiatives.
Other generic economic disclosure of company’s financial performance, such as
information found in an income statement or a balance sheet, is not awarded any
score.
There are also substantial differences among the four individual performance indicators
within the social aspects of sustainability. The percentages of disclosure for the four
performance indicators are shown in Table 6.6 and they are arranged in descending
order. The labour performance indicator (LAP) has the highest percentage at 37.92%,
while the human rights performance indicator (HRP) has the lowest percentage at only
7.57%. Companies tend to report more social information through labour related data
and issues such as information on the company’s employment, occupational health and
safety, staff training and diversity in employment. This is in line with findings of prior
studies: companies are under tighter scrutiny due to increased awareness of social
issues related to child labour protection and public concern about labour exploitation
(Deegan & Islam, 2014; Islam & Deegan, 2008; Kamal & Deegan, 2013). Recent years
have also seen an increase in companies disclosing more social information on other
150

labour issues such as occupational health and safety, diversity in employment and
equal opportunity in gender (Yongvanich & Guthrie, 2005). Companies that provided
more disclosures in these areas have included information such as comparisons with
previous targets or more details at absolute and normalised format through a
comparison with industry averages. Companies may also report this information at
disaggregated level based on different project sites. The new scoring index identified
companies that were disclosing these additional information and awarded them with
higher scores.
As the sampled companies are operating in the resources industry, most of them have
employees working in mining and other mineral exploration projects who are highly
concerned about occupational health and safety issues. In the pilot study, most
companies have included this information by reporting on the lost time frequency injury
rate (LTIFR). The Australian Standards, an independent not-for-profit organisation that
develops the national standards for a safe and sustainable environment, defined LTIFR
as an occurrence that results in a fatality, permanent disability or time lost from work of
one day/shift or more (Standards Australia, 1990). Companies will tend to compare the
company performance in the year to that of the set targets and industry averages. They
may also provide LTIFR with a breakdown rate for different project sites with details in
the form of number of incidents or as a percentage of a comparable performance scale.
These factors may explain the higher percentage of disclosure found in LAP.
To further explore the differences among the three aspects of sustainability (economic,
environmental and social), statistical tests were performed using SPSS and results
obtained were used for hypotheses testing. This pilot study also performed statistical
tests to determine if there are significant differences between the disclosures among
the four performance indicators in the social aspect of sustainability.
6.3.5 Hypothesis testing
This pilot study examined the initial hypotheses that were developed and discussed in
Chapter Three. The hypotheses were tested for the existence of relationships between
the extent of sustainability disclosures in the annual reports, standalone sustainability
151
reports (the dependent variables) and selected company characteristics (the
independent variables). Initially, the main hypotheses were tested to determine
relationships between each of the company characteristics and the total sustainability
disclosure. Subsequently, each of the company characteristics were tested against
each of the three aspects of sustainability – (A) Economic, (B) Environmental and (C)
Social. The results of the hypotheses testing provided useful preliminary findings for the
main study.
6.3.5.1 Hypotheses 1: Company size- H1, H1A, H1B and H1C
H1: There is a positive relationship between company size and the extent of total
sustainability disclosure provided by companies in the resources industry.
H1A: There is a positive relationship between company size and the extent of total
economic disclosure provided by companies in the resources industry.
H1B: There is a positive relationship between company size and the extent of total
environmental disclosure provided by companies in the resources industry.
H1C: There is a positive relationship between company size and the extent of total
social disclosure provided by companies in the resources industry.
Company size was tested with three proxies: market capitalisation, total revenue and
total assets. As explained in section 6.3, the non-parametric Kendall’s tau-b test was used to
test the hypotheses. The results showed that all three proxies had significant positive
correlations with total sustainability, economic, environmental and social disclosure. As a
result, the main hypothesis and all the three subsequent hypotheses were supported.
The statistical tests performed are considered robust as an additional bootstrapping
process was performed with 1000 bootstrap samples with a 95% confidence interval.
Bootstrapping provides a better estimation of the properties of the sampling distribution
in the case where the sample lacks normality (Field, 2013). According to Field (2013),
the results obtained from the bootstrap can confirm the robustness when the robust
confidence intervals obtained from the bootstrapping do not cross zero. In addition,
based on the effect size as suggested in Cohen (1988), the results indicated a medium
152
effect as all of the correlation coefficients are above 0.2 and below 0.5. A summary of
the detailed results is presented in Table 6.9 below.
Table 6.9 Kendall’s tau-b correlation results for Hypotheses 1 (company size)
Proxy for
Company Size
Total
Sustainability
Disclosure
Economic
Disclosure
Environmental
Disclosure
Social
Disclosure
Market
capitalisation
0.368**
[0.151, 0.553]
0.243*
[-0.049, 0.483]
0.295**
[0.096, 0.480]
0.369**
[0.161, 0.554]
Total revenue 0.360**
[0.101, 0.585]
0.255**
[0.019, 0.464]
0.323**
[0.072, 0.548]
0.295**
[0.048, 0.522]
Total assets 0.436**
[0.228 0.625]
0.284**
[0.046, 0.498]
0.431**
[0.211, 0.611]
0.398**
[0.194, 0.587]
Note: **Correlation is significant at the 0.01 level (1-tailed).
*Correlation is significant at the 0.05 level (1-tailed).
Bias corrected accelerated bootstrap 95% confidence interval reported in brackets.
6.3.5.2 Hypotheses 2: Company financial performance- H2, H2A, H2B and
H2C
H2: There is a positive relationship between company financial performance and the
extent of total sustainability disclosure provided by companies in the resources
industry.
H2A: There is a positive relationship between company financial performance and the
extent of total economic disclosure provided by companies in the resources
industry.
H2B: There is a positive relationship between company financial performance and the
extent of total environmental disclosure provided by companies in the resources
industry.
H2C: There is a positive relationship between company financial performance and the
extent of total social disclosure provided by companies in the resources industry.
Six proxies were used in hypotheses tests related to company financial performance.
Kendall’s tau-b test was also used for this set of hypotheses. All the different proxies
reflected positive correlation with the dependent variables. However, the results of the
hypotheses varied among the different proxies used. Most of them showed a significant
positive correlation to the dependent variables when operating revenue, earnings
153
before interest and tax (EBIT) and book value per share were used as proxies for
company financial performance. However, contrary results were obtained when ROE
and year-end share price were used. Hence, the set of hypotheses tests for H2 is only
partially supported. In the cases where the hypotheses were supported, the effect size
is considered to be medium according to Cohen (1988). Table 6.10 below summaries
the results for hypotheses 2.
Statistical testing has shown a significant strong positive correlation
(r=0.851,pvalue<0.001) exists between ROA and ROE. This implies that the two
proxies will yield a similar result and thus only one of the two variables is used in the
main study. As total assets is used as a proxy for company size in hypotheses one,
ROE is selected instead of ROA for the main study so that the impacts from both
company equities and assets are included in this study.
Table 6.10 Kendall’s tau-b correlation results for Hypotheses 2 (company financial
performance)
Proxy for
Company
Financial
Performance
Total
Sustainability
Disclosure
Economic
Disclosure
Environmental
Disclosure
Social
Disclosure
Operating revenue 0.361**
[0.104, 0.586]
0.244*
[-0.007, 0.464]
0.312**
[0.058, 0.547]
0.288**
[0.050, 0.509]
EBIT 0.286**
[0.013, 0.515]
0.180*
[-0.076, 0.431]
0.268**
[0.022, 0.483]
0.253*
[-0.011, 0.497]
ROE 0.096
[-0.131, 0.299]
0.123
[-0.095, 0.332]
0.095
[-0.120, 0.303]
0.044
[-0.189, 0.257]
Book value per
share
0.354**
[0.097, 0.574]
0.324**
[0.094, 0.521]
0.324**
[0.110, 0.517]
0.263**
[-0.004, 0.497]
Year-end share price 0.107
[-0.171, 0.358]
0.199*
[-0.042, 0.401]
0.086
[-0.167, 0.299]
0.110
[-0.150, 0.356]
Note: **Correlation is significant at the 0.01 level (1-tailed).
*Correlation is significant at the 0.05 level (1-tailed).
Bias corrected accelerated bootstrap 95% confidence interval reported in brackets.
154

6.3.5.3 Hypotheses 3: Board composition
Independent directors H3(i), multiple directorships H3(ii), CEO duality
H3(iii), women directors H3(iv), sustainability committee H3(v)
Table 6.11 below indicates the sets of hypotheses that were tested. A summary of the
results, including the respective statistical methods used, is provided in the table.
155
Table 6.11 Hypotheses 3 and the statistical methods used
Proxies for company
board composition
Hypotheses and Results Statistical
methods
Statistical results
Independent directors H3(i): There is a positive relationship between the proportion of
independent directors on the board and the extent of total
sustainability disclosure+ provided by companies in the
resources industry.
Supported hypothesis H3(i)**, H3(i)B* and H3(i)C*. H3(i)A was not
supported.
Kendall’s tau-B
correlation
Correlation coefficient
[Bootstrap interval]
H3(i): 0.276** [0.071 - 0.479]
H3(i)A: 0.163 [-0.034 – 0.359]
H3(i)B: 0.204* [-0.027 – 0.435]
H3(i)C: 0.241* [0.038 – 0.432]
Multiple directorships H3(ii): There is a positive relationship between the proportion of
directors that hold multiple directorships on the board and the
extent of total sustainability disclosure+ provided by companies
in the resources industry.
Supported hypothesis H3(ii)*. All 3(ii)A*, H3(ii)B** and H3(ii)C*
were supported.
Kendall’s tau-B
correlation
Correlation coefficient
[Bootstrap interval]
H3(ii): 0.239* [0.020 - 0.454]
H3(ii)A: 0.213* [0.008 – 0.419]
H3(ii)B: 0.284** [0.060 – 0.505]
H3(ii)C: 0.190* [-0.025 – 0.399]
CEO Duality H3(iii): Companies in the resources industry with CEO duality provide
lesser extent of total sustainability disclosure+.
Supported H3(iii)A. Hypothesis H3(iii), H3(iii)B and H3(iii)C were
not supported.
Mann-Whitney test H3(iii): U=82.5, p-value=0.099
H3(iii)A: U=72.0, p-value=0.049
H3(iii)B: U=82.5, p-value=0.099
H3(iii)C: U=85.0, p-value=0.121
Women directors H3(iv): There is a positive relationship between the proportion of
women directors on the board and the extent of total
sustainability disclosure+ provided by companies in the
resources industry.
Supported hypothesis H3(iv)**. All H3(iv)A**, H3(iv)B* and
H3(iv)C** were supported.
Kendall’s tau-B
correlation
Correlation coefficient
[Bootstrap interval]
H3(iv): 0.329** [0.119 - 0.501]
H3(iv)A: 0.320** [0.107 – 0.528]
H3(iv)B: 0.240* [-0.029 – 0.470]
H3(iv)C: 0.323** [0.113 – 0.501]
Sustainability committee H3(v): Companies in the resources industry with a sustainability
committee provide greater extent of total sustainability
disclosure+.
Supported hypothesis H3(v). All H3(v)A, H3(v)B and H3(v)C were
supported.
Mann-Whitney test H3(v): U=97.5, p-value=0.001
H3(v)A: U=142.5, p-value=0.013
H3(v)B: U=112.5, p-value=0.002
H3(v)C: U=115.5, p-value=0.002

Note: +To replace total sustainability disclosure to (A) economic disclosure for hypothesis A; (B) environmental disclosure for hypothesis B; and (C) social disclosure for hypothesis C.
**Significant at 0.01 level (1-tailed). *Significant at 0.05 level (1-tailed). Bias corrected accelerated bootstrap 95% confidence interval reported in brackets.
145

Table 6.11 above summarises the results of different sets of hypothesis tests relating
to company board composition. There were significant positive correlations found
between the total sustainability disclosures and the three proxies of the board
composition: the proportion of independent directors (H3i), proportion of directors
that hold multiple directorships (H3ii), and proportion of women directors (H3iv). This
result is consistent among the economic, environmental and social aspects of
sustainability.
Except for hypothesis H3(i)A, all other hypotheses were supported.
The sets of hypotheses on CEO duality (H3iii) and sustainability committee (H3v)
were analysed using a Mann-Whitney test. Of the total 46 companies in pilot study, 7
(15.2%) companies had CEO duality and 39 (84.8%) were without. The statistical
results indicated that companies in the resources industry with CEO duality were not
providing a significantly different total extent of sustainability disclosures compared
to those without CEO duality as the significance (p-value=0.099) was greater than
0.05 and the null hypothesis was retained. This result was consistent with the
environmental (p-value=0.099) and the social aspect (p-value=0.121), but differed
with the economic aspect (p-value=0.049). Companies without CEO duality (mean
rank= 25.25) were disclosing significantly more economic disclosures than those
with CEO duality (mean rank=14.29).
All the hypotheses on sustainability committee (H3v) were supported. There were 18
(39.1%) companies that have a sustainability committee and 28 (60.9%) were
without. Companies that have a sustainability committee (mean rank = 32.08) were
providing a significantly greater extent of total sustainability disclosures than those
without (mean rank = 17.98). This result was consistent for all three aspects of
sustainability disclosures.
6.3.5.4 Hypotheses 4: Type of resources extracted - H4, H4A, H4B and H4C
158
H4: There are differences in the extent of total sustainability disclosure provided by
companies in the metals and mining sector compared to those in the energy
and utilities sector.
H4A: There are differences in the extent of economic disclosure provided by
companies in the metals and mining sector compared to those in the energy
and utilities sector.
H4B: There are differences in the extent of environmental disclosure provided by
companies in the metals and mining sector compared to those in the energy
and utilities sector.
H4C: There are differences in the extent of social disclosure provided by companies
in the metals and mining sector compared to those in the energy and utilities
sector.
A Mann-Whitney U test revealed no significant differences in the extent of total
sustainability disclosure, total hard disclosures and total soft disclosures between the
two sectors. Similar results were also obtained from a Mann-Whitney U test that was
performed on the three aspects of sustainability disclosures for companies in the two
different sectors. Table 6.12 below indicates the details of the results from the
statistical tests. The significance levels (p-values) in all the tests were more than
0.05, indicating that the mean ranks of all the various tested variables were
significantly the same between the two sectors. Hence, the entire set of hypotheses
four was not supported and this indicated that there were no significant differences in
sustainability disclosures between companies in the Metals and Mining (MM) sector
and the Energy and Utilities (EU) sector. These consistent results suggest that
similar sustainability reporting practices exist among companies operating in these
two sectors. It also suggests that the two sectors are representative of the resources
industry as a whole.
Table 6.12 Results of Mann-Whitney U test between MM and EU sectors
Variable Significance
(p-value)
Mean rank
of MM
Mean rank
of EU
Mann-
Whitney U
Standardised Test
statistic (z-value)
Total disclosures
0.921 23.30 23.70 260.00 -0.099
Hard disclosures
0.939 23.35 23.65 261.00 -0.077
Soft disclosures 0.676 24.33 22.67 283.50 0.418
159
Economic
disclosures
0.841 23.11 23.89 255.50 -0.200
Environmental
disclosures
0.783 22.96 24.04 252.00 -0.275
Social disclosures
0.606 22.48 24.52 241.00 -0.516
Note: n denotes total number of cases. There are 23 companies in each of the two (MM and EU) sectors
6.3.5.5 Hypothesis 5: Hard and soft disclosures - H5
H5: Companies in the resources industry provide more soft disclosure items than hard
disclosure items.
A Wilcoxon signed rank Test revealed that companies in the resources industry were
providing more disclosure in soft items than hard items. This result is statistically
significant (p < 0.001) and hence H5 is supported. In fact, a further analysis reveals
that all 46 companies included in this pilot study disclosed more soft than hard
disclosure items. This suggests that companies tend to provide a significantly greater
number of soft rather than hard sustainability disclosures in their reports. This is
probably because it is generally easier to provide more generic soft disclosure items
that are difficult for stakeholders to verify.
6.3.5.6 Hypothesis 6: Disclosures among the three aspects of sustainability -
H6
H6: Companies in the resources industry provide more environmental disclosures than
social and economic disclosures in their sustainability disclosures.
The results of the Friedman’s Test indicated that there was a statistically significant
difference in the disclosures across the economic, environmental and social aspects
of sustainability (Chi-Square=46.44, df=2, n=46, p<0.001). Inspection of the median
values showed a decrease in percentage of disclosure from economic (Md = 33.33%)
to social (Md = 15.95%) to environmental (Md = 12.12%). This ranking is, however,
different when the mean rank is reviewed. The arrangement in a descending order is
160

from economic (mean rank = 2.82) to environmental (mean rank = 1.65) to social
(mean rank = 1.53). Although the rankings are different, economic disclosure was the
highest in both measures. Hence, H6 is not supported. The inconsistent result in the
rankings suggests further evaluation is required to review the differences among the
four performance indicators within the combined social disclosures.
A follow up test using Friedman two ANOVA was conducted on the four performance
indicators within the social disclosure. The results of the Friedman’s Test indicated
that there was a statistically significant difference in the disclosures among the labour,
society, product responsibility and human rights performance indicators within the
social aspects of sustainability (Chi-Square= 76.45, df=3, n=46, p<0.001). Inspection
of the median values showed a decrease in the percentage of disclosure from labour
(Md = 38.89%) to society (Md = 10.00%) to product responsibility (Md = 5.00%) to
human rights (Md = 0.93%). This ranking yields consistent results when the mean
rank is reviewed.
The results from the two Friedman’s Test suggest that significant differences among
the four social performance indicators may have caused the inconsistent ranking
results. This indicates the need to evaluate the extent of social disclosure by
considering the four social performance indicators separately rather than combining
them into one single social disclosure item.
6.4 Implications for Main Research
The pilot study has achieved the set objectives through the application of the newly
developed scoring index to 46 listed companies in the resources industry of Australia.
The validity and feasibility of the scoring index are demonstrated through the awarded
scores that were able to differentiate companies with more sustainability information
disclosed in their reports from those with less sustainability information disclosed in
their reports. The pilot study has assisted in the compilation of a list of standardised
scoring criteria to ensure that consistency is maintained in the scoring process for the
main study. A recording worksheet has also prescribed a comprehensive list of data to
be collected. The final scoring of each company is consolidated using a summary
161

score sheet. The design, methods and scoring criteria have been reviewed and
improved from the pilot study for the main study. The preliminary results that were
obtained in the pilot study are used to compare those from the main study in the next
chapter.
CHAPTER 7
DATA ANALYSIS, RESULTS AND DISCUSSION
Unlike traditional instruments used for sustainability disclosures that do not measure
and reflect companies’ sustainability performance (Atkins et al., 2015; Cho et al.,
2012; Deegan & Gordon, 1996; Gray, 2010; Gray & Milne, 2002; Hopwood, 2009;
Milne & Gray, 2013), this study measures the quality of sustainability reporting of
companies in the Australian resources industry using a newly developed scoring
index. The scoring index was pilot tested and the results and implications for the main
study were discussed in the previous chapter. The analysis is expanded to a larger
sample that included the use of the scoring index to evaluate the annual financial
reports and stand-alone sustainability reports of 133 companies. This chapter reports
the results obtained from statistical testing using the Statistical Package for Social
Science (SPSS) and discusses the empirical results applicable to the hypotheses.
The implications from these results are also presented.
7.1 Descriptive Results
Table 7.1 below summarises the descriptive statistics of scores awarded to the sample
companies under the different categories of the new scoring index. A detailed record
of the scores awarded to the sampled companies is contained in Appendix 7-1.
Generally, the companies studied had few sustainability disclosures. On average, the
companies were disclosing only 20.94% of the total disclosures. They disclosed
162
14.68% more soft disclosures (33.30%) than hard disclosures (18.62%). These results
correspond to those found in the pilot study. They are also consistent with the results
from prior studies which found that companies were generally producing disclosures
that rarely provide quantitative information relating to actual outcomes that could be
verified (Dong & Burritt, 2010; Frost, 2007; Guthrie et al., 2008).
The results also reveal that there is vast diversity in companies’ disclosure items. The
large range of scores among the various categories of disclosure items, shown in Table
7.1, indicates the vast differences in the companies’ disclosures on sustainability
information. These results are in line with prior studies that found most companies were
producing generally low amount of sustainability disclosures with disclosure items that
varied immensely in their content (Dong & Burritt, 2010; Guenther et al., 2006; Rao et al.,
2012).
Table 7.1 Descriptive statistics for dependent variables
Categories in
scoring index
Maximum
Possible
Scores
Mean Median Standard
Deviation
Minimum-
Maximum
Range
A1: Governance 9 5.69 5.00 2.04 2 -9 7
A2: Credibility 5 1.33 0.00 1.66 0 - 5 5
A3: Performance Indicators
A3: Economic 18 6.95 6.00 3.82 0 – 18 18
A3: Environmental 66 11.59 7.00 11.57 0 -59 59
A3: Social–Labour 36 11.35 11.00 7.25 0 – 31 31
A3: Social-Human
Rights (HR) 54 2.83 0.00 6.21 0 -32 32
A3: Social-Society 30 2.68 1.00 4.13 0 – 26 26
A3: Social-Product
Responsibility (PR) 30 3.54 0.00 5.72 0 – 29 29
A4: Spending 2 0.59 0.00 0.72 0 – 2 2
A5: Vision 7 5.33 7.00 2.44 0 -7 7
A6: Initiatives 3 0.36 0.00 0.77 0 – 3 3
A7: Disclosure of Management Approach (DMA)
A7: Economic 3 1.56 1.00 0.79 0 – 3 3
A7: Environmental 9 2.92 2.00 2.12 0 – 9 9
A7: Social–Labour 6 2.90 3.00 1.47 0 – 6 6
A7: Social-HR 9 0.97 0.00 1.94 0 – 9 9
163
A7: Social-Society 5 0.79 1.00 1.02 0 – 5 5
A7: Social-PR 5 0.81 0.00 1.24 0 – 5 5
Total Hard (A1
to A4)
250
46.55
(18.62%)
36.00
(14.40%) 35.17 10 - 203 193
Total Soft (A5
to A7)
47
15.65
(33.30%)
14.00
(29.79%) 8.99 2 - 47 45
Total Disclosure
(A1 to A7)
297
62.20
(20.94%)
50.00
(16.84%) 43.74 12 - 248 236
Note: Percentage in brackets is the percentage of the maximum possible score in the respective category.
Consistent with most empirical research in sustainability disclosures, this study found
companies in Australian resources industry providing very minimal disclosures (Dong
& Burritt, 2010; Frost, 2007). The mean of the total disclosure (category A1 to A7)
was merely 20.94%, which is way below the passing mark of 50%. To exacerbate the
problem, all 133 sample companies reported more soft than hard disclosure items.
These results indicated the two-fold problems of sustainability reporting practices
among companies in the Australian resources industry. Firstly, the level of
sustainability disclosures was low. Secondly, the low level of disclosure consisted
mainly of soft disclosure items that relate to generic non-verifiable information that
suggests a low quality of sustainability disclosure.
The large range in values indicates the presence of extreme scores. Hence, in this
case, the median is considered to be a better measure of the average than the mean
as the median is relatively not affected by extreme scores (Field, 2013). As shown in
Table 7.1 above, there are 7 out of 17 categories (41.18%) that have zero as their
median. This suggests that, on average, the sample companies had no disclosure in
seven categories: credibility (A2), two social performance indicators (A3: Social) –
human rights and product responsibility, spending (A4), initiatives (A6), two
disclosure of management approach (DMA, A7) – human rights and product
responsibility.
7.2 Results of Hypothesis Testing
This study investigates the correlations between the three aspects of sustainability
disclosures - economic, environmental and social - and selected company
164

characteristics - company size, financial performance, board composition, and
industry sector. Non-parametric analyses were applied for all the hypotheses testing
because the distribution of the data was not normal. Appendix 7-2 and 7-3 contain
the details of the independent variables (company characteristics) of the sample
companies.
As explained in Chapter 4 on methodology, Kendall’s tau-b was used for
nonparametric correlation analysis for testing of Hypotheses 1, 2, 3(i), 3(ii) and 3(iv).
The statistical tests performed are considered robust as an additional bootstrapping
process was performed with 1000 bootstrap samples with a 95% confidence interval.
Mann-Whitney test was used to test Hypotheses 3(iii), 3(v) and 4 to compare two
conditions between independent samples as the assumption of normality is violated
in the distribution (Field, 2013). The Wilcoxon signed ranks Test and Friedman Two-
Way Test were used for Hypotheses 5 and 6 respectively.
7.2.1 Hypotheses 1: Company size
The first set of hypotheses examines the correlation between company size and the
extent of sustainability disclosure (H1), economic disclosure (H1A), environmental
disclosure (H1B), and social disclosure (H1C). These hypotheses were proposed as:
H1: There is a positive relationship between company size and the extent of total
sustainability disclosure provided by companies in the resources industry.
H1A: There is a positive relationship between company size and the extent of total
economic disclosure provided by companies in the resources industry.
H1B: There is a positive relationship between company size and the extent of total
environmental disclosure provided by companies in the resources industry.
H1C: There is a positive relationship between company size and the extent of total social
disclosure provided by companies in the resources industry.
Three proxies, namely, market capitalisation, total revenue, and total assets were
used for company size. The results from the non-parametric Kendall’s tau-b tests
showed that the three proxies had significant positive correlations with all the
165
dependent variables tested. The first set of hypotheses were fully supported
statistically (onetailed, p<0.001, N=133). Table 7.2 below summarises the results
from the Kendall’s tau-b tests for correlation. The correlation coefficients, the
respective p-values, and results of bootstraps are presented. Among the three
proxies used for company size, total assets appear to have the strongest positive
correlation with each of the dependent variables.
Table 7.2 Kendall’s tau-b correlation results for Hypotheses 1 (company size)
Proxy for
Company Size
Total
Sustainability
Disclosure
Economic
Disclosure
Environmental
Disclosure
Social
Disclosure
Market capitalisation 0.332***
[0.217, 0.432]
0.247***
[0.135, 0.352]
0.260***
[0.135, 0.375]
0.341***
[0.242, 0.445]
Total revenue
exclude
interest
revenue
0.296***
[0.173, 0.412]
0.217***
[0.085, 0.341]
0.239***
[0.108, 0.358]
0.303***
[0.180, 0.415]
Total assets 0.421***
[0.317, 0.513]
0.302***
[0.170, 0.418]
0.344***
[0.234, 0.449]
0.400***
[0.300, 0.489]
Note: ***Correlation is significant at the 0.001 level (1 tailed), Bias corrected accelerated bootstrap 95% confidence interval
reported in brackets.
These results are in line with those obtained in prior research (Andrikopoulos &
Kriklani, 2013; Ho & Taylor, 2007; Jones et al., 2007; Tagesson et al., 2009) and the
pilot study. The results suggest that large companies report more sustainability
disclosures. The large companies also disclose more in all the three aspects of
sustainability. This study confirms the significant positive correlations between
company size and extent of sustainability disclosures using a new measurement that
emphasises verifiable sustainability performance. This further suggests that large
companies have demonstrated better sustainability performance than smaller
companies.
Large companies tend to have stronger financial capabilities and resources to
engage in more sustainability reporting (Ho & Taylor, 2007; Jones et al., 2007;
166

Tagesson et al., 2009). Patten (1992) suggested that the legitimacy theory also
explains this phenomenon as larger companies normally attract greater publicity and
more scrutiny from their stakeholders and are more likely to provide more
sustainability disclosures to legitimise their business activities. Adams et al. (1998)
also found that larger companies across all six European countries (Netherlands,
Switzerland, France, Germany, Sweden and the United Kingdom) provided more
sustainability disclosures in all three categories examined – environmental,
employee and ethical issues.
7.2.2 Hypotheses 2: Company financial performance
The next set of hypotheses examines the correlation between company financial
performance and the extent of sustainability disclosure (H2), economic disclosure (H2A),
environmental disclosure (H2B), and social disclosure (H2C). The company financial
performance was represented by operating revenue, earnings before interest and tax
(EBIT), return of equity (ROE), book value per share, and year-end share price. The
hypotheses were suggested as:
H2: There is a positive relationship between company financial performance and the
extent of total sustainability disclosure provided by companies in the resources
industry.
H2A: There is a positive relationship between company financial performance and
the extent of total economic disclosure provided by companies in the
resources industry.
H2B: There is a positive relationship between company financial performance and
the extent of total environmental disclosure provided by companies in the
resources industry.
H2C: There is a positive relationship between company financial performance and
the extent of total social disclosure provided by companies in the resources
industry.
Hypothesis 2, which focused on total sustainability disclosure, was fully supported by all
the five proxies that were used to represent company financial performance.
167
Kendall’s tau-b’s correlation coefficient showed a significant positive relationship
between total sustainability disclosures and company financial performance with
bootstrapping tested. However, the results were not consistent among the other
three hypotheses H2A, H2B and H2C. Table 7.3 below presents the results obtained
from the Kendall’s tau-b tests that were performed to analyse the second set of
hypotheses.
Table 7.3 Kendall’s tau-b correlation results for Hypotheses 2 (company financial
performance)
Proxy for
Company
Financial
Performance
Total
Sustainability
Disclosure
Economic
Disclosure
Environmental
Disclosure
Social
Disclosure
Operating revenue 0.313***
[0.179, 0.432]
0.234***
[0.096, 0.369]
0.254***
[0.122, 0.375]
0.305***
[0.185, 0.417]
EBIT 0.160**
[0.022, 0.293]
0.116*
[-0.026, 0.262]
0.113*
[-0.035, 0.259]
0.165**
[0.021, 0.308]
ROE 0.140**
[0.039, 0.247]
0.097
[-0.009, 0.218]
0.108*
[-0.004, 0.224]
0.133*
[0.029, 0.253]
Book value per
share
0.403***
[0.305, 0.494]
0.305***
[0.185, 0.424]
0.307***
[0.198, 0.418]
0.356***
[0.243, 0.454]
Year-end share price 0.310***
[0.201, 0.425]
0.251***
[0.135, 0.368]
0.225***
[0.116, 0.339]
0.293***
[0.177, 0.404]
Note: ***Correlation is significant at the 0.001 level (1 tailed), **Correlation is significant at the 0.01 level (1
tailed), *Correlation is significant at the 0.05 level (1 tailed), Bias corrected accelerated bootstrap 95%
confidence interval reported in brackets.
As shown in Table 7.3 above, the hypothesis H2A was supported when operating
revenue, book value per share and year-end share price were used as the proxies
168

for company financial performance. There was a significant positive correlation
between economic disclosure and company financial performance (p-value < 0.001,
1 tailed). The positive correlation was also significant (p-value < 0.05, 1 tailed) when
EBIT was used, but the bootstrapping test indicated a cross through the zero mark.
There was no significant result (p-value = 0.058) obtained with the use of ROE.
Hypothesis H2B was partially supported with three out of the five proxies used
yielding significant results with robust tests of bootstrapping (p-value < 0.001, 1
tailed). Although there was also a significant positive correlation between
environmental disclosure and company performance when EBIT and ROE were
used as the proxies (p-value < 0.05, 1 tailed), the robust test of bootstrapping was
not passed in the case when both proxies were used.
Hypothesis H2C, however, was fully supported with all the five proxies used. The
Kendall’s tau-b’s correlation coefficients with bootstrapping showed a significant positive
relationship between social disclosure and company financial performance.
Comparing the above results with those obtained in the pilot study, more significant
results were obtained in this main study with the use of a larger sample. The
inconsistent results obtained with the use of different proxies for company financial
performance are in line with those from prior studies (Ho & Taylor, 2007; Jones et al.,
2007). Ho and Taylor (2007) investigated the relationship between total sustainability
disclosure and company financial performance measured by leverage, liquidity and
profitability. Their research, which focused on companies in the United States and
Japan, obtained a generally negative correlation that implied companies with poorer
financial performance were providing more sustainability disclosures. This
correlation, however, was not consistent among the different proxies used. In the
Australian context, Jones et al. (2007) also observed similar inconsistent results.
Contrary to Ho and Taylor, Jones et al. found a generally positive correlation
between company financial performance and sustainability disclosure with nine
different proxies that were used to measure company financial performance.
However, similar to Ho and Taylor, not all of the statistical tests performed in Jones et
169

al.’s study yielded significant results and not all the nine proxies had similar positive
relationships to sustainability disclosure.
The use of different proxies to measure company financial performance and the
different methods that were used to measure sustainability disclosure have
contributed to the inconsistent results (Ho & Taylor, 2007; Jones et al., 2007;
Tagesson et al., 2009). In addition, the problem of multicollinearity that commonly
exists among different proxies used for company financial performance (Tagesson et
al., 2009) has also made it difficult to interpret the correlation between sustainability
disclosure and company financial performance. Multicollinearity was checked at the
stage of the pilot study for this research. Among the proxies used, only ROE and
return on asset (ROA) were found to have strong positive correlation. As a result,
only ROE was used in the main study to measure company financial performance as
total assets was used as a proxy for company size in Hypotheses 1.
7.2.3 Hypotheses 3: Board composition
The board of directors (BOD) of a company, which represents the highest level of
management in a company, has a major impact on a company’s reporting practices
and procedures (Fama & Jensen, 1983; Keasey & Wright, 1993). The composition of
the BOD has major implications on how the BOD can effectively fulfil its role in
providing effective management to the company (Goodstein et al., 1994; Pfeffer,
1972; Webb, 2004). Prior research supports board diversity as diversity generally
promotes more discussion of ideas to improve performance (Chandler, 2005; van
Knippenberg, De Dreu, & Homan, 2004) and diversity implies that members are
more representative of the different stakeholders (Wang & Dewhirst, 1992). Kang et
al. (2007) defined board diversity as “variety in the composition of the BOD” (p. 195).
Prior literature has identified that a company’s board composition influences
companies’ sustainability reporting (Michelon & Parbonetti, 2012; Post et al., 2011;
Rao et al., 2012; Rupley et al., 2012; Siregar & Bachtiar, 2010; Webb, 2004). This
study focuses on the examination of five attributes of board diversity namely the
proportion of independent directors, proportion of directors with multiple
170

directorships, presence of CEO duality (i.e. company CEO acting as board
chairman), proportion of female directors, and existence of a sustainability
committee.
7.2.3.1 Hypotheses 3(i): Proportion of independent directors
This set of hypotheses investigates the correlation between the proportion of
independent directors and the extent of sustainability disclosure (H3i), economic
disclosure (H3iA), environmental disclosure (H3iB) and social disclosure (H3iC).
According to agency theory, it is important to have a majority of independent
directors in a company’s BOD (Fama & Jensen, 1983; Jensen & Meckling, 1976).
While there is no dispute about the importance of having a larger proportion of
independent directors in the BOD, there are differences in the definition of
independence (Kang et al., 2007). This study adopts the definition developed by the
Australian Securities Exchange (ASX) Corporate Governance Council (CGC). ASX
CGC defines an independent director as
in the case of an externally managed listed entity, a director of
the entity who is also an executive of the listed entity or a child
entity and, in the case of an externally managed listed entity, a
director of the responsible entity who is also an executive of the
responsible entity or a related body corporate. (Australian
Securities Exchange Corporate Governance Council, 2014, p.
37)
This implies that the director is not in a relationship that might influence materially his
or her independent judgement and to act in the best interest of a company’s
stakeholders.
Prior studies have found that companies with a greater proportion of independent
directors are disclosing more sustainability information (Post et al., 2011; Rao et al.,
2012; Rupley et al., 2012). Hence, the set of hypotheses was proposed as:
171

H3(i): There is a positive relationship between the proportion of independent
directors on the board and the extent of total disclosure provided by
companies in the resources industry.
H3(i)A: There is a positive relationship between the proportion of independent
directors on the board and the extent of economic disclosure provided by
companies in the resources industry.
H3(i)B: There is a positive relationship between the proportion of independent
directors on the board and the extent of environmental disclosure provided
by companies in the resources industry.
H3(i)C: There is a positive relationship between the proportion of independent
directors on the board and the extent of social disclosure provided by
companies in the resources industry.
The results from the non-parametric Kendall’s tau-b on a one-tailed test indicated
that there were significant positive correlations between the proportion of
independent directors and the total sustainability disclosure (Kendall’s tau-b
correlation coefficient, Ʈ= 0.135, p= 0.013, N= 133), economic disclosure (Ʈ= 0.122,
p= 0.027, N= 133), and social disclosure (Ʈ= 0.125, p= 0.020, N= 133). Hence,
Hypotheses H3(i), H3(i)A and
H3(i)C were supported. The results were robust with the bootstrap tests passed at a 95%
confidence interval. However, no significant statistical result was obtained to support
Hypotheses H3(i)B on environmental disclosure (Ʈ= 0.083, p= 0.090, N= 133).
These results vary from those obtained in the pilot study. In both the pilot study and
the main study, there were significant positive correlations between the proportion of
independent directors and total sustainability disclosure (H3i) and social disclosure
(H3iC). In the pilot study, no significant correlation was found between the proportion
of independent directors and economic disclosure (H3iA) but a significant positive
correlation was found in the main study. However, the results for environmental
disclosure (H3iB) indicate the reverse, as a significant positive correlation was found
in the pilot study but not in the main study.
172

A significant positive correlation was found between the proportion of independent
directors and total sustainability disclosure. This result supports prior research that
found a similar relationship between the proportion of independent directors and total
sustainability disclosure (Post et al., 2011; Rao et al., 2012; Rupley et al., 2012).
Post et al. (2011) adapted and scored sustainability disclosures using Clarkson et
al.’s (2008) environmental index on 78 companies that were in the 2006 and 2007
list of Fortune 1000 American companies. They found a similar significant positive
correlation between the proportion of independent directors and total sustainability
disclosures. They also found the same relationship existed among the individual
categories: governance disclosure, credibility disclosure, and environmental
performance indicators. These categories coincide respectively with A1, A2 and A3
of
Clarkson et al.’s index and the new scoring index developed for this study. However,
Post et al. used only six out of the ten environmental performance indicators in
Clarkson et al.’s index A3 category. This is also different to a total of eleven
environmental performance indicators used in the new scoring index of the current
study.
In contrast to the correlations found in Post et al. (2011) between the proportion of
independent directors and environmental disclosure, this study, which uses a greater
number of environmental performance indicators, did not yield a significant result.
This could be attributed to the differences between the two studies in the following
areas: geographical location, company industry type, number of environmental
indicators used and period of study.
The significant results that supported Hypotheses H3(i), H3(i)A and H3(i)C indicate
that board diversity in the form of board independence measured by the proportion
of independent directors increases the extent of total sustainability, economic and
social disclosures of companies. Independent members are placed on the board to
assist companies achieve their goals by monitoring, influencing and providing
external perspectives that will enhance transparency in the information presented to
a more diverse group of stakeholders (Rupley et al., 2012). Having greater board
independence in the BOD broadens the external perspectives of the BOD and
173

encourages the exposure of more sustainability information. This conclusion
concurs with the findings in Post et al. (2011). Post et al. suggested that independent
directors tend to be more concerned with a company’s reputation and sustainability.
They claimed that the independent directors may enhance companies’ sustainability
performance through their recommendations to set up an environmental issues
committee, to implement an accredited program such as ISO14001, to demand more
in-depth environmental reports and to ensure better environmental practices
according to government initiatives. They also suggested that independent directors
tend to have a different perspective when considering investments in environmental
issues. The independent directors may place greater emphasis on long term
economic benefits compared to those in the short term.
7.2.3.2 Hypotheses 3(ii): Proportion of multiple directorships
The set of Hypotheses 3(ii) examines the correlation between the proportion of
directors on the board that hold multiple directorships and the extent of sustainability
disclosure (H3ii), economic disclosure (H3iiA), environmental disclosure (H3iiB) and
social disclosure (H3iiC).
Directors serving on multiple boards are exposed to different company practices and
they gain knowledge through interacting with other board members (Rupley et al.,
2012). In the context of sustainability disclosure, directors with multiple directorships
may acquire better exposure to different sustainability practices. These directors,
who are better equipped with sustainability knowledge and techniques in reporting,
are expected to provide more sustainability disclosure. Thus, the hypotheses were
suggested as follows:
H3 (ii): There is a positive relationship between the proportion of directors on the
board that hold multiple directorships and the extent of total sustainability
disclosure provided by companies in the resources industry.
H3(ii)A: There is a positive relationship between the proportion of directors on the
board that hold multiple directorships and the extent of economic disclosure
provided by companies in the resources industry.
174

H3(ii)B: There is a positive relationship between the proportion of directors on the
board that hold multiple directorships and the extent of environmental
disclosure provided by companies in the resources industry.
H3(ii)C: There is a positive relationship between the proportion of directors on the
board that hold multiple directorships and the extent of social disclosure
provided by companies in the resources industry.
The results from the non-parametric Kendall’s tau-b tests showed that all the
hypotheses were fully supported statistically (one-tailed, N=131). These results were
based on a sample size of 131, instead of the total 133 sample companies, as there
were two companies that did not record the information of multiple directorships of
their BOD in their annual reports. Significant positive correlations were found
between the proportion of directors on the board that hold multiple directorships and
the total sustainability disclosure (Ʈ= 0.179, p= 0.002), economic disclosure (Ʈ=
0.211, p= 0.001), environmental disclosure (Ʈ= 0.199, p= 0.001), and social
disclosure (Ʈ= 0.133, p= 0.015). These robust results were obtained with
bootstrapping performed at 95% confidence level. Hence, the results fully supported
the set of Hypotheses 3(ii). Similar results are found in the pilot study and also in
Rupley et al.’s (2012) study.
These consistent results support the reasons suggested by Rupley et al. (2012) that
having more directors with multiple directorships in the BOD provides the board with
a better understanding and exposure to sustainability reporting practices and this,
consequently, increases the extent of sustainability disclosure.
7.2.3.3 Hypotheses 3(iii): CEO duality
The next set of hypotheses, Hypothesis 3(iii), was tested to determine whether CEO
duality, which refers to the same person performing the roles of both the board chair
and the CEO of a company, results in a lesser extent of sustainability disclosure.
Adams, Almeida, and Ferreira (2005) claimed that CEOs with these dual positions
are likely to have increased power over other board members and this reduces the
independence of the board. This view was supported by Forker (1992) who asserted
175
that CEO duality promotes the ‘dominant personality’ in CEOs and this tends to
result in less disclosure. Thus, the hypotheses were proposed as:
H3(iii): Companies in the resources industry with CEO duality provide lesser extent of
total sustainability disclosure.
H3(iii)A: Companies in the resources industry with CEO duality provide lesser extent of
economic disclosure.
H3(iii)B: Companies in the resources industry with CEO duality provide lesser extent of
environmental disclosure.
H3(iii)C: Companies in the resources industry with CEO duality provide lesser extent of
social disclosure.
The sample was coded into two categories to differentiate those companies that had
CEO duality from those that did not. Of the total sample of 133 companies, only 17
companies (12.78%) had CEO duality and the remaining 116 companies (87.22%)
did not. The Mann-Whitney U test is used to compare the extent of disclosures
reported by the two categories of companies. The result from a Mann-Whitney U test
indicated that there was no statistically significant difference in the total sustainability
disclosure by companies with CEO duality compared to those without, thus
Hypothesis H3(iii) was not supported. However, companies with CEO duality were
reporting a significantly lesser extent of economic, environmental and social
disclosures than those companies without CEO duality. Hence, the remaining
hypotheses, H3(iii)A,
H3(iii)B and H3(iii)C were supported. Table 7.4 below presents the results from
MannWhitney U tests that were performed to analyse the above set of hypotheses.
Table 7.4 Results of Mann-Whitney U test for Hypotheses H3(iii) on CEO duality
Variable Significance
(p-value)
Mean rank
of
companies
without
CEO
Duality
Mean rank
of
companies
with CEO
Duality
MannWhitney
U
Standardised
Test statistic
(z-value)
Effect
Size, r =
z /
square
root of
N
Total
disclosures
0.148 68.81 54.65 1196 1.445 0.125
176
Economic
disclosures
0.022 69.91 47.18 1323 2.297 0.199
Environmental
disclosures
0.017 70.05 46.18 1340 2.392 0.207
Social
disclosures
0.029 69.79 47.97 1310 2.182 0.189
Note: N= Number of total cases = 133. Number of companies without CEO duality = 116, Number of companies with CEO duality =
17 companies.
The results shown in Table 7.4 indicate that although companies with CEO duality
disclosed significantly less information in the economic, environmental and social
disclosure, the effects in each of the disclosures were considered small as they were
below 0.3 (Cohen, 1988). These small effects found in each of the individual three
aspects of sustainability may have contributed to the contrary result where no
significant difference was found when the total sustainability disclosure was tested.
These results were also different to those found in the pilot study when economic
disclosure was the only disclosure that was found to be significantly different
between companies that had CEO duality and those that did not. A similar result
was, however, obtained by Michelon and Parbonetti (2012) and Rupley et al. (2012)
as they found no evidence to indicate that companies with CEO duality were
disclosing less economic, environmental and social information.
7.2.3.4 Hypotheses 3(iv): Proportion of women directors
The proportion of women directors on the BOD is another characteristic analysed in
this set of hypotheses. Many prior studies have found a positive correlation between
the proportion of women directors and sustainability reporting (Rao et al., 2012;
Rupley et al., 2012). In line with these, the set of hypotheses was proposed as:
H3 (iv): There is a positive relationship between the proportion of women directors
on the board and the extent of total sustainability disclosure provided by
companies in the resources industry.
177

H3(iv)A: There is a positive relationship between the proportion of women directors
on the board and the extent of economic disclosure provided by companies
in the resources industry.
H3(iv)B: There is a positive relationship between the proportion of women directors
on the board and the extent of environmental disclosure provided by
companies in the resources industry.
H3(iv)C: There is a positive relationship between the proportion of women directors
on the board and the extent of social disclosure provided by companies in
the resources industry.
The results from the Kendall’s tau-b tests showed that all the hypotheses were fully
supported statistically (one-tailed, N=133). Significant positive correlations were
found between the proportion of women directors on the board and the total
sustainability disclosure (Ʈ= 0.281, p< 0.001), economic disclosure (Ʈ= 0.227, p=
0.001), environmental disclosure (Ʈ= 0.216, p= 0.001), and social disclosure (Ʈ=
0.288, p< 0.001). The robustness of the tests was increased through the
performance of bootstrapping at 95% confidence level. Hence, the results fully
supported the set of Hypotheses 3(iv). Similar results were found in the pilot study.
Recent research has seen an increased interest in investigating the impact of
women directors on BOD performance. Many have found that having women
director on the BOD has resulted in improved board effectiveness and better
governance practice (Adams & Ferreira, 2009). Women directors are generally found
to have less attendance problems than male directors (Adams & Ferreira, 2009).
Companies are also found to be engaging in more sustainability reporting when the
proportion of women directors in the BOD increases (Rao et al., 2012; Rupley et al.,
2012). The results from this study support these prior findings.
Descriptive statistics from this study revealed that 99 companies out of the total 133
companies (74.4%) do not have women directors on the BOD. 20.3% of the
companies had only one woman director and the remaining 5.3% had two women
directors. Despite the low percentage of women directors in these companies, the
significant positive correlation obtained in this study has indicated that women
178

directors can contribute substantially to better sustainability reporting. A similar result
was also found in Rao et al.’s (2012) study.
7.2.3.5 Hypotheses 3(v): Sustainability committee
The final characteristic of the BOD examined in this set of hypotheses relates to the
existence of a sustainability committee. Companies with a sustainability committee
have demonstrated their proactive efforts on sustainability through the establishment
of a specialised committee to manage sustainability issues. In line with this
argument, the set of hypotheses was suggested as:
H3(v): Companies in the resources industry with a sustainability committee
provide greater extent of total sustainability disclosure.
H3(v)A: Companies in the resources industry with a sustainability committee
provide greater extent of economic disclosure.
H3(v)B: Companies in the resources industry with a sustainability committee
provide greater extent of environmental disclosure.
H3(v)C: Companies in the resources industry with a sustainability committee
provide greater extent of social disclosure.
The sample was grouped into two categories according to whether a company had a
sustainability committee before a Mann-Whitney U test was performed on the data.
Out of a total of 133 companies studied, 32 companies (24.06%) had a sustainability
committee and the remaining 101 companies (75.94%) did not. The results from
Mann-Whitney U tests indicated the presence of significant differences in the total
sustainability disclosure, economic disclosure, environmental, and social disclosure
by companies with a sustainability committee compared to those that were without
(p< 0.001, two-tailed). Hence, all the hypotheses in the set of Hypothesis H3(v) were
supported. The Mann-Whitney U test indicated that companies with a sustainability
committee reported a greater extent of total sustainability disclosures. They were
also providing more information in all the individual aspects of sustainability
compared to those companies without a sustainability committee. The effect size for
the disclosure was considered medium as each of them is above 0.3 (Cohen, 1988).
179
Table 7.5 below summarises the results of the Mann-Whitney test for Hypotheses
H3(v).
Table 7.5 Results of Mann-Whitney U test for Hypotheses H3(v) on sustainability
committee
Variable Mean rank of
companies
with a
sustainability
committee
Mean rank of
companies
without a
sustainability
committee
MannWhitney
U
Standardised
Test statistic
(z-value)
Effect Size, r
= z /
square
root of N
Total
disclosures
99.97 56.55 561 -5.554 0.482
Economic
disclosures
88.72 60.12 921 -3.700 0.321
Environmental
disclosures
96.75 57.57 664 -5.025 0.436
Social
disclosures
98.22 57.11 617 -5.262 0.456
Note: N= Number of total cases = 133. Number of companies with a sustainability committee = 32, Number of companies without a
sustainability committee = 101.
These results are consistent with those from the pilot study, but differ from those in
Rupley et al. (2012). Rupley et al. (2012) did not find companies with a sustainability
committee were disclosing more sustainability information. Michelon and Parbonetti
(2012), however, found “weak evidence” (p. 503) of the relationship between the
presence of a sustainability committee and social disclosure. They described these
contrary results as “quite surprising” (p. 503) and suggested that some of these
traditional proxies, such as independent directors, CEO duality and presence of
sustainability committee, that were normally used for board composition may not be
sufficient to represent the service role of the board. Another possible reason for this
is that many companies may not have a sustainability committee. Until the recent
decade, not many companies had a specialised committee to manage sustainability
issues. Those who did have a committee may not have members that are
wellequipped and trained to know how and what sustainability information to
disclose. These reasons may have provided explanations for the non-significantly
different extent of sustainability information disclosed by companies with a
sustainability committee.
180

In this study, the presence of a sustainability committee has shown enhancement in
the extent of sustainability disclosure with medium effect. This indicates that
companies with a sustainability committee have additional and dedicated resources
to help companies improve their sustainability initiatives and performance. Unlike
prior studies with contrary findings, the contribution of the sustainability committees
in the sample has been demonstrated through a greater extent of sustainability
disclosures found in the companies’ reports.
7.2.4 Hypotheses 4: Type of resources extracted
While many studies have focused on companies in environmentally sensitive
industries such as the resources industry, most of them have focused on comparing
these companies to those that were operating in non-environmentally sensitive
industries (Gibson & O'Donovan, 2007; Suttipun & Stanton, 2012; Wood & Ross,
2008). Others have only examined either the mining sector (Perez & Sanchez, 2009;
Soutar, Christopher, & Cullen, 1998; Yongvanich & Guthrie, 2005) or the oil and gas
sector (Dong & Burritt, 2010). A study that compared the disclosures between the
mining and oil and gas industry was performed by Guenther et al. (2006). They
found some differences in the disclosures of companies in the two sectors while
Perez and Sanchez (2009) that focused on mining sector and Dong and Burritt
(2010) that focused on oil and gas discovered some similarities. In view of the
contrary results from the different studies, this study proposed alternative
hypotheses as follows:
H4: There are differences in the extent of total sustainability disclosure provided by
companies in the metals and mining sector compared to those in the energy
and utilities sector.
H4A: There are differences in the extent of economic disclosure provided by
companies in the metals and mining sector compared to those in the energy
and utilities sector.
181

H4B: There are differences in the extent of environmental disclosure provided by
companies in the metals and mining sector compared to those in the energy
and utilities sector.
H4C: There are differences in the extent of social disclosure provided by companies
in the metals and mining sector compared to those in the energy and utilities
sector.
The sample was classified into two different categories according to the sectors –
metals and mining (M&M) and energy and utilities (E&U) based on the type of
resources extracted. There were 73 companies in the sample that operated in the
E&U sector and 66 companies in the M&M sector. A Mann-Whitney U test was
performed on the data. The results from the Mann-Whitney U tests indicated that
there were no significant differences in the total sustainability disclosure, economic
disclosure, environmental disclosure, and social disclosure by companies that were
operating in the two different sectors (p> 0.1, two-tailed). Hence, all the hypotheses
in the set of Hypothesis H4 (H4, H4A, H4B and H4C) were not supported. These
results were in line with those obtained in the pilot study, but were contrary to those
found in Guenther et al.’s (2006) study.
Further tests were performed on the different categories of the dependant variables,
A1 to A7, using the Mann-Whitney U test to investigate any significant differences
between the disclosures of companies in the M&M and E&U sectors. There were no
significant differences in the information disclosed in the total hard and soft
disclosure items between companies operating in the two sectors. Except for the
social performance indicator on human rights (A3-HRP), sustainability initiatives (A6)
and disclosure on management approach on economic aspect (A7-ECP), all the
remaining dependent variables indicated no significant differences. The results from
the MannWhitney U test indicated that companies operating in the M&M sector were
disclosing significantly more information in A3-HRP (p = 0.05, two tailed), A6 (p <
0.001, two tailed) and A7-ECP (p = 0.016, two tailed) than those operating in the
E&U sector. The calculated effects for A3-HRP, A6 and A7-HRP were 0.170, 0.309
and 0.209 respectively, and they were considered to be between small to medium
(Cohen, 1988).
182

Similar tests were performed to investigate whether company characteristics were
significantly different between companies in the two sectors. Proxies of the
independent variables for company size, financial performance and board
composition were used in the analysis. Results showed that the market capitalisation
of companies in the M&M sector (mean rank = 80.75, n = 60) were significantly
larger than those in the E&U sector (mean rank = 55.7, n = 73), U = 3015, z = 3.73,
p < 0.001, two-tailed. The effect can be described as medium (r = 0.323).
Companies in the M&M sector also performed better than those in the E&U sector
when three of the proxies – return on equity, book value per share and year-end
share price – for company financial performance were analysed in a Mann-Whitney
U test. However, companies in the two sectors did not show significant differences
for the proportion of the independent directors, the proportion of directors with
multiple directorships and the proportion of women directors.
The results suggest that companies operating in the M&M and E&U sectors share
relatively similar sustainability reporting practices. While companies in the M&M
sector tend to have a larger market capitalisation and they perform better financially,
they have a fairly similar board composition. These results indicate that the two
sectors are representative of the resources industry as a whole. However, they were
not consistent with those found in Guenther et al. (2006) where companies in the two
sectors have placed a different emphasis on various environmental performance
indicators. They found that companies in the mining sector have disclosed more
information in areas such as land use and rehabilitation while companies operating
in the oil and gas sector have disclosed more details on transportation methods and
oil spill incidents. However, this study did not yield a similar outcome as the result did
not support hypothesis H3B when environmental disclosure was tested. Instead, this
study found that disclosures provided by companies in the M&M and E&U sector
differ in three categories: social performance indicator on human rights (A3-HRP),
sustainability initiatives (A6), and disclosure on management approach on economic
aspect (A7). These differences were not found in Guenther et al.’s study as they
focused solely on the environmental aspect; the economic and social aspects of
sustainability were not investigated.
183

7.2.5 Hypothesis 5: Hard and soft disclosures
This study adopts a new scoring scale to measure companies’ sustainability disclosures.
The disclosure items were classified into two broad categories: hard and soft disclosure
items. Each of the hard disclosure items is awarded a score that ranges from 0 to 6. A point
is awarded to each disclosure item that includes information in comparison to each of the
following six indicators: peers or industry, previous period, targets, aggregate and
normalised form, and disaggregate level.
Prior research has found that companies are generally disclosing broad categories of
data with very diverse disclosure items (Dong & Burritt, 2010; Guenther et al., 2006;
Rao et al., 2012). This suggests that managers prefer to provide the minimal
information through soft disclosure items such as proclaiming a vision statement to
satisfy mandatory requirements and their stakeholders. They tend to avoid reporting
the hard disclosure items that require detailed quantitative data to verify
improvements in sustainability performance by comparing the actual performance
with prior periods and pre-set targets. Hence, this study has proposed the
hypothesis as:
H5: Companies in the resources industry provide more soft disclosure items than hard
disclosure items.
The total raw scores of both the hard and soft disclosure were recoded as a
percentage of their maximum possible scores in the hard (250) and soft disclosure
categories (47) to facilitate comparison. Table 7.6 below displays the descriptive
statistics for the percentages of hard and soft disclosures. In the category of hard
disclosure, the percentage of disclosure has a minimum of 4% and a maximum of
81%. In the soft disclosure category, companies reported a minimum of 4% and
there were companies that reported a full 100%. The results in Table 7.6 indicate that
every company in the sample disclosed more soft than hard disclosure items.
184
Table 7.6 Descriptive statistics for hard and soft disclosures
Item Mean Median Standard
Deviation
Minimum-Maximum
Percentage of hard
disclosure (A1 – A4) 18.62% 14.40% 14.07% 4% - 81%
Percentage of soft
disclosure (A5 – A7) 33.31% 29.79% 19.13% 4% - 100%
Difference
(Percentage of soft
disclosure Minus
Percentage of
hard
disclosure
14.69% 14.60% 7.57% 0% - 37%
A Wilcoxon signed rank test was performed to compare the companies’ disclosures
on hard and soft items. The percentage of disclosures in the two categories was
used for the test. As anticipated from the descriptive results above, the statistical test
showed no tied ranks and negative ranks. The result displayed all positive ranks
which indicated that all the sample companies reported more soft disclosure items
than hard disclosure items. The result is significant (p < 0.001, two tailed) and the
effect, r = 0.868, was considered large as it was greater than 0.5 (Cohen, 1988).
Hence, H5 is supported. This is in line with the result in the pilot study. Also, as in the
pilot study, all companies studied were reporting more soft than hard disclosure
items.
This result supports prior studies which found that companies are providing broad
coverage of soft disclosure items that tend to be relatively generic and very little
disclosures in hard items that provide quantitative information (Dong & Burritt, 2010;
Perez & Sanchez, 2009; Yongvanich & Guthrie, 2005). Dong and Burritt, who studied
185

the Australian oil and gas industry, found that companies “rarely provide quantitative
information to enable readers to access actual outcomes and achievements in
numerical terms against predictions” (p. 116). Perez and Sanchez (2009) also found
that reports produced by mining companies included only a few indicators that
disclose information “relative to output levels and almost none is compared to
standards or regional levels” (p. 957). Yongvanich and Guthrie (2005), who also
focused on the mining industry, found consistent results that companies rarely
reported the specific performance indicators. These consistent results suggest that
companies tend to provide significantly more soft than hard sustainability disclosure
items in their reports because it is easier for companies to provide more generic soft
disclosure items that are difficult for stakeholders to verify. Data that require specific
effort to collect are seldom reported (Guenther et al., 2006).
This study found similar results in the research on resources industry dating back to
2005 (Yongvanich & Guthrie, 2005). This implies that companies in the resources
industry have made little progress in the last decade. While sustainability disclosure
seems to have increased in volume in the recent decade (Adams & Frost, 2007;
Crawford & Williams, 2010; Frost, 2007), the quality of information provided to the
users of the sustainability reports has not changed. Companies are still reporting
very generic and brief information without providing important and crucial
sustainability information that is essential to make strategic business decisions.
7.2.6 Hypothesis 6: Disclosures among the three aspects of sustainability
Companies are encouraged to provide comprehensive sustainability disclosures in
all three aspects of sustainability – economic, environmental and social. Companies
operating in environmentally sensitive industries are normally under close scrutiny by
regulators and their stakeholders. As these companies’ business activities have
major and direct impacts on the environment, stakeholders are concerned with how
the companies are managing problems such as pollution and waste management
that may give rise to potential future compliance costs for the companies. Thus,
these companies tend to disclose more environmental disclosures to address their
stakeholders’ concerns (Deegan & Gordon, 1996). In addition, companies in
186
Australia that operate in an environmentally related industry are required to produce
mandatory disclosures in their annual reports (Frost, 2007). As a result, it is
expected that companies operating in the Australian resources industry will focus on
the environmental aspect of sustainability over the economic and social aspects.
Hence, the hypothesis was proposed as:
H6: Companies in the resources industry provide more environmental disclosures than
social and economic disclosures in their sustainability disclosures.
Scores awarded under the hard disclosure category A3 that relates to the specific
performance indicators of the various aspects of sustainability were used in the
analysis for this hypothesis. The raw scores of different performance indicators
under the economic, environmental and social aspects were totalled. The social
aspect was further classified into the following four sub-categories: labour, human
rights, social and product responsibility. The total raw scores were reported as a
percentage of their respective maximum scores. A summary of the descriptive
statistics is presented in Table 7.7.
Table 7.7 Descriptive statistics of hard disclosure items in category A3 (performance
indicators)
Categories in scoring index Percentage of disclosure*
Mean Median
A3: Economic (ECP_Max) 38.60% 33.33%
A3: Environmental (ENP_Max) 17.56% 10.61%
A3: Social
(TotalSOP_Max)
Labour (LAP_Max) 31.52% 30.56% Percentage of
disclosure in total
social aspect:
Mean=13.6%
Median=10.67%
Human rights (HRP_Max) 5.25% 0.00%
Society (SOP_Max) 8.92% 3.33%
Product Responsibility (PRP_Max) 11.80% 0.00%
Note: *Percentage of disclosures = (Total raw scores of performance indicators / Maximum possible scores) in respective
aspect
A Friedman two way ANOVA test was first applied to three dependent variables that
have been reported to their respective percentage of disclosures: Economic
(ECP_Max), Environmental (ENP_Max) and Social (TotalSOP_Max). The results of
187

the test indicated that rankings of disclosures varied significantly across the three
aspects of sustainability (economic disclosure, environmental disclosure, social
disclosure), Chi-Square = 175.77, df= 2, p < 0.001. Inspection of the median values
showed a decrease in percentage of disclosure from economic (Md = 33.33%) to
social (Md = 10.67%) to environmental (Md = 10.61%). This ranking is, however,
different when the mean rank is reviewed. The arrangement in a descending order is
from economic (mean rank = 2.92) to environmental (mean rank = 1.68) to social
(mean rank = 1.40). Despite the different results, economic disclosure had the highest
188

