1
Chapter 1: Introduction to the Study
Unemployment is a major challenge in developing countries, and efforts to curb
the phenomenon have taken various forms. Officials in many developing countries have
adopted tax incentives to attract foreign investment for employment creation, poverty
alleviation, and economic growth (Li, 2016). Botswana is among the countries whose
officials employ tax incentives to attract investment in the manufacturing, mining, and
financial sectors of the economy. Tax incentives have not been successful in these sectors
owing to various factors such as limited infrastructure development (Moyo, 2016).
However, the labor-intensive nature of the tourism sector has the potential to create jobs
and reduce the 18% unemployment rate in Botswana (Trading Economics, n.d.). The
results of this study may contribute to the reduction of the high unemployment in
Botswana, including youth unemployment, by providing insight on the impact of tax
incentives on job creation.
In 2019, the youth unemployment rate in Botswana was estimated at 37.8%, with
female youth unemployment at 36.4% and male youth unemployment at 39%
(International Labor Organization [ILO], n.d.). Poverty is one of the most pressing social
ills affecting young people in Botswana. The 2015–2016 Botswana Multi Topic
Household Survey estimated the national poverty head count ratio at 16.3%, with large
disparities between rural and urban areas (Statistics Botswana, 2018). Statistics Botswana
(2018) estimated rural poverty at 24.2%, with rural villages at 13.4% and cities and towns
at 9.4%. The Gini coefficient of consumption inequality was estimated at .52 in 2015–
2016, indicating the vast and growing inequality in Botswana. This study suggests

2
solutions to the persistent and endemic poverty and inequality in Botswana through
employment creation, with particular emphasis on youth.
In this chapter, I provided a background of the study, defined the problem of the
research, and explained the purpose of the study. Further, I stated the research questions
(RQs) and hypotheses, provided a synopsis of the theoretical framework, and discussed
the nature of the study. The chapter also includes some important definitions that were
used in the study and concluded with a discussion of the assumptions, scope and
delimitations, limitations, and theoretical and social significance of the study.
Background
The use of tax incentives by developing countries across the world to attract FDI
with the intention of creating employment is prominent. For example, government
officials in South Africa introduced a pay-as-you-earn tax reduction for the first 24
months of employment for companies that hired people between the ages of 18 and 29
years from January 2014 to February 2019 (KPMG, 2019). According to KPMG (2019),
in the case of Rwanda, the government offers a preferential corporate income tax rate of
0% for large-scale international investors with their headquarters or regional office in
Rwanda that provide Rwandans with jobs and training. Serbia also extends a 10-year tax
holiday to large-scale companies that provide at least 100 jobs and retain the employees
for the duration of the tax holiday period (PwC, n.d.). Tax incentives are preferential tax
treatments offered by governments to investors to promote a set objective for economic
development (United Nations, 2018). Tax incentives include measures such as tax
holidays and tax exemptions, used by governments to lure investors to identified sectors

3
within their economies. United Nations (2018) stated that tax holidays can be an
exemption from profit or other tax for a specified period of time or a tax rate reduction. In
some instances, tax holidays are a combination of both forms. Some studies have found
evidence that tax incentives are effective in attracting FDI only to the extent that they are
well coordinated. For instance, in their study of the relationship between FDI inflows and
tax incentives in Nigeria, Ndubuisi et al. (2018) concluded that the proper coordination of
tax incentives was necessary for attracting FDI inflows into the relevant sectors. Lodhi
(2017), in his study of the use of tax incentives in Pakistan, also concluded that the
transparent application of tax incentives was more efficient for attracting FDI and
achieving economic development. Conversely, Li (2016) found supporting empirical
evidence suggesting that tax incentives are potentially harmful for the mobilization of
resources by governments.
The economy of Botswana is highly reliant on the mineral sector, specifically on
diamond production. Diamond mining has been the most dominant sector in terms of
exports, revenue source, and gross domestic product (GDP) share in Botswana, with
diamonds accounting for 90.6% and 88.2% of total goods exports in 2019 and 2020,
respectively (Statistics Botswana, 2021). Preliminary figures from the International
Monetary Fund (IMF, 2020a) indicated that the share of diamond exports as a percentage
of GDP in Botswana would amount to 23% and 28.7% in 2019 and 2020, respectively.
Mineral revenues, composed mainly of diamonds, are expected to contribute
approximately 36% to total government revenues in the 2021–2022 financial year
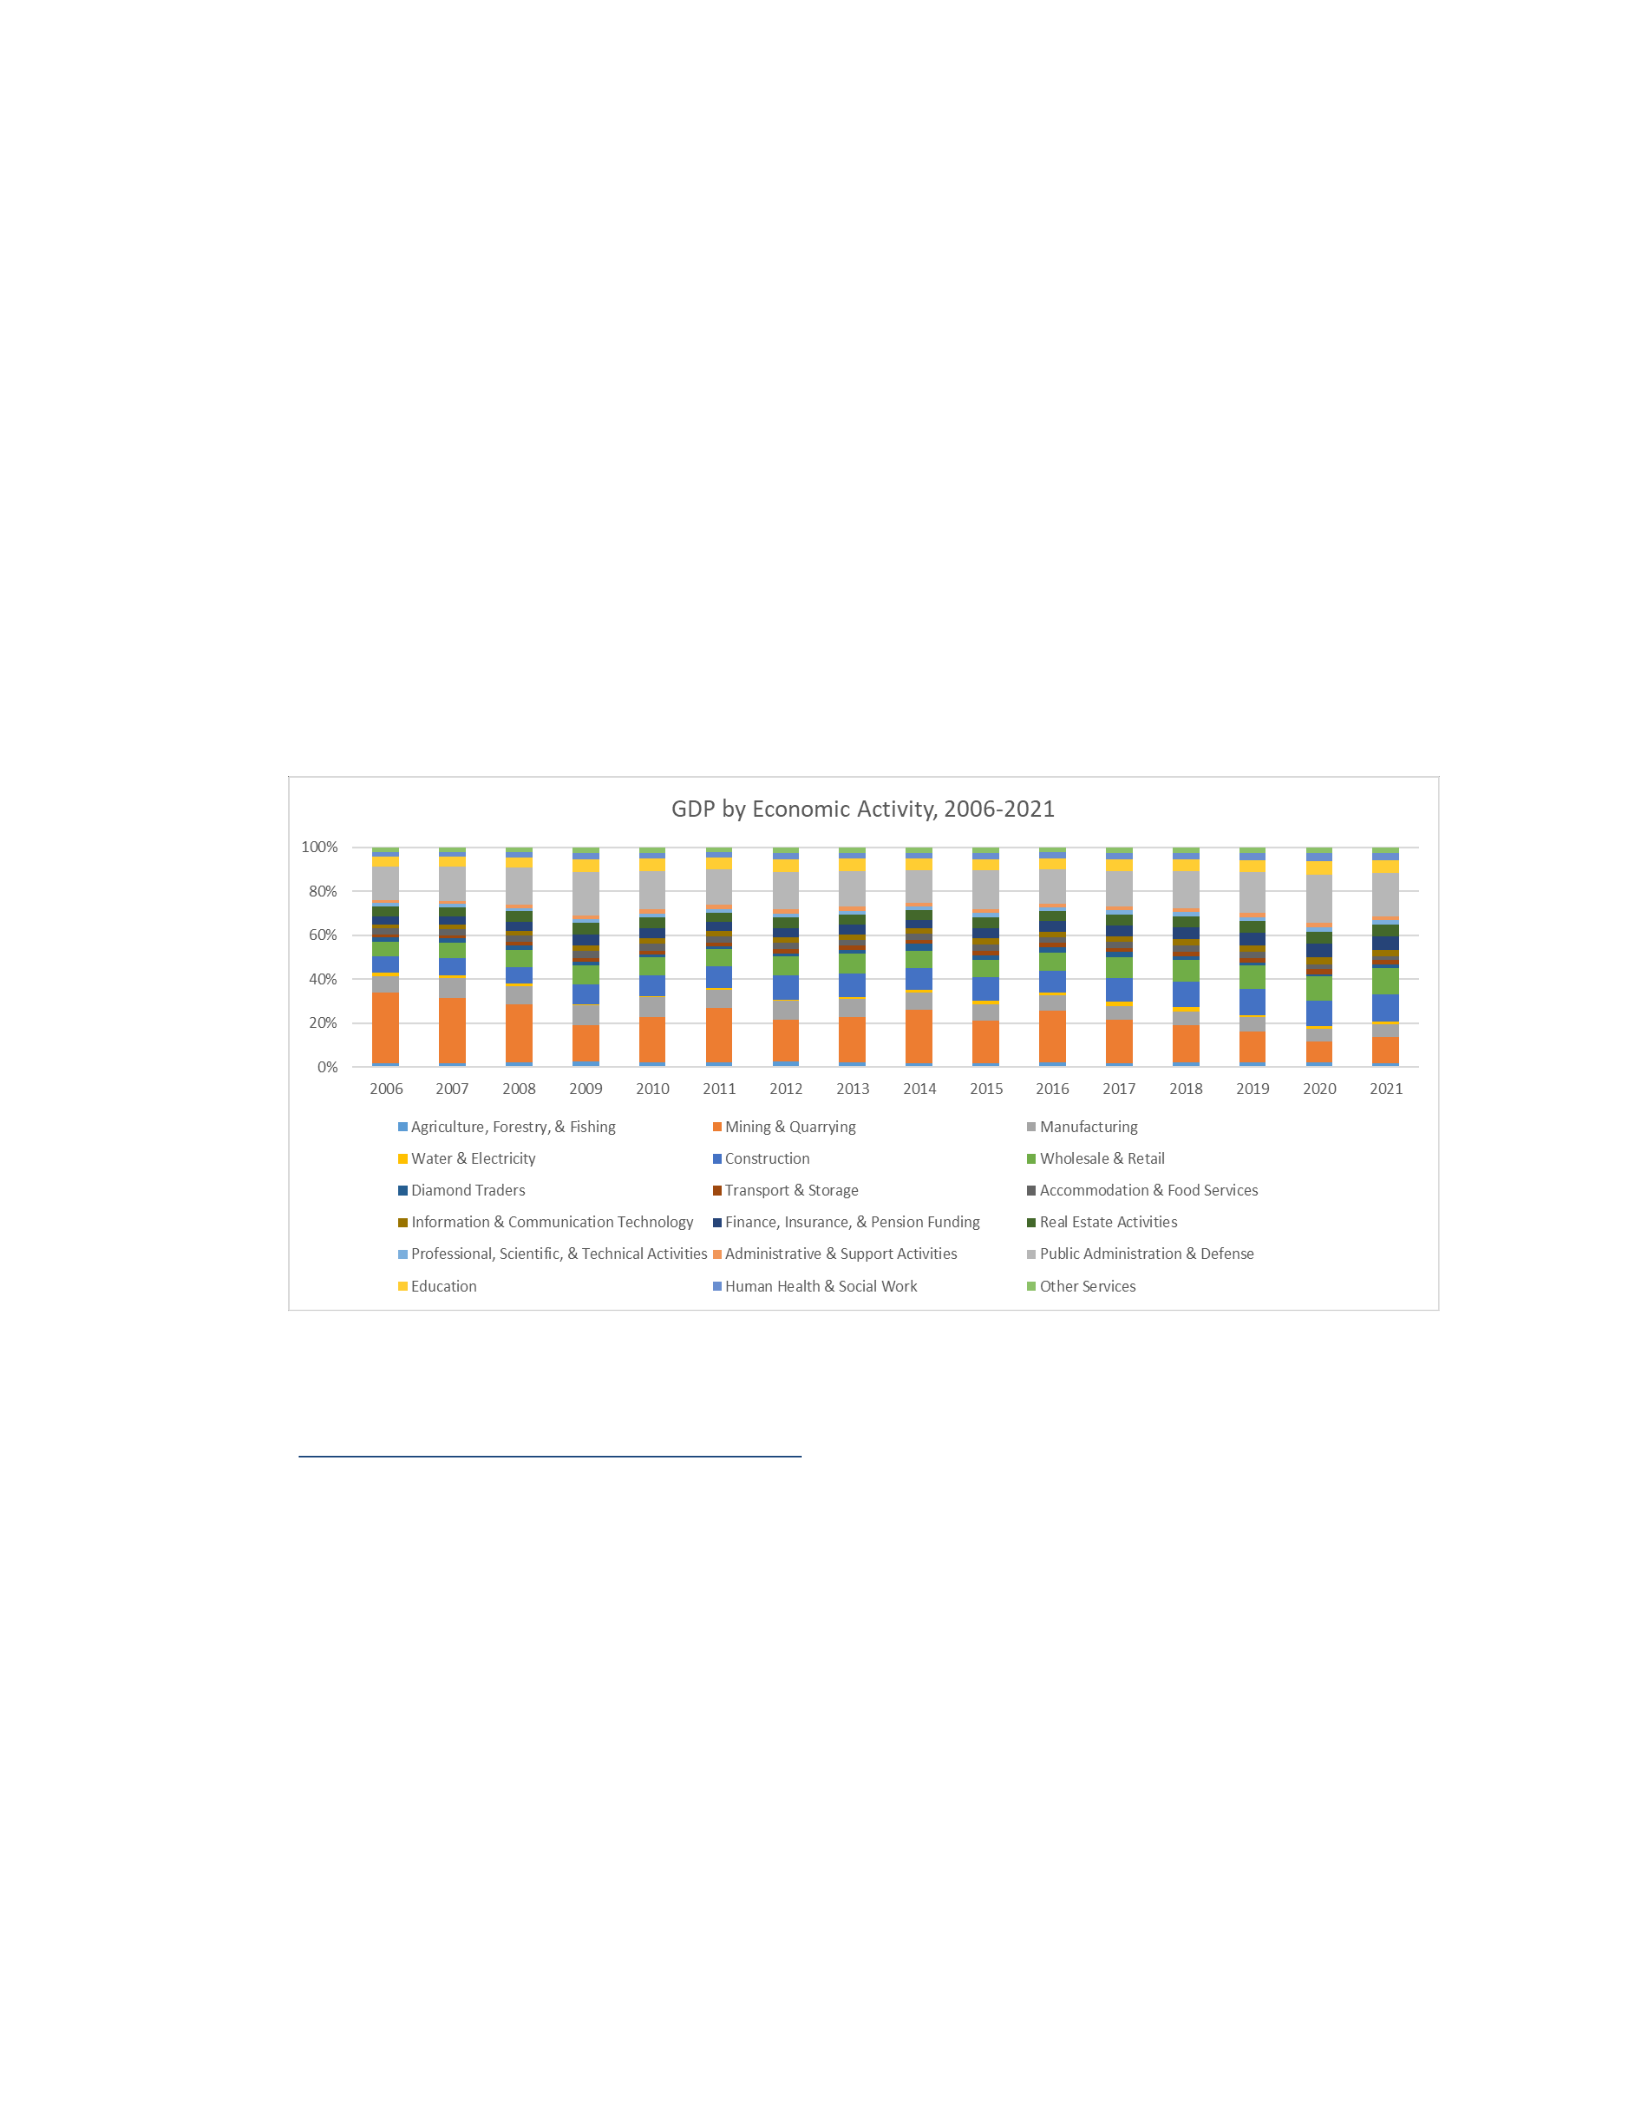
(Botlhale, 2021). Figure 1 shows GDP contribution by economic activity in Botswana for
4
the period 2006 to 2021. The contribution of mining to GDP began declining only in
2017, giving way to public administration and defense as the most dominant sector.
According to IMF (2020a), the declining trend in mining receipts was exacerbated by the
competition resulting from the increasing consumer demand for synthetic diamonds and
higher production costs associated with deep mining.
Figure 1
Gross Domestic Product (GDP) by Economic Activity, 2006–2021
Note. Author’s compilation. Adapted from Statistics Botswana Data Portal, n.d.
(https://botswana.opendataforafrica.org/). In the public domain.
Past efforts aimed at diversifying the Botswana economy have largely been
unsuccessful, resulting in low FDI and high unemployment (Government of Botswana,
2008). Some of the efforts to diversify the economy included the setting up of the
Business and Economic Advisory Council (BEAC) in 2005 and the adoption of the

5
Economic Diversification Drive in 2010 (Besada, 2018). The role of the BEAC was to
identify the challenges of the country in achieving economic diversification; and to
formulate a strategy and action plan; and identify key projects for achieving economic
diversification (Government of Botswana, 2008). BEAC produced an action plan and a
strategy for economic diversification and sustainable growth that cabinet approved in
2006 and 2008, respectively. According to Botlhale (2021), the government
diversification efforts cannot be evaluated for efficiency at this stage due to lack of
results.
Barczikay et al. (2020) suggested that the proximity of Botswana to South Africa
does not bode well for Botswana’s diversification efforts. Two factors are relevant in this
regard. The first is that South Africa has a large and growing manufacturing sector and is
aggressively pursuing its industrialization goals. Second, Botswana belongs to the
Southern African Customs Union (SACU), an arrangement that sees the country reaping
substantial revenues through an agreed revenue sharing formula among the five member
States of the Union, Botswana, Eswatini, Lesotho, Namibia, and South Africa. SACU
revenues contribute a significant share to Botswana’s government revenues and
importing more from the region increases the revenue of the country. As at 2019, the
SACU revenue share in the Botswana budget was 32% in 2017–2018, accounting for
9.8% of GDP (IMF, 2020a). According to Barczikay et al. (2020), this reliance on the
SACU arrangement is unproductive for the diversification efforts of the country.
In addition, the Government of Botswana (2008) suggested that the
ineffectiveness of citizen empowerment policies contributed to the inward-looking

6
mindset of citizens that was not conducive for private sector development and FDI. The
citizen economic empowerment policies of the past did not encourage openness and
competition, but a sense of entitlement to government handouts. In 2008, the Government
of Botswana adopted a strategy for economic diversification and sustainable growth to
reduce dependence on the non-renewable mineral resources and improve private sector
participation in the economy. One of the elements of the strategy was to encourage
banking and financial services (Government of Botswana, 2008). To that end, the
government offered foreign companies that registered with the International Financial
Services Center (IFSC) some tax incentives. Specifically, such companies qualify for a
reduction in the corporate income tax (Magombeyi et al., 2017). Other tax benefits for
IFSC-registered companies include a 200% tax trading rebate, an exemption from value
added tax and tax on capital gains and disposal of shares. According to KPMG (2016),
for a company to qualify for the tax incentive, preapproval that is dependent on job
creation and training of citizens is required. The IFSC was established in 2003 to promote
offshore financial investment. In the case of Botswana, tax incentives have traditionally
been used to attract investment into the mining and manufacturing sectors, and most
recently to the financial sector (Magombeyi et al., 2017). According to Moyo (2016), the
World Bank did not find tax incentives useful for the growth of the manufacturing sector
in Botswana. Moyo attributed the ineffectiveness of tax incentives to other factors like
weak infrastructure. Moussa et al. (2015) applied a quantitative comparison approach to
shed light on the differences in developing and developed countries in the
implementation of tax incentives to promote investment. Their findings suggested that in

7
the case of a resource-rich developing country, targeted tax incentives were more useful
for generating adequate resources from their tax regimes. Applying targeted tax
incentives toward the tourism sector in Botswana might be a relevant strategy to enhance
growth and create jobs in that sector.
Garsous et al. (2017) indicated that the use of fiscal incentives in developing
countries has been successful in attracting local investment and creating jobs in the
tourism sector using a differences-in-differences estimation approach between the
treatment and control groups. In their analysis of the impact of tax incentives on job
creation in Brazil, Garsous et al. found robust evidence that tax incentives were effective
in creating jobs in the Sudene area. Garsous et al. observed that the introduction of a
fiscal incentive in Sudene in 2002 led to a 39% increase in direct jobs in the tourism
sector between 2002 and 2009. Similarly, in their spatial regression discontinuity design
analysis of China’s western regions between 2002 and 2010, Deng et al. (2019) found
evidence that tax reductions were effective in improving the performance of tourism
firms.
Previous researchers have examined the impact of tax incentives on attracting
FDI, creating employment, and enhancing the development of economies. For example,
Thuita (2017), conducting a survey of 72 firms, found that tax holidays were beneficial
for attracting and retaining FDI in Kenya, particularly in the export processing zones that
support the manufacturing sector. In contrast, in their study, Etim et al. (2019) observed
that, overall, there was no significant relationship between tax policy incentives and FDI
in Nigeria using evidence from 1999 to 2017. Hsu et al. (2019) also conducted a study of

8
the relationship between tax incentives and FDI in China using provincial-level panel
data between 1998 and 2008 and found no significant impact.
Several quantitative studies have been done to assess the impact of tax incentives
on the tourism sector in developing countries. Ponjan et al. (2016) applied a computable
general equilibrium (CGE) model to assess the impact of short-term tax cuts on the
performance of the tourism sector in Thailand. Ponjan et al. concluded that tax cuts were
efficient for alleviating temporary challenges in the tourism sector. Deng et al. (2019)
used a regression discontinuity design in the tourism sector in China’s western region,
based on the Western Development Strategy, and found a tax burden reduction to be
among the factors that influenced the flourishing of the sector. No such quantitative study
has been carried out in the case of Botswana. Accordingly, I examined the impact of
targeting tax incentives at the tourism sector in Botswana and the resultant expected FDI
and job creation by applying the multiple linear regression analysis.
Problem Statement
The unemployment rate in Botswana continues to pose a major challenge to
policymakers. According to Trading Economics (n.d.), the unemployment rate averaged
approximately 18.87% between 1991 and 2020. In an effort to create employment, the
government of Botswana has prioritized economic diversification away from raw
diamond extraction and export over the years. This is being done through the use of
strategies for promoting industrialization, including good governance, institutional
development, and industrial policy (Moyo, 2016). In particular, the government
introduced a 15% company tax regime for manufacturing enterprises, which the World

9
Bank did not find impactful on the growth of the manufacturing sector (Moyo, 2016). A
possible explanation for the ineffectiveness of this strategy is that tax incentives are not
accompanied by supporting instruments such as infrastructure development. Ndubuisi et
al. (2018) observed that developing countries have continued to use tax incentives
extensively to attract foreign direct investment (FDI) and generate employment and tax
revenues. However, governments have not identified which sectors benefit the economy
more by receiving tax incentives.
Several studies have been carried out on the impact of tax exemptions on
economic development in developing countries. Sari et al. (2015) noted the effectiveness
and efficiency of tax holidays for attracting FDI to the industrial sector in Indonesia, with
a positive impact on employment creation and economic development. Studies have
found the tourism sector to be more labor-intensive than the manufacturing sector in
some developing countries, suggesting that the tourism sector has the potential to reduce
unemployment in developing countries (Garsous et al., 2017). Globally, travel and
tourism represented 10.3% of the GDP and 10% of direct and indirect jobs in 2019
(World Travel and Tourism Council [WTTC], 2020). In Botswana, the travel and tourism
sector contributed 13.4% and 8.9% to GDP and employment, respectively, in 2018
(WTTC, 2019). By attracting FDI to the tourism sector through targeted tax incentives,
the government of Botswana might reduce the high unemployment rate in the country,
especially the youth unemployment that was estimated at 37.8% in 2019 (ILO, n.d.).

10
Purpose of the Study
The purpose of this quantitative study was to determine the impact of tax
incentives on FDI and employment creation in Botswana, using evidence from the
mining and tourism sectors. Findings from this study may be beneficial for the revision of
public policy, particularly tax policy, which may lead to economic diversification in
Botswana. According to Besada et al. (2018), economic diversification away from heavy
reliance on natural resources in Botswana has mostly been unsuccessful. The lack of
success can largely be attributed to the heavy concentration of investment in the natural
resource sector (Besada et al., 2018; Makoni, 2015). Besada et al. also postulated that the
government diversification policy was incoherent and was, therefore, a deterrent to
attracting FDI in labor and technology intensive sectors. Likewise, Makoni (2015)
suggested an active role for government in supporting policies for other economic
sectors, such as tourism and agriculture, to diversify away from diamond mining.
Therefore, I examined what impact tax incentives have on attracting FDI and creating
employment in the tourism sector. I used one dependent variable; unemployment, and
four independent variables: tax incentives, GDP, human capital, and FDI.
Research Questions and Hypotheses
The RQs and null and alternative hypotheses were as follows:
RQ1: What is the impact of tax incentives on FDI and employment creation in
Botswana?
H01: There is no impact of tax incentives on FDI and/or employment creation in
Botswana.

11
Ha1: There is an impact of tax incentives on FDI and/or employment creation in
Botswana.
RQ2: What is the mediating role of FDI in tax incentives and employment
creation in Botswana?
H02: FDI plays no role mediating role in tax incentives and employment creation
in Botswana.
Ha2: FDI plays a mediating role in tax incentives and employment creation in
Botswana.
Theoretical Foundation for the Study
The theoretical foundation of this study was premised on the Keynesian economic
theory, crafted by John Maynard Keynes in 1936, which states that the government is
responsible for generating full employment and economic growth. According to Garcia
(2020), Keynesian economics asserts that unemployment is an impediment to economic
growth and prosperity. To restore growth and prosperity, the state should boost effective
demand to return to full employment of all potential workers in the economy by
encouraging the investment spending of private firms (Wolff et al., 2012). According to
Wolff et al. (2012), shaping the behavior of investors to boost investment would enhance
production, leading to employment creation and income generation.
Several studies have alluded to the strong positive correlation between investment
spending and job creation. For instance, Habanabakize et al. (2018) found evidence that
aggregate expenditure in general creates jobs in the South African manufacturing sector
and concluded that increasing investment spending would result in sustainable job

12
creation in South Africa. Onodugo et al. (2017) also found that spending and job creation
in Nigeria were positively related in the medium and long run, suggesting that
government should direct policy toward boosting private sector investment. Private sector
investment has the potential to create employment, however, the government should
create a conducive environment for the private sector to thrive.
Private sector involvement in job creation should be based on a coherent public
policy framework, clearly stating the role of government and other market players.
According to Keynesian economic theory, state intervention could correct the effects of
capitalism to yield a better equilibrium with less unemployment and more output (Wolff
et al., 2012). Keynesians blame unemployment on the failure of capitalism, but believe it
is the role of the state to facilitate investment by capitalists (Coddington, 1983). This
study addressed the impact of the government of Botswana’s intervention to target tax
incentives toward the tourism sector on employment and economic diversification.
Specifically, the Keynesian economic theory in this context was used to answer the RQs
regarding how the government of Botswana can influence investment in the tourism
sector using tax incentives to generate employment and income in that sector.
In Chapter 2, I further expounded on the theoretical framework to explain the role
of government in ensuring full employment in the economy. I provided examples from
the literature to illustrate how the various governments have applied the Keynesian
economic theory to generate employment by intervening in the investment decisions of
firms.

13
Nature of the Study
I used the quantitative research method for the study. Quantitative research is
useful for understanding relationships between and/or among variables. According to
Babbie (2014), quantitative researchers use numerical data for analysis. I used numerical
data to test some hypotheses on the impact of tax incentives on FDI and employment
creation in Botswana. All data for this study were publicly available from the
Government of Botswana, Statistics Botswana, Bank of Botswana, and other
international sources, including the World Bank, World Tourism Organization, and
WTTC. I collected secondary data on taxes, FDI, and employment in the mining and
tourism sectors in Botswana for the study. Additional data included GDP, human capital,
and the legislation and regulations on taxes and tax incentives. In addition, I used an
internet search to locate data for the study.
I selected a time series design for the study, which is a quasi-experimental model
that is appropriate for program evaluation or policy impact (O’Sullivan et al., 2017).
Time series provide data on variables periodically over time (Koutsoyiannis, 1977). For
this study, I analyzed secondary data on FDI and the employment rate in the tourism
sector in Botswana, and made a determination about how the data vary over time. I first
plotted the data in graphs to determine the relationship among them. O’Sullivan et al.
(2017) suggested that it was important to visually analyze data to note any points of
divergence and identify patterns. As discussed in O’Sullivan et al., the types of variations
to observe in time-series analysis are long-term, cyclical, seasonal, and irregular
variations. Long-term trends are observed as upward or downward movements in the data

14
over many years. Cyclical variations are recurring changes that are observed within a
long-term trend, with cycles lasting between 1 and 5 years. Seasonal variations are
observed when some phenomena occur seasonally. Irregular variations are changes that
cannot be associated with any trends or variations.
I applied the multiple linear regression analysis to analyze the time series data.
Therefore, in this study, the multiple linear regression method was employed using time
series secondary data on tax rates, FDI, GDP, human capital, and employment in the
mining and tourism sectors. According to Koutsoyiannis (1977), regression analysis
works best with data that are randomly selected from a population. However, time series
data are not randomly selected and economic phenomena are stochastic in nature
(Koutsoyiannis, 1977).
The data range for the study was 1989 to 2021. Time series data for employment
in the tourism sector in Botswana were available from 1995, and 2021 was the most
recent year available for all variables for this study (see Appendix). For 1989 to 1994, I
used proxy data for employment in the tourism sector. This study used one dependent
variable; unemployment, and four independent variables; tax incentives, GDP, human
capital, and FDI. Accordingly, I employed a multiple linear regression analysis to
determine the relationship among these variables. I specified a model based on these
variables, which included a random component termed the random variable, stochastic
term, or error term. The purpose of the error term in a regression is to take into account
the errors in the relationship between the dependent and independent variables
(Koutsoyiannis, 1977). These errors include (a) omission of other variables that may

15
influence the dependent variable from the model (b) unpredictable human patterns of
behavior, (c) imperfect model specification, (d) errors of aggregation, and (e) errors of
measurement (Koutsoyiannis, 1977). Statistical Package for the Social Sciences (SPSS)
software was used to run the regression analysis and compute the relevant statistical tests
for this study.
Definitions
Corporate income tax: A tax that is levied by government on business profits
(Tax Foundation, n.d.).
Foreign direct investment (FDI): “Purchase of a substantial ownership in, or
construction of, a factory/operation in a country by an overseas agent” (Miles et al., 2005,
p. 590).
Gross domestic product (GDP): “The total value of output produced in a country
without any adjustment for the depreciation of capital. GDP also equals the sum of
income earned domestically by both nationals and foreign citizens working in the
country” (Miles et al., 2005, p. 591).
Tax incentives: Tax concessions that are offered to a selection of taxpayers with
the objective of attracting investments for the benefit of the economy. Tax incentives can
be in the form of tax exemptions for certain economic sectors, tax holidays for a specified
time duration, credits and investment allowances for selected projects, preferential tax
rates and import tariffs for some goods, and deferral of tax liability in an economic crisis
(United Nations, 2018).

16
Unemployment rate: The proportion of the labor force that is actively seeking
work and remains out of work (Miles et al., 2005).
Youth unemployment rate: The proportion of young people aged between 15 and
35 years who are unemployed (Statistics Botswana, 2020).
Assumptions
To adequately analyze time series data using multiple linear regression, there are
some assumptions that should be satisfied, based on the ordinary least squares (OLS)
method. The underlying assumption in an OLS model is of independence (Pickett et al.,
2005). Several assumptions fall under the assumption of independence and largely
address the residuals of the model. According to O’Sullivan et al. (2017), testing for
autocorrelation in the residual term is an important step before analyzing time series data.
O’Sullivan defined autocorrelation as the nonrandom relationship observed in a variable
over time. Autocorrelation presents biases in statistical significance tests, leading to
inaccurate results (O’Sullivan et al., 2017). The residuals in the proposed model for the
study should, therefore, be free from autocorrelation. Pickett et al. (2005) highlighted
additional assumptions regarding the residuals, including that i) the residuals have a
constant variance with the mean of residuals as close to 0 as possible. and ii) the residuals
are normally and independently distributed. Also, Pickett et al. noted that it was
important to ensure that all variables contained in the model are statistically significant,
with no essential variables omitted. In this study, the assumption was that all the
necessary variables are included in the model. I further assumed that the residuals in the
model were normally and independently distributed, with constant variance and a mean

17
that is not significantly different from 0. Finally, I worked on the assumption that the
secondary data used for the research were accurate and reliable.
Scope and Delimitations
The scope of the study was limited to the tourism sector in Botswana due to its
potential for growth and its labor-intensive nature. In addition, tax incentives have
previously not been applied to the sector despite its employment creation potential. Tax
incentives have been used in the manufacturing and mining sectors in the past and they
have not yielded the expected results. I also ran regressions using data from the mining
sector for purposes of comparison. The specific delimitations of this study included the
country, Botswana, and the sectors, mining and tourism. I also specifically targeted FDI
and not domestic investment due to the importance of FDI in the economic growth and
development of the recipient country. Chiwira et al. (2016) alluded to the value addition
aspects of FDI to the economic policies of developing countries, including technology
and skills transfer.
I applied the Keynesian theory on unemployment because it advocates for
government intervention. Another theory that could be applied is the new classical
theory; however, the proponents of this particular theory support free markets (Ogujiuba,
2020). According to the new classical theory, when firms take the decision to increase
investment, the resultant productivity increases will lead to increased employment
(Ogujiuba, 2020). Therefore, the new classical theory was not applicable for this study
because it does not refer to government intervention but to firms’ decision to invest.

18
Limitations
Using different sources of data resulted in a mismatch in the timing of the data.
Data for this study were sourced from the Government of Botswana, Statistics Botswana,
Bank of Botswana, World Bank, World Tourism Organization, and WTTC. Also,
economic variables tend to exhibit the same movement patterns over time and that
resulted in slight multicollinearity in the study model. According to Koutsoyiannis
(1977), multicollinearity can lead to an inaccurate and unstable model. Another factor
that could affect the stability of a model is the number of cases in the study. O’Sullivan et
al. (2017) suggested a minimum of 30 cases for stability in the model. While the study
had 32 cases, it is considered a bit low, potentially leading to an unstable regression
model. However, Laher (2016) suggested using the effect size and confidence interval as
measures to determine the significance of the study results as opposed to simply relying
on a large sample size. Therefore, I used the effect size and confidence interval to
determine the significance of the study results.
I limited the study to the use of FDI to create employment, however, there are
other public policies that could be adopted and implemented to reduce unemployment.
For example, governments may adopt labor market policies that are geared toward
employment creation in the economy. Caponi (2017) provided evidence that the
government wage setting policy positively impacts employment in the private sector and
creates regional balance in unemployment reduction in Italy.

19
As a result of the focus on two sectors, generalizability to other sectors of the
economy is limited. The results are also not generalizable to other countries because of
the focus on Botswana.
I used employment in the accommodation and food sector as a proxy for
employment in the tourism sector. Therefore, employment figures in the tourism sector
other than accommodation and food were excluded. Employment figures in the informal
sector were also excluded due to the difficulty in obtaining data in that sector.
Significance
There has been limited research on the impact of the application of tax incentives
on other sectors of the economy of Botswana. Studies carried out in other parts of the
world provided insights into the use of tax incentives for investment and economic
growth and development. For instance, the government of Canada has applied robust tax
policies to attract FDI and encourage economic growth and development (Adebayo,
2018). Adebayo noted that the government of Canada applies one of the lowest corporate
taxes in the G7 to attract business investment. Additionally, Canada applies the principles
of right of establishment and full national treatment for foreign companies. The lessons
from Canada may be applied to the case of Botswana to guide the appropriate
implementation of tax incentives.
Significance to Practice and/or Policy
The results of this study provided policymakers in Botswana with insights into
sectors that should be targeted for tax incentives. Decisions about targeting the right
sectors will lead to the economic diversification that the country needs to create

20
employment and reduce poverty. The poverty rate in Botswana is defined as the
percentage of the population that lives below the poverty datum line (PDL). The PDL is
computed by assessing the cost of a basic basket of goods and services necessary to
sustain a household (Statistics Botswana, 2018). According to Statistics Botswana, the
poverty rate in Botswana is 16.3% nationally, with 24.2% of the rural population living
below the PDL.
Significance to Social Change
By specifically observing the trends in tax incentives and their impact on
employment creation in Botswana, this study provided solutions to the diversification of
the economy of Botswana to create jobs and reduce poverty. Diversifying the economy of
Botswana will result in positive social change through reducing the number of
unemployed youth and collecting more taxes for better provision of public services.
Reducing unemployment results in social cohesion by reducing crime and building
productive communities. Khambule et al. (2017) recommended private sector-led job
creation as a measure to provide a safety net for people with a view to enhancing social
cohesion in South Africa. The current research will benefit the government of Botswana
and other stakeholders interested in creating employment and contribute to the literature
on public policy to aid our understanding of which sectors of the economy can lead to job
creation and an expansion of the tax base.
Summary
Efforts to address the rampant unemployment in Botswana, including economic
diversification and citizen economic empowerment, have yielded insignificant results.

21
The government has previously used tax incentives to attract FDI into certain sectors of
the economy such as mining and finance, aimed at creating jobs for the economy.
However, the government has not employed the same tax incentives into other labor-
intensive sectors of the economy such as tourism. I investigated the impact of tax
incentives on attracting FDI and creating employment in the tourism sector in Botswana
through comparison with the mining sector.
In Chapter 1, I provided the background to the study, defined the problem and
purpose of the study, and presented the RQs addressed in the study. I also summarized
the nature of the study, provided definitions, assumptions, scope and delimitations, and
limitations of the study. I also outlined the overview of the theoretical framework
underlying the study, which were expounded on in Chapter 2.
In addition to expanding on the theoretical framework in Chapter 2, I delved into
an in-depth review of the literature surrounding tax incentives and FDI and how they are
used for economic development and employment creation in developed and developing
countries. In Chapter 2, I also explored how previous authors on the same subject have
utilized the various models and theories into their research and used their results to guide
the study. I also provided an overview of Botswana’s tax policy and the tourism policy in
Botswana and neighboring countries.
22
Chapter 2: Literature Review
Introduction
Unemployment in Botswana is a continuous problem for policymakers with the
rate steadily increasing over the years. According to Trading Economics (n.d.), the
unemployment rate in Botswana in the early 1990s was below 14%, gradually increasing
to over 20% by the middle of the decade before declining sharply to about 16% at the
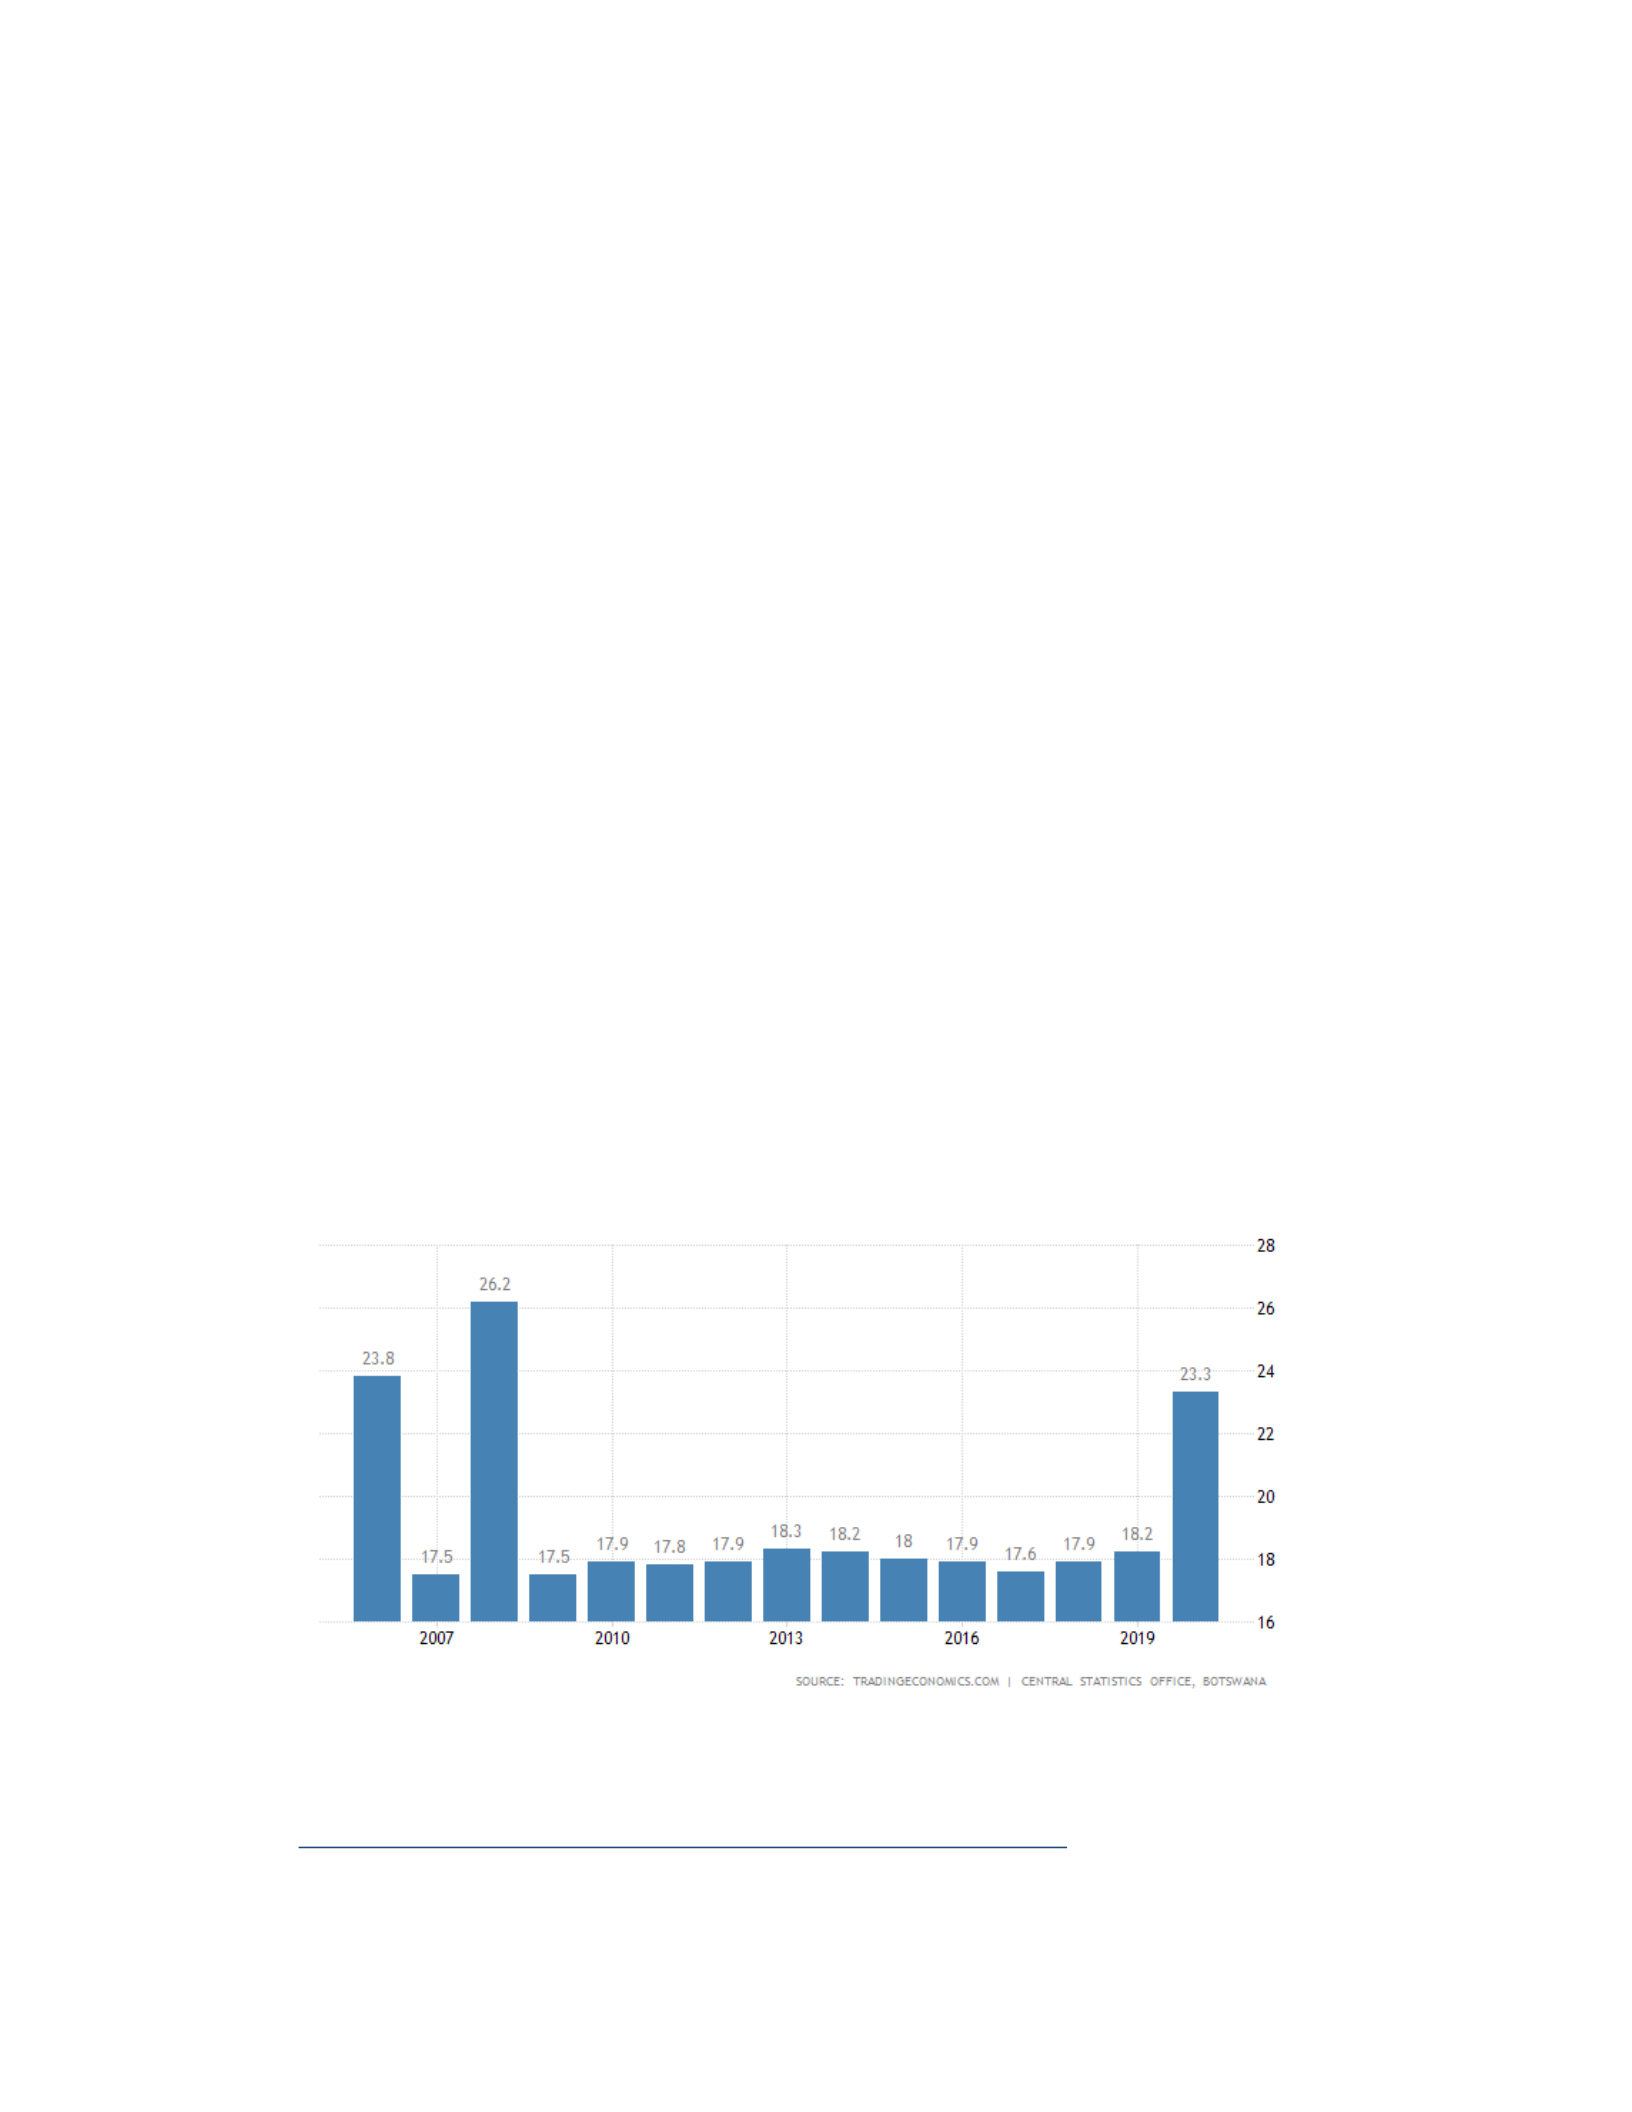
turn of the century. The unemployment rate increased again and peaked at 26% in 2008
before declining to 17.5% in 2009 and it held steady between 17.9% and 18.3% from
2010 to 2019 (Trading Economics, n.d.). However, the unemployment rate spiked from
18.2% in 2019 to 23.3% in 2020 (Trading Economics, n.d.). Figure 2 presents the
unemployment rate for Botswana from 2006 to 2020.
Figure 2
Unemployment Rate for Botswana, 2006–2020
Note. Adapted from Trading Economics, n.d.,
(https://tradingeconomics.com/botswana/unemployment-rate). In the public domain.

23
Presenting the budget speech to Parliament, the Minister of Finance and
Economic Development attributed the rise in unemployment in 2020 to measures taken to
combat the COVID-19 pandemic that affected the entire world, including lockdowns and
border closures (Government of Botswana, 2021a). The government continues to find
strategies to deal with the endemic unemployment rate, which is disproportionately
affecting the youth. The youth unemployment rate in Botswana in 2020 was estimated at
approximately 38% (ILO, n.d.). One of the strategies is the development of a National
Employment Policy, which includes a strategic focus on strengthening the capability of
the private sector to create employment (Government of Botswana, 2021b).
Previous attempts to create employment included the diversification of the
economy away from mining, especially raw diamond exports. The then President Festus
Mogae, established a Business and Economic Advisory Council in 2005 and tasked it
with defining a strategy and action plan to address constraints to Botswana’s
diversification efforts (Government of Botswana, 2008). One of the tasks of the BEAC
was to ensure a suitable environment for FDI. The government of Botswana recognizes
well-structured FDI as an enabler of economic growth and diversification. The strategy
for economic diversification, which was adopted by cabinet in 2008, highlighted a
competitive tax structure and incentive scheme as a tactic to attract investment
(Government of Botswana, 2008). The government sought to review the tax system to
simplify it and improve tax administration for attracting both foreign and domestic
investment in technology and value-adding service sectors. An incentive scheme with
low regulations and relaxed tax rules specifically for free zones was planned for

24
attracting FDI. Additionally, the approach emphasized added advantages for companies
that create new employment and improve staff technical skills. Diversifying the economy
by targeting tax incentives toward the tourism sector, which is labor-intensive, might help
reduce the unemployment rate in Botswana. Garsous et al. (2017) found evidence that the
tourism sector is more labor-intensive than the manufacturing sector in some developing
countries. Accordingly, the government of Botswana would benefit more by directing tax
incentives at the tourism sector rather than the current dispensation of targeting the
manufacturing sector. In fact, evidence suggests that the 15% company tax regime for the
manufacturing sector was not effective in growing the sector (Moyo, 2016).
The purpose of this quantitative study was to, therefore, examine the impact of tax
incentives on attracting FDI and creating employment in the tourism sector in Botswana.
The findings of the study may guide tax policy revision, particularly with the aim of
aiding government’s diversification efforts. I used multiple linear regression analysis to
examine the relationship between tax incentives and FDI and employment in the mining
and tourism sectors in Botswana.
In this chapter, I presented the literature search strategy used for the study, the
theoretical foundation of the study, and the literature review on the main concepts used in
the study. In addition, I presented the literature review specifically related to the variables
under study in Botswana.
Literature Search Strategy
I consulted the Walden library extensively for the literature search. I also
employed Google Scholar and Google to guide and supplement the literature search. In

25
the Walden library, I accessed articles through the School of Public Policy and
Administration’s link. The link had direct access to several databases such as Thoreau,
Business Source Complete, and ProQuest. For Google Scholar and Google, I sourced
some of the articles directly but accessed others through the Walden library. For the
literature on the theoretical foundation and the multiple linear regression analysis method,
I used an internet search and textbooks. I accessed resources from the Government of
Botswana, including the National Development Plan (NDP) and Budget Speech, through
an internet search. The international sources that I consulted include the World Bank and
IMF databases, the WTTC, and the World Tourism Organization.
The search focused mainly on the literature between the period 2015 and 2021
and was limited to peer-reviewed work using filters on both Google Scholar and Walden
University library. For seminal literature, particularly on theoretical work and methods, I
consulted books and articles from as far back as 1977. For government and international
sources, there was no time limit.
The key words guiding the literature review were tax incentives, targeted tax
incentives, tax holidays, tax exemptions, corporate tax rate, employment, unemployment,
youth unemployment, FDI, tourism sector, developing countries, Africa, and Botswana. I
also performed searches for the Keynesian theory of employment and the Keynesian
general theory. Further, I searched the literature using a combination of key words to
narrow down the search. Such combinations included tax incentives and tourism, tax
incentives and employment creation, tax incentives and FDI, tax incentives and tourism,
corporate tax rate and FDI in Botswana.

26
Theoretical Foundation for the Study
In analyzing the theoretical foundation of this study, it was important to
understand the various types of unemployment that exist. Hardwick et al. (1994)
discussed three main causes of unemployment, being, i) natural unemployment – with
four types – search unemployment, structural unemployment, seasonal unemployment,
and residual unemployment, ii) excessive real wage unemployment, and iii) demand-
deficient unemployment. According to Hardwick et al., natural unemployment is the
number of unemployed people during a long-run equilibrium in the labor market.
Excessive real wage unemployment results from real wages that are higher than the
market rate. Demand-deficient unemployment refers to unemployment caused by low
demand for labor as a result of the low demand for goods and services. In this study, I
placed emphasis on demand-deficient unemployment, also known as Keynesian
unemployment.
The main theory that I applied in this study was, therefore, the Keynesian
economic theory of employment. Crafted by John Maynard Keynes in 1936, the
Keynesian theory of employment apportioned the responsibility of generating full
employment and economic growth to the government. The Keynesian theory stated that
the level of income and resultant employment in the economy was determined by
aggregate demand, with firms cutting back on production and employment where there is
inefficient production of goods (Hardwick et al., 1994). Aggregate demand is the
combined demand of goods and services by consumers, firms, government, and
foreigners and is presented as:

27
AD = C + I + G + X – M
where:
AD = aggregate demand
C = household consumption of goods and services
I = firms’ demand for investment goods
G = government consumption of goods and services
X = exports
M = imports
The Keynesian theory further stated that solving unemployment, which is caused
by inefficient markets, required boosting aggregate demand through state intervention
(Wolff et al., 2012). Three ways in which government can intervene to raise effective
demand include raising government expenditure, cutting taxes, or lowering interest rates
(Miles et al., 2005).
The most important underlying assumption of the Keynesian theory is that wages
and prices are fixed. According to Hardwick et al. (1994), this assumption means that in
the short-run, firms will adjust the quantity they produce in response to changes in
demand, leading to the economy operating at less than full employment. The Keynesian
theory postulates that a fall in investment spending by private businesses is the reason for
an economy operating at less than full employment (Wolff et al., 2012). According to
Wolff et al., the Keynesian theory further postulates that markets cannot adequately
increase the aggregate demand in the economy to increase the levels of employment. In
this instance, the invisible hand would guide the economy back to full employment by

28
cutting taxes to stimulate private investment (Wolff et al., 2012). The cut in taxes would
be the government intervention necessary to reduce unemployment.
Using the four components of aggregate demand: government consumption,
household consumption, total net exports, and total investment, Habanabakize et al.
(2018) sought out to investigate the effect of the Keynesian theory of employment in the
manufacturing sector in South Africa. The authors found a positive long-run relationship
between aggregate expenditure and employment creation in the manufacturing sector in
South Africa. Habanabakize et al. concluded that while investment spending contributed
less than other components, increasing it would be beneficial for sustainable job creation
in South Africa.
RQ1 was, What is the impact of tax incentives on FDI and employment creation
in Botswana? The RQ built upon the Keynesian theory of employment by testing how the
government intervention of offering tax incentives to foreign investors in the tourism
sector can affect the level of FDI and, therefore, employment in the sector.
Literature Review Related to Key Variables and/or Concepts
In this section, I reviewed the main literature related to the key variables of the
study. Specifically, I reviewed the economic policy concepts of economic diversification,
tax policy and tax incentives, employment, with particular emphasis on youth
unemployment and employment creation strategies, and FDI as it relates to economic
growth and employment creation. I further described the concepts of interest as they
relate to Botswana, including the evolution of tax policy and tax incentives, FDI, the

29
tourism sector, unemployment trends, and the economic diversification drive in
Botswana.
Economic Diversification
Economic diversification is usually pursued by governments in their efforts to
facilitate economic growth and employment creation. United Nations (2017) indicated
that the lack of economic diversification was the major impediment for commodity-
dependent countries to reach their goals of structural transformation for sustainable and
inclusive development. Mono-cultural economies like Nigeria, which is highly dependent
on oil exports, have adopted economic diversification policies to create jobs. Oil and gas
exports contribute 85% to total revenue in Nigeria (Olamide et al., 2019). According to
Olamide et al., the government of Nigeria developed and adopted a Strategy for
Economic Diversification and National Development in 2008 to help diversify the
economy through various institutional and structural measures. Also, the government of
Nigeria engaged in protectionist measures such as restriction of agricultural and industrial
goods imports with limited success in diversification and labor productivity (IMF, 2021).
Lashitew et al. (2020) also stated that economic diversification away from the
extractive sector was important for employment creation, particularly in the
manufacturing and services sectors. For example, a rapid expansion of the services and
industrial sectors in Laos fueled by foreign and public investment resulted in a 20%
increase in employment between 2003 and 2013 (Lashitew et al., 2020). In the case of
Oman, the government adopted a diversification strategy, “Tanfeedh” to create

30
employment through private sector development in the logistics, manufacturing, and
tourism sectors (Lashitew et al., 2020).
Some governments opt to use tax policy to facilitate their economic
diversification plans. KPMG (2018) found that many African countries offered tax
incentives to attract FDI into their manufacturing, agricultural, and industrial sectors,
with others like Kenya and Cameroon offering incentives in the financial services sector.
Specifically, more countries aimed to diversify their economies from the extractives
sector by introducing new and amended incentives to attract investment into
manufacturing and services industries.
Tax Policy and Tax Incentives
Tax policy plays a crucial role in the decision of a government to offer tax
incentives for reaching a set economic development policy target. Garsous et al. (2017)
used the example of the Sudene area in Brazil to demonstrate the effectiveness of targeted
tax incentives in creating employment in the tourism sector. The results of the study by
Garsous et al. were indicative of the positive implications of the proper use of fiscal
policy to drive the economic objective of employment creation. Similarly, Calgano et al.
(2018) found compelling evidence in their study on the use of targeted economic
incentives that states are more likely to use incentives to influence economic goals such
as reducing unemployment and budget deficits. Awunyo-Vitor et al. (2018) also found
evidence that targeting incentives to the agricultural sector resulted in the improved
performance of the economy of Ghana, with evident overall economic growth. Fiscal

31
policy can be beneficial for developing countries only to the extent that it is properly
applied.
Despite evidence that tax incentives are useful for influencing development in
developing countries, some researchers have disclaimed the usefulness of tax incentives
for economic targets. For instance, Li (2016) argued that tax incentives were potentially
harmful for resource mobilization efforts of developing countries. Li further found
evidence of the ineffectiveness of tax incentives for attracting FDI, arguing instead for
strong fiscal discipline as a strategy for attracting foreign investment. This argument was
consistent with the findings by Munongo et al. (2017) who concluded that stable
macroeconomic conditions and other important nontax factors were more suitable for
attracting FDI to developing countries. Hsu et al. (2019) also concluded, in their GMM
study on the impact of tax incentives on FDI for the period 1998 to 2008, that tax
incentives were not a sufficient policy for attracting FDI. Hsu et al. (2019) carried out the
study following the decision of the government of China to terminate tax incentives in
2008. The authors found that, rather, market size and geographic location were major
determinants of FDI, indicating that the decision of the government to stop extending tax
incentives was appropriate. Although tax incentives may be important for economic
development, a holistic tax policy that is consistent with other economic policies might
be more relevant in attracting FDI and influencing development outcomes in developing
countries.
Redonda et al. (2019) also emphasized the improvement in the design of tax
incentives within the Group of 20 (G20) for efficiency in their use by companies and

32
benefits by governments. The authors noted that often, tax incentives were designed to
excessively benefit businesses at massive fiscal losses to governments. Siyanbola et al.
(2017) highlighted the importance of monitoring and tracking of the administration of tax
incentives against the expected economic goals as a means to measure the efficiency of
the incentives. The economic targets that tax incentives aim to improve include economic
growth, poverty reduction, and employment creation.
Employment
Youth Unemployment
Youth unemployment is a major challenge of modern times. Omeje et al. (2020)
contended that the various social ills facing the youth in Nigeria were directly as a result
of the high rates of youth unemployment. Also directly affected by the high youth
unemployment rates are the rate of economic growth and diversification. In a study on
public employment policies in Italy, Caponi (2017) noted that the youth unemployment
rate was four times higher than the general unemployment, a trend also observed in much
of Europe. In the case of Oman, youth unemployment was estimated at 50% (Lashitew et
al. 2020). Khambule et al. (2017) also noted that the youth unemployment rate in South
Africa was over 50%. In East Africa, 60% of the unemployed population are the youth
(Alfonsi et al., 2020).
The COVID-19 pandemic that affected the entire world, leading to
unprecedented measures to contain the spread of the virus, including lockdowns and
various containment measures, resulted in increases in youth unemployment rates.
According to ILO (2021), youth employment fell by 8.7% in at the height of the

33
pandemic in 2020, compared to 3.7% for the adult population, disproportionately
affecting young women.
The high youth unemployment rates across the world often result in high poverty
and inequality levels and other social ills. WTTC (2019) stated that high unemployment
rates had a direct impact on societal outcomes, directly contributing to poverty,
inequality, and societal exclusion. As such, it is imperative that governments propose
lasting employment creation strategies to address the social ills resulting from high
unemployment.
Employment Creation Strategies
Governments are responsible for setting economic policies that guide
employment creation in both the public and private sectors. Caponi (2017) used the case
of Italy to demonstrate how the wage setting policy of government influenced private
sector employment. In a two region two sector model, Caponi found that homogenous
wage setting resulted in long-run reduction in unemployment across the regions in Italy.
Tsaurai (2018) used pooled OLS and fixed effects for their study on the impact of FDI on
employment creation in Brazil, Russia, India, China, and South Africa (BRICS countries)
and found that policies that enhanced financial development, economic growth, and
human capital development were more effective in triggering the employment creation
benefits of FDI in those countries.
Some governments have supported microcredit schemes as a strategy for creating
employment. Tria et al. (2022) undertook a systematic review of the literature from 1998
to 2021 involving microcredit and employment creation. The authors concluded that

34
microcredit was important for generating employment both in the formal and informal
sectors. Other countries have adopted or strengthened their active labor market policies to
reduce unemployment risks. ILO (2022) outlined several such policies by both developed
and developing countries aimed at increasing the employability of the unemployed. In the
United Kingdom, the Kickstart and Restart programs, aimed at supporting employers
who create new jobs and getting the unemployed into work (ILO, 2022). In India, the
government supports unemployed rural populations through a rural employment scheme.
In the wake of the COVID-19 pandemic and the resultant response required for
the economic recovery, governments across the world have employed fiscal and
monetary policies and direct support to sectors that were negatively impacted by the
pandemic. The most popular response by many governments was to implement fiscal
stimulus packages, with developing countries rolling out in excess of 15% of their GDP
and developing countries only less than 3% (IMF, 2020b). The IMF indicated that
investment was deemed to be crucial in creating jobs in a crisis, with larger short and
medium-to-long term fiscal multipliers than public consumptions, taxes, or direct
transfers. Therefore, facilitating both public and FDI should be a priority for governments
aiming to fast-track economic growth and employment creation.
Foreign Direct Investment
Foreign Direct Investment and Economic Growth
FDI has been proven to positively impact economic growth in many developing
countries. Chiwira et al. (2016) observed a long-term significant relationship between
FDI and economic growth in Botswana. Lawal (2018) also observed a strong positive

35
relationship between FDI and GDP in Nigeria, driven by changes in GDP. Gupta et al.
(2016) also examined the link between FDI and economic growth in BRICS countries
and confirmed that a long-run causal relationship from GDP to FDI existed in Brazil,
India, and China. Awunyo-Vitor et al. (2018) found a positive relationship between FDI
in the agricultural sector and economic growth in Ghana, suggesting that government
policies and incentives should be directed at attracting FDI.
In contrast, Awolusi et al. (2017) found a negligible impact of FDI on economic
growth in some selected African countries. However, Awolusi et al. noted that fiscal
incentives played a crucial role in attracting FDI to strengthen economic growth and
create employment. Additionally, Gupta et al. found no evidence of a short- or long-run
relationship between FDI and economic growth, but rather identified several factors that
negatively impact the relationship in Russia and South Africa, including lack of
infrastructure and structural weaknesses. In the case of Macedonia, low production costs
and subsidies for training and construction of manufacturing plants were instrumental in
attracting FDI (Miftari, 2016). It is important for developing countries to create a
conducive environment for FDI to positively contribute to economic growth.
Although many developing countries are able to attract FDI into their economies,
not many are able to effectively channel it to improve their productive capacity. For
instance, Hlavacek et al. (2019) cited the case of the Czech Republic where research and
development did not effectively contribute to economic growth. However, in the same
study, the authors observed an overall positive influence of FDI and government
investment incentives on the economic development of many regions in the Czech

36
Republic. Research in some selected developing European Union countries showed that
countries that had a developed institutional framework were better able to attract FDI
(Buterin et al., 2018). Buterin et al. concluded that countries with a good institutional
framework attracted foreign investors, resulting in improved economic growth. The key
to effectively using FDI to improve economic growth and development lies in the ability
of countries to provide a conducive environment for investment to thrive.
Foreign Direct Investment and Employment Creation
FDI inflows are important for creating employment opportunities in developed
and developing countries. In their study of FDI and employment in Japan, Kodama et al.
(2018) pointed to increased female labor participation in foreign firms owing from a
corporate culture that is gender inclusive. In the case of developing countries, FDI that
creates employment is critical given the state of unemployment in that category of
countries. In Nigeria, where the unemployment challenge is persistent, Osabohien et al.
(2020) observed a significant positive long-run relationship between FDI and
employment. Using the Johansen co-integration model and the fully modified ordinary
least squares, Osabohien et al. found that a unit increase in FDI led to a .97 increase in
employment. The evidence that FDI promotes job creation in developing countries was
also supported by Karimov et al. (2020) in their analysis of the impact of FDI in Turkey,
which indicated a significant relationship between FDI and reduction of unemployment
leading to overall economic stability. In Poland, income and property tax exemptions
contributed to the amount of FDI inflows into the special economic zones in the country,
with a positive net effect on job creation (Slusarczyk, 2018).

37
Although FDI flows are increasing, developing countries have to be cautious
about the quality of jobs that are created in their economies as a result of the FDI. Basu et
al. (2017) found that although FDI significantly contributed to job creation in the services
sector in India, the quality of jobs was poor, with a disproportionate contribution to gross
value added. Basu et al. recommended that the government of India should reform the
labor laws to attract more FDI that can generate jobs, and to engage in massive skills
development for creation of better quality jobs. Khodeir (2016) also suggested some
policy reforms for African countries to derive maximum benefits from Chinese
investments. In particular, Khodeir recommended removal of labor market rigidities
through policy transparency in African countries. Khodeir further recommended that
African countries’ education policies focus on vocational education and training to
adequately skill their labor force for Chinese investments.
In the case of emerging market economies, the evidence that FDI supports job
creation is not clear. For example, Bayar et al. (2017) found mixed results in their study
of selected emerging market economies pointing to a positive long-run influence of FDI
on unemployment in some countries, a negative influence in others, and no discernible
relationship in additional countries. However, the long-run relationship between FDI and
unemployment was positive in the overall panel, indicating the importance of FDI for
employment creation in emerging market economies.

38
Economic Policy in Botswana
Tax Policy
Tax is an important public resource mobilization tool for most countries,
providing the much needed revenue to run the affairs of government. Tax can be used by
a government to stimulate production or curb excess aggregate demand. The government
of Botswana uses a progressive tax regime that excludes receipts or accruals of a capital
nature, with special provisions for the IFSC, manufacturing, and mining companies
(Besada et al., 2018). While the regular corporate tax rate is 22% for citizens and 30% for
non-citizens, the government of Botswana administers development incentives for
manufacturing and financial companies, including a reduced corporate tax rate of 15% at
the approval of the minister of finance and economic development (KPMG, 2018).
The government of Botswana recognized that tax reductions could be used to
attract domestic and foreign investment through tax reforms aimed at promoting special
economic zones and stimulating production and employment creation in the process
(Government of Botswana, 2016). Specifically, the government would offer tax
exemptions to projects implemented under special economic zones, with emphasis on
FDI that brings managerial and technology transfer. The government announced an
incentive package for export-oriented businesses, including a 5% corporate tax rate for
the first 10 years of operation and 10% thereafter, land and property transfer duty waiver,
and property tax exemption for the first 5 years of operation (KPMG, 2021).

39
Foreign Direct Investment
The Government of Botswana (2016) recognized FDI as a driver of economic
growth. Efforts by the government to attract FDI during NDP 10, specifically through the
Botswana Investment and Trade Centre (BITC), have yielded success in the past, with
FDI increasing almost twofold between 2010 and 2014 (Government of Botswana, 2016).
However, the government identified some challenges in attracting investment during
NDP 10 that would be addressed during NDP 11. Notably, the lack of a coherent
government structure to deal with investors was identified as a major deterrent to foreign
investors. FDI inflows to Botswana are mostly targeted toward the mining sector
(Chiwira et al., 2016).
In their multi-model econometric study on the relationship between FDI and
economic growth in Botswana, Chiwira et al. (2016) concluded that the government of
Botswana should continue to pursue a policy of attracting FDI due to the significant
relationship they observed. In their application of the Johansen co-integration test, the
authors specifically observed a long-term relationship between FDI and economic
growth. With the Granger causality tests, the direction of influence was not clear,
however, the existence of a relationship between the two variables was discernable.
Musakwa et al. (2019) sought to determine the causal relationship between FDI and
poverty in a tri-variate framework using the (Error Correction Model) ECM-based
Granger-causality test with data from 1980 to 2017 in Botswana. Using household
consumption expenditure, infant mortality rate, and life expectancy as proxies for
poverty, Musakwa et al. found that there was a unidirectional flow from FDI to poverty,

40
particularly on the infant mortality and life expectancy variables. Therefore, Musakwa et
al. concluded that the government of Botswana ought to vigorously promote FDI
attracting policies as a measure to reduce poverty in the country.
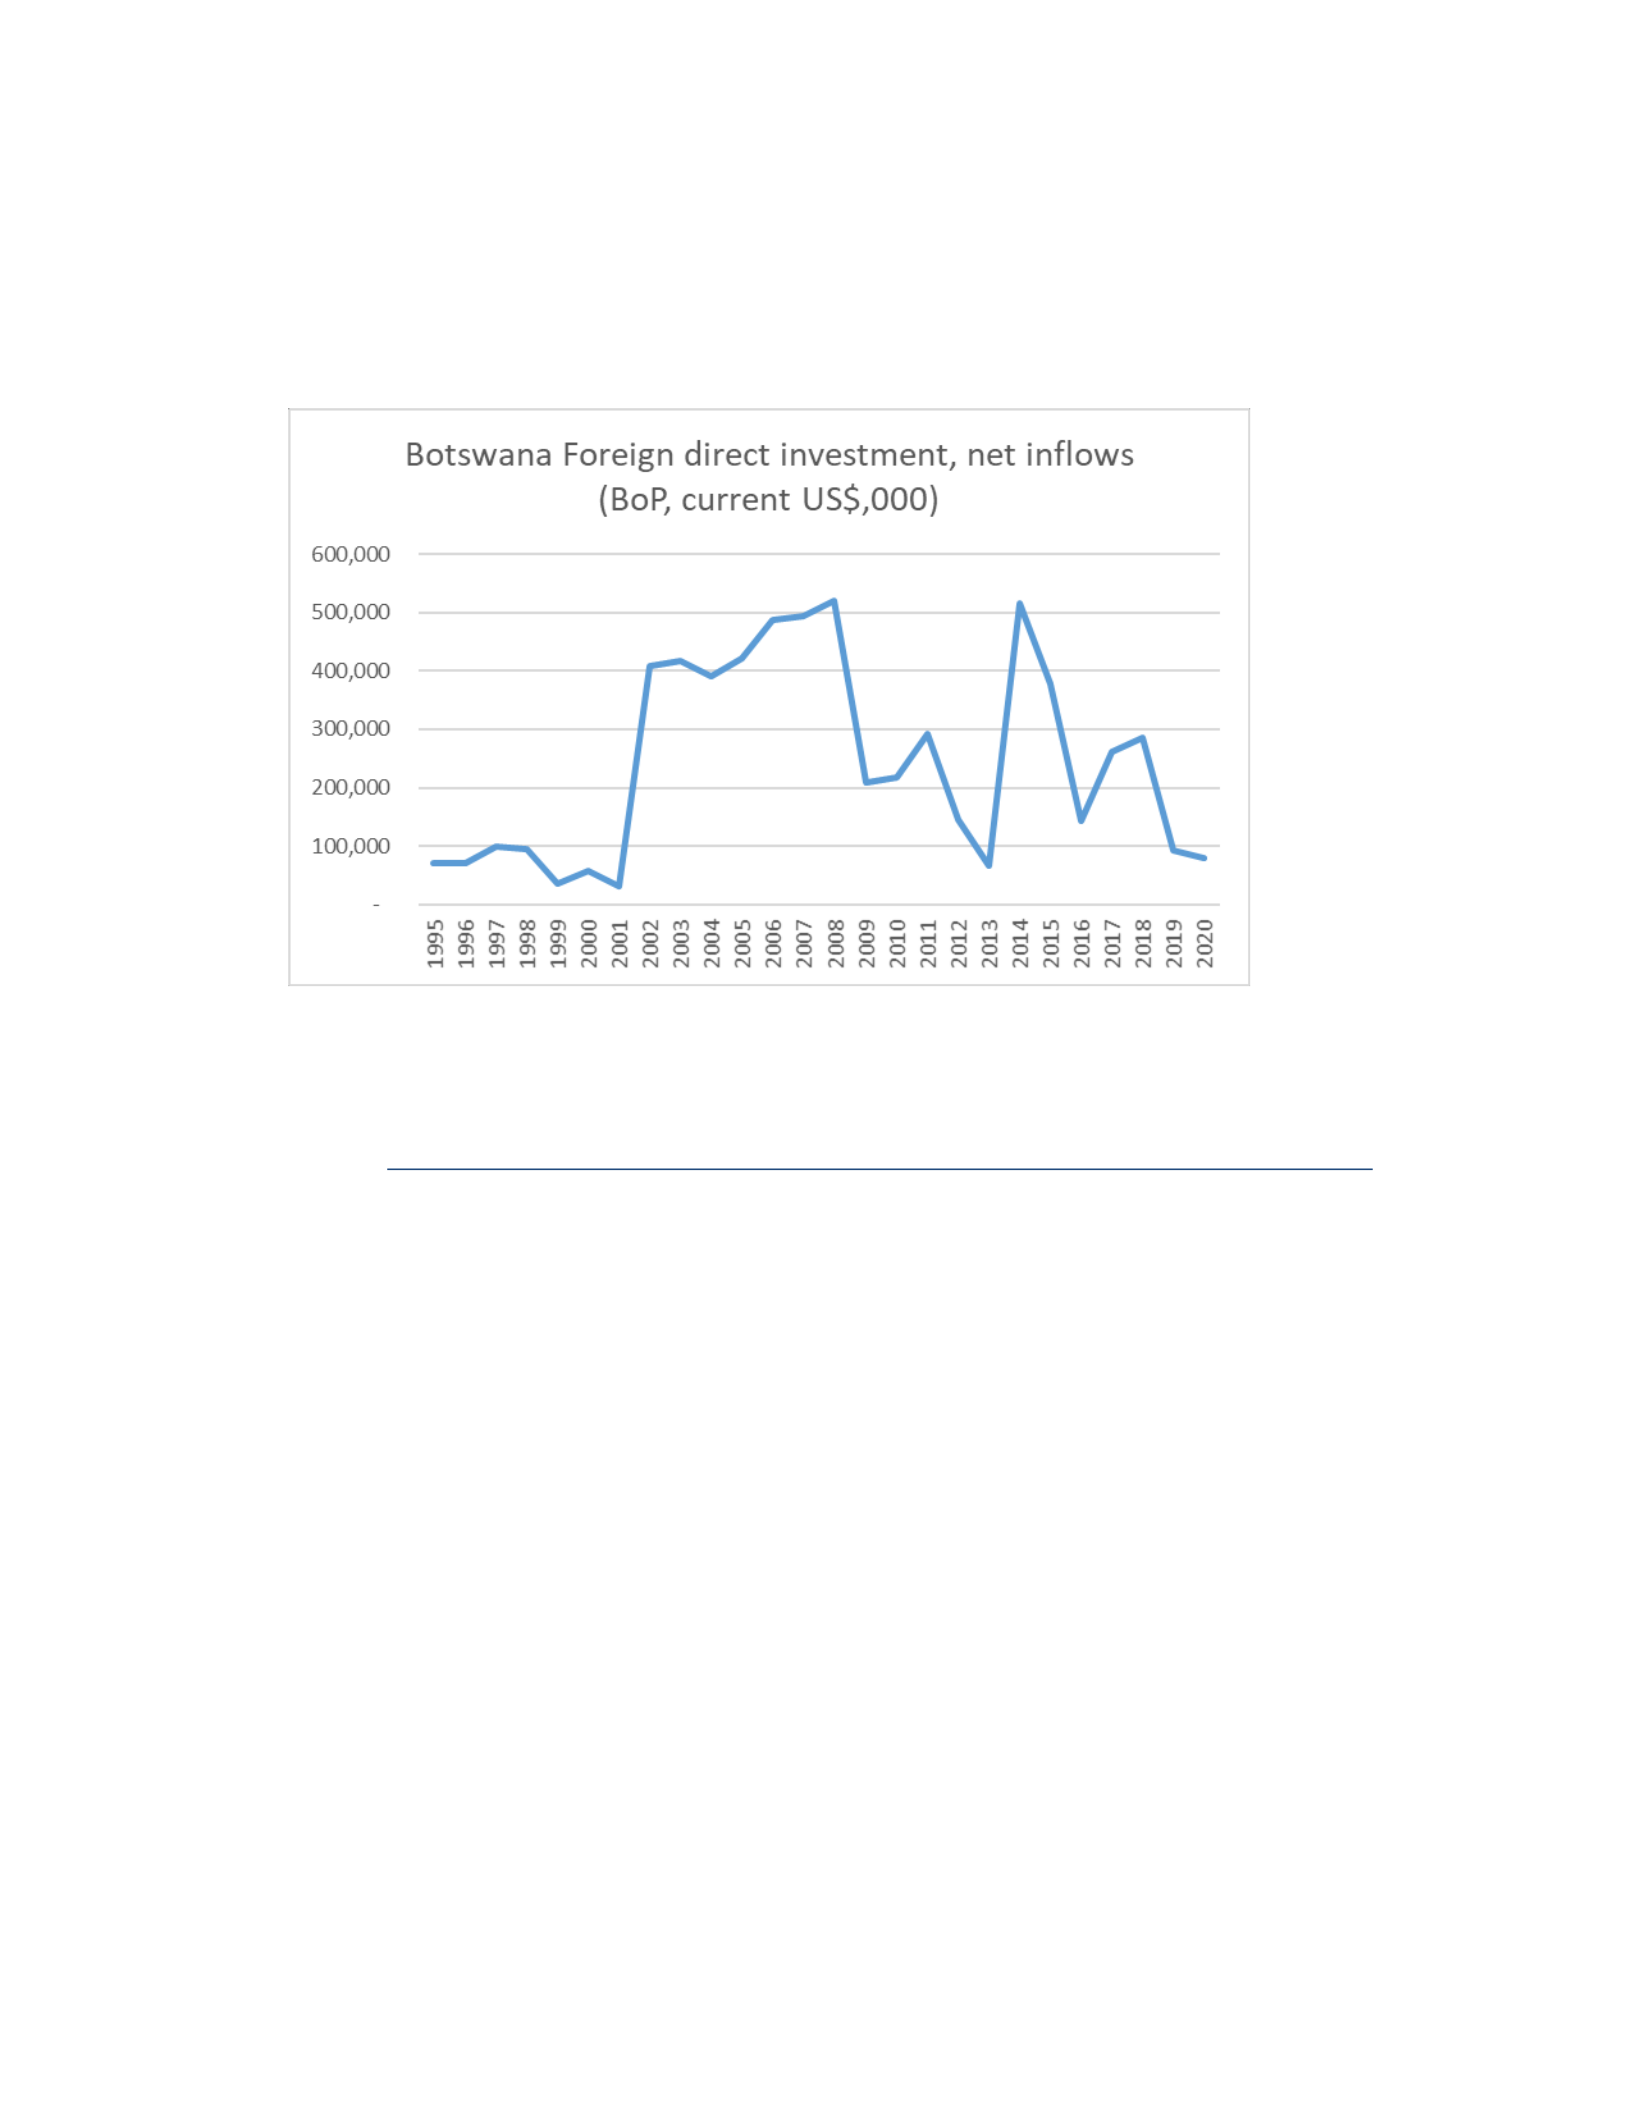
Figure 3 presents FDI net inflows to Botswana from 1995 to 2020. The figure
depicts volatility in the FDI inflows, suggesting that a strategy by the government to
sustain inflows is of critical importance. The Government of Botswana (2016) attributed
the doubling of FDI from approximately U.S. $250,000,000 to just over U.S.
$500,000,0000 between 2010 and 2014 to a conducive macroeconomic environment and
targeted investment initiatives that led to an improvement in the ease of doing business in
Botswana. FDI inflows dropped between 2014 and 2016, partially attributable to the
commodity crash during that period. Generally, Botswana’s FDI inflows are susceptible
to shocks because it is more targeted to the mineral sector, which is subject to volatility.
Magombeyi et al. (2017) indicated that most of the deals between the government and
multinational corporations were based on building the capacity of the extractive sector.
Overall, FDI inflows were hampered by restrictive investment policies and industrial land
access, labor localization policy, and shortage of skilled labor, among others
(Mangombeyi et al., 2017).
41
Figure 3
Foreign Direct Investment for Botswana (Net Inflows), 1995–2020
Note. The currency is U.S. $ in thousands. Adapted from the World Bank Data Portal,
n.d.-a, (https://data.worldbank.org/indicator/BX.KLT.DINV.CD.WD?locations=BW). In
the public domain.
Tourism Sector
The tourism sector has established itself as an important contributor to the
economy, both globally and in Botswana. Travel and tourism contributed 10.4% to global
GDP in 2019, with 25% of employment created in the sector (WTTC, 2021). WTTC
estimated that in Botswana during the same period, travel and tourism contributed 9.6%
to total GDP and about 8.4% to total employment. The advent of the COVID-19
pandemic brought about a complete shift in travel and tourism as governments across the
world implemented strict lockdowns to contain the spread of the virus. Global GDP was

42
estimated to have declined by 3.7% in 2020 and in contrast, the travel and tourism GDP
change was estimated at -49.1%, a trend that was noticed in most parts of the world
(WTTC, 2021). In the case of Botswana, real GDP declined by 8% while travel and
tourism saw a decline similar to global trends at 48.6% (WTTC, 2021).
Long before the pandemic, the government of Botswana had adopted a cluster-
based agenda that focused on tourism as one of the sectors to diversify the economy
(Government of Botswana, 2016). According to the Government of Botswana, the
cluster-based model was expected to drive export-led growth and attract FDI and increase
employment and labor productivity in the process. In recognition of the important role of
tourism in the country, the government sought to provide an enabling environment for
tourism businesses. Some of the targeted improvements included simplifying procedures
for land access and licensing.
Botswana offers a unique tourism experience, with a largely nature-based tourism
offering the wilderness and wildlife. According to Botswana Tourism (2018), 38% of the
total land area of the country was devoted to wildlife management areas, allowing
animals to roam in the wild. Studies indicated that tourism was concentrated in the north
of the country and adopted a low-volume-high-cost model to reduce the number of
tourists for preservation and conservation of the climate-sensitive wildlife (IMF, 2018;
Nare et al., 2017). Preserving wildlife in Botswana is necessary to promote the tourism
sector and nurture it as an important economic sector that contributes to employment
creation.

43
Unemployment Trends
Unemployment is one of the major social challenges that Botswana faces.
Hardwick et al. (1994) defined unemployment as the number of people who are willing
and able to work but cannot find jobs. Youth unemployment is of particular concern to
policymakers in Botswana. The ILO (n.d.) estimated the youth unemployment rate in
Botswana at 37.8% in 2020, which is untenable. The youth unemployment rate as
measured by the ILO refers to the total labor force of ages 15 to 24 years (Trading
Economics, n.d.). The definition of youth in Botswana is people between the ages of 15
and 35 years (Statistics Botswana, 2018). The youth unemployment rate was an estimated
25.1% out of a youth population of 36.1% of the total population surveyed in the 2015–
2016 Botswana Multi-Topic Household Survey. There is a clear indication that the youth
unemployment rate continues to rise amidst the rising poverty and inequality in the
country. The 2015–2016 Botswana Multi-Topic Household Survey indicated that 15.1%
of unemployed youth were from poor households, with 43% males and 57% females, and
47% from rural areas, 37.9% from urban villages, and 15.1% from cities and towns
(Statistics Botswana, 2018).
While youth unemployment shows growing trends, it is not in isolation from the
general unemployment trends in the country. A 2017 survey revealed that 73% of the
respondents cited unemployment as the top most challenge that government ought to
address (Matandare, 2018). The unemployment rate in Botswana has been persistent over
the years, averaging 18.87% between 1991 and 2020 (Trading Economics, n.d.). The
Minister of Finance and Economic Development indicated that the unemployment rate in

44
the last quarter of 2020 had increased to 24.5% up from 23.2% in the first quarter
(Government of Botswana, 2021). Matandare (2018) attributed the general high
unemployment level to the inability of the economy to create sufficient jobs. In
recognition of the long-term deficiency of jobs, the government named the NDP 11,
which was adopted in December 2016, “Inclusive Growth for the Realization of
Sustainable Employment Creation and Poverty Eradication” to create employment
opportunities for the people of Botswana. One of the national priorities for the realization
of NDP 11 theme is developing diversified sources of economic growth, encompassing
the long sought after economic diversification, among other strategies (Government of
Botswana, 2016). Economic diversification has been a strategy of the government of
Botswana for many years to create employment and reduce poverty.
Economic Diversification Drive
Botswana is highly reliant on natural resources extraction as its main revenue
source. Efforts to diversify the economy away from natural resources have largely been
futile. Besada et al. (2018) attributed the lack of success in diversification to the heavy
foreign investment in the natural resources sector, which is capital intensive and does not
create much employment. Past efforts aimed at diversifying the economy included the
Financial Assistance Policy, which offered grants to small-, medium-, and large-scale
productive enterprises to support start-ups and existing businesses in their operations, as
part of the government’s industrial development policy (World Bank, 1993). The
Financial Assistance Policy and other investment and industrial promotion initiatives
were subsequently replaced by the Citizen Entrepreneurial Development Agency

45
(CEDA) in 2001. The establishment of CEDA was a response to the 1999 National
Conference on Citizen Economic Empowerment to streamline the various government
financial assistance initiatives and promote citizen-owned businesses to facilitate
diversification (CEDA, n.d.).
The Business and Economic Advisory Council was established by then President
Festus Mogae in 2005 to proffer recommendations for the successful diversification of
the economy. One of the recommendations of the BEAC was for the government to
promote affordable high-volume tourism and to attract FDI in highly specialized
technology and medical fields through offering incentives in tax, land, and labor (Besada
et al., 2018). However, the skills shortages in these fields may frustrate the efforts of
government at diversifying the economy into those areas. The Government of Botswana
(2016) highlighted the limitation in human skills, especially in technology, as one of the
challenges faced by the country in the review of NDP 10. Hence, one of the strategies to
accelerate job creation during NDP 11 was to improve skills development. Skills
development would be achieved through several measures key among which is the
retooling and upgrading of skills to match the wider economy requirements (Government
of Botswana, 2016).
Data Analysis Methods
There is clear divergence in the literature on the application of tax incentives for
attracting FDI. In this study, I established the application of tax incentives to attract FDI
and create employment in Botswana and sought to apply the most relevant data analysis
method. Awolusi et al. (2017) applied the Ordinary Least Squares regression analysis,

46
augmented with the two-stage least squares (2SLS) and a dynamic panel estimation in
their study on FDI and economic growth in Africa. The authors used GDP as their
dependent variable, measured in current U.S. dollar. The independent variables were
gross capital formation and FDI, both measured as a percentage of GDP, HDI as a proxy
for labor, ratio of secondary and tertiary school enrolment to the population as a proxy for
human capital, import of machinery as a proxy for international technology transfers, and
total factor productivity. The authors identified a number of weaknesses in their model
specification, including the use of secondary and tertiary enrolment, which may not
reflect the true state of human capital in a country. They also indicated that the import of
machinery may not be a true reflection of the technology transfer effected by foreign
companies. I aligned the choice of variables and model specification to Awolusi et al.,
with a few modifications based on the Keynesian theory of growth.
Siyanbola et al. (2017) also applied OLS to investigate the impact of tax
incentives on economic and industrial growth in Ghana and Nigeria between 2011 and
2014. The authors used GDP, tax revenues, and tax incentives as the variables for the
model, including an error term and time. Siyanbola et al. undertook a thorough analysis
of the assumptions of the OLS regression analysis. I followed some of the tests used by
Siyanbola et al. to carry out the various tests of the assumptions of regression analysis,
including the Durbin-Watson statistic to test for serial correlation.
Although Habanabakize et al. (2018) used a Vector Autoregressive model with
Johansen co-integration approach to estimate employment in the manufacturing sector in
South Africa, some of the variables they selected for their study informed the choice of

47
variables for this study. Habanabakize et al. used employment as their dependent variable
with the independent variables as household consumption, government spending, gross
capital formation as a proxy for investment, and net exports.
Summary and Conclusions
The Keynesian theory of employment posits that boosting aggregate demand
through government intervention by cutting government expenditure, reducing taxes, or
reducing interest rates will result in employment creation. In this study, I investigated the
impact of reducing taxes in the tourism sector in Botswana on employment creation.
Unemployment, particularly youth unemployment, is a major social challenge that the
government of Botswana continues to contend with. Past efforts by the government to
deal with the challenge of unemployment included economic diversification away from
the mining sector through tax, land, and labor incentives (Besada et al., 2018). Tax and
other incentives are important considerations for developing countries that wish to attract
FDI as part of their diversification efforts. Although the literature is inconclusive on the
impact of tax incentives on FDI, some studies have shown a positive relationship between
FDI and some economic indicators such as poverty, economic growth, and employment
creation (Karimov et al., 2020; Musakwa et al., 2019; Osabohien et al., 2020; Slusarczyk,
2018).
Several studies have been carried out using various data analysis tools to
investigate the impact of FDI on economic growth and employment. Some studies
observed a positive relationship between FDI and economic growth (Chiwira et al., 2016;
Lawal, 2018), while others found a negligible or non-existent relationship (Awolusi et al.,

48
2017; Gupta et al., 2016). In studies analyzing the relationship between FDI and
employment creation, the results showed a positive relationship between the two
variables. The data analysis methods used in the various studies ranged from OLS
(Awolusi et al., 2017), pooled OLS (Tsaurai, 2018), Vector Autoregressive model
(Habanabakize et al., 2018), fully modified OLS (Osabohien, 2020), and 2SLS (Awolusi
et al., 2017), and involving Johansen co-integration (Chiwira et al., 2016; Habanabakize
et al., 2018, Osabohien, 2020) and Granger causality tests (Chiwira et al., 2016). I applied
the multiple linear regression analysis method, with the Durbin-Watson test and
scatterplots to check and eliminate problems associated with time series data like
autocorrelation.
The government of Botswana has previously used tax incentives to attract FDI
into the mining, manufacturing, and financial sectors of the economy to create
employment and some studies have indicated that such efforts have been unsuccessful
(Besada et al., 2018; Moyo, 2016). I, therefore, investigated how the use of tax incentives
in the tourism sector might help create employment in Botswana. The results of the study
may contribute to the correct application of tax incentives and enhance public
policymaking in Botswana.
In Chapter 3, I discussed the research design and methodology that was employed
in the study. I also discussed the data analysis techniques applied in the study, including
the measurement of variables and software used.

49
Chapter 3: Research Method
Introduction
The purpose of this quantitative study was to determine the impact of tax
incentives on FDI and employment creation in Botswana, using evidence from the
tourism sector. I examined the impact of targeting tax incentives at the tourism sector in
Botswana and the resultant expected FDI and job creation by applying the multiple linear
regression analysis. Findings from this study may be beneficial for the revision of public
policy, particularly tax policy, which may lead to economic diversification in Botswana.
Economic diversification in Botswana has largely been unsuccessful, mostly as a result of
the heavy concentration of investment in the natural resource sector (Besada et al.; 2018,
Makoni, 2015).
Structurally, in this chapter, I discussed the research design as it relates to the RQs
and the rationale behind the choice. I then described the methodology that the study
employed, including the variables investigated and the sampling procedures. I further
discussed the econometric model that was used and explained why it was best suited for
this study. Additionally, I outlined the sources of data that were used and attested to their
reputability and then justified the length of series selected for the study. I also outlined
the data analysis plan, including the statistical tests that were performed, the underlying
assumptions for the statistical analyses performed, identified the software used in the
statistical analysis, and explained how the results were interpreted. I concluded by
explaining the threats to validity and ethical procedures as they relate to the study and
provided a summary and transition to the next chapter.

50
Research Design and Rationale
In this study, I applied the quantitative research tradition. Yilmaz (2013) defined
quantitative research as empirical research into a social problem that tests an existing
theory by use of variables presented in numerical data using statistical analysis to
determine if the theory explains or predicts the variables presented. The quantitative
research tradition entails developing models to understand the relationships between one
or more independent variables and a dependent variable (Dietz et al., 2009). In this study,
the dependent variable is the employment rate and the independent variables are tax
incentives, FDI, GDP, and human capital. I ran two regressions, with one using the
employment rate in the mining sector and the other using the employment rate in the
tourism sector. The independent variables are the same in both equations. The rationale
for running the two regressions was to make a comparison between the impact of tax
incentives on employment in the two sectors and then make a determination of where the
tax incentives are more effective.
According to Yilmaz (2013), the purpose of quantitative studies is threefold –to
generalize the findings to other settings; for prediction; and for causal explanation of
relationships through deduction. In this study, I aimed to explain the cause-effect
relationship between employment creation and FDI through reduced corporation tax. The
quantitative research tradition allows for an objective analysis of the variables under
study (Yilmaz, 2013). The purpose of this study was to, therefore, present an objective
explanation of the relationship among the variables under observation.

51
Specifically, I applied a time series design, which is a quasi-experimental model
for program evaluation or policy impact. The estimation technique that was used is the
multiple linear regression analysis. The rationale for the selection of the multiple linear
regression analysis was that it is an appropriate method for concurrently estimating the
effects of many variables (Schroeder et al., 2018). This study had five variables. The
multiple linear regression analysis method was adequate to estimate the effects of the
four independent variables—tax incentives, GDP, human capital, and FDI—on the
dependent variable, the employment rate. The RQs and null and hypotheses of this study
were as follows:
RQ1: What is the impact of tax incentives on FDI and employment creation in
Botswana?
H01: There is no impact of tax incentives on FDI and/or employment creation in
Botswana.
Ha1: There is an impact of tax incentives on FDI and/or employment creation in
Botswana.
RQ2: What is the mediating role of FDI in tax incentives and employment
creation in Botswana?
H02: FDI plays no role mediating role in tax incentives and employment creation
in Botswana.
Ha2: FDI plays a mediating role in tax incentives and employment creation in
Botswana.
52
Methodology
Population
For the population of the study, I selected the country Botswana. I used
secondary data to assess the impact of tax incentives on FDI and employment in two
critical sectors, mining and tourism in Botswana. I applied secondary data on the
corporate tax rate, FDI, employment in the mining and tourism sectors, GDP, and human
capital over the period 1989 to 2021 to address the RQs under study.
Procedures for Recruitment, Participation, and Data Collection
I used secondary data on the corporate tax rate, FDI, employment in the mining
and tourism sectors in Botswana, GDP, and human capital derived from the Government
of Botswana, Statistics Botswana, Bank of Botswana, the IMF, the World Bank, WTTC,
and World Tourism Organization. All these data sources are open to the public and there
are no restrictions nor special requirements for accessing the data. The selected data
sources are also highly reputable and internationally acceptable. I used annual data
covering the period from 1989 to 2021 (see Appendix). Although data for FDI and
corporate tax were available before 1995, data on employment in the tourism sector were
only available from 1995. For the period 1989 to 1994, I used a proxy for employment in
the tourism sector.
Corporate income tax data were available from the Government of Botswana,
specifically from policy statements on the prevailing rate. I sourced the data on FDI
inflows for Botswana from the World Bank Data portal at https://data.worldbank.org and
53
were downloaded in Microsoft Excel. I used employment in the hotel and restaurants
sector as a proxy for employment in the tourism sector and the data were sourced from
the Statistics Botswana Data portal at https://statsbots.org.bw and the International
Monetary Fund Data portal https://imf.org. Employment data in the mining sector
included figures for quarrying and was sourced from the Statistics Botswana Data portal
and IMF Data portal. GDP data were also obtained from the Statistics Botswana Data
portal, while data on human capital, proxied by the human development index, were
sourced from the World Bank Data portal.
Sampling and Sampling Procedures
I did not develop a sampling plan since there were no subjects to interview. The
choice of country for the study was Botswana. The length of time-series selected was
1989 to 2021 for the five variables that were studied, corporate tax rate, FDI, GDP,
human capital, and employment in the tourism sector. All final data for the variables were
available. I used existing secondary data from publicly available sources. Specifically, I
collected time series data for employment in the tourism sector, corporate tax, GDP,
human capital, and FDI in Botswana from 1989 to 2021 for the study.
Data Cleaning and Screening
No data cleaning was required because the data were from reputable sources and
had undergone various data collection methods, including cleaning and screening. There
were no missing values in the data. I used SPSS to depict the variables in histograms for a
visual display and inspected them for any missing data. I checked the data for normality,
randomness of the error term, homoscedasticity, autocorrelation, and multicollinearity

54
using scatterplots, the Durbin-Watson statistics, and correlation analysis. The data were
in violation of some of the assumptions, and I transformed the data into first differences.
Instrumentation and Operationalization of Constructs
Variables
I used the employment rate as the dependent variable and two variables—tax
incentives and FDI—as the main independent variables. The other independent variables
that were added to the model are real GDP growth rate and human capital, which are
some of the additional determinants of employment. The employment rate was measured
in the mining and tourism sectors separately to run two regressions. I also investigated
the mediating role of FDI in tax incentives and employment. Tax incentives are expected
to lead to an increase in FDI and, therefore, to employment.
Operationalization of Constructs
Employment Rate. The employment rate was measured as a percentage of the
total employment. The first regression used the employment rate in the mining sector and
the second regression measured the employment rate in the tourism sector. The tourism
sector used the hotel and restaurants sector as a proxy and the mining sector included
quarrying since the sectors are classified that way by Statistics Botswana.
Tax Incentives. Tax incentives were proxied by the corporate tax rate that the
Government of Botswana applies to the manufacturing, mining, and financial sectors and
was measured as a percentage per annum. Tax rates are indicated as a percentage
annually. For the regression analysis, the tax incentive will be introduced in the model as

55
a dummy variable, taking the value 0 prior to the introduction of the incentive from 1990
to 1994, and taking the value 1 from 1995 to 2021.
Foreign Direct Investment. FDI was measured as a percentage of GDP annually.
Gross Domestic Product. The real GDP annual growth rate is a major
determinant of employment in the economy.
Human Capital. Human capital, proxied by the human development index
(HDI), is a major determinant of employment.
Hypotheses
I tested the following null and alternative hypotheses:
H01: There is no impact of tax incentives on FDI and/or employment creation in
Botswana.
Ha1: There is an impact of tax incentives on FDI and/or employment creation in
Botswana.
H02: FDI plays no role mediating role in tax incentives and employment creation
in Botswana.
Ha2: FDI plays a mediating role in tax incentives and employment creation in
Botswana.
Method
Awolusi et al. (2017) used multiple linear regression analysis, in particular the
Ordinary Least Squares method, to analyze the impact of FDI on economic growth in
Central African Republic, Egypt, Kenya, Nigeria, and South Africa using data from 1980

56
to 2014. Their study was premised on a modified growth model employed by Agrawal et
al. (2011) and was specified as follows:
Y = f (K, L, FDI, H, ITT)
with the multiple linear regression equation specified as follows:
Yi,t = β0 + β1 Ki.t + β2 Li.t + β3 FDIi.t + β4 Hi.t + β5 ITTi.t + µi + εi,t
where
Y = gross domestic product
K = Gross Capital Formation
L = labor force
FDI = foreign direct investment
H = human capital
ITT = international technology transfer
β0 = TFP
μi = country specific effects
εi,t = the error term.
For this study, I applied the Awolusi et al. (2017) model with some modifications
to take into account the Keynesian theory of growth. Two models were run with
employment in the mining and tourism sectors as the dependent variables modelled
against corporate tax and FDI in Botswana. Running two models in the two sectors was
meant to determine where tax incentives are most effective for creating employment. I
applied a dummy to represent the tax incentive from 1995 to 2021 and no tax incentive
from 1990 to 1994 to determine the impact on FDI and employment in the mining and

57
tourism sectors. Specifically, I applied the tax used to incentivize firms in the mining,
manufacturing and financial services sectors to determine the effect of a lower tax on FDI
and employment in the mining and tourism sectors. The model specification was:
LM = f (T, FDI, GDP, H) and
LT = f (T, FDI, GDP, H)
with the multiple linear regressions specified as:
𝐿𝑀𝑖.𝑡 = 𝛽0 + 𝛽1𝑇𝑖.𝑡 + 𝛽2 𝐹𝐷𝐼𝑖.𝑡 + 𝛽3 𝐺𝐷𝑃𝑖.𝑡 + 𝛽4𝐻𝑖.𝑡 + 𝜀𝑖.𝑡
𝐿𝑇𝑖.𝑡 = 𝛽0 + 𝛽1𝑇𝑖.𝑡 + 𝛽2 𝐹𝐷𝐼𝑖.𝑡 + 𝛽3 𝐺𝐷𝑃𝑖.𝑡 + 𝛽4𝐻𝑖.𝑡 + 𝜀𝑖.𝑡
where:
LM = employment in the mining sector
LT = employment in the tourism sector
T = tax incentives, proxied by corporate tax rate in the mining, manufacturing and
financial services sectors, and introduced as a dummy variable (0=no incentive; 1=tax
incentive)
FDI = foreign direct investment
GDP = real gross domestic product growth rate
H = human capital, proxied by the Human Development Index (HDI)
εi,t = the error term
In the first regression, employment in the mining sector, the dependent variable,
was modelled against four independent variables, tax incentives, FDI, GDP, and human
capital. In the second regression, employment in the tourism sector as the dependent
variable was modelled against tax incentives, FDI, GDP, and human capital as the

58
independent variables. I also investigated the mediating role of FDI in tax incentives and
employment.
Data Analysis Plan
I used the SPSS software for the data analysis since it is suitable for multiple
linear regression analysis. SPSS is a statistical package that has the ability to analyze
large data sets with ease (Rahman et al., 2021). SPSS allows for the easy exportation of
data from other programs such as Microsoft Excel. After inputting the data into Microsoft
Excel, I exported it to SPSS for analysis.
Descriptive Statistics
The data were tabulated for easy presentation. The data were presented in graphs,
specifically histograms, to check for normality. O’Sullivan et al. (2017) suggested that it
was important to visually analyze data to note any points of divergence and identify
patterns. As discussed in O’Sullivan et al., the types of variations to observe in time-
series analysis are long-term, cyclical, seasonal, and irregular variations. Long-term
trends are observed as upward or downward movements in the data over many years.
Cyclical variations are recurring changes that are observed within a long-term trend, with
cycles lasting between 1 and 5 years. Seasonal variations are observed when some
phenomena occur seasonally. Irregular variations are changes that cannot be associated
with any trends or variations.
Measures of Central Tendency
Following the data presentation on graphs, the mean, median, mode, variance, and
standard deviation were calculated. The mean of a population is expected to remain

59
constant from sample to sample. The mean of the error term is expected to be 0 at all
times, while the variance is expected to be 0 with a normal distribution (Koutsoyiannis,
1977).
Methods of Statistical Evaluation
To test the hypotheses, I used the correlation coefficient and the standard error of
the estimates. According to Koutsoyiannis (1977), the standard error test is the most
appropriate for testing the significance of parameter estimates, normally as a two-tail test
at the 5% level of significance (p.123). Koutsoyiannis further purported that smaller
standard errors implied the statistical significance of the estimates. The correlation
coefficient, on the other hand, measures the extent to which the changes in the dependent
variable are determined by the changes in the independent variables (Koutsoyiannis,
1977). To test for the overall significance of the model, I computed the F-statistic at the
5% level of significance. If F*>F, where F* is the computed F-statistic and F is the
theoretical F-statistic, the null hypothesis is rejected. If F*<F, the null hypothesis is
accepted.
Mediation Analysis
I also tested for the mediating role of FDI in tax incentives and employment using
SPSS. According to Warner (2013), mediation in regression analysis is used to determine
the influence of one causal variable on a dependent variable through another variable. In
the study model, I expected FDI to affect employment through tax incentives and I
studied that effect to confirm the relationship. The test for the significance of the model
was the same method as for the multiple linear regression analysis.

60
Assumptions of Time Series Data
However, before running the regressions, I checked the model for the fulfillment
of the assumptions of time series data. Some of the assumptions underlying time series
data, particularly in reference to the error term, are outlined by Koutsoyiannis (1977) and
O’Sullivan et al. (2017). It is to be recalled that the purpose of the error term in a
regression is to take into account the errors in the relationship between the dependent and
independent variables (Koutsoyiannis, 1977). These errors include: i) omission of other
variables that may influence the dependent variable from the model; ii) unpredictable
human patterns of behavior, iii) imperfect model specification; iv) errors of aggregation;
and v) errors of measurement (Koutsoyiannis, 1977).
The first assumption concerns the randomness of the error term. The errors of
measurement of the dependent variable should not exhibit a pattern (Koutsoyiannis,
1977). The second assumption is that of the 0 mean of the error term, where all the error
terms drawn from a population are either positive, negative, or 0, and add up to 0.
According to Koutsoyiannis, the assumption of a 0 mean is aimed at satisfying the
algebraic rules regarding economic phenomena to ensure a good fit of the true line. The
first two assumptions about the error term do not have any formal test but should be
determined a priori.
The assumption of homoscedasticity is the third one and assumes constant
variance of the error term for all values of the explanatory variable. A violation of the
assumption of homoscedasticity implies that significance tests and confidence intervals
cannot be conducted and the prediction of the regression would be inefficient

61
(Koutsoyiannis, 1977). I used scatterplots to observe the pattern of the dispersion of the
error terms around the regression line. According to Koutsoyiannis, constant distance of
the error terms around the regression line indicated homoscedasticity while increasing or
decreasing variations indicated heteroscedasticity. The solution to heteroscedasticity is to
transform the model to obtain constant variance of the error term (Koutsoyiannis, 1977).
One critical assumption that ought to be satisfied is testing for autocorrelation in
the residual term to avoid errors in the regression analysis. According to O’Sullivan et al.
(2017), testing for autocorrelation in the residual term is an important step before
analyzing time series data. O’Sullivan defined autocorrelation as the nonrandom
relationship observed in a variable over time. Autocorrelation presents biases in statistical
significance tests, leading to inaccurate results (O’Sullivan et al., 2017). I tested for
autocorrelation in the model using scatter diagrams and plotting the residuals against their
lagged values as suggested by Koutsoyiannis (1977). Also, I applied the Durbin-Watson
(DW) test for a more accurate prediction of autocorrelation in the model. Koutsoyiannis
indicated that the DW test was appropriate for small samples. Since the model had only
32 series, the DW test was the appropriate test to apply. Koutsoyiannis outlined the steps
for undertaking a DW test and that is the procedure that I followed in this study.
Siyanbola et al. (2017) applied the DW test to check for autocorrelation in their sample
size of 4 years.
I tested the null hypothesis that the error terms were not correlated at first-order
against the alternative hypothesis that the error terms were correlated at first order. I
applied the DW-statistic, d, with a value between 0 and 4, to test the null hypothesis. The

62
DW –statistic is interpreted as follows: if d ≈ 2, there is no autocorrelation, if d = 0, there
is perfect positive autocorrelation, and if d = 4, there is perfect negative autocorrelation. I
used the sample error terms to compute the empirical value of the DW-statistic, d*, and
compared the result with the theoretical values of d, being the values that provide the
critical values of the DW test at the upper, du, and lower, dL, levels at the 5% level of
significance (Koutsoyiannis, 1977). The interpretation is as follows: if d* < du or d* > (4
- du), reject the null hypothesis of no autocorrelation, and if du < d* < (4 - du), accept the
null hypothesis of no autocorrelation.
If autocorrelation is detected in the model, the necessary remedial steps should be
taken as suggested by Koutsoyiannis (1977). If the autocorrelation is caused by omitted
variables, the missing variables should be identified and added. If it is misspecification of
the mathematical form of the regression, the model should be transformed to logarithms
or any other appropriate form.
Additionally, the assumption of multicollinearity is crucial in conducting
regression analysis. It is important to determine the presence of linear or near linear
relationships among the independent variables (Koutsoyiannis, 1977). If there is perfect
multicollinearity between the explanatory variables, the estimates of the coefficients are
rendered indeterminate and the standard errors of the estimates will be large
(Koutsoyiannis, 1977, p. 234). I used the variance inflation factor (VIF) to detect
multicollinearity in the regression model. According to Vorosmarty et al. (2020), VIF
uses variance to estimate how much the regression coefficient is inflated and it has the
advantage of simplicity. There are several corrective measures that can be taken in the

63
event of multicollinearity, depending on the severity of the effect on the model. If the
effect is severe, I should apply extraneous quantitative information or add more time
series to the model. Koutsoyiannis (1977) suggested the addition of information to
improve a model whose purpose is to estimate the individual coefficients. The threshold
for determining multicollinearity was set at 2 as proposed by Vorosmarty et al. (2020).
Threats to Validity
Quasi-experimental designs use existing groups to assign subjects to groups and
are, therefore, subject to several threats to validity (Office of Research & Doctoral
Services, 2015). When conducting an experimental or quasi-experimental research, it is
important to evaluate the threats to validity, including internal and external validity.
Internal Validity
Internal validity relates to the steps taken to ensure that the outcome of the
research is a result of the manipulation of the independent variables and that the effects of
other external variables are duly eliminated (Laher, 2016). Some of the threats to internal
validity that might be applicable to this study are history and instrumentation.
History
Other unrelated events may occur simultaneously with independent variables and
cause changes in the dependent variable, posing a threat to the internal validity of the
model (Onwuegbuzie, 2000). The threat of history can be eliminated by undertaking a
thorough review of the literature to determine the events that might have occurred and
had an impact on the dependent variable. Accordingly, I reviewed the literature
thoroughly to ensure that the relevant independent variables were included in the

64
regression analysis. I also acknowledged other independent variables that have an effect
on the dependent variable that were excluded from the model. To that end, I carried out
tests for the assumptions underlying regression analysis to ensure that the model was
rigorous.
Instrumentation
Onwuegbuzie (2000) explained that the threat of instrumentation to internal
validity was the inconsistency of scores from a measure as a result of the inconsistent
scoring or observation of data in various situations. In this study, to ensure consistency in
the observed scores, I collected data from reputable sources that apply standardized and
harmonized measures of statistics.
External Validity
External validity refers to the process of generalizing the results of the study to
other circumstances or point in time, usually as a result of a small sample size (Babbie,
2014). According to Laher (2016), external validity implies generalizing study results
across people, settings, and times, and is referred to as population validity, ecological
validity, and temporal validity, respectively. Since the sample size in this study had just
over 30 observations, one of the recommendations would be for other researchers to
replicate the study in other jurisdictions.
Ethical Procedures
The study involved carrying out quantitative research that applied archival data
from governmental and international sources. Since the research did not include human
participants, there was no need for agreements and permissions for access. The ethical

65
considerations regarding this study were quite limited. The data that I used for the study
were publicly available online. However, I followed the relevant procedures to obtain
permission from the Institutional Review Board to undertake the study.
Summary
In this chapter, I outlined the research design that I used in the study and how it
was relevant for responding to the RQs. I applied multiple linear regression analysis to
time series data from 1989 to 2021 to determine the impact of targeted tax incentives on
employment creation in Botswana using evidence from the mining and tourism sectors in
Botswana. I also determined the mediating role of FDI in tax incentives and employment
using SPSS. I outlined the data analysis plan, highlighting that the correlation coefficient
and the standard error of estimates were used to test the hypotheses of the regression
model. I further set out the assumptions of regressions and how tests were carried out and
correction effected for in the model for violation of the assumptions. I outlined the threats
to validity that are inherent in quasi-experimental research and concluded by stating the
ethical procedures that were followed in undertaking the study. In Chapter 4, I undertook
the tests outlined in Chapter 3 and presented the study results.

66
Chapter 4: Results
Introduction
The purpose of this quantitative study was to determine the impact of tax
incentives on FDI and employment creation in Botswana, using evidence from the
mining and tourism sectors. The RQs and hypotheses were:
RQ1: What is the impact of tax incentives on FDI and employment creation in
Botswana?
H01: There is no impact of tax incentives on FDI and/or employment creation in
Botswana.
Ha1: There is an impact of tax incentives on FDI and/or employment creation in
Botswana.
RQ2: What is the mediating role of FDI in tax incentives and employment
creation in Botswana?
H02: FDI plays no role mediating role in tax incentives and employment creation
in Botswana.
Ha2: FDI plays a mediating role in tax incentives and employment creation in
Botswana.
In the rest of this chapter, I presented the data collection plan and reported the
results of the data analysis according to the various RQs and hypotheses, including
presenting the descriptive statistics. I concluded by summarizing the results section.
67
Data Collection
My main data sources were the Government of Botswana, Statistics Botswana,
Bank of Botswana, the IMF Data Portal, and the World Development Indicators from the
World Bank. Statistics Botswana data linked to Open Data for Africa, which provided
data on the HDI. I collected data from 1989 to 2021. Table 1 summarizes the data sources
for all the variables.
Table 1
Data Sources
Variable
Definition
Data source
LM
Employment rate in the mining sector as a
percentage of total employment
Statistics Botswana
LT
Employment rate in the tourism sector as a
percentage of total employment
Statistics Botswana
T
Corporate tax rate offered in the
incentivized sectors, included in the
model as a dummy variable taking the
value 0 from 1990 to 1994, and the value
1 from 1995 onwards.
Government of Botswana,
various publications
GDP
Annual percentage growth rate
World Development
Indicators, World Bank
FDI
Net inflows of foreign direct investment as
a percentage of GDP
World Development
Indicators, World Bank
H
Human Development Index
Our World in Data
Data Analysis
I depicted the data in histograms on SPSS and ran the descriptive statistics,
including the number of observations, and minimum and maximum values, to check for
completeness and missing values. I also used the histograms to check for normality of the
variables. I further used the Shapiro-Wilk Test to confirm the normality of the data. I
used scatterplots and correlation analysis to observe the relationship between the
68
variables, including testing for randomness of the error term, homoscedasticity,
autocorrelation, and multicollinearity.
Results
Table 2 presents the descriptive statistics of the variables, including the mean,
standard deviation, skewness, and kurtosis. The values for skewness lie between -2 and 0.
Although the data were slightly skewed, with larger values dominating the data set, the
results were acceptable. The kurtosis results, however, indicated that the GDP and FDI
were higher than 3 but acceptable as normal distributions, while employment in the
mining and tourism sectors and H were all found to be normally distributed.
Table 2
Descriptive Statistics
Statistic
Variable
LM
LT
T
GDP
FDI
H
Minimum
1.3
3.4
0
-14.1
-6.9
.578
Maximum
3.9
5.1
1
11.4
7.5
.722
M
3.044
4.356
.84
4.066
1.853
.634
SD
.6355
.4008
.369
5.459
2.482
.534
Skewness
-1.122
-.205
-1.988
-1.594
-.828
.464
Kurtosis
1.068
-.018
2.078
3.393
4.396
-1.513
Observations
32
32
32
32
32
32
I then presented the data in graphs for a visual appreciation and to determine the
trends over time. Figure 4 presents all the graphs for employment in the mining sector,
employment in the tourism sector, GDP growth, FDI, and H.
69
Figure 4
Bar Graphs of Data, 1990–2021
To confirm the distribution of the data, I ran the normality tests on SPSS. The
Shapiro-Wilk test is more appropriate for small samples. My population contained 32
cases, therefore, I relied on the Shapiro-Wilk test for the normality test. The results are
presented in Table 3. The test results indicated that employment in the tourism sector was
0
1
2
3
4
5
1990 1997 2004 2011 2018
Employment (mining)
Year
0
1
2
3
4
5
6
1990 1997 2004 2011 2018
Employment (tourism)
Year
-20
-15
-10
-5
0
5
10
15
1990 1997 2004 2011 2018
GDP growth
Year
-10
-5
0
5
10
1990 1997 2004 2011 2018
FDI
Year
0
0.2
0.4
0.6
0.8
1990 1997 2004 2011 2018
H
Year
70
normally distributed while all other variable deviated from a normal distribution at 5%
significance level.
Table 3
Shapiro-Wilk Test Results
Statistic
Variable
LM
LT
T
GDP
FDI
H
Shapiro-Wilk
statistic
.905
.969
.438
.872
.886
.821
df
32
32
32
32
32
32
p
.008
.475
<.001
.001
.003
<.001
To ensure a normal distribution for all the variables, I transformed all the
variables, apart from employment in the tourism sector, into first differences. I re-ran the
normality tests for all the transformed variables and employment in the tourism sector.
The results are presented in Table 4.
Table 4
Shapiro-Wilk Test Results for the Transformed Data
Statistic
Variable
LT
T
LM_DIFF
GDP_DIFF
FDI_DIFF
H_DIFF
Shapiro-
Wilk
statistic
.969
.438
.973
.945
.837
.937
df
32
32
32
32
32
32
p
.475
<.001
.578
.104
<.001
.063
All the variables attained normality following the transformation except for FDI. I
did not remove FDI from the variables used in the analysis, given its importance and
significance to respond to the RQs. I conducted the descriptive analysis of the
transformed data as presented in Table 5.
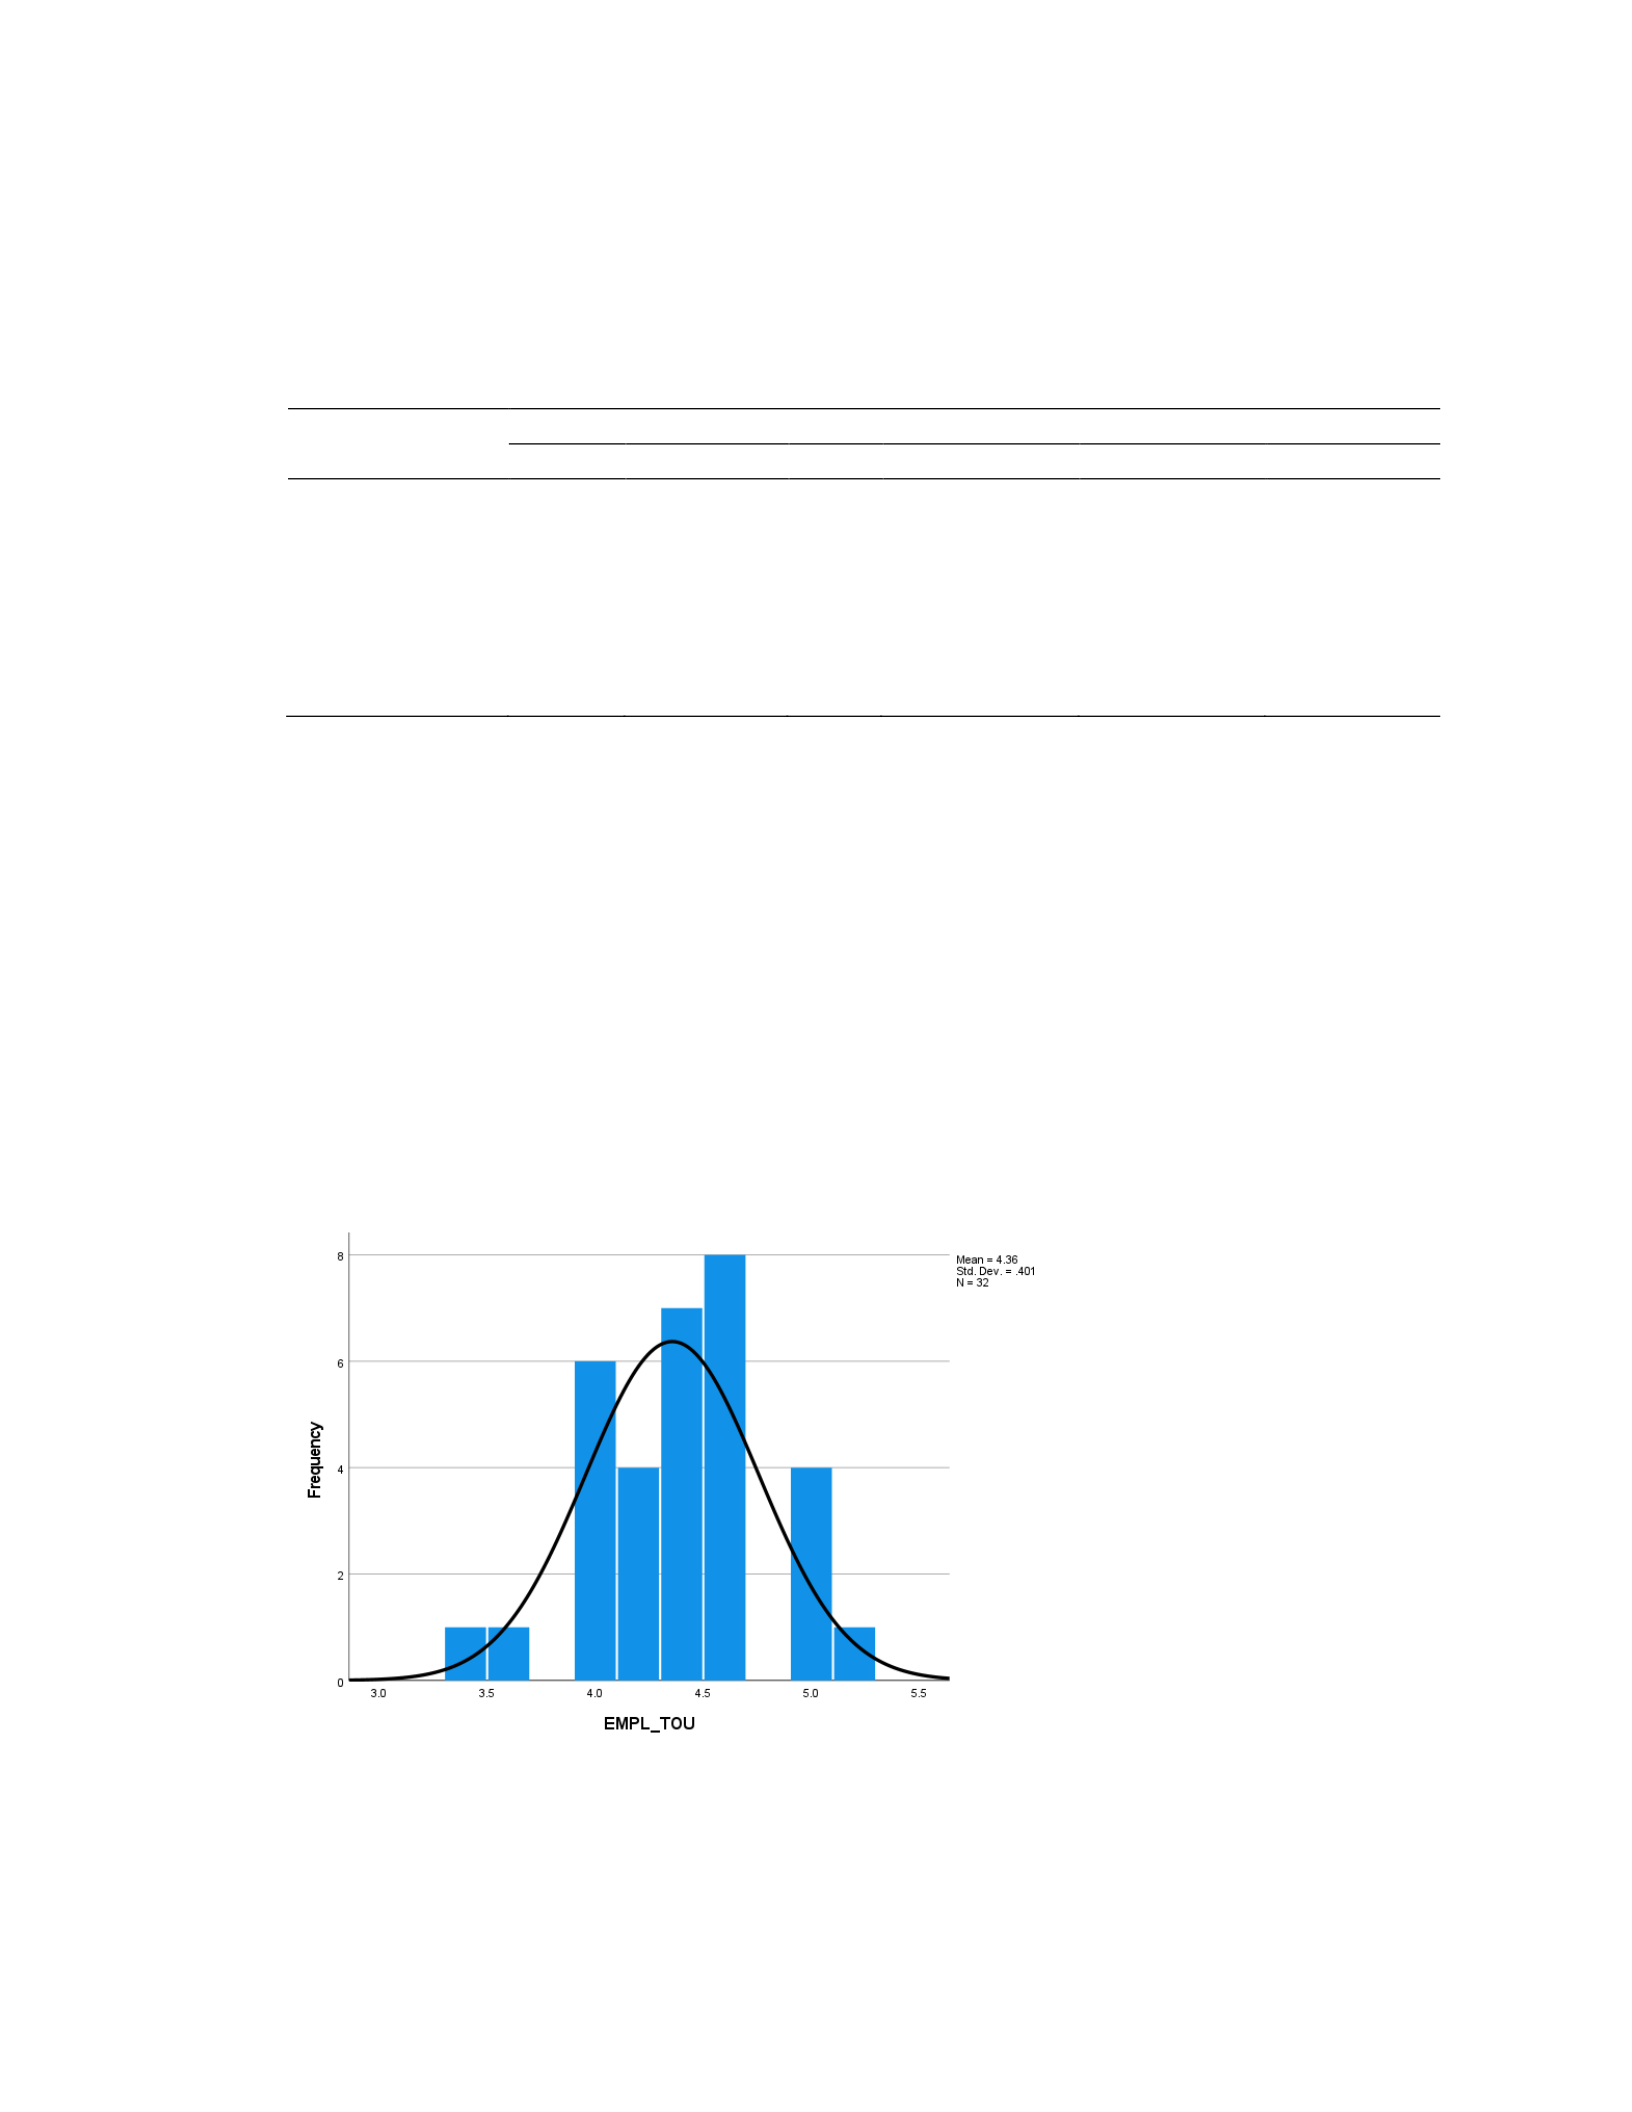
71
Table 5
Descriptive Statistics for the Transformed Data
Statistic
Variable
LT
LM_DIFF
T
GDP_DIFF
FDI_DIFF
H_DIFF
Minimum
3.4
-1.0
0
-17.4
-6.9
-.020
Maximum
5.1
.7
1
24.2
6.9
.014
M
4.356
-.063
.84
.209
-.033
.003
SD
.4008
.3757
.369
8.602
2.417
.007
Skewness
-.205
-.414
-1.98
.833
.668
-.961
Kurtosis
-.018
.441
2.07
1.519
4.363
1.894
Observations
32
32
32
32
32
32
The Kurtosis results showed an improvement, with only FDI (1) indicating a
value larger than 2. To confirm the normality assumption and for a visual presentation, I
plotted all the variables on graphs. Figure 5 is a normality graph for employment in the
tourism sector.
Figure 5
Histogram of Employment in the Tourism Sector
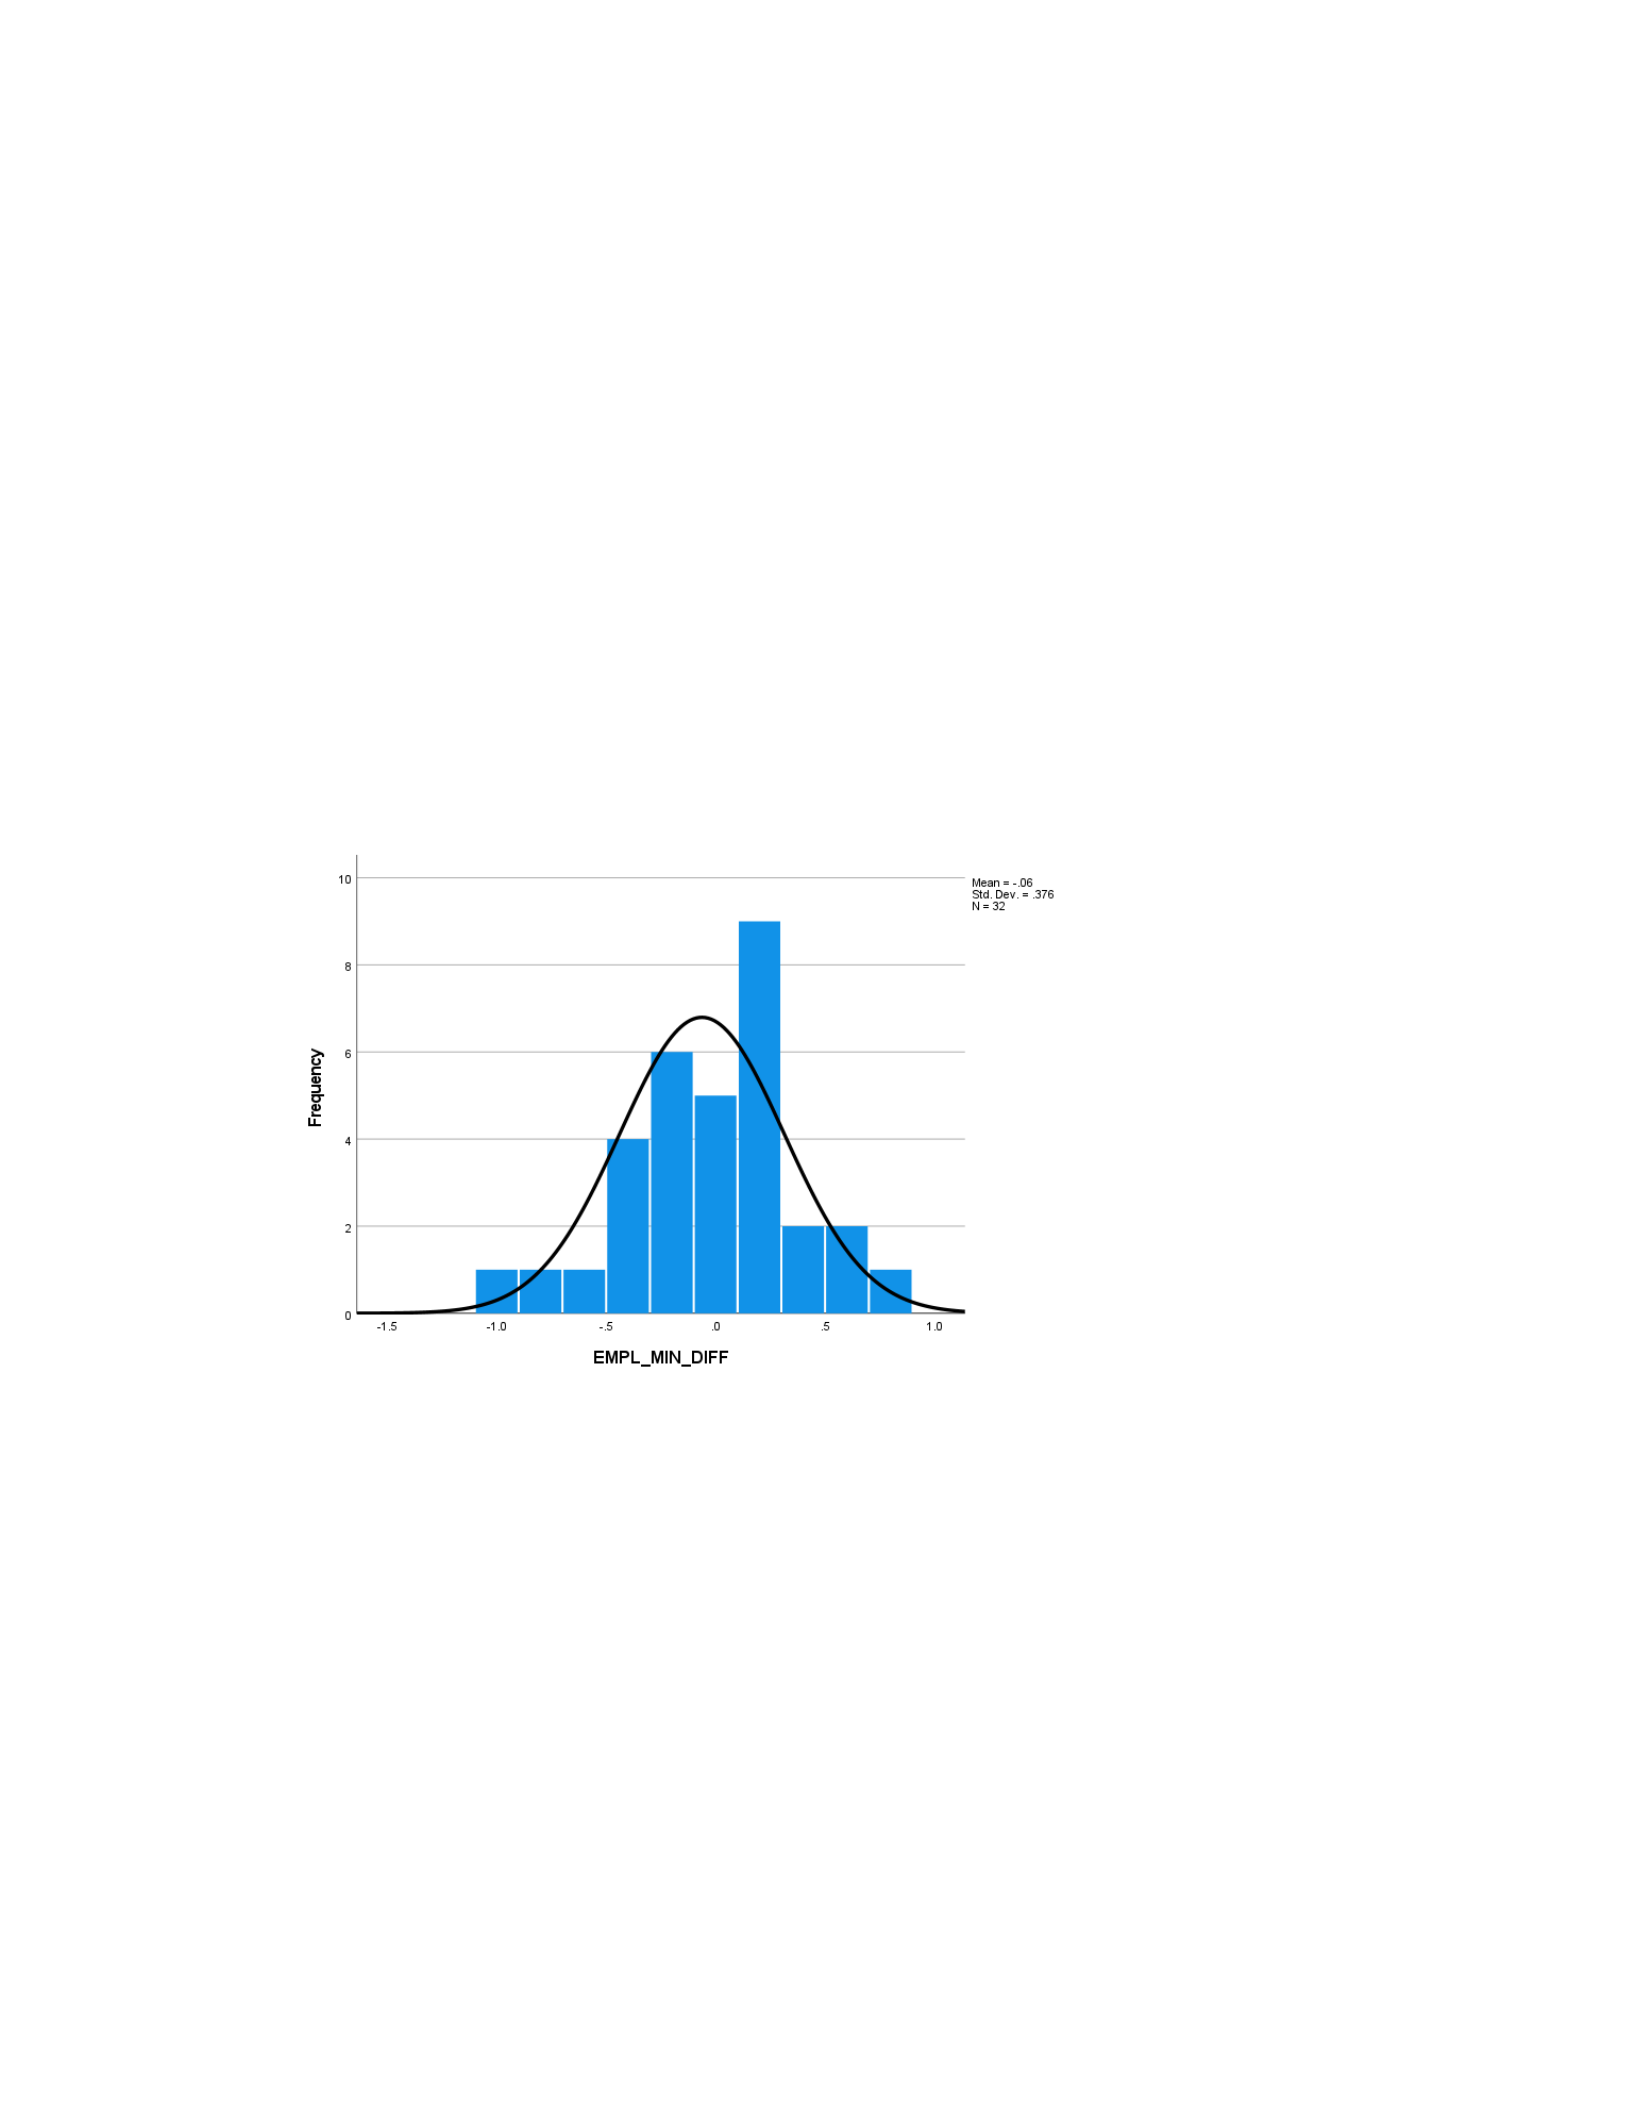
72
The graph in Figure 5 indicates that employment in the tourism sector was
normally distributed. Figures 6 and 7, the histograms presenting the data at first
difference for employment in the mining sector and GDP, respectively, indicate normal
distributions. The histogram for H at first difference, represented in Figure 9, is slightly
right skewed but acceptable. For FDI at first differences, in Figure 8, the curve depicts a
distribution that is not normal.
Figure 6
Histogram of LM_DIFF
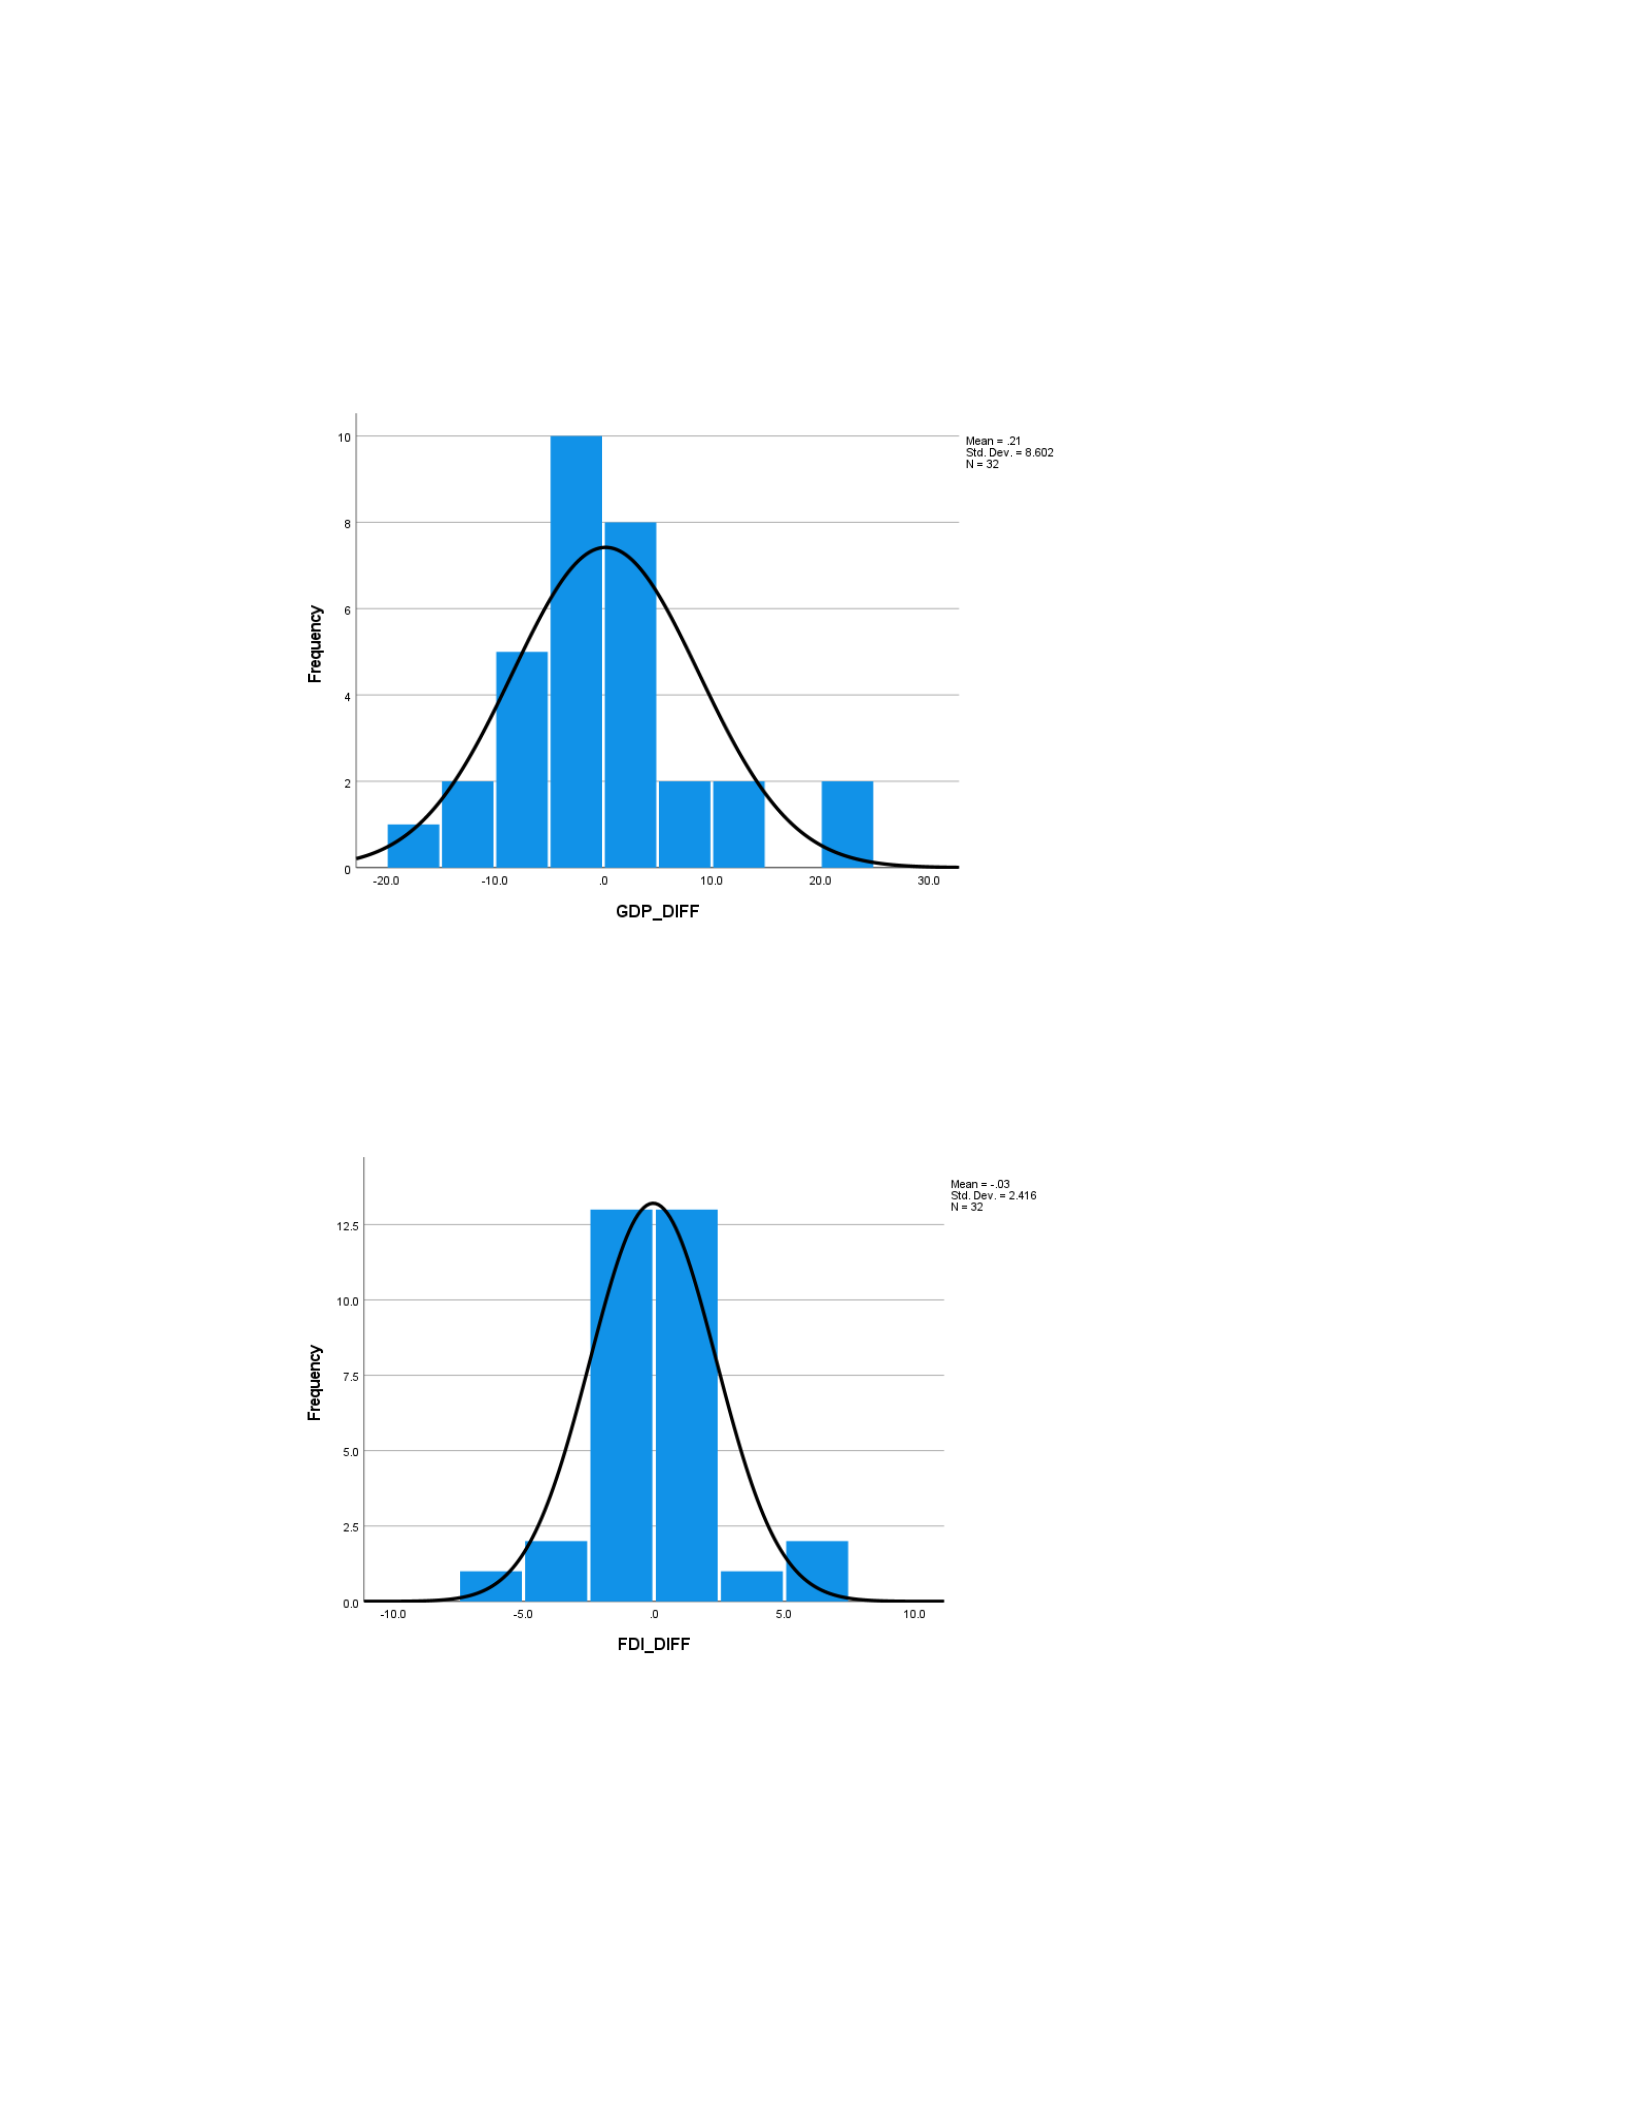
73
Figure 7
Histogram of Gross Domestic Product (GDP)
Figure 8
Histogram of FDI_DIFF
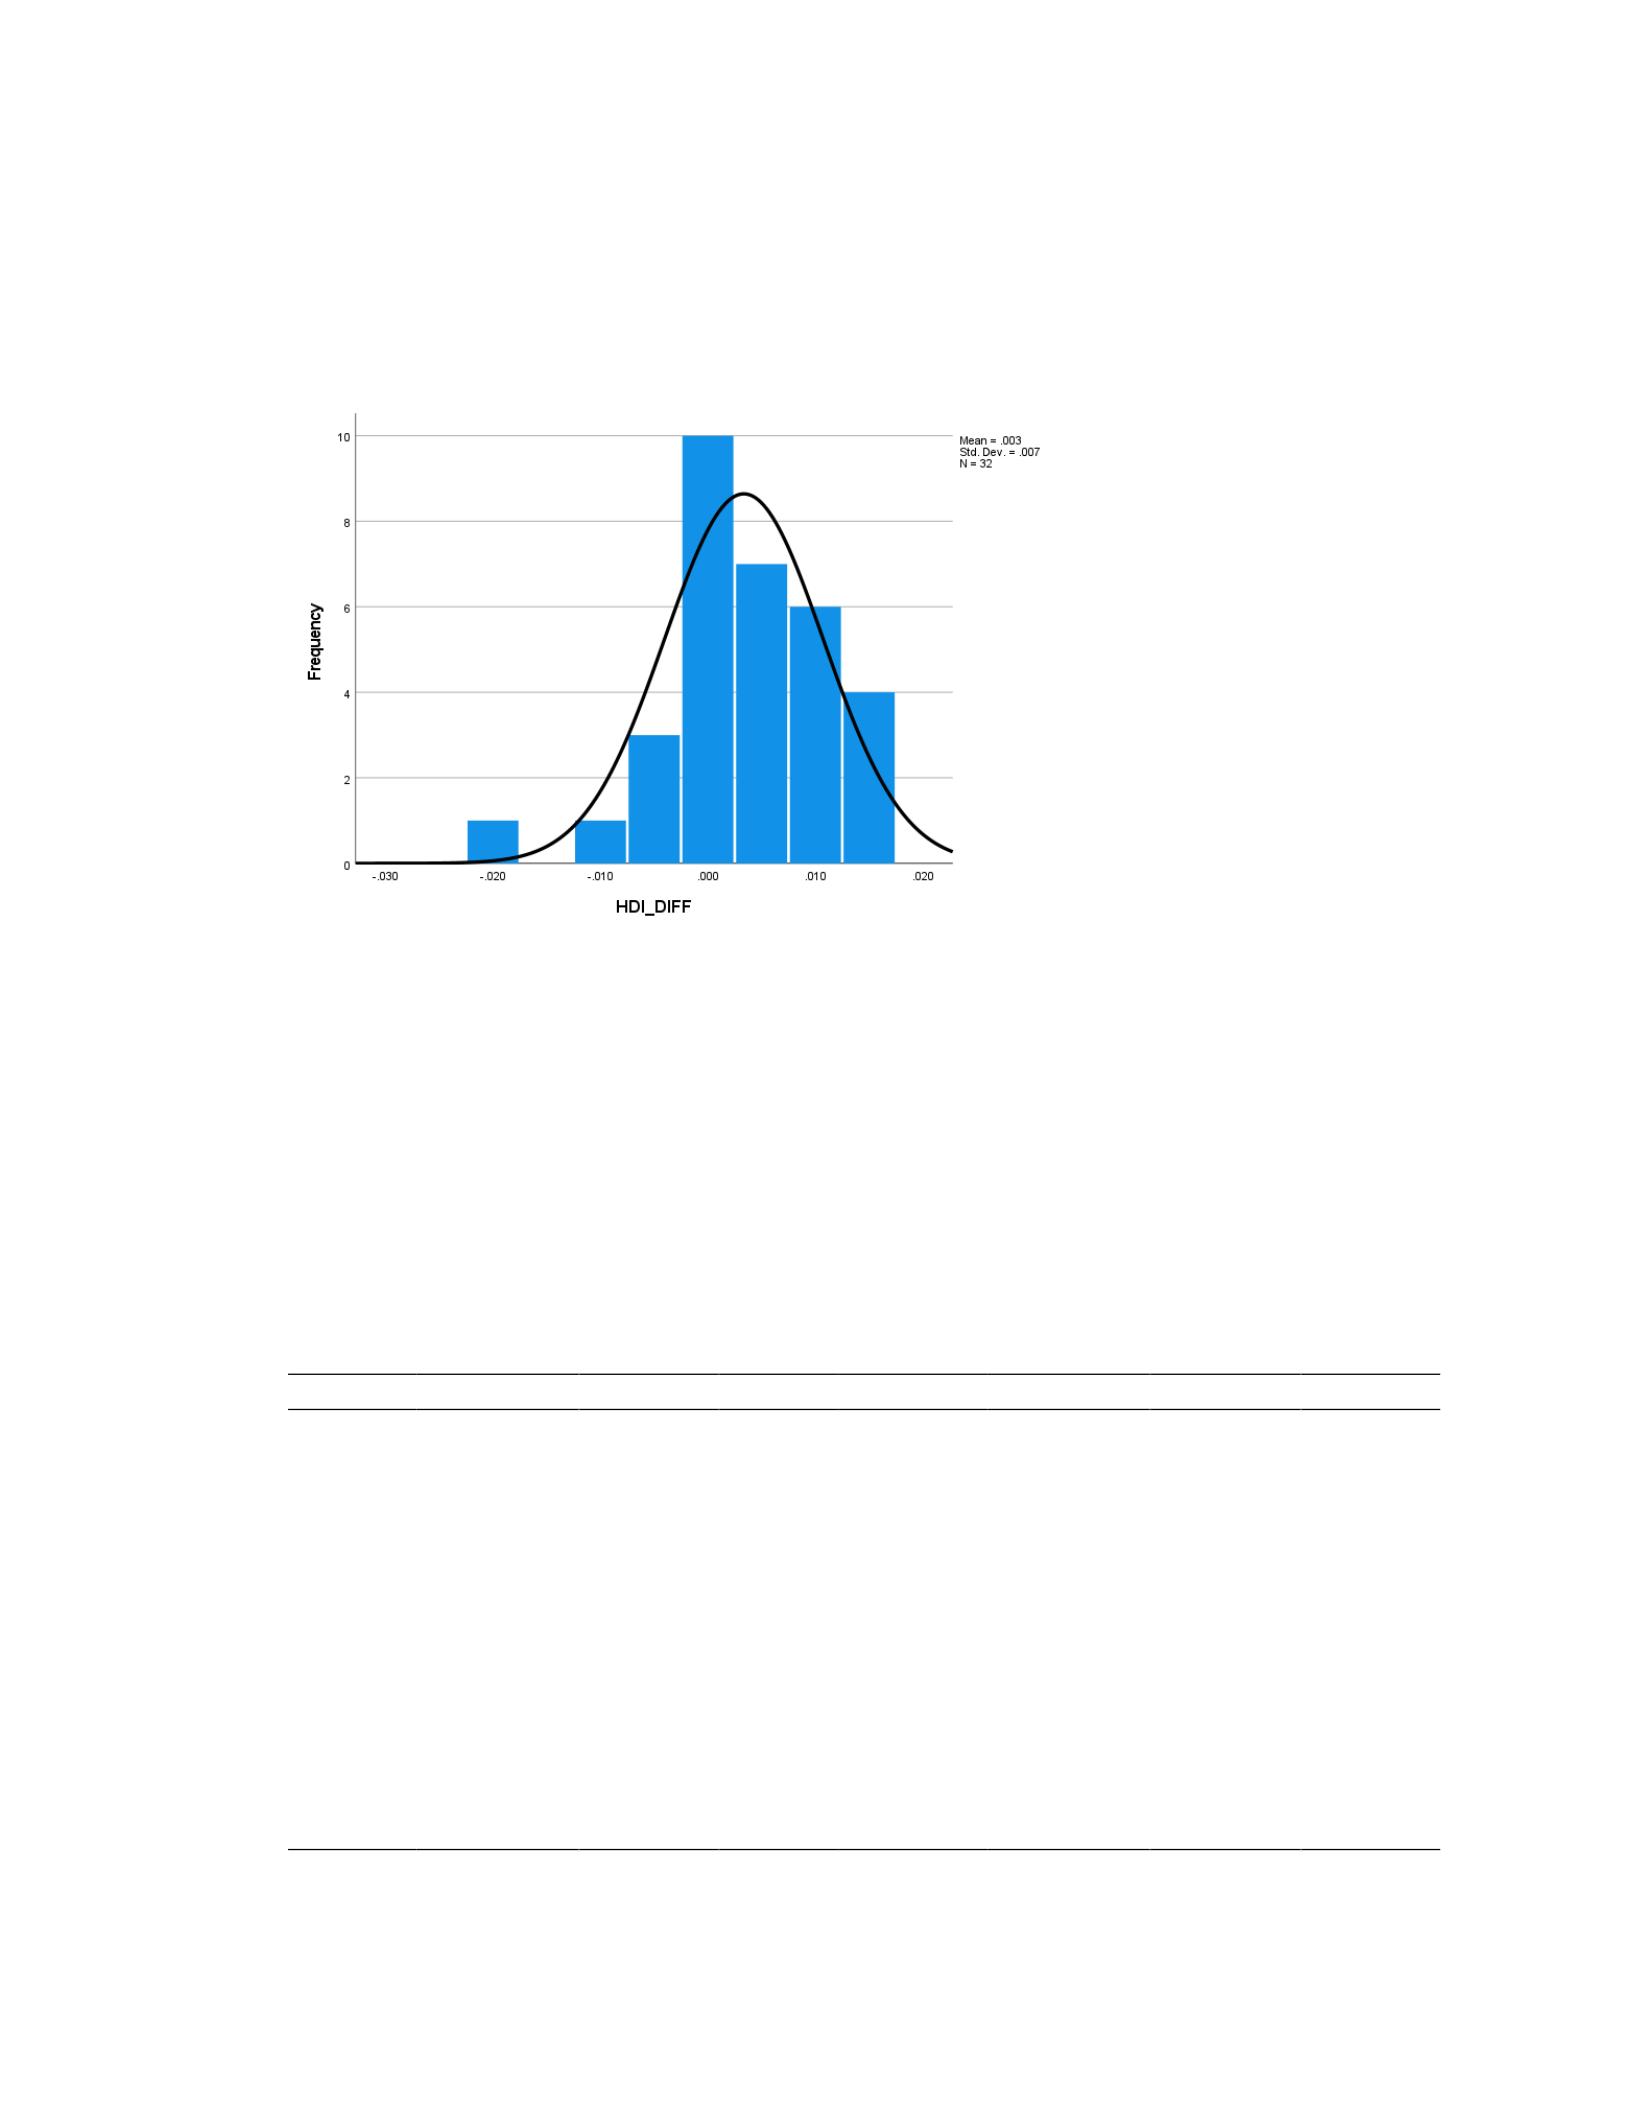
74
Figure 9
Histogram of H_DIFF
With these visual presentations of the transformed data, I proceeded to check the data for
multicollinearity, an important assumption in regression analysis. I ran the Pearson
Correlation to check for the assumption of linearity.
Table 6
Pearson Correlations
LT
LM_DIFF
T
GDP
DIFF
FDI_DIFF
H_DIFF
LT
Pearson r
1
.219
.236
-.030
.014
.534**
p (2-tailed)
.228
.194
.872
.939
.002
N
32
32
32
32
32
32
LM_DIFF
Pearson r
.219
1
.137
.230
-.008
-.078
p (2-tailed)
.228
.455
.205
.963
.671
N
32
32
32
32
32
32
T
Pearson r
.236
.137
1
.017
.055
.293
p (2-tailed)
.194
.455
.928
.764
.104
N
32
32
32
32
32
32
GDP_DIF
F
Pearson r
-.030
.230
.017
1
.208
-.060
p (2-tailed)
.872
.205
.928
.253
.743
N
32
32
32
32
32
32
FDI_DIFF
Pearson r
.014
-.008
.055
.208
1
-.235
75
p (2-tailed)
.939
.963
.764
.253
.195
N
32
32
32
32
32
32
H_DIFF
Pearson r
.534**
-.078
.293
-.060
-.235
1
p (2-tailed)
.002
.671
.104
.743
.195
N
32
32
32
32
32
32
** Correlation is significant at the 0.01 level (2-tailed).
Table 6 presents the Pearson correlation results. The results indicated a weak
negative correlation between employment in the tourism sector and GDP, a weak positive
correlation between employment in the tourism sector and FDI, and a moderate positive
correlation between employment in the tourism sector and H. The results also indicated a
weak positive correlation between employment in the mining sector and GDP, and both
FDI and H had a weak negative correlation with employment in the mining sector. Only
the correlation between employment in the tourism sector and H was significant at .002.
To further check for the linearity assumption, I produced scatterplots of the
residuals. Figure 10 presents the scatterplot for the residuals of employment in the mining
sector and indicates that the assumption of homoscedasticity is met.
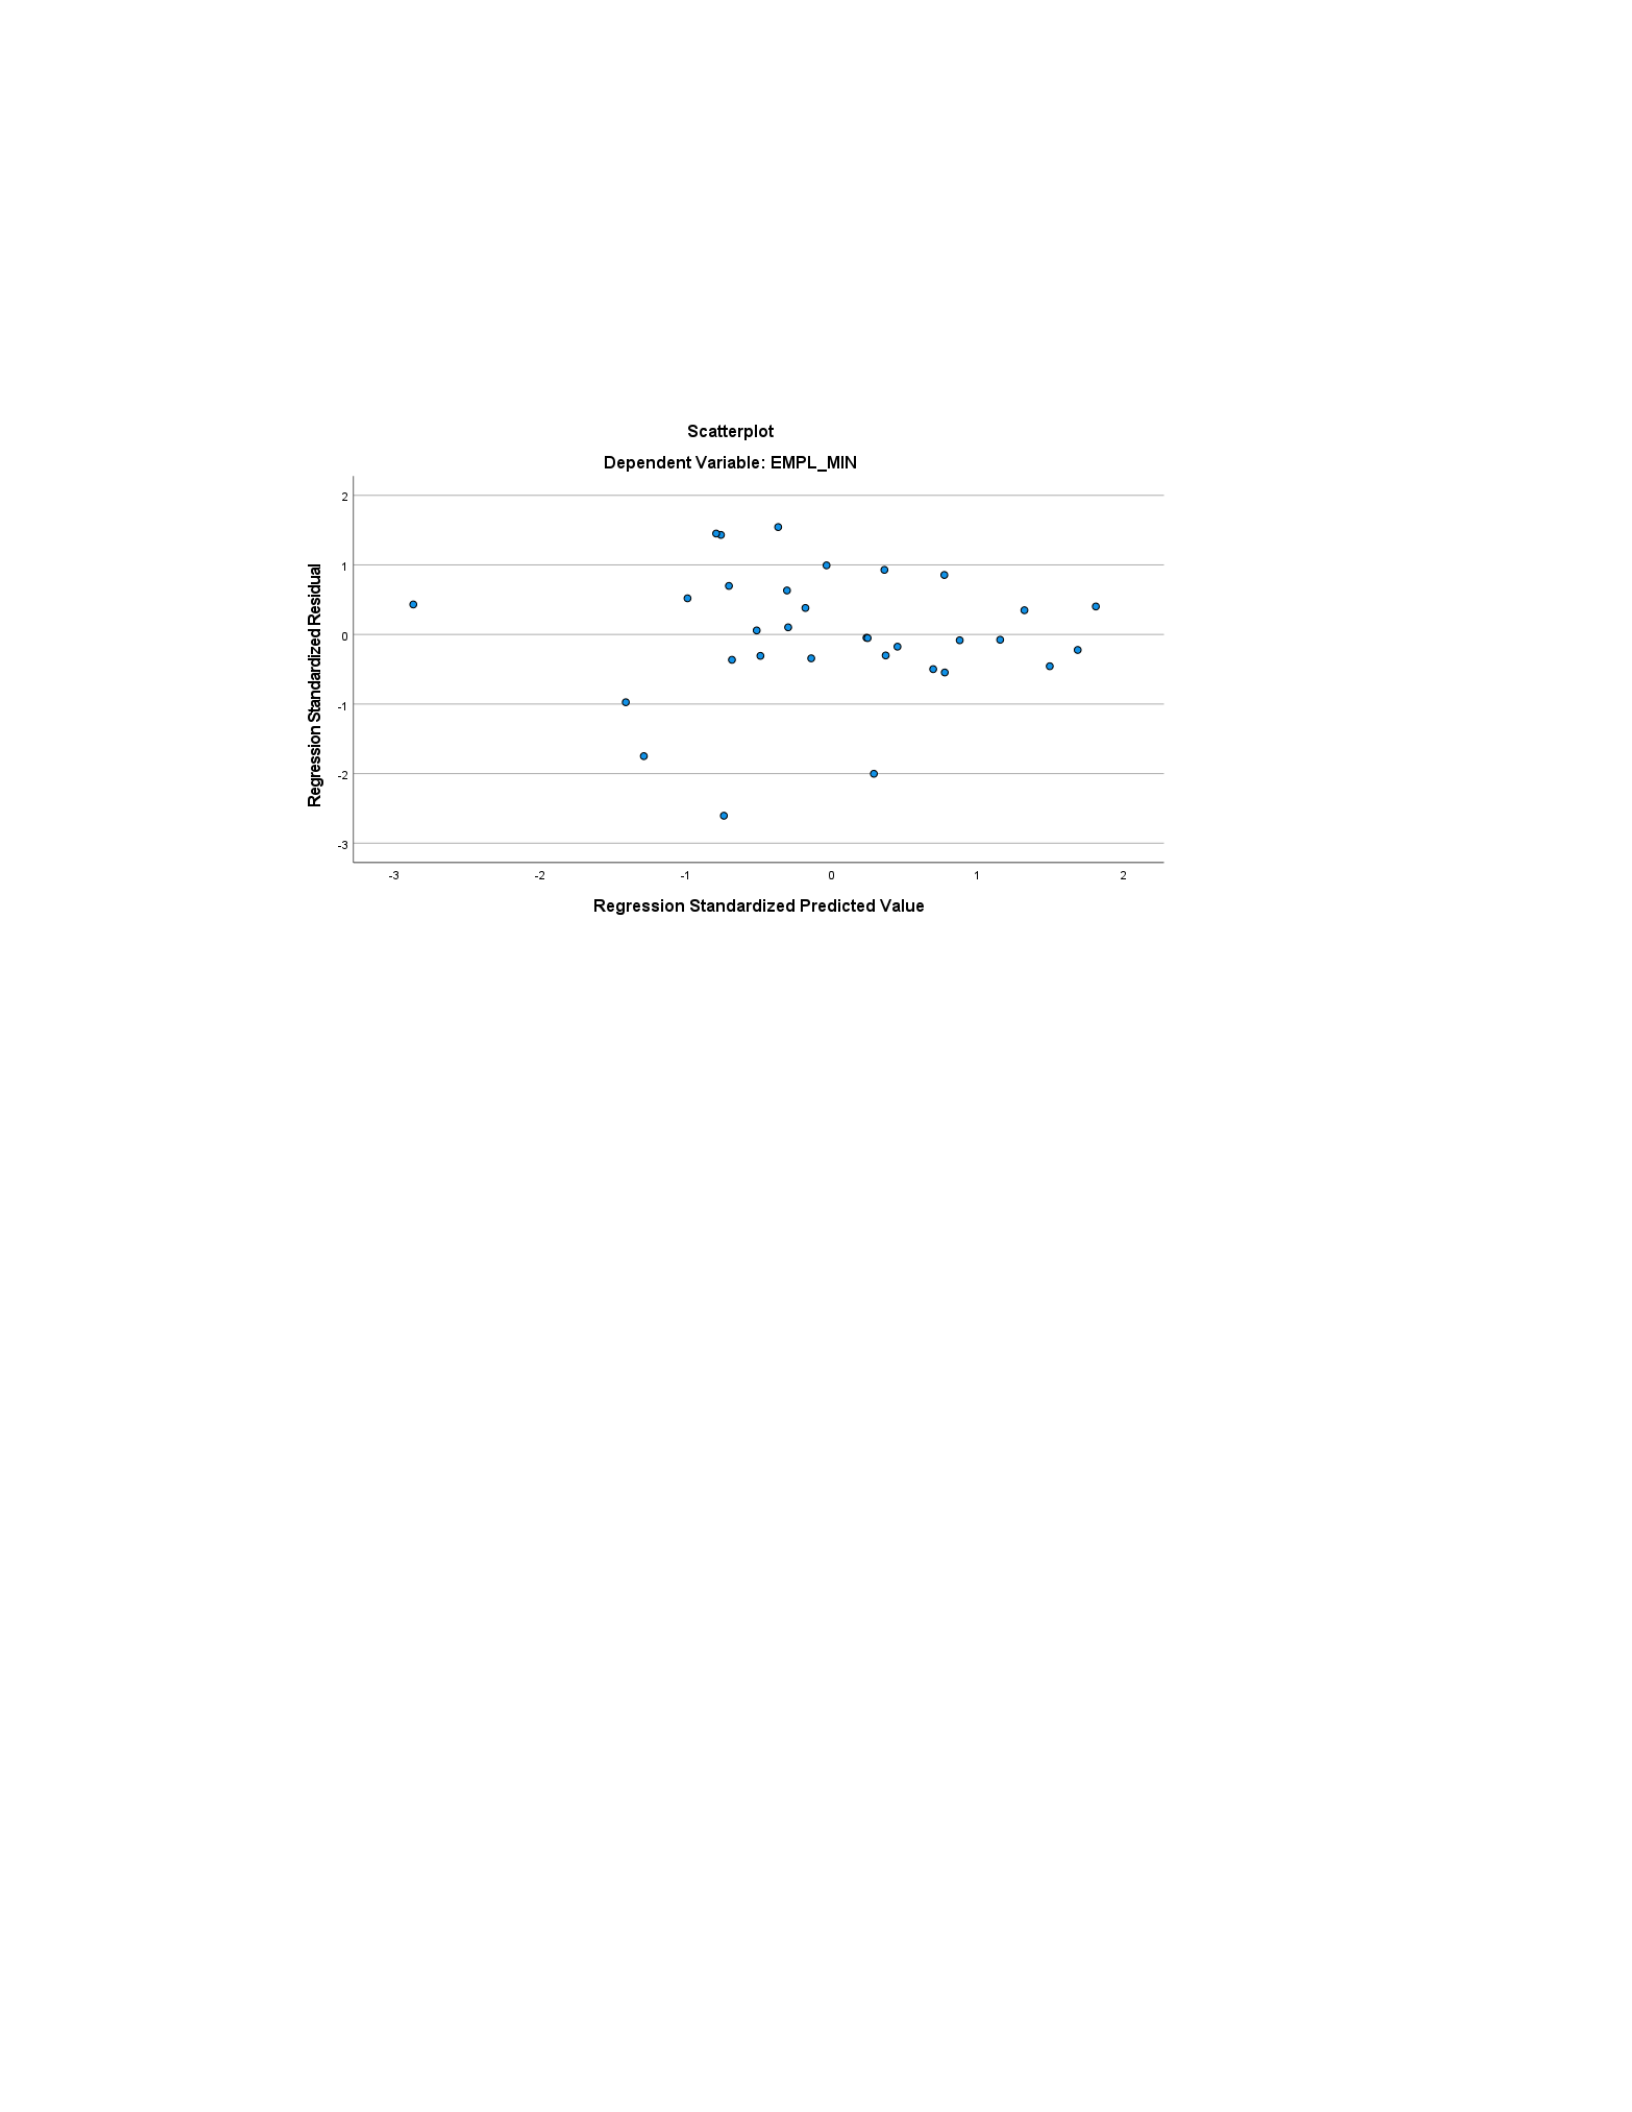
76
Figure 10
Scatterplot of Employment in the Mining Sector
Figure 11 shows the residuals for employment in the tourism sector and that the
assumption of homoscedasticity is met. I tested for multicollinearity by using the VIF in
SPSS. The VIF values for employment in the tourism sector as the dependent variable
and GDP, FDI, and H as the independent variable are all slightly above 1, indicating
moderate correlation between the dependent and independent variables. The results are
presented in Table 7.
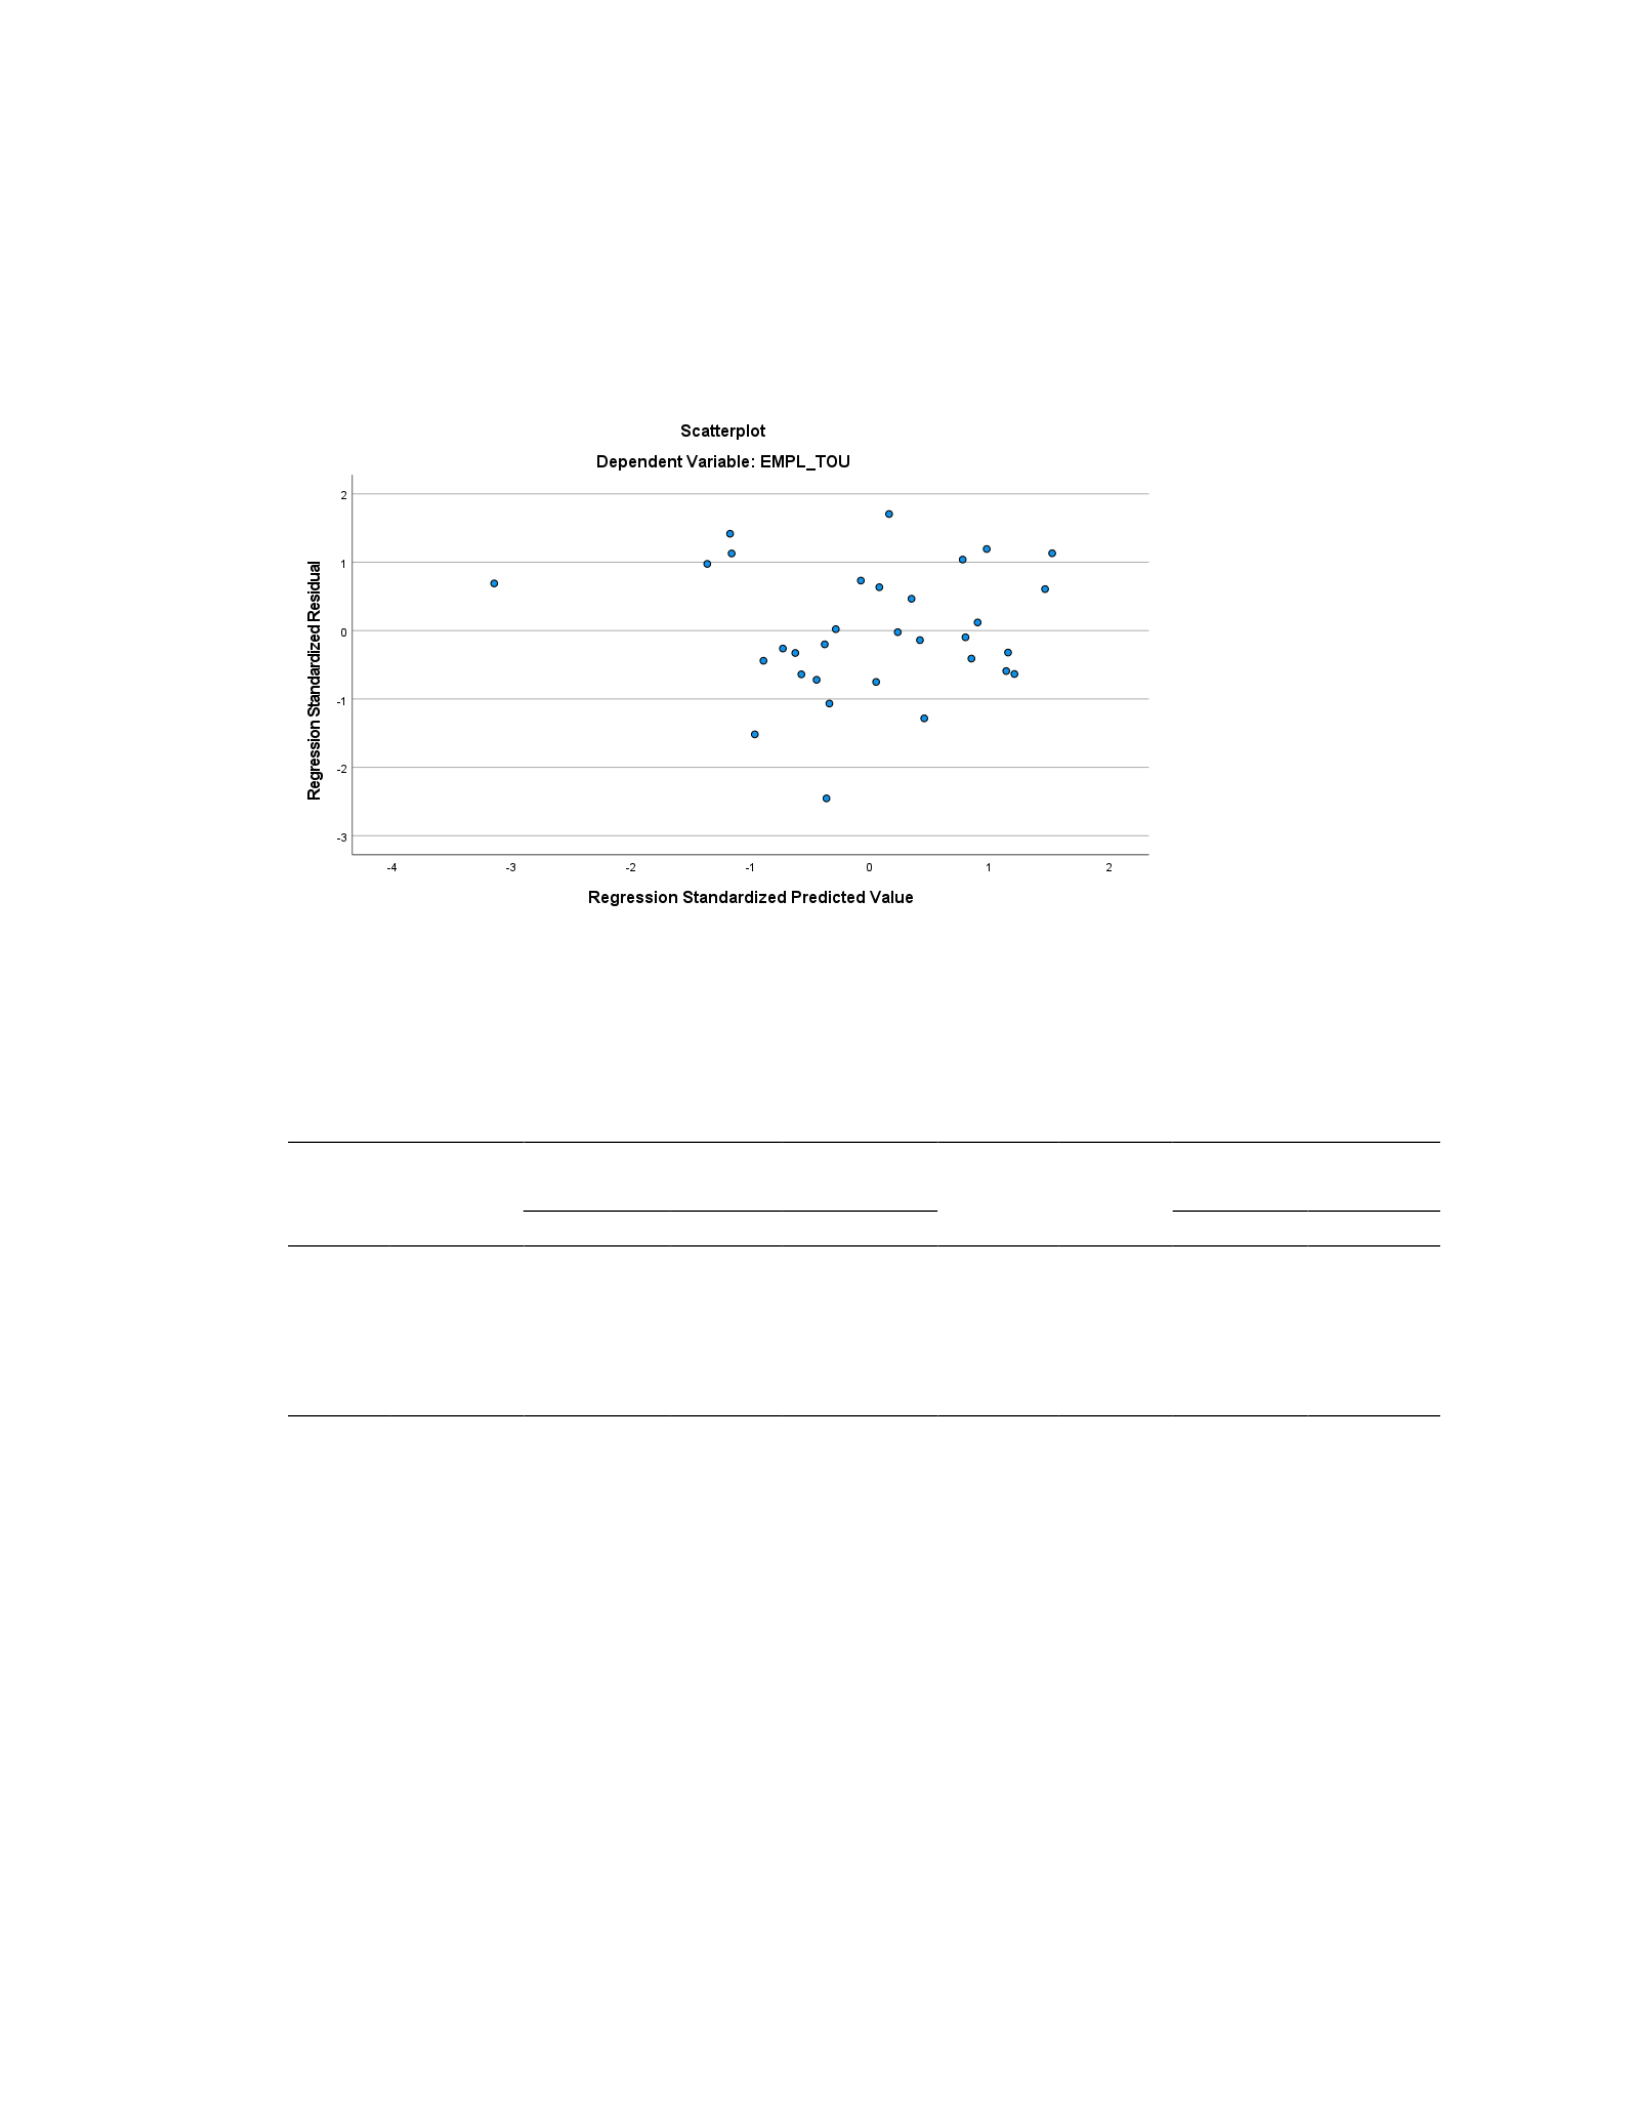
77
Figure 11
Scatterplot of Employment in the Tourism Sector
Table 7
Coefficients (LT)
Model
Unstandardized
Coefficients
Standardized
Coefficients
t
p
Collinearity statistic
B
SE
β
Tolerance
VIF
1
(Constant)
4.254
.069
61.986
<.001
GDP_DIF
F
-.001
.007
-.027
-.169
.867
.957
1.045
FDI_DIFF
.025
.027
.153
.929
.361
.907
1.103
H_DIFF
30.833
8.788
.568
3.509
.002
.944
1.059
Note. The dependent variable was LT.
Using employment in the mining sector as the dependent variable and GDP, FDI,
and H as the independent variables also produced VIF values slightly more than 1,
indicating moderate correlation between the variables (see Table 8).
78
Table 8
Coefficients (LM_DIFF)
Coefficients a
Model
Unstandardized
Coefficients
Standardized
Coefficients
t
p
Collinearity statistics
B
SE
β
Tolerance
VIF
1
(Constant)
-.051
.075
-.685
.499
GDP_DIF
F
.011
.008
.241
1.290
.208
.957
1.045
FDI_DIF
F
-.012
.030
-.078
-.406
.688
.907
1.103
H_DIFF
-4.162
9.576
-.082
-.435
.667
.944
1.059
a The dependent variable was LM_DIFF.
Analyses and Results for Research Questions 1 and 2
After conducting all the tests to check for the fulfillment of the assumptions of
time series data, I ran the regressions to address RQs 1 and 2. RQ1 was, What is the
impact of tax incentives on FDI and employment creation in Botswana? To answer the
question, I ran two regressions. In the first regression, I modelled employment in the
mining sector, the dependent variable, against tax incentives, GDP, FDI, and H. In the
second regression, I used employment in the tourism sector as the dependent variable,
with tax incentives, GDP, FDI, and H as the independent variables.
I examined the relationship between employment in the mining sector as the
dependent variable and tax incentives, FDI, GDP, and H as the independent variables.
Table 9 presents the model summary. The DW-statistic, at 1.769, indicated that there was
no autocorrelation in the model. The R2 of .091 indicates that the independent variables
caused about 9% of the changes in the dependent variable.
𝐿𝑀𝑖.𝑡 = 𝛽0 + 𝛽1𝑇𝑖.𝑡 + 𝛽2 𝐹𝐷𝐼𝑖.𝑡 + 𝛽3 𝐺𝐷𝑃𝑖.𝑡 + 𝛽4𝐻𝑖.𝑡 + 𝜀𝑖.𝑡
79
Table 9
Model Summary (LM_DIFF)
Model summary a
Model
R
R2
Adjusted R2
SE estimate
Durbin-
Watson
1
.302 b
.091
-.043
.3837
1.769
a The dependent variable was LM_DIFF.
b The predictors: (constant) were H_DIFF, GDP_DIFF, T, and FDI_DIFF.
Table 10 presents the analysis of variance. The F-statistic was .679, and the model
was insignificant at .613. My null hypothesis was that there is no impact of tax incentives
on FDI and/or employment creation in Botswana and my alternative hypothesis was that
there is an impact of tax incentives on FDI and/or employment creation in Botswana.
Since the F-statistic was found to be insignificant, I accepted the null hypothesis that
there is no impact of tax incentives on FDI and/or employment creation in Botswana.
Table 10
Analysis of Variance (LM_DIFF)
ANOVA a
Model
SS
df
MS
F
p.
1
Regression
.400
4
.100
.679
.613 b
Residual
3.975
27
.147
Total
4.375
31
a. The dependent variable was LM_DIFF.
b. The predictors: (constant) were H_DIFF, GDP_DIFF, T, and FDI_DIFF.
80
Table 11
Coefficients (LM_DIFF)
Coefficients a
Model
Unstandardized
coefficients
Standardized
coefficients
t
p
Collinearity statistics
B
SE
β
Tolerance
VIF
1
(Constant)
-.195
.173
-1.131
.268
T
.183
.197
.179
.926
.363
.898
1.114
GDP_DIFF
.010
.008
.240
1.277
.212
.956
1.046
FDI_DIFF
-.016
.030
-.101
-.521
.607
.892
1.121
H_DIFF
-7.114
10.116
-.140
-.703
.488
.851
1.175
a The dependent variable was LM_DIFF.
I ran another regression with employment in the tourism sector as the dependent
variable and tax incentives, GDP, FDI, and H. Table 12 presents the model summary and
the R2 indicates that 31% of the variations in the dependent variable are caused by the
independent variables. The DW-statistic is 1.594, indicating that there is no
autocorrelation in the model.
𝐿𝑇𝑖.𝑡 = 𝛽0 + 𝛽1𝑇𝑖.𝑡 + 𝛽2 𝐹𝐷𝐼𝑖.𝑡 + 𝛽3 𝐺𝐷𝑃𝑖.𝑡 + 𝛽4𝐻𝑖.𝑡 + 𝜀𝑖.𝑡
Table 12
Model Summary (LT)
Model summary a
Model
R
R2
Adjusted R2
SE of the
estimate
Durbin-Watson
1
.557 b
.311
.208
.3566
1.594
a The dependent variable was LT.
b The predictors: (constant) were H_DIFF, GDP_DIFF, T, and FDI_DIFF.
81
Table 13 presents the analysis of variance and the model was significant at 5%
level of confidence, with the F-statistic at 3.040, p = .034, which is less than .05,
indicating that at least one independent variable was a predictor of LT, employment in
the tourism sector.
Table 13
Analysis of Variance (LT)
ANOVA a
Model
SS
df
MS
F
p.
1
Regression
1.546
4
.387
3.040
.034 b
Residual
3.433
27
.127
Total
4.979
31
a The dependent variable was LT.
b The predictors: (constant) were H_DIFF, GDP_DIFF, TAX, and FDI_DIFF.
The coefficients table indicates that only H at first difference was significant at
5%, t=3.152, p=.004, which shows that it was the only variable that explained the
variation in employment in the tourism sector. TAX, GDP_DIFF, and FDI_DIFF were all
insignificant, indicating that they did not cause the variations in the dependent variable.
Table 14
Coefficients (LT)
Coefficients a
Model
Unstandardized
Coefficients
Standardized
Coefficients
t
p
Collinearity statistics
B
SE
β
Tolerance
VIF
1
(Constant)
4.195
.161
26.111
<.001
TAX
.075
.183
.069
.407
.687
.898
1.114
GDP_DIF
F
-.001
.008
-.028
-.170
.866
.956
1.046
FDI_DIFF
.024
.028
.145
.854
.400
.892
1.121
82
H_DIFF
29.628
9.400
.546
3.152
.004
.851
1.175
a The dependent variable was LT.
RQ2 was, What is the mediating role of FDI in tax incentives and employment
creation in Botswana? To answer the question, I ran mediation analysis firstly for
employment in the mining sector as the dependent variable and secondly for employment
in the tourism sector as the dependent variable. Because all the variables were previously
presented in graphs, I did not repeat that step.
I ran three regressions to (1) predict the dependent variable, LM, from the
independent variable, TAX, (2) predict the mediatory variable, FDI, from the causal
variable, TAX, and (3) predict the outcome variable, LM, from both TAX and FDI. Table
15 presents the ANOVA for employment in the mining sector and tax incentives. I found
the overall significance of tax incentives on employment in the mining sector to be
statistically significant at F(1,31)=4.331, p=.046. The overall significance of TAX on
FDI was also found to be statistically significant at p=.004 as presented in Table 16.
Table 15
Analysis of Variance (LM)
ANOVA a
Model
SS
df
MS
F
P
1
Regression
1.579
1
1.579
4.331
.046 b
Residual
10.939
30
.365
Total
12.519
31
a The dependent variable was LM.
b The predictor: (constant) was TAX.
83
Table 16
Analysis of Variance (FDI)
ANOVA a
Model
SS
df
MS
F
p.
1
Regression
47.565
1
47.565
9.947
.004 b
Residual
143.455
30
4.782
Total
191.020
31
a The dependent variable was FDI.
b The predictor: (constant) was TAX.
Table 17
Model Summary (LM)
Model summary a
Model
R
R2
Adjusted R2
SE of the
estimate
Durbin-Watson
1
.438 b
.192
.136
.5906
.612
a The dependent variable was LM.
b The predictors: (constant) were FDI and TAX.
Table 18
Analysis of Variance (LM)
ANOVA a
Model
SS
df
MS
F
P
1
Regression
2.402
2
1.201
3.443
.046 b
Residual
10.117
29
.349
Total
12.519
31
a The dependent variable was LM.
b The predictors: (constant) were FDI and TAX.
84
The regression for the outcome variable, LM and both TAX and FDI indicates
that only TAX was statistically significant at p=.014, while FDI was insignificant. From
the model summary in Table 17, R2=.192, indicating that only 19% of the variation in
LM was explained by TAX and FDI. The model was significant at F(2, 31)=3.443,
p=.046.
I found the overall effect of TAX on LT to be statistically insignificant. However,
the results presented in Table 21 showing the unstandardized coefficients for LT as the
dependent variable and TAX and FDI as the independent variables indicated that FDI
was statistically significant at p=.018. The model summary (see Table 19) shows that
R2=.223, indicating that 22% of the variations in the dependent variables were explained
by the independent variables. The ANOVA, presented in Table 20 shows that the model
was significant with F(2,31)=4.163, p=.026.
Table 19
Model Summary (LT)
Model summary a
Model
R
R2
Adjusted R2
SE of the
estimate
Durbin-Watson
1
.472 b
.223
.169
.3652
1.408
a The dependent variable was LT.
b The predictors: (constant) were FDI and TAX.
Table 20
Analysis of Variance (LT)
ANOVA a
Model
SS
df
MS
F
p
85
1
Regression
1.110
2
.555
4.163
.026 b
Residual
3.868
29
.133
Total
4.979
31
a The dependent variable was LT.
b The predictors: (constant) were FDI and TAX.
Table 21
Coefficients (LT)
Coefficients a
Model
Unstandardized
Coefficients
Standardized
Coefficients
t
p
Collinearity
statistics
B
SE
β
Tolerance
VIF
1
(Constant)
4.215
.166
25.383
<.001
TAX
.000
.205
.000
.002
.999
.751
1.3
3
FDI
.076
.030
.472
2.499
.018
.751
1.3
3
a The dependent variable was LT.
Findings for Research Question 1
RQ1 concerned the impact of tax incentives on FDI and employment creation in
Botswana. The null hypothesis was that there is no impact of tax incentives on FDI
and/or employment creation in Botswana. The results for the regression with employment
in the mining sector as the dependent variable established that there was no impact of tax
incentives on FDI and/or employment creation in Botswana. I, therefore, accepted the
null hypothesis that there is no impact of tax incentives on FDI and/or employment
creation in Botswana using evidence from the mining sector. However, running a
regression with employment in the tourism sector as the dependent variable yielded

86
different results. The results indicated that there was an impact of tax incentives on FDI
and/or employment creation in Botswana. I, therefore, rejected the null hypothesis.
Findings for Research Question 2
RQ2 was aimed at finding out the mediating role of FDI in tax incentives and
employment creation in Botswana. For the regression with employment in the mining
sector as the dependent variable, tax incentives had an impact on the dependent variable
and FDI was found to be insignificant. I, therefore, accepted the null hypothesis that FDI
plays no mediating role in tax incentives and employment creation in Botswana using
evidence from the mining sector. Using employment in the tourism sector, FDI had an
impact on the dependent variable and tax incentives had an impact on FDI. In this regard,
I rejected the null hypothesis that FDI plays no mediating role in tax incentives and
employment creation in Botswana using evidence from the tourism sector.
Summary
I presented the results of my regression analyses in this chapter. I responded to
two RQs using secondary data sourced from the Government of Botswana, Statistics
Botswana, Bank of Botswana, IMF, and World Bank and Open Data for Africa. I used
multiple regression analysis to respond to RQ1 to investigate the impact of tax incentives
on FDI and employment creation in Botswana, using employment in the mining and
tourism sectors as the dependent variables. I also ran mediation analysis to test for the
mediating role of FDI in tax incentives and employment creation in Botswana, again
using employment in the mining and tourism sectors as the independent variables.

87
The regression results for employment in the mining sector indicated that there
was no impact of tax incentives on FDI and/or employment creation in Botswana.
Running the regression with employment in the tourism sector as the dependent variable
yielded significant results and I accepted the alternative hypothesis that there was an
impact of tax incentives on FDI and/or employment creation on Botswana. A thorough
investigation, however, indicated that only H caused changes in the dependent variable.
To further understand the relation among the variables, I used mediation analysis
to determine the mediating role of tax incentives in FDI and employment creation. The
results indicated that tax incentives had an influence on employment in the mining sector,
while FDI did not. On the other hand, FDI was found to have a positive effect on
employment in the tourism sector. Tax incentives had a positive impact on FDI.
Therefore, I concluded that tax incentives had a positive impact on FDI, which in turn
had a positive impact on employment in the tourism sector. In the next chapter, I
discussed the analysis of my results, and presented the conclusion of the study and made
recommendations for further research based on my findings. Finally, I discussed the
implications of the study for positive social change.

88
Chapter 5: Discussion, Conclusions, and Recommendations
Introduction
The purpose of this quantitative study was to determine the impact of tax
incentives on FDI and employment creation in Botswana. I used evidence from the
mining and tourism sectors to determine where tax incentives are best suited to attract
FDI and subsequently create more employment. The study was motivated by the high
unemployment rate in Botswana and the need to find a solution to the challenge.
Estimated at 18%, the unemployment rate further results in prevalent poverty and
inequality in Botswana (Statistics Botswana, 2018). The national poverty head count ratio
was estimated at 16.3% in 2015–2016, while the Gini coefficient of consumption
inequality was estimated at .52 (Statistics Botswana, 2018). Tax incentives have
primarily been used in the mining and financial sectors in Botswana, and in this study, I
set out to determine what impact these might have on employment creation if directed to
the tourism sector.
The results indicated that there was no impact of tax incentives applied in the
mining sector on FDI and/or employment creation. When applied to the tourism sector,
the model was significant. However, the results indicated H was a predictor of
employment in the tourism sector. Tax, FDI, and GDP were all not good predictors of the
variation in employment in the tourism sector.
Interpretation of the Findings
Studies on the use of tax incentives to attract FDI to influence economic outcomes
have been carried out over time. Some studies cited in the literature found a positive

89
relationship between FDI and economic outcomes, including economic growth and
employment creation. For instance, Lawal (2018) found a strong positive relationship
between FDI and GDP in Nigeria, similar to findings of a positive relationship between
FDI in the agricultural sector and economic growth in Ghana by Awunyo-Vitor et al.
(2018). Others found a negligible relationship between FDI and some economic
outcomes, suggesting that other policies apart from tax incentives could be used to attract
FDI for employment creation. An example is Awolusi et al. (2017), who found a
negligible impact of FDI on economic growth in some selected African countries.
Multiple regression analysis was with employment in the mining sector as the dependent
variable and tax incentives, FDI, GDP, and H as the independent variables. No evidence
was found that the independent variables have an influence on the dependent variable.
However, using employment in the tourism sector as the dependent variable produced
significant results, indicating that there was an impact of tax incentives on FDI and/or
employment creation in Botswana. The results showed that H had an influence on the
dependent variable, employment in the tourism sector. This finding is consistent with
recommendations from other studies for governments to adequately skill their labor
forces to generate quality jobs (Basu et al., 2017; Khodeir, 2016). The Government of
Botswana (2016) also identified skills development as a key strategy to achieve
employment creation.
The study was based on the Keynesian theory of employment, which argues that
boosting aggregate demand through government intervention by cutting government
expenditure, reducing taxes, or reducing interest rates will result in employment creation.

90
In this study, I sought to investigate the impact of reducing taxes on employment creation
using evidence from the mining and tourism sectors. The regression results for
employment in the mining sector indicated that there was no impact of tax incentives on
FDI and/or employment creation in Botswana. Running the regression with employment
in the tourism sector as the dependent variable yielded significant results, and the null
hypothesis was accepted that there was an impact of tax incentives on FDI and/or
employment creation on Botswana. However, only H was found to be significant in the
model. I also carried out mediation analysis to further understand the relationship among
the variables. The results indicated that tax incentives had an influence on employment in
the mining sector, while FDI did not. On the other hand, FDI was found to have a
positive effect on employment in the tourism sector. Tax incentives had a positive impact
on FDI. Therefore, I concluded that tax incentives have a positive impact on FDI, which
in turn have a positive impact on employment in the tourism sector. The results
disconfirmed the null hypothesis that FDI plays no mediating role in tax incentives and
employment creation in Botswana. The findings from my study are consistent with the
Keynesian theory of employment that reducing taxes has a positive effect on employment
creation.
Limitations of the Study
I used archival data from various sources, which might have affected the accuracy
of the results. Although the data were from reputable sources like the World Bank, IMF,
the Government of Botswana, and other sources, I cannot vouch for the accuracy of the
data. In addition, proxy data were used for employment in the tourism sector due to

91
unavailability of the exact data on that variable. FDI flows were also used when the FDI
stock might have been a better indicator of FDI. The choice of employment in the tourism
sector might also have yielded results that are not consistent with the theory on
employment due to the seasonality of the industry. Perhaps the application of tax
incentives to the agricultural sector might have yielded more accurate results. Further,
multiple regression analysis was used, which is not robust given its linearity assumption
that is rarely applicable in real life data.
Recommendations
The results of the study indicated that H positively impacted on employment in
the tourism sector. Further, the findings indicated that FDI played a mediating role in tax
incentives and employment in the tourism sector. The government should, therefore,
invest in skills development for employment creation. The government of Botswana
should also consider using tax incentives in the tourism sector to encourage FDI into the
sector. Additionally, the government should consider developing policies aimed at
attracting domestic investment into the tourism sector to enhance employment creation in
that sector.
Future studies should consider examining the impact of tax incentives and FDI on
the agricultural sector, which is also labor intensive. Other labor-intensive sectors may
also be studied to assess the impact of applying tax incentives to attract FDI in those
sectors. Additionally, future studies may use domestic investments as one of the
variables. Future studies may also consider using the FDI stock instead of FDI flows.
Also, applying other methodologies apart from multiple regression analysis might yield

92
better results. For instance, the two stage least squares regression analysis might be a
better estimation technique considering the interdependence of the variables in this study.
Further, other researchers may replicate this study in other jurisdictions.
Implications
Implications for Society
In this study, I focused on the impact of targeting tax incentives to the tourism
sector to attract FDI to that sector and enhance job creation. The results of the regression
were significant, indicating that there was an impact of tax incentives on FDI and/or
employment in the tourism sector. These results are important for the government of
Botswana to create employment, with a positive impact on individuals who are employed
in the tourism sector, providing a spillover effect into related sectors. The spillover effect
may also be felt in the families of the employed individuals who will provide a social
safety net for their various families, with an expected overall benefit to society at large
through improved social cohesion.
Implications for Practice and/Policy
Policymakers can also benefit from the results of the study by understanding the
impact of tax incentives on the tourism sector. Also they can be alerted to the fact that
there is need to invest more in education and skills development to create more jobs. The
study results further indicated that H had a positive impact in employment in the tourism
sector, influenced by the mediating effect of FDI.

93
Conclusion
The findings from the study indicated that the model with employment in the
mining sector as the dependent variable yielded insignificant results, with tax incentives,
GDP, FDI, and H as the independent variables. However, using employment in the
tourism sector yielded significant results. Nevertheless, the results with employment in
the tourism sector as the dependent variable indicated that only H was the significant
variable, suggesting that it drove the increase in employment in the tourism sector. This
link between H and employment creation is consistent with the recommendations from
Basu et. al (2017), Khodeir (2016), and Magombeyi et. al. (2017) that it was important to
adequately skill the labor force to attract investments aimed at generation of decent jobs.
The finding on the mediating role of FDI in tax incentives and employment
creation indicated that FDI plays a mediating role in tax incentives and employment in
the tourism sector, while no such effect was found for employment in the mining sector.
This finding was consistent with Garsous et al. (2017) that targeted tax incentives were
effective in creating employment in the tourism sector of the Brazilian Sudene area.
However, this result should be interpreted with caution considering that the findings of
RQ1 that only H was a significant indicator of employment in the tourism sector. While
tax incentives can be used to attract FDI for employment creation in the tourism sector,
skills development should be prioritized to create decent jobs. These combined
interventions will ensure that the authorities in Botswana are better able to tackle the
challenge of persistent unemployment in Botswana, which stood at 23.6% in 2022
(World Bank, n.d.-c).
94
References
Adebayo, O. O. (2018). Taxation and economic diversification as tools for a sustainable
economy: Lessons from Canada [Master’s thesis, University of Manitoba].
MSpace.
https://mspace.lib.umanitoba.ca/bitstream/handle/1993/33561/adebayo_oluwaseyi
.pdf?sequence=1&isAllowed=y
Alfonsi, L., Bandiera, O., Bassi, V., Burgess, R., Rasul, I., Sulaiman, M., & Vitali, A.
(2020). Tackling youth unemployment: Evidence from a labor market experiment
in Uganda. Econometrica, 88(6), 2369–2414. https://doi.org/10.3982/ECTA15959
Awolusi, O. D., Adeyeye, O. P., & Pelser, T. G. (2017). Foreign direct investment and
economic growth in Africa: A comparative analysis. International Journal of
Sustainable Economy, 9(3), 183–198. https://doi.org/10.1504/IJSE.2017.085062
Awunyo-Vitor, D., & Sackey, R. A. (2018). Agricultural sector foreign direct investment
and economic growth in Ghana. Journal of Innovation and Entrepreneurship, 7,
Article 15. https://doi.org/10.1186/s13731-018-0094-3
Babbie, E. (2013). The practice of social research (13th ed.). Cengage Learning.
Basu, S., & Ghosh, S. (2017). FDI in India: Understanding the implications for growth
and job creation. Journal of Management and Public Policy, 9(1), 5–16.
https://doi.org/10.5958/0976-0148.2017.00005.1
Bayar, Y., & Sasmaz, M. U. (2017). Impact of foreign direct investment on
unemployment in emerging market economies: A co-integration analysis.
International Journal of Business and Economic Sciences Applied Research,
95
10(3), 90–96. https://doi.org/10.25103/ijbesar.103.07
Besada, H., & O’Bright, B. (2018). Policy impacts on Africa’s extractive sector:
Botswana, diamond dependence, and diversification in the post-diamond period.
Revue Gouvernance, 15(2), 86–105. https://doi.org/10.7202/1058089ar
Botlhale, E. (2021). Public revenue diversification in Botswana during crisis times.
Forum for Development Studies, 48(2), 271–288.
https://doi.org/10.1080/08039410.2021.1898464
Botswana Tourism. (2018). Annual report, 2017/2018.
https://www.flipsnack.com/botswanatourism/bto-201718-annual-report/full-
view.html
Buterin, V., Grdinic, M., & Drazenovic, B. O. (2018). Impact of institutional framework
and tax policy on foreign direct investment in selected European Union countries.
In H. Ribeiro, D. Naletina, & A.L. da Silva (Eds.), 35th International Scientific
Conference on Economic and Social Development – “Sustainability from an
Economic and Social Perspective” book of proceedings (pp. 129–141). Varazdin
Development and Entrepreneurship Agency. https://www.esd-
conference.com/upload/book_of_proceedings/Book_of_Proceedings_esdLisbon2
018_Online.pdf
Calcagno, P. T., & Hefner, F. L. (2018). Targeted economic incentives: An analysis of
state fiscal policy and regulatory conditions. The Review of Regional Studies, 48,
71–91. https://doi.org/10.2139/ssrn.3169394
Caponi, V. (2017). Public employment policies and regional unemployment differences.
96
Regional Science and Urban Economics, 63, 1–12.
https://doi.org/10.1016/j.regsciurbeco.2016.11.005
Chiwira, O. & Kambeu, E. (2016). Foreign direct investment and economic growth in
Africa: A dynamic causality test. British Journal of Economics, Management, and
Trade, 11(3), 1–8. https://doi.org/10.9734/BJEMT/2016/21723
Citizen Entrepreneurial Development Agency. (n.d.). Background.
https://www.ceda.co.bw/background
Coddington, A. (1983). Keynesian economics: The search for first principles. Routledge.
Deng, T., Hu, Y., & Ma, M. (2019). Regional policy and tourism: A quasi-natural
experiment. Annals of Tourism Research, 74, 1-16.
https://doi.org/10.1016/j.annals.2018.10.001
Etim, R. S., Jeremiah, M. S., & Jeremiah, O. O. (2019). Attracting foreign direct
investment (FDI) in Nigeria through effective tax policy incentives. International
Journal of Applied Economics, Finance and Accounting, 4(2), 36-44.
https://doi.org/10.33094/8.2017.2019.42.36.44
Garcia, J. D. (2020). Keynesian economics. Salem Press Encyclopedia.
Garsous, G., Corderi, D., Velasco, M., & Colombo, A. (2017). Tax incentives and job
creation in the tourism sector of Brazil’s SUDENE Area. World Development, 96,
87-101. https://doi.org/10/1016/j.worlddev.2017.02.034
Government of Botswana. (2008). Botswana Excellence: A Strategy for Economic
Diversification and Sustainable Growth.
https://www.greengrowthknowledge.org/sites/default/files/downloads/policy-
97
database/A%20Strategy%20for%20Economic%20Diversification%20and%20Sus
tainable%20Growth.pdf
Government of Botswana. (2016). National Development Plan 11, April 2017-March
2023. http://extwprlegs1.fao.org/docs/pdf/bot175398.pdf
Government of Botswana. (2021a). 2021 Budget Speech. www.parliament.gov.bw
Government of Botswana. (2021b). National Employment Policy for Botswana.
Government Printer.
Gupta, P. & Singh, A. (2016). Causal nexus between foreign direct investment and
economic growth: A study of BRICS nations using VECM and Granger causality
test. Journal of Advances in Management Research, 13(2), 179-202.
https://doi.org/10.1108/JAMR-04-2015-0028
Habanabakize, T. & Muzindutsi, P. (2018). Analysis of the Keynesian theory of
employment and sectoral job creation: The case of the South African
manufacturing sector. Folia Oeconomica Stetinensia, 18(1).
https://doi.org/10.2478/foli-2018-0010
Hardwick, P., Khan, B., & Langmead, J. (1994). An Introduction to Modern Economics
(4th ed). Longman.
Hlavacek, P. & Janacek, J. (2019). The influence of foreign direct investment and public
incentives on the socio-economic development of regions: An empirical study
from the Czech Republic. Economic and Management, 22(3).
https://doi.org/10.15240/tul/001/2019-3-001
Hsu, M., Lee, J., Leon-Gonzales, R., & Zhao, Y. (2019). Tax incentives and foreign
98
direct investment in China. Applied Economics Letters, 26(9), 777-780.
https://doi.org/10.1080/13504851.2018.1495817
Human Development Index. (n.d.). https://countryeconomy.com/hdi/botswana
International Labor Organization. (n.d.). Country Profiles.
https://ilostat.ilo.org/data/country-profiles/
International Labor Organization. (2021). Youth Employment in Times of COVID: A
global review of COVID-19 policy responses to tackle (un)employment and
disadvantage among young people.
https://www.ilo.org/emppolicy/pubs/WCMS_823751/lang--en/index.htm
International Monetary Fund. (n.d.). Country Data.
https://www.imf.org/en/Countries/BWA#countrydata
International Monetary Fund. (1998). Botswana: Selected Issues and Statistical
Appendix. https://www.imf.org/en/Publications/CR/Issues/2016/12/30/Botswana-
Selected-Issues-and-Statistical-Appendix-2618
International Monetary Fund. (2018, September 5). Botswana: 2018 Article IV
Consultation. IMF Country Report No. 18/268 [Press release].
https://www.imf.org/en/Publications/CR/Issues/2018/09/05/Botswana-2018-
Article-IV-Consultation-Press-Release-Staff-Report-and-Statement-by-the-46209
International Monetary Fund. (2020a, March 18). Botswana: Staff Report for the 2019
Article IV Consultation [Press release].
https://www.imf.org/en/Publications/CR/Issues/2020/03/18/Botswana-2019-
Article-IV-Consultation-Press-Release-Staff-Report-and-Statement-by-the-49276
99
International Monetary Fund. (2020b). Fiscal Monitor: Policies for the Recovery.
https://www.imf.org/en/Publications/FM/Issues/2020/09/30/october-2020-fiscal-
monitor#Full%20Report%20and%20Executive%20Summary
International Monetary Fund. (2021, February 5). Nigeria: 2020 Article IV Consultation.
IMF Country Report No. 21/33 [Press release].
https://www.imf.org/en/Publications/CR/Issues/2021/02/05/Nigeria-2020-Article-
IV-Consultation-Press-Release-Staff-Report-and-Statement-by-the-50064
Jefferis, K. (2016). Public Finance and Mineral Revenues in Botswana, Technical
Report. “The Global Partnership for Wealth Accounting and Valuation of
Ecosystem Services (WAVES): Report of the Botswana Preparation Phase.”
Centre for Applied Research and Econsult Botswana.
http://econsult.co.bw/tempex/file/Mineral%20revenues%20and%20public%20fin
ance_final_compressed.pdf
Karimov, M., Paradi-Dolgos, A., & Pavlin, R. K. (2020). An empirical analysis of the
relationship between foreign direct investment and unemployment rate: Evidence
from Turkey. European Research Studies Journal, 23(1), 453-464.
https://doi.org/10.35808/ersj/1562
Khambule, I. & Siswana, B. (2017). How inequalities undermine social cohesion: A case
study of South Africa. G20 Insights. https://doi.org/10.13140/RG.2.2.16250.2400
Khodeir, A. N. (2016). The impact of Chinese direct investments on employment in
Africa. Journal of Chinese Economic and Foreign Trade Studies, 9(2), 86-101.
https://doi.org/10.1108/JCEFTS-03-2016-0009
100
Koutsoyiannis, A. (1977). Theory of econometrics (2nd ed). Macmillan.
KPMG. (2016). Africa Incentive Survey 2016.
https://home.kpmg/content/dam/kpmg/pdf/2016/05/africa-incentive-survey-
2016.pdf
KPMG. (2018). Africa Incentive Survey: Transforming opportunities into value.
https://assets.kpmg/content/dam/kpmg/za/pdf/2018/November/Africa_Incentive_
Survey_2017_2018_2nd%20Edition.pdf
KPMG. (2019). Investing in Africa: A guide to tax/incentives in Africa.
https://assets.kpmg/content/dam/kpmg/ng/pdf/tax/ng-incentives-in-africa.pdf
KPMG. (2021). Botswana Tax & Budget Summary 2021/2022.
https://assets.kpmg/content/dam/kpmg/bw/pdf/Revised%20Botswana%20Tax%2
0and%20Budget%20Summary%202021-2022_210521.pdf
Laher, S. (2016). Ostinato rigore: Establishing methodological rigour in quantitative
research. South African Journal of Psychology, 43(3), 316-327.
https://doi.org/10.1177/0081246316649121
Lashitew, A. A., Ross, M. L., & Werker, E. (2020). What drives successful economic
diversification in resource-rich countries? The World Bank Research Observer,
0(0), 1-33. https://doi.org/10.1093/wbro/lkaa001
Lawal, K. K. (2018). Assessment of the Impact of Corporation Tax Incentives on Foreign
Direct Investment (FDI) in Nigeria. African Tax Research Network Working
Paper Series, 19, 1-24. African Tax Administration Forum.
Layser, M, D. (2019). A typology of place-based investment tax incentives. Washington
101
and Lee Journal of Civil Rights and Social Justice, 403, 1-18.
https://doi.org/10.2139/ssrn.3381394
Li, Q. (2016). Fiscal decentralization and tax incentives in the developing world. Review
of International Political Economy, 23(2), 232-260.
https://doi.org/10.1080/09692290.2015.1086401
Lodhi, K. M. (2017). Tax incentives and impact on investment in Pakistan. Abasyn
Journal of Social Sciences, 10(1), 192-211.
Magombeyi, M. T. & Odhiambo, N. M. (2017). Foreign direct investment in Botswana:
Trends, reforms, and challenges. Journal of Accounting and Management, 7(1),
15-32.
Makoni, P. L. (2015). Foreign direct investment – The case of Botswana. ŒCONOMICA
11(4), 160-173.
Miftari, F. (2016). Foreign direct investment and fiscal stimulation in Balkans: Evidence
from Albania, Kosovo, and Macedonia. In Primorac, Z., Bussoli, C., & Recker, N
(Eds.). 16th International Scientific Conference on Economic and Social
Development - “The legal challenges of modern world” book of proceedings (pp.
160-173). Varazdin Development and Entrepreneurship Agency.
https://www.wir.ue.wroc.pl/info/book/WUTff753d26c111453eb7f5907d2b43043
b/
Miles, D. & Scott, A. (2005). Macroeconomics: Understanding the wealth of nations
(2nd ed). John Wiley & Sons.
Moussa, S. N., Deyi, J., & Lin, L. (2015). Analysis of Guinean new mining fiscal regime:
102
Considerations for improvement. Resources Policy, 46, 113-126.
https://doi.org/10.1016/j.resourcepol.2015.04.007
Moyo, T. (2016). Promoting Industrialization in Mauritius, South Africa and Botswana:
Lessons for the future. Africa Development, XLI (3), 139-163.
Munongo, S., Akanbi, O. A., & Robinson, Z. (2017). Do tax incentives matter for
investment? A literature review. Business and Economic Horizons, 13(2),
152-168. https://doi.org/10.15208/beh.2017.12
Ndubuisi, J., & Urhoghide, R. O. (2018). Tax incentives and foreign direct investment
flows in Nigeria. Annals of the University of Petrosani, Economics, 18(1),
121-132.
Nsiah, H. (2017). Government policies, foreign direct investment (FDI) and
socioeconomic development: The case of Ghana. [Doctoral dissertation, Saint
Louis University]. ProQuest Dissertations & Theses Global.
Ogujiuba, K., & Cornellisen, M. (2020). Macroeconomic theory and unemployment: A
comparison between the Keynesian and New Classical Model. ACTA
Universitatis Danubius (Economica), 16(2), 71-88.
Olamide, O. F., Kalu. A. E., Solomon, O., & John, O. (2019). Economic diversification
and national development in Nigeria: Challenges and prospects. International
Journal of Mechanical Engineering and Technology, 10(8), 98-108.
https://doi.org/10.34218/IJMET.10.8.2019.008
Omeje, A. N., Mba, A. J., & Ugwu, M. O. (2020). Youth empowerment and
entrepreneurship in Nigeria: Implication for economic diversification. SAGE
103
Open, October-December 2020, 1-12. https://doi.org/10.1177/2158244020982996
Onodugo, V. A., Obi, K. O., Anowor, A. F., Nwonye, N. G., & Ofoegbu, G. N. (2017).
Does public spending affect unemployment in an emerging market? Risk and
Governance Control: Financial Markets and Institutions, 7(1), 32-40.
https://doi.org/10.22495/rgcv7i1art4
Onwuegbuzie, A. J. (2000). Expanding the framework of internal and external validity in
quantitative research. Annual Meeting of the Association for the Advancement of
Educational Research (pp. 1-63). US Department of Education.
Osabohien, R., Awolola, O. D., Matthew, O., Itua, O. Q., & Elomien, E. (2020). Foreign
direct investment inflow and employment in Nigeria. Investment Management
and Financial Innovations, 17(1), 77-84.
https://doi.org/10.21511/imfi.17(1).2020.07
O’Sullivan, E., Rassel, G. R., Berner, M., & Taliaferro, J. D. (2017). Research methods
for public administrators (6th ed.). Routledge.
Our World in Data. (n.d.). https://ourworldindata.org/human-development-
index#country-by-country-perspective-over-the-last-three-decades
Pickett, J. C., Reilly, D. P., & McIntyre, R. M. (2005). How to select a most efficient
OLS model for a time-series data. The Journal of Business Forecasting, 24(2),
11-15.
Ponjan, P, & Thirawat, N. (2016). Impacts of Thailand’s tourism tax cut: A CGE
analysis. Annals of Tourism Research 61, 45-62.
https://doi.org/10.1016/j.annals.2016.07.015
104
PwC. (n.d.). Worldwide Tax Summaries, Serbia: Corporate- tax credits and incentives.
https://taxsummaries.pwc.com/serbia/corporate/tax-credits-and-incentives
Rahman, A., & Muktadir, M. G. (2021). SPSS: An imperative quantitative data analysis
tool for social science research. International Journal of Research and Innovation
in Social Science, 5(10), 300-302. https://doi.org/10.47772/IJRISS.2021.51012
Redonda, A., de Sarralde, S. D., Hallerberg, M., Johnson, L., Melamud, A., Rozemberg,
R., Schwab, J., & von Haldenwang, C. (2019). Tax expenditure and the treatment
of tax incentives for investment. Economics: The Open-Access, Open-Assessment
E-Journal, 13(2019–12), 1-12. https://doi.org/10.5018/economics-
ejournal.ja.2019-12
Sari, N., Dewi, M. S., & Sun, Y. (2015). Indonesia: The effect of tax holiday on
economic growth related to foreign investment. Procedia-Social and Behavioral
Sciences, 211, 1008-1015. https://doi.org/10.1016/j.sbspro.2015.11.134
Schroeder, L. D., Sjoquist, D. L., & Stephan, P. E. (2018). Multiple linear regression. In:
Understanding Regression Analysis: An introductory guide. SAGE Publications.
Siyanbola, T. T., Adedeji, S. B., Adegbie, F. F., & Rahman, M. M. (2017). Tax
incentives and industrial/economic growth of sub-Saharan African States. Journal
of Advanced Research in Business and Management Studies, 7 (2), 78-90.
Slusarczyk, B. (2018). Tax incentives as a main factor to attract foreign direct
investments in Poland. Administratie si Management Public, 30, 67-81.
https://doi.org/10.24818/amp/2018.30-05
Statistics Botswana. (n.d.). https://statsbots.org.bw
105
Statistics Botswana. (n.d.). Data Portal. https://botswana.opendataforafrica.org/
Statistics Botswana. (2017). Multi-Topic Household Survey 2015/16: Economic Activity
Stats Brief. http://www.statsbots.org.bw/botswana-multi-topic-household-survey-
201516-stats-brief
Statistics Botswana. (2018). Multi-Topic Household Survey 2015/16.
http://www.statsbots.org.bw/sites/default/files/publications/Botswana%20Multi%
20Topic%20Household%20Survey%20REPORT%202015%2016.pdf
Statistics Botswana. (2020). Quarterly Multi-Topic Survey: Labour Force Module Report
Quarter 4: 2020. https://www.statsbots.org.bw/sites/default/files/MULTI-
TOPIC%20SURVEY%20QUARTER%204%202020%20LABOUR%20FORCE
%20MODULE%20REPORT.pdf
Statistics Botswana. (2021). International Merchandise Trade Statistics: Monthly Digest-
January 2021.
https://www.statsbots.org.bw/sites/default/files/IMTS%20January%202021.pdf
Tax Foundation. (n.d.). Tax Basics. https://taxfoundation.org/tax-basics/corporate-
income-tax-cit/
Thuita, G. W. (2017). An Investigation of the Effect of Tax Incentives on the FDIs: A
Case of EPZs in Athi River Kenya. Journal of Accounting, Finance, and Auditing
Studies, 3(1). 17-36.
Trading Economics. (n.d.). Botswana Unemployment Rate.
https://tradingeconomics.com/botswana/unemployment-rate
Tria, D., Harun, M., Alam, M., &Wang, M. (2022). Microcredit as a strategy for
106
employment creation: A systematic review of literature. Cogent Economics &
Finance, 10(1). https://doi.org/10.1080/23322039.2022.2060552
Tsaurai, K. (2018). Exploring the Employment Effect of FDI in BRICS: Does
Conditionalities Matter? Acta Universitatis Danubius, OEconomica, 14(3), 86-
103.
United Nations. (2017). Commodities and Development Report 2017: Commodity
Markets, Economic Growth, and Development.
https://unctad.org/system/files/official-document/suc2017d1_en.pdf
United Nations. (2018). Design and assessment of tax incentives in developing countries.
https://www.un.org/esa/ffd/wp-content/uploads/2018/02/tax-
incentives_eng.pdfUrban, J. B., and van Eeden-Moorefield, B. M. (2018). In:
Designing and proposing your research project. 111-117, Chapter 9. American
Psychological Association.
Vorosmarty, G., & Dobos, I. (2020). Green purchasing frameworks considering firm size:
a multicollinearity analysis using variance inflation factor. Supply Chain Forum:
An International Journal, 21(4), 290-301.
https://doi.org/10.1080/16258312.2020.1776090
Walden University, Office of Research & Doctoral Services. (2015, August 13).
Overview of qualitative research methods [Video file].
https://www.youtube.com/watch?v=IsAUNs-IoSQ
Warner, R. M. (2013). Applied statistics: From bivariate through multivariate techniques
(2nd ed.). SAGE Publications.
107
Wolff, R. D., & Resnick, S. A. (2012). Contending economic theories: neoclassical,
Keynesian, and Marxian. The MIT Press.
World Bank. (1993). Opportunities for Industrial Development in Botswana: An
Economy in Transition.
https://documents1.worldbank.org/curated/en/778911468767961121/pdf/multi0pa
ge.pdf
World Bank. (n.d.-a). Data.
https://data.worldbank.org/indicator/BX.KLT.DINV.CD.WD?locations=BW
World Bank. (n.d.-b) Data.
https://data.worldbank.org/indicator/BX.KLT.DINV.WD.GD.ZS?locations=BW
World Bank. (n.d.-c). Data.
https://data.worldbank.org/indicator/SL.UEM.TOTL.NE.ZS?locations=BW
World Bank (n.d.-d). World Development Indicators.
https://databank.worldbank.org/source/world-development-indicators
World Travel & Tourism Council. (2019). Botswana 2019 Annual Research: Key
Highlights. https://wttc.org
World Travel & Tourism Council. (2020). Travel and Tourism: Economic Impact 2020.
https://wttc.org/Research/Economic-Impact
World Travel and Tourism Council. (2021). Botswana 2021 Annual Research: Key
Highlights. https://wttc.org/Research/Economic-Impact
Yilmaz, K. (2013). Comparison of quantitative and qualitative research traditions:
Epistemological, theoretical, and methodological differences. European Journal