


1
1
THE INFLUENCE OF INVESTOR SENTIMENT AND
MACROECONOMIC FACTORS ON THE HERDING BEHAVIOR OF
LARGE-CAP CRYPTOCURRENCY INVESTORS
Introduction:
In the current era of technological and information development, people seem to be
increasingly aware of the importance of investing. In line with these developments, the types
of investments offered today are increasingly diverse, such as gold, stocks, bonds, deposits,
mutual funds, peer-to-peer lending, and the current hot one is cryptocurrency. The
cryptocurrency market in the past decade has experienced a very rapid growth spurt (Yi et al.
2018; Liu et al. 2019). Cryptocurrency is a form of investment with a form of virtual
(intangible) currency, not issued by a country, and allows the issuer of the currency to raise
money without involving venture capitalists, and can be traded without the terms and
conditions of the issuing company of the cryptocurrency like shares in general (Lee et al.
2018; Setiawan 2020).
Cryptocurrency in Indonesia has been officially regulated as an investment instrument
with the type of commodity traded on the futures exchange according to the letter of the
Coordinating Minister for the Economy Number S-302/M.EKON/09/2018 (Perayunda and
Mahyuni 2022) with the crypto asset trading market regulated by Bappebti Regulation No. 8
of 2021 concerning Guidelines for the Implementation of Crypto Asset Physical Market
Trading on the Futures Exchange (Bappebti 2021).
The cryptocurrency trading market in Indonesia itself is experiencing a very high trend
of public interest, even the latest data currently shows the number of cryptocurrency investors
who beat capital market investors. The following is a comparison chart of the increase in the
number of cryptocurrency and capital market investors over the past two years based on data
from the Indonesian Ministry of Finance in Figure.
Reporting from data from the Indonesian Ministry of Finance (Kemenkeu), capital
market investor data in 2020 was recorded at 3.9 million investors, increased rapidly by 92%
to 7.5 million investors in 2021 and continued to grow until the latest data in June 2022 was
recorded at 9.1 million investors. On the other hand, the number of cryptocurrency investors
has increased almost twice as much a s the capital market, from the original 4 million
investors in 2020, increasing rapidly by 180% to 11.2 million investors in 2021 and this figure

continues to grow until the latest data in June 2022 was recorded at 15.1 million investors.
The value of cryptocurrency transactions in Indonesia in 2021 according to Bappebti as
reported by Databoks - Katadata by Annur (2022) in just a year experienced a huge increase
of 1,222%. The following is a graph of the increase and shares for the last two years based on
Bappebti data in Figure 2.
The international survey institute Gemini also shows that Indonesia is the largest crypto
adopter in the world along with Brazil with an adoption rate of 41% in 2021 (Gemini 2022).
The following is a comparison chart of the percentage of crypto adoption in the world based
on the Gemini survey in Figure 3.
According to the latest data from the Commodity Futures Trading Supervisory Agency
(Bappebti) in 2021, the five main types of cryptocurrencies that are very popular or widely
traded in Indonesia include Bitcoin (BTC), Ethereum (ETH), Binance Coin (BNB), Ripple
(XRP), and Cardano (ADA) as reported by CNN Indonesia (10 Money 2021). Apart from
being popular, these cryptocurrencies are the ones with a high market capitalization (large-
cap) above 10 billion USD. In investing in cryptocurrencies, especially for lay investors, it is
highly recommended to look at the market capitalization value. Apart from the fundamentals
of crypto assets that are still unclear in origin (Liu et al. 2019), according to Danial et al.
(2022) the popularity of cryptocurrency can be seen from the size of its market capitalization.
Although the market capitalization value cannot illustrate the full potential of the currency, it
can be seen from the market capitalization. However, a high market capitalization may
indicate that vanishing risk, scam risk, and other non-systematic risks are less likely.
In addition to the increasing trend of investment interest, cryptocurrencies in general
have a much higher holding period return (HPR) than other popular investment types in
Indonesia over the past four years. This can be seen from the comparison of the value of the
large-cap cryptocurrency index, Royalton Crypto Index (CRIX), with several investment
indices in Indonesia, such as the dollar to rupiah exchange rate (USD-IDR), gold price per
gram, JCI price, and LQ45. The following is the price comparison data of popular investment
indices in Indonesia with cryptocurrencies in 2018-2022 in Table 1.
The data in Table 1 above can illustrate that if investors hold their money to invest in
the large-cap cryptocurrency market for four years from the beginning of 2018 to August
2022, they will get more than three times the return, or about 336.14%. This is far above the
HPR of other types of investments, which only stands at 0.65% - 48.82%.
In addition to generating a high holding period return (HPR), the value of the large-cap

3
cryptocurrency index (CRIX) has a very high level of volatility each year among other types
of investments. Volatility refers to the high price fluctuations of investment instruments that
reflect market uncertainty and risk (Wisudanto et al. 2021). The following is a comparison
chart of the annual volatility level of popular investment indices in Indonesia with large-cap
cryptocurrency in 2018-2022 in Figure 5.
In Figure 5 above, it is clear that the annual volatility level of the large-cap
cryptocurrency index (CRIX) is much higher among other popular investment indices. In line
with the previous data in Table 1, the price of large-cap cryptocurrencies tends to go up and
down drastically every year. The phenomenon of a drastic increase in the price of large-cap
cryptocurrencies in just one year occurred in 2021, where the average price of
cryptocurrencies in the CRIX index per year increased by 397.69% from IDR 12,263,838 in
2020 to IDR 61,036,232 in 2021, and a drastic decline occurred the following year with the
average price of cryptocurrencies in the CRIX index per year decreasing by 27.63% from IDR
61,036,232 in 2021 to IDR 44,174,598 in August 2022.
Furthermore, unlike the capital / stock market which has upper and lower auto-rejection
rules as a limitation on stock prices, because according to Sapuric and Kokkinaki (2014) the
cryptocurrency market moves freely according to the movement of investor demand and
supply, as a result of this, it is possible that cryptocurrency prices can rise as high as possible,
and allow cryptocurrencies to fall as low as the phenomenon of the Terra currency (LUNA)
which fell by 99.98% to a price of almost zero rupiah (Rp0.000035) in May 2022 due to
simultaneous selling by investors (Safitri 2022). In fact, as reported by CNBC Indonesia
(Price of 2022) at
On April 5, 2022, the Terra currency (LUNA) recorded its highest price since its inception, at
Rp1,720,221.48. Thus, while investments in cryptocurrencies can generate potentially huge
r e t u r n s , they can also carry very high risks.
In addition, the movement of cryptocurrency returns on the CRIX index tends to move
together or be positively correlated in the last five years. The inter-asset return correlation of
cryptocurrencies in the CRIX index for 2018-2022 is shown in Figure 6 below.
It can be seen in Figure 6 above that the inter-asset correlation has a tendency for
markets to appear highly correlated with each other in the last five years. The high inter-asset
correlation may indicate that investors are indicated to have similar perceptions regarding the
information of these assets, and when one of these cryptos experiences significant price or
return changes, other cryptos also tend to experience similar changes. The phenomenon of

drastic price increases and decreases and the high inter-asset correlation indicate that there is a
tendency for cryptocurrency investors to irrationally buy and sell clustered assets following
market consensus.
The classical paradigm of finance theory or the efficient market hypothesis theory by
Fama (1970) assumes that investors make rational decisions. The assumption assumes that
investors should base their financial decisions on knowledge, expectations, and experience in
the capital market. However, subsequent research by Tversky and Kahneman (1973) showed
that no investor's rationality is perfect, in other words, investors are often irrational. One of
the latest developments that is a counterpoint to EMH theory is the emergence of behavioral
finance theory, which is finance from the perspective of social science, including psychology
and sociology. According to Pompian (2021) that "normal" people are very likely to behave
irrationally in making their decisions, and in fact there are almost no people who behave
perfectly rationally, especially in financial matters.
As in the capital market, research by Delfabbro et al. (2021); and Caporale and Plastun
(2019) mentioned that there are several factors of irrational investor behavior that seem to
influence the amount of cryptocurrency trading or investment, especially in ordinary
investors, including: fear of missing out (FOMO), being easily influenced by false or
misleading social media influencers, and overreaction. When investors experiencing FOMO,
there are indications of investors' tendency to follow the majority of the market without
considering fundamental analysis or the risks involved. In addition, the influence of popular
narratives or recommendations from social media influencers without conducting in-depth
analysis may result in the tendency of investors to follow the recommended actions of the
majority. Furthermore, when there is news or new information about cryptocurrency,
investors may overreact and jump on the bandwagon to buy or sell assets without careful
rational consideration. This shows that there are indications that investors tend to follow the
market consensus and rely heavily on the actions of other investments, rather than acting
alone in selling or buying investment assets.
The behavior of following the market consensus is called herding behavior. As for
herding behavior according to Jabeen et al. (2022) is a behavior that leads investors to put
aside their personal information to follow the crowd, even the realization of their personal
information has been believed to be accurate.
The consequences of herding behavior include mispricing of assets because investors do
not act on the information available in the market properly due to their irrational behavior

5
(Vidal-Tomás et al. 2019). In addition, herding behavior is feared to exacerbate volatility,
destabilize the market, and increase the fragility of the financial system in that market
(Bikhchandani and Sharma 2000). Therefore, analyzing the presence of herding behavior in
cryptocurrency markets is especially important for investors, as the herding phenomenon will
lead to an inefficient market, where asset pricing models based on rational valuation cannot be
applied properly, especially since the high volatility of cryptocurrencies can be caused by
herding behavior (Vidal-Tomás et al. 2019; Bogdan et al. 2022).
In the Indonesian capital market, (Rizal and Damayanti 2019; Anggara and Mustafa
2020; Sadewo and Cahyaningdyah 2022) successfully identified herding behavior in the
Indonesian Islamic capital market, sectoral stocks, and IDX80 stocks. The three studies
successfully showed that herding behavior occurs only when investor sentiment on the capital
market is bearish (down market). This means that the study indicates a relationship between
investor sentiment and herding behavior in the capital market in Indonesia.
Furthermore, recent studies have tried to analyze factors that influence herding behavior
in the capital market, including investor sentiment, and macroeconomic or monetary policies
in a country such as interest rates and inflation rates. Choi and Yoon's (2020) research tried to
analyze the relationship between investor sentiment and herding behavior in South Korea
using the proxy of the volatility index in the South Korean composite stock index market
(VKOSPI), and Zhang and Giouvris (2022) used the CBOE Volatility Index (VIX) proxy
variable in their research. Both studies successfully showed that the volatility index or
investor fear index as a proxy for investor sentiment positively affects the herding behavior of
investors in the capital market.
There are several studies such as Gong and Dai (2017) trying to analyze the relationship
between macroeconomic factors in China on the Shanghai Stock Exchange and the Shenzhen
Stock Exchange, Wibowo (2021) using macroeconomic factors in 12 countries with emerging
market and developed country categories, and research by Wicaksono and Falianty (2022)
using Indonesian macroeconomic factors in analyzing their relationship with herding behavior
in the capital market. The three studies successfully showed that monetary policy as a
macroeconomic indicator in a country such as interest rates, inflation, and exchange rates
positively affect the herding behavior of investors in the capital market.
However, in the cryptocurrency market, the factors that influence such herding behavior
have not been well explored and require additional analysis. Only a few studies have recently
emerged to identify the herding behavior of investors in the cryptocurrency market. For

example, Vidal-Tomás et al. (2019) conducted research on the behavior towards the
cryptocurrency market in 2015-2017. The results showed that there is a contribution of
market capitalization to herding behavior in cryptocurrency, so investors base their decisions
on the performance of major cryptocurrencies (large market capitalization). In addition, Ballis
and Drakos (2020) conducted research on herding behavior on cryptocurrencies in 2015-
2018. The results showed the existence of herding behavior, especially when the
cryptocurrency market was rising. From the previous research above, the results of previous
studies examining herding behavior in cryptocurrency are still limited to identifying the
presence / absence of herding behavior in the market, and there are still few who further
examine what factors influence the herding behavior.
Cryptocurrencies as part of a new investment asset class can be affected by a wide
range of factors, including evolving regulation (Hougan and Lawant 2021). Research by Blau
et al. (2021); Smales (2021); and Phochanachan et al. (2022) reveal that cryptocurrency can
be used as an inflation hedge especially in the short-run and is not recommended to be an
inflation hedge in the long run. According to Bouri et al. (2017) an asset can be categorized as
a hedge if on average it is negatively correlated with other assets. Therefore, there are
indications that macroeconomic conditions have an influence on cryptocurrency market
movements.
Not only at the global level, the large-cap cryptocurrency market is also indicated to
respond similarly to Indonesia's macroeconomic policies, namely when the benchmark
interest rate in Indonesia (BI7DRR) and the inflation rate fall, cryptocurrency prices tend to
rise, and vice versa. The following is a graph of Indonesia's macroeconomic movements and
the large-cap cryptocurrency index (CRIX) in 2020-2022 in Figure 7.
1.1 Efficient Market Hypothesis
Efficient market hypothesis (EMH) is an efficient market concept popularized by
Eugene Fama and has become an important concept in the development of most financial
theories. The EMH theory states that markets are efficient if prices always fully reflect
available information (Fama 1970). In addition, the theory states that market participants will
not be able to reap excess revenues using only current information because market prices in an
efficient market can only be changed by unexpected new information (Kang et al. 2022).
The EMH theory is generally divided into three versions of the hypothesis based on
"overall available information" (Bodie et al. 2021), namely:

7
1) efficient market in weak form: The weak form hypothesis asserts that the prices of investment
assets already reflect all the information that can be obtained by examining market trading
data such as past price history, trading volume, or interest rates on short selling;
2) efficient market in semi-strong form: The semi-strong form hypothesis states that all publicly
available information about a company's prospects should be reflected in its stock price. Such
information includes past market trading data, fundamental data on the company's product
line, the quality of its management, the composition of its balance sheet, patents held, earnings
estimates, and its accounting practices;
3) efficient market in strong form: The strong form of the efficient market hypothesis states that
stock prices reflect all relevant information, even including information available only to
company insiders.
The current rapidly growing literature attempts to apply the EMH to cryptocurrencies.
The previous research rejected the hypothesis, such as in the study (Caporale et al. 2018; Hu
et al. 2019) which stated that the EMH theory, especially in the main cryptocurrency market
or large-cap cryptocurrency, including Bitcoin, was rejected so that the study concluded that
the large-cap cryptocurrency market was inefficient.
1.2 Herding Behavior
Herding behavior is when investors decide to imitate others or the market consensus
rather than following their own beliefs and information (Devenow and Welch 1996).
Bikhchandani and Sharma (2000) define "intentional" herding behavior as a clear intention to
imitate the behavior of other investors, which can disrupt the market and increase volatility.
The paper further states that such herding behavior can be differentiated based on its intensity.
In contrast to intentional herding, "spurious" herding behavior is the result of where the
group faces a decision problem that is not clear-cut.
Herding behavior in behavioral finance scholarship generates a greater number of
empirical studies than theoretical studies, because it is difficult to measure the exact extent of
herding behavior in real financial markets (Choi and Yoon 2020). Most empirical studies with
a focus on herding behavior show that investors who follow others can generate important
information and gain maximum profits (Devenow and Welch 1996). Furthermore,
Bikhchandani and Sharma (2000) reveal several reasons why herding behavior can occur in
financial markets. First, making decisions based on the decisions of previous investors thus
causing information-based and cascades. Second, fund managers' mistrust of other fund
managers can damage their reputation (reputation-based). Third, and this is only relevant for

financial planners/managers who invest on behalf of others, the incentives provided by
compensation schemes and terms of employment may be such that such imitation schemes are
rewarded (compensation-based).
Many methods of measuring herding behavior have been used in empirical studies, such
as the Lakonishock, Shleifer, and Vishny (LSV) model, and the Portfolio Change Measure
(PCM), however, due to the lack of information at the investor level for practical reasons,
research is moving in a different direction to capture market herding behavior by examining
the existence of a relationship between asset return dispersion and market returns. Based on
such an approach, Christie and Huang (1995) suggest the Cross-Section Standard Deviation
(CSSD) model and argue that when there is herding behavior in the market, the dispersion of
average returns is expected to be lower. They also found that, for extreme market movements
(up and down 1% and 5% for market returns), investors will tend to mimic the actions of
other investors in the market. However, the weakness of CSSD is that it is easily affected by
outliers empirically, making it difficult to find evidence of herding behavior under normal
conditions (Chang et al. 2020). Furthermore (Chang et al. 2000) improvised the dispersion
measurement and suggested a model using the absolute value of the return deviation, or called
the Cross- Section Absolute Deviation (CSAD) model. To date, the most popular approach is
CSAD, as other measurement methods require investor ownership information and use lower
frequency data than the CSAD method (Choi and Yoon 2020).
The CSAD method in recent studies is not only used in the stock market, studies such as
(Vidal-Tomás et al. 2019; Ballis and Drakos 2020; Haykir and Yagli 2022; Lobão 2022) used
the method on cryptocurrencies, and the research ultimately succeeded in proving that there
was a herding phenomenon in cryptocurrencies.
1.3 Investor Sentiment
Investor sentiment according to Wisudanto et al. (2021) represents market trends that
can affect investor buying interest. Meanwhile, Mehrani et al. (2016) define investor
sentiment as an individual's feeling of confidence or excessive despair over the situation. An
empirical definition of investor sentiment has also been put forward by Simon and Wiggins
(2001) who say that sentiment can be defined as the deviation between expected stock returns
and actual returns, as well as attitudes towards future market direction. From these three
definitions, it emphasizes the psychological factors of investors, namely beliefs or feelings
towards certain situations.
Several previous studies have examined investor sentiment and its effect on the capital /

9
stock market, such as research by Wisudanto et al. (2021) which examines the effect of
investor sentiment, market volatility, and returns on the IPO market on the Indonesia Stock
Exchange. In addition, Handoko and Supramono's (2017) research examines stock market
investor sentiment on the Indonesia Stock Exchange using the LQ45 and PEFINDO25 index
samples during the terrorism/bomb attack in the Sarinah area. Furthermore, other studies have
tried to see the effect of investor sentiment on herding behavior in the capital / stock market,
such as research by Choi and Yoon (2020) with the object of stock exchange research in South
Korea, and Zhang and Giouvris (2022) who examined the effect of sentiment, crisis, and
volatility behavior on market herding behavior in BRICS countries (Brazil, Russia, India,
China, and South Africa).
In the context of cryptocurrencies, indications of negative sentiment point to uncertainty
about cryptocurrency price and return movements and the factors driving their prices (Mokni
et al. 2022), mainly due to the threat of bubbles and fraud due to unclear origins (Liu et al.
2019). On the other hand, positive sentiment leads to another belief that cryptocurrencies are
perceived as a hedge against inflationary conditions (Gemini 2022). However, research
linking cryptocurrency markets to investor sentiment appears limited and has not been able to
draw conclusions about comprehensively exploring the explanatory and predictive power of
investor sentiment (Mokni et al. 2022). Therefore, in addition to using the cryptocurrency
volatility index (CVI) proxy, this study will use the Crypto Fear and Greed Index (FGI)
which can provide more empirical evidence to explore the sophisticated relationship between
investor sentiment and herding behavior as referenced (Mokni et al. 2022; Saggu 2022).
1.4 Macroeconomics
Indonesian people according to the Gemini survey (2022) are investing in
cryptocurrency in droves because cryptocurrency is considered an inflation hedge. Inflation is
one of the macroeconomic indicators in a country that describes the general increase in the
prices of goods and services continuously within a certain period of time arising from
pressure from the supply side (cost push inflation), from the demand side (demand pull
inflation), and from inflation expectations (BI 2020). Apart from inflation, interest rates are
another form of macroeconomic indicator in a country. According to Bodie et al. (2021)
interest rates are the number of dollars earned per dollar invested per period. The benchmark
interest rate referred to as Indonesia's macroeconomic indicator, namely the BI Rate, which
has now changed its name to the BI-7 Days Repo Rate (BI7DRR), is a policy interest rate that
is used as a benchmark interest rate.

Research on macroeconomic factors and their relationship with herding has begun to be
found, but until now it has been explored by very few researchers, especially in the
cryptocurrency market. For example, Gong and Dai (2017) explored the influence of
macroeconomic factors (monetary policy), exchange rate fluctuations with herding behavior,
but still within the scope of the Chinese stock market. In addition, Jabeen et al. (2022) who
explored the influence of macroeconomic factors, fundamentals, and herding behavior on
stock returns in Pakistan. Therefore, this study will try to adapt the research by using the
object of large-cap cryptocurrency research.
1.5 Cryptocurrency
Cryptocurrency is a new form of digital money operated through blockchain technology
and developed after the 2008 financial crisis (Danial et al. 2022). After the launch of Bitcoin
by Satoshi Nakamoto in 2009 as the first cryptocurrency, many cryptocurrency issuers began
to develop alternatives to Bitcoin, these currencies were termed alternative coins or "altcoins"
(Alexandria 2022). To date, there are more than 13,267 cryptocurrencies listed in the global
crypto market (CoinGecko 2022).
There are two popular terms in the crypto investment world: coin and token. They are
distinguished by their "taxonomy", with the term cryptocurrency referring to coins, and
cryptotoken referring to tokens (Burniske and Tatar 2018). Coins are cryptocurrencies that can
operate independently or to a single unit of the cryptocurrency (Alexandria 2022). Tokens, on
the other hand, are digital units designed with utility in mind, providing access and use of a
larger cryptoeconomic system (Alexandria 2022). The difference between the two is that
coins are cryptocurrencies that can operate independently, while tokens depend on coins as a
platform to operate (Investopedia 2021a).
Cryptocurrencies such as Bitcoin, Ethereum, and the majority of other altcoins in
circulation are obtained by the process of mining (mining) (Danial et al. 2022). The mining
process in question is solving a mathematical problem with the help of a computer that has
considerable computational capabilities and is high-speed and in limited supply in some
cryptocurrencies such as Bitcoin (Lee et al. 2018). Because not everyone has these
capabilities, cryptocurrencies are widely traded, so in practice there are exchange rates
between cryptocurrencies or cryptocurrency prices in fiat currency conversions at fluctuating
prices following the demand and supply of these currencies (Setiawan 2020). As with gold,
the majority of mined cryptocurrencies have the following

17
There is a limited supply and many investors see cryptocurrencies as investment assets with
the hope of selling them when the price rises more (Danial et al. 2022).
However, it should be remembered that in investing activities, in addition to the level of
return received, investors must also consider the risks that may occur in an investment. The
main problem in investing in cryptocurrencies is that in addition to having a high rate of
return, it also has a higher risk of loss and volatility than other conventional investment assets
such as stocks and gold (Setiawan 2020). This is in line with what was explained earlier, that
herding behavior deliberately carried out by irrational investor attitudes will disrupt the
market and increase volatility (Bikhchandani and Sharma 2000). Factors that affect herding
behavior in the capital / stock market have been widely explained by various studies such as
in research (Gong and Dai 2017; Choi and Yoon 2020; Jabeen et al. 2022). However, in the
cryptocurrency market, the herding behavior has not been explored as well as the stock
market.
1.6 Previous Research
There are several studies related to the identification of herding behavior in capital
markets and cryptocurrencies, as well as research on the influence between investor sentiment
and macroeconomic factors in a country with the herding behavior of cryptocurrency
investors. Research on herding behavior using dispersion of asset returns and market returns
was first proposed by Christie and Huang (1995) where the purpose of the study was to
answer whether equity returns indicate the presence of herding behavior on the part of
investors during periods of market stress. To prove the proposition, the CSSD (return
dispersion) model was used to capture herding behavior using a research sample of daily and
monthly returns of companies listed on the New York Stock Exchange (NYSE). The results
show that when individual asset returns are herding around the market consensus, dispersion
is predicted to be relatively low.
Then the research of Chang et al. (2000) tried to improvise the CSSD model with the
CSAD model (absolute return dispersion), the study examined the investment behavior of
market participants in different international markets, namely the US, Hong Kong, Japan,
South Korea, and Taiwan, specifically with respect to their tendency to exhibit herding
behavior. The results found no evidence of herding behavior among market participants in the
US and Hong Kong and partial evidence of herding in Japan. However, for South Korea and
Taiwan, the two emerging markets in the sample, researchers documented significant
evidence of herding behavior.

18
Furthermore, many studies have tried to use both models and compare the results, such
as the research of Lee et al. (2015). The study aims to provide evidence of herding behavior
by investors in Taiwan during the period January 4, 2000 to December 28, 2012. In addition,
this study also looked at the effect of return, volume, volatility, S&P500, volatility index
(VX), and financial crisis with herding behavior.
by using the CSAD return dispersion regression model. The results yielded three findings,
first, researchers found evidence of herding behavior based on the CSAD model. Second,
CSAD return dispersion in Taiwan shows a positive relationship with the US market and
financial crisis, and a negative effect with interest rates. Third, we find asymmetric herding
behavior under different conditions for market returns, trading volume, VX, and interest rates.
Fourth, Taiwanese investors consistently exhibit herding behavior in different quantiles
during different market conditions.
Gong and Dai's (2017) research is also similar to the above research which tries to
identify herding behavior in the capital market, compare the two methods, and relate it to
macroeconomic factors in a country. The study investigated interest rates and exchange rates
to be the driving factors of herding behavior in the Chinese stock market. This study uses a
sample of macroeconomic factors in China (interest rates and exchange rates), as well as
company return data listed on the Shanghai Stock Exchange and Shenzhen Stock Exchange
from July 21, 2005 to June 30, 2016. The method used is the CSSD and CSAD models, and in
seeing the effect of these macroeconomic factors, the CSAD return dispersion regression
model is used. The results show that the increase in interest rates and the depreciation of the
Chinese currency (CNY) will encourage herding behavior and this phenomenon is mainly
manifested in the down market.
In the Indonesian capital market, (Rizal and Damayanti 2019; Anggara and Mustafa
2020; Sadewo and Cahyaningdyah 2022) successfully identified herding behavior in the
Indonesian Islamic capital market, sectoral stocks, and IDX80 stocks. The three studies
successfully showed that herding behavior occurs only when investor sentiment in the capital
market is bearish (down market). This means that the research indicates a relationship
between investor sentiment and herding behavior in the capital market in Indonesia.
Furthermore, Wibowo (2021) used macroeconomic factors in 12 countries with
emerging market categories including Indonesia and several developed countries, as well as
research by Wicaksono and Falianty (2022) which used Indonesian macroeconomic factors in
analyzing its relationship with herding behavior in the capital market. Both studies

19
successfully showed that monetary policy as a macroeconomic indicator in a country such as
interest rates, inflation, and exchange rates positively affect the herding behavior of investors
in the capital market.
In addition, research (Choi and Yoon 2020; Zhang and Giouvris 2022) attempts to link
herding behavior with investor sentiment. Both studies only use the CSAD model to examine
the effect, because the CSAD measurement method is considered superior to other models
that require investor ownership information and use lower frequency data than the CSSD
method. In line with Chang et al. (2020) which states that the CSAD model is not easily
affected by outliers empirically, making it easier to find evidence of herding behavior under
normal conditions, unlike its predecessor model, CSSD. Choi and Yoon's (2020) research
using a sample of companies listed on KOSPI and KOSDAQ (South Korea) from January
2003 to December 2018 shows that the behavior of herding behavior in normal conditions,
unlike its predecessor, CSSD.
Adverse herding occurs in low trading volume and low volatility periods, in addition to
the relationship between investor sentiment and herding behavior has a strong effect (reverse
herding). In addition, Zhang and Giouvris (2022) examined the effect of sentiment, crisis, and
volatility behavior on market herding behavior in BRICS countries (Brazil, Russia, India,
China, and South Africa). The results showed that higher volatility will lead to an increase in
herding behavior (characterized by a decrease in the value of CSAD). In addition, the higher
the 'fear index' of investors has an influence on increasing herding behavior (evidenced by a
decrease in the value of CSAD). However, this can only be proven partially which only
applies during the Covid-19 crisis for all countries except China. Meanwhile, the crisis has no
effect on increasing herding behavior.
Later studies (Vidal-Tomás et al. 2019; Ballis and Drakos 2020; Lobão 2022) tried to
identify herding behavior in the cryptocurrency market. Research by Vidal-Tomás et al.
(2019) using the CSSD and CSAD models confirmed the existence of herding behavior in
digital currencies only during market downturns with the contribution of market capitalization
to herding behavior in cryptocurrencies, so investors base their decisions on the performance
of major cryptocurrencies (large market capitalization). Using the same model and similar
research results Ballis and Drakos (2020) found that investors in the "top" sector of the
cryptocurrency market act irrationally and copy the decisions of others without reference to
their own beliefs. Furthermore, research by Lobão (2022) who narrowed his research only to
cryptocurrencies with the title "green cryptocurrencies", with the same model and method
20
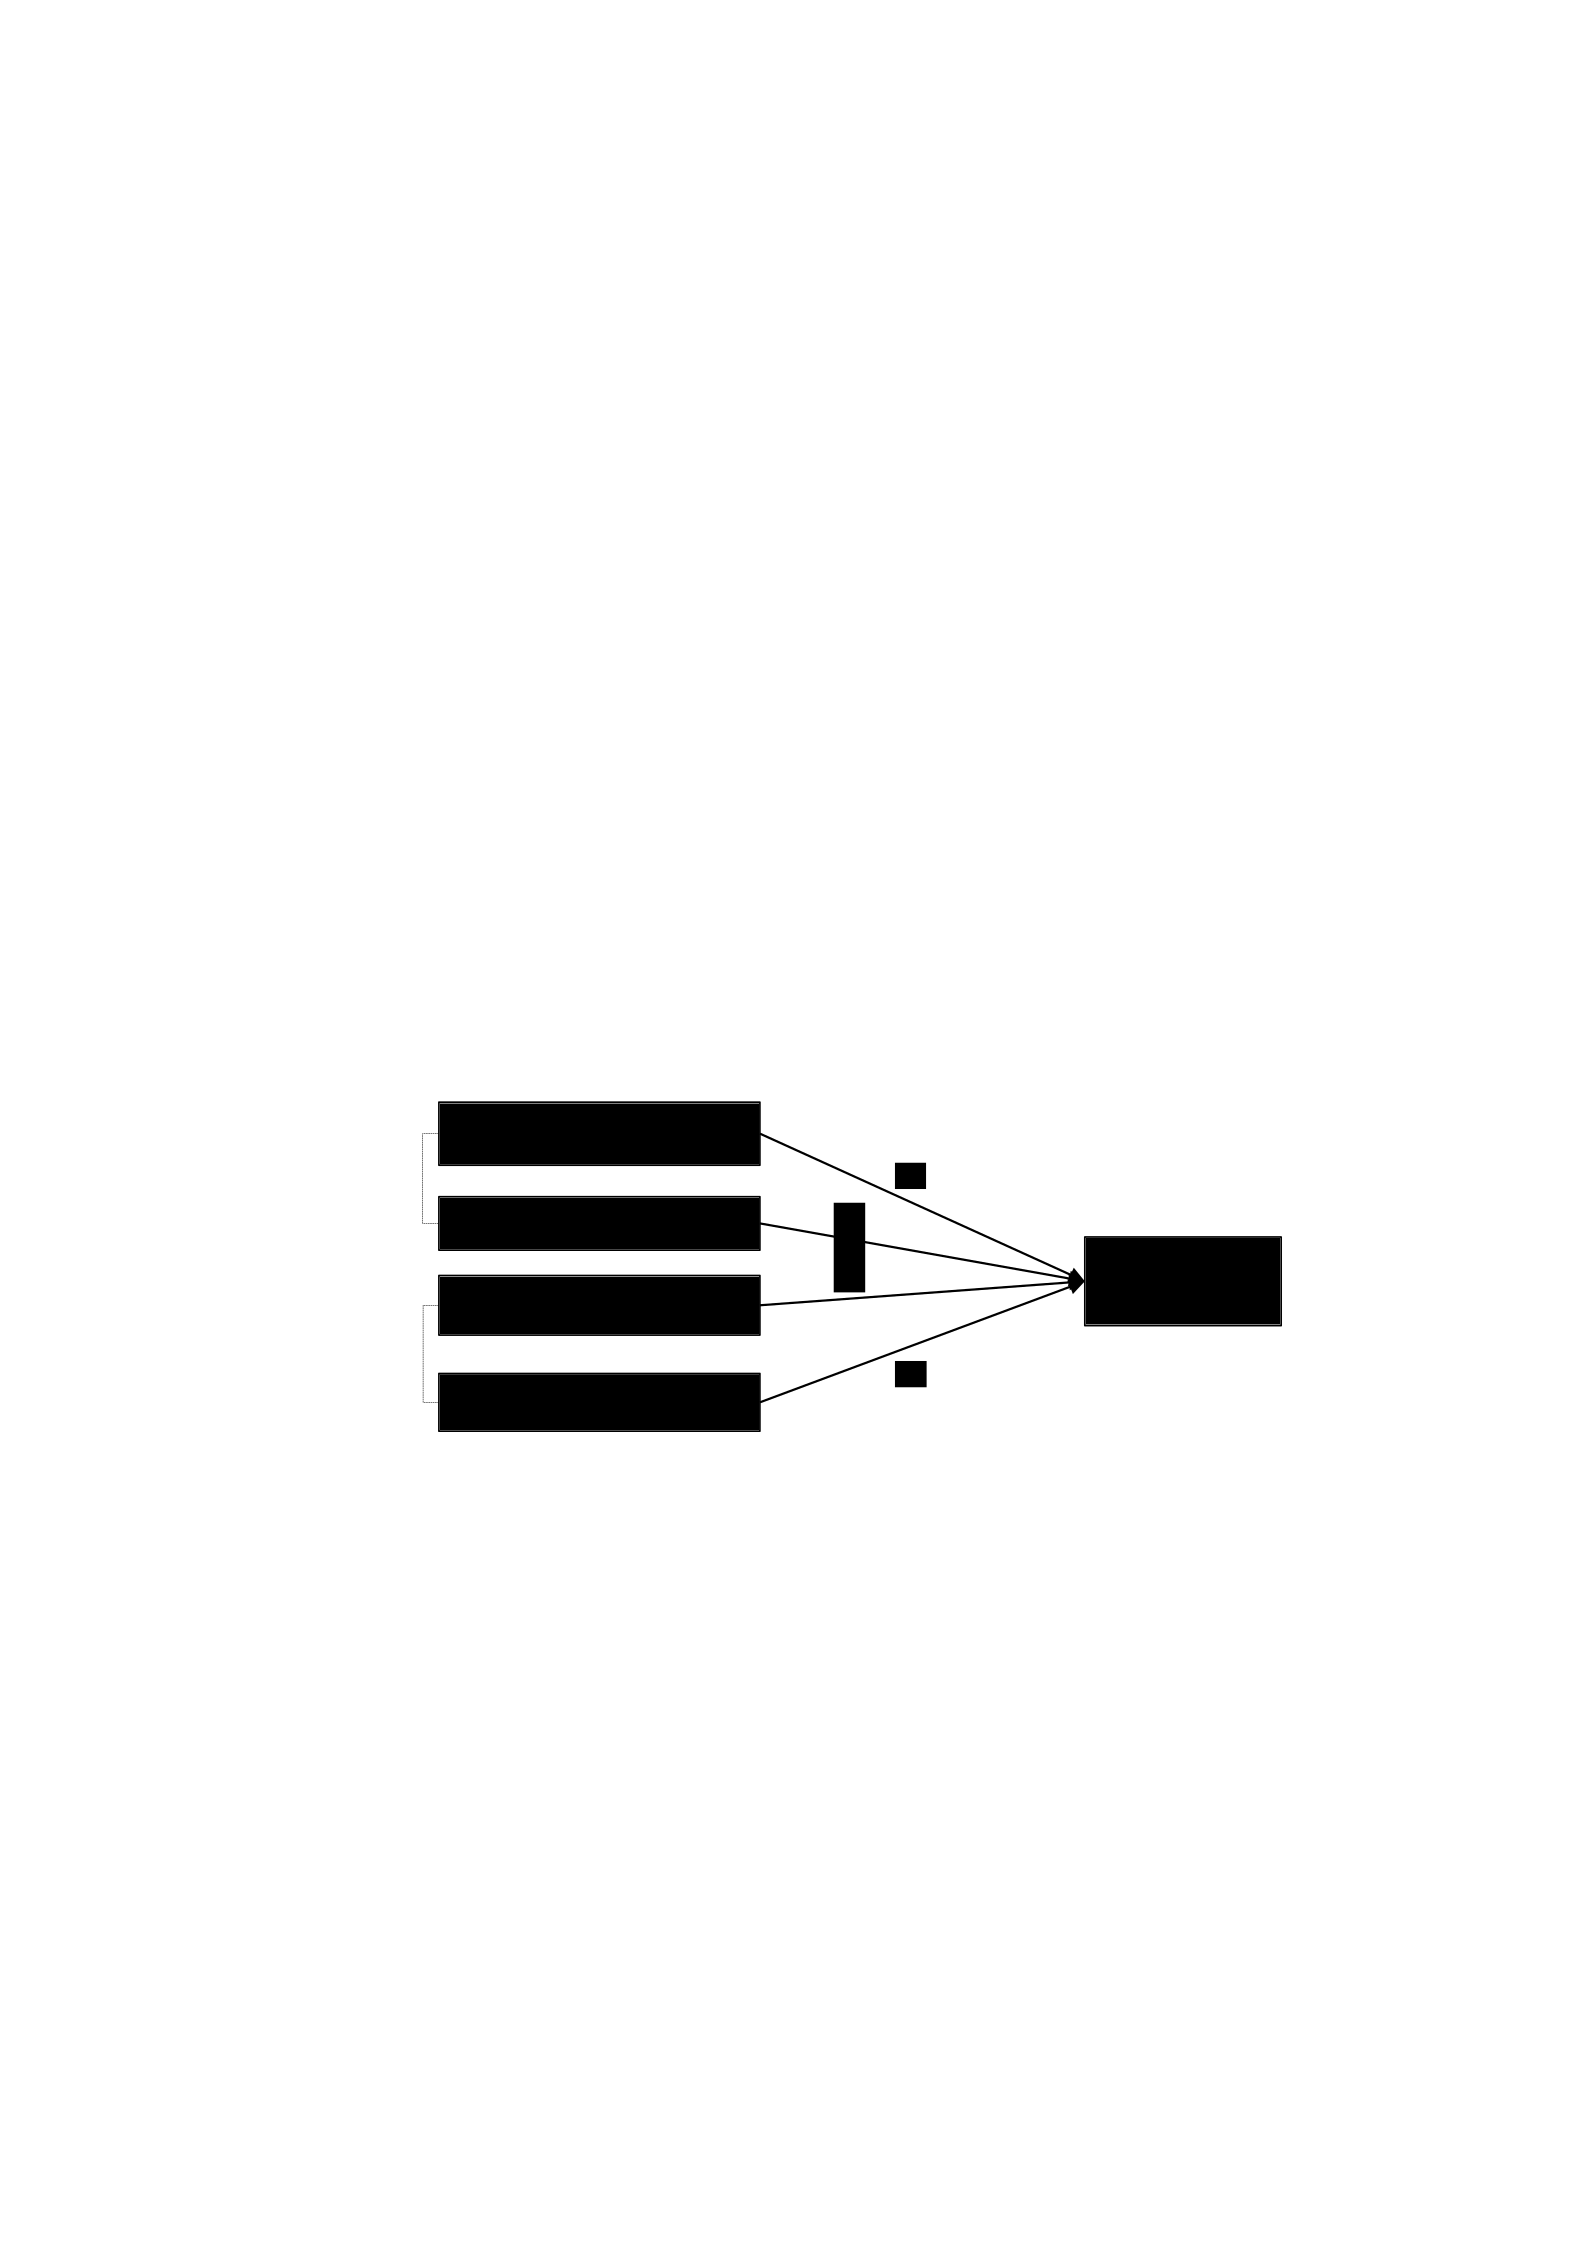
Inflation Rate (X )3
Interest Rate (X )4
Volatility (X )1
Investor Fear (X )2
Herding Behavior
of Large-Cap
Cryptocurrency
Investors (Y)
H3b
H2b
H3a
H2a
herding behavior among investors in green cryptocurrencies did not exist in the entire
sample.
Based on the previous studies above, it can be seen that herding behavior in financial
markets, both capital/stock markets and cryptocurrency markets can be well proven with the
CSAD model. In addition, investor sentiment such as volatility and investor fear index ('fear'
index) positively affect herding behavior, and macroeconomic factors also positively affect
herding behavior. However, these studies are still limited to the scope of the capital market.
Therefore, this study will analyze the effect of these external factors on herding behavior with
the object of large-cap cryptocurrency research.
1.7 Research Hypothesis
This study was conducted to determine the tendency of herding behavior in the large-
cap cryptocurrency market, as well as the influence of investor sentiment and Indonesian
macroeconomic factors (inflation and interest rates) on cryptocurrency herding behavior.
Based on the theory and empirical results found in the literature, the research conceptual
framework is formulated in Figure 9.
Sentiment
Investor
H1
Macroeconomics
Indonesia
Figure 9 Research conceptual framework
Based on the formulation of the model above, the hypotheses proposed in this study
include:
1.7.1 The tendency of herding behavior in the large-cap cryptocurrency market
As in the capital market, cryptocurrency investors are often irrational in their
investments. Delfabbro et al. (2021) mentioned that there are several factors of irrational
investor behavior that seem to influence the amount of cryptocurrency trading or investment,
especially in ordinary investors, including: fear of missing out (FOMO) and being easily
influenced by pseudo or misleading social media influencers. This behavior implies that

21
investors tend to follow market sentiment and rely heavily on the actions of other investments,
not acting alone in the activity of selling or buying investment assets, especially investment in
cryptocurrency has a risk of fraud due to its unclear origin (Liu et al. 2019).
Herding behavior according to Jabeen et al. (2022) is a behavior that leads investors to
put aside their personal information to follow the crowd, even the realization of their personal
information has been believed to be accurate. The consequences of this herding behavior
include asset prices that will not be appropriate (mispricing) because investors do not act
according to the information available in the market correctly due to their irrational behavior
(Vidal-Tomás et al. 2019). Ballis and Drakos' (2020) research successfully demonstrated the
existence of herding behavior, especially when the cryptocurrency market is rising.
Furthermore, research by Vidal-Tomás et al. (2019) showed that there is a contribution of
market capitalization to herding behavior in cryptocurrency, so investors base their decisions
on the performance of major cryptocurrencies (large market capitalization). Based on the
above concepts, theories and empirical results, the following hypothesis can be proposed:
H1 : Investors in the large-cap cryptocurrency market tend to behave
herding.
1.7.2 The influence of investor sentiment on herding behavior in the large-cap cryptocurrency
market
Investor sentiment according to Wisudanto et al. (2021) represents market trends that
can influence investors' buying interest. Meanwhile, Mehrani et al. (2016) defines investor
sentiment as an individual's feelings of overconfidence or despair towards a situation.
According to Choi and Yoon (2020), the investment behavior of market participants is related
to many factors, such as trading strategies, market volatility, the behavior of other market
participants, changes in company value, and economic fluctuations.
The volatility index is commonly used as a proxy for investor sentiment (Economou et
al. 2015; Smales 2017; Choi and Yoon 2020). Volatility refers to fluctuations in the price of
investment instruments that reflect market uncertainty and risk (Wisudanto et al. 2021). The
latest research uses the fear index on the Crypto Fear and Greed Index (FGI) obtained from
alternative.me as a proxy for investor sentiment which is believed to provide more empirical
evidence to explore the current relationship of investor sentiment in the cryptocurrency
market as referenced (Mokni et al. 2022; Saggu 2022). Based on research (Lee et al. 2015;
Zhang and Giouvris 2022), the high value of the investor sentiment index (volatility or
investor fear index) in the capital market has a significant effect in reducing the value of

22
CSAD return dispersion, which implies the effect of volatility on herding behavior. The
research of Sheikh et al. (2023) shows that investor optimism in the Pakistani capital market
affects the herding behavior of investors in reverse (reverse-herding), or in other words,
investor fear affects the herding behavior of investors. Based on the concepts, theories and
empirical results above, the following hypothesis can be proposed:
H2a: Overall/aggregate cryptocurrency volatility has a positive effect on investor herding
behavior in the large-cap cryptocurrency market.
H2b: Fear of large-cap cryptocurrency investors has a positive effect on herding behavior
in the large-cap cryptocurrency market.
1.7.3 The influence of Indonesian macroeconomic factors on herding behavior on the large-cap
cryptocurrency market
Research (Blau et al. 2021; Smales 2021; Phochanachan et al. 2022) reveals that
cryptocurrency can be used as an inflation hedge, especially in the short-run. On the other
hand, Wardoyo et al. (2020) mentioned that cryptocurrency can be used as a hedge against
conditions of monetary uncertainty in Indonesia. Implicitly, this research proves that
cryptocurrency and inflation are negatively correlated, because according to Bouri et al.
(2017) an asset can be categorized as a hedge if on average it is negatively correlated with
other assets.
Research into the influence of Indonesian macroeconomic factors directly on the
cryptocurrency market has not been well explored. However, research by Wang et al. (2022)
has proven that there is strong evidence that global macroeconomic indicators have an
influence on Bitcoin market fluctuations or volatility. According to Hougan and Lawant
(2021) cryptocurrencies as part of a new investment asset class can be influenced by a wide
range of factors, including evolving regulations.
Research (Gong and Dai 2017; Wibowo 2021; Wicaksono and Falianty 2022)
successfully shows that monetary policy as a macroeconomic indicator in a country such as
interest rates, inflation, and exchange rates have a significant effect in reducing the value of
CSAD return dispersion which implies the influence of macroeconomic factors on herding
behavior. Based on the concept, theory and empirical results above, the following hypothesis
can be proposed:
H3a: Inflation rate in Indonesia has a positive effect on behavior
herding in the large-cap cryptocurrency market.
H3b: The benchmark interest rate in Indonesia has a positive effect on behavior

23
herding in the large-cap cryptocurrency market.
3.1 Framework of Thought
The cryptocurrency market in the past decade has experienced a very rapid growth spurt
(Yi et al. 2018; Liu et al. 2019), especially after being legalized as an investment instrument
on the Indonesian futures exchange, now many people are flocking to invest in
cryptocurrency as evidenced by the number of investors as of June 2022 can exceed the
number of capital market investors.
However, problems arise when these investment activities are carried out rashly by
cryptocurrency investors who have behaviors including: fear of missing out on something that
is happening or fear of missing out (FOMO), influence from pseudo or misleading social
media influencers, and overreaction (Caporale and Plastun 2019; Delfabbro et al. 2021). This
shows that sometimes cryptocurrency investors, especially lay investors, act not based on
their own information or ignore their beliefs due to the nature of FOMO, the influence of
social media influencers' pseudo-information, and overreaction. In other words, there are
indications of investor herding behavior in the cryptocurrency market. Herding behavior is a
condition where investors decide to imitate others or market consensus rather than following
their own beliefs and information (Devenow and Welch 1996). Bikhchandani and Sharma
(2000) reveal one of the reasons why herding behavior can occur in financial markets, namely
investor decisions that are based on the decisions of previous investors, causing information-
based and cascades.
According to Bappebti data in 2021, the type of cryptocurrency that is popular in
Indonesia is a type of cryptocurrency with a high market capitalization (large-cap) with a
capitalization value of more than 10 billion USD. This is in line with Danial et al. (2022) who
said that the popularity of investing in cryptocurrency can be seen from the size of the
cryptocurrency market capitalization, and it is recommended to invest in this type of
cryptocurrency.
The positive sentiment of investors towards cryptocurrencies is thought to be because
many investors consider investing in cryptocurrencies as a hedge against inflationary
conditions (Gemini 2022). Investors tend to follow market sentiment or rely heavily on the
actions of other investments and act to sell or buy, or such behavior is called herding
behavior. Research on this herding behavior and investor sentiment as an influencing factor in
the capital market has been proven by Choi and Yoon (2020). In addition, macroeconomic
factors such as inflation and interest rates have been shown to affect herding behavior in the

24
capital market (Gong and Dai 2017; Jabeen et al. 2022).
Therefore, this research will analyze herding behavior by focusing on large-cap
cryptocurrencies using the Cross-Sectional Absolute Deviation (CSAD) model method in
accordance with the research reference of Chang et al. (2000). In addition, this research will
more broadly explain what factors influence herding behavior by using the CSAD model.
independent variables of investor sentiment and Indonesian macroeconomic factors using
multiple linear regression method according to the adaptation of previous research models
(Gong and Dai 2017; Choi and Yoon 2020; Jabeen et al. 2022). The framework of this
research can be seen in Figure 9.
3.2 Data Type and Source
The type and source of data used in this research is secondary data. The data sources
needed in this research data are cryptocurrency price closing data based on daily price reports
of large-cap cryptocurrencies obtained from CoinGecko (coingecko.com), Indonesian
macroeconomic data (inflation rates and interest rates) from the Bank Indonesia website
(bi.go.id), and investor sentiment data, namely the Crypto Volatility Index (CVI) from the
Investing.com website and the Crypto Fear and Greed Index from the alternative.me website.
Other supporting data related to the topic of this research are obtained from books, articles,
and electronic media.
3.3 Sampling Method
The sample was drawn using purposive sampling with the criteria of cryptocurrency
with the largest capitalization (large-cap) based on the constituent criteria of the Royalton
CRIX index as one of the references in the cryptocurrency study of Lee et al. (2018) as of
January 2023. According to Danial et al. (2022) market capitalization value is the fastest way
to determine the level of popularity of a cryptocurrency. Although the capitalization value
cannot describe the overall potential of the cryptocurrency, a high market capitalization value
can indicate that the risk of vanishing risk, scam risk, and other non-systematic risks will be
less likely (Danial et al. 2022). The sample period selected is a slice of the cryptocurrency
trading period and the proxy for each independent variable, namely April 2019 to December
2022. It is intended that all variables including cryptocurrency data can be described properly
and completely. Based on the above criteria, the selected cryptocurrency samples include
Bitcoin (BTC), Ethereum (ETH), Binance Coin (BNB), Ripple (XRP), and Cardano (ADA).
3.4 Analysis Method
Data processing and descriptive analysis were carried out using Microsoft Excel 365
25
application in processing data on prices, returns, inflation rates, interest rates, CVI index, and
Crypto Fear and Greed Index. In addition, Eviews 10 was also used for multiple linear
regression analysis, and Minitab for visualization of time-series analysis. Quantitative data
processing is done by first identifying daily price reports of cryptocurrencies and proxy data
of independent variables in the period April 01, 2019 - April 01, 2019.
December 31, 2022 with a total of 1371 sample observations. After that, we continued to
analyze herding behavior using the cross-sectional absolute deviation (CSAD) approach as
referenced (Chang et al. 2000) with modifications to the independent variable model
involving explanatory factors that affect herding behavior as referenced (Choi and Yoon
2020; Haykir and Yagli 2022; Lobão 2022; Yousaf and Yarovaya 2022; Youssef 2022). The
steps in further data analysis are as follows.
3.4.1 Investigating the Herding Behavior of Large-Cap Cryptocurrency Markets
According to Chang et al. (2000) CSAD is not a measure of behavior herding. However,
the relationship between return dispersion (𝐶𝑆𝐴𝐷𝑡) with 𝑅𝑚,𝑡 which is used to detect herding
behavior. The determination of The relationship between return dispersion and market return
is a derivative of rational asset pricing model. Based on the CAPM rational asset pricing
model by Black (1972), the return dispersion relationship is not only upwardly related to
market returns, but linearly related. Therefore, Chang et al. (2000) showed through partial
derivation that if market participants tend to follow aggregate market behavior and ignore
their own decisions during periods of large average price movements, or herding behavior,
then the linear and ascending relationship between return dispersion and market returns will
no longer hold. In other words, herding behavior occurs when the relationship between return
dispersion is decreasing and non-linear.
Therefore, the return dispersion (𝐶𝑆𝐴𝐷𝑡) is regressed as the dependent variable with the
absolute value of the market return and the squared value of the market return.
market returns as an independent variable to investigate the behavior of the
herding in the market with the following formula:
CSAD
R
R
2
t 0 1 m,t 2 m ,t
( 4
)
The identification of herding behavior is tested through hypotheses while answering the
first hypothesis (H1) in this study according to the reference (Bouri et al. 2021):

26
𝑚
,
𝑡
a. Null Hypothesis (H0 ):
H0a : Herding behavior cannot be identified H0b : There is a tendency of anti-herding behavior
(when 𝛾2 > 0 and significant)
b. Hypothesis 1 (H1 ): There is a tendency of herding behavior
(when 𝛾2 < 0 and significant)
3.4.2 Analyzing the Influence of Investor Sentiment and Indonesian Macroeconomic Factors
on Large-Cap Cryptocurrency Market Herding Behavior
To analyze the influence of investor sentiment and Indonesian macroeconomic factors
on the herding behavior of the large-cap cryptocurrency market, a linear regression analysis
will be conducted with the modification of the previous CSAD model by adding independent
variables which are adaptations of research (Gong and Dai 2017; Choi and Yoon 2020;
Sheikh et al. 2023) as follows:
CSADt
𝐶𝑆𝐴𝐷𝑡 : Cross sectional absolute deviation value in period-t
0 : Regression intercept value
𝛾𝑖 : Regression coefficient value on independent variable-i
|𝑅𝑚,𝑡| : The absolute value of the market return in period-t
𝑅2 : The squared value of the market return in period-t
𝑅𝐶𝑉𝐼,𝑡 : The return value of the cryptocurrency volatility index (CVI) in period-t
𝑅𝐹𝐺𝐼,𝑡 : The return value of the Crypto Fear and Greed Index (FGI) index in period-t.
∆𝐼𝑛𝑓𝑙𝑎𝑡𝑖𝑜𝑛𝑡𝑡 : Difference value of inflation rate in Indonesia in period-t.
∆𝐼𝑛𝑡𝑒𝑟𝑒𝑠𝑡𝑡 : The value of the difference in interest rates in Indonesia (BI7DRR)
in period-t.
𝜀 : Regression error
The hypothesis from equation (5) above is similar in implication to the hypothesis stated
in regression equation (4), according to (Gong and Dai 2017; Choi and Yoon 2020; Sheikh et
al. 2023) if the regression coefficient values of 𝛾3, 𝛾5, and 𝛾6 on each independent variable in
each regression equation (4) are similar to the hypothesis stated in regression equation (4).
equation is negative and significant, which implies that

27
29
Overview of the Research Sample
This study uses a sample of five cryptocurrency coins with the largest market
capitalization category (large-cap) as of January 2023 which are listed as constituents of
Royalton CRIX and listed on the CoinMarketCap website (coinmarketcap.com) as referenced
in the study (Lee et al. 2018; Liu et al. 2019). As for the cryptocurrencies chosen to be the
object of research, they include: Bitcoin (BTC), Ethereum (ETH), Binance Coin (BNB),
Ripple (XRP), and Cardano (ADA).
Bitcoin is the first cryptocurrency to offer a pure peer-to-peer electronic payment
system so that online payments can occur directly from one party to another without
intermediary financial institutions or in other words, the transaction system is carried out in a
decentralized manner (Nakamoto 2008). After the rise of Bitcoin, alternatives to the
cryptocurrency emerged, known as "altcoins". The amount of Bitcoin supply is very limited
to only about 21 million Bitcoin, and currently about 92% or 19 million Bitcoin are transacted
on the market (CoinMarketCap 2023).
Three years after the release of Bitcoin, in 2012 the Ripple (XRP) currency emerged as
an alternative cryptocurrency to Bitcoin (altcoin). The fundamental difference between this
currency and Bitcoin and most other cryptocurrencies is that the system is not fully
decentralized (Danial et al. 2022). The currency (XRP) was developed by Ripple Labs. In
addition, XRP is not a not-minable coin because all currencies in circulation are pre-mined
(Lee et al. 2018). Therefore, the only way to get the currency is by buying and selling directly
on the cryptocurrency market. However, like Bitcoin, XRP remains open source in its coding,
and still uses a decentralized peer-to-peer system although not as pure as Bitcoin
(Investopedia 2021b).
Then, in 2013, a new innovative currency emerged, Ethereum (ETH). As with altcoins
in general, Ethereum was created based on Bitcoin innovations with some key differences
(Ethereum 2022). The main difference with other cryptocurrencies, especially Bitcoin, is that
Ethereum wants to be a place where application users can run programs in their decentralized
system through a smart contracts program called ERC-20, which is why many other
cryptotokens can run on the Ethereum platform (Danial et al. 2022). The currency can be
mined and uses a pure peer-to-peer decentralized system just like Bitcoin (Investopedia
2022).
Two years after the issuance of Ethereum, in 2015 Charles Hoskinson, who is a co-
founder of Ethereum, founded Cardano (ADA) and successfully launched the altcoin in 2017
28
(IOHK 2017). Cardano was launched with a Proof-of-Stake (PoS) system as a form of
efficiency from Bitcoin and other altcoins with Proof-of-Work (PoW) mining systems that
require computerized power that tends to be wasteful and not efficient.
environmentally friendly (Danial et al. 2022). However, due to this efficiency, the PoS system
does not incentivize complex mathematical solvers or miners like the PoW system (Cardano
2021). Therefore, the Cardano currency cannot be mined (Danial et al. 2022).
In the same year that Cardano (ADA) was launched, the Binance Coin (BNB) currency
was launched by Binance Exchange with the initial purpose of creation as a utility token for
discounted crypto trading on the Bitcoin Exchange online marketplace platform based on the
ERC-20 (Ethereum) network (Investopedia 2021c). However, Binance Coin has now become
the native cryptocurrency of Binance's own blockchain, known as Binance Chain
(Investopedia 2021c). Just like the cryptocurrencies Ripple (XRP) and Cardano (ADA),
Binance Coin (BNB) is not designed with a Proof-of- Work (PoW) system so it cannot be
mined (CoinMarketCap 2022a).
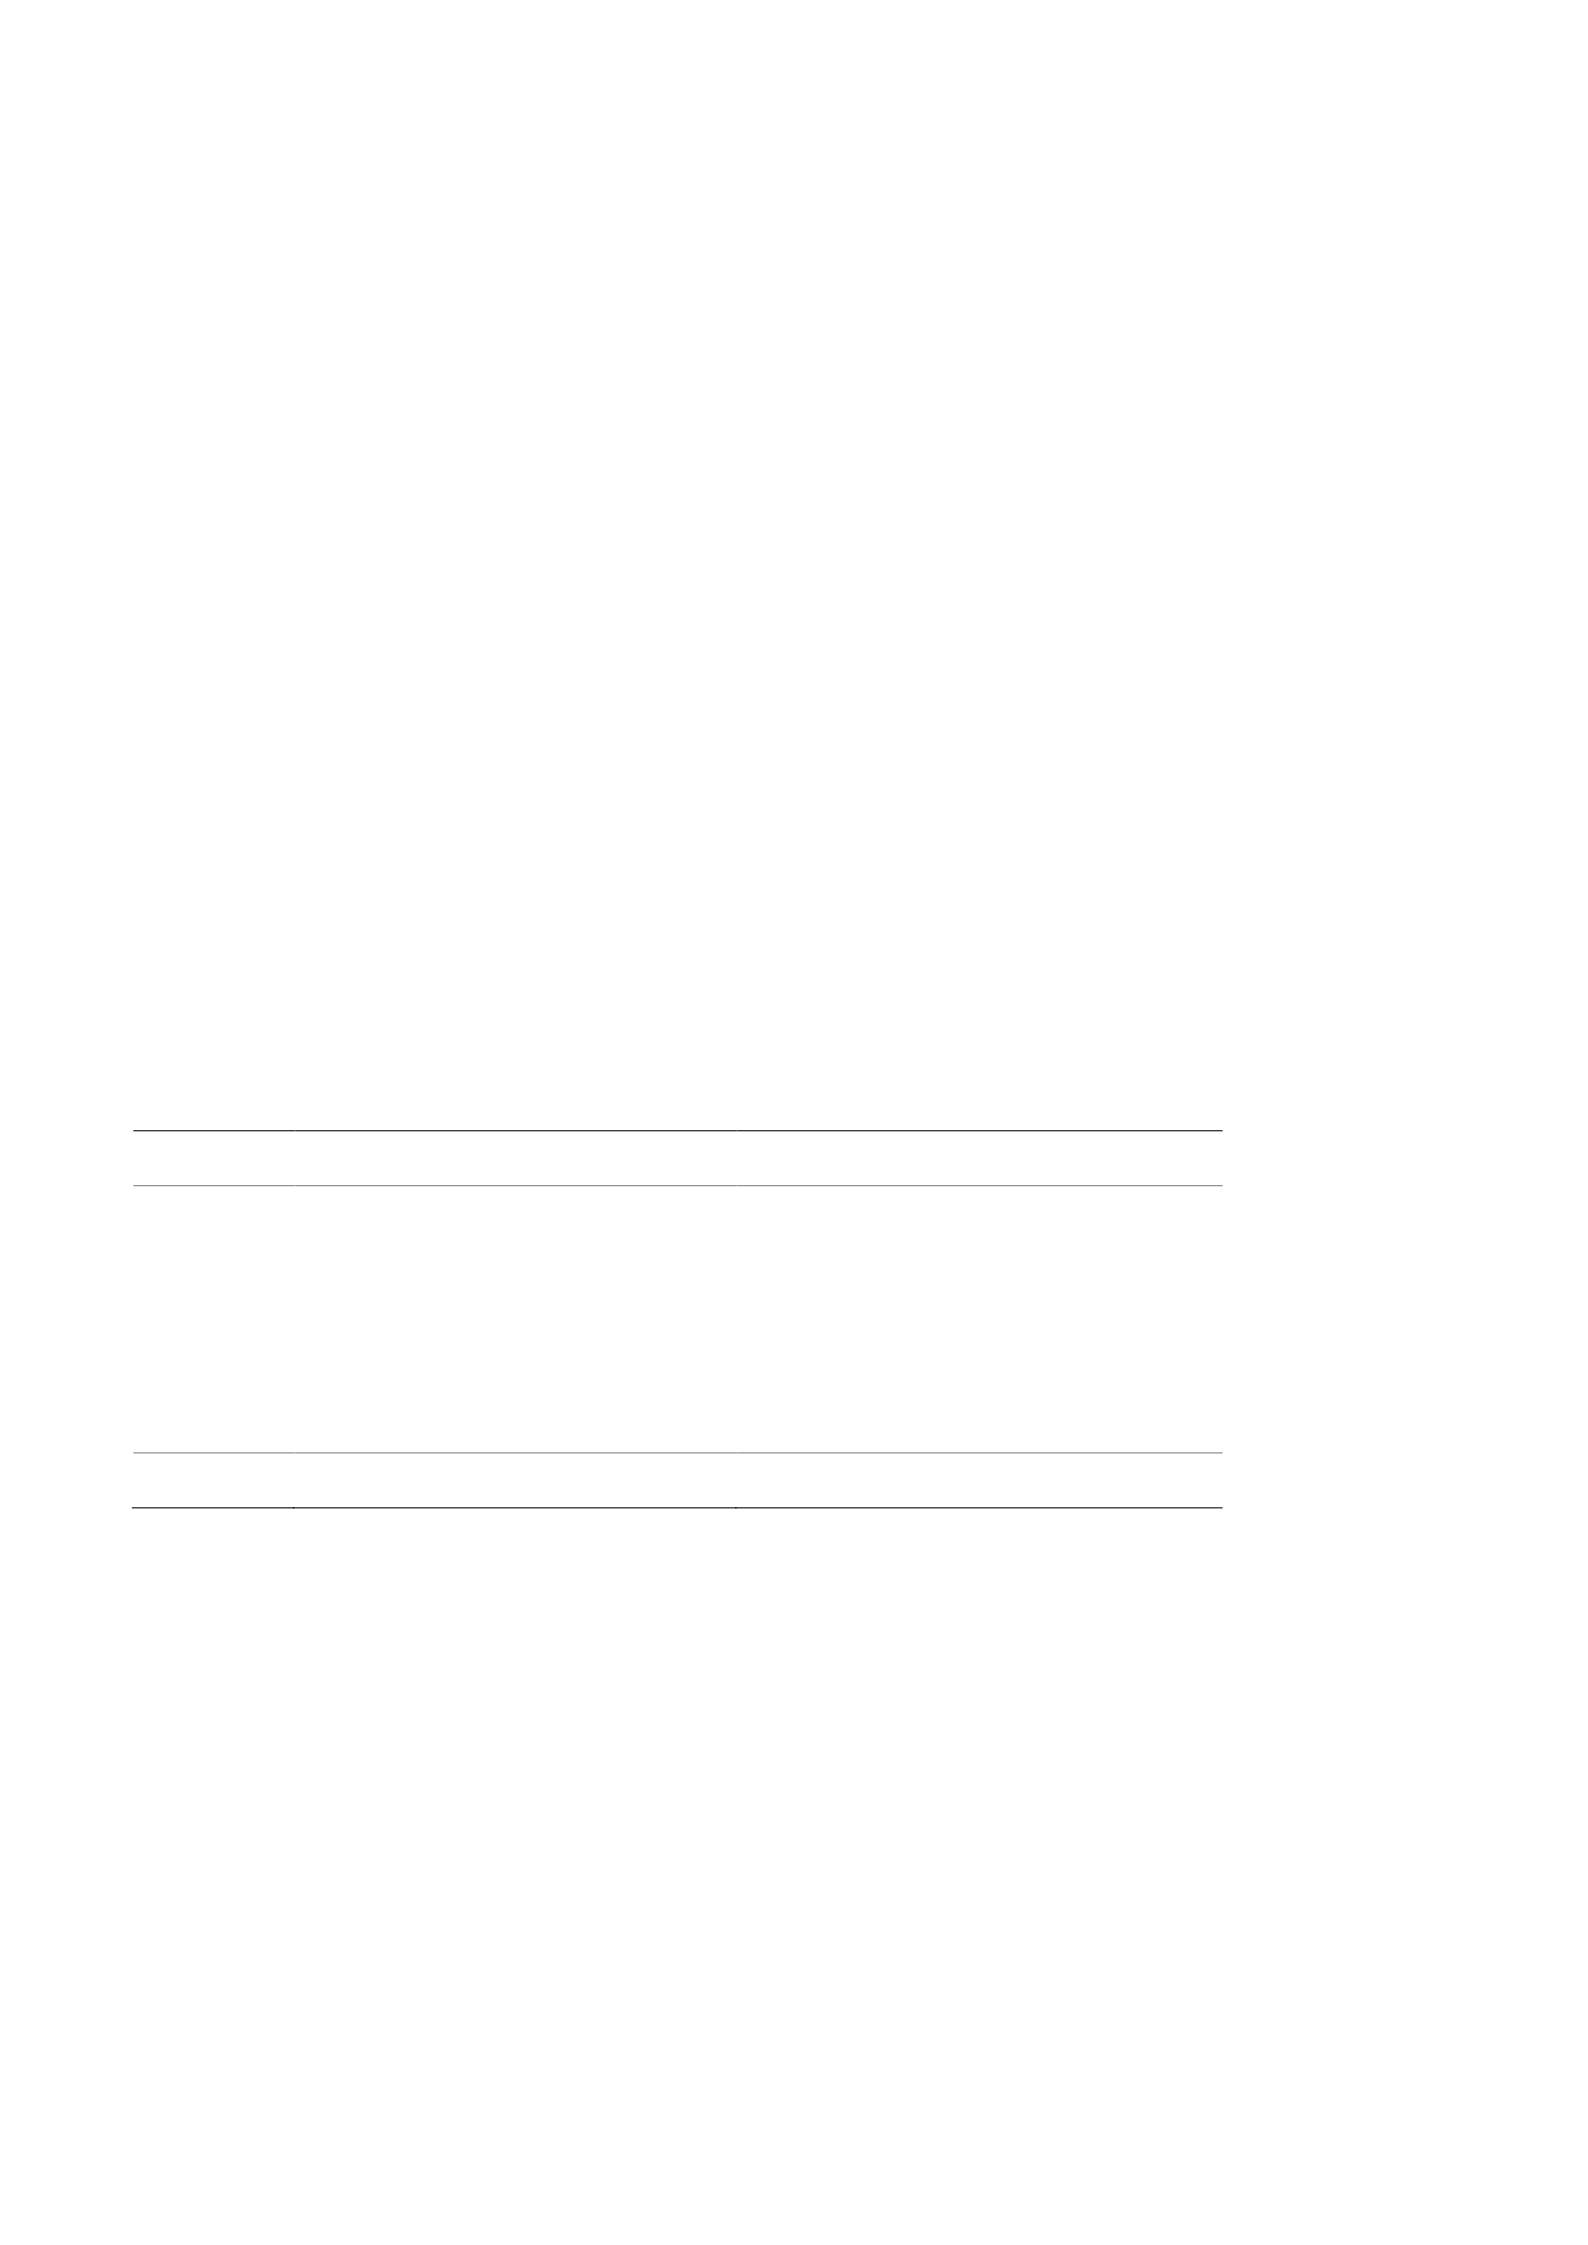
Table 3 Percentage dominance of market capitalization of the research sample
No.
Cryptocurrency
Market Capitalization (%)
1
Bitcoin (BTC)
40,09
2
Ethereum (ETH)
18,41
3
Binance Coin (BNB)
4,95
4
Ripple (XRP)
2,15
5
Cardano (ADA)
1,07
Total
66,67
Based on Table 3 above, the five research samples show the dominance of a very large
percentage of market capitalization to more than half of the market capitalization of all
cryptocurrencies, namely up to 66.67%. Of the five sample cryptocurrencies, Bitcoin (BTC) is
the most dominant with a dominance percentage of 40.09%, while Cardano (ADA) is the least
among the other sample c r y p t o c u r re n c i e s at 1.07%.
4.1 Descriptive Statistical Analysis
Descriptive statistical analysis is used to provide an overview of the research object
data. The observation period is from April 01, 2019 to December 31, 2022 with a total of
1371 samples. The descriptive statistical results for the daily returns of each sample during the
29
study period can be seen in Table 4.
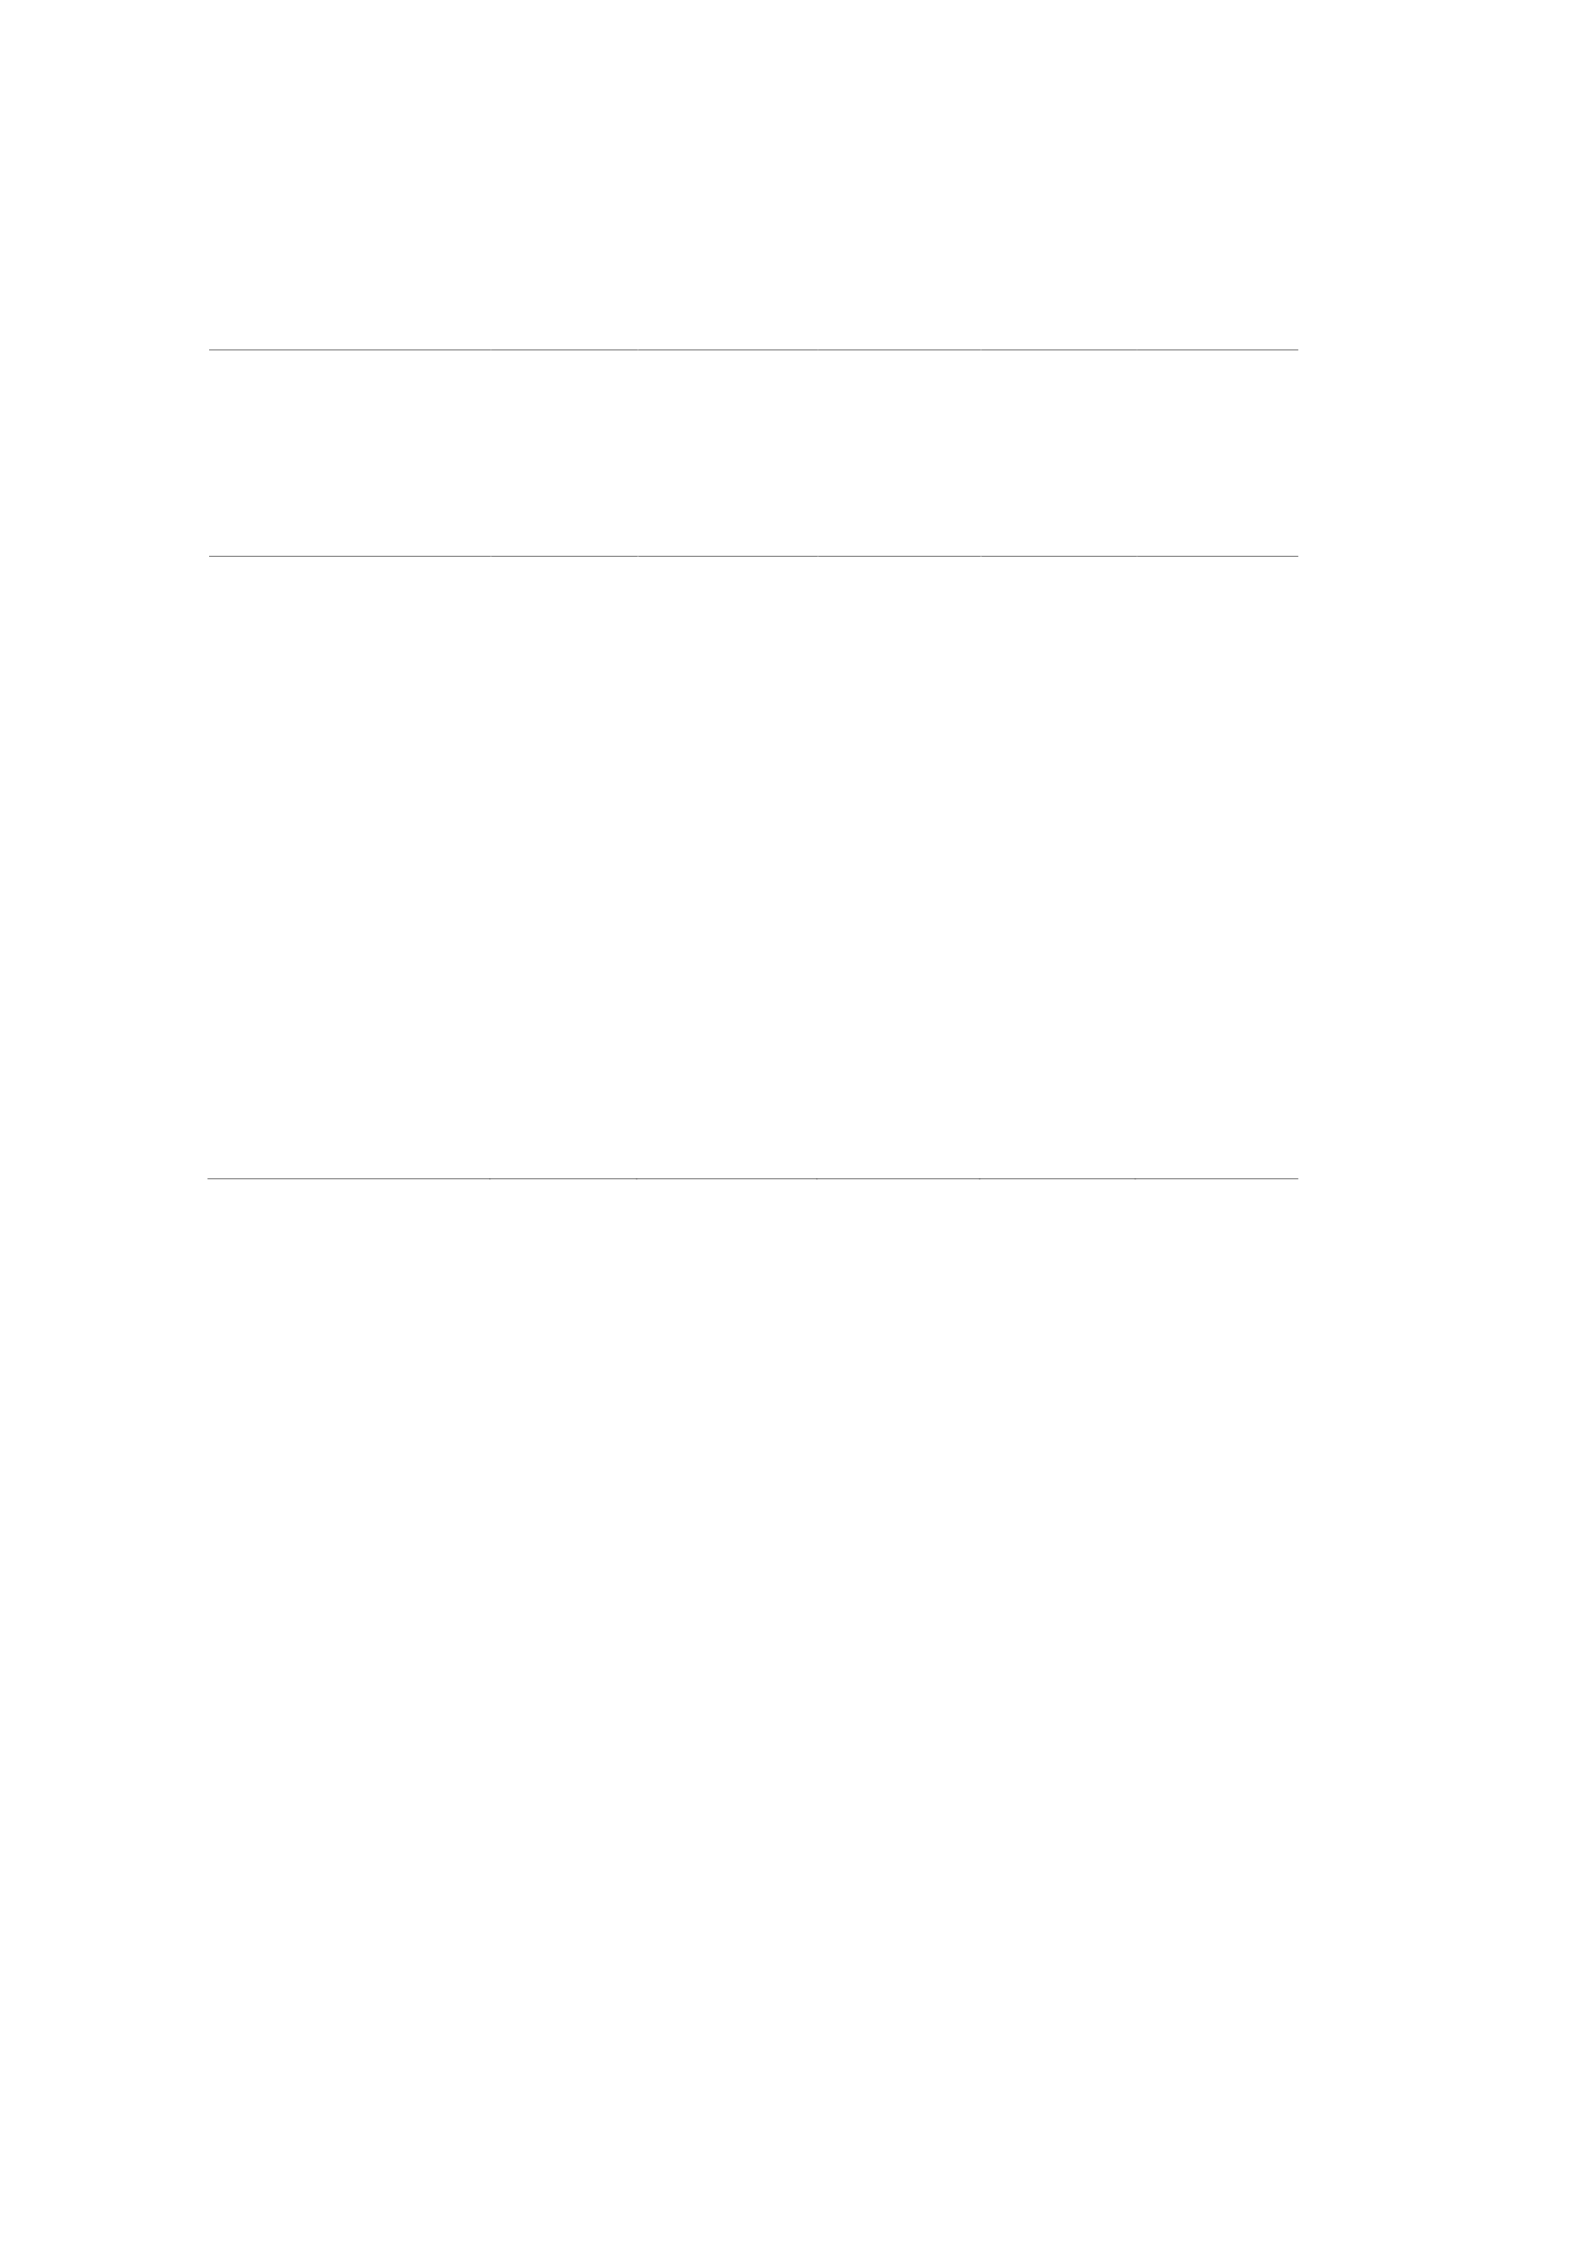
Table 4 Descriptive statistics of daily return rate of each sample
Bitcoi
n
(BTC
)
Ethereum
(ETH)
Binance
Coin
(BNB)
Ripple
(XRP)
Cardan
o
(ADA)
Average (%)
-
0,036
7
0,1363
0,2379
0,1188
0,0658
Median (%)
0,124
4
0,5505
0,1916
0,1564
0,0447
Minimum (%)
-
13,97
60
-30,0301
-
37,9052
-
38,163
4
-
27,761
2
Maximum (%)
13,56
34
21,7519
55,6456
35,626
2
20,826
8
Standard
deviation (%)
3,824
4
5,0299
6,5961
6,6582
5,7469
Source: data processed (2023)
Based on Table 4 above, from 1371 observation period points, it is known that Binance
Coin (BNB) has the highest average asset return value of 0.2379% with the highest return
increase that can reach 55.6456%, while Bitcoin (BTC) has the lowest average return value of
-0.0367% with the lowest return increase that only reaches 13.5634%. On the other hand,
Ripple (XRP) has the highest standard deviation value of 6.6582% with the sharpest decline
in return value reaching -38.1634%, while Bitcoin (BTC) has the lowest standard deviation
value of 3.8244% with the lowest decline value of -13.9760%.
The descriptive statistical results for market/sample average daily returns (Rm,t) and
cross-sectional absolute deviation (CSAD) values during the study period can be seen in
Table 5. The average return during the entire sample period is positive with a value of
0.1293% and the return fluctuates from -47.9608% to 18.8657%. These results indicate the
high volatility of the large-cap cryptocurrency market with a standard deviation of 4.3252%.
Meanwhile, the daily average value of CSAD is 1.6131% which shows the high
deviation/dispersion of returns from market consensus.
𝑚
,
𝑡
𝑚
,
𝑡
4.2 Herding Behavior in Large-Cap Cryptocurrency Markets
This study uses the CSAD approach by Chang et al. (2000) with the Newey and West
(1987) econometric estimator approach to test the herding behavior of the large-cap
cryptocurrency market. The following are the results of testing herding behavior in the large-
cap cryptocurrency market in Table 7.
Table 7 Test results of herding behavior on large-cap cryptocurrency in aggregate
Dependent Variable: 𝑪𝑺𝑨𝑫𝒕
Independent
Variable
Coeffici
ent
Coefficient
Value
t-
statistic
p-value
(%)
(intercept)
α0
0,0098***
16,555
0
0,00
|𝑹𝒎.𝒕|
γ1
0,2322***
7,3005
0,00
𝑹𝟐
𝒎
,
𝒕
γ2
-0,1944**
-2,4381
1,49
***, ** and * indicate significance levels at 1%, 5% and 10%, respectively.
Based on the regression results above, the resulting CSAD equation is as follows:
𝐶𝑆𝐴𝐷𝑡 = 0.0098 + 0.2322|𝑅𝑚,𝑡| - 0.1944𝑅2 + 𝜀
The regression intercept value (𝛼0 ) of 0.0098 indicates that if there is no increase or
decrease in the large-cap cryptocurrency market return (𝑅𝑚,𝑡 = 0), the dispersion value of the
large-cap cryptocurrency return (CSADt) will be equal to 0.0098 or 0.98%. The very small
value of 𝛼0 close to zero indicates that all average returns
all assets move almost in unison with market returns.
In addition, the coefficient on the linear component of |𝑅𝑚,𝑡|, namely (𝛾1 ), is positive
and significant, indicating that there is a positive and significant linear relationship between
CSADt and |𝑅𝑚,𝑡 |. However, simultaneously the coefficient on the non-linear component of 𝑅2 ,
namely (𝛾2 ) is negative and significant. Therefore, the linear relationship is no longer valid
and the negative coefficient indicates that the higher the large-cap market return is, the more
significant it is.

31
𝑚
,
𝑡
cryptocurrency, the change in return dispersion will lead to a rapid decline, confirming the
herding behavior in the large-cap cryptocurrency market.
Under normal/stable market conditions, investors tend to have different perceptions in
investment/trading decisions, resulting in a high level of variability in asset returns with the
market as indicated by high return dispersion. However, in herding market conditions, when
the market experiences a strong trend of price changes, investors tend to follow the market
trend so that trading that was originally diverse with a high level of return dispersion will
decrease significantly. The strong price change trend is then captured by the market squared
return (𝑅2 ) (Chang et al. 2000). This shows that when herding behavior occurs, investors are
encouraged to take the same action as the majority (follow along) so that there is uniformity
between the average return between assets (cross-return) and the market return.
As for the calculation of a partial decrease in the first derivative of the CSADt equation
above with the absolute average value of the market return, |𝑅𝑚,𝑡 |, which has been attached
in Appendix 1, it is found that the value of CSADt reaches
maximum when the value of |𝑅 ∗ value is 59.72% with the maximum value of CSADt
𝑚
,
𝑡
|
by 0.0791 or 7.91%. These results show that the greater
the absolute mean value of the market return, especially when it is more than 59.72%, the
dispersion measure starts to decrease or increase the uniformity between the market return and
the average cross-asset return.
Thus, the non-linear relationship between market return and market return dispersion
implies that large-cap cryptocurrency market participants tend to follow aggregate market
behavior and ignore their own investment decisions and priorities during periods of large
average price movements while confirming that the linear relationship between dispersion and
market return no longer holds and confirming the model of Chang et al. (2000) model is
suitable for this study. The following illustrates the non-linear relationship between CSADt and
market returns in Figure 10.
Based on these empirical results, investors in the large-cap cryptocurrency market tend
to behave herding behavior as evidenced during the aggregate sample period April 2019 -
December 2022. These results are in line with research (Vidal-Tomás et al. 2019; Ballis and
Drakos 2020) which shows that investors in the "top" sector (large-cap) of the cryptocurrency
market act irrationally and imitate the decisions of others without reference to their own
beliefs. However, the results contradict research by (Amirat and Alwafi 2020; Lobão 2022;

32
Yousaf and Yarovaya 2022) which states that herding behavior in cryptocurrency cannot be
proven.
Herding behavior according to Bogdan et al. (2022) is a dynamic behavior. Therefore,
to obtain comprehensive implications, further testing is carried out on a subsample period
using a rolling-window regression model of herding behavior in the large-cap cryptocurrency
market in different time-varying variations. In determining the window size of research
observations, there is no standard / golden rule for determining the right window size
(Stavroyiannis and Babalos 2017). In this section, the determination of the window size of
research observations is carried out first by trial and error iterative regression, the results of
which are attached in Appendix 2 using the initial sample base/initial research period (April
01, 2023) by increasing the number of observations in successive 30-day intervals until an
observation period is found with the result of 𝛾2 which is the most suitable for the study.
consistent with previous aggregate observations (negative and significant).
The trial and error that has been carried out produces a window size that meets 661
observations while confirming that the size of the sample period affects the results of testing
herding behavior in the market, especially cryptocurrency.
The following are the results of testing herding behavior in the large-cap
cryptocurrency market based on time variation using a rolling-window of 661 observations
with a step of one observation period in Figure 12.
Based on the results of the rolling-window analysis shown in Figure 12 above, it is
found that the coefficient 𝛾2 is significant at a p-value < 10%, which is marked with a red line
below the 10% mark, as well as a negative sign marked with a green line in the initial
subsample observations.
(start) on April 01, 2019 until the final subsample observation (end) on January 02, 2022.
This shows that the event of investor herding behavior in the large-cap cryptocurrency
market can be clearly identified in the subsample period.
In addition, in this time span, the decrease in the coefficient 𝛾2 occurs from the start
range of April 01, 2019 to the end range of May 20, 2021.
The decline indicates that herding behavior was very strong in that period (Chang et al. 2000;
Gong and Dai 2017). The following is an overview of the large-cap cryptocurrency market
conditions represented by the CRIX index in Figure 13.

4.3 The Effect of Investor Sentiment and Indonesian Macroeconomic Factors on the
Herding Behavior of Large-Cap Cryptocurrency Markets
After testing the tendency of herding behavior in the large-cap cryptocurrency market,
the influence of investor sentiment and Indonesian macroeconomics on the herding behavior
of the large-cap cryptocurrency market was analyzed using the modified CSAD equation
with multiple linear regression analysis. The regression results use sample data in the
aggregate of five large-cap cryptocurrencies and two investor sentiment indices, namely the
CVI index representing the aggregate cryptocurrency volatility, the FGI index representing
the level of fear and greed of cryptocurrency investors, and two Indonesian macroeconomic
factors, namely inflation and interest rates. The regression results are listed in Table 8.
Table 8 Test results of the effect of investor sentiment and Indonesian macroeconomic factors on
the herding behavior of the aggregate large-cap cryptocurrency market
Dependent Variable: 𝑪𝑺𝑨𝑫𝒕
Independent
Variable
Coeffici
ent
Coefficient
Value
t-
statistic
p-value
(%)
(intercept)
α0
0,0097***
16,184
3
0,00
|𝑹𝒎.𝒕|
γ1
0,2373***
7,5475
0,00
𝑹𝟐
𝒎
,
𝒕
γ2
-0,1923**
-2,2820
2,26
𝑹𝑪𝑽𝑰
,
𝒕
γ3
0,0019
0,2394
81,08
𝑹𝑭𝑮𝑰
,
𝒕
γ4
0,0057***
4,2351
0,00
𝚫𝑰𝒏𝒇𝒍𝒂𝒕𝒊𝒐𝒏𝒕𝑹
𝟐
𝒎
,
𝒕
γ5
-
6183,4830***
-3,2147
0,13
𝚫𝑰𝒏𝒕𝒆𝒓𝒆𝒔𝒕𝒕𝑹
𝟐
𝒎
,
𝒕
γ6
-236,9904
-0,2807
77,90
In the regression results, it is found that the coefficient of γ3 is positive and insignificant,
indicating that the overall cryptocurrency volatility has a positive effect on herding behavior
in the large-cap cryptocurrency market fails to be proven in aggregate.
However, the coefficient γ4 is positive and significant, indicating that any increase in the
value of the FGI index will increase the value of CSADt, w h i c h i s equivalent to if the FGI index
decreases, which represents that investors are afraid, it will reduce the dispersion of returns

41
which then increases the uniformity between asset cross-returns and market returns.
Therefore, the fear of large-cap cryptocurrency investors has a positive effect on herding
behavior in the aggregate large-cap cryptocurrency market was successfully proven.
In addition, on Indonesian macroeconomic factors, it is found that the coefficient γ5 i s
negative and significant, indicating that any change in the inflation rate in Indonesia will
reduce the dispersion of returns which then increases the uniformity between asset cross-
returns and market returns, or has a positive effect on herding behavior in the large-cap
cryptocurrency market. However, the coefficient γ6 i s negative but insignificant, indicating
that changes in the interest rate in Indonesia have a positive effect on herding behavior in the
large-cap cryptocurrency market.
Based on the results of these empirical tests, it can be concluded that of each of the two
investor sentiments and Indonesian macroeconomic factors tested, only the movement of the
FGI index and the inflation rate have an influence on herding behavior in the large-cap
cryptocurrency market in the aggregate sample period April 2019 - December 2022.
Furthermore, further testing is carried out using the same model as the time-varying test
on the previous herding behavior, namely rolling-window regression to confirm the condition
of external factors (investor sentiment and Indonesian macroeconomic factors) in the
subsample period can affect the herding behavior of the large-cap cryptocurrency market in
different time-varying variations. The following are the results of testing the effect of investor
sentiment on the herding behavior of the large-cap market
Based on the rolling-window analysis results shown in Figure 16 above, it is found that
the coefficient of 𝛾3 is insignificant at all subsample observation points. This is consistent
with the aggregate regression results which show that 𝛾3 is insignificant at a p-value < 10%
during the study period. The results indicate that the rise and fall of the overall volatility of
cryptocurrencies represented by the CVI index has no influence on the herding behavior of
the large-cap cryptocurrency market under overall market conditions.
The coefficient 𝛾4 is significant at a p-value < 10% at almost all observation points.
Although the significance of the coefficient 𝛾4 is not consistent across all observation poin
ts,
th
e overall coefficient 𝛾 is significant at a p-value < 10% at almost all observation points.
4

is positive at all observation points. Therefore, the rolling- window results are in line with the
previous aggregate results that investor optimism in the specific large-cap cryptocurrency
market represented by an increase in the value of the FGI index will increase the value of
CSAD, which means a decrease in the level of large-cap cryptocurrency herding behavior. In
other words, cryptocurrency large-cap herding behavior occurs when investors feel
pessimistic about what will happen to the cryptocurrency large-cap market in both the short
and long term.
The results of this study are in line with research (Sheikh et al. 2023) on Pakistan and
research (Economou et al. 2018) which shows that investor fear affects investor herding
behavior or investor optimism / greed affects investor herding behavior in reverse (reverse-
herding).
In the context of cryptocurrencies, the emotions/sentiment of investors in the large-cap
cryptocurrency market is very influential on these market movements (Güler 2021; Anamika
et al. 2021). As explained earlier, investor emotions/sentiment in cryptocurrency can be
attributed to the Covid-19 phenomenon which makes many investors fear that they will lose
money due to the decline in the value of cryptocurrency, causing investors to join the
bandwagon or sell their assets in droves.
As it is known that cryptocurrency is a type of asset with very high volatility/risk (Liu et
al. 2019). When investor pessimism hits the cryptocurrency market due to the Covid-19
phenomenon, negative social-media influencer opinions on cryptocurrencies, or other
negative sentiment phenomena, investors will tend to be risk averse (Delfabbro et al. 2021).
As for the possibility of high volatility/risk, investors feel that the market has the potential to
experience greater losses than potential profits. As a result, herding behavior can occur when
these pessimistic investors join the majority of investors who then follow the trend of selling
assets. Such herding behavior can lead to excessive and irrational price movements in the
cryptocurrency market. When many investors decide to sell en masse due to pessimism, it can
cause a sharp decline in value/price and create a panic selling cycle as happened in the Covid-
19 phenomenon and negative news related to the Tesla company that decided to stop
transactions using Bitcoin previously described. This can parallel the negative sentiment in
the market and encourage more investors to go with the flow and sell their assets, even though
it is most likely not based on strong technical or fundamental analysis.
The overall/aggregate cryptocurrency volatility represented by the CVI index fails to be
proven to have an effect on herding behavior in the large-cap cryptocurrency market

47
supported by research (Rubbaniy et al. 2021) which explains that the cryptocurrency market
volatility index with different market specifications does not become a reference for investors
in deciding to invest in other cryptocurrency markets. This is also supported by research
(Rahman and Ermawati 2020) in Indonesia and Thailand which shows that herding behavior
in the market in Indonesia and Thailand has no effect on the large-cap cryptocurrency market.
Therefore, empirically, the overall cryptocurrency volatility has a positive effect on
herding behavior in the large-cap cryptocurrency market empirically fails to be proven.
However, the fear of large-cap cryptocurrency investors is proven to have a positive effect on
herding behavior in the large-cap cryptocurrency market. Based on the empirical test results,
it can be concluded that of the two investor sentiments tested, only the movement of the FGI
index has an influence on the herding behavior of the large-cap cryptocurrency market.
Furthermore, the following are the results of testing the effect of Indonesian
macroeconomic factors on the herding behavior of the large-cap cryptocurrency market based
on time variation using a rolling-window of 661 observations with a step of one observation
period in Figure 17.
Based on the results of the rolling-window analysis shown in Figure 17 above, it is
found that the coefficient 𝛾5 is significant at a p-value <10% as well as negative in the initial
observation period (start) on May 10, 2020 to the final observation period (end) on July 27,
2022.
4.5 Managerial Implications
Based on the research results, given the existence of herding behavior in the large-cap
cryptocurrency market, the market is proven to be inefficient in accordance with research
(Urquhart 2016; Vidal-Tomás et al. 2019). Market efficiency is formed by investors as market
participants themselves, because it is investors who provide interpretations and reactions to
existing information and have an impact on cryptocurrency prices. Therefore, it is important
for investors to carefully consider fundamental and technical analysis before making
investment decisions and not rely on market reactions or collective actions of other investors
as herding behavior can lead to investors falling for market trends that may be irrational with
unnatural price fluctuations. In addition, policymakers play a role in ensuring that markets
operate fairly and efficiently. Therefore, both global and local policymakers need to establish
adequate regulations to improve the efficiency of the cryptocurrency market. Such regulations
include investment limitation regulations or auto-rejection systems as in the capital market
when cryptocurrency market fluctuations are deemed to exceed reasonable limits, as well as

risk warnings provided by investment platforms to investors. This can reduce the risk of large
losses to investors due to herding behavior that occurs. In addition, it is important to provide
better education and financial literacy to the general public regarding cryptocurrency
investments and the risks involved in such investments. Proper education can help investors
make more rational decisions.
Furthermore, Indonesia as one of the countries with the largest percentage of large-cap
cryptocurrency market adopters in the world, the macroeconomic level, especially inflation in
Indonesia, is proven to have a contribution / influence on herding behavior in the market, and
according to Choi and Shin (2022) cryptocurrency is not resilient to the value of inflation.
Therefore, investors need to diversify with assets that are resilient to changes in Indonesia's
macroeconomic levels. It is important for investors to set a hedging strategy by using assets
that are not related / correlated with economic policies in a country to protect the portfolio
from greater losses, such as bonds, especially sukuk, which have proven to be resistant or
unaffected by economic policy uncertainty (Reboredo and Naifar 2017) and can be a hedge
for cryptocurrency investments, especially during times of crisis (Karim et al. 2022).

49

