


FUEL, SUBSIDIES AND NATIONAL INDEPENDENCE
ARIZONA STATE UNIVERSITY
ECN 211 - MACROECONOMIC PRINCIPLES
WEEK 3
CEPU BLOCK AND THE NATION MANDIRI:
Negotiations between Pertamina and Exxon Mobil (EM) to reach an agreement to
exploit the Cepu Block wells have been very tough.The negotiations have started a long time
ago.When I was still sitting as a member of the Government Board of Commissioners for
Pertamina ex official, the US Government had already intervened.
EM's top leader, then Ambassador Ralph Boyce, and finally President George W.
Bush all pressured the Indonesian government not to allow EM to benefit from the oil in the
Cepu Block. All foreign contractors are allowed to explore with clear rules and conditions. So
there was no need for a lot of negotiations involving the presidents of both parties. The
allotment of negotiations was because EM, which had to be rejected from the start, did not
want to negotiate at all.
For sale Tommy Soeharto:
According to Kwik Kian Gie (2006) Tommy Soeharto originally had a license to
exploit oil in the "small" Cepu well. The license expired in 2010, and was sold to EM.
Knowing there were 600 million barrels of oil reserves, EM proposed that the contact
between Indonesia and EM be extended to 2030 with a detailed business deal.
At that time, Pertamina's legal status was still perum. According to the law, it was the
Board of Government Commissioners for Pertamina (DKPP), consisting of five ministers,
that had the right to make the decision by acclamation. Otherwise, the decision was made by
the president. Three DKPP members agreed, two refused to be extended. As acclamation was
not achieved, President Megawati received the "hot ball".
Before the decision was taken, Pertamina's legal entity changed from perum to
persero. Ultimate power lies with the shareholder, the government. However, because the
legal form was a persero, the government had to pretend to be

Giving authority to the Board of Directors of Pertamina. It turns out that the
Pertamina Board of Directors under Widya Purnama did not want to give up in fighting for
the interests of the people. But since the government and the US President intervened, it will
be interesting to see if after being taken over by the president the decision becomes more
lenient than what Widya Purnama wanted?
We explore the pro-con arguments of continuing with EM or 100 percent exploitation
by Pertamina. Why is EM insistent? Because they found 600 million barrels of oil. Later it
was stated that the content was 1.2 billion to two billion barrels.
Contract is contract, after 2010 the Cepu Block must be 100 percent exploited by
Pertamina. The reason is simple, if EM insists, the profit must be large. So, if it is fully
exploited by Pertamina, 100 percent of the profit goes to Pertamina. Can Pertamina?
Pertamina's Managing Director at the time, Baihaki The judge stated that he could afford it,
especially since it was located on Java Island and easily accessible. The apartise can be
rented, not inviting EM as an employer. Are there funds, obviously there are, because many
banks are lining up to give credit if the oil content is so large.
Bung Karno's Message:
After 60 years of independence, should 92 percent of Indonesia's oil be exploited by
foreigners? Now is the time to increase Indonesia's share in its own oil exploitation. For the
Cepu Block in particular, this well is a starting point for the strategy.
About two Wan after becoming Pertamina's Managing Director, Baihaki and his staff
gave a presentation to me as the then Coordinating Minister for Economic Affairs about his
policy. It was stated that his vision and mission was to make Pertamina a world-class
company capable of developing itself into a multinational company, such as BP, Shell, and
EM.
Pertamina is already a large organization, while oil reserves continue to shrink, and
oil is a nonrenewable resource. So if reserves are shrinking, Pertamina must become a large
multinational company so that crude oil sources are obtained from anywhere. Otherwise,
what will Pertamina's organization do with its depleted oil reserves?
That is why President Aburrahman Wahid at that time ordered me to approve
Pertamina to take the risk of investing in exploration anywhere. I advised that it should be
scrutinized so that the risks taken were already well calculated risk.

When EM's Executive Vice President approached me and tried to convince me, I said,
"Please, can I learn to be a company like you in my own country, using my own oil reserves
as initial capital? Is EM not taking big risks when it starts, which you describe as scary? I am
not an Inlander."
I recounted Bung Karno's stance on limiting foreign exploitation of natural resources.
Another, "We keep it in the ground until our engineers are able to work on it themselves,"
said Bung Karno. Another reference is part of Bung Hatta's pleidoi at the 1932 Scheveningen
trial. In the trial, it was questioned whether the Indonesian people were able to be
independent in the independent world desired by Bung Hatta and Indonesian students who
joined the Indonesian Association in the Netherlands.
Bung Hattab said, "I would rather see the archipelago sink into the sea than be
colonized by gentlemen. The judges acquitted Bung Hatta, but in the Dutch East Indies, on the
same grounds, three years earlier, Bung Karno was sentenced to banishment and
imprisonment. Should we have a colonized spirit until now? President Yudhoyono should not
obey EM's wishes and not be afraid of US pressure. The government should not be involved
in business deals.
MAMAD AND DJAJANG DIALOG ABOUT FUEL SUBSIDIES:
Like everyone else, Mamad and Djadjang watched a lot of TV full of presidential
campaign programs. The campaigners were of course many famous economists and almost all
of them had the title of doctor, even many were professors. Mamad (M) and Djadjang (D) are
economics students and only in their third year, so they don't have much knowledge. But, a
little bit, if only the basics are enough to understand.
They did not understand one thing, and that was the fuel subsidy. The discussion went
as follows:
D : Mad, have you noticed the fears of the economists who are the success team of the presidential
candidates about the crazy increase in fuel subsidies. They keep saying how the new president
will handle it, whoever is elected.
M : I noticed that Djang. I just don't understand what is meant by subsidy?
D : For example, you really need the simplest house, and it costs Rp 10 million, but you only have
Rp 8 million.I'm kind and give you the shortfall of Rp 2 million for free.That's called me
giving you a subsidy of Rp 2 million so you can buy a house.

M : So you actually spent Rp 2 million of real money to donate to me?
D: Obviously, can I print fake money without getting caught?
M : I ask this because the economists say the government will be battered to spend tens of trillions
of rupiah in fuel subsidies. I don't understand why if the price of fuel on the world market is
high, the government must spend money? T h e petroleum is right, in the bowels of
Indonesia?
D: Yes, that very simple house that you mentioned, is also in Depok? So what did you say?
M : The house belongs to the developer and to build the house the developer actually spent Rp 9.5
million. He wants 0.5 million profit. So he set a fixed price of Rp 10 million.
D : Yes, but in terms of oil, no one owns it. It's in the bowels of the Indonesian earth and belongs
to all the people, right? If it is sucked out until the price of the crude oil comes out, is it not
there? That is, the crude oil doesn't cost any money?
M : Did you suck it out with your mouth? To suck oil out of the earth is expensive equipment and
these are all real expenses. How can you say that no money is spent?
D : There's mad, I'm not as good as you, but if you don't understand sucking oil, you need
equipment.
You're insulting me.
M : What do you mean by that?
D : You know mad, we record all the costs of equipment and costs for human labor that must be
incurred to extract oil. Then we add the cost of cultivation until it becomes gasoline. In that
process, we produce various kinds of products that are sold. We subtract the sales results.
Doesn't a number come out? This number must be much smaller than the price of gasoline
per liter, be it premium or premix.
M : It's hard to talk to you, it's the oil that is sucked out that is the most expensive and by you it is
valued at 0. Which is obviously far below the price of gasoline per liter!
D : If it's not valued at 0, then how much is it valued at?
M : Yes, the price that is determined daily by the oil market in New York and announced by Reuters,
which now soars to USD 40 per barrel. If this is added to your calculations, the price is
exorbitant but the government only receives Rp 1,850 for premium and Rp 2150 for premix.
Imagine the loss! The finance minister said the loss is above Rp 50 trillion!
D: That's only true if the government buys the crude oil. The crude oil was not bought by Mad? So

no money was spent. How can it be called a loss?
M : Yes, but if it was sold on the world market, would it make a lot of money? Now the
opportunity to earn a lot of money is lost. That's what the government says it loses because it
has to subsidize.
D : Oh, so what is meant by subsidy is that no money is spent, but only losses on paper, or in the
mind while grumbling, "Damn, if only I didn't need to meet the gasoline needs of my own
people, I could make a big profit," So that's what the finance minister thought, all members of
the DPR
, and those economists?
M: Yes, and it's in accordance with the in-depth theory they learned at school. You're still a third-
year student, so you can't understand a doctor, let alone a professor.
D: Oh that's why the finance minister said "Because of the high price of oil in the world market,
our subsidy has swelled by around Rp 53 trillion... Then he said it again." And the final
impact was an increase in the budget deficit of Rp 1.2 trillion: At first I was confused, the
subsidies increased so much, how come the impact on the budget deficit was only so small?
Eh, it's called subsidies and there's no money coming out, right Mad?
M : Yes Djang, that's called abstract thinking. The smarter people are, the more abstract their
thinking becomes.
D : What does that mean, Mad, to be more abstract?
M : Do you remember that our lecturer always started his first lecture with a joke saying that we
are here to do scientific work. And the definition of science is often the art of making very
simple things very complicated.
D : Indeed, but it's still great Mad, because by making things complicated, he does show that his
brain is very clever because it can string together so many factors that are complicated.
M : Yes, because it's in the clouds, then it has very little to do with my stomach. Hungry is full and
full is hungry.
D : What else do you mean?
M : In terms of oil, the stomach of the Indonesian people is not too hungry, but is described as very
hungry. In terms of the state budget, the stomachs of hungry people are said to be full.
D : Now you're making things up. You're the one who now wants to be pretentious so that I'm
confused and think you're smart. Isn't that right Mad?

M : No, you don't. Look at our 2004 state budget. The definition, right, says only Rp 24.92 trillion
or 1.2 percent of GDP.
D : So, what do you think?
M : In my opinion, all the money that is spent without caring what it is for, including to pay debts,
deducting what comes in, is a loss of Rp 89.9 trillion or 4.49 percent of GDP. This is real
spending, which makes our stomachs as small people feel real hungry, because that much
money must be spent real. Just look, paying interest and debt alone is already Rp 131.2
trillion of the entire State budget of Rp 471.03 trillion.
D : Oh, so in terms of fuel subsidies, our full stomach is actually described as hungry. In the case
of the state budget, our hungry stomach is described as full?
M : I think that's the essence of it. In fancy language, a subsidy is an opportunity loss. If the
government sold all the fuel that belongs to the Indonesian people on the international
market, the government would earn a lot of money. But because the oil in the belly of the
earth belongs to the people, we must fulfill their needs. It is not free, but the price of crude oil
is still quite high compared to the cost of production. The production cost is only around Rp
500 per liter. It is sold at Rp 1,850 for premium and Rp 2,150 for premix. So the government
is still profitable if we don't compare it with international prices.
D : Who determines the international price?
M : The New York oil market, the volume of which is only 30 percent of all oil trading in the
world. And only Reuters is allowed to broadcast the development of these prices, as is the
monopoly on broadcasting the prices of various foreign currencies every minute.
D : Ah, how fantastic is that. Maybe you're making it up.
M: Indeed Djang, who are we? We're only third-year students. And not at UI, but at USC. M: Did
you go to the University of Southern California?
D : No, we're both studying at the University next to Ciputra, right?
M : But the matter is actually more complicated than what we are talking about, because there are
exports, then there are imports with low quality, then there is profit sharing. Then there's
prorate and there's in kind and so on. There's also PT Petral, which is used for all sorts of
things.
D : Indeed, but the core of the problem I think is not wrong. Man we went to college first, and we
asked our lecturer further.

RAISING GASOLINE PRICES PREMIUM
The title of this paper is not the usual, "Repeal the fuel subsidy".Why? First, the term
"petrol" is better understood by the common people than fuel.Second, with the current price
of premium petrol, Rp 1810 per liter, the government is not providing a subsidy at all.
Instead, the government earns excess cash
The kerosene below the earth's surface is extracted to the top of the earth's
surface.This costs Rp X per liter.The crude oil above the earth's surface is processed into
gasoline.This costs Rp Y per liter. The gasoline must be transported to gas stations.The cost
is Rp Z per liter.So, Rp X + Rp Y + Rp Z = 10 US dollars per barrel.One barrel is equal to
159 liters.If the exchange rate of one US dollar is equal to Rp 8600, then the entire cost for
one liter is (10 x Rp 8600): 159 – Rp 540.88 rounded to 540 per liter.
As we know, premium gasoline is sold at a price of Rp 1810 per li t e r . So, for every
liter of premium gasoline sold, the government has a n excess of money of Rp 1810 per
liter less the expenditure of money of Rp 540.From the point of view of the outflow of
money, the government has an excess of cash. Why is it said that the government subsidizes?
UNDERSTANDING SUBSIDIES:
The government feels that it is subsidizing people who buy premium gasoline because
if premium gasoline were sold abroad, it would currently cost US$50 per barrel. At the same
exchange rate, which is Rp 8,600 per US dollar. The price of crude oil abroad per barrel is 50
Rc 8,600 per Rp 430,000. The per liter is divided by 159 or equal to Rp 2,704.4, rounded to Rp
2,700. This is the price of crude oil abroad. If it is made into gasoline, plus the three costs
mentioned earlier, namely the cost of siphoning refining, and transportation, which in total
amounts to Rp 540 per liter, then the price of gasoline abroad is Rp. 2,700 Rp 540 = Rp 3,240
per liter.
The difference between the price of gasoline abroad, which is Rp 3,240 per liter, and
the price of gasoline in Indonesia, which is Rp 1,810 per liter or Rp 1,430 per liter, is called a
subsidy. The government feels it is subsidizing because it cannot sell gasoline at world prices
due to its obligation to meet the needs of the people for premium gasoline at the low price of
only Rp 1,810 per liter.

The government is annoyed that it cannot sell its gasoline abroad at Rp 3,240 per liter.
Had it not had to sell to its own people at Rp 1,810, the government would have gained
additional revenue from the so-called "subsidy" of Rp 3,240-Rp 1,810 or Rp 1,430 per liter.
Imagine how much opportunity is lost. Yes, it's opportunity lost, not cash.
So it is clear that the name subsidy is an abstract notion that does not imply any
money outflow at all. In reality, the government is getting surplus money. It's just that the
surplus is not as large as if Indonesians were required to buy domestically produced gasoline
at world prices.
HOW MUCH EXCESS MONEY GOVERNMENT:
I could not get an exact figure because I could not get the quantity of crude oil that
belongs to the Indonesian people. About 92 percent of our crude oil is extracted by foreign
contractors. The proceeds are shared between the foreign contractors and the Indonesian
people, who own the crude oil. The calculation is very complicated.
What we often hear is a production sharing contract between the government,
represented by Pertamina, and a foreign contractor with a ratio of 85 percent for Indonesia
and 15 percent for the foreign contractor. However, there are other factors that complicate
things, such as so-called cost recovery, prorata, and in kind, making it difficult for us to get
the money we need.
The exact number. So let's just say that the net crude oil that the Indonesian people are
entitled to is Q liters per year. The excess money per year, yes Q liters multiplied by Rp
1,270 earlier. This is a lot of money. If we suppose that the net crude oil production to which
the Indonesian nation is entitled is 70% of 1.125 million barrels per day, this is equal to 70%
X 1.125 million barrels or 787,500 barrels per day or 125,212,500 liters per day, namely
787,500 barrels made into liters by multiplying by 159 (1 barrel = 159 liters). Per year, yes
multiplied by 365 to 45,702,562,500 liters. The excess money per liter is Rp 1,270. so, the
excess money per year is 45,702,562,500 X Rp 1,270 or Rp 58,042,254,375,000.
MUST IMPORT:
Our gasoline needs per year are 60 million kiloliters or 60,000,000,000 liters. The
production, as we saw earlier, is only 45,702,526,500 liters. So we have to import

14,297,437,500 liters. This has to be paid for by the world at Rp 3,240 per liter, or Rp
46,323,697,500,000. So there is an excess of money of Rp 58,042,254,375,000, but there are
import needs with an amount of money of Rp 46,323,697,500,000. As a result, there is still an
excess of money of Rp 11,718,556,875,000. So, even though some of the gasoline needs must
be imported at world prices, there is still excess cash of Rp 11,718,556,875,000. The question
arises, is the price of premium gasoline of Rp 1,810 per liter not too cheap? It seems that a
bottle of Coca Cola in a restaurant is sold for Rp 10,000 to Rp 15,000. So, if it is to be raised,
It is appropriate, as long as the increase is not too burdensome. By raising the price of
premium gasoline, the government does receive more revenue. This income can be used for
good purposes or corrupted. However, to say that by raising the price of premium gasoline the
government has to spend around Rp 10 trillion per month is clearly incorrect. The truth is that
the excess money amounted to Rp 11.73 trillion per year.
The whole picture of this paper is a gross oversimplification of reality. The same
applies to the figures. This paper is a model for getting a real understanding. So, it is not the
exact numbers that are important. The point is simply to explain that without raising the price
of premium gasoline the government is already surplus cash from the entire exploitation of
crude oil to make premium gasoline.
Whether the price is too low to be raised is another matter. However, don't scare the
people by saying that if it is not raised to world prices the government will have to spend Rp
10 trillion per month, and as a result the State's finances will go bankrupt. Moreover, this
article only discusses premium gasoline, not firstx and firstx plus gasoline and gas, all of
which are surplus and even more expensive.*
POLICY FUNDAMENTALS FUEL:
The price of fuel has been raised, the hope is now that the price that has risen is
temporarily valid for a relatively long time, so that on the basis of this new price the business
world can calculate and make plans. I'd be grateful if there was a guarantee that the
government wouldn't raise it again until 2009. Is that possible?
Many times I, along with many others, have questioned the relevance of world oil
prices to the prices charged to Indonesian consumers who own their own oil. If the
government is consistent with the idea that fuel prices should be brought to the same level as
those on the international market, it is clear that there is no certainty that fuel prices will not

rise again if world oil prices continue to rise.
It's good to question the basics now so that we have a handle on future policies.
Crude oil is priced at zero. First, it is necessary to clarify the view that Indonesian
crude oil prices are priced at zero if they do not refer to world oil prices. This is not true.
When the price of premium gasoline was still Rp 1,810 per liter, crude oil was priced at
Rp1,270 per liter, which is the consumer price of Rp 1,810 per liter minus lifting, refining
and transportation costs of Rp 540 per liter. After the increase to Rp 2,400 per liter, crude oil
is priced at Rp 1,860 per liter. Not zero!
Which market mechanism? It is said that if our economic system is not a communist
economic system, all goods are valued at prices that are formed through the market
mechanism. Clearly, the price is the point of intersection between the demand curve and the
supply curve. As we all know, all are interested in buying and all are interested in selling.
From the masses The points of the buyers are set at the center line. That's the demand curve.
The same applies to the formation of the supply curve. The question is, where are the
demand and supply curves plotted to determine their intersection? In New York. Is there any
Indonesian crude oil traded there? Practically none, because Indonesia's entire oil production
is already insufficient to meet the needs of its own people. How much of the world's crude oil
production is traded in New York? Only 30 percent. The 70 percent is monopolized by giant
oil companies from upstream to downstream.
We know there are many forms of markets, including perfect competition,
monopolistic competition, oligopoly, duopoly, and monopoly. The market in New York is
similar to perfect competition. The oil market in Indonesia is clearly a monopoly, and the
monopoly is given to Pertamina at a price set by the government.
The prices set by the government are not as high as those of a private monopolist.
Instead, the government sets prices that are as low as possible so that they are affordable to
the many people who are still poor and have very low purchasing power.
So, the government's monopoly position is not used to obtain maximum profits, but is
used to carry out its social functions in accordance with the spirit and mandate of article 33 of
our Constitution. Therefore, the supply curve cannot be drawn as it is in the textbooks,
because its behavior not profit maximization.
Why does the economic team in the government then act and behave like a private
monopolist and forget its social function in setting the price of oil that belongs to the people?

Isn't it for Indonesian oil and gas products that work not the invisible hands of the market
mechanism, but the invisible hands of political forces, interests and idiologies?
I understand, so that the proceeds of its larger sales can be used for good purposes
also for the people, but who determines the priority that the government on the contrary
squeeze the people in terms of oil in order to pamper it in the field of education and health?
So, with policies that are protested by many people, the government actually wants to
increase justice
Justice says that only the rich enjoy too cheap gasoline. This is not true. The largest
share of vehicles that consume premium are motorcycles
bajaj, mikrolet, pick ups and trucks carrying goods, angkot, ojek and many more poor people
or groups with mediocre income. rich people use pertamax and pertamax plus gasoline.
If you want to be fair, clear, concrete and right on target, sedan and mpv cars with
capacities above a certain cc are taxed as high as possible. why then become a patchwork?
The people are squashed, then treated with so-called compensation.
Those who are squeezed by their stomachs until they become hungry, the cure is
education and cheap health services. For people who too poor and hungry. Education
becomes abstract, however important in the long run. And people who are too poor, with an
improved education, in the long run will die in the middle of the road from hunger.
Cheap health services are indeed provided, but why be made healthy first by being told
to lack food because of the rising prices of basic goods?
There is the word subsidy. Because it fundamentally has to follow the market
mechanism in New York, the price difference between the New York market and the price set
by the Indonesian government is called a subsidy. This brings more confusion. Although the
price of gasoline is set very low, it does not mean that the price of crude oil is priced at zero.
With the current price of premium gasoline at Rp 2,400 per liter, crude oil is priced at
Rp 1,860 per liter. The government thus earns excess cash of Rp 1,860 per liter for every liter
of premium gasoline extracted from the earth. Indonesian. So the term subsidy is not the
same as money out. But because the word subsidy usually means money out, whether we
realize it or not.
The government has come to believe that subsidies are synonymous with spending
money. This is a very strange and confusing statement. The government's latest statement
reads; if gasoline prices are not raised, the government will lose around Rp 60 trillion.

However, if the price of gasoline is raised, the government can provide compensation to the
poor in the amount of Rp 7.9 trillion.
Let's go through the sentence. The price of premium gasoline has been raised from Rp
1,810 to Rp 2,400 per liter. Has this increase left the government with a surplus of Rp 17.9
trillion or more, which is used to support the poor?
I asked many people who subscribe to the notion that subsidies are synonymous with
money out. They said, with a premium gasoline price of Rp 2,400 per liter
government finances are still in the red. It's just that it's no longer Rp 60 trillion. Let's say that
the loss from Rp 60 trillion has become Rp 20 trillion. If the government is still short of Rp
20 trillion, how come it can support the poor to the tune of Rp 17.9 trillion? This is what
makes some members of the House of Representatives very eager to use their right of inquiry to
have a comprehensive and true picture.
It is indeed very complicated, because there are so many crude oil products, not to
mention the derivatives. Therefore, our appreciation is doubled for the members of the House
of Representatives who want to know everything through the right of inquiry.
Cash principle or accrual principle? Another oddity, the fuel post in the APBN is the
quantity multiplied by the price of oil on the international market, which will never be
received by the government, why? Because the prevailing price in Indonesia is set by the
government at a much lower price. Therefore, to compensate, a figure is included on the
expenditure side of the APBN with a post called "fuel subsidy". By itself the post "Fuel
Subsidy" is also a figure that is never issued. This is how the state budget is prepared violates
the cash basis principle. Law No. 17/2003 on state finances Article 36 indicates that the
accrual basis will be applied, but as a transitional regulation with a five-year grace period. I
think now it is still not treated with its implementing regulations.
Article 36 refers to articles 1 number 13, 14, 15, and 16, which are stated as an
accrual system. Article 1 number 13 reads: "state revenue is central government revenue that
is recognized as an increase in net worth." The price prevailing in the world market is not the
government's right, because the government sets its own right for premium gasoline at Rp
2,400 per liter. Not Rp 3,240 per liter if it is based on the NEW YORK market price of crude
oil of US$50 per barrel, and one US$ response equals Rp 8,600.
Law No. 17/2003 on state finances is unable to formulate and elaborate the correct
cash principle and accrual principle, because the minds of the lawmakers in relation to the
meaning of the word subsidy for oil and gas

Net imports are often explained that up to Rp 60 trillion is really money spent,
because we have to export crude oil and gasoline. the amount of production is less than the
amount of consumption. Indeed, but not 100 percent of the needs are imported. What is
imported is the difference between the production that Indonesia is entitled to and
consumption. However, the amount that must be spent is balanced by the amount of excess
money from all production that Indonesia is entitled to. just for example, we refer to premium
gasoline. for each liter, the government has excess money of Rp. 1,860 as explained earlier
(Rp 2,400 - Rp 540). Exactly how much of this surplus money and exactly how much money
is needed for imports is never revealed, however complicated it may be because there are so
many crude oil products.
INFLATION AND DEFLATION:
Inflation is the scourge of the modern economy. It is one of the major persistent
threats that will undermine or even destroy decades of economic growth if unleashed and
unbridled. It is feared by global central bankers and forces the implementation of monetary
policies that are inherently unpopular. It makes some people unfair between the rich and
impoverishes others.
Historically inflation has destroyed entire economies and changed the course of
human history. Inflation was one of the forces that unraveled the Roman Empire two
thousand years ago and the Soviet Union two decades ago. At the time of writing Venezuela
is recovering from an inflation rate of over 100% and Egypt is rioting about higher fuel
prices.
The impact of severe inflation often goes far beyond the economy. In the most telling
story in modern history, horrific inflation was triggered by the Republic in Germany at the
end of World War I which caused prices to rise to such extraordinary levels that the exchange
rate of the German Mark to the Dollar exceeded 3000000000000-1! This resulting economic
collapse created a political black hole that eventually saw the rise of the National Socialist
Party and Adolf Hitler, who exploited the collapse to become Chancellor of Germany in
January 1933.
Inflation is a mirror image, deflation, has less of a dark historical legacy, but remains
an economic problem which is serious.
Deflation defined price behavior during the Great Depression in the 1930s and has
emerged as an economy in Japan in the current period.

This chapter explores the dual economic phenomena of inflation and deflation at an
initial level. We will start by defining inflation and explain how it is measured in modern
economies. Then we will explore the construction of the two main price indices, the
Consumer Price Index and the Producer Price Index, and will follow that with a lengthy
discussion of why inflation and deflation are so harmful. Finally, using the models developed
in this chapter, we will explore the modern causes of inflation and consider the basic policy
responses designed to curb inflation or stimulate the economy out of deflation.
This chapter does not offer the final word on inflation and deflation. The range of
policy responses available to inflation and deflation are discussed in more detail in later
chapters. Likewise, the complicated impact of exchange rates on the international inflation
rate is also deferred to the next chapter on international trade and exchange rates.
I. Definition:
Inflation is a general term used in many contexts, there is no generally accepted
definition of inflation, nor is there a general agrteement on what constitutes an acceptable
level of inflation, inflation In general it can be said that inflation is a measure of the general
increase in the price level in the economy, represented usually by an inclusive price index,
such as the Consumer Price Index in the United States. The term indicates many individual
prices increasing together rather than one or two isolated prices, such as the price of gasoline
in an otherwise calm price environment.
The inflation rate is usually expressed as the annual growth rate in prices (again,
measured by an index) even if measured over a shorter period of time.
For example, if a radio report states that "consumer prices rose at an inflation rate of
four percent last quarter," that usually means the Consumer Price Index for All Urban
Consumers (the most quoted index) rose over the past three months at an annualized rate of
about four percent, and the press generally refers to the current inflation rate as about four
percent.
Deflation refers to a general decline in prices or price levels as measured by an inclusive
price index and, again, does not refer to isolated price declines, such as natural gas
declining in price, in an otherwise stable price environment.
During healthy economic times when the economy experiences neither inflation nor
deflation, terms such as price stability may describe the price environment of the economy at

the time.
So at what point in the economy is inflation price stability a desirable status (i.e. the
economy experiences inflation, which is almost always seen as a problem)? Although all
economists recognize that the higher the inflation rate, the more serious the economic
problem (explained later), what constitutes the threshold moving from good to bad and from
bad to worse depends on the economist and to some extent on the context. Shown in Table 1
are the somewhat arbitrary thresholds used by your teacher in his lectures and writings. Other
economists will have thresholds a little louder than this, yet others are a little looser.
When you look at Table 1 it is clear that a nominal amount of inflation, usually less
than 3%, is acceptable and may even be good for the economy. But any sustained rate above
2.5% or 3% would be seen as a potential problem, and the higher the rate, the more serious
and dangerous the problem would be. Part of the reason for this is because once inflation
moves up high into the single-digit range and then the double-digit range, it begins to self-
compound to higher levels. In other words, once it reaches a certain level, it sets in motion a
series of forces that tend to move automatically to higher levels (explained later). To be clear,
12% inflation will automatically become 15% inflation and then 20% inflation if it doesn't
handled by using severe and relentless anti-inflationary policies. Once inflation moves above
the 20% range, the lessons of history tell us that the propensity for self-inflation is so great
that inflation becomes explosive and potentially devastating for the economy.
Inflation has the potential to turn the economy into a hole smoking black.
At this point it is useful to look at a graph showing the inflation rate in the United
States through a series of decades. Figure 1 CPI Inflation: 1960-2011 shows that the annual
inflation rate, as measured by the most quoted inflation index in the United States, the
Consumer Price Index for Urban Consumers, US Medium Cities, All Goods, which is released
monthly (although the graph uses annual data). The vertical green line represents the trough
of the business cycle, the purple line the threshold between deflation and price stability
(which shows that we had a small episode of deflation, which is very unusual, in 2009), and
the dashed yellow line represents the approximate threshold, according to Table 1, moving
from a region of price stability into a region of moderate and possibly higher inflation. The
average annual inflation rate over this period has been around 4%.
By inspection, though, it is abundantly clear that the US economy has suffered two

dangerous bouts of inflation over this fifty-year period, moving in 1980 into the range
identified in Table 1 as hyper-inflation. That was indeed a disastrous year (30-year fixed
mortgage rates home loans were above 15% at the time) and it was only cured by a truly
Draconian policy response (described in the lecture) that threw the economy into a very deep
and serious recession.
The chart also shows that over the past decade inflation has not been a problem in the
United States.
II. How Inflation is Measured and Inflation Rate is Calculated:
Figure 1 shows the annual inflation rate as measured by the Consumer Price Index.
This section will explain how the index is determined and how the inflation rate is calculated
from the index. This section will also discuss the construction of other price indices such as
the Producer Price Index and special price indices that are used to deflate nominal national
GDP estimates to their actual (inflation-adjusted) growth rates.
II.1. Consumer Price Index:
As the name implies, the Consumer Price Index (CPI) is an index - one number - not a
growth rate. The index itself is based on a large recurring survey conducted by a government
agency, the Bureau of Labor Statistics (BLS), a division of the US Department of Labor.
Generally, surveys try to evaluate and re-evaluate the prices of various goods
purchased by the customer Consumers. The CPI and related statistics are released monthly,
first in the form of a press release and then immediately thereafter in a database available to
anyone who visits the CPI website. Since the CPI is an index, it is normal for a base, and the
base currently used is the average of the raw index for the 36 months of the calendar
year1982-1984, which is then assigned a value of 100.
Each month BLS data collectors use personal visits and phone calls to retail stores,
medical facilities and other businesses that serve consumers to collect price data on more than
80,000 items in more than 200 categories of goods, ranging from chicken eggs to liters of
motor oil to college tuition and postage costs. The price data is reviewed and adjusted
(because quality, packaging, and a myriad of other issues can affect the definition of a
commodity - what is a "large" egg, for example), then each price is multiplied by a weight
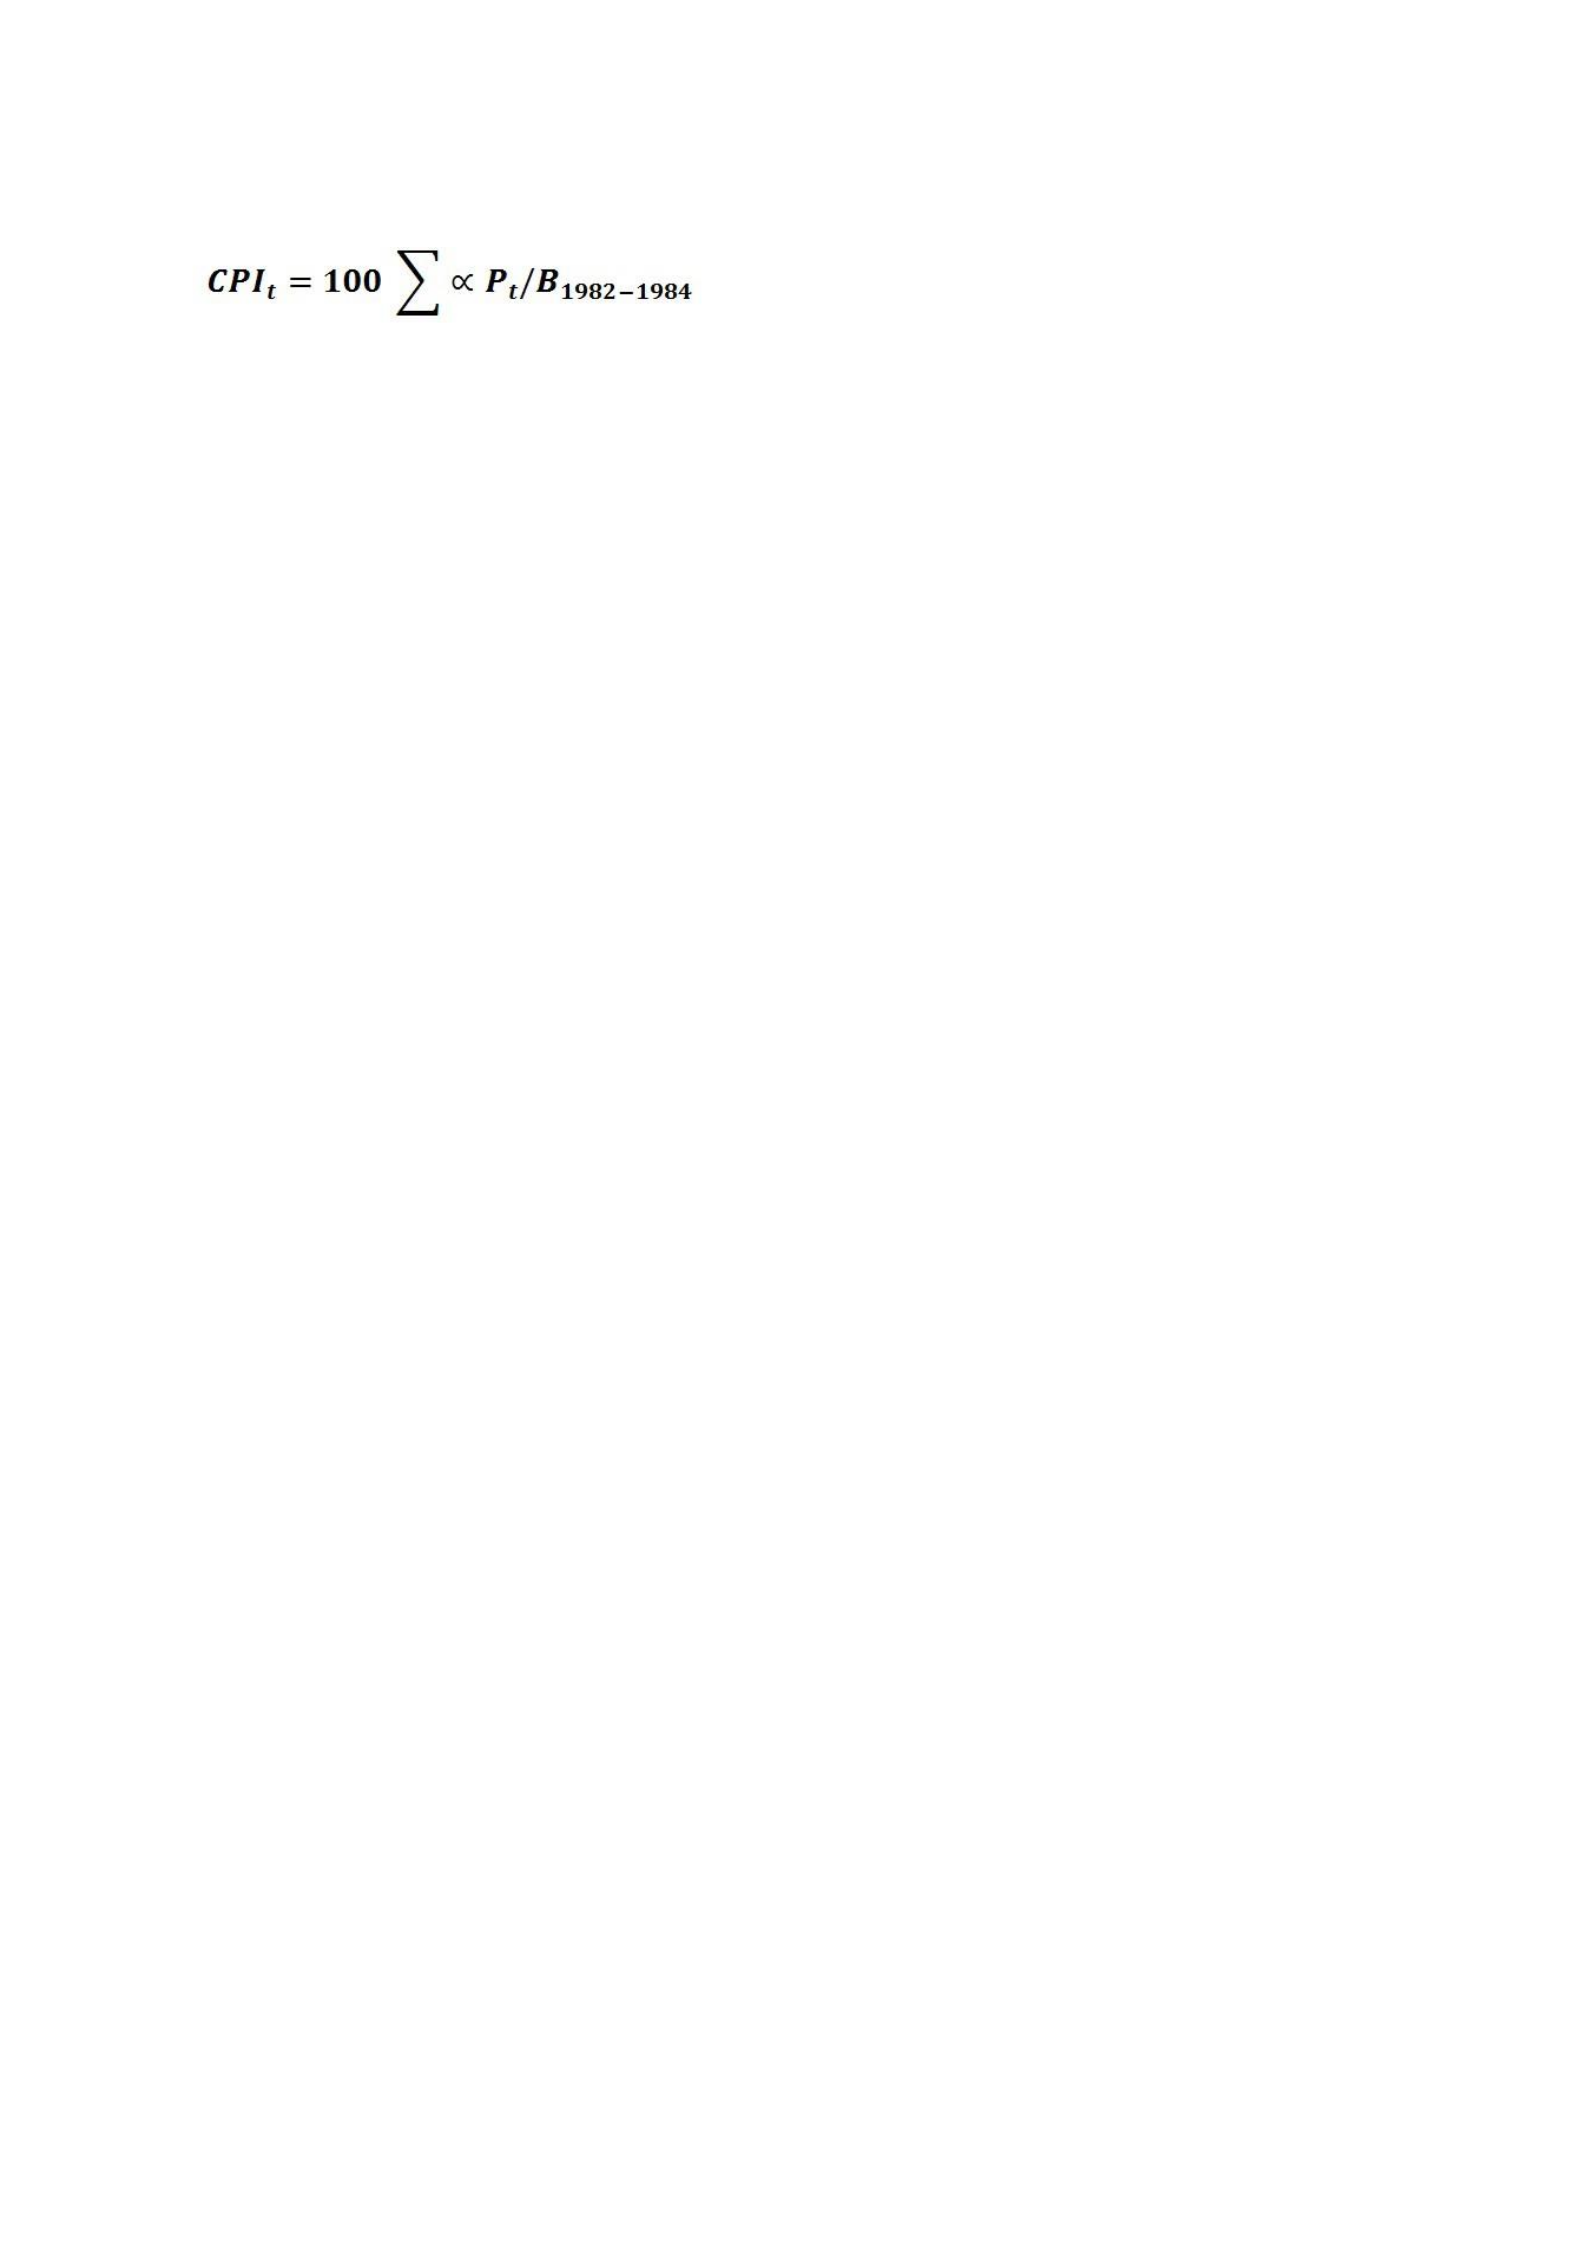
and then summed into a single index:
where α is the corresponding weight (changes periodically, but not monthly) and P is one of
thousands of prizes. Summed, the weighted value is divided by the base, average of the
standardized CPI (basically a formula for the left-hand division sign) for the 36 months 1982
to 1984. It will be interpreted that if the CPI equals110, then prices have increased by about
10% since the base period.
The sum of these alphas shown above is called the market basket by BLS and is
intended to roughly represent the percentage of monthly consumer expenditure as a group
spent on the overall category and each of the smaller components within the category, so that
the alphas all add up to 100%. For example, in January 2013 the weight for the Food category
equaled 15.261%, and the sub-category within Food for Fruit and Vegetables equaled
1.287%. Within that category, the weight for Bananas equaled 0.081%. This can be
interpreted that by BLS estimates, US consumers spent 15.261% of their monthly expenditure
on food, 1.287% on fruits and vegetables, and 0.081% on bananas.
Those weights, which change more or less every two years, are based on consumption
surveys provided by thousands of households. At any given time around 7,000 families are
asked to keep a personal diary of absolutely everything they buy for a period of two weeks,
which is then collected by the BLS. During the two survey periods year the BLS will collect
about 28,000 weekly diaries and, for additional information, will conduct about 60,000
interviews per quarter.
Table 2 shows the weights and components of some major CPI categories along with
some smaller components (randomly selected for interest) for the January 2013 release. The
CPI is released with both seasonally adjusted (SA) (where seasonal price behavior is
statistically smoothed out) and not seasonally adjusted (NSA) data. The weights discussed
above can be seen (they are rounded) as well as the aggregate and individual category index
numbers. Also shown is the annualized inflation rate over the previous twelve months for
each category (the method for calculating which is explained below).
As can be seen, the overall index now stands at 230.3, meaning that prices in general
have more than doubled since the base period. Looking down the columns in the individual
indices, it can be seen that the maintenance Medical care has experienced an inflation rate
that is higher than the overall index, while clothing (apparel) has increased by only 24.7%
over the entire 30-year period, and recreation costs even less. The cost of communication
equipment (computers, telephones and the like) has completely deflated - falling in nominal
value (meaning that these devices are cheaper than they used to be in absolute dollars).
Many students are concerned and perhaps even annoyed to see that tuition fees and
charges rank as one of the most inflated categories across all CPI listings, at 636 representing
a sixfold increase in prices since the base period. You would think that students would
complain about this.
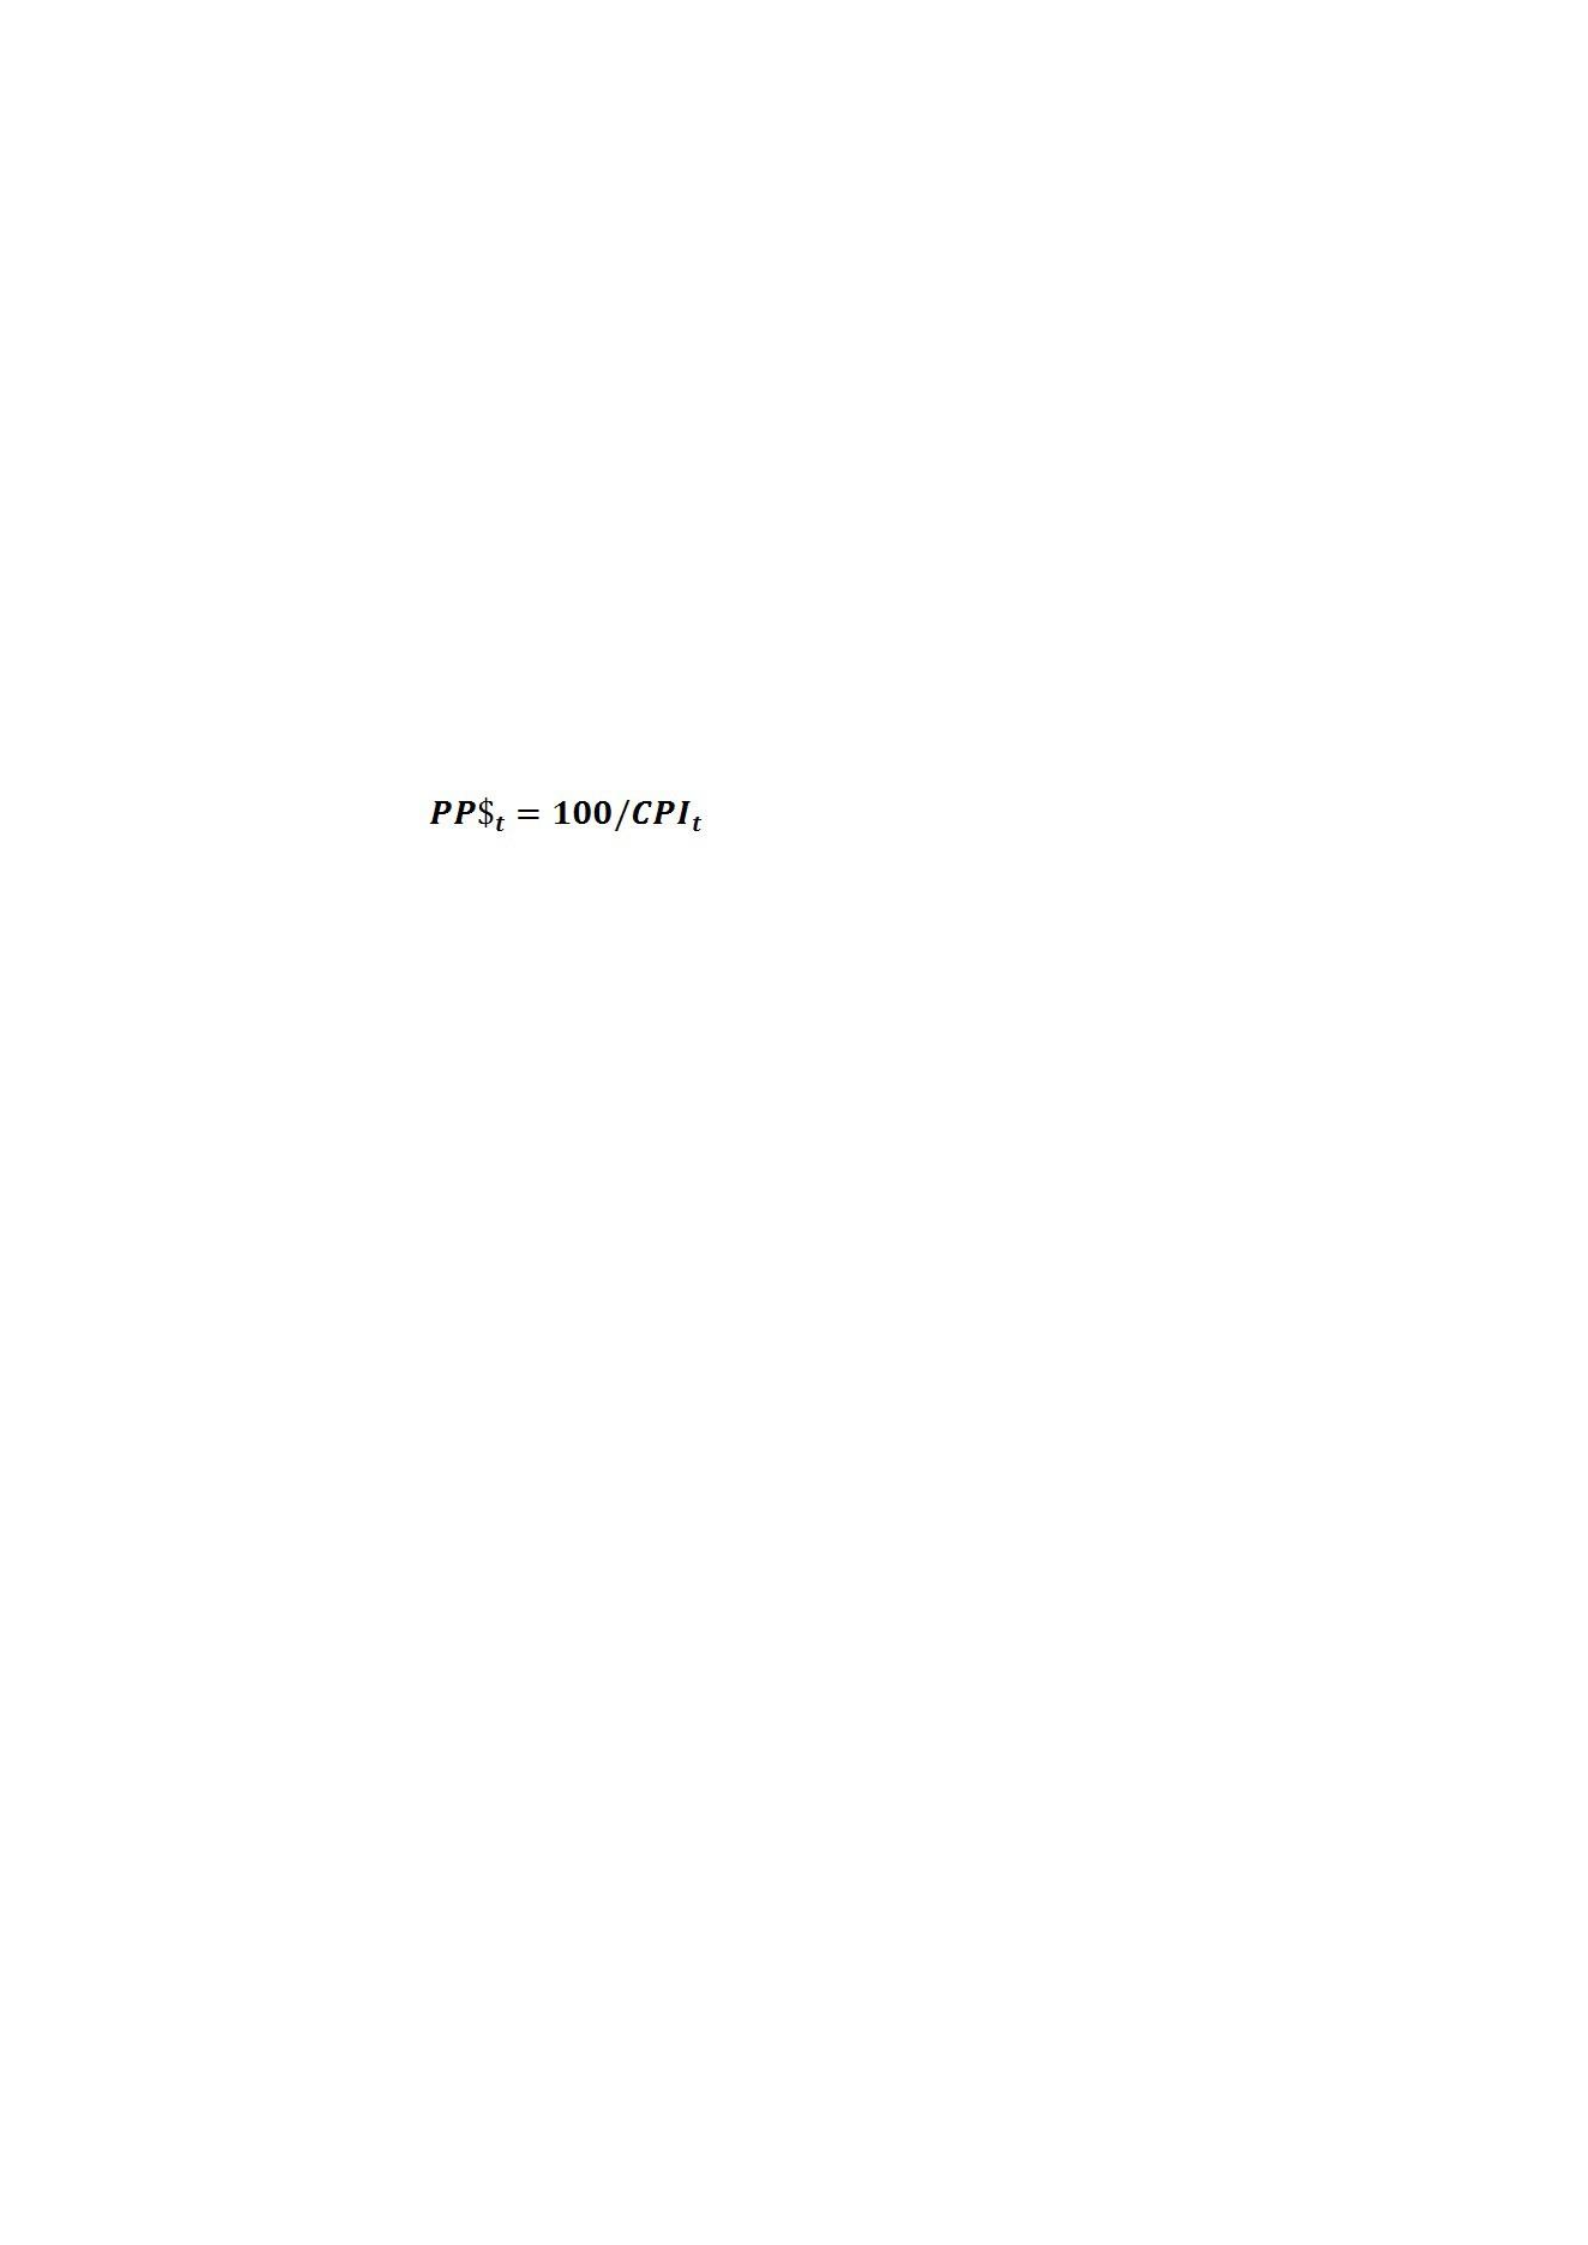
Table 2 also shows the memo item, Dollar Power Purchase, at $0.434. This value is
equal to
which is a measure of how much a dollar will buy now compared to what it bought in the
base period. in January 2013 a dollar was worth forty-three cents compared to 1982-1984
dollars.
II.2. Calculating Inflation Rate from Price Index:
A price index is a single value known by its base, but the value has no inherent
meaning. Any inflation index becomes more useful when it turns into an inflation rate. This
section shows how the Consumer Price Index turns into an inflation rate.
Usually the annual rate is calculated as a discrete growth rate. General formula for
discrete transformation This expressed as a decimal point is which can be translated to say
that the rate of change over any time t is equal to the index value at time t divided by the
index value in the previous period (t-1) minus one. To express it as a percentage, this value
above is times multiplied by 100. Hence one way to calculate the annual rate of change in
consumer prices is to take the December CPI for each year and calculate the annual rate for
that year using the December CPI of the previous year. For example, to calculate the
December-to-December annual inflation rate for 2011.
Given that the CPI for December 2010 was 219.18 and for December 2011 was
225.67, the December-to-December inflation rate was so analysts can say that the inflation
rate for 2011 as measured by the CPI is slightly below three percent.
For example, given that the CPI for December 2010 was 219.18 and for November
2010 was 218.80, then the annual inflation rate for December is
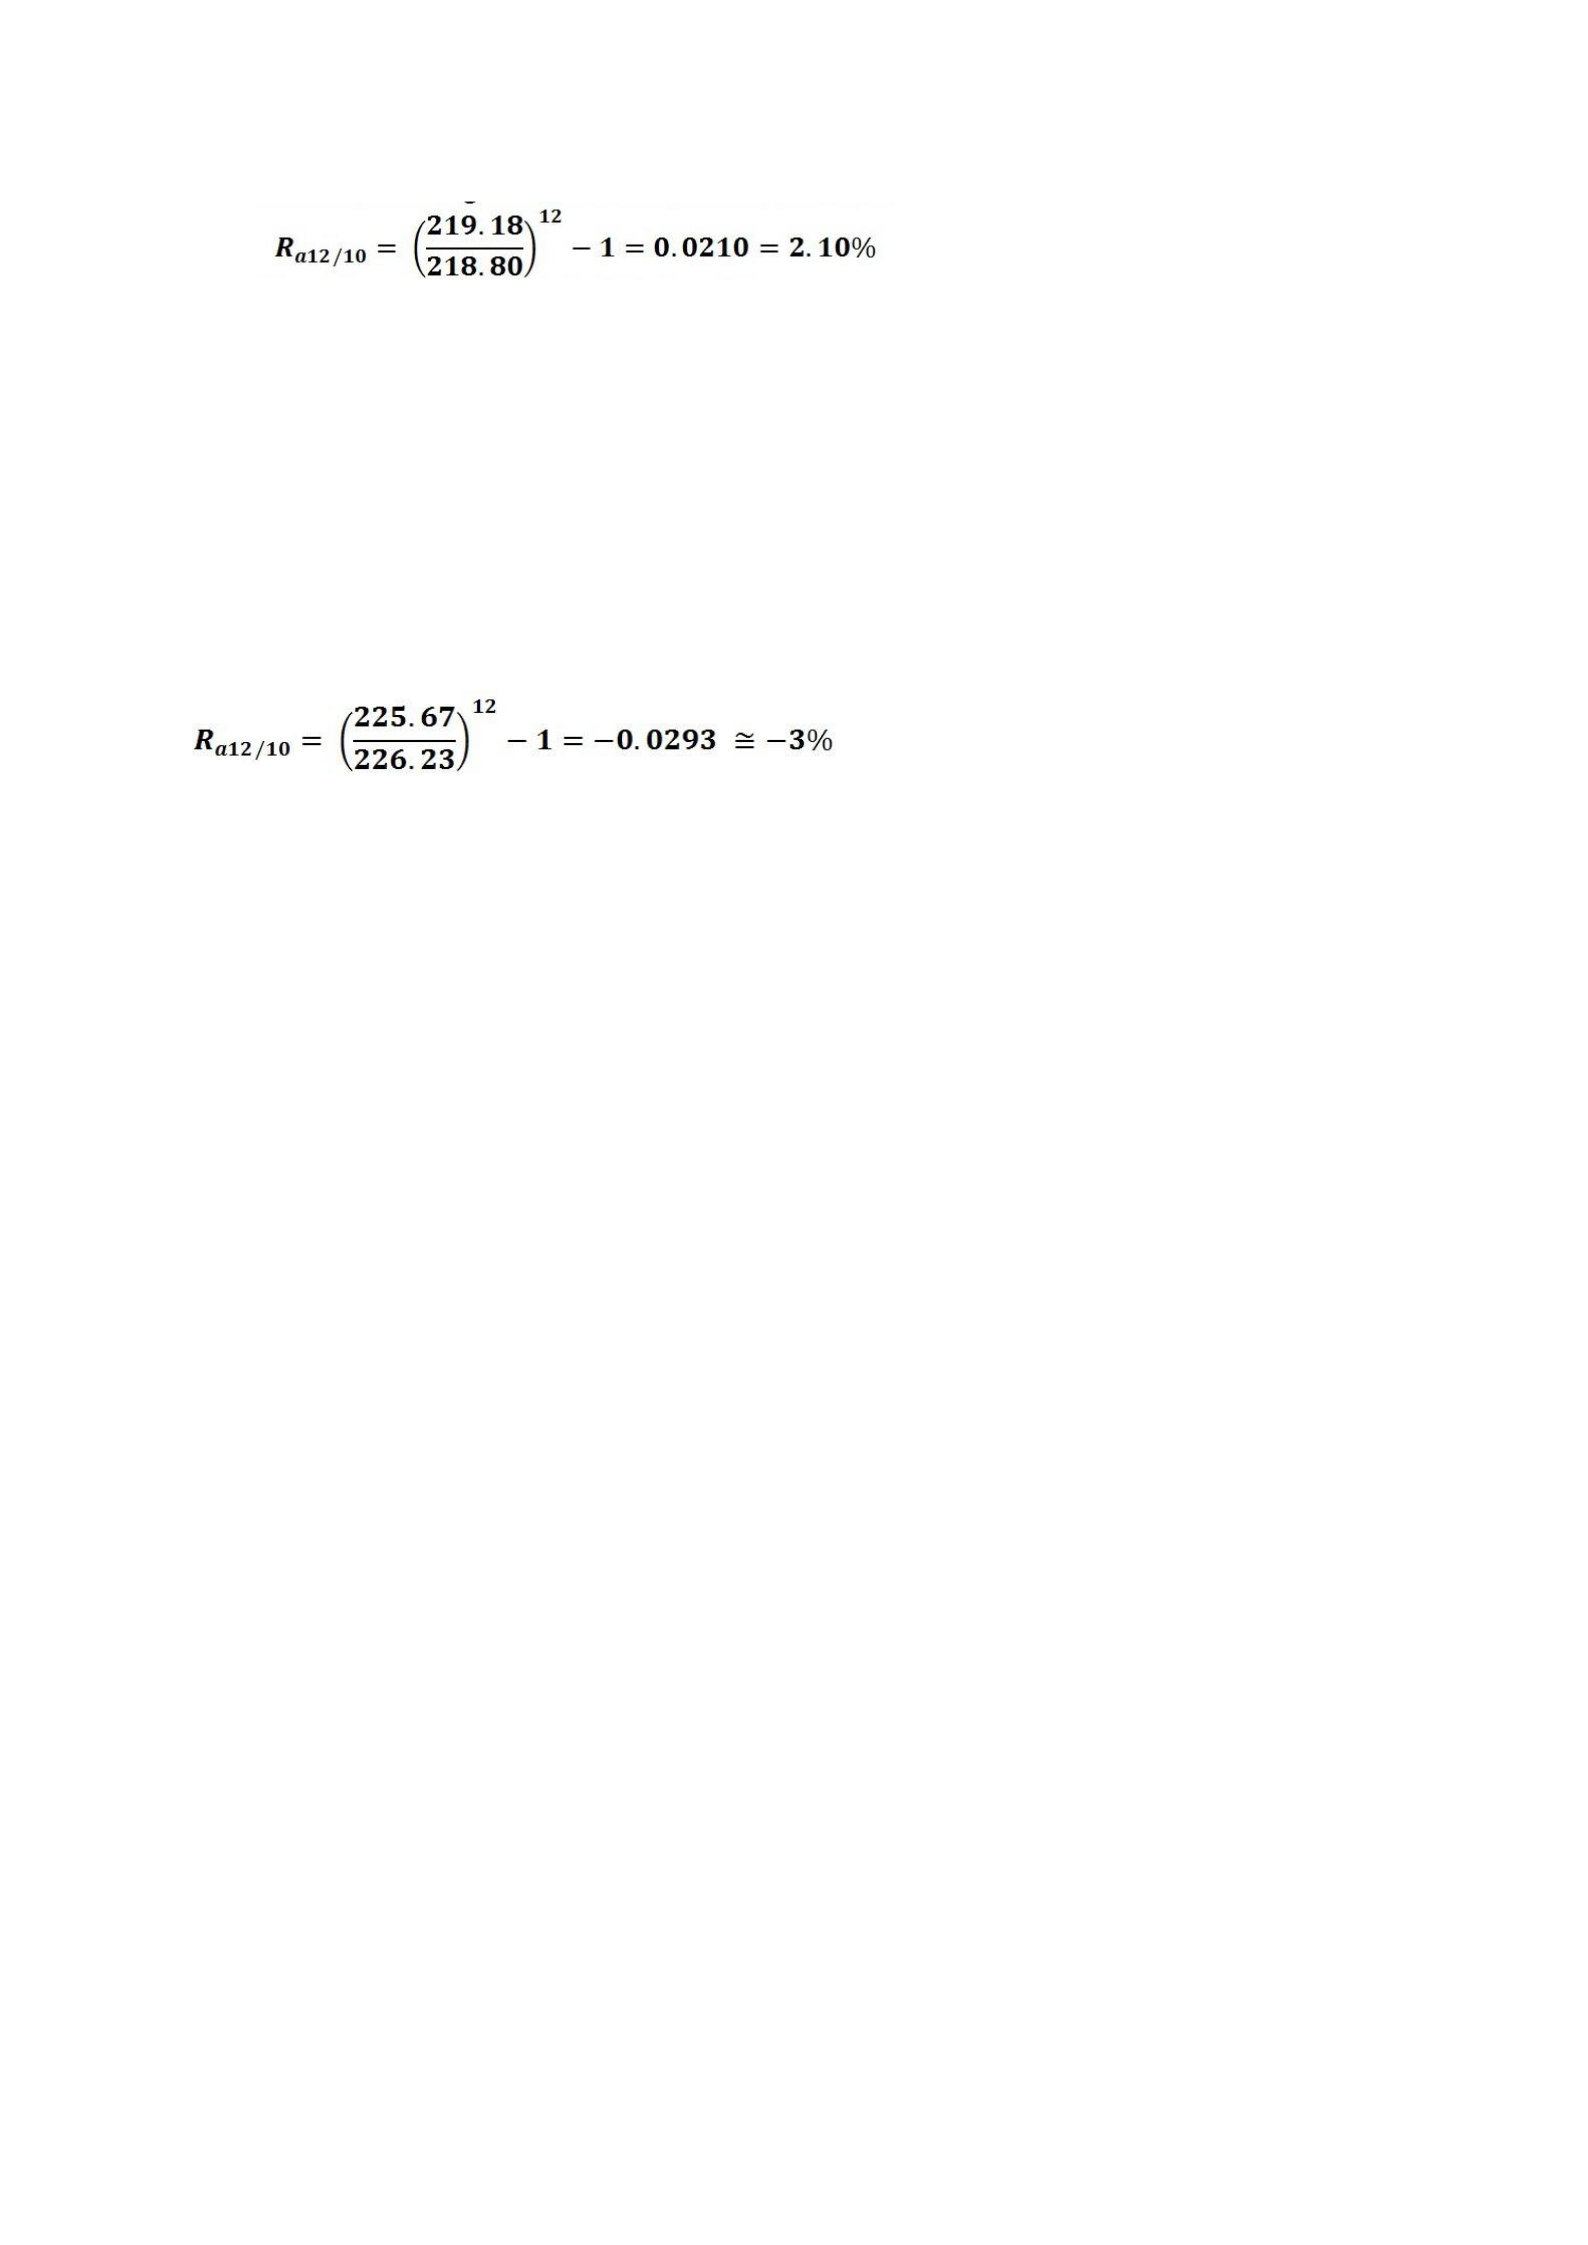
First though it is because monthly values can be very volatile, given that annual rates
are calculated by compounding, any volatility in monthly numbers will result in greater
volatility in compounded annual values calculated from those numbers. For example, we saw
above that the CPI for December 2011 was 225.67. It turns out that the CPI for November
2011 was a higher number at 226.23! This would mean that the annual inflation rate
(actually, the deflation rate) in December 2011 was
To prevent this misleading volatility it is best to use annual comparisons (such as the
December-to-December example above).
II.3. Producer Price Index:
In addition to the CPI, the Bureau of Labor Statistics also publishes a series of indices
called the Producer Price Index (PPI) for Producer Price Index is the price received by
domestic producers for the goods and services they produce and is generally divided into two
categories, commodity prices such as natural gas, various agricultural products, and industrial
chemicals, and finished goods, ranging from bakery products and roasted coffee to pet food,
passenger cars, and costume jewelry. More than 10,000 products are itemized in the Producer
Price Index, which used to be called the Wholesale Price Index, a name perhaps more
descriptive of its current application.
II. 4 monthly data samples for PPI surveys of over 25,000 businesses (participation is
voluntary) providing over
100,000 price quotation.
The two aggregations of the PPI that are used as key economic statistics are the
Producer Price Index for finished goods and the Producer Price Index for all commodities,
although other aggregations such as raw materials, agricultural products, and finished energy
goods will gain media attention if they show unusual price movements in key economic
sectors. This is partly because prices in the PPI are often leading indicators of where prices
are likely to go weeks or months later in the consumer sector, as reflected ultimately in the

CPI. For example, if crude oil prices or wholesale gasoline prices rise in the respective PPIs, if
that price increase is sustained it is likely to show up in the part of the CPI dedicated to
transportation costs.
An aggregate index, such as the Producer Price Index for all commodities, is a
weighted sum of individual commodities, and uses the same weighting technique of that
described above for the CPI. The determination of weights, however, is more arbitrary and
often slow to change. Given that prices are collected in surveys of commercial producers, some
weights are based more or less on the producer's duties than weights based on the relative
importance of the commodity or good in question in the producer's general income stream.
Basically, if the sales of one commodity's sales are twice that of another, the former will have
two weights. For commodities, weights are also calculated by estimating the relative gross
value of shipments - if the value of crude oil shipped is twice the value of natural gas, crude
oil will have twice the weight of natural gas. Figure 2 - Finished Goods and Commodities PPI
compared The CPI-U compares the Finished Goods Producer Price Index and the
Commodities Producer Price Index to the Consumer Price Index using annualized monthly
rates for the six years between 2007 and 2013. As expected, the PPI for commodities is much
more stable than the other two and shows that over the course of more than one year
commodity prices generally declined, provoking a decline also in finished goods and even a
slight deflation in consumer goods (Figure 1 does not show this clearly as annual data is
being used there).
Generally commodity prices (oil and other energy products, grains and other
agricultural products, copper and other metals and so on) will be much more volatile that
prices of either finished goods or consumer goods and services because they are bought and
sold in competitive global markets and are subject to sometimes extreme variations in supply
and demand, weather in the case of crops a n d energy products (hurricanes in the past have
severely impacted oil and natural gas prices for short periods of time, and even the general
cycle of growth in emerging economies such as China, India, and Brazil.
Because of the extreme volatility month to month the values for each measure of the
PPI are not reliable as indicators although they are more useful when the data are
mathematically smoothed over several months at a time. Nonetheless a clear trend in
consumer prices, whether inflation or deflation, is often anticipated by a previous trend of
rising commodity or finished good producer prices. The reason is quite simple - many
consumer goods are made from these commodities, such as gasoline from oil and breakfast

cereal from wheat. The extent of the relationship can be complicated. First, not all businesses
in competitive markets can actually pass on cost increases through corresponding price
increases. The airline industry, for example, has historically found it difficult to to pass on
fuel price increases to ticket prices because the industry is highly competitive. In other cases,
such as breakfast cereals, the commodity makes up only a small fraction of the price so
consumers are good, so a 30% increase in the price of wheat can lead to only a 5% increase in
the product on the shelf. On the other hand, crude oil is such an important part of gasoline,
when crude oil prices rise or fall, gasoline prices follow and rather quickly.
III. Core Inflation and Deflation Rate:
Since this volatility discussed above is commodity-dependent, the Bureau of Labor
Statistics also calculates a value for the CPI that excludes food and energy and calls it the
Core Rate.
See Figure 3 CPI (all items) less food and energy (Core Rate) which compares the
CPI for all items to the Core Rate, which removes all food and energy data from the
calculation. Clearly the Core Rate is a more stable overall CPI because it strips out the most
volatile categories of consumer goods, those dependent on volatile commodity prices. In the
first year of the deep recession that began in the fourth quarter of 2007, commodity prices in
general, including oil and gasoline, plummeted so severely that consumer prices for food and
energy, despite having a combined weight of only 15% (see Table 1), dragged the overall CPI
deep into deflationary territory, as can be seen in the chart. But when food and energy prices
were stripped out, deflation was minimized considerably (although there was still mild
deflation).
It is very clear by inspection that the Core Rate is generally more volatile than the
headline CPI for all of them (and this greater volatility extends to years prior to 2007).
Because so much emphasis is placed on the importance of the CPI number and the monthly
data releases (and revisions of previous data) that are followed by financial markets and
others, the financial media usually give as much importance to the Core Rate as the overall
CPI so that volatility is not mistaken for a general trend of either inflation or deflation which
really does not exist. Basically a crude attempt to remove some of the white noise found in
CPI volatility.
This is not to say, however, that food and energy prices are unimportant. When
gasoline prices run above $4.00 per gallon as they did in the spring of 2013 it may have a
slight negative impact on other categories of consumer spending, which could lower the real

GDP growth rate given the importance of consumer spending in the US economy.
III.1. Effect of Inflation and Deflation:
The measurement of price trends would be little more than an academic exercise were
it not for the fact that extreme price trends in either direction are extremely dangerous in an
economy and can wreak havoc on wealth and income. Inflation is such a dangerous
phenomenon that central banks around the world, such as the Federal Reserve System itself
and the European Central Bank in the Eurozone, see fighting inflation as their main job
(although since 2007 most of their activities have been oriented towards keeping the financial
crisis from getting worse, but as the data in the section above shows, at least for the United
States, inflation hardly mattered during the crisis). Inflation and deflation have completely
different effects on the economy so they will be considered separately, starting with inflation.
III.2. The Effect of Inflation After Wealth and Income:
Although inflation is generally harmful to the economy - hyperinflation can destroy
the economy and in the past it has not been true that inflation harms every player in the
economy. Although inflation can destroy wealth and income (explained below), it also has the
pernicious effect of redistributing wealth and income, and does so unfairly.
Generally, unexpected inflation (the important role of inflation expectations discussed
in the next section) in the range of say 6% to 15%, will redistribute wealth and income from
economic cohorts such as renters, frugal, lenders (especially those who lend at fixed interest
rates for loans such as long-term mortgages), retired people (especially if living on a fixed or
limited income), and many of the working population in general.
In the case of the general working population, research has shown that generally
wages and other forms of nominal income do not keep up with the general rate of inflation
once inflation becomes excessive, partly because employers are under no obligation to raise
wages just because there is inflation but also because much labor is fixed by contracts that are
slow to change or simply unresponsive to rapidly emerging inflation, a phenomenon in
economic research called "wage stickiness."
This same inflation though will often benefit owners of real assets, such as real estate
and especially real estate financed with long-term fixed-rate mortgages (such as 30-year fixed-
rate mortgages), but also other commodities, such as precious metals, valuable collectibles
and other such assets. Inflation benefits any class of borrowers who are able to borrow at a

fixed rate, which includes mortgages as mentioned above, but also any form of market debt,
such as long-term bonds initially sold at a fixed price (and therefore will benefit businesses or
governments only who have financed with such bonds).
The above paragraph implies that anyone who is skilled and wealthy enough to
anticipate inflation, even as a possibility rather than a certainty, can create a type of financial
investments that not only protect against the dangers of inflation but also benefit from it. It
should be clear from the examples given that if one regards the prospect of inflation as a
possibility (due, for example, to current government policy - more on that below) then the
purchase of real estate, either a primary residence or a second or rental home, with minimal
down payments financed with a 30 year fixed rate mortgage at a relatively low interest rate (a
combination of options that has certainly been available since 2010 until the time this was
written in Spring 2013), may be the soundest investment a private investor could make. It is
irrelevant that the real estate market went bust in 2007. It happened because of speculative
excess, a complete lack of effective regulation, and a combination of incompetency and fraud
driven by the greed of some of the world's largest banks.
Democratically elected governments are likely to survive periods of severe inflation,
but like real estate speculators governments sometimes have an incentive to let inflation run
for at least two reasons. First, very policies that have the potential to generate inflation, such
as running large budget deficits that are partially monetized by the central bank authority can
be very popular with (naive?) voters who benefit from the excess, at least until inflation
shows up and becomes a problem (sometimes long after the politicians responsible have left
office). Secondly, inflation can substantially reduce the real value of government debt, just as
it does for the government private mortgage debt.
Therefore if not all are harmed by inflation, that indeed some benefit, then the
political pressure to curb inflation can be mixed and complicated. Not all players will
necessarily be on board.
Finally it should be clear that the reallocation of wealth and income during
inflationary episodes is disconnected from economic productivity and inherently unfair. After
all, it penalizes savers and rewards debtors and speculators and at least temporarily rewards
incompetence in government services.
III.3. Inflation Tends to Self-Perpetuate:
Once inflation starts, it tends to get worse over time if it is not addressed with

aggressive policies designed to stop inflation. By way of example, this means that 3%
inflation will soon become 5% inflation, and at some point that will become double digits
(10% or above) and worse.
The reasons are several and complex (and discussed in fuller detail below). First,
emerging moderate inflation in some markets tends to accelerate demand for products from
those markets, which can compound inflationary pressures for products in those markets. This
seems to be especially true for real estate, certain durable goods such as cars, and key
commodities for manufacturers and industrial users.
The real estate market provides a good example. For homeowners, once down-
payment and startup fees paid, the real cost of owning a home is the monthly house payment,
which in turn is determined by the purchase price of the home and the interest rate on the
mortgage loan. Both variables will usually increase during inflationary episodes. That the
value of houses will rise should be obvious - the only situation where it will not be
inflationary is in all consumer categories except housing, which will be scarce.
But for reasons to be explained later, interest rates also increase during periods of inflation,
so much so that
so that generally the mortgage rate for new mortgages that are
issued will always be two (or more) percentages or above the underlying inflation rate. This
means that if the inflation rate is 12%, then 30-year fixed-rate mortgages will be 14% or
higher!
What difference will that make to the monthly payment? This is shown by the best
example. See Table 3 - Monthly Payment for Select Mortgage Value at Select Interest Rate. This
table is meant to illustrate What might happen to the monthly payment if a prospective home
buyer waited to purchase a home that at the beginning of the inflation period was available
for financing with a mortgage of $300,000 at 5% interest on a 30-year fixed-rate mortgage
(this assumes that several down payments would be made on this home, leaving the principal
after the down payment was made of $300,000). The monthly payment on this home would
be $1,610. Just to see the effect of the interest rate alone on such a mortgage, if the same
home were available at an interest rate of 6% over 5%, the monthly payment would be almost
$190 more per month (about half the car payment). Interest rates matter. Remember as this is
discussed that if the consumer does not buy the house with a loan for $300,000 at 5%, for him
the payment is completely fixed for 30 years, or until he sells the house. It doesn't matter if
the country has inflation like the Weimer Republic - for him the cost of housing remains at

$1,610 per month plus property taxes and insurance.
But this same consumer also understands that if she procrastinates and fails to buy the
house and it goes up in value to $400,000 and the rate goes to 6%, now the exact same house
has a monthly payment of $400,000.
2.398. It is very clear that if the house went to $450,000 at 9%, the house now effectively
costs also more than double (and note that the house itself went up in value by only 50%) and
she has missed out, as it is highly unlikely that her salary doubled over the same period.
Mature consumers understand this all too well. They can easily develop a mentality of
that they should strike when they can, and will accelerate the decision to buy a house if they
start expecting inflation in the near future. This kind of activity has the potential to become a
national mania and when it does, inflation expectations become a self-fulfilling prophecy
whether or not the original expectation had any logical merit - a very dangerous economic
environment.
Consumers may think the same way about autos as they do about houses, and
consumers in developing countries will hoard food if they think it will become unaffordable
(a severe and common problem in hyperinflation in developing or poor countries), and
businesses will accelerate purchases of key commodities such as oil or copper if they
anticipate commodity inflation. Every one of these examples and many others that can be
provided accelerates demand for at least the product or commodity in question, exacerbating
inflation that already exists. What is bad becomes worse.
To be a little more formal about this, recall in Table 2 that the purchasing power of
the dollar based on 19,821,984 averages has declined to $0.434 from the base year. This
means that if inflation pushes the CPI for all items from its current level of around 230 to,
say, 400, then the purchasing power of the same dollar declines to 25 cents. That is definitely
an incentive to spend money before it decays further. It is this accelerated spending plan that
will compound inflation.
IV, Economic Impact of Inflation Policy Response
Surprisingly, one of the most harmful economic effects of inflation arises from the
anticipation of what governments, and especially central bank authorities, are going to do
about it. As mentioned above, inflation tends to be self-propagating (it automatically gets
worse) and as economists working in the Federal Reserve System and other central banks

know, monetary policy thus tends to become very aggressive when inflation threatens. Anti-
inflationary policies tend to be Draconian and can have a devastating short-term impact on the
economy.
A detailed discussion of inflation policy responses is discussed below in a later lecture
on the Federal Reserve System, but a summary overview of some of the more extreme policy
effects can be introduced here. Generally, the Federal Reserve System, our nation's central
banking authority, responds to inflation by tightening credit availability and raising interest
rates, effectively making credit more expensive and more difficult to obtain.
Consumers and businesses will at least slow down their use of credit and
consequently credit-financed spending will decline, removing some of the inflationary
pressure. This general increase in interest rates, which can be quite severe if the inflation
threat is serious, can have an adverse impact on key industries such as real estate and
consumer durables and can even spread to spending categories not typically affected by high
interest rates. The resulting decline can be large enough to push recession.
To make things easier, policymakers can To make matters worse, if inflation is
already in place and strong (say with the CPI increasing at a rate higher than the inflation rate
of 5% per year), then market interest rates will already be high and rising to reflect inflation -
the market nominal interest rate is almost always higher than the underlying inflation rate. For
example, if the underlying inflation rate is 6%, the long-term mortgage interest rate will not
be 4%, it will be something like 8% or even higher. Therefore, when policy makers as the
Federal Reserve System tighten credit to fight inflation, interest rates are sent soaring to
higher levels. Although inflation is the root of the problem, high and rising interest rates are
also a problem, and given that interest rates must be forced higher, this essentially means that
the problem must be deliberately made worse before it gets better! Figure 4 - The Volcker
Correction 1979, an old lecture slide that has been used as an example for two decades,
clearly shows the effect described above. Earlier in this chapter in Figure 1 CPI Inflation:
1960-2011 we saw that the economy had two very serious bouts of inflation in the 1970s.
Both of these two inflations occurred during Jimmy Carter's presidency (and were one of the
reasons why Carter lost the 1980 presidential election to Ronald Reagan). As can be seen in
Figure 4, by 1979 inflation had become such a problem that long-term mortgage rates were so
high long had soared to levels above 10% and even the annual interest paid on the 3-month
US Treasury Bill, normally less than 4%, had also soared into double-digit territory. This was
unacceptable, so President Carter appointed a known inflation fighter named Paul Volcker as

Chairman of the Board of Governors of the Federal Reserve System in August 1979. It took
several months for Volcker to consolidate his power and consider his options, but finally in a
famous meeting in October 1979 of the Federal Reserve Open Market Committee (the policy-
making body of the Federal Reserve System) Volcker and other committee members decided
to embark on an aggressive anti-inflationary policy, imposing a severe credit contraction and
a large increase in interest rates. The date of the meeting is reflected as the vertical red line in
Figure 4. As can be clearly seen, mortgage rates, already at dangerous levels, soared higher,
eventually to levels above 15%! Moreover, rates stayed above 1979 levels for more than 5
years! Equally important, rates did not return to healthy levels for almost a decade. Figure 1
makes it clear that this policy definitely worked, but at what cost! It was clearly a case of
making the situation worse so that it could eventually get better. A second clear policy lesson
emerges from this example: it is much, much better to pay a price to prevent inflation than to
let inflation arise and then fix it. The latter is a very damaging proposition indeed.
IV. 1. The Impact of Inflation on Financial Markets and Business Environment:
The impact of inflation on any given business depends on how well equipped the
business is to respond to inflation or even benefit from inflation. Businesses with large
inventories of raw materials and processed goods (such as oil inventories or copper stocks)
may actually benefit from inflation in the short term. Likewise, businesses that are large
enough and in a favorable competitive environment may be in a position to pass on rising
costs as price increases to consumers, and if they succeed in deferring wage increases to their
workforce, they may actually benefit from general price increases. But constant re-pricing
and trying to stay ahead of the inflation curve is stressful, the battle is relentless and the
eternal uncertainty of where prices will go next finally takes its toll. Businesses tend to be
conservative with their long-term investment decisions as long as inflationary episodes,
which can have a retarding effect on GDP growth in important areas such as fixed
investment. This problem becomes particularly acute for large-scale fixed investment projects
that have to be financed by borrowing. Borrowing costs will always be above the inflation
rate, so long-term borrowing becomes impossible and funds dry up. For example, the
underlying inflation rate is 8%. All borrowing rates will be above 8%, a figure on a 10-year
company might be 10% to 12%, compared to possibly only 5% during a normal year. What
corporate treasurer would lock in a loan for, say, $100 million for a decade at a rate double
the historical rate? Not only would the need for cash to service payments be high, but if

inflation recovers and market prices return to normal, corporations with long-dated loans are
locked into the inflation rate for the duration of the loan.
This problem is especially acute in commercial and residential real estate. Mortgage
rates soar during inflationary periods, raising payments to unsustainable levels, seriously
damaging sales. See Figure 5 - CPI Inflation, 30-year Mortgage Rate and US Treasury 10-
year Note Rate. As can be clearly seen from this historic example, when the inflation rate as
measured by the CPI soared into the double-digit range twice between 1978 and 1985, the
national average rate on 30-year fixed-rate mortgages stayed above 10% and at one point
touched 18%! As we've seen, the monthly payments on any given home at that rate would be
somewhere between two and three times the payments made. Clearly both commercial and
residential real estate construction would be anemic at such high interest rates. One might
think that at least stock prices in the financial markets would increase during inflationary
episodes because stock prices, after all, are a type of price and don't all prices rise during
inflation?
It turns out that stock prices really do poorly during inflationary episodes. See Figure
Dow Jones Industrial Average Index During Inflationary Years, graph taken from a lecture
from another class taught by the author. The graph shows the performance of the venerable
stock market index during the same inflationary period discussed above, from the early 1970s
to the end of 1982. Again, as can be seen, twice during this period the inflation rate jumped
above 10%. On January 1, 1971, the Dow Jones Industrial Average stood at 868.60. On July
1, 1982, more than a decade later and during the worst inflation episode of the modern era,
The same index stood at 808.60 on net share price did not increase slightly during this entire
period.
Furthermore, it is clear by inspection of Figure 6 that as inflation worsens, the market
plummets, but as the price picture improves, the market recovers. It is easy to see that the
peak of the market neatly coincided with the trough of prices in 1972, hence the plunge as the
latter surged. Then the same pattern repeated itself. After 1980 the inverse correlation broke
down for a while, but after 1982 (not shown) when it was clear that inflation had licked and
was not returning, the
IV. 2. The stock market started the biggest and longest bull market in history.
Part of the reason for the tepid performance is related to the poor business conditions
discussed above, especially in the trading area where financing is critical. But other more

fundamental issues for stocks can arise. High interest rates that limit loan demand also
represent a nominal yield available to investors and notes, bonds, and other interest-bearing
financial assets. These high nominal yields can lead to so-called portfolio shifts from stocks
to bonds.
This phenomenon is represented in Figure 7 Securities Portfolio Showing Shift in
Preference from Bond Stocks in the Hypothetical Portfolio During the Inflation Period.
Generally a large investment portfolio - especially one managed by professionals -
will include some mixed composition of stocks and interest-bearing bonds and notes, such as
the 70/30 split represented in Figure 7. As economic conditions change, investors and
portfolio managers will shift the relative composition of their portfolio away from one
component in favor of another, an activity called rebalancing. Figure 7 shows rebalancing
shifting the portfolio composition from 70% stocks and 30% bonds to 60% bonds and only
40% stocks. The only way this can be done is by selling stocks and buying bonds, which will
depress stock prices if done on a large enough scale.
So why do investors balance, causing portfolio shifts in favor of bonds and away from
stocks during inflationary periods? As stated above, the nominal yield of interest-bearing
assets such as notes and bonds will increase with inflation, easily to areas above 10%. Even
though the real (inflation-adjusted) yields on these assets are still low, perhaps only 2% or
3%, capital gains on stocks must still compete with the nominal yields on such bonds to
remain competitive, which is very difficult to do done. In other words, as long as inflation is
10%, a 10-year bond may have a nominal yield of 12.5%, a real yield of just 2.5%. But to
compete with this, the stock price (or price plus dividends) must still rise the full 12.5%.
That's a tough metric for stocks to meet, so safer bets start moving funds from stocks to
bonds, and down goes the stock market, as seen in Figure 6.
V. Economic Cost of Deflation
Deflation, a general decline in the price level, which would be measured today by
several months of negative growth rates of the CPI or other major price indices, is not
considered a common threat in the United States. Although the CPI actually registered
negative growth rates in some months during the 2008-2009 recession, the price declines
were shallow and short-lived.
Deflation has been an important part of US history in the past, however. See Figure 8
- Deflation During the Great Depression. As can be seen, deflation appeared in the United

States of America after World War I and endemic during the Great Depression. Even the
terrible depth and duration of the Great Depression can largely be explained by the extremely
adverse financial effects of deflation.
In many ways serious deflation, with deep price declines lasting for months or even
years, can be more damaging to an economy than all but the worst inflation. Deflation is
particularly damaging to financial markets and financial institutions.
Generally deflation reduces the capacity of those in debt to honor their debt
commitments, or to put it more simply, debtors are unable to pay their debts. Nominal
income, including business receipts and wages, decline during recessions, but debt
- especially mortgage debt - remains nominally fixed. In other words, debt for $10,000 does
not become debt for only $8000 just because inflation has set in or because wages have
fallen. But if wages have actually fallen then debt as a percentage of income (the means to
repay the debt) increases, eventually to a level that makes debt impossible. Financial
insolvency grows, which hurts lenders as much as borrowers.
The deflation of the Great Depression is easier to understand if we remember that the
United States was still an agricultural economy in the 1930s. The sharp deflation seen after
1920 was the opposite of the tremendous inflation of global agricultural commodity prices,
such as wheat and corn, experienced during the terrible war in Europe. So many European
acreage farms were disrupted by the trench warfare that swept across France and Germany
that for nearly three years the United States became the world's "breadbasket," to use a
common term for those times, and farm prices soared in the United States. In the years
immediately following the war those same prices plummeted. They did not plunge to a new
low - they simply returned from the high levels seen during the trip to their pre-war levels.
When deflation returned after the stock market crash in the fall of 1929, once again farm
prices led the way, but this time it was due to a general collapse in demand. Agricultural and
home mortgage credit had flourished during the prosperous 1920s, a period when farmers
were enjoying their prosperity and using debt to finance purchase some of the new consumer
gadgets of the "Roaring 20s," as the era was called. The new Model T automobile,
manufactured by the Ford Motor Company and available for about $300 would be found in
every self-respecting farmer's stable. For example, wholesale wheat prices stood at about
$1.00 per bushel in 1914. They jumped above $2.00 per bushel after 1917 and reached a high
of $2.45 per bushel in early 1920, about 18 months after the November 1918 Armistice. They
quickly fell after 1920, stabilized through the 1920s (but never went above $1.75 per bushel),

then plunged to a disastrous low below
$0.50 per bushel in 1932, wiping out many indebted farmers.
As agricultural commodity prices began to slump, debt - especially mortgage debt
service became a growing problem. Banks and businesses suffered as a result compounding
the depression, spreading from agriculture to manufacturing and consumer spending,
triggering a deflationary spiral. Panicked bank customers demanded their deposits, triggering
the infamous bank runs of the era. Bank failures became so endemic that newly elected
President Franklin Delano Roosevelt had to declare a "Banking Holiday" as his first act of
office on March 9, 1933. All commercial banks were closed for audit and when they were
allowed to resume business ten days later, nearly a third of all banks remained closed for
good, and another third had been forcibly merged into the healthy third. Prices stabilized by
1934 but the lesson had been learned - deflation is destructive and should be avoided,
especially in countries with high debt levels high.
Although the United States is not threatened with serious levels of deflation, small
exporting countries are. In 2012 Japan, an advanced industrialized country that remains
vulnerable to inflation and deflation due to their large export trade, began to experience
deflation rates so serious that, after a change in government, they embarked on a very
aggressive expansionary monetary policy designed to trigger deliberately modest inflation.
VI. Causes of Inflation from Modeling Point of View
Popular explanations of the causes of inflation are often too simplistic to provide a
viable explanation of this complicated economic phenomenon. It is sometimes said that
"inflation is caused by too much money chasing too few goods." Although this is an attractive
explanation it is not really supported by the facts, because however money may be defined,
there have been significant bouts of inflation that have not been accompanied by substantial
monetary expansion and monetary expansion that did not trigger inflation.
What follows will therefore be an attempt to explain the causes of inflation, and some
options for remedial measures, using two models, the Aggregate Supply/Aggregate Demand
(AS/AD) Model introduced in Chapter 2 of this series, and the Loan Fund Model, introduced
in The development of these models is not explained here and the reader should be
thoroughly familiar with the models before starting this section. If not familiar with the
model, the two chapters should be read.

VI.1. Conventional Demand-Pull Inflation Explained by the UAS/
modelAD
Figures 9 and 10 The Effect of a Surge in Aggregate Demand After the Inflation Rate,
Case(a) and Case(b) offer a simple explanation for the most common form of inflation,
Demand-Pull Inflation. Generally, Demand-Pull inflation is caused by some kind of strong
economic stimulus, usually but not necessarily triggered by some kind of stimulating
government policy, which causes demand to surge, as represented in both Figure 9 and Figure
10. The comparison between the two cases is meant to illustrate that the inflationary effect of
an expansionary stimulus depends entirely on the context in which the stimulus takes place.
In Figure 9 stimulus is triggered when the economy is coming out of recession,
unemployment is high, and businesses are running at reduced capacity (where the Capacity
Utilization Rate, for example, may be below 75%). Given that resources are not fully utilized
and the economy has room to expand without experiencing inflationary pressures, the
stimulus results in strong growth in real GDP (presumably the goal of the stimulus) with very
little inflation.
10 shows that even if the same stimulus is applied when the economy is already running at
near full capacity, with low levels of unemployment and, emerging resource shortages in key
commodity areas, such as oil and metals, or labor shortages in key skill areas, such as
technology, or at a time when the economy is already running at near full capacity, it is likely
that the stimulus will have a negative impact on the economy.
The Capacity Utilization Rate is above 85%, so the stimulus generates little in the
way of real growth rather than generating inflation. The stronger the stimulus, the greater the
inflation. In a few words, the effects of a strong stimulus on real GDP growth and inflation
depend on entirely on the context in which the stimulus takes place. Of course the question
immediately arises as to what kind of demand stimulus can cause such sizable shifts in the
demand curves represented in Figure 9 and Figure 10.
It is certainly possible for the stimulus to come from the private sector, especially in
smaller economies where the surge might be explained by overseas demand due to a
favorable exchange move. Likewise if the private sector expands credit rapidly without
government policy accommodation, which is certainly possible, or consumers and businesses
for whatever reason wind up spending their savings (a process called deleveraging) then
aggregate demand may expand for their reasons as well. But in a mature and large economy
like the United States that does not depend so much on foreign trade, a strong stimulus or

contraction of aggregate demand in a short period of time is likely to occur because of
government policy of some kind or another. If policy is a consequence of government
spending and/or weight decisions, then a shift in the aggregate demand curve is a
consequence of fiscal policy, whether intentional or unintentional (some fiscal policies are
unplanned, or poorly planned). If the shift in aggregate demand is engineered by the nation's
central banking authority, the Federal Reserve System in the case of the United States (which
is almost always planned to a meticulous degree) then the shift in the demand curve is the
result of monetary policy. And of course sometimes the impact on aggregate demand is the
result of both in combination.
VI. 2. Impact of Fiscal Policy Causes on Aggregate Demand as a Possibility
Demand-Pull Inflation
Although any advanced discussion of fiscal policy should include the impact of
government spending at the state and local level in addition to the federal level, in the United
States individual state, county, and municipal governments do not implement fiscal policy
with the goal of influencing the economy. They tax to fund services and deliver services that
their constituents approve through voting. The economic impact is certainly there, but it
generally would not be the cause of inflation or the amount of medicine for inflation in the
United States. In the context of discussing the causes of inflation, the only sizable influence will
be found at the federal level. In general, if the federal government runs a ba l a n c e d budget,
any increase or decrease in spending will likely have a neutral effect on aggregate demand.
As federal government spending increases, with a balanced budget tax receipts must also rise
accordingly, which lowers after-tax disposable income, the primary source of consumer and
business spending, so personal spending will fall by about as much as the increase in
government spending, which has a neutralizing effect on aggregate demand. There will be no
inflationary stimulus from a balanced budget even if federal government spending increases.
However, when the federal government runs a budget deficit, which occurs whenever
government spending is greater than revenues from taxes and other taxes. If deficit growth
occurs because the government has cut taxes without cutting spending, a common
phenomenon in the United States as it i s politically popular, then the surge in demand will
come from the private sector as consumers and businesses spend their tax cut windfall. If the
growth in budget deficits is due to a surge in government spending that is not matched by tax
increases, one of the most common causes of large demand shifts in global governance (and

one of the most common causes of inflation as a result) the impact on aggregate demand is
clear - it will shift outward and large and growing deficits will cause strong outward shifts. If
by the time this happens the economy is already running at near full capacity as the
hypothetical example in Figure 10, then the cause of inflation is well established - the cause of
inflation is because the government is living beyond it's means. But even this simple
explanation requires further explanation, as the explanation must consider how the deficit is
financed before the explanation is complete.
VI. 3. Why Expansionary Fiscal Policy is Usually Accompanied by Monetary Policy:
Accommodating, While it seems obvious that a strong deficit-financed fiscal
expansion would lead to demand-pull inflation as described above in Figure 10, there is a bit
more to the story. Before we concluding that budget deficits are always expansionary, we
need to evaluate the impact of budget deficits on interest rates and the impact of their rates on
aggregate demand.
When looking at the Fund Loan Modeld nature of Chapter 3 of this series, we should
keep in mind that because deficits are financed by selling interest-bearing financial assets in a
competitive market, and that borrowing competes with private lending, funding large deficits
will have a tendency to push interest rates upward. This is shown in Figure 11 - The Effect of
Budget Deficits on Interest Rates, which is taken directly from Chapter 3. As explained in that
chapter, this effect on interest rates can contribute to an economic phenomenon called crowding
out. Due to higher interest rates, consumer and business spending funded by borrowing will
decline to some extent due to the higher cost of securing personal loans - Government
spending will crowd out private spending. Consider, for example, mortgages. If federal
budget deficit financing pushes up competitive mortgage rates by, say, two percent, that will
inevitably result in a decline in mortgage applications, which in turn will have a
contractionary effect on housing construction. Although the degree of crowding out is
unlikely to be absolute (where every penny gained in federal government spending is lost in
private spending), deficit financed spending will inevitably be watered down by the impact
on private debt financed spending. In other words, the Aggregate Demand Curve will not
shift very much, whether in inflationary territory or not.
However, the Loan Fund Model also shows us that if fiscal expansion is accompanied
by commoditized monetary policy, which is represented in Figure 12, then interest rates will
not rise - in fact they may fall - and the impact on the Aggregate Demand Curve of the two

policies combined may be very strong. If Aggregate Demand already in the inflationary
region of the Aggregate Supply Curve, represented earlier by Figure 10, then inflation will be
the final outcome. Figure 12 should also make it clear that if aggressive expansionary
monetary policy occurs even in the absence of an expansionary deficit-fueled fiscal policy,
that policy can by itself cause inflation. But historically these two expansive policies tend to
go together, especially when one is looking for causes of demand-pull inflation episodes.
VII. The role of expected inflation in Inflation Compounding:
If there is an aggregate-demand stimulus of the type discussed in the section above,
the resulting inflation is hardly the end of the story. Rather, it is essentially the beginning of a
new story.
Why? Because once inflation starts, it automatically gets worse. This previous
explanation is offered above in section III.2.
The reason can again be explained by another application of the Aggregate Demand
Model. In previous chapters we learned about the formation of economic expectations, and in
the context of this discussion, inflation expectations. This refers to the formation of any
general expectation on the part of the consuming public or business community that inflation
is imminent.
Inflation expectations are usually classified as either rational inflation expectations or
adaptive inflation expectations.
The former category generally refers to the rapid shaping of inflation expectations by
professionals, particularly in areas such as finance, economics, or policy, who anticipate
inflation because they believe the chain of events they witness will logically cause inflation,
or at least have a high probability of causing inflation. They understand enough about the
economy and how it works to know the chain of cause and effect that leads to especially bad-
inflationary policies.
Adaptive inflation expectations, on the other hand, are more often associated with the
general public, arising as a result of experienced inflation. Over time, once inflation is
experienced, more is expected.
Why the difference? Generally, rational expectations are faster to form because they
will form before the actual phenomenon is observed, a requirement that defines adaptive
expectations. Therefore, the higher the level of rational expectations, the faster the formation

of inflation expectations.
None of this would matter if the formation of inflation expectations had no impact on
aggregate demand. But, unfortunately, it does. The formation of adaptive inflation
expectations accelerates latent aggregate demand, causing an outward shift in the Aggregate
Demand Curve, as shown in Figure 13- The secondary effect of Adaptive Inflation
Expectations After the Inflation Rate. According to the logic of the model, no matter what
causes the shift in the Aggregate Demand Curve from AD1 to Ad2 (say the fiscal/monetary
expansion discussed earlier), the mere experience of the shift will cause a secondary
inflation-enhanced shift in the Aggregate Demand Curve from Ad2 too AD3.
By inspection, it can be seen that therefore if the formation of adaptive inflation
expectations causes the Aggregate Demand Curve to shift further outward as shown, then this
explains why once inflation is underway, it automatically tends to be worse.
The formation of rational inflation expectations differs in that it does not require a
genuine shift from AD1 to AD2. Rational inflation expectations may form simply because a
sufficient number of economic agents may logically conclude that the fiscal/monetary
expansion set in motion has inflation as the final, logical outcome. In this case, a modest
amount of inflation may occur simply because it is predicted!
VIII. Stagflation - Inflation with recession
Demand-pull inflation is by far the most common form of inflation, but the use of the
Supple Aggregate Demand model to explain it above makes it clear that when demand-pull
inflation is running strong, the economy is at least running at near full capacity and GDP is
likely at a very high growth rate.
But some historical inflations have been characterized by high inflation rates
accompanied by recessions - a phenomenon called stagflation (stagnation with inflation). See
Figure 14 - Stagflation in the US Economy, which refers to the period between 1970 and
1985 when the United States suffered two separate episodes of stagflation. As can be seen in
the late 1974 US, the economy suffered an almost double digit inflation rate but the economy
was in recession. And although it was short-lived, inflation returned again in 1981 and the
economy dipped into a more serious recession in 1982 when GDP growth turned below
minus two percent.
This phenomenon cannot be explained as demand-pull inflation. But it can be

explained by the Aggregate Demand Model. See Figure 15- stagflation, and Costs.
Push Inflation. In this scenario, inflation comes from the cost-push side and is represented by
a downward shift in the Aggregate Supply Curve. 18 In the case of the time horizon
represented by Figure 14, the single most significant contribution to cost-push pressures in
the United States was due to the large increase in the price of imported oil, mainly caused by
the two OPEC oil embargoes, the first in 1973 and the second in 1979. Oil and oil distillates
played such a large role in the economy in those years that the increase in crude oil imports
had a diffuse effect throughout the economy.
Figure 16-The Relative Rise of Gasolinevs Food Prices during the OPEC Oil
Embargo compares the relative rise of food prices, which represent the main consumer costs
apart from fuel, compared to gasoline prices, representing the main oil-derived energy prices,
between 1967 and 1981. (An inset shows price inflation) gasoline only, unchanged and
smoothed).
The data is taken from the CPI for the period. Both prices are normalized to values of
100 at the beginning so that a direct comparison can be made. As can be seen both food and
gasoline prices rose strongly over the period. But on the internet, gasoline prices rose more
than fourfold over the period in question, whereas food rose a multiple of just two-and-a-half.
Significant disruptions to essential input commodities could be the cause of future
stagflations, including oil and energy-related products, food products, metals, or even water
in regions where water is a scarce commodity. Smaller countries that are more prone to
import prices of essential goods, such as Japan, South Korea, and many South American and
African countries, are all potentially vulnerable to supply-shock inflation.
In the United States, the biggest future supply-shock threat may be skilled labor in key
industries such as health care. Health care currently weighs 7.2% in the CPI and we have seen
that health care costs are rising faster than any other cost in the United States, and threatens to
look above 10% going forward, introducing a modern crisis of sector cost inflation, which is
a double-digit or very high rate of cost-push inflation largely confined to one sector. Rising
healthcare costs are not limited to the shortage of skilled labor in healthcare alone, but the
lack of trained professionals will likely contribute to healthcare sector inflation moving
forward.
Another category of cost-pressure inflation can be classified as import cost inflation
which can be a consequence of the local currency devaluing. For example, if the US Dollar

reduces in value relative to foreign currencies such as the Euro, then the cost of imports
originating from Europe will rise. For example, if the Dollar cost of a single Euro rises from
$1.35 to $1.50, then imports worth 10 Euros, say a bottle of wine, will rise in price from
$13.50 to $15.00. The explanation of this complicated form of inflation, however, will have
to wait until the discussion of exchange rate determination and its effects.

