


●Demand assume consumers can pay for the goods and are willing to pay for the goods
○Consumers' choice however are constrained by their income
■Cannot have everything, forced to make decisions
○Income is scare so purchase decisions interdependent
■EX: Buying more video games means less movie tickets
○Partial analysis
■Choosing one market over the other?
●Theory of consumer choice → each consumer spends income in the way that yields the greatest
amount of satisfaction, happiness, or utility
●Measuring utility → how much value/satisfaction you receive
○Util – unit of pleasure, happiness
○Units of another good willing to give up to get some good
■How many movie tickets you are willing to give up for a new video game
○Money
■How much you are willing to give up for a video game
●When you give up money for a game, what are you really giving up
●Purpose of utility analysis
○How people behave, not what people think
●Total monetary utility (known as TU)
○Maximum amount of money a consumer is willing to give up in exchange for a quantity
of a good
●Marginal utility (known as MU)
○The maximum amount of money consumer is willing to pay for one more unit of good
■Marginal utility is the change of TU over the change in quantity
Quantity
Total utility
Marginal utility
0
1
2
3
4
5
6
7
0
10
18
24
28
30
31
25
10 - 0 = 10
18 - 10 = 8
6
4
2
1
-6
OPTIMAL PURCHASE RULE:
- If MU > Price → BUY MORE
- MU = Price → OPTIMAL
- MU < Price → BUY LESS
- When the marginal utility is 0 or greater that is considered diminishing marginal utility
CHAPTER 5: FOCUS ON CONSUMER CHOICE, INDIVIDUAL AND MARKET DEMAND
- When consuming more of a good, often the marginal utility decreases
- It can reach to a negative number
- “Law” of diminishing marginal utility
- Additional units of commodity are worth less and less to a consumer in money terms
- As the individuals consumption increases, the marginal utility of each additional unit
decreases
- Essentially if individual consumption increase, MU decreases
- If individual consumption decrease, MU increases
●As a person consumers more of a commodity
○Total utility increases but at a decreasing rate (MU > 0 leads to TU increases and MU
being diminishing
○Marginal utility from that good decreases
●Exceptions to decreasing marginal utility
○Alcohol and stamps for collectors
●Very scare goods have high marginal utility but little total utility
○Diamond water paradox (diamond is not essential but water is essential at a decreasing
rate)
●Anomalies
○Increases MU
■Ex: arts and addictive quality
●Using marginal utility, the optimal purchase rule
○Best promotes the decision makers objective
○It tests if and by how much
■Small change in direction
■Move things toward or away from goal
■If marginal utility is less than total utility, do not buy!
○NEVER MAKE DECISIONS BASED ON TOTAL BUT MARGINAL
●How many pizzas should you buy?
○Goal is to maximize net utility
■Total net utility = total utility of pizzas – total utility of money you give up
○Using marginal analysis
■But more pizzas as long as net marginal utility is greater than or equal to zero
●Marginal net utility = marginal utility - price
○Follows the same optimal rule of MU
●The more you buy something can indicate its benefit is large (applies to marginal)
●To maximize net total utility, consume up to the point that MU = P
○EX: amazon can track marginal utility based on your orders, they can use it to figure out
your price point
●Marginal utility schedule = demand schedule
○Marginal utility curve = demand curve
●The role of diminishing marginal utility
○As price falls, a consumer would buy more to the point that MU = new price
○Since marginal utility diminishes, the only way to do this increases quantity bought
○So as price falls, quantity demanded increase (the law of demand)
●Consumer behave as if we followed the optimal purchase rule
●Real cost of purchase: opportunity cost or good that must be given up as a result of the purchase
○Any decision there is a trade off due to scarcity
○Opportunity cost of a purchase can be more or less than its price
■EX: you buy a new car for 30K and you take 5 hours from work to buy it, what is
the opportunity cost?
■30K + 5 (multiplied by hourly wage)
●Consumer surplus (also known as total net utility)
○Difference between how much you are willing to pay (how much you value the quantity
of a good) and what you do pay
●Goal of consumer → maximize consumer surplus
○This idea is consistent with the optimal purchase rule
■TNU = TU - total expenditure (price x quantity)
●MNU = net consumer surplus (per unit consumer surplus)
●The market demand curve
○The horizontal sum of individual demand curves
○For each price add up each person’s quantity demanded
●Exceptions to the “law” of demand
○When people judge quality on the basis of price
○Snob appeal to signal one’s wealth
Properties of budget line
- Point of budget line show the maximum amount of goods a consumer can buy
- Points below imply that spending < budget
- Points above the line are not available since income is too little
Indifference Curves
- Higher indifference curves yield higher total utility
- Every point on a higher indifference curve preferred to any point on lower curve
- Never intersect
- Negative slope
- Round toward the axes – bowed in
SLOPE OF INDIFFERENCE CURVE
- Marginal rate of substitution (MRS) between the two commodities
- Maximum amount of one commodity a consumer willing to give up for one more unit of another
commodity
SLOPE OF BUDGET LINE
- The amount of one commodity that the market requires an individual to give up to obtain one
additional unit of another commodity without any charge in the amount of money spent
SUMMARY OF IT: how the slop of budget line and indifference curve are related
- The slope of the indifference curve indicated the term at which the consumer is willing to trade
one commodity for another
- The slope of the budget line reports the terms at which the market allows the consumer to trade
one good for another
- If income rises, more willing to buy more (both the budget line and indifference curve increases)
- More demand!!
- If price falls, more willing to buy more (the budget kind of slants and the indifference curve
follows as well)
- More demand too :)
CHAPTER 6: DEMAND AND ELASTICITY
●Elasticity is a measure of responsiveness
○How responsive is quantity demanded to a change in price, price of related goods, income
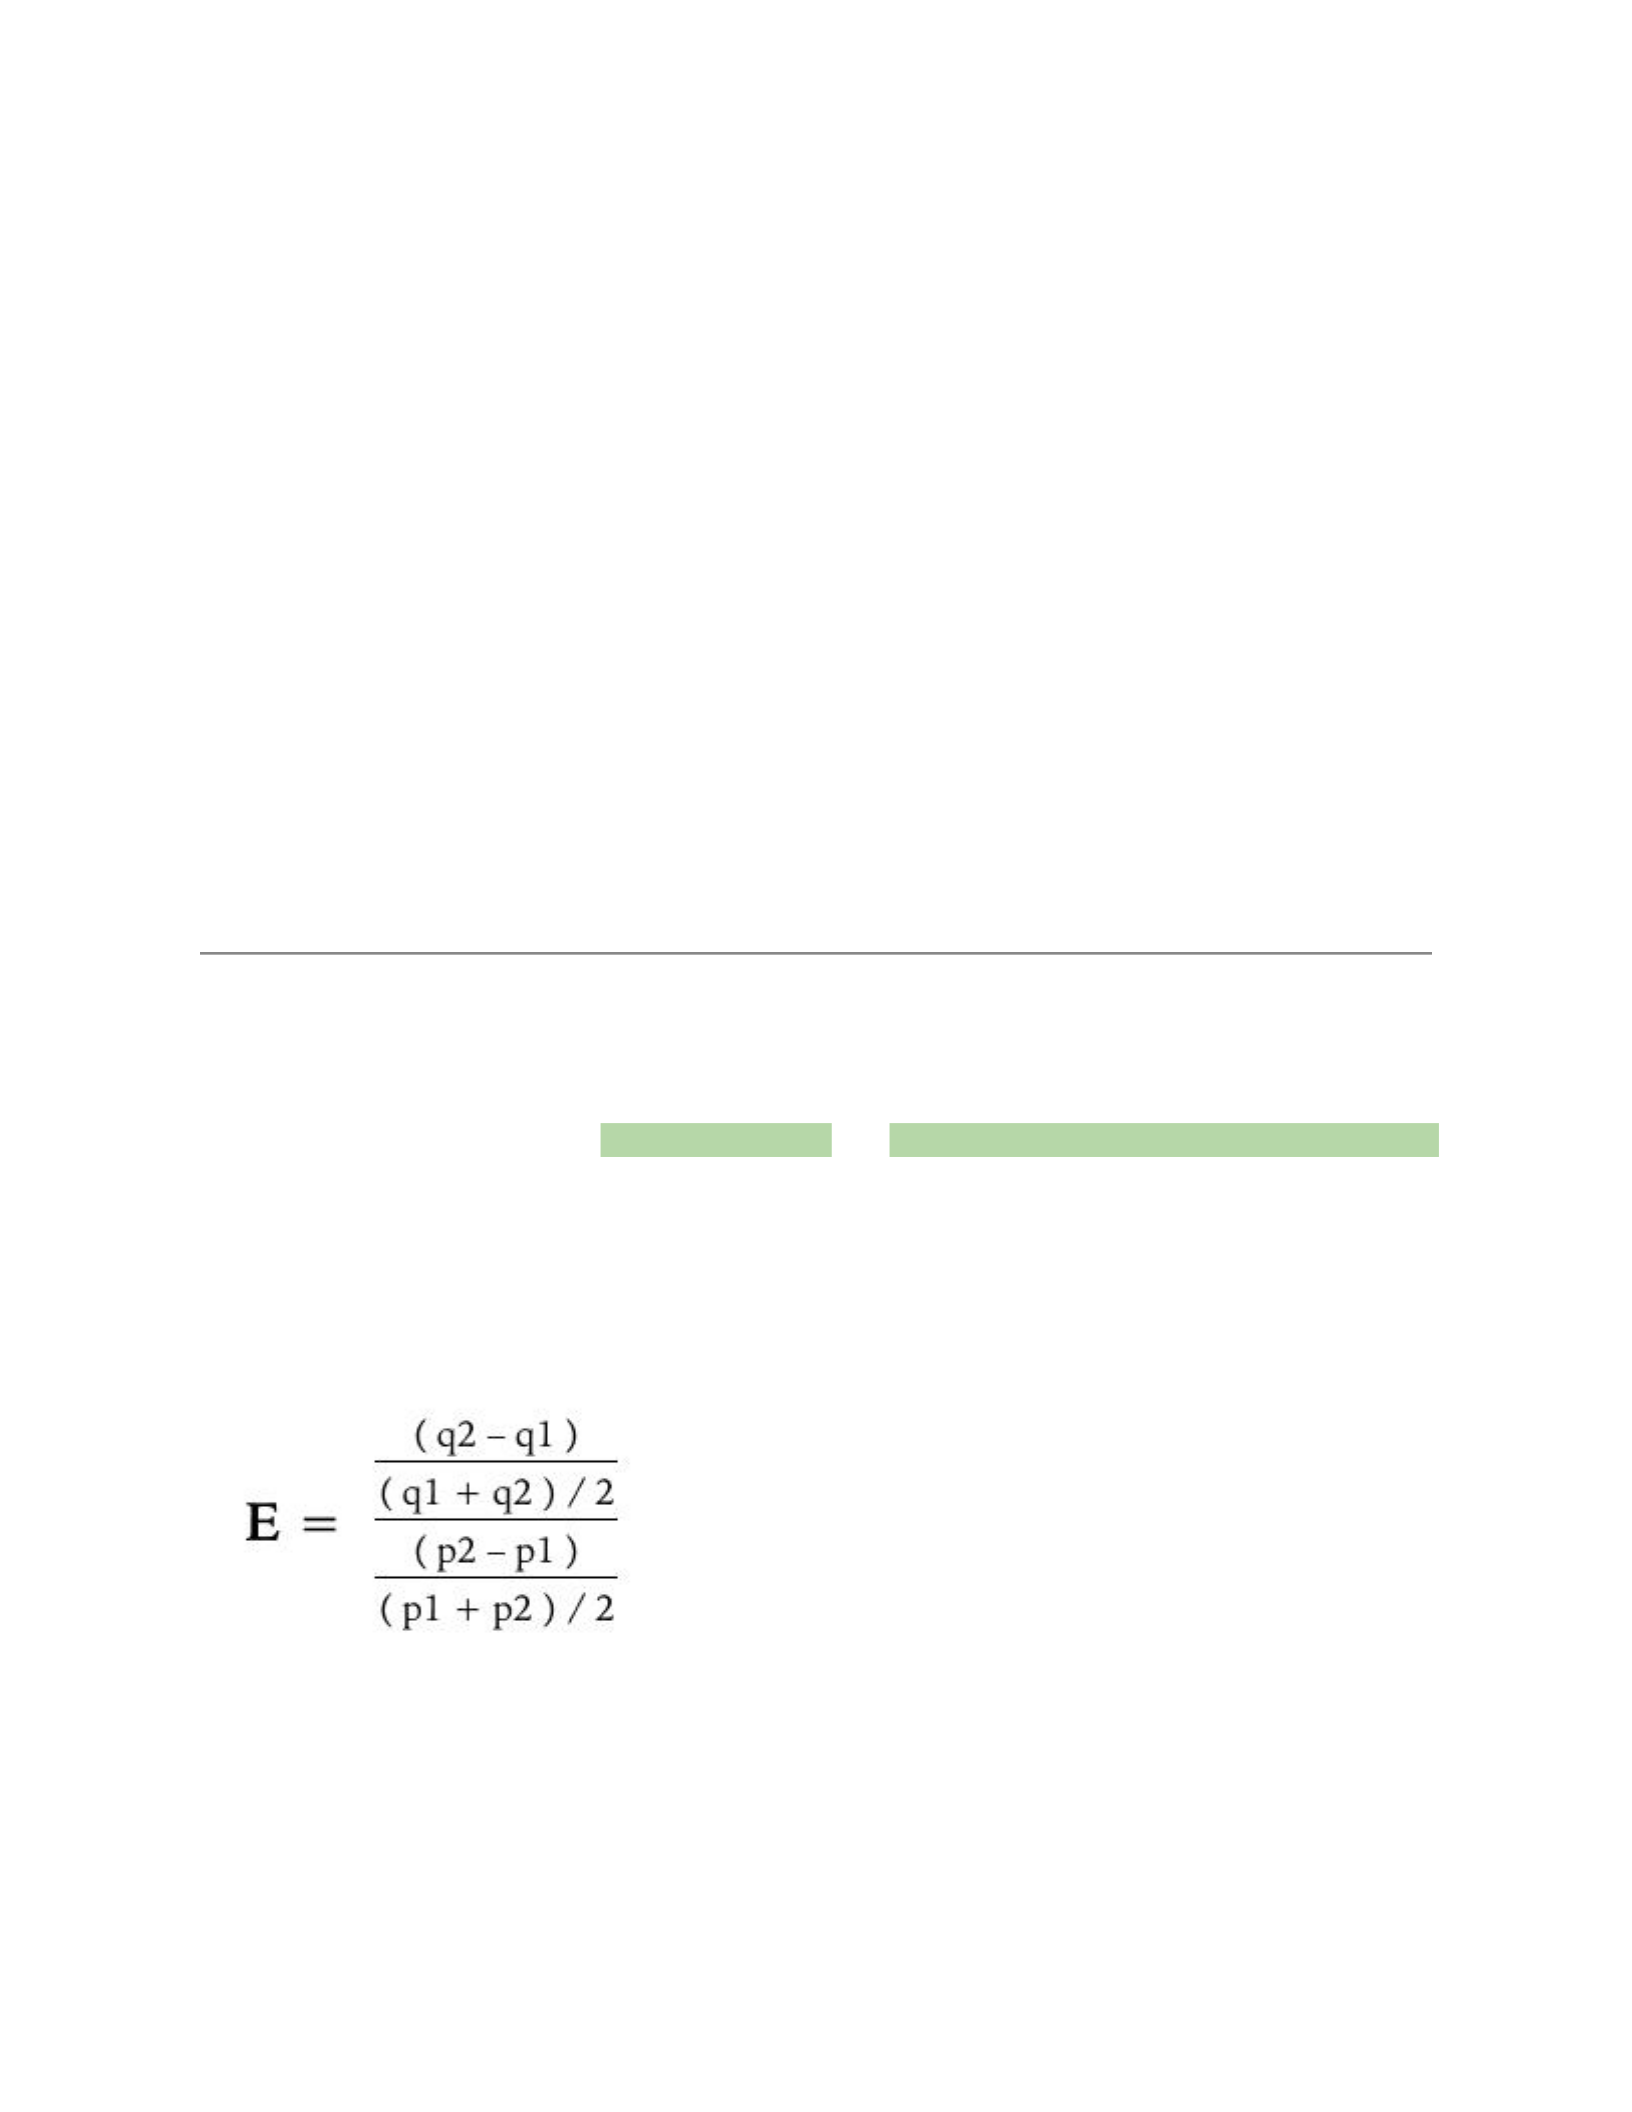
●Price of Elasticity of demand
○Ratio of percentage change in quantity demanded to percentage change in price
■ED = (percentage change of quantity demanded) divided by (percentage change
of price)
- If the Q’s and P’s are flipped it results in the same answer
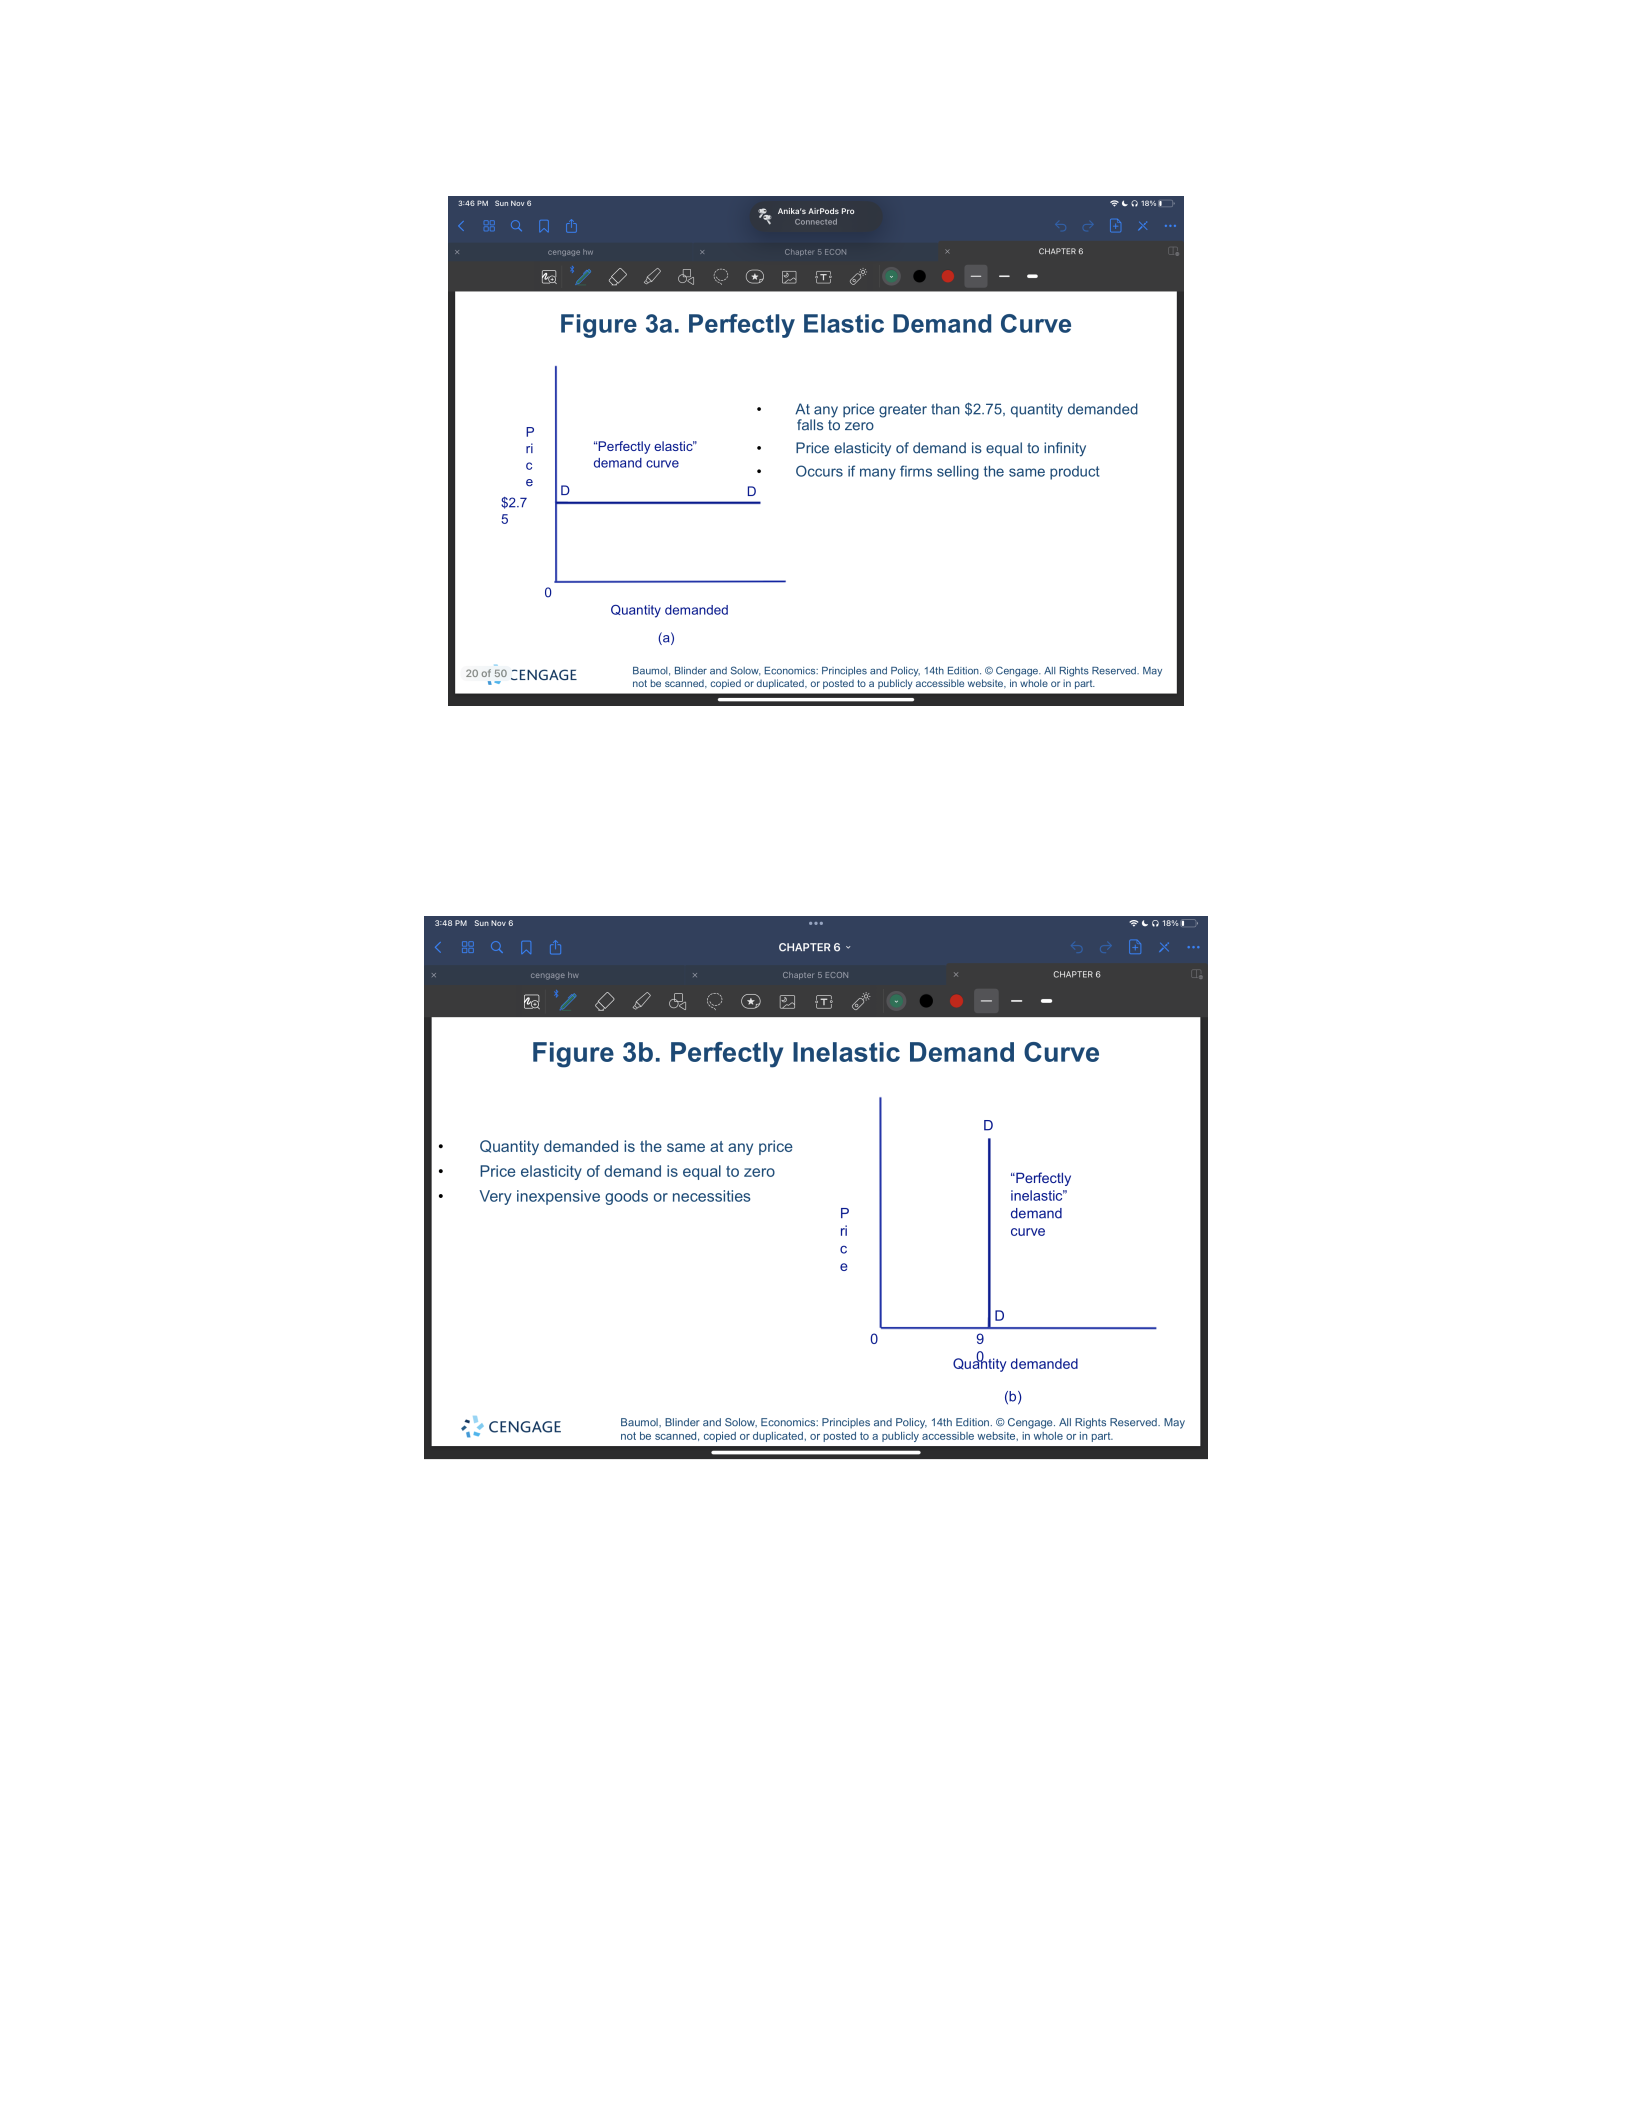
PERFECTLY ELASTIC DEMAND CURVE
- At any price greater than $2.75, quantity demanded falls to zero
- Price elasticity of demand is equal to infinity
- Occurs if many firms selling the same product
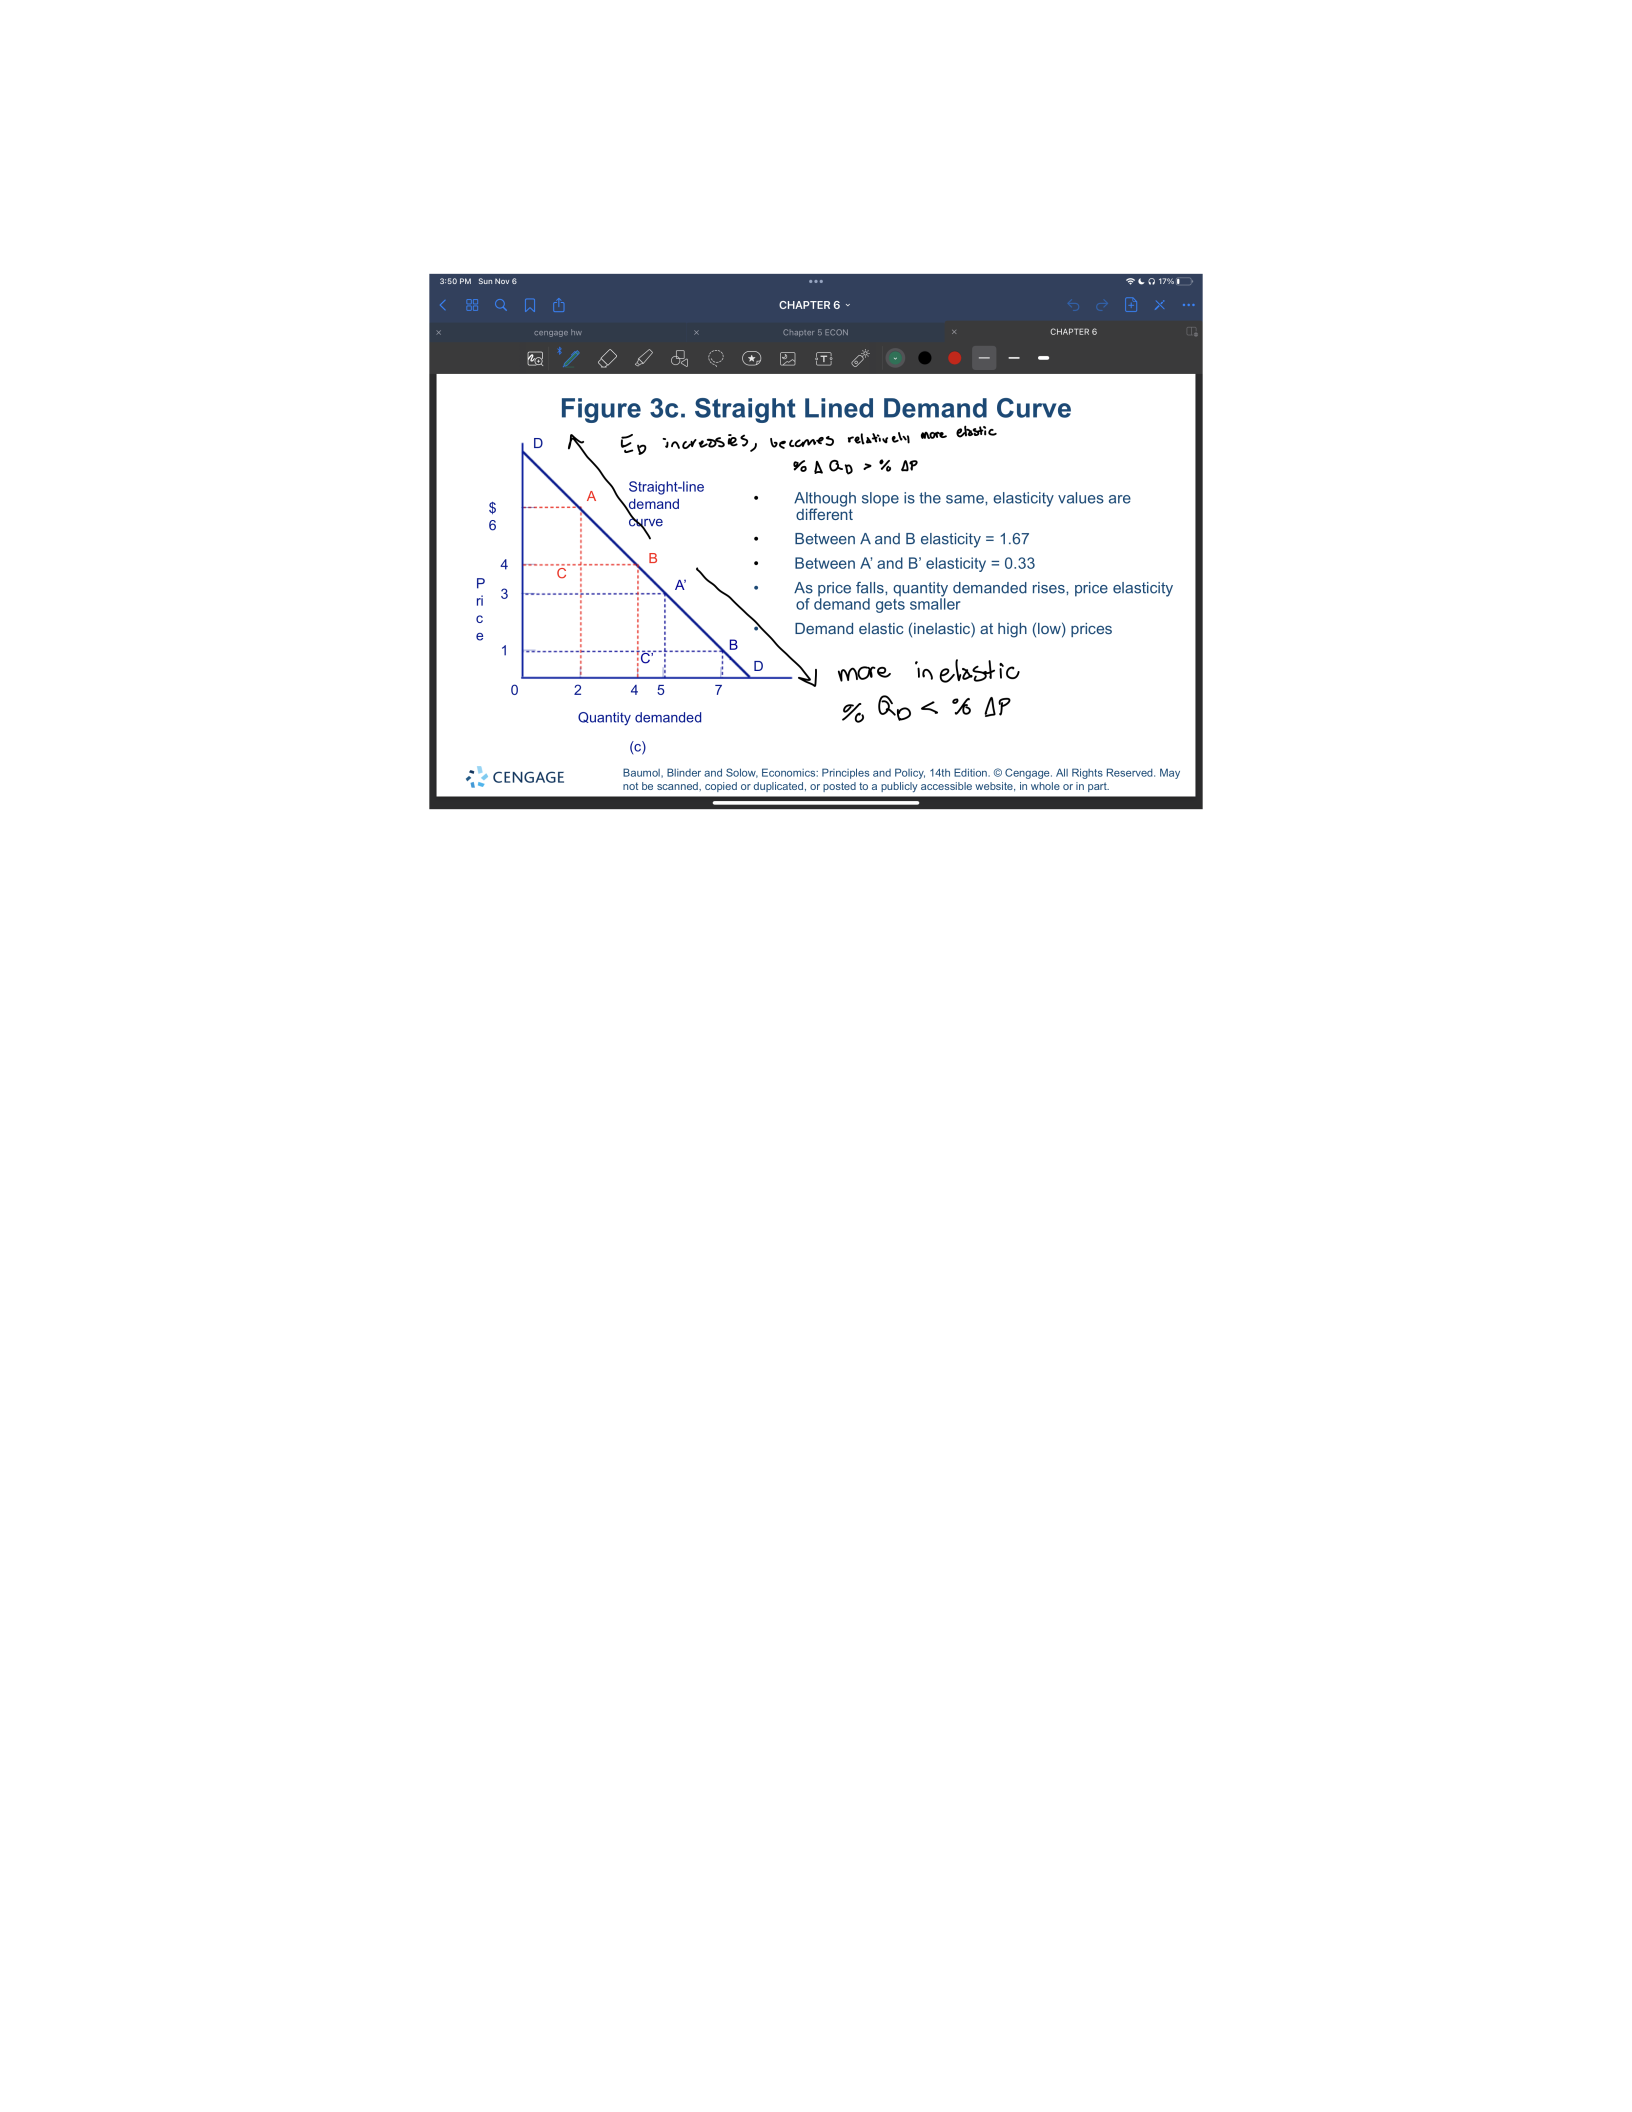
PERFECTLY INELASTIC DEMAND CURVE
- Quantity demanded is the same at any price
- Price elasticity of demand is equal to zero
- Very inexpensive goods or necessities
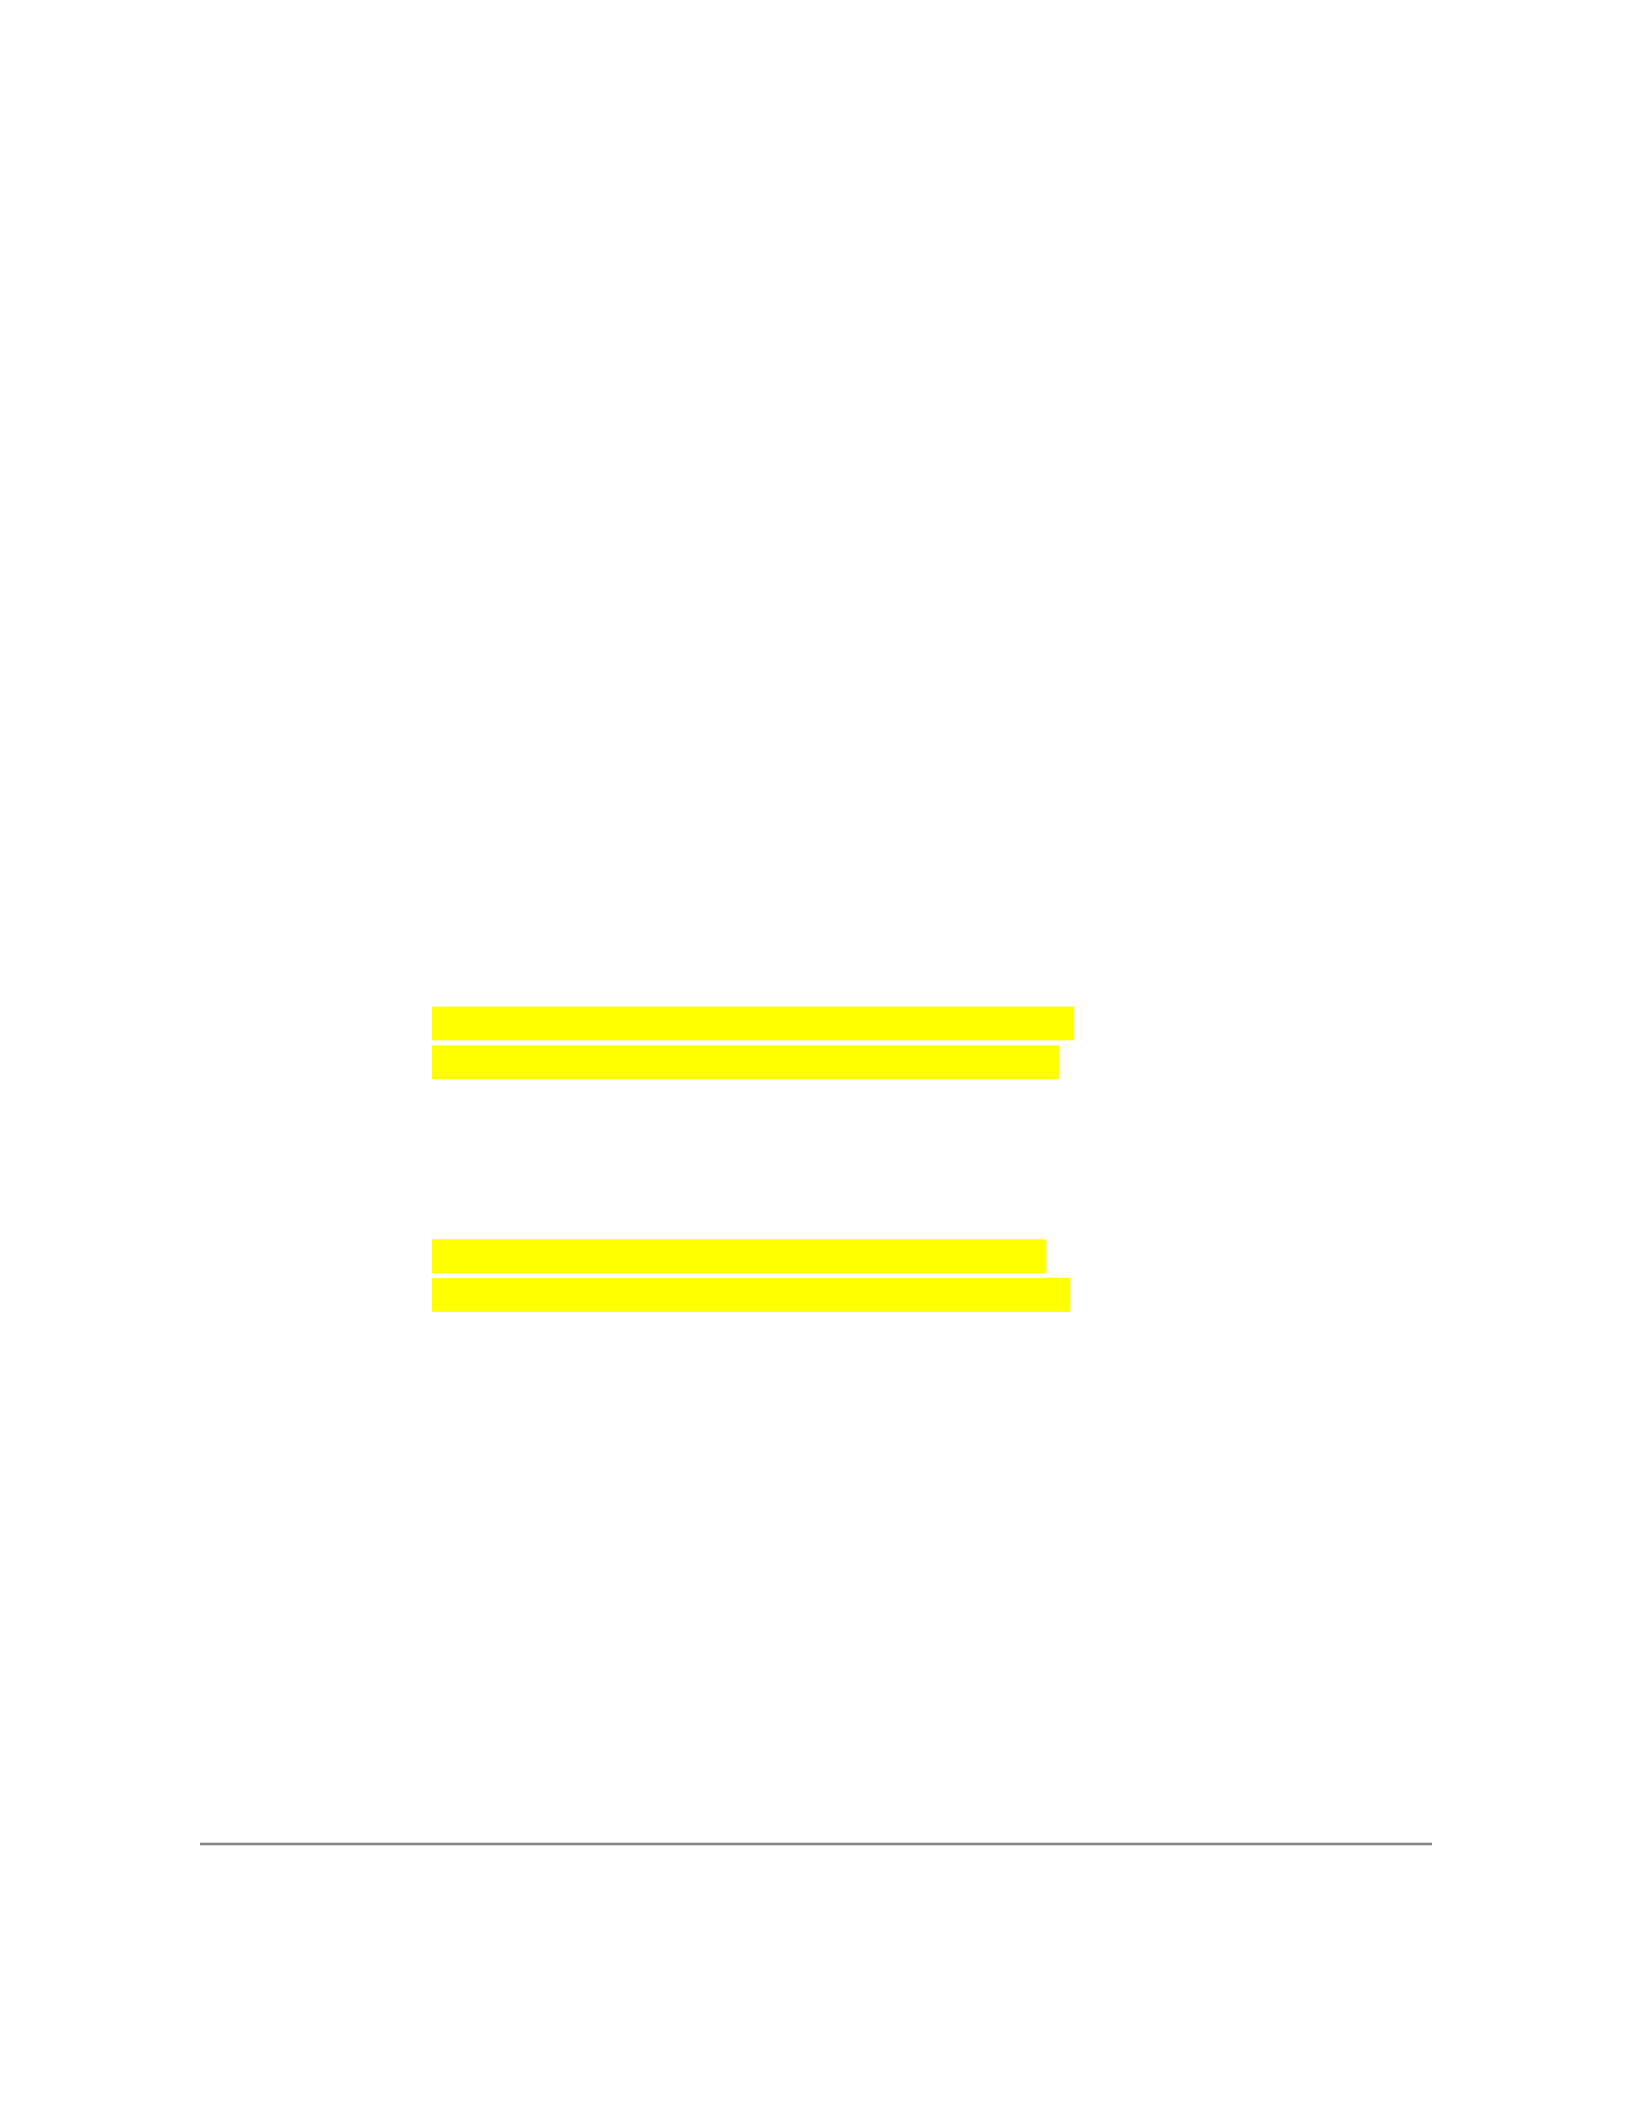
STRAIGHT LINED DEMAND CURVE
1. If ED > 1 than it is elastic
2. If ED < 1 than inelastic
- Why do some goods have highly elastic demand curves while others have highly inelastic
demand curves?
a. Nature of the good
i. If the good is a necessity then demand is relatively … inelastic
ii. If the good is a luxury, then demand is relatively … elastic
b. Availability of close substitutes
i. If good has few substitutes, demand is relatively … inelastic
ii. If the good is narrowly defined (coca cripses vs. cereal) demand is relatively…
elastic
1. Has more alternatives!
c. Share of consumers budget
i. If the purchase takes a large part of the budget, demand is relatively… elastic
ii. If small part of budget, inelastic
d. Passage of time
i. Short run demand curves tend be relatively inelastic
1. Less time to buy something is inelastic
ii. Long run demand curved are relatively elastic
- Total revenue is also called total expenditure
- TR = P times Q
- If price increase and total revenue decrease , ELASTIC
- If price decrease and total revenue increase, ELASTIC
- If price increase and total revenue increase, INELASTIC
- If price decrease and total revenue decrease, INELASTIC
- If price increase and TR remains constant, UNIT ELASTIC
- If price decrease and TR remains constant, UNIT ELASTIC
- Unit elastic = 1?
- Elasticity in Income (ED) = percentage of change for quantity demanded divided by
percentage change for income
- Increase in change of quantity demanded over increase in income = positive,
accounted toward normal goods
- Decreased quantity demand over increase in income = negative, accounted
toward inferior goods
CROSS ELASTICITY OF DEMAND
- Ratio of percentage change in quantity demanded of X to percentage change in price of Y
- Determines the relationship between two goods
- Substitute
- Cut in price on one good, decreases the quantity demanded of the other good
- Increase in price of one good, increases the quantity demanded of the other good
- Cross price elasticity → POSITIVE
- If cross price elasticity is greater than 1 it is elastic
- If cross price elasticity is less than 1 it is inelastic
- Compliments
- Cut in price of one good, increases the quantity demanded of the other good
- Increase in price of one good, decrease the quantity demaned of the other good
- Cross price elasticity → negative
- If cross price elasticity is less than -1 it is elastic
- If cross price elasticity 0 > cross > -1 it is inelastic
- Why are cross price elasticity values important for antitrust cases?
- To see if they are strong substitutes
- Demand curve is depicted for
- A particular time period
- Obersered data for different dates
- Is a hypothetical quantity reasons to set of potential prices
- An optimal decision
- Best serves the objective of the decision maker
- Selected by explicit and implicit comparison with possible alternative choices
CHAPTER 7: PRODUCTION, INPUTS, AND COSTS: BUILDING BLOCKS FOR SUPPLY
ANALYSIS
●Short run (some restrictions involved)
○Some of the firm's cost commitments will not have ended
○Ex: having to pay for rent 2 years
○Owning a pizza parlor, being able to change the amount of workers you hire but not being
able to change the place or facility that is being rented
●Long run (no restrictions)
○For all the firms current commitments to come to an end
■After 2 years, not having to pay rent
○Here all the inputs can be varied and production processes can be changed
●Fixed costs, costs that cannot be changed (short run)
●Variable costs, costs that can be changed (long run)
●Total Physical Product (TPP)
○Total output from different quantities of an input, holding all other inputs constant
■also known as:
●The amount of output that can be produced as one input changes, with all
the other inputs held constant
NUMBER OF CARPENTERS
TOTAL PRODUCT
MPP
0
1
2
3
4
5
6
0
4
12
24
32
35
30
4
8
12
8
3
-5
MPP = change of total physical product over change in quantity
- If MPP > 0 and MPP is increasing, TPP is increasing at a increasing rate
- If MPP > 0 and MPP is decreasing, TPP is increasing at a decreasing rate
- If MPP < 0 TPP is decreasing
NUMBER OF
CARPENTERS
TOTAL
PRODUCT
MPP
Marginal Revenue
Product (MPP X
Poutput)
AVERAGE
PHYSICAL
PRODUCT
(TPP/OUTPUT)
0
1
2
3
4
5
6
0
4
12
24
32
35
30
4
8
12
8
3
-5
$60K
$120K
$180K
$120K
$45K
$-75K
4
6
8
8
7
5
●Average physical product (APP)
○Output per unit of input
○APP = TPP/X, where X = quantity of the input
●Marginal physical product (MPP)
○Increase in total output of a one-unit increase in the input quantity all other inputs
constant
●If MRP > Pinput
○Use more input
●If MRP = Pinput
○Optimal quantity of input
●If MRP < Pinput
○Use less input
●Firm’s goals is to maximus profits
○Profit = total revenue - total costs
○Profit maximized when MRP = P
*marginal revenue product helps decide if the input is worth it but only holds true when there is
diminishing marginal returns
●The more of the input you use, the return you get is less than the previous return
●“Law” of diminishing marginal returns
○An increase in the amount of any one input holding the amounts of all others constant
ultimately leads to lower marginal returns to the expanding input
■The law holds…
●Changing one thing might not be enough → leads to diminishing returns
●Marginal revenue product (MRP) of an input
○Additional revenue the producer earns from the increased sales when it used an additional
unit of the input
○MRP = MPP x Price of output
- If an input becomes more expensive compared to the other input, the firm will use less of the
expensive input and more of the less expensive one
- Ex: MRP/$ of carpenters = MRP/$ of tools
- The price of tools however increased soon which lead to more carpenters and less
use of tools
- Variable costs
- Costs of the firms operations that depend on firm’s output
- Fixed costs
- Costs of an input that does not change when output changes
- A cost that the firm requires to produce any output at all
*over a certain period of time, the fixed cost may change and become a variable cost in the long run
- Total Cost (TC) = total variable cost (tvc) + total fixed cost (tfc)
- Average total cost (AC or ATC) =
- TC divided by quantity of output
- TVC divided by quantity of output + TFC divided by quantity of output
- Marginal cost (MC) =
- Change in total cost divided by change in quantity
- Change in TVC divided by change in quantity + change is TFC divided by change in
quantity
- Total costs
- Fixed costs plus variable costs
- Includes opportunity cost (this is added to the variable costs)
- Marginal variable cost (MVC)
- Increase in total cost (results from a one-unit increase in the output quantity) holding the
other inputs constant
- Ex: how much does it cost to produce one more garage?
- If marginal < average, the average goes down
- If marginal > average, the average goes up
- Average fixed cost
- AFC = total fixed costs divided by total output = TFC/Q
- Marginal fixed cost
- Always equal to zero
- There is no change in MFC
EX: table that can help understand the concepts a bit better
Number of garages
Total fixed costs
(thousand of $ per year)
Marginal fixed costs
Average fixed cost
(thousand of $ per
garage)
0
1
2
3
4
5
6
7
8
9
10
12
12
12
12
12
12
12
12
12
12
12
0
0
0
0
0
0
0
0
0
0
0
–
12
6
4
3
2.4
2
1.7
1.5
1.33
1.2
- When graphing the AFC, it gets really low and eventually gets close to zero
- Average fixed costs fall as output increases
- Marginal physical product increases as output increases
- When a firm grows large, there is an increase in administrative costs and average costs rise as
output expands
- Important to note: at what putput level average cost starts to rise varies from one industry
to the nest
- Depends on the relative size of fixed costs
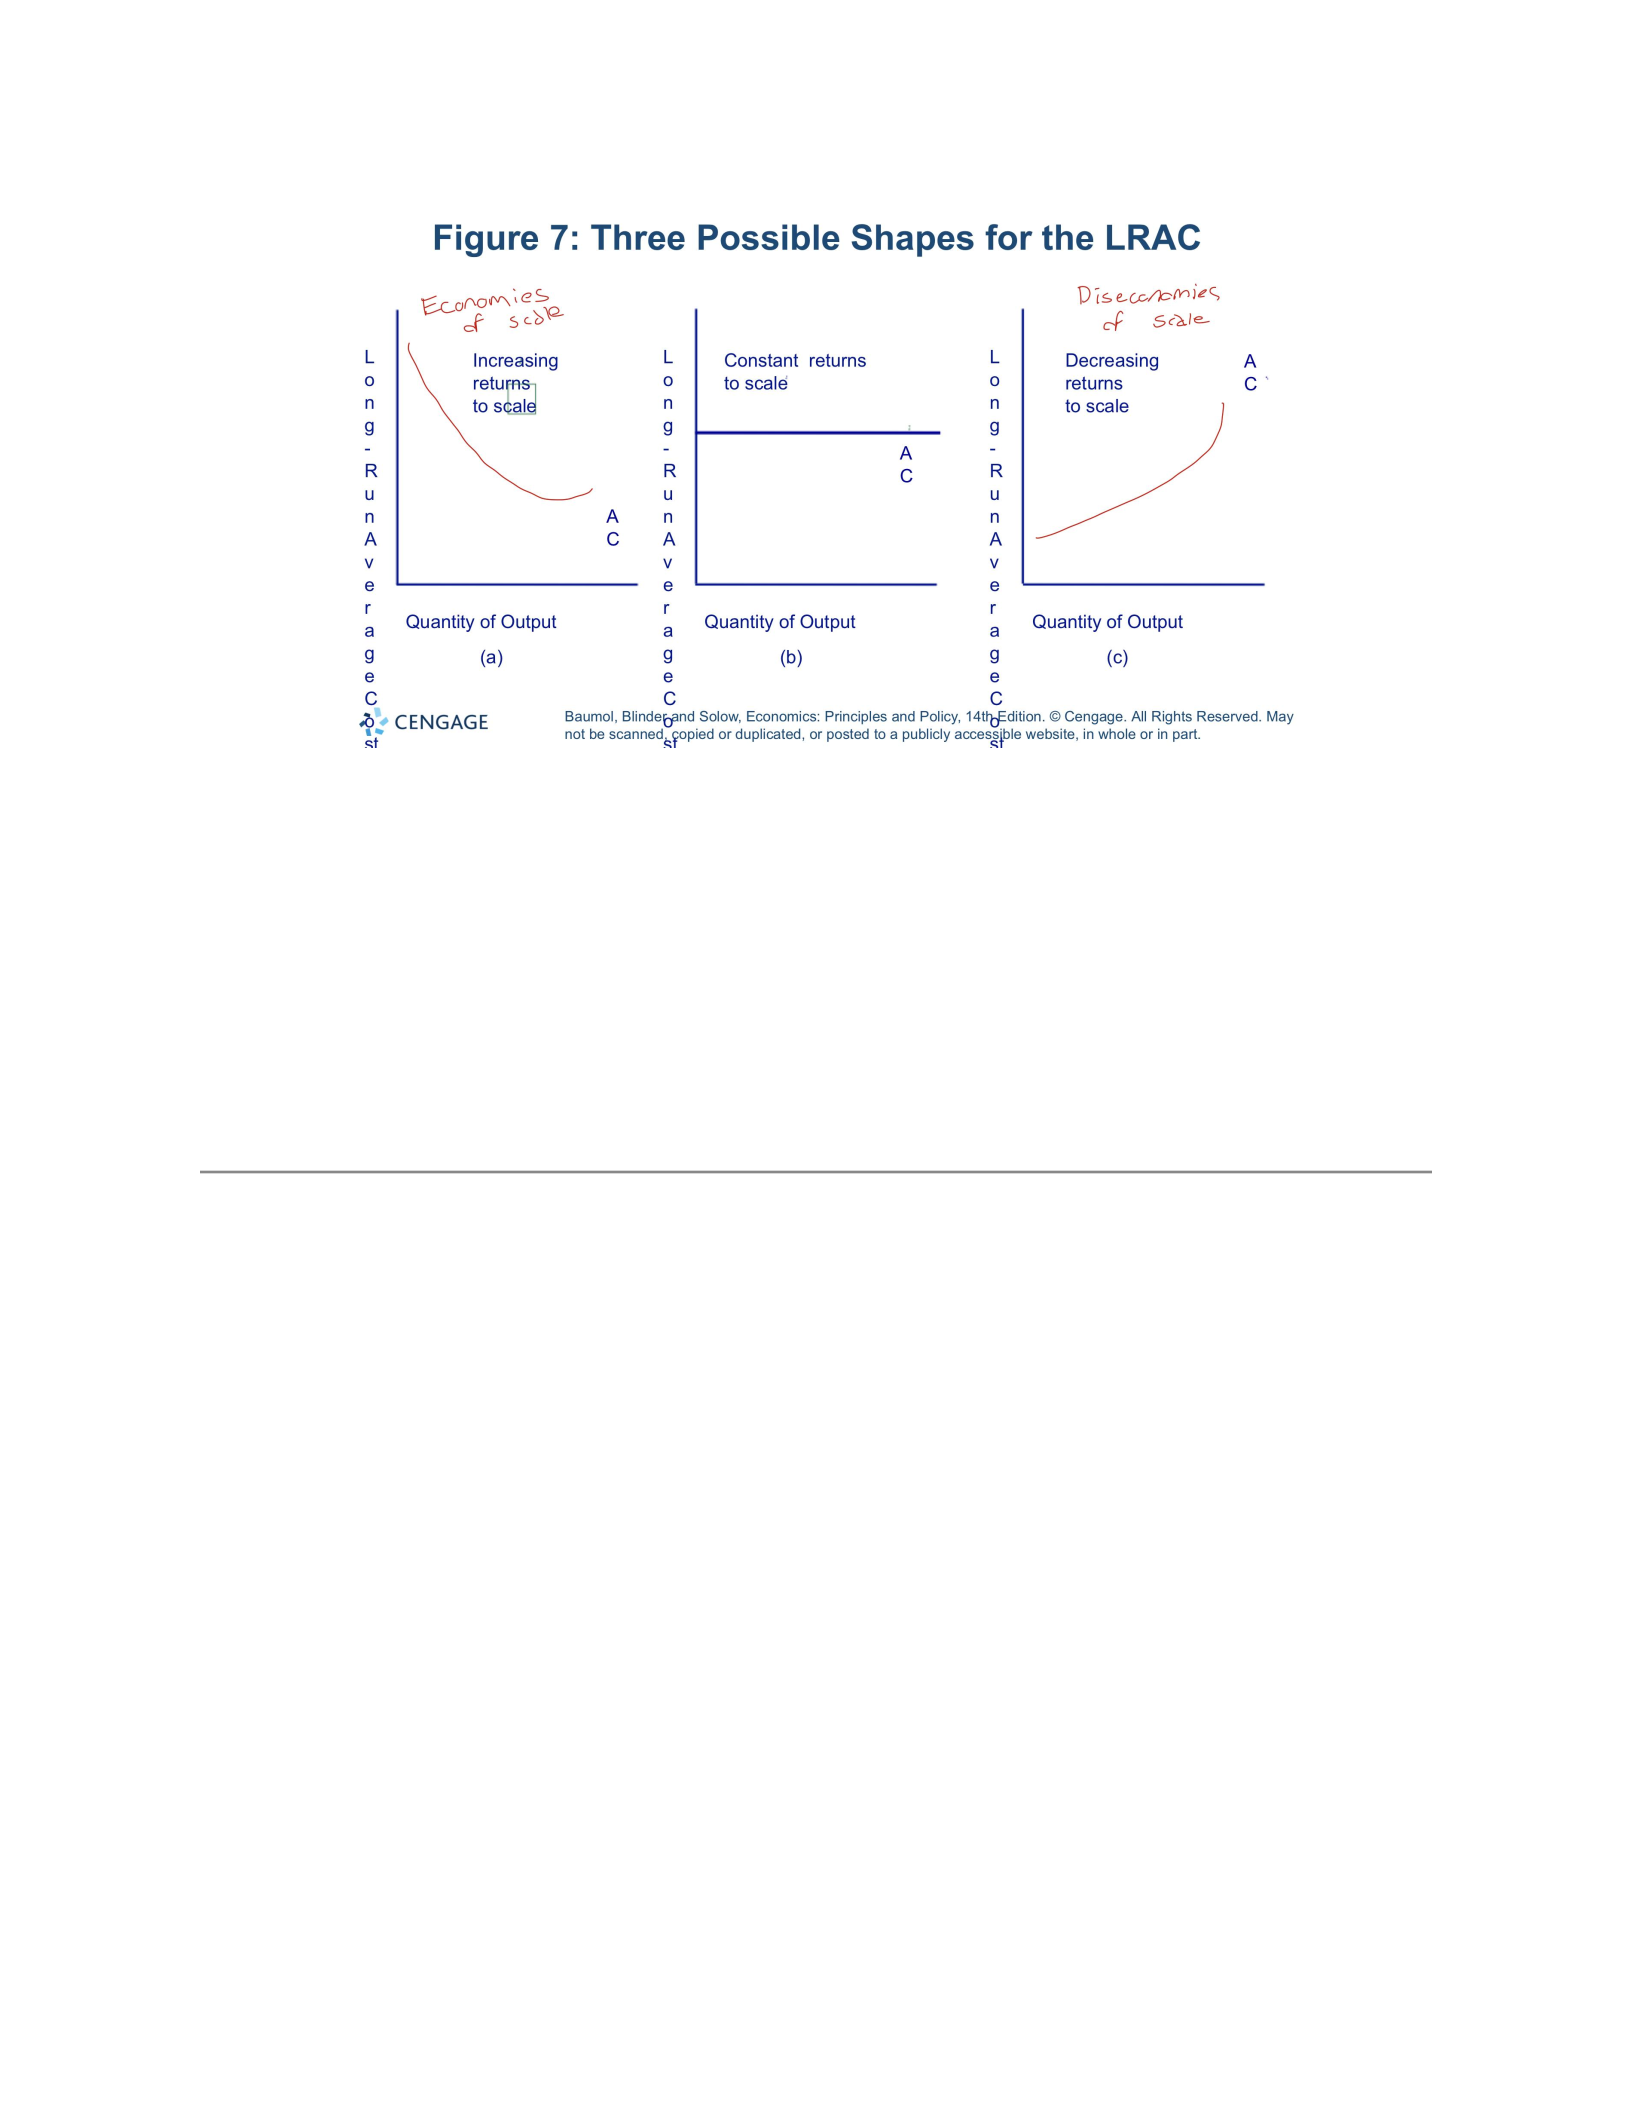
ECONOMIES OF SCALE
●Economies of scale or increasing returns to scale
○Increase inputs by X%, output rises by more than X%
■Determined by technology
○Long run average cost curve declines as output expands
●Constant return to scale
○Increase inputs by X%, output rises by X%
○Long run average cost curve constant
●Decreasing returns to scale
○Increase input by X%, output rises by less than X%
○Long run average cost curve rises as output expands
ECONOMIES OF SCALE CONTINUED:
●Returns to a single input (diminishinf returns)
○How mich does output expand, if a firm use more on one input, all else equal
●Returns to scale (economies of scale)
○How much does output expand if all inputs are increased by the same percentage
●Diminishing returns to a single input may show decreasing, constant, or increasing returns
*note: actual business decisions will at best approximate cost-minimizing ideal
CHAPTER 8: OUTPUT, PRICE AND PROFIT: THE IMPORTANT OF MARGINAL ANALYSIS
●Optimal decision
○The decision that best achieves the decision maker’s goal
●A firm does not set price and quantity
○If a firm sets a price for its product, quantity sold determined by consumers
○If a firm sets a quantity to sell, market determines the price
●Total profit = total revenue - total cost (includes opportunity cost)
●Explicit: direct cost, wages,
●Implicit: not stated for example neighbor asking your help to clean the garage but you wanting to
watch football, if neighborhood ask on wednesday no biggy but if they ask on saturday you miss
football (the football game be an implicit cost)
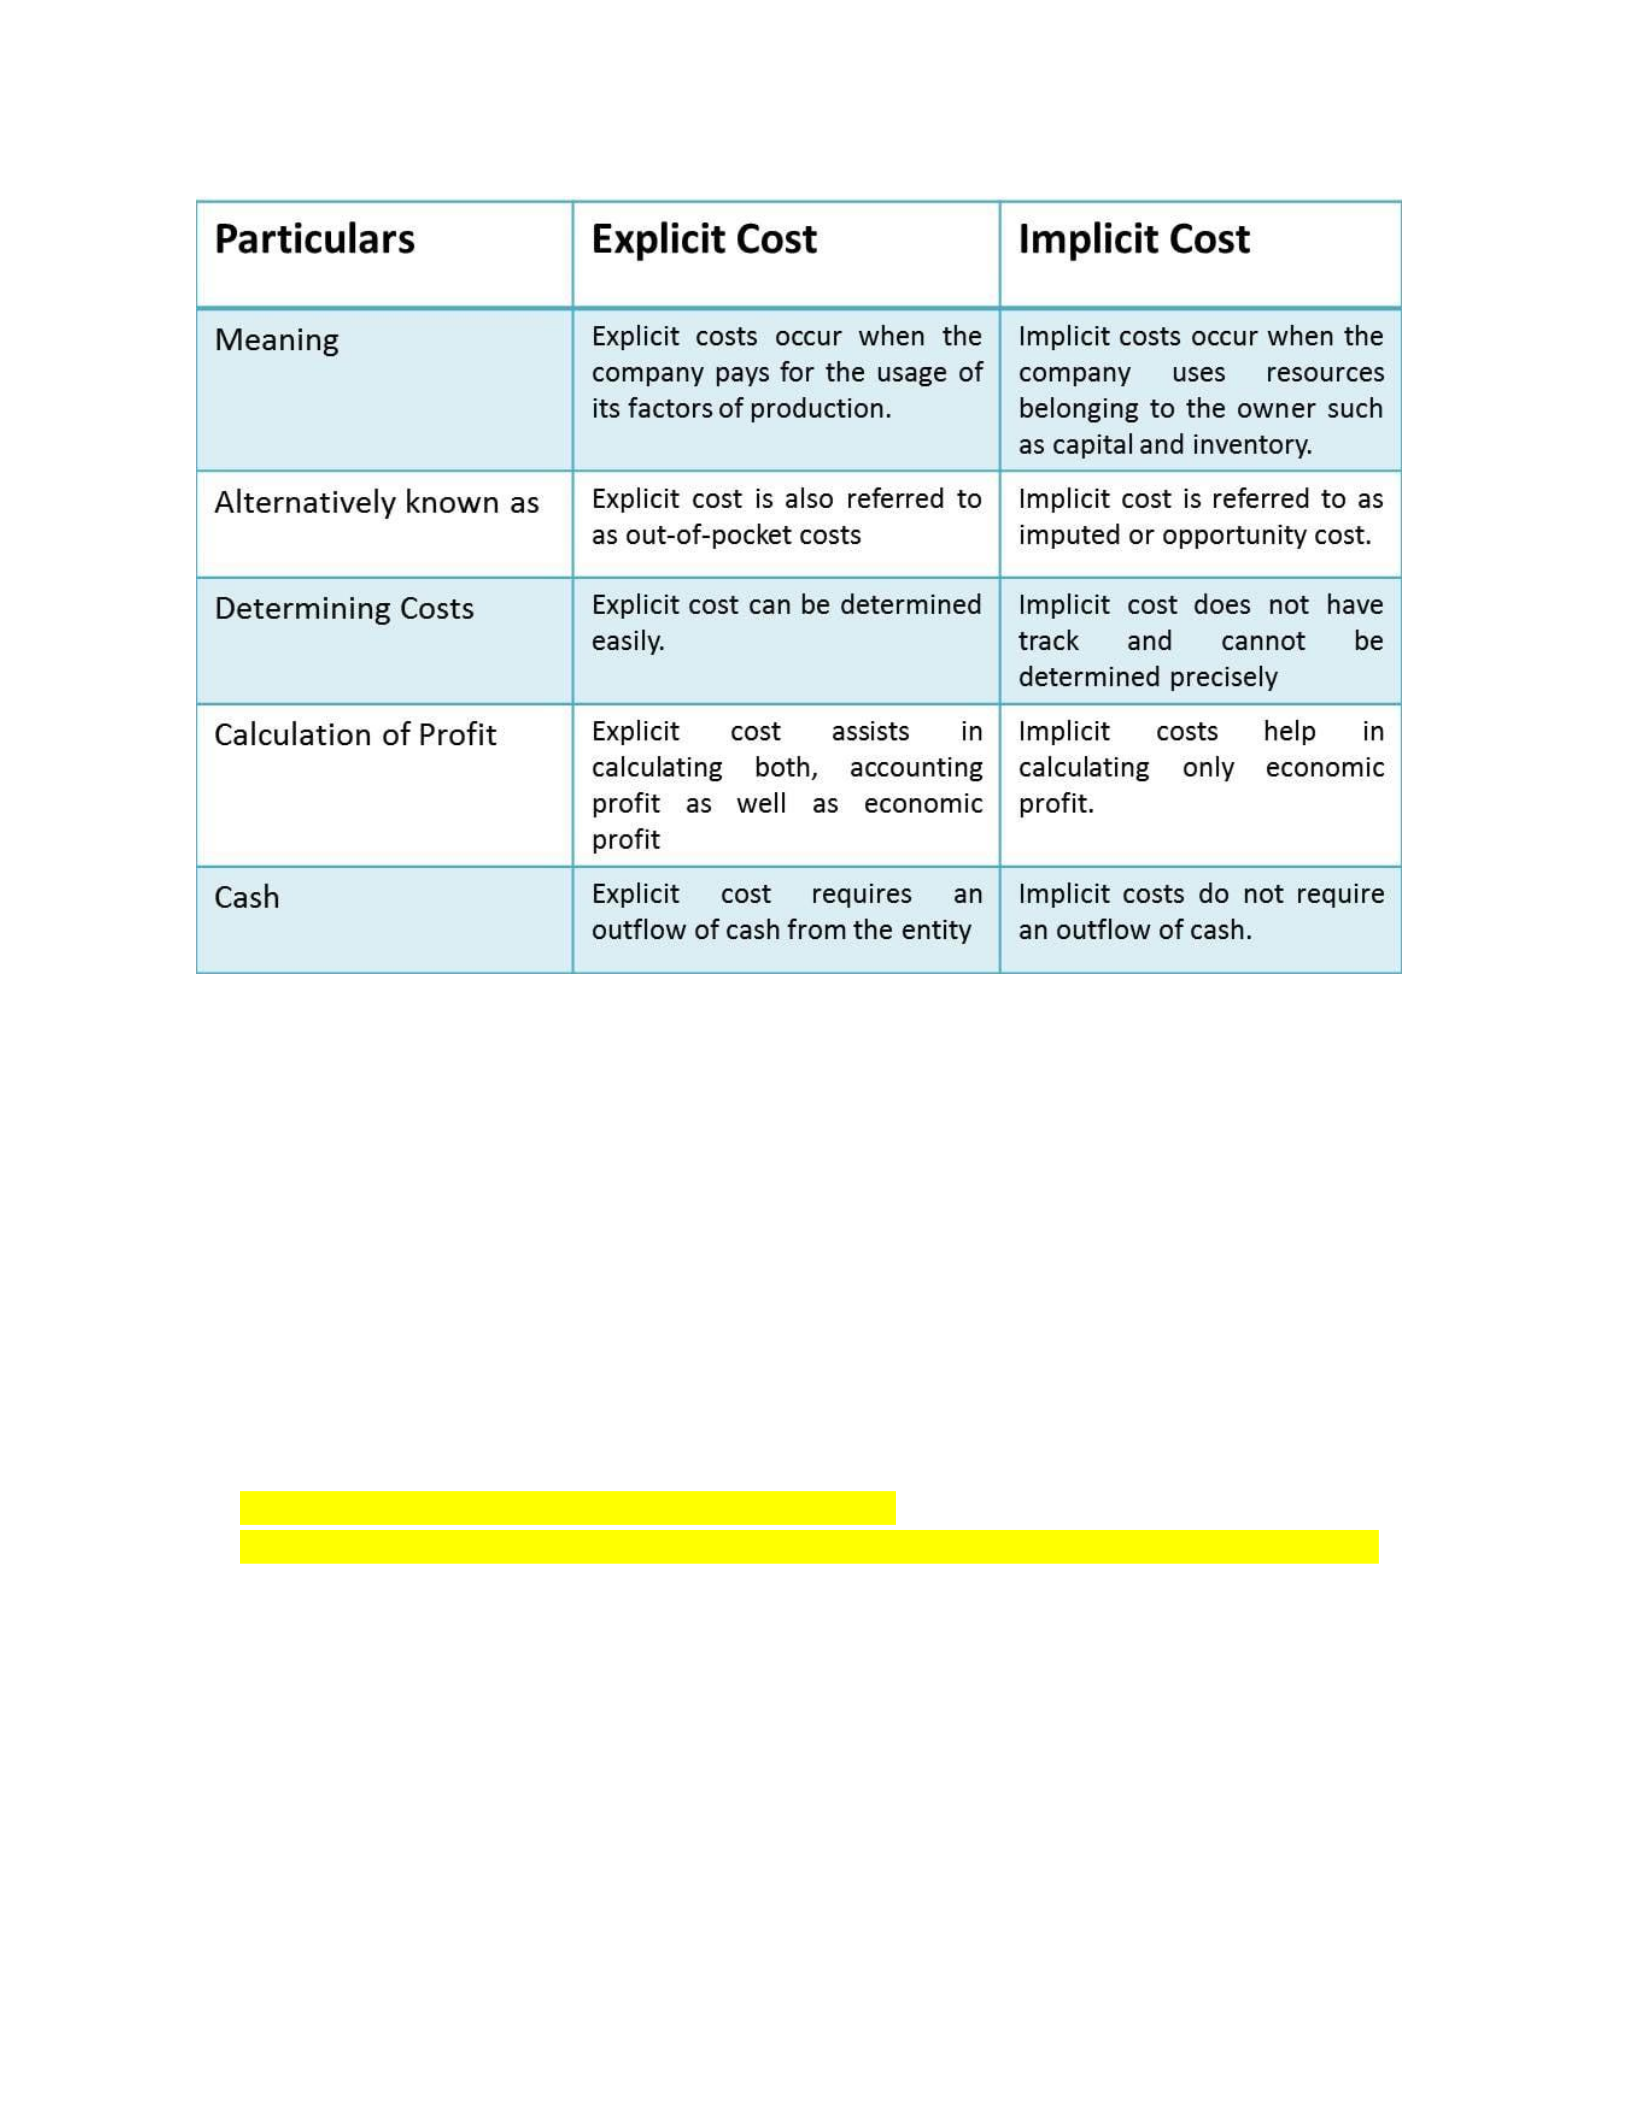
●Economic cost (also known to be opportunity cost) = explicit cost + implicit cost
●Accounting cost = explicit cost
●Economic cost = total revenue - implicit cost - explicit cost
●Economic profit = accounting profit - implicit cost
○Economic profit > 0 optimal
■Firm is doing better with their resources compared to another firm
○Economic profit = 0 satisfaction
■Firm is doing very will with their resource compared to another firm
○Economic profit < 0 , less than satisfaction, there is another item doing better
●Accounting profit = total revenue - explicit cost
WHY INCLUDE OPPORTUNITY COSTS WHEN CALCULATING PROFIT:
1. If some resources treated as “free”, leads to overuse
2. Profits including opportunity cost can tell a firm whether they should continue selling a good
- Accounting profit: measure the companies profitability compared to their alternative
Economic Profit and Optimal Decision Making:
- Economic profit of the decision in question =
- Accounting profit - implicit cost
- Accounting profit of the decision in question - accounting profit of the best
available alternative
- Economic profit of the decision > 0, only if it is more profitable in the
accountant’s measurement than the alternative
- Ex: suppose after graduation you have two options
- Job with google paying 80k per year
- Opening a bike shop
- You decide to open a bike shop and have an accounting profit of 50k
- The economic profit would be 50k - 80k = -30k
- You want an economic lost of 30k
- Total Revenue (TR)
- Amount of money firm receives from consumers
- TR = P times Q
- Average revenue
- TR / Q
- Marginal revenue
- Addition to total revenue form the addition of one unit to total output
- MR = TR 1 - TR 0
- Total profit = total revenue/Q - total cost/ Q
- (P times Q)/Q - (AC X Q)/Q
- Average profit = total profit / Q
- Marginal profit = change in total profit / change in quantity
- Also is marginal profit = marginal revenue - marginal cost
CHART TO HELP UNDERSTAND THE CONCEPTS ABOVE:
GARAGES PER
YEAR
PRICE = AVERAGE
REVENUE PER
GARAGE
TOTAL REVENUE
PER YEAR (IN
THOUSANDS)
MARGINAL
REVENUE PER
ADDED GARAGE (IN
THOUSANDS)
0
1
2
3
4
5
6
7
8
9
10
–
30
28
26
24
22
20
18
16
14
12
0
30
56
78
96
110
120
126
128
126
120
30
26
22
18
14
10
6
2
-2
-6
- Marginal cost > average cost goes up
- Marginal cost < average cost goes down
- Marginal cost and marginal variable cost is the same thing
- Total variable cost is using the fixed cost to subtract
TABLE TO HELP UNDERSTAND:
GARAGES PER
YEAR
TOTAL COST PER
YEAR (IN
THOUSANDS)
MARGINAL COST
PER ADDED
GARAGE (IN
THOUSANDS)
AVERAGE COST PER
GARAGE (IN
THOUSANDS)
0
1
2
3
4
5
6
7
8
9
10
12
40
56
66
74
80
87
96
112
144
190
28
16
10
8
6
7
9
16
32
46
–
40
28
22
18.5
16
14.5
13.7
14
16
19
- Profit maximization (this is Q*)
- For each level of output calculate TR -TC
- Find the largest value
- Graphically, find the largest gap between the TR and TC curves
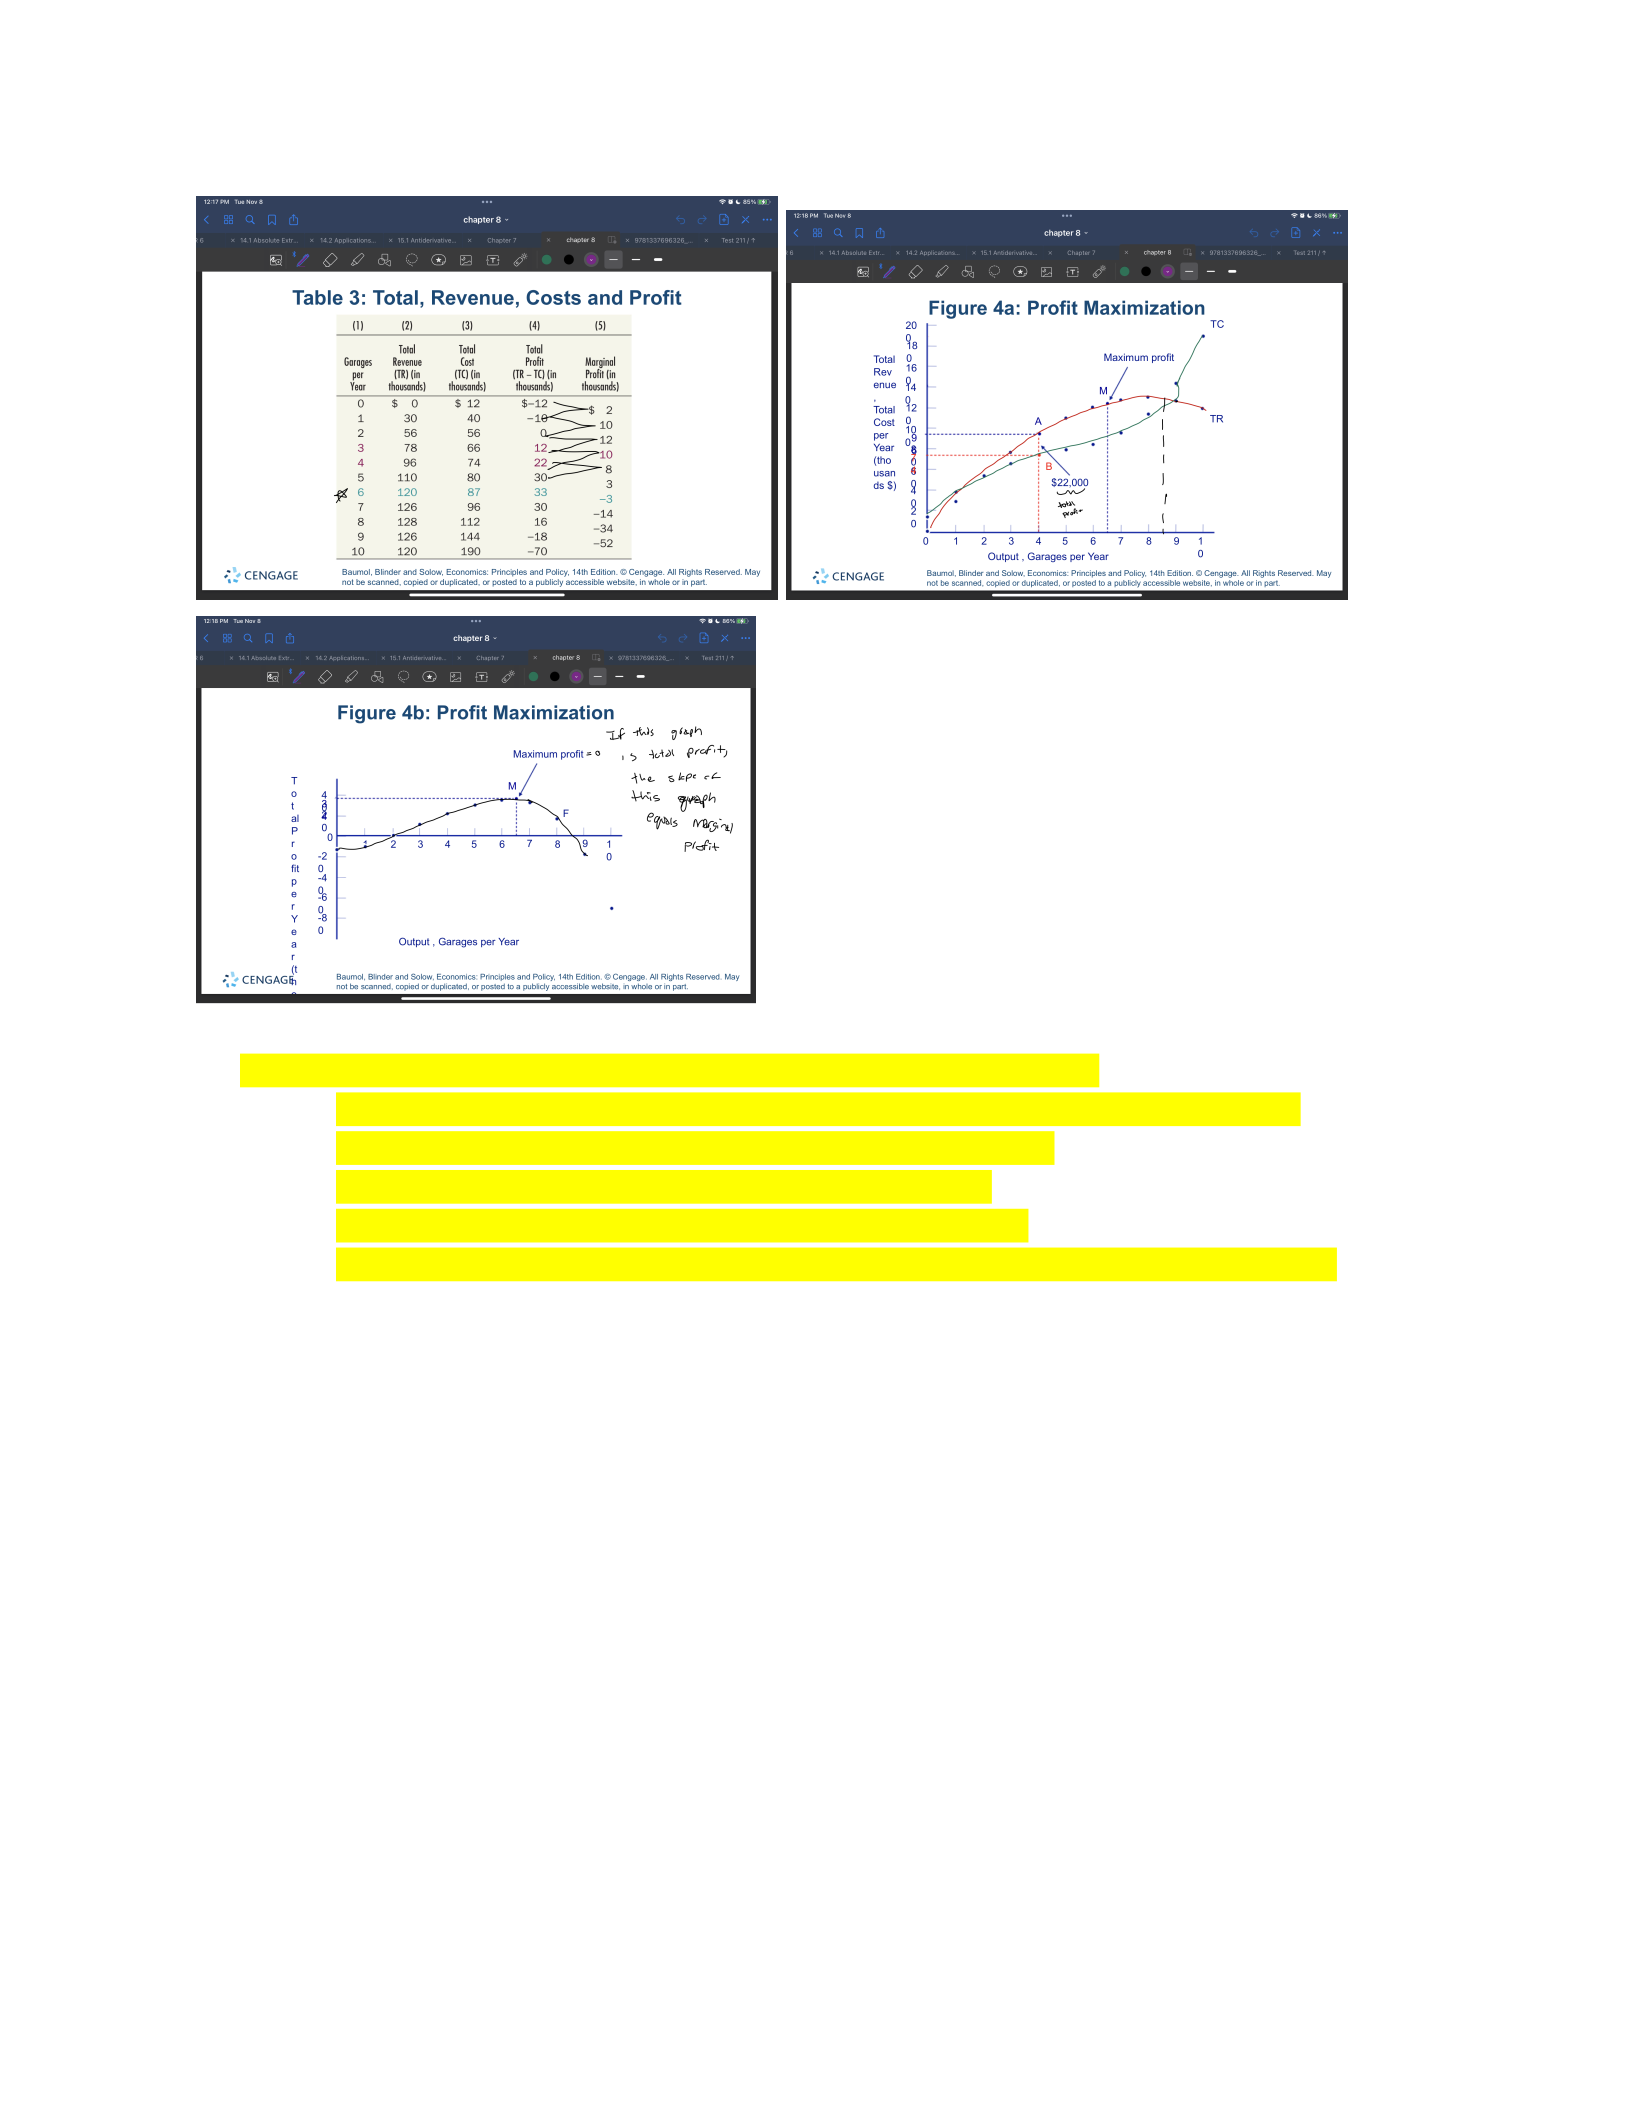
- Marginal profit = change in total profit divided by change in quantity
- Definition: the additional to total profit resulting from one more unit of output
- If MR > MC → MP > 0 produce more (increase output)
- If MR = MC → MP = 0 optimal (profit maximized)
- If MR < MC → MP < 0 produce less (decrease output)
- Change of total revenue is marginal revenue, change in total cost is marginal cost
- To maximise total profit, follow the optimal rule but using MR and MC or MP and 0
- How do we get the profit maximizing price?
- The demand curve
- 3 steps to profit maximizing:
- Find Q*
- MR = MC, go to Xaxis
- Find price
- From q* go straight up to the demand curve and go to y-axis to find price
- Find AC
- From Q* so up to AC curve and go to y-axis
●Consumer surplus (also known as total net utility)
○Difference between how much you are willing to pay (how much you value the quantity
of a good) and what you do pay (market price)
●Producers surplus
○Different between the market price of the item sold and the lowest price the producer
would be willing to provide for that item
○PS = Price - marginal cost
○Note: producer surplus is not the same as profit
■Producer surplus only considers variable costs and not fixed costs
*marginal cost is all variable cost
- Marginal analysis applies to many decisions
- If you want to maximise something
- Net benefit = total benefit - total cost
- Choose quantity that the marginal benefit = (approx.) marginal cost
- Keep maximizing as long as MB > MC
- Stop maximizing (go back) where MB < MC
- Cost tend to go up or straight, benefit tend to go down
- Fixed cost should not change unless a certain factor comes to play
- If the firm’s fixed cost increases
- Do nothing
- MC = MR remain
- This means profit maximizing (Q*) stays the same
- So long as it pays the firm to stay in business
NOTE: decisions based on average cost and revenue only lead to missed opportunities, stick to marginal
cost and revenue! They help with any decision
- If frms behave optimally, their actions are consistent with marginal analysis
- If marginal < average
- Average decreases
- If marginal > average
- Average increases
- If marginal = average
- Average has no change

