


Introduction Corporate Social
According to the Committee Encouraging Corporate Philanthropy (CECP) 2014, a
nonprofit coalition of 150 CEOs of the world’s largest companies, the amount of corporate
donations among the majority of U.S. corporations listed in Fortune 500 has been increasing
steadily in the last decade and is expected to increase in the coming years. Walmart Stores Inc.,
for instance, spent more than $ 311 million in corporate donations in 2013. Similarly, Chevron
Corporation spent upwards of $274 million in corporate donations in 2013. The largest U.S.
firms and their CEOs are responding to the growing emphasis on social responsibility to give
something back to their employees, the community, and society at large. Commonly referred to
as “doing well by doing good” (Embley, 1993; Falck & Heblich, 2007), such efforts can help
businesses address stakeholders’ demand for social as well as economic goals. There is a belief
that ongoing engagement in corporate social responsibility (CSR) has a positive impact on
people around the world while contributing to corporations’ business success. Such belief in the
importance of CSR has become a major business trend among U.S. corporations.
CSR as a business practice and philosophy has taken an important place in the way
businesses operate and serve their stakeholders. CSR refers to “context-specific organizational
actions and policies that take into account stakeholders’ expectations and the triple bottom line of
economic, social, and environmental performance” (Aguinis, 2011, p. 855). This definition
indicates that businesses should have responsibility beyond their immediate economic concern
and should act in a way that contributes and enhances broader societal goals. CSR primarily
embraces economic, legal, ethical, and philanthropic responsibilities and the dimensions of CSR
include the obligations a business has to its stakeholder’s groups (Carroll, 1991). Over the past
half century, CSR has increasingly been integrated into mainstream business thinking, and

nowadays, most U.S. publicly-traded firms (e.g., Microsoft, Google, and Walt Disney) claim to
engage in some form of CSR. The main benefits of engaging in CSR include generating
intangible assets, including building corporate reputation and employee commitment, and
tangible assets, including the positive impact on financial performance. Research in this area
suggests that being a socially responsible business helps create goodwill, build a positive
organizational image, differentiate them from their competitors, and, as a result, promote
longterm profits for business (Boynton, 2013). Indeed, more firms increasingly embrace CSR as
their employees demand their firms to be socially responsible, customers expect better business
practices, and investors realize the economic rewards of sustainable business models. Beyond the
immediate task environment, business CSR engagement also serves the needs of communities
around the world and fulfills the responsibilities businesses have to the public.
1.2 The Importance of Corporate Philanthropy
Corporate philanthropy is considered one of the core dimensions of CSR (Aguinis &
Clavas, 2012; Carroll, 1991; Porter & Kramer, 2002). The origin of corporate philanthropy in the
U.S. dates back to the rise of industrial age in the 19th and early 20th century, when businessmen
like Henry Ford and John D. Rockefeller established philanthropic foundations (Dietlin, 2011).
Corporate philanthropy has since been transformed from piecemeal individual philanthropic acts
(e.g., philanthropy mainly driven by morality) to a major aspect of corporate CSR practices.
Corporate philanthropy is, nowadays, a widespread business practice in large multinationals as
well as small-and medium-sized firms across the globe. Despite the dominant altruistic
orientation, corporate philanthropy has increasingly complemented the firm’s strategic activities
and enhanced the firm’s social and financial performance (Porter & Kramer, 2002). Therefore, it

can be argued that corporate philanthropy has evolved dramatically from a basic moral obligation
to a strategically-driven activity of the firm. As Porter and Kramer (2002, p. 58) put it,
“True strategic giving, by hand, addresses important social and economic goals simultaneously,
targeting areas of competitive context where the company and society both benefit because the
firm brings unique assets and expertise.”
Corporate philanthropy can often be “the most cost-effective way for a firm to improve its
competitive context” (Porter & Kramer, 2002, p. 9). Many firms invest a significant amount of
resource expenditures on philanthropy in order to build a strong company image. For example, a
2013 report from the Committee Encouraging Corporate Philanthropy indicates that 59 percent
of the largest Fortune 100 firms donated significantly more in 2012 compared to 2007, the year
before the global recession sets in, and aggregate giving rose by 42% ($4.48 billion) from 2007
to 2012. The ten largest U.S. corporations donated over 2.1 billion dollars in 2013 and this figure
has increased in 2014. Many firms provide support to nonprofits and social causes primarily
through company-sponsored foundations as well as corporate direct giving, both of which are
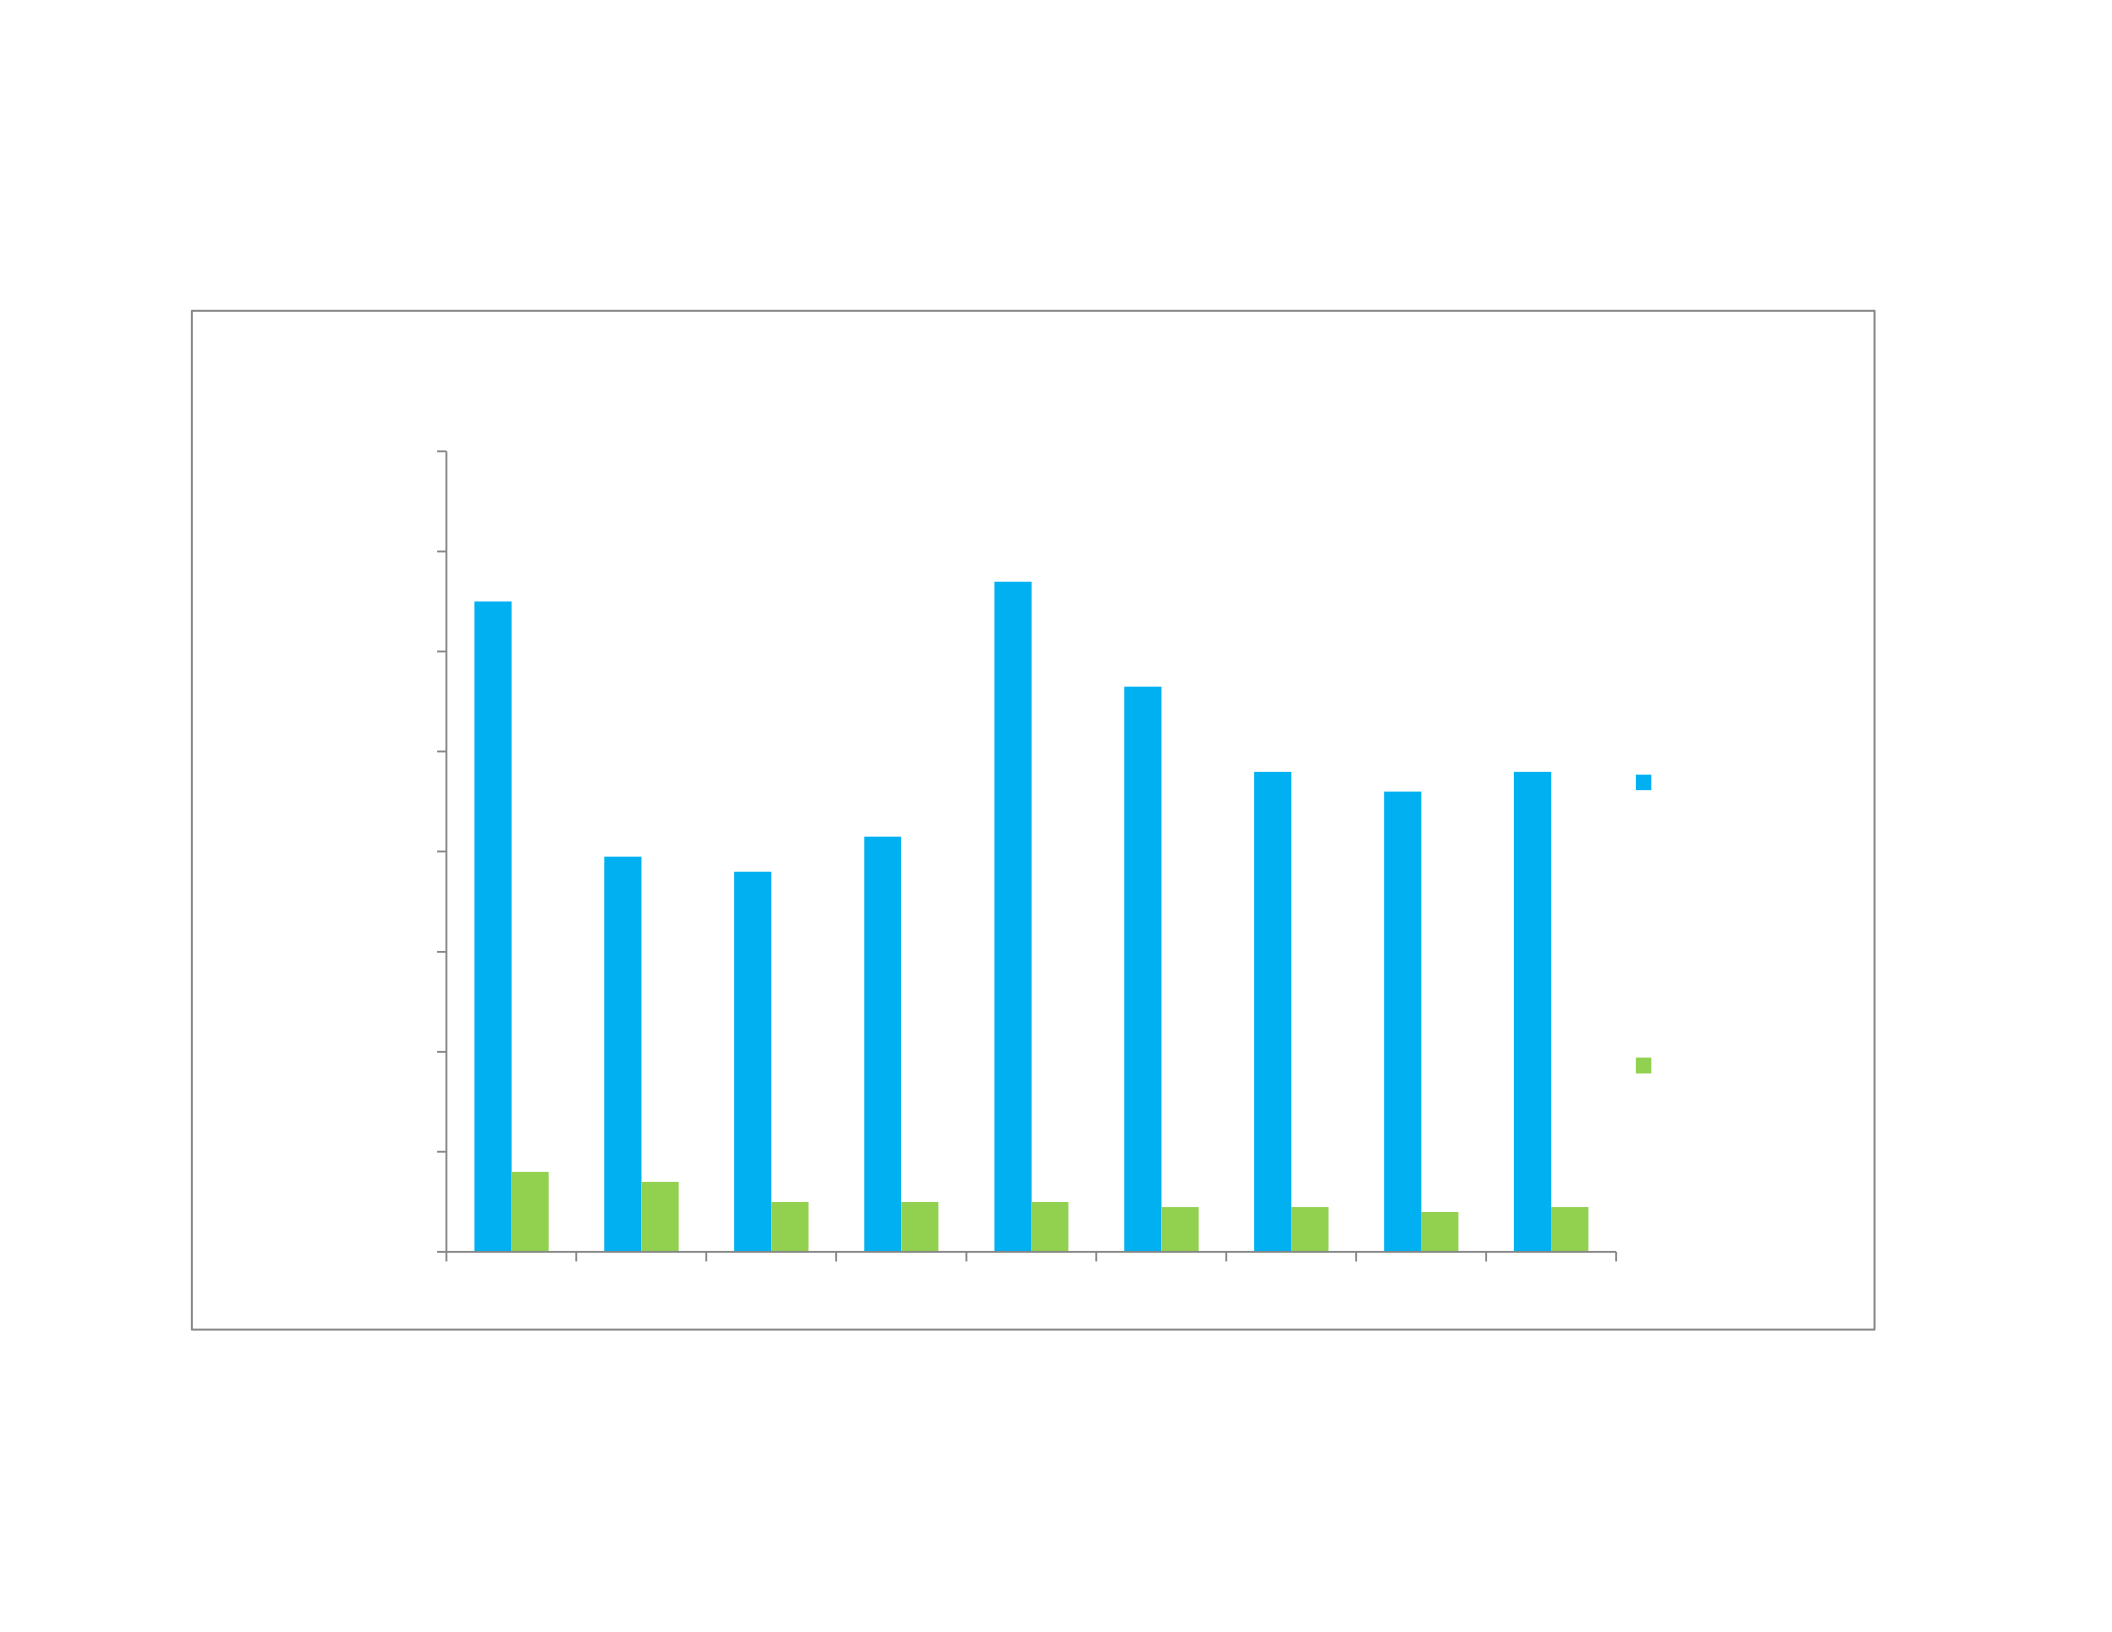
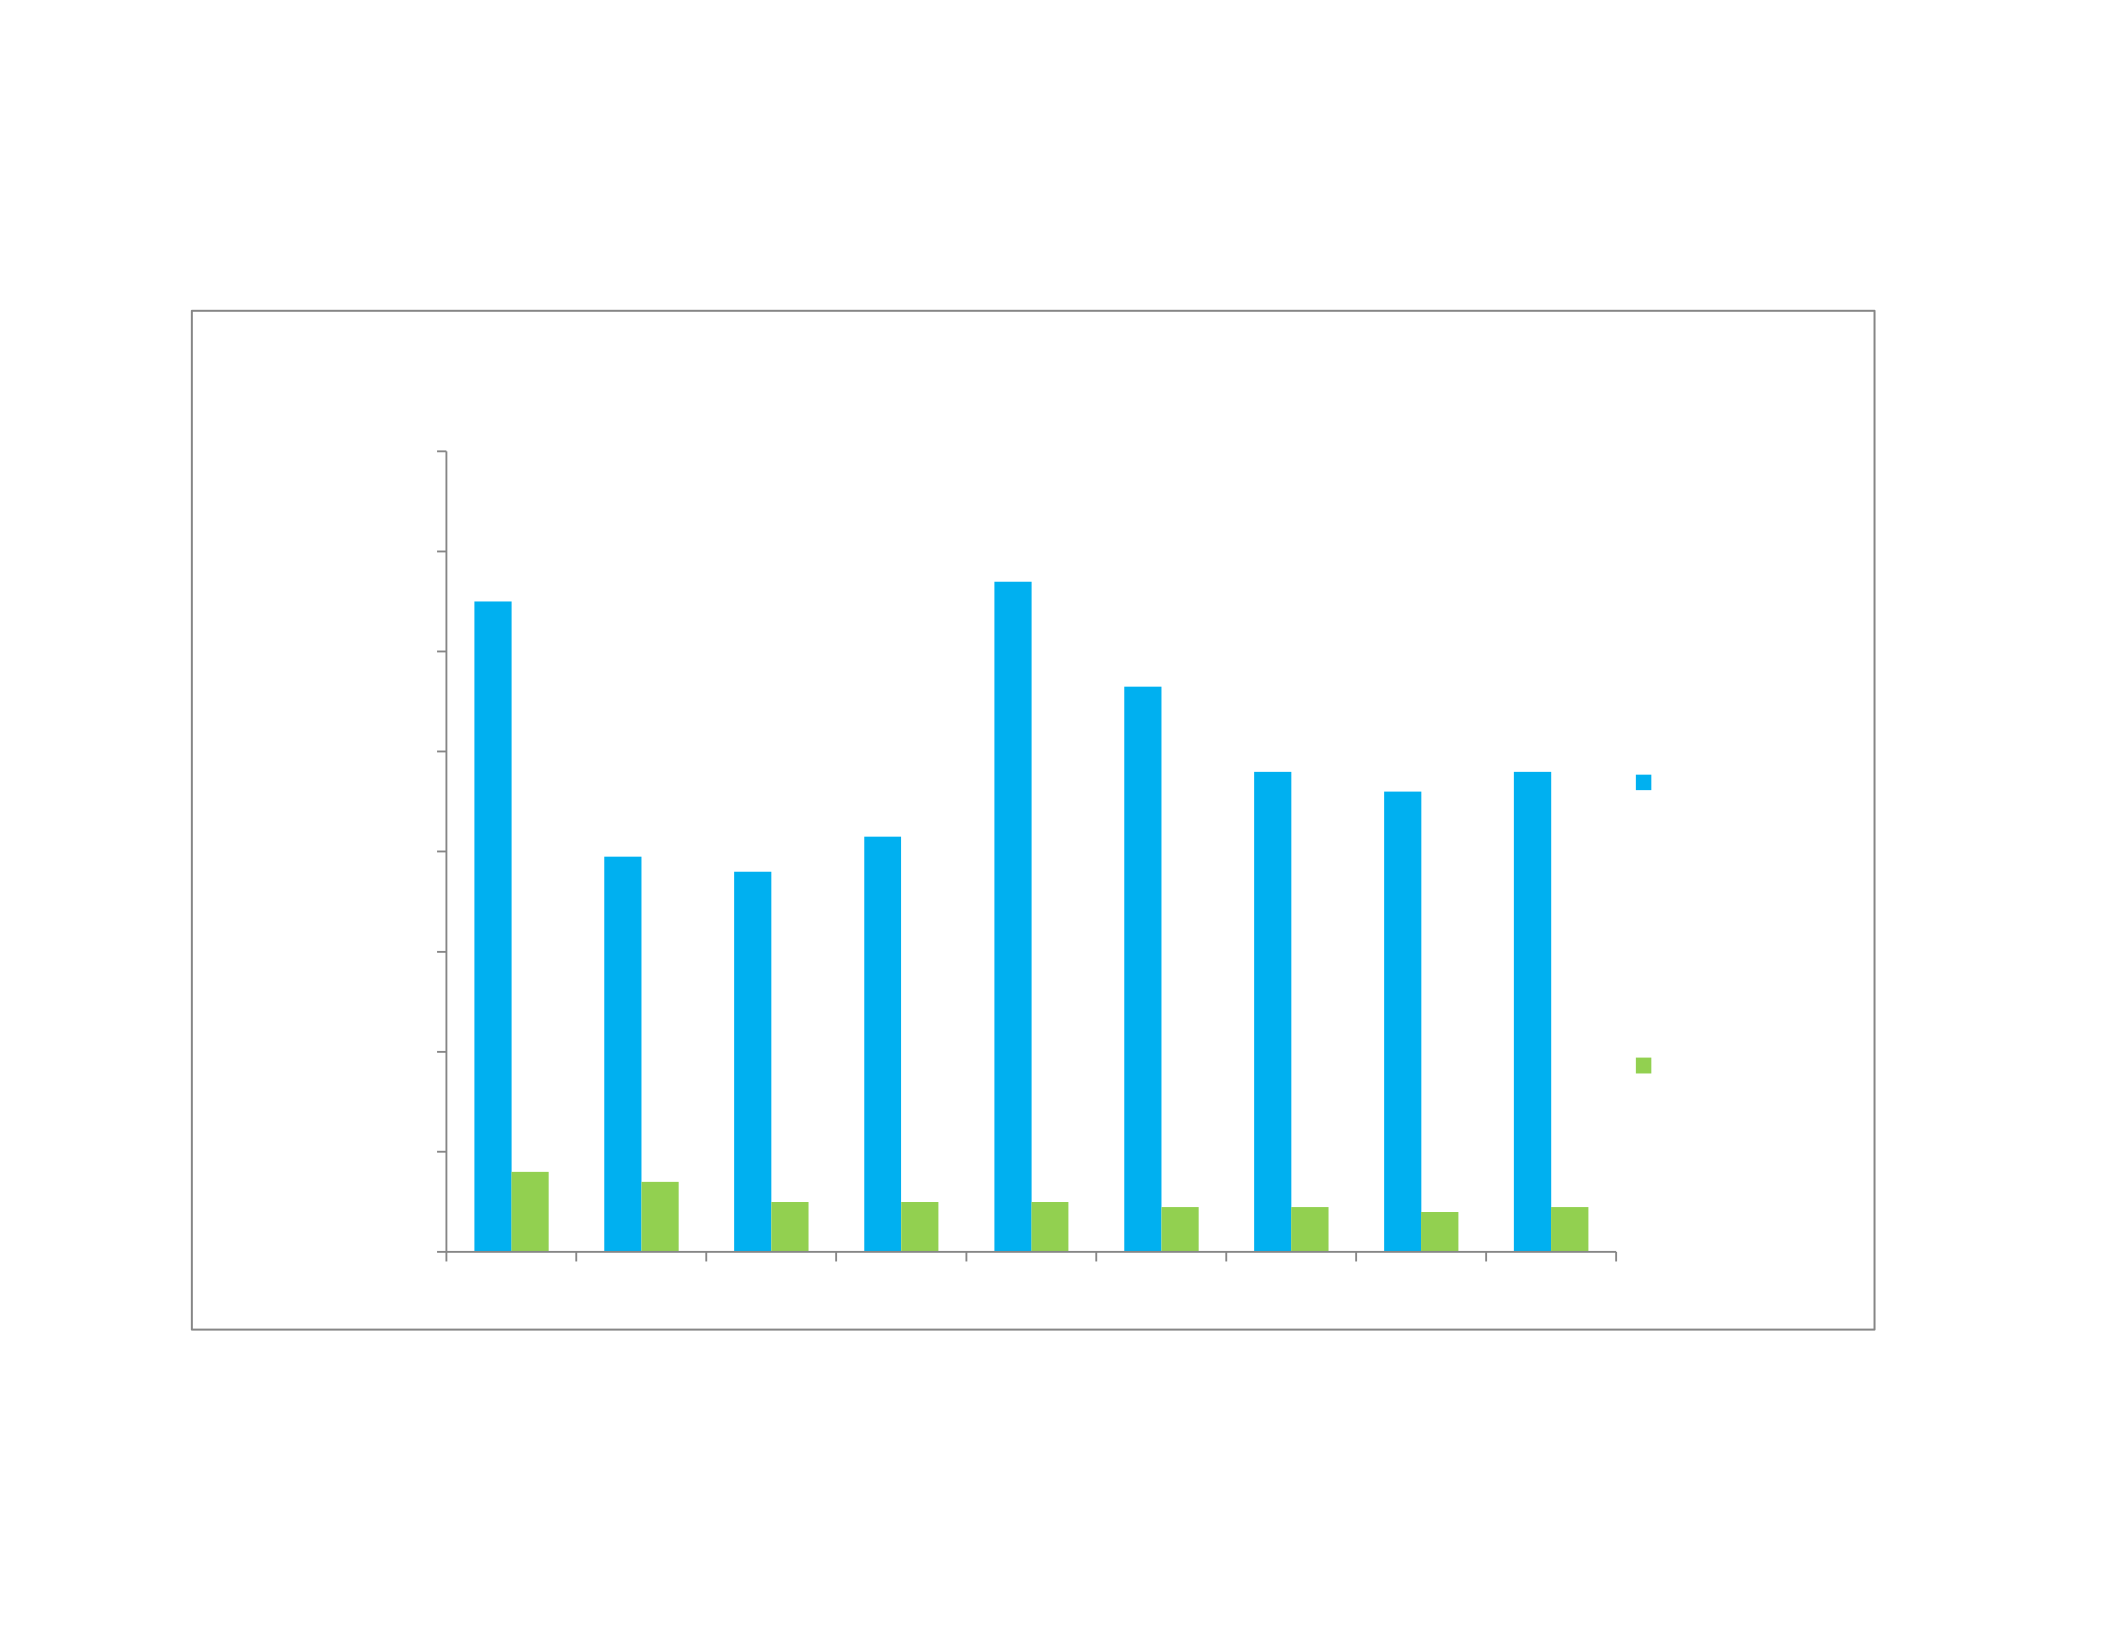
closely tied with the parent company’s business interests. As shown in Figure 1 below, the largest
U.S. firms and their foundations have increased charitable giving during the past decade (2001-
2012). Similarly, as shown in Figure 2 below, the largest 100 U.S. corporations have increased
total charitable giving both as a percentage of pre-tax profit and as a percentage of revenue
especially after the global recession in 2008.
Indeed, the increasing commitment of corporate resources to philanthropic causes reflects
a widely-held belief among business executives that philanthropy can be “strategic” in that it can
make a substantial impact on society while improving business value and reputation for the firm
(Carroll & Shabana, 2010; Walker, 2002). According to a 2010 survey by CECP, 77 percent of

CEOs noted that “the most important action they can take to prepare for 2020 is to embed social
engagement into business strategy and organizational structure.” For example, Ronald A.
Williams, the CEO of Aetna noted that that “public companies can move the collective needle by
using their human and financial resources to innovative in ways that benefit both private interests
and the public good” (Weiss, Kerdahy & Kneale, 2008, p. 5). Ivan Seidenberg, Chairman and
CEO, Verizon Communications Inc., commented in CECP that “our belief is that corporate
philanthropy expands the business. You can expand the capabilities of your customer base,
business and society by doing the right thing.” These and other executive views also highlight an
important fact that corporate philanthropy can be driven by leadership values and studying
leaders’ background can help extend our knowledge of the role of corporate philanthropy in
improving firm performance.
Figure 1. U.S. Corporate Foundation Philanthropic Giving from 2001 to 2012 (2,629 Corporate Foundations)
Source: The Foundation Center as of January 27, 2015
3.28 3.43 3.47 3.43
4 4.1
4.4 4.56 4.69
4.91
5.18
5.55
0
1
2
3
4
5
6
2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012
Billion$
Total charitable giving
5
Figure 2. Total Charitable Giving among Fortune 100 Firms between 2004 and 2012
Source: Committee Encouraging Corporate Philanthropy as of January 27, 2015
1.3
0.79 0.76
0.83
1.34
1.13
0.96 0.92 0.96
0.16 0.14 0.1 0.1 0.1 0.09 0.09 0.08 0.09
0
0.2
0.4
0.6
0.8
1
1.2
1.4
1.6
2004 2005 2006 2007 2008 2009 2010 2011 2012
Total charitable
giving as a % of
pre-tax profit
Total charitable
giving as a % of
revenue
Million$

6

Despite the stated purpose of enhancing a firm’s public visibility and reputation by engaging in
corporate philanthropy, firms face some criticisms from stakeholders on the tangible benefits of
philanthropy. Some scholars (e.g. Devinney, 2009; Friedman, 1970) have supported this skeptical
perspective arguing that a firm exists primarily to generate economic returns, not to solve societal
problems. Friedman (1970, p. 6) argues that the single social responsibility of business is to “engage in
business activities designed to increase its profit.” On the contrary, other scholars (e.g. Godfrey, 2005;
Wang & Qian, 2011) have strongly supported the positive role of corporate philanthropy in improving
firm performance. These scholars argue that corporate philanthropy can generate positive stakeholder
support which in turn improves a firm’s financial performance. In an effort to address the critics’
concerns on the use of corporate resources toward charitable contributions, firms are increasingly
turning to the strategic use of philanthropy. Research suggests that strategic philanthropy can play a key
role in developing value-creating relationships with primary stakeholders and enhancing a company’s
image (Buchholtz, Amason & Rutherford, 1999; Saiia, Carroll & Buchholtz, 2003). Strategic

philanthropy can also serve as “a common meeting ground for the opponents and proponents of
corporate philanthropy” (Buchholtz et al., 1999, p. 169). Large firms are fundamentally responsible for
strategic philanthropy in practice because they have systematic structures (Marquis & Lee, 2013). For
example, large firms have corporate foundations, employee committees to oversee corporate giving, and
staff functions devoted to the effort to manage their social responsibilities (McAlister & Ferrell, 2002).
In marketing practice, strategic philanthropy has been often associated with cause-related marketing to
support social responsibility (File & Prince, 1998; Vanhamme, Lindgreen, Reast & van Popering, 2012;
Varadarajan & Menon,
1988). Both practices have some dissimilarities in terms of primary focus, time frame, and costs
(McAlister & Ferrell, 2002). Strategic philanthropy focuses on organizing itself, is ongoing, and tends to
require moderate to high resource commitment. On the other hand, cause-related marketing focuses on
the firm’s products, has a limited duration, and involves minimal resource commitment. Both strategic
philanthropy and cause-related marketing help enhance societal welfare and improve the reputation of a

firm. Stakeholder theory (Freeman, 1984) offers an important theoretical support for the relationship
between corporate philanthropy and firm performance, suggesting that favorable social performance is a
requirement for business legitimacy, and tends to be positively associated with firm performance over
the long term.
Donaldson and Preston (1995, p. 82) also suggest that firms respond to “ethical considerations (e.g.
engaging in philanthropy) which are often consistent with long-run increases in profit and value.”
Importantly, the positive effect of corporate philanthropy on the firm provides a reason why there
is a need to examine the relationship between CEO characteristics and corporate philanthropy. Since
corporate philanthropy has become an important strategic tool that organizational senior leaders
manipulate, they are more involved in assessing and shaping corporate strategies (Porter & Krammer,
2002). In addition, past research argues that a firm’s social activities should be met by corporate goals
determined by CEOs who constantly make strategic decisions and choices (Choi & Wang, 2007; Wood,
1991). Furthermore, it has been suggested that CEOs are the primary decision-makers of the

organization such that an examination of CEOs’ attitudes and values toward philanthropy provides
needed insight into the social responsibility actions in general and philanthropic function in particular
(Dennis, Buchholtz, & Butts, 2009). Accordingly, it can be suggested that the relationship between CEO
characteristics and corporate philanthropy should receive much attention. In the following section, I will
provide a brief discussion on the major research gaps that I seek to address in order to advance the
understanding of the leadership predictors of corporate philanthropy and the implications for firm
performance.
1.3 Statement of the Problem
Previous studies have focused on why firms engage in corporate philanthropy (Adams &
Hardwick, 1998; Brammer & Millington, 2005; Fombrun & Shanley, 1990; Godfrey, 2005; Turban &
Greening, 1997; Wang & Qian, 2011; Williams & Barrett, 2000). These studies have shown that
engagement in corporate philanthropy can lead to increased employee loyalty (e.g., employee
commitment), favorable community image (e.g., corporate reputation), and positive media coverage

(e.g., recovering tarnished reputation). As such, it can be suggested that consequences of corporate
philanthropy have been extensively explored to answer the question, “why should a firm give?”
Meanwhile, antecedents of corporate philanthropy have been explored to answer the question, “what
drives firms to give?” The predominant discussion among scholars has been on the managerial (e.g.
Buchholtz et al., 1999; Choi & Wang, 2007; Marquis & Lee, 2013; Wang & Coffey, 1992),
organizational (Adams & Hardwick, 1998;
Brammer & Millington, 2006; Seifert, Morris & Bartkus, 2003), and industry (Amato & Amato, 2007,
2012; Useem, 1988) drivers of corporate philanthropy. Specifically, past research suggested that firms
engage in corporate philanthropy as a means to simultaneously and directly benefit business interests
and those of a beneficiary organization (Saiia et al., 2003; Marx, 1999). The extent to which firms
engage in corporate philanthropy can vary depending on organizational factors, such as firm size,
organizational slack, and advertising intensity (Dennis et al., 2009; Saiia et al., 2003; Wang & Qian,
2011). Past research on corporate philanthropy has generally discussed the intersection of business goals

and the larger societal good help improve the firm’s competitive position (Maas & Liket, 2011; Saiia et
al., 2003). In sum, it can be argued that previous studies of corporate philanthropy have developed from
three aspects, “why give,”
“what leads to give,” and “give strategically.”
Unlike the extensive discussion on firm-level predictors, managerial perspective on corporate
philanthropy has not received much attention (e.g., how, why, and to what degree individuals, such as
CEOs, engage in corporate philanthropy). This line of inquiry is consistent with a recent study’s
(Aguinis and Glavas, 2012) observation that corporate social activities, including corporate philanthropy,
research is virtually absent from journals devoted to organizational behavior and micro-level human
resources management. Therefore, there is a need to focus more on the micro level (e.g., do
characteristics of individuals influence firms’ philanthropic engagement?) than on the macro level (e.g.
are organizational outcomes of corporate philanthropy beneficial to the firm?). In addition, there might
be some link between CEO characteristics and corporate philanthropy. Several scholars suggest that

CEOs think strategically about philanthropy to enhance brand name recognition, employee productivity,
and even to overcome regulatory obstacles (Seifert et al., 2003; Smith, 1994). Despite the growing
interest in the effect of CEO characteristics on CSR in general and philanthropy in particular, the
relationship between CEO characteristics and corporate philanthropy is under-developed and has not
received close empirical scrutiny.
Past research (e.g. Choi & Wang, 2007; Godfrey, 2005) has focused more on CEOs moral
background and characteristics, such as CEOs’ integrity and altruism, to explain a firm’s philanthropic
decisions. These studies, however, leave room for further explanation as to whether CEO characteristics
predict corporate philanthropy. This is because corporate philanthropy can be driven not only by non-
business community issues related to CEO altruism but also by business-related issues, both of which
benefit the firm’s strategic position. To fill this research gap, I draw from the upper echelon theory
(Carpenter, Geletkanycz & Sanders, 2004; Hambrick & Mason, 1984) to explore how leaders’
background characteristics might influence their firms’ engagement in corporate philanthropy. Thomas

and Simerly (1994) suggest that the demographic characteristics of CEOs (e.g., age, functional
background, and education) offer reliable proxies for visible social activities of CEOs. Pedersen and
Neergaard (2009) also suggest that managerial perceptions of corporate social activities, including
corporate philanthropy, are influenced by a great deal of heterogeneity (e.g., age, gender, education, and
functional backgrounds). In addition, it might be that founder CEOs have wide strategic options and
more power over their boards (Mousa & Wales, 2012) and such status can influence corporate
philanthropy. Despite the practical importance of the relationship between founder status and corporate
philanthropy, that relationship has not received empirical investigation.
Firm size, organizational slack, and advertising intensity have been explored as important
organizational factors that influence corporate philanthropy (Dennis et al., 2009; Seifert et al., 2003;
Wang & Qian, 2011). What scholars argue is that bigger firms with more slack resources and advertising
intensity have a positive association with corporate philanthropy. What is missing from these discussions
is firm age as an important organizational context. In other words, the relationship between firm age and

corporate philanthropy has not received much scholarly attention. For instance, Logsdon, Reiner and
Burke (1990) observed in an exploratory study that firm age might be significant in explaining
placement of corporate philanthropy. Particularly, past research has suggested that older firms tend to be
increasingly inflexible so that firm age may be an important indicator of reduced executive discretion
(Finkelstein, Hambrick & Cannella, 2009). Although the individual CEO’s influence on corporate
philanthropy might vary as a firm grows, the role of firm age on the relationship between CEO
background characteristics and corporate philanthropy has not received much attention. Therefore, it is
worth exploring this relationship.
Although corporate philanthropy has developed from a wide range of theoretical frameworks,
scholars have not yet given much thought to whether firms proactively engage in corporate philanthropy
to strengthen their business and corporate strategies. Particularly, the relationship between corporate
philanthropy and unrelated diversification is under-developed. Unrelated diversification is one of core
business strategies which help firms expand new markets. For example, when firms pursue unrelated

diversification strategies, they usually experience a wide range of varying demands from stakeholders in
distant industries or their subsidiaries (Chatterjee & Wernerfelt, 1991). Corporate philanthropy can
generate reputational assets in the new market (Hess, Rogovsky & Dunfee, 2002), strengthen marketing
and branding initiatives (Lii & Lee, 2012; Ricks Jr, 2005), and improve relations with local governments
(Wang & Qian, 2011). From this phenomenon, it can be suggested that firms can consider philanthropic
activities as part of long- term competitiveness and a means to strategically open new markets.
In addition, it is likely that the pressure for engaging in corporate philanthropy would increase
among international firms with business activities across countries and culture. Deresky (1997) suggests
that the philanthropic activities of multinational corporations that operate in foreign countries may be
characterized as strategic, clearly targeted, and linked to the overall objectives of the firm. In addition,
when firms expand their businesses in a foreign market
(Sharfman, Shaft & Tihanyi, 2004), they experience a wide range of stakeholder’ pressures.

Corporate philanthropy can be used as a means of reducing these challenges. Despite the importance of
corporate philanthropy on a firm’s internationalization, there is a lack of theoretical explanation and
empirical evidence as to whether corporate philanthropy advances a firm’s internationalization strategy.
Similarly, expansive global strategic posture (in terms of geographic market diversification) can help
firms leverage R&D costs and knowledge across countries (Carpenter & Fredrickson, 2001; Kim &
Mauborgne, 1991). It has been suggested that corporate philanthropy may be an opportunity for
internationally operating firms, but also for investing in legitimacy in a region considered to be the main
emerging market for the country (Bohnsack, 2012; Whiteman, Muller, Van der Voort, Wijk, Meijs, &
Pique, 2005). It is reasonable to expect that firms are encouraged to engage in corporate philanthropy to
develop a commanding international presence. In sum, I explore how CEOs’ background characteristics
predict the degree of firms’ engagement in corporate philanthropy and the complimentary theoretical
relationship between corporate philanthropy and a firm’s diversification profile (such as unrelated
diversification and global strategic posture).

1.4 Purpose of the Study & Research Questions
In this dissertation, I examine the effect of CEOs’ background characteristics on corporate
philanthropy and firm diversification profile. More specifically, I examine the relationships between
CEOs’ background characteristics and corporate philanthropy. In doing so, I focus on four aspects of
CEO background characteristics (i.e. CEO founder status, functional background, civic engagement, and
education) and examine whether they are associated with the degree of firms engagement in corporate
philanthropy.
First, what is the relationship between CEO founder status and corporate philanthropy?
Founder CEOs are likely to hold a psychological bond with their firms (Peterson, Galvin &
Lange, 2012). Founder CEOs’ intrinsic motivation could lead them to engage in socially responsible
activities that meet various stakeholder demands, such as corporate philanthropy. Second, what is the
relationship between CEO functional background and corporate philanthropy? Corporate social
performance can be a reflection of CEO functional background

(Melo, 2012). Thus, it might be anticipated that a certain aspect of a CEO’s past work experience in jobs
within functional areas of organizations can influence corporate philanthropy. Third, what is the
relationship between CEO civic engagement and corporate philanthropy? CEOs often serve as active
members in community groups or associations and they participate in civic affairs as part of their
strategic mission. Doing so can be motivated by a desire to create the local community development and
a more stable political environment that ensures their business profitability. Fourth, what is the
relationship between CEO education and corporate philanthropy? Bennett (2012) argues that better
educated people have wider mental horizons that cause individuals to recognize the value of charities
concerned with the external environment. Therefore, it is expected that CEOs’ education can play an
important role in determining the choice and emphasis on corporate philanthropy. In addition, I examine
the moderating role of firm age on the relationship between CEO background characteristics and
corporate philanthropy. Although older firms would be expected to be more well-known and have

greater philanthropic engagement, it is reasonably expected that a CEO’s influence on corporate
philanthropy varies as a firm grows.
Furthermore, I examine the role of corporate diversification profile on corporate philanthropy
and firm performance. Past research suggests that firms increase philanthropic expenditures strategically
as a means to open new markets where they are not familiar with and the pressures for engaging in
corporate philanthropy increase among international firms (Merz,
Peloza & Chen, 2010). Specifically, I examine a firm’s diversification strategy as the mechanism
through which corporate philanthropy influences firm performance. Since the ultimate goal of a firm’s
social activities, including corporate philanthropy, is to maximize performance, it is worth exploring the
interaction, including corporate philanthropy – firm performance relationship through the mechanism of
corporate diversification profile.

In sum, there are four major under-developed research areas in the literature that will be
explored in this dissertation. First, there is a need to examine the relationship between CEO background
characteristics and corporate philanthropy. Second, the role of firm age on the relationship between CEO
background characteristics and corporate philanthropy should receive much attention. Third, whether
firms proactively engage in corporate philanthropy to strengthen their unrelated diversification strategies
should receive an empirical investigation. Fourth, the relationship between corporate philanthropy and
firm performance needs to be examined particularly under corporate diversification profile (e.g. how
corporate philanthropy influences firm performance through unrelated diversification and global
strategic posture). I intend to answer the following three research questions:
1) Do CEO background characteristics influence the level of corporate philanthropy? If so, why?
2) Does firm age moderate the relationships between CEO background characteristics and the level
of corporate philanthropy?

3) Does corporate diversification profile mediate the relationship between the level of corporate
philanthropy and firm performance?
1.5 Significance & Contributions of the Dissertation
1.5.1 Contributions to Corporate Philanthropy Research
In this dissertation, I offer several contributions for research. First, this dissertation contributes to
the growing scholarly interests in terms of CEOs’ influence on corporate philanthropy. It has been
suggested that CEOs are requiring greater strategic accountability in corporate giving programs (Saiia et
al, 2003) and that corporations undertake strategic philanthropy as long as direct economic benefits can
be gained by doing so (Sánchez, 2000). Therefore, an examination of whether CEO background
characteristics influence corporate philanthropy helps to fulfill research interests.
Second, I extend the literature on corporate philanthropy to examine the strategic use of
philanthropy. It has been suggested that traditional altruistic models of philanthropy are becoming less
relevant because it is generally considered a non-strategic explanation of corporate giving which ignores

the profit maximization goal and other strategic goals of the firm (Neiheisel, 1994; Sánchez, 2000).
Corporate giving activities have evolved into far more strategically market-oriented approaches like
targeted grants intended to optimize economic return as well as social returns per philanthropic dollar
(Sherblom, 2007).
Third, drawing upon the institutional and stakeholder perspectives, I offer a new attempt to
empirically examine the link between corporate philanthropy and unrelated diversification. For example,
faced with various challenges (e.g., social, legal, and regulatory), corporate diversification increases a
variety of stakeholder pressures in the firm’s external environment that arise (Brammer, Millington &
Pavelin, 2006; Sharfman et al., 2004). In addition, highly diversified firms not only suffer from a lack of
coherence in terms of underlying resources
(Montgomery & Wernerfelt, 1988) but they also have to deal with heavy stakeholder demands.
These pressures might be mitigated when engaging in corporate social activities through which unrelated
diversifiers can manage a wide range of stakeholders’ demands.

Fourth, although previous studies (Markides & Williamson, 1994; Palepu, 1985; Rumelt, 1974)
suggest a negative relationship between unrelated diversification and (short-term) financial performance,
this dissertation provides a different perspective to corporate diversification strategy. For example,
corporate philanthropy helps to generate reputation and branding initiatives in the new markets so that it
can improve the firm’s market positions (Hess et al., 2002; Ricks Jr, 2005). In this dissertation, I provide
scholars with a promising suggestion that unrelated diversification may not necessarily be an inferior
strategy for the firm.
1.5.2 Contributions to Practice
In this dissertation, I offer several contributions for practice. First, understanding of how CEO
background characteristics (e.g., CEO status, functional background, civic engagement, and education
level) can be applied to corporate philanthropy helps to explain the rationale behind decisions to engage
in corporate philanthropy. Therefore, I answer what leads CEOs to engage in corporate philanthropy and
further why some CEOs engage in more corporate philanthropy than others. Second, I provide managers

with practicability of corporate philanthropy. For example, strategic use of philanthropic expenditures
can support a community project in developing countries (Porter & Kramer, 2002; Sánchez, 2000)
because better community conditions are good for business (e.g., when the standard of living is
increased, product demand is increased).
Third, I provide managers with a promising notion that engaging in corporate philanthropy can
help firms with diversification and market entry strategies. Scholars argue that a firm’s philanthropic
engagement in developing countries can enhance the firm’s reputation and get easier access to the
market (Bohnsack, 2012; Brammer et al., 2006). There might be a positive relationship between
corporate philanthropy and international presence. In addition, it is suggested that corporate
philanthropy can offer an opportunity for internationally operating firms as well as for investing in
business legitimacy. In this dissertation, I can provide managers with practicability that international
firms can strengthen their competitive context by engaging in corporate philanthropy. Fourth, I provide
insights on business legitimacy by suggesting that firms are seen as legitimate actors by local

stakeholders to the extent they engage in corporate philanthropy. Goyal (2006) and Wang and Qian
(2011) suggest that philanthropic activities of multinational firms in the host countries would be a
signaling device to demonstrate that they have long-term intentions consistent with the local
expectations. Thus, I suggest that firms can receive supportive responses from the host countries
governments by engaging in corporate philanthropy.
1.6 Definition of Key Terms
Corporate social responsibility (CSR) refers to “context-specific organizational actions and
policies that take into account stakeholders’ expectations and the triple bottom line of economic, social,
and environmental performance” (Aguinis, 2011, p. 855).
Diversification refers to “the entry of a firm or business unit into new lines of activity, either by
processes of internal business development or acquisition, which entail changes in its administrative
structure, systems, and other management processes” (Ramanujam &

Varadarajan, 1989, p. 525). There are two types of diversification, such as related diversification and
unrelated diversification. Related diversification refers to a diversification built around a core
organizational capability (Ramanujam, 1987; Rumelt, 1982). It occurs when firms expand their areas
closely related to their primary activities and areas of technical expertise. Unrelated diversification refers
to a diversification that drives to move into unrelated lines of business (Ramanujam, 1987; Rumelt,
1982). It occurs where firms expand their operations into markets or products beyond current resources
and capabilities.
Corporate philanthropy refers to the practice of “giving firm resources to invest in business-
related issues and non-business community issues that also benefit the firm’s strategic position and,
ultimately, its bottom line” (Saiia et al., 2003, p. 170). This definition helps to explain why some firms
still donate in non-business areas more than others. They do so because they believe that giving non-
business issues would enhance their public image which can be used for gaining business legitimacy in
developing countries (Wang & Qian, 2011).

Global strategic posture (GSP) refers to “the degree to which a firm is dependent on foreign
sales and production and to the geographic dispersion of this dependence” (Carpenter, Sanders &
Gregersen, 2001, p. 497). It has been suggested that GSP reflects the relative significance of foreign
markets and operations in sustaining the firm as well as their geographic dispersion (Sullivan, 1994).
Therefore, GSP can be used for measuring firm internationalization (Carpenter & Fredrickson, 2001;
Levy, 2005). GSP are normally measured by three dimension originally developed by Sullivan (1994):
foreign sales, foreign production, and geographic diversity. Foreign sales reflect the relative significance
of foreign market. Foreign production reflects the degree to which a firm depends on foreign-owned
assets and resources. Geographic diversity reflects the extent to which a firm has subsidiaries associated
with globalization of operations and markets. Several scholars used GSP to explain a firm’s
internationalization strategy (Carpenter et al., 2001; Carpenter & Fredrickson, 2001; Levy, 2005).

1.7 Organization of the Dissertation
This dissertation consists of six chapters. The first chapter provides an introduction about the
importance of corporate philanthropy, statement of the problem, major research questions as well as the
contributions of the dissertation. Chapter two presents a comprehensive and extensive review of the
literature on corporate social responsibility and the antecedents and consequences of corporate
philanthropy with the role of leadership in corporate philanthropy. Chapter three presents the research
model, theoretical foundations, and summary of theoretically-driven hypotheses. Chapter four presents
the research design including target sample, measures, as well as statistical techniques. Chapter five
presents and highlights the results of statistical analyses, including summary of findings and summary of
hypotheses. Chapter six discusses the results from Chapter five, the implications to research and
practice, limitations, future research directions, and conclusion.

CHAPTER II
LITERATURE REVIEW
This chapter provides a comprehensive review of the corporate philanthropy research.
The first section begins with a systematic review of the literature on the relationship between Corporate
Social Responsibility (CSR) and firm performance as well as the leadership determinants of CSR. In the
second section, I discuss the theoretical conceptualizations of corporate philanthropy with a comparative
review of the traditional and strategic philanthropy literatures. In the third section, I discuss the
managerial, organizational and industry level antecedents and consequences of corporate philanthropy
with a particular emphasis on the link between leadership attributes and corporate philanthropy. In the
fourth section, I present a comprehensive review of research on the link between corporate philanthropy
and corporate strategy. The chapter then concludes with a contingency view of corporate philanthropy.
2.1 How Does Corporate Social Responsibility (CSR) Influence Firm Performance?

CSR refers to “context-specific organizational actions and policies that take into account
stakeholders’ expectations and the triple bottom line of economic, social, and environmental
performance” (Aguinis, 2011, p. 855). Specifically, the demand for business CSR initiatives has been
significantly higher around the world over the last several decades. Accordingly, firms nowadays are
expected to act more proactively to fulfill their CSR expectations as responsible corporate citizens to the
society (Wang & Hsu, 2011). Since engaging in CSR is considered a socially responsible investment for
the firm, how CSR influences firm performance has been an important issue among organizational
scholars (Agle, Mitchell & Sonnenfeld, 1999; Aguinis & Glavas, 2012; Orlitzky, Schmidt & Rynes,
2003). Even though there are some debates as to whether CSR helps to improve firm performance, an
extensive line of research has empirically explored how CSR boosts firms’ competitive advantage,
thereby ensuring value creation and satisfaction for stockholders and customers (Cox, Brammer &
Millington, 2004; Lev, Petrovits & Radhakrishnan, 2010).

The topic of whether CSR can have a positive effect on firm performance has generated
extensive discussions among scholars and practitioners. Friedman (1970) provides the classical
economic perspective that management has one responsibility and that is to maximize the profits of its
shareholders. Past research suggests that socially responsive firms incur higher direct costs and reap
lower profits than socially unresponsive firms (Aupperle, Carroll & Hatfield; 1985;
Devinney, 2009). In addition, some scholars have used agency theory that “good social performance
comes at the expense of good financial performance because social performance makes use of firm
resources in ways that confers significant managerial benefits rather than returning those resources to
shareholders” (Brammer & Millington, 2008, p. 1329). They argued that firms would better spend their
resources on value-added internal projects or return to shareholders rather than invest in CSR. Despite
these perspectives, there has been a growing institutional and societal pressure on businesses to pursue a
socially responsible operation for the last couple of decades and a number of institutional approaches
can explain this trend. Jones (1995) suggests that firms facing repeated transactions with stakeholders

based on trust and cooperation are encouraged to be honest, trustworthy, and ethical because they
believe that the returns to such behavior are high. In addition, a majority of empirical evidence suggests
a significant positive relationship between CSR and financial performance (Aguinis & Glavas, 2012;
Peloza, 2009). For example, Peloza (2009) reviewed 128 studies that explored the relationship between
CSR and financial outcomes and found that, almost 60 % showed a positive relationship, less than 15 %
a negative relationship and mixed findings from the rest of the studies. Recently, Aguinis and Glavas
(2012) summarized the overall empirical evidence on CSR-performance relationship in a wide range of
organizational fields as follows (p. 947):
“Working for socially responsible companies leads to increased organizational identification
(Carmeli, Gilat, & Waldman, 2007), employee engagement (Glavas
& Piderit, 2009), retention (Jones, 2010), organizational citizenship behavior (Lin,

Lyau, Tsai, Chen, & Chiu, 2010), employee commitment (Maignan, Ferrell & Hult, 1999),
employee creative involvement (Glavas & Piderit, 2009), and improved employee
relations (Glavas & Piderit, 2009).”
In the 21th century, the influence of CSR on a firm performance is an important concern to a
firm’s stakeholders so that firms should consider CSR as part of their strategies (Lantos, 2001). Given
the ultimate responsibility of firms meets the needs of stakeholders, firms should fulfil stakeholders’
demands while also devoting resources to CSR. Such seemingly contrasting demands are leading more
firms to embrace strategic CSR or strategic use of philanthropy. Carroll (2001), for instance, argues that
strategic CSR can accomplish strategic business goals, including good deeds, are believed to be good for
business as well as for society. Several scholars have discussed strategic aspects of CSR. Porter and
Kramer (2006) argue that CSR should be seen as one of core business strategies in a firm, indicating that
the firm can benefit from its social investment. Maignan et al. (2005) also argue that CSR can serve as

an attractive, valuable resource offering competitive advantage for enhancing business performance
because it can be used as a means of conducting business strategies.
2.1.1 What Role Do Organizational Leaders Play in Fostering CSR?
In an attempt to link organizational leaders (e.g., CEOs) to CSR, scholars have focused on three
aspects of CEO background characteristics: values, compensation levels, and personal attributes
(experiences). For example, CEO integrity can be relevant to CSR such that leader vision and integrity
will increase CSR values to shareholders. Waldman and Siegel (2008) argue that leader integrity to
personal morality can yield positive outcomes for business and may actually be the driver of CSR
strategies in organizations. Ketola (2006) also argues that leader integrity is an important component in
his or her successful promotion of CSR activities at the firm. In addition, the relationship between CEO
compensation and CSR has received some attention. For instance, McGuire, Dow and Argheyd (2003)
empirically examined the relationship between the level of CEO compensation and corporate social
performance (CSP) but they did not find any positive relation. However, Jiraporn and Chintrakarn

(2013) using a sample of 1,370 firms found that when the CEO power (as measured by the total
compensation) goes beyond a certain threshold, more powerful CEOs significantly reduce CSR
investments. Furthermore, several scholars examined the professional background of CEOs and
corporate social performance (Mazutis, 2014; Simerly, 2003; Thomas & Simerly, 1994). They found that
corporate social performance can be interpreted as a reflection of CEOs’ professional background.
Do organizational leaders play a role in promoting CSR? This question has long attracted
extensive research (Fabrizi, Mallin & Michelon, 2014; Jiraporn & Chintrakarn, 2013). As senior leaders,
CEOs and their top management teams are charged with the responsibility of formulating business and
sustainability strategy (Strand, 2013; Wood, 1991). Indeed, today’s corporate leaders play an important
role in pursuing an effective CSR agenda (Bielak, Bonini &
Oppenheim, 2007; Fabrizi et al., 2014;Godos-Díez, Fernández-Gago & Martínez-Campillo, 2011;
Mazutis, 2014). For example, CEOs engage in CSR related activities in response to growing pressures
from key stakeholders groups, such as customers and employees (Bielak et al., 2007). In addition, while

pressures from employees, customers, and other stakeholders can play a crucial role in CEOs’
willingness to engage in CSR, CEOs recognize that CSR can give their firms an opportunity to gain a
competitive advantage as well as address societal needs (Bielak et al., 2007). In addition, Godos-Díez et
al. (2011) using a sample of 149 CEOs found that those closer to the steward model are more inclined to
attach great importance to ethics and CSR, and to implement CSR practices. Fabrizi et al (2014) using a
sample of 597 U.S. firms extended the role of CEO’s incentives on CSR and found that non-monetary
incentives have a positive effect on CSR. Mazutis (2014) using a sample of 349 firms found the link
between CEO open executive orientation (such as a liberal worldview and output functional
experiences) and positive CSR initiative adoption over time. In this sense, it can be argued that the
relationship between leadership and CSR has become an important topic of research in the area of
leadership studies (Bielak et al., 2007; Godos-Díez et al., 2011; Fabrizi et al., 2014; Mazutis, 2014).
Transformational leadership helps represent the understanding of CSR in particular.
Transformational leadership is comprised of four major components (Avolio, Bass & Jung, 1999;

Bass & Riggio, 2006): (1) Idealized Influence (ability of leader to attract admiration and respect and
desire to follow from subordinates), (2) Inspirational Motivation (ability of leader to communicate clear
vision and create enthusiasm about future), (3) Intellectual Stimulation (ability of leader to encourage
creativity and unconventional and status quo-challenging problem-solving among followers), and (4)
Individual Consideration (ability of leader to accept individual differences and actively provide feedback
and interaction with followers).
Organizational scholars argue that transformational leadership has been found to influence CSR
behavior among some firms (Du, Swaen, Lindgreen & Senthat, 2013; McWilliams, Siegel & Wright,
2006).
McWilliams et al (2006), for instance, suggest that strategic leadership theory can be applied to
CSR and that transformational leadership will be positively correlated with the tendency of companies to
engage in CSR. They explored the degree of transformational leadership using CEOs of 112 large US
and Canadian firms and found that intellectual stimulation (which is one dimension of transformational

leadership components) was a predictor of the firm’s propensity to engage in strategically oriented CSR
that were more likely to be related to the firm’s corporate and business-level strategies (e.g.,
differentiation and reputation building). In addition, Du et al. (2013) in a survey of 440 U.S firms found
that firms with greater transformational leadership are more likely to engage in institutional CSR
practices, whereas transactional leadership is not associated with such practices. Furthermore, it has been
suggested that charismatic leadership with self-concepts of followers can be related to CSR. For
example, leaders have values and moral justifications which provide followers with motivational effects
such that charismatic leaders can help connect one’s identify with greater social causes (Shamir, House
& Arthur, 1993).
In conclusion, the empirical evidence on the relationship between CSR and firm performance
seems to be inconclusive (Peloza, 2009). However, more recent studies suggest that there is a positive
association between CSR and firm performance (Aguinis & Glavas, 2012; Chen & Wang, 2015). In
addition, since some firms consider CSR as part of their core corporate strategy and CEOs are

chargewith the responsibility of formulating corporate strategy, the relationship between leadership
characteristics and CSR is particularly important. Furthermore, it can be suggested that understanding of
three aspects of CEOs (values, compensation, and experiences) helps to link CEO background
characteristics and CSR. As mentioned in section 2.1.1, there is a certain interrelationship between
CEOs and CSR. Table 1 below provides an

2.2 Conceptualization of Corporate Philanthropy as a Dimension of CSR
Corporate philanthropy has traditionally focused on how a firm would voluntary allocate
its slack resources to charitable or social causes that are not typically business-related (Carroll,
1991; Wartick, Wood & Czinkota, 1998). Friedman (1970, p. 8) points out the problem of
corporate giving for the following statement and argues, “Firms operate under a moral mandate
to make as much money for the stakeholders as they can in order to solve problems that the
corporation did not cause.” He treats corporate giving as a waste of corporate resources. In
addition, several scholars have suggested that traditional philanthropic activities may not
purposely align with the strategic goals and resources of the organization (Marx, 1998, 1999;
McAlister & Ferrell, 2002). Notably, the traditional ways of corporate philanthropy have since
early 1990s shifted more dominantly towards strategically motivated giving, called strategic
philanthropy. For example, firms having a strong sense of CSR are turning away from traditional
giving and toward a more market-driven, strategic, and bottom-line approach to philanthropy
(Saiia et al., 2003). Given this phenomenon, there is a need to conceptualize corporate
philanthropy in a way that distinguishes traditional philanthropy from the strategic kind. In doing
so, I will focus on two areas. First, how was philanthropy viewed by businesses historically?
Second, how has this traditional view changed over time and become an integral part of business
operation – strategic philanthropy? Third, what are the benefits of corporate philanthropy?
Traditional philanthropy is different from strategic philanthropy in two ways. First,
traditional philanthropy is generally considered a non-strategic explanation of corporate giving
(Sharfman, 1994). It has the singular goal of helping others that may not be linked to corporate
interests so that it is considered independent from the operating pressures of generating profit
(Sánchez, 2000). On the other hand, strategic philanthropy involves the close alignment of

CSR as a business practice and philosophy has taken an important place in the way
businesses operate and serve their stakeholders. CSR refers to “context-specific organizational
actions and policies that take into account stakeholders’ expectations and the triple bottom line of
economic, social, and environmental performance” (Aguinis, 2011, p. 855). This definition
indicates that businesses should have responsibility beyond their immediate economic concern
and should act in a way that contributes and enhances broader societal goals. CSR primarily
embraces economic, legal, ethical, and philanthropic responsibilities and the dimensions of CSR
include the obligations a business has to its stakeholder’s groups (Carroll, 1991). Over the past
half century, CSR has increasingly been integrated into mainstream business thinking, and
nowadays, most U.S. publicly-traded firms (e.g., Microsoft, Google, and Walt Disney) claim to
engage in some form of CSR. The main benefits of engaging in CSR include generating
intangible assets, including building corporate reputation and employee commitment, and
tangible assets, including the positive impact on financial performance. Research in this area
suggests that being a socially responsible business helps create goodwill, build a positive
organizational image, differentiate them from their competitors, and, as a result, promote
longterm profits for business (Boynton, 2013). Indeed, more firms increasingly embrace CSR as
their employees demand their firms to be socially responsible, customers expect better business
practices, and investors realize the economic rewards of sustainable business models. Beyond the
immediate task environment, business CSR engagement also serves the needs of communities
around the world and fulfills the responsibilities businesses have to the public.
1.2 The Importance of Corporate Philanthropy
Corporate philanthropy is considered one of the core dimensions of CSR (Aguinis &

Clavas, 2012; Carroll, 1991; Porter & Kramer, 2002). The origin of corporate philanthropy in the
U.S. dates back to the rise of industrial age in the 19th and early 20th century, when businessmen
like Henry Ford and John D. Rockefeller established philanthropic foundations (Dietlin, 2011).
Corporate philanthropy has since been transformed from piecemeal individual philanthropic acts
(e.g., philanthropy mainly driven by morality) to a major aspect of corporate CSR practices.
Corporate philanthropy is, nowadays, a widespread business practice in large multinationals as
well as small-and medium-sized firms across the globe. Despite the dominant altruistic
orientation, corporate philanthropy has increasingly complemented the firm’s strategic activities
and enhanced the firm’s social and financial performance (Porter & Kramer, 2002). Therefore, it
can be argued that corporate philanthropy has evolved dramatically from a basic moral obligation
to a strategically-driven activity of the firm. As Porter and Kramer (2002, p. 58) put it,
“True strategic giving, by hand, addresses important social and economic goals simultaneously,
targeting areas of competitive context where the company and society both benefit because the
firm brings unique assets and expertise.”
Corporate philanthropy can often be “the most cost-effective way for a firm to improve its
competitive context” (Porter & Kramer, 2002, p. 9). Many firms invest a significant amount of
resource expenditures on philanthropy in order to build a strong company image. For example, a
2013 report from the Committee Encouraging Corporate Philanthropy indicates that 59 percent
of the largest Fortune 100 firms donated significantly more in 2012 compared to 2007, the year
before the global recession sets in, and aggregate giving rose by 42% ($4.48 billion) from 2007
to 2012. The ten largest U.S. corporations donated over 2.1 billion dollars in 2013 and this figure
has increased in 2014. Many firms provide support to nonprofits and social causes primarily
through company-sponsored foundations as well as corporate direct giving, both of which are

closely tied with the parent company’s business interests. As shown in Figure 1 below, the largest
U.S. firms and their foundations have increased charitable giving during the past decade (2001-
2012). Similarly, as shown in Figure 2 below, the largest 100 U.S. corporations have increased
total charitable giving both as a percentage of pre-tax profit and as a percentage of revenue
especially after the global recession in 2008.
Indeed, the increasing commitment of corporate resources to philanthropic causes reflects
a widely-held belief among business executives that philanthropy can be “strategic” in that it can
make a substantial impact on society while improving business value and reputation for the firm
(Carroll & Shabana, 2010; Walker, 2002). According to a 2010 survey by CECP, 77 percent of
CEOs noted that “the most important action they can take to prepare for 2020 is to embed social
engagement into business strategy and organizational structure.” For example, Ronald A.
Williams, the CEO of Aetna noted that that “public companies can move the collective needle by
using their human and financial resources to innovative in ways that benefit both private interests
and the public good” (Weiss, Kerdahy & Kneale, 2008, p. 5). Ivan Seidenberg, Chairman and
CEO, Verizon Communications Inc., commented in CECP that “our belief is that corporate
philanthropy expands the business. You can expand the capabilities of your customer base,
business and society by doing the right thing.” These and other executive views also highlight an
important fact that corporate philanthropy can be driven by leadership values and studying
leaders’ background can help extend our knowledge of the role of corporate philanthropy in
improving firm performance.
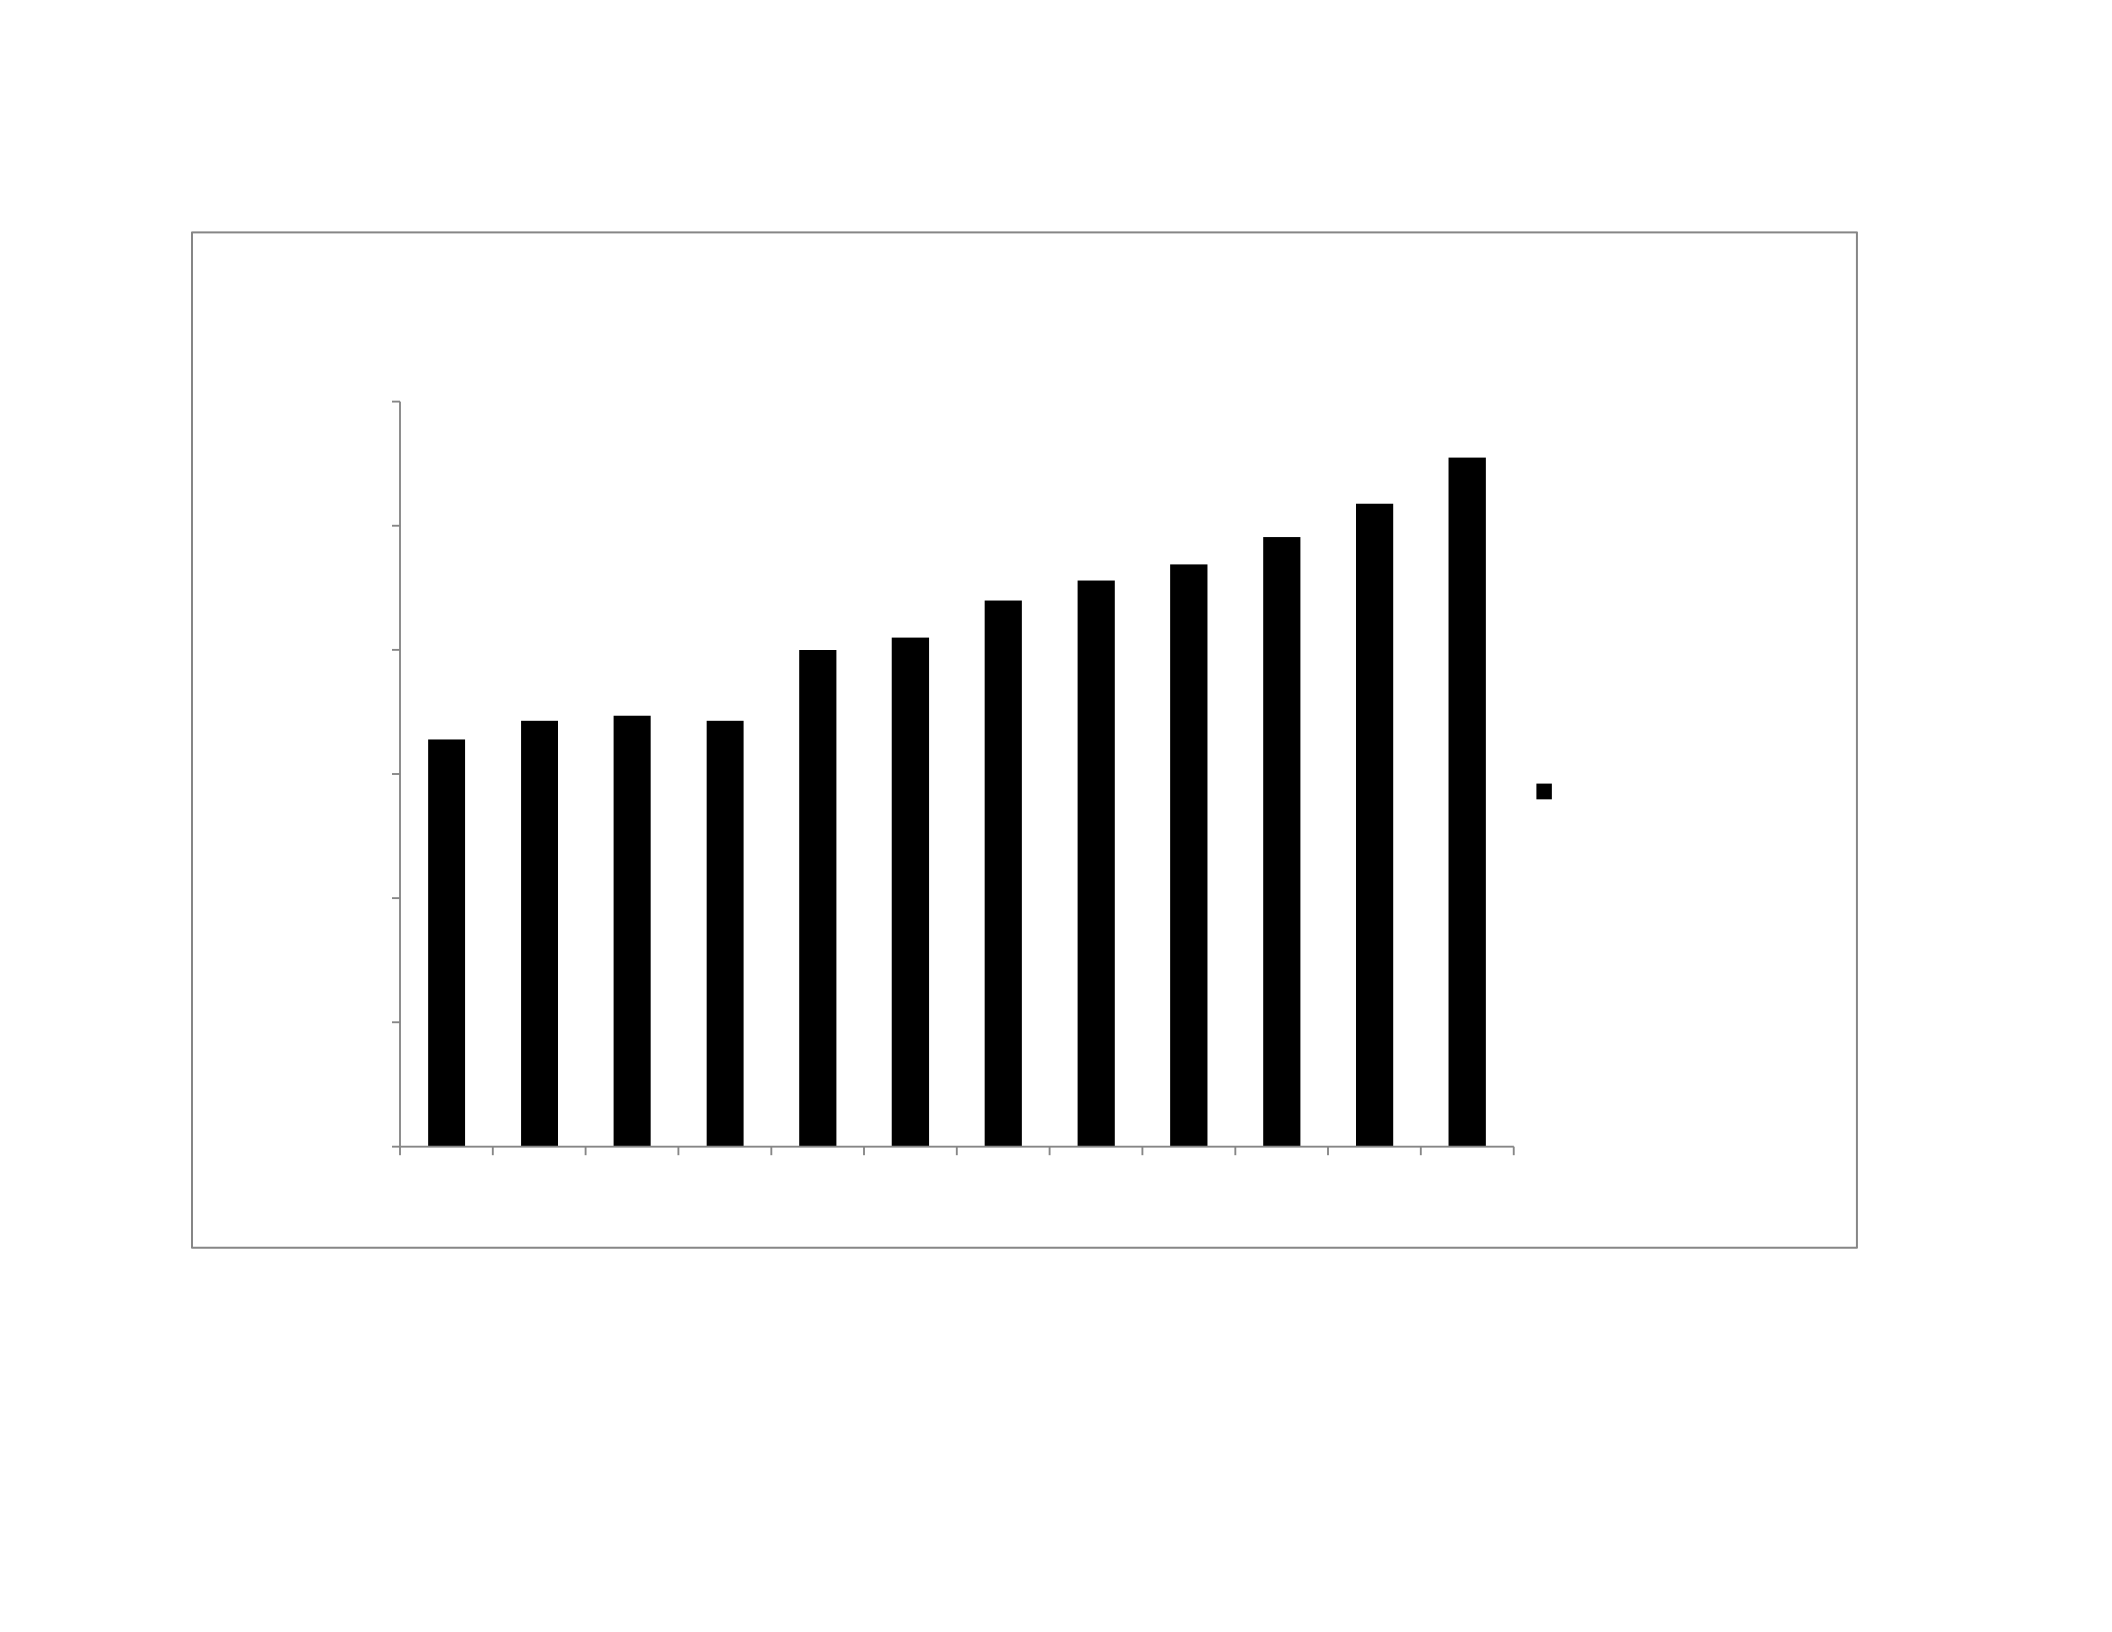
Figure 1. U.S. Corporate Foundation Philanthropic Giving from 2001 to 2012 (2,629 Corporate Foundations)
Source: The Foundation Center as of January 27, 2015
3.28 3.43 3.47 3.43
4 4.1
4.4 4.56 4.69
4.91
5.18
5.55
0
1
2
3
4
5
6
2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012
Billion$
Total charitable giving
5
Figure 2. Total Charitable Giving among Fortune 100 Firms between 2004 and 2012
Source: Committee Encouraging Corporate Philanthropy as of January 27, 2015
1.3
0.79 0.76
0.83
1.34
1.13
0.96 0.92 0.96
0.16 0.14 0.1 0.1 0.1 0.09 0.09 0.08 0.09
0
0.2
0.4
0.6
0.8
1
1.2
1.4
1.6
2004 2005 2006 2007 2008 2009 2010 2011 2012
Total charitable
giving as a % of
pre-tax profit
Total charitable
giving as a % of
revenue
Million$

6

Despite the stated purpose of enhancing a firm’s public visibility and reputation by
engaging in corporate philanthropy, firms face some criticisms from stakeholders on the tangible
benefits of philanthropy. Some scholars (e.g. Devinney, 2009; Friedman, 1970) have supported
this skeptical perspective arguing that a firm exists primarily to generate economic returns, not to
solve societal problems. Friedman (1970, p. 6) argues that the single social responsibility of
business is to “engage in business activities designed to increase its profit.” On the contrary,
other scholars (e.g. Godfrey, 2005; Wang & Qian, 2011) have strongly supported the positive role
of corporate philanthropy in improving firm performance. These scholars argue that corporate
philanthropy can generate positive stakeholder support which in turn improves a firm’s financial
performance. In an effort to address the critics’ concerns on the use of corporate resources toward
charitable contributions, firms are increasingly turning to the strategic use of philanthropy.
Research suggests that strategic philanthropy can play a key role in developing value-creating
relationships with primary stakeholders and enhancing a company’s image (Buchholtz, Amason
& Rutherford, 1999; Saiia, Carroll & Buchholtz, 2003). Strategic philanthropy can also serve as
“a common meeting ground for the opponents and proponents of corporate philanthropy”
(Buchholtz et al., 1999, p. 169). Large firms are fundamentally responsible for strategic
philanthropy in practice because they have systematic structures (Marquis & Lee, 2013). For
example, large firms have corporate foundations, employee committees to oversee corporate
giving, and staff functions devoted to the effort to manage their social responsibilities (McAlister
& Ferrell, 2002). In marketing practice, strategic philanthropy has been often associated with
cause-related marketing to support social responsibility (File & Prince, 1998; Vanhamme,
Lindgreen, Reast & van Popering, 2012; Varadarajan & Menon,
1988). Both practices have some dissimilarities in terms of primary focus, time frame, and costs
(McAlister & Ferrell, 2002). Strategic philanthropy focuses on organizing itself, is ongoing, and

tends to require moderate to high resource commitment. On the other hand, cause-related
marketing focuses on the firm’s products, has a limited duration, and involves minimal resource
commitment. Both strategic philanthropy and cause-related marketing help enhance societal
welfare and improve the reputation of a firm. Stakeholder theory (Freeman, 1984) offers an
important theoretical support for the relationship between corporate philanthropy and firm
performance, suggesting that favorable social performance is a requirement for business
legitimacy, and tends to be positively associated with firm performance over the long term.
Donaldson and Preston (1995, p. 82) also suggest that firms respond to “ethical considerations
(e.g. engaging in philanthropy) which are often consistent with long-run increases in profit and
value.”
Importantly, the positive effect of corporate philanthropy on the firm provides a reason
why there is a need to examine the relationship between CEO characteristics and corporate
philanthropy. Since corporate philanthropy has become an important strategic tool that
organizational senior leaders manipulate, they are more involved in assessing and shaping
corporate strategies (Porter & Krammer, 2002). In addition, past research argues that a firm’s
social activities should be met by corporate goals determined by CEOs who constantly make
strategic decisions and choices (Choi & Wang, 2007; Wood, 1991). Furthermore, it has been
suggested that CEOs are the primary decision-makers of the organization such that an
examination of CEOs’ attitudes and values toward philanthropy provides needed insight into the
social responsibility actions in general and philanthropic function in particular (Dennis,
Buchholtz, & Butts, 2009). Accordingly, it can be suggested that the relationship between CEO
characteristics and corporate philanthropy should receive much attention. In the following
section, I will provide a brief discussion on the major research gaps that I seek to address in order

to advance the understanding of the leadership predictors of corporate philanthropy and the
implications for firm performance.
1.3 Statement of the Problem
Previous studies have focused on why firms engage in corporate philanthropy (Adams &
Hardwick, 1998; Brammer & Millington, 2005; Fombrun & Shanley, 1990; Godfrey, 2005;
Turban & Greening, 1997; Wang & Qian, 2011; Williams & Barrett, 2000). These studies have
shown that engagement in corporate philanthropy can lead to increased employee loyalty (e.g.,
employee commitment), favorable community image (e.g., corporate reputation), and positive
media coverage (e.g., recovering tarnished reputation). As such, it can be suggested that
consequences of corporate philanthropy have been extensively explored to answer the question,
“why should a firm give?” Meanwhile, antecedents of corporate philanthropy have been
explored to answer the question, “what drives firms to give?” The predominant discussion
among scholars has been on the managerial (e.g. Buchholtz et al., 1999; Choi & Wang, 2007;
Marquis & Lee, 2013; Wang & Coffey, 1992), organizational (Adams & Hardwick, 1998;
Brammer & Millington, 2006; Seifert, Morris & Bartkus, 2003), and industry (Amato & Amato,
2007, 2012; Useem, 1988) drivers of corporate philanthropy. Specifically, past research
suggested that firms engage in corporate philanthropy as a means to simultaneously and directly
benefit business interests and those of a beneficiary organization (Saiia et al., 2003; Marx, 1999).
The extent to which firms engage in corporate philanthropy can vary depending on
organizational factors, such as firm size, organizational slack, and advertising intensity (Dennis
et al., 2009; Saiia et al., 2003; Wang & Qian, 2011). Past research on corporate philanthropy has
generally discussed the intersection of business goals and the larger societal good help improve
the firm’s competitive position (Maas & Liket, 2011; Saiia et al., 2003). In sum, it can be argued
that previous studies of corporate philanthropy have developed from three aspects, “why give,”

“what leads to give,” and “give strategically.”
Unlike the extensive discussion on firm-level predictors, managerial perspective on
corporate philanthropy has not received much attention (e.g., how, why, and to what degree
individuals, such as CEOs, engage in corporate philanthropy). This line of inquiry is consistent
with a recent study’s (Aguinis and Glavas, 2012) observation that corporate social activities,
including corporate philanthropy, research is virtually absent from journals devoted to
organizational behavior and micro-level human resources management. Therefore, there is a need
to focus more on the micro level (e.g., do characteristics of individuals influence firms’
philanthropic engagement?) than on the macro level (e.g. are organizational outcomes of
corporate philanthropy beneficial to the firm?). In addition, there might be some link between
CEO characteristics and corporate philanthropy. Several scholars suggest that CEOs think
strategically about philanthropy to enhance brand name recognition, employee productivity, and
even to overcome regulatory obstacles (Seifert et al., 2003; Smith, 1994). Despite the growing
interest in the effect of CEO characteristics on CSR in general and philanthropy in particular, the
relationship between CEO characteristics and corporate philanthropy is under-developed and has
not received close empirical scrutiny.
Past research (e.g. Choi & Wang, 2007; Godfrey, 2005) has focused more on CEOs moral
background and characteristics, such as CEOs’ integrity and altruism, to explain a firm’s
philanthropic decisions. These studies, however, leave room for further explanation as to whether
CEO characteristics predict corporate philanthropy. This is because corporate philanthropy can
be driven not only by non-business community issues related to CEO altruism but also by
business-related issues, both of which benefit the firm’s strategic position. To fill this research
gap, I draw from the upper echelon theory (Carpenter, Geletkanycz & Sanders, 2004; Hambrick

& Mason, 1984) to explore how leaders’ background characteristics might influence their firms’
engagement in corporate philanthropy. Thomas and Simerly (1994) suggest that the demographic
characteristics of CEOs (e.g., age, functional background, and education) offer reliable proxies
for visible social activities of CEOs. Pedersen and Neergaard (2009) also suggest that managerial
perceptions of corporate social activities, including corporate philanthropy, are influenced by a
great deal of heterogeneity (e.g., age, gender, education, and functional backgrounds). In
addition, it might be that founder CEOs have wide strategic options and more power over their
boards (Mousa & Wales, 2012) and such status can influence corporate philanthropy. Despite the
practical importance of the relationship between founder status and corporate philanthropy, that
relationship has not received empirical investigation.
Firm size, organizational slack, and advertising intensity have been explored as important
organizational factors that influence corporate philanthropy (Dennis et al., 2009; Seifert et al.,
2003; Wang & Qian, 2011). What scholars argue is that bigger firms with more slack resources
and advertising intensity have a positive association with corporate philanthropy. What is missing
from these discussions is firm age as an important organizational context. In other words, the
relationship between firm age and corporate philanthropy has not received much scholarly
attention. For instance, Logsdon, Reiner and Burke (1990) observed in an exploratory study that
firm age might be significant in explaining placement of corporate philanthropy. Particularly,
past research has suggested that older firms tend to be increasingly inflexible so that firm age
may be an important indicator of reduced executive discretion (Finkelstein, Hambrick &
Cannella, 2009). Although the individual CEO’s influence on corporate philanthropy might vary
as a firm grows, the role of firm age on the relationship between CEO background characteristics
and corporate philanthropy has not received much attention. Therefore, it is worth exploring this
relationship.

Although corporate philanthropy has developed from a wide range of theoretical
frameworks, scholars have not yet given much thought to whether firms proactively engage in
corporate philanthropy to strengthen their business and corporate strategies. Particularly, the
relationship between corporate philanthropy and unrelated diversification is under-developed.
Unrelated diversification is one of core business strategies which help firms expand new markets.
For example, when firms pursue unrelated diversification strategies, they usually experience a
wide range of varying demands from stakeholders in distant industries or their subsidiaries
(Chatterjee & Wernerfelt, 1991). Corporate philanthropy can generate reputational assets in the
new market (Hess, Rogovsky & Dunfee, 2002), strengthen marketing and branding initiatives
(Lii & Lee, 2012; Ricks Jr, 2005), and improve relations with local governments (Wang & Qian,
2011). From this phenomenon, it can be suggested that firms can consider philanthropic activities
as part of long- term competitiveness and a means to strategically open new markets.
In addition, it is likely that the pressure for engaging in corporate philanthropy would
increase among international firms with business activities across countries and culture. Deresky
(1997) suggests that the philanthropic activities of multinational corporations that operate in
foreign countries may be characterized as strategic, clearly targeted, and linked to the overall
objectives of the firm. In addition, when firms expand their businesses in a foreign market
(Sharfman, Shaft & Tihanyi, 2004), they experience a wide range of stakeholder’ pressures.
Corporate philanthropy can be used as a means of reducing these challenges. Despite the
importance of corporate philanthropy on a firm’s internationalization, there is a lack of
theoretical explanation and empirical evidence as to whether corporate philanthropy advances a
firm’s internationalization strategy. Similarly, expansive global strategic posture (in terms of
geographic market diversification) can help firms leverage R&D costs and knowledge across
countries (Carpenter & Fredrickson, 2001; Kim & Mauborgne, 1991). It has been suggested that

corporate philanthropy may be an opportunity for internationally operating firms, but also for
investing in legitimacy in a region considered to be the main emerging market for the country
(Bohnsack, 2012; Whiteman, Muller, Van der Voort, Wijk, Meijs, & Pique, 2005). It is reasonable
to expect that firms are encouraged to engage in corporate philanthropy to develop a
commanding international presence. In sum, I explore how CEOs’ background characteristics
predict the degree of firms’ engagement in corporate philanthropy and the complimentary
theoretical relationship between corporate philanthropy and a firm’s diversification profile (such
as unrelated diversification and global strategic posture).
1.4 Purpose of the Study & Research Questions
In this dissertation, I examine the effect of CEOs’ background characteristics on corporate
philanthropy and firm diversification profile. More specifically, I examine the relationships
between CEOs’ background characteristics and corporate philanthropy. In doing so, I focus on
four aspects of CEO background characteristics (i.e. CEO founder status, functional background,
civic engagement, and education) and examine whether they are associated with the degree of
firms engagement in corporate philanthropy.
First, what is the relationship between CEO founder status and corporate philanthropy?
Founder CEOs are likely to hold a psychological bond with their firms (Peterson, Galvin &
Lange, 2012). Founder CEOs’ intrinsic motivation could lead them to engage in socially
responsible activities that meet various stakeholder demands, such as corporate philanthropy.
Second, what is the relationship between CEO functional background and corporate
philanthropy? Corporate social performance can be a reflection of CEO functional background
(Melo, 2012). Thus, it might be anticipated that a certain aspect of a CEO’s past work experience
in jobs within functional areas of organizations can influence corporate philanthropy. Third, what

is the relationship between CEO civic engagement and corporate philanthropy? CEOs often
serve as active members in community groups or associations and they participate in civic affairs
as part of their strategic mission. Doing so can be motivated by a desire to create the local
community development and a more stable political environment that ensures their business
profitability. Fourth, what is the relationship between CEO education and corporate
philanthropy? Bennett (2012) argues that better educated people have wider mental horizons that
cause individuals to recognize the value of charities concerned with the external environment.
Therefore, it is expected that CEOs’ education can play an important role in determining the
choice and emphasis on corporate philanthropy. In addition, I examine the moderating role of
firm age on the relationship between CEO background characteristics and corporate
philanthropy. Although older firms would be expected to be more well-known and have greater
philanthropic engagement, it is reasonably expected that a CEO’s influence on corporate
philanthropy varies as a firm grows.
Furthermore, I examine the role of corporate diversification profile on corporate
philanthropy and firm performance. Past research suggests that firms increase philanthropic
expenditures strategically as a means to open new markets where they are not familiar with and
the pressures for engaging in corporate philanthropy increase among international firms (Merz,
Peloza & Chen, 2010). Specifically, I examine a firm’s diversification strategy as the mechanism
through which corporate philanthropy influences firm performance. Since the ultimate goal of a
firm’s social activities, including corporate philanthropy, is to maximize performance, it is worth
exploring the interaction, including corporate philanthropy – firm performance relationship
through the mechanism of corporate diversification profile.

In sum, there are four major under-developed research areas in the literature that will be
explored in this dissertation. First, there is a need to examine the relationship between CEO
background characteristics and corporate philanthropy. Second, the role of firm age on the
relationship between CEO background characteristics and corporate philanthropy should receive
much attention. Third, whether firms proactively engage in corporate philanthropy to strengthen
their unrelated diversification strategies should receive an empirical investigation. Fourth, the
relationship between corporate philanthropy and firm performance needs to be examined
particularly under corporate diversification profile (e.g. how corporate philanthropy influences
firm performance through unrelated diversification and global strategic posture). I intend to
answer the following three research questions:
4) Do CEO background characteristics influence the level of corporate philanthropy? If so,
why?
5) Does firm age moderate the relationships between CEO background characteristics and
the level of corporate philanthropy?
6) Does corporate diversification profile mediate the relationship between the level of
corporate philanthropy and firm performance?
1.5 Significance & Contributions of the Dissertation
1.5.1 Contributions to Corporate Philanthropy Research
In this dissertation, I offer several contributions for research. First, this dissertation
contributes to the growing scholarly interests in terms of CEOs’ influence on corporate
philanthropy. It has been suggested that CEOs are requiring greater strategic accountability in
corporate giving programs (Saiia et al, 2003) and that corporations undertake strategic
philanthropy as long as direct economic benefits can be gained by doing so (Sánchez, 2000).

Therefore, an examination of whether CEO background characteristics influence corporate
philanthropy helps to fulfill research interests.
Second, I extend the literature on corporate philanthropy to examine the strategic use of
philanthropy. It has been suggested that traditional altruistic models of philanthropy are
becoming less relevant because it is generally considered a non-strategic explanation of corporate
giving which ignores the profit maximization goal and other strategic goals of the firm
(Neiheisel, 1994; Sánchez, 2000). Corporate giving activities have evolved into far more
strategically market-oriented approaches like targeted grants intended to optimize economic
return as well as social returns per philanthropic dollar (Sherblom, 2007).
Third, drawing upon the institutional and stakeholder perspectives, I offer a new attempt
to empirically examine the link between corporate philanthropy and unrelated diversification. For
example, faced with various challenges (e.g., social, legal, and regulatory), corporate
diversification increases a variety of stakeholder pressures in the firm’s external environment that
arise (Brammer, Millington & Pavelin, 2006; Sharfman et al., 2004). In addition, highly
diversified firms not only suffer from a lack of coherence in terms of underlying resources
(Montgomery & Wernerfelt, 1988) but they also have to deal with heavy stakeholder demands.
These pressures might be mitigated when engaging in corporate social activities through which
unrelated diversifiers can manage a wide range of stakeholders’ demands.
Fourth, although previous studies (Markides & Williamson, 1994; Palepu, 1985; Rumelt,
1974) suggest a negative relationship between unrelated diversification and (short-term) financial
performance, this dissertation provides a different perspective to corporate diversification
strategy. For example, corporate philanthropy helps to generate reputation and branding
initiatives in the new markets so that it can improve the firm’s market positions (Hess et al.,

2002; Ricks Jr, 2005). In this dissertation, I provide scholars with a promising suggestion that
unrelated diversification may not necessarily be an inferior strategy for the firm.
1.5.2 Contributions to Practice
In this dissertation, I offer several contributions for practice. First, understanding of how
CEO background characteristics (e.g., CEO status, functional background, civic engagement, and
education level) can be applied to corporate philanthropy helps to explain the rationale behind
decisions to engage in corporate philanthropy. Therefore, I answer what leads CEOs to engage in
corporate philanthropy and further why some CEOs engage in more corporate philanthropy than
others. Second, I provide managers with practicability of corporate philanthropy. For example,
strategic use of philanthropic expenditures can support a community project in developing
countries (Porter & Kramer, 2002; Sánchez, 2000) because better community conditions are
good for business (e.g., when the standard of living is increased, product demand is increased).
Third, I provide managers with a promising notion that engaging in corporate
philanthropy can help firms with diversification and market entry strategies. Scholars argue that a
firm’s philanthropic engagement in developing countries can enhance the firm’s reputation and
get easier access to the market (Bohnsack, 2012; Brammer et al., 2006). There might be a
positive relationship between corporate philanthropy and international presence. In addition, it is
suggested that corporate philanthropy can offer an opportunity for internationally operating firms
as well as for investing in business legitimacy. In this dissertation, I can provide managers with
practicability that international firms can strengthen their competitive context by engaging in
corporate philanthropy. Fourth, I provide insights on business legitimacy by suggesting that firms
are seen as legitimate actors by local stakeholders to the extent they engage in corporate
philanthropy. Goyal (2006) and Wang and Qian (2011) suggest that philanthropic activities of

multinational firms in the host countries would be a signaling device to demonstrate that they
have long-term intentions consistent with the local expectations. Thus, I suggest that firms can
receive supportive responses from the host countries governments by engaging in corporate
philanthropy.
1.6 Definition of Key Terms
Corporate social responsibility (CSR) refers to “context-specific organizational actions
and policies that take into account stakeholders’ expectations and the triple bottom line of
economic, social, and environmental performance” (Aguinis, 2011, p. 855).
Diversification refers to “the entry of a firm or business unit into new lines of activity,
either by processes of internal business development or acquisition, which entail changes in its
administrative structure, systems, and other management processes” (Ramanujam &
Varadarajan, 1989, p. 525). There are two types of diversification, such as related diversification
and unrelated diversification. Related diversification refers to a diversification built around a
core organizational capability (Ramanujam, 1987; Rumelt, 1982). It occurs when firms expand
their areas closely related to their primary activities and areas of technical expertise. Unrelated
diversification refers to a diversification that drives to move into unrelated lines of business
(Ramanujam, 1987; Rumelt, 1982). It occurs where firms expand their operations into markets or
products beyond current resources and capabilities.
Corporate philanthropy refers to the practice of “giving firm resources to invest in
business-related issues and non-business community issues that also benefit the firm’s strategic
position and, ultimately, its bottom line” (Saiia et al., 2003, p. 170). This definition helps to
explain why some firms still donate in non-business areas more than others. They do so because

they believe that giving non-business issues would enhance their public image which can be used
for gaining business legitimacy in developing countries (Wang & Qian, 2011).
Global strategic posture (GSP) refers to “the degree to which a firm is dependent on
foreign sales and production and to the geographic dispersion of this dependence” (Carpenter,
Sanders & Gregersen, 2001, p. 497). It has been suggested that GSP reflects the relative
significance of foreign markets and operations in sustaining the firm as well as their geographic
dispersion (Sullivan, 1994). Therefore, GSP can be used for measuring firm internationalization
(Carpenter & Fredrickson, 2001; Levy, 2005). GSP are normally measured by three dimension
originally developed by Sullivan (1994): foreign sales, foreign production, and geographic
diversity. Foreign sales reflect the relative significance of foreign market. Foreign production
reflects the degree to which a firm depends on foreign-owned assets and resources. Geographic
diversity reflects the extent to which a firm has subsidiaries associated with globalization of
operations and markets. Several scholars used GSP to explain a firm’s internationalization
strategy (Carpenter et al., 2001; Carpenter & Fredrickson, 2001; Levy, 2005).
1.7 Organization of the Dissertation
This dissertation consists of six chapters. The first chapter provides an introduction about
the importance of corporate philanthropy, statement of the problem, major research questions as
well as the contributions of the dissertation. Chapter two presents a comprehensive and extensive
review of the literature on corporate social responsibility and the antecedents and consequences
of corporate philanthropy with the role of leadership in corporate philanthropy. Chapter three
presents the research model, theoretical foundations, and summary of theoretically-driven
hypotheses. Chapter four presents the research design including target sample, measures, as well
as statistical techniques. Chapter five presents and highlights the results of statistical analyses,

including summary of findings and summary of hypotheses. Chapter six discusses the results
from Chapter five, the implications to research and practice, limitations, future research
directions, and conclusion.

CHAPTER II
LITERATURE REVIEW
This chapter provides a comprehensive review of the corporate philanthropy research.
The first section begins with a systematic review of the literature on the relationship between
Corporate Social Responsibility (CSR) and firm performance as well as the leadership
determinants of CSR. In the second section, I discuss the theoretical conceptualizations of
corporate philanthropy with a comparative review of the traditional and strategic philanthropy
literatures. In the third section, I discuss the managerial, organizational and industry level
antecedents and consequences of corporate philanthropy with a particular emphasis on the link
between leadership attributes and corporate philanthropy. In the fourth section, I present a
comprehensive review of research on the link between corporate philanthropy and corporate
strategy. The chapter then concludes with a contingency view of corporate philanthropy.
2.1 How Does Corporate Social Responsibility (CSR) Influence Firm Performance?
CSR refers to “context-specific organizational actions and policies that take into account
stakeholders’ expectations and the triple bottom line of economic, social, and environmental
performance” (Aguinis, 2011, p. 855). Specifically, the demand for business CSR initiatives has
been significantly higher around the world over the last several decades. Accordingly, firms
nowadays are expected to act more proactively to fulfill their CSR expectations as responsible
corporate citizens to the society (Wang & Hsu, 2011). Since engaging in CSR is considered a
socially responsible investment for the firm, how CSR influences firm performance has been an
important issue among organizational scholars (Agle, Mitchell & Sonnenfeld, 1999; Aguinis &
Glavas, 2012; Orlitzky, Schmidt & Rynes, 2003). Even though there are some debates as to
whether CSR helps to improve firm performance, an extensive line of research has empirically

explored how CSR boosts firms’ competitive advantage, thereby ensuring value creation and
satisfaction for stockholders and customers (Cox, Brammer & Millington, 2004; Lev, Petrovits &
Radhakrishnan, 2010).
The topic of whether CSR can have a positive effect on firm performance has generated
extensive discussions among scholars and practitioners. Friedman (1970) provides the classical
economic perspective that management has one responsibility and that is to maximize the profits
of its shareholders. Past research suggests that socially responsive firms incur higher direct costs
and reap lower profits than socially unresponsive firms (Aupperle, Carroll & Hatfield; 1985;
Devinney, 2009). In addition, some scholars have used agency theory that “good social
performance comes at the expense of good financial performance because social performance
makes use of firm resources in ways that confers significant managerial benefits rather than
returning those resources to shareholders” (Brammer & Millington, 2008, p. 1329). They argued
that firms would better spend their resources on value-added internal projects or return to
shareholders rather than invest in CSR. Despite these perspectives, there has been a growing
institutional and societal pressure on businesses to pursue a socially responsible operation for the
last couple of decades and a number of institutional approaches can explain this trend. Jones
(1995) suggests that firms facing repeated transactions with stakeholders based on trust and
cooperation are encouraged to be honest, trustworthy, and ethical because they believe that the
returns to such behavior are high. In addition, a majority of empirical evidence suggests a
significant positive relationship between CSR and financial performance (Aguinis & Glavas,
2012; Peloza, 2009). For example, Peloza (2009) reviewed 128 studies that explored the
relationship between CSR and financial outcomes and found that, almost 60 % showed a positive
relationship, less than 15 % a negative relationship and mixed findings from the rest of the

studies. Recently, Aguinis and Glavas (2012) summarized the overall empirical evidence on
CSR-performance relationship in a wide range of organizational fields as follows (p. 947):
“Working for socially responsible companies leads to increased organizational
identification (Carmeli, Gilat, & Waldman, 2007), employee engagement (Glavas
& Piderit, 2009), retention (Jones, 2010), organizational citizenship behavior (Lin,
Lyau, Tsai, Chen, & Chiu, 2010), employee commitment (Maignan, Ferrell & Hult,
1999), employee creative involvement (Glavas & Piderit, 2009), and improved
employee relations (Glavas & Piderit, 2009).”
In the 21th century, the influence of CSR on a firm performance is an important concern to
a firm’s stakeholders so that firms should consider CSR as part of their strategies (Lantos, 2001).
Given the ultimate responsibility of firms meets the needs of stakeholders, firms should fulfil
stakeholders’ demands while also devoting resources to CSR. Such seemingly contrasting
demands are leading more firms to embrace strategic CSR or strategic use of philanthropy.
Carroll (2001), for instance, argues that strategic CSR can accomplish strategic business goals,
including good deeds, are believed to be good for business as well as for society. Several scholars
have discussed strategic aspects of CSR. Porter and Kramer (2006) argue that CSR should be
seen as one of core business strategies in a firm, indicating that the firm can benefit from its
social investment. Maignan et al. (2005) also argue that CSR can serve as an attractive, valuable
resource offering competitive advantage for enhancing business performance because it can be
used as a means of conducting business strategies.
2.1.1 What Role Do Organizational Leaders Play in Fostering CSR?

In an attempt to link organizational leaders (e.g., CEOs) to CSR, scholars have focused on
three aspects of CEO background characteristics: values, compensation levels, and personal
attributes (experiences). For example, CEO integrity can be relevant to CSR such that leader
vision and integrity will increase CSR values to shareholders. Waldman and Siegel (2008) argue
that leader integrity to personal morality can yield positive outcomes for business and may
actually be the driver of CSR strategies in organizations. Ketola (2006) also argues that leader
integrity is an important component in his or her successful promotion of CSR activities at the
firm. In addition, the relationship between CEO compensation and CSR has received some
attention. For instance, McGuire, Dow and Argheyd (2003) empirically examined the
relationship between the level of CEO compensation and corporate social performance (CSP) but
they did not find any positive relation. However, Jiraporn and Chintrakarn (2013) using a sample
of 1,370 firms found that when the CEO power (as measured by the total compensation) goes
beyond a certain threshold, more powerful CEOs significantly reduce CSR investments.
Furthermore, several scholars examined the professional background of CEOs and corporate
social performance (Mazutis, 2014; Simerly, 2003; Thomas & Simerly, 1994). They found that
corporate social performance can be interpreted as a reflection of CEOs’ professional
background.
Do organizational leaders play a role in promoting CSR? This question has long attracted
extensive research (Fabrizi, Mallin & Michelon, 2014; Jiraporn & Chintrakarn, 2013). As senior
leaders, CEOs and their top management teams are charged with the responsibility of
formulating business and sustainability strategy (Strand, 2013; Wood, 1991). Indeed, today’s
corporate leaders play an important role in pursuing an effective CSR agenda (Bielak, Bonini &
Oppenheim, 2007; Fabrizi et al., 2014;Godos-Díez, Fernández-Gago & Martínez-Campillo,
2011; Mazutis, 2014). For example, CEOs engage in CSR related activities in response to

growing pressures from key stakeholders groups, such as customers and employees (Bielak et al.,
2007). In addition, while pressures from employees, customers, and other stakeholders can play a
crucial role in CEOs’ willingness to engage in CSR, CEOs recognize that CSR can give their
firms an opportunity to gain a competitive advantage as well as address societal needs (Bielak et
al., 2007). In addition, Godos-Díez et al. (2011) using a sample of 149 CEOs found that those
closer to the steward model are more inclined to attach great importance to ethics and CSR, and
to implement CSR practices. Fabrizi et al (2014) using a sample of 597 U.S. firms extended the
role of CEO’s incentives on CSR and found that non-monetary incentives have a positive effect
on CSR. Mazutis (2014) using a sample of 349 firms found the link between CEO open
executive orientation (such as a liberal worldview and output functional experiences) and
positive CSR initiative adoption over time. In this sense, it can be argued that the relationship
between leadership and CSR has become an important topic of research in the area of leadership
studies (Bielak et al., 2007; Godos-Díez et al., 2011; Fabrizi et al., 2014; Mazutis, 2014).
Transformational leadership helps represent the understanding of CSR in particular.
Transformational leadership is comprised of four major components (Avolio, Bass & Jung, 1999;
Bass & Riggio, 2006): (1) Idealized Influence (ability of leader to attract admiration and respect
and desire to follow from subordinates), (2) Inspirational Motivation (ability of leader to
communicate clear vision and create enthusiasm about future), (3) Intellectual Stimulation
(ability of leader to encourage creativity and unconventional and status quo-challenging
problem-solving among followers), and (4) Individual Consideration (ability of leader to accept
individual differences and actively provide feedback and interaction with followers).
Organizational scholars argue that transformational leadership has been found to influence CSR
behavior among some firms (Du, Swaen, Lindgreen & Senthat, 2013; McWilliams, Siegel &
Wright, 2006).

McWilliams et al (2006), for instance, suggest that strategic leadership theory can be
applied to CSR and that transformational leadership will be positively correlated with the
tendency of companies to engage in CSR. They explored the degree of transformational
leadership using CEOs of 112 large US and Canadian firms and found that intellectual
stimulation (which is one dimension of transformational leadership components) was a predictor
of the firm’s propensity to engage in strategically oriented CSR that were more likely to be
related to the firm’s corporate and business-level strategies (e.g., differentiation and reputation
building). In addition, Du et al. (2013) in a survey of 440 U.S firms found that firms with greater
transformational leadership are more likely to engage in institutional CSR practices, whereas
transactional leadership is not associated with such practices. Furthermore, it has been suggested
that charismatic leadership with self-concepts of followers can be related to CSR. For example,
leaders have values and moral justifications which provide followers with motivational effects
such that charismatic leaders can help connect one’s identify with greater social causes (Shamir,
House & Arthur, 1993).
In conclusion, the empirical evidence on the relationship between CSR and firm
performance seems to be inconclusive (Peloza, 2009). However, more recent studies suggest that
there is a positive association between CSR and firm performance (Aguinis & Glavas, 2012;
Chen & Wang, 2015). In addition, since some firms consider CSR as part of their core corporate
strategy and CEOs are charged with the responsibility of formulating corporate strategy, the
relationship between leadership characteristics and CSR is particularly important. Furthermore, it
can be suggested that understanding of three aspects of CEOs (values, compensation, and
experiences) helps to link CEO background characteristics and CSR. As mentioned in section
2.1.1, there is a certain interrelationship between CEOs and CSR. Table 1 below provides an
overview of research on the role of leadership in fostering CSR.

CSR as a business practice and philosophy has taken an important place in the way
businesses operate and serve their stakeholders. CSR refers to “context-specific organizational
actions and policies that take into account stakeholders’ expectations and the triple bottom line of
economic, social, and environmental performance” (Aguinis, 2011, p. 855). This definition
indicates that businesses should have responsibility beyond their immediate economic concern
and should act in a way that contributes and enhances broader societal goals. CSR primarily
embraces economic, legal, ethical, and philanthropic responsibilities and the dimensions of CSR
include the obligations a business has to its stakeholder’s groups (Carroll, 1991). Over the past
half century, CSR has increasingly been integrated into mainstream business thinking, and
nowadays, most U.S. publicly-traded firms (e.g., Microsoft, Google, and Walt Disney) claim to
engage in some form of CSR. The main benefits of engaging in CSR include generating
intangible assets, including building corporate reputation and employee commitment, and
tangible assets, including the positive impact on financial performance. Research in this area
suggests that being a socially responsible business helps create goodwill, build a positive
organizational image, differentiate them from their competitors, and, as a result, promote
longterm profits for business (Boynton, 2013). Indeed, more firms increasingly embrace CSR as
their employees demand their firms to be socially responsible, customers expect better business
practices, and investors realize the economic rewards of sustainable business models. Beyond the
immediate task environment, business CSR engagement also serves the needs of communities
around the world and fulfills the responsibilities businesses have to the public.
1.2 The Importance of Corporate Philanthropy
Corporate philanthropy is considered one of the core dimensions of CSR (Aguinis &

Clavas, 2012; Carroll, 1991; Porter & Kramer, 2002). The origin of corporate philanthropy in the
U.S. dates back to the rise of industrial age in the 19th and early 20th century, when businessmen
like Henry Ford and John D. Rockefeller established philanthropic foundations (Dietlin, 2011).
Corporate philanthropy has since been transformed from piecemeal individual philanthropic acts
(e.g., philanthropy mainly driven by morality) to a major aspect of corporate CSR practices.
Corporate philanthropy is, nowadays, a widespread business practice in large multinationals as
well as small-and medium-sized firms across the globe. Despite the dominant altruistic
orientation, corporate philanthropy has increasingly complemented the firm’s strategic activities
and enhanced the firm’s social and financial performance (Porter & Kramer, 2002). Therefore, it
can be argued that corporate philanthropy has evolved dramatically from a basic moral obligation
to a strategically-driven activity of the firm. As Porter and Kramer (2002, p. 58) put it,
“True strategic giving, by hand, addresses important social and economic goals simultaneously,
targeting areas of competitive context where the company and society both benefit because the
firm brings unique assets and expertise.”
Corporate philanthropy can often be “the most cost-effective way for a firm to improve its
competitive context” (Porter & Kramer, 2002, p. 9). Many firms invest a significant amount of
resource expenditures on philanthropy in order to build a strong company image. For example, a
2013 report from the Committee Encouraging Corporate Philanthropy indicates that 59 percent
of the largest Fortune 100 firms donated significantly more in 2012 compared to 2007, the year
before the global recession sets in, and aggregate giving rose by 42% ($4.48 billion) from 2007
to 2012. The ten largest U.S. corporations donated over 2.1 billion dollars in 2013 and this figure
has increased in 2014. Many firms provide support to nonprofits and social causes primarily
through company-sponsored foundations as well as corporate direct giving, both of which are

closely tied with the parent company’s business interests. As shown in Figure 1 below, the largest
U.S. firms and their foundations have increased charitable giving during the past decade (2001-
2012). Similarly, as shown in Figure 2 below, the largest 100 U.S. corporations have increased
total charitable giving both as a percentage of pre-tax profit and as a percentage of revenue
especially after the global recession in 2008.
Indeed, the increasing commitment of corporate resources to philanthropic causes reflects
a widely-held belief among business executives that philanthropy can be “strategic” in that it can
make a substantial impact on society while improving business value and reputation for the firm
(Carroll & Shabana, 2010; Walker, 2002). According to a 2010 survey by CECP, 77 percent of
CEOs noted that “the most important action they can take to prepare for 2020 is to embed social
engagement into business strategy and organizational structure.” For example, Ronald A.
Williams, the CEO of Aetna noted that that “public companies can move the collective needle by
using their human and financial resources to innovative in ways that benefit both private interests
and the public good” (Weiss, Kerdahy & Kneale, 2008, p. 5). Ivan Seidenberg, Chairman and
CEO, Verizon Communications Inc., commented in CECP that “our belief is that corporate
philanthropy expands the business. You can expand the capabilities of your customer base,
business and society by doing the right thing.” These and other executive views also highlight an
important fact that corporate philanthropy can be driven by leadership values and studying
leaders’ background can help extend our knowledge of the role of corporate philanthropy in
improving firm performance.
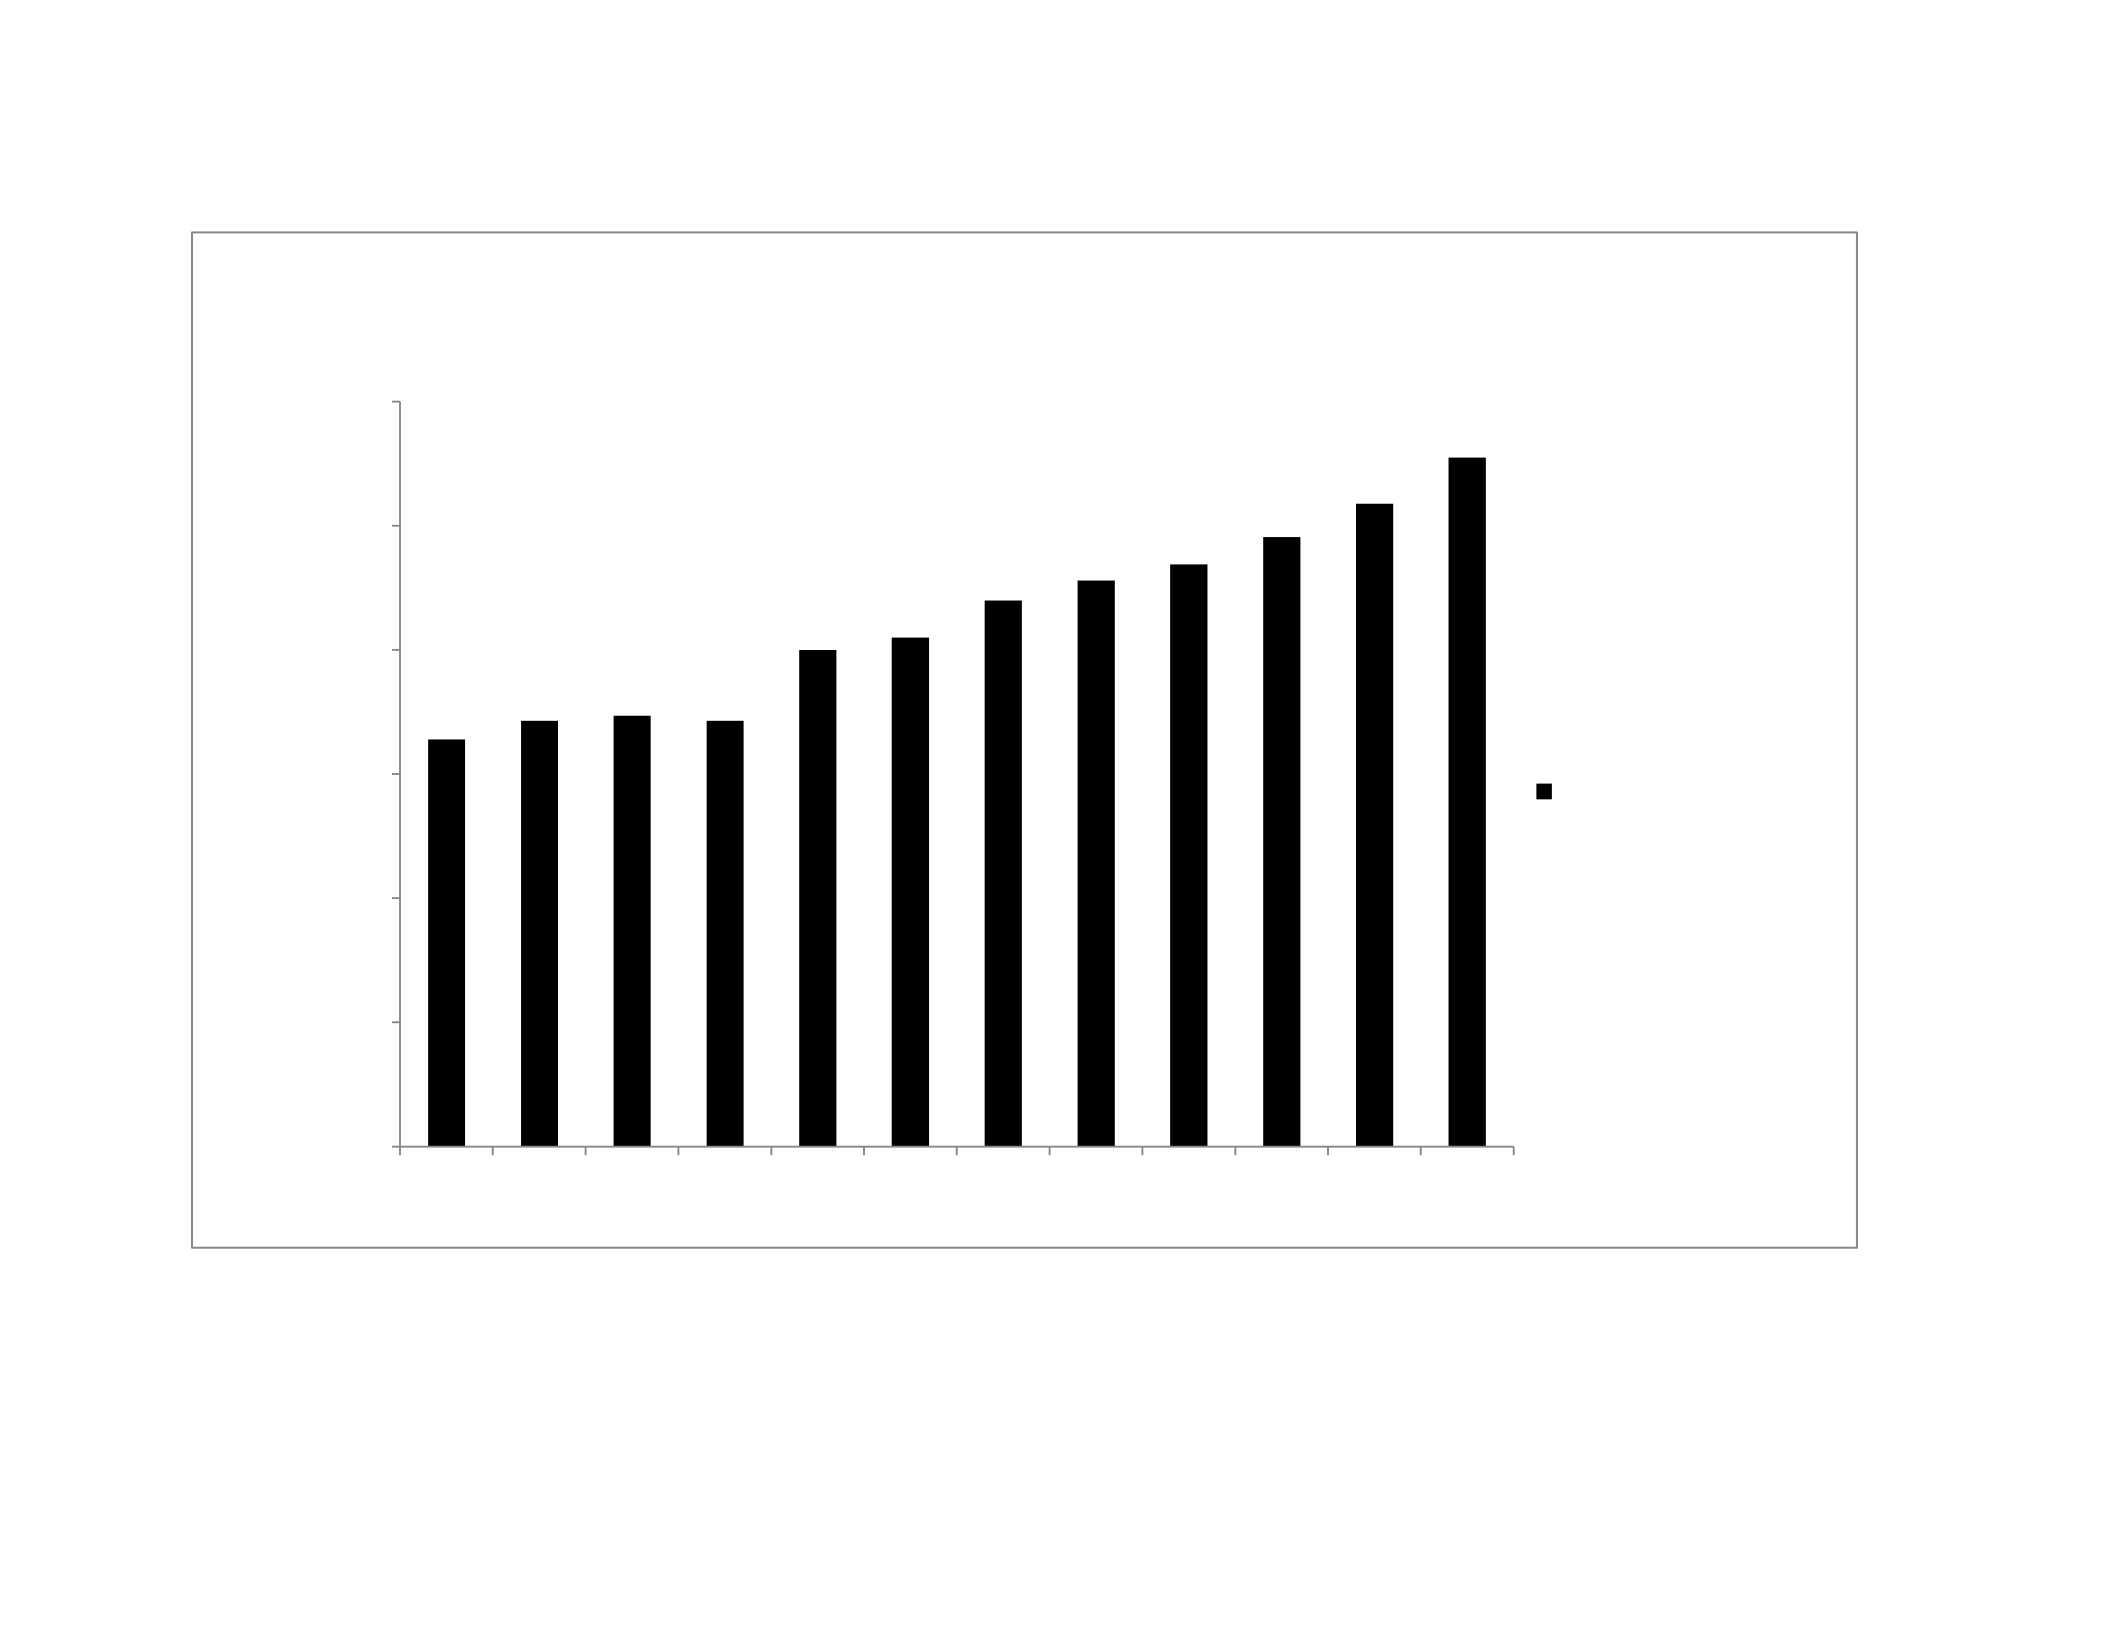
Figure 1. U.S. Corporate Foundation Philanthropic Giving from 2001 to 2012 (2,629 Corporate Foundations)
Source: The Foundation Center as of January 27, 2015
3.28 3.43 3.47 3.43
4 4.1
4.4 4.56 4.69
4.91
5.18
5.55
0
1
2
3
4
5
6
2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012
Billion$
Total charitable giving
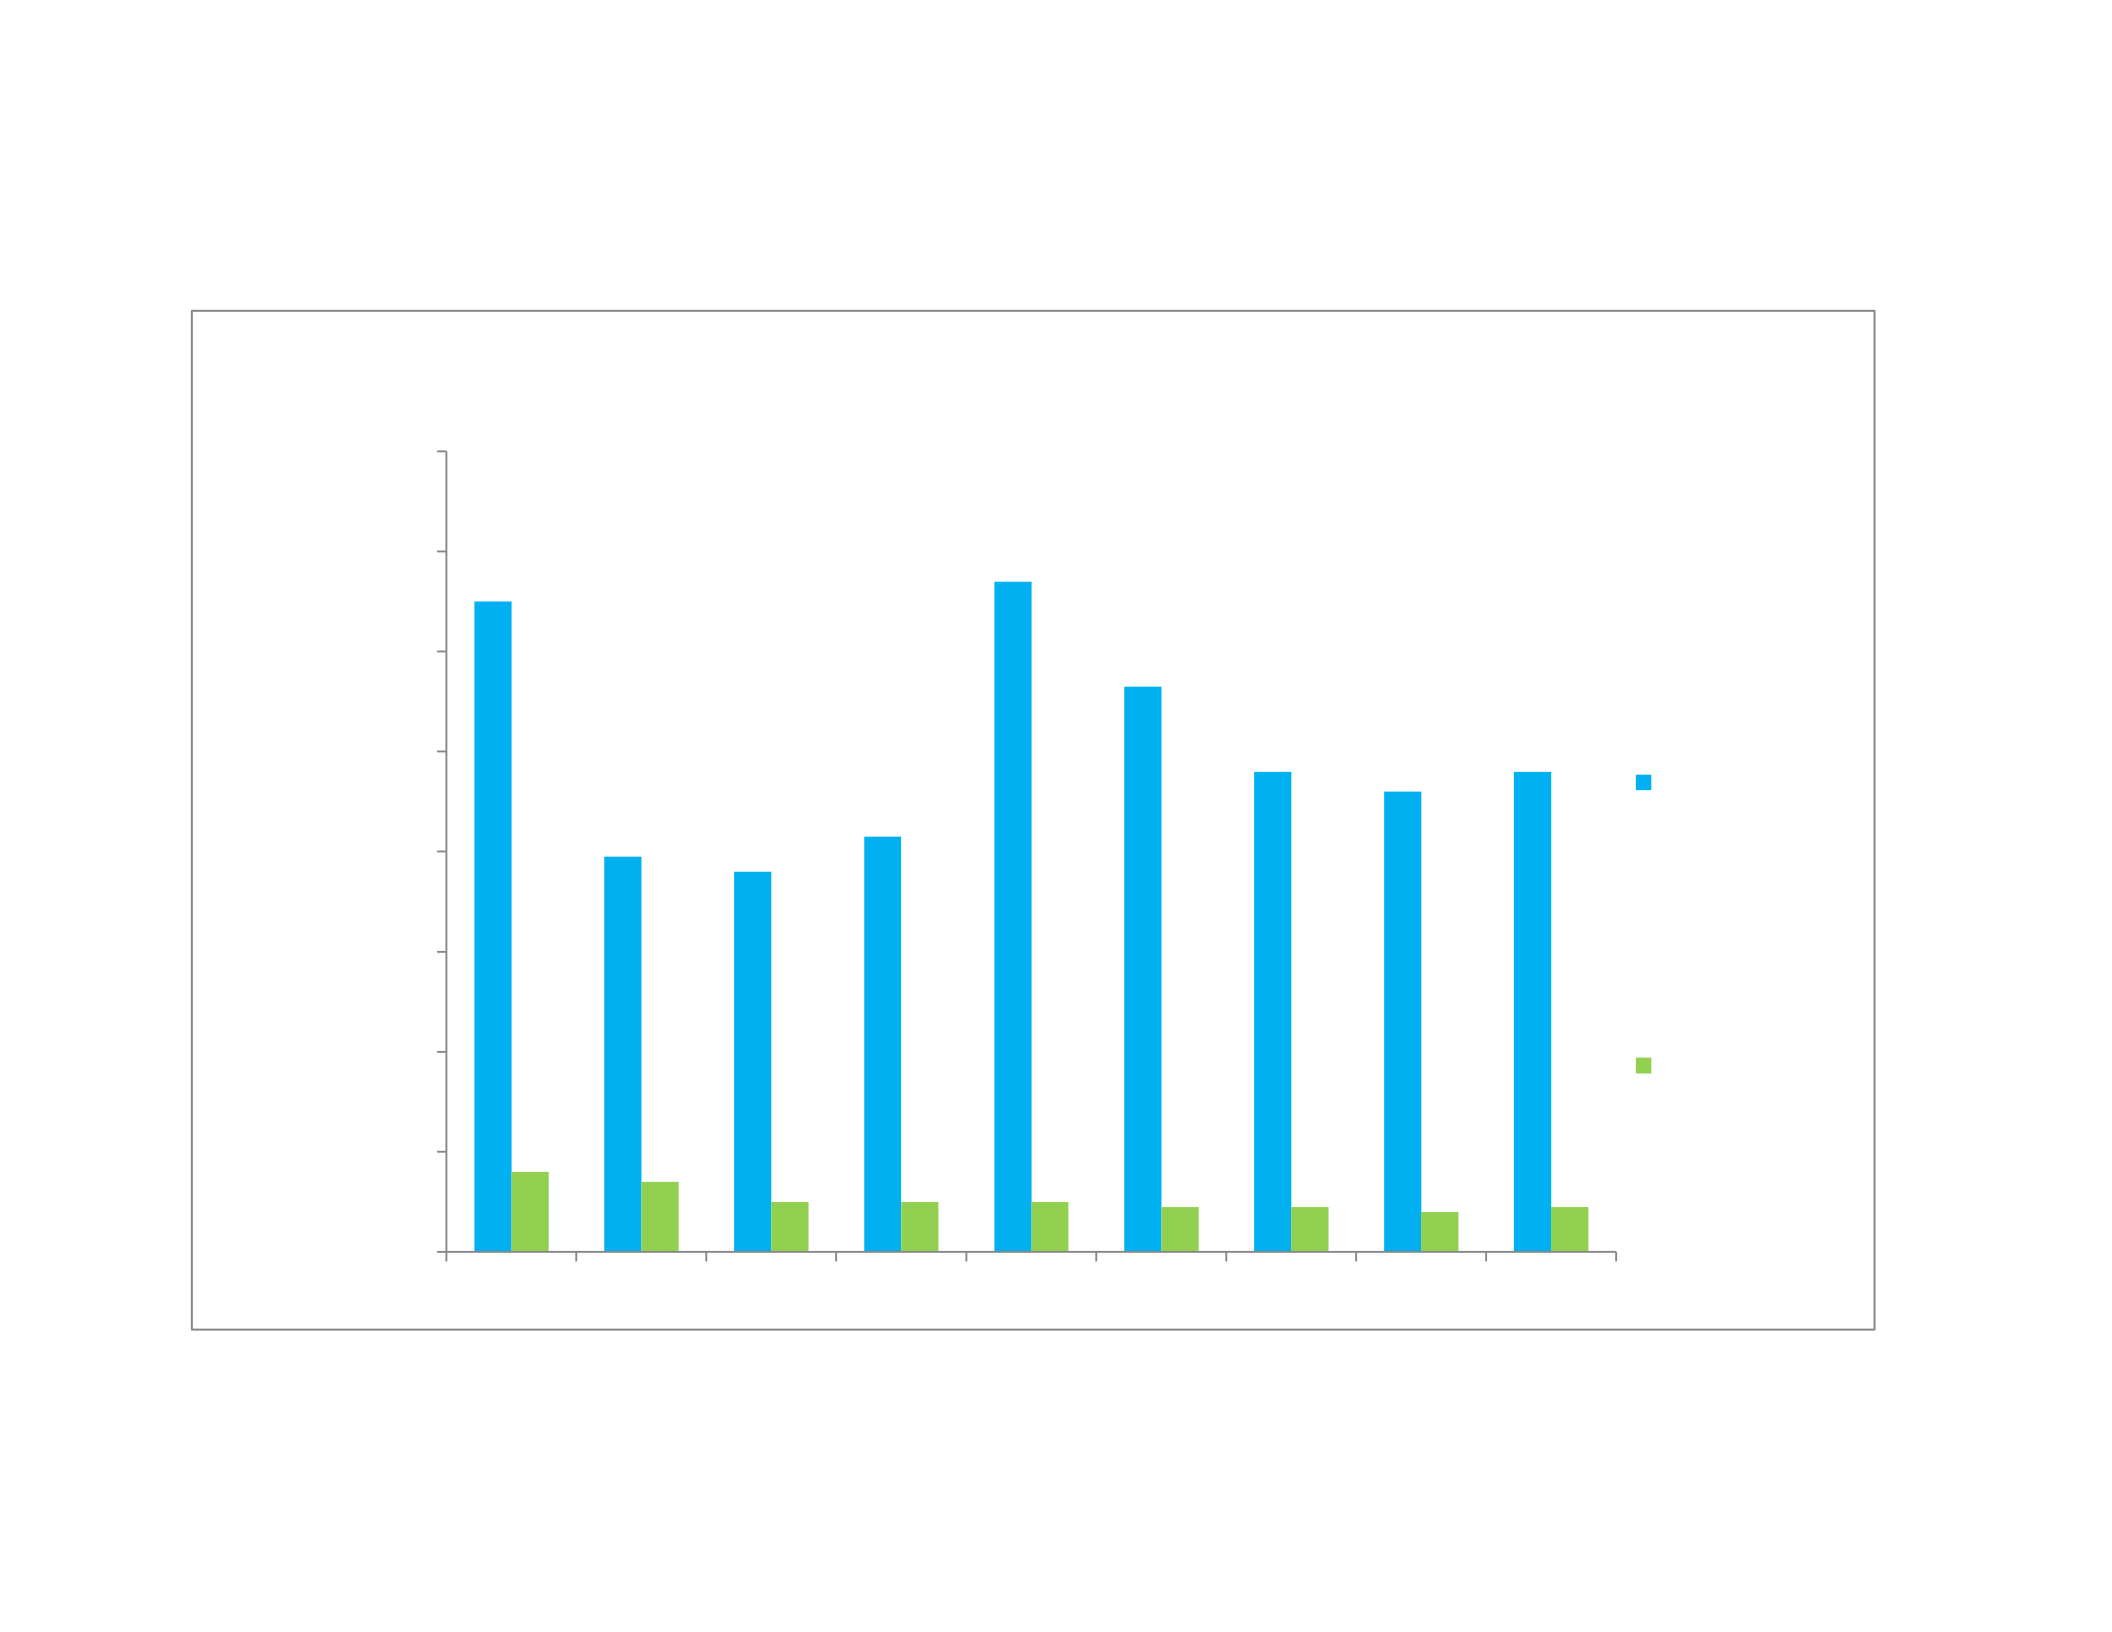
5
Figure 2. Total Charitable Giving among Fortune 100 Firms between 2004 and 2012
Source: Committee Encouraging Corporate Philanthropy as of January 27, 2015
1.3
0.79 0.76
0.83
1.34
1.13
0.96 0.92 0.96
0.16 0.14 0.1 0.1 0.1 0.09 0.09 0.08 0.09
0
0.2
0.4
0.6
0.8
1
1.2
1.4
1.6
2004 2005 2006 2007 2008 2009 2010 2011 2012
Total charitable
giving as a % of
pre-tax profit
Total charitable
giving as a % of
revenue
Million$

6

Despite the stated purpose of enhancing a firm’s public visibility and reputation by
engaging in corporate philanthropy, firms face some criticisms from stakeholders on the tangible
benefits of philanthropy. Some scholars (e.g. Devinney, 2009; Friedman, 1970) have supported
this skeptical perspective arguing that a firm exists primarily to generate economic returns, not to
solve societal problems. Friedman (1970, p. 6) argues that the single social responsibility of
business is to “engage in business activities designed to increase its profit.” On the contrary,
other scholars (e.g. Godfrey, 2005; Wang & Qian, 2011) have strongly supported the positive role
of corporate philanthropy in improving firm performance. These scholars argue that corporate
philanthropy can generate positive stakeholder support which in turn improves a firm’s financial
performance. In an effort to address the critics’ concerns on the use of corporate resources toward
charitable contributions, firms are increasingly turning to the strategic use of philanthropy.
Research suggests that strategic philanthropy can play a key role in developing value-creating
relationships with primary stakeholders and enhancing a company’s image (Buchholtz, Amason
& Rutherford, 1999; Saiia, Carroll & Buchholtz, 2003). Strategic philanthropy can also serve as
“a common meeting ground for the opponents and proponents of corporate philanthropy”
(Buchholtz et al., 1999, p. 169). Large firms are fundamentally responsible for strategic
philanthropy in practice because they have systematic structures (Marquis & Lee, 2013). For
example, large firms have corporate foundations, employee committees to oversee corporate
giving, and staff functions devoted to the effort to manage their social responsibilities (McAlister
& Ferrell, 2002). In marketing practice, strategic philanthropy has been often associated with
cause-related marketing to support social responsibility (File & Prince, 1998; Vanhamme,
Lindgreen, Reast & van Popering, 2012; Varadarajan & Menon,
1988). Both practices have some dissimilarities in terms of primary focus, time frame, and costs
(McAlister & Ferrell, 2002). Strategic philanthropy focuses on organizing itself, is ongoing, and

tends to require moderate to high resource commitment. On the other hand, cause-related
marketing focuses on the firm’s products, has a limited duration, and involves minimal resource
commitment. Both strategic philanthropy and cause-related marketing help enhance societal
welfare and improve the reputation of a firm. Stakeholder theory (Freeman, 1984) offers an
important theoretical support for the relationship between corporate philanthropy and firm
performance, suggesting that favorable social performance is a requirement for business
legitimacy, and tends to be positively associated with firm performance over the long term.
Donaldson and Preston (1995, p. 82) also suggest that firms respond to “ethical considerations
(e.g. engaging in philanthropy) which are often consistent with long-run increases in profit and
value.”
Importantly, the positive effect of corporate philanthropy on the firm provides a reason
why there is a need to examine the relationship between CEO characteristics and corporate
philanthropy. Since corporate philanthropy has become an important strategic tool that
organizational senior leaders manipulate, they are more involved in assessing and shaping
corporate strategies (Porter & Krammer, 2002). In addition, past research argues that a firm’s
social activities should be met by corporate goals determined by CEOs who constantly make
strategic decisions and choices (Choi & Wang, 2007; Wood, 1991). Furthermore, it has been
suggested that CEOs are the primary decision-makers of the organization such that an
examination of CEOs’ attitudes and values toward philanthropy provides needed insight into the
social responsibility actions in general and philanthropic function in particular (Dennis,
Buchholtz, & Butts, 2009). Accordingly, it can be suggested that the relationship between CEO
characteristics and corporate philanthropy should receive much attention. In the following
section, I will provide a brief discussion on the major research gaps that I seek to address in order

to advance the understanding of the leadership predictors of corporate philanthropy and the
implications for firm performance.
1.3 Statement of the Problem
Previous studies have focused on why firms engage in corporate philanthropy (Adams &
Hardwick, 1998; Brammer & Millington, 2005; Fombrun & Shanley, 1990; Godfrey, 2005;
Turban & Greening, 1997; Wang & Qian, 2011; Williams & Barrett, 2000). These studies have
shown that engagement in corporate philanthropy can lead to increased employee loyalty (e.g.,
employee commitment), favorable community image (e.g., corporate reputation), and positive
media coverage (e.g., recovering tarnished reputation). As such, it can be suggested that
consequences of corporate philanthropy have been extensively explored to answer the question,
“why should a firm give?” Meanwhile, antecedents of corporate philanthropy have been
explored to answer the question, “what drives firms to give?” The predominant discussion
among scholars has been on the managerial (e.g. Buchholtz et al., 1999; Choi & Wang, 2007;
Marquis & Lee, 2013; Wang & Coffey, 1992), organizational (Adams & Hardwick, 1998;
Brammer & Millington, 2006; Seifert, Morris & Bartkus, 2003), and industry (Amato & Amato,
2007, 2012; Useem, 1988) drivers of corporate philanthropy. Specifically, past research
suggested that firms engage in corporate philanthropy as a means to simultaneously and directly
benefit business interests and those of a beneficiary organization (Saiia et al., 2003; Marx, 1999).
The extent to which firms engage in corporate philanthropy can vary depending on
organizational factors, such as firm size, organizational slack, and advertising intensity (Dennis
et al., 2009; Saiia et al., 2003; Wang & Qian, 2011). Past research on corporate philanthropy has
generally discussed the intersection of business goals and the larger societal good help improve
the firm’s competitive position (Maas & Liket, 2011; Saiia et al., 2003). In sum, it can be argued
that previous studies of corporate philanthropy have developed from three aspects, “why give,”

“what leads to give,” and “give strategically.”
Unlike the extensive discussion on firm-level predictors, managerial perspective on
corporate philanthropy has not received much attention (e.g., how, why, and to what degree
individuals, such as CEOs, engage in corporate philanthropy). This line of inquiry is consistent
with a recent study’s (Aguinis and Glavas, 2012) observation that corporate social activities,
including corporate philanthropy, research is virtually absent from journals devoted to
organizational behavior and micro-level human resources management. Therefore, there is a need
to focus more on the micro level (e.g., do characteristics of individuals influence firms’
philanthropic engagement?) than on the macro level (e.g. are organizational outcomes of
corporate philanthropy beneficial to the firm?). In addition, there might be some link between
CEO characteristics and corporate philanthropy. Several scholars suggest that CEOs think
strategically about philanthropy to enhance brand name recognition, employee productivity, and
even to overcome regulatory obstacles (Seifert et al., 2003; Smith, 1994). Despite the growing
interest in the effect of CEO characteristics on CSR in general and philanthropy in particular, the
relationship between CEO characteristics and corporate philanthropy is under-developed and has
not received close empirical scrutiny.
Past research (e.g. Choi & Wang, 2007; Godfrey, 2005) has focused more on CEOs moral
background and characteristics, such as CEOs’ integrity and altruism, to explain a firm’s
philanthropic decisions. These studies, however, leave room for further explanation as to whether
CEO characteristics predict corporate philanthropy. This is because corporate philanthropy can
be driven not only by non-business community issues related to CEO altruism but also by
business-related issues, both of which benefit the firm’s strategic position. To fill this research
gap, I draw from the upper echelon theory (Carpenter, Geletkanycz & Sanders, 2004; Hambrick

& Mason, 1984) to explore how leaders’ background characteristics might influence their firms’
engagement in corporate philanthropy. Thomas and Simerly (1994) suggest that the demographic
characteristics of CEOs (e.g., age, functional background, and education) offer reliable proxies
for visible social activities of CEOs. Pedersen and Neergaard (2009) also suggest that managerial
perceptions of corporate social activities, including corporate philanthropy, are influenced by a
great deal of heterogeneity (e.g., age, gender, education, and functional backgrounds). In
addition, it might be that founder CEOs have wide strategic options and more power over their
boards (Mousa & Wales, 2012) and such status can influence corporate philanthropy. Despite the
practical importance of the relationship between founder status and corporate philanthropy, that
relationship has not received empirical investigation.
Firm size, organizational slack, and advertising intensity have been explored as important
organizational factors that influence corporate philanthropy (Dennis et al., 2009; Seifert et al.,
2003; Wang & Qian, 2011). What scholars argue is that bigger firms with more slack resources
and advertising intensity have a positive association with corporate philanthropy. What is missing
from these discussions is firm age as an important organizational context. In other words, the
relationship between firm age and corporate philanthropy has not received much scholarly
attention. For instance, Logsdon, Reiner and Burke (1990) observed in an exploratory study that
firm age might be significant in explaining placement of corporate philanthropy. Particularly,
past research has suggested that older firms tend to be increasingly inflexible so that firm age
may be an important indicator of reduced executive discretion (Finkelstein, Hambrick &
Cannella, 2009). Although the individual CEO’s influence on corporate philanthropy might vary
as a firm grows, the role of firm age on the relationship between CEO background characteristics
and corporate philanthropy has not received much attention. Therefore, it is worth exploring this
relationship.

Although corporate philanthropy has developed from a wide range of theoretical
frameworks, scholars have not yet given much thought to whether firms proactively engage in
corporate philanthropy to strengthen their business and corporate strategies. Particularly, the
relationship between corporate philanthropy and unrelated diversification is under-developed.
Unrelated diversification is one of core business strategies which help firms expand new markets.
For example, when firms pursue unrelated diversification strategies, they usually experience a
wide range of varying demands from stakeholders in distant industries or their subsidiaries
(Chatterjee & Wernerfelt, 1991). Corporate philanthropy can generate reputational assets in the
new market (Hess, Rogovsky & Dunfee, 2002), strengthen marketing and branding initiatives
(Lii & Lee, 2012; Ricks Jr, 2005), and improve relations with local governments (Wang & Qian,
2011). From this phenomenon, it can be suggested that firms can consider philanthropic activities
as part of long- term competitiveness and a means to strategically open new markets.
In addition, it is likely that the pressure for engaging in corporate philanthropy would
increase among international firms with business activities across countries and culture. Deresky
(1997) suggests that the philanthropic activities of multinational corporations that operate in
foreign countries may be characterized as strategic, clearly targeted, and linked to the overall
objectives of the firm. In addition, when firms expand their businesses in a foreign market
(Sharfman, Shaft & Tihanyi, 2004), they experience a wide range of stakeholder’ pressures.
Corporate philanthropy can be used as a means of reducing these challenges. Despite the
importance of corporate philanthropy on a firm’s internationalization, there is a lack of
theoretical explanation and empirical evidence as to whether corporate philanthropy advances a
firm’s internationalization strategy. Similarly, expansive global strategic posture (in terms of
geographic market diversification) can help firms leverage R&D costs and knowledge across
countries (Carpenter & Fredrickson, 2001; Kim & Mauborgne, 1991). It has been suggested that

corporate philanthropy may be an opportunity for internationally operating firms, but also for
investing in legitimacy in a region considered to be the main emerging market for the country
(Bohnsack, 2012; Whiteman, Muller, Van der Voort, Wijk, Meijs, & Pique, 2005). It is reasonable
to expect that firms are encouraged to engage in corporate philanthropy to develop a
commanding international presence. In sum, I explore how CEOs’ background characteristics
predict the degree of firms’ engagement in corporate philanthropy and the complimentary
theoretical relationship between corporate philanthropy and a firm’s diversification profile (such
as unrelated diversification and global strategic posture).
1.4 Purpose of the Study & Research Questions
In this dissertation, I examine the effect of CEOs’ background characteristics on corporate
philanthropy and firm diversification profile. More specifically, I examine the relationships
between CEOs’ background characteristics and corporate philanthropy. In doing so, I focus on
four aspects of CEO background characteristics (i.e. CEO founder status, functional background,
civic engagement, and education) and examine whether they are associated with the degree of
firms engagement in corporate philanthropy.
First, what is the relationship between CEO founder status and corporate philanthropy?
Founder CEOs are likely to hold a psychological bond with their firms (Peterson, Galvin &
Lange, 2012). Founder CEOs’ intrinsic motivation could lead them to engage in socially
responsible activities that meet various stakeholder demands, such as corporate philanthropy.
Second, what is the relationship between CEO functional background and corporate
philanthropy? Corporate social performance can be a reflection of CEO functional background
(Melo, 2012). Thus, it might be anticipated that a certain aspect of a CEO’s past work experience
in jobs within functional areas of organizations can influence corporate philanthropy. Third, what

is the relationship between CEO civic engagement and corporate philanthropy? CEOs often
serve as active members in community groups or associations and they participate in civic affairs
as part of their strategic mission. Doing so can be motivated by a desire to create the local
community development and a more stable political environment that ensures their business
profitability. Fourth, what is the relationship between CEO education and corporate
philanthropy? Bennett (2012) argues that better educated people have wider mental horizons that
cause individuals to recognize the value of charities concerned with the external environment.
Therefore, it is expected that CEOs’ education can play an important role in determining the
choice and emphasis on corporate philanthropy. In addition, I examine the moderating role of
firm age on the relationship between CEO background characteristics and corporate
philanthropy. Although older firms would be expected to be more well-known and have greater
philanthropic engagement, it is reasonably expected that a CEO’s influence on corporate
philanthropy varies as a firm grows.
Furthermore, I examine the role of corporate diversification profile on corporate
philanthropy and firm performance. Past research suggests that firms increase philanthropic
expenditures strategically as a means to open new markets where they are not familiar with and
the pressures for engaging in corporate philanthropy increase among international firms (Merz,
Peloza & Chen, 2010). Specifically, I examine a firm’s diversification strategy as the mechanism
through which corporate philanthropy influences firm performance. Since the ultimate goal of a
firm’s social activities, including corporate philanthropy, is to maximize performance, it is worth
exploring the interaction, including corporate philanthropy – firm performance relationship
through the mechanism of corporate diversification profile.

In sum, there are four major under-developed research areas in the literature that will be
explored in this dissertation. First, there is a need to examine the relationship between CEO
background characteristics and corporate philanthropy. Second, the role of firm age on the
relationship between CEO background characteristics and corporate philanthropy should receive
much attention. Third, whether firms proactively engage in corporate philanthropy to strengthen
their unrelated diversification strategies should receive an empirical investigation. Fourth, the
relationship between corporate philanthropy and firm performance needs to be examined
particularly under corporate diversification profile (e.g. how corporate philanthropy influences
firm performance through unrelated diversification and global strategic posture). I intend to
answer the following three research questions:
7) Do CEO background characteristics influence the level of corporate philanthropy? If so,
why?
8) Does firm age moderate the relationships between CEO background characteristics and
the level of corporate philanthropy?
9) Does corporate diversification profile mediate the relationship between the level of
corporate philanthropy and firm performance?
1.5 Significance & Contributions of the Dissertation
1.5.1 Contributions to Corporate Philanthropy Research
In this dissertation, I offer several contributions for research. First, this dissertation
contributes to the growing scholarly interests in terms of CEOs’ influence on corporate
philanthropy. It has been suggested that CEOs are requiring greater strategic accountability in
corporate giving programs (Saiia et al, 2003) and that corporations undertake strategic
philanthropy as long as direct economic benefits can be gained by doing so (Sánchez, 2000).

Therefore, an examination of whether CEO background characteristics influence corporate
philanthropy helps to fulfill research interests.
Second, I extend the literature on corporate philanthropy to examine the strategic use of
philanthropy. It has been suggested that traditional altruistic models of philanthropy are
becoming less relevant because it is generally considered a non-strategic explanation of corporate
giving which ignores the profit maximization goal and other strategic goals of the firm
(Neiheisel, 1994; Sánchez, 2000). Corporate giving activities have evolved into far more
strategically market-oriented approaches like targeted grants intended to optimize economic
return as well as social returns per philanthropic dollar (Sherblom, 2007).
Third, drawing upon the institutional and stakeholder perspectives, I offer a new attempt
to empirically examine the link between corporate philanthropy and unrelated diversification. For
example, faced with various challenges (e.g., social, legal, and regulatory), corporate
diversification increases a variety of stakeholder pressures in the firm’s external environment that
arise (Brammer, Millington & Pavelin, 2006; Sharfman et al., 2004). In addition, highly
diversified firms not only suffer from a lack of coherence in terms of underlying resources
(Montgomery & Wernerfelt, 1988) but they also have to deal with heavy stakeholder demands.
These pressures might be mitigated when engaging in corporate social activities through which
unrelated diversifiers can manage a wide range of stakeholders’ demands.
Fourth, although previous studies (Markides & Williamson, 1994; Palepu, 1985; Rumelt,
1974) suggest a negative relationship between unrelated diversification and (short-term) financial
performance, this dissertation provides a different perspective to corporate diversification
strategy. For example, corporate philanthropy helps to generate reputation and branding
initiatives in the new markets so that it can improve the firm’s market positions (Hess et al.,

2002; Ricks Jr, 2005). In this dissertation, I provide scholars with a promising suggestion that
unrelated diversification may not necessarily be an inferior strategy for the firm.
1.5.2 Contributions to Practice
In this dissertation, I offer several contributions for practice. First, understanding of how
CEO background characteristics (e.g., CEO status, functional background, civic engagement, and
education level) can be applied to corporate philanthropy helps to explain the rationale behind
decisions to engage in corporate philanthropy. Therefore, I answer what leads CEOs to engage in
corporate philanthropy and further why some CEOs engage in more corporate philanthropy than
others. Second, I provide managers with practicability of corporate philanthropy. For example,
strategic use of philanthropic expenditures can support a community project in developing
countries (Porter & Kramer, 2002; Sánchez, 2000) because better community conditions are
good for business (e.g., when the standard of living is increased, product demand is increased).
Third, I provide managers with a promising notion that engaging in corporate
philanthropy can help firms with diversification and market entry strategies. Scholars argue that a
firm’s philanthropic engagement in developing countries can enhance the firm’s reputation and
get easier access to the market (Bohnsack, 2012; Brammer et al., 2006). There might be a
positive relationship between corporate philanthropy and international presence. In addition, it is
suggested that corporate philanthropy can offer an opportunity for internationally operating firms
as well as for investing in business legitimacy. In this dissertation, I can provide managers with
practicability that international firms can strengthen their competitive context by engaging in
corporate philanthropy. Fourth, I provide insights on business legitimacy by suggesting that firms
are seen as legitimate actors by local stakeholders to the extent they engage in corporate
philanthropy. Goyal (2006) and Wang and Qian (2011) suggest that philanthropic activities of

multinational firms in the host countries would be a signaling device to demonstrate that they
have long-term intentions consistent with the local expectations. Thus, I suggest that firms can
receive supportive responses from the host countries governments by engaging in corporate
philanthropy.
1.6 Definition of Key Terms
Corporate social responsibility (CSR) refers to “context-specific organizational actions
and policies that take into account stakeholders’ expectations and the triple bottom line of
economic, social, and environmental performance” (Aguinis, 2011, p. 855).
Diversification refers to “the entry of a firm or business unit into new lines of activity,
either by processes of internal business development or acquisition, which entail changes in its
administrative structure, systems, and other management processes” (Ramanujam &
Varadarajan, 1989, p. 525). There are two types of diversification, such as related diversification
and unrelated diversification. Related diversification refers to a diversification built around a
core organizational capability (Ramanujam, 1987; Rumelt, 1982). It occurs when firms expand
their areas closely related to their primary activities and areas of technical expertise. Unrelated
diversification refers to a diversification that drives to move into unrelated lines of business
(Ramanujam, 1987; Rumelt, 1982). It occurs where firms expand their operations into markets or
products beyond current resources and capabilities.
Corporate philanthropy refers to the practice of “giving firm resources to invest in
business-related issues and non-business community issues that also benefit the firm’s strategic
position and, ultimately, its bottom line” (Saiia et al., 2003, p. 170). This definition helps to
explain why some firms still donate in non-business areas more than others. They do so because

they believe that giving non-business issues would enhance their public image which can be used
for gaining business legitimacy in developing countries (Wang & Qian, 2011).
Global strategic posture (GSP) refers to “the degree to which a firm is dependent on
foreign sales and production and to the geographic dispersion of this dependence” (Carpenter,
Sanders & Gregersen, 2001, p. 497). It has been suggested that GSP reflects the relative
significance of foreign markets and operations in sustaining the firm as well as their geographic
dispersion (Sullivan, 1994). Therefore, GSP can be used for measuring firm internationalization
(Carpenter & Fredrickson, 2001; Levy, 2005). GSP are normally measured by three dimension
originally developed by Sullivan (1994): foreign sales, foreign production, and geographic
diversity. Foreign sales reflect the relative significance of foreign market. Foreign production
reflects the degree to which a firm depends on foreign-owned assets and resources. Geographic
diversity reflects the extent to which a firm has subsidiaries associated with globalization of
operations and markets. Several scholars used GSP to explain a firm’s internationalization
strategy (Carpenter et al., 2001; Carpenter & Fredrickson, 2001; Levy, 2005).
1.7 Organization of the Dissertation
This dissertation consists of six chapters. The first chapter provides an introduction about
the importance of corporate philanthropy, statement of the problem, major research questions as
well as the contributions of the dissertation. Chapter two presents a comprehensive and extensive
review of the literature on corporate social responsibility and the antecedents and consequences
of corporate philanthropy with the role of leadership in corporate philanthropy. Chapter three
presents the research model, theoretical foundations, and summary of theoretically-driven
hypotheses. Chapter four presents the research design including target sample, measures, as well
as statistical techniques. Chapter five presents and highlights the results of statistical analyses,

including summary of findings and summary of hypotheses. Chapter six discusses the results
from Chapter five, the implications to research and practice, limitations, future research
directions, and conclusion.

CHAPTER II
LITERATURE REVIEW
This chapter provides a comprehensive review of the corporate philanthropy research.
The first section begins with a systematic review of the literature on the relationship between
Corporate Social Responsibility (CSR) and firm performance as well as the leadership
determinants of CSR. In the second section, I discuss the theoretical conceptualizations of
corporate philanthropy with a comparative review of the traditional and strategic philanthropy
literatures. In the third section, I discuss the managerial, organizational and industry level
antecedents and consequences of corporate philanthropy with a particular emphasis on the link
between leadership attributes and corporate philanthropy. In the fourth section, I present a
comprehensive review of research on the link between corporate philanthropy and corporate
strategy. The chapter then concludes with a contingency view of corporate philanthropy.
2.1 How Does Corporate Social Responsibility (CSR) Influence Firm Performance?
CSR refers to “context-specific organizational actions and policies that take into account
stakeholders’ expectations and the triple bottom line of economic, social, and environmental
performance” (Aguinis, 2011, p. 855). Specifically, the demand for business CSR initiatives has
been significantly higher around the world over the last several decades. Accordingly, firms
nowadays are expected to act more proactively to fulfill their CSR expectations as responsible
corporate citizens to the society (Wang & Hsu, 2011). Since engaging in CSR is considered a
socially responsible investment for the firm, how CSR influences firm performance has been an
important issue among organizational scholars (Agle, Mitchell & Sonnenfeld, 1999; Aguinis &
Glavas, 2012; Orlitzky, Schmidt & Rynes, 2003). Even though there are some debates as to
whether CSR helps to improve firm performance, an extensive line of research has empirically

explored how CSR boosts firms’ competitive advantage, thereby ensuring value creation and
satisfaction for stockholders and customers (Cox, Brammer & Millington, 2004; Lev, Petrovits &
Radhakrishnan, 2010).
The topic of whether CSR can have a positive effect on firm performance has generated
extensive discussions among scholars and practitioners. Friedman (1970) provides the classical
economic perspective that management has one responsibility and that is to maximize the profits
of its shareholders. Past research suggests that socially responsive firms incur higher direct costs
and reap lower profits than socially unresponsive firms (Aupperle, Carroll & Hatfield; 1985;
Devinney, 2009). In addition, some scholars have used agency theory that “good social
performance comes at the expense of good financial performance because social performance
makes use of firm resources in ways that confers significant managerial benefits rather than
returning those resources to shareholders” (Brammer & Millington, 2008, p. 1329). They argued
that firms would better spend their resources on value-added internal projects or return to
shareholders rather than invest in CSR. Despite these perspectives, there has been a growing
institutional and societal pressure on businesses to pursue a socially responsible operation for the
last couple of decades and a number of institutional approaches can explain this trend. Jones
(1995) suggests that firms facing repeated transactions with stakeholders based on trust and
cooperation are encouraged to be honest, trustworthy, and ethical because they believe that the
returns to such behavior are high. In addition, a majority of empirical evidence suggests a
significant positive relationship between CSR and financial performance (Aguinis & Glavas,
2012; Peloza, 2009). For example, Peloza (2009) reviewed 128 studies that explored the
relationship between CSR and financial outcomes and found that, almost 60 % showed a positive
relationship, less than 15 % a negative relationship and mixed findings from the rest of the

studies. Recently, Aguinis and Glavas (2012) summarized the overall empirical evidence on
CSR-performance relationship in a wide range of organizational fields as follows (p. 947):
“Working for socially responsible companies leads to increased organizational
identification (Carmeli, Gilat, & Waldman, 2007), employee engagement (Glavas
& Piderit, 2009), retention (Jones, 2010), organizational citizenship behavior (Lin,
Lyau, Tsai, Chen, & Chiu, 2010), employee commitment (Maignan, Ferrell & Hult,
1999), employee creative involvement (Glavas & Piderit, 2009), and improved
employee relations (Glavas & Piderit, 2009).”
In the 21th century, the influence of CSR on a firm performance is an important concern to
a firm’s stakeholders so that firms should consider CSR as part of their strategies (Lantos, 2001).
Given the ultimate responsibility of firms meets the needs of stakeholders, firms should fulfil
stakeholders’ demands while also devoting resources to CSR. Such seemingly contrasting
demands are leading more firms to embrace strategic CSR or strategic use of philanthropy.
Carroll (2001), for instance, argues that strategic CSR can accomplish strategic business goals,
including good deeds, are believed to be good for business as well as for society. Several scholars
have discussed strategic aspects of CSR. Porter and Kramer (2006) argue that CSR should be
seen as one of core business strategies in a firm, indicating that the firm can benefit from its
social investment. Maignan et al. (2005) also argue that CSR can serve as an attractive, valuable
resource offering competitive advantage for enhancing business performance because it can be
used as a means of conducting business strategies.
2.1.1 What Role Do Organizational Leaders Play in Fostering CSR?

In an attempt to link organizational leaders (e.g., CEOs) to CSR, scholars have focused on
three aspects of CEO background characteristics: values, compensation levels, and personal
attributes (experiences). For example, CEO integrity can be relevant to CSR such that leader
vision and integrity will increase CSR values to shareholders. Waldman and Siegel (2008) argue
that leader integrity to personal morality can yield positive outcomes for business and may
actually be the driver of CSR strategies in organizations. Ketola (2006) also argues that leader
integrity is an important component in his or her successful promotion of CSR activities at the
firm. In addition, the relationship between CEO compensation and CSR has received some
attention. For instance, McGuire, Dow and Argheyd (2003) empirically examined the
relationship between the level of CEO compensation and corporate social performance (CSP) but
they did not find any positive relation. However, Jiraporn and Chintrakarn (2013) using a sample
of 1,370 firms found that when the CEO power (as measured by the total compensation) goes
beyond a certain threshold, more powerful CEOs significantly reduce CSR investments.
Furthermore, several scholars examined the professional background of CEOs and corporate
social performance (Mazutis, 2014; Simerly, 2003; Thomas & Simerly, 1994). They found that
corporate social performance can be interpreted as a reflection of CEOs’ professional
background.
Do organizational leaders play a role in promoting CSR? This question has long attracted
extensive research (Fabrizi, Mallin & Michelon, 2014; Jiraporn & Chintrakarn, 2013). As senior
leaders, CEOs and their top management teams are charged with the responsibility of
formulating business and sustainability strategy (Strand, 2013; Wood, 1991). Indeed, today’s
corporate leaders play an important role in pursuing an effective CSR agenda (Bielak, Bonini &
Oppenheim, 2007; Fabrizi et al., 2014;Godos-Díez, Fernández-Gago & Martínez-Campillo,
2011; Mazutis, 2014). For example, CEOs engage in CSR related activities in response to

growing pressures from key stakeholders groups, such as customers and employees (Bielak et al.,
2007). In addition, while pressures from employees, customers, and other stakeholders can play a
crucial role in CEOs’ willingness to engage in CSR, CEOs recognize that CSR can give their
firms an opportunity to gain a competitive advantage as well as address societal needs (Bielak et
al., 2007). In addition, Godos-Díez et al. (2011) using a sample of 149 CEOs found that those
closer to the steward model are more inclined to attach great importance to ethics and CSR, and
to implement CSR practices. Fabrizi et al (2014) using a sample of 597 U.S. firms extended the
role of CEO’s incentives on CSR and found that non-monetary incentives have a positive effect
on CSR. Mazutis (2014) using a sample of 349 firms found the link between CEO open
executive orientation (such as a liberal worldview and output functional experiences) and
positive CSR initiative adoption over time. In this sense, it can be argued that the relationship
between leadership and CSR has become an important topic of research in the area of leadership
studies (Bielak et al., 2007; Godos-Díez et al., 2011; Fabrizi et al., 2014; Mazutis, 2014).
Transformational leadership helps represent the understanding of CSR in particular.
Transformational leadership is comprised of four major components (Avolio, Bass & Jung, 1999;
Bass & Riggio, 2006): (1) Idealized Influence (ability of leader to attract admiration and respect
and desire to follow from subordinates), (2) Inspirational Motivation (ability of leader to
communicate clear vision and create enthusiasm about future), (3) Intellectual Stimulation
(ability of leader to encourage creativity and unconventional and status quo-challenging
problem-solving among followers), and (4) Individual Consideration (ability of leader to accept
individual differences and actively provide feedback and interaction with followers).
Organizational scholars argue that transformational leadership has been found to influence CSR
behavior among some firms (Du, Swaen, Lindgreen & Senthat, 2013; McWilliams, Siegel &
Wright, 2006).

McWilliams et al (2006), for instance, suggest that strategic leadership theory can be
applied to CSR and that transformational leadership will be positively correlated with the
tendency of companies to engage in CSR. They explored the degree of transformational
leadership using CEOs of 112 large US and Canadian firms and found that intellectual
stimulation (which is one dimension of transformational leadership components) was a predictor
of the firm’s propensity to engage in strategically oriented CSR that were more likely to be
related to the firm’s corporate and business-level strategies (e.g., differentiation and reputation
building). In addition, Du et al. (2013) in a survey of 440 U.S firms found that firms with greater
transformational leadership are more likely to engage in institutional CSR practices, whereas
transactional leadership is not associated with such practices. Furthermore, it has been suggested
that charismatic leadership with self-concepts of followers can be related to CSR. For example,
leaders have values and moral justifications which provide followers with motivational effects
such that charismatic leaders can help connect one’s identify with greater social causes (Shamir,
House & Arthur, 1993).
In conclusion, the empirical evidence on the relationship between CSR and firm
performance seems to be inconclusive (Peloza, 2009). However, more recent studies suggest that
there is a positive association between CSR and firm performance (Aguinis & Glavas, 2012;
Chen & Wang, 2015). In addition, since some firms consider CSR as part of their core corporate
strategy and CEOs are charged with the responsibility of formulating corporate strategy, the
relationship between leadership characteristics and CSR is particularly important. Furthermore, it
can be suggested that understanding of three aspects of CEOs (values, compensation, and
experiences) helps to link CEO background characteristics and CSR. As mentioned in section
2.1.1, there is a certain interrelationship between CEOs and CSR. Table 1 below provides an
overview of research on the role of leadership in fostering CSR.

CSR as a business practice and philosophy has taken an important place in the way
businesses operate and serve their stakeholders. CSR refers to “context-specific organizational
actions and policies that take into account stakeholders’ expectations and the triple bottom line of
economic, social, and environmental performance” (Aguinis, 2011, p. 855). This definition
indicates that businesses should have responsibility beyond their immediate economic concern
and should act in a way that contributes and enhances broader societal goals. CSR primarily
embraces economic, legal, ethical, and philanthropic responsibilities and the dimensions of CSR
include the obligations a business has to its stakeholder’s groups (Carroll, 1991). Over the past
half century, CSR has increasingly been integrated into mainstream business thinking, and
nowadays, most U.S. publicly-traded firms (e.g., Microsoft, Google, and Walt Disney) claim to
engage in some form of CSR. The main benefits of engaging in CSR include generating
intangible assets, including building corporate reputation and employee commitment, and
tangible assets, including the positive impact on financial performance. Research in this area
suggests that being a socially responsible business helps create goodwill, build a positive
organizational image, differentiate them from their competitors, and, as a result, promote
longterm profits for business (Boynton, 2013). Indeed, more firms increasingly embrace CSR as
their employees demand their firms to be socially responsible, customers expect better business
practices, and investors realize the economic rewards of sustainable business models. Beyond the
immediate task environment, business CSR engagement also serves the needs of communities
around the world and fulfills the responsibilities businesses have to the public.
1.2 The Importance of Corporate Philanthropy
Corporate philanthropy is considered one of the core dimensions of CSR (Aguinis &

Clavas, 2012; Carroll, 1991; Porter & Kramer, 2002). The origin of corporate philanthropy in the
U.S. dates back to the rise of industrial age in the 19th and early 20th century, when businessmen
like Henry Ford and John D. Rockefeller established philanthropic foundations (Dietlin, 2011).
Corporate philanthropy has since been transformed from piecemeal individual philanthropic acts
(e.g., philanthropy mainly driven by morality) to a major aspect of corporate CSR practices.
Corporate philanthropy is, nowadays, a widespread business practice in large multinationals as
well as small-and medium-sized firms across the globe. Despite the dominant altruistic
orientation, corporate philanthropy has increasingly complemented the firm’s strategic activities
and enhanced the firm’s social and financial performance (Porter & Kramer, 2002). Therefore, it
can be argued that corporate philanthropy has evolved dramatically from a basic moral obligation
to a strategically-driven activity of the firm. As Porter and Kramer (2002, p. 58) put it,
“True strategic giving, by hand, addresses important social and economic goals simultaneously,
targeting areas of competitive context where the company and society both benefit because the
firm brings unique assets and expertise.”
Corporate philanthropy can often be “the most cost-effective way for a firm to improve its
competitive context” (Porter & Kramer, 2002, p. 9). Many firms invest a significant amount of
resource expenditures on philanthropy in order to build a strong company image. For example, a
2013 report from the Committee Encouraging Corporate Philanthropy indicates that 59 percent
of the largest Fortune 100 firms donated significantly more in 2012 compared to 2007, the year
before the global recession sets in, and aggregate giving rose by 42% ($4.48 billion) from 2007
to 2012. The ten largest U.S. corporations donated over 2.1 billion dollars in 2013 and this figure
has increased in 2014. Many firms provide support to nonprofits and social causes primarily
through company-sponsored foundations as well as corporate direct giving, both of which are

closely tied with the parent company’s business interests. As shown in Figure 1 below, the largest
U.S. firms and their foundations have increased charitable giving during the past decade (2001-
2012). Similarly, as shown in Figure 2 below, the largest 100 U.S. corporations have increased
total charitable giving both as a percentage of pre-tax profit and as a percentage of revenue
especially after the global recession in 2008.
Indeed, the increasing commitment of corporate resources to philanthropic causes reflects
a widely-held belief among business executives that philanthropy can be “strategic” in that it can
make a substantial impact on society while improving business value and reputation for the firm
(Carroll & Shabana, 2010; Walker, 2002). According to a 2010 survey by CECP, 77 percent of
CEOs noted that “the most important action they can take to prepare for 2020 is to embed social
engagement into business strategy and organizational structure.” For example, Ronald A.
Williams, the CEO of Aetna noted that that “public companies can move the collective needle by
using their human and financial resources to innovative in ways that benefit both private interests
and the public good” (Weiss, Kerdahy & Kneale, 2008, p. 5). Ivan Seidenberg, Chairman and
CEO, Verizon Communications Inc., commented in CECP that “our belief is that corporate
philanthropy expands the business. You can expand the capabilities of your customer base,
business and society by doing the right thing.” These and other executive views also highlight an
important fact that corporate philanthropy can be driven by leadership values and studying
leaders’ background can help extend our knowledge of the role of corporate philanthropy in
improving firm performance.
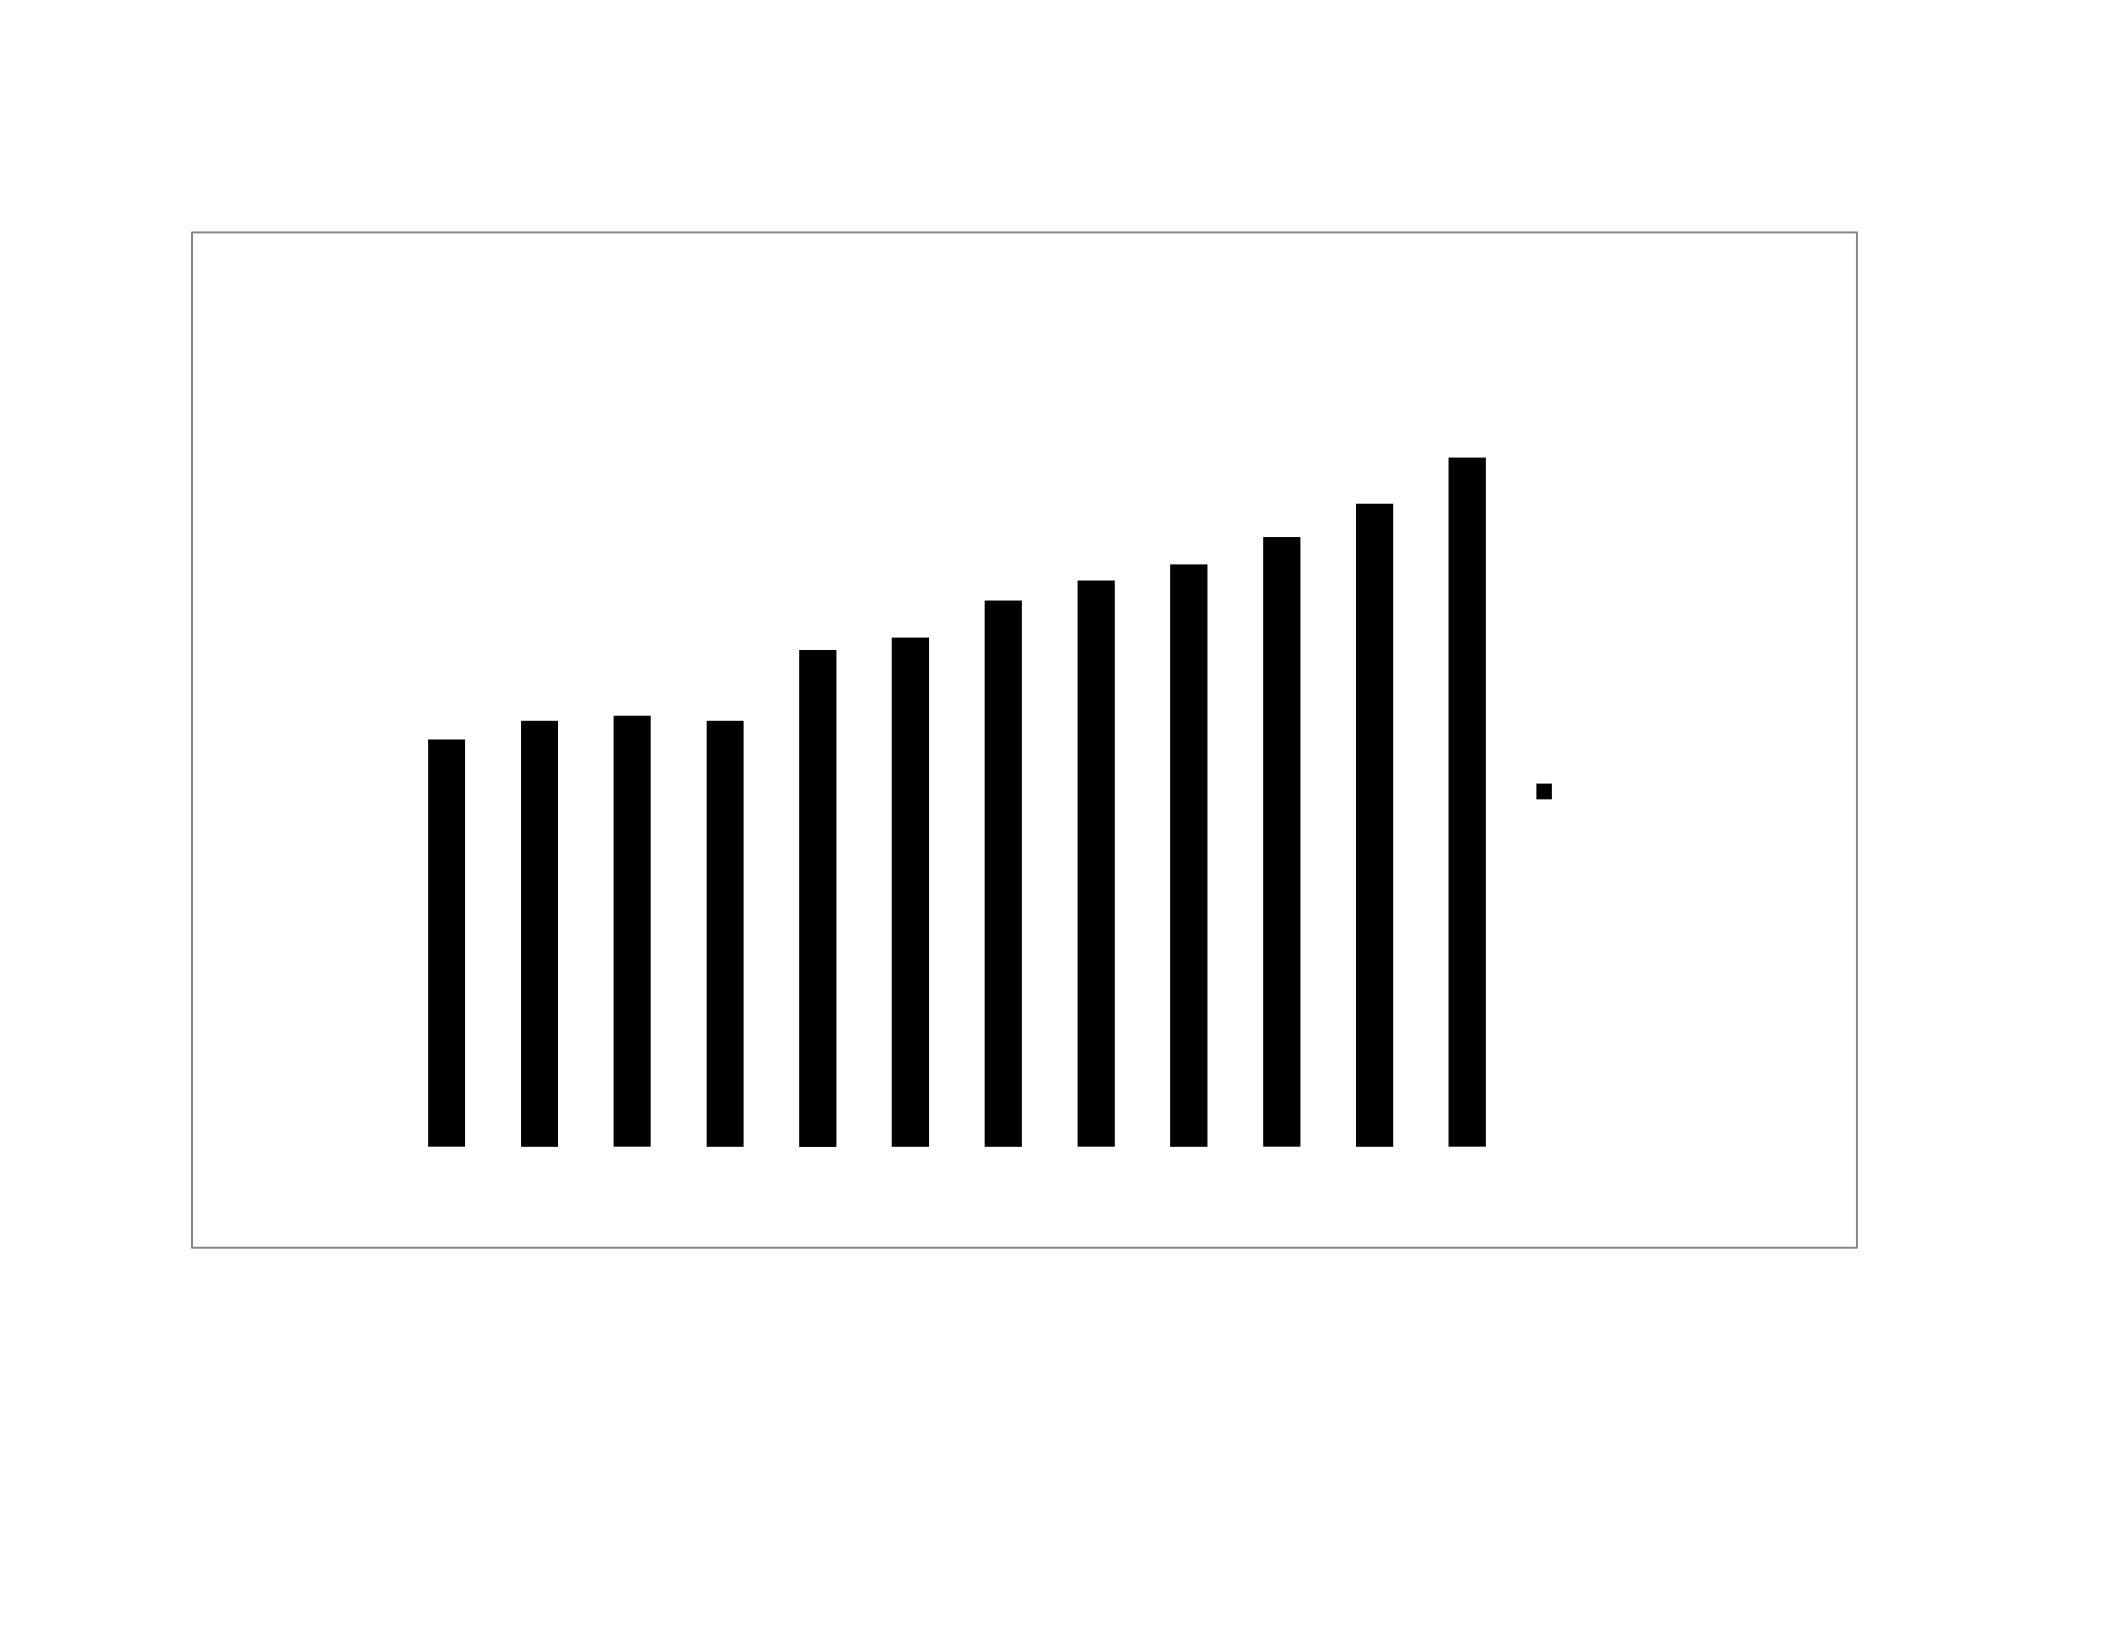
Figure 1. U.S. Corporate Foundation Philanthropic Giving from 2001 to 2012 (2,629 Corporate Foundations)
Source: The Foundation Center as of January 27, 2015
3.28 3.43 3.47 3.43
4 4.1
4.4 4.56 4.69
4.91
5.18
5.55
0
1
2
3
4
5
6
2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012
Billion$
Total charitable giving
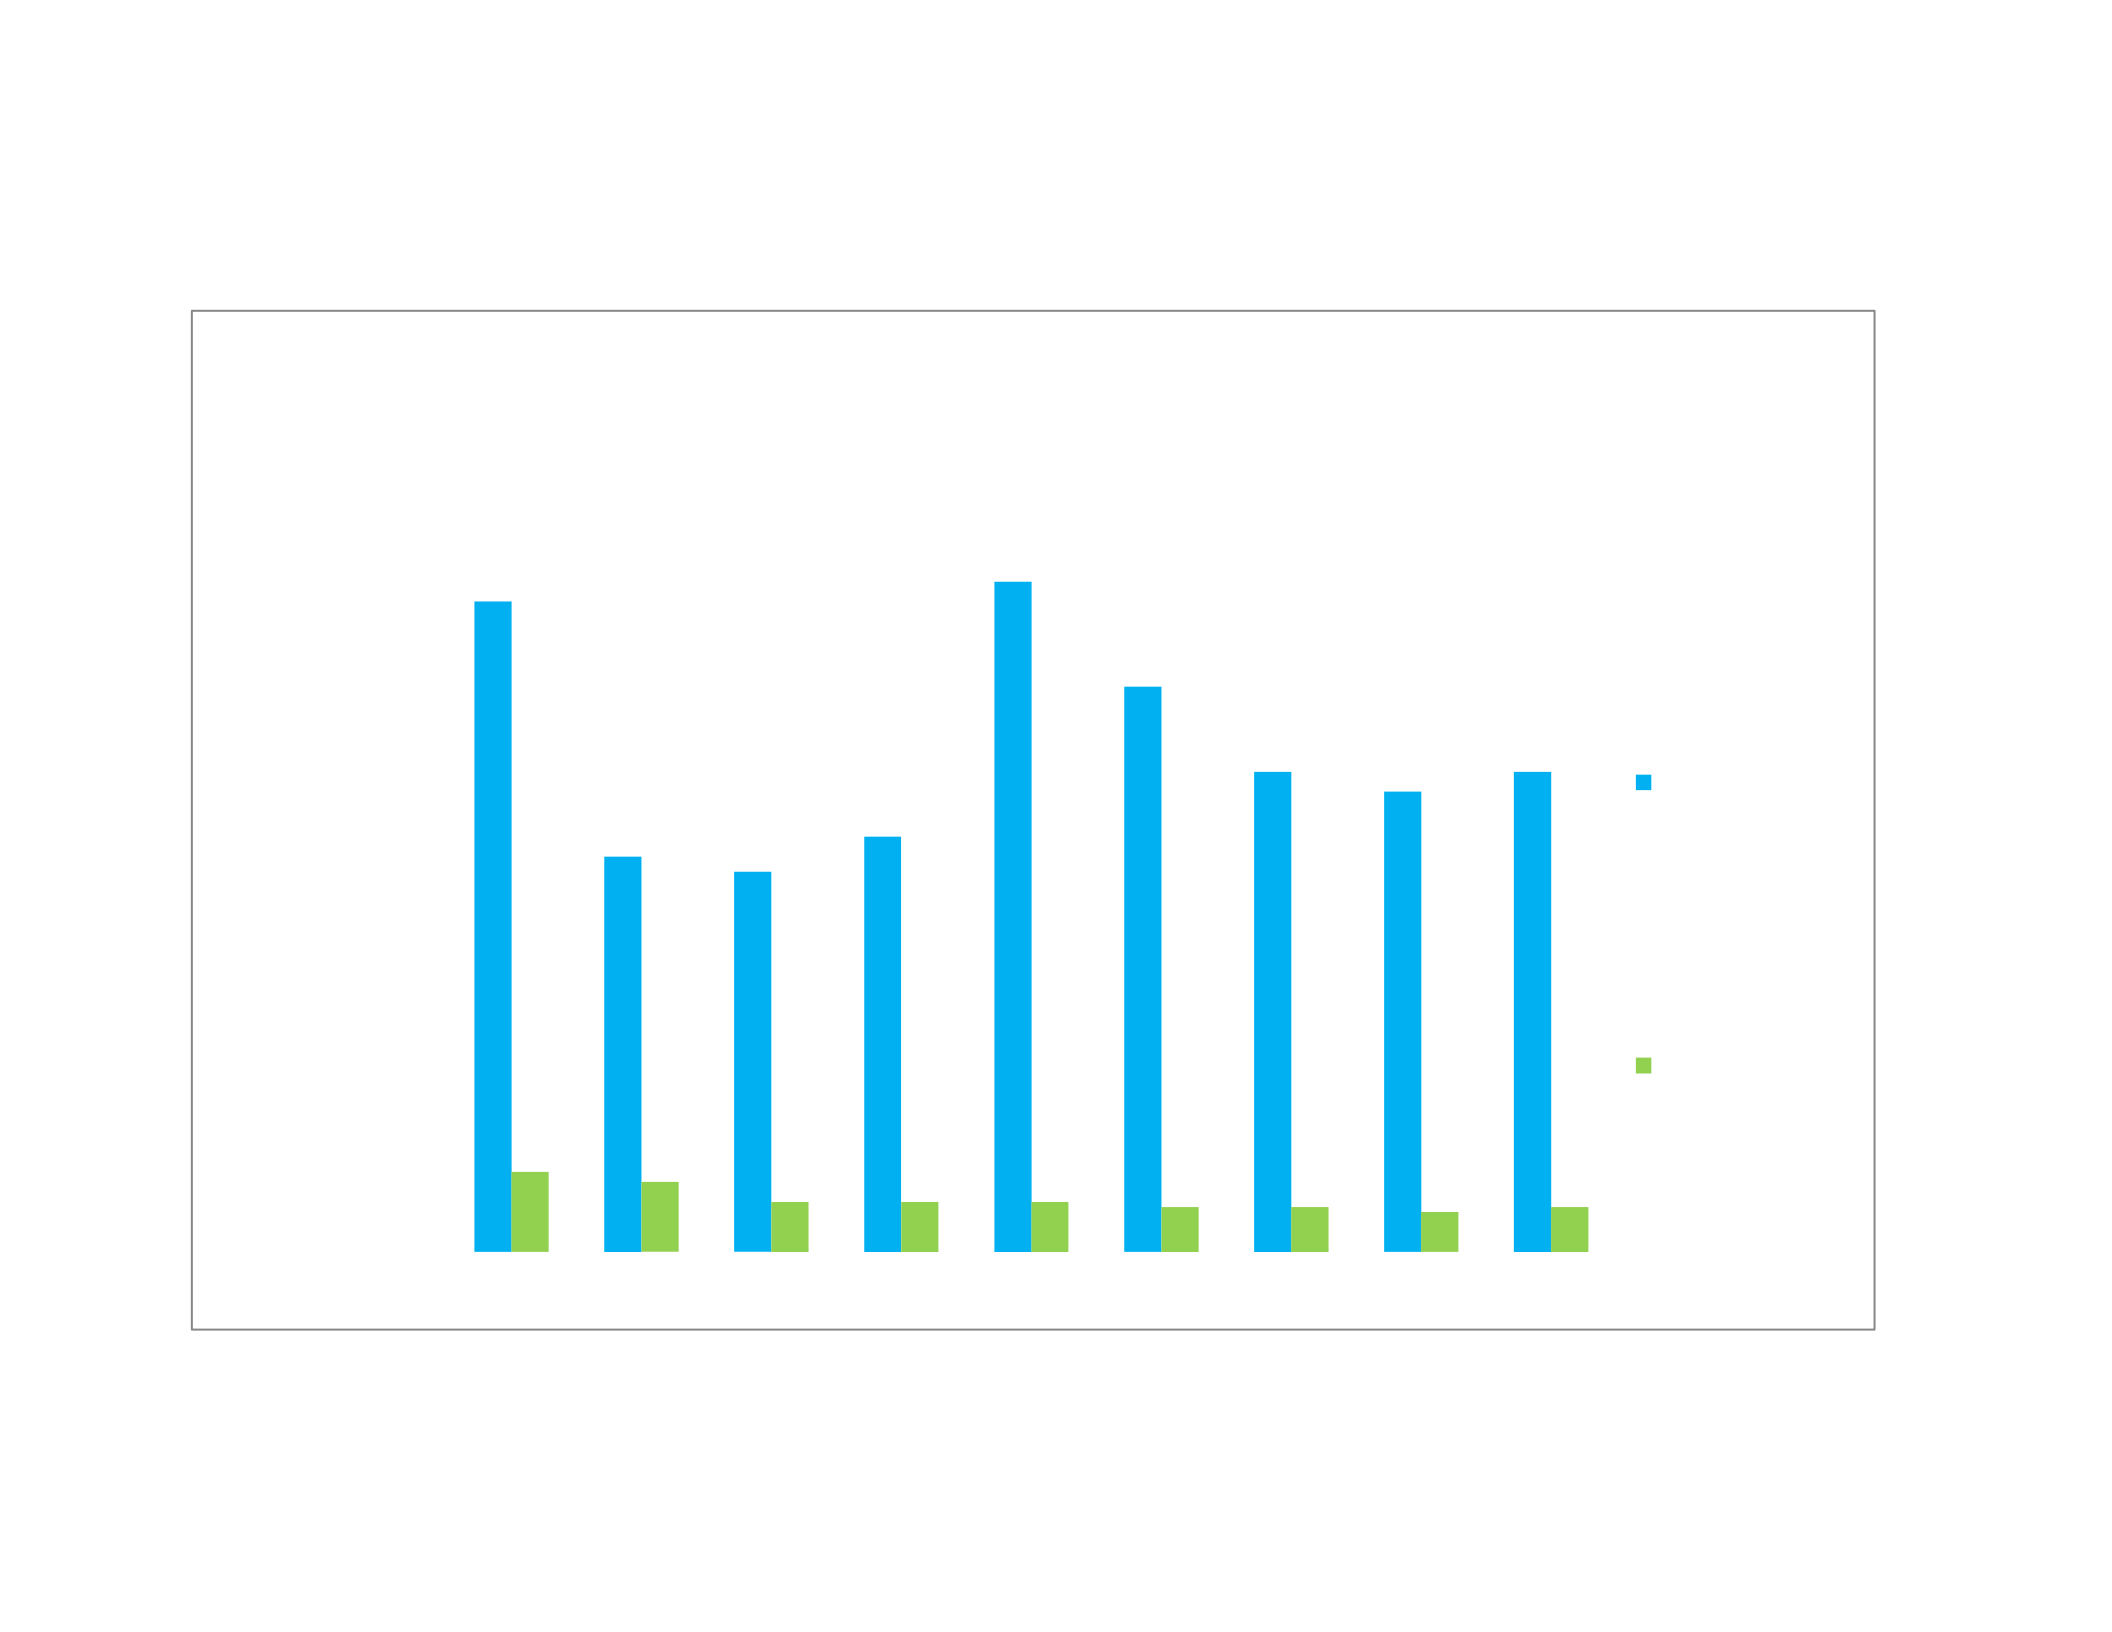
5
Figure 2. Total Charitable Giving among Fortune 100 Firms between 2004 and 2012
Source: Committee Encouraging Corporate Philanthropy as of January 27, 2015
1.3
0.79 0.76
0.83
1.34
1.13
0.96 0.92 0.96
0.16 0.14 0.1 0.1 0.1 0.09 0.09 0.08 0.09
0
0.2
0.4
0.6
0.8
1
1.2
1.4
1.6
2004 2005 2006 2007 2008 2009 2010 2011 2012
Total charitable
giving as a % of
pre-tax profit
Total charitable
giving as a % of
revenue
Million$

6

Despite the stated purpose of enhancing a firm’s public visibility and reputation by
engaging in corporate philanthropy, firms face some criticisms from stakeholders on the tangible
benefits of philanthropy. Some scholars (e.g. Devinney, 2009; Friedman, 1970) have supported
this skeptical perspective arguing that a firm exists primarily to generate economic returns, not to
solve societal problems. Friedman (1970, p. 6) argues that the single social responsibility of
business is to “engage in business activities designed to increase its profit.” On the contrary,
other scholars (e.g. Godfrey, 2005; Wang & Qian, 2011) have strongly supported the positive role
of corporate philanthropy in improving firm performance. These scholars argue that corporate
philanthropy can generate positive stakeholder support which in turn improves a firm’s financial
performance. In an effort to address the critics’ concerns on the use of corporate resources toward
charitable contributions, firms are increasingly turning to the strategic use of philanthropy.
Research suggests that strategic philanthropy can play a key role in developing value-creating
relationships with primary stakeholders and enhancing a company’s image (Buchholtz, Amason
& Rutherford, 1999; Saiia, Carroll & Buchholtz, 2003). Strategic philanthropy can also serve as
“a common meeting ground for the opponents and proponents of corporate philanthropy”
(Buchholtz et al., 1999, p. 169). Large firms are fundamentally responsible for strategic
philanthropy in practice because they have systematic structures (Marquis & Lee, 2013). For
example, large firms have corporate foundations, employee committees to oversee corporate
giving, and staff functions devoted to the effort to manage their social responsibilities (McAlister
& Ferrell, 2002). In marketing practice, strategic philanthropy has been often associated with
cause-related marketing to support social responsibility (File & Prince, 1998; Vanhamme,
Lindgreen, Reast & van Popering, 2012; Varadarajan & Menon,
1988). Both practices have some dissimilarities in terms of primary focus, time frame, and costs
(McAlister & Ferrell, 2002). Strategic philanthropy focuses on organizing itself, is ongoing, and

tends to require moderate to high resource commitment. On the other hand, cause-related
marketing focuses on the firm’s products, has a limited duration, and involves minimal resource
commitment. Both strategic philanthropy and cause-related marketing help enhance societal
welfare and improve the reputation of a firm. Stakeholder theory (Freeman, 1984) offers an
important theoretical support for the relationship between corporate philanthropy and firm
performance, suggesting that favorable social performance is a requirement for business
legitimacy, and tends to be positively associated with firm performance over the long term.
Donaldson and Preston (1995, p. 82) also suggest that firms respond to “ethical considerations
(e.g. engaging in philanthropy) which are often consistent with long-run increases in profit and
value.”
Importantly, the positive effect of corporate philanthropy on the firm provides a reason
why there is a need to examine the relationship between CEO characteristics and corporate
philanthropy. Since corporate philanthropy has become an important strategic tool that
organizational senior leaders manipulate, they are more involved in assessing and shaping
corporate strategies (Porter & Krammer, 2002). In addition, past research argues that a firm’s
social activities should be met by corporate goals determined by CEOs who constantly make
strategic decisions and choices (Choi & Wang, 2007; Wood, 1991). Furthermore, it has been
suggested that CEOs are the primary decision-makers of the organization such that an
examination of CEOs’ attitudes and values toward philanthropy provides needed insight into the
social responsibility actions in general and philanthropic function in particular (Dennis,
Buchholtz, & Butts, 2009). Accordingly, it can be suggested that the relationship between CEO
characteristics and corporate philanthropy should receive much attention. In the following
section, I will provide a brief discussion on the major research gaps that I seek to address in order

to advance the understanding of the leadership predictors of corporate philanthropy and the
implications for firm performance.
1.3 Statement of the Problem
Previous studies have focused on why firms engage in corporate philanthropy (Adams &
Hardwick, 1998; Brammer & Millington, 2005; Fombrun & Shanley, 1990; Godfrey, 2005;
Turban & Greening, 1997; Wang & Qian, 2011; Williams & Barrett, 2000). These studies have
shown that engagement in corporate philanthropy can lead to increased employee loyalty (e.g.,
employee commitment), favorable community image (e.g., corporate reputation), and positive
media coverage (e.g., recovering tarnished reputation). As such, it can be suggested that
consequences of corporate philanthropy have been extensively explored to answer the question,
“why should a firm give?” Meanwhile, antecedents of corporate philanthropy have been
explored to answer the question, “what drives firms to give?” The predominant discussion
among scholars has been on the managerial (e.g. Buchholtz et al., 1999; Choi & Wang, 2007;
Marquis & Lee, 2013; Wang & Coffey, 1992), organizational (Adams & Hardwick, 1998;
Brammer & Millington, 2006; Seifert, Morris & Bartkus, 2003), and industry (Amato & Amato,
2007, 2012; Useem, 1988) drivers of corporate philanthropy. Specifically, past research
suggested that firms engage in corporate philanthropy as a means to simultaneously and directly
benefit business interests and those of a beneficiary organization (Saiia et al., 2003; Marx, 1999).
The extent to which firms engage in corporate philanthropy can vary depending on
organizational factors, such as firm size, organizational slack, and advertising intensity (Dennis
et al., 2009; Saiia et al., 2003; Wang & Qian, 2011). Past research on corporate philanthropy has
generally discussed the intersection of business goals and the larger societal good help improve
the firm’s competitive position (Maas & Liket, 2011; Saiia et al., 2003). In sum, it can be argued
that previous studies of corporate philanthropy have developed from three aspects, “why give,”

“what leads to give,” and “give strategically.”
Unlike the extensive discussion on firm-level predictors, managerial perspective on
corporate philanthropy has not received much attention (e.g., how, why, and to what degree
individuals, such as CEOs, engage in corporate philanthropy). This line of inquiry is consistent
with a recent study’s (Aguinis and Glavas, 2012) observation that corporate social activities,
including corporate philanthropy, research is virtually absent from journals devoted to
organizational behavior and micro-level human resources management. Therefore, there is a need
to focus more on the micro level (e.g., do characteristics of individuals influence firms’
philanthropic engagement?) than on the macro level (e.g. are organizational outcomes of
corporate philanthropy beneficial to the firm?). In addition, there might be some link between
CEO characteristics and corporate philanthropy. Several scholars suggest that CEOs think
strategically about philanthropy to enhance brand name recognition, employee productivity, and
even to overcome regulatory obstacles (Seifert et al., 2003; Smith, 1994). Despite the growing
interest in the effect of CEO characteristics on CSR in general and philanthropy in particular, the
relationship between CEO characteristics and corporate philanthropy is under-developed and has
not received close empirical scrutiny.
Past research (e.g. Choi & Wang, 2007; Godfrey, 2005) has focused more on CEOs moral
background and characteristics, such as CEOs’ integrity and altruism, to explain a firm’s
philanthropic decisions. These studies, however, leave room for further explanation as to whether
CEO characteristics predict corporate philanthropy. This is because corporate philanthropy can
be driven not only by non-business community issues related to CEO altruism but also by
business-related issues, both of which benefit the firm’s strategic position. To fill this research
gap, I draw from the upper echelon theory (Carpenter, Geletkanycz & Sanders, 2004; Hambrick

& Mason, 1984) to explore how leaders’ background characteristics might influence their firms’
engagement in corporate philanthropy. Thomas and Simerly (1994) suggest that the demographic
characteristics of CEOs (e.g., age, functional background, and education) offer reliable proxies
for visible social activities of CEOs. Pedersen and Neergaard (2009) also suggest that managerial
perceptions of corporate social activities, including corporate philanthropy, are influenced by a
great deal of heterogeneity (e.g., age, gender, education, and functional backgrounds). In
addition, it might be that founder CEOs have wide strategic options and more power over their
boards (Mousa & Wales, 2012) and such status can influence corporate philanthropy. Despite the
practical importance of the relationship between founder status and corporate philanthropy, that
relationship has not received empirical investigation.
Firm size, organizational slack, and advertising intensity have been explored as important
organizational factors that influence corporate philanthropy (Dennis et al., 2009; Seifert et al.,
2003; Wang & Qian, 2011). What scholars argue is that bigger firms with more slack resources
and advertising intensity have a positive association with corporate philanthropy. What is missing
from these discussions is firm age as an important organizational context. In other words, the
relationship between firm age and corporate philanthropy has not received much scholarly
attention. For instance, Logsdon, Reiner and Burke (1990) observed in an exploratory study that
firm age might be significant in explaining placement of corporate philanthropy. Particularly,
past research has suggested that older firms tend to be increasingly inflexible so that firm age
may be an important indicator of reduced executive discretion (Finkelstein, Hambrick &
Cannella, 2009). Although the individual CEO’s influence on corporate philanthropy might vary
as a firm grows, the role of firm age on the relationship between CEO background characteristics
and corporate philanthropy has not received much attention. Therefore, it is worth exploring this
relationship.

Although corporate philanthropy has developed from a wide range of theoretical
frameworks, scholars have not yet given much thought to whether firms proactively engage in
corporate philanthropy to strengthen their business and corporate strategies. Particularly, the
relationship between corporate philanthropy and unrelated diversification is under-developed.
Unrelated diversification is one of core business strategies which help firms expand new markets.
For example, when firms pursue unrelated diversification strategies, they usually experience a
wide range of varying demands from stakeholders in distant industries or their subsidiaries
(Chatterjee & Wernerfelt, 1991). Corporate philanthropy can generate reputational assets in the
new market (Hess, Rogovsky & Dunfee, 2002), strengthen marketing and branding initiatives
(Lii & Lee, 2012; Ricks Jr, 2005), and improve relations with local governments (Wang & Qian,
2011). From this phenomenon, it can be suggested that firms can consider philanthropic activities
as part of long- term competitiveness and a means to strategically open new markets.
In addition, it is likely that the pressure for engaging in corporate philanthropy would
increase among international firms with business activities across countries and culture. Deresky
(1997) suggests that the philanthropic activities of multinational corporations that operate in
foreign countries may be characterized as strategic, clearly targeted, and linked to the overall
objectives of the firm. In addition, when firms expand their businesses in a foreign market
(Sharfman, Shaft & Tihanyi, 2004), they experience a wide range of stakeholder’ pressures.
Corporate philanthropy can be used as a means of reducing these challenges. Despite the
importance of corporate philanthropy on a firm’s internationalization, there is a lack of
theoretical explanation and empirical evidence as to whether corporate philanthropy advances a
firm’s internationalization strategy. Similarly, expansive global strategic posture (in terms of
geographic market diversification) can help firms leverage R&D costs and knowledge across
countries (Carpenter & Fredrickson, 2001; Kim & Mauborgne, 1991). It has been suggested that

corporate philanthropy may be an opportunity for internationally operating firms, but also for
investing in legitimacy in a region considered to be the main emerging market for the country
(Bohnsack, 2012; Whiteman, Muller, Van der Voort, Wijk, Meijs, & Pique, 2005). It is reasonable
to expect that firms are encouraged to engage in corporate philanthropy to develop a
commanding international presence. In sum, I explore how CEOs’ background characteristics
predict the degree of firms’ engagement in corporate philanthropy and the complimentary
theoretical relationship between corporate philanthropy and a firm’s diversification profile (such
as unrelated diversification and global strategic posture).
1.4 Purpose of the Study & Research Questions
In this dissertation, I examine the effect of CEOs’ background characteristics on corporate
philanthropy and firm diversification profile. More specifically, I examine the relationships
between CEOs’ background characteristics and corporate philanthropy. In doing so, I focus on
four aspects of CEO background characteristics (i.e. CEO founder status, functional background,
civic engagement, and education) and examine whether they are associated with the degree of
firms engagement in corporate philanthropy.
First, what is the relationship between CEO founder status and corporate philanthropy?
Founder CEOs are likely to hold a psychological bond with their firms (Peterson, Galvin &
Lange, 2012). Founder CEOs’ intrinsic motivation could lead them to engage in socially
responsible activities that meet various stakeholder demands, such as corporate philanthropy.
Second, what is the relationship between CEO functional background and corporate
philanthropy? Corporate social performance can be a reflection of CEO functional background
(Melo, 2012). Thus, it might be anticipated that a certain aspect of a CEO’s past work experience
in jobs within functional areas of organizations can influence corporate philanthropy. Third, what

is the relationship between CEO civic engagement and corporate philanthropy? CEOs often
serve as active members in community groups or associations and they participate in civic affairs
as part of their strategic mission. Doing so can be motivated by a desire to create the local
community development and a more stable political environment that ensures their business
profitability. Fourth, what is the relationship between CEO education and corporate
philanthropy? Bennett (2012) argues that better educated people have wider mental horizons that
cause individuals to recognize the value of charities concerned with the external environment.
Therefore, it is expected that CEOs’ education can play an important role in determining the
choice and emphasis on corporate philanthropy. In addition, I examine the moderating role of
firm age on the relationship between CEO background characteristics and corporate
philanthropy. Although older firms would be expected to be more well-known and have greater
philanthropic engagement, it is reasonably expected that a CEO’s influence on corporate
philanthropy varies as a firm grows.
Furthermore, I examine the role of corporate diversification profile on corporate
philanthropy and firm performance. Past research suggests that firms increase philanthropic
expenditures strategically as a means to open new markets where they are not familiar with and
the pressures for engaging in corporate philanthropy increase among international firms (Merz,
Peloza & Chen, 2010). Specifically, I examine a firm’s diversification strategy as the mechanism
through which corporate philanthropy influences firm performance. Since the ultimate goal of a
firm’s social activities, including corporate philanthropy, is to maximize performance, it is worth
exploring the interaction, including corporate philanthropy – firm performance relationship
through the mechanism of corporate diversification profile.

In sum, there are four major under-developed research areas in the literature that will be
explored in this dissertation. First, there is a need to examine the relationship between CEO
background characteristics and corporate philanthropy. Second, the role of firm age on the
relationship between CEO background characteristics and corporate philanthropy should receive
much attention. Third, whether firms proactively engage in corporate philanthropy to strengthen
their unrelated diversification strategies should receive an empirical investigation. Fourth, the
relationship between corporate philanthropy and firm performance needs to be examined
particularly under corporate diversification profile (e.g. how corporate philanthropy influences
firm performance through unrelated diversification and global strategic posture). I intend to
answer the following three research questions:
10) Do CEO background characteristics influence the level of corporate philanthropy? If so,
why?
11) Does firm age moderate the relationships between CEO background characteristics and
the level of corporate philanthropy?
12) Does corporate diversification profile mediate the relationship between the level of
corporate philanthropy and firm performance?
1.5 Significance & Contributions of the Dissertation
1.5.1 Contributions to Corporate Philanthropy Research
In this dissertation, I offer several contributions for research. First, this dissertation
contributes to the growing scholarly interests in terms of CEOs’ influence on corporate
philanthropy. It has been suggested that CEOs are requiring greater strategic accountability in
corporate giving programs (Saiia et al, 2003) and that corporations undertake strategic
philanthropy as long as direct economic benefits can be gained by doing so (Sánchez, 2000).

Therefore, an examination of whether CEO background characteristics influence corporate
philanthropy helps to fulfill research interests.
Second, I extend the literature on corporate philanthropy to examine the strategic use of
philanthropy. It has been suggested that traditional altruistic models of philanthropy are
becoming less relevant because it is generally considered a non-strategic explanation of corporate
giving which ignores the profit maximization goal and other strategic goals of the firm
(Neiheisel, 1994; Sánchez, 2000). Corporate giving activities have evolved into far more
strategically market-oriented approaches like targeted grants intended to optimize economic
return as well as social returns per philanthropic dollar (Sherblom, 2007).
Third, drawing upon the institutional and stakeholder perspectives, I offer a new attempt
to empirically examine the link between corporate philanthropy and unrelated diversification. For
example, faced with various challenges (e.g., social, legal, and regulatory), corporate
diversification increases a variety of stakeholder pressures in the firm’s external environment that
arise (Brammer, Millington & Pavelin, 2006; Sharfman et al., 2004). In addition, highly
diversified firms not only suffer from a lack of coherence in terms of underlying resources
(Montgomery & Wernerfelt, 1988) but they also have to deal with heavy stakeholder demands.
These pressures might be mitigated when engaging in corporate social activities through which
unrelated diversifiers can manage a wide range of stakeholders’ demands.
Fourth, although previous studies (Markides & Williamson, 1994; Palepu, 1985; Rumelt,
1974) suggest a negative relationship between unrelated diversification and (short-term) financial
performance, this dissertation provides a different perspective to corporate diversification
strategy. For example, corporate philanthropy helps to generate reputation and branding
initiatives in the new markets so that it can improve the firm’s market positions (Hess et al.,

2002; Ricks Jr, 2005). In this dissertation, I provide scholars with a promising suggestion that
unrelated diversification may not necessarily be an inferior strategy for the firm.
1.5.2 Contributions to Practice
In this dissertation, I offer several contributions for practice. First, understanding of how
CEO background characteristics (e.g., CEO status, functional background, civic engagement, and
education level) can be applied to corporate philanthropy helps to explain the rationale behind
decisions to engage in corporate philanthropy. Therefore, I answer what leads CEOs to engage in
corporate philanthropy and further why some CEOs engage in more corporate philanthropy than
others. Second, I provide managers with practicability of corporate philanthropy. For example,
strategic use of philanthropic expenditures can support a community project in developing
countries (Porter & Kramer, 2002; Sánchez, 2000) because better community conditions are
good for business (e.g., when the standard of living is increased, product demand is increased).
Third, I provide managers with a promising notion that engaging in corporate
philanthropy can help firms with diversification and market entry strategies. Scholars argue that a
firm’s philanthropic engagement in developing countries can enhance the firm’s reputation and
get easier access to the market (Bohnsack, 2012; Brammer et al., 2006). There might be a
positive relationship between corporate philanthropy and international presence. In addition, it is
suggested that corporate philanthropy can offer an opportunity for internationally operating firms
as well as for investing in business legitimacy. In this dissertation, I can provide managers with
practicability that international firms can strengthen their competitive context by engaging in
corporate philanthropy. Fourth, I provide insights on business legitimacy by suggesting that firms
are seen as legitimate actors by local stakeholders to the extent they engage in corporate
philanthropy. Goyal (2006) and Wang and Qian (2011) suggest that philanthropic activities of

multinational firms in the host countries would be a signaling device to demonstrate that they
have long-term intentions consistent with the local expectations. Thus, I suggest that firms can
receive supportive responses from the host countries governments by engaging in corporate
philanthropy.
1.6 Definition of Key Terms
Corporate social responsibility (CSR) refers to “context-specific organizational actions
and policies that take into account stakeholders’ expectations and the triple bottom line of
economic, social, and environmental performance” (Aguinis, 2011, p. 855).
Diversification refers to “the entry of a firm or business unit into new lines of activity,
either by processes of internal business development or acquisition, which entail changes in its
administrative structure, systems, and other management processes” (Ramanujam &
Varadarajan, 1989, p. 525). There are two types of diversification, such as related diversification
and unrelated diversification. Related diversification refers to a diversification built around a
core organizational capability (Ramanujam, 1987; Rumelt, 1982). It occurs when firms expand
their areas closely related to their primary activities and areas of technical expertise. Unrelated
diversification refers to a diversification that drives to move into unrelated lines of business
(Ramanujam, 1987; Rumelt, 1982). It occurs where firms expand their operations into markets or
products beyond current resources and capabilities.
Corporate philanthropy refers to the practice of “giving firm resources to invest in
business-related issues and non-business community issues that also benefit the firm’s strategic
position and, ultimately, its bottom line” (Saiia et al., 2003, p. 170). This definition helps to
explain why some firms still donate in non-business areas more than others. They do so because

they believe that giving non-business issues would enhance their public image which can be used
for gaining business legitimacy in developing countries (Wang & Qian, 2011).
Global strategic posture (GSP) refers to “the degree to which a firm is dependent on
foreign sales and production and to the geographic dispersion of this dependence” (Carpenter,
Sanders & Gregersen, 2001, p. 497). It has been suggested that GSP reflects the relative
significance of foreign markets and operations in sustaining the firm as well as their geographic
dispersion (Sullivan, 1994). Therefore, GSP can be used for measuring firm internationalization
(Carpenter & Fredrickson, 2001; Levy, 2005). GSP are normally measured by three dimension
originally developed by Sullivan (1994): foreign sales, foreign production, and geographic
diversity. Foreign sales reflect the relative significance of foreign market. Foreign production
reflects the degree to which a firm depends on foreign-owned assets and resources. Geographic
diversity reflects the extent to which a firm has subsidiaries associated with globalization of
operations and markets. Several scholars used GSP to explain a firm’s internationalization
strategy (Carpenter et al., 2001; Carpenter & Fredrickson, 2001; Levy, 2005).
1.7 Organization of the Dissertation
This dissertation consists of six chapters. The first chapter provides an introduction about
the importance of corporate philanthropy, statement of the problem, major research questions as
well as the contributions of the dissertation. Chapter two presents a comprehensive and extensive
review of the literature on corporate social responsibility and the antecedents and consequences
of corporate philanthropy with the role of leadership in corporate philanthropy. Chapter three
presents the research model, theoretical foundations, and summary of theoretically-driven
hypotheses. Chapter four presents the research design including target sample, measures, as well
as statistical techniques. Chapter five presents and highlights the results of statistical analyses,

including summary of findings and summary of hypotheses. Chapter six discusses the results
from Chapter five, the implications to research and practice, limitations, future research
directions, and conclusion.

CHAPTER II
LITERATURE REVIEW
This chapter provides a comprehensive review of the corporate philanthropy research.
The first section begins with a systematic review of the literature on the relationship between
Corporate Social Responsibility (CSR) and firm performance as well as the leadership
determinants of CSR. In the second section, I discuss the theoretical conceptualizations of
corporate philanthropy with a comparative review of the traditional and strategic philanthropy
literatures. In the third section, I discuss the managerial, organizational and industry level
antecedents and consequences of corporate philanthropy with a particular emphasis on the link
between leadership attributes and corporate philanthropy. In the fourth section, I present a
comprehensive review of research on the link between corporate philanthropy and corporate
strategy. The chapter then concludes with a contingency view of corporate philanthropy.
2.1 How Does Corporate Social Responsibility (CSR) Influence Firm Performance?
CSR refers to “context-specific organizational actions and policies that take into account
stakeholders’ expectations and the triple bottom line of economic, social, and environmental
performance” (Aguinis, 2011, p. 855). Specifically, the demand for business CSR initiatives has
been significantly higher around the world over the last several decades. Accordingly, firms
nowadays are expected to act more proactively to fulfill their CSR expectations as responsible
corporate citizens to the society (Wang & Hsu, 2011). Since engaging in CSR is considered a
socially responsible investment for the firm, how CSR influences firm performance has been an
important issue among organizational scholars (Agle, Mitchell & Sonnenfeld, 1999; Aguinis &
Glavas, 2012; Orlitzky, Schmidt & Rynes, 2003). Even though there are some debates as to
whether CSR helps to improve firm performance, an extensive line of research has empirically

explored how CSR boosts firms’ competitive advantage, thereby ensuring value creation and
satisfaction for stockholders and customers (Cox, Brammer & Millington, 2004; Lev, Petrovits &
Radhakrishnan, 2010).
The topic of whether CSR can have a positive effect on firm performance has generated
extensive discussions among scholars and practitioners. Friedman (1970) provides the classical
economic perspective that management has one responsibility and that is to maximize the profits
of its shareholders. Past research suggests that socially responsive firms incur higher direct costs
and reap lower profits than socially unresponsive firms (Aupperle, Carroll & Hatfield; 1985;
Devinney, 2009). In addition, some scholars have used agency theory that “good social
performance comes at the expense of good financial performance because social performance
makes use of firm resources in ways that confers significant managerial benefits rather than
returning those resources to shareholders” (Brammer & Millington, 2008, p. 1329). They argued
that firms would better spend their resources on value-added internal projects or return to
shareholders rather than invest in CSR. Despite these perspectives, there has been a growing
institutional and societal pressure on businesses to pursue a socially responsible operation for the
last couple of decades and a number of institutional approaches can explain this trend. Jones
(1995) suggests that firms facing repeated transactions with stakeholders based on trust and
cooperation are encouraged to be honest, trustworthy, and ethical because they believe that the
returns to such behavior are high. In addition, a majority of empirical evidence suggests a
significant positive relationship between CSR and financial performance (Aguinis & Glavas,
2012; Peloza, 2009). For example, Peloza (2009) reviewed 128 studies that explored the
relationship between CSR and financial outcomes and found that, almost 60 % showed a positive
relationship, less than 15 % a negative relationship and mixed findings from the rest of the

studies. Recently, Aguinis and Glavas (2012) summarized the overall empirical evidence on
CSR-performance relationship in a wide range of organizational fields as follows (p. 947):
“Working for socially responsible companies leads to increased organizational
identification (Carmeli, Gilat, & Waldman, 2007), employee engagement (Glavas
& Piderit, 2009), retention (Jones, 2010), organizational citizenship behavior (Lin,
Lyau, Tsai, Chen, & Chiu, 2010), employee commitment (Maignan, Ferrell & Hult,
1999), employee creative involvement (Glavas & Piderit, 2009), and improved
employee relations (Glavas & Piderit, 2009).”
In the 21th century, the influence of CSR on a firm performance is an important concern to
a firm’s stakeholders so that firms should consider CSR as part of their strategies (Lantos, 2001).
Given the ultimate responsibility of firms meets the needs of stakeholders, firms should fulfil
stakeholders’ demands while also devoting resources to CSR. Such seemingly contrasting
demands are leading more firms to embrace strategic CSR or strategic use of philanthropy.
Carroll (2001), for instance, argues that strategic CSR can accomplish strategic business goals,
including good deeds, are believed to be good for business as well as for society. Several scholars
have discussed strategic aspects of CSR. Porter and Kramer (2006) argue that CSR should be
seen as one of core business strategies in a firm, indicating that the firm can benefit from its
social investment. Maignan et al. (2005) also argue that CSR can serve as an attractive, valuable
resource offering competitive advantage for enhancing business performance because it can be
used as a means of conducting business strategies.
2.1.1 What Role Do Organizational Leaders Play in Fostering CSR?

In an attempt to link organizational leaders (e.g., CEOs) to CSR, scholars have focused on
three aspects of CEO background characteristics: values, compensation levels, and personal
attributes (experiences). For example, CEO integrity can be relevant to CSR such that leader
vision and integrity will increase CSR values to shareholders. Waldman and Siegel (2008) argue
that leader integrity to personal morality can yield positive outcomes for business and may
actually be the driver of CSR strategies in organizations. Ketola (2006) also argues that leader
integrity is an important component in his or her successful promotion of CSR activities at the
firm. In addition, the relationship between CEO compensation and CSR has received some
attention. For instance, McGuire, Dow and Argheyd (2003) empirically examined the
relationship between the level of CEO compensation and corporate social performance (CSP) but
they did not find any positive relation. However, Jiraporn and Chintrakarn (2013) using a sample
of 1,370 firms found that when the CEO power (as measured by the total compensation) goes
beyond a certain threshold, more powerful CEOs significantly reduce CSR investments.
Furthermore, several scholars examined the professional background of CEOs and corporate
social performance (Mazutis, 2014; Simerly, 2003; Thomas & Simerly, 1994). They found that
corporate social performance can be interpreted as a reflection of CEOs’ professional
background.
Do organizational leaders play a role in promoting CSR? This question has long attracted
extensive research (Fabrizi, Mallin & Michelon, 2014; Jiraporn & Chintrakarn, 2013). As senior
leaders, CEOs and their top management teams are charged with the responsibility of
formulating business and sustainability strategy (Strand, 2013; Wood, 1991). Indeed, today’s
corporate leaders play an important role in pursuing an effective CSR agenda (Bielak, Bonini &
Oppenheim, 2007; Fabrizi et al., 2014;Godos-Díez, Fernández-Gago & Martínez-Campillo,
2011; Mazutis, 2014). For example, CEOs engage in CSR related activities in response to

growing pressures from key stakeholders groups, such as customers and employees (Bielak et al.,
2007). In addition, while pressures from employees, customers, and other stakeholders can play a
crucial role in CEOs’ willingness to engage in CSR, CEOs recognize that CSR can give their
firms an opportunity to gain a competitive advantage as well as address societal needs (Bielak et
al., 2007). In addition, Godos-Díez et al. (2011) using a sample of 149 CEOs found that those
closer to the steward model are more inclined to attach great importance to ethics and CSR, and
to implement CSR practices. Fabrizi et al (2014) using a sample of 597 U.S. firms extended the
role of CEO’s incentives on CSR and found that non-monetary incentives have a positive effect
on CSR. Mazutis (2014) using a sample of 349 firms found the link between CEO open
executive orientation (such as a liberal worldview and output functional experiences) and
positive CSR initiative adoption over time. In this sense, it can be argued that the relationship
between leadership and CSR has become an important topic of research in the area of leadership
studies (Bielak et al., 2007; Godos-Díez et al., 2011; Fabrizi et al., 2014; Mazutis, 2014).
Transformational leadership helps represent the understanding of CSR in particular.
Transformational leadership is comprised of four major components (Avolio, Bass & Jung, 1999;
Bass & Riggio, 2006): (1) Idealized Influence (ability of leader to attract admiration and respect
and desire to follow from subordinates), (2) Inspirational Motivation (ability of leader to
communicate clear vision and create enthusiasm about future), (3) Intellectual Stimulation
(ability of leader to encourage creativity and unconventional and status quo-challenging
problem-solving among followers), and (4) Individual Consideration (ability of leader to accept
individual differences and actively provide feedback and interaction with followers).
Organizational scholars argue that transformational leadership has been found to influence CSR
behavior among some firms (Du, Swaen, Lindgreen & Senthat, 2013; McWilliams, Siegel &
Wright, 2006).

McWilliams et al (2006), for instance, suggest that strategic leadership theory can be
applied to CSR and that transformational leadership will be positively correlated with the
tendency of companies to engage in CSR. They explored the degree of transformational
leadership using CEOs of 112 large US and Canadian firms and found that intellectual
stimulation (which is one dimension of transformational leadership components) was a predictor
of the firm’s propensity to engage in strategically oriented CSR that were more likely to be
related to the firm’s corporate and business-level strategies (e.g., differentiation and reputation
building). In addition, Du et al. (2013) in a survey of 440 U.S firms found that firms with greater
transformational leadership are more likely to engage in institutional CSR practices, whereas
transactional leadership is not associated with such practices. Furthermore, it has been suggested
that charismatic leadership with self-concepts of followers can be related to CSR. For example,
leaders have values and moral justifications which provide followers with motivational effects
such that charismatic leaders can help connect one’s identify with greater social causes (Shamir,
House & Arthur, 1993).
In conclusion, the empirical evidence on the relationship between CSR and firm
performance seems to be inconclusive (Peloza, 2009). However, more recent studies suggest that
there is a positive association between CSR and firm performance (Aguinis & Glavas, 2012;
Chen & Wang, 2015). In addition, since some firms consider CSR as part of their core corporate
strategy and CEOs are charged with the responsibility of formulating corporate strategy, the
relationship between leadership characteristics and CSR is particularly important. Furthermore, it
can be suggested that understanding of three aspects of CEOs (values, compensation, and
experiences) helps to link CEO background characteristics and CSR. As mentioned in section
2.1.1, there is a certain interrelationship between CEOs and CSR. Table 1 below provides an
overview of research on the role of leadership in fostering CSR.

CSR as a business practice and philosophy has taken an important place in the way
businesses operate and serve their stakeholders. CSR refers to “context-specific organizational
actions and policies that take into account stakeholders’ expectations and the triple bottom line of
economic, social, and environmental performance” (Aguinis, 2011, p. 855). This definition
indicates that businesses should have responsibility beyond their immediate economic concern
and should act in a way that contributes and enhances broader societal goals. CSR primarily
embraces economic, legal, ethical, and philanthropic responsibilities and the dimensions of CSR
include the obligations a business has to its stakeholder’s groups (Carroll, 1991). Over the past
half century, CSR has increasingly been integrated into mainstream business thinking, and
nowadays, most U.S. publicly-traded firms (e.g., Microsoft, Google, and Walt Disney) claim to
engage in some form of CSR. The main benefits of engaging in CSR include generating
intangible assets, including building corporate reputation and employee commitment, and
tangible assets, including the positive impact on financial performance. Research in this area
suggests that being a socially responsible business helps create goodwill, build a positive
organizational image, differentiate them from their competitors, and, as a result, promote
longterm profits for business (Boynton, 2013). Indeed, more firms increasingly embrace CSR as
their employees demand their firms to be socially responsible, customers expect better business
practices, and investors realize the economic rewards of sustainable business models. Beyond the
immediate task environment, business CSR engagement also serves the needs of communities
around the world and fulfills the responsibilities businesses have to the public.
1.2 The Importance of Corporate Philanthropy
Corporate philanthropy is considered one of the core dimensions of CSR (Aguinis &

Clavas, 2012; Carroll, 1991; Porter & Kramer, 2002). The origin of corporate philanthropy in the
U.S. dates back to the rise of industrial age in the 19th and early 20th century, when businessmen
like Henry Ford and John D. Rockefeller established philanthropic foundations (Dietlin, 2011).
Corporate philanthropy has since been transformed from piecemeal individual philanthropic acts
(e.g., philanthropy mainly driven by morality) to a major aspect of corporate CSR practices.
Corporate philanthropy is, nowadays, a widespread business practice in large multinationals as
well as small-and medium-sized firms across the globe. Despite the dominant altruistic
orientation, corporate philanthropy has increasingly complemented the firm’s strategic activities
and enhanced the firm’s social and financial performance (Porter & Kramer, 2002). Therefore, it
can be argued that corporate philanthropy has evolved dramatically from a basic moral obligation
to a strategically-driven activity of the firm. As Porter and Kramer (2002, p. 58) put it,
“True strategic giving, by hand, addresses important social and economic goals simultaneously,
targeting areas of competitive context where the company and society both benefit because the
firm brings unique assets and expertise.”
Corporate philanthropy can often be “the most cost-effective way for a firm to improve its
competitive context” (Porter & Kramer, 2002, p. 9). Many firms invest a significant amount of
resource expenditures on philanthropy in order to build a strong company image. For example, a
2013 report from the Committee Encouraging Corporate Philanthropy indicates that 59 percent
of the largest Fortune 100 firms donated significantly more in 2012 compared to 2007, the year
before the global recession sets in, and aggregate giving rose by 42% ($4.48 billion) from 2007
to 2012. The ten largest U.S. corporations donated over 2.1 billion dollars in 2013 and this figure
has increased in 2014. Many firms provide support to nonprofits and social causes primarily
through company-sponsored foundations as well as corporate direct giving, both of which are

closely tied with the parent company’s business interests. As shown in Figure 1 below, the largest
U.S. firms and their foundations have increased charitable giving during the past decade (2001-
2012). Similarly, as shown in Figure 2 below, the largest 100 U.S. corporations have increased
total charitable giving both as a percentage of pre-tax profit and as a percentage of revenue
especially after the global recession in 2008.
Indeed, the increasing commitment of corporate resources to philanthropic causes reflects
a widely-held belief among business executives that philanthropy can be “strategic” in that it can
make a substantial impact on society while improving business value and reputation for the firm
(Carroll & Shabana, 2010; Walker, 2002). According to a 2010 survey by CECP, 77 percent of
CEOs noted that “the most important action they can take to prepare for 2020 is to embed social
engagement into business strategy and organizational structure.” For example, Ronald A.
Williams, the CEO of Aetna noted that that “public companies can move the collective needle by
using their human and financial resources to innovative in ways that benefit both private interests
and the public good” (Weiss, Kerdahy & Kneale, 2008, p. 5). Ivan Seidenberg, Chairman and
CEO, Verizon Communications Inc., commented in CECP that “our belief is that corporate
philanthropy expands the business. You can expand the capabilities of your customer base,
business and society by doing the right thing.” These and other executive views also highlight an
important fact that corporate philanthropy can be driven by leadership values and studying
leaders’ background can help extend our knowledge of the role of corporate philanthropy in
improving firm performance.
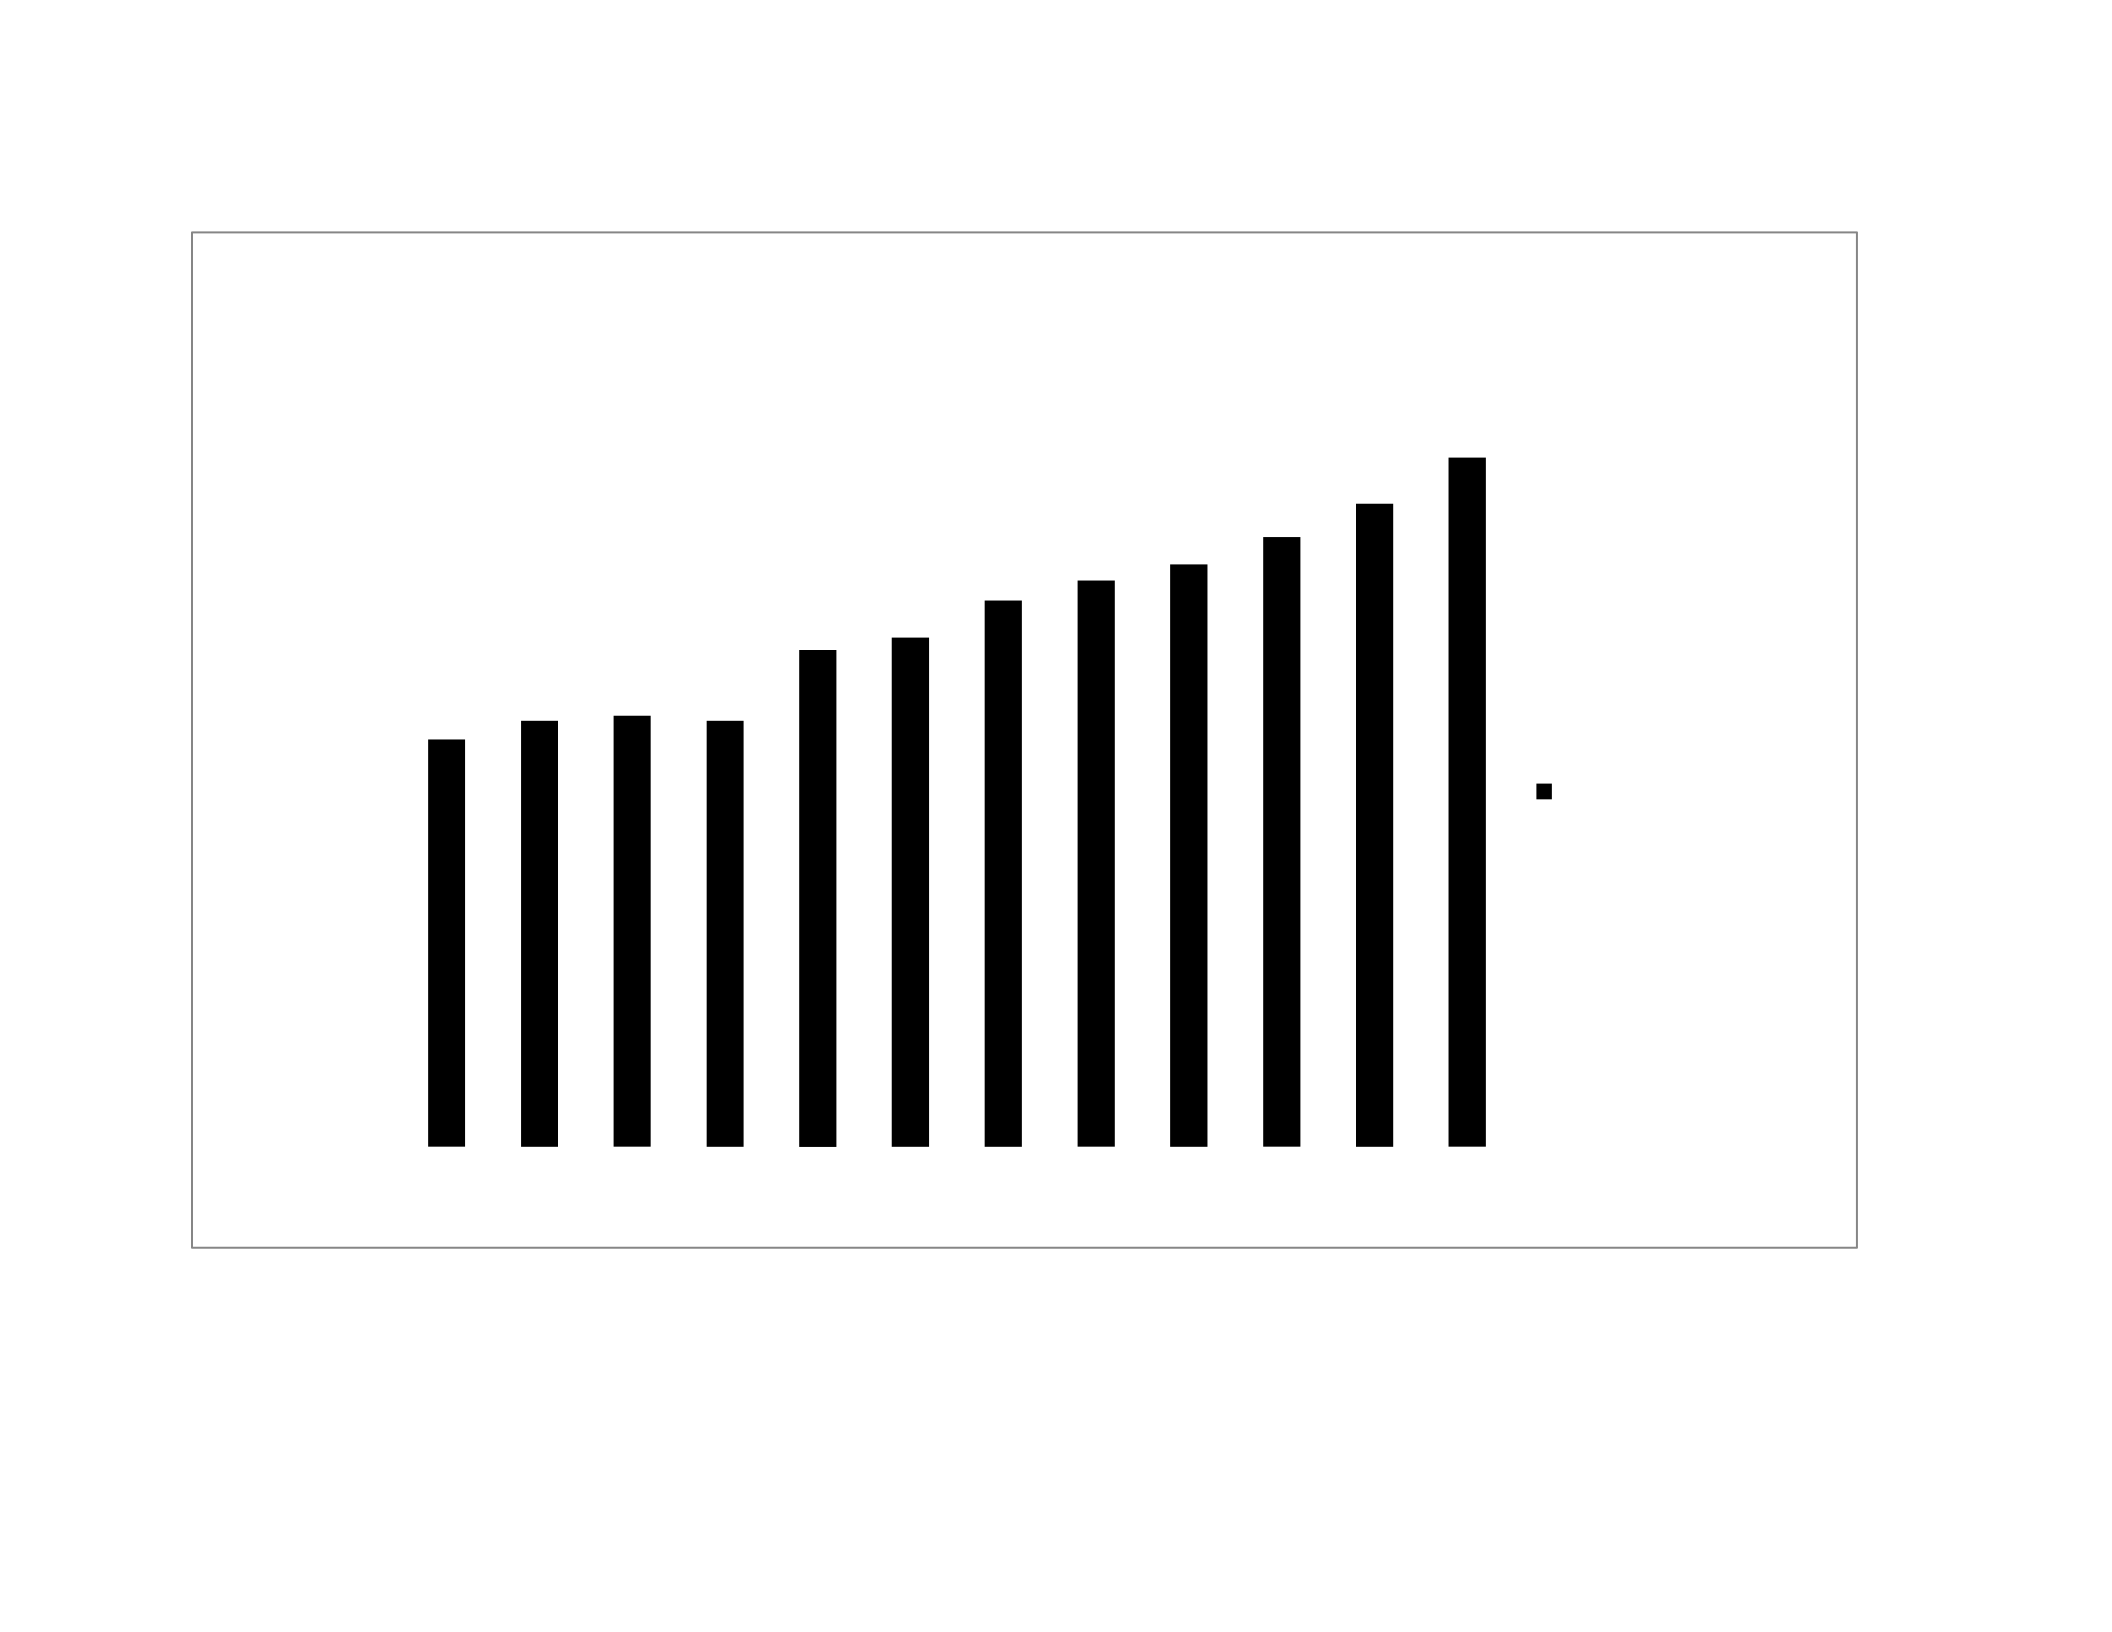
Figure 1. U.S. Corporate Foundation Philanthropic Giving from 2001 to 2012 (2,629 Corporate Foundations)
Source: The Foundation Center as of January 27, 2015
3.28 3.43 3.47 3.43
4 4.1
4.4 4.56 4.69
4.91
5.18
5.55
0
1
2
3
4
5
6
2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012
Billion$
Total charitable giving
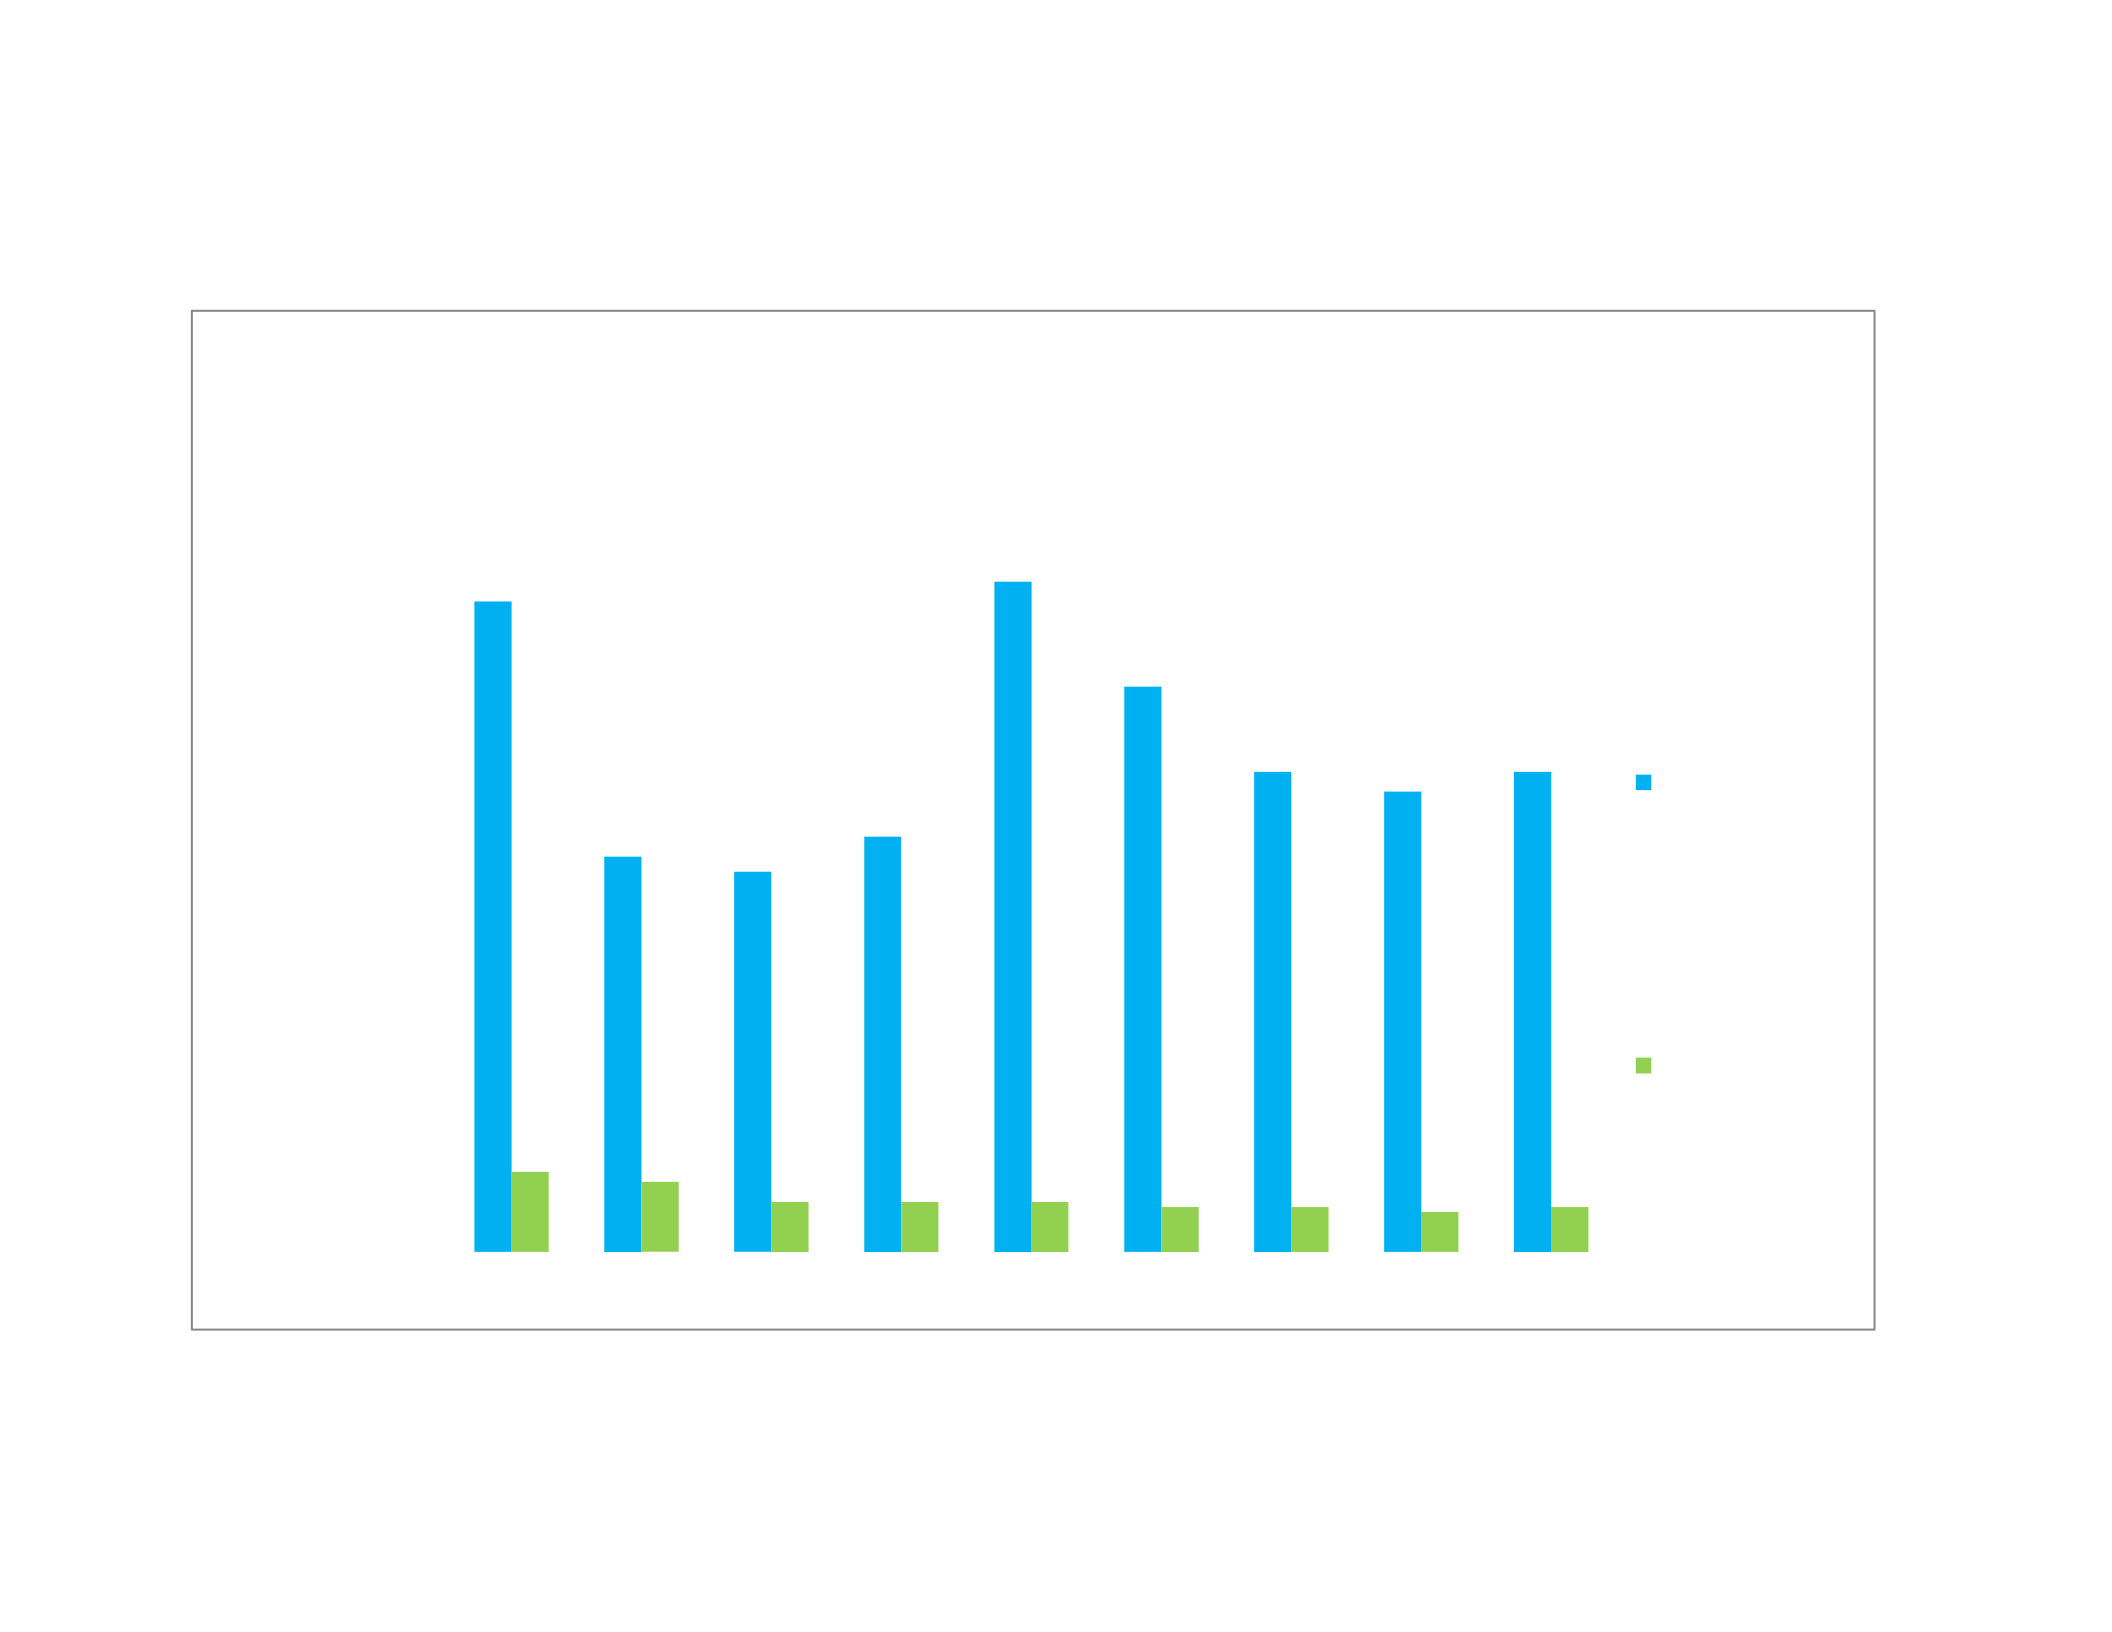
5
Figure 2. Total Charitable Giving among Fortune 100 Firms between 2004 and 2012
Source: Committee Encouraging Corporate Philanthropy as of January 27, 2015
1.3
0.79 0.76
0.83
1.34
1.13
0.96 0.92 0.96
0.16 0.14 0.1 0.1 0.1 0.09 0.09 0.08 0.09
0
0.2
0.4
0.6
0.8
1
1.2
1.4
1.6
2004 2005 2006 2007 2008 2009 2010 2011 2012
Total charitable
giving as a % of
pre-tax profit
Total charitable
giving as a % of
revenue
Million$

6

Despite the stated purpose of enhancing a firm’s public visibility and reputation by
engaging in corporate philanthropy, firms face some criticisms from stakeholders on the tangible
benefits of philanthropy. Some scholars (e.g. Devinney, 2009; Friedman, 1970) have supported
this skeptical perspective arguing that a firm exists primarily to generate economic returns, not to
solve societal problems. Friedman (1970, p. 6) argues that the single social responsibility of
business is to “engage in business activities designed to increase its profit.” On the contrary,
other scholars (e.g. Godfrey, 2005; Wang & Qian, 2011) have strongly supported the positive role
of corporate philanthropy in improving firm performance. These scholars argue that corporate
philanthropy can generate positive stakeholder support which in turn improves a firm’s financial
performance. In an effort to address the critics’ concerns on the use of corporate resources toward
charitable contributions, firms are increasingly turning to the strategic use of philanthropy.
Research suggests that strategic philanthropy can play a key role in developing value-creating
relationships with primary stakeholders and enhancing a company’s image (Buchholtz, Amason
& Rutherford, 1999; Saiia, Carroll & Buchholtz, 2003). Strategic philanthropy can also serve as
“a common meeting ground for the opponents and proponents of corporate philanthropy”
(Buchholtz et al., 1999, p. 169). Large firms are fundamentally responsible for strategic
philanthropy in practice because they have systematic structures (Marquis & Lee, 2013). For
example, large firms have corporate foundations, employee committees to oversee corporate
giving, and staff functions devoted to the effort to manage their social responsibilities (McAlister
& Ferrell, 2002). In marketing practice, strategic philanthropy has been often associated with
cause-related marketing to support social responsibility (File & Prince, 1998; Vanhamme,
Lindgreen, Reast & van Popering, 2012; Varadarajan & Menon,
1988). Both practices have some dissimilarities in terms of primary focus, time frame, and costs
(McAlister & Ferrell, 2002). Strategic philanthropy focuses on organizing itself, is ongoing, and

tends to require moderate to high resource commitment. On the other hand, cause-related
marketing focuses on the firm’s products, has a limited duration, and involves minimal resource
commitment. Both strategic philanthropy and cause-related marketing help enhance societal
welfare and improve the reputation of a firm. Stakeholder theory (Freeman, 1984) offers an
important theoretical support for the relationship between corporate philanthropy and firm
performance, suggesting that favorable social performance is a requirement for business
legitimacy, and tends to be positively associated with firm performance over the long term.
Donaldson and Preston (1995, p. 82) also suggest that firms respond to “ethical considerations
(e.g. engaging in philanthropy) which are often consistent with long-run increases in profit and
value.”
Importantly, the positive effect of corporate philanthropy on the firm provides a reason
why there is a need to examine the relationship between CEO characteristics and corporate
philanthropy. Since corporate philanthropy has become an important strategic tool that
organizational senior leaders manipulate, they are more involved in assessing and shaping
corporate strategies (Porter & Krammer, 2002). In addition, past research argues that a firm’s
social activities should be met by corporate goals determined by CEOs who constantly make
strategic decisions and choices (Choi & Wang, 2007; Wood, 1991). Furthermore, it has been
suggested that CEOs are the primary decision-makers of the organization such that an
examination of CEOs’ attitudes and values toward philanthropy provides needed insight into the
social responsibility actions in general and philanthropic function in particular (Dennis,
Buchholtz, & Butts, 2009). Accordingly, it can be suggested that the relationship between CEO
characteristics and corporate philanthropy should receive much attention. In the following
section, I will provide a brief discussion on the major research gaps that I seek to address in order

to advance the understanding of the leadership predictors of corporate philanthropy and the
implications for firm performance.
1.3 Statement of the Problem
Previous studies have focused on why firms engage in corporate philanthropy (Adams &
Hardwick, 1998; Brammer & Millington, 2005; Fombrun & Shanley, 1990; Godfrey, 2005;
Turban & Greening, 1997; Wang & Qian, 2011; Williams & Barrett, 2000). These studies have
shown that engagement in corporate philanthropy can lead to increased employee loyalty (e.g.,
employee commitment), favorable community image (e.g., corporate reputation), and positive
media coverage (e.g., recovering tarnished reputation). As such, it can be suggested that
consequences of corporate philanthropy have been extensively explored to answer the question,
“why should a firm give?” Meanwhile, antecedents of corporate philanthropy have been
explored to answer the question, “what drives firms to give?” The predominant discussion
among scholars has been on the managerial (e.g. Buchholtz et al., 1999; Choi & Wang, 2007;
Marquis & Lee, 2013; Wang & Coffey, 1992), organizational (Adams & Hardwick, 1998;
Brammer & Millington, 2006; Seifert, Morris & Bartkus, 2003), and industry (Amato & Amato,
2007, 2012; Useem, 1988) drivers of corporate philanthropy. Specifically, past research
suggested that firms engage in corporate philanthropy as a means to simultaneously and directly
benefit business interests and those of a beneficiary organization (Saiia et al., 2003; Marx, 1999).
The extent to which firms engage in corporate philanthropy can vary depending on
organizational factors, such as firm size, organizational slack, and advertising intensity (Dennis
et al., 2009; Saiia et al., 2003; Wang & Qian, 2011). Past research on corporate philanthropy has
generally discussed the intersection of business goals and the larger societal good help improve
the firm’s competitive position (Maas & Liket, 2011; Saiia et al., 2003). In sum, it can be argued
that previous studies of corporate philanthropy have developed from three aspects, “why give,”

“what leads to give,” and “give strategically.”
Unlike the extensive discussion on firm-level predictors, managerial perspective on
corporate philanthropy has not received much attention (e.g., how, why, and to what degree
individuals, such as CEOs, engage in corporate philanthropy). This line of inquiry is consistent
with a recent study’s (Aguinis and Glavas, 2012) observation that corporate social activities,
including corporate philanthropy, research is virtually absent from journals devoted to
organizational behavior and micro-level human resources management. Therefore, there is a need
to focus more on the micro level (e.g., do characteristics of individuals influence firms’
philanthropic engagement?) than on the macro level (e.g. are organizational outcomes of
corporate philanthropy beneficial to the firm?). In addition, there might be some link between
CEO characteristics and corporate philanthropy. Several scholars suggest that CEOs think
strategically about philanthropy to enhance brand name recognition, employee productivity, and
even to overcome regulatory obstacles (Seifert et al., 2003; Smith, 1994). Despite the growing
interest in the effect of CEO characteristics on CSR in general and philanthropy in particular, the
relationship between CEO characteristics and corporate philanthropy is under-developed and has
not received close empirical scrutiny.
Past research (e.g. Choi & Wang, 2007; Godfrey, 2005) has focused more on CEOs moral
background and characteristics, such as CEOs’ integrity and altruism, to explain a firm’s
philanthropic decisions. These studies, however, leave room for further explanation as to whether
CEO characteristics predict corporate philanthropy. This is because corporate philanthropy can
be driven not only by non-business community issues related to CEO altruism but also by
business-related issues, both of which benefit the firm’s strategic position. To fill this research
gap, I draw from the upper echelon theory (Carpenter, Geletkanycz & Sanders, 2004; Hambrick

& Mason, 1984) to explore how leaders’ background characteristics might influence their firms’
engagement in corporate philanthropy. Thomas and Simerly (1994) suggest that the demographic
characteristics of CEOs (e.g., age, functional background, and education) offer reliable proxies
for visible social activities of CEOs. Pedersen and Neergaard (2009) also suggest that managerial
perceptions of corporate social activities, including corporate philanthropy, are influenced by a
great deal of heterogeneity (e.g., age, gender, education, and functional backgrounds). In
addition, it might be that founder CEOs have wide strategic options and more power over their
boards (Mousa & Wales, 2012) and such status can influence corporate philanthropy. Despite the
practical importance of the relationship between founder status and corporate philanthropy, that
relationship has not received empirical investigation.
Firm size, organizational slack, and advertising intensity have been explored as important
organizational factors that influence corporate philanthropy (Dennis et al., 2009; Seifert et al.,
2003; Wang & Qian, 2011). What scholars argue is that bigger firms with more slack resources
and advertising intensity have a positive association with corporate philanthropy. What is missing
from these discussions is firm age as an important organizational context. In other words, the
relationship between firm age and corporate philanthropy has not received much scholarly
attention. For instance, Logsdon, Reiner and Burke (1990) observed in an exploratory study that
firm age might be significant in explaining placement of corporate philanthropy. Particularly,
past research has suggested that older firms tend to be increasingly inflexible so that firm age
may be an important indicator of reduced executive discretion (Finkelstein, Hambrick &
Cannella, 2009). Although the individual CEO’s influence on corporate philanthropy might vary
as a firm grows, the role of firm age on the relationship between CEO background characteristics
and corporate philanthropy has not received much attention. Therefore, it is worth exploring this
relationship.

Although corporate philanthropy has developed from a wide range of theoretical
frameworks, scholars have not yet given much thought to whether firms proactively engage in
corporate philanthropy to strengthen their business and corporate strategies. Particularly, the
relationship between corporate philanthropy and unrelated diversification is under-developed.
Unrelated diversification is one of core business strategies which help firms expand new markets.
For example, when firms pursue unrelated diversification strategies, they usually experience a
wide range of varying demands from stakeholders in distant industries or their subsidiaries
(Chatterjee & Wernerfelt, 1991). Corporate philanthropy can generate reputational assets in the
new market (Hess, Rogovsky & Dunfee, 2002), strengthen marketing and branding initiatives
(Lii & Lee, 2012; Ricks Jr, 2005), and improve relations with local governments (Wang & Qian,
2011). From this phenomenon, it can be suggested that firms can consider philanthropic activities
as part of long- term competitiveness and a means to strategically open new markets.
In addition, it is likely that the pressure for engaging in corporate philanthropy would
increase among international firms with business activities across countries and culture. Deresky
(1997) suggests that the philanthropic activities of multinational corporations that operate in
foreign countries may be characterized as strategic, clearly targeted, and linked to the overall
objectives of the firm. In addition, when firms expand their businesses in a foreign market
(Sharfman, Shaft & Tihanyi, 2004), they experience a wide range of stakeholder’ pressures.
Corporate philanthropy can be used as a means of reducing these challenges. Despite the
importance of corporate philanthropy on a firm’s internationalization, there is a lack of
theoretical explanation and empirical evidence as to whether corporate philanthropy advances a
firm’s internationalization strategy. Similarly, expansive global strategic posture (in terms of
geographic market diversification) can help firms leverage R&D costs and knowledge across
countries (Carpenter & Fredrickson, 2001; Kim & Mauborgne, 1991). It has been suggested that

corporate philanthropy may be an opportunity for internationally operating firms, but also for
investing in legitimacy in a region considered to be the main emerging market for the country
(Bohnsack, 2012; Whiteman, Muller, Van der Voort, Wijk, Meijs, & Pique, 2005). It is reasonable
to expect that firms are encouraged to engage in corporate philanthropy to develop a
commanding international presence. In sum, I explore how CEOs’ background characteristics
predict the degree of firms’ engagement in corporate philanthropy and the complimentary
theoretical relationship between corporate philanthropy and a firm’s diversification profile (such
as unrelated diversification and global strategic posture).
1.4 Purpose of the Study & Research Questions
In this dissertation, I examine the effect of CEOs’ background characteristics on corporate
philanthropy and firm diversification profile. More specifically, I examine the relationships
between CEOs’ background characteristics and corporate philanthropy. In doing so, I focus on
four aspects of CEO background characteristics (i.e. CEO founder status, functional background,
civic engagement, and education) and examine whether they are associated with the degree of
firms engagement in corporate philanthropy.
First, what is the relationship between CEO founder status and corporate philanthropy?
Founder CEOs are likely to hold a psychological bond with their firms (Peterson, Galvin &
Lange, 2012). Founder CEOs’ intrinsic motivation could lead them to engage in socially
responsible activities that meet various stakeholder demands, such as corporate philanthropy.
Second, what is the relationship between CEO functional background and corporate
philanthropy? Corporate social performance can be a reflection of CEO functional background
(Melo, 2012). Thus, it might be anticipated that a certain aspect of a CEO’s past work experience
in jobs within functional areas of organizations can influence corporate philanthropy. Third, what

is the relationship between CEO civic engagement and corporate philanthropy? CEOs often
serve as active members in community groups or associations and they participate in civic affairs
as part of their strategic mission. Doing so can be motivated by a desire to create the local
community development and a more stable political environment that ensures their business
profitability. Fourth, what is the relationship between CEO education and corporate
philanthropy? Bennett (2012) argues that better educated people have wider mental horizons that
cause individuals to recognize the value of charities concerned with the external environment.
Therefore, it is expected that CEOs’ education can play an important role in determining the
choice and emphasis on corporate philanthropy. In addition, I examine the moderating role of
firm age on the relationship between CEO background characteristics and corporate
philanthropy. Although older firms would be expected to be more well-known and have greater
philanthropic engagement, it is reasonably expected that a CEO’s influence on corporate
philanthropy varies as a firm grows.
Furthermore, I examine the role of corporate diversification profile on corporate
philanthropy and firm performance. Past research suggests that firms increase philanthropic
expenditures strategically as a means to open new markets where they are not familiar with and
the pressures for engaging in corporate philanthropy increase among international firms (Merz,
Peloza & Chen, 2010). Specifically, I examine a firm’s diversification strategy as the mechanism
through which corporate philanthropy influences firm performance. Since the ultimate goal of a
firm’s social activities, including corporate philanthropy, is to maximize performance, it is worth
exploring the interaction, including corporate philanthropy – firm performance relationship
through the mechanism of corporate diversification profile.

In sum, there are four major under-developed research areas in the literature that will be
explored in this dissertation. First, there is a need to examine the relationship between CEO
background characteristics and corporate philanthropy. Second, the role of firm age on the
relationship between CEO background characteristics and corporate philanthropy should receive
much attention. Third, whether firms proactively engage in corporate philanthropy to strengthen
their unrelated diversification strategies should receive an empirical investigation. Fourth, the
relationship between corporate philanthropy and firm performance needs to be examined
particularly under corporate diversification profile (e.g. how corporate philanthropy influences
firm performance through unrelated diversification and global strategic posture). I intend to
answer the following three research questions:
13) Do CEO background characteristics influence the level of corporate philanthropy? If so,
why?
14) Does firm age moderate the relationships between CEO background characteristics and
the level of corporate philanthropy?
15) Does corporate diversification profile mediate the relationship between the level of
corporate philanthropy and firm performance?
1.5 Significance & Contributions of the Dissertation
1.5.1 Contributions to Corporate Philanthropy Research
In this dissertation, I offer several contributions for research. First, this dissertation
contributes to the growing scholarly interests in terms of CEOs’ influence on corporate
philanthropy. It has been suggested that CEOs are requiring greater strategic accountability in
corporate giving programs (Saiia et al, 2003) and that corporations undertake strategic
philanthropy as long as direct economic benefits can be gained by doing so (Sánchez, 2000).

Therefore, an examination of whether CEO background characteristics influence corporate
philanthropy helps to fulfill research interests.
Second, I extend the literature on corporate philanthropy to examine the strategic use of
philanthropy. It has been suggested that traditional altruistic models of philanthropy are
becoming less relevant because it is generally considered a non-strategic explanation of corporate
giving which ignores the profit maximization goal and other strategic goals of the firm
(Neiheisel, 1994; Sánchez, 2000). Corporate giving activities have evolved into far more
strategically market-oriented approaches like targeted grants intended to optimize economic
return as well as social returns per philanthropic dollar (Sherblom, 2007).
Third, drawing upon the institutional and stakeholder perspectives, I offer a new attempt
to empirically examine the link between corporate philanthropy and unrelated diversification. For
example, faced with various challenges (e.g., social, legal, and regulatory), corporate
diversification increases a variety of stakeholder pressures in the firm’s external environment that
arise (Brammer, Millington & Pavelin, 2006; Sharfman et al., 2004). In addition, highly
diversified firms not only suffer from a lack of coherence in terms of underlying resources
(Montgomery & Wernerfelt, 1988) but they also have to deal with heavy stakeholder demands.
These pressures might be mitigated when engaging in corporate social activities through which
unrelated diversifiers can manage a wide range of stakeholders’ demands.
Fourth, although previous studies (Markides & Williamson, 1994; Palepu, 1985; Rumelt,
1974) suggest a negative relationship between unrelated diversification and (short-term) financial
performance, this dissertation provides a different perspective to corporate diversification
strategy. For example, corporate philanthropy helps to generate reputation and branding
initiatives in the new markets so that it can improve the firm’s market positions (Hess et al.,

2002; Ricks Jr, 2005). In this dissertation, I provide scholars with a promising suggestion that
unrelated diversification may not necessarily be an inferior strategy for the firm.
1.5.2 Contributions to Practice
In this dissertation, I offer several contributions for practice. First, understanding of how
CEO background characteristics (e.g., CEO status, functional background, civic engagement, and
education level) can be applied to corporate philanthropy helps to explain the rationale behind
decisions to engage in corporate philanthropy. Therefore, I answer what leads CEOs to engage in
corporate philanthropy and further why some CEOs engage in more corporate philanthropy than
others. Second, I provide managers with practicability of corporate philanthropy. For example,
strategic use of philanthropic expenditures can support a community project in developing
countries (Porter & Kramer, 2002; Sánchez, 2000) because better community conditions are
good for business (e.g., when the standard of living is increased, product demand is increased).
Third, I provide managers with a promising notion that engaging in corporate
philanthropy can help firms with diversification and market entry strategies. Scholars argue that a
firm’s philanthropic engagement in developing countries can enhance the firm’s reputation and
get easier access to the market (Bohnsack, 2012; Brammer et al., 2006). There might be a
positive relationship between corporate philanthropy and international presence. In addition, it is
suggested that corporate philanthropy can offer an opportunity for internationally operating firms
as well as for investing in business legitimacy. In this dissertation, I can provide managers with
practicability that international firms can strengthen their competitive context by engaging in
corporate philanthropy. Fourth, I provide insights on business legitimacy by suggesting that firms
are seen as legitimate actors by local stakeholders to the extent they engage in corporate
philanthropy. Goyal (2006) and Wang and Qian (2011) suggest that philanthropic activities of

multinational firms in the host countries would be a signaling device to demonstrate that they
have long-term intentions consistent with the local expectations. Thus, I suggest that firms can
receive supportive responses from the host countries governments by engaging in corporate
philanthropy.
1.6 Definition of Key Terms
Corporate social responsibility (CSR) refers to “context-specific organizational actions
and policies that take into account stakeholders’ expectations and the triple bottom line of
economic, social, and environmental performance” (Aguinis, 2011, p. 855).
Diversification refers to “the entry of a firm or business unit into new lines of activity,
either by processes of internal business development or acquisition, which entail changes in its
administrative structure, systems, and other management processes” (Ramanujam &
Varadarajan, 1989, p. 525). There are two types of diversification, such as related diversification
and unrelated diversification. Related diversification refers to a diversification built around a
core organizational capability (Ramanujam, 1987; Rumelt, 1982). It occurs when firms expand
their areas closely related to their primary activities and areas of technical expertise. Unrelated
diversification refers to a diversification that drives to move into unrelated lines of business
(Ramanujam, 1987; Rumelt, 1982). It occurs where firms expand their operations into markets or
products beyond current resources and capabilities.
Corporate philanthropy refers to the practice of “giving firm resources to invest in
business-related issues and non-business community issues that also benefit the firm’s strategic
position and, ultimately, its bottom line” (Saiia et al., 2003, p. 170). This definition helps to
explain why some firms still donate in non-business areas more than others. They do so because

they believe that giving non-business issues would enhance their public image which can be used
for gaining business legitimacy in developing countries (Wang & Qian, 2011).
Global strategic posture (GSP) refers to “the degree to which a firm is dependent on
foreign sales and production and to the geographic dispersion of this dependence” (Carpenter,
Sanders & Gregersen, 2001, p. 497). It has been suggested that GSP reflects the relative
significance of foreign markets and operations in sustaining the firm as well as their geographic
dispersion (Sullivan, 1994). Therefore, GSP can be used for measuring firm internationalization
(Carpenter & Fredrickson, 2001; Levy, 2005). GSP are normally measured by three dimension
originally developed by Sullivan (1994): foreign sales, foreign production, and geographic
diversity. Foreign sales reflect the relative significance of foreign market. Foreign production
reflects the degree to which a firm depends on foreign-owned assets and resources. Geographic
diversity reflects the extent to which a firm has subsidiaries associated with globalization of
operations and markets. Several scholars used GSP to explain a firm’s internationalization
strategy (Carpenter et al., 2001; Carpenter & Fredrickson, 2001; Levy, 2005).
1.7 Organization of the Dissertation
This dissertation consists of six chapters. The first chapter provides an introduction about
the importance of corporate philanthropy, statement of the problem, major research questions as
well as the contributions of the dissertation. Chapter two presents a comprehensive and extensive
review of the literature on corporate social responsibility and the antecedents and consequences
of corporate philanthropy with the role of leadership in corporate philanthropy. Chapter three
presents the research model, theoretical foundations, and summary of theoretically-driven
hypotheses. Chapter four presents the research design including target sample, measures, as well
as statistical techniques. Chapter five presents and highlights the results of statistical analyses,

including summary of findings and summary of hypotheses. Chapter six discusses the results
from Chapter five, the implications to research and practice, limitations, future research
directions, and conclusion.

CHAPTER II
LITERATURE REVIEW
This chapter provides a comprehensive review of the corporate philanthropy research.
The first section begins with a systematic review of the literature on the relationship between
Corporate Social Responsibility (CSR) and firm performance as well as the leadership
determinants of CSR. In the second section, I discuss the theoretical conceptualizations of
corporate philanthropy with a comparative review of the traditional and strategic philanthropy
literatures. In the third section, I discuss the managerial, organizational and industry level
antecedents and consequences of corporate philanthropy with a particular emphasis on the link
between leadership attributes and corporate philanthropy. In the fourth section, I present a
comprehensive review of research on the link between corporate philanthropy and corporate
strategy. The chapter then concludes with a contingency view of corporate philanthropy.
2.1 How Does Corporate Social Responsibility (CSR) Influence Firm Performance?
CSR refers to “context-specific organizational actions and policies that take into account
stakeholders’ expectations and the triple bottom line of economic, social, and environmental
performance” (Aguinis, 2011, p. 855). Specifically, the demand for business CSR initiatives has
been significantly higher around the world over the last several decades. Accordingly, firms
nowadays are expected to act more proactively to fulfill their CSR expectations as responsible
corporate citizens to the society (Wang & Hsu, 2011). Since engaging in CSR is considered a
socially responsible investment for the firm, how CSR influences firm performance has been an
important issue among organizational scholars (Agle, Mitchell & Sonnenfeld, 1999; Aguinis &
Glavas, 2012; Orlitzky, Schmidt & Rynes, 2003). Even though there are some debates as to
whether CSR helps to improve firm performance, an extensive line of research has empirically

explored how CSR boosts firms’ competitive advantage, thereby ensuring value creation and
satisfaction for stockholders and customers (Cox, Brammer & Millington, 2004; Lev, Petrovits &
Radhakrishnan, 2010).
The topic of whether CSR can have a positive effect on firm performance has generated
extensive discussions among scholars and practitioners. Friedman (1970) provides the classical
economic perspective that management has one responsibility and that is to maximize the profits
of its shareholders. Past research suggests that socially responsive firms incur higher direct costs
and reap lower profits than socially unresponsive firms (Aupperle, Carroll & Hatfield; 1985;
Devinney, 2009). In addition, some scholars have used agency theory that “good social
performance comes at the expense of good financial performance because social performance
makes use of firm resources in ways that confers significant managerial benefits rather than
returning those resources to shareholders” (Brammer & Millington, 2008, p. 1329). They argued
that firms would better spend their resources on value-added internal projects or return to
shareholders rather than invest in CSR. Despite these perspectives, there has been a growing
institutional and societal pressure on businesses to pursue a socially responsible operation for the
last couple of decades and a number of institutional approaches can explain this trend. Jones
(1995) suggests that firms facing repeated transactions with stakeholders based on trust and
cooperation are encouraged to be honest, trustworthy, and ethical because they believe that the
returns to such behavior are high. In addition, a majority of empirical evidence suggests a
significant positive relationship between CSR and financial performance (Aguinis & Glavas,
2012; Peloza, 2009). For example, Peloza (2009) reviewed 128 studies that explored the
relationship between CSR and financial outcomes and found that, almost 60 % showed a positive
relationship, less than 15 % a negative relationship and mixed findings from the rest of the

studies. Recently, Aguinis and Glavas (2012) summarized the overall empirical evidence on
CSR-performance relationship in a wide range of organizational fields as follows (p. 947):
“Working for socially responsible companies leads to increased organizational
identification (Carmeli, Gilat, & Waldman, 2007), employee engagement (Glavas
& Piderit, 2009), retention (Jones, 2010), organizational citizenship behavior (Lin,
Lyau, Tsai, Chen, & Chiu, 2010), employee commitment (Maignan, Ferrell & Hult,
1999), employee creative involvement (Glavas & Piderit, 2009), and improved
employee relations (Glavas & Piderit, 2009).”
In the 21th century, the influence of CSR on a firm performance is an important concern to
a firm’s stakeholders so that firms should consider CSR as part of their strategies (Lantos, 2001).
Given the ultimate responsibility of firms meets the needs of stakeholders, firms should fulfil
stakeholders’ demands while also devoting resources to CSR. Such seemingly contrasting
demands are leading more firms to embrace strategic CSR or strategic use of philanthropy.
Carroll (2001), for instance, argues that strategic CSR can accomplish strategic business goals,
including good deeds, are believed to be good for business as well as for society. Several scholars
have discussed strategic aspects of CSR. Porter and Kramer (2006) argue that CSR should be
seen as one of core business strategies in a firm, indicating that the firm can benefit from its
social investment. Maignan et al. (2005) also argue that CSR can serve as an attractive, valuable
resource offering competitive advantage for enhancing business performance because it can be
used as a means of conducting business strategies.
2.1.1 What Role Do Organizational Leaders Play in Fostering CSR?

In an attempt to link organizational leaders (e.g., CEOs) to CSR, scholars have focused on
three aspects of CEO background characteristics: values, compensation levels, and personal
attributes (experiences). For example, CEO integrity can be relevant to CSR such that leader
vision and integrity will increase CSR values to shareholders. Waldman and Siegel (2008) argue
that leader integrity to personal morality can yield positive outcomes for business and may
actually be the driver of CSR strategies in organizations. Ketola (2006) also argues that leader
integrity is an important component in his or her successful promotion of CSR activities at the
firm. In addition, the relationship between CEO compensation and CSR has received some
attention. For instance, McGuire, Dow and Argheyd (2003) empirically examined the
relationship between the level of CEO compensation and corporate social performance (CSP) but
they did not find any positive relation. However, Jiraporn and Chintrakarn (2013) using a sample
of 1,370 firms found that when the CEO power (as measured by the total compensation) goes
beyond a certain threshold, more powerful CEOs significantly reduce CSR investments.
Furthermore, several scholars examined the professional background of CEOs and corporate
social performance (Mazutis, 2014; Simerly, 2003; Thomas & Simerly, 1994). They found that
corporate social performance can be interpreted as a reflection of CEOs’ professional
background.
Do organizational leaders play a role in promoting CSR? This question has long attracted
extensive research (Fabrizi, Mallin & Michelon, 2014; Jiraporn & Chintrakarn, 2013). As senior
leaders, CEOs and their top management teams are charged with the responsibility of
formulating business and sustainability strategy (Strand, 2013; Wood, 1991). Indeed, today’s
corporate leaders play an important role in pursuing an effective CSR agenda (Bielak, Bonini &
Oppenheim, 2007; Fabrizi et al., 2014;Godos-Díez, Fernández-Gago & Martínez-Campillo,
2011; Mazutis, 2014). For example, CEOs engage in CSR related activities in response to

growing pressures from key stakeholders groups, such as customers and employees (Bielak et al.,
2007). In addition, while pressures from employees, customers, and other stakeholders can play a
crucial role in CEOs’ willingness to engage in CSR, CEOs recognize that CSR can give their
firms an opportunity to gain a competitive advantage as well as address societal needs (Bielak et
al., 2007). In addition, Godos-Díez et al. (2011) using a sample of 149 CEOs found that those
closer to the steward model are more inclined to attach great importance to ethics and CSR, and
to implement CSR practices. Fabrizi et al (2014) using a sample of 597 U.S. firms extended the
role of CEO’s incentives on CSR and found that non-monetary incentives have a positive effect
on CSR. Mazutis (2014) using a sample of 349 firms found the link between CEO open
executive orientation (such as a liberal worldview and output functional experiences) and
positive CSR initiative adoption over time. In this sense, it can be argued that the relationship
between leadership and CSR has become an important topic of research in the area of leadership
studies (Bielak et al., 2007; Godos-Díez et al., 2011; Fabrizi et al., 2014; Mazutis, 2014).
Transformational leadership helps represent the understanding of CSR in particular.
Transformational leadership is comprised of four major components (Avolio, Bass & Jung, 1999;
Bass & Riggio, 2006): (1) Idealized Influence (ability of leader to attract admiration and respect
and desire to follow from subordinates), (2) Inspirational Motivation (ability of leader to
communicate clear vision and create enthusiasm about future), (3) Intellectual Stimulation
(ability of leader to encourage creativity and unconventional and status quo-challenging
problem-solving among followers), and (4) Individual Consideration (ability of leader to accept
individual differences and actively provide feedback and interaction with followers).
Organizational scholars argue that transformational leadership has been found to influence CSR
behavior among some firms (Du, Swaen, Lindgreen & Senthat, 2013; McWilliams, Siegel &
Wright, 2006).

McWilliams et al (2006), for instance, suggest that strategic leadership theory can be
applied to CSR and that transformational leadership will be positively correlated with the
tendency of companies to engage in CSR. They explored the degree of transformational
leadership using CEOs of 112 large US and Canadian firms and found that intellectual
stimulation (which is one dimension of transformational leadership components) was a predictor
of the firm’s propensity to engage in strategically oriented CSR that were more likely to be
related to the firm’s corporate and business-level strategies (e.g., differentiation and reputation
building). In addition, Du et al. (2013) in a survey of 440 U.S firms found that firms with greater
transformational leadership are more likely to engage in institutional CSR practices, whereas
transactional leadership is not associated with such practices. Furthermore, it has been suggested
that charismatic leadership with self-concepts of followers can be related to CSR. For example,
leaders have values and moral justifications which provide followers with motivational effects
such that charismatic leaders can help connect one’s identify with greater social causes (Shamir,
House & Arthur, 1993).
In conclusion, the empirical evidence on the relationship between CSR and firm
performance seems to be inconclusive (Peloza, 2009). However, more recent studies suggest that
there is a positive association between CSR and firm performance (Aguinis & Glavas, 2012;
Chen & Wang, 2015). In addition, since some firms consider CSR as part of their core corporate
strategy and CEOs are charged with the responsibility of formulating corporate strategy, the
relationship between leadership characteristics and CSR is particularly important. Furthermore, it
can be suggested that understanding of three aspects of CEOs (values, compensation, and
experiences) helps to link CEO background characteristics and CSR. As mentioned in section
2.1.1, there is a certain interrelationship between CEOs and CSR. Table 1 below provides an
overview of research on the role of leadership in fostering CSR.

CSR as a business practice and philosophy has taken an important place in the way
businesses operate and serve their stakeholders. CSR refers to “context-specific organizational
actions and policies that take into account stakeholders’ expectations and the triple bottom line of
economic, social, and environmental performance” (Aguinis, 2011, p. 855). This definition
indicates that businesses should have responsibility beyond their immediate economic concern
and should act in a way that contributes and enhances broader societal goals. CSR primarily
embraces economic, legal, ethical, and philanthropic responsibilities and the dimensions of CSR
include the obligations a business has to its stakeholder’s groups (Carroll, 1991). Over the past
half century, CSR has increasingly been integrated into mainstream business thinking, and
nowadays, most U.S. publicly-traded firms (e.g., Microsoft, Google, and Walt Disney) claim to
engage in some form of CSR. The main benefits of engaging in CSR include generating
intangible assets, including building corporate reputation and employee commitment, and
tangible assets, including the positive impact on financial performance. Research in this area
suggests that being a socially responsible business helps create goodwill, build a positive
organizational image, differentiate them from their competitors, and, as a result, promote
longterm profits for business (Boynton, 2013). Indeed, more firms increasingly embrace CSR as
their employees demand their firms to be socially responsible, customers expect better business
practices, and investors realize the economic rewards of sustainable business models. Beyond the
immediate task environment, business CSR engagement also serves the needs of communities
around the world and fulfills the responsibilities businesses have to the public.
1.2 The Importance of Corporate Philanthropy
Corporate philanthropy is considered one of the core dimensions of CSR (Aguinis &

Clavas, 2012; Carroll, 1991; Porter & Kramer, 2002). The origin of corporate philanthropy in the
U.S. dates back to the rise of industrial age in the 19th and early 20th century, when businessmen
like Henry Ford and John D. Rockefeller established philanthropic foundations (Dietlin, 2011).
Corporate philanthropy has since been transformed from piecemeal individual philanthropic acts
(e.g., philanthropy mainly driven by morality) to a major aspect of corporate CSR practices.
Corporate philanthropy is, nowadays, a widespread business practice in large multinationals as
well as small-and medium-sized firms across the globe. Despite the dominant altruistic
orientation, corporate philanthropy has increasingly complemented the firm’s strategic activities
and enhanced the firm’s social and financial performance (Porter & Kramer, 2002). Therefore, it
can be argued that corporate philanthropy has evolved dramatically from a basic moral obligation
to a strategically-driven activity of the firm. As Porter and Kramer (2002, p. 58) put it,
“True strategic giving, by hand, addresses important social and economic goals simultaneously,
targeting areas of competitive context where the company and society both benefit because the
firm brings unique assets and expertise.”
Corporate philanthropy can often be “the most cost-effective way for a firm to improve its
competitive context” (Porter & Kramer, 2002, p. 9). Many firms invest a significant amount of
resource expenditures on philanthropy in order to build a strong company image. For example, a
2013 report from the Committee Encouraging Corporate Philanthropy indicates that 59 percent
of the largest Fortune 100 firms donated significantly more in 2012 compared to 2007, the year
before the global recession sets in, and aggregate giving rose by 42% ($4.48 billion) from 2007
to 2012. The ten largest U.S. corporations donated over 2.1 billion dollars in 2013 and this figure
has increased in 2014. Many firms provide support to nonprofits and social causes primarily
through company-sponsored foundations as well as corporate direct giving, both of which are

closely tied with the parent company’s business interests. As shown in Figure 1 below, the largest
U.S. firms and their foundations have increased charitable giving during the past decade (2001-
2012). Similarly, as shown in Figure 2 below, the largest 100 U.S. corporations have increased
total charitable giving both as a percentage of pre-tax profit and as a percentage of revenue
especially after the global recession in 2008.
Indeed, the increasing commitment of corporate resources to philanthropic causes reflects
a widely-held belief among business executives that philanthropy can be “strategic” in that it can
make a substantial impact on society while improving business value and reputation for the firm
(Carroll & Shabana, 2010; Walker, 2002). According to a 2010 survey by CECP, 77 percent of
CEOs noted that “the most important action they can take to prepare for 2020 is to embed social
engagement into business strategy and organizational structure.” For example, Ronald A.
Williams, the CEO of Aetna noted that that “public companies can move the collective needle by
using their human and financial resources to innovative in ways that benefit both private interests
and the public good” (Weiss, Kerdahy & Kneale, 2008, p. 5). Ivan Seidenberg, Chairman and
CEO, Verizon Communications Inc., commented in CECP that “our belief is that corporate
philanthropy expands the business. You can expand the capabilities of your customer base,
business and society by doing the right thing.” These and other executive views also highlight an
important fact that corporate philanthropy can be driven by leadership values and studying
leaders’ background can help extend our knowledge of the role of corporate philanthropy in
improving firm performance.
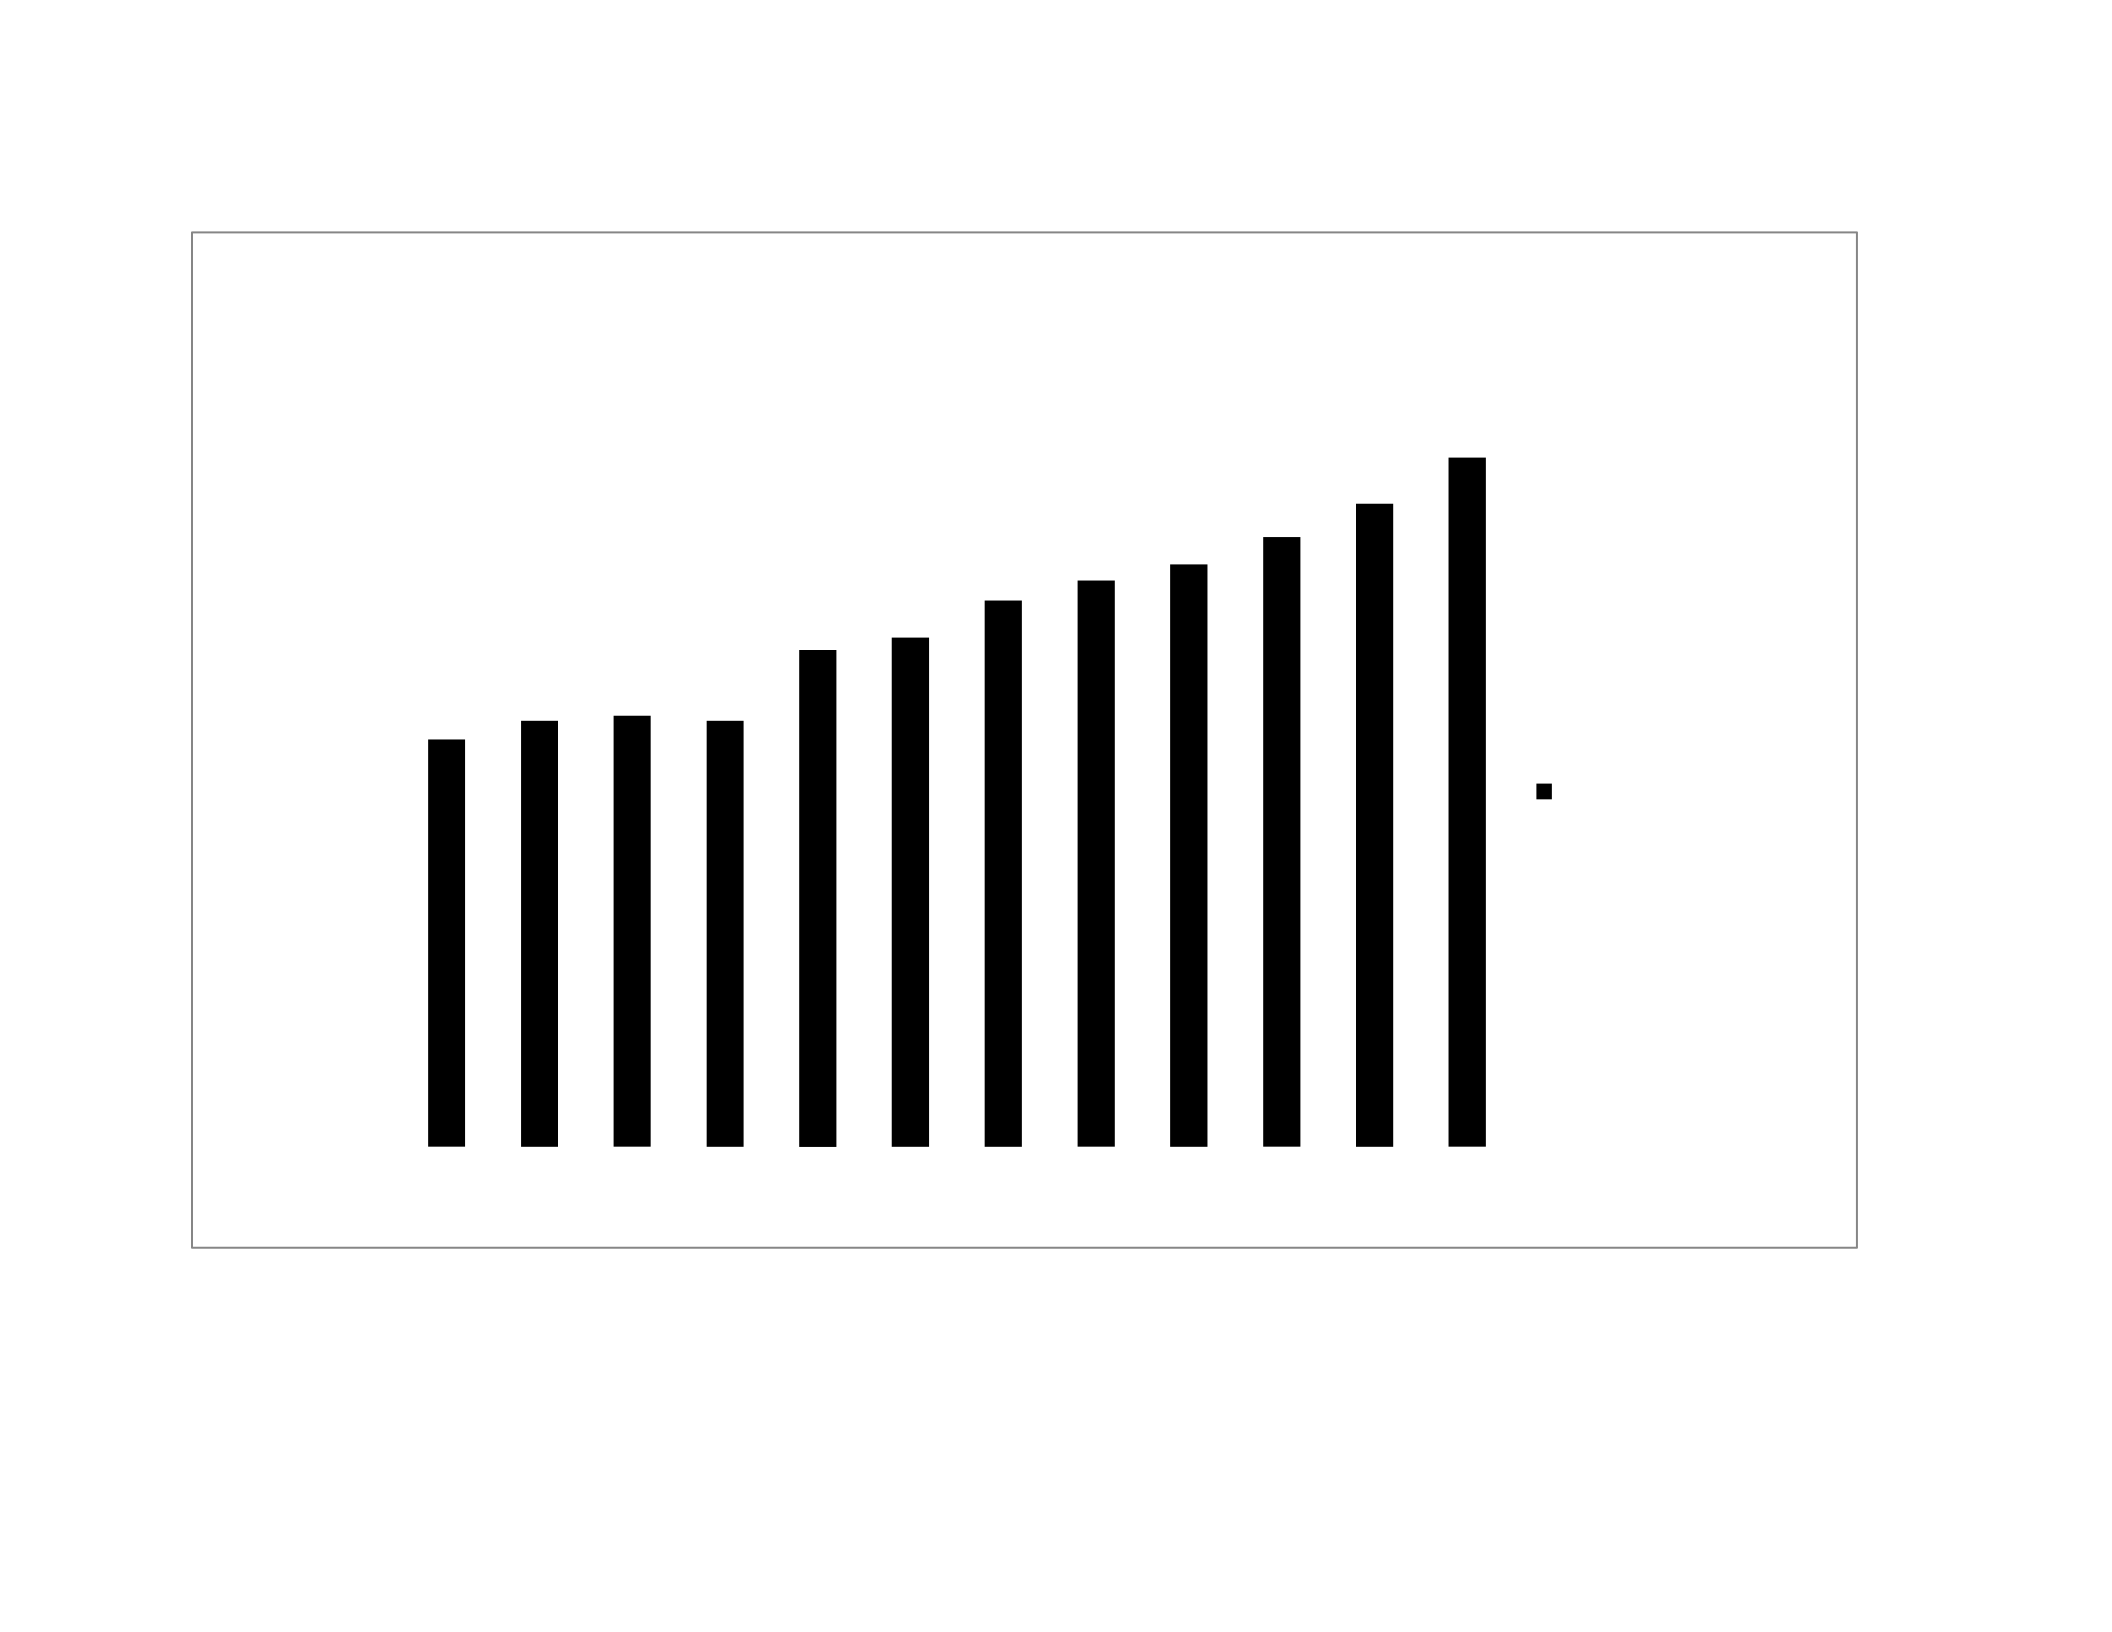
Figure 1. U.S. Corporate Foundation Philanthropic Giving from 2001 to 2012 (2,629 Corporate Foundations)
Source: The Foundation Center as of January 27, 2015
3.28 3.43 3.47 3.43
4 4.1
4.4 4.56 4.69
4.91
5.18
5.55
0
1
2
3
4
5
6
2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012
Billion$
Total charitable giving
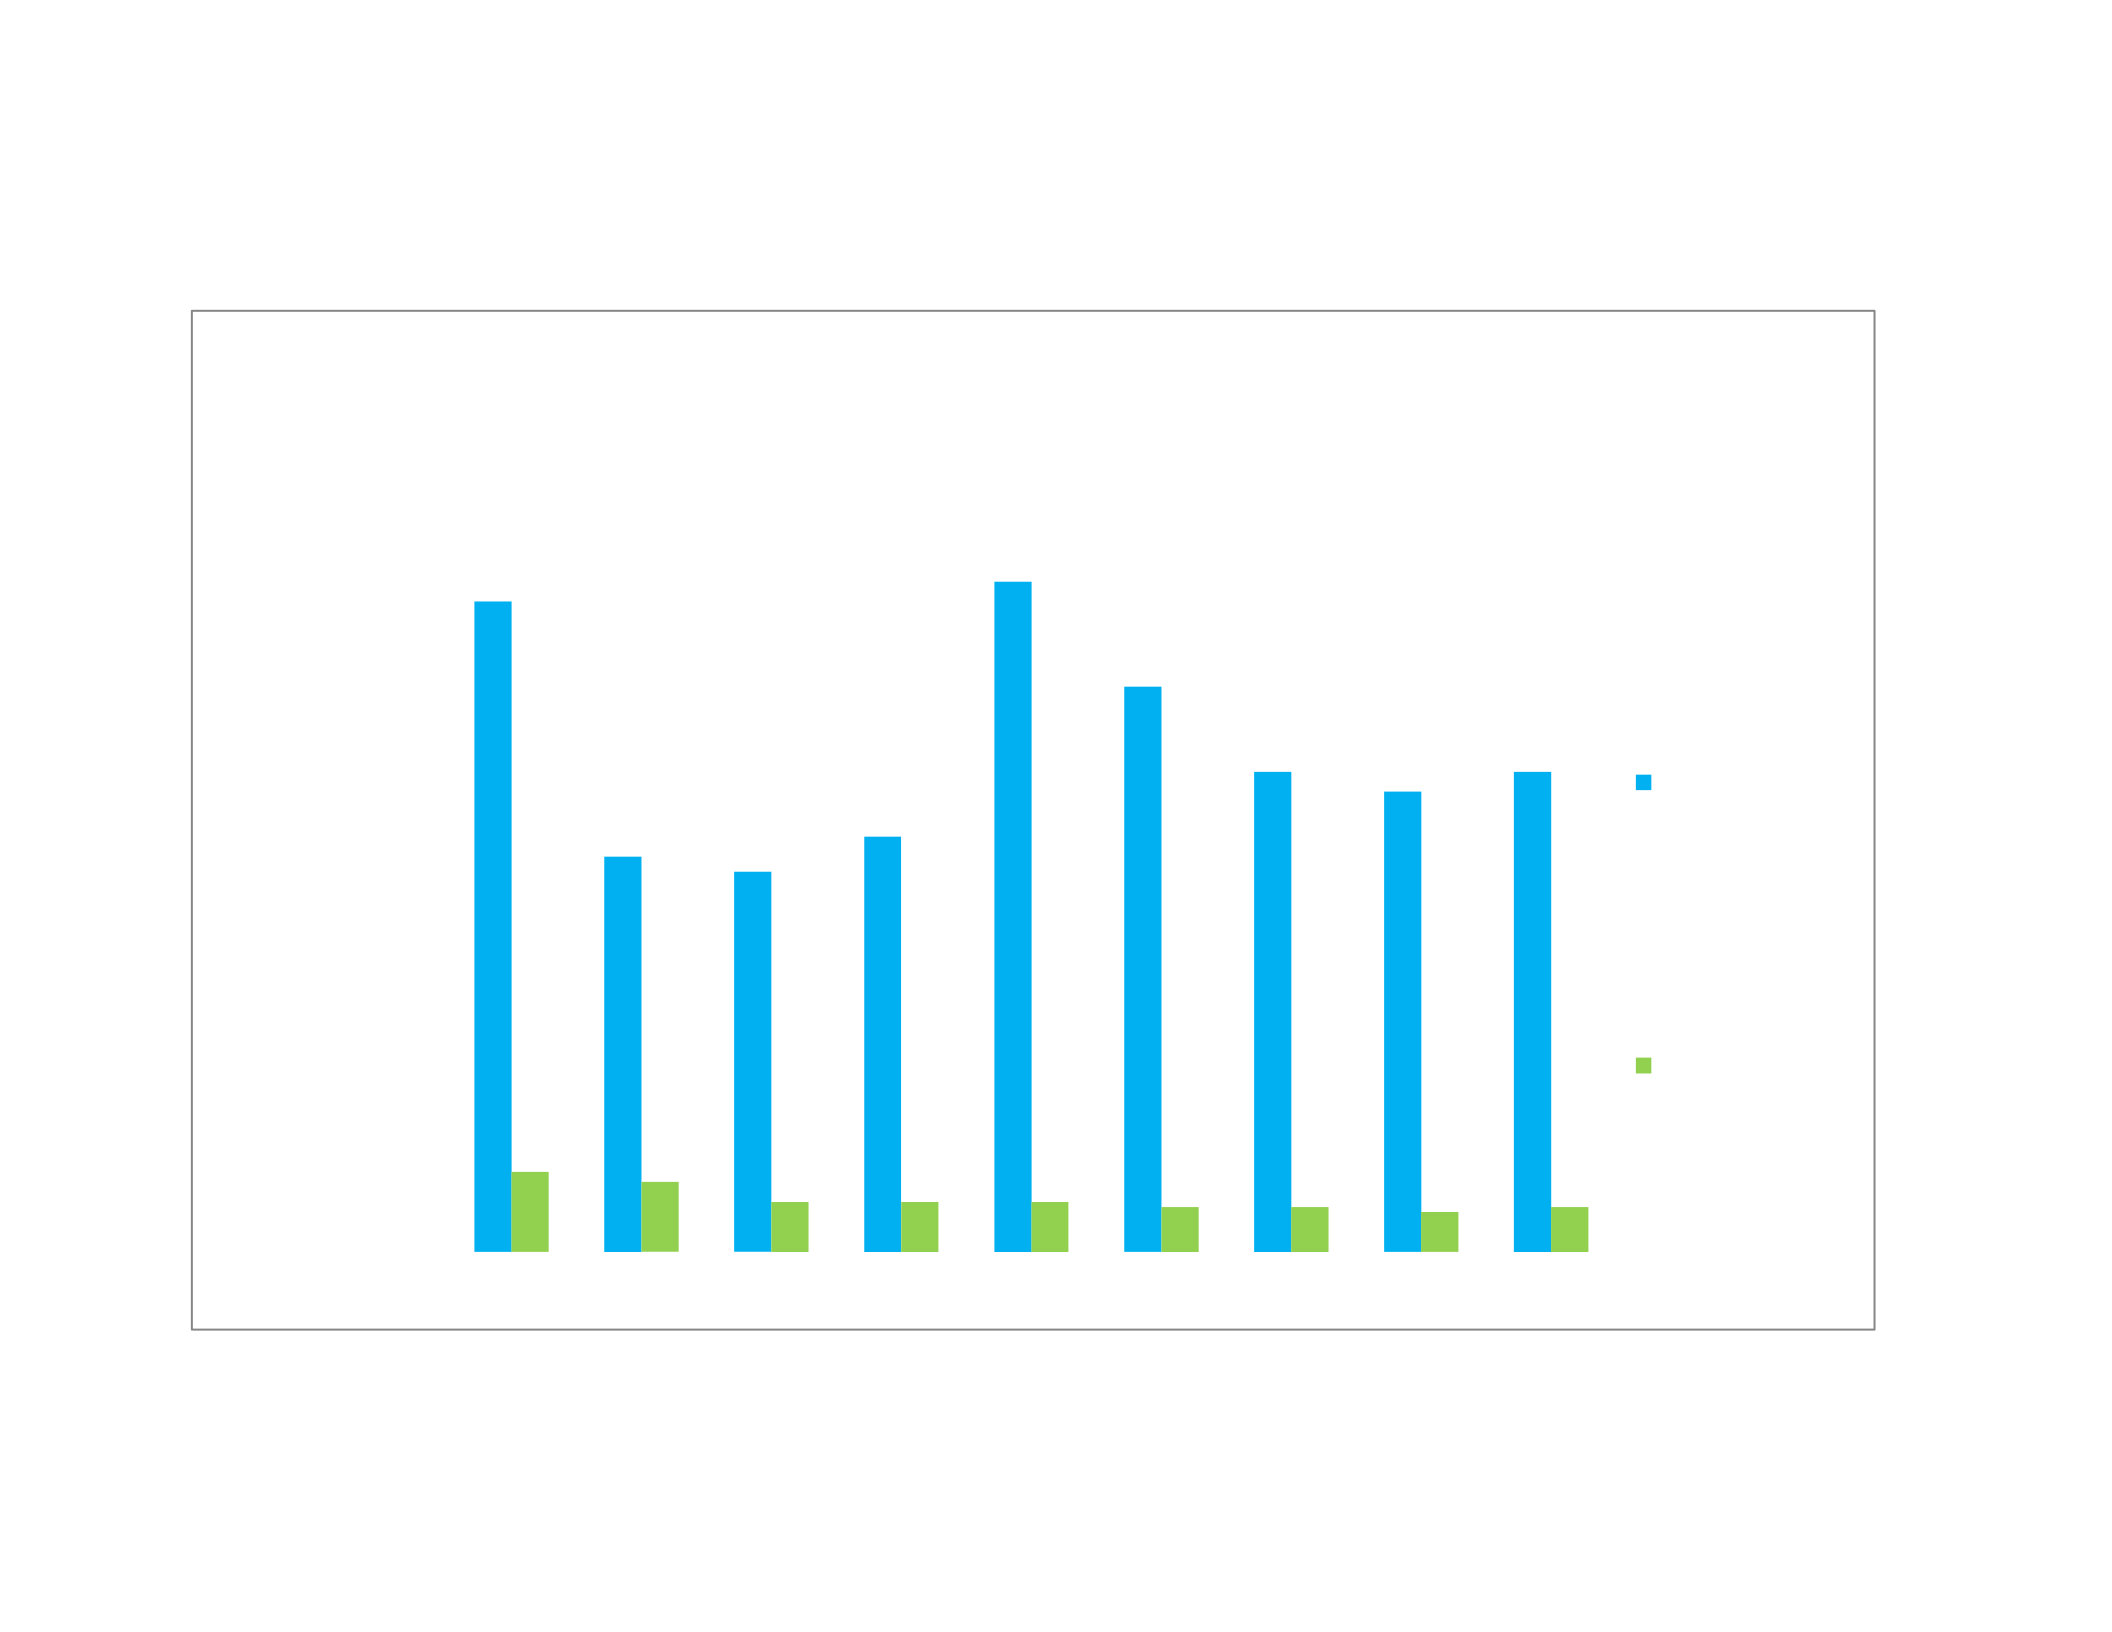
5
Figure 2. Total Charitable Giving among Fortune 100 Firms between 2004 and 2012
Source: Committee Encouraging Corporate Philanthropy as of January 27, 2015
1.3
0.79 0.76
0.83
1.34
1.13
0.96 0.92 0.96
0.16 0.14 0.1 0.1 0.1 0.09 0.09 0.08 0.09
0
0.2
0.4
0.6
0.8
1
1.2
1.4
1.6
2004 2005 2006 2007 2008 2009 2010 2011 2012
Total charitable
giving as a % of
pre-tax profit
Total charitable
giving as a % of
revenue
Million$

6

Despite the stated purpose of enhancing a firm’s public visibility and reputation by
engaging in corporate philanthropy, firms face some criticisms from stakeholders on the tangible
benefits of philanthropy. Some scholars (e.g. Devinney, 2009; Friedman, 1970) have supported
this skeptical perspective arguing that a firm exists primarily to generate economic returns, not to
solve societal problems. Friedman (1970, p. 6) argues that the single social responsibility of
business is to “engage in business activities designed to increase its profit.” On the contrary,
other scholars (e.g. Godfrey, 2005; Wang & Qian, 2011) have strongly supported the positive role
of corporate philanthropy in improving firm performance. These scholars argue that corporate
philanthropy can generate positive stakeholder support which in turn improves a firm’s financial
performance. In an effort to address the critics’ concerns on the use of corporate resources toward
charitable contributions, firms are increasingly turning to the strategic use of philanthropy.
Research suggests that strategic philanthropy can play a key role in developing value-creating
relationships with primary stakeholders and enhancing a company’s image (Buchholtz, Amason
& Rutherford, 1999; Saiia, Carroll & Buchholtz, 2003). Strategic philanthropy can also serve as
“a common meeting ground for the opponents and proponents of corporate philanthropy”
(Buchholtz et al., 1999, p. 169). Large firms are fundamentally responsible for strategic
philanthropy in practice because they have systematic structures (Marquis & Lee, 2013). For
example, large firms have corporate foundations, employee committees to oversee corporate
giving, and staff functions devoted to the effort to manage their social responsibilities (McAlister
& Ferrell, 2002). In marketing practice, strategic philanthropy has been often associated with
cause-related marketing to support social responsibility (File & Prince, 1998; Vanhamme,
Lindgreen, Reast & van Popering, 2012; Varadarajan & Menon,
1988). Both practices have some dissimilarities in terms of primary focus, time frame, and costs
(McAlister & Ferrell, 2002). Strategic philanthropy focuses on organizing itself, is ongoing, and

tends to require moderate to high resource commitment. On the other hand, cause-related
marketing focuses on the firm’s products, has a limited duration, and involves minimal resource
commitment. Both strategic philanthropy and cause-related marketing help enhance societal
welfare and improve the reputation of a firm. Stakeholder theory (Freeman, 1984) offers an
important theoretical support for the relationship between corporate philanthropy and firm
performance, suggesting that favorable social performance is a requirement for business
legitimacy, and tends to be positively associated with firm performance over the long term.
Donaldson and Preston (1995, p. 82) also suggest that firms respond to “ethical considerations
(e.g. engaging in philanthropy) which are often consistent with long-run increases in profit and
value.”
Importantly, the positive effect of corporate philanthropy on the firm provides a reason
why there is a need to examine the relationship between CEO characteristics and corporate
philanthropy. Since corporate philanthropy has become an important strategic tool that
organizational senior leaders manipulate, they are more involved in assessing and shaping
corporate strategies (Porter & Krammer, 2002). In addition, past research argues that a firm’s
social activities should be met by corporate goals determined by CEOs who constantly make
strategic decisions and choices (Choi & Wang, 2007; Wood, 1991). Furthermore, it has been
suggested that CEOs are the primary decision-makers of the organization such that an
examination of CEOs’ attitudes and values toward philanthropy provides needed insight into the
social responsibility actions in general and philanthropic function in particular (Dennis,
Buchholtz, & Butts, 2009). Accordingly, it can be suggested that the relationship between CEO
characteristics and corporate philanthropy should receive much attention. In the following
section, I will provide a brief discussion on the major research gaps that I seek to address in order

to advance the understanding of the leadership predictors of corporate philanthropy and the
implications for firm performance.
1.3 Statement of the Problem
Previous studies have focused on why firms engage in corporate philanthropy (Adams &
Hardwick, 1998; Brammer & Millington, 2005; Fombrun & Shanley, 1990; Godfrey, 2005;
Turban & Greening, 1997; Wang & Qian, 2011; Williams & Barrett, 2000). These studies have
shown that engagement in corporate philanthropy can lead to increased employee loyalty (e.g.,
employee commitment), favorable community image (e.g., corporate reputation), and positive
media coverage (e.g., recovering tarnished reputation). As such, it can be suggested that
consequences of corporate philanthropy have been extensively explored to answer the question,
“why should a firm give?” Meanwhile, antecedents of corporate philanthropy have been
explored to answer the question, “what drives firms to give?” The predominant discussion
among scholars has been on the managerial (e.g. Buchholtz et al., 1999; Choi & Wang, 2007;
Marquis & Lee, 2013; Wang & Coffey, 1992), organizational (Adams & Hardwick, 1998;
Brammer & Millington, 2006; Seifert, Morris & Bartkus, 2003), and industry (Amato & Amato,
2007, 2012; Useem, 1988) drivers of corporate philanthropy. Specifically, past research
suggested that firms engage in corporate philanthropy as a means to simultaneously and directly
benefit business interests and those of a beneficiary organization (Saiia et al., 2003; Marx, 1999).
The extent to which firms engage in corporate philanthropy can vary depending on
organizational factors, such as firm size, organizational slack, and advertising intensity (Dennis
et al., 2009; Saiia et al., 2003; Wang & Qian, 2011). Past research on corporate philanthropy has
generally discussed the intersection of business goals and the larger societal good help improve
the firm’s competitive position (Maas & Liket, 2011; Saiia et al., 2003). In sum, it can be argued
that previous studies of corporate philanthropy have developed from three aspects, “why give,”

“what leads to give,” and “give strategically.”
Unlike the extensive discussion on firm-level predictors, managerial perspective on
corporate philanthropy has not received much attention (e.g., how, why, and to what degree
individuals, such as CEOs, engage in corporate philanthropy). This line of inquiry is consistent
with a recent study’s (Aguinis and Glavas, 2012) observation that corporate social activities,
including corporate philanthropy, research is virtually absent from journals devoted to
organizational behavior and micro-level human resources management. Therefore, there is a need
to focus more on the micro level (e.g., do characteristics of individuals influence firms’
philanthropic engagement?) than on the macro level (e.g. are organizational outcomes of
corporate philanthropy beneficial to the firm?). In addition, there might be some link between
CEO characteristics and corporate philanthropy. Several scholars suggest that CEOs think
strategically about philanthropy to enhance brand name recognition, employee productivity, and
even to overcome regulatory obstacles (Seifert et al., 2003; Smith, 1994). Despite the growing
interest in the effect of CEO characteristics on CSR in general and philanthropy in particular, the
relationship between CEO characteristics and corporate philanthropy is under-developed and has
not received close empirical scrutiny.
Past research (e.g. Choi & Wang, 2007; Godfrey, 2005) has focused more on CEOs moral
background and characteristics, such as CEOs’ integrity and altruism, to explain a firm’s
philanthropic decisions. These studies, however, leave room for further explanation as to whether
CEO characteristics predict corporate philanthropy. This is because corporate philanthropy can
be driven not only by non-business community issues related to CEO altruism but also by
business-related issues, both of which benefit the firm’s strategic position. To fill this research
gap, I draw from the upper echelon theory (Carpenter, Geletkanycz & Sanders, 2004; Hambrick

& Mason, 1984) to explore how leaders’ background characteristics might influence their firms’
engagement in corporate philanthropy. Thomas and Simerly (1994) suggest that the demographic
characteristics of CEOs (e.g., age, functional background, and education) offer reliable proxies
for visible social activities of CEOs. Pedersen and Neergaard (2009) also suggest that managerial
perceptions of corporate social activities, including corporate philanthropy, are influenced by a
great deal of heterogeneity (e.g., age, gender, education, and functional backgrounds). In
addition, it might be that founder CEOs have wide strategic options and more power over their
boards (Mousa & Wales, 2012) and such status can influence corporate philanthropy. Despite the
practical importance of the relationship between founder status and corporate philanthropy, that
relationship has not received empirical investigation.
Firm size, organizational slack, and advertising intensity have been explored as important
organizational factors that influence corporate philanthropy (Dennis et al., 2009; Seifert et al.,
2003; Wang & Qian, 2011). What scholars argue is that bigger firms with more slack resources
and advertising intensity have a positive association with corporate philanthropy. What is missing
from these discussions is firm age as an important organizational context. In other words, the
relationship between firm age and corporate philanthropy has not received much scholarly
attention. For instance, Logsdon, Reiner and Burke (1990) observed in an exploratory study that
firm age might be significant in explaining placement of corporate philanthropy. Particularly,
past research has suggested that older firms tend to be increasingly inflexible so that firm age
may be an important indicator of reduced executive discretion (Finkelstein, Hambrick &
Cannella, 2009). Although the individual CEO’s influence on corporate philanthropy might vary
as a firm grows, the role of firm age on the relationship between CEO background characteristics
and corporate philanthropy has not received much attention. Therefore, it is worth exploring this
relationship.

Although corporate philanthropy has developed from a wide range of theoretical
frameworks, scholars have not yet given much thought to whether firms proactively engage in
corporate philanthropy to strengthen their business and corporate strategies. Particularly, the
relationship between corporate philanthropy and unrelated diversification is under-developed.
Unrelated diversification is one of core business strategies which help firms expand new markets.
For example, when firms pursue unrelated diversification strategies, they usually experience a
wide range of varying demands from stakeholders in distant industries or their subsidiaries
(Chatterjee & Wernerfelt, 1991). Corporate philanthropy can generate reputational assets in the
new market (Hess, Rogovsky & Dunfee, 2002), strengthen marketing and branding initiatives
(Lii & Lee, 2012; Ricks Jr, 2005), and improve relations with local governments (Wang & Qian,
2011). From this phenomenon, it can be suggested that firms can consider philanthropic activities
as part of long- term competitiveness and a means to strategically open new markets.
In addition, it is likely that the pressure for engaging in corporate philanthropy would
increase among international firms with business activities across countries and culture. Deresky
(1997) suggests that the philanthropic activities of multinational corporations that operate in
foreign countries may be characterized as strategic, clearly targeted, and linked to the overall
objectives of the firm. In addition, when firms expand their businesses in a foreign market
(Sharfman, Shaft & Tihanyi, 2004), they experience a wide range of stakeholder’ pressures.
Corporate philanthropy can be used as a means of reducing these challenges. Despite the
importance of corporate philanthropy on a firm’s internationalization, there is a lack of
theoretical explanation and empirical evidence as to whether corporate philanthropy advances a
firm’s internationalization strategy. Similarly, expansive global strategic posture (in terms of
geographic market diversification) can help firms leverage R&D costs and knowledge across
countries (Carpenter & Fredrickson, 2001; Kim & Mauborgne, 1991). It has been suggested that

corporate philanthropy may be an opportunity for internationally operating firms, but also for
investing in legitimacy in a region considered to be the main emerging market for the country
(Bohnsack, 2012; Whiteman, Muller, Van der Voort, Wijk, Meijs, & Pique, 2005). It is reasonable
to expect that firms are encouraged to engage in corporate philanthropy to develop a
commanding international presence. In sum, I explore how CEOs’ background characteristics
predict the degree of firms’ engagement in corporate philanthropy and the complimentary
theoretical relationship between corporate philanthropy and a firm’s diversification profile (such
as unrelated diversification and global strategic posture).
1.4 Purpose of the Study & Research Questions
In this dissertation, I examine the effect of CEOs’ background characteristics on corporate
philanthropy and firm diversification profile. More specifically, I examine the relationships
between CEOs’ background characteristics and corporate philanthropy. In doing so, I focus on
four aspects of CEO background characteristics (i.e. CEO founder status, functional background,
civic engagement, and education) and examine whether they are associated with the degree of
firms engagement in corporate philanthropy.
First, what is the relationship between CEO founder status and corporate philanthropy?
Founder CEOs are likely to hold a psychological bond with their firms (Peterson, Galvin &
Lange, 2012). Founder CEOs’ intrinsic motivation could lead them to engage in socially
responsible activities that meet various stakeholder demands, such as corporate philanthropy.
Second, what is the relationship between CEO functional background and corporate
philanthropy? Corporate social performance can be a reflection of CEO functional background
(Melo, 2012). Thus, it might be anticipated that a certain aspect of a CEO’s past work experience
in jobs within functional areas of organizations can influence corporate philanthropy. Third, what

is the relationship between CEO civic engagement and corporate philanthropy? CEOs often
serve as active members in community groups or associations and they participate in civic affairs
as part of their strategic mission. Doing so can be motivated by a desire to create the local
community development and a more stable political environment that ensures their business
profitability. Fourth, what is the relationship between CEO education and corporate
philanthropy? Bennett (2012) argues that better educated people have wider mental horizons that
cause individuals to recognize the value of charities concerned with the external environment.
Therefore, it is expected that CEOs’ education can play an important role in determining the
choice and emphasis on corporate philanthropy. In addition, I examine the moderating role of
firm age on the relationship between CEO background characteristics and corporate
philanthropy. Although older firms would be expected to be more well-known and have greater
philanthropic engagement, it is reasonably expected that a CEO’s influence on corporate
philanthropy varies as a firm grows.
Furthermore, I examine the role of corporate diversification profile on corporate
philanthropy and firm performance. Past research suggests that firms increase philanthropic
expenditures strategically as a means to open new markets where they are not familiar with and
the pressures for engaging in corporate philanthropy increase among international firms (Merz,
Peloza & Chen, 2010). Specifically, I examine a firm’s diversification strategy as the mechanism
through which corporate philanthropy influences firm performance. Since the ultimate goal of a
firm’s social activities, including corporate philanthropy, is to maximize performance, it is worth
exploring the interaction, including corporate philanthropy – firm performance relationship
through the mechanism of corporate diversification profile.

In sum, there are four major under-developed research areas in the literature that will be
explored in this dissertation. First, there is a need to examine the relationship between CEO
background characteristics and corporate philanthropy. Second, the role of firm age on the
relationship between CEO background characteristics and corporate philanthropy should receive
much attention. Third, whether firms proactively engage in corporate philanthropy to strengthen
their unrelated diversification strategies should receive an empirical investigation. Fourth, the
relationship between corporate philanthropy and firm performance needs to be examined
particularly under corporate diversification profile (e.g. how corporate philanthropy influences
firm performance through unrelated diversification and global strategic posture). I intend to
answer the following three research questions:
16) Do CEO background characteristics influence the level of corporate philanthropy? If so,
why?
17) Does firm age moderate the relationships between CEO background characteristics and
the level of corporate philanthropy?
18) Does corporate diversification profile mediate the relationship between the level of
corporate philanthropy and firm performance?
1.5 Significance & Contributions of the Dissertation
1.5.1 Contributions to Corporate Philanthropy Research
In this dissertation, I offer several contributions for research. First, this dissertation
contributes to the growing scholarly interests in terms of CEOs’ influence on corporate
philanthropy. It has been suggested that CEOs are requiring greater strategic accountability in
corporate giving programs (Saiia et al, 2003) and that corporations undertake strategic
philanthropy as long as direct economic benefits can be gained by doing so (Sánchez, 2000).

Therefore, an examination of whether CEO background characteristics influence corporate
philanthropy helps to fulfill research interests.
Second, I extend the literature on corporate philanthropy to examine the strategic use of
philanthropy. It has been suggested that traditional altruistic models of philanthropy are
becoming less relevant because it is generally considered a non-strategic explanation of corporate
giving which ignores the profit maximization goal and other strategic goals of the firm
(Neiheisel, 1994; Sánchez, 2000). Corporate giving activities have evolved into far more
strategically market-oriented approaches like targeted grants intended to optimize economic
return as well as social returns per philanthropic dollar (Sherblom, 2007).
Third, drawing upon the institutional and stakeholder perspectives, I offer a new attempt
to empirically examine the link between corporate philanthropy and unrelated diversification. For
example, faced with various challenges (e.g., social, legal, and regulatory), corporate
diversification increases a variety of stakeholder pressures in the firm’s external environment that
arise (Brammer, Millington & Pavelin, 2006; Sharfman et al., 2004). In addition, highly
diversified firms not only suffer from a lack of coherence in terms of underlying resources
(Montgomery & Wernerfelt, 1988) but they also have to deal with heavy stakeholder demands.
These pressures might be mitigated when engaging in corporate social activities through which
unrelated diversifiers can manage a wide range of stakeholders’ demands.
Fourth, although previous studies (Markides & Williamson, 1994; Palepu, 1985; Rumelt,
1974) suggest a negative relationship between unrelated diversification and (short-term) financial
performance, this dissertation provides a different perspective to corporate diversification
strategy. For example, corporate philanthropy helps to generate reputation and branding
initiatives in the new markets so that it can improve the firm’s market positions (Hess et al.,

2002; Ricks Jr, 2005). In this dissertation, I provide scholars with a promising suggestion that
unrelated diversification may not necessarily be an inferior strategy for the firm.
1.5.2 Contributions to Practice
In this dissertation, I offer several contributions for practice. First, understanding of how
CEO background characteristics (e.g., CEO status, functional background, civic engagement, and
education level) can be applied to corporate philanthropy helps to explain the rationale behind
decisions to engage in corporate philanthropy. Therefore, I answer what leads CEOs to engage in
corporate philanthropy and further why some CEOs engage in more corporate philanthropy than
others. Second, I provide managers with practicability of corporate philanthropy. For example,
strategic use of philanthropic expenditures can support a community project in developing
countries (Porter & Kramer, 2002; Sánchez, 2000) because better community conditions are
good for business (e.g., when the standard of living is increased, product demand is increased).
Third, I provide managers with a promising notion that engaging in corporate
philanthropy can help firms with diversification and market entry strategies. Scholars argue that a
firm’s philanthropic engagement in developing countries can enhance the firm’s reputation and
get easier access to the market (Bohnsack, 2012; Brammer et al., 2006). There might be a
positive relationship between corporate philanthropy and international presence. In addition, it is
suggested that corporate philanthropy can offer an opportunity for internationally operating firms
as well as for investing in business legitimacy. In this dissertation, I can provide managers with
practicability that international firms can strengthen their competitive context by engaging in
corporate philanthropy. Fourth, I provide insights on business legitimacy by suggesting that firms
are seen as legitimate actors by local stakeholders to the extent they engage in corporate
philanthropy. Goyal (2006) and Wang and Qian (2011) suggest that philanthropic activities of

multinational firms in the host countries would be a signaling device to demonstrate that they
have long-term intentions consistent with the local expectations. Thus, I suggest that firms can
receive supportive responses from the host countries governments by engaging in corporate
philanthropy.
1.6 Definition of Key Terms
Corporate social responsibility (CSR) refers to “context-specific organizational actions
and policies that take into account stakeholders’ expectations and the triple bottom line of
economic, social, and environmental performance” (Aguinis, 2011, p. 855).
Diversification refers to “the entry of a firm or business unit into new lines of activity,
either by processes of internal business development or acquisition, which entail changes in its
administrative structure, systems, and other management processes” (Ramanujam &
Varadarajan, 1989, p. 525). There are two types of diversification, such as related diversification
and unrelated diversification. Related diversification refers to a diversification built around a
core organizational capability (Ramanujam, 1987; Rumelt, 1982). It occurs when firms expand
their areas closely related to their primary activities and areas of technical expertise. Unrelated
diversification refers to a diversification that drives to move into unrelated lines of business
(Ramanujam, 1987; Rumelt, 1982). It occurs where firms expand their operations into markets or
products beyond current resources and capabilities.
Corporate philanthropy refers to the practice of “giving firm resources to invest in
business-related issues and non-business community issues that also benefit the firm’s strategic
position and, ultimately, its bottom line” (Saiia et al., 2003, p. 170). This definition helps to
explain why some firms still donate in non-business areas more than others. They do so because

they believe that giving non-business issues would enhance their public image which can be used
for gaining business legitimacy in developing countries (Wang & Qian, 2011).
Global strategic posture (GSP) refers to “the degree to which a firm is dependent on
foreign sales and production and to the geographic dispersion of this dependence” (Carpenter,
Sanders & Gregersen, 2001, p. 497). It has been suggested that GSP reflects the relative
significance of foreign markets and operations in sustaining the firm as well as their geographic
dispersion (Sullivan, 1994). Therefore, GSP can be used for measuring firm internationalization
(Carpenter & Fredrickson, 2001; Levy, 2005). GSP are normally measured by three dimension
originally developed by Sullivan (1994): foreign sales, foreign production, and geographic
diversity. Foreign sales reflect the relative significance of foreign market. Foreign production
reflects the degree to which a firm depends on foreign-owned assets and resources. Geographic
diversity reflects the extent to which a firm has subsidiaries associated with globalization of
operations and markets. Several scholars used GSP to explain a firm’s internationalization
strategy (Carpenter et al., 2001; Carpenter & Fredrickson, 2001; Levy, 2005).
1.7 Organization of the Dissertation
This dissertation consists of six chapters. The first chapter provides an introduction about
the importance of corporate philanthropy, statement of the problem, major research questions as
well as the contributions of the dissertation. Chapter two presents a comprehensive and extensive
review of the literature on corporate social responsibility and the antecedents and consequences
of corporate philanthropy with the role of leadership in corporate philanthropy. Chapter three
presents the research model, theoretical foundations, and summary of theoretically-driven
hypotheses. Chapter four presents the research design including target sample, measures, as well
as statistical techniques. Chapter five presents and highlights the results of statistical analyses,

including summary of findings and summary of hypotheses. Chapter six discusses the results
from Chapter five, the implications to research and practice, limitations, future research
directions, and conclusion.

CHAPTER II
LITERATURE REVIEW
This chapter provides a comprehensive review of the corporate philanthropy research.
The first section begins with a systematic review of the literature on the relationship between
Corporate Social Responsibility (CSR) and firm performance as well as the leadership
determinants of CSR. In the second section, I discuss the theoretical conceptualizations of
corporate philanthropy with a comparative review of the traditional and strategic philanthropy
literatures. In the third section, I discuss the managerial, organizational and industry level
antecedents and consequences of corporate philanthropy with a particular emphasis on the link
between leadership attributes and corporate philanthropy. In the fourth section, I present a
comprehensive review of research on the link between corporate philanthropy and corporate
strategy. The chapter then concludes with a contingency view of corporate philanthropy.
2.1 How Does Corporate Social Responsibility (CSR) Influence Firm Performance?
CSR refers to “context-specific organizational actions and policies that take into account
stakeholders’ expectations and the triple bottom line of economic, social, and environmental
performance” (Aguinis, 2011, p. 855). Specifically, the demand for business CSR initiatives has
been significantly higher around the world over the last several decades. Accordingly, firms
nowadays are expected to act more proactively to fulfill their CSR expectations as responsible
corporate citizens to the society (Wang & Hsu, 2011). Since engaging in CSR is considered a
socially responsible investment for the firm, how CSR influences firm performance has been an
important issue among organizational scholars (Agle, Mitchell & Sonnenfeld, 1999; Aguinis &
Glavas, 2012; Orlitzky, Schmidt & Rynes, 2003). Even though there are some debates as to
whether CSR helps to improve firm performance, an extensive line of research has empirically

explored how CSR boosts firms’ competitive advantage, thereby ensuring value creation and
satisfaction for stockholders and customers (Cox, Brammer & Millington, 2004; Lev, Petrovits &
Radhakrishnan, 2010).
The topic of whether CSR can have a positive effect on firm performance has generated
extensive discussions among scholars and practitioners. Friedman (1970) provides the classical
economic perspective that management has one responsibility and that is to maximize the profits
of its shareholders. Past research suggests that socially responsive firms incur higher direct costs
and reap lower profits than socially unresponsive firms (Aupperle, Carroll & Hatfield; 1985;
Devinney, 2009). In addition, some scholars have used agency theory that “good social
performance comes at the expense of good financial performance because social performance
makes use of firm resources in ways that confers significant managerial benefits rather than
returning those resources to shareholders” (Brammer & Millington, 2008, p. 1329). They argued
that firms would better spend their resources on value-added internal projects or return to
shareholders rather than invest in CSR. Despite these perspectives, there has been a growing
institutional and societal pressure on businesses to pursue a socially responsible operation for the
last couple of decades and a number of institutional approaches can explain this trend. Jones
(1995) suggests that firms facing repeated transactions with stakeholders based on trust and
cooperation are encouraged to be honest, trustworthy, and ethical because they believe that the
returns to such behavior are high. In addition, a majority of empirical evidence suggests a
significant positive relationship between CSR and financial performance (Aguinis & Glavas,
2012; Peloza, 2009). For example, Peloza (2009) reviewed 128 studies that explored the
relationship between CSR and financial outcomes and found that, almost 60 % showed a positive
relationship, less than 15 % a negative relationship and mixed findings from the rest of the

studies. Recently, Aguinis and Glavas (2012) summarized the overall empirical evidence on
CSR-performance relationship in a wide range of organizational fields as follows (p. 947):
“Working for socially responsible companies leads to increased organizational
identification (Carmeli, Gilat, & Waldman, 2007), employee engagement (Glavas
& Piderit, 2009), retention (Jones, 2010), organizational citizenship behavior (Lin,
Lyau, Tsai, Chen, & Chiu, 2010), employee commitment (Maignan, Ferrell & Hult,
1999), employee creative involvement (Glavas & Piderit, 2009), and improved
employee relations (Glavas & Piderit, 2009).”
In the 21th century, the influence of CSR on a firm performance is an important concern to
a firm’s stakeholders so that firms should consider CSR as part of their strategies (Lantos, 2001).
Given the ultimate responsibility of firms meets the needs of stakeholders, firms should fulfil
stakeholders’ demands while also devoting resources to CSR. Such seemingly contrasting
demands are leading more firms to embrace strategic CSR or strategic use of philanthropy.
Carroll (2001), for instance, argues that strategic CSR can accomplish strategic business goals,
including good deeds, are believed to be good for business as well as for society. Several scholars
have discussed strategic aspects of CSR. Porter and Kramer (2006) argue that CSR should be
seen as one of core business strategies in a firm, indicating that the firm can benefit from its
social investment. Maignan et al. (2005) also argue that CSR can serve as an attractive, valuable
resource offering competitive advantage for enhancing business performance because it can be
used as a means of conducting business strategies.
2.1.1 What Role Do Organizational Leaders Play in Fostering CSR?

In an attempt to link organizational leaders (e.g., CEOs) to CSR, scholars have focused on
three aspects of CEO background characteristics: values, compensation levels, and personal
attributes (experiences). For example, CEO integrity can be relevant to CSR such that leader
vision and integrity will increase CSR values to shareholders. Waldman and Siegel (2008) argue
that leader integrity to personal morality can yield positive outcomes for business and may
actually be the driver of CSR strategies in organizations. Ketola (2006) also argues that leader
integrity is an important component in his or her successful promotion of CSR activities at the
firm. In addition, the relationship between CEO compensation and CSR has received some
attention. For instance, McGuire, Dow and Argheyd (2003) empirically examined the
relationship between the level of CEO compensation and corporate social performance (CSP) but
they did not find any positive relation. However, Jiraporn and Chintrakarn (2013) using a sample
of 1,370 firms found that when the CEO power (as measured by the total compensation) goes
beyond a certain threshold, more powerful CEOs significantly reduce CSR investments.
Furthermore, several scholars examined the professional background of CEOs and corporate
social performance (Mazutis, 2014; Simerly, 2003; Thomas & Simerly, 1994). They found that
corporate social performance can be interpreted as a reflection of CEOs’ professional
background.
Do organizational leaders play a role in promoting CSR? This question has long attracted
extensive research (Fabrizi, Mallin & Michelon, 2014; Jiraporn & Chintrakarn, 2013). As senior
leaders, CEOs and their top management teams are charged with the responsibility of
formulating business and sustainability strategy (Strand, 2013; Wood, 1991). Indeed, today’s
corporate leaders play an important role in pursuing an effective CSR agenda (Bielak, Bonini &
Oppenheim, 2007; Fabrizi et al., 2014;Godos-Díez, Fernández-Gago & Martínez-Campillo,
2011; Mazutis, 2014). For example, CEOs engage in CSR related activities in response to

growing pressures from key stakeholders groups, such as customers and employees (Bielak et al.,
2007). In addition, while pressures from employees, customers, and other stakeholders can play a
crucial role in CEOs’ willingness to engage in CSR, CEOs recognize that CSR can give their
firms an opportunity to gain a competitive advantage as well as address societal needs (Bielak et
al., 2007). In addition, Godos-Díez et al. (2011) using a sample of 149 CEOs found that those
closer to the steward model are more inclined to attach great importance to ethics and CSR, and
to implement CSR practices. Fabrizi et al (2014) using a sample of 597 U.S. firms extended the
role of CEO’s incentives on CSR and found that non-monetary incentives have a positive effect
on CSR. Mazutis (2014) using a sample of 349 firms found the link between CEO open
executive orientation (such as a liberal worldview and output functional experiences) and
positive CSR initiative adoption over time. In this sense, it can be argued that the relationship
between leadership and CSR has become an important topic of research in the area of leadership
studies (Bielak et al., 2007; Godos-Díez et al., 2011; Fabrizi et al., 2014; Mazutis, 2014).
Transformational leadership helps represent the understanding of CSR in particular.
Transformational leadership is comprised of four major components (Avolio, Bass & Jung, 1999;
Bass & Riggio, 2006): (1) Idealized Influence (ability of leader to attract admiration and respect
and desire to follow from subordinates), (2) Inspirational Motivation (ability of leader to
communicate clear vision and create enthusiasm about future), (3) Intellectual Stimulation
(ability of leader to encourage creativity and unconventional and status quo-challenging
problem-solving among followers), and (4) Individual Consideration (ability of leader to accept
individual differences and actively provide feedback and interaction with followers).
Organizational scholars argue that transformational leadership has been found to influence CSR
behavior among some firms (Du, Swaen, Lindgreen & Senthat, 2013; McWilliams, Siegel &
Wright, 2006).

McWilliams et al (2006), for instance, suggest that strategic leadership theory can be
applied to CSR and that transformational leadership will be positively correlated with the
tendency of companies to engage in CSR. They explored the degree of transformational
leadership using CEOs of 112 large US and Canadian firms and found that intellectual
stimulation (which is one dimension of transformational leadership components) was a predictor
of the firm’s propensity to engage in strategically oriented CSR that were more likely to be
related to the firm’s corporate and business-level strategies (e.g., differentiation and reputation
building). In addition, Du et al. (2013) in a survey of 440 U.S firms found that firms with greater
transformational leadership are more likely to engage in institutional CSR practices, whereas
transactional leadership is not associated with such practices. Furthermore, it has been suggested
that charismatic leadership with self-concepts of followers can be related to CSR. For example,
leaders have values and moral justifications which provide followers with motivational effects
such that charismatic leaders can help connect one’s identify with greater social causes (Shamir,
House & Arthur, 1993).
In conclusion, the empirical evidence on the relationship between CSR and firm
performance seems to be inconclusive (Peloza, 2009). However, more recent studies suggest that
there is a positive association between CSR and firm performance (Aguinis & Glavas, 2012;
Chen & Wang, 2015). In addition, since some firms consider CSR as part of their core corporate
strategy and CEOs are charged with the responsibility of formulating corporate strategy, the
relationship between leadership characteristics and CSR is particularly important. Furthermore, it
can be suggested that understanding of three aspects of CEOs (values, compensation, and
experiences) helps to link CEO background characteristics and CSR. As mentioned in section
2.1.1, there is a certain interrelationship between CEOs and CSR. Table 1 below provides an
overview of research on the role of leadership in fostering CSR.

CSR as a business practice and philosophy has taken an important place in the way
businesses operate and serve their stakeholders. CSR refers to “context-specific organizational
actions and policies that take into account stakeholders’ expectations and the triple bottom line of
economic, social, and environmental performance” (Aguinis, 2011, p. 855). This definition
indicates that businesses should have responsibility beyond their immediate economic concern
and should act in a way that contributes and enhances broader societal goals. CSR primarily
embraces economic, legal, ethical, and philanthropic responsibilities and the dimensions of CSR
include the obligations a business has to its stakeholder’s groups (Carroll, 1991). Over the past
half century, CSR has increasingly been integrated into mainstream business thinking, and
nowadays, most U.S. publicly-traded firms (e.g., Microsoft, Google, and Walt Disney) claim to
engage in some form of CSR. The main benefits of engaging in CSR include generating
intangible assets, including building corporate reputation and employee commitment, and
tangible assets, including the positive impact on financial performance. Research in this area
suggests that being a socially responsible business helps create goodwill, build a positive
organizational image, differentiate them from their competitors, and, as a result, promote
longterm profits for business (Boynton, 2013). Indeed, more firms increasingly embrace CSR as
their employees demand their firms to be socially responsible, customers expect better business
practices, and investors realize the economic rewards of sustainable business models. Beyond the
immediate task environment, business CSR engagement also serves the needs of communities
around the world and fulfills the responsibilities businesses have to the public.
1.2 The Importance of Corporate Philanthropy
Corporate philanthropy is considered one of the core dimensions of CSR (Aguinis &

Clavas, 2012; Carroll, 1991; Porter & Kramer, 2002). The origin of corporate philanthropy in the
U.S. dates back to the rise of industrial age in the 19th and early 20th century, when businessmen
like Henry Ford and John D. Rockefeller established philanthropic foundations (Dietlin, 2011).
Corporate philanthropy has since been transformed from piecemeal individual philanthropic acts
(e.g., philanthropy mainly driven by morality) to a major aspect of corporate CSR practices.
Corporate philanthropy is, nowadays, a widespread business practice in large multinationals as
well as small-and medium-sized firms across the globe. Despite the dominant altruistic
orientation, corporate philanthropy has increasingly complemented the firm’s strategic activities
and enhanced the firm’s social and financial performance (Porter & Kramer, 2002). Therefore, it
can be argued that corporate philanthropy has evolved dramatically from a basic moral obligation
to a strategically-driven activity of the firm. As Porter and Kramer (2002, p. 58) put it,
“True strategic giving, by hand, addresses important social and economic goals simultaneously,
targeting areas of competitive context where the company and society both benefit because the
firm brings unique assets and expertise.”
Corporate philanthropy can often be “the most cost-effective way for a firm to improve its
competitive context” (Porter & Kramer, 2002, p. 9). Many firms invest a significant amount of
resource expenditures on philanthropy in order to build a strong company image. For example, a
2013 report from the Committee Encouraging Corporate Philanthropy indicates that 59 percent
of the largest Fortune 100 firms donated significantly more in 2012 compared to 2007, the year
before the global recession sets in, and aggregate giving rose by 42% ($4.48 billion) from 2007
to 2012. The ten largest U.S. corporations donated over 2.1 billion dollars in 2013 and this figure
has increased in 2014. Many firms provide support to nonprofits and social causes primarily
through company-sponsored foundations as well as corporate direct giving, both of which are

closely tied with the parent company’s business interests. As shown in Figure 1 below, the largest
U.S. firms and their foundations have increased charitable giving during the past decade (2001-
2012). Similarly, as shown in Figure 2 below, the largest 100 U.S. corporations have increased
total charitable giving both as a percentage of pre-tax profit and as a percentage of revenue
especially after the global recession in 2008.
Indeed, the increasing commitment of corporate resources to philanthropic causes reflects
a widely-held belief among business executives that philanthropy can be “strategic” in that it can
make a substantial impact on society while improving business value and reputation for the firm
(Carroll & Shabana, 2010; Walker, 2002). According to a 2010 survey by CECP, 77 percent of
CEOs noted that “the most important action they can take to prepare for 2020 is to embed social
engagement into business strategy and organizational structure.” For example, Ronald A.
Williams, the CEO of Aetna noted that that “public companies can move the collective needle by
using their human and financial resources to innovative in ways that benefit both private interests
and the public good” (Weiss, Kerdahy & Kneale, 2008, p. 5). Ivan Seidenberg, Chairman and
CEO, Verizon Communications Inc., commented in CECP that “our belief is that corporate
philanthropy expands the business. You can expand the capabilities of your customer base,
business and society by doing the right thing.” These and other executive views also highlight an
important fact that corporate philanthropy can be driven by leadership values and studying
leaders’ background can help extend our knowledge of the role of corporate philanthropy in
improving firm performance.
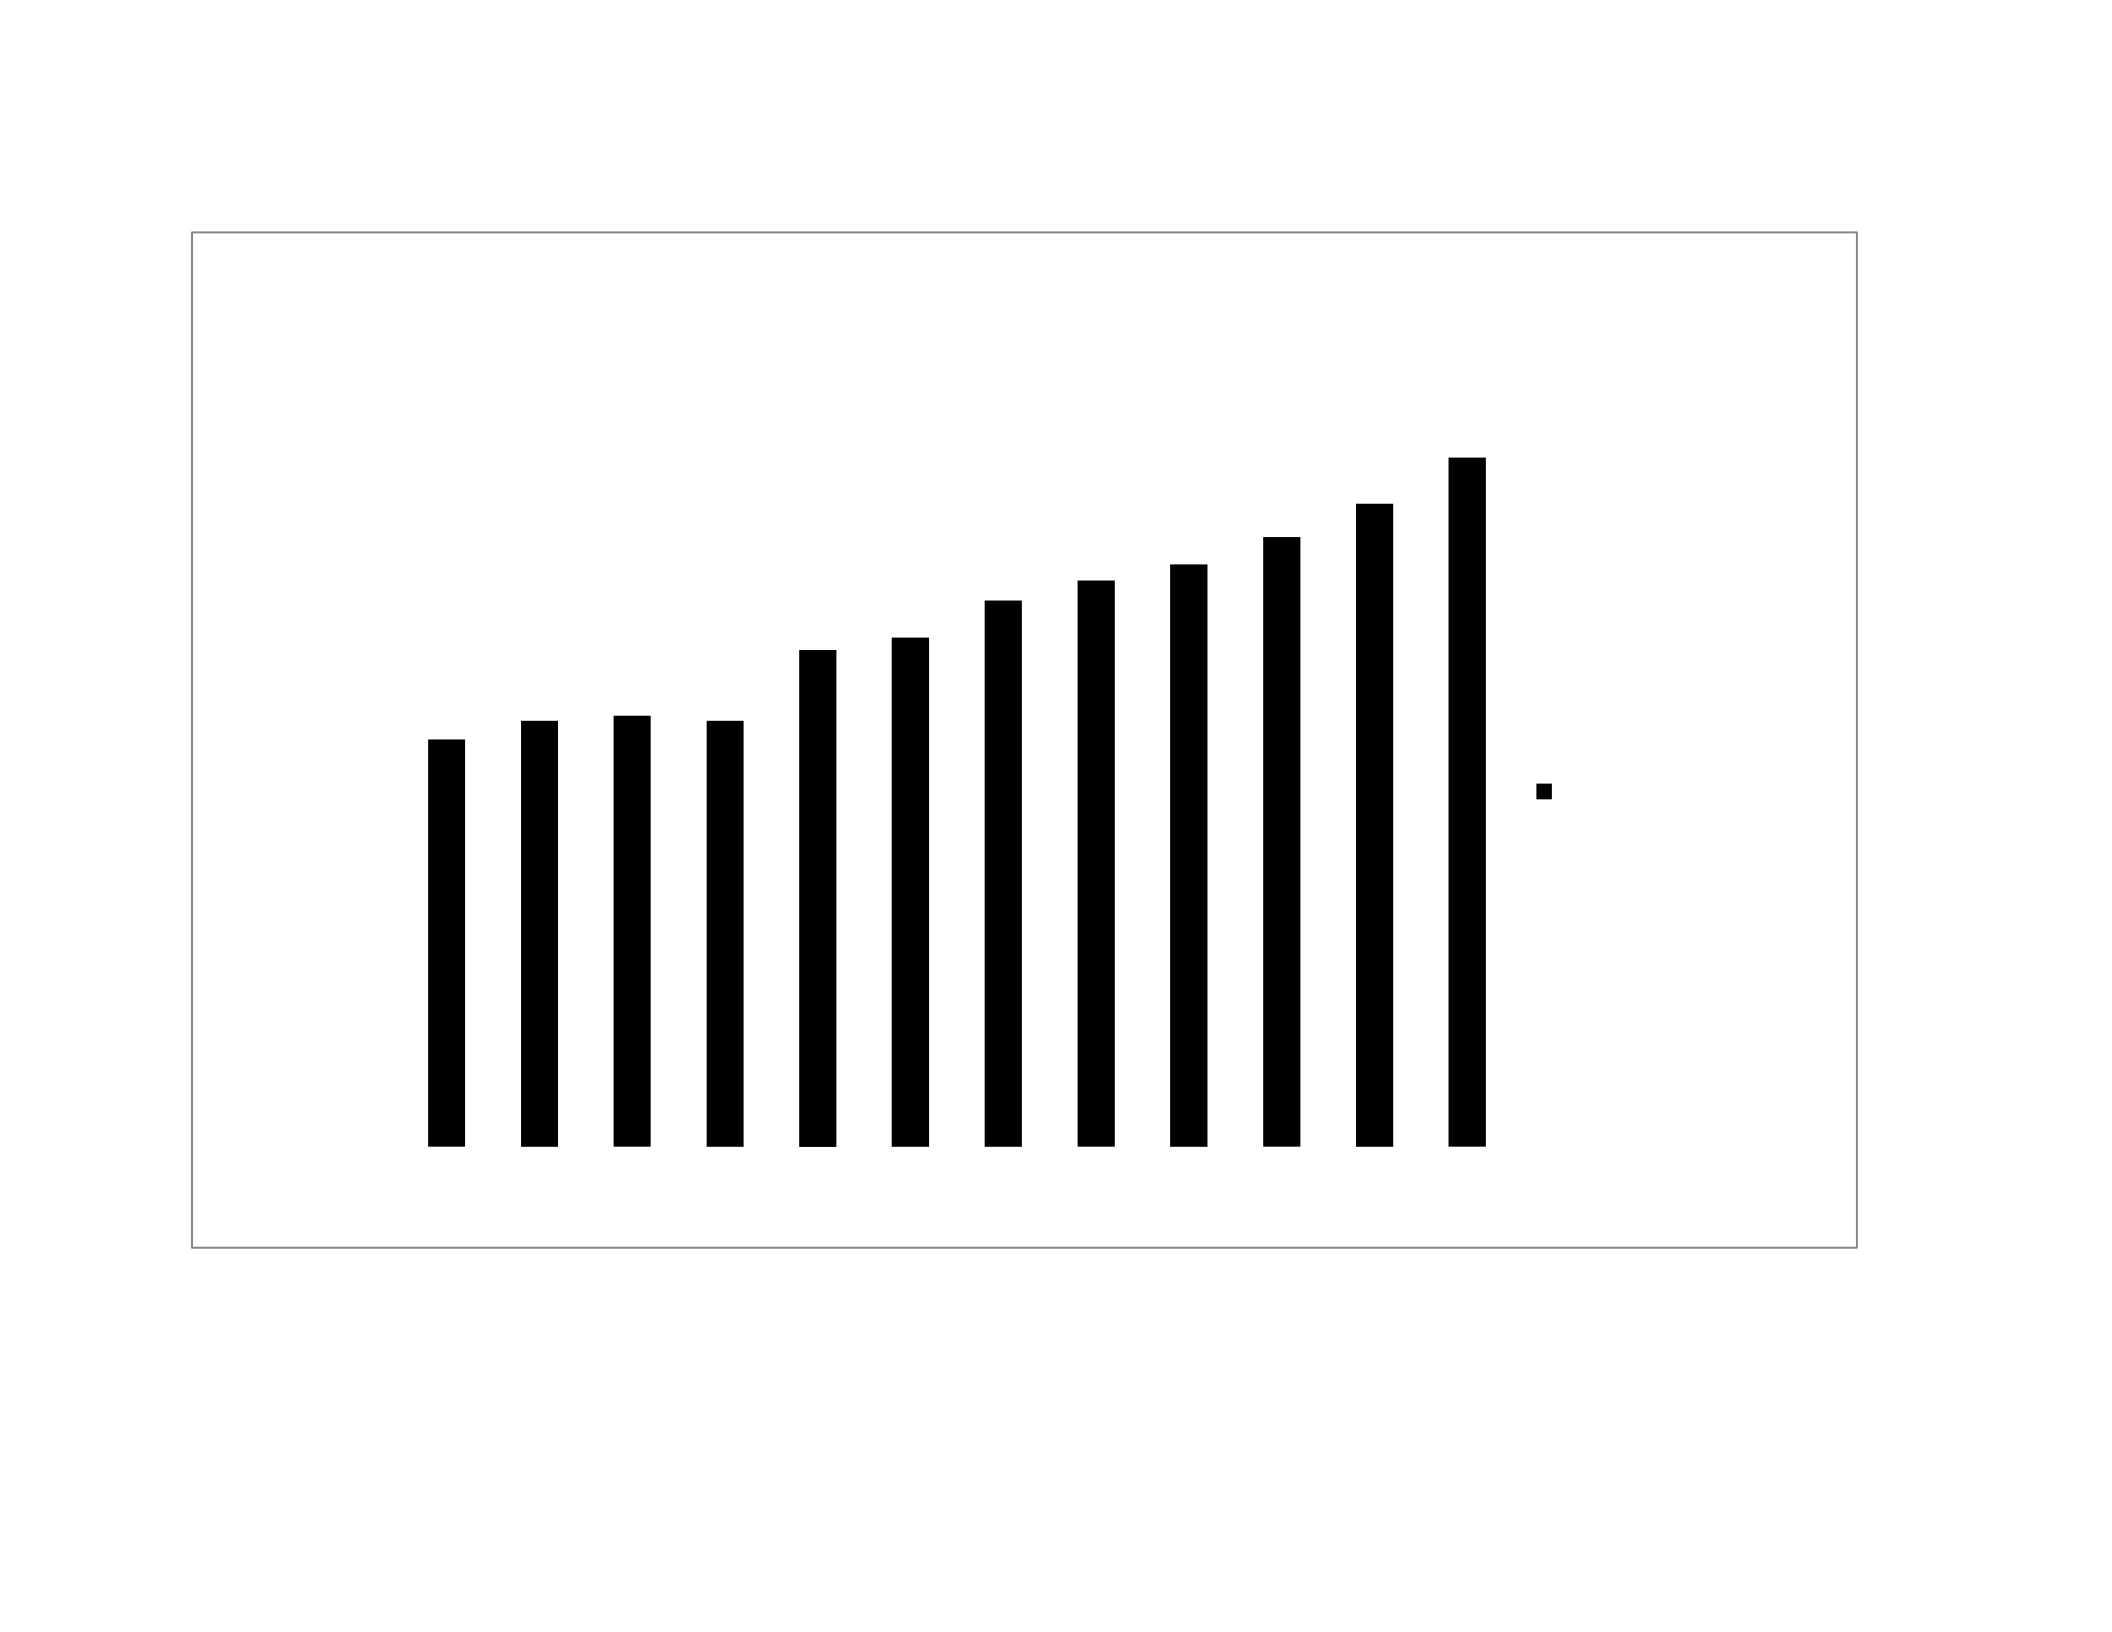
Figure 1. U.S. Corporate Foundation Philanthropic Giving from 2001 to 2012 (2,629 Corporate Foundations)
Source: The Foundation Center as of January 27, 2015
3.28 3.43 3.47 3.43
4 4.1
4.4 4.56 4.69
4.91
5.18
5.55
0
1
2
3
4
5
6
2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012
Billion$
Total charitable giving
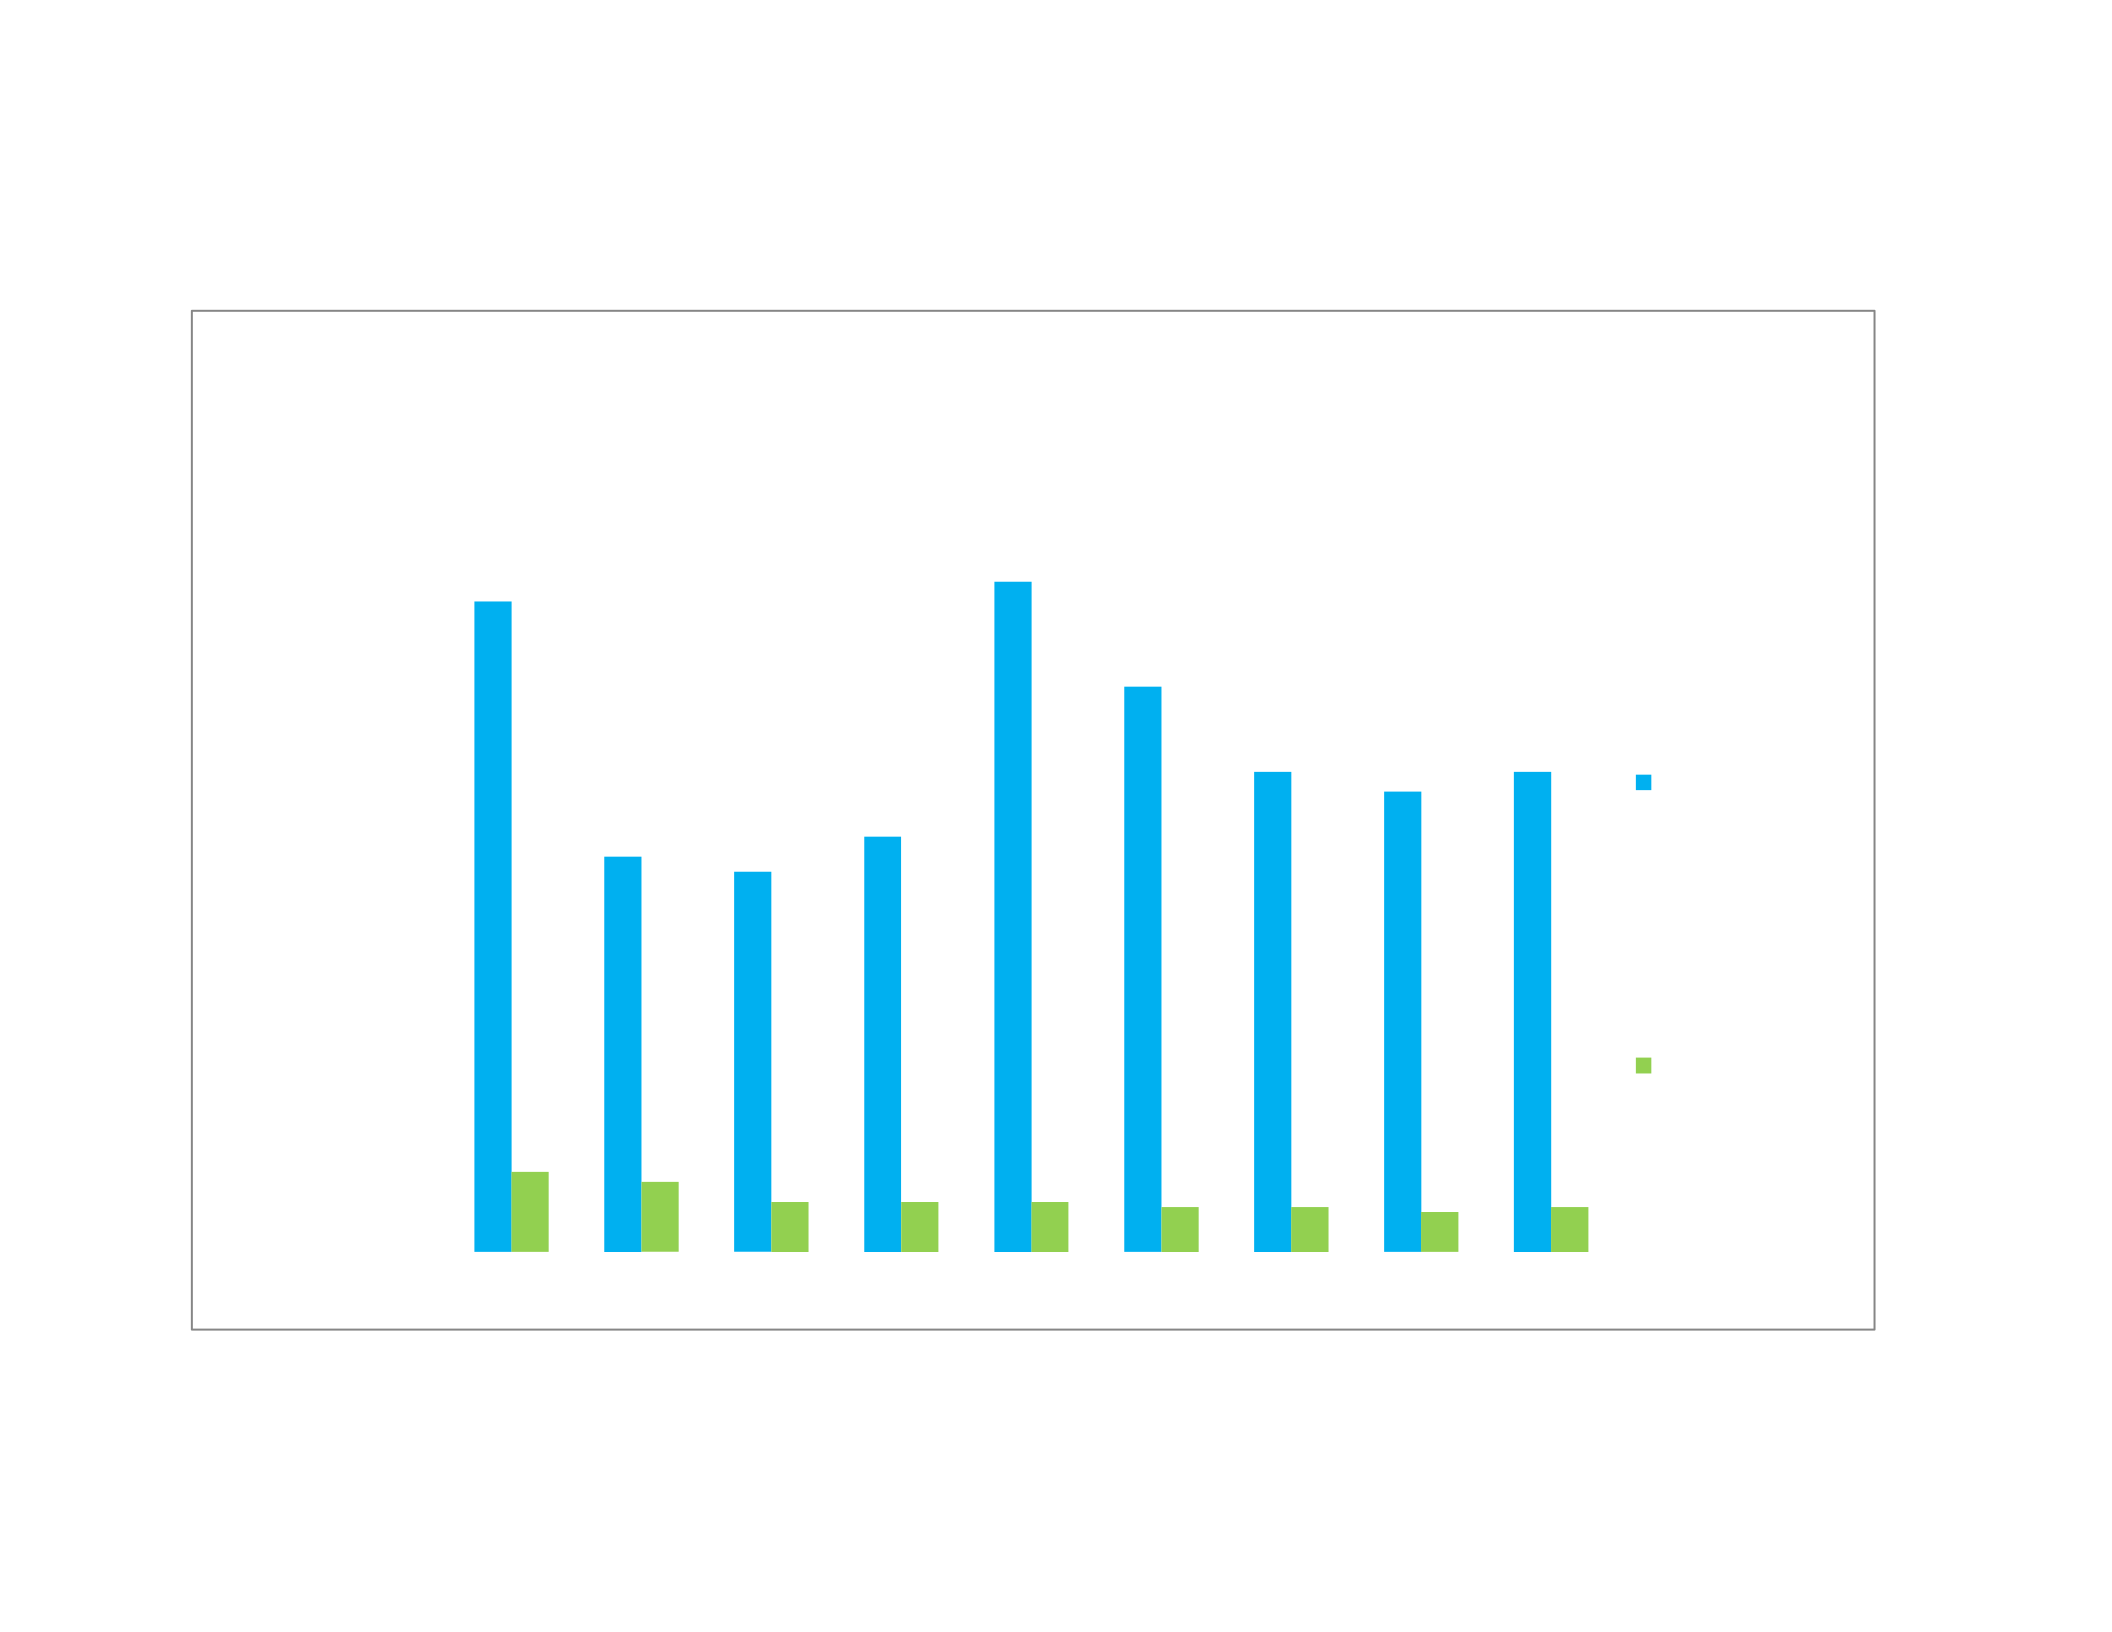
5
Figure 2. Total Charitable Giving among Fortune 100 Firms between 2004 and 2012
Source: Committee Encouraging Corporate Philanthropy as of January 27, 2015
1.3
0.79 0.76
0.83
1.34
1.13
0.96 0.92 0.96
0.16 0.14 0.1 0.1 0.1 0.09 0.09 0.08 0.09
0
0.2
0.4
0.6
0.8
1
1.2
1.4
1.6
2004 2005 2006 2007 2008 2009 2010 2011 2012
Total charitable
giving as a % of
pre-tax profit
Total charitable
giving as a % of
revenue
Million$

6

Despite the stated purpose of enhancing a firm’s public visibility and reputation by
engaging in corporate philanthropy, firms face some criticisms from stakeholders on the tangible
benefits of philanthropy. Some scholars (e.g. Devinney, 2009; Friedman, 1970) have supported
this skeptical perspective arguing that a firm exists primarily to generate economic returns, not to
solve societal problems. Friedman (1970, p. 6) argues that the single social responsibility of
business is to “engage in business activities designed to increase its profit.” On the contrary,
other scholars (e.g. Godfrey, 2005; Wang & Qian, 2011) have strongly supported the positive role
of corporate philanthropy in improving firm performance. These scholars argue that corporate
philanthropy can generate positive stakeholder support which in turn improves a firm’s financial
performance. In an effort to address the critics’ concerns on the use of corporate resources toward
charitable contributions, firms are increasingly turning to the strategic use of philanthropy.
Research suggests that strategic philanthropy can play a key role in developing value-creating
relationships with primary stakeholders and enhancing a company’s image (Buchholtz, Amason
& Rutherford, 1999; Saiia, Carroll & Buchholtz, 2003). Strategic philanthropy can also serve as
“a common meeting ground for the opponents and proponents of corporate philanthropy”
(Buchholtz et al., 1999, p. 169). Large firms are fundamentally responsible for strategic
philanthropy in practice because they have systematic structures (Marquis & Lee, 2013). For
example, large firms have corporate foundations, employee committees to oversee corporate
giving, and staff functions devoted to the effort to manage their social responsibilities (McAlister
& Ferrell, 2002). In marketing practice, strategic philanthropy has been often associated with
cause-related marketing to support social responsibility (File & Prince, 1998; Vanhamme,
Lindgreen, Reast & van Popering, 2012; Varadarajan & Menon,
1988). Both practices have some dissimilarities in terms of primary focus, time frame, and costs
(McAlister & Ferrell, 2002). Strategic philanthropy focuses on organizing itself, is ongoing, and

tends to require moderate to high resource commitment. On the other hand, cause-related
marketing focuses on the firm’s products, has a limited duration, and involves minimal resource
commitment. Both strategic philanthropy and cause-related marketing help enhance societal
welfare and improve the reputation of a firm. Stakeholder theory (Freeman, 1984) offers an
important theoretical support for the relationship between corporate philanthropy and firm
performance, suggesting that favorable social performance is a requirement for business
legitimacy, and tends to be positively associated with firm performance over the long term.
Donaldson and Preston (1995, p. 82) also suggest that firms respond to “ethical considerations
(e.g. engaging in philanthropy) which are often consistent with long-run increases in profit and
value.”
Importantly, the positive effect of corporate philanthropy on the firm provides a reason
why there is a need to examine the relationship between CEO characteristics and corporate
philanthropy. Since corporate philanthropy has become an important strategic tool that
organizational senior leaders manipulate, they are more involved in assessing and shaping
corporate strategies (Porter & Krammer, 2002). In addition, past research argues that a firm’s
social activities should be met by corporate goals determined by CEOs who constantly make
strategic decisions and choices (Choi & Wang, 2007; Wood, 1991). Furthermore, it has been
suggested that CEOs are the primary decision-makers of the organization such that an
examination of CEOs’ attitudes and values toward philanthropy provides needed insight into the
social responsibility actions in general and philanthropic function in particular (Dennis,
Buchholtz, & Butts, 2009). Accordingly, it can be suggested that the relationship between CEO
characteristics and corporate philanthropy should receive much attention. In the following
section, I will provide a brief discussion on the major research gaps that I seek to address in order

to advance the understanding of the leadership predictors of corporate philanthropy and the
implications for firm performance.
1.3 Statement of the Problem
Previous studies have focused on why firms engage in corporate philanthropy (Adams &
Hardwick, 1998; Brammer & Millington, 2005; Fombrun & Shanley, 1990; Godfrey, 2005;
Turban & Greening, 1997; Wang & Qian, 2011; Williams & Barrett, 2000). These studies have
shown that engagement in corporate philanthropy can lead to increased employee loyalty (e.g.,
employee commitment), favorable community image (e.g., corporate reputation), and positive
media coverage (e.g., recovering tarnished reputation). As such, it can be suggested that
consequences of corporate philanthropy have been extensively explored to answer the question,
“why should a firm give?” Meanwhile, antecedents of corporate philanthropy have been
explored to answer the question, “what drives firms to give?” The predominant discussion
among scholars has been on the managerial (e.g. Buchholtz et al., 1999; Choi & Wang, 2007;
Marquis & Lee, 2013; Wang & Coffey, 1992), organizational (Adams & Hardwick, 1998;
Brammer & Millington, 2006; Seifert, Morris & Bartkus, 2003), and industry (Amato & Amato,
2007, 2012; Useem, 1988) drivers of corporate philanthropy. Specifically, past research
suggested that firms engage in corporate philanthropy as a means to simultaneously and directly
benefit business interests and those of a beneficiary organization (Saiia et al., 2003; Marx, 1999).
The extent to which firms engage in corporate philanthropy can vary depending on
organizational factors, such as firm size, organizational slack, and advertising intensity (Dennis
et al., 2009; Saiia et al., 2003; Wang & Qian, 2011). Past research on corporate philanthropy has
generally discussed the intersection of business goals and the larger societal good help improve
the firm’s competitive position (Maas & Liket, 2011; Saiia et al., 2003). In sum, it can be argued
that previous studies of corporate philanthropy have developed from three aspects, “why give,”

“what leads to give,” and “give strategically.”
Unlike the extensive discussion on firm-level predictors, managerial perspective on
corporate philanthropy has not received much attention (e.g., how, why, and to what degree
individuals, such as CEOs, engage in corporate philanthropy). This line of inquiry is consistent
with a recent study’s (Aguinis and Glavas, 2012) observation that corporate social activities,
including corporate philanthropy, research is virtually absent from journals devoted to
organizational behavior and micro-level human resources management. Therefore, there is a need
to focus more on the micro level (e.g., do characteristics of individuals influence firms’
philanthropic engagement?) than on the macro level (e.g. are organizational outcomes of
corporate philanthropy beneficial to the firm?). In addition, there might be some link between
CEO characteristics and corporate philanthropy. Several scholars suggest that CEOs think
strategically about philanthropy to enhance brand name recognition, employee productivity, and
even to overcome regulatory obstacles (Seifert et al., 2003; Smith, 1994). Despite the growing
interest in the effect of CEO characteristics on CSR in general and philanthropy in particular, the
relationship between CEO characteristics and corporate philanthropy is under-developed and has
not received close empirical scrutiny.
Past research (e.g. Choi & Wang, 2007; Godfrey, 2005) has focused more on CEOs moral
background and characteristics, such as CEOs’ integrity and altruism, to explain a firm’s
philanthropic decisions. These studies, however, leave room for further explanation as to whether
CEO characteristics predict corporate philanthropy. This is because corporate philanthropy can
be driven not only by non-business community issues related to CEO altruism but also by
business-related issues, both of which benefit the firm’s strategic position. To fill this research
gap, I draw from the upper echelon theory (Carpenter, Geletkanycz & Sanders, 2004; Hambrick

& Mason, 1984) to explore how leaders’ background characteristics might influence their firms’
engagement in corporate philanthropy. Thomas and Simerly (1994) suggest that the demographic
characteristics of CEOs (e.g., age, functional background, and education) offer reliable proxies
for visible social activities of CEOs. Pedersen and Neergaard (2009) also suggest that managerial
perceptions of corporate social activities, including corporate philanthropy, are influenced by a
great deal of heterogeneity (e.g., age, gender, education, and functional backgrounds). In
addition, it might be that founder CEOs have wide strategic options and more power over their
boards (Mousa & Wales, 2012) and such status can influence corporate philanthropy. Despite the
practical importance of the relationship between founder status and corporate philanthropy, that
relationship has not received empirical investigation.
Firm size, organizational slack, and advertising intensity have been explored as important
organizational factors that influence corporate philanthropy (Dennis et al., 2009; Seifert et al.,
2003; Wang & Qian, 2011). What scholars argue is that bigger firms with more slack resources
and advertising intensity have a positive association with corporate philanthropy. What is missing
from these discussions is firm age as an important organizational context. In other words, the
relationship between firm age and corporate philanthropy has not received much scholarly
attention. For instance, Logsdon, Reiner and Burke (1990) observed in an exploratory study that
firm age might be significant in explaining placement of corporate philanthropy. Particularly,
past research has suggested that older firms tend to be increasingly inflexible so that firm age
may be an important indicator of reduced executive discretion (Finkelstein, Hambrick &
Cannella, 2009). Although the individual CEO’s influence on corporate philanthropy might vary
as a firm grows, the role of firm age on the relationship between CEO background characteristics
and corporate philanthropy has not received much attention. Therefore, it is worth exploring this
relationship.

Although corporate philanthropy has developed from a wide range of theoretical
frameworks, scholars have not yet given much thought to whether firms proactively engage in
corporate philanthropy to strengthen their business and corporate strategies. Particularly, the
relationship between corporate philanthropy and unrelated diversification is under-developed.
Unrelated diversification is one of core business strategies which help firms expand new markets.
For example, when firms pursue unrelated diversification strategies, they usually experience a
wide range of varying demands from stakeholders in distant industries or their subsidiaries
(Chatterjee & Wernerfelt, 1991). Corporate philanthropy can generate reputational assets in the
new market (Hess, Rogovsky & Dunfee, 2002), strengthen marketing and branding initiatives
(Lii & Lee, 2012; Ricks Jr, 2005), and improve relations with local governments (Wang & Qian,
2011). From this phenomenon, it can be suggested that firms can consider philanthropic activities
as part of long- term competitiveness and a means to strategically open new markets.
In addition, it is likely that the pressure for engaging in corporate philanthropy would
increase among international firms with business activities across countries and culture. Deresky
(1997) suggests that the philanthropic activities of multinational corporations that operate in
foreign countries may be characterized as strategic, clearly targeted, and linked to the overall
objectives of the firm. In addition, when firms expand their businesses in a foreign market
(Sharfman, Shaft & Tihanyi, 2004), they experience a wide range of stakeholder’ pressures.
Corporate philanthropy can be used as a means of reducing these challenges. Despite the
importance of corporate philanthropy on a firm’s internationalization, there is a lack of
theoretical explanation and empirical evidence as to whether corporate philanthropy advances a
firm’s internationalization strategy. Similarly, expansive global strategic posture (in terms of
geographic market diversification) can help firms leverage R&D costs and knowledge across
countries (Carpenter & Fredrickson, 2001; Kim & Mauborgne, 1991). It has been suggested that

corporate philanthropy may be an opportunity for internationally operating firms, but also for
investing in legitimacy in a region considered to be the main emerging market for the country
(Bohnsack, 2012; Whiteman, Muller, Van der Voort, Wijk, Meijs, & Pique, 2005). It is reasonable
to expect that firms are encouraged to engage in corporate philanthropy to develop a
commanding international presence. In sum, I explore how CEOs’ background characteristics
predict the degree of firms’ engagement in corporate philanthropy and the complimentary
theoretical relationship between corporate philanthropy and a firm’s diversification profile (such
as unrelated diversification and global strategic posture).
1.4 Purpose of the Study & Research Questions
In this dissertation, I examine the effect of CEOs’ background characteristics on corporate
philanthropy and firm diversification profile. More specifically, I examine the relationships
between CEOs’ background characteristics and corporate philanthropy. In doing so, I focus on
four aspects of CEO background characteristics (i.e. CEO founder status, functional background,
civic engagement, and education) and examine whether they are associated with the degree of
firms engagement in corporate philanthropy.
First, what is the relationship between CEO founder status and corporate philanthropy?
Founder CEOs are likely to hold a psychological bond with their firms (Peterson, Galvin &
Lange, 2012). Founder CEOs’ intrinsic motivation could lead them to engage in socially
responsible activities that meet various stakeholder demands, such as corporate philanthropy.
Second, what is the relationship between CEO functional background and corporate
philanthropy? Corporate social performance can be a reflection of CEO functional background
(Melo, 2012). Thus, it might be anticipated that a certain aspect of a CEO’s past work experience
in jobs within functional areas of organizations can influence corporate philanthropy. Third, what

is the relationship between CEO civic engagement and corporate philanthropy? CEOs often
serve as active members in community groups or associations and they participate in civic affairs
as part of their strategic mission. Doing so can be motivated by a desire to create the local
community development and a more stable political environment that ensures their business
profitability. Fourth, what is the relationship between CEO education and corporate
philanthropy? Bennett (2012) argues that better educated people have wider mental horizons that
cause individuals to recognize the value of charities concerned with the external environment.
Therefore, it is expected that CEOs’ education can play an important role in determining the
choice and emphasis on corporate philanthropy. In addition, I examine the moderating role of
firm age on the relationship between CEO background characteristics and corporate
philanthropy. Although older firms would be expected to be more well-known and have greater
philanthropic engagement, it is reasonably expected that a CEO’s influence on corporate
philanthropy varies as a firm grows.
Furthermore, I examine the role of corporate diversification profile on corporate
philanthropy and firm performance. Past research suggests that firms increase philanthropic
expenditures strategically as a means to open new markets where they are not familiar with and
the pressures for engaging in corporate philanthropy increase among international firms (Merz,
Peloza & Chen, 2010). Specifically, I examine a firm’s diversification strategy as the mechanism
through which corporate philanthropy influences firm performance. Since the ultimate goal of a
firm’s social activities, including corporate philanthropy, is to maximize performance, it is worth
exploring the interaction, including corporate philanthropy – firm performance relationship
through the mechanism of corporate diversification profile.

In sum, there are four major under-developed research areas in the literature that will be
explored in this dissertation. First, there is a need to examine the relationship between CEO
background characteristics and corporate philanthropy. Second, the role of firm age on the
relationship between CEO background characteristics and corporate philanthropy should receive
much attention. Third, whether firms proactively engage in corporate philanthropy to strengthen
their unrelated diversification strategies should receive an empirical investigation. Fourth, the
relationship between corporate philanthropy and firm performance needs to be examined
particularly under corporate diversification profile (e.g. how corporate philanthropy influences
firm performance through unrelated diversification and global strategic posture). I intend to
answer the following three research questions:
19) Do CEO background characteristics influence the level of corporate philanthropy? If so,
why?
20) Does firm age moderate the relationships between CEO background characteristics and
the level of corporate philanthropy?
21) Does corporate diversification profile mediate the relationship between the level of
corporate philanthropy and firm performance?
1.5 Significance & Contributions of the Dissertation
1.5.1 Contributions to Corporate Philanthropy Research
In this dissertation, I offer several contributions for research. First, this dissertation
contributes to the growing scholarly interests in terms of CEOs’ influence on corporate
philanthropy. It has been suggested that CEOs are requiring greater strategic accountability in
corporate giving programs (Saiia et al, 2003) and that corporations undertake strategic
philanthropy as long as direct economic benefits can be gained by doing so (Sánchez, 2000).

Therefore, an examination of whether CEO background characteristics influence corporate
philanthropy helps to fulfill research interests.
Second, I extend the literature on corporate philanthropy to examine the strategic use of
philanthropy. It has been suggested that traditional altruistic models of philanthropy are
becoming less relevant because it is generally considered a non-strategic explanation of corporate
giving which ignores the profit maximization goal and other strategic goals of the firm
(Neiheisel, 1994; Sánchez, 2000). Corporate giving activities have evolved into far more
strategically market-oriented approaches like targeted grants intended to optimize economic
return as well as social returns per philanthropic dollar (Sherblom, 2007).
Third, drawing upon the institutional and stakeholder perspectives, I offer a new attempt
to empirically examine the link between corporate philanthropy and unrelated diversification. For
example, faced with various challenges (e.g., social, legal, and regulatory), corporate
diversification increases a variety of stakeholder pressures in the firm’s external environment that
arise (Brammer, Millington & Pavelin, 2006; Sharfman et al., 2004). In addition, highly
diversified firms not only suffer from a lack of coherence in terms of underlying resources
(Montgomery & Wernerfelt, 1988) but they also have to deal with heavy stakeholder demands.
These pressures might be mitigated when engaging in corporate social activities through which
unrelated diversifiers can manage a wide range of stakeholders’ demands.
Fourth, although previous studies (Markides & Williamson, 1994; Palepu, 1985; Rumelt,
1974) suggest a negative relationship between unrelated diversification and (short-term) financial
performance, this dissertation provides a different perspective to corporate diversification
strategy. For example, corporate philanthropy helps to generate reputation and branding
initiatives in the new markets so that it can improve the firm’s market positions (Hess et al.,

2002; Ricks Jr, 2005). In this dissertation, I provide scholars with a promising suggestion that
unrelated diversification may not necessarily be an inferior strategy for the firm.
1.5.2 Contributions to Practice
In this dissertation, I offer several contributions for practice. First, understanding of how
CEO background characteristics (e.g., CEO status, functional background, civic engagement, and
education level) can be applied to corporate philanthropy helps to explain the rationale behind
decisions to engage in corporate philanthropy. Therefore, I answer what leads CEOs to engage in
corporate philanthropy and further why some CEOs engage in more corporate philanthropy than
others. Second, I provide managers with practicability of corporate philanthropy. For example,
strategic use of philanthropic expenditures can support a community project in developing
countries (Porter & Kramer, 2002; Sánchez, 2000) because better community conditions are
good for business (e.g., when the standard of living is increased, product demand is increased).
Third, I provide managers with a promising notion that engaging in corporate
philanthropy can help firms with diversification and market entry strategies. Scholars argue that a
firm’s philanthropic engagement in developing countries can enhance the firm’s reputation and
get easier access to the market (Bohnsack, 2012; Brammer et al., 2006). There might be a
positive relationship between corporate philanthropy and international presence. In addition, it is
suggested that corporate philanthropy can offer an opportunity for internationally operating firms
as well as for investing in business legitimacy. In this dissertation, I can provide managers with
practicability that international firms can strengthen their competitive context by engaging in
corporate philanthropy. Fourth, I provide insights on business legitimacy by suggesting that firms
are seen as legitimate actors by local stakeholders to the extent they engage in corporate
philanthropy. Goyal (2006) and Wang and Qian (2011) suggest that philanthropic activities of

multinational firms in the host countries would be a signaling device to demonstrate that they
have long-term intentions consistent with the local expectations. Thus, I suggest that firms can
receive supportive responses from the host countries governments by engaging in corporate
philanthropy.
1.6 Definition of Key Terms
Corporate social responsibility (CSR) refers to “context-specific organizational actions
and policies that take into account stakeholders’ expectations and the triple bottom line of
economic, social, and environmental performance” (Aguinis, 2011, p. 855).
Diversification refers to “the entry of a firm or business unit into new lines of activity,
either by processes of internal business development or acquisition, which entail changes in its
administrative structure, systems, and other management processes” (Ramanujam &
Varadarajan, 1989, p. 525). There are two types of diversification, such as related diversification
and unrelated diversification. Related diversification refers to a diversification built around a
core organizational capability (Ramanujam, 1987; Rumelt, 1982). It occurs when firms expand
their areas closely related to their primary activities and areas of technical expertise. Unrelated
diversification refers to a diversification that drives to move into unrelated lines of business
(Ramanujam, 1987; Rumelt, 1982). It occurs where firms expand their operations into markets or
products beyond current resources and capabilities.
Corporate philanthropy refers to the practice of “giving firm resources to invest in
business-related issues and non-business community issues that also benefit the firm’s strategic
position and, ultimately, its bottom line” (Saiia et al., 2003, p. 170). This definition helps to
explain why some firms still donate in non-business areas more than others. They do so because

they believe that giving non-business issues would enhance their public image which can be used
for gaining business legitimacy in developing countries (Wang & Qian, 2011).
Global strategic posture (GSP) refers to “the degree to which a firm is dependent on
foreign sales and production and to the geographic dispersion of this dependence” (Carpenter,
Sanders & Gregersen, 2001, p. 497). It has been suggested that GSP reflects the relative
significance of foreign markets and operations in sustaining the firm as well as their geographic
dispersion (Sullivan, 1994). Therefore, GSP can be used for measuring firm internationalization
(Carpenter & Fredrickson, 2001; Levy, 2005). GSP are normally measured by three dimension
originally developed by Sullivan (1994): foreign sales, foreign production, and geographic
diversity. Foreign sales reflect the relative significance of foreign market. Foreign production
reflects the degree to which a firm depends on foreign-owned assets and resources. Geographic
diversity reflects the extent to which a firm has subsidiaries associated with globalization of
operations and markets. Several scholars used GSP to explain a firm’s internationalization
strategy (Carpenter et al., 2001; Carpenter & Fredrickson, 2001; Levy, 2005).
1.7 Organization of the Dissertation
This dissertation consists of six chapters. The first chapter provides an introduction about
the importance of corporate philanthropy, statement of the problem, major research questions as
well as the contributions of the dissertation. Chapter two presents a comprehensive and extensive
review of the literature on corporate social responsibility and the antecedents and consequences
of corporate philanthropy with the role of leadership in corporate philanthropy. Chapter three
presents the research model, theoretical foundations, and summary of theoretically-driven
hypotheses. Chapter four presents the research design including target sample, measures, as well
as statistical techniques. Chapter five presents and highlights the results of statistical analyses,

including summary of findings and summary of hypotheses. Chapter six discusses the results
from Chapter five, the implications to research and practice, limitations, future research
directions, and conclusion.

CHAPTER II
LITERATURE REVIEW
This chapter provides a comprehensive review of the corporate philanthropy research.
The first section begins with a systematic review of the literature on the relationship between
Corporate Social Responsibility (CSR) and firm performance as well as the leadership
determinants of CSR. In the second section, I discuss the theoretical conceptualizations of
corporate philanthropy with a comparative review of the traditional and strategic philanthropy
literatures. In the third section, I discuss the managerial, organizational and industry level
antecedents and consequences of corporate philanthropy with a particular emphasis on the link
between leadership attributes and corporate philanthropy. In the fourth section, I present a
comprehensive review of research on the link between corporate philanthropy and corporate
strategy. The chapter then concludes with a contingency view of corporate philanthropy.
2.1 How Does Corporate Social Responsibility (CSR) Influence Firm Performance?
CSR refers to “context-specific organizational actions and policies that take into account
stakeholders’ expectations and the triple bottom line of economic, social, and environmental
performance” (Aguinis, 2011, p. 855). Specifically, the demand for business CSR initiatives has
been significantly higher around the world over the last several decades. Accordingly, firms
nowadays are expected to act more proactively to fulfill their CSR expectations as responsible
corporate citizens to the society (Wang & Hsu, 2011). Since engaging in CSR is considered a
socially responsible investment for the firm, how CSR influences firm performance has been an
important issue among organizational scholars (Agle, Mitchell & Sonnenfeld, 1999; Aguinis &
Glavas, 2012; Orlitzky, Schmidt & Rynes, 2003). Even though there are some debates as to
whether CSR helps to improve firm performance, an extensive line of research has empirically

explored how CSR boosts firms’ competitive advantage, thereby ensuring value creation and
satisfaction for stockholders and customers (Cox, Brammer & Millington, 2004; Lev, Petrovits &
Radhakrishnan, 2010).
The topic of whether CSR can have a positive effect on firm performance has generated
extensive discussions among scholars and practitioners. Friedman (1970) provides the classical
economic perspective that management has one responsibility and that is to maximize the profits
of its shareholders. Past research suggests that socially responsive firms incur higher direct costs
and reap lower profits than socially unresponsive firms (Aupperle, Carroll & Hatfield; 1985;
Devinney, 2009). In addition, some scholars have used agency theory that “good social
performance comes at the expense of good financial performance because social performance
makes use of firm resources in ways that confers significant managerial benefits rather than
returning those resources to shareholders” (Brammer & Millington, 2008, p. 1329). They argued
that firms would better spend their resources on value-added internal projects or return to
shareholders rather than invest in CSR. Despite these perspectives, there has been a growing
institutional and societal pressure on businesses to pursue a socially responsible operation for the
last couple of decades and a number of institutional approaches can explain this trend. Jones
(1995) suggests that firms facing repeated transactions with stakeholders based on trust and
cooperation are encouraged to be honest, trustworthy, and ethical because they believe that the
returns to such behavior are high. In addition, a majority of empirical evidence suggests a
significant positive relationship between CSR and financial performance (Aguinis & Glavas,
2012; Peloza, 2009). For example, Peloza (2009) reviewed 128 studies that explored the
relationship between CSR and financial outcomes and found that, almost 60 % showed a positive
relationship, less than 15 % a negative relationship and mixed findings from the rest of the

studies. Recently, Aguinis and Glavas (2012) summarized the overall empirical evidence on
CSR-performance relationship in a wide range of organizational fields as follows (p. 947):
“Working for socially responsible companies leads to increased organizational
identification (Carmeli, Gilat, & Waldman, 2007), employee engagement (Glavas
& Piderit, 2009), retention (Jones, 2010), organizational citizenship behavior (Lin,
Lyau, Tsai, Chen, & Chiu, 2010), employee commitment (Maignan, Ferrell & Hult,
1999), employee creative involvement (Glavas & Piderit, 2009), and improved
employee relations (Glavas & Piderit, 2009).”
In the 21th century, the influence of CSR on a firm performance is an important concern to
a firm’s stakeholders so that firms should consider CSR as part of their strategies (Lantos, 2001).
Given the ultimate responsibility of firms meets the needs of stakeholders, firms should fulfil
stakeholders’ demands while also devoting resources to CSR. Such seemingly contrasting
demands are leading more firms to embrace strategic CSR or strategic use of philanthropy.
Carroll (2001), for instance, argues that strategic CSR can accomplish strategic business goals,
including good deeds, are believed to be good for business as well as for society. Several scholars
have discussed strategic aspects of CSR. Porter and Kramer (2006) argue that CSR should be
seen as one of core business strategies in a firm, indicating that the firm can benefit from its
social investment. Maignan et al. (2005) also argue that CSR can serve as an attractive, valuable
resource offering competitive advantage for enhancing business performance because it can be
used as a means of conducting business strategies.
2.1.1 What Role Do Organizational Leaders Play in Fostering CSR?

In an attempt to link organizational leaders (e.g., CEOs) to CSR, scholars have focused on
three aspects of CEO background characteristics: values, compensation levels, and personal
attributes (experiences). For example, CEO integrity can be relevant to CSR such that leader
vision and integrity will increase CSR values to shareholders. Waldman and Siegel (2008) argue
that leader integrity to personal morality can yield positive outcomes for business and may
actually be the driver of CSR strategies in organizations. Ketola (2006) also argues that leader
integrity is an important component in his or her successful promotion of CSR activities at the
firm. In addition, the relationship between CEO compensation and CSR has received some
attention. For instance, McGuire, Dow and Argheyd (2003) empirically examined the
relationship between the level of CEO compensation and corporate social performance (CSP) but
they did not find any positive relation. However, Jiraporn and Chintrakarn (2013) using a sample
of 1,370 firms found that when the CEO power (as measured by the total compensation) goes
beyond a certain threshold, more powerful CEOs significantly reduce CSR investments.
Furthermore, several scholars examined the professional background of CEOs and corporate
social performance (Mazutis, 2014; Simerly, 2003; Thomas & Simerly, 1994). They found that
corporate social performance can be interpreted as a reflection of CEOs’ professional
background.
Do organizational leaders play a role in promoting CSR? This question has long attracted
extensive research (Fabrizi, Mallin & Michelon, 2014; Jiraporn & Chintrakarn, 2013). As senior
leaders, CEOs and their top management teams are charged with the responsibility of
formulating business and sustainability strategy (Strand, 2013; Wood, 1991). Indeed, today’s
corporate leaders play an important role in pursuing an effective CSR agenda (Bielak, Bonini &
Oppenheim, 2007; Fabrizi et al., 2014;Godos-Díez, Fernández-Gago & Martínez-Campillo,
2011; Mazutis, 2014). For example, CEOs engage in CSR related activities in response to

growing pressures from key stakeholders groups, such as customers and employees (Bielak et al.,
2007). In addition, while pressures from employees, customers, and other stakeholders can play a
crucial role in CEOs’ willingness to engage in CSR, CEOs recognize that CSR can give their
firms an opportunity to gain a competitive advantage as well as address societal needs (Bielak et
al., 2007). In addition, Godos-Díez et al. (2011) using a sample of 149 CEOs found that those
closer to the steward model are more inclined to attach great importance to ethics and CSR, and
to implement CSR practices. Fabrizi et al (2014) using a sample of 597 U.S. firms extended the
role of CEO’s incentives on CSR and found that non-monetary incentives have a positive effect
on CSR. Mazutis (2014) using a sample of 349 firms found the link between CEO open
executive orientation (such as a liberal worldview and output functional experiences) and
positive CSR initiative adoption over time. In this sense, it can be argued that the relationship
between leadership and CSR has become an important topic of research in the area of leadership
studies (Bielak et al., 2007; Godos-Díez et al., 2011; Fabrizi et al., 2014; Mazutis, 2014).
Transformational leadership helps represent the understanding of CSR in particular.
Transformational leadership is comprised of four major components (Avolio, Bass & Jung, 1999;
Bass & Riggio, 2006): (1) Idealized Influence (ability of leader to attract admiration and respect
and desire to follow from subordinates), (2) Inspirational Motivation (ability of leader to
communicate clear vision and create enthusiasm about future), (3) Intellectual Stimulation
(ability of leader to encourage creativity and unconventional and status quo-challenging
problem-solving among followers), and (4) Individual Consideration (ability of leader to accept
individual differences and actively provide feedback and interaction with followers).
Organizational scholars argue that transformational leadership has been found to influence CSR
behavior among some firms (Du, Swaen, Lindgreen & Senthat, 2013; McWilliams, Siegel &
Wright, 2006).

McWilliams et al (2006), for instance, suggest that strategic leadership theory can be
applied to CSR and that transformational leadership will be positively correlated with the
tendency of companies to engage in CSR. They explored the degree of transformational
leadership using CEOs of 112 large US and Canadian firms and found that intellectual
stimulation (which is one dimension of transformational leadership components) was a predictor
of the firm’s propensity to engage in strategically oriented CSR that were more likely to be
related to the firm’s corporate and business-level strategies (e.g., differentiation and reputation
building). In addition, Du et al. (2013) in a survey of 440 U.S firms found that firms with greater
transformational leadership are more likely to engage in institutional CSR practices, whereas
transactional leadership is not associated with such practices. Furthermore, it has been suggested
that charismatic leadership with self-concepts of followers can be related to CSR. For example,
leaders have values and moral justifications which provide followers with motivational effects
such that charismatic leaders can help connect one’s identify with greater social causes (Shamir,
House & Arthur, 1993).
In conclusion, the empirical evidence on the relationship between CSR and firm
performance seems to be inconclusive (Peloza, 2009). However, more recent studies suggest that
there is a positive association between CSR and firm performance (Aguinis & Glavas, 2012;
Chen & Wang, 2015). In addition, since some firms consider CSR as part of their core corporate
strategy and CEOs are charged with the responsibility of formulating corporate strategy, the
relationship between leadership characteristics and CSR is particularly important. Furthermore, it
can be suggested that understanding of three aspects of CEOs (values, compensation, and
experiences) helps to link CEO background characteristics and CSR. As mentioned in section
2.1.1, there is a certain interrelationship between CEOs and CSR. Table 1 below provides an
overview of research on the role of leadership in fostering CSR.

CSR as a business practice and philosophy has taken an important place in the way
businesses operate and serve their stakeholders. CSR refers to “context-specific organizational
actions and policies that take into account stakeholders’ expectations and the triple bottom line of
economic, social, and environmental performance” (Aguinis, 2011, p. 855). This definition
indicates that businesses should have responsibility beyond their immediate economic concern
and should act in a way that contributes and enhances broader societal goals. CSR primarily
embraces economic, legal, ethical, and philanthropic responsibilities and the dimensions of CSR
include the obligations a business has to its stakeholder’s groups (Carroll, 1991). Over the past
half century, CSR has increasingly been integrated into mainstream business thinking, and
nowadays, most U.S. publicly-traded firms (e.g., Microsoft, Google, and Walt Disney) claim to
engage in some form of CSR. The main benefits of engaging in CSR include generating
intangible assets, including building corporate reputation and employee commitment, and
tangible assets, including the positive impact on financial performance. Research in this area
suggests that being a socially responsible business helps create goodwill, build a positive
organizational image, differentiate them from their competitors, and, as a result, promote
longterm profits for business (Boynton, 2013). Indeed, more firms increasingly embrace CSR as
their employees demand their firms to be socially responsible, customers expect better business
practices, and investors realize the economic rewards of sustainable business models. Beyond the
immediate task environment, business CSR engagement also serves the needs of communities
around the world and fulfills the responsibilities businesses have to the public.
1.2 The Importance of Corporate Philanthropy
Corporate philanthropy is considered one of the core dimensions of CSR (Aguinis &

Clavas, 2012; Carroll, 1991; Porter & Kramer, 2002). The origin of corporate philanthropy in the
U.S. dates back to the rise of industrial age in the 19th and early 20th century, when businessmen
like Henry Ford and John D. Rockefeller established philanthropic foundations (Dietlin, 2011).
Corporate philanthropy has since been transformed from piecemeal individual philanthropic acts
(e.g., philanthropy mainly driven by morality) to a major aspect of corporate CSR practices.
Corporate philanthropy is, nowadays, a widespread business practice in large multinationals as
well as small-and medium-sized firms across the globe. Despite the dominant altruistic
orientation, corporate philanthropy has increasingly complemented the firm’s strategic activities
and enhanced the firm’s social and financial performance (Porter & Kramer, 2002). Therefore, it
can be argued that corporate philanthropy has evolved dramatically from a basic moral obligation
to a strategically-driven activity of the firm. As Porter and Kramer (2002, p. 58) put it,
“True strategic giving, by hand, addresses important social and economic goals simultaneously,
targeting areas of competitive context where the company and society both benefit because the
firm brings unique assets and expertise.”
Corporate philanthropy can often be “the most cost-effective way for a firm to improve its
competitive context” (Porter & Kramer, 2002, p. 9). Many firms invest a significant amount of
resource expenditures on philanthropy in order to build a strong company image. For example, a
2013 report from the Committee Encouraging Corporate Philanthropy indicates that 59 percent
of the largest Fortune 100 firms donated significantly more in 2012 compared to 2007, the year
before the global recession sets in, and aggregate giving rose by 42% ($4.48 billion) from 2007
to 2012. The ten largest U.S. corporations donated over 2.1 billion dollars in 2013 and this figure
has increased in 2014. Many firms provide support to nonprofits and social causes primarily
through company-sponsored foundations as well as corporate direct giving, both of which are

closely tied with the parent company’s business interests. As shown in Figure 1 below, the largest
U.S. firms and their foundations have increased charitable giving during the past decade (2001-
2012). Similarly, as shown in Figure 2 below, the largest 100 U.S. corporations have increased
total charitable giving both as a percentage of pre-tax profit and as a percentage of revenue
especially after the global recession in 2008.
Indeed, the increasing commitment of corporate resources to philanthropic causes reflects
a widely-held belief among business executives that philanthropy can be “strategic” in that it can
make a substantial impact on society while improving business value and reputation for the firm
(Carroll & Shabana, 2010; Walker, 2002). According to a 2010 survey by CECP, 77 percent of
CEOs noted that “the most important action they can take to prepare for 2020 is to embed social
engagement into business strategy and organizational structure.” For example, Ronald A.
Williams, the CEO of Aetna noted that that “public companies can move the collective needle by
using their human and financial resources to innovative in ways that benefit both private interests
and the public good” (Weiss, Kerdahy & Kneale, 2008, p. 5). Ivan Seidenberg, Chairman and
CEO, Verizon Communications Inc., commented in CECP that “our belief is that corporate
philanthropy expands the business. You can expand the capabilities of your customer base,
business and society by doing the right thing.” These and other executive views also highlight an
important fact that corporate philanthropy can be driven by leadership values and studying
leaders’ background can help extend our knowledge of the role of corporate philanthropy in
improving firm performance.
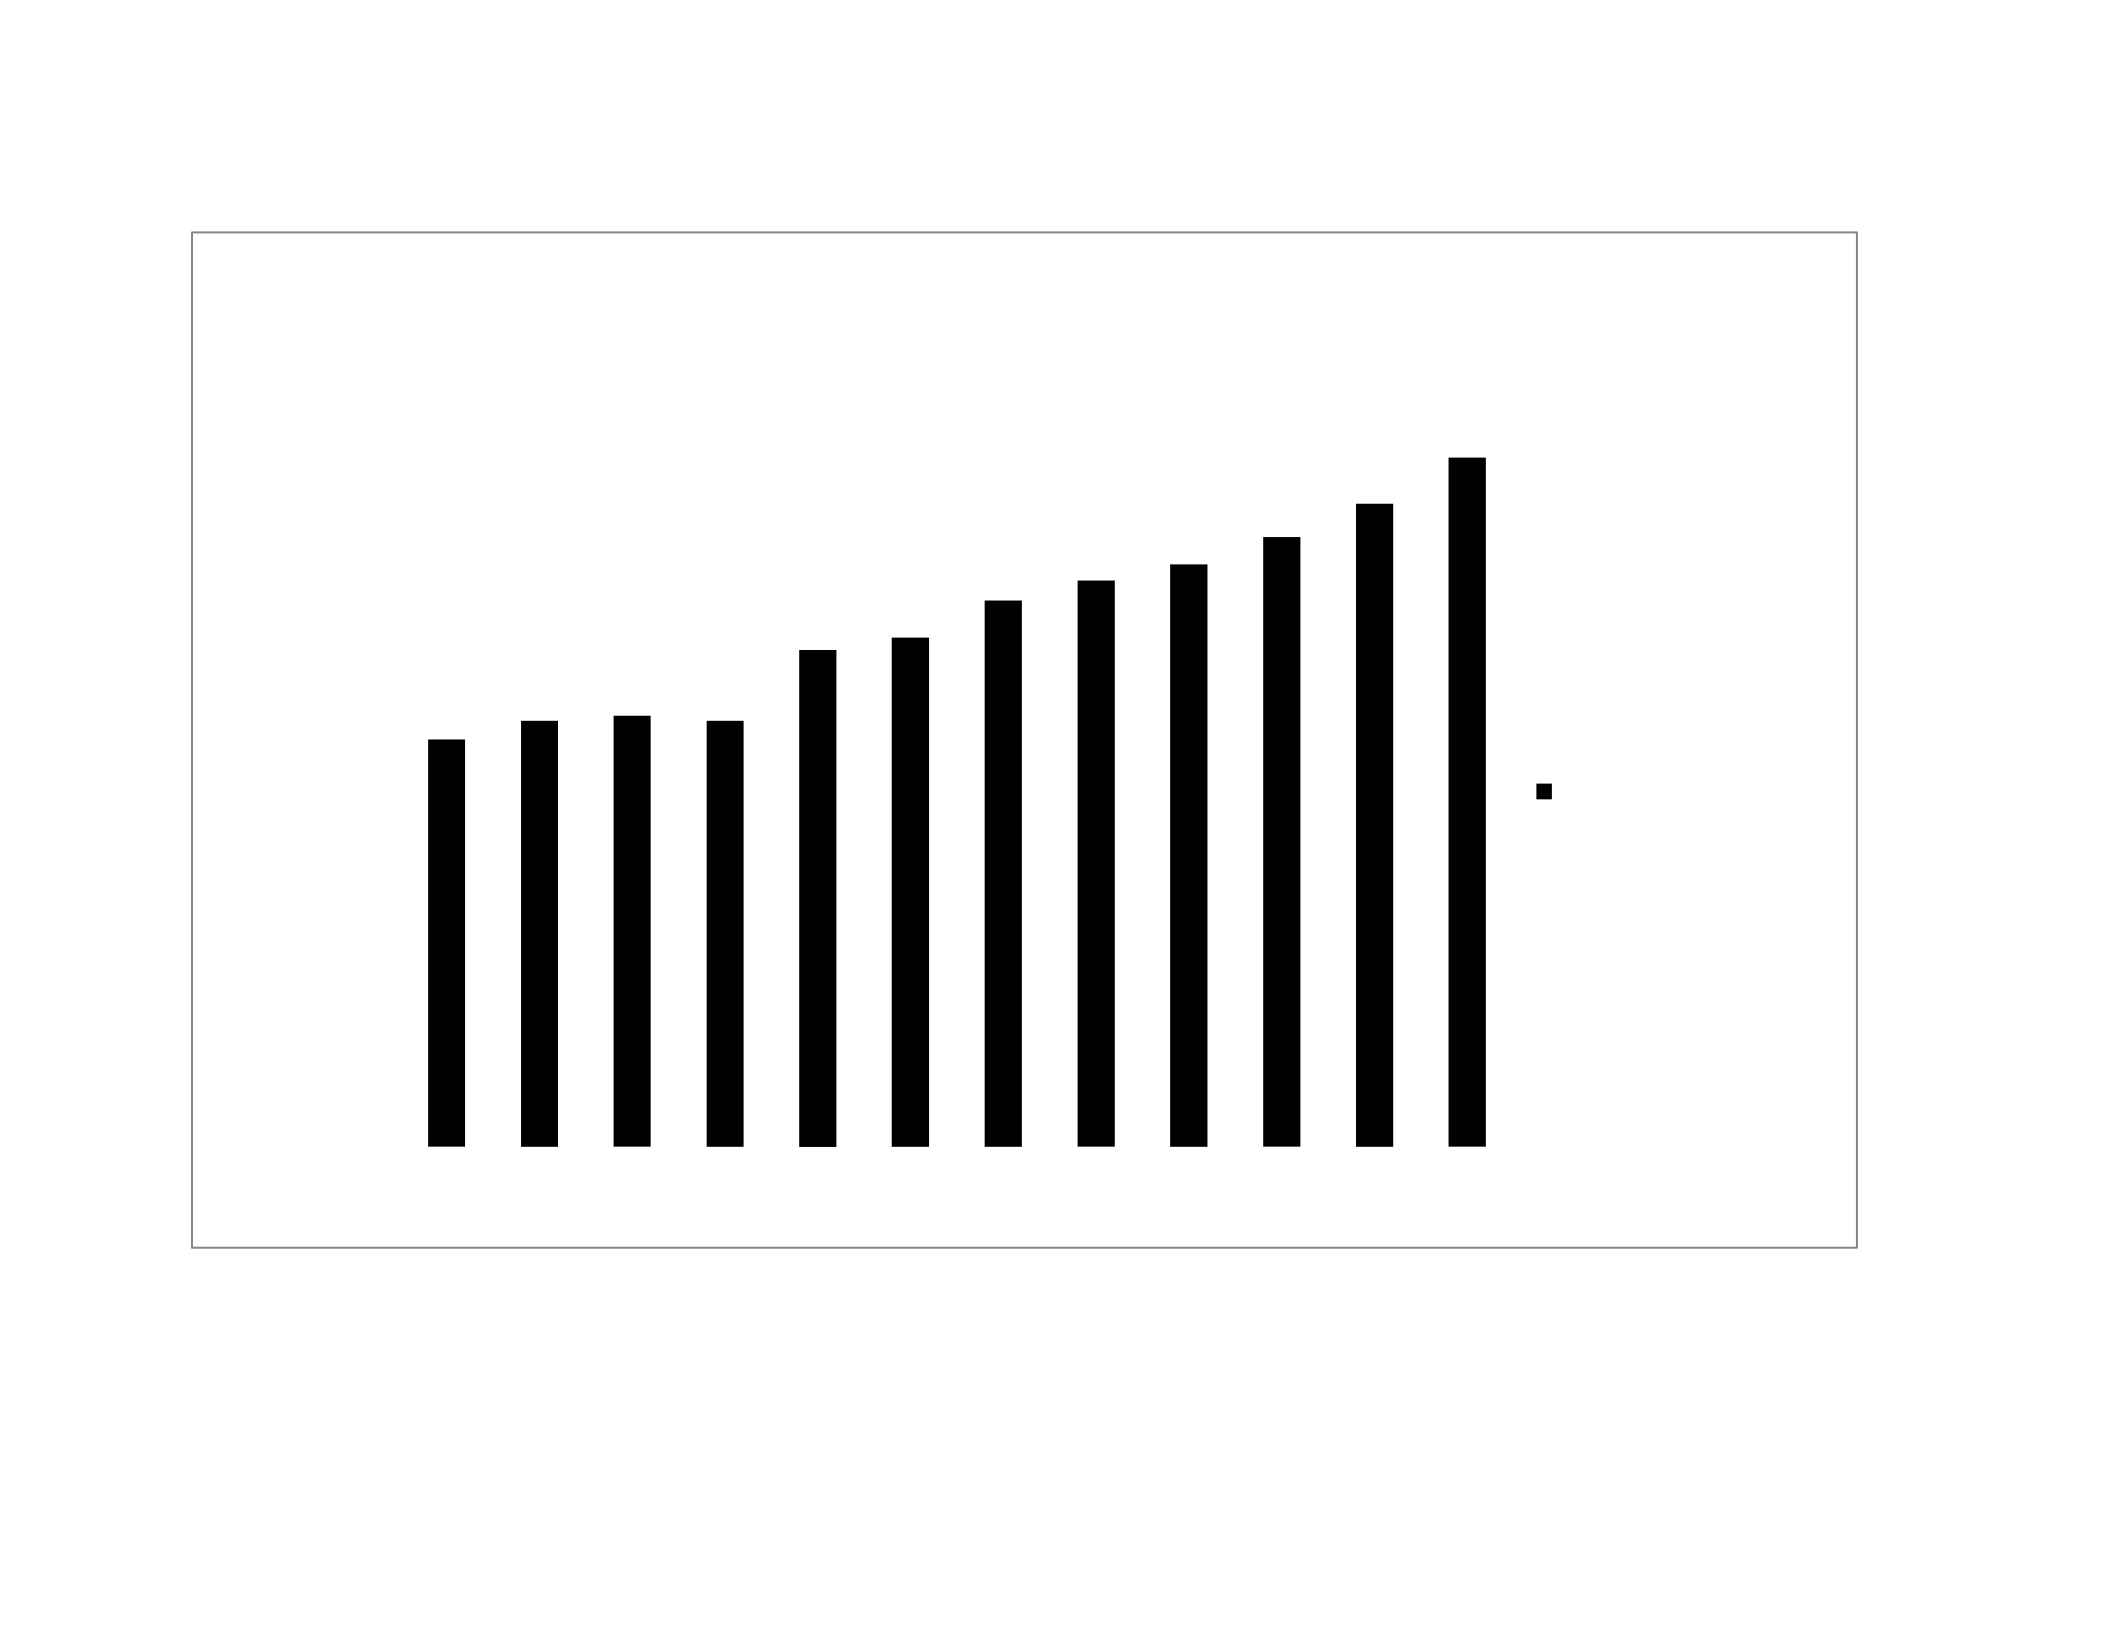
Figure 1. U.S. Corporate Foundation Philanthropic Giving from 2001 to 2012 (2,629 Corporate Foundations)
Source: The Foundation Center as of January 27, 2015
3.28 3.43 3.47 3.43
4 4.1
4.4 4.56 4.69
4.91
5.18
5.55
0
1
2
3
4
5
6
2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012
Billion$
Total charitable giving
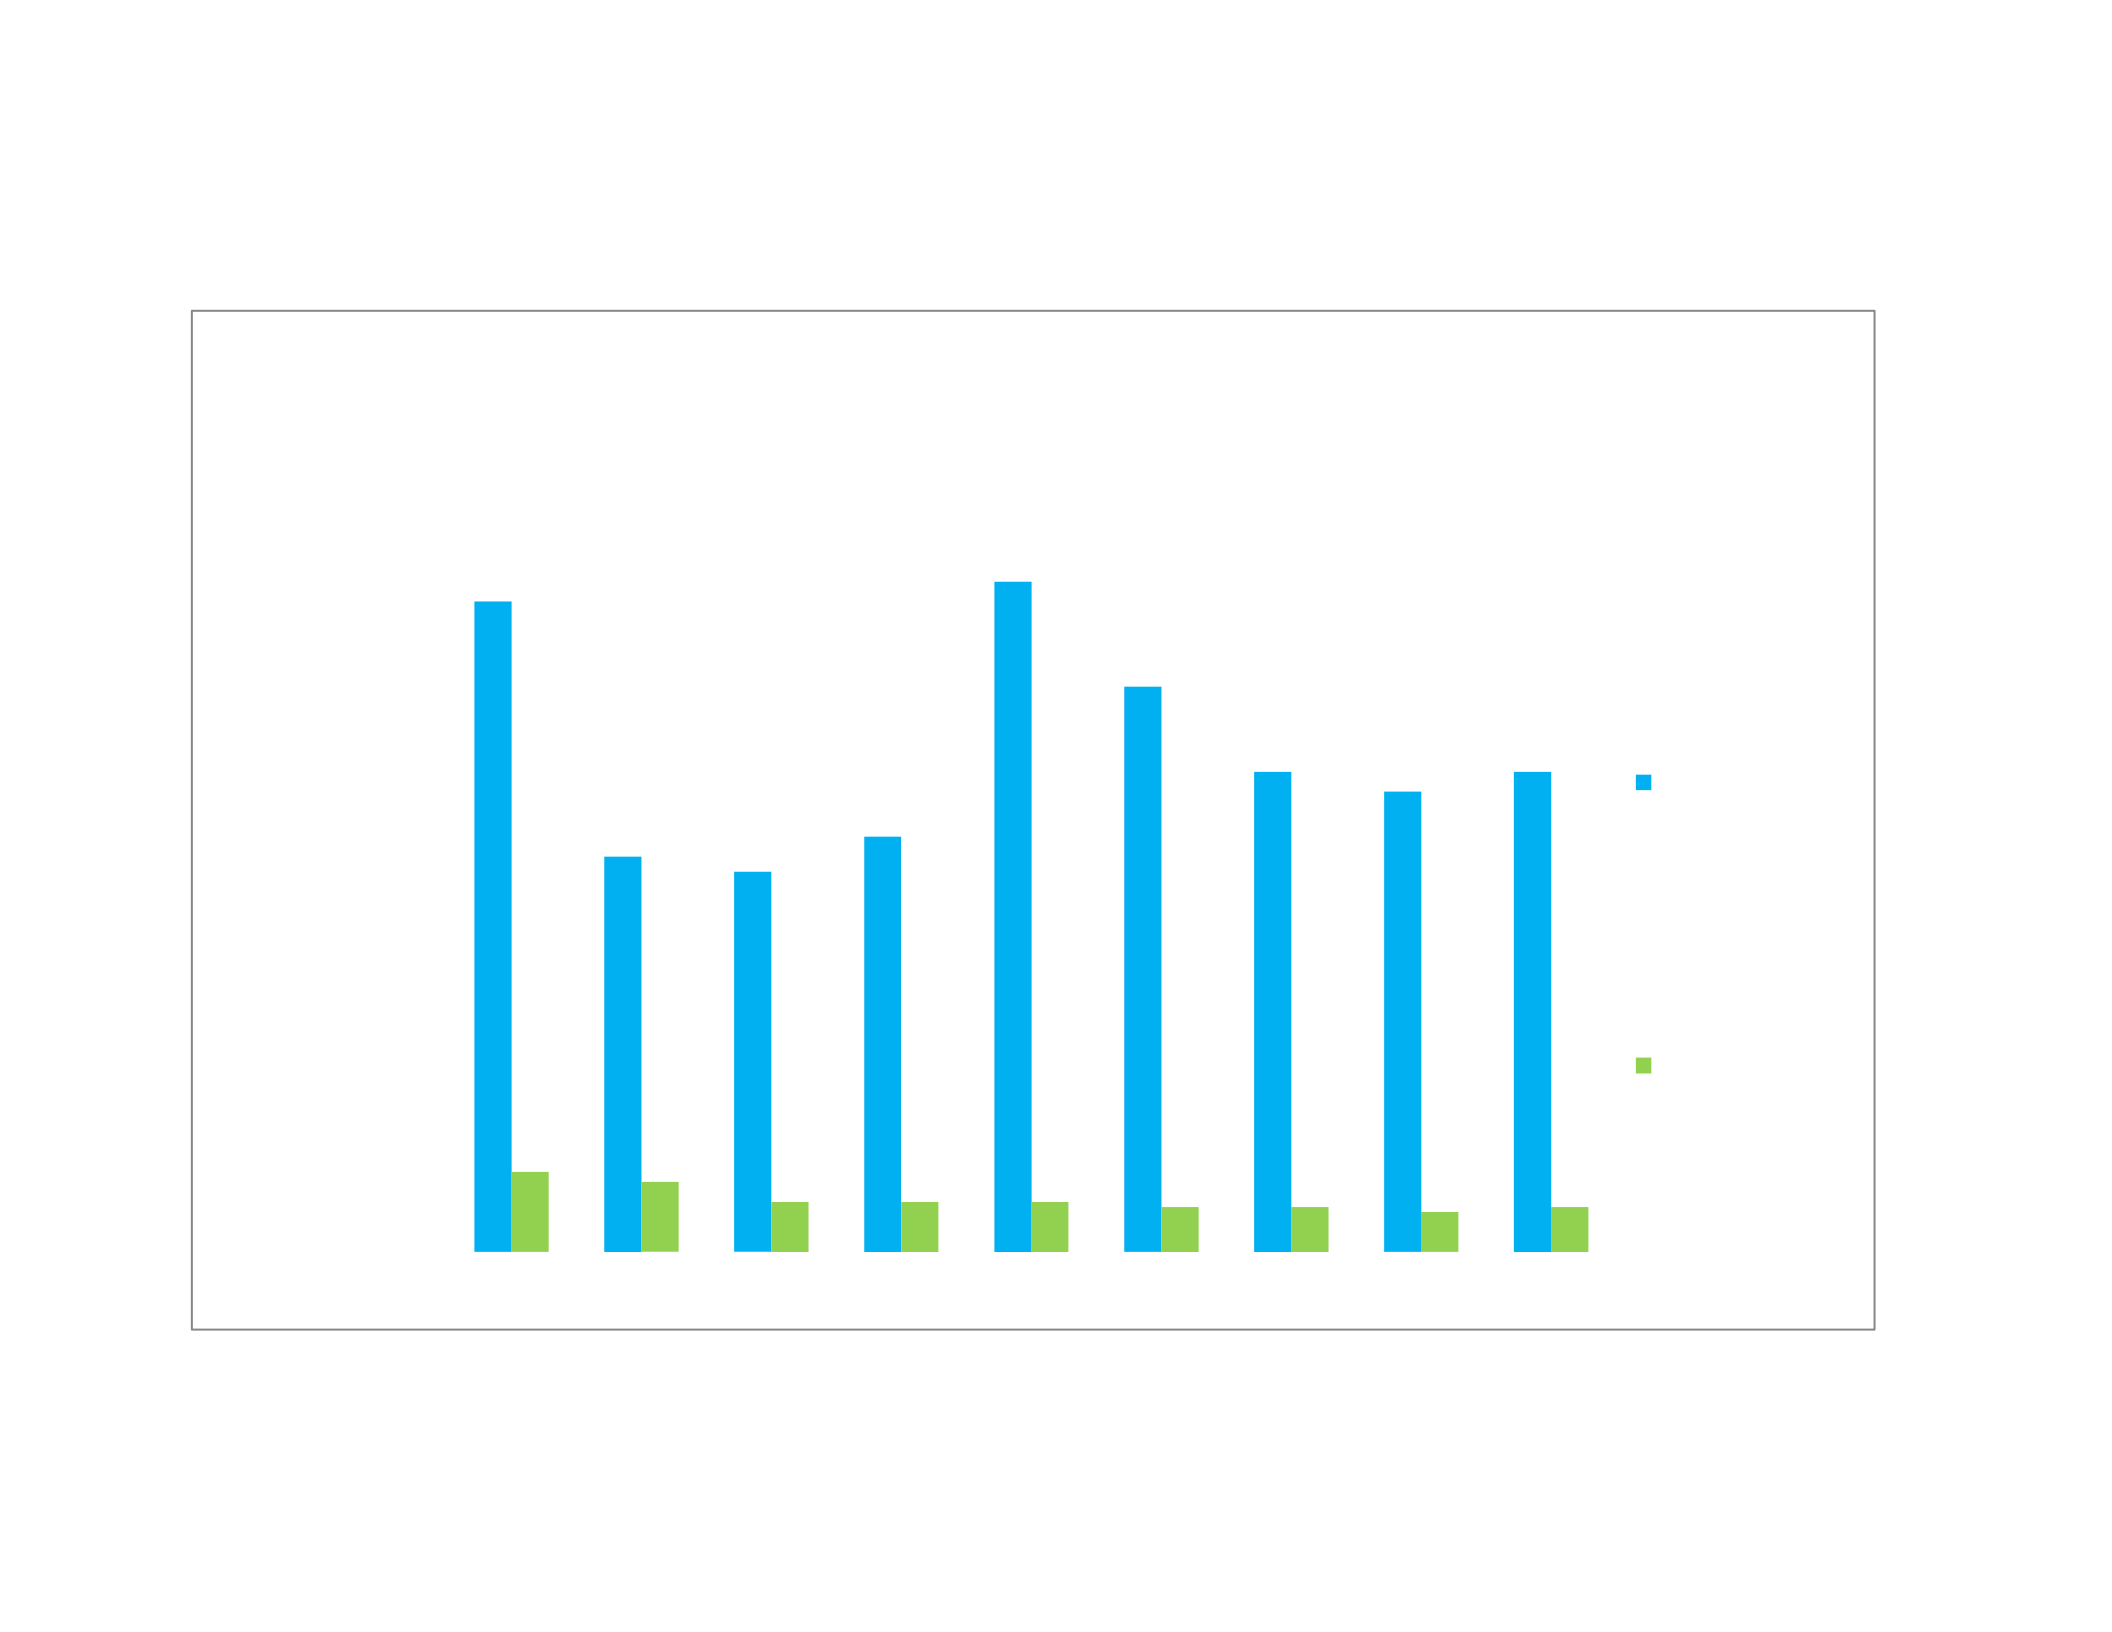
5
Figure 2. Total Charitable Giving among Fortune 100 Firms between 2004 and 2012
Source: Committee Encouraging Corporate Philanthropy as of January 27, 2015
1.3
0.79 0.76
0.83
1.34
1.13
0.96 0.92 0.96
0.16 0.14 0.1 0.1 0.1 0.09 0.09 0.08 0.09
0
0.2
0.4
0.6
0.8
1
1.2
1.4
1.6
2004 2005 2006 2007 2008 2009 2010 2011 2012
Total charitable
giving as a % of
pre-tax profit
Total charitable
giving as a % of
revenue
Million$

6

Despite the stated purpose of enhancing a firm’s public visibility and reputation by
engaging in corporate philanthropy, firms face some criticisms from stakeholders on the tangible
benefits of philanthropy. Some scholars (e.g. Devinney, 2009; Friedman, 1970) have supported
this skeptical perspective arguing that a firm exists primarily to generate economic returns, not to
solve societal problems. Friedman (1970, p. 6) argues that the single social responsibility of
business is to “engage in business activities designed to increase its profit.” On the contrary,
other scholars (e.g. Godfrey, 2005; Wang & Qian, 2011) have strongly supported the positive
role of corporate philanthropy in improving firm performance. These scholars argue that
corporate philanthropy can generate positive stakeholder support which in turn improves a firm’s
financial performance. In an effort to address the critics’ concerns on the use of corporate
resources toward charitable contributions, firms are increasingly turning to the strategic use of
philanthropy. Research suggests that strategic philanthropy can play a key role in developing
value-creating relationships with primary stakeholders and enhancing a company’s image
(Buchholtz, Amason & Rutherford, 1999; Saiia, Carroll & Buchholtz, 2003). Strategic
philanthropy can also serve as “a common meeting ground for the opponents and proponents of
corporate philanthropy” (Buchholtz et al., 1999, p. 169). Large firms are fundamentally
responsible for strategic philanthropy in practice because they have systematic structures
(Marquis & Lee, 2013). For example, large firms have corporate foundations, employee

committees to oversee corporate giving, and staff functions devoted to the effort to manage their
social responsibilities (McAlister & Ferrell, 2002). In marketing practice, strategic philanthropy
has been often associated with cause-related marketing to support social responsibility (File &
Prince, 1998; Vanhamme, Lindgreen, Reast & van Popering, 2012; Varadarajan & Menon,
1988). Both practices have some dissimilarities in terms of primary focus, time frame, and costs
(McAlister & Ferrell, 2002). Strategic philanthropy focuses on organizing itself, is ongoing, and
tends to require moderate to high resource commitment. On the other hand, cause-related
marketing focuses on the firm’s products, has a limited duration, and involves minimal resource
commitment. Both strategic philanthropy and cause-related marketing help enhance societal
welfare and improve the reputation of a firm. Stakeholder theory (Freeman, 1984) offers an
important theoretical support for the relationship between corporate philanthropy and firm
performance, suggesting that favorable social performance is a requirement for business
legitimacy, and tends to be positively associated with firm performance over the long term.
Donaldson and Preston (1995, p. 82) also suggest that firms respond to “ethical considerations
(e.g. engaging in philanthropy) which are often consistent with long-run increases in profit and
value.”
Importantly, the positive effect of corporate philanthropy on the firm provides a reason
why there is a need to examine the relationship between CEO characteristics and corporate

philanthropy. Since corporate philanthropy has become an important strategic tool that
organizational senior leaders manipulate, they are more involved in assessing and shaping
corporate strategies (Porter & Krammer, 2002). In addition, past research argues that a firm’s
social activities should be met by corporate goals determined by CEOs who constantly make
strategic decisions and choices (Choi & Wang, 2007; Wood, 1991). Furthermore, it has been
suggested that CEOs are the primary decision-makers of the organization such that an
examination of CEOs’ attitudes and values toward philanthropy provides needed insight into the
social responsibility actions in general and philanthropic function in particular (Dennis,
Buchholtz, & Butts, 2009). Accordingly, it can be suggested that the relationship between CEO
characteristics and corporate philanthropy should receive much attention. In the following
section, I will provide a brief discussion on the major research gaps that I seek to address in
order to advance the understanding of the leadership predictors of corporate philanthropy and the
implications for firm performance.
1.3 Statement of the Problem
Previous studies have focused on why firms engage in corporate philanthropy (Adams &
Hardwick, 1998; Brammer & Millington, 2005; Fombrun & Shanley, 1990; Godfrey, 2005;
Turban & Greening, 1997; Wang & Qian, 2011; Williams & Barrett, 2000). These studies have
shown that engagement in corporate philanthropy can lead to increased employee loyalty (e.g.,

employee commitment), favorable community image (e.g., corporate reputation), and positive
media coverage (e.g., recovering tarnished reputation). As such, it can be suggested that
consequences of corporate philanthropy have been extensively explored to answer the question,
“why should a firm give?” Meanwhile, antecedents of corporate philanthropy have been
explored to answer the question, “what drives firms to give?” The predominant discussion
among scholars has been on the managerial (e.g. Buchholtz et al., 1999; Choi & Wang, 2007;
Marquis & Lee, 2013; Wang & Coffey, 1992), organizational (Adams & Hardwick, 1998;
Brammer & Millington, 2006; Seifert, Morris & Bartkus, 2003), and industry (Amato & Amato,
2007, 2012; Useem, 1988) drivers of corporate philanthropy. Specifically, past research
suggested that firms engage in corporate philanthropy as a means to simultaneously and directly
benefit business interests and those of a beneficiary organization (Saiia et al., 2003; Marx, 1999).
The extent to which firms engage in corporate philanthropy can vary depending on
organizational factors, such as firm size, organizational slack, and advertising intensity (Dennis
et al., 2009; Saiia et al., 2003; Wang & Qian, 2011). Past research on corporate philanthropy has
generally discussed the intersection of business goals and the larger societal good help improve
the firm’s competitive position (Maas & Liket, 2011; Saiia et al., 2003). In sum, it can be argued
that previous studies of corporate philanthropy have developed from three aspects, “why give,”
“what leads to give,” and “give strategically.”

Unlike the extensive discussion on firm-level predictors, managerial perspective on
corporate philanthropy has not received much attention (e.g., how, why, and to what degree
individuals, such as CEOs, engage in corporate philanthropy). This line of inquiry is consistent
with a recent study’s (Aguinis and Glavas, 2012) observation that corporate social activities,
including corporate philanthropy, research is virtually absent from journals devoted to
organizational behavior and micro-level human resources management. Therefore, there is a
need to focus more on the micro level (e.g., do characteristics of individuals influence firms’
philanthropic engagement?) than on the macro level (e.g. are organizational outcomes of
corporate philanthropy beneficial to the firm?). In addition, there might be some link between
CEO characteristics and corporate philanthropy. Several scholars suggest that CEOs think
strategically about philanthropy to enhance brand name recognition, employee productivity, and
even to overcome regulatory obstacles (Seifert et al., 2003; Smith, 1994). Despite the growing
interest in the effect of CEO characteristics on CSR in general and philanthropy in particular, the
relationship between CEO characteristics and corporate philanthropy is under-developed and has
not received close empirical scrutiny.
Past research (e.g. Choi & Wang, 2007; Godfrey, 2005) has focused more on CEOs moral
background and characteristics, such as CEOs’ integrity and altruism, to explain a firm’s
philanthropic decisions. These studies, however, leave room for further explanation as to

whether CEO characteristics predict corporate philanthropy. This is because corporate
philanthropy can be driven not only by non-business community issues related to CEO altruism
but also by business-related issues, both of which benefit the firm’s strategic position. To fill this
research gap, I draw from the upper echelon theory (Carpenter, Geletkanycz & Sanders, 2004;
Hambrick & Mason, 1984) to explore how leaders’ background characteristics might influence
their firms’ engagement in corporate philanthropy. Thomas and Simerly (1994) suggest that the
demographic characteristics of CEOs (e.g., age, functional background, and education) offer
reliable proxies for visible social activities of CEOs. Pedersen and Neergaard (2009) also suggest
that managerial perceptions of corporate social activities, including corporate philanthropy, are
influenced by a great deal of heterogeneity (e.g., age, gender, education, and functional
backgrounds). In addition, it might be that founder CEOs have wide strategic options and more
power over their boards (Mousa & Wales, 2012) and such status can influence corporate
philanthropy. Despite the practical importance of the relationship between founder status and
corporate philanthropy, that relationship has not received empirical investigation.
Firm size, organizational slack, and advertising intensity have been explored as important
organizational factors that influence corporate philanthropy (Dennis et al., 2009; Seifert et al.,
2003; Wang & Qian, 2011). What scholars argue is that bigger firms with more slack resources
and advertising intensity have a positive association with corporate philanthropy. What is

missing from these discussions is firm age as an important organizational context. In other
words, the relationship between firm age and corporate philanthropy has not received much
scholarly attention. For instance, Logsdon, Reiner and Burke (1990) observed in an exploratory
study that firm age might be significant in explaining placement of corporate philanthropy.
Particularly, past research has suggested that older firms tend to be increasingly inflexible so that
firm age may be an important indicator of reduced executive discretion (Finkelstein, Hambrick
& Cannella, 2009). Although the individual CEO’s influence on corporate philanthropy might
vary as a firm grows, the role of firm age on the relationship between CEO background
characteristics and corporate philanthropy has not received much attention. Therefore, it is worth
exploring this relationship.
Although corporate philanthropy has developed from a wide range of theoretical
frameworks, scholars have not yet given much thought to whether firms proactively engage in
corporate philanthropy to strengthen their business and corporate strategies. Particularly, the
relationship between corporate philanthropy and unrelated diversification is under-developed.
Unrelated diversification is one of core business strategies which help firms expand new
markets. For example, when firms pursue unrelated diversification strategies, they usually
experience a wide range of varying demands from stakeholders in distant industries or their
subsidiaries (Chatterjee & Wernerfelt, 1991). Corporate philanthropy can generate reputational

assets in the new market (Hess, Rogovsky & Dunfee, 2002), strengthen marketing and branding
initiatives (Lii & Lee, 2012; Ricks Jr, 2005), and improve relations with local governments
(Wang & Qian, 2011). From this phenomenon, it can be suggested that firms can consider
philanthropic activities as part of long- term competitiveness and a means to strategically open
new markets.
In addition, it is likely that the pressure for engaging in corporate philanthropy would
increase among international firms with business activities across countries and culture. Deresky
(1997) suggests that the philanthropic activities of multinational corporations that operate in
foreign countries may be characterized as strategic, clearly targeted, and linked to the overall
objectives of the firm. In addition, when firms expand their businesses in a foreign market
(Sharfman, Shaft & Tihanyi, 2004), they experience a wide range of stakeholder’ pressures.
Corporate philanthropy can be used as a means of reducing these challenges. Despite the
importance of corporate philanthropy on a firm’s internationalization, there is a lack of
theoretical explanation and empirical evidence as to whether corporate philanthropy advances a
firm’s internationalization strategy. Similarly, expansive global strategic posture (in terms of
geographic market diversification) can help firms leverage R&D costs and knowledge across
countries (Carpenter & Fredrickson, 2001; Kim & Mauborgne, 1991). It has been suggested that
corporate philanthropy may be an opportunity for internationally operating firms, but also for

investing in legitimacy in a region considered to be the main emerging market for the country
(Bohnsack, 2012; Whiteman, Muller, Van der Voort, Wijk, Meijs, & Pique, 2005). It is
reasonable to expect that firms are encouraged to engage in corporate philanthropy to develop a
commanding international presence. In sum, I explore how CEOs’ background characteristics
predict the degree of firms’ engagement in corporate philanthropy and the complimentary
theoretical relationship between corporate philanthropy and a firm’s diversification profile (such
as unrelated diversification and global strategic posture).
1.4 Purpose of the Study & Research Questions
In this dissertation, I examine the effect of CEOs’ background characteristics on
corporate philanthropy and firm diversification profile. More specifically, I examine the
relationships between CEOs’ background characteristics and corporate philanthropy. In doing so,
I focus on four aspects of CEO background characteristics (i.e. CEO founder status, functional
background, civic engagement, and education) and examine whether they are associated with the
degree of firms engagement in corporate philanthropy.
First, what is the relationship between CEO founder status and corporate philanthropy?
Founder CEOs are likely to hold a psychological bond with their firms (Peterson, Galvin &
Lange, 2012). Founder CEOs’ intrinsic motivation could lead them to engage in socially
responsible activities that meet various stakeholder demands, such as corporate philanthropy.

Second, what is the relationship between CEO functional background and corporate
philanthropy? Corporate social performance can be a reflection of CEO functional background
(Melo, 2012). Thus, it might be anticipated that a certain aspect of a CEO’s past work experience
in jobs within functional areas of organizations can influence corporate philanthropy. Third, what
is the relationship between CEO civic engagement and corporate philanthropy? CEOs often
serve as active members in community groups or associations and they participate in civic affairs
as part of their strategic mission. Doing so can be motivated by a desire to create the local
community development and a more stable political environment that ensures their business
profitability. Fourth, what is the relationship between CEO education and corporate
philanthropy? Bennett (2012) argues that better educated people have wider mental horizons that
cause individuals to recognize the value of charities concerned with the external environment.
Therefore, it is expected that CEOs’ education can play an important role in determining the
choice and emphasis on corporate philanthropy. In addition, I examine the moderating role of
firm age on the relationship between CEO background characteristics and corporate
philanthropy. Although older firms would be expected to be more well-known and have greater
philanthropic engagement, it is reasonably expected that a CEO’s influence on corporate
philanthropy varies as a firm grows.

Furthermore, I examine the role of corporate diversification profile on corporate
philanthropy and firm performance. Past research suggests that firms increase philanthropic
expenditures strategically as a means to open new markets where they are not familiar with and
the pressures for engaging in corporate philanthropy increase among international firms (Merz,
Peloza & Chen, 2010). Specifically, I examine a firm’s diversification strategy as the mechanism
through which corporate philanthropy influences firm performance. Since the ultimate goal of a
firm’s social activities, including corporate philanthropy, is to maximize performance, it is worth
exploring the interaction, including corporate philanthropy – firm performance relationship
through the mechanism of corporate diversification profile.
In sum, there are four major under-developed research areas in the literature that will be
explored in this dissertation. First, there is a need to examine the relationship between CEO
background characteristics and corporate philanthropy. Second, the role of firm age on the
relationship between CEO background characteristics and corporate philanthropy should receive
much attention. Third, whether firms proactively engage in corporate philanthropy to strengthen
their unrelated diversification strategies should receive an empirical investigation. Fourth, the
relationship between corporate philanthropy and firm performance needs to be examined
particularly under corporate diversification profile (e.g. how corporate philanthropy influences

firm performance through unrelated diversification and global strategic posture). I intend to
answer the following three research questions:
22) Do CEO background characteristics influence the level of corporate philanthropy? If so,
why?
23) Does firm age moderate the relationships between CEO background characteristics and
the level of corporate philanthropy?
24) Does corporate diversification profile mediate the relationship between the level of
corporate philanthropy and firm performance?
1.5 Significance & Contributions of the Dissertation
1.5.1 Contributions to Corporate Philanthropy Research
In this dissertation, I offer several contributions for research. First, this dissertation
contributes to the growing scholarly interests in terms of CEOs’ influence on corporate
philanthropy. It has been suggested that CEOs are requiring greater strategic accountability in
corporate giving programs (Saiia et al, 2003) and that corporations undertake strategic
philanthropy as long as direct economic benefits can be gained by doing so (Sánchez, 2000).
Therefore, an examination of whether CEO background characteristics influence corporate
philanthropy helps to fulfill research interests.

Second, I extend the literature on corporate philanthropy to examine the strategic use of
philanthropy. It has been suggested that traditional altruistic models of philanthropy are
becoming less relevant because it is generally considered a non-strategic explanation of
corporate giving which ignores the profit maximization goal and other strategic goals of the firm
(Neiheisel, 1994; Sánchez, 2000). Corporate giving activities have evolved into far more
strategically market-oriented approaches like targeted grants intended to optimize economic
return as well as social returns per philanthropic dollar (Sherblom, 2007).
Third, drawing upon the institutional and stakeholder perspectives, I offer a new attempt
to empirically examine the link between corporate philanthropy and unrelated diversification.
For example, faced with various challenges (e.g., social, legal, and regulatory), corporate
diversification increases a variety of stakeholder pressures in the firm’s external environment
that arise (Brammer, Millington & Pavelin, 2006; Sharfman et al., 2004). In addition, highly
diversified firms not only suffer from a lack of coherence in terms of underlying resources
(Montgomery & Wernerfelt, 1988) but they also have to deal with heavy stakeholder demands.
These pressures might be mitigated when engaging in corporate social activities through which
unrelated diversifiers can manage a wide range of stakeholders’ demands.
Fourth, although previous studies (Markides & Williamson, 1994; Palepu, 1985; Rumelt,
1974) suggest a negative relationship between unrelated diversification and (short-term)

financial performance, this dissertation provides a different perspective to corporate
diversification strategy. For example, corporate philanthropy helps to generate reputation and
branding initiatives in the new markets so that it can improve the firm’s market positions (Hess
et al., 2002; Ricks Jr, 2005). In this dissertation, I provide scholars with a promising suggestion
that unrelated diversification may not necessarily be an inferior strategy for the firm.
1.5.2 Contributions to Practice
In this dissertation, I offer several contributions for practice. First, understanding of how
CEO background characteristics (e.g., CEO status, functional background, civic engagement,
and education level) can be applied to corporate philanthropy helps to explain the rationale
behind decisions to engage in corporate philanthropy. Therefore, I answer what leads CEOs to
engage in corporate philanthropy and further why some CEOs engage in more corporate
philanthropy than others. Second, I provide managers with practicability of corporate
philanthropy. For example, strategic use of philanthropic expenditures can support a community
project in developing countries (Porter & Kramer, 2002; Sánchez, 2000) because better
community conditions are good for business (e.g., when the standard of living is increased,
product demand is increased).
Third, I provide managers with a promising notion that engaging in corporate
philanthropy can help firms with diversification and market entry strategies. Scholars argue that

a firm’s philanthropic engagement in developing countries can enhance the firm’s reputation and
get easier access to the market (Bohnsack, 2012; Brammer et al., 2006). There might be a
positive relationship between corporate philanthropy and international presence. In addition, it is
suggested that corporate philanthropy can offer an opportunity for internationally operating firms
as well as for investing in business legitimacy. In this dissertation, I can provide managers with
practicability that international firms can strengthen their competitive context by engaging in
corporate philanthropy. Fourth, I provide insights on business legitimacy by suggesting that
firms are seen as legitimate actors by local stakeholders to the extent they engage in corporate
philanthropy. Goyal (2006) and Wang and Qian (2011) suggest that philanthropic activities of
multinational firms in the host countries would be a signaling device to demonstrate that they
have long-term intentions consistent with the local expectations. Thus, I suggest that firms can
receive supportive responses from the host countries governments by engaging in corporate
philanthropy.
1.6 Definition of Key Terms
Corporate social responsibility (CSR) refers to “context-specific organizational actions
and policies that take into account stakeholders’ expectations and the triple bottom line of
economic, social, and environmental performance” (Aguinis, 2011, p. 855).

Diversification refers to “the entry of a firm or business unit into new lines of activity,
either by processes of internal business development or acquisition, which entail changes in its
administrative structure, systems, and other management processes” (Ramanujam &
Varadarajan, 1989, p. 525). There are two types of diversification, such as related diversification
and unrelated diversification. Related diversification refers to a diversification built around a
core organizational capability (Ramanujam, 1987; Rumelt, 1982). It occurs when firms expand
their areas closely related to their primary activities and areas of technical expertise. Unrelated
diversification refers to a diversification that drives to move into unrelated lines of business
(Ramanujam, 1987; Rumelt, 1982). It occurs where firms expand their operations into markets
or products beyond current resources and capabilities.
Corporate philanthropy refers to the practice of “giving firm resources to invest in
business-related issues and non-business community issues that also benefit the firm’s strategic
position and, ultimately, its bottom line” (Saiia et al., 2003, p. 170). This definition helps to
explain why some firms still donate in non-business areas more than others. They do so because
they believe that giving non-business issues would enhance their public image which can be used
for gaining business legitimacy in developing countries (Wang & Qian, 2011).
Global strategic posture (GSP) refers to “the degree to which a firm is dependent on
foreign sales and production and to the geographic dispersion of this dependence” (Carpenter,

Sanders & Gregersen, 2001, p. 497). It has been suggested that GSP reflects the relative
significance of foreign markets and operations in sustaining the firm as well as their geographic
dispersion (Sullivan, 1994). Therefore, GSP can be used for measuring firm internationalization
(Carpenter & Fredrickson, 2001; Levy, 2005). GSP are normally measured by three dimension
originally developed by Sullivan (1994): foreign sales, foreign production, and geographic
diversity. Foreign sales reflect the relative significance of foreign market. Foreign production
reflects the degree to which a firm depends on foreign-owned assets and resources. Geographic
diversity reflects the extent to which a firm has subsidiaries associated with globalization of
operations and markets. Several scholars used GSP to explain a firm’s internationalization
strategy (Carpenter et al., 2001; Carpenter & Fredrickson, 2001; Levy, 2005).
1.7 Organization of the Dissertation
This dissertation consists of six chapters. The first chapter provides an introduction about
the importance of corporate philanthropy, statement of the problem, major research questions as
well as the contributions of the dissertation. Chapter two presents a comprehensive and extensive
review of the literature on corporate social responsibility and the antecedents and consequences
of corporate philanthropy with the role of leadership in corporate philanthropy. Chapter three
presents the research model, theoretical foundations, and summary of theoretically-driven
hypotheses. Chapter four presents the research design including target sample, measures, as well

as statistical techniques. Chapter five presents and highlights the results of statistical analyses,
including summary of findings and summary of hypotheses. Chapter six discusses the results
from Chapter five, the implications to research and practice, limitations, future research
directions, and conclusion.

CHAPTER II
LITERATURE REVIEW
This chapter provides a comprehensive review of the corporate philanthropy research.
The first section begins with a systematic review of the literature on the relationship between
Corporate Social Responsibility (CSR) and firm performance as well as the leadership
determinants of CSR. In the second section, I discuss the theoretical conceptualizations of
corporate philanthropy with a comparative review of the traditional and strategic philanthropy
literatures. In the third section, I discuss the managerial, organizational and industry level
antecedents and consequences of corporate philanthropy with a particular emphasis on the link
between leadership attributes and corporate philanthropy. In the fourth section, I present a
comprehensive review of research on the link between corporate philanthropy and corporate
strategy. The chapter then concludes with a contingency view of corporate philanthropy.
2.1 How Does Corporate Social Responsibility (CSR) Influence Firm Performance?
CSR refers to “context-specific organizational actions and policies that take into account
stakeholders’ expectations and the triple bottom line of economic, social, and environmental
performance” (Aguinis, 2011, p. 855). Specifically, the demand for business CSR initiatives has
been significantly higher around the world over the last several decades. Accordingly, firms

nowadays are expected to act more proactively to fulfill their CSR expectations as responsible
corporate citizens to the society (Wang & Hsu, 2011). Since engaging in CSR is considered a
socially responsible investment for the firm, how CSR influences firm performance has been an
important issue among organizational scholars (Agle, Mitchell & Sonnenfeld, 1999; Aguinis &
Glavas, 2012; Orlitzky, Schmidt & Rynes, 2003). Even though there are some debates as to
whether CSR helps to improve firm performance, an extensive line of research has empirically
explored how CSR boosts firms’ competitive advantage, thereby ensuring value creation and
satisfaction for stockholders and customers (Cox, Brammer & Millington, 2004; Lev, Petrovits
& Radhakrishnan, 2010).
The topic of whether CSR can have a positive effect on firm performance has generated
extensive discussions among scholars and practitioners. Friedman (1970) provides the classical
economic perspective that management has one responsibility and that is to maximize the profits
of its shareholders. Past research suggests that socially responsive firms incur higher direct costs
and reap lower profits than socially unresponsive firms (Aupperle, Carroll & Hatfield; 1985;
Devinney, 2009). In addition, some scholars have used agency theory that “good social
performance comes at the expense of good financial performance because social performance
makes use of firm resources in ways that confers significant managerial benefits rather than
returning those resources to shareholders” (Brammer & Millington, 2008, p. 1329). They argued

that firms would better spend their resources on value-added internal projects or return to
shareholders rather than invest in CSR. Despite these perspectives, there has been a growing
institutional and societal pressure on businesses to pursue a socially responsible operation for the
last couple of decades and a number of institutional approaches can explain this trend. Jones
(1995) suggests that firms facing repeated transactions with stakeholders based on trust and
cooperation are encouraged to be honest, trustworthy, and ethical because they believe that the
returns to such behavior are high. In addition, a majority of empirical evidence suggests a
significant positive relationship between CSR and financial performance (Aguinis & Glavas,
2012; Peloza, 2009). For example, Peloza (2009) reviewed 128 studies that explored the
relationship between CSR and financial outcomes and found that, almost 60 % showed a positive
relationship, less than 15 % a negative relationship and mixed findings from the rest of the
studies. Recently, Aguinis and Glavas (2012) summarized the overall empirical evidence on
CSR-performance relationship in a wide range of organizational fields as follows (p. 947):
“Working for socially responsible companies leads to increased organizational
identification (Carmeli, Gilat, & Waldman, 2007), employee engagement (Glavas
& Piderit, 2009), retention (Jones, 2010), organizational citizenship behavior (Lin,

Lyau, Tsai, Chen, & Chiu, 2010), employee commitment (Maignan, Ferrell & Hult,
1999), employee creative involvement (Glavas & Piderit, 2009), and improved
employee relations (Glavas & Piderit, 2009).”
In the 21th century, the influence of CSR on a firm performance is an important concern
to a firm’s stakeholders so that firms should consider CSR as part of their strategies (Lantos,
2001). Given the ultimate responsibility of firms meets the needs of stakeholders, firms should
fulfil stakeholders’ demands while also devoting resources to CSR. Such seemingly contrasting
demands are leading more firms to embrace strategic CSR or strategic use of philanthropy.
Carroll (2001), for instance, argues that strategic CSR can accomplish strategic business goals,
including good deeds, are believed to be good for business as well as for society. Several
scholars have discussed strategic aspects of CSR. Porter and Kramer (2006) argue that CSR
should be seen as one of core business strategies in a firm, indicating that the firm can benefit
from its social investment. Maignan et al. (2005) also argue that CSR can serve as an attractive,
valuable resource offering competitive advantage for enhancing business performance because it
can be used as a means of conducting business strategies.
2.1.1 What Role Do Organizational Leaders Play in Fostering CSR?

In an attempt to link organizational leaders (e.g., CEOs) to CSR, scholars have focused
on three aspects of CEO background characteristics: values, compensation levels, and personal
attributes (experiences). For example, CEO integrity can be relevant to CSR such that leader
vision and integrity will increase CSR values to shareholders. Waldman and Siegel (2008) argue
that leader integrity to personal morality can yield positive outcomes for business and may
actually be the driver of CSR strategies in organizations. Ketola (2006) also argues that leader
integrity is an important component in his or her successful promotion of CSR activities at the
firm. In addition, the relationship between CEO compensation and CSR has received some
attention. For instance, McGuire, Dow and Argheyd (2003) empirically examined the
relationship between the level of CEO compensation and corporate social performance (CSP) but
they did not find any positive relation. However, Jiraporn and Chintrakarn (2013) using a sample
of 1,370 firms found that when the CEO power (as measured by the total compensation) goes
beyond a certain threshold, more powerful CEOs significantly reduce CSR investments.
Furthermore, several scholars examined the professional background of CEOs and corporate
social performance (Mazutis, 2014; Simerly, 2003; Thomas & Simerly, 1994). They found that
corporate social performance can be interpreted as a reflection of CEOs’ professional
background.

Do organizational leaders play a role in promoting CSR? This question has long attracted
extensive research (Fabrizi, Mallin & Michelon, 2014; Jiraporn & Chintrakarn, 2013). As senior
leaders, CEOs and their top management teams are charged with the responsibility of
formulating business and sustainability strategy (Strand, 2013; Wood, 1991). Indeed, today’s
corporate leaders play an important role in pursuing an effective CSR agenda (Bielak, Bonini &
Oppenheim, 2007; Fabrizi et al., 2014;Godos-Díez, Fernández-Gago & Martínez-Campillo,
2011; Mazutis, 2014). For example, CEOs engage in CSR related activities in response to
growing pressures from key stakeholders groups, such as customers and employees (Bielak et
al., 2007). In addition, while pressures from employees, customers, and other stakeholders can
play a crucial role in CEOs’ willingness to engage in CSR, CEOs recognize that CSR can give
their firms an opportunity to gain a competitive advantage as well as address societal needs
(Bielak et al., 2007). In addition, Godos-Díez et al. (2011) using a sample of 149 CEOs found
that those closer to the steward model are more inclined to attach great importance to ethics and
CSR, and to implement CSR practices. Fabrizi et al (2014) using a sample of 597 U.S. firms
extended the role of CEO’s incentives on CSR and found that non-monetary incentives have a
positive effect on CSR. Mazutis (2014) using a sample of 349 firms found the link between CEO
open executive orientation (such as a liberal worldview and output functional experiences) and
positive CSR initiative adoption over time. In this sense, it can be argued that the relationship

between leadership and CSR has become an important topic of research in the area of leadership
studies (Bielak et al., 2007; Godos-Díez et al., 2011; Fabrizi et al., 2014; Mazutis, 2014).
Transformational leadership helps represent the understanding of CSR in particular.
Transformational leadership is comprised of four major components (Avolio, Bass & Jung, 1999;
Bass & Riggio, 2006): (1) Idealized Influence (ability of leader to attract admiration and respect
and desire to follow from subordinates), (2) Inspirational Motivation (ability of leader to
communicate clear vision and create enthusiasm about future), (3) Intellectual Stimulation
(ability of leader to encourage creativity and unconventional and status quo-challenging
problem-solving among followers), and (4) Individual Consideration (ability of leader to accept
individual differences and actively provide feedback and interaction with followers).
Organizational scholars argue that transformational leadership has been found to influence CSR
behavior among some firms (Du, Swaen, Lindgreen & Senthat, 2013; McWilliams, Siegel &
Wright, 2006).
McWilliams et al (2006), for instance, suggest that strategic leadership theory can be
applied to CSR and that transformational leadership will be positively correlated with the
tendency of companies to engage in CSR. They explored the degree of transformational
leadership using CEOs of 112 large US and Canadian firms and found that intellectual
stimulation (which is one dimension of transformational leadership components) was a predictor

of the firm’s propensity to engage in strategically oriented CSR that were more likely to be
related to the firm’s corporate and business-level strategies (e.g., differentiation and reputation
building). In addition, Du et al. (2013) in a survey of 440 U.S firms found that firms with greater
transformational leadership are more likely to engage in institutional CSR practices, whereas
transactional leadership is not associated with such practices. Furthermore, it has been suggested
that charismatic leadership with self-concepts of followers can be related to CSR. For example,
leaders have values and moral justifications which provide followers with motivational effects
such that charismatic leaders can help connect one’s identify with greater social causes (Shamir,
House & Arthur, 1993).
In conclusion, the empirical evidence on the relationship between CSR and firm
performance seems to be inconclusive (Peloza, 2009). However, more recent studies suggest that
there is a positive association between CSR and firm performance (Aguinis & Glavas, 2012;
Chen & Wang, 2015). In addition, since some firms consider CSR as part of their core corporate
strategy and CEOs are charged with the responsibility of formulating corporate strategy, the
relationship between leadership characteristics and CSR is particularly important. Furthermore, it
can be suggested that understanding of three aspects of CEOs (values, compensation, and
experiences) helps to link CEO background characteristics and CSR. As mentioned in section

2.1.1, there is a certain interrelationship between CEOs and CSR. Table 1 below provides an
overview of research on the role of leadership in fostering CSR.

