


1
Section 1: Foundation of the Study
The goal of a hedge fund manager is to consistently provide superior performance
using dynamic strategies (Almeida et al., 2020). Cui and Kolokolova (2020) and Muteba
Mwaba (2017) attributed superior performance to either manager timing skill, asset
selection ability, or a combination of both. However, Limam et al. (2017), Stafylas and
Andrikopoulos (2020), Cai et al. (2018), and Racicot and Théoret (2018) provided
evidence that hedge fund performance is subject to structural breaks, discrete shifts,
market volatility, and time-varying properties of hedge fund dynamics. Under severe
market conditions, various hedge fund strategies are likely to have different exposures to
changes in market risk factors based on varying volatility regimes (Agarwal et al.,
2018a).
Investment decisions rely on each strategy's risk/reward ratio, which requires
managers to use the appropriate style analyses in the hedge fund market (Stafylas &
Andrikopoulos, 2020). Skilled timing managers deliver excess returns by timing market
liquidity and predicting both market and volatility conditions (Cao et al., 2018a). On the
other hand, selecting managers deliver consistently excessive returns due to their
selecting abilities (Cui & Kolokolova, 2020). However, when managers fail to forecast
sudden shocks, which results in unexpected trends in asset prices, they deliver low
returns. The purpose of this study was not to evaluate the skills of hedge fund managers
directly, but to examine the relationship between risk exposure, volatility forecasting, and
the financial performance of hedge funds.

2
Background of the Problem
In the last two decades, from 2000 to 2020, hedge funds became popular in
producing absolute returns in varying market conditions. Despite the success of hedge
funds, they remained susceptible to losses during the financial crisis of 2007-2009
(Metzger & Shenai, 2019; Zhang et al., 2021). During the global financial crisis of 2007-
2009, the total number of assets managed by the hedge fund industry declined by
approximately 33% (Billio et al., 2017; Page & Panariello, 2018). The authors attributed
the problem to hedge funds' exposure to new types of market risk factors. Furthermore,
evaluating hedge funds using conventional methodologies may be inadequate (Chevalier
& Darolles, 2019).
Hedge funds use varying investment strategies to produce higher returns than
traditional assets (Cai et al., 2018). Consequently, the returns of hedge funds show
abnormal and dynamic risk characteristics. Some researchers have come up with models
to capture the hedge fund return dynamics (Almeida et al., 2020; Balcilar et al., 2017;
Shin et al., 2018). The authors identified the regime-switching model as the most efficient
model to capture time-varying risk exposure for hedge funds that are conditional on
various market situations. Forecasting volatility captures the asymmetry and changes in
the hedge fund returns characteristics (Limam et al., 2017). Xaba et al. (2017) found that
using Markov regime-switching modeling was more accurate to forecast nonlinear time
series. This study was an attempt to evaluate hedge fund performance relationships with
volatility dynamics and market risk factors to understand market behavior and drivers of
return.

3
Problem Statement
Poor hedge fund performance can negatively impact the financial performance of
a business organization (Metzger & Shenai, 2019; Zhang et al., 2021). During the global
financial crisis of 2007-2009, the total number of assets managed by the hedge fund
industry declined by approximately 33% (Billio et al., 2017; Page & Panariello, 2018;
Stoforos et al., 2017).). The general business problem is that hedge funds have a negative
effect on company profits in a downturned market. The specific business problem is that
some managers do not understand the relationship between risk exposure, volatility
forecasting, and financial performance of hedge funds.
Purpose Statement
The purpose of this quantitative correlational study was to examine the
relationship between risk exposure, volatility forecasting, and the financial performance
of hedge funds. The independent variables were volatility forecasting, and risk exposure.
The dependent variable was the financial performance of hedge funds. The targeted
population comprised archival data from hedge fund databases in South Africa. The
implication for positive social change includes the potential to provide organizational
leaders who partner with hedge funds the ability to maximize profit by diversifying risk
in volatile market conditions. Using an investment tool to dispel uncertainty in various
market conditions is a financial means to foster a positive change (Sosner & Steblea-
Lora, 2022). Accordingly, through partnerships with foundations and nonprofit
organizations, hedge funds may help organization leaders fund projects in local
communities.

4
Nature of the Study
Researchers may use quantitative, qualitative or mixed method approaches to
conduct a study (Morgan, 2018; Zoellner & Harris, 2017). A quantitative method of
research was suitable for this study as it is used to identify solutions through statistical
data analysis and provide explanations of predictions and causal relationships (Köhler et
al., 2017). Further, the quantitative method was appropriate for this study because the
purpose was to examine the relationship between variables. A qualitative method is
applicable when a researcher intends to understand the experiences and attitudes of
people in a business or social setting (Mohajan, 2018). A mixed methods approach
includes both quantitative and qualitative methods (Brannen, 2017). Researchers employ
the mixed methods approach to combine the qualitative and quantitative methodologies
when analyzing both textual and numerical data (Brannen, 2017; Williamson et al.,
2020). Therefore, the qualitative portion of a mixed methods approach was not
appropriate for this study.
Researchers may use a correlation design to examine the ability of the variables to
predict an outcome (Zyphur & Pierides, 2020). A correlation design was appropriate for
this study because of its purpose in examining the efficacy of modern portfolio constructs
predicting financial performance of hedge funds. Other designs such as experimental and
quasi-experimental comparative designs are appropriate when researchers seek to
examine how independent variables may influence a dependent variable (Cortina, 2020).
I did not manipulate the variables, and I did not randomize the secondary data during the

5
collection process. An experimental research design was, therefore, not appropriate for
this study, and the correlation design was most appropriate.
Research Question
Is there a statistical significant relationship between risk exposure, volatility
forecasting, and financial performance of hedge funds?
Hypotheses
H0: There is no statistically significant relationship between risk exposure,
volatility forecasting, and financial performance of hedge funds.
Ha: There is a statistically significant relationship between risk exposure,
volatility forecasting, and financial performance of hedge funds.
Theoretical Framework
Markowitz (1952) developed the modern portfolio theory to explain how to
reduce a portfolio’s risk and increase the expected rate of return when combining
uncorrelated asset classes. Markowitz demonstrated that researchers could use the
variance of the rate of return to calculate a portfolio’s risk. Furthermore, Markowitz
derived the statistical formula for computing the covariance of a portfolio (Shadabfar &
Cheng, 2020). With the covariance formula, Markowitz was able to demonstrate the
importance of diversifying investments to reduce risks effectively.
Diversification is the core concept of the modern portfolio theory, and is also a
concept used to calculate risk (Tan & Trinidad, 2018). Markowitz contended that, over
time, a diversified portfolio reduces volatility more efficiently than one that isn’t
diversified. Based on the analysis, the most prominent tenets of the modern portfolio

6
theory are (a) an assumption that markets are efficient, and markets use this information
to determine security prices; (b) investors receive higher returns for using high-risk
investments over time; (c) adding high-risk, low-correlation asset classes to a portfolio
can increase the expected rate of return and decrease volatility; and (d) investors can
diversify passive asset class fund portfolios over time to deliver the highest expected rate
of return (Markowitz, 1952). Similarly, Markowitz identified the key constructs of the
modern portfolio theory as (a) volatility forecasting and (b) risk exposure. As applied to
this study, the independent variables (modern portfolio constructs) were measured using
archived data collected from publicly and privately accessible databases to predict the
financial performance of hedge funds. The MPT applies to this study because the goal is
to examine variables that may relate to the financial performance of hedge funds.
Operational Definitions
Capital markets: Capital markets include regulated markets where all-size
capitalized companies can acquire funding for their short and long-term investments,
including core corporations and expansion (Cao et al., 2018a).
Financial bubble: Financial bubble refers to an economic phase characterized by
a sudden rise in asset prices followed by their reduction. Unjustifiable investor behavior
can create a surge in asset prices (Jang & Kang, 2019).
Funds of funds: Funds of funds refers to an investment strategy of owning a
portfolio of other investment funds. A fund of fund invests in other hedge-funds instead
of investing in particular securities (Getmansky et al., 2019).

7
Hedge fund management and incentive fees: The management fee is usually set at
2% of the total asset, and is paid to the hedge fund manager for asset management. The
incentive or performance fee can be up to 20% of the fund's profit. The incentive fee is to
reward the hedge fund manager for good performance, including taking higher risks
(Ben-David et al., 2020).
Hedge funds: Hedge funds or alternative investments are a collective of private
investment vehicles that allow different investors to combine their money (Getmansky et
al., 2019). The funds are under the management of an investment manager according to
terms and conditions set in the fund prospectus. Hedge funds use dynamic trading
strategies to seek absolute returns, regardless of the market condition (Stafylas et al.,
2018a).
Institutional investor: An institutional investor is an organization that trades
securities in significant quantities or a large sum of money, such as banks, pension funds,
investment advisers, insurance companies, and mutual funds. Institutional investors are
often eligible for preferential treatment and lower commission (Kolokolova et al., 2020).
Regime-switches: Regime-switches are structural changes in the market.
According to the risk environment, the regime represents good and bad or up/down
equity market conditions (Stafylas et al., 2017).
Assumptions, Limitations, and Delimitations
Assumptions
Assumptions, which are statements, issues, ideas, or positions the researcher
accepts without verification during a study, are an accepted part of the research process

8
(AbuRaya & Gomaa, 2020; Foss & Hallberg, 2017). In this study, there were three
assumptions. The first assumption was that the sample represents the population I
inferred. The second assumption was that the data were accurate and performed the
measurements. Finally, the third assumption is that the hedge fund return data included
all the necessary elements before assigning value for the quality.
Limitations
Researchers confront some limitations when performing a research study.
Limitations are potential weaknesses of a study out of the researcher's control (Harari &
Lee, 2021). Limitations usually relate to the study's design and methodologies, such as
bias or specific statistical models (Ross & Bibler Zaidi, 2019). The first limitation is
associated with the generalizability of study findings due to a specific time sampling
period (Greener, 2018). Because hedge funds report voluntarily to commercial databases,
hedge fund data can have biases (Joenväärä et al., 2021b). The two biases that have
significant impact on hedge fund data include survivorship bias and backfill bias
(Hutchinson et al., 2021). The second limitation arises from the bias inherent in archival
data. Some biases that may exist in databases can also influence hedge fund empirical
research (Aragon & Nanda, 2017). The sample in this study was subject to the bias of
missing time series data (Kiss et al., 2017). In addition, hedge fund returns are subject to
delisting bias because managers can choose when and which funds to disclose to the data
vendor (Aragon & Nanda, 2017). The final limitation is the generalization of the study
findings to the hedge fund industry.

9
Delimitations
Delimitations are actions taken by the researcher to determine the study's scope or
boundaries (Theofanidis & Fountouki, 2018). Unlike assumptions and limitations,
delimitations are under the researcher’s control. This doctoral study's first delimitation
was the research problem's scope, which includes the theoretical perspectives and
variables of interest. The second delimitation was the restriction of the specific study
period, as the sample time frame puts restrictions on the examined study results. The third
delimitation relates to the restriction to a geographical area in South Africa. Thus, the
conclusion might infer only to hedge funds based in South Africa.
Significance of the Study
Contribution to Business Practice
Hedge fund managers and individual investors stand to benefit from this study.
Hedge fund managers may benefit from a better understanding of effective methods to
reduce portfolio risks by diversifying assets to maximize the expected rates of return
(Stafylas et al., 2017). Also, individual investors such as retirees could have a better
understanding of their invested funds (Stafylas et al., 2017). Furthermore, business
owners could use volatility forecasting as a risk management tool to price derivatives and
hedge risks (Gaetano, 2018). In addition, the results of the study might positively impact
the financial professionals' ability to predict the market volatility (Xaba et al., 2017).
Thus, a better assessment of the impact varying economic conditions or business phases
have on the risk dynamics of the strategies.

10
Implications for Social Change
The implication for positive social change includes the potential to provide
organizational leaders who partner with hedge funds the ability to maximize profit by
diversifying risk in volatile market conditions. The ability to use an investment tool to
dispel uncertainty in various market conditions is a financial means to foster positive
change (Sosner & Steblea-Lora, 2022). Well-informed investors make profitable
decisions that could generate advantages for the societies and organizations to which they
contribute. Accordingly, through partnerships, hedge funds can help leaders of
foundations and nonprofit organizational fund projects in local communities.
A Review of the Professional and Academic Literature
The purpose of this quantitative study was to investigate the relationship between
risk exposure, volatility forecasting, and financial performance. The literature review was
an essential component of the research study as it provides an extensive analysis of the
subject area, defines the theoretical framework, and substantiates the research problem
(Snyder, 2019). Investigating how hedge funds can be used as potential alternative
investments for investors, as well as comprehension of hedge fund performance and
fund-specific characteristics were part of the professional and academic literature review.
Search Strategy
I used the peer-reviewed articles and journals found in Walden University's
library databases to conduct the academic literature search. The databases included
Business Source Complete, Sage, ProQuest, ScienceDirect, ABI/INFORM, Dissertations,
Directory of Open Access Journals, Google Scholar, and Emerald Management Journals.
11
The keywords used included industry-specific terms such as hedge funds, mutual funds
forecasting volatility, volatility, equity markets, modern portfolio management, efficient
market hypothesis, risk exposure in the market, regime-switching models, hedge funds
risk management, performance persistence, liquidity, hedge funds characteristics, hedge
fund managers, behavioral finance, value investing, beta, time-varying risk, Hedge funds
in South Africa, and performance evaluation.
Table 1
Summary of Literature Review Resources
Reference type
> 5 Years
< 5 Years
Total
Peer-reviewed Journals
191
37
228
Nonpeer-reviewed Journals
5
5
Dissertations
0
0
0
Books
2
3
5
Government or Corporate Sites
5
5
Total
203
40
243
The literature review content included 243 sources, one website, three books, and
one dissertation. Out of the total cited sources, 228 (94%) journals were peer-reviewed,
and 203 (84%) of the sources were current within 5 years of my expected graduation
date. The literature review structure begins with the background discussion of the
theoretical framework grounding the study, including the models describing the
theoretical link between risk and return. The seminal literature is grounded on modern
portfolio theory (MPT) by Markowitz (1952) as the theoretical framework to investigate
the relationship between risk exposure, volatility forecasting, and financial performance
of hedge funds. During the research, I identified additional models to extend the MPT
and to discuss the key themes (Bedoui et al., 2020).

12
The second part of the section covers the following supporting and contrasting
theories: (a) value investing theory (Graham et al., 1934) and (b) behavioral finance
theory (Tversky & Kahneman, 1974). The central part of the literature review covers the
critical analysis and synthesis of the sources on each study variable: (a) volatility
forecasting, (b) risk exposure, and (c) the financial performance of hedge funds. The
literature review chapter will conclude with a summary of critical contents and an
overview of primary objectives.
Modern Portfolio Theory
This study is grounded in the modern portfolio theory (MPT). I used the MPT for
this purpose because it supports the principle of diversification, which is a risk
management technique for investors and fund managers (Arize et al., 2019). Harry
Markowitz is the founder of the modern portfolio theory, which is an influential
economic theory to engage in finance and investment practices (Markowitz, 1952).
Markowitz proposed two principles for portfolio construction and optimization via MPT:
(a) the mean-variance model or risk-return model, and (b) the efficient frontier. The
mean-variance model focuses on an asset's risk and return elements (Moulya et al., 2019).
In this model, the investors allot weights to each asset or risky securities to create a
portfolio in a vector format. Oliinyk and Kozmenko (2019) recommended that investors
construct portfolios by allotting optimal weights on the risky assets to minimize the risk
of the expected return. Bender et al. (2019) compared alternative weighting schemes for
constructing portfolios. The authors recommended constructing portfolios of factors

13
based on average variance values because they describe details comprehensively due to
the explicit use of input factors.
Investors gain the expected return of an asset by accepting the variance of an
asset's returns or risk (Schadler & Steurer, 2019). Simultaneously, by diversifying
securities in a portfolio, an investor can reduce the expected return variance. Thus, an
investor who aspires to reduce the volatility of portfolios' total returns may seek funds
with lower returns and, therefore, lower risk. Xin Rui et al. (2018) examined the
relationship between risk in financial investment and the expected return. The research
findings correspond to those found by Zhu et al., (2020), noting a significant positive
relationship between risk and return during up markets.
According to MPT, an investor can use each asset's mean return and the mean-
variance of that asset to determine both (a) the expected return and (b) the expected
variance of a portfolio, respectively. Also, the investor can determine the covariance
between assets by using the correlating coefficient between the returns of the assets in the
portfolio (Markowitz, 1952). The mean-variance model postulates that the assets'
historical returns influence future returns (Sui et al., 2020). The variables are obtainable
from archival data in the market. The investor can calculate the proportion of each asset
to allocate in the portfolio using weights. The expected return of the portfolio as follows:
E(Rport) = wa ERa + wb ERb + …, where table 2 describes all terms.
14
Table 2
Term Description for Expected Return for Portfolio using MPT
Term
Description
E(Rport)
Expected return on the portfolio
wa
Individually weighted of asset a in the portfolio
ERa
Expected return on the asset a
wb
Individually weighted of asset b in the portfolio
ERb
Expected return on the asset b
Note. From “Portfolio Selection” by H. Markowitz, 1952, Journal of Finance, 7(1), p. 77.
(https://doi.org/10.1111/j.1540-6261.1952.tb01525.x)
The MPT postulates that investors are risk-averse or risk-neutral, and thus try to
maximize the trade-off between risk and expected return in investment decisions (Guo et
al., 2019). Thus, investors and fund managers can create an investment portfolio
representing the investor's perceptions and requirements, ultimately leading to a
collection of efficient portfolios known as the efficient frontier (Siswanah, 2020).
Furthermore, each level of expected return on the efficient frontier has minimum
volatility, and each volatility level has the maximum expected return. The MPT showed
that the return rate variance is an appropriate measure of portfolio risk under certain
assumptions (Gruszka & Szwabinski, 2020). The variance formula indicates the
importance of diversifying investments to reduce the total risk of a portfolio. Thus, MPT
allows investors to minimize risk and maximize their wealth.
Managers aim to select an optimal portfolio along the efficient frontier to meet the
investor's profile and utility function (Zavera, 2017). In this case, Zavera applied the
MPT to evaluate the performance and risk of portfolios in the Romanian stock market,
using historical data from 2010 to 2015 of the gas sectors, energy sector, and food sector

15
to create three securities. From these, Zavera (2017) determined the efficient frontier and
the portfolio's minimum variance. The study findings were negative returns because of
the inadequate sample size for the study. Also, this lack of information makes it difficult
to make decisions for the investor. Besides the diversification component, the MPT has
an inherent strategy of low asset classes' low correlation (Arize et al., 2019). Assets can
lower volatility when in an uncorrelated combination. Bessler et al. (2017) found that a
broader diversification by adding government bonds enhances portfolio optimization
benefits. Also, Oliinyk and Kozmenko (2019) showed that portfolio diversification grants
higher returns for a given risk for the minimum-variance portfolio; the variability in
returns is due to variability in allocation in estimating weights.
Investors and fund managers desire better downside risk protection. Lin and Wu
(2018) found that risk-adjusted returns, volatility, diversification, correlation, and
downside protection allow investors to search for tools to customize portfolios and
improve performance. Wu et al. (2020) recommended a differential evolution algorithm
to dissipate financial and portfolio risks under certain conditions. However, Bessler et al.
(2017) suggested incorporating alternative asset classes, such as commodities and hedge
funds, to improve the risk-free rate. Simonian and Wu (2019) applied the regression
method to replicate hedge fund strategies to build portfolios for hedging risks and
increase returns. The term hedge fund is an alternative investment that aims to increase
risk-adjusted performance or absolute returns (Getmansky et al., 2019).
Markowitz (1952) found that risk could not be diversified entirely away from an
investment. Each investment has two main types of risk: (a) systematic risks, beta β, and

16
(b) unsystematic risks. Systematic risks are part of a security's risk that originate from
external factors affecting the whole market; systematic risks cannot be diversified away
(Xin Rui et al., 2018). Examples of such factors are interest rates, inflation, liquidity,
equity, credit, wars, fiscal, monetary policies, and pandemics. Avkiran (2018) found the
systematic risk to be related to macroeconomic shifts associated with the market
conditions.
Unsystematic risks refer to specific risks part of a security risk caused by factors
unique to a firm (Xin Rui et al., 2018). According to Puspitaningtyas (2017), this risk can
diversify away because it originates from internal factors (microeconomic). Sources of
specific risks include company management, credit rating, lawsuits, marketing strategies,
strikes, and other related issues unique to the company. In summary, a portfolio's
systematic risk of assets is correlated to market factors, while unsystematic risks are not
correlated.
Assumptions and Limitations of MPT
Markowitz (1952) based the model on the following assumptions (a) Investors are
rational and risk-averse, which may not apply to all investors. Stork et al. (2020) found
evidence contrasting the theories that assume rational expectations and support the
bounded rationality theory of behavioral heterogeneity. Alternatively, Taffler et al.
(2017) found that the prospect theory asserts that investment decisions stem from various
behavioral biases that encourage the investors from rationality (b) Markets are efficient.
All information is available to all investors. However, behavioral theories attest that the
market is inefficient because of frequent anomalies (Filbeck et al., 2017). Also,

17
Senarathne (2019) pointed out that bounded rational theory explains that not all market
participants have access to all information to make possible decisions, (c) Identifies an
asset's return with a normal distribution. However, the real world’s correlation between
asset returns is not constant (Xin Rui et al., 2018). (d) The mean-variance model
presumes that the assets' expected return stems from the mean of the assets' historical
returns. Jones (2017) argues that the archival method ignores risk factors that impact
assets' returns.
Capital Asset Pricing Model (CAPM)
The CAPM is a continuation of the MPT that attempts to assess the price of risk
of assets. Sharpe (1964) and Lintner (1965) introduced the CAPM to model the
relationship between risk and expected return for equities. The CAPM is a simplified and
more practical extension of Markowitz's MPT and is applicable to assess the relationship
between risk and return rate. The model bases its theory on the two aspects of risk,
systematic and unsystematic (Fernando, 2018). As discussed, the MPT shows that
diversification cannot eliminate systematic risk. The model also allows an investor to
evaluate a portfolio's expected return, given the risk β. (Puspitaningtyas, 2017). Hence,
the CAPM evolved to determine the systematic risks in a portfolio.
Sharpe (1992) built the CAPM on the basis of fundamental assumptions about the
capital market and investors' operation: First, all investors have identical expectations,
and all information is freely available to all market participants simultaneously.
Secondly, investors are rational and seek to maximize their utility, and high expected
returns at a lower risk. Third, all investors can borrow or lend any money at a risk-free
18
rate of return. Fourth, there is a linear relationship between the expected return rate of an
asset and its risk. The fifth assumption is that transactions are exempt from any fees or
tax costs. The sixth assumption is that markets are efficient; investors do not affect prices
and have the same odds for the expected return. Most of these assumptions have a
drawback for unrealistic reflection of the actual market. Sharpe (1992) formulated the
CAPM based on the principle that an asset's return rate equals risk plus the risk-free rate.
The following formula represents the CAPM is as follows:
E(Ra) = Rf + βa (ERm - Rf ), where table 3 describes all terms
Table 3
Term Description for CAPM Equation
Term
Description
E(Ra)
Expected return on asset a
Rf
Risk-free rate return of an asset (10-year government bond-yield)
E(Rm)
Expected return of market, m or Index
βa
Systematic risk (beta) of asset a
Note. From “Capital asset prices: A theory of market equilibrium under conditions of risk” by W. F. Sharpe, 1964,
Journal of Finance, 19(3), p. 432. (https://doi.org/10.2307/2977928)
The beta (β) coefficient measures an asset's relative sensitivity to market
movements: the asset's risk exposure. Black and Scholes (1973) studied price movements
in stock portfolios relative to the Stock Exchange between 1931 and 1965. From these
Black and Scholes (1973) confirmed the linear relationship between the returns of their
stock portfolios and their betas. However, Fama and French (1993) found that the
difference in betas over time did not justify stocks' performance in the portfolio. The
equation for expected returns represents the relationship between an asset's risk and
return, named the Security Market Line (SML). The efficient frontier graph rearranges to
19
illustrate the performance of individual assets. In the SML equation, the coefficient of
beta, βa, is as follows:
βa = cov(a* m) / ρ2m , where table 4 describes all terms
Table 4
Term Description for Beta in the SML Equation
Term
Description
βa
Systematic risk (beta) for asset a
cov(a* m)
Covariance between asset a, and market m or index.
ρ2m
Variance on returns on the market m or index
Note. From “Capital asset prices: A theory of market equilibrium under conditions of risk” by W. F. Sharpe, 1964,
Journal of Finance, 19(3), p. 439. (https://doi.org/10.2307/2977928)
For the average asset, beta is equal to or greater than 1; then, it contributes higher
than average risk to the portfolio (Bolander et al., 2017). If the beta is less than zero, the
securities will perform well when the market does poorly and vice versa
(Puspitaningtyas, 2017). Thus, the CAPM model can help investors determine the sources
of common equity risk factors in a portfolio. Unlike traditional funds, hedge funds
evaluate relative and absolute returns performance. The relative return requires the fund
manager to compare performance to other investment instruments such as other funds,
hedge funds, and indexes (Zhang et al., 2021). Also, performance comparison requires a
time frame.
On the other hand, absolute returns or risk-adjusted returns require a performance
comparison to the other hedge fund strategies (Hwang et al., 2017). Hentati-Kaffel and de
Peretti (2015) conducted a nonparametric study to examine the randomness and
persistence of hedge funds' relative returns. In this case, Hentati-Kaffel and de Peretti
used Hedge Fund Research (HFR) data, from January 2000 to December 2012, and the
20
S&P500 as a benchmark. The study concluded that about 80% of the absolute returns
were random, and the event-driven and relative value strategies present clustering in
relative return. The study confirms that hedge funds' relative returns vary with a
benchmark.
Beta β represents a fund's systematic risks, α, alpha represents the non-systematic
return generated by an asset (Puspitaningtyas, 2017). Furthermore, the unsystematic risk
does not relate to market factors. However, the alpha coefficient is related to the hedge
fund manager's skills and critical quantitative skills when allocating assets to hedge fund
managers (Frydenberg et al., 2017). Consequently, the most efficient hedge fund strategy
will yield a risk-adjusted return with systematic risk factors. Jensen (1968) highlighted
the importance of a better understanding portfolio risks when analyzing alpha. The
Jensen equation is as follows:
E(Ra) = αa + Rf +βa (ERm - Rf ) - Ɛa where table 5 describes all terms
Table 5
Term Description for Jensen Equation
Term
Description
E(Ra)
Expected return of asset a
αa
Risk adjusted return of an asset a, or performance measure
Rf
Risk-free rate return of an asset (3-month government bond-yield)
βa
Systematic risk (beta) of asset a
Ɛa
Error term. For asset a, idiosyncratic term will be zero
Note. From “The performance of mutual funds in the period.” by M. C. Jensen, 1968, Journal of Finance, 23(2), p. 393.
(https://doi.org/10.1111/j.1540-6261.1968.tb00815.x)
Jensen's equation above shows a method to evaluate the risk-adjusted return of a
portfolio. Jiang et al. (2022) confirmed by remarking that a manager's alpha is a

21
testament to time the market effectively. Still, it is more complex to evaluate hedge fund
returns than for classical funds. Unlike mutual funds, a hedge fund manager emphasizes
evaluating absolute returns (Swartz & Emami-Langroodi, 2018). According to Almeida
et al. (2020), managers generate relative returns required by comparing returns to a
benchmark over a set time. On the other hand, to generate absolute returns, the manager
compares them to other strategies. A hedge fund strategy's primary goal is to perform a
risk-adjusted return uncorrelated with systematic risk factors (Puspitaningtyas, 2017).
The CAPM model assumes that the variance in asset returns is linear, depending on the
market's risk factors. However, the drawback of using the CAPM to assess hedge fund
returns relative to risk is that hedge fund returns do not have a normal distribution.
Arbitrage Pricing Theory (APT).
The APT is a different approach to the CAPM to evaluate asset prices. Ross
(1976) adapted a multifactor model to mitigate the limitations presented by the CAPM.
The APT is based on a linear process like the CAPM but with fewer assumptions. The
main difference is that although the CAPM is not a complicated model, it is not easy to
verify empirically. The underlying assumption essential for the CAPM on the natural
economic conditions makes it challenging to study the impact of the capital market on an
investor's decision or performance (Yildiz & Erzurumlu, 2018). The APT specifies
several risk factors and expands the definition of systematic investment risk (Frydenberg
et al., 2017). The authors found that some of the factors could be statistical or
fundamental. Roll and Ross (1980) identified the three underlying assumptions of the
APT as follows: (a) prices of securities, governed by multiple factors, which have
22
categories such as macroeconomic or specific risk factors, (b) diversification erases the
unsystematic risk (specific risk) in a portfolio. Lastly, if a portfolio is well-diversified,
investors will have no arbitrage opportunity. The APT incorporates all the assumptions in
the following equation:
E(Ra) = Rf + β1 F1 + β2 F2 + . βn Fn + Ɛa, where table 6 describes all terms
Table 6
Term Description for Expected Return of an Asset using the APT
Term
Description
E(Ra)
Expected return of asset a
Rf
Risk-free rate return of an asset (3-month government bond-yield)
βn Fn
Price relationship between risk premium and (n beta factors)
Fn
Risk premium related to the nth risk factor
Ɛa
Error term. For asset a, idiosyncratic term will be zero
Note. From “The performance of mutual funds in the period.” by M. C. Jensen, 1968, Journal of Finance, 23(2), p. 393.
(https://doi.org/10.1111/j.1540-6261.1968.tb00815.x)
The APT extends the CAPM, and identifies the risk factors (Fernando, 2018).
Thus, the APT users apply the model to determine the relevant factors that might affect
the asset's returns. Roll and Ross (1980) concluded that the important factors would
include: (a) the variation in inflation, (b) variation in risk premiums and market risk, (c)
change in the amount of industrial production, and (d) change in interest rates.
Ultimately, the CAPM and APT are similar, as they aim to estimate the expected returns
of assets or portfolios.
Several studies investigated methods to derive risk exposures from hedge fund
return data (Hespeler & Loiacono, 2017; Mestre, 2021; Stafylas et al., 2017). Frei and
Hughes (2013) adapted the Posterior Cramer-Rao Bound (PCRB) concept from Sharpe's

23
(1992) earlier study when analyzing hedge fund portfolios of varying securities within an
asset class. The authors applied the PCRB to several hedge fund models to demonstrate
its efficiency in assessing the achievable accuracy of return-based hedge fund exposure.
The authors claimed that the model is appropriate when a researcher lacks access to
hedge fund data. Also, the authors demonstrated that for a manager to achieve an accurate
exposure estimate, they need to consider the following variables (a) covariance of asset
factor, (b) variance of the idiosyncratic error, and (c) value of fund's exposure.
Frydenberg et al. (2017) used the multifactor quantile regression model to
determine which risk factors affect an asset's various hedge fund strategies. The authors
collected data from the Hedge Fund Research (HFR) database containing statistics for
more than 7,000 funds ranging from April 1, 2003, to March 6, 2009. The authors
modeled nine indexes in the study to determine any differences in estimated risk
exposures using quantiles regression compared to the ordinary least squares (OLS)
approach. The analysis revealed that the OLS approach only revealed the risk factors that
contribute to the average return of a hedge fund strategy but failed to account for how the
different risk factors affect tail risk. However, the quantile regression approach
determined the difference in investment styles in each hedge-fund category.
Efficient Market Hypothesis (EMH)
The Efficient Market Hypothesis (EMH) connects to the MPT and is also relevant
to this study. Karp and Van Vuuren (2019) observed that MPT and its precepts evolved
from the EMH. Academic researchers and practitioners use the EMH to study price
movement in the market (Cao et al., 2018b). Fama (1970) described the EMH as a

24
measure of how the financial markets rapidly process publicly available new information.
Also, Karki (2018) defined the EMH as the Random Walk Theory, demonstrating that
stock price changes fully reflect available information about the firm's value.
Furthermore, the firms are cannot make excess profits from exploiting this information.
Thus, the EMH is a concept of information efficiency and the market's ability to analyze
the data into prices.
Fama (1970) conducted an empirical analysis of the EMH using the fair game
model based on the following assumptions: (a) When market prices fully reflect all
available information, the market is informationally efficient (Cao et al., 2018b), (b)
When market conditions are efficient, only new information creates volatility. However,
stock prices vary with the news, which affects macroeconomic factors (Okonkwo, 2019).
EMH has another assumption, which asserts that investors' reactions, on average, are
appropriately in a normal distribution pattern (Kristoufek & Vosvrda, 2018). On the
contrary, investors, and financial markets are characterized by nonlinear dynamic systems
of interacting agents who rapidly process new information (Mallikariuna & Rao, 2019;
Rehman, 2020). Tiwari et al. (2017) argued that fractals provide a realistic market risk
framework for prices.
In his empirical work, Fama (1970) introduced three market efficiency versions
strong-form, semi-strong, and weak form efficiency. A weak-form efficient market if the
current prices indicate all historical or past information. Prices follow the random walk,
and investors cannot use technical analysis to earn an excess return. Thus, the stock
return is serially uncorrelated, and has a constant mean and normal distribution

25
(Kristoufek & Vosvrda, 2018). When public and future expectations fully reflect an
efficient market in a semi-strong form, neither technical nor fundamental analysis can
trace a stock's behavior pattern. A condition necessary for abnormal returns is for market
participants to access private information because all publicly available information
shows current prices. The strong-form efficient markets include all information in the
public and private market and reflects in current prices. Thus, all investors can earn
abnormal profits in this form of efficiency. Fama (1970) proposed these three conditions
to attain strong-form market efficiency: (a) no transaction fees, (b) free access to relevant
information, and (c) a similar way of assessing stocks by all investors. However, Fama
(1970) also noted that these conditions do not represent fundamental financial markets.
Furthermore, infringing on these conditions does not necessarily infer inefficiency, but it
is potential aid.
Cao et al. (2018b) and Cao et al. (2018a) studied hedge fund literature and found
that hedge fund trading enhances market efficiency. In comparing the impact of trading
by mutual funds and hedge funds on the stock prices, the studies found that the aggregate
flows to hedge funds correct the market pricing, while mutual funds worsen it. Hwang et
al. (2017) confirmed the positive impact of hedge fund trading on financial markets. The
authors showed that hedge fund returns negatively correlate with market flow changes,
suggesting hedge funds increase market efficiency. Also, Guptha and Rao (2018) report a
positive relationship between hedge fund return shocks and subsequent returns,
suggesting that hedge fund investors have more information than other investors.

26
Related and Contrasting Theories
To incorporate enough literature into the modern portfolio theory section, I will
discuss two other theories related to and contrasting with the MPT. The two theories
include the behavioral finance theory and the value investment theory. Academic
researchers and practitioners use the value investing theory to evaluate the current
investment price, and the firm’s profit relative to market performance (Zhang, 2019).
Behavioral financial theory can replace the mean-variance portfolio theory, CAPM, asset
CAPM, and other risk models related to expected returns (Mei & Nogales, 2018).
Behavioral Finance Theory
Behavioral finance theory is a contrasting theory to the modern portfolio theory in
this study. Traditional finance theories like the EMH, MPT, or CAPM assume that
investors are rational and maximize utility. However, behavioral economists argue that
emotional and psychological factors shape investors' decision-making processes (Ahmad
et al., 2017). There are two branches of behavioral finance: (a) micro and (b) macro
(Statman, 2017). Micro behavioral finance studies focus on individual investors'
behavior, and macro studies focus on anomalies in the market that behavioral models
may account for (Statman, 2017). Investment decision-making incorporates micro and
macro factors (Ahmad et al., 2017). This review will focus on both branches of
behavioral finance to study investor behavior using the prospect theory components.
The current theories in behavioral finance are the bounded rational theory of
Simon (1955), the prospect theory by Tversky and Kahneman (1974), and the adaptive
theory by Tinbergen (1939). Behavioral finance originates from philosophical and

27
psychological views, which assumes investor irrationality and inefficient financial
markets (Ahmad et al., 2017). The prospect theory is used to understand the decision
behavior of investors in financial markets (Abdin et al., 2019; Madaan & Singh, 2019).
The primary presumption of the prospect theory is that investors are more risk-averse
than have a desire for potential gains (Abdin et al., 2019). Ahmad et al. (2017)
documented that investor decision-making has two thinking systems, the cognitive and
the biased systems. The cognitive system leads to errors known as cognitive heuristics.
On the other hand, biases in decision-making arise from investor sentiment,
emotion, and mood. Strömbaäck et al. (2017) defined cognitive heuristics decisions as a
simple rule of thumb that explains how investors make decisions and solve problems.
Abdin et al. (2017) divided the cognitive heuristics include the following three factors of
investor behavior:
1. Availability, the tendency for investors to use available information
2. Hindsight, which refers to the investor's behavior to use past events or
experiences to predict future events
3. Representativeness explains how investors use stereotypes when making
decisions
4. Mental accounting, procedure investors, use to direct and measure financial
activities
Abdin et al. (2019) showed that mental accounting has a significant positive effect
on all anomalies. Areiqat et al. (2019) used four behavior biases to study investor

28
emotional decision-making behavior; overconfidence bias, regret aversion, herd behavior,
and loss aversion.
Herd behavior occurs when investors observe and imitate others' behavior during
market distress (Yu et al., 2018). Also, it occurs when investors herd and ignore their
decisions and follow others. Mertzanis and Allam (2018) found that herding is high
during market anomalies and price bubbles. Chhapra et al. (2018) concluded that herd
bias does not impact investors’ decision-making. However, Madaan and Singh (2019)
found that herd bias strongly influences investors' investment decisions.
Overconfidence is a psychological bias that steers an investor to overestimate
skill, knowledge or perceive the probability of a result occurring (Joo & Durri, 2017). In
behavioral finance, overconfidence leads to excessive trading volume, higher price
volatility, and return variability. Mushinada and Veluri (2018) showed that
overconfidence about comprehending and processing information could make investors
overreact. Abdin et al. (2017) revealed that overconfidence is a negative predictor that
forecasts the performance of investors during market anomalies. However, Chu et al.
(2017) attested that financial literacy makes confidence in investors suitable for financial
management decisions. Regret aversion bias occurs when investors fear their decisions
will not reward gains (Golman et al., 2017). For example, regret aversion bias may cause
the investor to hold on to losing positions for a long time because of fear of making
wrong decisions. Abdin et al. (2019) showed that regret eversion bias positively affects
fundamental market anomalies. Loss aversion bias occurs when investor perceives
avoiding losses as more critical than gains (Areiqat et al., 2019).

29
According to Ahmad et al. (2017), individual investors react to behavioral biases
such as herding, overconfidence, and hindsight compared to institutional investors. The
researchers found that mental accounting bias affects institutional investors. Shantha
(2019) suggested that most market participants make emotional reactions and heuristic
decisions. Furthermore, there are two types of market participants: Emotional crowds and
behavioral data investors (BDIs). Emotional crowds react to unfolding events, and BDIs
make decisions based on the analysis of available data. Some studies support heuristics in
rewarding decision-making, and some are against it (Chhapra et al., 2018; Rehan &
Umer, 2017). When an investor must make an investment decision, the investor has to
invest without prior knowledge of the outcome.
The MPT posits that rational investors arbitrage away price distortions caused by
irrational investors (Swartz & Emami-Langroodi, 2018). Hence, rational investors are
more influential in the financial pricing process. However, Economou et al. (2018);
Hudson et al. (2018) argued that emotional crowds control markets' pricing and volatility.
The events that cause crowd reactions may be short-lived, but their effects tend to last
longer (Madaan & Singh, 2019). The price distortions are significant and persistent
enough that the BDIs can use them as an opportunity to build portfolios (Wang et al.,
2018). Subsequently, the behavioral finance theory posits that BDIs have higher returns
than emotional crowds. Hedge fund managers receive management and incentive fees for
excess returns they generate (Mitchell et al., 2019). The fees lead to hedge fund
managers' return-chasing behavior due to fund return volatility and investor behavior.

30
Also, fewer regulatory restraints increase hedge fund managers' risk-taking behavior and
the perception of skilled investors (Chhapra et al., 2018).
Value Investment Theory
Graham et al. (1934) presented in the seminal book publication on value investing
and security analysis. Value investing involves identifying and purchasing underpriced
securities in the market through fundamental analysis to profit (Kok et al., 2017). An
example includes public stocks that trade at discounted prices, with low price-to-earnings
(P/E) or price-to-book (P/B) ratios. Graham et al.’s (1934) seminal work classified
investing into two distinct categories: (a) growth investing and (b) value investing.
Growth investing refers to a company's value, including estimating the stock value
(Graham et al., 1934).
By re-examining the modern portfolio theory from the value investing
perspective, investor behavior is not rational decision-makers (Graham et al., 1934).
Also, value investors prefer avoiding risk and not trading risk for return. However, this
practice contrasts with one of the modern portfolio theory tenets: risk relates to return
(Xin Rui et al., 2018). The value investing theory is suitable for the long term, whereas
the MPT tends to be short-term oriented (Gimeno et al., 2020). For example, using
variance or standard deviation as risk is a short-term strategy. Also, the MPT aligns with
the tenets of efficient market hypotheses and asset pricing models. In value investing,
publicly available information from value investors generates consistent long-term
returns. Cao et al. (2018a) documented that using the information to construct portfolios

31
resulted in higher than market returns without high risks. Thus, making the efficient
market hypotheses obsolete.
Furthermore, value investors do not follow the MPT strategy of diversifying to
reduce risk (Gimeno et al., 2020). The authors documented that diversification in value
investing is not widespread because of the stock screening process. The stocks with low
price-to-earnings ratios yield high dividends and are subject to high tax rate fees (Ghaeli,
2017). Again, this goes against the MPT, which assumes no tax charges. To evaluate the
performance using value investing, Sondakh (2019) used listed financial service firms on
the Indonesia stock exchange from 2015 to 2018. Sondakh (2019) analyzed the effect of
dividend policies, liquidity, profitability, and firm size on firm value. The study results
show that liquidity and firm size have a significantly positive effect on firm value,
dividend policies have significantly negative effect, while profitability has no effect.
Sondakh (2019) suggested that investors consider the ratio of dividend, liquidity,
profitability, and firm size policies when investing in a firm they pick.
Sahoo (2017) showed that value stocks outperform when markets are down or up,
good or bad, and when the news is good or bad, without high risk. An explanation could
be investor bias of irrational behavior by overestimating, optimistic, and overreacting
(Chhapra et al., 2018). Another issue the authors found is that the undervalued securities
prices in a downturned market could be inaccurate as the market continues to drop.
Risk Exposure Variable
Hedge funds are a component of the financial system and the hedge fund industry.
The hedge fund strategies include using derivatives, non-traditional assets, and engaging

32
in long/short positions in any financial instrument (Agarwal et al., 2017a; Gao et al.,
2018a). However, such flexible practices expose hedge fund strategies to risk factors,
including complex risk exposures that vary according to style and market environment
(Stafylas et al., 2017). It is helpful for managers and investors to know current risk
exposures to estimate a portfolio, gain insight into a manager's skill, and replicate
strategies. Hedge fund managers vary the exposure of assets to changes in
macroeconomic conditions and fluctuating market conditions (Agarwal et al., 2018a).
The researchers suggest that hedge fund managers vary the portfolio exposure timely by
predicting the fluctuating macroeconomic variables.
Statistical Characteristics of Hedge Funds Return
The principal purpose of hedge funds is to make absolute returns at lower risk
levels unaffected by varying financial markets (Shin et al., 2018). Unlike traditional
investment funds, hedge funds are subject to few regulatory requirements, which allows
for flexible investment strategies (Metzger & Shenai, 2019). For example, hedge fund
managers can combine long/short positions and invest in non-traditional asset classes.
Swartz and Emami-Langroodi (2018) documented that researchers and investors can
classify hedge funds into alternative strategies with specific characteristics, such as style,
asset uses, returns, risk profile, and liquidity. Also, their strategies are grouped into two
key components, to assess hedge fund returns, beta and alpha (Joenväärä et al., 2021b;
Stafylas et al., 2018a). Beta (β) measures the volatility of the returns generated from the
exposure to various asset classes (Frydenberg et al., 2017). In contrast, alpha (γ) shows

33
the return generated by the manager's skill. Kapil and Gupta (2019) used this concept to
classify the investment strategies of hedge funds to determine performance.
Market Neutrality
Market-neutral hedge funds aim to generate uncorrelated returns to market returns
and return volatility (Joenväärä et al., 2021b). Also, the study's findings concluded that
hedge funds correlate less with traditional assets than mutual funds with market indices.
Joenväärä et al. (2021b) documented two types of hedge fund strategies; (a) Strategies
that have a low correlation to the market and (b) Strategies that correlate with the market
or specific index movement. Patton (2009) proposed to classify market neutrality into
four concepts to create a method to measure non-neutrality:
Mean Neutrality. Establishes that a fund's expected return is neutral or
negatively related to the downturned market. This neutral environment ignores the
relationship between the fund and the market when it generates positive returns (Patton,
2009). This test can apply to test market neutrality controlling for hedge fund exposure to
other sources of risk.
Variance Neutrality. Variance neutrality is another form of neutrality, where the
risk of funds is neutral to market risk. The test is applicable where the variance is the
measurement of risk. Agarwal et al. (2017a) applied the variance neutrality test to
examine the influence of uncertainty on hedge fund returns by aggregate volatility.
Value-at-Risk Neutrality. The (VaR) provides an environment where the market
return does not affect a portfolio. Crego and Galvez (2018) applied the value-at-risk
(VaR) neutrality test to investigate the dependence of hedge funds’ returns on the market

34
portfolio. The study results concluded that the VaR for market-neutral hedge funds
increases when market returns are more negative than positive. Also, the correlation
between market-neutral funds and the stock market varies with the economic state.
Tail Neutrality. Tail risk is the possibility of significant losses in portfolio
returns (Agarwal et al., 2017b). Therefore, investors are tail risk-averse, and there is a
positive relationship between expected return and tail risk (Mhalla et al., 2020). Shin et
al. (2017) conducted a bootstrap analysis to determine that the tail risk timing ability was
because of managerial skill. The authors used a sample of 6147 equity-oriented hedge
funds from 1996-2012 to investigate managers' time market tail risk by adjusting their
portfolios' market exposure to changes to market tail risk. The study's analysis showed
that a manager's tail risk timing skill persists over time, indicating managerial skill.
Non-Linearity
The dynamic use of long and short hedge fund positions produces a nonlinear
relationship between the returns and market returns (Fung & Hsieh, 1997a, 2001, &
2004). The studies' results confirmed other studies that hedge funds have nonlinear
returns (Cai et al., 2018; Huang et al., 2018). Also, the nonlinear exposures vary over
time, according to market conditions. Several studies recommend incorporating a
nonlinear relationship between hedge funds and market returns when analyzing the risk-
return characteristics of hedge funds (Hambuckers et al., 2018; Stafylas et al., 2018a).
Agarwal and Naik (2004) used buy-and-hold and option-based risk factors to
identify various hedge fund strategies' linear and nonlinear risks. The authors performed
an analysis at the index level and individual level. The characterization of nonlinear risk-

35
return relationships found that hedge funds show significant exposure to Fama and
French's (1993) three-factor model and Cahart's (1997) momentum factor. Fung and
Hsieh (2001), Mitchell and Pulvino (2001) tested neutrality on individual hedge fund
strategies and extracted systematic risk factors. The authors used the Asset Based Style
(ABS) approach, where the market index time can hold a more extended position to allow
trend-following strategies.
A comparable study by Fung et al. (2002) used the ABS method to extract the
well-known sources of risk associated with fixed-income hedge funds. The authors
identified the ABS factors and could associate them with most fixed-income hedge funds.
The findings had enormous implications for asset allocation and identifying the
significant risks. Thus, in selecting the best variation of strategies that can increase alpha.
Baker et al. (2017) applied multivariate regression to identify the factors of high-moment
risks. Evidence from the study factors relating to leverage, incentives, and strategy is
statistically significant in explaining all moments.
Skewness and Kurtosis
Skewness and kurtosis are characteristics of hedge fund returns, known as high-
moment risks (Amin & Kat, 2003). Skewness measures the deviation symmetry of the
hedge fund return distribution, and kurtosis measures the amount of extreme hedge fund
performance (Knif et al., 2020). Also, a positive skewness implies higher expected
returns and more minor losses. The Sharpe ratio assumes that hedge fund returns have a
normal distribution (Sharpe, 1992). However, hedge fund returns mostly have negative
skewness and high kurtosis because of the dynamic nature and nonlinear distribution

36
(Stoforos et al., 2017). Therefore, the Sharpe ratio is unsuitable as a performance measure
for hedge funds. Kapil and Gupta (2019) examined monthly hedge funds' returns to
account for the performance of various strategies. The author found that return
distribution mostly deviates from the mean and is skewed negatively with excess positive
kurtosis. The author could infer that the skewness and kurtosis occur because of the
strategies' dynamic nature and the bias from data collection from hedge fund indexes.
Fang and Almeida (2018) recommend including higher moments when modeling
hedge fund returns. The arguments for incorporating higher moments are that hedge fund
returns do not have a normal distribution and investors' choice for high positive skewness
and low kurtosis. The study’s evidence shows that most hedge funds outperform the
market index during the study period, based on the Sharpe ratio performance method.
However, the results were different by underperforming the market index with the
inclusion of skewness and kurtosis funds. Thus, the author suggests the inclusion of
skewness and kurtosis when analyzing hedge fund returns.
Hedge Funds Classification
When analyzing hedge funds, a broader system of classifying them is to group
them into a two-step process (Stafylas et al., 2018b): (1) Assessing the fund's exposure to
fluctuating market conditions and (2) Evaluating an aspect of exposure on the funds'
risk/return characteristics. The technique leads to the emergence of three broad hedge
fund categories: (a) event-driven funds, (b) non-directional funds, and (c) directional
funds.

37
Event-Driven Funds
Strategies in the event-driven or arbitrage funds category aim to profit by focusing
on investing in opportunities occurring in exceptional situations or events (Falkowski et
al., 2020). The uncertainty of an event provides an opportunity to benefit by allocating
funds to the issue's asset at the moment. The strategies in this category include distressed
securities, merger arbitrage, risk arbitrage, and event-driven. Gao et al. (2018b) prove
that hedge fund managers with more skills at exploiting rare disaster events can deliver
superior expected fund performance with limited risk. Also, the funds are less exposed to
disaster risk, and the managers possess skills in managing leverage and timing extreme
market conditions.
Non-Directional Funds
Non-directional or equity funds strategies aim to eliminate risk exposures to the
financial market movements by low correlation with the market (Fang & Almeida, 2018;
Joenväärä et al., 2021b). Also, non-directional strategies are independent of any market
trends and increase returns by exploiting market inefficiencies and arbitrage
opportunities. The category strategies include fixed-income, market-neutral, convertible
arbitrage, and multi-strategy (Frydenberg et al., 2017).
Directional Funds
The market-directional hedge funds display a high correlation with the market and
seek high returns. Also, they use high leverage and adopt strategies that represent bets on
the direction of markets (Frydenberg et al., 2017). Examples of market directional
category strategies include global/macro, long-short equity, emerging markets, short bias,

38
and managed futures (Frydenberg et al., 2017). Hong et al. (2018) used the multifactor
model to examine hedge fund strategies during varying market conditions. From the
study Hong et al. (2018) discovered that the multi-strategy, global macro and managed
futures were the few strategies that could generate considerable alpha in a downturned
market.
Data Evaluation
It is common for researchers to classify hedge funds in terms of their investment
styles. Some researchers, such as Kapil and Gupta (2019); Gerhard and Rupert (2017),
used a classification scheme created by database vendors. Other authors like Almeida et
al. (2020) and Newton et al. (2021) used hedge fund indices provided by the database
providers, ignoring the indices' representation's limitations. Most researchers use more
than one database to mitigate bias because of hedge fund managers' voluntary inclusion,
such as Metzger and Shenai (2019); Hespeler and Loiacono (2017).
The Hedge Fund Industry in South Africa (SA)
South Africa’s hedge fund sector is still in its infancy compared to its global
counterpart. The first hedge fund began in 1995 and grew to 1.4 billion Rands by 2002
(HedgeNews Africa, 2021). Also, the lending market facilitated short selling in the
1990s, and by 2013, assets under management were part of the strategies. Muteba
Mwamba (2017) identified the causes of growth in the hedge fund industry in South
Africa as individuals seeking high investment returns in alternative investments and
academics pursuing research on hedge funds' performance workings. Before 2012, hedge
funds in SA were subject to few regulatory requirements until the National Treasury and

39
Financial Services Board (FSB) proposed a regulatory framework for hedge funds
(CISCA, 2015). In 2015, the Collective Investment Scheme Control Act (CISCA)
effectively published new hedge fund regulations (CISCA, 2015). Hedge fund managers
had to register their management companies and portfolios within twelve months. Also,
managers had to comply with investor protection per the regulations. South Africa is one
of the few countries that enacted a comprehensive regulation for hedge fund instruments.
The regulation aims to protect investors better, manage systemic risk spillovers, improve
transparency, and oversee the financial market's progress (Bouamara et al., 2017).
However, this contrasts with the sentiment that light regulations give hedge funds the
advantage of engaging in flexible investments relative to traditional funds.
Macroeconomic Factors in SA
The economic and productivity growth has been declining in South Africa since
2015 (Kreuser & Newman, 2018). However, this study focuses on the economic factors
that may impact the stock market return, volatility, inflation rate, and the short-term
interest rate. Ten sectors make up the JSE. The sectors include basic materials,
industrials, consumer goods, health care, consumer services, oil and gas,
telecommunications, financials, technology, and utilities (Szczygielski et al., 2020).
According to Szczygielski et al. (2020), the performance of each sector varies according
to the macroeconomic factor that impacts it. The macroeconomic conditions affecting
stock market factors include the Gross Domestic Product (GDP), inflation, and interest
rates (Szczygielski et al., 2020). Interest rates are part of external and part of domestic
microeconomic factors (Madaree, 2018). Mitra (2017) used dynamic cointegration to

40
investigate the relationship between the effective exchange rate and the total stock
transactions in South Africa between 1979 and 2014. The results revealed a significant
positive correlation between the exchange rate and the total value of stock transactions in
South Africa.
Jeelani et al. (2019) used the ordinary least squares technique to examine the
structural changes in microeconomic variables such as GDP, interest rate, and exchange
rates. The findings revealed that major economic events impacted the microeconomic
variables. A low GDP harms investors, businesses, productivity, and uncertainty (Ceruttia
et al., 2017). Understanding the macroeconomic factors of South Africa's market is
necessary to proxy systematic influences for performing studies that model
macroeconomic factors (French, 2017).
Hedge Fund Style Analysis
Style analysis is a component in hedge fund literature that focuses on risk
exposure. The analysis examines dynamic hedge fund strategies' exposure to various
systemic risk factors (Hespeler & Loiacono, 2017). Also, the risks vary since they can
engage in short/long positions in any financial instrument and use high leverage. Fung
and Hsieh (2004) found that investing flexibility and the ability to leverage positions are
salient features that enhance hedge fund returns but potentially add to market volatility.
In hedge fund literature, the risk exposure analysis is in three phases. The first is the
classical linear model, which assumes a constant variance, such as the CAPM (Sharpe,
1964) and the APT (Ross, 1976) derived from modern portfolio theory. The CAPM only
accounts for the market risk. Fama and French (1993) extend the CAPM by introducing

41
the three-factor model by adding two factors based on size (SMB) and value (HML-high
minus low bond value ratio).
Carhart (1997) extends the 3-factor model by introducing momentum (MOM) to a
four-factor model. The momentum of a stock is the tendency for its trend. The beta
represents the exposure to the risk factor (systematic risk). However, the focus of the
study is more on the economic association of the exposure. The second phase adapts to
the Asset-Based Style Factors (ABS-Factors). It incorporates location factors that proxies
for buy-and-hold strategies on equity, bond, and commodity markets to control nonlinear
risk exposures of hedge funds (Agarwal & Naik, 2004; Bali et al., 2014). However, the
ABC factor model does not account for hedge funds' dynamic property or the market risk
factor's regime volatility.
The next phase is the addition of models that account for dynamic economic risk
factors. Fung et al. (2008) employed the breakpoint analysis to examine the structural
breaks in hedge fund risk exposures from September 1998 to March 2000. The study's
findings revealed significant structural breaks in hedge fund risk during the study period.
The authors confirmed that the structural breaks were associated with the long-term
capital crisis in 1998 and the internet bubble in 2000. Bollen and Whaley (2009)
introduced the changepoint regression models to examine the time-varying risk exposures
of hedge funds. The study results showed that excluding time-varying risk exposures of
hedge funds leads to inaccurate risk and return estimates. Siegmann and Stefanova (2017)
discovered optimal change-points in the relationship between beta and liquidity during
market turmoil or structural change.

42
Racicot and Théoret (2019) used the regime-switching model to study hedge
funds' risk exposures to traditional asset class factors in different regimes. The study
findings confirmed that hedge funds face nonlinear, option-like risks. Racicot and
Théoret (2019) used the regime-switching process to show that higher moment risk is
conditional to volatility. Another study by Zheng and Osmer (2018) employed the
Markov regime-switching model to investigate the dynamic effect of aggregate stock
market sentiment on various hedge fund strategies' performance. The researchers
examined the effect of investor sentiment on the relationship between investor sentiment
during pessimistic periods. The study analysis found that investor sentiment affects hedge
fund performance during optimistic periods. Furthermore, the relative-event hedge fund
strategies responded to the shocks.
The remaining part of the analysis of the most significant risk exposures
underlying the hedge fund styles: Directional funds or equity hedge strategy take
long/short positions. Literature like from Billio et al. (2018); Stafylas et al. (2017).
evaluate the following group of factors using the model: (a) Equity factors, (b) Volatility
factors, (c) Interest rate and credit risk factors, (d) Fama and French (1993) factors, (e)
Commodity factors, (f) Currency factors, and (g) Emerging markets factors. The studies
found that funds present exposures to various macro conditions. The analysis in the study
section aims to track the behavior using the macroeconomic models.
Volatility Forecasting Variable
In financial markets, volatility refers to the changeable variance of asset returns.
Bhowmik and Wang (2020) described volatility as the statistical measure of the standard

43
deviation of dispersion around the mean. A unique trait of volatility is that it is not
observable, making financial analysts eager to determine the approximate conditional
variance (Bhowmik & Wang, 2020). Other researchers define volatility as a measure to
which asset prices variate randomly as a time series component (Emenogu et al., 2020;
Schreder, 2018). Thus, volatility mainly describes the rate and magnitude of changes in
prices.
The frequent fluctuation of the broad capital market may cause uncertainty and
impact investors' confidence about the value of assets (Maqsood et al., 2017). The
authors also suggested that the public and investors believe the volatility is the cause of
the market-wide movements, especially the down market movement. However, the
down-market movements do not always relate to a specific news event. Manyang et al.
(2017) showed that risk-averse and neutral investors generally pull back from the market
during high price fluctuation market movements, thereby distorting the capital market.
Market volatility is unavoidable in the financial system, and modeling, volatility,
forecasting, and correlations are fundamentally crucial for all market participants
(Schreder, 2018). Studies focusing on volatility have been increasing in importance
because it contributes to liquidity to the financial system (Agarwal et al., 2017a, 2019;
Lee & Nguyen, 2017). The primary motivators to conduct volatility forecasts are the
prominent role of volatility as a risk management tool and portfolio management.
Volatility makes investors more risk-averse because of uncertainty (Rupande et
al., 2019). Forecasting volatility can help risk-averse investors make decisions (Ahmad et
al., 2017). For example, a high volatility investment could present a possible opportunity

44
for a risk-tolerant investor with higher risk and possible significant profits (Markowitz,
1952). Therefore, knowing or predicting the volatility benefits the investors, especially
those willing to potentially take a high risk to earn high returns. There are two basic
approaches to forecasting volatility. The first approach is a time series or parametric,
extracting information about the variance of future returns from historical volatility
returns (Grable & Heo, 2017). Also, it uses non-constant volatility techniques such as
generalized autoregressive conditional heteroscedasticity (GARCH), ARCH, and
stochastic volatility models, to capture the clustering in volatility over time. The second
approach is non-parametric or implied volatility and extracts the market's expectation
about future volatility from observable option prices using implied volatility indices (Liu
et al., 2021). The implied methods employ techniques such as Black-Scholes, introduced
by Black and Scholes (1973). Furthermore, the model uses high-frequency data on
volatility trading.
Some authors believe that the time series models are superior because they
capture stylized parametric volatility characteristics, including persistence, a prominent
trait of financial volatility (El Jebari, & Hakmaoui, 2017; Emenogu et al., 2020). On the
other hand, others believe the implied volatility approach outranks the time series models
because it cannot accurately forecast high-frequency volatility (Balcilar et al., 2017;
Yang et al., 2019). For this reason, it has led researchers to propose combining both
models for favorable results. Among the challenges a researcher may face in modeling
volatility are the stylized facts or financial market volatility patterns. Financial market
volatility has several characteristics that are acknowledgeable in the literature. For

45
instance, Baltas and Kosowski (2019) reinforced the existence of volatility clustering and
supported the ARCH behavior of financial time series. Grable and Heo (2017) also found
that volatilities vary across time and asset classes.
Stylized Market Volatility
The financial time series has some established characteristics of financial market
volatility. Most volatility forecasting models incorporate the salient features of the design
(Kaya & Yarbaşi, 2021; Xaba et al., 2017). This section highlights and briefly describes
some of the characteristics relating to this study. The features include asymmetry
(leverage), volatility clustering, fat tail (leptokurtic) distribution, and autocorrelation
(Ardia et al., 2018, 2019). Forecasting volatility includes selecting stylized properties
such as asymmetry, leverage, persistence, and mean reversion (Dai et al., 2020).
Fat Tail or Leptokurtic Distribution. Leptokurtic refers to the return
distribution curve with higher peaks that deviate from the median. Racicot and Théoret
(2018) show that long-term negative increases the downside risk and failure. Skewness
values higher than 3 lead to leptokurtic, and higher kurtosis values lead leptokurtic
(Swartz & Emami-Langroodi, 2018). Hedge fund returns deviate from the median and
left-skewed (negative), and have leptokurtic distribution because of the nonlinear
investment style (Baker et al., 2017). Also, Fang and Almeida (2018) recommend
allowing for skewness and kurtosis to improve the forecasting analysis.
Volatility Clustering. Clustering refers to the fluctuations of uneven financial
asset returns in contrast to even variations (Bhowmik & Wang, 2020). With volatility
clustering, significant price changes can follow another large price change in an

46
unpredictable direction (Kumar & Biswal, 2019). Volatility clustering and persistence
produce leptokurtic distribution in financial series (Racicot & Théoret, 2018). Also,
volatility clustering implies that present-day volatility shocks may influence the
expectations of future volatilities. Herbert et al. (2018) found the existence of volatility
clustering and asymmetry (leverage effect) in the Nigerian stock market and that the
clustering is persistent. Similarly, Oseifuah and Korkpoe (2019) found that the
Johannesburg Stock Market (JSE) market returns' volatility features include clustering
and leptokurtic.
Volatility Asymmetry. Volatility asymmetry is another essential characteristic in
the financial markets, especially in the equity markets (Racicot & Théoret, 2018).
According to Xie and Wang (2018), volatility asymmetry reacts to declining markets by
rising. The leverage effect if volatility increases because previous day returns are
negative (El Jebari & Hakmaoui, 2017). The leverage effect is the asymmetric reaction to
fluctuating returns of the same size. Bhowmik and Wang (2020) stated that leverage
indicates negative news, and stock falls, leading to rising leverage effect and thus, an
increase of the degree of stock volatility. Zaiane and Jrad (2020) used APARCH to
investigate the dynamic linkages between the exchange rate (US Dollar) and theTunisia
stock market. The APARCH model was appropriate to study persistent long memory and
asymmetry in both markets. The study results showed that volatility shocks could create
sudden changes in the dynamic correlations. Mashamba and Magweva (2019) evidenced
leverage effects in the market in South Africa. Mohohlo and Hall (2018) found that
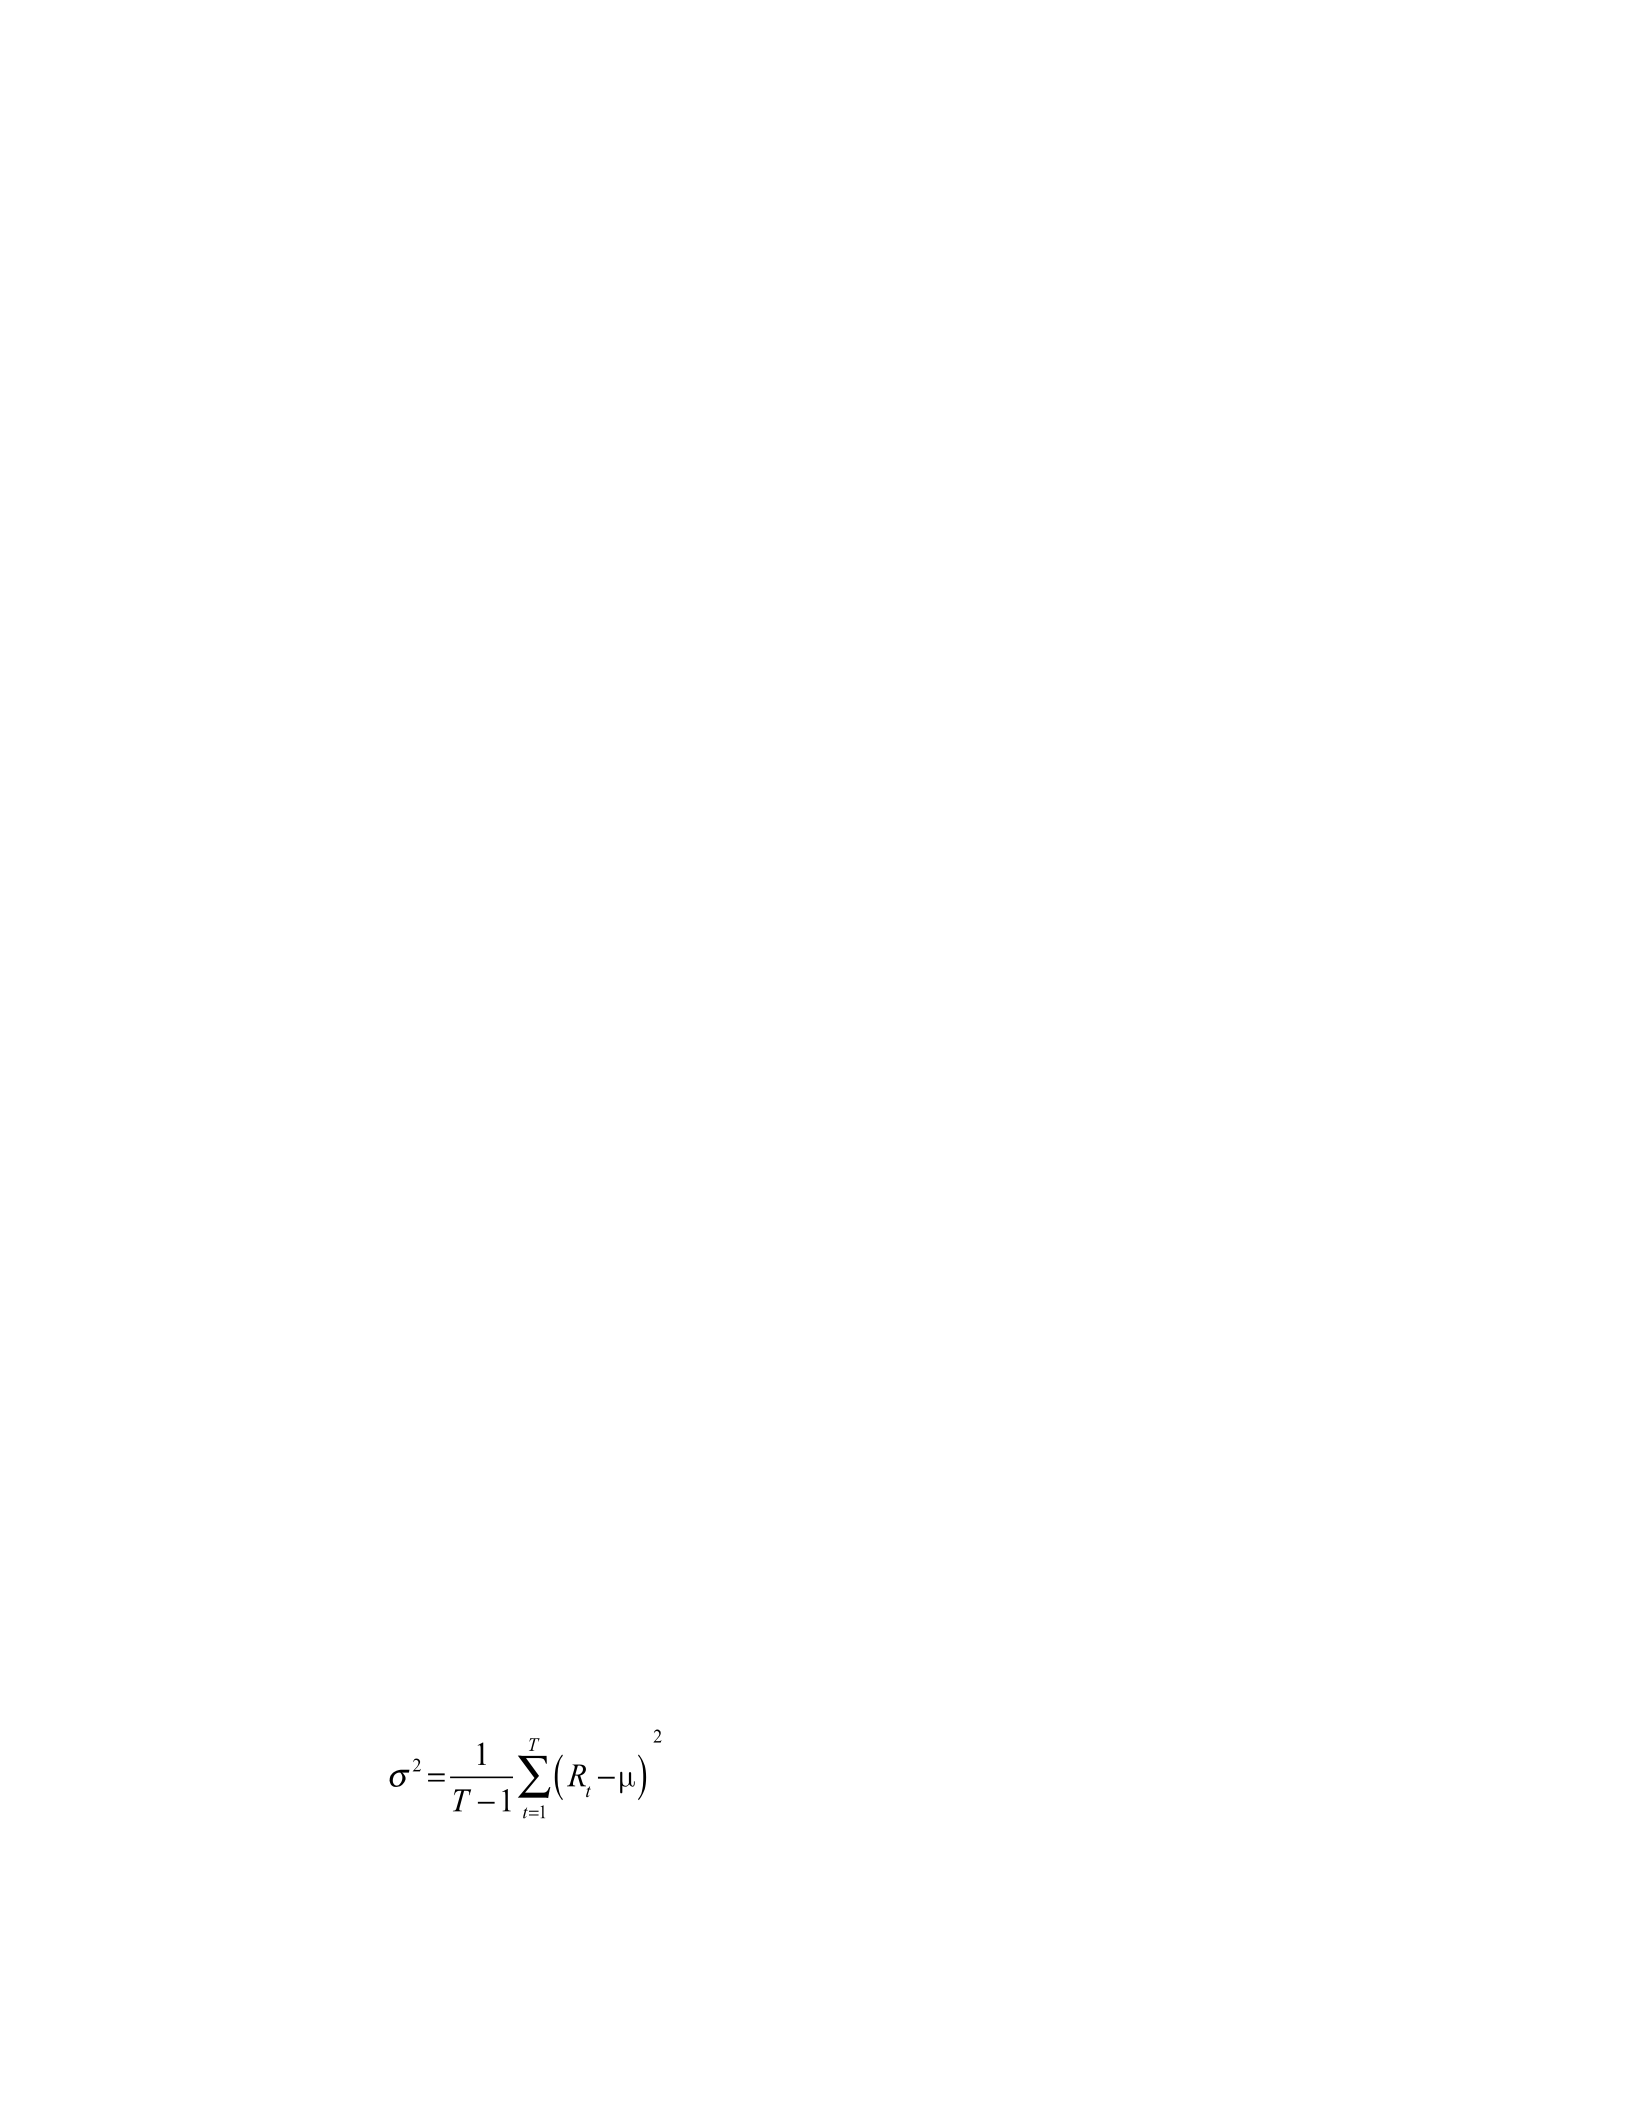
47
operational leverage has no impact on the capital structure in South Africa except for the
industrial sector of the economy.
Autocorrelation. When stock returns are uncorrelated or exhibit weak
autocorrelation, they are dependent (El Jebari & Hakmaoui, 2017). Also, high
autocorrelation values indicate long memory of volatility persistence. The slow decay in
autocorrelation in returns is a sign of long memory. Persistency of volatility poses a
direct threat to the prices of assets (Emenogu & Adenomon, 2018). Volatility persistence
goes against the main principle of EMH, which is that stock prices incorporate all
available information making it impossible to forecast the prices. However, the long
memory process implies that the current prices could be predetermined by previous
prices, which results from autocorrelations rates in prices. Also, the autocorrelation rate
takes a long time to decay; thus, the current shock to the volatility would have long-
lasting effects. Amudha and Muthukamu (2018) used GARCH models to estimate the
volatility of the trends within India Stock Exchange from April 2003 to Sept 2015. The
results showed volatility which displays the clustering and persistence of stocks.
Volatility Forecasting Models
An accurate estimate and forecasting of volatility depend on capturing the most
stylized facts (Di Sanzo, 2018; Pan et al., 2017). According to Gaetano (2018), the
variance of a sample data set σ2 can be used to measure the volatility statistically.
Additionally, the volatility can be calculated from several serial observations as follows:
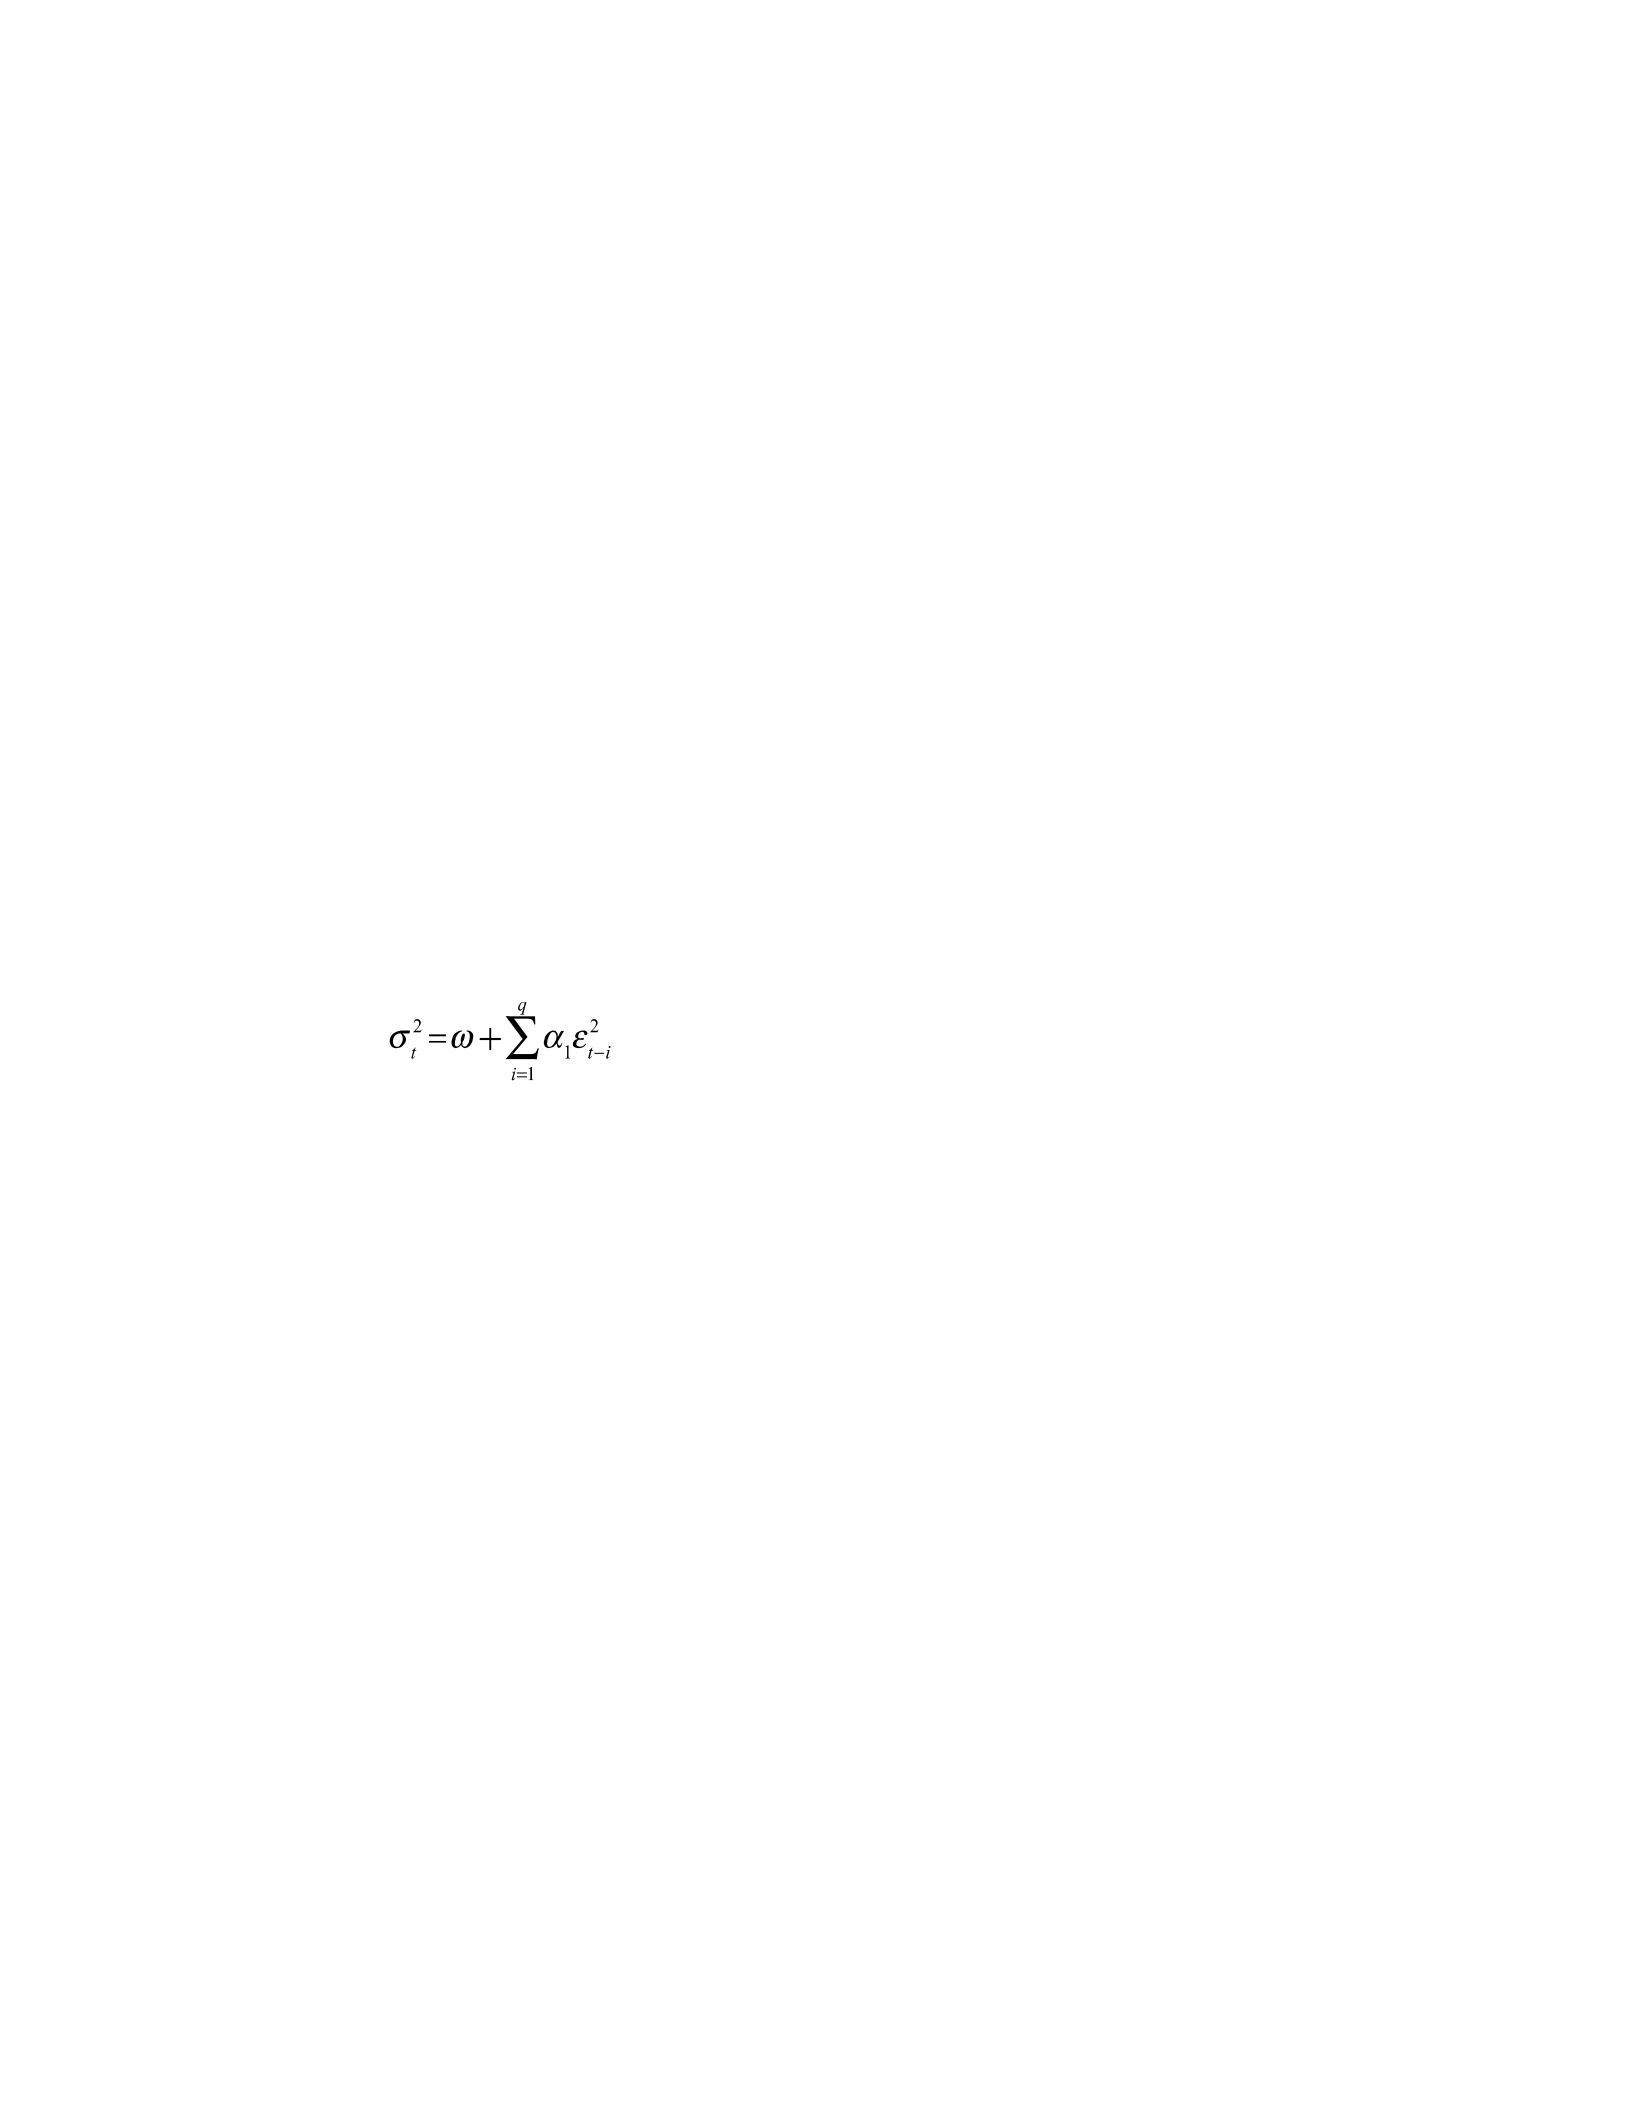
48
Where μ is the average return, T is the forecasting period, and Rt, is the excess on
hedge fund return. Engle (1982) introduced the Autoregressive Conditional
Heteroskedasticity (ARCH) model when analyzing and forecasting financial volatility
and economic time series data (Engle, 1982). Engle (1982) 's ARCH model is a linear
function aimed to capture volatility clustering. The following formulae represent the
ARCH (q) model:
rt = μ + εt and εt = σt zt
Where rt = return on an asset at time t, μ = average returns, and εt = residual
returns at time t, zt is independent and evenly distributed with N (0,1) with mean zero
and variance of 1. The formula below shows the conditional variance of ARCH as:
The limitations of the model are ω > 0 and α ≥ 0 (for all i = 1, , q) to ensure
s
t
2
is positive. The parameter is the conditional variance (volatility) at time t, is the squared
error at time t-1 from the mean equation, and q represents the number of lags. According
to Engle (1982), the error variance subject to q logs of the squared residual terms is
necessary to determine the volatility clustering. Bollerslev (1986) extended the ARCH to
the Generalized Autoregressive Conditional Heteroskedasticity (GARCH) model that
combines the mean equation and the conditional variance. The GARCH model is
specified as follows:
The mean equation: rt = μ + εt
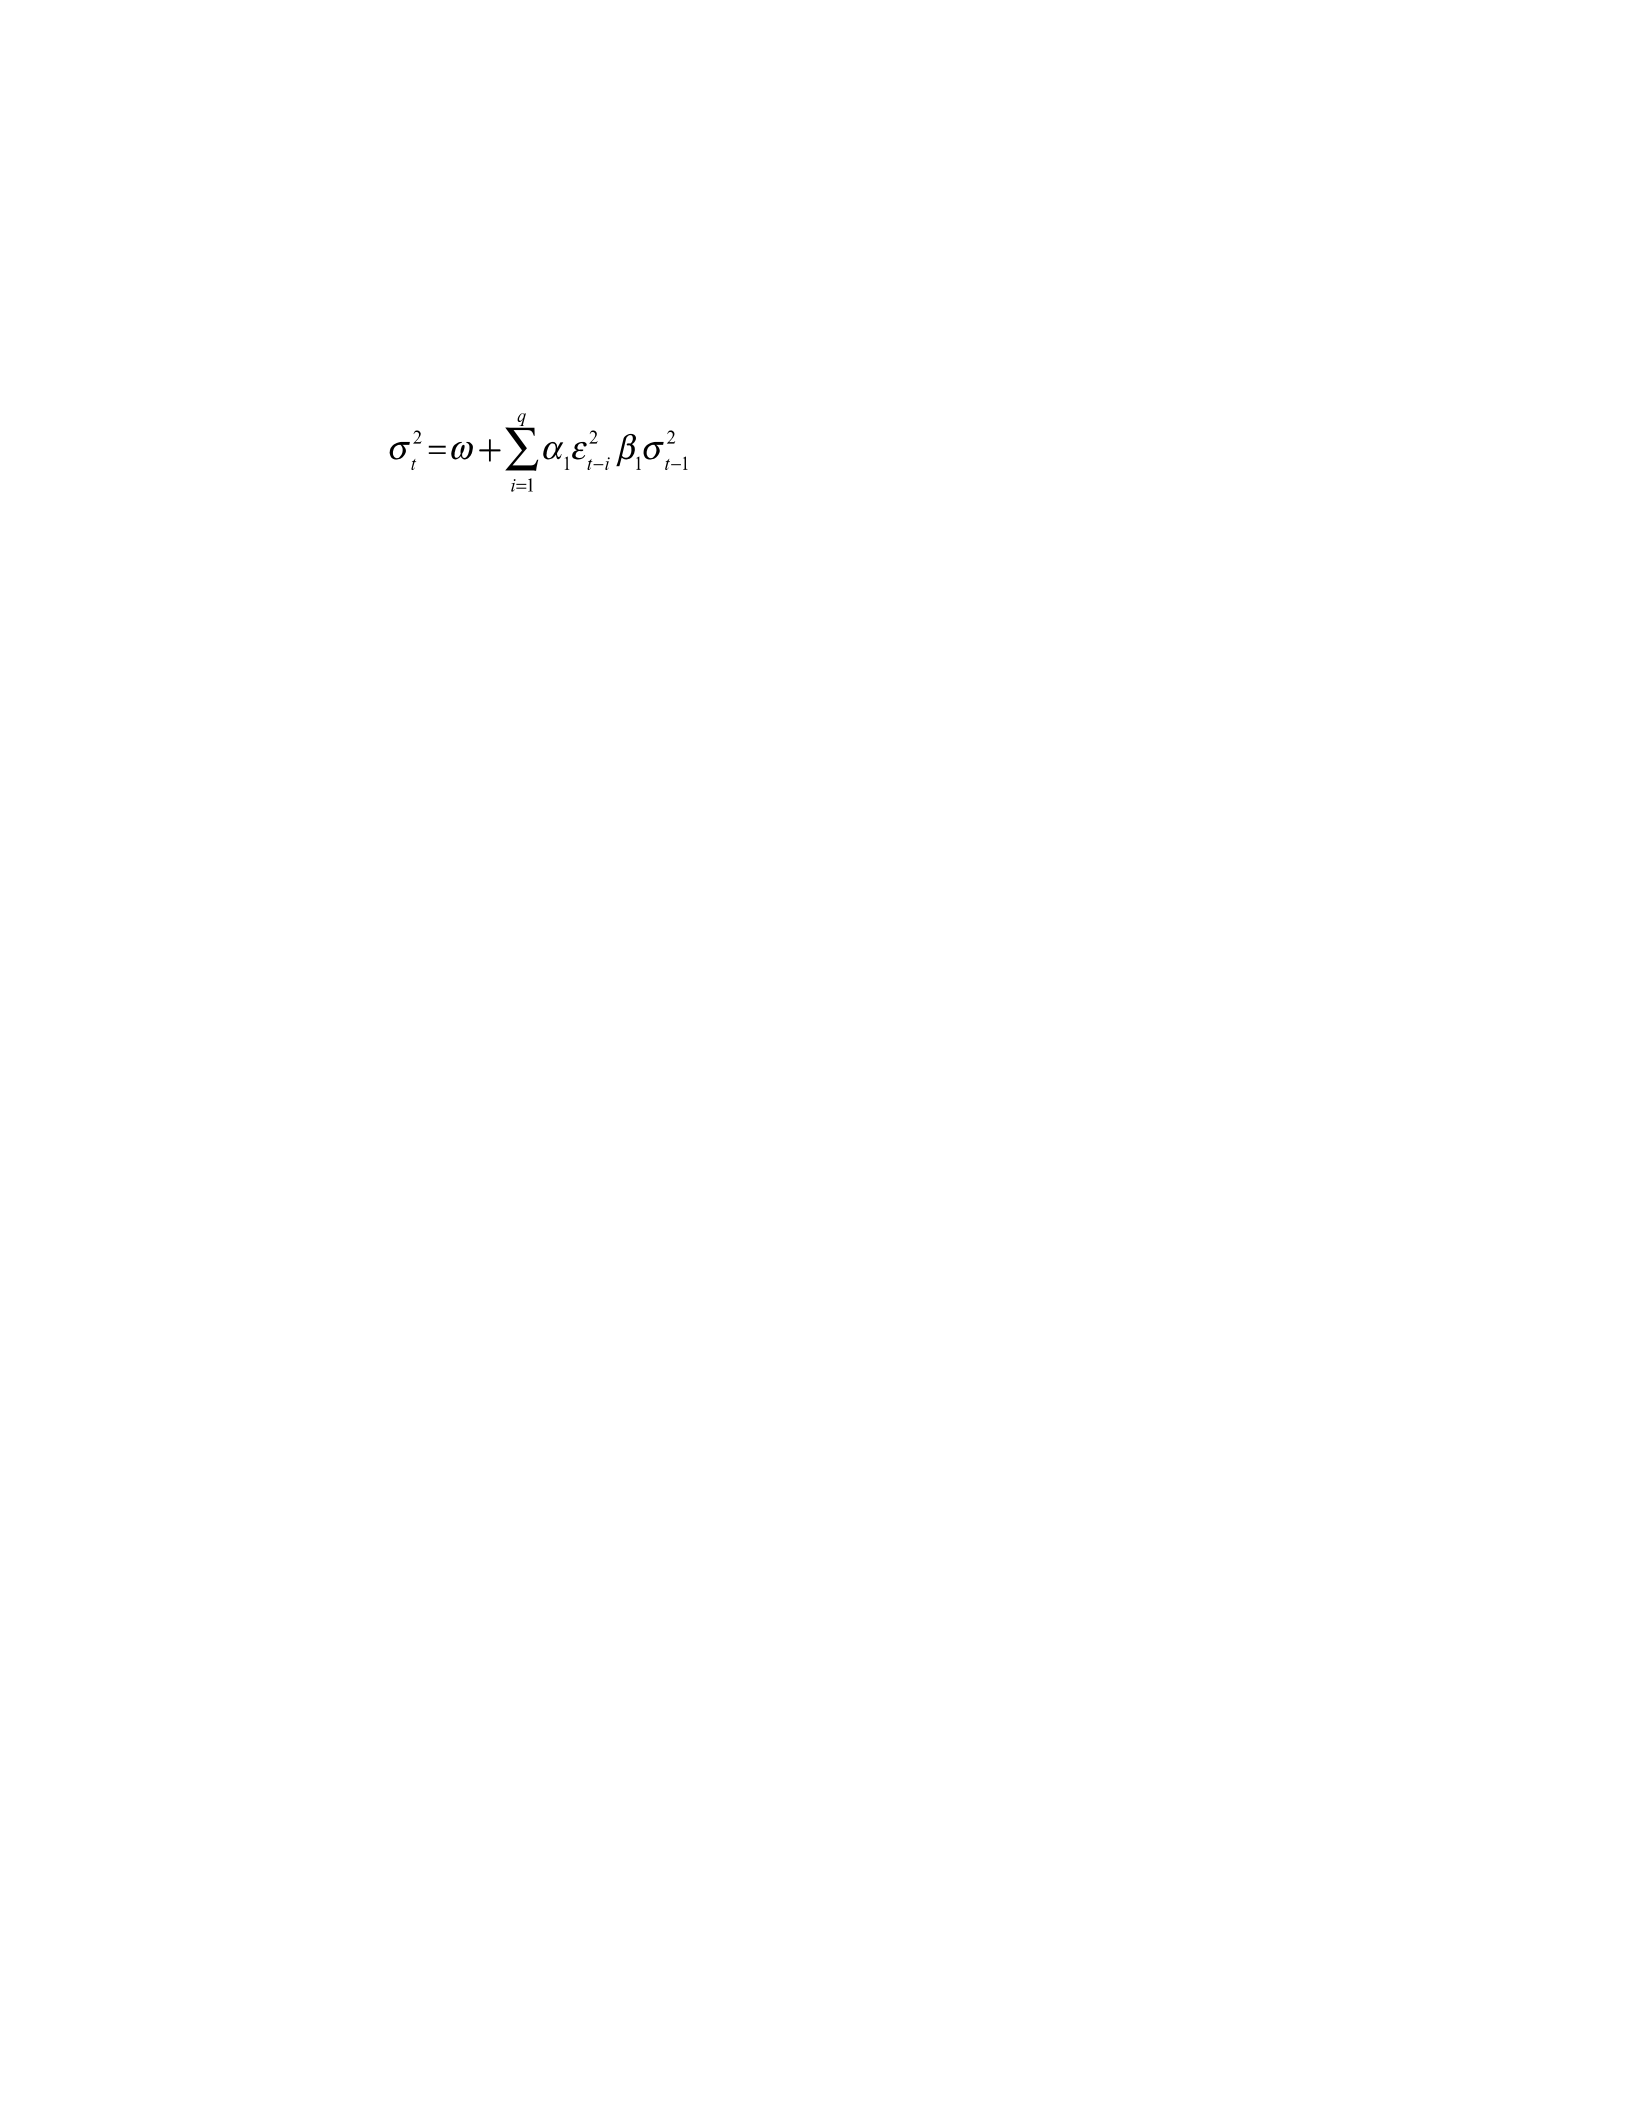
49
Where rt = return on asset at time t, μ = average returns, εt = residual returns at
time t. The conditional variance is shown below:
Where
s
t
2
denotes to the conditional variance at time t, ω defines the
unconditional variance,
e
t-i
2
denotes to the squared residual at time t-1 from the mean
(ARCH) equation, α1 is the first ARCH parameter, β1 is the first GARCH parameter, and
s
t
2
is the last period forecast variance in the GARCH equation. The limitations for the
GARCH model specify α1 ≥ 0 and β1 ≥ 0 must be met for
e
t-i
2
to be positive (Nelson,
1991). Researchers could use the total of the two terms to determine the short- term
dynamic volatility time series (Gaetano, 2018). Also, the conditional variance has
persistent attribute, and the parameters add up to 1. The GARCH and GARCH-M models
capture leptokurtosis and volatility clustering attributes in financial time series (Gaetano,
2018). However, GARCH models cannot capture the asymmetry of the financial data; the
symmetric models assume that bad and good news of the same magnitude has the same
effect on the market (Wu & Hou, 2019). Ndei et al. (2019) used GARCH (1,1) to model
the market return from the Nairobi securities exchange in the presence of structural
breaks. The findings from the study revealed that the GARCH (1,1) model could capture
volatility symmetric and asymmetric effects. Al Rahahleh and Kao (2018) found that the
GARCH (1,1) model overestimates the asymmetry during high volatility periods.
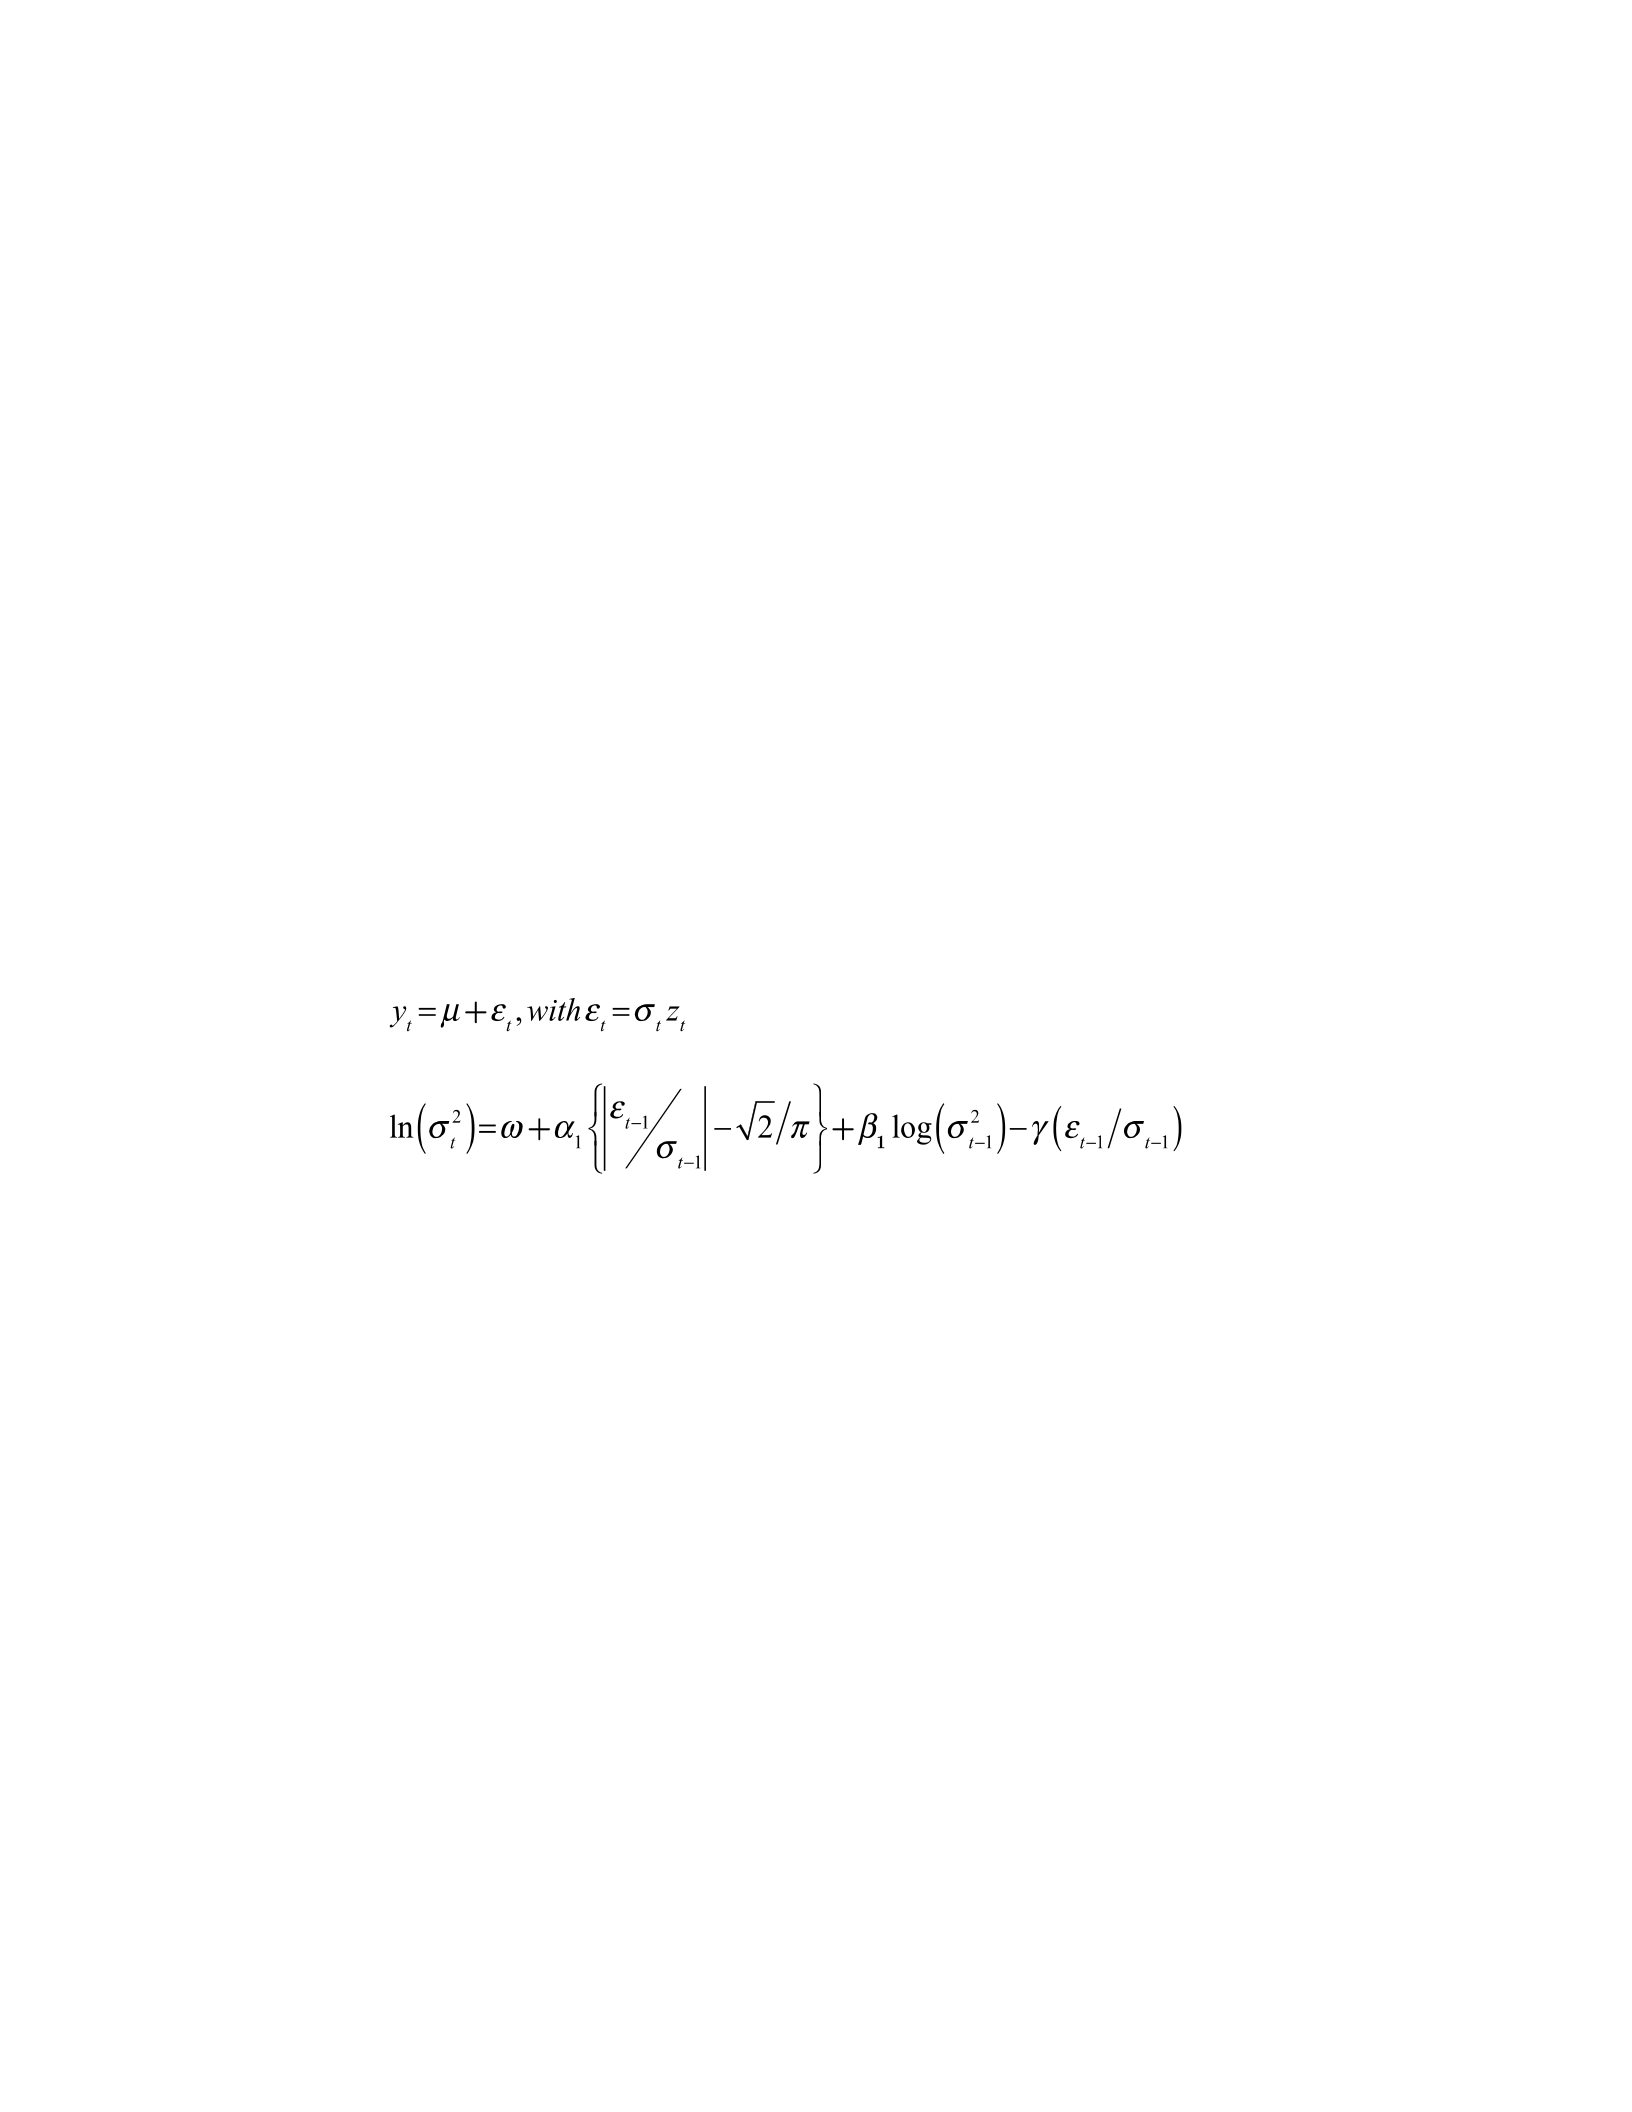
50
The ARCH and GARCH models cannot eliminate excess kurtosis in the return
series and fail to capture skewness (Brooks, 2019). Nelson (1991) introduced asymmetric
GARCH models (EGARCH, TGARCH, and APGARCH) to address the limitations of
the ARCH and GARCH models. The GARCH variant models can capture the asymmetry
of financial returns (Abdennadher & Hallara, 2018). According to Oseifuah and Korkpoe
(2019), EGARCH, TGARCH, and APGARCH models are nonlinear and can model time-
varying volatilities. Nelson (1991) 's EGARCH model extends the GARCH model of
Bollerslev (1986) by accounting for skewness/asymmetric effect or leverage and
persistence of shocks in conditional variance. The following equation shows the
EGARCH model:
Where γ measures the asymmetry, or the leverage, and αi stands for the magnitude
or the symmetric effect. If γi = 0, or the coefficient is 0, the implication is that both
positive and negative shocks of the same magnitude have the same effect on the
volatility. If γi ≠ 0, implies the presence of the effect asymmetry. The leverage effect is
exponential rather than quadratic, forecasting the conditional variance will be positive
(Fernando, 2018). To test for leverage effects in the volatility by the hypothesis that γi >
0, a positive coefficient means positive shocks tend to produce high volatility in the short
term than negative shocks of the same magnitude (Fernando, 2018). The opposite would
apply in the case of γi < 0. Ewing and Malik (2016) studied the presence of volatility
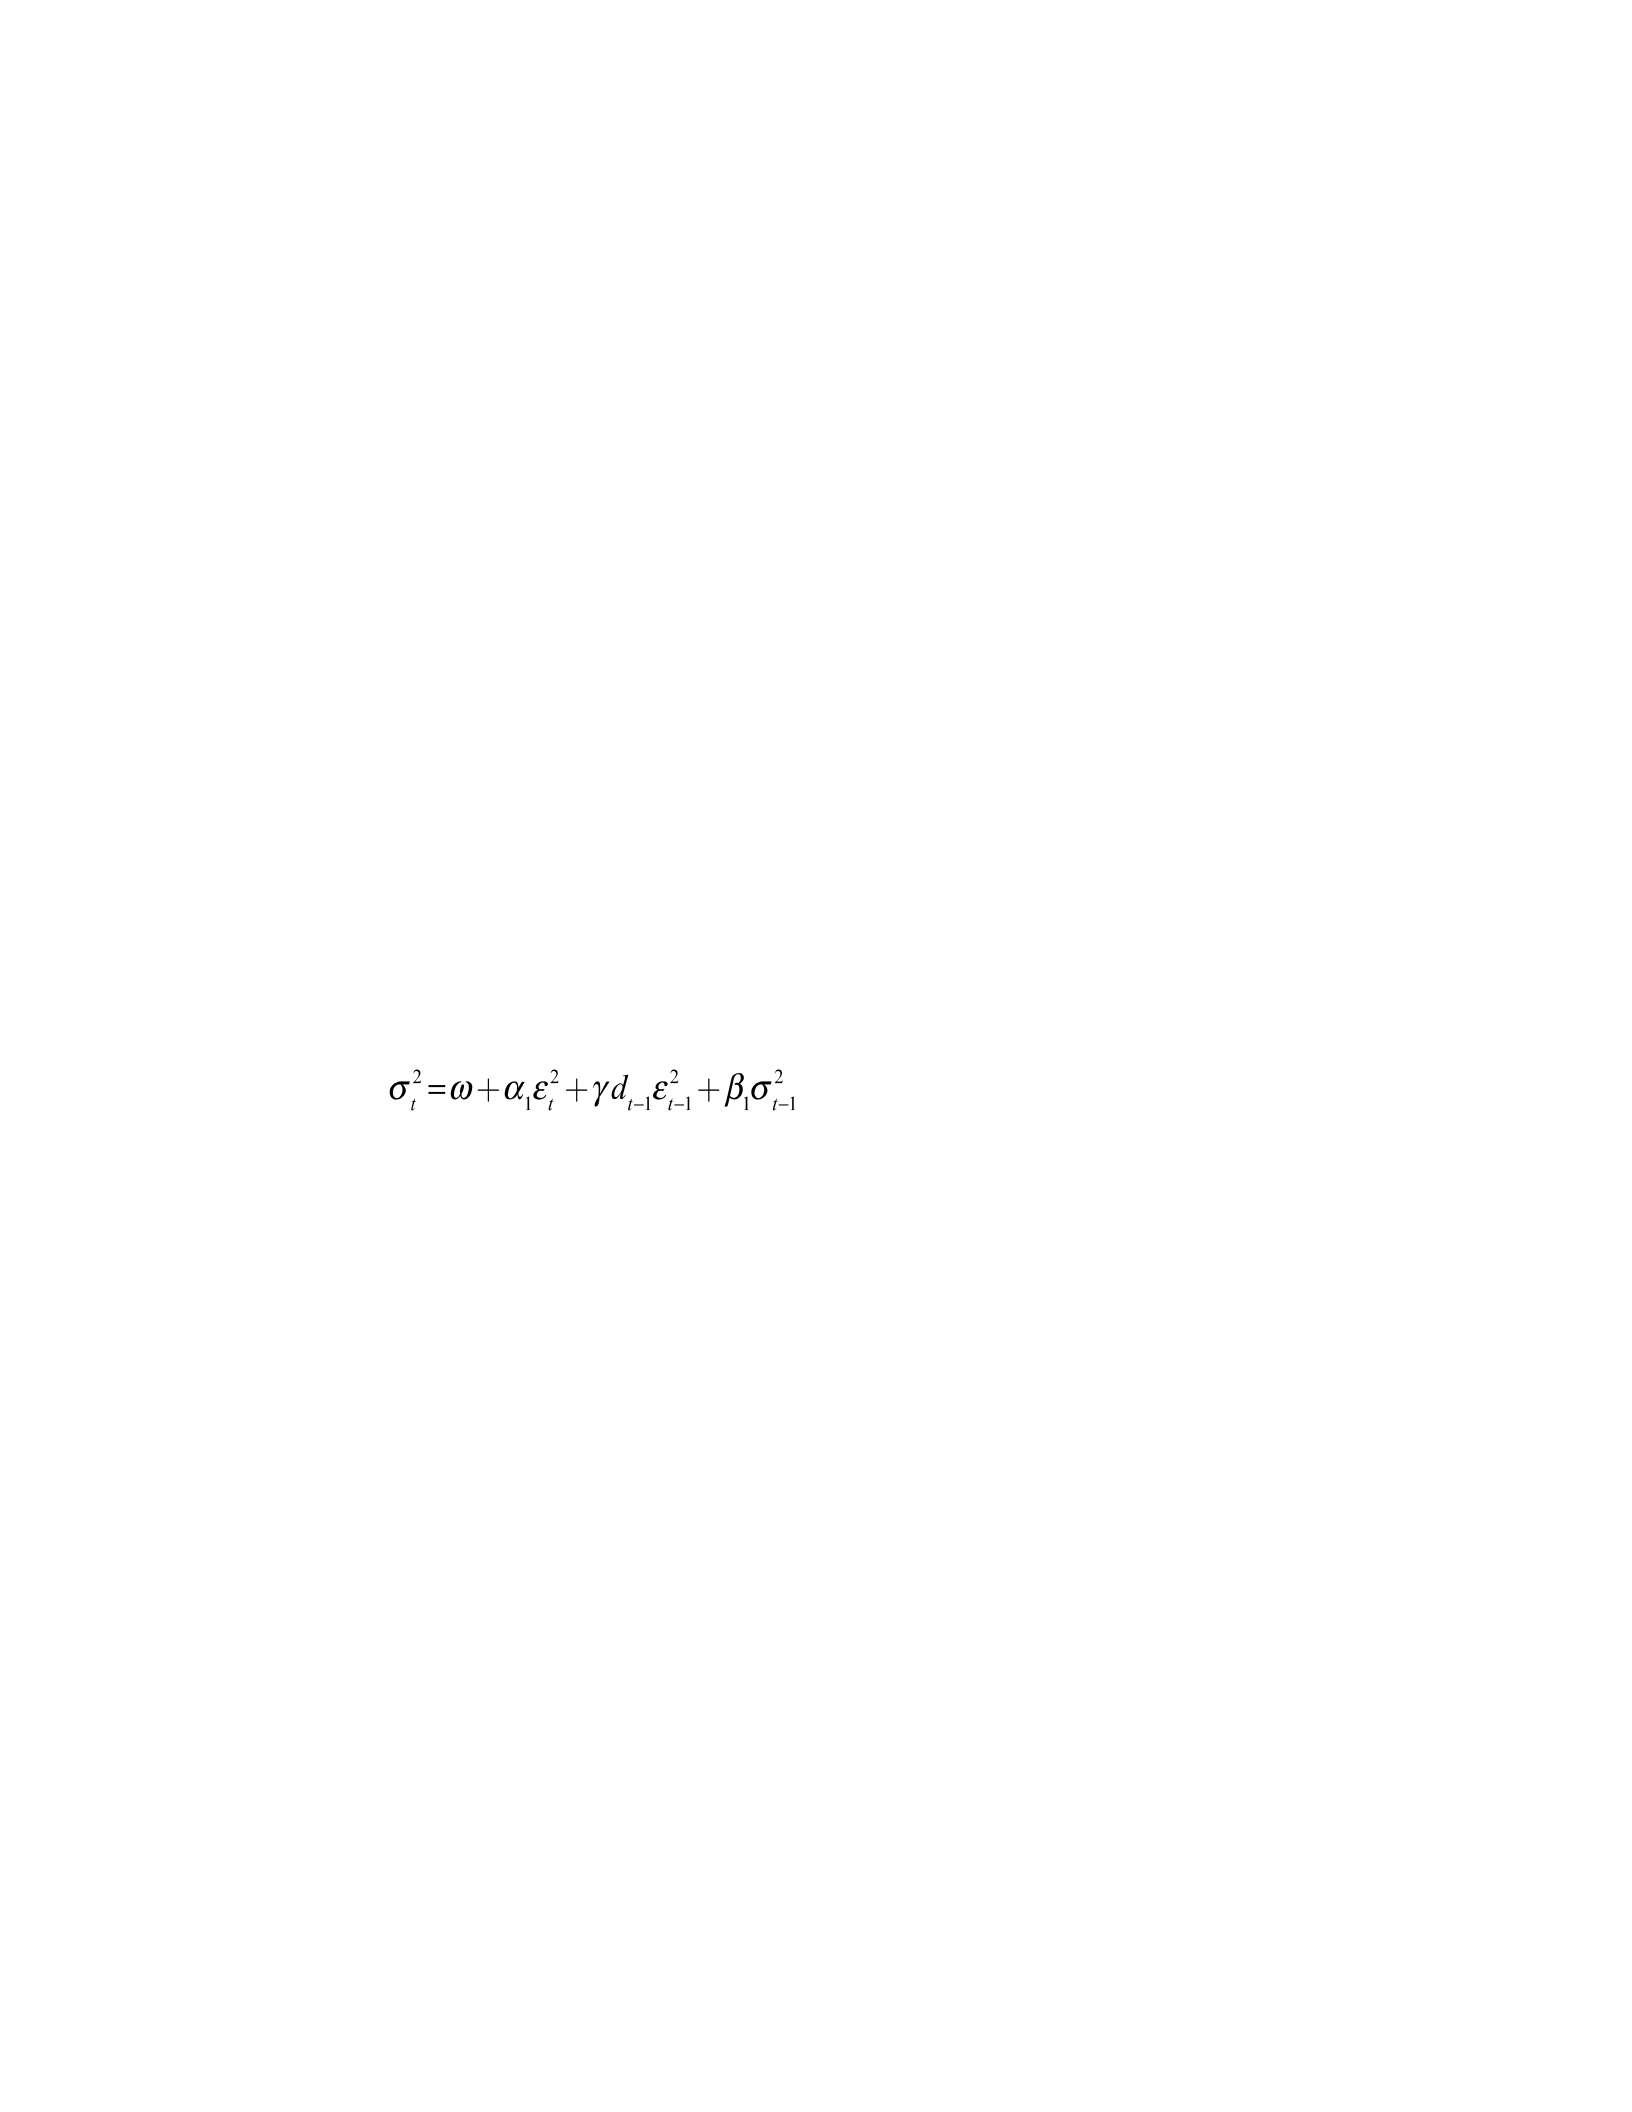
51
spillover between oil prices and the U.S. stock market using the EGARCH model.
Initially, the results from the study showed no volatility spillover. However, when the
authors added structural breaks, they found volatility spillover between the U.S and
China markets. Though the EGARCH model is applicable to forecast various financial
features, it reacts slowly to market shifts (Emenogu et al., 2020). Also, the dynamics of
risk exposures limit the EGARCH model by not changing regimes, which characterize
hedge fund returns.
The TGARCH model presented by Rabemananjara and Zakoian (1993) and
Glosten et al. (1993) captures both the positive and negative effects of asymmetry. The
TGARCH equation has an artificial variable, d to account for the asymmetry or leverage
effect. The conditional variance is given by:
In this model, if
e
t-1
≥ 0, then good news, and if
e
t-1
< 0, bad news, and total
effects are given by (αi + γi) ε2t-1. Also,
e
t-1
and
e
t-1
have a differential effect on the
conditional variance. Good news impacts α, while bad news impacts (αi + γi) (Ndei et al.,
2019). The γ parameter represents the asymmetry or leverage. If γ > 0 indicates the
leverage effect is present, the parameter represents the asymmetry or leverage, and bad
news has a more powerful effect on volatility than good news (Saranya & Prasanna,
2018). On the other hand, if γ ≠ 0, the news impact is asymmetric. Ding et al. (1993)
introduced the APARCH model as an extension of the GARCH model. The conditional
variance is shown as follows:
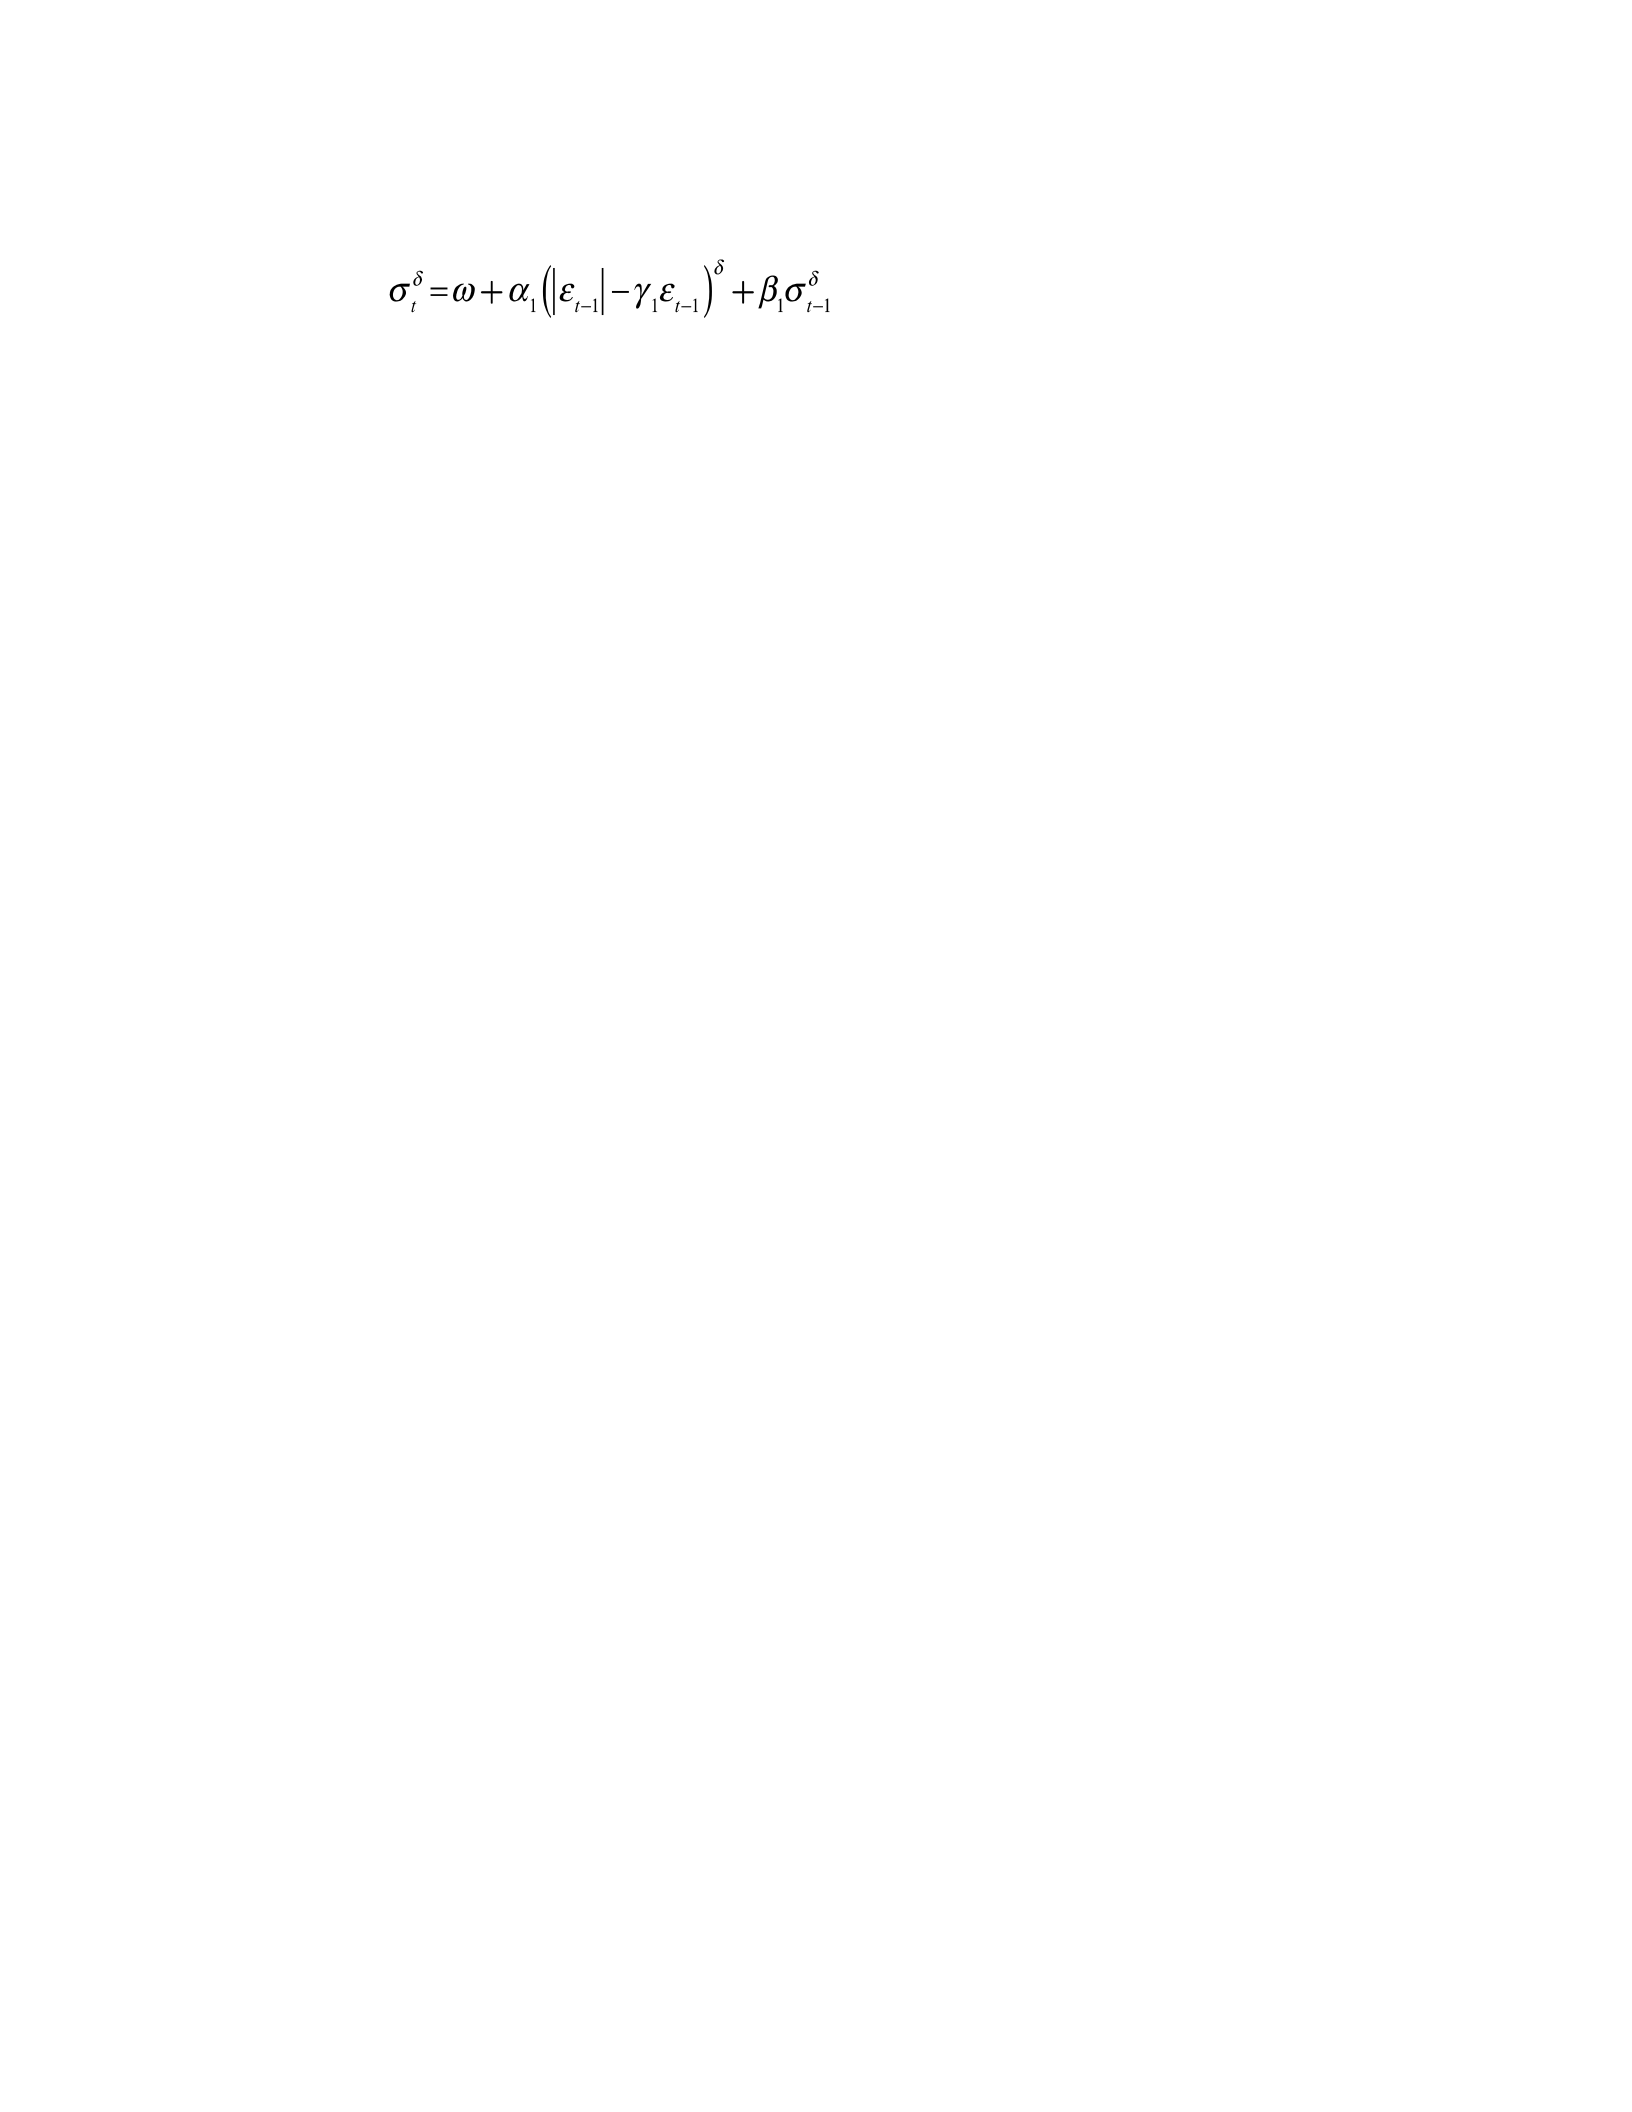
52
Where δ denotes the asymmetric power term, enhances the model’s flexibility.
The leverage effect parameter γ tests the asymmetry up to order r (Ndei et al., 2019).
Also, the main advantage of APARCH model is its flexibility and that it captures all
features by EGARCH, and TGARCH. The limitations to the model are δ > 0,| γi | ≤ 1 for i
= 1 , r, γi = 0 for all i > r, and r ≤ p.
Hamilton (1989) proposed the Markov Regime-Switching (MRS) as a time series
technique to capture the shifts in the market during a recession. Gray (1996) further
generalized the Markov regime-switching methods to ARCH models. Klaassen (2002)
introduced the MRS GARCH by differentiating two regimes with different volatilities
levels. The Markov regime-switching model makes it possible to analyze time-varying
hedge fund risk exposures to different market regimes that include risk factors (Balcilar
et al., 2017). A simple regime-switching model does not account for market risk factor
regimes. The results identify different regimes with periods of levels of volatilities for
most hedge fund indices. The out-of-sample forecasting shows the accuracy of the MS-
GARCH regime-switching model. Forecast volatility, the hedge fund risk factors are
necessary. The multifactor models are the foundation of the valuation process in asset
management applications (Lambert & Platania, 2020). Following Billio et al. (2012), the
baseline for the analysis is the Fama and French (1996) eight factors: All-World Index
(market proxy), small-large risk (to capture liquidity risk), credit spread (credit risk
proxy), and VIX (volatility proxy) risk factors. The hedge fund strategies will be on the
index list.
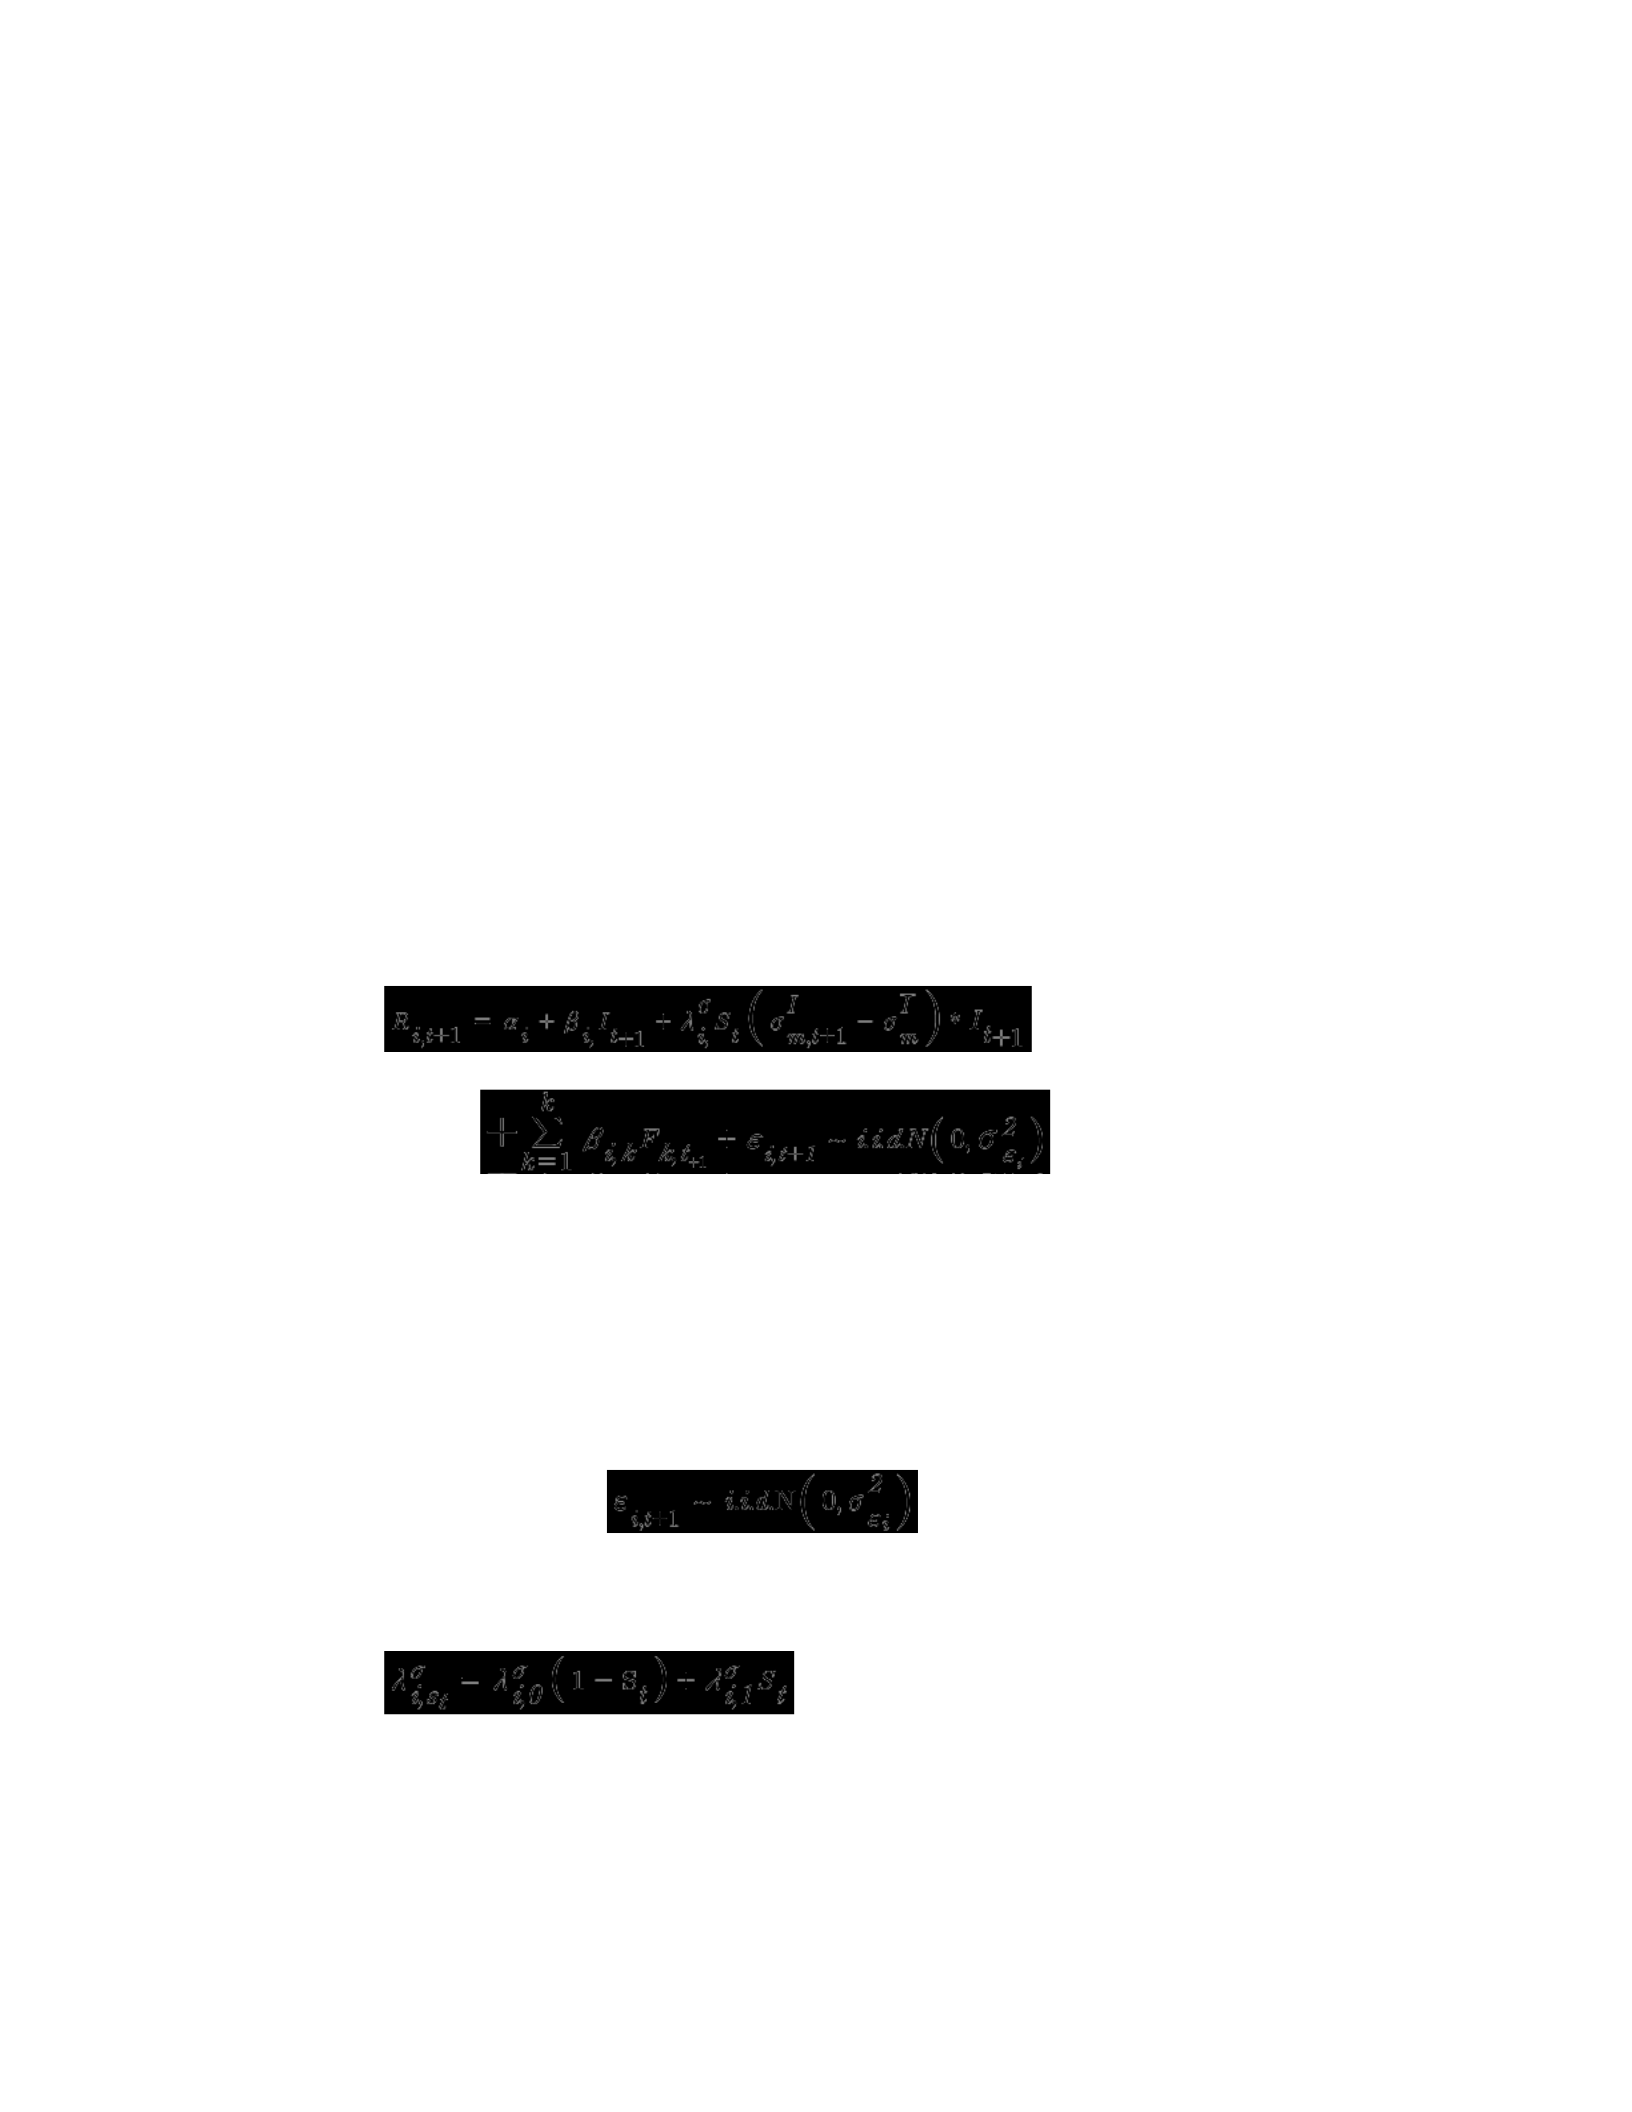
53
In this section, I examined the relationship between the hedge fund performance
and the forecast of the volatility of the hedge fund returns across different volatility
regimes. Furthermore, I will investigate the exposure in hedge funds to a selection of
market risk factors. Camacho et al. (2018) describe the MRS as a technique to capture
discrete shifts and structural breaks. The focus of this section is to examine hedge fund
excess return to adjust for exposure based on market volatility forecasts. I employed two
different models to conduct the analysis. First, I tested the nonlinear TGARCH model to
assess the asymmetric reaction of the performance of hedge funds to a positive and
negative change in volatility. The second model will use the Markov regime-switching
state-dependent volatility timing model (Hamilton, 1989):
If the value
l
i,St
s
of state-dependent volatility-timing is negative, it indicates that
the manager has sufficient market volatility timing skills and can adjust the fund's
performance's market exposure before the market volatility level fluctuates. The
conditional error term is , and the state-dependent volatility-
timing is as follows:
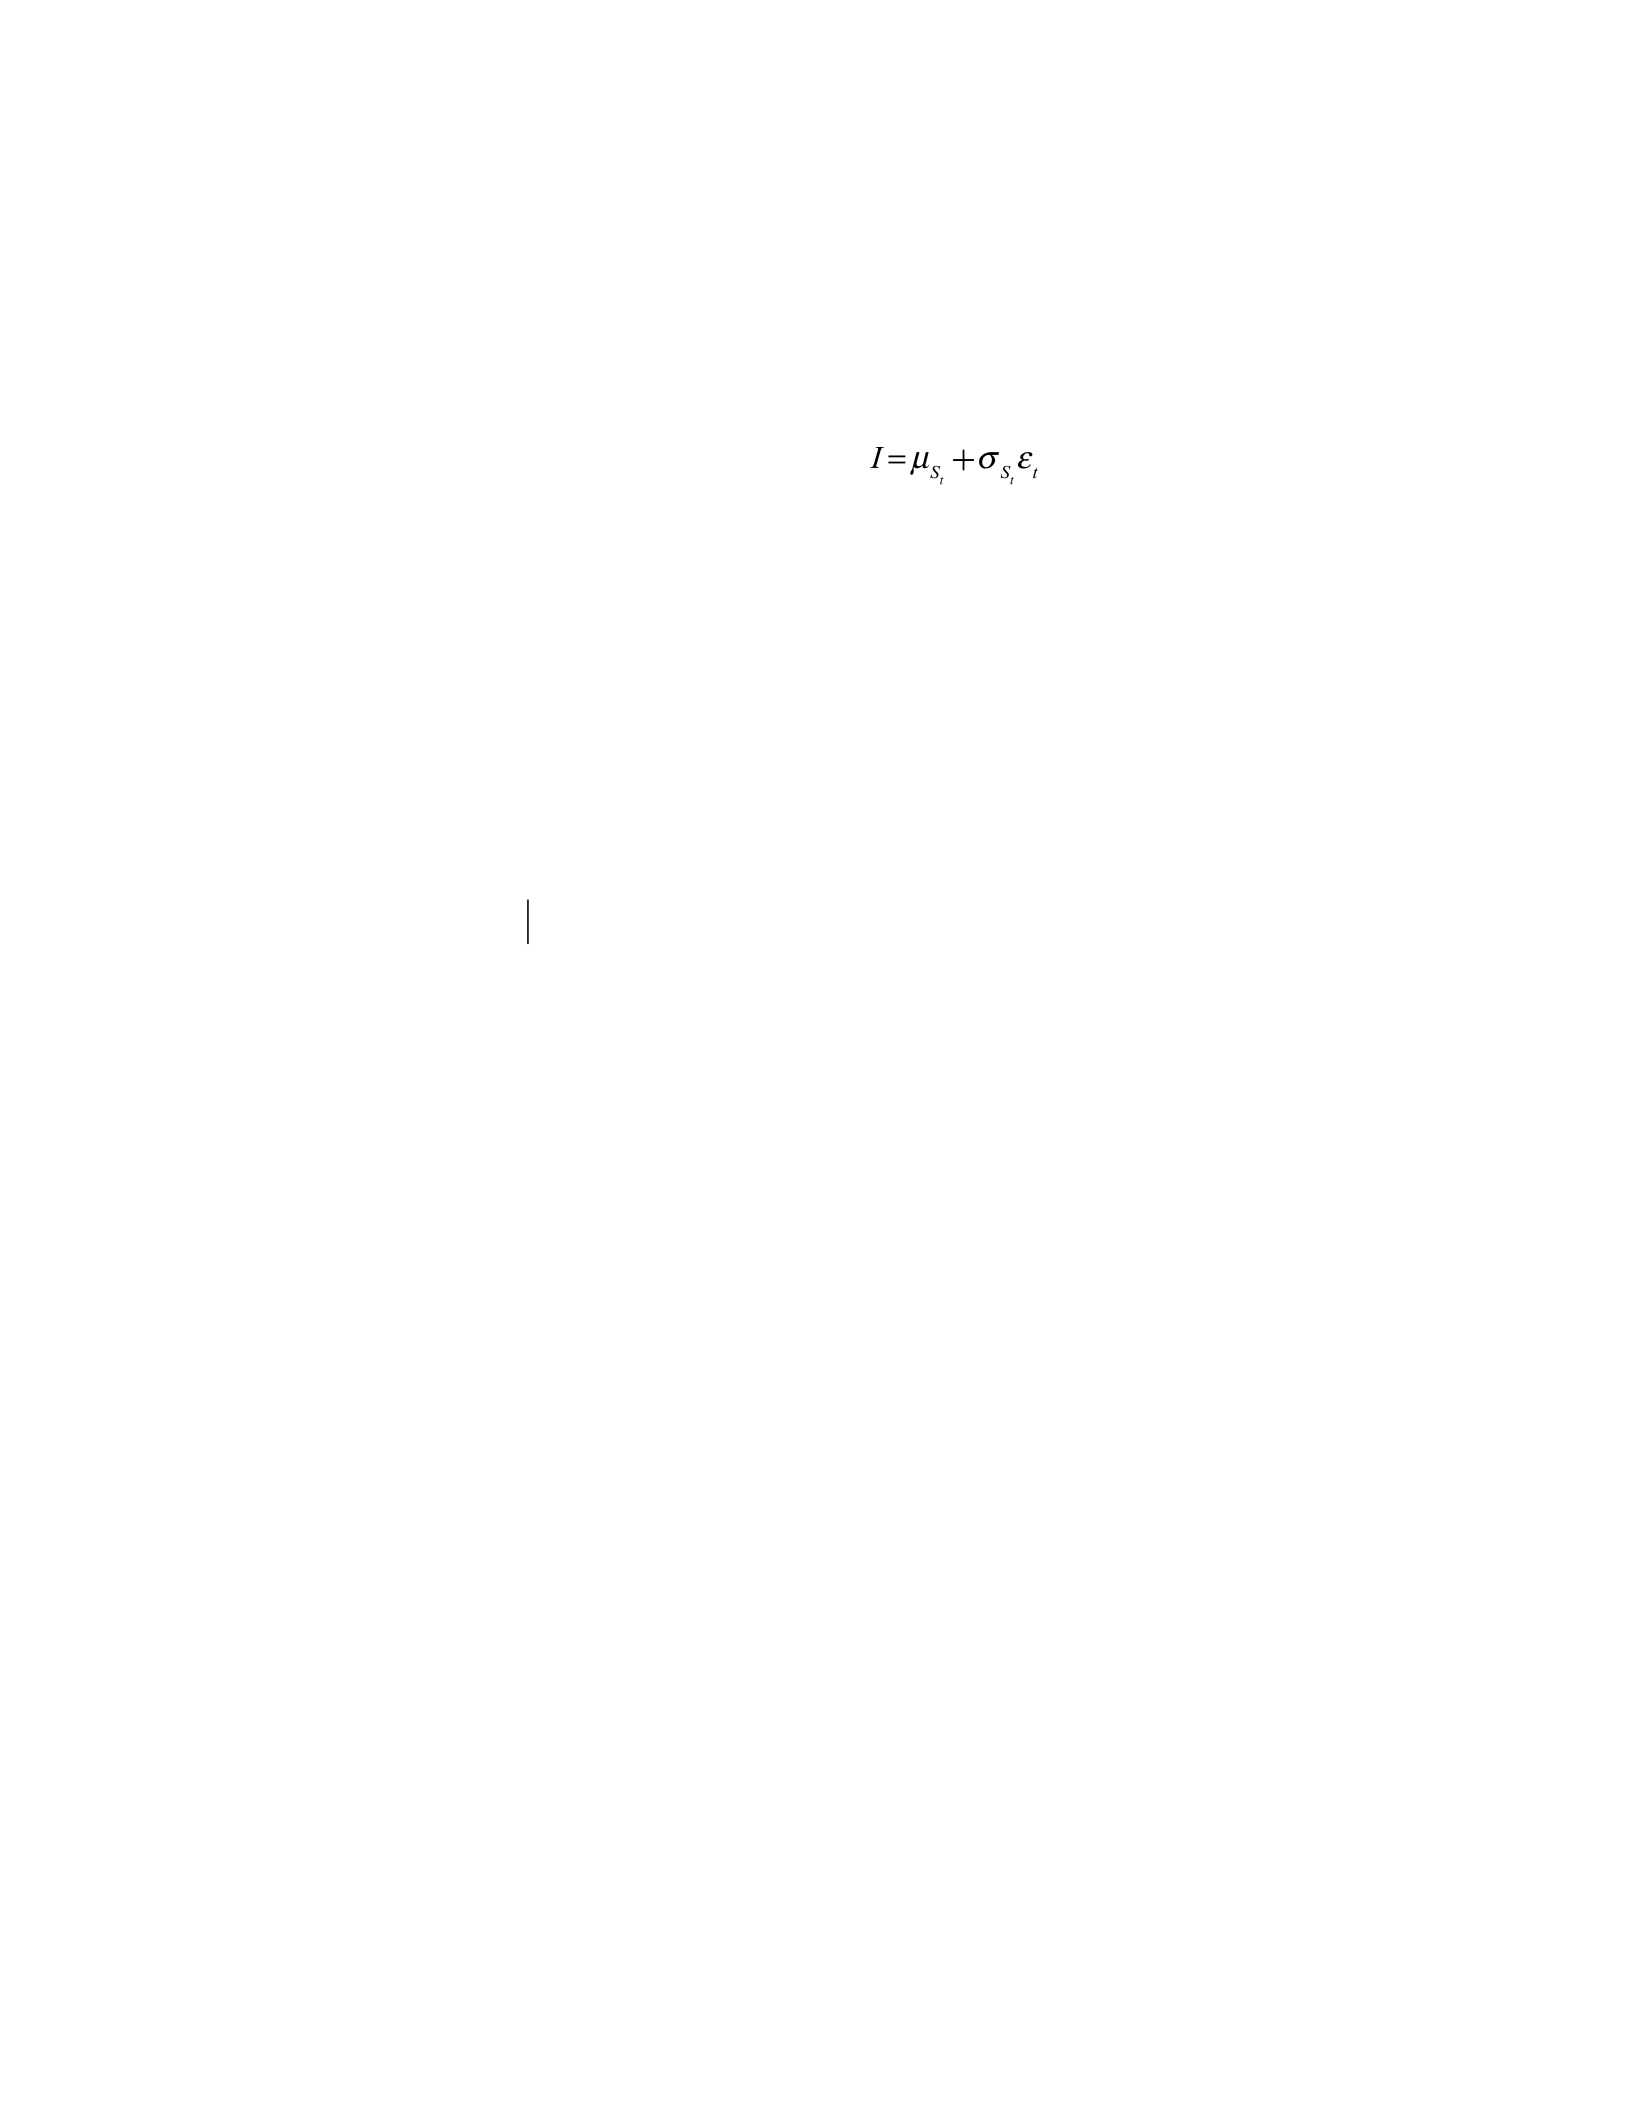
54
According to Billio et al. (2018), the state-dependent market volatility timing
l
i,St
s
, is
identified by two conditional regimes as follows:
Rit-1 = α + βSt It + ωμt
According to Camacho et al. (2018), the Markov regime model has the following
parameters:
StStÎ0,1
}
{
( )
, St is Markov chain, n is the number of states, and P is the
transition probability matrix. For n = 2 states, St = {0,1}. Camacho et al. (2018) revealed
that that the Markov chain St is presented by the following transition probability matrix P.
P S1t=S1tS1t-1=S1t-1ù
û
é
ë=P
00 P
10
P
01 P
11
æ
è
ç
ç
ö
ø
÷
÷
Table 7 below has the term description for the parameters.
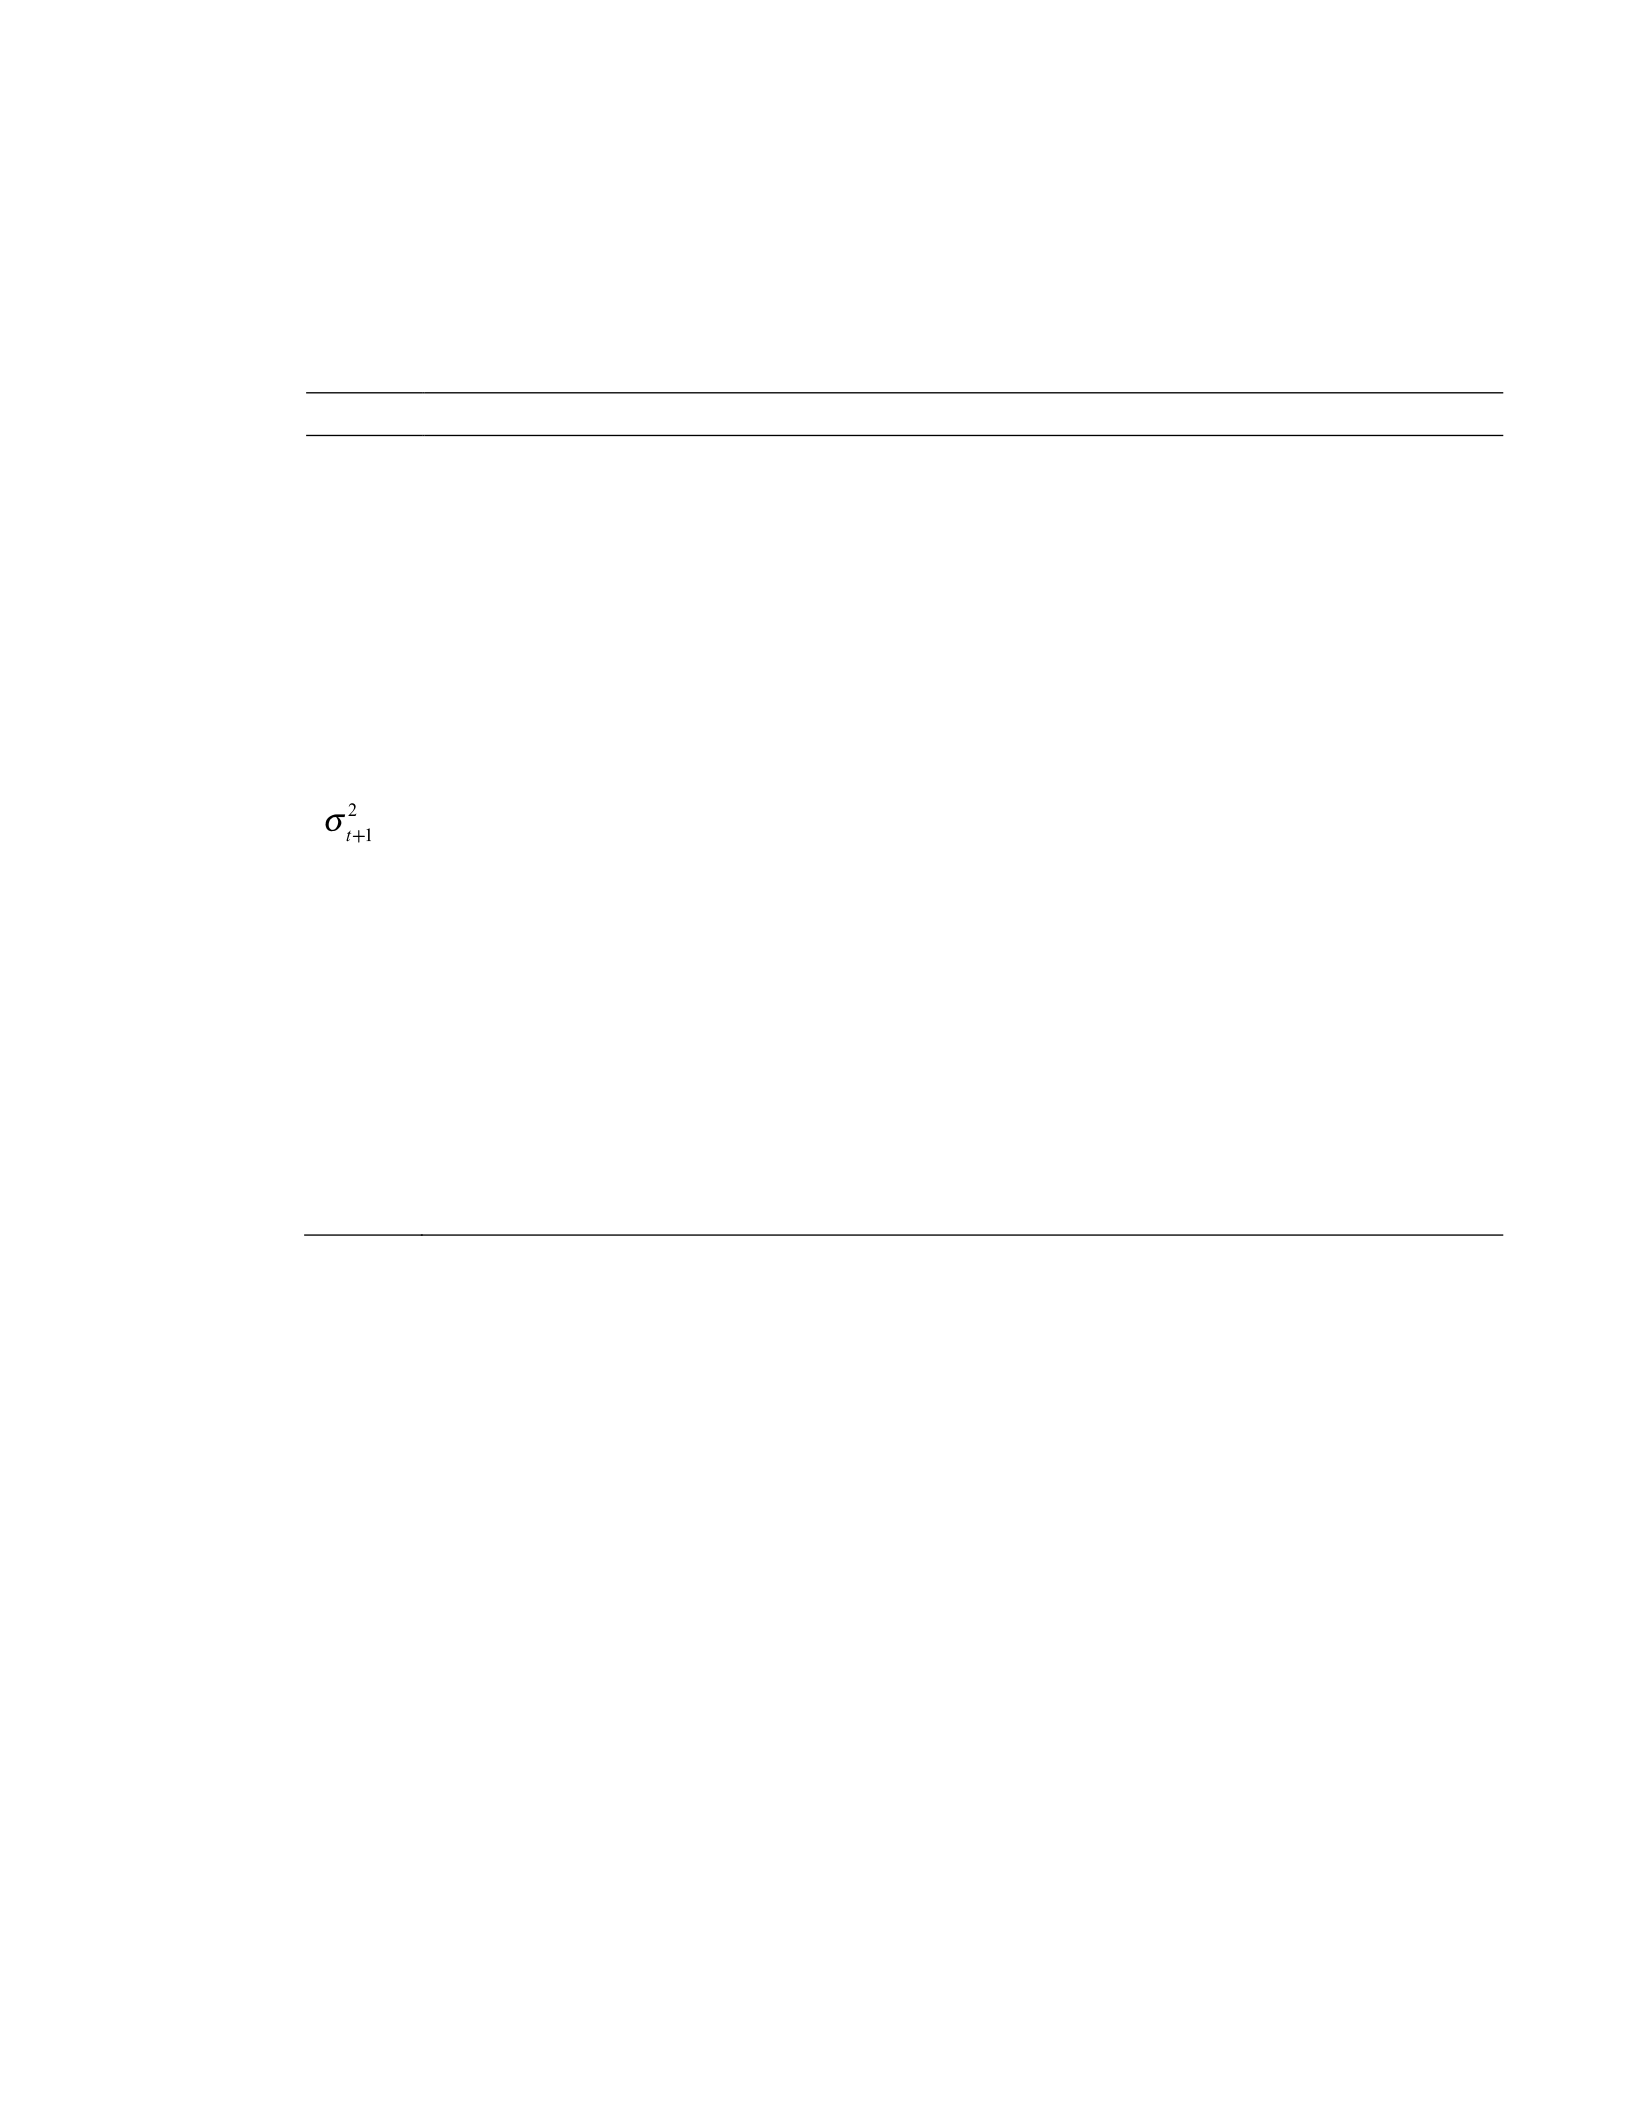
55
Table 7
Terms of Description for the Equations
Term
Description
Ri,t + 1
monthly excess return on hedge fund styles at time t + 1
αt
Adjusted performance of hedge fund securities in time interval, t
It+1
Market factor in month t + 1
t
time interval in months
s
m
m
Average market volatility level
l
i,St
s
State-dependent volatility-timing
Zt,
Markov chain proxy for non-linear factors not captured by hedge funds and market risk factors.
Market volatility level at time t + 1
Ɵk,
Linear factor loading of the hedge fund on the k-th risk factor
Fkt +1,
Systematic factor on the k-th factor at time t + 1.(See table 10)
β,
Coefficient of exposure, and varies in various n state regimes H
St,
Regime indicator, Markov chain for n states, total n=2 (state 0, 1,)
σ2
Conditional variance
σ
Actual observed volatility
µt
Average return over T periods
ϵt
Residual term or deviated return value from estimated mean return at time, t.
ω,
Idiosyncratic risk factor
Forecasting Performance Evaluation
This study follows Poon and Granger’s (2003) work to evaluate the adequacy of
the fitted model using the in-sample. For the in-sample, the goodness fit statistics method
is appropriate to evaluate the models such as Akaike Information Criteria (AIC) and the
Bayesian Information Criteria (BIC) (Bayer & Cribari-Neto, 2017). In this study, the
significance of the second regime is not a comparison, but goodness-of-fit is the focus of
this forecasting performance. According to Bayer and Cribari-Neto (2017), different
models are only suitable for various loss functions. To quantify the forecasting

56
performance of each model, a regression of the volatility forecasts the observed volatility
and derives the coefficient value of (R2).
The out-of-sample analyses comprise a period from January 2020 to December
2020 for twelve months. In this study, I will employ two loss functions to assess the out-
of-sample forecasting performance of the models: Root Mean Square Error (RMSE) and
Mean Absolute Error (MAE). The out-of-sample and in-sample performance from the
TGARCH and MRS models will be measured using the RMSE and MAE loss functions.
If the in-sample output value from RMSE and MAE is greater than the out-of-sample, the
forecast model is adequate (Khattak & Wali, 2017).
Financial Performance of Hedge Funds Variable
There is two strands of performance measures in the literature of hedge fund
performance analysis (Stafylas & Andrikopoulos, 2020): (1) returns-based performance
evaluation and (2) portfolio holdings-based performance evaluation (Stafylas et al.,
2017). The returns-based approach is beta premium. In the returns-based method, the
volatility of the returns relates to the risk exposure to the market (Agarwal et al., 2018a).
The portfolio holdings-based approach generates alpha, designed to evaluate the
manager's skill. A manager can use the return-based performance technique to evaluate
systematic risk exposures of hedge funds (Frydenberg et al., 2017). Hedge fund returns
exhibit nonlinear and option-based strategies, and the analysis focuses on regression
approaches to regress the factors that proxy the strategies (Stafylas et al., 2017). The
portfolio holdings-based performance approach focuses on unsystematic risks, making it

57
appropriate for evaluating a fund manager's skill. This study includes combining both
approaches to evaluate the variables of the research.
Benchmarking
Unlike mutual funds, where the benchmarks are relative, such as the S&P 500,
hedge funds use indices (Pilbeam & Preston, 2019). Joenväärä et al. (2021a) cautioned on
the importance of selecting the appropriate benchmark and technique because using the
wrong methods could lead to error. Almeida et al. (2020) propose using a set of assets as
benchmarks to evaluate hedge fund performance. The most basic performance
measurement model is Jensen's alpha based on CAPM, where the fund's return is monthly
risk-adjusted (Fama & French, 1993). The CAPM as the market proxy is the only factor
as a benchmark. From here, the CAPM extends to the Fung and Hsieh (2001, 2004)
multi-factor model to capture the abnormal performance of hedge funds, given the many
strategies and risk factors. Also, the Sharpe ratio can assess risk-adjusted performance
(Stafylas et al., 2018a). The Sharpe ratio is equal to the monthly return of the hedge fund
index. The Sharpe ratio is scaled by the fund's return volatility as measured by the
standard deviation. The Sharpe and CAPM models evaluate and rank hedge fund
managers and are subject to criticism because they ignore their characteristics (Agarwal
et al., 2018a). Platanakis and Sutcliffe (2017); Oikonomou et al. (2018) provide robust
and innovative ways to manage the risk inherent in hedge fund returns. Silva et al. (2017)
employed the Black-litterman portfolio model (BL) benchmark to estimate risk and make
forecasts efficiently. The BL model weighs the portfolios to evaluate the returns.

58
Performance Persistence
Persistence in performance is a sought-after skill by fund managers and investors,
as it is a direct test of the hedge fund manager's skill. However, past studies' conflicting
results have weakened the certainty of performance persistence (Sun et al., 2018).
Literature on hedge fund performance persistence is in three parts: (1) analysis of hedge
fund performance and persistence in up and down markets and sustainability, (2) analysis
of hedge fund market exposure, such as neutral market funds, and (3) hedge funds as
diversification tool (Joenväärä et al., 2018).
The first field compares the performance of hedge funds to mutual funds
(Agarwal et al., 2018b). Proponents of hedge funds argue that the low correlation of
traditional alternative assets' returns makes a better risk-return trade-off (Cao et al.,
2018a; Kolokolova et al., 2020; Stafylas et al., 2018a). Furthermore, this low correlation
is with traditional assets enhanced by the exemption from the Security Exchange Act of
1934. Thus, providing more flexibility with different investment options to generate
persistent returns. Other studies found no evidence of performance persistence for hedge
funds (Barth et al., 2021; Bollen et al., 2021). The authors found that hedge funds
positively correlated with the S & P 500 during bear or down markets.
Some studies found strong evidence of at least short-term performance persistence
for hedge funds (Agarwal et al., 2018a; Joenväärä et al., 2021b). Agarwal et al. (2018a)
combined four hedge fund databases: Eurekahedge, HFR, Lepper TASS, and
Morningstar. The researchers examined the information from the data for persistence in
returns. Evidence from the study showed the short-term persistence of alpha. Other

59
studies challenged the short-term performance persistence of hedge funds (Cui &
Kolokolova, 2020; Sun et al., 2018). Other studies found that performance persistence
varies based on the market environment and investment strategies (Ilerisoy et al., 2018;
Metzger & Shenai, 2019). While Agarwal et al. (2017b) found more substantial
performance persistence when using monthly, quarterly, or semi-annual returns instead of
annual data.
Liquidity
Another essential feature contributing to hedge fund performance persistence is
illiquidity (Hwang et al., 2017). The authors found evidence of high stock prices resulting
from hedge fund liquidity returns during the financial crisis of 2007-2009. Another study
by Kolokolova et al. (2020) observed unstable corporate bond yields, resulting from
hedge fund liquidity during that period. Ilerisoy et al. (2018) provide evidence of a
relationship between hedge fund performance, market risk, and funding liquidity risk.
The authors show that the funding liquidity risk is an influential factor in hedge fund
performance.
Fee Structure
The hedge fund fee structure includes the annual operational fee of 2% of assets
under management, and an incentive fee of 20% of the returns (Fung et al., 2021). The
researchers observed that higher feed leads to higher performance for the institution, and
the fee structure is a driving feature of liquidity. Kolokolova and Mattes (2018) argued
that higher management fees lead to less aggressive risk styles. Low performance at the
beginning of the year leads to conservative techniques to increase the chance of survival.

60
Gao et al. (2018a) show that management fee does not motivate managers to pursue
performance as funds grow. The authors conclude that the size of the management fee
exceeds the fund's profit.
Lock-Up and Restrictions
Lock-up and restrictions are policies or a period imposed on investors from
withdrawing funds early (Getmansky et al., 2019). Lock-up and restriction are other
components of illiquidity in hedge fund performance (Getmansky et al., 2019). The lock-
up period is the outflow term of performance, and the inflow restriction is the closure to
new investor periods (Getmansky et al., 2019). Giannetti and Kahraman (2018) found
that hedge funds with excessive share restrictions are more likely to trade against
mispricing equities than unrestricted funds. Aiken et al. (2021) confirmed that hedge fund
performance positively correlates with restraining withdrawal capital.
Leverage
Hedge fund investors employ leverage in the strategies to increase returns and
volatility of any strategy (Getmansky et al., 2019). Leverage involves borrowing money
from banks or brokers to use individual hedge funds or strategy groups (Getmansky et al.,
2019). Other studies suggest that high leverage affects hedge fund returns distribution
(Baker et al., 2017; Molyboga et al., 2017). Baker et al. (2017) confirmed their first
hypothesis that leverage correlates with negative skewness due to asymmetric payoff
from derivatives. The authors also found that, despite controlling for persistence, the
leverage variable predicts the future hedge fund return distribution.

61
Market Timing
Market conditions may affect the properties of assets and fund managers'
investment strategies, affecting performance persistence. Cai et al. (2018) documented
the market timing ability of hedge funds, especially during down and volatile market
conditions. Agarwal et al.(2018a) investigate hedge funds’ exposure to different financial
and microeconomic risk factors by decomposing alpha, traditional beta return, and exotic
beta return and examining investor flows' sensitivity to return components. Their results
indicate a weak persistence to exposure. Like Crego and Galvez (2018), evidence from
the study shows that market-neutral hedge funds can adjust their strategies according to
the economic state. Finally, Falkowski et al. (2020) examine various hedge fund
strategies' effectiveness during varying market conditions. Findings from the analysis
indicate that the specific strategies were effective in a particular market condition, and
others did well in another environment. Also, others performed well in hybrid conditions.
Performance Measurement Models
Hedge funds use a variety of dynamic trading strategies and use derivatives,
short-selling, and leverage (Gao et al., 2018a; Zheng & Osmer, 2018). The hedge fund
characteristics feature nonlinear returns, exposure to risk factors, and strategies that
change over time (Agarwal et al., 2018a; Falkowski et al., 2020). This thesis aimed to
examine the dynamic features.
Non-Parametric Models
Performance analysis for hedge funds differs from traditional assets because the
returns have a low correlation with market indices (Canepa et al., 2020). Thus, using the

62
CAPM, or Jensen's (1968) ratio, is inappropriate as a measurement tool for hedge funds.
The CAPM's alpha can be helpful as the market proxy or benchmark for hedge fund
performance. Fama and French's (1993) model extends CAPM's model by using the size
and the book price ratio to develop the three-factor model. The expected return is a linear
combination of various factors and affiliates. Carhart (1997) added momentum to the
Fama-French' (1993) model as a fourth factor to account for trend-following strategies in
the stock market. However, hedge funds are flexible and can choose from various classes
to employ dynamic strategies (Metzger & Shenai, 2019). Fung and Hsieh's (1997b, 2004)
model captures eight standard fund asset classes when analyzing risk factors to explain
the performances. The risk factors include (1) the market index factor (MKT), (2) the size
spread factor (SMB) of Fama and French (1993), (3) the Book-to-market ratio factor
(HMLt) by Fama and French (1993), (4) Book-to-market ratio factor (HMLt ) by Fama
and French (1993), (5) Moment factor (MOMt ) by Cahart (1997), (6) Interest rate and
credit risk factor, (7) MSCI Emerging Markets Equity Index, (MSCIEMt), and (8) Option
risk factor (Agarwal & Naik, 2004).
Parametric Models
Linear asset models cannot account for the dynamic properties of hedge fund
returns. To overcome the limitations of traditional or non-parametric approaches, several
researchers have developed models to account for hedge fund characteristics (Cao et al.,
2018a; Shin et al., 2018). Agarwal et al. (2017b) applied a factor model to investigate
hedge fund index exposure. Mero (2016) created the Markov regime-switching (MRS)
framework to account for macroeconomic indicators. The framework also has an
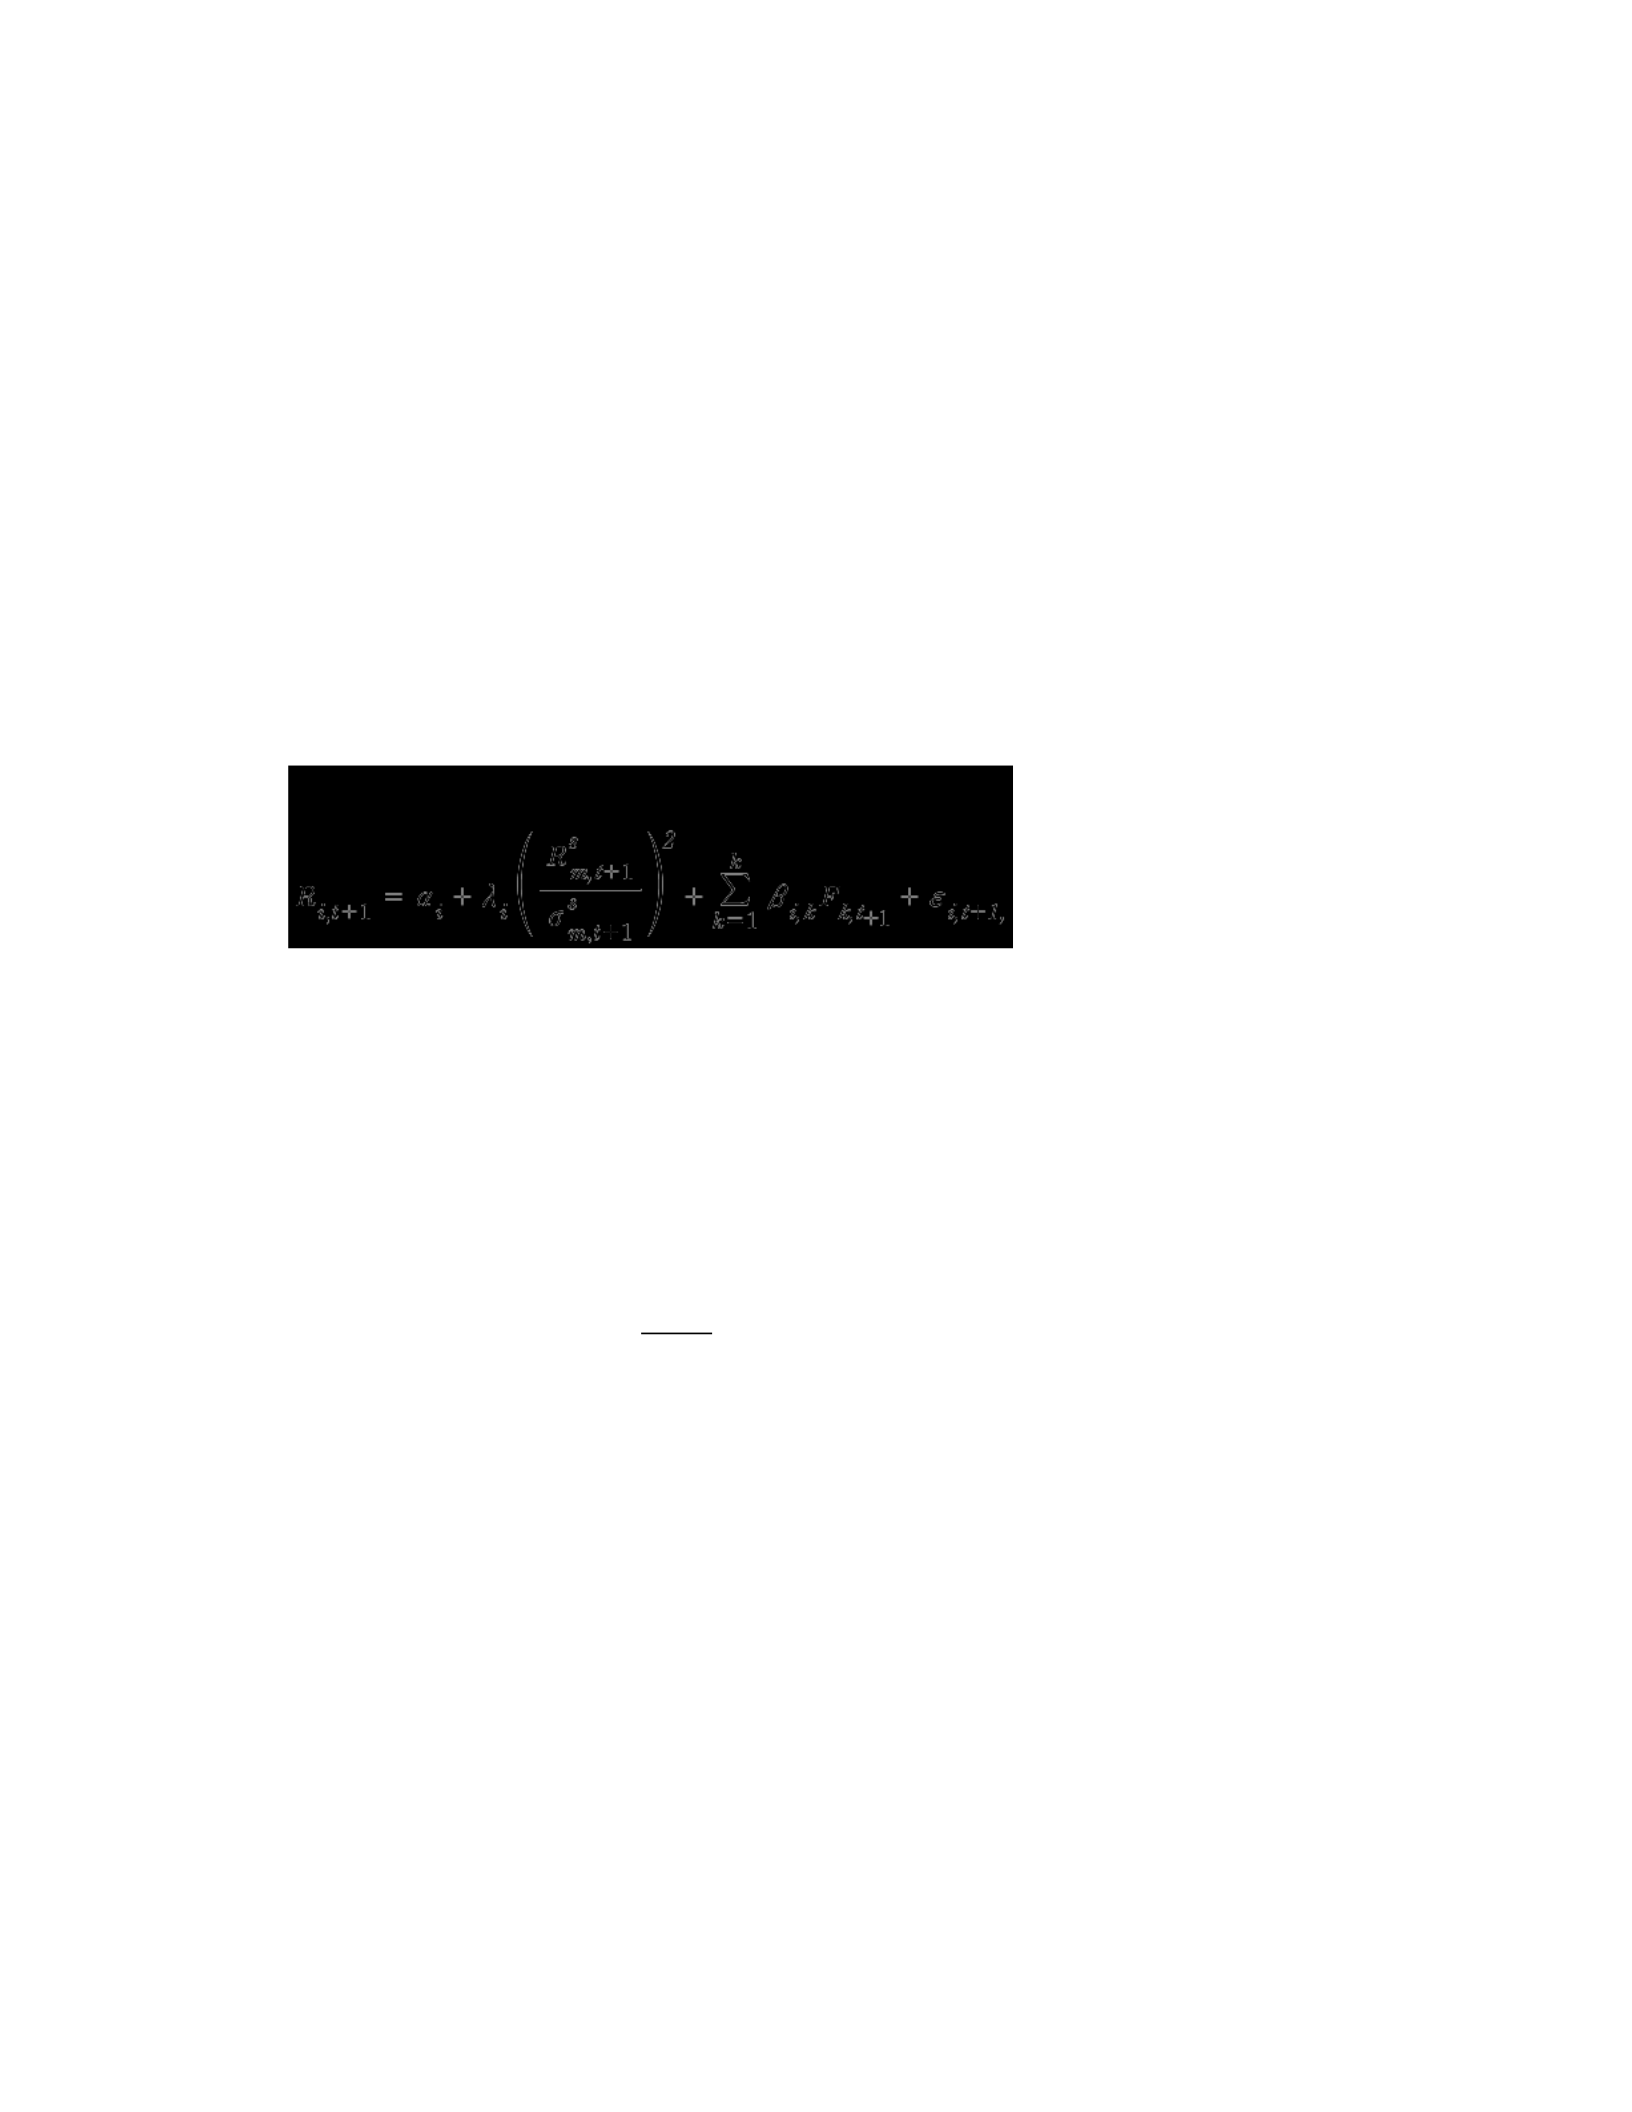
63
investment decision-making process. Cai et al. (2018) studied equity-oriented hedge fund
strategies to analyze hedge fund risks relating to nonlinear factor loading. The authors
focused on the dynamic factors that switch from a regular regime or state to two other
regimes with high or low volatility characteristics. This study analysis employs the
Markov regime-switching model from (Hamilton, 1989). In this model, Chen and Liang
(2007) combined the timing measure to Jensen's (1972) model relating to the Sharpe ratio
to allow risk-adjusted performance measurement as follows:
e
i,t+1∼i.i.d.N0,
se
i
2
( )
Where
Rm,t+1
s
is the return from the stock market at time t + 1;
s
m,t+1
s
is the stock
market volatility level; and
l
i
is the timing skill of the manager. Chen and Liang (2007)
proposed the timing term
Rm,t+1
s
s
m,t+1
s
æ
è
çö
ø
÷
2
, which is associated with the Sharpe ratio of the
market, which lead to risk adjusted returns.
Hedge Fund Data Bias
Some authors have reported biases in hedge fund data because of managers'
voluntary reporting (Ben-David et al., 2020; Jorion & Schwarz, 2019). Ben-David et al.
(2020) used data from BarclayHedge and TASS to study three return biases from 1994-
1918: survivorship bias, delisting bias, and backfill bias. Survivorship bias occurs when

64
hedge fund managers exclude liquidated/dead funds. Further, survivorship bias may
cause liquidity bias, resulting in inhomogeneity data (Agarwal et al., 2017b). Ultimately,
the lack of homogeneity of the database construction rules may impact the study's
analysis and findings.
Backfill bias occurs when a hedge fund manager cherry picks surviving funds to
report and drops low-performing funds (Jorion & Schwarz, 2019). The authors cautioned
researchers to mitigate the biases as they may skew study analysis and results. Joenväärä
et al. (2021b) discussed two approaches to address backfill bias. The first approach is the
ad-hoc cut-off, where the researcher excludes the first 12-24 months of funds’ returns.
The second approach is the listing date method, where the researcher removes all data
before the listing date in the database. Jorion and Schwarz (2019) developed an algorithm
to identify backfill listings and amputate them from the central funds to mitigate the
backfill bias. In addition, hedge fund returns are subject to delisting bias (Aragon &
Nanda, 2017). Delisting bias occurs when managers strategically report a selected group
of returns late to vendors, sometimes months after occurrence (Aragon & Nanda, 2017).
Furthermore, the manager may strategically drop the low-performing returns, making it
difficult for researchers to sample the excluded data. Delisting returns become missing
data, causing upward bias in returns. Forsberg et al. (2018) found that managers are more
likely to delist funds that underperform. Forsberg et al. (2018) suggest finding and
amputating the incomplete data to control for delisting bias.

65
Transition
In Section 1, I justified using a quantitative correlational research study to
examine the relationship between risk exposure, volatility forecasting, and the financial
performance of hedge funds. Section 1 includes the background of the problem,
highlighting the dynamic nature of hedge fund characteristics for managers to adapt to
their trading strategies accordingly. Also included in Section1 is the problem statement
for this study, discussing the general and specific business problem. A discussion on the
purpose statement, assumptions, limitations, delimitations, nature of the study, and the
academic literature review are also part of Section 1. The nature of the study discussion
includes the research method and design. The academic literature review includes the
theoretical framework, analysis, and literature synthesis on the variables.
In Section 2 of this doctoral study, I included a description of my role of as the
researcher, justified the implementation of research methodologies and design to validate
analysis. Also included in Section 2 is a discussion of ethical considerations, participants,
target population, and data collection procedures. The final section, Section 3, includes
pre-data analyzing procedures, findings, application to professional practice, implications
for social change, recommendations for action, and conclusion.

66
Section 2: The Project
In Section 2, I provided an overview and justification of the chosen research
methodology and design for this study. The section begins with a purpose restatement,
followed by a description of my role as the researcher in the data collection procedure.
This section also includes information about (a) population sampling, (b) data collection,
(c) data collection technique, (d) data analysis technique, and (e) reliability and validity.
The section concludes with a transition summary statement.
Purpose Statement
The purpose of this quantitative correlational study was to examine the
relationship between risk exposure, volatility forecasting, and financial performance of
hedge funds. The independent variables were volatility forecasting and risk exposure.
The dependent variable was the financial performance of hedge funds. The targeted
population comprises archival data from hedge fund databases in South Africa. The
implication for positive social change includes the potential to provide organizational
leaders who partner with hedge funds the ability to maximize profit by diversifying risk
in volatile market conditions. Using an investment tool to dispel uncertainty in various
market conditions is a financial means to foster positive change (Tarhani & Ameli, 2016).
Accordingly, through partnerships, hedge funds may help leaders of foundations and
nonprofit organizations fund projects in local communities.
Role of the Researcher
As the researcher in this study, my role included collecting, organizing, analyzing
the secondary data, and interpreting the findings objectively. Using existing data is cost-

67
effective and convenient if the researcher can analyze the data to address the research
question (Martins et al., 2018). Part of performing my role included collecting secondary
numerical data from website sources. Köhler et al. (2017) confirmed the use of statistical
software in data analysis. I analyzed the data to determine if a relationship existed
between the variables relating to the financial performance of hedge funds. In addition, I
identified the effect of independent variables on the dependent variable in the financial
performance of hedge funds. Finally, I used statistical analysis to make valid inferences
and conclusions.
In a qualitative research study, the researcher is the primary data collection
instrument because the researcher gathers the data through interviews, observations, and
focus groups (Mason-Bish, 2019). In this study, I was not the data collection instrument
because I used secondary data to perform the study data analysis. My role was to comply
with the ethical principles and guidelines in the Belmont Report. The Belmont Report of
1979 provides an ethical framework that includes respect, beneficence, and justice as
virtues researchers must follow when working with participants (U.S. Department of
Health and Human Services, 2016). During this research, I did not use human participants
and the ethical concerns identified in the Belmont Report did not apply.
My role as a quantitative researcher was to remain objective from my interests,
bias, and experiences when interpreting and presenting the study results. Furthermore, the
quantitative researcher is to practice ethical conduct and avoid influence by any
organization to maintain the integrity of the research (Edwards, 2020). In this study, there
were no boundary issues because I did not have any association with the industry or topic

68
of study. Also, I did not associate with hedge fund managers in this profession. In
addition, as the researcher, I did not provide investment advice on hedge funds related to
this study. Ultimately, my role as a researcher was to uphold the highest ethical standards
throughout the research process.
Participants
For this doctoral study, there were no human participants. Data for this study
came from secondary sources relating to South Africa-based hedge funds. The data
included historical monthly returns for hedge fund indices from the online database. The
choice to use monthly returns was because hedge fund managers’ report performance
monthly to hedge fund databases (Shin et al., 2017). The retrieved data assisted in
addressing the research question. Other data for this study included the financial
information from Bloomberg as used in the performance evaluation variable.
For a quantitative correlational study, secondary data is an acceptable strategy
(Queirós et al., 2017). Queirós et al. (2017) explained that using archival data is both
more cost and time effective when compared to using primary data. Martins et al. (2018)
highlighted the advantages of using secondary data, which include providing easier
access to international data that would have been costly and time-consuming. In addition,
by using secondary data, the researcher can access a large volume of historical data to
conduct several statistical analyses (Cave & Stumm, 2021). The absence of human
participants limits the risks identified in the 1976 Belmont Report and compliance
requirements; however, I followed the report's guidance when in contact with humans
during of the study.

69
Research Method and Design
Research Method
Research methodology is a technique that researchers use to collect, analyze, and
interpret information to reach conclusions (Scholtz et al., 2020). Research methods can
be quantitative, qualitative, or mixed method (Morgan, 2018; Zoellner & Harris, 2017).
The researcher selects any one of the methods to conduct a study and address the research
question (Williamson et al., 2020). The quantitative research method is an objective and
systematic process of using numeric data to measure a phenomenon and produce findings
(Ghauri et al., 2020). Researchers use the quantitative approach to examine the
relationships between variables by statistically analyzing numerical data to make
inferences (Köhler et al., 2017). Köhler et al. (2017) explained that the statistical
inferences are generalizable to the larger population to answer the research question. I
used the quantitative method for this study because I sought to examine the relationship
between the variables.
The focus of researchers using qualitative method is to explore a phenomenon
using non-numerical data (Nowell et al., 2017; Williamson et al., 2020). The qualitative
research method is appropriate for understanding a social or human problem from
multiple perspectives (Mohajan, 2018). Similarly, researchers use the mixed study
approach to combine the qualitative and quantitative methodologies to analyze textual
and numerical data (Brannen, 2017). Neither the mixed method nor the qualitative
method were appropriate for this study because I did not explore people's experiences or

70
attitudes. Therefore, the qualitative method and the qualitative portion of a mixed-method
approach were not appropriate for this study, and the quantitative was the logical choice.
Research Design
Quantitative researchers can use correlational, experimental, or quasi-
experimental designs to conduct research (Podsakoff & Podsakoff, 2019). Researchers
use the correlational design to measure the strength of the relationship between two
variables (Zyphur & Pierides, 2020). Researchers also use the correlational design to
identify an association between variables (Yang et al., 2021). The correlational design
was applicable for this study because the objective was to assess the relationship between
independent variables (risk exposure and volatility forecasting) and a dependent variable
(financial performance).
The causal-comparative design appeared to be an option for this study, but it was
not suitable. Researchers use causal-comparative design to compare groups in order to
explain existing differences between them on the same variable of interest (Gøtzsche-
Astrup, 2018). Gøtzsche-Astrup (2018) explained that researchers use causal-comparative
design to show that a relationship exists between variables and the consequences of
differences that already exist between two groups. In this quantitative correlational
design, I did not seek to understand the differences between groups; rather, I examined
the relationship within a group. Furthermore, causal-comparative design allows the
researcher to make inferences about causation and the correlational design does not.
The experimental designs involve manipulating variables to assess the cause-and-
effect relationship between them (Podsakoff & Podsakoff, 2019). Researchers conduct

71
the experimental design to determine the ideal values of variables that support the cause-
and-effect relationship rather than an association between variables (Cortina, 2020).
Furthermore, researchers using the true-experimental design assign variables to a group
or manipulate an independent variable. In a quasi-experimental design, the researcher
does not assign the variables randomly, and instead, uses a control group (Yang et al.,
2021). However, in correlational studies, there is no manipulation of variables (Yang et
al., 2021). Therefore, the experimental design was not suitable to address the research
question for this study.
Population and Sampling
Population
A population refers to the summation of elements that the researcher wants to
generate for the results (Hickey & Sollmann, 2018). The general population of this study
encompasses all the asset classes under management in the hedge fund industry. The
target population of this doctoral study includes monthly returns of hedge funds in South
Africa between July 2007 to December 2020 from databases. The data also include the
annual performance of the Johannesburg Stock Exchange (JSE) All Share Index (ALSI)
as the market proxy to measure the surplus return of each hedge fund, along with the
Morgan Stanley Capital International Index (MSCI) performance over the same period
for robust analysis of risk exposure analysis.
Population Alignment with Research Question
The target population for this quantitative correlational study aligned with the
research question with the variables of risk exposure, volatility forecasting, and financial

72
performance. I regressed the monthly returns over the study period to determine the
financial performance (dependent variable). Also, running the style analysis on the
monthly returns allowed me to examine the hedge fund strategies' exposures relative to
risk factors during the study period (independent variable). Finally, I used the indices
from monthly returns to explain the hedge fund volatility and forecasting (independent
variable). A sampling approach is essential for researchers when exploring datasets,
including determining the appropriate sample size (Trafimow & Myüz, 2019).
Sampling
The two methods of collecting samples include probabilistic and nonprobabilistic
sampling (Sharma, 2017). I used the probabilistic sampling strategy in selecting a sample
of South Africa hedge fund data from databases. I did not use the nonprobabilistic
sampling technique because it does not allow to make inferences about the population
(West, 2017). Quantitative researchers use probabilistic sampling approach to generalize
the findings from the sample to the study population (Sharma, 2017). The probabilistic
sampling strategy was appropriate because the goal was to draw inferences of the entire
population of hedge funds based upon the study sample. However, some there are some
disadvantages for using the probabilistic sampling technique which include being tedious
and time consuming, especially when the sample size is large (Schuster et al., 2022;
West, 2017).
A simple random sampling was the suitable probabilistic sampling method for
this study. The simple random sampling strategy allows every member of the population
an equal chance of selection (Muneer et al., 2017). The sample comprised of time series

73
data between July 2007 and December 2020. The data yielded 150 observations of
monthly returns of hedge fund indices. The sample comprised of both live and dead funds
from HedgeNews Africa database. In this study, survivorship bias in the sample may
affect the study findings by inflating the performance (Gao et al., 2018a). Furthermore,
potential survivorship bias may produce false conclusions about the relationship between
volatility and performance. To mitigate survivorship bias, the dataset comprised post-
1994 data, consisting of dead and live funds (Barth et al., 2021; Jiang et al., 2022;
Joenväärä et al., 2021a). In addition, backfill bias in the sample may create upward biased
time-series returns for macro funds (Joenväärä et al., 2018; Jorion & Schwarz, 2019).
Backfill bias could also lead to incorrect relationship findings between hedge fund
performance, systematic risks, and volatility. Following the approach by Barth et al.
(2021), Forsberg et al. (2018), Gao et al. (2018b), and Jiang et al. (2022), to address
backfill bias, I eliminated the first 24 month return observations of each fund.
The reason for selecting the simple random sampling technique is because it
enables the use of historical data. The advantage of using the simple random sampling
technique is that it enables the researcher to reduce possible selection bias and minimize
the potential for findings with skewness (Mahalua et al., 2019). Mahalua et al. (2019)
also suggested that researchers use the probabilistic simple random technique when they
require minimal knowledge of the target population. Furthermore, the probabilistic
simple random technique could make a strong representation of the target population.
Another advantage of using the probabilistic simple random technique is that selecting an
individual member in the sample does not affect other members in the sample (Ali &
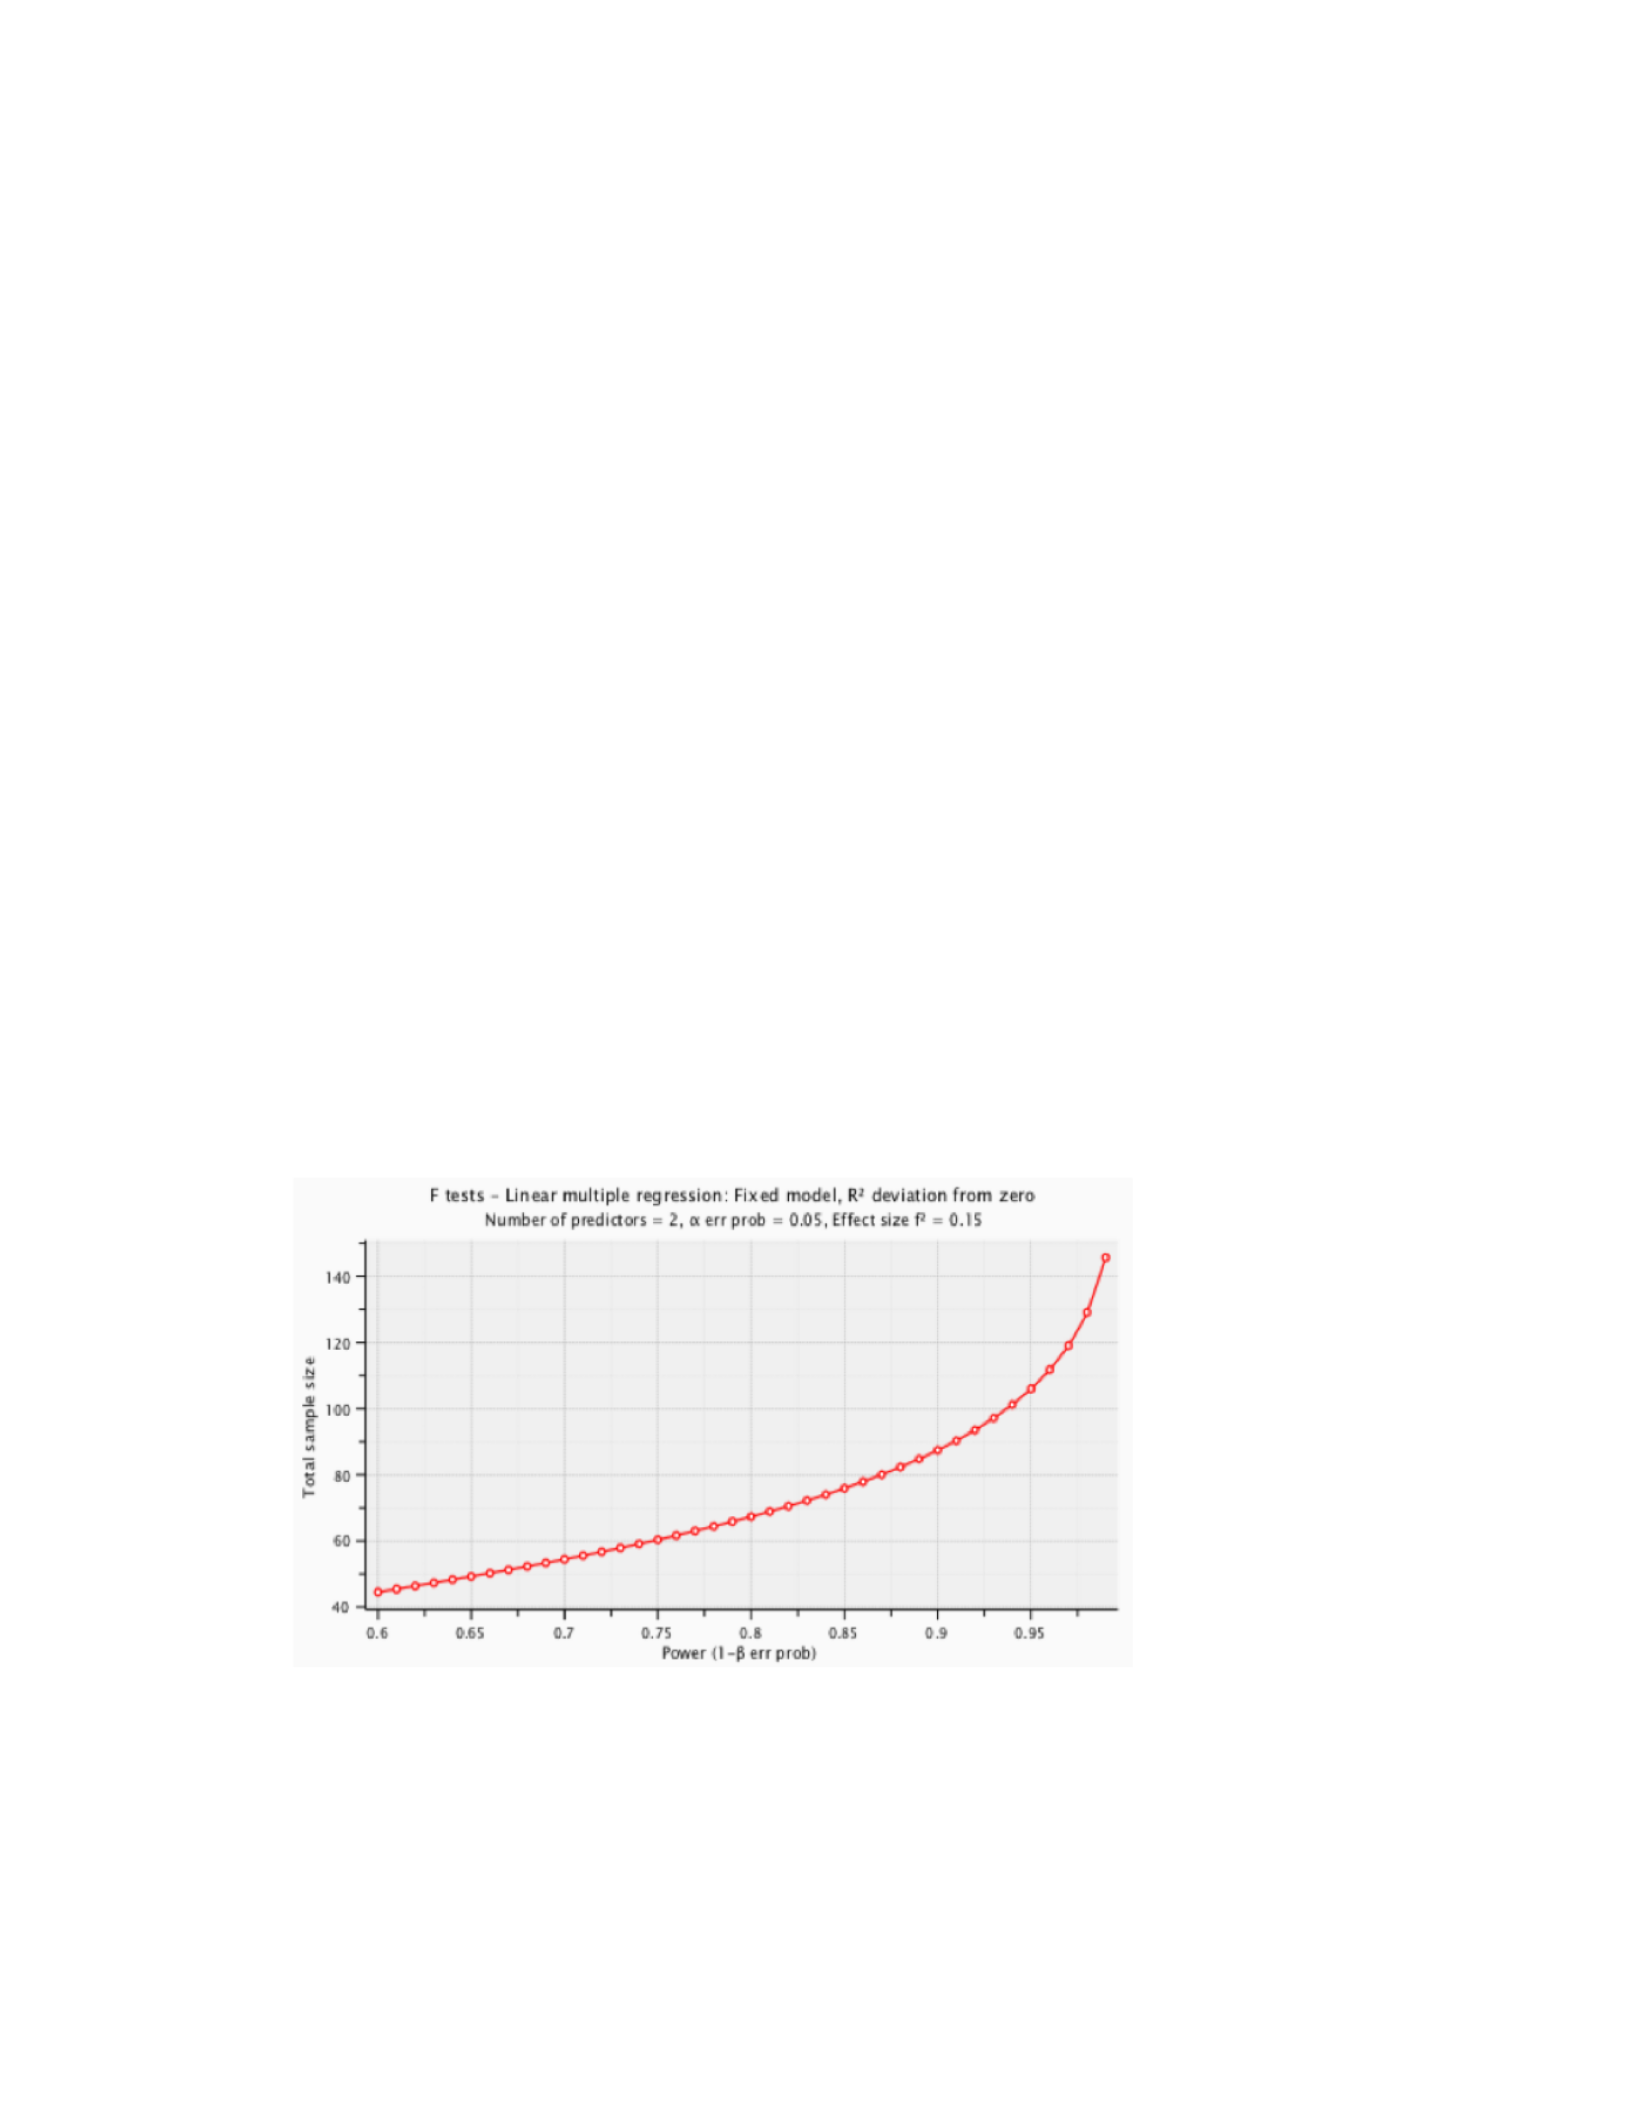
74
Shukla, 2020). The sampling choice aligned with the sample in this study because the
data comprised of a monthly return time series. However, the simple random technique
has a potential weakness of requiring a large sample to attain a representative population
(Serdar et al., 2021).
G* Power is the statistical software package researchers use to perform a priori
sample size analysis (Faul et al., 2009). I used the G*Power Version 3.1 to determine the
appropriate sample size for this study. A priori power analysis with the assumptions of
medium effect size (f2 = .15), type I error (α = .05), and two predictor variables. The
priori analysis indicates a minimum size of 68 sample observations to attain the power of
0.8 (Fig. 1). Increasing the power to 0.99 leads to 146 sample observations (see Table 8).
Figure 1
Relationship between effect size and the sample size at power 0.8 for F-Tests Linear
Multiple Regression
Also see the minimum sample size for a different range of powers and effect
sizes, shown in the table below.
75
Table 8
Minimum Sample Size for Selected Powers and Effect Size
Power
Effective Size
0.8
0.85
0.95
0.99
Small (0.02)
485
550
776
1073
Medium (0.15)
68
76
107
146
Large (0.35)
31
35
48
65
A sample size between 68 and 146 observations was acceptable for this study.
The sample of 146 observations yields a study period of 12years, between July 2007 and
December 2019. Therefore, the sample of 150 observations ranging between July 2007
and December 2020 was the appropriate size for this study.
Ethical Research
Researchers have an ethical responsibility to conduct research with integrity,
regardless of the research methodology (Zyphur & Pierides, 2017). I obtained the IRB
approval from Walden University before collecting and analyzing data, with the licence
number 02-03-22-0552772. I obtained secondary data from public and private electronic
data sources. The ethical protocols in the Belmont Report (U.S. Department of Health,
2016) apply to human research subjects (Friesen et al., 2017). The Belmont Report of
1979 provides an ethical framework that includes respect, beneficence, and justice that
researchers must follow when working with participants (U.S. Department of Health,
2016). I did not use human subjects in this study.
Consequently, the consent documents include (a) informing participants about the
study purpose, (b) possible risks in the study, (c) potential benefits, (d) voluntary
participation, and (e) the process for withdrawal from the study. I maintained

76
confidentiality by limiting access to the data and securely storing and protecting data in
electronic folders with a password. Finally, I will delete the data five years after the
study’s publication.
Data Collection Instruments
I did not use a data collection instrument in this study. The data originate from
secondary sources. Martins et al. (2018) described secondary data as information from
existing sources. Quantitative researchers may use secondary data for statistical analysis
(Queirós et al., 2017). Theofanidis and Fountouki (2018) also reported that researchers
set boundaries for the research by establishing delimitations for a framework for
recording and analyzing the information. This study involved scaling each variable based
on measurement techniques researchers used to measure variables in previous studies.
The data for this study included monthly time series from the online HedgeNews Africa
(HNA) database from July 2007 to December 2020 (HNA, 2021). The HNA database
provides the most timely, accurate, and independent source of information covering
alternative investment space across the emerging African continent and the South African
hedge fund industry (HNA, 2021). I converted the hedge fund return rates from South
African Rand terms (ZAR) to U.S Dollars (USD) for all strategies for analysis.
Other secondary data sources were the Bloomberg database using the Bloomberg
terminal, I-Net Bridge, and the South African Reserve Bank (SARB). Bloomberg is
among the most global providers of timely, accurate, and high-quality financial news and
information to more than 300,000 trading desks (Guidotti, 2019). Beyond information,
the Bloomberg terminal system allows market participants to monitor and analyze real-

77
time financial market data for informed decisions. I-Net Bridge is a South African
financial services company that provides electronic economic data, financial market data,
and market intelligence (I-Net Bridge, 2021). The SARB provides high-quality
economic, policy-relevant, and financial statistics that present a holistic view of the South
African equities market (SARB, 2021).
The purpose of this study was to examine the relationship between risk exposure,
volatility forecasting, and the financial performance of hedge funds. The datasets
incorporated the variables, and I utilized them to determine the relationship between the
three variables. Risk exposure is one of the variables in this study. Several studies applied
the style analysis to investigate the risk exposure of funds to gain insight into the impact
of factors on performance (Billio et al., 2018; Hespeler & Loiacono, 2017; Stafylas &
Andrikopoulos, 2020). The style analysis includes a regression process between fund
returns against risk factors (Frydenberg et al., 2017). The HNA database provided the
source for monthly hedge fund returns. Using the Bloomberg terminal, I sourced the JSE
(ALSI) returns and the Morgan Stanley Capital International (MSCI) index from the
Bloomberg database for the study period. I also sourced sample data for risk factors from
I-Net Bridge. The beta coefficient represents a standard measure of a fund's exposure to
movements in the market's return (Frydenberg et al., 2017). If the market beta coefficient
value is zero and an asset contains a beta coefficient of zero, it indicates no correlation
with the market index (Mestre, 2021). Also, a positive beta of the asset shows that the
asset follows the market movements and has higher risk exposure. Several researchers
used the beta coefficient to measure risk exposure in various areas of financial studies

78
(Agarwal et al., 2018a; Gerhard & Rupert, 2017; Hwang et al., 2017; Yurteri Kösedağli
et al., 2021).
Volatility forecasting is the second independent variable in this study. Previous
research indicates that volatility forecasting in financial instruments demonstrates a direct
association with performance (Gaetano, 2018; Limam et al., 2017). In this study, I used
an autoregressive model to perform volatility forecasting. Autoregressive Conditional
Heteroskedasticity models (ARCH) are statistical techniques that suggest the subsequent
period volatility is conditional on the current period volatility, including the time-varying
nature of volatility (Ndei et al., 2019). Researchers may use ARCH and its variant of
family models to forecast volatility in time-series data with a non-linear model without
assuming constant variance (Mashamba & Magweva, 2019). The HNA database served
as the source for the hedge fund returns for the study period. I sourced the returns on the
JSE (ALSI), MSCI index, South African Volatility Index (SAVI), and MSCI Emerging
Market Stock Index from the Bloomberg database for the study period using the
Bloomberg terminal. In addition, I sourced the exogenous factors from I-Net Bridge and
SARB. The asset return volatility measures how much the returns move around their
mean (Greaves, 2018). Some volatility measures include standard deviation, beta, R-
squared, and alpha (Ardia et al., 2018). Previous researchers have supported the standard
deviation or variance as a measurement of uncertainty or risk (Ardia et al., 2018;
Gaetano, 2018; Greaves, 2018; Siddiqui & Roy, 2019). The standard deviation has
advantages because extreme values do not affect how it functions (Greaves, 2018).
Furthermore, it indicates its magnitude by the cluster level or shocks, and it is more

79
precise and reliable than the other measurements. I used the Root Mean Square Error
(RMSE) to assess the accuracy of the forecasting performance of the models. The RMSE
compares the out-of-sample of forecast performance of the models. The forecasting
model with the lowest value of RMSE is the most accurate (Al Rahahleh & Kao, 2018).
The financial performance of hedge funds represents the dependent variable in
this study. Like the independent variables, I retrieved secondary data from HNA,
Bloomberg database, I-Net Bridge, and SARB. Alpha represents the measurement of
funds' performance (Kapil & Gupta, 2019). Also, the regression intercept of several
market factors on the hedge fund excess returns to measure the performance. Risk-
adjusted performance measures include the Sharpe, Sortino, omega, and Calmar ratios
(Newton et al., 2021). The Sharpe ratio is inappropriate to measure hedge funds'
performance because it assumes that returns produce a normal distribution (Metzger &
Shenai, 2019). The Sortino, omega, and Calmar ratios use volatility as risk, making them
unsuitable for measuring hedge fund performance (Kapil & Gupta, 2019). This study
included evaluating the hedge fund performance measure by augmenting the Capital
Asset Pricing Model (CAPM) of the Sharpe ratio by factoring in the changing state of the
economy, systematic risk factors, and market timing component. Previous researchers
have supported the time-varying factor approach to evaluate alpha (Bouamara et al.,
2017; Chen & Kawaguchi, 2018; Metzger & Shenai, 2019; Newton et al., 2021)
In this study, the measurement scale for the dependent variable, the financial
performance of hedge funds, is the ratio scale. The basis for financial performance of
hedge funds is the time series returns from assets measured as ratio scale. Also, the

80
measurement for the independent variable, the volatility forecasting variable was ratio
scale. The second independent variable, the risk exposure variable, was an ordinal scale
with eleven sub-variables: (a) market index (ALSI), (b) size spread factor (SMB), (c)
book-to-market factor (HML), (d) moment factor (MOM), (e) equity markets index
(MSCI), (f) emerging markets equity index (MSCIEM), (g) option risk factor (SAVI), (h)
10- year government bond (10-Yr-bond), (i) 3- month T-Bill (j) metal commodities (k)
exchange rate risk (US/ZAR). Content validity, criterion-related validity, and construct
validity did not apply in this study because I did not use instruments.
Data Collection Technique
The research question of this quantitative correlational study is as follows: Is there
a statistically significant relationship between risk exposure, volatility forecasting, and
the financial performance of hedge funds? The data collection method for this study
involved sourcing data from secondary sources. I collected secondary data for this study
from websites linking to HNA, Bloomberg terminal, SARB, and I-NET Bridge databases
between 2007 and 2020. Yerpude and Singhal (2017) revealed that collecting data using
automated real-time systems increases the accuracy of forecasting output. The SARB
distributes data through an online terminal which allows users to download data (SARB,
2021). The data terminal allows users to download time series data and easily export it to
excel. Significantly, the system provides the researcher with a time series code and uses
keywords to search (SARB, 2021).
The Bloomberg terminal includes an online tutorial and data acquisition
instructions (Guidotti, 2019). In addition, a researcher can transfer data from the

81
Bloomberg terminal to other software programs like Excel and SPSS for sorting and
analysis. I-NET service provides a workstation for users to access electronic data and
support operating the terminal (I-Net Bridge, 2021). Furthermore, the electronic terminal
incorporates a web application and a data feed system with analytic tools. Finally, the
HNA database provides an online terminal for users to download and transfer data to
various programs, like the Excel spreadsheet (HedgeNews Africa, 2021).
After obtaining the IRB's approval, I extracted the data through the electronic
terminals from the databases for the study period between 2007 and 2020. The first step
was to ensure that sources comprised the relevant data to answer the research question
(Olabode et al., 2018). I used the variables in this study to filter the data from respective
database terminals. The study variables include risk exposure, volatility forecasting, and
the financial performance of hedge funds. The data from sources aligned with variables
as presented in Table 9.
82
Table 9
Systematic Risks Data, Sources, for Risk Exposure Variables
Factors (Data)
Source
Monthly returns net-of-all-fees, relating to the hedge fund strategy indices
HNA
Equity factors:
1. Market (MKT) JSE (ALSI)
Bloomberg
2. Morgan Stanley Capital International (MSCI) index
Bloomberg
3. MSCI Emerging Markets Equity Index, (MSCIEMt)
Bloomberg
4. Size factor (SMBt) by Fama and French (1993)
I-NET
5.Book-to-market ratio factor (HMLt) by Fama and French (1993)
I-NET
6. Moment factor (MOMt) by Cahart (1997)
I-NET
Option risk factor (Agarwal and Naik (2004):
7. South African Volatility Index (SAVI)-implied volatility
I-NET
Interest rate and credit risk factor:
8. ZAR 10-year South Africa government yields
SARB
Exchange rate factor:
9. Fluctuations in the Rand-Dollar exchange rate (USDt)
Bloomberg
Commodity factor:
10. World metal prices (METt)
I-NET
Spread:
11. Spread: the difference between market return and the 3-month treasury
bill (risk-free rate, rf)
SARB
The second step included:(a) downloading the data onto an Excel spreadsheet, (b)
organizing the data for all variables, and (d) importing the data into SPSS for statistical
analysis. Weston et al. (2019) recommended that secondary researchers document the
data using code, including precise instructions, before the statistical analysis. Arslan
(2019) also proposed code-creating tools such as the codebook package. Tools like the
codebook help secondary researchers with reliability procedures, missing patterns,
storage, plot data, and web interface. Further, the auto code tool includes meta-data, such
as variable names and labels (Arslan, 2019).

83
Retrieving secondary data from electronic databases has both advantages and
disadvantages for this study. Olabode et al. (2018) stated that collecting electronic data
allows unrestricted access to broad international samples at a limited cost. According to
Yerpude and Singhal (2017), automated secondary data collection is more appropriate for
time series forecasting. Furthermore, the web interface and storage systems grant
researchers unlimited access to data and transfer it to statistical software for analysis
(Arslan, 2019). There is some drawback to employing secondary data. Pernollet et al.
(2017) opined that preparation errors in archival data might affect the study results'
reliability. Because of the voluntary nature of reporting, there is a possibility of missing
or incomplete data in hedge fund databases (Aragon & Nanda, 2017). The missing data
set might exclude the researcher's vital information to address the research question
(Weston et al., 2019). Furthermore, missing or incomplete data may generate bias,
affecting the relationship between the variables (Olabode et al., 2018). Cheng et al.
(2017) suggested that pilot studies are significant steps to evaluate the possible threats to
the validity of empirical research. Fink et al. (2021) pointed out that the primary purpose
of a pilot study is to assess the measurement characteristics of the instruments. However,
a pilot study was not appropriate for this study because of the use of secondary data.
Data Analysis
The research question of this study is as follows: Is there a statistically significant
relationship between risk exposure, volatility forecasting, and the financial performance
of hedge funds? The independent variables are risk exposure and volatility forecasting.

84
The dependent variable is the financial performance of hedge funds. This study involved
answering the research question by testing the following hypotheses:
H0: There is no statistically significant relationship between risk exposure,
volatility forecasting, and financial performance of hedge funds.
Ha: There is a statistically significant relationship between risk exposure,
volatility forecasting, and financial performance of hedge funds.
I used the multiple regression model to analyze the data in this study. Multiple
regression is a statistical technique that allows researchers to examine relationships
between one dependent variable and several independent variables (Green & Salkind,
2017). According to Jelusic (2017), the multiple regression method is valuable in
quantifying the degree of association between variables. The multiple regression analysis
is appropriate for this study because the research question is about a predictive
relationship between one dependent variable and two independent variables. While I
opted to use the multiple regression approach, I did consider using other techniques like
the Analysis of Variance (ANOVA) and logistic regression.
The ANOVA is a statistical technique that researchers can use to measure the
statistical mean difference between samples (Green & Salkind, 2017). Furthermore,
Green and Salkind (2017) also noted that the ANOVA test applies when the dependent
variable is continuous while the independent variables are categorical. The focus of this
study was not to examine the mean and group differences between samples. Moreover,
the independent variables are not categorical. Therefore, the ANOVA test was not
applicable to this study. Another option was logistic regression. Logistic regression

85
analysis is another statistical technique that researchers use to examine the relationship
between a dichotomous, binary dependent variable and independent explanatory variables
(Bergtold et al., 2018). Given that the focus of this study did not predict the binary
dependent variable, this made the logistic regression approach unsuitable for this study.
Quantitative researchers use data cleaning and screening procedures to refine raw
data to a suitable format for statistical analysis (Kiss et al., 2017). Data cleaning refers to
the process data analysts use to edit invalid data from the dataset (Bashir & Wei, 2018).
Kiss et al. (2017) also recommend performing data cleaning methods to improve the
quality to minimize the possibility of false positives in the study results. At the same
time, screening involves detecting the anomaly in the dataset (Arslan, 2019). Data
screening starts with establishing the raw data characteristics (Wang & Wang, 2020).
Arslan (2019) suggested performing data screening to ensure that data are ready for
analysis. Furthermore, the quality of acceptable analysis is subjective to the initial phase
of data screening. Data cleaning and screening include standardization, coding, and
reporting (Arslan, 2019). The data cleaning and screening procedures suitable for this
study include scanning, coding, identifying missing values, validation, and implementing
treatment techniques.
Missing data is inevitable in secondary datasets (Coertjens et al., 2017). Most
databases contain duplicate, incomplete, and missing values (Agbehadji et al., 2018).
This research included employing archival information from hedge fund databases.
Agarwal et al. (2017b) noted that managers' voluntary disclosure of hedge funds provides
the source of missing and incomplete data in hedge fund databases. Furthermore, missing

86
data are problematic when a researcher intends to examine events' occurrence or
variations of change over time (Bashir & Wei, 2018). There are various methods to
mitigate missing data, including imputation techniques. According to Kiss et al. (2017),
methods to consider addressing missing data include (a) listwise deletion, (b) pairwise
deletion and, (c) Expectation-Maximization (EM). The listwise deletion method excludes
all data cases with missing values (Bashir & Wei, 2018). The listwise deletion approach
involves excluding all data cases with missing values. However, time series data involve
removing the time intervals when there is missing data for specific data. The downside to
the listwise deletion method is that it can cause bias and fragment time series data,
distorting the study results (Agbehadji et al., 2018).
The pairwise deletion approach involves deleting the whole variable with the
missing values and substituting it with the median or unconditional mean (Kiss et al.,
2017). Kiss et al. (2017) also noted that a drawback of the pairwise method could
compromise the power of statistical tests because the estimated data could exhibit bias.
The EM approach reconstructs the missing data by estimating the variance or covariance
(Bashir & Wei, 2018). However, Kiss et al. (2017) argued that the EM approach would
affect time series more under multivariate applications. I adopted the listwise approach
for this study to identify the contaminated data and address missing data.
There are assumptions in any statistical analysis (Plonsky & Ghanbar, 2018).
Bergtold et al. (2018) reported that the assumptions associated with using multiple
regression are as follows: (a) multicollinearity, (b) linearity, (c) outliers, (d) normality, (e)
homoscedasticity and (f) independence of residuals. Multicollinearity occurs when two

87
independent variables are highly correlated, as high as 0.8 to 0.9 (Green & Salkind,
2017). The violation of the multicollinearity assumption in a study may inflate the
variances of the parameter estimates, which may result in questionable p-values (Plonsky
& Ghanbar, 2018). Consequently, incorrect conclusions about relationships between the
independent and dependent variables. Theoretically, it would be challenging to determine
which highly correlated predictor variable is related to the hedge fund's performance. I
examined a bivariate correlation matrix of the predictor variables from the SPSS software
output. A correlation coefficient less than 0.8 is acceptable (Hirk et al., 2019).
Linearity assumes a linear relationship between independent and dependent
variables (Josephat & Ame, 2018). To check for linearity, I visually inspect the
scatterplot of the relationship between the variables using SPSS. A straight line indicates
that the assumption is present. Outliers represent observations or scores whose values
highly differ from the data set under study (Ernst & Albers, 2017). Yuen and Ortiz (2017)
stated that outliers could arise from various sources, like incorrect recording observations
of data. To locate outliers, I visually inspected the scatterplot, histograms, box plot, or
frequency distributions using the SPSS software. Another method to locate outliers
includes converting data to z-scores (Ernst & Albers, 2017). One solution is removing the
outliers from data analysis (Green & Salkind, 2017). However, dropping the data or
outliers may cause bias in the study results (Yuen & Ortiz, 2017). Dropping outliers can
be justified when: (a) they are out-of-range, and misentered data and (b) missing.
Normality assumes that the distribution of residuals is normal (Hirk et al., 2019). Some of
the tests for normality include the following: (a) observing the normal probability-

88
probability plot (Q-Q), (b) histogram, or (c) a Shapiro-Wilk and Kolmogorov-Snairnov
tests using the SPSS software (Ernst & Albers, 2017).
Homoscedasticity refers to assuming the variability in scores should be constant
across all independent variable levels (Ernst & Albers, 2017). Homoscedasticity
assumption can lead to bias in the findings, and alter the overall analysis, thus weaken the
statistical power (Dattalo, 2018). Ernst and Albers (2017) observed that a weak power
increases the potential occurrence of Type I error. Consequently, Type I error results in
inaccurate F-test results and discrepant conclusions. To assess the presence of
homoscedasticity, a visual inspection of the Normal Probability Plot (P-P) of the
Regression Standardized Residual using the SPSS software (Dattalo, 2018). Also, I
observed the scatterplot from SPSS software. A funnel shape indicates the assumption is
unacceptable, and a random array of dots indicates that the homoscedasticity assumption
is acceptable (Green & Salkind, 2017). Finally, the independence of residuals refers to
the residual difference between each observed and the average predicted value of the
dependent variables (Hirk et al., 2019). Ernst and Albers (2017) suggested using the
Durbin-Watson test to determine autocorrelation for serial correlation between errors.
Thus, I used the same procedure to test for the independence of the residual assumption.
To combat the possible influence of violations of statistical assumptions, I
employed a bootstrapping technique. Researchers use the bootstrapping technique to
address the violation of assumptions (Dattalo, 2018). According to Dattalo (2018), the
bootstrapping technique is equally appropriate as an alternative to statistical inference
without relying on assumptions to quantify the uncertainty. Violating assumptions could

89
lead to an unreliable and invalid analysis of data (Ernst, & Albers, 2017). Therefore, I
used the bootstrapping technique to address the possible influence of assumption
violations. I employed the Statistical Packages for Social Science (SPSS), version 25, for
this doctoral study to analyze the data. The SPSS software translates numerical and non-
numerical information into data for statistical analysis (Green & Salkind, 2017). The
SPSS software provides specific output parameters for interpretation as follows:
(a) F value, (b) B, (c) R2, (d) β, (e) SE B, (f) Sig (p), and (g) t results.
F value or the F-ratio of the analysis of variance, including the sig p values,
applies to ascertain if the null hypothesis is accepted or rejected (Shyti & Valera, 2018).
A sig p-value less than 0.05 could lead to the rejection of the null hypothesis (Shyti &
Valera, 2018). B refers to the unstandardized coefficient of the predictor variable of the
study (Josephat & Ame, 2018). Researchers use the B value to predict that the magnitude
of a factor of the dependent variable will change by a unit change in the independent
variable, given that all other independent variables stay constant (Josephat & Ame,
2018). β refers to the standardized coefficient of the predictor variable and is the slope of
the regression line that mathematically represents the linear regression equation (Davino
et al., 2020). The β coefficient represents the magnitude of change related to a one-unit
change in each independent variable (Davino et al., 2020). SE B represents the standard
error for the predictor variable's unstandardized coefficient, which indicates the degree of
irregularity in the data (Hirk et al., 2019). The standard error of the estimate refers to the
standard deviation of the error term and is derived by the square root of the mean square
residual (Hirk et al., 2019). R2 is the percentage measure of the variance in the dependent
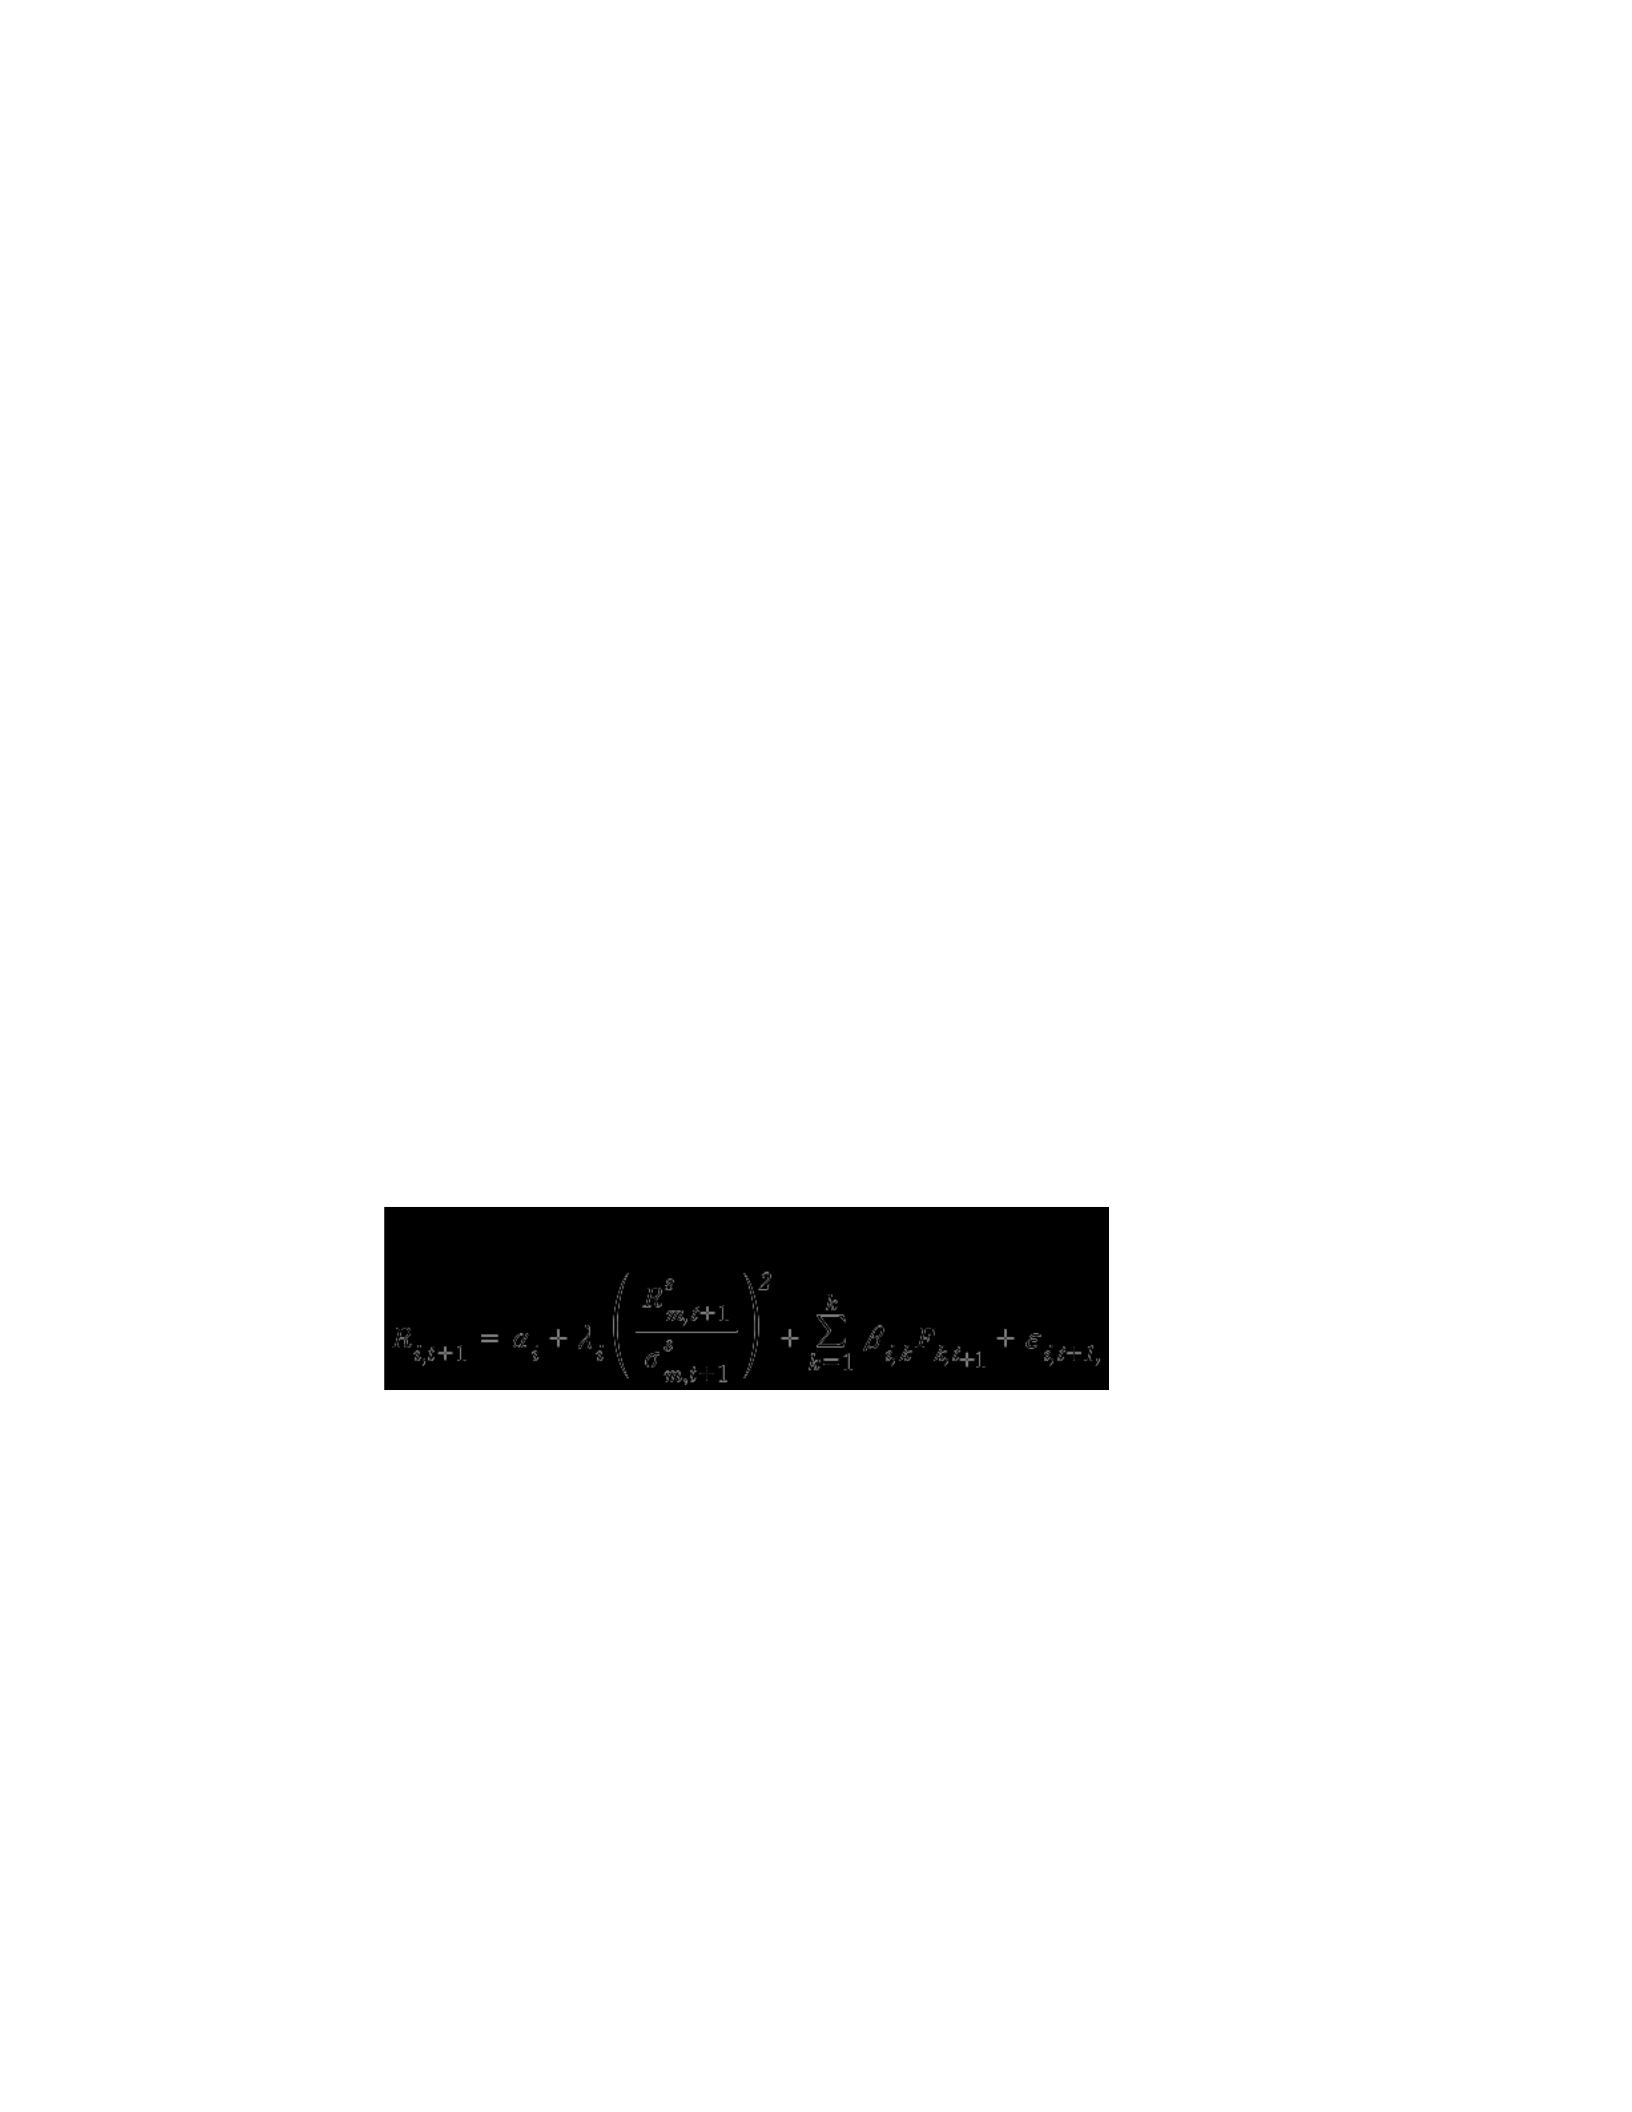
90
variable that relates to the independent variable (Josephat & Ame, 2018). The t statistic
measures the distance of a parameter from its notional value and standard error
(Andronov, 2017). Researchers determine the t-statistic when the parameter estimate
value in a regression model differs from the actual parameter estimate and is divided by
the standard error (Andronov, 2017). Sig (p) represents the statistical significance of each
independent variable (Pfeiffer et al., 2017). The p-value is the likelihood that the actual
value associated with the independent variable in the population is zero. A sig p-
value less than 0.05 could lead to the rejection of the null hypothesis (Pfeiffer et al.,
2017).
I used the Markov regime-switching model to compute the risk-adjusted
performance of hedge funds (Hamilton, 1989). In this model, Chen and Liang (2007)
combined the timing measure to Jensen's (1972) model relating to the Sharpe ratio to
allow risk-adjusted performance measurement as follows:
e
i,t+1∼i.i.d.N0,
se
i
2
( )
(see Table 7 for terms of description)
Study Validity
The two types of study validity are internal and external (Sürücü & Maslakçi,
2020). According to Thomas et al. (2018), internal validity represents the extent to which
the results of a study support a causal relationship between variables. When researchers

91
use an experimental design, there is a potential risk of internal validity (Rahi, 2017). For
a quantitative correlational study, internal validity does not apply. However, there are
potential threats to statistical conclusion validity.
A researcher could attain statistical conclusion validity by using appropriate
statistics to infer the association between dependent and independent variables (West,
2017). According to Muneer et al. (2017), failing to address threats to statistical
conclusion validity could lead to inaccurate inferences like type I or type II errors. Serdar
et al. (2021) described type I error as the probability of rejecting a true null hypothesis
and type II as the probability of accepting a factually false null hypothesis. Factors that
could affect the statistical conclusion validity include (a) reliability of the instruments, (b)
data assumptions, and (c) sample size (Bergtold et al., 2018). The reliability of
instruments relates to the internal consistency of the instruments of the study. I did not
use an instrument to collect data; I employed secondary data. Therefore, internal
consistency in this study should not be a concern.
When using multiple regression, the data assumptions are normality, linearity,
homoscedasticity, and multicollinearity (Bergtold et al., 2018). According to Josephat
and Ame (2018), the assumption for linearity indicates that the relationship between the
dependent and independent variables is linear. The scatterplot feature on SPSS can help
researchers check for normality, linearity, and homoscedasticity (West, 2017). I visually
examined the scatterplot to determine the linearity of data in this study. According to
Yuen and Ortiz (2017), outliers can impact the results of a regression analysis.
Furthermore, researchers can use a histogram from the SPSS program to locate any

92
outliers. Data assumptions are the primary threat to the validity of this doctoral study.
Violating the data assumption may lead to Type I or Type II errors (West, 2017). To
mitigate the violation of data assumptions, I ran a bootstrapping technique using SPSS.
The sample size in a quantitative study is essential to assist researchers in
determining the statistical significance between variables (Rahi, 2017). Serdar et al.
(2021) claimed that increasing the sample size would increase the power level,
decreasing the probability of generating type I and II errors. Trafimow (2018) suggested
that researchers use a priori power analysis to determine an adequate sample size.
Thomas et al. (2018) suggested that researchers select an effective size to estimate the
sample size for a specified power (1- β) and significance level (α) at the planning phase
of the research. I performed an a priori power analysis using the G*Power software to
select an adequate sample size of 150 observations in this study. Moreover, I employed a
statistical power of 0.95 at an alpha of 0.5 to minimize the threat to the statistical
conclusion validity.
External validity represents the extent to which the researcher can generalize the
study findings to the broader populations, various settings, and different measurements
(Sürücü & Maslakçi, 2020). Mahalua et al. (2019) explained that a probabilistic sampling
strategy could improve the external validity of a study by increasing the generalizability.
According to Trafimow & Myüz (2019), researchers can overcome threats to external
validity by using an adequate sample size representing the target population. Palazón-Bru
et al. (2017) also noted that a sample that does not represent the target population
adequately could lead to selection bias, which may threaten external validity. Researchers

93
cannot use a biased sample to generalize findings to a larger population (Mang et al.,
2021). In addition, I used a random sampling technique to select the sample size because
it represents the study population. I used inferential statistical techniques like hypothesis
testing and regression analysis to generalize the study’s population. The study's sample
size comprised hedge funds that invest in South African financial markets. Similar to the
selection process of Kumar and Kumar (2017), the sample included a monthly return time
series of hedge fund indices from July 2007 to December 2020. The results may not
represent the entire global hedge fund industry, threatening validity (Theofanidis &
Fountouki, 2018). Consequently, the findings may include limitations due to the sample
size, characteristics, and period chosen.
Transition and Summary
Section 2 contains narratives on the purpose of the research, my role as a
researcher, the research method, design, and ethical procedures. Furthermore, in Section
2, I discussed sampling techniques, data collection methods and instruments, data
analysis presentation, and the study validity. In Section 3, I presented the study findings,
and discussed the implication for social change and business practices. In addition, I
included recommendations for future research, reflections, and concluding remarks for
the study.

94
Section 3: Application to Professional Practice and Implications for Change
Introduction
The purpose of this quantitative correlational study was to examine the
relationship between risk exposure, volatility forecasting, and the financial performance
of hedge funds. The independent variables were risk exposure and volatility forecasting.
The dependent variable was the financial performance of hedge funds compared to the
benchmark performance of the Johannesburg stock exchange, ALSI. The model showed
that at F (2, 149) = 238, p < 0.001, R2 = .950, risk exposure and volatility forecasting
significantly predicted the financial performance of hedge funds. Hence, the null
hypothesis was rejected, and the alternative hypothesis was accepted.
Presentation of the Findings
This subsection includes a discussion of assumptions testing, descriptive statistics,
and inferential statistics results, provides a theoretical discussion about the findings, and
concludes with a concise summary. I employed multiple linear regression, with a sample
consisting of 150 monthly observations from July 2007 to December 2020, to address the
relationship between risk exposure, volatility forecasting, and the financial performance
of hedge funds. The employment of bootstrapping with 1,000 samples was applied to
address the violation of the assumptions where appropriate. Hence, bootstrapping of 95%
confidence intervals is presented where applicable.
Test of Assumptions
For the multiple regression, I assessed six assumptions: independence of residuals
(autocorrelation), linearity, normality, stationary, homoscedasticity, multicollinearity,
95
outliners, and heteroskedasticity. I included all the cleaned samples in the analysis. It is
necessary to meet all assumptions in regression analysis to avoid spurious regressions
(Plonsky & Ghanbar, 2018).
Multicollinearity
Multicollinearity was evaluated by viewing the correlation coefficients between
the predictor variables. All bivariate correlation coefficients between the predictor
variables were small. Therefore, there was no evidence of multicollinearity assumption
violation. Table 11 shows the correlation coefficients.
Table 10
Correlation Coefficients Among Study Variables
Variable
Sub-
Variables
ALSI
SMB
HML
MO
M
MSCI
EM
SAV
I
10Y
R
3mth
COM
US/ZA
R
Risk
Exposure
ALSI
1
SMB
0.873
1
HML
0.630
0.179
1
-
MOM
-
0.141
-
0.146
-
0.057
1
MSCI
0.715
0.671
0.130
-
0.145
1
MSCIEM
0.720
0.734
0.201
-
0.099
0.860
1
SAVI
0.096
0.110
0.023
0.061
-0.026
-0.096
1
10Y
-
0.130
-
0.274
-
0.088
-
0.017
-0.251
-0.307
-
0.091
1
3mth
0.094
0.078
0.003
-
0.026
-0.020
-0.065
-
0.084
-
0.047
1
COM
0.299
0.352
0.008
0.015
0.277
0.277
0.443
0.038
-
0.257
1
US/ZAR
-
0.295
-
0.402
-
0.165
0.061
-0.596
-0.714
0.144
0.571
-
0.016
-
0.401
1
Volatility
Forecasting
0.021
-
0.075
-
0.083
0.076
0.068
0.060
0.011
0.032
-
0.073
0.044
0.017

96
Outliers, Normality, Linearity, Homoscedasticity, and Independence of Residuals
I investigated outliers, normality, linearity, homoscedasticity, and independence
of residuals by examining the normality P-P plots, box plots, and the scatterplot of the
standardized residuals from SPSS. The examination indicated there was a violation of
outliers’ assumption. Figure 2 shows the normality P-P plots of the standardized
residuals. The failure of the standardized residuals to lie in a straight line against the
predicted value supports the presence of outliers and the normality assumption violation
(Josephat & Ame, 2018). Figure 3 shows the scatterplot of the standard residuals. The
lack of a clear or systematic pattern in the scatterplot supports the tenability of the
violation of the linearity, homoscedasticity, and independence of residuals assumptions. I
computed 1,000 bootstrapping samples to address any possible influence of assumption
violations and reported 95% confidence intervals, based on the bootstrap samples where
appropriate.
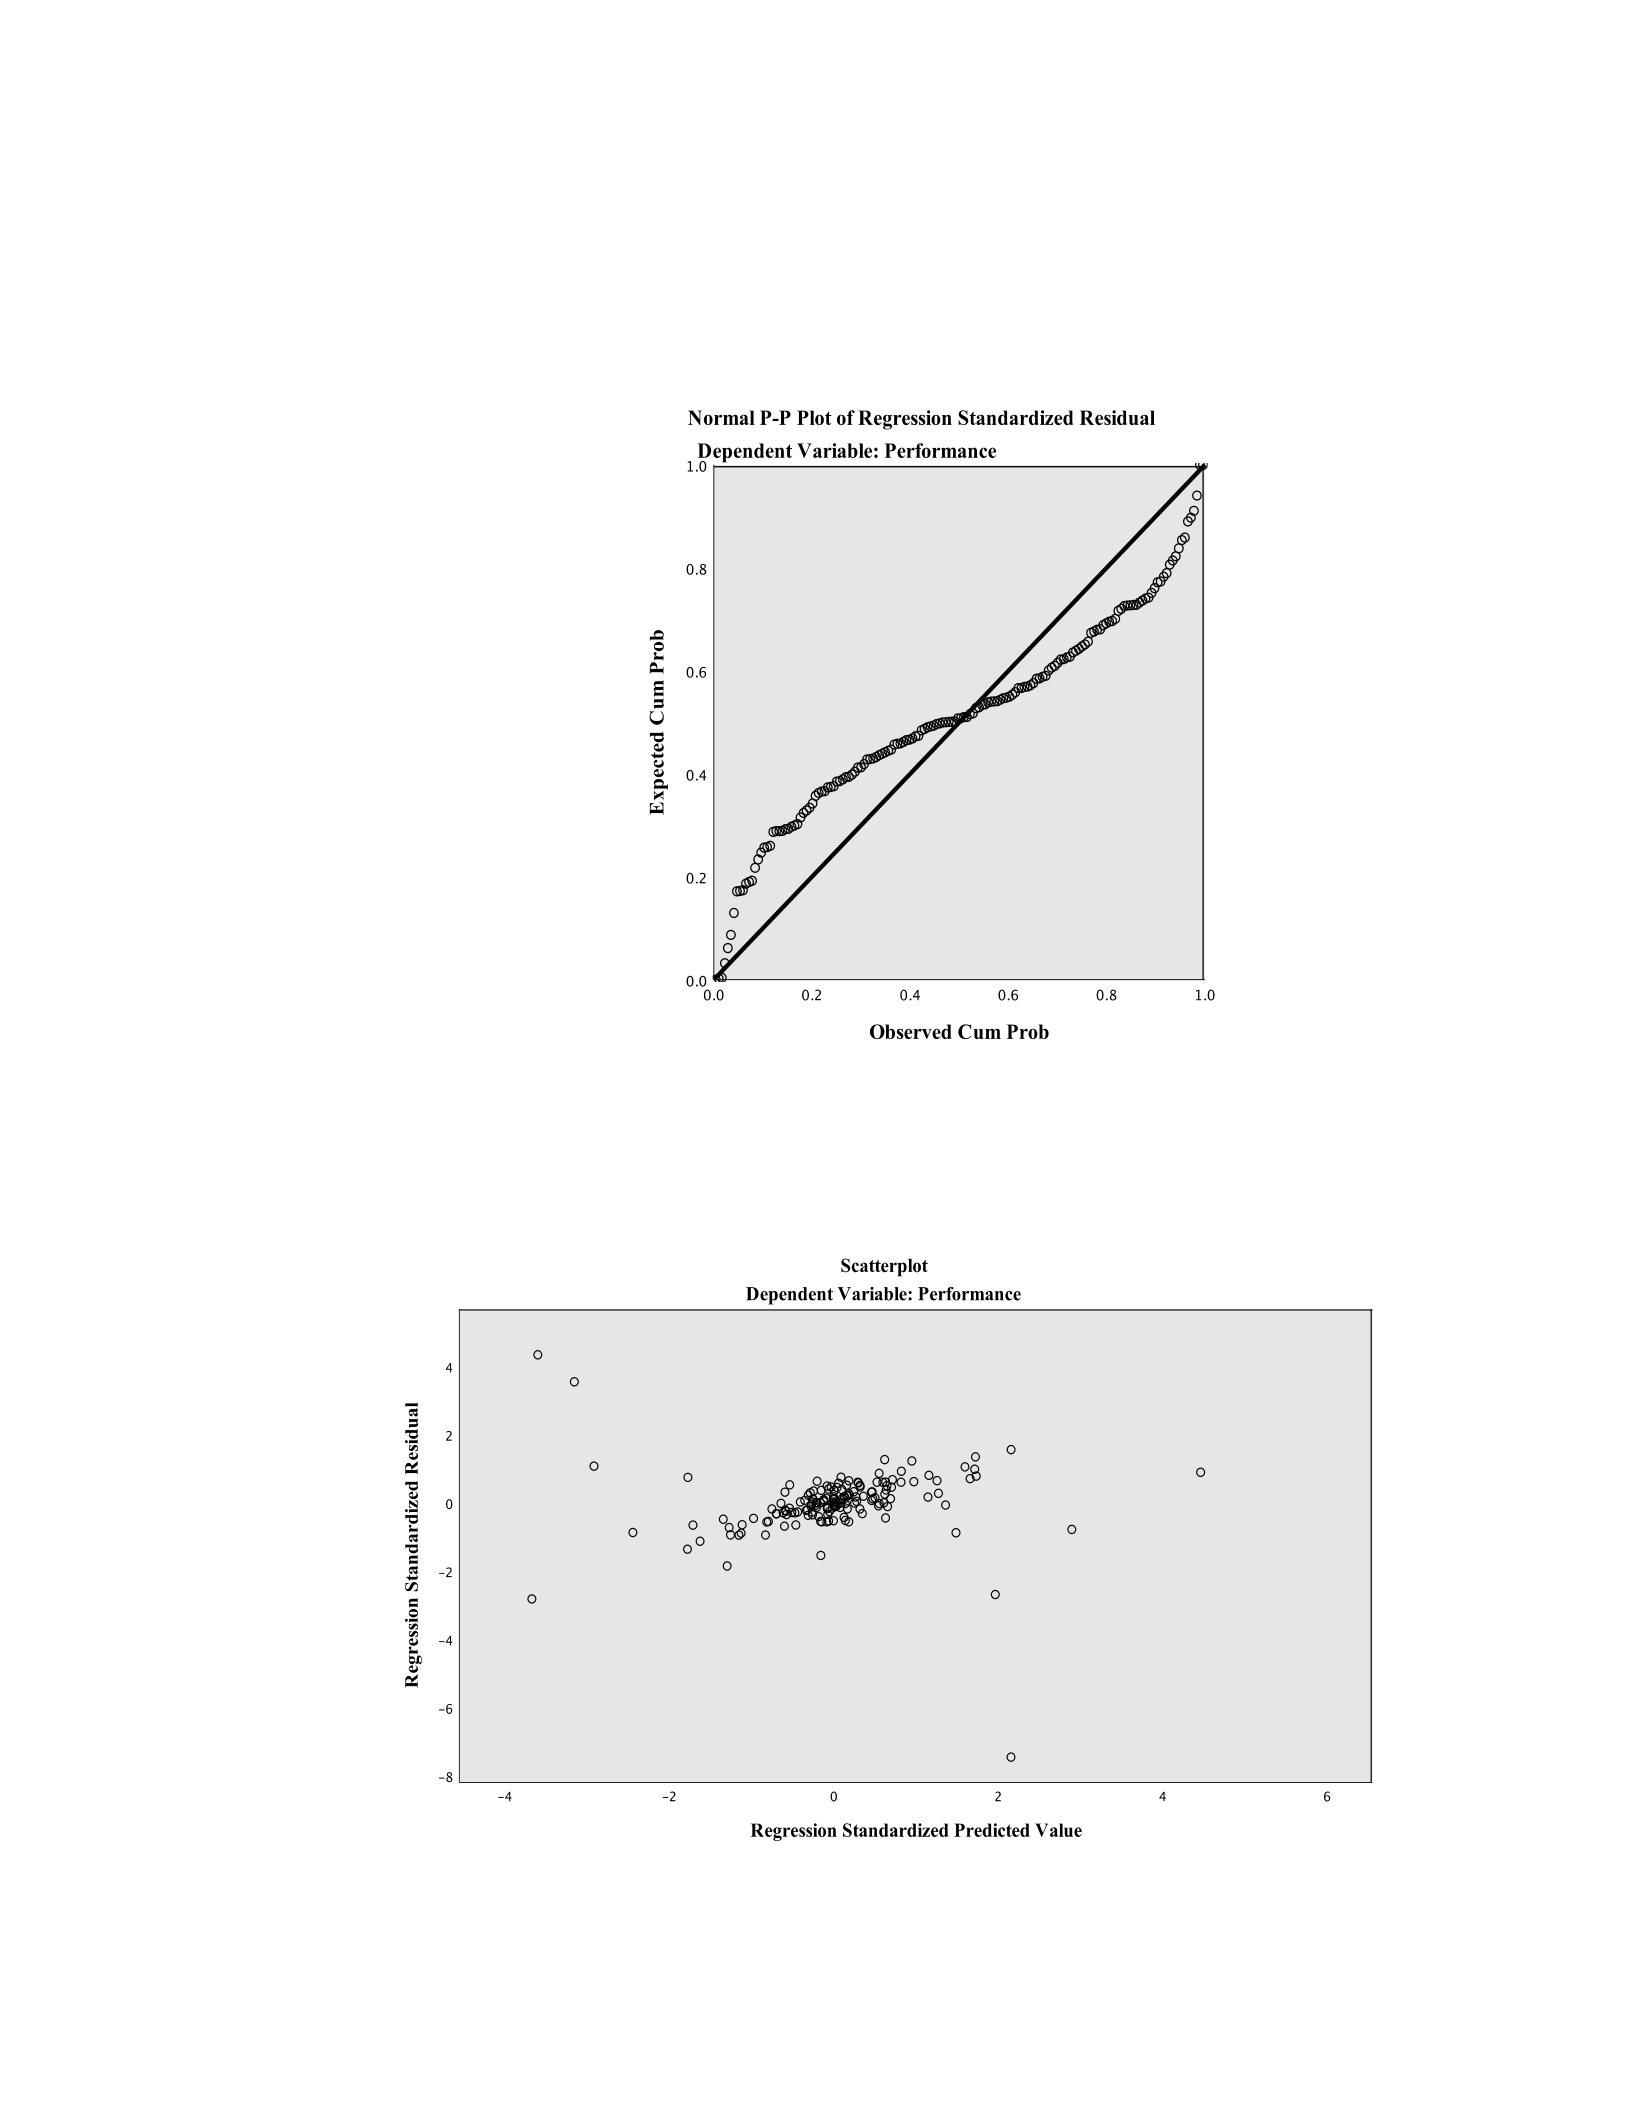
97
Figure 2
Normality of plot (P-P) of the regression standardized residuals
Figure 3
Scatterplot of the standardized residuals
98
Descriptive Statistics
The data consists of 150 observations of monthly returns from July 2007 to
December 2020 and eliminated six because of missing data, which resulted in 144
observations. Table 12 presents descriptive statistics of study variables.
Table 11
Means and Standard Deviations for Quantitative Study Variables
Variable
M
M 95%
Bootstrap CI
SD
SD 95%
Bootstrap CI
Performance
0.123
[-0.02, 0.27]
1.00
[0.80, 1.19]
Volatility Forecasting
0.04
[0.04, 0.04]
0.004
[0.003, 0.005]
Risk Exposure
2.9
[2.05, 3.35]
.28
[.25, .44]
Note: N = 144
Inferential Results
The study involved using the standard multiple linear regression, α = 0.05 (two-
tailed), to examine the efficacy of risk exposure, volatility forecasting, and the financial
performance of hedge funds. The independent variables were risk exposure and volatility
forecasting. The dependent variable was financial performance. The null hypothesis was
that there was no statistically significant relationship between risk exposure, volatility
forecasting, and the financial performance of hedge funds. The alternative hypothesis was
that there is a statistically significant relationship between risk exposure, volatility
forecasting, and the financial performance of hedge funds. The preliminary analysis took
place to assess whether the assumptions of multicollinearity, outliers, normality,
homoscedasticity, and independence of residuals were met. The results of the preliminary
analyses included a violation of outliers, normality, and homoscedasticity assumptions.
99
However, they did not include any serious violation of the independence of residuals
assumption (see Tests of Assumptions section).
The model as a whole was able to significantly predict hedge funds’ financial
performance at F (2, 149) = 238, p < 0.001, R2 = 0.932. The R2 (0.932) value indicated
that approximately 93% of hedge fund financial performance variations are accounted for
by the linear combination of the predictor variables. Risk exposure and volatility
forecasting were statistically significant in the final model. Table 12 shows the regression
summary of the study. The final regression equation is as follows:
Performance = α + β1(Volatility forecasting) + β3(ALSI) + β4(SMB) + β5(HML) +
β6(MOM) + β7(MSCI) + β8(MSCIEM) + β9(SAVI) + β10(10Yr-Bond) + β11(3month T-
Bill) + β12(Commodities) + β13(US/ZAR) + e
Table 12
Regression Analysis Summary for Predictor Variables
Variable
B
SE Β
β
t
p
Lower
Bound
Upper
Bound
Volatility
Forecasting
-3.685
4.444
-0.016
-0.829
0.408
-12.466
5.096
Risk Exposure
0.00
0.00
.00
.00
.00
ALSI
1.421
1.021
0.136
1.393
0.166
-0.596
3.438
SMB
-0.012
0.055
-0.004
-0.209
0.835
-0.120
0.097
HML
-1.345
0.982
-0.059
-1.369
0.173
-3.285
0.596
MOM
0.013
0.198
0.001
0.068
0.946
-0.378
0.405
MSCI
0.894
0.834
0.090
1.073
0.285
-0.753
2.542
MSCIEM
-0.155
0.823
-0.017
-0.188
0.851
-1.780
1.471
SAVI
0.033
0.167
0.004
0.199
0.842
-0.296
0.363
(table continues)
100
Variable
B
SE Β
β
t
p
Lower
Bound
Upper
Bound
10Yr-Bond
-0.438
0.493
-0.021
-0.889
0.376
-1.413
0.536
3-mth T-Bill
-8.947
0.950
-0.789
-9.417
<0.001
-10.824
-7.070
COM
-0.496
0.350
-0.030
-1.418
0.158
-1.187
0.195
US/ZAR
-0.061
0.755
-0.003
-0.081
0.936
-1.552
1.430
Note. N= 144; B = unstandardized coefficient; β = standardized coefficient
Volatility Forecasting
The negative slope for volatility forecasting (-3.685) as a predictor of hedge
funds' financial performance indicated a 3.685 decrease in performance for each one-
point increase in volatility forecasting. In other words, hedge funds' financial
performance tends to decrease as volatility forecasting increases. The squared semi-
partial coefficient (sr2) that was an estimate of how much variance in hedge funds'
financial performance was uniquely predictable from volatility forecasting at 0.03,
indicating that 3% of the variance in hedge funds' financial performance is uniquely
accounted for by volatility forecasting when risk exposure is controlled.
Risk Exposure
The categories of risk exposure variable (i.e., ALSI, SMB, HML, MOM, MSCI,
MSCIEM, SAVI, 10Yr-bond, 3mth-bill, Commodities, and SA/ZAR Exchange rate)
helped to determine the occurrence and magnitude of hedge funds financial performance.
The 3-month T-bill rate was the significant predictor of hedge funds' financial
performance at the 1% level, accounting for the highest contribution (B = -8.947).

101
Analysis Summary
The purpose of this quantitative correlational study was to examine the
relationship between risk exposure, volatility forecasting, and the financial performance
of hedge funds. I used multiple linear regression to examine the risk exposure and
volatility forecasting ability to predict the value of the financial performance of hedge
funds. Assumptions surrounding multiple regression were assessed with the assessment
results, including violations of outliers, normality, homoscedasticity, and independence
of residual assumptions. The model used in this study, as a whole, was able to
significantly predict the financial performance of hedge funds, F (2, 149) = 238, p <
0.001, R2 = .950. Volatility forecasting and risk exposure provide helpful predictive
information about the financial performance of hedge funds
Theoretical Conversation on Findings
The findings of this study align with the findings of Markowitz (1952). For
example, Stafylas et al. (2017) identified that investors could increase returns by taking
more significant risks. Bedoui et al. (2020) concluded in this research that the MPT was
valid for investigating the standard deviation optimization. Further, Joenväärä et al.
(2021b) identified that hedge funds' returns move in the opposite directions if there is a
positive or negative change in the stock market. The findings from this study extended
and supported Markowitz's (1952) MPT. The premise of MPT is that the expected return
and variances of assets in which a hedge fund manager constructs hedge funds is based
on their customers' risk preferences (Moulya et al., 2019).

102
The findings of this study indicated no significant relationship between volatility
forecasting and the financial performance of hedge funds. The model used in this study,
as a whole, was able to significantly predict the financial performance of hedge
funds, F (2, 149) = 238, p < 0.001, R2 = .950. The negative slope of volatility forecasting
(-0.016) as a predictor of hedge funds' financial performance indicated a 0.016 decrease
in volatility forecasting for a unit’s increase in performance. The findings of this study
supported the findings of Abdennadher and Hallara (2018), who showed that the shifts
explained changes in the return volatilities of equity hedge funds returns.
The findings of this study indicated varying relationships between risk exposure
categories and the financial performance of hedge funds. In this study, the 3-month T-bill
rate had a significant relationship with the financial performance of hedge funds at 1%
from 2007 to 2020. The negative slope of the 3-month T-bill variable (-0.789) as a
predictor of financial performance of hedge funds indicated there was 0.678. The market
index (ALSI) did not contribute significantly to the model (B = 1.421) and had the
highest slope β = 0.136, indicating the highest hedge fund exposure in the analysis.
Frydenberg et al. (2017) findings indicated that the momentum effect (MOM) and market
index (NYSE) were significant at the level of 1% during the recession period. However,
MOM was also significant during the whole period of study, from 1994 to 2015.
Frydenberg et al. (2017) confirmed that hedge fund managers vary the risk exposure of
assets to changing market conditions, indicating managers’ skills.
Similarly, Agarwal et al. (2018a) show that hedge fund managers vary the
portfolio exposure timely by predicting the fluctuating macroeconomic variables. The

103
outcome of this study contrasted with a study conducted by Gerhard and Rupert (2017).
Gerhard and Rupert (2017) examined the relationship between commodity, equity
indices, and hedge fund performance, reporting that MSCIEM and the market index
(S&P 500) were highly significant during the analysis period from 1990 to 2010.
Applications to Professional Practice
The financial performance of hedge fund attracts market participants seeking
higher returns in various market conditions (Schreder, 2018; Shin et al., 2017). One of the
sources of the superior performance of hedge fund managers is skills in market timing
and volatility to adapt the funds' market exposure (Cui & Kolokolova, 2020; Muteba
Mwaba, 2017). The study's findings may be of practical significance to investors and
fund managers because: (a) I based the study design on the decision-making to assess
investment risk, and (b) I highlighted the movement of underlying macroeconomic
variables that correlate with hedge fund performance.
Market participants should account for risks when making investment decisions
(Stafylas & Andrikopoulos, 2020). The results of this study highlight the necessity of risk
dynamics assessment. Simultaneously, timing the market and predicting future levels of
volatility allows the managers to adapt the funds' risk exposure for higher performance or
reduce losses (Cao et al., 2018a). Furthermore, the research findings may provide
essential information to assist investors or managers in determining the impact of varying
economic conditions on the risk dynamics of the hedge fund strategies.

104
Implications for Social Change
The implication of the study results could serve two potential purposes. The first
is that leaders of investment corporations may: (a) factor in the importance of market
pricing when making investment decisions and (b) ensure that superior performance
relates to knowledge of market risks and volatility. Thus, the right timing of investments
could increase a firm's profits and resources to drive social change. Firms that create
profits or increase value have a competitive edge, which allows them to invest in socio-
economic projects that drive change (Sosner & Steblea-Lora, 2022). The implications for
a positive social change of this study include the potential to improve communities by
providing more jobs for local people.
Another implication for a positive social change includes the potential to provide
corporate leaders with a better understanding of factors that drive the financial
performance of hedge funds. The possibility exists to improve the tools for managers to
maximize financial performance by timing market returns and predicting levels of
volatility. The social change implication includes the potential to improve relationships
between leaders, fund managers of the corporation, investors, and shareholders.
Recommendations for Action
The results of this study are consistent with other research on hedge fund
performance (Kapil & Gupta, 2019; Metzger & Shenai, 2019; Zhang et al., 2021). The
performance of hedge funds is an indicator of the manager’s skill (Shin et al., 2017).
Also, the findings from this study supported the validity of MPT, and I recommend that
managers use MPT as a basis for portfolio management strategies. I found a significant

105
relationship between risk exposure, volatility forecasting, and performance. Based on the
findings on these variables, my recommendation for hedge fund managers includes the
risk exposure to maximize financial performance. Risk exposure refers to using
systematic risk factors of hedge funds to evaluate financial performance. I recommend
hedge fund managers allocate strategies by adjusting the funds’ performance market
exposure.
The study results are relevant to fund managers and scholars. The results may
help fund managers make investment decisions or portfolio selections under varying
market conditions. Finally, scholars may use the findings as a foundation for further
research or comparison to other areas of hedge fund literature or models. I intend to
publish the results of this study in the Pro-Quest dissertation database and other scholarly
journals so other scholars, practitioners, and business professionals can have access.
Furthermore, I intend to present the findings to stakeholders via conferences, seminars,
and training workshops.
Recommendations for Further Research
In this study, I examined the relationship between risk exposure, volatility
forecasting, and the financial performance of hedge funds. This study has some
limitations; therefore, recommendations for future studies are necessary. The
performance variable focuses on hedge fund returns in South Africa from 2007 to 2020.
Recommendations for future researchers include expanding to other markets or regions.
Furthermore, I would recommend further research on using different techniques to
analyze performance and increasing the number of years for data analysis. The findings

106
of this study could improve business practices by providing managers with insight into
asset selectivity.
Reflections
In concluding this study, my goal was to gain insight into market risk exposure of
hedge funds, volatility, and the effect on performance. There were few surprises during
the process, especially during the data collection phase. Unfortunately, unlike mutual
funds, accessing hedge fund data from databases is extremely expensive. I had to acquire
the necessary funds to purchase the data. After purchasing, there is a waiting period for a
background check before downloading. In addition, for several weeks, I reviewed the
fields that contained the data required for analysis. Though, this task was a grueling, the
process yielded an effective source for the study.
Conclusion
The primary purpose of the quantitative correlational study was to examine hedge
funds as a potential source of investment profits for individual and corporate investors
without loss. The aim was to determine if a statistically significant relationship exists
between risk exposure, volatility forecasting, and the financial performance of hedge
funds. I examined the relationship between the variables using a multiple regression
model, and a sample consisting of 144 observations of 86 managed funds.
The findings revealed a significant relationship between variables because the p-
values were less than the alpha of 0.05. Consequently, I rejected the null hypothesis; H0:
There is no statistically significant relationship between risk exposure, volatility
forecasting, and financial performance of hedge funds for the period 2007 and 2020.

107
According to the findings, investors and managers may use risk exposure and volatility as
indicators of future hedge fund performance

108
References
Abdennadher, E., & Hallara, S. (2018). Structural breaks and stock market volatility in
emerging countries. International Journal of Business and Risk Management,
1(1), 9-16. https://doi.org/10.12691/ijbm-1-1-2
Abdin, S. Z. U., Farooq, O., Sultana, N., & Farooq, M. (2017). The impact of heuristics
on investment decision and performance: Exploring multiple mediation
mechanisms. Research in International Business and Finance, 42, 674-688.
https://doi.org/10.1016/j.ribaf.2017.07.010
Abdin, S. Z. U., Waqas, M., & Ahmad, M. (2019). A test of market efficiency using
stock market anomalies: A behavioral approach. Middle East Journal of
Management, 6(5), 551-573. https://doi.org/10.1504/mejm.2019.101922
AbuRaya, R., & Gomaa, Y. A. (2020). Philosophical assumptions, methodological
choices and research design: E-Learners versus non E-Learners. 2020 Sixth
International Conference on e-Learning (econf), 2020, pp. 374-380.
https://doi.org/10.1109/econf51404.2020.9385478
Agarwal, V., Aragon, G. O., & Shi, Z. (2019). Liquidity transformation and financial
fragility: Evidence from funds of hedge funds. Journal of Financial and
Quantitative Analysis, 54(6), 2355-2381.
https://doi.org/10.1017/S0022109018001369
Agarwal, V., Arisoy, Y. E., & Naik, N. Y. (2017a). Volatility of aggregate volatility and
hedge fund returns. Journal of Financial Economics, 125(3), 491-510.
https://doi.org/10.1016/j.jfineco.2017.06.015

109
Agarwal, V., Green, T. C., & Ren, H. (2018a). Alpha or beta in the eye of the beholder:
What drives hedge fund flows? Journal of Financial Economics, 127(3), 417-434.
https://doi:org/10.1016/j.jfineco.2018.01.006
Agarwal, V., & Naik, N. Y. (2004). Risks and portfolio decisions involving hedge funds.
Review of Financial Studies, 17(1), 63-98. https://doi.org/10.1093/rfs/hhg044
Agarwal, V., Ruenzi, S., & Weigert, F. (2017b). Tail risk in hedge funds: A unique view
from portfolio holdings. Journal of Financial Economics, 125(3), 610-636.
https://doi.org/10.1016/j.jfineco.2017.06.006
Agarwal, V., Ruenzi, S., & Weigert, F. (2018b). Unobserved performance of hedge
funds. SSRN Electronic Journal. https://doi.org/10.2139/ssrn.3288468
Agbehadji, I. E., Millham, R. C., Fong, S. J., & Yang, H. (2018). Bioinspired
computational approach to missing value estimation. Mathematical Problems in
Engineering, 2018, 1-16. doi:10.1155/2018/9457821
Ahmad, Z., Ibrahim, H., & Tuyon, J. (2017). Behavior of fund managers in Malaysian
investment management industry. Qualitative Research in Financial Markets,
9(3), 205-239. https://doi.org/10.1108/qrfm-08-2016-0024
Aiken, A. L., Clifford, C. P., Ellis, J. A., & Huang, Q. (2021). Funding liquidity risk and
the dynamics of hedge fund lockups. Journal of Financial and Quantitative
Analysis, 56(4), 1321-1349. https://doi.org/10.1017/s0022109020000393
Ali, A., & Shukla, D. (2020). A comparative study on parameter estimation methods for
big data analysis based on random sample. International Journal of Scientific &
Technology Research, 9(2), 3480-3486. https//www.ijstr.org

110
Almeida, C., Ardison, K., & Garcia, R. (2020). Nonparametric assessment of hedge fund
performance. Journal of Econometrics, 214(2), 349-378.
https://doi.org/10.1016/j.jeconom.2019.08.002
Al Rahahleh, N., & Kao, R. (2018). Forecasting volatility: Evidence from the Saudi stock
market. Journal of Risk and Financial Management, 11(4), 84-102.
https://doi.org/10.3390/jrfm11040084
Amin, G. S., & Kat, H. M. (2003). Stocks, bonds, and hedge funds. Journal of Portfolio
Management, 29(4), 113-120. https://doi.org/10.3905/jpm.2003.319900
Amudha, R., & Muthukamu, M. (2018). Modeling symmetric and asymmetric volatility
in the Indian stock market. Indian Journal of Finance, 12(11), 23-36.
https://doi.org/10.17010/ijf/2018/v12i11/138196
Andronov, A. (2017). Markov-modulated multivariate linear regression. Acta et
Commentationes Universitatis Tartuensis de Mathematica, 21(1), 43-50.
https://doi.org/10.12697/acut,.2017.21.03
Aragon, G. O., & Nanda, V. (2017). Strategic delays and clustering in hedge fund
reported returns. Journal of Financial and Quantitative Analysis, 52(1), 1-35.
https://doi.org/10.1017/s0022109016000715
Ardia, D., Bluteau, K., Boudt, K., & Catania, L. (2018). Forecasting risk with Markov-
switching GARCH models: A large-scale performance study. International
Journal of Forecasting, 34(4). 733-747.
https://doi.org/10.1016/j.ijforecast.2018.05.004
Ardia, D., Bluteau, K., & Rüede, M. (2019). Regime changes in Bitcoin GARCH

111
volatility dynamics. Finance Research Letters, 29, 266–271.
https://doi.org/10.1016/j.frl.2018.08.009
Areiqat, A. Y., Abu-Rumman, A., Al-Alani, Y. S., & Alhorani, A. (2019). Impact of
behavioral finance on stock investment decisions applied study on a sample of
investors at Amman stock exchange. Academy of Accounting and Financial
Studies Journal, 23(2), 1-16. https://www.abacademies.org
Arize, A. C., Guo, T., Malindretos, J., & Verzani, L. (2019). Financial advice and
portfolio diversification. Accounting and Finance Research, 8(4), 178-185.
https://doi.org/10.5430/afr.v8n4p178
Arslan, R. C. (2019). How to automatically document data with the codebook package to
facilitate data reuse. Advances in Methods and Practices in Psychological
Science, 2(2), 169-187. https://doi.org/10.1177/2515245919838783
Avkiran, N. K. (2018). Explaining systemic risk in money market funds. Theoretical
Economics Letters, 8(09), 1525-1552. https://doi.org/10.4236/tel.2018.89098
Badea, L., Armeanu, D., Panait, I., & Gherghina, S. C. (2019). A Markov regime
switching approach towards assessing resilience of Romanian collective
investment undertakings. Sustainability, 11(5), 1325-1349.
https://doi.org/10.3390/su11051325
Bahloul, S., Mroua, M., & Naifar, N. (2017). The impact of macroeconomic and
conventional stock market variables on Islamic index returns under regime
switching. Borsa Istanbul Review, 17(1), 62-74.
https://doi.org/10.1016/j.bir.2016.09.003

112
Baker, H. K., Chkir, I., Saadi, S., & Zhong, L. (2017). What drives the high moments of
hedge fund returns? Applied Economics, 49(8), 738-755.
https://doi.org/10.1080/00036846.2016.1205723
Balcilar, M., Gupta, R., & Kotze, K. (2017). Forecasting South African macroeconomic
variables with a Markov-switching small open-economy dynamic stochastic
general equilibrium model. Empirical Economics, 53(1), 117-135.
https://doi.org/10.1007/s00181-016-1157-6
Bali, T. G., Brown, S. J., & Caglayan, M. O. (2014). Macroeconomic risk and hedge fund
returns. Journal of Financial Economics, 114(1), 1-19.
https://doi.org/10.1016/j.jfineco.2014.06.008
Baltas, N., & Kosowski, R. (2019). Demystifying time-series momentum strategies:
Volatility estimators, trading rules and pairwise correlations. SSRN Electronic
Journal. https://doi.org/10.2139/ssrn.2140091
Barth, D., Joenväärä, J., Kauppila, M., & Wermers, R. R. (2021). The hedge fund
industry is bigger (and has performed better) than you think. SSRN Electronic
Journal. https://ssrn.com/abstract=3544181
Bashir, F., & Wei, H.-L. (2018). Handling missing data in multivariate time series using a
vector autoregressive model-imputation (VAR-IM) algorithm. Neurocomputing,
276, 23-30. https://doi.org/10.1016/j.neucom.2017.03.097
Bayer, F. M., & Cribari-Neto, F. (2017). Model selection criteria in beta regression with
varying dispersion. Communications in Statistics Simulation-Simulation and
Computation, 46(1), 729-746. https://doi.org/10.1080/03610918.2014.977918

113
Bedoui, R., Noiali, S., & Hamdi, H. (2020). Hedge funds portfolio optimization using a
vine copula-GARCH-EVT-CVaR model. International Journal of
Entrepreneurship and Small Business, 39(1/2), 121-148.
https://doi.org/10.1504/ijesb.2020.104247
Ben-David, I., Birru, J., & Rossi, A. (2020). The performance of hedge fund performance
fees. SSRN Electronic Journal. https://doi.org/10.2139/ssrn.3630723
Bender, J., Blackburn, T., & Sun, X. (2019). Clash of the titans: Factors portfolios versus
alternative weighting schemes. The Journal of Portfolio Management, 45(3), 38-
49. https://doi.org/10.3905/jpm.2019.45.3.038
Bergtold, J. S., Yeager, E. A., & Featherstone, A. M. (2018). Inferences from logistic
regression models in the presence of small samples, rare events, nonlinearity, and
multicollinearity with observational data. Journal of Applied Statistics, 45(3),
528-546. https://doi.org/10.1080/02664763.2017.1282441
Bessler, W., Opfer, H., & Wolff, D. (2017). Multi-asset portfolio optimization and out-
of-sample performance: An evaluation of Black-Litterman, mean-variance, and
naive diversification approaches. The European Journal of Finance, 23(1), 1-30.
https://doi.org/10.1080/1351847X.2014.953699
Bhowmik, R., & Wang, S. (2020). Stock market volatility and return analysis: A
systematic literature review. Entropy, 22(5), 522-540.
https://doi.org/10.3390/e22050522
Billio, M., Casarin, R., & Osuntuyi, A. (2018). Markov switching GARCH models for
Beyesian hedging on energy futures markets. Energy Economics, 70, 545-562.

114
https://doi.org/10.1016/j.eneco.2017.06.001
Billio, M., Getmansky, M., & Pelizzon, L. (2012). Dynamic risk exposures in hedge
funds. Computational Statistics & Data Analysis, 56(11), 3517-3532.
https://doi.org/10.1016/j.csda.2010.08.015
Billio, M., Sherman, M. G., & Pelizzon, L. (2017). Financial crisis and evaporating
diversification benefits of hedge funds. Oxford Scholarship Online.
https://doi.org/10.1093/oso/9780190607371.003.0024
Black, F., & Scholes, M. (1973). The pricing of options and corporate liabilities. Journal
of Political Economy, 81(3), 637-657. https://doi.org/10.1086/260062
Bolander, W., Dugan, R., & Jones, E. (2017). Time, change, and longitudinally emergent
conditions: Understanding and applying longitudinal growth modeling in sales
research. Journal of Personal Selling & Sales Management, 37(2), 153-159.
https://doi.org/10.1080/08853134.2017.1314187
Bollen, N. P. B., Joenväärä, J., & Kauppila, M. (2021). Hedge fund performance: End of
an era? Financial Analysts Journal, 77(3), 109–132.
https://doi.org/10.1080/0015198X.2021.1921564
Bollen, N. P. B., & Whaley, R. E. (2009). Hedge fund risk dynamics: Implications for
performance appraisal. The Journal of Finance, 64(2), 985-1035.
https//doi.org/10.1111/j.1540-6261.2009.01455x
Bollerslev, T. (1986). Generalized autoregressive conditional heteroscedasticity. Journal
of Econometrics, 31(3), 307-327. https://doi.org/10.1016/0304-4076(86)90063-1
Bouamara, N., Boudt, K., Peeters, B., & Thewissen, J. (2017). The alpha and beta of

115
equity hedge UCITS funds: Implications for momentum investing. Factor
Investing, 415-446. https://doi.org/10.1016/b978-1-78548-201-4.50016-7
Brannen, J. (2017). Mixing methods: Qualitative and quantitative research. Routledge.
Brooks, C. (2019). Introductory econometrics for finance.
https://doi.org/10.1017/9781108524872.
Cai, B., Cheng, T., & Yan, C. (2018). Time-varying skills (versus luck) in U.S. active
mutual funds and hedge funds. Journal of Empirical Finance, 49, 81-106.
https://doi.org/10.1016/j.jempfin.2018.09.001
Camacho, M., Perez-Quiros, G., & Poncela, P. (2018). Markov-switching dynamic factor
models in real time. International Journal of Forecasting, 34(4), 598-611.
https//doi.org/10.1016/j.ijforecast.2018.05.002
Canepa, A., de la O. Gonzalez, M., & Skinner, F. S. (2020). Hedge fund strategies: A
non-parametric analysis. International Review of Financial Analysis, 67, 1057-
5219. https://doi.org/10.1016/j.irfa.2019.101436
Cao, C., Chen, Y., Goetzmann, W. N., & Liang, B. (2018a). Hedge funds and stock price
formation. Financial Analysts Journal, 74(3), 54-68.
https://doi.org/10.2469/faj.v74.n3.4
Cao, C., Liang, B., Lo, A. W., & Petrasek, L. (2018b). Hedge fund holdings and stock
market efficiency. Review of Asset Pricing Studies, 8(1), 77-116.
https://doi.org/10.1093/rapstu/rax015/3806675
Carhart, M. M. (1997). On persistence in mutual fund performance. The Journal of
Finance, 52(1), 57-82. https://doi.org/10.1111/j.1540-6261.1997.tb03808.x

116
Cave, S. N., & Stumm, S. (2021). Secondary data analysis of British population cohort
studies: A practical guide for educational researchers. British Journal of
Educational Psychology, 91(2), 531-546. https://doi.org/10.1111/bjep.12386
Ceruttia, E., Claessens, S., & Laevenc, L. (2017). The use and effectiveness of
macroprudential policies: New evidence. Journal of Financial Stability, 28, 203-
224. https://doi.org/10.1016/j.jfs.2015.10.004
Chen, J., & Kawaguchi, Y. (2018). Multi-factor asset-pricing models under Markov
regime switches: Evidence from the Chinese stock market. International Journal
of Financial Studies, 6(2), 54-73. https://doi.org/10.3390/ijfs6020054
Cheng, A., Kessler, D., Mackinnon, R., Chang, T. P., Nadkarni, V. M., Hunt, E. A.,
Duval-Arnould, J., Lin, Y., Pusic, M., & Auerbach, M. (2017). Conducting
multicenter research in healthcare simulation: Lessons learned from the INSPIRE
network. Advances in Simulation, 2(6), 1-14. https://doi.org/10.1186/s41077-017-
0039-0
Chevalier, C., & Darolles, S. (2019). Trends everywhere? The case of hedge fund styles.
Journal of Asset Management, 20(6), 442-468. https://doi.org/10.1057/s41260-
019-00141-5
Chhapra, I. U., Kashif, M., Rehan, R., & Bai, A. (2018). An empirical investigation of
investor's behavior biases on financial decision making. Asian Journal of
Empirical Research, 8(3), 99-109.
https://doi.org/10.18488/journal.1007/2018.7.3/1007.3.99.109
Chu, Z., Wang, Z., Xiao, J. J., & Zhang, W. (2017). Financial literacy, portfolio choice

117
and financial well-being. Social Indicators Research, 132(2), 799-820.
https://doi.org/10.1007/s11205-016-1309-2
Coertjens, L., Donche, V., De Maeyer, S., Vanthournout, G., & Van Petegem, P. (2017).
To what degree does the missing-data technique influence the estimated growth in
learning strategies over time? A tutorial example of sensitivity analysis for
longitudinal data. PLOS ONE,12(9), 1-21.
https://doi.org/10.1371/journal.pone.0182615
Collective Investment Scheme Control Act (CISCA): Financial Services Board. (2015
April). Determination of the requirements for hedge funds.
http://www.gpwonline.co.za/Pages/default.aspx
Cortina, J. M. (2020). On the whys and hows of quantitative research. Journal of
Business Ethics, 167(1), 19-29. https://doi.org/10.1007/s10551-019-04195-8
Crego, J., & Galvez, J. (2018). Cyclical dependence and timing in market neutral hedge
funds. SSRN Electronic Journal, 1-41. https://doi.org/10.2139/ssrn.3179531
Cui, X., & Kolokolova, O. (2020). Do hedge fund managers work harder under pressure?
A unique view from hedge fund flow-related trading. SSRN Electronic Journal, 1-
30. https://doi.org/10.2139/ssrn.3426553
Dai, Z., Zhou, H., Dong, X., & Kang, J. (2020). Forecasting stock market volatility: A
combination approach. Discreet Dynamics in Nature and Society, 2020, 1-9.
https://doi.org/10.1155/2020/1428628
Dattalo, P. (2018). Determining sample size using fast and slow thinking. Journal of
Social Service Research, 44(2), 180-190.

118
https://doi.org/10.1080/01488376.2018.1436632
Davino, C., Romano, R., & Vistocco, D. (2020). On the use of quantile regression to deal
with heterogeneity: The case of multi-block data. Advances in Data Analysis and
Classification, 14(4), 771-784. https://doi.org/10.1007/s11634-020-00410-x
Ding, Z., Granger, C. W. J., & Engle, R. F. (1993). A long memory property of stock
market returns and a new model. Journal of Empirical Finance, 1(1), 83-106.
https://doi.org/10/1016/0927-5398(93)90006-d
Di Sanzo, S. (2018). A Markov switching long memory model of crude oil price return
volatility. Energy Economics, 74, 351-359.
https://doi.org/10.1016/j.eneco.2018.06.015
Economou, F., Hassapis, C., & Nikolaos, P. (2018). Investors’ fear and herding in the
stock market. Applied Economics, 50(34), 3654-3663.
https://doi.org/10.1080/00036846.2018.1436145
Edwards, J. R. (2020). The peaceful coexistence of ethics and quantitative research.
Journal of Business Ethics, 167(1), 31-40. https://doi.org/10.1007/s10551-019-
04197-6
El Jebari, O., & Hakmaoui, A. (2017). Modeling persistence of volatility in the Moroccan
exchange market using fractionally integrated EGARCH. The Turkish Economic
Review, 4(4), 388-399. https://www.kspjournals.org
Emenogu, N. G., & Adenomon, M. O. (2018). The effect of high positive autocorrelation
on the performance of GARCH family models. Preprints.
https://doi.org/10.20944/preprints201811.0381.v1

119
Emenogu, N. G., Adenomon, M. O., & Nweze, N. O. (2020). On the volatility of daily
stock returns of total Nigeria Plc: Evidence from GARCH models, value-at-risk
and backtesting. Financial Innovation, 6(1), 8-33. https://doi.org/10.1186/s40854-
020-00178-1
Engle, R. F. (1982). Autoregressive conditional heteroscedasticity with estimates of the
variance of United Kingdom inflation. Econometrica, 50(4), 987-1007.
https://doi.org/10.2307/1912773
Ernst, A. F., & Albers, C. J. (2017). Regression assumptions in clinical psychology
research practice -A systematic review of common misconceptions. PeerJ, 5,
e3323. https://doi.org/10.7717/peerj.3323
Ewing, B. T., & Malik, F. (2016). Volatility spillovers between oil prices and the stock
market under structural breaks. Global Finance Journal, 29, 12-23.
https://doi.org/10.1016/j.gfj.2015.04.008
Falkowski, M., Sierpinska-Sawicz, A., & Szczepankowski, P. (2020). The effectiveness
of hedge fund investment strategies under various market conditions.
Contemporary Economics, 14(2), 127-143. https://doi.org/10.5709/ce.1897-
9254.336
Fama, E. F. (1970). Efficient capital markets: A review of theory and empirical work.
The Journal of Finance, 25(2), 383-417. https://doi.org/10.1111/j.1540-
6261.1970.tb00518.x
Fama, E. F., & French, K. R. (1993). Common risk factors in the returns on stocks and
bonds. Journal of Financial Economics, 33(1), 3-56.

120
https://doi.org/10.1016/0304-405x(93)90023-5
Fama, E. F., & French, K. R. (1996). Multifactor explanations of asset pricing anomalies.
The Journal of Finance, 51(1), 55-84
Fang, E., & Almeida, C. (2018). Are higher-order factors useful in pricing the cross-
section of hedge fund returns? SSRN Electronic Journal.
https://doi.org/10.2139/ssrn.3211540
Faul, F., Erdfelder, E., Buchner, A., & Lang, A. G. (2009). Statistical power analyses
using G*Power 3.1: Tests for correlation and regression analyses. Behavior
Research Methods, 41(4), 1149-1160. https://doi.org/10.3758/BRM.41.4.1149
Fernando, A. (2018). Macroeconomic impact on stock market returns and volatility:
Evidence from Sri Lanka. Business and Economics Journal, 9(4), 1-15.
https://doi.org/10.4172/2151-6219.1000379
Filbeck, G., Ricciardi, V., Evensky, H. R., Fan, S. Z., Holzhauer, H. M., & Spieler, A.
(2017). Behavioral finance: A panel discussion. Journal of Behavioral and
Experimental Finance, 15(1), 52-58. https://doi.org/10.1016/j.jbef.2017.07.008
Fink, M. C., Radkowitsch, A., Bauer, E., Sailer, M., Kiesewetter, J., Schmidmaier, R.,
Siebeck, M., Fischer, F., & Fischer, M. R. (2021). Simulation research and
design: A dual-level framework for multi-project research programs. Educational
Technology Research and Development, 69(2), 809-841.
https://doi.org/10.1007/s11423-020-09876-0
Forsberg, D. F., Gallagher, D. R., & Warren, G. J. (2018). Identifying hedge fund skill
using peer cohorts. Financial Analysts Journal, 1-70.

121
https://doi.org/10.2139/ssrn.3104261
Foss, N. J., & Hallberg, N. L. (2017). Changing assumptions and progressive change in
theories of strategic organization. Strategic Organization, 15(3), 410-422.
https://doi.org/10.1177/1476127016671099
Frei, C. W., & Hughes, P. (2013). Exploring limitations of return-based exposure
estimation for hedge funds. The Journal of Alternative Investments, 16(3), 48-63.
https://doi.org/10.3905/jai.2013.16.3.048
French, J. (2017). Macroeconomic forces and arbitrage pricing theory. Journal of
Comparative Asian Development, 16(1), 1-20.
https://doi.org/10.1080/15339114.2017.1297245
Friesen, P., Kearns, L., Redman, B., & Caplan, A. L. (2017). Rethinking the Belmont
report? The American Journal of Bioethics, 17(7), 15-21.
https://doi.org/10.1080/15265161.2017.1329482
Frydenberg, S., Hrafnkelson, K., Bromseth, V. S., & Westgaard, S. (2017). Hedge fund
strategies and time varying alphas and betas. The Journal of Wealth Management,
19(4), 44-60. https://doi.org/10.3905/jwm.2017.19.4.044
Fung, H., Xu, X. E., & Yau, J. (2002). Global hedge funds: Risk, return, and market
timing. Financial Analysts Journal, 58(6), 19-30.
https://doi.org/10.2469/faj.v58.n6.2483
Fung, W., Hsieh, D., Naik, N., & Teo, M. (2021). Hedge fund franchises. Management
Science, 67(2), 1199-1226. https://doi.org/10.1287/mnsc.2019.3516
Fung, W., & Hsieh, D. A. (1997a). Survivorship bias and investment style in the returns

122
of CTAs. The Journal of Portfolio Management, 24(1), 30-41.
https://doi.org/10.3905/jpm.1997.409630
Fung, W., & Hsieh, D. A. (1997b). Empirical characteristics of dynamic trading
strategies: The case of hedge funds. Review of Financial Studies, 10(2), 275-302.
https://doi.org/10.1093/rfs/10.2.275
Fung, W., & Hsieh, D. A. (2001). The risk in hedge fund strategies: Theory and evidence
from trend followers. Review of Financial Studies, 14(2), 313-341.
https://doi.org/10.1093/rfs/14.2.313
Fung, W., & Hsieh, D. A. (2004). Hedge fund benchmarks: A risk-based approach.
Financial Analysts Journal, 60(5), 65-80. https://doi.org/10.2469/faj.v60.n5.2657
Fung, W., Hsieh, D. A., Naik, N. Y., & Ramadoria, T. (2008). Hedge funds:
Performance, risk, and capital formation. The Journal of Finance, 63(4), 1777-
1803. https://doi.org/10.1111/j.1540-6261.2008.01374.x
Gaetano, D. (2018). Forecast combinations for structural breaks in volatility: Evidence
from BRICS countries. Journal of Risk and Financial Management, 11(4), 64-77.
https://doi.org/10.3390/jrfm11040064
Gao, C., Haight, T., & Yin, C. (2018a). Size, age, and the performance life cycle of hedge
funds. SSRN Electronic Journal. https://doi.org/10.2139/ssrn.3169312
Gao, G. P., Gao, P., & Song, Z. (2018b). Do hedge funds exploit rare disaster concerns?
The Review of Financial Studies, 31(7), 2650-2692.
https://doi.org/10.1093/rfs/hhy027
Gerhard, L., & Rupert, B. (2017). Relationship of commodity and equity indices on

123
hedge fund performance. Journal of Finance and Economics, 5(3), 136-144.
https://doi.org/10.12691/jfe-5-3-6
Getmansky, M., Liang, B., Schwarz, C., & Wermers, R. (2019). Share restrictions and
investor flows in the hedge fund industry. SSRN Electronic Journal.
https://doi.org/10.2139/ssrn.2692598
Ghaeli, M. R. (2017). Price-to-earnings ratio: A state-of-art review. Accounting, 3(2),
131-136. https://doi.org/10.5267/j.ac.2016.7.002
Ghauri, P., Grønhaug, K., & Strange, R. (2020). Research methods in business studies.
https://doi.org/10.1017/9781108762427
Giannetti, M., & Kahraman, B. (2018). Open-end organizational structures and limits to
arbitrage. The Review of Financial Studies, 31(2), 773-810.
https://doi.org/10.1093/rfs/hhx057
Gimeno, R., Lobán, L., & Vicente, L. (2020). A neural approach to the value investing
tool F-score. Finance Research Letters, 37, 1-6.
https://doi.org/10.1016/j.frl.2019.101367
Glosten, L. R., Jagannathan, R., & Runkle, D. E. (1993). On the relationship between the
expected value and the volatility on the nominal excess returns on stocks. The
Journal of Finance, 48(5), 1779-1801. https://doi.org/10.1111/j.1540-
6261.1993.tb05128x
Golman, R., Hagmann, D., & Loewenstein, G. (2017). Information avoidance. Journal of
Economic Literature, 55(1), 96-135. https://doi.org/10.1257/jel.20151245
Gøtzsche-Astrup, O. (2018). The time for causal designs: Review and evaluation of

124
empirical support for mechanisms of political radicalization. Aggression and
Violent Behavior, 39, 90-99. https://doi.org/10.1016/j.avb.2018.02.003
Grable, J. E., & Heo, W. (2017). Insights into the relationship between risk tolerance and
market volatility. Journal of Financial Service Professionals, 71(1), 17-20.
https://www.ebschost.com
Graham, B., Dodd, D. L. F., & Cottle, S. (1934). Security Analysis (Volume 452).
McGraw-Hill
Gray, S. F. (1996). Modeling the conditional distribution of interest rates as a regime-
switching process. Journal of Financial Economics, 42(1), 27-62.
https://doi.org/10.1016/0304-405X(96)00875-6
Greaves, J. G. (2018). Modeling with ARIMA-ARCH/GARCH techniques to estimate
weekly exchange rate of Liberia. Research Journal of Finance and Accounting,
9(8), 79-102. https://www.iiste.org
Green, S., & Salkind, N. (2017). Using SPSS for Windows and Macintosh, (8th ed.).
Upper Saddle River: Pearson education, Inc.
Greener, S. (2018). Research limitations: The need for honesty and common sense.
Interactive Learning Environments, 26(5), 567-568.
https://doi.org/10.1080/10494820.2018.1486785
Gruszka, J., & Szwabinski, J. (2020). Best portfolio management strategies for synthetic
and real assets. Physica A: Statistical Mechanical and its Applications, 539, 1-19.
https://doi.org/10.1016/j.physa.2019.122938
Guidotti, E. (2019). RbIDatalicense: R Interface to Bloomberg data license.

125
https://doi.org/10.13140/RG.2.2.23216.71680
Guo, X., Chan, R. H., Wong, W., & Zhu, L. (2019). Mean-variance, mean-VaR, and
mean-CVaR models for portfolio selection with background risk. Risk
Management, 21(2), 73-98. https://doi.org/10.1057/s41283-018-0043-2
Guptha, K. S. K., & Rao, R. P. (2018). The causal relationship between financial
development and economic growth: An experience with BRICS economics.
Journal of Social and Economic Development, 20(2), 308-326.
https://doi.org/10.1007/s40847-018-0071-5
Hambuckers, J., Groll, A., & Kneib, T. (2018). Understanding the economic determinants
of the severity of operational losses: A regularized generalized Pareto regression
approach. Journal of Applied Econometrics, 33(6), 898-935.
https://doi.org/10.1002/jae.2638
Hamilton, J. D. (1989). A new approach to the economic analysis of non-stationary time
series and the business cycle. Econometrics, 57(2), 357-384.
doi:10.2307/1912559
Harari, L., & Lee, C. (2021). Intersectionality in quantitative health disparities research:
A systematic review of challenges and limitations in empirical studies. Social
Science & Medicine, 277, 1-11. https://doi.org/10.1016/j.socscimed.2021.113876
HedgeNews Africa. (2021). Hedge fund online publications.
http://www.hedgenewsafrica.com
Hentati-Kaffel, R., & de Peretti, P. (2015). Detecting performance persistence of hedge
funds. Economic Modeling, 47, 185-192.

126
https://doi.org/10.1016/j.econmod.2015.02.029
Herbert, W. E., Ugwuanyi, G. O., & Nwaocha, E. I. (2018). Volatility clustering,
leverage effects and risk-return trade-off in the Nigerian stock market. Journal of
Finance and Economics, 7(1), 1-13. https://doi.org/10.1269/jfe-7-1-1
Hespeler, F., & Loiacono, G. (2017). Monitoring systemic risk in the hedge fund sector.
Quantitative Finance, 17(12), 1859-1883.
https://doi.org/10.1080/14697688.2017.1357969
Hickey, J. R., & Sollmann, R. (2018). A new mark-recapture approach for abundance
estimation of social species. PLOS ONE, 13(12), 1-14.
https://doi.org/10.1371/journal.pone.0208726
Hirk, R., Hornik, K., & Vana, L. (2019). Multivariate ordinal regression models: An
analysis of corporate credit ratings. Statistical Methods & Applications, 28(3),
507-539. https://doi.org/10.1007/s10260-018-00437-7
Hong, F., Huang, W., & Zhao, X. (2018). Sunk cost as a self-management device.
Management Science, 65(5), 2216-2230. https://doi.org/10.1287/mnsc.2018.3032
Huang, J. Z., Liechty, J., & Rossi, M. (2018). Return smoothing and its implications for
performance analysis of hedge funds. The Journal of Finance & Data Science,
4(4), 203-222. https://doi.org/10.1016/j.jfds.2018.05.002
Hudson, Y., Yan, M., & Zhang, D. (2018). Herd behavior & investor sentiment: Evidence
from UK mutual funds. SSRN Electronic Journal.
https://doi.org/10.2139/ssrn.3222312
Hutchinson, M. C., Nguyen, Q. M. N., & Mulcahy, M. (2021). Private hedge fund firms’

127
incentives and performance: Evidence from audited filings. The European
Journal of Finance, 1-16. https://doi.org/10.1080/1351847X.2021.1954966
Hwang, I., Xu, S., In, F., & Kim, T. S. (2017). Systemic risk and cross-section hedge
fund returns. Journal of Empirical Finance, 42, 109-130.
https://doi.org/10.1016/j.jempfin.2017.03.002
Ilerisoy, M., Sa-Aadu, J., & Tiwari, A. (2018). Market liquidity, funding liquidity, and
hedge fund performance. SSRN Electronic Journal.
https://doi.org/10.2139/ssrn.2441771
I-Net Bridge. (2021). Financial services. http:www.inet.co.za
Jang, J., & Kang, J. (2019). Probability of price crashes, rational speculative bubbles, and
the cross-section of stock returns. Journal of Financial Economics, 132(1), 222-
247. https://doi.org/10.1016/j.jfineco.2018.10.005
Jeelani, I., Albert, A., & Azevedo, R. (2019). Are visual search patterns predictive of
hazard recognition performance? Empirical investigation using eye-tracking
technology. Journal of Construction Engineering and Management, 145(1),
04018115. https://doi.org/doi.org/10.1061/(asce)co.1943-7863.0001589
Jelusic, A. (2017). Modelling tourist consumption to achieve economic growth and
external balance: Case of Croatia. Tourism and Hospitality Management, 23(1),
87-104. https://doi.org/10.20867/thm.23.1.5
Jensen, M. C. (1968). The performance of mutual funds in the period 1945-1964. The
Journal of Finance, 23(2), 389-416. https://doi.org/10.1111/j.1540-
6261.1968.tb00815.x

128
Jensen, M. C. (1972). Optimal utilization of market forecasts and the evaluation of
investment performance. SSRN Electronic Journal, 1-34.
https://doi.org/10.2139/ssrn.350426
Jiang, G. J., Liang, B., & Zhang, H. (2022). Hedge fund manager skill and style-shifting.
Management Science, 68(3), 2284-2307. https://doi.org/10.1287/mnsc.2020.3945
Joenväärä, J., Kauppila, M., & Kahra, H. (2021a). Hedge fund portfolio selection with
fund characteristics. Journal of Banking & Finance, 132, 1-17.
https://doi.org/10.1016/j.jbankfin.2021.106232
Joenväärä, J., Kauppila, M., Kosowski, R., & Tolonen, P. (2021b). Hedge fund
performance: Are stylized facts sensitive to which database one uses?. Critical
Finance Review, 10(2), 271-327. https://doi.org/10.1561/10400000104
Joenväärä, J., Kosowski, R., & Tolonen, P. (2018). The effect of investment constraints
on hedge fund investor returns. SSRN Electronic Journal.
https://doi.org/10.2139/ssrn.2362430
Jones, C. K. (2017). Modern portfolio theory, digital portfolio theory and intertemporal
portfolio choice. American Journal of Industrial and Business Management,
7(07), 833-854. https://doi.org/10.4236/ajibm.2017.77059
Joo, B. A., & Durri, K. (2017). Influence of overconfidence, optimism and pessimism on
the rationality of the individual investors: An empirical analysis. Pacific Business
Review International, 9(12), 7-13. https://www.pbr.co.in
Jorion, P., & Schwarz, C. (2019). The fix is in: Properly backing out backfill bias. The
Review of Financial Studies, 32(12), 5048-5099.

129
https://doi.org/10.1093/rfs/hhz024
Josephat, P. K., & Ame, A. (2018). Effect of testing logistic regression assumptions on
the improvement of the propensity scores. International Journal of Statistics and
Applications,8(1), 9-17. https://doi.org/10.5923/j.statistics.20180801.02
Kapil, S., & Gupta, J. (2019). Performance characteristics of hedge fund indices.
Theoretical Economics Letters, 9(06), 2176-2197.
https://doi.org/10.4236/tel.2019.96138
Karki, D. E. (2018). Stock market responses to macroeconomic dynamics: Testing for
long-run equilibrium in Nepal. Pravaha, 24(1), 64-82.
https://doi.org/10.3126/pravaha.v24i1.20227
Karp, A., & Van Vuuren, G. (2019). Investment implications of the fractal market
hypothesis. Annals of Financial Economics, 14(1), 1-127.
https://doi.org/10.1142/S2010495219500015
Kaya, A., & Yarbaşi, İ. Y. (2021). Forecasting of volatility in stock exchange markets by
MS-GARCH approach: An application of Borsa Istanbul. Journal of Research in
Economics, Politics & Finance, 6(1), 16-35.
https://doi.org/10.30784/epfad.740815
Khattak, A. J., & Wali, B. (2017). Analysis of volatility in driving regimes extracted from
basic safety messages transmitted between connected vehicles. Transportation
Research Part C: Emerging Technologies, 84, 48-73.
https://doi.org/10.1016/j.trc.2017.08.004
Kiss, G. D., Savai, M., & Udvari, B. (2017). Missing data bias on a selective hedging

130
strategy. Journal of Competitiveness, 9(1), 5-19.
https://doi.org/10.7441/joc.2017.01.01
Klaassen, F. (2002). Improving GARCH volatility forecasts with regime-switching
GARCH. Empirical Economics, 27(2), 363-394.
https://doi.org/10.1007/s001810100100
Knif, J., Koutmos, D., & Koutmos, G. (2020). Higher co-moment CAPM and hedge fund
returns. Atlantic Economic Journal, 48(1), 99–113.
https://doi.org/10.1007/s11293-020-09659
Köhler, T., Landis, R. S., & Cortina, J. M. (2017). From the editors: Establishing
methodological rigor in quantitative management learning and education research:
The role of design, statistical methods, and reporting standards. Academy of
Management Learning & Education, 16(2), 173-192.
https://doi.org/10.5465/amle.2017.0079
Kok, U. W., Ribando, J., & Sloan, R. (2017). Facts about formulaic value investing.
Financial Analysts Journal, 73(2), 81-99. https://doi.org/10.2469/faj.v73.n2.2
Kolokolova, O., Lin, M. T., & Poon, S. H. (2020). Too big to ignore? Hedge fund flows
and bond yields. Journal of Banking & Finance, 112, 1-50.
https://doi.org/10.1016/j.jbankfin.2017.12.009
Kolokolova, O., & Mattes, A. (2018). A time to scatter stones, and a time to gather them:
The annual cycle in hedge fund risk taking. Financial Review, 53(4), 669-704.
https//doi.org/10.1111/fire.12169
Kreuser, C. F., & Newman, C. (2018). Total factor productivity in South African

131
manufacturing firms. South African Journal of Economics, 86, 40-78.
https://doi.org/10.1111/saje.12179
Kristoufek, L., & Vosvrda, M. (2018). Herding, minority game, market clearing and
efficient markets in a simple spin model framework. Communications in
Nonlinear Science and Numerical Stimulation, 54, 148-155.
https://doi.org/10.1016/j.cnsns.2017.05.025
Kumar, A., & Biswal, S. K. (2019). Impulsive clustering and leverage effect of emerging
stock market with special reference to Brazil, India, Indonesia, and Pakistan.
Journal of Advanced Research in Dynamical and Control Systems, 11(11), 33-37.
https://doi.org/10.5373/jardcs/v11sp11/20192925
Kumar, J., & Kumar, S. (2017). Big data time series analysis: An approach with the size
of the time series. International Journals of Advanced Research in Computer
Science and Software Engineering, 7(6), 767-774.
https://doi.org/10/23956/ijarcsse/V716/0220
Lambert, M., & Platania, F. (2020). The macroeconomic drivers in hedge fund beta
management. Economic Modelling, 91, 65-80.
https://doi.org/10.1016/j.econmod.2020.04.016
Lee, S. K., & Nguyen, L. T. P. (2017). Comparative study of volatility forecasting
models: The case of Malaysia, Indonesia, Hing Kong and Japan stock markets.
Economics World, 5(4), 299-310. https://doi.org/10.17265/2328-
7144/2017.04.002
Limam, M. A., Terraza, V., & Terraza, M. (2017). Hedge fund return dynamics: Long

132
memory and regime switching. International Journal of Financial Research, 8(4),
148-166. https://doi.org/10.5430/ijfr.v8n4p148
Lin, C., & Wu, H. (2018). Multiperiod Telser's safety-first portfolio selection with regime
switching. Discrete Dynamics in Nature and Society, 1-18.
https://doi.org/10.1155/2018/1832926
Lintner, J. (1965). Security prices, risk, and maximal gains from diversification. The
Journal of Finance, 20(4), 587-615. https://doi.org/10.1111/j.1540-
6261.1965.tb02930.x
Liu, M. Y., Chuang, W. I., & Lo, C. L. (2021). Options-implied information and the
momentum cycle. Journal of Financial Markets, 53, 1-55.
https://doi.org/10.1016/j.finmar.2020.100565
Madaan, G., & Singh, S. (2019). An analysis of behavioral biases in investment
decisions-making. International Journal of Financial Research, 10(4), 55-67.
https://doi.org/10.5430/ijfr.v10n4p55
Madaree, S. (2018). Factor structure of South African financial stocks. South African
Journal of Economic and Management Sciences, 21(1), 1-12.
https://doi.org/10.4102/sajems.v21i1.2001
Mahalua, F., Chissengue, G., Uamba, J., Pereira, I., Mabjaia, E., & Vilanculos, A. (2019).
Importance of applying statistical sampling to increase confidence in financial
statements. International Journal of Accounting Research, 7(01), 1-5.
https://doi.org/10.35248/2472-114x.19.7.198
Mallikarjuna, M., & Rao, R. P. (2019). Evaluation of forecasting methods from selected

133
stock market returns. Financial Innovation, 5(1), 1-40.
https://doi.org/10.1186/s40854-019-0157-x
Mang, J., Küchenhoff, H., Meinck, S., & Prenzel, M. (2021). Sampling weights in
multilevel modelling: An investigation using PISA sampling structures. Large-
scale Assessments in Education, 9(1), 1-39. https://doi.org/10.1186/s40536-021-
00099-0
Manyang, M. P., Samuel, M., & Wilsom, M. (2017). Factors affecting investment
decision in portfolio management: A survey of the listed companies in Nairobi
securities exchange. Journal of Business and Management, 19(9), 72-78.
https://doi.org/10.9790/487X-1909037278
Maqsood, A., Safdar, S., Shafi, R., & Lelit, N. J. (2017). Modeling stock market volatility
using GARCH models: A case study of Nairobi Securities Exchange (NSE). Open
Journal of Statistics, 7(2), 369-381. https://doi.org/10.4236/ojs.2017.72026
Markowitz, H. (1952). Portfolio selection. Journal of Finance, 7(1), 77-91.
https://doi.org/10.1111/j.1540-6261.1952.tb01525.x
Martins, F. S., Cunha, J. A. C. d., & Serra, F. A. R. (2018). Secondary data in research:
Uses and opportunities. PODIUM Sport, Leisure and Tourism Review, 7(3), 1-4.
https://doi.org/10.5585/podium.v7i3.316
Mashamba, T., & Magweva, R. (2019). Dynamic volatility behavior of stock markets in
southern Africa. Journal of Economic and Financial Sciences, 12(1), 1-8.
https://doi.org/10.4102/jef.v12i1.396
Mason-Bish, H. (2019). The elite delusion: Reflexivity, identity and positionality in

134
qualitative research. Qualitative Research, 19(3), 263-276.
https://doi.org/10.1177/1468794118770078
Mei, X., & Nogales, F. J. (2018). Portfolio selection with proportional transaction costs
and predictability. Journal of Banking & Finance, 94, 131-151.
https://doi.org/10.1016/j.jbankfin.2018.07.012
Mero, G. (2016). Measuring hedge fund performance: A Markov regime-switching with
false discoveries approach. SSRN Electronic Journal.
https://doi.org/10.2139/ssrn/2737385
Mertzanis, C., & Allam, N. (2018). Political instability and herding behavior: Evidence
from Egypt’s stock market. Journal of Emerging Market Finance, 17(1), 29-59.
https://doi.org/10.1177/0972652717748087
Mestre, R. (2021). A wavelet approach of investing behaviors and their effects on risk
exposures. Financial Innovation, 7(1), 1-37. https://doi.org/10.1186/s40854-021-
00239-z
Metzger, N., & Shenai, V. (2019). Hedge fund performance and after the crisis. A
comparative analysis of strategies 2007-2017. International Journal of Financial
Studies, 7(15), 1-31. https://doi.org/10.3390/ijs7010015
Mhalla, L., Hambuckers, J., & Lambert, M. (2020). Extremal connectedness and systemic
risk of hedge funds. SSRN Electronic Journal.
https://doi.org/10.2139/ssrn.3519295
Mikalef, P., Pappas, I. O., Krogstie, J., & Giannakos, M. (2018). Big data analytics
capabilities: A systematic literature review and research agenda. Information

135
Systems and e-Business Management, 16(3), 547-578.
https://doi.org/10.1007/s10257-017-0362-y
Mitchell, D., Muthuraman, K., & Titman, S. (2019). Hedge fund compensation: Incentive
fees and performance intervals. SSRN Electronic Journal.
https://doi.org/10.2139/ssrn.3318622
Mitchell, M., & Pulvino, T. (2001). Characteristics of risk and return in risk arbitrage.
The Journal of Finance, 56(6), 2135-2175. https://doi.org/10.1111/0022-
1082.00401
Mitra, R. (2017). Stock market and foreign exchange market integration in South Africa.
World Development Perspectives, 6, 32-34.
https://doi.org/10.1016/j.wdp.2017.05.001
Mohajan, H. K. (2018). Qualitative research methodology in social sciences and related
subjects. Journal of Economic Development, Environment and People, 7(1), 23-
48. https://doi.org/doi.org/10.26458/jedep.v7i1.571
Mohohlo, M. T., & Hall, J. H. (2018). The impact of operating leverage on the capital
structure of Johannesburg stock exchange-listed firms before and after the 2008
global financial crisis. Journal of Economic and Financial Sciences, 11(1), 164-
174. https://doi.org/10.4102/jef.v11i1.164
Molyboga, M., Baek, S., & Bilson, J. O. (2017). Assessing hedge fund performance with
institutional constraints: Evidence from CTA finds. Journal of Asset
Management, 18, 547-565. https://doi.org/10.101057/s41260-017-0053-8
Morgan, D. L. (2018). Living within blurry boundaries: The value of distinguishing

136
between qualitative and quantitative research. Journal of Mixed Methods
Research, 12(3), 268-279. https://doi.org/10.1177/1558689816686433
Moulya, V. H., Mohammadi, A., & Mallikarjunappa, T. (2019). Optimal vs 1/N
diversification and portfolio evaluation: A study on Indian stock market. Asian
Journal of Management, 10(3), 248-256. https://doi.org/10.5958/2321-
5763.2019.00039.8
Muneer, S., Shabbir, J., & Khalil, A. (2017). Estimation of finite population mean in
simple random sampling and stratified random sampling using two auxiliary
variables. Communications in Statistics-Theory and Methods, 46(5), 2181-2192.
http://doi.org/10.1080/03610926.2015.1035394
Mushinada, V. N. C., & Veluri, V. S. S. (2018). Investors overconfidence behavior at
Bombay stock exchange. International Journal of Managerial Finance, 14(5),
613-632. https://doi.org/10.1108/IJMF-05-2017-0093
Muteba Mwamba, J. W. (2017). An empirical evaluation of hedge fund managerial skills
using Bayesian techniques. Asian Academy of Management Journal of Accounting
and Finance, 13(1), 63-82. https://doi.org/10.21315/aamjaf2017.13.1.3
Ndei, C. M., Muchina, S., & Waweru, K. (2019). Modeling stock market return volatility
in the presence of structural breaks. International Journal of Research in Business
and Social Science, 8(5), 156-171. https://doi.org/10.20525/ijrbs.v8i5.308
Nelson, D. B. (1991). Conditional heteroskedasticity in asset returns: A new approach.
Econometrica, 59(2), 347-370. https://doi.org/10.2307/2938260
Newton, D., Platanakis, E., Stafylas, D., Sutcliffe, C., & Ye, X. (2021). Hedge fund

137
strategies, performance & diversification: A portfolio theory & stochastic
discount factor approach. The British Accounting Review, 53(5), 1-58.
https://doi.org/10.1016/j.bar.2021.101000
Nowell, L. S., Norris, J. M., White, D. E., & Moules, N. J. (2017). Thematic analysis:
Striving to meet the trustworthiness criteria. International Journal of Qualitative
Methods, 16(1), 1-13. https://doi.org/10.1177/1609406917733847
Oikonomou, I., Platanakis, E., & Sutcliffe, C. (2018). Socially responsible investment
portfolios: Does the optimization process matter? The British Accounting Review,
50(4), 379-401. https://doi.org/10.1016/j.bar.2017.10.003
Okonkwo, J. J. (2019). Volatility of stock return and selected macroeconomic variables:
Evidence from Nigeria stock exchange. International Journal of Academic
Research in Business & Social Sciences, 9(6), 185-201.
https://doi.org/10.6007/ijarbss/v9-i6/5934
Olabode, S. O., Bakare, A. A., & Olateju, O. I. (2018). An assessment of the reliability of
secondary data in management science research. LASU Journal of Employment
Relations & Human Resource Management, 1(1), 182-194.
https://doi.org/10.36108/ljerhrm/8102.01.0102
Oliinyk, V., & Kozmenko, O. (2019). Optimization of investment portfolio management.
Serbian Journal of Management, 14(2), 373-387. https://doi.org/10.5937/sjm14-
16806
Oseifuah, E., & Korkpoe, C. H. (2019). A Markov regime switching approach to
estimating the volatility of Johannesburg stock exchange (JSE) returns.

138
Investment Management and Financial Innovations, 16(1), 215-225.
https://doi.org/10.21511/imfi.16(1).2019.17
Page, S., & Panariello, R. A. (2018). When diversification fails. Financial Analysis
Journal, 74(3), 19-32. https://doi.org/10.2469/faj.v74.n3.3
Palazón-Bru, A., Folgado-de la Rosa, D. M., Cortés-Castell, E., López-Cascales, M. T.,
& Gil-Guillén, V. F. (2017). Sample size calculation to externally validate scoring
systems based on logistic regression models. PLOS ONE, 12(5), 1-11.
https://doi.org/10.1371/journal.pone.0176726
Pan, Z., Wang, Y., Wu, C., & Yin, L. (2017). Oil price volatility and macroeconomic
fundamentals: A regime switching GARCH-MIDAS model. Journal of Empirical
Finance, 43, 130-142. https://doi.org/10.1016/j.jempfin.2017.06.005
Patton, A. J. (2009). Are market neutral hedge funds really market neutral? Review of
Financial Studies, 22(7), 2495-2530. https://doi.org/10.1093/rfs/hhn113
Pernollet, F., Coelho, C. R. V., & van der Werf, H. M. G. (2017). Methods to simplify
diet and food life cycle inventories: Accuracy versus data-collection resources.
Journal of Cleaner Production, 140, 410-420.
https://doi.org/10.1016/j.jclepro.2016.06.111
Pfeiffer, R. M., Redd, A., & Carroll, R. J. (2017). On the impact of model selection on
predictor identification and parameter inference. Computational Statistics, 32(2),
667-690. https://doi.org/10.1007/s00180-016-0690-2
Pilbeam, K., & Preston, H. (2019). An empirical investigation of the performance of
Japanese mutual funds: Skill or luck? International Journal of Financial Studies,

139
7(1), 6-22. https://doi.org/10.3390/ijfs7010006
Platanakis, E., & Sutcliffe, C. (2017). Asset-liability modeling and pension schemes: The
application of robust optimization to USS. The European Journal of Finance,
23(4), 324-352. https://doi.org/10.1080/1351847x2015.1071714
Plonsky, L., & Ghanbar, H. (2018). Multiple regression in L2 research: A methodological
synthesis and guide to interpreting R2 values. The Modern Language Journal,
102(4), 713-731. https://doi.org/10.1111/modl.12509
Podsakoff, P. M., & Podsakoff, N. P. (2019). Experimental designs in management and
leadership research: Strengths, limitations, and recommendations for improving
publishability. The Leadership Quarterly, 30(1), 11-33.
https://doi.org/10.1016/j.leaqua.2018.11.002
Poon, S., & Granger, C. W. J. (2003). Forecasting volatility in financial markets: A
review. Journal of Economic Literature, 41(2), 478-539.
https://doi.org/10.1257/jel.41.2.478
Puspitaningtyas, Z. (2017). Estimating systematic risk for the best investment decisions
on manufacturing company in Indonesia. Investment Management and Financial
Innovations, 14(1), 46-54. https://doi.org/10.21511/imfi.14(1).2017.05
Queirós, A., Faria, D., & Almeida, F. (2017). Strengths and limitations of qualitative and
quantitative research methods. European Journal of Education Studies, 3(9), 369-
387. https://doi.org/10.5281/zenodo.887089
Rabemananjara, R., & Zakoian, J. M. (1993). Threshold arch models and asymmetries in
volatility. Journal of Applied Econometrics, 8(1), 31-49.

140
https://doi.org/10.1002/jae.3950080
Racicot, F., & Théoret, R. (2018). Multi-moment risk, hedging strategies, and the
business cycle. International Review of Economics & Finance, 58, 637-675.
https://doi.org/10.1016/j.iref.2018.07.006
Racicot, F., & Théoret, R. (2019). Hedge fund return higher moments over the business
cycle. Economic Model, 73, 73-97.
https://doi.org/10.1016/j.econmod.2018.08.016
Rahi, S. (2017). Research design and methods: A systematic review of research
paradigms, sampling issues and instruments development. International Journal
of Economics & Management Sciences, 6(2), 403-408.
https://doi.org/10.4172/2162-6359.1000403
Rehan, R., & Umer, I. (2017). Behavioral biases and investor decisions. Market Forces
Research Journal, 12(2), 12-20. https://kiet.edu.pk/marketforces/index
Rehman, M. U. (2020). Dynamic correlation pattern amongst alternative energy market
for diversification opportunities. Journal of Economic Structures, 9(1), 16-40).
https://doi.org/10.1186/s40008-020-00197-2
Roll, R., & Ross, S. A. (1980). An empirical investigation of the arbitrage pricing theory.
Journal of Finance, 33(5), 1073-1103. https://doi.org/10.1111/j.1540-
6261.1980.tb02197x
Ross, P. T., & Bibler Zaidi, N. L. (2019). Limited by our limitations. Perspective on
Medical Education, 8(4), 261-264. https://doi.org/10.1007/s40037-019-00530-x
Ross, S. A. (1976). The arbitrage theory of capital asset pricing. Journal of Economic

141
Theory, 13(3), 341-360. https://doi.org/10.1016/0022-0531(76)90046-6
Rupande, L., Muguto, H. T., & Muzindutsi, P. F. (2019). Investor sentiment and stock
return volatility: Evidence from the Johannesburg stock exchange. Cogent
Economics & Finance, 7(1), 1-16.
https://doi.org/10.1080/23322039.2019.1600233
Sahoo, S. (2017). Do anchor investors create value for initial public offerings? An
empirical investigation. IIBM Management Review, 29(4), 259-279.
https://doi.org/10.1016/j.iimb.2017.11.004
Saranya, K., & Prasanna, P. K. (2018). Estimating stochastic volatility with jumps and
asymmetry in Asia markets. Financial Research Letters, 25, 145-153.
https://doi.org/10.1016/j.frl.2017.10.021
SARB. (2021). SARB strategy. https://www.resbank.co.za/en/home/what-we-do/SARB
strategy
Schadler, T., & Steurer, E. (2019). Portfolio selection based on a volatility measure
adjusted for irrationality. Archives of Business Research, 7(6), 277-283.
https://doi.org/10.14738/abr.76.6732
Scholtz, S. E., de Klerk, W., & de Beer, L. T. (2020). The use of research methods in
psychological research: A systematized review. Frontiers in Research Metrics
and Analytics, 5(1), 1-17. https://doi.org/10.3389/frma.2020.00001
Schreder, M. (2018). Volatility forecasting in practice: Exploratory evidence from
European hedge funds. Journal of Asset Management, 19(4), 245-258.
https://doi.org/10.1057/s41260-018-0082-y

142
Schuster, M., Strauch, E., Gugat, M., & Lang, J. (2022). Probabilistic constrained
optimization on flow networks. Optimization and Engineering, 23(2), 1-50.
https://doi.org/10.1007/s11081-021-09619-x
Senarathne, C. W. (2019). Do Fama-French common risk-factor portfolio investors herd
on a daily basis? Implications for common risk-factor regressions. Journal of
Capital Markets Studies, 3(2), 137-156. https://doi.org/10.1108/JCMS-06-2019-
0034
Serdar, C. C., Cihan, M., Yücel, D., & Serdar, M. A. (2021). Sample size, power and
effect size revisited: Simplified and practical approaches in pre-clinical, clinical
and laboratory studies. Biochemia Medica, 31(1), 27-53.
https://doi.org/10.11613/bm.2021.010502
Shadabfar, M., & Cheng, L. (2020). Probabilistic approach for optimal portfolio selection
using a hybrid Monte Carlo simulation and Markowitz model. Alexandria
Engineering Journal, 59(5), 3381-3393. https://doi.org/10.1016/j.aej.2020.05.006
Shantha, K. (2019). Individual investors' learning behavior and its impact on their herd
bias: An integrated analysis in the context of stock trading. Sustainability, 11(5),
1448-1469. https://doi.org/10.3390/su11051448
Sharma, G. (2017). Pros and cons of different sampling techniques. International Journal
of Applied Research, 3(7), 749-752. https://www.allresearchjournal.com
Sharpe, W. F. (1964). Capital asset prices: A theory of market equilibrium under
conditions of risk. The Journal of Finance, 19(3), 425-442.
https://doi.org/10.2307/2977928

143
Sharpe, W. F. (1992). Asset allocation: Management style and performance
measurement. The Journal of Portfolio Management, 18(2), 7-19.
https://doi.org/10.3905/jpm.1992.409394
Shin, J. S., Kim, M. K., Oh, D. J., & Kim, T. S. (2017). Option-implied tail risk, timing
by hedge funds, and performance. SSRN Electronic Journal.
https://doi.org/10.2139/ssrn.3016998
Shin, S., Smolarski, J., & Soydemir, G. (2018). Hedge funds: Risk and performance.
Journal of Financial Management, Markets, and Institutions, 6(1), 1850003 1-43.
https://doi.org/10.1142/s2591768418500034
Shyti, B., & Valera, D. (2018). The regression model for the statistical analysis of
Albanian economy. International Journal of Mathematics Trends and Technology
(IJMTT), 62(2), 90-96. https://doi.org/10.14445/22315373/IJMTT-V62P513
Siddiqui, S., & Roy, P. (2019). Predicting volatility and dynamic relation between stock
market, exchange rate and select commodities. Acta Universitatis Agriculturae et
Silviculturae Mendelianae Brunensis 67(6), 1597-1611.
https://doi.org/10.11118/actuan201967061597
Siebert, J., Groß, J., & Schroth, C. (2021). A systematic review of packages for time
series analysis. Engineering Proceeding, 5(1), 22-33.
https://doi.org/10.3390/engproc2021005022
Siegmann, A., & Stefanova, D. (2017). The evolving beta-liquidity relationship of hedge
funds. Journal of Empirical Finance, 44, 286-303.
https://doi.org/10.1016/j.jempfin.2017.04.002

144
Silva, T., Pinheiro, P. R., & Poggi, M. (2017). A more human-like portfolio optimization
approach. European Journal of Operational Research, 256 (1), 252-260.
https://doi.org/10.1016/j.ejor.2016.06.018
Simon, H. A. (1955). A behavioral model of rational choice. The Quarterly Journal of
Economics, 69(1), 99-118. https://doi.org/10.2307/1884852
Simonian, J., & Wu, C. (2019). Factors in time: Fine-tuning hedge fund replication. The
Journal of Portfolio Management, 45(3), 159-164.
https://doi.org/10.3905/jpm.2019.45.3.159
Siswanah, E. (2020). Comparative analysis of mean variance efficient frontier and
resampled efficient frontier for optimal stock portfolio formation. IPO Conference
Series: Materials Science and Engineering 846, 1-11.
https://doi.org/10.1088/1757-899X/846/1/012065
Snyder, H. (2019). Literature review as a research methodology: An overview and
guidelines. Journal of Business Research, 104, 333-339.
https://doi.org/10.1016/j.jbusres.2019.07.039
Sondakh, R. (2019). The effect of dividend policy, liquidity, profitability, and firm size
on firm value in financial service sector industries listed in Indonesia stock
exchange 2015-2018 period. Accountability, 8(2), 91-101.
https://doi.org/10.32400/ja.24760.8.2.2019.91-101
Sosner, N., & Steblea-Lora, R. (2022). Taxes, charity, and hedge funds: Tax implications
of charitable contributions of leveraged partnership interests. The Journal of
Wealth Management, 1, 165. https://doi.org/10.3905/jwm.2022.1.165

145
Stafylas, D., Anderson, K., & Uddin, M. (2017). Recent advances in explaining hedge
fund returns: Implicit factors and exposures. Global Finance Journal, 33, 69-87.
https://doi.org/10.1016/j.gfj.2016.08.001
Stafylas, D., Anderson, K., & Uddin, M. (2018a). Hedge fund performance attribution
under various market conditions. International Review of Financial Analysis, 56,
221-237. https://doi.org/10.1016/j.irfa.2018.01.006
Stafylas, D., Anderson, K., & Uddin, M. (2018b). Hedge fund index-engineering
methodologies: A comparison and demonstration. Applied Economics, 50(6), 596-
612. https://doi.org/10.1080/00036846.2017.1332746
Stafylas, D., & Andrikopoulos, A. (2020). Determinants of hedge fund performance
during ‘good’ and ‘bad’ economic periods. Research in International Business
and Finance, 52, 101130, 1-34. https://doi.org/10.1016/j.ribaf.2019.101130
Statman, M. X. (2017). Finance for normal people: How investors and markets behave.
Oxford University Press
Stoforos, C. E., Degiannakis, S., & Palaskas, T. B. (2017). Hedge fund returns under
crisis scenarios: A holistic approach. Research in International Business and
Finance, 42, 1196-1207. https://doi.org/10.1016/j.ribaf.2017.07.056
Stork, P. A., Vidojevic, M., & Zwinkels, R. C. J. (2020). Behavioral heterogeneity in
return expectations across equity style portfolios. International Review of
Finance, 21(4), 1225-1250. https://doi.org/10.1111/irfi.12323
Strömbaäck, C., Lind, T., Skagerlund, K., Västfjäll, D., & Tinghög, G. (2017). Does self-
control predict financial behavior and financial well-being? Journal of behavioral

146
and Experimental Finance, 14, 30-38. https://doi.org/10.1016/j.jbef.2017.04.002
Sui, Y., Hu, J., & Ma, F. (2020). A mean-variance portfolio selection model with
interval-valued possibility measures. Mathematical Problems in Engineering,
2020, 1-12. https://doi.org/10.1155/2020/4135740
Sun, Z., Wang, A. W., & Zheng, L. (2018). Only winners in tough times repeat: Hedge
fund performance persistence over different market conditions. Journal of
Financial and Quantitative Analysis, 53(5), 2199-2225.
https://doi.org/10.1017/s0022109018000200
Sürücü, L., & Maslakçi, A. (2020). Validity and reliability in quantitative research.
Business & Management Studies: An International Journal, 8(3), 2694-2726.
https://doi.org/10.15292/bmij.v8i3.1540
Swartz, L. M., & Emami-Langroodi, F. (2018). Relative value hedge funds: A behavioral
modeling of hedge fund risk and return factors. Journal of Behavioral Finance,
19(4), 462-482. https://doi.org/10.1080/15427560.2018.1434654
Szczygielski, J. J., Brummer, L., & Wolmarans, H. (2020). Are macroeconomic factors
adequate proxies for systematic influences in stock returns? South African
perspective. Investment Analysis Journal, 49(1), 34-52.
https://doi.org/10.2139/ssrn.3369798
Taffler, R. J., Spence, C., & Eshraghi, A. (2017). Emotional economic man: Calculation
and anxiety in fund management. Accounting, Organizations and Society, 61, 53-
67. https://doi.org/10.1016/j.aos.2017.07.003
Tan, J. J., & Trinidad, F. L. (2018). A real options model for loan portfolios of actively

147
traded Philippine universal banks. Journal of Global Entrepreneurship Research,
8(1), 1-24. https://doi.org/10.1186/s40497-018-9
Tarhani, F., & Ameli, O. Z. (2016). Business intelligence application model in hedge
funds supporting knowledge-based companies. Modern Applied Science, 10(12),
137-145. https://doi.org/10.5539/mas.v10n12p137
Theofanidis, D., & Fountouki, A. (2018). Limitations and delimitations in the research
process. Perioperative Nursing, 7(3), 155-162.
http://doi.org/10.5281/zenodo.2552022
Thomas, D. B., Oenning, N. S. X., & Goulart, B. N. G. de. (2018). Essential aspects in
the design of data collection instruments in primary health research. REVISTA
CEFAC, 20(5), 657-664. https://doi.org/10.1590/1982-021620182053218
Tinbergen, J. (1939). The dynamics of share-price formation. The Review of Economic
Statistics, 21(4), 153-160. https://doi.org/10.2307/1926601
Tiwari, A. K., Albulescu, C. T., & Yoon, S. M. (2017). A multifractal detrended
fluctuation analysis of financial market efficiency: Comparison using Dow Jones
sector ETF indices. Physica A: Statistical Mechanics and its Applications, 483,
182-192. https://doi.org/10.1016/j.physa.2017.05.007
Trafimow, D. (2018). An a priori solution to the replication crisis. Philosophical
Psychology, 31(8), 1188-1214. https://doi.org/10.1080/09515089.2018.1490707
Trafimow, D., & Myüz, H. A. (2019). The sampling precision of research in five major
areas of psychology. Behavior Research Methods, 51(5), 2039-2058.
https://doi.org/10.3758/s13428-018-1173-x

