


1
CHAPTER 1
INTRODUCTION
Overview
This chapter serves as an introduction, with the primary purpose of establishing
the foundation by introducing the study objectives. Within this section, we emphasize the
significance of voluntary risk management committees (VRMC), clarifying the study’s
purpose while discussing our research objectives. We begin by discussing the increased
necessity for organizations to enhance their corporate governance practices, particularly in
response to one of the most severe global financial crises in history, which scholars
attributed to failures in corporate risk management. Subsequently, we briefly discuss the
adoption of two influential corporate reform legislative policies concerning risk
governance in recent U.S. history. From this viewpoint, we highlight the differences
between the requirements for overseeing risk in the financial and nonfinancial aspects of a
firm. These discussions lead us to formulate our research questions that helped shape the
motivation behind this research. Finally, we provide an overview of the subsequent
chapters, which will be explored in detail throughout the study.
Background, Objectives, and Motivation for the Study
Practitioners have recently begun to emphasize the growing need to control all
dimensions of a firm’s corporate risk (Hines and Peters, 2015; Jia and Bradbury, 2020;
Moore and Brauneis, 2008; Schlich and Prybylski, 2009). Now more than ever, escalating
global disruptions have made overseeing an organization’s inherent risks a more vital role
in corporate governance due to increasing financial uncertainties. From the financial crisis
in 2008, caused by the ambiguous deregulation of financial firms (Amadeo, 2020), to

2
rising supply chain irregularities (Anser et al., 2021), organizations have increased their
focus on assessing corporate risk elements preemptively (e.g., operational, financial,
strategic, ESG, cybersecurity, bankruptcy, and natural disasters—just to name a few) that
can potentially jeopardize the firm’s existence (Harbert, 2019). Without having
appropriate risk-taking control and practices in place, uninformed decision-making can
cause long-term formidable damage to the organization (Tonello et al., 2012).
To broadly enhance the efficiency and stability of the financial system while
protecting both the firm’s assets and its investors, several federal regulations and
supplementary guidelines were issued to assist in strengthening the regulations of the
financial markets. Most notably, the Dodd-Frank Act (Dodd-Frank) and Sarbanes-Oxley Act
(SOX) are both considered the most recent influential corporate reform legislation intended
to safeguard stakeholders following the financial crisis.
The Dodd-Frank was enacted to protect against “instability in the U.S. financial
system” (Tonello et al. 2012). The Dodd-Frank, which was codified into law on July 21,
2010, provides financial risk provisions for publicly held financial firms with assets
exceeding $10 billion. It also enforces full transparency of records to the Federal Reserve
Board of Governors and requires these firms to develop a stand-alone risk management
committee (separate from the board of directors’ functions) to provide fiduciary oversight
of financial risk exposure that may hinder the firm’s achievement of its corporate objectives
(Dodd-Frank, 2010).
The SOX was also codified into law to enhance the standards used by all U.S.
public company boards, management, and public firms. This legislation comprises eleven
(11) sections ranging from corporate board responsibilities to assessing criminal penalties governed
by the Securities and Exchange Commission to enforce these new requirements. Section 404 of the

3
Act requires firms to maintain adequate internal control systems in place, along with
complementing risk oversight mechanisms, to enhance transparency against loose internal control
structures and procedures for financial reporting.
Although practitioners praise both the Dodd-Frank and The SOX for providing
institutional safeguards to protect against an impending financial crisis after the greatest
financial crisis of the 20th century (Acharya and Richardson, 2009; Malik et al. 2020),
both pieces of legislation fall short of requiring nonfinancial firms to possess a standalone
board-level risk management committee to adopt sophisticated risk management practices
in contrast to the highly focused financial institutions (Malik et al. 2020). While risk
management committees are becoming more prevalent within nonfinancial firms,
researchers claim still few organizations have established them (Muneer et al., 2021).
Instead, the audit committee remains the most prudent body to govern an organization’s
risk (Bates & Leclerc, 2009; Hines & Peters, 2015; Johnson, 2010; Keizer, 2010; Ng et al.,
2013) in nonfinancial firms. This can be inadvertently attributed to both Dodd-Frank and
SOX being so focused on the financial industry, to the exclusion of nonfinancial publicly
traded firms discounting the potential risky behavior outside financial institutions. Ishak et
al. (2017) argue that all firms have an obligation to lean forward and voluntarily
implement adequate business controls to manage risk, leveraging their commitment to
reduce “operational, financial and reputational risk” (p. 3). Despite the additional layers of
oversight that come with establishing a robust risk management committee, many
organizations elected not to develop this committee since it is not required by legislation
or governing oversight boards. Or, the lack of practical evidence that an established risk
management committee is closely linked to minimizing the cost of risk to the enterprise.
Thus, based on the above discussion, this study aims to investigate to what extent does a

4
nonfinancial firm’s decision to create a voluntary boardlevel risk management committee
relate to (1) the financial risk and (2) the financial health of the organization.
Additionally, we explore the compelling relationship between nonfinancial firms’
decision to create a voluntary board-level risk management committee and (3) credit risk,
which is often interconnected with the oversight governance and decision-making of the
organization’s performance indicators reflecting the financial health and risk activities of
the firm. Using data from the S&P 1500 index, we developed a mixture of small (S&P 600),
medium (S&P 400), and large (S&P 500) market capital firms to evaluate this relationship,
which is representative of approximately 90% of all U.S. stocks (Abebe & Acharya, 2022;
Vairavan & Zhang, 2020). These firms offer a wide of diverse organizational sizes and
industry segments across both financial and nonfinancial sectors.
In light of this, this study is motivated to examine the relationship of a VRMC on
leading risk indicators for nonfinancial firms and how its existence influences board risk
oversight. Initially, this study was driven by the limited amount of research on board
committees (Lee, 2020). Lee (2020) further articulates that there is very little research on
how both financial and nonfinancial committees are constructed and their corresponding
relationship on firm performance. Leaning forward into this argument, scholars assert that
the establishment of a VRMC remains minimally investigated (Hines, 2012; Ishak & Nor,
2017). In a later investigation, Hines et al. (2015) continue to express how prior empirical
research continues not to “definitively” evaluate the benefits of establishing a stand-alone
board-level committee to identify and manage the firm’s critical risk. Further, Carcello et
al. (2011) add that the practical outcomes of risk management committees need more
empirical studies. Based on the pool of literature surrounding the relationship of board
committees on establishing the functions of a voluntary board-level risk committee, there

5
remains a wide disparity in literature. Therefore, this study anticipates adding to the
marginalized gap in risk literature geared toward understanding this relationship.
Dissertation Structure
The study consists of four remaining chapters, each with a distinct focus. In
Chapter 2, we conduct a review of empirical literature shedding light on the intricate roles
and responsibilities of board committees while governing and monitoring a firm’s
potential risks. This chapter also incorporates relevant theoretical perspectives from
previous research on risk committees. In Chapter 3, we begin our first study using
research methodologies to test the hypotheses we have formulated. Specifically, we
investigate the relationship between the establishment of a VRMC and the financial
health and risk of nonfinancial firms. With a similar focus, Chapter 4 provides our second
study where we statistically test the relational hypothesis between the presence of a
VRMC and the short- and long-term credit ratings of a nonfinancial organization. Lastly,
Chapter 5 provides a comprehensive finding of both studies. It also provides a discussion of
the study’s practical implications, acknowledges its limitations, and identifies potential
avenues for future research.
CHAPTER 2
LITERATURE REVIEW
Chapter Introduction
While we expand on the introductory discussion within the previous chapter that
underscores the significance of comprehensive risk management due to the rising
challenges of global disruptions; we begin this chapter with an examination into the

6
critical roles VRMCs play in meeting the unique needs and challenges of each
organization. Drawing insights from existing literature, we also establish the theoretical
groundwork for understanding the practical objectives, structure, and operations of risk
management committees within an organizational setting. As such, this chapter plays a
pivotal role in developing our future study into the relationships for establishing a VRMC,
particularly in the context of nonfinancial firms where such a requirement does not exist.
Finally, we offer an overview of the chapter leading up to the exploration of our first
study.
The Roles of Board Committees
Most arguably, one of an organization’s greatest assets is its board of directors,
whose members are responsible for exercising governance over corporate operations while
capturing opportunities to drive organizational revenue and growth through innovation
(Kouzes & Posner, 1987). In today’s volatile business environments, organizations are
increasingly faced with creating value for their stakeholders despite unforeseen market
complexities (Mishra & Dasgupta, 2019). In addition to these unpredictable business
conditions, an increase in global market disruptions can exacerbate the organization’s
ability to thrive and compete. Through all this uncertainty, organizations must heavily rely
on the board of directors’ executive governance to steer them through various calamities
foreseen and unforeseen (Abebe & Myint, 2018; Shapiro et al., 2015).
This difficult and sometimes complex task (Baxt, 2005) comes with many layers
of regulatory restrictions and shareholder demands, which the board of directors must
consider while overseeing the future direction of the organization (Price, 2019). The
board of directors also creates policies governing company resources, goal setting, and
bylaw development while making decisions amidst competing organizational interests. To

7
undertake this task, many boards of directors establish small groups of highly specialized
directors to advise the full board of immediate and future challenges to proactively
minimize potential impending threats while maximizing the firm’s performance. Alces
(2011) reaffirms that the board’s responsibility is to provide critical directional guidance
and oversee senior management while making significant steering decisions for the firm.
Further, Ng et al. (2013) add that this expanded role creates a fiduciary monitoring and
oversight function needed to further increase confidence in public firms (Bainbridge,
2018) by attracting and retaining the support and trust of investors in both favorable and
unfavorable market conditions.
The Responsibility of the Board’s Committees for Monitoring
The success of a firm’s board of directors lies in its ability to effectively monitor
current and future financial and operational shifts. Specialized disciplines are needed to
identify, capture, and monitor wide-ranging threats (Abdullah et al., 2015) by recommending
decision-making strategies to respond to situational uncertainties (Hines & Peters, 2015).
Rather than relying solely on the entire board’s recommendation, this critical function is
delegated to specific board committees operating under the purview of the board of
directors. Once coined the governance “watchdog” (Tricker, 1994; Morgan, 1979, p. 161),
these committees set the tone for governance, ongoing monitoring, and accountability
expectations needed to carry out the best possible performance from challenges the
organization faces (Jaskyte, 2012). These fiduciary monitoring practices used to protect the
firm’s interests have prompted organizations to exercise corporate governance better over the
additional risk created by unforeseen events.
The evolution of board committees has occurred in response to the ever-changing
business environment, particularly due to recent business failures within the financial

8
sector. Several governing bodies (i.e., SEC, NASDAQ, and IRS) have required publicly
traded organizations to establish certain board committees to ensure the trustworthiness of
financial reporting (Ng et al., 2013). The three most commonly used board committees for
publicly held U.S. firms are compensation, nomination, and audit (Kolev et al., 2019),
each of which performs independent tasks within a firm’s corporate governance structure.
The compensation committee improves the board’s effectiveness by designing and
advising on executive compensation packages for top management (Sun et al., 2009). The
nominating committees support the selection of the newly qualified committee members
while evaluating the overall performance and makeup of the board (Soana & Crisci,
2017). The audit committee’s responsibilities are to (1) ensure the integrity of financial
statements and reporting, (2) ensure compliance with legal matters, and (3) ensure
effective financial and internal control parameters to identify material weaknesses and
fraud (JPMorganChase, 2020; Lockheed Martin, 2020; Workiva, 2020). Although these
three committees are the most common among U.S. firms, within the S&P 1500 index
firms, we observed 2,128 different subcommittees within our dataset governing the
board’s responsibilities for monitoring financial and operational performance.
As increasingly complex matters arise, the roles of subcommittees will continue to
evolve in response to continual changes established by governing bodies for publicly
traded companies (Tonello et al., 2012). Due to the increasing overwhelming oversight
responsibilities of both financial and performance operations by these committees (Brown
et al., 2009; Ng et al., 2013), many organizations also elect to establish a VRMC to assess
systemic risk in resolving strategic matters regarding imminent risk to the organization.

9
Introduction of Risk Management Committees
Risk management committees are primarily designed to evaluate risks that
jeopardize an organization’s survival (Hines & Peters, 2015). To identify and contend
with risk, boards have begun to establish risk management committees to ensure directors
have the knowledge, skills, and abilities necessary to align operational performance with
adequate risk assessments (Chams, 2019) more effectively. The risk management
committee has the overall responsibility for developing risk policies, procedures, and
cultural behaviors for the organization. Due to this expertise, the risk management
committee is better suited to perform specific evaluations on the unknown risks facing the
organization (Hines & Peters, 2015; Ishak et al., 2017; Ng et al., 2013). Also,
instructional regulatory guidance from SEC, NASDAQ, IRS, and Dodd-Frank provisions
(Infosys, 2007; Tonello et al., 2012) expanded the risk management committee’s role to
(1) assist in fulfilling its corporate governance role by evaluating potential risks of the
organization within both internal and external environments, including competitive,
technological, political, economic, and regulatory developments; (2) develop a risk management
framework to evaluate significant risk exposures, and (3) oversee the organization’s resources to
achieve its objectives (Appvion, 2013; Bunge, n.d.; Deloitte, 2014; Infosys, 2007). In all, the risk
management committee’s governing role is to provide the “big picture” view of potential
organizational threats (Tonello et al., 2012, p.
2), while developing a plan to mitigate financial and operational concerns.
Now more than ever, regulated organizations within the financial industry have
specific requirements regarding the need for risk management practices (Iahak, 2016). In
fact, most empirical studies that examine the role of risk management committees focus
on financially regulated organizations (Abdullah, 2015). This is because there is more

10
data available to examine. However, risk management committees are still voluntary for
nonfinancial unregulated industries (Iahak, 2016). Although established to improve
corporate governance, conversely, some researchers have found that risk management
committees may impair an organization’s ability to evaluate risk relative to strategy
operations (Bates & Lecierc, 2009; Hines & Peters, 2015). Others believe risk
management committees within an unregulated industry set the tone for the importance of
managing risk initiatives within an organization (Abdullah et al., 2015; Busa & Lee,
2021; Ishak et al., 2017). Oddly enough, some organizations choose not to form a VRMC,
as the overwhelming benefits of creating a risk management committee have been
addressed through previous empirical research (Busa & Lee, 2021). In fact, from a policy
standpoint, Dodd-Frank missed a clear opportunity to safeguard shareholders of
nonfinancial organizations by failing to require industries outside the financial sector to
add such board committees. This regulatory oversight serves as a strong antecedent for
poor regulatory business risk management practices for nonfinancial firms (Iahak, 2016).
The following section examines several theoretical frameworks used within previous
empirical studies regarding the practical usage of risk management committees.
Each subsection provides a theoretical view along with its applied relevance.
Introduction of Theoretical Frameworks and Risk Management Committees
Researchers have examined the effects of risk management committees (RMCs)
by applying various theoretical frameworks (Jia & Bradbury, 2020; Ishak et al., 2017) and
continue to evaluate the theoretical impacts of their implementation (Malik et al., 2021).
Gevutz (2003) presents a theoretical viewpoint that illustrates the board being subdivided
into three underlying factors, which indicate “the relationship of the directors to the
shareholders; the relationship of the directors to each other; and the relationship of the

11
directors to the corporation’s executives” (p. 4). Through Gevutz’s theoretical illustration,
we explore the “essence” of the committee’s fiduciary responsibility through agency,
organizational, and resource theories.
The following sections examine these theoretical frameworks by reviewing previous
empirical studies that explored the practical usage of risk management committees. Each
subsection provides a theoretic perspective, along with its practical significance within the
context of this research.
Agency Theory and Risk Management Committees Agency
theory is a prevalent behavioral philosophy within economics and management
research (Jensen & Meckling, 1976). According to Kolev et al. (2019), agency theory
is cited as the predominant framework being used in approximately 75% of board
committee research related to financial decision-making, corporate governance, and
risk management, with organizational theory being leveraged as a contributing factor.
The study of agency theory has helped scholars and practitioners understand the
relationship between agents within a firm. Through these interactions, conflicts of
interest on various levels of the firm become evident, ensuring that the risk-taking
decisions of managers ultimately align with the best interests of the firm and its
stakeholders, addressing information asymmetry that can arise when principals
delegate decisionmaking authority to agents to run the company on their behalf. Risk
management committees play a pivotal role between managers and shareholders as
they provide an additional oversight layer of monitoring and control by promoting
transparency and accountability within the firm (Carausu, 2015). Scholars have also
found evidence of agency theory in the egregious risky behavior of firm managers
(Jensen & Meckling, 1976). In such instances, a firm that develops a VRMC as a

12
component of its board oversight plays a pivotal role in ensuring that management
effectively oversees risks, consistent with the attributes of agency theory (Angbre,
2016; Nugraha et al., 2019). For these reasons, I leverage agency theory as an essential
component of the board’s decision to create a VRMC to help ensure that the best
intentions of all stakeholders are considered, which ultimately contributes to the
overall success of the firm.
Organization Theory and Risk Management Committees The
multiple ways organizations create value help us understand the interconnection
between a firm’s cultures, structure, and design. Together, these three elements allow
organizations to “diagnose problems, make adjustments” and monitor activities
needed to achieve optimal performance goals (Jones, 2013, p. 30).
Organizational theory conceptualizes this into functional relationships within both
individual organizations and the ecosystem in which they operate (Blomberg, 2020;
Jones, 2013). It also conceptualizes strategic management’s purpose to adapt as a
selfgoverning learning institution when informed decisions are required from risk-
triggered events (Sarta et al., 2021). With this ongoing learning functionality, scholars
maintain that organizational theory prompts organizations to continually mature from one
functional state to a future state, developing their organizational effectiveness along the
way (Jones, 2013, p. 32). Jones (2013) claimed the main goal of organizational theory is
“to find new and improved ways of using resources and capabilities to increase an
organization’s ability to create value, and hence, its performance” (2013, p. 32). The
expertise possessed by the risk management committee remains a critical component of
fulfilling the board’s fiduciary responsibilities. For this reason, risk management
committees, in many ways, support “forward-looking corporations” (Neef, 2005, p. 112),

13
developing “new operational behaviors vital to address the global corporate need of risk
management” (Neef, 2005, p. 112). Thus, for this study, we draw on the application of
organizational theory that supports a VRMC’s ability to influence the organization’s risk
culture by collaborating with various organizational functions to integrate risk
management practices throughout the firm.
Resource Theory and Risk Management Committees
Resource dependency theory was developed based on examining the need for
organizations to utilize external sources to maintain optimum performance for their existence
(Pfeffer & Salancik, 1978). Scholars have extended this definition within corporate
governance to suggest that the board’s personal attributes and diverse skills can serve as a
resource for the organization to succeed. Risk management committees are an extension of
organizations’ resources through which firms utilize their expertise on both internal and
external factors to identify and address risks that may arise from these resources (Abdullah
et al., 2017). Often, these committees are tasked with evaluating various risks ranging from
third-party vendor impacts, regulatory changes, process improvements, environmental
concerns, and contingency planning (Abdullah et al.,
2017).
In the context of this study, we utilize resource dependency theory to explain how
organizations often depend on external financing sources, such as credit ratings, to manage
operations while sustaining growth. Credit ratings play a pivotal role in the organization’s
ability to secure external funding. Risk management committees play a crucial role in
managing the firm’s creditworthiness and associated risks tied to external financing. This
includes overseeing the organization’s credit ratings and providing intermediary strategies

14
to maintain and enhance them. Effective risk management of the firm’s credit ratings is
imperative to ensure the safeguarding of the organization’s financial well-being.
Literature Gap and Research Question
The existing theories acknowledge the theoretical benefits and operational value
of risk management committees for boards that establish them, whether voluntarily or as a
requirement. Our review of a narrow collection of the literature reveals the positive
influence of VRMCs on various aspects of the firm, such as board structure and
characteristics (Sekome & Lemma, 2014; Yatim, 2010), risk-taking (Ng et al., 2013),
market risk disclosures (Al-Hadi et al., 2016), and corporate governance (Subramaniam et
al., 2009). However, in addition to this body of literature, there is small-scale research
exploring the relationship between VRMC presence and firm performance, which has
yielded mixed results. Toa and Hutchinson (2013) identified a positive relationship
between VRMCs and firm performance, whereas other studies such as those by Hines and
Peters (2015) and Hoque et al. (2013) found a negative association between VRMCs and
firm profitability. It is important to note that most of these studies were conducted in non-
U.S. regions, with the exception of Hines and Peters (2015) and Malik et al., (2020),
which focused on U.S. financial firms from 1994 to 2008 and 2005 to 2017 respectively.
Previous VRMC studies primarily focused on international markets like Malaysia,
South Africa, and Australia; however, our study concentrates on firms within the U.S.
market. Our dataset includes a comprehensive analysis of 10,257 U.S. firms spanning from
2008 to 2020, which broadens the scope beyond the 2008 timeframe used by Hines and
Peters in their 2015 study. Although Hines and Peters observed a negative correlation
between RMCs and profitability in their analysis of 47 firms, our research responds to the
call by Hines et al. to broaden this research beyond the Global Financial Crisis of 2008 to

15
comprehensively understand the propensity of firms for establishing a separate risk
management committee in various economical climates. In addition to our extensive
review of U.S. firms within our scope, we evaluated 10,248 observations across 1,091
firms. Among these organizations, 169 firms adopted a VRMC. As we observed Malik et
al.’s (2020) call to examine larger samples of firms, we pivoted to evaluate only a
standalone risk management committee, which Iselin (2020) asserts reflects the board’s
intentions to have a separate governing body responsible for improving the firm’s
oversight and performance role in various functioning areas such as compliance risk,
operational risk, strategic risk, and credit risk. Through this lens, we aim to empirically
address the following research question:
RQ 1: To what degree is there a trend in the establishment of separate VRMCs
among firms for the purpose of board-level risk governance and organizational wellbeing?
We note in recent years that the adoption of voluntary board-level risk
management committees has increased for nonfinancial firms to enhance their risk
management practices (Bugalla et al., 2012; Malik et al., 2020). Consequently, our paper
is of timely significance for practitioners in understanding the operational value of risk
management committees within firms. In Chapter 3, we conduct an analysis to explore the
benefits, relationships, advantages, and disadvantages associated with the implementation
of voluntary RMCs, particularly in terms of their relationship on the financial risk and
health of organizations.
CHAPTER 3
STUDY 1

16
Background and Hypothesis Development
The preponderance of research, along with the corresponding theory, suggests that
risk management committees are an integral component of the board of directors. Risk
management committees are well suited to monitor the organizations’ trajectory to
increase the firm’s overall risk management performance (Jia, 2019, p. 1053; Marsden &
Prevost, 2005). Due to the expertise needed to oversee the firm’s inherent risk, both
agency and organizational theory support the role of the risk management committee in
determining “risk management strategies, evaluating risk management operations and
assessing the appropriateness of risk management procedures” (Jia, 2019, p. 1053;
Subramaniam et al., 2009). De Villiers et al. (2022) argue that firms with separate (i.e.,
voluntary) risk management committees outperform firms without this function. Empirical
studies indicate that the future of corporate governance has been enhanced by the evolving
role of RMCs monitoring the company’s risk management practices. Rimin et al. (2021)
further suggested that the formation of a separate RMC enhances the overall board’s
effectiveness. Using a panel of commonly used industry financial ratios for measuring
risk, we applied several financial ratios used by industry practitioners to analyze the
financial relationship associated with VRMCs. We expect that the implementation of a
firm’s voluntary VRMC will have a significant relationship on measuring the
organization’s financial risk. This argument leads to the following hypotheses:
H1: The existence of a VRMC is related to the financial risk leverage of an organization.
H2: The existence of a VRMC is related to the financial risk solvency of an organization.
A risk management committee is not only concerned with the financial and strategic risks
of the firm but also with the entire financial health of the institution (Nocco & Stulz,

17
2006). These scholars also assert that the evaluation of financial metrics is critical to
maximizing the overall health risk of the organization. The absence of such
measurements is consistent with several studies indicating that the formation of an RMC
had an unfavorable effect on a firm’s health (Hines et al., 2015). Prior literature has also
reported mixed findings on the effects of RMCs (Bensaid et al., 2021). Though the
literature regarding the association between VRMCs and the financial health of the firm
seems inconclusive, no empirical studies evaluating this relationship were found. Due to
the strategic and intuitive nature of risk oversight provided by risk management
committees, we predict that risk management committees will have some influence on the
financial health of the firm (Jia et al., 2019). This argument leads to the following
hypotheses:
H3: The existence of a VRMC is related to the financial health soundness of an
organization.
H4: The existence of a VRMC is related to the financial health efficiency of an
organization.
Methodology
Sources of Data
For this study, we started by exploring the BoardEx global database, which is a
research portal that provides millions of executive profiles on public and private companies
(BoardEx, 2021). Scholars and practitioners utilize this database for statistical and
academic research in areas such as “leadership, management, diversity and inclusion,
governance, compensation, and networks” (BoardEx, 2021). Scholars have deemed the
usage of BoardEx reliable for researching firm performance, compensation, and finance
committee demographics (Basu & Lee 2020; El-Khatib et al., 2017; Kim, 2021).

18
To identify the relationship that VRMCs may have on organizations, we initially
queried data files from Compustat to explore both currently active and inactive
(unbalanced) publicly traded companies within the S&P1500 index during the calendar
years 2009 to 2017. Then, we queried key financial calculations (ratios) from the WRDS
Financial Ratio Suite and found 190,294 company observations, using several financial
soundness/solvency and efficiency ratios for firms designated within our selected scope.
We used these corporate financial ratios to measure the overall financial risk and health of
the organization.
Next, we queried BoardEx to obtain data regarding board subcommittees. Using the
same corresponding parameters as above for consistency purposes, we explored both active
and inactive (unbalanced) publicly traded companies within the S&P1500 index during
calendar years 2009 to 2020. We found 203,328 company observations using BoardEx’s
North America catalog portal, encompassing both financial and nonfinancial organizations.
With the subcommittees identified, we were able to pinpoint organizations possessing a
separate risk management committee. To recognize a firm with a separate risk management
committee, we identified and grouped the following committee names: “Risk,” “Risk
Assessment,” “Risk Evaluation,” “Risk Management,” “Risk Management and Finance,”
“Risk Oversight,” and “Risk Policy.” We then utilized Stata to collapse the yearly
observations and merged the data using the S&P ticker marker as the unique identifier to
link both BoardEx committee files with the Compustat financial data. This resulted in a
sample of 18,546 company observations related to 1,494 companies, of which 93 had a
separate risk management committee. Our focus was on evaluating only the nonfinancial
sector organizations, as we assert that both financial and nonfinancial firms have different
regulatory requirements that are not voluntary. Scholars argue the financial industry is

19
highly regulated, with risk management responsibilities for financial institutions (e.g.,
Dodd-Frank criteria), which require many financial firms to establish RMCs (Malik et al.,
2020). Thus, evaluating both sectors equally would be an inequitable comparison, making
the contrast unsound. For this reason, we excluded all financial firms within this dataset.
This reduced our dataset to 14,702 observations across 1,099 firms. After removing all
blank and duplicate cells, we were left with a final sample of 10,247 corporate line entries
within 1,091 companies, of which 30 firms remain to be reviewed. Lastly, we merged the
credit ratings with this list, which was limited to 2017, with much incomplete firm
information provided. This provided our final sample of 5,973 firm observations,
consisting of 903 firms, of which 21 adopted a VRMC.
Variables and Model Specification
To test the four hypotheses, we use the logistic regression model shown in Figure 1
to illustrate the variables for H1, H2, H3, and H4. We also provide the listing of all
variables in Table 1.
For H1: VRMC = α + β1(DegreeOfOperatingLeverage) + β2(DegreeOfFinancialLeverage)
+ β3(TotalDebt/Equity) + β2(Year) + β3(GICS) + β4(Number of Directors) +
β5(Number of Director Qualifications) + β6(Gender) + ε
For H2: VRMC = α + β1(TotalDebt/Equity) + β2(Year) + β3(GICS) + β4(Number of
Directors) + β5(Number of Director Qualifications) + β6(Gender) + ε
For H3: VRMC = α + β1(CashFlowMargin) + β2(CashBalance/TotalLiabilities) +
β3(TotalLiabilities/TotalAssets) + β4(TotalDebt/EBITDA) +
β5(LongtermDebt/TotalLiabilities) + Β6(CashFlow/TotalDebt) + β7(Year) +
β8(GICS) + β9(Number of Directors) + β10(Number of Director Qualifications)
+ β11(Gender) + ε
For H4: VRMC = α + Β1(AssetTurnover) + Β2(ReceivablesTurnover) +
Β3(SalesInvested/Capital) + β2(Year) + β3(GICS) + β4(Number of Directors)

20
+ β5(Number of Director Qualifications) + β6(Gender) + ε
Variables Descriptions
Using the BoardEx committee data and employing the same approach as Ling et al.
(2014), we assigned a dichotomous value for the VRMC with a value of one (1) if a risk
management committee exists and zero (0) if it does not. To assess both the financial risk
and financial health explored within this equation, leverage, solvency, financial soundness,
and efficiency ratios were measured as dependent variables, providing indicators of a
company’s financial health and risk positioning.
Independent Variable - Voluntary Risk Management Committee
The independent variable in this study is VRMCs as a dichotomous variable indicating
whether a firm possessed this board committee. Scholars suggest that firms possessing a
VRMC possibly represent the most effective way for the board to manage risk oversight
governance (Ling Liew et al, 2011; Sekome & Lemma, 2014). We explore this variable to
understand the value that VRMCs bring to the firm that adopts them.
Dependent Variables—Financial Risk Leverage Ratios
Degree of Operating Leverage
The degree of operating leverage measures a firm’s evaluation of operating income
to fixed and variable costs from sales. Essentially, this formula is used to measure the
firm’s break-even point and profit margin and provide how sales impact a firm’s operating
income. Additionally, the degree of operating leverage is a crucial tool for risk
management committees as it provides a clear understanding of how the company’s cost
structure and sales volume affect its financial stability while aiding in making informed
decisions to mitigate financial risks. In this study, we are analyzing this variable in the

21
context of understanding the firm’s decision to adopt a VRMC to monitor risk as a
potential indicator of financial default (Sari & Hutagaol, 2009). This factor is critical in
risk management as it directly relates to the firm’s ability to maintain financial stability
and meet its liabilities.
Degree of Financial Leverage
The degree of financial leverage measures a firm’s earnings per share to variations
in operating income (Gatsi et al., 2013). The degree of financial leverage is a metric used
for evaluating the future net income with the future changes in operating income, interest
payments, and debt payments. Once debt payments are required from an organization,
interest payments become a cost that can affect the firm’s breakeven for profit (Bragg,
2022). Additional debt may increase the firm’s default risk depending on the fluctuation
of income to cover debt and interest payments. As a result, we explore the degree of
financial leverage to understand the firm’s voluntary adoption of a risk management
committee to monitor company debt and its implications for financial risk.
Dependent Variables—Financial Risk Solvency Ratios
Total Debt-to-Total Assets
The total debt-to-total assets ratio is a crucial metric for risk management
committees as it provides insight into the financial structure and risk profile of a
company. The total debt-to-total asset ratio provides an evaluation of the firm’s assets that
are financed by debt. Practitioners use this ratio to determine if the firm is able to cover
its current debt obligations while providing a return on investment to its shareholders
(Yahya & Hidayat, 2020). Yahya and Hidayat (2020) define a high ratio as indicating that
the company has more debt than assets, possessing a default risk on future loan payments.
We use this variable to understand the firm’s decision to adopt a

22
VRMC to monitor the company’s liquidity risk.
Total Debt-to-Equity
The debt-to-equity ratio provides an indication that measures the proportion of
total debt and financial obligations to shareholders’ equity. A higher debt-equity ratio
indicates the firm is favorable with consistent cash flow. Conversely, a lower ratio
indicates a firm’s riskiness by being financed with debt equity (Siregar & Harahap, 2021).
This ratio is also crucial in assessing the company’s long-term solvency and stability.
High debt levels relative to equity can make the company more vulnerable in economic
downturns or when facing financial challenges. Thus, the total debt-to-equity ratio
becomes a key metric to provide a comprehensive view of a company’s financial leverage
and risk profile. We used this variable to understand the firm’s decision to adopt a risk
management committee to provide oversight of its potential relationship on the cost of
debt and the overall financial health of the company.
Dependent Variables—Financial Health Soundness Ratios
Cash Flow Margin
Cash flow margin (CFM) provides a measure of the effectiveness by converting
income into capital (Rohanova, 2019). The higher the CFM, the less exposed the firm is to
converting sales to capital, indicating profitability margins. A lower CFM indicates the
firm is exposed to a higher risk of higher cash flow. Following Sharma’s (2001)
evaluation, CFM is a critical benchmark of risk to determine if a firm will be unable to
produce sufficient cash to cover its debts. Thus, the CFM becomes a vital metric for the
adoption of a risk management committee as it provides insights into the financial health
and efficiency of a company. We used this variable to understand the firm’s rationale to

23
assist with monitoring and evaluating the company’s ability to generate cash from its sales
and manage its liquidity.
Cash Balance to Total Liabilities
The cash balance-to-total liability ratio provides the firm’s ability to cover all short-
term obligations with its own cash liquidity (Ilugbemi, 2020). This ratio is a direct measure
of its ability to cover short-term liabilities with its cash reserves. A higher ratio suggests a
strong liquidity position, which is crucial for meeting immediate financial obligations and for
handling unforeseen expenses. Practitioners also use this metric to assess the company’s
solvency. The cash balance-to-total liability ratio indicates how well equipped the company
is to handle its debts in the short term (Ilugbemi, 2020). A low ratio can signal potential
solvency issues, especially in adverse economic conditions. We observe this variable to better
understand a firm’s adoption of a risk management committee in overseeing its debt and cash
management strategies, planning for contingencies, and ensuring the company’s overall
financial stability.
Total Liabilities to Total Assets
The total liabilities-to-total assets ratio provides the firm’s position with the
company’s assets being financed with debt (Hayes, 2022). This ratio helps the committee
understand how much of the company’s assets are financed through liabilities. A high
ratio suggests a greater reliance on debt and other liabilities for financing assets, which
can indicate higher financial risk. Additionally, the total liabilities-to-total assets ratio is
an indicator of the company’s solvency. A high ratio may signal potential solvency issues,
as it implies that a significant portion of the company’s assets is obligated to creditors.
Further, this ratio is used to monitor the firm’s short-term liquidity and longterm stability.
It reflects the firm’s ability to meet its short-term obligations and sustain operations in the

24
long run. Thus, we used the total liabilities-to-total assets ratio as a variable to examine
the firm’s decision to adopt a risk management committee to monitor the firm’s use of
debt financing.
Total Debt to EBITDA
Total debt to earnings before interest, taxes, depreciation, and amortization
(EBITDA) ratio measures the firm’s ability to resolve its debts (Strischek, 2001).
Additionally, this ratio provides an indication of the operational timeframe needed to pay off
its liabilities. Commonly used by creditors, this ratio provides insight into whether the
company is at risk of defaulting on its debt payments (Strischek, 2001). Thus, we used this
variable as a critical metric to offer insight into understanding the adoption of the firm’s risk
management committees to monitor the firm’s financial leverage and ability to pay off its
debts.
Long-Term Debt to Total Liabilities
The long-term debt-to-total assets ratio provides an indicator of how much of the
total assets are financed with long-term debt. The greater the ratio, the more risk the
company possesses by owning less of the asset through debt. Following Sophonvit’s
(2021) research, long-term debt-to-total assets ratio was used as a key indicator to evaluate
the overall risk of the organization. A higher ratio indicates a greater reliance on long-term
debt, which can affect the company’s financial flexibility and risk profile. Additionally,
this metric signifies potential challenges in refinancing or servicing debt in the future,
especially if market conditions change. Therefore, we use this ratio to understand why the
firm chooses to establish a risk management committee to monitor how changes in
economic conditions, market trends, or operational shifts may impact the firm’s ability to
manage its long-term debt.

25
Cash Flow to Total Debt
The cash flow-to-debt ratio compares the firm’s operational cash flow to total
debt. The cash flow-to-debt provides an analysis of the timeframe for a firm to resolve its
debt from operating cash flow. The greater the firm’s ratio indicates, the stronger the
ability to pay off debt quickly. Conversely, having a lower ratio indicates the risk of
inability to make future debt payments. Jooste cites this indicator as “the best indicator” to
determine predictive financial failure (2007, p. 11). We evaluate this metric to understand
the firm’s decision to adopt a risk management committee to oversee strategic plans for
debt restructuring, refinancing, or paying down debt to improve the firm’s overall risk
profile.
Dependent Variables—Financial Health Efficiency Ratios
Asset Turnover
The asset turnover ratio provides the measurement of the overall efficiency of the
firm. This ratio evaluates the firm’s investment by combining the impact of both short-
and long-term assets. The higher the ratio, the more effectively the firm is utilizing its
funds (Fairfield & Yohn, 2001). Further, this ratio is used to help the firm make strategic
decisions regarding its assets, whether to invest in new assets, dispose of underutilized
assets, or find ways to increase revenue from existing assets. Thus, we examine the firm’s
decision to create a risk management committee to help the firm monitor the efficiency of
a company’s use of its assets to generate revenue and the potential relationship on changes
within the company’s performance.
Receivable Turnover
The receivable turnover asset ratio measures how quickly the firm recoups its
funds from customers (Wajo, 2021). Further, it indicates how effective a firm’s credit

26
policy is with its corresponding expense to maintain internal control procedures. A higher
value of this ratio indicates favorable conditions for the firm. In contrast, lower ratios
illustrate the firm’s poor credit policy while risking receivables being reported as a bad
debt (Wajo, 2021). We evaluate the firm’s decision to adopt a risk management committee
to evaluate how efficiently the company’s credit policies convert sales into cash and
mitigate the risk of bad debts.
Sales to Invested Capital
The sales-to-capital ratio is an efficiency ratio that measures the firm’s ability to
convert capital into revenue. This measurement provides the risk impact of the firm’s capital
invested in its operational cash flow (Cyganski, 2004). This metric also helps in identifying
areas where operational efficiencies can be improved to maximize sales from the existing
capital base. We used this variable to understand the rationale for a firm to voluntarily adopt
a risk management committee to understand the firm’s competitive position to predict future
sales growth while identifying areas for improvement.
Control Variables
Years
Years as a control variable is an approach to evaluate the potential impact of
timerelated factors using VRMCs and multifactorial variables being evaluated. We used the
time period from 2009 to 2017 to help us better understand the relationships between
variables within our study while also accounting for the impact of time trends during one of
the major global financial crises (Hines & Peters, 2015).

27
Gender
Gender as a control variable enhances the understanding of demographics
accounted for within gender-related factors influencing the adoption of a VRMC. This
diversity may lead to more thorough and comprehensive risk assessments and management
strategies. Controlling for gender allows us to examine if gender diversification is
associated with the adoption of a VRMC (Francoeur et al., 2008).
Number of Directors
Evaluating the number of directors on the board examines the potential impact of
the size or composition of a board of directors on its relationship with adopting a risk
management committee (Be´dard et al., 2004). A larger number of directors might
indicate greater diversity in terms of expertise, experience, and perspectives, which can be
critical for effective risk identification and management. We controlled for the number of
directors to examine the potential benefits of this diversity to drive the firm’s initiative to
adopt a VRMC.
Director Qualifications
Director qualifications consider the impact of the qualifications or expertise the
directors possess in relation to the adoption of a VRMC. We controlled for director
qualifications to allow for an evaluation of how the formation of a risk management
committee specifically contributes to an organization’s governance and risk management
effectiveness based on the influence of the directors’ backgrounds and skills (Sila &
Gonzalez Hagendorff, 2016). By doing so, we can examine if the qualifications of directors
can significantly influence their decision-making abilities and risk assessment capabilities
within the firm.
28
Global Industrial Classification Sectors
Global industrial classification sectors (GICS) are a widely accepted classification
system for categorizing companies into different sectors and industries. Incorporating
GICS sectors as a control variable accounts for the potential impact of industry-specific
factors (Dalziel, 2007). Different industries face unique sets of risks. Controlling for GICS
allows us to account for these industry-specific risks when evaluating the effectiveness
and adoption of risk management committees. We choose to control for GICS to
understand which specific industry requirements are more prone to adopting a
VRMC.
Table 1.
List of Variables for Study One
Category
Variables Type
IV
Voluntary risk management committee
Dichotomous
• 0 = Board’s absence of
VRMC
• 1 = Board VRMC presence
DV1
Cash flow margin
Scale
DV2
Cash balance to total liabilities
Scale
DV3
Cash flow to total debt
Scale
DV4
Total debt to EBITDA
Scale
DV5
Long-term debt to total liabilities
Scale
DV6
Total liabilities to total assets
Scale
DV7
Total debt to total assets
Scale
DV8
Total debt to equity
Scale
DV9
Asset turnover
Scale
DV10
Receivables turnover
Scale
DV11
Sales to invested capital
Scale
29
CV1
Years (CY2009–2020)
Scale
CV2
Gender
Nominal
CV3
GICS
Nominal
CV4
Director qualifications
Continuous
CV5
Number of directors
Continuous
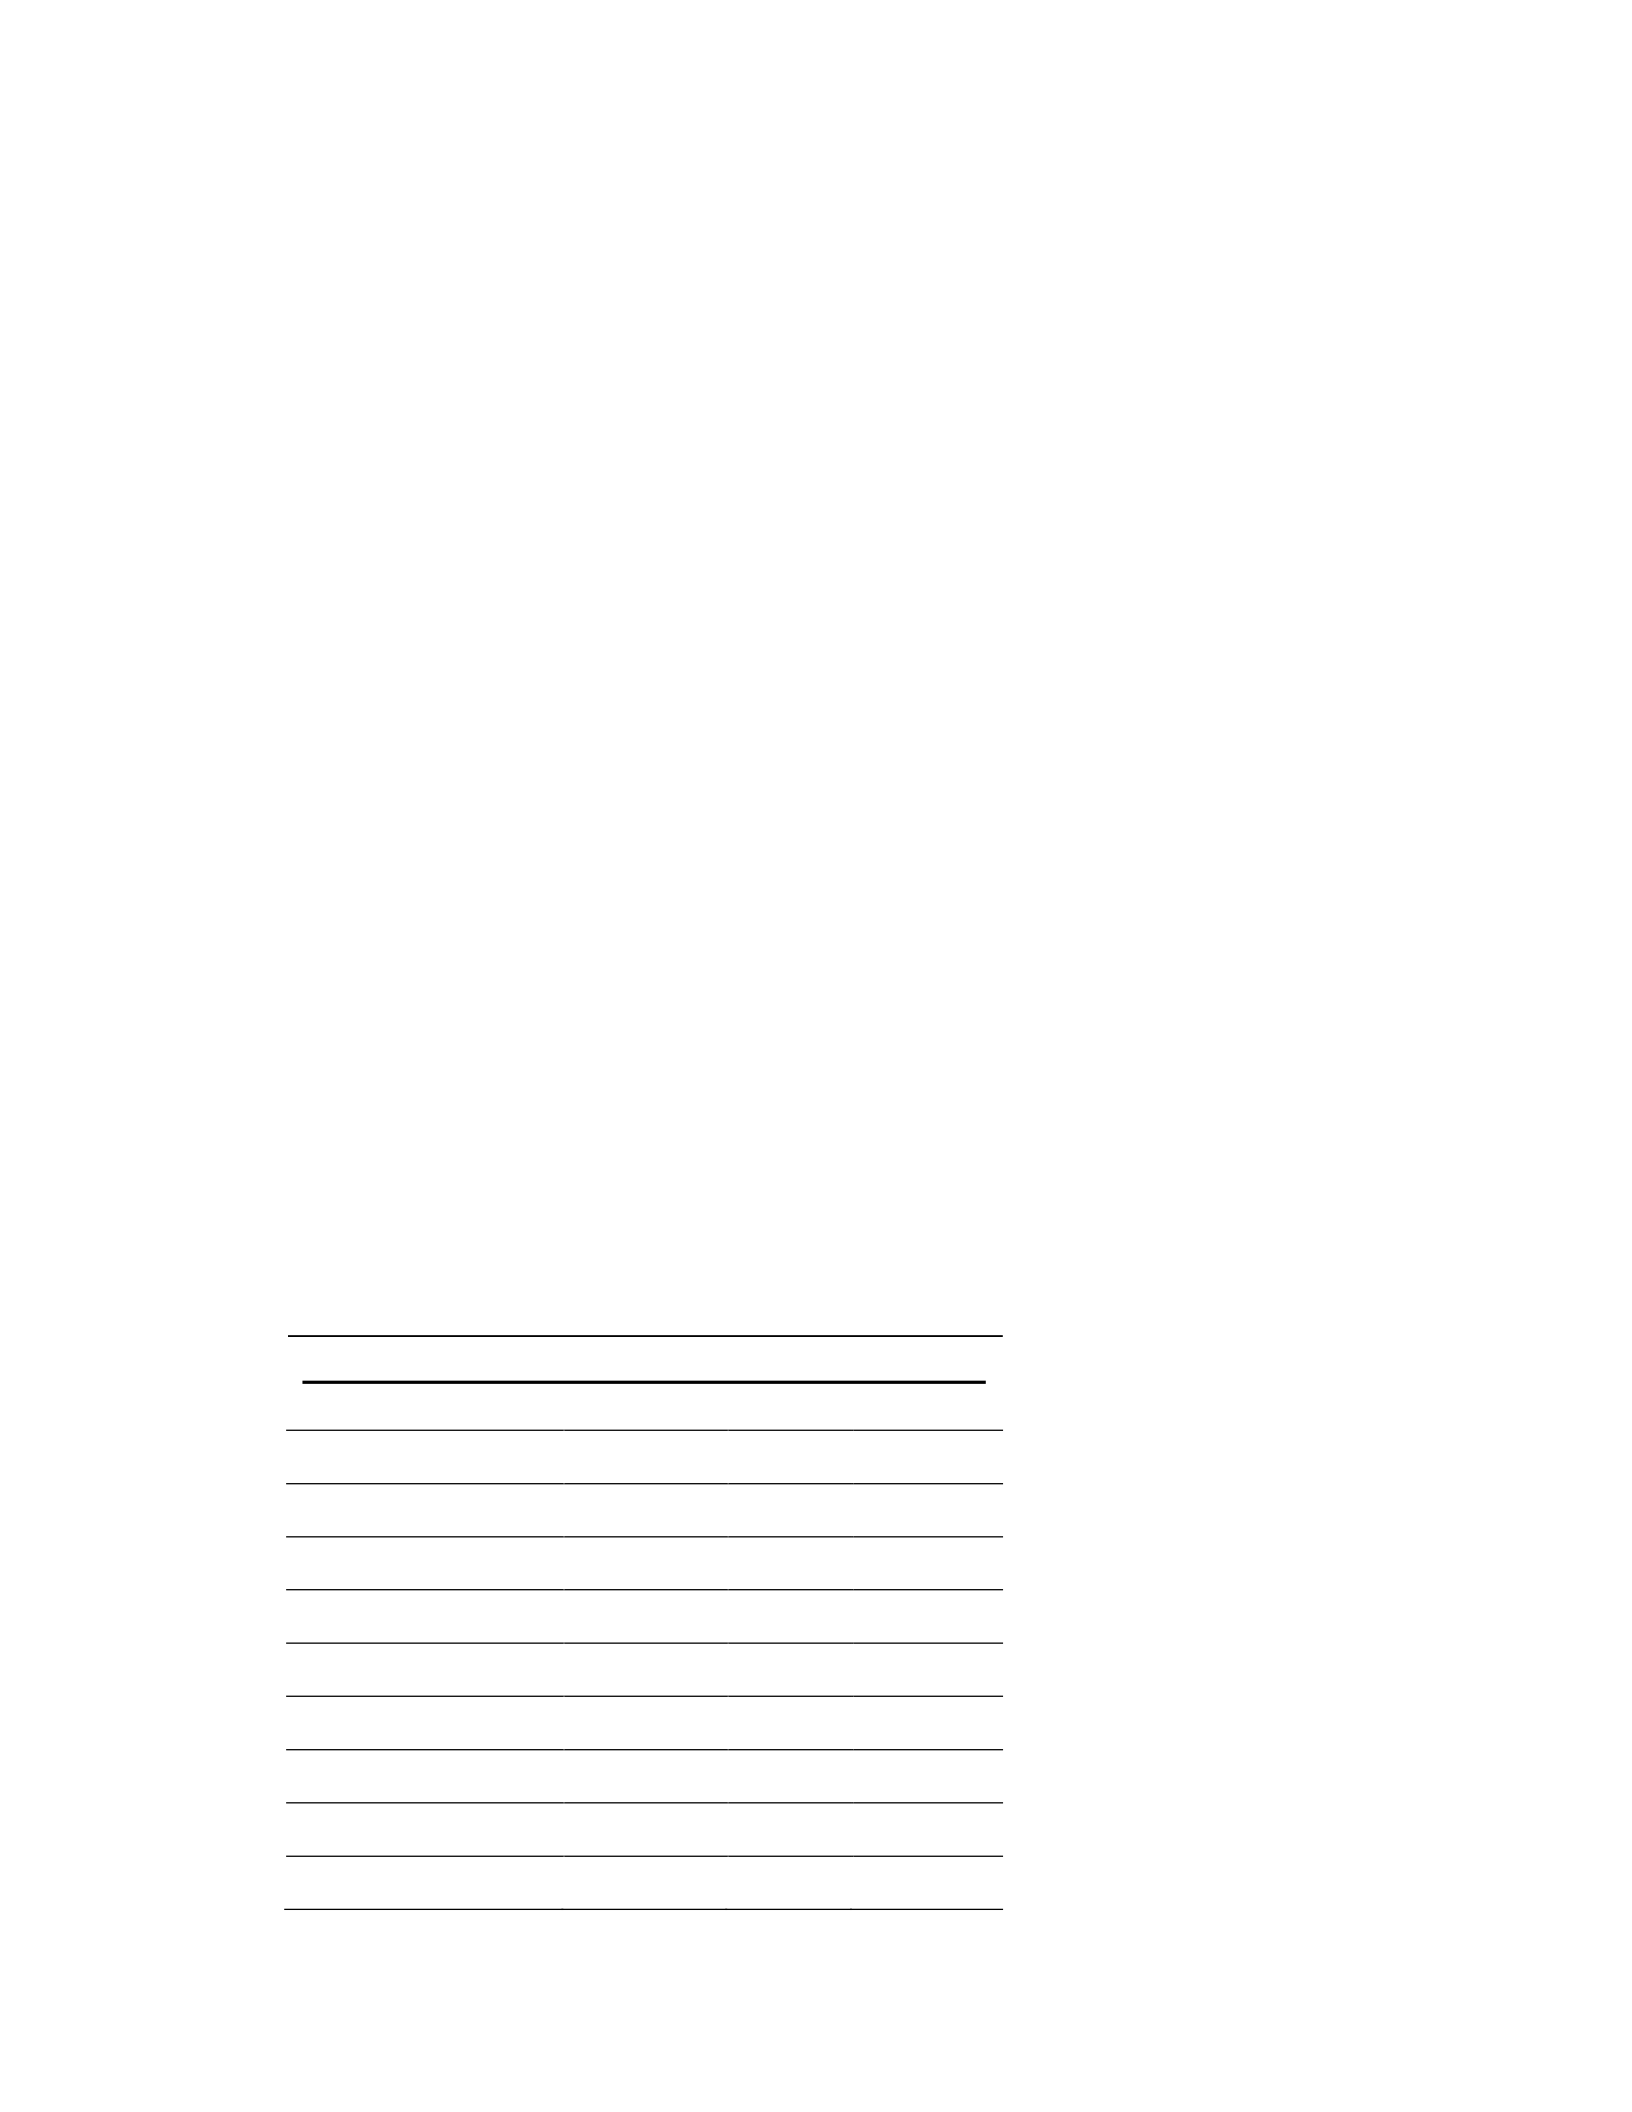
The research model in Figure 1 provides a graphical picture of the research hypothesis being
explored in this study. The visual diagram illustrates the hypothesized effect of a
VRMC on the financial risk and health of an organization.
Figure 1. Research Model.
30
Data Analysis and Results
To empirically analyze the research questions and hypotheses posed for this study,
a quantitative approach was chosen to investigate the effects of risk management
committees while assessing the association between research variables. This section
begins with descriptive statistics and industry analysis and concludes with hypothesis
testing.
Descriptive Statistics
Table 2 represents the descriptive statistics for nonfinancial firms’ data collected
from CY2009 to CY2017. It illustrates our sample with 5,973 observations, indicating
105 possessing a risk management committee. Exploring the trends since the enactment of
Dodd-Frank in 2010, we observe risk management committees have increased by 41% for
nonfinancial firms.
Table 2
Nonfinancial Firms’ VRMC Observations by Year (2009–2017)
Voluntary Risk Management Committee (VRMC)
Data Yrs. 0 1 Total
2009
107
5
112
2010
765
12
777
2011
787
12
799
2012
811
12
823
2013
810
13
823
2014
813
13
826
2015
838
16
854
2016
471
11
482
2017
466
11
477
31
Total
5,868
105
5,973
Table 3
Descriptive Statistics
Variable
Obs.
Mean
Std. Dev.
Min. Max.
Voluntary risk management committee
5973
0.0175
0.1314
0 1
Total debt to total assets
5973
0.5545
0.2409
0.029 3.806
Total debt to equity
5973
−0.4918
127.592
−9243.9 510.4
Degree of operational leverage
5973
−0.2616
212.596
−12291.518 3600.116
Degree of financial leverage
5973
0.9332
268.414
−8214.909 13968.75
Cash flow margin
5973
−0.0244
5.395
−279.46
3.607
Cash balance to total liabilities
5973
0.4617
0.9662
0
14.86
Total liabilities to total assets
5973
0.2577
0.2084
0
3.28
Total debt to EBITDA
5973
2.052
5.652
−141.32
179.565
Long-term debt to total liabilities
5973
0.3619
0.2276
0
0.976
Cash flow to total debt
5973
0.2598
0.4181
−9.923
7.91
Asset turnover
5973
1.052
0.7497
0.001
9.895
Receivables turnover
5973
23.528
253.792
0.036
17431.6
Sales to invested capital
5973
1.895
8.321
0.001
598.333
2009
5973
0.0187
0.1356
0
1
2010
5973
0.1300
0.3364
0
1
2011
5973
0.1337
0.3404
0
1
2012
5973
0.1337
0.3447
0
1
2013
5973
0.1337
0.3447
0
1
2014
5973
0.1382
0.3452
0
1
2015
5973
0.1429
0.3500
0
1
2016
5973
0.0806
0.2723
0
1
2017
5973
0.0798
0.2710
0
1
Gender ratio
Global Industry Classification Standard:
5973
0.8535
0.1068
0.25
1
10—Energy
5973
0.0498
0.2177
0
1
15—Materials
5973
0.0838
0.2772
0
1
20—Industrial
5973
0.2209
0.4149
0
1
25—Consumer discretionary
5973
0.1793
0.3836
0
1
30—Consumer staples
5973
0.0723
0.2590
0
1
35—Health care
5973
0.1237
0.3292
0
1
40—Financials
5973
0.0123
0.1106
0
1
45—Information technology
5973
0.1580
0.3648
0
1
50—Communication services
5973
0.0339
0.1812
0
1
55—Utilities
5973
0.0606
0.2386
0
l
60—Real estate
5973
0.0048
0.0695
0
1
32
Number of directors
5973
9.558
2.204
3
19
Number of directors qualifications
5973
25.482
11.704
0
94
Business Sector Descriptive Statistics
We examine the sectors identified for each of the corresponding observations
represented in this study. To do so, we utilize the GICS, which is a financial industry
standard, to categorize companies into sectors and industries. Developed by Morgan
Stanley Capital International (MSCI) and Standard & Poor’s (S&P), it provides a
consistent definition for global industry classification and is widely used by both industry
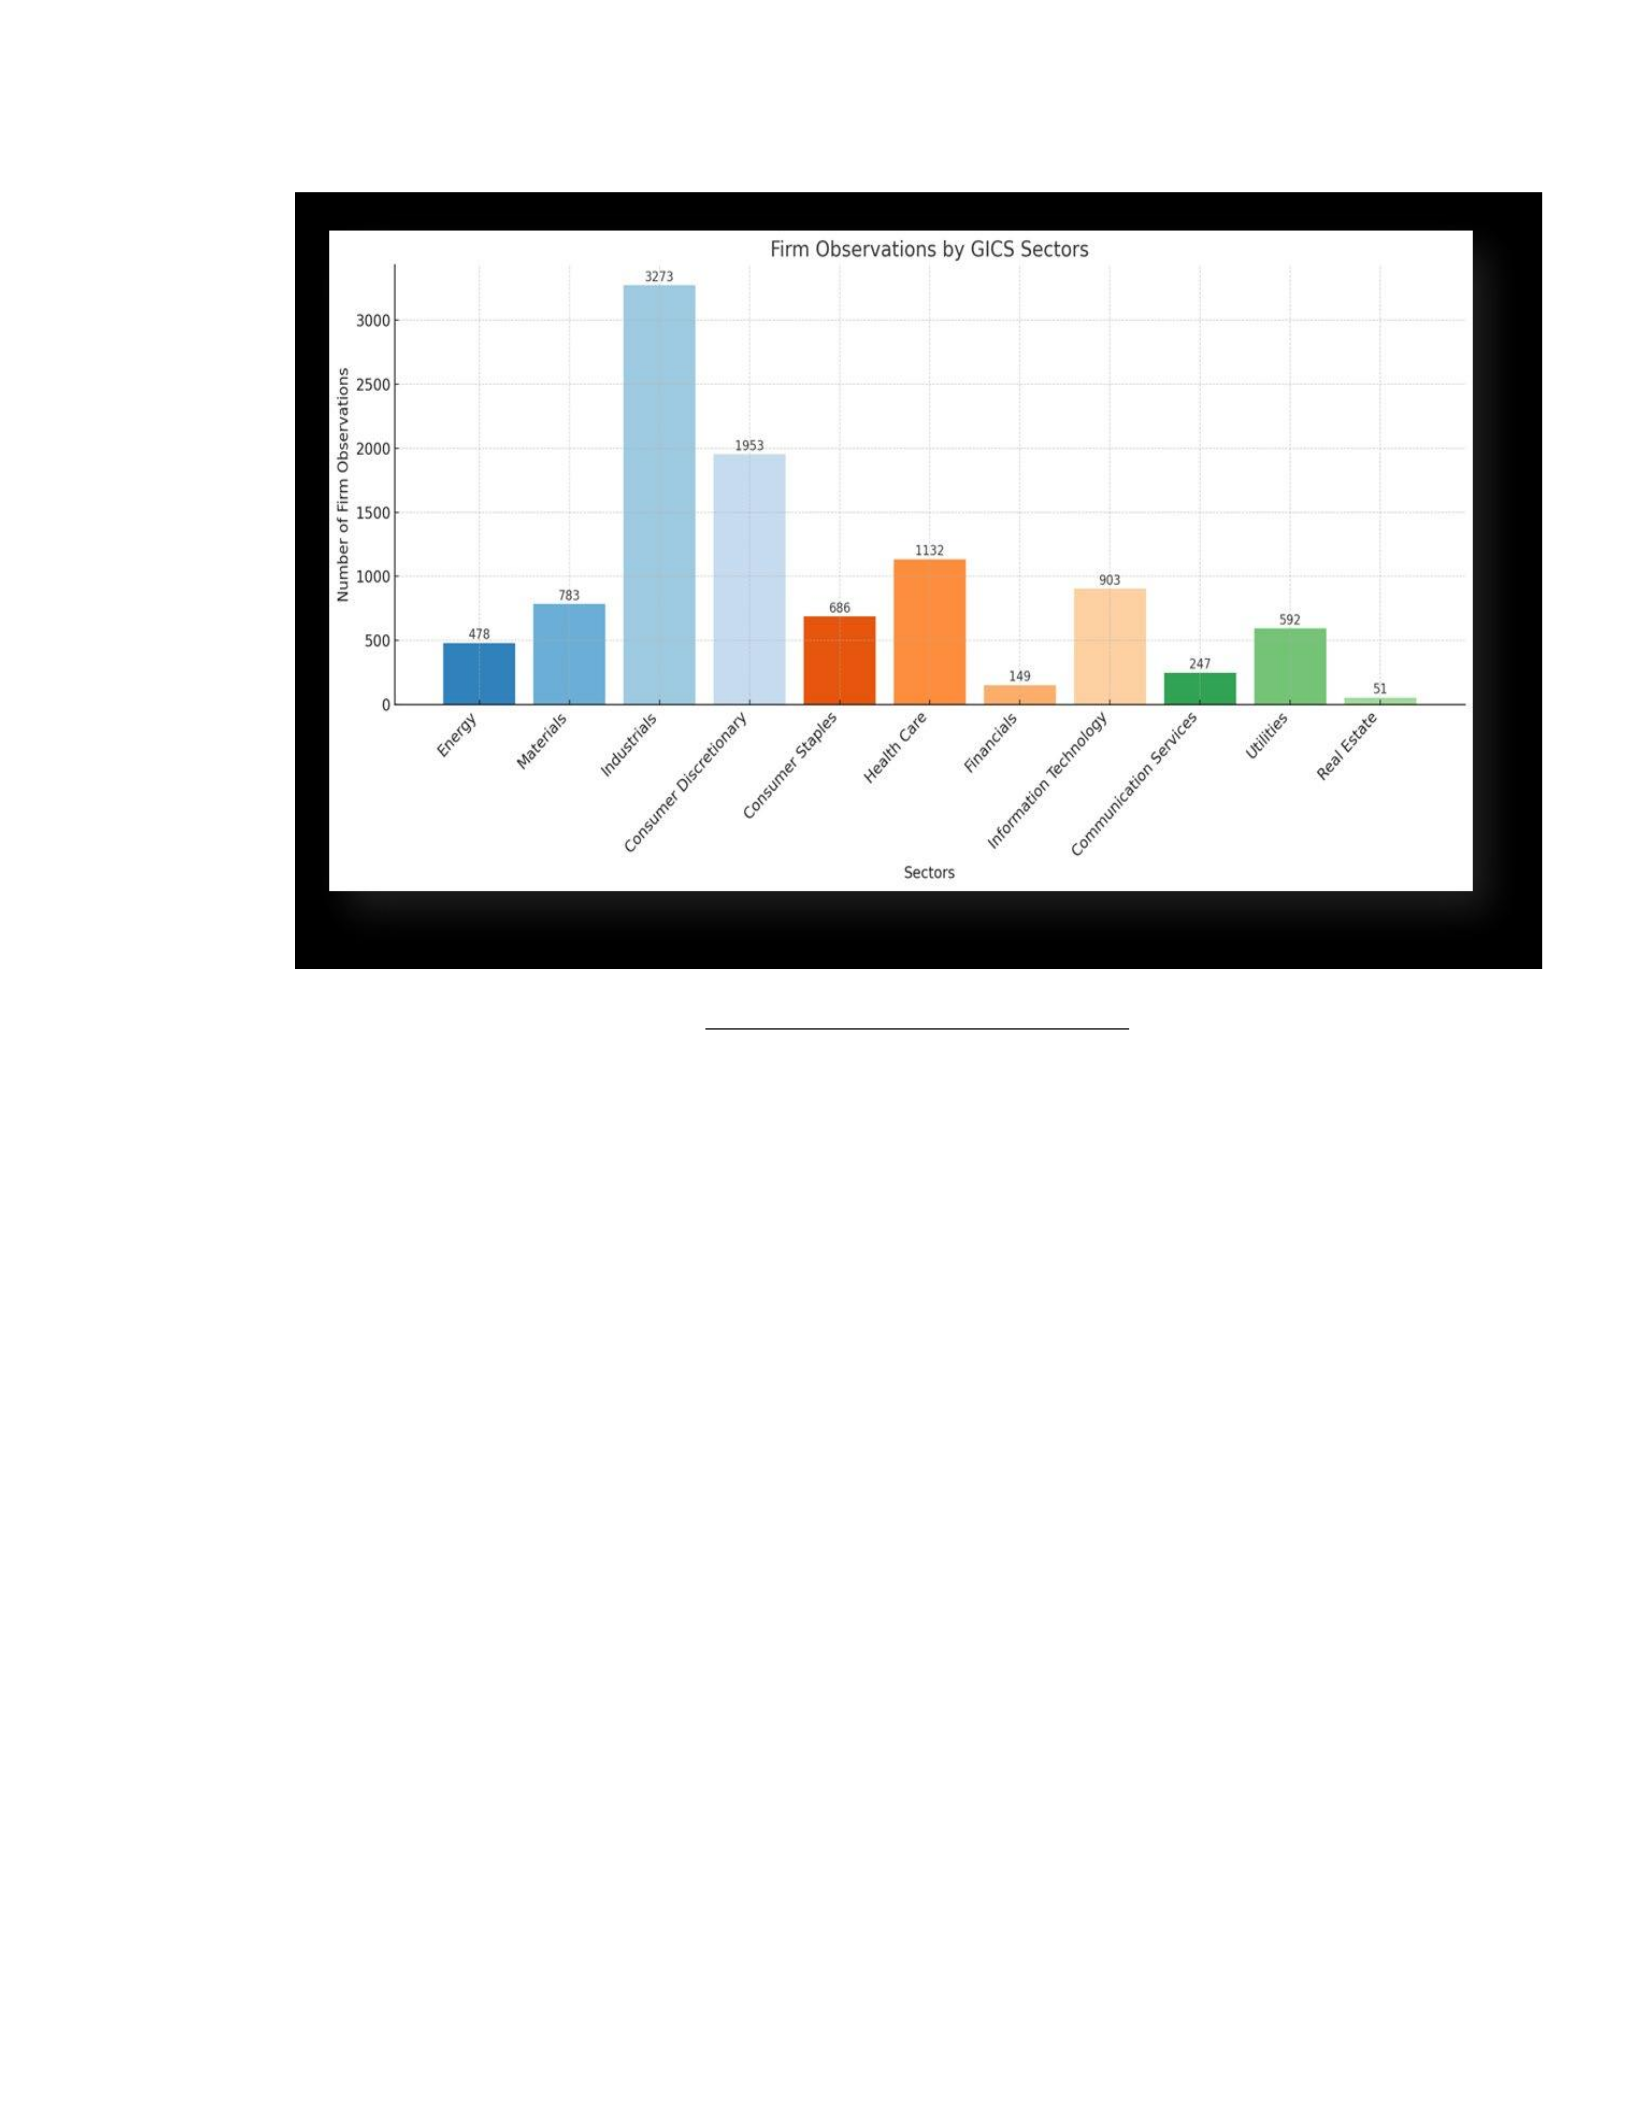
practitioners and scholars alike. Figure 2 displays the three most represented sectors in our
dataset: Industrials, with 3,273 observations, making up 32% of our sample; Consumer
Discretionary, with 1,953 observations, accounting for 19%; and Health Care, with 1,132
observations, contributing 11% to our sample.
33
Figure 2. Firm Observations by GICS Sectors.
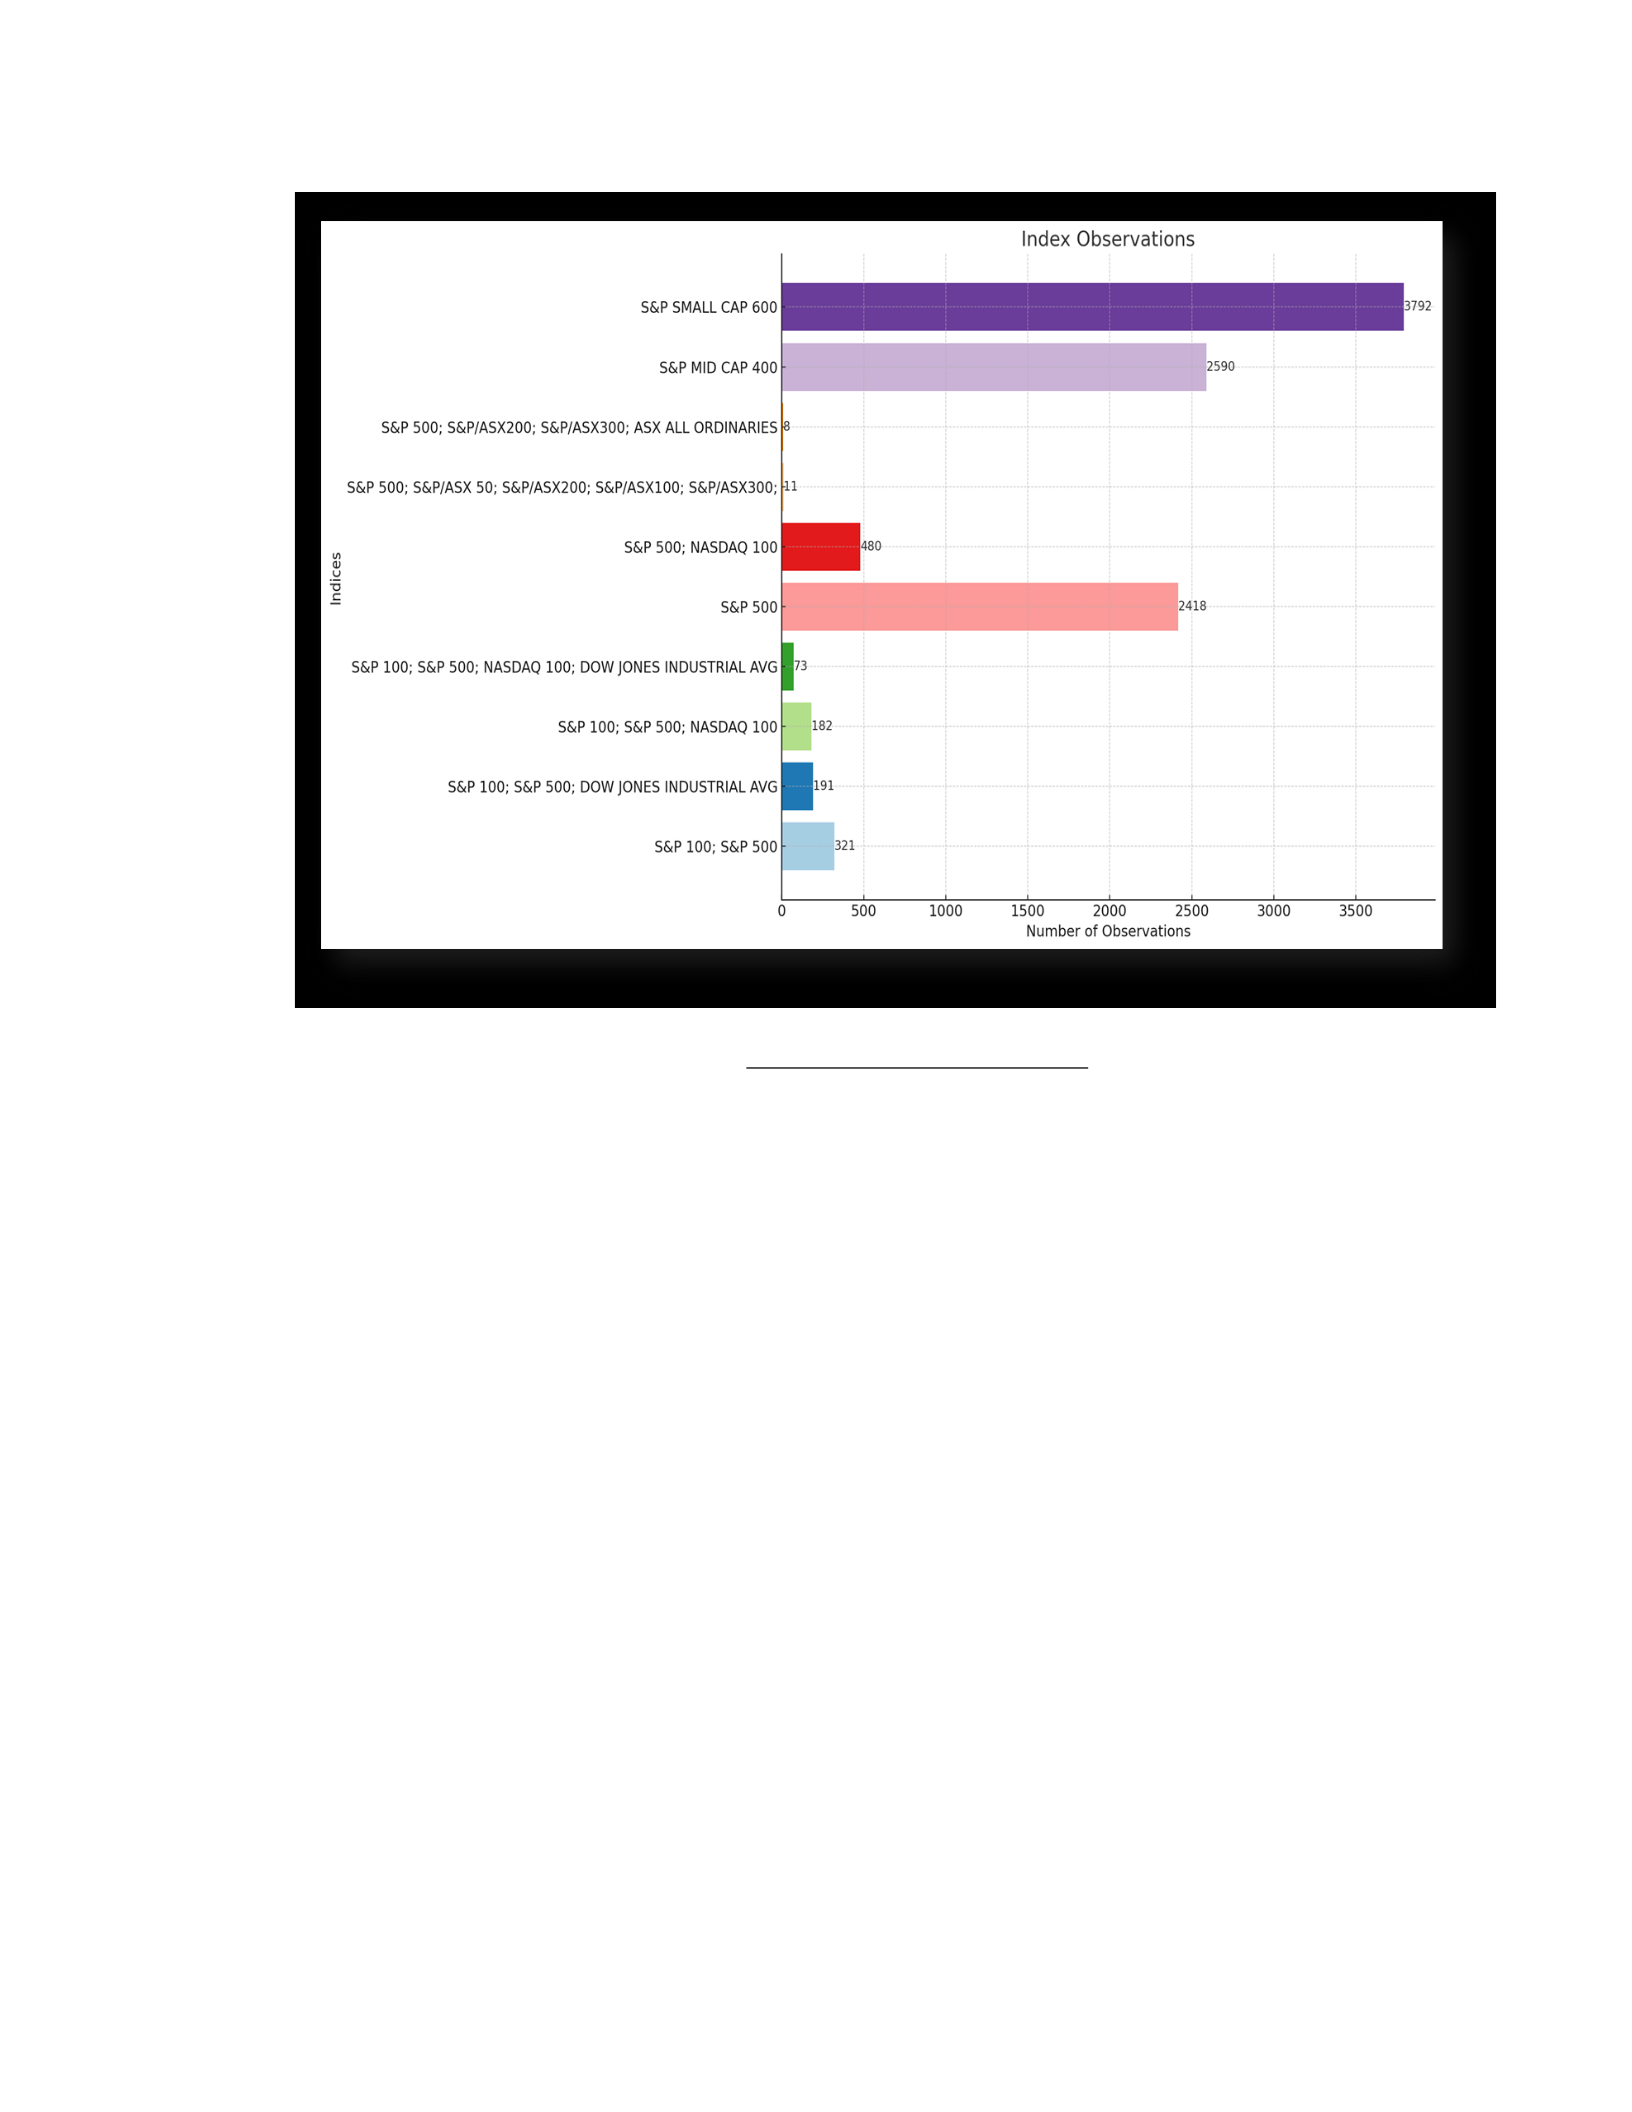
We also examine the S&P U.S. sector indices listed within our review. We find in
Figure 3 that 37.7% of the companies in our sample are designated as S&P SMALL CAP
600 index (3,792). Additionally, 25.7% of firms are listed within the S&P MID CAP 400
(2,590). Lastly, 24% of the firms listed are designated as S&P 500 index (2,418), which in
total accounts for approximately 87.4% of the firms being evaluated.
34
Figure 3. S&P Sector Indices Statistics.
Descriptive Analysis
Descriptive analysis in Table 3 is also used to determine the minimum, maximum, sum,
means, and standard deviation for all variables in the categorization. The dataset encompasses
various financial, operational, and organizational metrics for a sample of 5,973 entities. The
risk management committee has a mean of 0.0175 with a standard deviation of 0.1314. This
indicates on average that a small percentage of firms (0.0175) in this sample have a VRMC,
expressing that the presence of such committees is not prevalent. The predictive variables
shown in Table 3 provides the descriptive statistics for financial risk being examined using
several leverage and solvency ratios. For leverage, we observe both the degree of operating
leverage and the degree of financial leverage ratios. Likewise, for solvency, we examine total

35
debt-to-equity and total debt-to-asset ratios. The degree of operating leverage and degree of
financial leverage ratios means are −0.2616 and 0.9332 with corresponding standard deviations
of 212.596 and 268.414, respectively. The mean value of 0.9332 for degree of financial
leverage suggests a relatively high average financial leverage among the entities, reflecting a
reliance on debt in their capital structure. The total debt-to-asset ratio has a mean of 0.5545 and
a standard deviation of 0.2409, and the debt-to-equity ratio has a mean of −0.4918 and a
standard deviation of 127.592. The variables used in Table 3 provides descriptive statistics for
examining the financial health being explored by several financial soundness ratios and
efficiency ratios. For financial soundness, we observe the CFM, cash balance-to-total
liabilities, total liabilities-to-total assets, total debt-to-EBITDA, long-term debt-to-total
liabilities, and cash flow-to-total debt ratios. For efficiency, we examine the asset turnover,
receivable turnover, and sales-to-invested capital ratios. CFM and cash balanceto-total
liabilities ratio means are −0.0244 and 0.4617 with corresponding standard deviations of 5.395
and 0.9662, respectively. CFM with a mean of −0.0244 indicates a slightly negative CFM on
average, suggesting potential challenges in generating positive cash flows from operations.
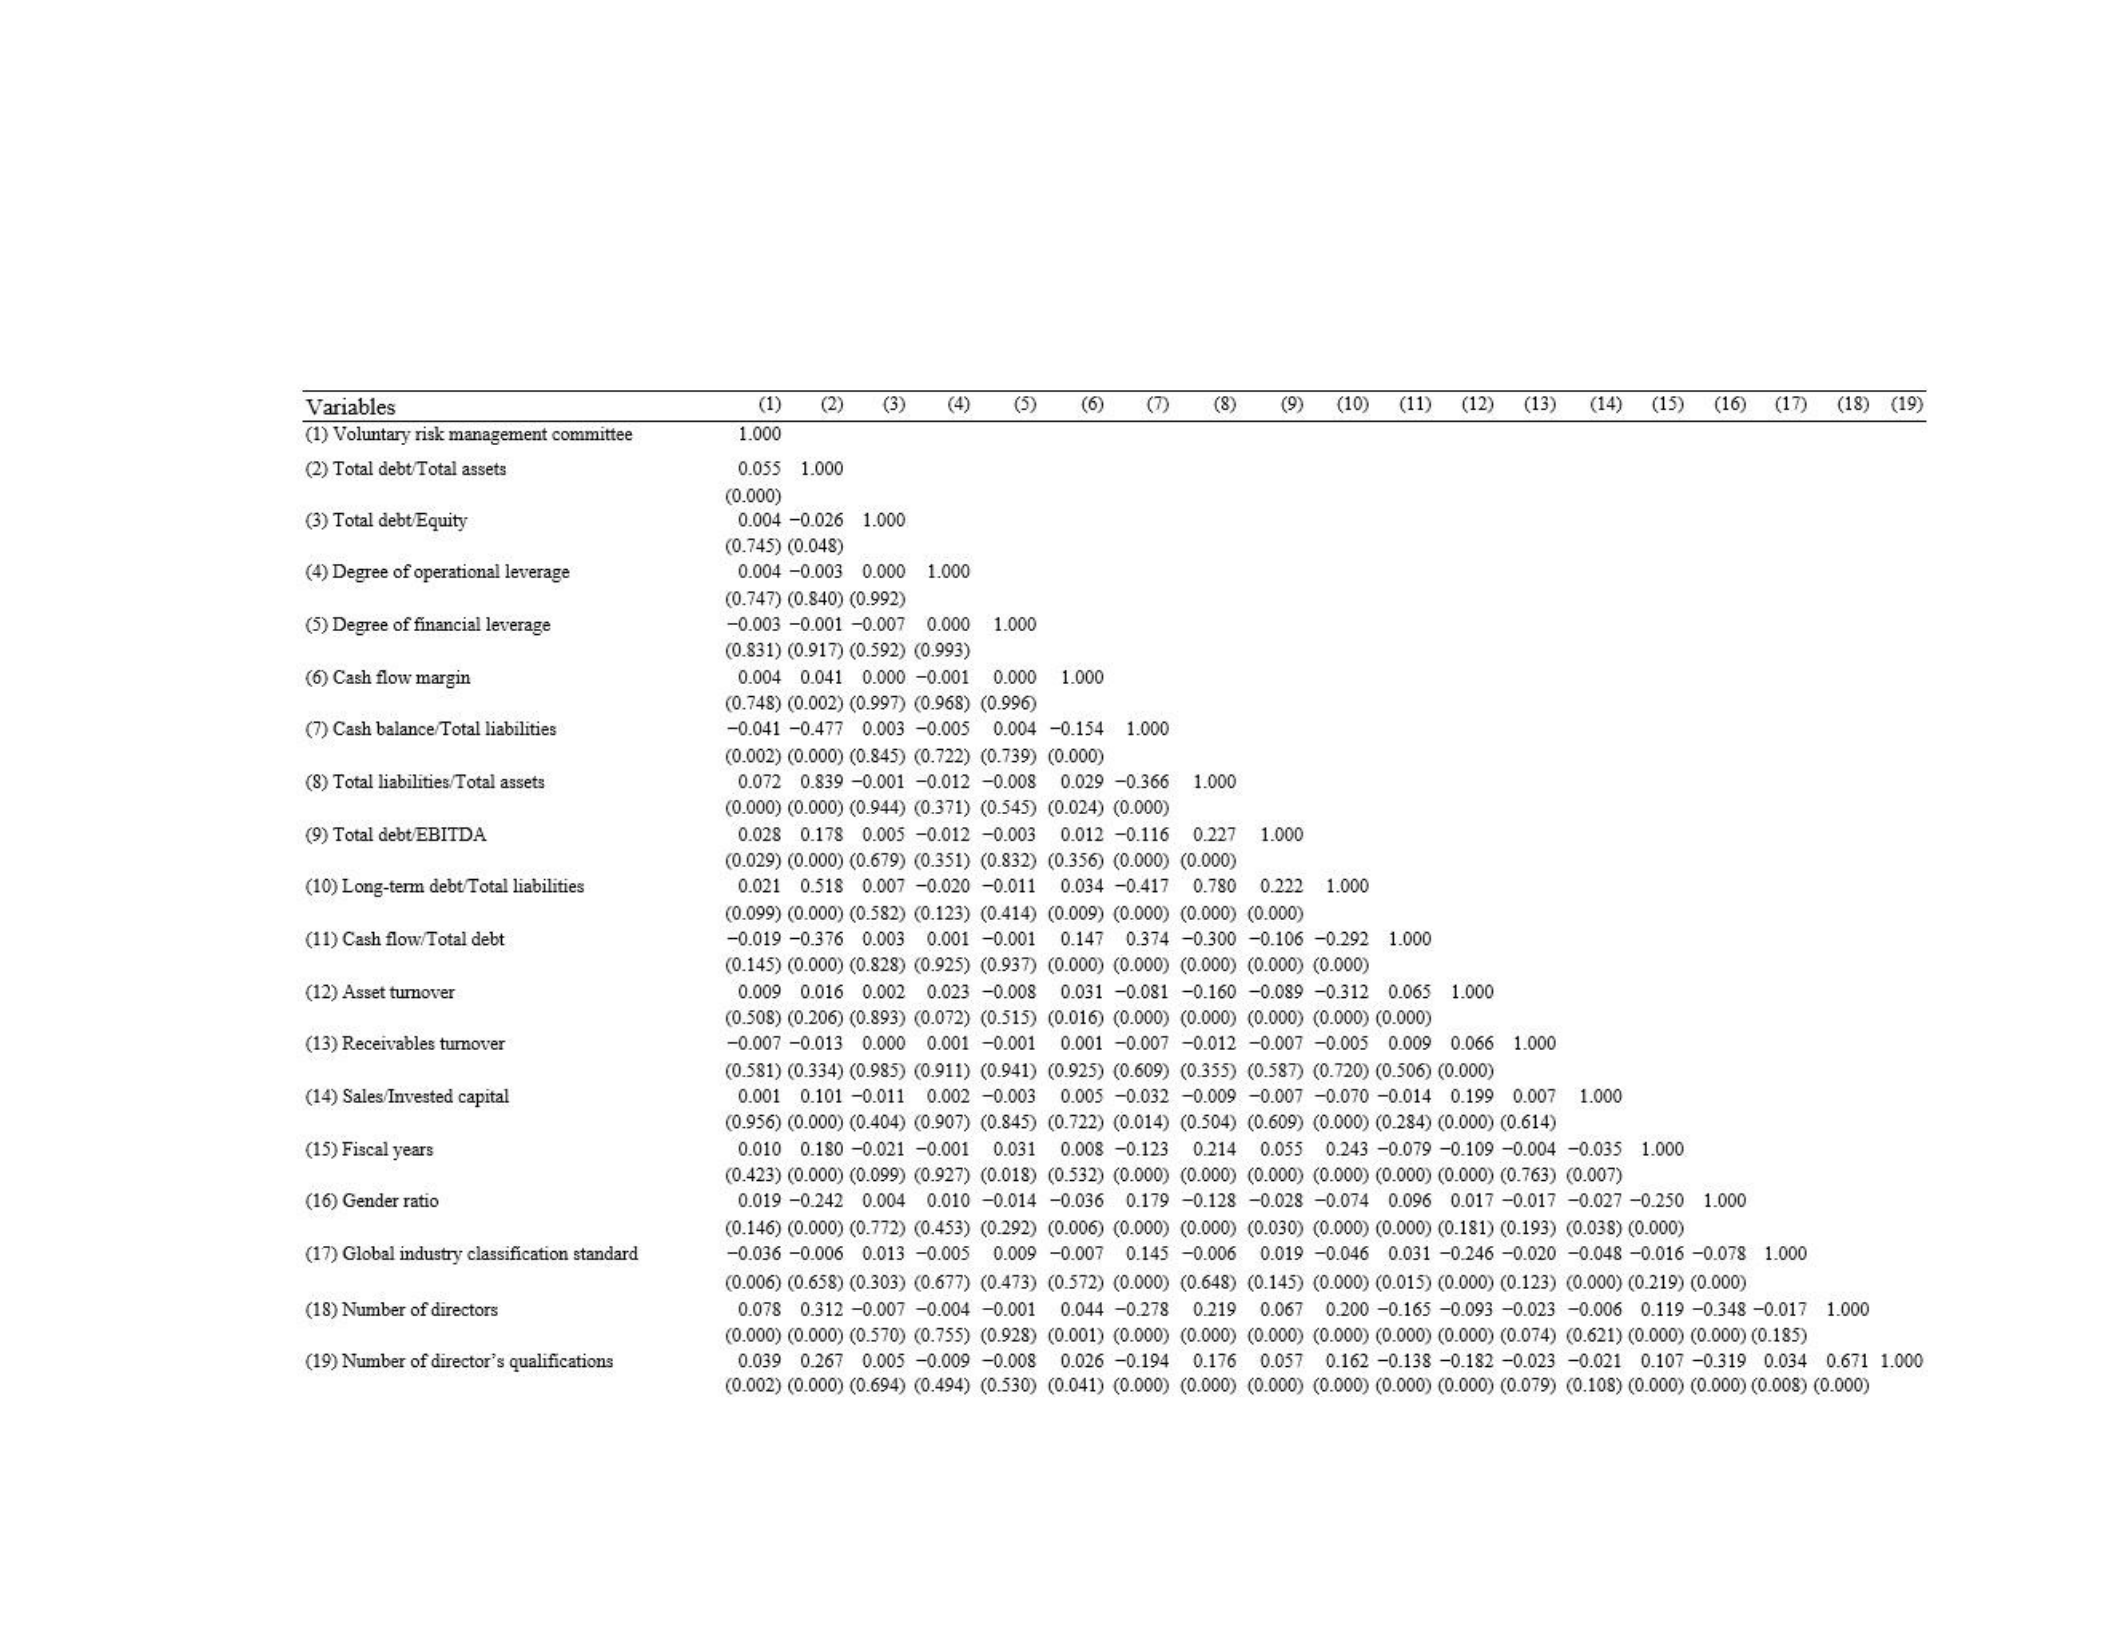
Table 4.
Correlation Analysis 1

37

38
The cash flow-to-total debt ratio means is 0.2598 with a corresponding standard
deviation of 0.4181. Total debt-to-EBITA and long-term debt-to-total liabilities ratios
have a mean of 2.052 and 0.3619 with a matching standard deviation of 5.652 and
0.2276, respectively. Total liabilities to total assets provide a mean of 0.2577 and a
standard deviation of 0.2084. The asset turnover ratio has a mean of 1.052 and a
standard deviation of 0.7497, which suggests moderate efficiency in utilizing assets to
generate sales. Receivable turnover and sales-to-invested capital ratios have means of
23.528 and
1.895 with corresponding standard deviations of 253.792 and 8.321, respectively.
The increasing trend in mean values over the fiscal years (2009 to 2015) suggests
a possible rise in interest in possessing a VRMC, potential trends in risk management
practices, and/or additional capture of data reporting availability during this period. The
gender ratio ranges from 0.25 to 1, representing the contrast of men’s and women’s
positions within the VRMCs. The high mean of 0.8535 indicates a predominantly high
men ratio, with a narrow standard deviation of 0.1068, suggesting a relatively low
variability of women on the board. The number of directors’ qualifications has a wide
range (0 to 94) with an average of 25.482, indicating variability in the qualifications
possessed by directors.
Hypothesis Testing
Correlations Analysis
The correlation matrix in Table 4 provides a detailed view of the relationships
among all variables used within the dataset. The statistical analysis of financial ratios
within the provided dataset reveals several significant correlations underscored by
pvalues below 0.05, denoting statistical significance. A notable positive correlation of

39
0.839 is observed between total debt to total assets and total liabilities to total assets,
indicating that increases in a firm’s total debt are proportionally reflected in its total
liabilities. This is a logical outcome given that debt is a major component of liabilities.
Conversely, the cash balance to total liabilities and total debt to total assets show a
significant negative correlation of r = −0.477, p < 0.00, suggesting that companies with
higher debt ratios usually have lower cash balances relative to their liabilities. This is
potentially due to the increased financial burden imposed by higher debt levels.
Furthermore, a strong positive correlation of r = 0.780, p < 0.00 between total liabilities
to total assets and long-term debt to total liabilities explains a trend where firms with
higher total liabilities relative to their assets tend to have a significant proportion of these
liabilities as long-term debt. This possibly indicates a strategic push toward long-term
financing.
Additionally, the cash flow/total debt and cash balance/total liabilities correlation
r = 0.374, p < 0.00 implies that firms with higher cash flow in relation to their total debt
also maintain higher cash reserves compared to their liabilities. This illustrates a firm’s
effective monitoring of liquidity management. The dataset also reveals a correlation
coefficient of r = 0.671, p < 0.00 between the number of directors and directors’
qualifications indicating that larger boards tend to comprise more qualified individuals to
possibly oversee the complexities and skillset needed to monitor larger organizations.
Lastly, the correlation of r = 0.518, p < 0.00 between total debt to total assets and
longterm debt to total liabilities suggests that firms with a higher debt-to-assets ratio are
more inclined toward long-term debt to correspond with their long-term strategic goals.
These correlations collectively shed light on the relationships between various financial

40
aspects of a firm, including debt management, liquidity, and solvency, emphasizing their
relationship to corporate financial health.
Regression Analysis
The regression analysis in Table 5 provides an understanding of the relationship
between the presence of a VRMC and several selected financial variables within our
scope. With Hypothesis 1, we explore whether the existence of a VRMC is related to the
financial risk leverage of an organization. To evaluate this hypothesis, we utilize the
degree of operating leverage and degree of financial leverage ratios as firm leverage
variables. We find no clear association between the degree of operational leverage and
the likelihood of having a VRMC (B = 2.53e06, p = 0.750). Similarly, we also observe no
significant relationship between financial leverage and the presence of a VRMC (B =
−1.38e06, p = 0.827). Thus, Hypothesis 1 cannot be supported.
Hypothesis 2 predicts that the existence of a VRMC is related to the financial risk
solvency of an organization. To evaluate this variable, we explore the association
between the firm possessing a VRMC and the total debt-to-equity ratio. The coefficient is
positive, but the relationship is not statistically significant (B = 6.25e06, p = 0.637),
indicating that the total debt-to-equity ratio is not a significant predictor of having a
VRMC. This finding implies that the existence of a VRMC does not have a substantial
relational role within the financial risk solvency of the nonfinancial firms within our
scope. Hence, Hypothesis 2 cannot be supported.
Hypothesis 3 predicts that the existence of a VRMC is related to the financial
health soundness of an organization. To evaluate these variables, we utilize the following
ratios: the CFM, cash balance to total liabilities, total liabilities to total assets, total debt
to EBITDA, long-term debt to total liabilities, and cash flow to total debt. We find CFM

41
(B = −0.000118, p = 0.717), cash balance-to-total liabilities (B = −0.0002503, p = 0.56),
debt to EBITDA (B = −0.000346, p = 0.263), cash flow to total debt (B = −0.002674, p =
0.263) ratios indicating no significant relationship between the firm’s financial health
soundness and the presence of a VRMC.
In contrast, two financial ratios show statistically significant relationship:
longterm debt to total liabilities (B = −0.064789, p = 0.001) and total liabilities to total
assets (B = −0.089971, p = 0.001). However, the association differed: long-term debt to
total liabilities is associated with a lower likelihood of having a VRMC, while total
liabilities to total assets are associated with a higher likelihood of having a VRMC. To
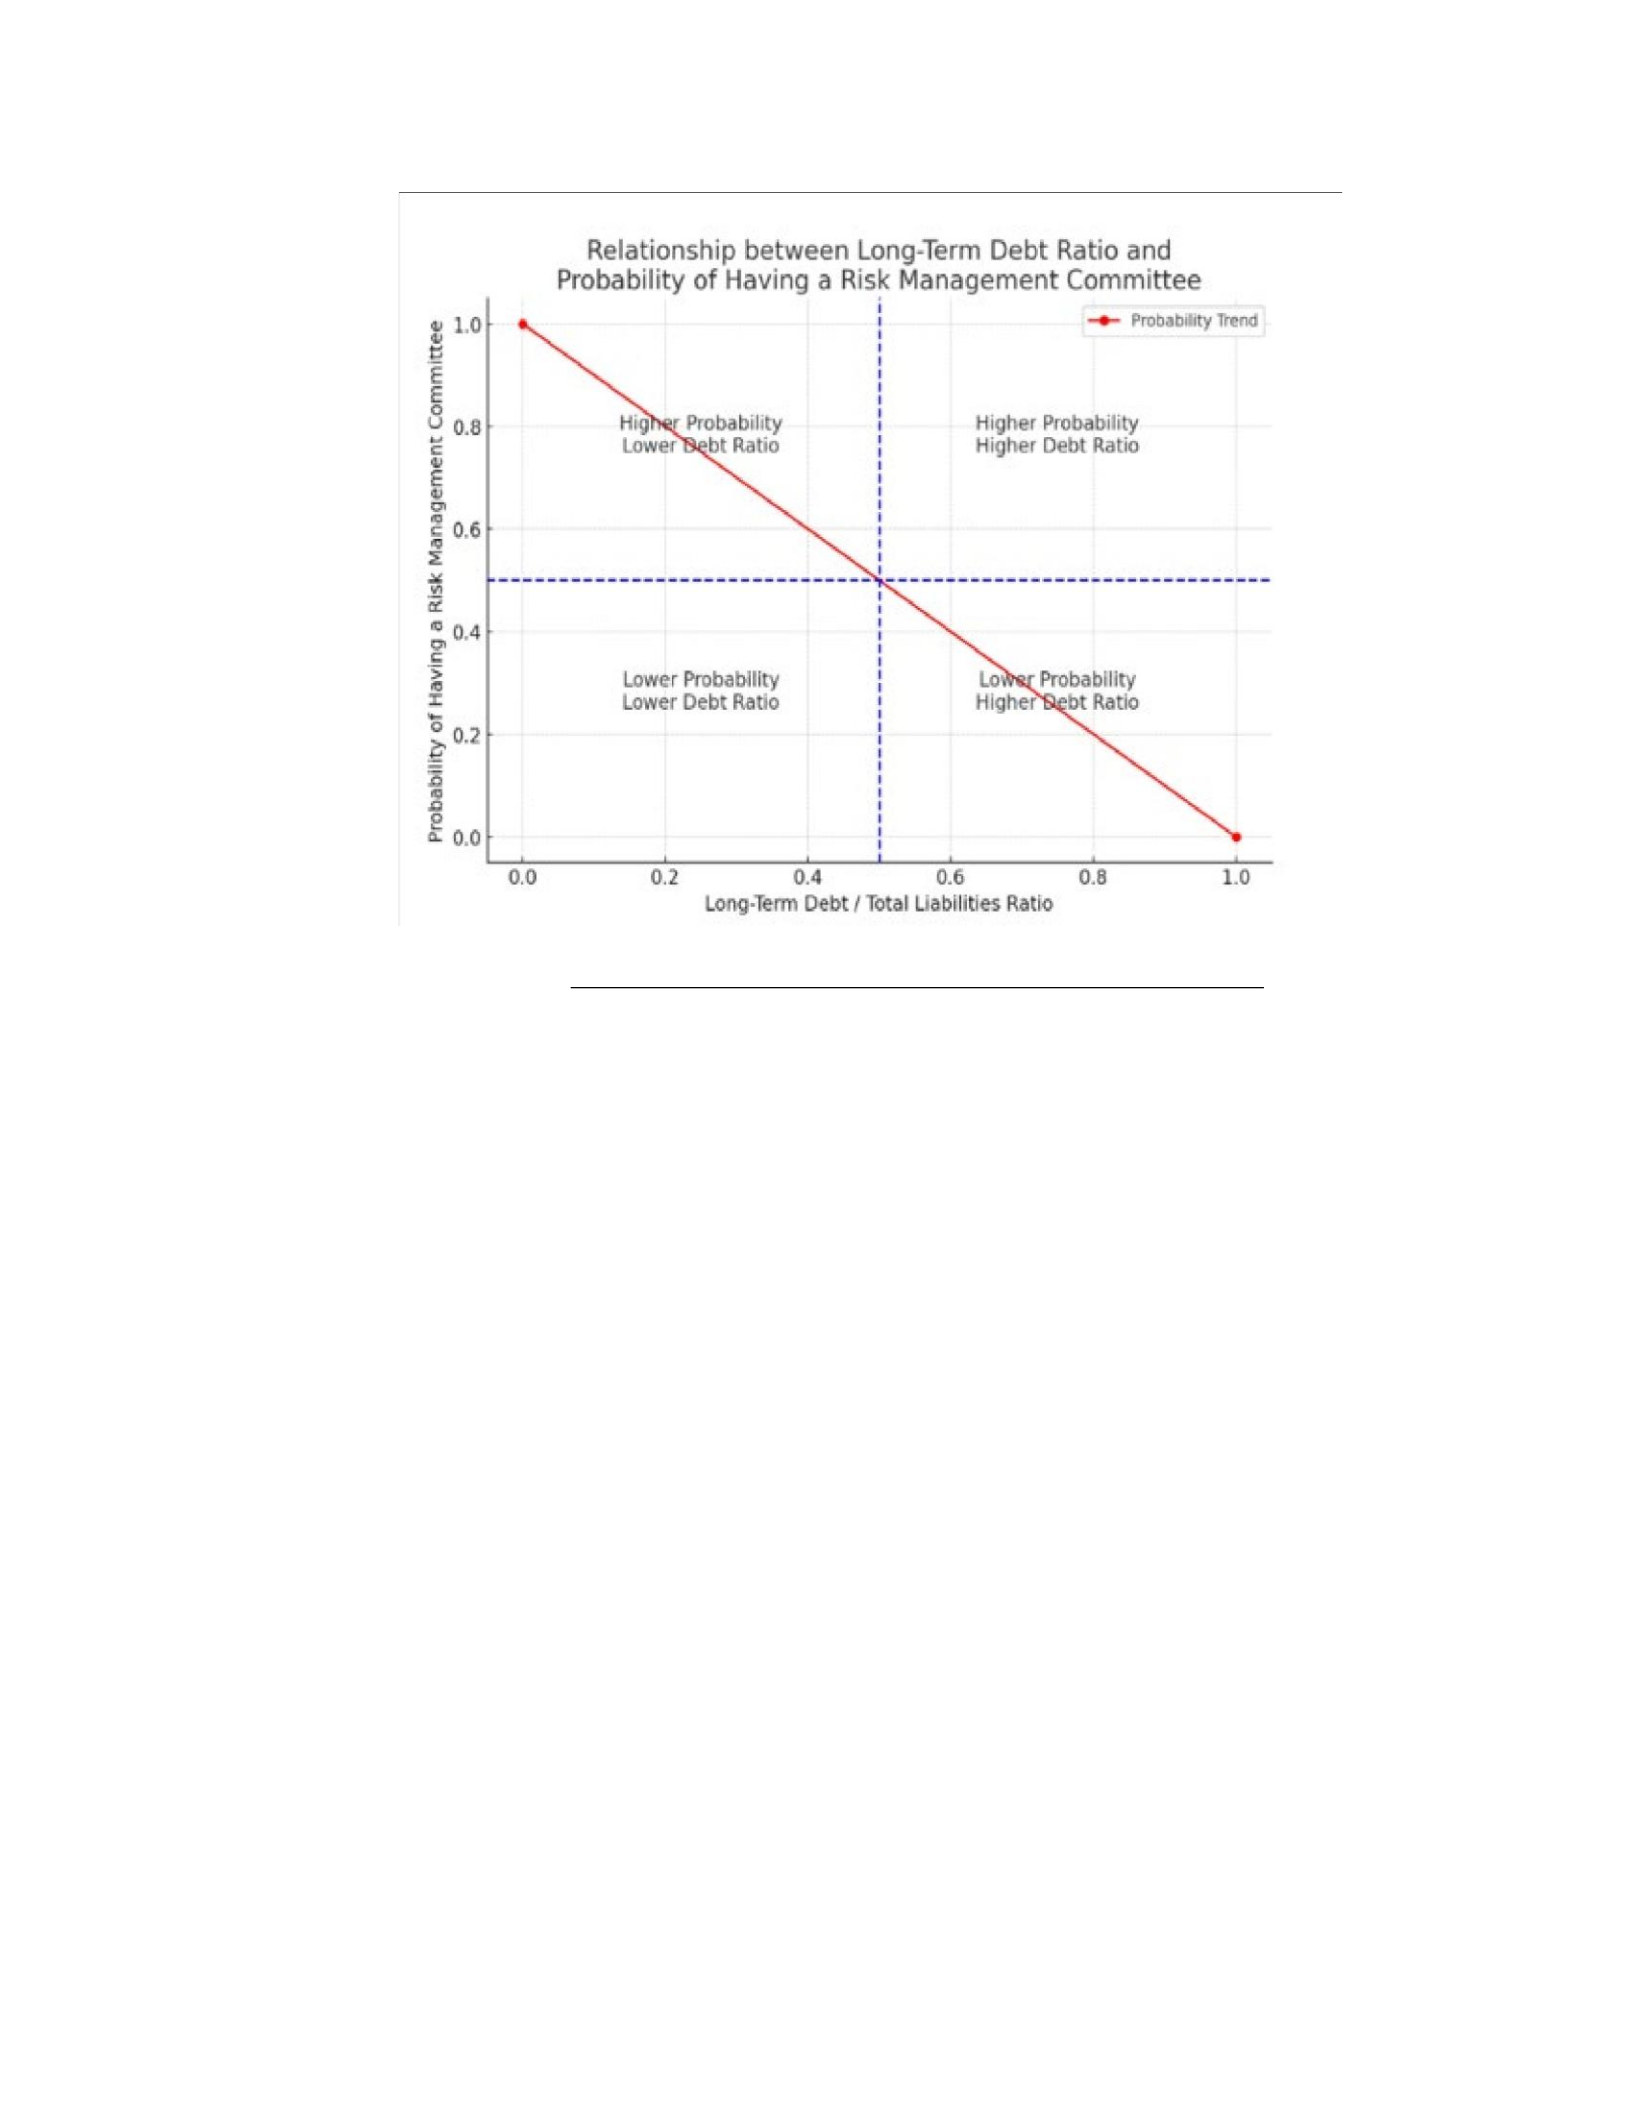
further illustrate this relationship, Figure 4 indicates that as the long-term debt/total
liabilities ratio increases (moving from left to right on the x-axis), the probability of
having a VRMC decreases (moving from top to bottom on the y-axis). This is shown by
the red line, which represents the negative correlation between the two variables. Thus,
holding other variables constant, an increase in long-term debt/total liabilities ratio is
associated with a decrease in the probability of possessing a VRMC. As the long-term
debt/total liabilities ratio increases, the likelihood of having a risk management
committee decreases. This scenario can exist when a firm with a higher long-term debt
may allocate its resources toward servicing this debt rather than investing in the
infrastructure for a risk management committee.

Table 5
Regression Analysis Showing the Effect of VRMC and Financial Risk Ratios
Voluntary risk management committee
Coef.
2.53e06
−1.38e06
6.25e06
−0.000118
−0.002503
0.002674
0.000346
−0.064789
0.089971
−0.000879
−1.79e06
−0.000061
−0.029541
−0.029926
−0.029885
−0.028100
−0.027513
−0.024333
−0.025260
−0.024084
St. Err.
7.95e06
6.30e06
0.000013
0.000326
0.002237
0.004582
0.000309
0.013521
0.013656
0.002774
6.71e06
0.000208
0.013239
0.013224
0.013207
0.013223
0.013242
0.013246
0.013937
t-value
0.32
−0.22
0.47
−0.36
−1.12
0.58
1.12
−4.79
6.59
−0.32
−0.27
−0.29
−2.23
−2.26
−2.26
−2.13
−2.08
−1.84
−1.81
−1.72
p-value
0.750
0.827
0.637
0.717
0.263
0.56
0.263
0.000
0.000
0.751
0.790
0.768
0.026
0.024
0.024
0.034
0.038
0.066
0.070
[95% Conf.
−0.000013
−0.0000137
−0.0000197
−0.000756
−0.0068881
−0.0063093
−0.0002597
−0.0912948
0.0632007
−0.0063168
−0.0000149
−0.0004682
−0.0554931
−0.0558505
−0.0557766
−0.0540218
−0.0534724
−0.0503
−0.0525806
−0.0514954
Interval]
0.0000181
0.000011
0.0000322
0.0005201
0.0018814
0.0116563
0.0009516
−0.0382846
0.1167408
0.0045588
0.0000114
0.0003459
−0.003588
−0.0040015
−0.003994
−0.0021781
−0.0015537
0.0016339
0.0020599
Sig.
***
***
**
**
**
**
**
*
*
*
Degree of operational leverage
Degree of financial leverage
Total debt/Equity
Cash flow margin
Cash balance/Total liability
Cash flow/Total debt
Total debt/EBITDA
Long-term debt/Total liability
Total liabilities/Total assets
Asset turnover
Receivables turnover
Sales/Invested capital
2009 (Base)
2010
2011
2012
2013
2014
2015
2016
2017
Gender ratio
Global industry classification Standard:
10 (Base)
15
0.070548
−0.000068
42
0.013983
0.017982
0.009596
3.92
−0.01
0.085
0.000
0.994
0.0352967
−0.0188793
0.0033281
0.1057984
0.0187432
***
Table 5
(continued)
20
−0.011305
0.008474
−1.33
0.182
−0.0279175
0.0053083
25
−0.011528
0.008883
−1.30
0.194
−0.0289411
0.0058853
30
−0.008739
0.010137
−0.86
0.389
−0.0286095
0.0111315
35
−0.024281
0.009129
−2.68
0.007
−0.0423247
−0.0065315
***
40
−0.02237
0.017000
−1.32
0.188
−0.0556945
0.0109546
45
−0.009511
0.008866
−1.07
0.283
−0.026892
0.0078692
50
−0.032544
0.012023
−2.71
0.007
−0.0561133
−0.008975
***
55
−0.014574
0.01062
−1.37
0.170
−0.0353916
0.0062443
60
−0.039787
0.025738
−1.55
0.122
−0.0902419
0.0106677
Number of directors
0.005618
0.001093
5.14
0.000
0.003476
0.0077596
***
Number of directors’ qualifications
−0.000195
0.000203
−0.96
0.337
−0.0005948
0.0002039
Constant
−0.050984
0.025581
−1.99
0.046
−0.1011325
−0.0008347
**
*** p < 0.01, ** p < 0.05, * p < 0.1

43
46
Figure 4. Long Term Ratio and the Probability of Adopting a VRMC.
Many of the financial decisions favor the fact that a company must carry on its
operations with the reliance on debt (Hanousek, 2011). Conversely, an agency problem
exists where investor confidence prompts investors or other stakeholders to advocate for
more direct control mechanisms or oversight, rather than a formal committee structure.
Additionally, we also find an increase in total liabilities to total assets is
associated with a higher likelihood of having a VRMC. Figure 5 depicts the relationship
between the total liabilities/total assets ratio and the probability of possessing a risk
management committee. As illustrated, the chart shows a positive correlation: as the total
liabilities/total assets ratio increases (moving from left to right on the x-axis), the
probability of having a risk management committee also increases (moving from bottom
to top on the y-axis). Holding other variables constant, an increase in total liabilities/total
assets ratio is associated with an increase in the probability of possessing a risk
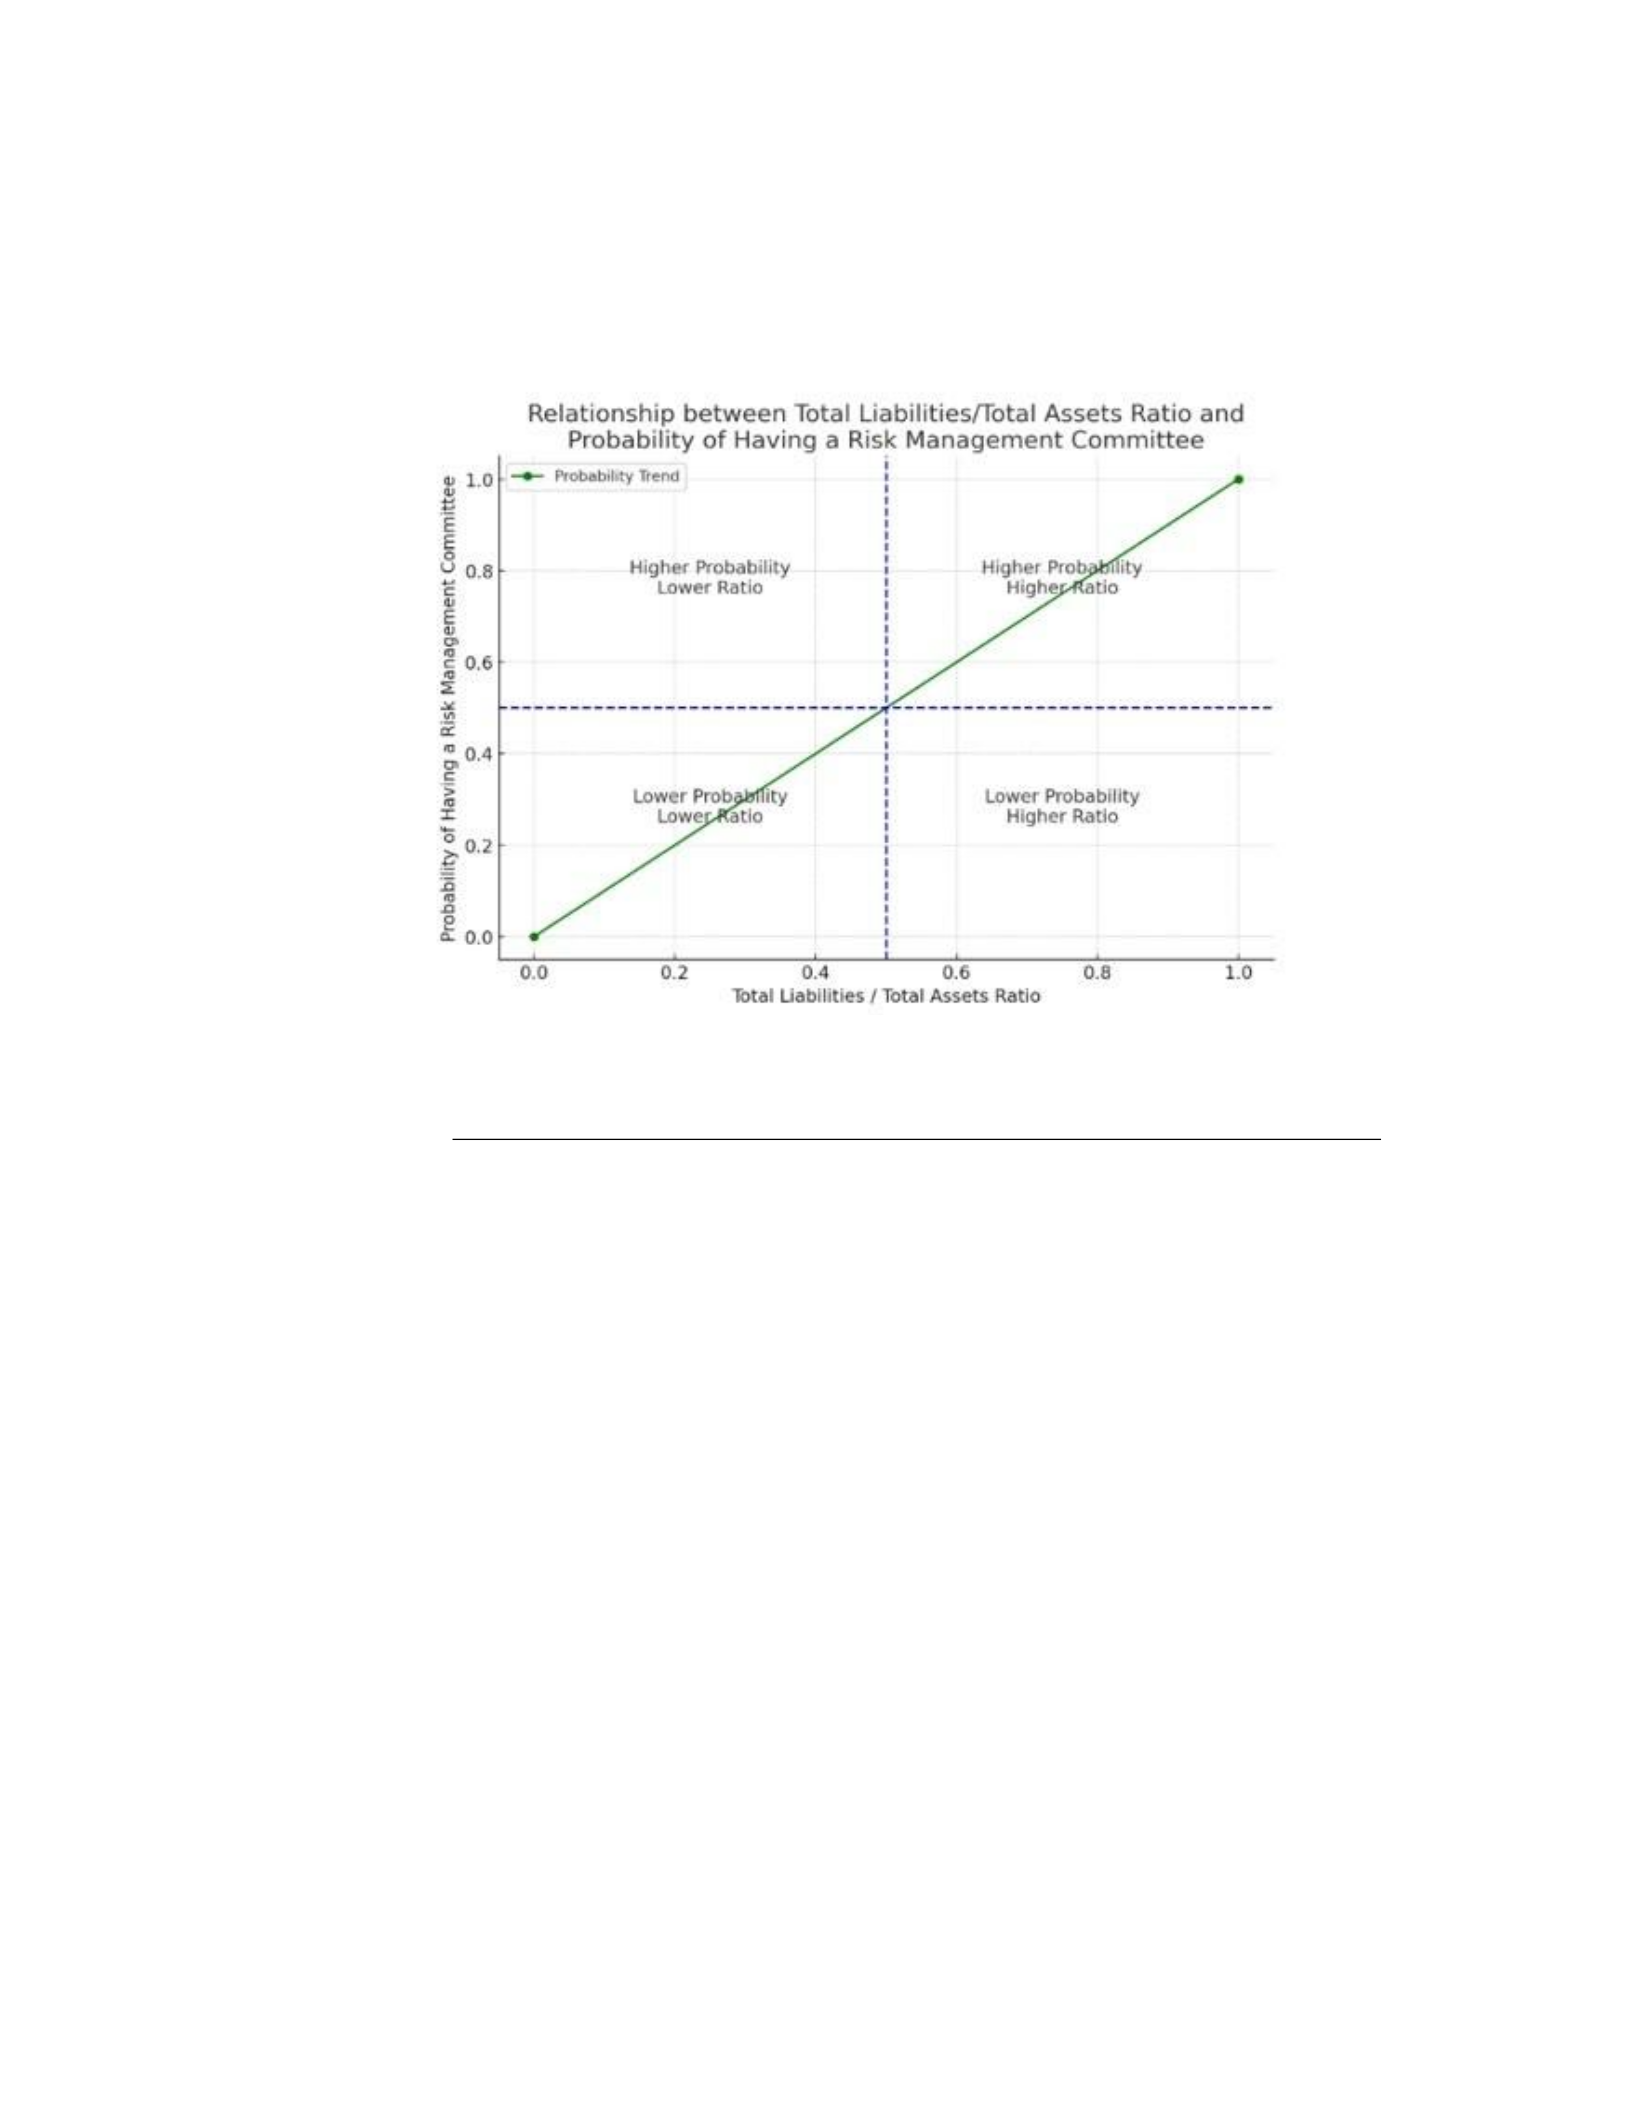
47
management committee. As the total liabilities/total assets ratio increases, the likelihood
of having a risk management committee increases.
Figure 5. Total Liabilities to Total Assets Ratio and the Probability of Adopting a VRMC.
This finding aligns more with the traditional decision for firms to adopt a VRMC.
A higher total liabilities/total assets ratio implies higher interest obligations and
repayment commitments, thus increasing the firm’s financial risk. A risk management
committee would be the critical mechanism to assist with mitigating these financial risks.
Additionally, higher liabilities can concern stakeholders about the firm’s solvency and
liquidity risks. Having specialized expertise of a risk management committee can provide
additional assurance that the firm is actively managing its risk profile. For Hypothesis 3,
we use several financial ratios to analyze similar data points offering different aspects of
the firm’s financial health. Also, using this approach provides a robust, comprehensive
evaluation of the organization’s financial stability instead of using one ratio. Since we

48
find significance in the diverse ratios we used for the firm’s financial soundness, we
consider Hypothesis 3 supported.
Hypothesis 4 predicts that the existence of a VRMC is related to the financial
health efficiency of an organization. To test this interaction, we evaluate traditional
efficiency ratios to examine the relationship between VRMCs’ presence on the firm’s
financial efficiency. Asset turnover has a negative coefficient and is not statistically
significant (B = 0.000879, p = 0.751), indicating no significant relationship between asset
turnover and the presence of a VRMC. The receivable turnover coefficient is negative
and not statistically significant (B = −1.79e06, p = 0.790), indicating no clear association
with the likelihood of having a VRMC. Lastly, sales-to-invested capital coefficient is not
statistically significant (B = −0.000061, p = 0.768), also suggesting no significant
relationship between the sales/invested capital ratio and the presence of a VRMC. These
findings imply that the existence of a VRMC does not have a relationship with the
financial health efficiency of nonfinancial firms within our scope. Hence, Hypothesis 4
cannot be supported.
Controlled Effects
The control variables are included in all the statistical models. Firstly, we evaluate
fiscal years from 2010 to 2017. All years from 2010 to 2017 show significant negative
coefficients compared to the base year 2009, with p-values ranging from 0.026 to 0.085.
This suggests a consistent and significant negative trend of firms possessing a VRMC
through the observation years from 2009. The 2 × 2 chart in Figure 6 illustrates the
relationship between the fiscal years of review and the likelihood of firms possessing
VRMCs. It shows a negative correlation: as time progresses (moving from left to right on
the x-axis, which represents normalized fiscal years), the likelihood of firms having

49
VRMCs decreases (moving from top to bottom on the y-axis). Holding other variables
constant, the negatively significant relationship between the fiscal years of review and the
presence of VRMCs implies that there is a statistical association indicating a decreasing
likelihood of firms possessing VRMCs as time progresses. This data provides several
reasons that might explain this trend. After the global financial crisis (GFC), there is a
noticeable shift toward integrating risk management into the fabric of organizational
decision-making processes (U.S. Securities and Exchange Commission, 2009). This
integration means that instead of relying solely on a risk committee, risk management
becomes a part of the strategic responsibilities of all executives and boards, thereby
diluting the focus on stand-alone committees. These guidelines often necessitate more
integrated and comprehensive risk management practices within the entire organization,
possibly reducing the need for a separate risk committee by embedding risk management
into every aspect of the organization’s operations. Additionally, some organizations might
have found that separate risk committees are not as effective or efficient in managing new
and emerging types of risks post-GFC. The fast-evolving nature of these risks requires a
more agile and cross-functional approach to risk management that can be better achieved
through direct management oversight with specialized functions rather than a traditional
compliance committee structure.
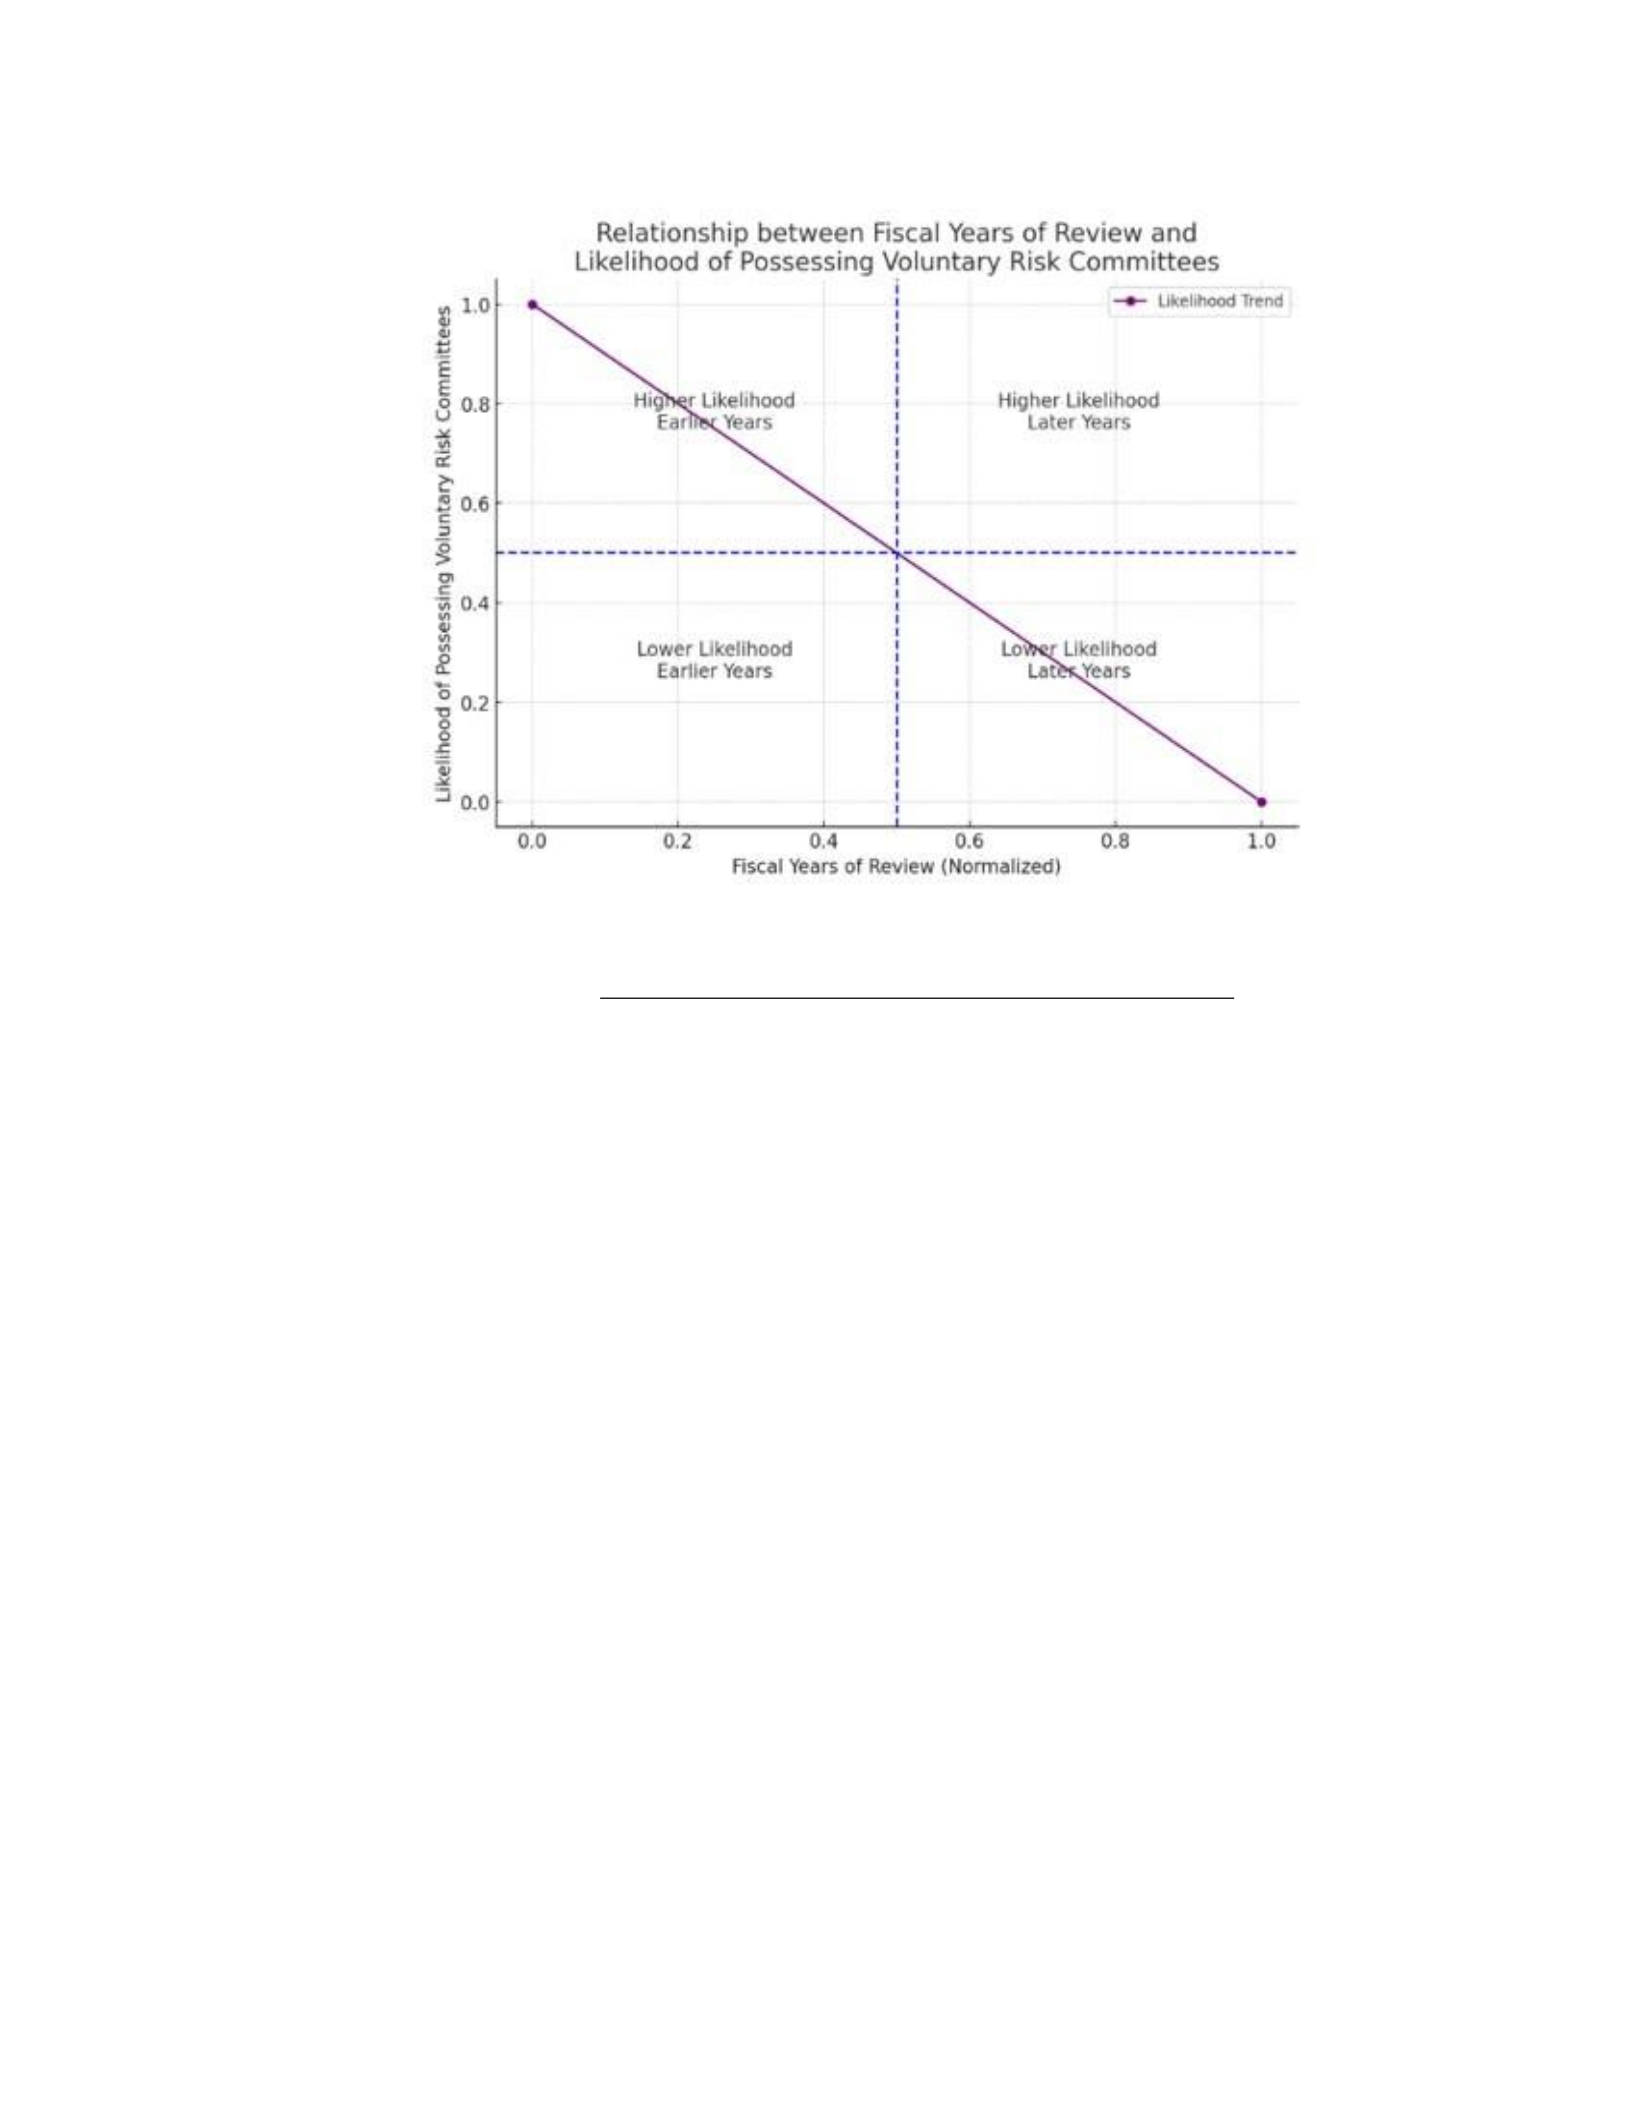
50
Figure 6. Fiscal Years and the Probability of Adopting a VRMC.
When evaluating gender effects within our sample, the coefficient indicates a
significant positive relationship between the gender ratio and the dependent variable (B =
0.070548, p = 0.000). This suggests that an increase in the gender ratio (more male
representation) is associated with a positive relational change with a firm having a risk
management committee. The 2 × 2 chart in Figure 7 illustrates the relationship between
the gender ratio of men on the board and the probability of having a risk management
committee.
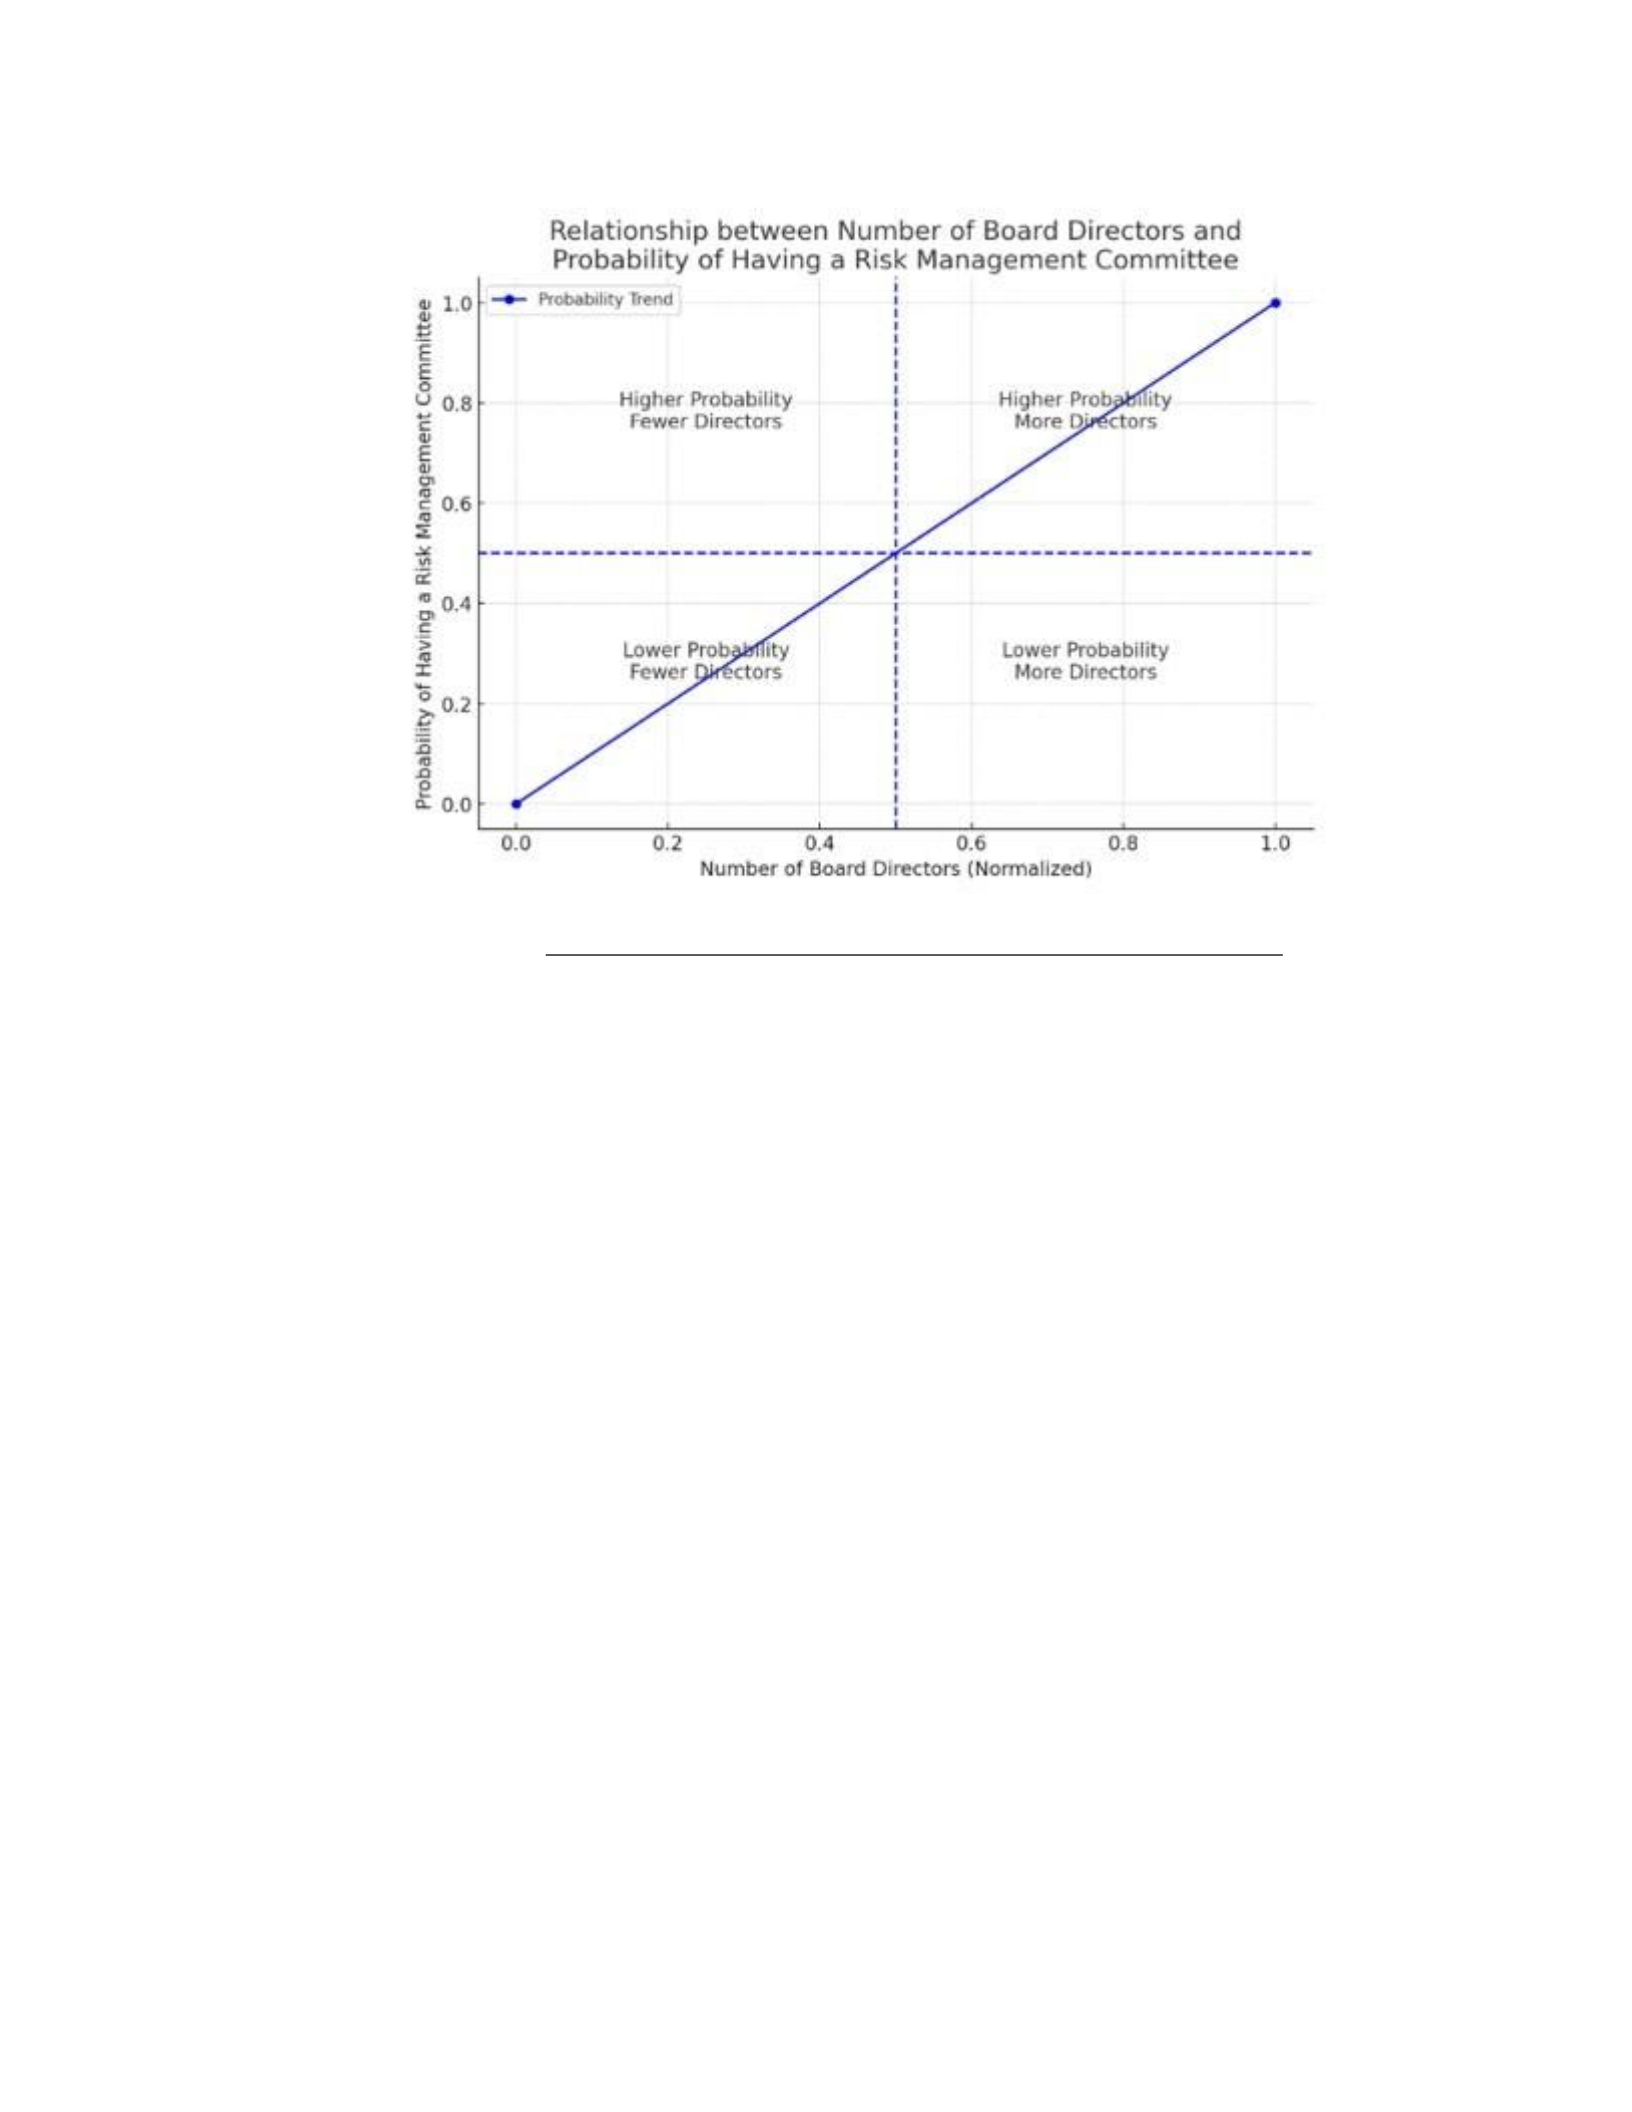
51
Figure 7. Number of Directors and the Probability of Adopting a VRMC.
The chart suggests a positive correlation. As the proportion of men on the board
increases (moving from left to right on the x-axis), the likelihood of the board having a
risk management committee also increases (moving from bottom to top on the y-axis).
Holding other variables constant, a higher gender ratio (more men representation on the
board) is associated with an increase in the probability of possessing a risk management
committee. As more men are on the board, the likelihood of having a risk management
committee increases. We find this trend interesting as research on gender differences in
risk perception and tolerance has produced mixed results. Alemany, Scarlata, and
Zacharakis (2020) suggest that men traditionally may exhibit higher risk tolerance than
women regarding financial decisions. Historically, corporate boards have been male
dominated, particularly in certain industries and regions. Leadership styles and
decisionmaking processes, as well as social networking norms, can also differ based on

52
the composition of a board. Firms with a higher proportion of men on their boards might
adhere to more traditional norms, which include the establishment of formal structures
and committees, such as risk management committees, as part of their operating
framework. However, the correlation between board composition and the adoption of risk
management committees does not imply causation, and the dynamics of board
decisionmaking are influenced by a complex interplay of factors that encompass gender.
Additionally, the push for diversity and inclusion in corporate governance suggest that the
composition of boards and their relationship to risk management will continue to evolve.
For the GICS, we find significant coefficients observed for GICS 35 – Health
Care (B = −0.024281, p = 0.007), and GICS 50 – Communication Services (B =
−0.032544, p = 0.007). This suggests that these industry sectors have adopted a risk
management committee compared to the other sectors. Holding other variables constant,
the negatively significant coefficient for the health care and communication service
industry sector suggests that companies within these sectors are less likely to have a
VRMC compared to companies in other industry sectors. Lastly, we examine the
significance of the number of directors within a firm. We find the coefficient (B =
0.005618, p = 0.000) indicates a significant positive relationship between the number of
directors and the firm possessing a VRMC. This indicates that more directors on the
board are associated with an increase in the adoption of a risk management committee.
The 2 × 2 chart in Figure 8 depicts the relationship between the number of board
directors and the probability of having a risk management committee.
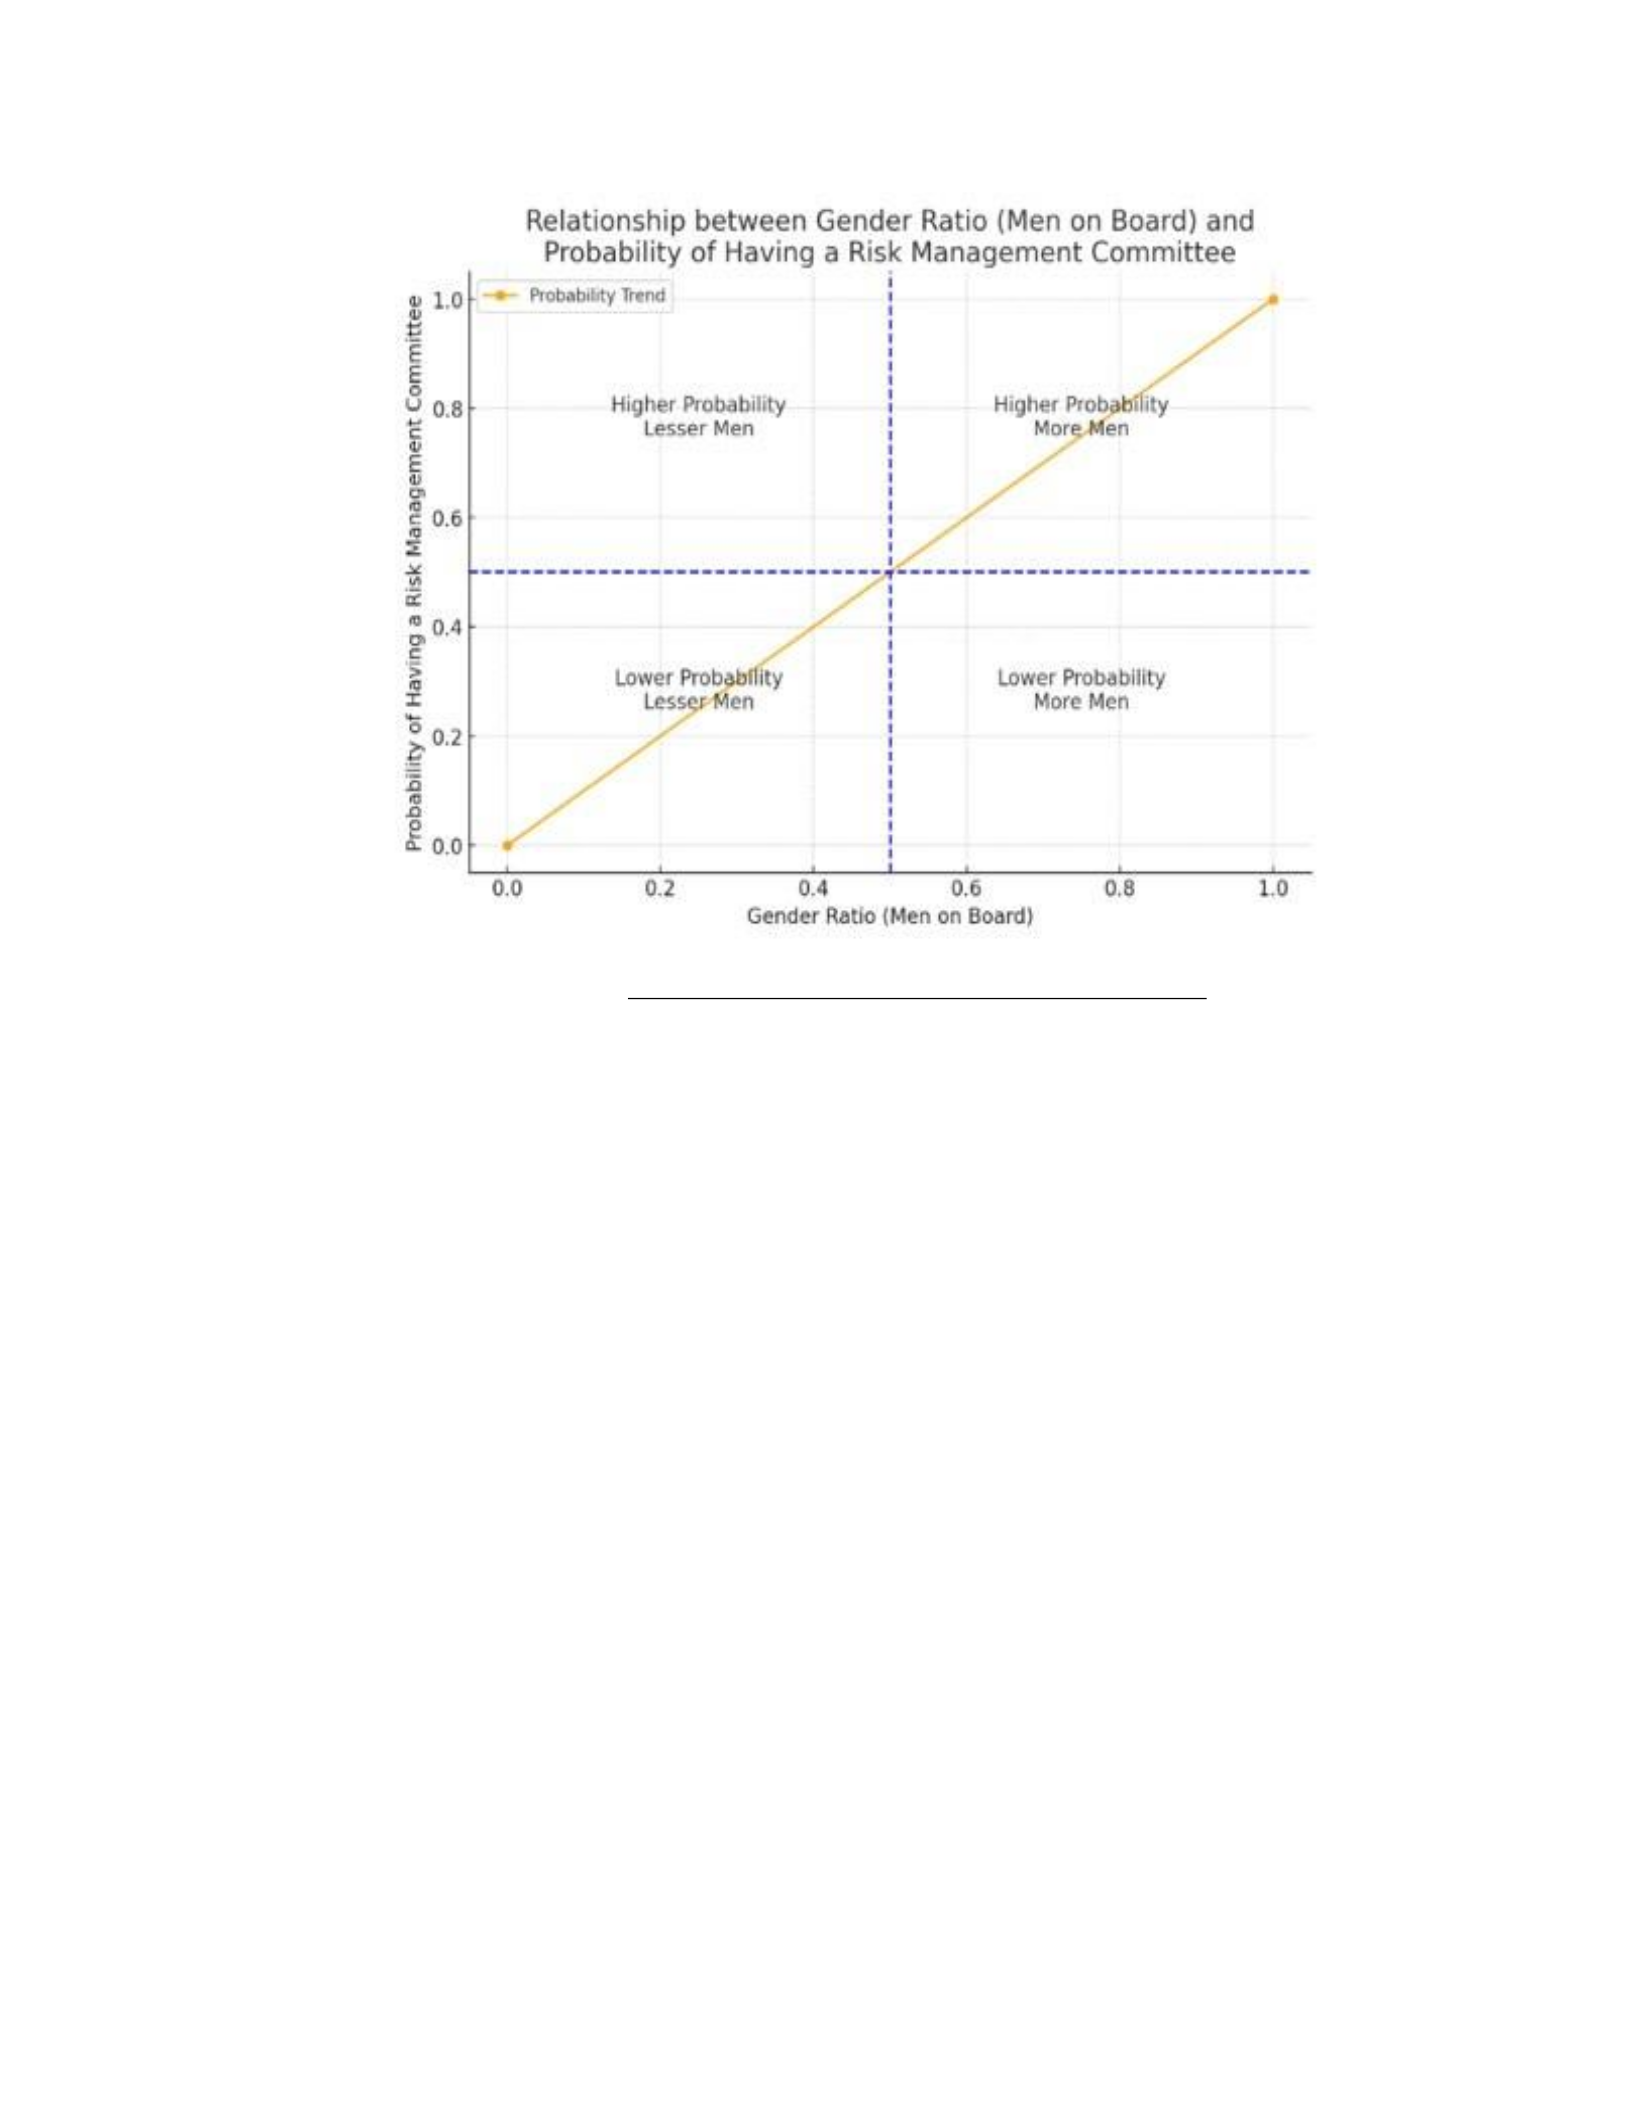
53
Figure 8. Gender and the Probability of Adopting a VRMC.
As illustrated, the chart indicates a positive correlation. As the number of board
directors increases (moving from left to right on the x-axis, which represents a
normalized scale of the number of directors), the probability of having a VRMC also
increases (moving from bottom to top on the y-axis). Holding other variables constant, an
increase in the number of directors’ ratio on the board is associated with an increase in
the probability of possessing a VRMC. As the number of board directors increases, the
likelihood of having a VRMC increases.
CHAPTER 4
STUDY 2

54
Background
Risk managers are often accountable to make risk-based decisions, steering the
enterprise through strategic, operational, or financial crisis to support the firm’s longterm
success (Liu, 2021). Adding a combination of compliance, reputational, cybersecurity,
and environmental uncertainties, risk managers must carefully manage and mitigate these
significant challenges to protect the current sustainability and future growth of the firm.
In recent years, scholars have highlighted the Global Financial Crisis (GFC) as a call for
firms to establish credit risk within their normal risk-based forecasting and operational
decision-making as a vital piece of their risk management practices. But the focus has
been primarily on financial firms (Mushafiq et al., 2021). Up until the financial crisis, and
now within some sectors, risk management frameworks varied widely in practice and
application; much less, account for extreme events and occurrences. Underestimating the
importance of a firm’s credit ratings can pose significant consequence as credit ratings are
critical factors that can impact the financial health, stability, and overall success of a
firm’s operations. Moreover, failure to adequately monitor credit ratings can potentially
lead to the firm’s inability to manage its cash flow and inventory, which may cause a
severe impact on its current operations. Credit risk among small- and medium-sized
organizations has been shown to be more impactful in enabling organizations to navigate
uncertainties. Liu (2021) has found that small- and medium-sized enterprises have
experienced a variety of challenges in understanding the competitive advantages of credit
utilization due to the lack of effective credit risk management. Thus, this challenge has
seriously restricted the future development of the firm. Poor management of the firm’s
credit ratings can impact its ability to obtain the lowest borrowing rates to increase
profitability, meet financial obligations, and maintain solvency. And additionally, credit

55
ratings are critical data inputs that investors and other market participants use to evaluate
future growth as part of their decision-making analysis (S&P). As such, poor credit
ratings can deter investor confidence and trust in the firm’s ability to manage its financial
obligations, while limiting its ability to invest in growth initiatives. Additionally, poor
credit ratings can hinder the firm’s ability to fund growth strategies and invest in research
and development opportunities. While default risk, higher borrowing costs, low investor
confidence, and limited access to financing are the antecedents for poor credit risk
management, overall, they provide loose management/internal controls over the firm’s
ability to manage its operations adequately. This critical risk management role leads us to
ponder whose important responsibility in the firm is to monitor the firm’s credit risk (i.e.,
credit rating) from an enterprise risk perspective. As we discussed within Study 1, the
role of the risk management committee is to monitor, assess, and mitigate inherent risk
that threatens the firm’s ability to meet its operational objectives. Moore and Brauneis
(2008) and Schlich and Prybylski (2009) identify credit risk as an integral part of a firm’s
enterprise framework that should be heavily monitored to ensure operational practices are
aligned with the organization’s goals and strategies. Credit ratings are directly tied to the
firm’s financial health, performance, and stability. It affects a firm’s liquidity while
ensuring that the continuity of operations and supply chains is fully operational to sustain
the firm’s operating income. Thus, credit ratings remain a critical element of the firm’s
operations to address ongoing conditions and should be monitored in parallel with
management’s enterprise risk strategies.
As discussed in Study 1, several firms monitor risk oversight at the board level,
while other firms either utilized the audit committee, a separate risk committee, or
embedded risk identification and mitigation practices within various operational

56
components in the firm. Additionally, the debate over whether a separate or voluntary
development of a risk management committee provides the maximum oversight to
enhance detection of oncoming risk events continues to remain relevant in the risk
management literature. Scholars assert that the establishment of a voluntary risk
management committee (VRMC) still remains minimally investigated (Ishak & Nor,
2017; Hines, 2012). Similar to Study 1, our research pivots to examine data from the
Standard & Poor’s (S&P) 1500 index firms to evaluate the relationship of a risk
management committee on a firm’s credit ratings. We examine this existence with a
mixture of small (S&P 600), medium (S&P 400), and large (S&P 500) firms, which
accounts for approximately 90% of all U.S. stocks (Vairavan & Zhang, 2020; Abebe &
Acharya, 2022). These firms offer a wide array of diverse organizational sizes and
industry segments across both financial and nonfinancial sectors. Secondly, we shifted
our research momentum to evaluate the presence of risk management committees using
resource dependency theory to offer insight into the relationship between VRMCs and
credit risk. This intersection in operational theory allows our research to examine how
organizations manage their dependencies on financial resources, particularly in terms of
accessing credit, in order to secure the financial means necessary for operational growth.
Earlier accounts of empirical studies explored the linkage between credit ratings
and common accounting and financial ratios (Horrigan, 1966). More recent studies
examine other determinants like environmental, social, and governance measurements
(Chodnicka-Jaworska, 2021), corporate social responsibility (Jiraporn et al., 2014), board
education levels (Papadimitri et al., 2020), and environmental efficiency (Chabowski et
al., 2019). We also found studies evaluating corporate governance and its relationship on
credit ratings (Ham & Koharki, 2016; Khatami et al., 2016), which are more aligned with

57
our study. However, our review of past and current literature did not provide any studies
that evaluate the correlation of a firm’s creation of a VRMC on its credit ratings. Due to
the study of board committees still relatively remaining an under-researched area within
academia, we endeavor to close this gap in the literature. The closest we found was a
study by Ashbaugh-Skaife et al. (2006), which found empirical findings to support the
enhancement of the firm governance, ultimately providing favorable credit ratings.
Following Ashbaugh-Skaife et al. (2006) approach and reasoning, the establishment of a
firm’s decision to set up a VRMC would create an internal management structure to
monitor the overall performance of the firm. S&P Global states that a firm’s culture and
attitude toward management and governance are among the leading factors for rating
scores. Furthermore, it confirms that management and governance factors are explicitly
reviewed for each credit rating provided. From this viewpoint, we address the following
research question:
RQ 2: To what extent has the formation of risk management committees related to
enhancing the firms’ management of credit ratings?
We believe effective firm management and overall governance include
influencing the organization’s credit factors. And effective organizational management
and strategic oversight include leveraging credit to increase the firm’s competitiveness.
Further, effective oversight active monitoring to know when the firm should utilize credit
rather than equity to prompt a future credit rating change, which supports strategic
expansion opportunities (Kisgen, 2007), should be directly monitored in line with the
firm’s future operational activities. Thus, active board involvement remains critical in
overseeing the organization’s credit risk profile in order to make effective financial and

58
strategic decisions, while executing operational initiatives to support the organization’s
financial goals. The board must dedicate effective oversight resources to manage its
credit risk, which includes the oversight of credit ratings. Thus, the responsibility for
monitoring credit ratings matters and is vital to the success of the organization. S&P
Global also confirms that poor management and governance contributes to reductions in
credit ratings. In simpler terms, S&P Global states that:
“if an enterprise has the ability to manage important strategic and operating
risks, then its management plays a positive role in determining its operational
success. Alternatively, weak management with a flawed operating strategy or an
inability to execute its business plan effectively is likely to substantially weaken its
firm’s credit profile.”
Considering this, the role of the firm’s risk management committee is to oversee and
manage various types of operational and strategic risk to sustain an organization during
unforeseen operational adversity. Hence, the management of credit risk and the
associated quality of credit ratings are crucial to the overall risk landscape of the
organization, which the risk committee integrates into its risk management process. The
adoption of a separate risk management committee can dedicate expert resources to
mitigating risk, making it one of its highest priorities to influence the credit quality of the
organization. Our research is timely and provides valuable insights for practitioners on
the strategic importance of a firm adopting a separate risk management committee to
uniformly manage the organization’s credit risk, as well as for developing and
implementing effective strategies to manage its credit ratings.
Hypothesis Development
The majority of academic studies, coupled with applicable theoretical
frameworks, highlight risk management committees as a crucial element of boards of
directors’ efforts toward enhancing a firm’s efficiency characteristics (Yatim, 2010; Jia &

59
Bradbury, 2020). Scholars contend that risk management committees, operating as
subcommittees, are aptly positioned to oversee the trajectory of organizations and
enhance the overall effectiveness of the firm’s risk management practices (Subramaniam
et al, 2009; Malik et al, 2020). Given the specialized knowledge required to oversee the
inherent and residual credit risk of the firm, resource theory supports the key role of the
risk management committee as an essential component of overall risk management of the
firm (Bathala & Rao, 1995; Jensen and Meckling, 1976; Fama and Jensen, 1983; Jones,
2013, p. 32). This committee is tasked with determining “risk management strategies,
evaluating risk management operations, and assessing the appropriateness of risk
management procedures” (Subramaniam et al., 2009; Jia, 2019, p. 1053). These
procedures include continuous ongoing monitoring of credit risk to maintain an excellent
credit rating, prompting a competitive advantage to access credit in support of its major
operations. With Jia et al. (2021) and Rimin et al. (2021) asserting that firms with a
distinct (i.e., voluntary) risk management committee exhibit superior performance
compared to those without this function, we endeavor to argue that credit risk being
managed by a separate risk management committee would illustrate the same positive
results. This argument leads to the following H1 and H2 hypotheses:
H1 – The existence of a voluntary risk management committee is related to the
short-term credit ratings of an organization.
H2 – The existence of a voluntary risk management committee is related to the
long-term credit ratings of an organization.
Our research focuses on two leading credit risk indicators – short-term and
longterm credit ratings. Additionally, we used S&P Global ratings as a widely recognized
industry benchmark to review potential correlations between both long-term and
shortterm credit ratings and the existence of a VRMC. We observed the short-term credit

60
ratings as an indicator of the firm’s creditworthiness to pay its short-term debt
obligations. Similarly, we observe long-term credit ratings as indicative of the firm’s
creditworthiness to manage its long-term debt obligations. Taken together, both leading
indicators provide the organization’s financial credit health and stability in both the near
and future terms. Thus, we expect the presence of a VRMC to have a favorable
relationship on the firm’s credit ratings, enabling the firm’s operational decision-makers
with the strategic credit tools to secure access to essential resources needed to make
profitable business decision for current and future strategic acquisitions.
Methodology
Sources of Data
Similar to Study 1, our initial approach involves a review of the BoardEx global
database (BoardEx), which provides an extensive listing of executive profiles pertaining
to both public and private companies (BoardEx, 2021). This resource is widely employed
by researchers and practitioners conducting academic research within areas such as
“leadership, management, diversity and inclusion, governance, compensation, and
networks” (Wharton Research Data Service (WRDS)). The suitability of BoardEx data
has been acknowledged by scholars in their research regarding various competencies,
including firm performance, compensation, and the demographics of finance committees
(El-Khatib et al., 2017; Basu and Lee, 2021; Kim, 2021). To explore the potential
influence that voluntary risk management committees have on organizations, we
extracted firm board data files from Compustat. We explored both presently active and
inactive (unbalanced) publicly traded companies within the S&P 1500 index, spanning
the calendar years 2009 to 2020. We found 190,294 company observations.

61
Next, we queried the BoardEx database platform to procure data pertaining to
board subcommittees. Utilizing the same parameters for consistency in our approach with
Compustat, our investigation encompassed both currently active and inactive
(unbalanced) publicly traded companies within the S&P 1500 index throughout the
calendar years 2009 to 2020. Utilizing BoardEx’s North America catalog portal, we
identified 203,328 company observations for both financial and nonfinancial firms. Once
we identified organizations’ subcommittees, we found entities, both financial and
nonfinancial, that possessed risk management committees.
To further refine our analysis, we separated the data into only nonfinancial
organizations to focus our examination on the presence of voluntary risk management
committees. We identified firms with risk management committees bearing titles as
“Risk,” “Risk Assessment,” “Risk Evaluation,” “Risk Management,” “Risk Management
and Finance,” “Risk Oversight,” and “Risk Policy.” Once we identified these committees,
we applied the S&P organizational ticker marker as a unique identifier to establish a
connection between BoardEx committee files and Compustat financial data. This resulted
in our dataset being reduced to 18,546 company line observations, which are associated
with 1,494 distinct companies; of which 93 had a separate risk management committee.
By doing so, this narrows our research to highlight only firms within the nonfinancial
sector.
As mentioned in Study 2, we contend that financial and nonfinancial firms are
subjected to unequal regulatory requirements, with the financial industry being imposed
with more stringent regulations such as those outlined in the Dodd-Frank Act, requiring
the establishment of risk management committees for financial institutions (Malik et al.
2020). Thus, an equitable comparison between the two sectors would be one-sided,

62
rendering such a contrast methodologically unsound. Thus, we excluded all financial
firms from our dataset, resulting in a refined dataset comprising of 14,702 observations
across 1,099 firms. Subsequent to the elimination of all blank and duplicate cells, our
final sample consisted of 10,247 corporate line entries within 1,091 companies; of which
30 firms possessing a risk management committee remained for evaluation. Lastly, we
merged the credit ratings, which were limited to data up to 2017, along with incomplete
data fields for several firms. After merging and cleaning the data, our final sample for
review comprised 5,973 firm observations, including 903 firms, of which 21 firms had
adopted a risk management committee.
Variables and Model Specification
To test the two hypotheses, we utilize the Probit regression model for modeling
binary outcome variables based on one or more predictor variables. Below is an
illustration of the variables for H1 and H2: We also provide the listing of all variables in
Table 6.
VRMC = α + β1(Short-Term Credit Ratings) + β2(Year) + β3(GICS) + β4(Number of
Directors) + β5(Number of Director Qualifications) + β6(Gender) + ε
VRMC = α + β1(Long-Term Credit Ratings) + β2(Year) + β3(GICS) + β4(Number of
Directors) + β5(Number of Director Qualifications) + β6(Gender) + ε
Variables Descriptions
Utilizing the BoardEx committee data and adhering to the same framework
established by Ling et al. (2014), we employed a dichotomous coding system for both
VRMC frameworks. A value of one (1) was assigned if a risk management committee
existed, and zero (0) denoted nonexistence. In evaluating the firm’s relationship to adopt
63
a VRMC, we measured the firm’s short- and long-term credit ratings as dependent
variables.
Independent Variable - Voluntary Risk Management Committee
The focal independent variable in this study pertains to VRMC. This variable
represents a dichotomous value indicating the presence or absence of this board
committee within a firm. Scholars have empirically found that firms with a VRMC
posture themselves effectively to navigate the governance of risk oversight for the firm
(Ling et al., 2014; Sekome et al., 2014). We evaluate this variable to comprehend the
intrinsic value of VRMCs while understanding the potential impact on a firm’s risk
management and creditworthiness.
Table 6
Listing of Variables
Category Variables
Type
IV
Voluntary risk management committee
Dichotomous
• 0 = Board’s absence of
VRMC
• 1 = Board VRMC presence
DV1
Short-term credit ratings
Ordinal
DV2
Long-term credit ratings
Ordinal
CV1
Years (CY2009–2017)
Scale
CV2
Gender
Nominal
CV3
GICS
Nominal
CV4
Director qualifications
Continuous
CV5
Number of directors
Continuous

64
Dependent Variables
Short-Term Credit Ratings
Short-term credit ratings are organizational assessments provided by credit rating
agencies that provide indicators of the potential for default on financial obligations,
typically within a year (S&P Global Ratings, n.d.). These indicators provide stakeholders
with insights into whether firms have the ability to repay its short-term obligations based
on their current financial condition and metrics. We utilized the S&P scale, ranging from
“A-1” for the highest level of creditworthiness in the short-term category to “D” for
entities that are in default, and converted them into an ordinal variable for regression
analysis. By doing so, we evaluate this variable to observe the relationship between the
adoption of a risk management committee and its association with the firm’s short-term
credit ratings.
Long-Term Credit Ratings
Long-term credit ratings are evaluations provided by credit rating agencies that
assess the firm’s creditworthiness and ability to cover its debts over an extended time
frame typically beyond a year. These ratings also assess the probability of default while
projecting future financial losses in the event of default (S&P Global Ratings, n.d.).
Additionally, long-term credit ratings evaluate the firm’s financial strength, repayment
history, along with future earnings that could potentially affect the firm’s ability to repay
its debts. Also, using the S&P scale, we applied a dichotomous range from “AAA” (the
highest level of creditworthiness) to “D” (default) and converted them into an ordinal
variable to apply regressions. This provides the avenue to observe the relationship

65
between the adoption of a risk management committee and its association with the firm’s
long-term credit ratings.
Control Variables
Years
Years as a control variable is a methodological approach used by Hines et al.
(2015) to enhance the impact of time-related factors using the predictor and response
variables being evaluated. Using the period 2009–2017 provides a better understanding of
the relational variables by controlling for the effects of time after the GFC of 2008.
Gender
Gender as a control variable enhances the rigor and validity of research by
accounting for the potential influence of gender-related factors within the VRMC. As
used by Francoeur et al. (2008), controlling for gender provides a platform to isolate and
examine the effects of other variables without the confounding impact of gender-related
differences. This aids in drawling more accurate conclusions about the relationship of
gender between variables (Francoeur et al. 2008).
Number of Directors
Using the number of directors on the VRMC considers the potential impact of the
size of the board of directors on the relationship between the VRMC and short- and
longterm credit rating variables within our study. Following Bédard, Chtourou, and
Courtea (2004) approach, using the quantity of the directors may enhance the validity of
research findings by accounting for the potential influence of board size on the variables
studied.

66
Director Qualifications
Director qualifications, as a control variable, measure the impact of the
qualifications that directors possess on the relationship between VRMC-independent
variables and short- and long-term credit ratings in this study. Using the example of Sila,
Gonzalez, and Hagendorff (2016), we employed this control variable in the context of
corporate governance and board effectiveness. Further, it accounts for the potential
influence of the expertise and qualifications of the board in adopting a risk management
committee while examining the observed variables.
Global Industry Classification Standard Sectors
Global Industry Classification Standard (GICS) is a widely accepted classification
system for categorizing companies into different sectors and industries. Incorporating
GICS sectors as a control variable accounts for the potential impact that industry-specific
factors cause, irrespective of other sectors. Following Dalziel’s (2007) lead, this control
helps researchers draw more accurate conclusions about the relationships being evaluated
while considering the unique characteristics of different sectors in the global economy.
Research Model
Figure 9 provides a graphical representation of the research hypotheses being
explored in this study. The visual diagram illustrates the hypothesized effect of an
adopted voluntary risk management committee on the short-term and long-term credit
ratings of an organization. Additionally, the diagram illustrates the control variables that
further explain the relationship between voluntary risk management committees and the
short- and long-term credit ratings of an organization.
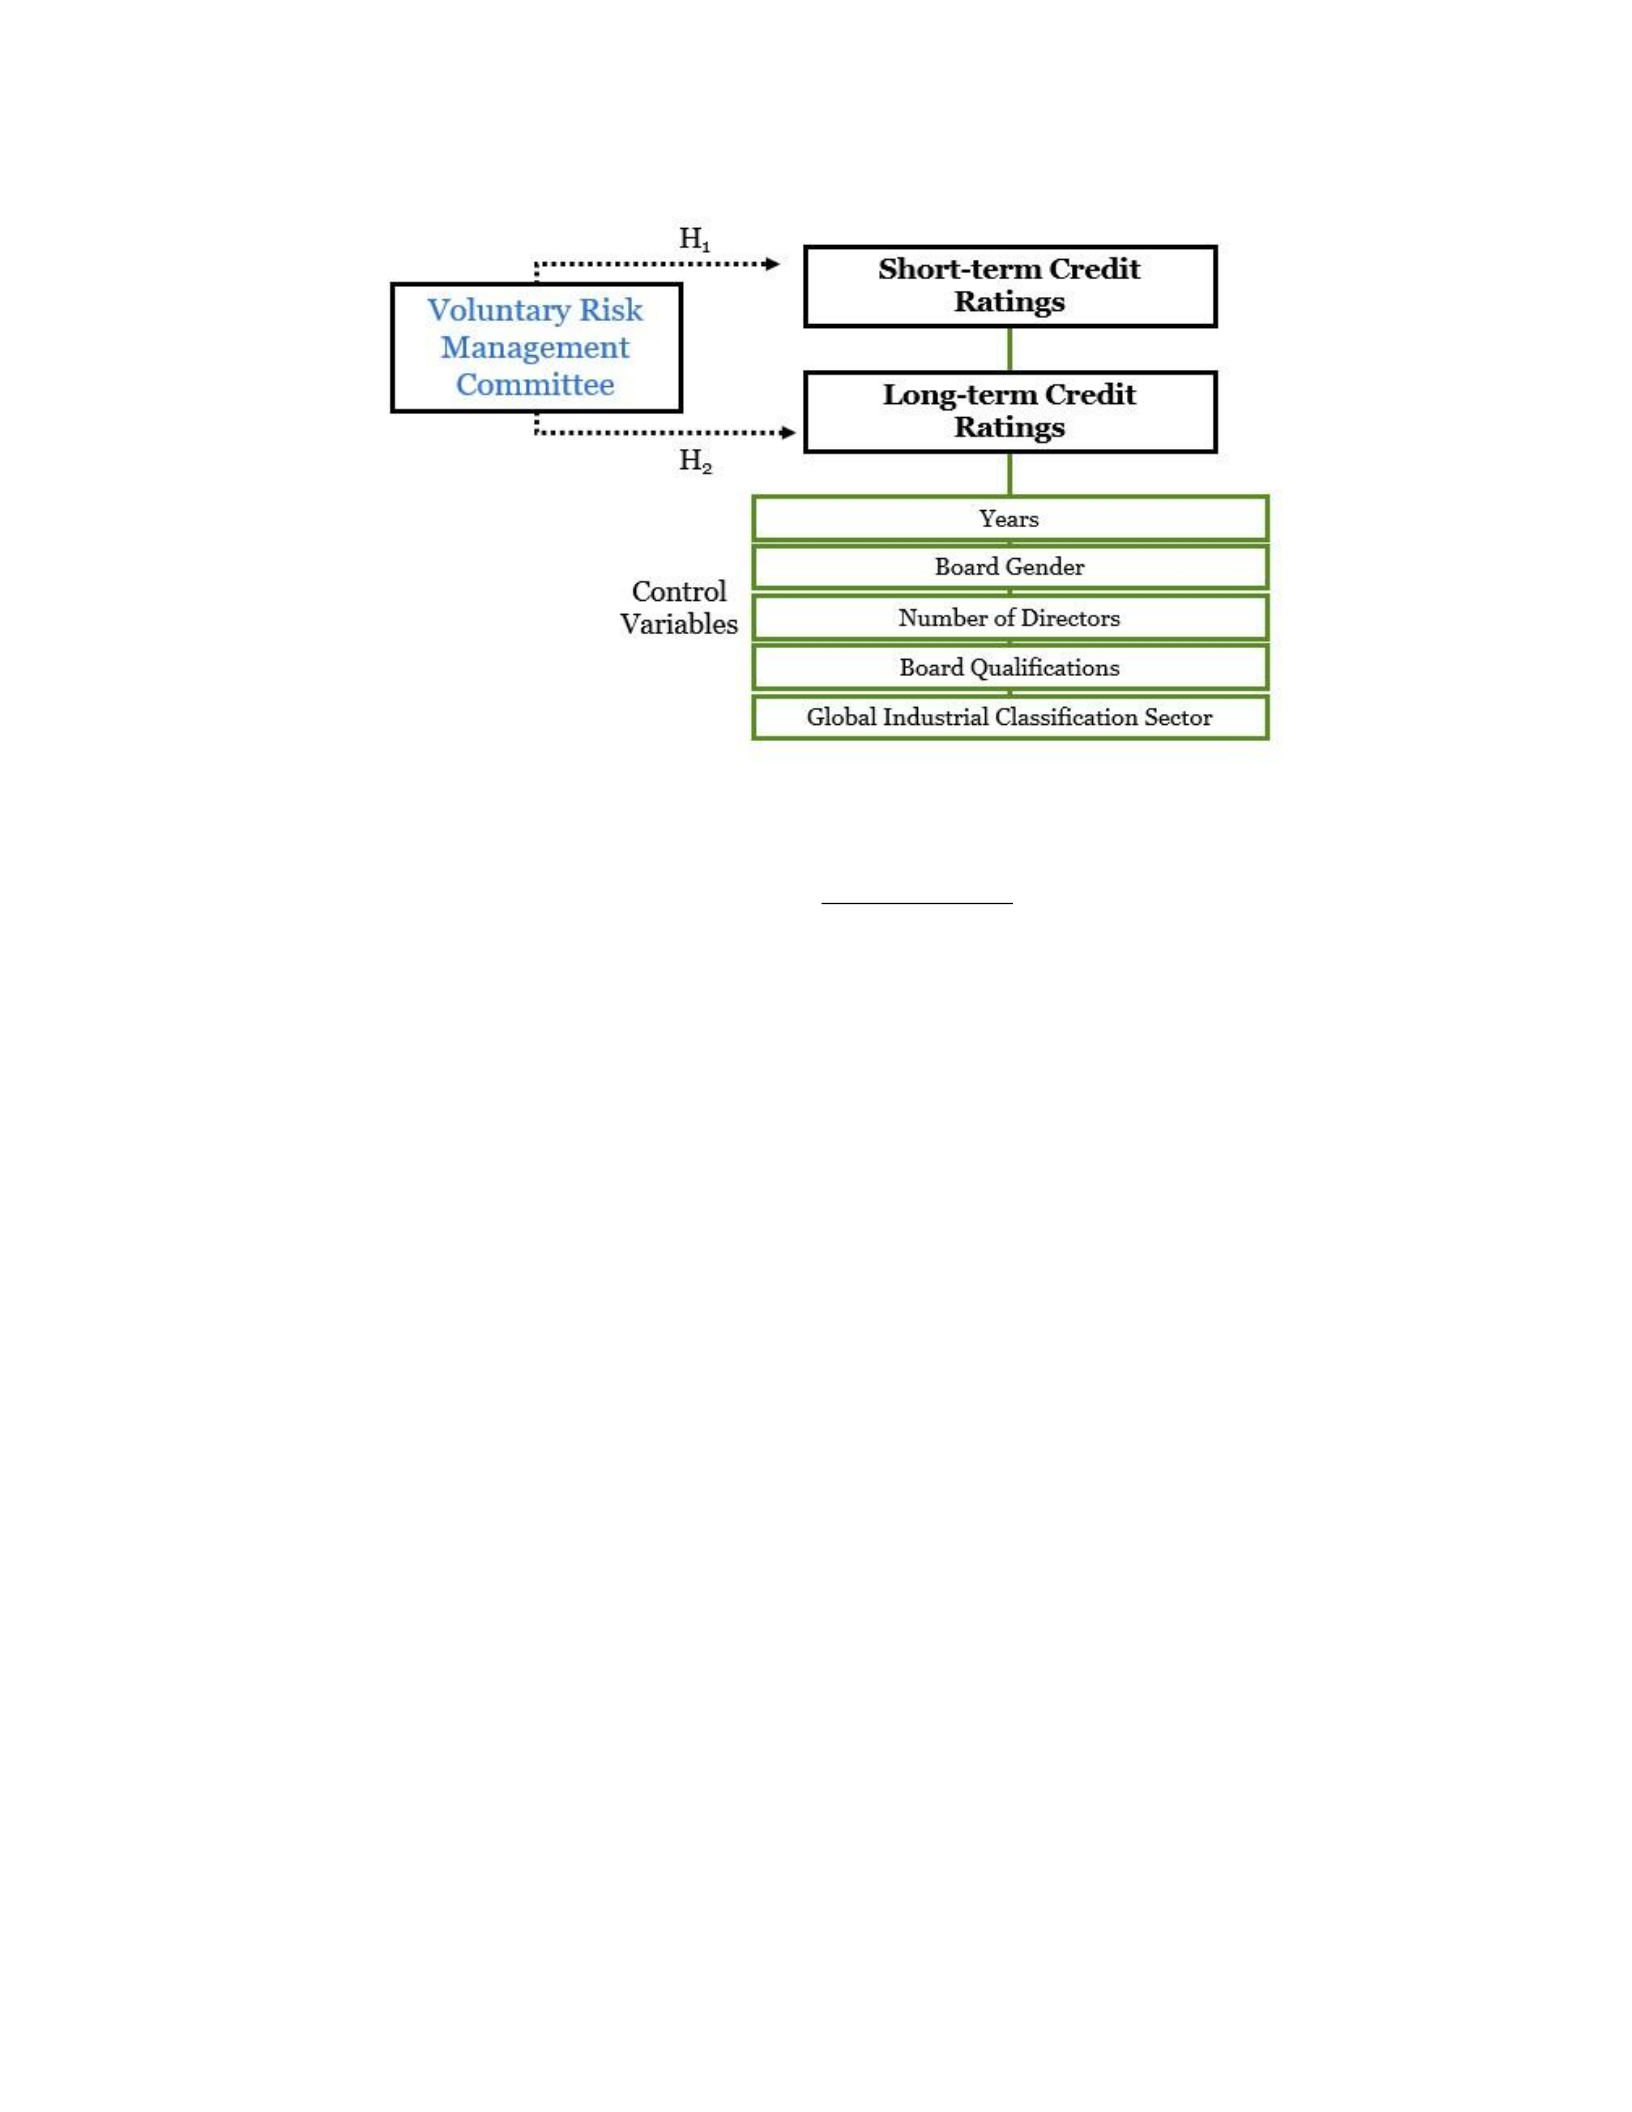
67
Figure 9. Research Model.
Data Analysis and Results
To empirically analyze the research questions and hypotheses posed in this study,
a quantitative approach was chosen to discover the effects of risk management
committees while evaluating the association between research variables (Creswell, 2012).
This section begins with descriptive statistics and industry analysis and concludes with
hypothesis testing. Table 2 (on page 32) represents the descriptive statistics for
nonfinancial firms’ data collected from 2009 to 2017. Table 2 also illustrates our sample
with 5,973 observations, listing 105 firms with a VRMC. Exploring the trends since the
enactment of Dodd-Frank (2010), risk management committees increased by 41% for
nonfinancial firms listed with this function.
Business Sector Descriptive Statistics
We examined the sectors identified for each of the corresponding 903 firms
represented in this study. To facilitate this analysis, we utilized the GICS, which is a

68
financial industry standard to categorize companies into sectors and industries. Jointly
developed by Morgan Stanley Capital International (MSCI) and S&P, the GICS provides
a comprehensive and uniform system for global industry classification into distinct
sectors, which is widely used by both industry practitioners and scholars in academia.
Figure 2 (on page 34) illustrates the GICS dataset, representing the top three predominant
sectors in our dataset as follows: industrials, with 3,273 observations, comprising 32% of
our sample; consumer discretionary, with 1,953 observations, accounting for 19%; and
health care, with 1,132 observations, contributing 11% of our sample.
Table 7.
Descriptive Statistics
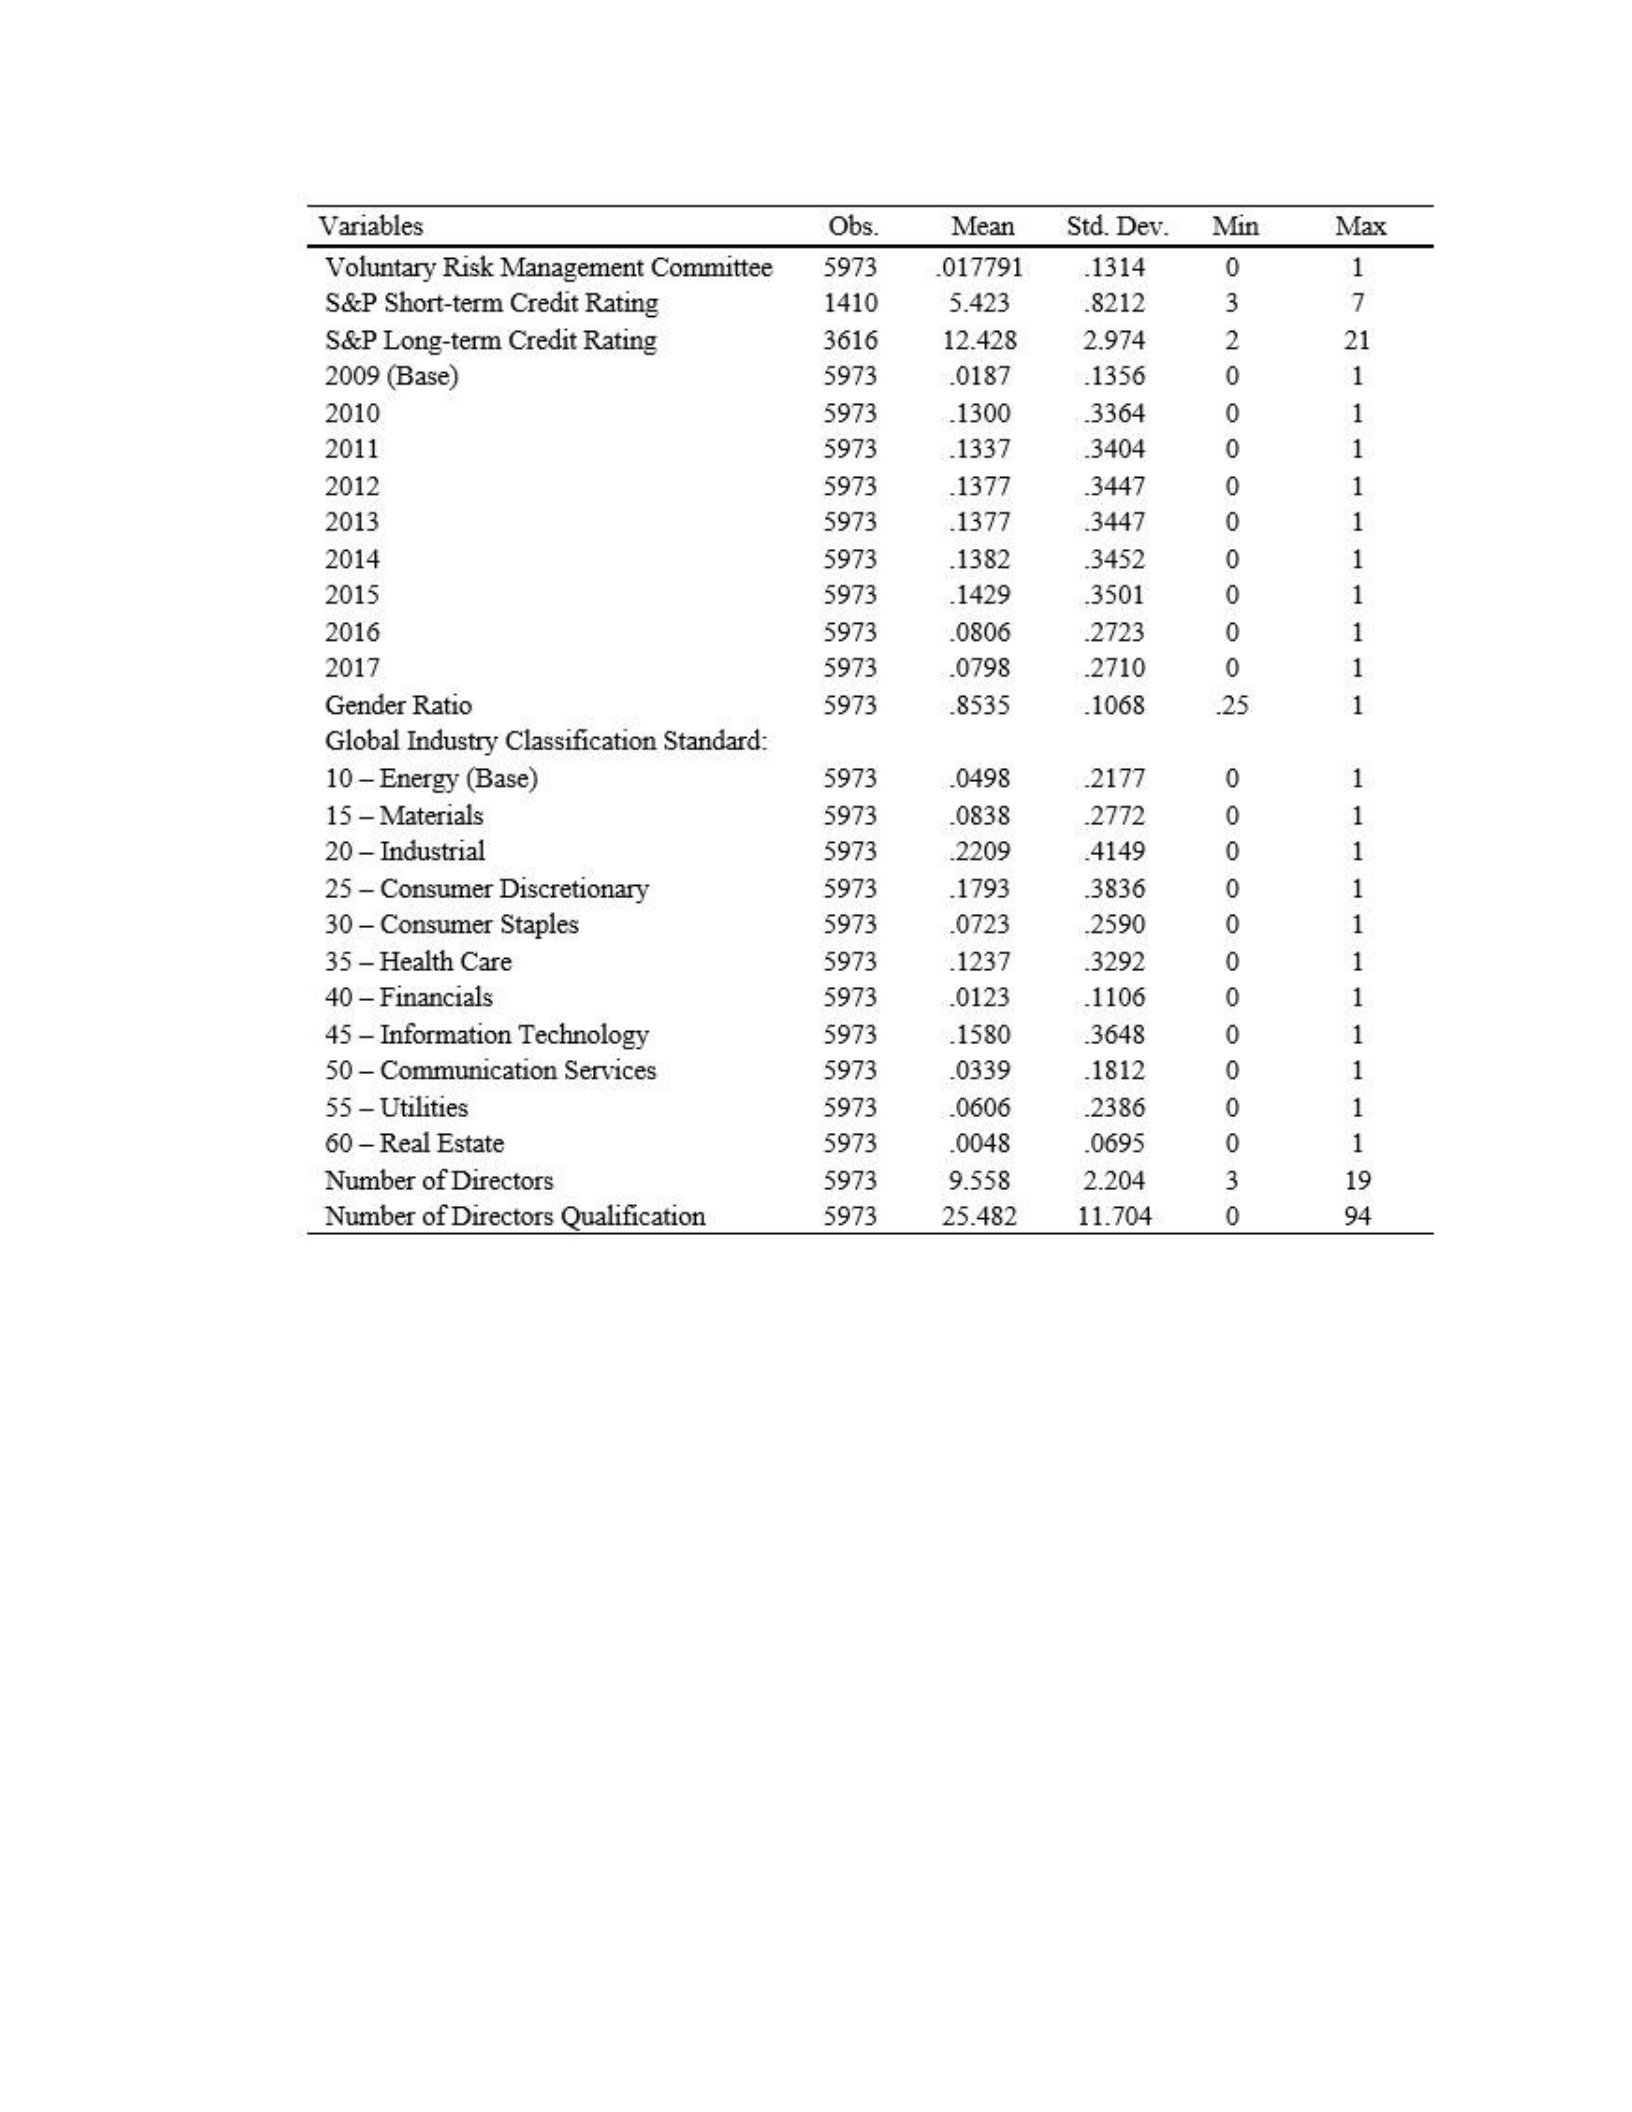
69
We also extended our examination to S&P U.S. sector indices listed within our
study. We found in Figure 3 (on page 35) that 37.7% of the companies in our sample were
classified as S&P SmallCap 600 index (comprising 3,792 companies). Additionally,
25.7% of firms were listed within the S&P MID CAP 400 (totaling 2,590 companies).
Lastly, 24% of the firms listed were designated as S&P 500 index (encompassing 2,418
companies). Collectively, these classifications account for approximately 87.4% of the
firms being evaluated in our research.

70
Descriptive Statistics
The descriptive statistics data shown in Table 7 provides insights into several
characteristics of the observed entities, such as the frequency of risk management
committees, credit ratings, and fiscal year observations, gender ratios, industry
classifications, and the composition of the boards. In terms of the voluntary risk
management committee, it has a mean of 0.0178 that suggests on average a small
proportion of organizations opted to establish a voluntary risk management committee.
The low mean suggests that the adoption of voluntary risk management committee is
small within our review. The S&P short-term credit rating values ranging from 3 to 7
have a mean of 5.423, which indicates that the entities have a relatively high short-term
credit rating worthiness across the entities being researched. Additionally, the narrow
standard S&P long-term credit rating values range from 2 to 21. The mean of 12.43
indicates a moderate to highly favorable average of long-term credit ratings. However,
the standard deviation (2.974) suggests some variability in long-term credit ratings
among the entities.
Table 8
Correlation Analysis 2
Variables
(1)
(2)
(3)
(4)
(5)
(6)
(7)
(8)
(1) Voluntary risk management committee
1.000
(2) S&P short-term credit ratings
0.075*
(0.005)
1.000
(3) S&P long-term credit ratings
0.030
0.921*
1.000
(0.067)
(0.000)
(4) Fiscal year
0.010
0.000
0.009
1.000
(0.423)
(0.989)
(0.568)
(5) Gender ratio
0.019
−0.084*
−0.298*
−0.250*
1.000
(0.146)
(0.002)
(0.000)
(0.000)
(6) Global Industry Classification Sector
−0.036*
−0.090*
0.099*
−0.016
−0.078*
1.000
(0.006)
(0.001)
(0.000)
(0.219)
(0.000)
(7) Number of directors
0.078*
0.187*
0.398*
0.119*
−0.348*
−0.017
1.000
(0.000)
(0.000)
(0.000)
(0.000)
(0.000)
(0.185)
(8) Number of director qualifications
0.039*
0.089*
0.411*
0.107*
−0.319*
0.034*
0.671*
1.000
(0.002)
(0.001)
(0.000)
(0.000)
(0.000)
(0.008)
(0.000)
Significance at p < .05

69

The fiscal year increasing trend in mean values over the years (2009 to 2017)
suggests a possible increase in observations or data availability during each time period
observed. The gender ratio ranges from 0.25 to 1, representing the dominant contrast of
men ratio within the VRMCs. The high mean of 0.8535 indicates a predominantly high
men ratio, illustrating a narrow standard deviation of 0.1068 that suggests a relatively
low variability of women representation on the board. Binary variables for the GICS
indicate the presence (1) or absence (0) of entities in various industry sectors. The
mean for each sector provides insights into the proportion of entities in each industry.
The number of directors indicates the count of directors in organizations ranging from
3 to 19. The mean of 9.558 suggests a moderate average number of directors, with a
standard deviation (2.204), indicating some variability across the firms being explored.
Number of directors qualification represents a numerical value related to the
qualification of directors ranging from 0 to 94. Exhibiting a mean of 25.48 indicates a
moderate average qualification level among directors. However, conversely, the
relatively high standard deviation (11.704) suggests substantial variability between
director qualifications. The GICS interpretation provides insights into the distribution
and variability of entities across different industry sectors. The industrial sector (GICS
20) has a high mean of 0.2209, suggesting the majority of firms we reviewed are within
this sector. Additionally, it has the largest standard deviation (.4149), indicating greater
variability. Firms within the consumer discretionary (GICS 25, μ = 1793, σ = 3836),
information technology (GICS 45, μ = 0.1793, σ = 0.3648), and health care (GICS 35,
μ = 0.1237, σ = 0.3292) sectors showed a moderate mean presence, with standard
deviations suggesting some variability within entity distribution between these sectors.
Materials (GICS 15, μ = 0.0838, σ = 0.2772), consumer staples (GICS 30, μ = 0.0723,

σ = 0.2590), and utilities (GICS 55, μ = 0.0606, σ = 0.2386) sectors displayed a
moderately low presence, with variability in standard deviation. Lastly, the energy
sector (GICS 10, μ = 0.0498, σ = 0.2177), communication services sector (GICS 50, μ
= 0.0339, σ = 0.1812), financials sector (GICS 40, μ = 0.0123, σ = 0.1106), and real
estate sector (GICS 60, μ = 0.0048, σ = 0.0695) illustrated very low means, suggesting
a limited presence of firms we reviewed falling within these sector, with a moderate to
small standard deviation indicating low variability.
Hypothesis Testing
Correlations Analysis
The correlation matrix in Table 8 provides insights into the interrelationships
between the variables in the dataset. The presence of a voluntary risk management
committee shows a positive correlation with both S&P short-term credit ratings of B =
0.075, p < 0.005, and S&P long-term credit ratings of B = 0.030, p < 0.07, suggesting
that entities that adopted such a committee tend to have slightly higher credit ratings.
Additionally, the positive correlation of B = 0.078, p < 0.00, for the number of directors
indicates that organizations with more directors are more likely to adopt a voluntary
risk management committee. The gender ratio shows a weak positive correlation of B =
0.019, p < 0.14, with the presence of a voluntary risk management committee,
indicating that a higher gender ratio of men on the board is associated with an increase
probability of adopting such a committee. In addition, the gender ratio also
demonstrates negative correlations with short-term credit ratings of B = −0.084, p <
0.002, and long-term credit ratings of B = −0.298, p < 0.00, suggesting that a higher
gender ratio of men on the board of directors is associated with slightly lower credit
ratings. The GICS of B = −0.036, p <
0.006, is negatively correlated with the presence of a voluntary risk management
committee, indicating that certain industry sectors are less likely to have adopted this
committee. The number of director qualifications displays positive correlations of B =
0.039, p < 0.002, with the presence of a voluntary risk management committee, along
with both short-term credit ratings of B = 0.089, p <0.001, and long-term credit ratings
of B = 0.411, p < 0.00, emphasizing the potential influence the qualifications of
directors have on these factors.
Table 9
Probit Regression Analysis– Short-term Credit Ratings
Voluntary Risk Management
Committee
Coef.
St. Err.
t-value
p-value
[95%
Conf
Sig
Interval]
S&P short-term credit rating
.2032
.1131
1.80
.072
-.0189
.4249
*
2009 (base)
2010
-1.296
.4637
-2.80
.005
-2.205
-.3873
***
2011
-1.292
.4685
-2.76
.006
-2.210
-.3736
***
2012
-1.311
.4703
-2.79
.005
-2.233
-.3890
***
2013
-1.279
.4698
-2.72
.006
-2.232
-.3580
***
2014
-1.371
.4813
-2.85
.004
-2.314
-.4271
***
2015
-1.215
.4714
-2.58
.010
-2.139
-.2909
***
2016
-1.197
.4729
-2.53
.011
-2.124
-.2699
**
2017
-1.353
.4957
-2.73
.006
-2.325
-.3813
***
Gender ratio
2.738
1.204
2.27
.023
.3781
5.098
**
Global Industry Classification
Standard:
20 – Industrial
-.1672
.2354
-0.71
.478
-.6286
.294
30 – Consumer staples
-.2122
.2634
-0.81
.420
-.7286
.304
55 – Utilities
-.5778
.3170
-1.82
.068
-1.199
.0435
*
Number of directors
.1925
.0465
4.14
.000
.1013
.2837
***
Number of directors qualifications
-.0114
.0103
-1.11
.268
-.0317
.0088
Constant
-5.394
1.494
-3.61
.000
-8.322
-2.467
***
*** p < .01, ** p < .05, * p <. 1

Lastly, we found that both S&P short-term credit ratings of B = 0.921, p < 0.00,
are highly correlated with S&P long-term credit ratings. To mitigate any
multicollinearity issues, we will regress both variables separately.
Regression Analysis
The Probit regression analysis in Table 9 offers significant insights into the
determinants influencing the adoption of a voluntary risk management committee
within the organizations we reviewed. In testing Hypothesis 1, we explore whether the
existence of a voluntary risk management committee is associated with the firm’s
credit ratings. To evaluate this hypothesis, we utilized the S&P short-term credit ratings
of the firms within our scope.
The S&P short-term credit ratings of B = 0.2032, p <0.072, suggest a positive
relationship between short-term credit ratings and the likelihood of having a risk
management committee, although the statistical significance is borderline. The 2 × 2
chart illustrates in Figure 10 the relationship between S&P short-term credit ratings
and the probability of a firm adopting a risk management committee. The chart
suggests that as S&P short-term credit ratings improve (moving from left to right on
the x-axis, which represents a normalized scale of credit ratings), the likelihood of the
firm adopting a risk management committee also increases (moving from bottom to
top on the y-axis). Each quadrant depicts a hypothetical scenario based on the
combination of these variables. While holding other variables constant, a higher S&P
short-term credit rating is linked to an increased probability of possessing a voluntary
risk management committee. Thus, as S&P short-term credit ratings improve, the
likelihood of having a risk management committee increases.
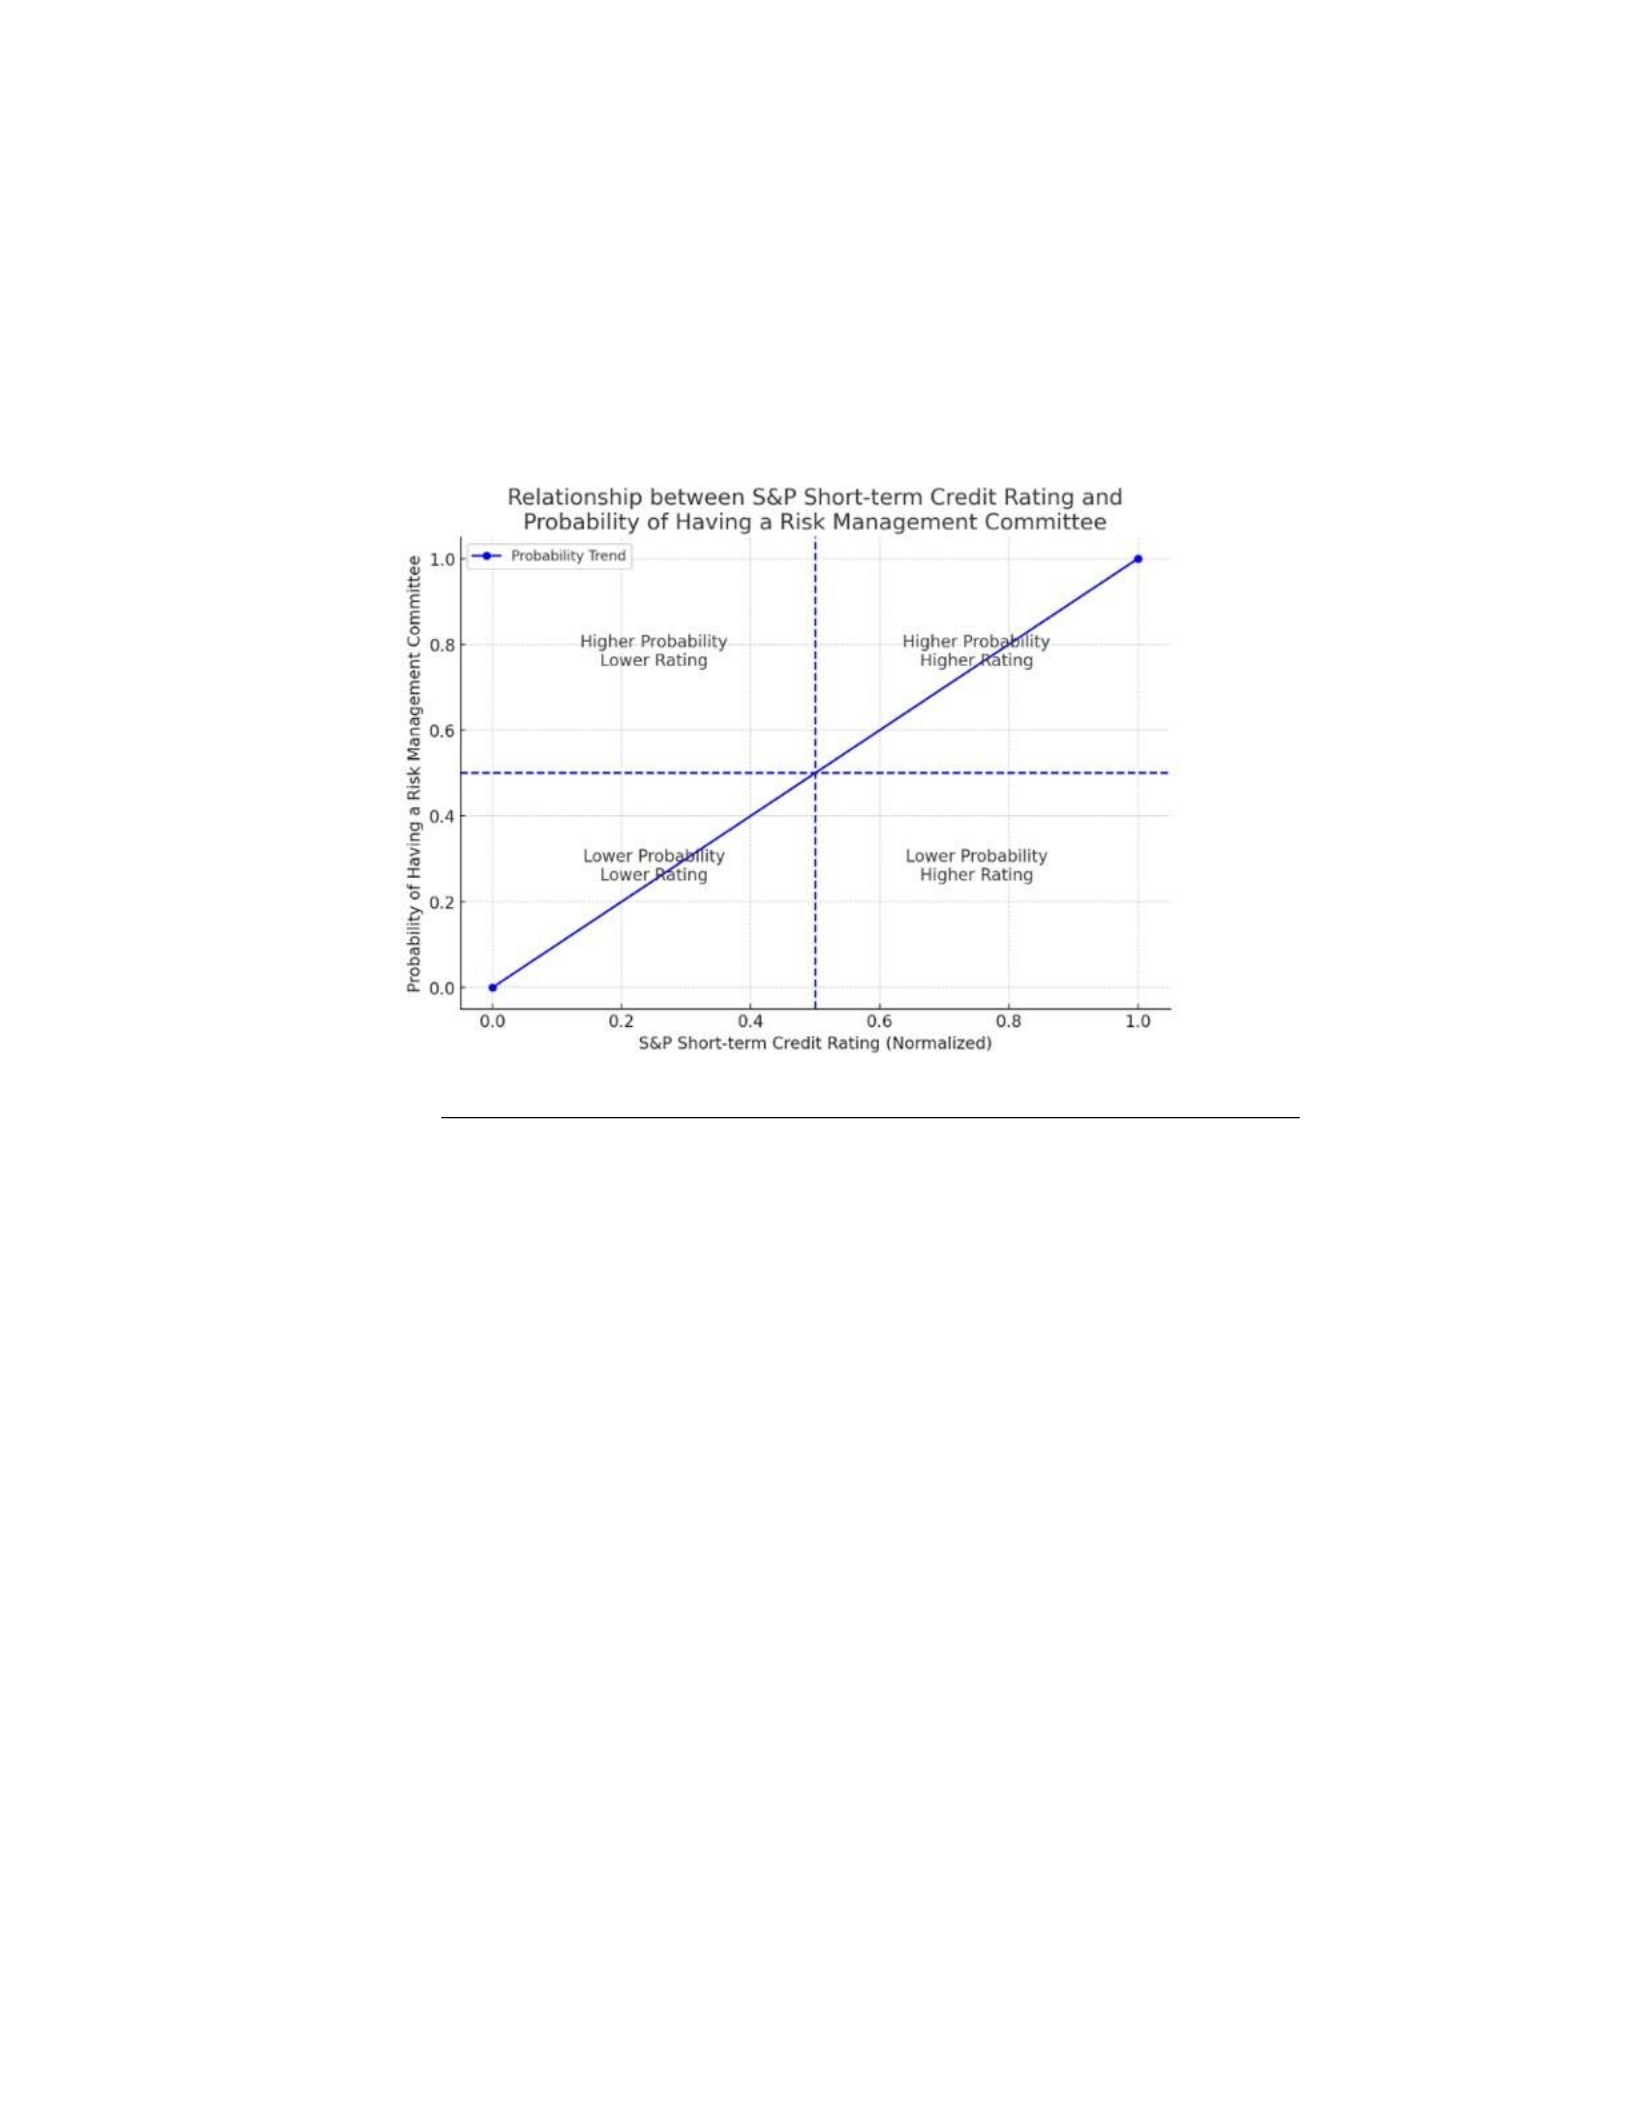
This data suggests that the presence of a voluntary risk management
committee indicates the firm is actively managing its corporate governance over its
financial operations, thus yielding enhanced oversight of the firm’s creditworthiness.
Figure 10. S&P Short-term Credit Ratings and the Probability of Adopting a VRMC.
For fiscal years 2009 through 2017, we observed negative coefficients ranging
from −1.197 to −1.371, all of which are statistically significant (p-values < 0.004 to
0.011). This indicates a consistent and significant decline in the likelihood of a firm
adopting a risk management committee over the years being observed, compared to the
base year of 2009. Figure 11 provides a 2 × 2 chart depicting the relationship between
the fiscal years reviewed and the likelihood of firms possessing a voluntary risk
management committee. As time progresses (moving from left to right on the x-axis,
which represents normalized fiscal years), the likelihood of firms having adopted a
voluntary risk management committee decreases (moving from top to bottom on the y-
axis), illustrating a negative relationship.
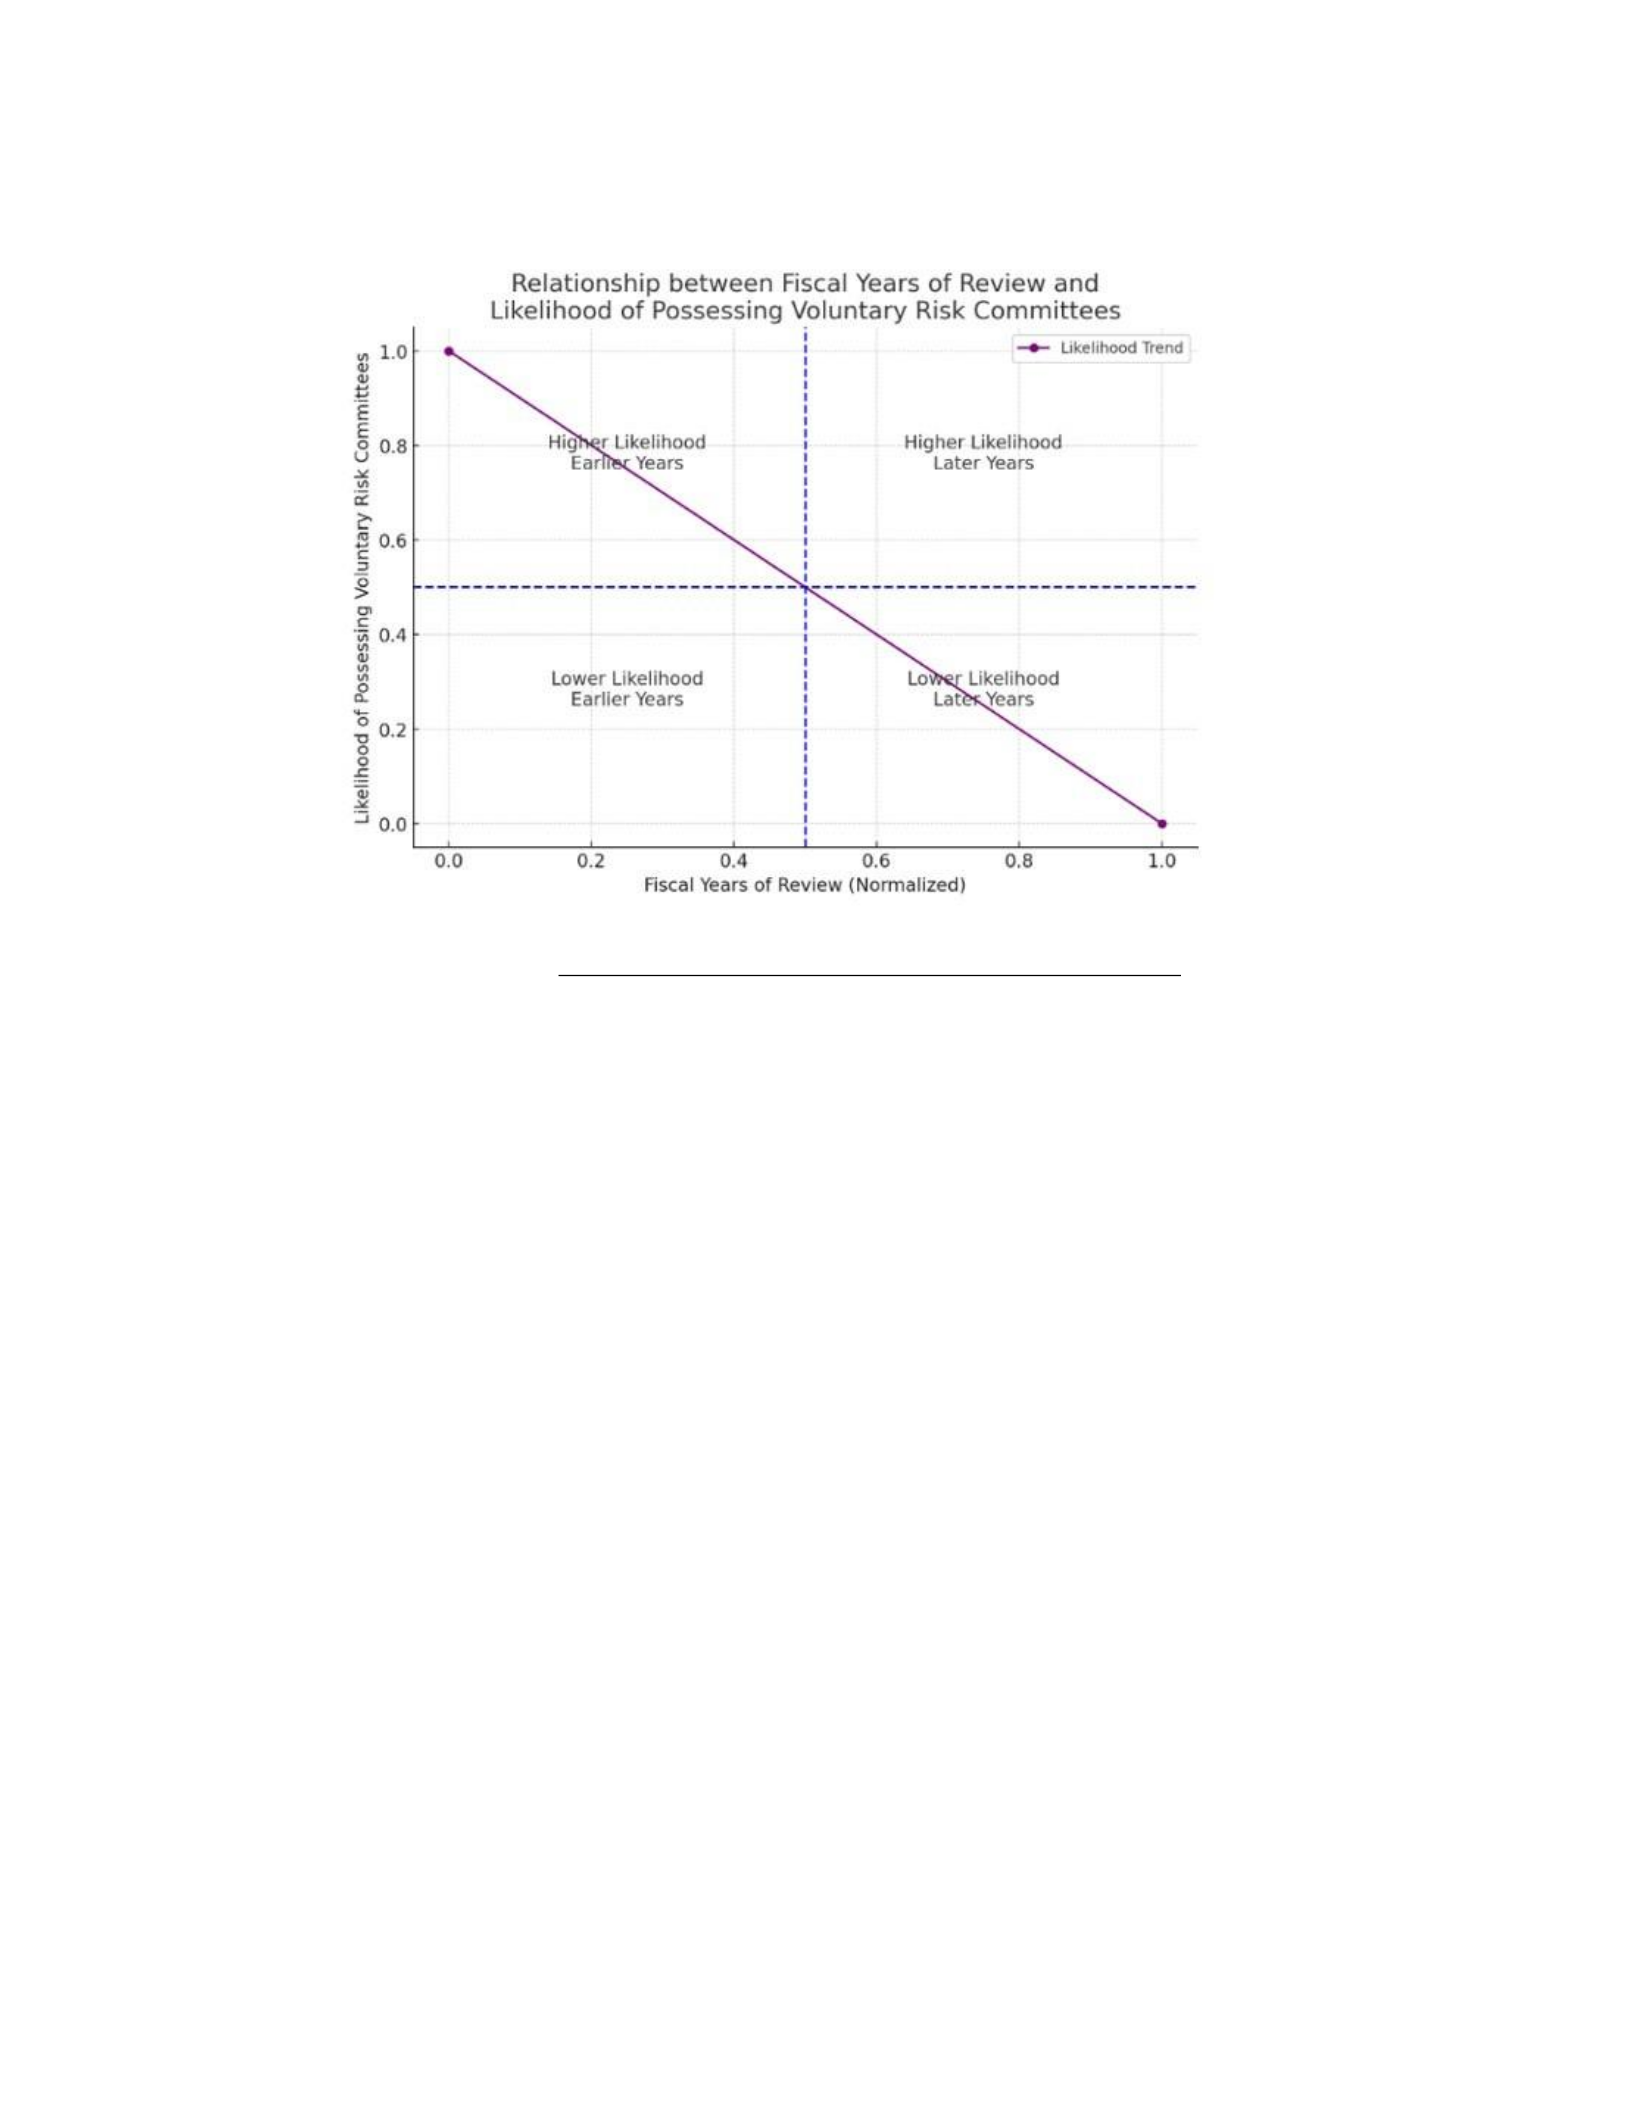
Figure 11. Fiscal Year and the Probability of Adopting a VRMC.
Holding all other variables constant, the negatively significant relationship
between the fiscal years and the presence of voluntary risk management committee
implies that there is a statistical association indicating a decreased likelihood of firms
possessing voluntary risk management committees as time progresses. Undoubtedly,
with continually escalating volatility and global disruption in our world economy, this
appears alarmingly and should prompt firms to secure their organizational assets and
growth with effective risk management. Chapelle (2023) compounds this statement by
adding, “risk management has never been so important.” However, since risk
management continues to evolve dynamically within perpetual stages within the firm,
firms may be moving toward embedding more internal controls within operational
processes rather than establishing potentially costly oversight risk mechanisms with a
separate VRMC.
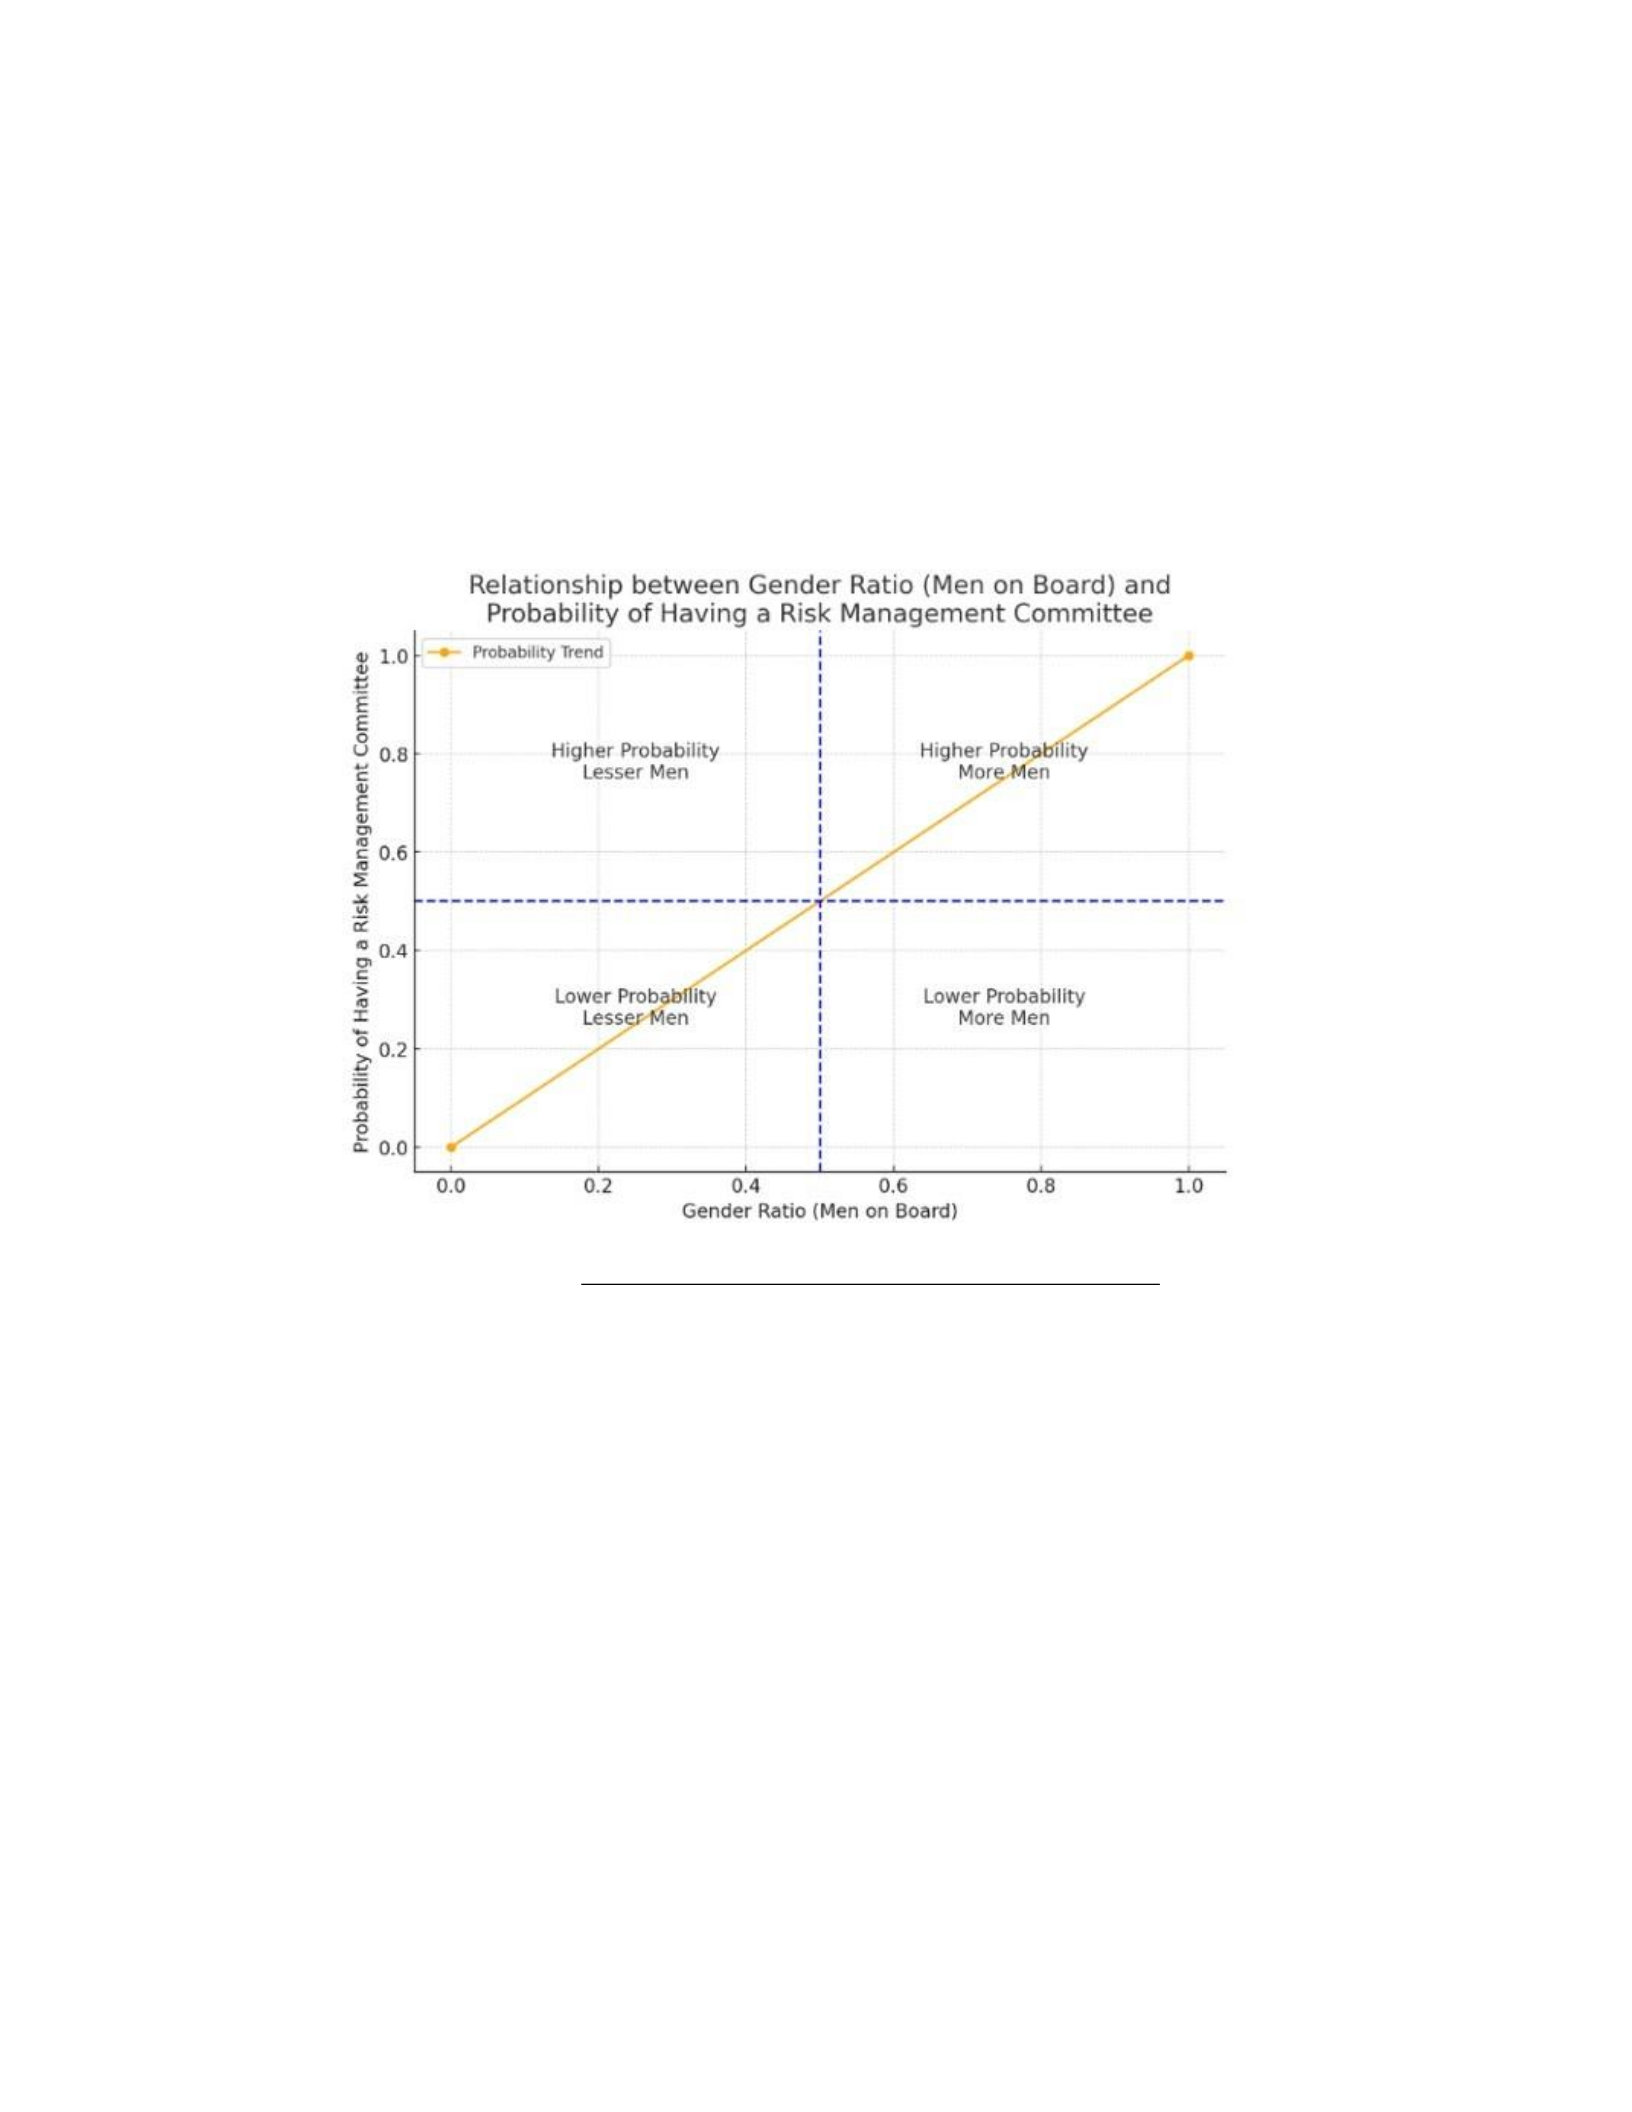
The gender ratio of B = 2.738, p < 0.023, suggests that a higher gender ratio is
associated with an increased likelihood of adopting a risk management committee.
Figure 12 presents a 2 × 2 chart illustrating the relationship between the gender ratio of
men on the board and the probability of establishing a voluntary risk management
committee.
Figure 12. Gender and the Probability of Adopting a VRMC.
We observed that as the proportion of men on the board increases (moving from
left to right on the x-axis), the likelihood of the board possessing a voluntary risk
management committee also increases (moving from bottom to top on the y-axis),
demonstrating a positive relationship between both variables. A higher gender ratio
(i.e., more men represented on the board) is associated with an increase in the
probability of establishing a voluntary risk management committee. As such, we found
that as the number of men on the board rises, the likelihood of these firms adopting a

voluntary risk management committee also increases. An extensive body of literature
has shown that men and women may perceive and tolerate risks differently (Byrnes et
al., 1999). Men, on average (Faccio et al., 2016), might be more inclined to take risks
and may leverage the strength of a formal risk management committee to oversee and
mitigate risk more effectively, thus balancing their liberal risk appetite practices.
In terms of industry sectors, only the utilities category (55) with B = −0.5778, p
< 0.068, indicates a potential negative association with the presence of a risk
management committee, albeit the statistical significance is borderline. When
controlling for all variables, the negatively significant coefficient for the utilities sector
suggests that companies within this sector are less likely to adopt a voluntary risk
management committee compared to companies in other industry sectors. We believe
this may be due to the utilities sector remaining in a highly regulated environment that
requires ongoing stable performance. As such, this sector’s stringent regulatory
oversight (Priest, 1993) can lend itself to a belief that external regulations are
sufficient for managing risks. In addition, controls must be sufficient in order to
provide ample services to the consumer. Thus, there might be a propensity for this
industry sector to dedicate a separate risk management committee, as its operational
and financial risks are more manageable and constant.
The number of directors of B = 0.1925, p < 0.001, indicates that organizations
with a larger number of directors are more likely to adopt a voluntary risk management
committee. The 2 × 2 chart illustrates, in Figure 13, the relationship between the
number of board directors and the probability of establishing a risk management
committee. As the number of board directors increases (moving from left to right on
the x-axis), the likelihood of adopting a voluntary risk management committee also
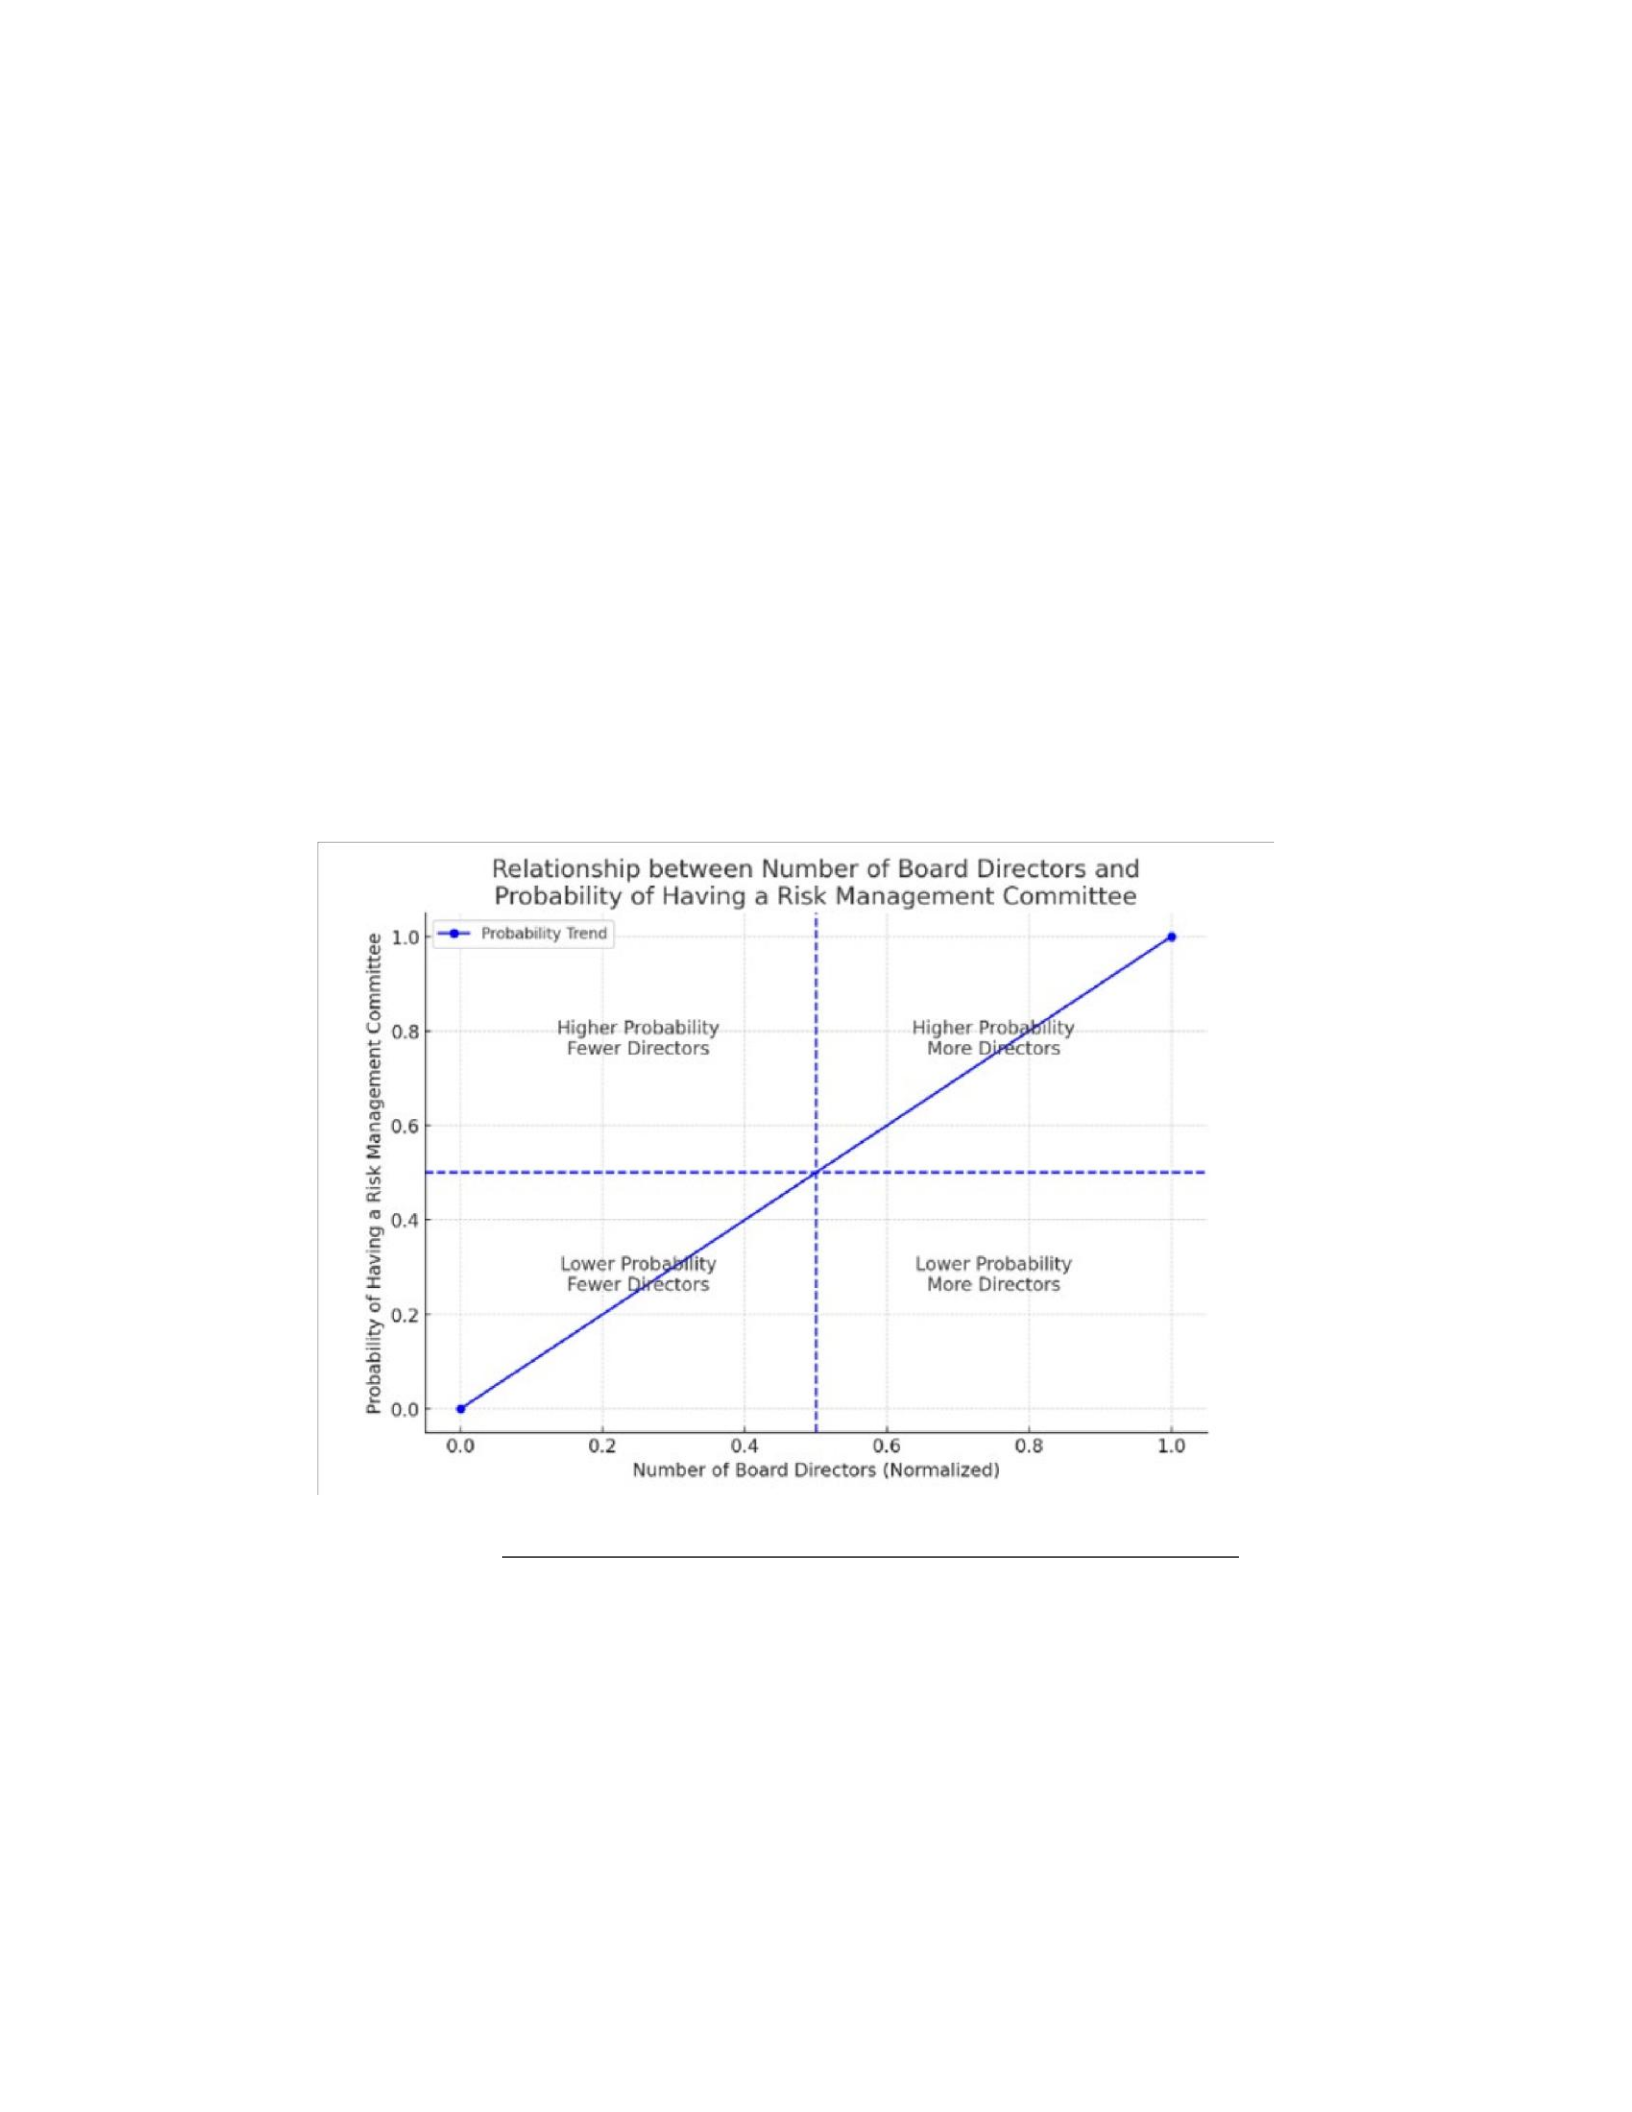
increases (moving from bottom to top on the y-axis), demonstrating a positive
relationship between both variables. Thus, an increase in the number of directors on the
board is associated with an increase in the probability of creating a separate risk
management committee. Subramaniam et al. (2009) found that the numbers of directors
provide increased diversity, knowledge, and experience to recognize the critical need to
develop a voluntary risk management committee. Thus, the more diverse the board of
directors is, the more emphasis the board can focus its efforts on governance, which
can promote the formation of a voluntary risk management committee.
Figure 13. Number of Directors and the Probability of Adopting a VRMC.
Now, as we transition from short-term credit rating results to evaluating long-
term credit ratings, Table 10 provides the regression analysis, offering insights into the
determinants to establishing a voluntary risk management committee within the scope
of firms we reviewed.
Table 10
Probit Regression Analysis – Long-term Credit Ratings
Voluntary Risk Management Coef. St. Err. t-value p-value [95% Sig
Committee Conf Interval]
S&P long-term credit rating
.01765
.0193
0.91
.362
-.0203
.0556
2009 (base)
2010
-.7442
.2986
-2.49
.013
-1.329
-.1589 **
2011
-.7651
.2992
-2.56
.011
-1.352
-.1786 **
2012
-.7251
.2960
-2.45
.014
-1.305
-.1448 **
2013
-.6731
.2938
-2.29
.022
-1.249
-.0971 **
2014
-.6600
.2938
-2.25
.025
-1.236
-.0841 **
2015
-.5378
.2883
-1.87
.062
-1.103
.0273 *
2016
-.6037
.2920
-2.07
.039
-1.176
-.0313 **
2017
-.5589
.2928
-1.91
.056
-1.133
.0149 *
Gender ratio
1.776
.6126
2.90
.004
.5754
2.977 ***
Global Industry Classification
Standard:
10 – Energy (base)
15 – Materials
-.157
.2217
-0.71
.478
-.5921
.2771
20 – Industrial
-.066
.1890
-0.35
.725
-.4368
.3040
25 – Consumer discretionary
-.097
.2015
-0.48
.630
-.4920
.2978
30 – Consumer staples
.015
.2183
0.07
.946
-.4131
.4428
45 – Information technology
-.153
.2236
-0.68
.494
-.5910
.2854
55 – Utilities
-.127
.2303
-0.55
.581
-.5786
.3243
Number of directors
.149
.0314
4.75
.000
.0875
.2106 ***
Number of director qualifications
-.012
.0066
-1.74
.081
-.0247
.0014 *
Constant
-4.185
.7883
-5.31
.000
-5.729
-2.639 ***
*** p < .01, ** p < .05, * p < .1
With Hypothesis 2, we explore whether the existence of a voluntary risk
management committee is related to the firm’s level of credit ratings. To evaluate this
hypothesis, we utilized the S&P long-term credit ratings. Notably, we found an S&P
long-term credit rating of B = 0.0176, p < 0.362, suggesting that there is no statistically
significant relationship between long-term credit ratings and the likelihood of

establishing a voluntary risk management committee. The lack of a significant
relationship between long-term credit ratings and the establishment of a voluntary risk
management committee may be due to subcommittees being formed in response to
internal operational or governmental needs rather than external credit evaluations.
Companies might prioritize risk management based on strategic, operational, or
regulatory considerations, which do not necessarily align with the factors relating to
their long-term credit ratings. Additionally, the importance of long-term credit ratings
depends on the firm’s specific strategic goals. While short-term ratings are important
for businesses that rely heavily on short-term borrowing to meet their operational
challenges through short-term financing, long-term ratings are more relevant for firms
looking to engage in long-term financing or strategic investments. Although the
creation of a risk management committee could evaluate both the short- and long-term
financial health and stability of the firm, more emphasis may be placed on short-term
goals to support the immediate operational performance of the firm. The fiscal year
variable shows a significant relationship of p < −0.1786 to 0.0273 with each
subsequent year from 2009 to 2017 associated with a decrease in the likelihood of
establishing a voluntary risk management committee, as evidenced by negative
coefficients ranging from r = −0.5378 to −0.7651. Further, the fiscal years from 2010
through 2016 are statistically significant, indicating a consistent decline in the firm’s
appetite to establish a risk management committee over this review period.
The 2 × 2 chart illustrates, in Figure 14, the relationship between the fiscal
years reviewed and the likelihood of firms adopting a voluntary risk management
committee. As time progresses (moving from left to right on the x-axis, which
represents normalized fiscal years), the likelihood of firms adopting a voluntary risk
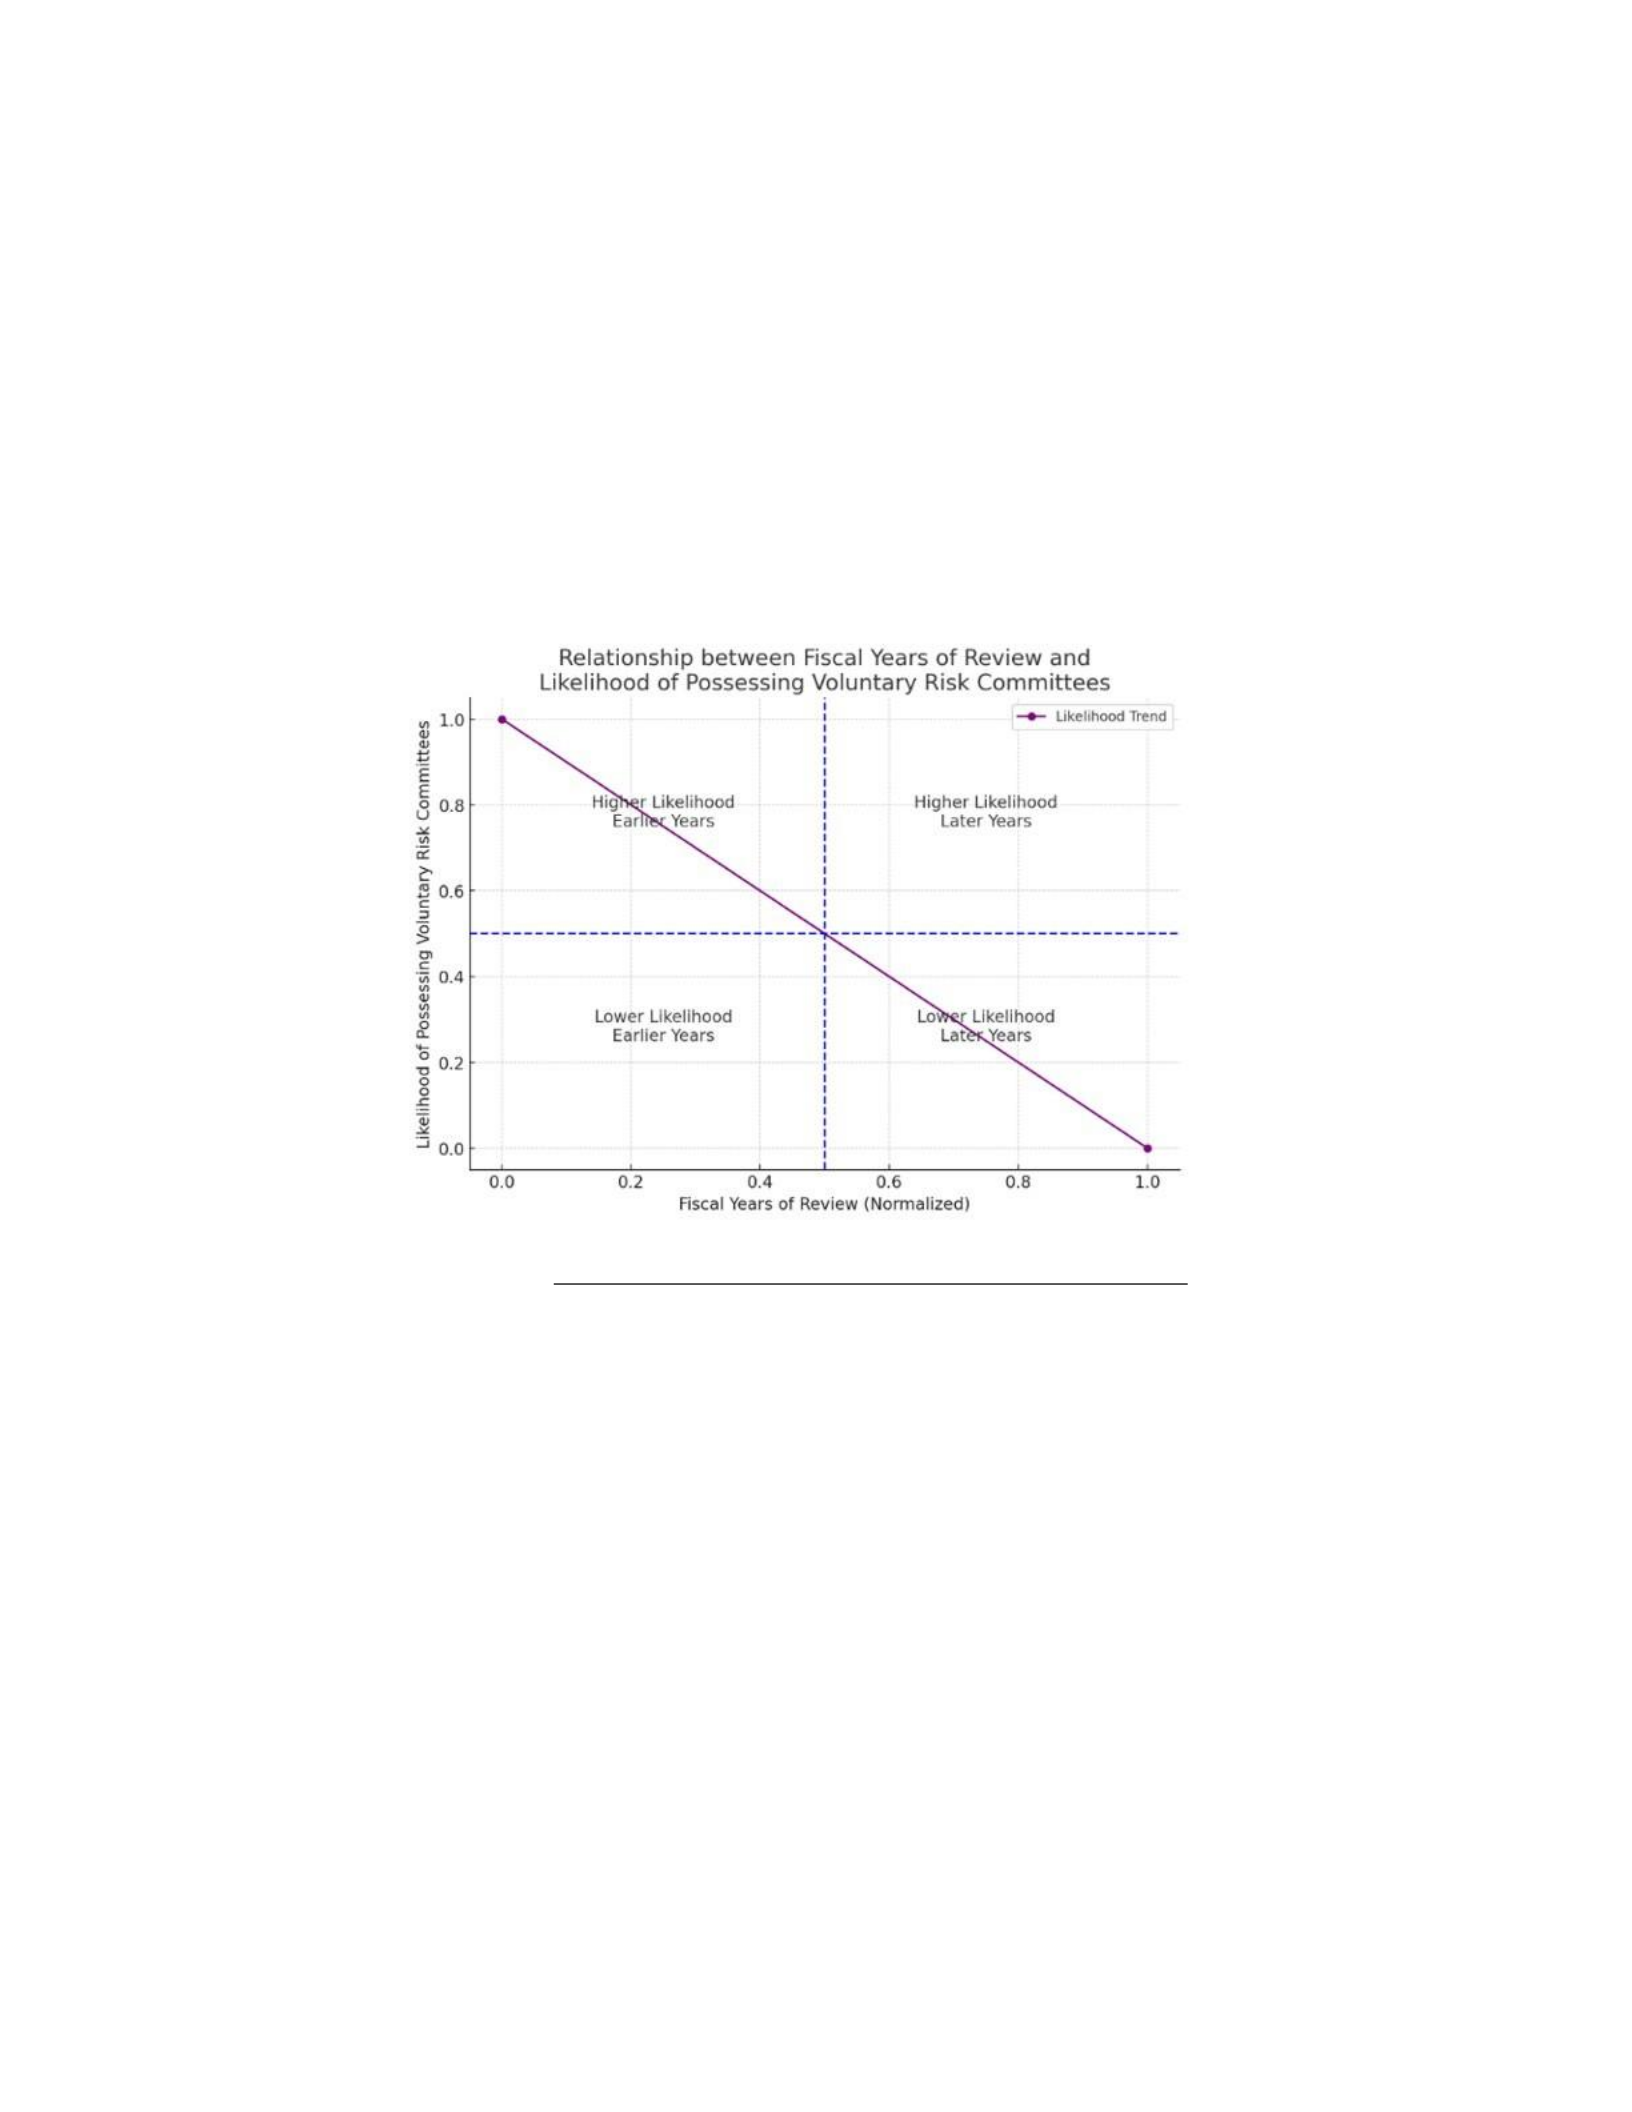
management committee decreases (moving from top to bottom on the y-axis). While
holding other variables constant, the negatively significant relationship between the
fiscal years and the establishment of voluntary risk management committees
statistically implies the decreasing likelihood of firms possessing a voluntary risk
management committee as time elapses.
Figure 14. Fiscal Years and the Probability of Adopting a VRMC.
The gender ratio variable of B = 1.776, p < 0.004, indicates a positive
coefficient, displaying that a higher gender ratio is associated with an increased
likelihood of establishing a voluntary risk management committee. The 2 × 2 chart
depicted in Figure 15 shows the relationship between the gender ratio of men on the
board and the probability of having a risk management committee. It illustrates that as
men on the board increases (moving from left to right on the x-axis), the likelihood of
the board adopting a voluntary risk management committee also increases (moving
from bottom to top on the y-axis). As more men are on the board, the likelihood of
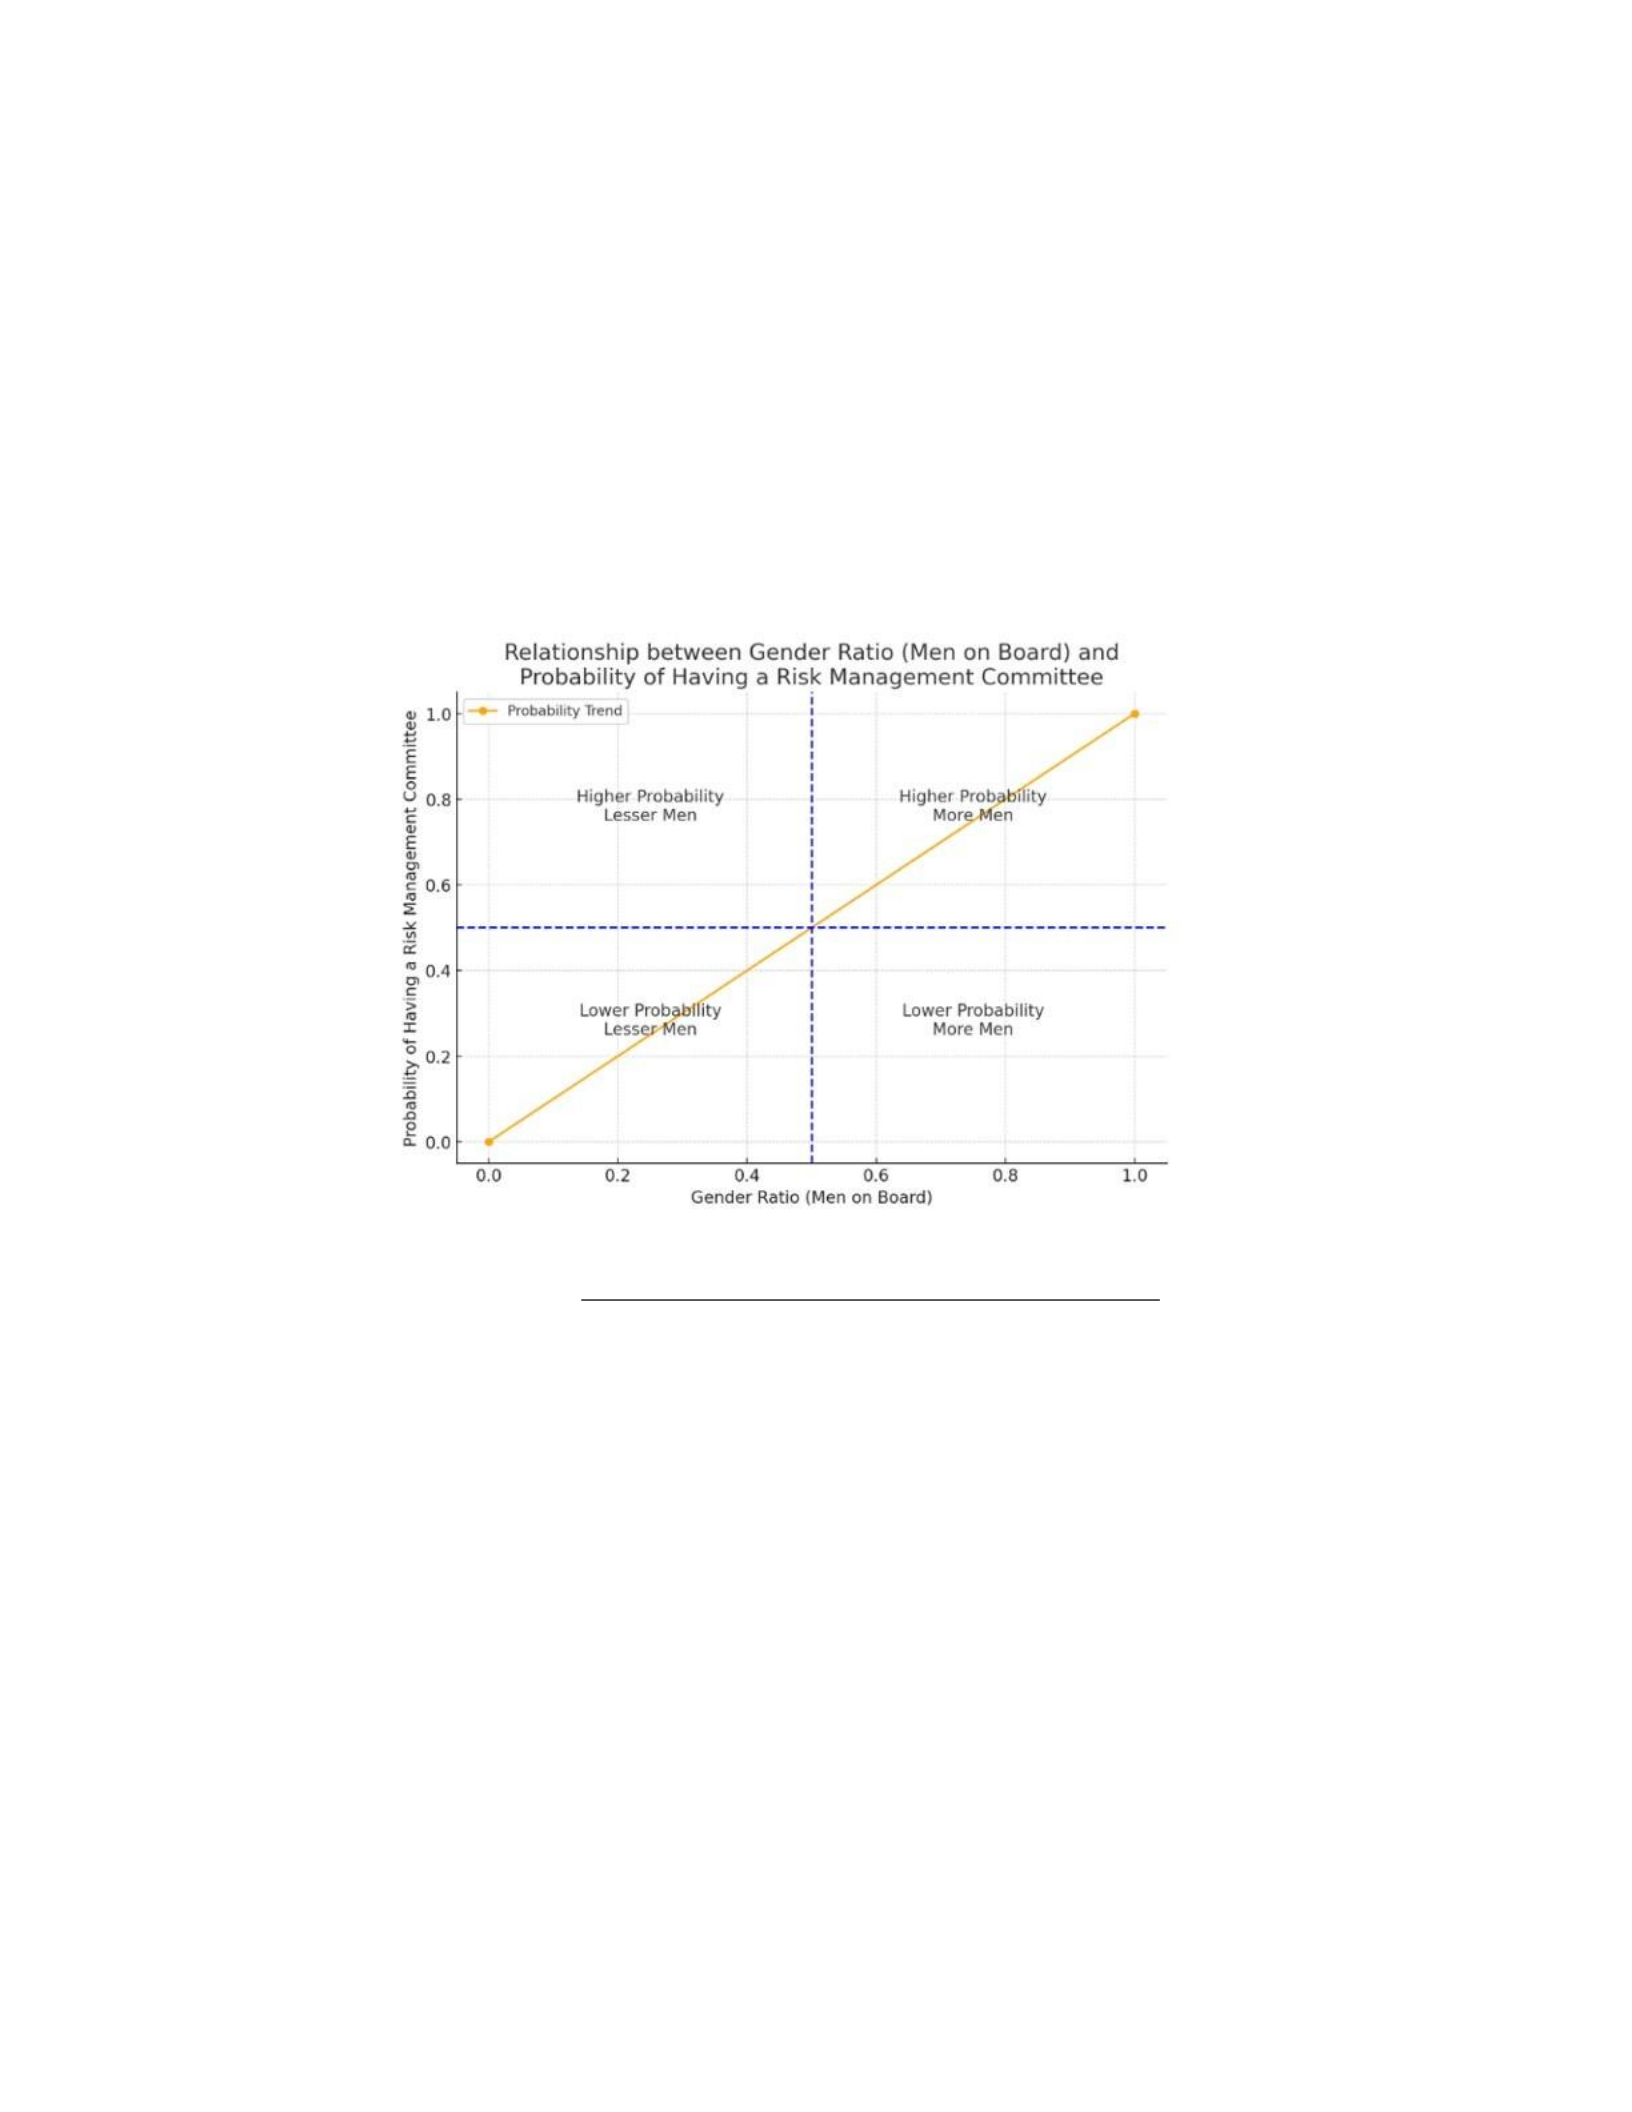
having a risk management committee increases. Similar to the previous finding on
short-term credit ratings, a substantial amount of literature suggests that, on average,
men tend to take more aggressive risks and could potentially benefit from establishing
a conservative board subcommittee to monitor and balance the firm’s risk acceptance
and tolerance levels (Faccio et al., 2016; Byrnes et al., 1999).
Figure 15. Gender and the Probability of Adopting a VRMC.
Among the industry sectors, none of the coefficients was found to be
statistically significant. This indicates that the industry classification may not have a
significant relationship on the board’s decision to voluntarily establish a risk
management committee. This may also be due to the firm embedding risk management
into the organization’s operations to manage potential risk procedurally, while
embracing risk management as an integral part of their overall business processes,
therefore, minimizing the need for a separate risk management committee.
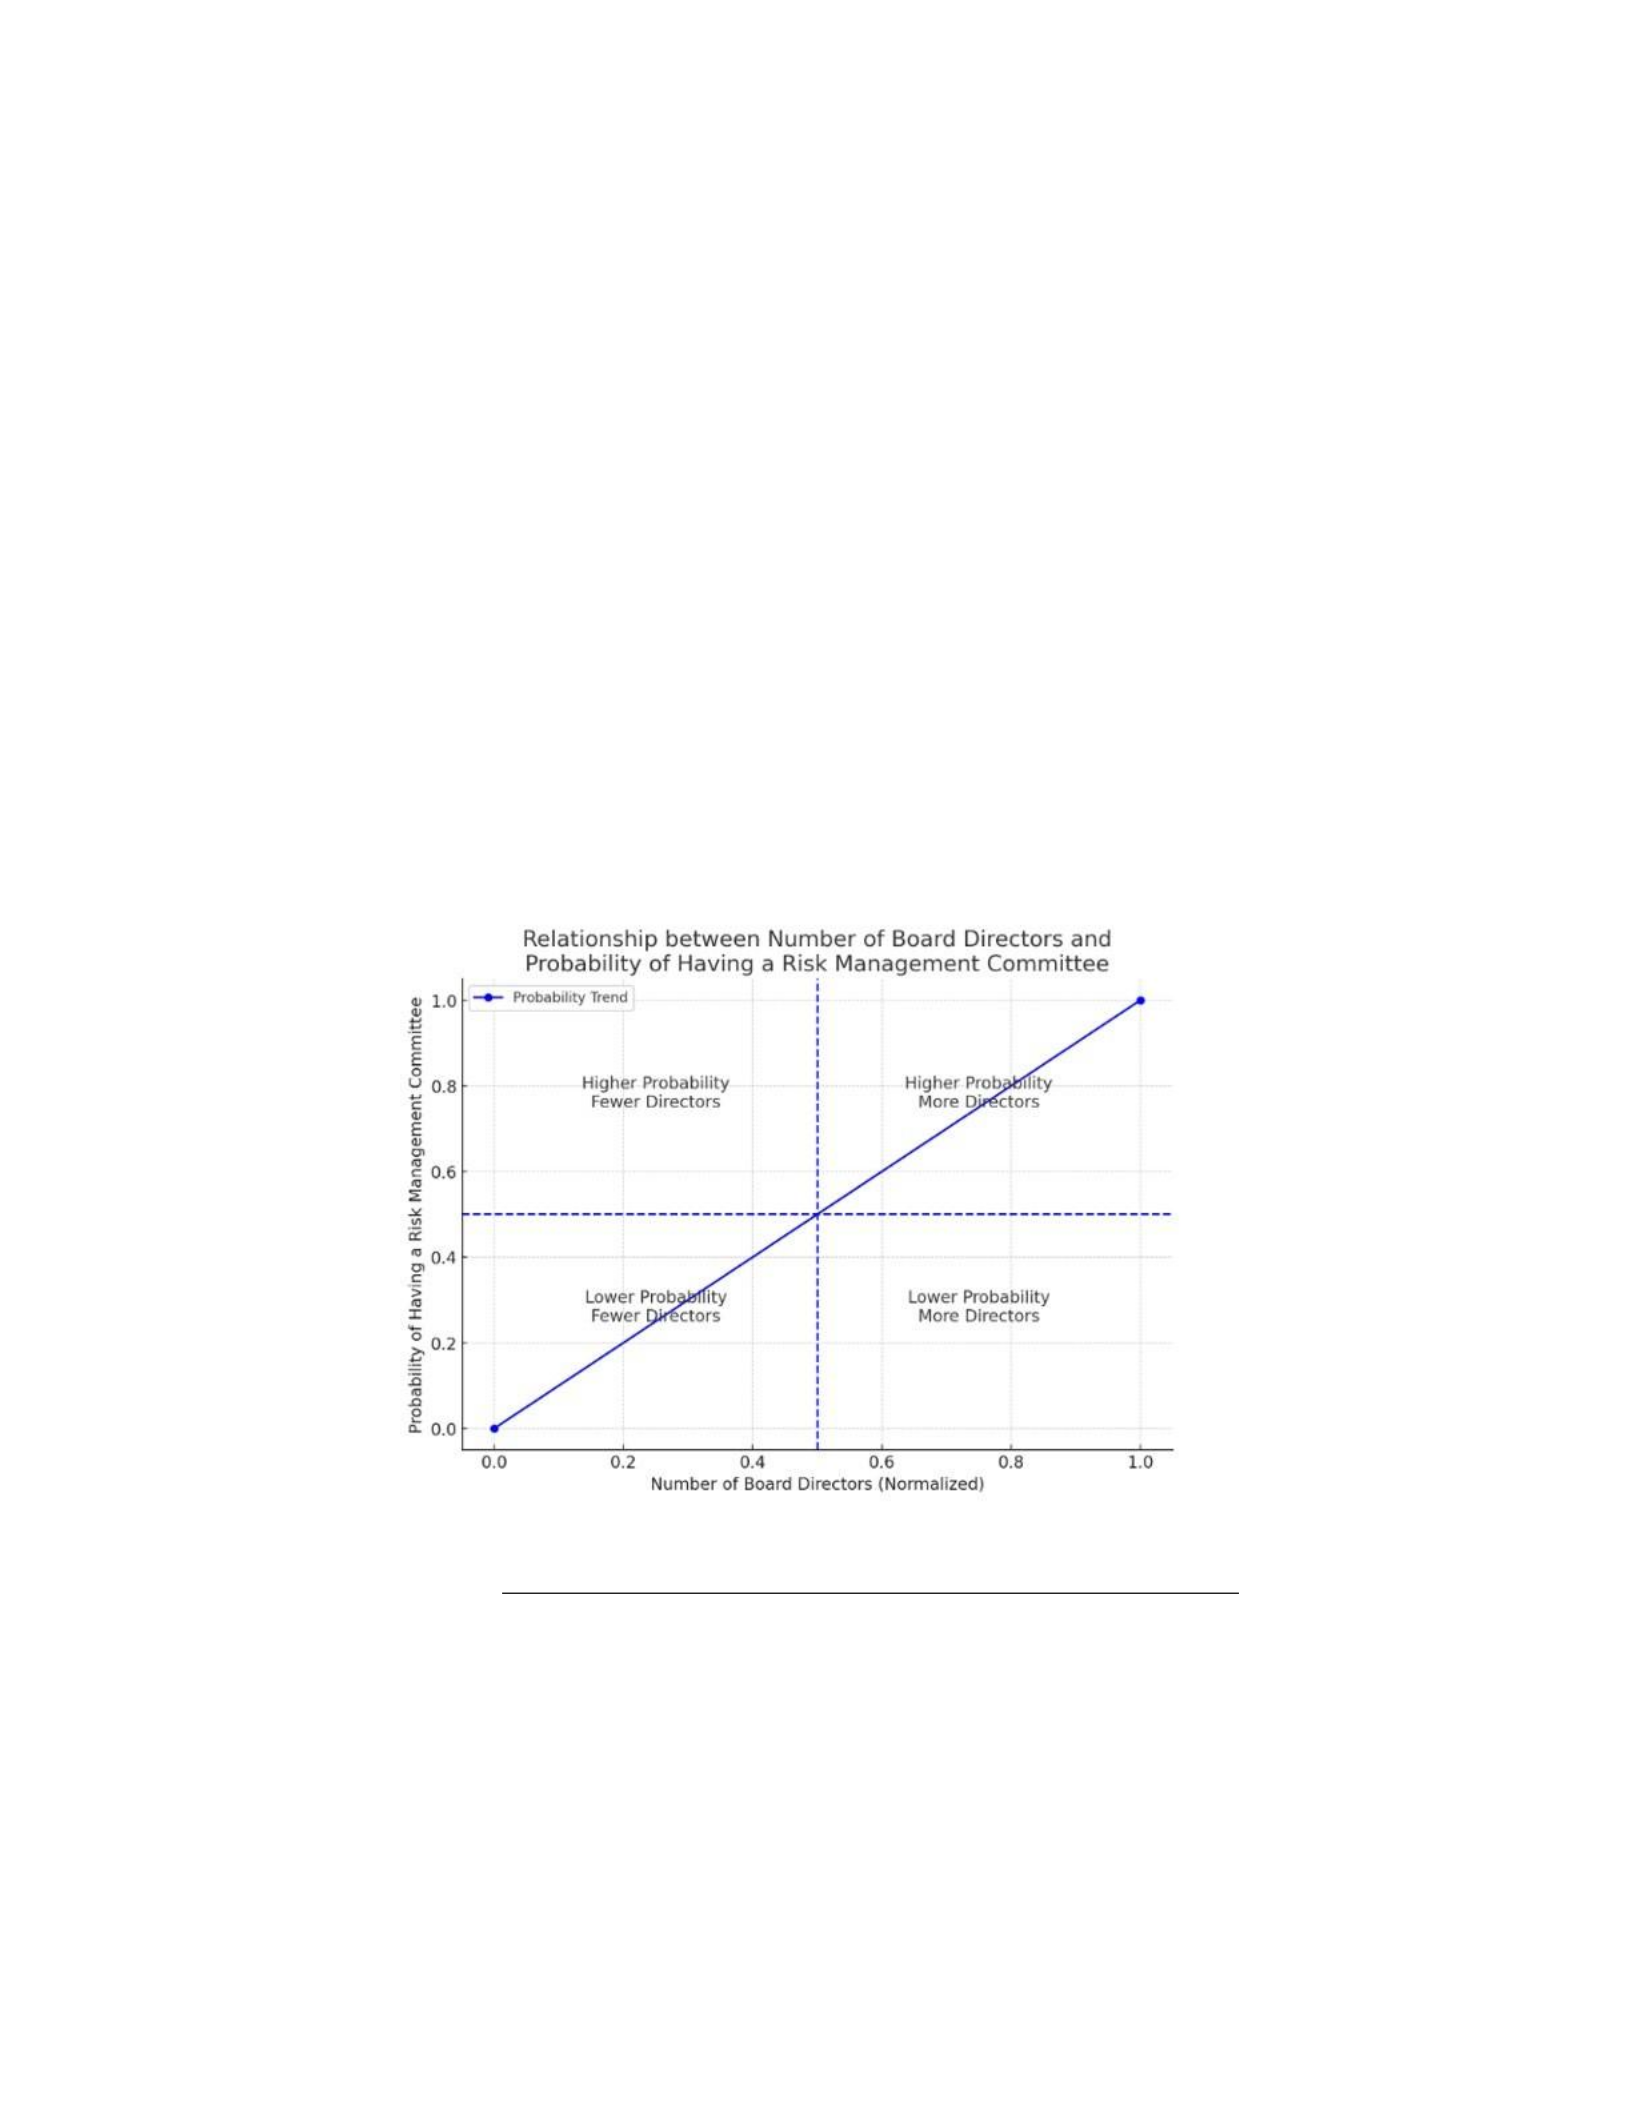
The number of directors variable shows a positive coefficient of B = 0.149, p <
0.000, indicating that organizations with a larger pool of directors are more likely to
establish a voluntary risk management committee. Figure 16, represented in a 2 × 2
chart, illustrates the relationship between the number of board directors and the
probability of establishing a voluntary risk management committee. There is a positive
correlation, where an increase in the number of board directors is associated with an
increase in the probability of the board establishing a risk management committee. As
such, as the number of individual board directors increases, the likelihood of the firm
establishing a voluntary risk management committee also increases.
Figure 16. Number of Directors and the Probability of Adopting a VRMC.
Lastly, we found that the number of director qualifications of B = −0.012, p <
0.081, has a negative coefficient, suggesting a significant negative relationship between
the number of director qualifications and the establishment of a voluntary risk

management committee. The 2 × 2 chart visualized in Figure 17 displays the
relationship between the number of qualifications among the board directors and the
probability of a firm establishing a voluntary risk management committee. The chart
shows that as the number of qualifications (normalized on the x-axis) increases among
the board of directors, the probability of the firm developing a voluntary risk
management committee (y-axis) decreases. Our findings align with the logical
conclusions drawn by Papadimitri et al. (2020), who, using a dataset of 1,618 firms
across 39 countries, explain how the firms’ credit ratings are positively related to the
education levels of the board leadership.
This explains a potential phenomenon where the more the board leadership has education
and qualification characteristics, which are seen as higher cognitive abilities for better
decision-making, the less inclined the board is to establish a separate voluntary risk
management committee to assist with strategic decisions. Thus, it may be perceived that
a board of directors with an increased knowledge pool of qualifications has less need for
a separate voluntary risk management committee to oversee the firm’s credit ratings.
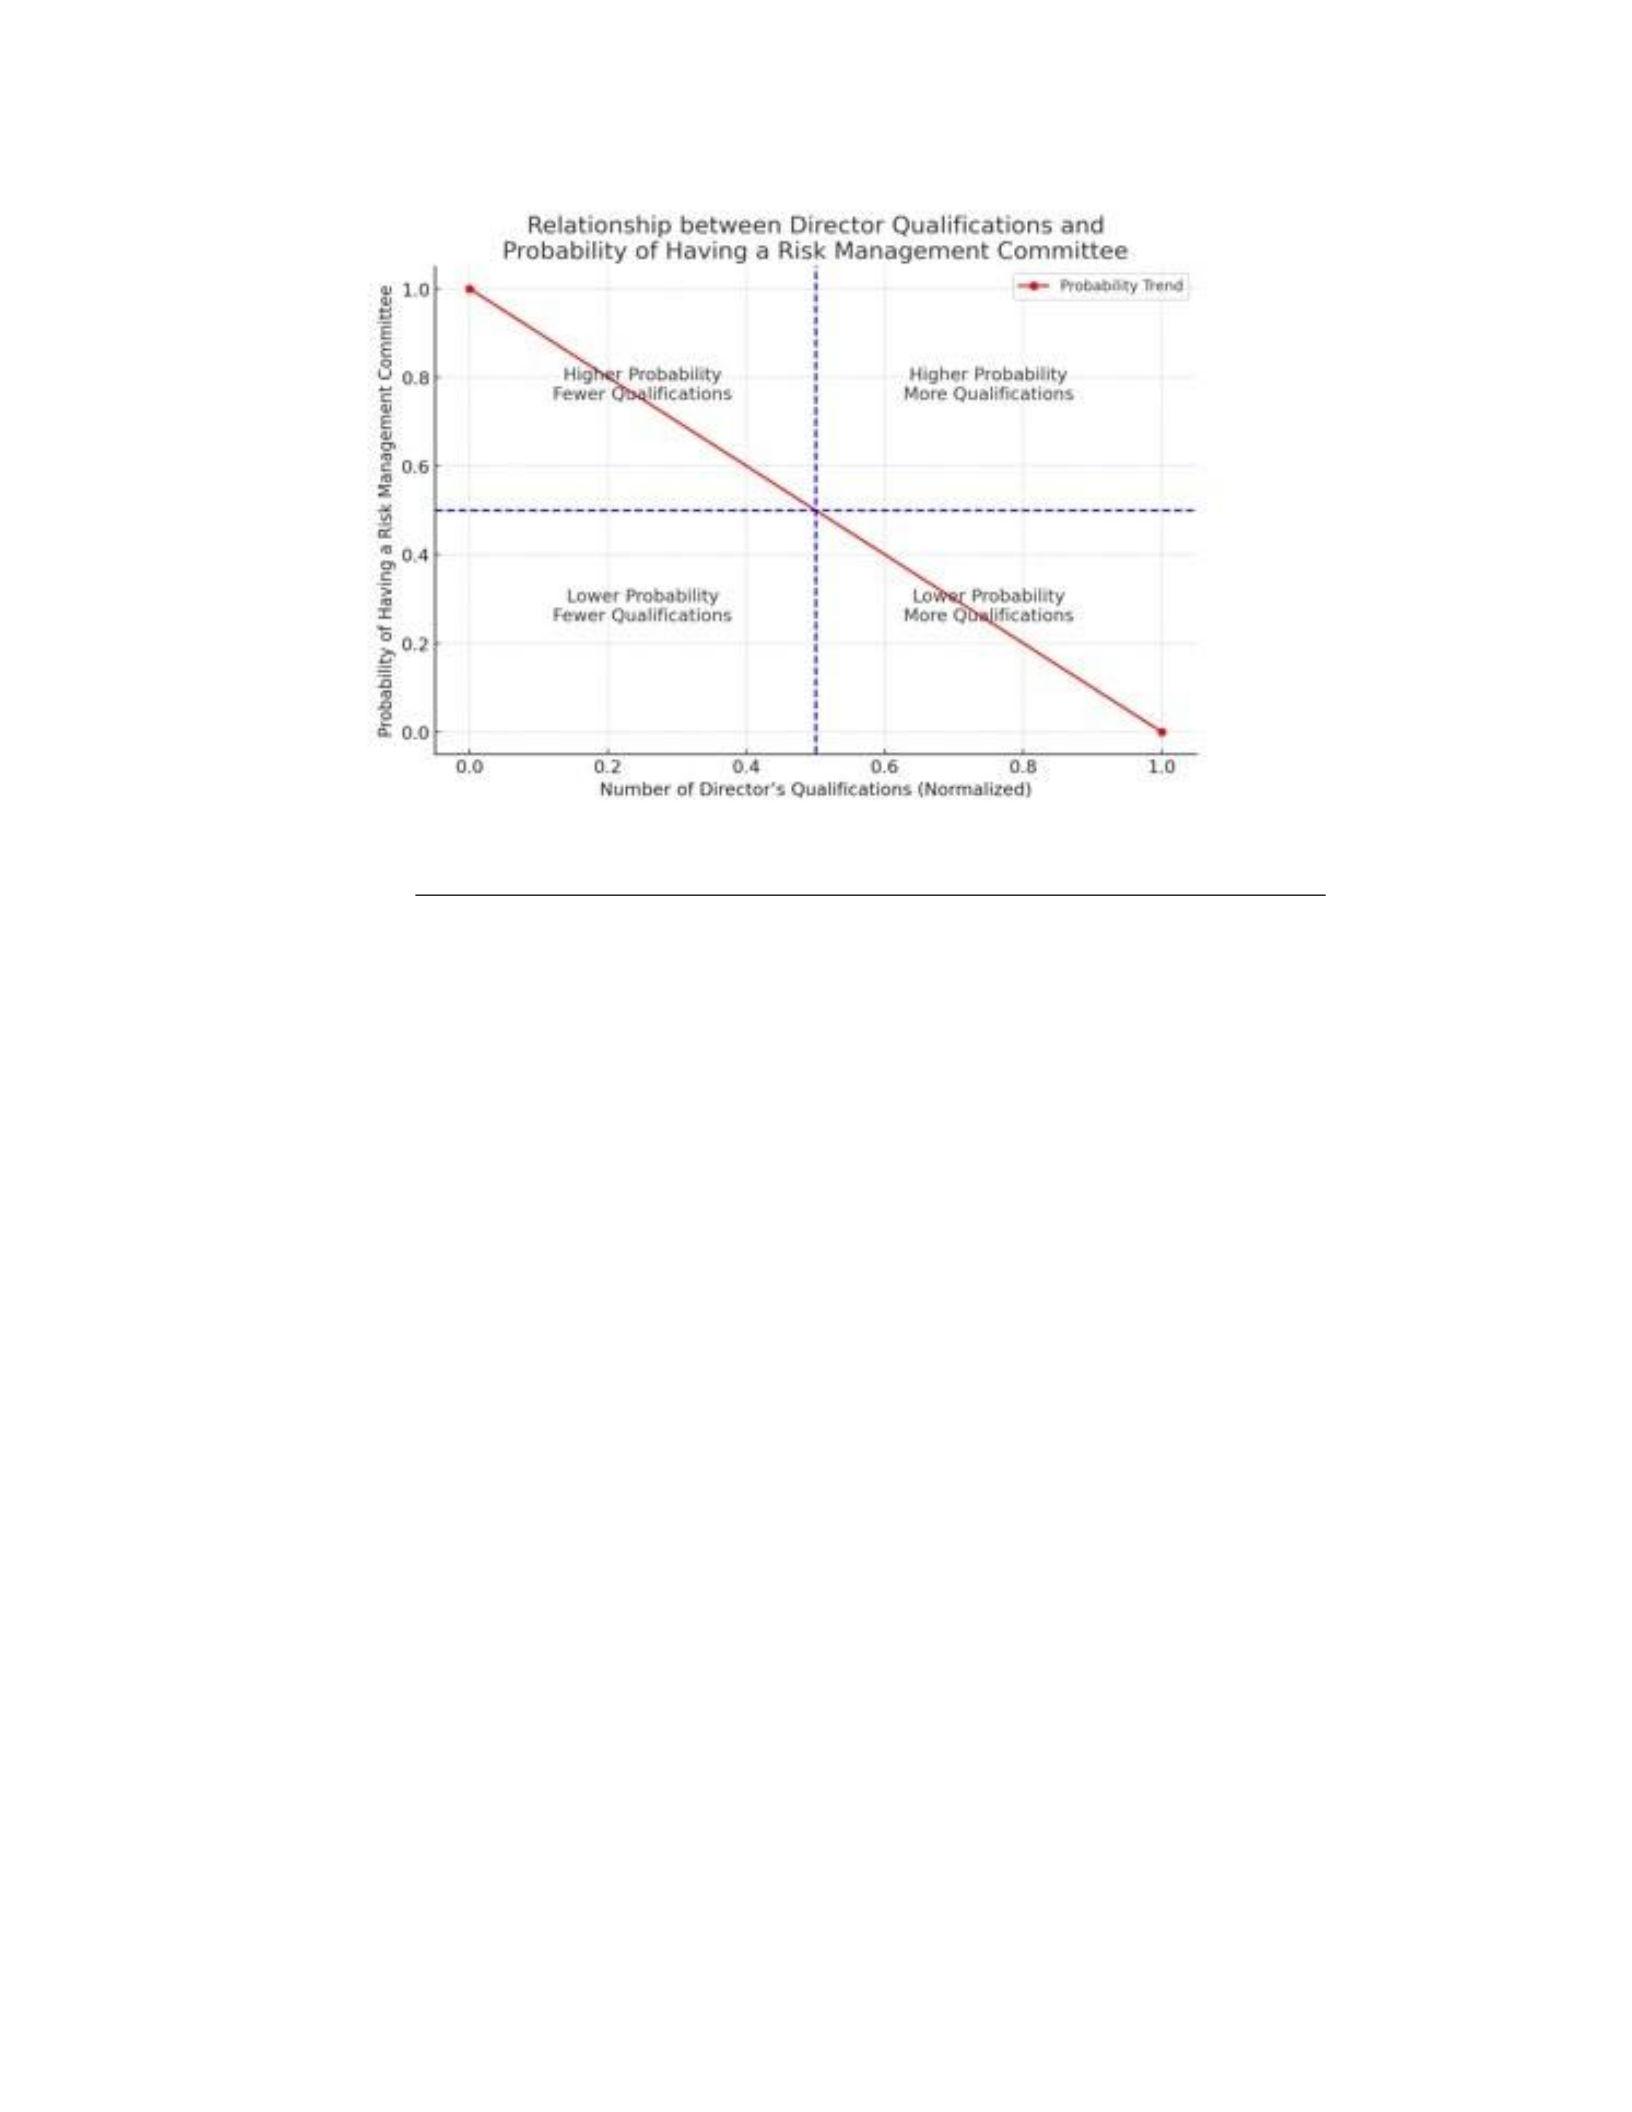
Figure 17. Number of Directors Qualifications and the Probability of Adopting a VRMC.
Summary of Findings and Introduction into Concluding Chapter
This research explores the relational association of risk management
committees (RMC) on S&P short- and long-term credit ratings. The results suggest that
the existence of a voluntary risk management committee is correlated with an increase
in a firm’s short-term credit ratings, but oddly enough, not significantly related to its
long-term credit ratings. As mentioned in Study 1, previous research has discussed the
importance of RMC as a vital element of a firm’s corporate governance (Moore and
Brauneis, 2008; Schlich and Prybylski, 2009). But questions continue to surface
regarding the inconsistent findings regarding the presence of RMCs (Malik et al.,
2020). Although, in philosophy and in application, risk management committees should
provide reasonable assurance for organizations to understand and manage risk
effectively in both the short and long term, our findings show the application of this
essential role merely depends on the unique credit circumstances within short-term and

long-term strategic priorities of each firm. Moreover, the board of directors within
these firms believes perceived lowrisk levels or risk exposure exists that does not
warrant a dedicated risk management committee, considering their extensive level of
qualifications for managing the firm. Although we are encouraged that our findings
reveal risk management committees to have a relationship with increase short-term
credit ratings, we believe our results remain consistent with a body of recent research
performed by other scholars (Hines et al., 2015; Ali et al., 2017; Alkilani et al., 2020;
Stulz, Tompkins, Williamson et al., 2021) who also indicate that the implementation of
a board-level risk committee does not strategically support the organization’s goals
through risk reduction.
CHAPTER 5
CONCLUSION, LIMITATIONS, AND APPLICATIONS
Chapter Introduction
This chapter reintroduces the purpose of this study and provides a summary
conclusion of the overall key findings for both studies (Section 5.2.1). The subsequent
discussion provides the research contribution relating to how risk practitioners utilize
the development of a voluntary risk management committee (Section 5.3). Finally, this
chapter concludes this research with our study limitations along with suggested future
research avenues (Section 5.4).
Purpose of the Study and Summary Conclusion
Summary Conclusion of Both Studies
This investigation was crafted to particularly study the importance of the
adoption of a voluntary risk management committee and their role in corporate

governance after the major financial crisis in 2008. After the 2008 GFC, risk
management committees became more prevalent to address deficiencies identified
during and after this crisis. These board-level established committees are tasked with
developing more sophisticated and proactive risk management strategies to prevent
future financial disasters. The effectiveness of a firm’s board of directors hinges on
their ability to monitor financial and operational changes. Thus, the evolution of board
committees, in response to financial sector failures, prompted regulators, along with
specialized corporate governance committees, to establish requirements for the
formation of board-level risk management committees to enhance corporate
governance practices and address complex matters, including systemic risks. Motivated
by this plausible corporate structure, Study 1 evaluated whether the establishment of a
voluntary risk management committee is related to the risk governance of the firm
(RQ1). Through this exploration, we also explored the firm’s impending credit risk
vulnerabilities brought about by the GFC. In Study 2, we evaluate the establishment of
a voluntary risk management committee and its relationship with the firms’ credit
ratings through effective oversight and strategic risk management practices (RQ2). To
evaluate the hypotheses developed from the research questions, this study utilized
regression analysis as a statistical method to ascertain the relationships among these
variables.
In regard to RQ1, we found that firms with long-term debt compared to their
total liabilities are less likely for the board to adopt a risk management committee.
However, we found that if the firm’s total liabilities compared to total assets increase,
the likelihood of the firm adopting a risk management committee also increases. Over
time, the trend is toward fewer voluntary risk management committees, especially in

health care and communication industries. We also found that having more board
directors, and more men on the board, increases the likelihood of having a risk
management committee.
With regard to RQ2, we found that firms with better short-term credit ratings,
more male board members, or larger boards are more likely to adopt a voluntary risk
management committee. Additionally, more qualified directors also tend to lead to the
creation of these committees. Furthermore, we observed that there was no relational
connection between long-term credit ratings and the creation of a voluntary risk
management committee. Moreover, similar to Study 1, the interest in forming these
committees was shown to drop over time, particularly in the utilities sector.
The findings of this study, as mentioned earlier, revealed mixed results
concerning the establishment of a voluntary risk management committee in relation to
assessing the firm’s financial health (i.e., financial soundness). We found that as the
longterm debt/total liabilities ratio increases, the likelihood of having a risk
management committee decreases. Further, we discovered when the total
liabilities/total assets ratio increases, the likelihood of having a risk management
committee also increases. It appears that firms are less concerned with developing a
risk management committee when using long-term debt, possibly due to the firm
focusing on more strategic shortterm operations. However, in contrast, we observed
that when a firm uses more debt than assets to operate its activities, firms are more
inclined to establish a voluntary risk management committee, as this may indicate a
higher risk of default. But more notably, we also observed that several financial ratios
related to risk, solvency, and efficiency did not provide a clear relationship with the
decision for a firm to adopt a voluntary risk management committee. This argument is

consistent with previous research that suggests firms using financial ratios in a
standardized way may cause inaccurate estimation of business risk (Lucic, 2014). This
was a major finding of our study, as financial ratios may not be the best way to
measure a firm’s risk within nonfinancial firms. Considering these findings, we would
argue that both quantitative and qualitative measures should be assessed to
comprehensively measure a firm’s enterprise risk.
Regarding our findings on short- and long-term credit rating, we observed that
as the S&P short-term credit ratings increase, the likelihood of having a risk
management committee increases. This data illustrates the firm’s deliberate measures
to actively and effectively manage its creditworthiness to secure the best financial
terms for borrowing funds to support its strategic operations. Surprisingly, our results
indicated that long-term credit ratings did not demonstrate any relationship with the
adoption of a voluntary risk management committee. This may possibly be due to the
development of a voluntary risk management committee not often being directly tied to
a firm’s long-term credit ratings, as many of these committees are developed due to
internal strategic, operational, or regulatory goals that may not directly correlate with
the firm’s credit ratings. The relationship to short-term credit ratings and the
development of a voluntary risk management committee often has a more immediate
impact on operational finance decisions, while long-term ratings are more regarding
long-term strategic investments (Güttler & Wahrenburg, 2007).
Lastly, we found, consistent with both studies, that the likelihood of having a
risk management committee increases when there are more men on the board
(Alemany et al., 2020). The negatively significant relationship between the fiscal years
under review and the presence of voluntary risk committees implies that there is a

statistical association indicating a decreasing likelihood of firms possessing a voluntary
risk committee as time progresses (Fraser & Henry, 2007; Ashby et al., 2019). The
negatively significant coefficient for the utilities sector suggests that companies within
this sector are less likely to have a voluntary risk management committee compared to
companies in other industry sectors. As the number of board directors increases, the
likelihood of having a risk management committee increases. This further supports the
arguments of Subramaniam et al. (2009) that suggest a risk management committee is
more likely to exist in firms with larger boards.
Application for Practice
Our research regarding the rewards of a voluntary risk management committee
contributes to the ongoing gap in research within board-level corporate risk governance
literature, as argued by Mushafiq et al. (2023) in several ways. It provides yet another
footprint within the growing body of empirical literature that offers mixed evidence
that the adoption of a voluntary risk management committee has a direct relational tie
with the financial risk ratios of the firm. Although our research finds a similar moderate
increase in nonfinancial firms creating a separate risk management committee (Bugalla
et al., 2012; Malik et al., 2020) after the GFC in 2008, they still remain underestimated
and underutilized. And possibly because of this underutilization, our research supports
that the financial risk ratio alone cannot predict the establishment of a voluntary risk
management committee. We lean into Lee’s (2020) argument that there still remains
limited knowledge on how firms organize their board committees. Considering this, we
assert that the adoption of a voluntary risk management committee should not be
identified through traditional financial risk ratios alone (i.e., accounting ratios) as a

measurement for risk identification but requires additional quantitative and qualitative
measures to fully understand its determinants and relationship for establishing a risk
management committee. Thus, our research continues to assert that risk management
committees need separate key risk indicators to be advantageous in determining the
value of the firm. Specific metrics should be required for VRMC to identify providing
a significant relational tie to the financial risk and health of an organization.
Lastly, in light of short-term credit ratings, we found a relational increase with
the establishment of a risk management committee. This provides great insight to the
board of directors that nonfinancial firms that voluntarily elected to adopt a risk
management committee have reflected better short-term credit ratings. As a result,
firms are traditionally more apt to receive lower borrowing costs, providing greater
access to capital markets, which is vital for operational stability and confidence among
investors, lenders, and other stakeholders.
In all, this study adds to the developing risk governance literature, indicating
that the creation of a voluntary risk management committee within nonfinancial firms
is more than a mere procedural perfunctory compliance function. It also follows Hines
et al. (2015) assertion that more specific parameters are needed for VRMC to be
effective in providing a significant relationship on the financial risk and health of an
organization.
Limitation and Future Research
With all research comes some limitations, and I believe they should be
discussed in this context.
First is the small sample size. With regard to the adoption of a separate
voluntary risk management committee for nonfinancial firms, in the absence of

regulatory requirements, it poses a challenge for a small number of firms with an
appetite to develop such a committee. We presume that as the interest in establishing a
risk management committee increases, or if a government mandate is issued, more data
will be available for evaluating in the future. Secondly is the time frame evaluated.
During the review period, only credit history data up until 2017 was available from
WRDS. As additional data becomes available, or if another platform with updated
ratings emerges, it may provide additional results.
As business risk strategies continue to evolve regarding the firm’s ability to
remain profitable and outperform its competitors, future researchers could further
study sectors individually to determine the relationship of a VRMC within varies
industries. Another avenue of research, which follows Lee’s (2020) assertion, is that
empirical work could be helpful to further understand specifically how VRMCs
operate within the firm to capture specialized metrics to evaluate their relation to risk
reduction. This includes exploring the maturity of a VRMC when assessing the
relationship with risk reduction outcomes (Fisher, 2021). Ames et al. (2018)
complement Lee and Fisher’s assertions by arguing that it takes the establishment of a
risk management committee five years to see an impact on firm performance. As such,
because our research only examines the relationship between the adoption of a risk
management committee within nonfinancial firms using secondary quantitative data,
researchers may find additional correlations using richer data points depending on the
maturity of the VRMC by employing a combination of both quantitative and
qualitative data. Lastly, another critical aspect that may warrant additional research
comes from observing the temporal U-shaped trend with the adoption of VRMCs

during the enaction of the Dodd-Frank Act of 2010. Amid the significant VRMC
increase between 2009 to 2015, to the sharp decline after 2016 suggests that firms may
be moving towards embedding risk management more seamlessly into their internal
operational processes. This evolution from a broad-level committee to a more strategic
integrated process-level approach underscores the need for further research into how
risk management practices are effectively adapted and integrated within corporate
governance structures.

