


Lectures Notes Importance of Small Businesses
Small businesses are a pillar of the U.S. economy, forming the largest group of exporters
and importers while serving as the largest source of employment (Office of the United States
Trade Representative, 2009). In the state of Louisiana, small businesses comprise the majority of
all employers, employing over half of the state’s private workforce (U.S. Small Business
Administration, 2014), and are key contributors to state export revenues (World Trade Center,
New Orleans, 2015). In the U.S. as a whole, approximately 50% of small businesses survive
more than five years and only a third survive more than 10 (SBA Frequently Asked Questions,
2012). In Louisiana, approximately 50% of small businesses survive more than five years, and
about 40% survive more than 10 years (U.S. Small Business Administration, 2014).
Absence of Strategic Planning and Failure of Small Businesses
Early research on the failure of small businesses identified the absence of strategic planning as a
primary cause (Ibrahim & Goodwin, 1985; Mayer & Goldstein, 1961; Mintzberg, 1979;
Crawford & Lefebvre, 1984; Crawford & Ibrahim, 1985; Nerone, 1997). Excessive optimism, a
failure to monitor results, and the absence of balanced growth also were identified as key factors
(Mayer & Goldstein, 1961; Mintzberg, 1979; Crawford & Lefebvre, 1984; Crawford & Ibrahim,
1985). In their 1982 study, Sexton and Van Auken found that small business owners and manager
often thought of strategic planning, but rarely took action. Several other studies determined that
not only was systematic strategic planning largely absent in small businesses, but also that what
little did take place was reactive, incremental, disorganized, sporadic, and inadequate (Still,
1974; Cooper, 1977; Crawford, R. L., & Ibrahim, A. B., 1985). As Nerone observed, "Most
entrepreneurs [small business owners] are doing their strategy on the back of a napkin, as they
sweat out making the Friday payroll” (Nerone, 1997, p. 9).

In a more recent article, Kraus, Harms, and Schwarz argue that strategic planning does
occur in small businesses, but that it is often performed intuitively without the use of planning
instruments (2006). In practice, small businesses plan in the short term, rather than focusing on
long-term objectives, and are typically reactive rather than proactive (Wang, Walker, &
Redmond, 2007). Small businesses that claim to plan for the future typically develop those plans
ad hoc and rarely write them down formally. Furthermore, the plans provide little guidance for
measuring or analyzing the performance of the small business (Wang et al., 2007). The literature
also indicates that strategic planning in small businesses is unstructured, informal, and irregular,
lacking in information (Gibb & Scott, 1985; Flavel, 1991; Balasundaram, 2009).
Correspondingly, small businesses have been described as shortsighted and strategically
narrowminded (Wang et al., 2007).
Benefits of Strategic Planning
This absence of strategic planning certainly counters much of the literature, which
indicates that small businesses should plan for the long term in order to effectively compete
(Wang et al., 2007). Small businesses that disregard strategic planning risk, at a minimum,
growth and performance and, at worst, their very survival (Wang et al., 2007). Understandably,
small business success is not determined by strategic planning alone; however, there are more
benefits to planning versus not planning (Wang et al., 2007).
Problem Statement
Strategic planning has been studied since the 1950's, but research has focused primarily
on larger organizations (Mazzarol, 2004). Research on strategic planning in small businesses is
still in the early stages (Kraus, Reiche, & Reschke, 2007). Furthermore, although small
businesses are vital to the Louisiana economy, little, if any, research on strategic planning in

Louisiana small businesses has been undertaken. While the existing literature suggests that
strategic planning is positively related to the performance of small businesses (Kraus, Harms, &
Schwarz, 2006; Balasundaram, 2009), most of them do not plan, for as yet unknown reasons
(Wang et al., 2007). Thus, Robinson and Pearce argue that “Research needs to provide specific
reasons why planning is not practiced in firms” (Robinson & Pearce, 1984, p. 135).
Understanding why small businesses do not engage in strategic planning, and how that omission
affects small business mortality, would enable consultants to better serve the small business
sector and public officials to improve public policy.
Purpose of Study
The primary purpose of this study is to determine the influence of selected factors that
influence small business owners’ perceived obstacles to strategic planning in Louisiana small
businesses.
Research Objectives
The dependent variable of this study is the propensity of Louisiana small businesses to
strategically plan. The independent variable of this study is Louisiana small business owners’
perceived obstacles to strategic planning.
The following specific objectives were formulated to guide this research study:
1. To describe small businesses in Louisiana on the following characteristics:
a) Years the organization has been in business;
b) Industry in which the small business is positioned;
c) Current number of full time and part time employees on the organization's
payroll;

d) Structure of the organization i.e. Limited Liability Corporation,
Subchapter S
Corporation, Partnership, etc.:
e) Existence of a written long term plan.
2. To describe small businesses in Louisiana on the perceived degree to which the
organization conducts strategic planning.
3. To describe small businesses in Louisiana perception regarding the following perceived
obstacles to strategic planning:
a) The perceived quality of the organization’s employees;
b) The perceived degree to which the organization’s leadership has
knowledge of the
planning process;
c) The perceived available time the organization has to strategically plan.
4. To determine if a relationship exists between Louisiana small business owners' perceived
obstacles to strategic planning and the following variables:
a) Industry in which the small business is positioned in;
b) Structure of the organization i.e. Limited Liability Corporation,
Subchapter S
Corporation, Partnership, etc.;
c) Years the organization has been in business;
d) Current number of full time and part time employees on the organization's
payroll;
e) The perceived degree to which the organization conducts strategic
planning;
f) Possession of a written long term plan.

5. To determine if a model exists explaining a significant portion of the variance in
Louisiana small business owners' perceived degree to which the small business conducts
strategic planning using the following characteristics:
a) Years the organization has been in business;
b) Industry in which the small business is positioned;
c) Current number of full time and part time employees on the organization's
payroll;
d) Structure of the organization i.e. Limited Liability Corporation,
Subchapter S
Corporation, Partnership, etc.;
e) The perceived degree to which the organization conducts strategic
planning;
f) The perceived quality of the organization’s employees;
g) The perceived degree to which the organization’s leadership has
knowledge of the
planning process;
h) The perceived available time the organization has to strategically plan;
i) Possession of a written long term plan.
Summary
Small businesses play an important role in the Louisiana economy. Prior research on
strategic planning has focused primarily on large businesses (Mazzarol, 2004); however, little
literature exists that focuses on Louisiana small business strategic planning. While the existing
literature implies that strategic planning is positively related to the performance of small
businesses (Kraus, Harms, & Schwarz, 2006; Balasundaram, 2009), most of them do not plan,
for as yet unknown reasons (Wang et al., 2007). Therefore, this study will explore the obstacles

to strategic planning as perceived by Louisiana small business owners. The results of this study
will benefit small business owners when employing strategic planning within their organizations,
consultants when advising small businesses during the strategic planning process, and public
officials when establishing public policy affecting small businesses.

CHAPTER II: REVIEW OF LITERATURE
Given how important small businesses are to the U.S. economy, many studies have
focused on what causes them to fail. The principal cause of small business failure has been
identified as a lack of strategic planning. Other key factors contributing to small business failures
are excessive optimism, lack of balanced growth, and failure to monitor results (Ibrahim &
Goodwin, 1985; Mayer & Goldstein, 1961; Mintzberg, 1979; Crawford & Lefebvre, 1984;
Crawford & Ibrahim, 1985).
The literature suggests that small businesses owners tend to not engage in systematic
strategic planning (Perry, 2001), even though they often consider it (Sexton & Van Auken,
1982). Furthermore, any planning that small businesses do undertake tends to be reactive,
unstructured, incremental, and sporadic (Still, 1974; Cooper, 1977; Crawford & Ibrahim, 1985).
Small business owners tend to focus on immediate rather than long-term objectives, planning
for the future in an ad hoc manner, and fail to make provisions for measuring performance
(Wang et al., 2007). The approach of small businesses to strategic planning is therefore
counterintuitive: although the literature highlights the benefits of strategic planning, most small
businesses do not plan for reasons that are not fully understood (Wang et al.,
2007).
U.S. Small Businesses
Small businesses play a vital role in the U.S. economy. Collectively, they are the largest
employer, the largest importer, and the largest exporter in the country (Office of the United States
Trade Representative, 2009). Small businesses, which are defined as those employing fewer than
500 individuals, comprise 99.9% of firms in the U.S. Furthermore, businesses employing fewer
than 20 individuals comprise 89.7% of U.S. small businesses. In 2008, small businesses

generated 46% of the private non-farm Gross Domestic Product (GDP) (Small Business Council,
2014).
Small businesses foster the growth of local economies by providing opportunities for
employment to people who otherwise may not be employable by larger organizations (Brown,
2011). During the 18-year period from 1992 to 2010, small business outpaced larger firms in job
creation 75% of the time (Graves, 2013). In general, small businesses generate 60-80% of all
new employment in the U.S. Small businesses also generate 16.5 times more patents per
employee when compared to larger firms (Graves, 2013)
Small businesses traditionally dominate industries such as construction and retail, as well
as form a crucial link in the supply chain for large-scale and capital-intensive manufacturing
industries such as defense, mining, automotive, and marine (Abdullah & bin Baker, 2000;
Robinson & Pearce, 1984; Wang et al., 2007; Wang, Rowe, & Cripps, 2006). Furthermore, small
businesses provide a competitive balance to industries that would otherwise be dominated solely
by larger firms (Wang et al., 2007).
However, despite the critical importance of small businesses in the U.S., only
approximately half survive past five years and roughly a third last for 10 years (SBA
Frequently Asked Questions, 2012).
Louisiana Small Businesses
Small businesses play a vital role in the Louisiana economy as well. In aggregate, they
account for 97.3% of employers in Louisiana and employ more than half, 54.5%, of the state's
private sector workforce. Businesses with 500 or more employees comprise the remaining 45.5%
(U.S. Small Business Administration, 2014). Federal, state, and local governments, as well as the
U.S. Postal Service, employ 321,569 public sector workers, or 6.95% of Louisiana’s population
(Molla, 2014). As noted in Table 1, the Small Business Administration (2014) reported that
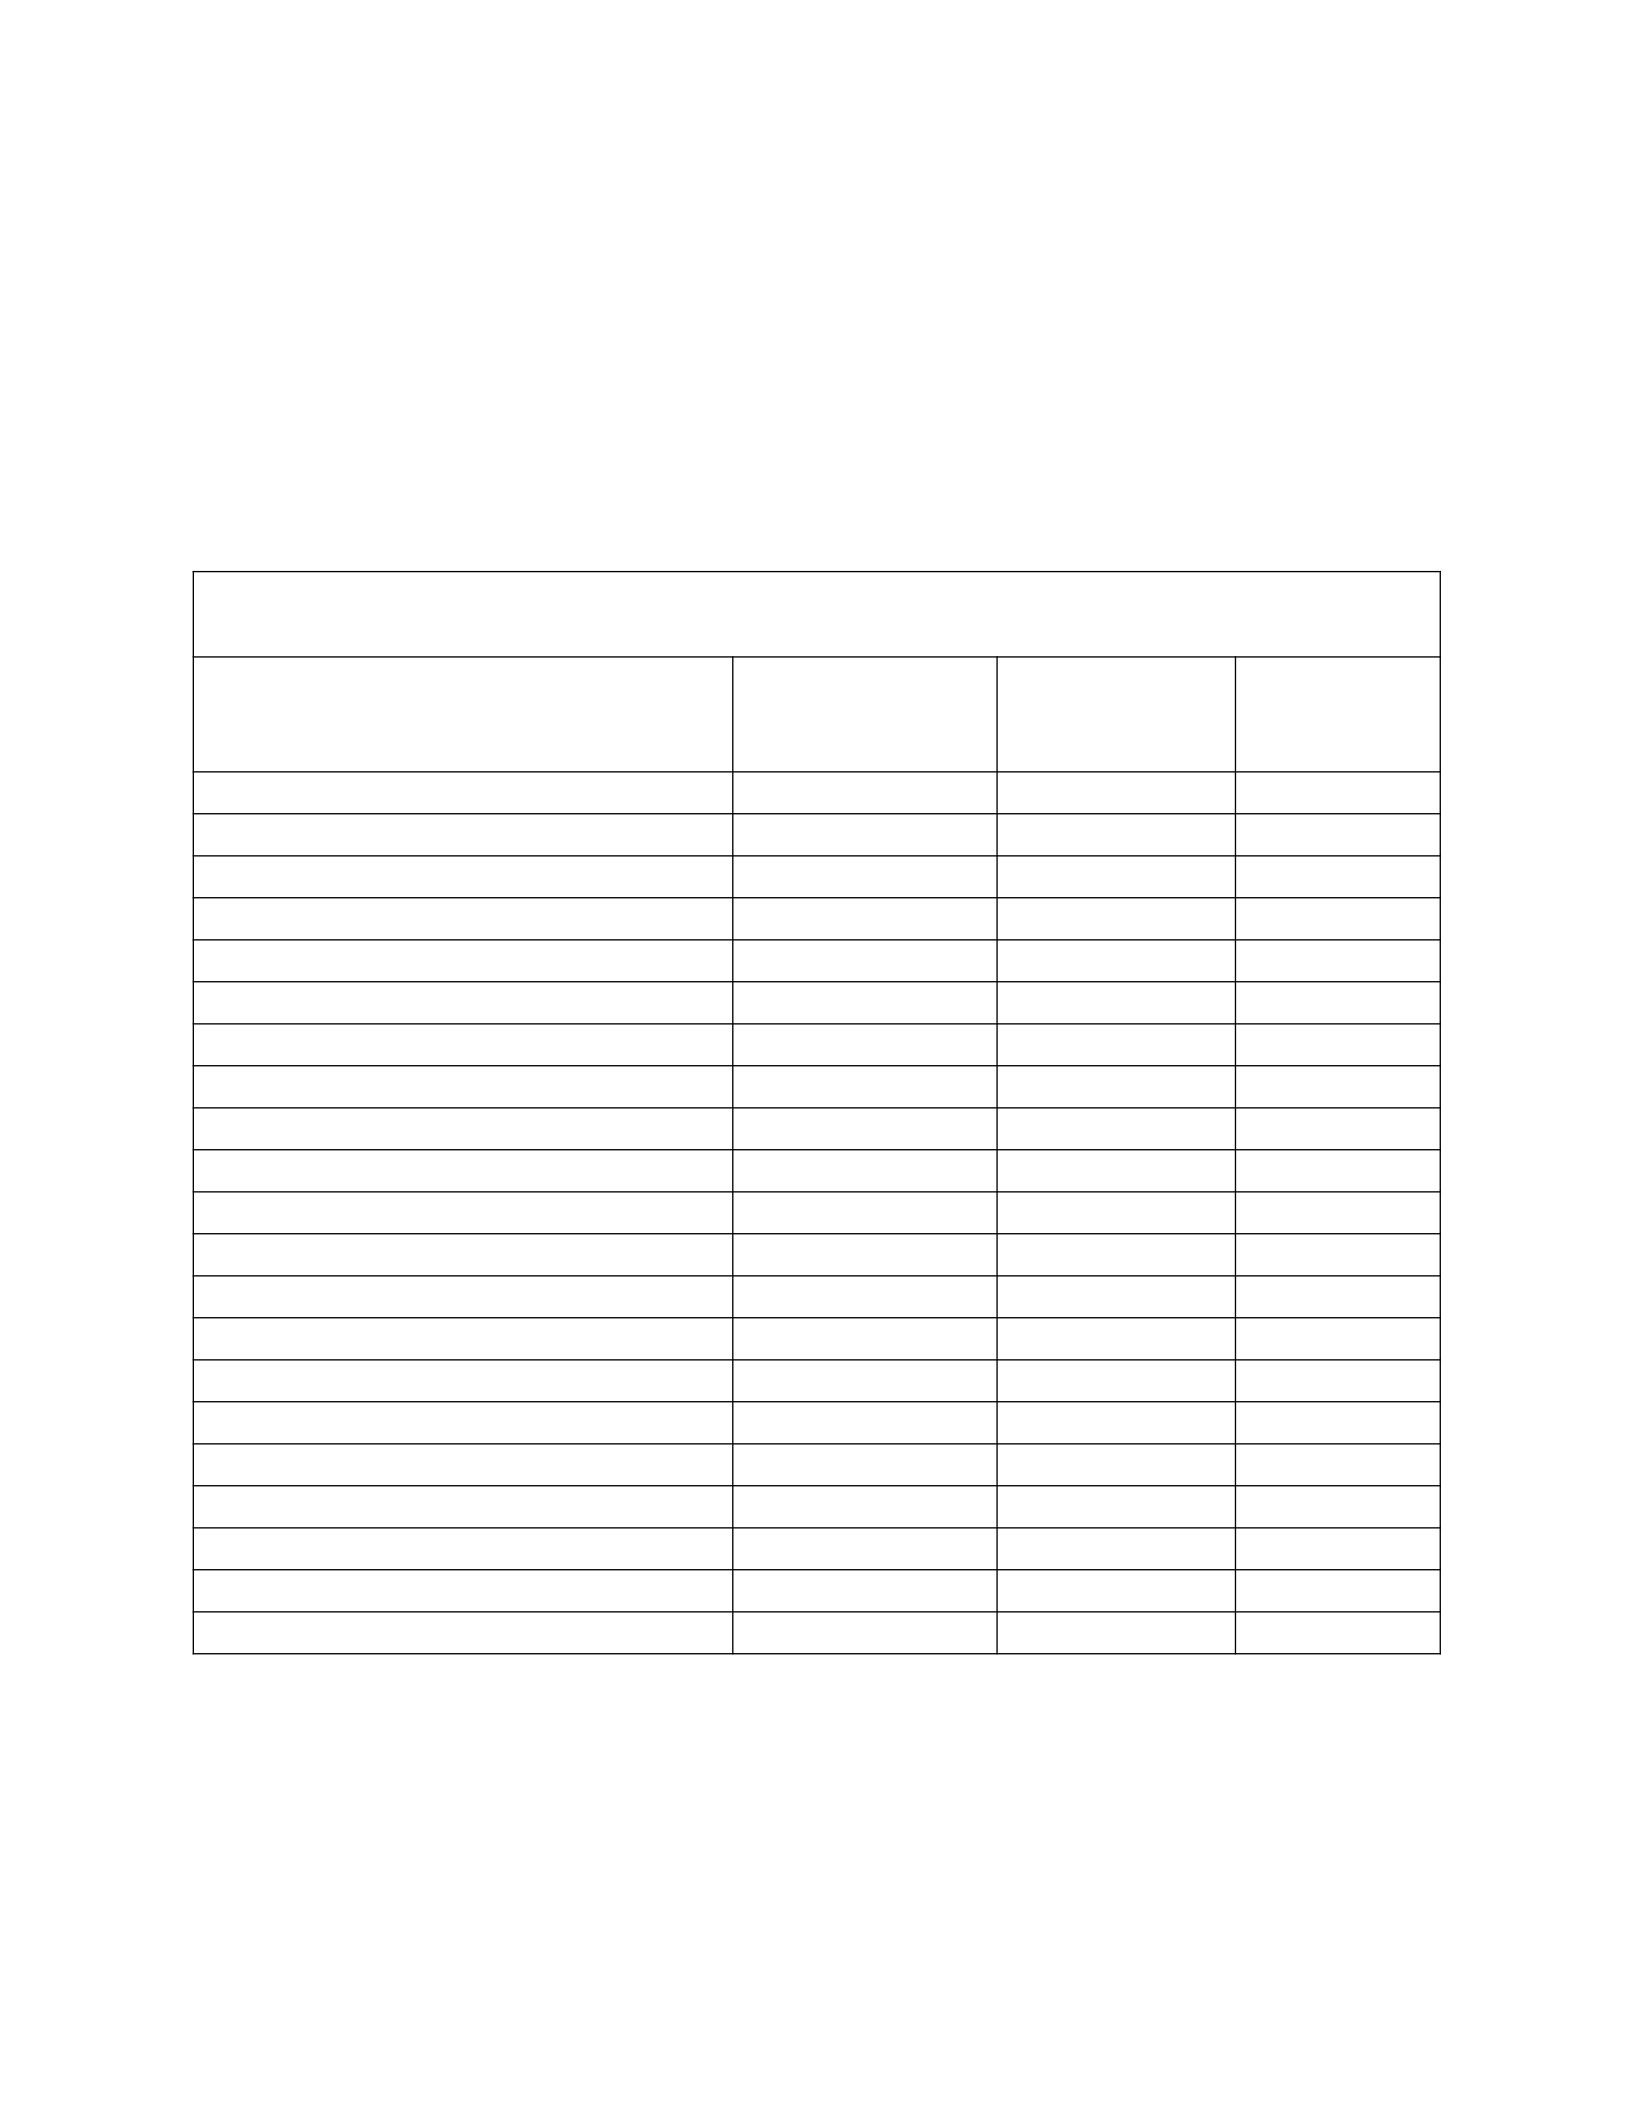
414,779 small businesses existed in the state of Louisiana in 2011. Of those businesses, only
78,451 had employees; 68,030 employed less than 20 individuals. The majority of the small
businesses, 336,328 or 80.7%, did not have employees. Overall, Louisiana small businesses
employ 875,974 individuals (U.S. Small Business Administration, 2014). (See Table 1)
Table 1 The Number of Louisiana Small Firms by Industry, 2011 (Ranked by Number Of Small
Employer Firms) Source: (U.S. Small Business Administration, 2014)
Number of Louisiana Small Firms by Industry, 2011 (ranked
by number of small employer firms)
Industry
Employer Firms
with
1-499 Employees
Employer Firms
with
1-19 Employees
Nonemployer
Firms
Professional, scientific, and tech svcs. 10,621 9,853 35,489
Retail trade 10,398 9,302 23,229
Health care & social assistance 9,646 8,060 30,124
Other services (except public admin.) 8,719 8,005 64,016
Construction 7,867 6,984 38,305
Accommodatin & food services 6,469 4,878 7,513
Wholesale trade 3,845 3,012 4,206
Admin., supp., waste mgt., remed.Svcs. 3,754 3,186 36,768
Finance & insurance 3,689 3,334 9,127
Real estate & renal & leasing 3,371 3,103 29,506
Transportation & warehousing 2,733 2,310 15,178
Manufacturing 2,706 2,027 4,251
Arts, entertainment, & recreation 1,272 1,080 13,143
Mining 1,196 935 6,277
Educational services 955 649 6,248
Forestry, etc. & agriculture support 566 525 9,654
Information 558 440 3,041
Management of comp. & enterprises 301 65 -
Utilities 203 182 253
Unclassified 177 177 -
Total 78,451 68,030 336,328
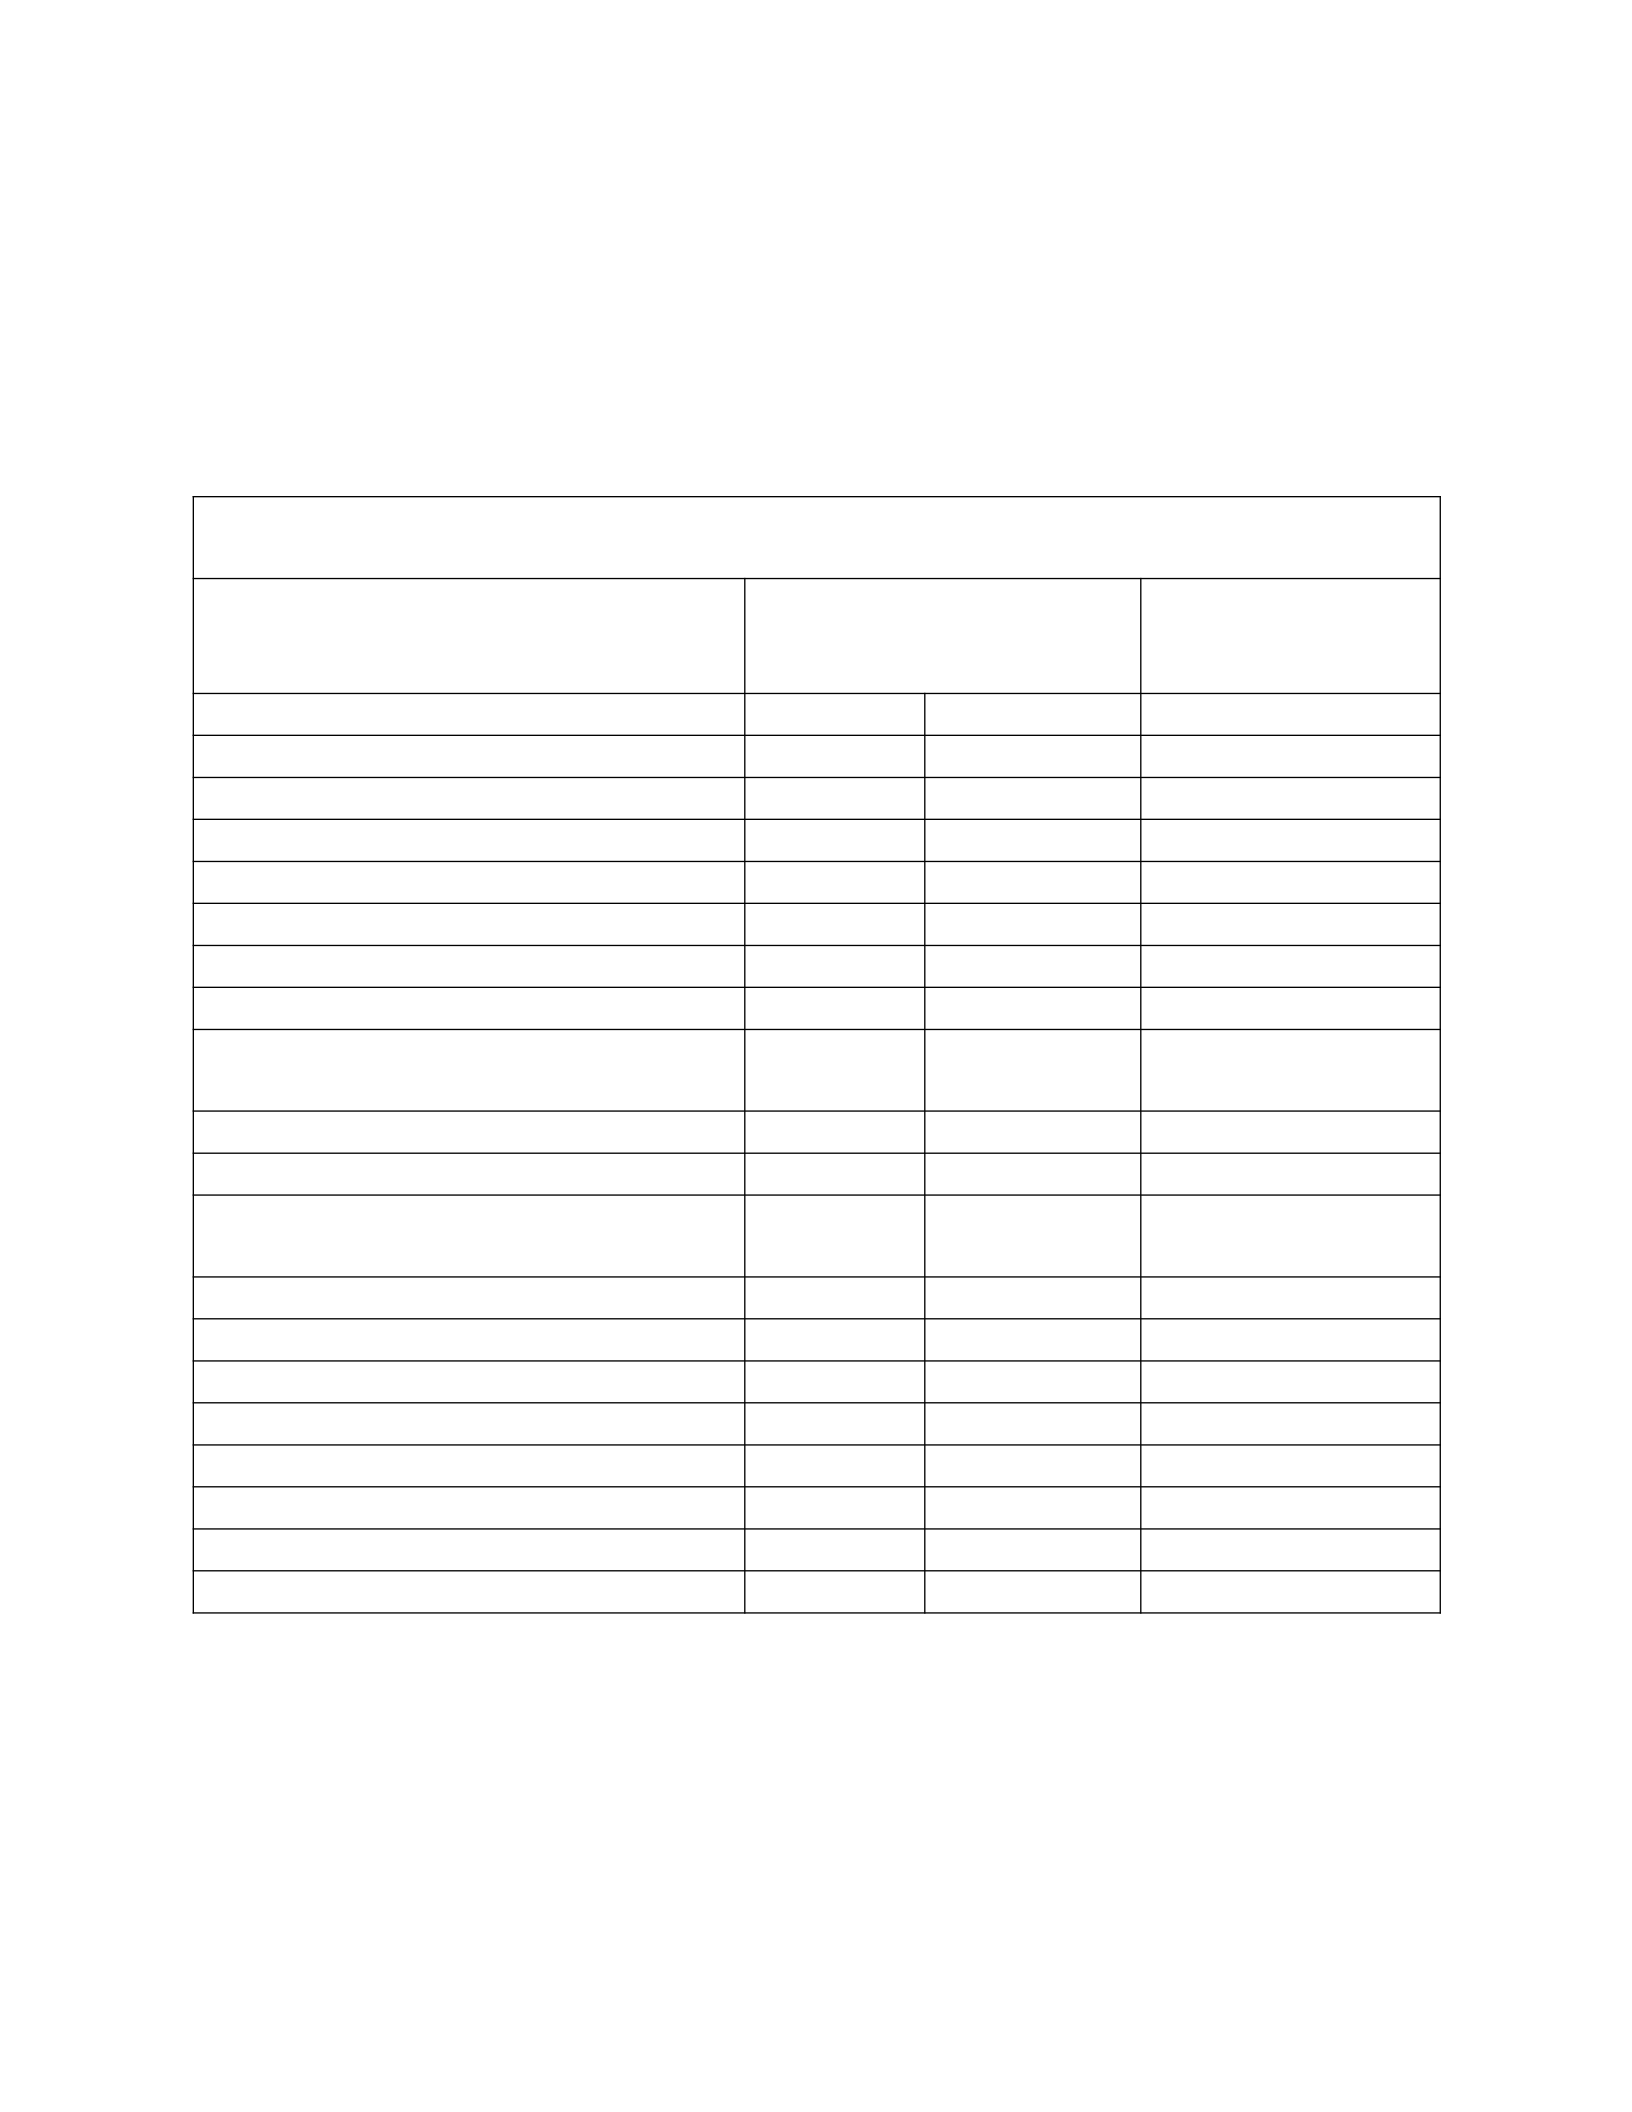
As noted in Table 2, the top four industries most populated by small businesses in
Louisiana are health care, social assistance, accommodation and food service, and retail trade. In
2012, 84.5% of the 4000 companies exporting goods were small firms. Louisiana export
revenues totaled more than $65 billion in 2014 (World Trade Center, New Orleans, 2015). The
small firms generated 34.8%, or $22.6 billion, of Louisiana's total export value (U.S. Small
Business Administration, 2014).
Table 2 Employment in Louisiana Small Firms by Industry and Firm Size, 2011 (Ranked by
Number of Small Employer Firms) Source: (U.S. Small Business Administration, 2014)
Employment in Louisiana by Industry and Firm Size, 2011
(ranked by small firm employment)
Industry Employment
Small Firms Total Firms
Small Firm Share
of Industry
Employment (%)
Health care & social assistance 156,785 282,985 55
Accommodation & food services 106,250 182,523 58
Retail trade 93,286 226,638 41
Construction 78,986 127,941 62
Professional, scientific, & tech. svcs. 66,888 88,171 76
Other services (except public admin.) 64,979 72,394 90
Manufacturing 50,963 125,820 41
Wholesale trade 46,893 75,009 63
Admin., sup., waste mgt., remed.
svcs. 46,211 100,856 46
Finance & insurance 34,913 66,255 53
Transportation & warehousing 30,771 65,367 47
Educational services
Real estate & rental & leasing 24,014 36,322 66
Mining 19,469 53,185 37
Arts, entertainment, & recreation 14,513 23,477 62
Information 7,340 23,722 31
Management of comp. & enterprises 6,173 20,468 30
Forestry, etc. & agriculture support 3,764 3,951 95
Utilities 2,454 - -
Unclassified - - -
Total 875,974 1,617,229 54
Similar to the national percentages, only 47.6% of Louisiana small businesses survive beyond
five years and roughly 37.4% remain in business more than 10 years (U.S. Small Business
Administration, 2014). Although small businesses are important to the Louisiana economy,

research on strategic planning in small businesses is largely absent from the literature. Instead,
research on strategic planning has focused primarily on larger organizations (Mazzarol, 2004).
Strategic Planning and Its Benefits
Given the risk of failure, small businesses are concerned with establishing a competitive
advantage that will ensure long-term survival (Galán, Monje, & Zúñiga-Vicente, 2009). Wankel
(2007) defined strategy as "an approach to reach corporate goals in order to be successful on a
long-term basis," and as "an attempt to prepare for all eventualities by abstraction and thus to
account for the complexity and the dynamics of the environment" (p. 74). Although businesses
cannot predict the future, they can prepare for it and align accordingly (Kraus, Reiche, &
Reschke, 2011). Strategic planning involves deducing how present developments will look in the
future, providing guiding principles and procedures for achieving specified goals. In other words,
strategic planning is an essential tool for strategic management, allowing businesses to stipulate
basic conditions for their future activities (Kraus et al., 2011).
Given its concern with competitive advantage, strategic planning focuses on establishing
long-term goals, developing plans to reach those goals, and distributing the resources needed to
achieve those goals (Stonehouse & Pemberton, 2002; O'Regan & Ghobadian, 2004; Wang et al.,
2007). As described by Kenichi Ohmae, "the purpose of strategic planning is to enable a business
to gain as efficiently as possible, a sustainable edge over its competitors" (as cited in O'Regan &
Ghobadian, 2004, p. 664; Wang et al., 2007). Businesses grow by acquiring new customers and
thus market share. Strategic planning spawns innovation by constantly seeking to develop new
services and products to bring to the market (Hill, 2011). A strategic business plan pairs the
objectives of a company with the needs of the marketplace. It not only defines company goals,
but also applies those goals to take advantage of available business opportunities by carefully

analyzing a particular company's strengths and weaknesses in meeting industry needs (Scott,
2011). Specifically, strategic planning helps a company identify a market need or customer
problem and create a product or service that efficiently and cost-effectively addresses the need or
solves the problem.
Planning also helps a company gain a clearer picture of the competition, allowing it to
develop strategies that take advantage of a competitor's weaknesses (Hill, 2011) and create
solutions that are significantly more beneficial to the customer than those provided by the
competition. Strategic planning compels a business to concentrate on specific areas in the
market, allowing for more effective business operations, and enables the business to learn as
much as it can about customer needs and potential opportunities in the market (Scott, 2011).
Correspondingly, a strategic plan includes extensive market research, exploration of industry
trends, and competitor analysis. A strategic plan shares many of the same components as a
business plan, such as an executive summary, marketing analysis, and financial statements, but is
more specific with respect to how the company will achieve its goals. For example, a strategic
business plan will attempt to identify a target market, reduce it to a manageable size, and
establish a strategy for acquiring that market (Scott, 2011).
Strategic planning is, fundamentally, brainstorming at its best. Since strategic planning
relies on creativity, its development involves intuition as much as management science. The more
small business owners understand their companies and industries, the better their strategic plans
will be (Pirraglia, 2011). As expressed by Drucker (1974), "it is necessary in strategic planning to
start separately with, 'What is our business?,' 'What will it be?,' and 'What should it be?'" (p.
122). Strategic planning demarcates where a company is heading (Pirraglia, 2011). The strategic
plan provides a road map for a business in which the management team fashions a longterm

vision for a larger, more profitable organization. In order to encourage company growth, strategic
planning involves envisioning potential activities that must be undertaken and potential expenses
that will have to be made (Hill, 2011). By using strategic planning, small business owners not
only become better positioned in the market, but also become experts in their respective
industries. The strategic plan also serves as an organizational tool, keeping the company on track
to meet its growth and financial objectives (Scott, 2011). Through an appraisal of past growth
and adjustments for further growth, strategic planning is critical for owners to understand the
trajectory of their companies (Scott, 2011).
In general, strategic planning is more common in small businesses that exhibit better
performance. Specifically, small businesses that engage in strategic planning are more likely to
achieve higher sales growth, returns on assets, margins on profit, and employee growth (Wang et
al., 2007). They tend to be more innovative, have more newly patented products, use new process
and management technologies, and achieve international growth (Wang et al., 2007). Most
significantly, small businesses that engage in strategic planning are less likely to fail
(Wang et al., 2007). Empirical studies have linked strategic planning to success (Kraus et al.,
2011), the implication being that strategic planning is essential for the success of a small business
(Pirraglia, 2011).
Perry (2001) found that in 152 failed firms and 152 non-failed firms, very little strategic
planning took place. However, some planning was performed in the non-failed businesses, which
suggests that the degree of planning may be related to whether the business fails. One limitation
of his (2001) study was that the independent variable—planning—and the phenomenon were
only weakly correlated.

Gibson, Cassar, and Wingham (2001) found that, of 2,956 firms for which data were
available, only 16.3% were described as regular planners, while 43.5% were non-planners. The
remaining 40.2% described themselves as irregular planners. Gibson et al. (2001) determined
that planners reported higher performance than non-planners, which indicated that planning and
performance are related.
In a study by Trow (1961), out of 51 companies in which planning occurred, 12 of 19
small firms (defined as up to 1000 employees) generated steady profits. The remaining
companies did not report on profitability. These findings suggest that firms that planned were
more profitable than those that did not.
Kraus et al. (2006) conducted a study of 290 firms with less than 50 employees. The
researchers used employee growth to measure firm performance. They found that a greater
degree of formalization, as indicated by the existence of a written strategic plan, was related to a
higher degree of performance.
The History and Components of a Strategic Plan
Modern strategic planning has taken a page from World War II, in which the U.S., its
allies, and its enemies developed strategies on the battlefield. Military commanders used these
strategies to help determine the strengths and weaknesses of each force. Using these processes,
they were able to observe the battlefield or environment and establish implementation plans and
command and control mechanisms (Nerone, 1997). The process of strategic planning was
successful because it allowed military strategists to follow proven approaches that literally had
been battle tested over centuries of documented warfare (Nerone, 1997). These strategies and the
eventual success of the allied forces were adopted by the private sector as military commanders
returned from Europe and entered the civilian workforce.

Early management theorists, including H. Igor Ansoff, Philip Selznick, George Steiner,
Peter Drucker, C.H. Hofer, D.E. Schendel, and Henry Mintzberg, are considered pioneers in the
field of strategic thinking (Nerone, 1997). Other notable theorist is Harvard Business School
professor Alfred Chandler, who “insisted that structure must follow strategy” (The Economist,
2007, para. 3), and Albert Humphrey, who created the SWOT Analysis, while working at the
Stanford Research Institute during the 1960’s (Stanford Research Institute Alumni Newsletter,
2005). A later theorist, Harvard Business School Professor Michael Porter, is considered to be the
founder of the modern field of strategy and regarded as the most influential thinker on
competitiveness and management (Harvard Business School, 2014).
H. Igor Ansoff devised one of the earliest strategic planning models, the Ansoff Matrix.
The Ansoff Matrix focused on options for business growth. Ansoff identified four types of
product-market strategies: market penetration, market development, product development
strategy, and diversification (Ansoff, 1957). According to Ansoff, a product-market strategy is a
“joint statement of a product line and the corresponding set of missions which the products are
designed to fulfill” (Ansoff, 1957, p. 114). The first of these, market penetration, he defined as an
“effort to increase company sales without departing from an original product-market strategy.
The company seeks to improve business performance either by increasing the volume of sales to
its present customers or by finding new customers for present products” (Ansoff, 1957, p. 114).
In contrast, market development is “[a] strategy in which the company attempts to adapt
its present product line (generally with some modification in the product characteristics) to new
missions” (Ansoff, 1957, p. 114). A product development strategy “develops products that have
new and different characteristics such as will improve the performance of the mission” (Ansoff,
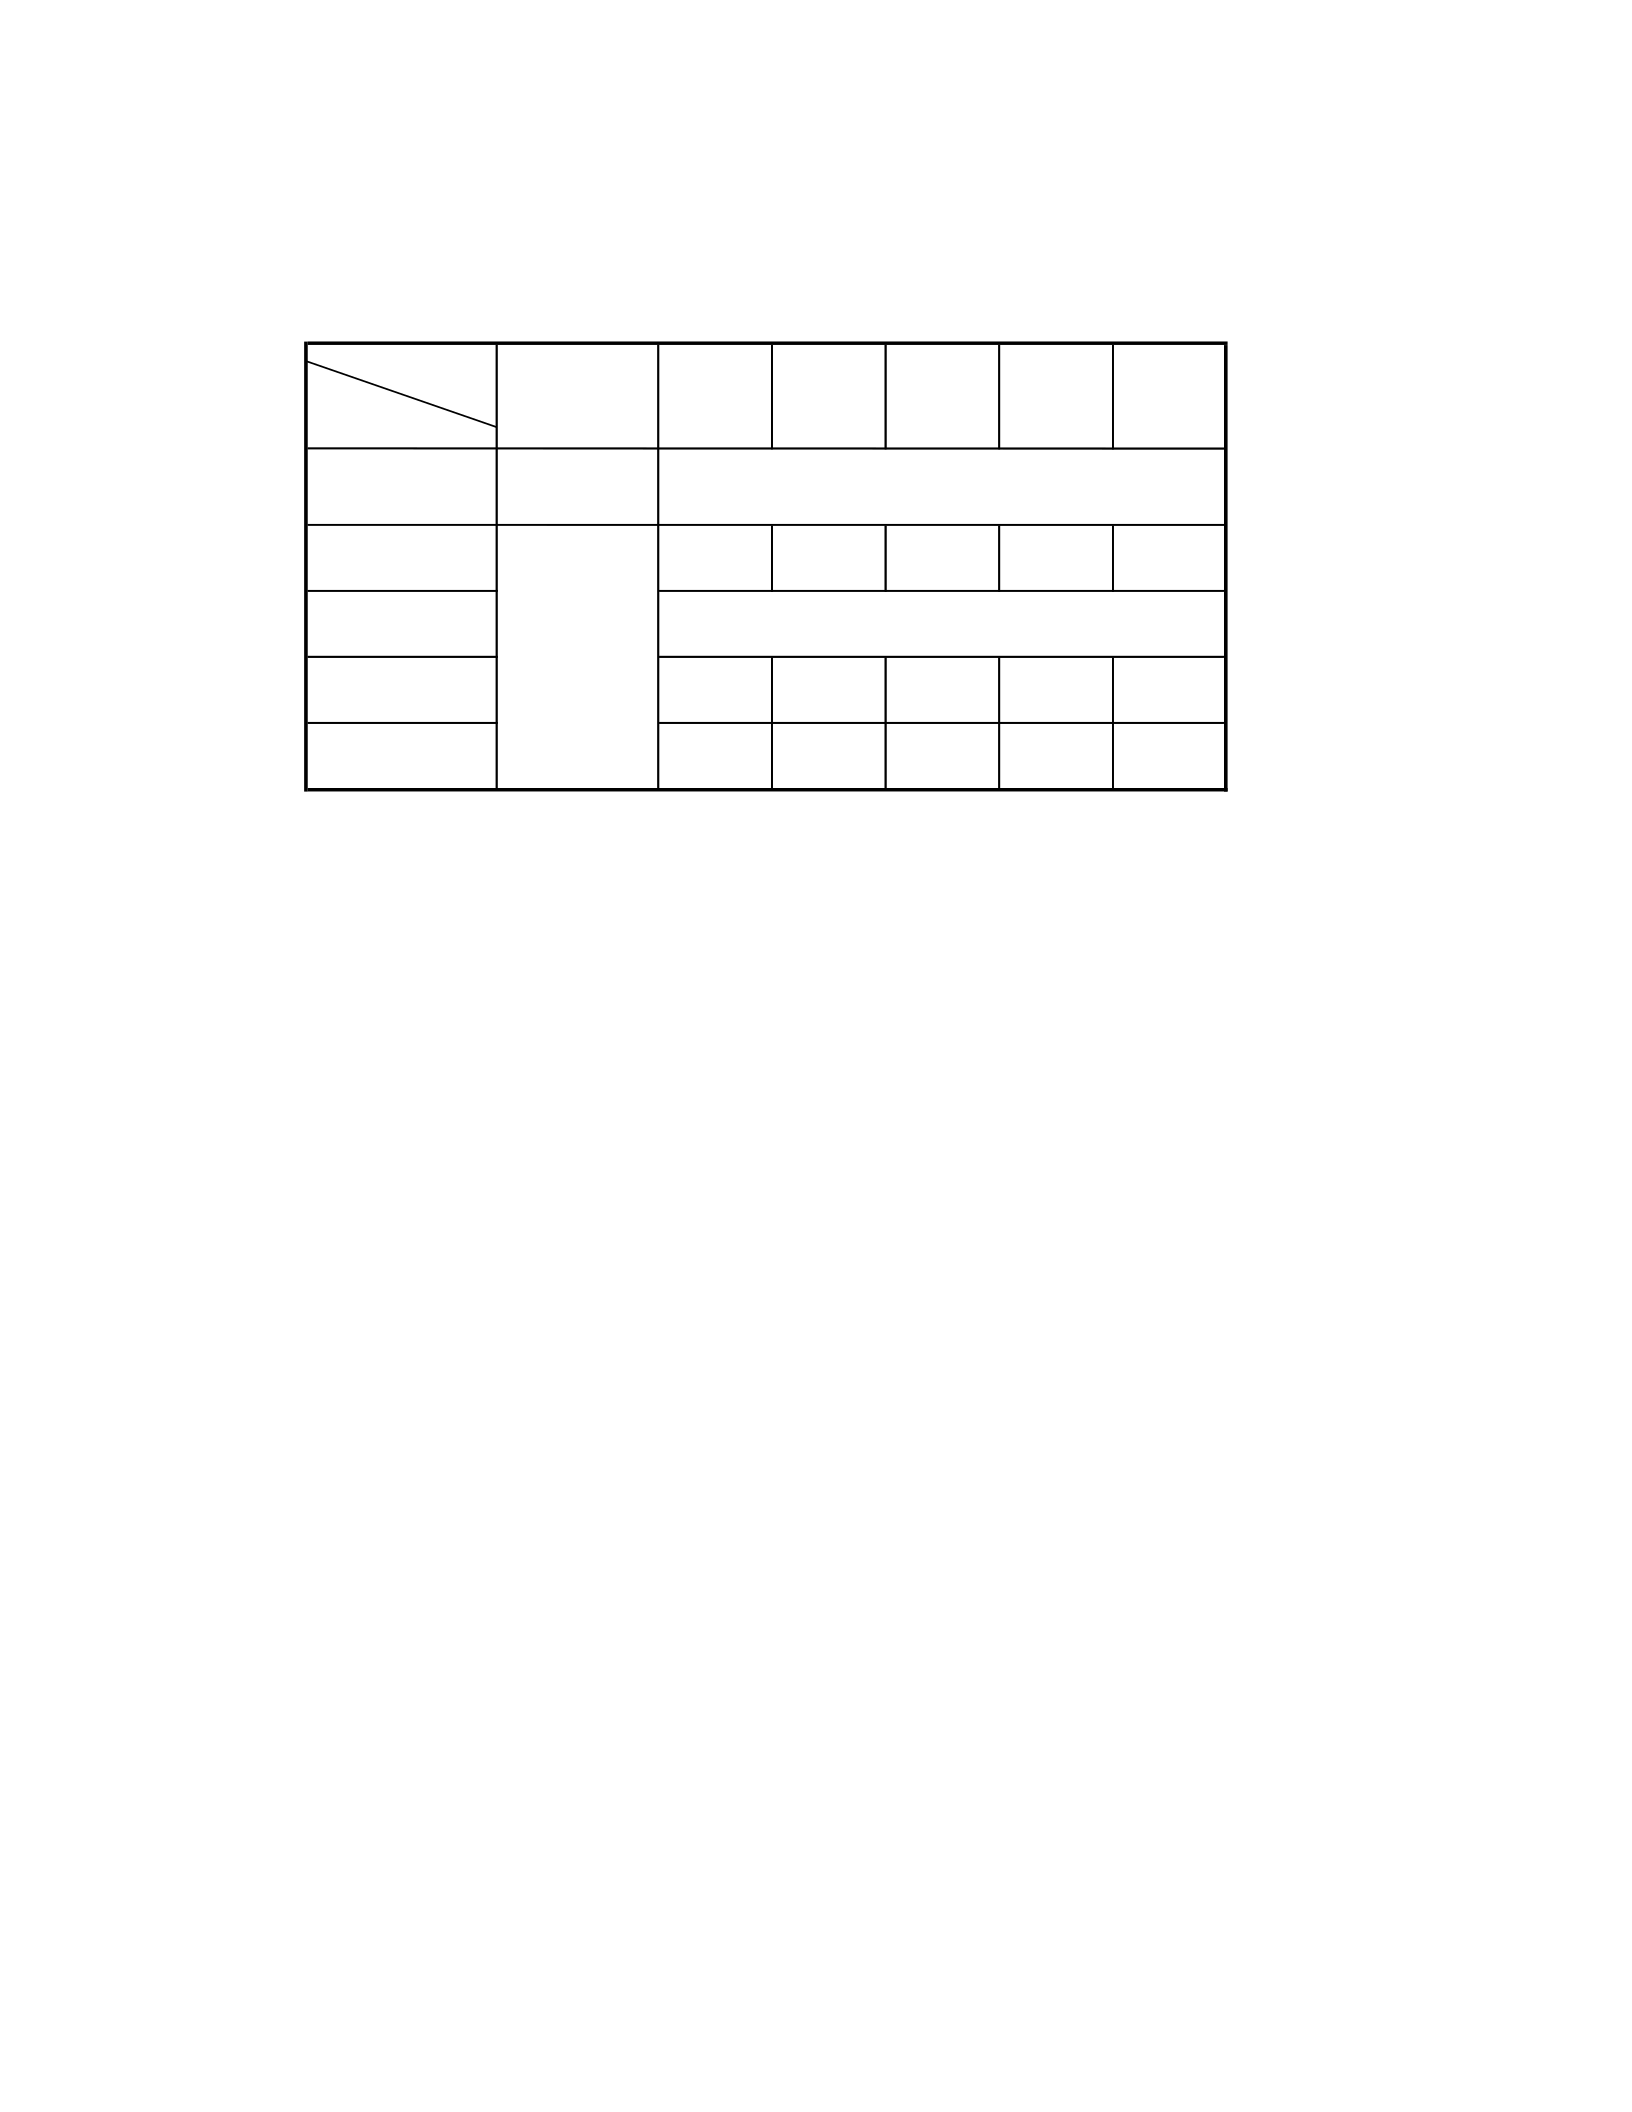
1957, p. 114). And diversification is “the final alternative. It calls for a simultaneous departure
from the present product line and the present market structure” (Ansoff, 1957, p. 114).
Figure 1 Product-Market Strategies for Business Growth Alternatives
Represents the product line and represents the corresponding set of missions. The pair of
and is a product-market strategy (Ansoff, 1957, p. 114).
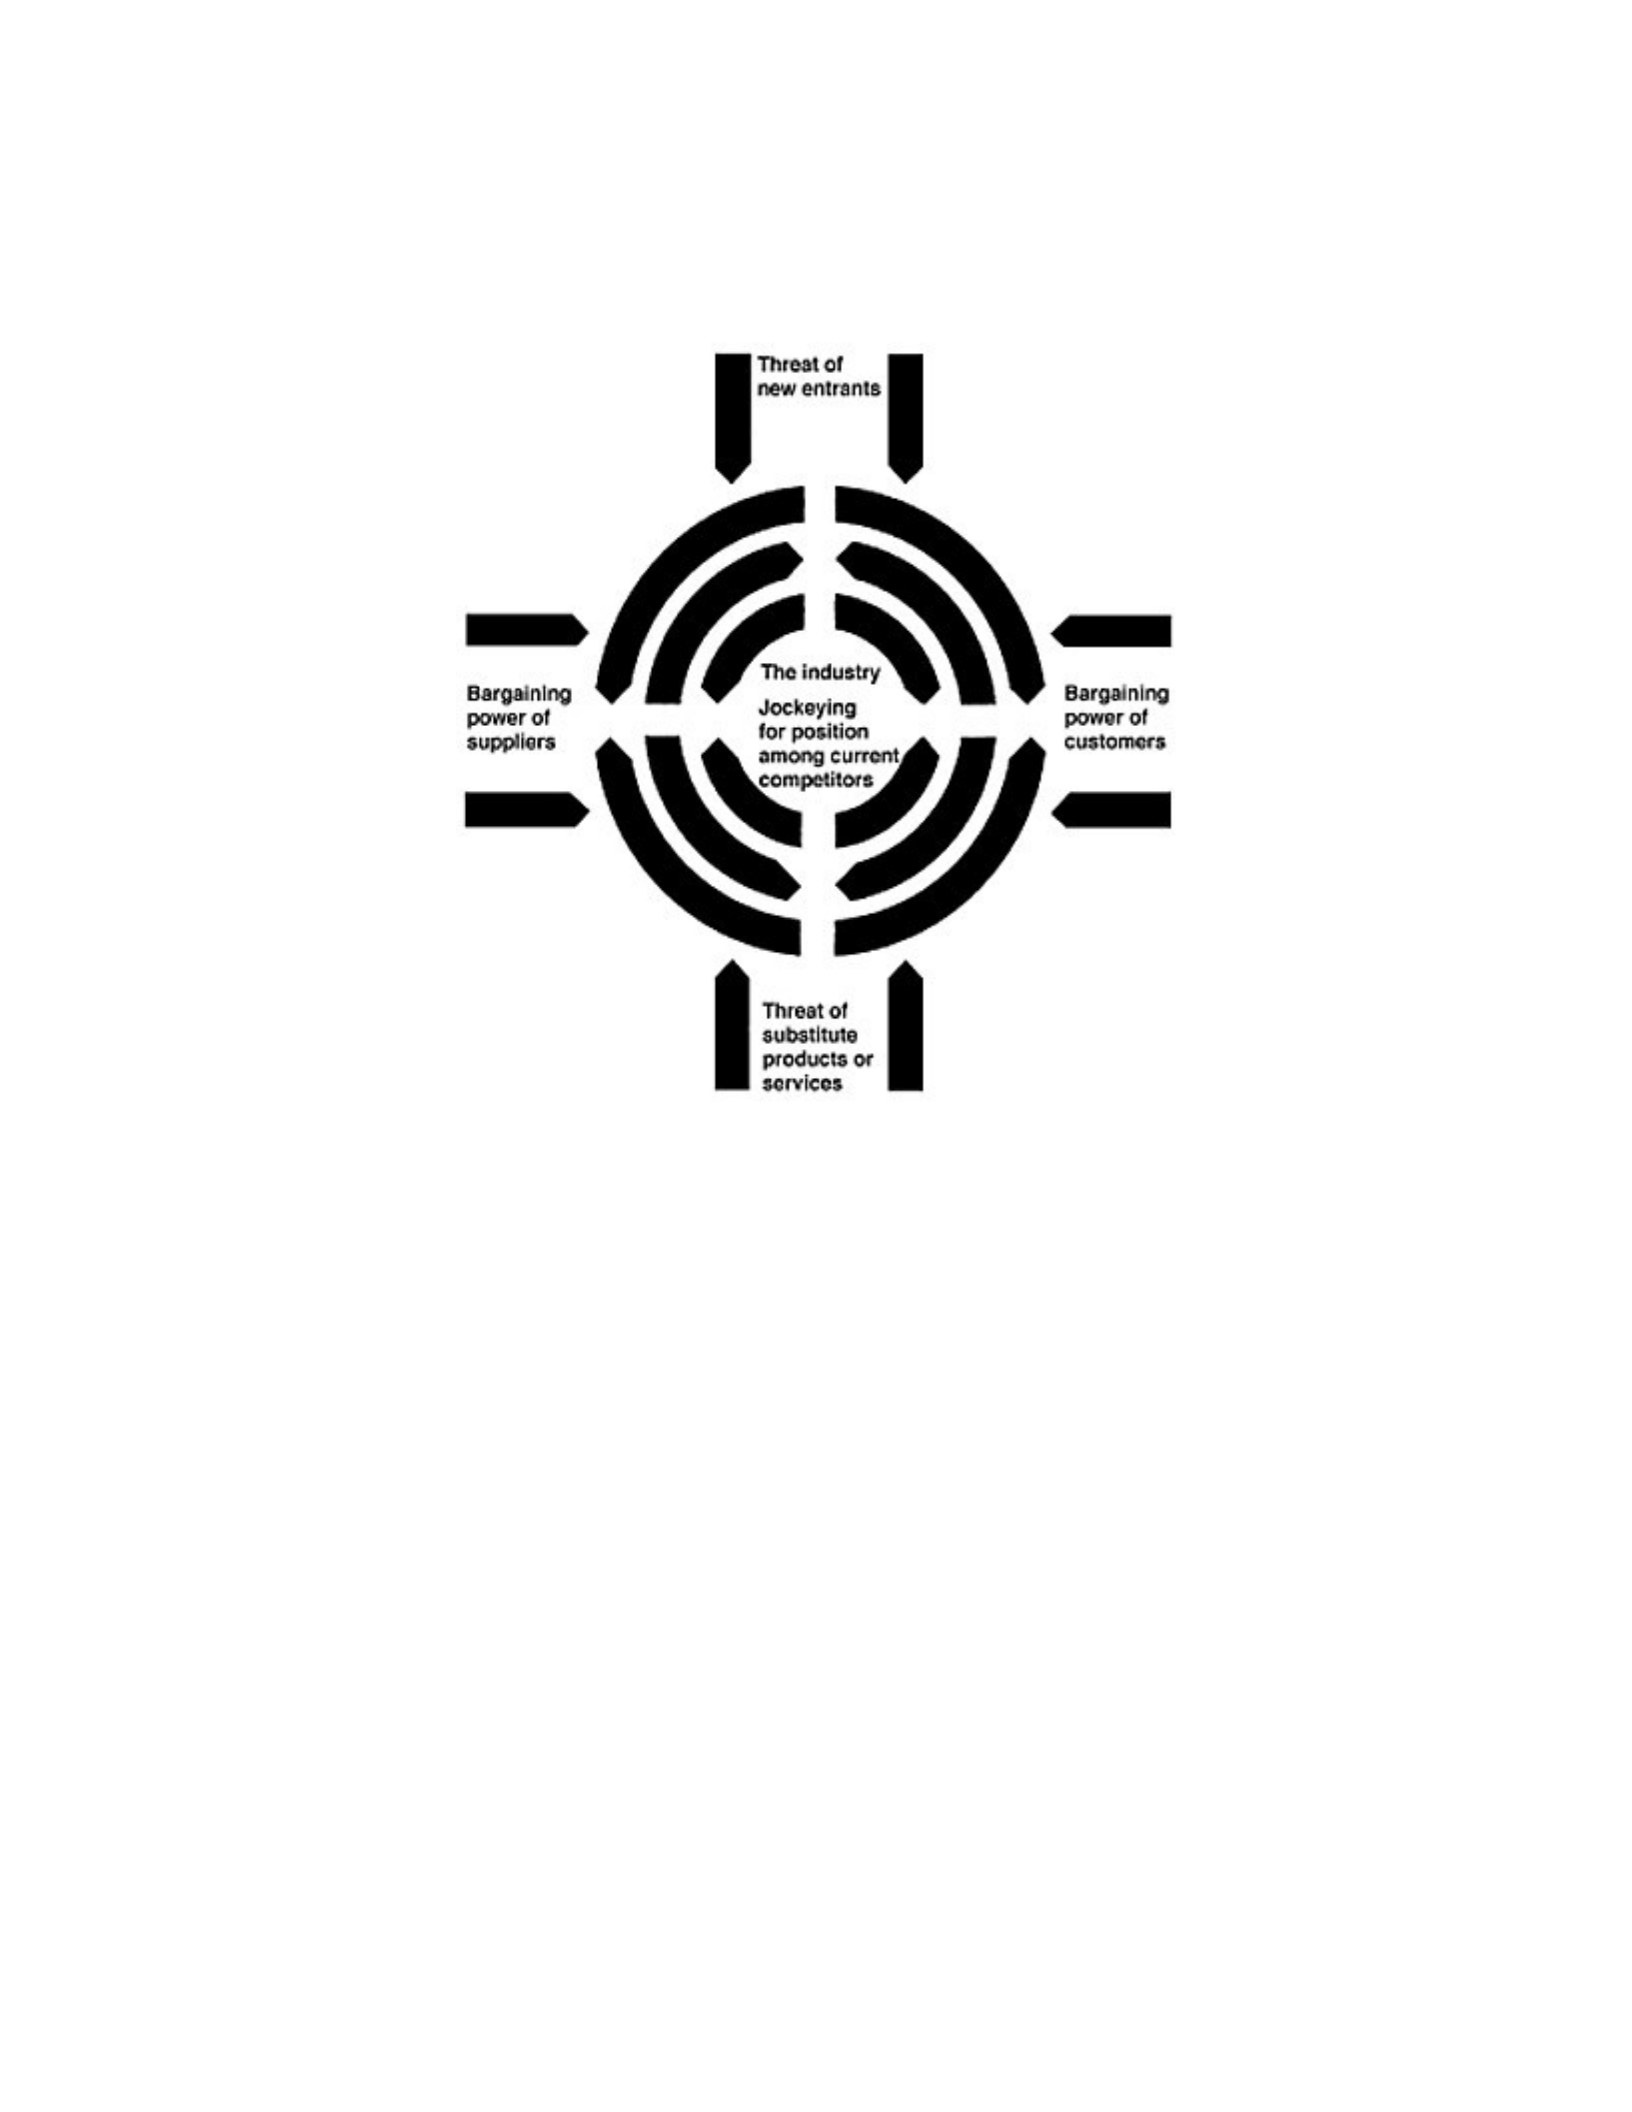
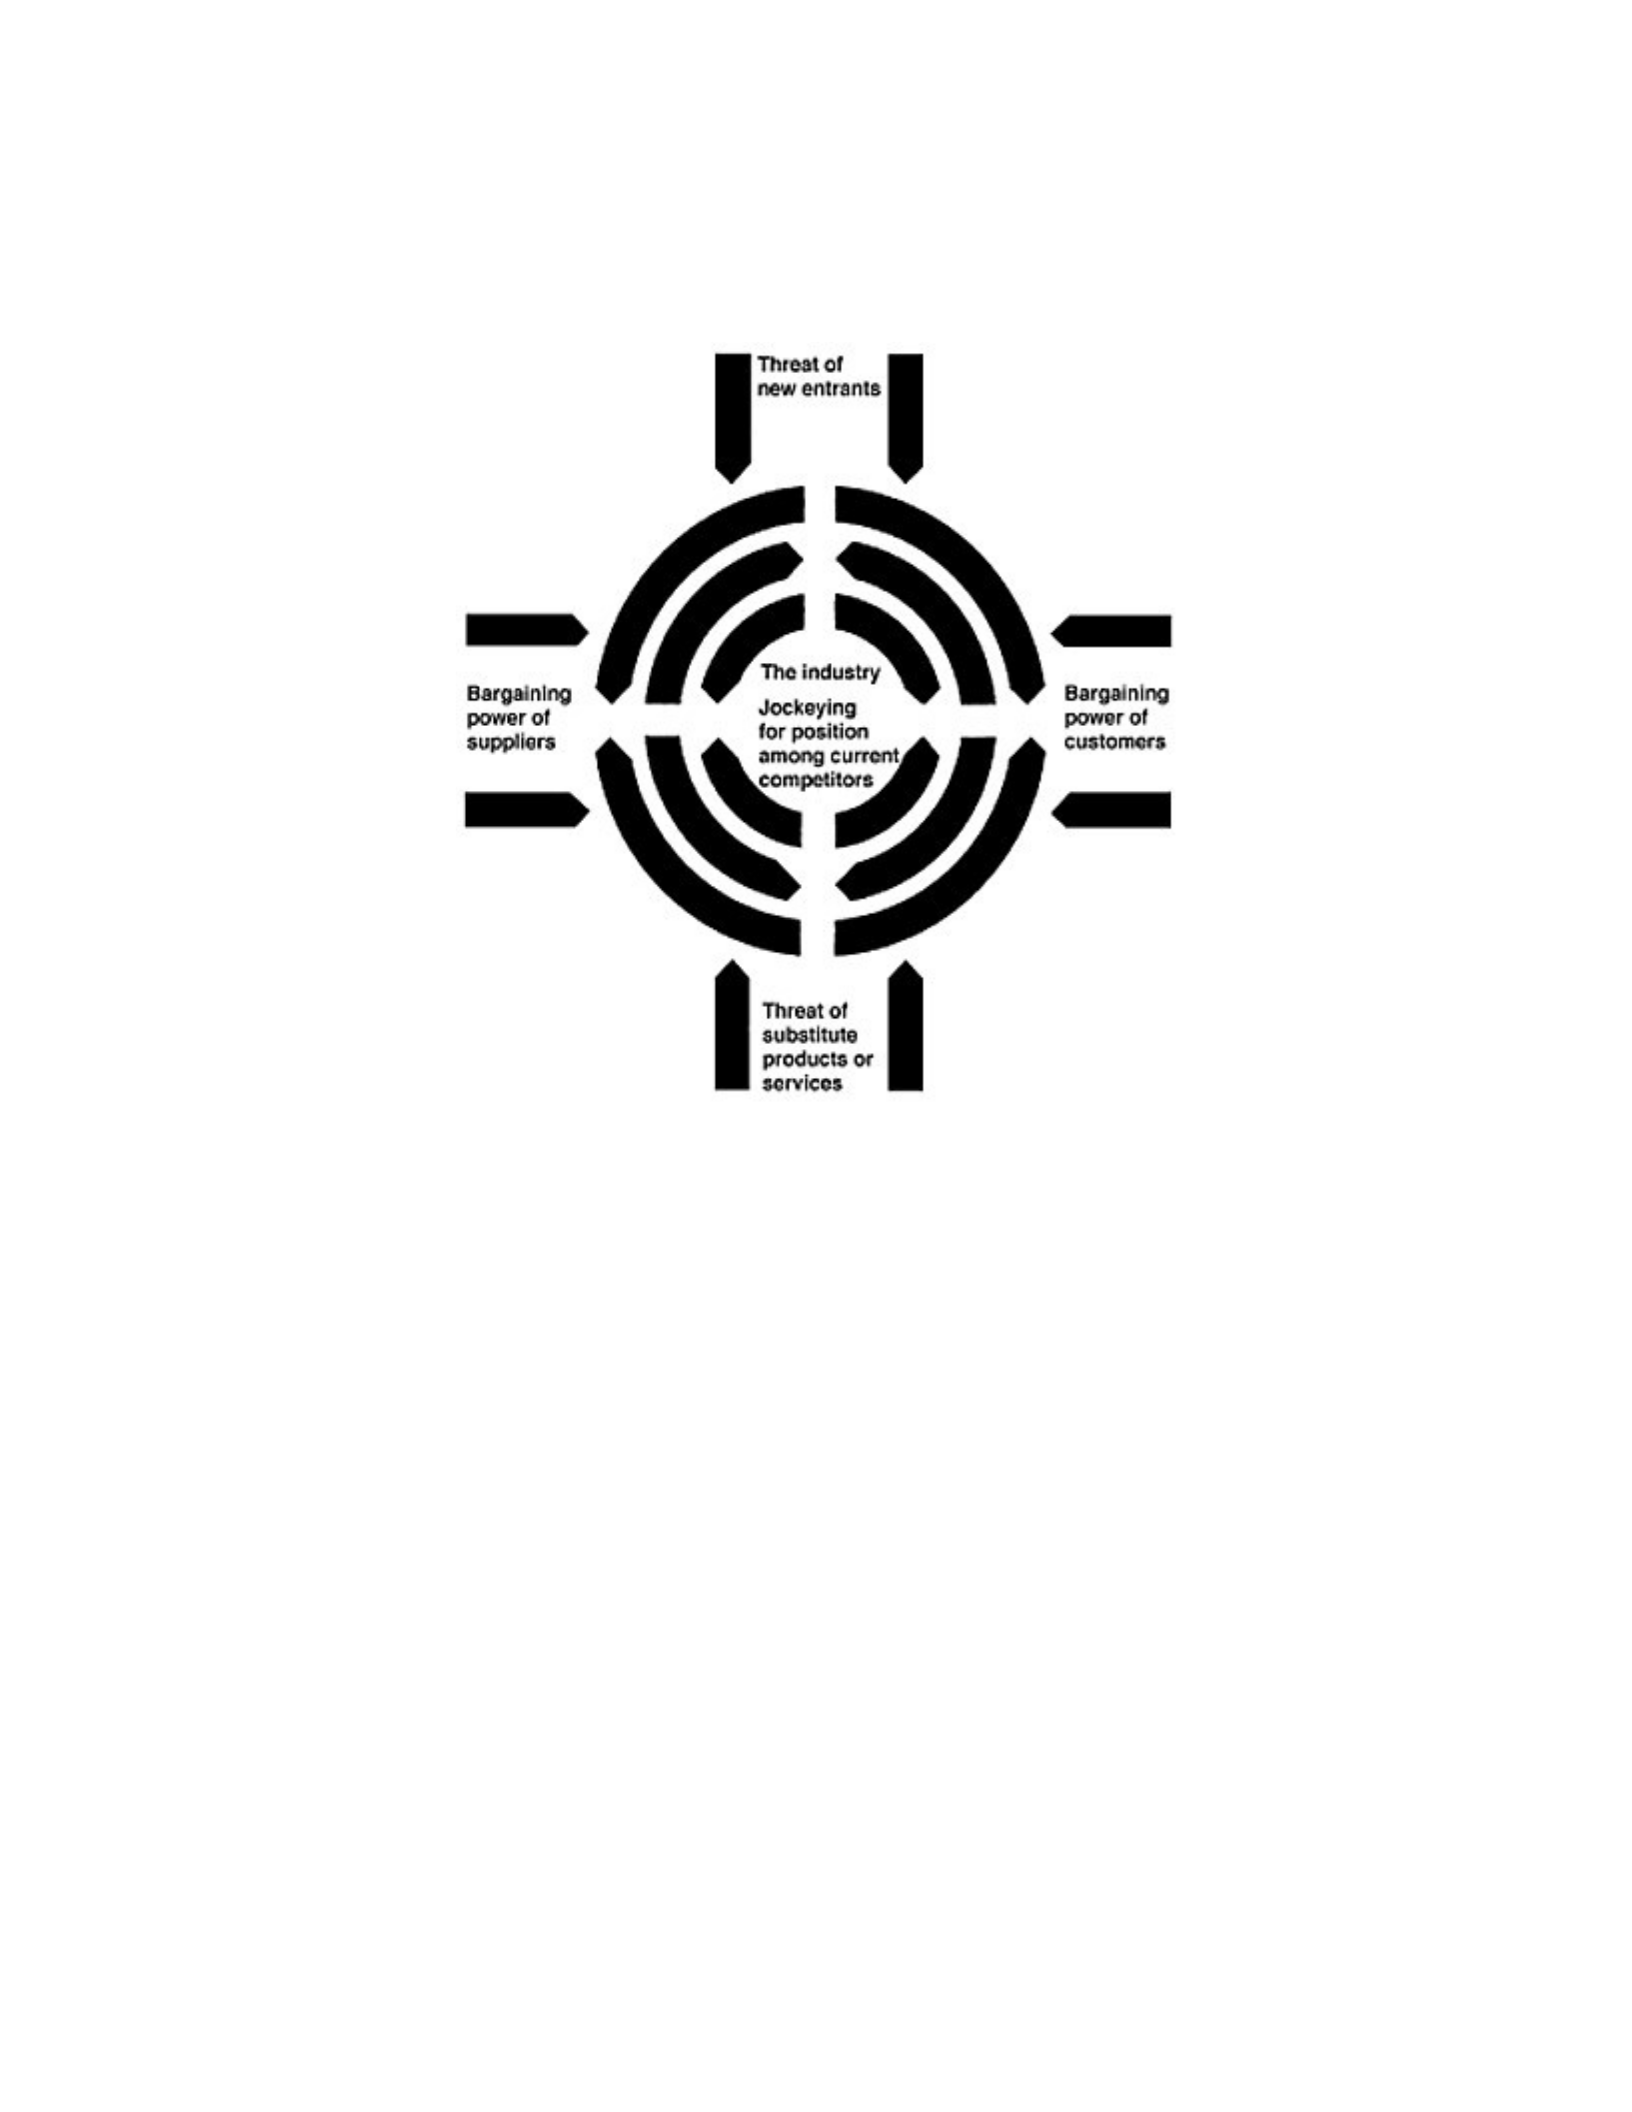
In 1979, The Harvard Business Review published Michael E. Porter’s “How Competitive
Forces Shape Strategy” (Harvard Business Review, 2008). In his article, Porter suggested that
there are five forces that shape an organization's strategy: the threats of new entrants, the
bargaining power of suppliers, the bargaining power of customers, and the threat of substitute
products and services. Porter argued that these four forces interact with the fifth force:
competitors jockeying for position within an industry (Harvard Business Review, 2008).
Porter theorized that the threats to new entrants consisted of six barriers: economies of
scale, product differentiation, capital requirements, cost disadvantages independent of size,
access to distribution channels, and government policy (Porter, 1979). Economies of scale force
market entrants to either enter the market on a large scale or consent to a cost handicap.
Economies of scale can act as barriers to distribution, financing, and utilization of the
organization’s sales force (Porter, 1979). The second barrier, product differentiation, forces
market entrants to spend large amounts of money on customer service and advertising in order to
Markets
Product Line
0
MARKET
Penetration
1
2
3
..
Market Development
DIVERSIFICATION
PRODUCT
DEVELOPMENT
01234..

demonstrate product differentiation and generate a brand identity (Porter, 1979). Capital
requirements force market entrants to spend large sums of non-recoverable funds on facilities,
customer credit, inventory, and research and development, in addition to advertisements. Due to
these constraints, capital requirements limit the pool of potential entrants (Porter, 1979). Cost
disadvantages force market entrants to realize that rivals who are already entrenched in the
market possess the inherent advantage of time. Market entrants must deal with learning and
experience curves, proprietary technologies, access to pre-inflation cost of materials, and
favorable locations (Porter, 1979). The fifth barrier, access to distribution channels, forces market
entrants to acquire channels for distributing products and services. Thus, selling efforts must
attempt to displace other rivals. If wholesale channels are limited and barriers are high, a market
entrant must create its own distribution channels (Porter, 1979). Finally, government policy can
limit market entrants to industries by mandating licensing requirements, regulatory requirements,
environmental standards, or access to raw materials (Porter, 1979). Porter states,
A company’s choice of suppliers to buy from or buyer groups to sell to should be viewed
as a crucial strategic decision. A company can improve its strategic posture by finding
suppliers or buyers who possess the least power to influence it adversely. (Porter, 1979,
p. 141)
Porter theorized that suppliers can exercise bargaining forces on market participants by
either reducing or increasing the quality or prices of goods and services. Thus, suppliers can
extract profits from a market and its participants (1979). For example, Porter argues that a group
of suppliers is powerful if it is more concentrated in comparison with the industry that it is
selling to (Porter, 1979). Additionally, suppliers are powerful if their products are highly
differentiated and unique, or if switching costs have developed. Switching costs can occur when
a buyer’s product is highly specified and production lines are coupled with the supplier's
manufacturing facilities. Switching costs then become fixed even when a buyer changes

suppliers (Porter, 1979). Furthermore, if a supplier does not have to compete with other products,
the supplier essentially has no reason to reduce prices or increase the quality of its product
(Porter, 1979). Moreover, if the supplier possesses the ability to integrate further into the market,
the buyer’s ability to improve purchasing terms is highly limited (Porter, 1979). Lastly, if the
buyer is simply not significant to the supplier, the supplier and buyers' interests are not aligned,
and thus the supplier has no real incentive to work with the buyer (Porter, 1979).
Porter theorized that buyers can exercise bargaining forces on market participants if they
purchase in large quantities. This approach would require that capacity remain high consistently,
which would be particularly difficult if fixed costs within the market were high (Porter, 1979).
Additionally, buyers can exercise their will if products are standard or not particularly
differentiated. In this case, buyers are not incentivized to purchase from any one specific
company but instead could pit companies against one another in an attempt to lower market
prices (Porter, 1979). Furthermore, if a particular component for a product represents a large part
of overall costs, buyers are incentivized to shop for more favorable pricing (Porter, 1979). And if
a buyer earns low profits, then the buyer would be incentivized to lower its purchasing costs.
Should a buyer earn higher profits, it is generally less sensitive to prices, assuming that the price
does not signify a large percentage of overall costs (Porter, 1979). Additionally, if the quality of
the product is of significant importance to the buyer, the buyer is typically less price sensitive
(Porter, 1979). In his article, Porter uses an example from the oil field industry, where equipment
failure can lead to huge losses (1979). Furthermore, when the industry’s product can pay for
itself over time, such as accounting or legal services where errors can be costly, the buyer is less
likely to be price sensitive (1979). Lastly, buyers can opt to produce their own materials, thus
removing the need for purchasing from a third party manufacturer. This threat provides leverage
to the buyer (Porter, 1979).
Figure 2 Porter’s Original 1979 Five Force Model, Source: (Porter, 1979).
Albert S. Humphrey created what was eventually dubbed the SWOT Analysis while
working at the Stanford Research Institute during the 1960’s. His research was funded by various
Fortune 500 companies who wished to identify deficiencies in corporate planning and create a
system to manage change. (Stanford Research Institute Newsletter, 2005).
Though Humphrey’s key finding were never published, as they were deemed too
controversial, he wrote them in the December 2005 Newsletter of the Stanford Research
Institutes Alumni Newsletter. They are as follows:
1) A business can be divided into two parts: The base business plus the development
business. The development business turns over every 5 to 7 years, 2) All people
measure what they get from their work and divide it by what they give to the work
and this reward/effort ratio is compared to others. If it perceived as too low, the
person slows down, 3) The introduction of a corporate planner upsets the sense of fair

play at senior level, making the job of the corporate planner impossible, 4) The gap
between what could
Absence of Strategic Planning and Failure of Small Businesses
Early research on the failure of small businesses identified the absence of strategic planning as a
primary cause (Ibrahim & Goodwin, 1985; Mayer & Goldstein, 1961; Mintzberg, 1979;
Crawford & Lefebvre, 1984; Crawford & Ibrahim, 1985; Nerone, 1997). Excessive optimism, a
failure to monitor results, and the absence of balanced growth also were identified as key factors
(Mayer & Goldstein, 1961; Mintzberg, 1979; Crawford & Lefebvre, 1984; Crawford & Ibrahim,
1985). In their 1982 study, Sexton and Van Auken found that small business owners and manager
often thought of strategic planning, but rarely took action. Several other studies determined that
not only was systematic strategic planning largely absent in small businesses, but also that what
little did take place was reactive, incremental, disorganized, sporadic, and inadequate (Still,
1974; Cooper, 1977; Crawford, R. L., & Ibrahim, A. B., 1985). As Nerone observed, "Most
entrepreneurs [small business owners] are doing their strategy on the back of a napkin, as they
sweat out making the Friday payroll” (Nerone, 1997, p. 9).
In a more recent article, Kraus, Harms, and Schwarz argue that strategic planning does
occur in small businesses, but that it is often performed intuitively without the use of planning
instruments (2006). In practice, small businesses plan in the short term, rather than focusing on
long-term objectives, and are typically reactive rather than proactive (Wang, Walker, &
Redmond, 2007). Small businesses that claim to plan for the future typically develop those plans
ad hoc and rarely write them down formally. Furthermore, the plans provide little guidance for
measuring or analyzing the performance of the small business (Wang et al., 2007). The literature
also indicates that strategic planning in small businesses is unstructured, informal, and irregular,
lacking in information (Gibb & Scott, 1985; Flavel, 1991; Balasundaram, 2009).

Correspondingly, small businesses have been described as shortsighted and strategically
narrowminded (Wang et al., 2007).
Benefits of Strategic Planning
This absence of strategic planning certainly counters much of the literature, which
indicates that small businesses should plan for the long term in order to effectively compete
(Wang et al., 2007). Small businesses that disregard strategic planning risk, at a minimum,
growth and performance and, at worst, their very survival (Wang et al., 2007). Understandably,
small business success is not determined by strategic planning alone; however, there are more
benefits to planning versus not planning (Wang et al., 2007).
Problem Statement
Strategic planning has been studied since the 1950's, but research has focused primarily
on larger organizations (Mazzarol, 2004). Research on strategic planning in small businesses is
still in the early stages (Kraus, Reiche, & Reschke, 2007). Furthermore, although small
businesses are vital to the Louisiana economy, little, if any, research on strategic planning in
Louisiana small businesses has been undertaken. While the existing literature suggests that
strategic planning is positively related to the performance of small businesses (Kraus, Harms, &
Schwarz, 2006; Balasundaram, 2009), most of them do not plan, for as yet unknown reasons
(Wang et al., 2007). Thus, Robinson and Pearce argue that “Research needs to provide specific
reasons why planning is not practiced in firms” (Robinson & Pearce, 1984, p. 135).
Understanding why small businesses do not engage in strategic planning, and how that omission
affects small business mortality, would enable consultants to better serve the small business
sector and public officials to improve public policy.

Purpose of Study
The primary purpose of this study is to determine the influence of selected factors that
influence small business owners’ perceived obstacles to strategic planning in Louisiana small
businesses.
Research Objectives
The dependent variable of this study is the propensity of Louisiana small businesses to
strategically plan. The independent variable of this study is Louisiana small business owners’
perceived obstacles to strategic planning.
The following specific objectives were formulated to guide this research study:
6. To describe small businesses in Louisiana on the following characteristics:
a) Years the organization has been in business;
b) Industry in which the small business is positioned;
c) Current number of full time and part time employees on the organization's
payroll;
d) Structure of the organization i.e. Limited Liability Corporation,
Subchapter S
Corporation, Partnership, etc.:
e) Existence of a written long term plan.
7. To describe small businesses in Louisiana on the perceived degree to which the
organization conducts strategic planning.
8. To describe small businesses in Louisiana perception regarding the following perceived
obstacles to strategic planning:
a) The perceived quality of the organization’s employees;

b) The perceived degree to which the organization’s leadership has
knowledge of the
planning process;
c) The perceived available time the organization has to strategically plan.
9. To determine if a relationship exists between Louisiana small business owners' perceived
obstacles to strategic planning and the following variables:
a) Industry in which the small business is positioned in;
b) Structure of the organization i.e. Limited Liability Corporation,
Subchapter S
Corporation, Partnership, etc.;
c) Years the organization has been in business;
d) Current number of full time and part time employees on the organization's
payroll;
e) The perceived degree to which the organization conducts strategic
planning;
f) Possession of a written long term plan.
10. To determine if a model exists explaining a significant portion of the variance in
Louisiana small business owners' perceived degree to which the small business conducts
strategic planning using the following characteristics:
a) Years the organization has been in business;
b) Industry in which the small business is positioned;
c) Current number of full time and part time employees on the organization's
payroll;
d) Structure of the organization i.e. Limited Liability Corporation,
Subchapter S
Corporation, Partnership, etc.;

e) The perceived degree to which the organization conducts strategic
planning;
f) The perceived quality of the organization’s employees;
g) The perceived degree to which the organization’s leadership has
knowledge of the
planning process;
h) The perceived available time the organization has to strategically plan;
i) Possession of a written long term plan.
Summary
Small businesses play an important role in the Louisiana economy. Prior research on
strategic planning has focused primarily on large businesses (Mazzarol, 2004); however, little
literature exists that focuses on Louisiana small business strategic planning. While the existing
literature implies that strategic planning is positively related to the performance of small
businesses (Kraus, Harms, & Schwarz, 2006; Balasundaram, 2009), most of them do not plan,
for as yet unknown reasons (Wang et al., 2007). Therefore, this study will explore the obstacles
to strategic planning as perceived by Louisiana small business owners. The results of this study
will benefit small business owners when employing strategic planning within their organizations,
consultants when advising small businesses during the strategic planning process, and public
officials when establishing public policy affecting small businesses.

CHAPTER II: REVIEW OF LITERATURE
Given how important small businesses are to the U.S. economy, many studies have
focused on what causes them to fail. The principal cause of small business failure has been
identified as a lack of strategic planning. Other key factors contributing to small business failures
are excessive optimism, lack of balanced growth, and failure to monitor results (Ibrahim &
Goodwin, 1985; Mayer & Goldstein, 1961; Mintzberg, 1979; Crawford & Lefebvre, 1984;
Crawford & Ibrahim, 1985).
The literature suggests that small businesses owners tend to not engage in systematic
strategic planning (Perry, 2001), even though they often consider it (Sexton & Van Auken,
1982). Furthermore, any planning that small businesses do undertake tends to be reactive,
unstructured, incremental, and sporadic (Still, 1974; Cooper, 1977; Crawford & Ibrahim, 1985).
Small business owners tend to focus on immediate rather than long-term objectives, planning
for the future in an ad hoc manner, and fail to make provisions for measuring performance
(Wang et al., 2007). The approach of small businesses to strategic planning is therefore
counterintuitive: although the literature highlights the benefits of strategic planning, most small
businesses do not plan for reasons that are not fully understood (Wang et al.,
2007).
U.S. Small Businesses
Small businesses play a vital role in the U.S. economy. Collectively, they are the largest
employer, the largest importer, and the largest exporter in the country (Office of the United States
Trade Representative, 2009). Small businesses, which are defined as those employing fewer than
500 individuals, comprise 99.9% of firms in the U.S. Furthermore, businesses employing fewer
than 20 individuals comprise 89.7% of U.S. small businesses. In 2008, small businesses

generated 46% of the private non-farm Gross Domestic Product (GDP) (Small Business Council,
2014).
Small businesses foster the growth of local economies by providing opportunities for
employment to people who otherwise may not be employable by larger organizations (Brown,
2011). During the 18-year period from 1992 to 2010, small business outpaced larger firms in job
creation 75% of the time (Graves, 2013). In general, small businesses generate 60-80% of all
new employment in the U.S. Small businesses also generate 16.5 times more patents per
employee when compared to larger firms (Graves, 2013)
Small businesses traditionally dominate industries such as construction and retail, as well
as form a crucial link in the supply chain for large-scale and capital-intensive manufacturing
industries such as defense, mining, automotive, and marine (Abdullah & bin Baker, 2000;
Robinson & Pearce, 1984; Wang et al., 2007; Wang, Rowe, & Cripps, 2006). Furthermore, small
businesses provide a competitive balance to industries that would otherwise be dominated solely
by larger firms (Wang et al., 2007).
However, despite the critical importance of small businesses in the U.S., only
approximately half survive past five years and roughly a third last for 10 years (SBA
Frequently Asked Questions, 2012).
Louisiana Small Businesses
Small businesses play a vital role in the Louisiana economy as well. In aggregate, they
account for 97.3% of employers in Louisiana and employ more than half, 54.5%, of the state's
private sector workforce. Businesses with 500 or more employees comprise the remaining 45.5%
(U.S. Small Business Administration, 2014). Federal, state, and local governments, as well as the
U.S. Postal Service, employ 321,569 public sector workers, or 6.95% of Louisiana’s population
(Molla, 2014). As noted in Table 1, the Small Business Administration (2014) reported that
414,779 small businesses existed in the state of Louisiana in 2011. Of those businesses, only
78,451 had employees; 68,030 employed less than 20 individuals. The majority of the small
businesses, 336,328 or 80.7%, did not have employees. Overall, Louisiana small businesses
employ 875,974 individuals (U.S. Small Business Administration, 2014). (See Table 1)
Table 1 The Number of Louisiana Small Firms by Industry, 2011 (Ranked by Number Of Small
Employer Firms) Source: (U.S. Small Business Administration, 2014)
Number of Louisiana Small Firms by Industry, 2011 (ranked
by number of small employer firms)
Industry
Employer Firms
with
1-499 Employees
Employer Firms
with
1-19 Employees
Nonemployer
Firms
Professional, scientific, and tech svcs. 10,621 9,853 35,489
Retail trade 10,398 9,302 23,229
Health care & social assistance 9,646 8,060 30,124
Other services (except public admin.) 8,719 8,005 64,016
Construction 7,867 6,984 38,305
Accommodatin & food services 6,469 4,878 7,513
Wholesale trade 3,845 3,012 4,206
Admin., supp., waste mgt., remed.Svcs. 3,754 3,186 36,768
Finance & insurance 3,689 3,334 9,127
Real estate & renal & leasing 3,371 3,103 29,506
Transportation & warehousing 2,733 2,310 15,178
Manufacturing 2,706 2,027 4,251
Arts, entertainment, & recreation 1,272 1,080 13,143
Mining 1,196 935 6,277
Educational services 955 649 6,248
Forestry, etc. & agriculture support 566 525 9,654
Information 558 440 3,041
Management of comp. & enterprises 301 65 -
Utilities 203 182 253
Unclassified 177 177 -
Total 78,451 68,030 336,328
As noted in Table 2, the top four industries most populated by small businesses in
Louisiana are health care, social assistance, accommodation and food service, and retail trade. In
2012, 84.5% of the 4000 companies exporting goods were small firms. Louisiana export
revenues totaled more than $65 billion in 2014 (World Trade Center, New Orleans, 2015). The
small firms generated 34.8%, or $22.6 billion, of Louisiana's total export value (U.S. Small
Business Administration, 2014).
Table 2 Employment in Louisiana Small Firms by Industry and Firm Size, 2011 (Ranked by
Number of Small Employer Firms) Source: (U.S. Small Business Administration, 2014)
Employment in Louisiana by Industry and Firm Size, 2011
(ranked by small firm employment)
Industry Employment
Small Firms Total Firms
Small Firm Share
of Industry
Employment (%)
Health care & social assistance 156,785 282,985 55
Accommodation & food services 106,250 182,523 58
Retail trade 93,286 226,638 41
Construction 78,986 127,941 62
Professional, scientific, & tech. svcs. 66,888 88,171 76
Other services (except public admin.) 64,979 72,394 90
Manufacturing 50,963 125,820 41
Wholesale trade 46,893 75,009 63
Admin., sup., waste mgt., remed.
svcs. 46,211 100,856 46
Finance & insurance 34,913 66,255 53
Transportation & warehousing 30,771 65,367 47
Educational services
Real estate & rental & leasing 24,014 36,322 66
Mining 19,469 53,185 37
Arts, entertainment, & recreation 14,513 23,477 62
Information 7,340 23,722 31
Management of comp. & enterprises 6,173 20,468 30
Forestry, etc. & agriculture support 3,764 3,951 95
Utilities 2,454 - -
Unclassified - - -
Total 875,974 1,617,229 54
Similar to the national percentages, only 47.6% of Louisiana small businesses survive beyond
five years and roughly 37.4% remain in business more than 10 years (U.S. Small Business
Administration, 2014). Although small businesses are important to the Louisiana economy,

research on strategic planning in small businesses is largely absent from the literature. Instead,
research on strategic planning has focused primarily on larger organizations (Mazzarol, 2004).
Strategic Planning and Its Benefits
Given the risk of failure, small businesses are concerned with establishing a competitive
advantage that will ensure long-term survival (Galán, Monje, & Zúñiga-Vicente, 2009). Wankel
(2007) defined strategy as "an approach to reach corporate goals in order to be successful on a
long-term basis," and as "an attempt to prepare for all eventualities by abstraction and thus to
account for the complexity and the dynamics of the environment" (p. 74). Although businesses
cannot predict the future, they can prepare for it and align accordingly (Kraus, Reiche, &
Reschke, 2011). Strategic planning involves deducing how present developments will look in the
future, providing guiding principles and procedures for achieving specified goals. In other words,
strategic planning is an essential tool for strategic management, allowing businesses to stipulate
basic conditions for their future activities (Kraus et al., 2011).
Given its concern with competitive advantage, strategic planning focuses on establishing
long-term goals, developing plans to reach those goals, and distributing the resources needed to
achieve those goals (Stonehouse & Pemberton, 2002; O'Regan & Ghobadian, 2004; Wang et al.,
2007). As described by Kenichi Ohmae, "the purpose of strategic planning is to enable a business
to gain as efficiently as possible, a sustainable edge over its competitors" (as cited in O'Regan &
Ghobadian, 2004, p. 664; Wang et al., 2007). Businesses grow by acquiring new customers and
thus market share. Strategic planning spawns innovation by constantly seeking to develop new
services and products to bring to the market (Hill, 2011). A strategic business plan pairs the
objectives of a company with the needs of the marketplace. It not only defines company goals,
but also applies those goals to take advantage of available business opportunities by carefully

analyzing a particular company's strengths and weaknesses in meeting industry needs (Scott,
2011). Specifically, strategic planning helps a company identify a market need or customer
problem and create a product or service that efficiently and cost-effectively addresses the need or
solves the problem.
Planning also helps a company gain a clearer picture of the competition, allowing it to
develop strategies that take advantage of a competitor's weaknesses (Hill, 2011) and create
solutions that are significantly more beneficial to the customer than those provided by the
competition. Strategic planning compels a business to concentrate on specific areas in the
market, allowing for more effective business operations, and enables the business to learn as
much as it can about customer needs and potential opportunities in the market (Scott, 2011).
Correspondingly, a strategic plan includes extensive market research, exploration of industry
trends, and competitor analysis. A strategic plan shares many of the same components as a
business plan, such as an executive summary, marketing analysis, and financial statements, but is
more specific with respect to how the company will achieve its goals. For example, a strategic
business plan will attempt to identify a target market, reduce it to a manageable size, and
establish a strategy for acquiring that market (Scott, 2011).
Strategic planning is, fundamentally, brainstorming at its best. Since strategic planning
relies on creativity, its development involves intuition as much as management science. The more
small business owners understand their companies and industries, the better their strategic plans
will be (Pirraglia, 2011). As expressed by Drucker (1974), "it is necessary in strategic planning to
start separately with, 'What is our business?,' 'What will it be?,' and 'What should it be?'" (p.
122). Strategic planning demarcates where a company is heading (Pirraglia, 2011). The strategic
plan provides a road map for a business in which the management team fashions a longterm

vision for a larger, more profitable organization. In order to encourage company growth, strategic
planning involves envisioning potential activities that must be undertaken and potential expenses
that will have to be made (Hill, 2011). By using strategic planning, small business owners not
only become better positioned in the market, but also become experts in their respective
industries. The strategic plan also serves as an organizational tool, keeping the company on track
to meet its growth and financial objectives (Scott, 2011). Through an appraisal of past growth
and adjustments for further growth, strategic planning is critical for owners to understand the
trajectory of their companies (Scott, 2011).
In general, strategic planning is more common in small businesses that exhibit better
performance. Specifically, small businesses that engage in strategic planning are more likely to
achieve higher sales growth, returns on assets, margins on profit, and employee growth (Wang et
al., 2007). They tend to be more innovative, have more newly patented products, use new process
and management technologies, and achieve international growth (Wang et al., 2007). Most
significantly, small businesses that engage in strategic planning are less likely to fail
(Wang et al., 2007). Empirical studies have linked strategic planning to success (Kraus et al.,
2011), the implication being that strategic planning is essential for the success of a small business
(Pirraglia, 2011).
Perry (2001) found that in 152 failed firms and 152 non-failed firms, very little strategic
planning took place. However, some planning was performed in the non-failed businesses, which
suggests that the degree of planning may be related to whether the business fails. One limitation
of his (2001) study was that the independent variable—planning—and the phenomenon were
only weakly correlated.

Gibson, Cassar, and Wingham (2001) found that, of 2,956 firms for which data were
available, only 16.3% were described as regular planners, while 43.5% were non-planners. The
remaining 40.2% described themselves as irregular planners. Gibson et al. (2001) determined
that planners reported higher performance than non-planners, which indicated that planning and
performance are related.
In a study by Trow (1961), out of 51 companies in which planning occurred, 12 of 19
small firms (defined as up to 1000 employees) generated steady profits. The remaining
companies did not report on profitability. These findings suggest that firms that planned were
more profitable than those that did not.
Kraus et al. (2006) conducted a study of 290 firms with less than 50 employees. The
researchers used employee growth to measure firm performance. They found that a greater
degree of formalization, as indicated by the existence of a written strategic plan, was related to a
higher degree of performance.
The History and Components of a Strategic Plan
Modern strategic planning has taken a page from World War II, in which the U.S., its
allies, and its enemies developed strategies on the battlefield. Military commanders used these
strategies to help determine the strengths and weaknesses of each force. Using these processes,
they were able to observe the battlefield or environment and establish implementation plans and
command and control mechanisms (Nerone, 1997). The process of strategic planning was
successful because it allowed military strategists to follow proven approaches that literally had
been battle tested over centuries of documented warfare (Nerone, 1997). These strategies and the
eventual success of the allied forces were adopted by the private sector as military commanders
returned from Europe and entered the civilian workforce.

Early management theorists, including H. Igor Ansoff, Philip Selznick, George Steiner,
Peter Drucker, C.H. Hofer, D.E. Schendel, and Henry Mintzberg, are considered pioneers in the
field of strategic thinking (Nerone, 1997). Other notable theorist is Harvard Business School
professor Alfred Chandler, who “insisted that structure must follow strategy” (The Economist,
2007, para. 3), and Albert Humphrey, who created the SWOT Analysis, while working at the
Stanford Research Institute during the 1960’s (Stanford Research Institute Alumni Newsletter,
2005). A later theorist, Harvard Business School Professor Michael Porter, is considered to be the
founder of the modern field of strategy and regarded as the most influential thinker on
competitiveness and management (Harvard Business School, 2014).
H. Igor Ansoff devised one of the earliest strategic planning models, the Ansoff Matrix.
The Ansoff Matrix focused on options for business growth. Ansoff identified four types of
product-market strategies: market penetration, market development, product development
strategy, and diversification (Ansoff, 1957). According to Ansoff, a product-market strategy is a
“joint statement of a product line and the corresponding set of missions which the products are
designed to fulfill” (Ansoff, 1957, p. 114). The first of these, market penetration, he defined as an
“effort to increase company sales without departing from an original product-market strategy.
The company seeks to improve business performance either by increasing the volume of sales to
its present customers or by finding new customers for present products” (Ansoff, 1957, p. 114).
In contrast, market development is “[a] strategy in which the company attempts to adapt
its present product line (generally with some modification in the product characteristics) to new
missions” (Ansoff, 1957, p. 114). A product development strategy “develops products that have
new and different characteristics such as will improve the performance of the mission” (Ansoff,
1957, p. 114). And diversification is “the final alternative. It calls for a simultaneous departure
from the present product line and the present market structure” (Ansoff, 1957, p. 114).
Figure 1 Product-Market Strategies for Business Growth Alternatives
Represents the product line and represents the corresponding set of missions. The pair of
and is a product-market strategy (Ansoff, 1957, p. 114).
In 1979, The Harvard Business Review published Michael E. Porter’s “How Competitive
Forces Shape Strategy” (Harvard Business Review, 2008). In his article, Porter suggested that
there are five forces that shape an organization's strategy: the threats of new entrants, the
bargaining power of suppliers, the bargaining power of customers, and the threat of substitute
products and services. Porter argued that these four forces interact with the fifth force:
competitors jockeying for position within an industry (Harvard Business Review, 2008).
Porter theorized that the threats to new entrants consisted of six barriers: economies of
scale, product differentiation, capital requirements, cost disadvantages independent of size,
access to distribution channels, and government policy (Porter, 1979). Economies of scale force
market entrants to either enter the market on a large scale or consent to a cost handicap.
Economies of scale can act as barriers to distribution, financing, and utilization of the
organization’s sales force (Porter, 1979). The second barrier, product differentiation, forces
market entrants to spend large amounts of money on customer service and advertising in order to
Markets
Product Line
0
MARKET
Penetration
1
2
3
..
Market Development
DIVERSIFICATION
PRODUCT
DEVELOPMENT
01234..

demonstrate product differentiation and generate a brand identity (Porter, 1979). Capital
requirements force market entrants to spend large sums of non-recoverable funds on facilities,
customer credit, inventory, and research and development, in addition to advertisements. Due to
these constraints, capital requirements limit the pool of potential entrants (Porter, 1979). Cost
disadvantages force market entrants to realize that rivals who are already entrenched in the
market possess the inherent advantage of time. Market entrants must deal with learning and
experience curves, proprietary technologies, access to pre-inflation cost of materials, and
favorable locations (Porter, 1979). The fifth barrier, access to distribution channels, forces market
entrants to acquire channels for distributing products and services. Thus, selling efforts must
attempt to displace other rivals. If wholesale channels are limited and barriers are high, a market
entrant must create its own distribution channels (Porter, 1979). Finally, government policy can
limit market entrants to industries by mandating licensing requirements, regulatory requirements,
environmental standards, or access to raw materials (Porter, 1979). Porter states,
A company’s choice of suppliers to buy from or buyer groups to sell to should be viewed
as a crucial strategic decision. A company can improve its strategic posture by finding
suppliers or buyers who possess the least power to influence it adversely. (Porter, 1979,
p. 141)
Porter theorized that suppliers can exercise bargaining forces on market participants by
either reducing or increasing the quality or prices of goods and services. Thus, suppliers can
extract profits from a market and its participants (1979). For example, Porter argues that a group
of suppliers is powerful if it is more concentrated in comparison with the industry that it is
selling to (Porter, 1979). Additionally, suppliers are powerful if their products are highly
differentiated and unique, or if switching costs have developed. Switching costs can occur when
a buyer’s product is highly specified and production lines are coupled with the supplier's
manufacturing facilities. Switching costs then become fixed even when a buyer changes

suppliers (Porter, 1979). Furthermore, if a supplier does not have to compete with other products,
the supplier essentially has no reason to reduce prices or increase the quality of its product
(Porter, 1979). Moreover, if the supplier possesses the ability to integrate further into the market,
the buyer’s ability to improve purchasing terms is highly limited (Porter, 1979). Lastly, if the
buyer is simply not significant to the supplier, the supplier and buyers' interests are not aligned,
and thus the supplier has no real incentive to work with the buyer (Porter, 1979).
Porter theorized that buyers can exercise bargaining forces on market participants if they
purchase in large quantities. This approach would require that capacity remain high consistently,
which would be particularly difficult if fixed costs within the market were high (Porter, 1979).
Additionally, buyers can exercise their will if products are standard or not particularly
differentiated. In this case, buyers are not incentivized to purchase from any one specific
company but instead could pit companies against one another in an attempt to lower market
prices (Porter, 1979). Furthermore, if a particular component for a product represents a large part
of overall costs, buyers are incentivized to shop for more favorable pricing (Porter, 1979). And if
a buyer earns low profits, then the buyer would be incentivized to lower its purchasing costs.
Should a buyer earn higher profits, it is generally less sensitive to prices, assuming that the price
does not signify a large percentage of overall costs (Porter, 1979). Additionally, if the quality of
the product is of significant importance to the buyer, the buyer is typically less price sensitive
(Porter, 1979). In his article, Porter uses an example from the oil field industry, where equipment
failure can lead to huge losses (1979). Furthermore, when the industry’s product can pay for
itself over time, such as accounting or legal services where errors can be costly, the buyer is less
likely to be price sensitive (1979). Lastly, buyers can opt to produce their own materials, thus
removing the need for purchasing from a third party manufacturer. This threat provides leverage
to the buyer (Porter, 1979).
Figure 2 Porter’s Original 1979 Five Force Model, Source: (Porter, 1979).
Albert S. Humphrey created what was eventually dubbed the SWOT Analysis while
working at the Stanford Research Institute during the 1960’s. His research was funded by various
Fortune 500 companies who wished to identify deficiencies in corporate planning and create a
system to manage change. (Stanford Research Institute Newsletter, 2005).
Though Humphrey’s key finding were never published, as they were deemed too
controversial, he wrote them in the December 2005 Newsletter of the Stanford Research
Institutes Alumni Newsletter. They are as follows:
1) A business can be divided into two parts: The base business plus the development
business. The development business turns over every 5 to 7 years, 2) All people measure
what they get from their work and divide it by what they give to the work and this
reward/effort ratio is compared to others. If it perceived as too low, the person slows

down, 3) The introduction of a corporate planner upsets the sense of fair play at senior
level, making the job of the corporate planner impossible, 4) The gap between what could
Absence of Strategic Planning and Failure of Small Businesses
Early research on the failure of small businesses identified the absence of strategic planning as a
primary cause (Ibrahim & Goodwin, 1985; Mayer & Goldstein, 1961; Mintzberg, 1979;
Crawford & Lefebvre, 1984; Crawford & Ibrahim, 1985; Nerone, 1997). Excessive optimism, a
failure to monitor results, and the absence of balanced growth also were identified as key factors
(Mayer & Goldstein, 1961; Mintzberg, 1979; Crawford & Lefebvre, 1984; Crawford & Ibrahim,
1985). In their 1982 study, Sexton and Van Auken found that small business owners and manager
often thought of strategic planning, but rarely took action. Several other studies determined that
not only was systematic strategic planning largely absent in small businesses, but also that what
little did take place was reactive, incremental, disorganized, sporadic, and inadequate (Still,
1974; Cooper, 1977; Crawford, R. L., & Ibrahim, A. B., 1985). As Nerone observed, "Most
entrepreneurs [small business owners] are doing their strategy on the back of a napkin, as they
sweat out making the Friday payroll” (Nerone, 1997, p. 9).
In a more recent article, Kraus, Harms, and Schwarz argue that strategic planning does
occur in small businesses, but that it is often performed intuitively without the use of planning
instruments (2006). In practice, small businesses plan in the short term, rather than focusing on
long-term objectives, and are typically reactive rather than proactive (Wang, Walker, &
Redmond, 2007). Small businesses that claim to plan for the future typically develop those plans
ad hoc and rarely write them down formally. Furthermore, the plans provide little guidance for
measuring or analyzing the performance of the small business (Wang et al., 2007). The literature
also indicates that strategic planning in small businesses is unstructured, informal, and irregular,
lacking in information (Gibb & Scott, 1985; Flavel, 1991; Balasundaram, 2009).

Correspondingly, small businesses have been described as shortsighted and strategically
narrowminded (Wang et al., 2007).
Benefits of Strategic Planning
This absence of strategic planning certainly counters much of the literature, which
indicates that small businesses should plan for the long term in order to effectively compete
(Wang et al., 2007). Small businesses that disregard strategic planning risk, at a minimum,
growth and performance and, at worst, their very survival (Wang et al., 2007). Understandably,
small business success is not determined by strategic planning alone; however, there are more
benefits to planning versus not planning (Wang et al., 2007).
Problem Statement
Strategic planning has been studied since the 1950's, but research has focused primarily
on larger organizations (Mazzarol, 2004). Research on strategic planning in small businesses is
still in the early stages (Kraus, Reiche, & Reschke, 2007). Furthermore, although small
businesses are vital to the Louisiana economy, little, if any, research on strategic planning in
Louisiana small businesses has been undertaken. While the existing literature suggests that
strategic planning is positively related to the performance of small businesses (Kraus, Harms, &
Schwarz, 2006; Balasundaram, 2009), most of them do not plan, for as yet unknown reasons
(Wang et al., 2007). Thus, Robinson and Pearce argue that “Research needs to provide specific
reasons why planning is not practiced in firms” (Robinson & Pearce, 1984, p. 135).
Understanding why small businesses do not engage in strategic planning, and how that omission
affects small business mortality, would enable consultants to better serve the small business
sector and public officials to improve public policy.

Purpose of Study
The primary purpose of this study is to determine the influence of selected factors that
influence small business owners’ perceived obstacles to strategic planning in Louisiana small
businesses.
Research Objectives
The dependent variable of this study is the propensity of Louisiana small businesses to
strategically plan. The independent variable of this study is Louisiana small business owners’
perceived obstacles to strategic planning.
The following specific objectives were formulated to guide this research study:
11. To describe small businesses in Louisiana on the following characteristics:
a) Years the organization has been in business;
b) Industry in which the small business is positioned;
c) Current number of full time and part time employees on the organization's
payroll;
d) Structure of the organization i.e. Limited Liability Corporation,
Subchapter S
Corporation, Partnership, etc.:
e) Existence of a written long term plan.
12. To describe small businesses in Louisiana on the perceived degree to which the
organization conducts strategic planning.
13. To describe small businesses in Louisiana perception regarding the following perceived
obstacles to strategic planning:
a) The perceived quality of the organization’s employees;

b) The perceived degree to which the organization’s leadership has
knowledge of the
planning process;
c) The perceived available time the organization has to strategically plan.
14. To determine if a relationship exists between Louisiana small business owners' perceived
obstacles to strategic planning and the following variables:
a) Industry in which the small business is positioned in;
b) Structure of the organization i.e. Limited Liability Corporation,
Subchapter S
Corporation, Partnership, etc.;
c) Years the organization has been in business;
d) Current number of full time and part time employees on the organization's
payroll;
e) The perceived degree to which the organization conducts strategic
planning;
f) Possession of a written long term plan.
15. To determine if a model exists explaining a significant portion of the variance in
Louisiana small business owners' perceived degree to which the small business conducts
strategic planning using the following characteristics:
a) Years the organization has been in business;
b) Industry in which the small business is positioned;
c) Current number of full time and part time employees on the organization's
payroll;
d) Structure of the organization i.e. Limited Liability Corporation,
Subchapter S
Corporation, Partnership, etc.;

e) The perceived degree to which the organization conducts strategic
planning;
f) The perceived quality of the organization’s employees;
g) The perceived degree to which the organization’s leadership has
knowledge of the
planning process;
h) The perceived available time the organization has to strategically plan;
i) Possession of a written long term plan.
Summary
Small businesses play an important role in the Louisiana economy. Prior research on
strategic planning has focused primarily on large businesses (Mazzarol, 2004); however, little
literature exists that focuses on Louisiana small business strategic planning. While the existing
literature implies that strategic planning is positively related to the performance of small
businesses (Kraus, Harms, & Schwarz, 2006; Balasundaram, 2009), most of them do not plan,
for as yet unknown reasons (Wang et al., 2007). Therefore, this study will explore the obstacles
to strategic planning as perceived by Louisiana small business owners. The results of this study
will benefit small business owners when employing strategic planning within their organizations,
consultants when advising small businesses during the strategic planning process, and public
officials when establishing public policy affecting small businesses.

CHAPTER II: REVIEW OF LITERATURE
Given how important small businesses are to the U.S. economy, many studies have
focused on what causes them to fail. The principal cause of small business failure has been
identified as a lack of strategic planning. Other key factors contributing to small business failures
are excessive optimism, lack of balanced growth, and failure to monitor results (Ibrahim &
Goodwin, 1985; Mayer & Goldstein, 1961; Mintzberg, 1979; Crawford & Lefebvre, 1984;
Crawford & Ibrahim, 1985).
The literature suggests that small businesses owners tend to not engage in systematic
strategic planning (Perry, 2001), even though they often consider it (Sexton & Van Auken,
1982). Furthermore, any planning that small businesses do undertake tends to be reactive,
unstructured, incremental, and sporadic (Still, 1974; Cooper, 1977; Crawford & Ibrahim, 1985).
Small business owners tend to focus on immediate rather than long-term objectives, planning
for the future in an ad hoc manner, and fail to make provisions for measuring performance
(Wang et al., 2007). The approach of small businesses to strategic planning is therefore
counterintuitive: although the literature highlights the benefits of strategic planning, most small
businesses do not plan for reasons that are not fully understood (Wang et al.,
2007).
U.S. Small Businesses
Small businesses play a vital role in the U.S. economy. Collectively, they are the largest
employer, the largest importer, and the largest exporter in the country (Office of the United States
Trade Representative, 2009). Small businesses, which are defined as those employing fewer than
500 individuals, comprise 99.9% of firms in the U.S. Furthermore, businesses employing fewer
than 20 individuals comprise 89.7% of U.S. small businesses. In 2008, small businesses

generated 46% of the private non-farm Gross Domestic Product (GDP) (Small Business Council,
2014).
Small businesses foster the growth of local economies by providing opportunities for
employment to people who otherwise may not be employable by larger organizations (Brown,
2011). During the 18-year period from 1992 to 2010, small business outpaced larger firms in job
creation 75% of the time (Graves, 2013). In general, small businesses generate 60-80% of all
new employment in the U.S. Small businesses also generate 16.5 times more patents per
employee when compared to larger firms (Graves, 2013)
Small businesses traditionally dominate industries such as construction and retail, as well
as form a crucial link in the supply chain for large-scale and capital-intensive manufacturing
industries such as defense, mining, automotive, and marine (Abdullah & bin Baker, 2000;
Robinson & Pearce, 1984; Wang et al., 2007; Wang, Rowe, & Cripps, 2006). Furthermore, small
businesses provide a competitive balance to industries that would otherwise be dominated solely
by larger firms (Wang et al., 2007).
However, despite the critical importance of small businesses in the U.S., only
approximately half survive past five years and roughly a third last for 10 years (SBA
Frequently Asked Questions, 2012).
Louisiana Small Businesses
Small businesses play a vital role in the Louisiana economy as well. In aggregate, they
account for 97.3% of employers in Louisiana and employ more than half, 54.5%, of the state's
private sector workforce. Businesses with 500 or more employees comprise the remaining 45.5%
(U.S. Small Business Administration, 2014). Federal, state, and local governments, as well as the
U.S. Postal Service, employ 321,569 public sector workers, or 6.95% of Louisiana’s population
(Molla, 2014). As noted in Table 1, the Small Business Administration (2014) reported that
414,779 small businesses existed in the state of Louisiana in 2011. Of those businesses, only
78,451 had employees; 68,030 employed less than 20 individuals. The majority of the small
businesses, 336,328 or 80.7%, did not have employees. Overall, Louisiana small businesses
employ 875,974 individuals (U.S. Small Business Administration, 2014). (See Table 1)
Table 1 The Number of Louisiana Small Firms by Industry, 2011 (Ranked by Number Of Small
Employer Firms) Source: (U.S. Small Business Administration, 2014)
Number of Louisiana Small Firms by Industry, 2011 (ranked
by number of small employer firms)
Industry
Employer Firms
with
1-499 Employees
Employer Firms
with
1-19 Employees
Nonemployer
Firms
Professional, scientific, and tech svcs. 10,621 9,853 35,489
Retail trade 10,398 9,302 23,229
Health care & social assistance 9,646 8,060 30,124
Other services (except public admin.) 8,719 8,005 64,016
Construction 7,867 6,984 38,305
Accommodatin & food services 6,469 4,878 7,513
Wholesale trade 3,845 3,012 4,206
Admin., supp., waste mgt., remed.Svcs. 3,754 3,186 36,768
Finance & insurance 3,689 3,334 9,127
Real estate & renal & leasing 3,371 3,103 29,506
Transportation & warehousing 2,733 2,310 15,178
Manufacturing 2,706 2,027 4,251
Arts, entertainment, & recreation 1,272 1,080 13,143
Mining 1,196 935 6,277
Educational services 955 649 6,248
Forestry, etc. & agriculture support 566 525 9,654
Information 558 440 3,041
Management of comp. & enterprises 301 65 -
Utilities 203 182 253
Unclassified 177 177 -
Total 78,451 68,030 336,328
As noted in Table 2, the top four industries most populated by small businesses in
Louisiana are health care, social assistance, accommodation and food service, and retail trade. In
2012, 84.5% of the 4000 companies exporting goods were small firms. Louisiana export
revenues totaled more than $65 billion in 2014 (World Trade Center, New Orleans, 2015). The
small firms generated 34.8%, or $22.6 billion, of Louisiana's total export value (U.S. Small
Business Administration, 2014).
Table 2 Employment in Louisiana Small Firms by Industry and Firm Size, 2011 (Ranked by
Number of Small Employer Firms) Source: (U.S. Small Business Administration, 2014)
Employment in Louisiana by Industry and Firm Size, 2011
(ranked by small firm employment)
Industry Employment
Small Firms Total Firms
Small Firm Share
of Industry
Employment (%)
Health care & social assistance 156,785 282,985 55
Accommodation & food services 106,250 182,523 58
Retail trade 93,286 226,638 41
Construction 78,986 127,941 62
Professional, scientific, & tech. svcs. 66,888 88,171 76
Other services (except public admin.) 64,979 72,394 90
Manufacturing 50,963 125,820 41
Wholesale trade 46,893 75,009 63
Admin., sup., waste mgt., remed.
svcs. 46,211 100,856 46
Finance & insurance 34,913 66,255 53
Transportation & warehousing 30,771 65,367 47
Educational services
Real estate & rental & leasing 24,014 36,322 66
Mining 19,469 53,185 37
Arts, entertainment, & recreation 14,513 23,477 62
Information 7,340 23,722 31
Management of comp. & enterprises 6,173 20,468 30
Forestry, etc. & agriculture support 3,764 3,951 95
Utilities 2,454 - -
Unclassified - - -
Total 875,974 1,617,229 54
Similar to the national percentages, only 47.6% of Louisiana small businesses survive beyond
five years and roughly 37.4% remain in business more than 10 years (U.S. Small Business
Administration, 2014). Although small businesses are important to the Louisiana economy,

research on strategic planning in small businesses is largely absent from the literature. Instead,
research on strategic planning has focused primarily on larger organizations (Mazzarol, 2004).
Strategic Planning and Its Benefits
Given the risk of failure, small businesses are concerned with establishing a competitive
advantage that will ensure long-term survival (Galán, Monje, & Zúñiga-Vicente, 2009). Wankel
(2007) defined strategy as "an approach to reach corporate goals in order to be successful on a
long-term basis," and as "an attempt to prepare for all eventualities by abstraction and thus to
account for the complexity and the dynamics of the environment" (p. 74). Although businesses
cannot predict the future, they can prepare for it and align accordingly (Kraus, Reiche, &
Reschke, 2011). Strategic planning involves deducing how present developments will look in the
future, providing guiding principles and procedures for achieving specified goals. In other words,
strategic planning is an essential tool for strategic management, allowing businesses to stipulate
basic conditions for their future activities (Kraus et al., 2011).
Given its concern with competitive advantage, strategic planning focuses on establishing
long-term goals, developing plans to reach those goals, and distributing the resources needed to
achieve those goals (Stonehouse & Pemberton, 2002; O'Regan & Ghobadian, 2004; Wang et al.,
2007). As described by Kenichi Ohmae, "the purpose of strategic planning is to enable a business
to gain as efficiently as possible, a sustainable edge over its competitors" (as cited in O'Regan &
Ghobadian, 2004, p. 664; Wang et al., 2007). Businesses grow by acquiring new customers and
thus market share. Strategic planning spawns innovation by constantly seeking to develop new
services and products to bring to the market (Hill, 2011). A strategic business plan pairs the
objectives of a company with the needs of the marketplace. It not only defines company goals,
but also applies those goals to take advantage of available business opportunities by carefully

analyzing a particular company's strengths and weaknesses in meeting industry needs (Scott,
2011). Specifically, strategic planning helps a company identify a market need or customer
problem and create a product or service that efficiently and cost-effectively addresses the need or
solves the problem.
Planning also helps a company gain a clearer picture of the competition, allowing it to
develop strategies that take advantage of a competitor's weaknesses (Hill, 2011) and create
solutions that are significantly more beneficial to the customer than those provided by the
competition. Strategic planning compels a business to concentrate on specific areas in the
market, allowing for more effective business operations, and enables the business to learn as
much as it can about customer needs and potential opportunities in the market (Scott, 2011).
Correspondingly, a strategic plan includes extensive market research, exploration of industry
trends, and competitor analysis. A strategic plan shares many of the same components as a
business plan, such as an executive summary, marketing analysis, and financial statements, but is
more specific with respect to how the company will achieve its goals. For example, a strategic
business plan will attempt to identify a target market, reduce it to a manageable size, and
establish a strategy for acquiring that market (Scott, 2011).
Strategic planning is, fundamentally, brainstorming at its best. Since strategic planning
relies on creativity, its development involves intuition as much as management science. The more
small business owners understand their companies and industries, the better their strategic plans
will be (Pirraglia, 2011). As expressed by Drucker (1974), "it is necessary in strategic planning to
start separately with, 'What is our business?,' 'What will it be?,' and 'What should it be?'" (p.
122). Strategic planning demarcates where a company is heading (Pirraglia, 2011). The strategic
plan provides a road map for a business in which the management team fashions a longterm

vision for a larger, more profitable organization. In order to encourage company growth, strategic
planning involves envisioning potential activities that must be undertaken and potential expenses
that will have to be made (Hill, 2011). By using strategic planning, small business owners not
only become better positioned in the market, but also become experts in their respective
industries. The strategic plan also serves as an organizational tool, keeping the company on track
to meet its growth and financial objectives (Scott, 2011). Through an appraisal of past growth
and adjustments for further growth, strategic planning is critical for owners to understand the
trajectory of their companies (Scott, 2011).
In general, strategic planning is more common in small businesses that exhibit better
performance. Specifically, small businesses that engage in strategic planning are more likely to
achieve higher sales growth, returns on assets, margins on profit, and employee growth (Wang et
al., 2007). They tend to be more innovative, have more newly patented products, use new process
and management technologies, and achieve international growth (Wang et al., 2007). Most
significantly, small businesses that engage in strategic planning are less likely to fail
(Wang et al., 2007). Empirical studies have linked strategic planning to success (Kraus et al.,
2011), the implication being that strategic planning is essential for the success of a small business
(Pirraglia, 2011).
Perry (2001) found that in 152 failed firms and 152 non-failed firms, very little strategic
planning took place. However, some planning was performed in the non-failed businesses, which
suggests that the degree of planning may be related to whether the business fails. One limitation
of his (2001) study was that the independent variable—planning—and the phenomenon were
only weakly correlated.

Gibson, Cassar, and Wingham (2001) found that, of 2,956 firms for which data were
available, only 16.3% were described as regular planners, while 43.5% were non-planners. The
remaining 40.2% described themselves as irregular planners. Gibson et al. (2001) determined
that planners reported higher performance than non-planners, which indicated that planning and
performance are related.
In a study by Trow (1961), out of 51 companies in which planning occurred, 12 of 19
small firms (defined as up to 1000 employees) generated steady profits. The remaining
companies did not report on profitability. These findings suggest that firms that planned were
more profitable than those that did not.
Kraus et al. (2006) conducted a study of 290 firms with less than 50 employees. The
researchers used employee growth to measure firm performance. They found that a greater
degree of formalization, as indicated by the existence of a written strategic plan, was related to a
higher degree of performance.
The History and Components of a Strategic Plan
Modern strategic planning has taken a page from World War II, in which the U.S., its
allies, and its enemies developed strategies on the battlefield. Military commanders used these
strategies to help determine the strengths and weaknesses of each force. Using these processes,
they were able to observe the battlefield or environment and establish implementation plans and
command and control mechanisms (Nerone, 1997). The process of strategic planning was
successful because it allowed military strategists to follow proven approaches that literally had
been battle tested over centuries of documented warfare (Nerone, 1997). These strategies and the
eventual success of the allied forces were adopted by the private sector as military commanders
returned from Europe and entered the civilian workforce.

Early management theorists, including H. Igor Ansoff, Philip Selznick, George Steiner,
Peter Drucker, C.H. Hofer, D.E. Schendel, and Henry Mintzberg, are considered pioneers in the
field of strategic thinking (Nerone, 1997). Other notable theorist is Harvard Business School
professor Alfred Chandler, who “insisted that structure must follow strategy” (The Economist,
2007, para. 3), and Albert Humphrey, who created the SWOT Analysis, while working at the
Stanford Research Institute during the 1960’s (Stanford Research Institute Alumni Newsletter,
2005). A later theorist, Harvard Business School Professor Michael Porter, is considered to be the
founder of the modern field of strategy and regarded as the most influential thinker on
competitiveness and management (Harvard Business School, 2014).
H. Igor Ansoff devised one of the earliest strategic planning models, the Ansoff Matrix.
The Ansoff Matrix focused on options for business growth. Ansoff identified four types of
product-market strategies: market penetration, market development, product development
strategy, and diversification (Ansoff, 1957). According to Ansoff, a product-market strategy is a
“joint statement of a product line and the corresponding set of missions which the products are
designed to fulfill” (Ansoff, 1957, p. 114). The first of these, market penetration, he defined as an
“effort to increase company sales without departing from an original product-market strategy.
The company seeks to improve business performance either by increasing the volume of sales to
its present customers or by finding new customers for present products” (Ansoff, 1957, p. 114).
In contrast, market development is “[a] strategy in which the company attempts to adapt
its present product line (generally with some modification in the product characteristics) to new
missions” (Ansoff, 1957, p. 114). A product development strategy “develops products that have
new and different characteristics such as will improve the performance of the mission” (Ansoff,
1957, p. 114). And diversification is “the final alternative. It calls for a simultaneous departure
from the present product line and the present market structure” (Ansoff, 1957, p. 114).
Figure 1 Product-Market Strategies for Business Growth Alternatives
Represents the product line and represents the corresponding set of missions. The pair of
and is a product-market strategy (Ansoff, 1957, p. 114).
In 1979, The Harvard Business Review published Michael E. Porter’s “How Competitive
Forces Shape Strategy” (Harvard Business Review, 2008). In his article, Porter suggested that
there are five forces that shape an organization's strategy: the threats of new entrants, the
bargaining power of suppliers, the bargaining power of customers, and the threat of substitute
products and services. Porter argued that these four forces interact with the fifth force:
competitors jockeying for position within an industry (Harvard Business Review, 2008).
Porter theorized that the threats to new entrants consisted of six barriers: economies of
scale, product differentiation, capital requirements, cost disadvantages independent of size,
access to distribution channels, and government policy (Porter, 1979). Economies of scale force
market entrants to either enter the market on a large scale or consent to a cost handicap.
Economies of scale can act as barriers to distribution, financing, and utilization of the
organization’s sales force (Porter, 1979). The second barrier, product differentiation, forces
market entrants to spend large amounts of money on customer service and advertising in order to
Markets
Product Line
0
MARKET
Penetration
1
2
3
..
Market Development
DIVERSIFICATION
PRODUCT
DEVELOPMENT
01234..

demonstrate product differentiation and generate a brand identity (Porter, 1979). Capital
requirements force market entrants to spend large sums of non-recoverable funds on facilities,
customer credit, inventory, and research and development, in addition to advertisements. Due to
these constraints, capital requirements limit the pool of potential entrants (Porter, 1979). Cost
disadvantages force market entrants to realize that rivals who are already entrenched in the
market possess the inherent advantage of time. Market entrants must deal with learning and
experience curves, proprietary technologies, access to pre-inflation cost of materials, and
favorable locations (Porter, 1979). The fifth barrier, access to distribution channels, forces market
entrants to acquire channels for distributing products and services. Thus, selling efforts must
attempt to displace other rivals. If wholesale channels are limited and barriers are high, a market
entrant must create its own distribution channels (Porter, 1979). Finally, government policy can
limit market entrants to industries by mandating licensing requirements, regulatory requirements,
environmental standards, or access to raw materials (Porter, 1979). Porter states,
A company’s choice of suppliers to buy from or buyer groups to sell to should be viewed
as a crucial strategic decision. A company can improve its strategic posture by finding
suppliers or buyers who possess the least power to influence it adversely. (Porter, 1979,
p. 141)
Porter theorized that suppliers can exercise bargaining forces on market participants by
either reducing or increasing the quality or prices of goods and services. Thus, suppliers can
extract profits from a market and its participants (1979). For example, Porter argues that a group
of suppliers is powerful if it is more concentrated in comparison with the industry that it is
selling to (Porter, 1979). Additionally, suppliers are powerful if their products are highly
differentiated and unique, or if switching costs have developed. Switching costs can occur when
a buyer’s product is highly specified and production lines are coupled with the supplier's
manufacturing facilities. Switching costs then become fixed even when a buyer changes

suppliers (Porter, 1979). Furthermore, if a supplier does not have to compete with other products,
the supplier essentially has no reason to reduce prices or increase the quality of its product
(Porter, 1979). Moreover, if the supplier possesses the ability to integrate further into the market,
the buyer’s ability to improve purchasing terms is highly limited (Porter, 1979). Lastly, if the
buyer is simply not significant to the supplier, the supplier and buyers' interests are not aligned,
and thus the supplier has no real incentive to work with the buyer (Porter, 1979).
Porter theorized that buyers can exercise bargaining forces on market participants if they
purchase in large quantities. This approach would require that capacity remain high consistently,
which would be particularly difficult if fixed costs within the market were high (Porter, 1979).
Additionally, buyers can exercise their will if products are standard or not particularly
differentiated. In this case, buyers are not incentivized to purchase from any one specific
company but instead could pit companies against one another in an attempt to lower market
prices (Porter, 1979). Furthermore, if a particular component for a product represents a large part
of overall costs, buyers are incentivized to shop for more favorable pricing (Porter, 1979). And if
a buyer earns low profits, then the buyer would be incentivized to lower its purchasing costs.
Should a buyer earn higher profits, it is generally less sensitive to prices, assuming that the price
does not signify a large percentage of overall costs (Porter, 1979). Additionally, if the quality of
the product is of significant importance to the buyer, the buyer is typically less price sensitive
(Porter, 1979). In his article, Porter uses an example from the oil field industry, where equipment
failure can lead to huge losses (1979). Furthermore, when the industry’s product can pay for
itself over time, such as accounting or legal services where errors can be costly, the buyer is less
likely to be price sensitive (1979). Lastly, buyers can opt to produce their own materials, thus
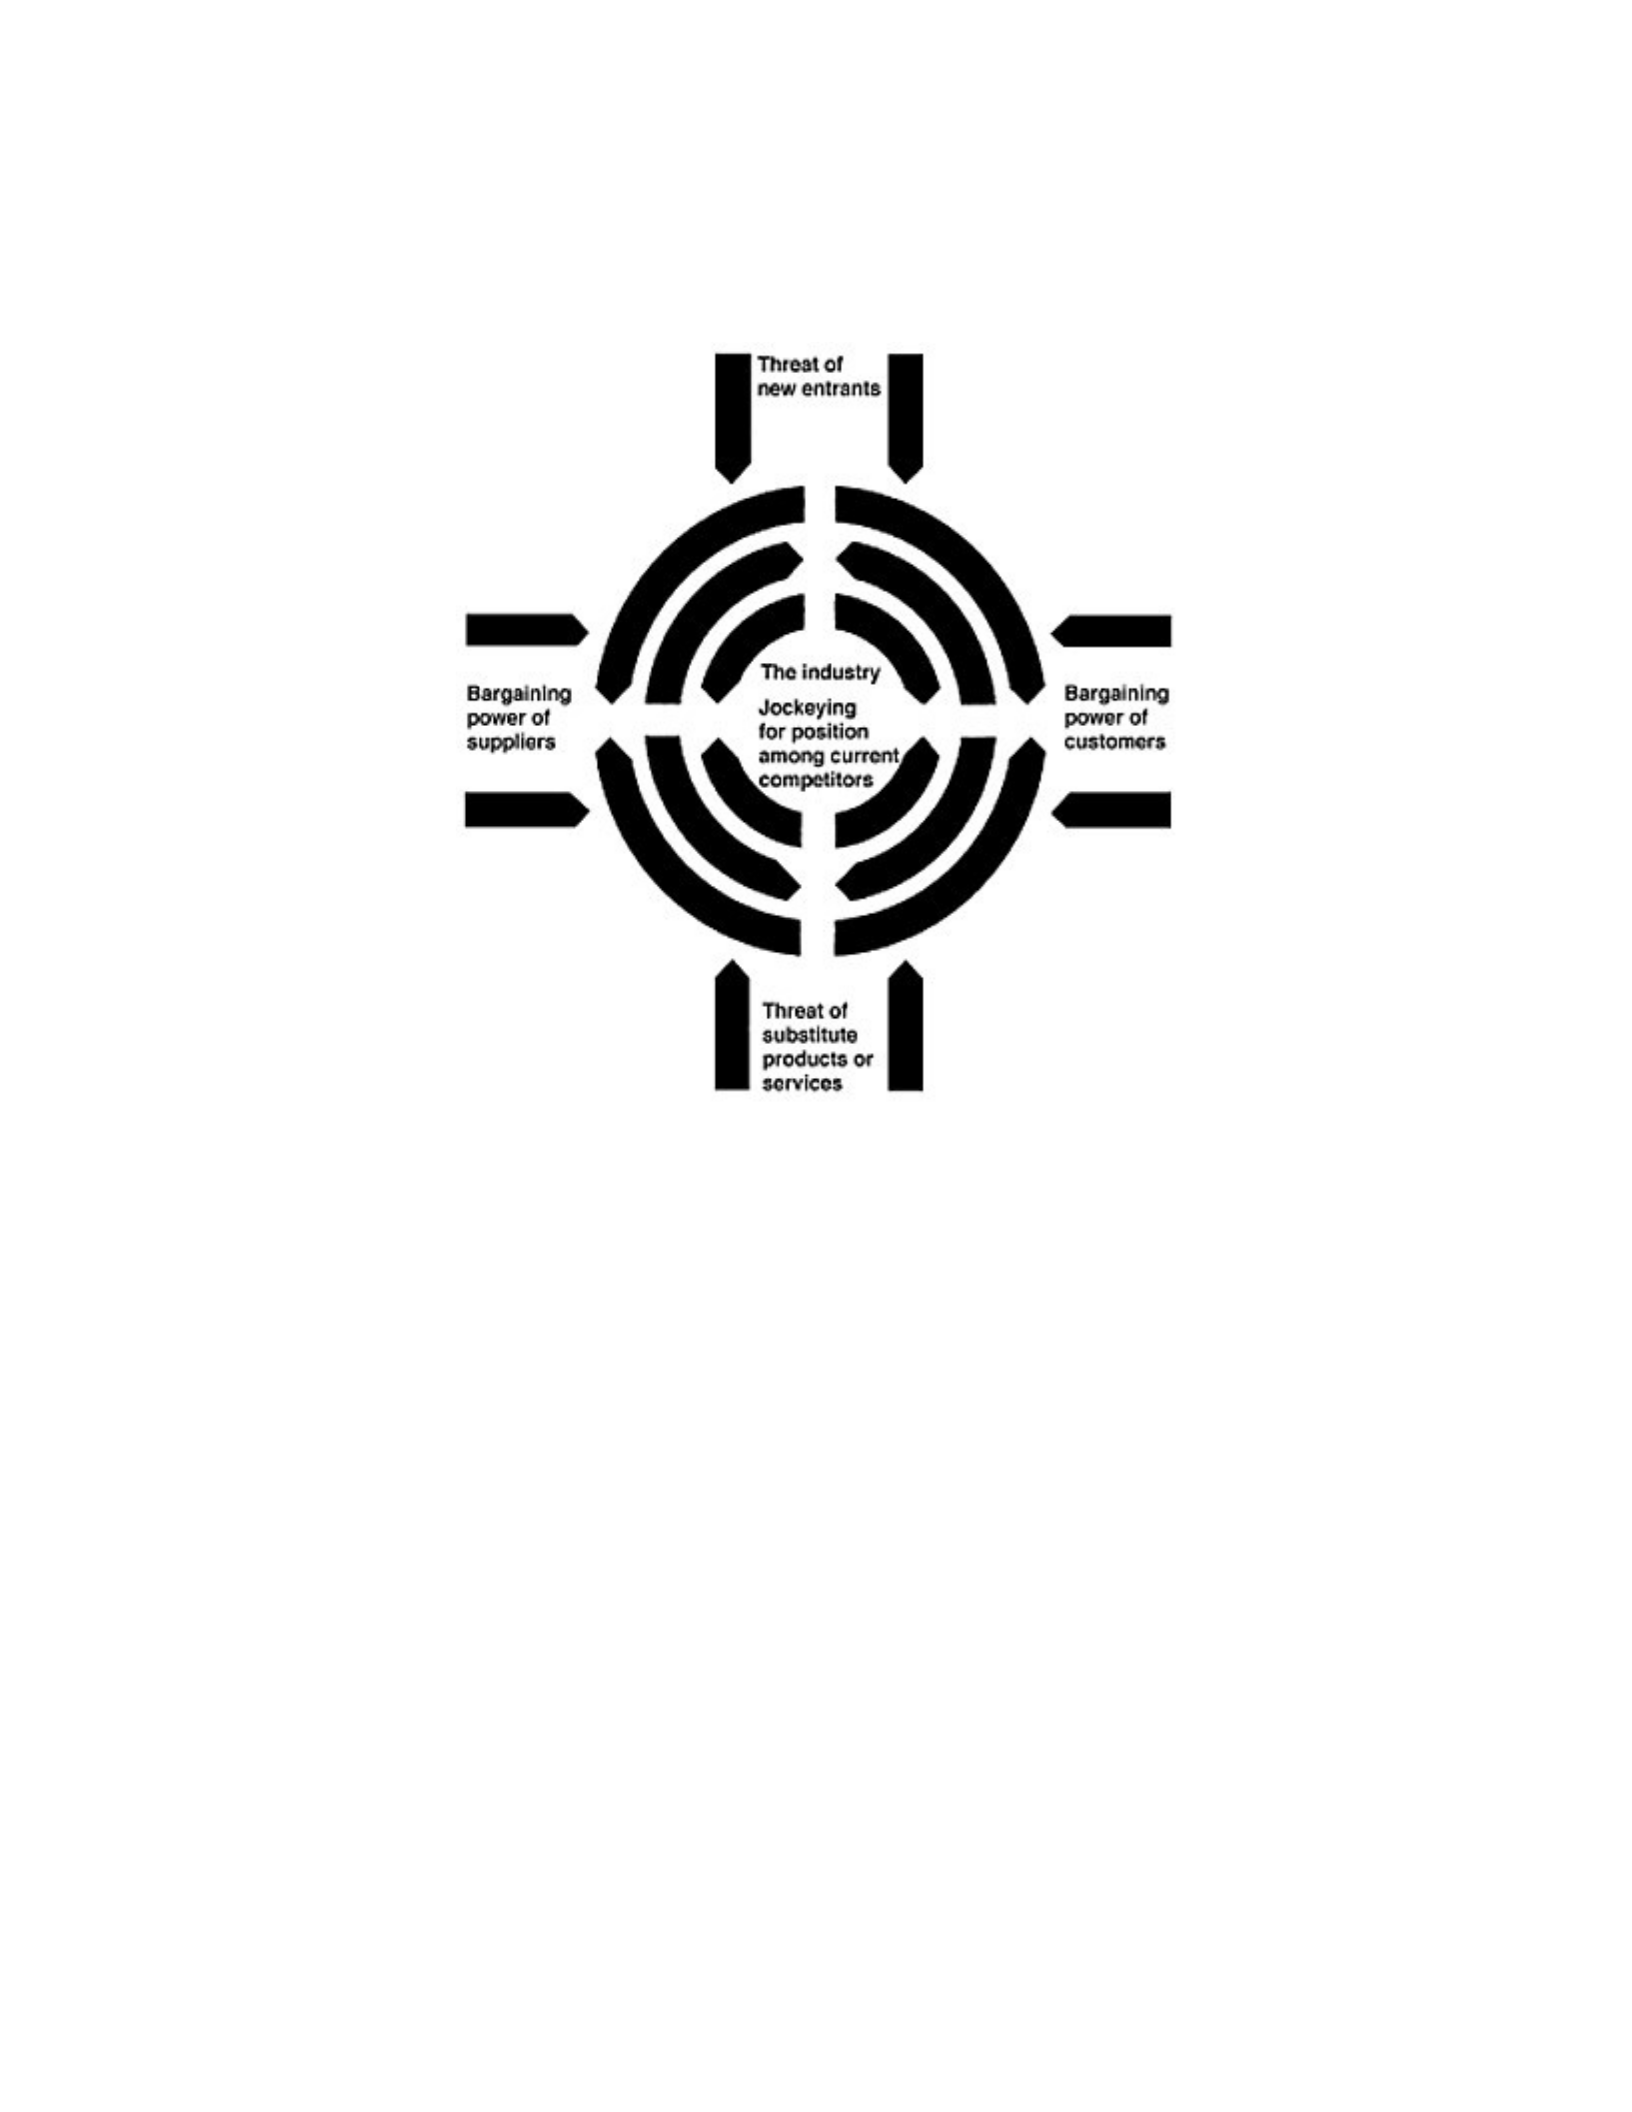
removing the need for purchasing from a third party manufacturer. This threat provides leverage
to the buyer (Porter, 1979).
Figure 2 Porter’s Original 1979 Five Force Model, Source: (Porter, 1979).
Albert S. Humphrey created what was eventually dubbed the SWOT Analysis while
working at the Stanford Research Institute during the 1960’s. His research was funded by various
Fortune 500 companies who wished to identify deficiencies in corporate planning and create a
system to manage change. (Stanford Research Institute Newsletter, 2005).
Though Humphrey’s key finding were never published, as they were deemed too
controversial, he wrote them in the December 2005 Newsletter of the Stanford Research
Institutes Alumni Newsletter. They are as follows:
1) A business can be divided into two parts: The base business plus the development
business. The development business turns over every 5 to 7 years, 2) All people measure
what they get from their work and divide it by what they give to the work and this
reward/effort ratio is compared to others. If it perceived as too low, the person slows

down, 3) The introduction of a corporate planner upsets the sense of fair play at senior
level, making the job of the corporate planner impossible, 4) The gap between what could
Absence of Strategic Planning and Failure of Small Businesses
Early research on the failure of small businesses identified the absence of strategic planning as a
primary cause (Ibrahim & Goodwin, 1985; Mayer & Goldstein, 1961; Mintzberg, 1979;
Crawford & Lefebvre, 1984; Crawford & Ibrahim, 1985; Nerone, 1997). Excessive optimism, a
failure to monitor results, and the absence of balanced growth also were identified as key factors
(Mayer & Goldstein, 1961; Mintzberg, 1979; Crawford & Lefebvre, 1984; Crawford & Ibrahim,
1985). In their 1982 study, Sexton and Van Auken found that small business owners and manager
often thought of strategic planning, but rarely took action. Several other studies determined that
not only was systematic strategic planning largely absent in small businesses, but also that what
little did take place was reactive, incremental, disorganized, sporadic, and inadequate (Still,
1974; Cooper, 1977; Crawford, R. L., & Ibrahim, A. B., 1985). As Nerone observed, "Most
entrepreneurs [small business owners] are doing their strategy on the back of a napkin, as they
sweat out making the Friday payroll” (Nerone, 1997, p. 9).
In a more recent article, Kraus, Harms, and Schwarz argue that strategic planning does
occur in small businesses, but that it is often performed intuitively without the use of planning
instruments (2006). In practice, small businesses plan in the short term, rather than focusing on
long-term objectives, and are typically reactive rather than proactive (Wang, Walker, &
Redmond, 2007). Small businesses that claim to plan for the future typically develop those plans
ad hoc and rarely write them down formally. Furthermore, the plans provide little guidance for
measuring or analyzing the performance of the small business (Wang et al., 2007). The literature
also indicates that strategic planning in small businesses is unstructured, informal, and irregular,
lacking in information (Gibb & Scott, 1985; Flavel, 1991; Balasundaram, 2009).

Correspondingly, small businesses have been described as shortsighted and strategically
narrowminded (Wang et al., 2007).
Benefits of Strategic Planning
This absence of strategic planning certainly counters much of the literature, which
indicates that small businesses should plan for the long term in order to effectively compete
(Wang et al., 2007). Small businesses that disregard strategic planning risk, at a minimum,
growth and performance and, at worst, their very survival (Wang et al., 2007). Understandably,
small business success is not determined by strategic planning alone; however, there are more
benefits to planning versus not planning (Wang et al., 2007).
Problem Statement
Strategic planning has been studied since the 1950's, but research has focused primarily
on larger organizations (Mazzarol, 2004). Research on strategic planning in small businesses is
still in the early stages (Kraus, Reiche, & Reschke, 2007). Furthermore, although small
businesses are vital to the Louisiana economy, little, if any, research on strategic planning in
Louisiana small businesses has been undertaken. While the existing literature suggests that
strategic planning is positively related to the performance of small businesses (Kraus, Harms, &
Schwarz, 2006; Balasundaram, 2009), most of them do not plan, for as yet unknown reasons
(Wang et al., 2007). Thus, Robinson and Pearce argue that “Research needs to provide specific
reasons why planning is not practiced in firms” (Robinson & Pearce, 1984, p. 135).
Understanding why small businesses do not engage in strategic planning, and how that omission
affects small business mortality, would enable consultants to better serve the small business
sector and public officials to improve public policy.

Purpose of Study
The primary purpose of this study is to determine the influence of selected factors that
influence small business owners’ perceived obstacles to strategic planning in Louisiana small
businesses.
Research Objectives
The dependent variable of this study is the propensity of Louisiana small businesses to
strategically plan. The independent variable of this study is Louisiana small business owners’
perceived obstacles to strategic planning.
The following specific objectives were formulated to guide this research study:
16. To describe small businesses in Louisiana on the following characteristics:
a) Years the organization has been in business;
b) Industry in which the small business is positioned;
c) Current number of full time and part time employees on the organization's
payroll;
d) Structure of the organization i.e. Limited Liability Corporation,
Subchapter S
Corporation, Partnership, etc.:
e) Existence of a written long term plan.
17. To describe small businesses in Louisiana on the perceived degree to which the
organization conducts strategic planning.
18. To describe small businesses in Louisiana perception regarding the following perceived
obstacles to strategic planning:
a) The perceived quality of the organization’s employees;

b) The perceived degree to which the organization’s leadership has
knowledge of the
planning process;
c) The perceived available time the organization has to strategically plan.
19. To determine if a relationship exists between Louisiana small business owners' perceived
obstacles to strategic planning and the following variables:
a) Industry in which the small business is positioned in;
b) Structure of the organization i.e. Limited Liability Corporation,
Subchapter S
Corporation, Partnership, etc.;
c) Years the organization has been in business;
d) Current number of full time and part time employees on the organization's
payroll;
e) The perceived degree to which the organization conducts strategic
planning;
f) Possession of a written long term plan.
20. To determine if a model exists explaining a significant portion of the variance in
Louisiana small business owners' perceived degree to which the small business conducts
strategic planning using the following characteristics:
a) Years the organization has been in business;
b) Industry in which the small business is positioned;
c) Current number of full time and part time employees on the organization's
payroll;
d) Structure of the organization i.e. Limited Liability Corporation,
Subchapter S
Corporation, Partnership, etc.;

e) The perceived degree to which the organization conducts strategic
planning;
f) The perceived quality of the organization’s employees;
g) The perceived degree to which the organization’s leadership has
knowledge of the
planning process;
h) The perceived available time the organization has to strategically plan;
i) Possession of a written long term plan.
Summary
Small businesses play an important role in the Louisiana economy. Prior research on
strategic planning has focused primarily on large businesses (Mazzarol, 2004); however, little
literature exists that focuses on Louisiana small business strategic planning. While the existing
literature implies that strategic planning is positively related to the performance of small
businesses (Kraus, Harms, & Schwarz, 2006; Balasundaram, 2009), most of them do not plan,
for as yet unknown reasons (Wang et al., 2007). Therefore, this study will explore the obstacles
to strategic planning as perceived by Louisiana small business owners. The results of this study
will benefit small business owners when employing strategic planning within their organizations,
consultants when advising small businesses during the strategic planning process, and public
officials when establishing public policy affecting small businesses.

CHAPTER II: REVIEW OF LITERATURE
Given how important small businesses are to the U.S. economy, many studies have
focused on what causes them to fail. The principal cause of small business failure has been
identified as a lack of strategic planning. Other key factors contributing to small business failures
are excessive optimism, lack of balanced growth, and failure to monitor results (Ibrahim &
Goodwin, 1985; Mayer & Goldstein, 1961; Mintzberg, 1979; Crawford & Lefebvre, 1984;
Crawford & Ibrahim, 1985).
The literature suggests that small businesses owners tend to not engage in systematic
strategic planning (Perry, 2001), even though they often consider it (Sexton & Van Auken,
1982). Furthermore, any planning that small businesses do undertake tends to be reactive,
unstructured, incremental, and sporadic (Still, 1974; Cooper, 1977; Crawford & Ibrahim, 1985).
Small business owners tend to focus on immediate rather than long-term objectives, planning
for the future in an ad hoc manner, and fail to make provisions for measuring performance
(Wang et al., 2007). The approach of small businesses to strategic planning is therefore
counterintuitive: although the literature highlights the benefits of strategic planning, most small
businesses do not plan for reasons that are not fully understood (Wang et al.,
2007).
U.S. Small Businesses
Small businesses play a vital role in the U.S. economy. Collectively, they are the largest
employer, the largest importer, and the largest exporter in the country (Office of the United States
Trade Representative, 2009). Small businesses, which are defined as those employing fewer than
500 individuals, comprise 99.9% of firms in the U.S. Furthermore, businesses employing fewer
than 20 individuals comprise 89.7% of U.S. small businesses. In 2008, small businesses

generated 46% of the private non-farm Gross Domestic Product (GDP) (Small Business Council,
2014).
Small businesses foster the growth of local economies by providing opportunities for
employment to people who otherwise may not be employable by larger organizations (Brown,
2011). During the 18-year period from 1992 to 2010, small business outpaced larger firms in job
creation 75% of the time (Graves, 2013). In general, small businesses generate 60-80% of all
new employment in the U.S. Small businesses also generate 16.5 times more patents per
employee when compared to larger firms (Graves, 2013)
Small businesses traditionally dominate industries such as construction and retail, as well
as form a crucial link in the supply chain for large-scale and capital-intensive manufacturing
industries such as defense, mining, automotive, and marine (Abdullah & bin Baker, 2000;
Robinson & Pearce, 1984; Wang et al., 2007; Wang, Rowe, & Cripps, 2006). Furthermore, small
businesses provide a competitive balance to industries that would otherwise be dominated solely
by larger firms (Wang et al., 2007).
However, despite the critical importance of small businesses in the U.S., only
approximately half survive past five years and roughly a third last for 10 years (SBA
Frequently Asked Questions, 2012).
Louisiana Small Businesses
Small businesses play a vital role in the Louisiana economy as well. In aggregate, they
account for 97.3% of employers in Louisiana and employ more than half, 54.5%, of the state's
private sector workforce. Businesses with 500 or more employees comprise the remaining 45.5%
(U.S. Small Business Administration, 2014). Federal, state, and local governments, as well as the
U.S. Postal Service, employ 321,569 public sector workers, or 6.95% of Louisiana’s population
(Molla, 2014). As noted in Table 1, the Small Business Administration (2014) reported that
414,779 small businesses existed in the state of Louisiana in 2011. Of those businesses, only
78,451 had employees; 68,030 employed less than 20 individuals. The majority of the small
businesses, 336,328 or 80.7%, did not have employees. Overall, Louisiana small businesses
employ 875,974 individuals (U.S. Small Business Administration, 2014). (See Table 1)
Table 1 The Number of Louisiana Small Firms by Industry, 2011 (Ranked by Number Of Small
Employer Firms) Source: (U.S. Small Business Administration, 2014)
Number of Louisiana Small Firms by Industry, 2011 (ranked
by number of small employer firms)
Industry
Employer Firms
with
1-499 Employees
Employer Firms
with
1-19 Employees
Nonemployer
Firms
Professional, scientific, and tech svcs. 10,621 9,853 35,489
Retail trade 10,398 9,302 23,229
Health care & social assistance 9,646 8,060 30,124
Other services (except public admin.) 8,719 8,005 64,016
Construction 7,867 6,984 38,305
Accommodatin & food services 6,469 4,878 7,513
Wholesale trade 3,845 3,012 4,206
Admin., supp., waste mgt., remed.Svcs. 3,754 3,186 36,768
Finance & insurance 3,689 3,334 9,127
Real estate & renal & leasing 3,371 3,103 29,506
Transportation & warehousing 2,733 2,310 15,178
Manufacturing 2,706 2,027 4,251
Arts, entertainment, & recreation 1,272 1,080 13,143
Mining 1,196 935 6,277
Educational services 955 649 6,248
Forestry, etc. & agriculture support 566 525 9,654
Information 558 440 3,041
Management of comp. & enterprises 301 65 -
Utilities 203 182 253
Unclassified 177 177 -
Total 78,451 68,030 336,328
As noted in Table 2, the top four industries most populated by small businesses in
Louisiana are health care, social assistance, accommodation and food service, and retail trade. In
2012, 84.5% of the 4000 companies exporting goods were small firms. Louisiana export
revenues totaled more than $65 billion in 2014 (World Trade Center, New Orleans, 2015). The
small firms generated 34.8%, or $22.6 billion, of Louisiana's total export value (U.S. Small
Business Administration, 2014).
Table 2 Employment in Louisiana Small Firms by Industry and Firm Size, 2011 (Ranked by
Number of Small Employer Firms) Source: (U.S. Small Business Administration, 2014)
Employment in Louisiana by Industry and Firm Size, 2011
(ranked by small firm employment)
Industry Employment
Small Firms Total Firms
Small Firm Share
of Industry
Employment (%)
Health care & social assistance 156,785 282,985 55
Accommodation & food services 106,250 182,523 58
Retail trade 93,286 226,638 41
Construction 78,986 127,941 62
Professional, scientific, & tech. svcs. 66,888 88,171 76
Other services (except public admin.) 64,979 72,394 90
Manufacturing 50,963 125,820 41
Wholesale trade 46,893 75,009 63
Admin., sup., waste mgt., remed.
svcs. 46,211 100,856 46
Finance & insurance 34,913 66,255 53
Transportation & warehousing 30,771 65,367 47
Educational services
Real estate & rental & leasing 24,014 36,322 66
Mining 19,469 53,185 37
Arts, entertainment, & recreation 14,513 23,477 62
Information 7,340 23,722 31
Management of comp. & enterprises 6,173 20,468 30
Forestry, etc. & agriculture support 3,764 3,951 95
Utilities 2,454 - -
Unclassified - - -
Total 875,974 1,617,229 54
Similar to the national percentages, only 47.6% of Louisiana small businesses survive beyond
five years and roughly 37.4% remain in business more than 10 years (U.S. Small Business
Administration, 2014). Although small businesses are important to the Louisiana economy,

research on strategic planning in small businesses is largely absent from the literature. Instead,
research on strategic planning has focused primarily on larger organizations (Mazzarol, 2004).
Strategic Planning and Its Benefits
Given the risk of failure, small businesses are concerned with establishing a competitive
advantage that will ensure long-term survival (Galán, Monje, & Zúñiga-Vicente, 2009). Wankel
(2007) defined strategy as "an approach to reach corporate goals in order to be successful on a
long-term basis," and as "an attempt to prepare for all eventualities by abstraction and thus to
account for the complexity and the dynamics of the environment" (p. 74). Although businesses
cannot predict the future, they can prepare for it and align accordingly (Kraus, Reiche, &
Reschke, 2011). Strategic planning involves deducing how present developments will look in the
future, providing guiding principles and procedures for achieving specified goals. In other words,
strategic planning is an essential tool for strategic management, allowing businesses to stipulate
basic conditions for their future activities (Kraus et al., 2011).
Given its concern with competitive advantage, strategic planning focuses on establishing
long-term goals, developing plans to reach those goals, and distributing the resources needed to
achieve those goals (Stonehouse & Pemberton, 2002; O'Regan & Ghobadian, 2004; Wang et al.,
2007). As described by Kenichi Ohmae, "the purpose of strategic planning is to enable a business
to gain as efficiently as possible, a sustainable edge over its competitors" (as cited in O'Regan &
Ghobadian, 2004, p. 664; Wang et al., 2007). Businesses grow by acquiring new customers and
thus market share. Strategic planning spawns innovation by constantly seeking to develop new
services and products to bring to the market (Hill, 2011). A strategic business plan pairs the
objectives of a company with the needs of the marketplace. It not only defines company goals,
but also applies those goals to take advantage of available business opportunities by carefully

analyzing a particular company's strengths and weaknesses in meeting industry needs (Scott,
2011). Specifically, strategic planning helps a company identify a market need or customer
problem and create a product or service that efficiently and cost-effectively addresses the need or
solves the problem.
Planning also helps a company gain a clearer picture of the competition, allowing it to
develop strategies that take advantage of a competitor's weaknesses (Hill, 2011) and create
solutions that are significantly more beneficial to the customer than those provided by the
competition. Strategic planning compels a business to concentrate on specific areas in the
market, allowing for more effective business operations, and enables the business to learn as
much as it can about customer needs and potential opportunities in the market (Scott, 2011).
Correspondingly, a strategic plan includes extensive market research, exploration of industry
trends, and competitor analysis. A strategic plan shares many of the same components as a
business plan, such as an executive summary, marketing analysis, and financial statements, but is
more specific with respect to how the company will achieve its goals. For example, a strategic
business plan will attempt to identify a target market, reduce it to a manageable size, and
establish a strategy for acquiring that market (Scott, 2011).
Strategic planning is, fundamentally, brainstorming at its best. Since strategic planning
relies on creativity, its development involves intuition as much as management science. The more
small business owners understand their companies and industries, the better their strategic plans
will be (Pirraglia, 2011). As expressed by Drucker (1974), "it is necessary in strategic planning to
start separately with, 'What is our business?,' 'What will it be?,' and 'What should it be?'" (p.
122). Strategic planning demarcates where a company is heading (Pirraglia, 2011). The strategic
plan provides a road map for a business in which the management team fashions a longterm

vision for a larger, more profitable organization. In order to encourage company growth, strategic
planning involves envisioning potential activities that must be undertaken and potential expenses
that will have to be made (Hill, 2011). By using strategic planning, small business owners not
only become better positioned in the market, but also become experts in their respective
industries. The strategic plan also serves as an organizational tool, keeping the company on track
to meet its growth and financial objectives (Scott, 2011). Through an appraisal of past growth
and adjustments for further growth, strategic planning is critical for owners to understand the
trajectory of their companies (Scott, 2011).
In general, strategic planning is more common in small businesses that exhibit better
performance. Specifically, small businesses that engage in strategic planning are more likely to
achieve higher sales growth, returns on assets, margins on profit, and employee growth (Wang et
al., 2007). They tend to be more innovative, have more newly patented products, use new process
and management technologies, and achieve international growth (Wang et al., 2007). Most
significantly, small businesses that engage in strategic planning are less likely to fail
(Wang et al., 2007). Empirical studies have linked strategic planning to success (Kraus et al.,
2011), the implication being that strategic planning is essential for the success of a small business
(Pirraglia, 2011).
Perry (2001) found that in 152 failed firms and 152 non-failed firms, very little strategic
planning took place. However, some planning was performed in the non-failed businesses, which
suggests that the degree of planning may be related to whether the business fails. One limitation
of his (2001) study was that the independent variable—planning—and the phenomenon were
only weakly correlated.

Gibson, Cassar, and Wingham (2001) found that, of 2,956 firms for which data were
available, only 16.3% were described as regular planners, while 43.5% were non-planners. The
remaining 40.2% described themselves as irregular planners. Gibson et al. (2001) determined
that planners reported higher performance than non-planners, which indicated that planning and
performance are related.
In a study by Trow (1961), out of 51 companies in which planning occurred, 12 of 19
small firms (defined as up to 1000 employees) generated steady profits. The remaining
companies did not report on profitability. These findings suggest that firms that planned were
more profitable than those that did not.
Kraus et al. (2006) conducted a study of 290 firms with less than 50 employees. The
researchers used employee growth to measure firm performance. They found that a greater
degree of formalization, as indicated by the existence of a written strategic plan, was related to a
higher degree of performance.
The History and Components of a Strategic Plan
Modern strategic planning has taken a page from World War II, in which the U.S., its
allies, and its enemies developed strategies on the battlefield. Military commanders used these
strategies to help determine the strengths and weaknesses of each force. Using these processes,
they were able to observe the battlefield or environment and establish implementation plans and
command and control mechanisms (Nerone, 1997). The process of strategic planning was
successful because it allowed military strategists to follow proven approaches that literally had
been battle tested over centuries of documented warfare (Nerone, 1997). These strategies and the
eventual success of the allied forces were adopted by the private sector as military commanders
returned from Europe and entered the civilian workforce.

Early management theorists, including H. Igor Ansoff, Philip Selznick, George Steiner,
Peter Drucker, C.H. Hofer, D.E. Schendel, and Henry Mintzberg, are considered pioneers in the
field of strategic thinking (Nerone, 1997). Other notable theorist is Harvard Business School
professor Alfred Chandler, who “insisted that structure must follow strategy” (The Economist,
2007, para. 3), and Albert Humphrey, who created the SWOT Analysis, while working at the
Stanford Research Institute during the 1960’s (Stanford Research Institute Alumni Newsletter,
2005). A later theorist, Harvard Business School Professor Michael Porter, is considered to be the
founder of the modern field of strategy and regarded as the most influential thinker on
competitiveness and management (Harvard Business School, 2014).
H. Igor Ansoff devised one of the earliest strategic planning models, the Ansoff Matrix.
The Ansoff Matrix focused on options for business growth. Ansoff identified four types of
product-market strategies: market penetration, market development, product development
strategy, and diversification (Ansoff, 1957). According to Ansoff, a product-market strategy is a
“joint statement of a product line and the corresponding set of missions which the products are
designed to fulfill” (Ansoff, 1957, p. 114). The first of these, market penetration, he defined as an
“effort to increase company sales without departing from an original product-market strategy.
The company seeks to improve business performance either by increasing the volume of sales to
its present customers or by finding new customers for present products” (Ansoff, 1957, p. 114).
In contrast, market development is “[a] strategy in which the company attempts to adapt
its present product line (generally with some modification in the product characteristics) to new
missions” (Ansoff, 1957, p. 114). A product development strategy “develops products that have
new and different characteristics such as will improve the performance of the mission” (Ansoff,
1957, p. 114). And diversification is “the final alternative. It calls for a simultaneous departure
from the present product line and the present market structure” (Ansoff, 1957, p. 114).
Figure 1 Product-Market Strategies for Business Growth Alternatives
Represents the product line and represents the corresponding set of missions. The pair of
and is a product-market strategy (Ansoff, 1957, p. 114).
In 1979, The Harvard Business Review published Michael E. Porter’s “How Competitive
Forces Shape Strategy” (Harvard Business Review, 2008). In his article, Porter suggested that
there are five forces that shape an organization's strategy: the threats of new entrants, the
bargaining power of suppliers, the bargaining power of customers, and the threat of substitute
products and services. Porter argued that these four forces interact with the fifth force:
competitors jockeying for position within an industry (Harvard Business Review, 2008).
Porter theorized that the threats to new entrants consisted of six barriers: economies of
scale, product differentiation, capital requirements, cost disadvantages independent of size,
access to distribution channels, and government policy (Porter, 1979). Economies of scale force
market entrants to either enter the market on a large scale or consent to a cost handicap.
Economies of scale can act as barriers to distribution, financing, and utilization of the
organization’s sales force (Porter, 1979). The second barrier, product differentiation, forces
market entrants to spend large amounts of money on customer service and advertising in order to
Markets
Product Line
0
MARKET
Penetration
1
2
3
..
Market Development
DIVERSIFICATION
PRODUCT
DEVELOPMENT
01234..

demonstrate product differentiation and generate a brand identity (Porter, 1979). Capital
requirements force market entrants to spend large sums of non-recoverable funds on facilities,
customer credit, inventory, and research and development, in addition to advertisements. Due to
these constraints, capital requirements limit the pool of potential entrants (Porter, 1979). Cost
disadvantages force market entrants to realize that rivals who are already entrenched in the
market possess the inherent advantage of time. Market entrants must deal with learning and
experience curves, proprietary technologies, access to pre-inflation cost of materials, and
favorable locations (Porter, 1979). The fifth barrier, access to distribution channels, forces market
entrants to acquire channels for distributing products and services. Thus, selling efforts must
attempt to displace other rivals. If wholesale channels are limited and barriers are high, a market
entrant must create its own distribution channels (Porter, 1979). Finally, government policy can
limit market entrants to industries by mandating licensing requirements, regulatory requirements,
environmental standards, or access to raw materials (Porter, 1979). Porter states,
A company’s choice of suppliers to buy from or buyer groups to sell to should be viewed
as a crucial strategic decision. A company can improve its strategic posture by finding
suppliers or buyers who possess the least power to influence it adversely. (Porter, 1979,
p. 141)
Porter theorized that suppliers can exercise bargaining forces on market participants by
either reducing or increasing the quality or prices of goods and services. Thus, suppliers can
extract profits from a market and its participants (1979). For example, Porter argues that a group
of suppliers is powerful if it is more concentrated in comparison with the industry that it is
selling to (Porter, 1979). Additionally, suppliers are powerful if their products are highly
differentiated and unique, or if switching costs have developed. Switching costs can occur when
a buyer’s product is highly specified and production lines are coupled with the supplier's
manufacturing facilities. Switching costs then become fixed even when a buyer changes

suppliers (Porter, 1979). Furthermore, if a supplier does not have to compete with other products,
the supplier essentially has no reason to reduce prices or increase the quality of its product
(Porter, 1979). Moreover, if the supplier possesses the ability to integrate further into the market,
the buyer’s ability to improve purchasing terms is highly limited (Porter, 1979). Lastly, if the
buyer is simply not significant to the supplier, the supplier and buyers' interests are not aligned,
and thus the supplier has no real incentive to work with the buyer (Porter, 1979).
Porter theorized that buyers can exercise bargaining forces on market participants if they
purchase in large quantities. This approach would require that capacity remain high consistently,
which would be particularly difficult if fixed costs within the market were high (Porter, 1979).
Additionally, buyers can exercise their will if products are standard or not particularly
differentiated. In this case, buyers are not incentivized to purchase from any one specific
company but instead could pit companies against one another in an attempt to lower market
prices (Porter, 1979). Furthermore, if a particular component for a product represents a large part
of overall costs, buyers are incentivized to shop for more favorable pricing (Porter, 1979). And if
a buyer earns low profits, then the buyer would be incentivized to lower its purchasing costs.
Should a buyer earn higher profits, it is generally less sensitive to prices, assuming that the price
does not signify a large percentage of overall costs (Porter, 1979). Additionally, if the quality of
the product is of significant importance to the buyer, the buyer is typically less price sensitive
(Porter, 1979). In his article, Porter uses an example from the oil field industry, where equipment
failure can lead to huge losses (1979). Furthermore, when the industry’s product can pay for
itself over time, such as accounting or legal services where errors can be costly, the buyer is less
likely to be price sensitive (1979). Lastly, buyers can opt to produce their own materials, thus
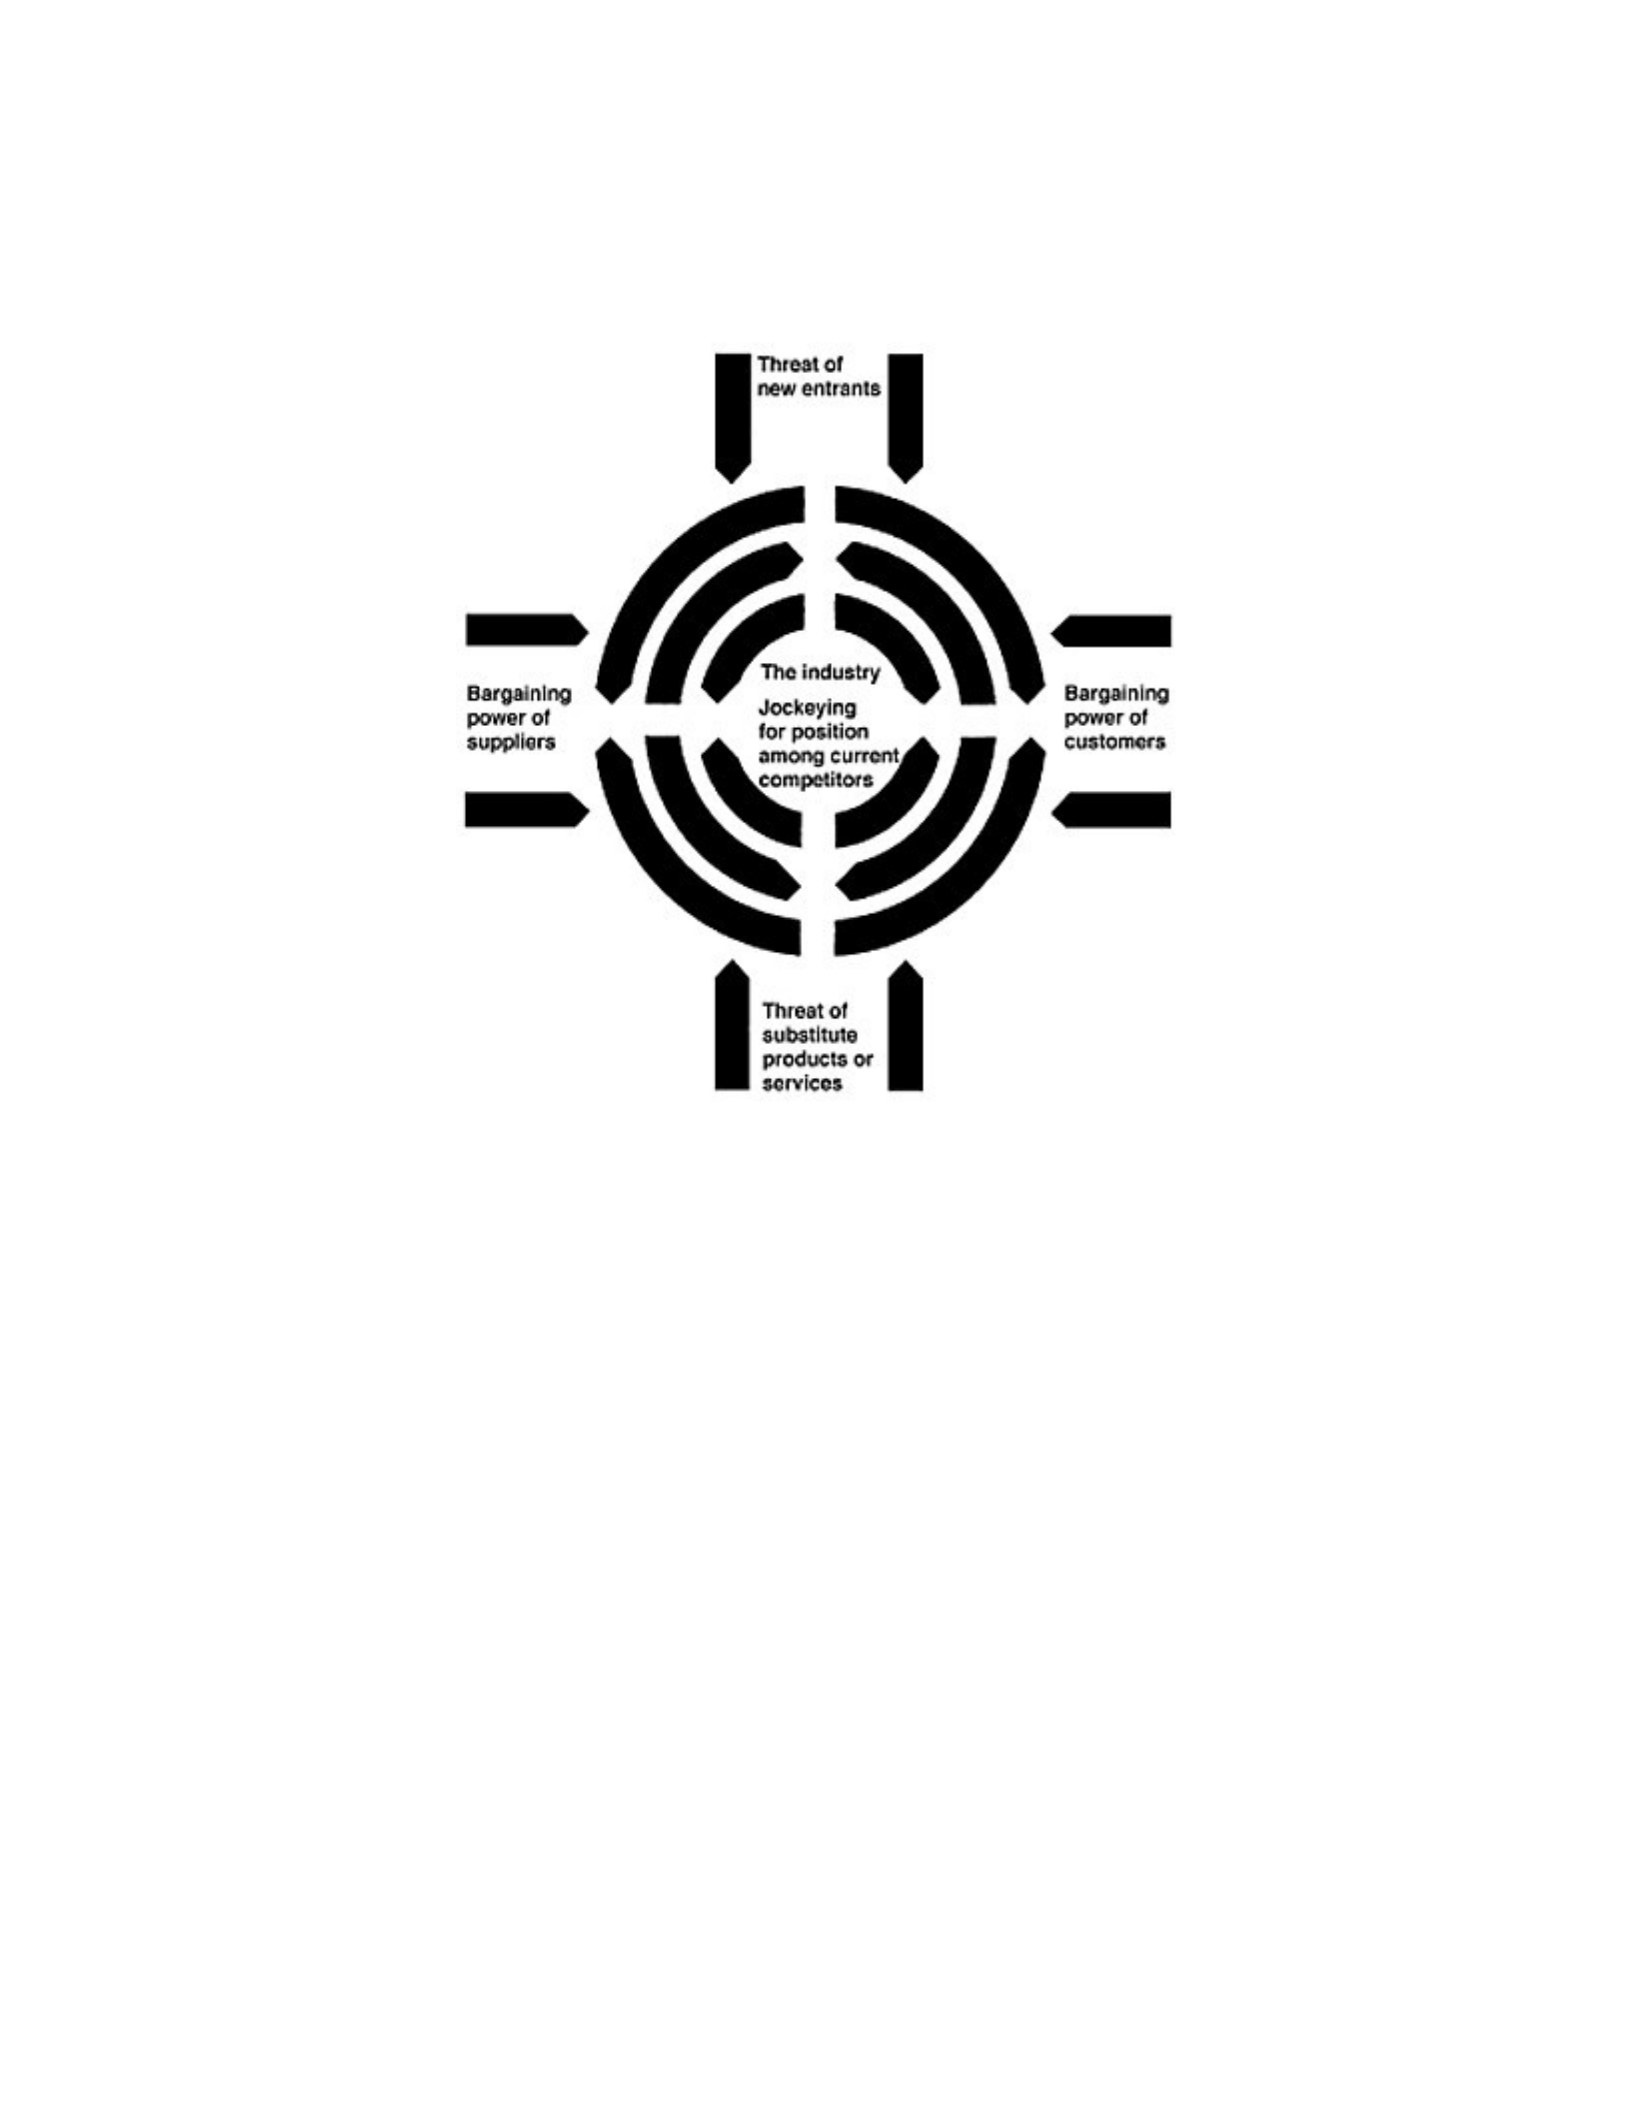
removing the need for purchasing from a third party manufacturer. This threat provides leverage
to the buyer (Porter, 1979).
Figure 2 Porter’s Original 1979 Five Force Model, Source: (Porter, 1979).
Albert S. Humphrey created what was eventually dubbed the SWOT Analysis while
working at the Stanford Research Institute during the 1960’s. His research was funded by various
Fortune 500 companies who wished to identify deficiencies in corporate planning and create a
system to manage change. (Stanford Research Institute Newsletter, 2005).
Though Humphrey’s key finding were never published, as they were deemed too
controversial, he wrote them in the December 2005 Newsletter of the Stanford Research
Institutes Alumni Newsletter. They are as follows:
1) A business can be divided into two parts: The base business plus the development
business. The development business turns over every 5 to 7 years, 2) All people measure
what they get from their work and divide it by what they give to the work and this
reward/effort ratio is compared to others. If it perceived as too low, the person slows

down, 3) The introduction of a corporate planner upsets the sense of fair play at senior
level, making the job of the corporate planner impossible, 4) The gap between what could
Absence of Strategic Planning and Failure of Small Businesses
Early research on the failure of small businesses identified the absence of strategic planning as a
primary cause (Ibrahim & Goodwin, 1985; Mayer & Goldstein, 1961; Mintzberg, 1979;
Crawford & Lefebvre, 1984; Crawford & Ibrahim, 1985; Nerone, 1997). Excessive optimism, a
failure to monitor results, and the absence of balanced growth also were identified as key factors
(Mayer & Goldstein, 1961; Mintzberg, 1979; Crawford & Lefebvre, 1984; Crawford & Ibrahim,
1985). In their 1982 study, Sexton and Van Auken found that small business owners and manager
often thought of strategic planning, but rarely took action. Several other studies determined that
not only was systematic strategic planning largely absent in small businesses, but also that what
little did take place was reactive, incremental, disorganized, sporadic, and inadequate (Still,
1974; Cooper, 1977; Crawford, R. L., & Ibrahim, A. B., 1985). As Nerone observed, "Most
entrepreneurs [small business owners] are doing their strategy on the back of a napkin, as they
sweat out making the Friday payroll” (Nerone, 1997, p. 9).
In a more recent article, Kraus, Harms, and Schwarz argue that strategic planning does
occur in small businesses, but that it is often performed intuitively without the use of planning
instruments (2006). In practice, small businesses plan in the short term, rather than focusing on
long-term objectives, and are typically reactive rather than proactive (Wang, Walker, &
Redmond, 2007). Small businesses that claim to plan for the future typically develop those plans
ad hoc and rarely write them down formally. Furthermore, the plans provide little guidance for
measuring or analyzing the performance of the small business (Wang et al., 2007). The literature
also indicates that strategic planning in small businesses is unstructured, informal, and irregular,
lacking in information (Gibb & Scott, 1985; Flavel, 1991; Balasundaram, 2009).

Correspondingly, small businesses have been described as shortsighted and strategically
narrowminded (Wang et al., 2007).
Benefits of Strategic Planning
This absence of strategic planning certainly counters much of the literature, which
indicates that small businesses should plan for the long term in order to effectively compete
(Wang et al., 2007). Small businesses that disregard strategic planning risk, at a minimum,
growth and performance and, at worst, their very survival (Wang et al., 2007). Understandably,
small business success is not determined by strategic planning alone; however, there are more
benefits to planning versus not planning (Wang et al., 2007).
Problem Statement
Strategic planning has been studied since the 1950's, but research has focused primarily
on larger organizations (Mazzarol, 2004). Research on strategic planning in small businesses is
still in the early stages (Kraus, Reiche, & Reschke, 2007). Furthermore, although small
businesses are vital to the Louisiana economy, little, if any, research on strategic planning in
Louisiana small businesses has been undertaken. While the existing literature suggests that
strategic planning is positively related to the performance of small businesses (Kraus, Harms, &
Schwarz, 2006; Balasundaram, 2009), most of them do not plan, for as yet unknown reasons
(Wang et al., 2007). Thus, Robinson and Pearce argue that “Research needs to provide specific
reasons why planning is not practiced in firms” (Robinson & Pearce, 1984, p. 135).
Understanding why small businesses do not engage in strategic planning, and how that omission
affects small business mortality, would enable consultants to better serve the small business
sector and public officials to improve public policy.

Purpose of Study
The primary purpose of this study is to determine the influence of selected factors that
influence small business owners’ perceived obstacles to strategic planning in Louisiana small
businesses.
Research Objectives
The dependent variable of this study is the propensity of Louisiana small businesses to
strategically plan. The independent variable of this study is Louisiana small business owners’
perceived obstacles to strategic planning.
The following specific objectives were formulated to guide this research study:
21. To describe small businesses in Louisiana on the following characteristics:
a) Years the organization has been in business;
b) Industry in which the small business is positioned;
c) Current number of full time and part time employees on the organization's
payroll;
d) Structure of the organization i.e. Limited Liability Corporation,
Subchapter S
Corporation, Partnership, etc.:
e) Existence of a written long term plan.
22. To describe small businesses in Louisiana on the perceived degree to which the
organization conducts strategic planning.
23. To describe small businesses in Louisiana perception regarding the following perceived
obstacles to strategic planning:
a) The perceived quality of the organization’s employees;

b) The perceived degree to which the organization’s leadership has
knowledge of the
planning process;
c) The perceived available time the organization has to strategically plan.
24. To determine if a relationship exists between Louisiana small business owners' perceived
obstacles to strategic planning and the following variables:
a) Industry in which the small business is positioned in;
b) Structure of the organization i.e. Limited Liability Corporation,
Subchapter S
Corporation, Partnership, etc.;
c) Years the organization has been in business;
d) Current number of full time and part time employees on the organization's
payroll;
e) The perceived degree to which the organization conducts strategic
planning;
f) Possession of a written long term plan.
25. To determine if a model exists explaining a significant portion of the variance in
Louisiana small business owners' perceived degree to which the small business conducts
strategic planning using the following characteristics:
a) Years the organization has been in business;
b) Industry in which the small business is positioned;
c) Current number of full time and part time employees on the organization's
payroll;
d) Structure of the organization i.e. Limited Liability Corporation,
Subchapter S
Corporation, Partnership, etc.;

e) The perceived degree to which the organization conducts strategic
planning;
f) The perceived quality of the organization’s employees;
g) The perceived degree to which the organization’s leadership has
knowledge of the
planning process;
h) The perceived available time the organization has to strategically plan;
i) Possession of a written long term plan.
Summary
Small businesses play an important role in the Louisiana economy. Prior research on
strategic planning has focused primarily on large businesses (Mazzarol, 2004); however, little
literature exists that focuses on Louisiana small business strategic planning. While the existing
literature implies that strategic planning is positively related to the performance of small
businesses (Kraus, Harms, & Schwarz, 2006; Balasundaram, 2009), most of them do not plan,
for as yet unknown reasons (Wang et al., 2007). Therefore, this study will explore the obstacles
to strategic planning as perceived by Louisiana small business owners. The results of this study
will benefit small business owners when employing strategic planning within their organizations,
consultants when advising small businesses during the strategic planning process, and public
officials when establishing public policy affecting small businesses.

CHAPTER II: REVIEW OF LITERATURE
Given how important small businesses are to the U.S. economy, many studies have
focused on what causes them to fail. The principal cause of small business failure has been
identified as a lack of strategic planning. Other key factors contributing to small business failures
are excessive optimism, lack of balanced growth, and failure to monitor results (Ibrahim &
Goodwin, 1985; Mayer & Goldstein, 1961; Mintzberg, 1979; Crawford & Lefebvre, 1984;
Crawford & Ibrahim, 1985).
The literature suggests that small businesses owners tend to not engage in systematic
strategic planning (Perry, 2001), even though they often consider it (Sexton & Van Auken,
1982). Furthermore, any planning that small businesses do undertake tends to be reactive,
unstructured, incremental, and sporadic (Still, 1974; Cooper, 1977; Crawford & Ibrahim, 1985).
Small business owners tend to focus on immediate rather than long-term objectives, planning
for the future in an ad hoc manner, and fail to make provisions for measuring performance
(Wang et al., 2007). The approach of small businesses to strategic planning is therefore
counterintuitive: although the literature highlights the benefits of strategic planning, most small
businesses do not plan for reasons that are not fully understood (Wang et al.,
2007).
U.S. Small Businesses
Small businesses play a vital role in the U.S. economy. Collectively, they are the largest
employer, the largest importer, and the largest exporter in the country (Office of the United States
Trade Representative, 2009). Small businesses, which are defined as those employing fewer than
500 individuals, comprise 99.9% of firms in the U.S. Furthermore, businesses employing fewer
than 20 individuals comprise 89.7% of U.S. small businesses. In 2008, small businesses

generated 46% of the private non-farm Gross Domestic Product (GDP) (Small Business Council,
2014).
Small businesses foster the growth of local economies by providing opportunities for
employment to people who otherwise may not be employable by larger organizations (Brown,
2011). During the 18-year period from 1992 to 2010, small business outpaced larger firms in job
creation 75% of the time (Graves, 2013). In general, small businesses generate 60-80% of all
new employment in the U.S. Small businesses also generate 16.5 times more patents per
employee when compared to larger firms (Graves, 2013)
Small businesses traditionally dominate industries such as construction and retail, as well
as form a crucial link in the supply chain for large-scale and capital-intensive manufacturing
industries such as defense, mining, automotive, and marine (Abdullah & bin Baker, 2000;
Robinson & Pearce, 1984; Wang et al., 2007; Wang, Rowe, & Cripps, 2006). Furthermore, small
businesses provide a competitive balance to industries that would otherwise be dominated solely
by larger firms (Wang et al., 2007).
However, despite the critical importance of small businesses in the U.S., only
approximately half survive past five years and roughly a third last for 10 years (SBA
Frequently Asked Questions, 2012).
Louisiana Small Businesses
Small businesses play a vital role in the Louisiana economy as well. In aggregate, they
account for 97.3% of employers in Louisiana and employ more than half, 54.5%, of the state's
private sector workforce. Businesses with 500 or more employees comprise the remaining 45.5%
(U.S. Small Business Administration, 2014). Federal, state, and local governments, as well as the
U.S. Postal Service, employ 321,569 public sector workers, or 6.95% of Louisiana’s population
(Molla, 2014). As noted in Table 1, the Small Business Administration (2014) reported that
414,779 small businesses existed in the state of Louisiana in 2011. Of those businesses, only
78,451 had employees; 68,030 employed less than 20 individuals. The majority of the small
businesses, 336,328 or 80.7%, did not have employees. Overall, Louisiana small businesses
employ 875,974 individuals (U.S. Small Business Administration, 2014). (See Table 1)
Table 1 The Number of Louisiana Small Firms by Industry, 2011 (Ranked by Number Of Small
Employer Firms) Source: (U.S. Small Business Administration, 2014)
Number of Louisiana Small Firms by Industry, 2011 (ranked
by number of small employer firms)
Industry
Employer Firms
with
1-499 Employees
Employer Firms
with
1-19 Employees
Nonemployer
Firms
Professional, scientific, and tech svcs. 10,621 9,853 35,489
Retail trade 10,398 9,302 23,229
Health care & social assistance 9,646 8,060 30,124
Other services (except public admin.) 8,719 8,005 64,016
Construction 7,867 6,984 38,305
Accommodatin & food services 6,469 4,878 7,513
Wholesale trade 3,845 3,012 4,206
Admin., supp., waste mgt., remed.Svcs. 3,754 3,186 36,768
Finance & insurance 3,689 3,334 9,127
Real estate & renal & leasing 3,371 3,103 29,506
Transportation & warehousing 2,733 2,310 15,178
Manufacturing 2,706 2,027 4,251
Arts, entertainment, & recreation 1,272 1,080 13,143
Mining 1,196 935 6,277
Educational services 955 649 6,248
Forestry, etc. & agriculture support 566 525 9,654
Information 558 440 3,041
Management of comp. & enterprises 301 65 -
Utilities 203 182 253
Unclassified 177 177 -
Total 78,451 68,030 336,328
As noted in Table 2, the top four industries most populated by small businesses in
Louisiana are health care, social assistance, accommodation and food service, and retail trade. In
2012, 84.5% of the 4000 companies exporting goods were small firms. Louisiana export
revenues totaled more than $65 billion in 2014 (World Trade Center, New Orleans, 2015). The
small firms generated 34.8%, or $22.6 billion, of Louisiana's total export value (U.S. Small
Business Administration, 2014).
Table 2 Employment in Louisiana Small Firms by Industry and Firm Size, 2011 (Ranked by
Number of Small Employer Firms) Source: (U.S. Small Business Administration, 2014)
Employment in Louisiana by Industry and Firm Size, 2011
(ranked by small firm employment)
Industry Employment
Small Firms Total Firms
Small Firm Share
of Industry
Employment (%)
Health care & social assistance 156,785 282,985 55
Accommodation & food services 106,250 182,523 58
Retail trade 93,286 226,638 41
Construction 78,986 127,941 62
Professional, scientific, & tech. svcs. 66,888 88,171 76
Other services (except public admin.) 64,979 72,394 90
Manufacturing 50,963 125,820 41
Wholesale trade 46,893 75,009 63
Admin., sup., waste mgt., remed.
svcs. 46,211 100,856 46
Finance & insurance 34,913 66,255 53
Transportation & warehousing 30,771 65,367 47
Educational services
Real estate & rental & leasing 24,014 36,322 66
Mining 19,469 53,185 37
Arts, entertainment, & recreation 14,513 23,477 62
Information 7,340 23,722 31
Management of comp. & enterprises 6,173 20,468 30
Forestry, etc. & agriculture support 3,764 3,951 95
Utilities 2,454 - -
Unclassified - - -
Total 875,974 1,617,229 54
Similar to the national percentages, only 47.6% of Louisiana small businesses survive beyond
five years and roughly 37.4% remain in business more than 10 years (U.S. Small Business
Administration, 2014). Although small businesses are important to the Louisiana economy,

research on strategic planning in small businesses is largely absent from the literature. Instead,
research on strategic planning has focused primarily on larger organizations (Mazzarol, 2004).
Strategic Planning and Its Benefits
Given the risk of failure, small businesses are concerned with establishing a competitive
advantage that will ensure long-term survival (Galán, Monje, & Zúñiga-Vicente, 2009). Wankel
(2007) defined strategy as "an approach to reach corporate goals in order to be successful on a
long-term basis," and as "an attempt to prepare for all eventualities by abstraction and thus to
account for the complexity and the dynamics of the environment" (p. 74). Although businesses
cannot predict the future, they can prepare for it and align accordingly (Kraus, Reiche, &
Reschke, 2011). Strategic planning involves deducing how present developments will look in the
future, providing guiding principles and procedures for achieving specified goals. In other words,
strategic planning is an essential tool for strategic management, allowing businesses to stipulate
basic conditions for their future activities (Kraus et al., 2011).
Given its concern with competitive advantage, strategic planning focuses on establishing
long-term goals, developing plans to reach those goals, and distributing the resources needed to
achieve those goals (Stonehouse & Pemberton, 2002; O'Regan & Ghobadian, 2004; Wang et al.,
2007). As described by Kenichi Ohmae, "the purpose of strategic planning is to enable a business
to gain as efficiently as possible, a sustainable edge over its competitors" (as cited in O'Regan &
Ghobadian, 2004, p. 664; Wang et al., 2007). Businesses grow by acquiring new customers and
thus market share. Strategic planning spawns innovation by constantly seeking to develop new
services and products to bring to the market (Hill, 2011). A strategic business plan pairs the
objectives of a company with the needs of the marketplace. It not only defines company goals,
but also applies those goals to take advantage of available business opportunities by carefully

analyzing a particular company's strengths and weaknesses in meeting industry needs (Scott,
2011). Specifically, strategic planning helps a company identify a market need or customer
problem and create a product or service that efficiently and cost-effectively addresses the need or
solves the problem.
Planning also helps a company gain a clearer picture of the competition, allowing it to
develop strategies that take advantage of a competitor's weaknesses (Hill, 2011) and create
solutions that are significantly more beneficial to the customer than those provided by the
competition. Strategic planning compels a business to concentrate on specific areas in the
market, allowing for more effective business operations, and enables the business to learn as
much as it can about customer needs and potential opportunities in the market (Scott, 2011).
Correspondingly, a strategic plan includes extensive market research, exploration of industry
trends, and competitor analysis. A strategic plan shares many of the same components as a
business plan, such as an executive summary, marketing analysis, and financial statements, but is
more specific with respect to how the company will achieve its goals. For example, a strategic
business plan will attempt to identify a target market, reduce it to a manageable size, and
establish a strategy for acquiring that market (Scott, 2011).
Strategic planning is, fundamentally, brainstorming at its best. Since strategic planning
relies on creativity, its development involves intuition as much as management science. The more
small business owners understand their companies and industries, the better their strategic plans
will be (Pirraglia, 2011). As expressed by Drucker (1974), "it is necessary in strategic planning to
start separately with, 'What is our business?,' 'What will it be?,' and 'What should it be?'" (p.
122). Strategic planning demarcates where a company is heading (Pirraglia, 2011). The strategic
plan provides a road map for a business in which the management team fashions a longterm

vision for a larger, more profitable organization. In order to encourage company growth, strategic
planning involves envisioning potential activities that must be undertaken and potential expenses
that will have to be made (Hill, 2011). By using strategic planning, small business owners not
only become better positioned in the market, but also become experts in their respective
industries. The strategic plan also serves as an organizational tool, keeping the company on track
to meet its growth and financial objectives (Scott, 2011). Through an appraisal of past growth
and adjustments for further growth, strategic planning is critical for owners to understand the
trajectory of their companies (Scott, 2011).
In general, strategic planning is more common in small businesses that exhibit better
performance. Specifically, small businesses that engage in strategic planning are more likely to
achieve higher sales growth, returns on assets, margins on profit, and employee growth (Wang et
al., 2007). They tend to be more innovative, have more newly patented products, use new process
and management technologies, and achieve international growth (Wang et al., 2007). Most
significantly, small businesses that engage in strategic planning are less likely to fail
(Wang et al., 2007). Empirical studies have linked strategic planning to success (Kraus et al.,
2011), the implication being that strategic planning is essential for the success of a small business
(Pirraglia, 2011).
Perry (2001) found that in 152 failed firms and 152 non-failed firms, very little strategic
planning took place. However, some planning was performed in the non-failed businesses, which
suggests that the degree of planning may be related to whether the business fails. One limitation
of his (2001) study was that the independent variable—planning—and the phenomenon were
only weakly correlated.

Gibson, Cassar, and Wingham (2001) found that, of 2,956 firms for which data were
available, only 16.3% were described as regular planners, while 43.5% were non-planners. The
remaining 40.2% described themselves as irregular planners. Gibson et al. (2001) determined
that planners reported higher performance than non-planners, which indicated that planning and
performance are related.
In a study by Trow (1961), out of 51 companies in which planning occurred, 12 of 19
small firms (defined as up to 1000 employees) generated steady profits. The remaining
companies did not report on profitability. These findings suggest that firms that planned were
more profitable than those that did not.
Kraus et al. (2006) conducted a study of 290 firms with less than 50 employees. The
researchers used employee growth to measure firm performance. They found that a greater
degree of formalization, as indicated by the existence of a written strategic plan, was related to a
higher degree of performance.
The History and Components of a Strategic Plan
Modern strategic planning has taken a page from World War II, in which the U.S., its
allies, and its enemies developed strategies on the battlefield. Military commanders used these
strategies to help determine the strengths and weaknesses of each force. Using these processes,
they were able to observe the battlefield or environment and establish implementation plans and
command and control mechanisms (Nerone, 1997). The process of strategic planning was
successful because it allowed military strategists to follow proven approaches that literally had
been battle tested over centuries of documented warfare (Nerone, 1997). These strategies and the
eventual success of the allied forces were adopted by the private sector as military commanders
returned from Europe and entered the civilian workforce.

Early management theorists, including H. Igor Ansoff, Philip Selznick, George Steiner,
Peter Drucker, C.H. Hofer, D.E. Schendel, and Henry Mintzberg, are considered pioneers in the
field of strategic thinking (Nerone, 1997). Other notable theorist is Harvard Business School
professor Alfred Chandler, who “insisted that structure must follow strategy” (The Economist,
2007, para. 3), and Albert Humphrey, who created the SWOT Analysis, while working at the
Stanford Research Institute during the 1960’s (Stanford Research Institute Alumni Newsletter,
2005). A later theorist, Harvard Business School Professor Michael Porter, is considered to be the
founder of the modern field of strategy and regarded as the most influential thinker on
competitiveness and management (Harvard Business School, 2014).
H. Igor Ansoff devised one of the earliest strategic planning models, the Ansoff Matrix.
The Ansoff Matrix focused on options for business growth. Ansoff identified four types of
product-market strategies: market penetration, market development, product development
strategy, and diversification (Ansoff, 1957). According to Ansoff, a product-market strategy is a
“joint statement of a product line and the corresponding set of missions which the products are
designed to fulfill” (Ansoff, 1957, p. 114). The first of these, market penetration, he defined as an
“effort to increase company sales without departing from an original product-market strategy.
The company seeks to improve business performance either by increasing the volume of sales to
its present customers or by finding new customers for present products” (Ansoff, 1957, p. 114).
In contrast, market development is “[a] strategy in which the company attempts to adapt
its present product line (generally with some modification in the product characteristics) to new
missions” (Ansoff, 1957, p. 114). A product development strategy “develops products that have
new and different characteristics such as will improve the performance of the mission” (Ansoff,
1957, p. 114). And diversification is “the final alternative. It calls for a simultaneous departure
from the present product line and the present market structure” (Ansoff, 1957, p. 114).
Figure 1 Product-Market Strategies for Business Growth Alternatives
Represents the product line and represents the corresponding set of missions. The pair of
and is a product-market strategy (Ansoff, 1957, p. 114).
In 1979, The Harvard Business Review published Michael E. Porter’s “How Competitive
Forces Shape Strategy” (Harvard Business Review, 2008). In his article, Porter suggested that
there are five forces that shape an organization's strategy: the threats of new entrants, the
bargaining power of suppliers, the bargaining power of customers, and the threat of substitute
products and services. Porter argued that these four forces interact with the fifth force:
competitors jockeying for position within an industry (Harvard Business Review, 2008).
Porter theorized that the threats to new entrants consisted of six barriers: economies of
scale, product differentiation, capital requirements, cost disadvantages independent of size,
access to distribution channels, and government policy (Porter, 1979). Economies of scale force
market entrants to either enter the market on a large scale or consent to a cost handicap.
Economies of scale can act as barriers to distribution, financing, and utilization of the
organization’s sales force (Porter, 1979). The second barrier, product differentiation, forces
market entrants to spend large amounts of money on customer service and advertising in order to
Markets
Product Line
0
MARKET
Penetration
1
2
3
..
Market Development
DIVERSIFICATION
PRODUCT
DEVELOPMENT
01234..

demonstrate product differentiation and generate a brand identity (Porter, 1979). Capital
requirements force market entrants to spend large sums of non-recoverable funds on facilities,
customer credit, inventory, and research and development, in addition to advertisements. Due to
these constraints, capital requirements limit the pool of potential entrants (Porter, 1979). Cost
disadvantages force market entrants to realize that rivals who are already entrenched in the
market possess the inherent advantage of time. Market entrants must deal with learning and
experience curves, proprietary technologies, access to pre-inflation cost of materials, and
favorable locations (Porter, 1979). The fifth barrier, access to distribution channels, forces market
entrants to acquire channels for distributing products and services. Thus, selling efforts must
attempt to displace other rivals. If wholesale channels are limited and barriers are high, a market
entrant must create its own distribution channels (Porter, 1979). Finally, government policy can
limit market entrants to industries by mandating licensing requirements, regulatory requirements,
environmental standards, or access to raw materials (Porter, 1979). Porter states,
A company’s choice of suppliers to buy from or buyer groups to sell to should be viewed
as a crucial strategic decision. A company can improve its strategic posture by finding
suppliers or buyers who possess the least power to influence it adversely. (Porter, 1979,
p. 141)
Porter theorized that suppliers can exercise bargaining forces on market participants by
either reducing or increasing the quality or prices of goods and services. Thus, suppliers can
extract profits from a market and its participants (1979). For example, Porter argues that a group
of suppliers is powerful if it is more concentrated in comparison with the industry that it is
selling to (Porter, 1979). Additionally, suppliers are powerful if their products are highly
differentiated and unique, or if switching costs have developed. Switching costs can occur when
a buyer’s product is highly specified and production lines are coupled with the supplier's
manufacturing facilities. Switching costs then become fixed even when a buyer changes

suppliers (Porter, 1979). Furthermore, if a supplier does not have to compete with other products,
the supplier essentially has no reason to reduce prices or increase the quality of its product
(Porter, 1979). Moreover, if the supplier possesses the ability to integrate further into the market,
the buyer’s ability to improve purchasing terms is highly limited (Porter, 1979). Lastly, if the
buyer is simply not significant to the supplier, the supplier and buyers' interests are not aligned,
and thus the supplier has no real incentive to work with the buyer (Porter, 1979).
Porter theorized that buyers can exercise bargaining forces on market participants if they
purchase in large quantities. This approach would require that capacity remain high consistently,
which would be particularly difficult if fixed costs within the market were high (Porter, 1979).
Additionally, buyers can exercise their will if products are standard or not particularly
differentiated. In this case, buyers are not incentivized to purchase from any one specific
company but instead could pit companies against one another in an attempt to lower market
prices (Porter, 1979). Furthermore, if a particular component for a product represents a large part
of overall costs, buyers are incentivized to shop for more favorable pricing (Porter, 1979). And if
a buyer earns low profits, then the buyer would be incentivized to lower its purchasing costs.
Should a buyer earn higher profits, it is generally less sensitive to prices, assuming that the price
does not signify a large percentage of overall costs (Porter, 1979). Additionally, if the quality of
the product is of significant importance to the buyer, the buyer is typically less price sensitive
(Porter, 1979). In his article, Porter uses an example from the oil field industry, where equipment
failure can lead to huge losses (1979). Furthermore, when the industry’s product can pay for
itself over time, such as accounting or legal services where errors can be costly, the buyer is less
likely to be price sensitive (1979). Lastly, buyers can opt to produce their own materials, thus
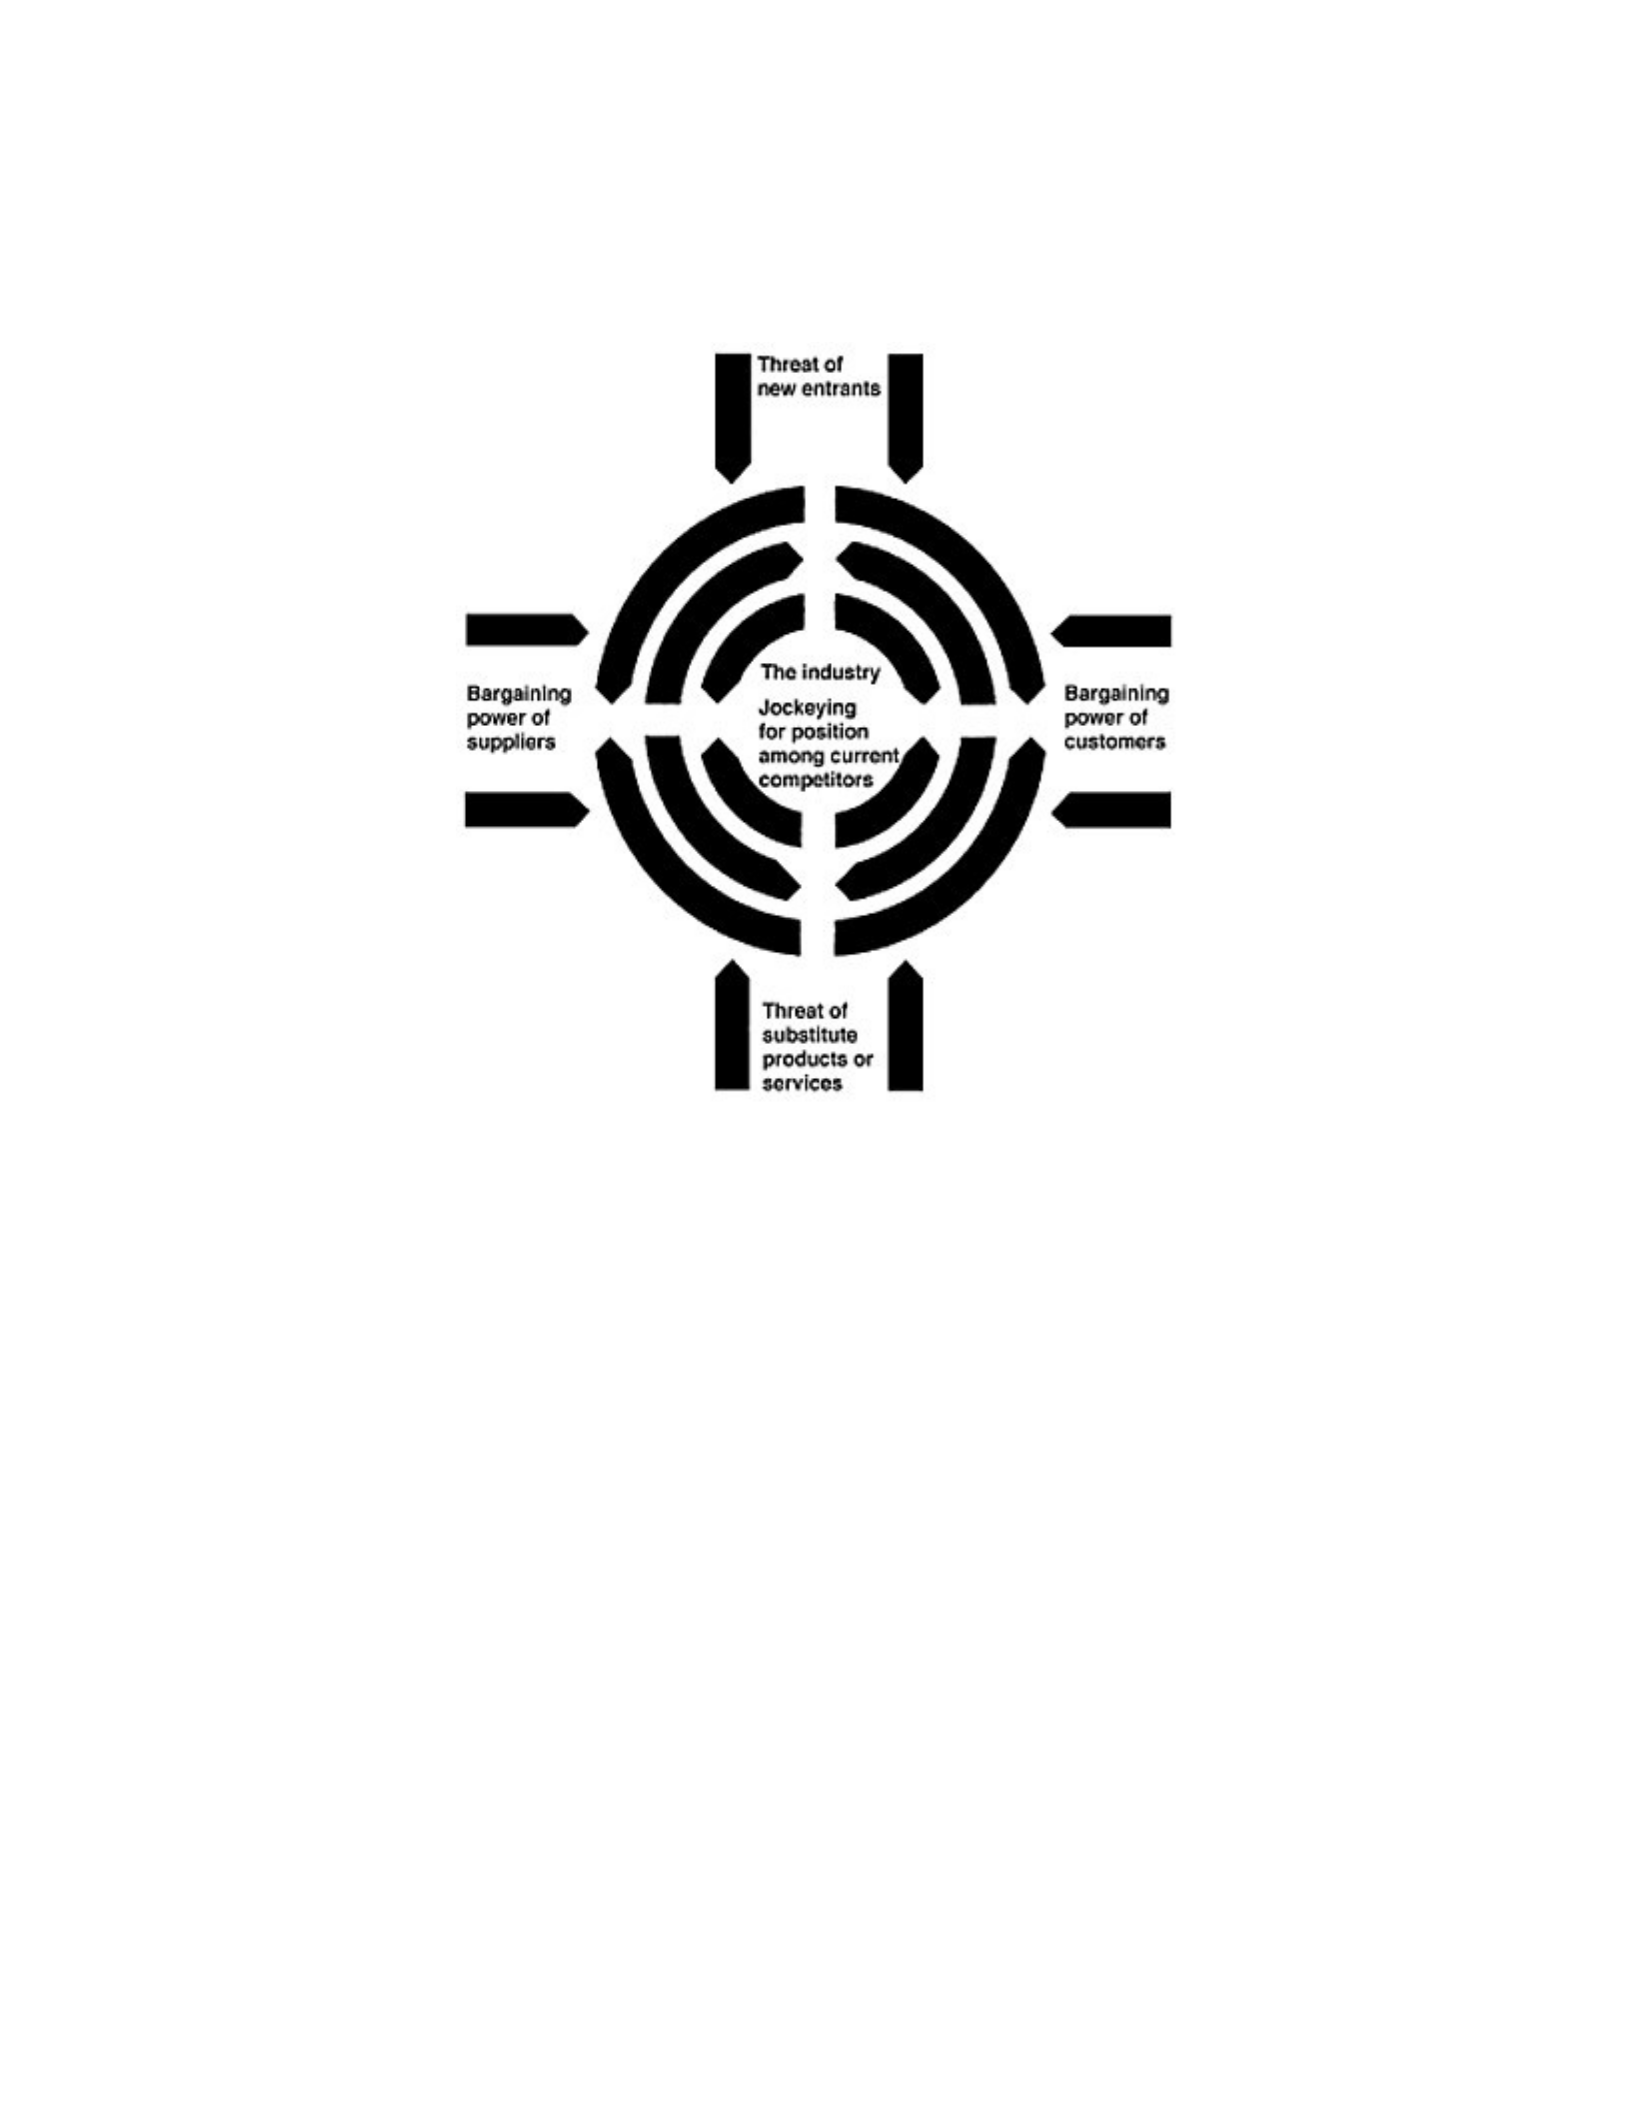
removing the need for purchasing from a third party manufacturer. This threat provides leverage
to the buyer (Porter, 1979).
Figure 2 Porter’s Original 1979 Five Force Model, Source: (Porter, 1979).
Albert S. Humphrey created what was eventually dubbed the SWOT Analysis while
working at the Stanford Research Institute during the 1960’s. His research was funded by various
Fortune 500 companies who wished to identify deficiencies in corporate planning and create a
system to manage change. (Stanford Research Institute Newsletter, 2005).
Though Humphrey’s key finding were never published, as they were deemed too
controversial, he wrote them in the December 2005 Newsletter of the Stanford Research
Institutes Alumni Newsletter. They are as follows:
1) A business can be divided into two parts: The base business plus the development
business. The development business turns over every 5 to 7 years, 2) All people measure
what they get from their work and divide it by what they give to the work and this
reward/effort ratio is compared to others. If it perceived as too low, the person slows

down, 3) The introduction of a corporate planner upsets the sense of fair play at senior
level, making the job of the corporate planner impossible, 4) The gap between what could

