MOTION PICTURE EXHIBITION INDUSTRY CASE ANALYSIS 2
Motion Picture Exhibition Industry Case Analysis
This study delves deeply into the motion picture exhibition industry. It mainly focuses on
the factors that affect the profitability of running and owning a movie theatre by ay assessing the
operating variables and the dynamics of the value chain. It also highlights trends that impact on
the constraints and decision making in the industry. Additionally, this analysis aims to reveal the
conditions of the industry and its key players that will enable the creation of strategies to
improve the critical operations of exhibitors. The information about the industry's external
environment, alternative ways of handling key challenges can be identified to allow businesses in
the industry to thrive.
The companies in the industry experiences force, especially external ones over which
there is no control. These forces may create opportunities or threats, leading to the success or
failure of constituent firms.
Although a significant time for an average American is spent on entertainment, including
movie viewing, a lot of people are finding alternative ways to enjoy movies outside the theatre.
Such alternatives include portable devices media viewing. On average, the rate of attendance and
sale of tickets have dropped dramatically in the past few years, recording the lowest point over a
decade.
Hard economic times, such as the recession of 2007, are bound to occur, suppressing the
purchasing and financial power of consumers. Unlike in the past where economic downtowns
would lead to increased sales of tickets for cinemas, such conditions may now lead to the
reduction of the sales owing to high ticket prices and the availability of substitutes.
There is a high supplier power in the movie exhibition industry since exhibitors depend
on the decisions of studio policymakers. Additionally, such factors as the sale and distribution of
MOTION PICTURE EXHIBITION INDUSTRY CASE ANALYSIS 3
DVD and product licensing also impact profoundly on the financial well-being of exhibitors.
Also, there are a few content providers who can decide on giving or withholding as well as
allowing exclusive distribution and display rights of movies in the industry. These providers also
choose the time to deliver content which may lead to profits or loses to the exhibitors.
The threat of new entrants in the movie exhibition industry is low. This is due to the
existing overcapacity of the screen and the consolidation of the sector in a combination of a
favorable market positioning, which avoids direct competition and rivalry among the major
players.
Youths in the 12-24 age brackets constitute the industry’s largest consumer, with their
movie ticket purchases representing about 40%. Additionally, about 50% of this group purchase
one or more ticket s in a month, thereby becoming major determinants of profits in the industry.
However, movie viewers lack cumulative bargaining power, and therefore their demands fail to
affect price changes significantly. Thus, buyer power is moderate.
The industry has a high risk of substitutes. The reason for this is that the value attached to
viewing movies in the cinema diminishes, there is an increasing number of similar entertainment
sources such as DVDs, and live streaming. Following the massive advancement in the
electronics, there are new options for media viewing, rapidly eroding the uniqueness of cinema.
The industry experiences a moderate intensity of rivalry. The past few years have seen
several competitors in the sector close down due to rising operation costs and industry
consolidation. As such, the number of screens has hit a record high, but the number of
competitors is a fifth smaller since 2000. Even then, there is an excessive number of screens,
driving the costs of exhibiting.
MOTION PICTURE EXHIBITION INDUSTRY CASE ANALYSIS 4
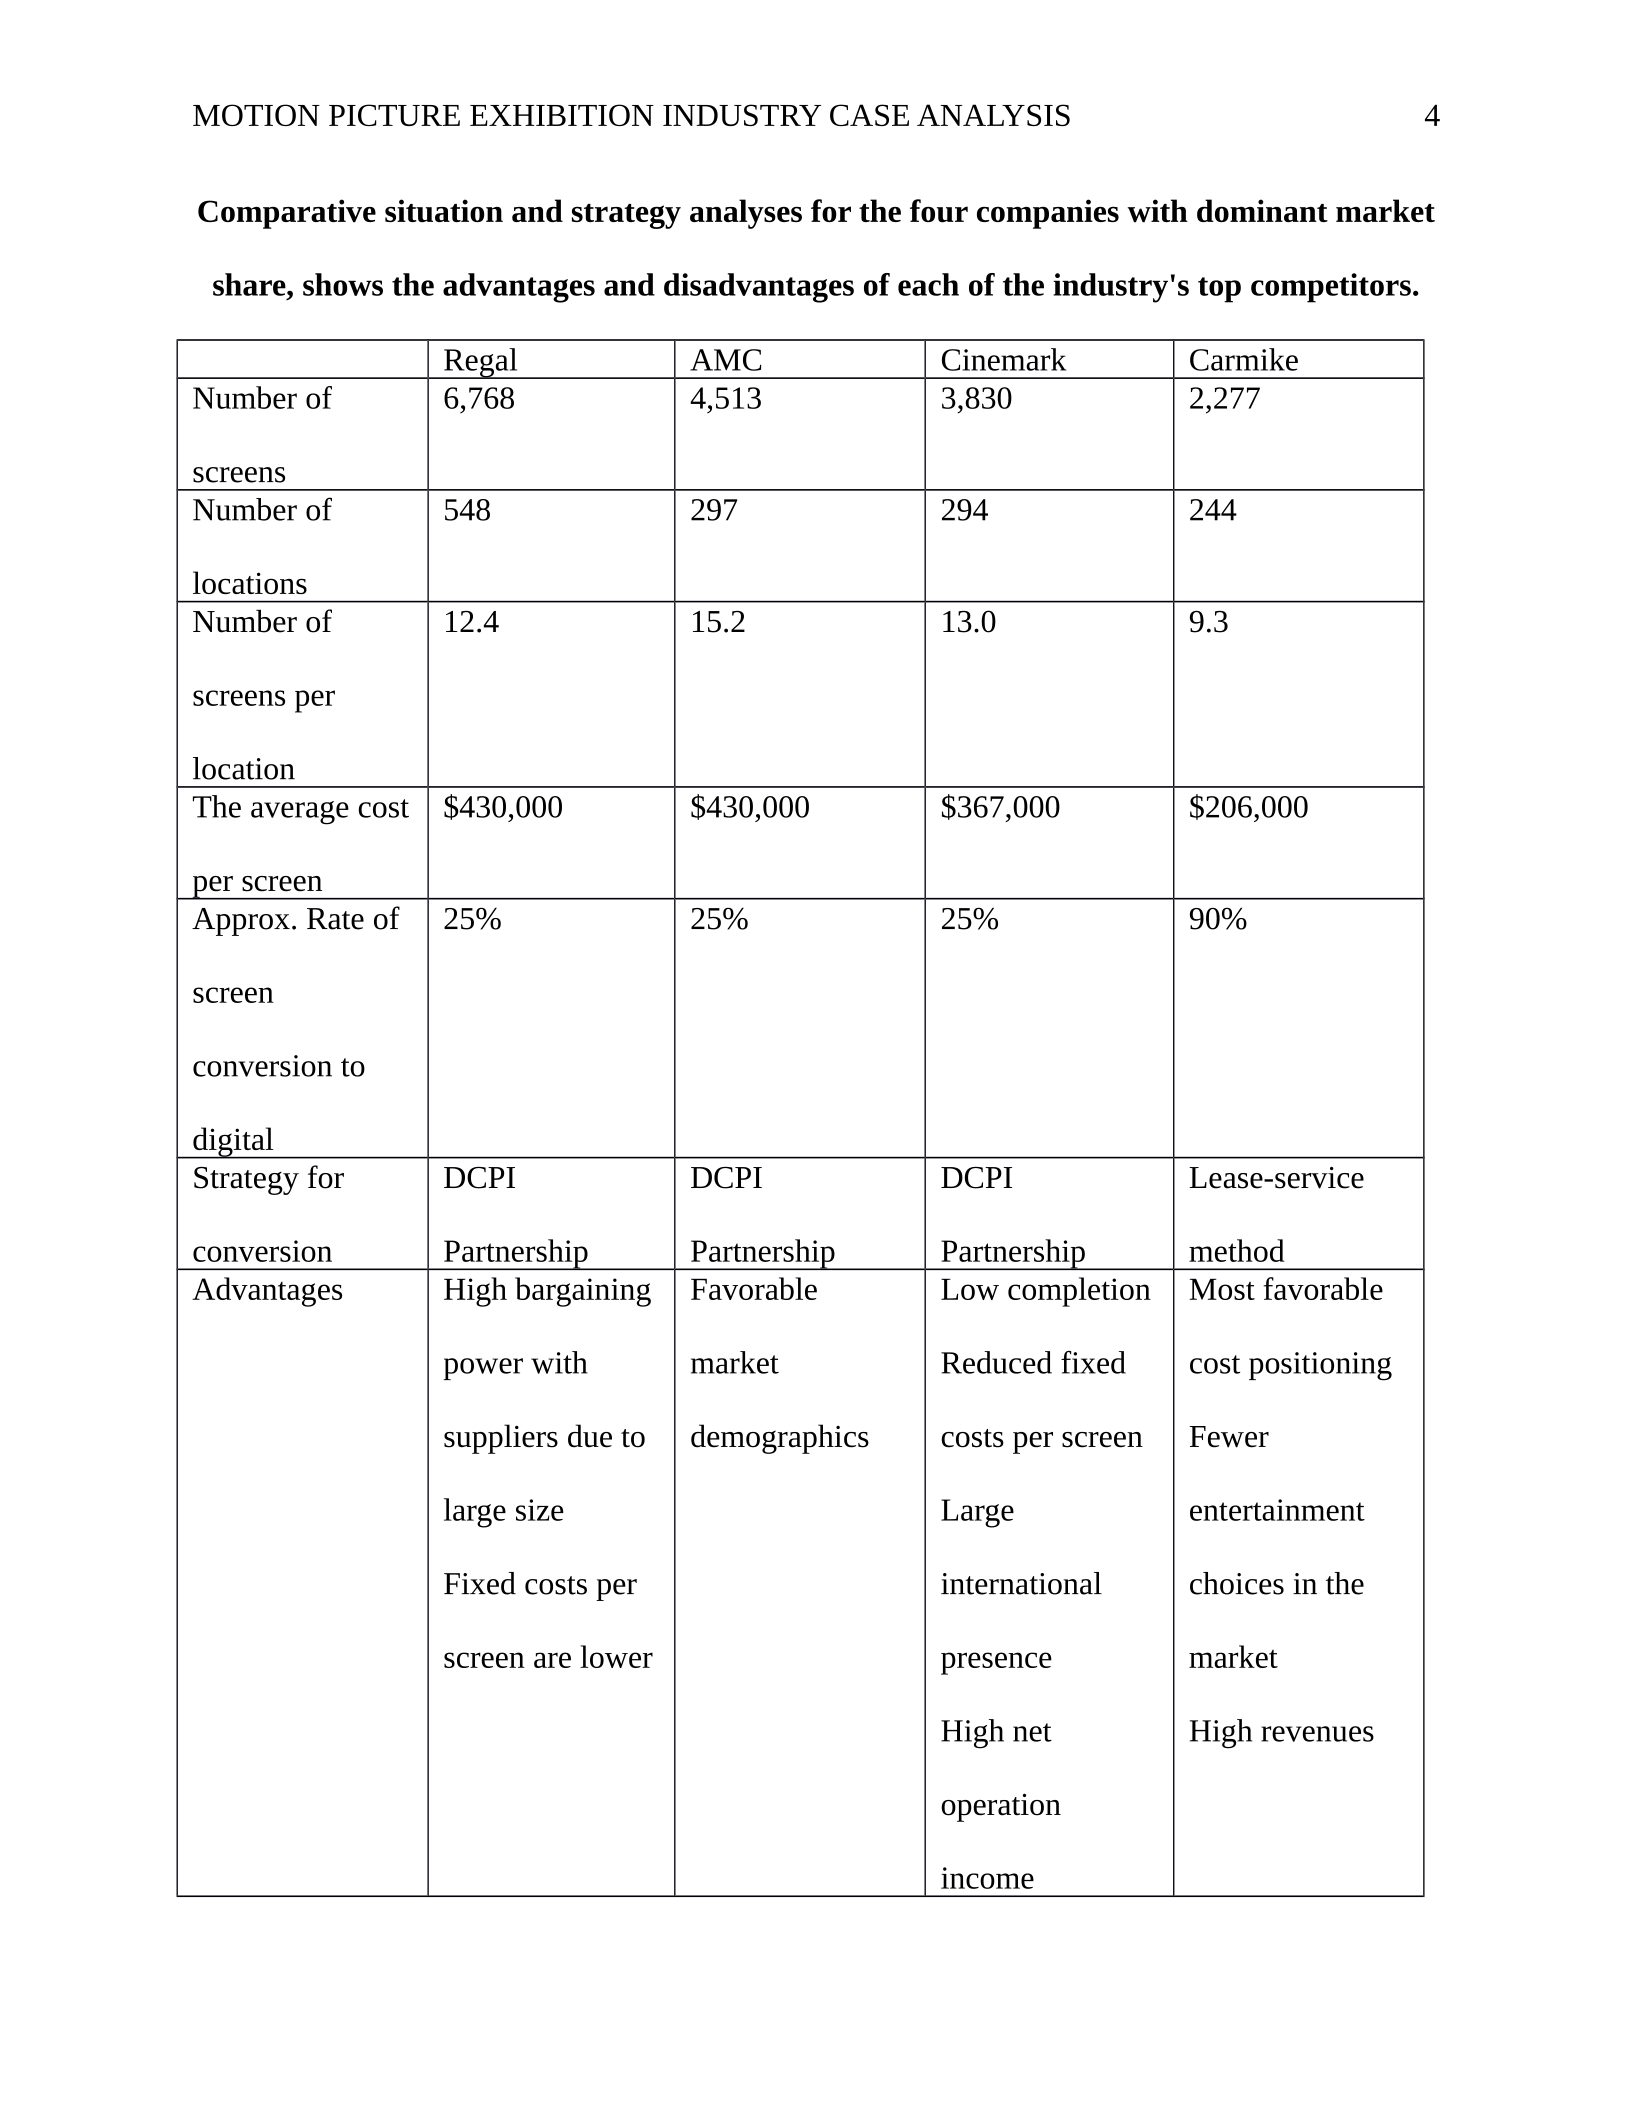
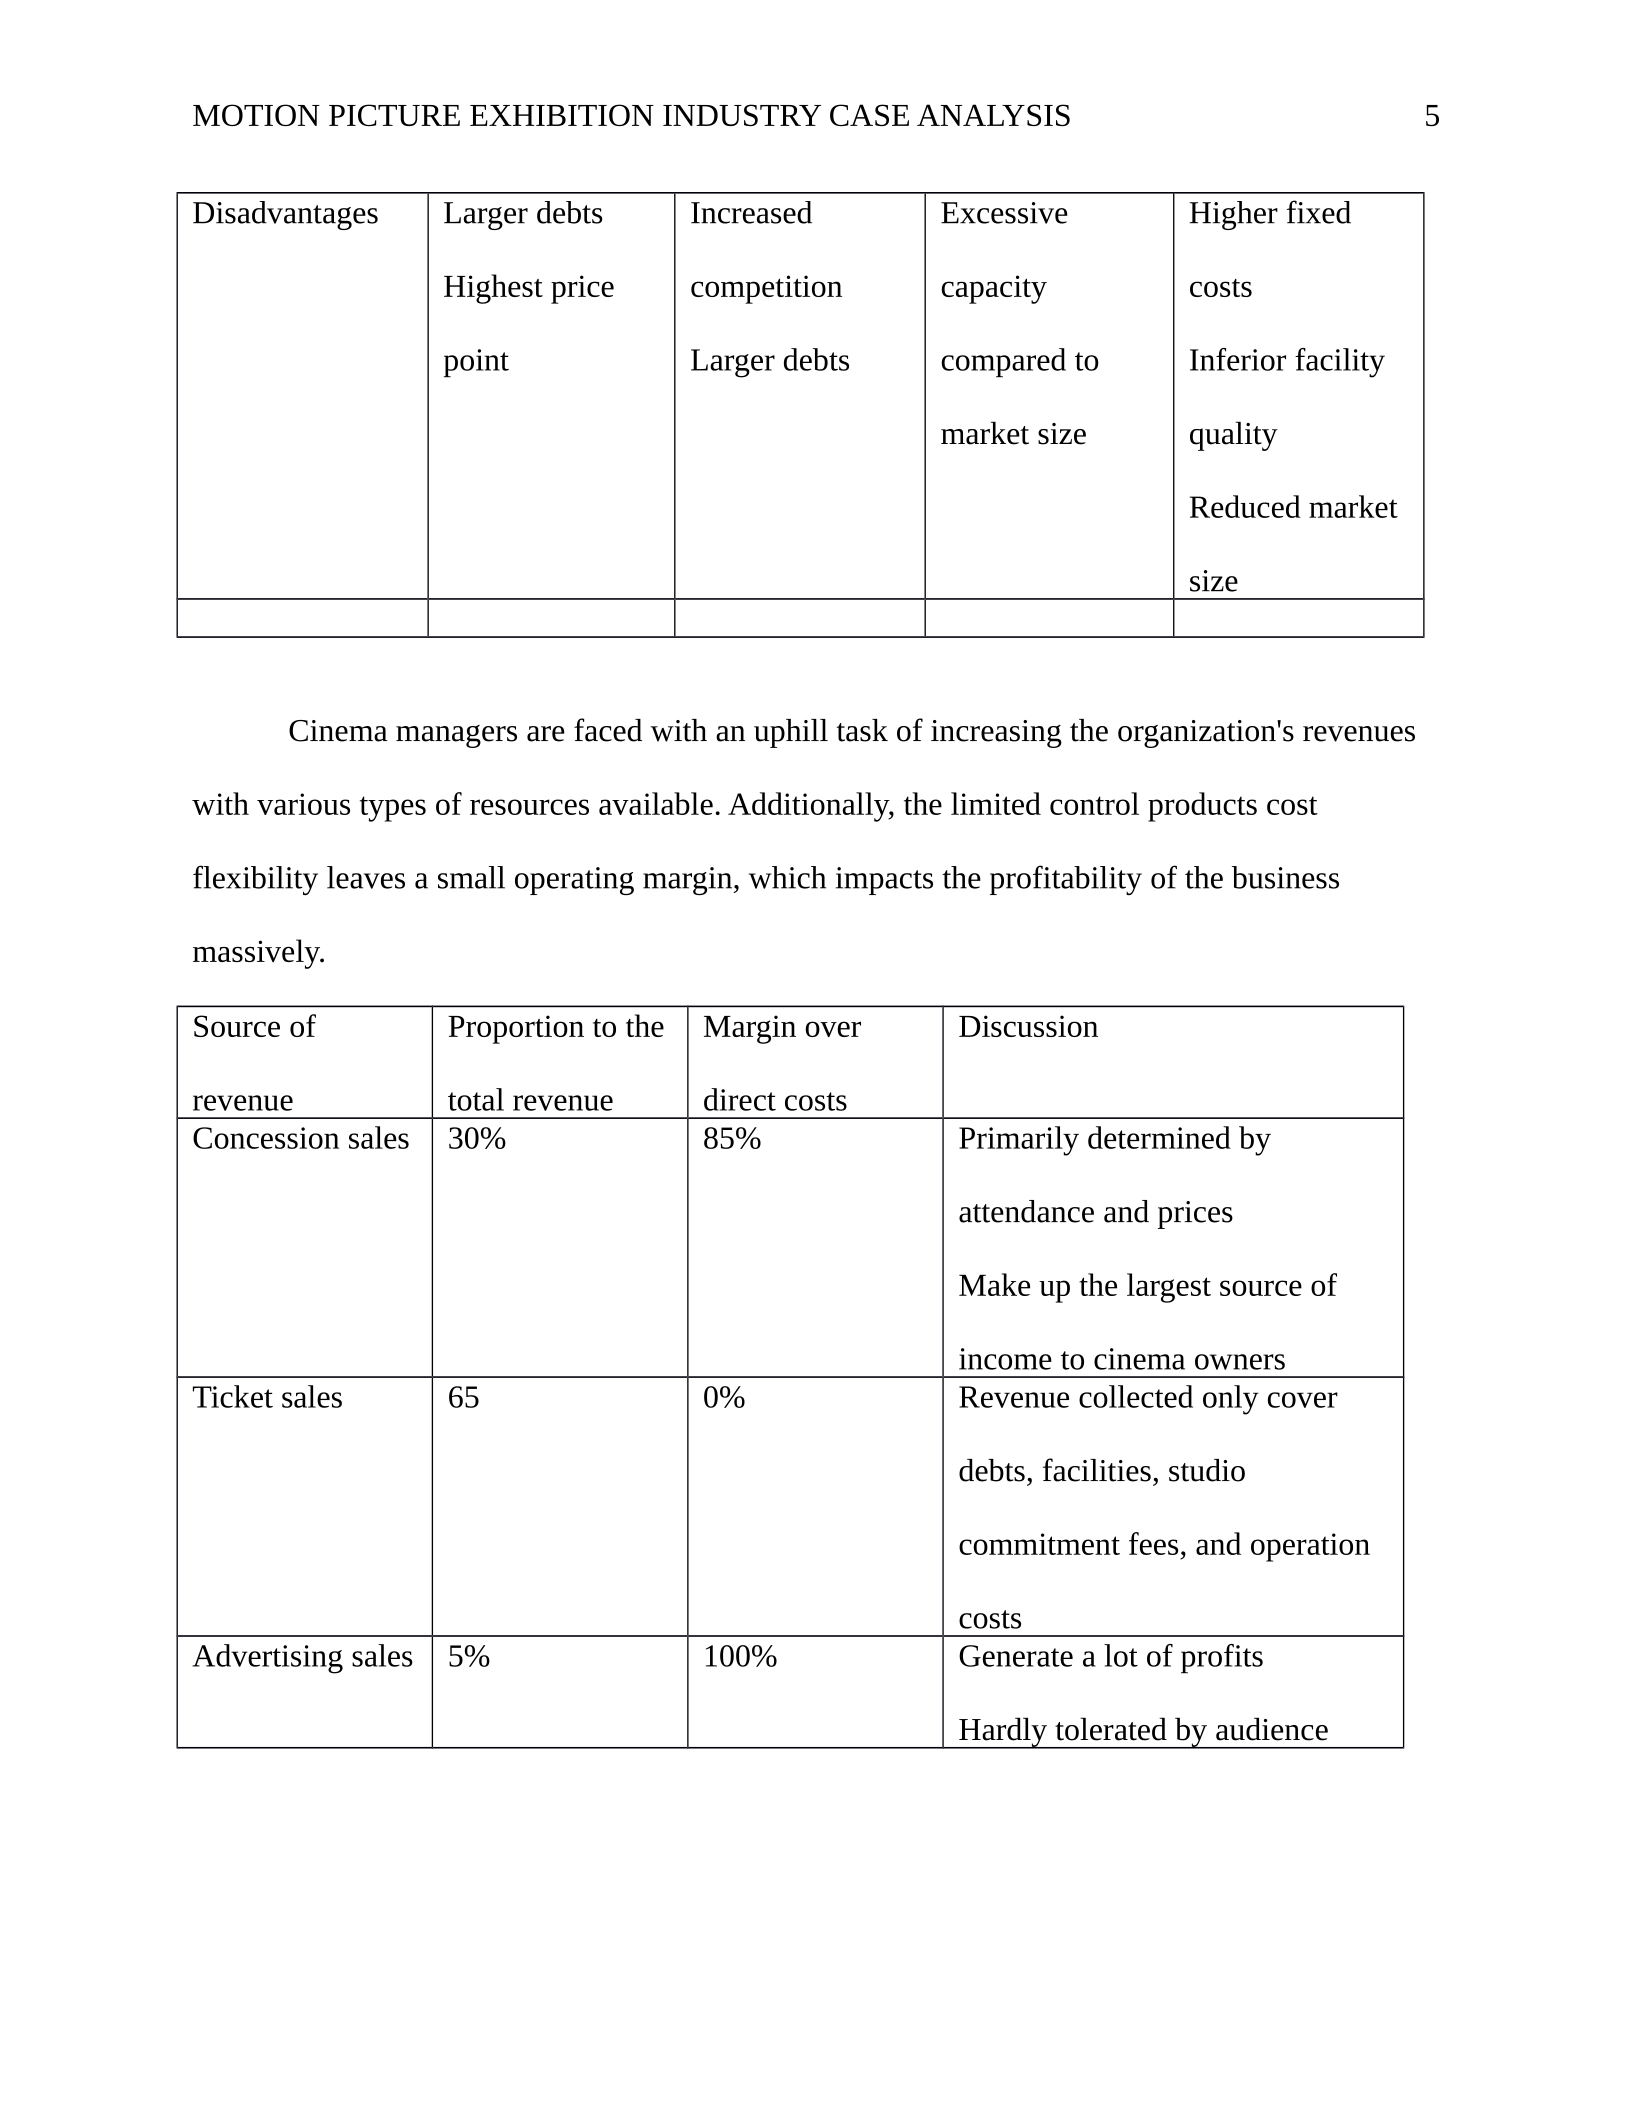
Comparative situation and strategy analyses for the four companies with dominant market
share, shows the advantages and disadvantages of each of the industry's top competitors.
Regal AMC Cinemark Carmike
Number of
screens
6,768 4,513 3,830 2,277
Number of
locations
548 297 294 244
Number of
screens per
location
12.4 15.2 13.0 9.3
The average cost
per screen
$430,000 $430,000 $367,000 $206,000
Approx. Rate of
screen
conversion to
digital
25% 25% 25% 90%
Strategy for
conversion
DCPI
Partnership
DCPI
Partnership
DCPI
Partnership
Lease-service
method
Advantages High bargaining
power with
suppliers due to
large size
Fixed costs per
screen are lower
Favorable
market
demographics
Low completion
Reduced fixed
costs per screen
Large
international
presence
High net
operation
income
Most favorable
cost positioning
Fewer
entertainment
choices in the
market
High revenues
MOTION PICTURE EXHIBITION INDUSTRY CASE ANALYSIS 5
Disadvantages Larger debts
Highest price
point
Increased
competition
Larger debts
Excessive
capacity
compared to
market size
Higher fixed
costs
Inferior facility
quality
Reduced market
size
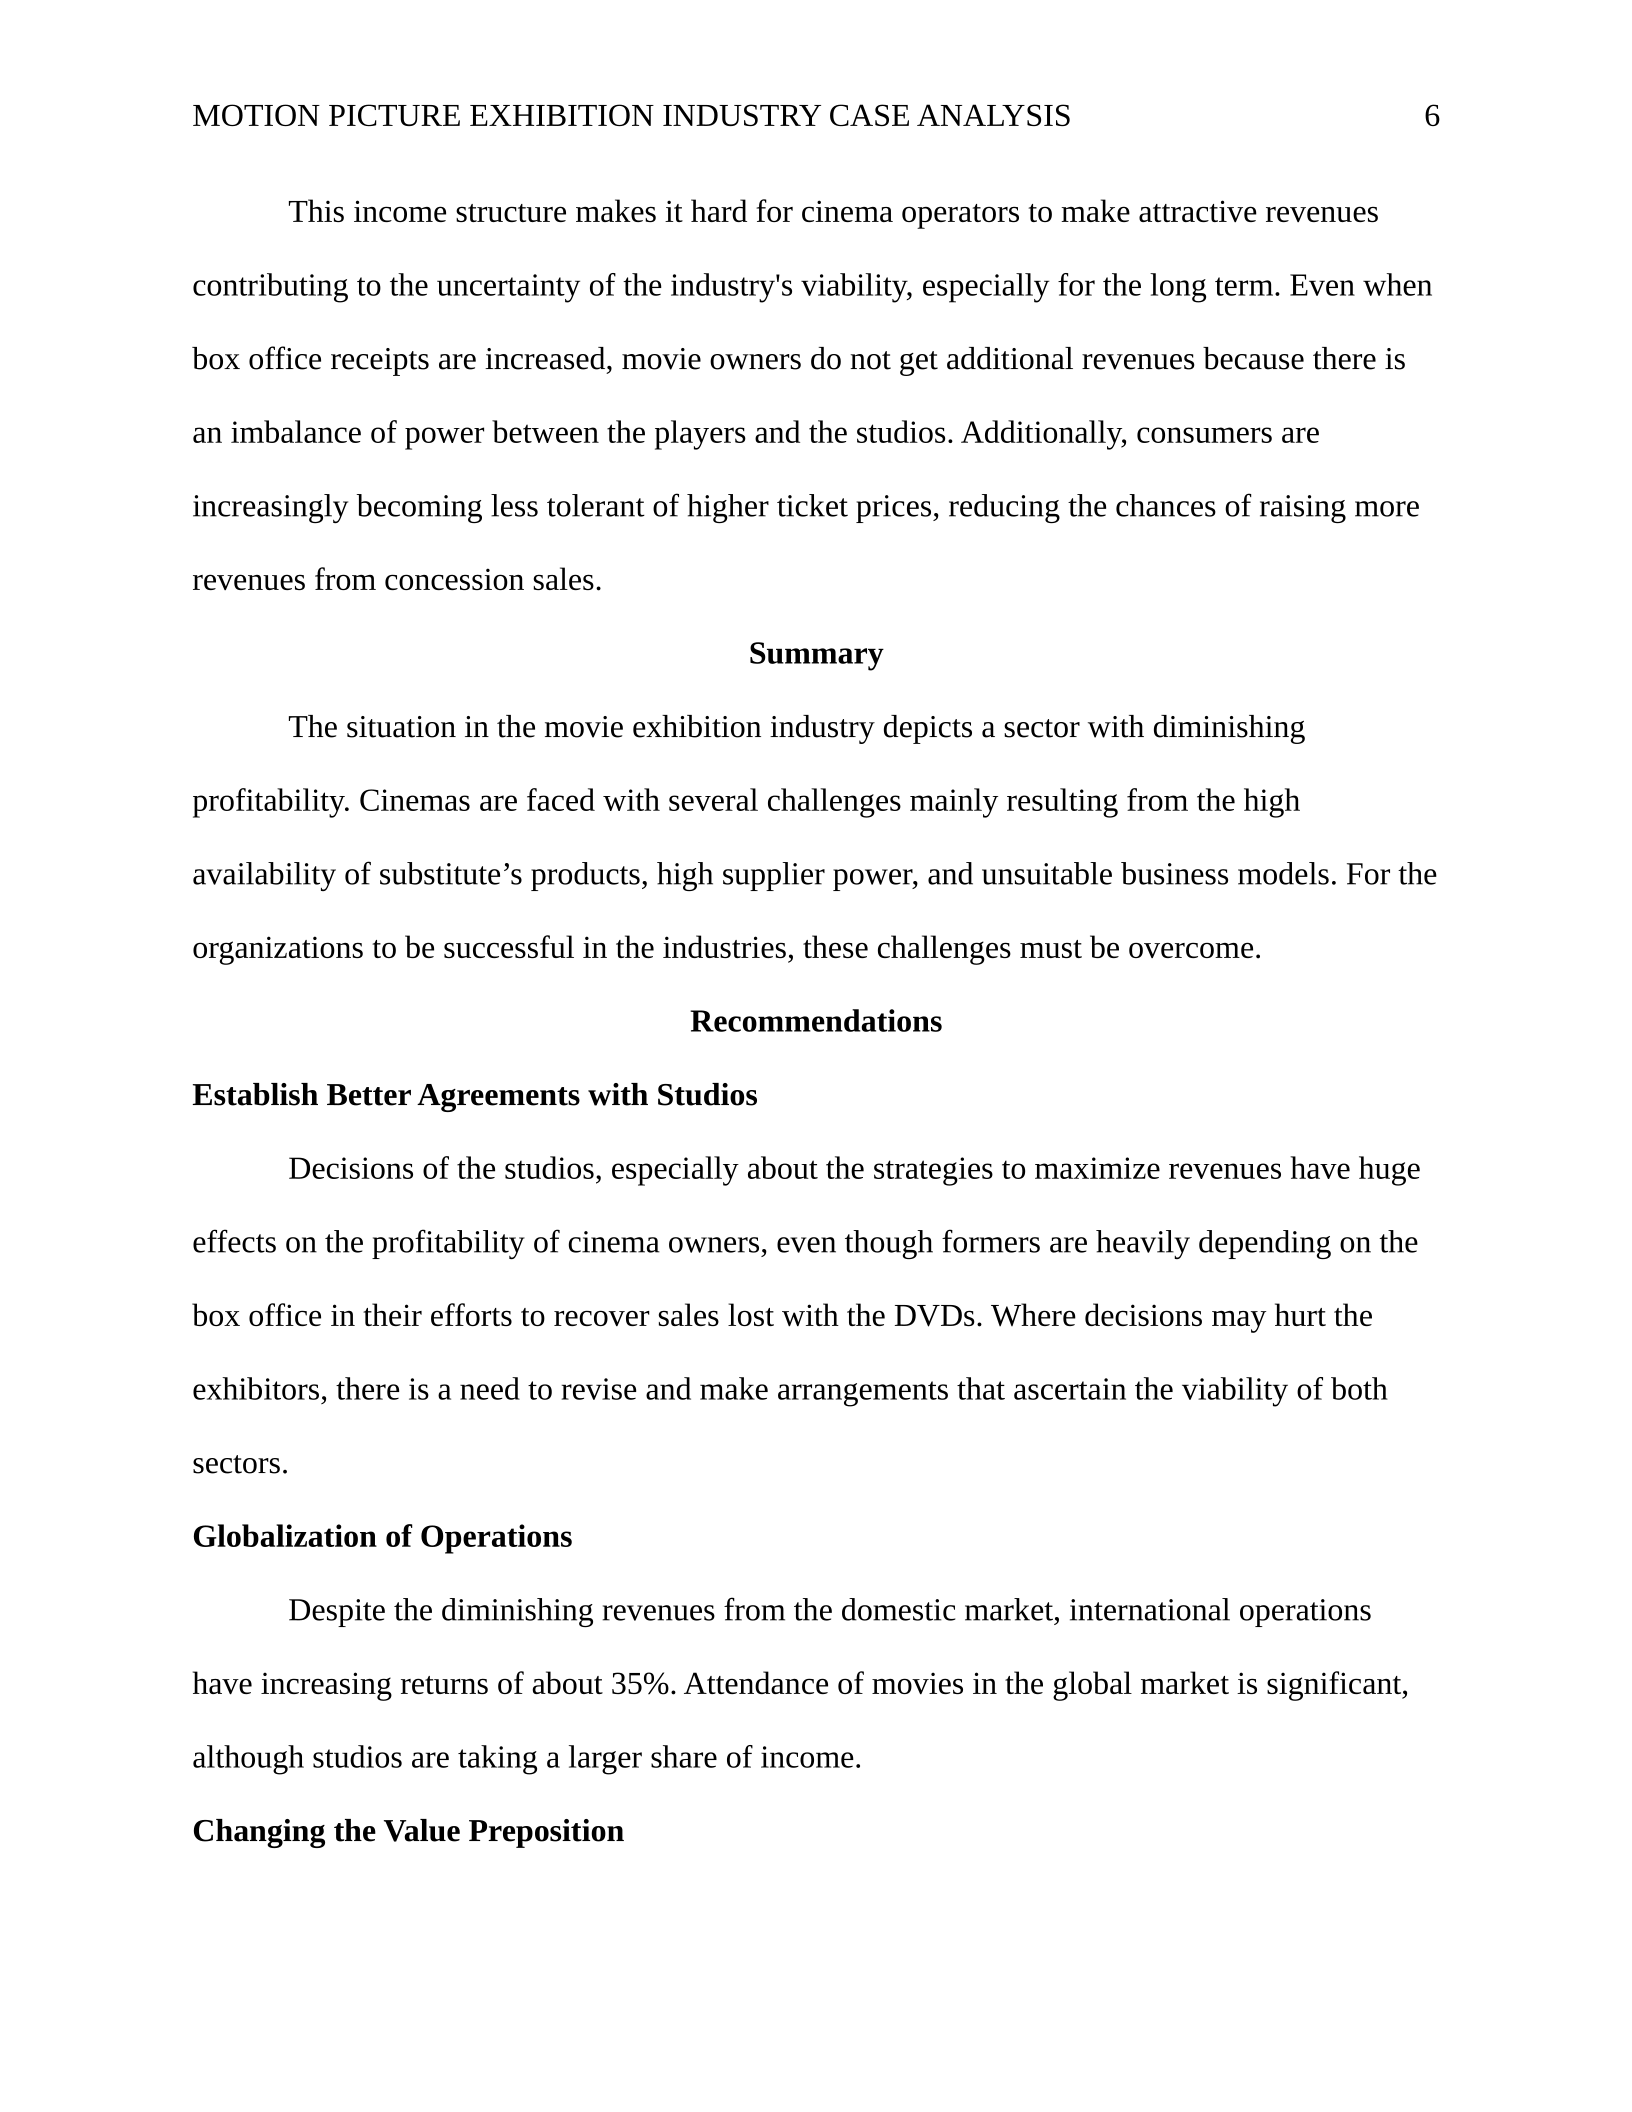
Cinema managers are faced with an uphill task of increasing the organization's revenues
with various types of resources available. Additionally, the limited control products cost
flexibility leaves a small operating margin, which impacts the profitability of the business
massively.
Source of
revenue
Proportion to the
total revenue
Margin over
direct costs
Discussion
Concession sales 30% 85% Primarily determined by
attendance and prices
Make up the largest source of
income to cinema owners
Ticket sales 65 0% Revenue collected only cover
debts, facilities, studio
commitment fees, and operation
costs
Advertising sales 5% 100% Generate a lot of profits
Hardly tolerated by audience
MOTION PICTURE EXHIBITION INDUSTRY CASE ANALYSIS 6
This income structure makes it hard for cinema operators to make attractive revenues
contributing to the uncertainty of the industry's viability, especially for the long term. Even when
box office receipts are increased, movie owners do not get additional revenues because there is
an imbalance of power between the players and the studios. Additionally, consumers are
increasingly becoming less tolerant of higher ticket prices, reducing the chances of raising more
revenues from concession sales.
Summary
The situation in the movie exhibition industry depicts a sector with diminishing
profitability. Cinemas are faced with several challenges mainly resulting from the high
availability of substitute’s products, high supplier power, and unsuitable business models. For the
organizations to be successful in the industries, these challenges must be overcome.
Recommendations
Establish Better Agreements with Studios
Decisions of the studios, especially about the strategies to maximize revenues have huge
effects on the profitability of cinema owners, even though formers are heavily depending on the
box office in their efforts to recover sales lost with the DVDs. Where decisions may hurt the
exhibitors, there is a need to revise and make arrangements that ascertain the viability of both
sectors.
Globalization of Operations
Despite the diminishing revenues from the domestic market, international operations
have increasing returns of about 35%. Attendance of movies in the global market is significant,
although studios are taking a larger share of income.
Changing the Value Preposition