


1
CHAPTER 1: INTRODUCTION
1.1 Trends in Agribusiness
The market performance of agribusiness firms traded on U.S. exchanges relative to their non-
agribusiness counterparts has been the subject of limited research. The recent downturn in the
overall market caused by the financial crisis has caused many investors to reassess their
investment strategies. A common reaction during uncertain economic periods is to shift money
investments to assets that carry less risk. The historically defensive nature of US food companies
makes them an appealing investment diversification opportunity during a period of high market
volatility (Dirks, 1958). Defensive stocks tend to remain stable under difficult conditions in the
economy as a whole (Ang et al., 2006). Volatility in a specific industry’s stock prices is related
to the level of risk that is associated with investing in the industry. Corporate financial risk can
be estimated by calculating the systematic risk estimator “beta”, as defined in the Capital Asset
Pricing Model (Sharpe, 1964), (Lintner, 1965). According to the New York University Stern
School of Business, the beta value for the US Food Processing Industry was 0.63, as of January
2009 (Damodaran, 2009). Thus, the historical evidence suggests that investing in the U.S. Food
Industry is less risky than investing in a market index.
Various trends in today’s society make investment in food-marketing firms an interesting
topic for research. First, human health education is becoming the subject of much global interest
and the demand for “healthy foods” on both a domestic and international level has increased
significantly. Past research has shown that consumers identify organic food products as having
additional nutritional value over food products grown with traditional methods (Hay, 1989). In
the United States organic food industry, sales have grown from just over $1 billion in 1990 to
approximately $19 billion in 2007 (Dimitri, 2002), (Nutrition Business Journal, 2008). Food

2
processors, like General Mills, Unilever, and Kellogg have taken notice of this trend and have
introduced their own organic product lines. As of 2006, food retail giant, Wal-Mart, offered more
than 400 organic food products (Associated Press, 2006). The global food market forces
agribusiness firms to constantly search for ways to increase market share (innovation, etc.), if
they are to remain profitable. Furthermore, the introduction of genetically modified (GMO) and
functional food products has been a worldwide topic of debate among producers and consumers.
GMO’s have been the subject of legislation reform in Brazil. As GMO’s become more accepted
worldwide and new markets begin to relax GMO restrictions, agribusiness firms involved in their
production stand to make tremendous profit. There is also an unprecedented demand for the
inputs used in agricultural production and agribusiness processing by non-agricultural industries.
The increase in competition for these inputs may influence the profitability of agribusiness firms,
which ultimately affects their share prices and dividend streams. For example, the increasing
demands for corn, sugarcane, and soybeans by firms involved in the production of ethanol and
biodiesel has decreased the available supply of these inputs for those agribusiness firms who
traditionally use these inputs in their production process. Consequently, companies that engage
in oil/gas exploration, alternative fuels, and other commodity related companies have been
reporting record profits over the past few years. Recent volatility in the crude oil market has only
strengthened this trend. Finally, the recent slump in the financial and banking sector has acted to
reinforce this movement towards stocks that are more defensive in nature (Kahn, 2008). That is
to say, defensive stocks lag behind downturns in the general market, i.e. have a beta value of less
than one.
There are, however, certain risk factors that are unique to the agricultural industry that
add uncertainty to investing in the sector. These include but are not limited to, weather and
natural disasters, biological and environmental factors, and the industry’s policy sensitive nature,

3
as a large portion of farm income are solely dependent on Farm Bill Policy, which is typically
renewed every seven years (Beierlein et al., 2003). The aforementioned factors provide a signal
for the need in understanding the sector specific risk and performance of agribusiness firms
relative to their non-agribusiness peers.
1.2 Goals
Two objectives are accomplished through this work. First, to provide a thorough review of the
limited existing literature that compares the financial performance of agribusiness firms relative
to non-agribusiness firms. Second, to contribute original research on the returns and risks
associated with a large-cap index of publicly traded US agribusiness companies. The second task
will be accomplished in two stages. First, a large-cap index of US agribusiness stocks using the
Economic Research Service’s definition of agribusiness as the framework for selection. Firms
eligible for inclusion in the index have US Economic Census Standard Industrial Classification
Codes (SIC codes) (US Census Bureau, 2009) that correspond to the ERS classification of firms
that are related to agriculture (Economic Research Service, 2005). The sample will be restricted
to large-cap domestic agribusinesses, traded on the three major US exchanges, and that have data
available from The Center for Research in Security Prices Daily Stock Price Dataset (CRSP)
(Center for Research in Security Prices, 2009). A large-cap company is defined as a firm ranking
in the top 70th percentile of the industry, by market capitalization. Second, the calculated risk and
return associated with the agribusiness index will be compared to that of the market as a whole.
Implications and further extensions of this research will also be provided.

4
CHAPTER 2: LITERATURE REVIEW
The literature review will be organized in three sections. First, literature that examines
agricultural businesses as an investment strategy; the attitude towards investment in agricultural
related companies in the investment and academic community will be explored. Second, this
section will cover the literature concerning stock index creation. In particular, in depth coverage
will be given to the mathematical methods for creating indices. The final section will provide a
review of the literature regarding proper means of comparing indices. For example, industry
accepted risk and return methods are explored.
2.1 Investing in Agribusiness
2.1.1 Unique to Agriculture
Much of the risk agribusinesses face is unique to the industry as it is subject to an unusual set of
external factors. Weather, environmental concerns, biological factors, and governmental policy
all affect the profitability of firms in the sector. It is also understood that fluctuations in a
country’s aggregate business cycle are closely related to the share of agricultural output in the
economy (Da-Rocha and Restuccia, 2006) and to farmland value (Bjornson, 1995). Countries
with a high share of employment in production agriculture are subject to higher fluctuations in
aggregate output than countries with little production agriculture employment. In fact, most of
the major American industrial business cycles from 1800 to WWI were caused by fluctuations in
the size of the cotton harvest that resulted from exogenous factors such as weather (Davis et al.,
2009). Therefore, it is important to understand how shocks like weather, international trade
restrictions, domestic farm policy, and the level of employment in the sector affect agricultural
output and cycles. The length these cycles (on input and output market prices) and their

5
relationship with US Gross Domestic Product is what is important from an investment
perspective.
2.1.2 Organics
Global sales of organic products are estimated to be growing at a rate between 10 and 20 percent
a year. Estimated U.S. sales of organic produce in 2001 ranged between $5.5 and $6.5 billion
dollars, as compared with $2.1 billion in 1995 and $3.3 billion in 1998 (Dimitri and Richman,
2000). The growing concern of fitness, health, toxin exposure, and a recent series of food safety
scares have acted to strengthen the trend towards the consumption of more organically grown
food products (Byrne et al., 1991), (Tregear et al., 1994), (Davies et al., 1995), (Dimitri, 2002),
(Willer and Yussefi, 2004). The North American market for organic products is experiencing the
highest growth worldwide. Organic food and drink sales in the US were estimated to be
approximately 14.5 billion in 2005. US consumer demand for organic products is expected to
remain strong and account for most global organic food revenues going forward (Willer and
Yussefi, 2004). This growth has occurred despite the fact that organic product premiums have
been estimated to range from 50 percent to 75 percent (Willer and Yussefi, 2004). Consequently,
for a family of four to adopt an organic only diet they would increase their annual food
expenditures by almost 50 percent (Brown and Sperow, 2005). Numerous studies have
presented organic consumer profiles and determined characteristics that make a person more
likely to purchase organic products (Byrne et al., 1991), (Govindasamy et al., 2001), (Thompson
and Kidwell, 1998), (Zepeda and Jinghan, 2007). These studies have found that consumers that
purchase organic food products are typically young, highly educated, females, high-income
earners, and have children living at home. Further research shows that parents of young children
are becoming increasingly aware of their children’s organophosphorus pesticide exposure (Hood,
2003). A highly publicized 2003 study of Seattle preschool children, showed that those children

6
who consumed organically grown produce and juices significantly decreased OP exposure as
compared to children who consumed conventionally grown produce and juices (Curl et al.,
2003). However, recent research indicates that the long-term health benefits of organic food
over non-organic products is inconclusive (Dangour et al., 2009). Given the previous research on
organic food consumption, it is likely that the organic industry will continually grow on both the
domestic and international level. Consequently, agribusinesses that operate in this high margin
industry should expect to see increases in their sales, which should ultimately make them more
profitable.
2.1.3 Growing Global Demand
Global population is expected to increase from 6.5 billion in 2005 to 9.1 billion by 2050. Most of
this growth (97.7 percent) is expected to come from less developed regions in the world (United
Nations, 2008). Population growth India and China alone should account for 22.3 percent of the
expected increase in world population by 2050. At the same time, incomes, measured by per-
capita Gross Domestic Product (GDP), are expected to continue to grow in countries that have
recently enjoyed industrialization. For instance, Korea, India, and Thailand experienced average
annual growth of 11.76, 10.03, and 8.52 percent, respectively, from 1998 to 2007 (United
Nations, 2008b). Indian and Chinese per-capita income is expected to increase by 5.7 and 5.8
percent, respectively, per year between now and 2020 with a similar, but slightly lower, income
growth expectation for Asia in general, Eastern Europe, and Sub-Saharan Africa (Rosegrant et
al., 2001). Research shows that as incomes in these areas rise and as more people move out of
rural areas to more densely populated areas, general food consumption patterns change. A 2001
study showed that, as incomes rise and populations become more urbanized, consumption
patterns shift from basic staple items to diets consisting of more processed foods and meat and
dairy products (Rosegrant et al., 2001). These changes in consumption patterns will put strains

7
on these developing nations’ agricultural production industry. Countries that are land poor will
become increasingly dependent on food imports to meet the growing demand and changing food
preferences of its citizens, while those countries that have abundant land endowments but are
cash strapped will convert more land in to agricultural use (Rosegrant et al., 2001). Many US
agribusiness firms have the necessary infrastructure and supply chain investments in place to
capitalize on the growing demands that will be placed on the global food and fiber industry by
these developing countries, and therefore they stand to earn large profits.
2.1.4 Biofuels/Ethanol Industry
The rate at which global ethanol production has increased in the last 10 years is remarkable. The
creation of such bio-based combustibles requires large masses of starch or sugar rich crops. In
fact, demand for corn to be used in the production of ethanol is expected to reach 5 billion
bushels by 2015 (United States Department of Agriculture, 2009). A 2007 study projected corn-
based ethanol production to increase to over 14 billion gallons by 2010 (Tokgoz et al., 2007). It
is clear that the global demand for feedstock based biofuels has been a major factor in the current
increase in global grain prices (Trostle, 2008), (Rosegrant, 2008). This increase in prices, has
served as a signal for farmers to increase the production of those crops that can be used in bio-
fuel conversion. In fact, ERS predicts planted acres of corn to increase every year until 2019
(Economic Research Service, 2009). Similar trends exist for other oil crops such as soybeans and
sugar cane. As global demand for these products continue to increase and the governmental
mandates on ethanol/gas mix requirements are maintained, companies involved in their
production will likely see increased revenues.
2.1.5 Impact on Agricultural Inputs Sector
Grain prices have recently reached all time highs. According to an ERS report, world grain
prices increased by 60 percent from 2006 to 2008 (Trostle, 2008). The aforementioned literature

8
indicates that this trend resulted from growing global demand for food, competition within grain
markets for their alternative uses, and changing tastes and preferences. This translates in to an
increase in farm profits and expected future earnings. In fact, net cash farm income has
established multiple record highs between 2004 and 2008 and reached a peak of more than 89
billion dollars in 2008 (Harris, 2008). Though, net farm income is expected to decline in the
near term from the high levels of 2008, it will remain historically strong and rebound to near-
record levels by the end of the USDA projections in 2018 (United States Department of
Agriculture, 2009). The accompanying increase in demand for agricultural products has
multiplier effect, which is felt throughout the agriculture input sector (equipment/machinery,
seed, fertilizer, pesticide, herbicides, etc…). Increased commodity prices will create derived
demand for farm inputs, which in turn will improve agribusiness input supplier profitability.
Many investors expect farmers to re-invest a portion of their income in on-farm capital
improvements (Shinkle and Marquardt, 2008). If this is the case, manufacturers of tractors,
combines, planters, sprayers, and tillage equipment can expect increased business. A 2008 ERS
report estimated the value of farm equipment purchases in 2008 was 4.8 billion (Harris, 2008).
2.1.6 Investor Interest
Within the past few years, analysts have seriously started examining agriculture stocks as a
potential source of diversification, long-term investment growth, and short-term protection from
downturn in the general market. Jeff Auxier, investor and founder of Auxier Asset Management,
spoke about the investment opportunity in agriculture in a recent interview with U.S. News &
World Report, “I think agriculture looks really bright over the next 10 years, if we maintain the
biodiesel mandates, with the demographics for baby boomers eating healthier, and then the 2-3
billion [new] customers [worldwide]… it looks really good from the investment standpoint”
(Wolgemuth, 2008). In another recent interview, David Fondrie, chief investment officer of

9
Heartland Advisors spoke of US farmers, “The farmer is now in a great position to spend…
[f]arm balance sheets are in great shape, the land is worth more, and prices are high for crops.
Farmers can now go out and buy more machinery as well as crop inputs like fertilizer and seed”.
In the same article, the author reported on a recent note to Morgan Stanley clients, where analyst
Robert Wertheimer wrote, “[John Deere] is still in the earlier stages of a multi-year boom in farm
equipment” (Marquardt, 2008). In a recent article, Senior Editor of U.S. News and World
Report, Kirk Shinkle, wrote that “despite some recent selling along with the rest of the market,
agriculture remains one of just a few bright spots enjoying solid fundamental growth and some
defensive characteristics” (Shinkle and Marquardt, 2008). These statements are supported by
former analyst and current Barron’s Magazine contributor, Michael Kahn, who noted that despite
recent poor performance in the general stock market, agriculture was a pocket of strength (Kahn,
2008). A 2002 study suggested that farm owners might be better off investing some equity of the
farm in a portfolio of food and agribusiness stocks rather than a well-diversified market based
portfolio (Duval and Featherstone, 2002). They found that even given the systematic and non-
systematic risk associated with such a portfolio, it is still a viable alternative to other value-added
portfolios for all the farms in their sample (Duval and Featherstone, 2002). A similar study
found that livestock farmers could diversify risk and capture value-added profits through
investing in a portfolio consisting of publicly traded value added firms in the meat processing
industry (Detre et al., 2007).
In summary, the US Agriculture sector is believed to carry less risk, enjoy higher risk
adjusted return, be defensive in nature as compared to a market portfolio, and be an area of
growth in the future. However, little research exists that attempts quantify these beliefs. What is
needed from an investment standpoint is an index comprised of agribusiness stocks that
summarizes the historical market performance of US Agribusiness firms. Such an index would
10
allow investors to understand how these stocks compare to non-agribusiness companies and the
market as a whole. Index and data service firms have recognized this growth in investor interest
in agriculturally related businesses. Two major agriculture-based indices have been published
within the past 6 years. In 2003, the Deutsche Boerse Group, a global exchange organization,
launched the DaxGlobal Agribusiness Index. The index tracks 46 domestic and international
firms in five major sectors; agriculture chemicals, agri-product operations, agriculture
equipment, livestock operations, and ethanol/biodiesel.1 In August 2007 Van Eck Global, a New
York based investment firm, launched the Market Vectors Agribusiness Exchange-Traded Fund
(ETF) which seeks to track, before fees and expenses, the performance of the DaxGlobal
Agribusiness Index. The ETF is publicly traded on the AMEX exchange under the ticker “MOO”
with a beta value of 0.89 and had year-to-date returns of 10.2 percent, as of May 2008. In June of
2009, Standard and Poor’s released the North American Agribusiness Index (S&P-AG) as the
industry’s first index. The S&P-AG index consists of 24 of the largest publicly traded
agribusiness companies trading on the U.S. and Canadian exchanges.2 The constituents of the
S&P-AG index are equally distributed between two clusters; Producers, Distributors, and
Processors; and Equipment and Materials Suppliers (Standard & Poor's, 2009). In an interview
on the day on the index’s launch, Liz Taxin, Director of Strategy Indices for Standard & Poor’s
Index Services, noted, “The Index was created based on external market demand from product
producers and distributers whose clients have voiced a preference for a regional version of the
popular S&P Global Agribusiness Index” (Guarino, 2009).
What is still missing though, is historical back testing of index methodology, as both of
these indices only provide a couple of years of historical data. Therefore, the main contribution
1 Appendix A contains the December 2009 list of constituent firms that make up the DAXGlobal Agribusiness Index
2 Appendix B contains the December 2009 list of constituent firms that make up the S&P North American
Agribusiness Index

11
of this study is the development of a continuous price series that summarizes the historical
performance and risk of the US agriculture sector during the past 39 years.
2.2 Stock Price Indices
Mathematical stock price indexing is popular means of aggregating stock price movements in
industries or an entire stock market. They are used as benchmarks to evaluate the performance of
professional money managers, create and monitor an index fund, measure market rates of return
in economic studies, for predicting future market movements, and as a proxy for a market
portfolio of risky assets (Reilly and Brown, 2003). U.S. industry indices have been used since
1884, when the Dow Jones Transportation Average was created to track price movements in the
US transportation industry. Today, there are market indices for almost every industrial sector in
the economy. The most widely followed major market indices in the US are the Standard and
Poor’s 500 (S&P 500) and the Dow Jones Industrial Average (DOW). Each index contains a
unique formula of stocks and follows one of two general mathematical weighting schemes. The
S&P 500 is a market-capitalization-weighted index of 500 stocks intended to be a representative
sample of the leading companies in the top US industries. The DOW is a price-weighted index
containing 30 “blue-chip” stocks in the top US industrial sectors. Because of their wide use in
financial and investment literature, these two indices will be used as proxies for the “market as a
whole” in this study.
2.2.1 Types of Indices
Each method consists of three main components: the security price, the security weight, and a
divisor. The security price is the value of the stock being indexed. In the case of a stock price
index, the price is simply the current value of one share of a firms stock. The security weight
depends on the type of index. The weight can be based on the number of outstanding shares for a
security, the market value of the security, the price of the security, or the index can be equally
12
weighted among all of the securities. The weighting scheme is what distinguishes one type of
index method from another. An index divisor is the basis for comparisons of the index over time
and a starting point to which adjustments must be made as the makeup of the underlying
securities change. In addition, since most indices are an aggregate of stock price values,
sometimes in the trillions of dollars, a divisor can be used to scale an index so that its number is
easier to track. Once the base year of the index is determined, the divisor is used to scale the
index to a base value, usually 10, 100, or 1000. Understanding the divisor is critically important
to understanding how indices are calculated. Further discussion of the divisor and the base year
can be found in the methods section.
The first and simplest method is the price-weighted index. In this method, the price of
each component stock is the only consideration when determining the value of the index. Found
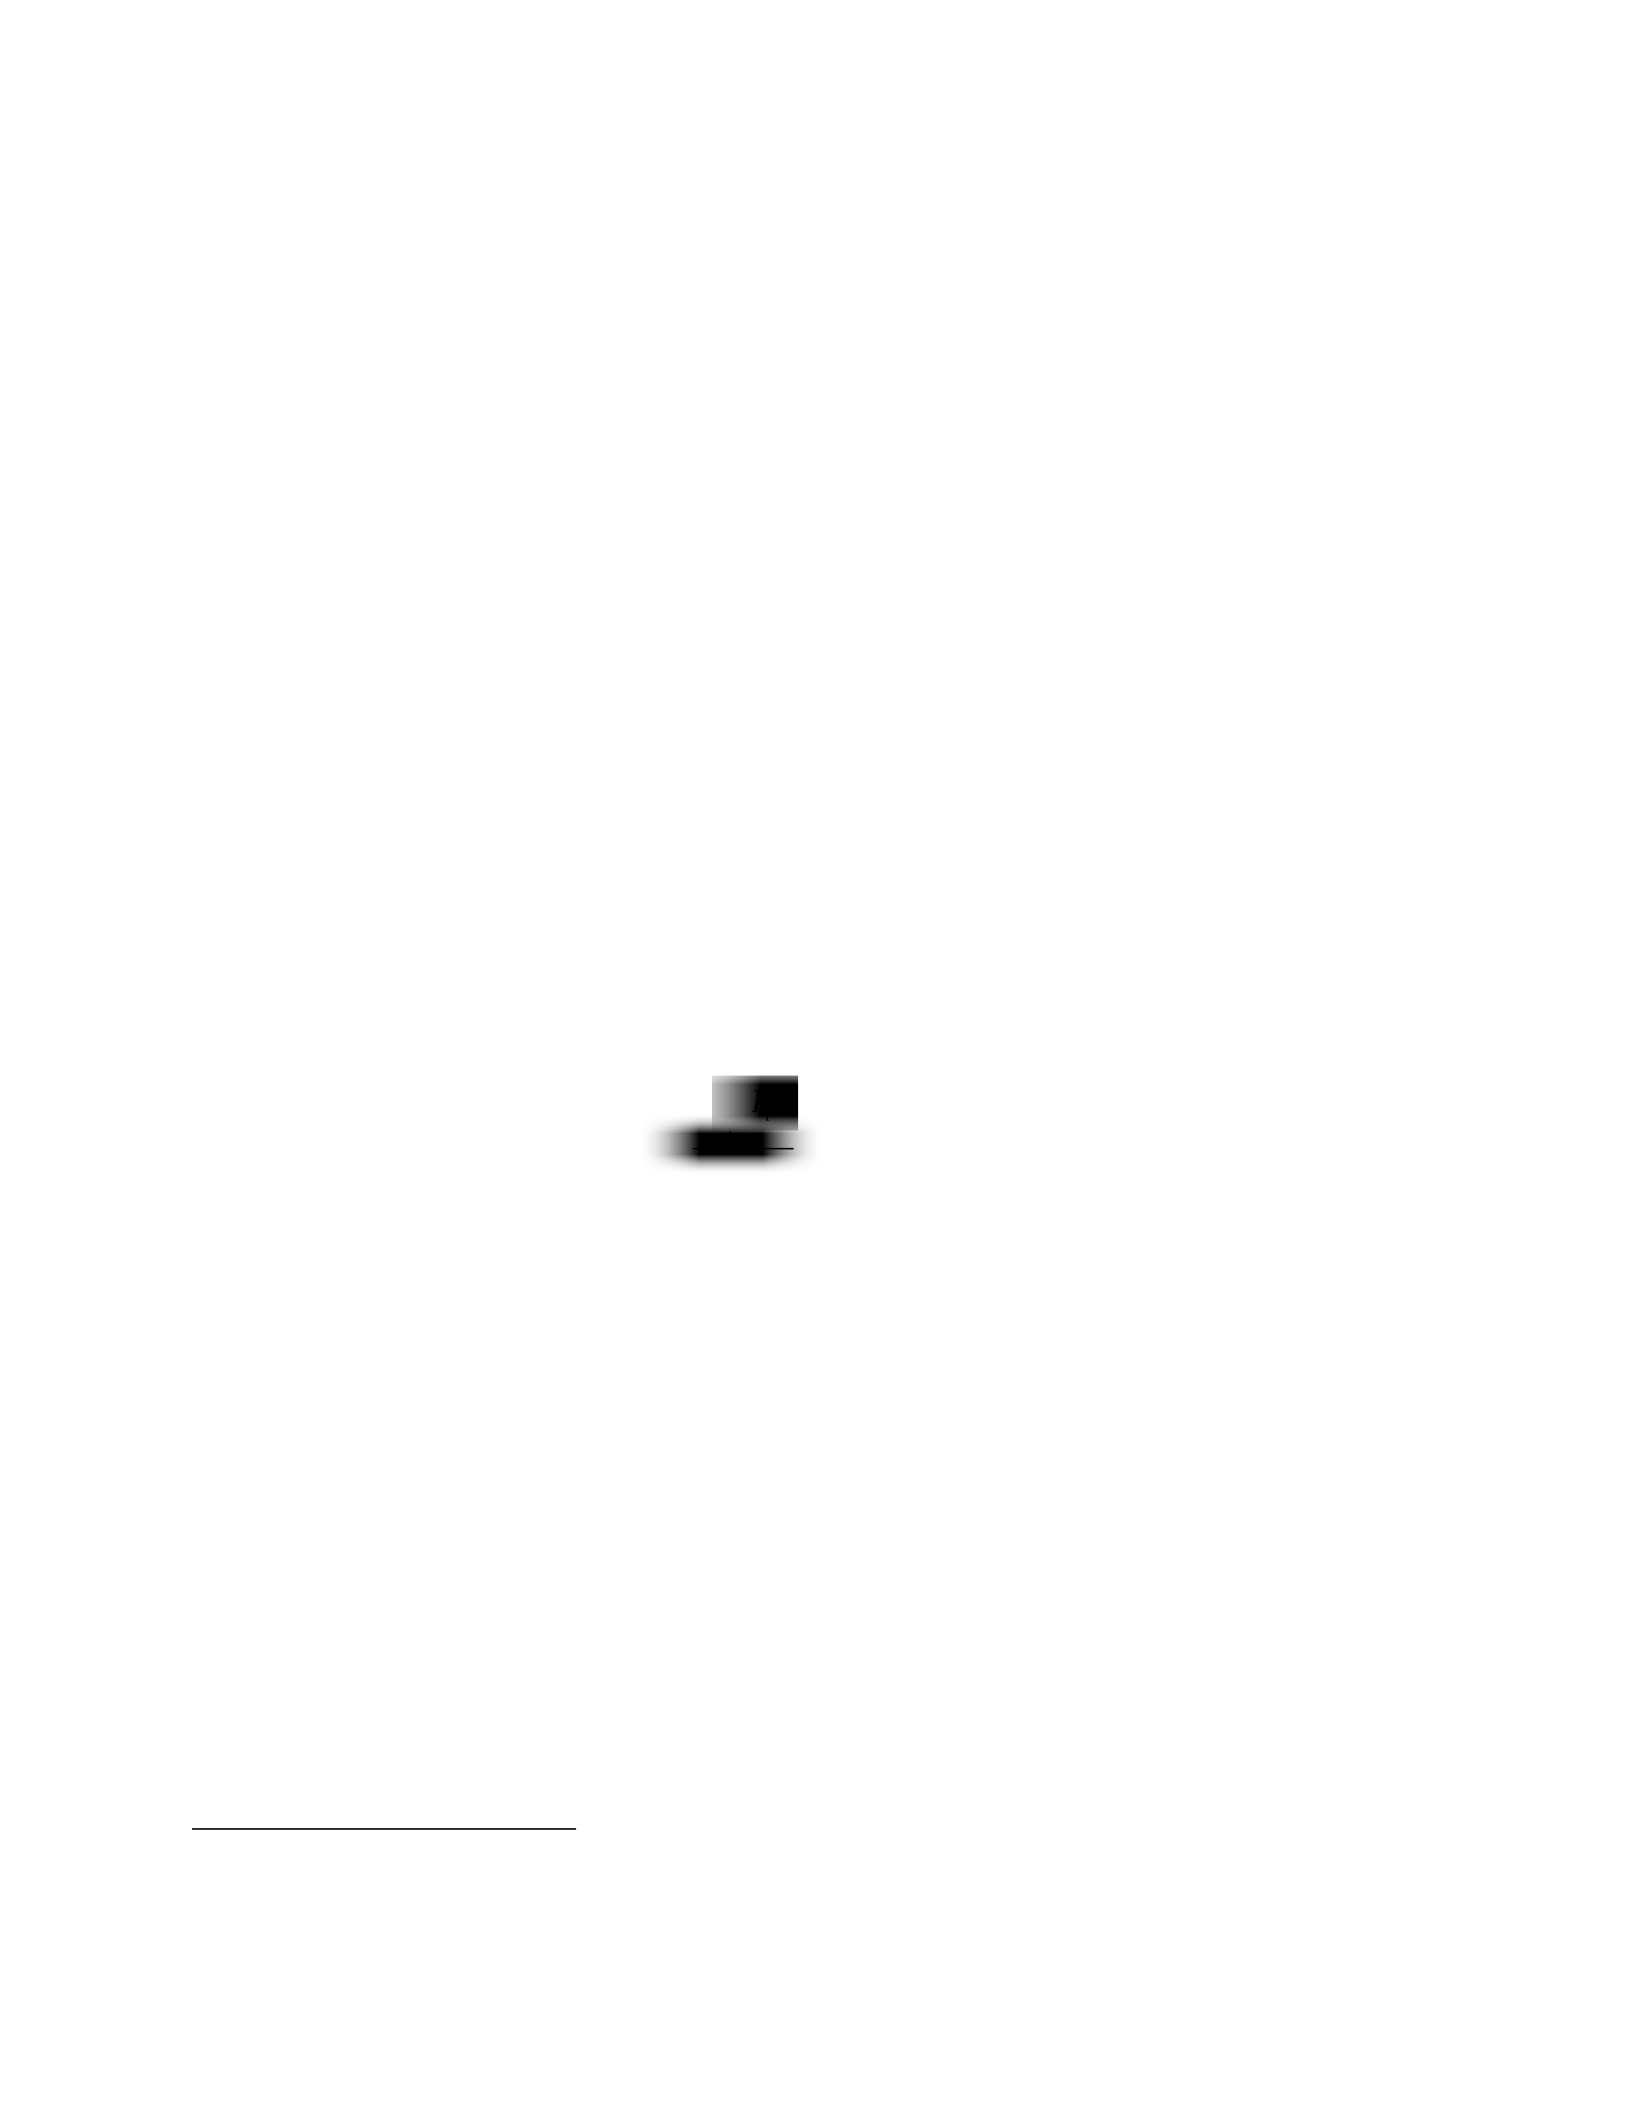
in equation (1) the calculation of the price-weighted index is:
i
i
P
Index Level Divisor
(1)
where the Index Level is determined by the sum of each security’s price, divided by a Divisor.
The Divisor is adjusted to account for changes in share counts and other changes in the sample
over time3. With this method, each company’s weight in the index depends on its price level and
therefore a 10 percent price movement in a $100 security, regardless of the size of the firm, will
have a larger influence in the value of the index than a similar movement in a $10 security.
3 Each index has its own list of events that will result in changes in the divisor.
13
Because of this flaw, price weighted indices are not widely used – although, with much criticism,
the DOW continues to utilize this method4.
The second type of index weighting method is market-capitalization weighting, also
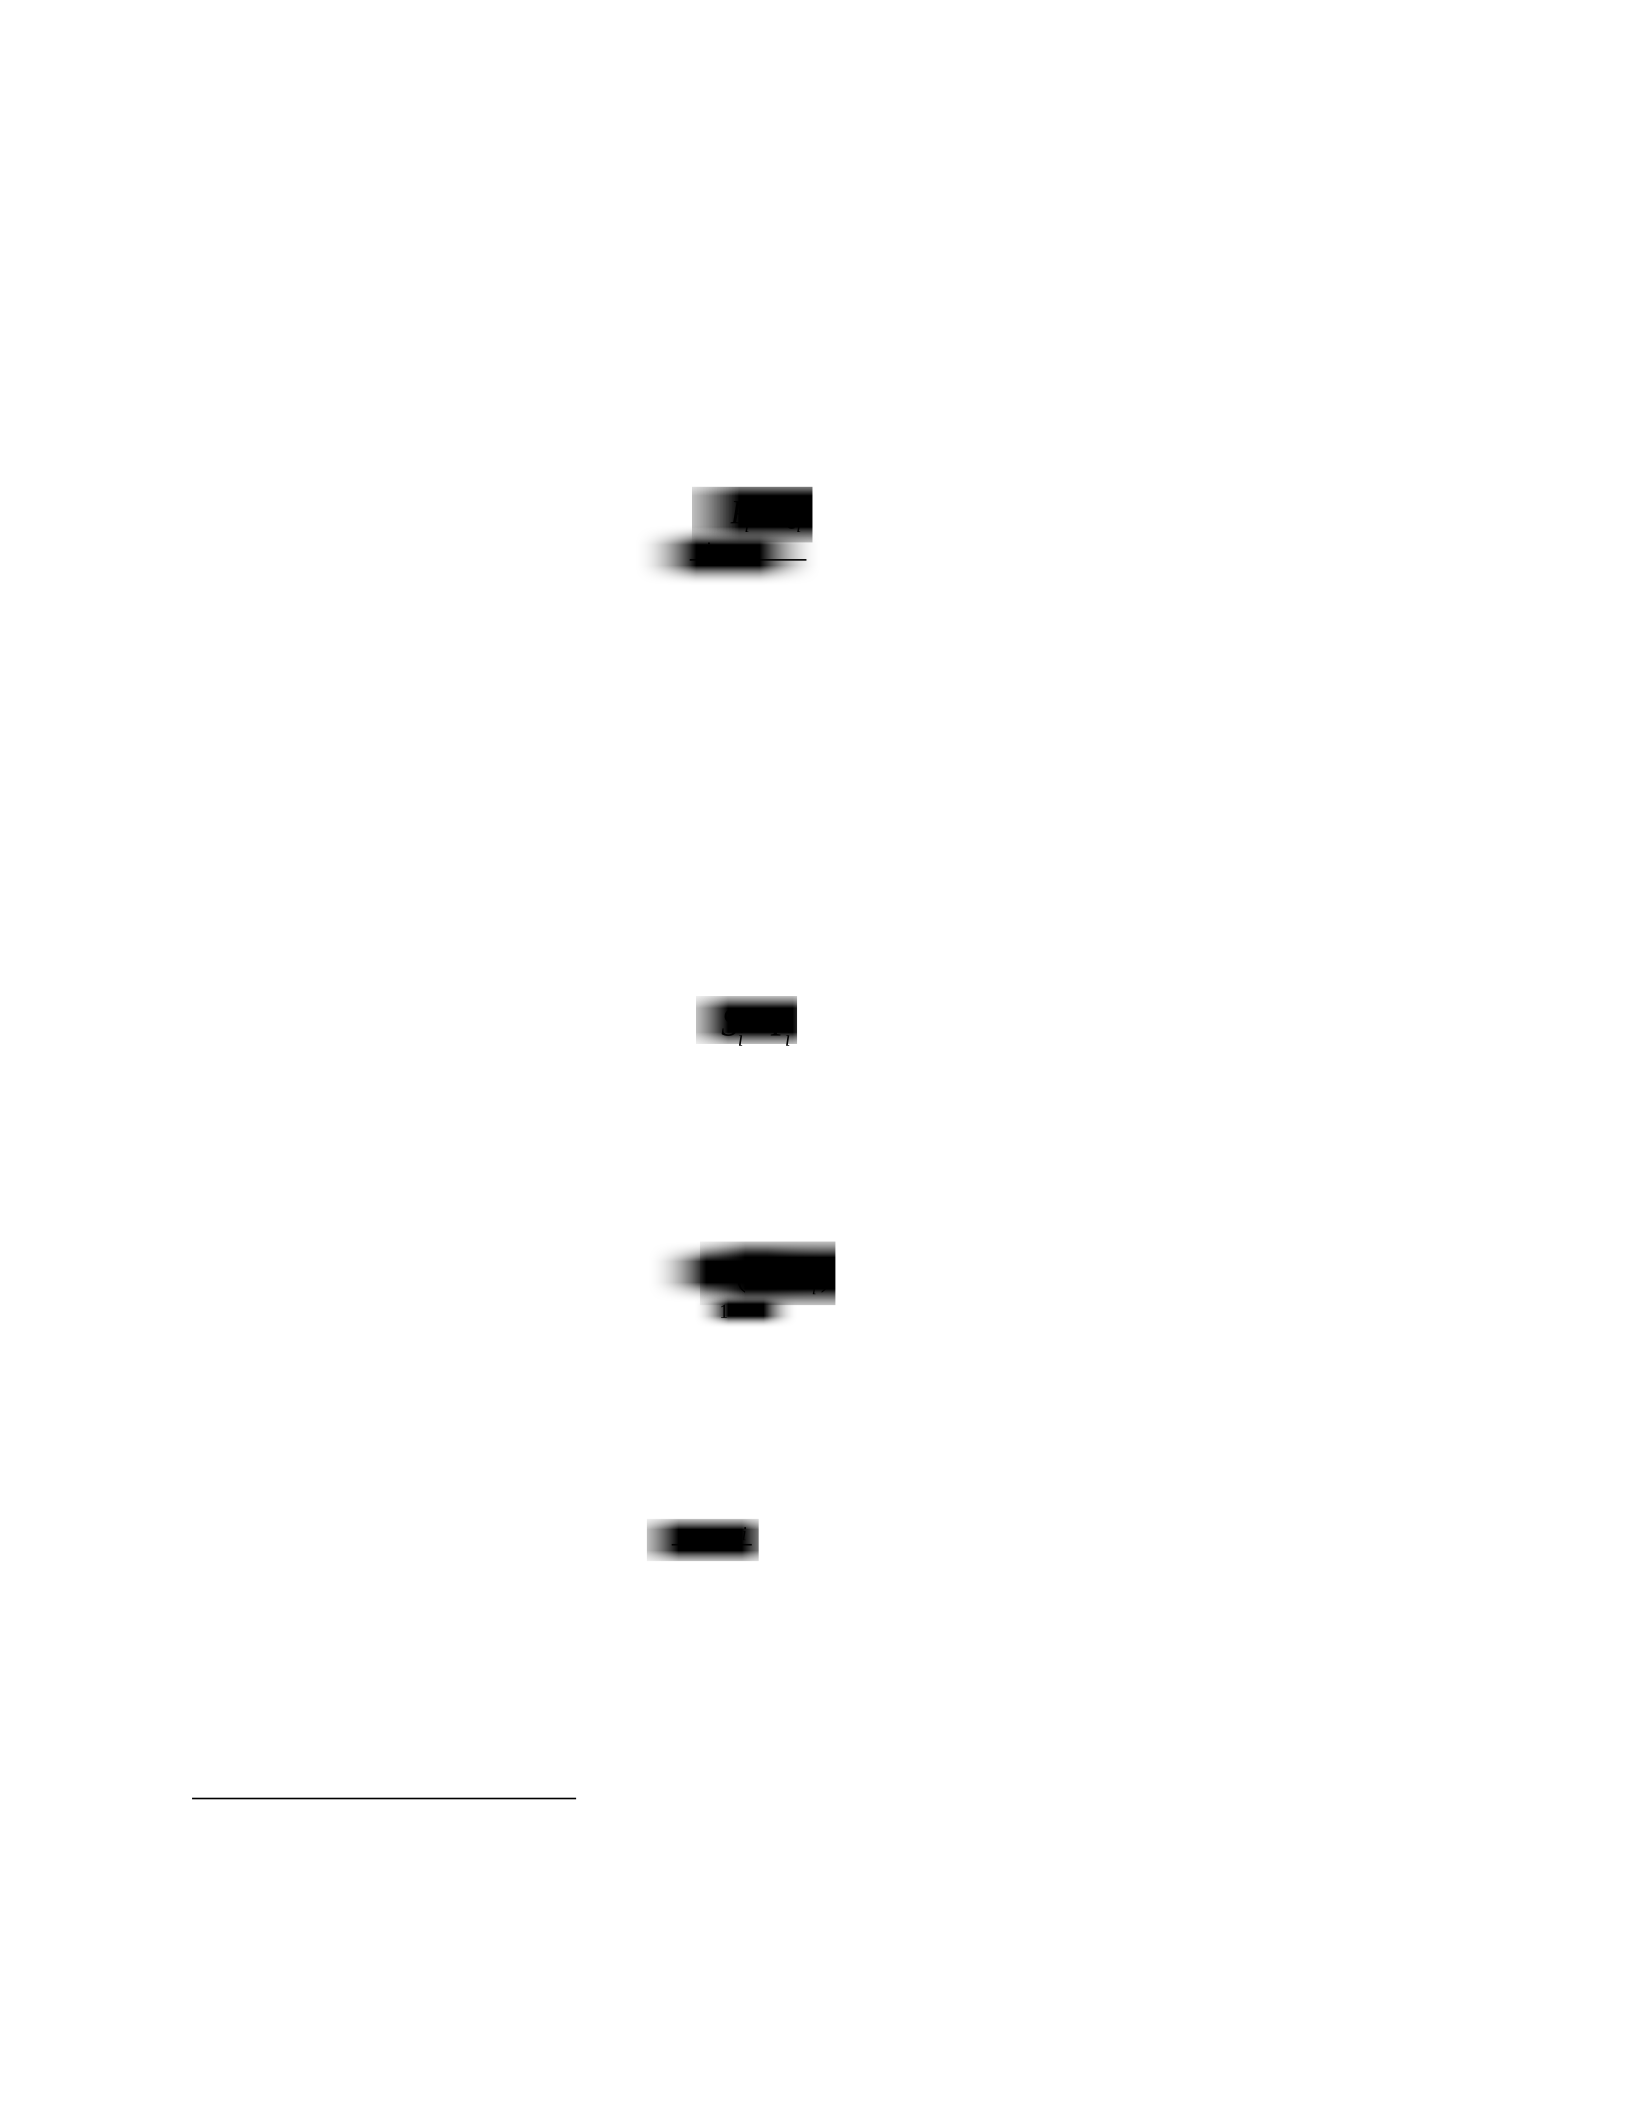
known as market-cap. The basic formula for a market-cap index is:
*
ii
i
PQ
Index Level Divisor
(2)
where the Index Level is determined by the sum of each security’s price multiplied by its
respective weight (Qi), divided by a Divisor. This method takes in to account the size of each
firm in the index and weights each security accordingly. The weight is calculated by determining
the percentage market value of each security in the index out of the total value of all securities
included. Daily market value (DMV) is determined by the following equation:
*
i i i
DMV S P
(3)
where the DMVi is the product of the number of outstanding shares (S) and the current market
price (P) of security “i”. The total market value of the index is given by equation (4) below:
1
()
n
i
i
IMV DMV
(4)
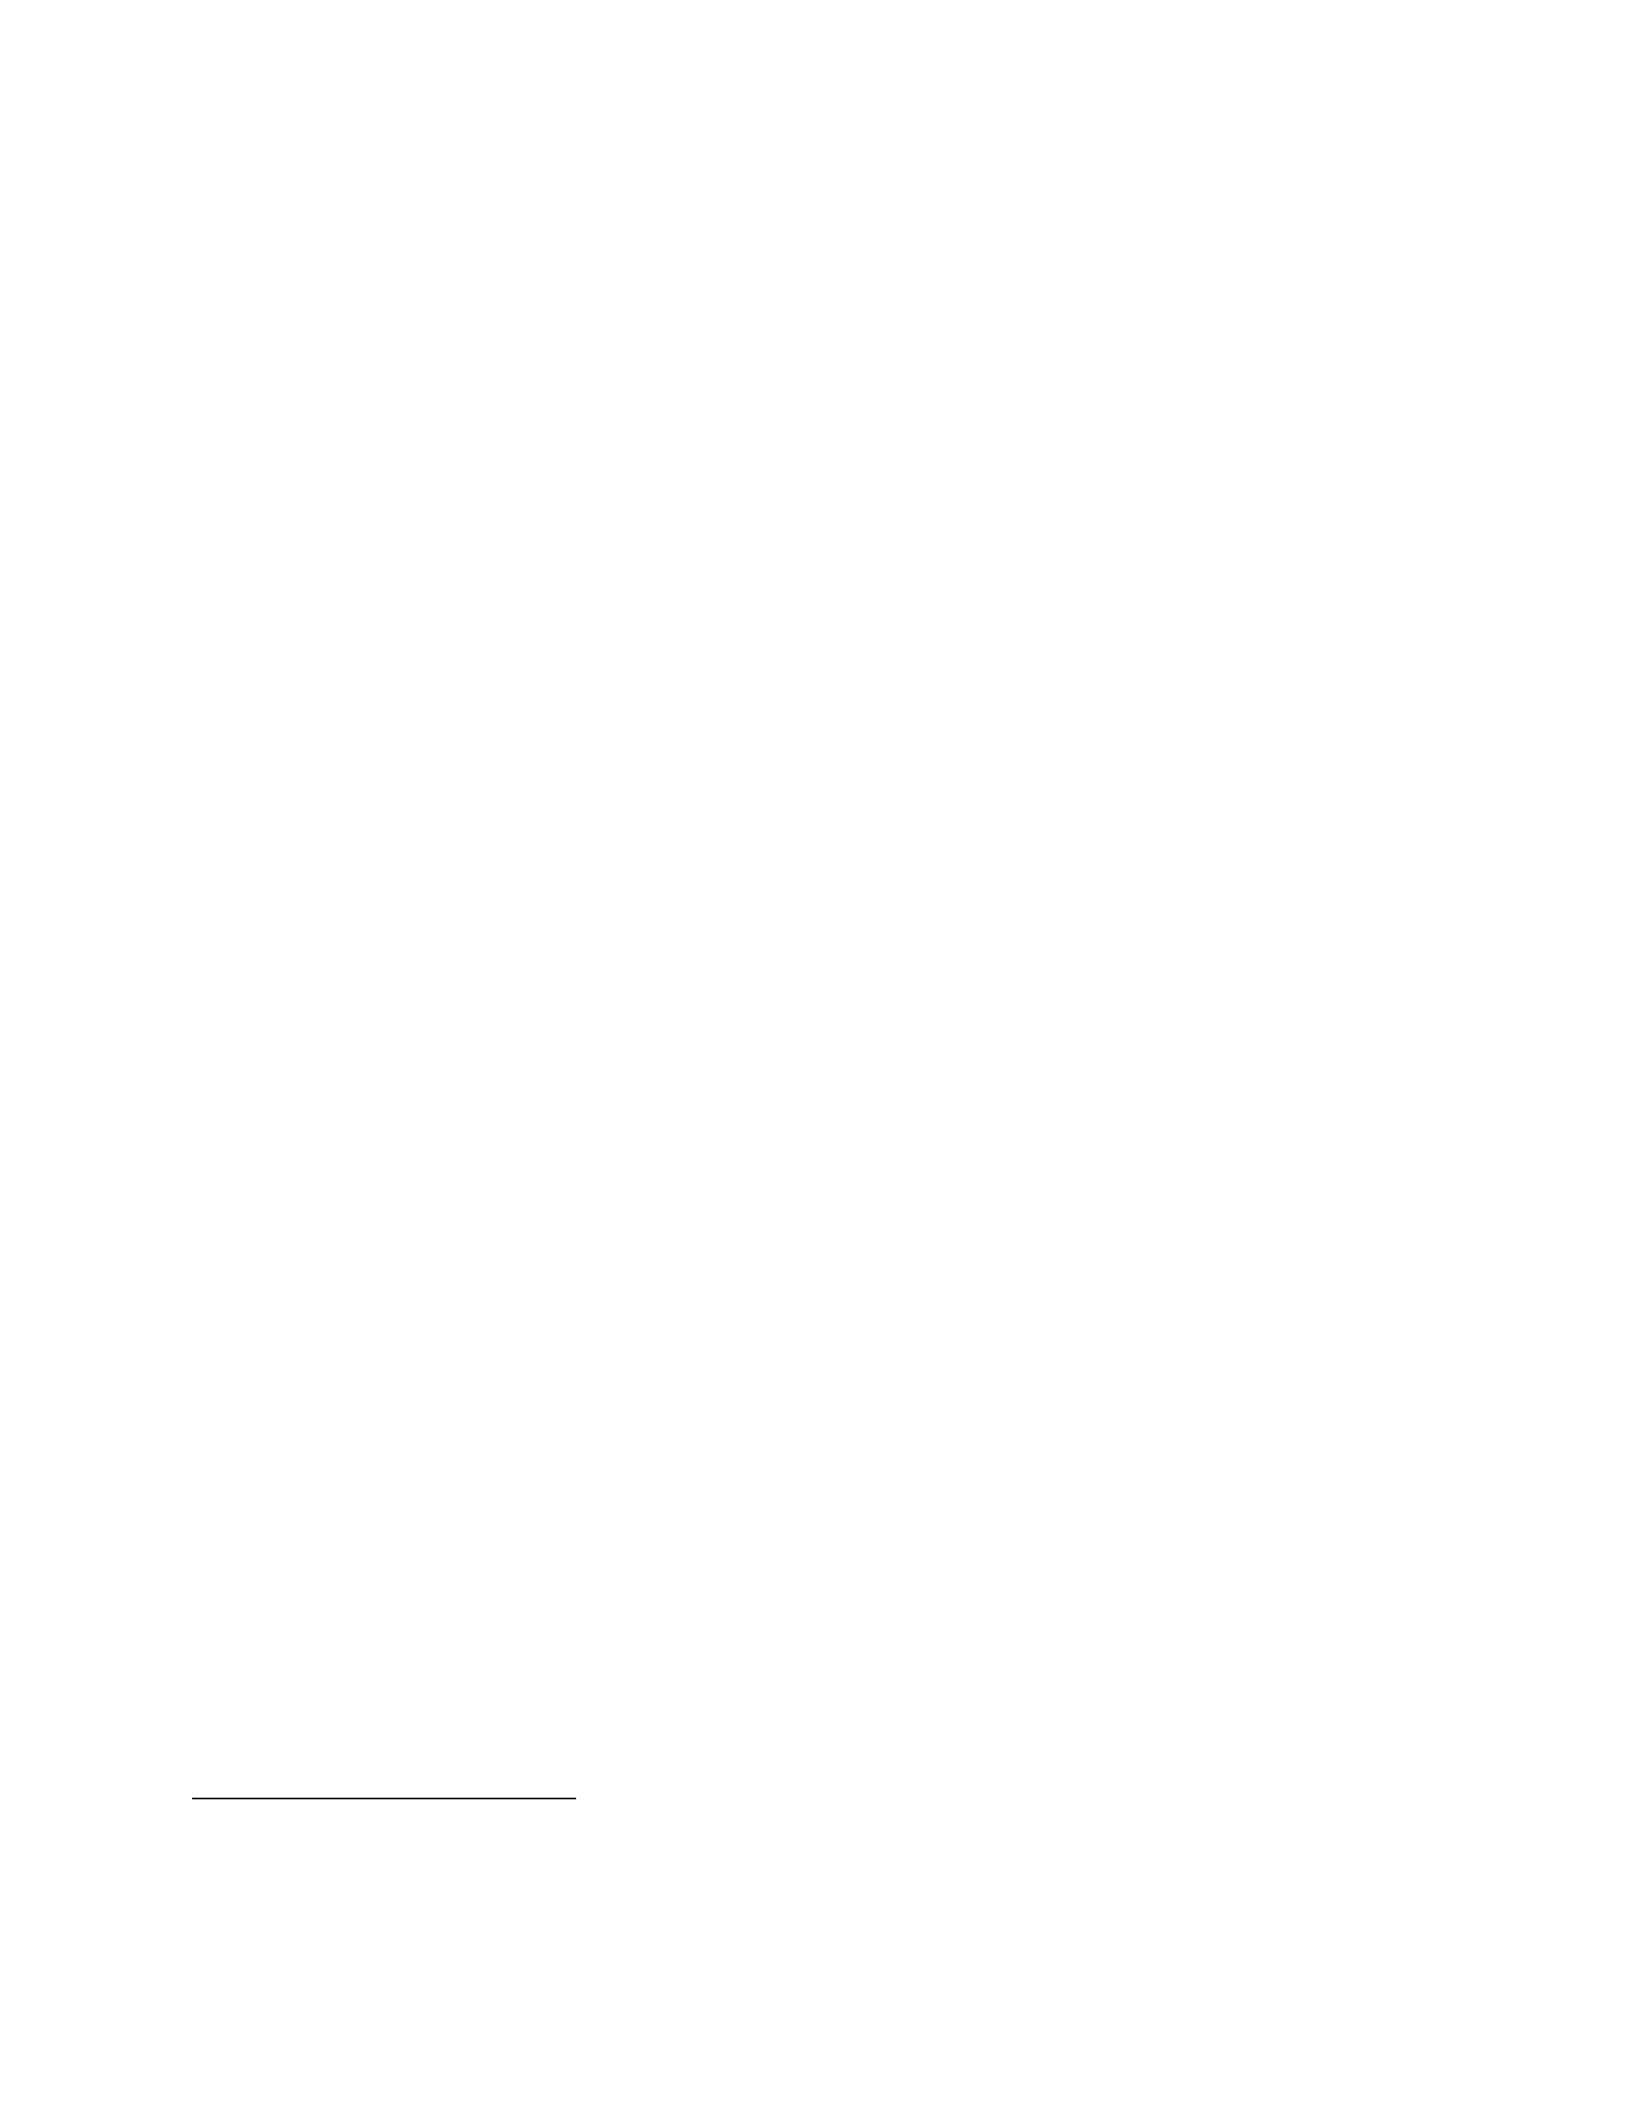
where the index market value (IMV) is given by the sum of each security’s DMV. The weight of
each stock is given by the ratio of its market value and the total market value of the index:
i
i
DMV
QIMV
(5)
where
i
Q
is the weight assigned to security i,
i
DMV
is the daily market value of security i, and
IMV
is the total market value of the index. Examples of market-cap indices are the S&P 500
4 For more information about investor criticism of the DJIA and other price-weighted indices, see “100 Years of the
DJIA,” section in The Wall Street Journal, 28 May 1996, R29-R56, and “What’s Behind the Trailing Performance
of the Dow Industrials vs. the S & P 500?” The Wall Street Journal, 20 August 1998, C1, C17.
14
(US), the Hang Seng Index (Hong Kong), and the FTSE 100 (Britain). This method is more
widely used by index service firms because firm size is accounted for in the index calculation.
Because of this characteristic, the market-cap method is the index calculation used in this study.
There are however, some limitations to this method. Due to the weighting method, the larger
firms in the index can crowd out the smaller ones as they generally carry more weight in the
index. In industries that are highly concentrated this can affect the validity of the index. To get
around this issue, many index managers set a per-firm cap, usually 8 to 10 percent of the total
index value per firm in the index.
2.3 Index Performance and Comparison
A vast body of academic literature exists concerning security price return, risk, and comparison
methods. Additionally, rating agencies, financial analysis firms, and index service providers
publish thousands of documents each year that explain new measures of security performance
and risk. The purpose of this section is to determine the proper measures of risk and return to be
used to analyze and compare stock indices.
2.3.1 Index Performance
Before a discussion of performance measures, it is important to note that the index in this study,
like most stock price indices, ignores dividend payments. Therefore, a true investment return
cannot be calculated, only a measure of price appreciation is calculable. It is possible to make an
adjustment for dividends in some cases by splicing an index with a dividend yield index (Wilson
and Jones, 2002). Recently, many index service and database firms have begun to publish
versions of popular indices that have been corrected for dividends payments5. However, it can be
argued that because dividend payments are somewhat constant and predictable, their value is
5 An example of such an index is the Center for Research in Security Prices indices on the S&P 500 that have been
corrected for dividends CenterforResearchinSecurityPrices. (2009). "CRSP Daily Stock Price Database." from
http://www.crsp.com/products/index.html..
15
already represented in the company’s stock price, which by definition is the current value of
expected future earnings. In the following discussion, any reference to “return” refers only to
change in the index’s price, not actually total investment return.
Most financial literature primarily involves return data, or change in price, instead of
prices of securities. There are many statistical advantages to using security returns. (Campbell et
al., 1997) argued that for average investors, returns are a complete and scale-free summation of
the investment opportunity and that return series are easier to handle that price series because of
their attractive statistical properties. Return calculation is an active area of academic research and
is an important issue for investors who need to make informed decision for their clients. The next
few sections will discuss simple return measures, holding period return measures, and risk
adjusted performance measures.
2.3.1.1 Simple Return Measures
A simple return measure, or rate of change, can be calculated for one or multiple periods of
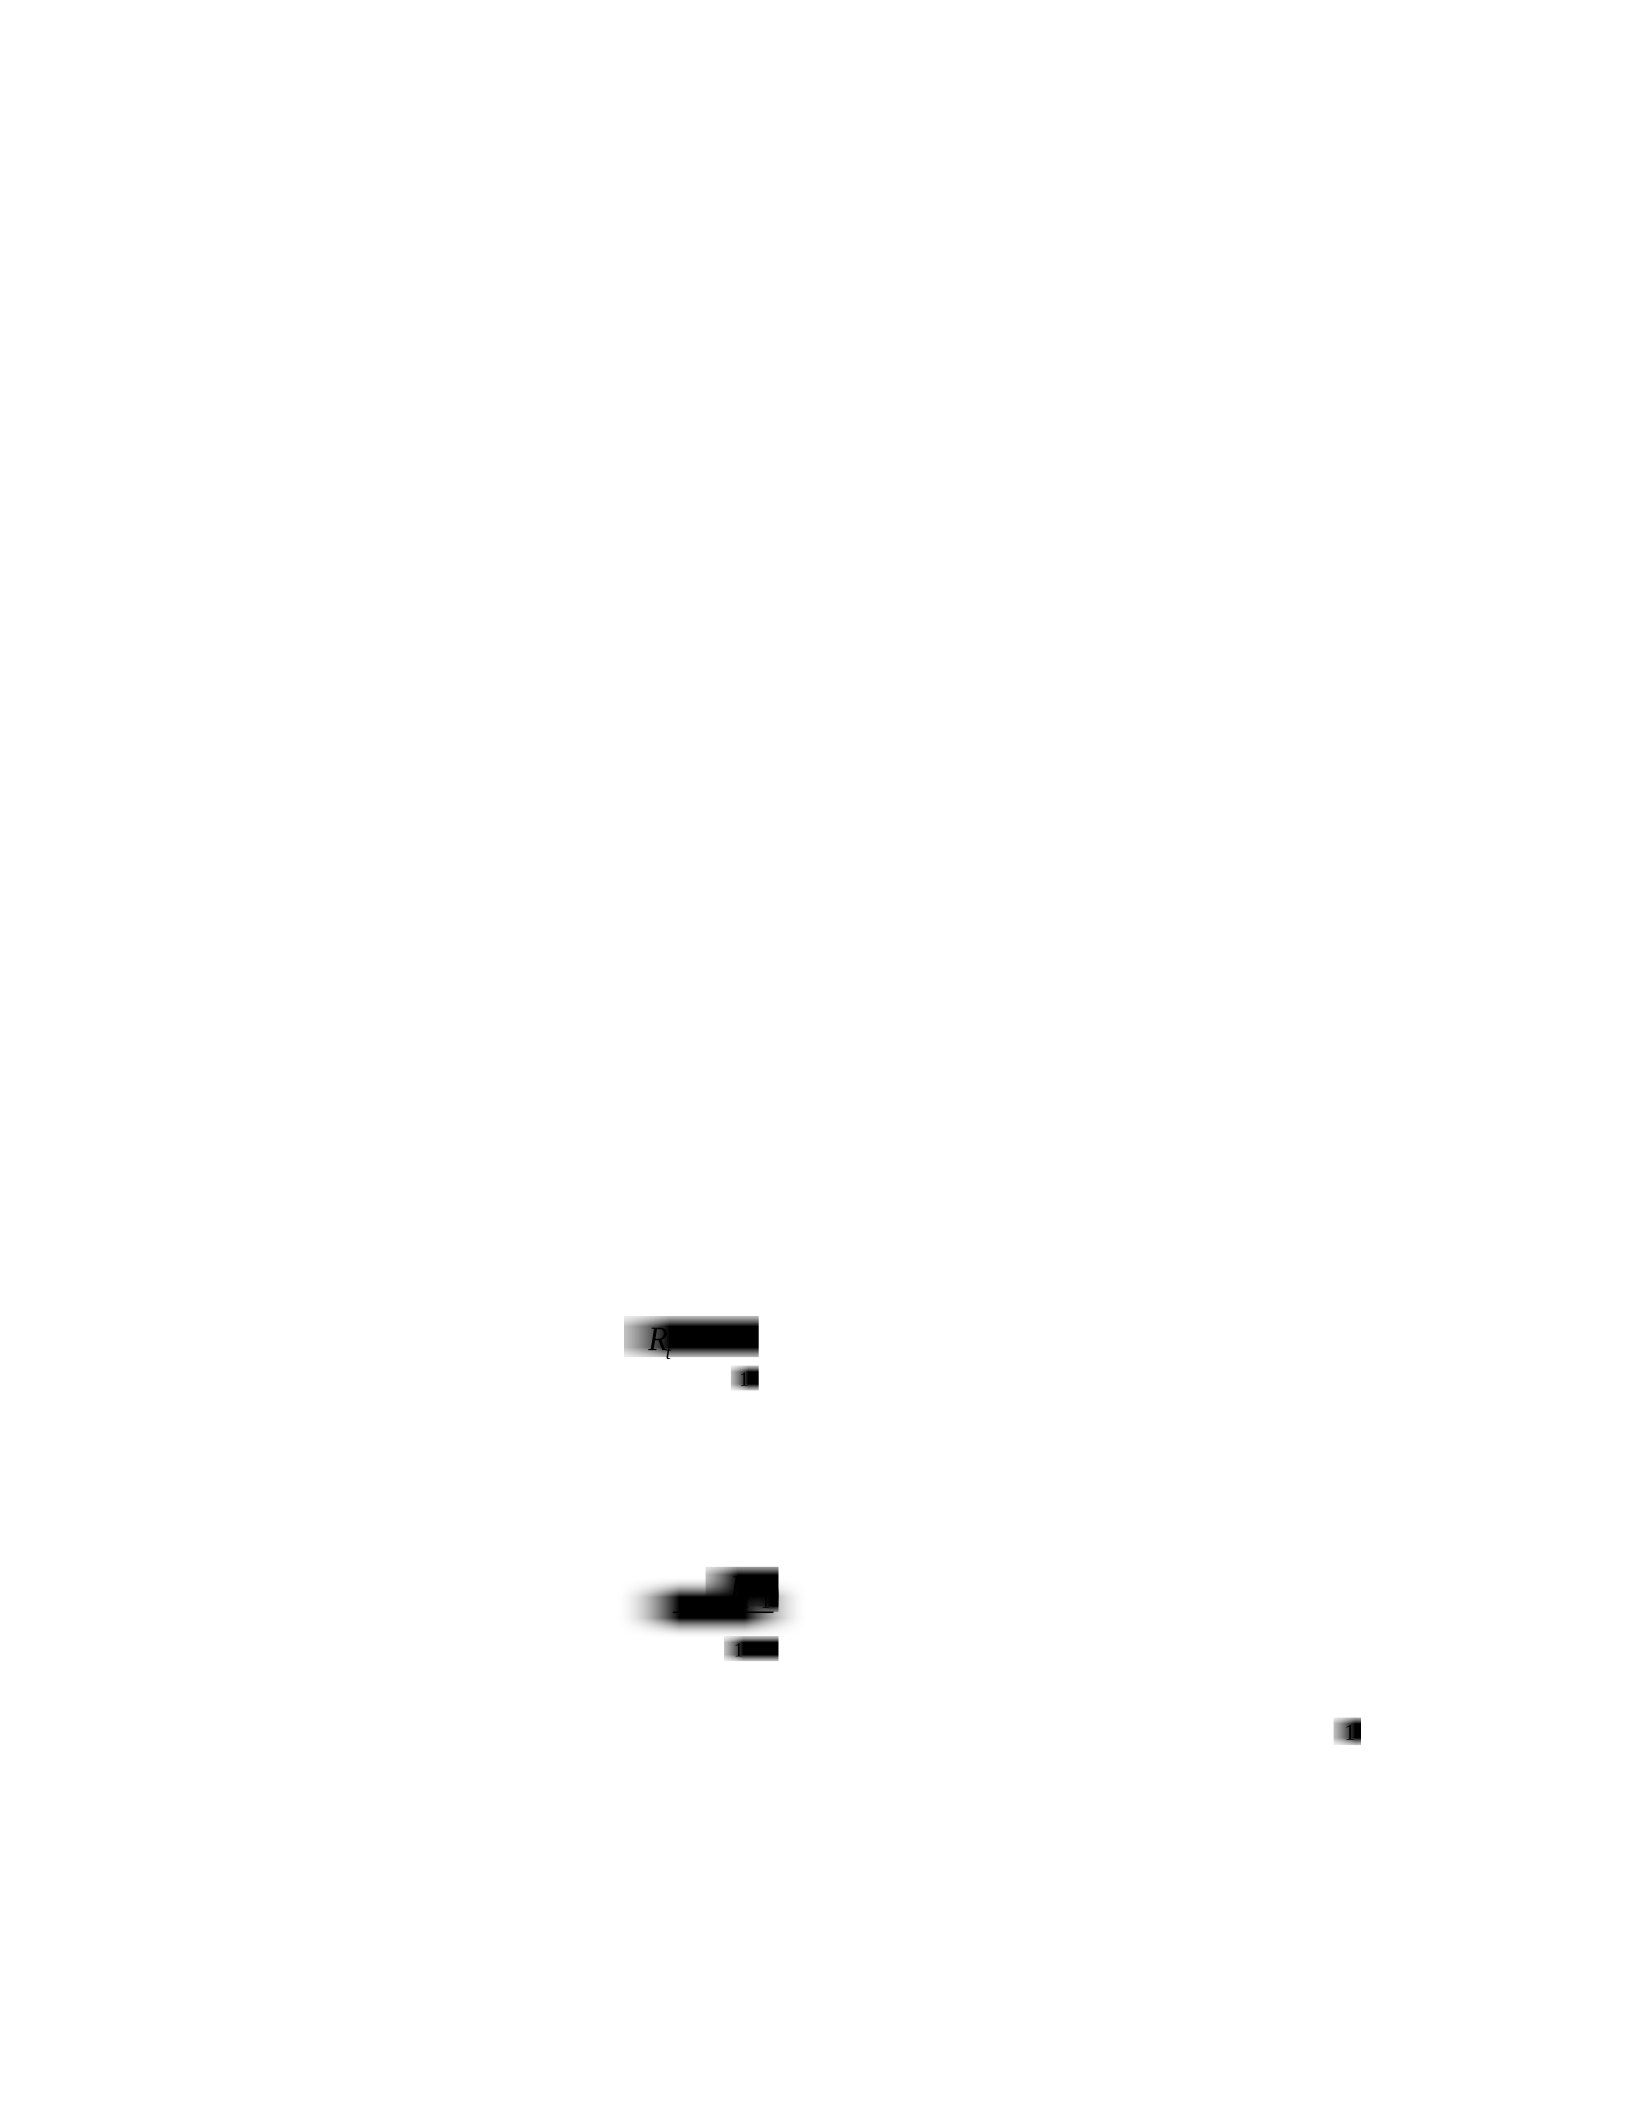
investment. From (Tsay, 2005), assuming no dividend payments, a one-period simple gross
return is given by:
1
1t
t
t
P
RP
(6)
moreover, the equivalent simple return is given by:
1
1
tt
t
t
PP
RP
(7)
where
t
R
is the return on trading day t,
t
P
is the security’s price on trading day t, and
1t
P
is the
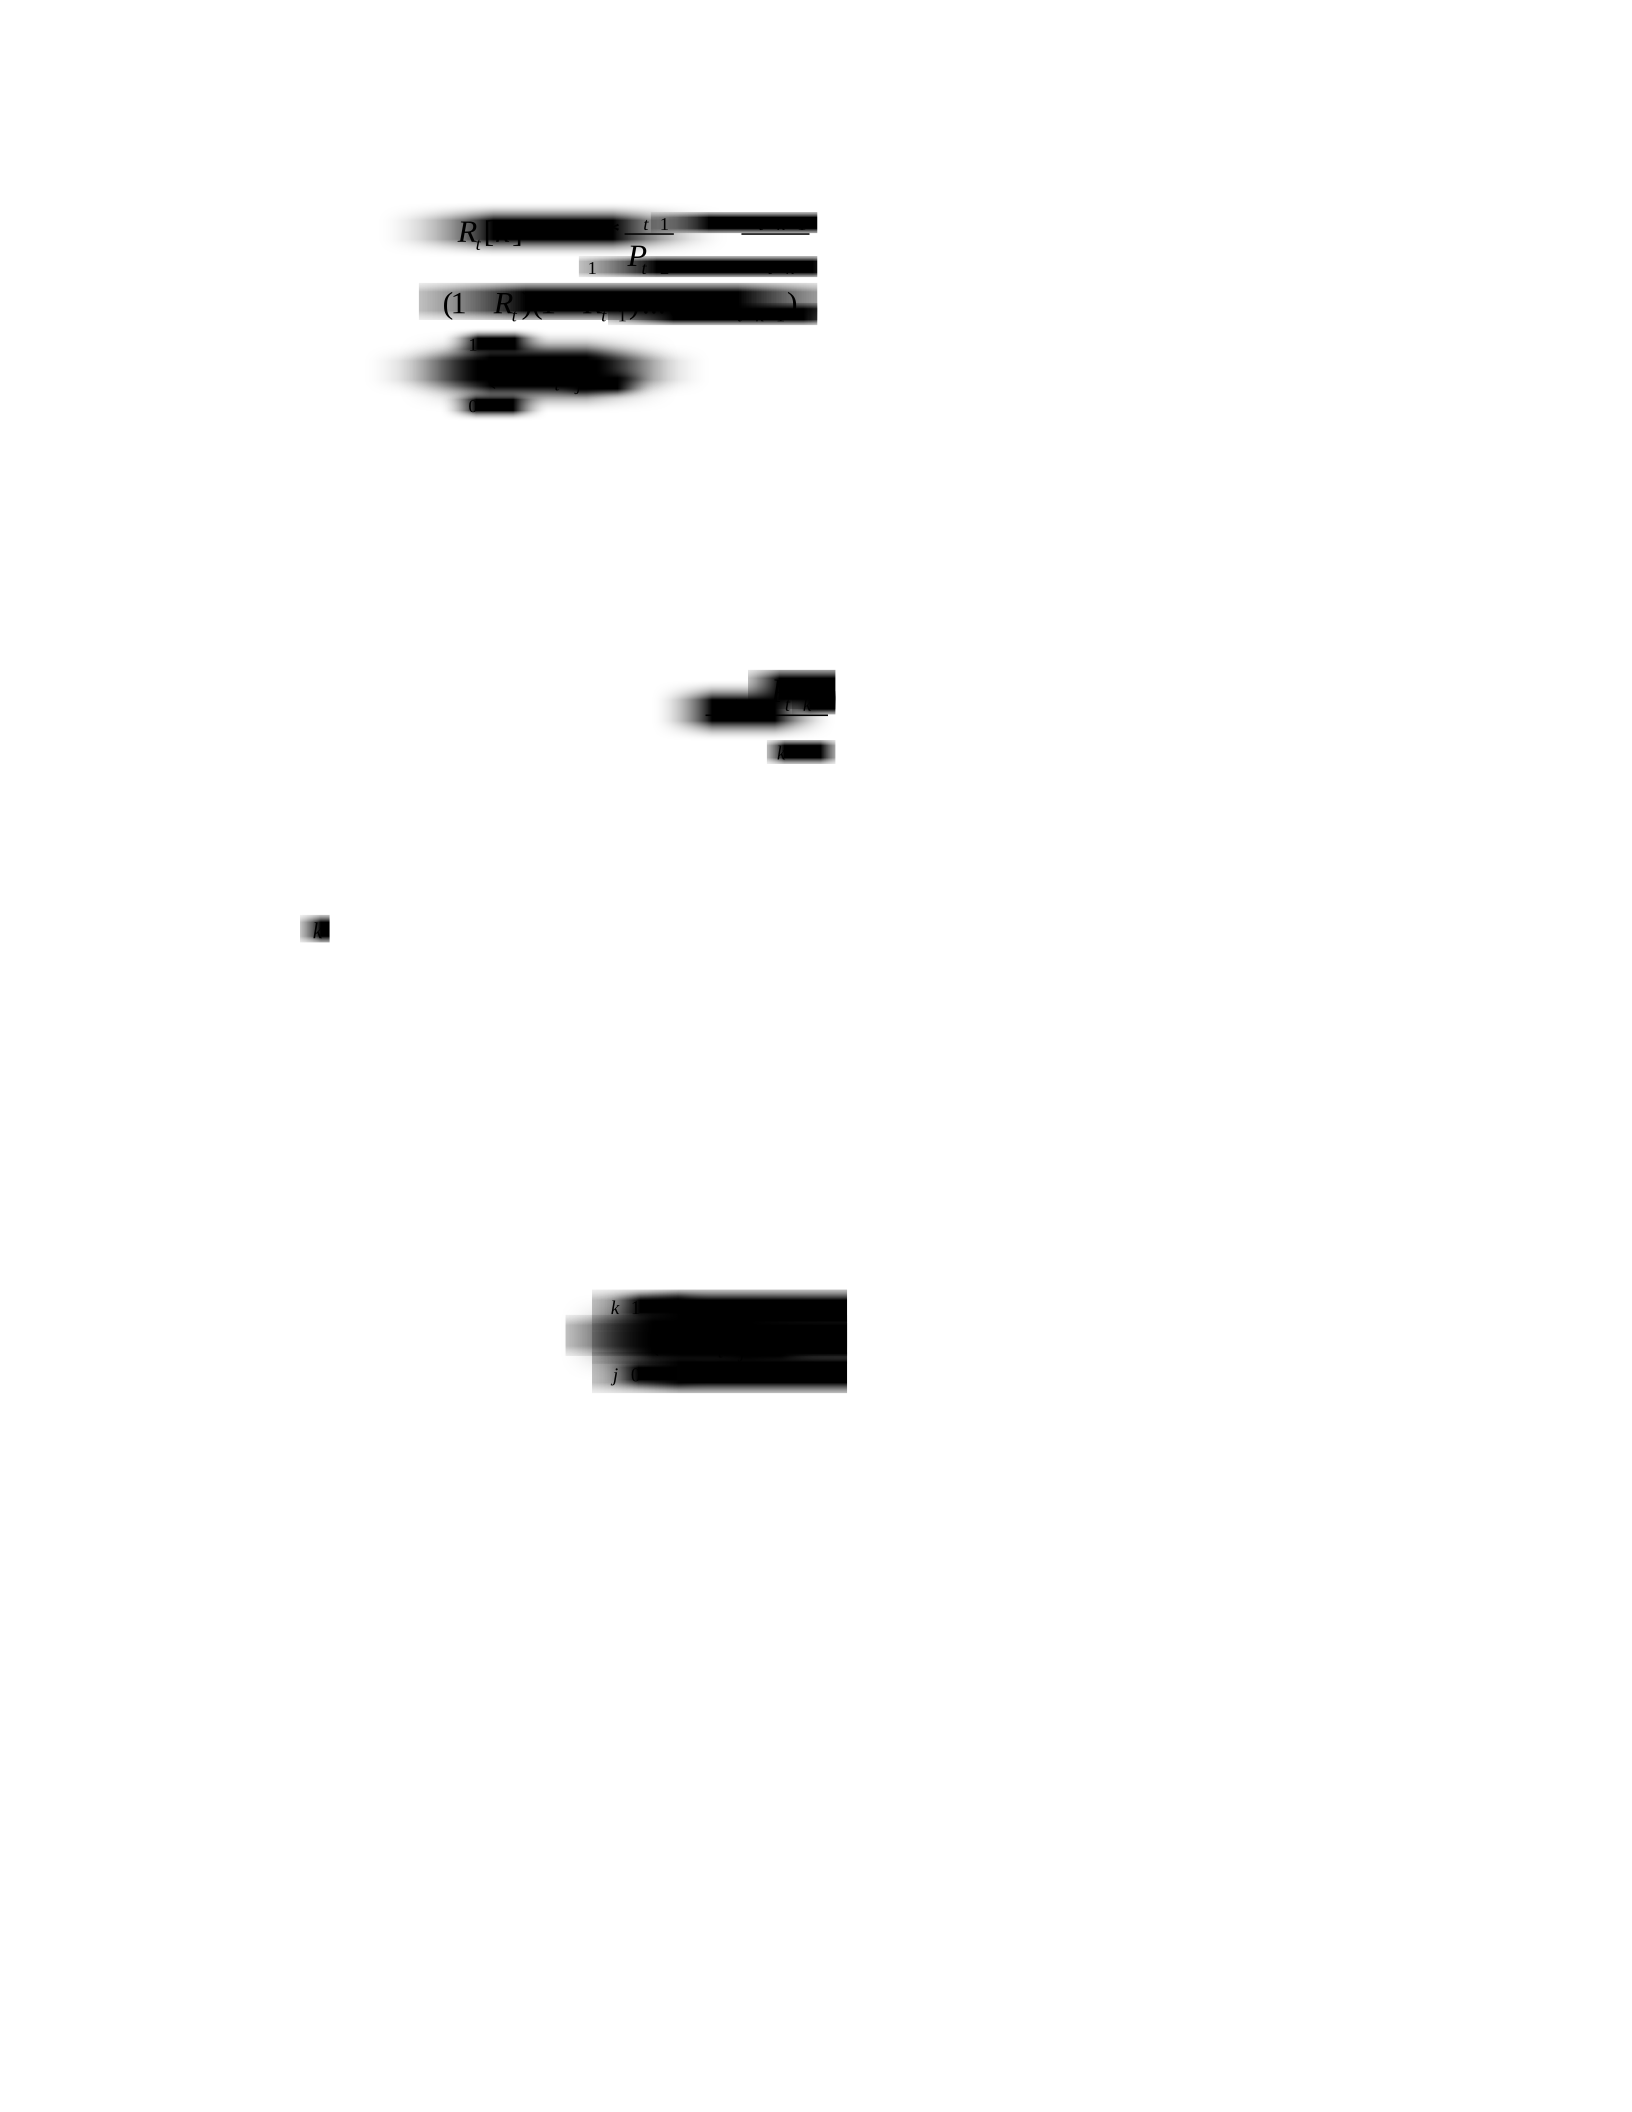
security’s price on day t-1. From (Tsay, 2005), the multi-period gross return calculation is given
by:
16
11
12
11
1
0
1 [ ] * *...*
(1 )(1 )...(1 )
(1 )
t t t k
t
t t t k
t t t k
k
tj
j
P P P
Rk P P P
R R R
R
(8)
where the security is held for k periods between the trading day t-k and t, and the k-period simple
gross return is the product of the one-period simple gross returns of all periods within the k
period. Therefore, the k-period simple return is:
()
[] t t k
t
tk
PP
Rk P
(9)
where
[]
t
Rk
is the simple multi-period return for the period k,
t
P
is the security’s price on date
t, and
tk
P
is the security’s price on date t-k.
2.3.1.2 Geometric Return
A geometric return is considered the industry standard for return reporting when a security is
held for a year or more. The following calculation, from (Campbell et al., 1997), is used to find
the geometric return (GR) of security i in time t:
1/
1
0
(1 ) 1
k
k
i
t t j
j
GR R
(10)
where the geometric return is equal to the multi-period simple gross return to the 1/k power and k
is the number of years in the holding period. The reported returns using this method will always
be smaller than returns calculated with the simple arithmetic method.
2.3.1.3 Risk Adjusted Returns
Investors are not always interested in a security’s return in itself. Rather, they are often
concerned with the security’s relative performance as compared to some risk-less security,
usually U.S. Treasury Bills. The resulting measure is often referred to as the “risk-adjusted
17
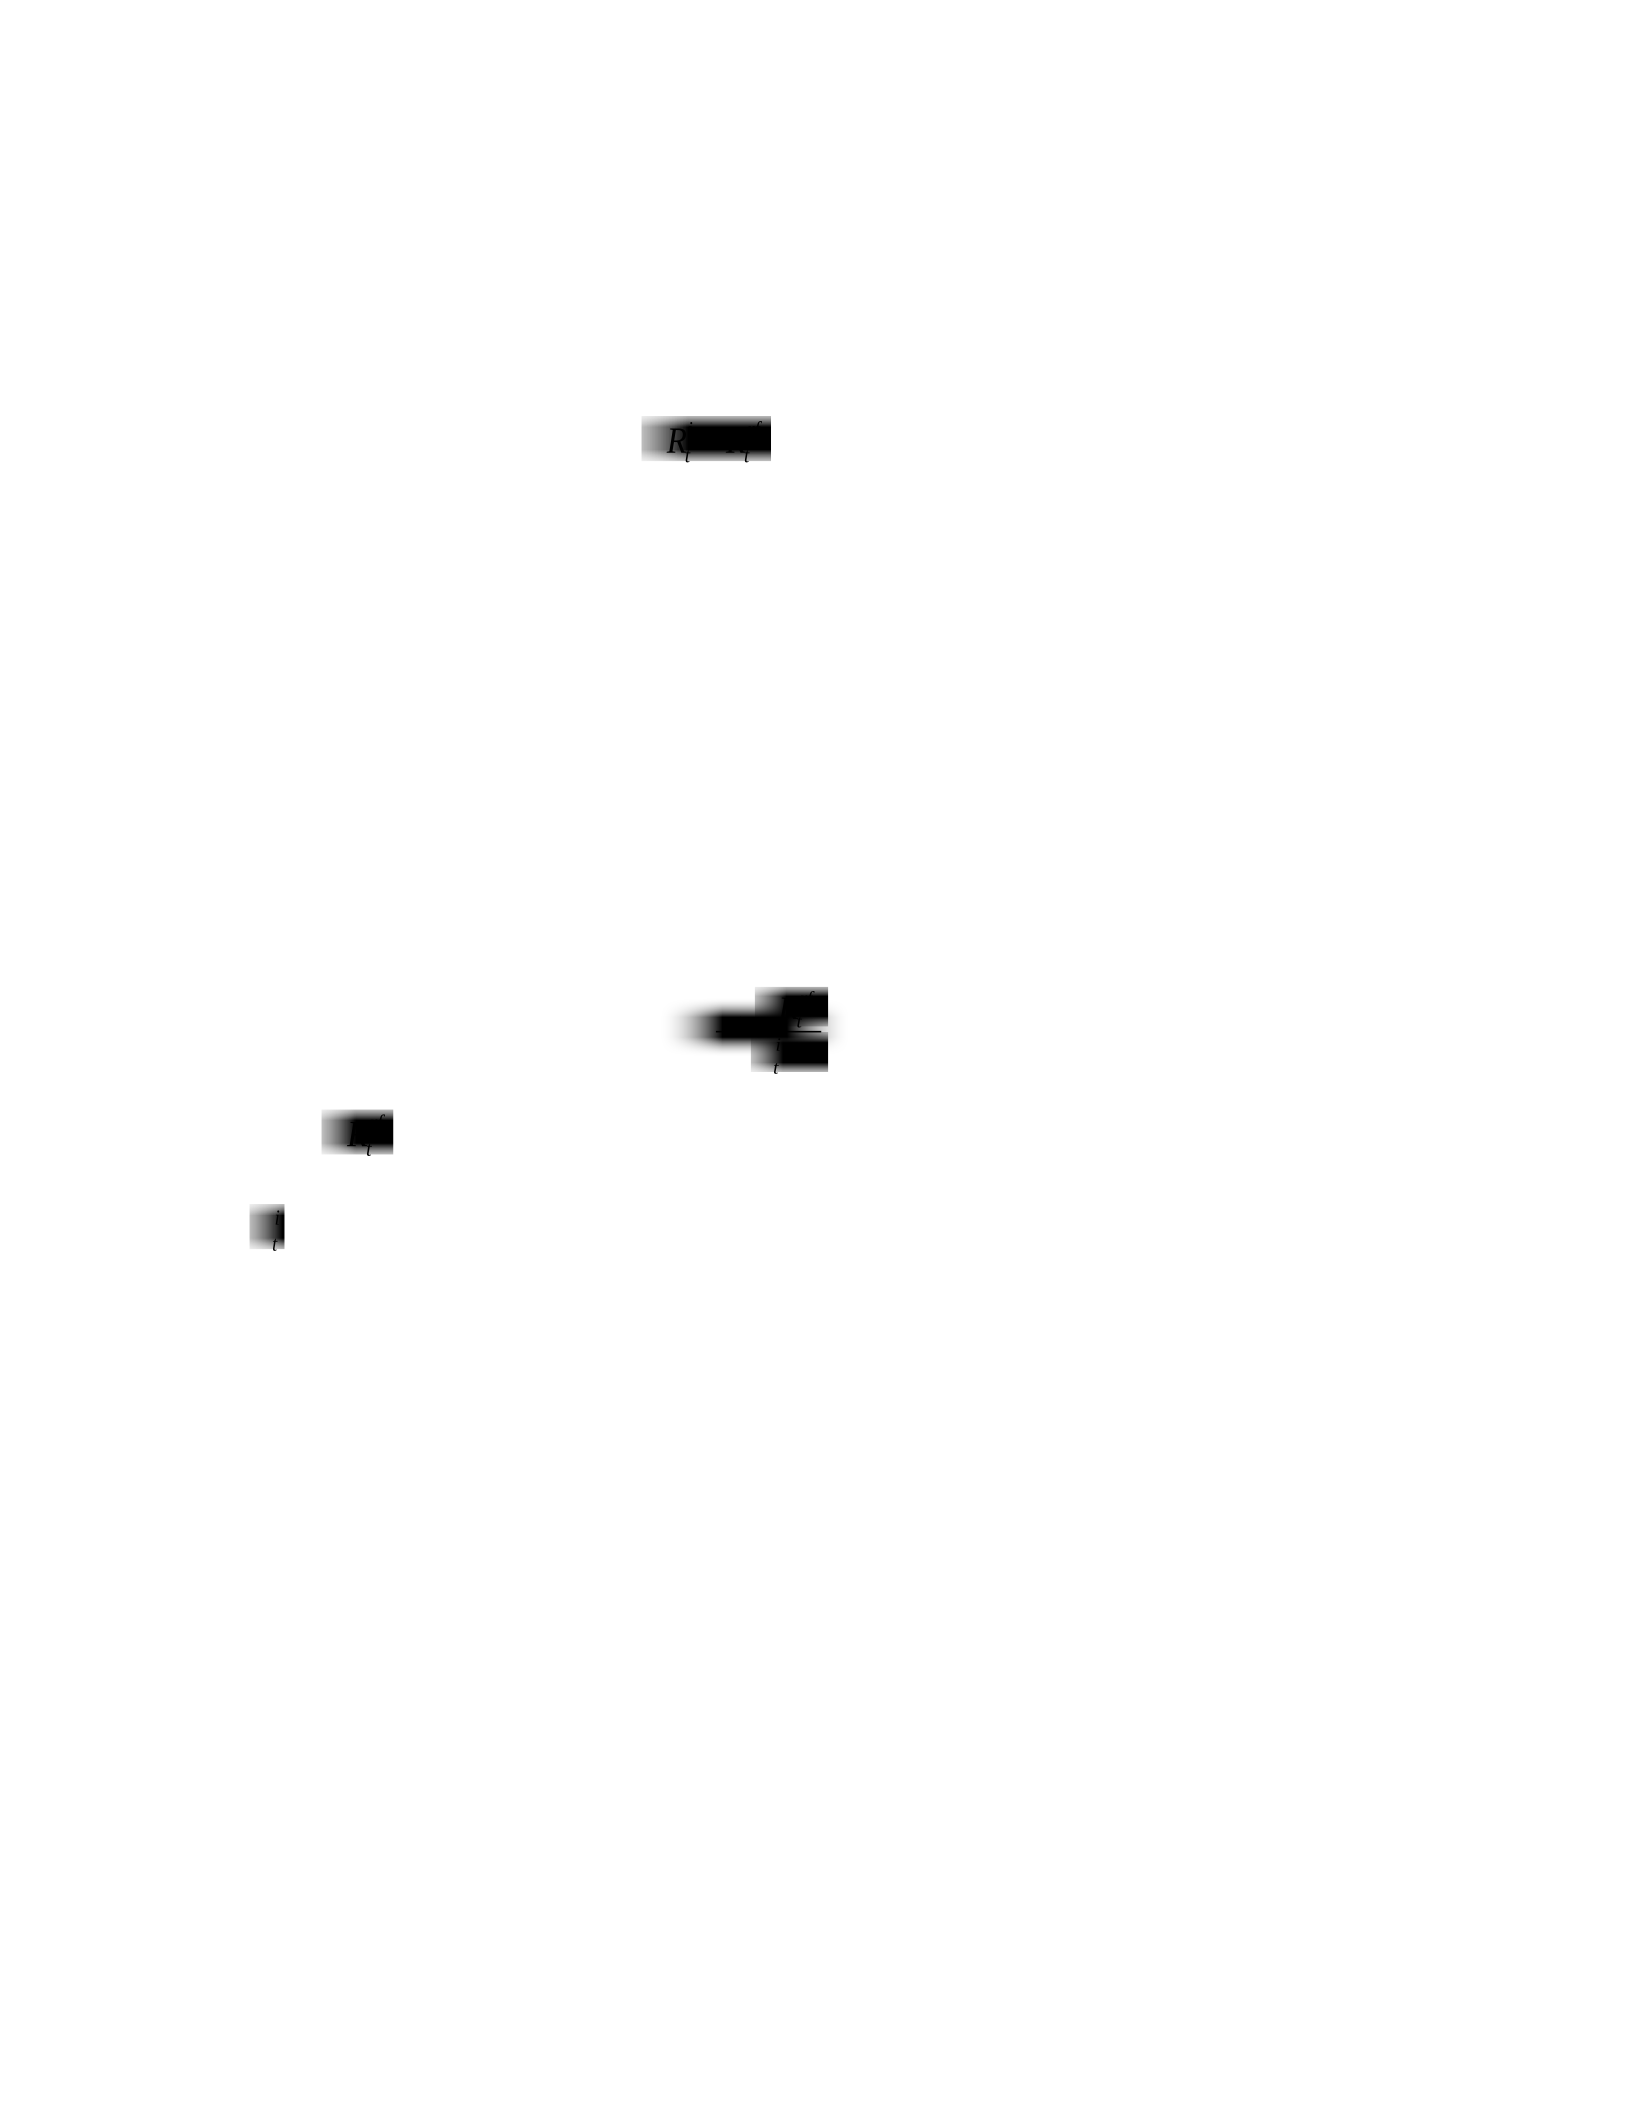
return”. Examples of these types of measures are excess return and the Sharpe Ratio. A
security’s excess return is the difference between the security’s return and the risk free security’s
return and is calculated as:
i i rf
t t t
Z R R
(11)
where
i
t
Z
is the excess return for security i on day t,
i
t
R
is the return on security i on day t, and
rf
t
R
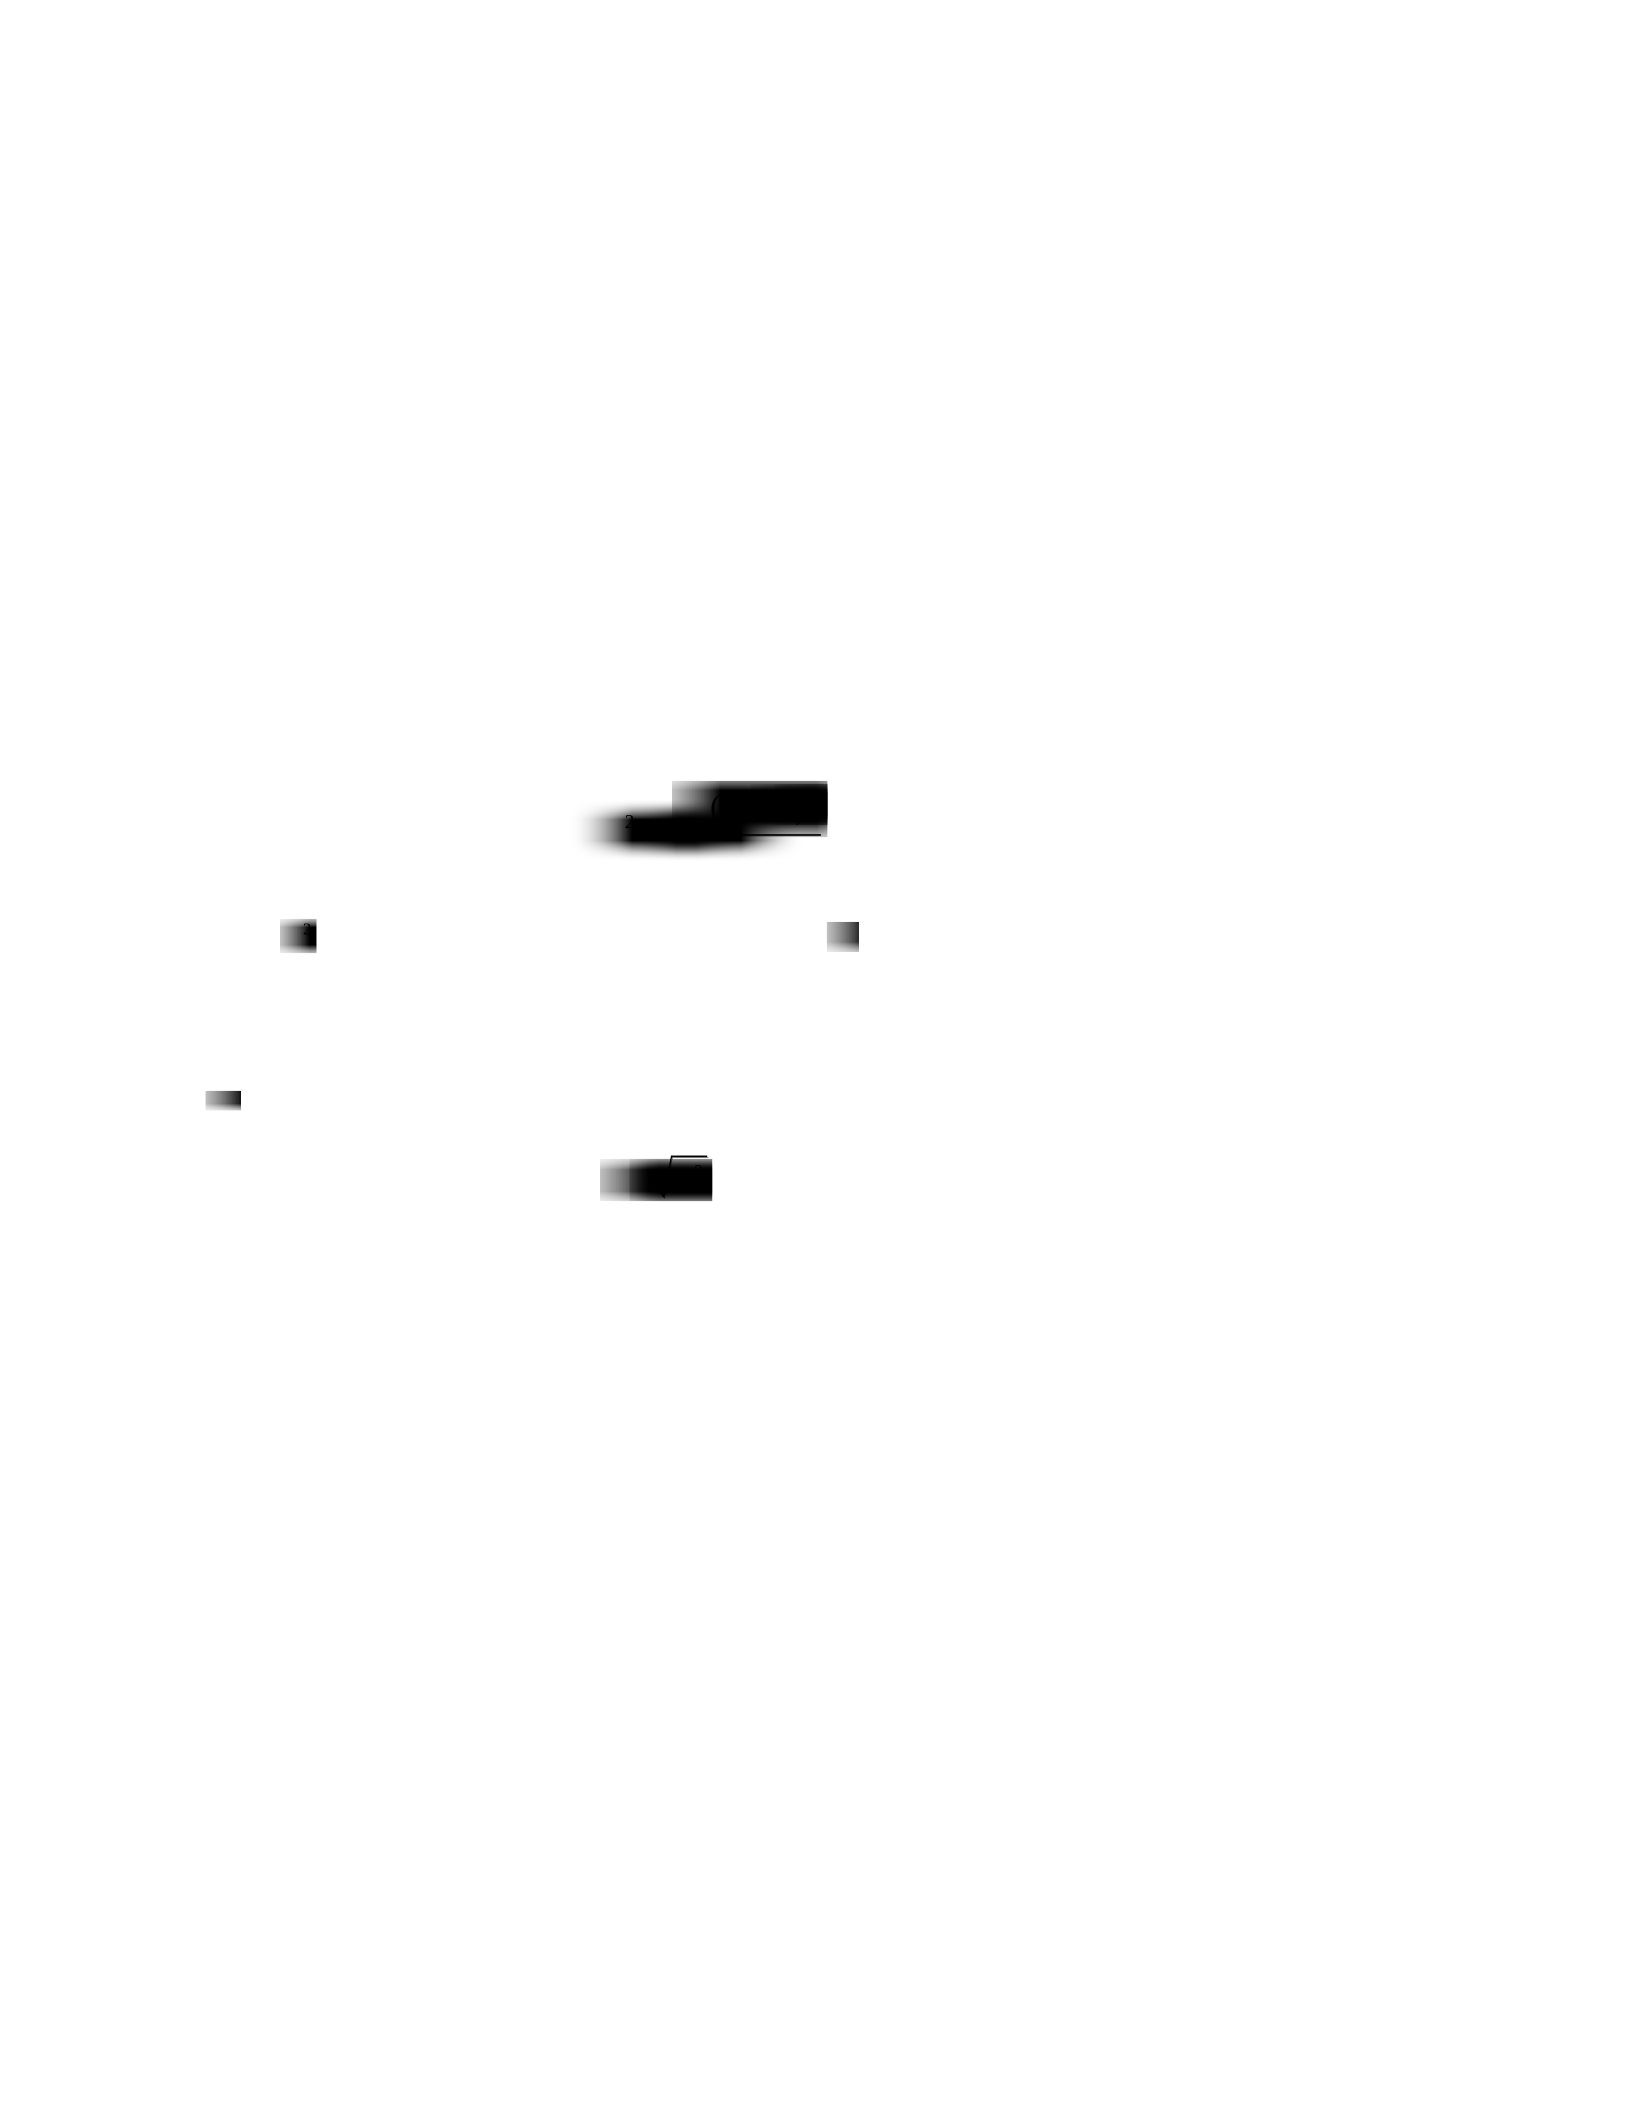
is the return on the risk free security on day t. Building on the excess return model, (Sharpe,
1966) developed a method that measures a security’s excess return per unit of risk, known as the
reward to variability ratio (R/V), or, the Sharpe Ratio. It is now considered to be one of the
most commonly used measure of risk-adjusted performance (Simons, 1998 and Lo,2002). The
Sharpe ratio at time t for security i can be expressed as:
i rf
itt
ti
t
RR
SharpeRatio
(12)
where
i rf
tt
RR
is the difference of security i’s return in time t and the risk-free return in time t,
and
i
t
is the standard deviation of security i in time t. The Sharpe Ratio essentially represents
the tradeoff between risk and return. Therefore, unlike simple return measures, the Sharpe Ratio
can be used as a standard of performance and risk ranking to compare different investment
options.
2.3.2 Index Risk
2.3.2.1Standard Deviation
When making investment decisions, investors are not only concerned with security performance,
but also with the risk associated with said security. By taking on additional price risk, an investor
will expect higher returns and it is understood that traditionally less risky assets will have lower
returns. Understanding how to measure this risk and the ability to compare assets of differing
18
configurations is necessary for informed investment decision making. Within the scope of this
study, security risk can be thought of as the uncertainty in price movement. Some of the most
widely used measures of price risk are; standard deviation, beta value, and value at risk. The
most basic measure of stock price variability is the standard deviation. In general, standard
deviation is defined as, a measure of dispersion calculated as the positive square root of variance
(Weiers, 2002). Variance is defined as a measure of dispersion based on the squared differences
between observed values and their mean (Weiers, 2002). In general, variance is given by
equation (13),
2
2()
i
x
N
(13)
where
2
is the variance,
i
x
is the ith data value, is the population mean, and
N
is the
number of data values in the population. The square root of the variance is the standard deviation
( ) or,
2
(14)
When applied to security price analysis, the standard deviation gives investors a measure of
daily, monthly, or annual variability of price movements.
2.3.2.2 Beta Value
In the introductory section of this study, the CAPM, or capital security pricing model was briefly
discussed. Specifically, the “beta” parameter within the CAPM framework was considered. A
security’s beta value gives investors an idea of the security’s returns relative to that of the
financial market as a whole. The beta value of the market portfolio is always one. A security
with a beta value of 1 or -1 means that its price is perfectly correlated with the market, while a
beta value of zero means that the security’s price is not correlated at all with the market. If the
beta value is less than one but positive, it means that the market and the security’s prices move in
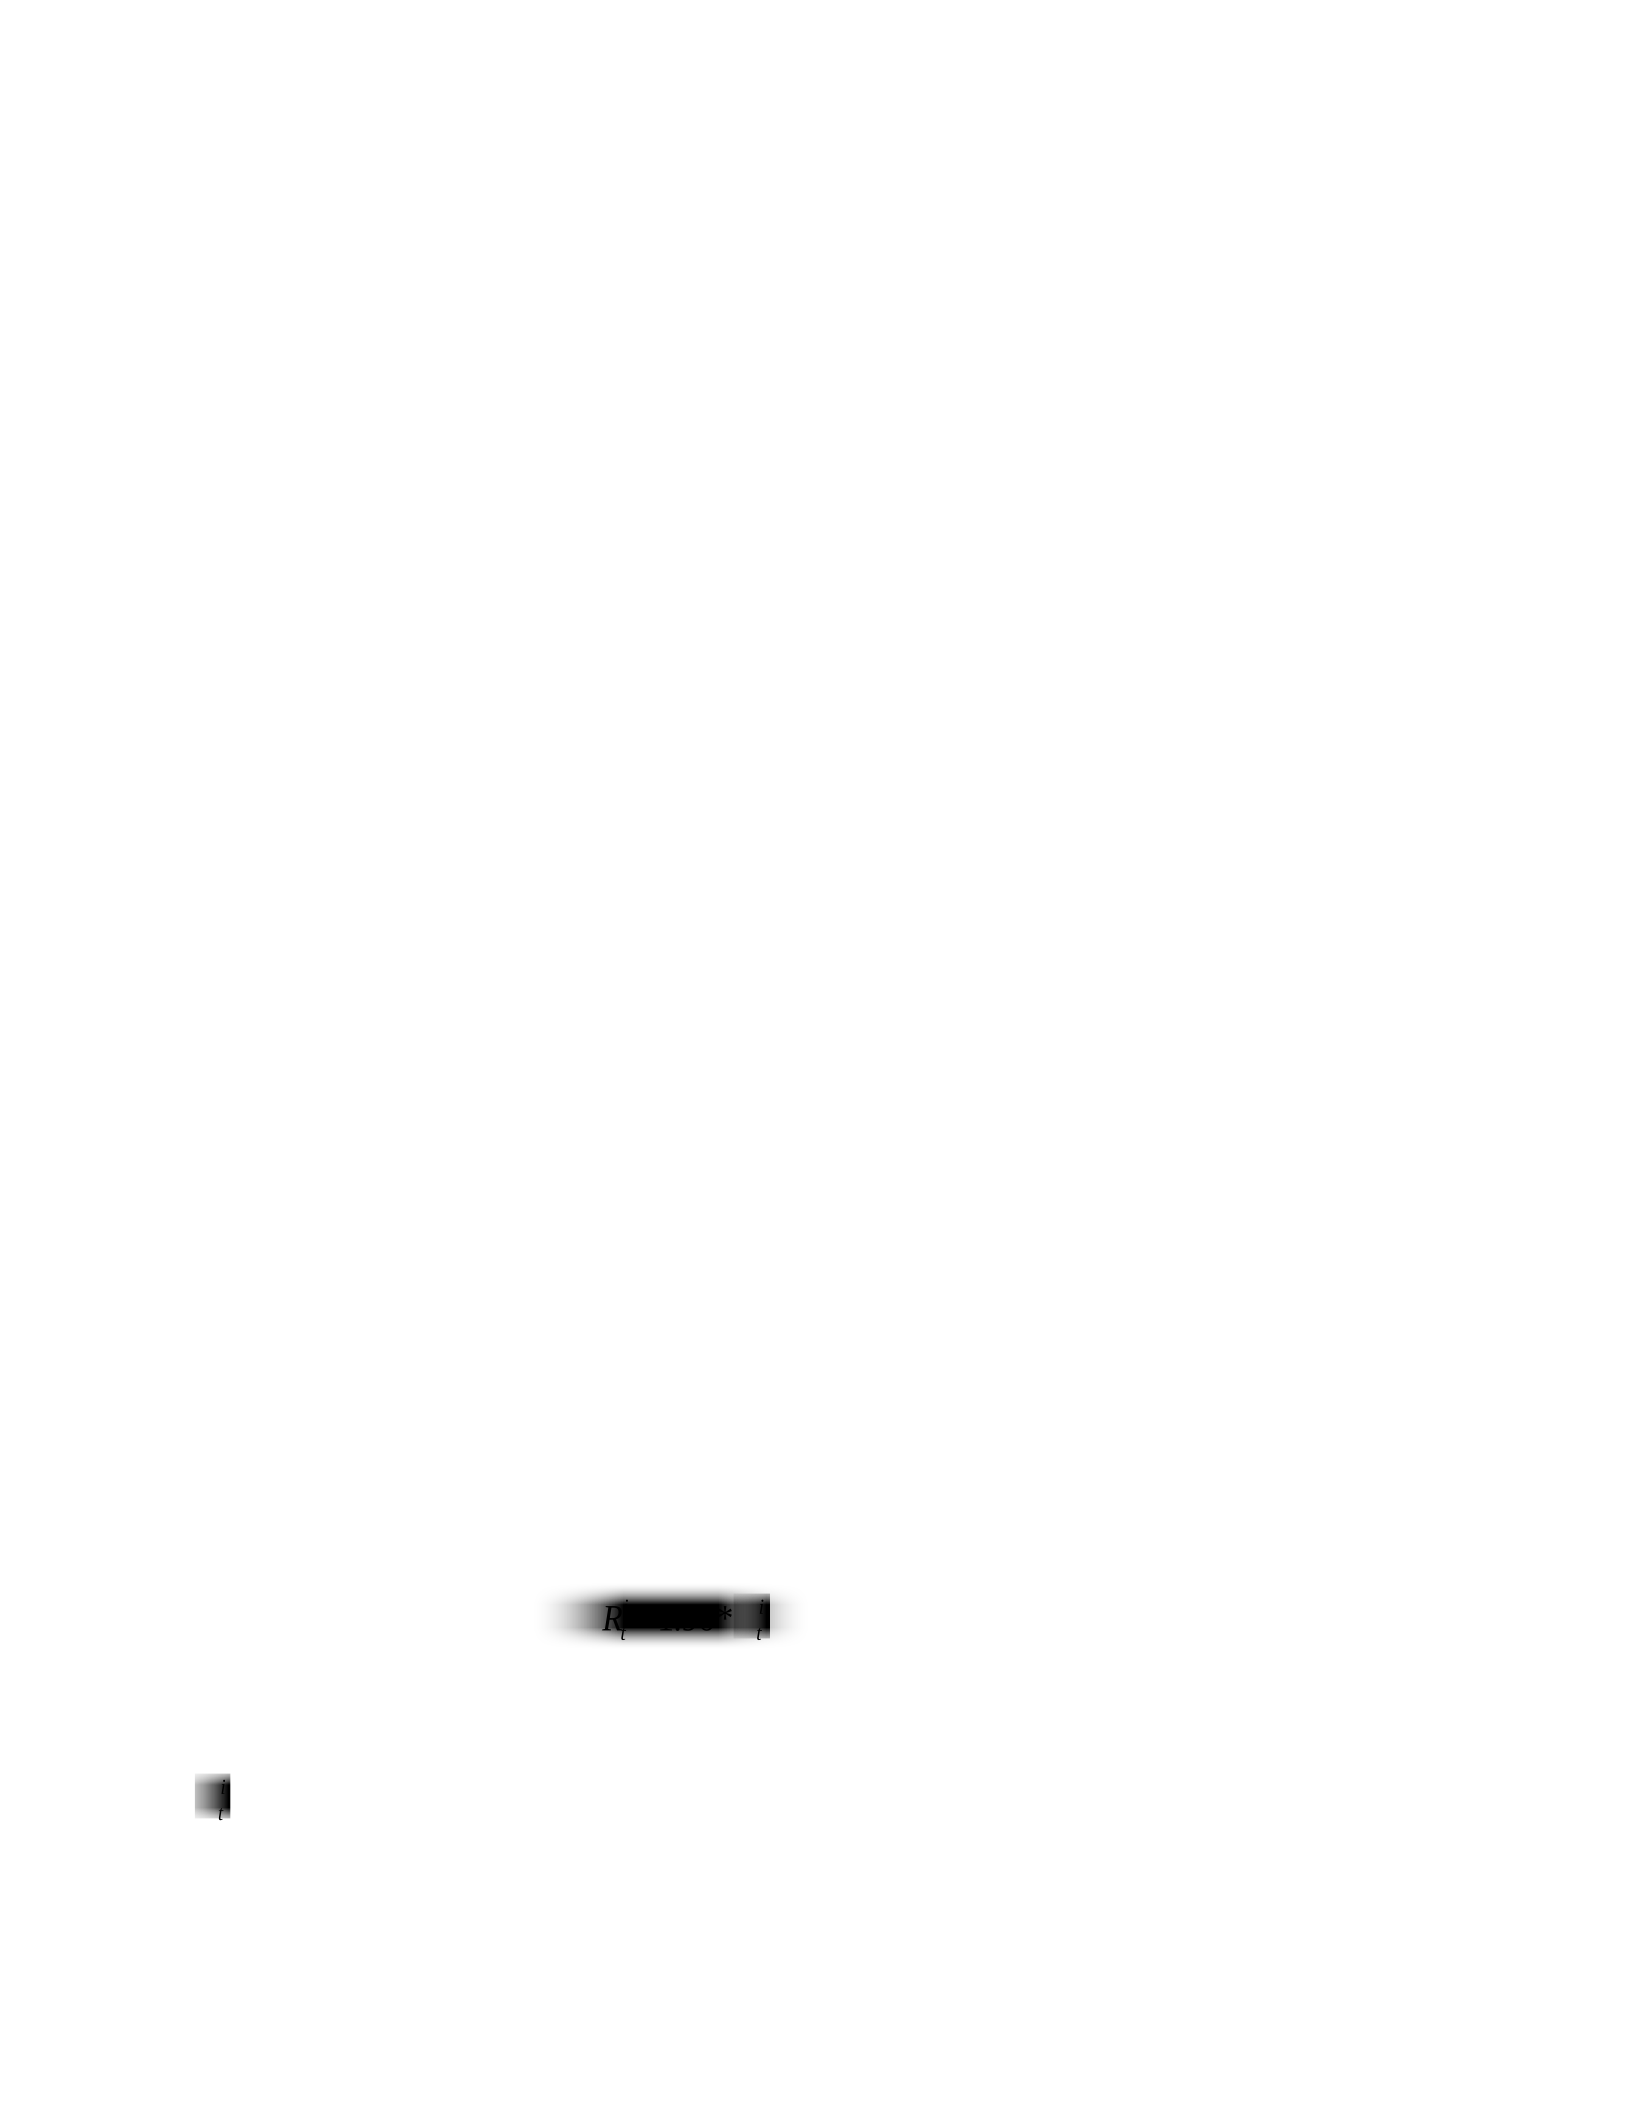
19
similar directions but with dissimilar magnitudes (positive correlation), while a negative beta
that’s greater than -1 means that they move in opposite directions but with dissimilar magnitudes
(negatively correlated). This powerful characteristic makes the beta value is a popular measure of
an assets statistical variance. A beta value can be estimated for individual companies through
simple regression analysis against a market proxy, such as the S&P 500. As previously
mentioned, the beta for the U.S. Food Processing Industry was estimated to be 0.65, indicating
that the sector lags behind market movements but still moves in similar directions. The broader
agricultural sector is believed to have the same characteristics though little research has been
published to test this hypothesis.
2.3.2.3 Value at Risk
Another popular measure of price risk is Value at Risk (VaR). The VaR measure was first used
to evaluate price risk associated with derivatives trading at major banks (Simons, 1998). The
measure was further popularized by the 1993 special report by the Group of Thirty, Derivatives:
Practices and Principles, which further recommended VaR for derivative risk analysis (Global
Derivatives Study Group, 1993). The VaR measure tells an investor how much the value of a
portfolio could decline over a given amount of time based on a given probability. To calculate
VaR, stock prices must be assumed to be distributed normally and, therefore, it is assumed that
95 percent of all deviation around the mean occurs within 1.96 standard deviations. Thus, the 5%
VaR calculation is given by:
1.96*
i i i
t t t
VaR R
(15)
where
i
t
VaR
is firm i’s value at risk for time period t,
i
t
R
is firm i’s return for time period t¸ and
i
t
is firm i’s standard deviation for time period t. This measure of risk is particularly useful for
investments that have significantly different compositions over time, such as an index or mutual

20
fund (Simons, 1998). Since this research is primarily concerned with the historical risk of
agriculturally related firms and not future or present risk, a VAR measure will not be calculated.
The measures mentioned above are universal and can be compared across investment
options. When comparing different investment possibilities, it is important to choose options for
comparison that are similar in composition. For instance, if an investor wanted to compare the
risk and return of a collection of small-cap stocks to the performance of small-cap stocks as a
whole, it would not be wise to choose the S&P 500 or Dow Jones Industrial Average, as they are
large-cap indices. A more suitable comparison index would the Standard and Poor’s small-cap
index. For the purposes of this study, the S&P 500 and the Dow Jones Industrial Average are
proper comparison indices, given that the AG Index is comprised of large-cap stocks.

21
CHAPTER 3: METHODS
3.1 Data
3.1.1 Overview
Daily closing stock prices, returns, and outstanding shares are collected from The Center for
Research in Security Prices Database (CRSP) though the Wharton Research Data Services
(WRDS) database. The CRSP US Stock Database contains end-of-day and month-end prices on
all New York Stock Exchange (NYSE) (December 31, 1925-Present), American Stock Exchange
(AMEX) (July 2, 1962-Present), and the National Association of Securities Dealers Automated
Quotations (NASDAQ) (December 14, 1972-Present) common stocks along with basic market
indices, distribution information, and total return calculations.
3.1.2 Firm Selection
The USDA’s Economic Research Service (ERS) provides a listing of industries closely tied to
production agriculture by the U.S. Economic Census Standard Industrial Classification Code
(SIC codes). SIC codes aggregate industries into related groups. For example; farm production,
agricultural services, forestry, and fishing; agricultural input industries; agricultural processing
and marketing industries; wholesale and retail trade of agricultural products; and indirect
agribusinesses. ERS defines farm and farm-related industries as those industries generally having
50 percent or more of their national work force employed in providing goods and services
necessary to satisfy the final demand for agricultural products and indirect agribusiness are those
industries having between 32 and 50 percent. Appendix C contains ERS’s listing of these sectors.
A list of publicly traded firms with SIC codes that correspond to the ERS classification of
agribusiness firms was generated using the CRSP database. The CRSP database is the leading
provider of the most comprehensive US historical stock market databases and is the most widely
22
used database in finance literature. The CRSP database contains daily price quotations for
common stocks, excluding preferred stock and including American Depositary Receipts, traded
on the New York and American stock exchanges and NASDAQ. Daily returns provide a more
accurate measure of market efficiency than monthly returns (Henderson, 1990), (Armitage,
1995), (MacKinlay, 1997). Daily data begin in July 1962. While NYSE data are available
throughout the entire period, AMEX data starts in 1962, and NASDAQ data begins in 1972.
For a stock to be eligible for inclusion in this study, the stock must have daily return data
in the CRSP database and have data available for a full year of trading. Any agribusiness firm
that did not have daily return data for the aforementioned dates was excluded from the choice
set. Appendix D provides a list of the firms, by years, which were dropped from the sample due
to missing data. Once a sample of eligible stocks was compiled, the sample was broken up in to
three sub-industry groups based upon the ERS classification grouped according to SIC codes:
farming stocks, closely related to farming, and peripherally related to farming. A full list of the
component industries in each group is provided in Appendix C. Within each industry group, only
the firms that make up the top 70th percentile based on market share were selected for the final
index selection.6 This selection process is repeated on the first trading day of each year in the
index calculation. A list of all firms included in each year’s index is provided, by permanent
number (PERMNO), in Appendices E and F. Finally, the daily closing prices (prc) and number
of outstanding shares (shrout) were obtained for each firm from the CRSP database. “Prc” is
defined by CRSP as the closing price or the negative bid/ask average for a trading day. If the
closing price is not available on any given trading day, the number in the price field has a
negative sign to indicate that it is a bid/ask average and not an actual closing price. If neither
6 The 70th percentile selection process is discussed in length in a later chapter.

23
closing price nor bid/ask average is available on a date, the value in the price field is set to zero.
Corrections were made to the data to eliminate any negative values, by using the absolute value
function in Microsoft Excel (abs()). When a daily price value was not available, the value for the
previous trading day was used. In the cases where data for consecutive days was not available,
the last available trading day value was used for up to 10 consecutive days of missing data. If
more than 10 consecutive days of data were missing from the dataset, the firm was removed
from the sample. “Shrout” is defined by CRSP as the number of publicly held shares, recorded in
thousands. This is sometimes referred to as the “float” or the number of outstanding shares that
are available to investors. Floated share counts exclude shares closely held by control groups,
other publicly traded companies, or government agencies. Using a floated share count reflects
the value available in the public markets.
The data collection, management, and risk and return calculations were completed in
Microsoft Excel 2007 and Access 2007. In addition to the included statistical functions of these
programs, the DigDB, Excel Analysis Tool Pack, and Macros Add-in tools were used.
3.2 Index Membership
The universe from which firms are selected is all publicly listed companies in the CRSP database
with a SIC code classification that corresponds to the ERS definition of agriculturally related
industries. The list generated via the CRSP database included 374 firms classified as “farming”,
“closely related to farming” or “peripherally related to farming” that were publicly traded at
sometime between January 1970 and December 2008. The universe was then narrowed down to
a set of stocks based on several criteria. First, for a stock to be considered for inclusion in the
index for a given year, say 1970, price and outstanding share count must be available for the full
year of 1970. The sample was then split based on the ERS subcategories of “farm and farm-
related industries”. These include farming, closely related to farming, and peripherally related to
24
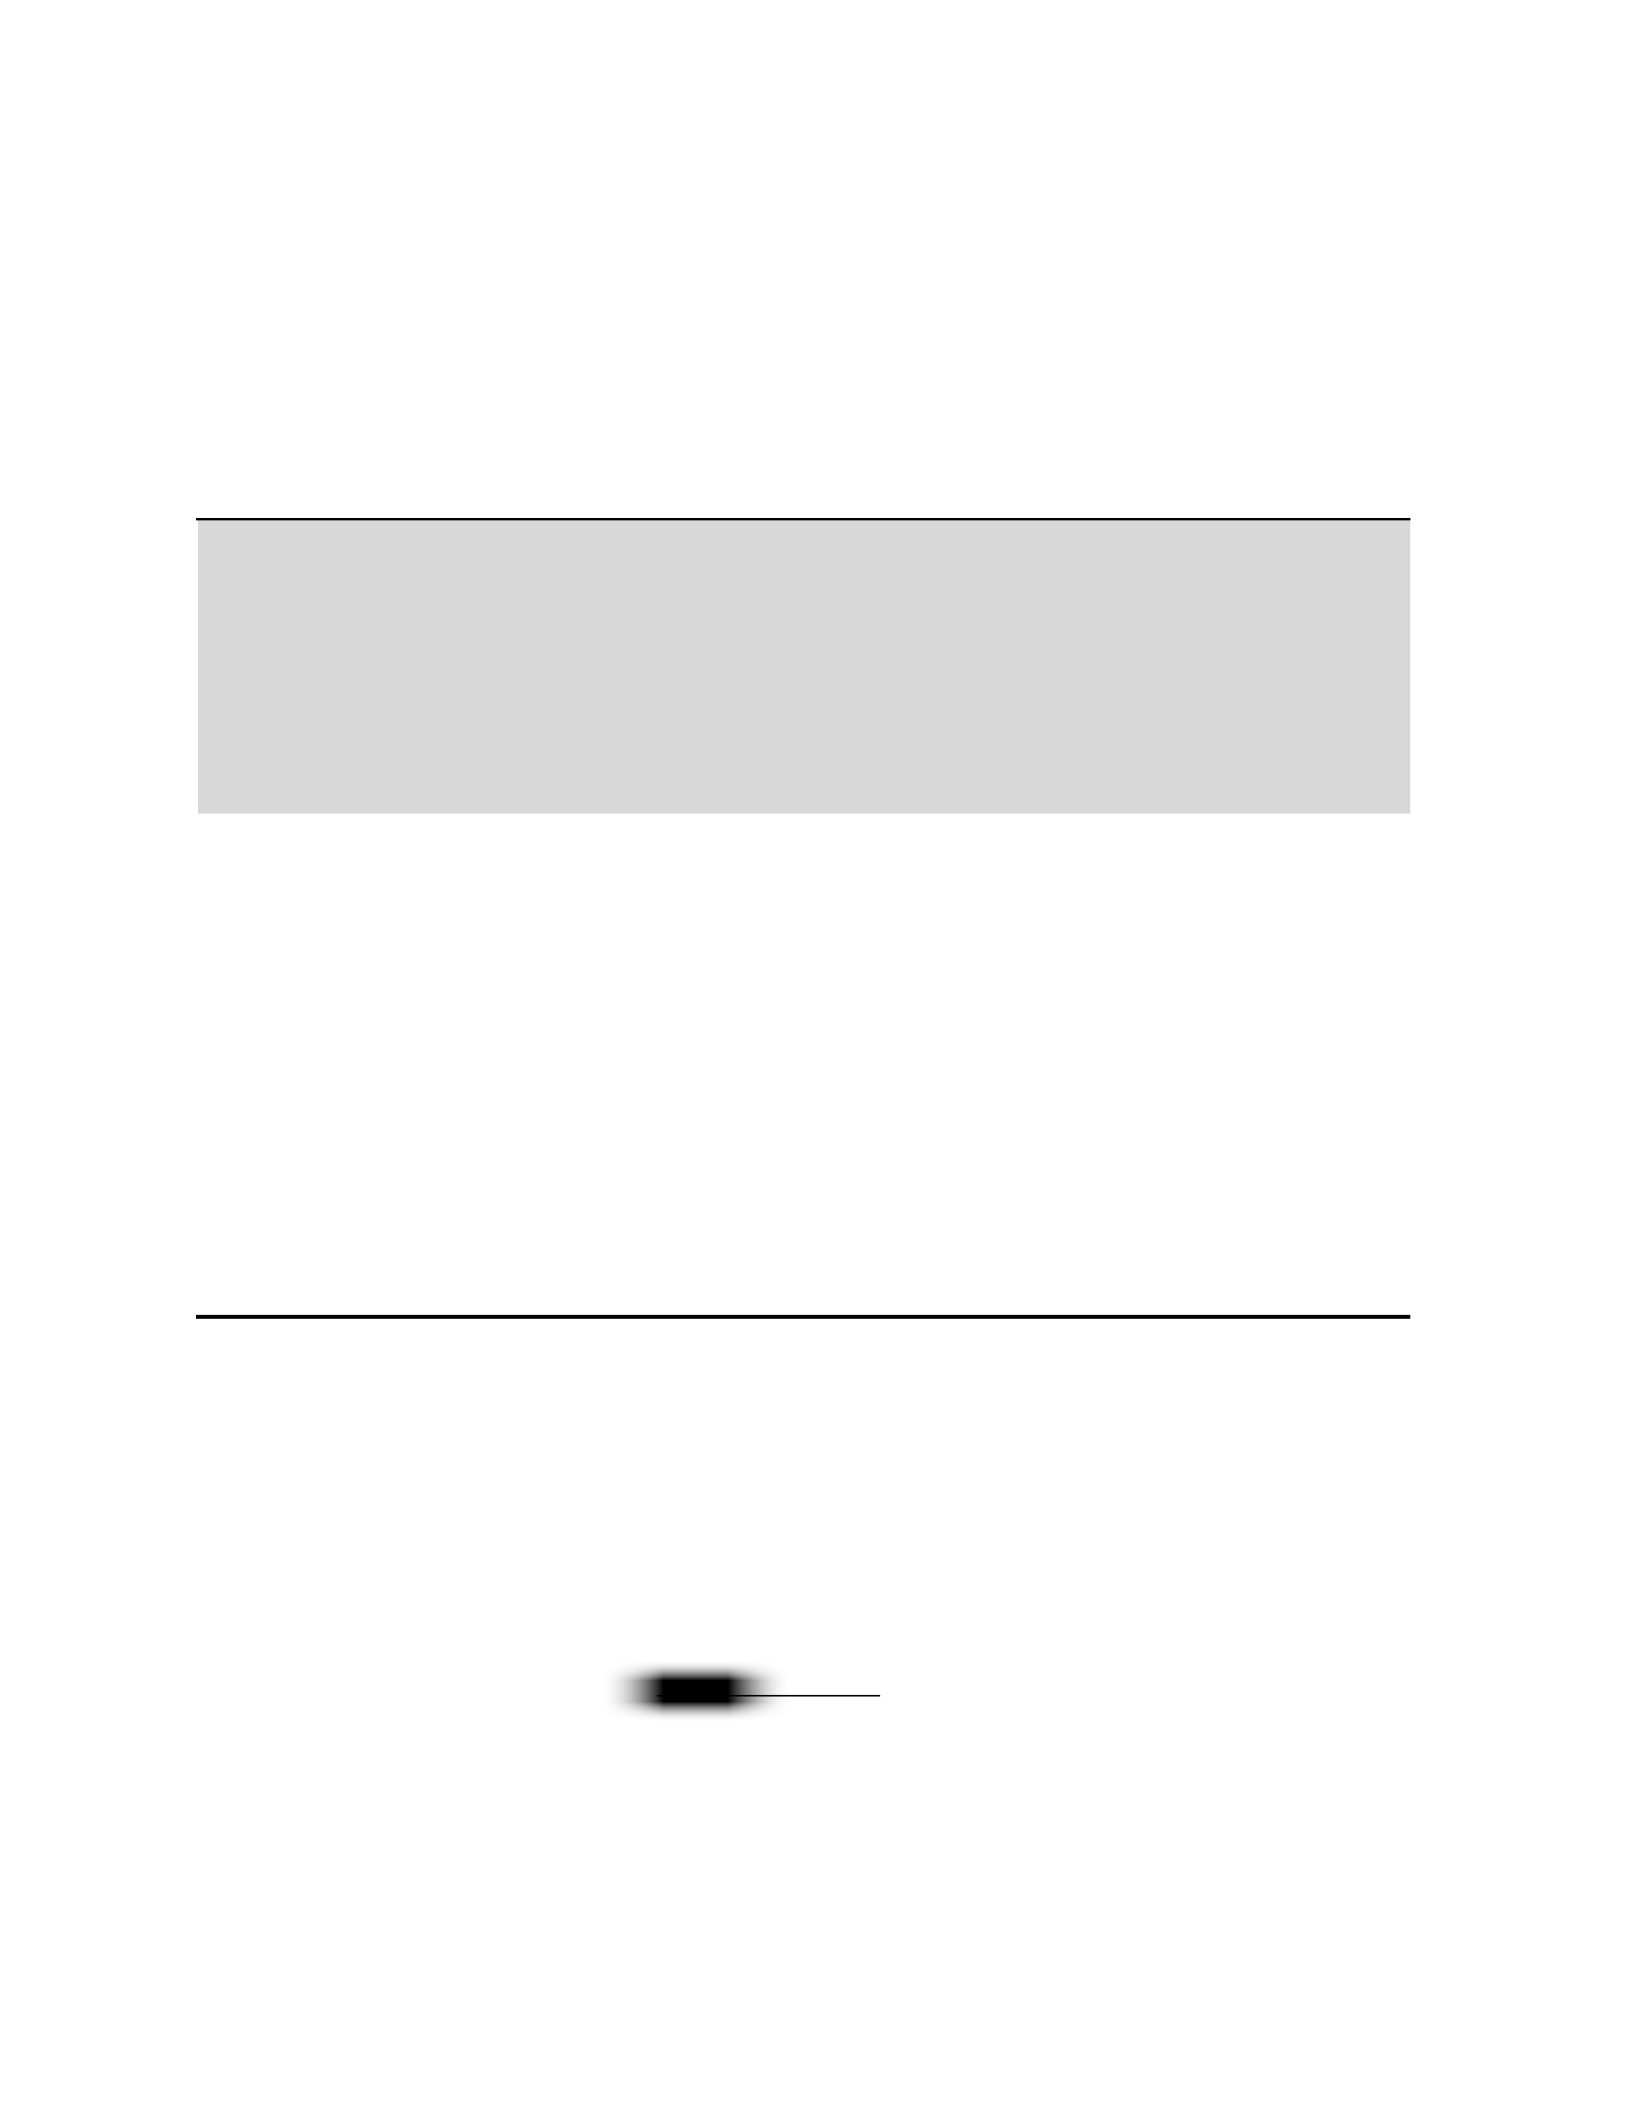
farming. Next, the sample size was reduced to include only the top 70th percentile of firms
among each of the three sub-categories. Please refer to Table 1 for a visual representation of this
step. Each year’s basket of potential firms was filtered to display only the first trading day’s
Table 1: Top 70th Percentile Selection
price and share count. The daily market value (DMV) was calculated for each firm by applying
equation (3) and then sorted from largest to smallest. Next, the total index market value is
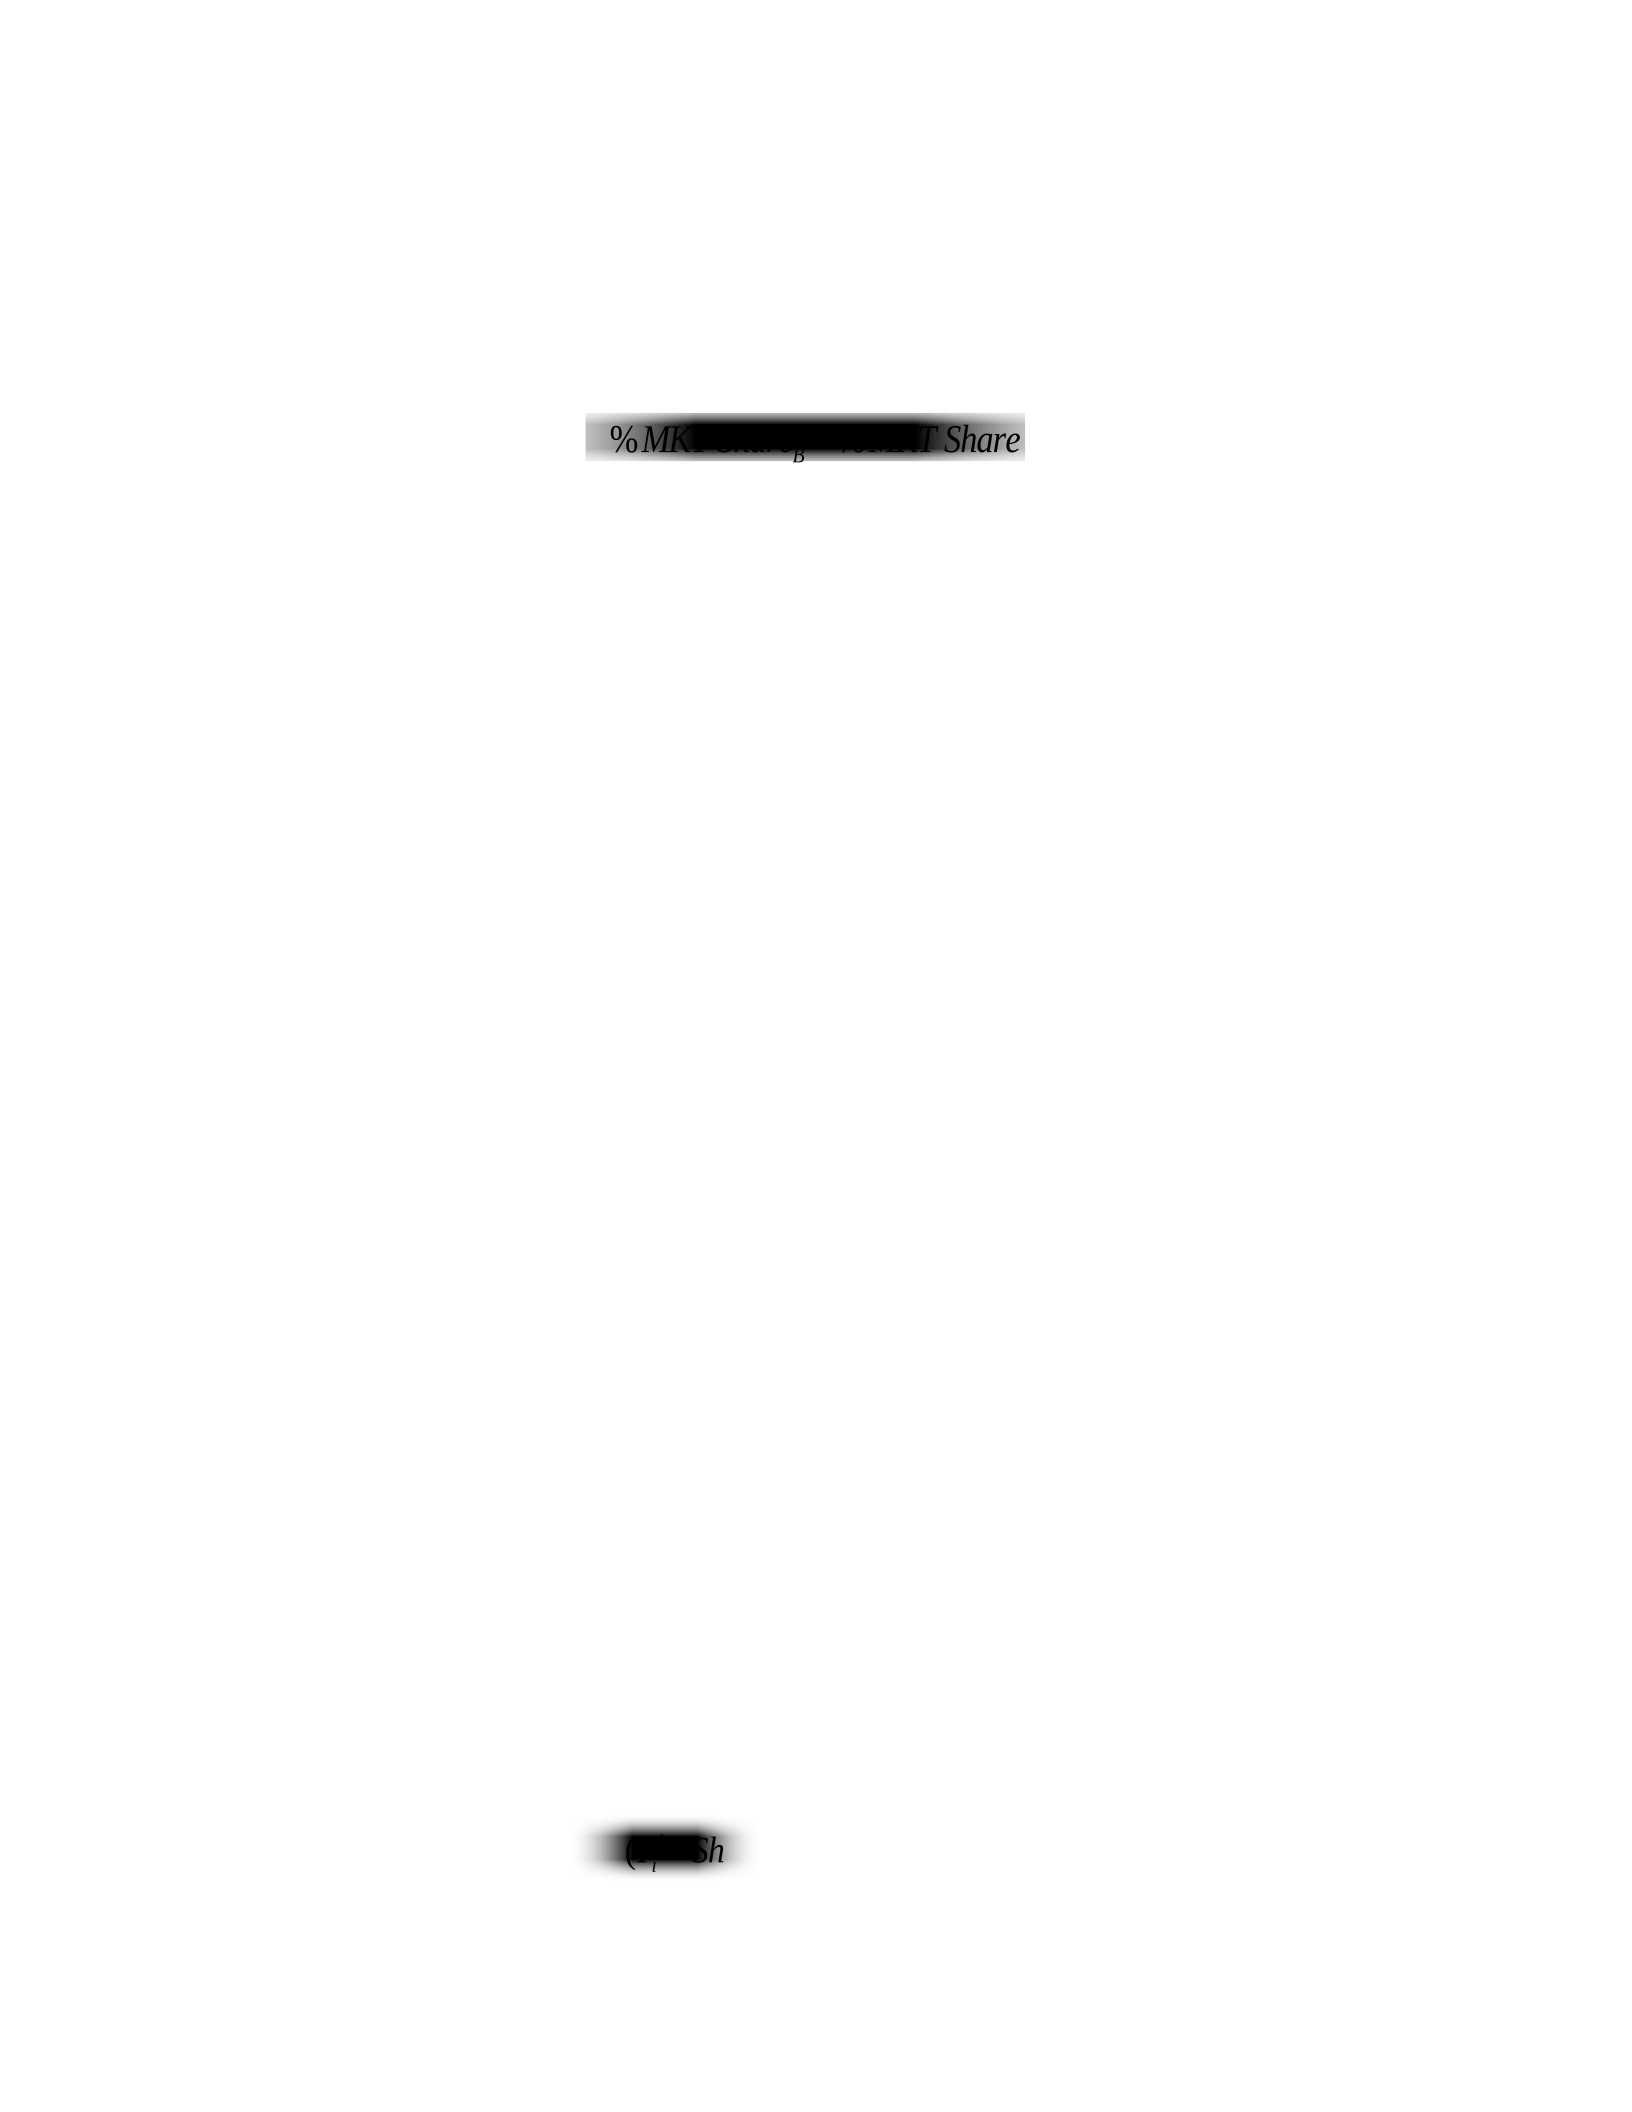
determined by using equation (4). Then, the percent market share is calculated for each firm by
equation (16):
%i
i
DMV
Market Share Total MKTValue
(16)
where the % Market Share for firm i is given by the daily market value of firm i divided by the
total market value of the index on the first trading day of the year. For example, from Table 1,
TRD Day Firm PRC SHROUT DMV
% MKT Share
CMPD Sum
1 A 94
220292000 20707448000 23.4% 23.4%
1 B 33.5
358815000 12020302500 13.6% 37.0%
1 C 28.63
360136000 10308893000 11.7% 48.7%
1 D 28
201187000 5633236000 6.4% 55.0%
1 E 41.38
133862000 5538540250 6.3% 61.3%
1 F 61.5
70860000 4357890000 4.9% 66.2%
1 G 31.38
129590000 4065886250 4.6% 70.8%
1 H 42.5
92244000 3920370000 4.4% 75.3%
1 I 41.25
81734000 3371527500 3.8% 79.1%
1 J 39
79366000 3095274000 3.5% 82.6%
1 K 17.63
162520000 2864415000 3.2% 85.8%
1 L 17.88
159715000 2854905625 3.2% 89.1%
1 M 54
48283000 2607282000 2.9% 92.0%
1 N 28.13
75190000 2114718750 2.4% 94.4%
1 O 29.75
60168000 1789998000 2.0% 96.4%
1 P 43.88
38203000 1676156625 1.9% 98.3%
1 Q 43
34657000 1490251000 1.7% 100.0%
Total MKT Value 88417094500
25
firm “A” has a DMV of $20,707,448,000 which represents 23.4 percent of the total market value
of all the firms in the index for this year within the same sub-group. Next, a compounding sum is
calculated as:
%%
B B A
CMPDSum MKT Share MKT Share
(17)
where the compounding sum equals the sum of the percent market share of firm “B” and the
percent market share of firm “A”, which is the firm immediately above firm “B” when sorted
from largest to smallest by DMV. This step is repeated until the CMPD Sum reaches 100 percent.
Finally, only those firms making up the top 70th percentile, or as close to it as possible, are
selected for inclusion in the index for the given year. This is illustrated in Table 1 above, by
those firms shaded in gray. In this example, only firms A, B, C, D, E, F, and G are selected for
inclusion; all other firms are dropped from the sample for year t because they are too small. This
procedure is performed separately for each sub-group; farming, closely related to farming, and
peripherally related to farming, so that the index represents the top 70th percentile of firms within
each of the three sub-groups. Once the final firm selections were made, the firms within each
sub-group were combined in to one worksheet. The final dataset was then split in to 39 separate
worksheets, organized by year from 1970 to 2008.
3.3 Index Methodology
The index calculation method utilized in this study is defined as the market-capitalization
method. As mentioned in an earlier chapter, it is the most widely used form of index calculation.
The index calculation is a very straightforward process, the first step of which involves
calculating the daily market value (DMV) for each firm in the index using the following
equation:
( * )
t t t
i i i
DMV P Shares
(18)
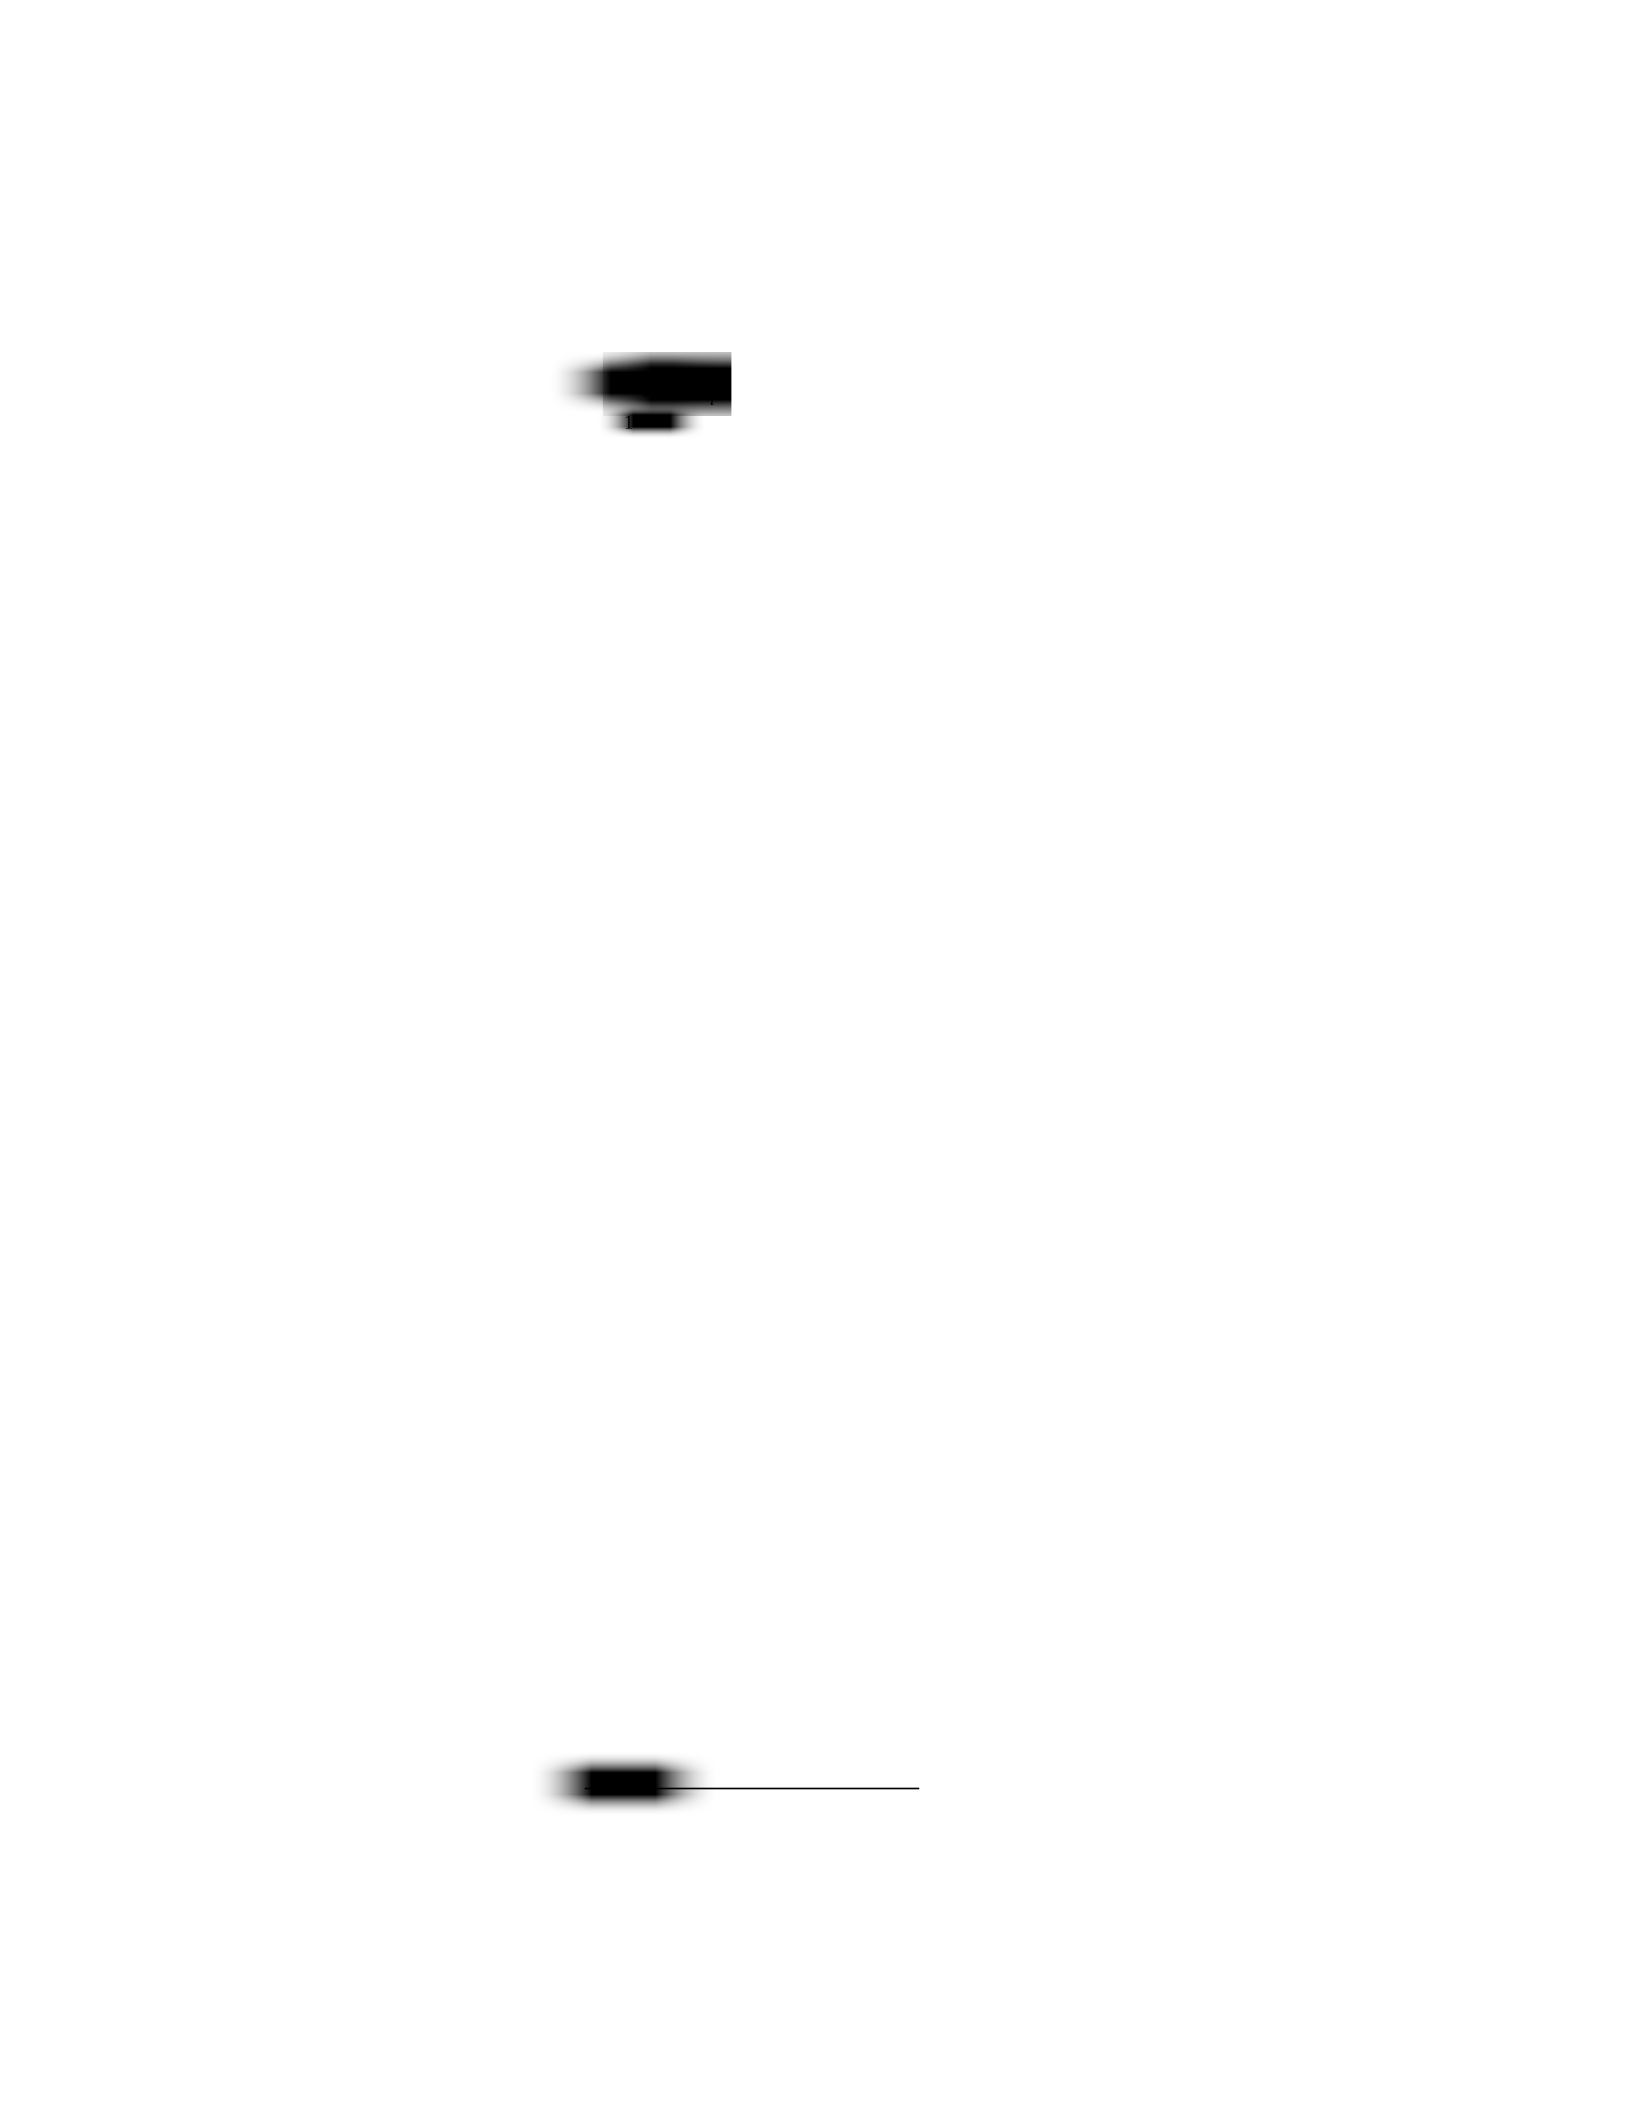
26
where the daily market value for security i in time t is the product of the price and the number of
outstanding shares of security i. The total index market value for a given day is calculated by:
1
nt
ti
i
IMV DMV
(19)
where
t
IMV
is the index market value at time t and
t
i
DMV
is the daily market value for firm i, at
time t. The symbol “t” represents the number of trading days in a given year, usually 253 day. A
table containing the number of trading days in each year is available in Appendix G. These steps
were repeated for each year in the study.
3.5 Index Scaling and Rebalancing
3.5.1 Scaling the Index Using a Divisor
On any given day, the total market value of an index of stocks can be in the billions or even
trillions of dollars. For example, on 5/8/1991 the total index value in this study was
$333,644,493,625.00. Tracking a number this large on a day-to-day basis can be a challenge in
itself; therefore, the index value is scaled so that it is easier to track. Many index service
companies utilize what is called a “divisor” to scale the index. To scale an index using a divisor
an index manager must first choose a base date and a base value. The actual base value is
irrelevant because it tells us nothing about the performance of the firms in the index. Investors
are more concerned with the incremental changes in that value. However, the initial value of the
divisor is dependent on the base value and is determined at the base date of the index. For
example, if the base date for an index is January 2, 2003 and the index manager defines the base
value at 100, the initial divisor is calculated by:
2,2003
100
Jan
initial
IndexMarketValue
Divisor
(20)
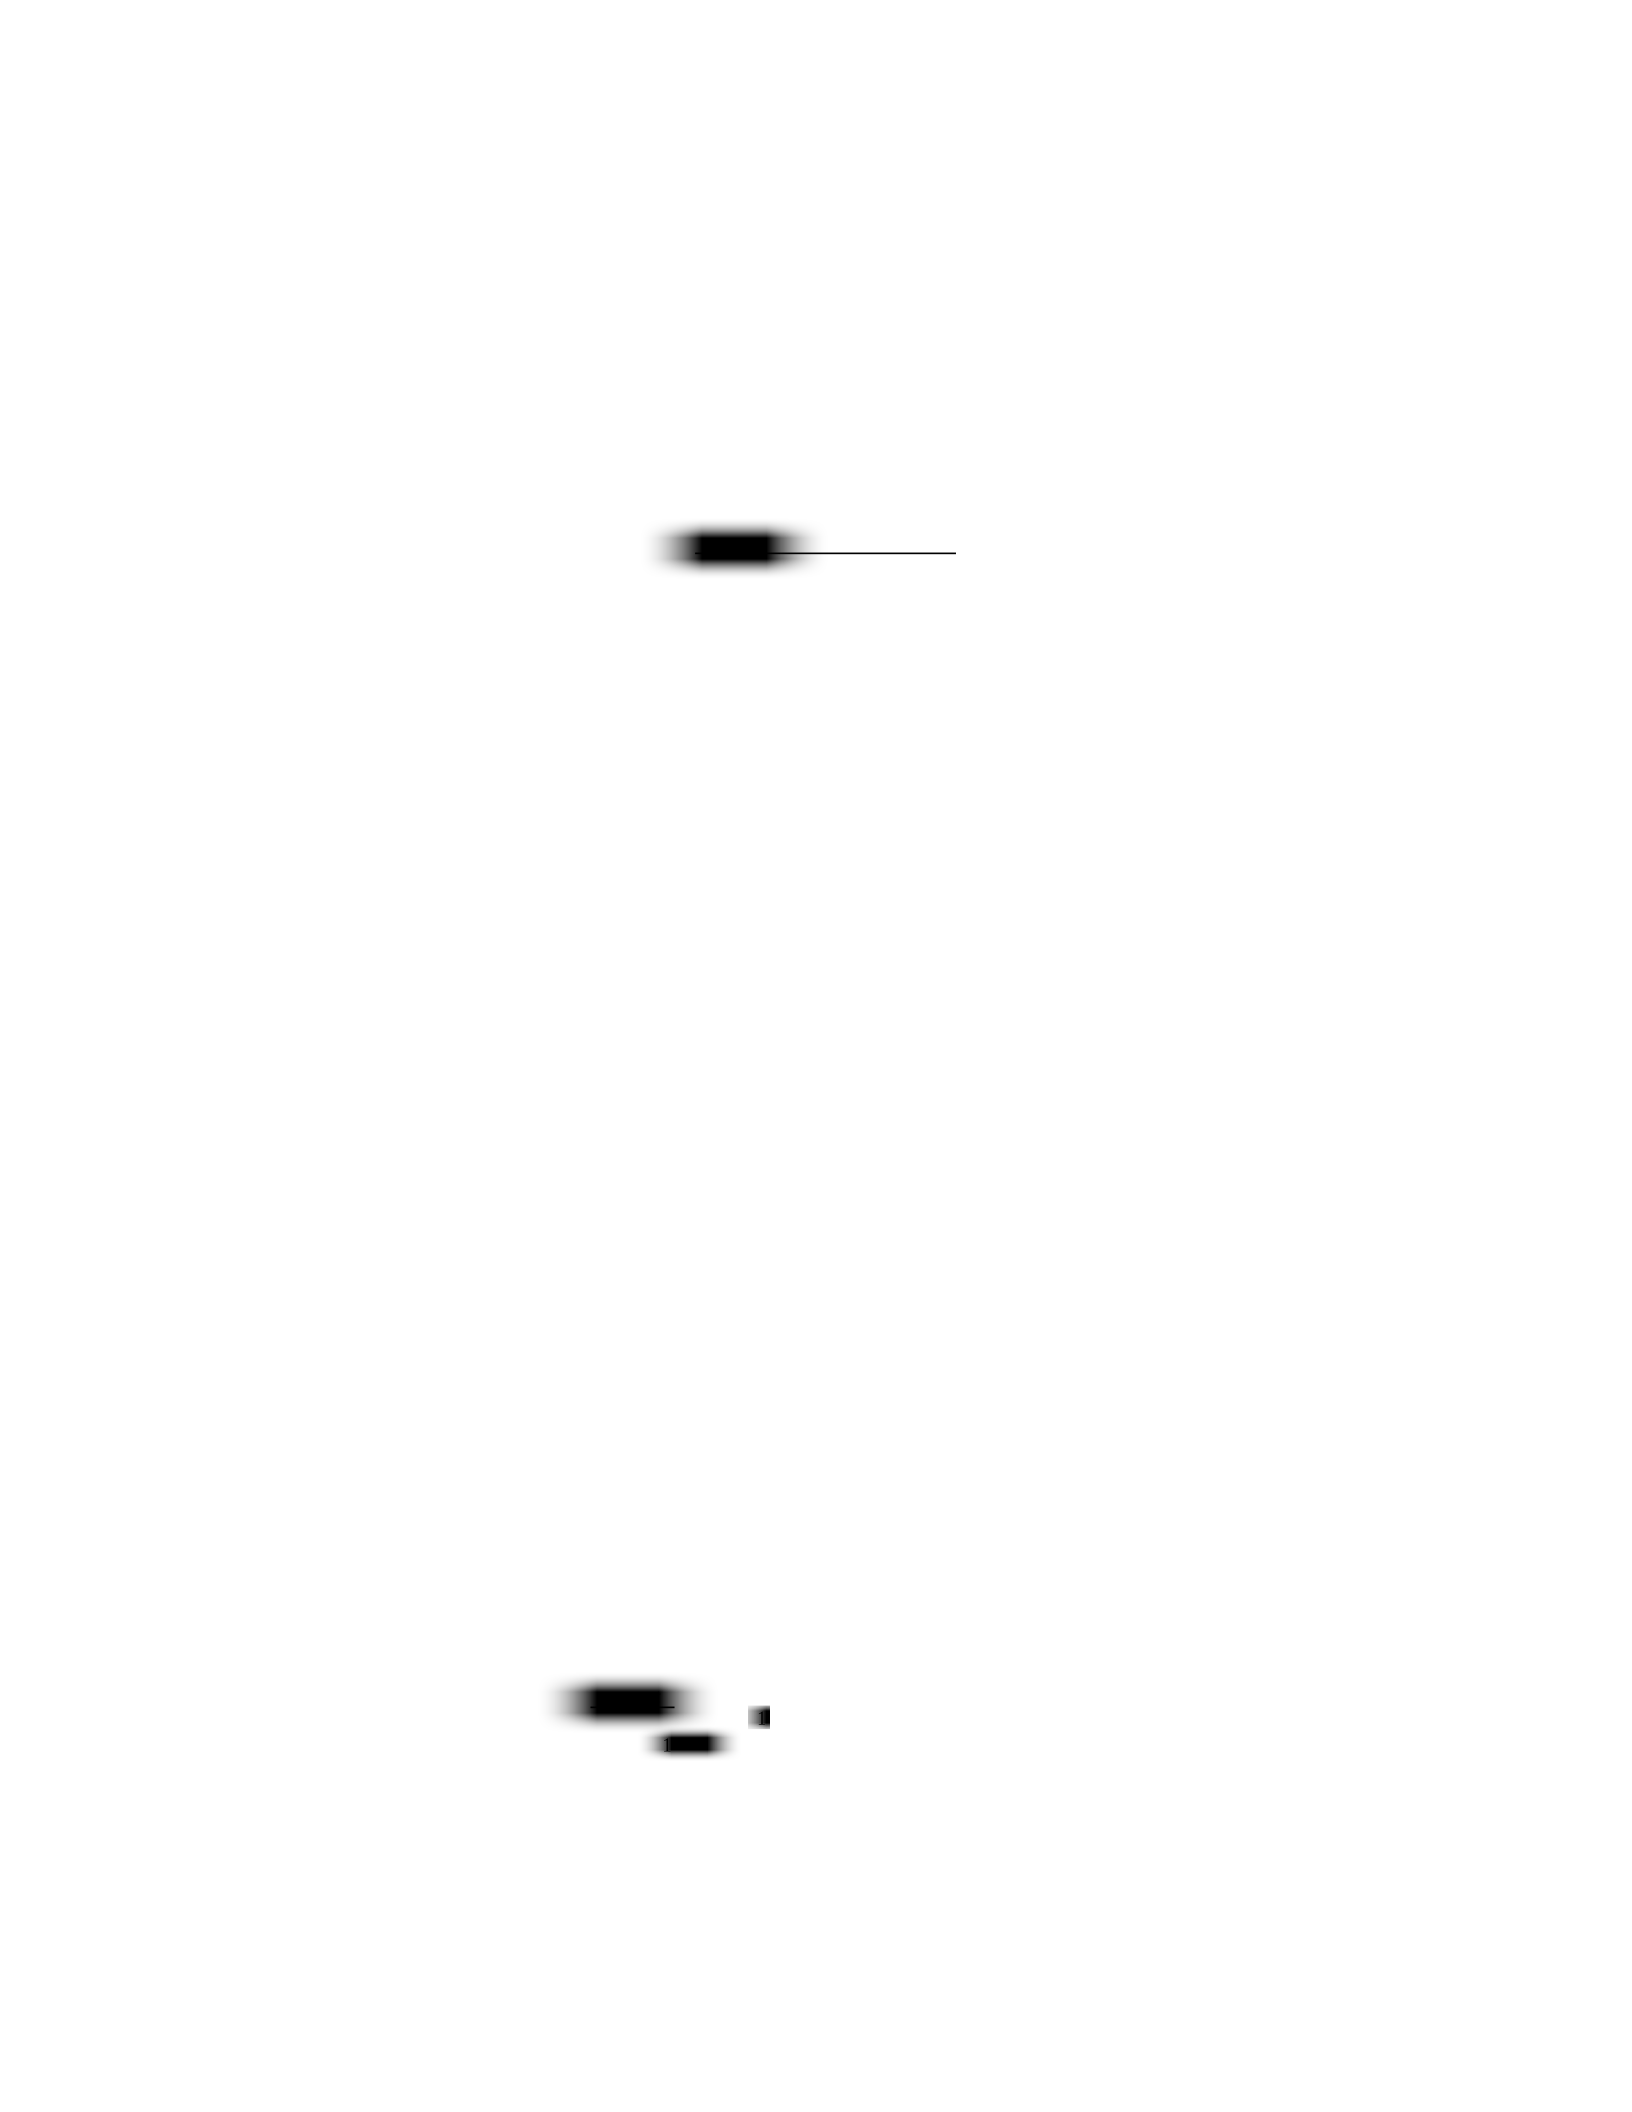
27
where
2,2003Jan
IndexMarketValue
is the total market value of the index on the base date.
Therefore, if the total market value of the index on the base date were $25,000,000, the divisor
would be 250,000. To get the scaled index value, simply divide the index market value by the
divisor using:
t
t
t
IndexMarketValue
Scaled IndexValue Divisor
(21)
where the scaled index value at time t is determined by dividing the index market value at time t
by the divisor at time t. Again, if the index market value is $25,000,000 and the divisor is
250,000 then the scaled index value will be 100. The scaled index value will always be the same
as the base value on the base date. Therefore, if the index market value increases to $26,500,000
on the next trading day the scaled index value will be 26,500,000/250,000, or 106, which
represents a 6 percent increase in value from the previous day. Note that the divisor in equation
(21) does have a time notation. This is because the index manager for maintenance purposes can
manipulate the value of the divisor.
3.5.2 Scaling the Index Using the Ratio Method
There are several ways to build and scale a market-value-weighted index. The most
straightforward is to use the method outlined in (Chartered Financial Analyst Institute, 2005),
which will be referred to as the “Ratio Method”. Like the divisor method, the first step is to
choose a base date and base value. In addition, the scaled index value is the base value on the
base date. However, in this case the scaled index value is given by:
1
1
*
t
tt
t
IMV
SIV SIV
IMV
(22)
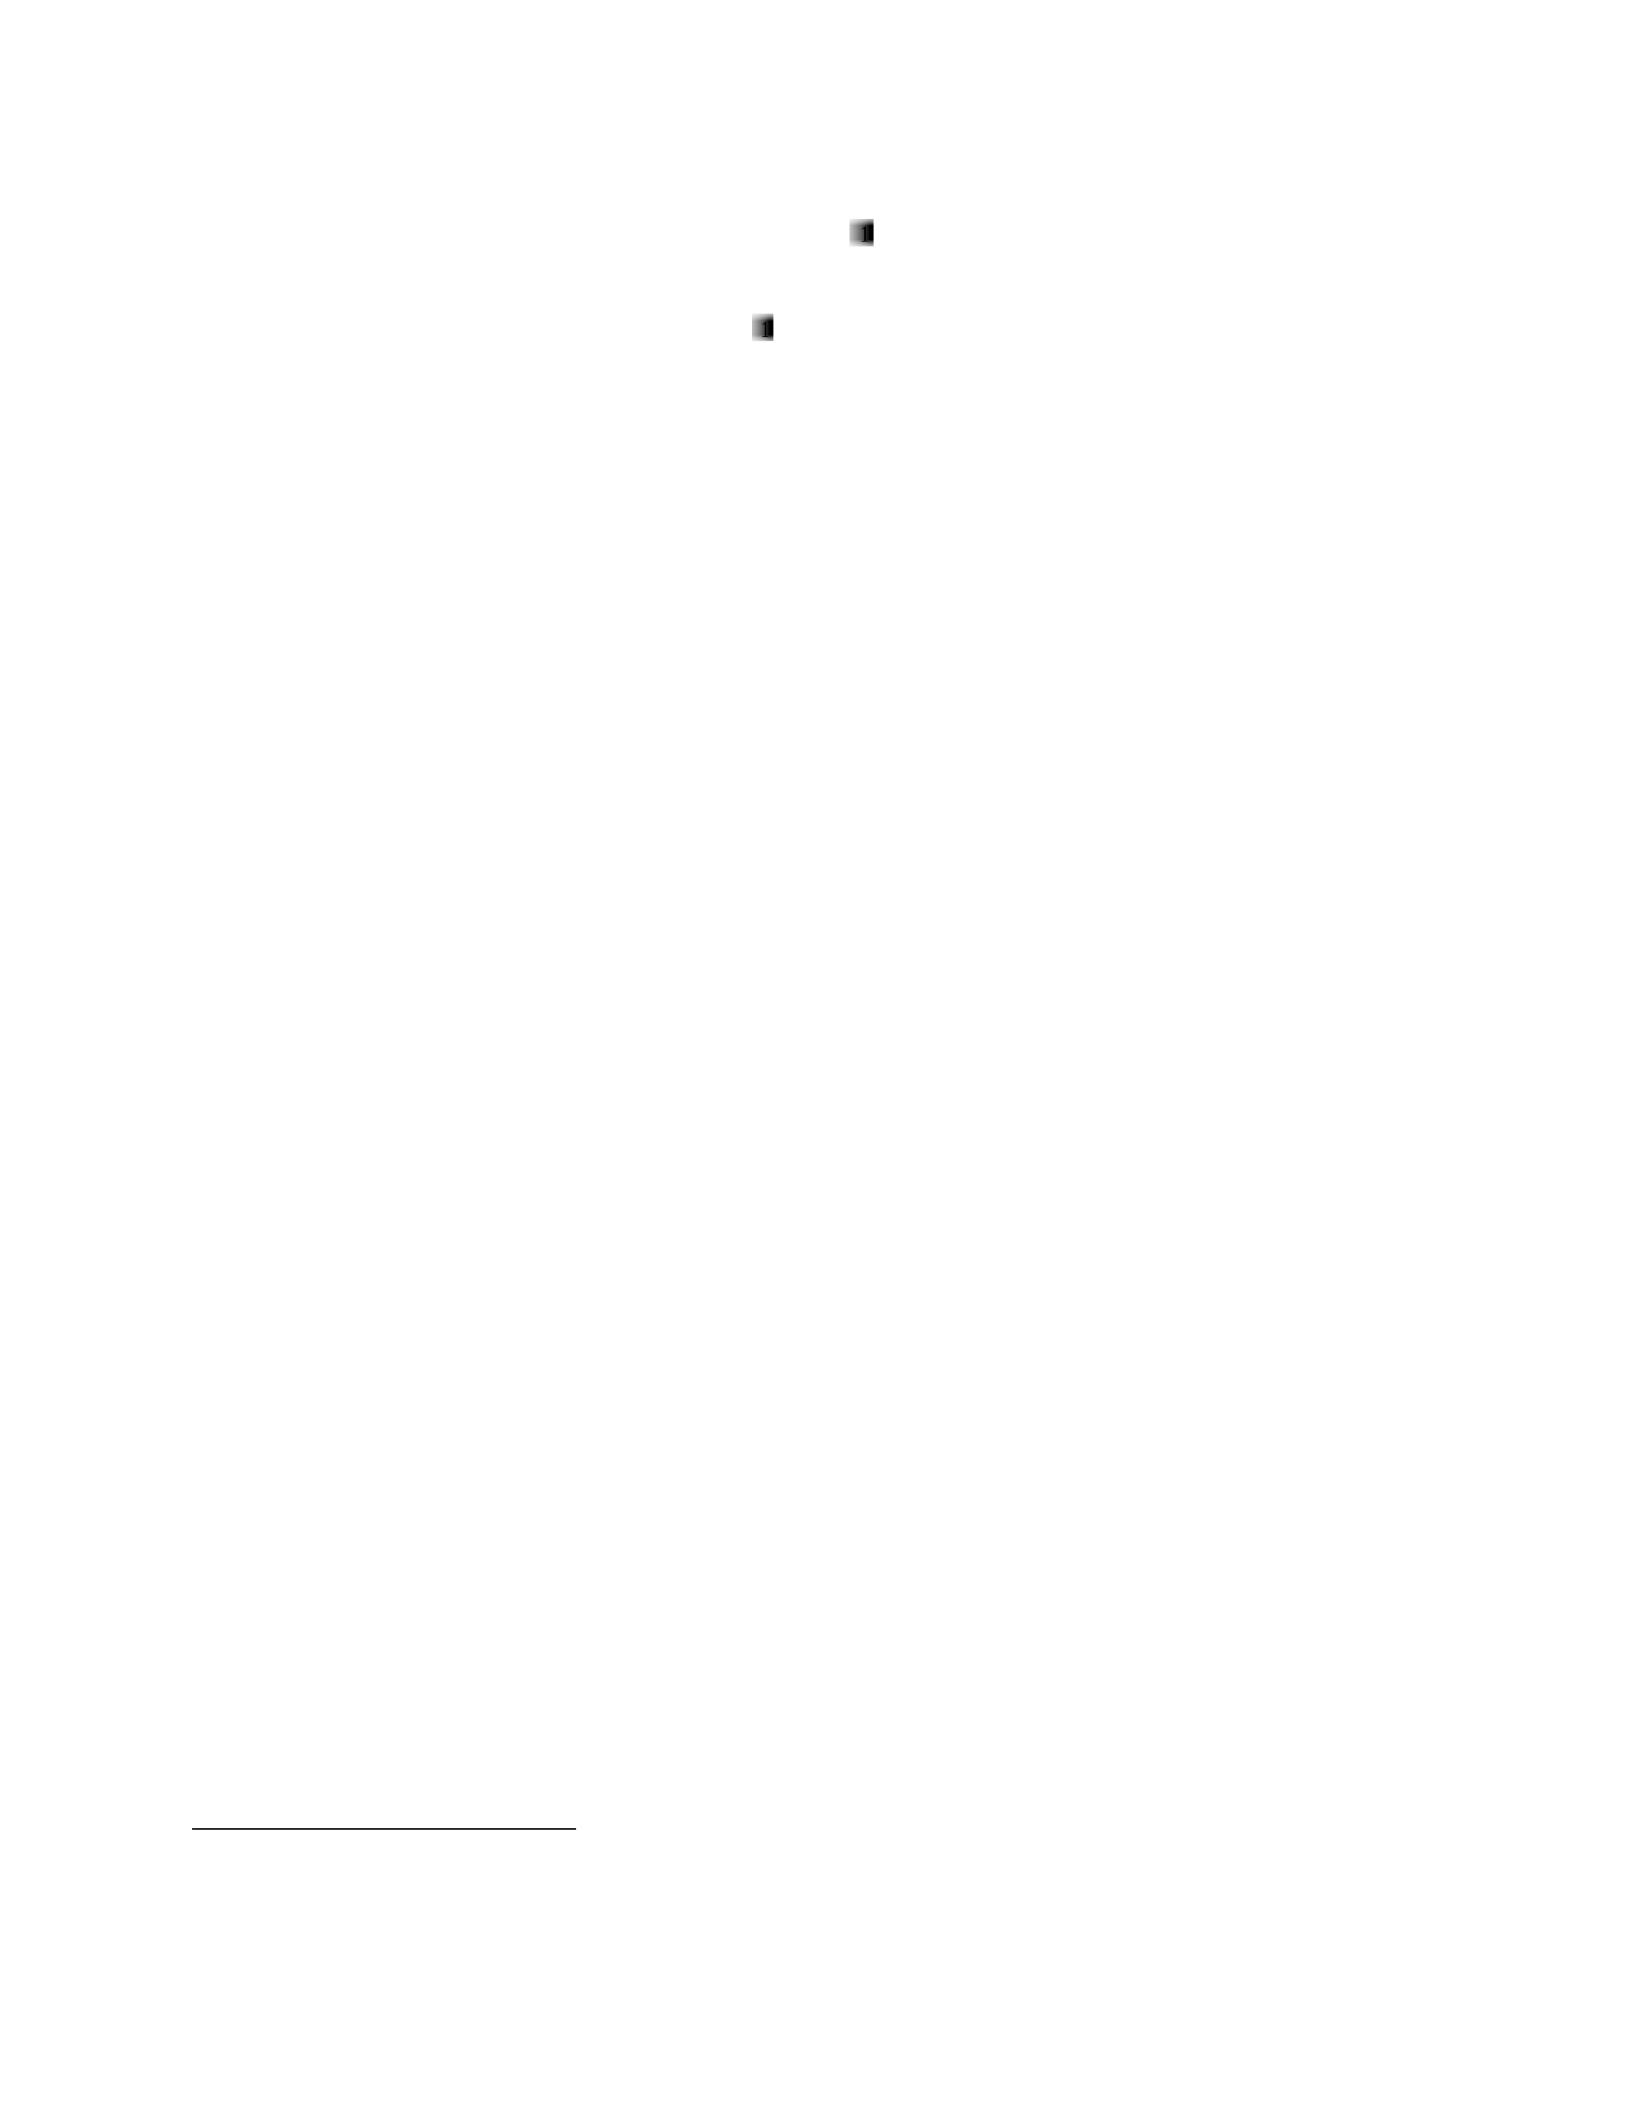
28
where
t
SIV
the scaled index value at time t is,
1t
IMV
is the index market value at time t-1,
t
IMV
is the index market value at time t, and
1t
SIV
is the scaled index value at time t-1. By taking the
ratio of today’s index market value and the previous day’s index market value then multiplying
it by the previous day’s SIV we can achieve the same goal of scaling the index market value to a
more manageable number. With this method, there is no need for a divisor.
3.5.3 Bi-Annual Corrections
3.5.3.1 Mid-Year Update
The number of shares available to the public for a given firm can change from day to day for
several reasons. If a company issues new shares to the public this number will rise, if they buy
back shares the number will reduce. Changes in share count can also occur due to acquisitions,
mergers and spin-offs, and several other corporate actions. All indices must have a clearly
defined method for accounting for these changes as they can drastically affect the accuracy of the
index. For example, the S&P 500 uses what they call the “5 percent rule”, where immediate
corrections to the index are made only when corporate action or any other force causes a firm’s
share count to change by more than 5 percent, (Standard & Poor's, 2009b). All other changes that
result in less than a 5 percent change are accumulated and made on a quarterly basis. For this
study, all changes in share counts, despite size, are accumulated and updated bi-annually. All
changes during trading days 1 through 126 and are updated on day 127 and changes during days
127 to the last trading day of the year and are updated on the first trading day of the next year.7.
This correction is calculated as:
7 Given the time constraints of this study it was not possible to track share count changes as closely as those
published indices like the S&P 500 or Dow Jones Industrial Average.
29
1 127
127 127
*,
*,
td t
ii
td
itd t
ii
P Shares if d
DMV P Shares if d
(23)
where
td
i
DMV
is the daily market value of firm i on day d in year t,
td
i
P
is the security price of
firm i on day d in year t,
1t
i
Shares
is the share count for firm i on day 1 in year t, and
127t
i
Shares
is
the share count for firm i on day 127 in year t. For all trading days preceding day 127, the
recorded share count on the first trading day of the year is used. For all trading days on or after
day 127, the recorded share count on the 127th day of trading is used.
3.5.3.2 Beginning of the Year Update
On the first trading day of each year, the index is rebalanced to account for two changes to its
makeup. First, all changes in share counts and second, all additions and deletions are made to the
constituents of the index. In a given year, the firms that make up the top 70th percentile of the
agricultural industry can change. Additions and deletions occur because each year some
companies are shutdown because of bankruptcy, new companies are started, some companies
grow, mergers occur, and others fall in market share. Making annual firm additions and deletions
ensures that the AG Index remains an up-to-date representation of the US agriculture sector.
These changes are only made at the beginning of each year; consequently, if a company is added
to the index in January, it cannot leave the index until the January of the next year.
3.5.4 Rebalancing the Index Using a Divisor
When changes are made to the index’s constituents or if share counts change, the index level
should not move up or down, as this change does not represent market price movement. To
ensure that an index’s level does not change when stocks are added or deleted, an adjustment
must be made to offset the change in market value. In the case of the S&P 500 and many other
indices, the divisor is used to accomplish this (Standard & Poor's, 2009b). The divisor, in this
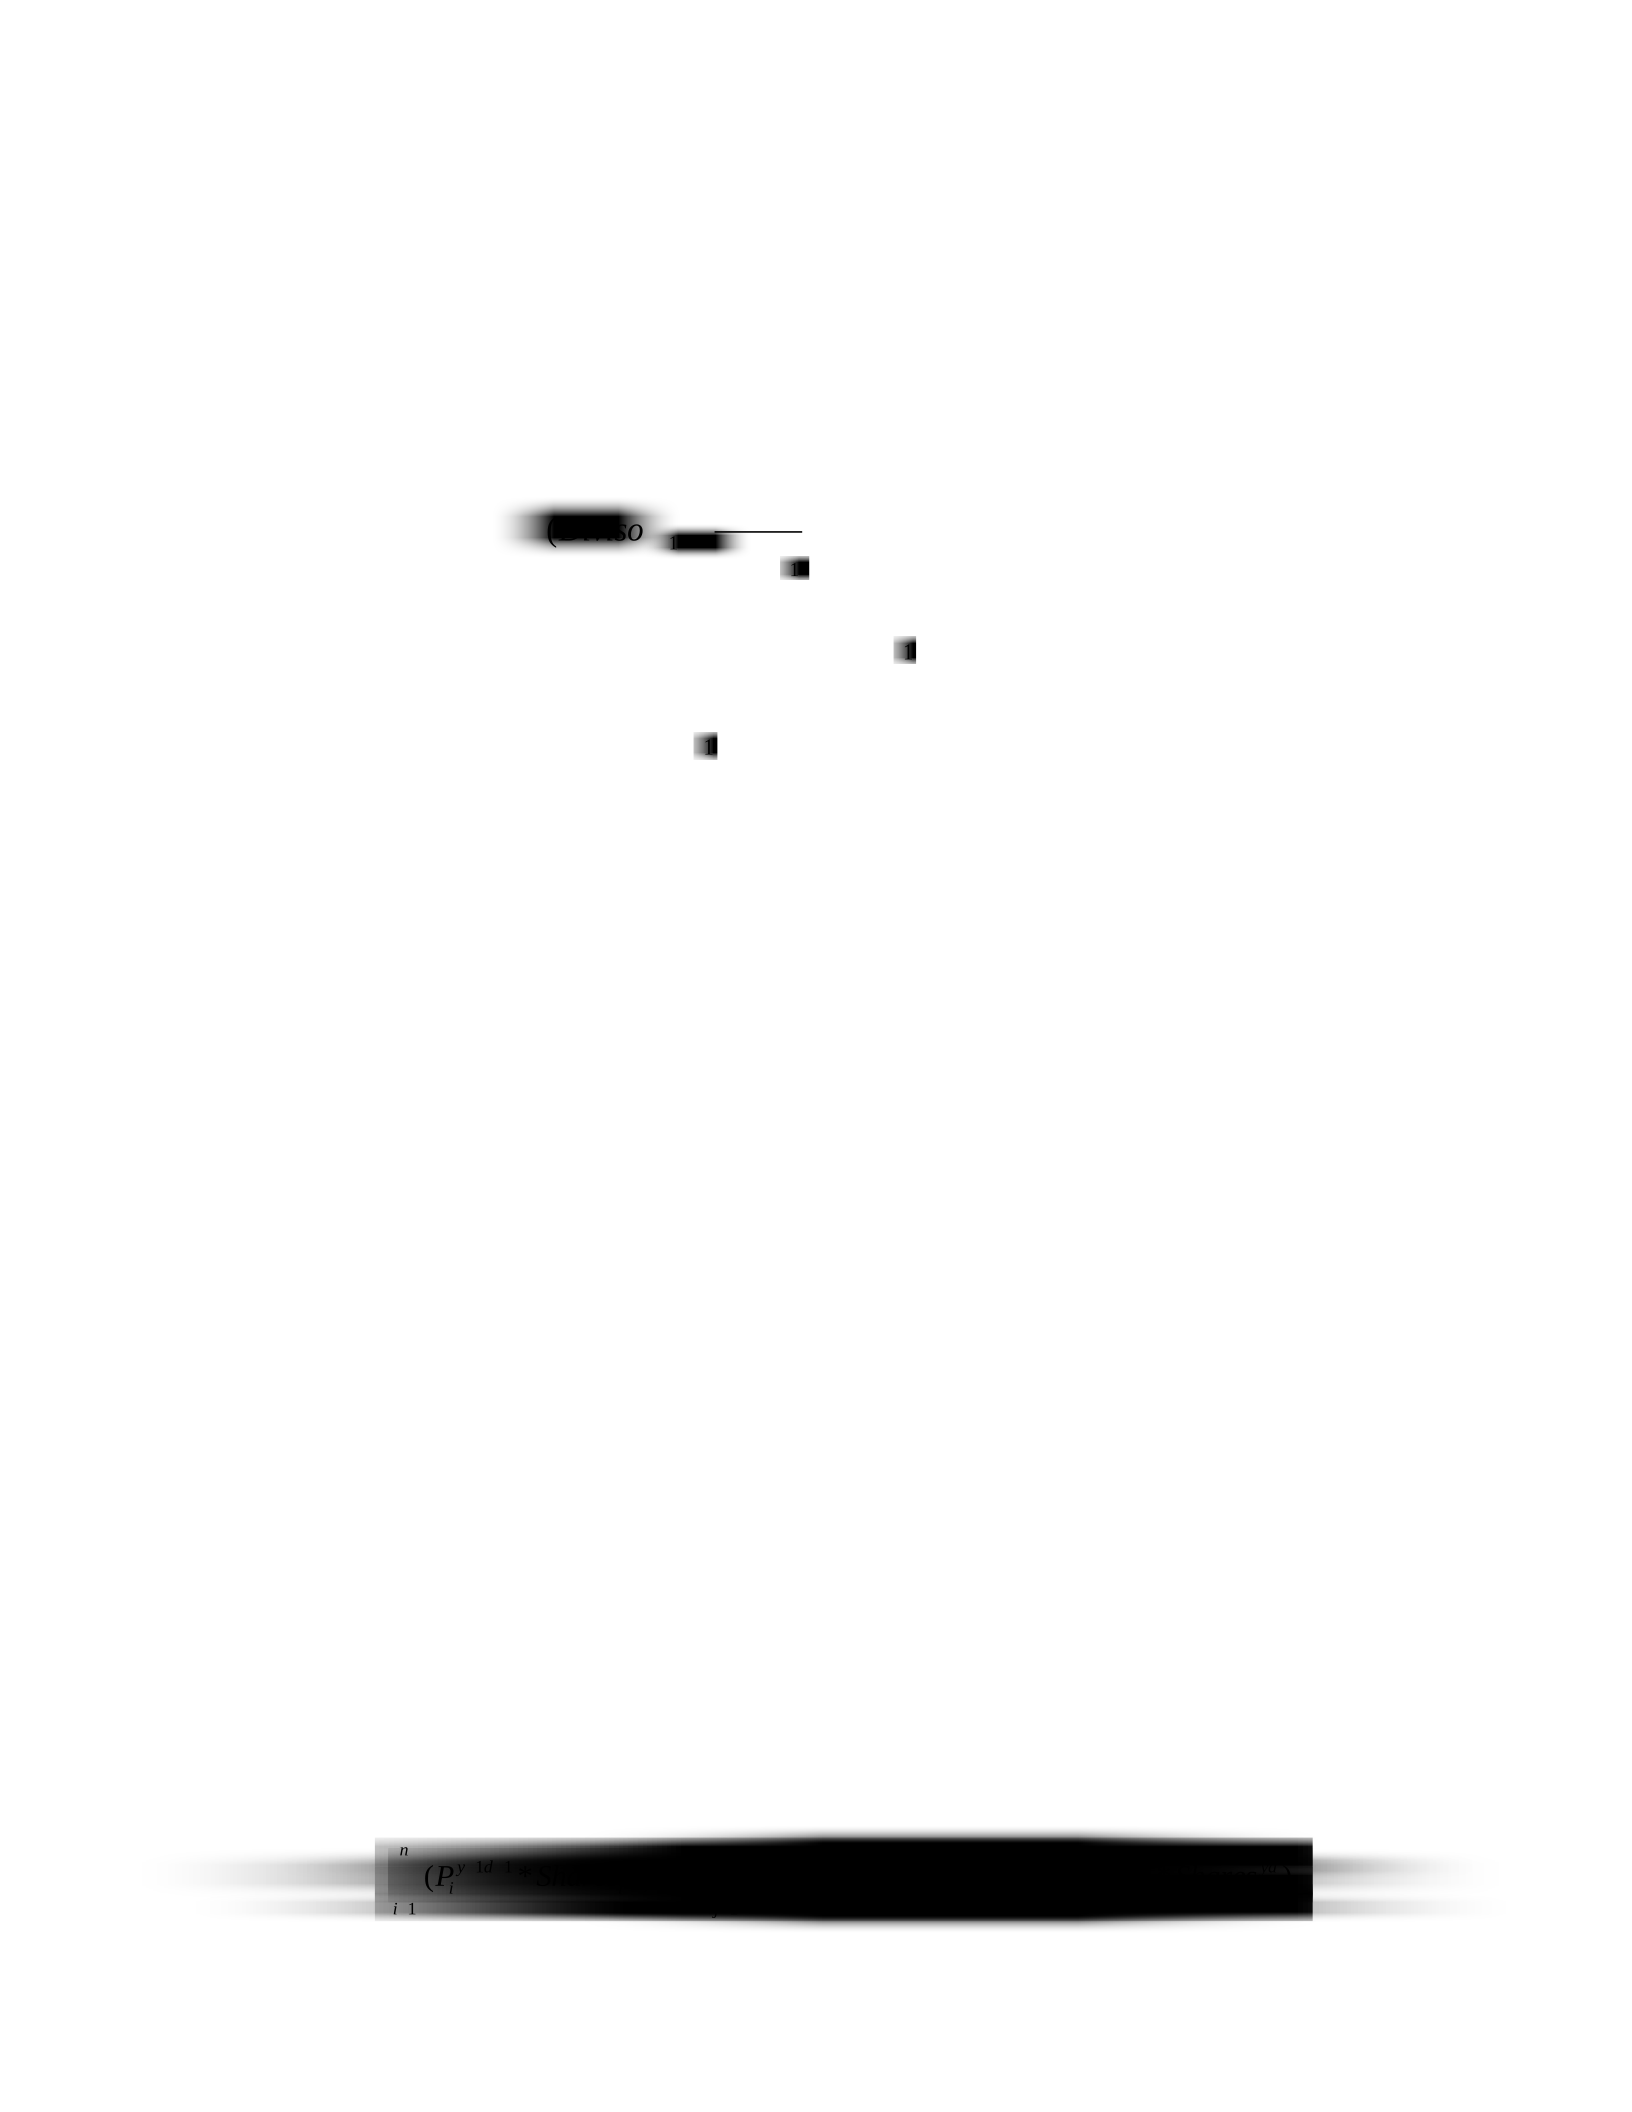
30
case, plays a crucial role in the ability to compare index levels over time as changes in the
constituents can affect the reliability of the index measure. For instance, if an index closes on
December 31, 1972 at 450 and after the close a new firm is added to the index, the index should
still open on January 2, 1973 at 450. This offset is accomplished by:
1
1
( )* t
tt
t
IMV
Divisor Divisor IMV
(24)
where
t
Divisor
is the new divisor at time t¸ is
1t
Divisor
is the old divisor at time t-1,
t
IMV
is the
index market value at time t, and
1t
IMV
is the index market value at time t-1. This new divisor is
used to scale the index until another rebalancing is required.
3.5.5 Rebalancing the Index Using the Ratio Method
A more general method used to rebalance the index to offset changes in the constituency and
share counts in the index over time is the ratio method (Chartered Financial Analyst Institute,
2005). With indices that are managed daily, this rebalancing is done after the market closes for
the day. Because the price data in this study is daily closing price, the intraday prices are not
available. Therefore, to properly rebalance the index after a constituent or share count change,
the index market value at time t (after the change) must be calculated using the prices from time
t-1 (before the change). This new index market value using the adjusted share counts and
updated basket of firms will be referred to from this point forward as the Adjustment Index
Market Value (AIMV). This adjustment figure must be calculated in the beginning of each year to
offset the change in constituents and the change in share counts, and at trading day 127 when
only the share counts are updated. The AIMV calculated at the beginning of each year is given
by:
1 1 1 1 1 1
11 1 1
( * ) ( * ) ( * )
n n n
y d yd y d yd y d yd
i i j j k k
i j k
AIMV P Shares P Shares P Shares
(25)
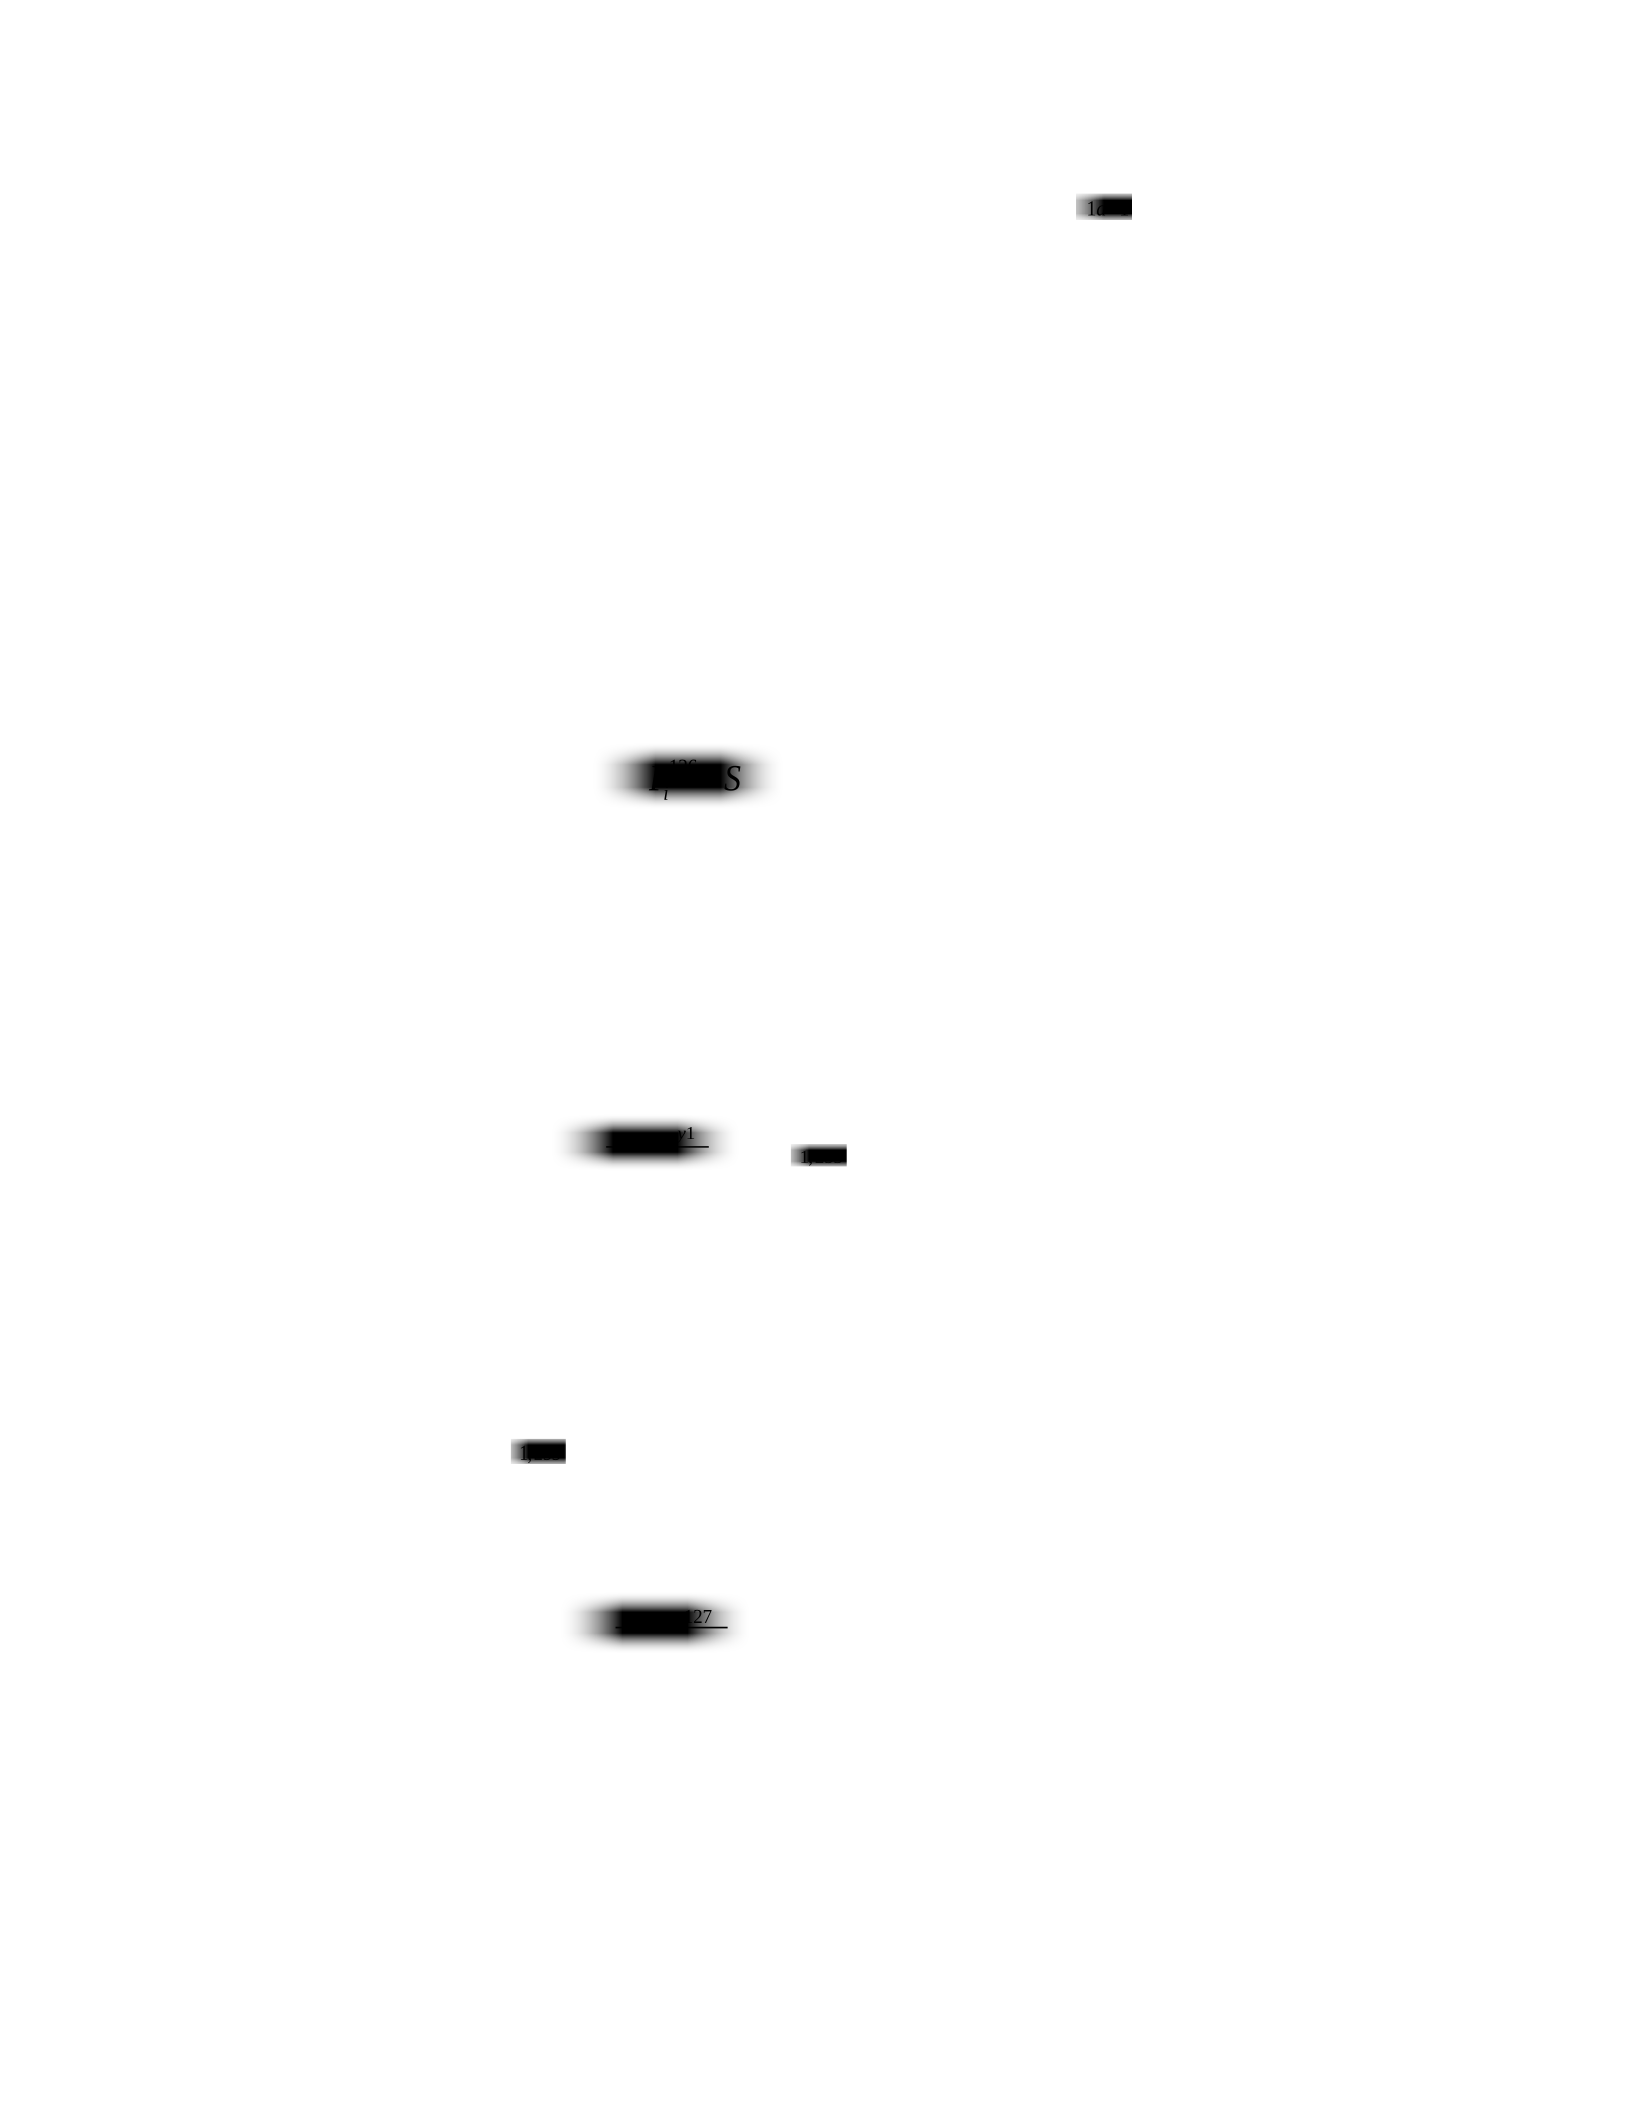
31
where
1
AIMV
is the adjusted index market value at trading day 1,
11yd
i
P
is the price for security
i on trading day d-1 in year y-1,
yd
i
Shares
is the share count for security i on trading day d in year
y, and so forth. The second bracketed section in the equation is the total market value of all the
firms that are being added to the index using the new share counts and the previous trading day’s
prices. The third bracketed section is the total market value of all the firms that are leaving the
index using the new share counts and the previous trading day’s prices. The AIMV at trading day
127 is given by:
126 127
127 *
ii
AIMV P Shares
(26)
where
127
AIMV
is the adjustment index market value at trading day 127,
126
i
P
is the price of
security i at trading day 126, and
127
i
Shares
is the updated share count for firm i at trading day
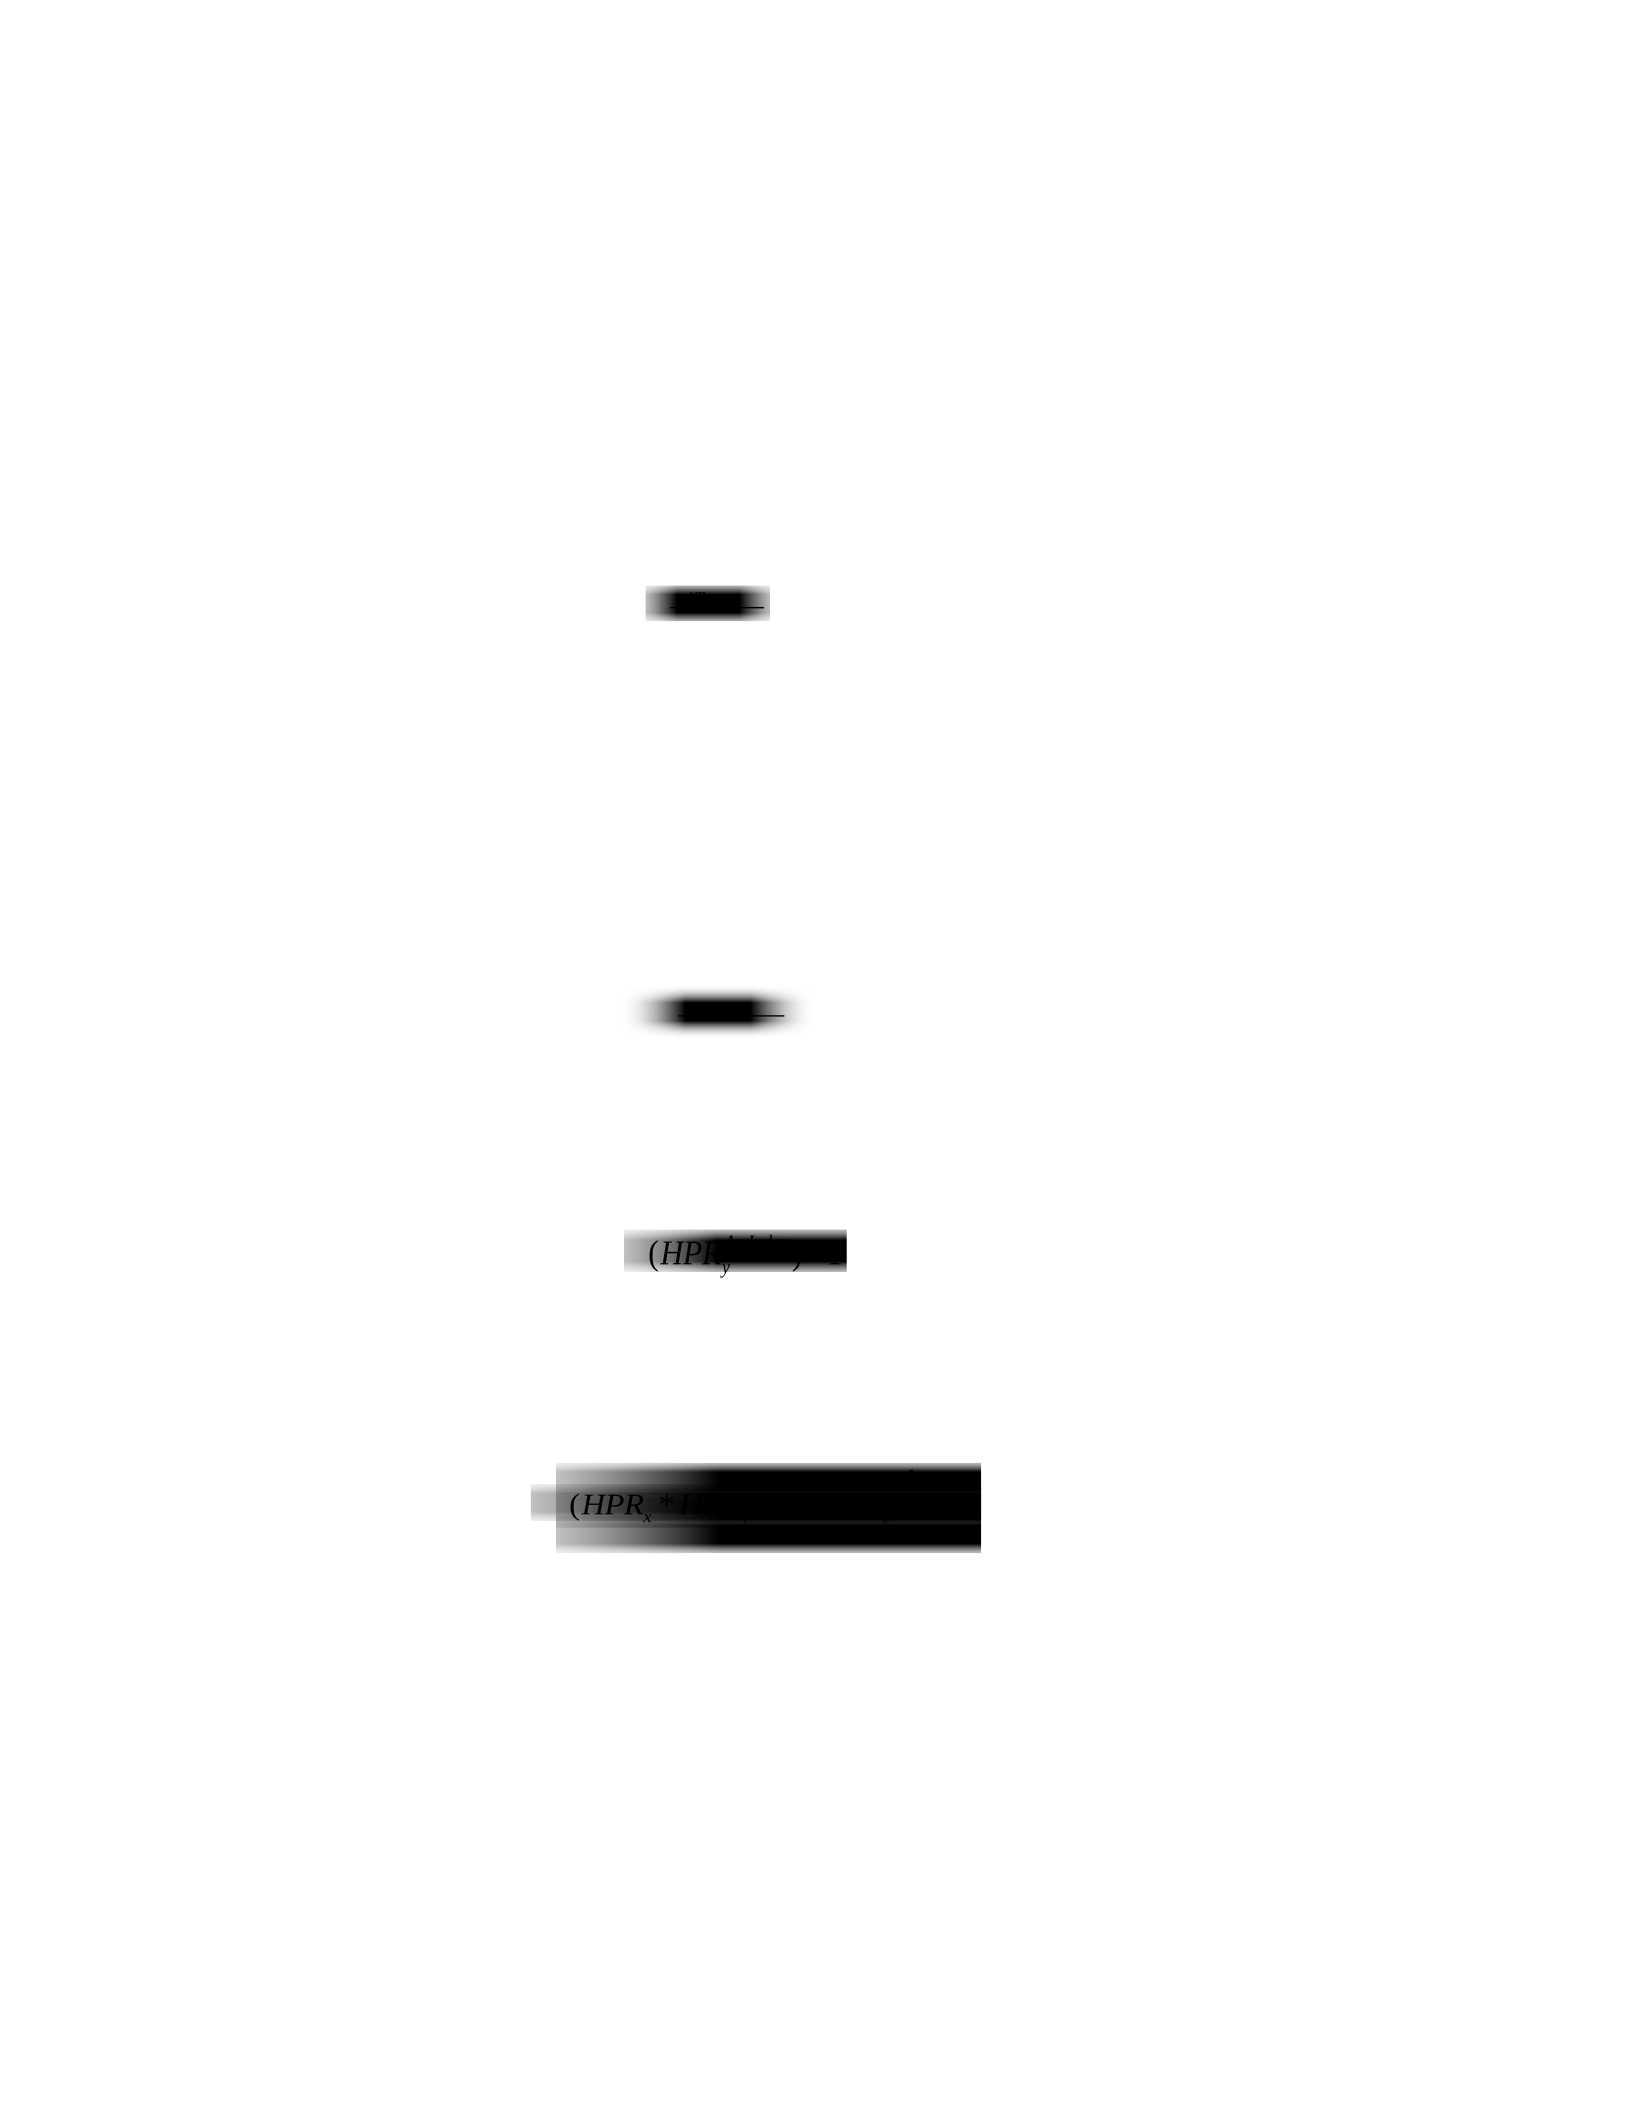
127. The rebalanced and scaled index value for the first trading day of each year is given by:
1
1 1,253
1
*
y
yy
y
IMV
SIV SIV
AIMV
(27)
where
1y
SIV
is the scaled index value at the rebalancing trading day 1 in year y,
1y
IMV
is the index
market value on trading day 1 in year y,
1y
AIMV
is the adjustment index market value on trading
day 1 in year y, and
1,253y
SIV
is the scaled index value from the last trading day of the previous
year. The rebalanced and scaled index value for the 127-trading day is given by:
127
127 126
127
*
IMV
SIV SIV
AIMV
(28)
where
127
SIV
is the scaled index value on trading day 127,
127
IMV
is the index market value on
trading day 127,
127
AIMV
is the adjustment index market value on trading day 127, and
126
SIV
is
the scaled index value on trading day 126.
32
3.6 Index Return
Within the contexts of this study, the term “return”, refers only to change in price from one
specified point in time to another, not investment return. That being said, the index’s return is
reported as a geometric return. The first step of this return calculation is to find the holding
period ratio (HPR) for each year of the index by:
1
Ag Index
yn
Ag Index
yAg Index
y
P
HPR P
(29)
where, the HPR for year y is given by the ratio of the price of the Ag Index in year y on day n
(the last trading day of year y) and the price of the Ag Index in year y on trading day 1 (the first
trading day of year y). For example, the holding period ratio in 1970 would be calculated as
follows:
1970
101.589
100
Ag Index
HPR
(30)
Therefore, the holding period ratio for 1970 would be 1.01589. To calculate the geometric return
(GR) for one period (year) you simple subtract 1 from the period’s HPR as:
( ) 1
Ag Index Ag Index
yy
GR HPR
(31)
In the case of 1970, the geometric return was 1.01589 - 1 = 0.01589 or 1.589 percent return. The
geometric return for more than one period is calculated by:
1
,( * *...* ) 1
Ag Index n
x z x y z
GR HPR HPR HPR
(32)
where
,
Ag Index
xz
GR
is the geometric return for period x through z,
x
HPR
is the holding period ratio for
period x,
y
HPR
is the holding period ratio for period y,
z
HPR
is the holding period ratio for period
z, and n is the total number of periods within the return calculation. For the period of 1970 to
1974, the geometric return calculation is given as follows:
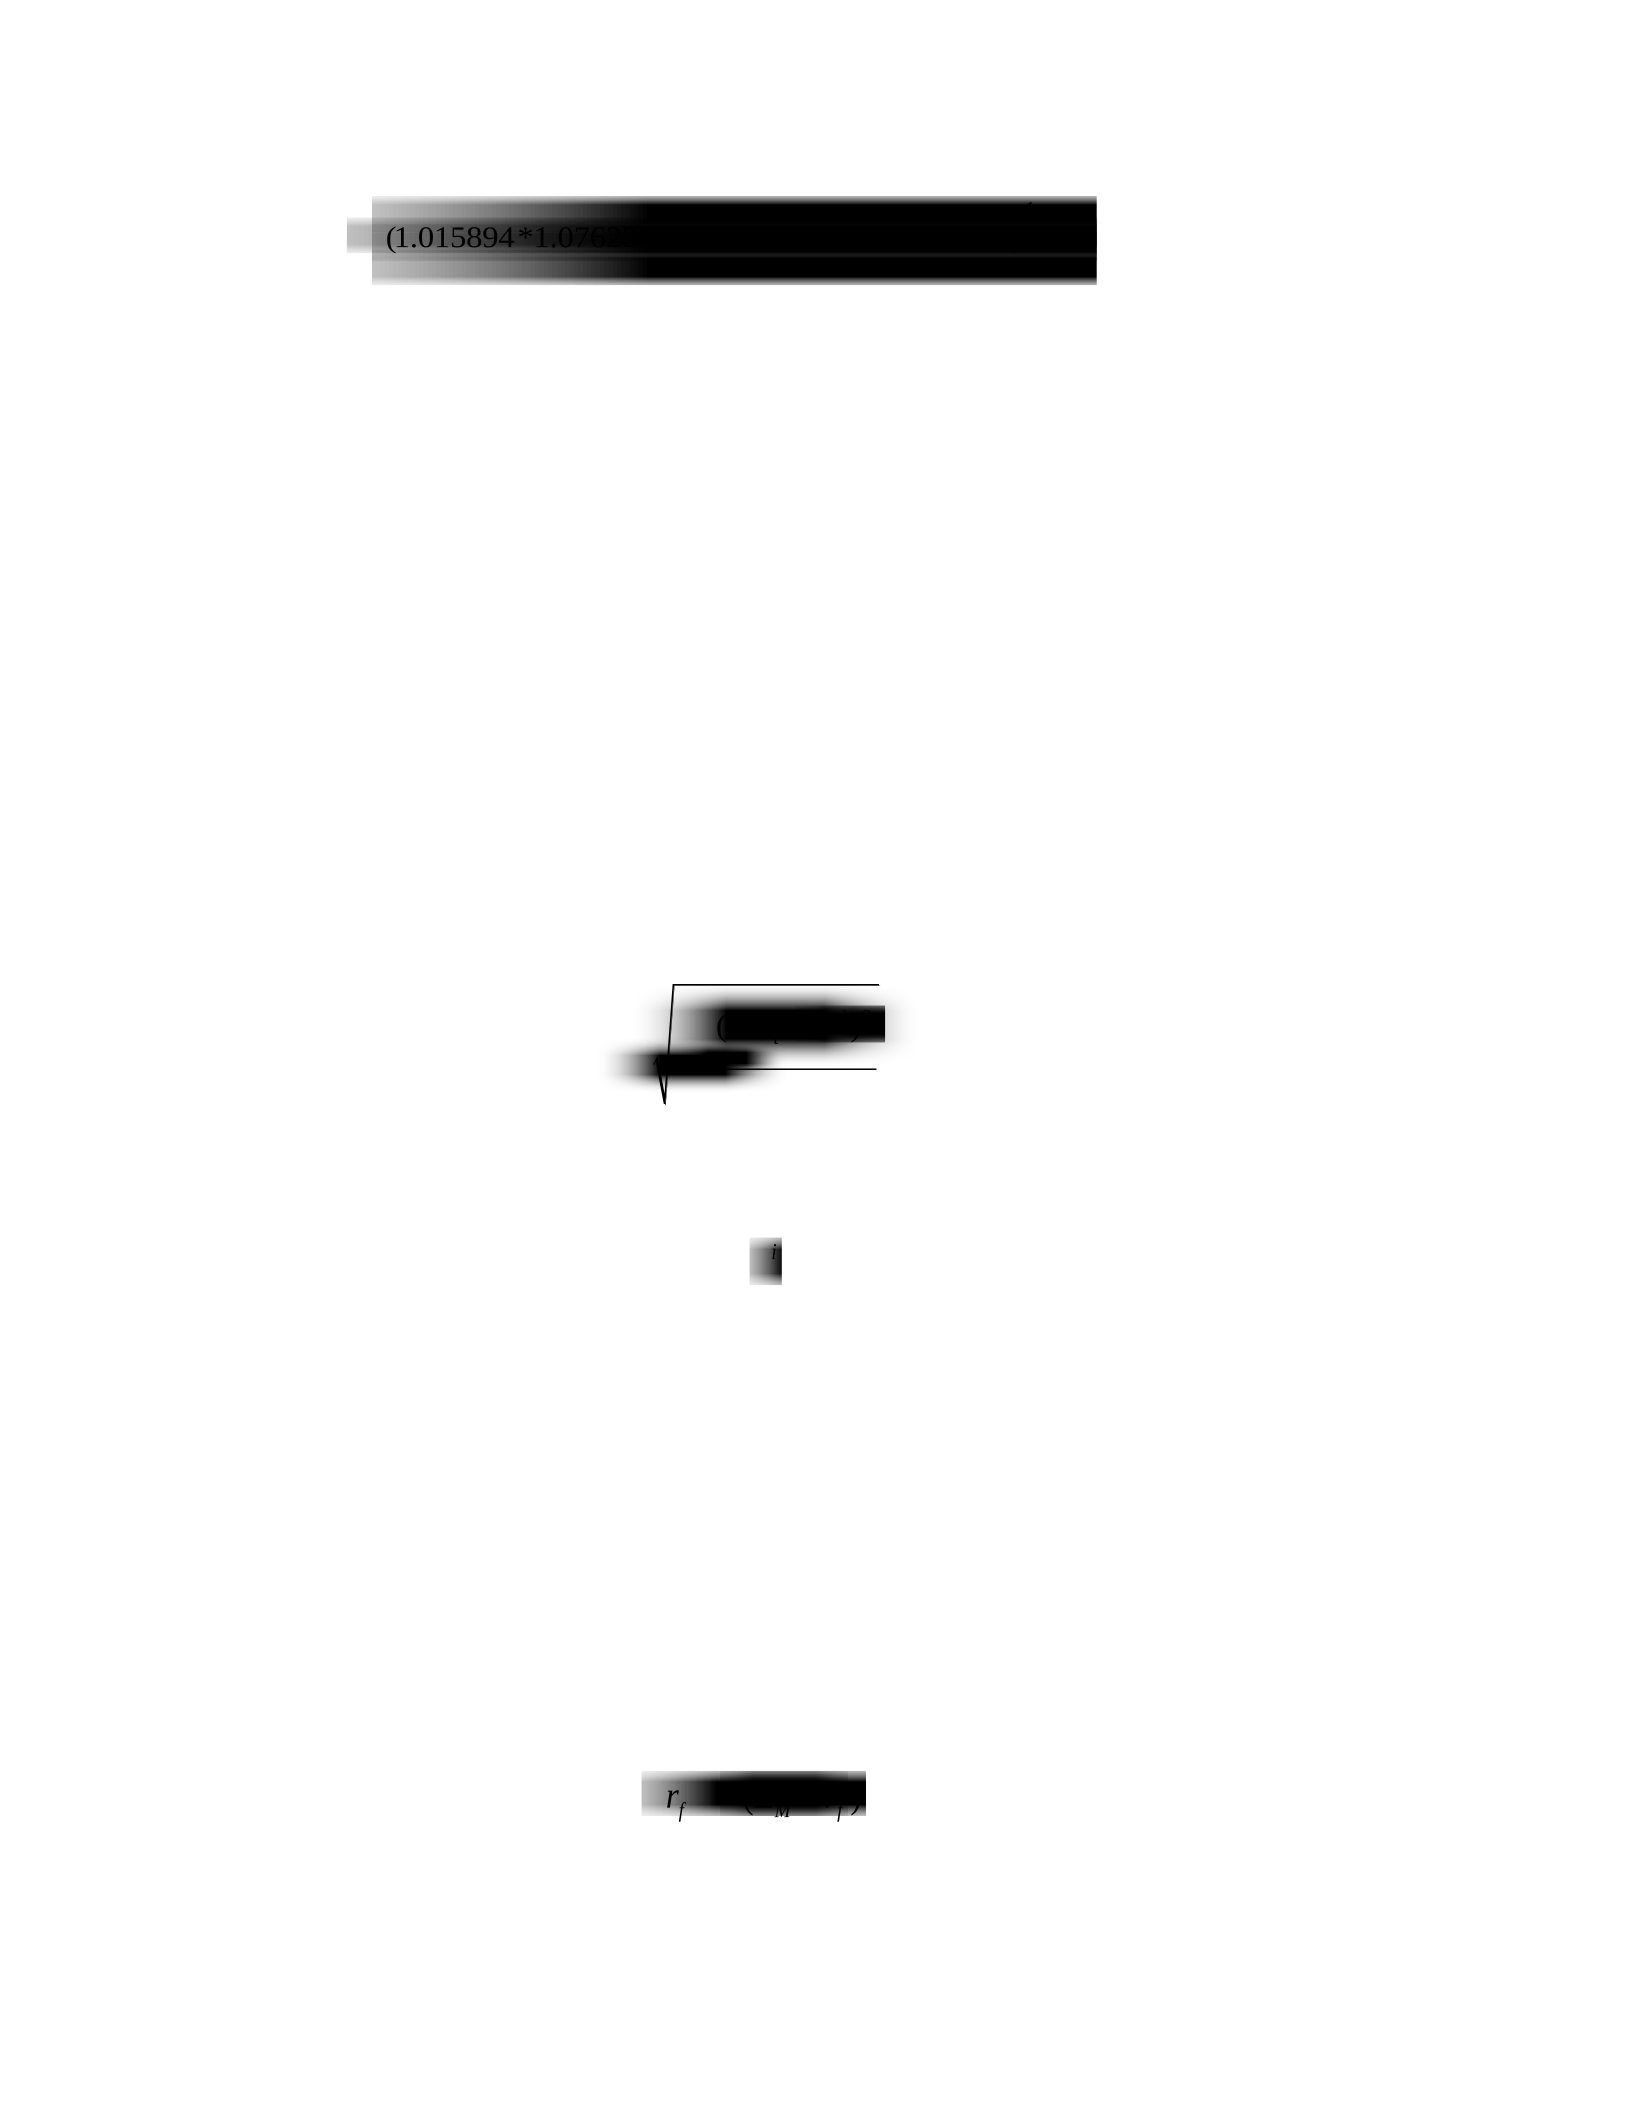
33
1
5
1970,1974 (1.015894*1.07623*1.01857*0.76175*0.68982) 1
Ag Index
GR
(33)
Therefore, the geometric return for the five-year period of 1970 to 1974 was -0.101625 or -
10.1625 percent. To ensure comparability across indices, the returns for all comparison indices
are calculated using the same methodology.
3.7 Index Risk and Risk Adjusted Performance
The reported measures of risk in this study are standard deviation and beta; and the Sharpe Ratio,
a measure of risk-adjusted returns. The resulting values are compared with those of the two
comparison indices (S&P 500 and Dow Jones Industrial Average).
The standard deviation (STDEV) of the AG Index as well as the comparison indices will
be calculated as:
2
1
()
nii
t
it
p
SIV
STDEV N
(34)
where
i
p
STDEV
is the standard deviation of index i during period p,
i
t
SIV
is the scaled index
value for index i for the tth trading day and
i
is the mean value of index i for period p, and N, is
the number of data values in period p.
Investors are not only concerned about the price risk of the security itself; rather, they are
also interested in its risk relative to some other securities. A popular measure that summarizes
the correlation between one security and a benchmark is its beta value. As previously mentioned
the beta measure is a component of the capital asset pricing model (CAPM). From (Perold,
2004), the CAPM is calculated by:
()
s f M f
E r E r
(35)
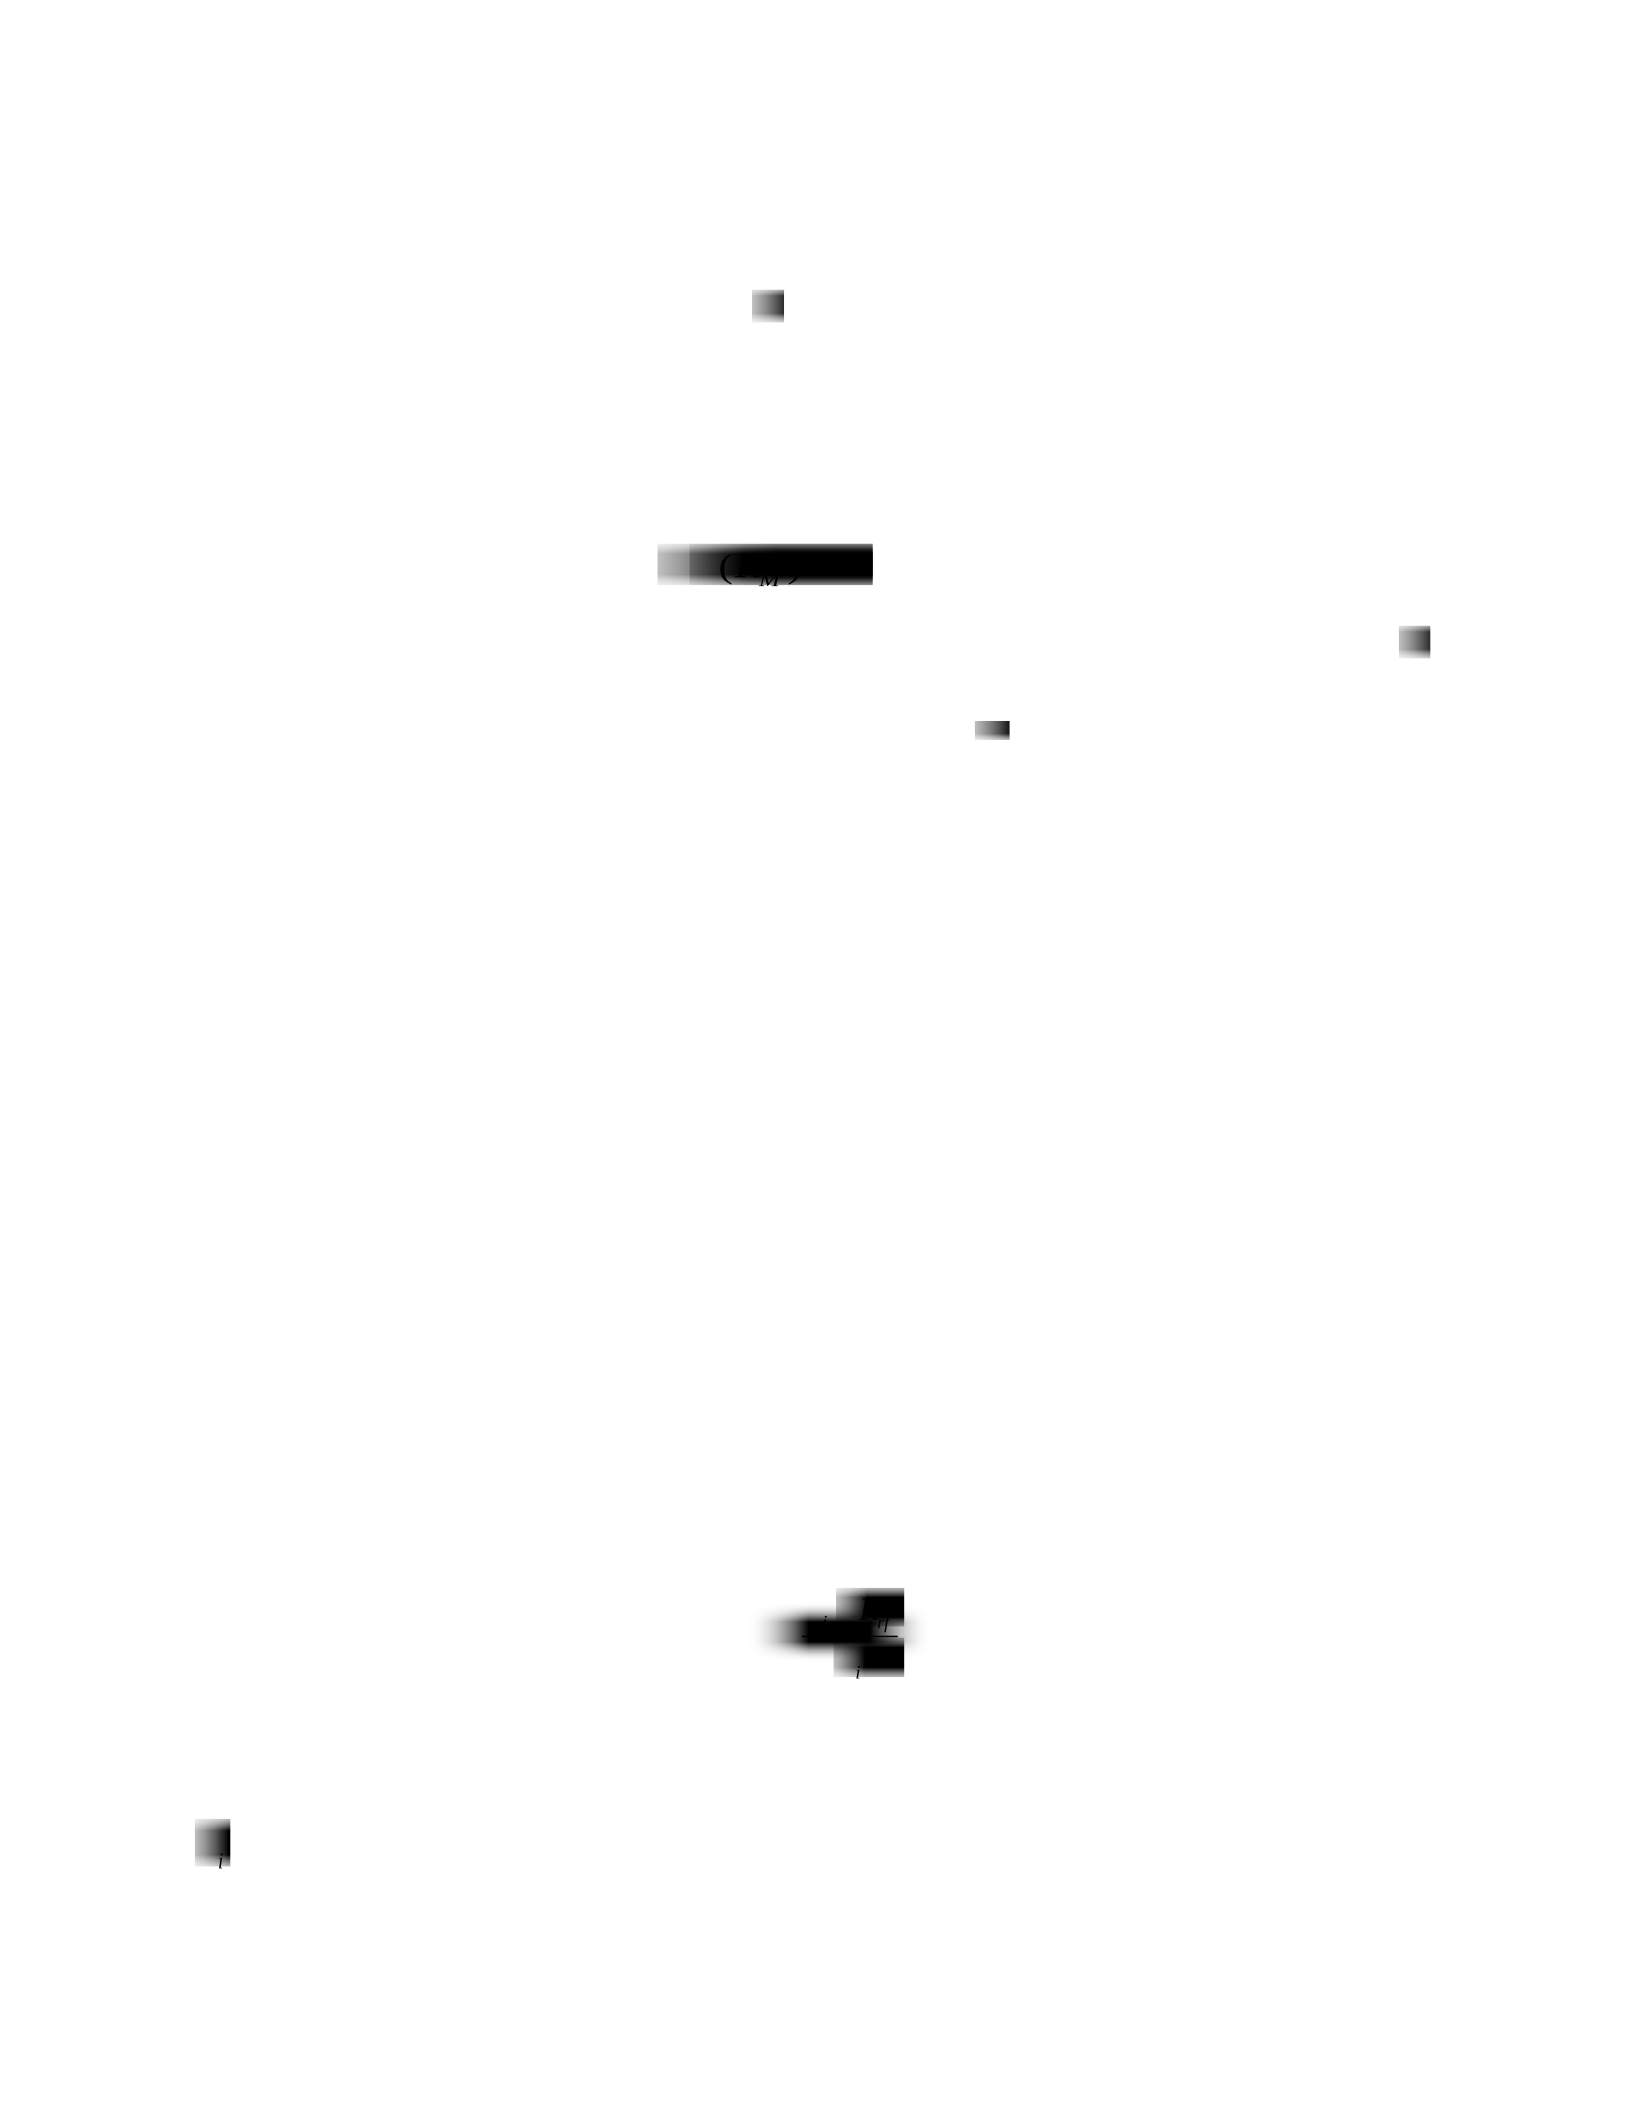
34
where
s
E
and
M
E
are the expected return from the security and the market portfolio,
respectively,
f
r
is the risk free return, and is the sensitivity of the security’s price to the
market, i.e., the security’s beta value. The security’s beta value is calculated by simply
regressing the security’s return against the market portfolio:
()
SM
RR
(36)
where
S
R
and
M
R
are the return series from the security and the market portfolio, respectively,
is the slope the regression line and the assets beta value, and is the error term. For the
purposes of this study, the S&P 500 was used as a proxy from the market portfolio. Short and
long-term measures are useful to investors making investment decisions on different time
horizons. Therefore, to test the belief that the U.S. agricultural sector is defensive in nature, the
beta value was calculated for the AG Index for each year in the study, each five-year, and each
10-year holding period.
In the beta calculation, the benchmark security is the market portfolio, which still
contains risk. However, investors are also concerned with a security’s performance and risk
relative to a riskless asset. Excess return measures, like the Sharpe Ratio, provide such
information to investors. Because this study is mainly concerned with the past performance of
US Agribusiness firms relative to the market as a whole, the ex post Sharpe Ratio is provided.
The ex post, Sharpe Ratio is given by:
i rf
i
i
RR
SharpeRatio
(37)
where
i
R
is the simple return of security i,
rf
R
is the simple return of the risk free security, and
i
is the standard deviation of security i. It is important to note that the Sharpe Ratio measure is
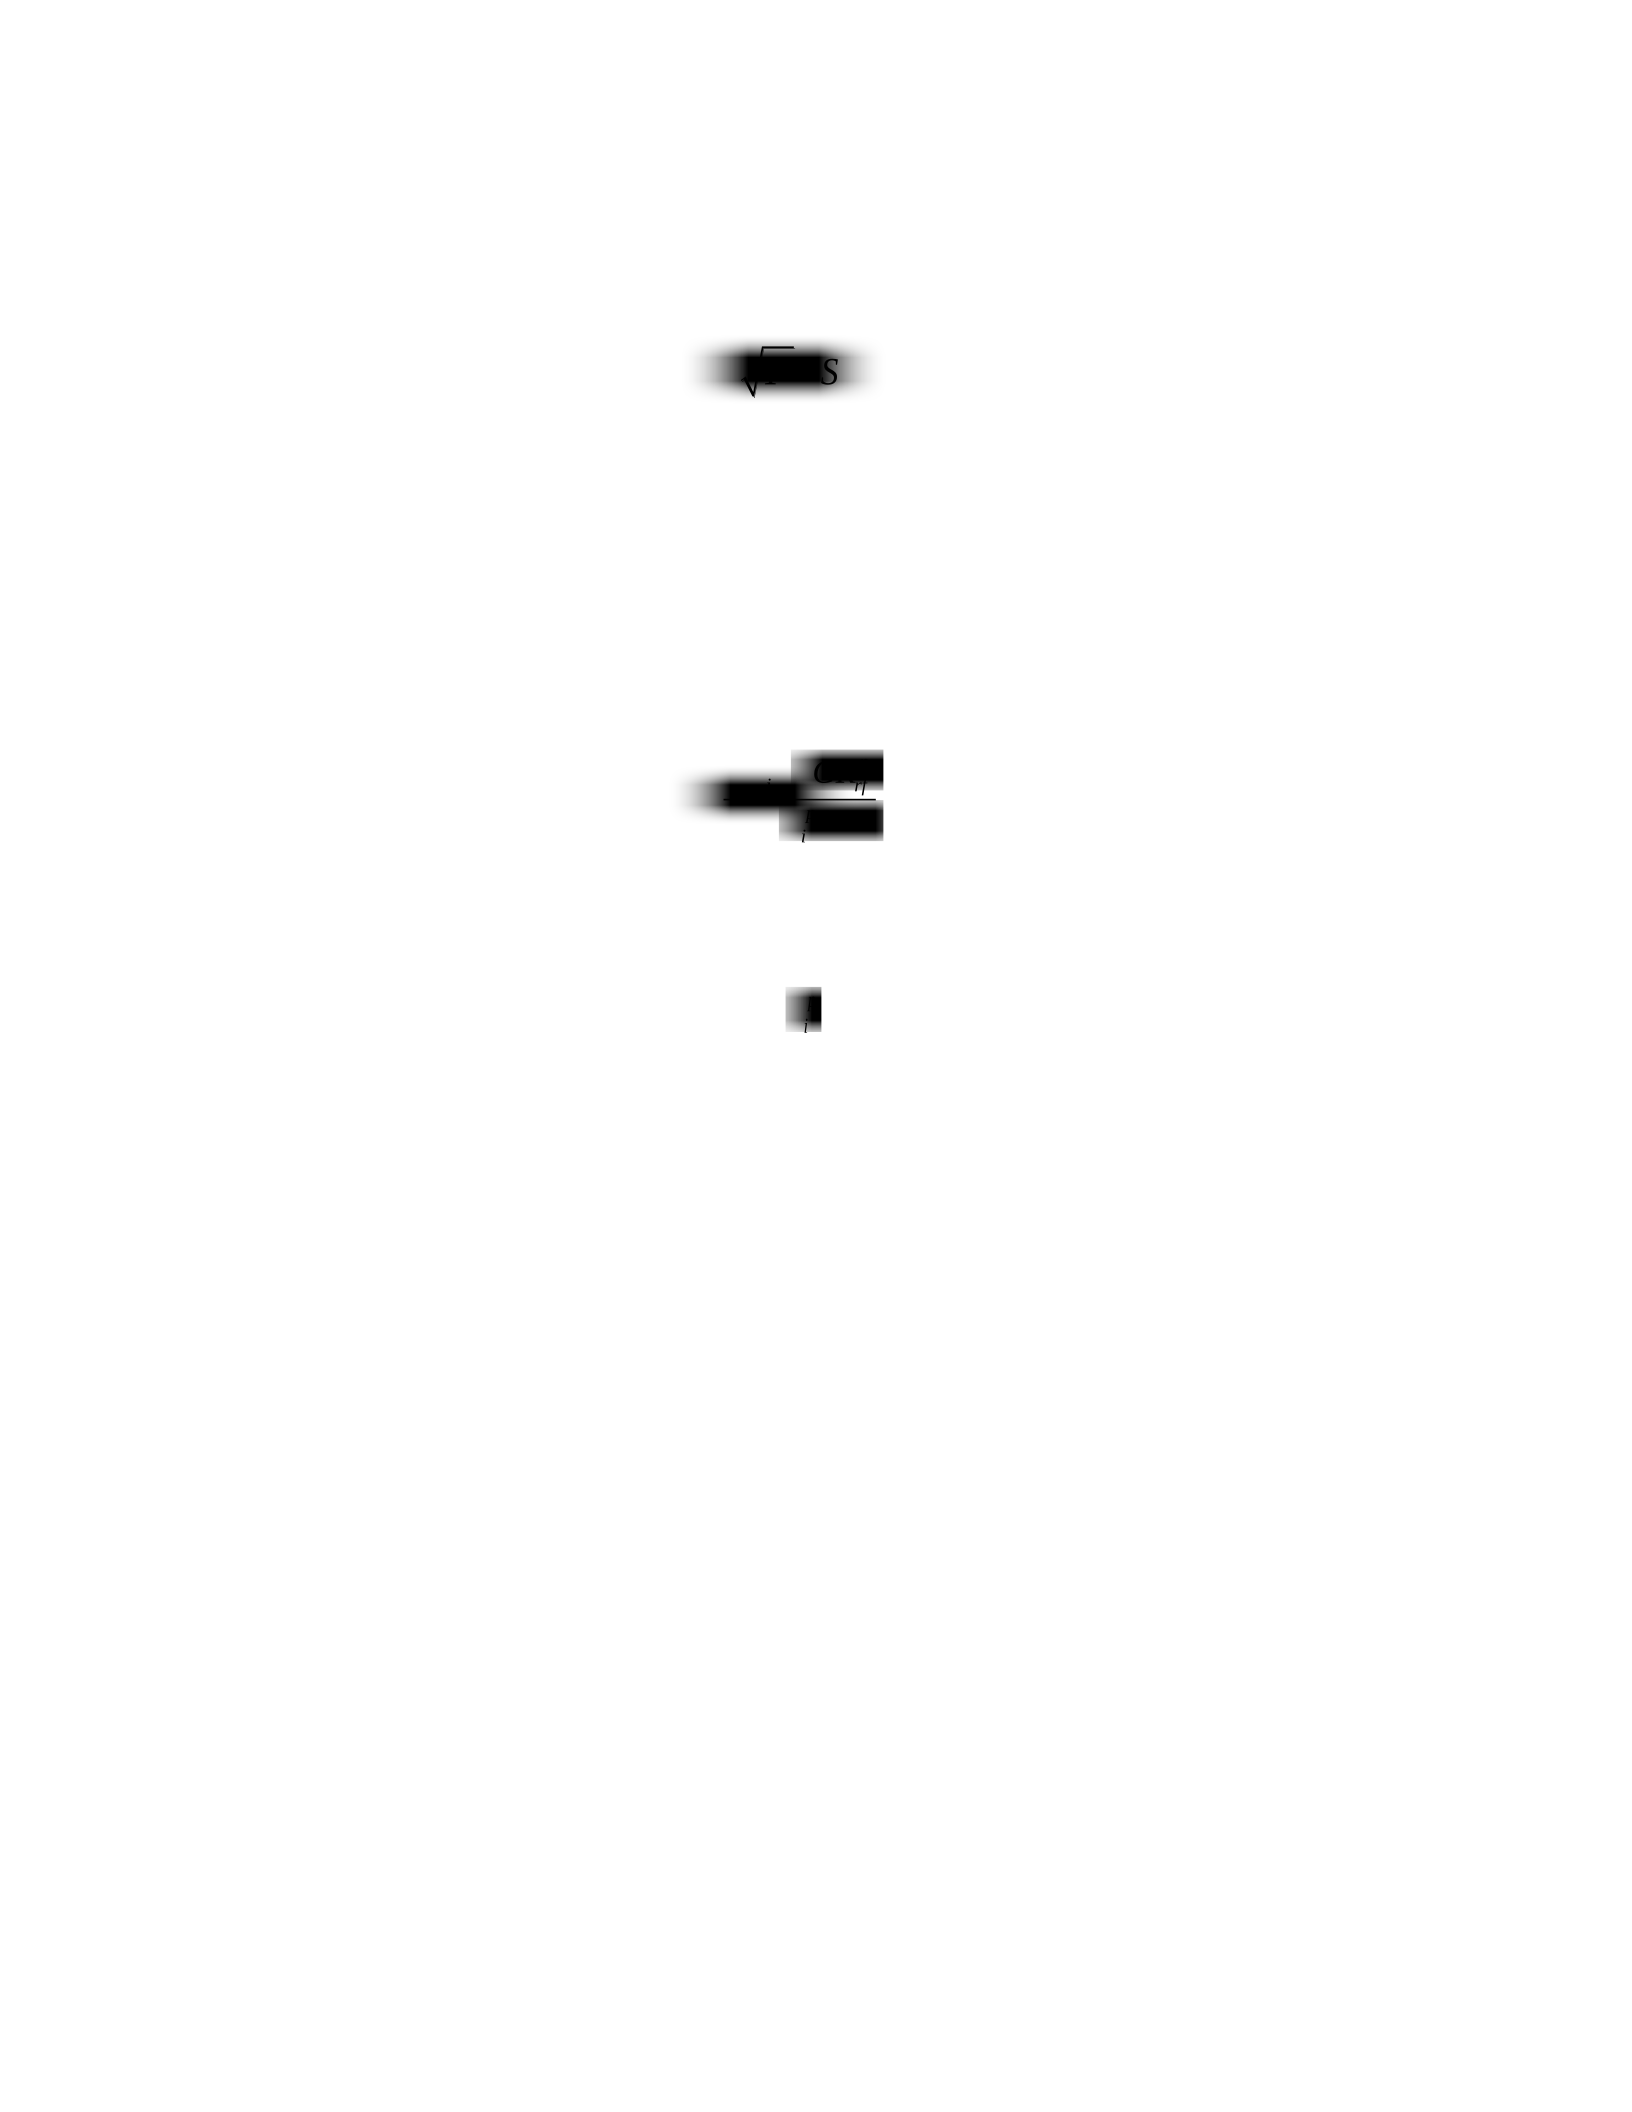
35
not independent of the time period over which it is measured (Sharpe, 1994). The commonly
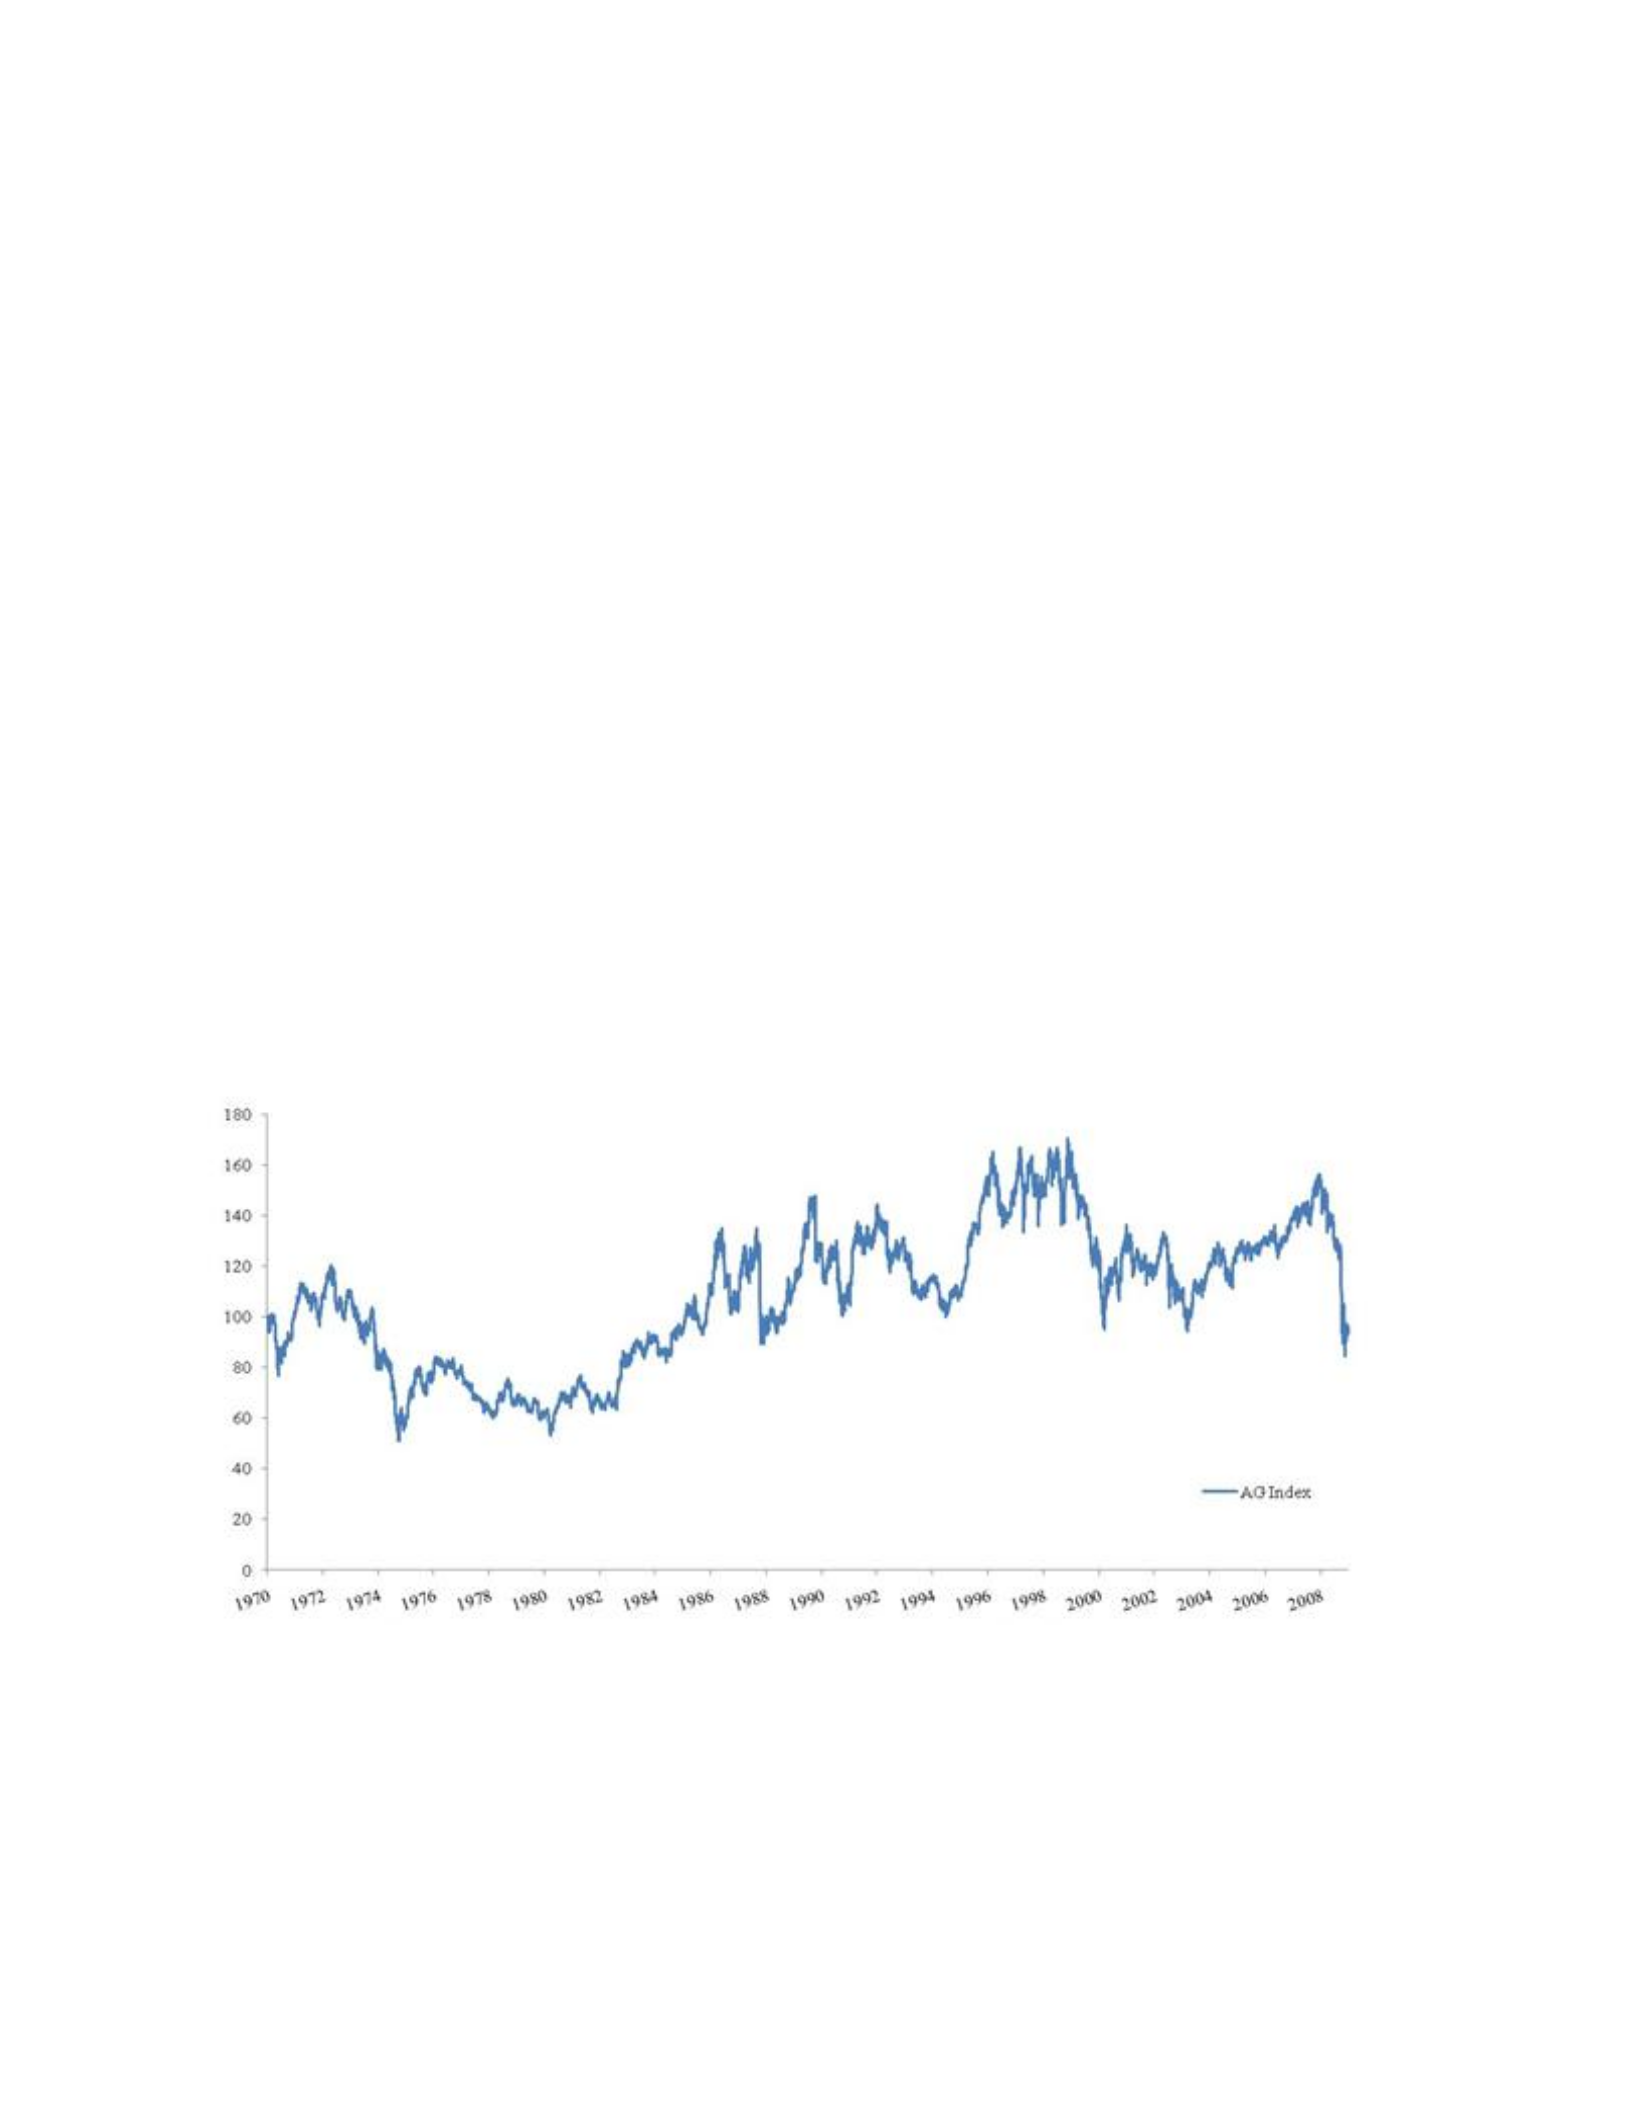
cited way to annualize the Sharpe Ratio measure (S) is given by:
1
*
T
SharpeRatio T SharpeRatio
(38)
where
T
SharpeRatio
is the annualized measure over T periods, and
1
SharpeRatio
is the one
period measure. However, this method has been shown to be correct in only a few rare statistical
circumstances (Lo, 2002). Therefore, from (Sharpe, 1994), the proper way to calculate multi-
period (p) Sharpe Ratio measures is given by,
pp
i rf
p
ip
i
GR GR
SharpeRatio
(39)
where,
p
i
GR
is the geometric return for security i during period p,
p
rf
GR
is the geometric return
for the risk free security, during period p, and
p
i
is the standard deviation of security i for period
p. When calculating risk adjusted return measures, special attention should be given to selecting
a proper proxy for the risk free security in the equation. Typically, short term (90 day) US
Treasury Bills are used, however, government securities are not entirely riskless, especially when
their maturity period is not matched to the investor’s time horizon (Roll, 1969). Therefore, daily
yield values for one, five, and ten year US Treasury Bills are used based on the corresponding
holding period return.
36
CHAPTER 4: RESULTS
The results will be organized in to five sections. The first section will discuss the AG Index
continuous price series, general characteristics of returns, and other descriptive statistics. The
second section will discuss the returns of the AG Index relative to the comparison indices.
Annual, 5-year, and 10-year holding period geometric returns will be provided. The third section
will compare the standard deviation of the AG Index and the comparison indices. The fourth
section will provide the results from the Sharpe Ratio calculation and the fifth and final section
will be a discussion of the estimated beta parameters.
4.1 Descriptive Statistics
Figure 1 below, shows the continuous price series of the agribusiness stock index from January
2, 1970 to December 31, 2008. The initial index value is 100, the lowest recorded value
Figure 1: AG Index Value (1970-2008)
was 50.82 on October 3, 1974, and the highest recorded value was 170.55 on November 23,
1998. The average index value was 108.17, median value was 110.54, and had standard
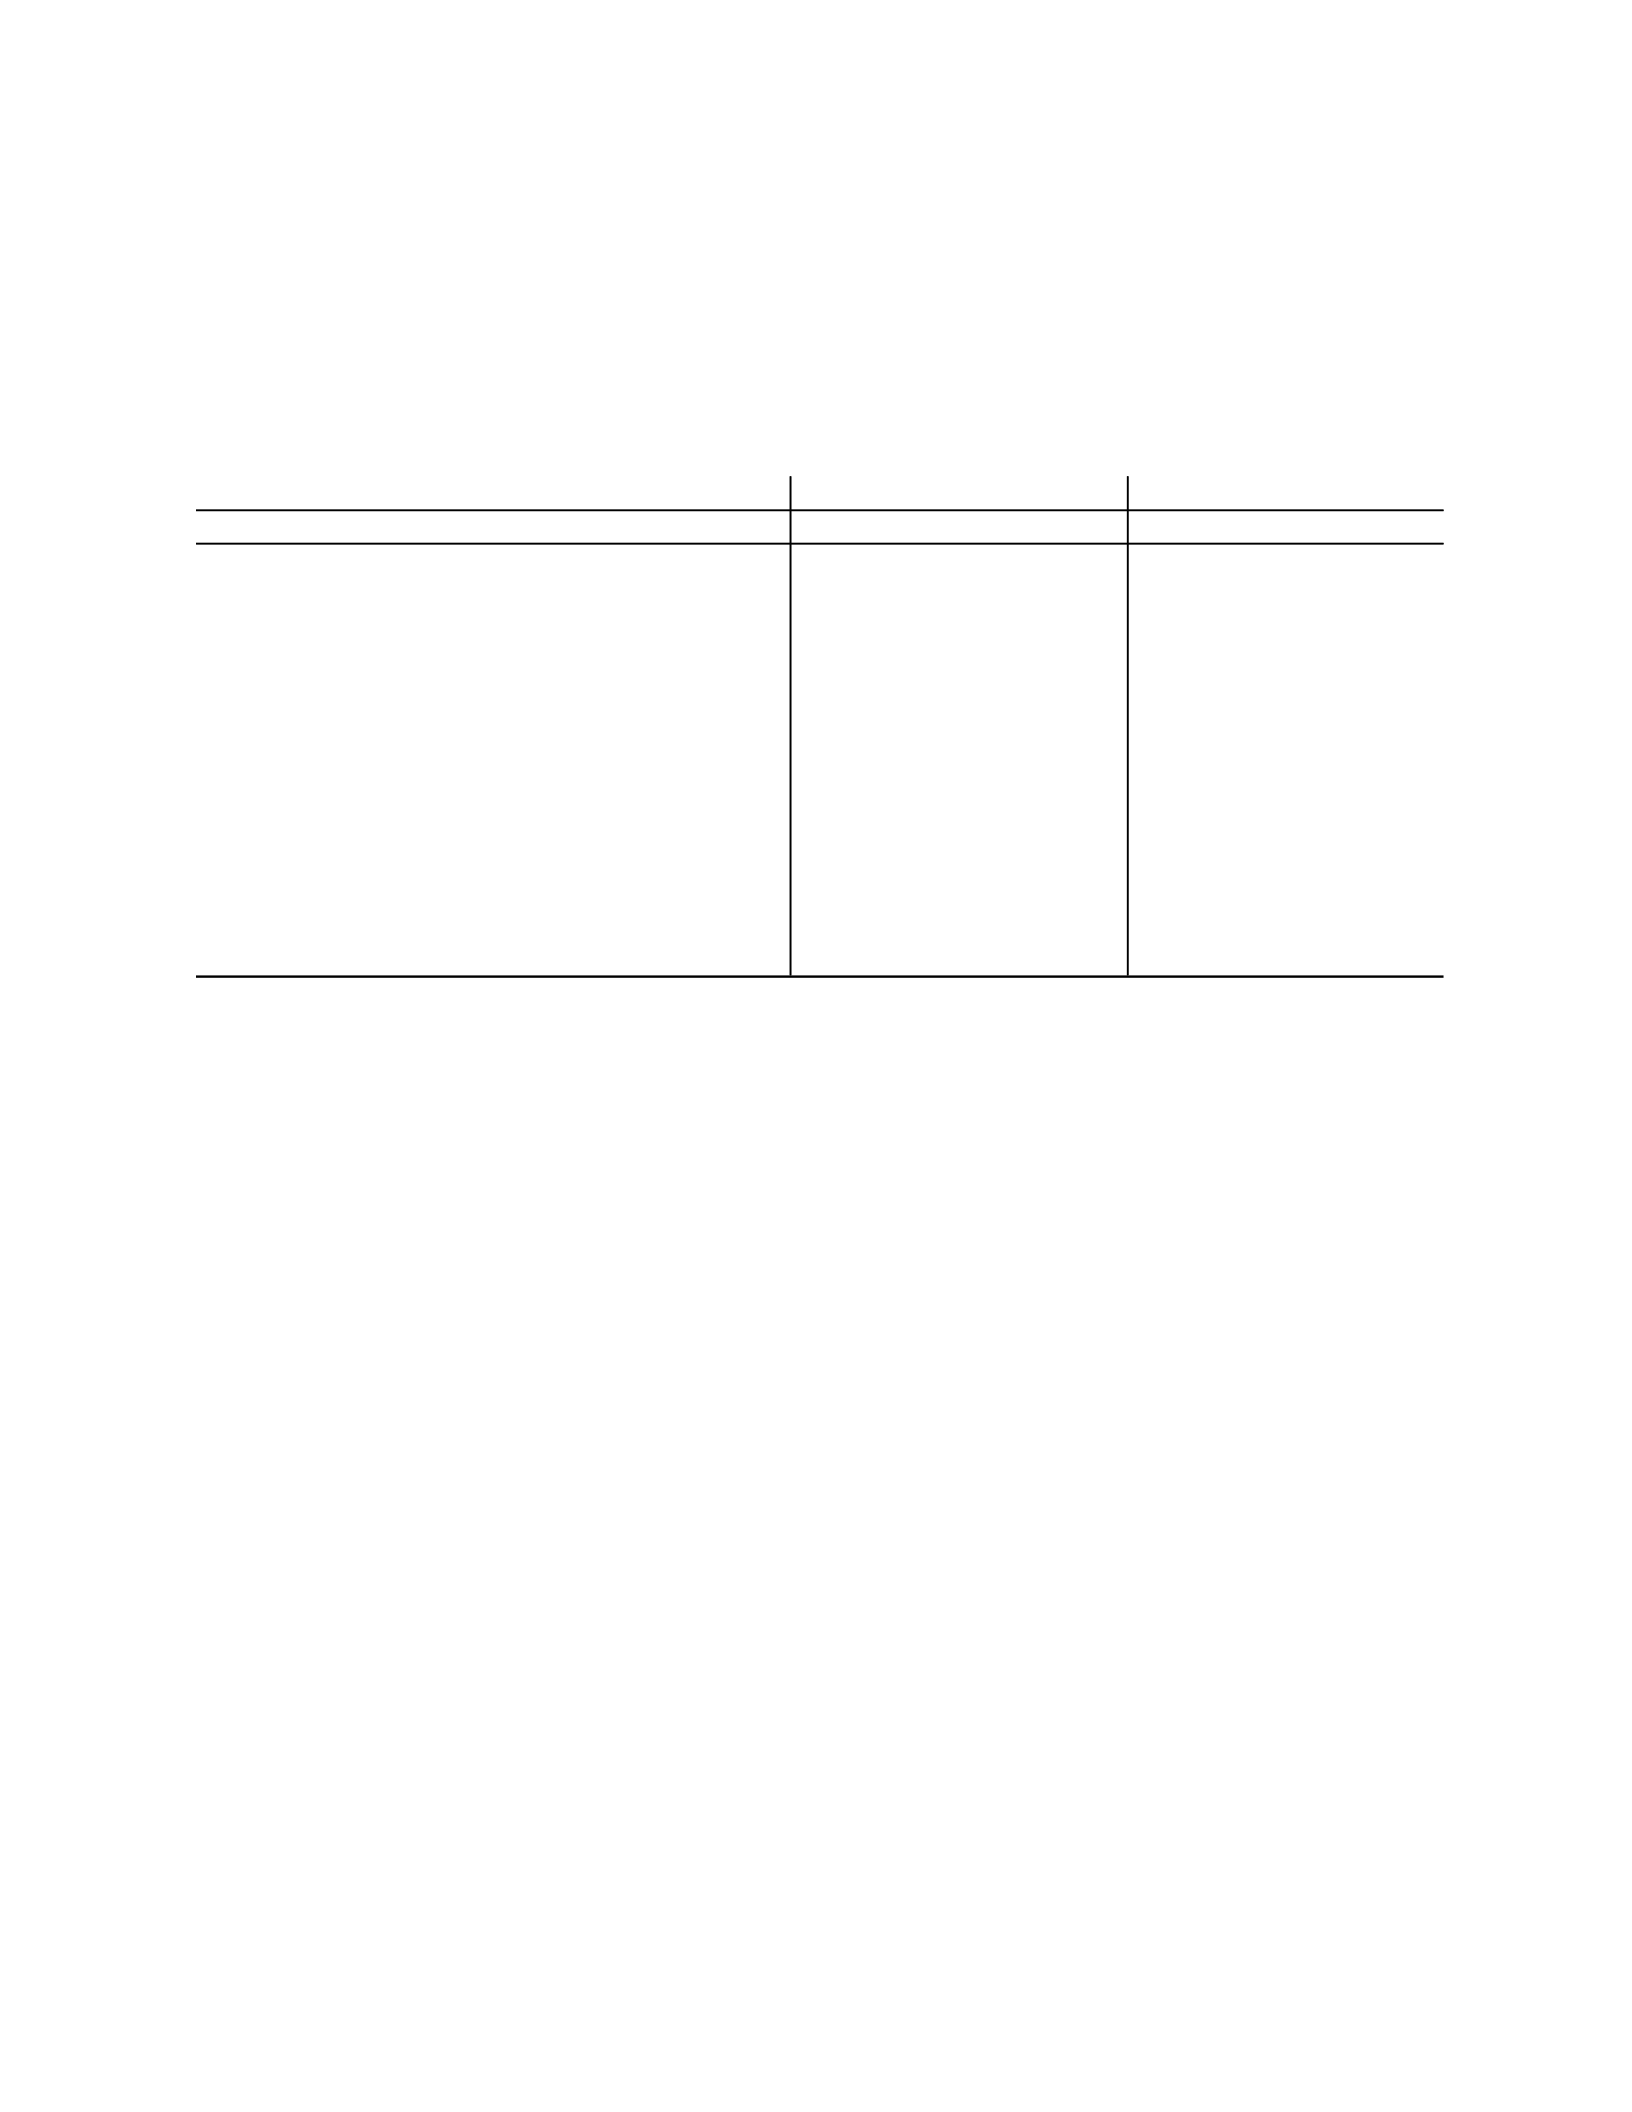
37
deviation of 27.87. From an investment standpoint, the index price is not as important as the
change in said price over time, or, the returns of the index in question. A larger version of this
figure is provided in Appendix H. Table 2 displays the daily simple return descriptive statistics
Table 2: Daily and Annual Descriptive Statistics
and the geometric annual return descriptive statistics for the AG Index and the two comparison
indices. As expected, daily and annual return calculations for the AG Index were less than that of
the comparison “market” indices while the AG Index daily and annual price variability,
measured by standard deviation, was lower than that of the comparison indices.
4.2 Annual, Five and Ten-Year Geometric Returns
The index of agribusiness stocks shows similar long-term returns to those of the two comparison
indices. Appendix I contains the annual geometric returns for the AG Index and the two
comparison indices for the period of 1970 to 2008. These results show that the values of these
three indices on average from year to year move together. The signs on the return values of the
three indices are identical for 26 of the 39 years of the study. Of the 13 years when the signs
differ, six differ only between the AG Index and one of the comparison indices. The relationship
between the AG Index and the comparison indices is better illustrated in graphical form. Figure 2
shows the annual geometric returns of AG Index and the S&P 500 for the period of 1970 to
Daily Annual Daily Annual Daily Annual
Mean 0.00005 0.01273 0.00029 0.06495 0.00030 0.07476
Standard Error 0.00010 0.02605 0.00011 0.02768 0.00011 0.02655
Median 0.00027 0.02894 0.00039 0.07136 0.00033 0.07179
Mode 0 0 0 0 0 0
Standard Deviation 0.01040 0.16265 0.01056 0.17284 0.01066 0.16581
Sample Variance 0.00011 0.02646 0.00011 0.02987 0.00011 0.02749
Kurtosis 16.86589 0.22506 22.84198 -0.04035 27.87884 -0.23721
Skewness -0.87764 -0.12207 -0.73049 -0.54564 -0.86131 -0.49628
Range 0.26245 0.74971 0.32047 0.71742 0.33691 0.67583
Minimum -0.15904 -0.36769 -0.20467 -0.37585 -0.22610 -0.32717
Maximum 0.10340 0.38202 0.11580 0.34157 0.11080 0.34866
Sum 0.49295 0.49643 2.82639 2.53315 2.94795 2.91576
Count 9845 39 9845 39 9845 39
AG Index Descriptive Statistics
S&P 500 Descriptive Statistics
DOW Descriptive Statistics
38
Figure 2: Annual Geometric Return, AG Index and the S&P 500 (1970-2008)
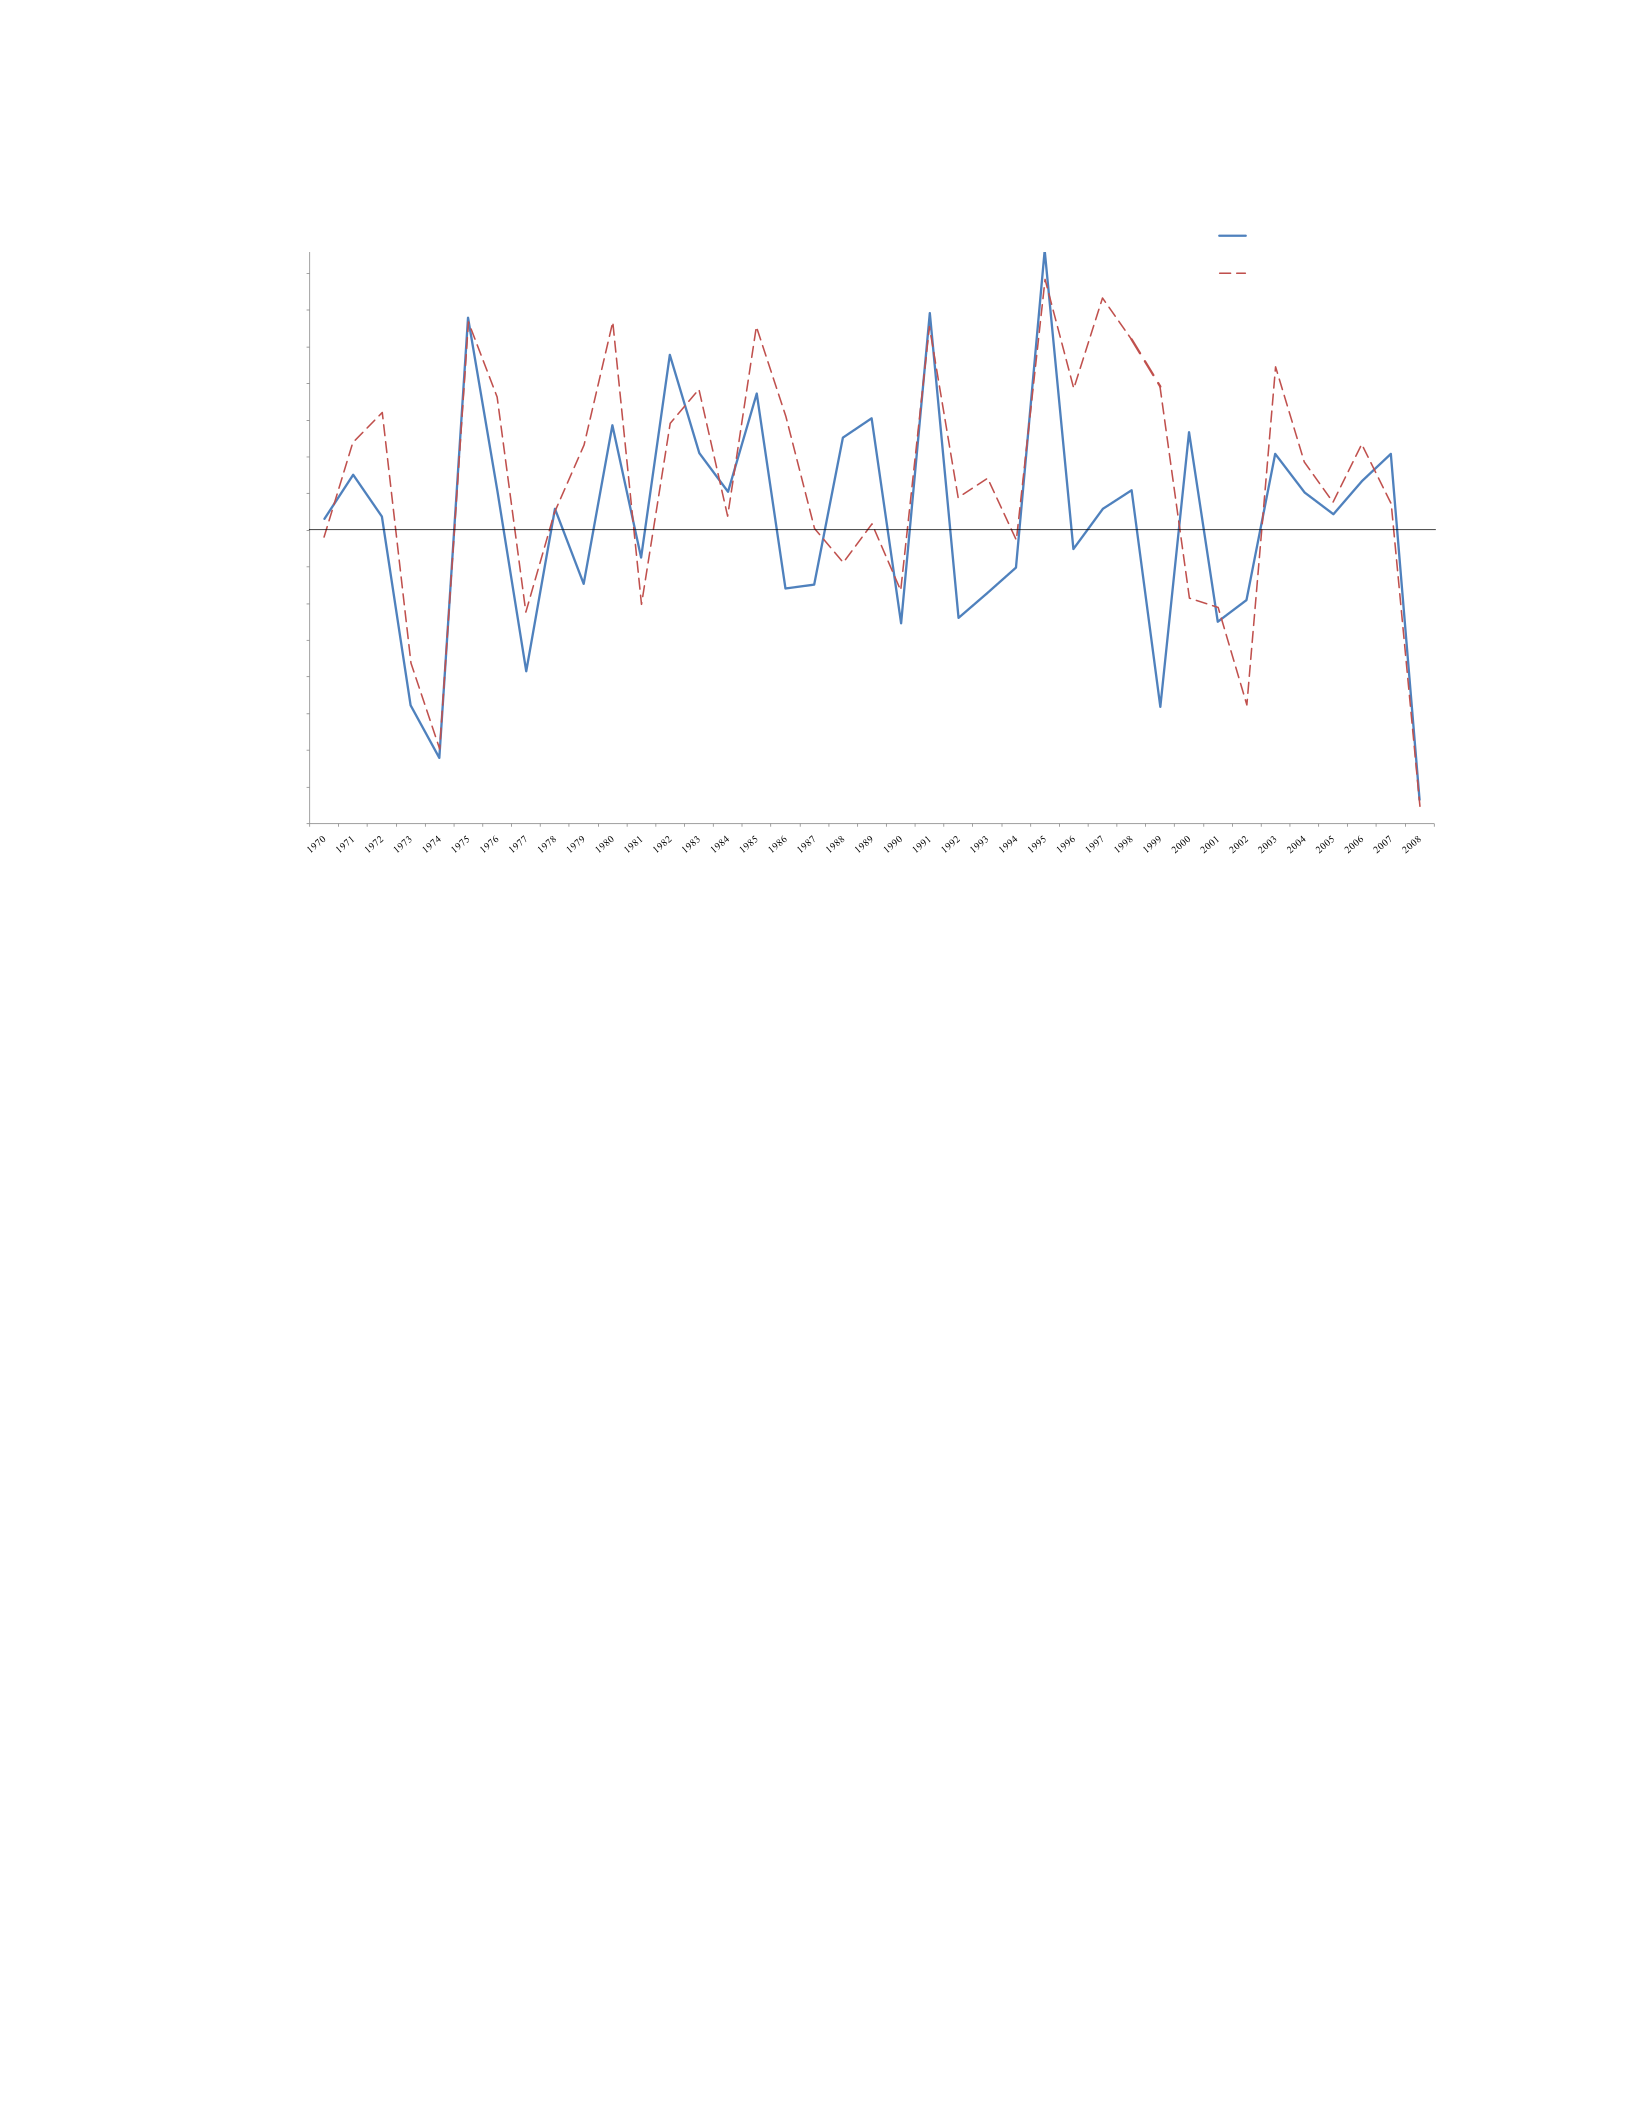
2008. The solid series is the annual geometric returns of the AG Index and the long dashed series
is the annual geometric returns of the S&P 500. It is clear that the two indices follow each other
closely, with a few exceptions. The periods of 1987 to 1990, 1992 to 1995, and 1997 to 2000 are
periods where the two series diverge. It is unclear what the cause of the divergence is, but it is
hypothesized that macroeconomic effects or agricultural sector specific effects are to blame.
Further extensions of this research should attempt to determine the effects of agriculture specific
indicators and macroeconomic factors (gross domestic product, inflation, and the value of the US
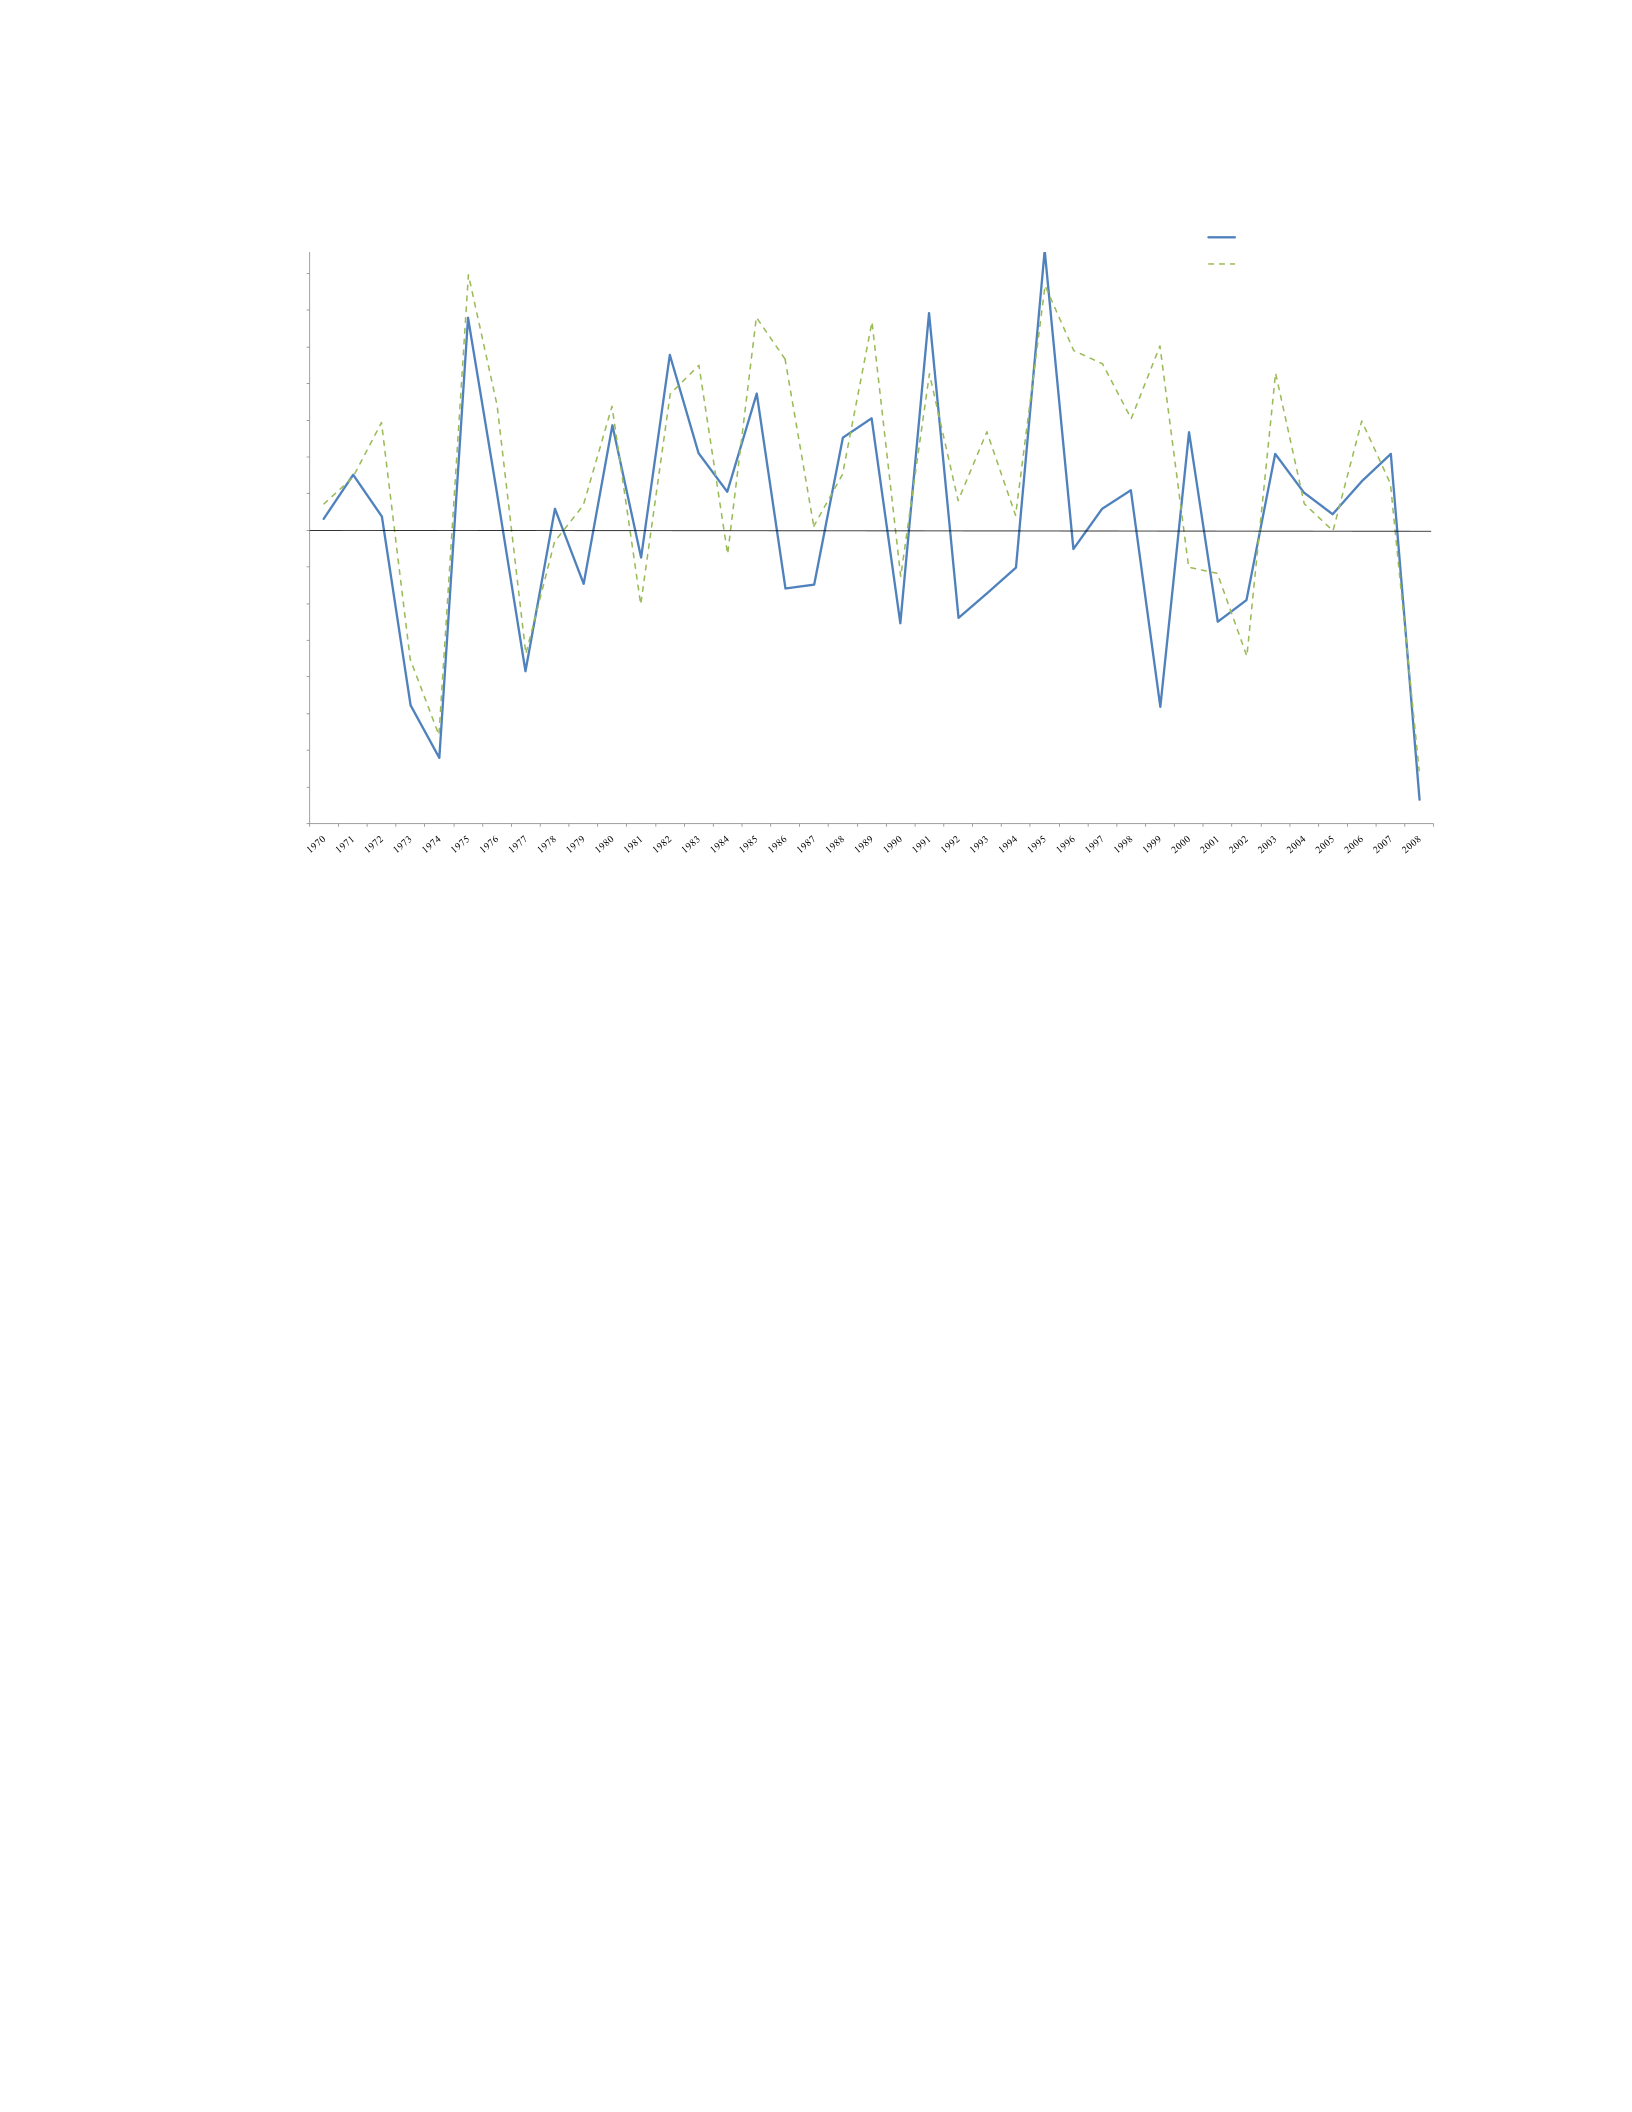
dollar) on the value of the AG Index. Figure 3 shows the annual geometric returns of AG Index
and the Dow Jones Industrial Average (DOW) for the period of 1970 to 2008. The short dashed
series is the annual geometric return for the DOW index and the solid series is the annual
geometric return of the AG Index. It is clear from the graph that the AG Index and the DOW
geometric return series follow each other closely with only two exceptions. During the periods of
-40%
-35%
-30%
-25%
-20%
-15%
-10%
-5%
0%
5%
10%
15%
20%
25%
30%
35%
AG Index -Geometric Return
S&P 500 - Geometric Return
39
Figure 3: Annual Geometric Return, AG Index and the Dow Jones Industrial Average (1970-
2008)
1992 to 1994 and 1999 to 2002, the two return series diverge. Again, it is hypothesized that
macroeconomic effects or agricultural sector specific effects are the cause of the divergence.
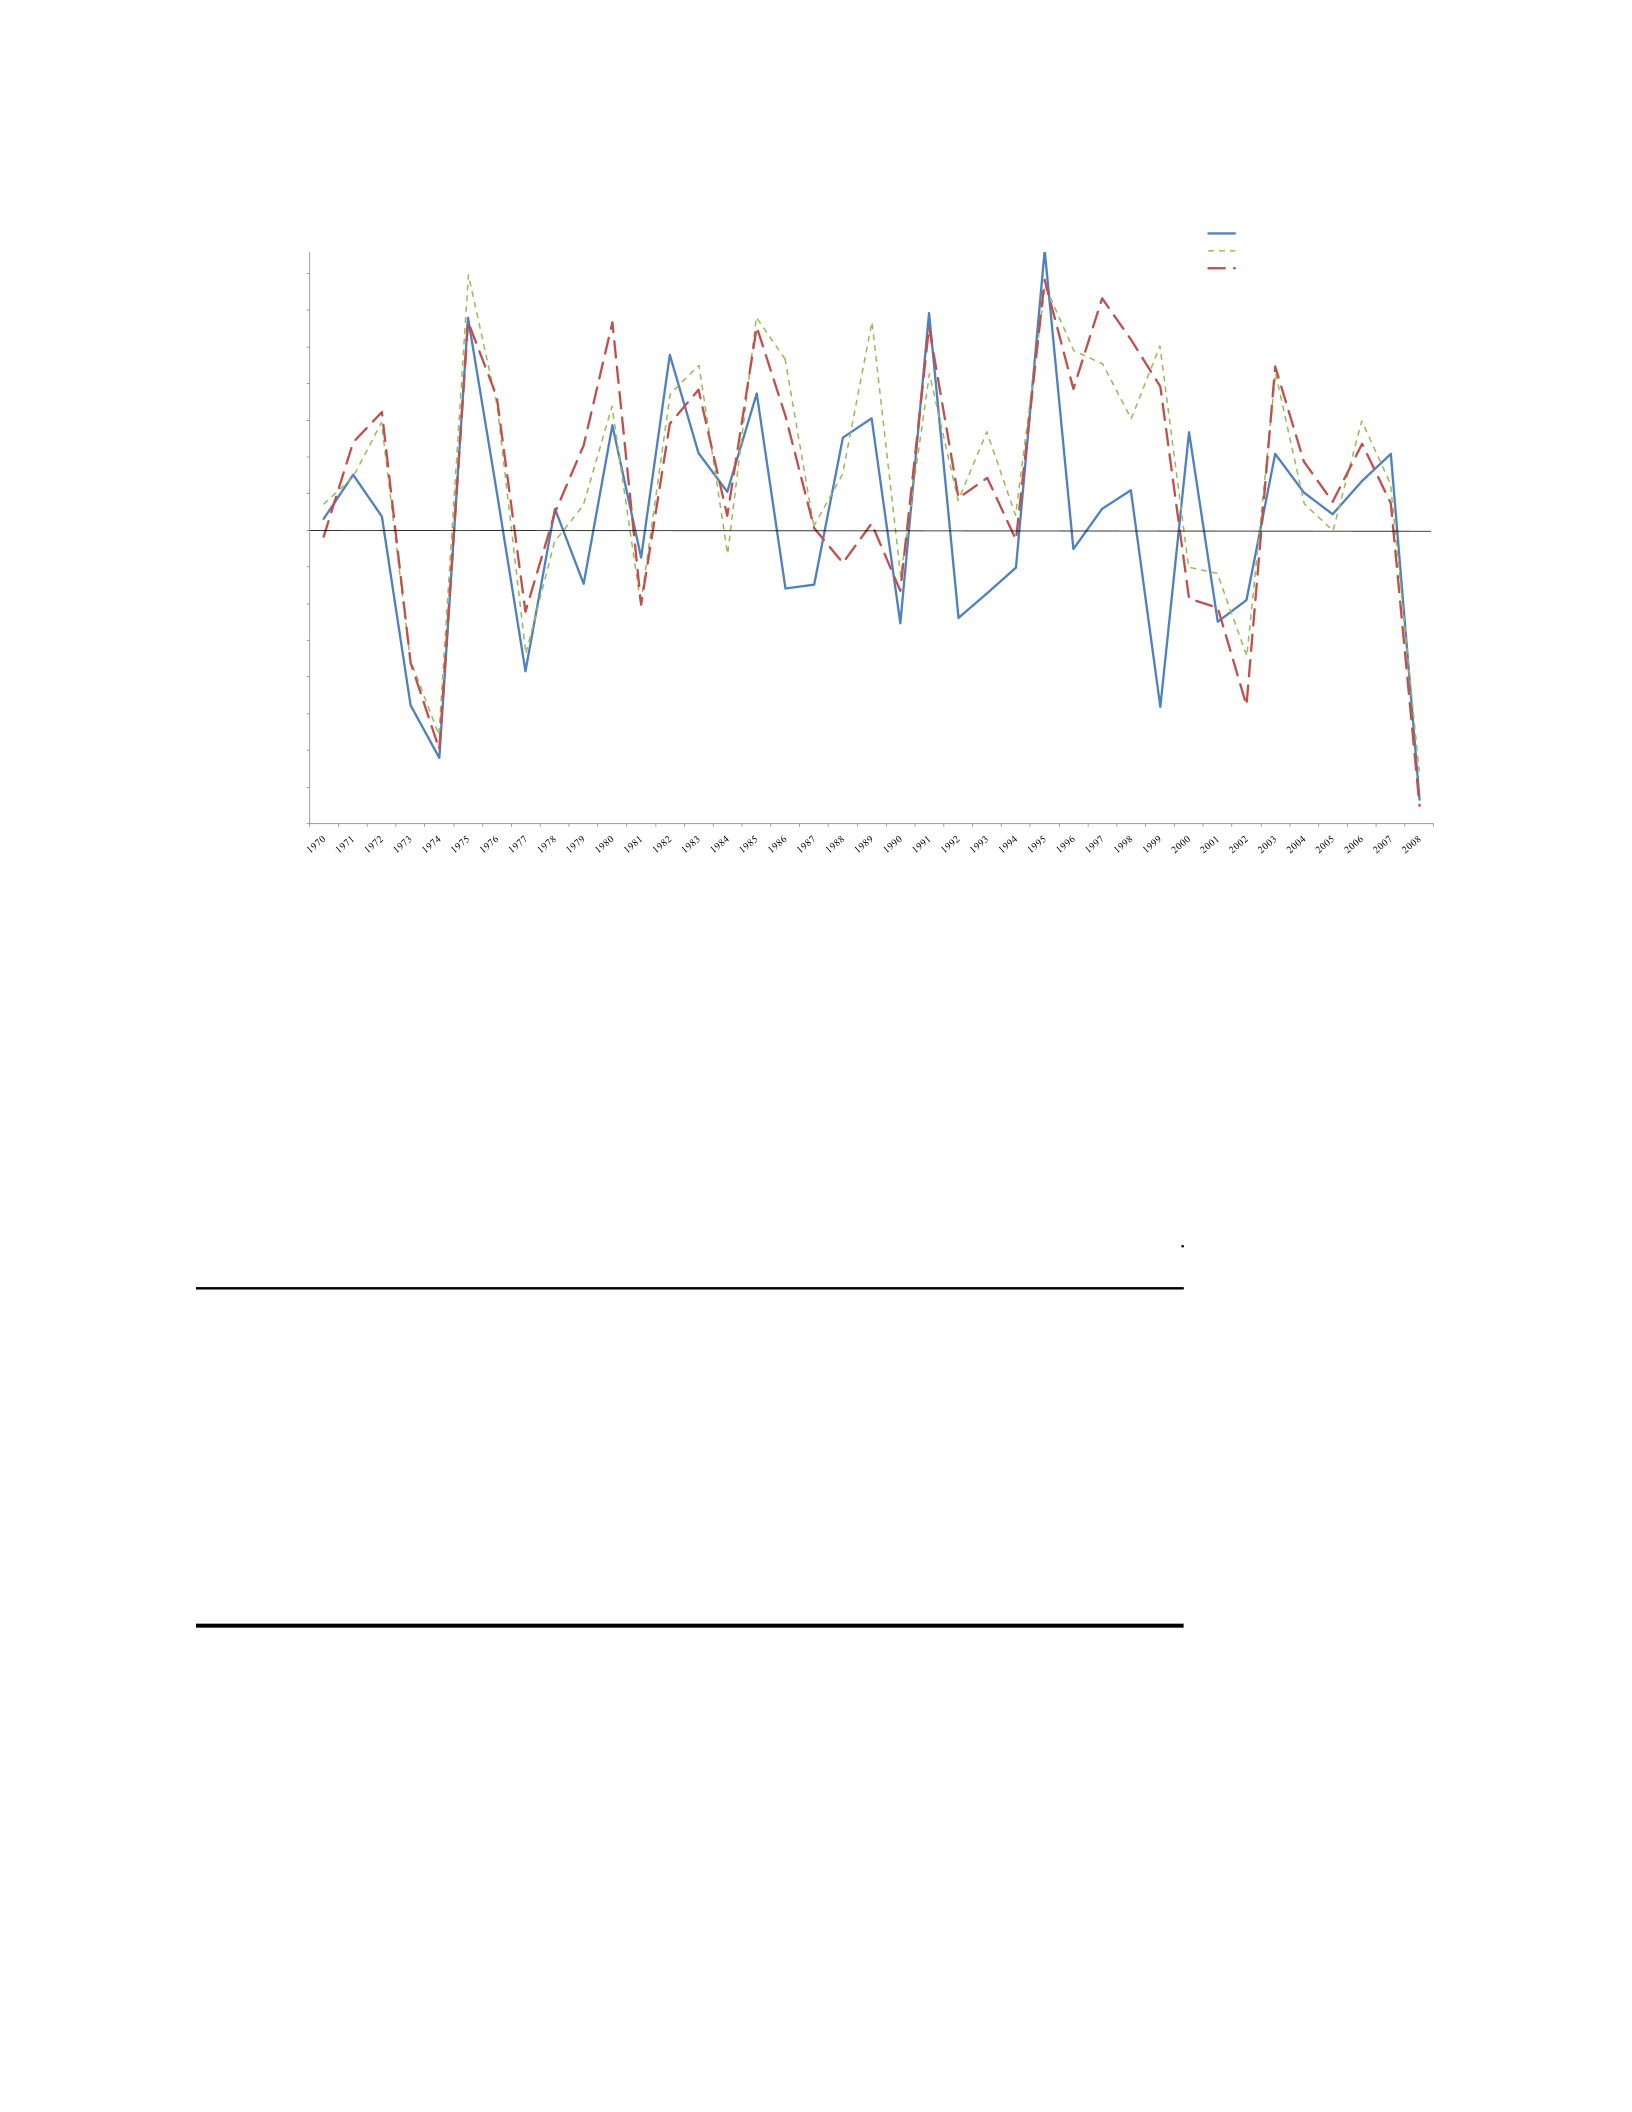
Figure 4 shows the annual geometric returns for the period 1970 to 2008 for the AG Index and
both of the comparison indices. It is clear from the graph that the three indices follow each other
with the exception of two periods. The periods of 1992 to 1994 and 1996 to 2000 show a clear
divergence between the three series. Specifically, the AG Index annual geometric returns are
lower than that of the two comparison indices during these periods. For a better look at the long-
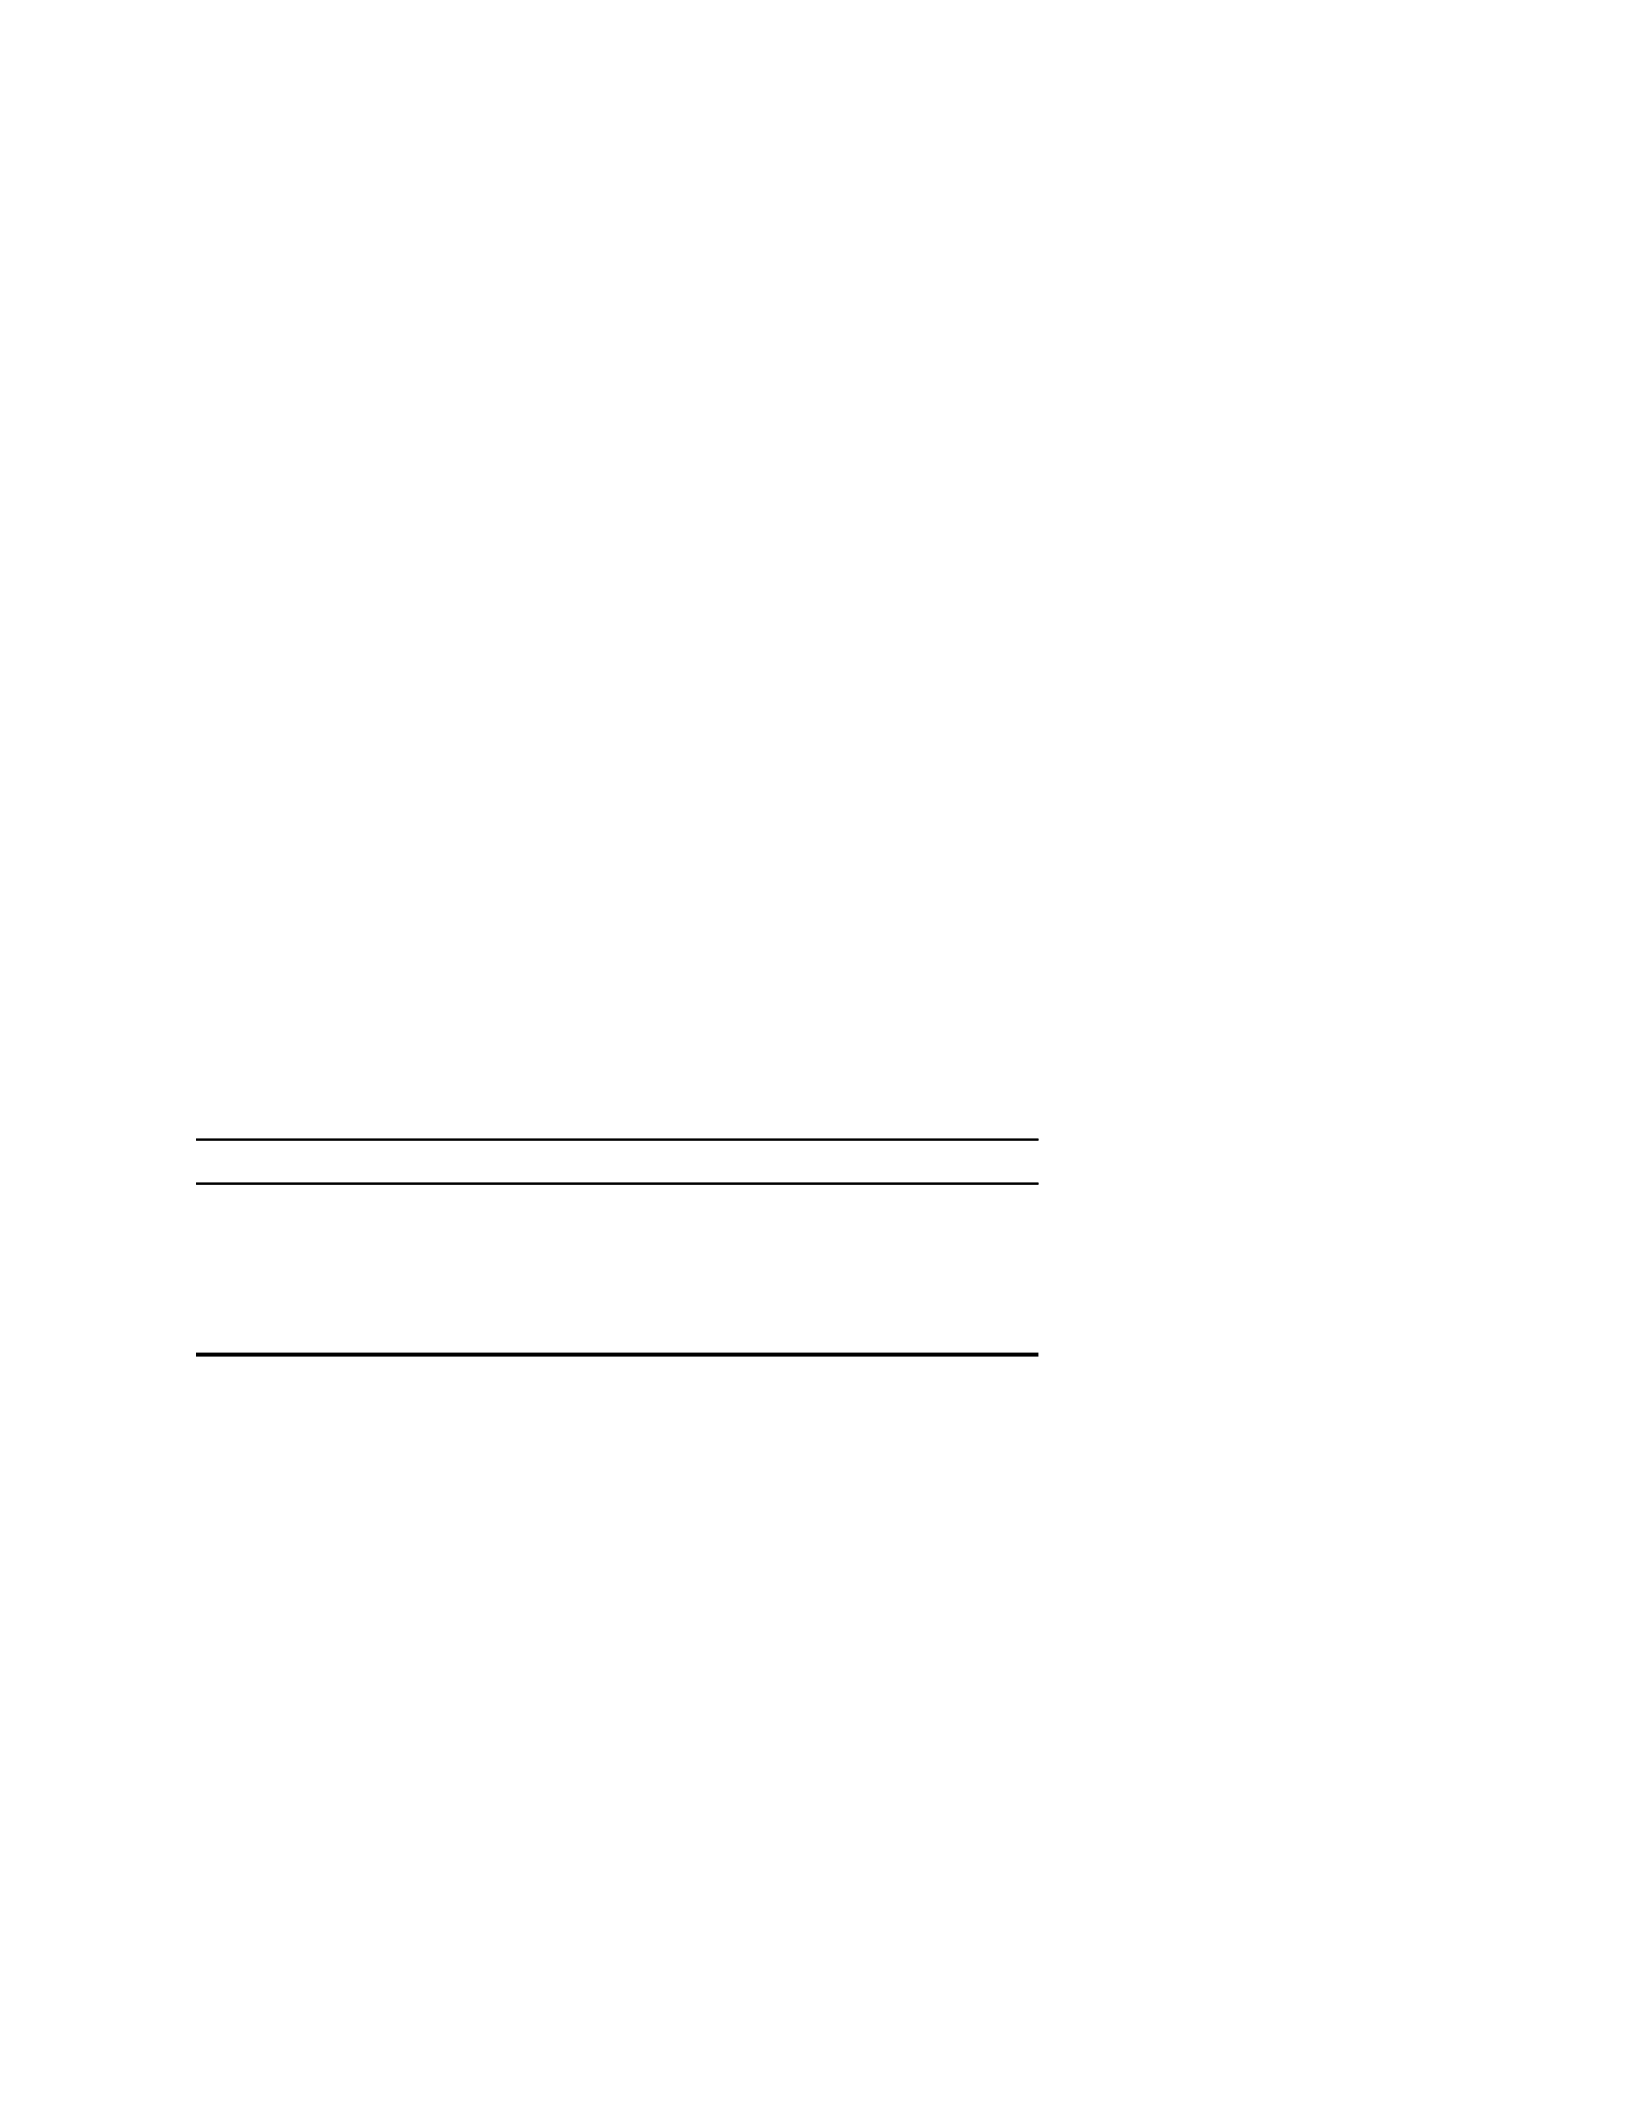
term performance of the AG Index, the return series was split in to five and ten-year holding
return periods. Table 3 contains the numerical value of the five-year holding period return for
AG Index and the comparison indices. Bolded values indicate five-year periods where the AG
Index outperformed both of the market indices and asterisked values indicate five-year periods
where the AG Index outperformed only one of the market indices. With the exception of two 5-
-40%
-35%
-30%
-25%
-20%
-15%
-10%
-5%
0%
5%
10%
15%
20%
25%
30%
35%
AG Index -Geometric Return
Dow Jones - Geometric Return
40
Figure 4: Annual Geometric Return, AG Index, S&P 500, and the Dow Jones Industrial Average
(1970-2008)
year periods (1990 to 1994 and 2000 to 2004), the three indices have identical signs. During the
2000-2004 period of divergence the AG Index, showed positive returns while the two
Table 3: Five-Year Geometric Returns, 1970-2008
comparison indices showed negative returns. The AG Index outperformed at least one of the
market indices three of the eight 5-year holding periods (1980-1984, 2000-2004, and 2005-
2008). Only in the 2000-2004 5-year holding period did the AG Index showed higher returns
than both of the comparison indices. For the period of 2005 to 2008, the AG Index showed less
-40%
-35%
-30%
-25%
-20%
-15%
-10%
-5%
0%
5%
10%
15%
20%
25%
30%
35%
AG Index -Geometric Return
Dow Jones - Geometric Return
S&P 500 - Geometric Return
Return Periods AG Index S&P 500 Dow Jones
1970-1974 -10.16246% -5.82437% -5.40806%
1975-1979 0.91591% 9.05409% 5.94676%
1980-1984 9.67176%* 9.95148% 8.12703%
1985-1989 5.64102% 7.37845% 17.19192%
1990-1994 -2.84233% 5.30378% 6.50936%
1995-1999 2.12043% 26.02835% 24.07875%
2000-2004 0.86133% -3.72495% -1.40965%
2005-2008 -6.59831%* -6.90884% -4.80796%
41
negative returns than that of the S&P 500 index at -6.59 to -6.91 percent respectively. The largest
divergence observed was during the period of 1995 to 1999 where the spread between the AG
Index and the S&P 500 and the DOW was 23.91 percent and 21.96 percent respectively. The
period of 1995 to 1999 saw tremendous growth in the general market, yet the AG Index did not
experience the same growth. Recent results suggest that investor interest in the US Agriculture
sector is justifiable as the most recent 5-year periods show the AG Index outperforming the
market. The ten-year holding period returns for the AG Index and the two comparison indices
show similar characteristics and are given in Table 4. The AG Index failed to outperform the
comparison indices in all but one of the four ten-year periods. The most recent decade of data
showed the AG Index in negative growth (-2.53 percent) though, the market indices were down
further (S&P 500 at -5.15 percent and the DOW at -2.93 percent). Three of the four periods
showed negative returns for the AG Index while the comparison indices showed negative returns
Table 4: Ten-Year Geometric Returns, 1970-2008
in only one of the four periods. The only ten-year period of positive AG Index returns was 1980
to 1989 at 7.64 percent, though this trailed behind the returns of the S&P 500 and the DOW at
8.66 and 12.57 percent respectively. Graphs of the five and ten-year geometric returns are
provided in Appendix J, K, L, and M.
4.3 Risk Comparisons
Appendix N contains the annual standard deviation results for the AG Index and the comparison
indices for the period of 1970 to 2008. Peak annual AG Index price variability was recorded in
Return Periods AG Index S&P 500 Dow Jones
1970-1979 -4.784259% 1.34218% 0.108491%
1980-1989 7.637525% 8.65735% 12.568268%
1990-1999 -0.391852% 15.20096% 14.958898%
2000-2008 -2.524920% -5.15324% -2.934733%
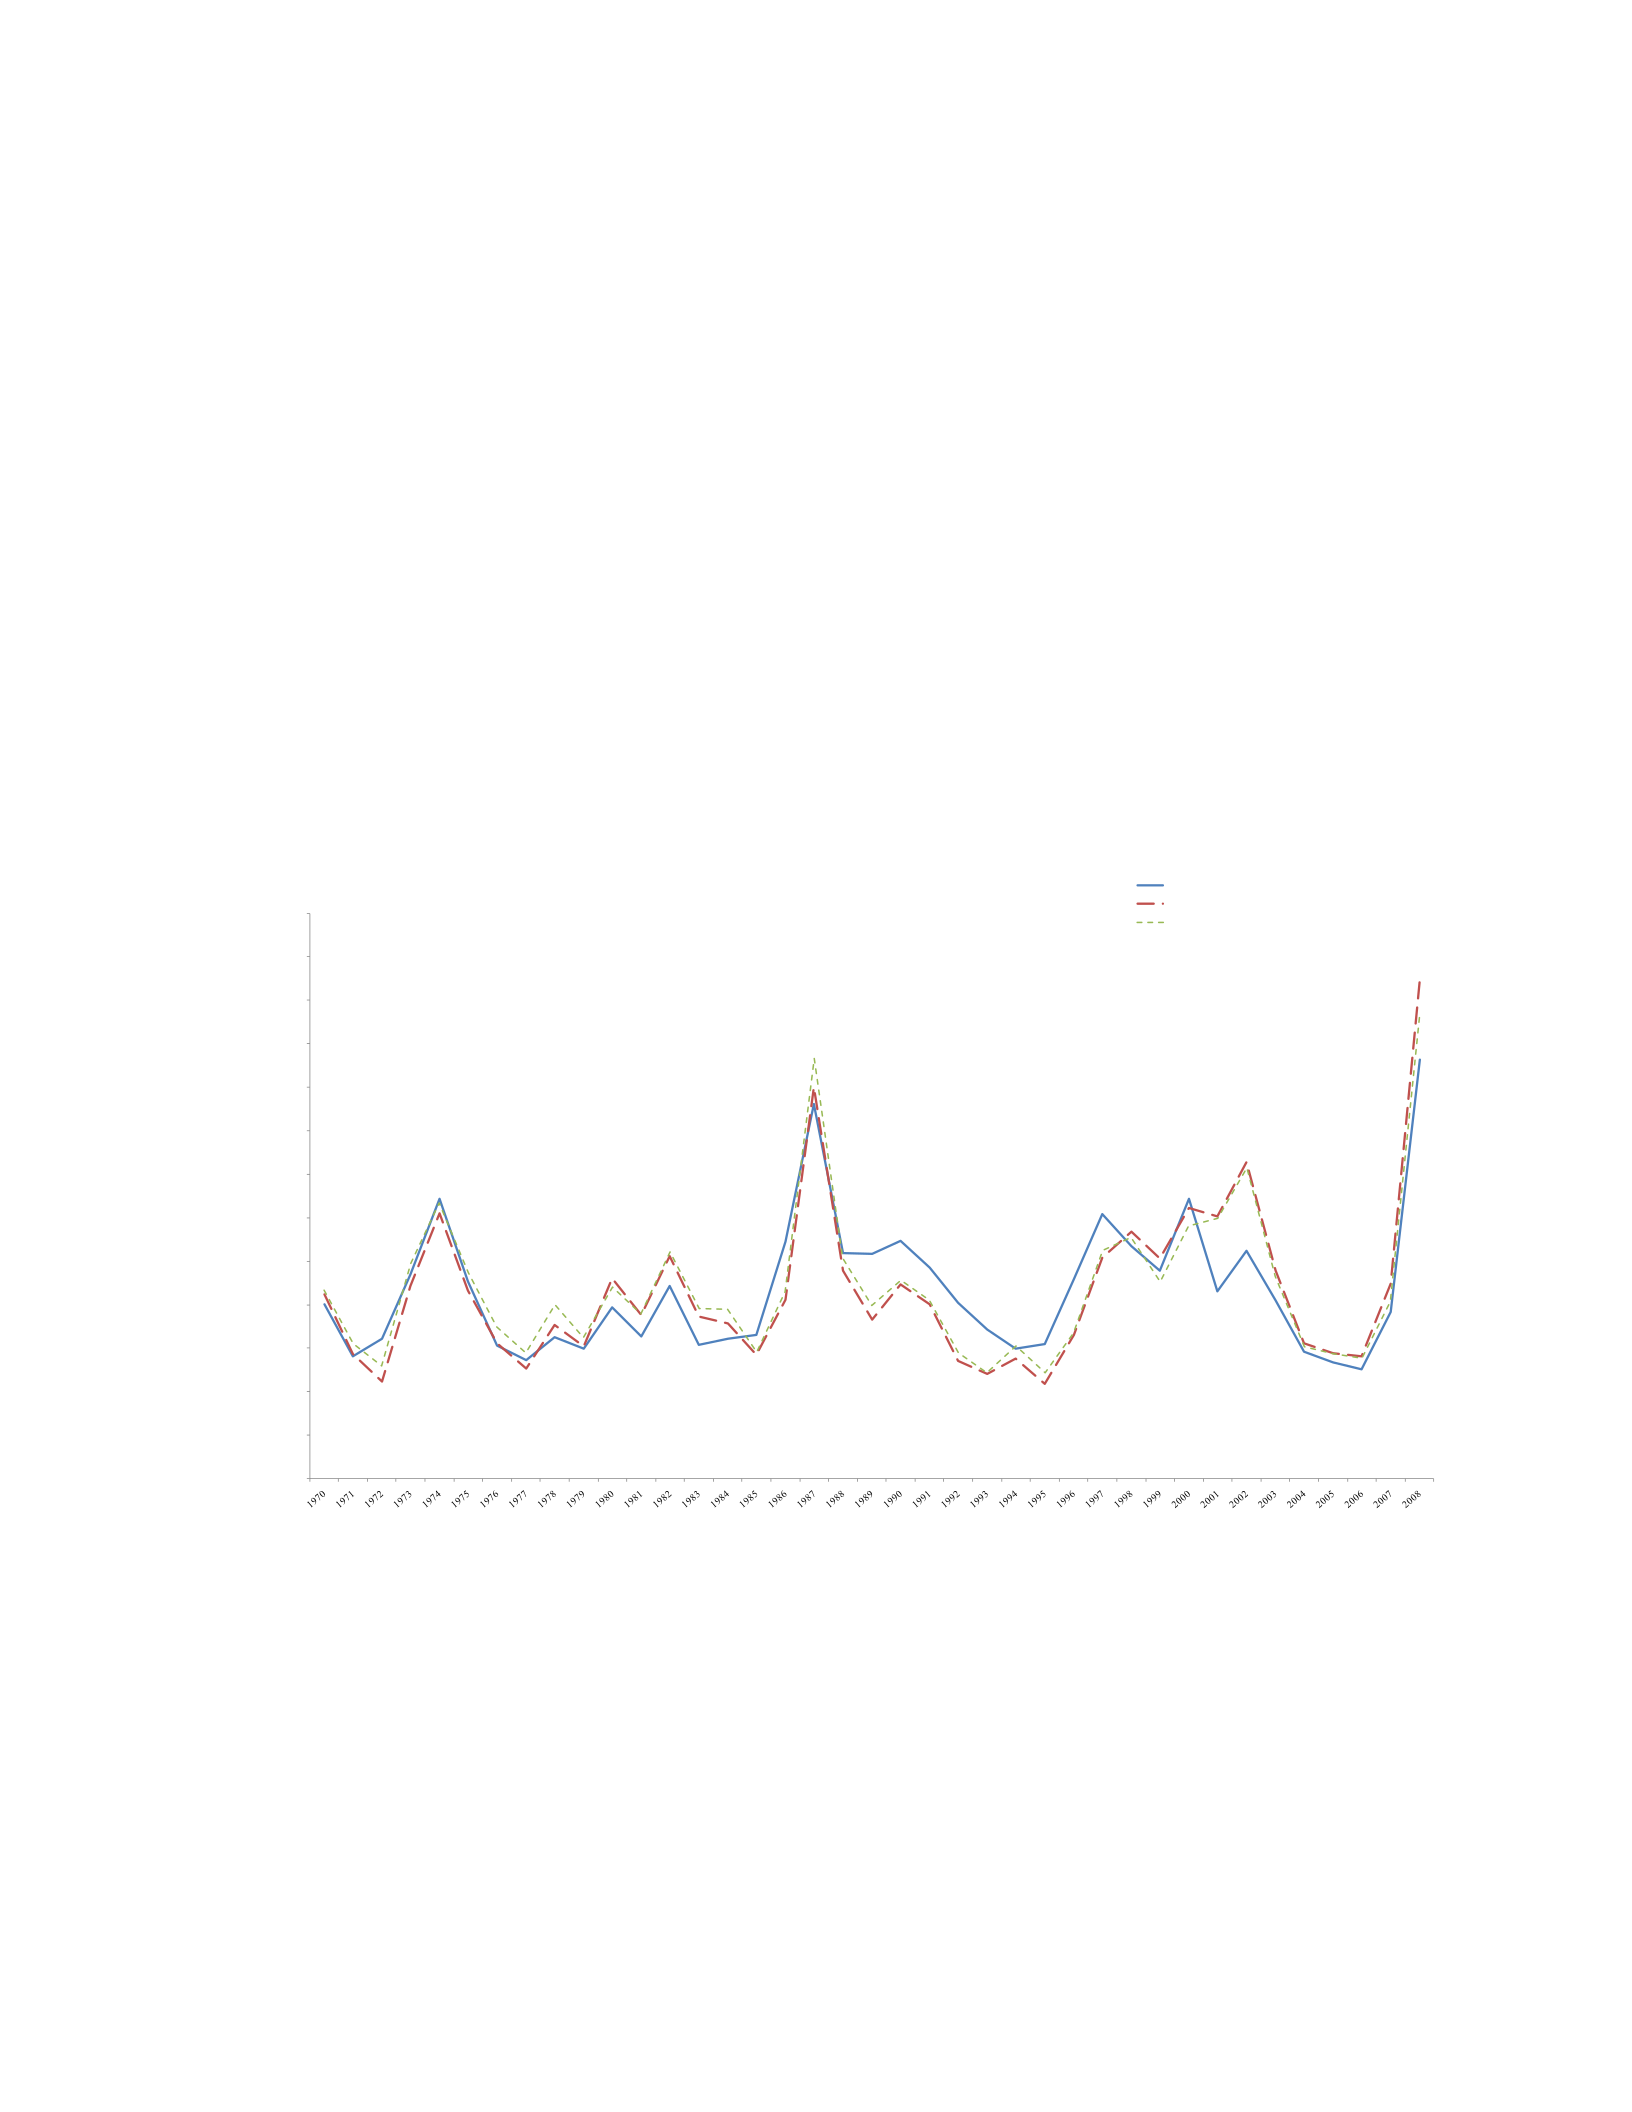
42
2008 at 2.167 percent, though this was lower than the S&P 500 and the DOW indices, which
were 2.58 and 2.39 percent, respectively. The lowest annual AG Index price variability was
recorded in 2006 at 0.57 percent, while the standard deviation for the S&P 500 and DOW were
0.63 and 0.62 respectively. Both the peak and lowest price variability numbers show that the AG
Index carried less price variability than that of the comparison indices. However, Figure 5 shows
that this trend was not true for the entire 1970 to 2008 period. The solid series represents the
annual standard deviation for the AG Index while the large dashed and small dashed lines
represent the S&P 500 and the DOW, respectively. The graph shows that the price variability of
the AG Index closely follows that of the comparison indices during the 1970’s but deviated from
Figure 5: Annual Standard Deviation, AG Index, S&P 500, and the Dow Jones Industrial
Average (1970-2008)
them during the early 1980’s. From 1978 to 1985, the AG Index showed less price risk than both
of the comparison indices did. The sharp increase in price variability during the late 1980’s was
felt equally across all three indices though the persistence of the risk was longer for the AG
0.0000%
0.2250%
0.4500%
0.6750%
0.9000%
1.1250%
1.3500%
1.5750%
1.8000%
2.0250%
2.2500%
2.4750%
2.7000%
2.9250%
AG Index -Standard Deviation
S&P 500 - Standard Deviation
Dow Jones Industrial Average -Standard Deviation
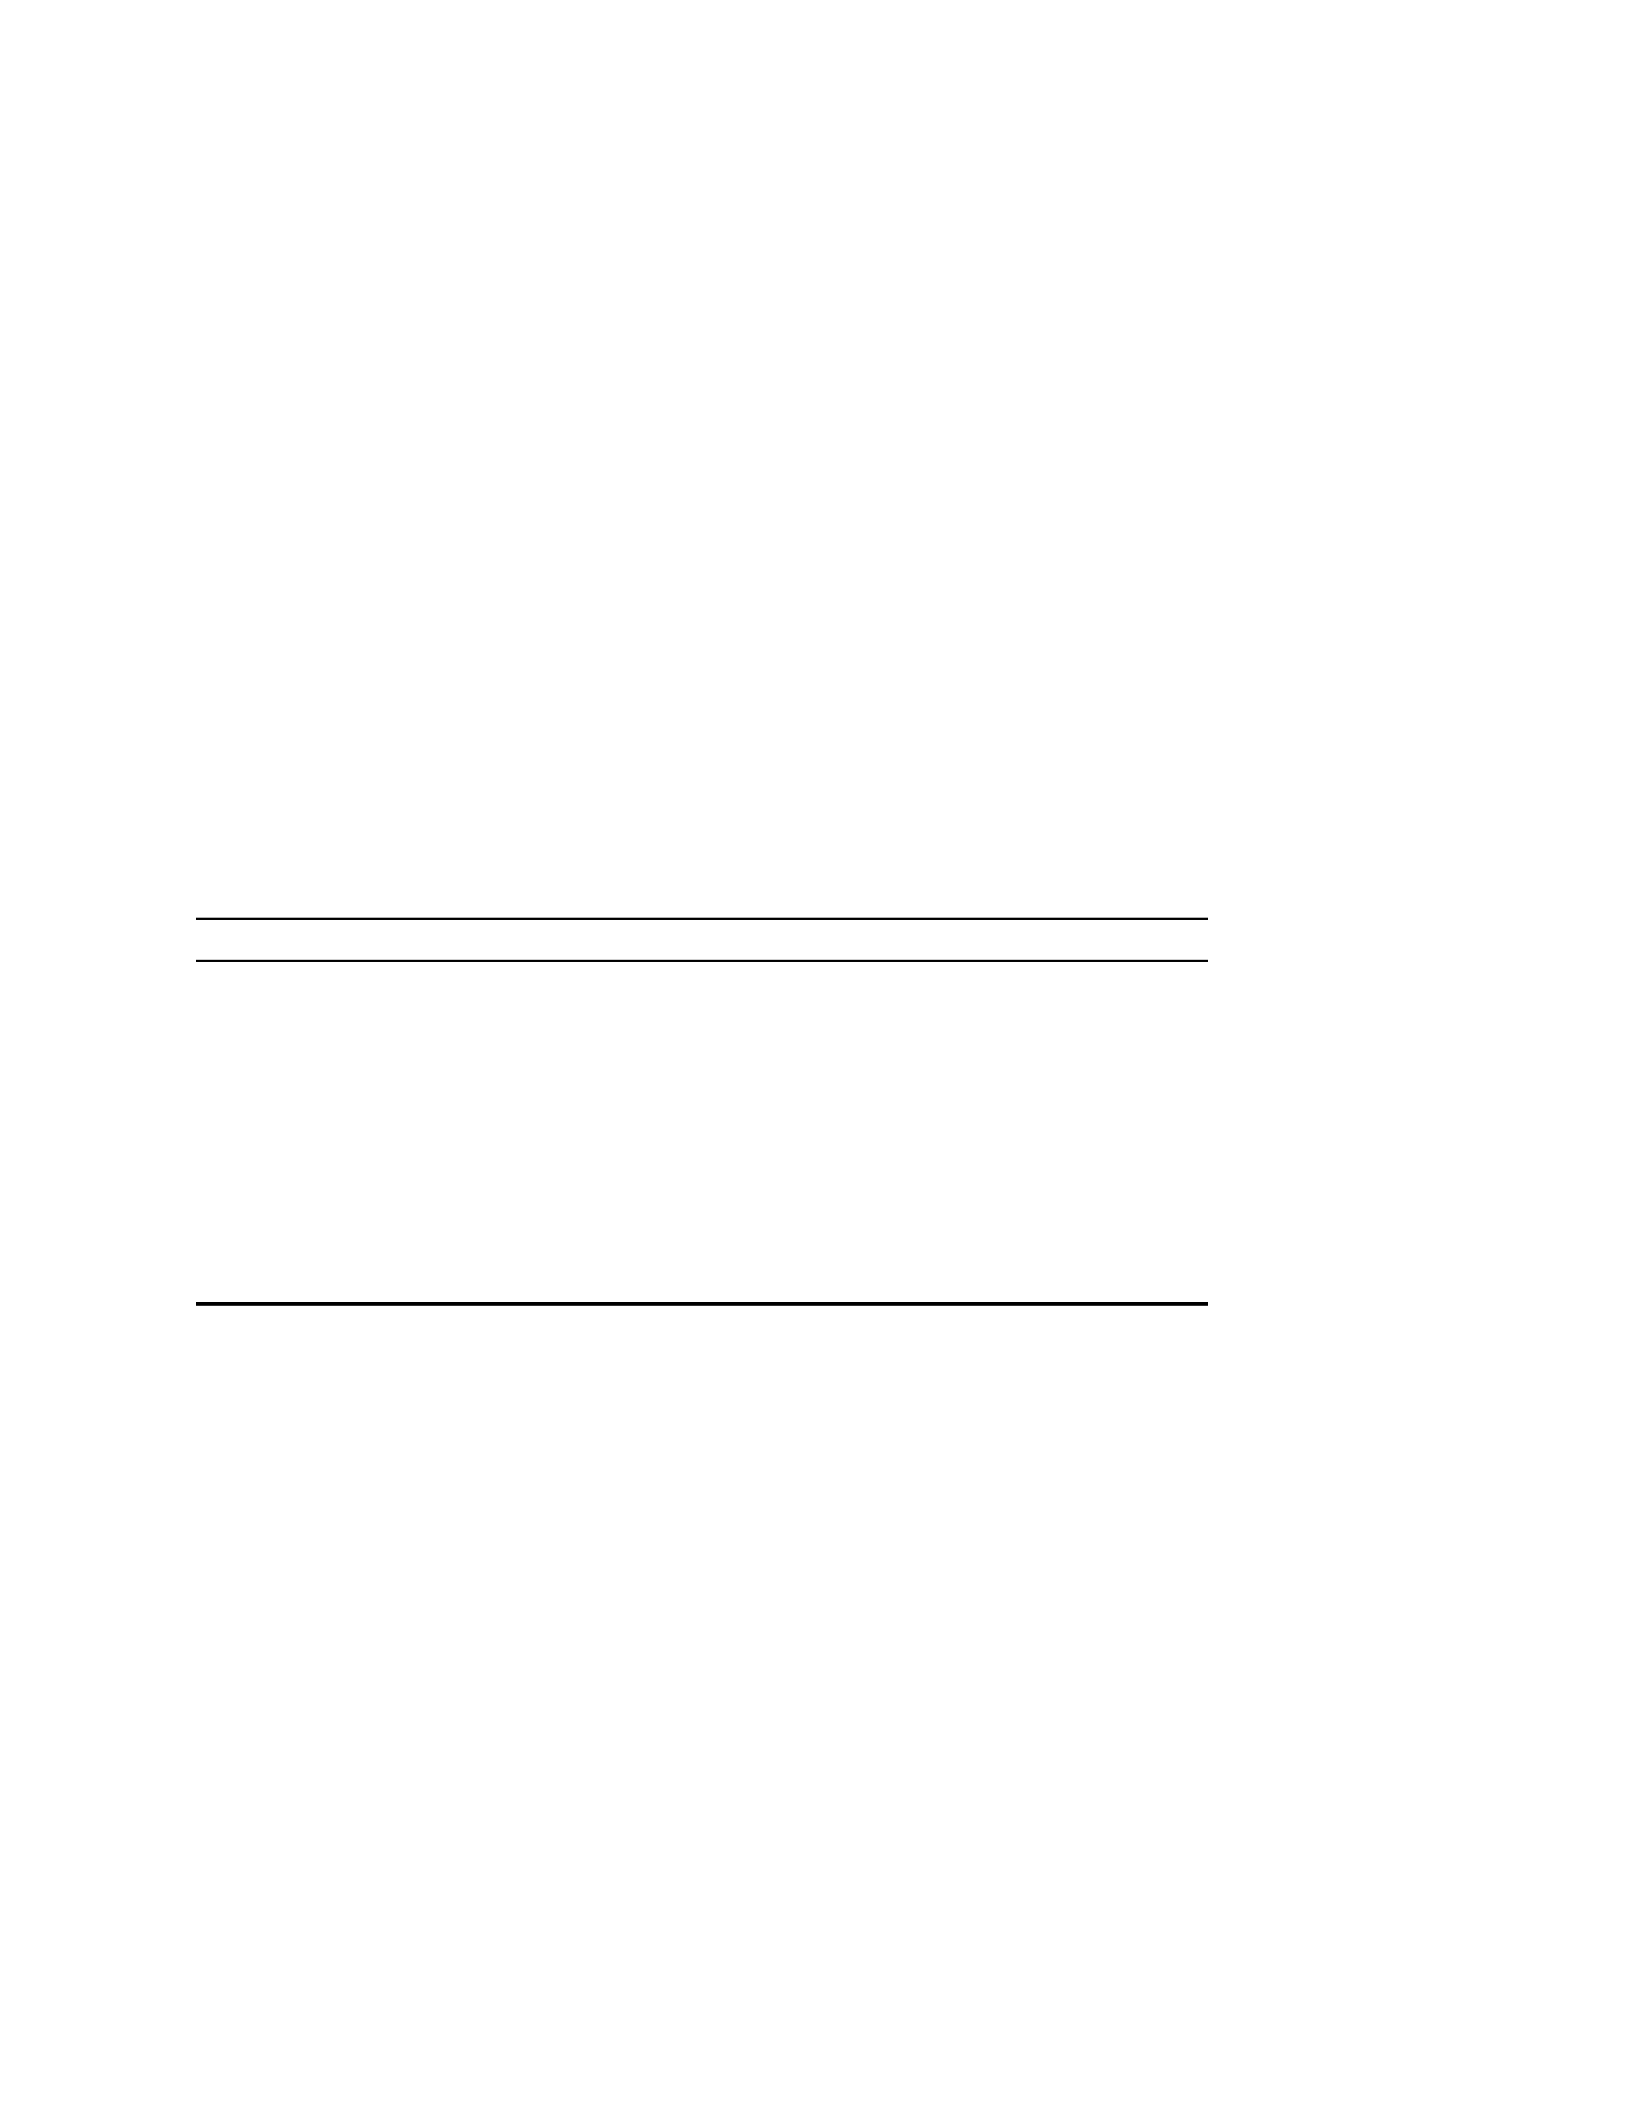
43
Index. This trend of higher AG Index variability continued in to the late 1990’s. From 2001 to
the end of the data period in 2008, the AG Index has shown to carry less price variability
indicating that the AG Index may be a safer investment than a general market based index. To
get a closer look at the story of price risk among the three indices in question, standard deviation
measures were calculated for five and ten-year holding periods. Table 5 contains the standard
deviation calculations for the AG Index and the two comparison indices. Bolded values indicate
a five-year period in which the AG Index showed less price variability than both of the
comparison indices did and an asterisked value indicated a five-year period when the AG Index
showed less price variability than one of the comparison indices. The AG Index showed less
Table 5: Five-Year Standard Deviation 1970-2008
price variability than at least one of the comparison indices in five of the eight five-year periods
and less than both comparison indices in three of five of those periods. Table 6 contains the ten-
year period standard deviation measures for the three indices. Again, bolded values indicate a
ten-year period in which the AG Index showed less price variability than both of the comparison
indices and an asterisked value indicated a ten-year period when the AG Index showed less price
variability than one of the comparison indices. The AG Index showed to have less price
variability than at least one of the comparison indices in three of the four ten-year periods.
During the most recent period, 2000 through 2008, the AG Index showed less price variability
Periods AG Index S&P 500 Dow Jones
1970-1974 1.00025%* 0.95185% 1.01169%
1975-1979 0.75790%* 0.75410% 0.83770%
1980-1984 0.81340% 0.94395% 0.96045%
1985-1989 1.30862% 1.20152% 1.28085%
1990-1994 0.95213% 0.75036% 0.78071%
1995-1999 1.10918% 1.01207% 0.99278%
2000-2004 1.05832% 1.26754% 1.23033%
2005-2008 1.24574% 1.46630% 1.36315%
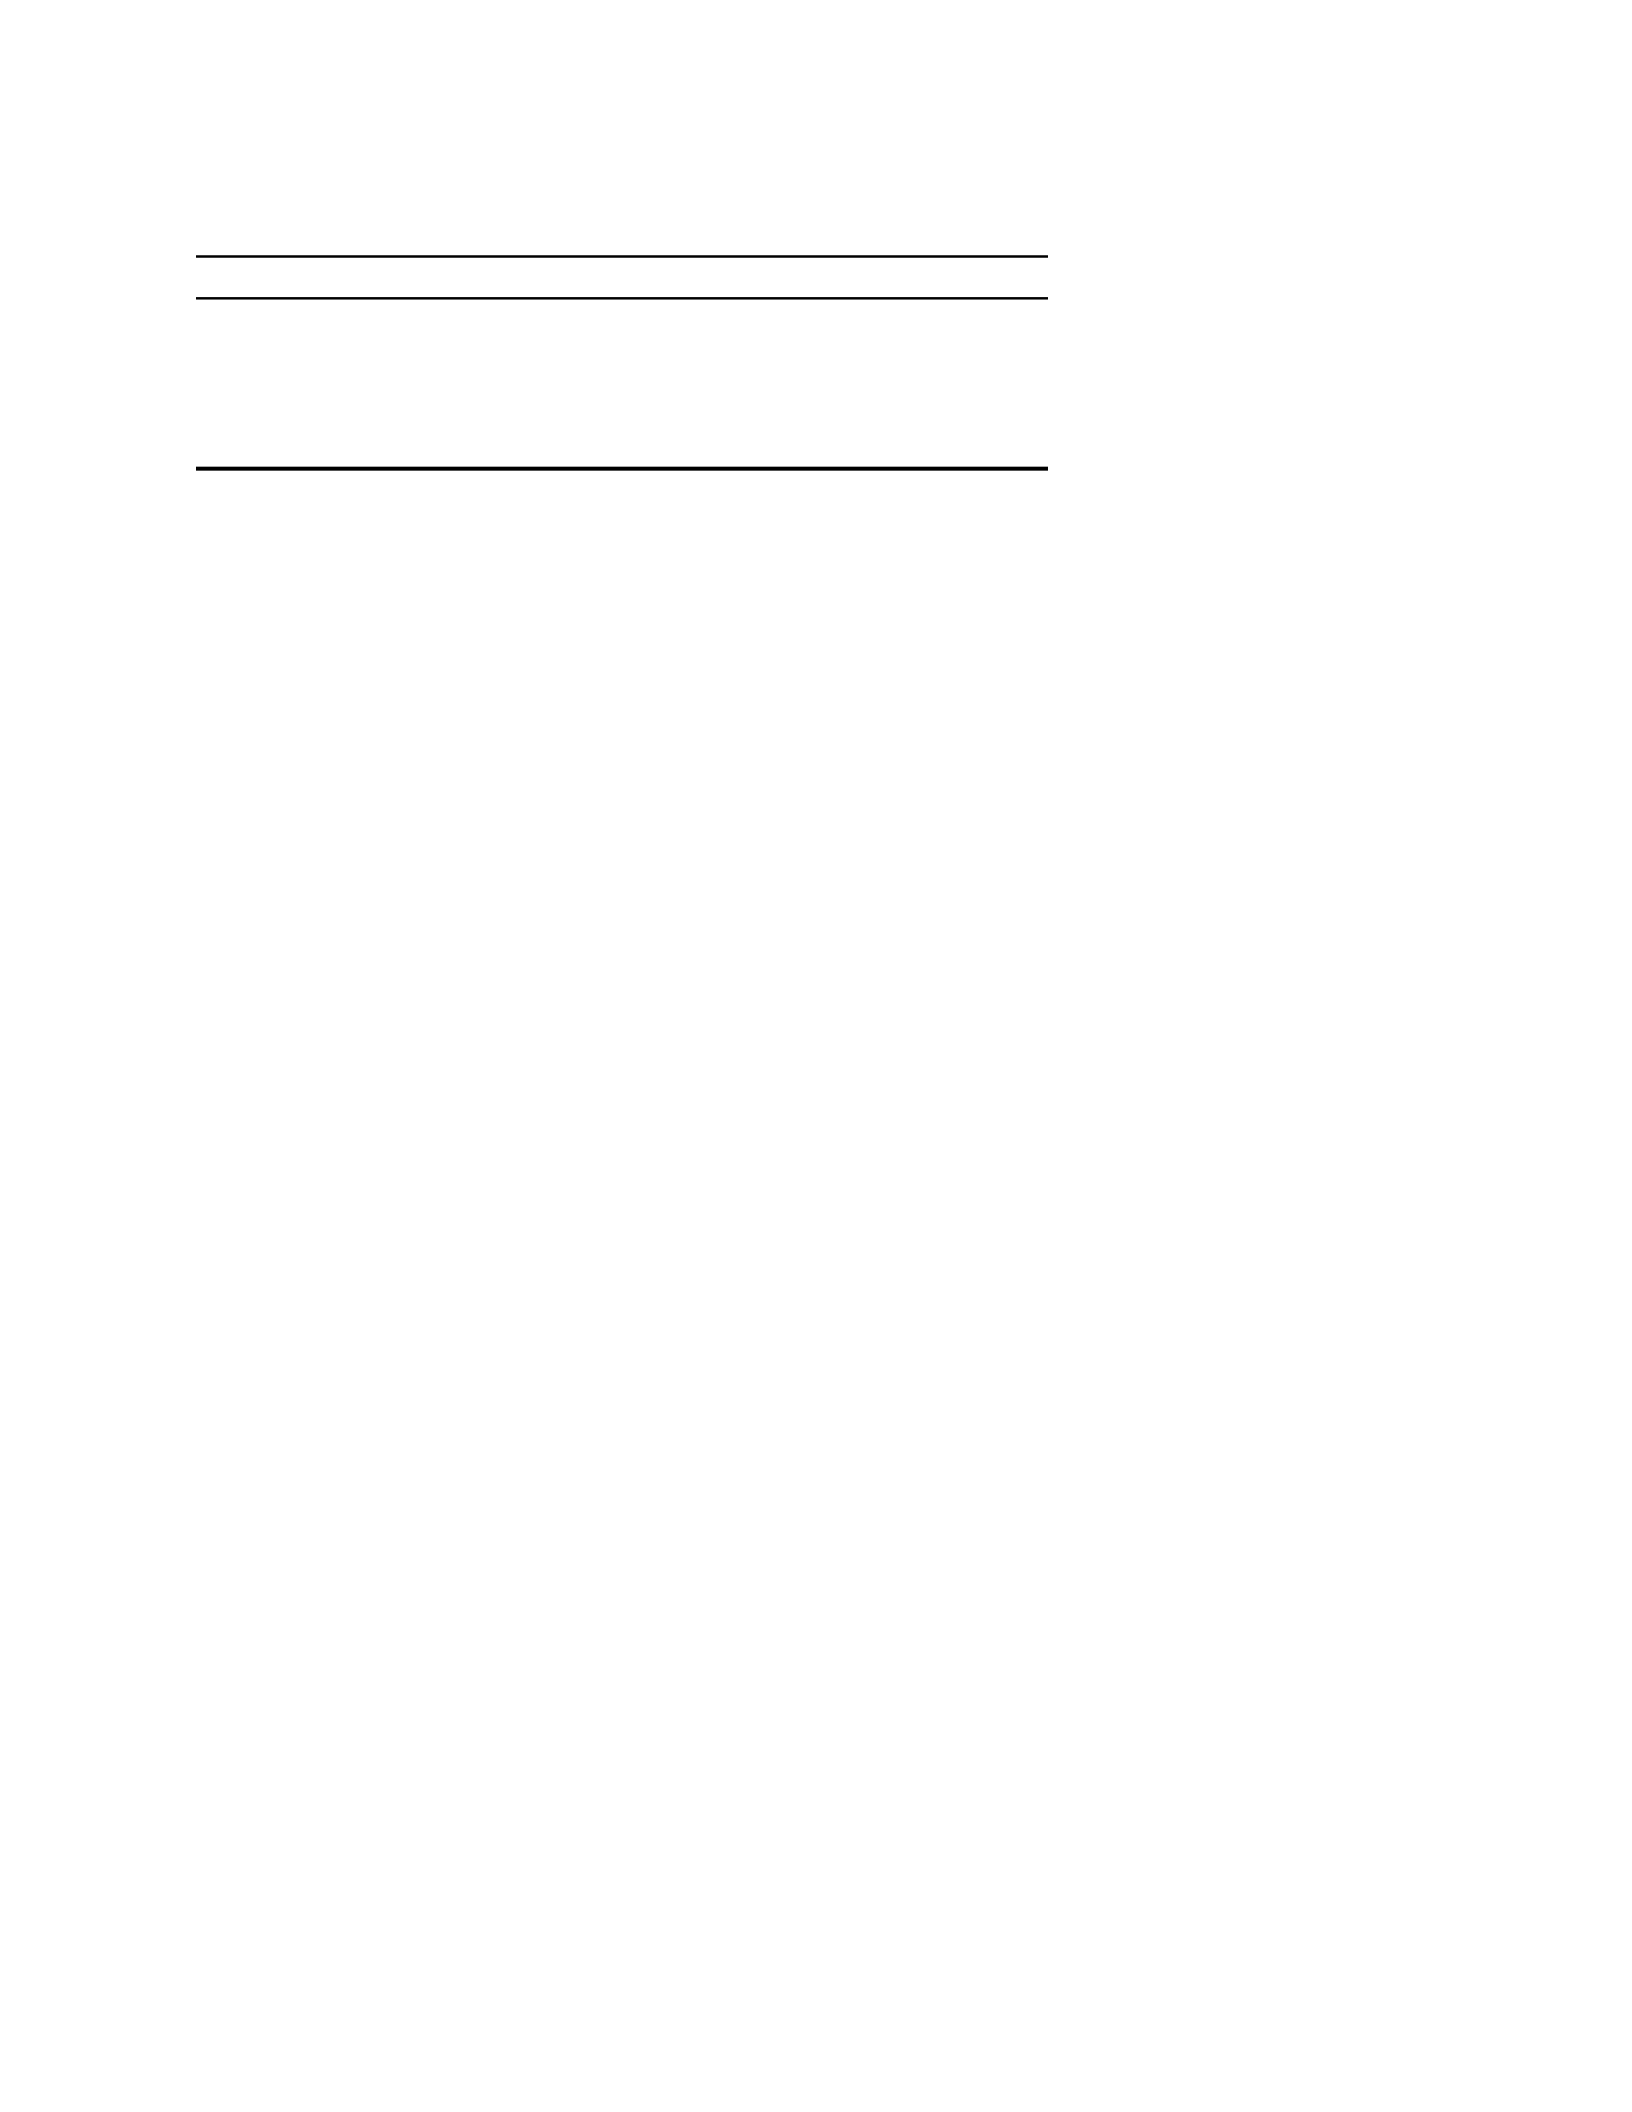
44
Table 6: Ten-Year Standard Deviation, 1970-2008
than both comparison indices. Five and ten-year standard deviation graphs are provided in
Appendices O, P, Q, and R.
Based on these preliminary results, it can be argued that the AG Index carried less price
variability risk during much of the 39 years of data than the market indices. However, further
analysis is needed to determine conclusively the price risk associated with investing in the US
Agricultural sector. Investors, in the hopes of getting large returns, are not always opposed to
price variability, (large standard deviation value). Rather, they are mainly concerned about
downside variability. Since the standard deviation, only reports variability in general with no
consideration of upward or downward variability, it only tells part of the story of the risk of a
security. “Risk adjusted return” measures, like the Sharpe Ratio, have gained popularity among
investors and analysts in recent years and are better measures of security performance.
4.4 Sharpe Ratio
A security’s Sharpe Ratio tells an investor how much excess return he/she is receiving per unit of
risk. Excess return is defined as the difference between the security’s return and the risk free rate.
The risk free rate proxy is dependent on the investment horizon. Annual Sharpe Ratio measures
are calculated using geometric returns on 1-year US Treasury Bills, five and ten-year Sharpe
Ratio measures are calculated using geometric returns on five and ten-year US Treasury Bills.
The risk measure used is standard deviation. Appendix S contains the annual Sharpe Ratio
calculations for the AG Index, S&P 500, and DOW for the period 1970 to 2008. Appendix T
Periods AG Index S&P 500 Dow Jones
1970-1979 0.88742%* 0.85890% 0.928756%
1980-1989 1.08912%* 1.08005% 1.131851%
1990-1999 1.033415% 0.89122% 0.893263%
2000-2008 1.144823% 1.35873% 1.290481%
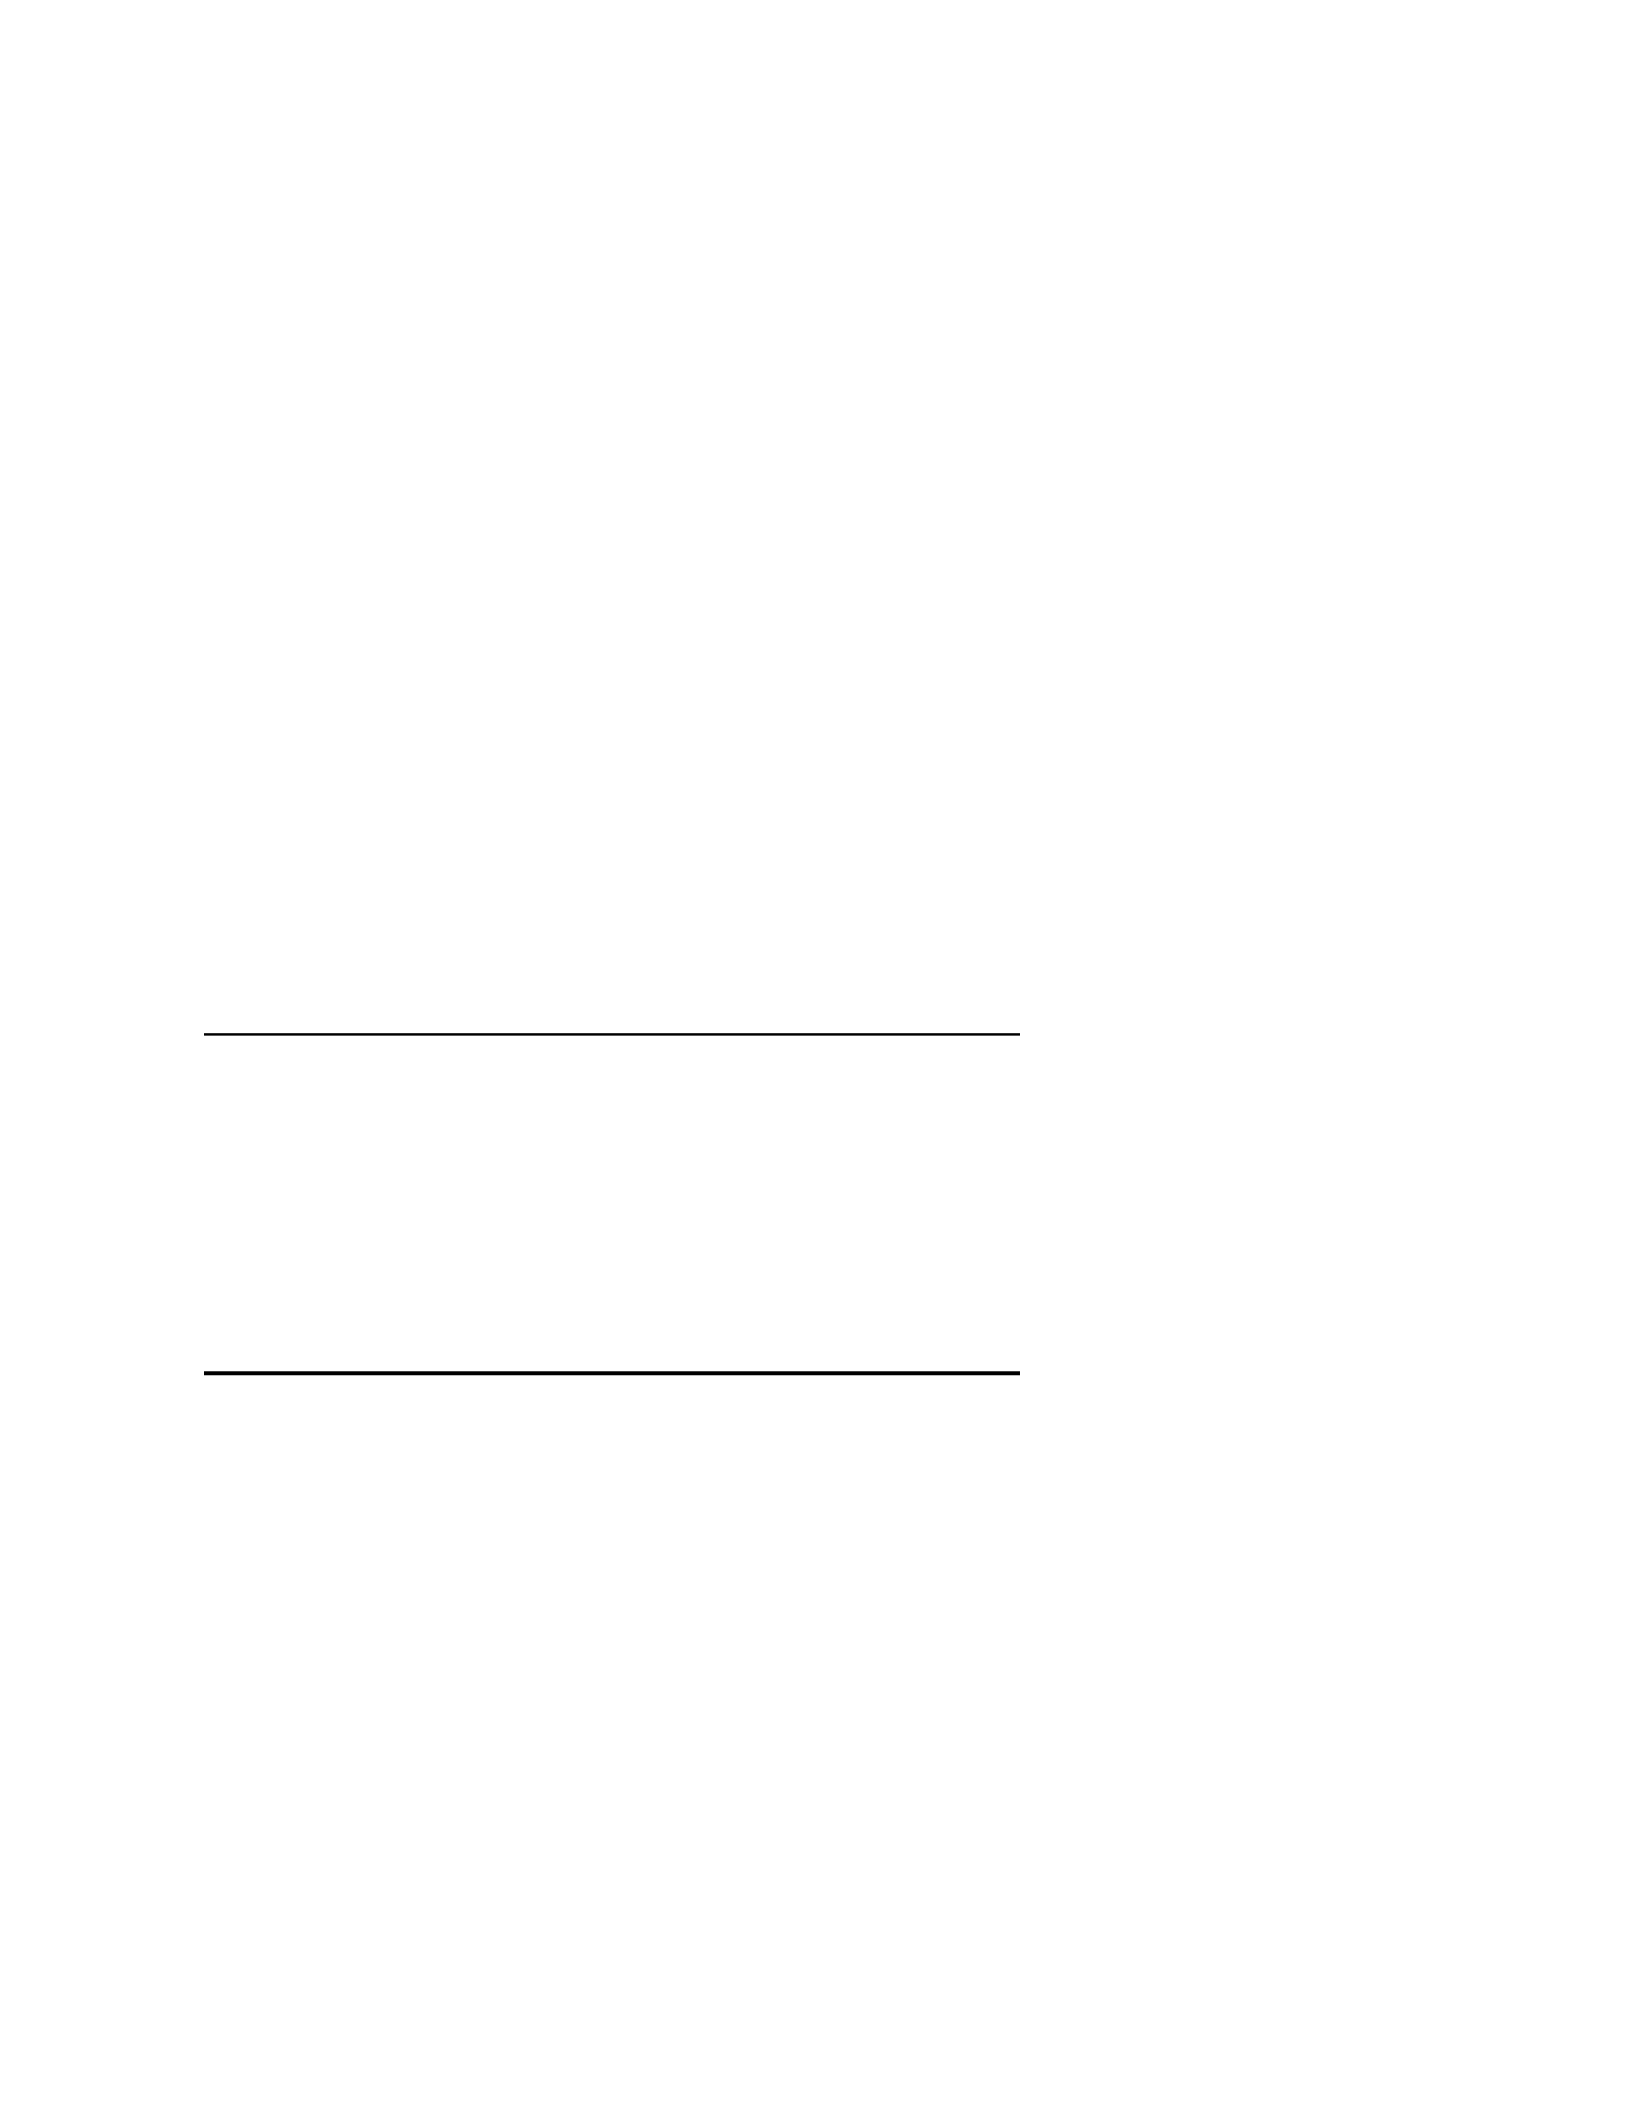
45
contains a line graph of the Sharpe Ratio series for all three indices from 1970 to 2008. For 14
out of the 39 years in the study, the AG Index showed higher excess returns per unit of risk
(larger Sharpe Ratio value) than at least one of the comparison indices. To explain the long-term
risk adjusted risk associated with the AG Index better, measure was calculated for five and ten-
year hold periods. Table 7 contains the five-year Sharpe Ratio calculations for the AG Index,
S&P 500, and the DOW for the period 1970 through 2008. Bolded values indicate a five-year
period in which the AG Index had a higher Sharpe Ratio value than both of the comparison
indices and an asterisked value indicates a five-year period when the AG Index had a higher
Sharpe Ratio value than one of the two comparison indices. These results indicate that the AG
Index showed higher excess returns per unit of risk than a market index in only three of the eight
Table 7: Five-Year Sharpe Ratio, 1970-2008
five-year periods. Both comparison indices showed positive returns per unit of risk for the period
of 1990 to 1994, while the AG Index a showed negative Sharpe Ratio value. During the period of
1995 to 1999, the market indices experienced tremendous growth, while the AG Index did not
exhibit similar risk reward tradeoff. Table 8 contains the ten-year Sharpe Ratio calculations for
the three indices. Again, bolded values indicate a ten-year period in which the AG Index showed
a higher Sharpe Ratio value than both of the comparison indices did. These results indicate that
Period AG Index S&P 500 DOW
1970-1974 -7.73 -3.55 -2.92
1975-1979 -7.76 2.95 -1.04
1980-1984 10.34 9.23 7.15
1985-1989 9.70 12.01 18.94
1990-1994 -3.10 6.83 8.10
1995-1999 5.82 30.28 28.82
2000-2004 12.92 7.23 9.32
2005-2008 9.02* 7.45 9.56
46
the AG Index enjoyed more excess returns per unit of risk than the comparison indices in only
the most recent of the four ten-year periods, 2000 through 2008. The most obvious divergence
Table 8: Ten-Year Sharpe Ratio, 1970-2008
among the three indices was during the 1990’s. The S&P 500 and DOW during this period
enjoyed high-risk adjusted returns at 19.71 and 19.36, respectively, while the AG Index showed
only 1.85% return per unit of risk. The five and ten-year Sharpe Ratio calculations, relative to the
annual calculations, provide less evidence that an investment in the AG Index would carry less
risk than an investment in a market index. However, these results mirror those of the returns and
Standard Deviation calculations, as the most recent periods show the AG Index outperforming
the two comparison indices. These most recent results legitimize current investor interest in the
sector. Graphs illustrating the five and ten-year Sharpe Ratio measures are provided in
Appendices U and V.
4.5 Beta Values
A security’s beta tells an investor how its return co-varies with a market portfolio. Therefore, it is
especially valuable for investors looking to diversify the risk associated with investing in certain
assets. To determine how the US agricultural sector co-varies with the market, beta parameters
were estimated for all 39 years, each of the 8 five-year holding periods, each of the 4 ten-year
holding periods, and over the entire holding period from 1970 to 2008. Table 9 summarizes the
results. During the 39 years in study, the AG Index beta value was greater than one only 8 years.
Therefore, during 31 out of the 39 in the sample, a 1 percent move
Periods AG Index S&P 500 Dow Jones
1970-1979 -8.19 -1.32 -2.55
1980-1989 9.77 10.79 13.75
1990-1999 1.85 19.71 19.36
2000-2008 7.75 4.61 6.57
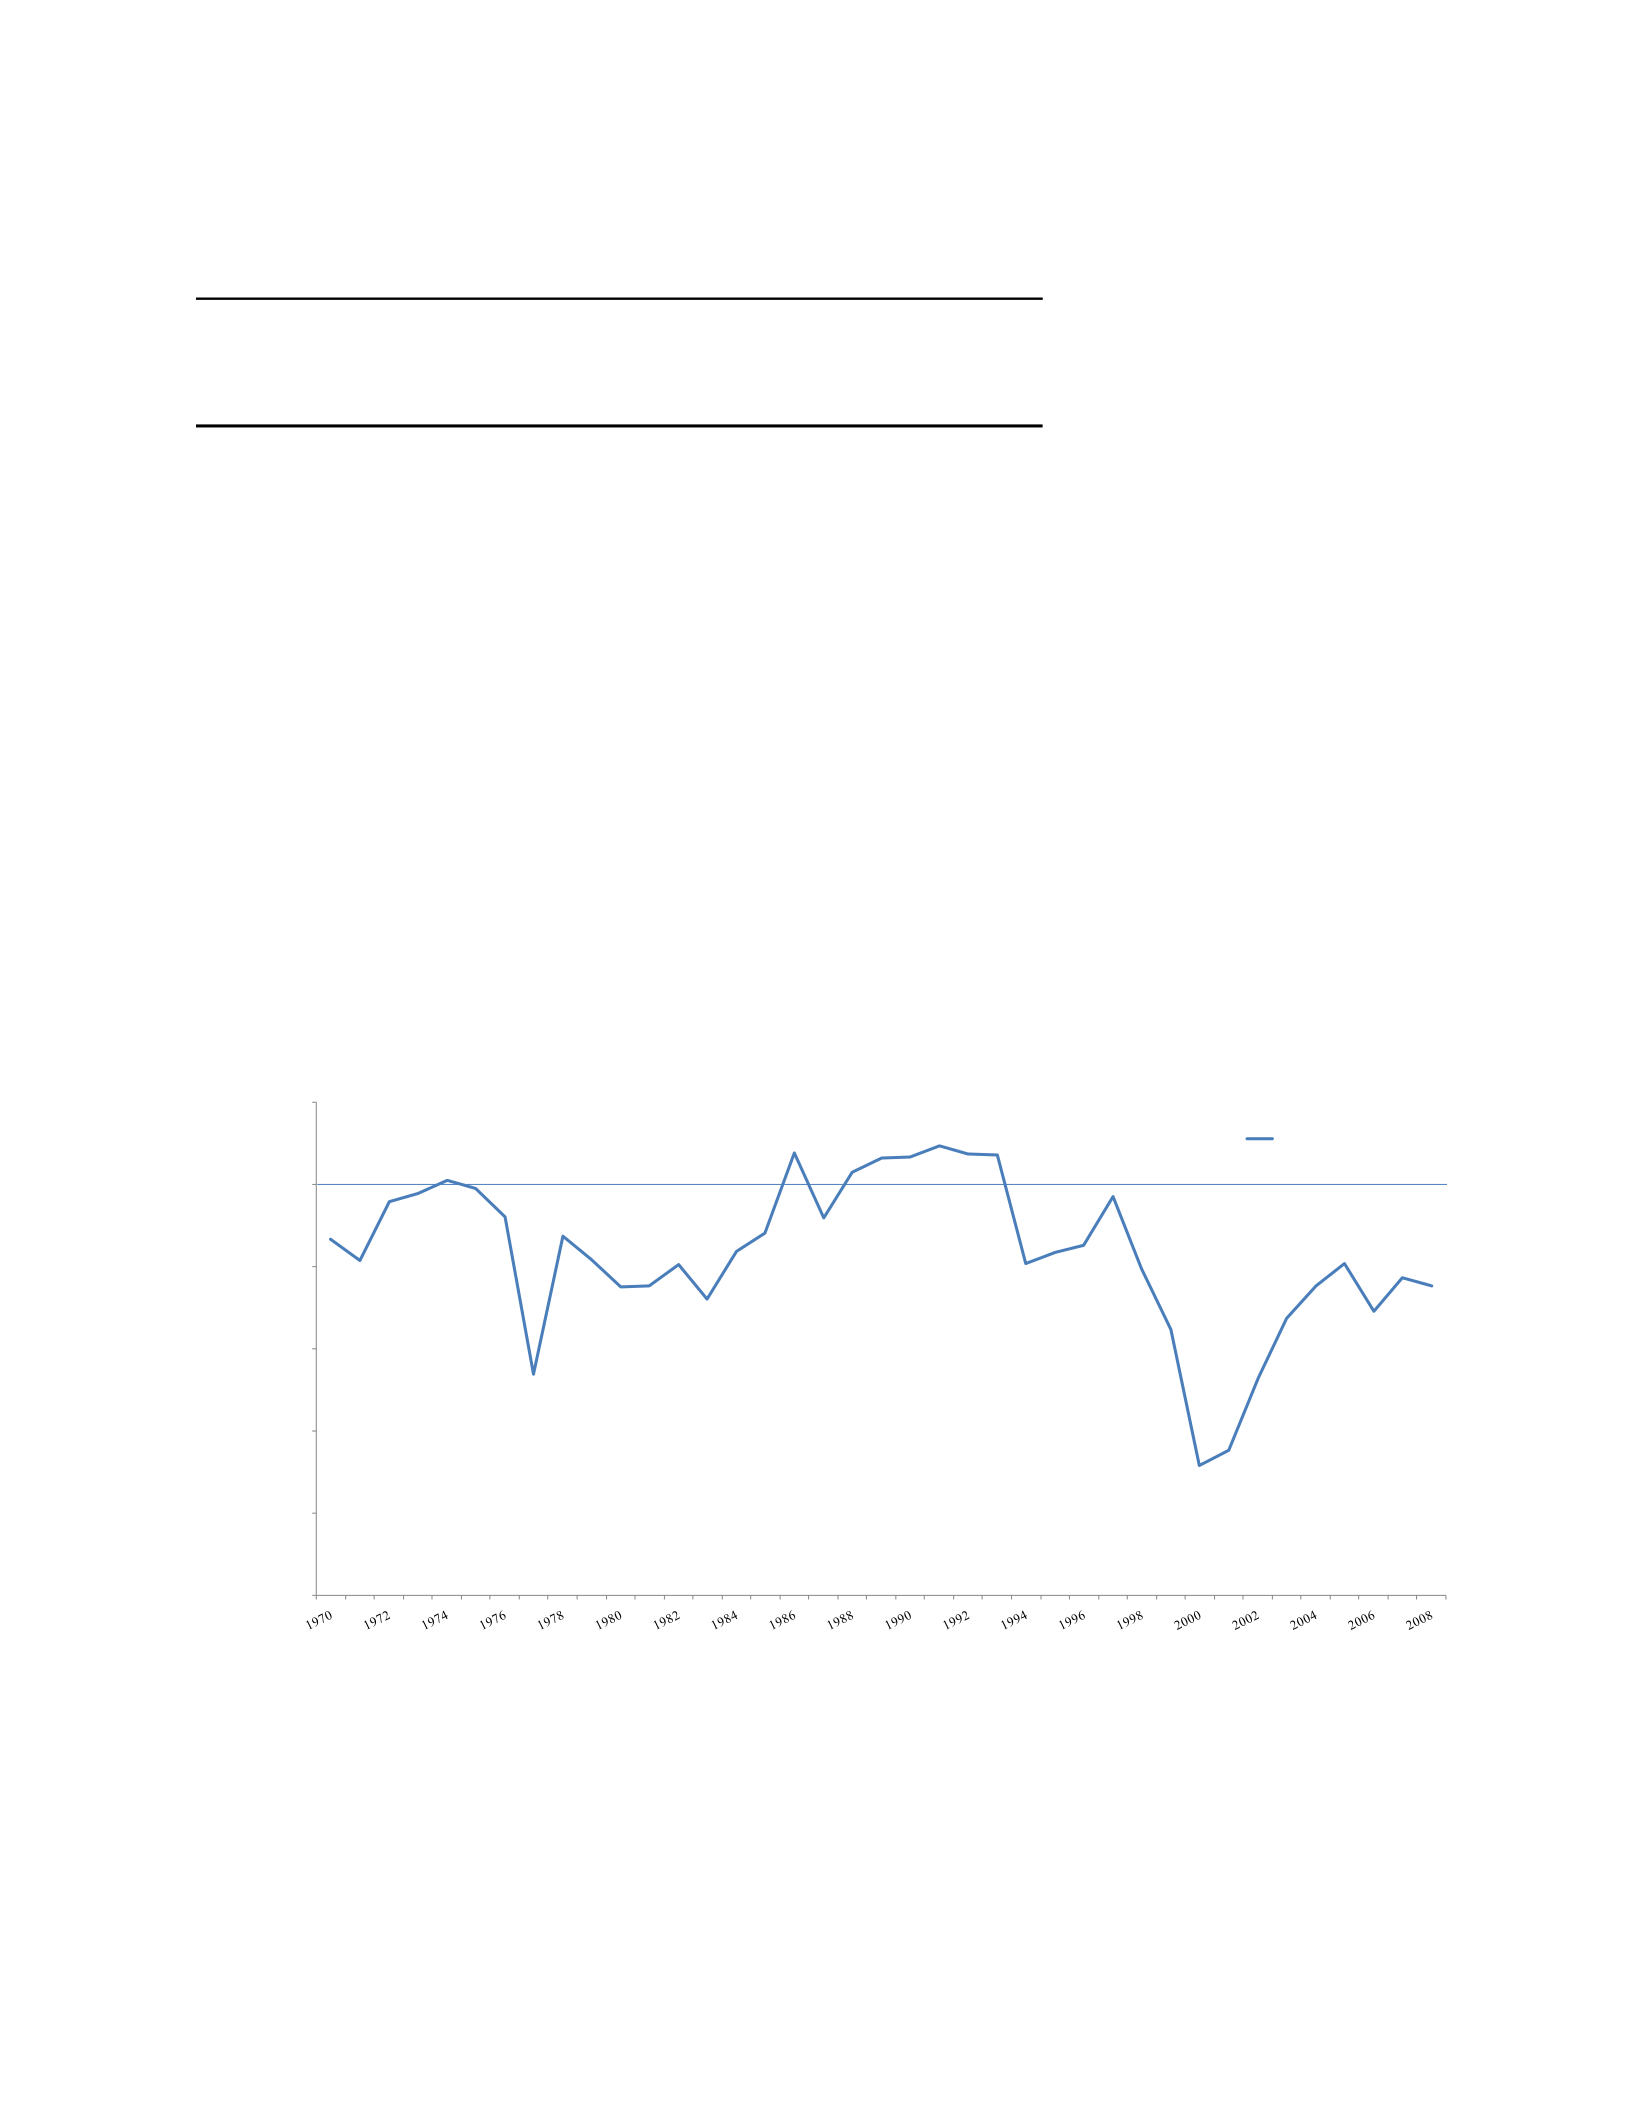
47
Table 9: Beta Value Estimation Summary, AG Index (1970-2008)
in the value of the market portfolio was followed by a less than 1 percent move in the AG Index.
Securities that share this characteristic are considered defensive in nature and are seen as good
investments when the general market sours. Appendix W contains the annual beta estimation for
the AG Index from 1970 to 2008. Refer to Figure 6 for an illustration of the annual beta value
estimation for the AG Index over the 39 years of study. This graph shows that the correlation of
the AG Index and the market portfolio (S&P 500) was not constant over time. Two large drops in
correlation were observed with the first in the late 70’s and second in the late 90’s. However, this
figure clearly shows that over most of the observed period, the AG Index had a beta value of less
Figure 6: Annual Beta Value Estimation, AG Index (1970-2008)
Holding Period Beta of < 1 Beta of > 1 Total Periods
1 year 31 839
Five-Year 7 1 8
Ten-Year 4 0 4
0
0.2
0.4
0.6
0.8
1
1.2
Annual Beta Value
48
than one. Five-year and ten-year beta estimations show identical results. They are provided in
Table 10 and Table 11. The AG Index had a beta value of greater than one in only one of the 8
five-year periods examined in this study. For the ten-year holding period beta estimations, all 4
Table 10: Five-year Average Beta Estimation
periods showed the AG Index to be defensive towards market movements. These results are
consistent with the a priori expectations of this study, the beta estimation of the US Food Sector
by NYU, and with the aforementioned investor sentiment regarding the US agricultural sector.
This information would be very valuable to investors seeking ways to diversify portfolio risk.
Table 11: Ten-year Average Beta Estimation
Five and ten-year estimated beta values are provided in graphical form in Appendix X and Y.
The beta value for the AG Index over the entire observed period was .793, indicating that the
long term reaction of the AG Index returns to the market was defensive.
Year AG Index Beta Estimation
1970-1974 0.952277005
1975-1979 0.874722411
1980-1984 0.774966197
1985-1989 0.96696327
1990-1994 1.042287329
1995-1999 0.811818249
2000-2004 0.471286473
2005-2008 0.757134992
Year AG Index Beta Estimation
1970-1979 0.921846822
1980-1989 0.89318051
1990-1999 0.894844709
2000-2008 0.617782228
49
CHAPTER 5: CONCLUSION
5.1 Discussion and Future Research
As expected, the AG Index has historically exhibited lower returns than the market indices;
however, data that is more recent has shown a shift in this paradigm. Preliminary evidence also
indicates that the sector carries less risk than the market as a whole. Over the past 39 years, the
US agriculture sector, as summarized by the AG Index, has shown to have a lower standard
deviation, higher excess return per unit of risk, and beta value of less than one. All of these
results indicate that the industry would be a wise investment during periods of high market
volatility. Additionally, in recent years the sector has outperformed the market indices.
Overall, the agricultural industry has undergone tremendous growth during the past 39
years. Refer to Table 12 for firm and market size statistics in 2009 dollars. The total market
value of the index, which represents only the top 70th percentile of firms in the sector, grew from
$24.675 billion in 1970 to $91.8 billion in 2008 in real terms, an increase of more than 270
percent. This increase in market value has occurred while the number of firms that make up the
top 70th percentile of the sector has decreased from an average of 53 firms throughout the 1970’s
Table 12: Average Firm Size and Average Real Market Value (1970-2008)
to 36.22 in the 2000’s. Refer to Appendix Z for a list of the number of firms included in the
index by year. In other words, an average of 36.22 firms in the 2000’s were, worth almost four
times what an average of 53 firms were worth in the 1970’s in real dollars (2009 dollars).
Moreover, the average real market value per firm increased over this period by more than 440
Decade Average # of Firms Average Real MKT Value Average Real MKT Value/Firm
1970's 53 24,675,675,000.00 465,578,773.58
1980's 54.7 30,180,185,000.00 551,740,127.97
1990's 43.6 71,827,484,000.00 1,647,419,357.80
2000's 36.22 91,620,218,000.00 2,529,547,708.45

50
percent. To summarize these results; the top 70th percentile of the US agriculture sector has
grown tremendously over the past 39 years, though the average market value per firm has grown
at almost twice the rate. It is quite clear that this trend is linked to the increasing concentration of
firms within the Agricultural sector. Consolidation and vertical integration can affect firm
profitability, therefore investors are likely to be interested in how these trends and how they
affect stock price value.
As noted in an earlier section, a limitation of many stock price indices is that dividend
payments are usually ignored. However, from an investor’s point of view, income from dividend
streams is often just as important as price growth. Furthermore, it can be argued that dividend
payments reduce retained earnings, which in turn imply lower future cash flows and
consequently, lower stock price return. Therefore, the lower stock price returns observed in the
AG Index over the past 39 year may be explained by higher dividend payments. This limitation
will be addressed in future research, however, some preliminary results suggest that the observed
lower returns of the AG Index, as compared to the market, may indeed be offset by the
comparably larger dividend yield associated with the agribusiness firms in the index. Current
dollar dividend payments per share were attained for all the firms included in the index in 2008.
Percent dividend, or “yield”, was calculated for each firm by dividing the share price of each
index by their respective dollar dividend payment. The average yield was calculated for the
entire index, by subsector, and by the top five and top ten firms in the AG Index. The same
calculations were completed for funds that follow the comparison indices and a fund that
represents the total market. Table 13 contains these preliminary dividend results. The top 5 and
10 firms included in the AG Index, as of 2008, had higher dividend yield than those top firms in
all three of the comparison indices. When all of firms included in the AG Index are considered,
the yield was somewhat lower than that of the market indices though a further segmentation of
51
Table 13: Average Dividend Yield, AG Index, S&P 500, Dow Jones Industrial Average, and the
Vanguard Total Market ETF (2009 Prices and Dividend Data)
the AG Index tells a more interesting story. When the average yield is calculated for each of the
three SIC code subcategories, it is clear that the “closely related to farming” category carries the
highest dividend yield among the three. These values are provided in Table 14. When compared
to the three market indices, the closely related to farming subsector shows higher or similar yield
potential. These results indicate that even though these three categories are involved to some
extent in satisfying the final demand for agricultural products, each one may have differing
characteristics. The results from the table below indicate that, from an investment standpoint, it
might be beneficial to drop the pure farming stocks and specify the index to represent the “first
Table 14: Average Dividend Yield by Subcategory, AG Index (2009 Prices and Dividend Data)
handlers” of raw agricultural products in the closely related to farming category. This includes
processors, marketers, and agricultural input firms. It is likely that each category has unique
performance and risk characteristics that can be exploited through different investment strategies.
Therefore, segmenting the larger US agriculture sector by specific characteristics such as firm
size or input versus output orientation could be very valuable to investors. Moreover, recent
literature suggests that farm owners looking to hedge some of their financial risk may be better
off investing in the larger Ag sector rather than just a market portfolio. Detre et al. (2007)
Average Yield AG Index
S&P 500 (Vanguard
500 "VFINX")
DOW (DIAMONDS
Trust "DIA")
Vanguard Total
Market (VTI)
Top 5 Firms 4.47% 2.13% 2.80% 2.13%
Top 10 Firms 3.30% 2.53% 2.84% 2.53%
All 2.16% 2.68% 3.06% 2.53%
Farming 0.55%
Closely Related to Farming 3.05%
Peripherally Related to Farming 2.43%
Average Yield

52
showed that an investment in both the AG sector and a market index could reduce downside risk
exposure as compared to an investment in only a market index. A possible application of this
research is the development of an investible Equity Traded Fund (ETF) or an agriculturally
related family of mutual funds. ETF’s are investible vehicles that are traded on a stock exchange
much like a normal stock. Investors purchase shares of an ETF, which replicates the performance
of an index of a basket of stocks, minus fees and expenses. Like stocks, commodities, or any
other tradable security, ETF’s can be shorted and their capital gains can be controlled. Therefore,
farm owners expecting poor farm returns can short a larger AG sector ETF to hedge on-farm
risk. Likewise, institutional investors looking to diversify portfolio risk could hold a portion of
investment capital in one of these tradable securities. Moreover, future projections of the AG
Index would be very useful to investors, as would projections of price risk. These estimations are
attainable through modern econometric methods such as autoregressive conditional
heteroskedasticity (ARCH) and generalized autoregressive conditional heteroskedasticity
(GARCH) volatility models. Future extension of this research will consider these issues.
As previously discussed, the role of seasonality and agricultural planting and harvest
cycles can affect performance and risk conditions in the sector. The effect of seasonality can be
felt on the demand and supply side of any market. This effect is particular important when
studying commodities and agribusiness companies. This is because one of the biggest
determinants of supply is weather and climate. Business cycles, by definition, are fluctuations in
economic activity along the long-term growth trend. Having the ability to determine where
businesses are in their cycle is of great benefit to the potential investor. Further research is
needed to determine the impact of these factors, as they are likely to affect the accuracy of price
projections.
Another valuable extension of this research would be to determine the impact of

53
changing macroeconomic factors on agribusiness profitability and stock prices. Examples of
these factors could include, US Gross Domestic Product, the value of the US dollar, the price of
gold, the price of oil and other commodities, and inflation. The links between these factors can
examined through simple correlation calculations.
In any statistical or financial study, it is important to discuss the limitations of the
methods and therefore the accuracy of results. As with most indices, dividends were ignored in
this study. Over long holding periods, dividend income can influence investment returns greatly.
Because dividends are ignored, the return calculations are only measures of price change from
one period to another, not investment return with dividends reinvested. Future extensions of the
AG Index will examine the possibility of correcting for dividends to determine a true investment
holding period return. Another limitation is the frequency by which share counts were updated.
A more accurate tracking of the US agricultural sector would require immediate corrective action
for large changes in share counts and quarterly correction of all small changes in share counts.
Lastly, the fees and transactional costs of investing in the AG Index are not included in this
study. Potential investors should closely evaluate these costs before making investment
decisions.
5.2 Summary
The growing global demand for food, popularity of organic products, and increasing competition
among the alternative uses of feed crops, are a few observable trends that have made investing
US agricultural sector an area of interest among investors. The rising prices of commodity crops
and subsequent increase in firm profitability have signaled famers to increase production. The
accompanying increase in demand for agricultural inputs such as feed, seed, and equipment, has
affected the profitability of US agribusiness firms involved in their production. Despite these
trends, little literature exists that analyzes the historical risk and return associated with investing

54
in publicly traded US agricultural securities. This study has provided original research on the
returns and risks associated with an investment in publicly traded agribusiness companies. This
was accomplished through the development of a large-cap agribusiness stock price index. The
resulting index is a continuous series that represents the largest US agribusiness firms over a 39-
year period. The calculated risk and return measures associated with the agribusiness index were
compared to that of the market as a whole. The results indicate that although the returns
associated with investing in the US agricultural sector were less than what could be expected by
investing in a market index, preliminary evidence indicates that the sector is less susceptible to
price variability and is defensive in nature.
55
REFERENCES
Ang, Andrew, J. Chen and Y. Xing (2006). "Downside Risk." The Review of Financial Studies
19(4): 1191-1239.
Armitage, S. (1995). "Event Study Methods and Evidence on Their Performance." Journal of
Economic Surveys 9(1): 25-52.
Associated Press. (2006). "Wal-Mart Goes Organic." MSNBC Online Retrieved March 19,
2009, from http:www.msnbc.msn.com/id/11977666/.
Beierlein, J. G., K. C. Schneeberger and D. D. Osburn (2003). Principles of Agribusiness
Management. Long Grove, IL, Waveland Press, Inc.
Bjornson, B. (1995). "The Impacts of Business Cycles on Returns to Farmland Investments."
American Journal of Agricultural Economics 77(3): 566-577.
Brown, C. and M. Sperow (2005). "Examining the Cost of an All-Organic Diet." Journal of Food
Distribution Research 36(01): 20-27.
Byrne, P. J., U. C. Toensmeyer, C. L. German and H. R. Muller (1991). "Analysis of Consumer
Attitude Toward Organic Produce and Purchase Likelihood." Journal of Food
Distribution Research 22: 49-62.
Campbell, J. Y., A. W. Lo and A. C. MacKinlay (1997). The Econometrics of Financial Markets.
Princeton, New Jersey, Princeton University Press.
Center for Research in Security Prices. (2009). "CRSP Daily Stock Price Database." from
http://www.crsp.com/products/index.html.
Chartered Financial Analyst Institute (2005). CFA Program Curriculum: Corporate Finance and
Equity, Pearson Custom Publishing.
Curl, C. L., R. A. Fenske and K. Elgethun (2003). "Organophosphorus Pesticide Exposure of
Urban and Suburban Preschool Children with Organic and Conventional Diets."
Environmental Health Perspectives 111(3): 377-382.
Da-Rocha, J. and D. Restuccia (2006). "The Role of Agriculture in Aggregate Business Cycles."
Review of Economic Dynamics 9: 455-482.
Damodaran, A. (2009). "Betas by Sector." Retrieved December 10, 2009, from
http://pages.stern.nyu.edu/~adamodar/New_Home_Page/datafile/Betas.html.
Dangour, A. D., S. K. Dodhia, A. Hayter, E. Allen, K. Lock and R. Uauy (2009). "Nutritional
quality of organic foods: a systematic review." American Journal of Clinical Nutrition 90:
680-685.
56
Davies, A., A. J. Tifferington and C. Cochrane (1995). "Who Buys Organic Food? A Profile of
the Purchasers of Organic Food in Northern Ireland." Brittish Food Journal 97: 17-24.
Davis, J. H., C. Hanes and P. Rhode. (2009). "Harvests and Business Cycles in Nineteenth-
Century America." Retrieved May 12, 2009, from http://ssrn.com/paper=1335711.
Detre, J. D., C. A. Wilson and A. W. Gray (2007). "Buying Stock in Value-Added Companies:
An Alternative Choice for Vertical Diversification?" Agricultural Finance Review 67(1):
175-196.
Dimitri, C and C. Green (2002). Recent Growth Patterns in the U.S. Organic Foods Market.
Economic Research Service. Washington D.C., U.S. Department of Agriculture.
Dimitri, C. and N. Richman (2000). Organic Food Markets in Transition. U.S. Department of
Agriculture and Henry A. Wallace Center for Agricultural and Environmental Policy.
Greenbelt, MD, Henry A. Wallace Center for Agricultural and Environmental Policy.
Policy Studies Report No.14.
Dirks, F. C. (1958). "Recent Investment Return on Industrial Stocks." The Journal of Finance
13(3): 370-385.
Duval, Y. and A. M. Featherstone (2002). "Interactivity and Soft Computing in Portfolio
Management: Should Farmers Own Food and Agribusiness Stocks?" American Journal
of Agricultural Economics 84(1): 120-133.
Economic Research Service. (2005). "Farm and Farm-Related Employment: SIC Industry
Groups and Components." Retrieved June, 02, 2008, from
http://www.ers.usda.gov/Data/FarmandRelatedEmployment/SIC-Industries2.htm.
Economic Research Service. (2009). "Agriculture Baseline Database: Baseline Data Delivery
System." Retrieved October 6, 2009, from
http://ers.usda.gov/data/baseline/default.asp?ERSTab=3.
Global Derivatives Study Group (1993). Derivatives: Practices and Principles, Group of Thirty.
Govindasamy, R., M. DeCongelio, J. Italia, B. Barbour and K. Anderson (2001). Empirically
Evaluating Consumer Characteristics and Satisfaction with Organic Products. New
Brunswick, New Jersey, The State University of New Jerset Rutgers.
Guarino, D. R. (2009). "S&P Launches Agribusiness Index for North America." Retrieved June
23, 2009, from
http://www2.standardandpoors.com/spf/pdf/index/20090623_AgribusinessNA-
Launch.pdf.
Harris, J. Michael (2008). Agricultural Income and Finance Outlook. Economic Research
Service. Washington D.C., U.S. Department of Agriculture. AIS-86.
57
Hay, J. (1989). "The Consumer's Perspective on Organic Food." Canadian Institute of Food
Science Technology Journal 22(2): 95-99.
Henderson, G. V., Jr. (1990). "Problems and Solutions in Conducting Event Studies." The
Journal of Risk and Insurance 57(2): 282-306.
Hood, E. (2003). "Organic Food for Thought: Lessening Children's Pesticide Exposure."
Environmental Health Perspectives 111(3): A166-A166.
Kahn, M. (2008). "Agriculture Sector Still Sprouting Winners." Retrieved March 19, 2009,
from
http://online.barrons.com/article/SB120027699343486619.html?mod=b_hpp_9_0%0900
2_b_online_exclusives_weekday_r1.
Lintner, J. V. (1965). "The Valuation of Risk Assets and the Selection of Risk Investments in
Stock Portfolios and Capital Budgets." Review of Economics and Statistics 47: 13-37.
Lo, A. W. (2002). "The Statistics of Sharpe Ratios." Financial Analysts Journal 58: 52.
MacKinlay, A. C. (1997). "Event Studies in Economics and Finance." Journal of Economic
Literature 35(1): 26-39.
Marquardt, K. (2008). "3 Farm-Equipment Stocks to Watch." Retrieved March 26, 2009, from
http://www.usnews.com/articles/business/economy/2008/01/24/3-farm-equipment-
stocks-to-watch.html?s_cid=related-links:TOP2.
Nutrition Business Journal (2008). "Organic Markets Overview." Nutrition Business Journal.
Perold, A. F. (2004). "The Capital Asset Pricing Model." The Journal of Economic Perspectives
18(3): 3-24.
Reilly, F. and K. Brown (2003). Investment Analysis Portfolio Management. Mason, Ohio,
Thomson Learning.
Roll, R. (1969). "Bias in Fitting the Sharpe Model to Time Series Data." The Journal of Financial
and Quantitative Analysis 4(3): 271-289.
Rosegrant, M. W. (2008). Biofuels and Grain Prices: Impacts and Policy Responses. U.S. Senate
Committee on Homeland Security and Government Affairs. Washington, D.C.,
International Food Policy Research Institute: 4.
Rosegrant, M. W., M. S. Paisner, S. Meijer and J. Witcover (2001). Global Food Projections to
2020: Energind Trend and Alternative Futures, International Food Policy Research
Institute.
58
Sharpe, W. F. (1964). "Capital Asset Prices: A Theory of Market Equilibrium Under Conditions
of Risk." Journal of Finance 19: 425 - 442.
Sharpe, W. F. (1966). "Mutual Fund Performance." The Journal of Business 39(1): 119-138.
Sharpe, W. F. (1994). "The Sharpe Ratio." The Journal of Portfolio Management 21(1): 49-58.
Shinkle, K. and K. Marquardt. (2008). "Investing in Commodities Funds." U.S. News and World
Report Retrieved March 18, 2009, from
http://www.usnews.com/articles/business/economy/2008/01/24/investing-in-
commodities-
funds.html?loomia_ow=t0:a41:g29:r6:c0.001378:b20319067&s_cid=loomia:a-long-
term-bull-on-agriculture.
Simons, K. (1998). "Risk-Adjusted Performance of Mutual Funds." New England Economic
Review September/October: 33-47.
Standard & Poor's (2009) "S&P Agribusiness North America Index." Index Fact Sheet, 2.
Standard & Poor's (2009b). Index Mathematics: Methodology. New York, The McGraw-Hill
Companies, Inc.
Thompson, G. and J. Kidwell (1998). "Explaining the Choice of Organic Produce: Cosmetic
Defects, Prices, and Consumer Preferences." American Journal of Agricultural
Economics 80: 277-288.
Tokgoz, S., A. Elobeid, J. Fabiosa, D. J. Hayes, B. A. Babcock, T. Yu, F. Dong, C. E. Hart and J.
C. Beghin (2007). Long-Term and Global Tradeoffs between Bio-Energy, Feed, and
Food. American Agricultural Economics Association Annual Meetings. Portland, OR.
Tregear, A., J.B. Dent and M.I. McGregor (1994). "The Demand for Organically-Growth
Produce." Brittish Food Journal 96: 21-26.
Trostle, R. (2008). Global Agricultural Supply and Demand: Factors Contributing to the Recent
Increase in Commodity Prices. Economic Research Service. Washington D.C., United
State Department of Agriculture. WRS-0801.
Tsay, Ruey S. (2005). Analysis of Financial Time Series. Hoboken, New Jersey, John Wiley &
Sons, Inc.
United Nations. (2008). "World Population Prospects: The 2008 Revision." UN Population
Database Retrieved October 5th, 2009, from http://esa.un.org/unpp/index.asp.
United Nations. (2008b). "Estimates of Per Capita GDP in US Dollars." United Nations Statistics
Division Retrieved October 5, 2009, from
http://unstats.un.org/unsd/snaama/selectionbasicFast.asp.
59
United States Department of Agriculture (2009). USDA Agricultural Projections to 2018.
Interagency Agricultural Projections Committee. Washington D.C., USDA Office of the
Chief Economist.
US Census Bureau. (2009). "Standard Industrial Classification (SIC) system." Retrieved June
12, 2009, 2009, from http://www.osha.gov/pls/imis/sic_manual.html.
Weiers, R. M. (2002). Introduction To Business Statistics. Belmont, CA, Wadsworth
Group/Thomson Learning.
Willer, H. and M. Yussefi (2004). "The World of Organic Agriculture: Statistics and Emerging
Trends." International Federation of Organic Agriculture Movements.
Wilson, J.W. and C. P. Jones (2002). "An Analysis of the S&P 500 Index and Cowles's
Extensions: Price Indexes and Stock Returns, 1870-1999." The Journal of Business 75(3):
505-533.
Wolgemuth, L. (2008). "A Long-Term Bull on Agriculture." U.S. News & World Report
Retrieved March 28, 2009, from
http://www.usnews.com/articles/business/economy/2008/01/24/a-long-term-bull-on-
agriculture.html.
Zepeda, L. and L. Jinghan (2007). "Characteristics of Organic Food Shoppers." Journal of
Agricultural and Applied Economics 39(1): 17-29.
60
APPENDIX A: DAX GLOBAL AGRIBUSINESS INDEX CONSTITUENTS (AS OF
DECEMBER 2009)
Company Name Country Trading Symbol Exchange
AGCO Corp United States AGCO NYSE
Agrium Inc Canada AGU NYSE
The Andersons Inc United States ANDE NasdaqGS
Astra Agro Lestari Indonesia AALI.JK JKT
AWB Ltd Australia AWB.AX ASX
BRF - Brasil Foods SA ADR Brazil
BRFS NYSE
Bunge Ltd (Bermuda) United States
BG NYSE
CF Industries Holdings United States
CF NYSE
China Agri Inds Hld Hong Kong CIDHF.PK Other OTC
Chiquita Brands Intl Inc United States
CQB NYSE
CNH Global NV Netherlands
CNH NYSE
Corn Products Intl United States
CNP NYSE
Cosan Ltd Brazil CZZ NYSE
Cresud SA Com Ind Argentina CRESY NasdaqGS
Darling Ing Intl Inc United States DAR NYSE
Del Monte Foods Co United States DLM NYSE
Glanbia Plc Ireland GL9.IR ISE
Golden Agri-Res Singapore 4G3A SES
Graincorp Ltd Australia GNC.AX ASX
Indofood Agri Res Singapore ZVF SES
Intrepid Potash United States IPI NYSE
IOI Corporation Ber Malaysia IOI MK KLS
Kuala L Kepong B Malaysia KLKB MK KLS
Lindsay Corp United States LNN NYSE
London Sumatr Ind Indonesia LSIP.JK JKT
Maple Leaf Foods Canada MFI.TO TOR
Nufarm Ltd Australia NUF.AX ASX
Nutreco Hldg Nv Netherlands NUO.AS AMS/AEX
Olam Intl Ltd Singapore O5I SES
Potash Corp. (US) Canada
POT NYSE
Smithfield Foods Inc United States
SFD NYSE
Soc Quimica Min ADR B Chile QYM NYSE
Tate & Lyle Britain 36IS.L LSE
Terra Industries Inc United States
TRA NYSE
Tyson Foods Inc A United States
TSN NYSE
Viterra Inc Canada VT.TO TOR
Wilmar Intl Ltd Singapore RTHA SES
Yara International Norway YAR.OL OSL
61
APPENDIX B: STANDARD AND POORS AGRIBUSINESS NORTH AMERICA INDEX
CONSTITUENTS (AS OF DECEMBER 2009)
Company Name Country Trading Symbol Exchange
AGCO Corp United States AGCO NYSE
Agrium Inc Canada AGU NYSE
Archer-Daniels-Midland Co United States ADM NYSE
BRF - Brasil Foods SA ADR Brazil BRFS NYSE
Bunge Ltd (Bermuda) United States BG NYSE
CF Industries Holdings United States CF NYSE
CNH Global NV Netherlands CNH NYSE
Cal Maine Foods Inc United States CALM NasdaqGS
Chiquita Brands Intl Inc United States CQB NYSE
Corn Products Intl United States CPO NYSE
Deere & Co United States DE NYSE
Fresh Del Monte Produce(Caymans) United States FDP NYSE
Hormel Foods Corp United States HRL NYSE
Kubota Corp ADR Japan KUB NYSE
Monsanto Co. United States MON NYSE
Mosaic Co United States MOS NYSE
Potash Corp. (US) Canada POT NYSE
Sanderson Farms United States SAFM NasdaqGS
Smithfield Foods Inc United States SFD NYSE
Sociedad Quimica y Minera de Chile -B (ADR) Chile SQM NYSE
Syngenta AG ADR Switzerland SYT NYSE
Terra Industries Inc United States TRA NYSE
Tyson Foods Inc A United States TSN NYSE
Viterra Inc Canada VT.TO Toronto
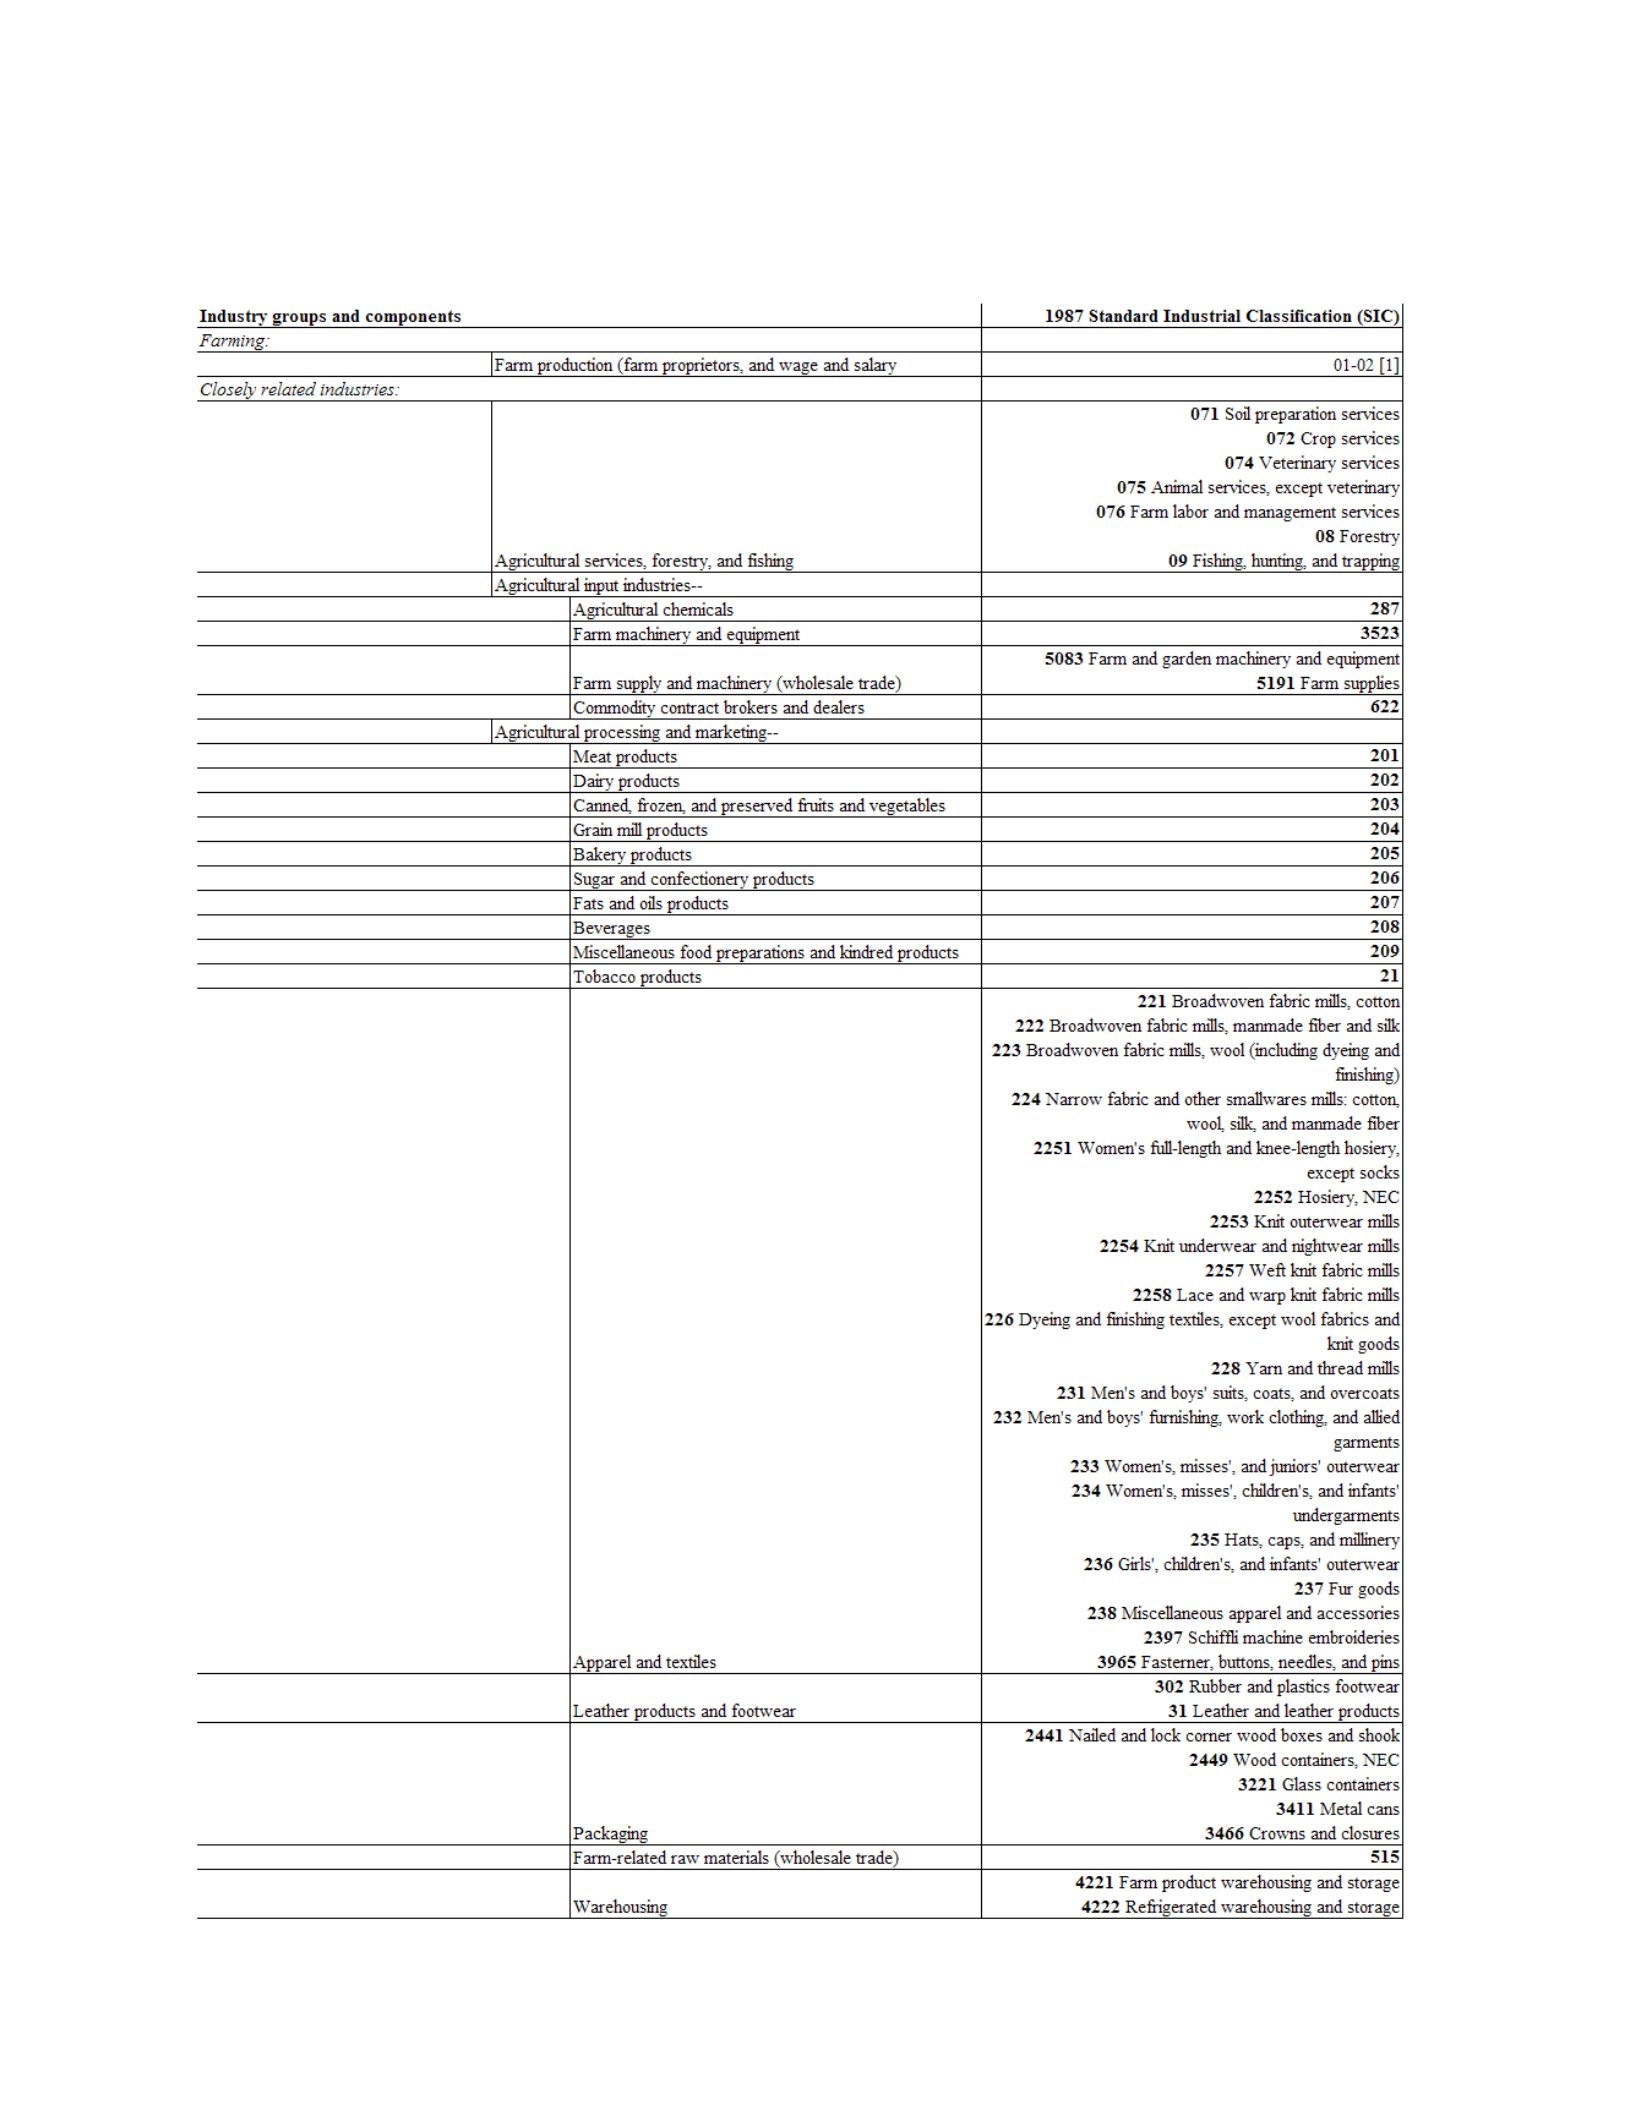
Industry
groups
and
components
1987
Standard
Industrial
Classification
(SIO)|
‘Farming.
[Farm
production
(farm
proprietors,
and
wage
and
salary
01-02
[1]
Closely
related
industries:
[Agricultural
services,
forestry,
and
fishing
(071
Soil
preparation
services|
072
Crop
services|
074
Veterinary
services
075
Animal
services,
except
veterinary|
076
Farm
labor
and
management
services
08
Forestry|
09
Fishing,
hunting.
and
trapping|
[Agricultural
input
industries
[Agricultural
chemicals
287
[Farm
machinery
and
equipment
3523
[Farm
supply
and
machinery
(wholesale
trade)
‘5083
Farm
and
garden
machinery
and
equipment
5191 Farm
supplies|
[Commodity
contract
brokers
and
dealers
62,
[Agricultural
processing
and
marketing
[Meat
products
201
[Dairy
products
202,
[Canned,
frozen,
and
preserved
fruits
and
vegetables
203;
[Grain
mill
products
204]
[Bakery
products
205]
Sugar
and
confectionery
products
206|
[Fats
and
oils
products
207
[Beverages
208|
[Miscellaneous
food
preparations
and
kindred
products
209]
[Tobacco
products
21]
[Apparel
and
textiles
221
Broadwoven
fabric
mills,
cotton]
222
Broadwoven
fabric
mills,
manmade
fiber
and
silk
223
Broadwaven
fahric
mills,
wool
(inchiding
dyeing
and
finishing)
224
Narrow
fabric
and
other
smallwares
mills:
cotton,
wool,
silk,
and
manmade
fiber|
2251
Women's
full-length
and
knee-length
hosiery,
except
socks
2252
Hosiery,
NEC|
2253
Knit
outerwear
mills|
2254
Knit
underwear and
nightwear
mills
2257
Weft
knit
fabric
mills|
2258
Lace
and
warp
knit
fabric
mills
1226
Dyeing and
finishing
textiles,
except
wool
fabrics
and|
knit
goods|
228
Yam
and
thread
mills|
231
Men's
and
boys’
suits,
coats,
and
overcoats|
232
Men's
and
boys'
furnishing,
work
clothing,
and
allied|
garments|
233
Women's,
misses’,
and
juniors'
outerwear|
234
Women's,
misses’,
children's,
and
infants|
undergarments|
235
Hats,
caps,
and
millinery|
236
Girls’,
children's,
and
infants’
outerwear
237
Fur
goods|
238
Miscellaneous
apparel
and
accessories
2397
Schifili
machine
embroideries|
3965
Fastemer,
buttons,
needles,
and
pins|
lLeather
products
and
footwear
302
Rubber
and
plastics
footwear|
31
Leather
and
leather
products
[Packaging
2441
Nailed
and
lock
corner
wood
boxes
and
shook|
2449
Wood
containers,
NEC|
3221
Glass
containers|
3411
Metal
cans|
3466
Crowns
and
closures|
[Farm-related
raw
materials
(Wholesale
trade)
515]
[Warehousing
4221 Farm
product
warehousing
and
storage|
4222
Refrigerated
warehousing
and
storage|
62
APPENDIX C: ECONOMIC RESEARCH SERVICE AGRIBUSINESS INDUSTRY GROUPS
BY STANDARD INDUSTRIAL CLASSIFICATION CODES
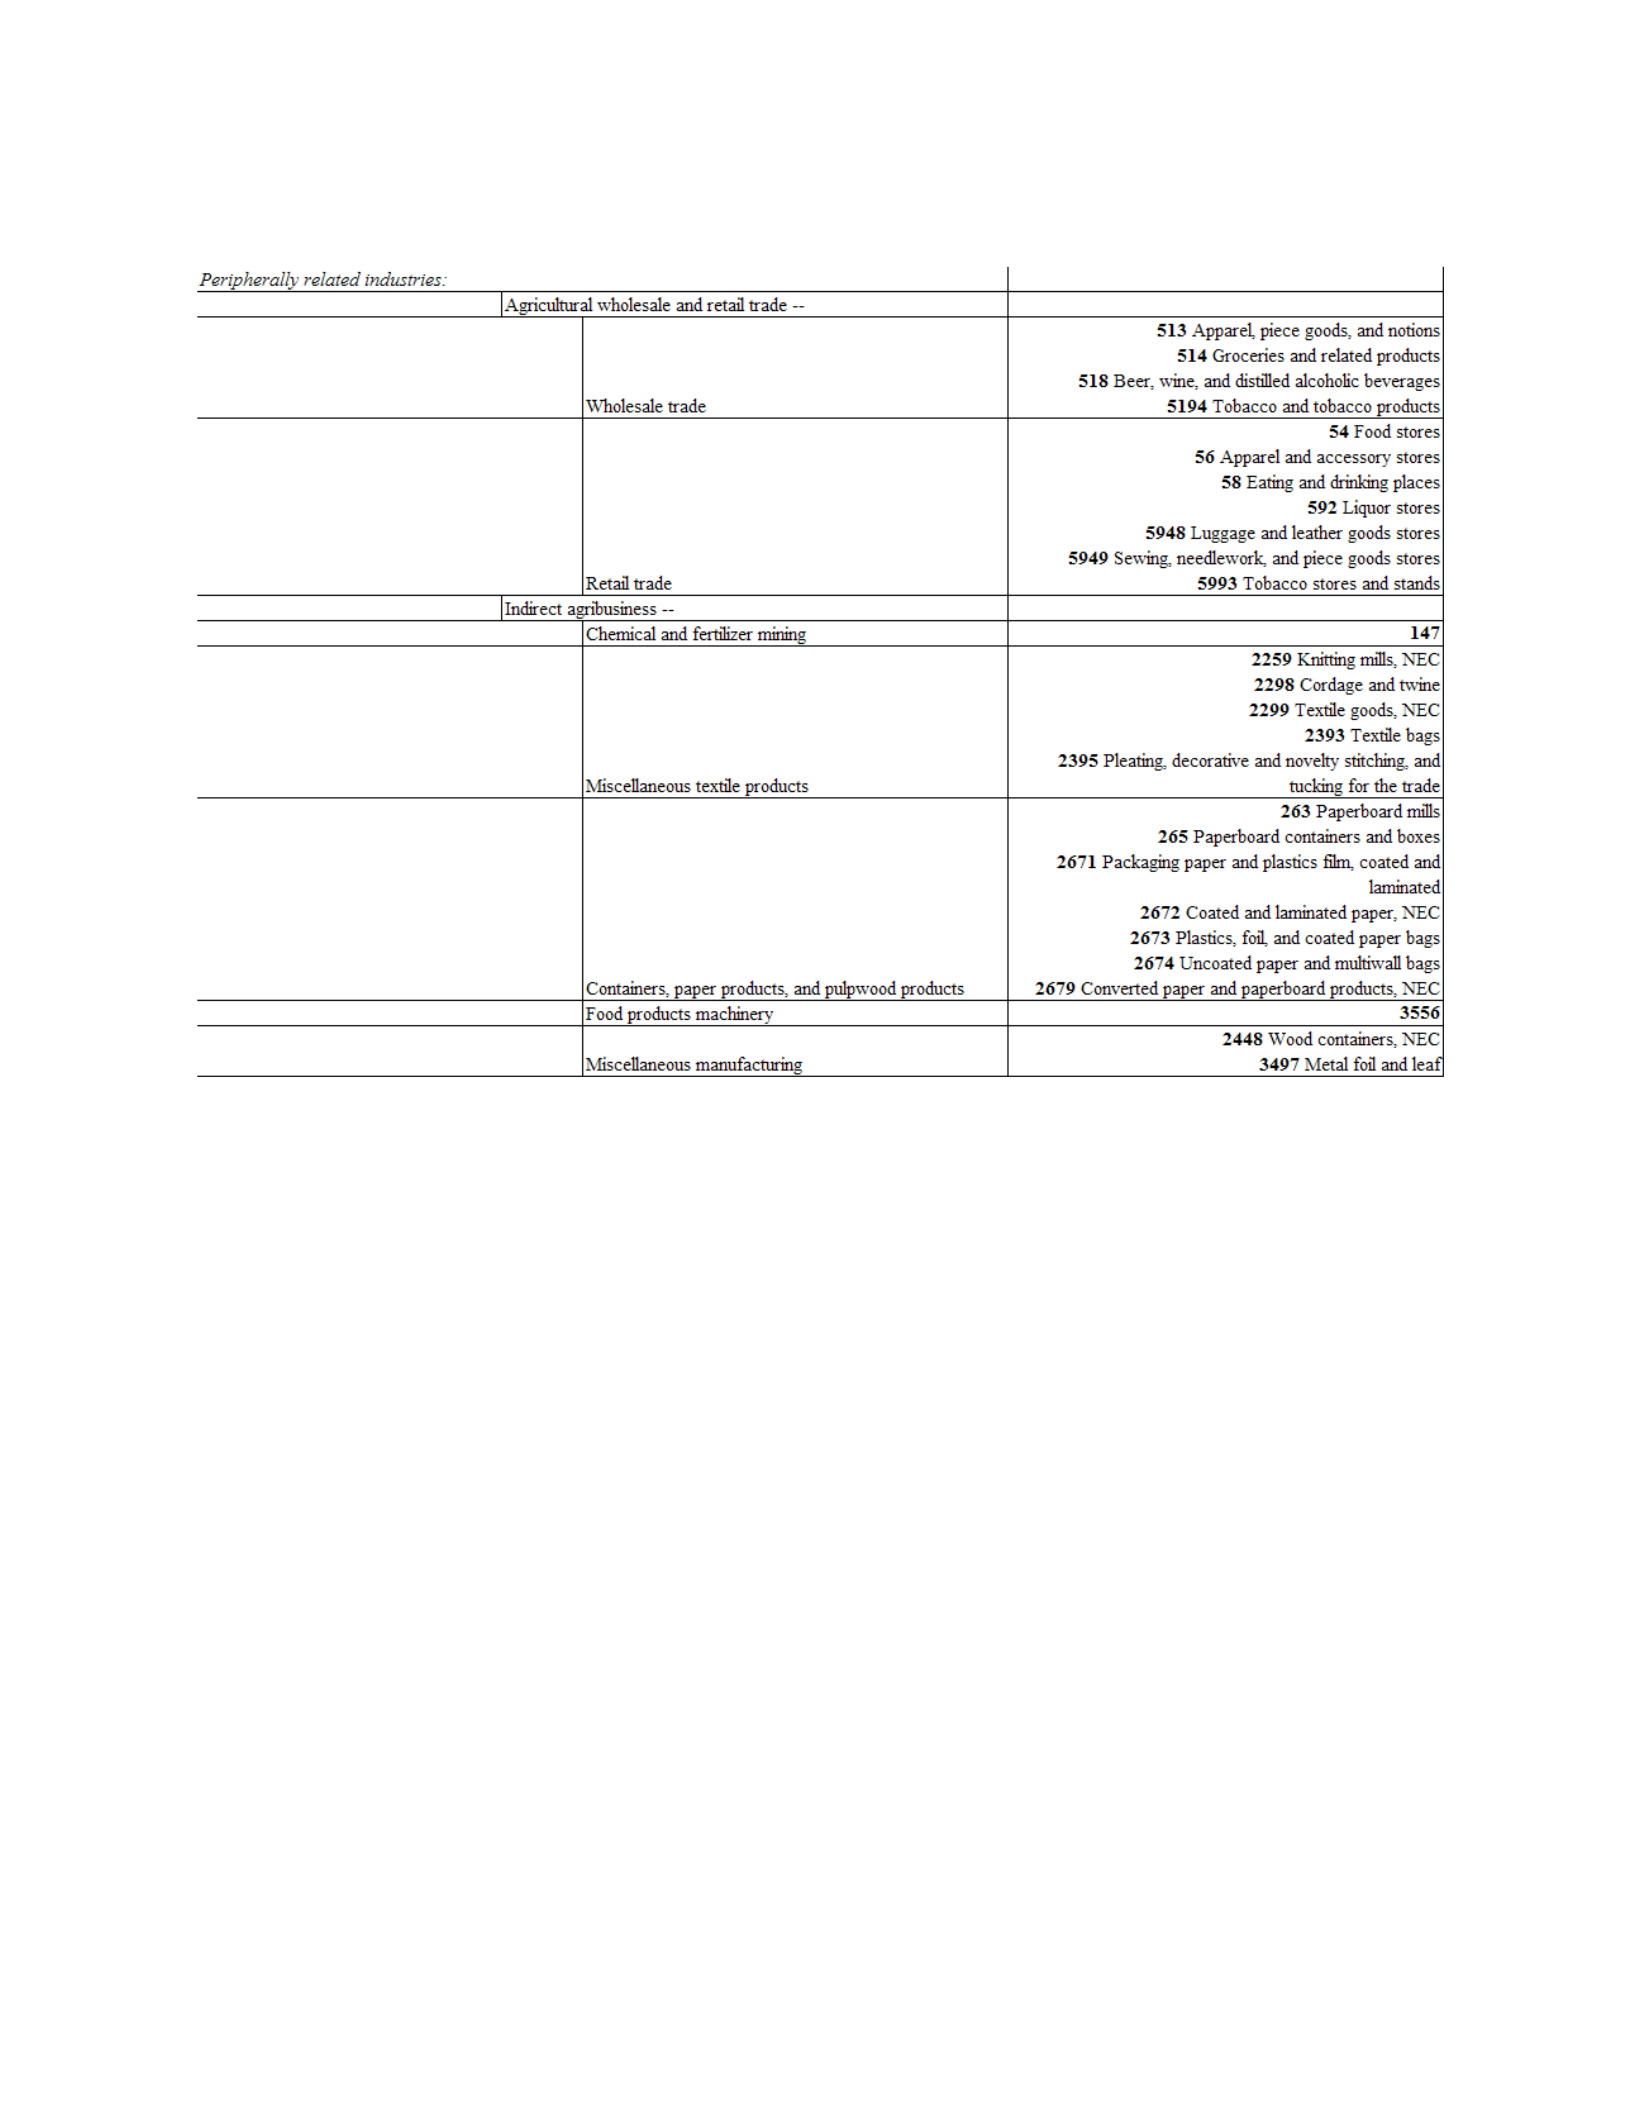
Peripherally
related
industries:
[Agricultural
wholesale
and
retail
trade
—
Wholesale
trade
‘513
Apparel,
piece
goods,
and
notions|
514
Groceries
and
related
products|
518
Beer,
wine,
and
distilled
alcoholic
beverages|
5194
Tobacco
and
tobacco
products|
[Retail
trade
‘54
Food
stores|
‘56
Apparel
and
accessory
stores|
‘58
Eating
and
drinking
places|
‘592
Liquor
stores
5948
Luggage
and
leather
goods
stores|
5949
Sewing,
needlework,
and
piece
goods
stores|
5993
Tobacco
stores
and
stands
[Indirect
a:
‘business
—
[Chemical
and
fertilizer
mining
147|
[Miscellaneous
textile
products
2259
Knitting
mills,
NEC|
2298
Cordage and
twine|
2299
Textile
goods,
NEC|
2393
Textile
bags
2395
Pleating,
decorative
and
novelty
stitching,
andl
tucking
for
the
trade|
|Containers,
paper
products,
and
pulpwood
products
263
Paperboard
mils
265
Paperboard
containers
and
boxes|
2671
Packaging
paper
and
plastics
film,
coated
and|
laminated
2672
Coated and
laminated
paper,
NEC|
2673
Plastics,
foil
and
coated
paper
bags
2674
Uncoated
paper
and
mutiwall
bags
2679
Converted
paper
and
paperboard
products,
NEC|
[Food
products
machinery
3556|
Miscellaneous
manufacturing
2448
Wood
containers,
NEC|
3497
Metal
foil
and
leat
63
(APPENDIX C CONTINUED)
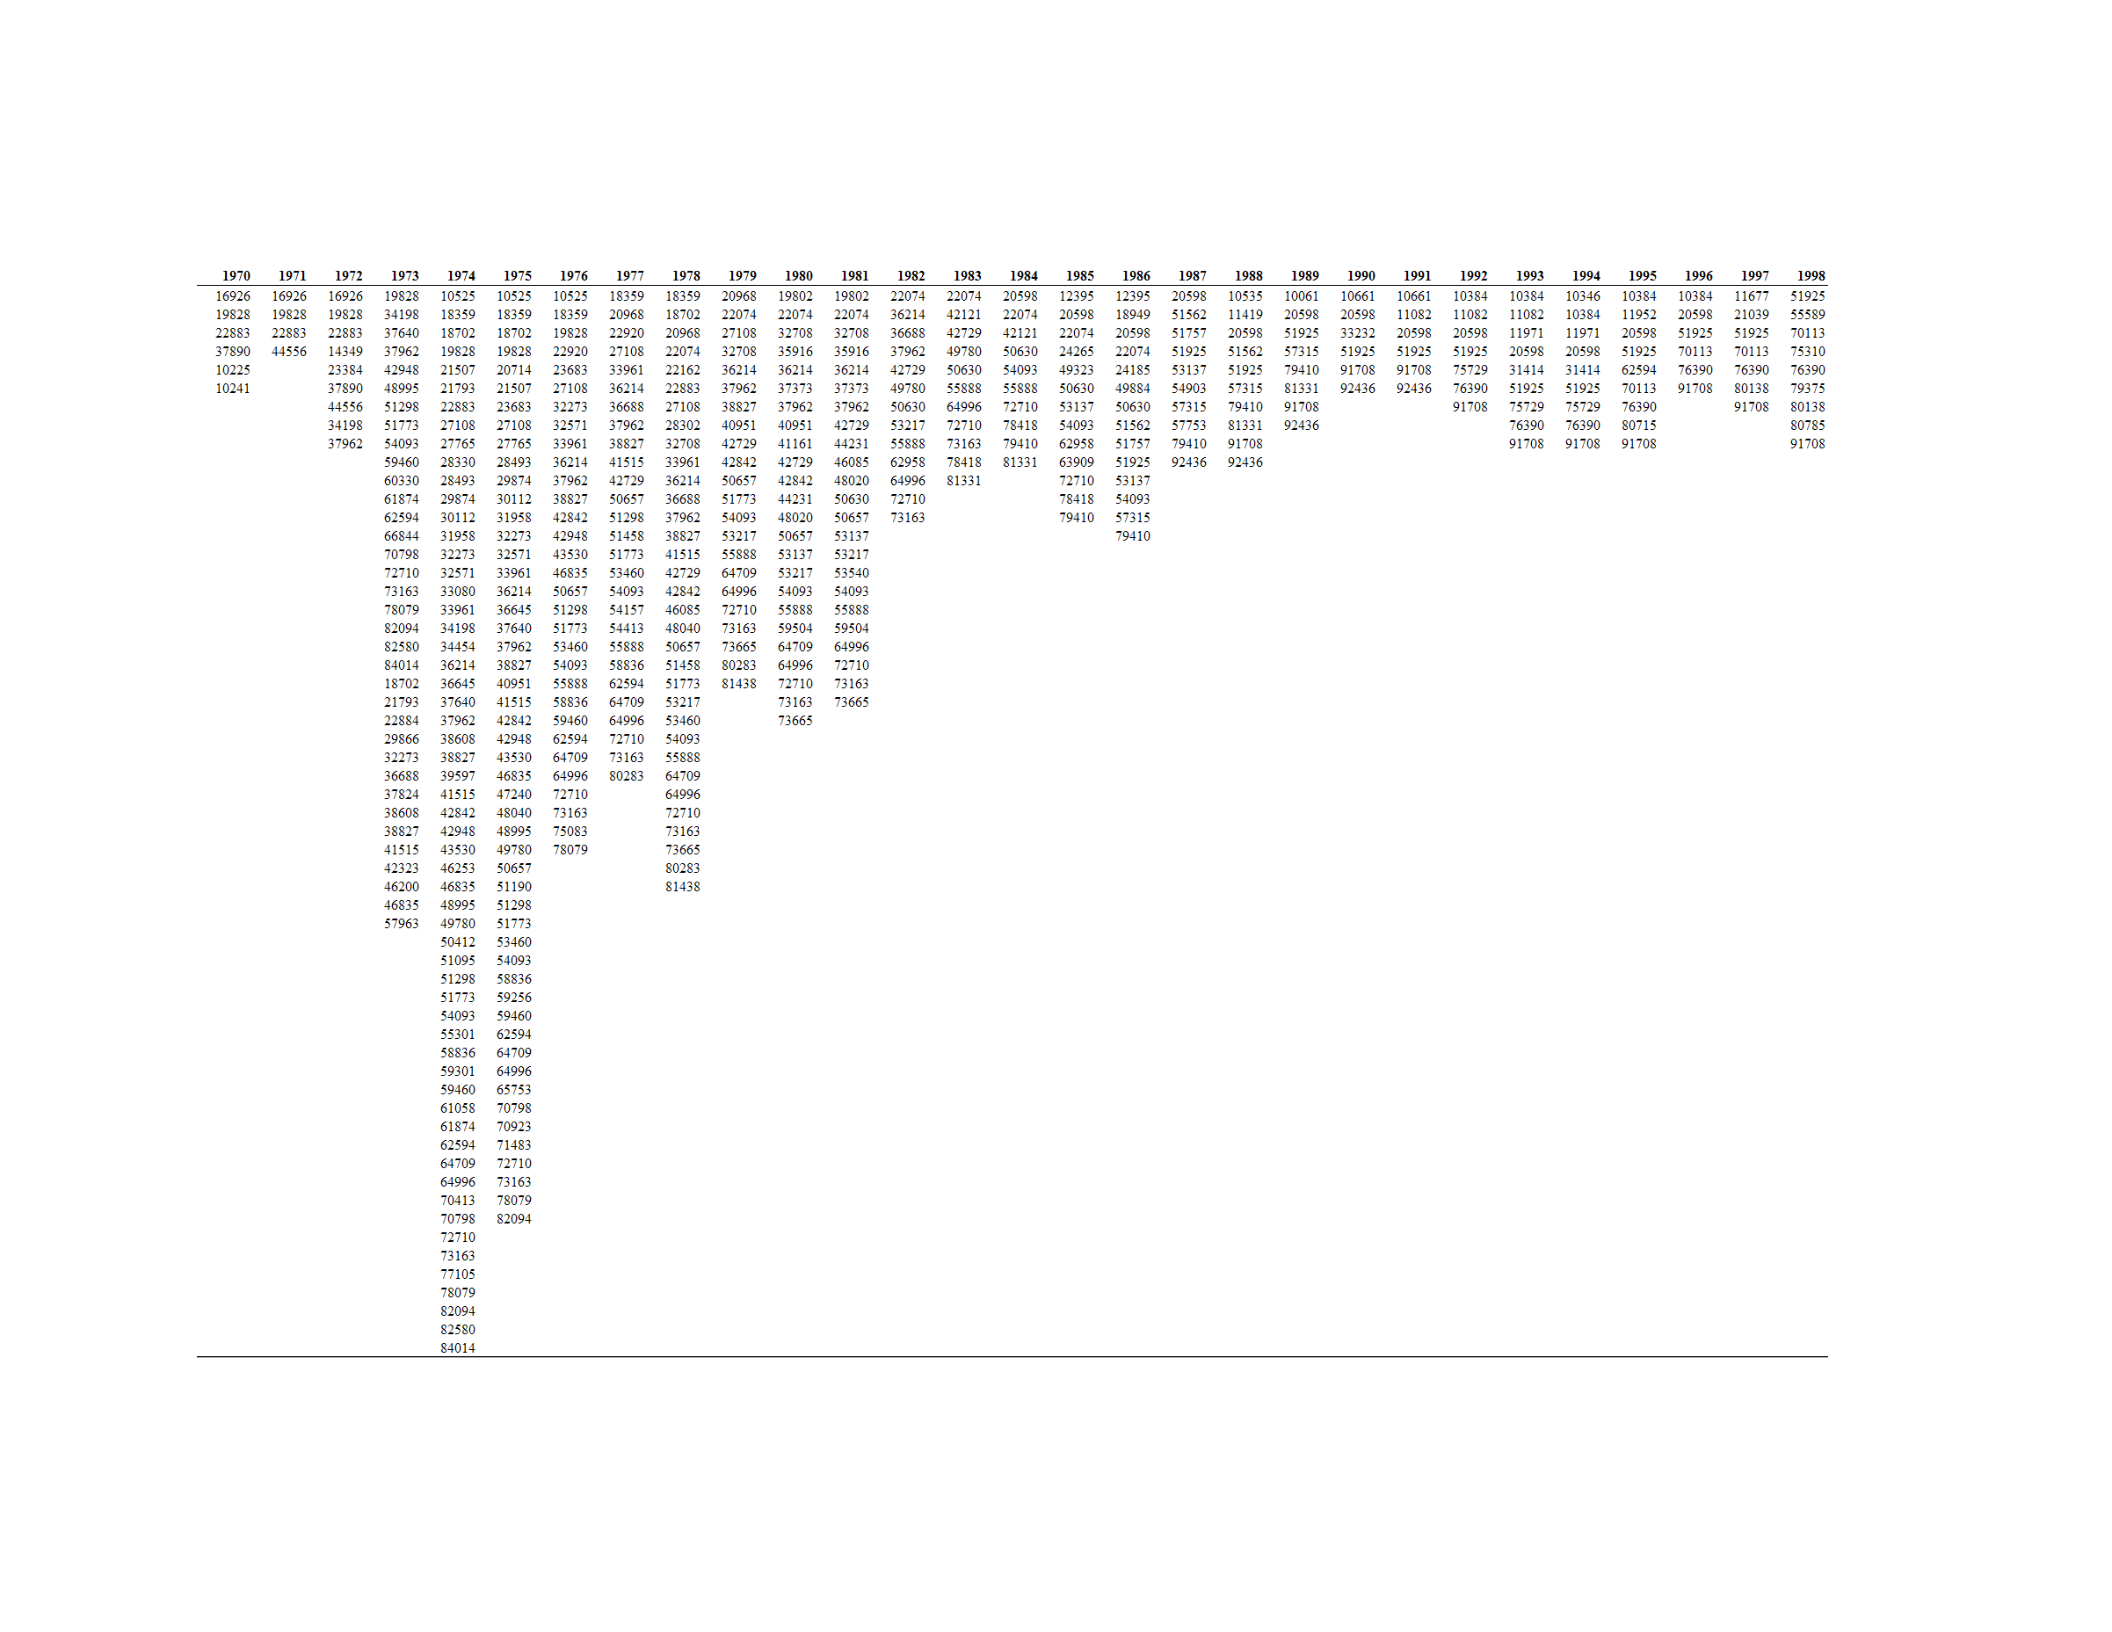
64
APPENDIX D: FIRMS DROPPED FROM THE INDEX BY CRSP PERMANENT NUMBER (1970-2008)*
* No firms were cut from the sample because of missing data for the following years: 1999, 2000, 2001, 2002, 2003, 2004, 2005, 2006, 2007, or 2008.
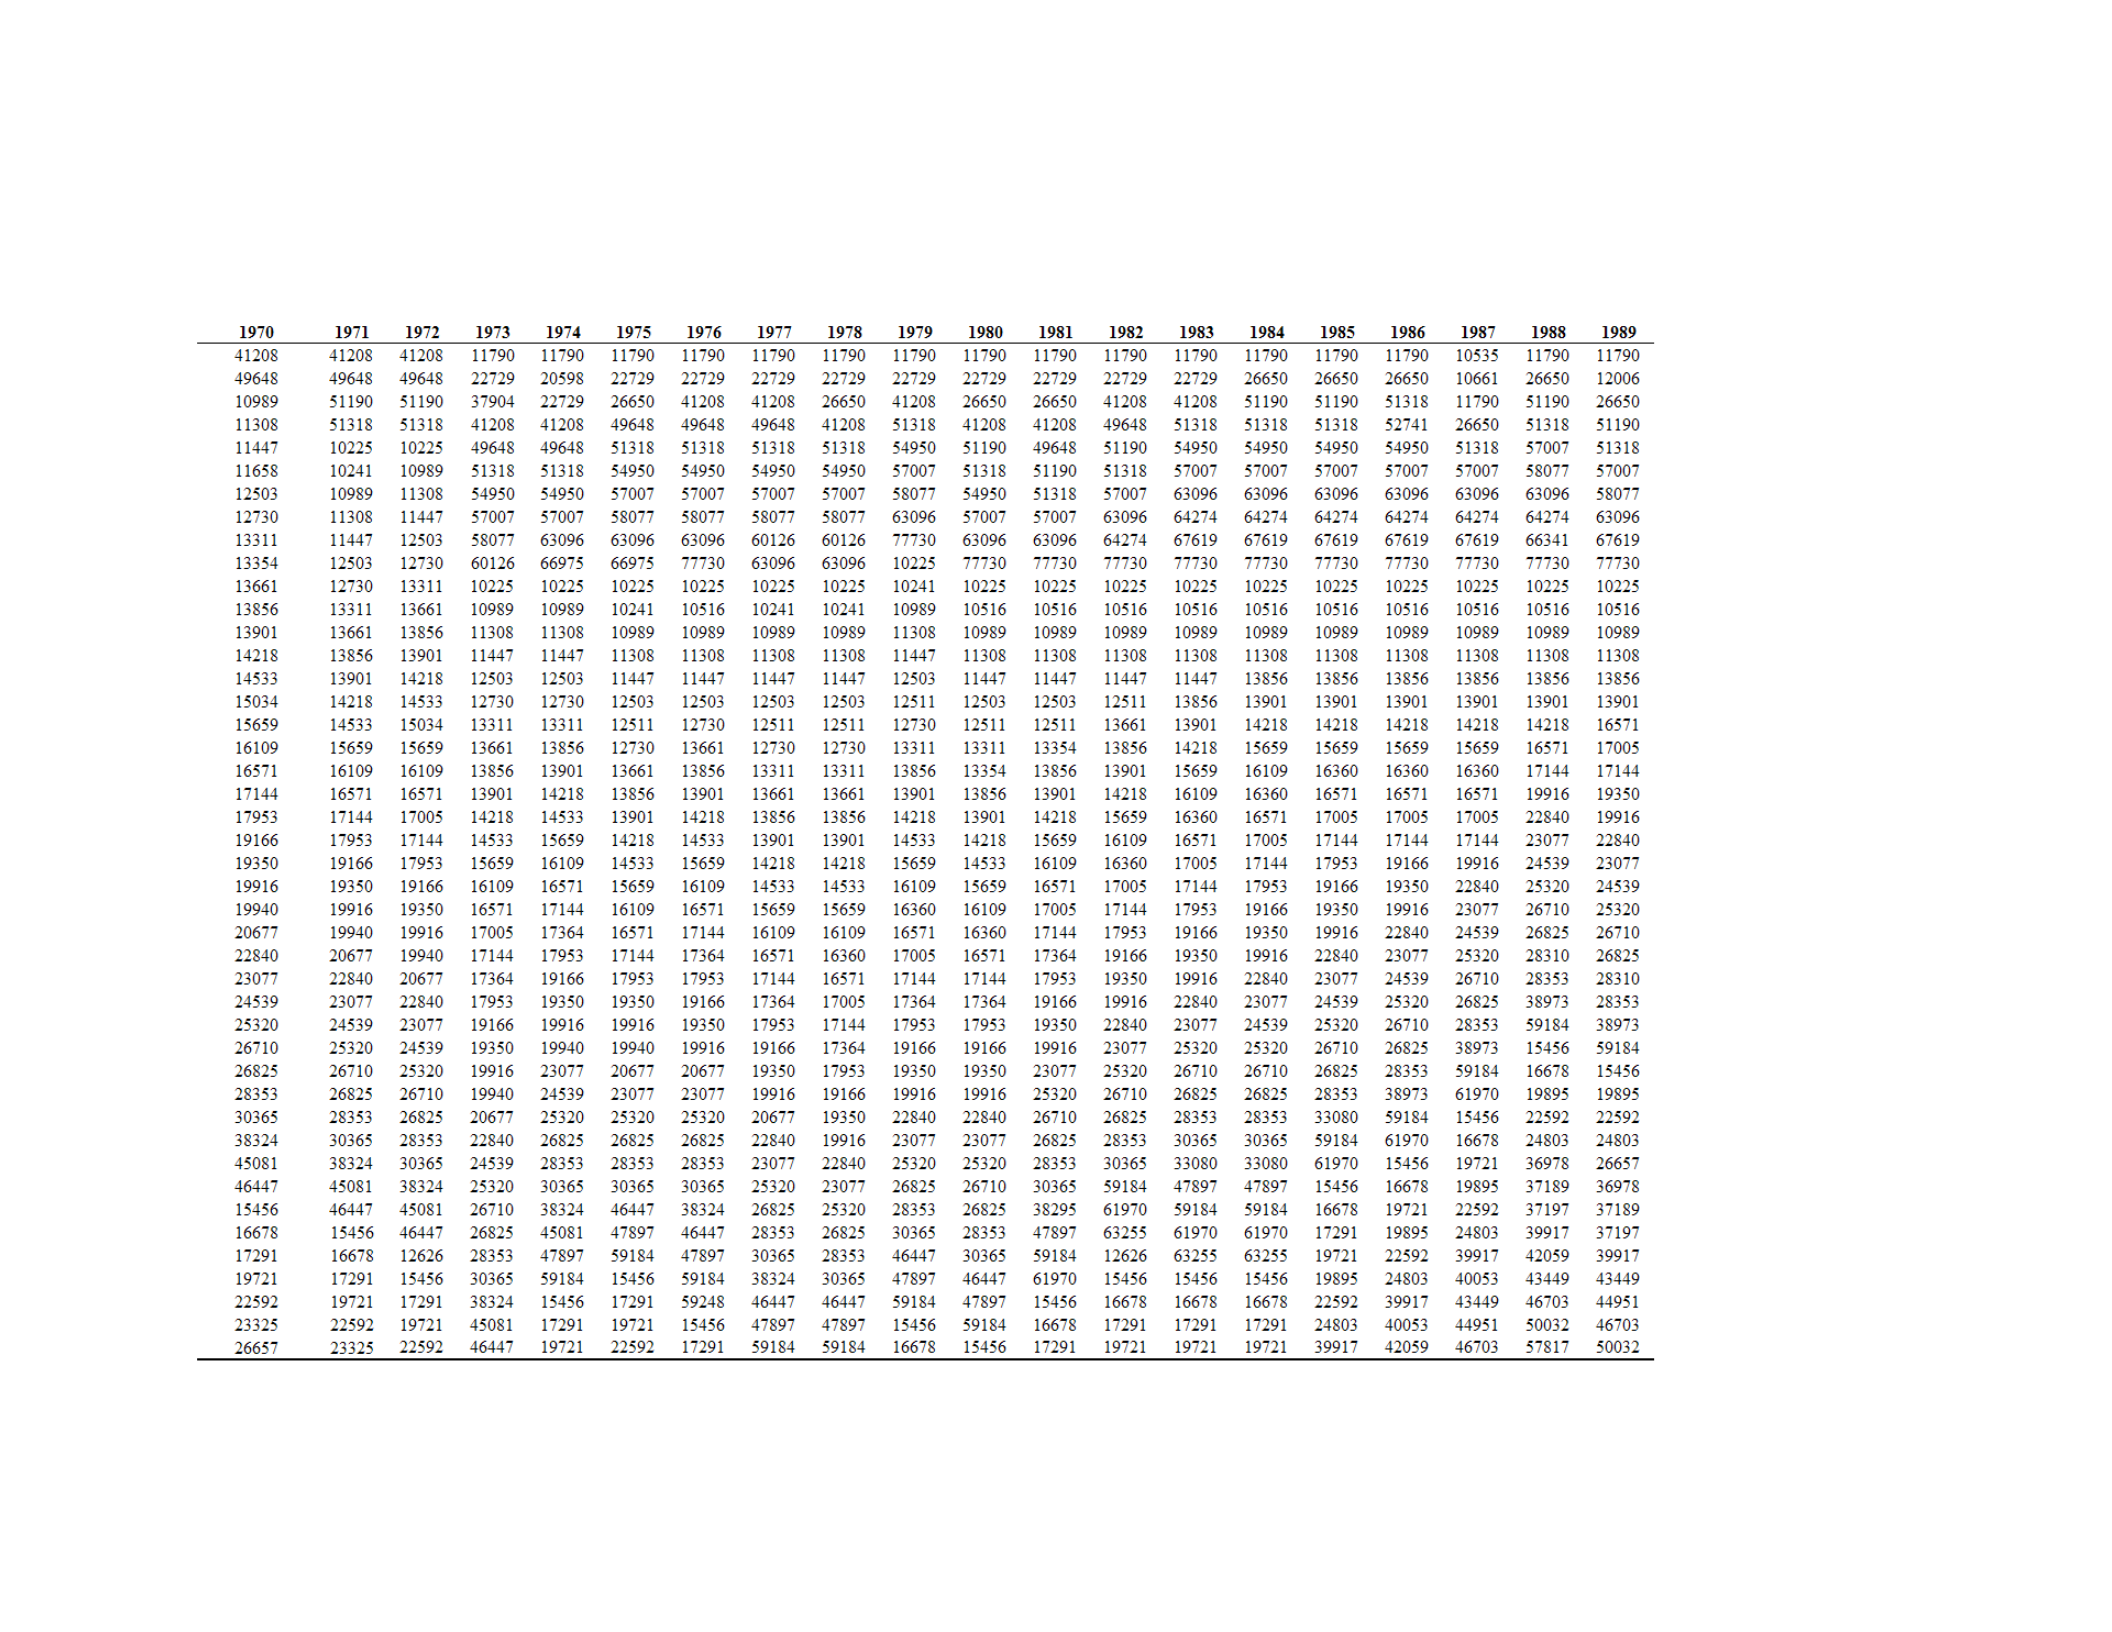
65
APPENDIX E: AG INDEX CONSTITUENTS BY CRSP PERMANENT NUMBER (1970-1989)
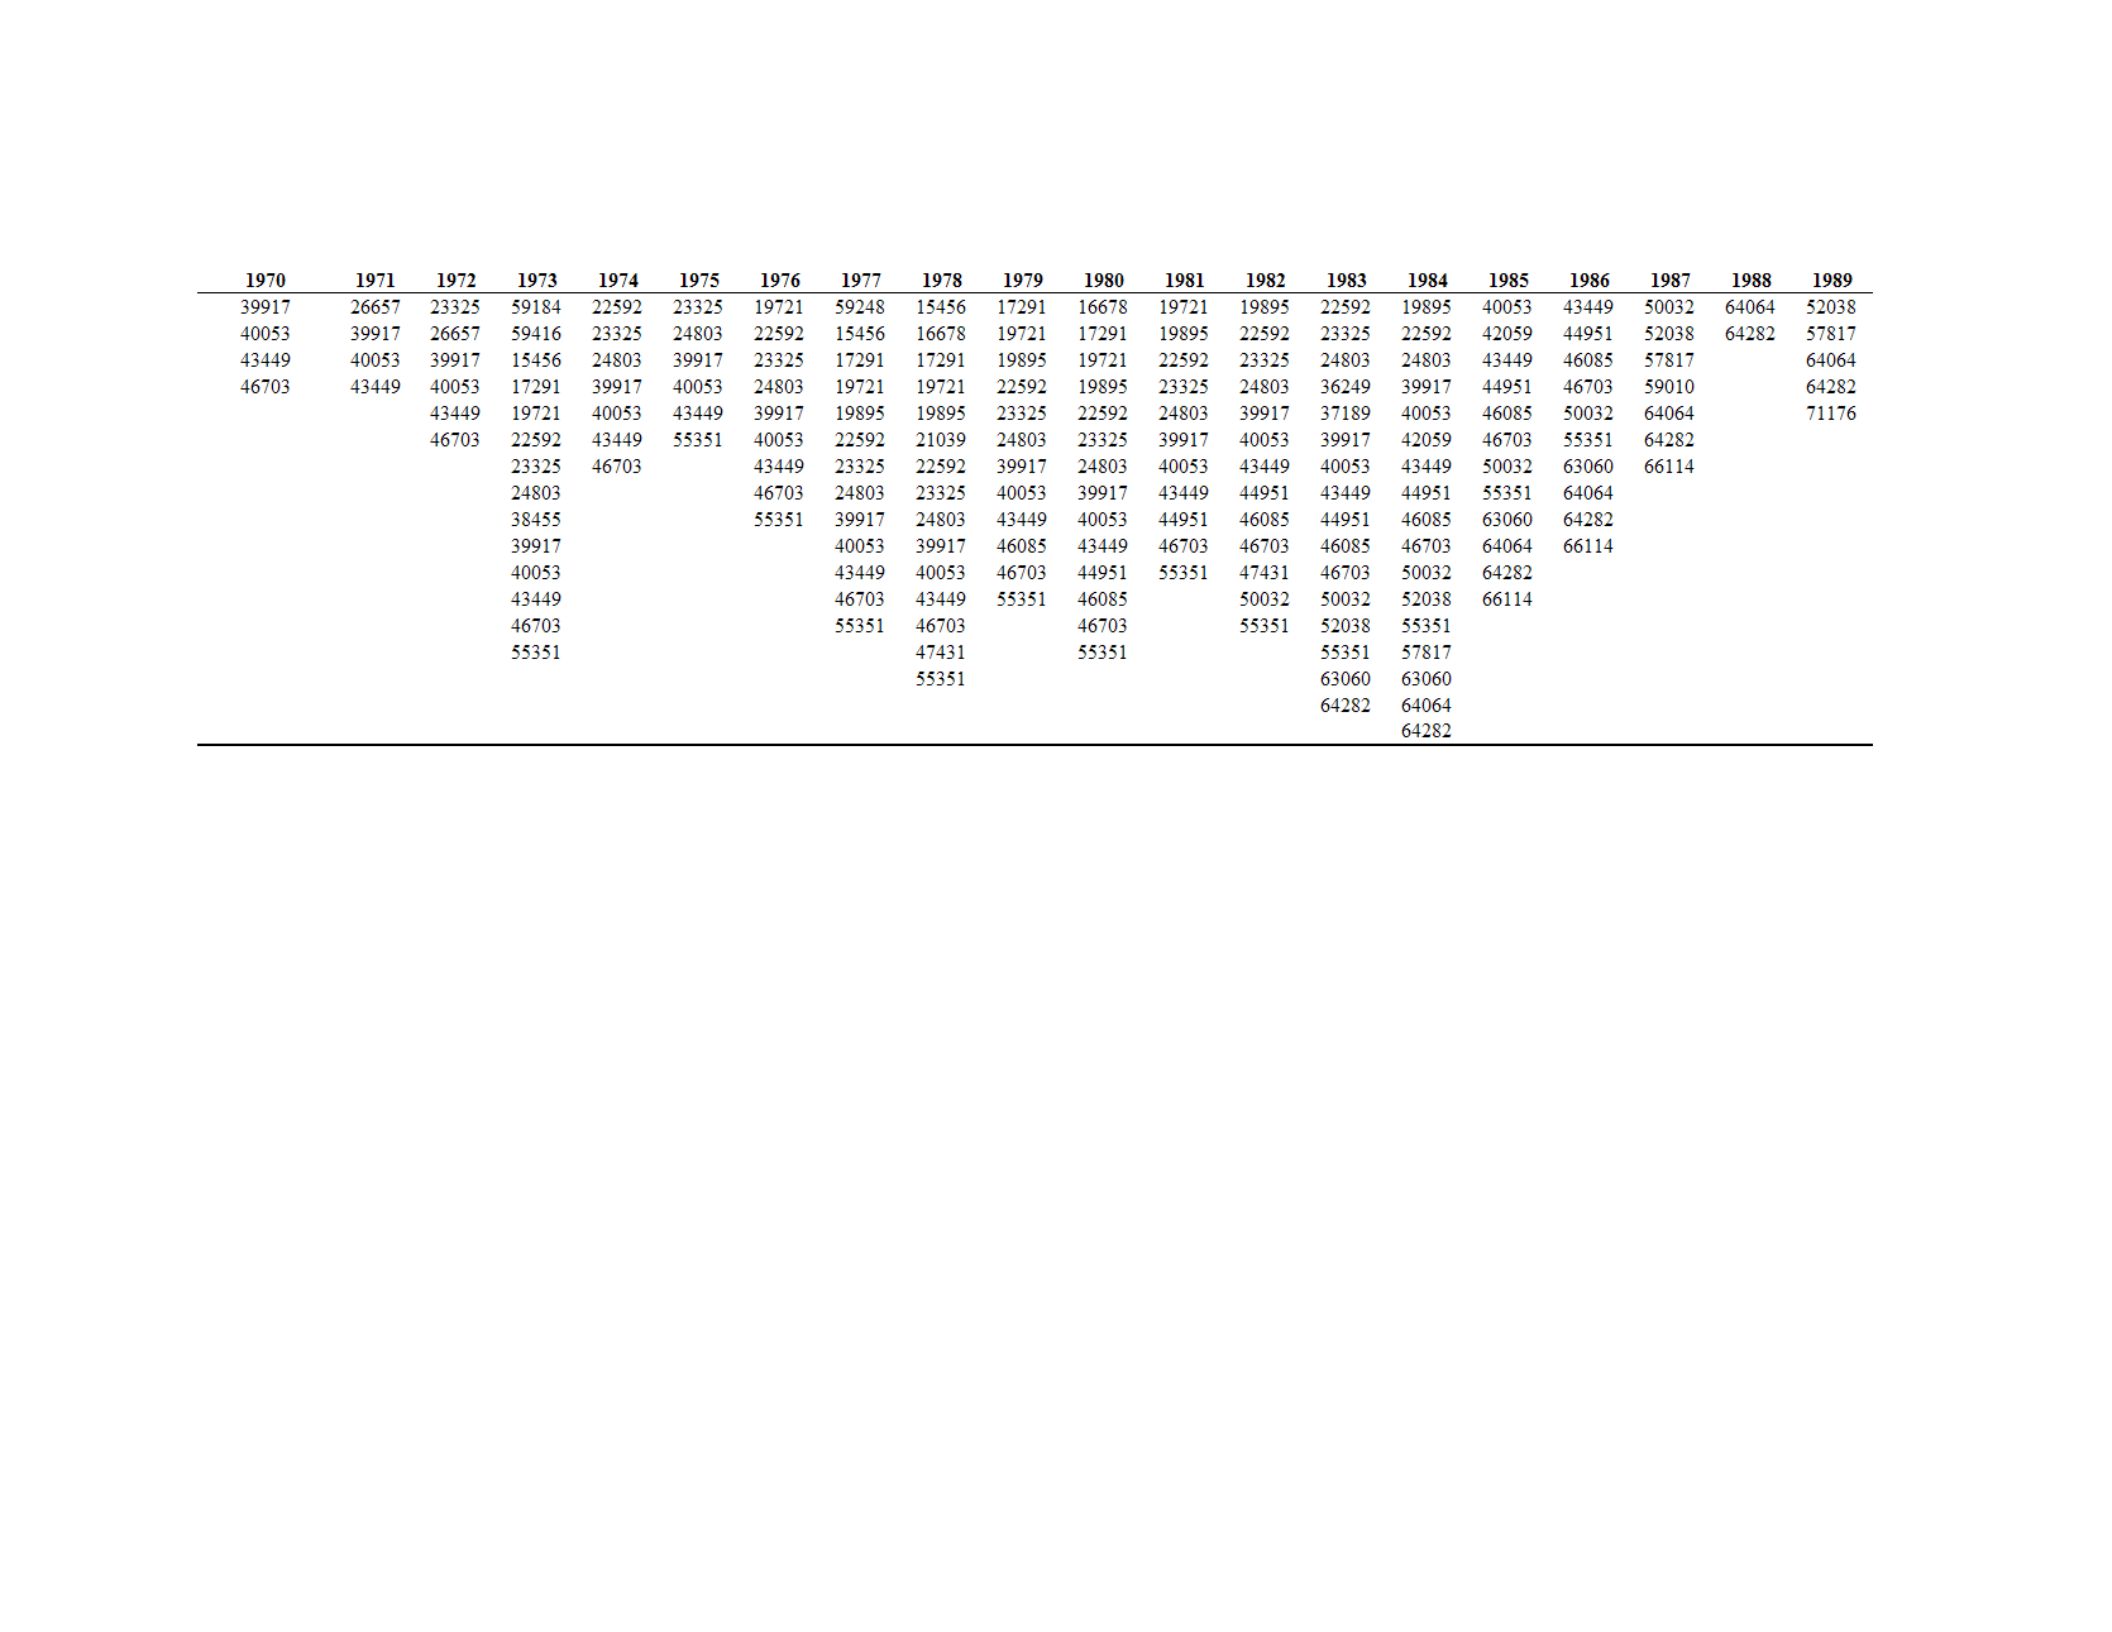
66
(APPENDIX E CONTINUED)
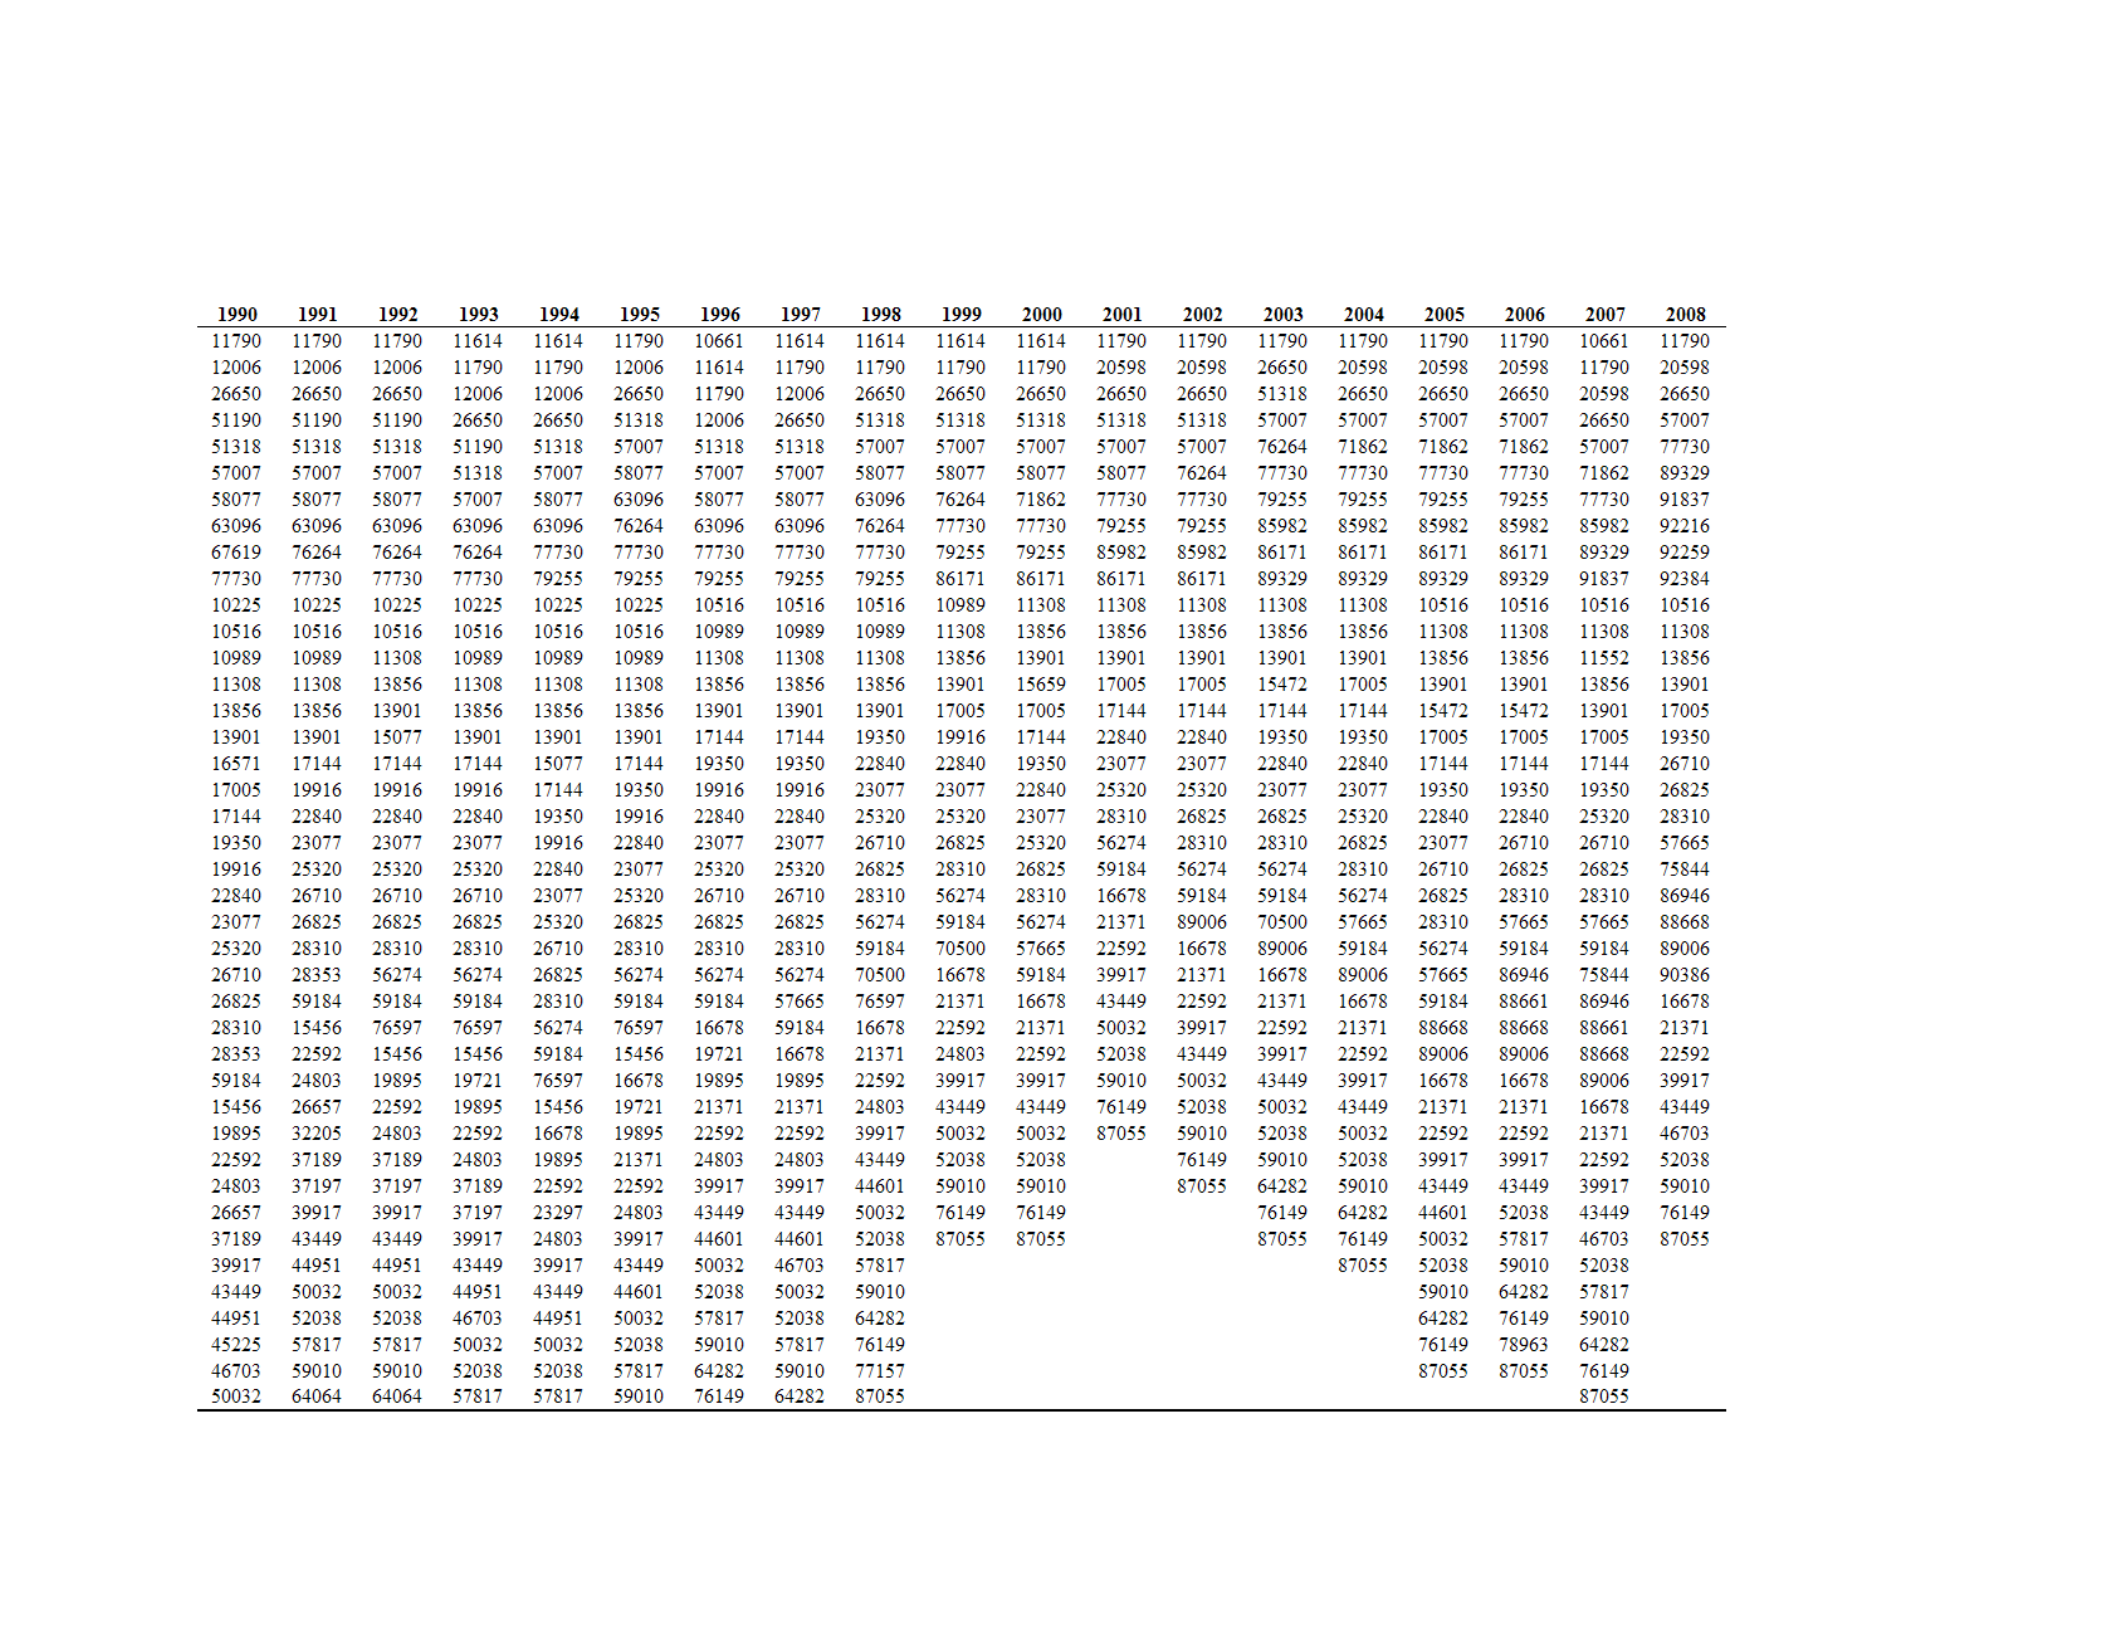
67
APPENDIX F: AG INDEX CCONSTITUENTS BY CRSP PERMANENT NUMBER (1990-2008)
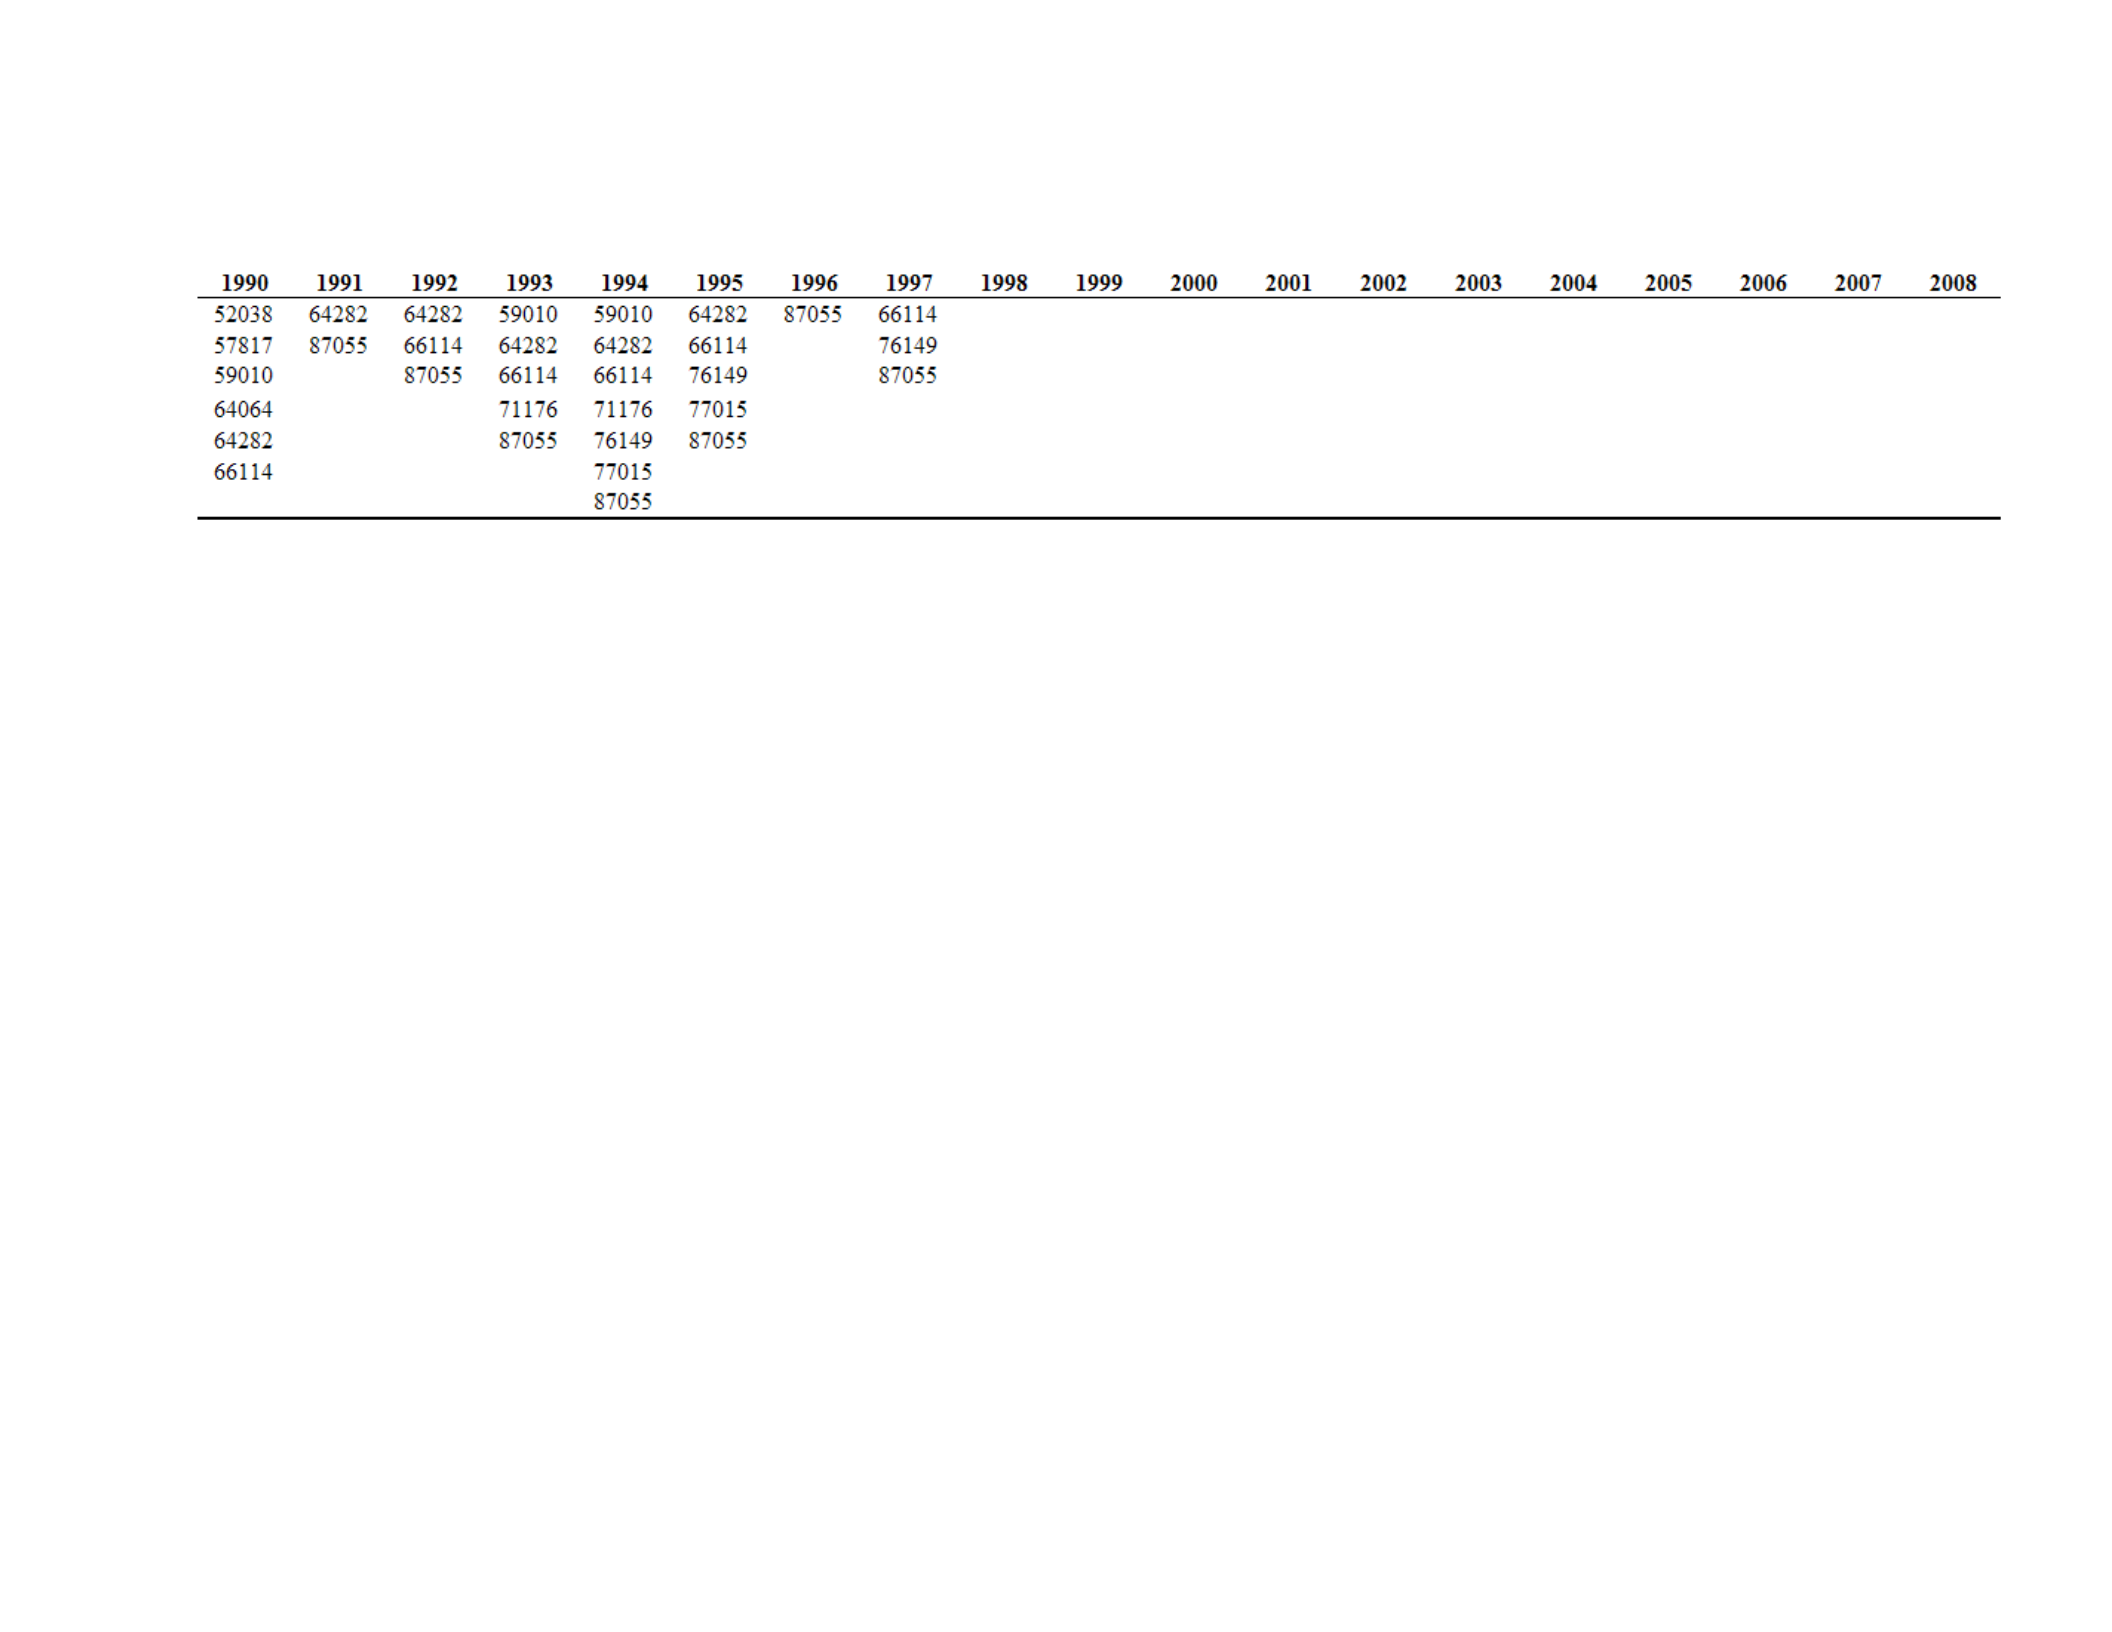
68
(APPENDIX F CONTINUED)
69
APPENDIX G: NUMBER OF TRADING DAYS BY YEAR (1970-2008)
Year # of Trading Days
1970 254
1971 253
1972 251
1973 252
1974 253
1975 253
1976 253
1977 252
1978 252
1979 253
1980 253
1981 253
1982 253
1983 253
1984 253
1985 252
1986 253
1987 253
1988 253
1989 252
1990 253
1991 253
1992 254
1993 253
1994 252
1995 252
1996 254
1997 253
1998 252
1999 252
2000 252
2001 248
2002 252
2003 252
2004 252
2005 252
2006 251
2007 251
2008 253
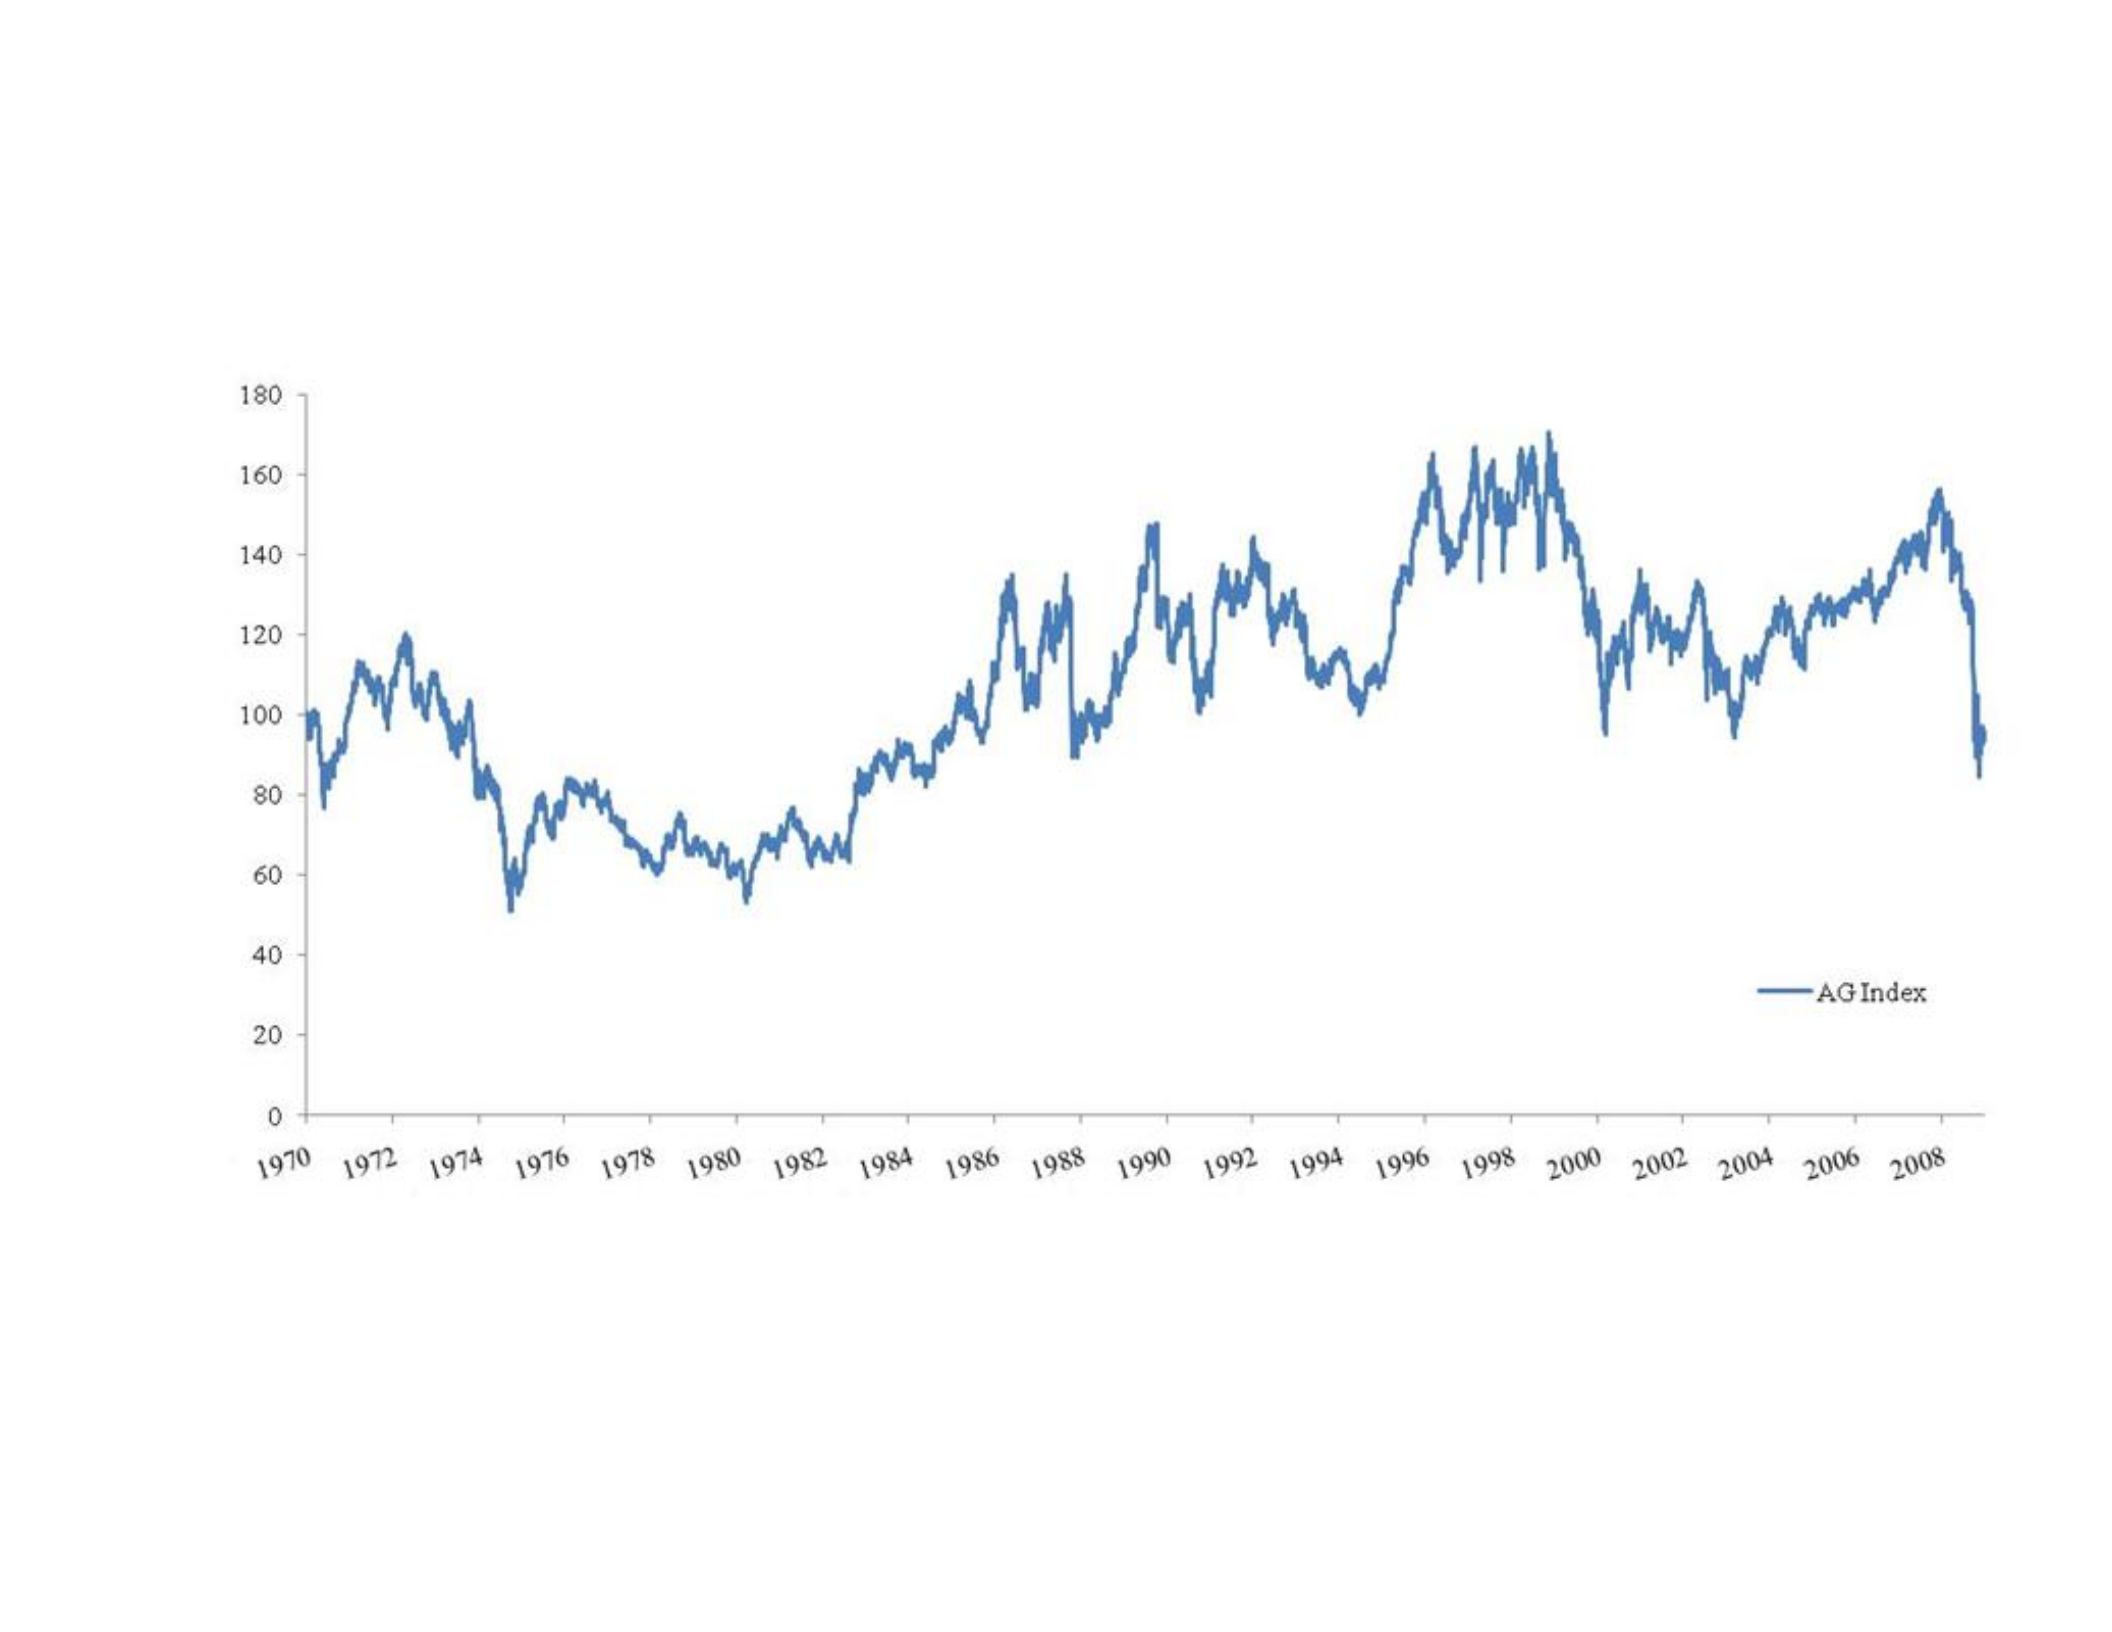
70
APPENDIX H: GRAPH - AG INDEX VALUE (1970-2008)
71
APPENDIX I: ANNUAL GEOMETRIC RETURN, AG INDEX, S&P 500, AND THE DOW
JONES INDUSTRIAL AVERAGE (1970-2008)
Period AG Index S&P 500 Dow Jones
1970 1.58935%* -0.91398% 3.67276%
1971 7.62254%* 12.00219% 7.17941%
1972 1.85683% 16.11095% 14.69920%
1973 -23.82525% -18.09404% -17.52675%
1974 -31.01787% -29.81163% -27.95211%
1975 29.02264%* 28.42090% 34.86646%
1976 5.30076% 18.21782% 16.99526%
1977 -19.23706% -11.12150% -16.86222%
1978 2.89380% 2.44084% -1.55673%
1979 -7.29580% 11.58896% 3.36694%
1980 14.28594% 28.36611% 16.90821%
1981 -3.72838% -10.11442% -10.05160%
1982 23.92878% 14.58367% 18.58541%
1983 10.52141% 19.22076% 22.55024%
1984 5.28449% 1.95074% -3.28640%
1985 18.68194% 27.76199% 29.01065%
1986 -7.87475% 15.54463% 23.29538%
1987 -7.36100% 0.25563% 0.59772%
1988 12.64345% -4.43463% 7.60799%
1989 15.31872%* 0.93106% 28.37586%
1990 -12.63256% -8.19317% -6.28045%
1991 29.62800% 27.76535% 21.38135%
1992 -11.97989% 4.42170% 4.05685%
1993 -8.54084% 7.13629% 13.44335%
1994 -5.04279% -1.32563% 2.07209%
1995 38.20239% 34.15739% 33.31110%
1996 -2.59837% 19.33369% 24.54529%
1997 2.90604% 31.67121% 22.75145%
1998 5.51871% 26.06970% 15.27161%
1999 -24.01794% 19.63602% 25.18273%
2000 13.38657% -9.27282% -5.01448%
2001 -12.48483% -10.53481% -5.86672%
2002 -9.45797% -23.80334% -17.19151%
2003 10.43562% 22.31940% 21.45101%
2004 5.20083%* 9.33170% 3.58468%
2005 2.17573%* 3.84417% -0.11119%
2006 6.68611% 11.78279% 14.89517%
2007 10.41616% 3.65382% 6.33531%
2008 -36.76891%* -37.58465% -32.71683%
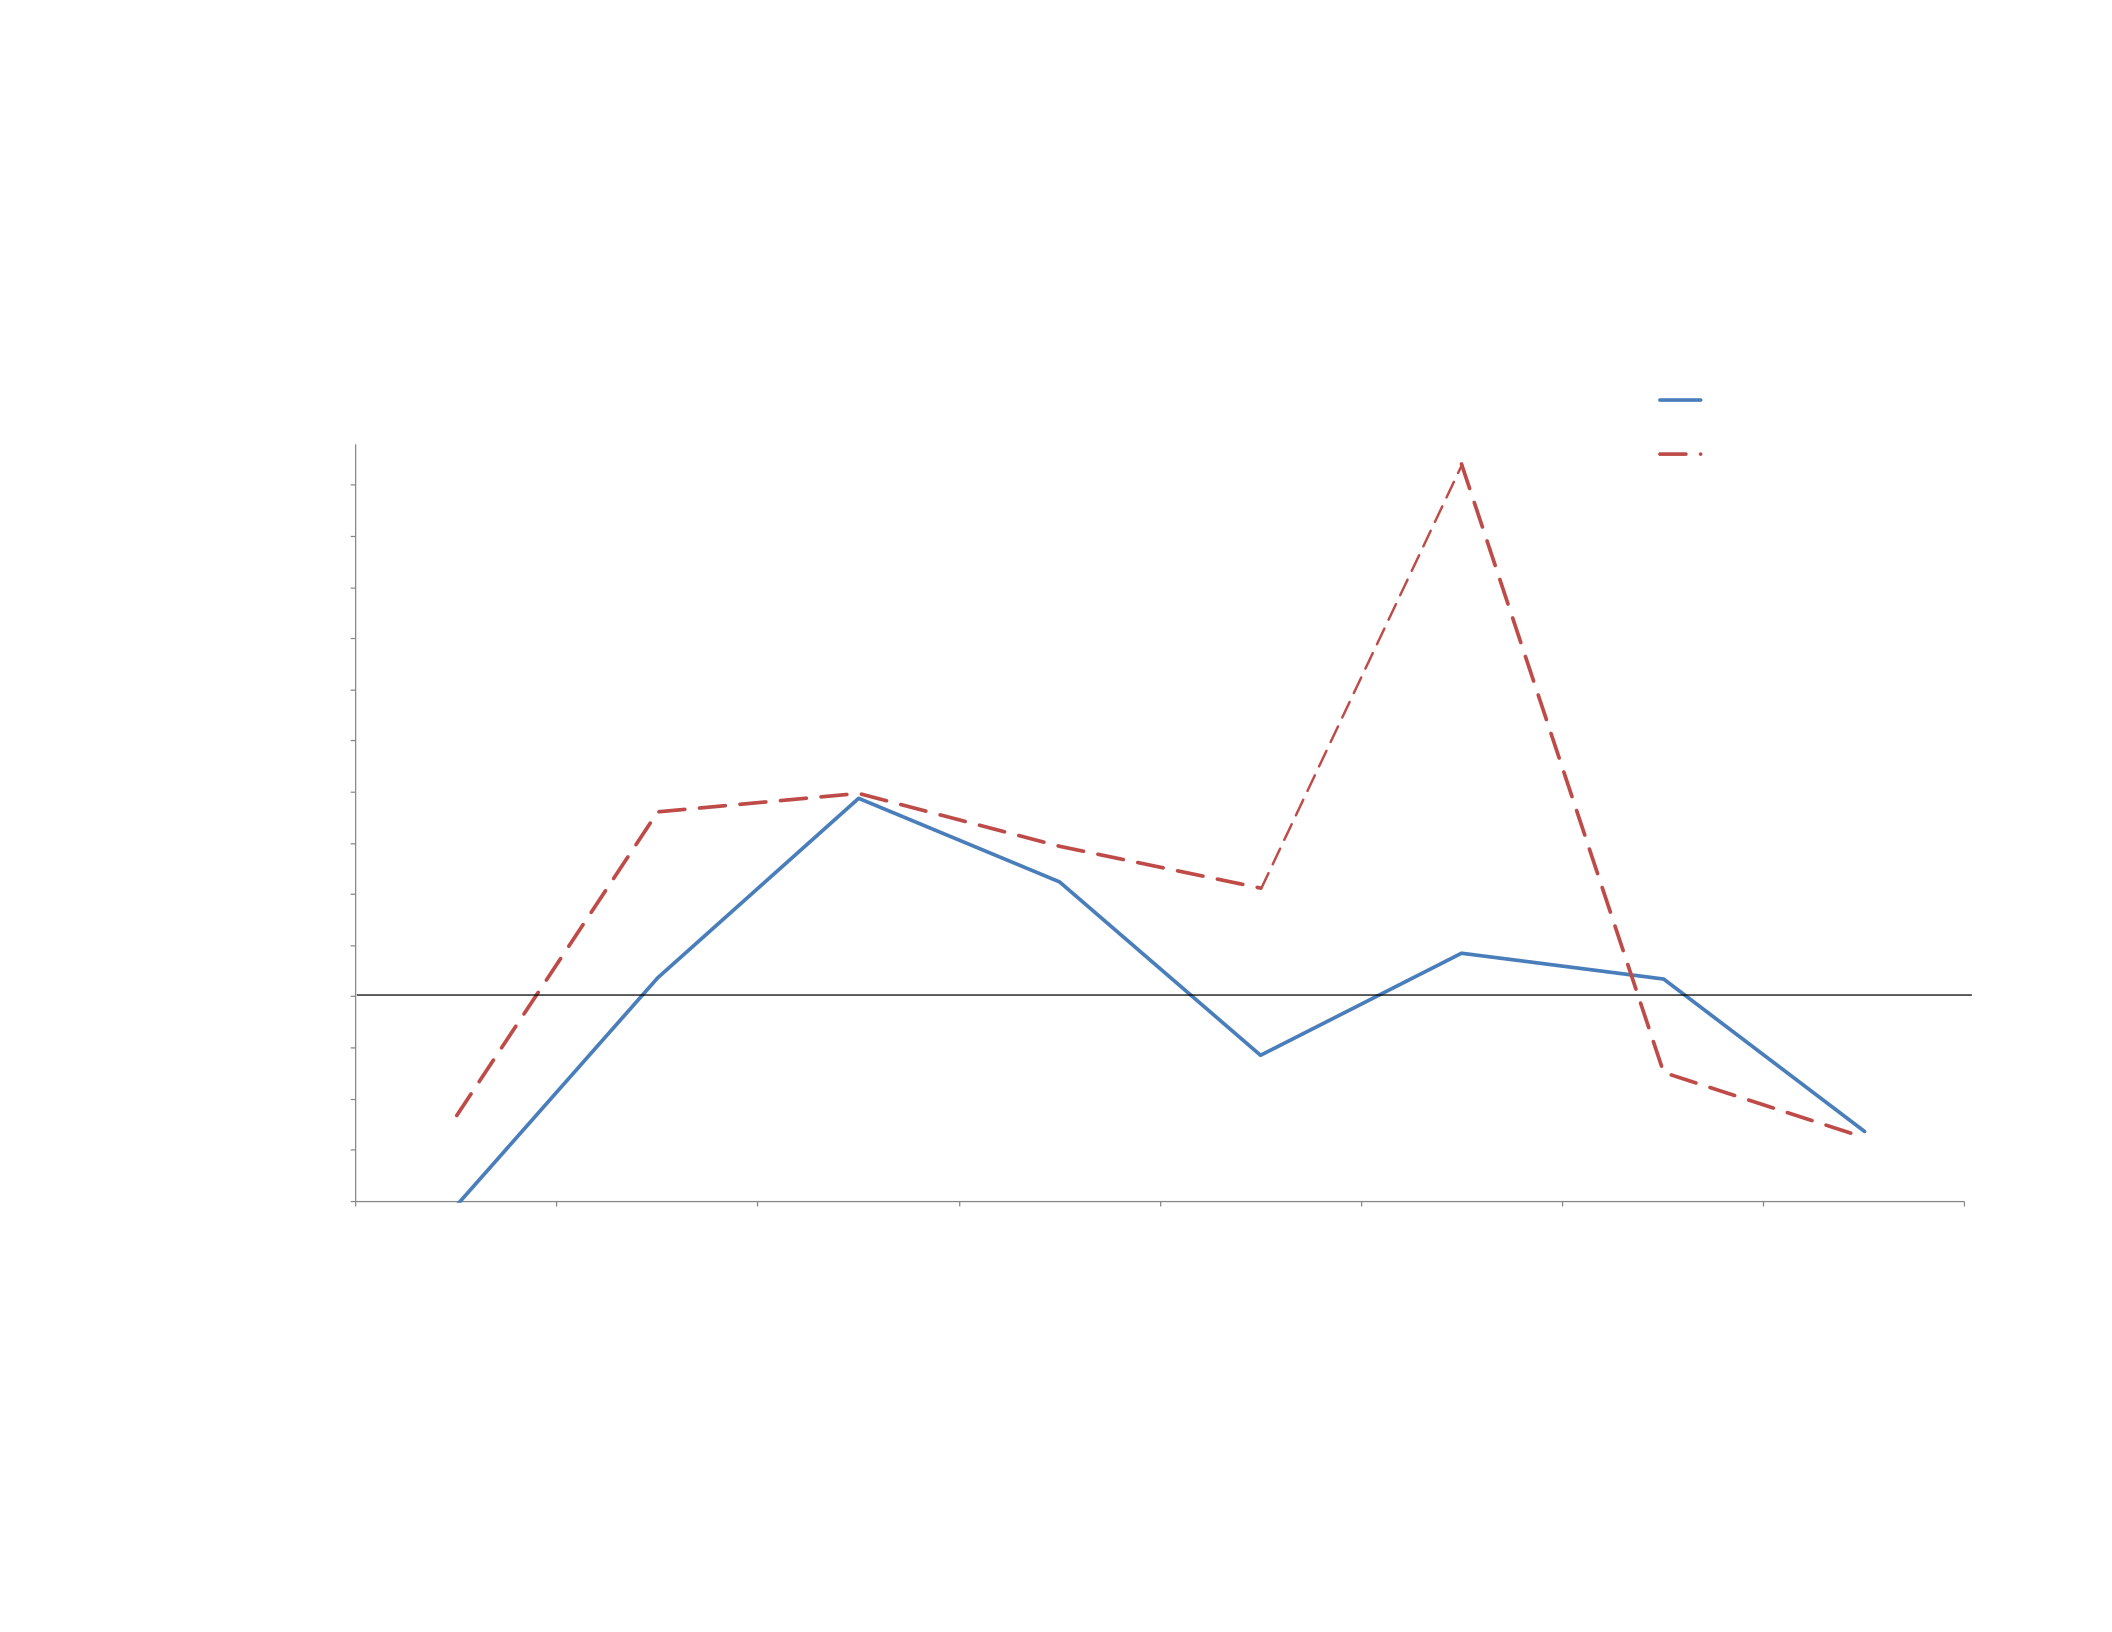
72
APPENDIX J: GRAPH - FIVE-YEAR GEOMETRIC RETURN, AG INDEX AND THE S&P 500 (1970-2008)
-10%
-8%
-5%
-3%
0%
3%
5%
8%
10%
13%
15%
18%
20%
23%
25%
1970-1974
1975-1979
1980-1984
1985-1989
1990-1994
1995-1999
2000-2004
2005-2008
AG Index -Geometric Return
S&P 500 - Geometric Return
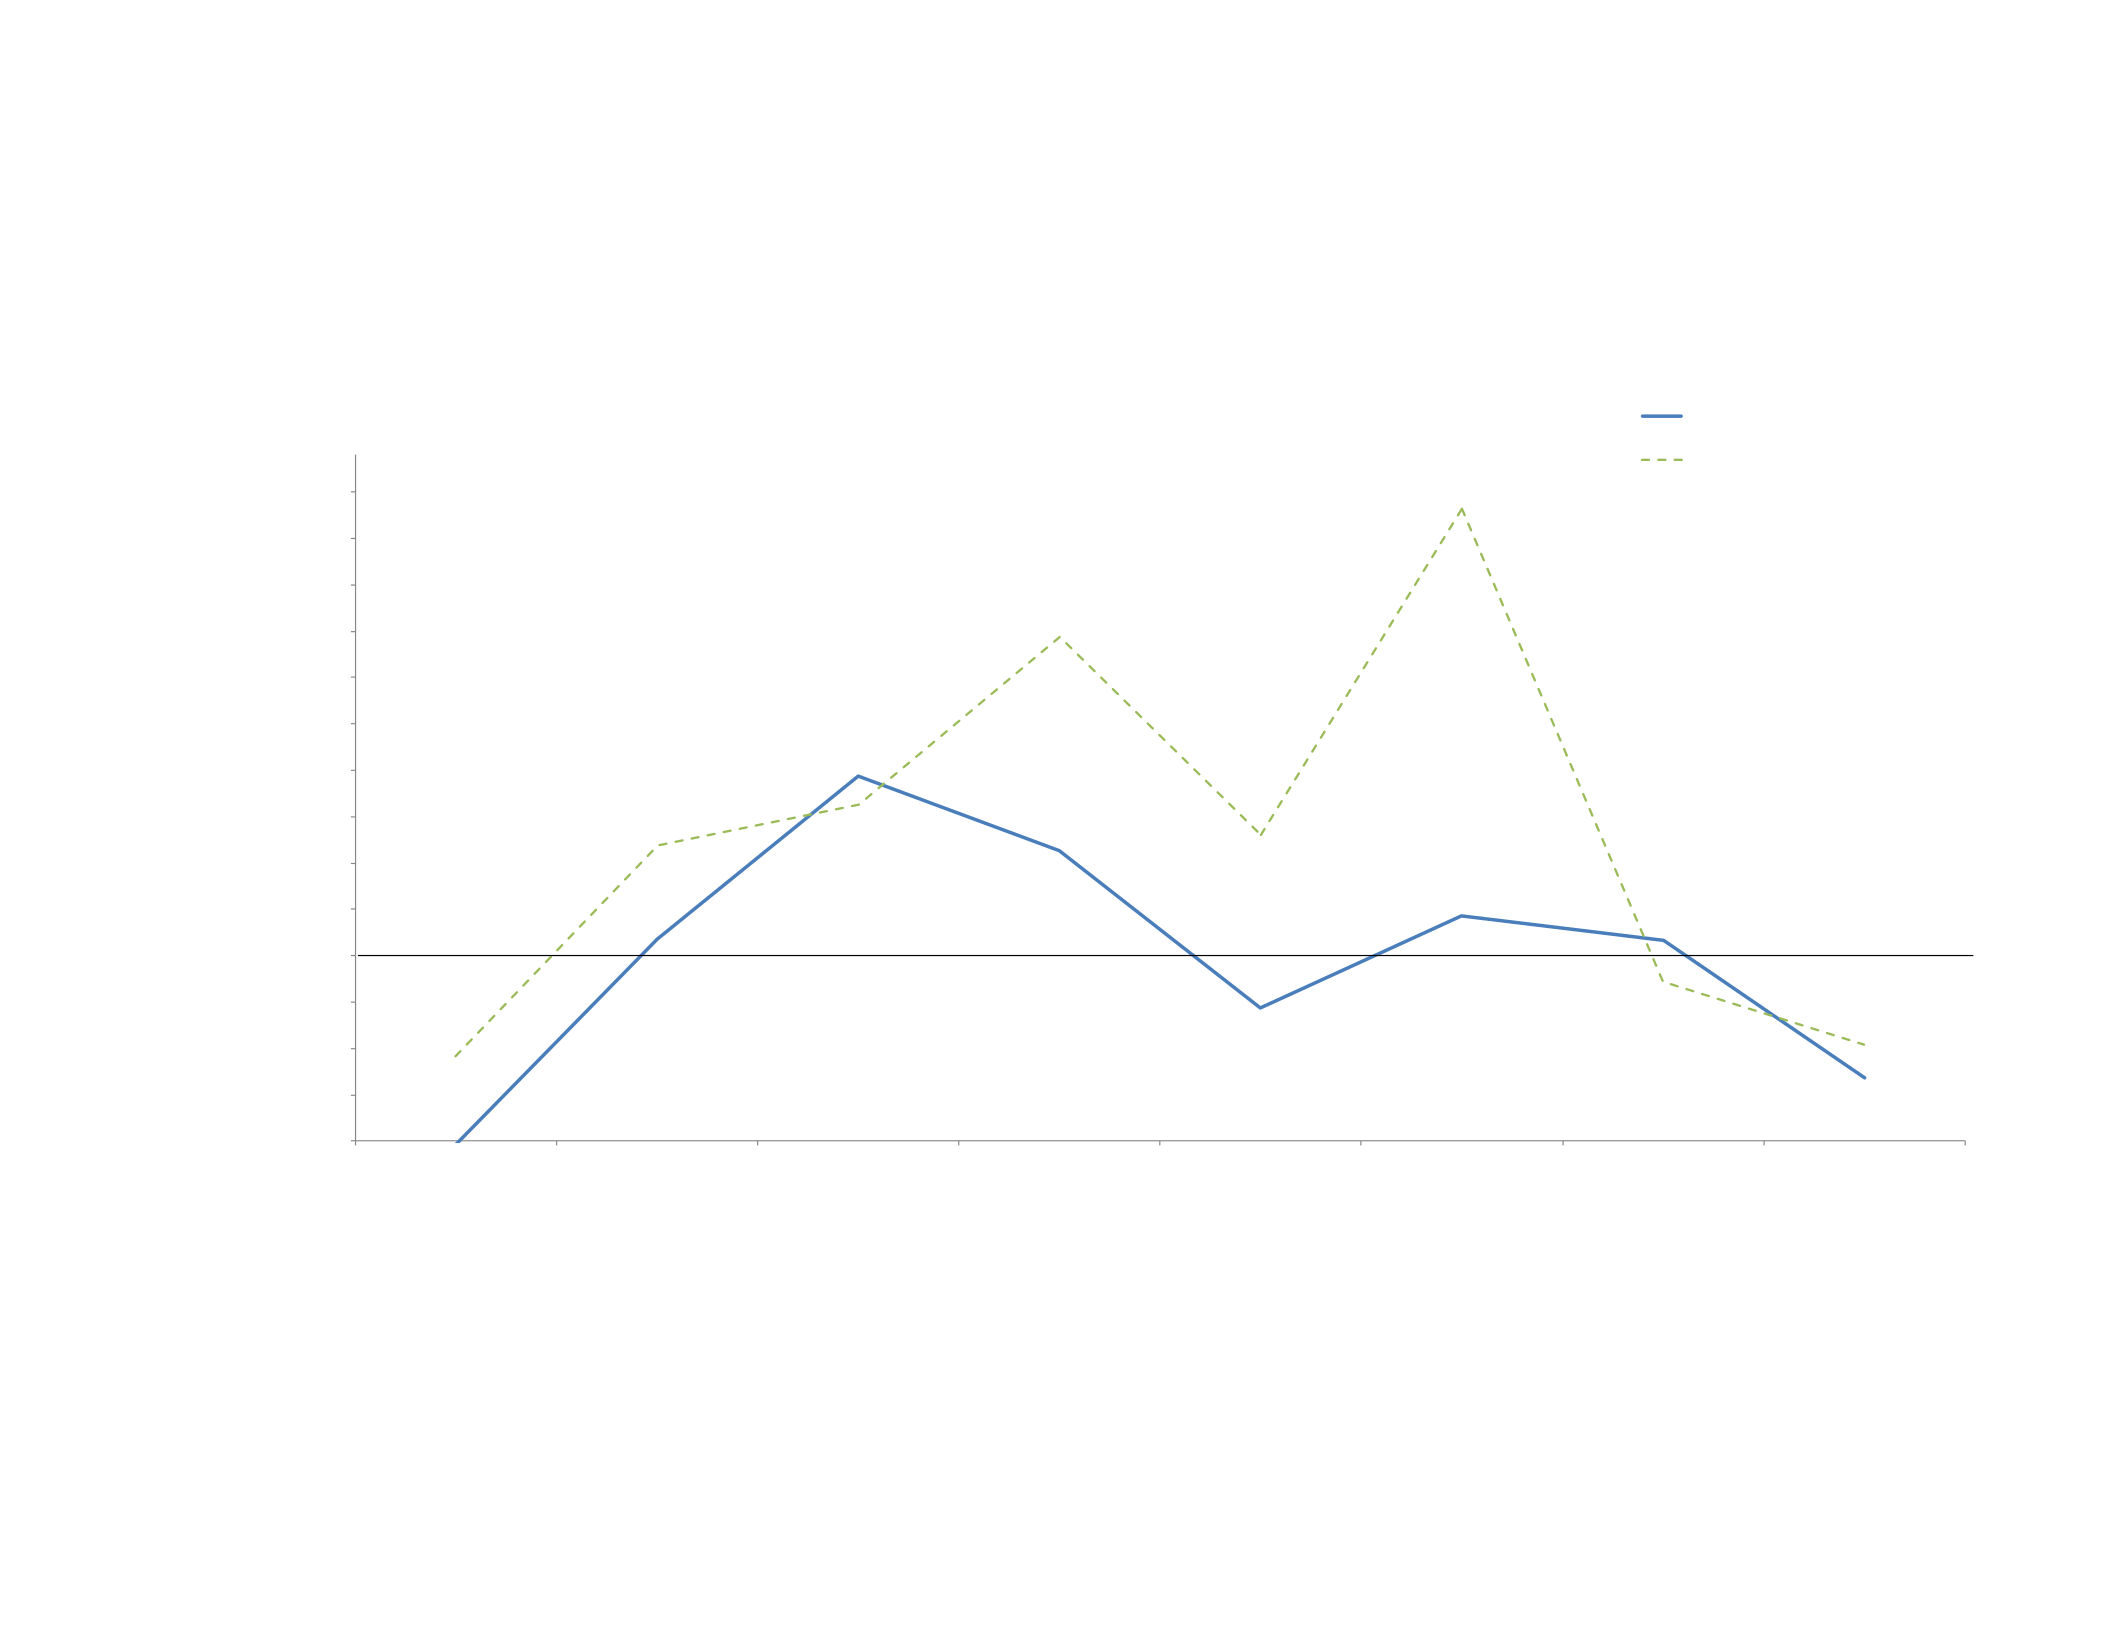
73
APPENDIX K: GRAPH - FIVE-YEAR GEOMETRIC RETURNS, AG INDEX AND THE DOW JONES INDUSTRIAL AVERAGE
(1970-2008)
-10%
-8%
-5%
-3%
0%
3%
5%
8%
10%
13%
15%
18%
20%
23%
25%
1970-1974
1975-1979
1980-1984
1985-1989
1990-1994
1995-1999
2000-2004
2005-2008
AG Index -Geometric Return
Dow Jones - Geometric Return
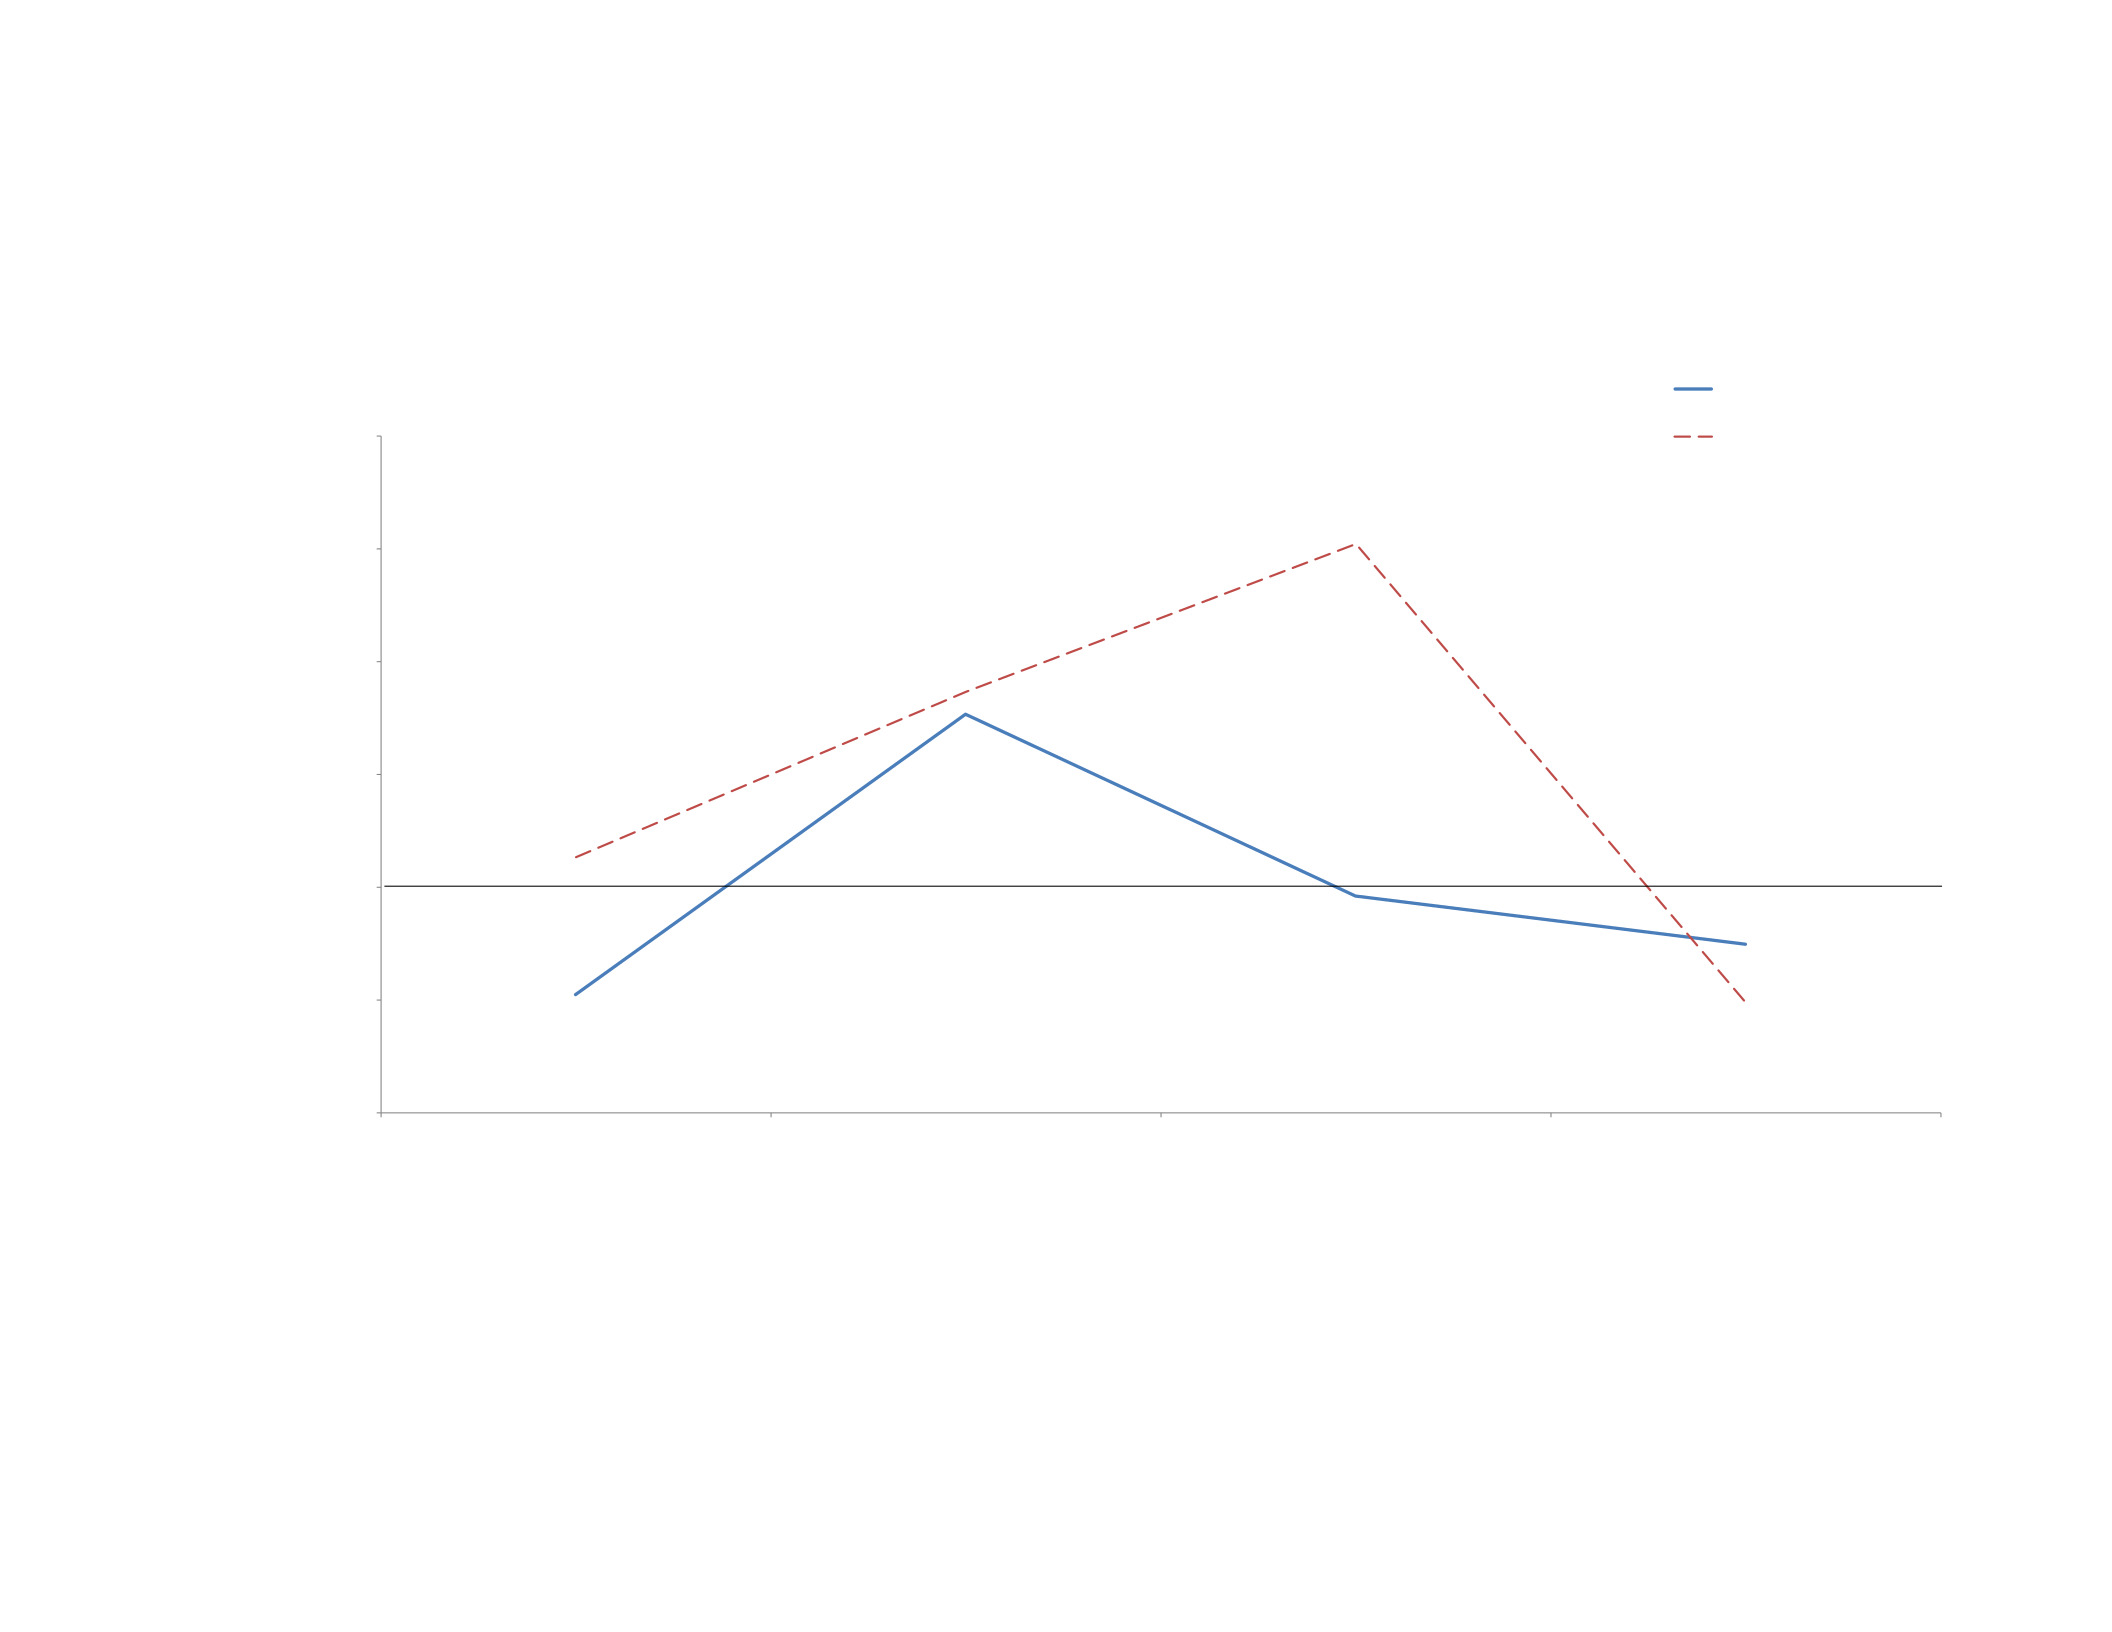
74
APPENDIX L: GRAPH - TEN-YEAR GEOMETRIC RETURN, AG INDEX AND THE S&P 500 (1970-2008)
-10%
-5%
0%
5%
10%
15%
20%
1970-1979
1980-1989
1990-1999
2000-2008
AG Index -Geometric Return
S&P 500 - Geometric Return
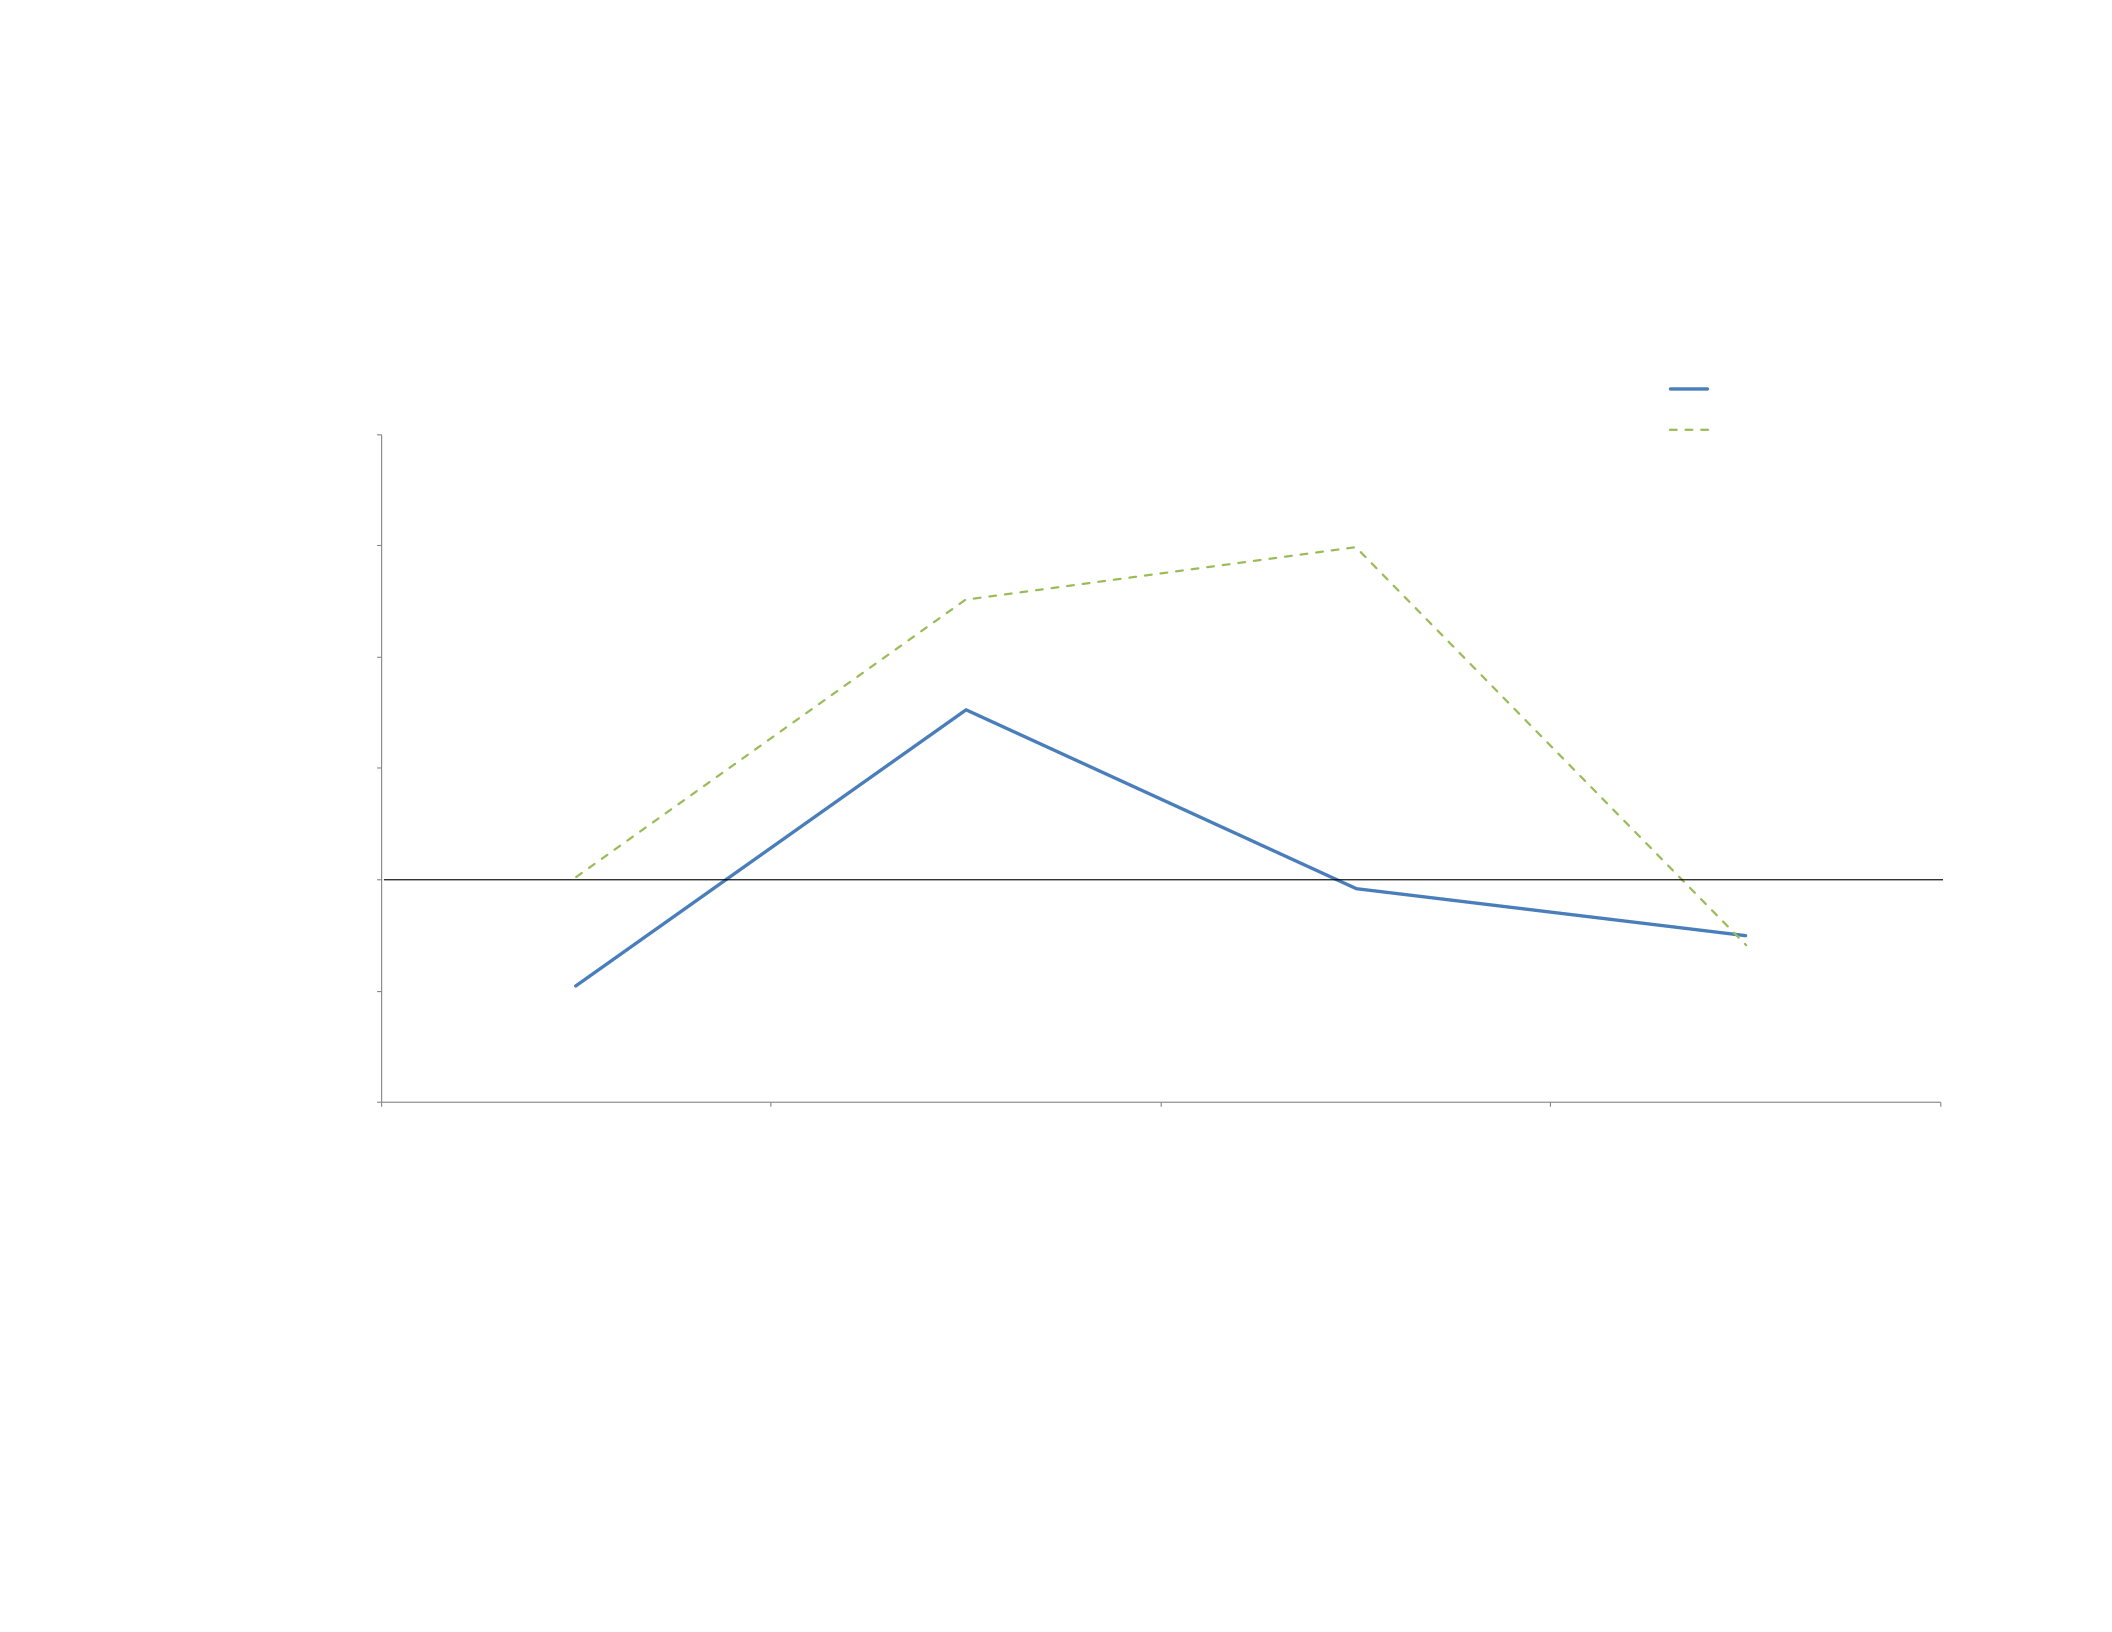
75
APPENDIX M: GRAPH - TEN-YEAR GEOMETRIC RETURN, AG INDEX AND THE DOW JONES INDUSTRIAL AVERAGE (1970-
2008)
-10%
-5%
0%
5%
10%
15%
20%
1970-1979
1980-1989
1990-1999
2000-2008
AG Index -Geometric Return
Dow Jones - Geometric Return

76
APPENDIX N: ANNUAL STANDARD DEVIATION, AG INDEX, S&P 500, AND THE
DOW JONES INDUSTRIAL AVERAGE (1970-2008)
Period AG Index S&P 500 DOW
1970 0.90105% 0.95275% 0.97498%
1971 0.63183% 0.64337% 0.69817%
1972 0.72247% 0.50143% 0.58341%
1973 1.054462%* 0.99686% 1.11397%
1974 1.44840% 1.37459% 1.42532%
1975 1.01992%* 0.97201% 1.06453%
1976 0.68944% 0.69961% 0.78396%
1977 0.6137%* 0.57171% 0.65196%
1978 0.73187% 0.79343% 0.89920%
1979 0.67311% 0.68321% 0.72922%
1980 0.88779% 1.03718% 0.98958%
1981 0.73533% 0.84738% 0.85165%
1982 0.99720% 1.15004% 1.17494%
1983 0.69442% 0.83913% 0.88138%
1984 0.72238% 0.80309% 0.87687%
1985 0.74251% 0.64026% 0.65332%
1986 1.22587% 0.92561% 0.96619%
1987 1.94011% 2.02469% 2.17207%
1988 1.16705% 1.07639% 1.14317%
1989 1.16294% 0.82257% 0.89521%
1990 1.23033% 1.00471% 1.02820%
1991 1.09214% 0.90074% 0.92297%
1992 0.90946% 0.60995% 0.65074%
1993 0.77174% 0.54182% 0.54651%
1994 0.67284%* 0.62012% 0.68747%
1995 0.69772% 0.49177% 0.54666%
1996 1.03093% 0.74210% 0.75439%
1997 1.36848% 1.14215% 1.17947%
1998 1.20128% 1.27802% 1.24968%
1999 1.07703%* 1.13838% 1.01829%
2000 1.44898% 1.39990% 1.30642%
2001 0.97118% 1.35793% 1.34533%
2002 1.17792% 1.63971% 1.60907%
2003 0.92359% 1.07516% 1.04479%
2004 0.65577% 0.69883% 0.68313%
2005 0.60236% 0.64780% 0.64881%
2006 0.56621% 0.63153% 0.62167%
2007 0.86385% 1.00700% 0.91558%
2008 2.16655% 2.58107% 2.38646%
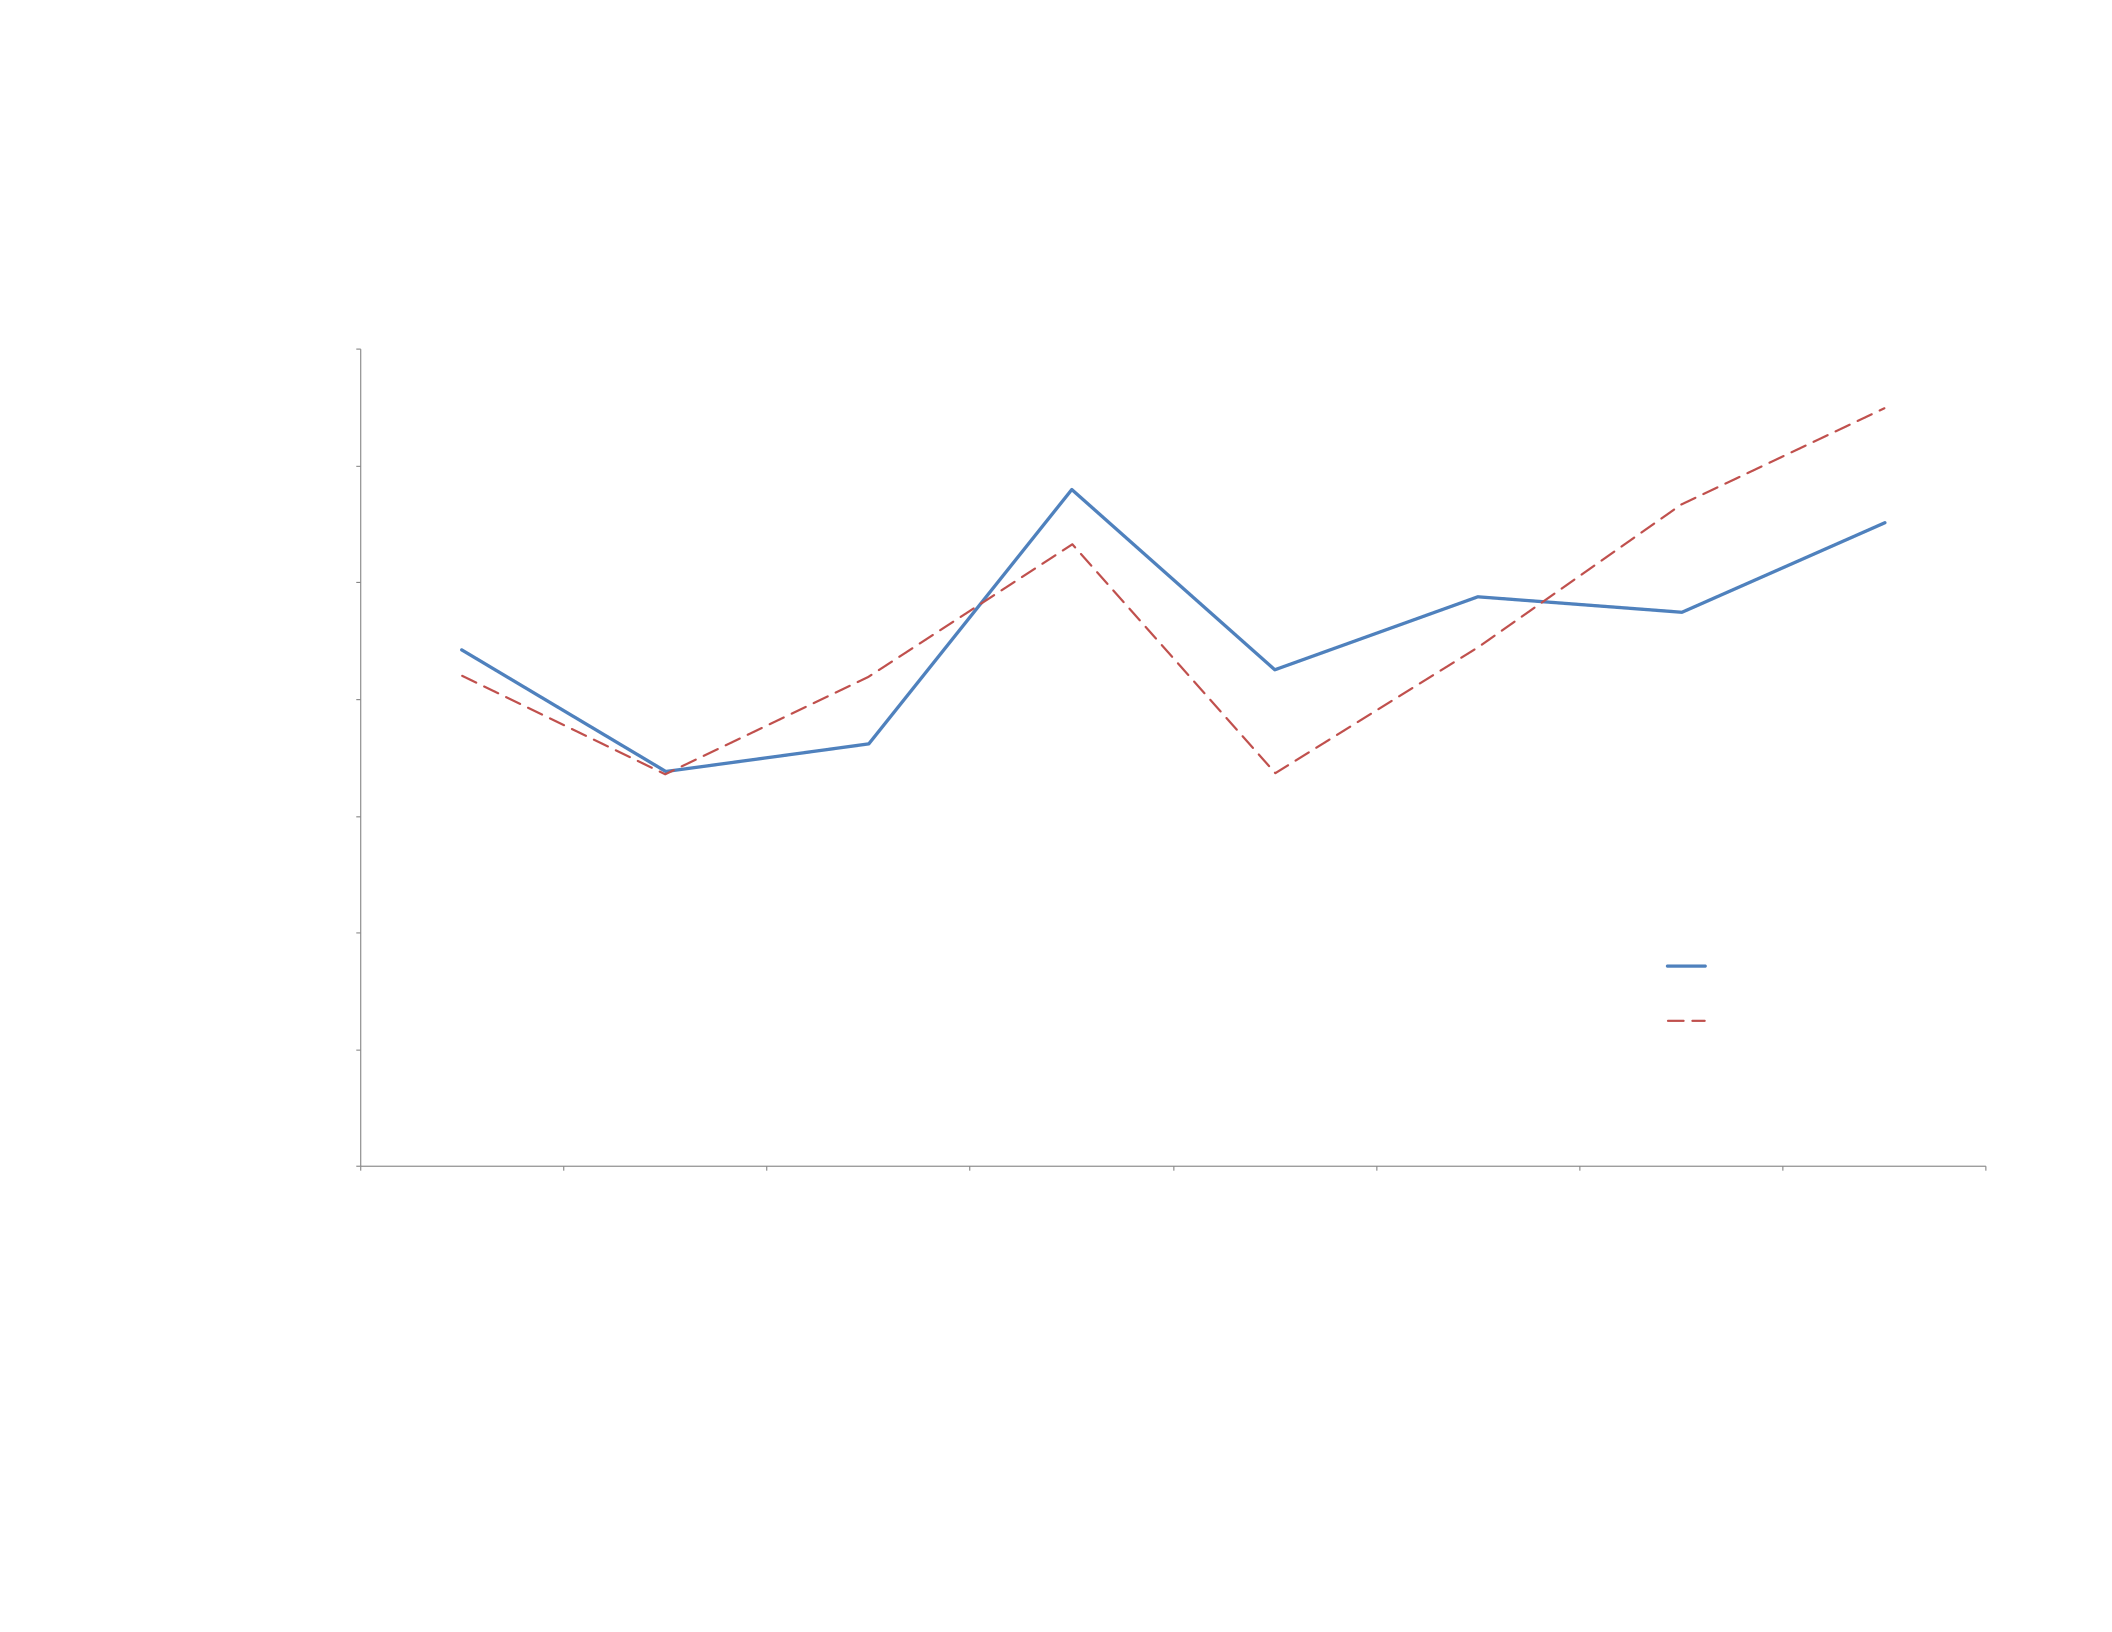
77
APPENDIX O: GRAPH - FIVE-YEAR STANDARD DEVIATION, AG INDEX AND THE S&P 500 (1970-2008)
0.0000%
0.2250%
0.4500%
0.6750%
0.9000%
1.1250%
1.3500%
1.5750%
1970-1974
1975-1979
1980-1984
1985-1989
1990-1994
1995-1999
2000-2004
2005-2008
AG Index -Standard Deviation
S&P 500 - Standard Deviation
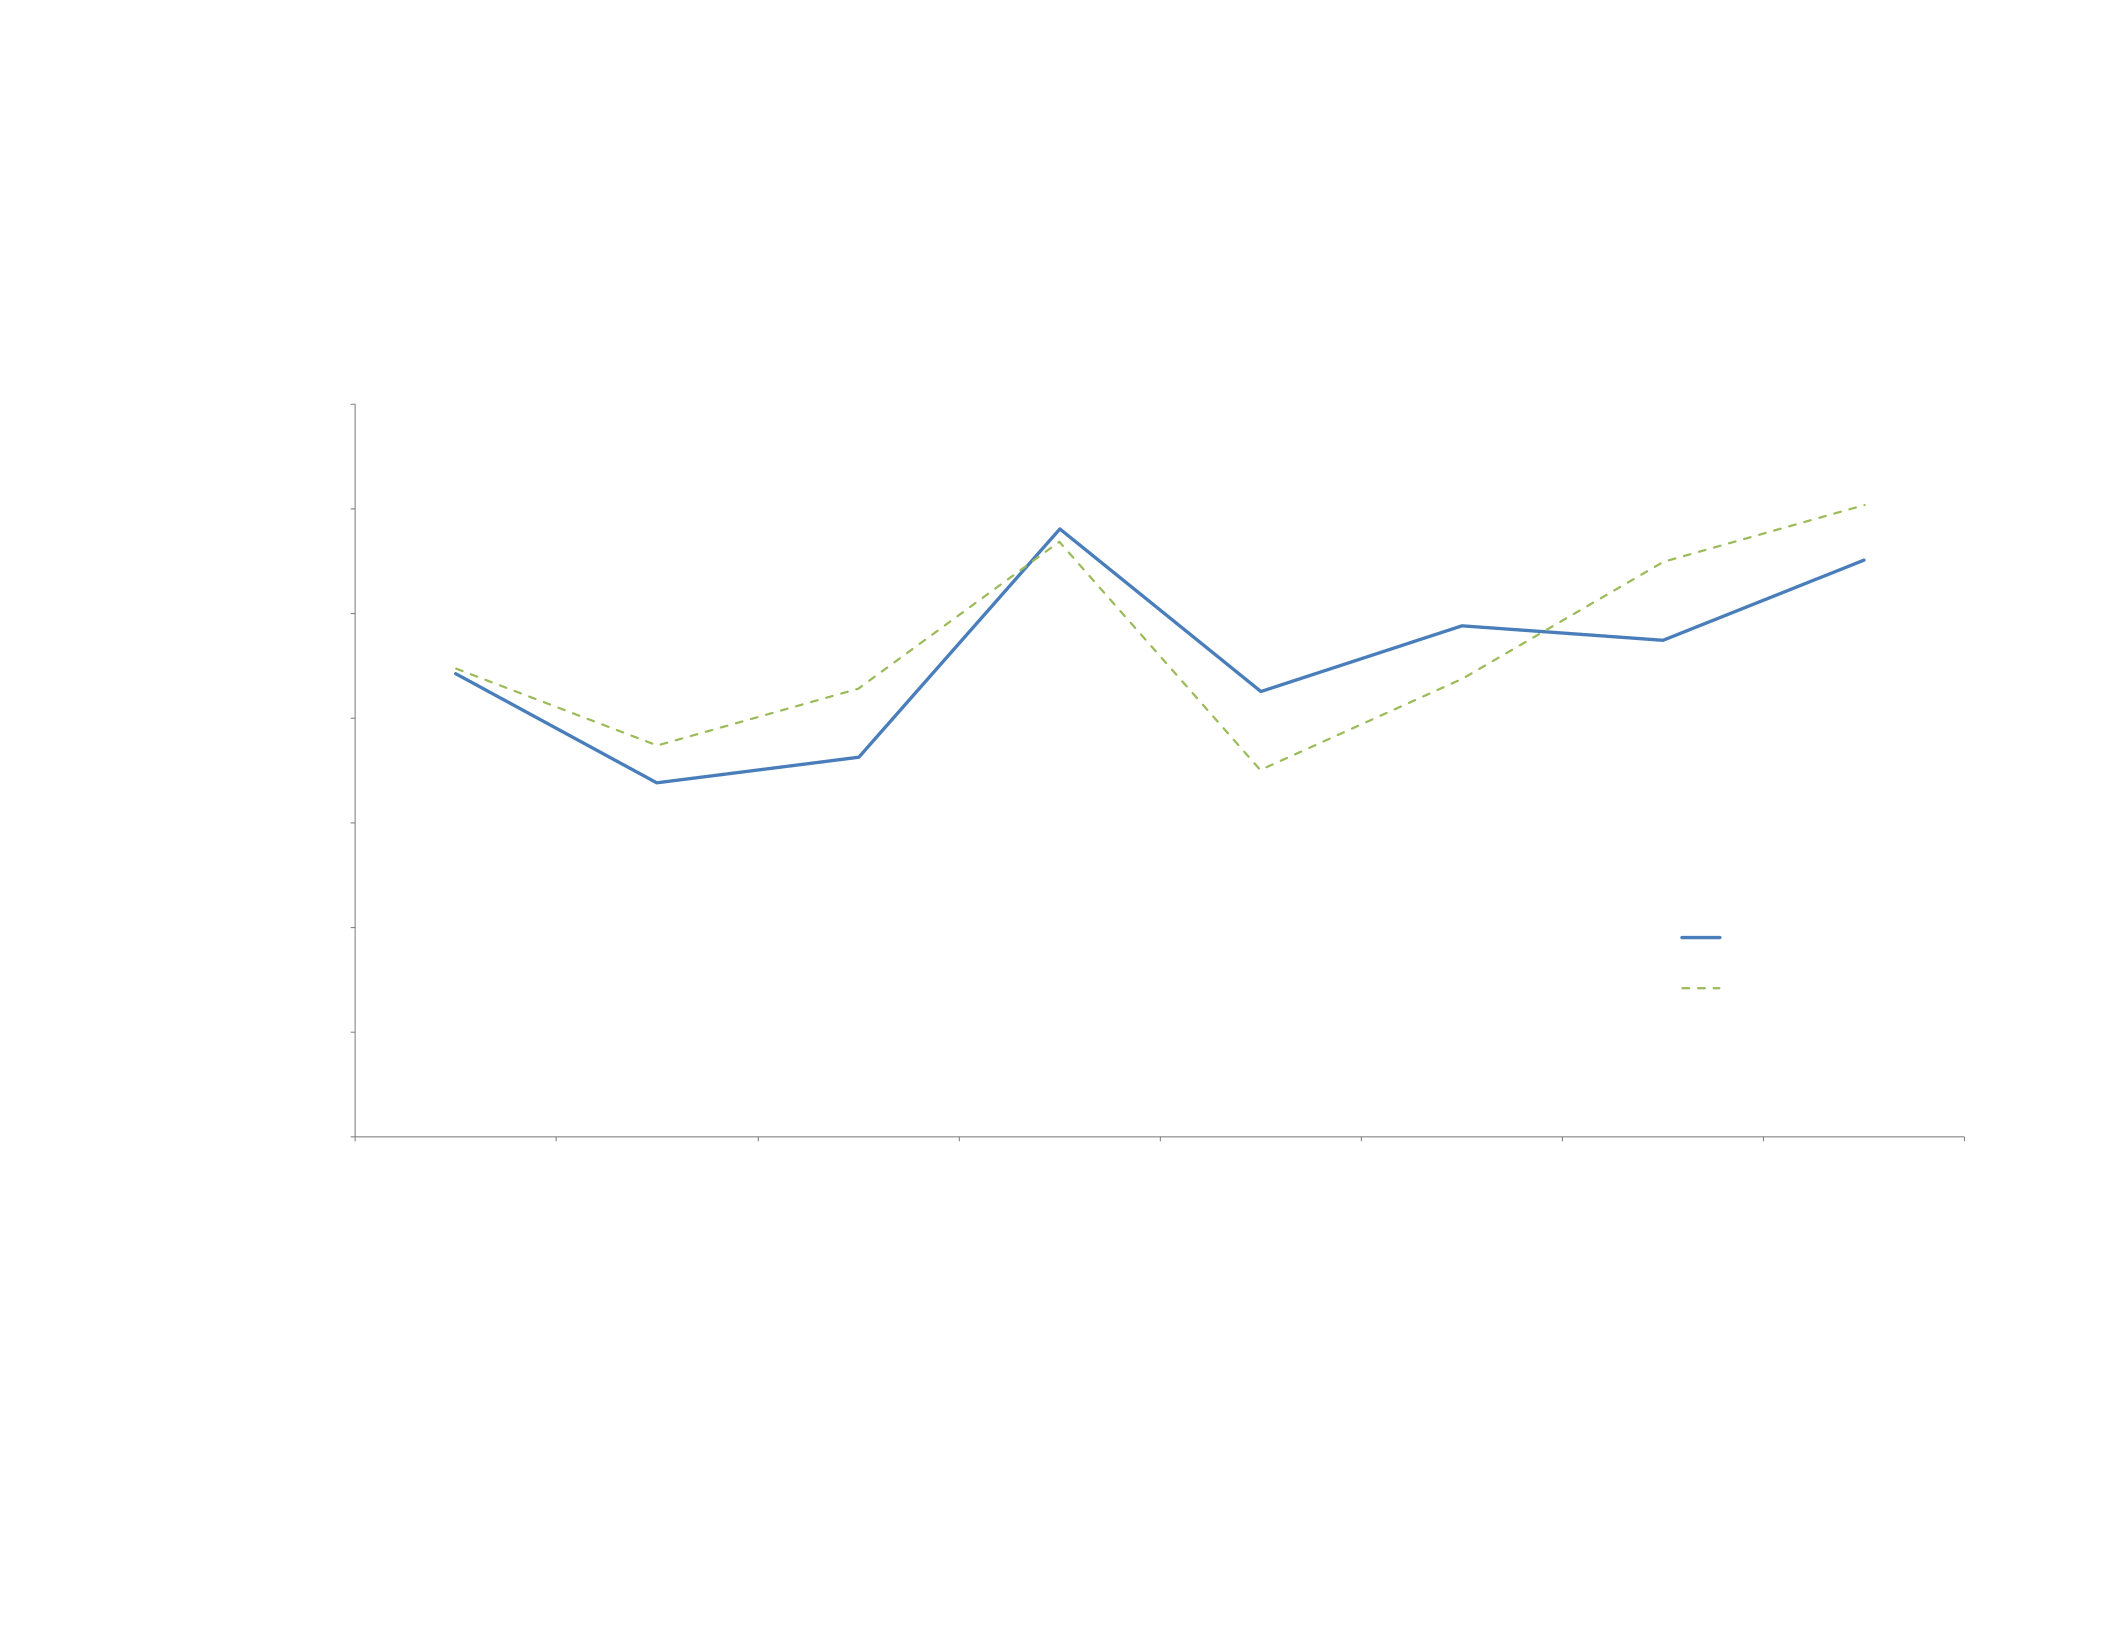
78
APPENDIX P: GRAPH - FIVE-YEAR STANDARD DEVIATION, AG INDEX AND THE DOW JONES INDUSTRIAL AVERAGE
(1970-2008)
0.0000%
0.2250%
0.4500%
0.6750%
0.9000%
1.1250%
1.3500%
1.5750%
1970-1974
1975-1979
1980-1984
1985-1989
1990-1994
1995-1999
2000-2004
2005-2008
AG Index -Standard Deviation
Dow Jones - Standard Deviation
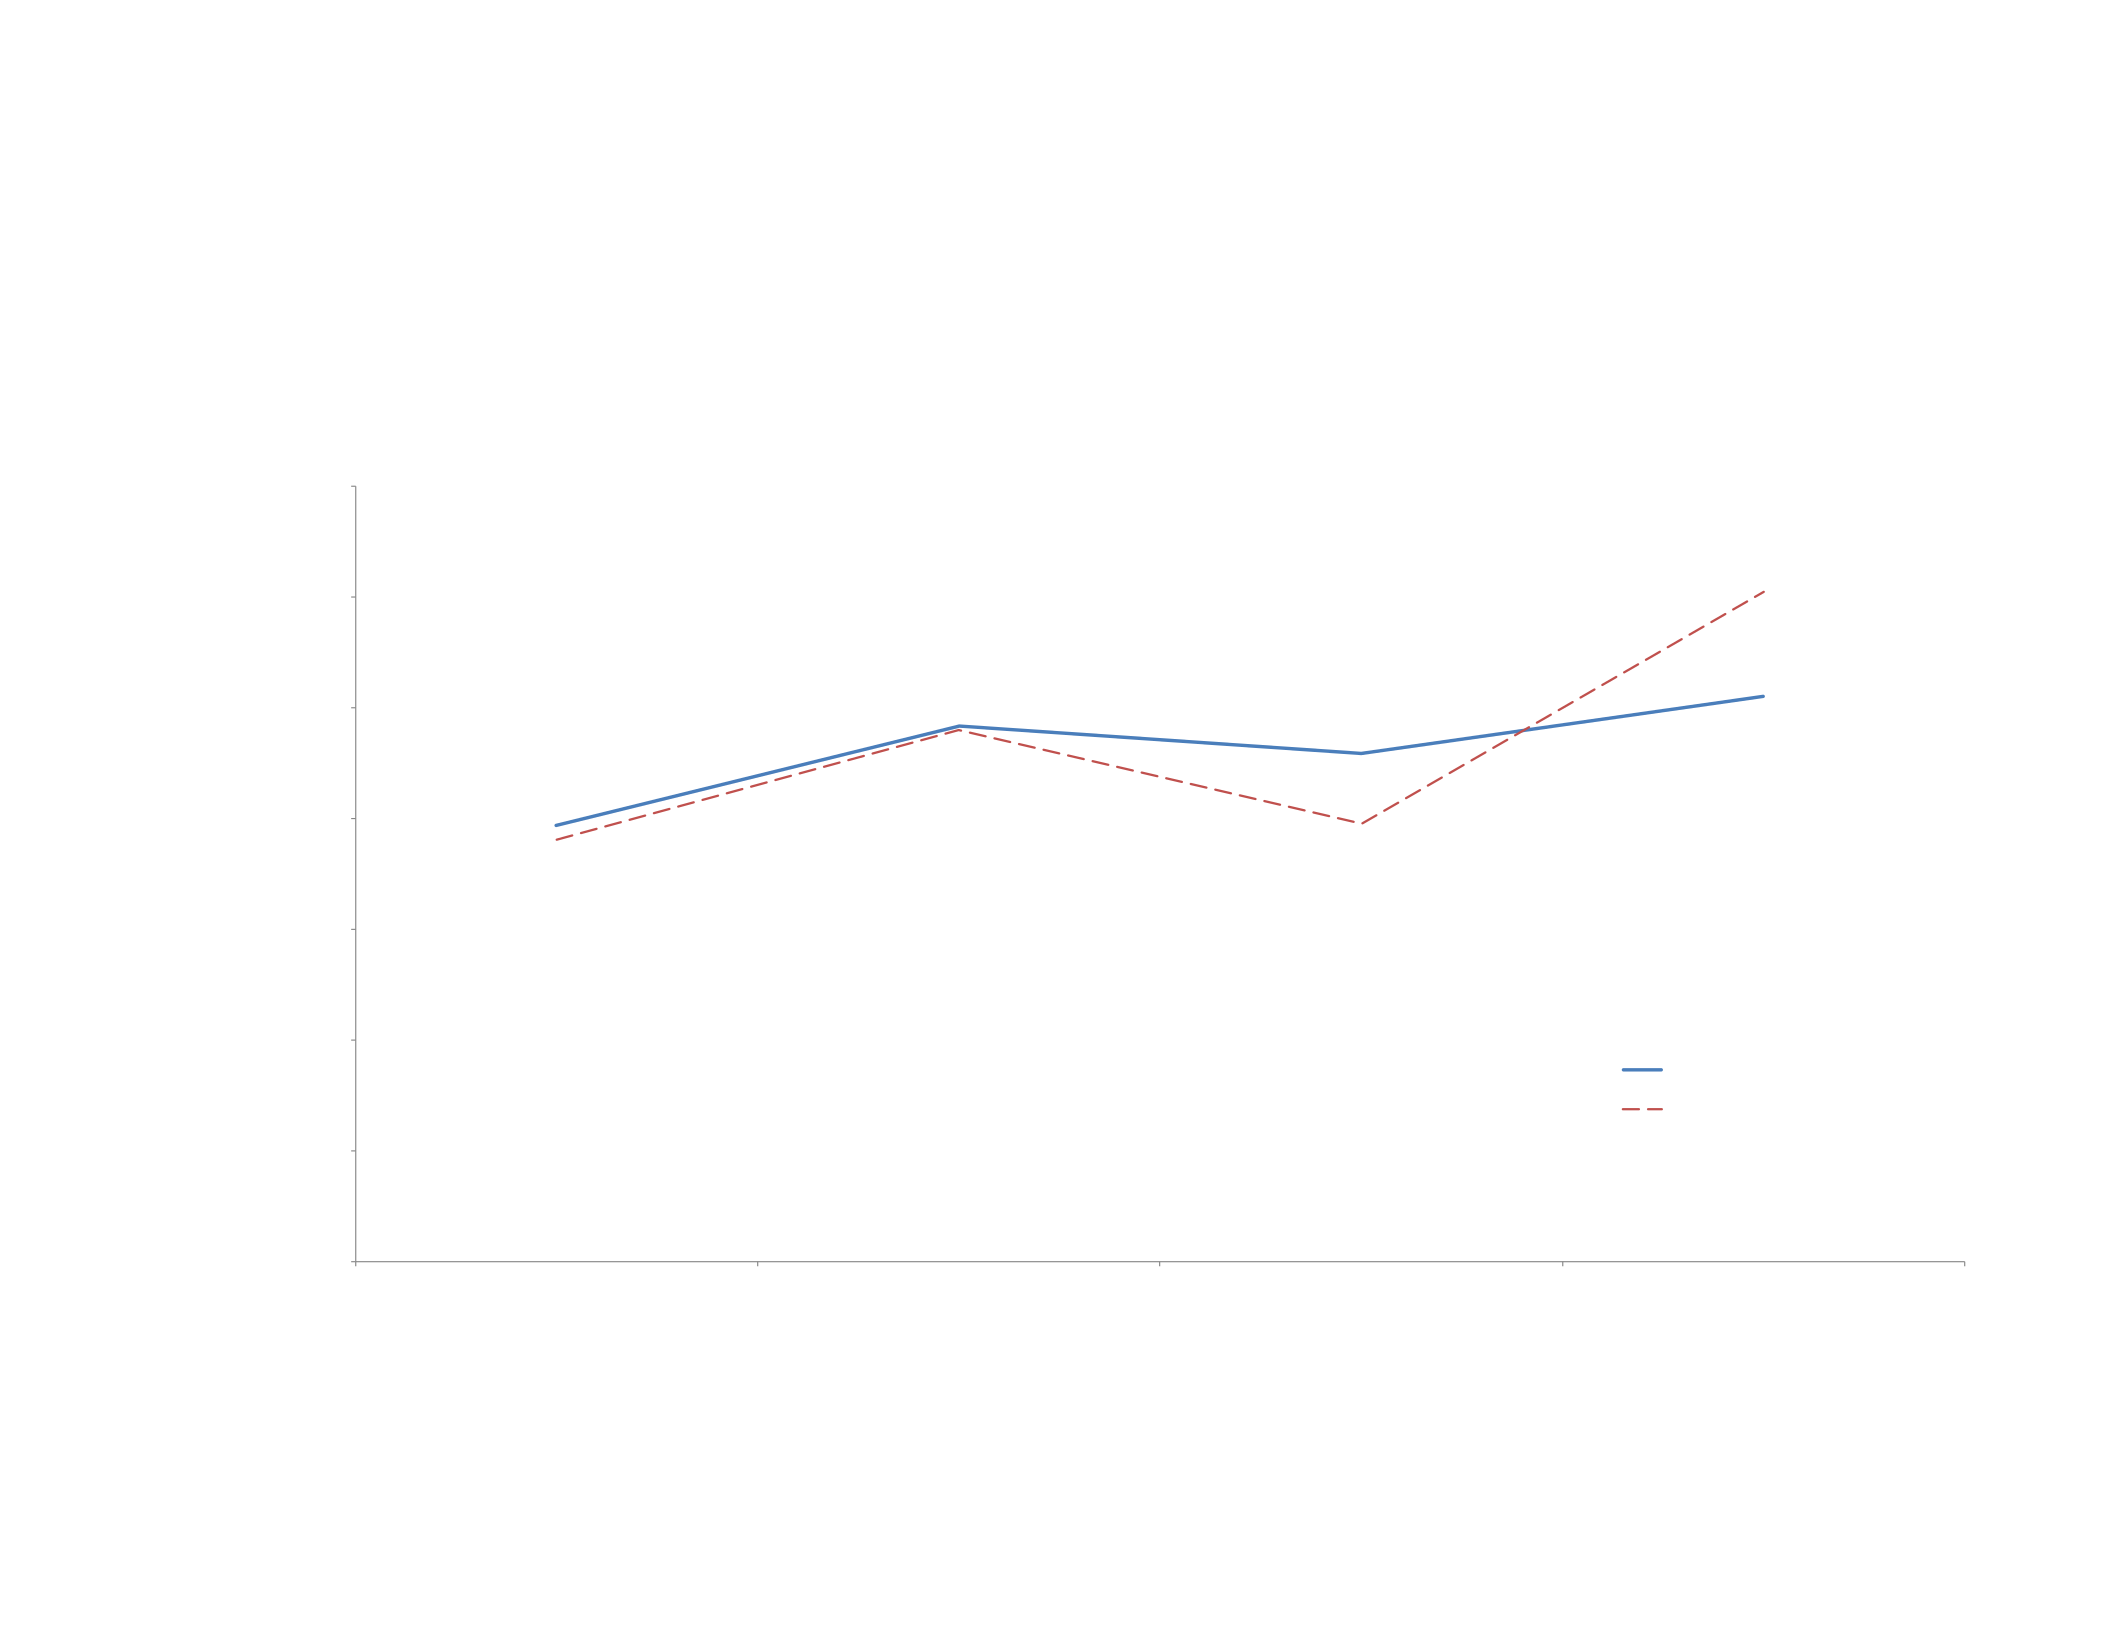
79
APPENDIX Q: GRAPH - TEN-YEAR STANDARD DEVIATION, AG INDEX AND THE S&P 500 (1970-2008)
0.0000%
0.2250%
0.4500%
0.6750%
0.9000%
1.1250%
1.3500%
1.5750%
1970-1979
1980-1989
1990-1999
2000-2008
AG Index -Standard Deviation
S&P 500 - Standard Deviation
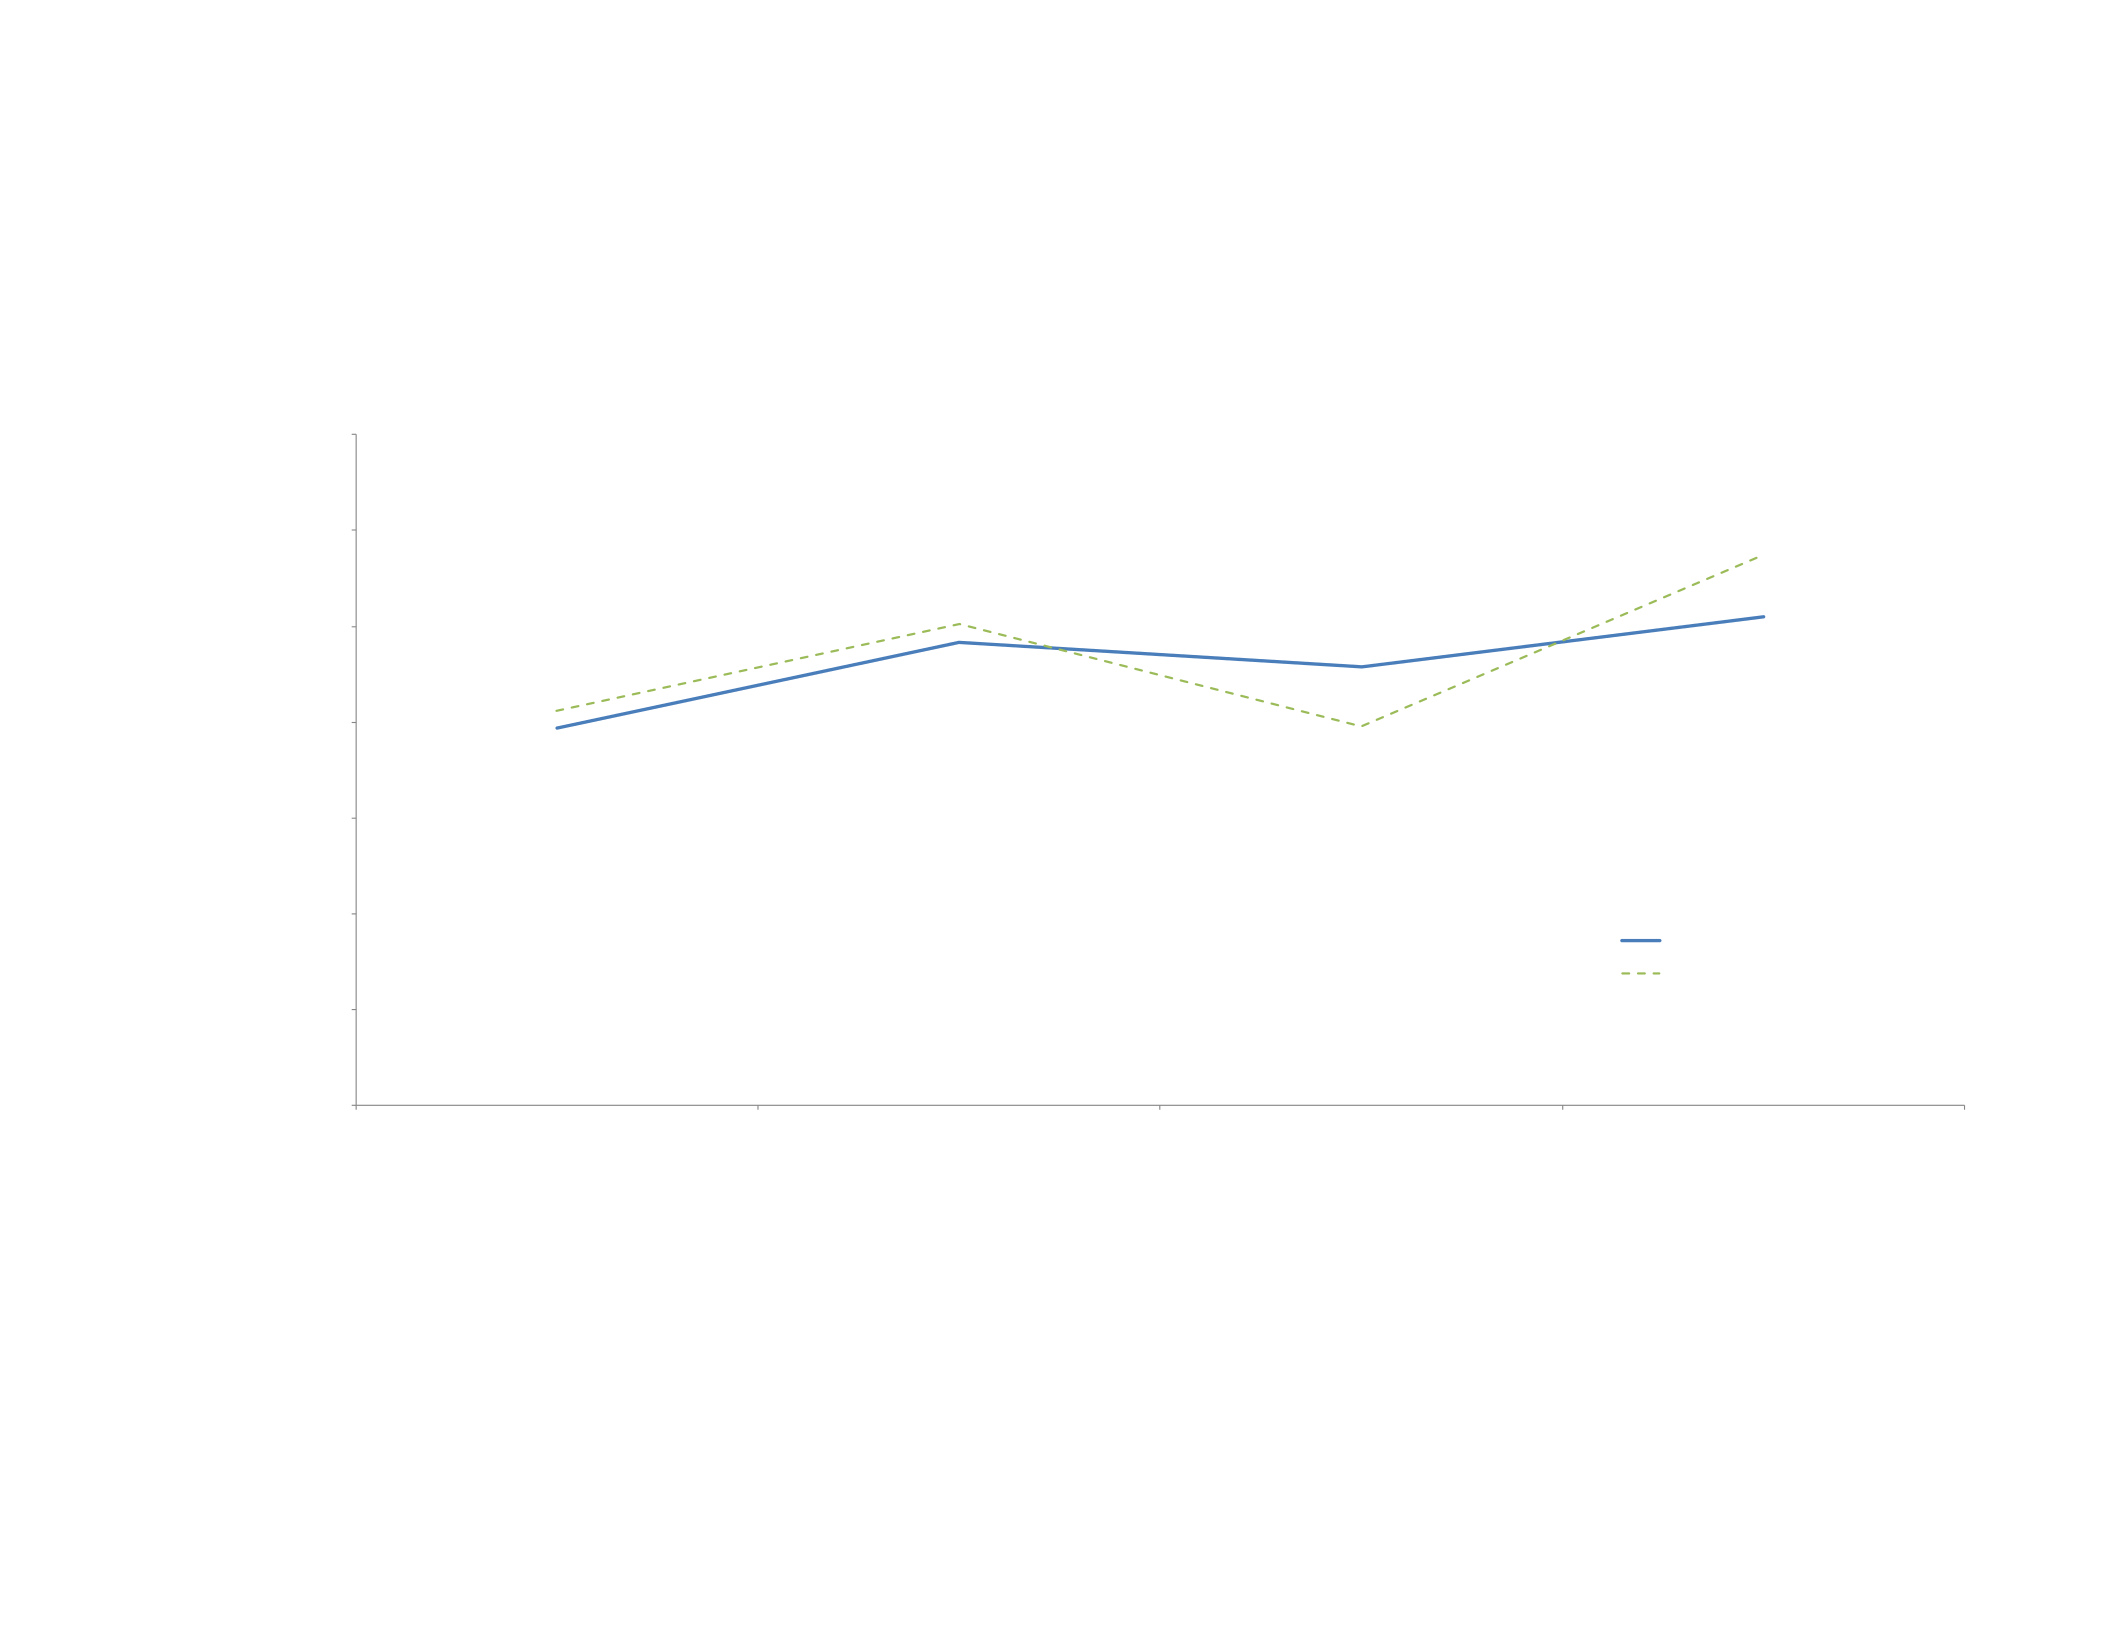
80
APPENDIX R: GRAPH - TEN-YEAR STANDARD DEVIATION, AG INDEX AND THE DOW JONES INDUSTRIAL AVERAGE
(1970-2008)
0.0000%
0.2250%
0.4500%
0.6750%
0.9000%
1.1250%
1.3500%
1.5750%
1970-1979
1980-1989
1990-1999
2000-2008
AG Index -Standard Deviation
Dow Jones - Standard Deviation
81
APPENDIX S: ANNUAL SHARPE RATIO, AG INDEX, S&P 500, AND THE DOW JONES
INDUSTRIAL AVERAGE (1970-2008)
Period AG Index S&P 500 DOW
1970 46.53 41.38 45.14
1971 26.86* 33.19 23.67
1972 -34.11 -20.73 -20.23
1973 -48.79 -45.86 -40.53
1974 -21.13* -21.39 -19.33
1975 43.43 44.95 47.10
1976 39.04 56.93 49.25
1977 -101.46 -94.72 -91.87
1978 -65.73 -61.20 -58.45
1979 -26.57 1.47 -9.90
1980 -2.57 11.37 0.34
1981 -4.88 -11.77 -11.64
1982 60.09 43.97 46.45
1983 -9.24 2.72 6.37
1984 19.50 13.39 6.29
1985 48.46 70.38 70.89
1986 11.62 40.69 47.01
1987 -14.70 -10.32 -9.47
1988 -11.58 -28.42 -16.22
1989 25.92* 19.15 48.25
1990 0.04 4.46 6.22
1991 62.72 73.98 65.28
1992 0.67 27.89 25.58
1993 -13.61 9.54 21.00
1994 -150.45* -157.25 -136.90
1995 95.39 127.12 112.80
1996 -8.90 17.19 23.82
1997 3.68 29.60 16.83
1998 18.77 33.73 25.85
1999 -50.68 -9.60 -5.29
2000 17.96 2.41 5.84
2001 46.39 34.61 38.40
2002 27.72 11.16 15.48
2003 23.50 31.24 31.32
2004 -159.69 -143.94 -155.66
2005 -91.00 -82.04 -88.01
2006 -13.19 -3.76 1.19
2007 50.18 36.33 42.89
2008 23.80 19.66 23.30
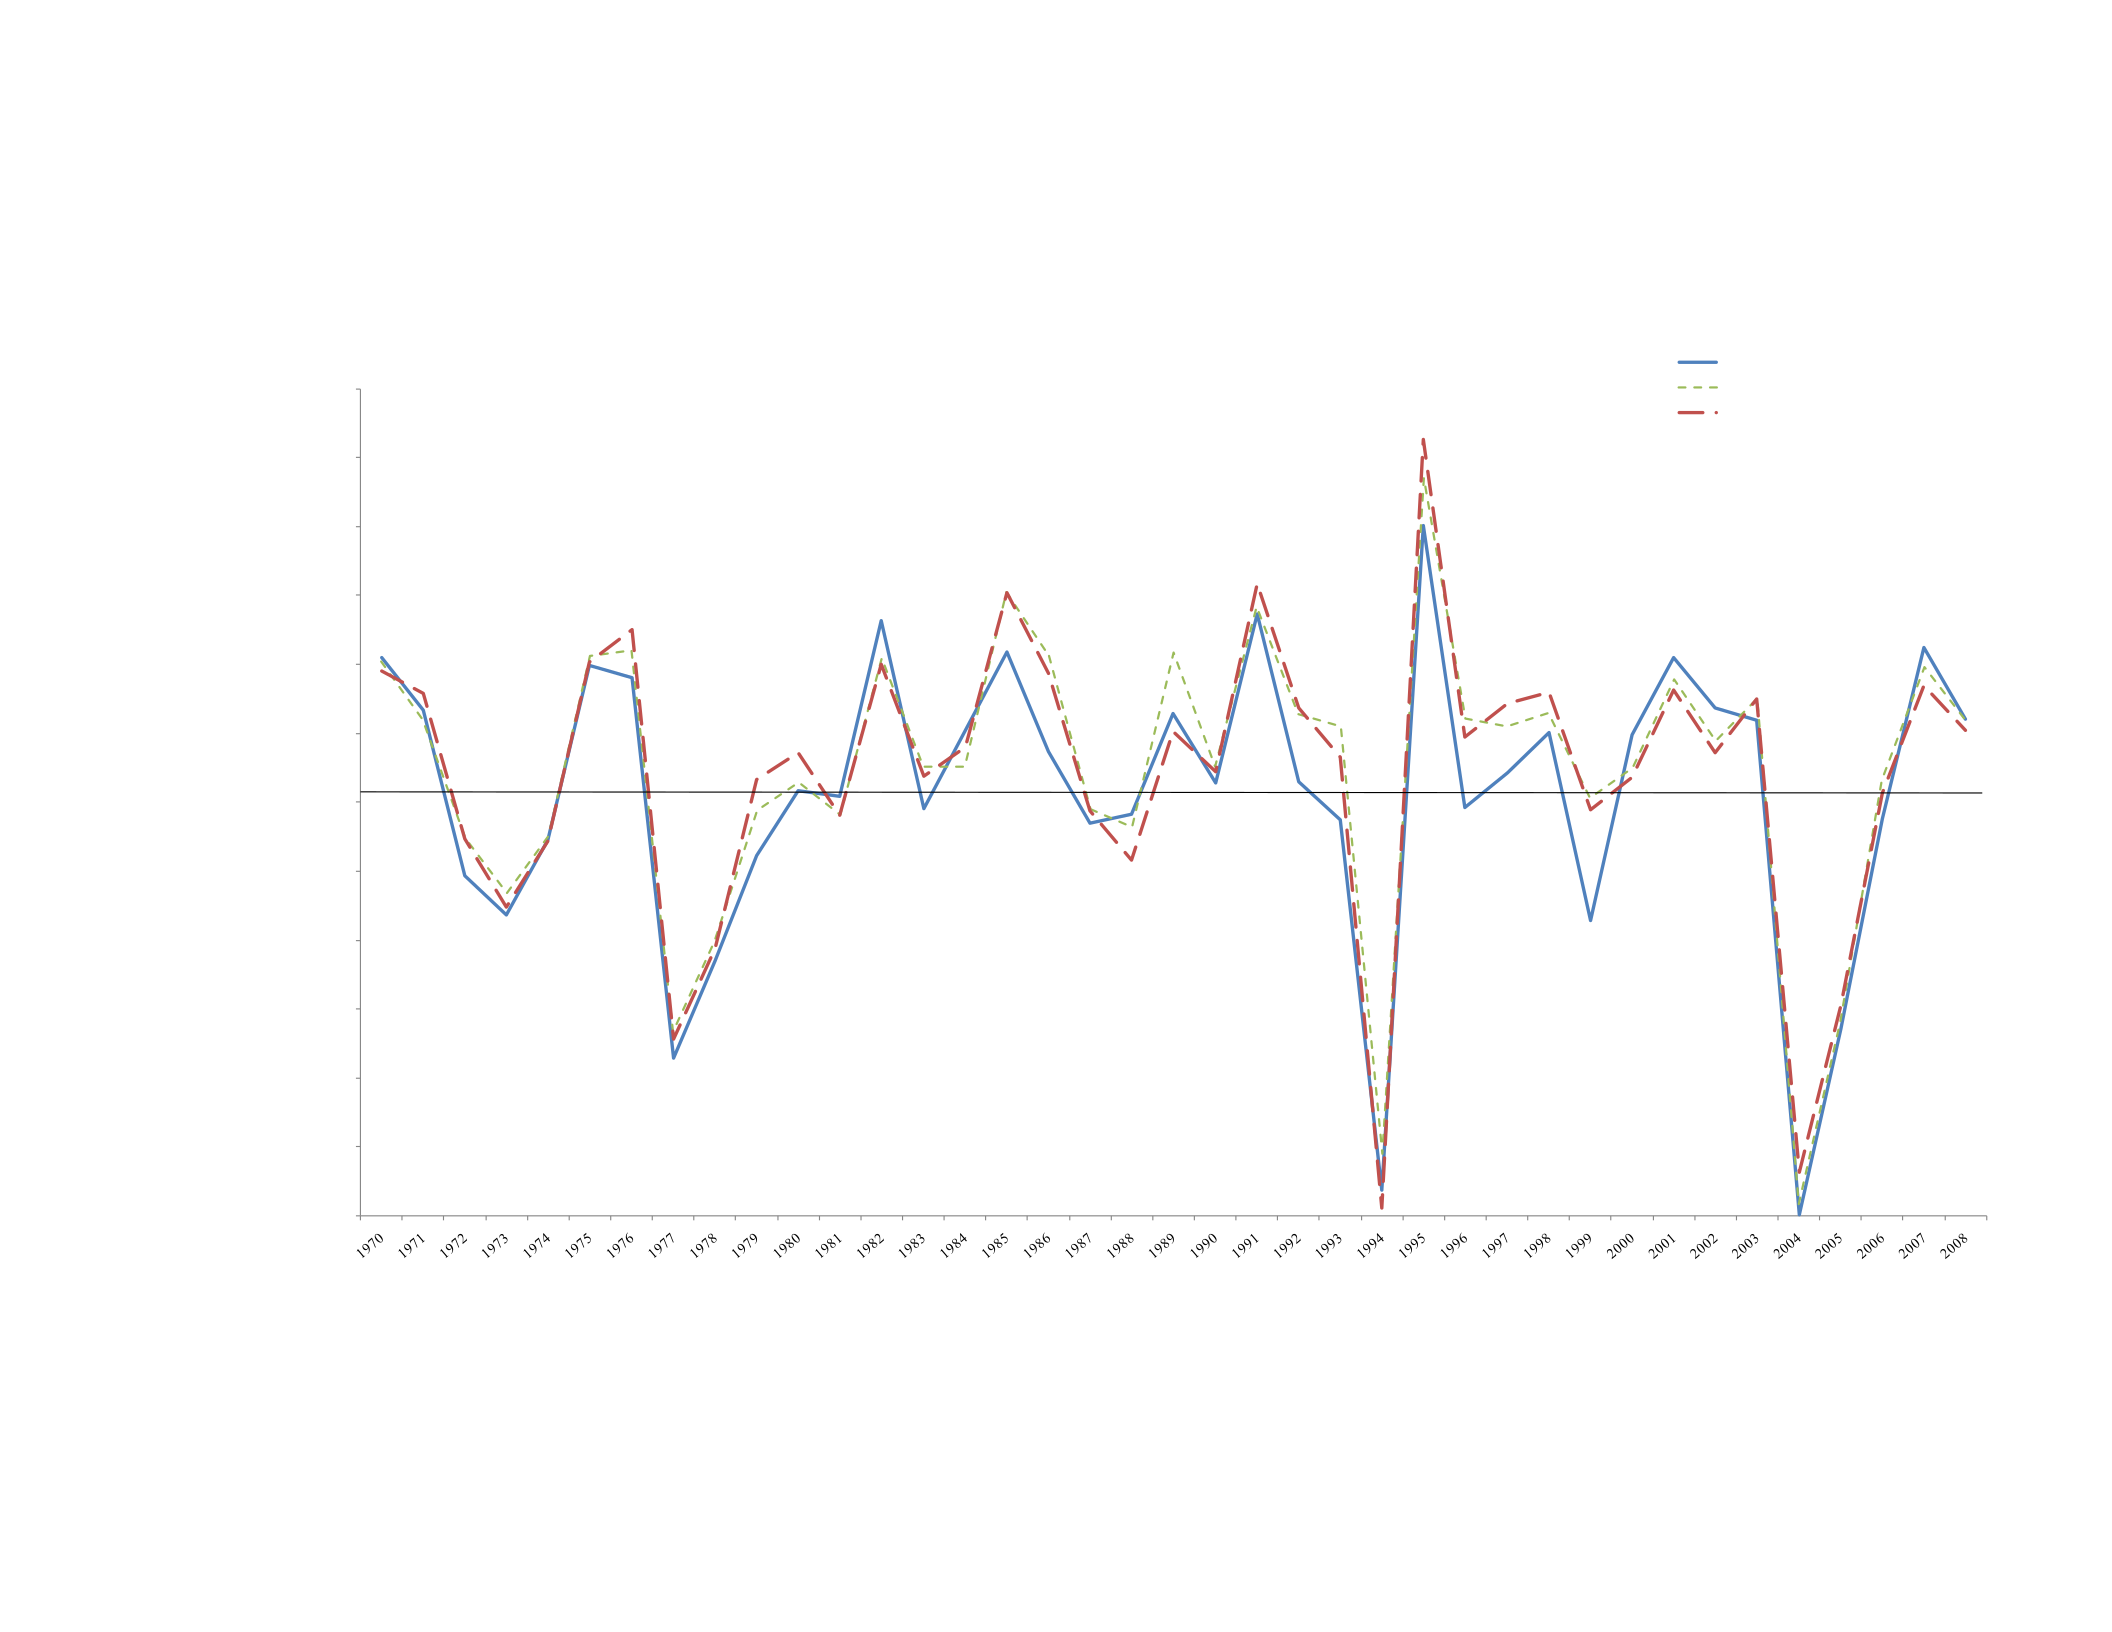
82
APPENDIX T: GRAPH - ANNUAL SHARPE RATIO, AG INDEX, S&P 500, AND THE DOW JONES INDUSTRIAL AVERAGE
(1970-2008)
-160.00
-134.50
-109.00
-83.50
-58.00
-32.50
-7.00
18.50
44.00
69.50
95.00
120.50
146.00
AG Index -Sharpe Ratio
Dow Jones - Sharpe Ratio
S&P 500 - Sharpe Ratio
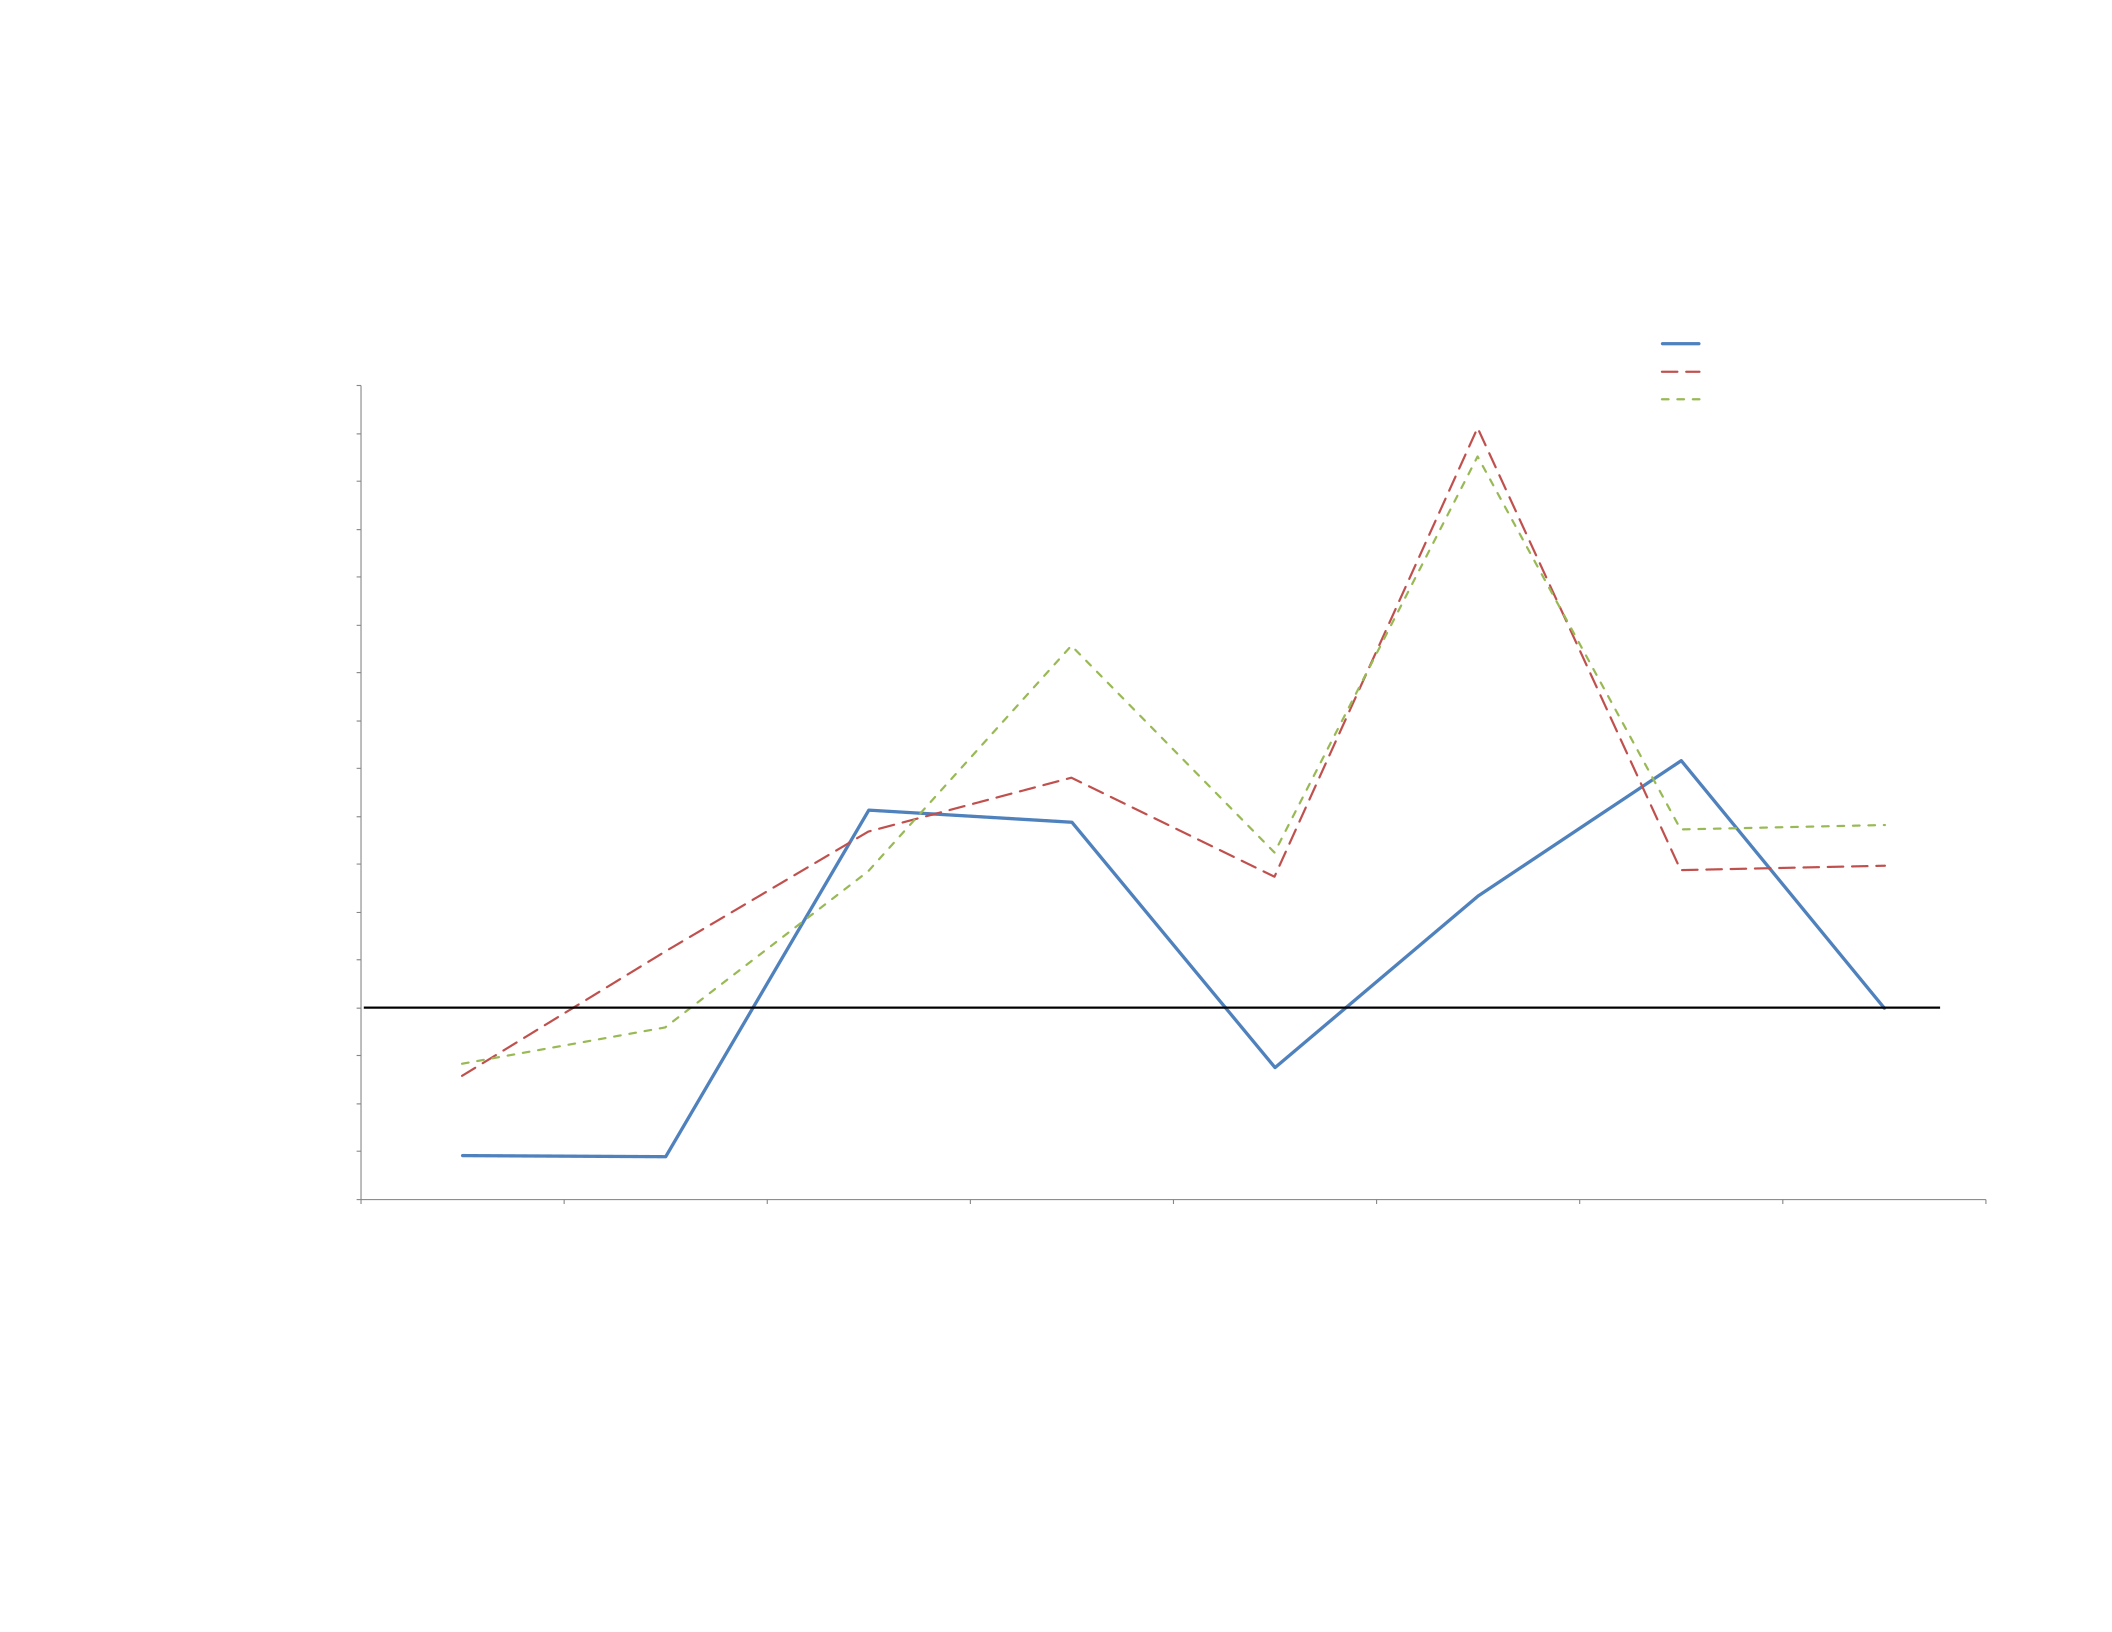
83
APPENDIX U: GRAPH – FIVE-YEAR SHARPE RATIO, AG INDEX, S&P 500, AND THE DOW JONES INDUSTRIAL AVERAGE
(1970-2008)
-10.00
-7.50
-5.00
-2.50
0.00
2.50
5.00
7.50
10.00
12.50
15.00
17.50
20.00
22.50
25.00
27.50
30.00
32.50
1970-1974
1975-1979
1980-1984
1985-1989
1990-1994
1995-1999
2000-2004
2005-2008
AG Index -Sharpe Ratio
S&P 500 - Sharpe Ratio
Dow Jones - Sharpe Ratio
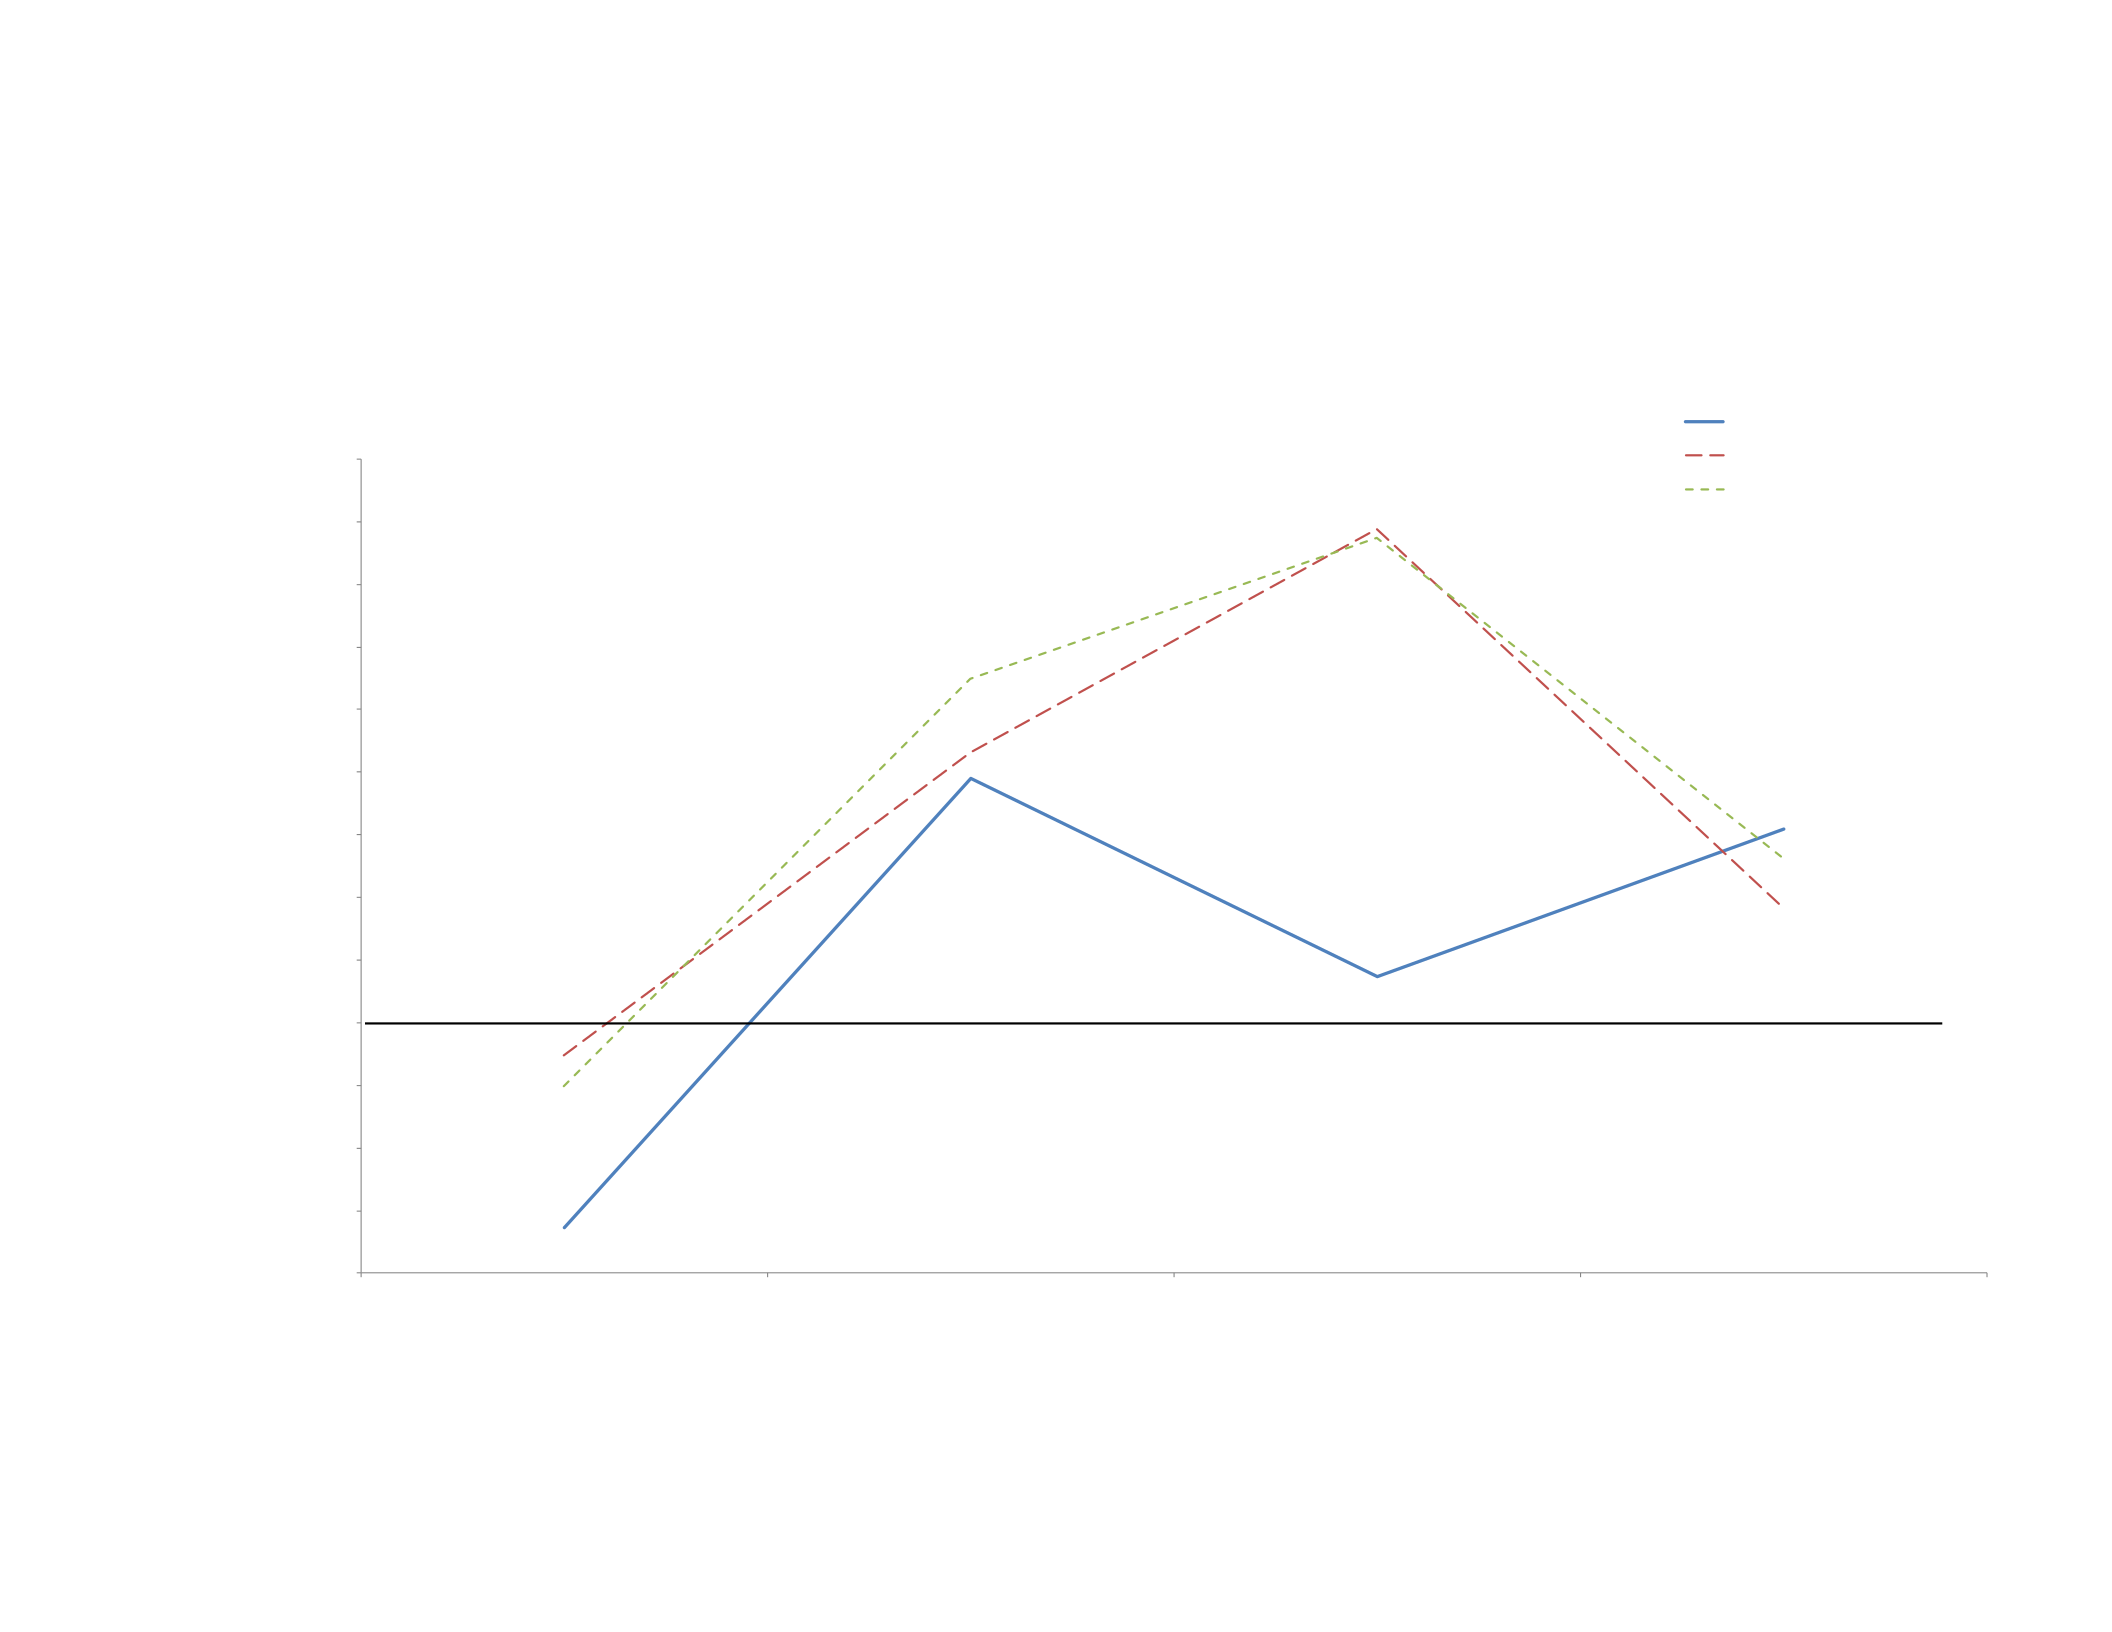
84
APPENDIX V: GRAPH – TEN-YEAR SHARPE RATIO, AG INDEX, S&P 500, AND THE DOW JONES INDUSTRIAL AVERAGE
(1970-2008)
-10.00
-7.50
-5.00
-2.50
0.00
2.50
5.00
7.50
10.00
12.50
15.00
17.50
20.00
22.50
1970-1979
1980-1989
1990-1999
2000-2008
AG Index -Sharpe Ratio
S&P 500 - Sharpe Ratio
Dow Jones - Sharpe Ratio
85
APPENDIX W: ANNUAL BETA VALUE ESTIMATION, AG INDEX (1970-2008)
Year AG Index
1970 0.8673522
1971 0.814655374
1972 0.957848146
1973 0.97733653
1974 1.010285371
1975 0.990376806
1976 0.92249389
1977 0.539339786
1978 0.875118904
1979 0.818083808
1980 0.751708057
1981 0.753252878
1982 0.806229279
1983 0.721237264
1984 0.836670553
1985 0.882333666
1986 1.076474714
1987 0.918651449
1988 1.030492438
1989 1.064008532
1990 1.068307286
1991 1.093708485
1992 1.07502552
1993 1.071220489
1994 0.807102592
1995 0.835797474
1996 0.852878645
1997 0.970509587
1998 0.794700964
1999 0.64788324
2000 0.314776233
2001 0.351949199
2002 0.527148295
2003 0.675452115
2004 0.754172555
2005 0.807023211
2006 0.692120307
2007 0.773707482
2008 0.754433291
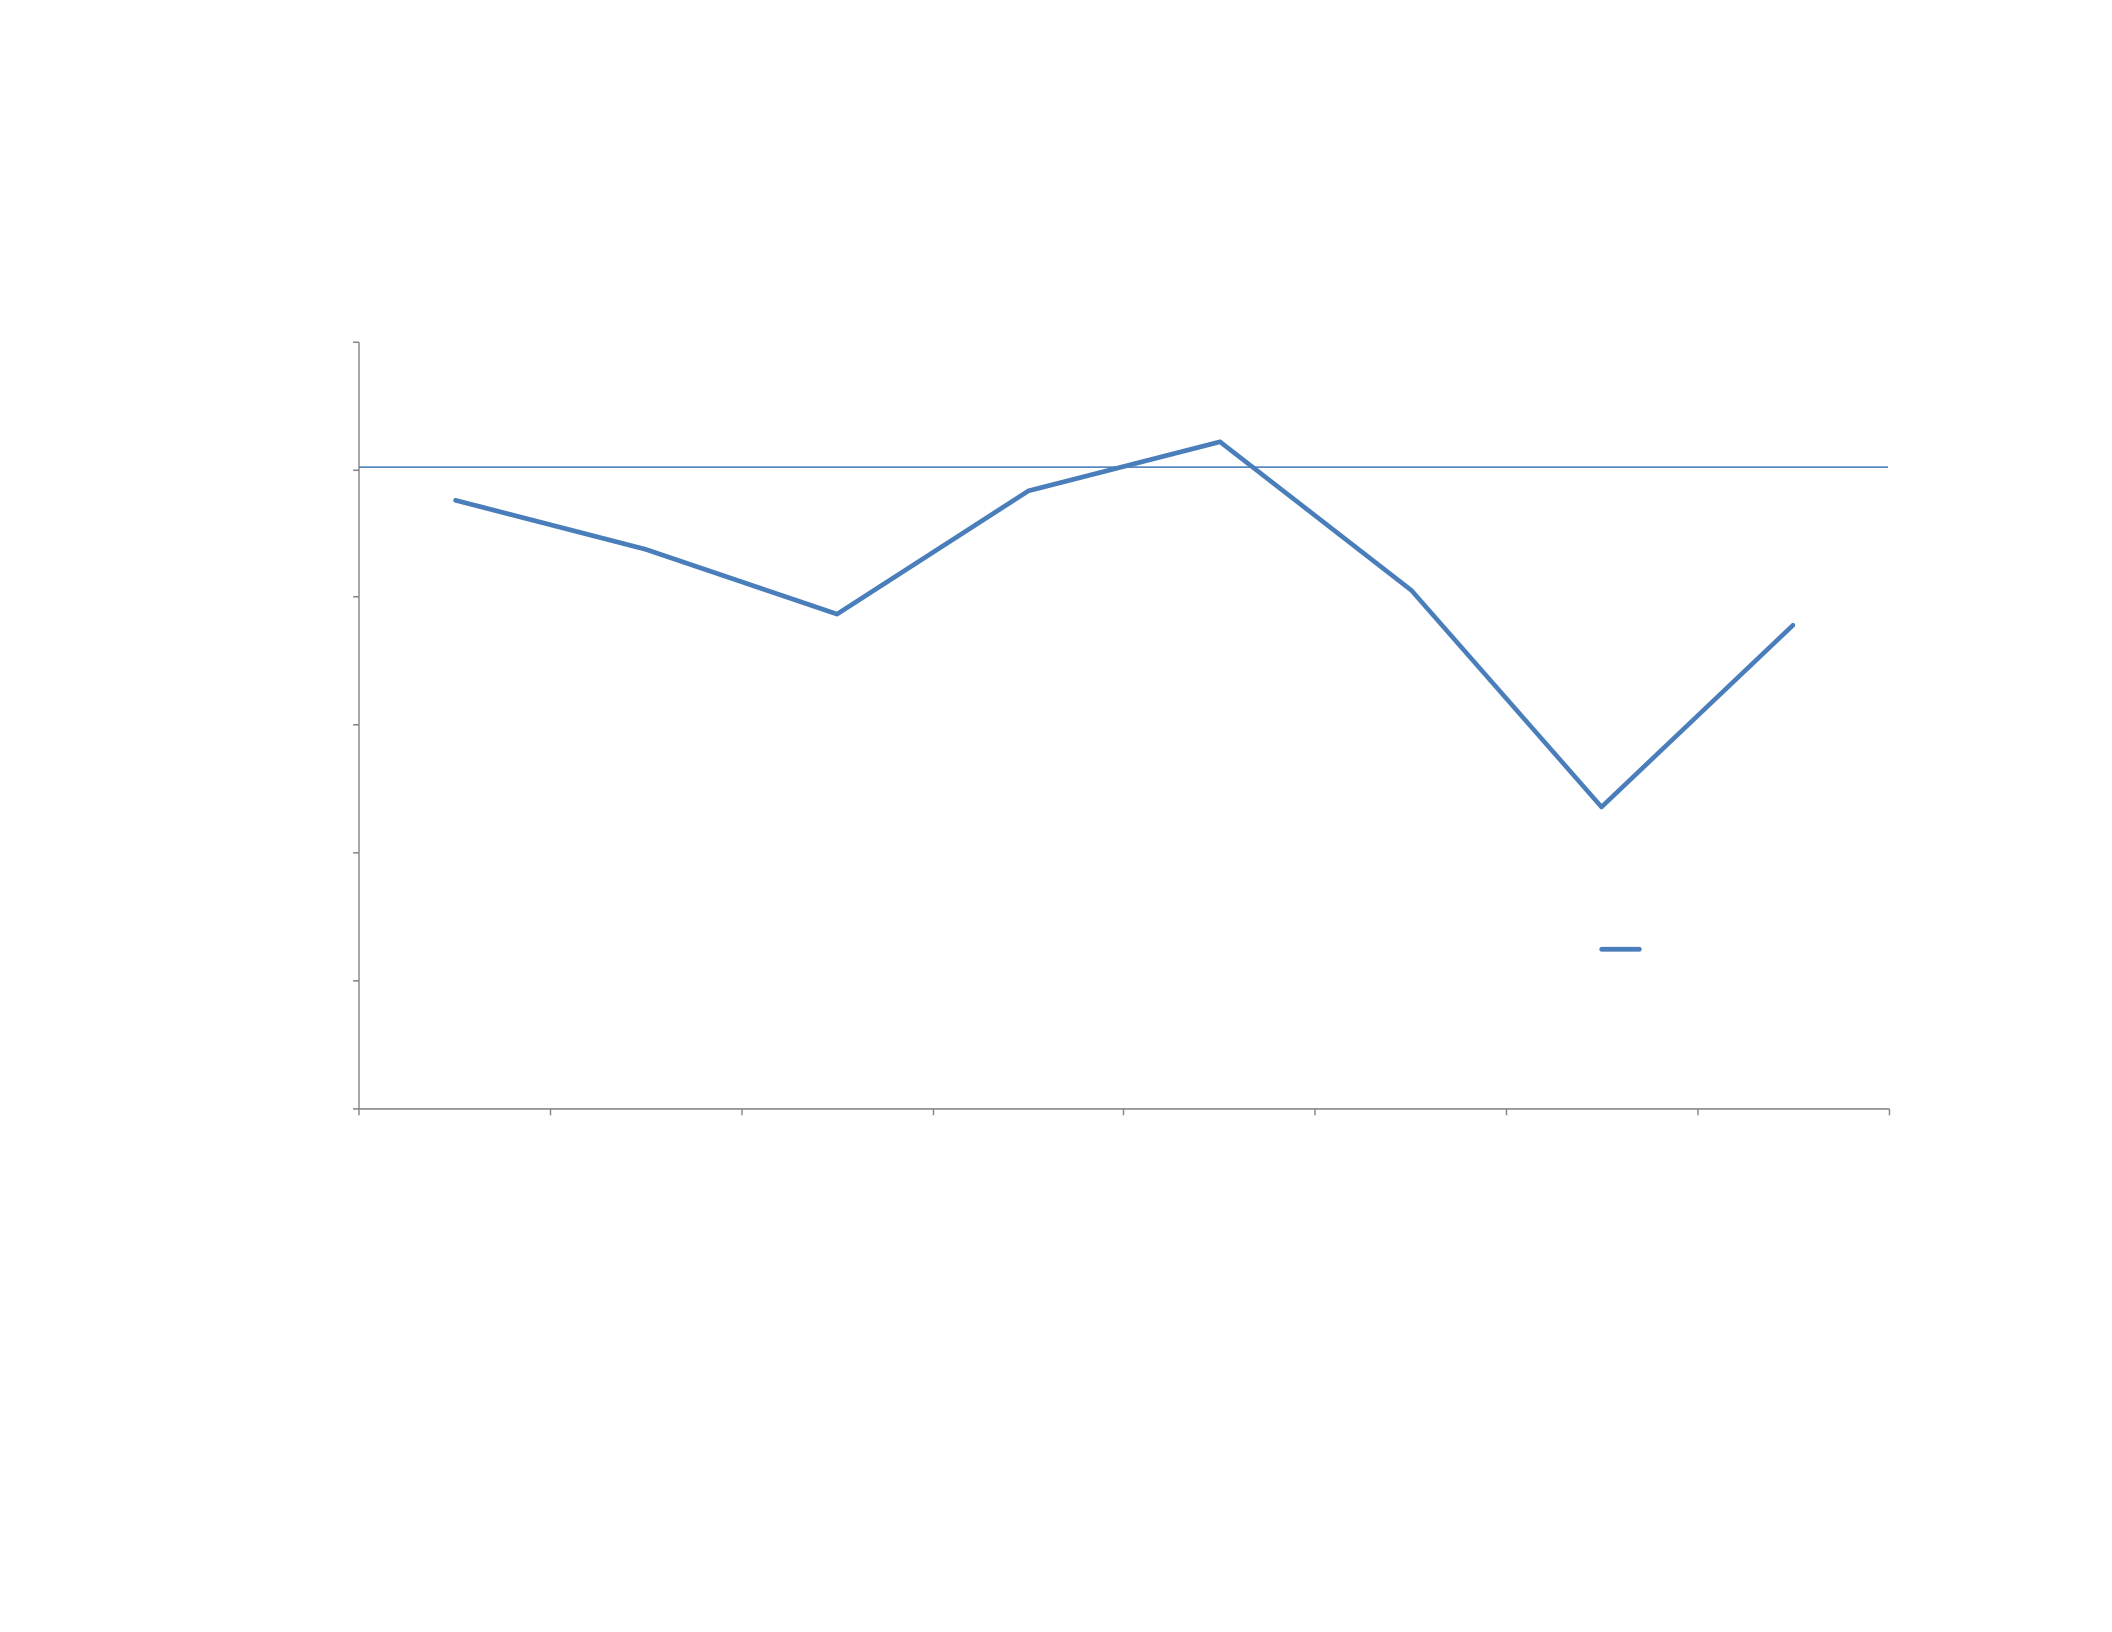
86
APPENDIX X: GRAPH - FIVE-YEAR BETA VALUE ESTIMATION, AG INDEX (1970-2008)
0
0.2
0.4
0.6
0.8
1
1.2
1970-1974
1975-1979
1980-1984
1985-1989
1990-1994
1995-1999
2000-2004
2005-2008
Five-Year Beta Value
87
APPENDIX Y: GRAPH - TEN-YEAR BETA VALUE ESTIMATION, AG INDEX (1970-2008)
0
0.1
0.2
0.3
0.4
0.5
0.6
0.7
0.8
0.9
1
1970-1979
1980-1989
1990-1999
2000-2008
Ten-Year Beta Value
88
APPENDIX Z: NUMBER OF FIRMS INCLUDED IN THE AG INDEX BY YEAR (1970-
2008)
Year # of Firms
1970 48
1971 48
1972 50
1973 58
1974 51
1975 50
1976 53
1977 57
1978 59
1979 56
1980 58
1981 55
1982 57
1983 60
1984 61
1985 56
1986 54
1987 51
1988 46
1989 49
1990 47
1991 43
1992 44
1993 46
1994 48
1995 46
1996 42
1997 44
1998 41
1999 35
2000 35
2001 31
2002 33
2003 35
2004 36
2005 40
2006 40
2007 41
2008 35

