


1
Section 1: Foundation of the Study
Businesses worldwide are vulnerable to fraud within their procurement setup, and
this affects revenue and corporate image. Although some managers in the Ghanaian
mining industry have implemented strategies that have effectively detected, controlled,
and prevented procurement fraud, others lack these strategies. Exploring successful
strategies used to detect, control, and prevent procurement fraud in the mining industry
will help save organizational revenue and reputation.
Background of the Problem
Procurement encompasses the acquiring goods and services required for the
organization’s operations (Rahmani et al., 2017). The incidence of procurement fraud in
today’s business environment is prevalent and has a far-reaching impact on the
company’s profitability and cost performance (Maniam & Peters, 2016). The complexity
of the networks in the supply chain exposes companies to procurement fraud.
Procurement fraud is cross-sectorial and the costliest white-collar crime (Horne et
al., 2018). Procurement fraud is a term for illicit acts like forgery, corruption,
misappropriation, false representation, concealment, and conspiracy perpetrated by
employees (Mufutau & Mojisola, 2016). The direct cost involved is enormous, but, in
most cases, the indirect costs of time and resources required to deal with reputational
damage and legal liabilities are higher (Chava et al., 2018). Declining commodity prices
and escalating production costs affect the margins of gold mining companies (KPMG,
2017). The risk of procurement fraud further threatens the survival of the mining

2
business. In this study, I explored successful strategies some procurement managers in
gold mining used to detect, prevent, and control procurement fraud.
Problem Statement
Procurement fraud has been rated second among the five most frequently reported
forms of economic crime, and it represents a potentially significant risk in most
organizations (McMahon et al., 2016; McNeal, 2019). In 2010, research estimated that
businesses worldwide lose over $2.9 trillion annually to economic crime (Maniam &
Peters, 2016). A survey conducted by PricewaterhouseCoopers (PWC, 2014) found that
procurement fraud constituted 29% of the losses from economic crime. The general
business problem is that managers in the mining industry lack strategies to detect control
and prevent fraudulent procurement practices resulting in loss of revenue. The specific
business problem is that some Ghanaian gold mining industry managers lack the
strategies to successfully detect, control, and prevent procurement fraud.
Purpose Statement
The purpose of this qualitative multiple case study is to explore the strategies used
by managers in the Ghanaian gold mining industry to detect, control, and prevent
procurement fraud successfully. The target population for this study was six procurement
managers from the major gold mining companies in Ghana who have successfully
detected, controlled, and prevented procurement fraud in their respective organizations.
An implication of this study that could affect social change is that managers in the gold
mining companies can increase funds budgeted for their corporate social initiatives by
reducing revenue lost through procurement fraud. Such funds can provide schools, roads,

3
hospitals, and portable drinking water required for the social wellbeing of the people in
communities.
Nature of the Study
I employed the qualitative methodology and a case study research design for this
study. Using the qualitative method gives the researcher insight into social life, the
experience, and people’s attitudes (Arseven, 2018; Creswell & Creswell, 2018; Popescul
& Jitaru, 2017). Nassaji (2015) argued that a researcher could collect quality data from
diverse sources because the qualitative method is broad. It is on this premise that I chose
the qualitative approach for this study. By contrast, the quantitative study method is about
numbers and is more appropriate when the researcher examines the relationships among
variables (Edmonds & Kennedy, 2017; Leavy, 2017). I did not intend to show
relationships among variables, making the quantitative method inappropriate for this
study. Lotte et al. (2018) explained that the mixed-method approach combines
quantitative and qualitative methods. The mixed-method approach, however, was not
appropriate for this study because it requires more significant resources and time than
those needed to conduct a single method study.
A case study design is an empirical inquiry into a contemporary phenomenon in a
real-world context (Mishra, 2018). Yin (2018) stated that the case study approach is more
explanatory and deals with traceable operational links. Yin further suggested three
situations where a case study design would be a preferred method, compared to the
others: (a) answering “how and why” research questions, (b) where the researcher has
little or no control over behavioral events and (c) where the focus of the study is

4
contemporary as opposed to entirely historical phenomenon. A narrative design is
concerned with stories of individual lives (Mohajan, 2018). A phenomenology design
helps determine a participant’s experience of a phenomenon (Pisarik et al., 2017), and the
object of ethnography design focuses on the culture of a group (Sharpe, 2018). The other
three research designs were not appropriate for this study because this study is about a
real phenomenon in the business environment, it is not about the culture of people or
about telling stories individual lives.
Research Question
What strategies do managers in the Ghanaian gold mining industry use to
successfully detect, control, and prevent procurement fraud?
Interview Questions
1. What is your understanding of procurement fraud?
2. What specific strategies do you have to detect, control, and prevent fraudulent
procurement activities?
3. How are these strategies documented and communicated to stakeholders?
4. How were the strategies accepted as a working took for detecting, controlling,
and preventing procurement fraud?
5. What challenges have you encountered implementing the strategies to detect,
control, and prevent procurement fraud?
6. How did you address the challenges of implanting the strategies to detect,
control, and prevent procurement fraud?

5
7. How have you assessed the effectiveness of the strategies for detecting,
controlling, and preventing procurement fraud?
8. What other comments or information would you want to share regarding
managerial strategies in detecting, controlling, and preventing procurement
fraud?
Conceptual Framework
Cressey created the fraud triangle theory in 1953. Cressey (1953) used the fraud
triangle to explain the factors that must be present for fraud. There are three key features
present when people commit fraud: (a) rationalization, (b) motivation or pressure, and (c)
opportunity (Prabowo et al., 2016). The theory serves as a framework to assist managers
in focusing on prevention and deterrence efforts.
Cressey (1953) suggested that rationalization is the primary trait of people
committing fraud for the first time. It may not apply to individuals who have consciously
planned to commit fraud or steal from an organization. Motivation or pressure examines
the driving forces behind the one committing fraud. Pressure or incentive is a push factor
for an individual to act illegitimately. Lastly, there should be an opportunity to commit
fraud and hide it to avoid being punished. Opportunity is the right of entry to a situation
where fraud occurs, such as weaknesses in internal controls, necessities of an operating
environment, management styles, and corporate culture (Rodgers et al., 2015). Detection,
prevention, and control of fraud require that management understands the causal factors
present in any fraudulent situation. Successfully preventing and controlling procurement
fraud would mean that management directs strategies towards the fundamental causes.

6
The fraud triangle applies to this study because it would be impossible for management to
have the necessary tools to deal with procurement fraud if the motivational factors for
committing fraud are unknown.
Operational Definitions
Corporate fraud: A sequence of illegal activities consciously and premeditatedly
carried out by members of an organization to serve their interests and harm others
(Gartner & Machado, 2018).
Economic crime: Includes all crime or illicit activities in the sphere of economics,
crime against property, and crime against the interest of service in commercial and other
organizations (Belousova, 2016).
Fraud: A situation where one person knowingly misrepresents a fact which
induces another to act or fail to act, causing damage to the party, relying on the
misrepresentation (Huber, 2017).
Procurement fraud: this is a situation where stakeholders within the procurement
process engage in activities against the procurement policy resulting in financial losses,
reputational damage to the entity they represent (Caulfield & Steckler, 2015).
Assumptions, Limitations, and Delimitations
Assumptions
A researcher’s assumptions are facts considered accurate but not verified (Mir,
2018; Schoenung & Dikova, 2016). The first assumption of this study was that qualitative
research is the most appropriate methodology for the study. Secondly, I assumed that the
chosen participants and case study companies would be helpful with identifying the

7
strategies required to detect, prevent, and control procurement fraud in the gold mining
industry. I assumed that the chosen participants understood the phenomenon under study
and would answer questions sincerely. Finally, I assumed that the phenomenon under
study is common to all gold mining companies.
Limitations
Limitations are circumstances in the research process beyond the researcher’s
control (Marshall & Rossman, 2016). One of the limitations of this study was that I
focused only on gold mining companies for strategies to detect, control, and prevent
procurement fraud. There may be more strategies for detecting, controlling, and
preventing procurement fraud from other business sectors. Another limitation was the
participants’ reluctance to answer the questions honestly without fear of losing their jobs.
I assured the participants of confidentiality to prevent such an occurrence. Lastly, the
potential for researcher bias during data analysis was another limitation as I work in the
same environment.
Delimitations
Delimitations are the scope or boundaries determined by the researcher for the
study (Isenring et al., 2016; Yin, 2018). One of the delimitations of this study was
interviewing procurement managers with experience in the subject matter from the case
study companies. Their designation and expertise in procurement and commercial
transactions for their respective companies portray their understanding of strategies to
detect, control, and prevent procurement fraud. One other delimitation was the

8
geographical coverage of the study; I limited the study to Ghana to have easy access to
the research participants during the interview and questionnaire distribution.
Significance of the Study
Managers and procurement practitioners can benefit from the results of this
research by understanding the nature of procurement fraud, the motivators, and strategies
to avert its occurrence. The study results might highlight strategies for corporate
executives to improve their corporate fraud detection and prevention efforts and serve as
a reference for procurement managers in the mining industry.
Contribution to Business Practice
Procurement fraud affects businesses in several ways: negative cost performance
metrics, the reputational damage that will negatively affect the external business
relationship with suppliers and customers alike, and loss of investor trust (Maniam &
Peters, 2016). Fraud can also influence the overall morale of the organizations’
workforce. Preventing or eliminating procurement fraud helps boost investor confidence
in the organization, which may result in more capital inflow needed to increase
productivity and profitability. External business partners (i.e., suppliers and customers)
may also feel confident in their dealings with organizations with more robust systems to
prevent fraud. Other groups that may benefit from the results of this research include
financial policymakers, auditors, private-sector legislators, and corporate fraud
investigators.

9
Implications for Social Change
Praszkeir and Nowak (2012) referred to the social change as an “alteration in
society’s social order which describes a systemic transformation, over time, in patterns of
thoughts, behavior, social relationships, institutions, and social structure” (p. 36). Social
change may be a change in informal rules or policies guiding a group or a simple
transformation in individuals’ social norms and values, status, or power. Understanding
successful strategies to detect, control, and prevent procurement fraud in Ghanian gold
mining has the potential to effect positive social change.
The operations of mining companies have a positive impact on the surrounding
communities. Through their social responsibility initiatives, managers of mining
companies provide social amenities like schools, hospitals, and roads and create jobs
through local content legislation and the payment of royalties to local authorities of the
catchment communities where they operate (Rodon and Levesque, 2015). Revenue losses
through procurement fraud affect companies financially (Rendon and Rendon, 2021). The
identified strategies could help managers in the gold mining companies take proactive
steps in dealing with fraudulent commercial practices that contribute to revenue losses,
enabling them to continue their support for people in the community.

10
A Review of the Professional and Academic Literature
The purpose of this study was to explore strategies used by managers in the gold
mining industry in Ghana to detect, control, and prevent procurement fraud. The
literature review consists of information obtained from peer-reviewed academic journals,
dissertations, books, professional trade journals, and professional reports. The topic for
the study was analyzed using the fraud triangle as the conceptual framework.
The primary research databases and libraries used for this literature review
include Walden University Library, Emerald Management Journals, Sage Premier,
ProQuest, EBSCO Primary, ABI/Inform Complete, Thoreau, Business Source Complete,
Google Scholar, Crossref Services, and Ulrich’s Periodicals Directory. The
terms/keywords that I used for my search include procurement fraud, corporate fraud,
fraud triangle, supply chain fraud, fraud detection, fraud prevention, fraud controls,
occupational fraud, and fraud diamond theory. I also used reference chaining to identify
other relevant and current articles for this study. I also ensured that at least 85% of the
sources for the literature review are 5 years or less to my anticipated completion date.
The structure of the literature review is on themes related to the topic for this
study. The main themes I reviewed include (a) fraud triangle, (b) of the fraud triangle, (c)
supporting/opposing theories to the fraud triangle, (d) corporate fraud, (e) procurement
fraud, (f) procurement fraud schemes, and (g) fraud prevention and detection strategies.

11
Fraud Definition
The term fraud has diverse definitions. For the purpose of this study, fraud is
defined as a deliberate, deceptive, and misleading act for personal gain or advantage
(Zandian and Keyvanpour (2017). Gaining advantage through fabrication, falsification,
misrepresentation, omission of facts, and plagiarism amounts to fraud (Tsegba & Upaa,
2015). Rajapakse and Malaba (2015) also argued that personal gain is a driving force
when employees commit fraud.
Fraud Triangle
Cressey’s (1953) theory, the fraud triangle, is a framework that explains the
reasoning behind people’s decision to commit fraud in the organization. It constitutes
three elements of fraudulent behavior: pressure, opportunity, and rationalization.
Cressey’s work serves as a foundation for much research on occupational fraud (Boyle et
al., 2015). Beyond academic research, Morales et al. (2014) claimed that the fraud
triangle provides fraud investigators a template that individualizes fraud with the
organization responsible for controlling it. From this perspective, the onus lies in the
organization to ensure effective monitoring of the three elements of the triangle through a
well-laid internal control. Fraud is not a social, political, or historical problem but a
problem at the confluence of the individual and the organization. Cressey researched 200
prisoners arrested for embezzlement incarcerated at various prisons and developed the
hypothesis that those in trusted positions believe that they can resolve their nonshareable
financial problems by violating the position of financial trust. Mui and Mailley (2015)
further argued that the nonshareable financial problem makes the perpetrator feel a

12
perceived financial burden motivating the crime. The perpetrator explores an opportunity,
perceives limited risk of being caught, and finally justifies his behavior by considering
his financial dilemma a unique situation. Gartner and Machado (2018) further argued that
the motivation of fraud is the existence of problems typically of financial nature that
cannot be shared or disclosed to others because of pride or ego. In essence, the fraudster
sees an opportunity and would try getting out of this problem discreetly by violating
financial trust and then rationalizing the fraudulent act by justifying it as necessary to
resolve the financial problem. The argument of authors (Mui and Mailey, 2015; Gartner
and Marchado, 2018) aligns with Cressey’s motivation for fraud frequently of financial
nature, the opportunity, and the justification. Cressey had inspiration from the work of
Reimer (1941), who also argued that there is a three-fraud-causing element when
someone commits a crime: the social pull (the opportunity), the social push (the
emergency), and the psycho-pathological element (Levi & Schuchter, 2015). Both
Reimer and Cressey’s work identified the motives and elements for committing fraud.
Therefore, the fraud triangle is a valuable tool that helps organizational managers identify
the causes or motives behind fraud to devise strategies to avert its occurrence.
The fraud triangle is the fundamental theory for explaining why people commit
fraud. Several authors (see Boyle et al., 2015; Levi & Schuchter, 2015; Raval, 2016;
Schnatterly et al., 2018) applied the fraud triangle to explain the causes of fraud and its
implication on business. Most literature on fraud used the fraud triangle as a framework
to understand how and why fraud occurs and analyze the risk to businesses (Andon et al.,
2015; Kramer, 2015; Lenz & Graycar, 2016). In recent times, the fraud triangle has been

13
developed and refined further in different fields of academia. Cressey’s (1953) work
forms the basis of categorizing risk factors for many international auditing standards
(Levi & Schuchter, 2015). Most of the current understanding of why people commit
fraud is grounded in the fraud triangle. Kramer (2015) analyzed three case studies using
the fraud triangle to explain the motivation for fraud in small businesses. Using the fraud
triangle, the author suggested that business owners prevent fraud by not trusting
employees too much and identifying perceived opportunities. Kramer further suggested
that if managers can raise the fraudster's perception of detection and reduce perceived
opportunity, fraud will reduce. The evidence in literature on the fraud triangle makes it a
valuable tool to understand why people commit fraud.
Although the fraud triangle has contributed immensely to the fight against fraud,
it has been reviewed and modified severally (Raval, 2016). Free (2015) reviewed popular
frameworks for fraud examination and identified three areas of potential academic
research and debate within organizations and regulatory bodies based on Cressey’s fraud
triangle. Free identified three underresearched areas: rationalization of fraudulent
behaviors by offenders, the nature of collusion in fraud, and regulatory attempts to
promote whistleblowing. Both authors (Raval, 2016; Free, 2015) improve the
understanding of the human element on the act of fraud. Whiles Raval sought to extend
the fraud triangle to explain the role of human desire, intensions, and actions in fraud,
Free’s work expounds this to include systems within the organization that encourages the
detection of fraud. The work of both authors set the pace for further research into

14
organizational strategies to detect, prevent, and control fraud with emphasis on
procurement.
Elements of the Fraud Triangle
Pressure
Pressure constitutes factors that motivate people to commit fraud regularly of financial
nature, where an individual find him/herself in a financial problem that cannot be shared
to seek help (Cressey, 1953). The pressure is the “motivation” that ignites fraud. If an
employee perceives that he or she can gain financially by committing fraud without been
caught, then that knowledge can stimulate the act of fraud (Kumar et al., 2018). Mangala
and Kumari (2015) referred to pressure as situations that accumulate stress and arouse the
desire to commit fraud. Cressey classified the nonshareable financial factors into six
categories: (a) difficulty in paying back debts, (b) personal failure, (c) business reversals,
(d) physical isolation, (e) status gaining, and (f) employer-employee relations. Several
other authors have given different examples of these categories. 95% of all fraud cases
are because of financial pressure. On the same line, Albrecht et al. (2015) identified
sudden financial shortfalls, living beyond one’s means, greed, imperfect credit standing,
and inability to obtain credit, unexpected significant medical expenditure as examples of
nonshareable financial pressure. Imoniana et al. (2016) also related the pressure to
experience in the individual’s life that creates the need for funds pushing the person to
defraud. In the above discussion the authors acknowledge that the key factor that pushes
individuals to engage in fraudulent activities is the desire for money to meet certain

15
lifestyles that goes beyond their basic needs. The motivators raised by these authors as
pressure element are personal to the individual committing the fraud.
The pressure to commit fraud could also come from organizational performance
goals given to employees. Employees and management commit fraud to meet
performance indicators and satisfy or exceed the expectations of key stakeholders
(Mishra & Singh, 2017). An unethical organizational culture increases the risk of
fraudulent activities (Judith, 2018; Sídoróv, 2015). From the ongoing discussion, pressure
was classified in diverse but interrelated ways. Free and Murphy (2016), however,
outlined problems with the various categorization of pressure. They made two arguments
against the categorization of pressure as external and internal. Firstly, the authors argued
that they should be both an external and related internal push for an individual to be
motivated by pressure to commit fraud. For example, an ill-treated employee in a
workplace (an external pressure) is not likely to commit fraud unless the employee is
angry or wants revenge (arguably an internal incentive). On the other hand, if an
employee perceives a financial benefit (an external incentive) from committing fraud,
then that employee will see this as an incentive to commit fraud if the employee is also
greedy or is in an awful financial situation (intrinsic incentives). Secondly, there is
always a bias in the perception of pressure because money is the result of fraud in most
cases (Free and Murphy, 2016). The fraudster must, therefore, perceive an innate ability
to take action to save the situation. (Suh et al., 2018). The fraudster's emotions and
perceptions are critical to understanding the motivation to commit fraud (Suh et al.,
2018).

16
In summary from the discussions by the various authors, pressure as an element of
fraud arise from two main sources; an individuals financial situation and the
organization’s pursue to meet financial targets. There are also non financial
organizational pressures that motivates fraud. For example workers’ dissatisfaction and
perceived unequal treatment in renumeration, promotion, and personnel development.
Opportunity
Opportunity is the second element needed for fraud to occur; it is the
circumstances that exist making it possible to commit fraud typically created by weak
internal controls or governance systems within an organization (Abdullahi & Mansor,
2015). According to Cressey (1953), opportunity does not necessarily have to exist;
however, fraudster must believe or assume its existence. Many researchers have argued
that among the factors that present opportunities for fraud, the more prevalent are weak
controls, no internal control, weak or nonexistent audit procedures, and an internal
environment that makes it easier to commit fraud (Boyle et al., 2015; Free & Murphy,
2016; Ghafoor et al., 2019; McNulty & Akhigbe, 2016)
The opportunity to commit fraud is seemingly always present for those who occupy
senior-level positions (Wells, 2018; Lisa & Hermanto, 2018; Bire et al., 2019) because
they have a comprehensive understanding and have access to critical information and
data, which gives them the ability to override even the most effectively designed controls
(Boyle et al. 2015). The underlying fact is that the fraudster has the knowledge and
chance to commit fraud and will do so because he/she is in a position of trust, is aware of
the weakness in the internal controls, and gathers enough information to be successful in

17
committing the fraud (Gartner & Machado, 2018; Ruankaew, 2016). For example, if an
employee is in a position to award contracts and has the power to authorize payment, then
the opportunity to commit fraud and conceal it is high because one person has control
over the whole process. The weakness in internal controls tends to reduce the possibility
of catching the fraudster, thereby offering the opportunity to commit fraud (Steinmeier,
2016). From the discussion it can be deduced that opportunity to commit fraud is present
where the organizations internal controls are weak or does not exist and the fraudsters
have access to critical information that can be used to their advantage. This also means
that if an individual is pressured and can rationalize his fraud intensions, the absence of
an opportunity will foil the fraudulent action.
Opportunity, according to Abdullahi and Mansor (2015), is in two forms: (a) the
organizations' exposure and vulnerability to manipulation and (b) the internal
environment that encourages fraud. Fraud occurs because internal controls break down,
and perpetrators successfully conceal it. Power and authority that individuals have also
given rise to opportunities if they are not regularly revised and supervised, or assigning
too much responsibility to one employee, with no control and segregation of duties
(Burke & Sanney, 2018). Some authors also have embraced certain organizational factors
allowing fraud (Huisman, 2016; Zyglidopoulos & Fleming, 2016). They argue that some
organizations are more prone to fraud because their structure, culture, and strategy make
it easier for fraud to occur. In summary, even though fraud is perpetrated by individuals
based on personal factors, organizational systems can also ease the fraud by presenting
opportunities that may exist or perceived to exist. Business leaders will have to develop

18
internal controls that will erase the perception of opportunity to commit fraud. From the
authors (Huisman, 2016; Zyglidopoulos & Fleming, 2016) opportunities arise from weak
controls or weak culture. Opportunity to commit fraud comes from the environment in
which the fraudster is. If the practices and culture reflects a support or depicts fraudulent
conduct, then the tendency to commit fraud is high.This implies that promoting an ethical
environment will influence the lack of opportunity to commit fraud.
Rationalization
Rationalization is the justification to make the wrong action or unethical behavior
look like something other than a crime (Abdullahi & Mansor, 2015). Abdullahi and
Mansor (2015) believed that an individual is more likely to engage in fraudulent behavior
if he/she can justify the action. Rationalization has many forms. It is, however, an
important factor encouraging the individual to act fraudulently (Dion, 2019). It is part of
the motivation to commit fraud because the offender does not see himself as a criminal
(Vousinas, 2019). The individual’s moral compass influences the level of rationalizing
fraud. However, according to Button and Shepherd (2019), this does not rule out the
possibility of otherwise honest individuals from fraudulent acts, especially in a highly
pressurized environment with very weak controls. Cressey (1953) suggested that
fraudsters rationalize their actions to resolve the nonshareable problem. The fraudsters
tend to make excuses such as, “I am just borrowing this, and I will pay it back later.”
They may think, “I am using this money to help my family”; they may also think what
they take is insignificant compared to the revenue the organization makes (Gartner &
Machado, 2018). From the discussions above, the individual mentally perceives that their

19
actions will not affect the company significantly and may not classify their actions as
fraud because theylack personal integrity. For example, a procurement officer who
engages a vendor to adjust prices to win a contract, may not see his action as fraudulent
just because the vendor supplied the items as required. The tendency to engage in
fraudulent activity is dependent on the individual’s ethical values and circumstances
(Alam et al., 2018). Abdullahi and Mansor (2015) also argued that an innate character
and external factors influence individual ethical behavior, job insecurity resulting from
downsizing, redundancy resentment from non promotion, and perceived unfairness in
remuneration. External factors will include management attitudes towards fraud risk and
disciplinary actions against perpetrators. The authors also argued that if previous
fraudulent action has gone unpunished or weakly dealt with, others may feel they can
also commit fraud and get away with it (Abdullahi and Mansor, 2015). The discussion on
the fraud triangle is centered around research on the assumption that, people who lack
integrity and morals are more likely to commit fraud and thereby placing the
responsibility on organizational managers to establish strong controls to make it difficult
for employees to commit fraud or easier to detect fraud. Although the fraud triangle
formed the basis for fraud research, it has also been subjected to considerable debate and
criticisms. Theses critisms pushed research further to fill the gaps found in the fraud
triangle introducing more theories for the motivation for fraud.
Criticisms and Limitations of the Fraud Triangle
Many professional auditors and standard setters have supported the fraud triangle
with the argument that investigators can quantify the incentive that led to the fraud during

20
analyses of financial statements, assess the opportunity to commit the fraud, and the
rationalization technique used to justify the fraud (Lokanan, 2018). Others have raised
arguments against the fraud triangle, believing that the explanation given by its
supporters has limitations and misinterpret the nature of fraudulent misconduct. Huber
(2017) believed that the fraud triangle has been overstretched and misused and was
originally not intended for the study of fraud. Huber argued that the fraud triangle only
exists in name and that Cressey’s (1953) initial study was on embezzlement, not fraud,
which means the fraud triangle has, over the years, been misused or misapplied. Huber
suggested that instead of the fraud triangle, Cressey should have called it the
embezzlement triangle, which links up to the study’s original purpose.
Opportunity does not consider situations where individuals come together to hatch
a plan to commit fraud and put it into action (Lokanan, 2015). The fraud triangle does not
assess the possibility of collusion and further fails to consider other social learning
factors that influence criminal behavior (Ahmad et al., 2019; Free, 2015; Morales et al.,
2014). Vousinas (2019) also argued that the fraud triangle does not help explain the
nature of all fraud perpetrators, and Cressey’s work is aging, making it quite unaligned to
new societal changes. Nonshareable financial pressure is most stressed in the fraud
triangle. Lokanan (2017) believed there are other sources of pressure other than financial
that could motivate fraud as millionaires without financial pressure also commit fraud.
All these arguments point to the fact that the fraud triangle does not cover every aspect of
why fraud occur as it is limited and focused on the individual without considering other
factors.

21
The principal motivation for the various limitations and criticism raised has been
the interpretation and understanding given by the antifraud community. While these
limitations and criticisms are valid of the fraud triangle, white-collar criminologists
suggested that one single theory or framework cannot adequately explain why fraud
occurs (Huber, 2017). Gill (2017) argued that the fraud triangle is not the ultimate for
dealing with all fraud but for the basic understanding of conditions that favor the
occurrence of fraud. Lokanan (2018) further stated that the fraud triangle, other than
being a scientific theory based on the method of science, should be a helpful framework
that aids in the understanding of why people commit fraud. Most of the authors agreed
that the fraud triangle, to some extent, provided a basis as to why people commit fraud. It,
however, falls short in considering other factors that may also play a role in fraudulent
acts.
Supporting Theories/Opponents of the Conceptual Framework
Fraud Diamond
Wolfe and Hermanson (2004) further extended the Fraud Triangle into the fraud
diamond by adding a fourth element; the capability of the person to engage in a
fraudulent act. According to the authors, in the presence of pressure, opportunity, and
rationalization, individual personality traits and abilities play a significant role in the
fraud. Boyle et al. (2015) argued that capability reflects traits of the potential fraudster
based on which he/she can identify, understand, and exploit weaknesses. The authors
argued that many fraud cases would not have been possible if the fraudster did not have
the capabilities to perpetrate the crime to its detail. The elements of the fraud diamond are

22
observable and non-observable (Puspasari, 2015). According to (Peltier-Rivest, 2018;
Wolfe & Hermanson, 2004), there are four observable traits of the capability to commit
fraud; the fraudster’s authoritative position in the organization, the capacity of the
fraudster to exploit weaknesses in systems, the confidence (ego) that no one can detect
the fraud, and the capability to deal with the stress created within an otherwise good
person when committing the fraud. Boyle et al. (2015) agreed and further added two
more traits of the capability to commit fraud; the ability to coerce others to move along
with him/her or to look away through persuasive skills and the ability to conceal the truth.
The capability element is the convertor that turns the opportunity into reality. It involves
the power to take decisions, technical knowledge, and trust (Mangala & Kumari, 2015).
The fraudster identifies the opportunity and can turn it into reality. Lenz and Graycar
(2016) also argued that the opportunity is a necessary element but not enough for fraud to
occur. From the arguments of (Boyle et al., 2015; Mangala and Kumari, 2015; Lenz and
Graycar, 2016), fraud can only be associated with the actions of the person who wills to
commit it. Not condemning the fraud triangle, all the authors agreed that even if all the
elements of the fraud triangle are present the fraudster should have the will power, skill
or capability to commit the fraud diamond is the extension of the fraud triangle. The
impetus to commit fraud, therefore, remains an internal human one. An individual
motivated to defraud requires an opportunity and understanding of the real opportunity to
defraud (Levi & Schuchter, 2015). The fraud diamond further expands the fraud triangle
to cater for other elements that researchers have observed as lacking in the fraud triangle.
The addition of capability requires organizational managers to understand the employees’

23
traits and abilities when assessing fraud risk and prevention. If there are employees
whose capabilities present a high risk to fraud, then strong controls need to be established
to prevent fraud from occurring.
Fraud Scale
Albrecht in 1984 proposed a more practical theory for detecting and preventing
fraud; the fraud scale substitutes the rationalization element of the fraud triangle for
personal integrity. The fraud scale provides that when pressures and opportunities are
high, and people have low integrity, occupational fraud is more likely to occur. On
the other hand, fraud risk is less likely to occur when pressure and opportunity are
lower with high personal integrity. Albrecht described situational pressures as the
immediate problem individuals experience within their environments; prevalent
among these are high personal debts and financial losses. Because rationalization is
not observable, the authors used personal integrity as a substitute for rationalization to
increase the model’s predictive ability. Albrecht believed that fraud is difficult to predict
because of the lack of a reliable profile of occupational fraudsters and suggested that the
likelihood of fraud is predictable by evaluating the relative forces of pressure,
opportunity, and personal integrity. The introduction of integrity makes it possible to
observe an individual’s decision with the decision-making processes and monitor
commitment to ethical decision-making (Vousinas, 2019). The personal integrity
element is associated with everyone’s code of ethical behavior. Albrecht’s arguments
are consistent with the arguments of at least one fraud expert (Belousova, 2016), who
argued that an individual’s moral compass determines or plays a significant role in

24
the individual’s judgment. An individual’s moral compass and integrity is one major
factor that influences fraud. The introduction of personal integrity means that, it is
possible for all the elements of the fraud triangle to be present but because an
individual has a high personal integrity will not commit fraud. There are individuals
who will not commit fraud despite the pressures they face, opportunities available,
and the justification available. This also means that an individual who lacks personal
integrity will not hesitate to commit fraud at the least opportunity and pressure.
Money, Ideology, Coercion, and Ego/Entitlement
Kranacher (2011) propounded the money, ideology, coercion, and ego/entitlement
(M.I.C.E) model, which seeks to extend the pressure element of the fraud triangle beyond
solely financial motivators. Fraudsters motivated by ideology tend to perpetrate fraud,
believing that their actions will positively impact society. Ideology is typically linked
with fraud schemes related to tax evasion and terrorism financing frequently moved by
ideological beliefs other than personal financial difficulties. Coercion explains fraud
schemes committed by individuals who, by themselves, will not commit a crime but are
forced or influenced by others to do so reluctantly. Such individuals might be in a
situation that weakens their ability to resist the act or defile the authority of the person
forcing them. Finally, ego/entitlement refers to factors that protect a person’s reputation
or social status other than financial needs. For some people, fraud is the only way to keep
their reputation or position of power in front of their society or families (Vousinas, 2019).
This social pressure can be a compelling motive to commit a fraudulent act to keep their
ego. Dorminey et al. (2012) argued that the MICE is easy to remember among the

25
fraud models, albeit it oversimplifies the motivations for fraud, and some
motivations fall under several categories. The MICE provide a broader framework
beyond pressure and rationalization to consider the probability of fraud by
considering an expanded set of motivators and therefore clears the limitations of the
fraud triangle.
Stimulus, capability, opportunity, rationalization, and ego
After analyzing all the other fraud models, Vousinas (2019), called for the
need for a revision, which will consider current developments and enhance the
understanding of the major factors why people commit fraud. He, therefore,
developed the SCORE, also known as the fraud pentagon. The SCORE acronym for
the words: stimulus, capability, opportunity, rationalization, and ego. Stimulus, just
like pressure in the fraud triangle, according to the author, comes in different forms
of high financial needs, the pressure to achieve high targets, work-related stress,
desire to achieve high professional goals in a short period (Georgios, 2019).
Capability is about the personal traits and abilities of the individual to commit fraud
when all other factors are present. Opportunity is a situation that makes it easier to
commit fraud. Rationalization has to do with justifying the fraud. The ego is
unconscious push elements the individual may not be aware of that make him/her
believe he/she can commit fraud without been caught (Georgios, 2019).
The discussions above show that, though the fraud triangle forms the basis for
fraud to occur it does not cover all the possible elements of such a broader
phenomenon. The subsequent theories enrich the discussion by expanding into other

26
elements that is not covered by the fraud triangle. The other theories discussed above
underscore the fact that personal traits contribute to whether an individual will
commit fraud or not. There are people who will never commit fraud even though
opportunities exist with pressure and can justify their action. There are also people
who will still commit fraud in the absence of opportunities, pressure and
justification.
Corporate Fraud
Corporate fraud is a challenge in today’s dynamic business environment. Intense
competition among businesses induced by globalization has forced organizations to fight
for profits and market share. Corporate fraud results in significant profit losses and erodes
investor confidence (Dong et al., 2018). Corporate fraud is simply the misuse of the
organizational system (Riyanarto et al., 2020). Wood and da Costa (2015) defined
corporate fraud as a chain of illegal actions done consciously by members of an
organization who manipulates processes and systems to serve their parochial interest at
the detriment of other parties. Such actions can result in losses for shareholders and other
stakeholders, which may expose the organization to regulatory challenges. Financial
misstatements, procurement irregularities, delay in disclosing information or non-
disclosure, bribery, insider trading are few examples (Zhang et al., 2018). Singleton and
Atkinson (2016) extended the definition to cover financial fraud committed by an
employee or a group of employees. A situation where employees intentionally misuse or
misappropriate the organization’s financial resources (Wood & da Costa, 2015). The

27
impact of corporate fraud could be direct in monetary cost, including costs associated
with investigating and remediation, and indirect in reputational damage, lost productivity,
and the related loss of business (Lokanan, 2015). Indirect impact includes damages to
employee morale, brand, company reputation, business relationships, consumer
confidence, weakened public trust, and ruined market share value, which may cause a
company to collapse eventually (Nawawi & Ahmad Saiful Azlin, 2018a). A bad
reputation affects the business relationship between companies and their investors and
other stakeholders. The detection of fraud also increases doubts on the credibility of
information put out by the organization (Yuan & Zhang, 2016). Mishra and Singh (2017)
argued that corporate fraud schemes are complex and economically affect the
organization and its partners. Corporate fraud has an enormous impact on organizational
sustainability, and managers and leaders need to ensure the right strategies are in place to
avoid its occurrence.
Forms of Corporate fraud
There are various forms of corporate fraud. However, the most widely recognized
forms according to (ACFE, 2018), are mainly three: asset misappropriation, corruption,
and financial statement fraud. Understanding the various forms of fraud helps to establish
mitigating strategies (Omar et al., 2015). The ACFE further stated that although these are
the primary forms of fraud, a fraud scheme often involves a combination of different
types of fraud. The association classified the different forms of corporate fraud in a
diagram called the fraud tree.
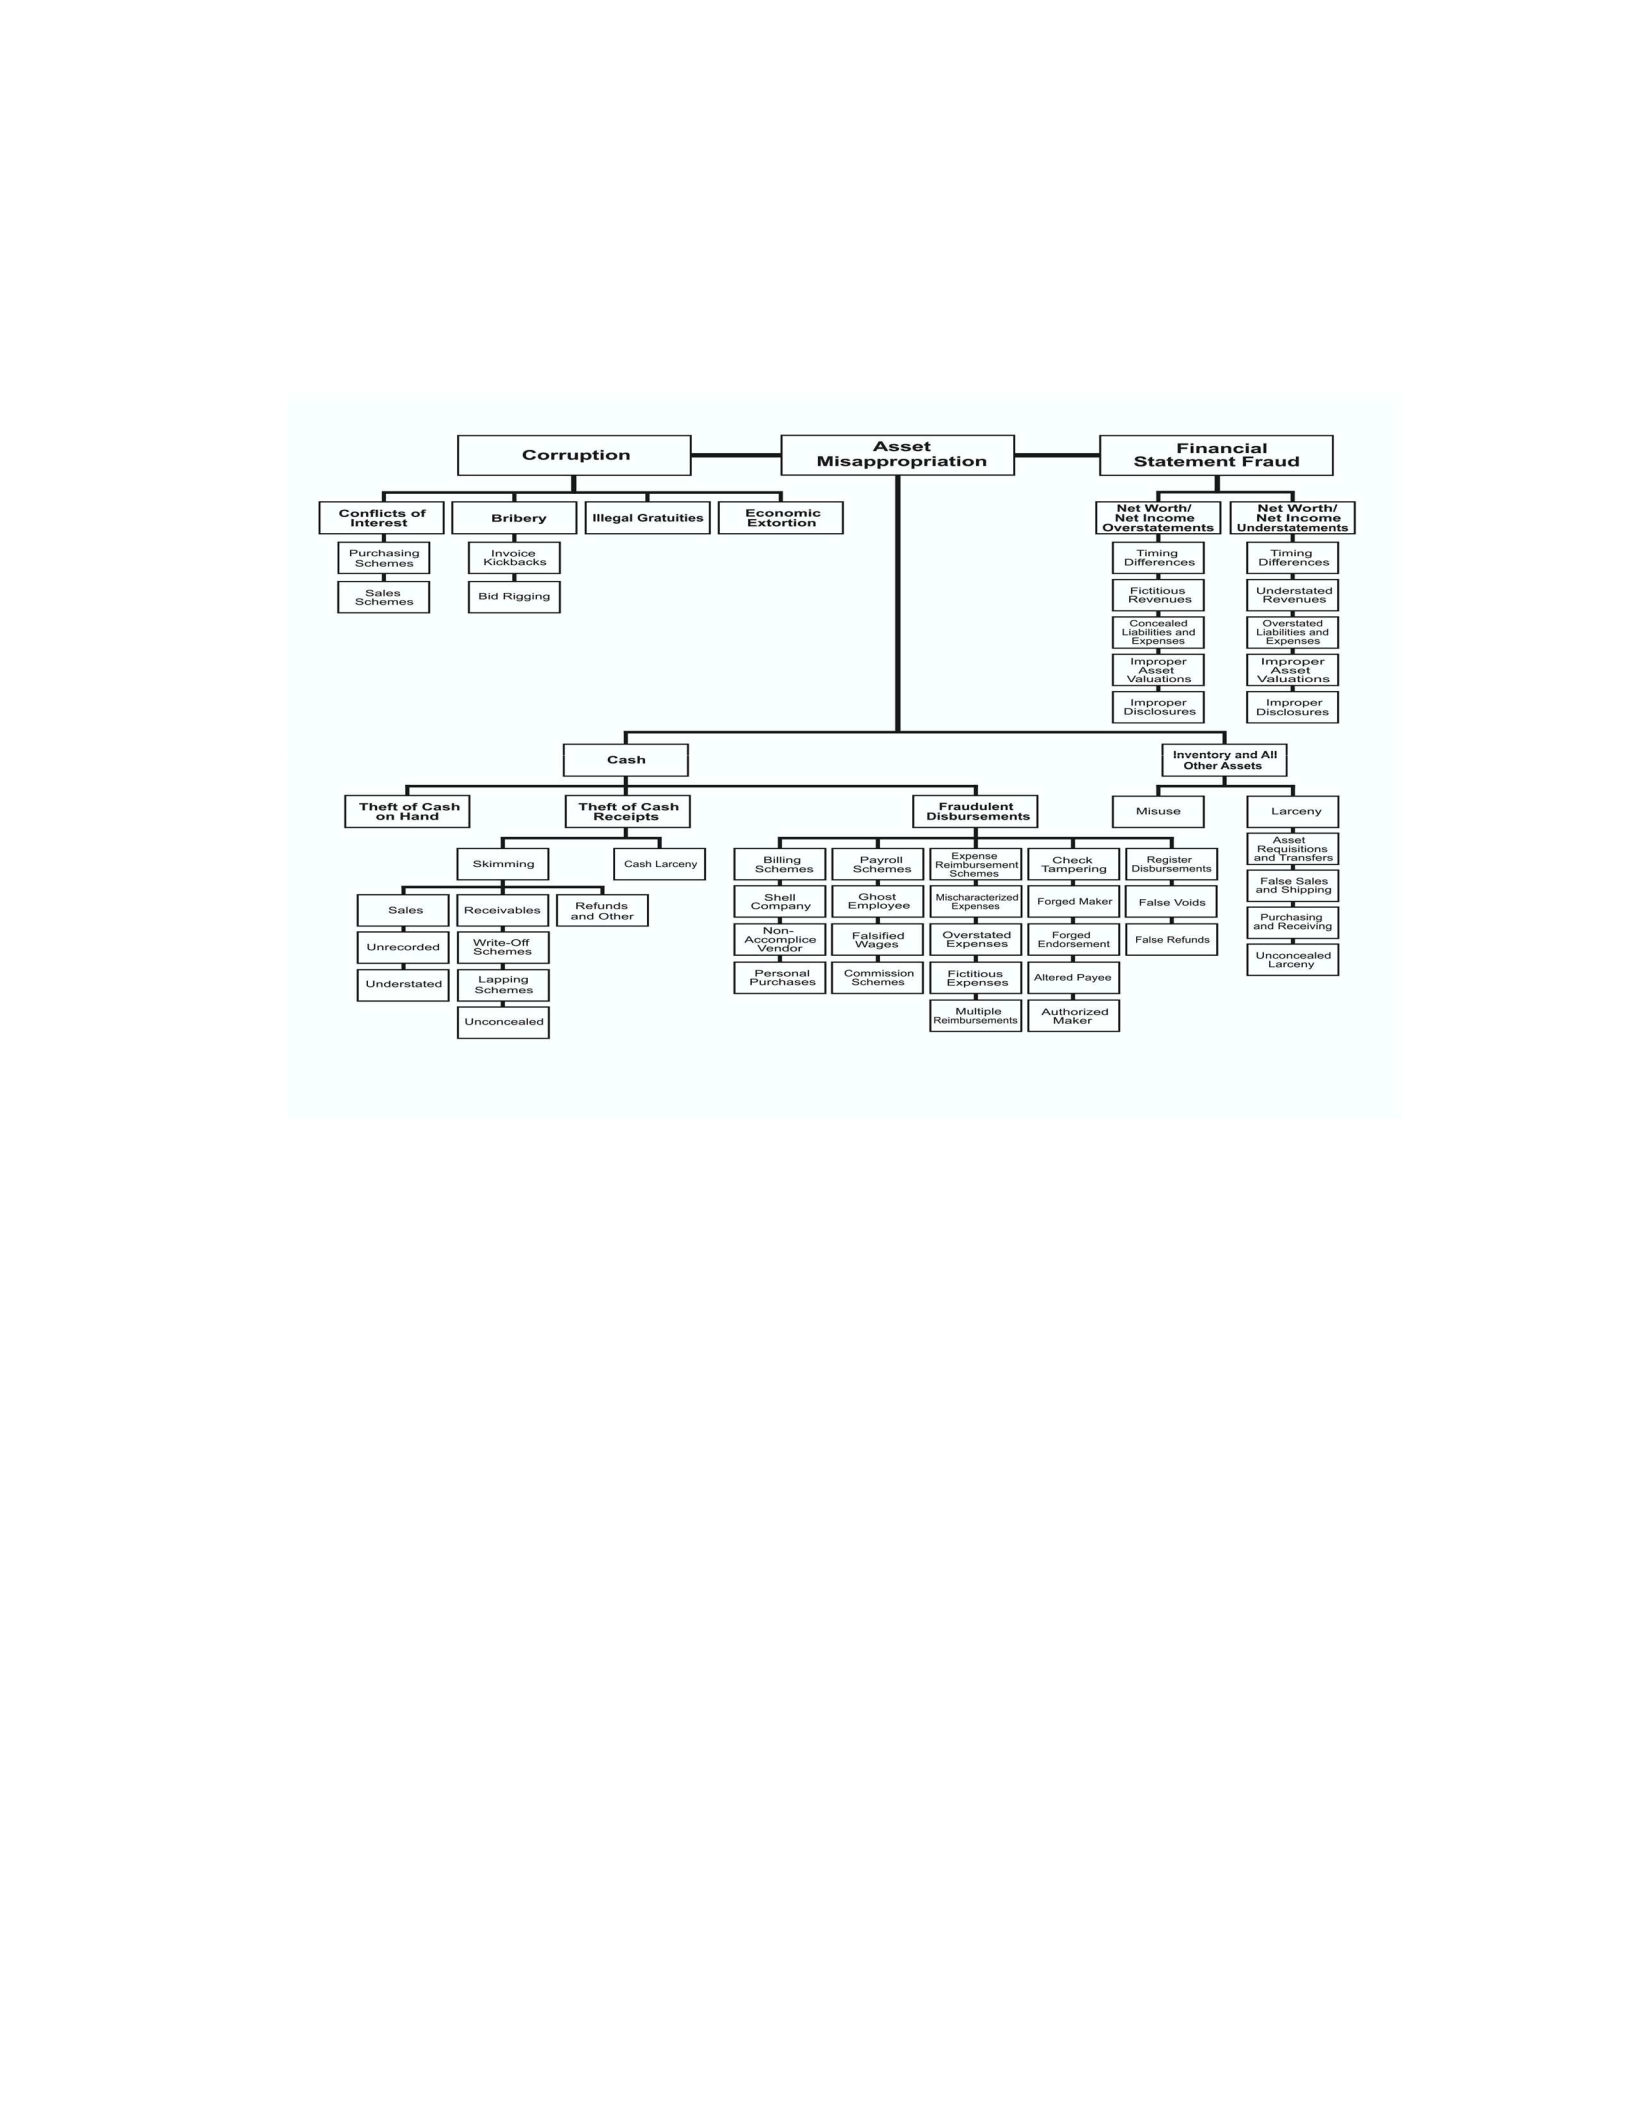
28
Figure 1
The Fraud Tree
Note. Reproduced with permission from ACFE (2018). Report to the Nations on
Occupational Fraud and Abuse. Copyright (2018) by the Association of Certified Fraud
Examiners
Asset Misappropriation
This type of occupational fraud happens when a person, group, or entity wrongly
diverts or misuses assets, money, or other resources for its benefit (Klein, 2015; Nawawi
& Ahmad Saiful Azlin, 2018b). This type of fraud occurs most frequently and constitutes
about 83% of all reported fraud cases. However, it records the lowest losses among the
three categories (ACFE, 2018). It is prevalent, mainly where internal controls are weak
(Lenz & Graycar, 2016). The ACFE reported asset misappropriations as theft of cash and
29
other financial resources by employees. Asset misappropriation schemes are in three
subcategories composed of nine different offense types, as shown in Table 1. Klein
(2015) argued that the most common among the subcategories of asset misappropriation
is theft and misuse of inventory and supplies. Glodstein (2015) identified poor accounting
records, inefficient data processing controls, frequent deficits in cash balances, lack of
management commitment to internal controls, and ineffective internal controls as major
red flags for asset misappropriation.
Table 1
Categories of Asset Misappropriation Fraud
Offense Type Description
Theft of cash receipts
Skimming Any scheme in which employees steal cash from an
organization before recording it in the organization’s books
and records
Cash larceny Any scheme in which employees steal cash from an
organization after recording in the organization’s books and
records
Fraudulent disbursements of cash
Billing Any scheme in which a person causes his or her employer to
issue a payment by submitting invoices for fictitious goods
30
and services, inflated invoices or invoices for personal
purchases
Expense reimbursement Any scheme in which an employee claims reimbursement of
fictitious or inflated business expenses
Cheque tampering Any scheme in which a person steals his or her employer’s
funds by intercepting, forging, or altering a cheque drawn on
the bank accounts of the organization
Payroll Any scheme in which an employee causes his or her employer
to issue payment by making false claims for compensation
Cash register disbursements Any scheme in which an employee makes false entries on a
cash register to conceal the fraudulent removal of cash
Other Schemes
Misappropriation of cash on hand Any scheme in which the perpetrator misappropriates cash
kept on hand at the victim organization’s premises
Noncash misappropriation Any scheme in which an employee steals or misuses non-cash
assets of the victim organization
Note. Reproduced with permission from ACFE (2018). Report to the Nations on
Occupational Fraud and Abuse. Copyright (2018) by the Association of Certified Fraud
Examiners.

31
Corruption
Corruption includes a range of activities and behavior from the misuse of position
or power for personal advantage. There is no single generally accepted definition for
corruption (Zyglidopoulos, 2016); however, it broadly includes bribery, illegal gratuities,
economic extortion, and conflicts of interest (Wells, 2018). Gorsira et al. (2018)
explained corruption on the line of individual and organizational factors. Gorsira et al.
(2018) argued that corruption results from an individual’s decision based on perceived,
more significant gains and perceived lower costs of corruption to the organization also a
bad culture or ethical climate induces unethical employee behavior (Jha & Panda, 2017).
Although not common, like asset misappropriation, the cost implication on a victimized
company is disruptive and potentially more significant. Peltier-Rivest (2018) claimed that
the organization is the first to suffer in any corrupt act and that employee’s knowledge of
unethical or corrupt behavior of management personnel affects their trust in the
organization’s ethical values, and they are likely to commit the same act and justify them.
Financial Statement Fraud
Financial statement fraud is the deliberate misrepresentation of the financial
condition of an organization in the financial statement given to stakeholders. The
misrepresentation may result from a deliberate misstatement or omission of figures in the
financial statement to deceive investors or other stakeholders (Mohamed & Handley-
Schachelor, 2015). This fraud classification includes false financial statements and
manipulation of accounting documents and reports that benefit the perpetrator. Repousis
(2016) argued that financial gain and enrichment might not be the sole objective for

32
committing this category of fraud; management may commit such frauds to attract
investors, demonstrate compliance with financial laws. Financial statement fraud includes
altered revenues, timing differences, omitted liabilities and expenses, improper
disclosures, and improper asset valuation. Mohamed and Handley-Schachelor (2015)
further argued that the motives behind financial statement fraud are (a) to mislead
investors and (b) to attain the organizations' expected goals. Whiles (Fligstein &
Roehrkasse, 2016; Free & Murphy, 2015) analyzed the causes and consequences of
financial statement fraud, (Albrecht et al., 2015) considered the ethics and motives of
financial statement fraud. Simha and Satyanarayana (2016), Kulikova and Sadarova
(2016) evaluated the role of internal auditors and internal controls in detecting financial
statement fraud. Dimitrijevic et al. (2015), Kramer (2015), also researched into the
corporate role in detecting financial statement fraud, and Brazel et al. (2015) studied how
investor perceives financial statement fraud. One thing is common to the various forms of
fraud in the organization, they all result in losses to the victim organization in areas like
revenue, reputation, and litigation.
The Procurement Process
The procurement function in an organization is responsible for acquiring goods
and services for various purposes (Stevenson, 2015). The procurement function has risen
to a higher level of importance in recent years because of the levels of spend and cost
implications (Weigel & Ruecker, 2017). Bildsten and Manley (2015) identified an eight-
stage process in organizational procurement (a) identifying the need; (b) establishing the
specification and scheduling the purchase; (c) identifying alternatives; (d) evaluating

33
alternative purchasing actions; (e) selecting the supplier; (f) negotiation and contracting;
(g) issuing the contract or order and (h) following up to secure delivery. Although the
stages highlighted above are generic, it also reflects a typical procurement process in the
mining industry. Lysons and Farrington (2016) suggested that established relationships
with vendors at the initial stages are necessary to ensure an effective procurement
process. Vendors or suppliers are required to bring their technical expertise to bear during
the specification stage of the procurement process, especially for first-time purchases
(Baily et al., 2015). The procurement process can become complicated due to decision-
making and communication over time, involving several project actors and relationships
with external organizations (Münch, 2015). According to the author, this complexity
arises because several people are making different decisions on goods and services that
have technical complexities and involving large sums of money.
Procurement Fraud
Procurement fraud is defined as an intentional deception to negatively influence
any stage of the procurement process to make a financial gain or cause a loss to the
organization (University College London, 2013). Procurement fraud can occur at
numerous stages across the procure to pay process and may involve both insiders and
outsiders to the victim organization. Globally, research has found that fraud occurred
most at the payment stage, followed closely by the vendor selection and invitation of
quotes/bids stages of the procure to pay process (Patterson et al., 2018). The procurement
process of a product or service can be complicated, especially in the mining industry,
where too many parties are involved. Procurement in the mining industry involves a

34
complex network of suppliers and subcontractors with inherent legal, financial, and
operational issues in the relationship (KPMG, 2017). This complexity opens the process
to high fraud risk from, need identification schemes to invoice falsifications (Putra et al.,
2018).
Investigating procurement fraud is often complicated because it can occur at any
stage of the procurement process, and individuals who commit the fraud have a deeper
understanding of the victim organization’s process (Putra et al., 2018). The author further
believes that the close working relationship between employees of the procurement and
payable units with vendors may provide an opportunity for complex fraud schemes
against the company by collusion. Caulfield and Steckler (2015) argued that fraud
schemes within the procurement process do not happen by chance; the perpetrators
willfully think through them. They get people to trust them and later take advantage of
the trust for their benefit. Free (2015) also argued that the fraudster begins with minor
incidents and then gets it to a bigger deal as he or she perceives no one knows and no one
is looking. Fraudsters start innocently, then raise their confidence level, and get involved
in more significant schemes (Sandhu, 2019). Rustiarini et al. (2019) argued that fraud is
human behavior related, and those who perpetrate this crime do so deliberately. Caulfield
and Steckler (2015) further argued that individuals who commit fraud are motivated by
several factors and characterized the fraudster into five personality profiles; (a)
situational fraudster; (b) deviant fraudsters; (c) multi-interest abusers; (d) well-
intentioned noncompliance employee and (e) disengaged noncompliance employee.

35
According to (Caulfield & Steckler, 2015), situational fraudsters are those
individuals within the procurement environment who are generally frustrated because
they perceive the organizational system has not treated them fairly or may have been
affected financially by an event that happened in the organization. From Caulfield’s
argument, such employees may have never harbored that intention when they joined the
company, but because of the situation they look out for weaknesses within the
procurement process and exploit them to make up for their loss. They tend to rationalize
their actions from the unfair treatment of their company.
Caulfield and Steckler (2015) describe deviant fraudsters as a significant threat to
the organization, and they are always on the lookout for opportunities to commit fraud.
They project themselves as hard working, always available to do any work, and hardly
take holidays. They usually are liked and trusted by others, especially their superiors and
colleagues, and usually will get people to stand in their defense when found culpable.
The multi-interest abuser is those individuals who will intentionally manipulate
the procurement system or process for their benefit or to the benefit of a third party. They
may not obtain any financial benefits but ensure a process favors their comrades or
family members. They are found to abuse the procurement process; for example, they
will draft product or contract specifications so that only their favorites will stand a chance
to win the bid. From the fraud triangle perspective, the multi-interest abuser commits
fraud because of the demands from friends or family members who need business, and
they find opportunity in the position to abuse the process because it lies in their power to

36
do so and tend to rationalize their action as the product or contract got executed in any
event (Caulfield & Steckler, 2015)
There are also the well-intentioned noncompliant employees present a significant
risk to procurement. They are those who will not get involved in the fraud themselves but
may directly or unnecessarily create the conditions for fraudsters to take advantage. They
believe that their deviation from the laid down procurement process will not harm the
company in any way or may believe it is to the cost advantage of the company to deviate
from the norm (Caulfield & Steckler, 2015)
The disengaged noncompliance employees are disgruntled or dissatisfied because
of perceived unfair remuneration or poor management of self-worth. They share similar
characteristics with situational fraudsters. Caulfield and Steckler’s categories of
fraudsters aligns with the supporting theories that extend the elements of fraud to include
personal traits of the fraudster. The discussion on the categories underscores the fact that
that an indinvidual’s personal traits contributes to fraud.
Procurement Fraud Schemes
Procurement fraud is possible at every stage of the procurement process and
involves insiders who are experts in the field or outsiders who do business with the
victim company. Procurement fraud can be committed by individual actors or through a
collusive arrangement among multiple individuals in the victim company. KPMG (2017)
found that employees of the victim company commit 65 percent of fraud identified with
the rest committed by external parties. Procurement fraud schemes include those
committed by collusion between employees and vendors, collusion between competing

37
contractors or vendors against the victim company, and schemes by employees acting
alone.
Collusion Between Employees and Vendors or Contractors
There are various schemes under this category, often involving individuals within
the organization’s procurement setup acting in collusion with the contractors or vendors
to defraud the organization for their gains in kickbacks, bribes, gifts, and others
(Rechtman, 2019). The association of certified fraud examiners (2018) identified bid
tailoring, splitting, manipulation, unauthorized sole-source acquisition, conflict of
interest, and need identification schemes as the primary schemes under this category.
A bid tailoring scheme often occurs when the employee or employees within the
procurement setup strongly influence the requirement of the bid or the product
specification to the extent they can change or modify it. The employee drafts bid
specification in a way that gives an unfair advantage to a vendor. Bid tailoring includes
broadening the scope of the service or specification of the product to get an otherwise
disqualified vendor into the competition, narrowing the scope of the service or
specification of the product to suit the capabilities of a favored contractor or vendor
(McNeal, 2019). Additionally, specifying the service or product vaguely to make way for
a price increase later, and order change abuse where the employee encourages the vendor
to submit a lower bid to win the contract with an assurance of changing the scope later to
accommodate price increases (ACFE, 2018). Some of the indicators of this kind of
scheme include (a) only one or few contractors or vendors responding to RFP, (b) the
similarity between specification and winning contractor’s product or service, (c) a

38
comparative analysis of previous purchases show a significantly broadened or narrowed
specification and, (d) a considerable number of sole sourcing to one contractor/vendor.
Bid splitting is where the procurement members break up larger projects of high
value into smaller projects so that each fall within the threshold that does not require
competitive bidding, encouraging sole sourcing to a favored contractor or vendor.
Significant signs for this scheme include two or more similar contracts to the same
contractor with a value just below the competitive bidding threshold separation of the
various elements of a service into different orders, i.e., different order for labor and
different order for materials with both below the threshold for competitive bidding but
when put together exceeds the threshold; and (c) consistent changes in the orders that
increase the value of the order (Wells, 2018)
Bid manipulation happens when the employee influences the bidding process to
give preferred contractors/ vendors an unfair advantage. The employee manipulates the
sourcing process by limiting the number of supplier bids are sought through means like
opening bids too early, requesting for bids during holidays or closing hours before a
weekend, leaking bid information to the preferred vendor, and shortening the submission
timelines for bids (Wells, 2018)
Need recognition scheme is where the employee in collusion with the vendor
assumes a need for a product or service for the victim company solely available from that
vendor but not needed by the company then receives a share of the amount paid for the
goods or service or even use the goods personally (ACFE, 2018; Haberbush, 2000).
Characteristics of such schemes include excessive inventory levels from excess

39
purchases, unjustifiable inventory write-offs to make way for the purchase of new items,
and a sudden hike in user requests for the item.
An unjustified sole source awards scheme happens where procurement members
choose to award contracts that should be competitive through a sole source without any
justification. Often, such awards are made directly citing exceptional circumstances
(Wells, 2018). Such schemes are characterized by; the bid amount just above or below
the competitive bidding limits; previously awarded contracts suddenly become non-
competitive, the lack of justifications or documentation for the decision, and split
purchases to avoid competitive bidding limits (ACFE, 2018).
Conflict of interest occurs when employees that influence the procurement
process have a personal interest that conflicts with their responsibilities. Wells (2018)
identified five different ways conflict of interest may occur; (a) an employee buys goods
or services through an agent who has control, (b) the employee is involved in other
business ventures with a vendor or contractor or its employee, (c) the employee has an
interest in a business that competes with the employer, (d) the employee accepts gifts,
favors, travel, entertainment, or fees from a vendor or contractor, and (e) the employee is
involved in unauthorized negotiation or accepts employment with current or prospective
vendors or contractors. Conflict of interest is a clear indication of corruption in
procurement (Deleanu et al., 2017). It arises when an employee in the procurement
section has an undisclosed legal or other beneficial interest in the vendor.

40
Collusion Among Contractors/Vendors
Contractors/vendors can also collude or individually commit fraud against a
company. The most common among schemes under this category is bid-rigging. Bid-
rigging is usually a collusion among competing companies to ensure one company wins
the bid at a pre-determined price (Chassang & Ortner, 2015; Conley & Decarolis, 2016).
Competing companies pre-determine the winner and limits competition (Asllani &
Statovci, 2018). The various schemes under bid-rigging include;
Bid Suppression occurs when competing contractors agree to allow only one
among them to submit a bid or withdraw a previously submitted bid so that another
competitor will win (Denise et al., 2013). Bid suppression agreements involve firms that
would compete for a contract refraining from bidding so that a designated firm's bid is
accepted (Jaspers, 2019). Clark et al. (2018) developed a model at a different level of
suppression that considers the incentives for the cartel of suppliers to eliminate non-
members from the market by refusing to share production technology with non-members
or influencing legislature to favor members.
A Bid rotation occurs when competing vendors agree to schedule to win bids in
turns (Wells, 2018). The vendors may decide to submit very high bids knowing those will
not be competitive, so one of them with the lowest bid win (Connor & Werner, 2018).
Bid rotation is an arrangement to ensure all companies get a fair share of the buying
company’s business. Bid rotation does not encourage competition, and the buying

41
company does not benefit from the advantages of competitive bidding (Denise et al.,
2013)
Complementary bidding occurs when competing contractors agree to submit bids
that will not pass the test. These contractors charge very high prices or even make
unreasonable terms on their bids while creating the impression they genuinely want the
business when they only want to complement the number of bids received (Connor &
Werner, 2018) and are intentionally taking themselves off the competition for the agreed
competitor to win (Denise et al., 2013). Here, one of the vendors refuses to bid, making
way for the other party to win and later sublet a part of the work to them in exchange for
not submitting a winning bid (Denise et al., 2013). Subcontracting is used to encourage
minor bidders’ participation. It is, however, an effective means to rig bids, especially
when the subcontractor can be the main contractor (Tam et al., 2018).
Aside from the schemes already mentioned, there are others that employees of the
victim company act alone. One such scheme is the creation of fictitious companies,
customarily known as shell companies. In such schemes, an employee or a group of
employees set up a company, get it registered as a vendor in the system, and award
contracts to themselves. Characteristics of such scheme involve employees able to raise a
purchase order, receive and approve payment for goods or services, paid vendors are not
on the company’s vendor list, employee or employees always following up on payment
of a vendor, employee or employees always submitting invoices of a vendor, and
invoiced goods cannot be physically seen (ACFE, 2018). Procurement fraud can take
different forms as discussed above and may include; invidual employees acting alone or

42
in collusion with external parties to the procurement process. Regardless of what form it
takes, it is evident the fraudsters circumvent the procurement process for their own
personal gains resulting in losses to the victim organization.
Risk Factors in Procurement Fraud
Dealing with Fraud, in general, requires the identification and assessment of the
risk factors. Button and Shepherd (2019) identified two broad categories of fraud risk
factors: organizational and individual factors, including remuneration, ethical work
climate, justice, disciplinary measures, opportunity, and personal traits. The authors
underscored that these factors together positively impact on the fraudster’s intention to
commit fraud. Bonny et al. (2015) identified some individual factors that make people
commit fraud, including financial hardship, living beyond their means, gambling, sudden
external financial pressure, internal/external pressure to steal, drug dependency, and
alcohol. Sandhu (2016) makes a strong case for certain individual traits that are potential
red flags for fraud; strong ambition, social loneliness, extended working hours,
dissatisfaction with their current job, justifying unethical behaviors, personal and
financial problems, and living beyond their financial means. In line with the
organizational factors, (Mangala & Kumari, 2015) identified inadequate remuneration
plans, unusual remuneration patterns, high industry competition, a close relationship with
suppliers, inadequate segregation of duties, ineffective supervision, and weak internal
controls as the most common risk factors in procurement fraud. Mufutau and Mojisola
(2016) also further identified the following as potential risk areas or factors for
procurement fraud to occur: (a) Unsuccessful implementation of controls in procurement,

43
(b) unknown vendor own recently established companies, (c) high turnover of purchasing
staff, (d) offering favors to vendors, (e) social bond between employees of a vendor
company and purchasing staff (e.g., joint vacation or leisure the activities), (f) non-
competitive and low-quality vendors consistently winning bids, (g) frequent reports of
suspicions of misconduct by purchasing staff. The above factors identified by the various
authors are red flags to procurement fraud. Where such issues raised above are seen in the
organization or in the procurement section of the organization there is a high risk of been
committed.
Procurement Fraud Prevention and Detection Strategies
Preventing fraud means that managers must put proactive measures to avoid it
from occurring (Adriana et al., 2018). Such measures to avoid fraud ensure an
environment with less opportunity for fraudulent activities to occur (Button et al., 2015).
Preventing and detecting procurement fraud requires an understanding of the fundamental
motivations for fraud. The fraud triangle offers the opportunity to understand the motives
behind the fraud. The motives for committing procurement fraud include looking for
money for personal gains, taking advantage of the weakness in the control systems
(Mufutau & Mojisola, 2016). Mangala and Kumari (2015) argued that gathering
information on fraud and its impact on the organization is the first step to preventing its
occurrence. Ach (2017), in his study on the prevention of procurement fraud in the public
sector, identified that a controlled environment that enhances accountability,
transparency, and professionalism is critical to maintaining a high standard of integrity in
procurement. Zamzami et al. (2016) discussed the role of internal auditors in preventing

44
and detecting fraud. The authors suggested that the most effective ways of detecting and
preventing fraud are operational audits, consistent internal controls, cash reviews, and an
effective code of sanctions against vendors and procurement staff. McMahon et al. (2016)
agreed and argued that because of the challenge in detecting fraud, preventing it from
occurring should be management’s top priority. The works of (Zamzami et al., 2016;
McMahon et al., 2016) highlight the need for internal controls and management role in
preventing procurement fraud. Patterson et al. (2018) also identified the need for
management commitment to ensure that preventive and detection controls effectively
deal with supply chain fraud. The authors argued that consistent interaction and
communication between management and employees would help identify potentially
fraudulent situations and prevent them.
The impact of procurement fraud on the victim organization can be very costly,
aside from the cost of investigation, legal action, and remedial actions, procurement fraud
also distracts management from its core focus negatively impacting productivity (KPMG,
2017). It is, therefore, critical for management and leaders alike to understand the
vulnerability of the procurement system to fraud and establish an approach to prevent,
detect, and control such misconduct. According to KPMG, such an approach should be
integrated and multifaceted to include prevention, detection, incident response, and
program maintenance.
Fighting fraud begins with a commitment from top management, developing and
preserving the right organizational culture. A culture of honesty and sincerity is critical to
preventing procurement fraud and ensures long-term business sustainability (Abdul Rasid

45
et al., 2018). Management also needs to ensure the promotion and communication of the
ethical values of honesty to employees by showing its commitment to such a course
(Mufutau & Mojisola, 2016). Gilbert and Wakefield (2018) also suggested the need to
establish fraud prevention and detection mechanisms collaboratively with appropriate
sanctions for offenders. In other words, management should be proactive with measures
to make it difficult for fraud to occur (Adriana et al., 2018). An organization’s code of
ethics which reinforces the belief that ethical behavior is essential and pivotal in the
organization’s ethical culture communicated down from management to employees
(McMahon et al., 2016)
Mufutau and Mojisola (2016) claimed that hiring the right people to undertake
procurement is also essential in preventing fraud. Making the right recruitment decisions
for key procurement positions is another way of preventing procurement fraud.
Background checks and regular training for employees on ethical values is an excellent
preventative strategy (Leistedt & Linkowski, 2016). Brody et al. (2015) reiterated the
need for recruitment managers to conduct a background check on employees including
resume verification, social media search, reference check, and a criminal record check.
The authors further suggested the use of honesty/integrity tests as a pre-employment
screening tool. All employees should be trained on policies and procedures to understand
the expectations and consequences for nonconformance. These consequences should be
deterring enough to include criminal prosecution and dismissal (An-An et al., 2017;
Nawawi & Ahmad Saiful Azlin, 2018b). Employees that commit fraud have previous
records from former engagements of dishonest behavior. An organization’s anti-fraud

46
may include systems that monitor the behavior of employees to identify red flags for
potentially fraudulent activity. Areas of fundamental interest when monitoring employees
will include e-mail communications; this could indicate behavioral patterns and help
detect employee’s intent to commit fraud (An-An et al., 2017).
Assessing the organizations' internal controls is also key to preventing fraud.
Internal controls are policies and procedures built by management and employees to
ensure that an organization's objective will be achieved (Manh & Thi, 2018). The
organization developed five-element internal control systems that constitute; (a) control
environment, (b) risk assessment, (c) control activities, (d) information and
communication, and (e) monitoring activities. The controls ensure consistent and reliable
financial reporting, protect assets against theft and misuse, and compliance with
applicable laws and regulations (Mufutau & Mojisola, 2016). The authors further argued
that procurement fraud often occurs when employees override internal controls
intentionally. Chiu et al. (2019) argued that it is necessary to regularly assess the
adequacy and effectiveness of the internal control system to identify and correct any
weakness that makes fraud possible. When internal controls are robust, more
accountability in managing resources enhances efficient operations and makes fraud
unattractive (Feng et al., 2015). Hajiha and Bazaz (2016) also believe that more robust
control systems enhance a higher level of compliance with set out policies and
procedures and deter employees from behaving unethically (Eklund et al., 2016).
However, weakness in the control systems provides an opportunity for fraud to occur,
leading to a decline in sales and the organization’s market value (Nawawi & Ahmad

47
Saiful Azlin, 2018a). Peltier-Rivest and Lanoue (2015) suggested that ultimately a robust
internal control system is an assurance mechanism for achieving the best performance
and protecting an organization from unexpected events, which includes a reduction in
fraudulent activities. Ensuring the effectiveness of existing controls is a crucial part of
prevention measures to fraud; this should be a regular exercise to identify and improve
weak areas. Although it is impossible to eradicate fraud, knowing where the risk lies
increases the possibility of preventing or detecting its occurrence (Rendon, 2016).
Internal control efforts require periodic review and improvement (Nusa et al., 2016)
Another effective way of preventing procurement fraud is the segregation of
duties (Bennett et al., 2015). Segregation of duties is to ensure that no one person takes
total control over the whole procurement transaction. An effective mechanism to
minimize procurement fraud is the segregation of duties (Andon et al., 2015; Imoniana &
Murcia, 2016; Bennett et al., 2015).
One of the internal control measures to control and deter fraud is the
establishment of a whistleblowing policy. Such a policy is an effective mechanism to
receive information about employees on illegal acts such as fraud (Near & Miceli, 2016).
Managers can detect fraudulent procurement acts through an effective whistleblowing
mechanism. (Gao et al., 2015). The channel for whistleblowing must be adequate to
conceal the blower’s identity to encourage people to use it. Most employees may prefer
the reporting channels to be managed outside the organizational environment by an
external party to ensure protection from retaliation and victimization (Gao et al., 2015).
Near and Miceli (2016) suggested that encouraging employees to have confidence in a

48
whistleblowing system requires management to disclose any wrongful act reported to all
employees so that reporting would mean management will investigate and act on the
information given. An effective whistleblowing system helps detect fraud, financial
losses, increase employee loyalty, and protect the organization’s image (Near & Miceli,
2016).
Legal action or prosecution of fraud perpetrators is not very common in many
organizations; however, it effectively prevents and controls procurement fraud. (Mangala
& Kumari, 2015). Initiating legal action against fraudulent employees is an excellent
strategy to communicate management intolerance for fraud and deter employees from
engaging in fraud ( Kanapickienė & Grundienė, 2015)
The United Nations Global Compact on the fight against corruption in the supply
chain provides specific guidelines for organizations in preventing fraud in the
procurement process. The guidelines provide the need to establish clear procedures for
the selection of suppliers, providing anti-corruption training, employees background
check, the giving or receipts of gifts, procedures for goods receipt, evaluating corruption
risk before entering a customer-supplier relationship, performing due diligence on
suppliers, customers, and intermediaries involved in the bidding process (UNGC, 2016).
Mufutau and Mojisola (2016) recommended that a preventative measure be
extended beyond the organization to consider its business partners. The authors suggested
that it is essential for the organization to know its suppliers and manage subcontractors
through background checks to avert any possibility of a conflict of interest and assess the
supplier’s capability to undertake a job. The (UNGC, 2016) further provides guidelines

49
worth considering in preventing procurement fraud from the perspective of the supplier;
(a) the organization should establish a code of conduct for suppliers, including
expectations on corruption; (b) the organization must ensure that the supplier’s personnel
receive training on anti-corruption laws and policies, the consequences of bribery, and
corruption for the supplier and employees; (c) monitor suppliers’ anti-corruption efforts
through audits.
A regular audit of procurement procedures and systems is also an effective means
of preventing and detecting procurement fraud. (Ghafran & Sullivan, 2017; Hoopes et al.,
2018) The organization should use both internal and external auditors to evaluate
adherence to procedures. Employees will not commit fraud if they are aware of these
audits. Gilmore-Allen (2015) suggested surprise audits on information systems to detect
alterations or tampering. The use of auditors as a tool for preventing fraud could be
beneficial but require complement with other controls as auditors at some point could
also be compromised (Gilmore-Allen, 2015). From the discussion, detecting and
controlling procurement fraud requires managements focus not only on personnel but
also the organizational systems that makes ir easy for fraud to occur. For any controls to
be effective the focus should be on both internal and external motivational factors.
Transition
Procurement fraud is very complex because there are various ways to commit it,
and managers need to consider all possible options when preventing or controlling it
(Mufutau & Mojisola, 2016). Procurement fraud is on the rise and has become a threat to
managing supply chains (Khan & Varma, 2017). In section 1, I introduced an overview

50
of the nature of procurement fraud and the various forms it takes. I also discussed various
strategies to detect, prevent, and control procurement fraud. Furthermore, section 1
included a discussion on the general and specific business problem, the purpose for
conducting this study, and the foundation of the study to explore the strategies used by
managers in Ghana’s gold mining industry to detect, prevent, and control procurement
fraud. I also presented a qualitative research methodology, the problem statement,
purpose statement, research questions, conceptual framework, and an academic literature
review of current knowledge on procurement fraud.
In section 2, I will restate the purpose statement, the role of the researcher, the
participants for this study, and the research method and design. Section 2 will also
include the sample, data analysis plan, data collection methods, and ethical
considerations.

51
Section 2: The Project
In Section 2 of this qualitative study, I will include the purpose statement and a
discuss my role as the researcher regarding data collection. I will also discuss the study
participants, the research method and design, and population and sampling. Finally, I
discuss ethical research, data collection instruments, techniques, data analysis, reliability,
and validity.
Purpose Statement
The purpose of this qualitative multiple case study was to explore the strategies
used by managers in the Ghanaian gold mining industry to successfully detect, control,
and prevent procurement fraud. The target population for the study consisted of six
procurement managers of the major gold mining companies in Ghana who have
successfully detected, controlled, and prevented procurement fraud in their respective
organizations. I assumed that managers in the mining companies can increase funds
budgeted for their corporate social initiatives by reducing revenue lost through
procurement fraud and using these funds to provide schools, roads, hospitals, and
portable drinking water required for the social well-being of the people in communities.
Role of the Researcher
The researcher plays an essential role in research. The researcher’s role is to
collect, analyze, organize, interpret, and understand data to determine the meaning of a
phenomenon (Kornhaber et al., 2015) and report the research outcome (Yin, 2018).
Additionally, the researcher’s role involves having an objective without bias, meaning

52
there is no initial definitive objective before enacting a qualitative study (Creswell &
Creswell, 2018).
Qualitative researchers are the primary instruments for data collection,
interpreting data through their lens (Ho, 2012). As the researcher, my role was to collect,
organize, and interpret data to report on the results and draw conclusions from them. I
conducted semistructured interviews with open-ended questions as I explored strategies
that managers in the mining industry use to detect, control, and prevent procurement
fraud. As the primary data collection instrument, I was responsible for avoiding biases
because they can affect the research outcome (see Berger, 2013). To mitigate biases,
researchers must identify their personal views to understand that of the participants
(Marshall & Rossman, 2016; Yin, 2018). I avoided biases by using member checking to
validate the participants views and recorded interviews for accurate transcription for data
integrity (see Yin, 2018). Using member checking in qualitative research maintains
validity and it is an integral part of creating trustworthiness in a qualitative study
(Candela, 2019).
Knowing that my professional and personal experience gives me knowledge on the topic,
I ensured that participants answered interview questions without any interference or
imposition of answers reflecting my views. I also ensured my personal biases, ideas, and
judgments did not influence the research through bracketing, a process of disregarding
personal biases, ideas, and judgment in research (see Sorsa et al., 2015). Additionally, the
researcher needs to be aware of personal and professional bias through self-reflection or
self-evaluation (Berger, 2013). As a young professional and the head of the supply chain

53
of a mining company in Ghana with two supply chain-related professional qualifications,
I am aware of the challenges in the sector when it comes to procurement. I joined my
current employer as a supervisor and witnessed several fraudulent acts in the procurement
process, influencing my choice of study. I have been part of an investigative team on a
fraud case and called to defend an action perceived to have breached established
procedures. I understand that this experience raised the possibility of bias as the
researcher and the primary data collection instrument. However, even though I was
familiar with the procurement process of the mining industry and had knowledge of the
phenomenon, I had no personal or professional relationship with the participants. I did
not expect any form of influence on the study. It is also the researcher’s role to ensure the
study was conducted ethically by protecting the participants as required by the National
Institute of Health regarding the protection of human research participants. I applied the
1979 Belmont Report, which covered consent, disclosure, confidentiality, anonymity, and
biases. I ensured participants understood the intent of the research and gained informed
consent from them by transparently disclosing every material fact in terms of their risk
exposure as participants in this study.
Using the same semistructured, open-ended questions for all participants also
helped to ensure consistency in the data collection. An interview protocol with open-
ended questions guides and enables a researcher to elicit the best possible responses from
participants. There are four stages for an interview protocol: (a) aligning research
questions with interview questions; (b) formulating an inquiry-based discussion on
specific information; (c) receiving helpful feedback on participants to enhance reliability;

54
and (d) orchestrating the interview protocol in actual conditions simulating space,
process, recording, rapport, and consent (Castillo-Montoya, 2016). I followed this
protocol with the same questions for each participant for consistency and fairness (see
Fusch & Ness, 2015).
Participants
Conducting a study requires the researcher to engage a sample of people to
represent the broader population. The population refers to organizations that share some
characteristics of the phenomenon under study (Asiamah et al., 2017). In a case study, the
selection of research participants depends on the research question. (Yin, 2018).
Participants should have characteristics that relate to the overarching research question
and the purpose of the study (Dasgupta, 2015; Zupancic et al., 2019). Developing
strategies to deal with procurement fraud lies with top management. Participants for this
study were procurement managers in the mining industry who successfully controlled,
detected, and prevented procurement fraud in their organizations.
There are several ways to access research participants. The sponsor approach
allows the researcher to access the participants through an executive leader (Fletcher et
al., 2016). The use of highly influential trusted people can influence the attitudes,
opinions, beliefs, and behaviors of people in the organization (Lim et al., 2018).
Gatekeepers are also an effective way a researcher can gain access to research
participants and establish a working relationship with them (deGama et al., 2016). I used
the gatekeeper approach by contacting the secretariat of a supply chain technical
committee as a gatekeeper for the contact details of the participants. I sent an initial email

55
to the participants and followed it up with a call to solicit their readiness to be part of this
study.
To get participants to be part of the study, the researcher must build a working
relationship. The researcher needs to build a rapport with the participants to avoid anxiety
in answering the interview questions. Rapport building facilitates working relationships
and allows the researcher to elucidate the rules of engagement to the participants
(Bowden & Galindo-Gonzalez, 2015). I used the interview protocol to establish a
working relationship with the participants. At the start of each interview, I reminded the
participants of the voluntary nature of their participation, assured them of confidentiality,
and explained my expectations.
Research Method and Design
Research Method
The choice of a research method and design is dependent on the topic and the
purpose of the study. The three critical elements of a research method are (a) the forms of
data collection, (b) analysis, and (c) interpretation (Abutabenjeh & Jaradat, 2018). The
researcher has a choice to use the quantitative method with close-ended questions, using
statistical analysis and interpretation method to get the overall results, or the qualitative
method with open-ended questions, using text and image analysis or interpreting themes
and patterns to get the overall results (Corbin & Strauss, 2015). Researchers may also use
the mixed method: a combination of quantitative and qualitative methods. The researcher
may choose a combination of qualitative and quantitative methods because of the
phenomenon’s complexity (Khoo-Lattimore et al., 2019). Other factors like time

56
available for the study, the purpose of the study, and the researcher’s personal experience
also influence the choice of research methods (Creswell & Creswell, 2018).
The quantitative methodology covers a range of specialized topics and
approaches. Within the scope of quantitative methodology, inferential statistics cover the
techniques researchers use to explore in-depth relationships between variables (Wang et
al., 2016). Generally, the underlying principles of quantitative research are deduction and
logic, focusing on measurable variables in human experience (Fan-Ko et al., 2018). The
researcher uses the quantitative method to establish the prevalence of practices,
behaviors, and beliefs and estimate how the strength of reciprocal causal associations
changes over time (Abutabenjeh & Jaradat, 2018). The purpose of this study was to
explore strategies used by managers in the mining industry in Ghana to deal with the
challenge of fraud in the procurement process, which made quantitative methods
inapplicable.
The mixed-method employs both quantitative and qualitative approaches. The
mixed method is increasingly becoming an accepted approach (Coyle et al., 2018;
Creswell, 2015). Mixed-methods include sequential mixed methods where the researcher
uses one method to expand further the findings of the other method, concurrent mixed
methods where the researcher uses both methods simultaneously and the transformative
methods where the researcher uses a theoretical lens as an overarching perspective within
a design that contains both quantitative and qualitative data (Abutabenjeh & Jaradat,
2018). Mixed-methods have been encouraged because of the flexibility to integrate with
other research approaches (Plano Clark & Ivankova, 2016), making it easier to address

57
complex problems (Ivankova, 2015). The underpinning objective of mixed-method
research is to infuse data sets from both quantitative and qualitative to arrive at justifiable
conclusions in one study (Ivankova, 2017). Despite the advantages of mixed methods, the
approach did not apply to the purpose of this study.
I employed the qualitative methodology for this study to explore strategies used
by managers to detect, control, and prevent procurement fraud. Using the qualitative
method gives the researcher insight into social life, the experience, and people’s attitudes
(Creswell & Creswell, 2018). In the qualitative method, the focus of the study is on a
natural setting with a phenomenon that the researcher does not seek to manipulate
(Dasgupta, 2015). Using qualitative method the researcher focuses on subjectivity,
individuality, and integrity to understand meanings, functions, goals, and intentions
(Bansal et al., 2018). Researchers also use qualitative methods to understand the meaning
people bring to a phenomenon (Wang et al., 2016). Qualitative methods are flexible and
adaptable and allow the researcher to adapt the methods to their specific research
questions, samples, or context of data collection, which means researchers can mold the
method to the needs of the data and the sample (Denzin & Lincoln, 2017; Gehman et al.,
2017). The qualitative method offers the researcher variety among different approaches
regarding the data and materials that can be analyzed, the assessed content, and the
coding and treatment (Bansal et al., 2018). Further, the qualitative method is most
appropriate, where the researcher’s focus is to understand how something happens rather
than the results (Dasgupta, 2015). I chose a qualitative method for this study because the

58
method was ideally suited to explore and understand strategies procurement managers
use to deal with procurement fraud, not to measure the phenomenon.
Research Design
The research design options for a qualitative study include ethnography, for
exploring beliefs and ideas of a group; phenomenology where the researcher explores the
collective experiences and meanings of several individuals about a given phenomenon or
event (Quay, 2015; Symeonides & Childs, 2015); and a narrative design where
researchers explore individuals’ life experiences and form a narrative (Marshall &
Rossman, 2016). These designs were not appropriate for this study because I did not
intend to explore individuals' experiences or beliefs of a group. In contrast, a case study
design is most appropriate for answering how and why research questions in a study when
investigating a phenomenon within a real-life context (Yin, 2018), which gives a fuller
understanding of the nature and complexity of the phenomenon (Moghadam et al., 2018).
The design is also appropriate for understanding complex social phenomena and events
surrounding organizational and managerial processes. Additionally, case study research
has more flexibility than other qualitative approaches such as grounded theory or
phenomenology. The design of case studies suits the case and research question (Sanders,
2019). Further, a case study gives an in-depth understanding of the viewpoint of several
participants using multiple data sources (Yazan, 2015).
In qualitative research using a case study, a researcher may choose a single or
multiple case design. A multiple case study is a strong base for theory building (Yin,
2018). Moreover, comparing different organizations gives rich data necessary for

59
discovering categories and developing and relating their theoretical properties, which are
necessary for further developing the emergent theory (Dasgupta, 2015). The reasons
supplied by these researchers helped me decide to use the multiple case study design for
this study.
Population and Sampling
The population for a study is the broader group the researcher wants to conclude
on (Etikan et al., 2016). Making population and sampling decisions in research has a link
to decisions on which research method to use (Abutabenjeh & Jaradat, 2018). The target
population for this study was six procurement managers from the major gold mining
companies in Ghana who have successfully implemented strategies to detect, control, and
prevent procurement fraud in their respective organizations.
I used the purposeful sampling method to choose the participants. A researcher
uses purposeful sampling to select cases that give in-depth and rich information to
provide insight and understanding of a phenomenon or topic of interest (Benoot et al.,
2016). This sampling method can be appropriate for case study research to validate a
sample because the researcher can establish common themes to cover multiple variations
of the topic of interest (Knechel, 2019; Thorne, 2016). Purposeful sampling is also a way
to avoid sample bias by selecting firms based on their relation to the phenomenon under
study (Bristowe et al., 2015; Morse, 2015). Purposive sampling is most used for
qualitative studies because rich data is collected and requires fewer resources with a
small sample size (Barratt et al., 2015). The criteria for selecting the participants included
the following: (a) have been in the current position at least 3 years, (b) have been in the

60
gold mining industry for at least 5 years, and (c) have implemented strategies for
detecting, controlling, and preventing procurement fraud.
Achieving data saturation is essential to qualitative research (Rowlands et al.,
2015). In qualitative research it is a way the researcher ensures the data collected is
accurate and valid. Data saturation is necessary to determine the sample size for a study
and it allows a combination of rich quality and a thick quantity of data (Fusch et al.,
2016). The sample size can influence data saturation, and even a small sample size of one
may be enough to achieve data saturation (Etikan et al., 2016). Data saturation is when no
new data is collected, no new patterns evolve, and no new codes emerge (Fusch & Ness,
2015; Tran et al., 2016). Using purposeful sampling with a small number of case study
participants assures the researcher of data saturation (Charles et al., 2015; Malterud et al.,
2016). Although achieving data saturation is high when using purposive sampling,
empirical generalizability is impossible during data analysis (Mikkonen et al., 2015). I
ensured data saturation by looking out for evidence of replication when I analyzed the
data (see Parker & Bull, 2015).
Ethical Research
Conducting ethical research and respecting and protecting participants’ human
rights and privacy is an essential requirement. The researcher’s responsibility is to ensure
that participants are protected (Scherzinger & Bobbert, 2017). The researcher must
adhere to the ethical guidelines to protect the right of human participants and ensure that
participants are respected (Metcalf & Crawford, 2016; Roberts, 2015). The researcher is

61
also responsible for protecting the anonymity of the research participants and storing the
collected data in a confidential manner (Mazorodze & Buckley, 2019).
I ensured approval from the institutional review board (IRB) before engaging the
interview participants. Upon IRB approval, I solicited voluntary participation from the
participants by sending them an email of a consent form, and they consented by reply to
the email with ‘I consent’ (see Wallace & Sheldon, 2015). The consent form adds to the
importance of ethically conducting a study with participants’ free will (Aarons et al.,
2015). I included in the consent form a statement of participants’ right to withdraw from
the study at any point without any challenge by writing to inform me of their withdrawal.
I also included a statement of assurance of confidentiality, an essential requirement in
ethical research (see Harriss & Atkinson, 2015). In protecting the participant’s identity, I
assigned alpha-numeric codes (i.e., A1, B1, C1) to each participant, where the letter
represents the company and the numbers of the participants. For clarity and verification, I
informed the participants of my intention to audio record the interviews. All consent
forms received are documented and electronically filed to verify agreement to contribute
to the study (see Yin, 2018). I did not offer any incentives to the participants.
I completed the National Institute of Health web-based training on protecting
human research participants and understand its requirements. I followed the guidelines
where applicable to protect the participants and refrained from data collection until IRB
approval. I also adhered to the Walden code of conduct and the guidelines provided in the
Belmont Report. I stored all data gathered from participants during the interviews and all

62
other documents in a protected external hard drive in a safe area. I intend to keep them
for 5 years before destroying them by burning.
Data Collection Instruments
The researcher in a qualitative study serves as the primary data collection
instrument (Rich & Misener, 2017). As the primary instrument, I could not have
separated myself from the research (see Fusch & Ness, 2015), and was responsible for
asking questions, listening to participants, taking records of responses, developing themes
from participants, giving feedback, and analyzing data gathered (see Rich & Misener,
2017). The other data collection instrument I used was semistructured interviews, which
required developing questions from established themes prepared to solicit in-depth
insight into the participants’ views on the phenomenon (DeJonckheere & Vaughn, 2019).
Interviews are the most used data collection instrument in qualitative studies (Yin, 2018).
Using semistructured interviews with open-ended questions allows the researcher to
collect rich data, as participants express their experiences in their own words (Twining et
al., 2017). The use of semistructured interviews also allows the researcher to ask the
same set of questions that will facilitate comparisons among responses from the
participants with the flexibility of asking follow-up questions (Yin, 2018).
I conducted face-to-face interviews with some of the participants, and for some,
the interview was virtual. The face-to-face approach helps the researcher observe
participants’ body language and gestures (Seitz, 2016). Additionally, researchers must
ask questions following an interview guide for structure and consistency (DeJonckheere
& Vaughn, 2019; Vohra, 2014), which helps achieve data saturation (Fusch & Ness,

63
2015). I developed and followed an interview protocol, which contained my introduction
to the participant, a summary of the purpose of the study, assurance of confidentiality,
and their role as participants (Appendix C)
To ensure that I did not miss any information given, I recorded the interviews
electronically, which helped me to capture exact responses from the participants,
preserving the full content of the interview and facilitated data analysis (see
Bahraminejad et al., 2015; Bristowe et al., 2015; Starr, 2014). I also took notes to
compliment the audio recording. To ensure the validity and reliability of the data
collected, I shared the initial analysis with the participants to review and confirm their
responses and possibly provide feedback. Allowing participants to review and confirm
responses is the process of member checking, which ensures reliability and validity (Birt
et al., 2016).
Organizational records and documentation are also good data sources for
qualitative research following a case study design. Combining data from documents and
interviews enriches the study’s outcome (Bayram et al., 2016). Assessing multiple data
sources leads to triangulation, another means of achieving saturation and validity (Fusch
et al., 2016; Morgan et al., 2017; Turner & Danks, 2014). Some participants shared with
me copies of the organization’s policy on commercial transactions and code of conduct.
Data Collection Technique
Data collection involves gathering and determining information that helps the
researcher find answers to research questions and evaluate results (Mays & Pope, 2019).
There are various techniques for collecting data in a qualitative study: (a) documentation,

64
(b) archival records, (c) interviews, (d) direct observation, (e) participant observation, and
(f) physical artifacts (Yazan, 2015). I conducted semistructured, face-to-face, and virtual
interviews with open-ended questions using audio recording, and reviewing company
documents. For the convenience of participants and to avert any distractions, the location
for the interview were decided by the participants. At the beginning of each interview, I
read out the consent form to the participants (see Appendix D). The interviews were
audio-recorded to capture the exact response from the participants for accuracy during
transcribing (see Speer & Stokoe, 2014). I ensured the validity and reliability of data
collected through the audio recording (see Neal, Neal, VanDyke, & Kornbluh, 2015).
Using audio recording has limitations; there is the likelihood of skipping responses
during transcription. Also, the audio quality can be affected if the interview location is
noisy (Neal et al., 2015).To avert this, I used two different devices at the same time for
the recording.
Using interviews in research comes with numerous advantages. Interviews are a
rich and vital source of evidence in a study (McIntosh & Morse, 2015). Interviews also
allow both researchers and participants the flexibility to express themselves in an open
discussion, enhancing the collection of valuable data (Anna-Maija et al., 2016).
Additionally, the researcher has contact with the respondent either face to face or via
phone, so there is the flexibility of clarifying all ambiguities and discussing other issues
that may come up (Buytaert et al., 2016). The researcher can rephrase questions that are
not clear to the participants (Laura et al., 2016).

65
Interviews as a data collection technique also have some disadvantages too.
Disadvantages include the likelihood of bias, poor recall, inaccurate articulation on the
part of the respondent, and the researcher may have to complement data gathered from
the interview with other sources of evidence to ensure reliability (Alderete & Davies,
2019). Also, there is a potential lack of interest in the topic by the participants despite
agreeing to participate (Drew, 2014). However, a face-to-face interview allows the
researcher to observe participants and gain a deeper understanding of the phenomenon,
and multiple observations may be required to enhance reliability (Marshall & Rossman,
2016).
Observation as a data collection technique allows the researcher to observe the
interviewees’ body language and gestures that impact their verbal responses (Marshall &
Rossman, 2016). During the interview, I also observed the participants. Using
observation allows for very accurate and reliable data to be collected; it improves the
precision of the research results and limits challenges from depending solely on
participants’ responses (Mike, 2017; Onwuegbuzie & Smit, 2018). Some limitations to
observation are that; the researcher cannot use observation to study past events,
observation alone cannot give a complete and factual reflection of an issue
(Onwuegbuzie, & Smit, 2018).
Using organizational records or documents in qualitative research complements
and enriches data collected during interviews. Documentation could be a source of
background information with broad coverage of data that is useful in contextualizing
one’s research within the subject or field and can also be a source of unobservable data

66
details (Bowen, 2009). Yin (2018) also suggested that documentation can contain the
exact names, references, and details of events covering a long period and several settings.
However, organizational documentation will require some investigative skills because
preparing it is without a research agenda (Bowen, 2009). O’Leary (2014) argued that it is
essential to subject documents to a thorough evaluation and investigation so not to
undermine the credibility of the research. Access to documents may be deliberately
withheld or cannot be easily retrieved (Yin, 2018).
Further, I sent participants a summary of the transcribed data to achieve validity
and reliability, emphasizing key points to check if it represents their responses. Using the
member checking process enhances the integrity of the study and removes biases.
Member checking is a quality control process (Birt et al., 2016). It allows the participants
to review collected data for accuracy and make corrections to enrich it (Roche et al.,
2015). After completing the analysis, I asked participants to review a summary of the
findings.
Data Organization Technique
Organizing data in a qualitative study is essential for the researcher to analyze
data, support findings, and protect participants’ confidentiality (Bernard et al., 2016; Yin,
2018). The data organization technique enhances the reliability of the study (Roer-Strier
& Sands, 2015). There are four principles of data collection: using multiple sources of
evidence, creating a case study database, maintaining a chain of evidence, and exercising
care in using data from electronic sources (Yin, 2018). Six sources of evidence for

67
qualitative study include documentation, archival records, interviews, direct observations,
participant-observation, and physical artifacts (Yin, 2018).
I used a reflective journal to make some notes of the depth of knowledge that
participants shared. A reflective journal is another means of ensuring the quality and
validity of qualitative data (Vicary et al., 2016). Researchers also use reflective journals
to avert biases and influences on the study’s conclusions (Peters & Halcomb, 2015).
Microsoft Excel and NVivo software are tools researchers use in qualitative data
organization, analysis, and reporting. The software can identify themes, evaluate
findings, and interpret them in answering the research questions (Robins & Eisen, 2017;
Zamawe, 2015). During the data analysis, I labeled and coded the data to identify patterns
and common themes. A coding system makes it easier to search, compare, and analyze
data by identifying patterns and themes (Bernard et al., 2016). Using codes also helps the
researcher translate specific responses into broader meanings and themes (Skjott
Linneberg & Korsgaard, 2019). I identified participants with alphanumeric codes such
A1, B2, and a generic name for all documents such as Document 1. To ensure an
organized data, I created a folder for each of the participants and case company. In that
folder, I kept respective documents from each participant labeled alphanumerically (e.g.,
A1 consent form, B2 interview transcript)
It is critical to secure data collected during research against loss, misuse,
unauthorized access, alteration, destruction, and disclosure (Schneider & Iacobucci,
2020). Researchers can ensure the protection of participants and the information collected
by putting in security measures that prevent unauthorized access to the data (Johnson,

68
2015). I stored all data collected on a password-protected external drive, together with
transcripts and audio recordings, in a locked cabinet to be destroyed after 5 years by
burning.
Data Analysis
When data is collected or gathered, the next step for the researcher is to analyze
and interpret the data to draw meaning from it (Cridland et al., 2015). Analyzing data at
this point means examining, categorizing, tabulating, and testing the data to come out
with findings (Noble & Smith, 2015). Triangulation is the process of combining data
from different sources to ascertain the reliability and trustworthiness of findings and
study results (Modell, 2015). The researcher uses triangulation to collect and evaluate
data of various levels and perspectives regarding document and interview materials
(Fusch & Ness, 2015). The researcher also uses triangulation to identify themes in data
from multiple sources (Johnson, 2015; Modell, 2015). Patton (2015) identified four types
of triangulation (a) data triangulation is the use of multiple sampling strategies, (b)
investigator triangulation involves multiple researchers, (c) theory triangulation is the use
of multiple theories to analyze the data (Modell, 2015), and (d) methodological
triangulation involves comparing multiple data sources in analyzing the data. I achieved
methodological triangulation by conducting semistructured interviews and reviewing
company documents. Methodological triangulation aids the researcher in overcoming the
weakness or the potential bias of using only one source of data (Joslin & Müller, 2016).
Fusch and Ness (2015) also advised that using a single data analysis method is
insuficient to represent a research phenomenon. Methodological triangulation allows the

69
researcher to combine data from interviews, company documents, and published
literature enhancing data validity (Wilson, 2016; Yin, 2018)
The data analysis process helps the researcher to draw meaning by categorizing
the data into groups or themes (Bengtsson, 2016). Data analysis, according to (Yin, 2018)
involves five steps below.
The compiling phase is the process of organizing the data to create a database.
The objective is to organize the data systematically before formal analysis starts. Yin
(2018) claimed that more orderly data is a prerequisite to more vital analyses and quality.
After the initial compilation, the researcher breaks down the data into fragments to reduce
and remove consistent themes of the phenomenon under study.
The reassembling process involves clustering and categorizing the labels into a
sequence of groups. At this point, the researcher makes connections with the data
collected and identifies patterns and themes. This stage involves developing the
narratives from the sequence of groups. Yin describes this stage as the craft of giving
meaning to the reassembled data and patterns.
According to Yin, the conclusion is an overall statement that captures the broader
significance of the study. Conclusion is the final stage where the researcher completes the
study and presents the results. Here the researcher states the processes and the methods of
the research and details any limitations.
I followed Yin’s suggestion to analyze the data for this study. I used the NVivo
software to arrange, analyze, and attain themes of the collected data. The NVivo software
can evaluate nodes within a complex matrix (Woods et al., 2016). Researchers have used

70
the software successfully to identify relations in the data and obtain new meanings and
patterns, evaluating consistencies and convergences in data (Mertens & Hesse-Biber,
2015).
To adequately represent a research phenomenon (Fusch & Ness, 2015), advise
using multiple data analysis methods. After collecting data through semistructured face-
to-face interviews, virtual interviews (telephone and teams), and review of company
documents. I transcribed the audio recording of each interview into a Microsoft word
document. I then uploaded the transcription into the NVivo software to code identify
emerging themes. The NVivo software can analyze interview data and create codes and
themes quicker for the study (Ruggunan, 2016).
I used the NVivo software to create labels from the data and break down words,
phrases to make meaning from the data (Bengtsson, 2016). I further used the NVivo
software to analyze the data and categorize similar responses from participants to form
larger groups of themes. I then identified the key themes by reassembling them until no
new ones emerged, achieving data saturation. ( Hennink et al., 2017). I employed
thematic analysis to interpret the data gathered from the interviews to identify patterns
(Crowe, Inder, & Porter, 2015). According to Crowe et al. (2015), researchers using
thematic analysis follow a five-step process; (a) building familiarity with the research
data by the repetition of the interview transcripts, (b) generating initial codes from the
reading while keeping the research question in mind, (c) identifying and grouping
themes by related ideas, (d) defining and naming the themes, (e) illustrating with
reference to the interview transcripts.

71
In interpreting the data, I used the emerging themes and patterns to create
narratives in line with the overarching research question and the literature review
specifically, aligning the identified themes through the lens of the fraud triangle. I also
compared the results of this study with other studies to explore strategies for managers in
gold mining companies to detect, control, and prevent procurement fraud.
Reliability and Validity
Researchers in qualitative studies are required to build trust in their research
conclusions and findings by ensuring that they present a statement of facts, uniformity,
and accuracy (Eisner, 2017). Building trust in a study requires an effective data analysis
technique that projects the reliability and validity of the study (Roller & Lavrakas, 2015).
Research reliability and validity encompasses several attributes (Taylor et al., 2015),
dependability, credibility, transferability, and confirmability (Morse, 2015; Roller &
Lavrakas, 2015).
Reliability
The decisions made by a researcher during a study may influence the result of the
study one way or the other, especially in a qualitative study when the researcher is the
primary data collection instrument. Researchers must be aware of their influence and
review their decision to prevent an impact on the reliability of the study (Yin, 2018).
Reliability is a critical element that supports the conclusions and results (Marshall &
Rossman, 2016). Reliability explains the extent to which study results and conclusions
drawn will be the same under similar conditions by repeating the study using the same
process (Yin, 2018). Reliability also means other researchers could repeat the study in

72
similar conditions and time and get consistent results (Marshall & Rossman, 2016; Rose
& Johnson, 2020). Reliability also relates to the consistency of the research findings over
time (Hayashi et al., 2019). I used a rigorous interview protocol and member checking
technique to enhance the dependability of this study. The researcher uses member
checking to ascertain the accuracy of the data collected because participants will have the
opportunity to confirm or challenge the responses recorded and any anomalies corrected
(Birt et al., 2016). All participants answered the same questions, and I used this technique
to ensure the study’s dependability and data saturation. (Rubin & Babbie, 2016).
Validity
Validity refers to the extent to which the findings of a study reflect the data
(Noble & Smith, 2015) According to (Leung, 2015) the suitability of research method,
design, sample size, data collection and analysis technique, and how they relate to the
overarching research question influences the validity of the study. Also, credibility,
transferability, and confirmability characterize the study’s validity (Roller & Lavrakas,
2015).
Credibility
The result of a qualitative study is a generalization from the sample to the target
population (Cypress, 2017; Leung, 2015; Noble & Smith, 2015). A study is said to have
credibility when the findings reflect the accurate picture of the phenomenon, and readers
and other researchers can trust without a doubt (Nyhan, 2015; Percy et al., 2015).
Merriam (2015) puts credibility as adopting the appropriate research method, effective
sampling technique, and data triangulation using diverse sources. I selected the research

73
participant through purposeful sampling, maintained a rapport with them throughout the
study, and used methodological triangulation and NVivo software to ensure credibility.
Several researchers have commended member checking as an effective means of
ensuring the credibility of a study (Connelly, 2016; Marshall & Rossman, 2016; Yin,
2018). When participants can confirm their responses to interview questions as recorded
by the researcher, it enhances the credibility of the information used to draw the findings
and conclusion of the study (Milosevic et al., 2018). I ensured that the data analysis and
interpretation were based on the participants’ knowledge and understanding based on
their responses and avoided imposing my personal view. I also ensured credibility
through member checking by sharing the analysis summary with participants and
ensuring that all feedback received were incorporated in the final analysis.
Transferability
Transferability is the extent to which research data and findings apply to another
study sometime in the future. Other researchers should use the results and findings of a
study for other research of similar interests (Bengtsson, 2016). Transferability also refers
to the extent to which the results and findings of a study apply to other organizations with
a similar phenomenon (Nowell et al., 2017). To ensure transferability, I recorded every
detail of data, and provided a complete description of findings and results so readers and
future researchers can assess transferability. According to Lub (2015), a detailed
description of the context, location, participants, and study analysis facilitates
transferability.

74
Confirmability
Yin (2018) argued that the researcher establishes confirmability by ensuring that
research findings reflect participant responses while mitigating researcher bias. The
researcher should demonstrate that the data represents and reflects the participants'
responses, not the researcher's viewpoint. I ensured conformability by recording,
transcribing, and reviewing responses from participants (Noble & Smith, 2015; Yardley,
2017). Using member checking will help the researcher avoid the possibility of
misinterpretation and misrepresentation (Leung, 2015). I have also kept copies of all
documents reviewed for verification and to substantiate findings (Venkatesh et al., 2016).
I used reflective journals and data triangulation to ensure conformability (Tong & Dew,
2016).
Data Saturation
According to Fusch and Ness (2015), reaching data saturation means that no new
themes relevant to the research question will emerge when other researchers replicate the
study. The authors claimed that qualitative researchers could reach data saturation by (a)
selecting an appropriate sample size, (b) using purposive sampling, (c) asking the same
questions to multiple participants, and (d) using data triangulation. Charles et al. (2015)
used the term informational redundancy to describe data saturation, a point where
additional data collection will have no value or contribution to the study. I ensured data
saturation by repeatedly asking the same question from all participants until no new
information emerged.

75
Transition and Summary
In section 2, I have discussed the different stages of the research project. These
steps included discussions on the purpose of the study, the role of the researcher,
participants, population, the research design, and methods. I have also discussed the data
collection instruments, techniques, data analysis, ethical considerations, and how I will
ensure the study's reliability and validity. In Section 3, I present the research findngs,
how the study results were appropriate for strategies to prevent, detect and control
procurement fraud, recommendations for action and further research, implications for
social change, and applications to professional practice.

76
Section 3: Application to Professional Practice and Implications for Change
The purpose of this qualitative multiple case study was to explore the strategies
used by managers in the Ghanaian gold mining industry to detect, control, and prevent
procurement fraud successfully. I used an interview protocol to conduct a semistructured
interview with six procurement managers who have at least 5 years of experience in
Ghana’s gold mining industry and 3 years of experience in their current position. I
conducted four of the interviews at the participants’ place of work, one outside the work
environment, and one through telephone conversation. I used the data collected from the
participants to address the overarching research question: “What strategies do managers
in the Ghanaian gold mining industry use to detect, control, and prevent procurement
fraud successfully?” I used member checking to validate findings with participants and
ensured validity and reliability through methodological triangulation by examining
published literature and company documents which included (a) company code of
conduct, (b) whistle-blowing policy, and (c) procurement policy and standard procedures.
This section describes the emerging themes from the interviews with procurement
managers regarding successful strategies for preventing, detecting, and controlling
procurement fraud in the gold mining industry. This section also includes the findings of
the study and addresses how the findings apply to professional practice, the implication
for social change, the recommendation for action, future research, and the conclusion of
the study.
77
Presentation of the Findings
The overarching research question for this multiple case study was “What
strategies do managers in the Ghanaian gold mining industry use to detect, control, and
prevent procurement fraud successfully?” I made audio recordings of all interviews,
transcribed them into Microsoft Word files, and sent the responses back through email to
participants for member checking to validate their responses and ensure accuracy. I then
uploaded the validated responses into the NVivo software for analysis and theme
identification. From the data analysis, the following three themes emerged: (a) internal
control is effective in preventing, controlling, and detecting procurement fraud; (b)
effective communication through ethics and anti-fraud training for employees; and
suppliers (c) realistic job descriptions with fair remuneration.
Table 2
Strategies Used to Prevent, Detect, and Control Procurement Fraud
Strategy
Frequency
mentioned.
Percentage of
participants
Internal controls
6 100%
Policy communication and training
5 83%
Realistic job descriptions with fair
remuneration
6 100%
78
Theme 1: Internal Control is Effective in Preventing, Controlling and Detecting
Procurement Fraud
The first theme that emerged from the data analysis is internal controls. From all
the participants, the organization’s internal controls are crucial to preventing and
controlling procurement fraud. The participants mentioned various internal control
measures established to avert the occurrence of procurement fraud: (a) periodic audit of
commercial transactions; (b) established company policies which include whistle-blower
policies, established code of conduct, procurement policies, and established anti-bribery
and corruption policies; (c) authority levels for transaction approval; and (d) the use of
information technology in the procurement process (procurement software). Table 3
below presents the frequency of the emerging themes and percentage responses.
Table 3
Frequency of Internal Control Measures by Participants
Internal control measures
Frequency
mentioned
Percentage of
participants
Periodic audit of commercial transactions
5 83%
Established company policies (whistle-
blower, code of conduct, conflict of
interest)
6 100%
Authority levels for transaction approval
5 83%
The use of Enterprise Resource Planning
procurement software
6 100%

79
Organizations adopt internal controls to secure their assets, improve the reliability
of their accounting records, prevent, and detect fraud (Mangala & Kumari, 2017). The
findings from the theme internal control reflected the literature on the effectiveness of
internal controls in preventing and detecting procurement fraud. For example, Mufutau
and Mojisola (2016) highlighted internal controls to prevent procurement fraud. The
authors suggested a combination of audit, code of conduct, whistleblowing, fraud risk
assessment, antifraud professionals’ services, reference check, data mining, firewall,
antifraud policies, and training as effective to fight against fraud. Salleh and Othman
(2016) also suggested that regular monitoring of internal controls and corporate
governance effectively reduces the occurrence of fraud.
The responses from all the participants showed that the establishment of various
internal control measures has averted or reduced the occurrence of fraud in their
respective organizations. P1 stated:
I think what has worked for us over the years is the measures we have put in place
internally, I mean the checks and balances, it starts from the very time an
employee joins the team, you go through an orientation of the company’s policies,
and after the orientation, you sign off as commitment to abide by the rules. There
are disciplinary actions attached to some of the policies, for example, the conflict
of interest, code of conduct, and anti-bribery and corruption (ABC policy). The
fact that people were required to sign these documents after the orientation makes
them scared to go contrary to the provisions.

80
P2 said,
Our internal controls are very tight, and this deters people from engaging in
anything unethical; even managers cannot just approve any transaction, you have
your limit, it is not possible to approve beyond your limits the system will not
allow it, there are half-year and end of year audits where procurement or the
entire supply chain is the focus.
From the responses, there are approval thresholds for initiated purchase orders for goods
and services. For most mining companies, the procurement officers are responsible for
initiating purchase orders in the electronic system, and then an alert can be automatically
sent to another officer depending on the value of the order. This response also reveals that
no one person can initiate an order and approve it himself. All the participants confirmed
that procurement officers responsible for initiating the orders in the system have no
authority to approve even a dollar value purchase order. On the other side, no manager
has a system authorization to raise an order. Aside from the controls in the ERP system,
these are explicit in the companies’ procurement policies. P3 stated:
We have in place policies and specific controls, e.g., periodic audits that include
midyear and end of year inventory counts and procurement audits by internal and
external auditors. This is a norm, and so you know you cannot hide any wrong
deed. The ERP procurement software is also a way of deterring people from
fraudulent deals; it has been programmed to have integrity functions that can raise
red alerts of any suspicious activity for scrutiny.

81
P4 disclosed:
For this company, we have come a long way in the fight against fraudulent
procurement activities, I can say that at the very beginning of the project, things
were not very structured, and people did things their way. However, as we started
production and established structures and procedures, people do things per the
rules. I will not say the policies have eliminated unethical or under-hand dealings,
but we will get there with periodic reviews of the procedures and policies.
The responses from all the participants showed that a robust internal control system
effectively prevents and detects procurement fraud. The responses confirmed research by
Manh and Thi (2018), who argued that achieving the objective of an organizational
policy is only possible through a robust internal control system. Mufutau and Mojisola
(2016) also argued that internal controls ensure compliance with applicable laws and
regulations. Some of the participants also explained that a consistent review of internal
controls makes it more robust over the period to avert fraud. This confirms the argument
of Chiu et al., (2019), Feng et al., (2015), and Hajiha and Bazaz (2016), who argued that
those robust internal controls make fraud unattractive to employees. Peltier-Rivest and
Lanoue (2015) further claimed that a robust internal control is an assurance mechanism.
Theme 1 is consistent with the conceptual framework of the fraud triangle, which
stipulates that for fraud to occur, an opportunity should exist. The study’s findings
revealed that a weak internal control, as suggested by Nawawi and Ahmad Saiful Azlin
(2018a), presents opportunities to commit fraud. As explained by P4, at the project
construction stage of the mine there are no policies and rules, creating opportunities for

82
fraud to occur. Such employees could rationalize their actions because they perceived
they were not flouting any rules. From the findings, robust internal controls could
eliminate the opportunities to commit fraud. Cressey (1953) said that employees commit
fraud when they identify opportunities, rationalize their thinking, and are under pressure.
The employee’s perception of a robust internal control influences their perceived
opportunity to commit fraud (Brown et al., 2016).
To ensure triangulation, I reviewed some of the policy documents of the
companies from which the participants were drawn. I observed specific details on the
code of conduct and ethical values; the procurement policy had specific thresholds and
responsibilities. I also reviewed a few training resources and documents on the issue of
ethics. I observed a common trend in the policies of the participating companies. The
numerous internal control policies revealed the organizational commitment to fight fraud.
This finding confirms Peters and Miniam (2016) argument that an organization’s culture,
environment, and ethical strategy play a role in whether employees have opportunities to
commit fraud.
Theme 2: Effective Communication Through Ethics and Antifraud Training for
Employees and Suppliers
The analysis showed that effective communication of policies on fraud through
training for both the company’s staff and its suppliers effectively prevents and detects
procurement fraud in the gold mining industry. Five of the participants mentioned
communication and training for supply chain stakeholders as one of the effective means
their companies have used to avert procurement fraud. The participants mentioned that it

83
was not enough to disseminate the company’s policies to its staff but periodically
organizing refresher training and roadshows to include the staff of major suppliers and
contractors has been critical in preventing procurement fraud. Apart from this, the
companies’ policies like antibribery and corruption, code of conduct, and conflict of
interest are summarized, printed, and pasted on major notice boards. They are also
electronically displayed on big screens at the lunch halls. Almost all the participants
mentioned that the organizational policies are on the company’s intranet easily accessible
to all workers. The findings of this study revealed that the system of communicating the
organizational policies, particularly on ethical business practices, helps maintain a high
level of ethical standards. P1, P2, P4, P5, and P6 discussed the periodic training of
procurement staff and suppliers on the company’s commitment to ethical business
dealings, and the various policies have been effective in preventing procurement fraud.
P2 noted,
Almost every quarter, there is training on the ABC and conflict of interest.
Anytime this training is organized, employees feel someone has done something
wrong. Sometimes an external expert facilitates the training on how to identify
fraudulent activities within the procurement process.
P4 stated
Our suppliers and contractors are also not left out on the quest to prevent fraud;
we believe they can influence employees to act unethically, so we organize
roadshows for them to understand our policies and the need to act ethically. They
are also informed of the whistleblower procedure, so they feel ok to report any

84
fraudulent act.
P5 agreed, stating,
When there is effective communication of policies, and the implications of going
against it, are clear to employees, they become conscious of their actions. When
procurement staffs are aware that suppliers or contractors know the policies with
the access to the whistleblowing line, they are careful how they conduct
themselves as they do not know which supplier can blow the whistle on them; we
have these policies. Just as we take safety issues on the mine seriously, so it is
with issues of fraud.
P6 explained,
Our employees do not commit fraud alone; they will collaborate with suppliers or
contractors in most cases. So, it is very effective to communicate and train both
sides; even if your employees are not doing it, suppliers can defraud the company.
For us, our training includes all and sundry in any transactional dealings. After
every training, everybody signs off attendance and gets small booklets that
summarize the main points discussed. If there is any breach, the first point of
investigation is to check these attendances and take the necessary action.
Most of the participants found effective communication of company policies and
antifraud training as effective in preventing procurement fraud. This finding aligns with
literature, as Robinson and Jonker (2017) suggested, training employees help them deal
with ethical dilemmas. Other authors (Aborbie, 2015; Albrecht et al., 2015; Kramer,
2015; Kummer et al., 2015) also confirmed that communication, training, and awareness

85
creation empowers managers and employees to eliminate opportunities for fraud in the
organization. Communication and training are also required for employees to understand
and appreciate management’s tone and commitment. This finding aligns with Suh and
Shim’s (2019) argument that a vibrant and proactive managerial efforts such as having an
‘ethical management tone’ with effective ethical training positively affect employees'
perceived corporate anti-fraud strategies. Participants acknowledged that an effective
communication and training program aids the understanding of the employee’s mindset.
They further confirmed the claim of Free and Murphy (2016) and Negurita and Ionescu
(2016) that the employee’s rationalization to commit fraud is quite elusive and
challenging and requires a greater sense of awareness. The participants also stated that
through communication and training, management gets to understand employees’
motives which confirms Cressey’s (1953) argument that it is vital to understand the
motive for committing fraud to deal with it. The theme aligns with the conceptual
framework in that managers can limit the rationalization of unethical behaviors and
eliminate opportunities for committing fraud through training and communication.
Theme: 3 Realistic Job Descriptions and Fair Remuneration.
From the findings, all participants believed that establishing clear and realistic job
descriptions with fair remunerations is key to preventing procurement fraud. The
participants noted when employees feel not well paid for their roles, they are likely to feel
cheated and use that as a rationale to commit fraud, especially for the procurement staff
who have access to the funds of the organization. The participants further noted that
when an employee is given too much responsibility over time, he may use that as a

86
rationale to indulge in fraud. Kennedy (2016) argued that providing incentives other than
regular income to employees who perform additional tasks well will take their minds off
fraud.
Participants identified as P1, P3, P4, and P5 noted that the perception about the
remuneration of mining workers puts much pressure on their finances. People perceive
mining workers as very well paid and rich, making them targets for financial assistance
from friends and family. In such an instance, they will resort to fraud to meet society’s
demands and status. The participants also discussed that the social recognition of mining
workers as very rich also makes some of them adopt a high social standard of living; if
they do not get what it takes to maintain that status, they may resort to fraud. e.g., P3
stated,
We know how people perceive the financial status of mine workers, and we also
know how some workers hold themselves in their various communities and the
lifestyle they adopt; if their remuneration is not reasonable, then it is a recipe for
disaster. Therefore, management and industry players have ensured fair
remuneration to prevent fraud occurrence.
P4 said,
Apart from monthly salaries, the company has instituted other monetary
incentives to complement the employees’ earnings. These incentives include
annual bonuses, profit sharing, performance-induced earnings, and access to
flexible compassionate loans just to ensure workers have sound minds to give
their best and avoid fraudulent acts.

87
The findings align with the arguments in the literature that confirm financial pressure as
the primary motivation for fraud (Albrecht et al., 2015; Imoniana et al., 2016). Mishra
and Singh (2017) argued that when employees are under much pressure to perform and
meet task goals, they are likely to commit fraud. Whiles Moorthy et al. (2015) support the
use of other incentives, they also caution the need for close monitoring to avert
mismanagement. The theme aligns with the conceptual framework; the fraud triangle as
the pressure element considers the lack of finance, lifestyle, social status as motivators
for fraud. The discussions revealed that employees who are well motivated according to
their job descriptions are less likely to engage in fraudulent acts. The financial need
creates the motivation for fraud and once provided, the likelihood for fraud to occur is
low.
Applications to Professional Practice
As companies expand and extend their geographic presence, the procurement
cycle becomes more complex and involves high monetary value and many transactions.
Such a situation gives rise to the temptations and opportunities to commit fraud and
presents significant challenges in detecting and preventing it from occurring. Global
statistics show that procurements occur at almost every stage of the procurement process
(Patterson et al., 2018). The risk is eminent in all business sectors. Business managers
across sectors can apply the findings of this study by incorporating some of the strategies
implemented by participants to detect, prevent, and control procurement fraud. It is
evident from the findings that procurement fraud can have a significant impact on the
organization. The findings of this study provide rich information and strategies for all

88
business managers for dealing with procurement fraud. The three emerging strategies
from this study contribute to applied business practice for detecting and preventing
procurement fraud. Using the findings of this study, business managers will understand
the use of internal controls, ethics and antifraud training, and clear job descriptions and
remuneration as a way of averting procurement fraud.
Internal controls, when effectively established, discourage unethical behavior and
solicit commitment to adhere to policies (Kumar et al., 2018). Business managers can use
communication and training to create awareness of antifraud policies, existing controls,
identifying fraud, and their impact on the organization. When employees are aware of
these, they are less likely to commit fraud. This will eliminate any justification to commit
fraud. Business managers can apply a realistic job description and realistic remuneration
to avert the occurrence of fraud.
Implications for Social Change
The findings of this study could benefit other business managers by implementing
strategies that managers in the gold mining companies have used to detect, prevent, and
control procurement fraud. Implementing such strategies will help business managers to
safeguard revenue losses from procurement fraud. Business managers will understand
from this study that having robust internal control in place prevents procurement fraud.
Also, ensuring that employees are given the right jobs and paid well will eliminate the
rationale for fraud. When implementing these identified strategies eliminates
procurement fraud, the organization will save money and other resources. Such savings
or resources could fund welfare projects for the companies’ communities, impacting

89
social change. The findings of this study impact social change in that implementing
identified strategies will impact the moral compass of employees to desist and change
from their fraudulent deeds. When procurement fraud is eliminated, revenue will
increase, which will improve the organization’s sustainability to create more avenues for
employment.
Recommendations for Action
The findings of this study lead to some suggestions for actions of business
managers in both public and private sectors to develop strategies to deal with
procurement fraud. Procurement and commercial managers also need to pay attention to
the findings of this study. Accountants and auditors can also use the findings of this
study. These groups of people influence the commercial transactions of most
organizations. I will make a few recommendations for action.
The establishment of robust internal control is critical to the fight against
procurement fraud. Not only should internal control be present, but managers must also
ensure a review of existing controls and update them to suit current happenings. Such
reviews will reveal and eliminate the inherent risk of fraud. Internal controls require
monitoring and review to achieve the objective of preventing fraud. From time to time,
internal auditors may query the procurement system just in case something has gone
wrong; in most cases, auditors will act after the fraud has occurred, which could be too
late. Managers need to establish procedures that will allow robust background checks on
suppliers and major contractors. Such background checks can ensure suppliers and

90
contractors have a reputable record and reveal any form of conflict of interest that may
lead to procurement fraud.
Managers need to ensure due diligence and adherence to established procedures
for every procurement initiated. Where there are shortfalls, there should be training to
close the gaps. The training of procurement staff should not be in isolation, but for the
staff of suppliers too. This is because, in most cases, procurement fraud results from the
collusion of these two parties. Finally, managers must pay fair wages to employees with
other incentives.
I hope to publish the findings of this study in academic and business journals. I
intend to present a summary of the findings through a report to the participants. I also
intend to hold conferences, seminars, and training programs and present the findings to
supply chain professionals. Through these means, I can disseminate the findings of this
study.
Recommendations for Further Research
One of the areas I would recommend for further research is analyzing the
limitations of internal controls’ effectiveness in preventing and detecting procurement
fraud. Also, I would recommend further quantitative research on the impact of
procurement fraud on organizational financial performance. This study was limited to
only gold mining companies in Ghana. I would recommend further research to cover a
wider geographical area across other sectors to confirm the effectiveness of identified
strategies in detecting, preventing, and controlling procurement fraud.

91
Reflections
As I reflect on the Doctor of Business Administration journey, it has been quite
challenging, and this study has broadened my understanding of procurement fraud and
the mitigating strategies in an organization. The extensive literature gave me an
understanding of the complexity of procurement fraud and the diverse ways to mitigate it.
In conducting the study, I ensured I put aside all my prejudice and bias. I collected and
analyzed the data without bias using an interview protocol to ensure I focused on the
participants’ responses.
I found the information and responses the participants gave interesting. I was not
very surprised when most of the responses showed some similarities because participants
came from the same industry. Another exciting part was that participants were so
passionate to share information on issues of fraud with me. Results from this study could
provide other business managers an insight into how to detect and prevent procurement
fraud in their organizations.
Conclusion
Every organization is vulnerable to procurement fraud. Because the procurement
function is the spending department of the organization and is responsible for all levels of
spending, the risk for fraud is very high. There are numerous reasons why fraud may
occur: greed, financial pressure, weak internal controls, which present employees with
opportunities to commit fraud and lifestyle. The impact of procurement fraud is
enormous as it does affect not only the organization’s revenue but also its corporate
image (Omar et al., 2015). It is imperative that business managers adopt effective

92
strategies to detect, prevent and control procurement fraud. The purpose of this
qualitative multiple case study was to explore successful strategies managers in gold
mining companies use to detect, prevent, and control procurement fraud. The findings of
this study have revealed three important strategies business managers can adopt to detect,
prevent, and control procurement fraud: internal controls, communication and training,
and realistic jobs with realistic remuneration. Also, establishing facilities that allow
employees to have access to funds outside their regular salaries is also effective in
preventing them from engaging in fraudulent acts. From the research findings, it is a fact
that business managers that establish robust measures to detect, prevent, and control
procurement fraud can eliminate opportunities and the rationalization factor of employees
to win the fight against fraud.
93
References
Aarons, G. A., Ehrhart, M. G., Farahnak, L. R., & Hurlburt, M. S. (2015). Leadership and
organizational change for implementation (LOCI): A randomized mixed method
pilot study of a leadership and organization development intervention for
evidence-based practice implementation. Implementation Science, 10,11-23.
https://doi.org/10.1186/s13012-014-0192-y
Abdul Rasid, S. Z., N’Guilla, S. A., Rohaida, B., & Jihad, M. (2018). Fraud prevention in
Malaysian small and medium enterprises (SMEs). Journal of Financial Crime,
25(2), 499-517. https://doi.org/10.1108/JFC-05-2017-0049
Abdullahi, R., & Mansor, N. (2015). Fraud triangle theory and fraud diamond theory.
Understanding the convergent and divergent for future research. International
Journal of Academic Research in Accounting, Finance and Management
Sciences, 5, 38-45. https://doi.org/10.6007/IJARAFMS/v5-i3/1823
Aborbie, S. (2015). Narrowing the gap of financial fraud detection in corporations (978-
1-321-66110-1) [Doctoral dissertation, Walden University]. ProQuest
Abutabenjeh, S., & Jaradat, R. (2018). Clarification of research design, research methods,
and research methodology: A guide for public administration researchers and
practitioners. Teaching Public Administration, 36(3), 237-258.
https://doi.org/10.1177/0144739418775787
Ach, M. (2017). The investigation and elimination of public procurement fraud in
government sectors (A case study in Indonesia’s procurement system: Cases from
2006 to 2012). International Journal of Economics and Financial Issues, 7(2),
94
145-154. https://dergipark.org.tr/tr/pub/ijefi/issue/32035/354457
Adriana, M. R., Basiruddin, R., Gunasegaran, M., & Siti Zaleha, A. R. (2018). The case
studies of fraud prevention mechanisms in the Malaysian medium enterprises.
Journal of Financial Crime, 4, 1024-1038. https://doi.org/10.1108/JFC-05-2017-
0034
Ahmad, N., Simbolon, R., & Simbolon, E. (2019, May). Are the model of fraud triangle
elements sufficient enough to prevent fraud? Evidence in North Sumatra
Province. [Paper presentation] 1st International Conference on Social Sciences
and Interdisciplinary Studies, Indonesia. https://doi.org/10.2991/icssis-18.2019.73
Alam, M. M., Asri, S., Obaid, R. R., Rafidi, M., Said, J. (2018). Integrating religiosity
into fraud triangle theory: Empirical findings from Malaysian enforcement
officer. Global Journal, 8(1),131-143. https://doi.org/10.31235/osf.io/wcyg4
Albrecht, C., Holland, D., Malagueño, R., Dolan, S., & Tzafrir, S. (2015). The role of
power in financial statement fraud schemes. Journal of Business Ethics, 131(4),
803-813. https://doi.org/10.1007/s10551-013-2019-1
Alderete, J., & Davies, M. (2019). Investigating perceptual biases, data reliability, and
data discovery in a methodology for collecting speech errors from audio
recordings. Language and Speech, 62(2), 281–317.
https://doi.org/10.1177/0023830918765012
An-An, C., Chi-Chen, L., Shaio, Y. H., & Yen, D. C. (2017). Fraud detection using fraud
triangle risk factors. Information Systems Frontiers, 19(6), 1343-1356.
https://doi.org/10.1007/s10796-016-9647-9
95
Andon, P., Free, C., & Scard, B. (2015). Pathways to accountant fraud: Australian
evidence and analysis. Accounting Research Journal, 28(1), 10-44.
https://doi.org/10.1108/arj-06-2014-0058
Anna-Maija, P., Hanna, K., Martin, J., & Mari, K. (2016). Systematic methodological
review: developing a framework for a qualitative semi-structured interview guide.
Journal of Advanced Nursing, 72, 2954–2965. https://doi.org/10.1111/jan.13031
Arseven, I. (2018). The use of qualitative case studies as an experiential teaching method
in the training of pre-service teachers. International Journal of Higher Education,
7(1), 111-125. https://doi.org/10.5430/ijhe.v7n1p111
Asiamah, N., Mensah, H. K., & Oteng-Abayie, E. (2017). General, target, and accessible
population: Demystifying the concepts for effective sampling. Qualitative Report,
22, 1607-1621. https://nsuworks.nova.edu/tqr/vol22/iss6/9
Association of Certified Fraud Examiners (2018). Report to the nations on occupational
fraud and abuse. 2016 global fraud study. Association of Certified Fraud
Examiners.
Asllani, G., & Statovci, B. (2018). Bid rigging in public procurement of list of essential
drugs-Kosovo case. Journal of Pharmaceutical Sciences and Research, 10(1),
188-191. https://www.researchgate.net/publication/322940048
Bahraminejad, N., Ibrahim, F., Riji, H. M., Majdzadeh, R., Hamzah, A., & Mohammadi,
N. K. (2015). Partner's engagement in community-based health promotion
programs: A case study of professional partner's experiences and perspectives in
Iran. Health Promotion International, 30, 963-975.
96
https://doi.org/10.1093/heapro/dau043
Baily, P., Crocker, B., Farmer, D., Jessop, D., & Jones, D. (2015). Procurement
principles and management. (11th ed.). Pearson Education
Bansal, P., Smith, W. K., & Vaara, E. (2018). New ways of seeing through qualitative
research. Academy of Management Journal, 61(4), 1189-1195.
https://doi.org/10.5465/amj.2018.4004
Barratt, M. J., Ferris, J. A., & Lenton, S. (2015). Hidden populations, online purposive
sampling, and external validity: Taking off the blindfold. Field Methods, 27, 3-21.
https://doi.org/10.1177/1525822X14526838
Bayram, H., Saka, M., & Kabapınar, F. (2016). The teaching processes of prospective
science teachers with different levels of science-teaching self-efficacy belief.
Educational Sciences: Theory & Practice, 16, 915-942.
https://doi.org/10.12738/estp.2016.3.0012
Belousova, S. V. (2016). Economic crimes. Problems of Economic Transition, 58, 776–
793. https://doi.org/10.1080/10611991.2016.1251223
Bengtsson, M. (2016). How to plan and perform a qualitative study using content
analysis. NursingPlus Open, 2, 8–14. https://doi.org/10.1016/j.npls.2016.01.001
Bennett, K., Rose, M., & Sarjoo, P. (2015). A boost to fraud risk assessments: Reviews
based on the updated COSO internal control-integrated framework may help
prevent fraud. Internal Auditor, 72(3), 22-24. https://iaonline.theiia.org
Benoot, C., Hannes, K., & Bilsen, J. (2016). The use of purposeful sampling in a
qualitative evidence synthesis: A worked example on sexual adjustment to a
97
cancer trajectory. BMC Medical Research Methodology, 16(1), 1–12.
https://doi.org/10.1186/s12874-016-0114-6
Berger, R. (2013). Now I see it, now I don’t: Researcher’s position and reflexivity in
qualitative research. Qualitative Research, 15(2), 219-234.
https://doi.org/10.1177/1468794112468475
Bernard, H. R., Wutich, A., & Ryan, G. W. (2016). Analyzing qualitative data:
Systematic approaches (2nd ed.). Sage.
Bildsten, L., & Manley, K. (2015). A framework for understanding purchasing in
building construction companies. Construction Management & Economics, 33,
865–879. https://doi.org/10.1080/01446193.2016.1164325
Bire, A. R., Sauw, H. M., & Maria, J. (2019). The effect of financial literacy towards
financial inclusion through financial training. International Journal of Social
Sciences and Humanities, 3(1), 186-192. https://doi.org/10.29332/ijssh.v3n1.280
Birt, L., Scott, S., Cavers, D., Campbell, C., & Walter, F. (2016). Member checking: A
tool to enhance trustworthiness or merely a nod to validation? Qualitative Health
Research, 26, 1802-1811. https://doi.org/10.1177/1049732316654870
Bonny, P., Goode, S., & Lacey, D. (2015). Revisiting employee fraud: Gender,
investigation outcomes and offender motivation. Journal of Financial Crime, 22,
447–467. https://doi.org/10.1108/JFC-04-2014-001
Bowden, C., & Galindo-Gonzalez, S. (2015). Interviewing when you’re not face-to-face:
The use of email interviews in a phenomenological study. International Journal
of Doctoral Studies, 10, 79-92. https://doi.org/10.28945/2104
98
Bowen, G. A. (2009). Document analysis as a qualitative research method. Qualitative
Research Journal, 9(2), 27-40. https://doi:10.3316/QRJ0902027
Boyle, D., Boyle, J., & Mahoney, D. (2015). Avoiding the fraud mind-set. Strategic
Finance, 97, 41-46. https://readperiodicals.com/201502/3592153721
Boyle, D., DeZoort, F., & Hermanson, D. (2015). The effect of alternative fraud model
use on auditors’ fraud risk judgments. Journal of Accounting Public Policy, 34,
578–59. https://doi.org/10.1016/j.jaccpubpol.2015.05.006
Brazel, J., Jones, K., Thayer, J., & Warne, R. (2015). Understanding investor perceptions
of financial statement fraud and their use of red flags: Evidence from the field.
Review of Accounting Studies, 20, 1373–1406. https://doi.org/10.1007/s11142-
015-932
Bristowe, K., Selman, L., & Murtagh, F. E. (2015). Qualitative research methods in renal
medicine: An introduction. Nephrology Dialysis Transplantation, 30, 1424-1431.
https://doi.org/10.1093/ndt/gfu410
Brody, R. G., Perri, F. S., & Van Buren, H. J. (2015). Further beyond the basic
background check: Predicting future unethical behavior. Business and Society
Review, 120, 549–576. https://doi.org/10.1111/basr.12074
Brown, O., Hays, J., & Stuebs, J. (2016). Modeling accountant whistleblowing intentions:
Applying the theory of planned behavior and the fraud triangle. Accounting & The
Public Interest, 16, 28-56. https://doi.org/10.2308/apin-51675
Burke, D. D., & Sanney, J. (2018). Applying the fraud triangle to higher education:
Ethical implications. Journal of Legal Studies Education, 35, 5-43.
99
https://doi.org/10.1111/jlse.12068.
Button, M., & Shepherd, D. (2019). Organizational inhibitions to addressing occupational
fraud: A theory of differential rationalization. Deviant Behavior, 40, 971-991.
https://doi.org/10.1080/01639625.2018.1453009
Button, M., Brooks, G., Lewis, C., & Shepherd, D. (2015). Fraud in overseas aid and the
challenge of measurement. Journal of Financial Crime, 22, 184-198.
https://doi.org/10.1108/jfc-02-2014-0006
Buytaert, W., Brozović, N., Mijic, A., O’Keeffe, J., & Sinha, R. (2016). The use of semi-
structured interviews for the characterization of farmer irrigation practices.
Hydrology and Earth System Sciences, 20, 1911–1924.
https://doi.org/10.5194/hess-20-1911-2016
Candela, A. G. (2019). Exploring the function of member checking. Qualitative Report,
24(3), 619-628. https://nsuworks.nova.edu/tqr
Castillo-Montoya, M. (2016). Preparing for interview research: The interview protocol
refinement framework. Qualitative Report, 21, 811-831.
https://nsuworks.nova.edu/tqr/vol21/iss5/2
Caulfield, T., & Steckler, S. (2015). Schemes of the fraudster: Beat them at their own
game. Contract Management, 55, 10-15. https://nebula.wsimg.com
Charles, C., Gentles, S. J., McKibbon, K. A., & Ploeg, J. (2015). Sampling in qualitative
research: Insights from an overview of the methods literature. Qualitative Report,
20, 1772-1789. http://nsuworks.nova.edu/tqr/
Chassang, S., & Ortner, J. (2015). Making collusion harder: Asymmetric information,
100
collusion, and crime. Journal of Political Economy, 5, 2108-2133.
https://doi.org//10.1086/699188
Chava, S., Huang, K., & Johnson, S. A. (2018). The dynamics of borrower reputation
following financial misreporting. Management Science, 64, 4775–4797.
https://doi.org/10.1287/mnsc.2017.2739
Chiu, T., Brown-Liburd, H., & Vasarhelyi, M. A. (2019). Performing tests of internal
controls using process mining: What could go wrong? CPA Journal, 89(6), 54-57.
https://www.cpajournal.com/2019/07/10/performing-tests-of-internal-controls-
using-process-mining
Clark, R., Coviello, D., Gauthier, J.-F., & Shneyerov, A. (2018). Bid rigging and entry
deterrence in public procurement: Evidence from an investigation into collusion
and corruption in Quebec. Journal of Law Economics & Organization, 3, 301–
363. https://doi.org/10.1093/jleo/ewy01
Conley, T. G., & Decarolis, F. (2016). Detecting bidders’ groups in collusive auctions.
American Economic Journal: Microeconomics, 8(2), 1-38.
https://doi.org/10.1257/mic.20130254
Connelly, L. M. (2016). Trustworthiness in qualitative research. MEDSURG Nursing,
25(6), 435-436.
https://link.gale.com/apps/doc/A476729520/AONE?u=anon~e06e5633&sid=goog
leScholar&xid=d0064d3c
Connor, J. M., & Werner, D. P. (2018). Variation in bid-rigging cartels’ overcharges: An
exploratory study. SSRN, 1. https://doi.org/10.2139/ssrn.3273988
101
Corbin, J., & Strauss, A. (2015). Basics of qualitative research techniques and procedures
for developing grounded theory (4th ed.). Sage.
Coyle, C. E., Curry, L., Feder, S., Schulman-Green, D., Plano Clark, V. L., Prust, M. L.,
& Toraman, S. (2018). Federal funding for mixed methods research in the health
sciences in the United States: recent trends. Journal of Mixed Methods Research,
3, 305-324. https://doi.org/10.1177/1558689816662578
Cressey, D. (1953). Other people’s money: A study in the social psychology of
embezzlement. Free Press.
Creswell, J. W. (2015). Revisiting mixed methods and advancing scientific practices. In
Hesse-Biber, S. N., Johnson, R. B. (Eds.), The Oxford handbook of multi-method
and mixed methods research inquiry (pp. 57-71). Oxford University Press.
Creswell, J. W., & Creswell, D.J. (2018). Research design: Qualitative, quantitative, and
mixed methods approaches. Sage.
Cridland, E. K., Caputi, P., Jones, S. C., & Magee, C. A. (2015). Qualitative research
with families living with autism spectrum disorder: Recommendations for
conducting semi structured interviews. Journal of Intellectual & Developmental
Disability, 40(1), 78-91. https://doi.org/10.3109/13668250.2014.964191
Crowe, M., Inder, M., & Porter, R. (2015). Conducting qualitative research in mental
health: Thematic and content analysis. Australian & New Zealand Journal of
Psychiatry, 49, 616-623. https://doi.org/10.1177/00048674155820523
Cypress, B. S. (2017). Rigor or reliability and validity in qualitative research:
Perspectives, strategies, reconceptualization, and recommendations. Dimensions
102
of Critical Care Nursing, 253-263.
https://doi.org/10.1097/DCC.0000000000000253
Dasgupta, M. (2015). Exploring the relevance of case study research. Vision, 19, 147-
160. https://doi.org/doi:10.1177/0972262915575661
deGama, N., Elias, S. R., & Peticca-Harris, A. (2016). A dynamic process model for
finding informants and gaining access in qualitative research. Organizational
Research Methods, 19, 376-401. https://doi.org/10.1177/1094428116629218
DeJonckheere, M., & Vaughn, L. M. (2019). Semistructured interviewing in primary care
research: a balance of relationship and rigour. Family Medicine and Community
Health, 7. https://doi.org/10.1136/fmch-2018-000057
Deleanu, L., Ferwerda, J., & Unger, B. (2017). Corruption in public procurement:
Finding the right indicators. European Journal on Criminal Policy and Research,
2, 245-267. https://doi.org/10.1007/s10610-016-9312-3
Denise, K., Kalubanga, M., & Kakwezi, P. (2013). The effects of fraudulent procurement
practices on public procurement performance. International Journal of Business
and Behavioral Sciences, 3, 17-21.
https://www.researchgate.net/publication/236208095
Denzin, N. K., & Lincoln, Y. S. (2017). The SAGE handbook of qualitative research (5th
ed.). Sage.
Dimitrijevic, D., Milovanovic, V., & Stancic, V. (2015). The role of a company's internal
control system in fraud prevention. Financial Internet Quarterly E-Finance, 11,
34–44. http://e-finanse.com/
103
Dion, M. (2019). Fraud and guilt: rationalization strategies and the relevance of
Kierkegaardian life-views. Journal of Financial Crime, 26, 607–622.
https://doi.org/10.1108/JFC-01-2018-0009
Dong, W., Liao, S., & Zhang, Z. (2018). Leveraging financial social media data for
corporate fraud detection. Journal of Management Information Systems, 35, 461–
487. https://doi.org/10.1080/07421222.2018.1451954
Dorminey, J., Fleming, A. S., Kranacher, M. J., & Riley, R. A., Jr. (2012). The evolution
of fraud theory. Issues in Accounting Education, 27, 555-579.
https://doi.org/10.2308/iace-50131
Drew, H. (2014). Overcoming barriers: Qualitative interviews with German elites.
Electronic Journal of Business Research Methods, 12, 77-86. http://ejbrm.com
Edmonds, W., & Kennedy, T. (2017). An applied guide to research designs:
Quantitative, qualitative, and mixed methods. Sage.
Eisner, E. W. (2017). The enlightened eye: Qualitative inquiry and the enhancement of
educational practice. Teachers College Press.
Eklund, T., Jokipii, A., & Länsiluoto, A. (2016). Internal control effectiveness; A
clustering approach. Managerial Auditing Journal, 31, 5-34.
https://doi.org/10.1108/maj-08-2013-0910
Etikan, I., Musa, S. A., & Alkassim, R. S. (2016). Comparison of convenience sampling
and purposive sampling. American Journal of Theoretical and Applied Statistics,
5, 1-4. https://doi.org/10.11648/j.ajtas.20160501.11
Fan-Ko, S., Long, A., Chun-Ying, C., Hui-Man, H., Yu-Chieh, H., & Yao, Y. (2018).
104
Rationale underpinning postgraduate student nurses' choice of research methods
used for their masters’ theses. Nurse Education in Practice, 33, 127-132.
https://doi.org/10.1016/j.nepr.2018.10.002
Feng, M., Li, C., McVay, S. E., & Skaife, H. A. (2015). Does ineffective internal control
over financial reporting affects a firm’s operations? Evidence from firms’
inventory management. The Accounting Review, 90, 529-557.
https://doi.org/10.2308/accr-50909
Fletcher, D., De Massis, A., & Nordqvist, M. (2016). Qualitative research practices and
family business scholarship: A review and future research agenda. Journal of
Family Business Strategy, 7, 8-25. https://doi.org/10.1016/j.jfbs.2015.08.001
Fligstein, N., & Roehrkasse, A. F. (2016). The causes of fraud in the financial crisis of
2007 to 2009. American Sociological Review, 4, 617 643.
https://doi.org/10.1177/0003122416645594
Free, C. (2015). Looking through the fraud triangle: A review and call for new directions.
Meditari Accountancy Research, 23, 175-196. https://doi.org/10.1108/MEDAR-
02-2015-0009
Free, C., & Murphy, P. (2016). Broadening the fraud triangle: Instrumental climate and
fraud. Behavioral Research in Accounting, 28, 41–56.
https://doi.org/10.2308/bria-51083
Fusch, P. I., Fusch, G. E., & Ness, L. R. (2016). How to conduct a mini-ethnographic
case study: A guide for novice researchers. The Qualitative Report, 22, 923-941.
http://nsuworks.nova.edu
105
Fusch, P., & Ness, L. (2015). Are we there yet? Data saturation in qualitative research.
Qualitative Report, 20, 1408-1416. http://tqr.nova.edu
Gao, J., Greenberg, R., & Wong-On-Wing, B. (2015). Whistleblowing intentions of
lower-level employees: The effect of reporting channel, bystanders, and
wrongdoer power status. Journal of Business Ethics, 126(1), 85–99.
https://doi.org/10.1007/s10551-013-2008-4
Gartner, I. R., & Machado, M. R. R. (2018). The Cressey hypothesis (1953) and an
investigation into the occurrence of corporate fraud: An empirical analysis
conducted in Brazilian banking institutions. Revista Contabilidade & Finanças,
29, 60–81. https://doi.org/10.1590/1808-057x201803270
Gehman, J., Glaser, V. L., Eisenhardt, K. M., Gioia, D., Langley, A., & Corley, K. G.
(2017). Finding theory method fit: A comparison of three qualitative approaches
to theory building. Journal of Management Inquiry, 27(3), 284-300.
https://doi.org/10.1177/1056492617706029
Georgios, L. V. (2019). Advancing theory of fraud: The S.C.O.R.E. model", Journal of
Financial Crime, 26, 372-381. https://doi.org/10.1108/JFC-12-2017-0128
Ghafoor, A., Zainuddin, R., & Mahdzan, N. S. (2019). Factors eliciting corporate fraud in
emerging markets: Case of firms subject to enforcement actions in Malaysia:
Journal of Business Ethics, 160(2), 587-608. https://doi.org/10.1007/s10551-018-
3877-3
Ghafran, C., & Sullivan, O. N. (2017). The impact of audit committee expertise on audit
quality: Evidence from UK audit fees. British Accounting Review, 49(6), 578-593.
106
https://doi.org/10.1016/j.bar.2017.09.008
Gilbert, M., & Wakefield, A. (2018). Tackling fraud effectively in central government
departments. Journal of Financial Crime, 25(2), 384-399.
https://doi.org/10.1108/JFC-01-2017-0006
Gill, J. (2017). The Fraud Triangle on Trial. Fraud Magazine. https://www.fraud-
magazine.com/article.aspx?id=4294999117
Gilmore-Allen, A. (2015). Tech fraud and the small business. Internal Auditor, 1, 20–21.
https://www.theiia.org/intauditor
Glodstein, D. (2015). Occupational fraud: Misappropriation of assets by an employee.
Journal of the International Academy for Case Studies, 21, 81-86.
https://www.alliedacademies.org/the-international-academy-for-case-studies/
Gorsira, M., Steg, L., Denkers, A., & Huisman, W. (2018). Corruption in organizations:
Ethical climate and individual motives. Administrative Sciences, 8, 4.
https://doi.org/10.3390/admsci8010004
Haberbush, K. L. (2000). Limiting the government’s exposure to bid rigging schemes: A
critical look at the sealed bidding regime. Public Contract Law Journal, 30, 97–
122. https://www.jstor.org/stable/25754428
Hajiha, Z., & Bazaz, M. S. (2016). Impact of internal control material weaknesses on
executive compensation: evidence from Iran. International Journal of Accounting,
Auditing and Performance Evaluation, 12, 70-84
https://doi.org/10.1504/ijaape.2016.073891
Harriss, D. J., & Atkinson, G. (2015). Ethical standards in sport and exercise science
107
research: 2016 update. International Journal of Sports Medicine, 36, 1121-1124.
https://doi.org/10.1055/s-0035-1565186
Hayashi, P., Abib, G., & Hoppen, N. (2019). Validity in qualitative research: A
processual approach. Qualitative Report, 24, 98-112.
https://nsuworks.nova.edu/tqr/vol24/iss1/8
Hennink, M. M., Kaiser, B. N., & Marconi, V. C. (2017). Code saturation versus meaning
saturation: how many interviews are enough?. Qualitative health research, 27(4),
591-608. https://journals.sagepub.com/doi/pdf/10.1177/1049732316665344
Ho, Z. J. Y. (2012). What makes hotel expatriates remain in their overseas assignments:
A grounded theory study. Qualitative Report, 17, 1-22.
https://nsuworks.nova.edu/tqr/vol17/iss26/1
Hoopes, J. L., Merkley, K. J., Pacelli, J., & Schroeder, J. H. (2018). Audit personnel
salaries and audit quality. Review of Accounting Studies, 23(3), 1096-1136.
https://doi.org/10.1007/s11142-018-9458-y
Horne, J., Lochner, H., & Venter, J. (2018). The red flag system as the gatekeeper in
tender fraud prevention and detection of misrepresentation. International Journal
of African Renaissance Studies, 13,129-143.
https://doi.org/10.1080/18186874.2018.1478655
Huber, W. C. (2017). Forensic accounting, fraud theory, and the end of the fraud triangle.
Journal of Theoretical Accounting Research. 2, 28-49.
https://www.researchgate.net/publication/319333659
Huisman, W. (2016). Criminogenic organizational properties and dynamics. Oxford
108
University Press.
Imoniana, J. O., & Murcia, F. D. (2016). Patterns of similarity of corporate frauds. The
Qualitative Report, 21(1), 143-162. https://nsuworks.nova.edu/tqr/vol21/iss1/12
Imoniana, J. O., Feitas, E. C. D., & Perera, L. C. J. (2016). Assessment of internal control
systems to curb corporate fraud - evidence from Brazil. African Journal of
Accounting, Auditing, and Finance, 5, 1.
https://doi.org/10.1504/ajaaf.2016.077592
Isenring, G. L., Mugellini, G., & Killias, M. (2016). The willingness to report employee
offences to the police in the business sector. European Journal of Criminology,
13(3), 372–392. https://doi.org/10.1177/1477370815623569
Ivankova, N. V. (2015). Mixed methods applications in action research: From methods
to community action. Sage.
Ivankova, N. V. (2017). Applying mixed methods in community-based action research: A
framework for engaging stakeholders with research as means for promoting
patient-centeredness. Journal of Nursing Research, 22, 282-294.
https://doi.org/10.1177/1744987117699655
Jaspers, J. D. (2019). Business cartels and organized crime: exclusive and inclusive
systems of collusion. Trends Organ Crime, 22, 414–432.
https://doi.org/10.1007/s12117-018-9350-y
Jha, C., & Panda, B. (2017). Individualism and corruption: A cross-country analysis.
economic papers. Journal of Applied Economics and Policy, 36, 60–74.
https://doi.org/10.1111/1759-3441.12163
109
Johnson, P. (2015). Evaluating qualitative research: Past, present, and future. Qualitative
research in organizations and management: An International Journal, 4, 320-324.
https://doi.org/10.1108/QROM-07-2015-1303
Joslin, R., & Müller, R. (2016). Identifying interesting project phenomena using
philosophical and methodological triangulation. International Journal of Project
Management, 34, 1043-1056. https://doi.org/10.1016/j.jiproman.2016.05-005
Judith, V. E. (2018). The organization of corporate crime: Introduction to special issue of
administrative sciences. Administrative Sciences, 8(3).
https://doi.org/10.3390/admsci803003
Kanapickienė, R., & Grundienė, Ž. (2015). The model of fraud detection in financial
statements by means of financial ratios. Procedia - Social and Behavioral
Sciences, 213, 321–327. https://doi.org/10.1016/j.sbspro.2015.11.545
Kennedy, E. (2016). Supply chain fraud. Strategic Finance, 97(11), 10.
https://www.proquest.com/openview/c365399b0d52f0ae73e5d4be41894394/1?pq
-origsite=gscholar&cbl=48426
Khan, D. A., & Varma, T. N. (2017). SAP system as vendor fraud detector. SSRN,
https://dx.doi.org/10.2139/ssrn.2968308
Khoo-Lattimore, C., Mura, P., & Yung, R. (2019). The time has come: a systematic
literature review of mixed methods research in tourism, Current Issues in
Tourism, 22, 1531-1550. https://doi.org/10.1080/13683500.2017.1406900
Klein, R. (2015). How to avoid or minimize fraud exposure. CPA Journal, 85, 6.
https://www.questia.com/magazine/1P3-3663040281
110
Knechel, N. (2019). What’s in a sample? why selecting the right research participants
matters. Journal of Emergency Nursing, 3, 332-334.
https://doi.org/10.1016/j.jen.2019.01.020
Kornhaber, R. A., de Jong, A. E. E., & McLean, L. (2015). Rigorous, robust, and
systematic: qualitative research and its contribution to burn care. An integrative
review. Burns, 41, 1619-1626. https://doi.org/10.1016/j.burns.2015.04.007
KPMG. (2017). India fraud survey report, KPMG Forensic, India.
https://www.kpmg.com/in/en/issueandinsights/articlespublications
Kramer, B. (2015). Trust, but verify: Fraud in small businesses. Journal of Small
Business and Enterprise Development, 22, 4-20. https://doi.org/10.1108/JSBED-
08-2012-0097
Kranacher, M. J. (2011). Forensic Accounting and Fraud Examination. John Wiley &
Sons.
Kulikova, L. I., & Sadarova, D. R. (2016). Internal control and compliance-control as
effective methods of management, detection, and prevention of financial
statement fraud. Electronic Business Journal, 15, 254-264. https://electronic-
businessjournal.com/images/2016/5/5.pdf
Kummer, T. F., Singh, K., & Best, P. (2015). The effectiveness of fraud detection
instruments in not-for-profit organizations. Managerial Auditing Journal, 30(4),
435-455. https://doi:org/10.1108/MAJ-08-2014-1083
Kumar, K., Sukanto, B., & Hicks, R. (2018). Employee perceptions of organization
culture with respect to fraud – where to look and what to look for. Pacific
111
Accounting Review, 30, 187-198. https://doi.org/10.1108/PAR-05-2017-0033
Laura, D., Maura, D., Philip, L., & Kathy, M. (2016). Sensitive interviewing in
qualitative research. Research in Nursing & Health, 39(6), 480–490.
https://doi.org/10.1002/nur.21743
Leavy, P. L. (2017). Research design: Quantitative, qualitative, mixed methods, arts-
based, and community-based participatory research approaches. The Guilford
Press.
Leistedt, S. J., & Linkowski, P. (2016). Fraud, individuals, and networks: A
biopsychosocial model of scientific frauds. Science and Justice, 56, 109-112.
https://doi.org/10.1016/j.scijus.2016.01.002
Lenz, P. J., & Graycar, A. (2016). Stealing from the boss: Who is looking? Journal of
Financial Crime, 23, 613-623. https://doi.org/10.1108/JFC-09-2015-0053
Leung, L. (2015). Validity, reliability, and generalizability in qualitative research.
Journal of Family Medicine and Primary Care, 4, 324-327. https://doi.org/10.4103/2249-
4863.161306
Levi, M., & Schuchter, A. (2015). Beyond the fraud triangle: Swiss and Austrian elite
fraudsters. Accounting Forum, 39, 176–187.
https://doi.org/10.1016/j.accfor.2014.12.001
Lim, R. B. T., Cheung, O. N., Tham, D. K. T., La, H. H., Win, T. T., Chan, R., & Wong,
M. L. (2018). Using qualitative and community-based engagement approaches to
gain access and to develop a culturally appropriate STI prevention intervention
for foreign female entertainment workers in Singapore. Globalization and Health,
112
14, 36. https://doi.org/10.1186/s12992-018-0358-5
Lisa, O., & Hermanto, B. (2018). The effect of tax amnesty and taxpayer awareness to
taxpayer compliance with financial condition as intervening variable.
International Research Journal of Management, IT and Social Sciences, 5(2),
227-236. https://sloap.org/journals/index.php/irjmis/article/view/90
Lokanan, M. (2015). Challenges to the fraud triangle: Questions on its usefulness.
Accounting Forum, 3, 1-24. https://doi.org/10.1016/j.accfor.2015.05.002
Lokanan, M. (2018). Informing the Fraud Triangle: Insights from differential association
theory. Journal of Theoretical Accounting Research, 14, 55–98.
https://doi.org/10.25316/IR-2447
Lokanan, M. E. (2017). Theorizing Financial Crimes as Moral Actions. European
Accounting Review, 27, 901-938. https://doi.org/10.1080/09638180.2017.1417144
Lotte, N. A., Mette, J. S., & Kirsten, K. R. (2018). A municipality-based vocational
rehabilitation programme for occupationally marginalized citizens: A study
protocol for a mixed methods study. BMC Health Service Research, 18.
https://doi.org/10.1186/s12913-018-3322-4
Lub, V. (2015). Validity in qualitative evaluation: linking purposes, paradigms, and
perspectives. International Journal of Qualitative Methods, 14(5), 1-8.
https://doi.org/10.1177/1609406915621406
Lysons, K., & Farrington, B. (2016). Procurement and Supply Chain Management (9
th
ed.). Pearson Education Limited
Malterud, K., Siersma, V. D., & Guassora, A. D. (2016). Sample size in qualitative
113
interview studies: Guided by information power. Qualitative Health Research, 26,
1753-1760. https://doi.org/10.1177/1049732315617444
Mangala, D., & Kumari, P. (2017). Auditors’ perceptions of the effectiveness of fraud
prevention and detection methods. Indian Journal of Corporate Governance,
10(2), 118-142. https://doi.org/10.1177/0974686217738683
Mangala, D., & Kumari, P. (2015). Corporate fraud prevention and detection: Revisiting
the literature. Journal of Commerce and Accounting Research, 4, 34-45.
https://ssrn.com/abstract=2678909
Manh, D. T., & Thi, T. H. L. (2018). The effect of internal control on asset
misappropriation: The case of Vietnam. Business & Economic Horizons, 14, 941–
953. https://doi.org/10.15208/beh.2018.64
Maniam, B., & Peters, S. (2016). Corporate fraud and employee theft: impacts and costs
on business. Journal of Business & Behavioral Sciences, 28, 104-117.
http://www.asbbs.org/files/2016/JBBS_28.2
Marshall, C., & Rossman, G. B. (2016). Designing qualitative research (6
th
ed.).
Sage.
Mays, N., & Pope, C. (2019). Quality in qualitative research. Qualitative research in
health care, 211-233. https://doi.org/10.1002/9781119410867.ch15
Mazorodze, A. H., & Buckley, S. (2019). Knowledge management in knowledge-
intensive organizations: Understanding its benefits, processes, infrastructure, and
barriers. South African Journal of Information Management, 1, 1-6.
https://doi.org/10.4102/sajim.v21i1.990
114
McIntosh, M. J., & Morse, J. M. (2015). Situating and constructing diversity in semi-
structured interviews. Global Qualitative Nursing Research, 2, 1–12.
https://doi.org/10.1177/2333393615597674
McMahon, R., Pence, D., Bressler, L., & Bressler, M. S. (2016). New tactics in fighting
financial crimes: Moving beyond the fraud triangle. Journal of Legal, Ethical &
Regulatory Issues, 19, 16–25.
https://www.abacademies.org/articles/jlerivol19number1.pdf"
McNeal, A. (2019). Combating contract and procurement fraud. Journal of Accountancy,
227(2), 24.
https://link.gale.com/apps/doc/A573094308/LT?u=minn4020&sid=LT&xid=f9a9
dde7
McNulty, J., & Akhigbe, A. (2016). What do a bank’s legal expenses reveal about its
internal controls and operational risk? Journal of Financial Stability, 30, 181-191.
https://doi.org/10.1016/j.jfs.2016.10.001
Merriam, S. (2015). Qualitative research: A guide to design and implementation (4th
ed.). Jossey-Bass.
Metcalf, J., & Crawford, K. (2016). Where are human subjects in big data research? The
emerging ethics divide. Big Data & Society, 3, 1-14.
https://doi.org/10.1177/2053951716650211
Mertens, D. M., & Hesse-Biber, S. (2015). Triangulation and mixed methods research.
Journal of Mixed Methods Research, 6(2), 75–79.
https://doi:10.1177/1558689812437100
115
Mike, A. (2017). Observational research, advantages, and disadvantages. Sage
Encyclopedia of Communication Research Methods.
https://doi.org/10.4135/9781483381411.n384
Mikkonen, K., Kyngäs, H., & Kaariainen, M. (2015). Nursing students’ experiences of
the empathy of their teachers: A qualitative study. Advances in Health Sciences
Education, 20, 669-682. https://doi.org/10.1007/s10459-014-9554-0
Milosevic, I., Bass, A. E., & Combs, G. M. (2018). The paradox of knowledge creation in
a high-reliability organization: A case study. Journal of Management, 44, 1174-
1201. https://doi.org/10.1177/0149206315599215
Mir, R. (2018). Embracing qualitative research: An act of strategic essentialism.
Qualitative Research in Organizations and Management, 13, 306-314.
https://doi.org/10.1108/QROM-09-2018-1680
Mishra, R. (2018). Configuration of volume flexibility in Indian manufacturing firms:
evidence from case studies. International Journal of Quality & Reliability
Management, 35(1), 232-265. https://doi.org/10.1108/IJQRM-12-2015-0174
Mishra, S., & Singh, G. (2017). Forensic accounting: An emerging approach to deal with
corporate frauds in India. Global Journal of Enterprise Information System, 9,
104-109. https://doi.org/10.18311/2017/15922
Modell, S. (2015). Theoretical triangulation and pluralism in accounting research: A
critical realist critique. Accounting, Auditing & Accountability Journal, 28, 1138-
1150. https://doi.org/10.1108/AAAJ-10-2014-1841
Moghadam, S., Mohammad, R., & Shiva, E. (2018). Toward developing a framework for
116
conducting case study research. International Journal of Qualitative Methods, 17,
1-10. https://doi.org/10.1177/1609406918817954
Mohajan, H. K. (2018). Qualitative research methodology in social sciences and related
subjects. Journal of Economic Development, Environmental and People, 7(1), 23-
48. https://doi.org/10.1007/s11136-017-1765-4
Mohamed, N., & Handley-Schachelor, M. (2015). Roots of responsibilities to financial
statement fraud control. Procedia Economics and Finance, 28, 46–52.
https://doi.org/10.1016/s2212-5671(15)01080-1
Moorthy, M. K., Seetharaman, A., Jaffar, N., & Foong, Y. P. (2015). Employee
perceptions of workplace theft behavior: A study among supermarket retail
employees in Malaysia. Ethics & Behavior, 25(1), 61–85.
https://doi.org/10.1080/10508422.2014.917416
Morales, J., Gendron, Y., & Guénin-Paracini, H. (2014). The construction of the risky
individual and vigilant organization: a genealogy of the fraud triangle. Accounting
Organizations and Society, 3, 170-194. https://doi.org/10.1016/j.aos.2014.01.006
Morgan, S. J., Pullon, S. R., Macdonald, L. M., McKinlay, E. M., & Gray, B. V. (2017).
Case study observational research: A framework for conducting case study
research where observation data are the focus. Qualitative Health Research, 27,
1060-1068. https://doi.org/10.1177/1049732316649160
Morse, J. M. (2015). Critical analysis of strategies for determining rigor in qualitative
inquiry. Qualitative Health Research, 25, 1212-1222.
https://doi.org/10.1177/1049732315588501
117
Mufutau, G. O., & Mojisola, O. V. (2016). Detection and prevention of contract and
procurement, fraud catalyst to organization profitability. Journal of Business and
Management, 18, 9-14. https://doi.org/10.9790/487X-18120914
Mui, G., & Mailley, J. (2015). A tale of two triangles: comparing the fraud triangle with
criminology’s crime triangle. Accounting Research Journal, 28, 45-58.
https://doi.org/10.1108/ARJ-10-2014-0092
Münch, O. (2015). First-Time-Right Procurement. Springer Gabler
Nassaji, H. (2015). Qualitative and descriptive research: Data type versus data analysis.
Language Teaching Research, 19, 129-132.
https://doi.org/10.1177/1362168815572747
Nawawi, A., & Ahmad Saiful Azlin, P. S. (2018a). Employee fraud and misconduct:
Empirical evidence from a telecommunication company. Information and
Computer Security, 26, 129-144. https://doi.org/10.1108/ICS-07-2017-0046
Nawawi, A., & Ahmad Saiful Azlin, P. S. (2018b). Internal controls and fraud -empirical
evidence from oil and gas company. Journal of Financial Crime, 25, 891–906.
https://doi.org/10.1108/JFC-07-2017-0067
Neal, J. W., Neal, Z. P., VanDyke, E., & Kornbluh, M. (2015). Expediting the analysis of
qualitative data in evaluation: A procedure for the rapid identification of themes
from audio recordings (RITA). American Journal of Evaluation, 36(1), 118-132.
https://doi:10.1177/1098214014536601
Near, J. P., & Miceli, M. P. (2016). After the wrongdoing: What managers should know
about whistleblowing. Business Horizons, 59(1), 105–114.

