


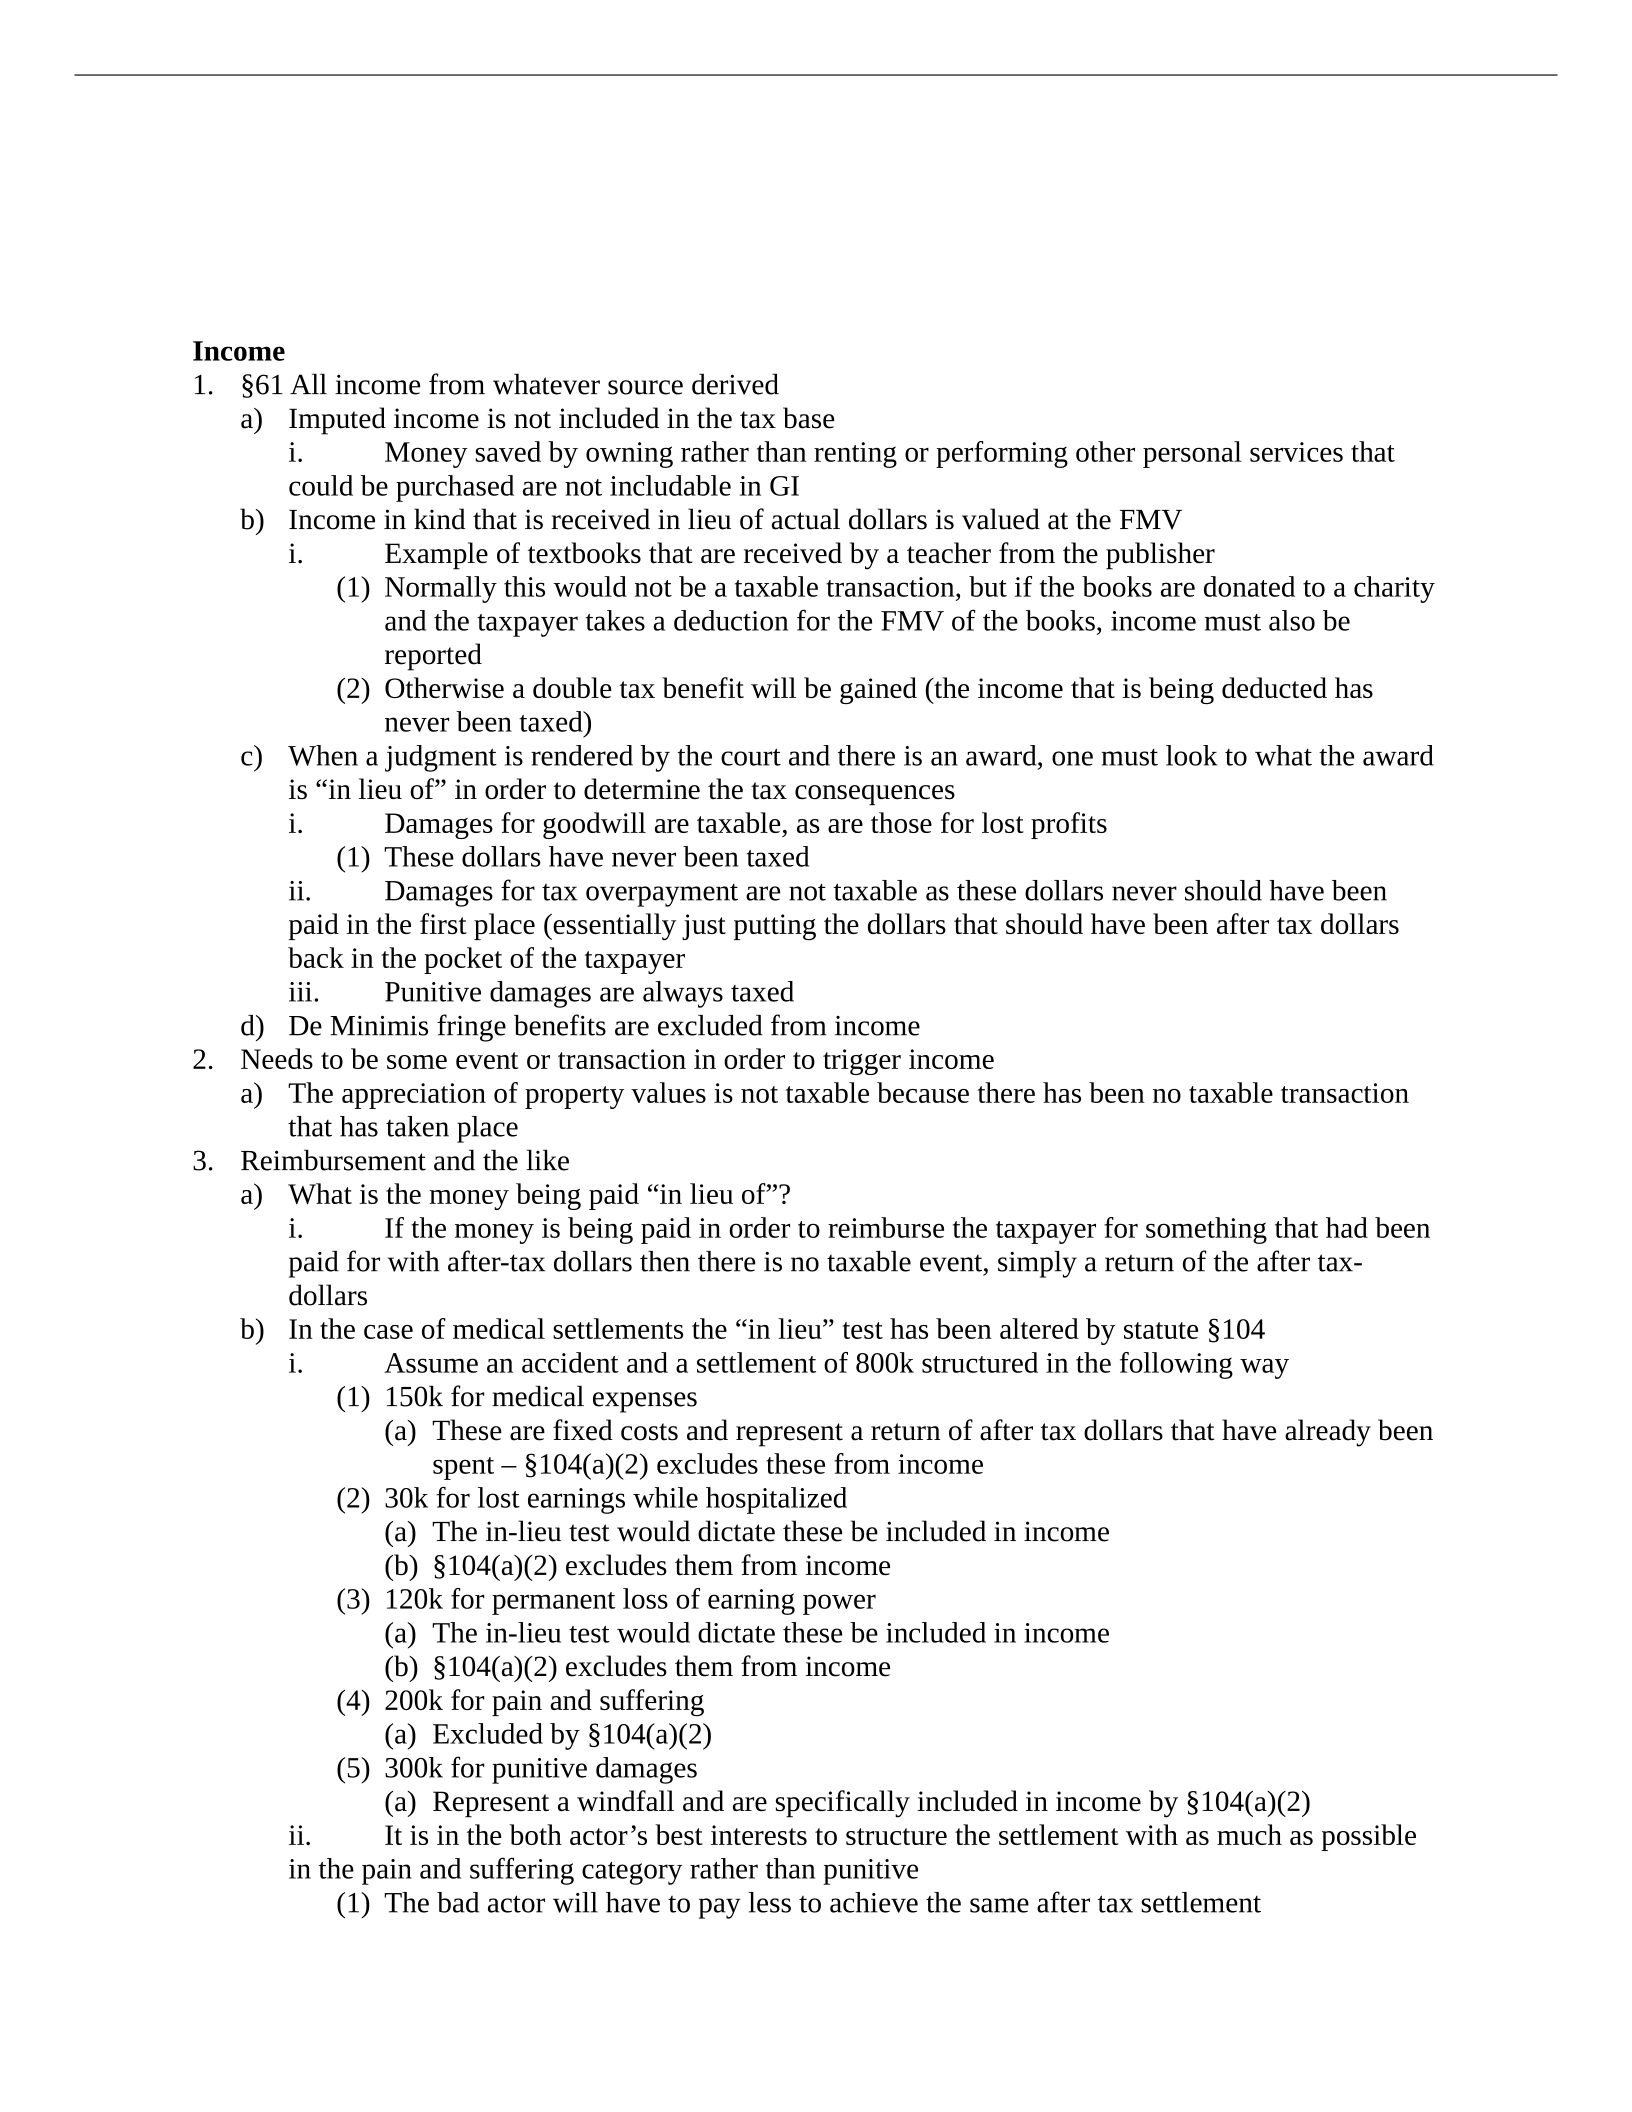
Income
1. §61 All income from whatever source derived
a) Imputed income is not included in the tax base
i. Money saved by owning rather than renting or performing other personal services that
could be purchased are not includable in GI
b) Income in kind that is received in lieu of actual dollars is valued at the FMV
i. Example of textbooks that are received by a teacher from the publisher
(1) Normally this would not be a taxable transaction, but if the books are donated to a charity
and the taxpayer takes a deduction for the FMV of the books, income must also be
reported
(2) Otherwise a double tax benefit will be gained (the income that is being deducted has
never been taxed)
c) When a judgment is rendered by the court and there is an award, one must look to what the award
is “in lieu of” in order to determine the tax consequences
i. Damages for goodwill are taxable, as are those for lost profits
(1) These dollars have never been taxed
ii. Damages for tax overpayment are not taxable as these dollars never should have been
paid in the first place (essentially just putting the dollars that should have been after tax dollars
back in the pocket of the taxpayer
iii. Punitive damages are always taxed
d) De Minimis fringe benefits are excluded from income
2. Needs to be some event or transaction in order to trigger income
a) The appreciation of property values is not taxable because there has been no taxable transaction
that has taken place
3. Reimbursement and the like
a) What is the money being paid “in lieu of”?
i. If the money is being paid in order to reimburse the taxpayer for something that had been
paid for with after-tax dollars then there is no taxable event, simply a return of the after tax-
dollars
b) In the case of medical settlements the “in lieu” test has been altered by statute §104
i. Assume an accident and a settlement of 800k structured in the following way
(1) 150k for medical expenses
(a) These are fixed costs and represent a return of after tax dollars that have already been
spent – §104(a)(2) excludes these from income
(2) 30k for lost earnings while hospitalized
(a) The in-lieu test would dictate these be included in income
(b) §104(a)(2) excludes them from income
(3) 120k for permanent loss of earning power
(a) The in-lieu test would dictate these be included in income
(b) §104(a)(2) excludes them from income
(4) 200k for pain and suffering
(a) Excluded by §104(a)(2)
(5) 300k for punitive damages
(a) Represent a windfall and are specifically included in income by §104(a)(2)
ii. It is in the both actor’s best interests to structure the settlement with as much as possible
in the pain and suffering category rather than punitive
(1) The bad actor will have to pay less to achieve the same after tax settlement
Federal Income Taxation
Fall 2002; Dean White
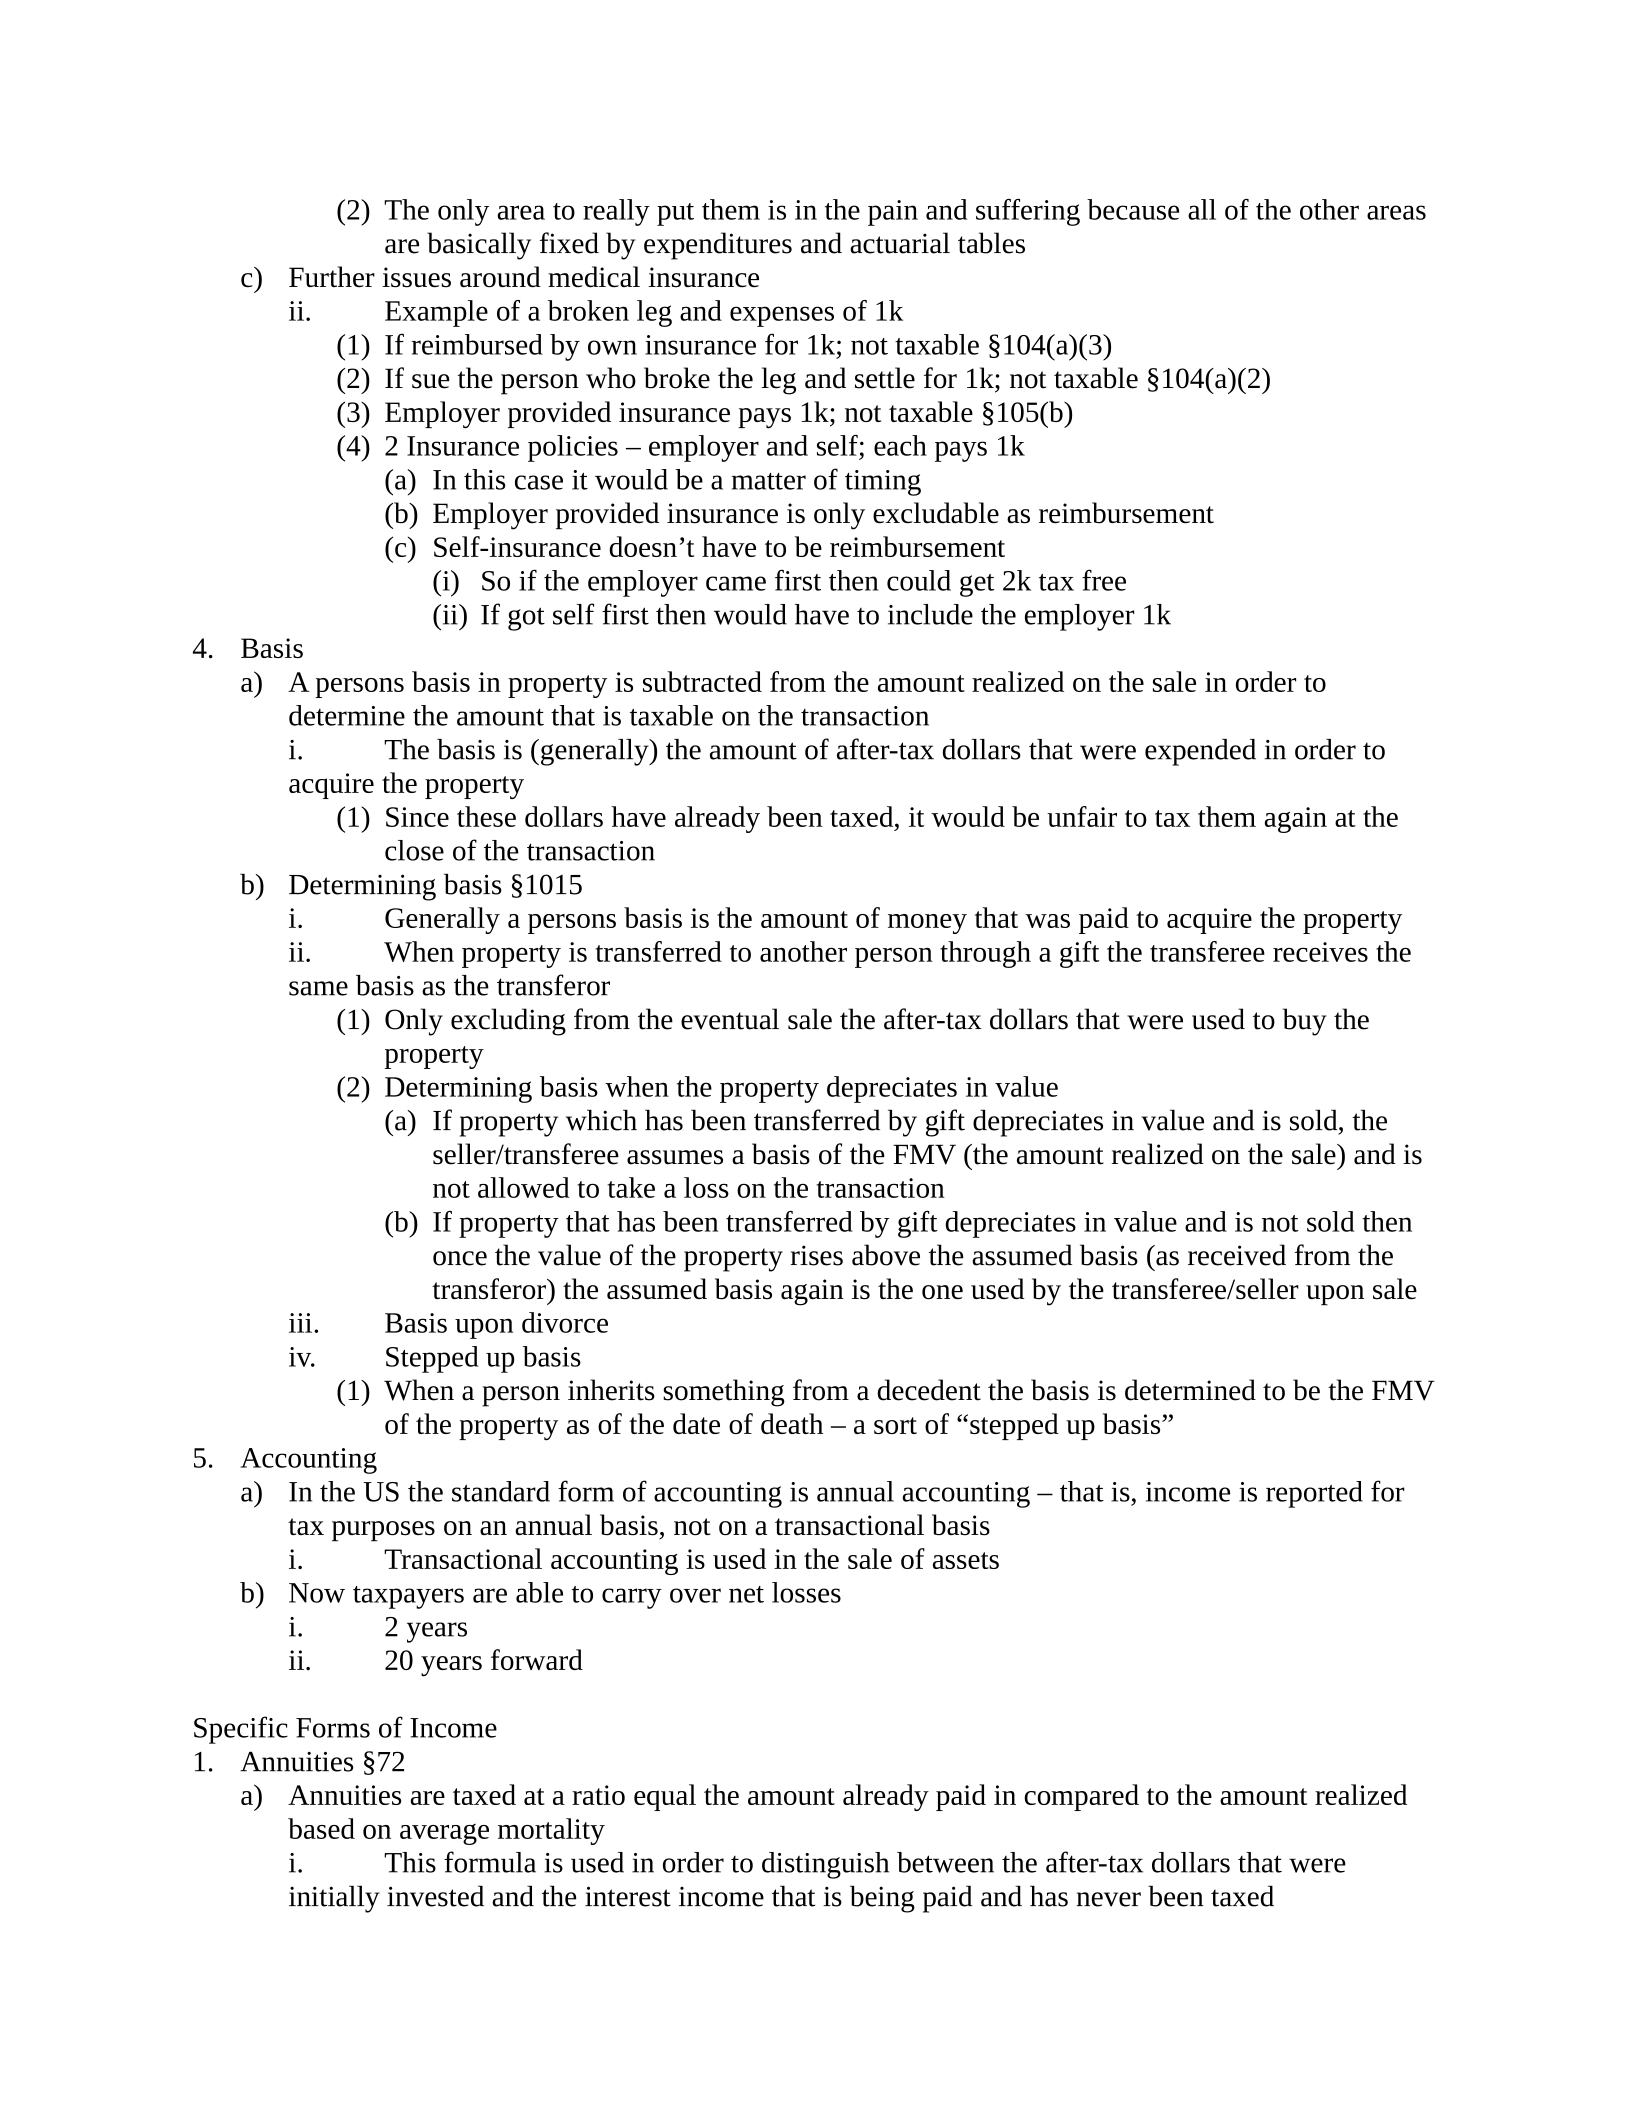
(2) The only area to really put them is in the pain and suffering because all of the other areas
are basically fixed by expenditures and actuarial tables
c) Further issues around medical insurance
ii. Example of a broken leg and expenses of 1k
(1) If reimbursed by own insurance for 1k; not taxable §104(a)(3)
(2) If sue the person who broke the leg and settle for 1k; not taxable §104(a)(2)
(3) Employer provided insurance pays 1k; not taxable §105(b)
(4) 2 Insurance policies – employer and self; each pays 1k
(a) In this case it would be a matter of timing
(b) Employer provided insurance is only excludable as reimbursement
(c) Self-insurance doesn’t have to be reimbursement
(i) So if the employer came first then could get 2k tax free
(ii) If got self first then would have to include the employer 1k
4. Basis
a) A persons basis in property is subtracted from the amount realized on the sale in order to
determine the amount that is taxable on the transaction
i. The basis is (generally) the amount of after-tax dollars that were expended in order to
acquire the property
(1) Since these dollars have already been taxed, it would be unfair to tax them again at the
close of the transaction
b) Determining basis §1015
i. Generally a persons basis is the amount of money that was paid to acquire the property
ii. When property is transferred to another person through a gift the transferee receives the
same basis as the transferor
(1) Only excluding from the eventual sale the after-tax dollars that were used to buy the
property
(2) Determining basis when the property depreciates in value
(a) If property which has been transferred by gift depreciates in value and is sold, the
seller/transferee assumes a basis of the FMV (the amount realized on the sale) and is
not allowed to take a loss on the transaction
(b) If property that has been transferred by gift depreciates in value and is not sold then
once the value of the property rises above the assumed basis (as received from the
transferor) the assumed basis again is the one used by the transferee/seller upon sale
iii. Basis upon divorce
iv. Stepped up basis
(1) When a person inherits something from a decedent the basis is determined to be the FMV
of the property as of the date of death – a sort of “stepped up basis”
5. Accounting
a) In the US the standard form of accounting is annual accounting – that is, income is reported for
tax purposes on an annual basis, not on a transactional basis
i. Transactional accounting is used in the sale of assets
b) Now taxpayers are able to carry over net losses
i. 2 years
ii. 20 years forward
Specific Forms of Income
1. Annuities §72
a) Annuities are taxed at a ratio equal the amount already paid in compared to the amount realized
based on average mortality
i. This formula is used in order to distinguish between the after-tax dollars that were
initially invested and the interest income that is being paid and has never been taxed
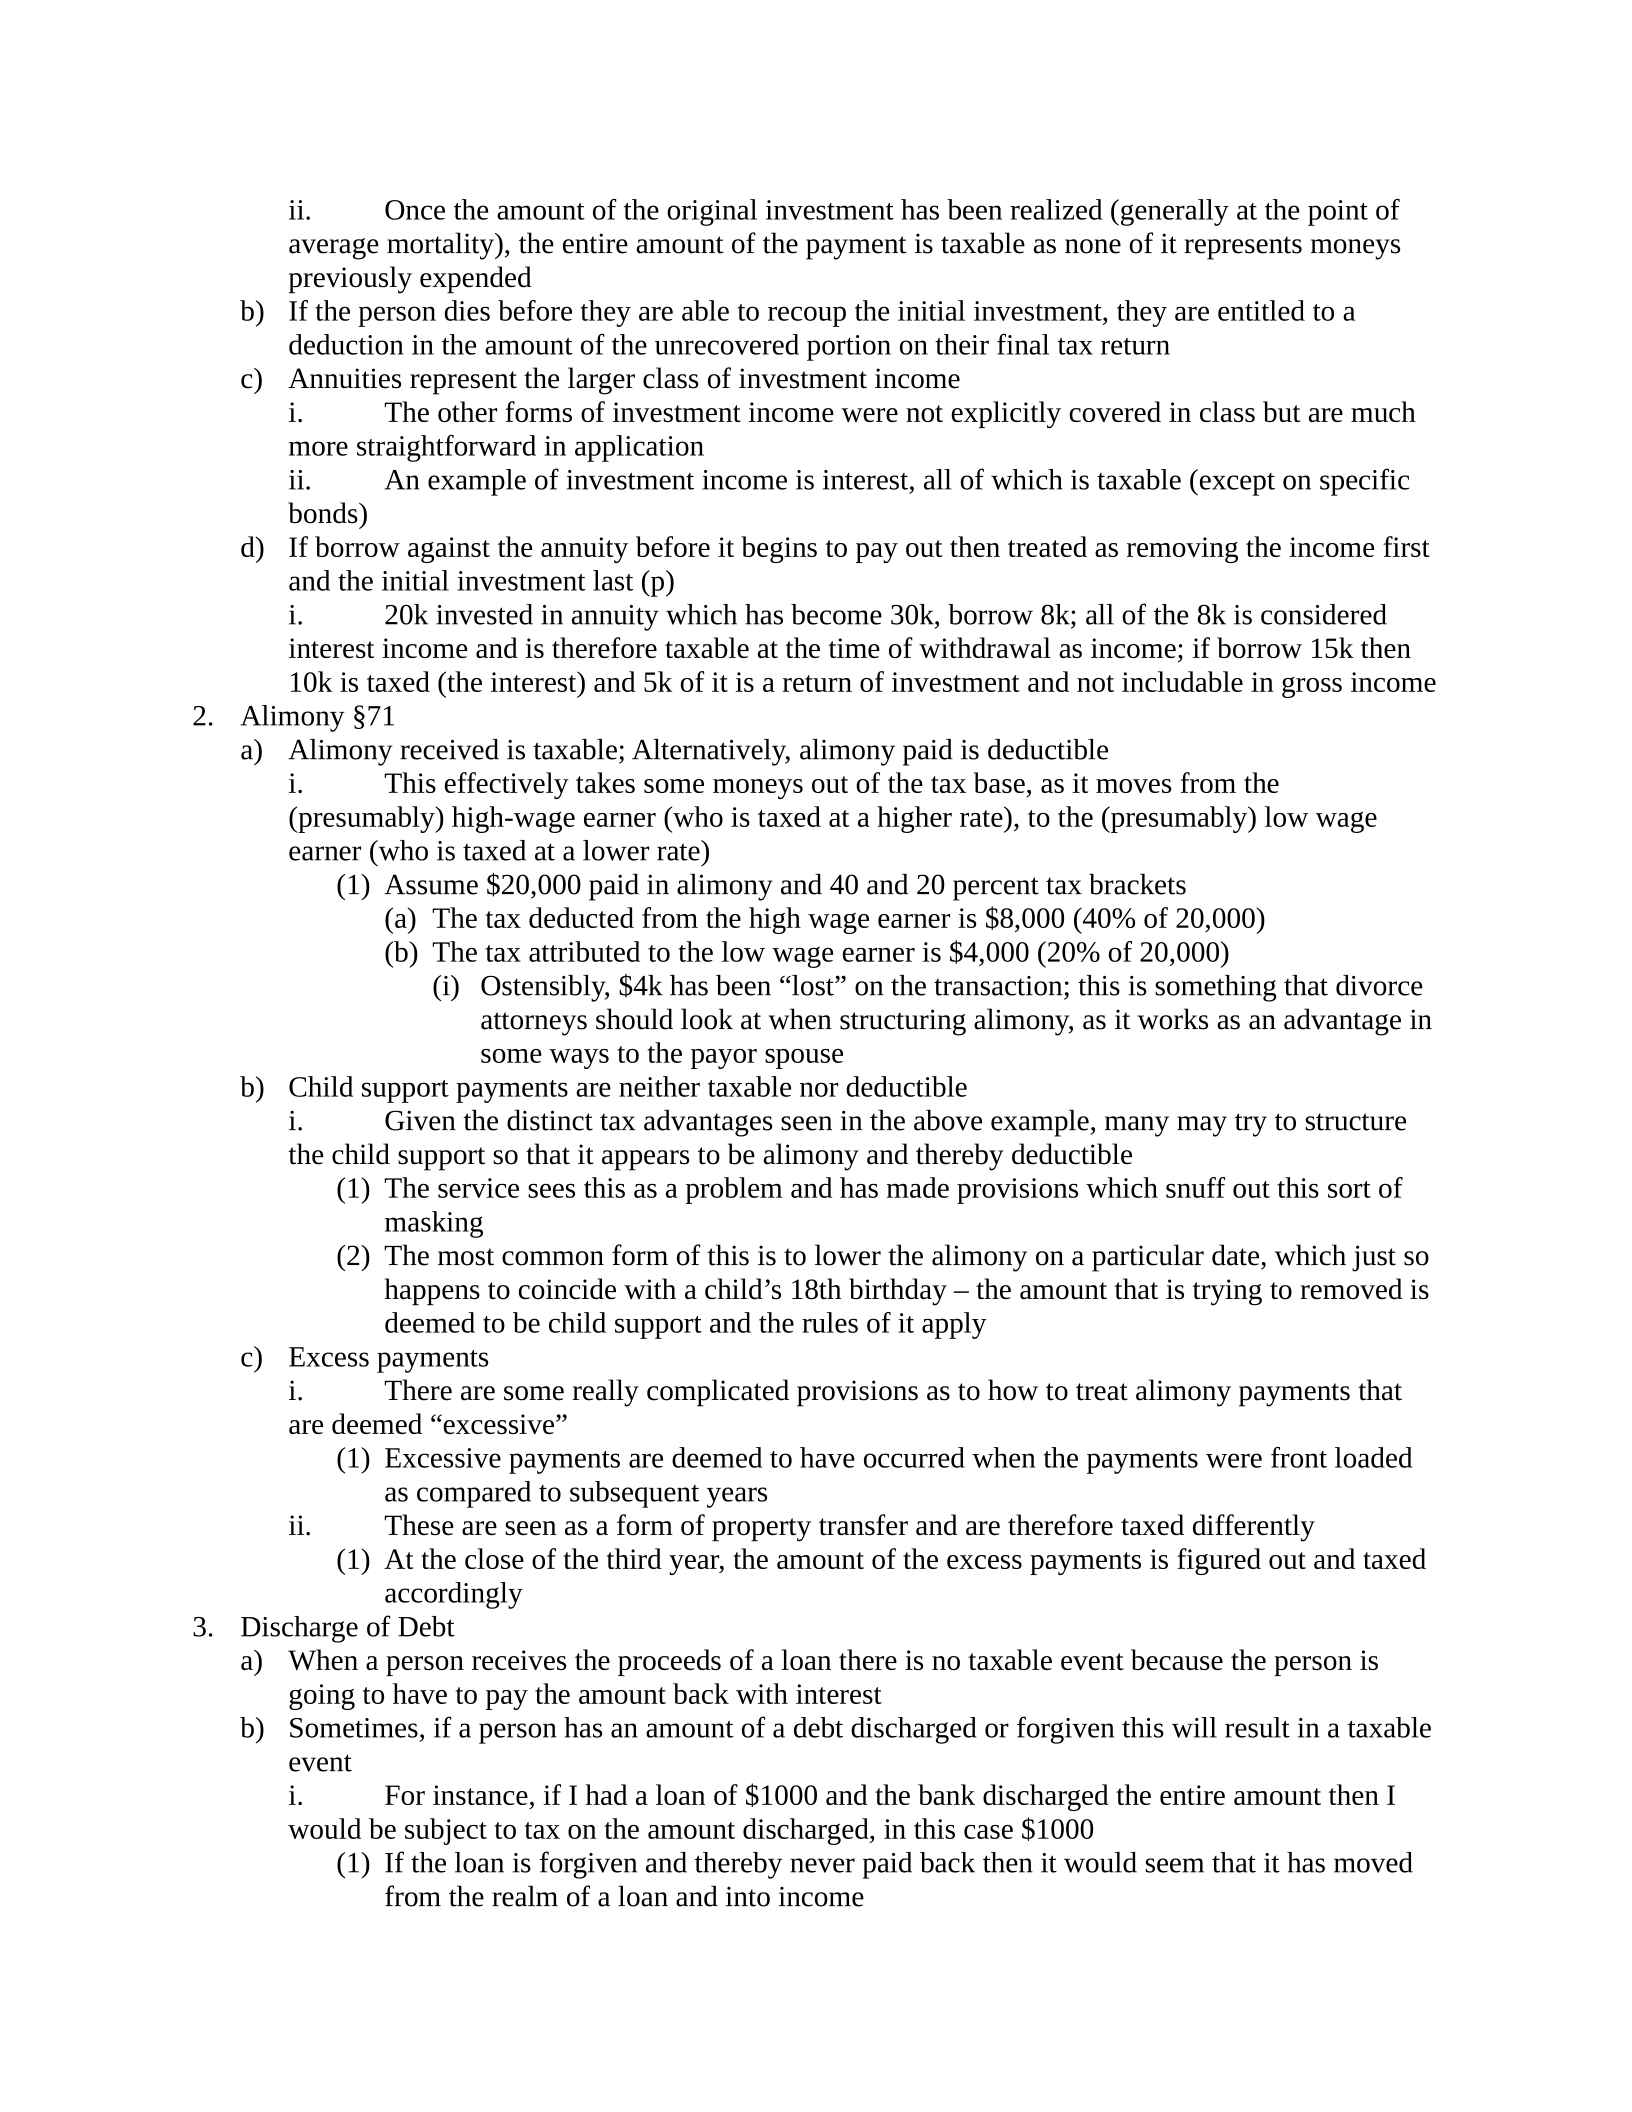
ii. Once the amount of the original investment has been realized (generally at the point of
average mortality), the entire amount of the payment is taxable as none of it represents moneys
previously expended
b) If the person dies before they are able to recoup the initial investment, they are entitled to a
deduction in the amount of the unrecovered portion on their final tax return
c) Annuities represent the larger class of investment income
i. The other forms of investment income were not explicitly covered in class but are much
more straightforward in application
ii. An example of investment income is interest, all of which is taxable (except on specific
bonds)
d) If borrow against the annuity before it begins to pay out then treated as removing the income first
and the initial investment last (p)
i. 20k invested in annuity which has become 30k, borrow 8k; all of the 8k is considered
interest income and is therefore taxable at the time of withdrawal as income; if borrow 15k then
10k is taxed (the interest) and 5k of it is a return of investment and not includable in gross income
2. Alimony §71
a) Alimony received is taxable; Alternatively, alimony paid is deductible
i. This effectively takes some moneys out of the tax base, as it moves from the
(presumably) high-wage earner (who is taxed at a higher rate), to the (presumably) low wage
earner (who is taxed at a lower rate)
(1) Assume $20,000 paid in alimony and 40 and 20 percent tax brackets
(a) The tax deducted from the high wage earner is $8,000 (40% of 20,000)
(b) The tax attributed to the low wage earner is $4,000 (20% of 20,000)
(i) Ostensibly, $4k has been “lost” on the transaction; this is something that divorce
attorneys should look at when structuring alimony, as it works as an advantage in
some ways to the payor spouse
b) Child support payments are neither taxable nor deductible
i. Given the distinct tax advantages seen in the above example, many may try to structure
the child support so that it appears to be alimony and thereby deductible
(1) The service sees this as a problem and has made provisions which snuff out this sort of
masking
(2) The most common form of this is to lower the alimony on a particular date, which just so
happens to coincide with a child’s 18th birthday – the amount that is trying to removed is
deemed to be child support and the rules of it apply
c) Excess payments
i. There are some really complicated provisions as to how to treat alimony payments that
are deemed “excessive”
(1) Excessive payments are deemed to have occurred when the payments were front loaded
as compared to subsequent years
ii. These are seen as a form of property transfer and are therefore taxed differently
(1) At the close of the third year, the amount of the excess payments is figured out and taxed
accordingly
3. Discharge of Debt
a) When a person receives the proceeds of a loan there is no taxable event because the person is
going to have to pay the amount back with interest
b) Sometimes, if a person has an amount of a debt discharged or forgiven this will result in a taxable
event
i. For instance, if I had a loan of $1000 and the bank discharged the entire amount then I
would be subject to tax on the amount discharged, in this case $1000
(1) If the loan is forgiven and thereby never paid back then it would seem that it has moved
from the realm of a loan and into income
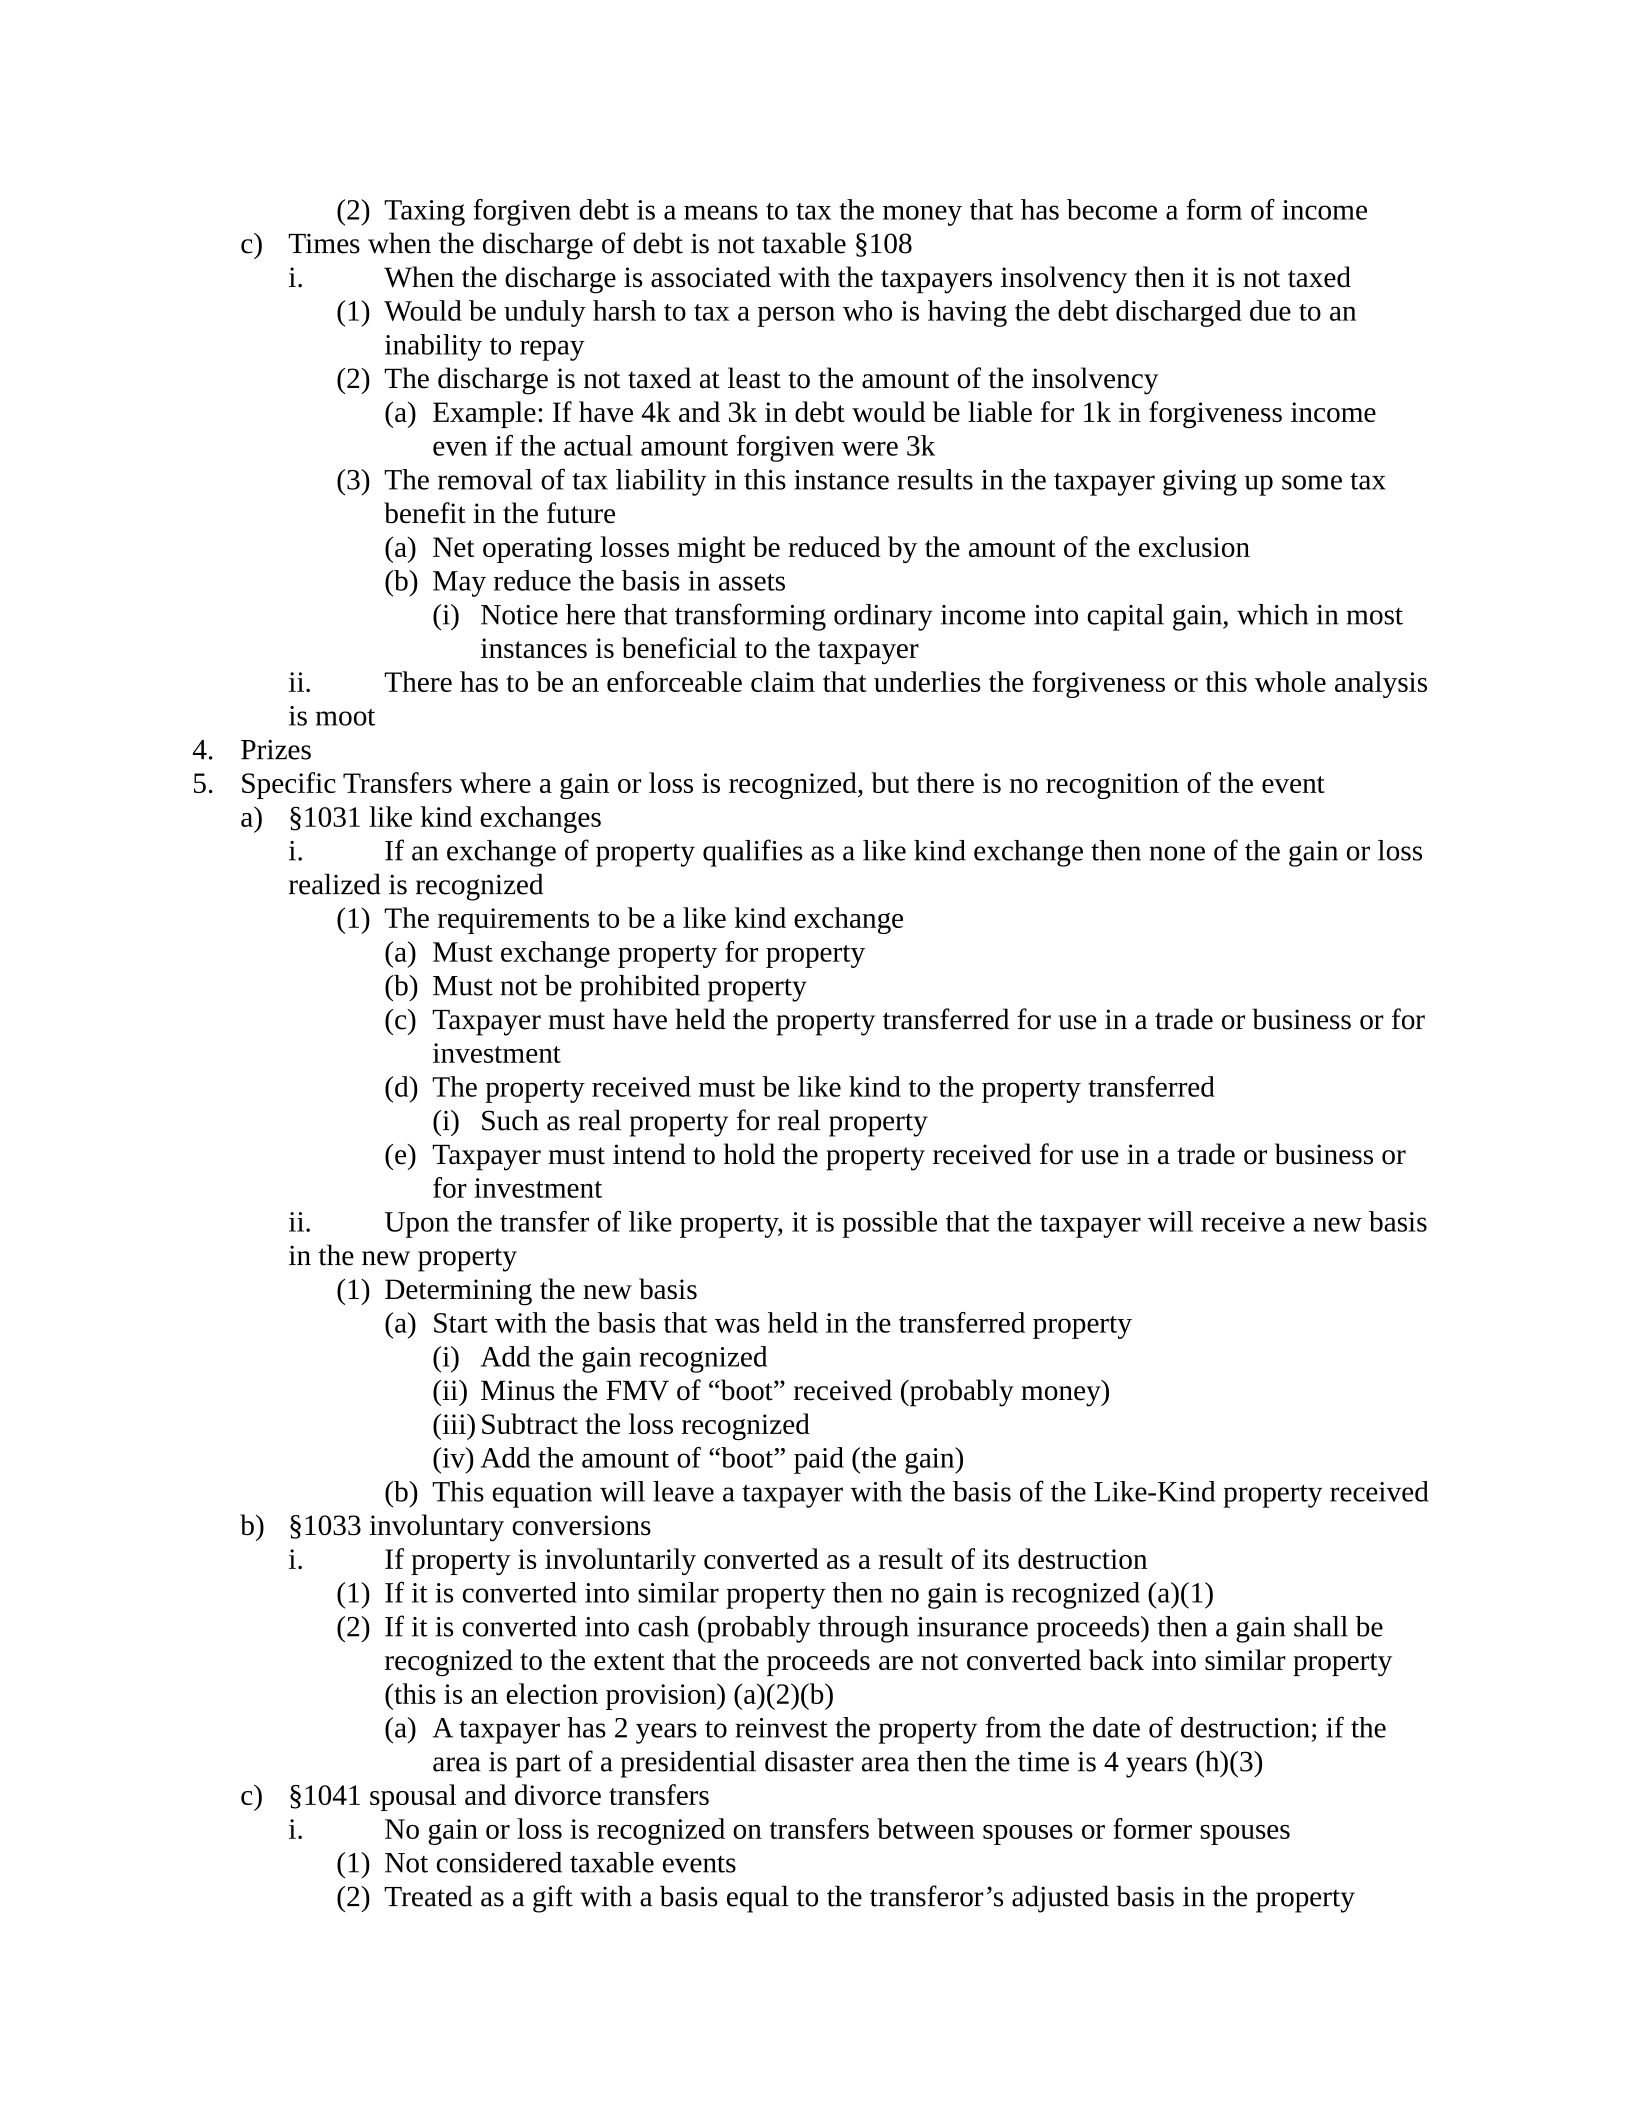
(2) Taxing forgiven debt is a means to tax the money that has become a form of income
c) Times when the discharge of debt is not taxable §108
i. When the discharge is associated with the taxpayers insolvency then it is not taxed
(1) Would be unduly harsh to tax a person who is having the debt discharged due to an
inability to repay
(2) The discharge is not taxed at least to the amount of the insolvency
(a) Example: If have 4k and 3k in debt would be liable for 1k in forgiveness income
even if the actual amount forgiven were 3k
(3) The removal of tax liability in this instance results in the taxpayer giving up some tax
benefit in the future
(a) Net operating losses might be reduced by the amount of the exclusion
(b) May reduce the basis in assets
(i) Notice here that transforming ordinary income into capital gain, which in most
instances is beneficial to the taxpayer
ii. There has to be an enforceable claim that underlies the forgiveness or this whole analysis
is moot
4. Prizes
5. Specific Transfers where a gain or loss is recognized, but there is no recognition of the event
a) §1031 like kind exchanges
i. If an exchange of property qualifies as a like kind exchange then none of the gain or loss
realized is recognized
(1) The requirements to be a like kind exchange
(a) Must exchange property for property
(b) Must not be prohibited property
(c) Taxpayer must have held the property transferred for use in a trade or business or for
investment
(d) The property received must be like kind to the property transferred
(i) Such as real property for real property
(e) Taxpayer must intend to hold the property received for use in a trade or business or
for investment
ii. Upon the transfer of like property, it is possible that the taxpayer will receive a new basis
in the new property
(1) Determining the new basis
(a) Start with the basis that was held in the transferred property
(i) Add the gain recognized
(ii) Minus the FMV of “boot” received (probably money)
(iii) Subtract the loss recognized
(iv) Add the amount of “boot” paid (the gain)
(b) This equation will leave a taxpayer with the basis of the Like-Kind property received
b) §1033 involuntary conversions
i. If property is involuntarily converted as a result of its destruction
(1) If it is converted into similar property then no gain is recognized (a)(1)
(2) If it is converted into cash (probably through insurance proceeds) then a gain shall be
recognized to the extent that the proceeds are not converted back into similar property
(this is an election provision) (a)(2)(b)
(a) A taxpayer has 2 years to reinvest the property from the date of destruction; if the
area is part of a presidential disaster area then the time is 4 years (h)(3)
c) §1041 spousal and divorce transfers
i. No gain or loss is recognized on transfers between spouses or former spouses
(1) Not considered taxable events
(2) Treated as a gift with a basis equal to the transferor’s adjusted basis in the property
ii. If between former spouses, must be incident to divorce
(1) Within 1 year after the dissolution or related to the cessation of the marriage
Exclusions
1. Insurance Premiums
2. Meals and Lodging §119
a) In order to qualify under the exclusion rule of §119 a 3 part test must be satisfied
i. Meals must be provided for the convenience of the employer and be for the benefit of the
employer
(1) Must be a substantial non-compensatory business reason for supplying them
(2) The most common example is an employee who is on call during meals
(a) When furnished during working hours to have the employee available for emergency
calls is a substantial non-compensatory business reason
(b) If the meal periods occur during peak office hours and meals are provided in order to
keep them short, that qualifies as a substantial non-compensatory business reason
(c) Providing a restaurant worker with a meal at work (during, immediately before or
after) is a substantial non-compensatory business reason
ii. Lodging must be on the business premises, a condition of employment, and for the
benefit of the employer
(1) Generally defined as where the employee works
(a) If the property is nearby, that probably won’t qualify
b) Qualified Campus Housing (the University President exercise)
i. The value of this housing is excluded, but amounts in excess of the lesser of
(1) 5% of the appraised value of the home; or
(2) The average rentals paid for similar property in the area minus the amount paid by the
individual employee
(3) Example of a 1M home
(a) 5% of the appraised value is 50k
(b) The average paid by others is 12k per year
(i) This number is generally much more difficult to ascertain
(c) Assume the President pays nothing;12k would not be available for exclusion
3. Inheritance §102
a) Generally GI doesn’t include value of property acquired by gift, bequest, devise or inheritance
i. Estate tax and gift tax on the tranferor are separate from the income tax
b) Income that is derived from an inheritance is taxable as ordinary income
i. Income is not inherited, rather is earned
c) Example: 100k estate with income to W for life and corpus to D
i. The income is taxed as it is earned by W
ii. When the corpus passes to D it passes without tax consequences
iii. If W eats into the corpus, that amount she eats into is not taxed
(1) In the end 100k of the estate will pass without tax consequences to the devisee
4. Gifts §102
a) A gift is a transfer made by a transferor motivated by detached and disinterested generosity
b) Whether or not something is a gift is a question of fact that the SC has said is to be determined by
the fact-finder (Duberstein)
c) If a transfer is deemed to be a gift then it’s value is excluded from income
d) What is the basis in the gift?
i. It would seem to the be basis that the transferor had in the property (if it even has a basis)
e) If something is exchanged for services rendered (even from Grandma) it doesn’t qualify as a gift
and is includable in income
5. Improvements made by lessee during lease term §109
a) GI does not include income (other than rent) that is derived by a lessor through improvement by
the lessee
b) No realizable event takes place
c) This specifically overruled the court in Bruun
Deductions
1. After GI is computed there are certain expenditures which a taxpayer may be able to deduct from the
GI
a) Deductions differ from exclusions in that they actually come off of the GI rather than never
appearing in the GI
i. One based on income (exclusions) the other based on expenditure (deduction)
2. Business Expenses §162
a) Taxpayers may deduct the ordinary and necessary expenses of carrying on a trade or business
i. Ordinary
(1) Expenses can’t be really outrageous for the type of business
ii. Necessary
(1) Needs to be appropriate and helpful to the business activity
(2) Has to be pretty extreme in order to not satisfy this prong of the definition
iii. Expense
(1) Only expenses are deductible, if the expenditure is found to be a capital expenditure, the
amount will be capitalized and recovered over time
iv. Of carrying on
v. A trade or business
(1) Must be engaged in a profit motive enterprise
b) Particular expenses that are allowed by §162
i. A taxpayer’s reasonable expenses of traveling while away from home on business are
deductible
(1) The travel needs to be primarily for business in order to be deductible
(2) Home is defined by the code as a person’s principal place of business
ii. Armed with that definition it makes sense to organize travel while at work in a particular
manner
3. Mixed Business and Personal Expenses
a) Hobby losses - §183
i. If the business doesn’t have a profit motive then the business is considered a hobby and
expenses are only deductible up to the amount of any income – no loss may be derived
(1) There are 9 factors the courts look at to determine if the business is motivated by profit
(a) Manner of operation
(b) Expertise
(c) Time and effort
(d) Assets that increase in value
(e) Similar success
(f) History of income or loss
(g) Amount of occasional profits, if any
(h) Taxpayer’s financial status
(i) Personal pleasure or recreation
(2) There is a presumption that if a business shows a profit in 3 of the previous 5 years
(ending in the taxable year at issue) that the business is motivated by profit
(a) For horse racing and the like the requirement is for 2 profitable years in the past 7
ii. If the business is deemed to be for profit then it may take all of the deductions that are
otherwise allowable
b) If the expense is deemed to be “ordinary and necessary” then the amount still may be limited in
some way – this is done by §274 which attempts to remove the personal aspect of some
expenditures
i. The expense then must pass muster as being connected with the business activity
(1) Direct Relation Test; or
(a) Expectation of deriving income from the expenditure
(b) Active engagement by the taxpayer
(c) Principal character of the event was business
(d) Taxpayer and a business associate must be present
(2) Associated With Test (less stringent)
(a) Must be associated with the active conduct of a trade or business and the
entertainment directly preceded or followed a substantial and bona fide business
discussion
(i) Must show that had a clear business purpose in making the expenditure, such as
to obtain new business or encourage the continuation of an existing business
relationship; and includes those close to the person being entertained such as a
spouse or close family member
(ii) Facts of the individual case will determine if a meeting constitutes a substantial
and bona fide business discussion – and the discussion must be substantial in
relation to the entertainment
ii. If the expense satisfies these requirements then it will be 50% deductible
(1) This is to try and remove the personal aspect of the expenditure and only be able to
deduct the amount that was spent on the entertaining of others
iii. The taxpayer must also be able to substantiate the expenditures
(1) The amount of the expense
(2) The circumstances under which incurred
(3) The business purpose
(4) The business relationship to the taxpayer of the person receiving the benefit of the
expense
4. Personal Expenses
a) Personal business expenses are not deductible
i. Examples of personal business expenses include
(1) The cost of childcare
(2) The cost of clothing
(a) Clothing is deductible if can show
(i) Required as a condition of employment
(ii) Not adaptable to general usage as ordinary clothing
(iii) It is not so worn
(b) If the taxpayer can wear it outside of work then not deductible
(3) Commuting from home is not deductible
(a) If creative then there is a way to make commuting deductible but not generally likely
b) Medical Expenses §104, §213
i. Able to deduct amounts that are spent on medical care that exceed 7.5% of AGI
(1) Example: If have AGI of 100k and medical expenses of 20k
(a) 7.5% of AGI is 7.5k
(b) May deduct 12.5k of the medical expenses
(i) The portion that is in excess of 7.5% of AGI
(2) What if in the next year taxpayer is reimbursed 20k?
(a) The 12.5k that was deducted in the prior year is going to be taxable income
(b) The 7.5k that was not deducted is not included in GI because it is a reimbursement
(3) What if only reimbursed 19k?
(a) 12.5 goes into taxable income to get rid of the double tax benefit
(b) 6.5 is excluded and you’re out 1k
(i) Just as it would have been if all in the same year
(4) What if only reimbursed 11k?
(a) Would have to include the entire 11k
(b) Turns out exactly as it would have if the entire thing had happened in one year
ii. Amounts under 7.5% of AGI are not deductible
c) Local Taxes are deductible
d) Qualified Interest is deductible
i. This generally includes interest from a home mortgage, home equity loan, and interest
from one other residence that is used at least 2 weeks per year for personal purposes
ii. Interest from personal items is not deductible
(1) This includes, auto loans, credit card interest and interest on credit lines incurred for
personal purposes (not secured by the home)
Capital Expenditures §263
1. No deduction is allowed for any amount paid out for new buildings or for permanent improvements
or betterments made to increase the value of any property or for the restoration of property.
Exceptions apply to:
a) Research and development expenditures
b) Soil and water conservation expenditures
c) Expenditures to remove impediments to the handicapped or elderly
d) §179 expenses
i. All of the exceptions are treated as ordinary and necessary expenses and are deductible in
the year expended
2. When an expenditure is made it characterized as either an ordinary or a capital expenditure, and this
at times is a contentious issue, as its classification has bearing on the deductibility of the expense
a) Ordinary expenditures are deducted in the year in which they occur, this has the effect of
lowering GI
b) Capital expenditures are deducted over the useful life of the asset
3. Characterization
a) The courts have employed a number of ways to determine if something is a capital asset
i. Separate asset test: When a separate and distinct asset is created, the amounts expended
in the creation are capital expenditures
ii. Spending money today on an asset that will last longer than today and will be used to
generate income longer than today
iii. Future benefits: Even if a separate asset is not created, if the expenditure creates a more
than insignificant future benefit to the taxpayer then it is a capital asset
b) There has been much discussion over whether something qualifies as an ordinary expense or a
capital expense
c) If a business constructs their own asset, the depreciation and wages that were used in the
construction (which would normally be fully deductible in the year of incurrence) are rolled into
the cost of acquiring the asset, and thus are capital expenditures not deductible in the year
incurred (Idaho Power)
4. Capital Recovery
a) There are different timing schemes for the recovery of the amount expended on capital assets
i. Capital recovery right away occurs in some instances if the property qualifies as §179
property
ii. Capital recovery during ownership
(1) The property is depreciated according to its code mandated useful life – the lengths of
these useful lives has been an area of much change in the past 20 years
(2) The amount of the depreciation is reduced from the basis of the asset and is deducted
against ordinary income
iii. Capital recovery last
(1) This is the case when dealing with raw real property – no depreciation is allowed and the
taxpayer recovers all of their investment as their basis upon the sale or disposition of the
property
Timing of Income
1. The installment Method (§453) is used when dealing with deferred payment sales, which occur when
at least one of the payments occurs in a year after the year of sale
a) The installment method allows taxpayers to spread the recognition of gain from a sale over the
taxable years in which the seller receives payments
i. Under this approach, a portion of each payment is a non-taxable return of basis and the
remaining amount is income from the sale
ii. The payment that is received as part of an installment contract is multiplied by the gross
profit ratio to determine the amount of the payment that is included in GI
(1) GPR is the gross profit (price minus basis) divided by the total contract price (price
minus qualifying debt)
2. Imputed Interest §483
a) When the sales price of property does not include adequate interest (as judged by the service)
then the code imputes the proper amount of interest into the contract using OID procedures
i. This effectively doesn’t allow a seller to include more income as capital gains rather than
ordinary income (which is probably taxed at a higher rate)
ii. Buyers also get less of a basis in the property which has implications when figuring
depreciation and the “losses” that may be generated with them; but on the flip side there is the
chance that they will be able to deduct these amounts as interest payments (provided they qualify
as such)
b) The calculations for reaching this amount are really complicated and not worth going into, so
long as know this concept then should be OK
3. Restricted Property §83 (most likely stock transfers that occur after a set amount of time)
a) In General (a) A taxpayer who receives restricted property as compensation must include the
excess of the value over the amount paid for the property in the first year in which the property is
transferable, or the taxpayer’s rights are not subject to a substantial risk of forfeiture
i. Example: T will receive 1000 shares of stock as compensation on the condition that T
remains with the company for 4 years. After 4 years T must include the value of the stock in GI
(minus basis which is zero in this case) because there is no substantial risk of forfeiture after 4
years
b) Election (b): The taxpayer may elect to include the value of the property at the time it is received
rather than waiting for the restrictions to lapse. If do this then include the value minus what paid
for it. This is the best choice for property that will increase in value up to the time of lapse.
i. Example: T could include 250 shares each year as they are received in income (minus
what paid), then if increase in value when the substantial risk of forfeiture is over there would be
no tax bill if the shares have increased in value
(1) This election must be made within 30 days after the transfer of the property
Powered by TCPDF (www.tcpdf.org)

