


● Business organizations fall into one of two categories:
○ Organizations that are not taxable entities
■ Sole proprietorships, partnerships, limited liability companies (LLCs), and
S corporations
■ Owners are the taxpayers
○ Corporations (regular or C Corporations) that are persons and taxpayers
■ Basically double taxation
● Sole proprietorship: an unincorporated business activity owned by one individual
○ Simplest form of business organization
○ Sole proprietor owns assets and is personally liable
○ ¾ businesses reported to IRS are this
○ Schedule C (Profit or Loss From Business) reports taxable income of Form 1040
■ Part 1: gross income from sale of goods to customers or services
■ Part 2: deductible op exp and cost recovery deductions
○ QBI Deduction: from TCJA 2017 - Section 199A
■ Goal is to lower effective tax rate on business profit earned by
passthrough entities
■ Deductions attributable to trade/business are taken into account for QBI
■ Qualified property is defined as tangible business property subject to
depreciation
■ QBI is reduced by:
● 1) deductible portion of self-employment taxes
● 2) self-employed health insurance deduction
● 3) deduction for contributions to qualified retirement plans
■ Tentative QBI deduction = 20% QBI earned by an individual taxpayer
through a sole proprietorship, partnership, or S corp
■ QBI deduction cannot exceed the greater of:
● 50% of W-2 wages paid by a qualified trade or business
● The sum of 25% of W-2 wages plus 2.5% of the unadjusted basis
of qualified property used by the business
■ Final QBI deduction is subject to an overall limitation based on taxable
income - CANNOT exceed 20% taxable income computer without regard
to the QBI DEDUCTION and ANY NET CAPITAL GAIN
○ Qualified business does not include health, law, accounting, actuarial science,
performing arts, consulting, athletics, financial services, brokerage services,
investing, and investment management
○ QBI excludes investment income, gains, losses, deductions, guaranteed pmts
○ EXEMPTION FOR LOWER INCOME TAXPAYERS
■ If taxpayers 2020 taxable income (prior to QBI deduction) is less than
● 326,000 (married filing jointly)
● 163,300 (all other individuals),
■ The QBI deduction is 20% of business income, including services
Chapter 10 Textbook Notes - The Taxation of Business Income

● 2019 thresholds: $321,400(married jointly) and $160,725(married
separately), and $160,700 (all other individuals)
■ If taxable income exceeds the threshold by less than $100,000 (married)
or $50,000… deduction is phased down by 1% for every dollar above the
threshold
■ WORKSHEET SOLVES THIS IN APPENDIX 10A
○ Sole Proprietorship Losses
■ If operates at a loss and loss is deductible, it carries to Form 1040 to be
deducted against other income
■ Current deduction for the loss may be limited
■ Excess business losses (overall net loss greater than $518,000 for
married jointly or $259,000 all other individuals in 2020 tax year)
● 2019: $510,000 married joint, $255,000 all others
● Excess business losses are nondeductible and carry forward as
NOL deduction (indefinitely at 80% of taxable income each yr)
○ Cash Flow Implications
■ After-tax cash belongs to individual owner
● Can retain for use in business
● Spend for personal consumption
● Invest in other income-producing property (not on schedule C)
○ Dispositions of Business Assets
■ Recognized gains and losses reported on Form 4797 (sale of business
property) NOT on Schedule C
■ Tax consequences are based on rules in ch8 and 9 (1245, 1231, etc)
○ Interest Expense
■ If borrowed money for business purpose, interest paid is deductible on
Schedule C, subject to net business interest limitation (Ch 6)
■ Can’t deduct interest paid on debt incurred to purchase consumer goods
■ If owner fails to service the business debt, they are personally liable and
nonbusiness assets can be taken by creditos
○ Home Office Deduction
■ Home office for sole proprietorship - expenses may qualify as business
deduction (tough requirements)
● Must be exclusively used on a regular basis at the principal place
to meet with patients, clients, customers
● Fixed location used exclusively for administrative/mgt activities
■ Limited to taxable income of the business before deduction (no loss)
○ Unemployment and FICA Tax
■ Employer payroll tax has two components
● Social security of 6.2% and Medicare 1.45% total compensation
● Base for SS was $132,900 (2019) and $137,700(2020)
■ Or years after 2012, employee payroll = employer payroll tax
○ Additional Medicare Tax on Employees
■ If wage exceeds certain threshold (see textbook), extra 0.9% tax

○ Income Tax Withholding on Employee Compensation
■ Employers are required to withhold federal income tax from compensation
paid to their employees
■ Employers remit withholding to US treasury throughout the year
■ Information summarized on W-2
○ Income Tax Consequences to the Employer
■ Business organizations can deduct gross compensation paid to their
employees
○ Self-Employment Tax
■ Sole proprietors themselves are not employees & do not receive a salary
■ Pay federal self-employment (SE) tax on their business income
● Line 31 of Schedule C
■ SS tax 12.4% base amt net earnings & Medicare 2.9% total net earnings
● SS base is 132,900 and 137,700 (2019-2020)
■ SE tax is not progressive
● Partnerships - unincorporated entities created by a contractual agreement among two or
more business associates
○ Forming a Partnership
■ Draft an agreement by the prospective partners (legal contract stipulating
rights and obligations and the % profits/losses allocable to each
■ Gives partners flexibility to customize business arrangement to suit them
■ Oral partnership agreements count as binding, but not as much
○ General partnership: all partners have unlimited personal liability for debts
○ Limited partnership: one or more limited partners are liable for partnership debt
only to the extent of their capital contributions to the partnership
■ Must have at least one general partner
○ Limited Liability Partnerships (LLPs): general partners are not personally liable
for malpractice-related claims from any other partner, but are personally liable for
the debts of the LLP
○ Limited Liability Companies: unincorporated legal entity owned by one or more
members
■ Every member has limited liability for LLC’s debts
■ LLC is good: one owner-level tax on income and limited liability for
business debt - an ATTRACTIVE OPTION
○ Tax Basis in Partnership Interests
■ Partnerships are legal entities and accounting entities
■ Equity interest in a partnership is an intangible asset
■ Interests are considered illiquid assets bc it’s hard to dispose of interest
■ Partnerships can borrow money in their own name
■ General partners must contribute funds to generate enough cash to
service debt/ unpaid liabilities
○ Partnership Reporting Requirements
■ Taxable income generated by partnership activities is measured and
characterized @ entity level

■ Items of gross income and deduction relating strictly to business
operations are reported on form 1065
■ Net is reported on line 22 as ordinary income or loss
■ Income is allocated among the partners according to agreement
■ Net profit is taxed directly to the partners; tax rate depends on whether
partner is an individual or corporation
■ Considered a PASSTHROUGH ENTITY
■ Separately stated items on Schedule K retain tax character as they pass
through the partners (gain or loss on securities, non-operations
● Tax Consequences to Partners
○ Distributive Shares and Cash Flows
■ Schedule K-1 details partner’s distributive share of ordinary income and
separately stated items. Tells people where to include on tax return
■ Must pay tax on distributive share of partnership taxable income
○ Guaranteed Payments
■ Given from partnership based on value of work (like salaries)
■ Partnership deducts these payments in computing income
■ Payments do not require FICA payroll tax, no W-2 Form
○ Self-Employment Income
■ Individual general partners are self-employed, so they have SE tax and
medicare tax
○ QBI Deduction and Excess Business Loss Limitation
■ Partners who are not corporations may be eligible
■ Computed by the partner, not the partnership
■ Noncorporate partners must apply excess business loss limitation
■ Limitation is applied by each partner, not by the partnership as a whole
■ Does not affect partner’s basis in their partnership interest
● Adjusting the Basis of a Partnership Interest
○ When a partner is allocated share of partnership income but does not receive
cash distribution, partner makes an additional investment in the partnership
■ Entitled to recover this at some future date
○ When receives a cash distribution, treated as a nontaxable return of the
investment - captured as positive and negative year end adjustments to tax basis
○ Guaranteed payments, self-employment taxes, and QBI deduction have NO
IMPACT ON PARTNER’S BASIS IN THEIR PARTNERSHIP INTEREST
● Basis Limitation on Loss Deductions
○ Partners may deduct their distributive share of partnership losses for the year
■ Must reduce basis in interest by share of losses, (Not below zero)
■ Excess losses not deductible in the current year, carryforward indefinitely
● Subchapter S Corporations
○ Subchapter S corporation: is a corporate entity, organized as such under state
law (before LLCs)
■ Limited liability of their shareholders (creditors have no claim on personal
assets of the shareholders)

○ Subchapter S is a passthrough entity - business income is allocated and taxed
directly to the shareholders - almost identical to partnership rules
○ Income or loss allocated among shareholders based on % ownership of the
corporation’s outstanding stock
● Eligible corporations - 3 statutory requirements
○ Only individuals, estates, certain trusts, and tax-exempt may be shoulders
■ Nonresident aliens cannot be shareholders
○ Number of shareholders is limited to 100. Family may elect for all family
members to be treated as ONE shareholder
○ Corporation can have only a single class of outstanding common stock
■ Cannot include preferred stock in capital structure
○ No statutory limits on S corporation’s invested capital, volume of sales, or
number of employees (can be very large enterprises)
● Subchapter S Election
○ Eligible corporation because S corp by unanimous election of shareholders and
is permanent for the life of the corporation unless majority revokes election
■ Immediately terminated if eligibility is compromised (would be then
subject to corporate income tax & not a passthrough entity)
■ Usually can’t elect again for 5 years
● Tax Basis in S Corporation Stock
○ Initial tax basis in stock = cash + adjusted basis of any property transferred to the
corporation in exchange for the stock
○ Debt is not transferred as personal liability for any shareholder (never changes
basis, even if shareholder has guaranteed the debt
● Tax Consequences to Shareholders
○ S corp issues Schedule K-1 (shareholder’s share of income, credits, deductions,
etc.) to each shareholder
■ Informs the owners of their pro rata share of business income/loss and
any separately stated items
○ Corporate income is taxed at individual rates and shareholders pay the tax (cash
received is irrelevant to determining taxable income)
● QBI Deduction and Excess Business Loss Limitation
○ S corp shareholders may be eligible for QBI, computed by shareholder
○ Excess business loss limitation also applies to each shareholder
● Salary Payments
○ An owner (shareholder) can be an employee of an S corporation
■ Receive salaries as compensation for their services
○ Corporation and employee pay the FICA payroll tax on the salary & corp
withholds federal income tax
■ Issues K-1 and W-2 to shareholder/employee
■ S corp shareholders are NOT self-employed, NO SE TAX
○ Salary payments are generally deductible in computing ordinary income for the
business
■ payroll tax cost of salary payment creates incentive for S corporations to
understate salary payable to shareholders
● Adjusting the Basis of S Corporation Stock
○ Shareholders make positive and negative adjustments to basis by their share of
corporations income or losses for the year
○ Cash distributed by an S corporation to a shareholder is a nontaxable return of
investment that reduces stock basis
○ Basis Limitation on Loss Deductions
■ Losses are currently deductible only to the extent of the owner’s
investment
■ A shareholder can deduct only an amount of a loss that reduces his stock
basis to zero
■ If shareholder has basis in debt obligation, can also deduct loss to reduce
debt basis to zero
■ Investment that can be recovered through tax deductions = equity
investment and investment as a corporate creditor
Chapter 11 Textbook Notes: The Corporate Taxpayer
● Legal Characteristics of Corporations
○ A corporation is an entity formed under state law to conduct a business
enterprise
○ Closely held corporations: privately owned by relatively small number of
shareholders
○ Publicly held corporations: traded on established securities markets (NYSE)
○ Limited liability of shareholders: rights of corporate creditors extend only to
corporate assets and not to personal assets of the owners
○ Unlimited life: corporations are persons and separate/distinct from their owners -
so legal existence is not affected by changes in shareholders
○ Free transferability: stock in publicly held corporations is a highly liquid assets, so
they have access to millions of potential investors
■ May not be there in closely held corporations
■ Buy-sell agreement: may prohibit the owner from disposing of the stock
without approval of other shareholders, or may restrict from transferring to
anyone but current corporation shareholders
○ Centralized management: corporation is not directly managed by its owners -
managerial decisions are made by board of directors appointed by and acting on
behalf of the shareholders and by the officers hired by the board of directors
■ Shareholders of closely held corporations usually serve on the board and
are employed as corporate officers
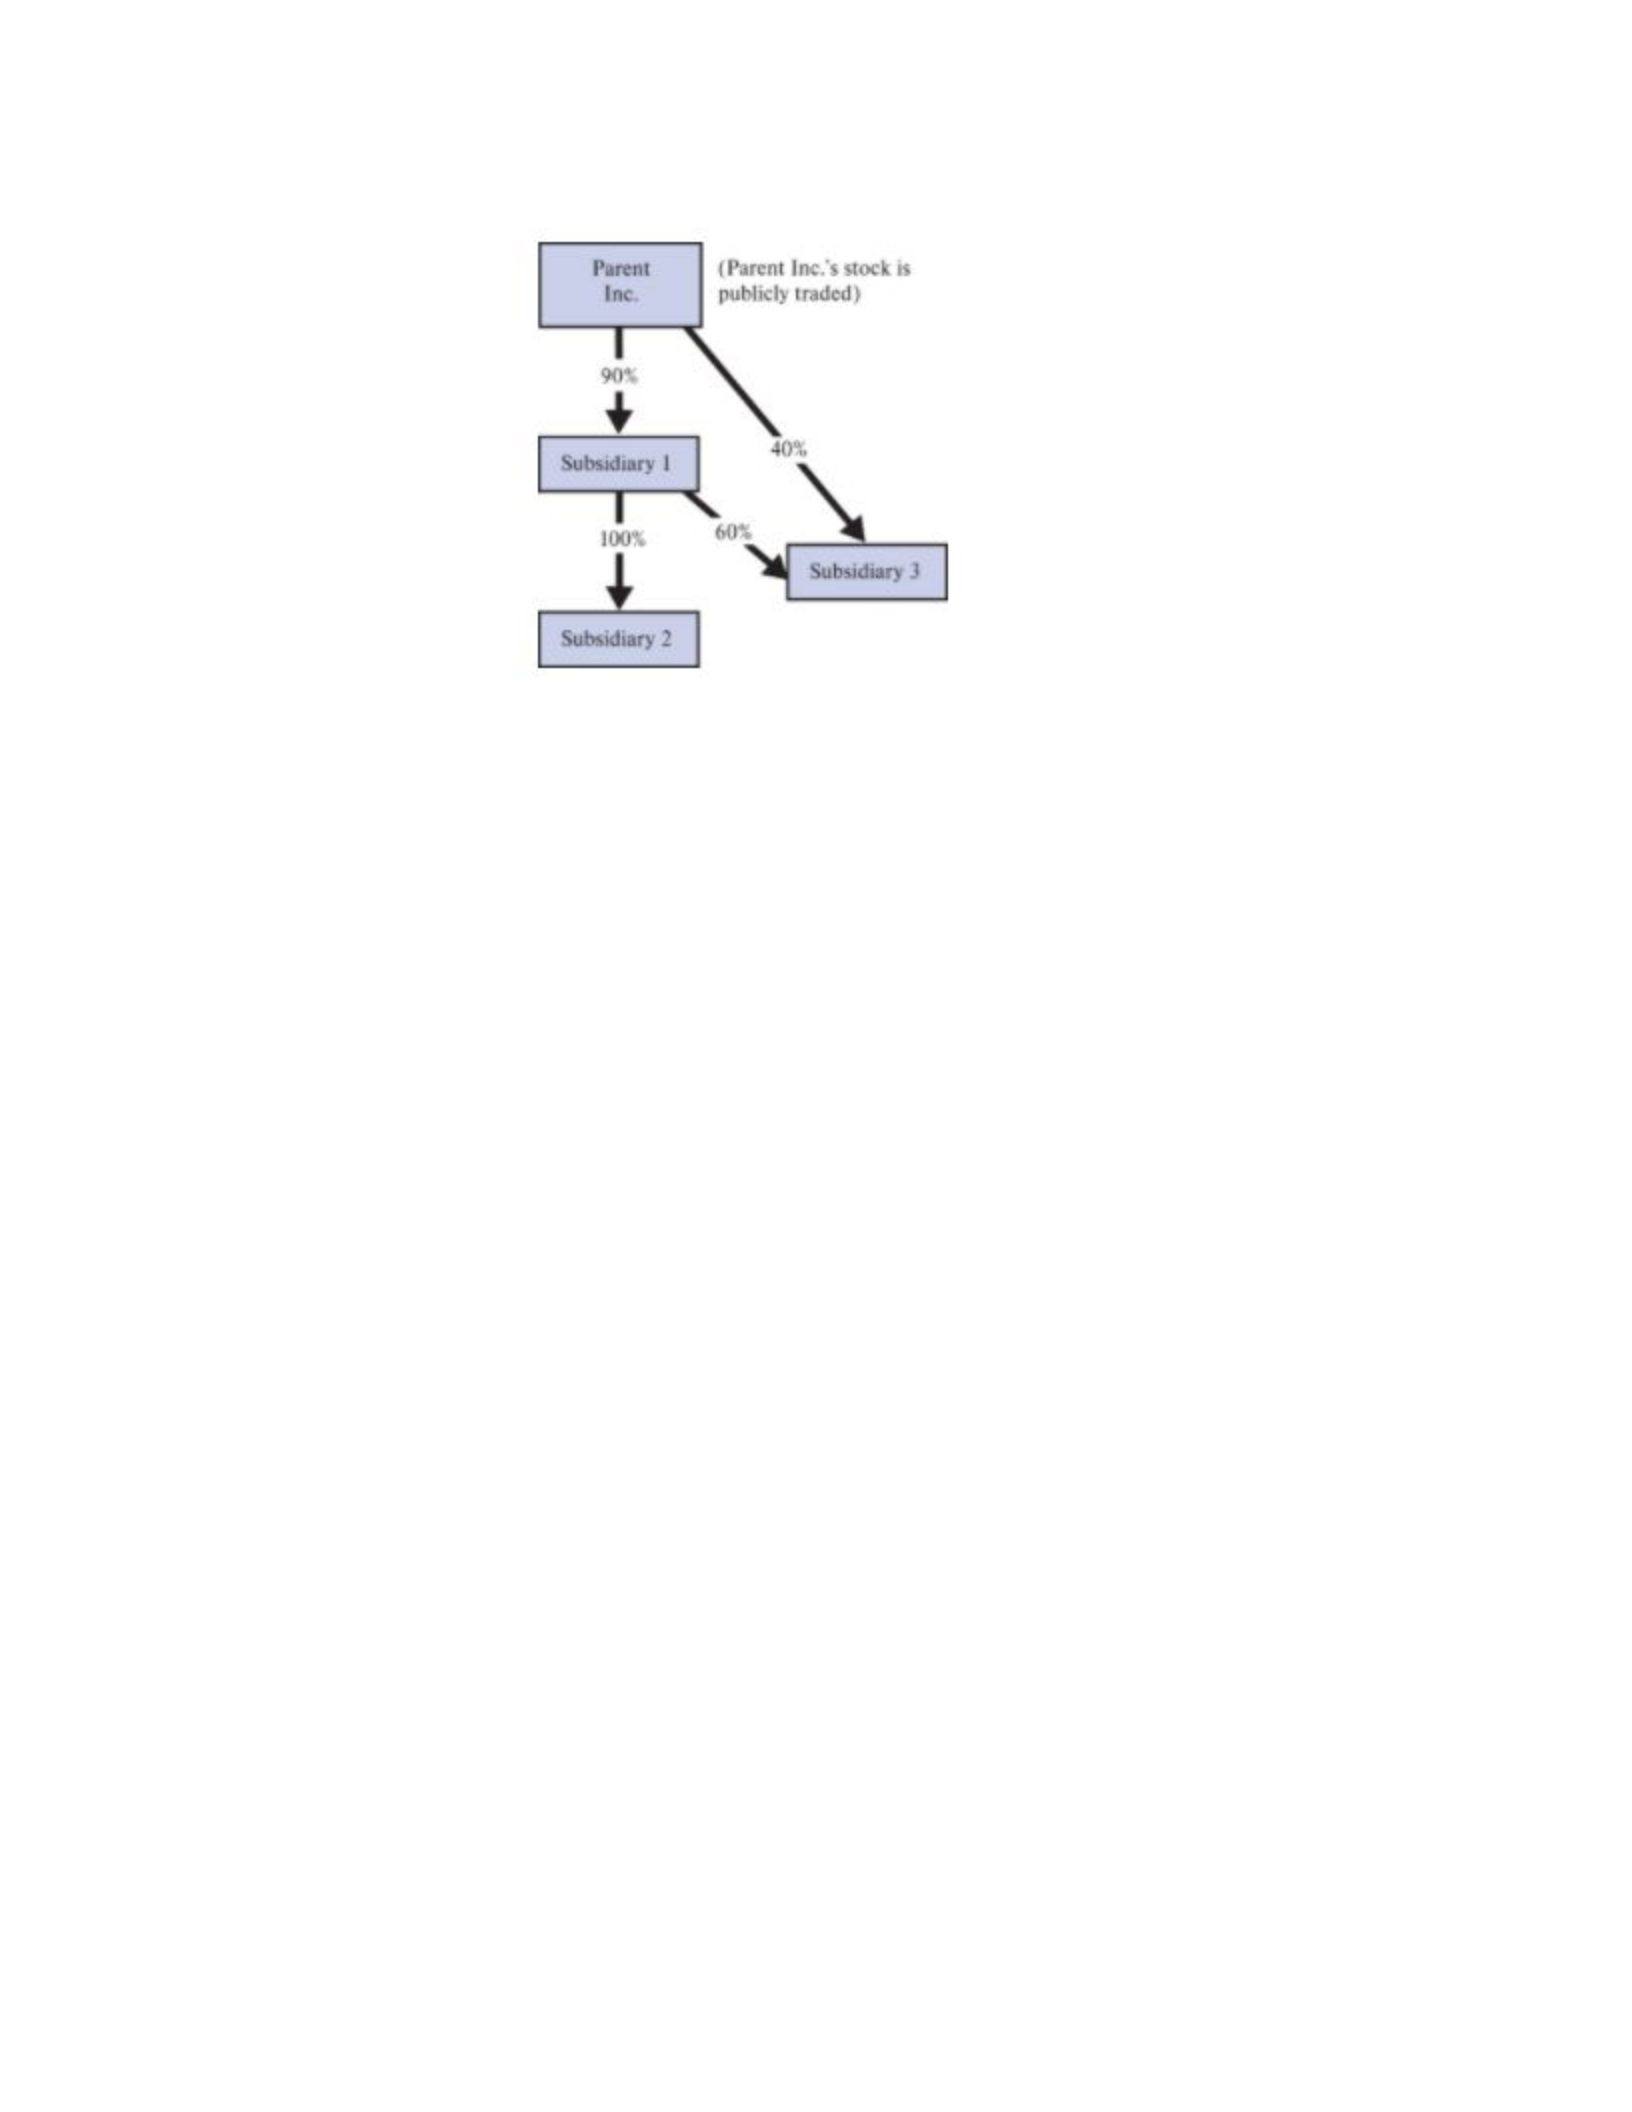
○ Affiliated group: consist of a parent corporation that directly owns 80% or more of
at least one subsidiary corporation plus all other subsidiaries that are 80% owned
within the group
■ Only taxable domestic corporations can be included in affiliated group
■
■ Tax law treats affiliated entities as one entity (consolidated tax return)
■ Major advantage = net loss generated by one corporate member can
offset the taxable income generated by other members
● Nonprofit Corporations: usually nontaxable entities
○ Any corporation formed exclusively for “religious, charitable, scientific, testing for
public safety, literary, or educational purposes, or to foster national or
international amateur sports competition” is exempt from federal income taxation
■ Tax-exempt organization that conducts a profitable sideline activity
unrelated to its philanthropic purpose may be liable for corporate tax on
unrelated business taxable income
○ TCJA enacted two new excise taxes that apply to certain tax-exempt
organizations for tax years beginning after 12/31/17.
■ Excise tax of 1.4% on net investment income of certain private colleges
● Only to institutions with at least 500 students and at least
$500,000 of assets per student
■ Tax-exempt organization is now subject to corporate income tax on
compensation in excess of $1 million paid to its five highest compensated
employees
● Computing Corporate Taxable Income
○ Corporations report taxable income and calculate federal tax on that income on
Form 1120
○ Taxable income = gross income - allowable deductions
○ Special rules that apply only to corporate taxpayers:
■ Limitation on deductibility of corporate charitable contributions
● Limited to 10% of taxable income before the deductions
● Contributions in excess of this limit are carried forward
■ Dividends received deduction
● Corporations that receive dividends from other taxable, domestic
corporations are entitled to this deduction
● Noncorporate shareholders are not eligible
● TCJA altered treatment of foreign dividends after 2017
● Dividends received from domestic corps: deduction = % of total
dividends included in gross income
○ If recipient owns < 20%, deduction = 50% dividends rcvd
○ If owns 20-80%, deduction = 65% dividends rcvd
○ If owns >= 80%, deduction = 100% dividends received
○ THIS ONLY APPLIES AFTER 12/31/17, or different #s
○ Reconciling Book Income and Taxable Income
■ Until 2004, reconciliation was on Schedule M-1, Form 1120
■ Schedule M-3 is used for corps with total assets of $10 million or more
● More detailed information
■ M-1 is organized so that unfavorable book/tax differences (that increase
taxable income) are on the left side of the form, and favorable differences
(that decrease taxable income) are on the right side of the form
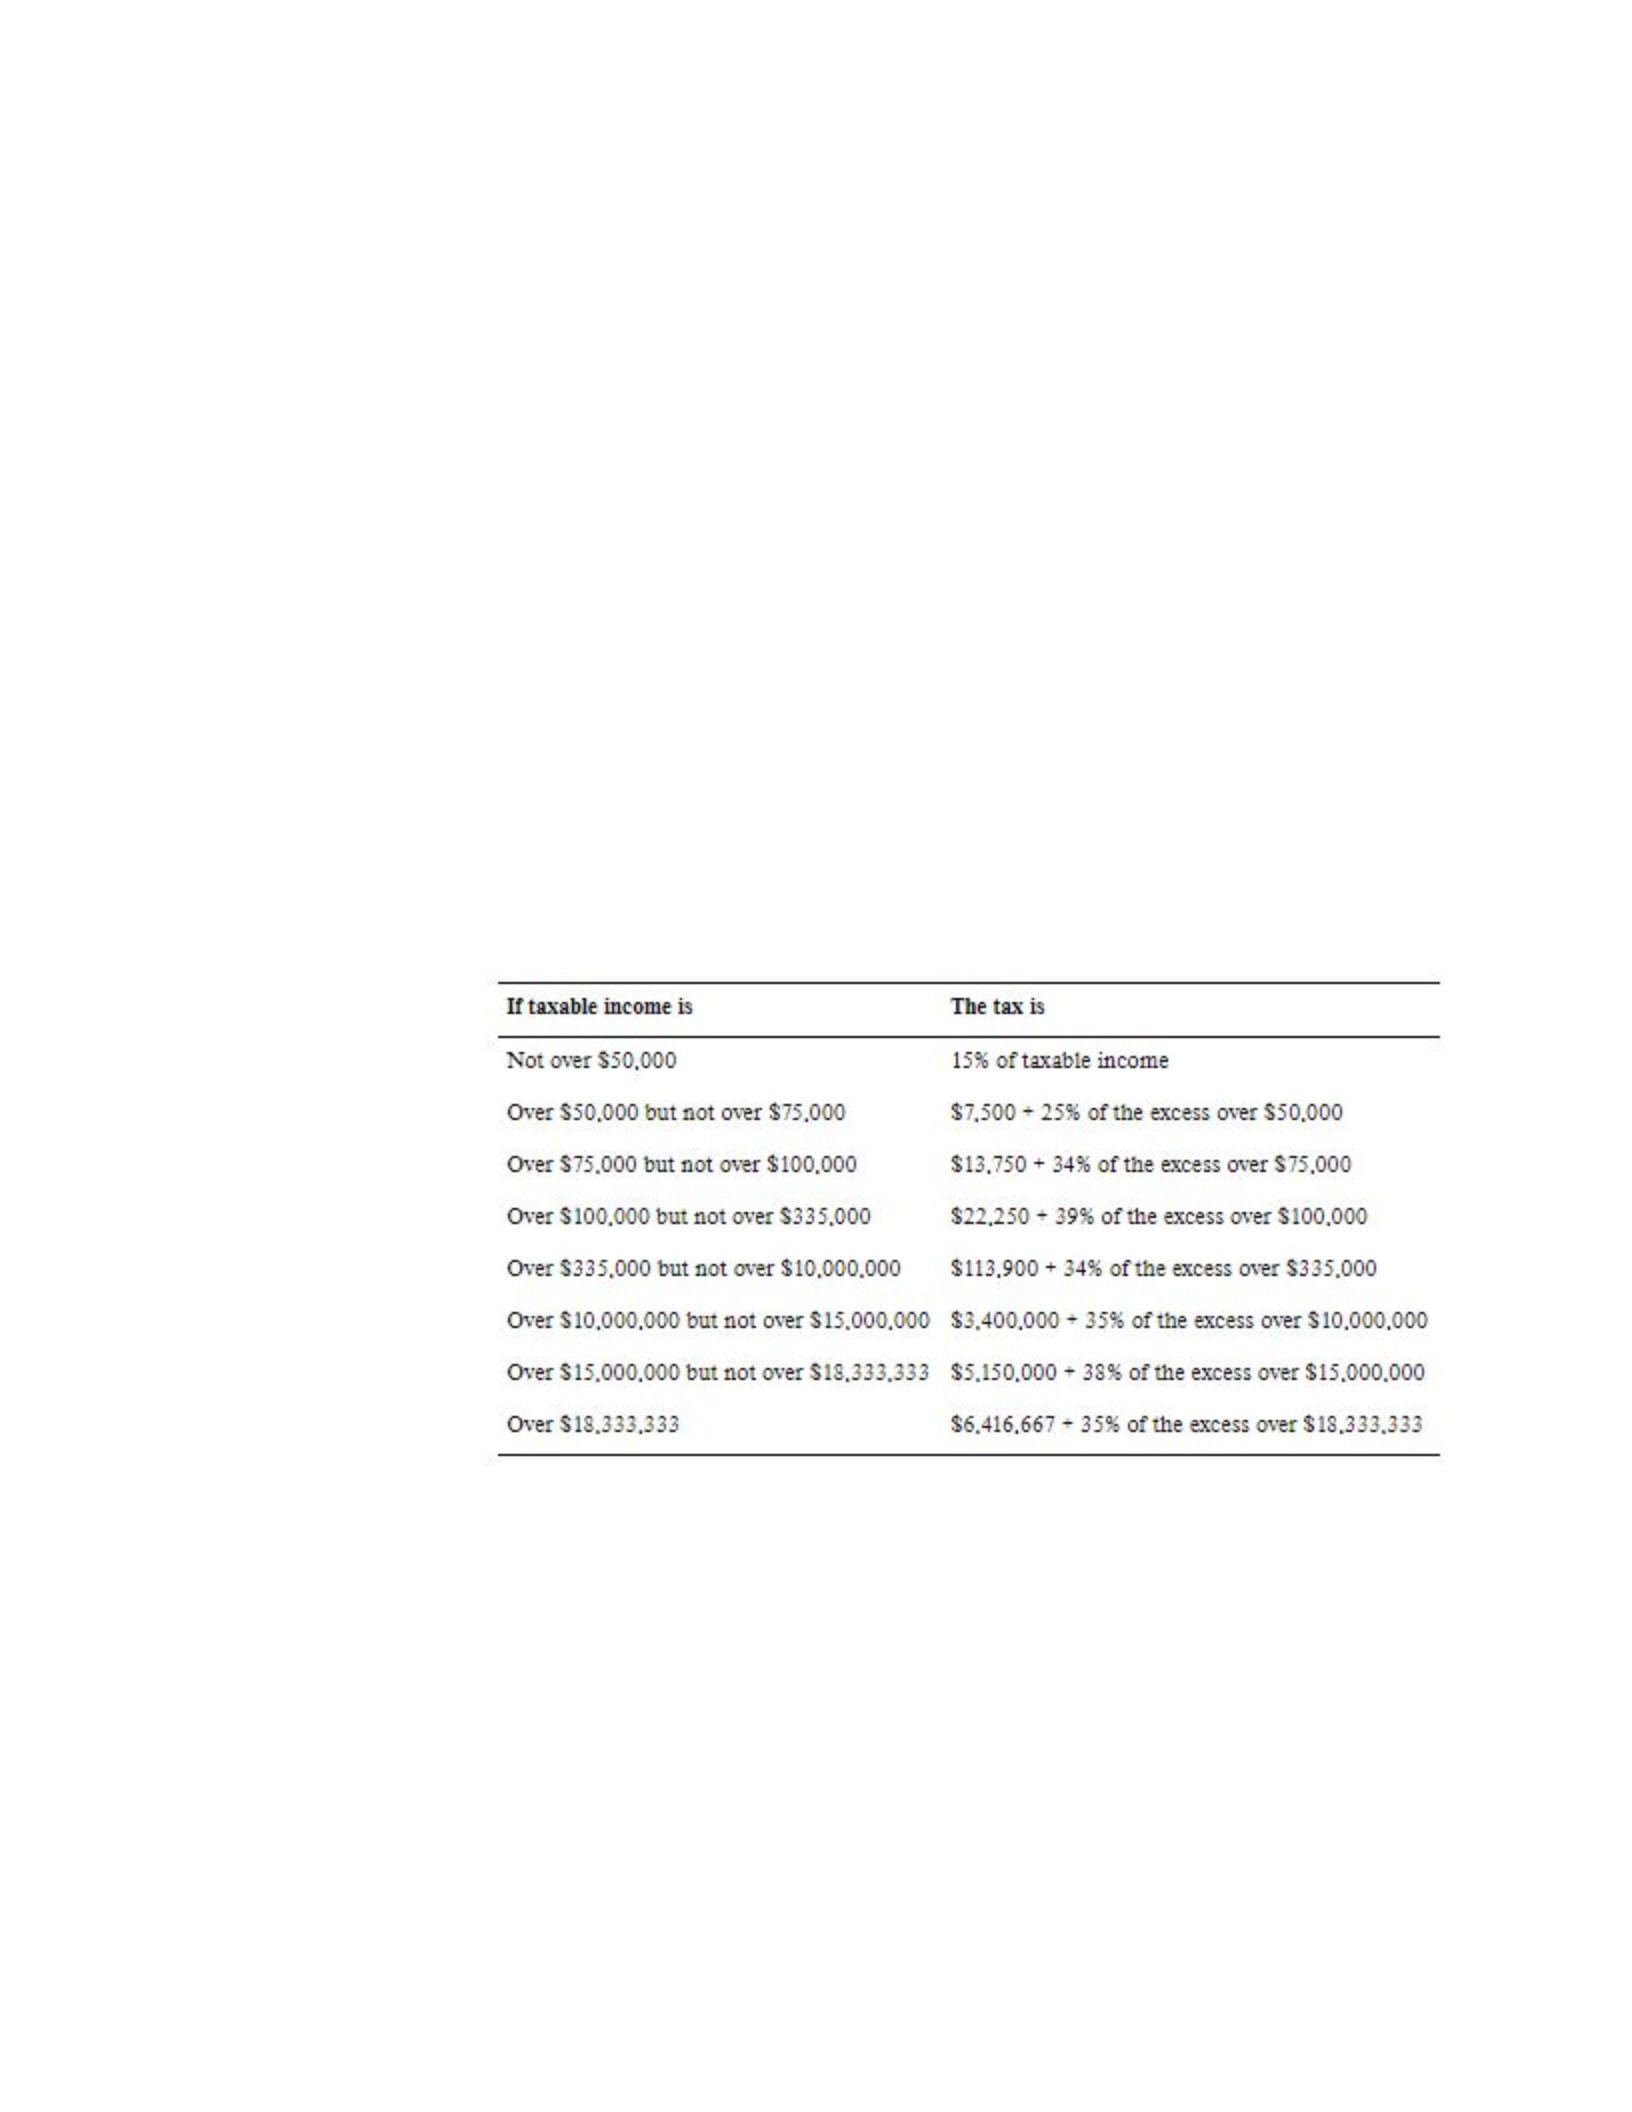
● Computing the Regular Corporate Tax
○ After computing taxable income, calculate the federal income tax on the income
○ Determine the corporation's regular tax.
■ AFTER 12/31/17, there is a FLAT RATE OF 21%
■ BEFORE THAT:
■
● Tax Credits
○ Corporate (or noncorporate) taxpayer’s regular tax is offset by any tax credits for
which taxpayer is eligible
○ Tax credit = direct dollar for dollar reduction in tax liability
■ Value of a credit is greater than the value of a deduction of the same amt
○ Tax credits are generally nonrefundable (can reduce tax to zero but not more)
○ Excess credit can be carried back or forward to reduce tax in a different year
○ Tax credits are equivalent to a preferential tax rate
■ Utilize the character variable to reduce tax liability
○ Instruments of fiscal policy & are enacted by Congress to increase the efficiency
of the tax system as an agent of economic change

○ General business credit = sum of 26 different credits for the tax year
■ Most of those are only available to a small # of businesses
○ Rehabilitation Credit
■ Applies to those who renovate or reconstruct buildings certified as historic
structures by the U.S. Dept of the Interior
■ Credit = 20% of rehabilitation costs of certified historic structure
■ Claimed over a 5 year period beginning in tax year when structure is
placed in service
■ Designed to incentivize urban renewal projects that are financially hard
○ Other popular tax credits: research activities credit, empowerment zone
employment credit, low-income housing credit, tax credit for alternative-fuel
vehicles
○ Minimum Tax Credit
■ Alternative minimum tax (AMT) is a second federal tax system parallel to
the regular one, enacted corporate AMT for political reasons
■ Ensures that every corporation pays a “fair share” of the federal tax
burden
■ AMT is repealed for tax years after 12/31/17 (TCJA)
■ Minimum tax credit = when AMT is paid, and is usable in the future only
against regular tax liability
● Payment and Filing Requirements
○ Corporations must pay federal income tax for the year in 4 installments
■ Each installment is 25% of annual tax & due by 15th of 4th, 6th, 9th and
12th months of the taxable year
■ If you fail to make requirements, incur an underpayment penalty
■ Required installments must total 100% of tax reported on Form 1120
● Safe harbor provision
○ Filing deadlines before 12/31/15: by 15th day of 3rd month following close of
taxable year
○ Filing deadlines after 12/31/15: file by 15th day of 4th month following close of
taxable year (changed from above because of transportation act)
■ Those who file delinquent returns may incur late-filing penalties
■ Must pay any estimated balance due by the initial due date of the return
even if they file an extended tax return
■ If assets > $10 million, must file electronically
● Distributions of Profits to Investors
○ Business profit flowing through to investors as interest is not taxed at the
corporate level but only to the investors
○ Corporate stockholders may receive return on investment in the form of dividends
■ Corporations CANNOT deduct dividend payments in computation of their
taxable income (taxed twice)
■ Non Deductibility of dividend payments creates a bias in favor of debt
financing (a corporation that raises capital by borrowing can deduct the
interest paid on the debt)

● 21% tax rate makes after tax cost of capital for only 79% b4 tax
cost
● Fed govg pays 21% of return on creditors investment
■ Nontax costs associated w debt financing usually outweigh the savings
from the corporate interest deduction
● Alternatives to Double Taxation
○ Treat corporations as passthrough entities by requiring them to allocate income
to their shareholders on an annual basis
■ Shareholders would include share of corporate earnings in gross income
& pay tax accordingly
■ This would be administratively hard (if not impossible) for publicly held
corporations

