


budget’s operating income for actual volume achieved is $38,000, while the static budget’s
operating income is $35,000. What is the flexible budget variance for operating income?
2. Josh Agency's actual operating income for the current year is $25,000. The flexible budget’s
operating income for actual volume achieved is $32,000, while the static budget’s operating
income is $35,000. What is the sales volume variance for operating income?
3. Alex has a material standard of 1 pound per unit of output. Each pound has a standard
price of $26 per pound. During July, Alex paid $132,200 for 4,950 pounds, which they
used to produce 4,700 units.
a. What is the direct materials quantity variance?
b. What is the direct materials price variance?
.
4. Adam has a direct labor standard of 2 hours per unit of output. Each employee has a
standard wage rate of $22.50 per hour. During July, Adam paid $189,500 to employees
for 8,890 hours worked. 4,700 units were produced during July.
a. What is the direct labor rate variance?
b. What is the direct labor efficiency variance?
ACC241 Extra Practice Questions – Chapter 10
1. Ashley Catering reported actual operating income for the current year of $40,000. The flexible
5. The following information describes a company's usage of direct labor in a recent period:
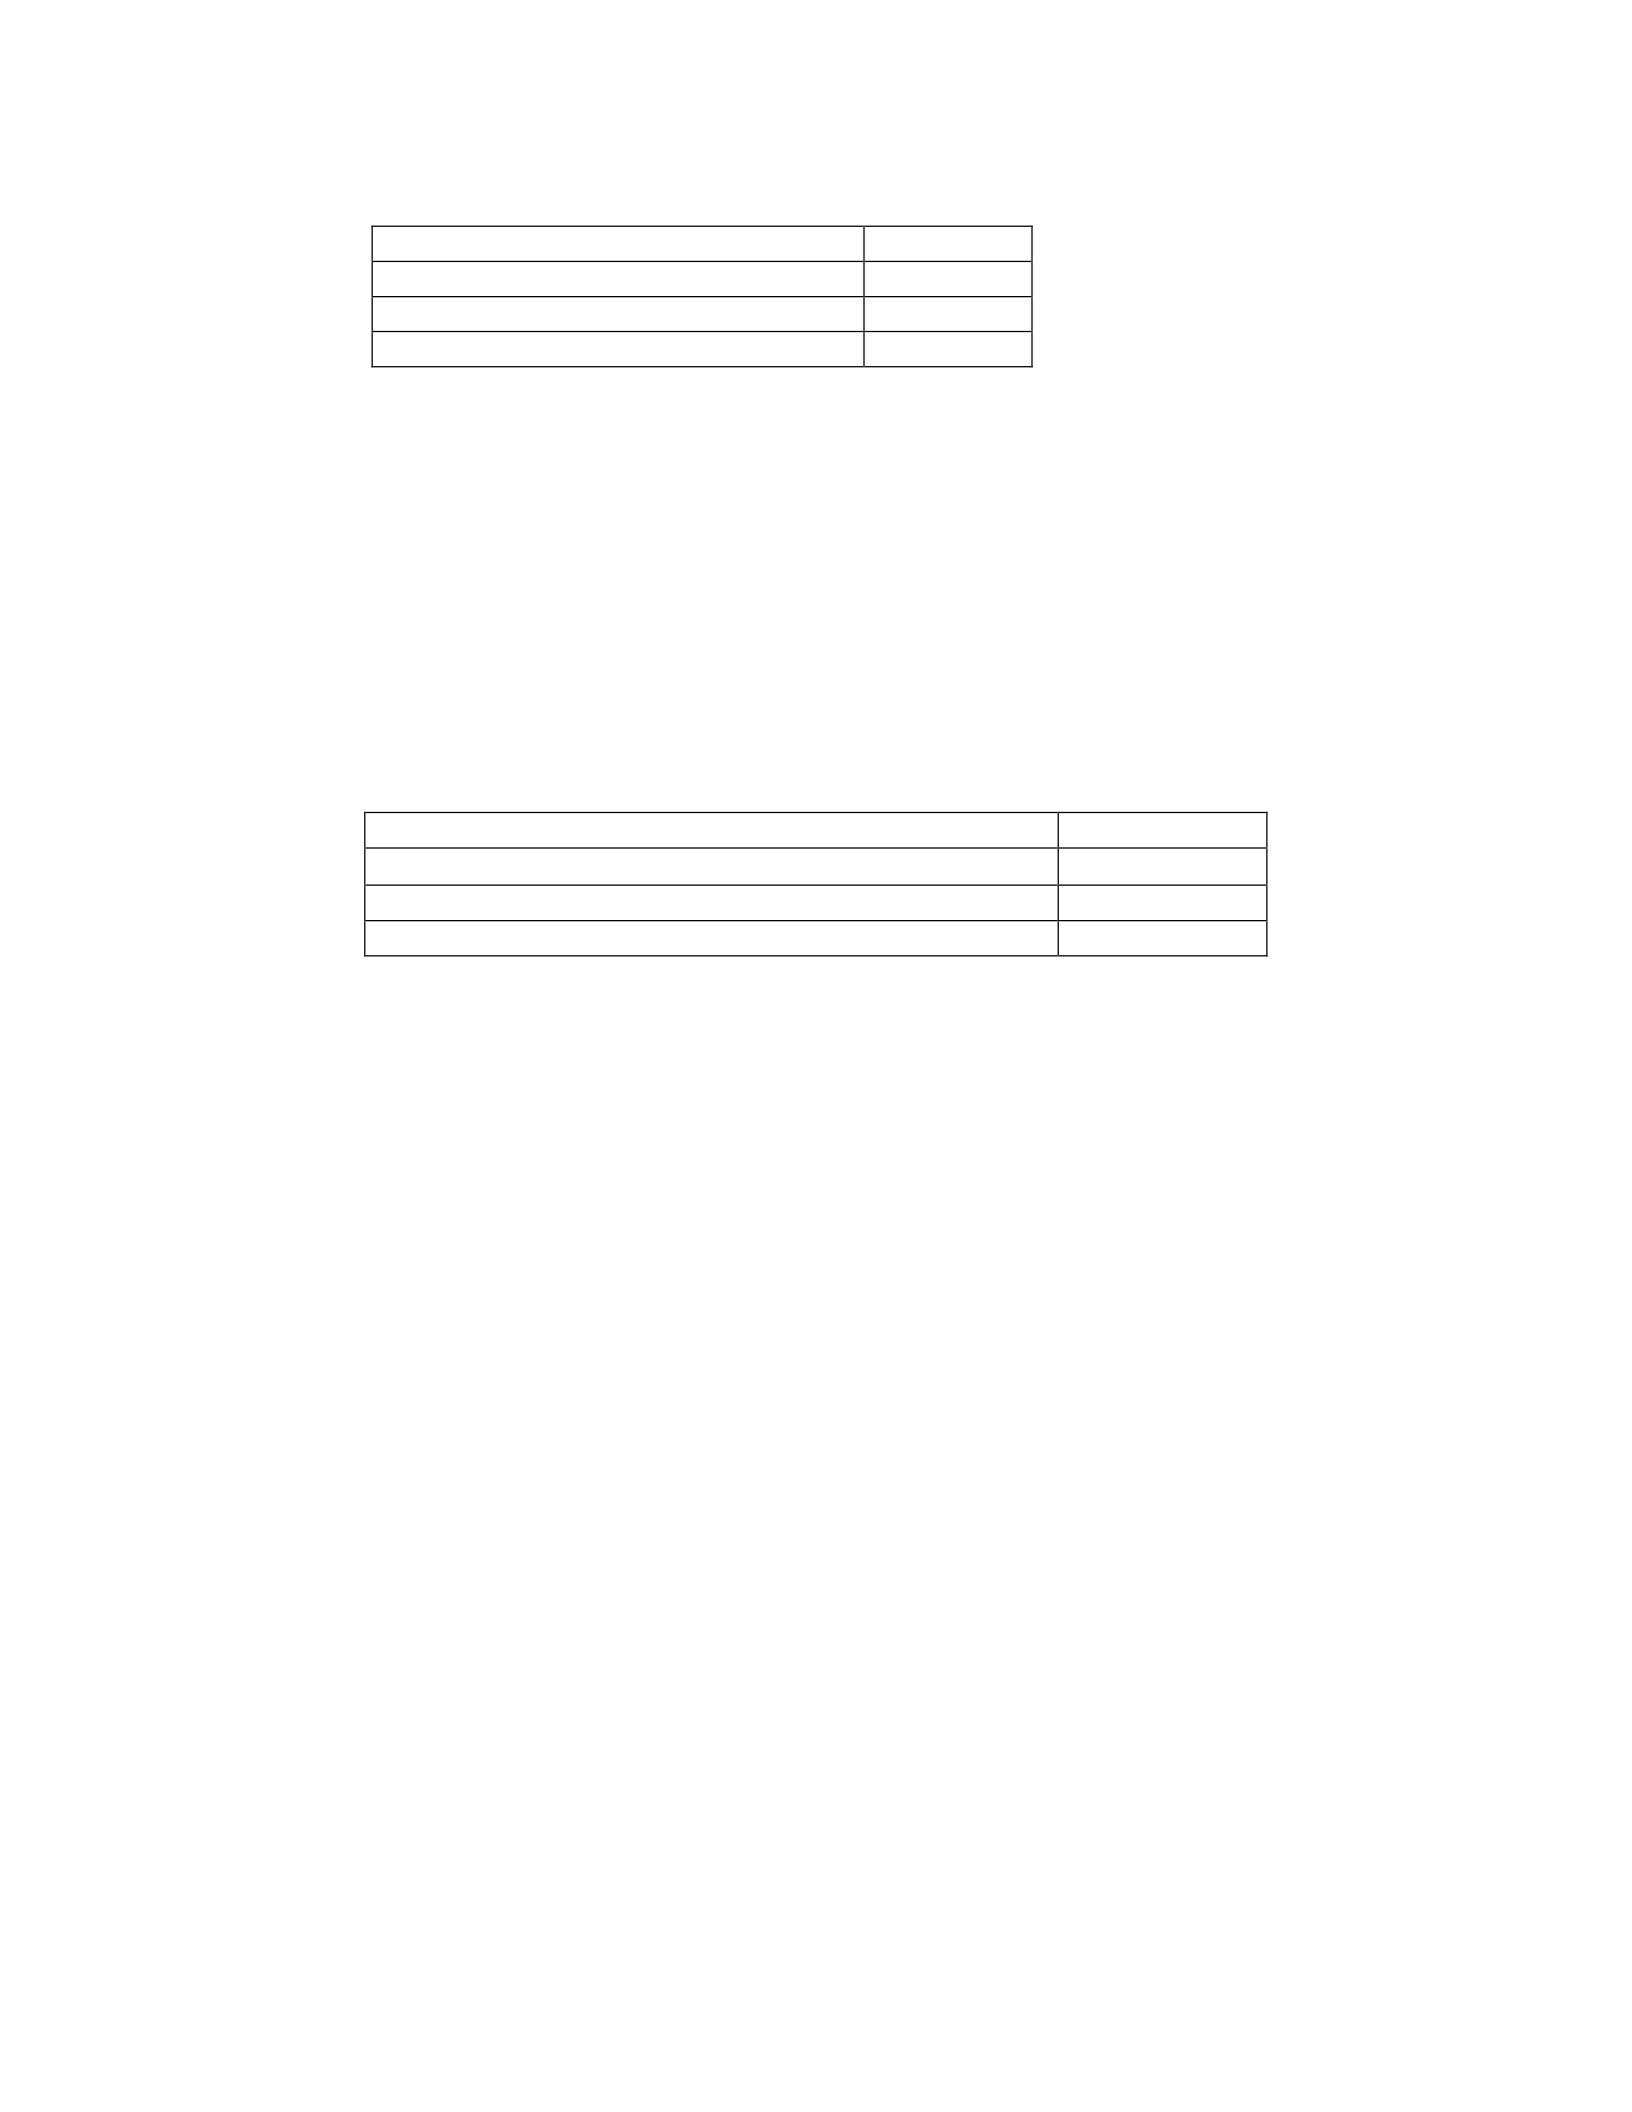
Actual direct labor hours used
32,500
Actual rate per hour
$18.00
Standard rate per hour
$16.50
Standard hours for units produced
32,000
a. How much is the direct labor efficiency variance?
b. How much is the direct labor price (rate) variance?
6. Monika Corporation’s direct labor costs and related information for the month of April were as
follows:
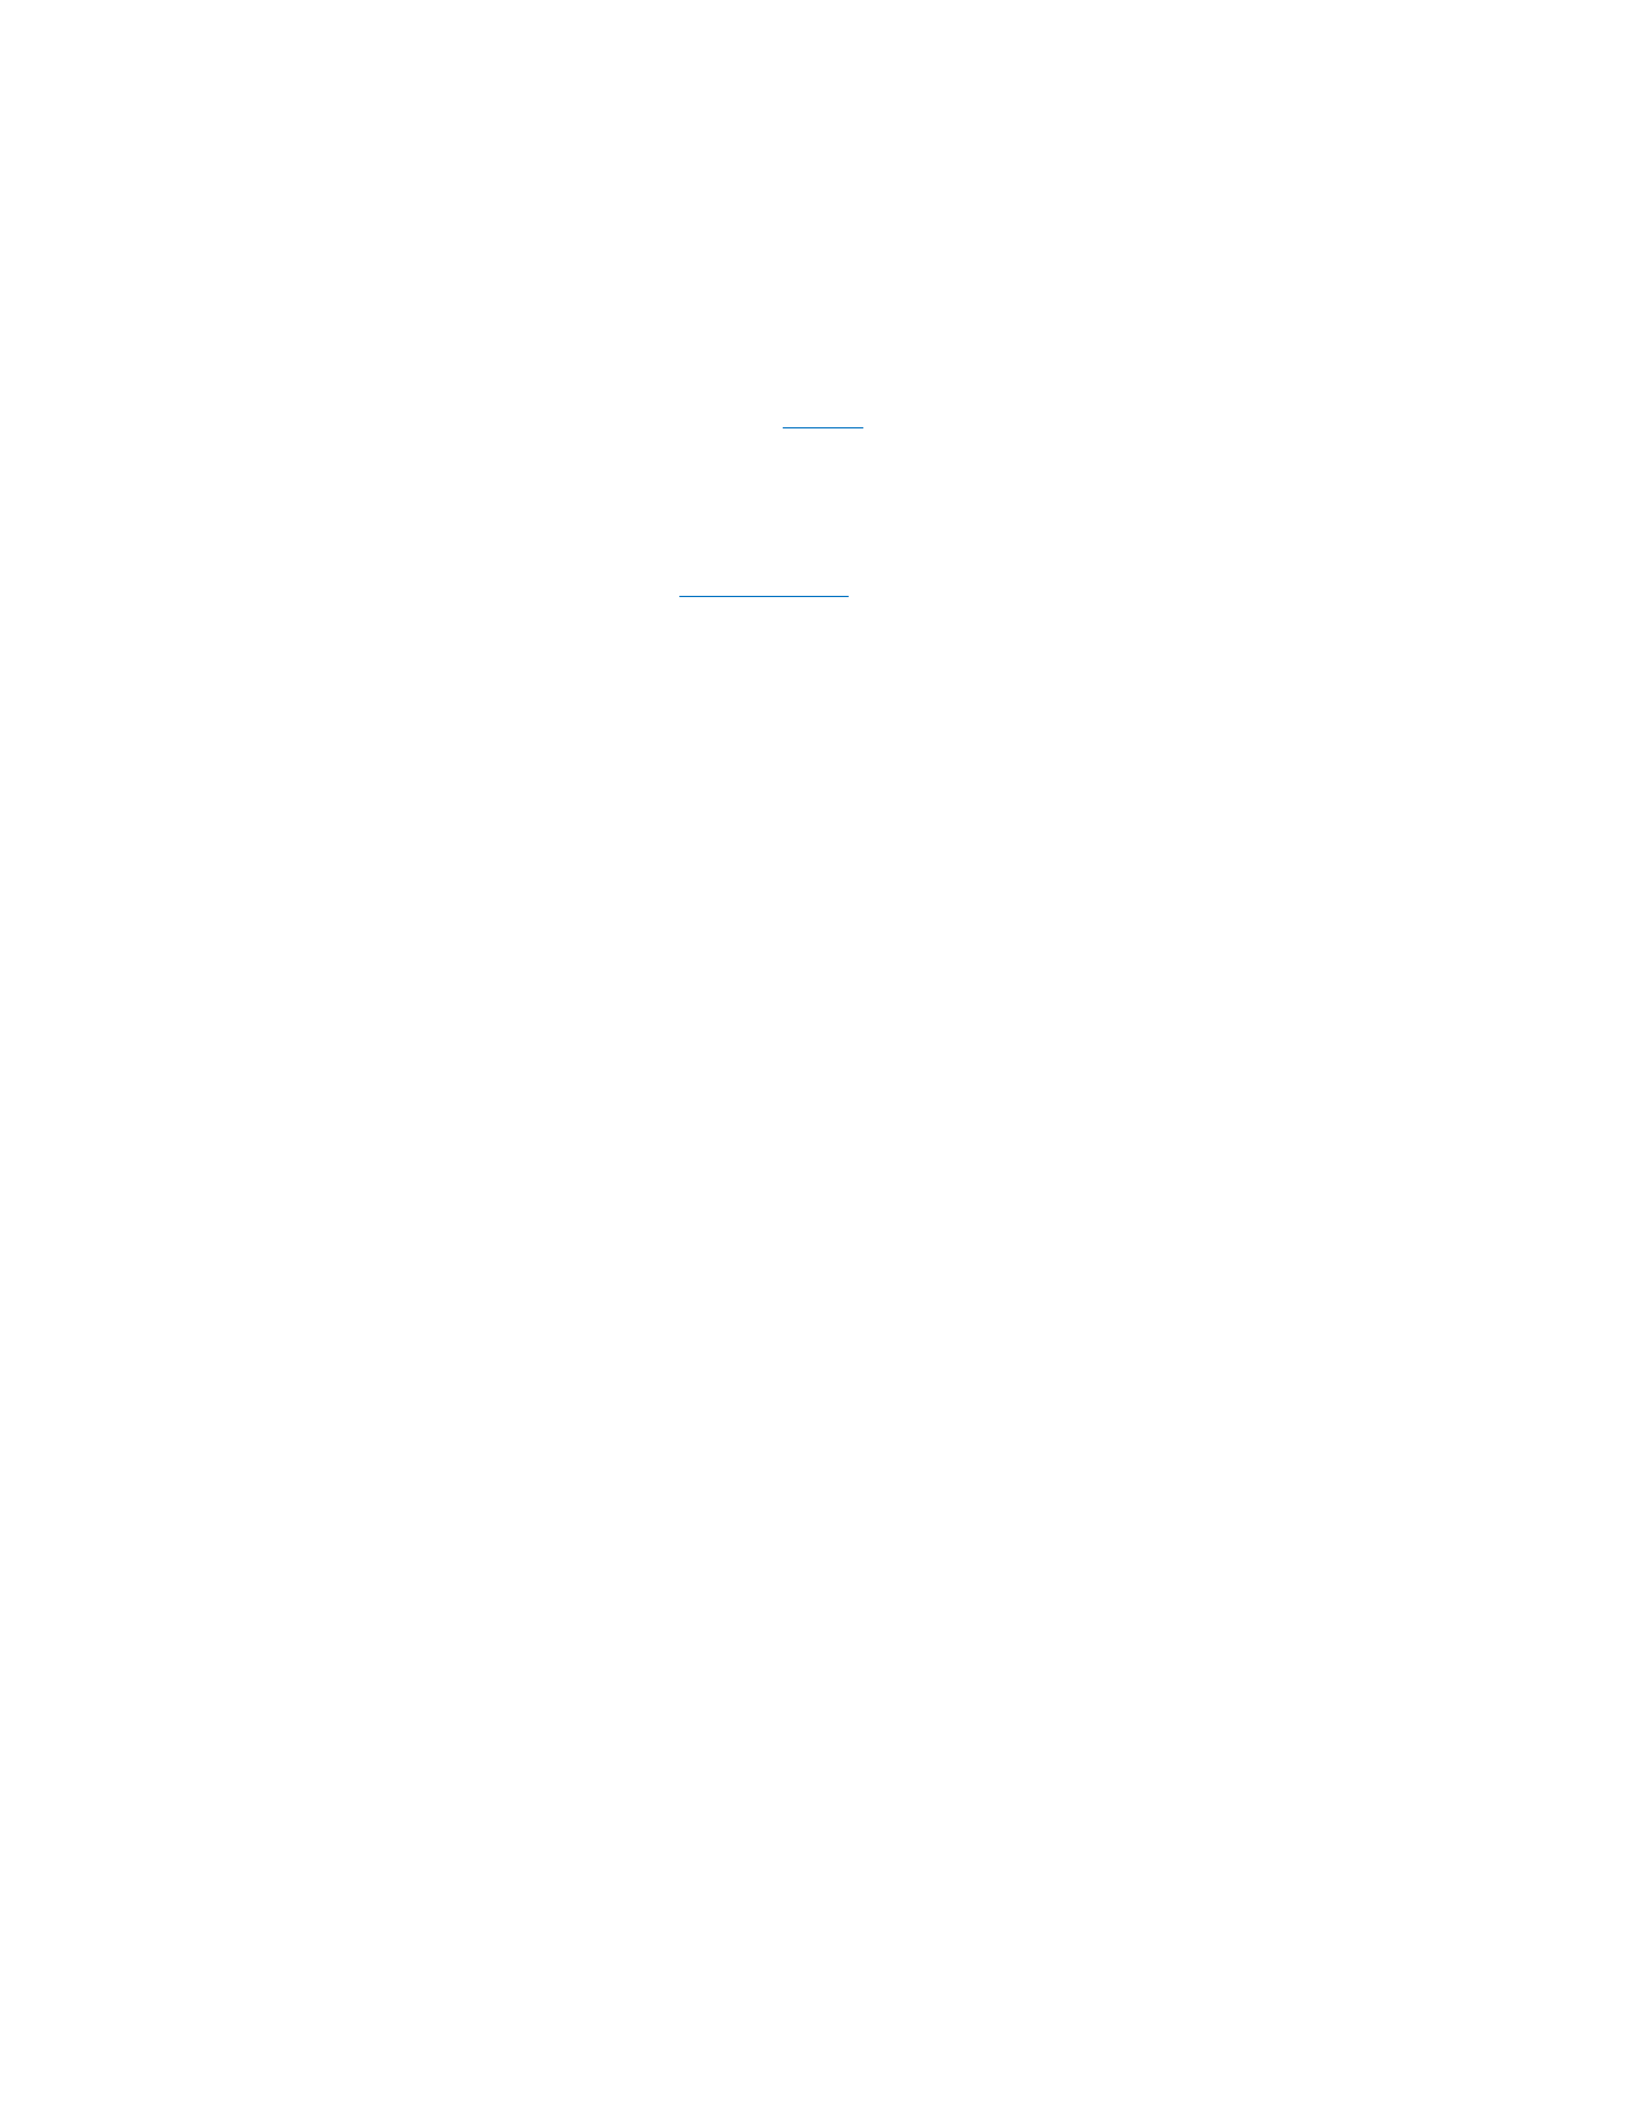
Actual total direct labor-hours
1,200
Standard total direct labor-hours
1,000
Total direct labor cost
$ 10,440
Unfavorable direct labor price (rate) variance
$ 1,500
a. What is A.K. London Corporation’s direct labor quantity (efficiency) variance?
Solutions
1. Actual income $40,000
-Flexible budget income
Flexible budget variance $+2,000
38,000
2. Flexible budget income $32,000
-Static budget income
Sales volume variance $-3,000
35,000
3. a. $26 (4,700 × 1 - 4,950) = $6,500 unfavorable.
b. $132,200 - (4,950 × $26) = $3,500 unfavorable.
4. a. $22.50 × 8,890 - $189,500 = $10,525 favorable.
b. $22.50 × [(4,700 × 2) - 8,890] = $11,475 favorable.

5.
a. Labor efficiency var = ( Actual quantity – Std quantity at act units ) x Std
price $8, 250 U = (32,500 – 32,000 ) x 16.50
b. Labor price var.= (Actual rate per unit – Std rate per unit) x actual quantity
$48,750 U = (18.00- $16.50 ) x 32,500
6.
Labor price var. = (Actual price per unit – Std price per unit) x actual
quantity
$1500 = {(10,440 / 1200) – std price} x 1200
Std price = (8.70 x1200) /1500 = $7.45
Labor efficiency var = (Actual quantity – Std quantity at act units) x Std price
$1,490U = (1,200 – 1,000) x 7.45

