


ACC 241 Exam 3 Materials
Profit Planning
Steps taken by a business to achieve their desired level of profits
Accomplished by preparing a number of budgets
Culminates in an integrated business plan referred to as the master budget
Used to communicate management’s plans throughout the organization, allocate resources &
coordinate activities
Budgets
A budget is a quantitative plan for acquiring & using resources over a specified period of time (typically
1 year; can be a 12-month continuous)
Once prepared, actual performance is compared to the budget to ensure goals are achieved
A master budget is a summary of a company’s detailed budget & is an important part of planning &
control
The strategic plan identifies objectives & strategies; typically covers 5 years or more
Master Budget
Advantages of Budgeting
The development of a master budget offers many benefits & advantages to a company. Budgets are an
effective means of communicating & articulating management’s plans throughout the organization.
They force managers to think about & plan for the future & provide a means of allocating resources for
effective use. The budgeting process can uncover bottlenecks & inefficiencies, fostering proactive
implementation of process & organizational improvements
Budgets coordinate & integrate the activities of an entire organization, ensuring that individual
operating units work in harmony to achieve common organization’s performance & take corrective
actions as needed
Budgeting Approach
Most Budgets:
Conform to Company’s Fiscal Year Prepared on a Monthly Basis
Self-imposed or participative budgets are prepared with the full cooperating & participation of the
responsible managers
Increase Buy-In Minimize Resentment
Increases Accuracy Eliminate Excuses
Provides for Adequate:
Culminates in the Creation of a:
Includes Targets
For
Cash Budget
Planning
Budgeted Income
Statement
Budgeted Balance
Sheet
Control
ACC 241 Chapter 9 Lecture
The Master Budget & Responsibility Accounting
Self Imposed Budgets
Must be scrutinized for budgetry slack or padding Can cause an organization to under perform
Often lack sufficient strategic direction Most companies use management imposed targets
Human Factors & Budgeting
Budgets must have complete support from key management positions; if not, lower levels of the
organization will not be committed
It is important that budgets not be used to pressure or blame employees (breeds tension, resentment,
mistrust)
Budgets should be used to foster cooperation & productivity
Reasonable budgets prevent undesired behavior
Budget Committee
Responsible for budget policy & budget preparation
Consists of president, vice presidents in charge of various functions such as sales, production,
purchasing; & the chief financial officer & controller
Sets targets & calendar
Resolves difficulties & disputes
Approves the final budget
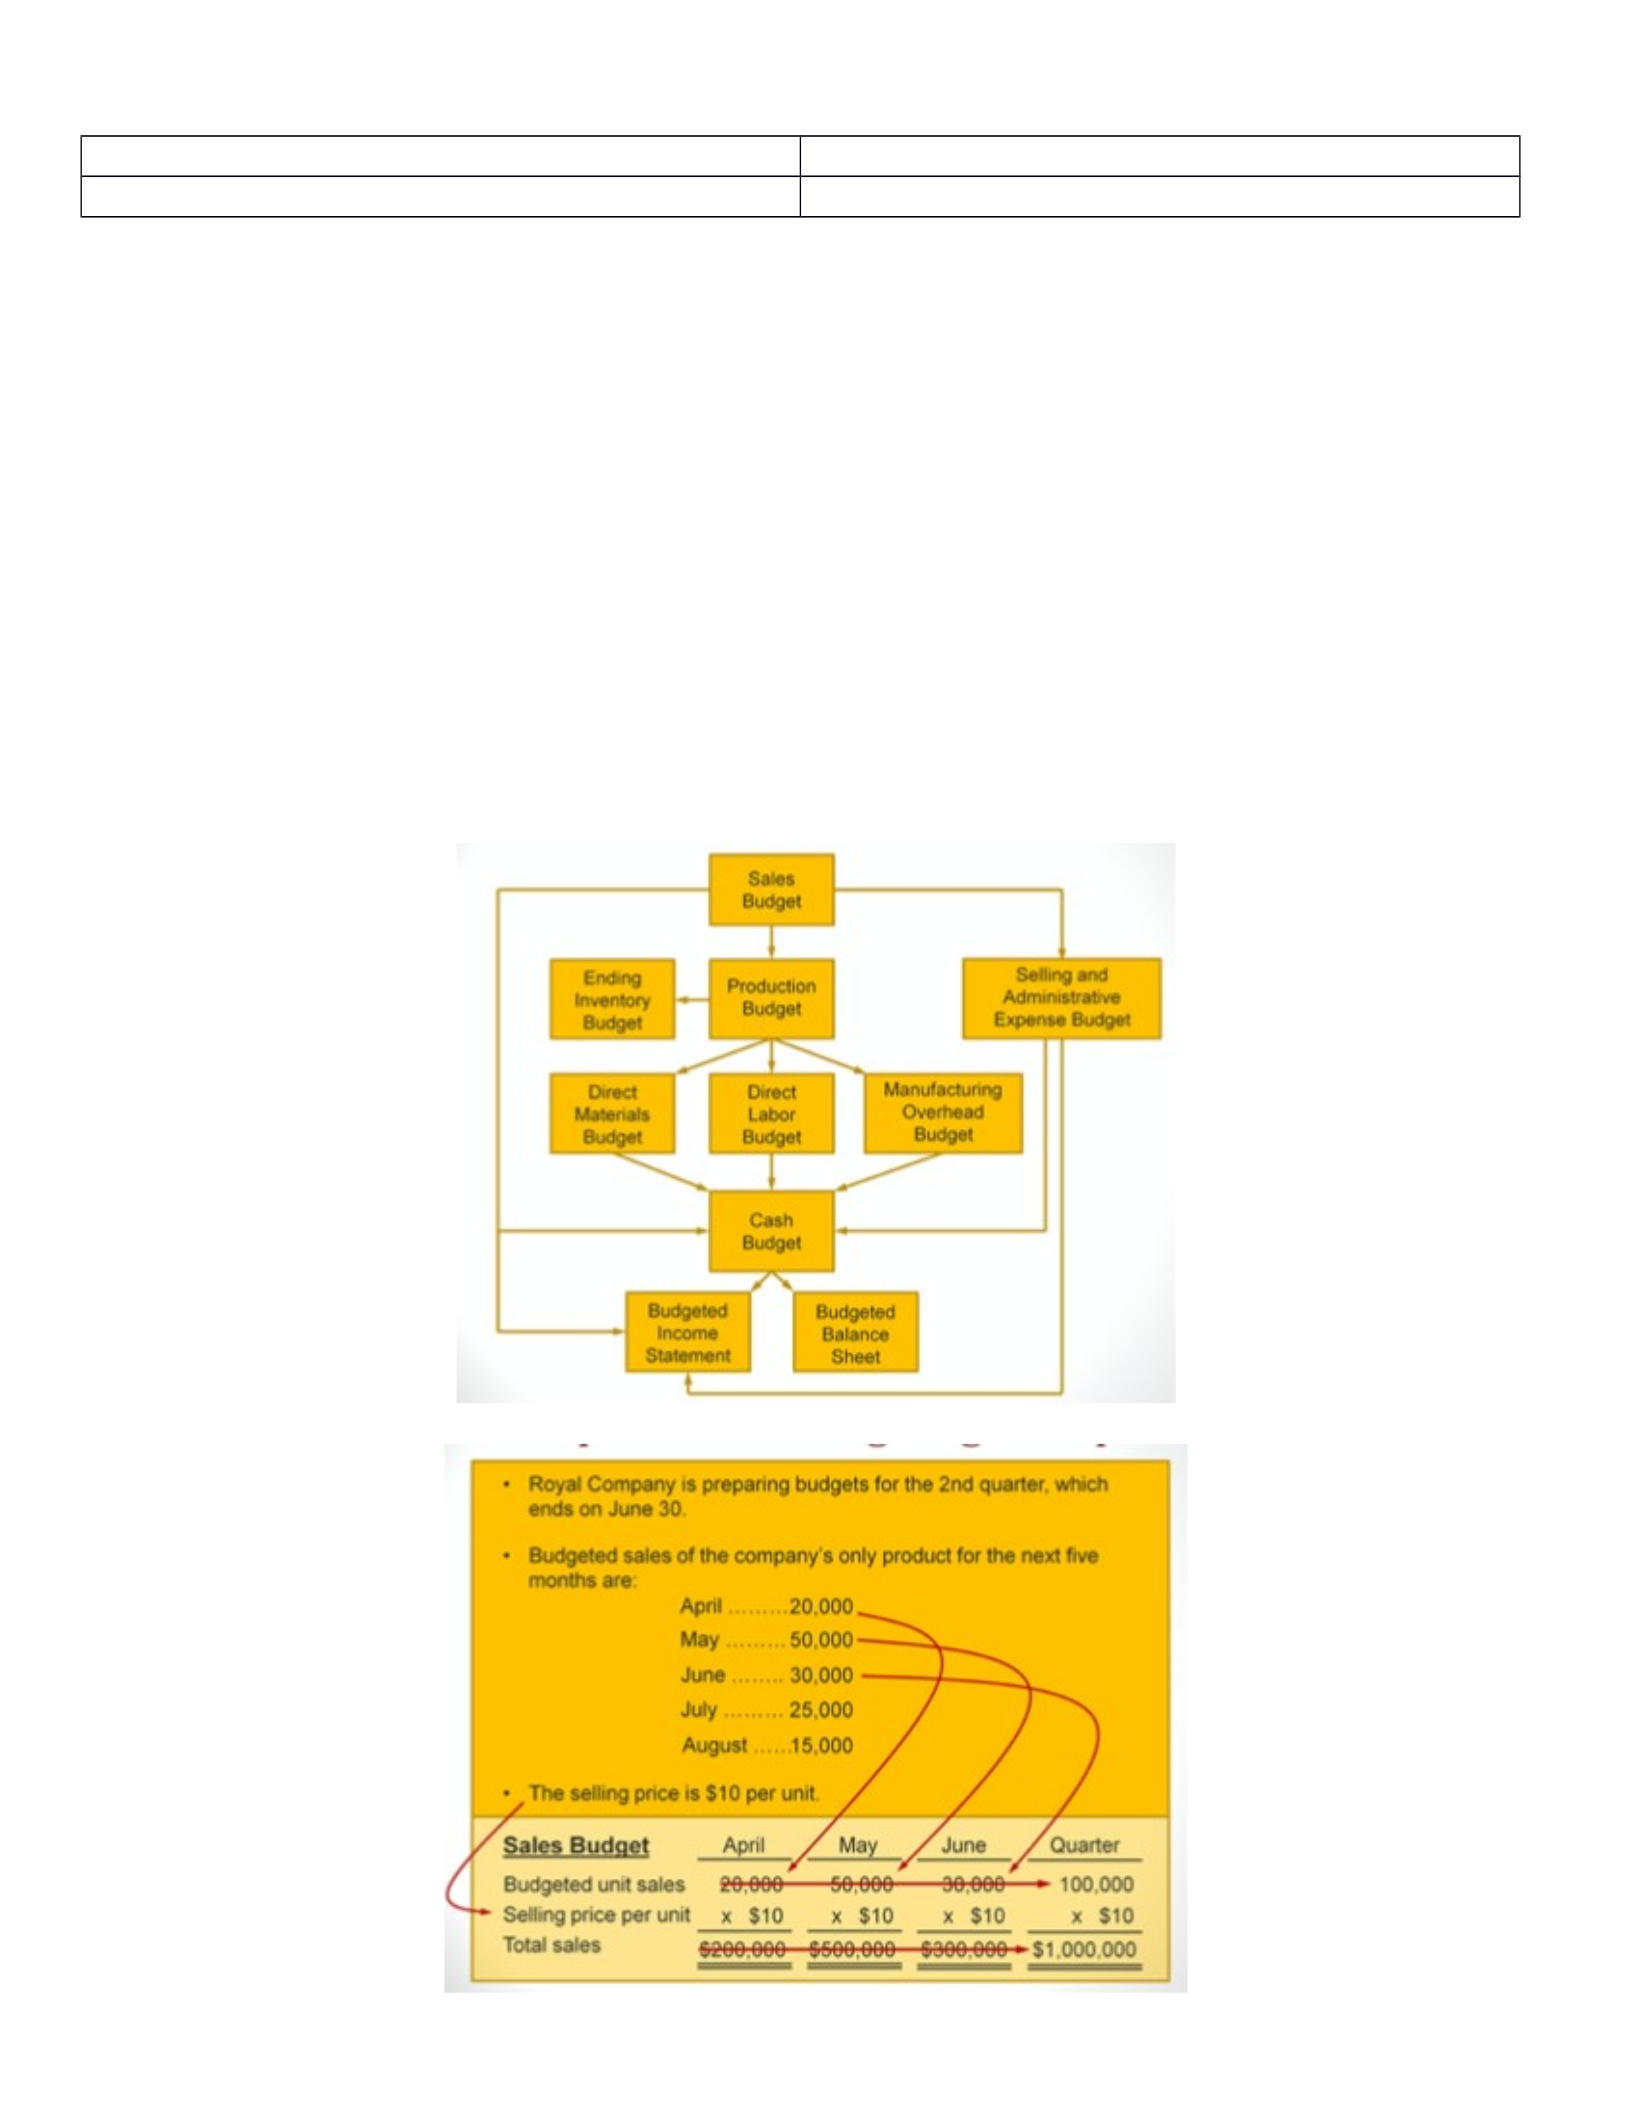
Master Budget Overview
Comprehensive Budgeting Example
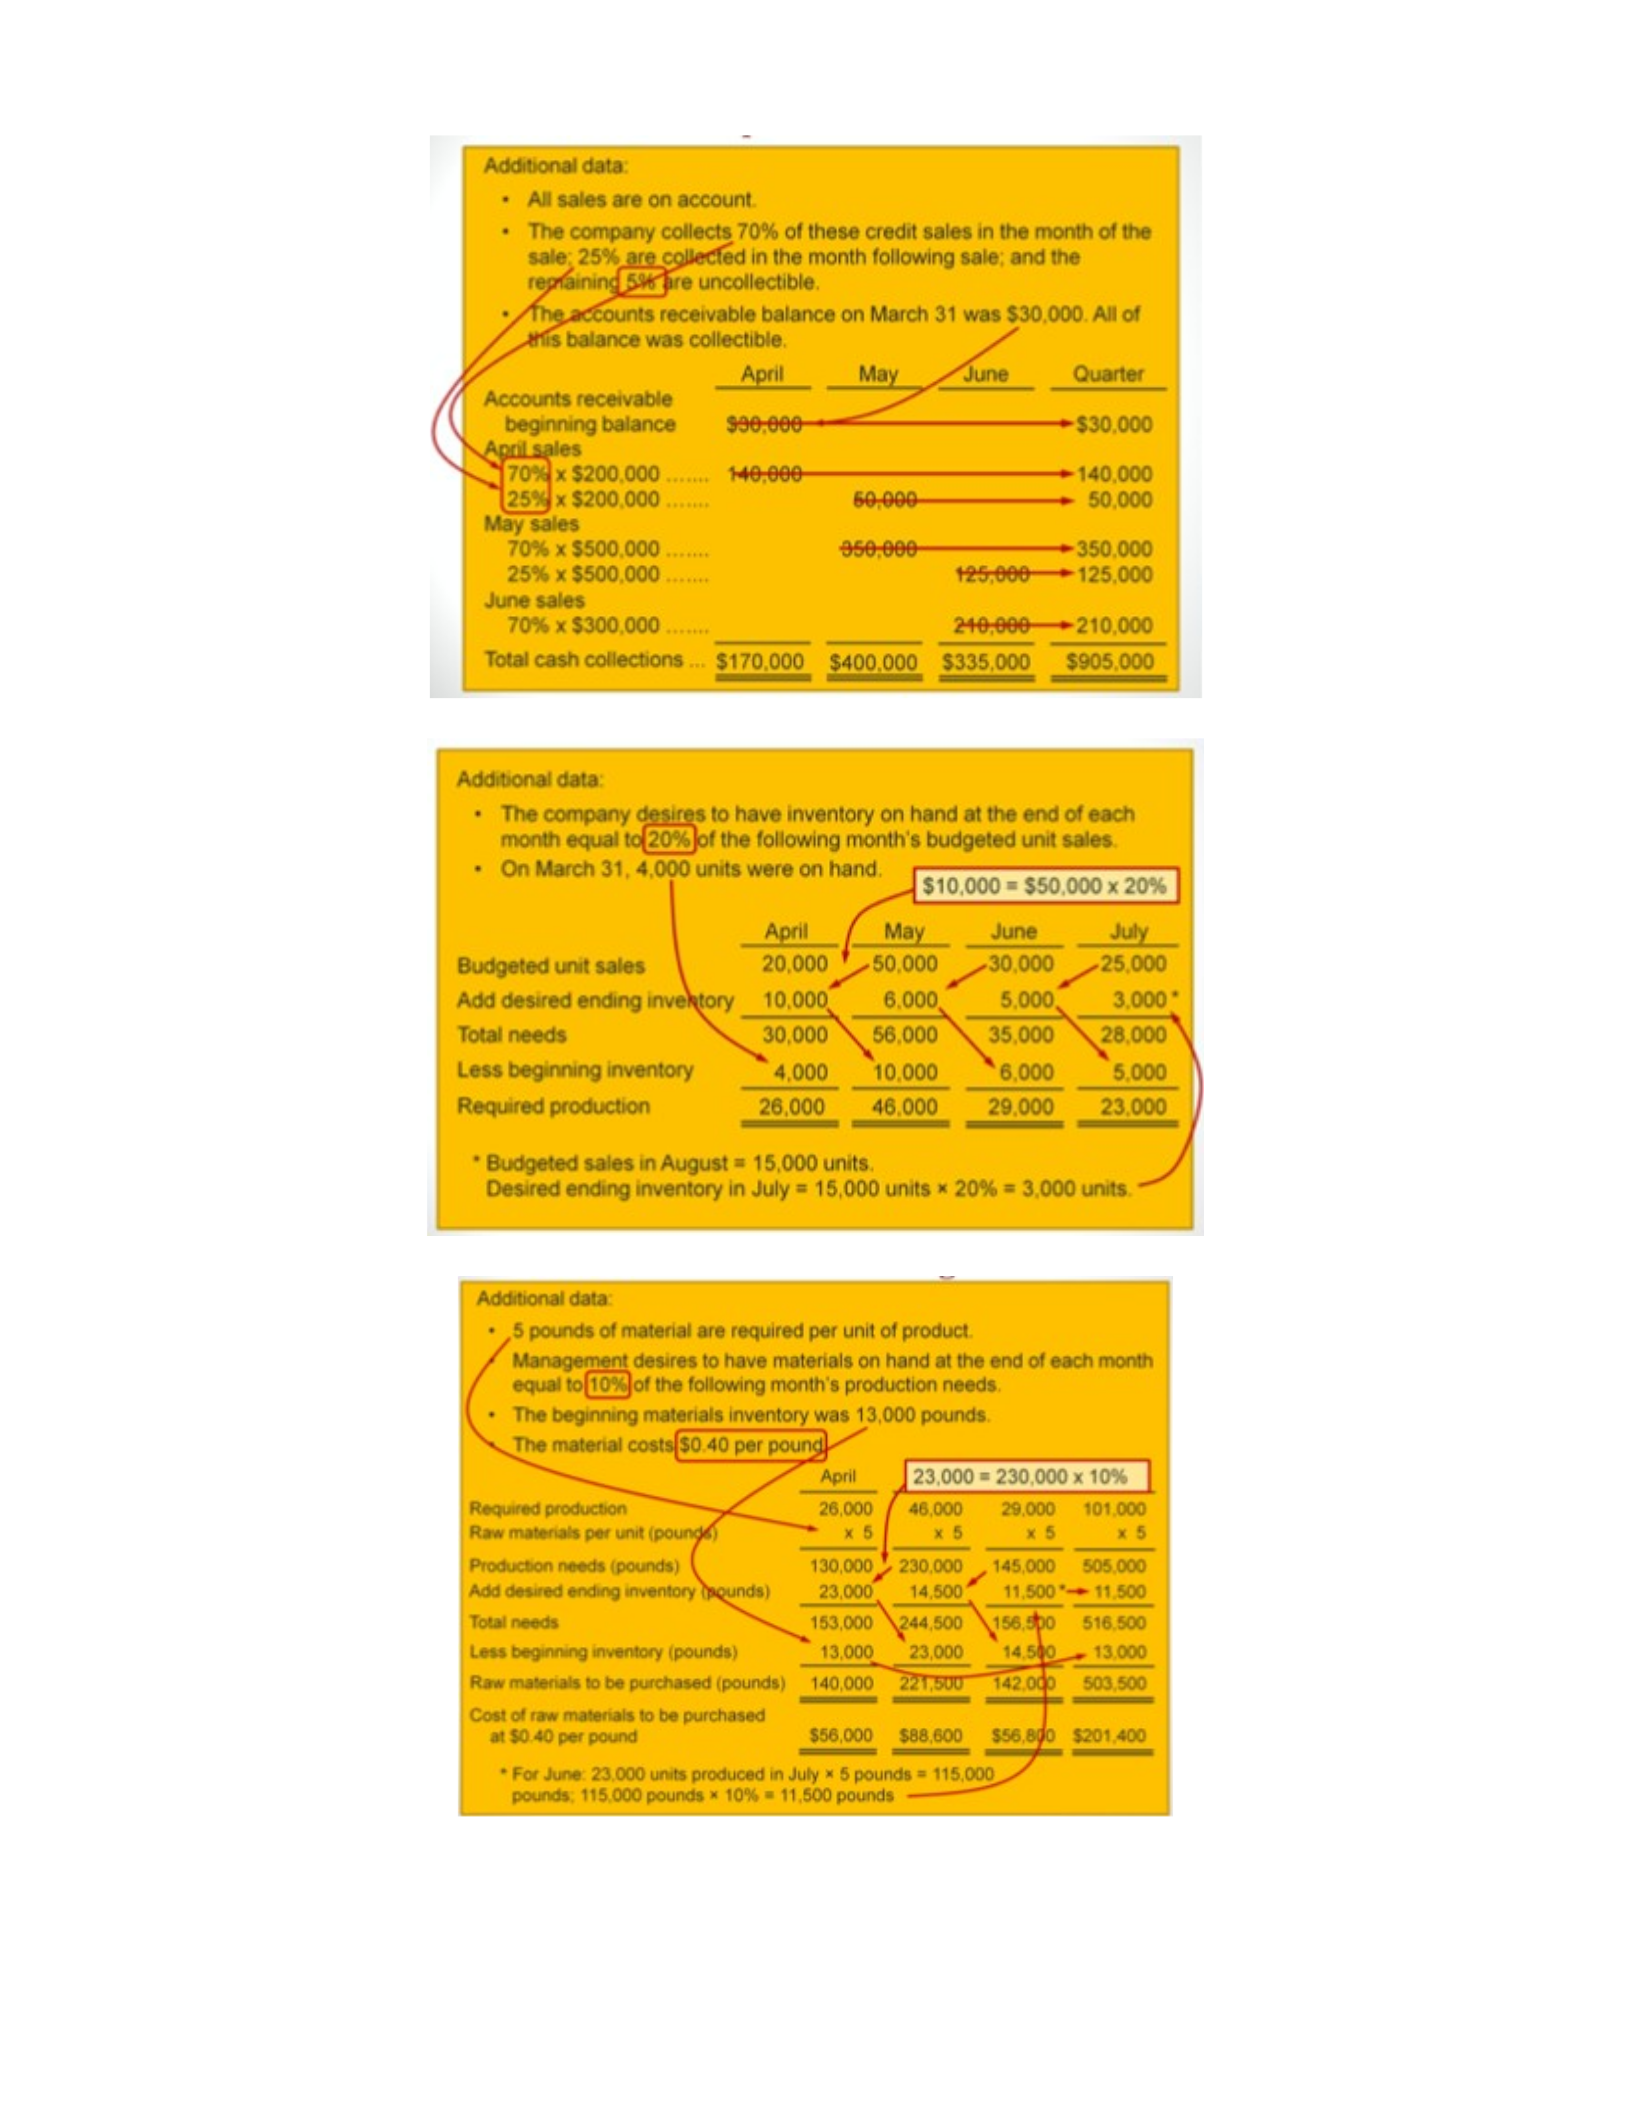
Schedule of Expected Cash Collections
Production Budget
Direct Materials Budget
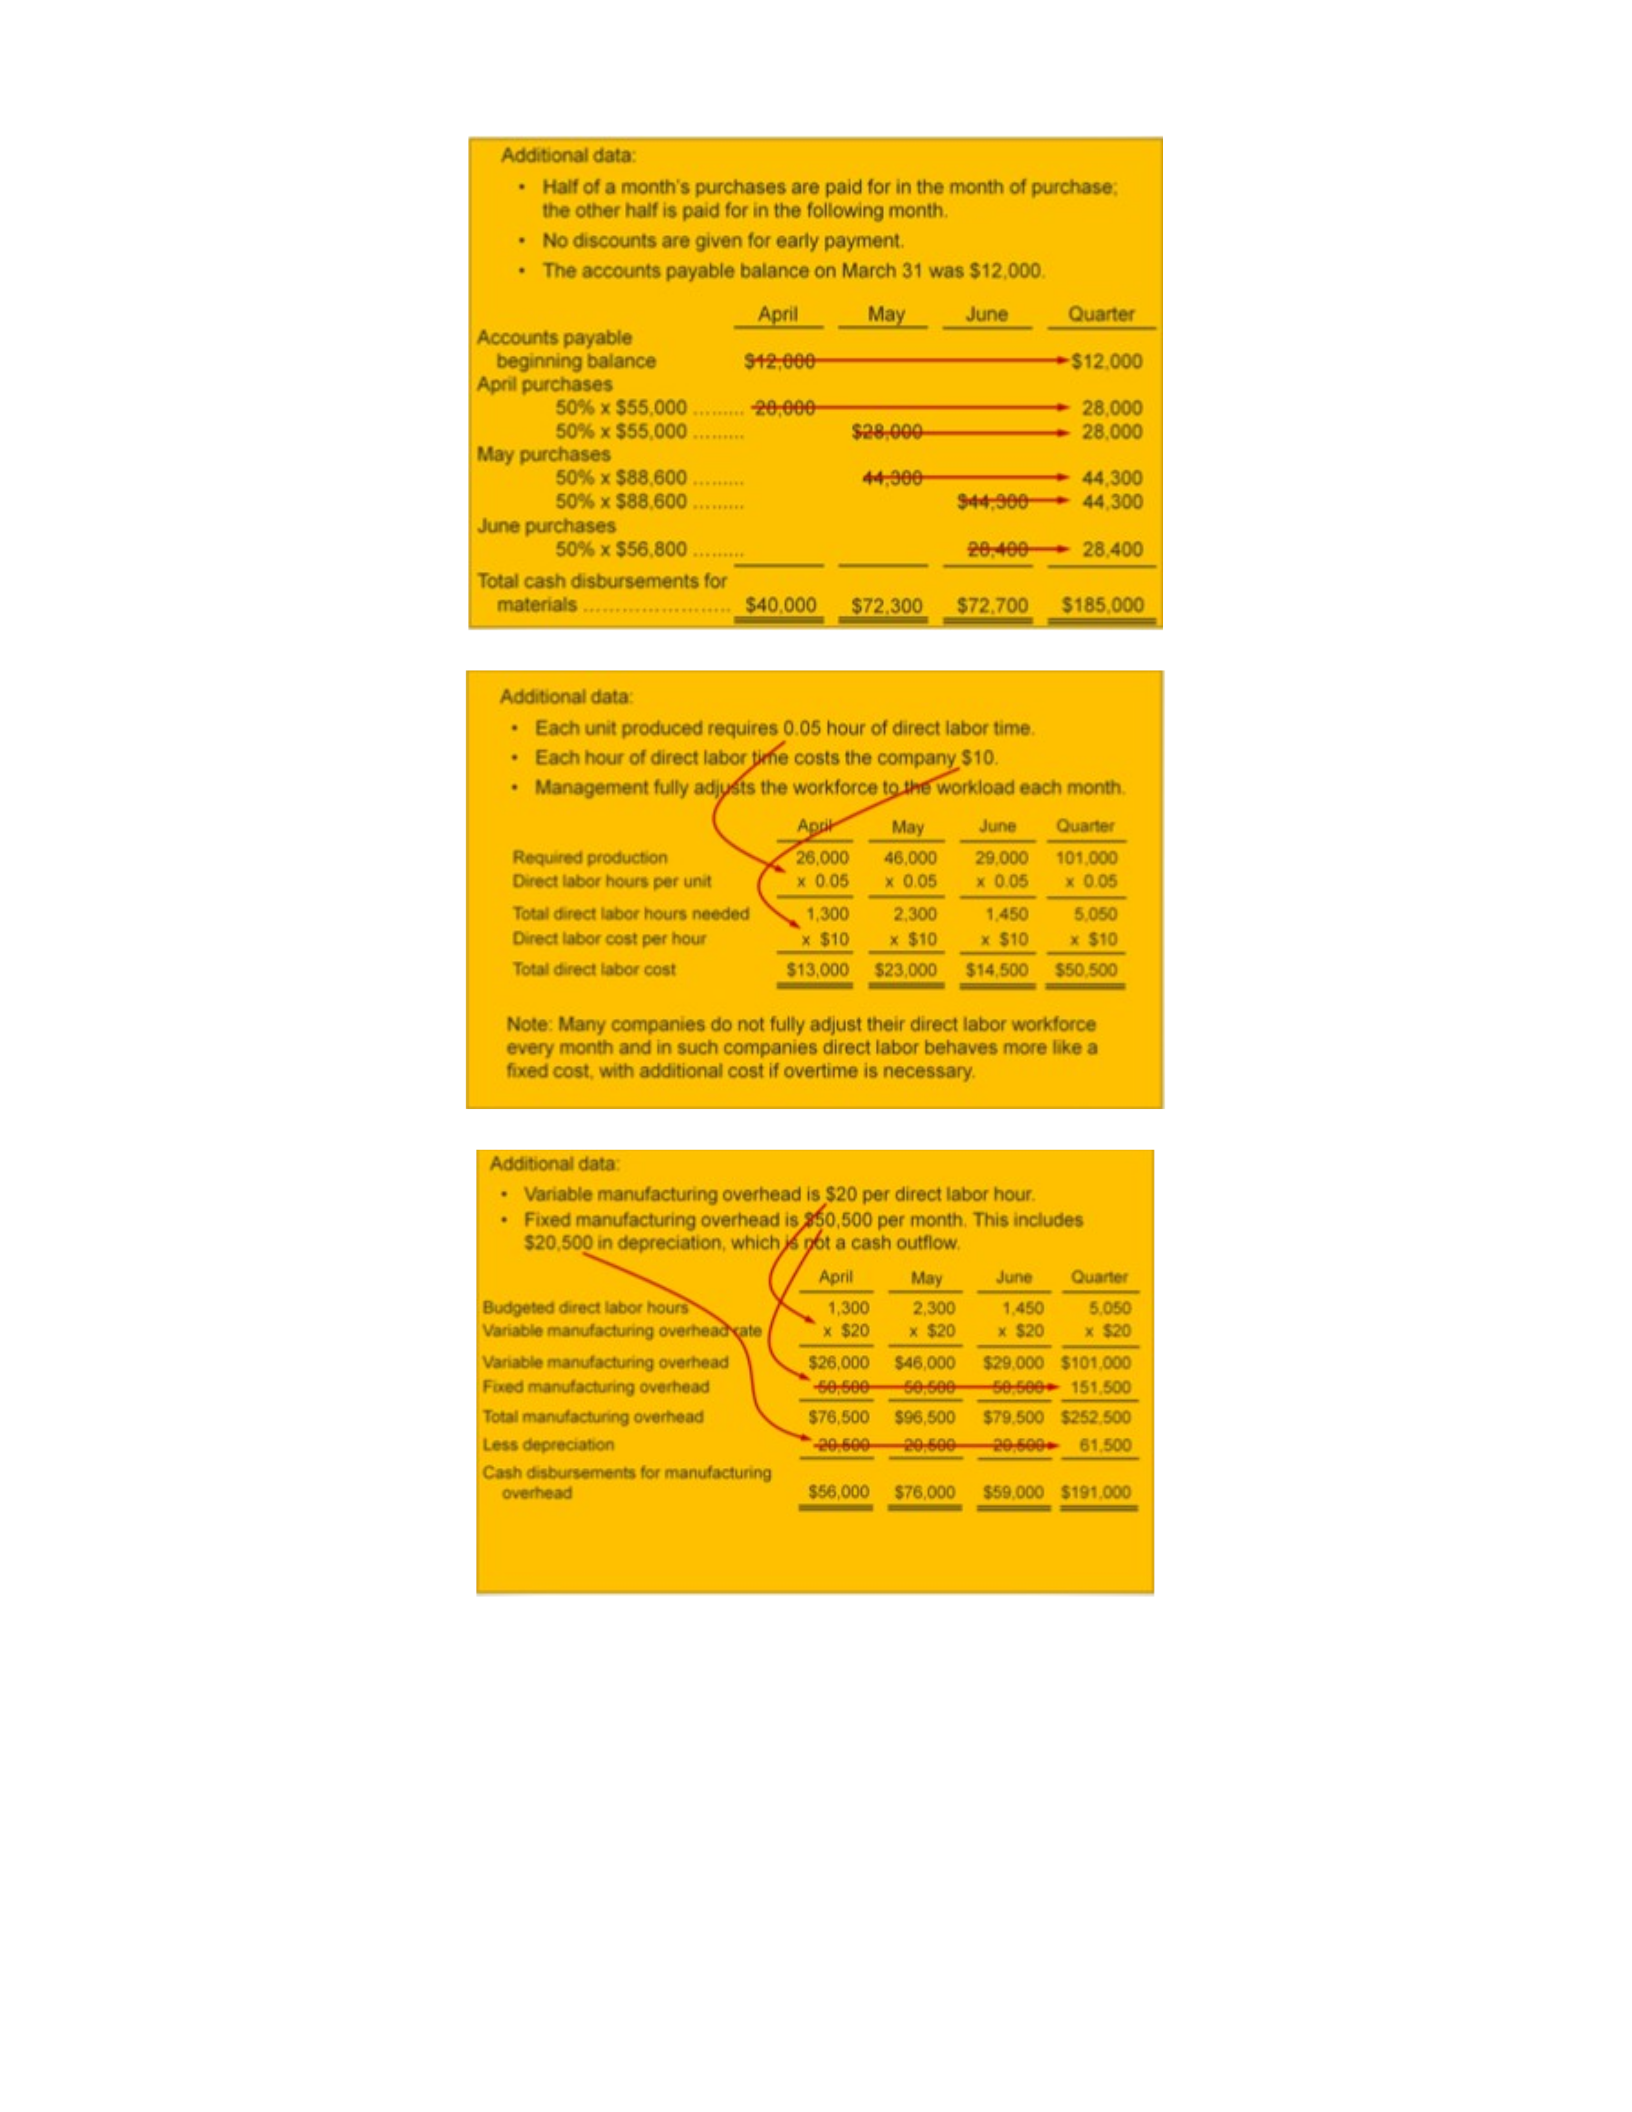
Schedule of Expected Cash Disbursements for Material
Direct Labor Budget
Manufacturing Overhead Budget
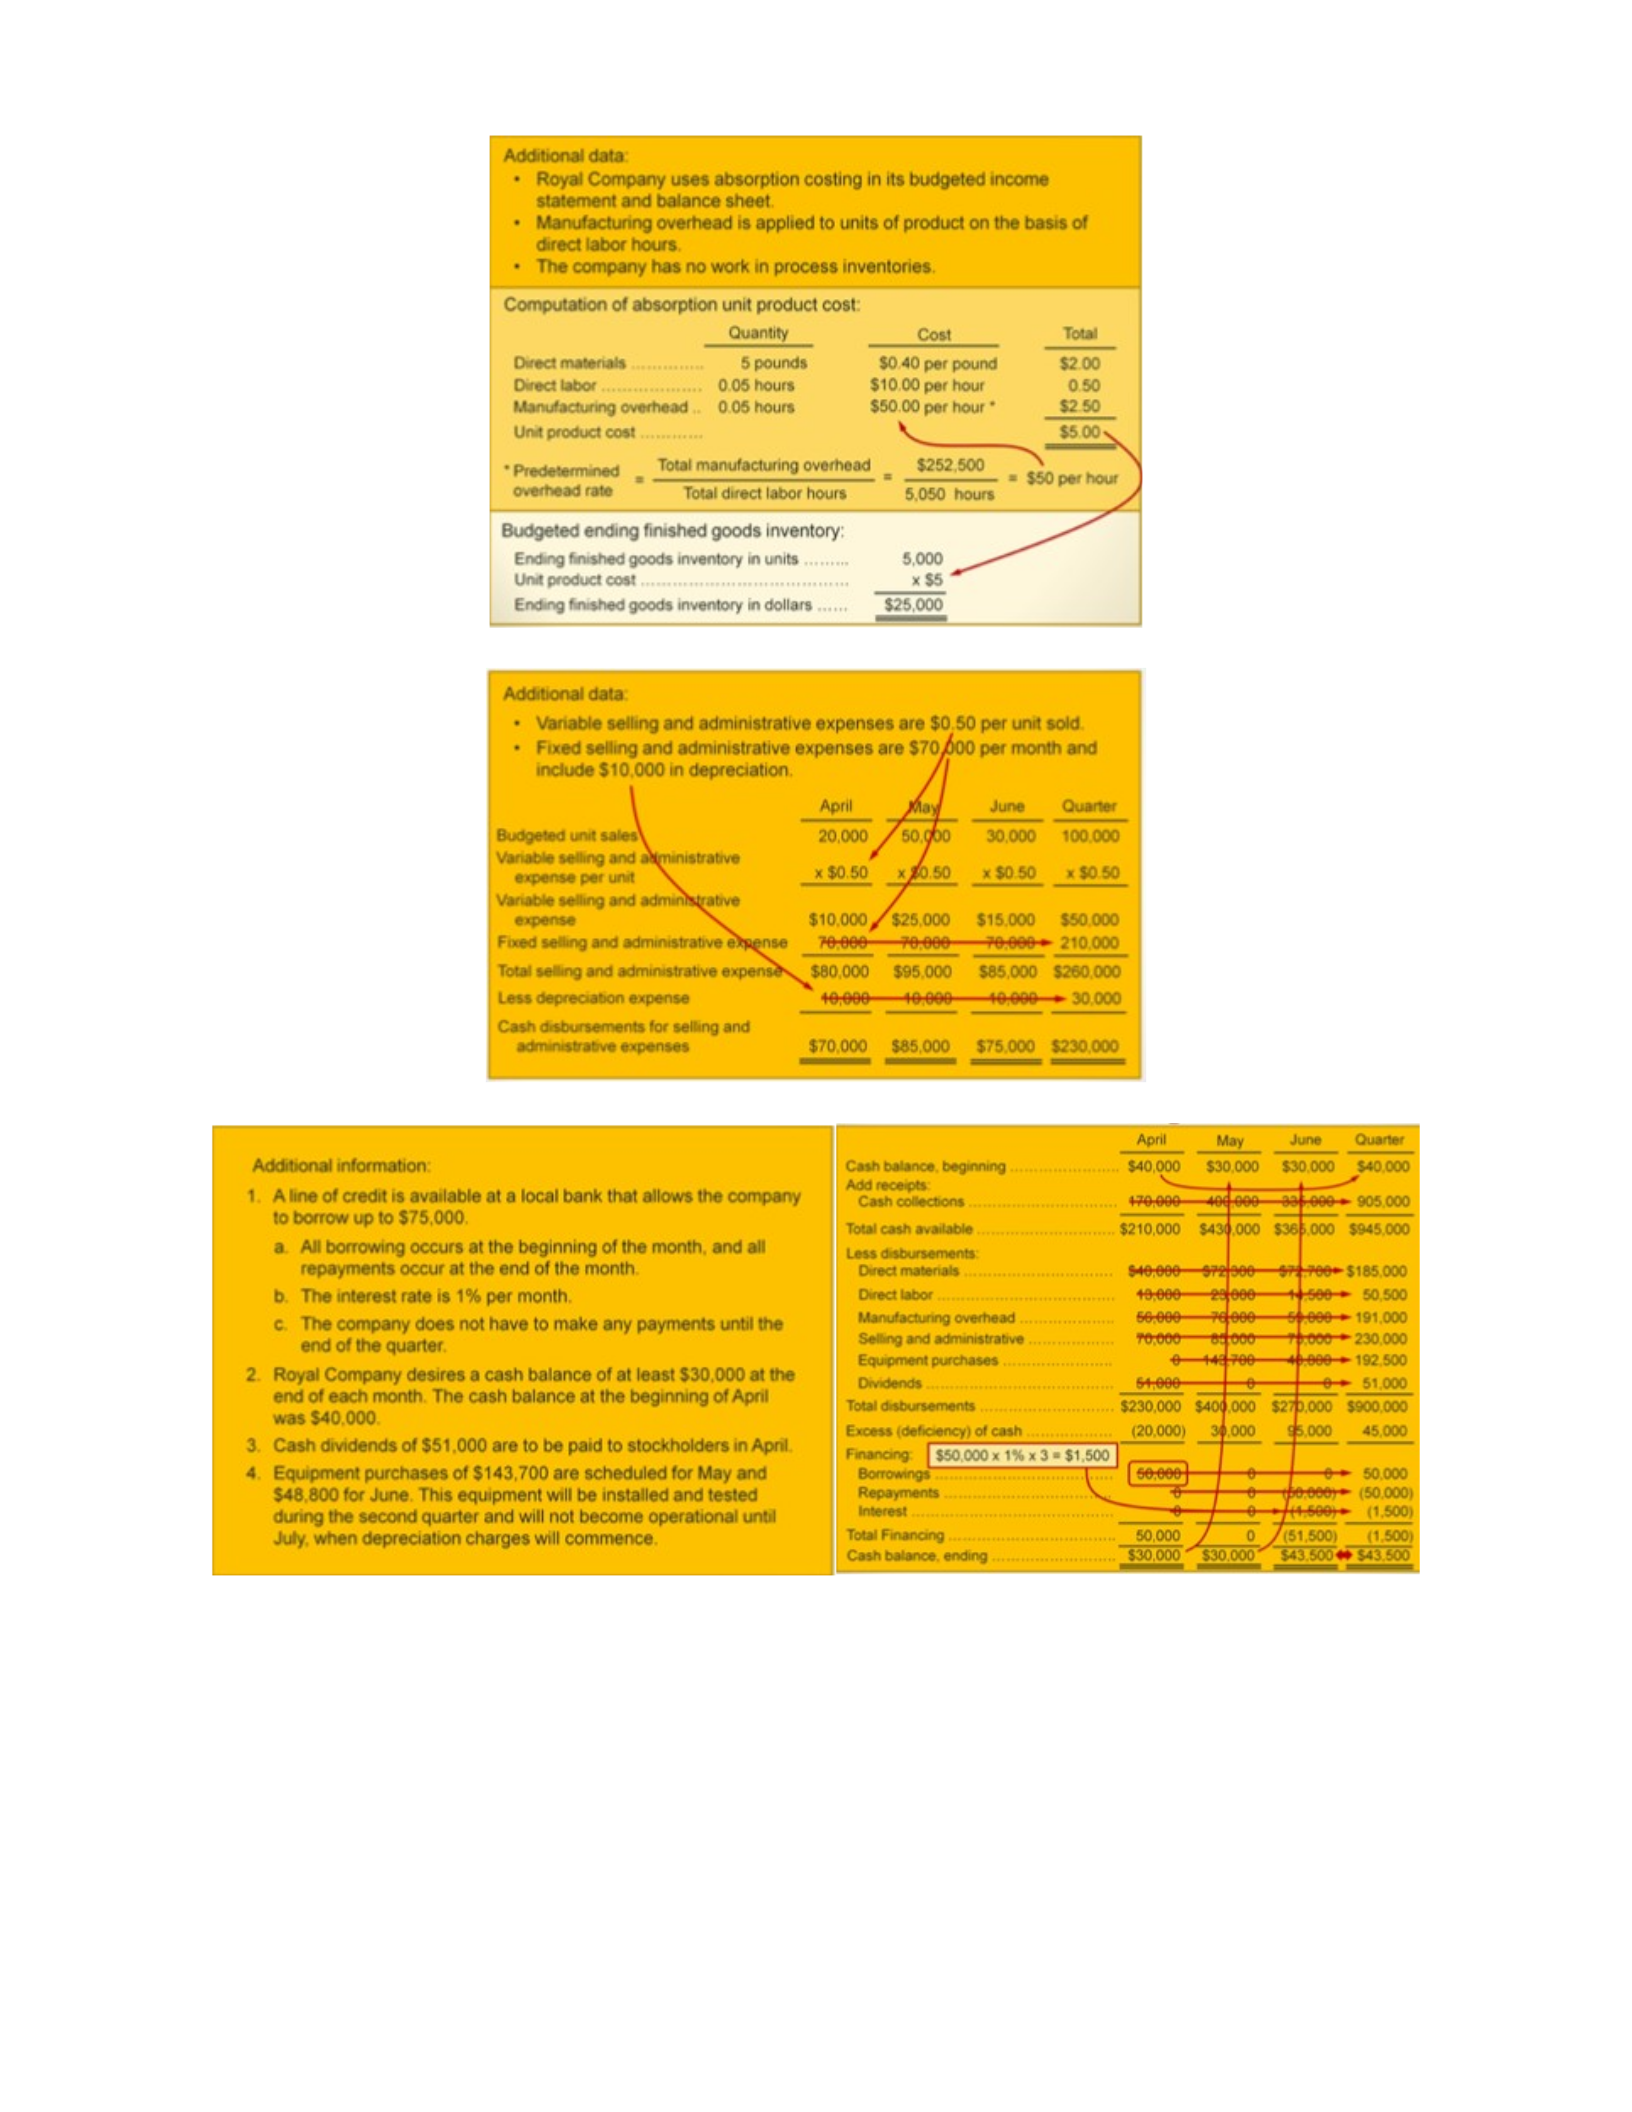
Ending Finished Goods Inventory Budget
Selling & Administrative Expense Budget
Cash Budget
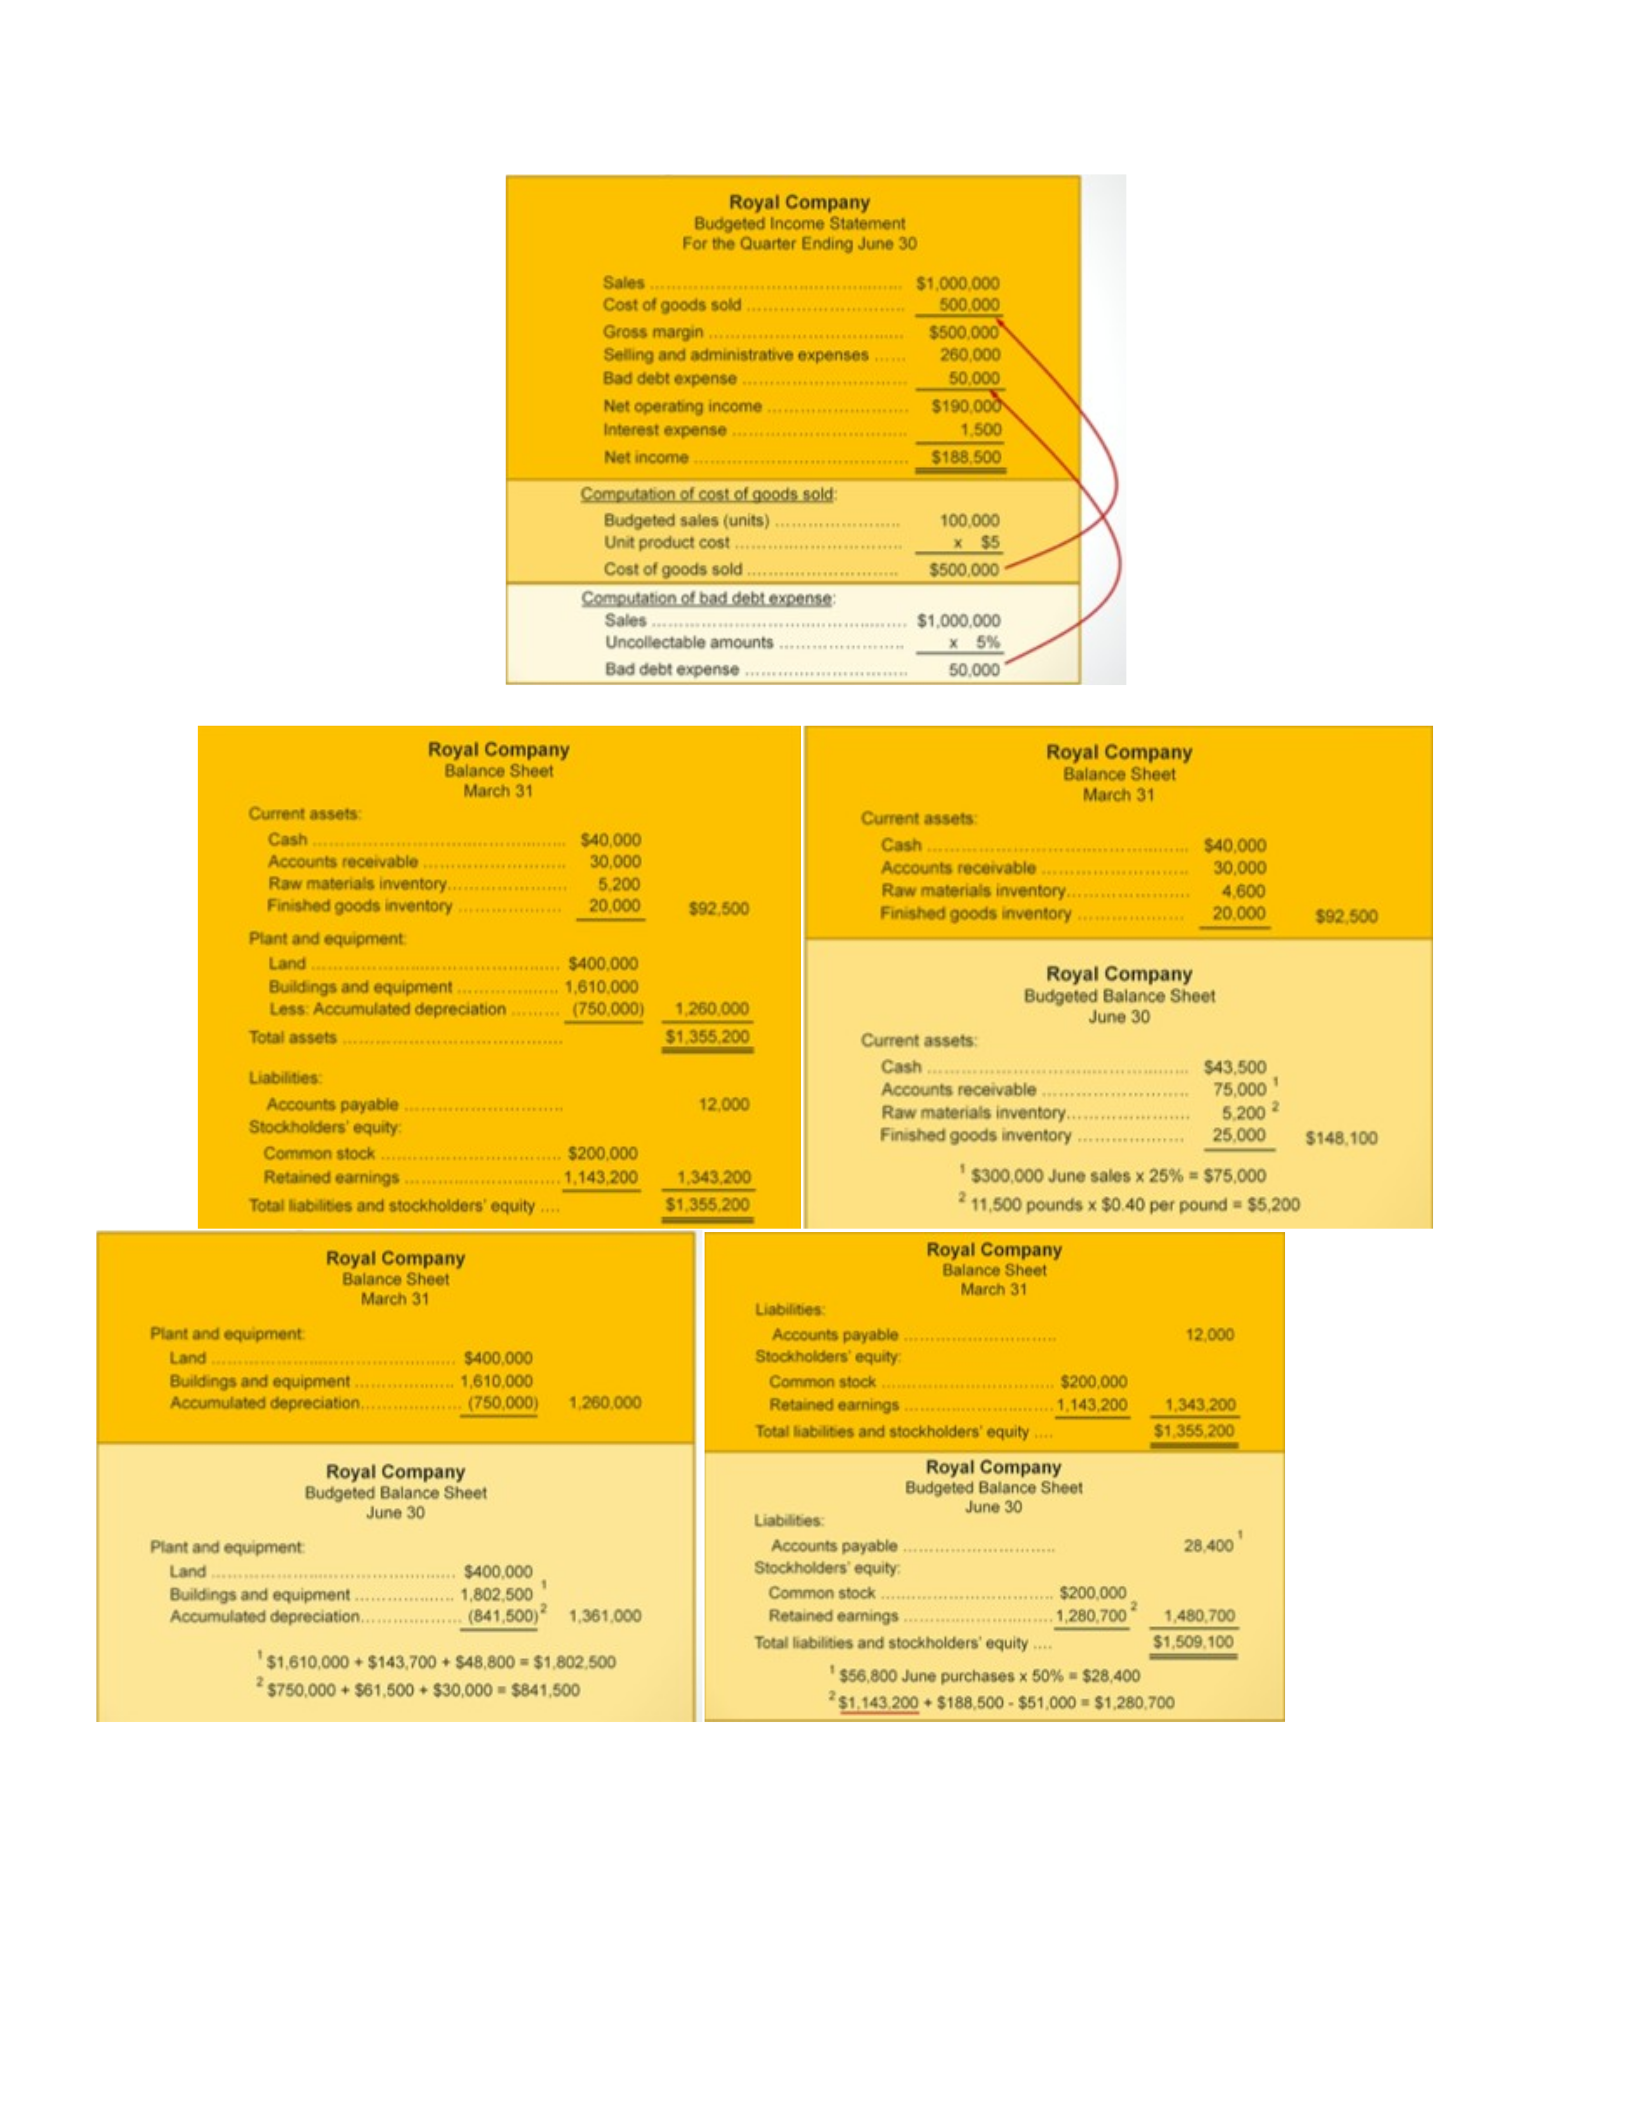
Budgeted Income Statement
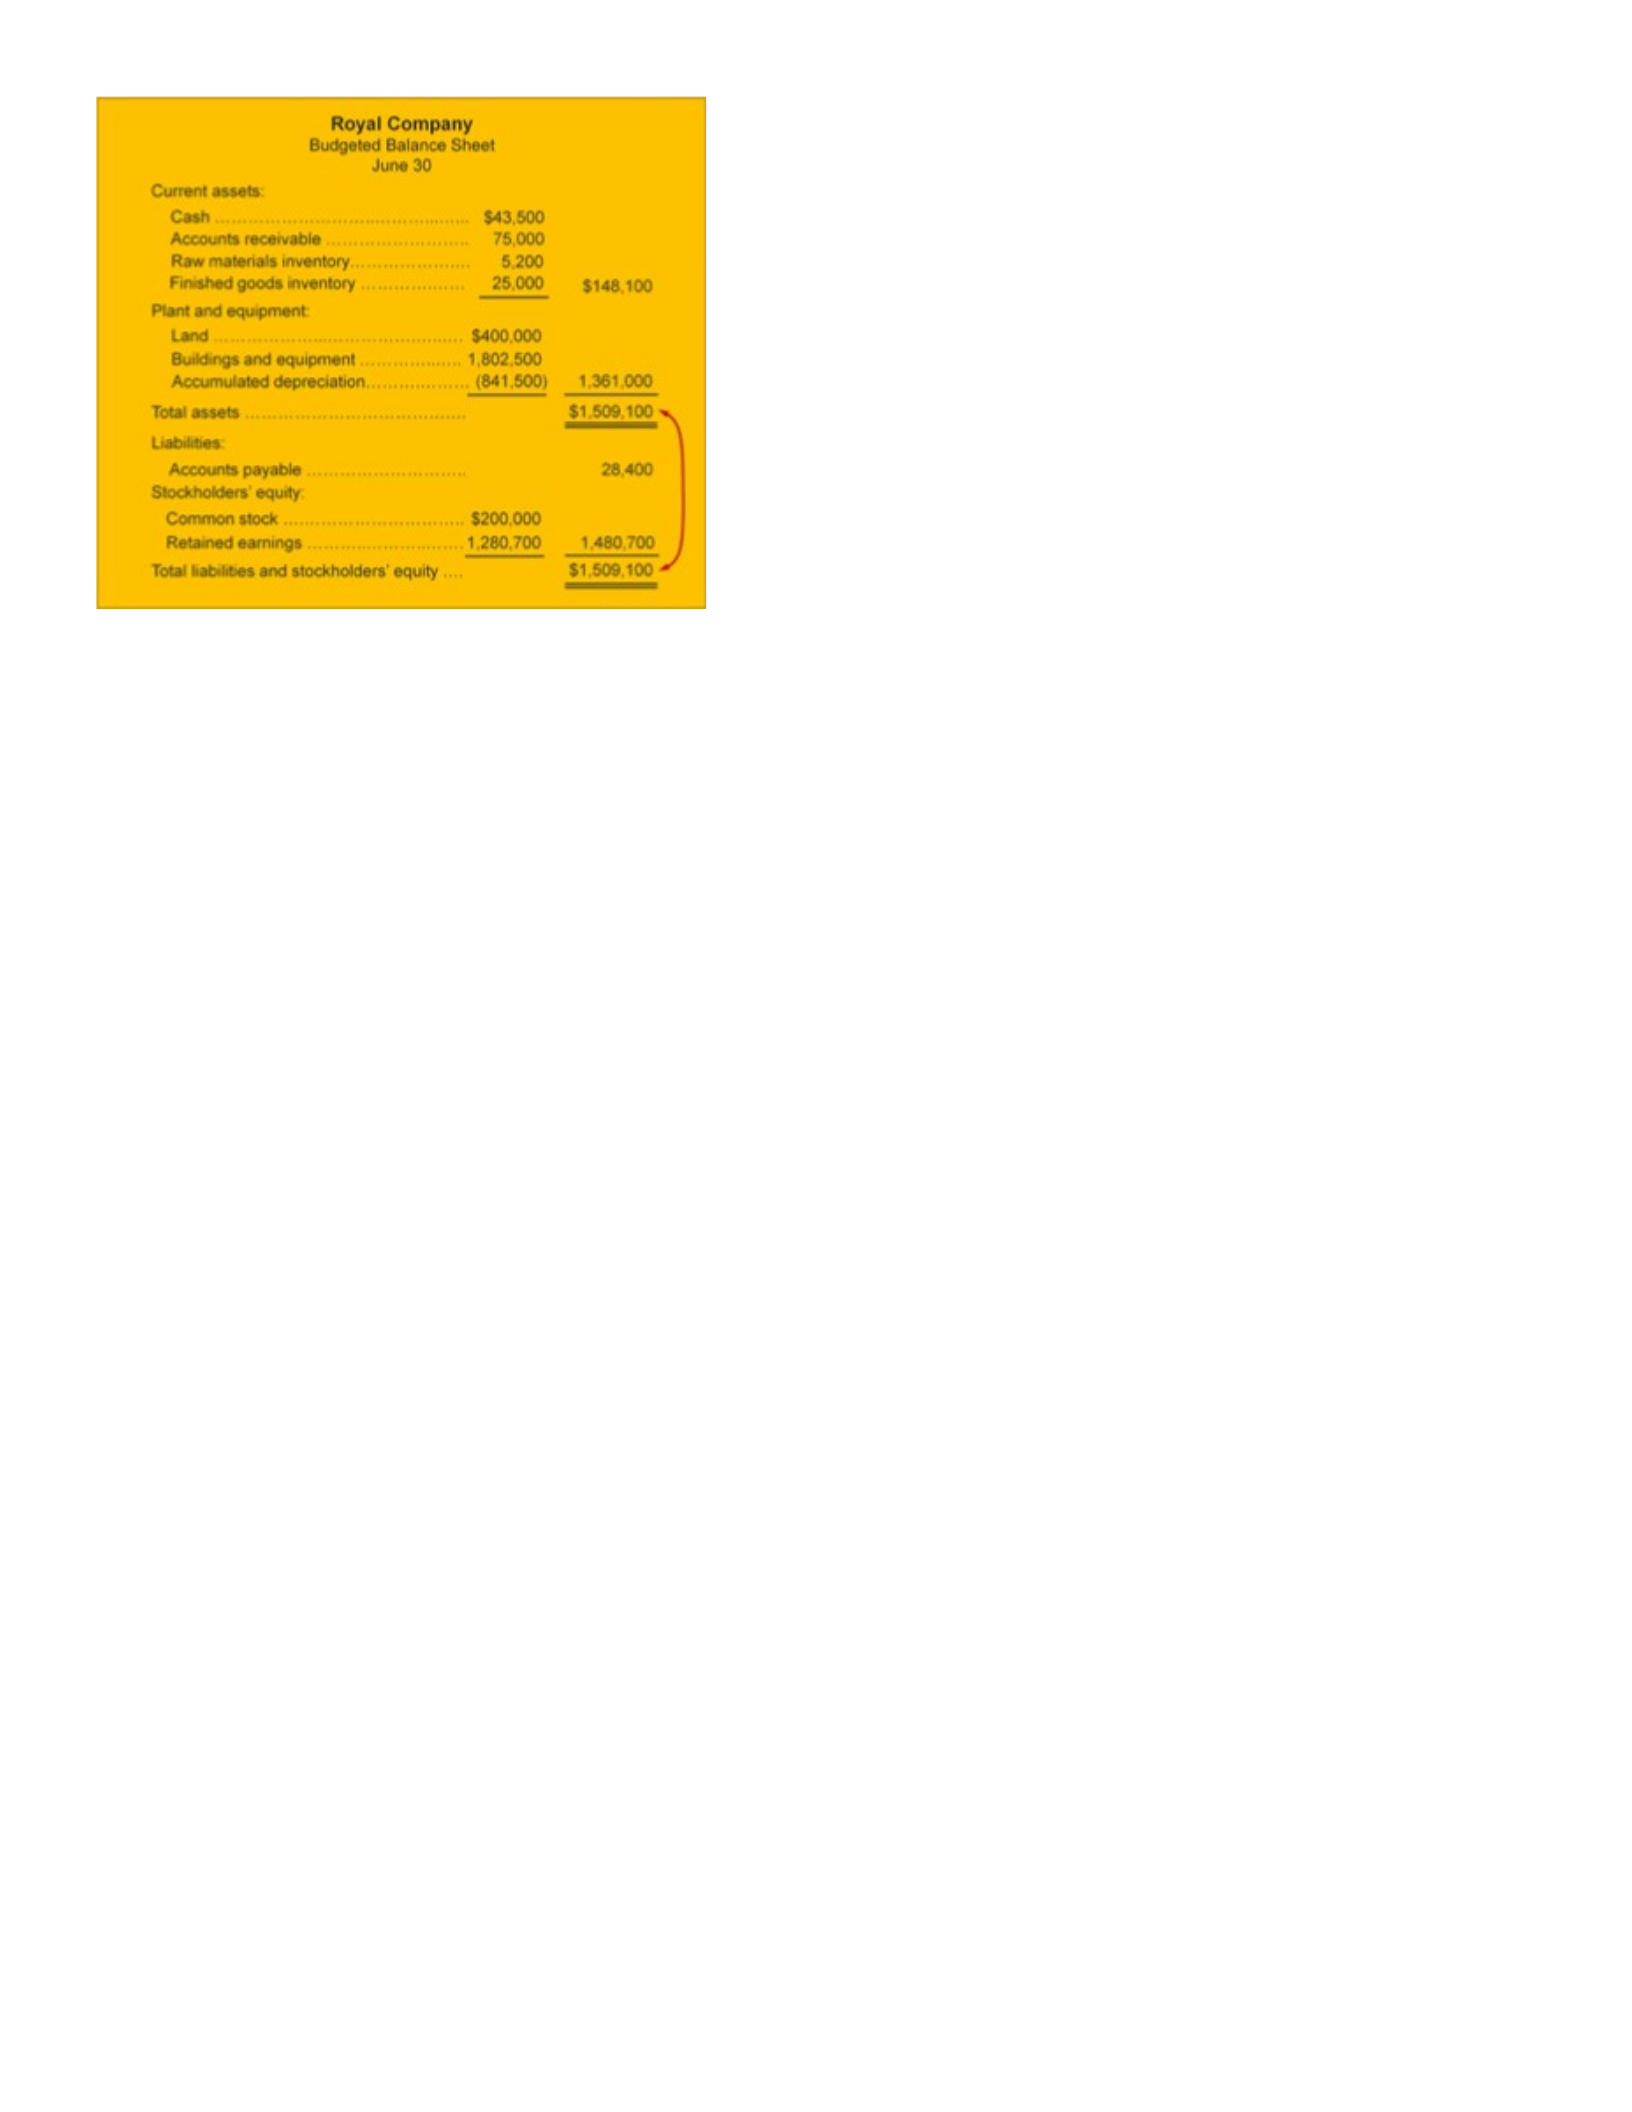
Budgeted Balance Sheet
Responsibility Accounting
Each line item in the budget is made the responsibility of a manager who is held accountable for
deviations from the goal
A manager is held responsible for those items that they can actually control to a significant extent
When actual results fall short of the budget, managers are not penalized but instead are expected to
understand the problem, take corrective action & be able to explain the circumstances to higher
management
It is important that:
oWithin the responsibility accounting system, all revenues & costs be assigned to managers so
that nothing falls through the cracks
oVariances from the plan be identified and acted upon promptly
oManagers are not punished for deviations from the plan
Responsibility Centers
Cost Center
oManager has control over costs only
oService departments (accounting, finance, legal) are typically classified as cost centers
oManagers are expected to minimize costs while providing services demanded by their
“customers”
Revenue center
oManager has control over revenues only
oMarketing departments are often evaluated as revenue centers
oMarketing departments set prices, develop product/service promotion strategies & formulate
sales projections
Profit center
oManager has control over both costs & revenues
oManager is expected to generate revenues & manage costs to achieve desired level of profits
oProfit center managers are often evaluated by comparing actual profit to budgeted profit
Investment center
oManager has control over costs, revenues, and investments in operating assets
oManager initiates investment proposals & is responsible for achieving investment objectives
oManagers evaluated with return on investment and/or residual income measures
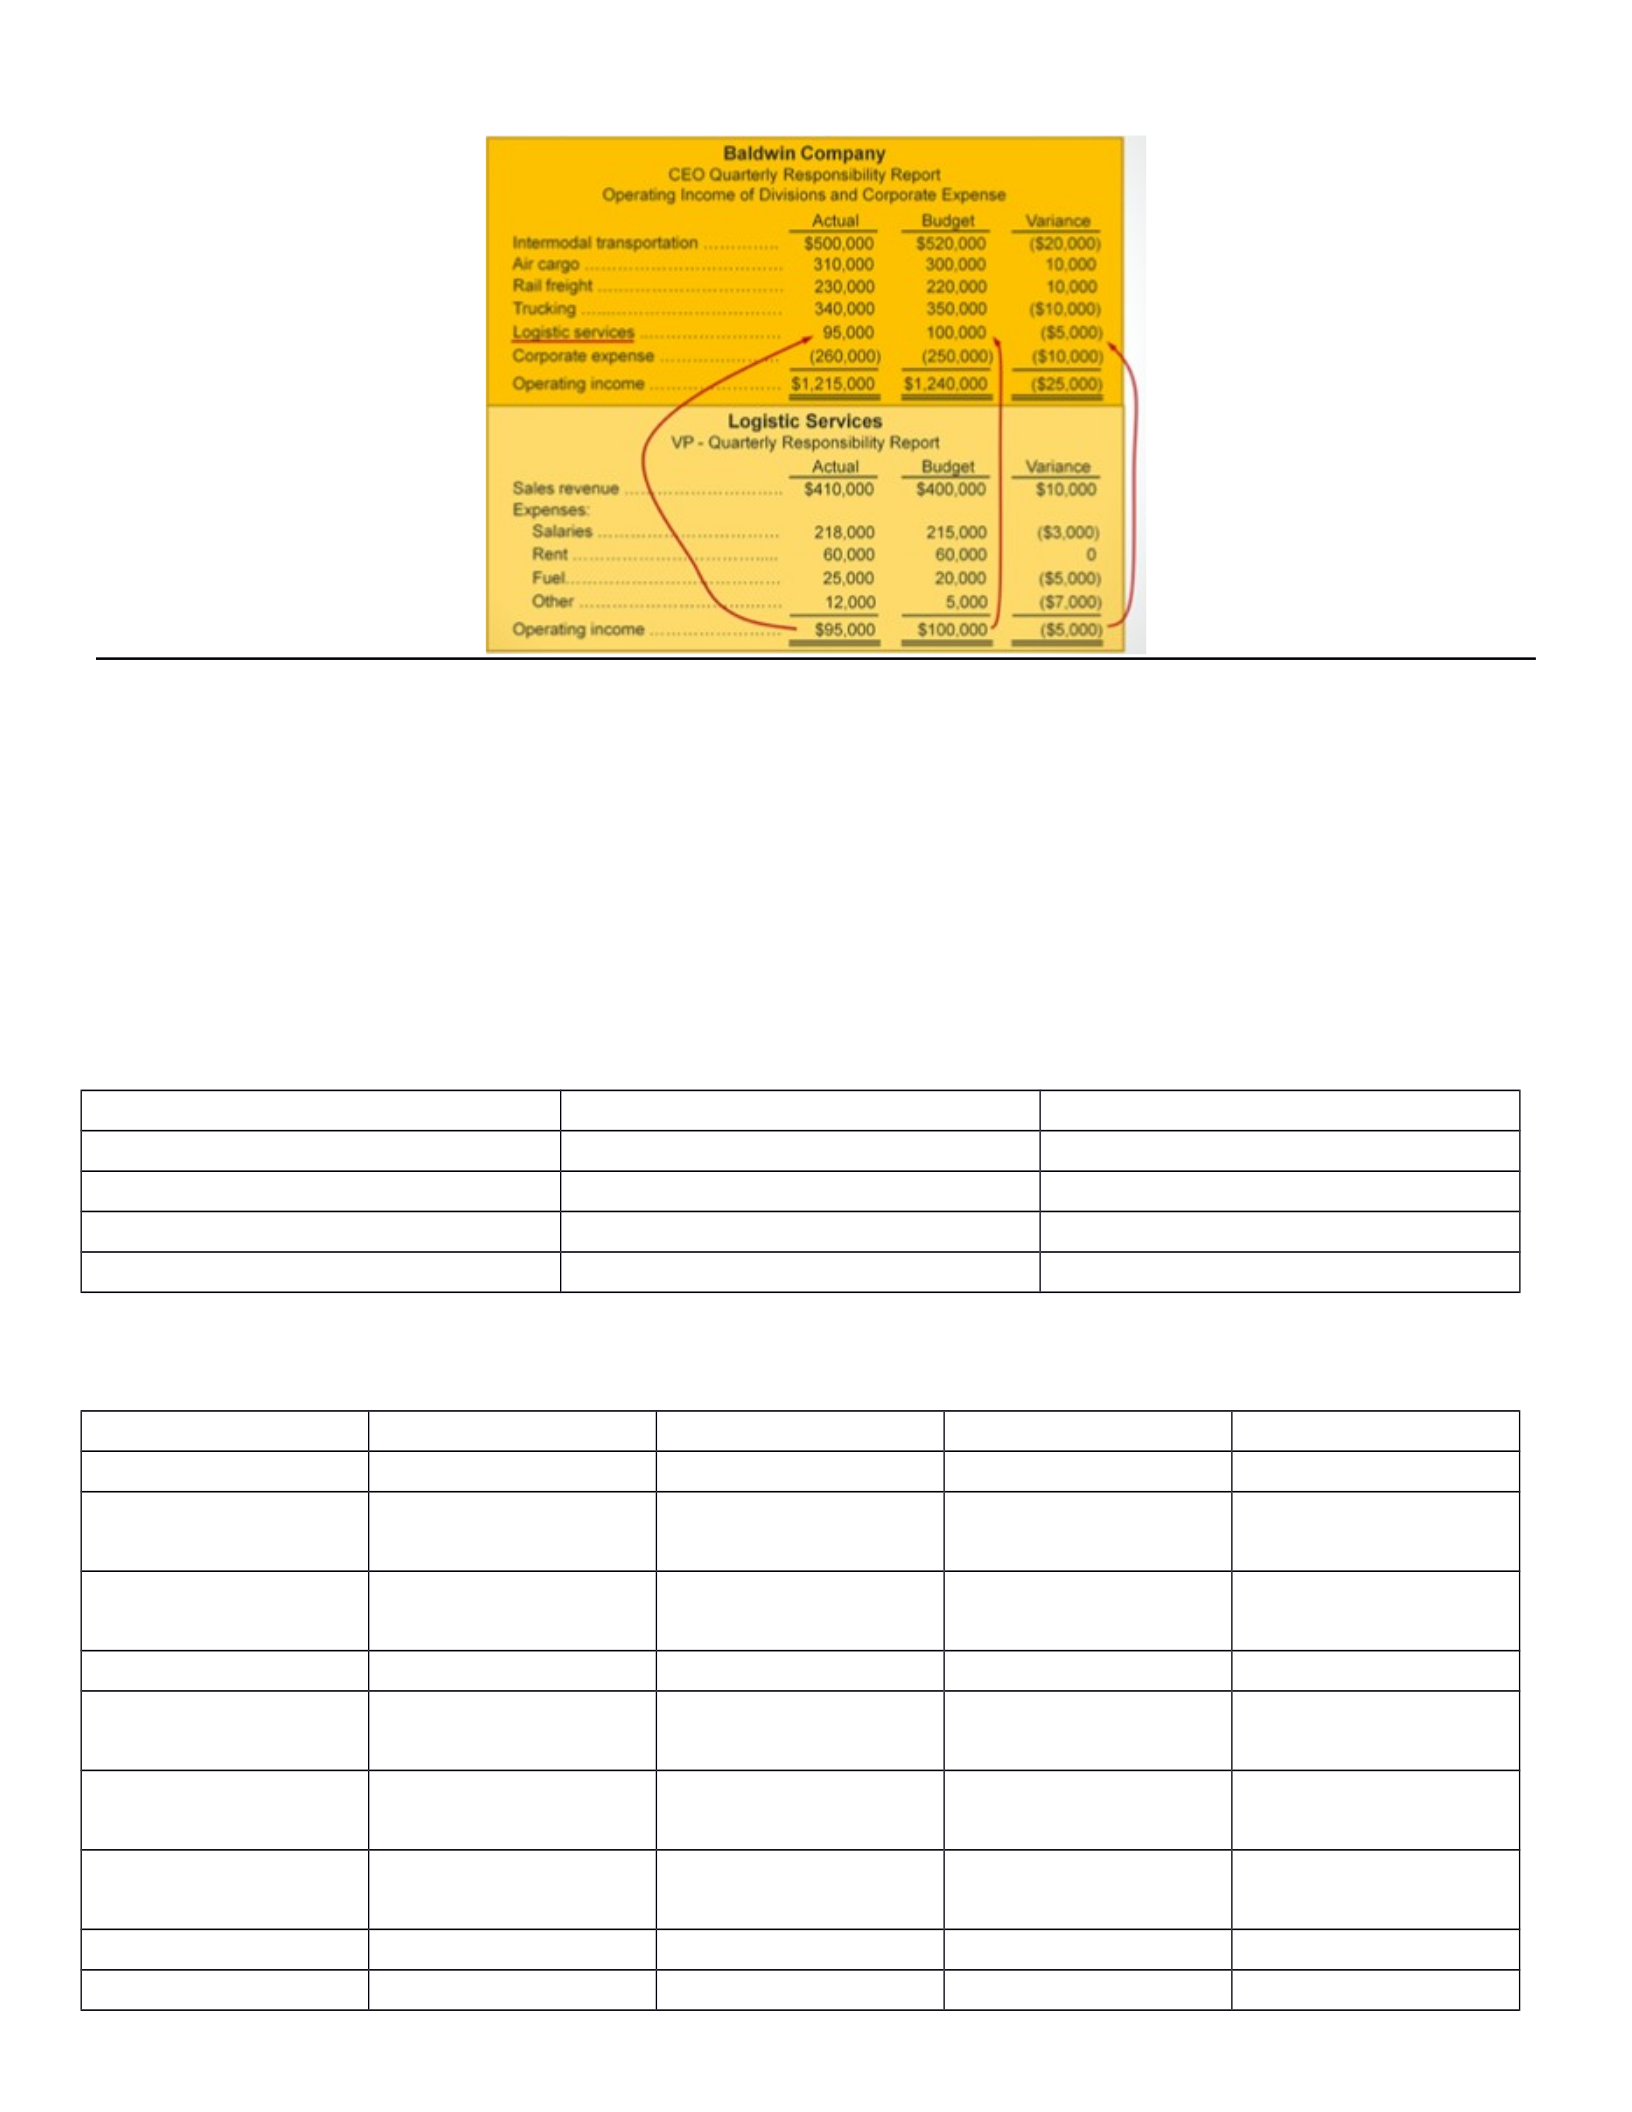
Responsibility Accounting Performance Report
ACC 241 Chapter 9 Activity Solutions
Activity 1: Sales & Cash Collections Budgets
Duke Sports Medicine, Inc. offers two types of physical exams for students: the basic physical & the extended
physical. The charge for the basic physical is $105 per exam while the charge for the extended physical is $160
per exam. Duke expects to perform 240 basic physicals & 170 extended physicals in July, 250 basic and 230
extended in August 75 basic & 90 extended in September.
The company’s sales are 20% cash & 80% credit. Cash collections of credit sales are 50% in the month of the
sale, 40% in the month after the sale, 8% two months after the sale & 2% are never collected. Total sales in
May were forecasted at $45,000 and in June were forecasted at $50,000.
(a) For May & June (from quarter 1), what were forecasted cash vs. credit sales for each month?
May June
Total Revenue $45,000 $50,000
Cash (20%) $9000 $10,000
Credit (80%) $36,000 $40,000
(b) prepare the sales budget for the 2nd quarter (July through September) with a column for each month & for
the quarter in total. separate cash vs. credit sales.
July August September Total
Basic Exams 240 250 75 565
Selling Price per
exam
$105 $105 $105 $105
Basic Exam
Revenue
$25,200 $26,250 $7,875 $59,325
Extended exams
performed
170 230 90 490
Selling price per
exam
$160 $160 $160 $160
Extended exam
Revenue
$27,200 $36,800 $14,400 $78,400
TOTAL REVENUE $52,400 $63,050 $22,275 $137,725
Cash (20%) $10,480 $12,610 $4,455 $27,545
Credit (80%) $41,920 $50,440 $17,820 $110,180
(c) prepare the cash collections budget for the 2nd quarter (July through September) with a column for each
month & one in total
July August September Total
Cash $10,480 $12,610 $4,455 $27,545
CREDIT
COLLECTIONS
Current Month
(50%)
41,920 X 50% =
$20,960
50,440 X 50% =
$25,220
17,820 X 20%=
$8,910
Previous Month
(40%)
$40,000 of June
Sales X 40% =
$16,000
41,920 of July X
40% =
$16,768
50,440 of August X
40% =
$20,176
2 months ago (8%) $36,000 of May X
8% =
$2,880
40,000 of June X
8%=
$3200
41,920 X 8% =
$3,354
Total collections for
each month
$50,320 $57,798 $36,895 $145,013
TOTAL REVENUE $52,400 $63,050 $22,275 $137,725
(d) why do monthly totals of sales differ from the monthly total of cash collections?
Activity 2: Production, DM & DL Budgets
Bullen & Company makes & sells high quality glare filters for computer monitors. The following data has been
assembled for 2016:
January February March April May
Estimated sales
(in units)
20,000 24,000 16,000 18,000 20,000
The filters usually sell for $75 per unit. Each filter uses 2 pounds of direct materials that cost an average of $5
per pound. Each filter takes 1.5 DLH to produce & DL workers are paid $15 per hour.
At December 31, the company had 6,000 filters in ending finished goods inventory. The company has a policy
that the ending finished goods inventory in any month must be 30% of the following month’s expected sales.
The company has a policy that it will have 10% of the following month’s direct material needs on hand at the
end of each month. At the end of December, there were 4400 pounds of DM on hand in RM inventory.
(a) prepare a production budget for the 1st quarter (January – March) with a column for each month & for the
quarter.
Beginning Inventory + Production – Sales = Ending Inventory
Therefore: Production = Ending Inventory + Sales – Beginning Inventory
January February March Quarter 1 April May
Estimated
sales (in
units)
20,000 24,000 16,000 60,000 18,000 20,000
Required
ending FG
inventory
7200 (30% of
January)
4800 (30% of
March)
5400 (30% of
April)
5400 (same
as March
inventory)
6000 (30% of
May)
Will be 30%
of June
(30% of next
month’s
sales)
Unit sales 20,000 24,000 16,000 60,000 18,000
+ desired
ending
inventory
7200 4800 5400 5400 6000
= units
needed
27,200 28,800 21,400 65,400 24,000
Less:
Beginning FG
Inventory
6000 7200 4800 6000 5400
= production
(in units)
21,200 21,600 16,600 59,400 18,600
(b) what would production budget be for April?
18,600 units
(c) prepare the direct materials budget for the first quarter of 2015 (January – March) with a column for each
month & for the quarter.
January February March Quarter 1 April
Units to be
produced
21,200 21,600 16,600 59,400 18,600
DM needed per
unit
22222
Total DM
needed for
production
42,400 43,200 33,200 118,800 37,200
Desired ending
RM inventory
4,320 (10% of
December)
3,320 (10% of
March)
3,720 (10% of
April)
3,720 (same as
march)
(10% of next
month’s usage)
Total DM
needed for
production
42,400 43,200 33,200 118,800
+ desired
ending RM
inventory
4,320 3,320 3,720 3,720
= total quantity
of RM needed
46,720 46,520 36,920 122,520
- beginning RM
inventory
4400
(December)
4320 (January) 3320 (February) 4400 (January
amount)
= quantity to
purchase
42,320 42,200 33,600 118,120
Average cost of
RM per pound
$5 $5 $5 $5
TOTAL DM
BUDGET
$211,600 $211,000 $168,000 $590,000
(d) prepare the direct labor budget for the 1st quarter of 2015 (January – March) with a column for each month
& for the quarter.
January February March Quarter 1
Units to be
produced
21,200 21,600 16,600 59,400
DLH per unit 1.5 1.5 1.5 1.5
Total DLH needed 31,800 32,400 24,900 89,100
Cost per DLH $15 $15 $15 $15
Total DL Cost $477,000 $486,000 $373,500 $1,336,500
Activity 3: Manufacturing Overhead & Operating Expenses Budget
Continue with the information from Activity 2. Assume that variable manufacturing overhead is $2.50 per
direct labor hour & the company’s fixed manufacturing overhead is expected to be $80,000 per month (no
depreciation). The company’s variable operating expenses are expected to be $3 per unit produced & fixed
monthly operating expenses include $5000 for salaries, $3000 for rent & $2500 for depreciation.
(a) prepare the manufacturing overhead budget for the 1st quarter of 2015 (January – March) with a column
for each month & for the quarter.
January February March Quarter 1
Total DLH needed 31,800 32,400 24,900 89,100
VMHOH per DLH 2.5 2.5 2.5 2.5
Total VMHOH $79,500 $81,000 $62,250 $222,750
Fixed MOH 80,000 80,000 80,000 80,000
Total MOH $159,500 $161,000 $142,250 $462,750
(b) Prepare the operating expenses budget for the 1st quarter of 2015 (January – march) with a column for
each month & for the quarter.
January February March Quarter 1
Total units 21,200 21,600 16,600 59,400
Op. Exp per unit
Produced
$3 $3 $3 $3
Total Variable
Operating Exp.
$63,600 $64,800 $49,800 $178,200
Salaries 5000 5000 5000 15,000
Rent 3000 3000 3000 9000
Depreciation 2500 2500 2500 7500
Total operating
expense
$74,100 $75,300 $60,300 $209,700
January February March Quarter 1
Total operating
expenses
$74,100 $75,300 $60,300 $209,700
LESS: depreciation 2500 2500 2500 7500
Total CASH
operating exp.
$71,600 $72,800 $57,800 $202,200
Activity 4: Cash Payments Budget
We are continuing with the information from activity #2 and #3. Assume that the company pays for 60% of its
DM purchases in the month of purchase & the remainder the following month. December’s DM purchases
totaled $200,000. DL, MOH and Operating expenses are paid in the month they are incurred.
Prepare the cash payments budget for the 1st quarter of 2015 (January – March) with a column for each month
& for the quarter.
December January February March Quarter 1
DM Purchases –
from Activity 2
$200,000 $211,600 $211,000 $168,000
Payment of
current month
DM purchases
(60%)
$126,960 $126,600 $100,800 $354,360
Payment of
prior month
DM purchases
(40%)
$80,000 $84,640 $84,400 $249,040
DL – from
activity 2
$477,000 $486,000 $373,500 $1,336,500
MOH – from
activity 3
$159,500 $161,000 $142,250 $462,750
Operating
expenses (less
depreciation) –
from activity 3
$71,600 $72,800 $57,800 $202,200
$915,060 $931,040 $758,750 $2,604,850
Activity 5: Integrated Budget
Hamill Merchandising prepares budgets quarterly. The following information is available for use in planning the
2nd quarter budget for 2015:
Balance sheet as of March 31,2015:
Assets Liabilities & Stockholders’ Equity
Cash 3000 Accounts payable 26,000
Accounts receivable 28,000 Dividends payable 17,000
Inventory 24,000 Capital stock 2000
Prepaid insurance 2000 Retained earnings 37,000
Building & equipment (net) 25,000
Total assets 82,000 Total liabilities & equity 82,000
Actual & forecasted sales for selected months in 2015 are as follows:
MONTH SALES REV OPERATING EXP
January (actual) 60,000 18,000
February (actual) 50,000 19,000
March (actual) 40,000 15,000
April (forecasted) 50,000 18,000
May (forecasted) 60,000 18,000
June (forecasted) 70,000 15,000
July (forecasted) 90,000 22,000
August (forecasted) 80,000 22,000
Other pertinent information:
All sales are on account with 30% collected in the month of the sale & 70% collected in the following
month
COGS is equal to 60% of sales
Ending inventories should be equal to 80% of next month’s COGS
Purchases during any given month are paid 20% in the month of each quarter & are paid during the 1st
month of the following quarter
The prepaid insurance is for five more months & depreciation is $1000 per month
The company is subject to a corporate tax rate of 30%
REQUIRED:
Prepare the following budgets for the second quarter of the year:
Sales & cash receipts for each month in the 2nd quarter
Purchases, operating expenses, & cash disbursements for each month in the 2nd quarter
Budgeted income statement for each month and for the quarter
Compare the cash receipts & cash disbursements budgets. What does this tell you?
Chapter 9 Homework
(1) Smith manufacturing produces self-watering planters for use in upscale retail establishments. Sales
projections for the first five months of the upcoming year show the estimated unit sales of the planters each
month to be as follows:
Number of planters to be sold
January 3400
Februar
y
3800
March 3300
April 4900
May 4600
Inventory at the start of the year was 850 planters. The desired inventory of planters at the end of each month
should be equal to 25% of the following month’s budgeted sales. Each planter requires three pounds of
polypropylene (a type of plastic). The company wants to have 20% of the polypropylene required for the next
month’s production on hand at the end of each month. The polypropylene costs $0.20 per pound.
a. prepare a production budget for each month in the first quarter of the year, including production in units for
each month and for the quarter.
Smith Manufacturing
Production Budget
For the Months of January through March
January February March Quarter
Unit sales 3400 3800 3300 10,500
Add: Desired
ending inventory
950 825 1225 1225
Total needed 4350 4625 4525 11,725
Less: beginning
inventory
850 950 825 850
Units to produce 3500 3675 3700 10,875
b. prepare a direct materials budget for the polypropylene for each month in the 1st quarter of the year,
including the pounds of polypropylene required and the total cost of the polypropylene to be purchased.
Strat by preparing the direct materials budget through the total quantity needed, then complete the budget.
Smith Manufacturing
Direct Materials Budget
For the months of January through March
January February March Quarter
Units to be
produced
3500 3675 3700 10,875
Multiply by:
quantity of direct
materials needed
per unit
3 3 3 3
Quantity needed
for production
10,500 11,025 11,100 32,625
Plus: desired
ending inventory
of direct materials
2205 2220 2895 2895
Total quantity
needed
12,705 13,245 13,995 35,520
Less: beginning
inventory of direct
materials
2100 2205 2220 2100
Quantity to
purchase
10,605 11,040 11,775 33,420
Multiply by: cost
per pound
$.20 $.20 $.20 $.20
Total cost of direct
materials
purchases
2,121 2208 2355 6684
(2) Juda industries manufactures three models of a product in a single plant with two departments: cutting &
assembly. The company has estimated costs for each of the three product models, the Imperial, the Regal, and
the royal models.
The company is currently analyzing direct labor hour requirements for the upcoming year:
Budgeted unit production for each of the products is as follows:
Number of units to be produced
Cutting Assembly
Estimated hours per unit
Imperial 1.5 2
Regal 1.8 2.2
Royal 1 2.4
Direct labor hour rate $11 $12
Product model:
Imperial 590
Regal 760
Royal 880
Prepare a direct labor budget for the upcoming year that shows the budgeted direct labor costs for each
department and for the company as a whole.
Juda Industries
Direct Labor Budget
For the Upcoming Year
Imperial Regal Royal Total
Cutting department
Units to be
produced
590 760 880
Multiply by: direct
labor hours per
unit
1.5 1.8 1.0
Total cutting hours
required
885 1368 880
Multiply by: direct
labor costs per
hour
11 11 11
Budgeted direct
labor cost
9735 15,048 9680 34,463
Assembly
department
Units to be
produced
590 760 880
Multiply by: direct
labor hours per
unit
2 2.2 2.4
Total assembly
hours required
1180 1672 2112
Multiply by: direct
labor cost per hour
12 12 12
Budgeted direct
labor cost
14,160 20,064 25,344 59,568
Total budgeted
direct labor cost
23,895 35,112 35,024 94,031
(3) the rouse company is in the process of preparing its manufacturing overhead budget for the upcoming year.
Sales are projected to be 49,000 units. Information about the various manufacturing overhead costs follows:
Variable rate per unit Total fixed costs
Indirect materials $1.10
Supplies $0.90
Indirect labor $0.60 $69,000
Plant utilities $0.10 $30,000
Repairs & maintenance $0.40 $18,000
Depreciation on plant &
equipment
$42,000
Insurance on plant & equipment $29,000
Plant supervision $67,000
Prepare the manufacturing overhead budget for the rouse company for the upcoming year.
The Rouse Company
Manufacturing Overhead Budget
For the Upcoming Year
Projected sales (units) 49,000
Variable manufacturing overhead costs:
Indirect supplies $53,900
Supplies 44,100
Indirect labor 29,400
Plant utilities 4900
Repairs & maintenance 19,600
Total variable manufacturing overhead $151,900
Fixed manufacturing overhead costs:
Indirect labor $69,000
Plant utilities 30,000
Repairs and maintenance 18,000
Depreciation on plant and equipment 42,000
Insurance on plant and equipment 29,000
Plant supervision 67,000
Total fixed manufacturing overhead $255,000
Total manufacturing overhead $406,900
Chapter 9 Quiz
(1) Victoria Corporation manufactures quality vases. Budgeted sales & production data for the vases are as
follows:
Month 1 budgeted unit sales : 2500
Month 2 budgeted unit sales : 2200
Month 3 budgeted unit sales: 3500
Month 1 budgeted unit production : 2900
Month 2 budgeted unit production : 2500
Month 3 budgeted unit production : 3000
Raw material required for each finished unit (in pounds) : 1
Each vase requires one pound of clay in its manufacture. Vitoria corporation has a policy that the inventory of
clay at the end of each months needs to be equal to 30% of the production needs for the following month. At
the beginning of January, 870 pounds of clay were in inventory. How many pounds of clay would Victoria
Corporation need to purchase in February (month 2)
Material required for month 2
budgeted unit production
2500
Add: desired ending inventory 900 =3000 X 30% X 1
Total materials needs 3400
Less: beginning inventory 750 = 2500 X 30% X 1
Purchase in February (month 2) 2650
(2) Mighty Corporation manufactures end tables. Each end table requires .50 direct labor hours in its
production. Mighly corporation has a direct labor rate of $14 per direct labor hour. The production budget
shows mighty corporation plans to produce 1500 end tables in March and 600 end tables in April. What is the
total combined direct labor cost that mighty corporation should budget in March and April?
Particulars March April
Budget tables (A) 1500 600
Required labor hours per each
table (B)
.50 .50
Direct labor rate (C) $14 $14
Direct labor cost (A) x (B) x (C) 10,500 4200
Calculate total labor cost 10,500 + 4200 = 14,700
(3) Whistle Works manufactures safety whistle keychains. They have the following information available to
prepare their master budget
MOH Costs
Variable MOH Costs $2 per unit produced
Fixed MOH costs $226,000
Other info:
Units produced in 2016 49,000
Units sold in 2016 46,500
Whistle works sells each whistle for $8. It’s been determined that each units costs $6.50 to manufacture. How
much is total budget MOH costs for the year ended 2016?
Variable MOH Costs $2 X 49,000 produced in 2016
Add: Fixed MOH costs 226,000
Total = 324,000
(4) whistle works manufactures safety whistle keychains. They have the following info available to prepare
their master budget:
Operating Expenses
Variable operating costs $.75 per unit sold
Fixed operating costs $475,000
Other info:
Units produced in 2016: 42,000
Units sold in 2016: 40,500
Whistle works sells each whistle for $12. It’s been determined that each unit costs $7.25 to manufacture. How
much is total budgeted operating expenses for the year ended 2016?
Variable operating costs $.75 per unit sold X 40,500
Add: fixed operating expenses $475,000
Total Operating Costs: $505,375
(5) managers may intentionally build slack into the budget
(1) to acquire the resources, they need in the event the organization implements a budget cut
(2) because they are uncertain about the future
(3) to make their performance appear better
(4) all of the above are true
(6) Brockman company is preparing its cash budget for the upcoming month. The budgeted beginning cash
balance is expected to be $35,000. Budgeted cash disbursements are $124,000, while budgeted cash receipts
are $128,000. Brockman company wants to have an ending cash balance of $47,000. How much would
Brockman company need to borrow to achieve its desired ending cash balance?
Beginning cash balance 35,000
Add: budgeted receipts 128,000
Less: budgeted disbursements 124,000
= 39,000
Borrowing amount
Desired ending cash balance 47,000
Less: budgeted cash balance 39,000
= 8,000
(7) which of the following budgets is the cornerstone of the master budget?
Sales
(8) Loyal pet company expects to sell 6000 beefy dog treats in January and 7000 in February for $2 each. What
will be the total sales revenue reflected in the sales budget for those months
January 6000 X 2 = 12000
February 7000 X 2 = 14000
(9) Totz company produces jump ropes. Totz company has the following sales projections for the upcoming
year:
First quarter budgeted rope sales in units 16,000
Second quarter budgeted jump rope sales in units 35,000
Third quarter budgeted jump rope sales in units 23,000
Fourth quarter budgeted jump rope sales in units 28,000
Inventory at the beginning of the year was 3900 jump ropes. Totz company wants to have 20% of the next
quarter’s sales in units at the end of each quarter. How many jump ropes should Totz company produce during
the 1st quarter?
Production unit = sale unit + desired ending inventory – beginning inventory
= 16000 + (35000 X 205%) – 3900
= 19,100
(10) distribution corporation collects 60% of a month’s sales in the month of sale, 35% in the month following
sale, and 5% in the second month following sale. Budgeted sales for the upcoming 4 months are:
April $140,000
May $170,000
June $250,000
July $230,000
The amount of cash that will be collected in July is budgeted to be:
Computation of budgeted cash collected in July
Month
May budgeted sales
5% in the second month following sale ($170,000 *
5%)
8500
June Budgeted Sales
35% in the month following sale (250,000 * 35%)
87,500
July Budgeted Sales
60% of sales collected in month of sale (230,000 X
60%)
138,000
TOTAL cash collected in July Month 234,000
Chapter 10: Performance Evaluation
Decentralization
as companies grow, it is not uncommon for them to decentralize their operations, moving from a
centralized structure, where all decisions are made by a core group of managers, to a structure that
disperses decision making authority throughout the organization
Frees top management’s time
Supports use of expert knowledge
Improves customer relations
Provides training
Improves motivation & retention
Disadvantages of decentralization
Duplication of costs
Lack of goal congruence
Hampers innovation
Lack of “big picture” perspective
Lack of overall coordination
Performance evaluation systems
Promote goal congruence & coordination
oProvide incentives for coordinating subunit activities and direct them toward achieving
company’s goals
Communicate expectations
oDisseminate company goals to subunit level and identifying critical performance objectives
Motivate unit managers
oFinancial incentives may be offered to unit managers for accomplishing performance objectives
Provide feedback
oProvide upper management with information needed to maintain control over the entire
organization
Benchmarking
oCompares subunit performance against past performance, other subunits, competitors and
industry best practices
Responsibility centers
Cost center
oManagers has control over costs only
oService departments (accounting, finance, legal) are typically classified as cost centers
oManagers are expected to minimize costs while providing services demanded by their
“customers”
Revenue center
oManager has control over revenues only
oMarketing departments are often evaluated as revenue centers
oMarketing departments set prices, develop product/service promotion strategies and formulate
sales projections
Profit center
oManager has control over both costs and revenues
oManager is expected to generate revenues and manage costs to achieve desired level of profits
oProfit center managers are often evaluated by comparing actual profit to budgeted profit
Investment center
oManager has control over costs, revenues, and investments in operating assets
oManager initiates investment proposals and is responsible for achieving investment objectives
oManagers evaluated with return on investment and/or residual income measures
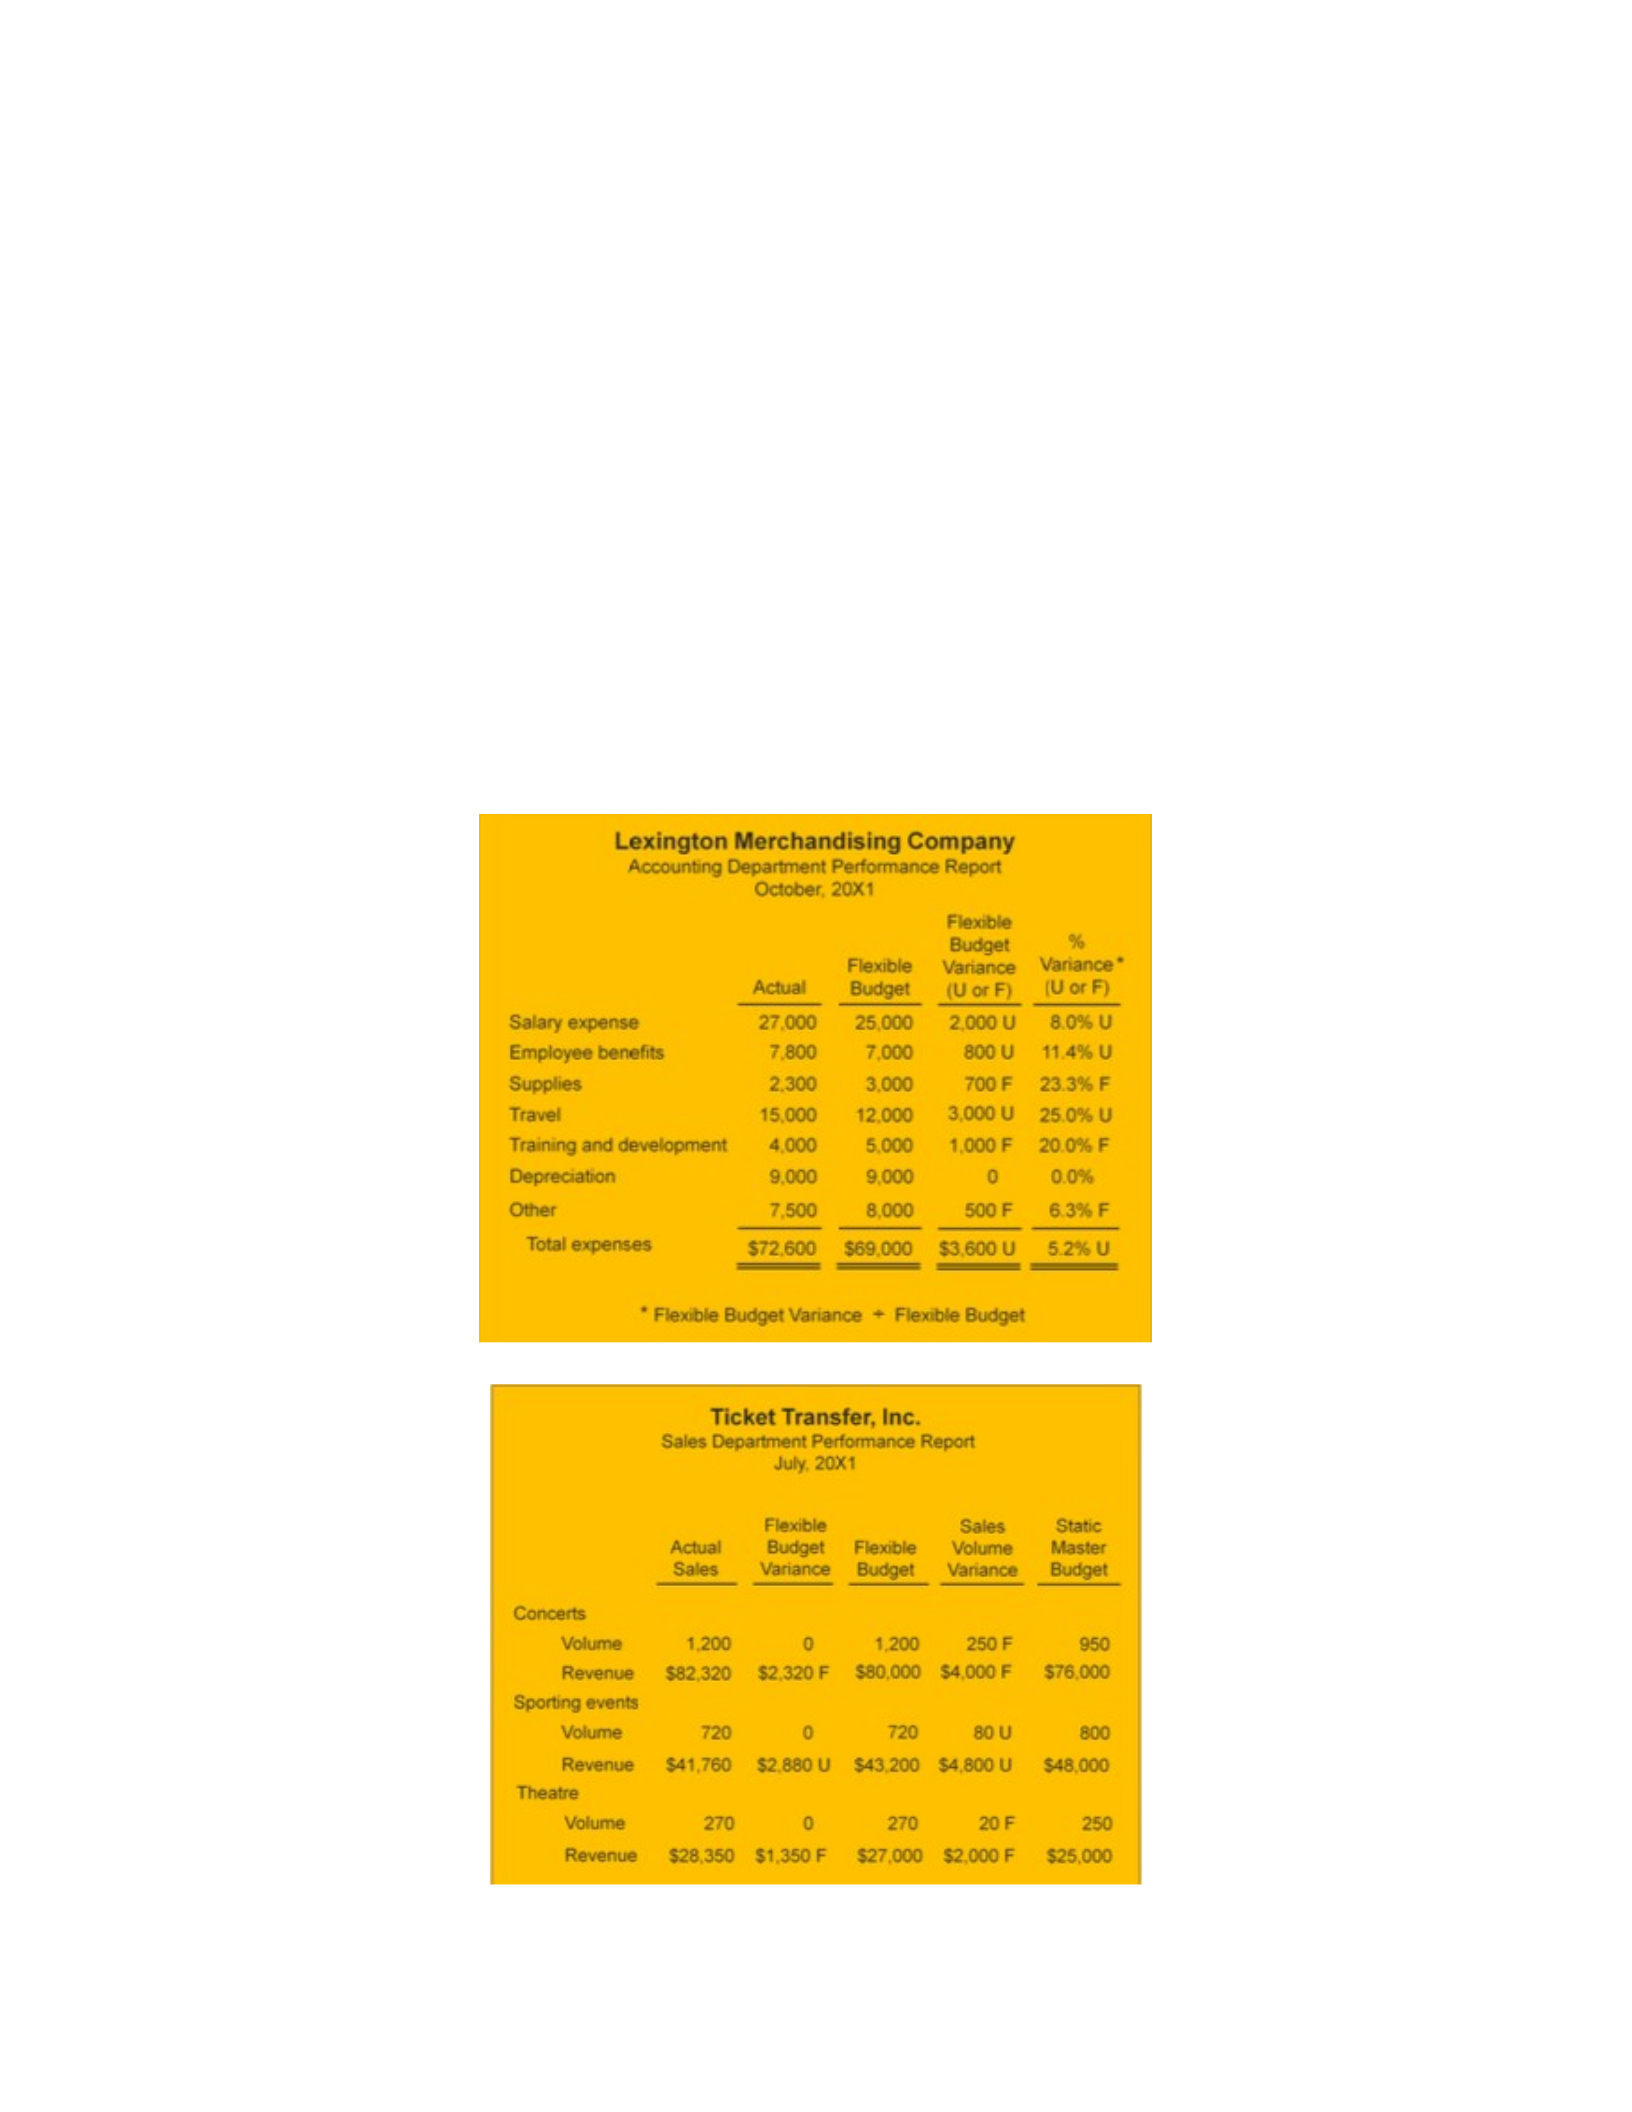
Cost center performance report
Revenue Center Performance Report
Profit center performance report
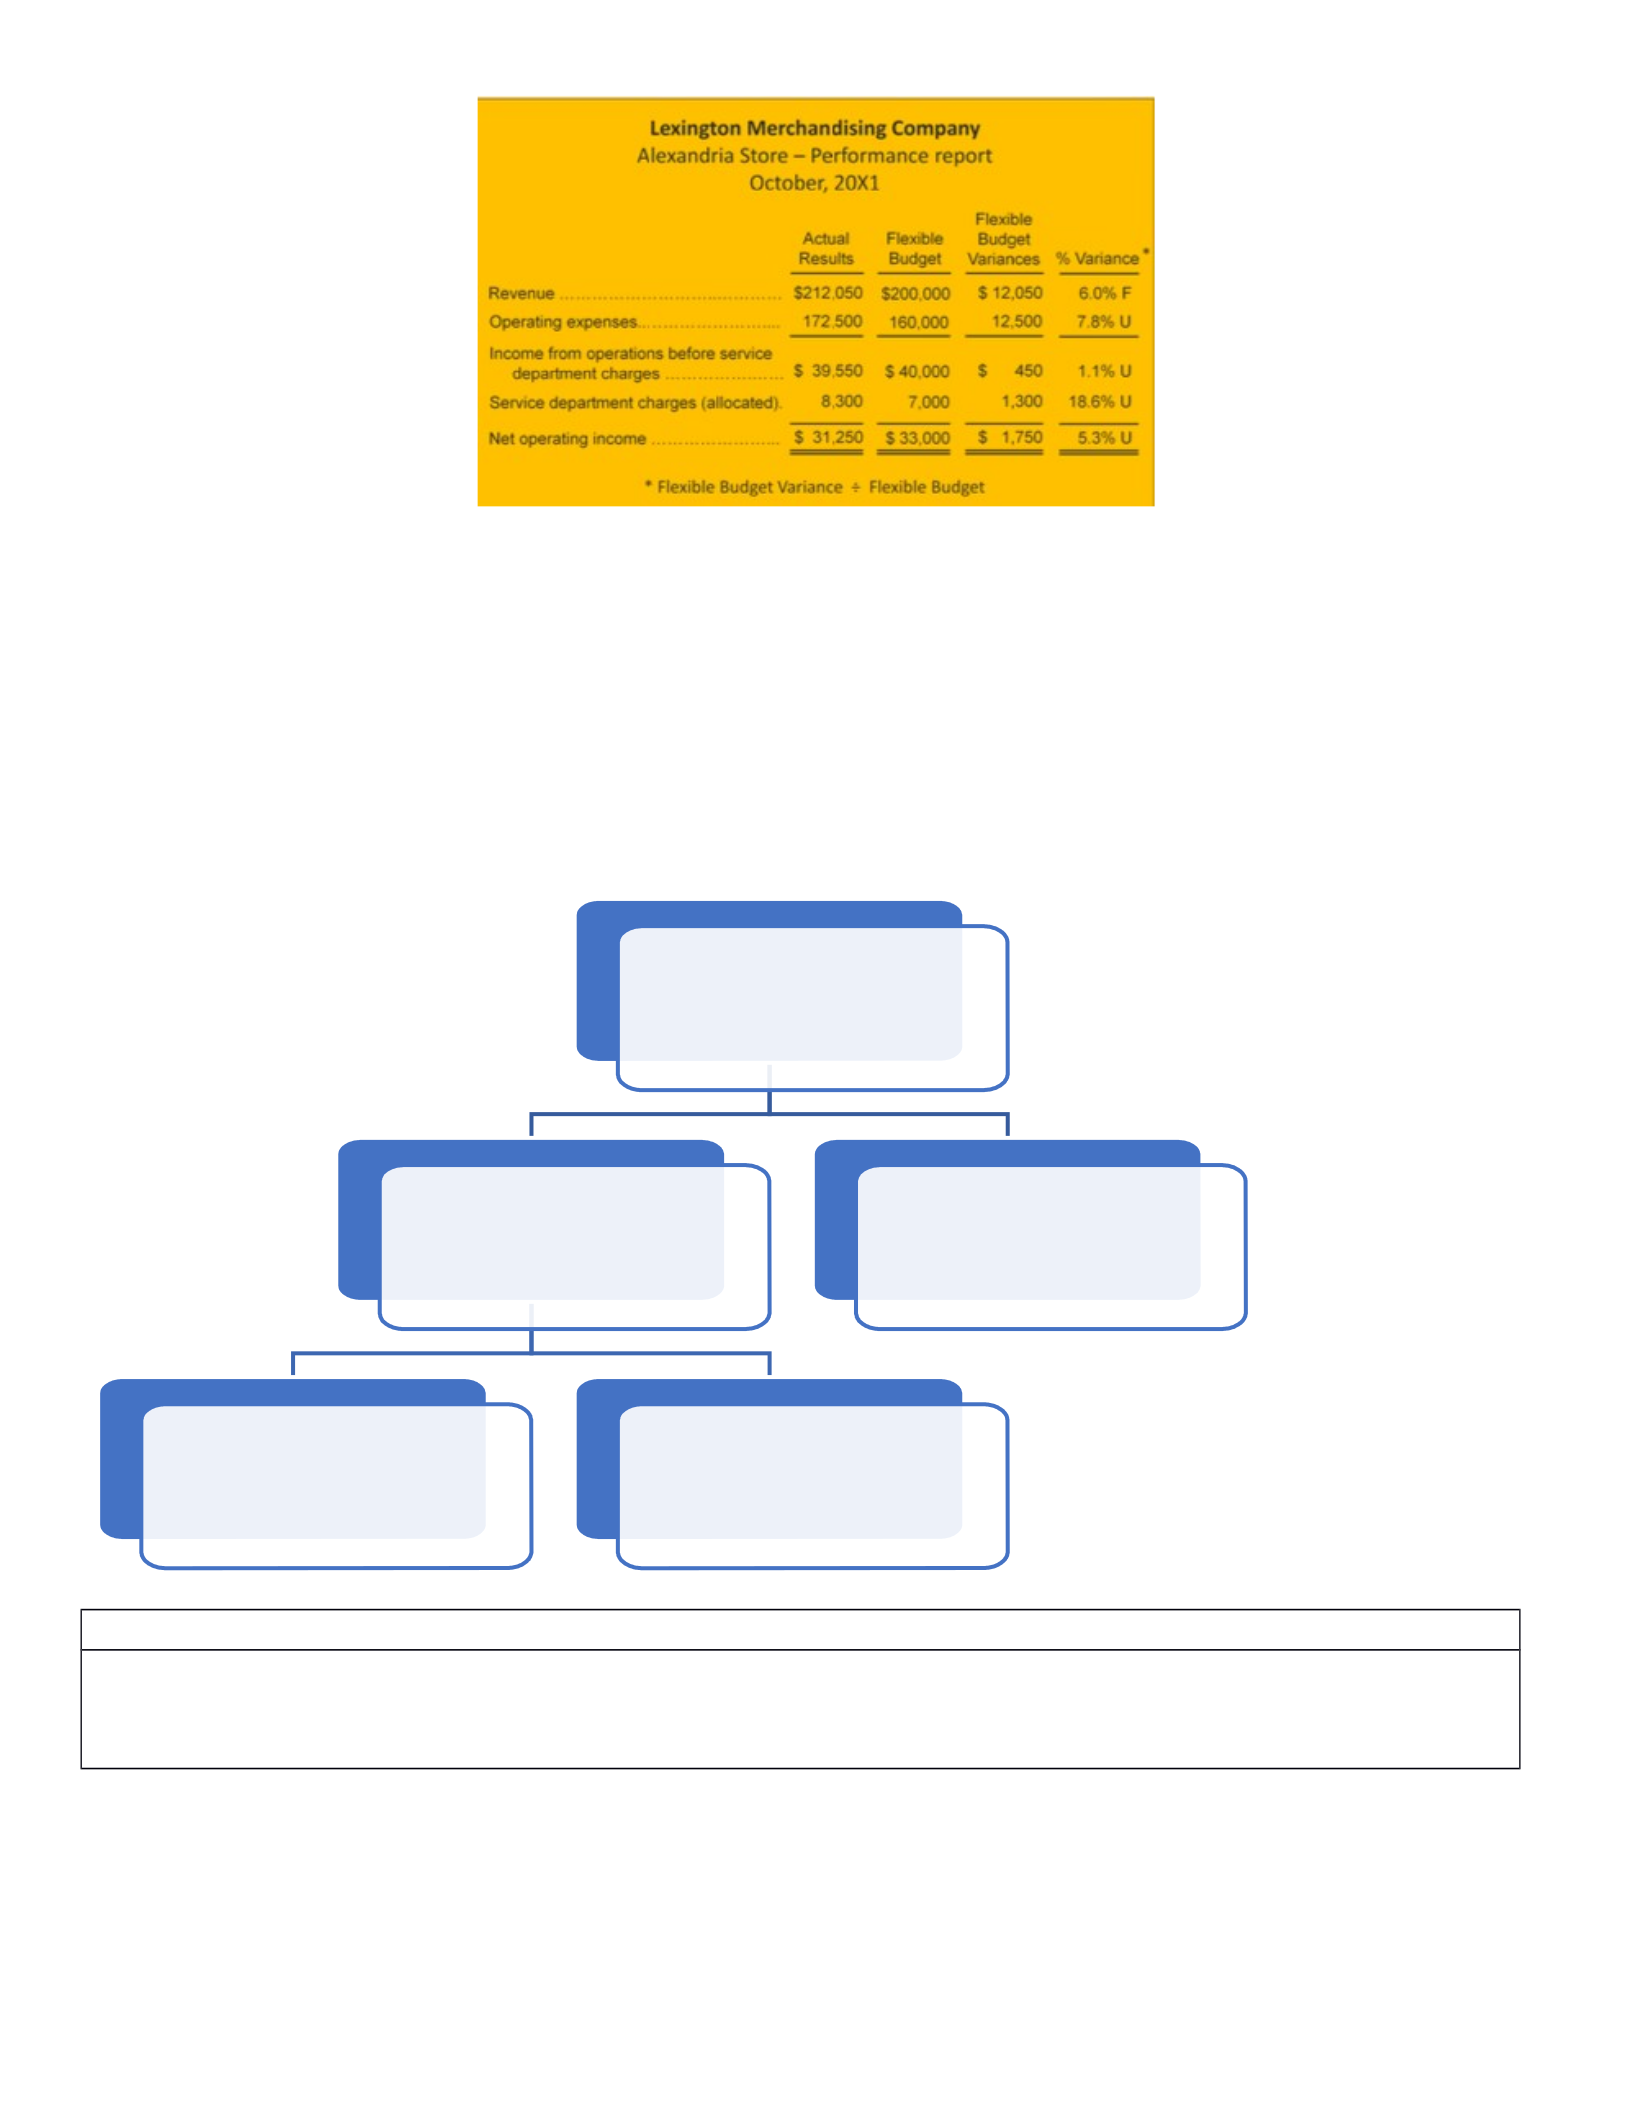
Centralized services
Performance Measures for Investment Centers
Investment Center Performance Measures (KPIs)
These measures take into consideration:
1. the center’s operating income
2. the center’s assets
®Return on investment (ROI)
®Residual income (RI)
®Economic value added (VA)
Return on investment
= net operting income / total assets
top management
decision: provide
centralized service
departments?
Yes: charge subunits
for their use of
centralized service
departments?
Yes: centralized
service deparment
costs are allocated to
subunits
No: centralized
services are provided
"free of charge"
No: subunits must
provide or outsource
their own services
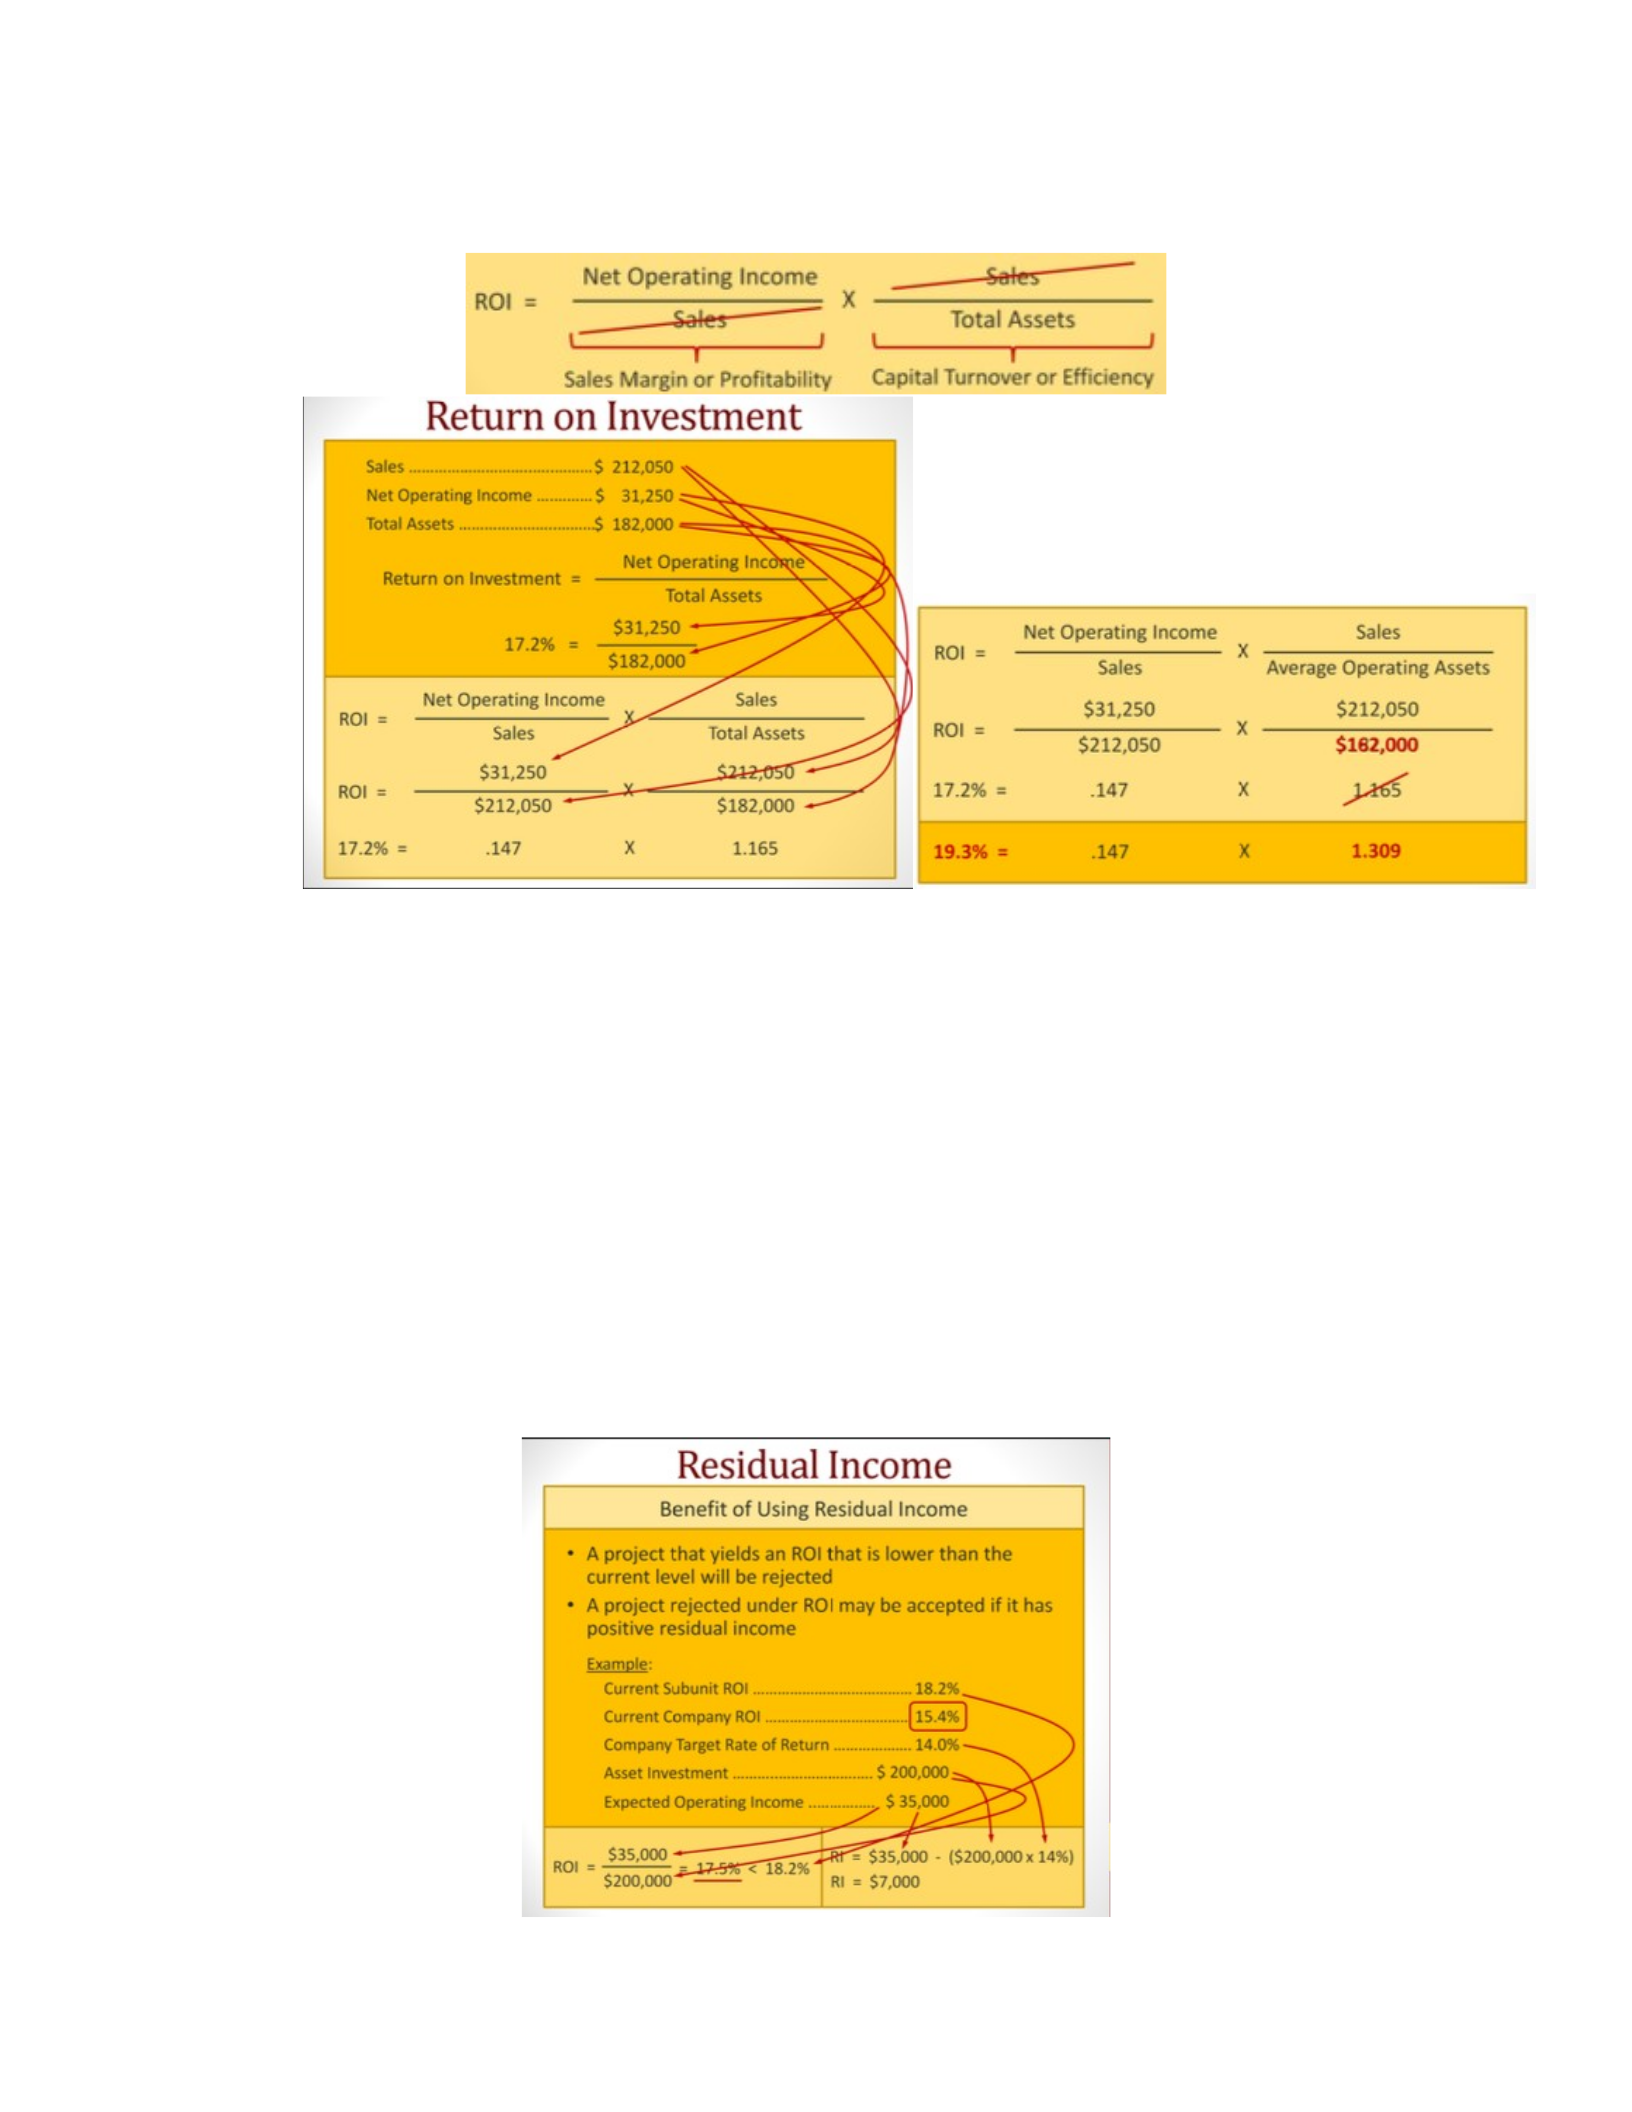
The higher the return on investment, the greater the profit earned of each dollar of investment in the
subunit’s operating assets
The ROI calculation can be decomposed to provide inight into how ROI can be improved:
Criticisms of return on investment
Attempts to improve ROI by reducing costs, increasing sales or reducing investment may not be
consistent with the company’s overall strategic initiatives or may be “near sighted”
Managers inherit many commited costs that they have no control over, yet they have their performance
measured (via ROI) against them
Managers may reject investments beneficial to the company as a whole because they are detrimental
to the ROI of their investment center
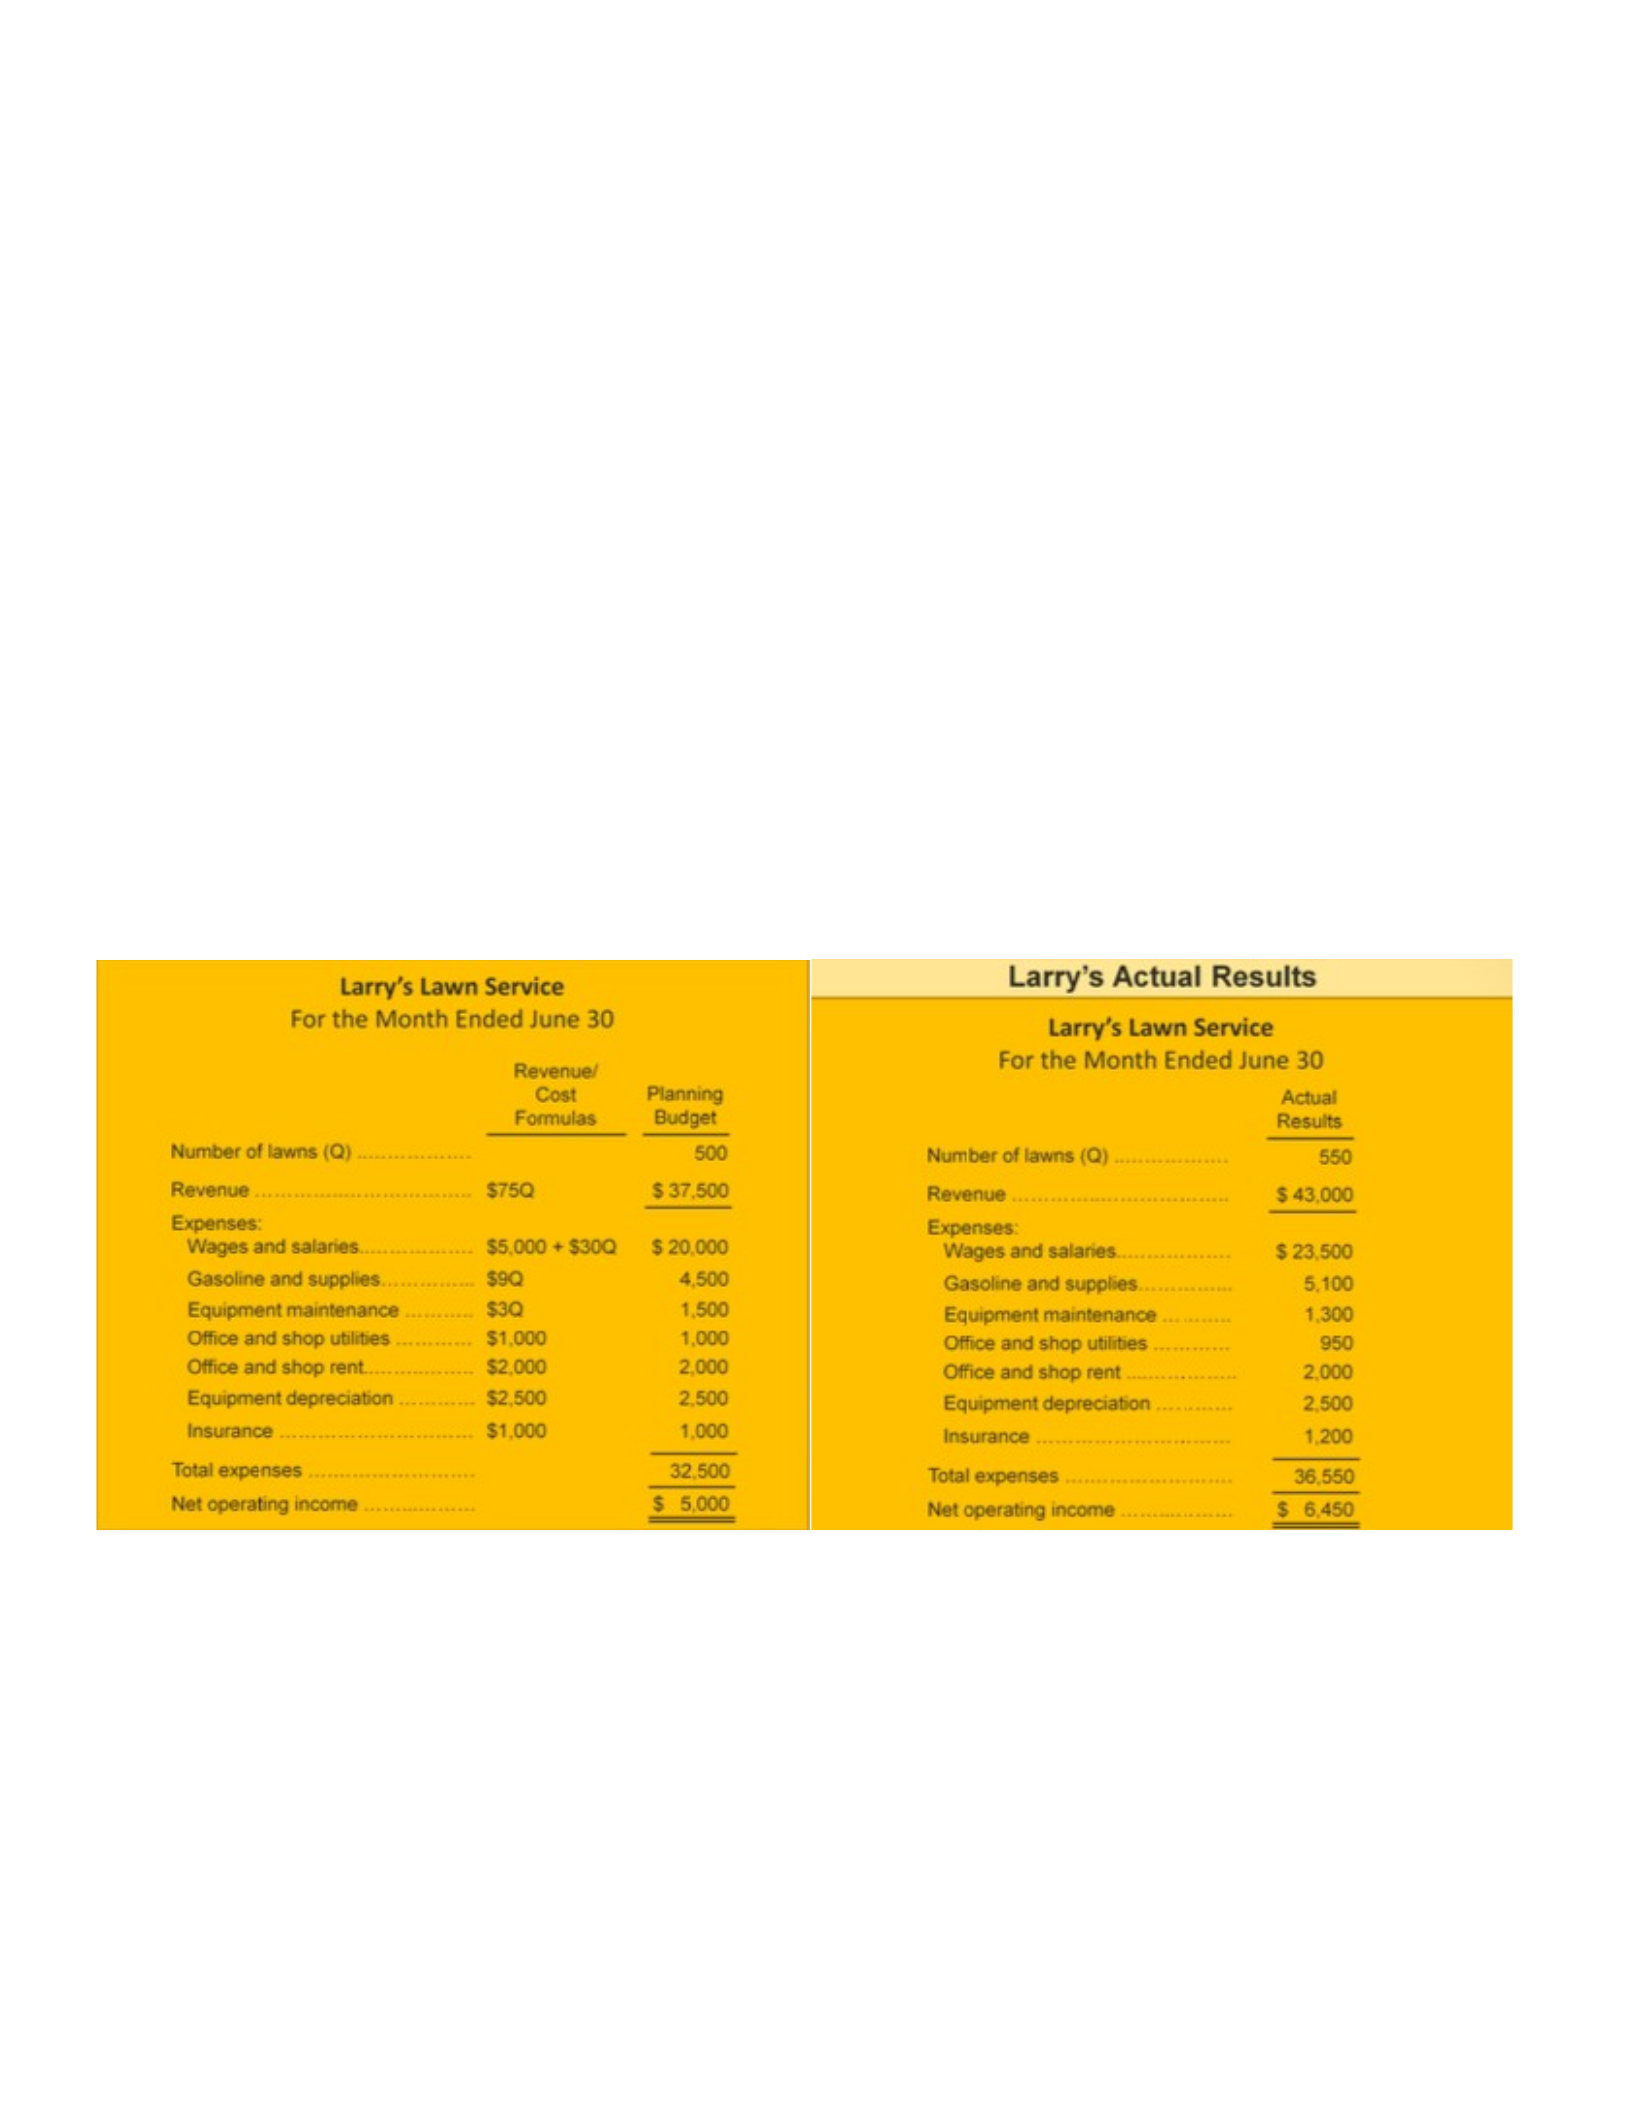
Residual income
Equals the net operating income that an investment center earns above the minimum required return
on its operating assets
Residual income = net operarting income - ( total assets * minimum required rate of return)
A positive RI indicates subunit is excceeding management’s expectations
A negative RI indiicated subunit is NOT meeting management’s expectations
The objective is to maximize the total amount of residual income
Residual income limitations
Residual income cannot be used to compare the performance of different divisons of different sizes
Larger divisions tend to have more residual income than smaller ones do
Percentage change in residual income from one per to the next can be used to compare the
performance of disparate business segments
Characterisitics of flexible budgets
Planning budgets are prepared before the period begins for a single, planned level of activity
Comparing static planning budgets with actual costs is like comparing apples and oranges
Performance evaluation is difficult when actual acitivty differs from the planned level of activity
When the actual activity level differs from what was planned, it is misleading to evaluate performance
by comparing actual revenues and costs to the static, unchanged planning budget
A flexible budget provides estimates of what revenues and costs should be for any level of activity,
within a specified budget
Show costs that have been incurred at the actual level of activity, enabling “apples to apples” cost
comparisons
oHelp managers control costs
oImprvoe performance evaluation
Deficiencies of the static planning budget
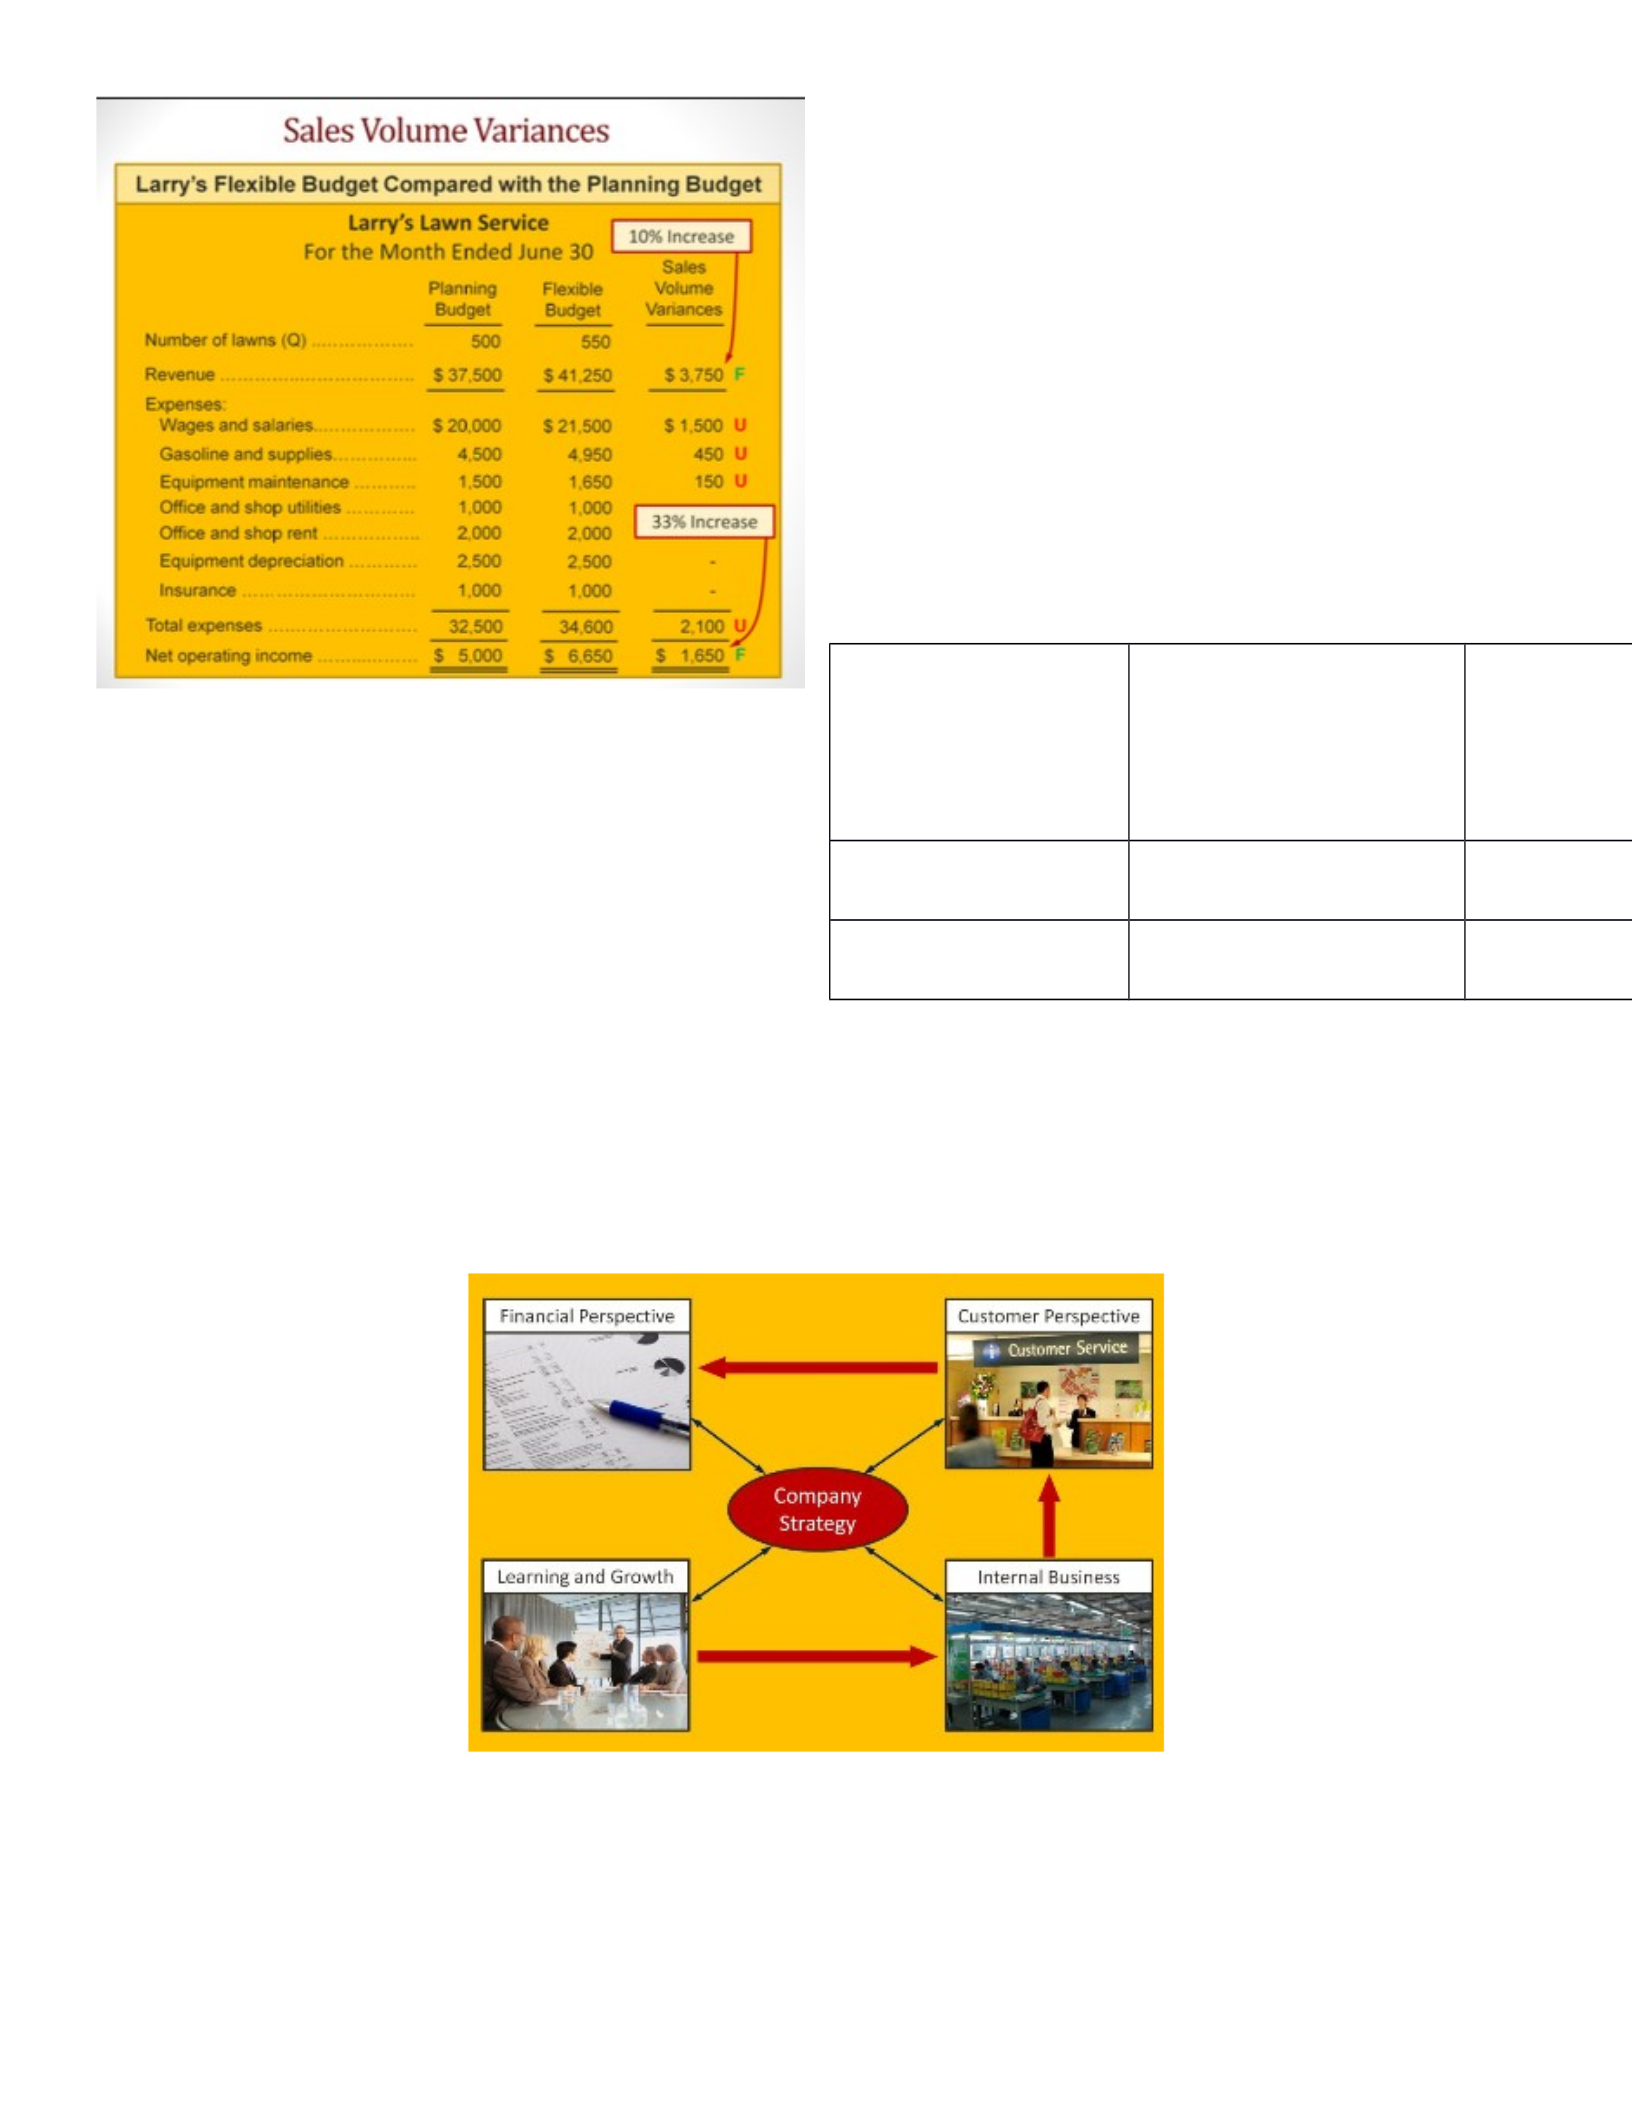
Larry’s lawn service example
Larry’s lawn service provides lawn care in a planned community where all laws are approximately the
same size
At the end of may, larry prepared his June budget based on mowing 500 lawns
Larry felt the number of lawns mowed in a month would be the best way to measure overall activity for
his business
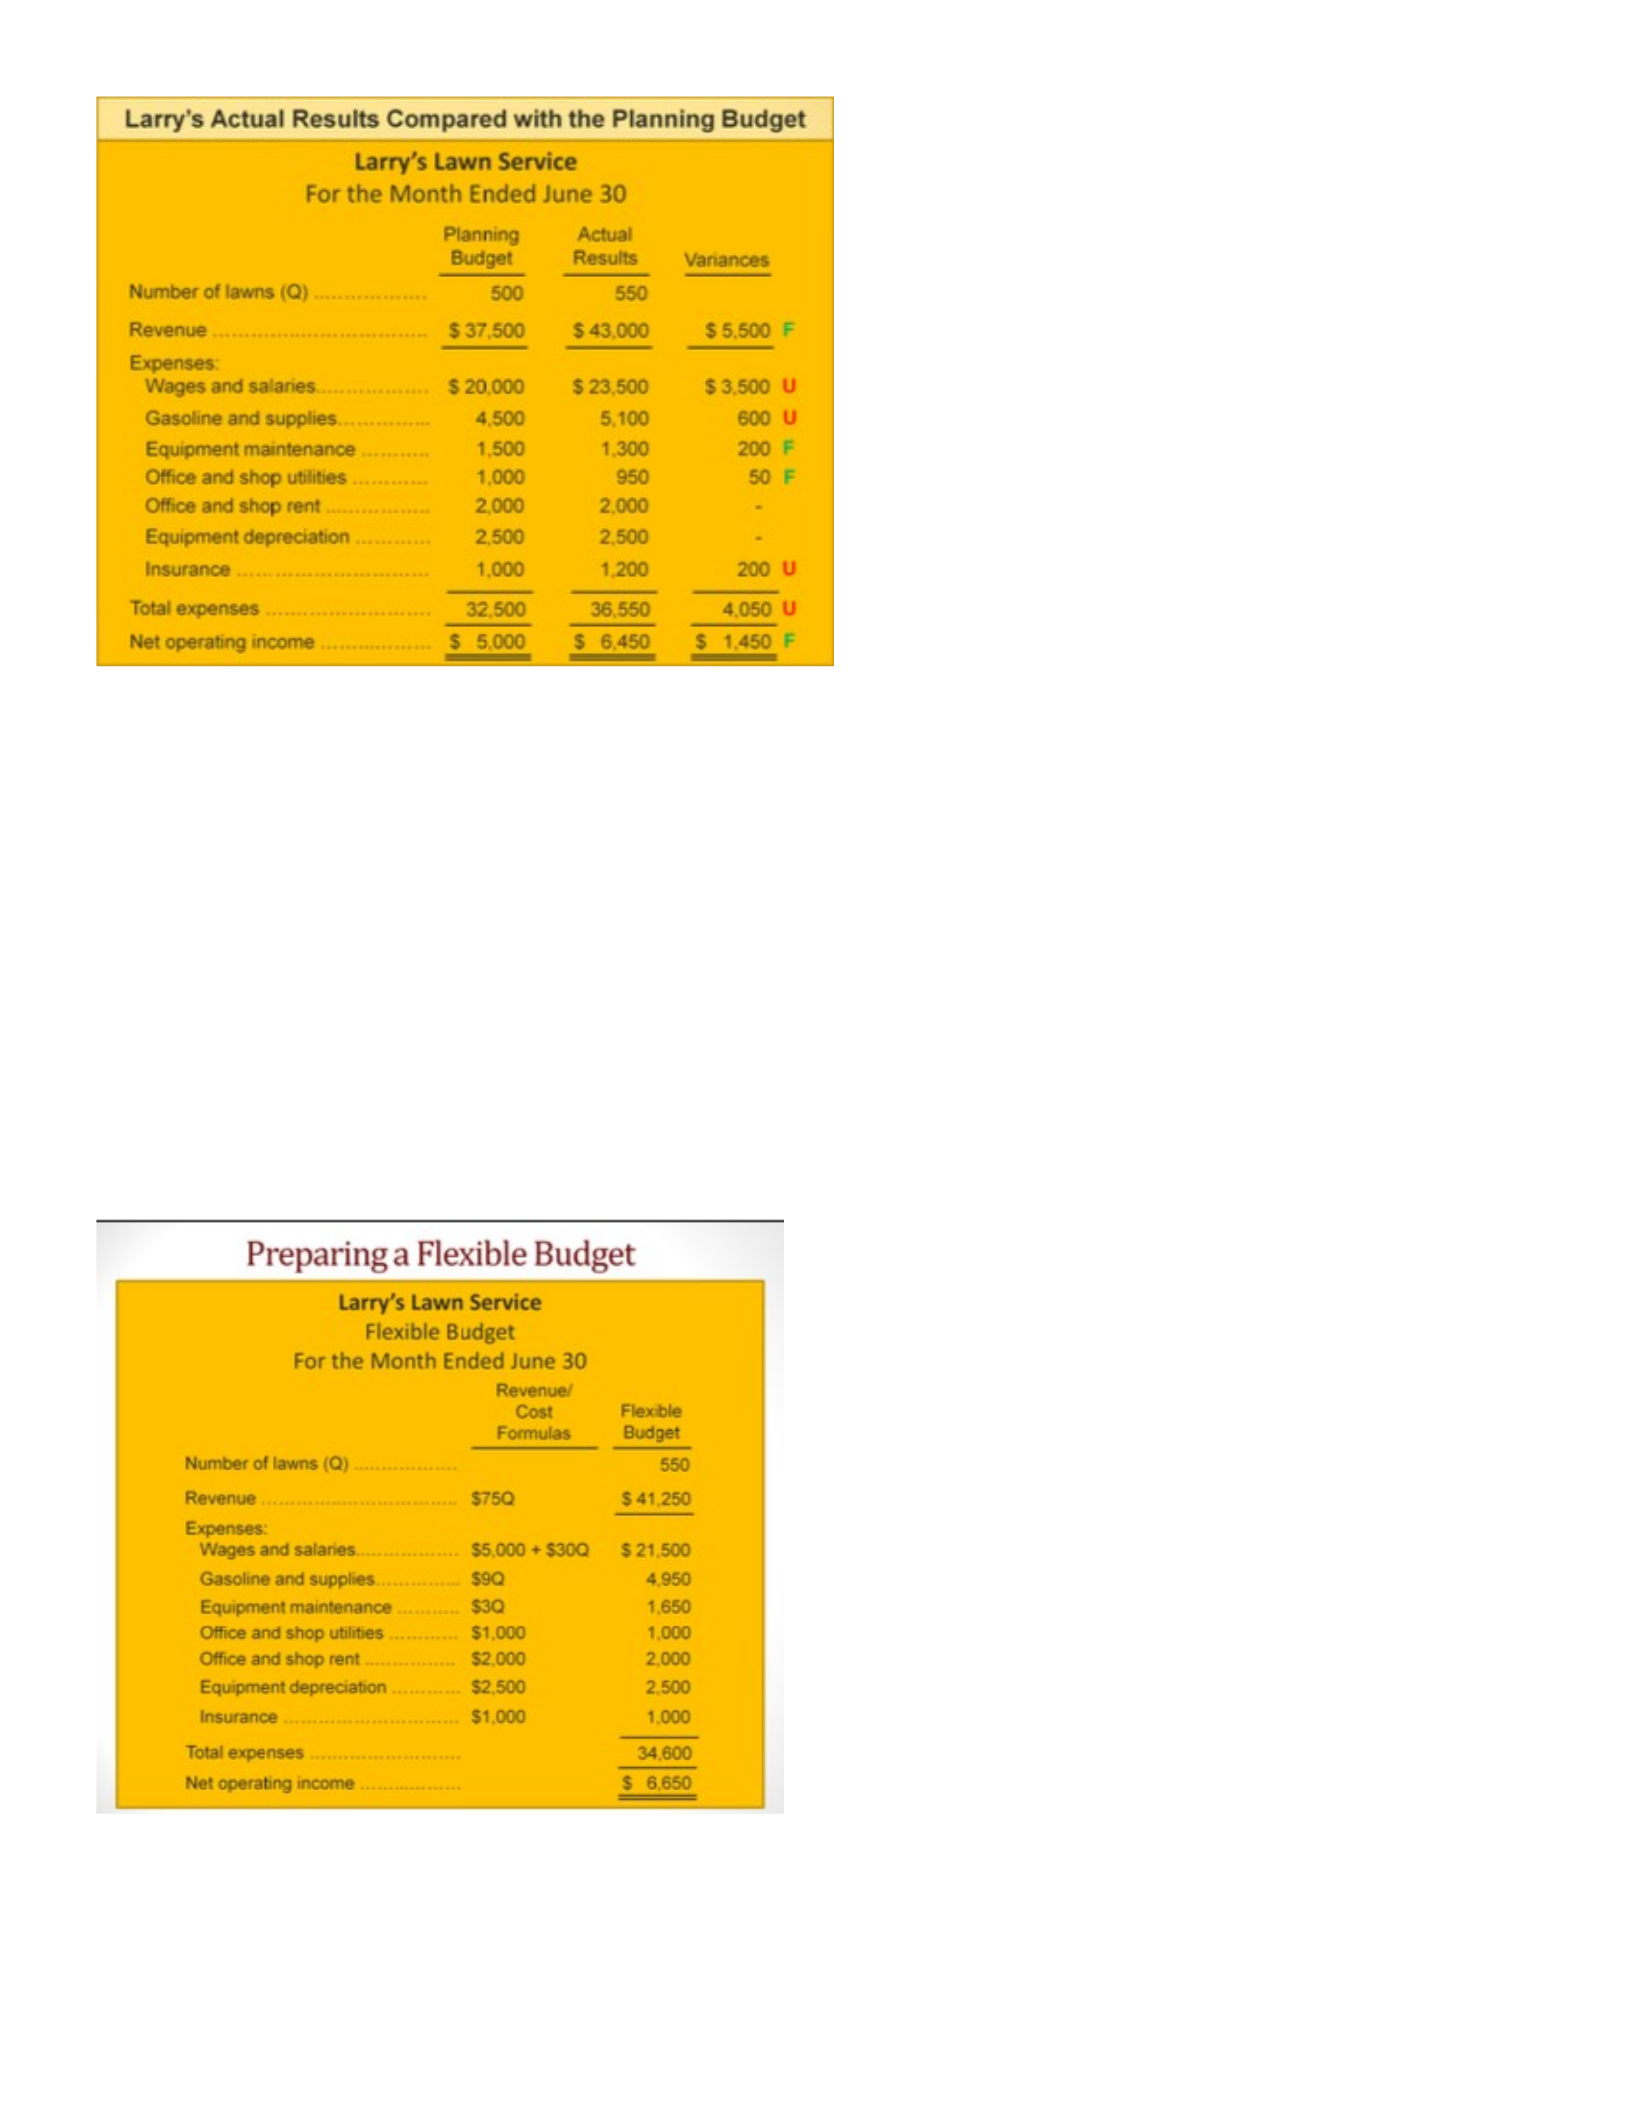
The answer is unclear because the actual activity level (550 lawns) does not equal the planned activity
level (500 lawns)
It is difficult to answer the questions using a static budget
Actual activity is above planned activity
Shouldn’t the variable costs be higher if actual activity is higher?
The relevant question is:
o“how much of the cost variances are due to higher activity and how much are due to cost
control?”
To answer the question, we must FLEX the budgeted to the actual level of activity
How a flexible budget works
To FLEX a budget, we need to remember that:
oTotal variable costs change in direct proportion to changes in activity
oTotal fixed costs remain unchanged within relevant range
Let’s prepare a budget for Larry’s lawn service
Sales Volume Variances
Flexible budget revenues & expenses
Planning budget revenues & expenses
VS
The difference between the budget amounts are
called sale volume variance
Flexible Budget Variances
Flexible budget revenue
Actual revenue
VS
The difference is a revenue variance
Flexible budget cost
Actual cost
VS
The difference is an expense or spending
variance
Key Performance Indicators
Company goals Examples of
Critical factors
and
corresponding
KPIs
Critical factors Customer satisfaction Operational
efficiency
Key performance
indicators (KPIs)
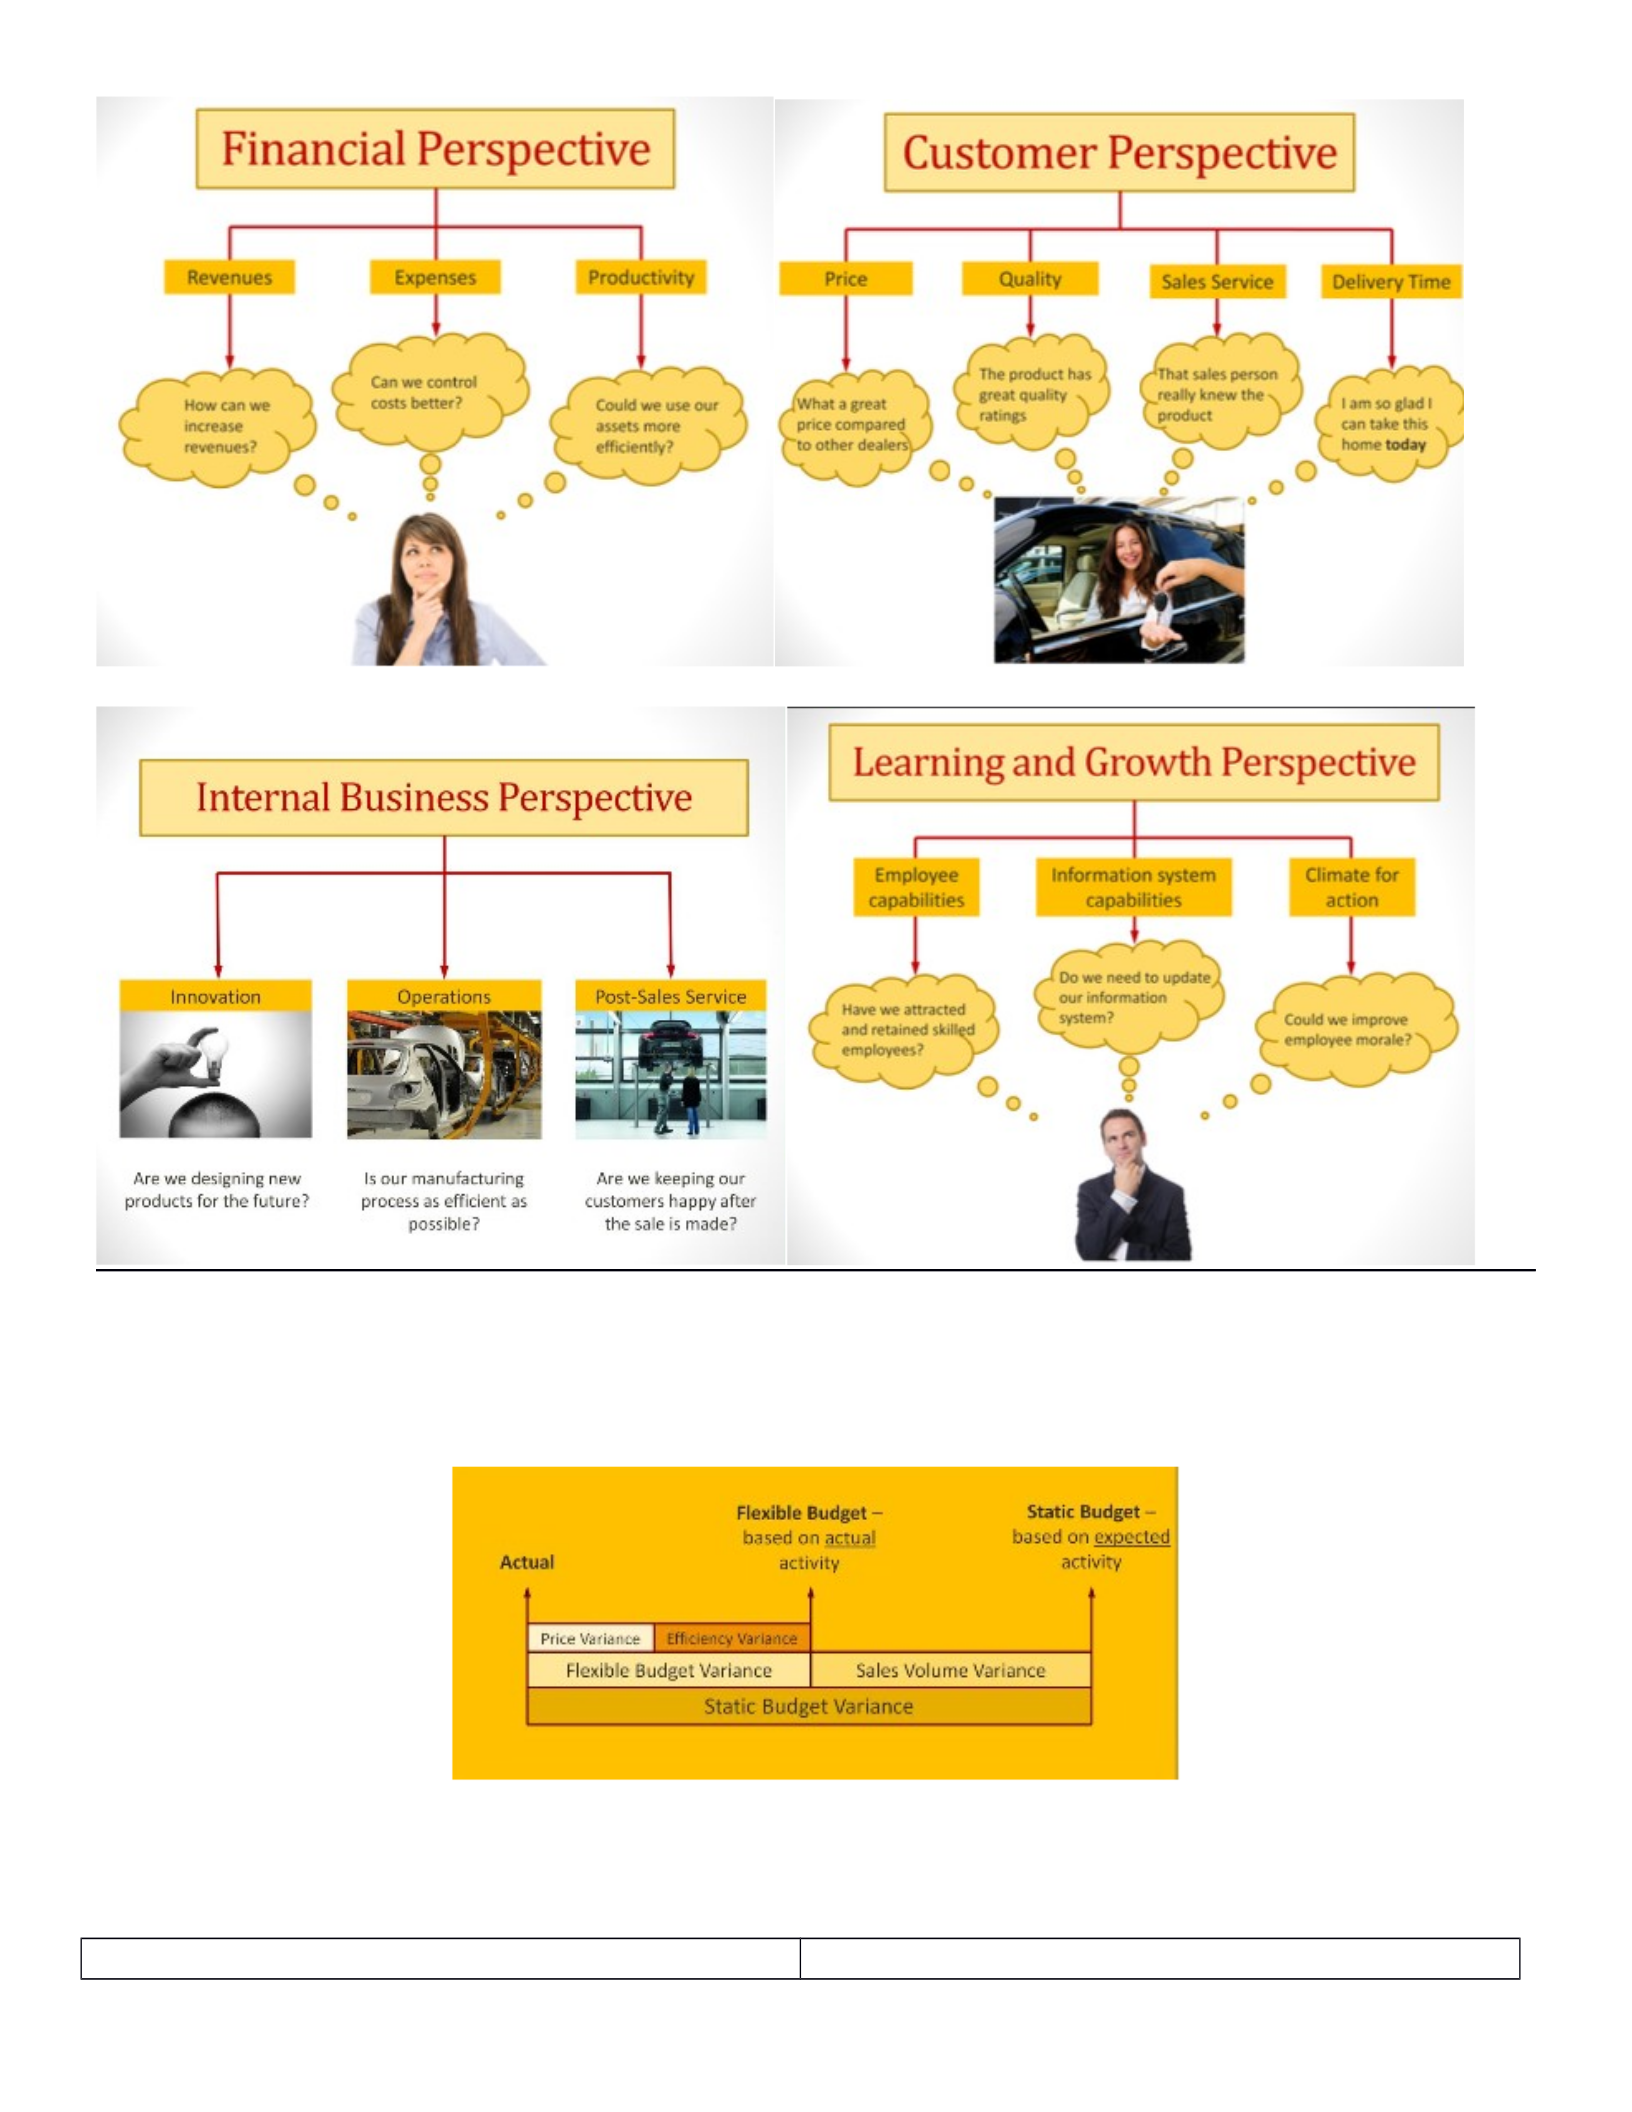
Market share Yield rate
Balanced Scorecard
Chapter 11 Lecture: Standard Costs & Variances
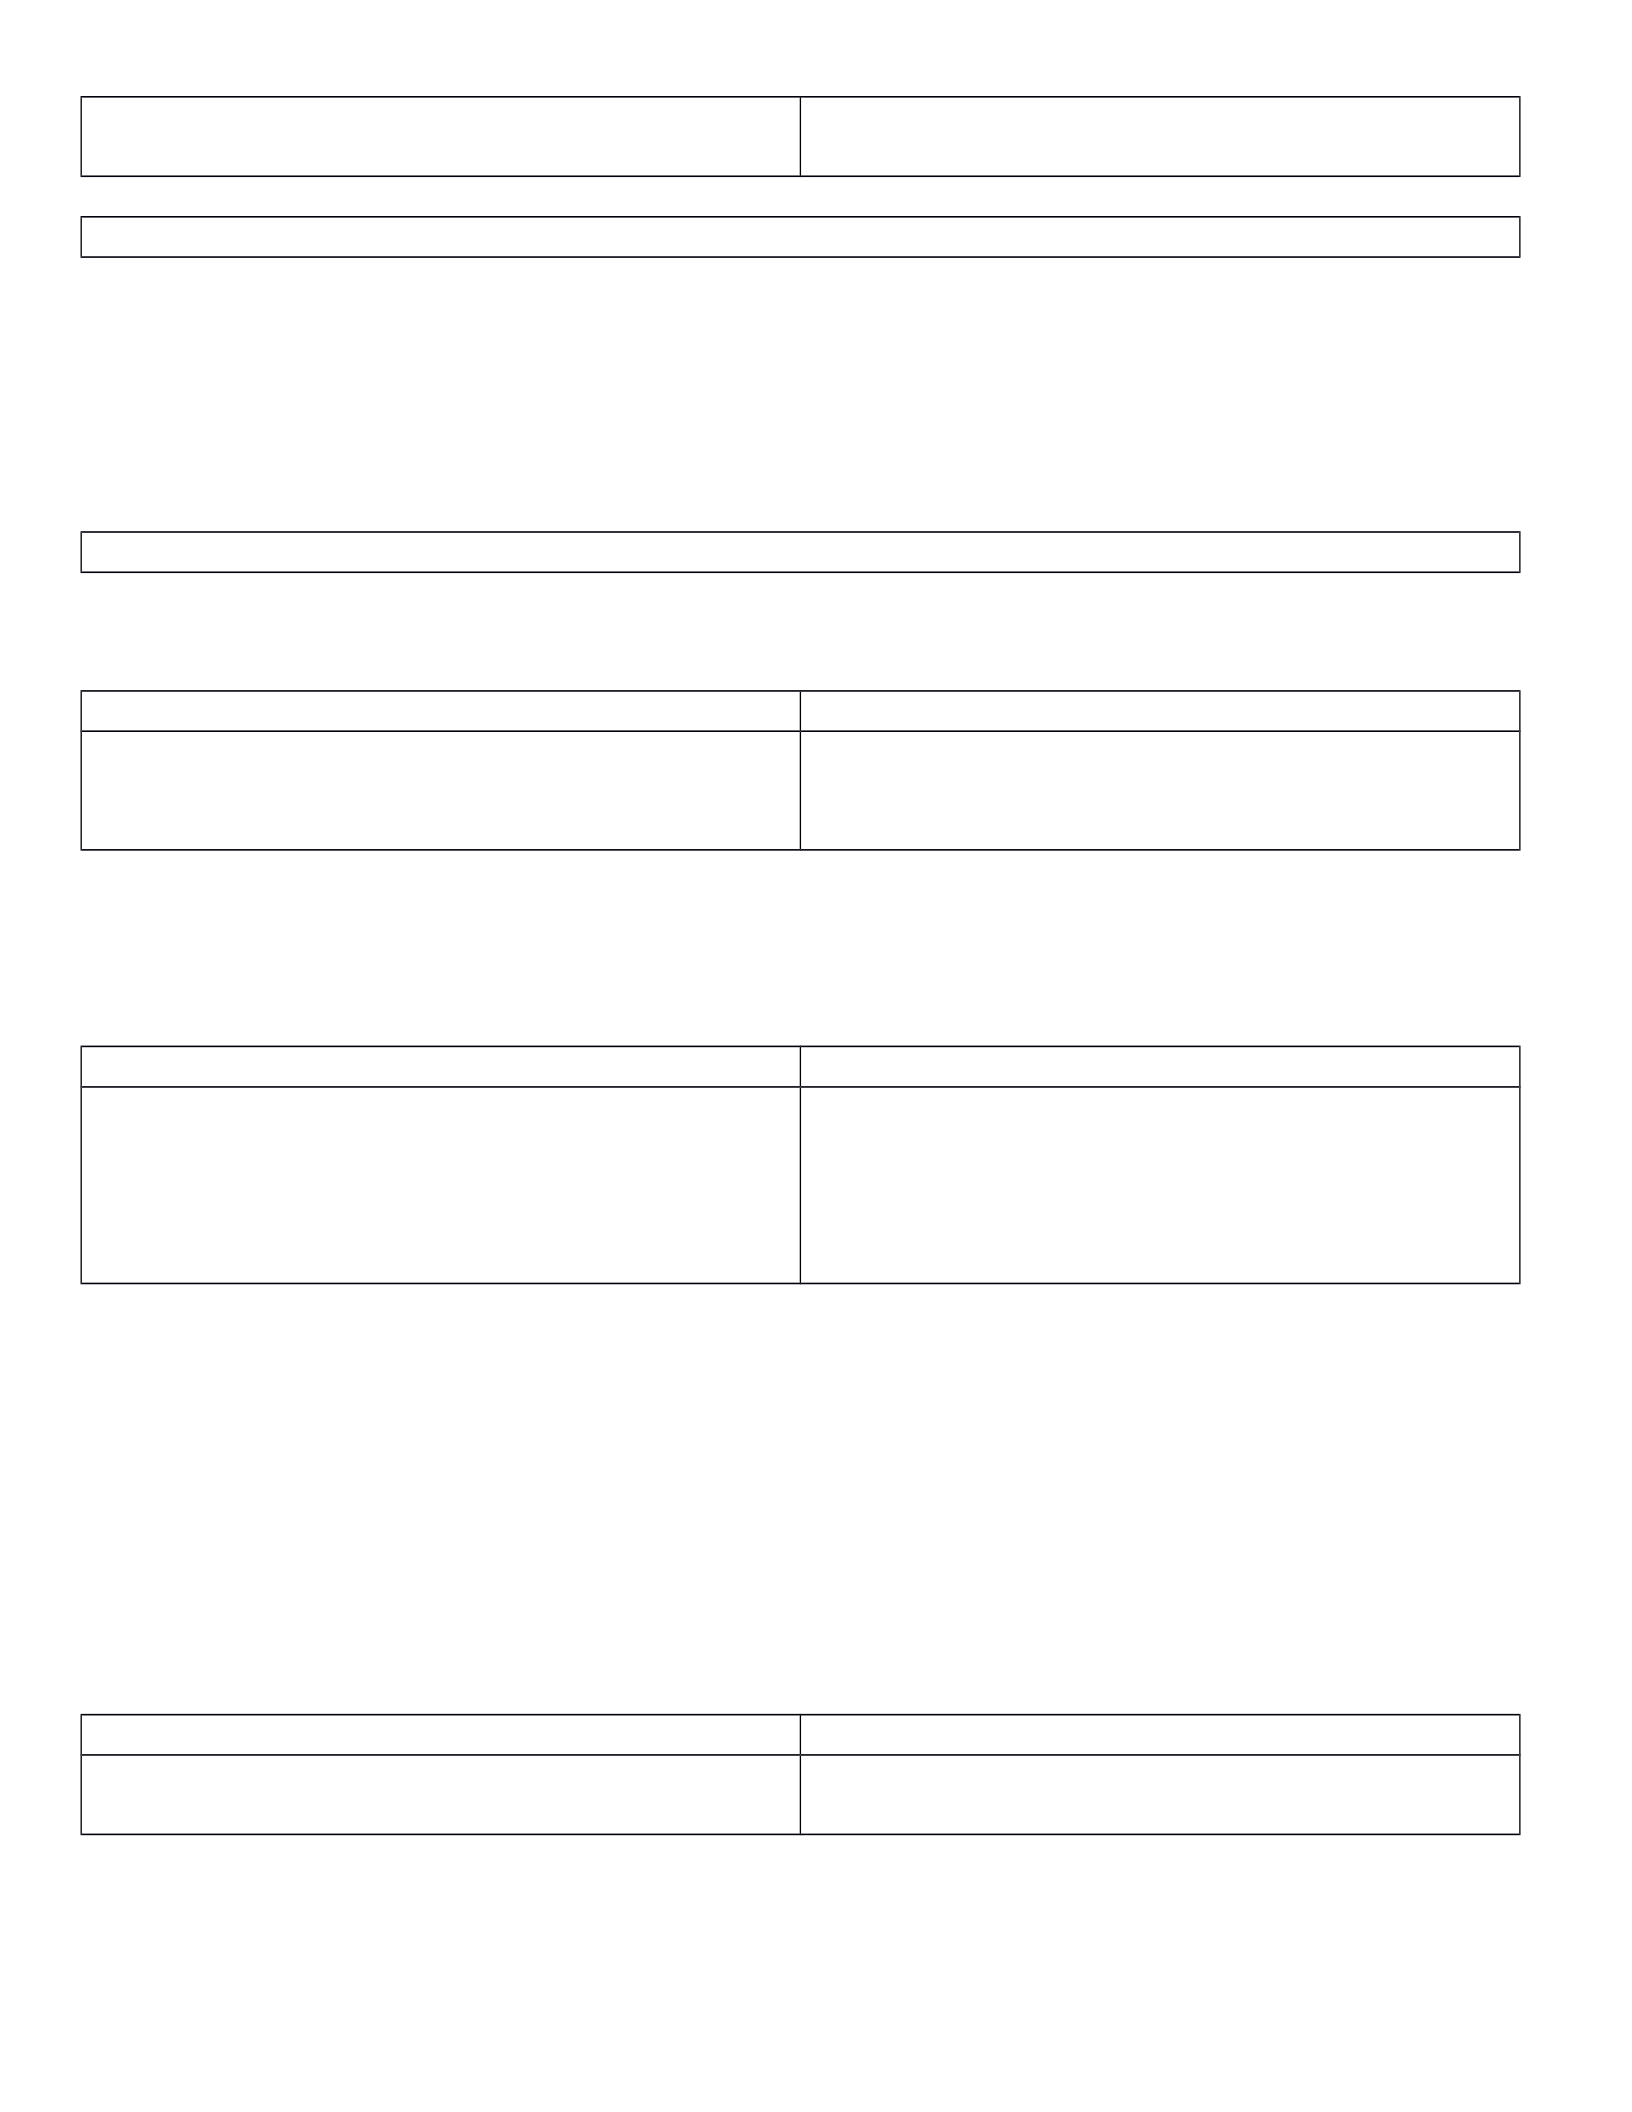
Relationship between standard cost & flexible budget variances
Standards Costs
Budgets are aggregate measures of performances for a given level of activity
Developing standards for unit amounts, as well as total amounts, can enhance control
Developing unit standards costs involves two decisions:
Quantity Price
The amount of input that should be used per unit of
output (quantity standard)
The price that should be paid for the quantity of
input to be used (price standard)
Companies also set standards for manufacturing overhead rates
Standard development
Standards are developed using historical data, engineering estimates and input from operating
personnel
Historical data may include undesired inefficiencies
Engineering estimates assume optimum efficiency and may be unachievable
Operating personnel should have significant input in developing standards to enhance “buy-in”
UNIT STANDARD COST = Quantity Standards * Price Standard
Type of standards
Standards are generally classified as either:
Ideal Currently attainable
Demand maximum efficiency (no slack, machine
breakdowns, or lack of skill)
Can be achieved under efficient operating conditions
(allowance made for normal breakdowns,
interruptions, less than perfect skill levels)
Currently attainable standards offer the most behavioral benefits, extracting higher performance levels
than “ideal” standards
Standard cost system adoption
Standard costs systems are implemented to:
Improve planning & Control Facilitate product costing
Unit standards are a fundamental element of
flexible budgets
Overall variances can be “decomposed” into
more meaningful price and efficiency
variances
Costs are assigned to products using quantity
and price standards for:
Direct material, direct labor, and MOH
Costs are readily available for pricing
decisions
Standard product costs
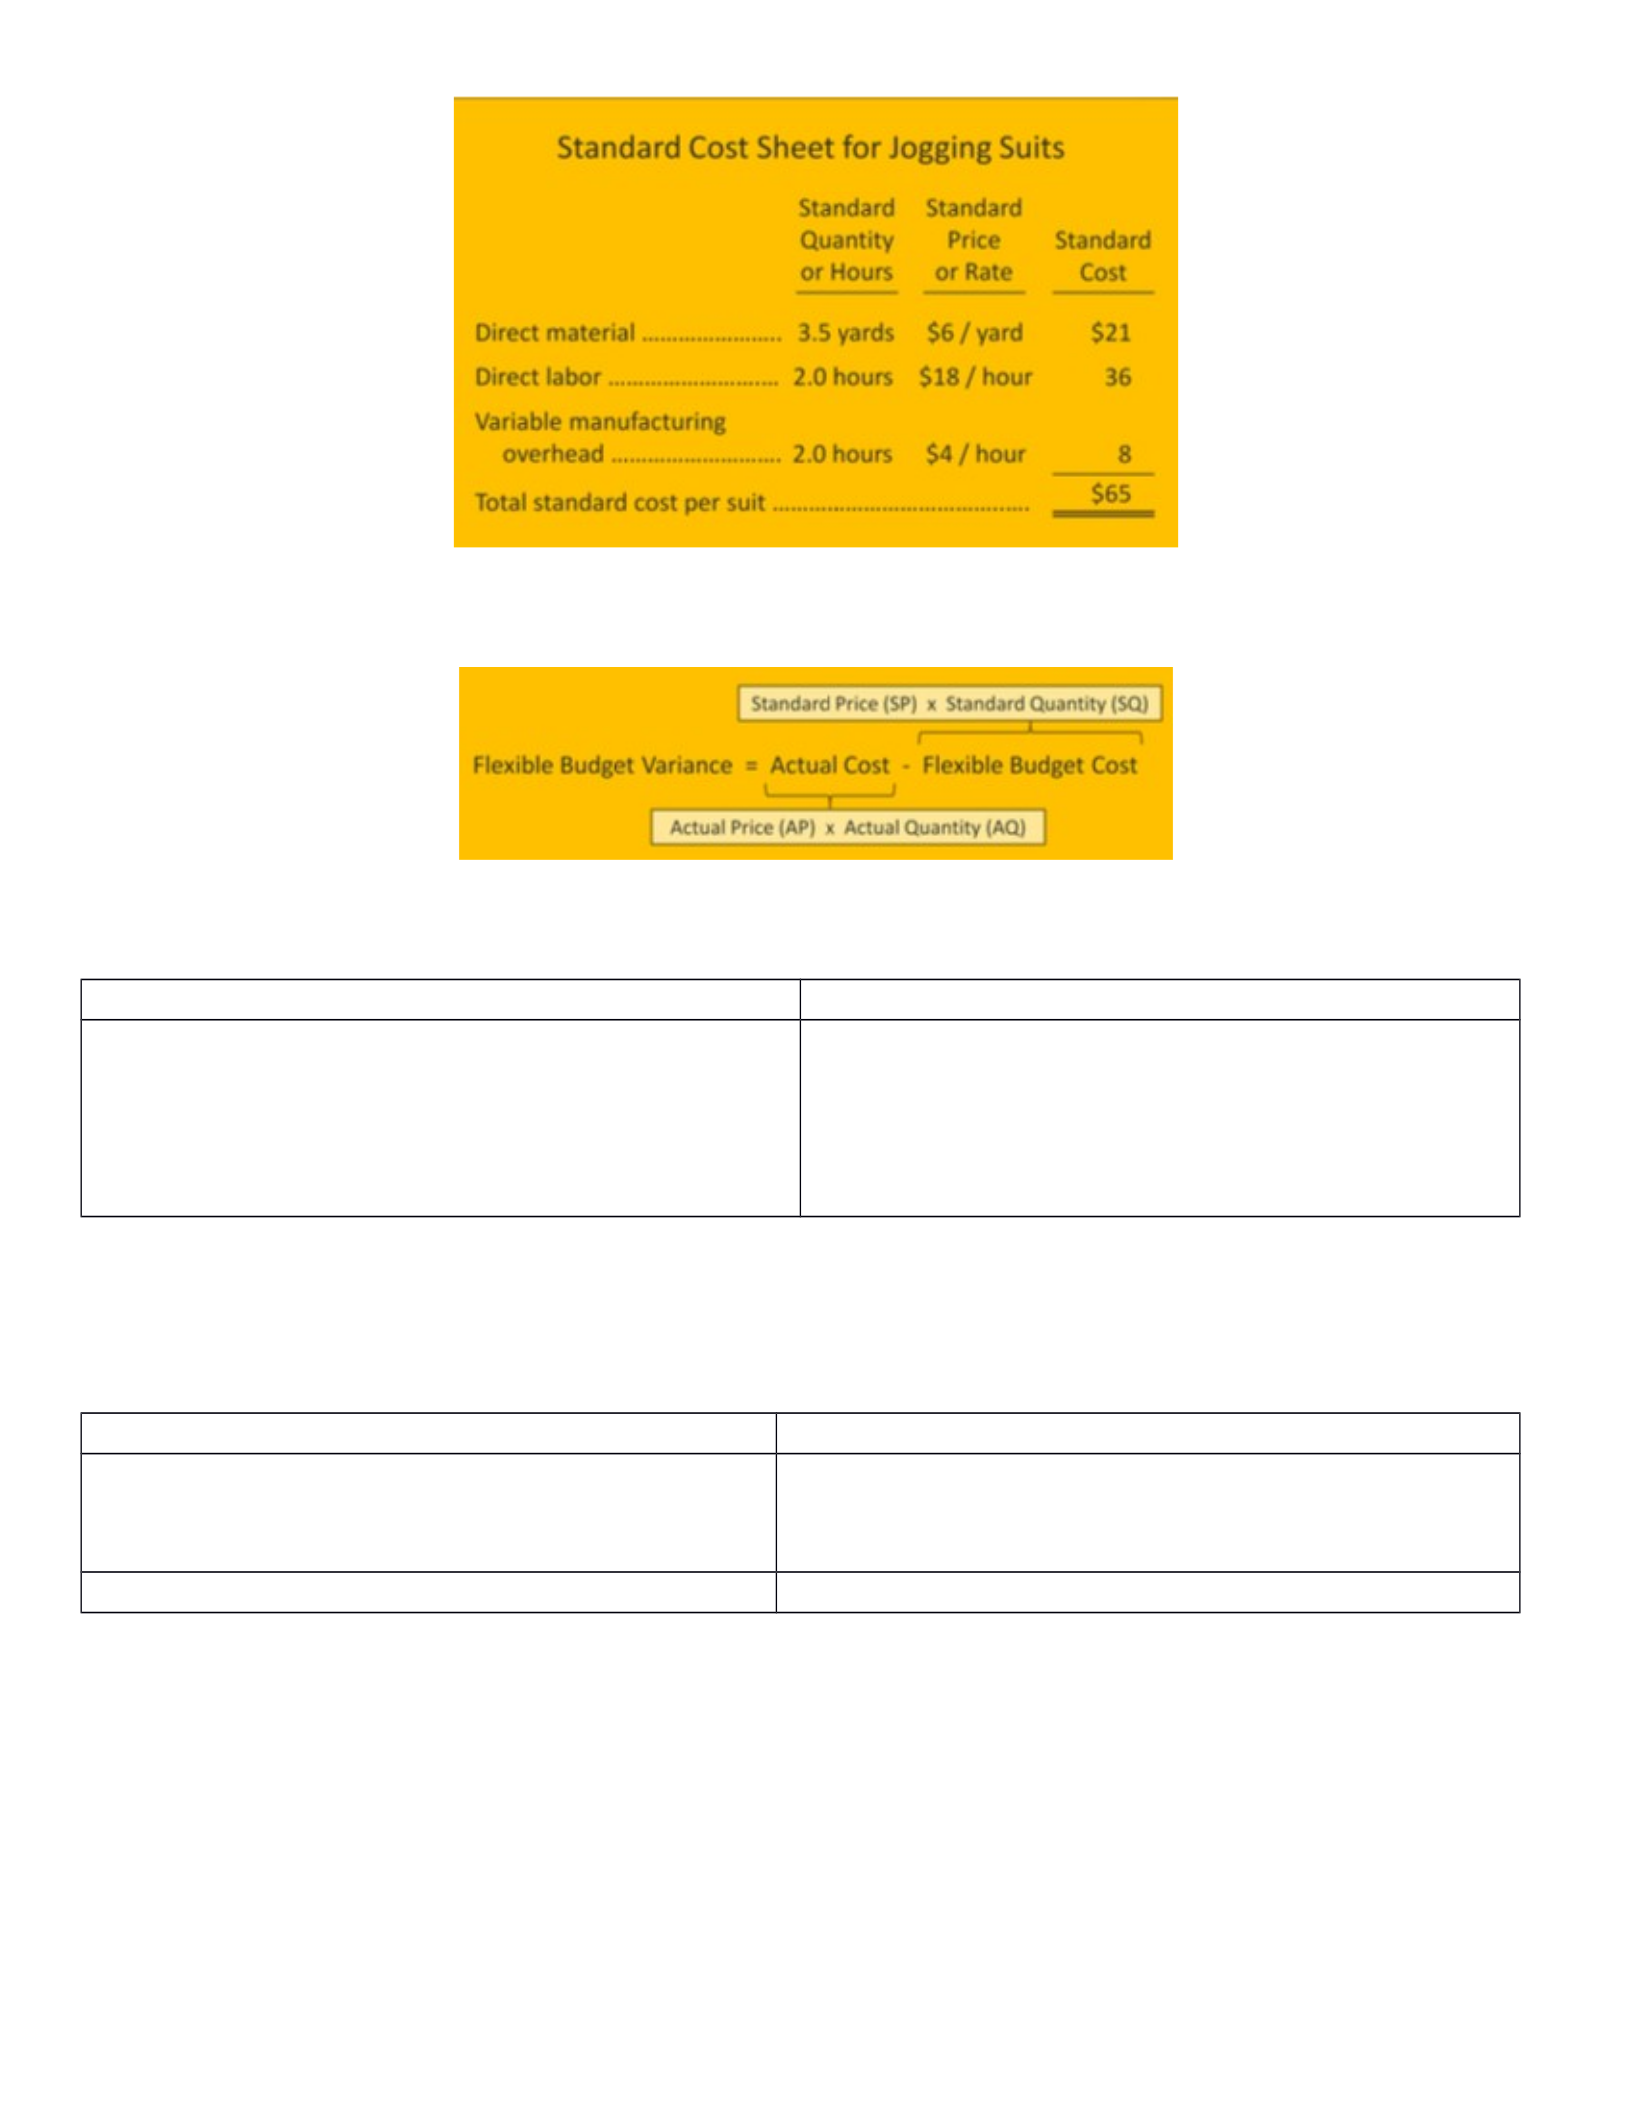
Standards Cost Sheet
Identifies:
Standard usage
Standard price
Standard cost
For each element of:
Direct material
Direct labor
MOH
Standard quantity of material Standard quantity of hours
The amount of materials that should be consumed
to produce one unit of output
The amount of direct labor hours that should be
used to produce one unit of output
Standard Cost Example
Variance Analysis
Costs that should have been incurred for an actual level of activity are calculated and compared to
actual costs as follows:
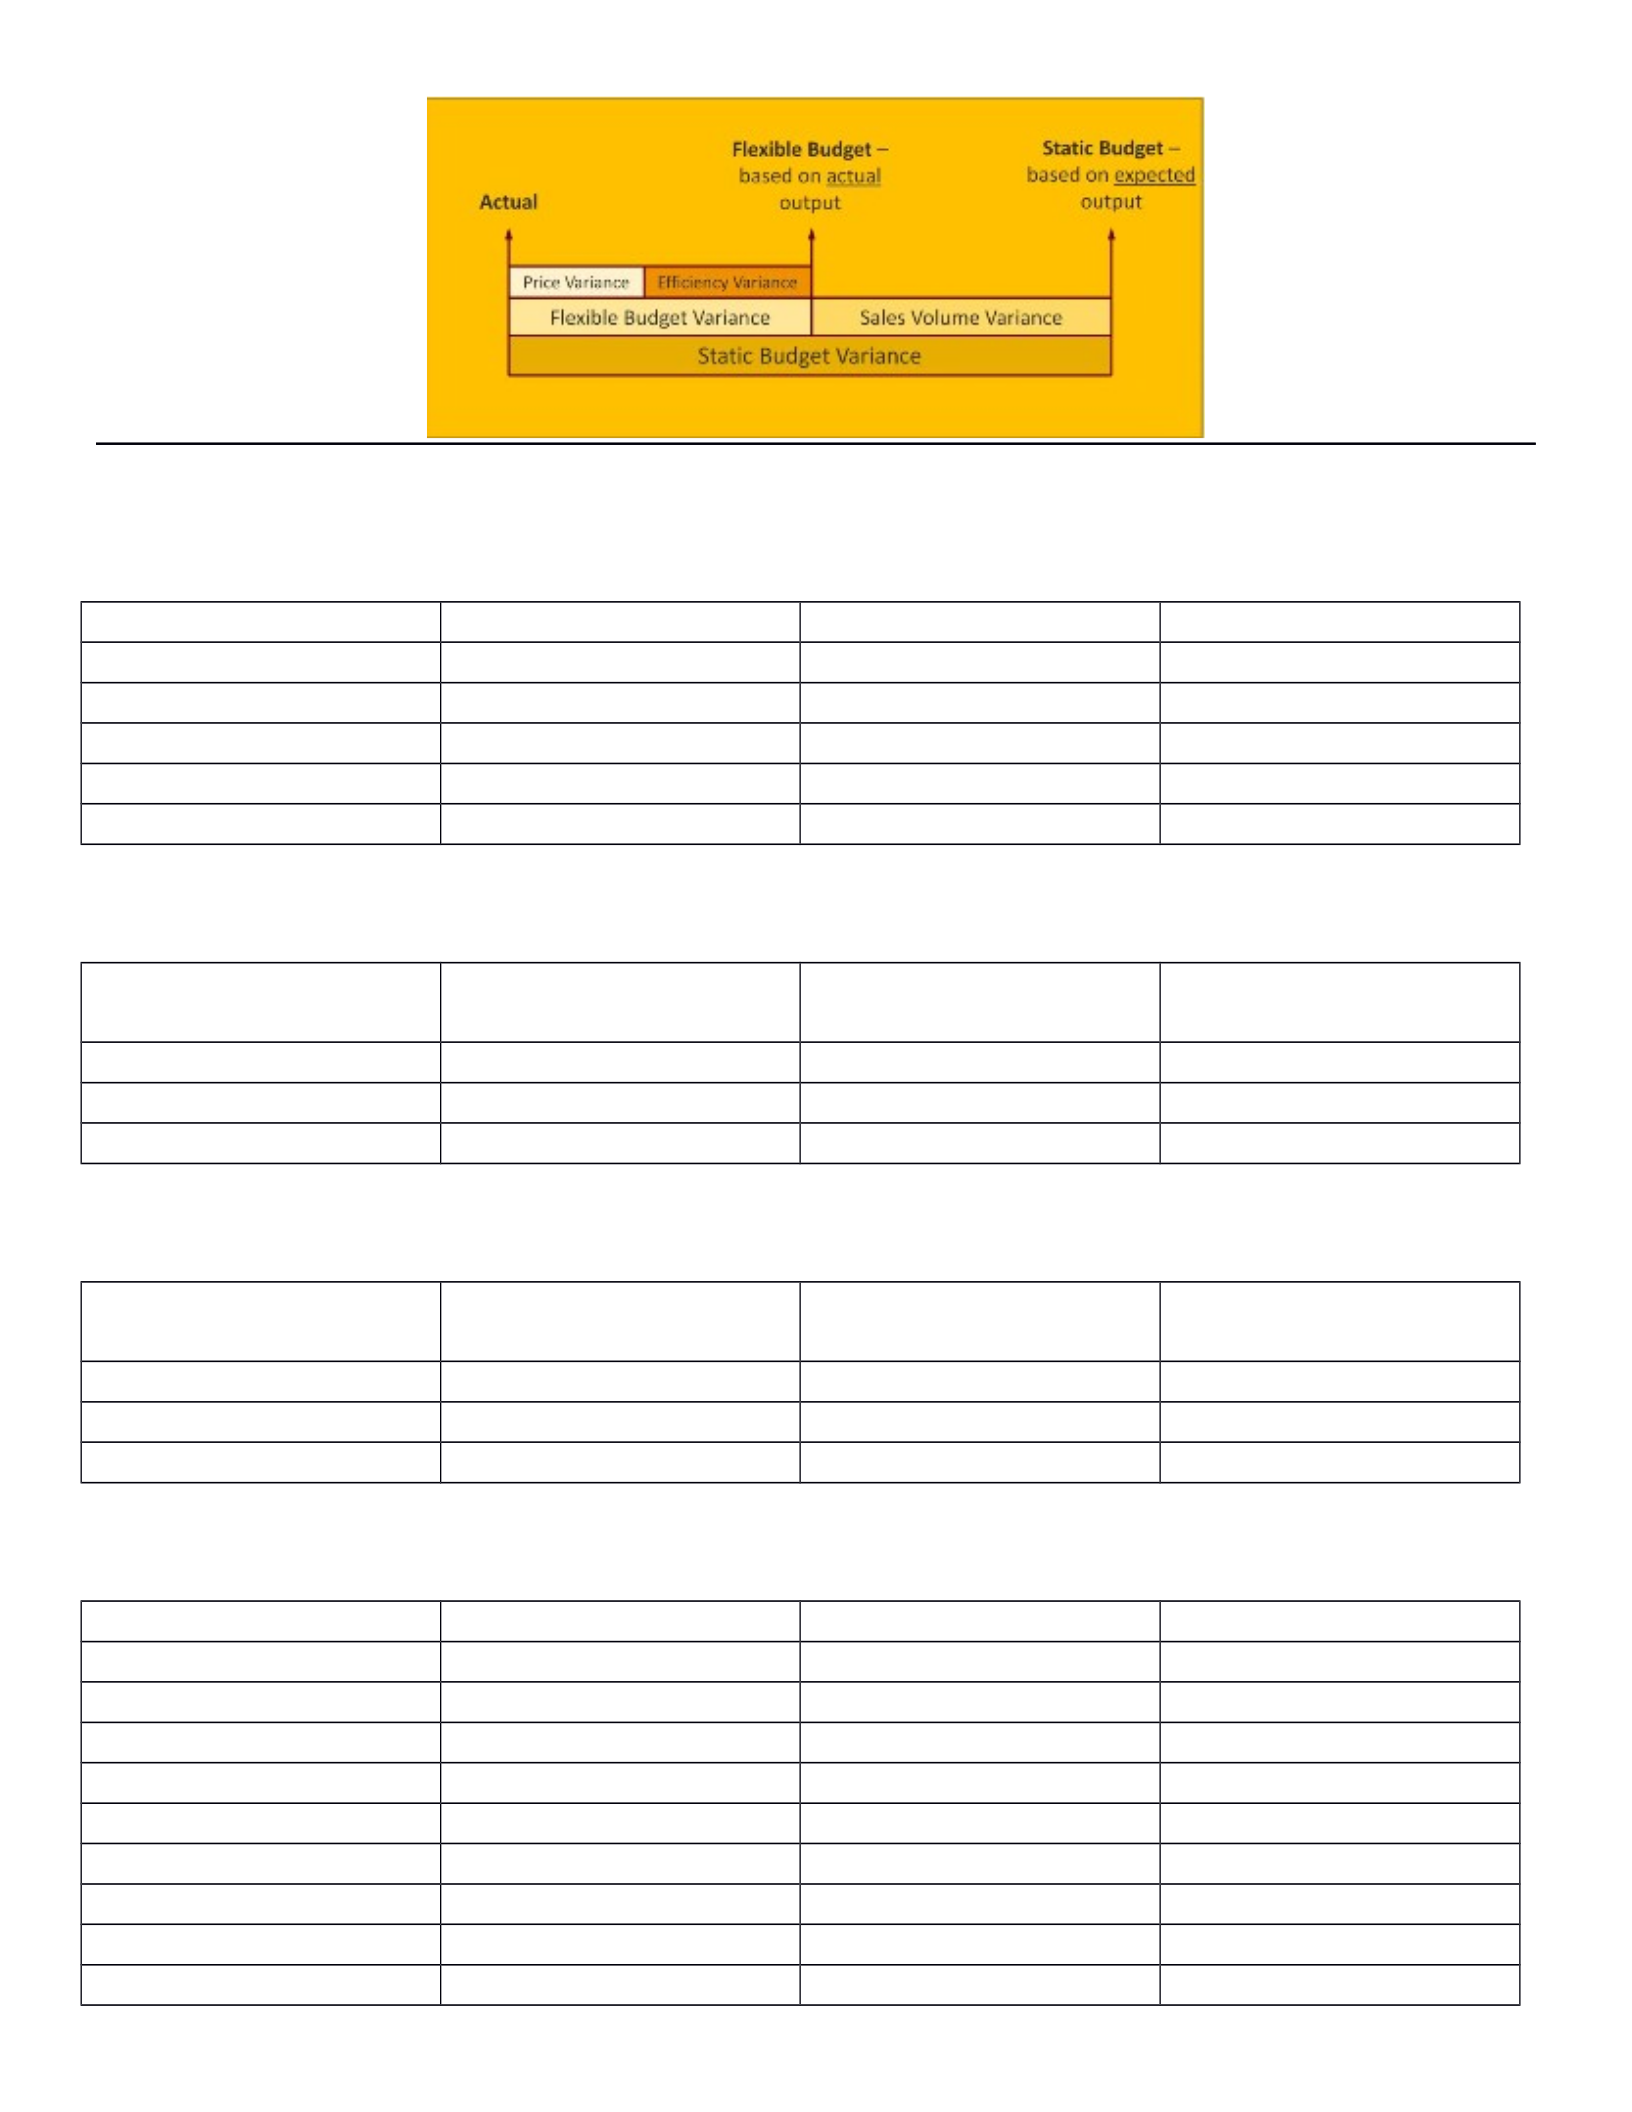
The flexible budget variance should be decomposed to assign responsibility for price variances
(purchasing and personnel) and efficiency variances (production)
Price & Efficiency Variances
Price variances Efficiency variances
Also referred to as rate variances
Favorable price variance occurs when actual
price is less than standard price
Unfavorable price variance occurs when
actual price is more than standard price
Also referred to as usage
Favorable usage variance occurs when actual
usage is less than standard usage
Unfavorable usage variance occurs when
actual usage is more than standard usage
Favorable and unfavorable are not synonymous with good and bad regarding variances
Price/Usage Variance Computation
(1) actual quantity of input, at actual price AQ * AP
(2) actual quantity of input, at standard price AQ * SP
(3) standard quantity allowed for actual output, at standard price SQ * SP
Price Variance (1) – (2) Efficiency variance (2) – (3)
Material price variance
Labor rate variance
Variable overhead spending variance
Materials efficiency variance
Labor efficiency variance
Variable overhead efficiency variance
Flexible Budget variance (1) – (3)
Variance Analysis
Actual performance rarely aligns with standards nor is it expected to
Management should have an established range of acceptable performance (control limits)
Variance falling within the range are assumed to be normal
Variances exceeding the range should be investigated. Controllable factors should be addressed.
Variances due to uncontrolled factors may warrant adjusting standards
Beware of offsetting price & efficiency variances
Direct materials variance
(1) actual quantity of input, at actual price AQ * AP
(2) actual quantity of input, at standard price AQ * SP
(3) standard quantity allowed for actual output, at standard price SQ * SP
20,000 yards * $5.40 per yard = $108,000
20,000 yards * $6 per yard = $120,000
17,500 yards * $6 per yard = $105,000
Price variance (1) – (2) Efficiency variance (2) – (3)
Price variance, $12,000 favorable Efficiency variance $15,000 unfavorable
Flexible budget variance (1) – (3) = unfavorable $3000
Price Variances Efficiency Variances
Purchasing managers are typically
responsible for direct material price variances
Emphasis on meeting or beating the standard
can bring on undesired behavior (sacrifice
quality, purchase larger quantities, to obtain
discounts)
Beware, favorable variance could be related
to purchasing lower grade materials
Production managers are typically
responsible for direct material efficiency
variances
Reducing waste, scrap and rework are done
to meet standard
Emphasis on meeting or beating standards
can lead to undesired behavior (allowing
defective goods to be transferred to finished
goods)
Direct Labor Variances
10,500 hours * $20 per hour = $210,000
10,500 hours * $18 per hour = $189,000
10,000 hours * $18 per hour = $180,000
Rate variance (1) – (2) Efficiency Variance (2) – (3)
Rate variance, $21,000 unfavorable Efficiency variance, $9000 unfavorable
Flexible budget variance (1) – (3) : unfavorable $30,000
Rate variances Efficiency variances
Responsibility for labor rate variances is
normally assigned to production managers
Actual labor rates rarely depart from
standard rates (market forces, union
contracts), when they do it is usually due to
overtime or use of high-skill labor for low skill
tasks
Beware, favorable variance could be related
to using under-skilled labor
Production managers are also normally
responsible for labor usage (efficiency)
variances
Responsibility may be shifted to others if
their performance adversely affects labor
efficiency (i.e. effect of breakdowns assigned
to maintenance department manager)
Emphasis on meeting or beating standards
can lead to undesired behavior
Relationship between standard cost & flexible budget variances
Chapter 11 Homework
(1) mountain peak coffee purchases green coffee beans from various suppliers and then roasts the coffee
beans in its roasting facility.
(a) what is the standard cost of producing one 15-pound case of roasted coffee beans?
Standard quantity * standard price = standard cost of input
Direct materials: 15 pounds $4 per pound = $60
Direct labor 0.25 hours * $15 per hour = $3.75
For Problem 1:
Direct materials 10 pounds * 2.50 per pound = 25
Direct labor .25 * $25 per hour =$6.25
Before we can calculate the standard cost of input for the variable MOH & fixed MOH, we must calculate the
standard price for each element. Lets begin with determining the standard price for variable MOH
Total variable MOH / (# of machine hours * Total # of cases expected
to produce)
= standard price
$3,000,000 / (0.2 * 600,000) = $25
For problem 1:
$4,200,000 / (0.20 * 700,000) = $30
Our next calculation is the standard price for the fixed MOH. Use the formula below to aid in your calculation.
Total fixed MOH / (# of machine hours * Total # of cases expected
to produce)
= standard price
$600,000 / (0.2 * 600,000) =$5.00
for problem 1:
$420,000 (0.20* 700,000) = $3
now, we can complete the calculations by determining the standard cost of input for both fixed and variable
manufacturing overhead and then calculate the standard cost of producing one 15-pound case
Standard quantity * standard price = standard cost of input
Direct materials 15 pounds * $4 per pound = $60
Direct labor 0.25 hours * $15 per hour = $3.75
Variable MOH 0.20 machine hours * $25 per hour =$5.00
Fixed MOH 0.20 machine hours * $5.00 per hour = $1.00
Total $69.75
For problem 1:
Direct materials: 10 pounds * $2.50 per pound = $25
Direct labor: 0.25 hours * $25 per hour = $6.25
Variable MOH 0.20 machine hours * $30 per hour = $6
Fixed MOH 0.20 machine hours * $3 per hour = $0.60
Total $37.85
(b) what is the standard gross profit per 15-pound case of roasted coffee beans?
Recall that gross profit is the amount of revenue left after the major expenses of a manufacturer have been
covered. The remaining amount is used to cover all other expenses. The standard gross margin formula has
been modified below to aid in the determination of gross profit
Selling price per case $85
Less: total standard cost of input 69.75
Gross profit: $15.25
For problem 2:
Selling price per case $80
Less: total standard cost of input 37.85
Gross profit $42.15
(2) Collegiate rings produced class rings. Its best-selling model has a direct materials standard of 9 grams of a
special alloy per ring. This special alloy has a standard cost of $65.30 per gram. In the past month, the
company purchased 10,000 grams of this alloy at a total cost of $651,000. A total of 9600 grams were used last
month to produce 1000 rings.
(a) what is the actual cost per gram of the special alloy that collegiate rings purchased last month?
Total cost of alloy purchased / quantity purchased = actual cost per unit (gram)
$651,000 / 10,000 =$65.10
(b) what is the direct material price variance?
Actual quantity
purchased *
(actual price - standard price) = DM price variance
10,000 * (65.10 - 65.30) $2,000 F
(c) what is the direct material quantity variance?
Standard price * (actual quantity used - standard quantity
allowed)
DM quantity variance
65.30 * (9600 -9000) = $39,180 U
®Standard quantity of DM per Unit * units manufactured = standard quantity allowed
®9 * 1000 = 9000

