


ACC241 Chapter 2 – Page 1
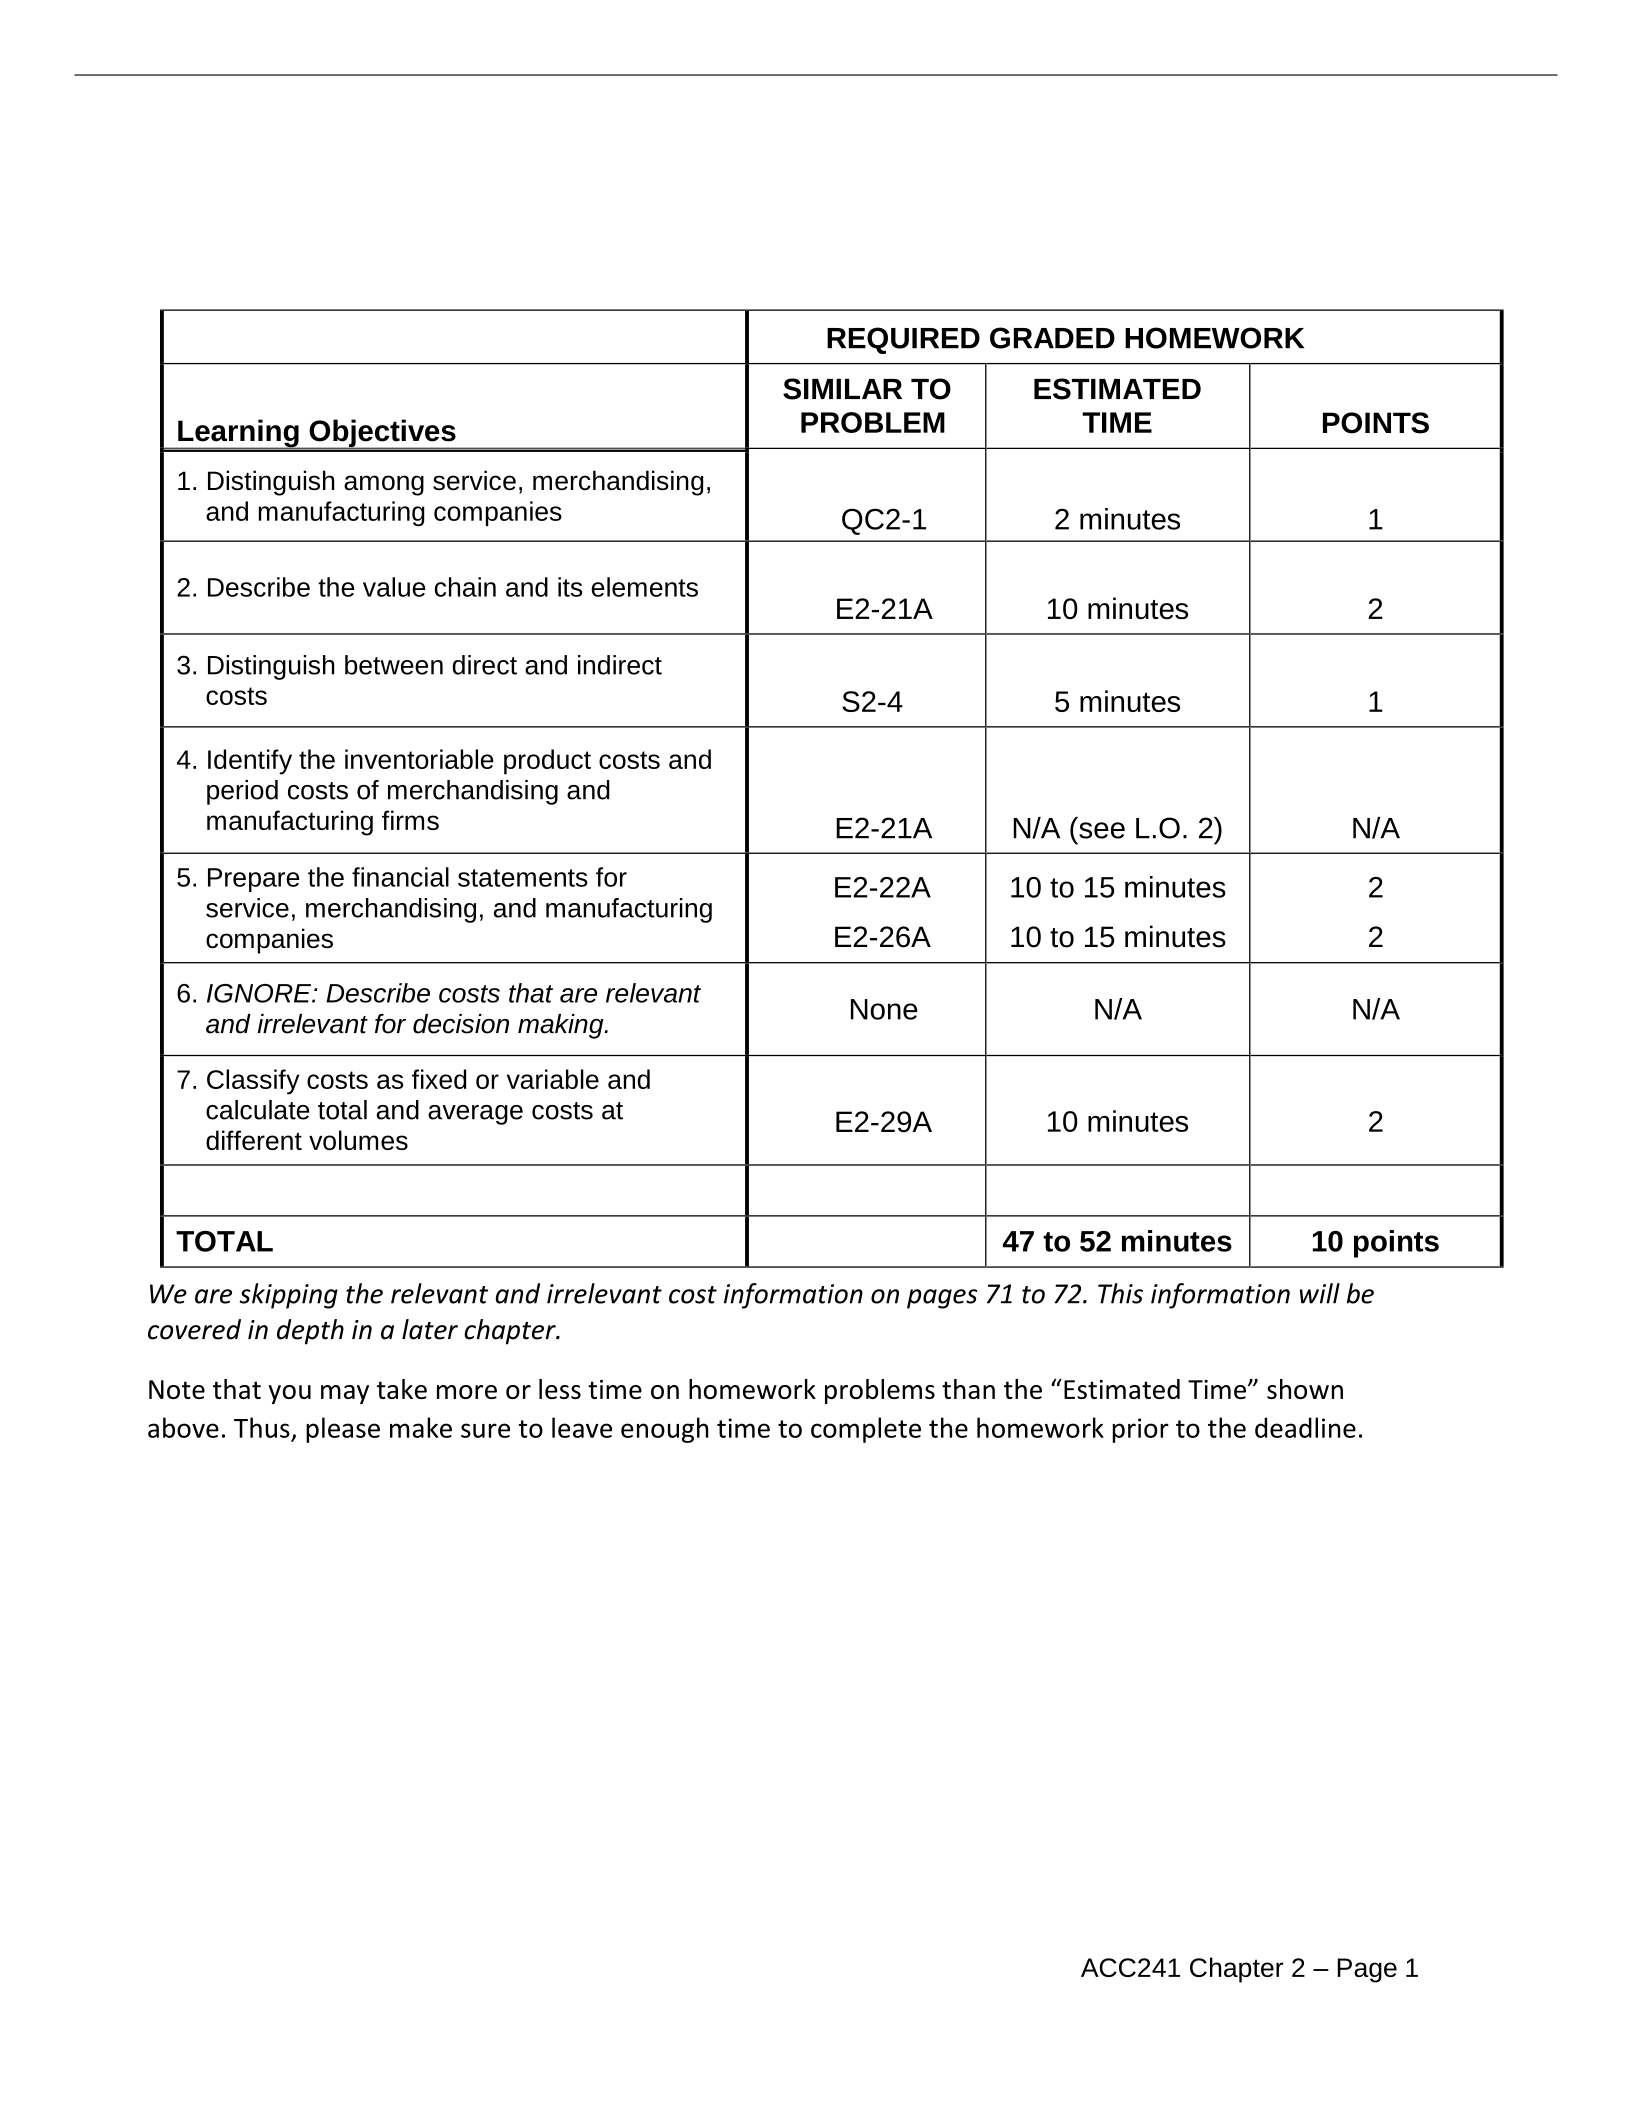
REQUIRED GRADED HOMEWORK
Learning Objectives
SIMILAR TO
PROBLEM
ESTIMATED
TIME
POINTS
1. Distinguish among service, merchandising,
and manufacturing companies
QC2-1
2 minutes
1
2. Describe the value chain and its elements
E2-21A
10 minutes
2
3. Distinguish between direct and indirect
costs
S2-4
5 minutes
1
4. Identify the inventoriable product costs and
period costs of merchandising and
manufacturing firms
E2-21A
N/A (see L.O. 2)
N/A
5. Prepare the financial statements for
service, merchandising, and manufacturing
companies
E2-22A
E2-26A
10 to 15 minutes
10 to 15 minutes
2
2
6. IGNORE: Describe costs that are relevant
and irrelevant for decision making.
None
N/A
N/A
7. Classify costs as fixed or variable and
calculate total and average costs at
different volumes
E2-29A
10 minutes
2
TOTAL
47 to 52 minutes
10 points
We are skipping the relevant and irrelevant cost information on pages 71 to 72. This information will be
covered in depth in a later chapter.
Note that you may take more or less time on homework problems than the “Estimated Time” shown
above. Thus, please make sure to leave enough time to complete the homework prior to the deadline.
Chapter 2 – Practice Problems and Homework
ACC241 Chapter 2 – Page 2
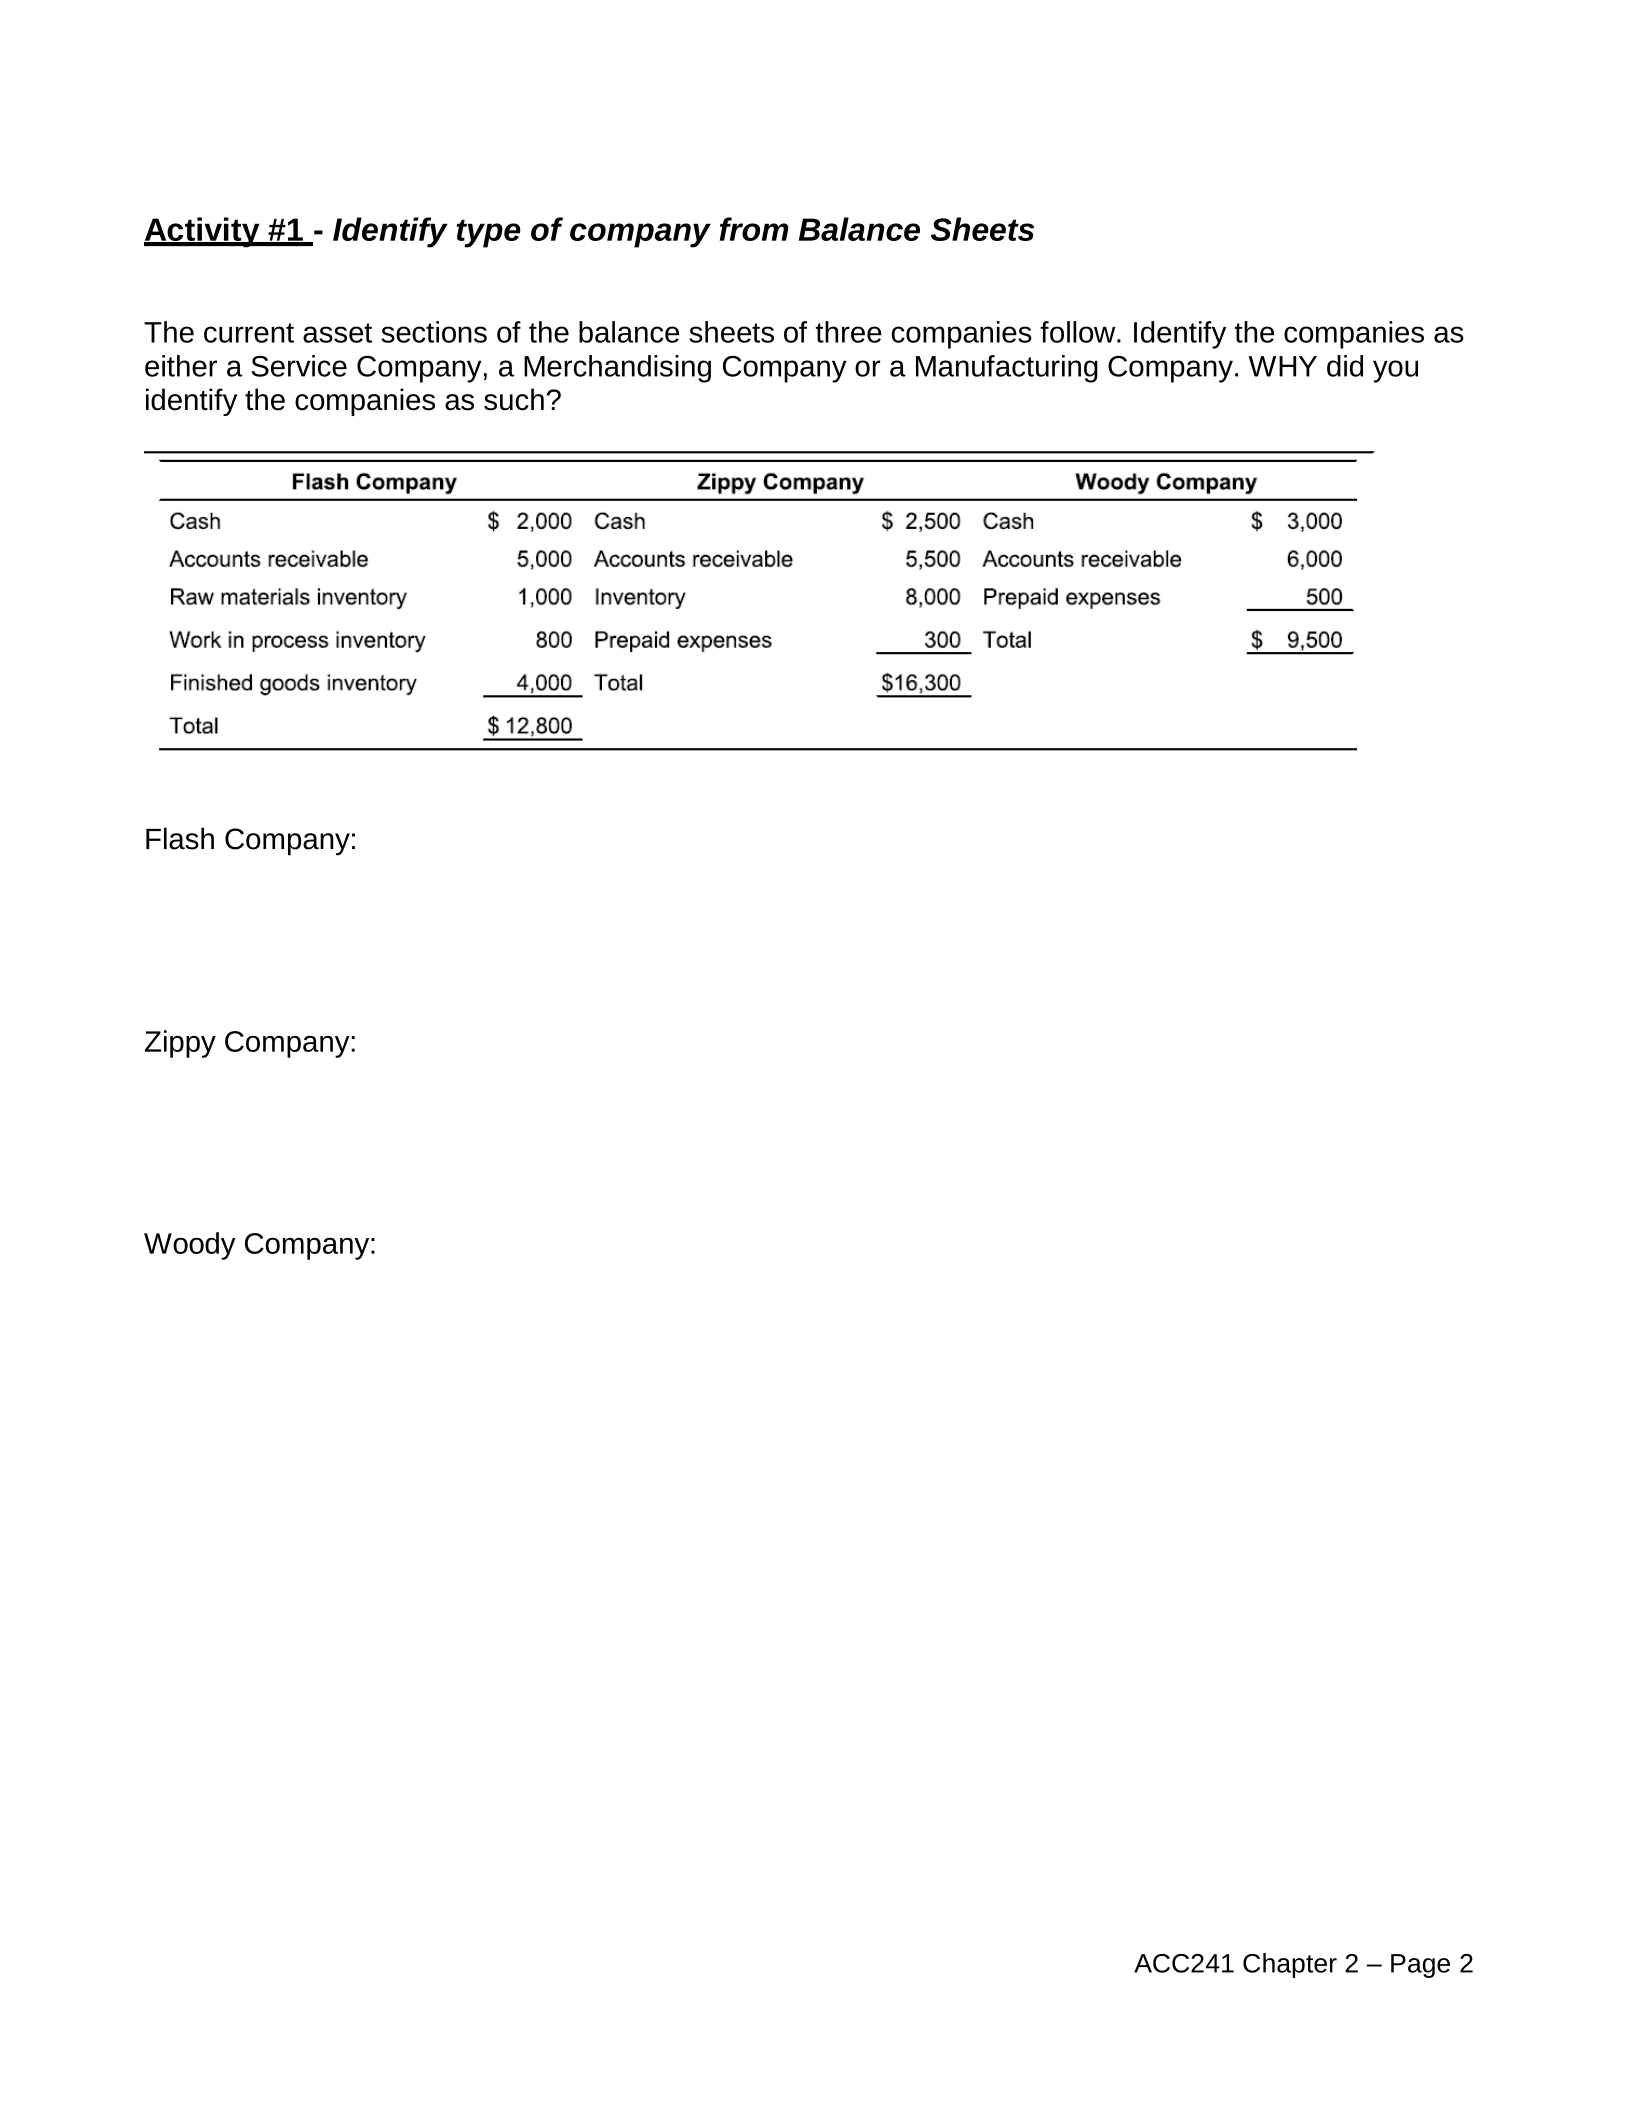
Activity #1 - Identify type of company from Balance Sheets
The current asset sections of the balance sheets of three companies follow. Identify the companies as
either a Service Company, a Merchandising Company or a Manufacturing Company. WHY did you
identify the companies as such?
Flash Company:
Zippy Company:
Woody Company:
ACC241 Chapter 2 – Page 3
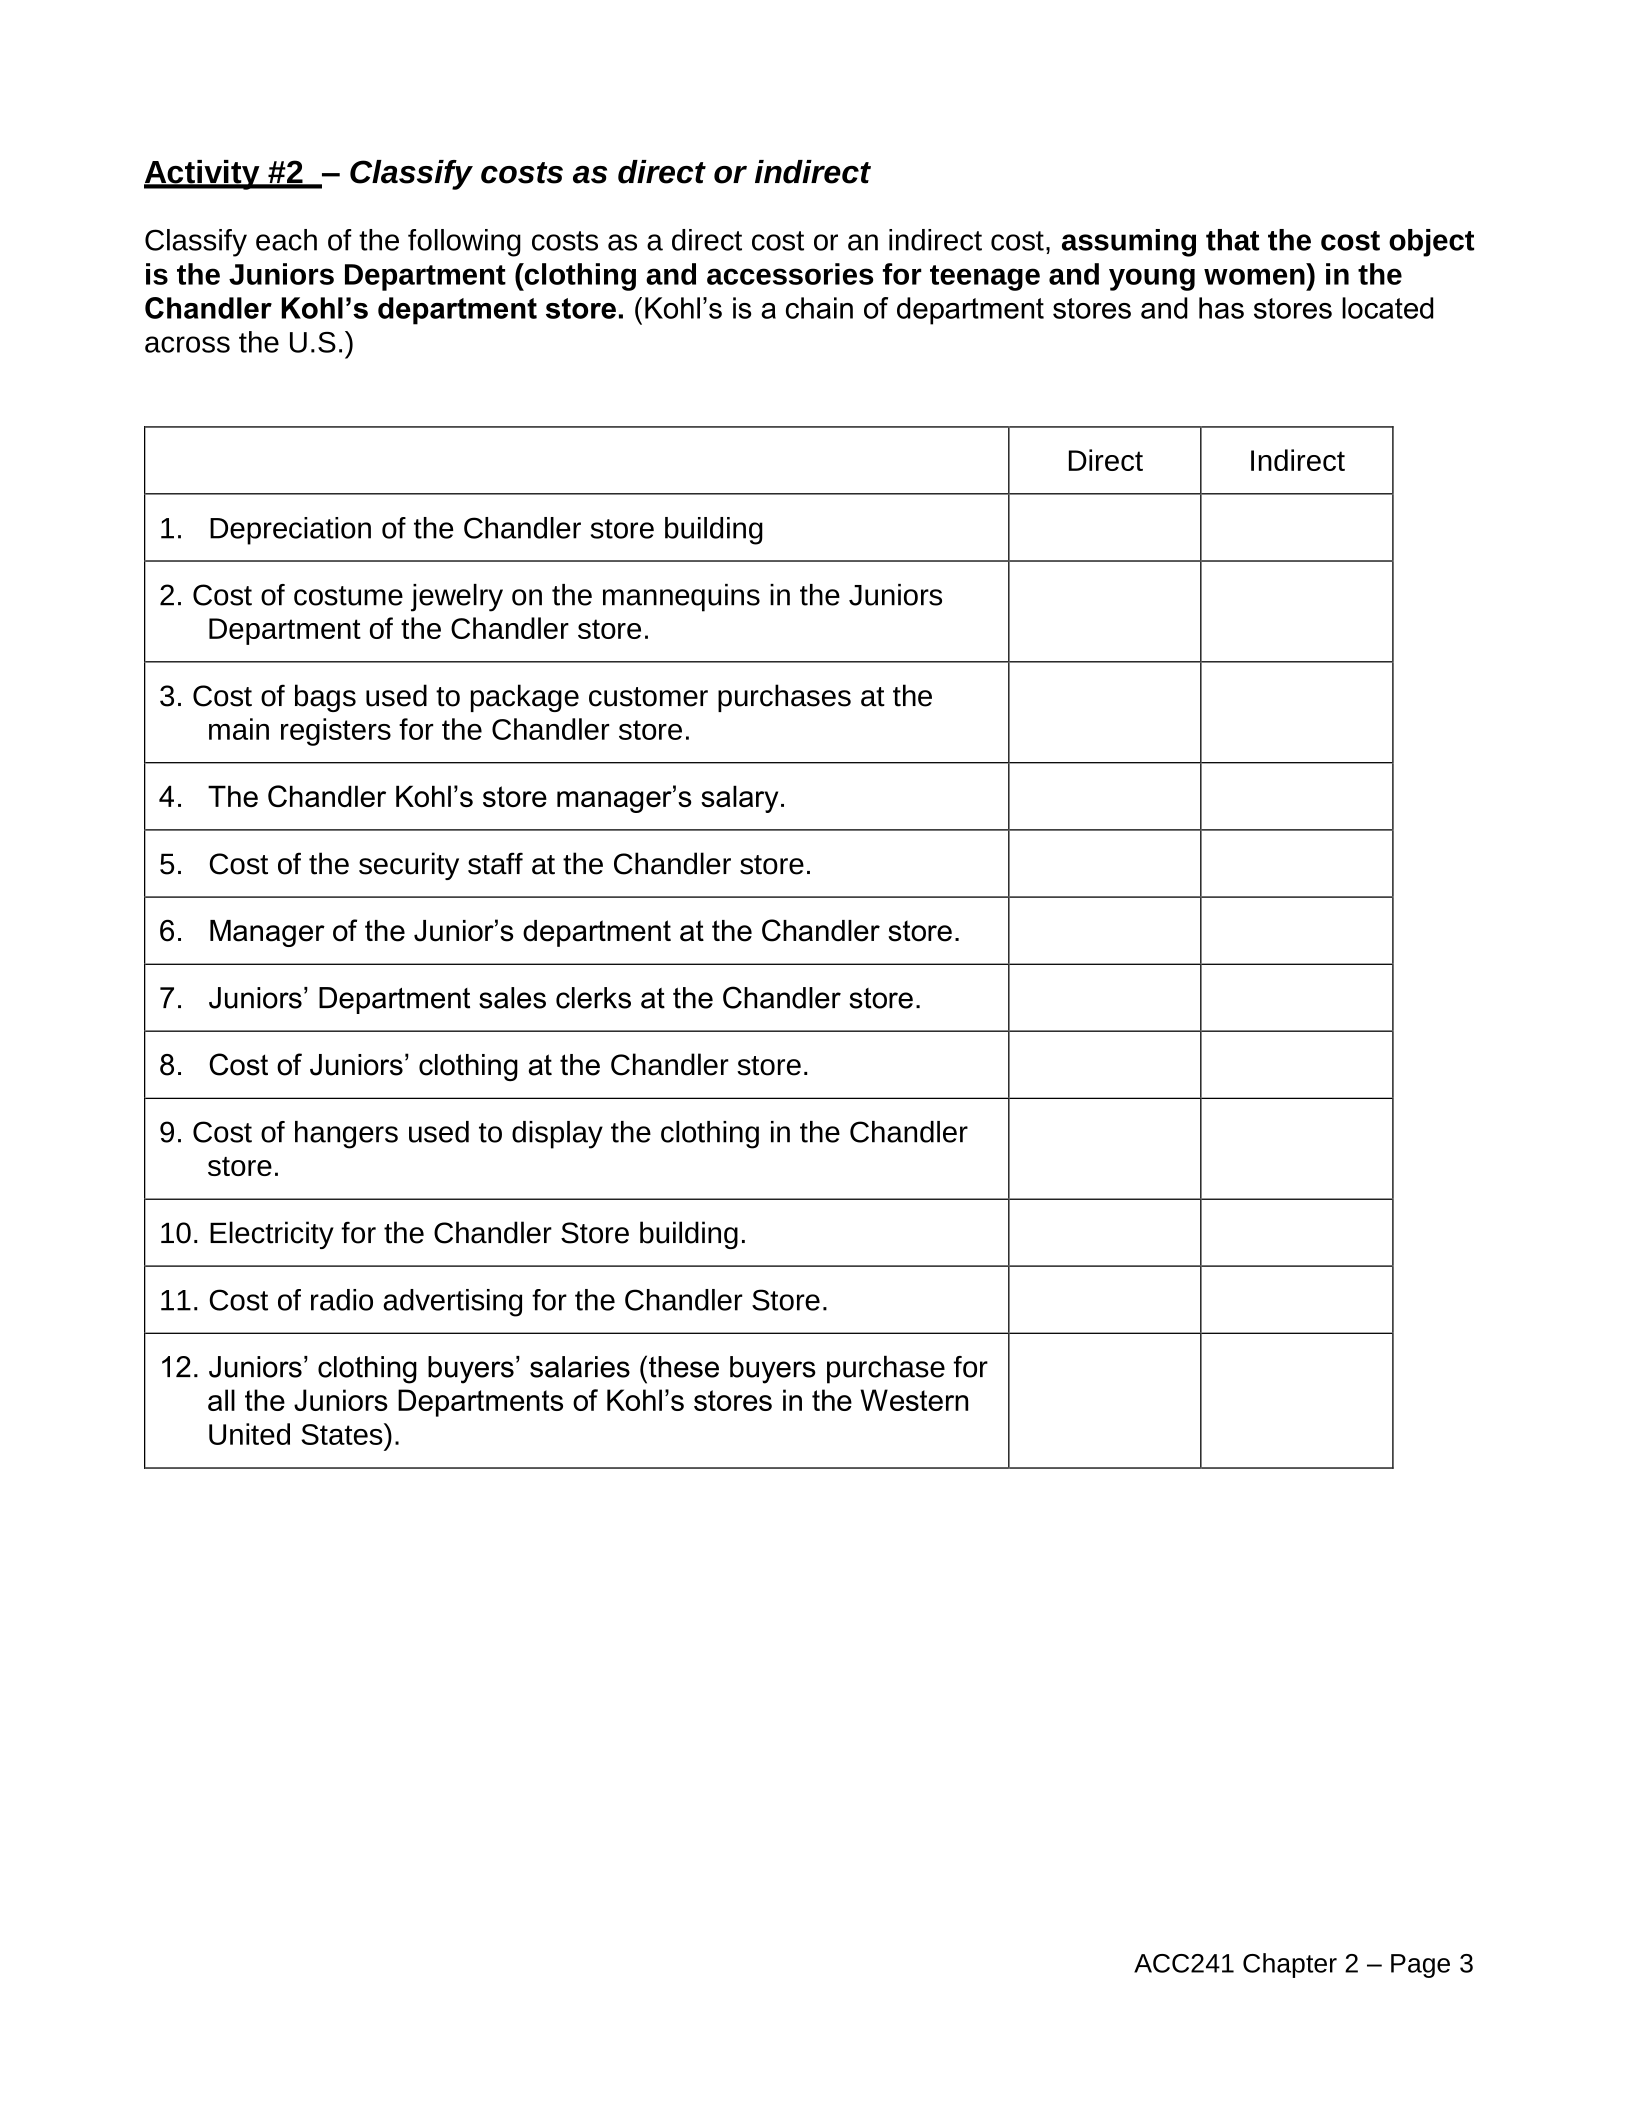
Activity #2 – Classify costs as direct or indirect
Classify each of the following costs as a direct cost or an indirect cost, assuming that the cost object
is the Juniors Department (clothing and accessories for teenage and young women) in the
Chandler Kohl’s department store. (Kohl’s is a chain of department stores and has stores located
across the U.S.)
Direct
Indirect
1. Depreciation of the Chandler store building
2. Cost of costume jewelry on the mannequins in the Juniors
Department of the Chandler store.
3. Cost of bags used to package customer purchases at the
main registers for the Chandler store.
4. The Chandler Kohl’s store manager’s salary.
5. Cost of the security staff at the Chandler store.
6. Manager of the Junior’s department at the Chandler store.
7. Juniors’ Department sales clerks at the Chandler store.
8. Cost of Juniors’ clothing at the Chandler store.
9. Cost of hangers used to display the clothing in the Chandler
store.
10. Electricity for the Chandler Store building.
11. Cost of radio advertising for the Chandler Store.
12. Juniors’ clothing buyers’ salaries (these buyers purchase for
all the Juniors Departments of Kohl’s stores in the Western
United States).
ACC241 Chapter 2 – Page 4
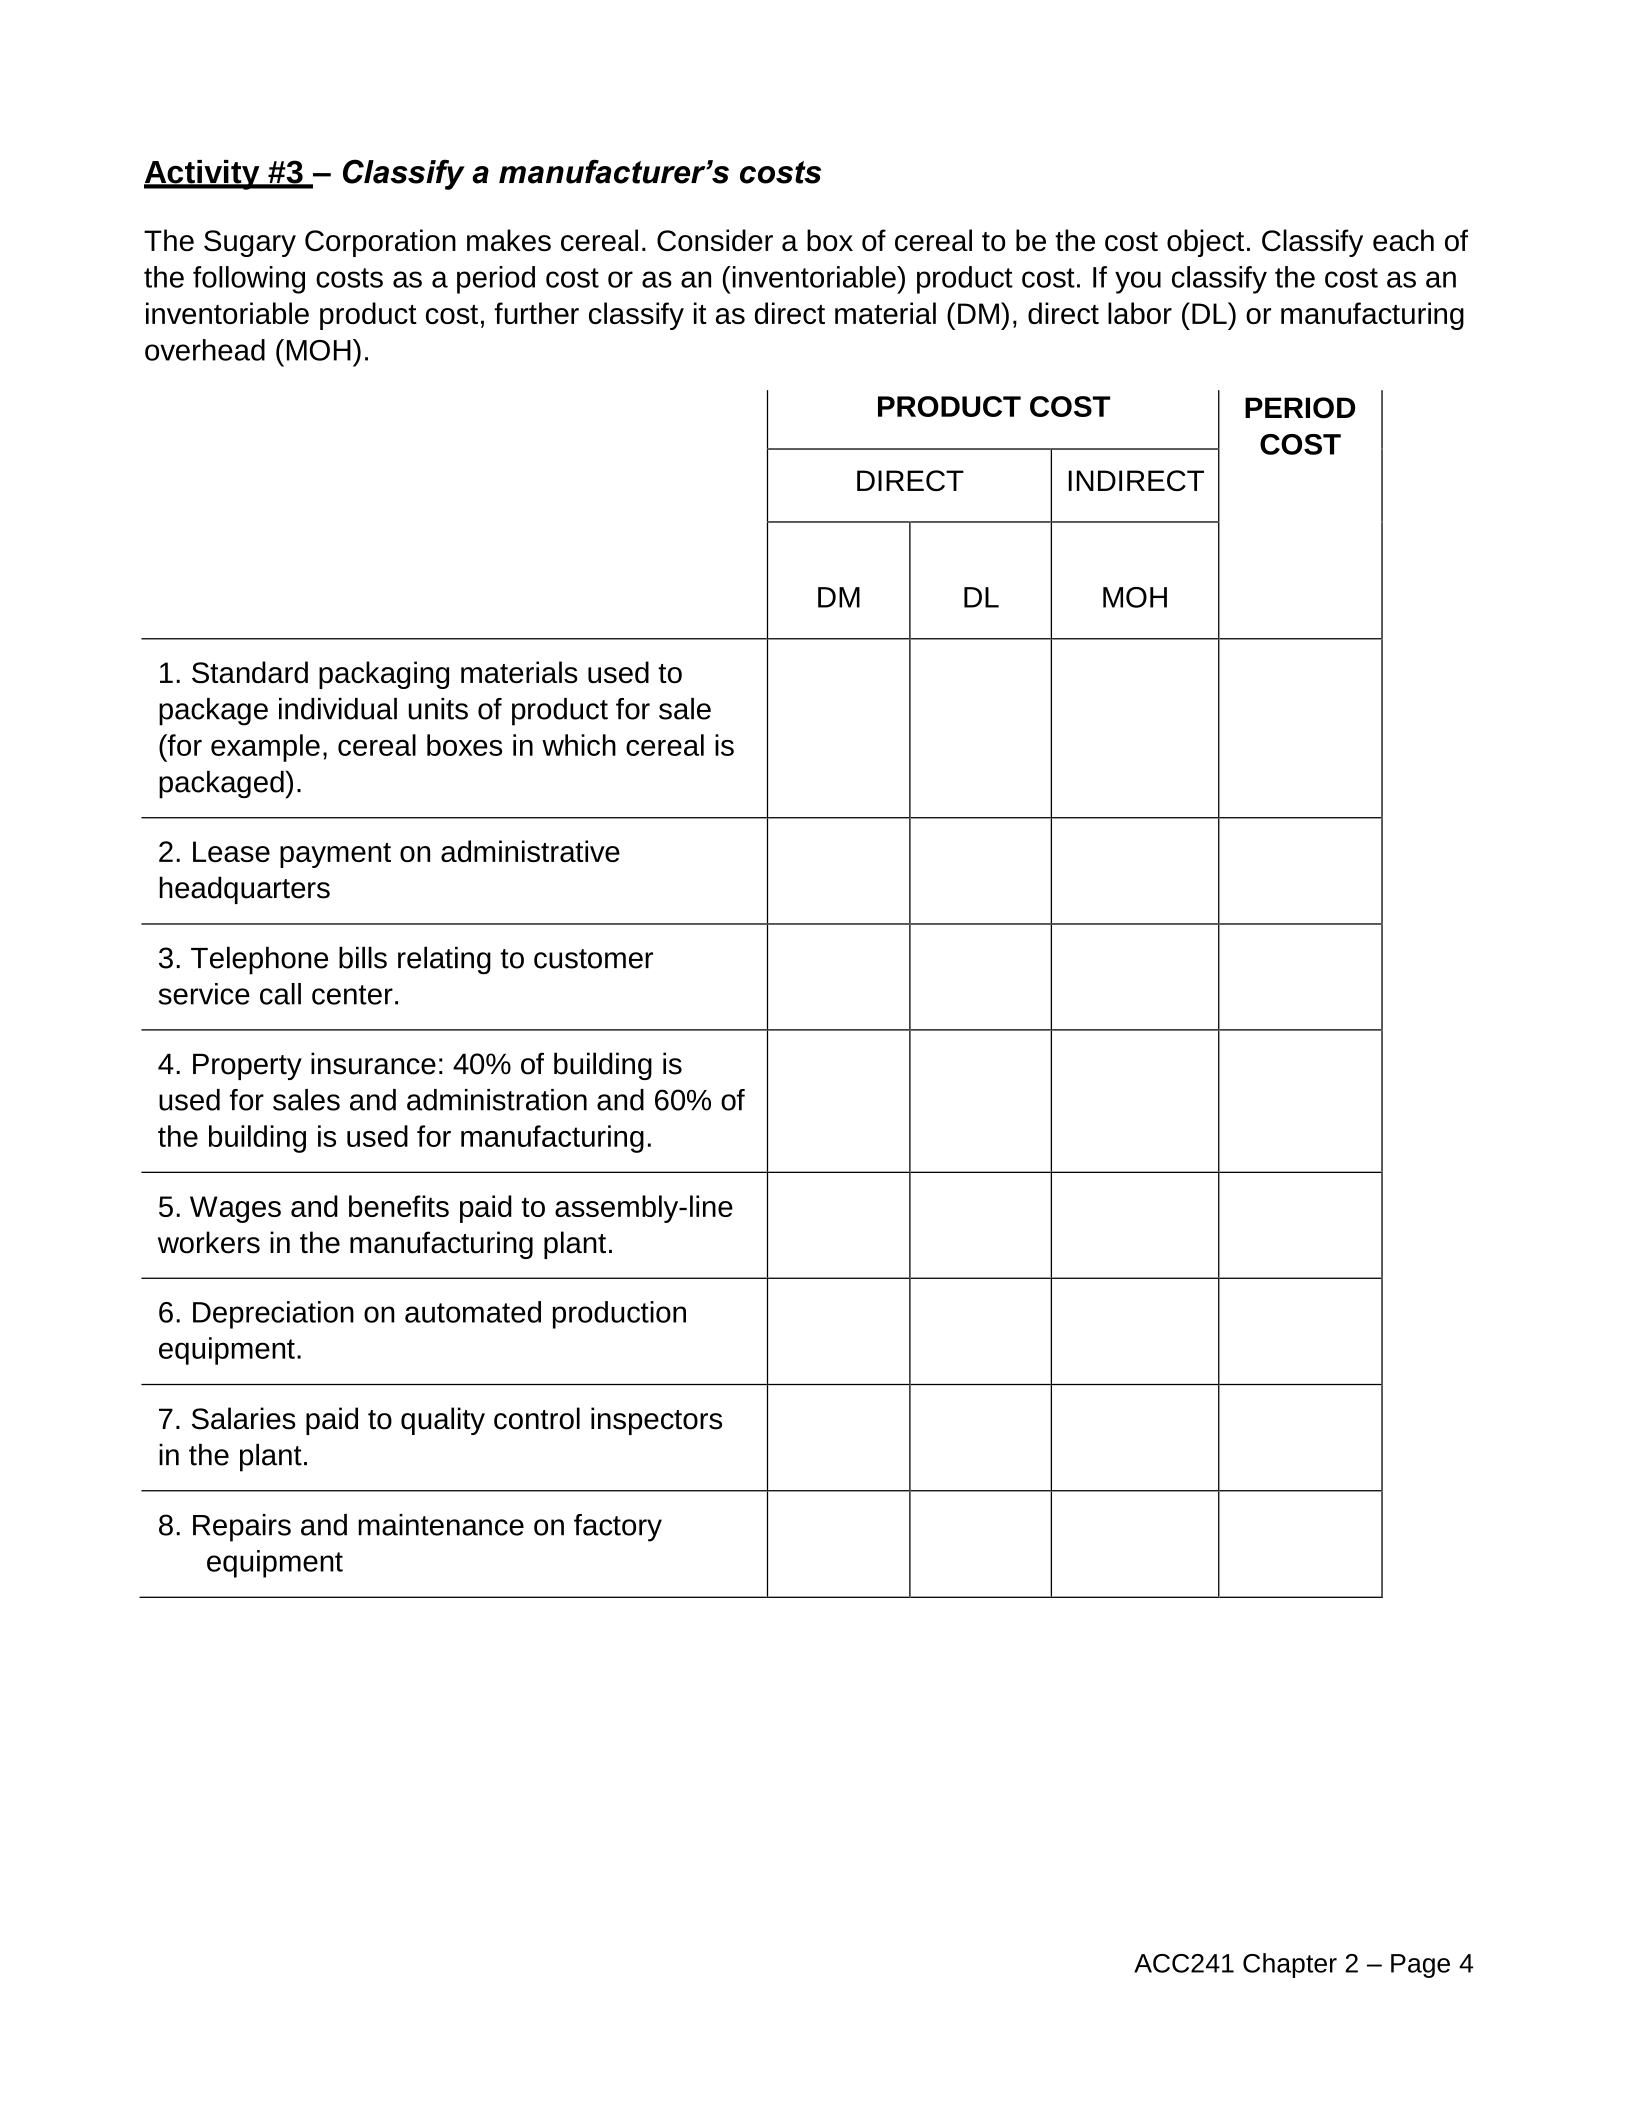
Activity #3 – Classify a manufacturer’s costs
The Sugary Corporation makes cereal. Consider a box of cereal to be the cost object. Classify each of
the following costs as a period cost or as an (inventoriable) product cost. If you classify the cost as an
inventoriable product cost, further classify it as direct material (DM), direct labor (DL) or manufacturing
overhead (MOH).
PRODUCT COST
PERIOD
COST
DIRECT
INDIRECT
DM
DL
MOH
1. Standard packaging materials used to
package individual units of product for sale
(for example, cereal boxes in which cereal is
packaged).
2. Lease payment on administrative
headquarters
3. Telephone bills relating to customer
service call center.
4. Property insurance: 40% of building is
used for sales and administration and 60% of
the building is used for manufacturing.
5. Wages and benefits paid to assembly-line
workers in the manufacturing plant.
6. Depreciation on automated production
equipment.
7. Salaries paid to quality control inspectors
in the plant.
8. Repairs and maintenance on factory
equipment
ACC241 Chapter 2 – Page 5
Activity #4 – Classify costs for a manufacturer
Suppose the cell phone manufacturer Kiwi Electronics provides the following information for its costs
last month (in million):
1.
Delivery expense to customers (via UPS)
$7
2.
Salaries of salespeople
4
3.
Chip set
56
4.
Exterior case for phone
9
5.
Assembly-line workers’ wages
10
6.
Technical customer support hotline
3
7.
Depreciation on plant and equipment
60
8.
Rearrange production process to
accommodate new robot
2
9.
1-800 (toll free) line for customer orders
5
10.
Salaries of scientists who developed new
phone model
11
Classify each of these costs according to whether they are product or period costs. For product (or
production) costs, break the costs down further into either Direct Material (DM), Direct Labor (DL) or
Manufacturing Overhead (MOH). For Period Costs, break down by value chain (R&D, Marketing,
Design, Distribution, Customer Service)
How much are the total inventoriable product costs?
How much are the total prime costs?
How much are the total conversion costs?
ACC241 Chapter 2 – Page 6
Activity #5 – Classify and calculate a manufacturer’s costs
Rustic Living Furniture Company manufactures furniture at its central Kentucky factory. Some of its
costs from the past year include:
1.
Wages paid to factory maintenance workers
$60,000
2.
Fabric used to upholster furniture
$8,000
3.
Wages paid to assembly-line workers
$100,000
4.
Lumber used to build product
$15,000
5.
Sales commissions
$7,500
6.
Insurance costs for factory
$21,000
7.
Freight-in (on raw materials)
$3,000
8.
Utilities in factory
$12,000
9.
Factory supervisor salary
$60,000
10.
Depreciation on factory equipment
$18,000
11.
Utilities in sales office
$26,500
12.
Costs of delivery to customers
$8,000
13.
Depreciation on sales office
$1,000
14.
Lubricants used in factory equipment
$500
Assuming the cost object is the furniture, classify each cost as one of the following: DM, DL, Indirect
Labor, Indirect Materials, other MOH or Period cost.
1.
Calculate total MOH costs. $
2.
Calculate total inventoriable product costs. $
3.
Calculate total prime costs. $
4.
Calculate total conversion costs. $
ACC241 Chapter 2 – Page 7
Activity #6 – Compute COGM and COGS
The following amounts were taken from the general ledger of the Excellent Manufacturing Company.
Compute the cost of goods manufactured and the cost of goods sold for the company for the year.
Raw materials inv. – beg. of year
$52,000
Depreciation – plant & equipment
$28,000
Raw materials inv. – end of year
46,000
Repairs & maintenance – plant
4,000
Work in process inv. – beg. of year
110,000
Insurance on plant
12,000
Work in process inv. – end of year
85,000
General and administration exp.
29,000
Finished goods inv. – beg. of year
26,000
Indirect labor
27,000
Finished goods inv. – end of year
54,000
Direct labor
178,000
Purchase of direct materials
37,000
Marketing expenses
62,000
ACC241 Chapter 2 – Page 8
Activity #7 – Compute Total and Average Costs
Sydney’s Sculptures reported the following information:
A. DM, DL and variable MOH is $25 per every sculpture they produce.
B. Fixed MOH costs are $10 million per year
C. The company currently produces and sells 1,000,000 units per year for $150 per unit
D. The demand for sculptures is heavily dependent upon the economy and next year’s economic
forecast is not good. Therefore, next year, the company only plans on producing and selling
800,000 units during the\ year. Management doesn’t anticipate any changes in the prices it
pays for materials, labor and MOH.
1. What is the TOTAL product cost for the current 1,000,000 units produced?
2. What is the current average product cost per unit?
3. What is the current average gross profit per unit?
4. What is the current fixed cost per unit?
5. What is the forecasted total product cost next year for the planned 800,000 units?
6. What is the forecasted average product cost per unit next year?
7. What is the forecasted average gross profit per unit next year?
8. What is the forecasted fixed cost per unit next year?
9. Why does the average product cost increase as production decreases?
10. What is the marginal cost of producing one additional sculpture?
Powered by TCPDF (www.tcpdf.org)

