


Chapter 1
Management Accounting ***
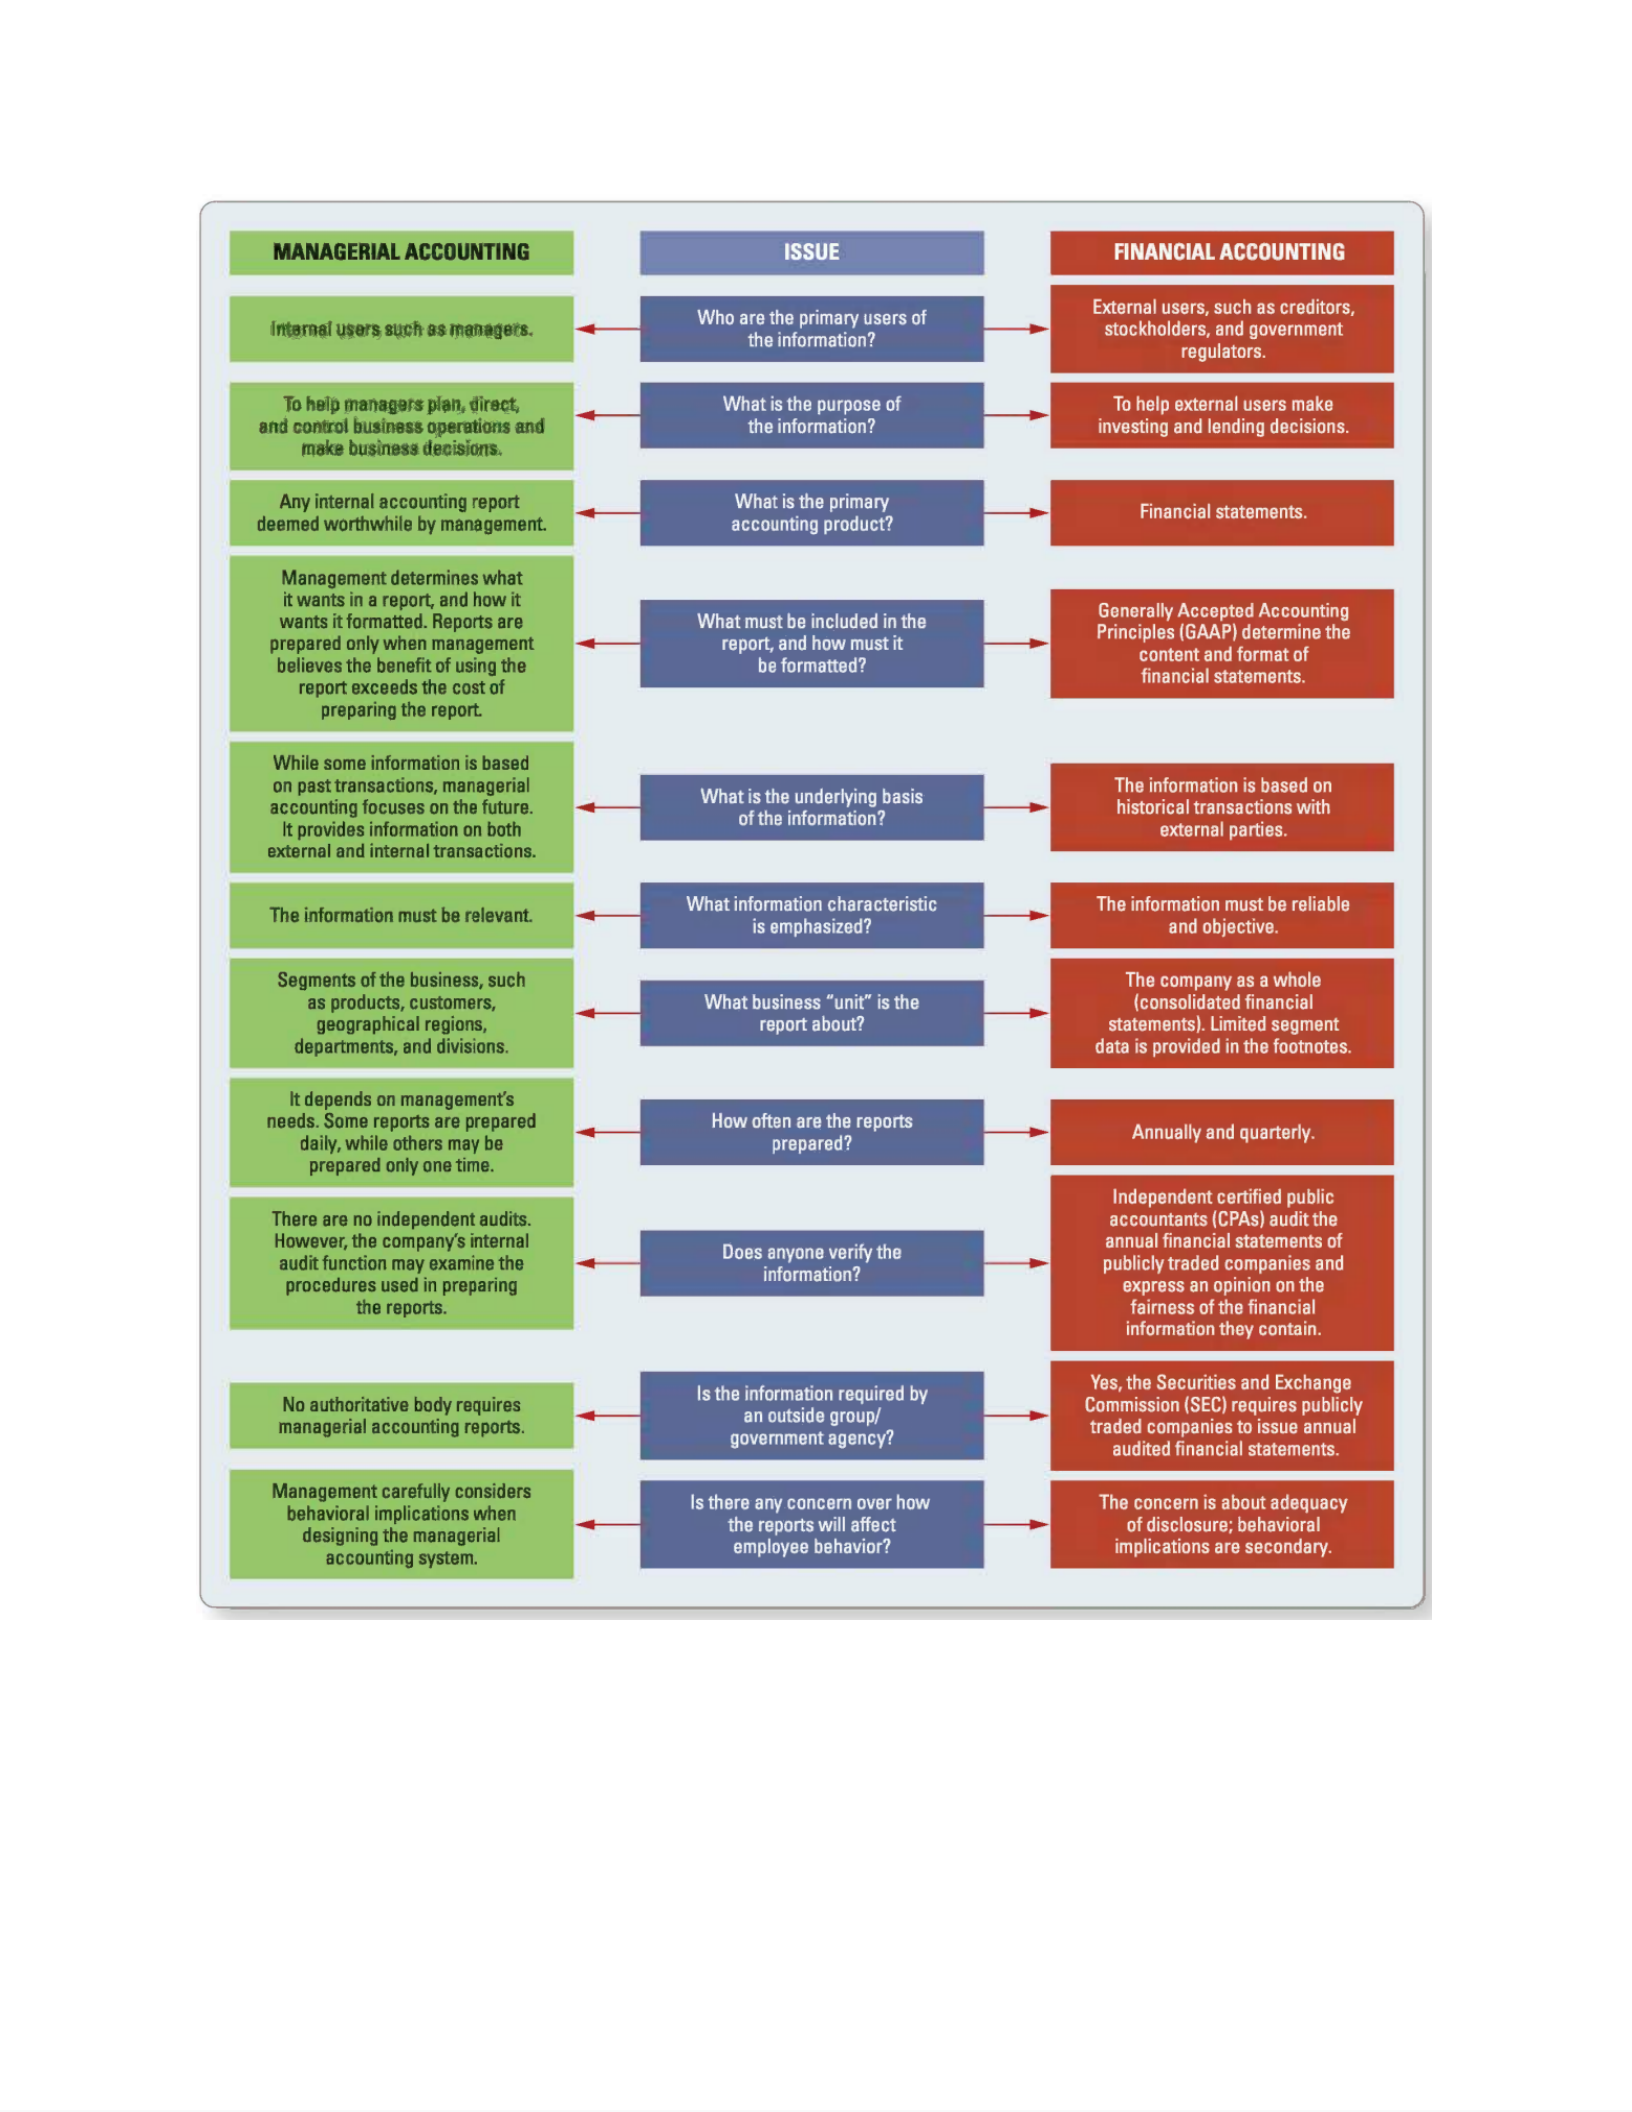
- Measures, analyzes, and reports financial and nonfinancial information to help
make decisions that achieve organizational goals
- Reports don’t need to be compliant with GAAP
- They are tailored for each organization
- Managers use management accounting information to:
- Develop, communicate, and implement strategies
- Help in all phases of of an organization including product design,
production, distribution, sales, and performance measurement
- The focus of these reports is on internal users
- Both backward and forward looking- analyze past performance and help
future profitability
- Strategic focus
- Timeliness
- Cost Accounting
Financial Accounting
- Focuses on reporting financial information to external parties such as investors,
governmental agencies such as the SEC and the IRS, creditors, banks and other
regulatory agencies
- Reports must follow GAAP (generally accepted accounting principles)
- Focus in on past performance, adherence to standards, scheduled reports
Management Accounting Objective
- Strategy: how an organization plans to use its capabilities to exploit the
opportunities available
- Cost leadership
- Product differentiation
- Management accounting helps make strategic decisions by answering:
- Who are our most important customers? What do they value and how can
we deliver it in the most competitive manner?
- What is the bargaining power of our customers and our suppliers? What
are the substitutes for our products? Who are our competitors?
- What resources do we have? How can we raise more resources? What
will it cost and how do we deliver value to our shareholders?
Manager’s Primary Responsibilities - Decision Making
-Planning :
- Selecting an organization’s goals and strategies
- Predicting results under various alternative ways of achieving those goals
- Deciding how to attain the desired goals
- Communicating the goals and how to achieve them to the entire
organization
-Directing :
- Identify the problem/uncertainties
- Obtain information
- Make predictions about the future
- Make decisions by choosing among alternatives
- Implement the decision, evaluate performance, and learn
- Control
- Taking actions that implement the planning decisions
- Evaluating past performance
- Providing feedback and learning to help future decision making
Ethics and Internal Reporting
- Managers are increasingly being held responsible for creating and maintaining
an ethical work environment including the reporting of accounting information
- Ethics refers to the standards of conduct for judging right from wrong
Chapter 2
Types of Companies
- Service
- Sell intangible product or provide a service
- No COGS on income statement
- No inventory on balance sheet
- Airlines, banks, insurance
- Merchandising
- Purchase inventory for resale - COGS on income statement
- Inventory on balance sheet
- Grocery stores, Walmart, Amazon
- Manufacturing
- Raw material, work in process, finished goods,
- Inventory on balance sheet - convert raw materials into finished goods
- COGS on income statement
- Car manufacturers, consumer product manufacturers
The Value Chain
- The activities that add value to the company’s products and services

- Research and development, design, production or purchases, marketing,
distribution, customer service
- Product cost + Period cost = Total cost
Reporting
- Internal reporting
- Include all costs incurred across the value chain
- Total cost: all resources used throughout the value chain
- Goal is to insure that the selling price determined covers all costs plus a
markup
- External reporting
- Must follow GAAP
- Relate to obtaining inventory
- Incurred in other functions of the value chain, “operating expenses” or
“selling, general, and administrative expenses”
- Product costs
- Incurred by manufacturers to product their products or by
merchandisers to purchase their products
- Necessary to manufacture the product
- Material, labor, manufacturing overheads
- Period costs
- Do not get treated as inventory, immediately expensed
- Non-manufacturing costs expensed during the period
- Selling and distribution expenses, renting office space, marketing
expense
Cost Objectives
- Anything for which managers want to know the cost. Toyota’s cost objects may
include the following:
- Individual unites
- Different models
- Alternative marketing strategies
- Geographic segments of the business
- Departments
- Sustainability incentives
Direct and Indirect Costs
- Direct costs
- Costs that can be directly identified or traced to a cost object, meaning the
company can readily identify or associate the cost with the cost object.
- Indirect costs
- Costs that cannot be directly identified or traced to a cost object
- These costs are indirectly related to the cost subject
- These costs are accumulated and then allocated to to the cost object
(based on some rationale and system)
Product Costs
- Direct materials
- Primary materials that become the physical part of the finished product
- B.B. + purchase - use = E.B.
- Direct labor
- Salaries of employees who physically convert raw materials into the
company’s product, work on the production floor
- Manufacturing Overhead
- All manufacturing costs other than DM and DL, including indirect
materials, indirect labor, and indirect manufacturing costs
- Indirect material: B.B. + purchases - used on the production floor = E.B.
- Indirect labor + insurance + depreciation + repairs
Prime and Conversion Costs
- Prime costs: direct materials + direct labor
- Conversion costs: manufacturing overhead + direct labor
Product Cost Flows
- Costs: material purchases, direct labor, manufacturing overhead, selling and
administrative
- Balance sheet inventories: raw materials, work in process, finished goods
- Income statement expenses: cost of goods sold, selling and administrative
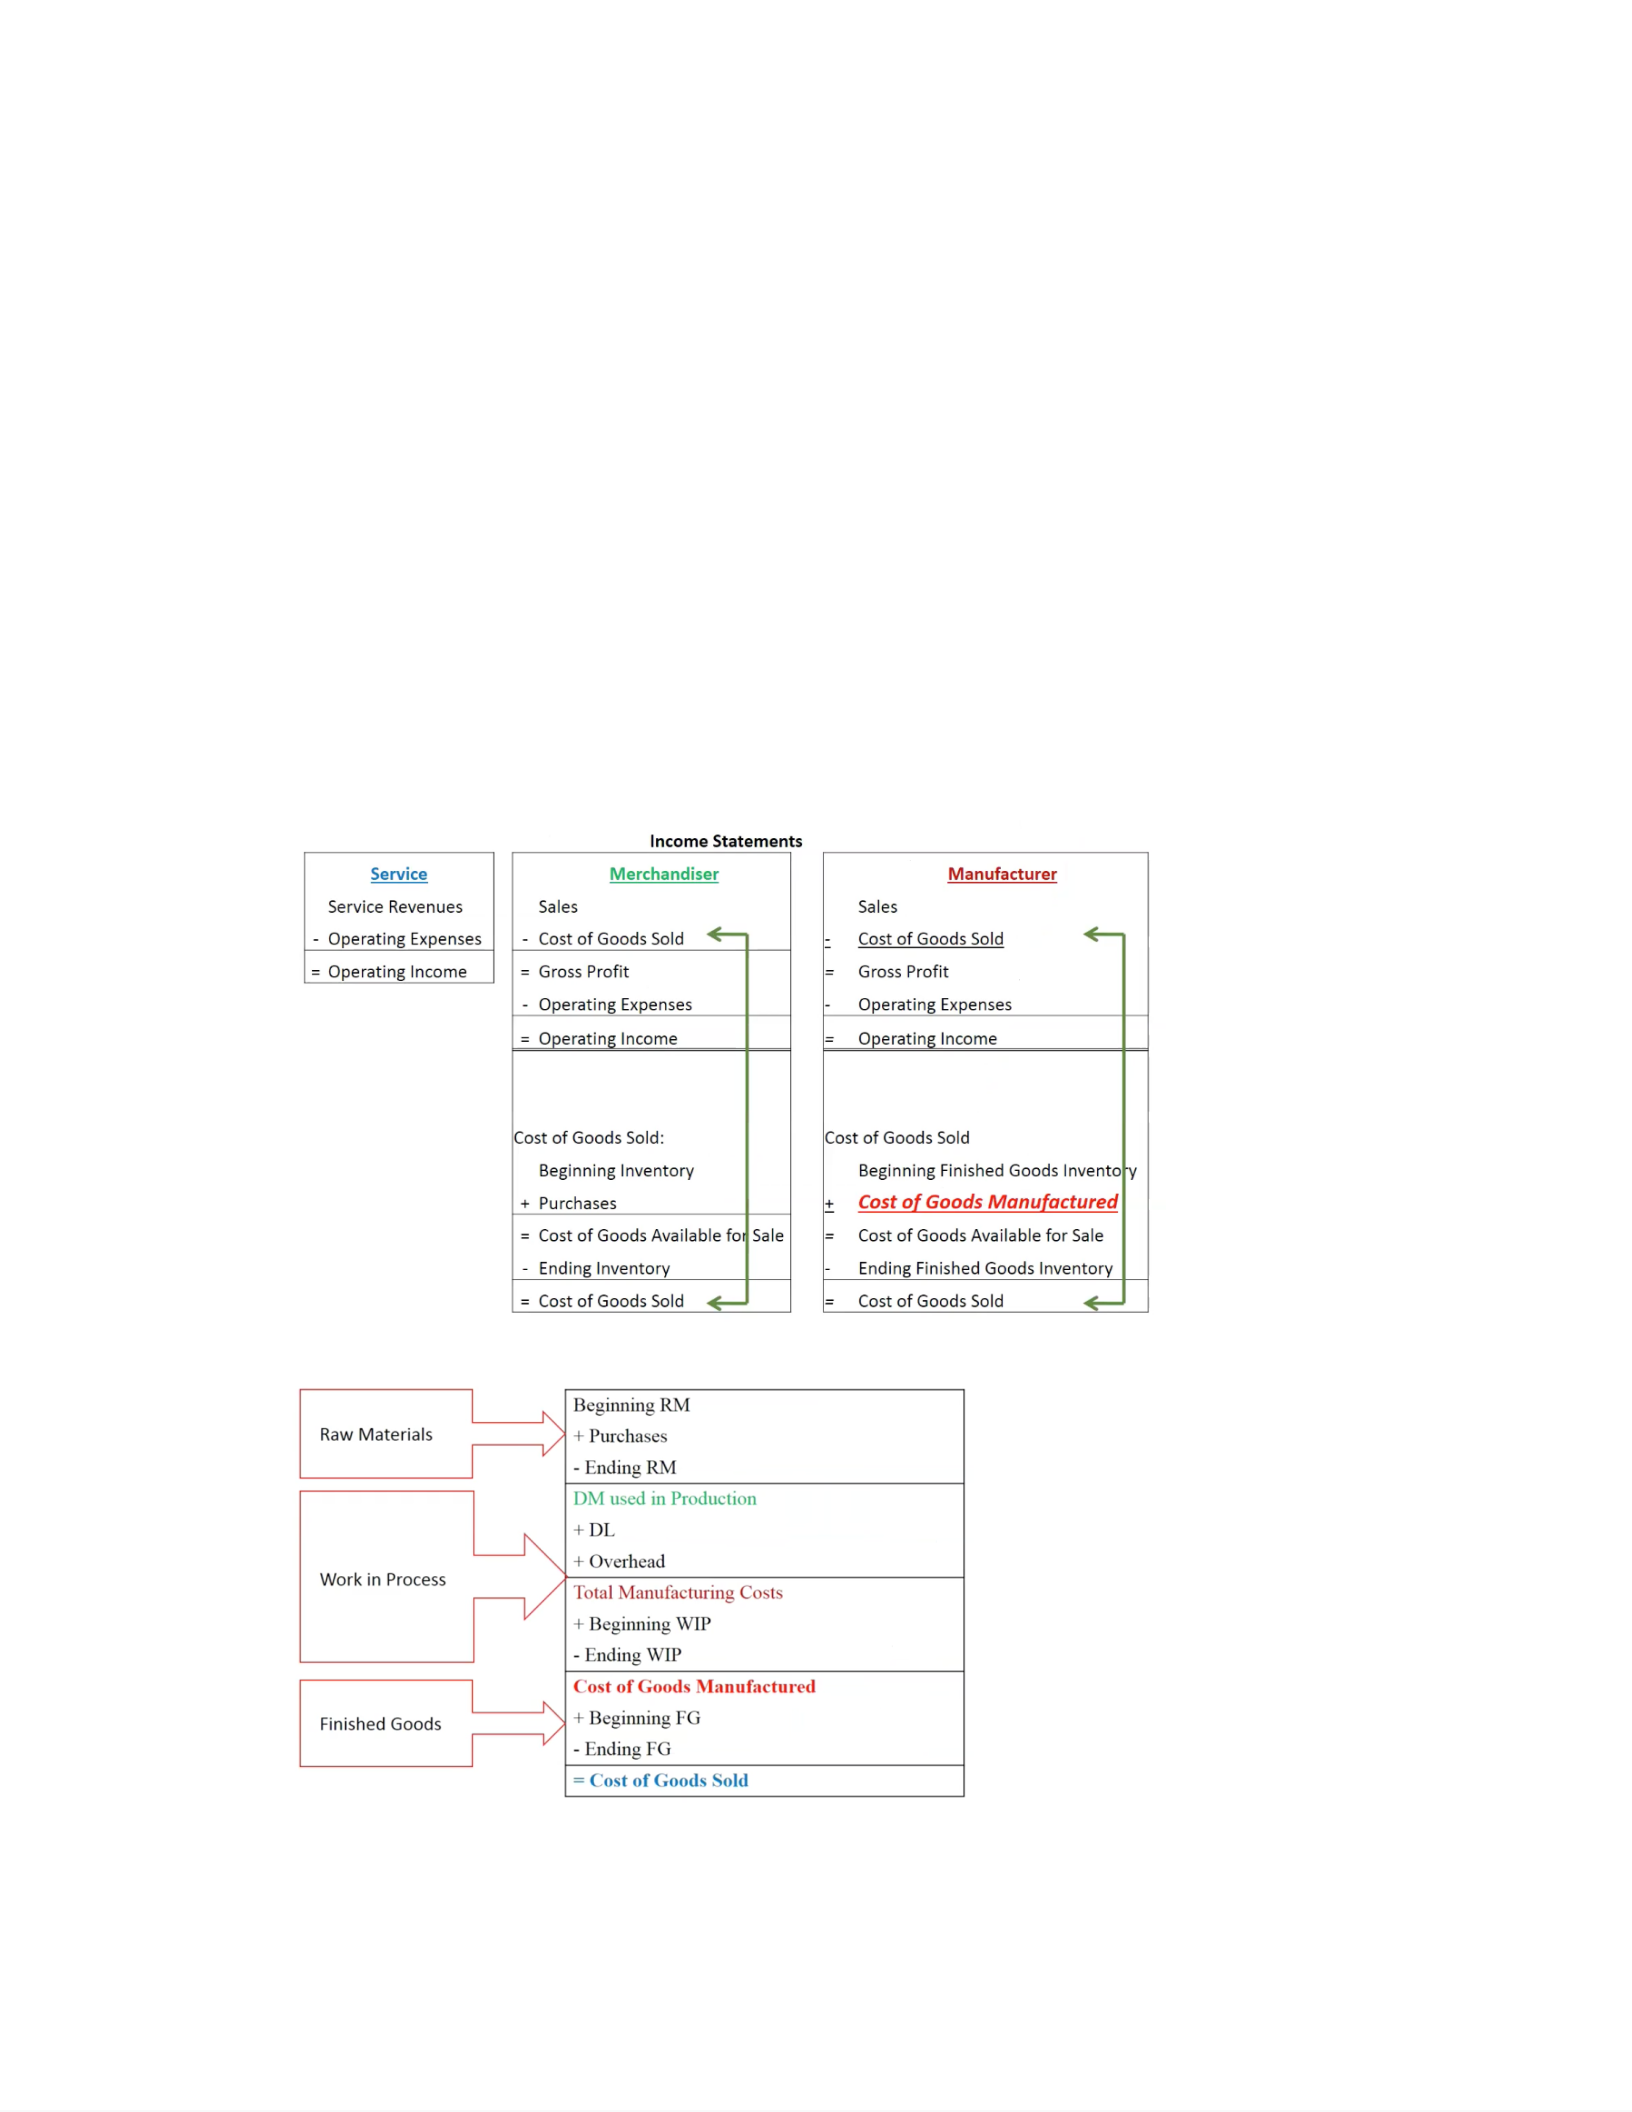
Income Statements
-
COGM/COGS Using Actual Costing
-
Classifications Based on Cost Behavior
- Total variable cost change in relation to output. Greater output entails greater
cost
- Total cost of microprocessors - More iPhones produced - More
microprocessors used - greater cost
- Total fixed costs remain the same regardless of output
- Factory rent – Remains the same regardless of how many iPhones are
produced
Chapter 2 Key Terms
Allocate
- The assignment, using some reasonable basis, of any indirect cost to one or
more cost objects
Assign
- Allocation of consumed resources to the consumer activities or cost objects.
Average Cost
- Production cost per unit of output, computed by dividing the total of fixed costs
and variable costs by the number of total units produced (total output).
Controllable Costs
- Expenditures that are subject to the discretion of a manager and, hence, can be
kept within predefined limits.
Conversion Costs
- The combined total of direct labor cost and manufacturing overhead incurred in
processing raw materials to a finished state.
Cost Object
- Anything for which cost data is desired by a manager, e.g., products, product
lines, customers, jobs, and organizational sub-units such as departments or
divisions of a company.
Cost Accumulation
- Gathering (collecting) costs (or resources used) in an organized manner
(department, activity, etc.)
Cost Assignment
- Allocating the accumulated cost to cost objects that have an indirect relationship
to resources used
Cost Tracing
- Tracing a direct relationship from a resource use to a cost object (product,
service. Department, etc.)
Cost of Goods Manufactured
- Total cost of all goods produced, which includes costs of material, labor, and
overhead, whether fixed or variable.
Differential Cost
- Any cost that differs between alternatives in a decision-making situation.
Direct Cost
- A cost that can be directly related to producing specific goods or performing a
specific service.
Direct Labor Cost

- An element of Prime Costs and Conversion Costs, the cost of compensating
employees who physically convert raw materials into finished products.
Direct Material
- Primary raw materials that become a physical part of a finished product whose
costs are traceable to the finished product.
Finished Goods Inventory
- Products completely manufactured, packaged, stored, and ready for sale to
customers.
Fixed Cost
- A cost that does not vary depending on production or sales levels, such as rent,
property tax, insurance, or interest expense.
Indirect Cost
- Manufacturing cost that cannot be easily seen in the product. Electricity, hazard
insurance on the factory building, and real estate taxes are examples of indirect
costs.
Indirect Labor
- An element of Conversion Costs, manufacturing labor costs that cannot be
directly tied to a finished product.
Indirect Materials
- An element of Manufacturing Overhead, materials used in the manufacture of
products that are difficult to trace to individual units (i.e. glue, small amounts of
lubricant).
Inventoriable Product Costs
- All costs of a product that are recorded as an asset (inventory) under US GAAP
(direct materials, direct labor and manufacturing overhead). These costs are not
expensed until the related product is sold.
Manufacturing Overhead
- All manufacturing costs that are not for direct materials and direct labor.
Marginal cost
- The increase or decrease in costs as a result of one more or one less unit of
output.
Other Indirect Manufacturing Costs
- All manufacturing overhead costs other than those associated with indirect
material and indirect labor.
Period Costs
- Expenses recognized as costs in the period in which they were incurred; often
referred to as operating expenses, or selling, general and administrative
expenses.
Prime Costs
- The sum of direct material and direct labor costs.
Raw Materials Inventory
- All raw materials, direct and indirect, not yet used in manufacturing.
Research and Development
- Investigative activities that a business chooses to conduct with the intention of
making a discovery that can either lead to the development of new products or
procedures, or to improvement of existing products or procedures.
Sunk Costs
- A historical or past cost that a company has already incurred and, therefore, is
irrelevant to the decision-making process.
Total Costs
- The cost of all resources used throughout the value chain.
Trace
- The ability to assign a direct cost to a cost object.
Value Chain
- Linked set of all value-creating processes or activities that convert basic input
materials into products or services for the final consumer.
Variable Costs
- A cost that is directly proportional to the volume of output produced.
Work-in-Process Inventory
- That part of a manufacturer's inventory that is in the production process and has
not yet been completed and transferred to the finished goods inventory (includes
direct material, direct labor, and manufacturing overhead).
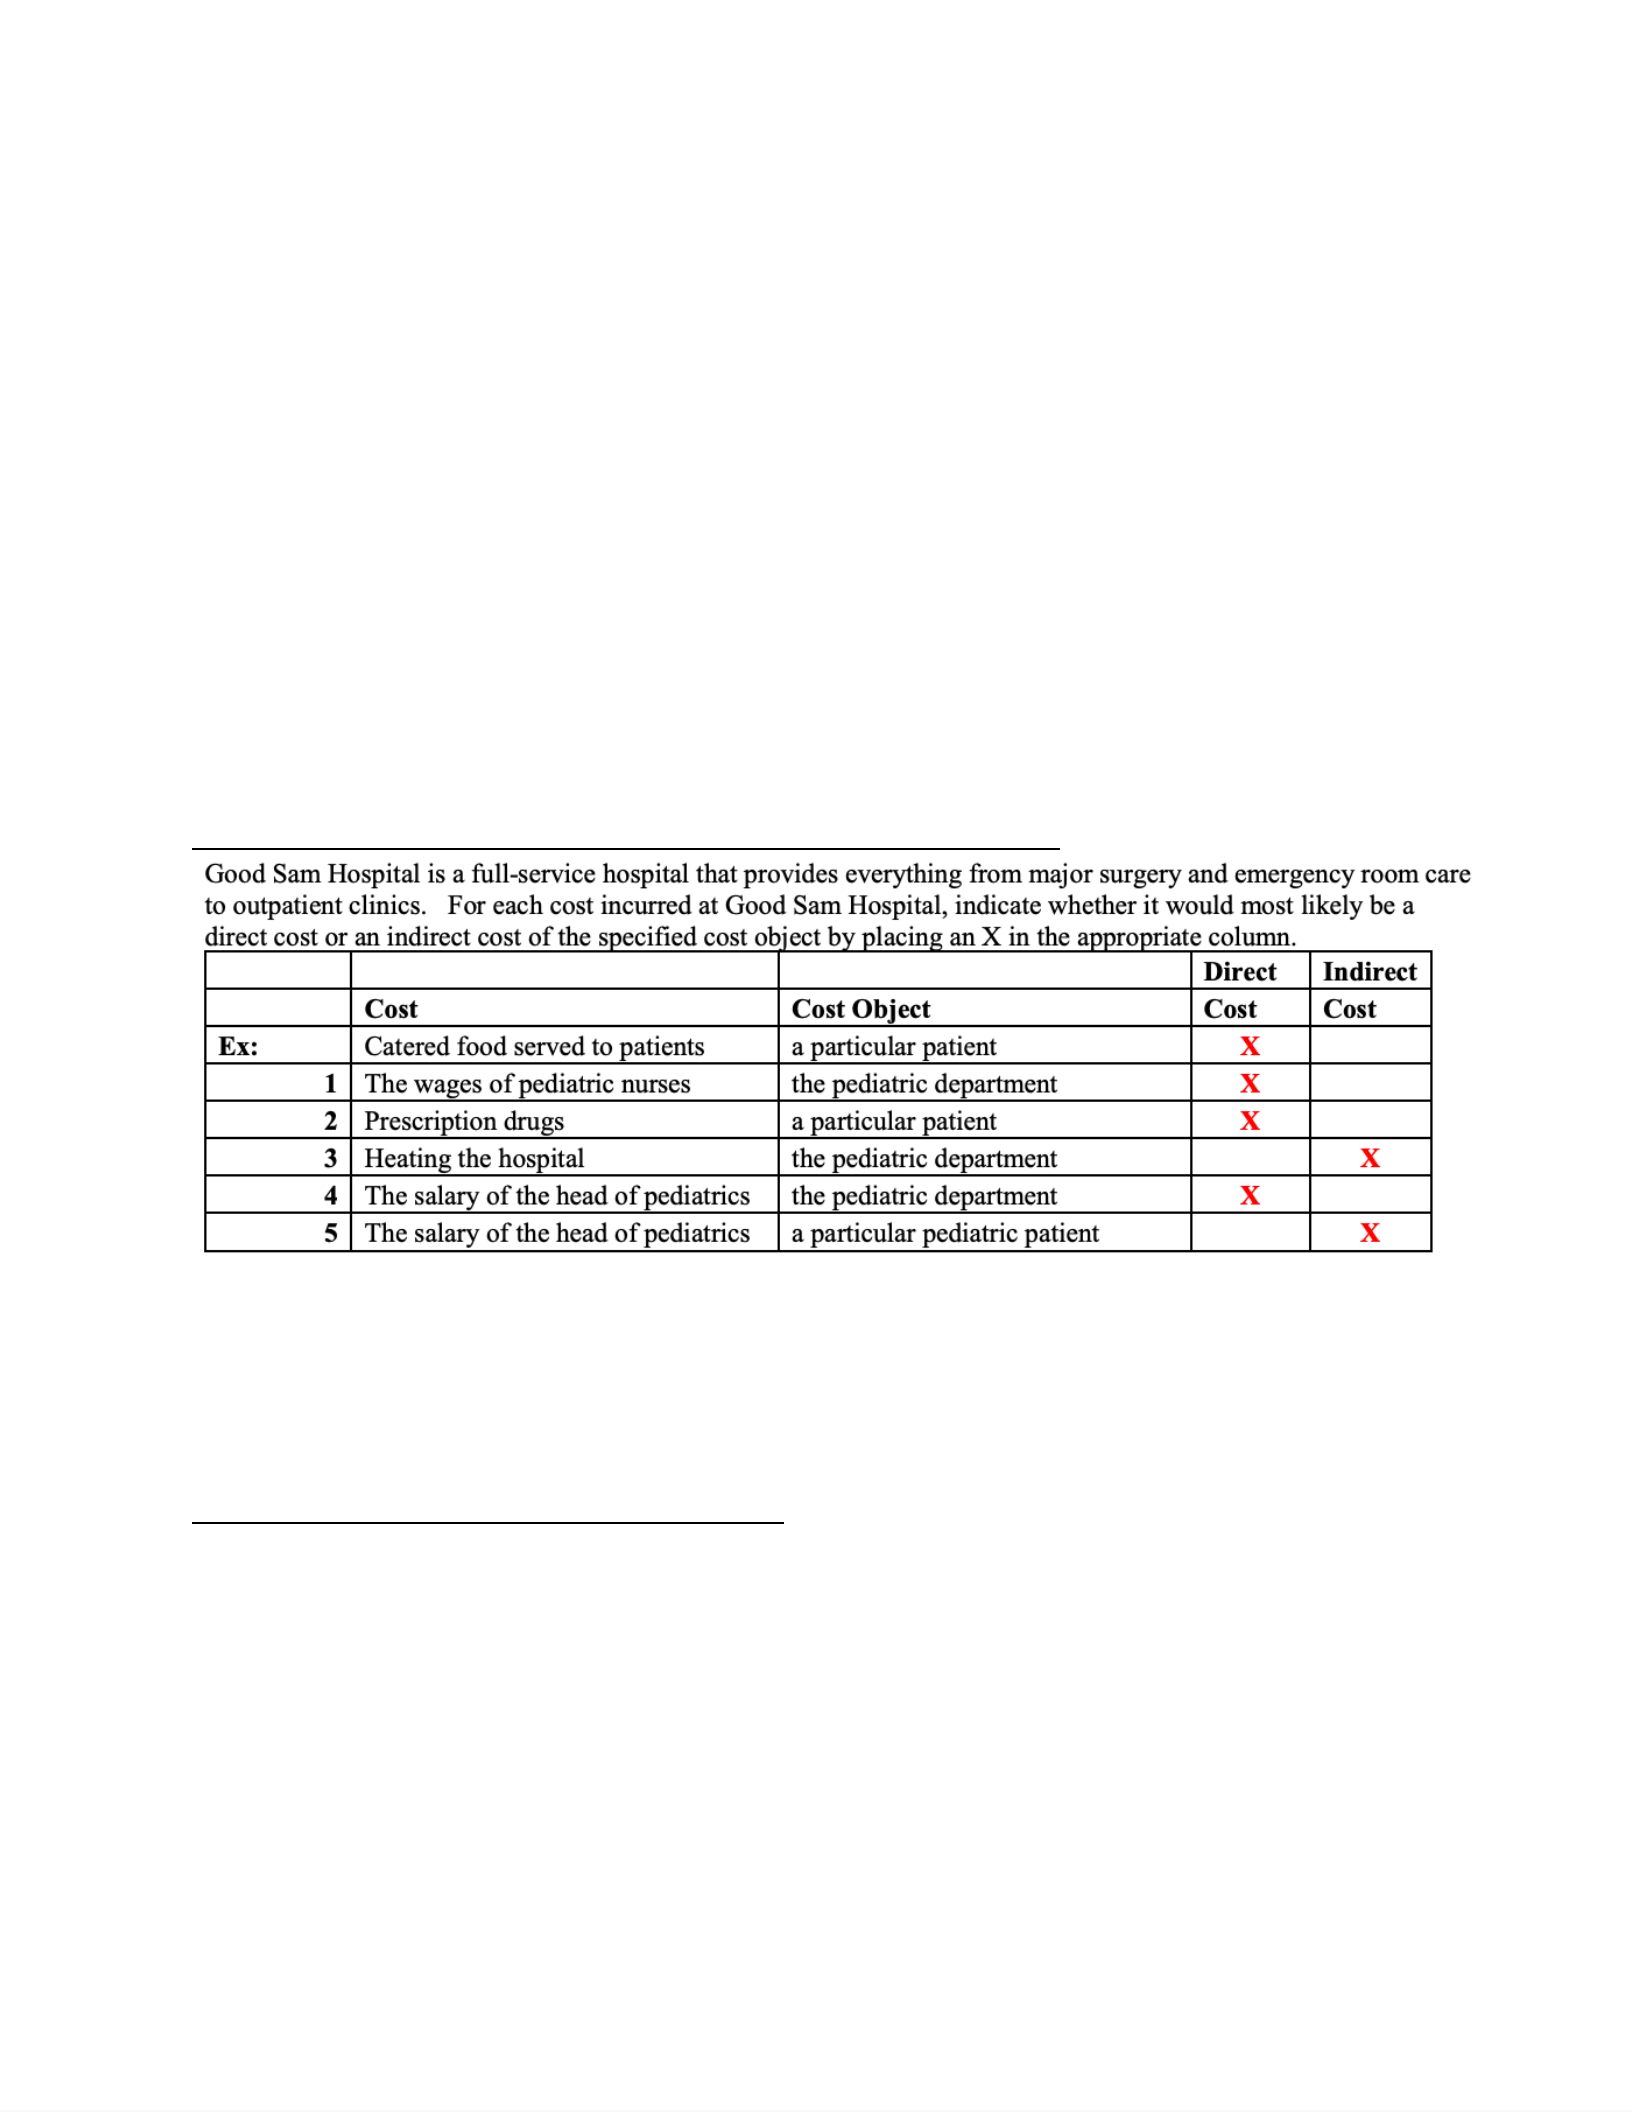
Chapter 2 Activity 1: Identifying Direct and Indirect Costs
Chapter 2 Activity 2: Product vs Period
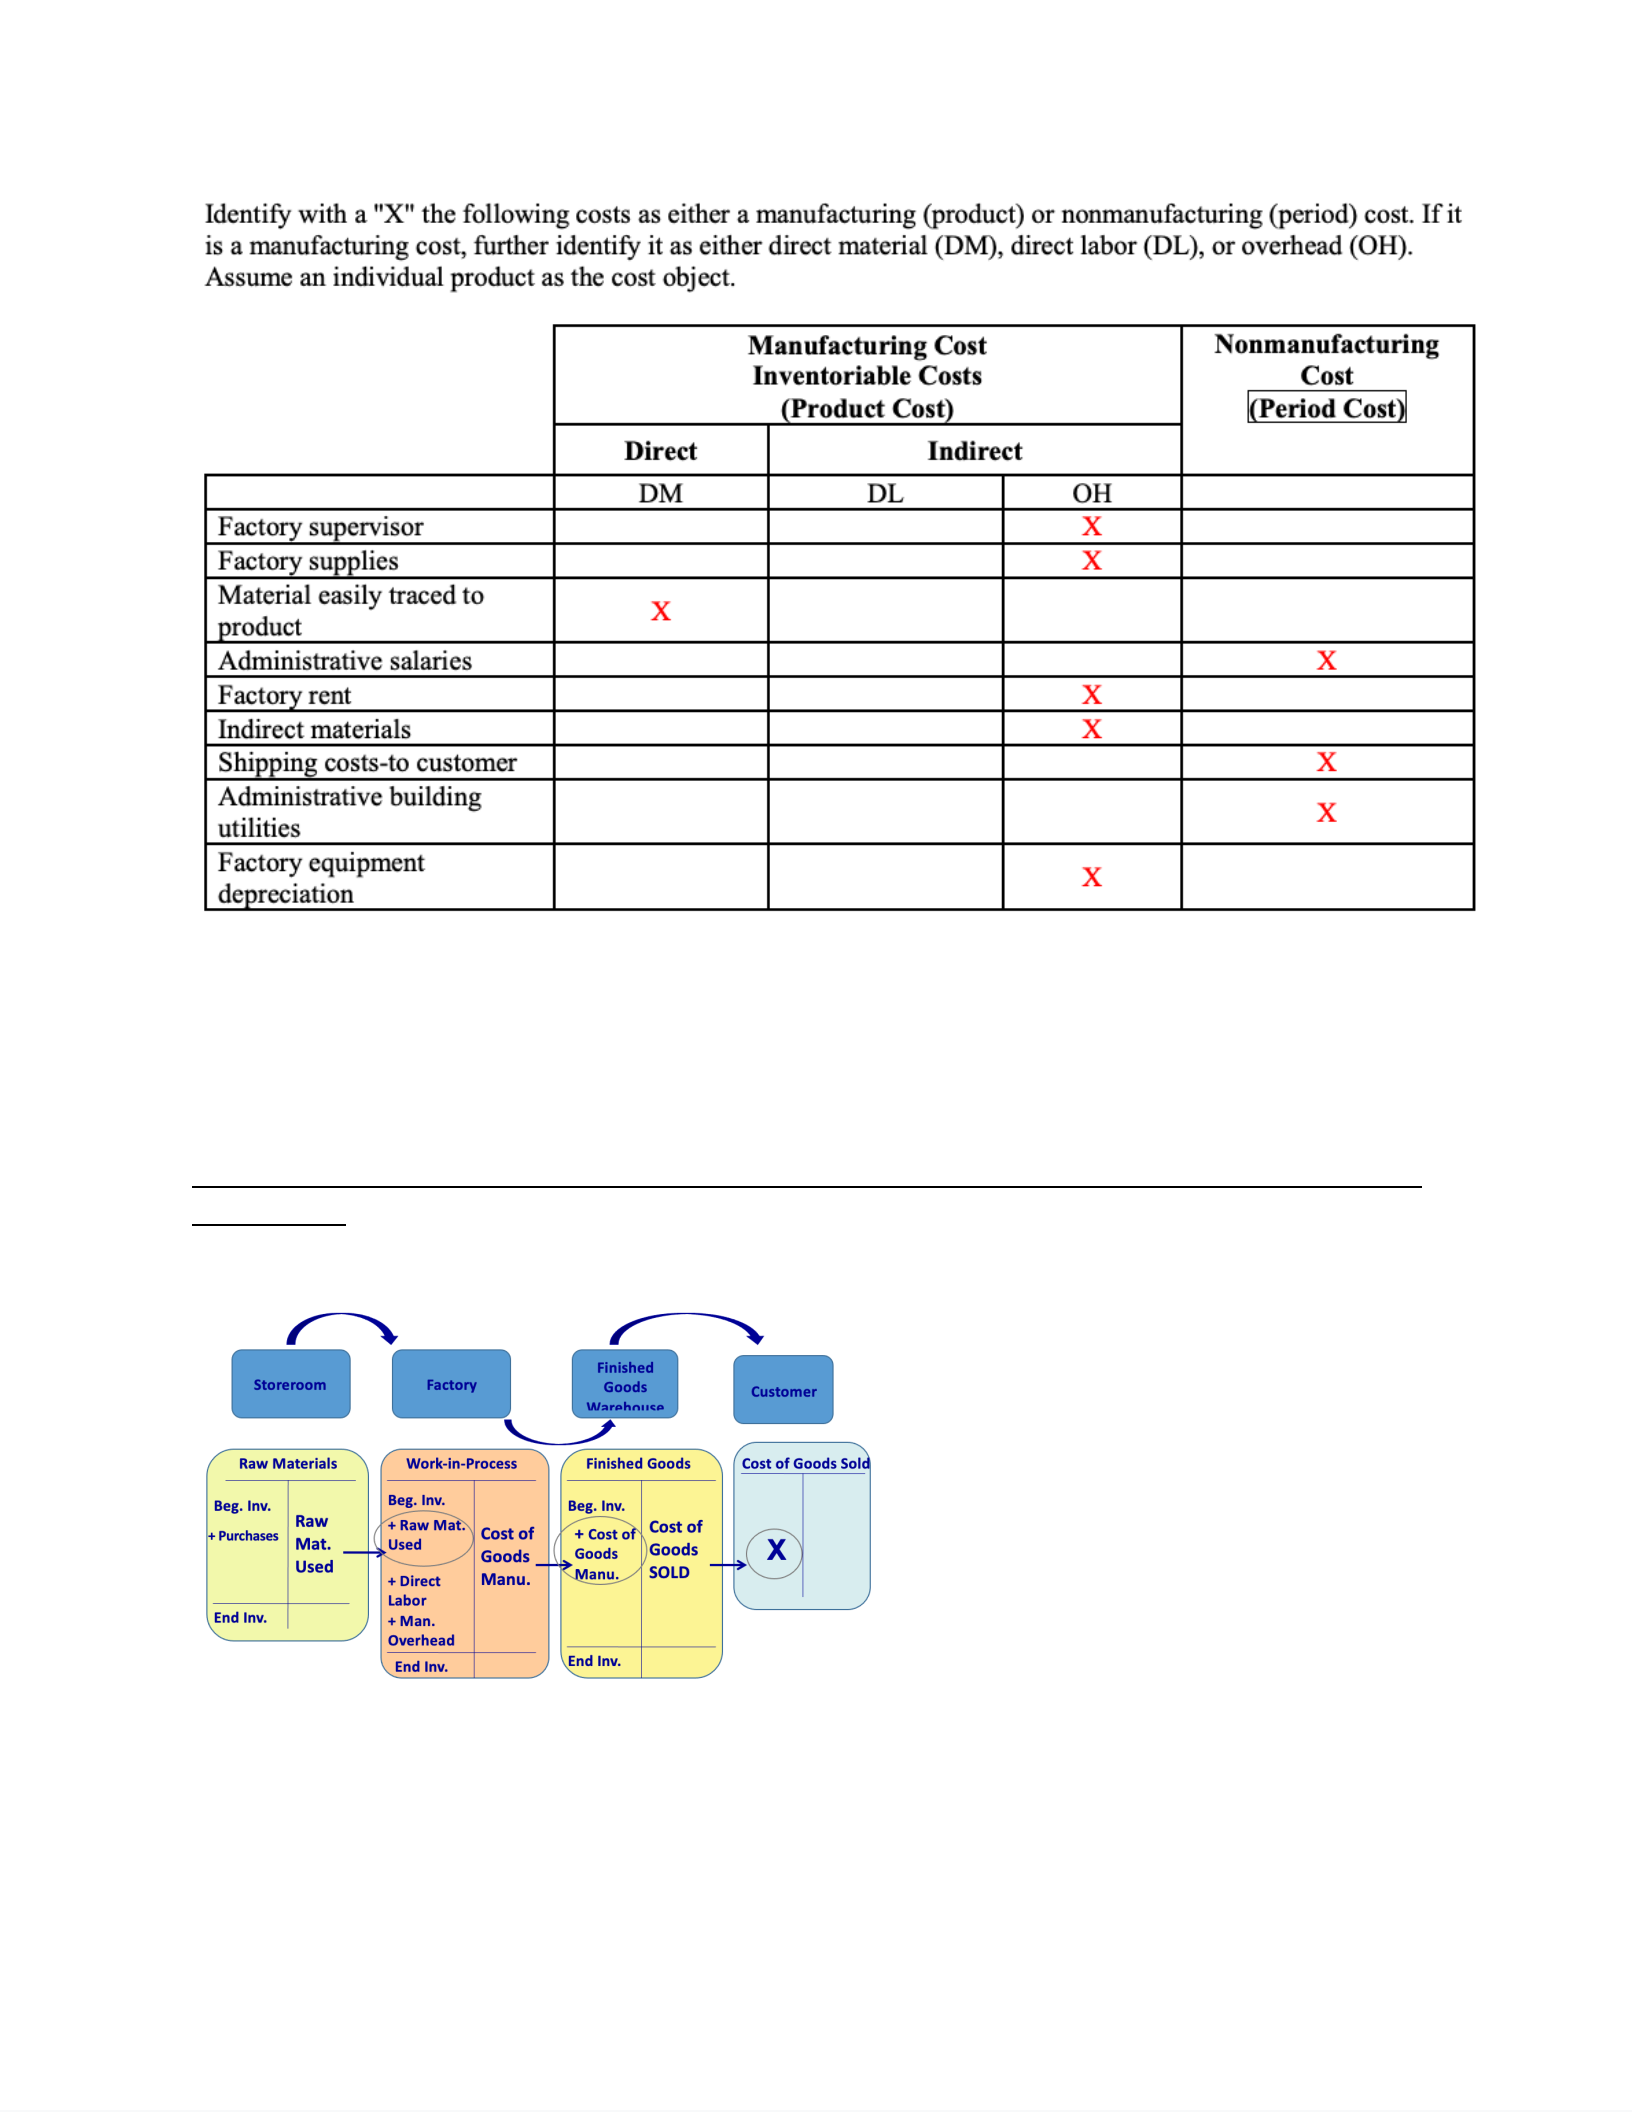
Chapter 2 Activity 3: Manufacturing Inventory Flow: – COGM & COGS – Income
Statement
Inventory Flow – Diagram
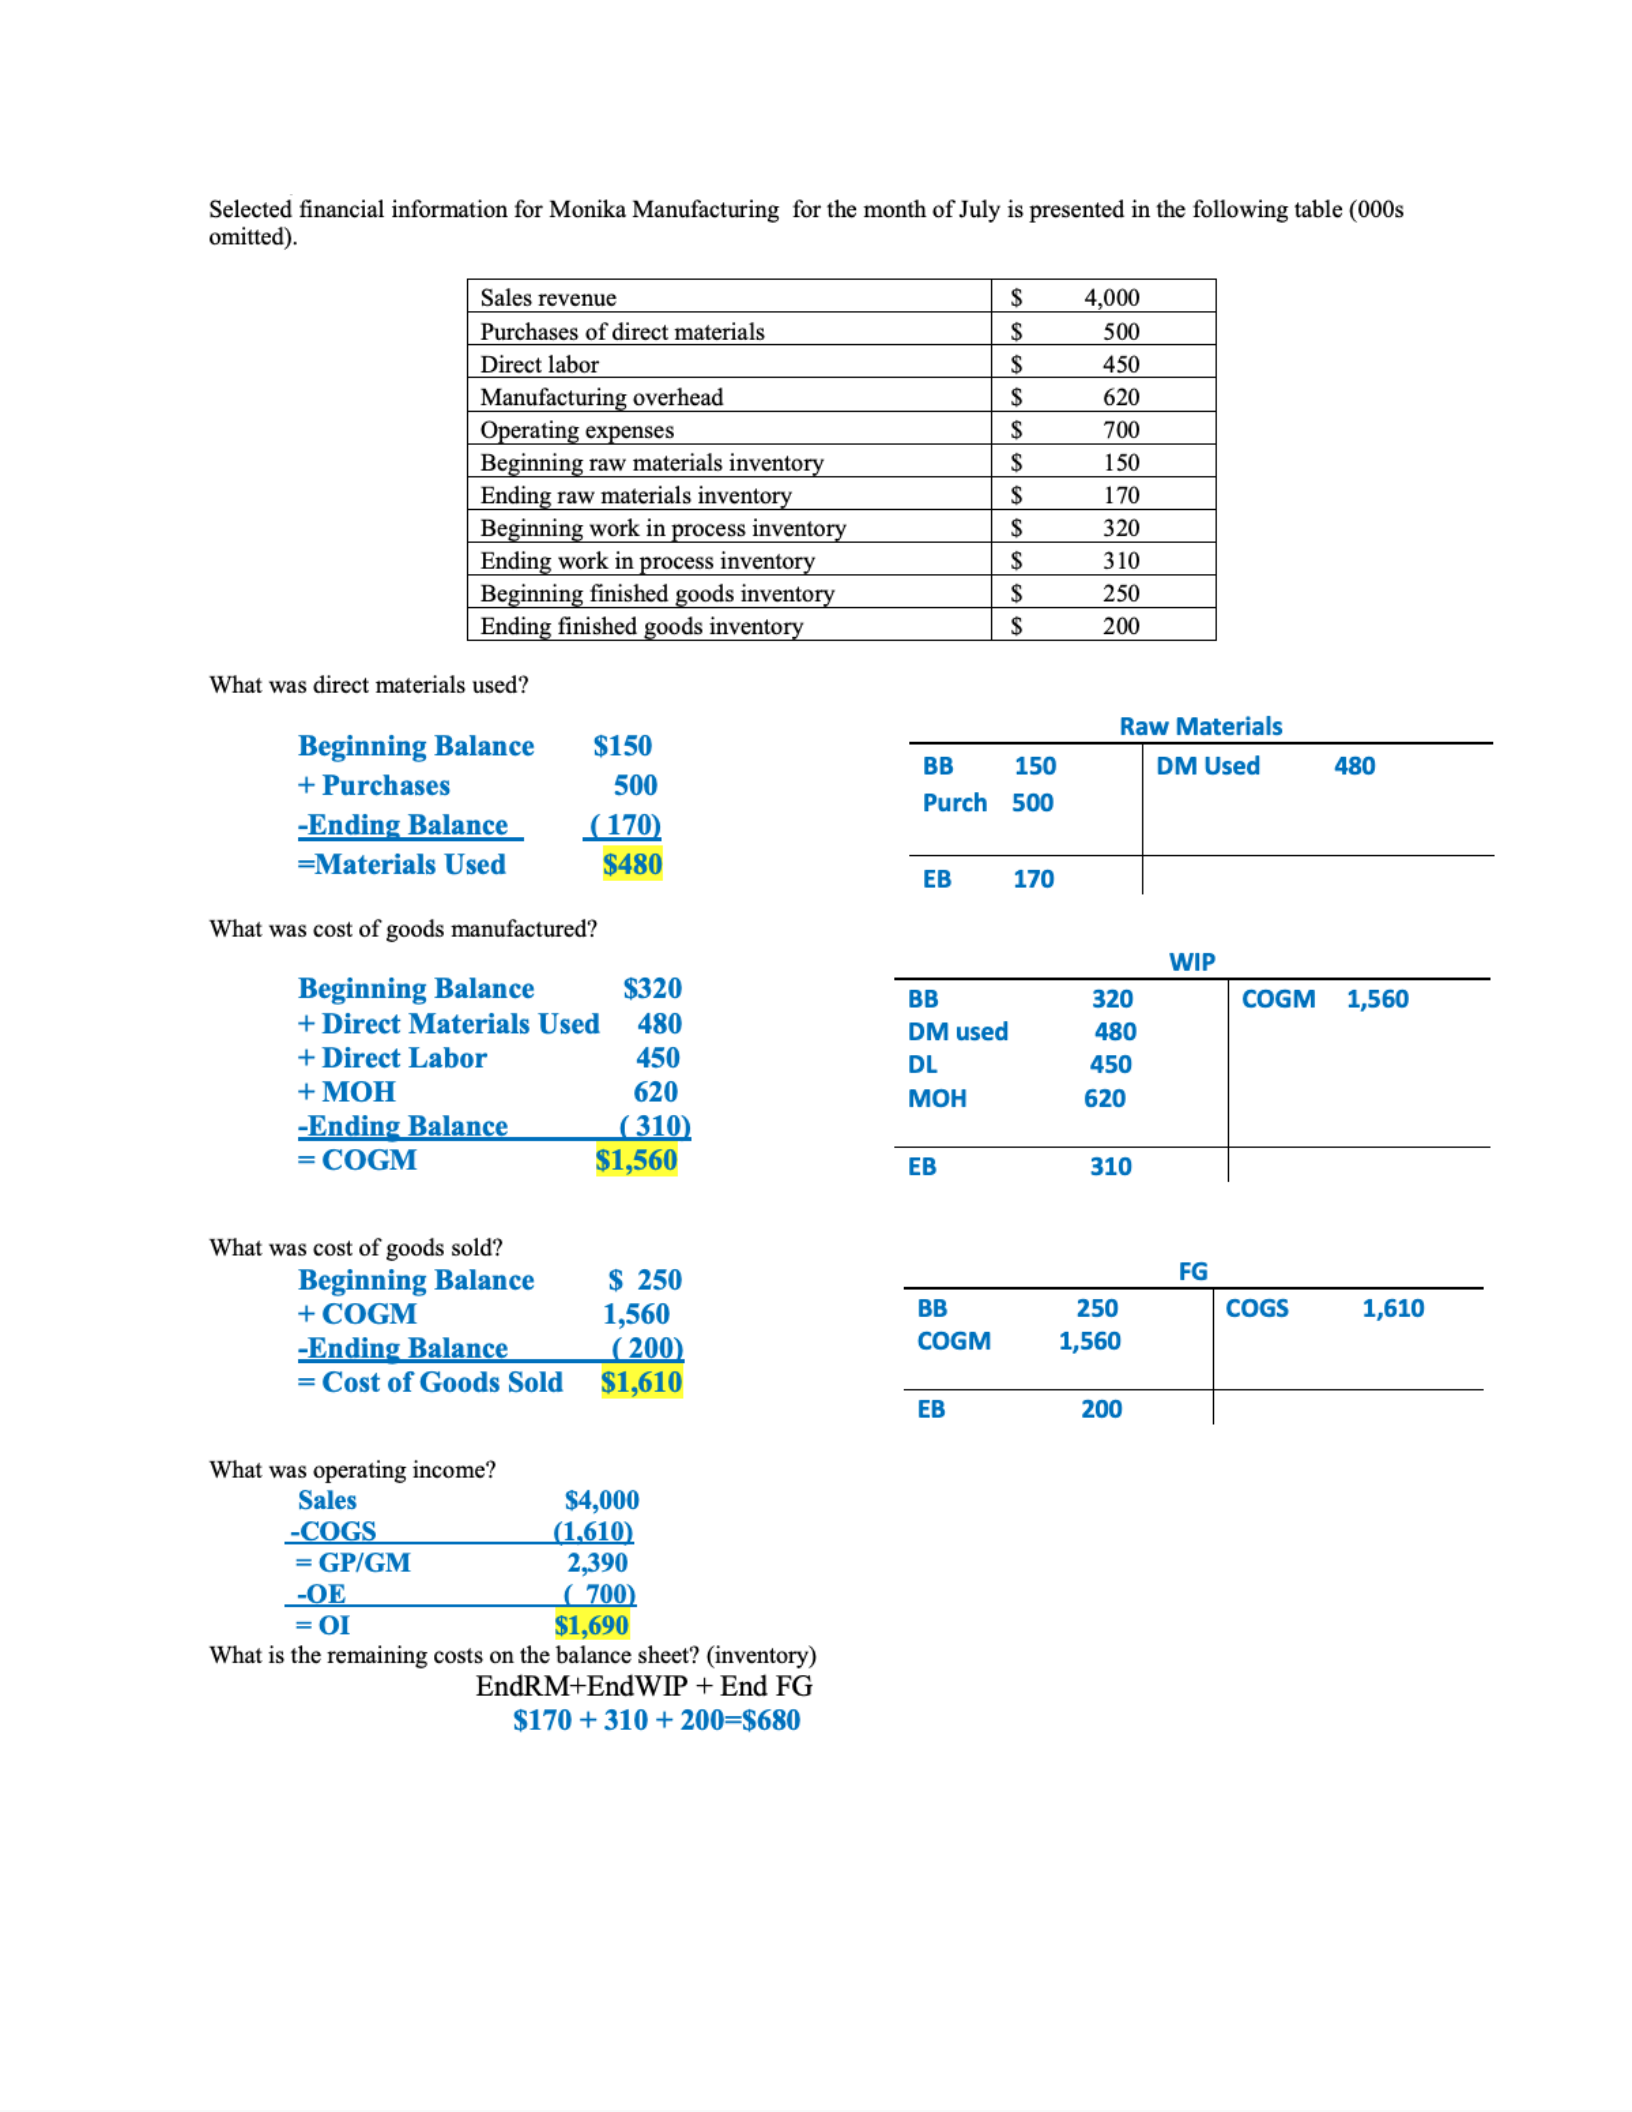
Selected
financial
information
for
Monika
Manufacturing
for
the
month
of
July
is
presented
in
the
following
table
(000s
omitted).
Sales
revenue
$
4,000
Purchases
of
direct
materials
3S
500
Direct
labor
$
450
Manufacturing
overhead
$
620
Operating
expenses
$
700
Beginning
raw
materials
inventory
$
150
Ending
raw
materials
inventory
$ 170
Beginning
work
in
process
inventory
$
320
Ending
work
in
process
inventory
$
310
Beginning
finished
goods
inventory
$
250
Ending
finished
goods
inventory
$
200
What
was
direct
materials
used?
Beginning
Balance
$150
Raw
Materials
BB
150
DM
Used
480
+
Purchases 500
Purch
500
-Ending
Balance
(170)
=Materials
Used
$480
EB
170
What
was
cost
of
goods
manufactured?
WIP
Beginning
Balance
$320
BB
320
COGM
1,560
+
Direct
Materials
Used
480
DM
used
480
+
Direct
Labor
450
DL
450
+MOH
620
MOH
620
-Ending
Balance
310
=
COGM
EB
310
What
was
cost
of
goods
sold?
Beginning
Balance
$
250
FG
+COGM
1,560
BB
250
COGS
1,610
-Ending
Balance
200
COGM
1,560
=
Cost
of
Goods
Sold
EB
200
What
was
operating
income?
Sales
$4,000
-COGS
(1,610)
=
GP/GM
2,390
-OE
700
=
Ol
What
is
the
remaining
costs
on
the
balance
sheet?
(inventory)
EndRM+EndWIP
+
End
FG
$170
+
310
+
200=$680
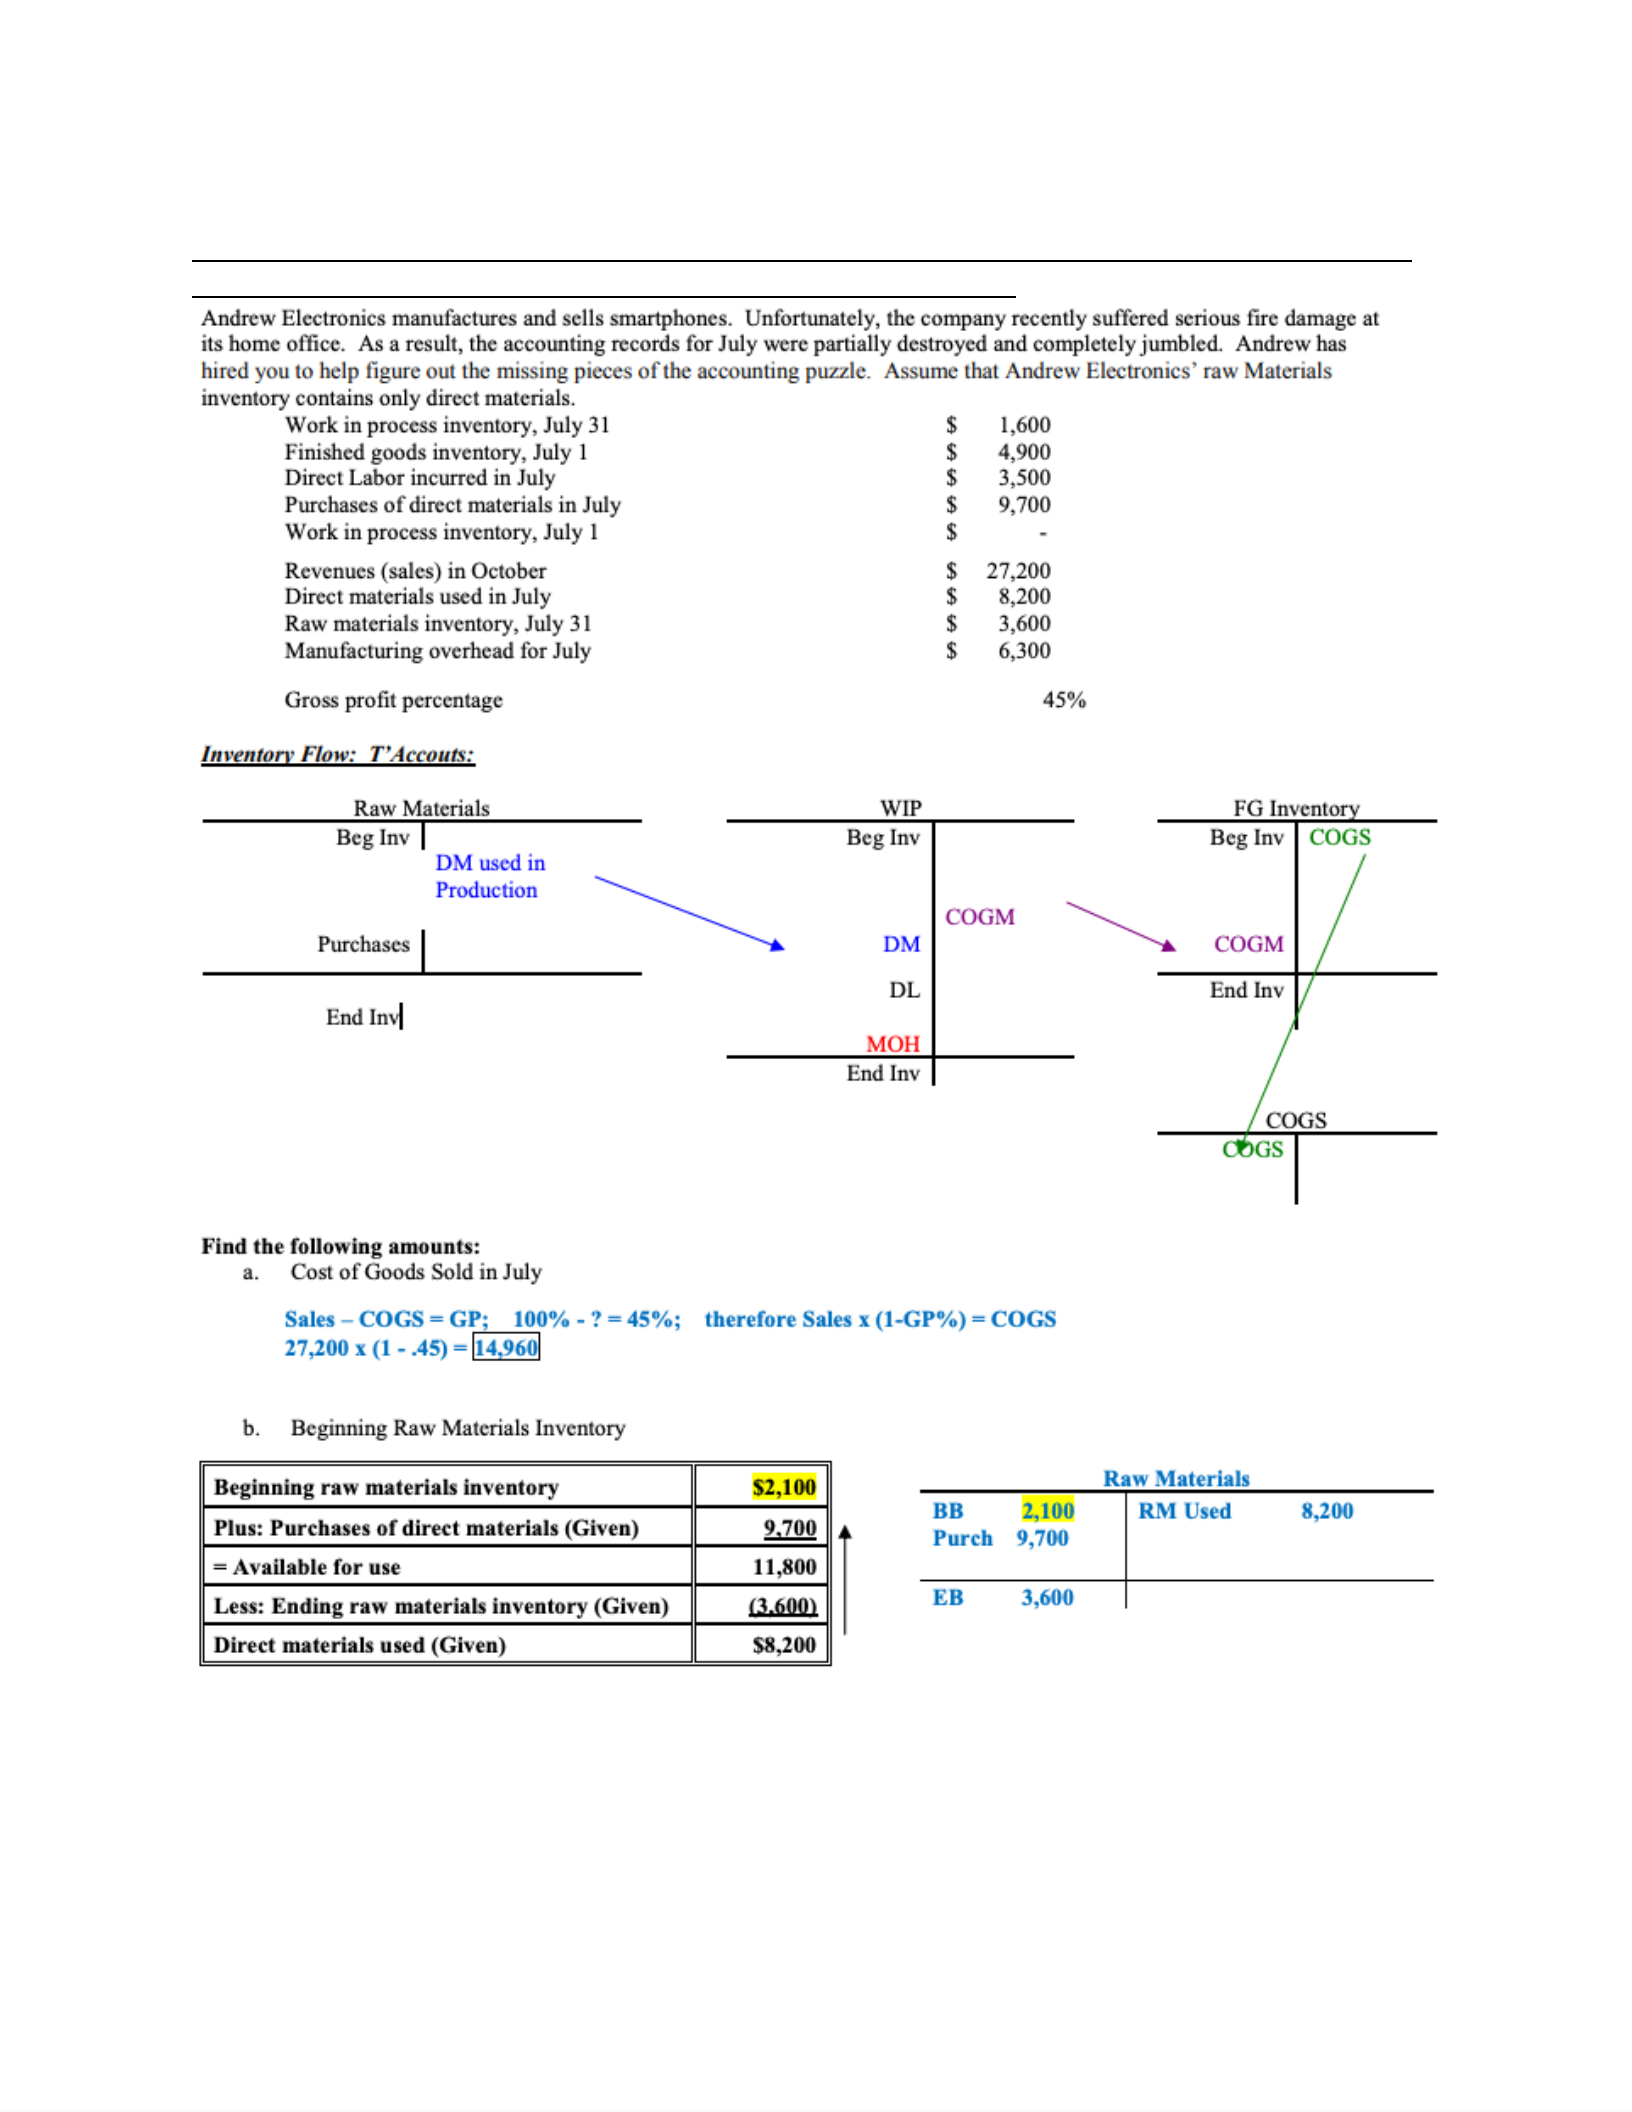
Andrew
Electronics
manufactures
and
sells
smartphones.
Unfortunately,
the
company
recently
suffered
serious
fire
damage
at
its
home
office.
As
a
result,
the
accounting
records
for
July
were
partially
destroyed
and
completely
jumbled.
Andrew
has
hired
you
to
help
figure
out
the
missing
pieces
of
the
accounting
puzzle.
Assume
that
Andrew
Electronics’
raw
Materials
inventory
contains
only
direct
materials.
Work
in
process
inventory,
July
31
$
1,600
Finished
goods
inventory,
July
|
$
©6490
Direct
Labor
incurred
in
July
$
63,500
Purchases
of
direct
materials
in
July
$
©=69,700
Work
in
process
inventory,
July
1
5
.
Revenues
(sales)
in
October
$
27,200
Direct
materials
used
in
July
$
8,200
Raw
materials
inventory,
July
31
$
§©63,600
Manufacturing
overhead
for
July
$
©6600
Gross
profit
percentage
45
faventory
Flaw:
F’Accouis:
Raw
Materials
WIP FG
Inventory
Beg
Inv
|
Beg
Inv
Beg
Inv
COGS
DM
used
in
Production
COGM
™,
Purchases
DM
COGM
DL
End
Inv
/
End
Inv|
MOH
End
Inv
COGS
chicas
Find
the
following
amounts:
a.
Cost
of
Goods
Sold
in
July
Sales
-COGS=GP;
100%
-?=45%;
therefore
Sales
x
(1-GP%)
=
COGS
27,200
x
(1
-
45)
=
(14,960
b.
Beginning
Raw
Materials
Inventory
Beginning
raw
materials
inventory
$2,100
_Raw
Materials
BB
2,100
RM
Used
8,200
Plus:
Purchases
of
direct
materials
(Given)
9.700
Purch
9.700
=
Available
for
use
11,800
Less:
Ending
raw
materials
inventory
(Given)
(3,600)
EB
3,600
Direct
materials
used
(Given)
$8,200
Chapter 2 Activity 4: Manufacturing Inventory Flow: – COGM & COGS – Income
Statement – Work backwards to find missing amounts
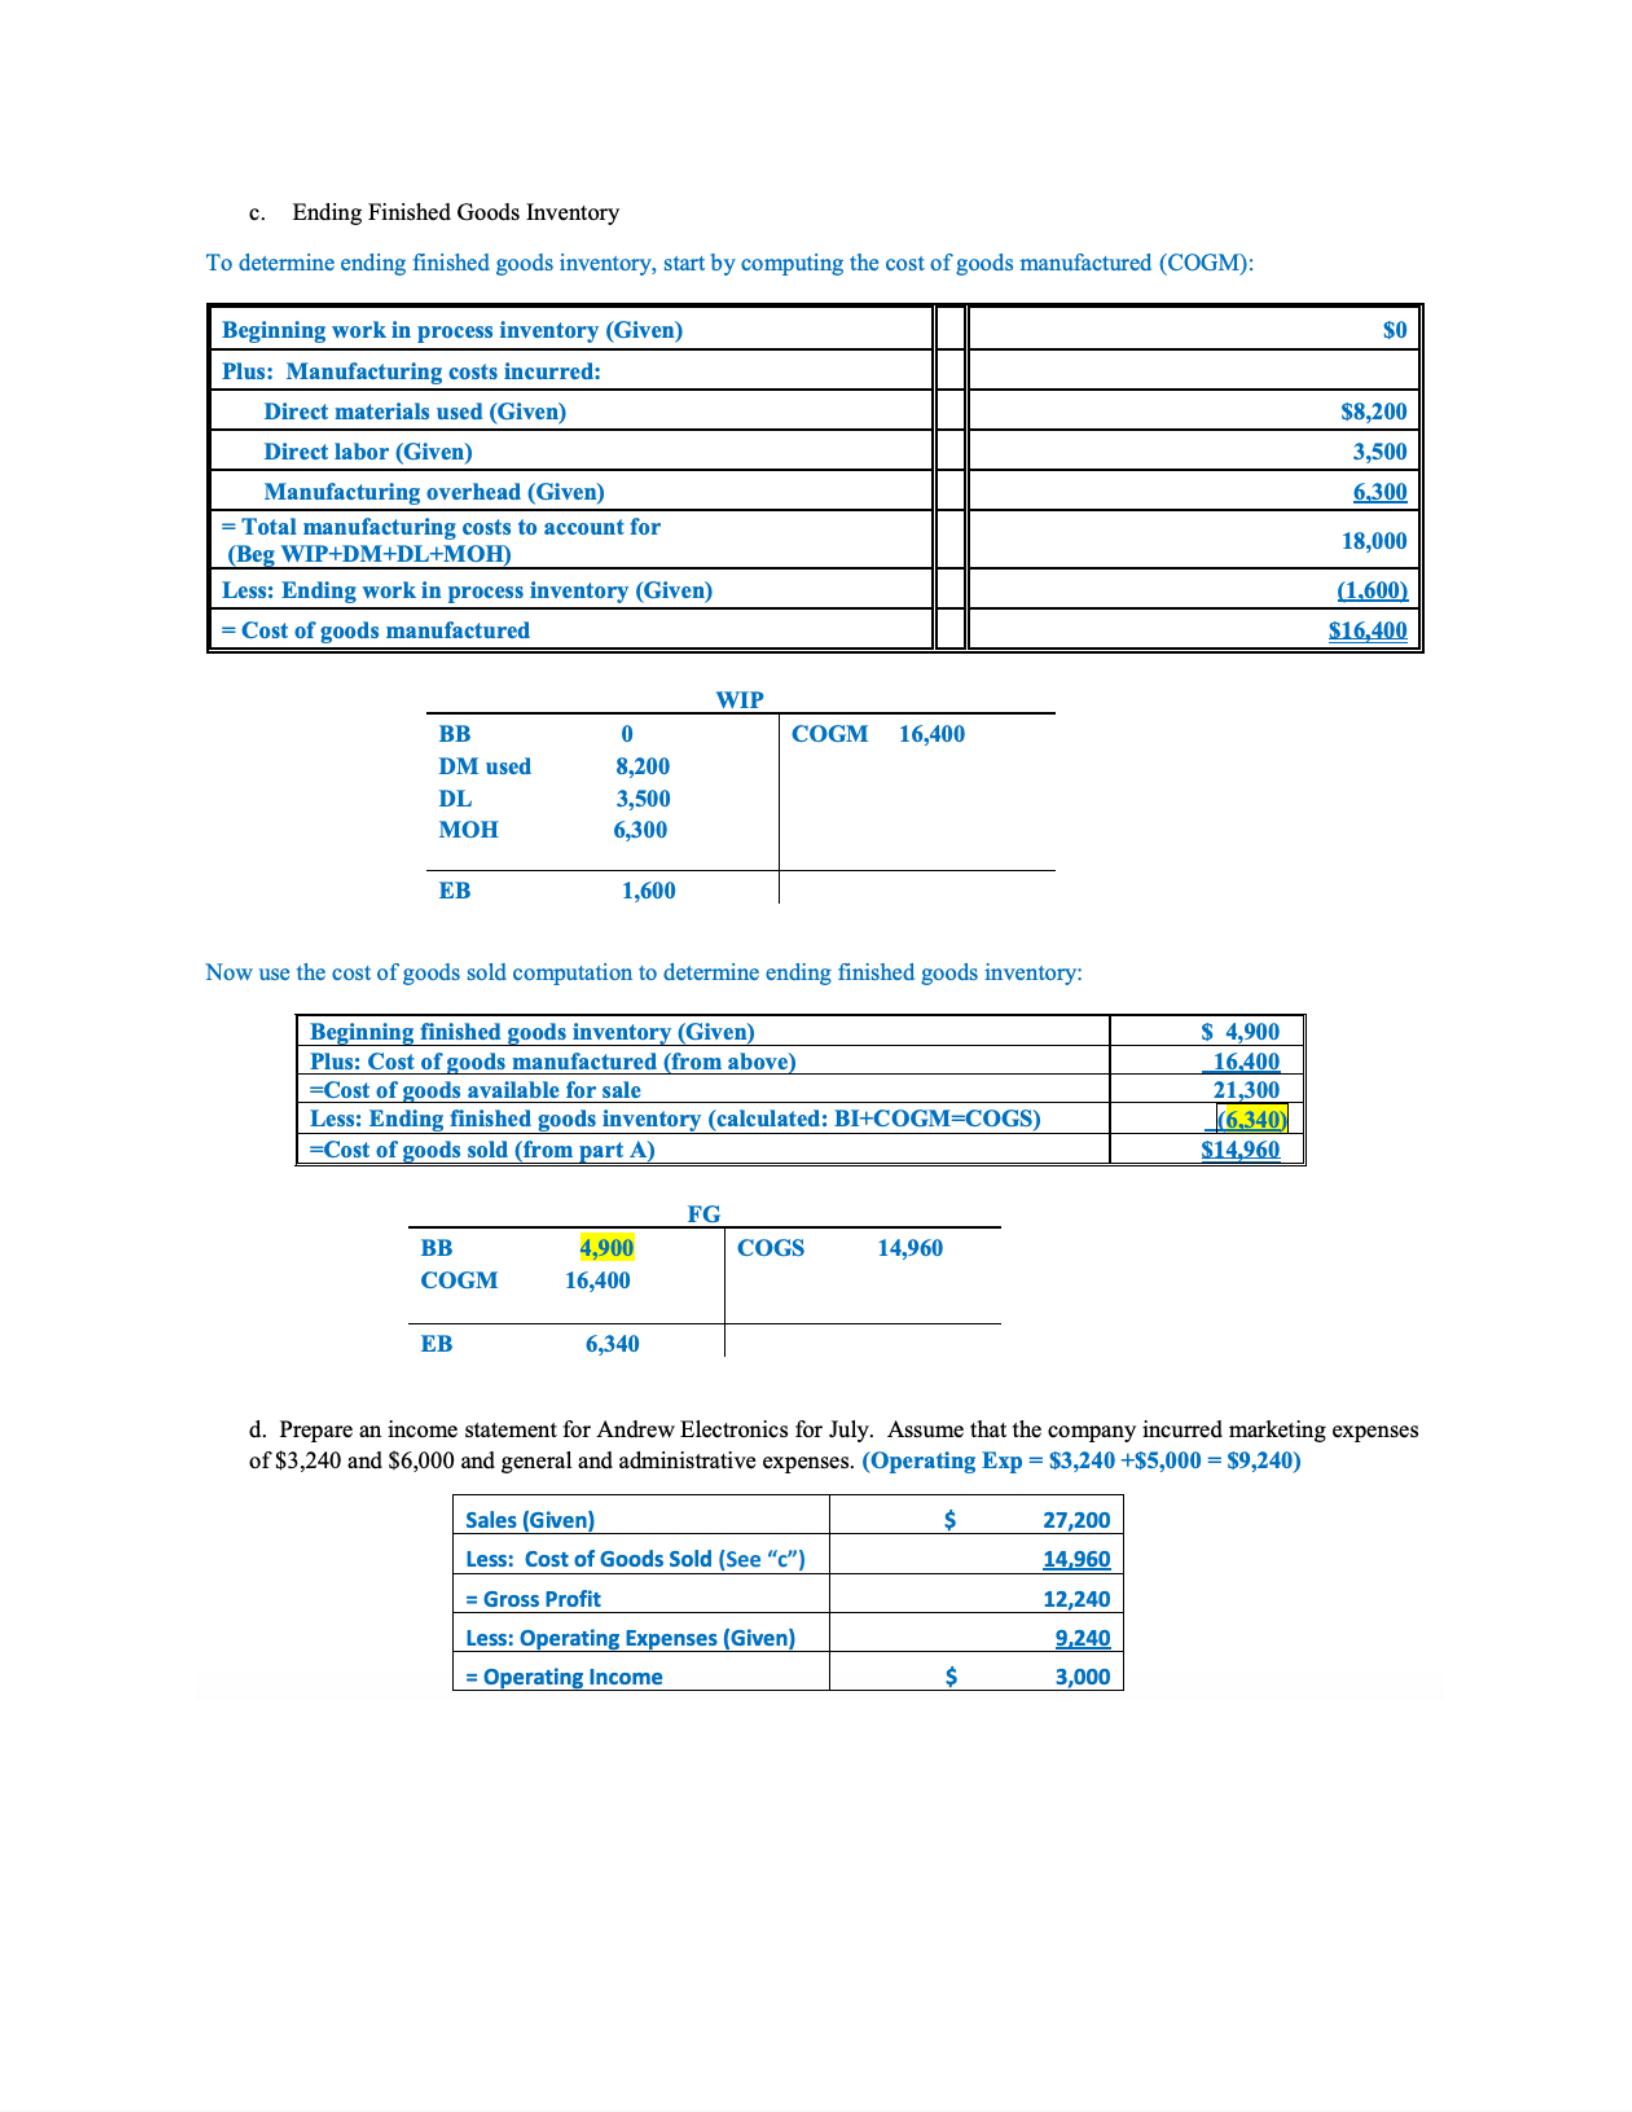
c.
Ending
Finished
Goods
Inventory
To
determine
ending
finished
goods
inventory,
start
by
computing
the
cost
of
goods
manufactured
(COGM):
Beginning
work
in
process
inventory
(Given)
$0
Plus:
Manufacturing
costs
incurred:
Direct
materials
used
(Given)
$8,200
Direct
labor
(Given)
3,500
Manufacturing
overhead
(Given)
6.300
=
Total
manufacturing
costs
to
account
for
18.000
(Beg
WIP+DM+DL+MOH)
,
Less:
Ending
work
in
process
inventory
(Given)
(1.600)
=
Cost
of
goods
manufactured
$16,400
WIP
BB
0
COGM
16,400
DM
used
8,200
DL
3,500
MOH
6,300
EB
1,600
Now
use
the
cost
of
goods
sold
computation
to
determine
ending
finished
goods
inventory:
Beginning
finished
goods
inventory
(Given)
$
4,900
Plus:
Cost
of
goods
manufactured
(from
above)
16.400
=Cost
of
goods
available
for
sale
21,300
Less:
Ending
finished
goods
inventory
(calculated:
BI+COGM=COGS)
(6.340)
=Cost
of
goods
sold
(from
part
A)
$14,960
FG
BB
4,900
COGS
14,960
COGM
16,400
EB
6,340
d.
Prepare
an
income
statement
for
Andrew
Electronics
for
July.
Assume
that
the
company
incurred
marketing
expenses
of
$3,240
and
$6,000
and
general
and
administrative
expenses.
(Operating
Exp
=
$3,240
+$5,000
=
$9,240)
Sales
(Given)
$
27,200
Less:
Cost
of
Goods
Sold
(See
“c”)
14,960
=
Gross
Profit
12,240
Less:
Operating
Expenses
(Given)
9,240
=
Operating
Income
S
3,000
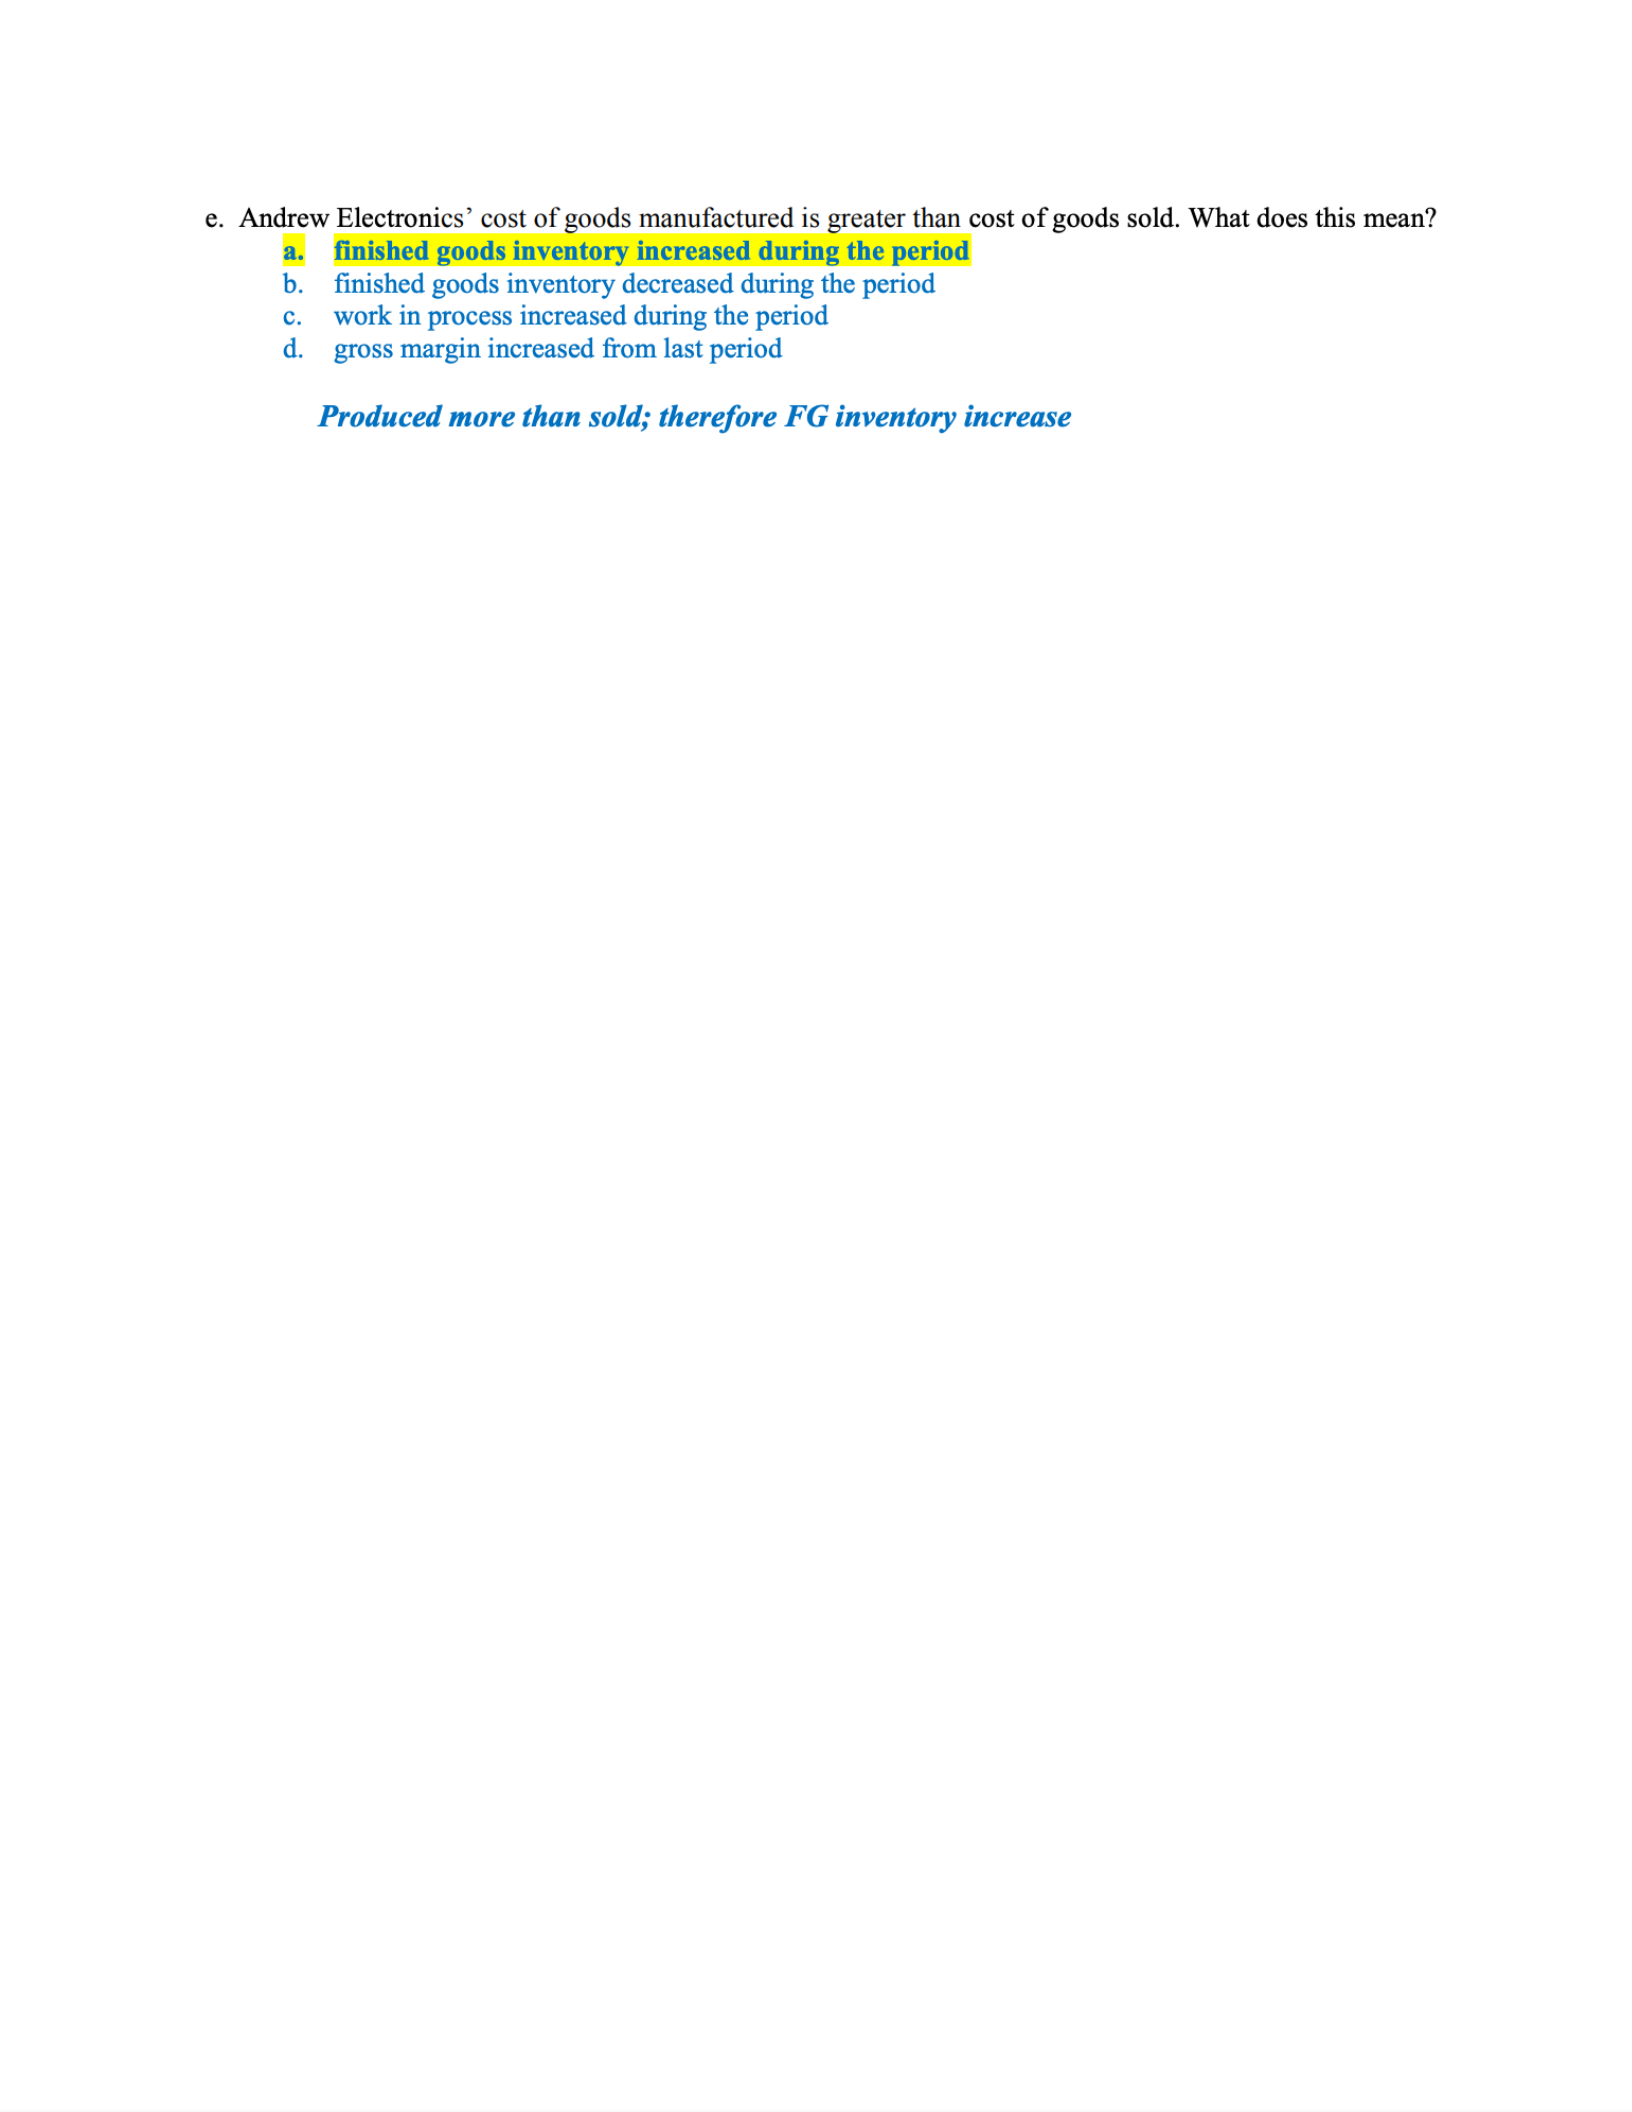
e.
“a
Electronics’
cost
of
cory
manufactured
is
othe
p
than
cost
of
goods
sold.
What
does
this
mean?
b.
finished
goods
inventory
decreased
during
the
period
c.
work
in
process
increased
during
the
period
d.
gross
margin
increased
from
last
period
Produced
more
than
sold;
therefore
FG
inventory
increase

