


18-17 (Objective 18-6) Distinguish between FOB destination and FOB
origin. What procedures should the auditor follow concerning acquisitions of
inventory on an FOB origin basis near year-end?
18-20 (Objective 18-3, 18-6) The following questions concern the
audit of accounts payable.
a. For effective internal control, the accounts payable department
generally should
(1) stamp, perforate, or otherwise cancel supporting documentation
after payment is mailed.
(2) ascertain that each requisition is approved as to price, quantity,
and quality by an authorized employee.
(3) omit information about the quantity ordered on the copy of the
purchase order forwarded to the receiving department prior to
receipt of goods.
(4) establish the agreement of the vendor’s invoice with the
receiving report and purchase order.
b. When using confirmations to provide evidence about the
completeness assertion for accounts payable, the appropriate
population most likely is
(1) vendors with whom the entity has previously done business.
(2) amounts recorded in the accounts payable subsidiary ledger.
(3) payees of checks drawn in the month after year-end.
(4) invoices filed in the entity’s open invoice file.
21-17 (Objective 21-1) The following questions concern internal
controls in the inventory and warehousing cycle. Choose the best
response.
a. Which of the following controls will most likely justify a reduced
assessed level of control risk for the occurrence assertion for
purchases of inventory?
(1) Receiving reports for inventory additions are accounted for and
entry of received goods into the purchases system is verified by
accounting clerks.
(2) The purchases system automatically updates the perpetual
inventory master file when transactions are entered into the
purchases journal.
(3) The perpetual inventory system will not allow an addition of
inventory to be posted without entry of a valid receiving report
number.
(4) At the close of each day, the system reconciles the perpetual
inventory master file to the inventory general ledger account and
generates an exception report when differences exist.
b. For control purposes, the quantities of materials ordered may be
omitted from the copy of the purchase order that is
(1) returned to the requisitioner.
(2) forwarded to the receiving department.
(3) forwarded to the accounting department.
(4) retained in the purchasing department’s files.
c. Which of the following procedures will best detect the theft of
valuable items from an inventory that consists of hundreds of
different items selling for $1 to $10 and a few items selling for
hundreds of dollars?
(1) Maintain a perpetual inventory master file of only the more
valuable items with frequent periodic verification of the validity of
the perpetuals.
(2) Have an independent CPA firm prepare an internal control report
on the effectiveness of the administrative and accounting controls
over inventory.
(3) Have separate warehouse space for the more valuable items
with sequentially numbered tags.
(4) Require an authorized officer’s signature on all requisitions for
the more valuable items.
21-18 (Objectives 21-1, 21-3) The following questions concern
testing the client’s internal controls for inventory and warehousing.
Choose the best response.
a. When an auditor tests a client’s cost accounting records, the
auditor’s tests are primarily designed to determine that
(1) costs have been correctly assigned to finished goods, work-in-
process, and cost of goods sold.
(2) quantities on hand have been computed based on acceptable
cost accounting techniques that reasonably approximate actual
quantities on hand.
(3) physical inventories are in substantial agreement with book
inventories.
(4) the internal controls are in accordance with accounting
standards and are functioning as planned.
b. The accuracy of perpetual inventory master files may be
established, in part, by comparing perpetual inventory records with
(1) purchase requisitions.
(2) receiving reports.
(3) purchase orders.
(4) vendor payments.
c. Which of the following sets of duties related to inventory and
warehousing causes the greatest concern about inadequate
segregation of duties?
(1) Individuals in charge of approving disbursements related to
inventory purchases have “read-only” ability to view the list of
vendors in the pre-approved vendor master file.
(2) Purchasing agents who arrange for shipment of raw materials
from vendors are responsible for verifying actual receipt of the
inventory items at the receiving dock.
(3) The receiving department has access to copies of the purchase
orders that exclude information about quantities ordered.
(4) Accounts payable personnel have access to receiving reports
and purchases orders in addition to vendor invoices for inventory
purchases.
21-19 (Objectives 21-1, 21-4, 21-5, 21-6) The following
questions deal with tests of details of balances and analytical
procedures for inventory. Choose the best response.
a. Which of the following procedures is the auditor least likely to
perform on the actual date the physical inventory count is
observed?
(1) Examine inventory to make sure that it is tagged by client count
teams.
(2) Watch for inventory items that are rust- or dust-covered or
otherwise damaged.
(3) Observe client count teams to determine if they are conducting
the physical inventory count in accordance with client policies and
procedures.
(4) Examine documentation supporting the acquisition of highly
material inventory items on hand at the count date.
b. An inventory turnover analysis is useful to the auditor because it
may detect
(1) inadequacies in inventory pricing.
(2) methods of avoiding cyclical holding costs.
(3) the existence of obsolete merchandise.
(4) the optimum automatic reorder points.
c. A CPA auditing inventory may appropriately apply attributes
sampling to estimate the
(1) average price of inventory items.
(2) percentage of slow-moving inventory items.
(3) dollar value of inventory.
(4) physical quantity of inventory items.
21-20 (Objectives 21-1, 21-3, 21-5, 21-6, 21-7) Items 1 through
8 are selected questions typically found in questionnaires used by
auditors to obtain an understanding of internal control in the
inventory and warehousing cycle. In using the questionnaire for a
client, a “yes” response to a question indicates a possible internal
control, whereas a “no” indicates a potential deficiency.
1. Is a detailed perpetual inventory master file maintained for raw
materials inventory?
2. Are physical inventory counts made by someone other than
storekeepers and those responsible for maintaining the perpetual
inventory master file?
3. Is the clerical accuracy of the final inventory compilation checked
by a person independent of those responsible for preparing it?
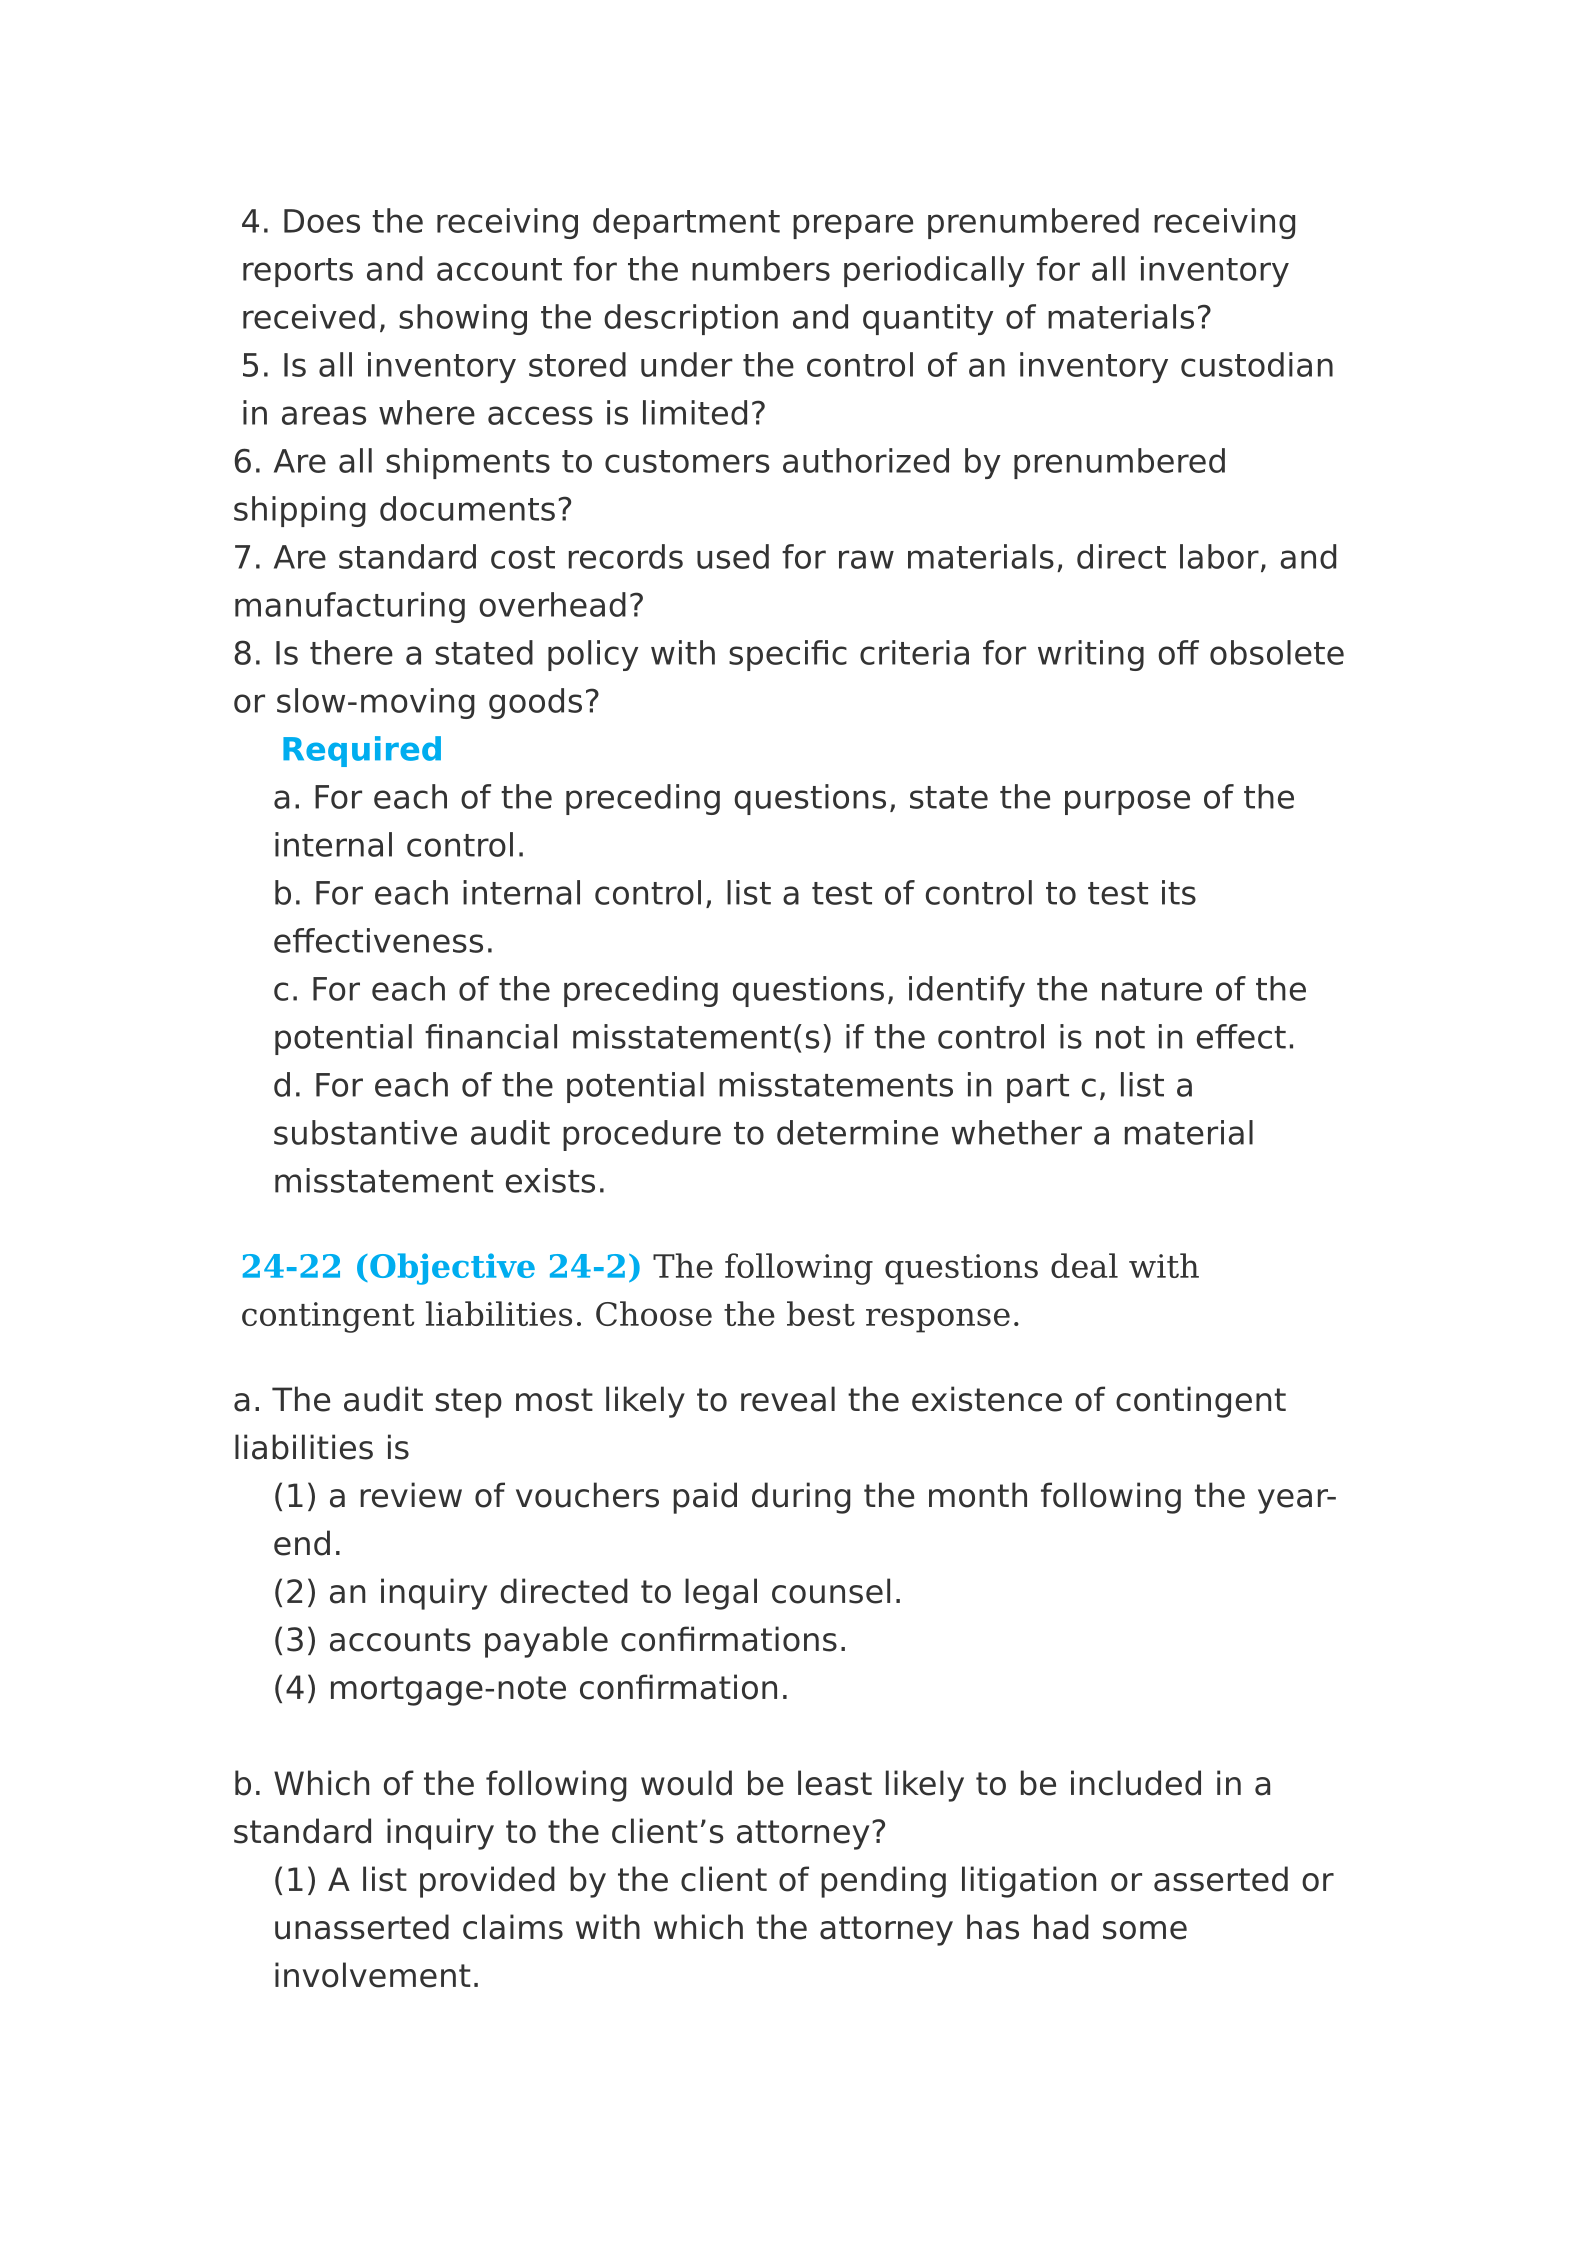
4. Does the receiving department prepare prenumbered receiving
reports and account for the numbers periodically for all inventory
received, showing the description and quantity of materials?
5. Is all inventory stored under the control of an inventory custodian
in areas where access is limited?
6. Are all shipments to customers authorized by prenumbered
shipping documents?
7. Are standard cost records used for raw materials, direct labor, and
manufacturing overhead?
8. Is there a stated policy with specific criteria for writing off obsolete
or slow-moving goods?
Required
a. For each of the preceding questions, state the purpose of the
internal control.
b. For each internal control, list a test of control to test its
effectiveness.
c. For each of the preceding questions, identify the nature of the
potential financial misstatement(s) if the control is not in effect.
d. For each of the potential misstatements in part c, list a
substantive audit procedure to determine whether a material
misstatement exists.
24-22 (Objective 24-2) The following questions deal with
contingent liabilities. Choose the best response.
a. The audit step most likely to reveal the existence of contingent
liabilities is
(1) a review of vouchers paid during the month following the year-
end.
(2) an inquiry directed to legal counsel.
(3) accounts payable confirmations.
(4) mortgage-note confirmation.
b. Which of the following would be least likely to be included in a
standard inquiry to the client’s attorney?
(1) A list provided by the client of pending litigation or asserted or
unasserted claims with which the attorney has had some
involvement.
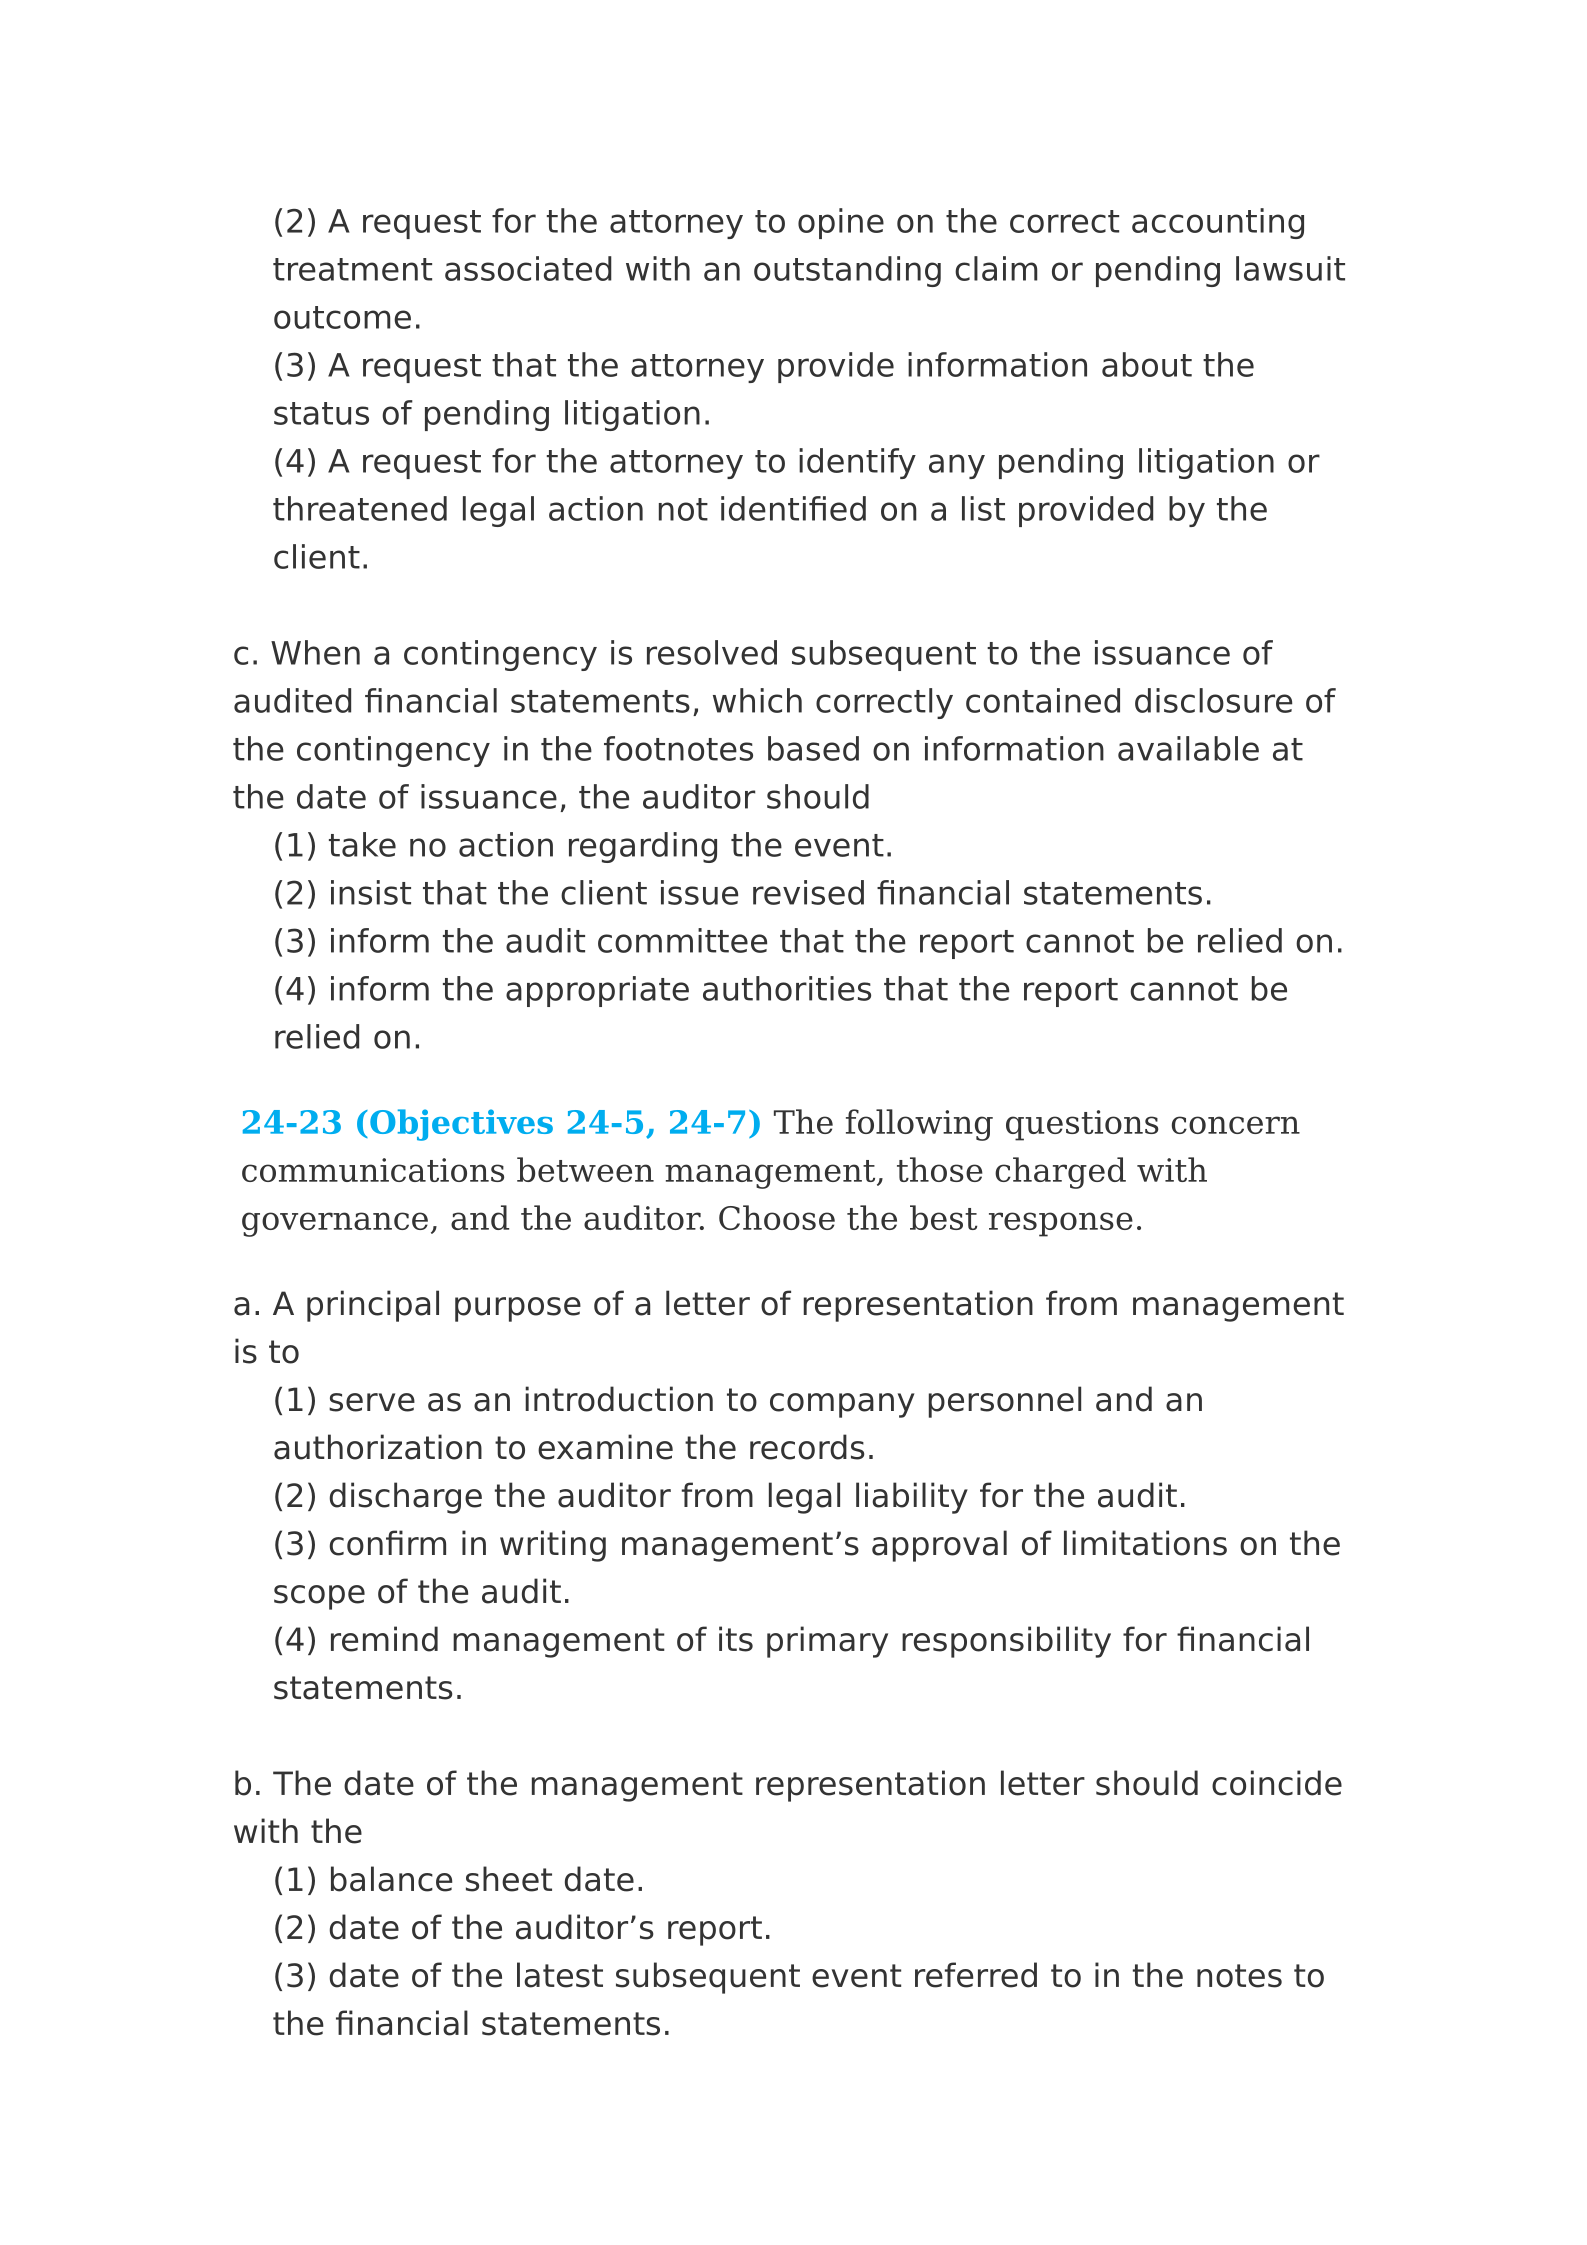
(2) A request for the attorney to opine on the correct accounting
treatment associated with an outstanding claim or pending lawsuit
outcome.
(3) A request that the attorney provide information about the
status of pending litigation.
(4) A request for the attorney to identify any pending litigation or
threatened legal action not identified on a list provided by the
client.
c. When a contingency is resolved subsequent to the issuance of
audited financial statements, which correctly contained disclosure of
the contingency in the footnotes based on information available at
the date of issuance, the auditor should
(1) take no action regarding the event.
(2) insist that the client issue revised financial statements.
(3) inform the audit committee that the report cannot be relied on.
(4) inform the appropriate authorities that the report cannot be
relied on.
24-23 (Objectives 24-5, 24-7) The following questions concern
communications between management, those charged with
governance, and the auditor. Choose the best response.
a. A principal purpose of a letter of representation from management
is to
(1) serve as an introduction to company personnel and an
authorization to examine the records.
(2) discharge the auditor from legal liability for the audit.
(3) confirm in writing management’s approval of limitations on the
scope of the audit.
(4) remind management of its primary responsibility for financial
statements.
b. The date of the management representation letter should coincide
with the
(1) balance sheet date.
(2) date of the auditor’s report.
(3) date of the latest subsequent event referred to in the notes to
the financial statements.
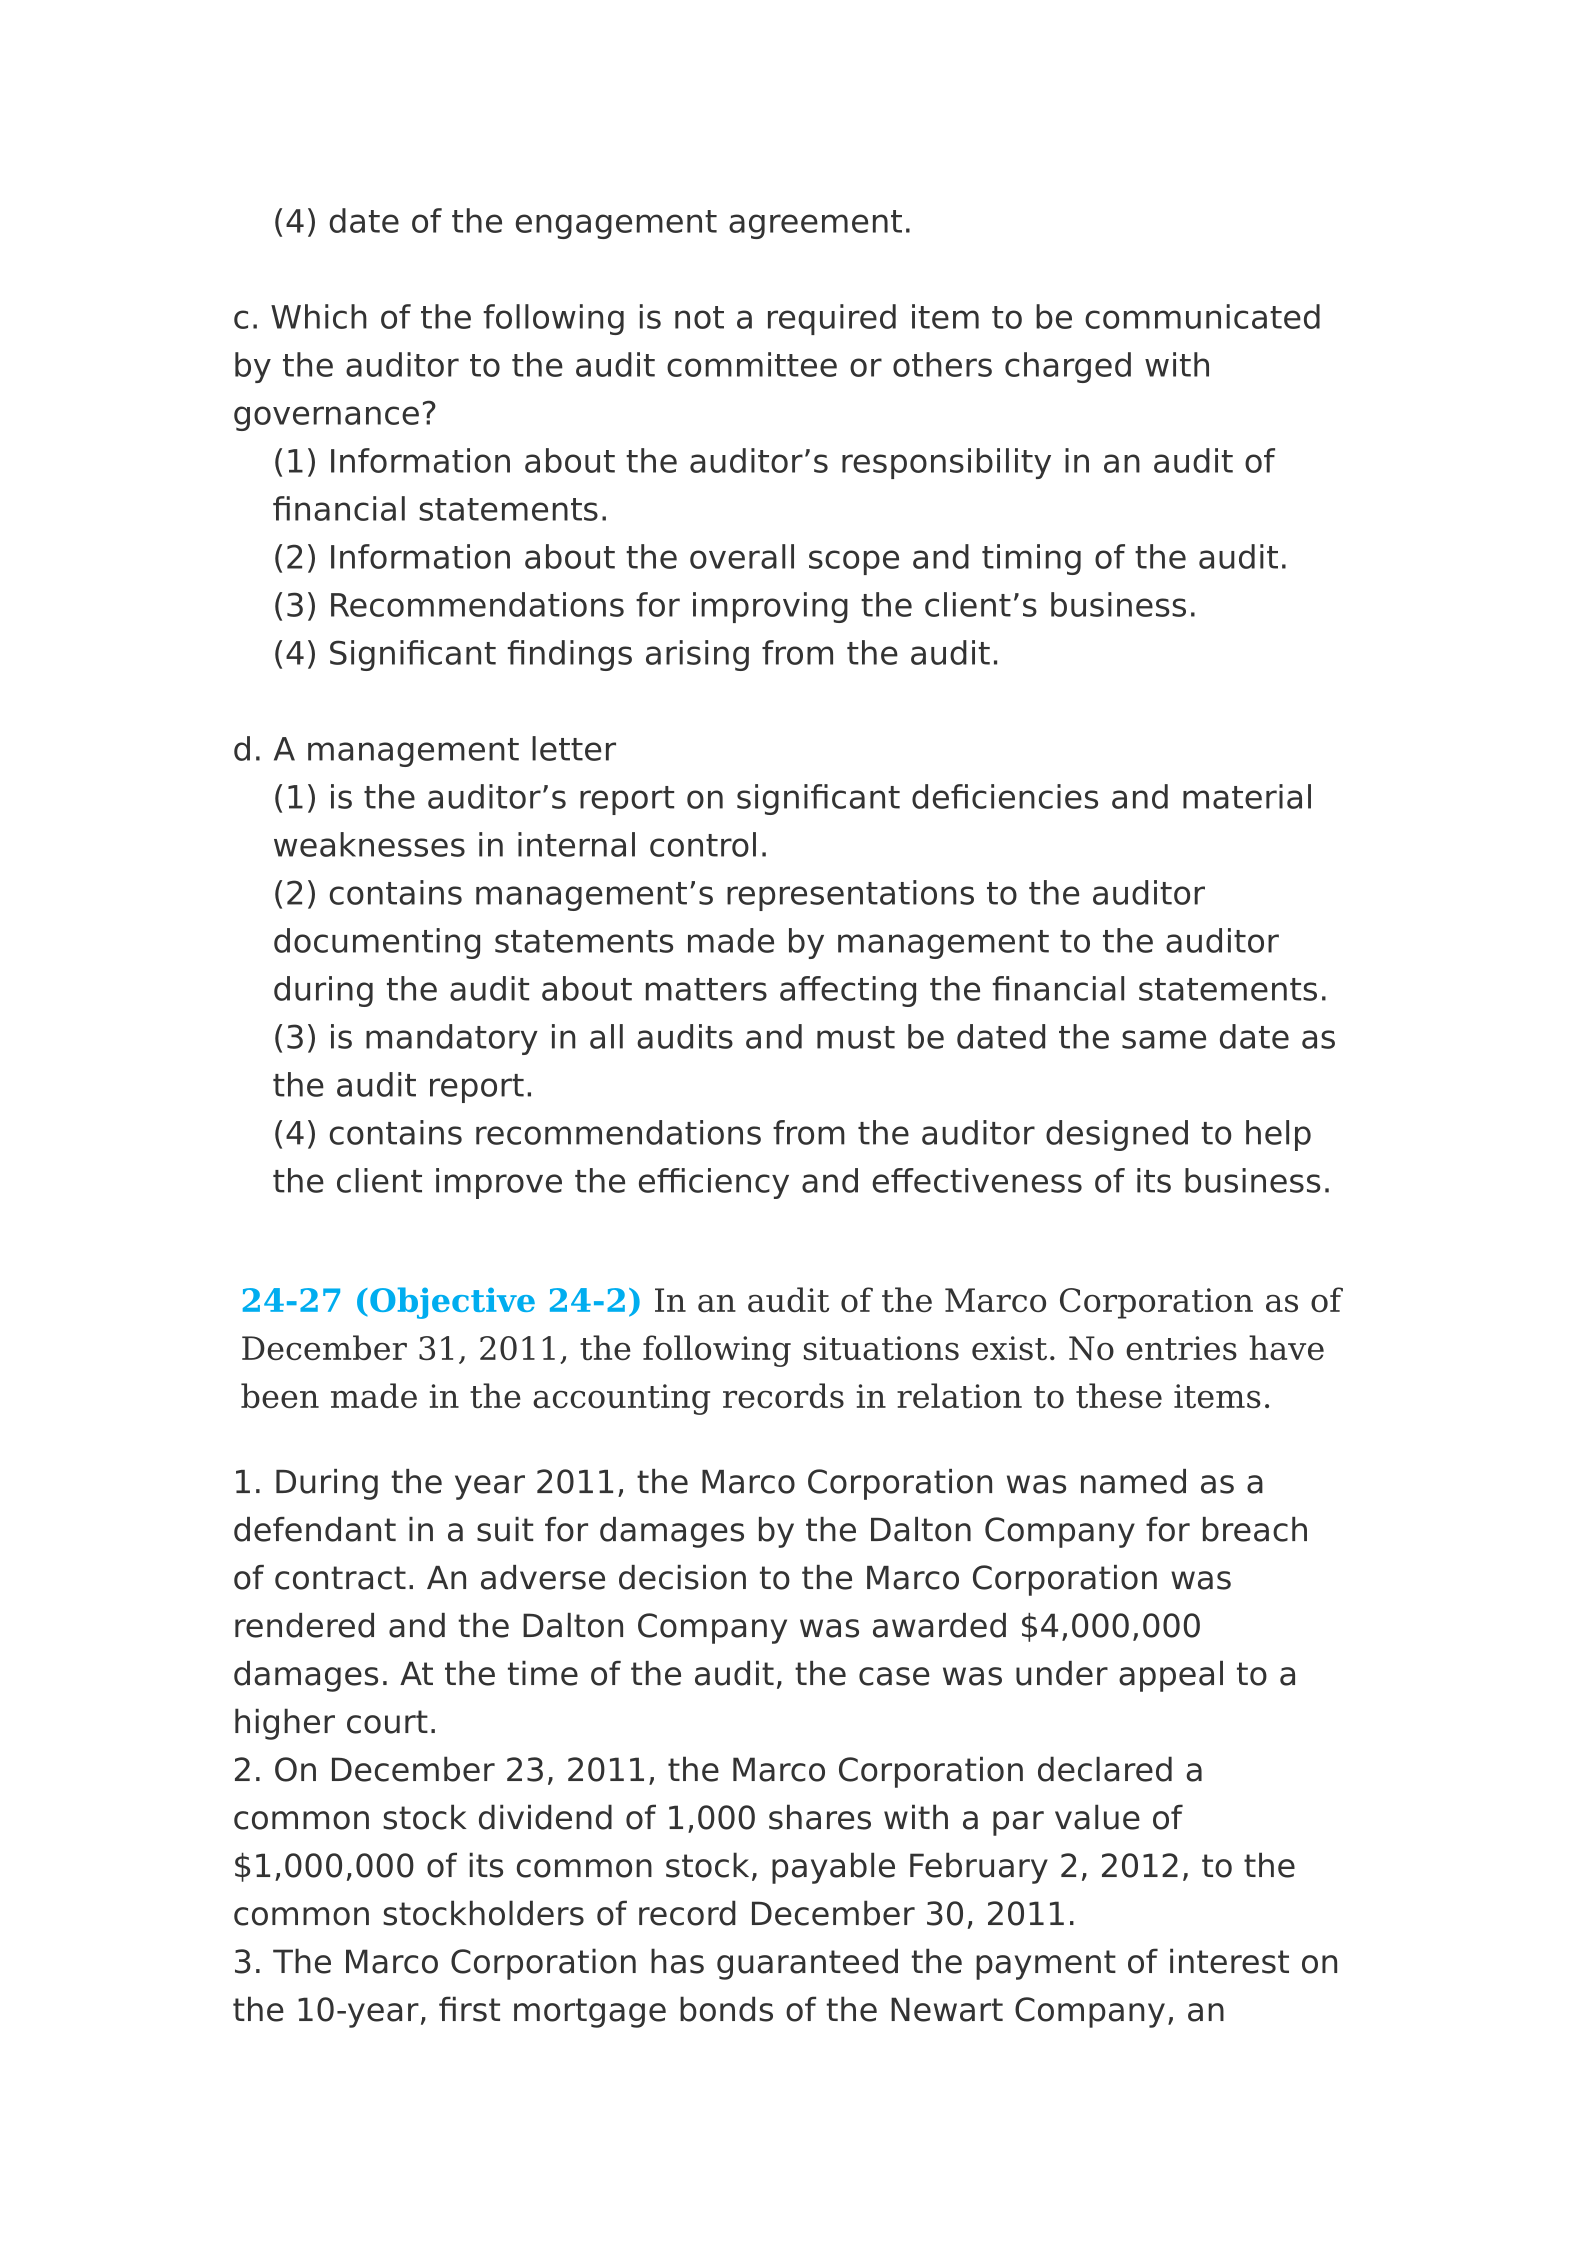
(4) date of the engagement agreement.
c. Which of the following is not a required item to be communicated
by the auditor to the audit committee or others charged with
governance?
(1) Information about the auditor’s responsibility in an audit of
financial statements.
(2) Information about the overall scope and timing of the audit.
(3) Recommendations for improving the client’s business.
(4) Significant findings arising from the audit.
d. A management letter
(1) is the auditor’s report on significant deficiencies and material
weaknesses in internal control.
(2) contains management’s representations to the auditor
documenting statements made by management to the auditor
during the audit about matters affecting the financial statements.
(3) is mandatory in all audits and must be dated the same date as
the audit report.
(4) contains recommendations from the auditor designed to help
the client improve the efficiency and effectiveness of its business.
24-27 (Objective 24-2) In an audit of the Marco Corporation as of
December 31, 2011, the following situations exist. No entries have
been made in the accounting records in relation to these items.
1. During the year 2011, the Marco Corporation was named as a
defendant in a suit for damages by the Dalton Company for breach
of contract. An adverse decision to the Marco Corporation was
rendered and the Dalton Company was awarded $4,000,000
damages. At the time of the audit, the case was under appeal to a
higher court.
2. On December 23, 2011, the Marco Corporation declared a
common stock dividend of 1,000 shares with a par value of
$1,000,000 of its common stock, payable February 2, 2012, to the
common stockholders of record December 30, 2011.
3. The Marco Corporation has guaranteed the payment of interest on
the 10-year, first mortgage bonds of the Newart Company, an
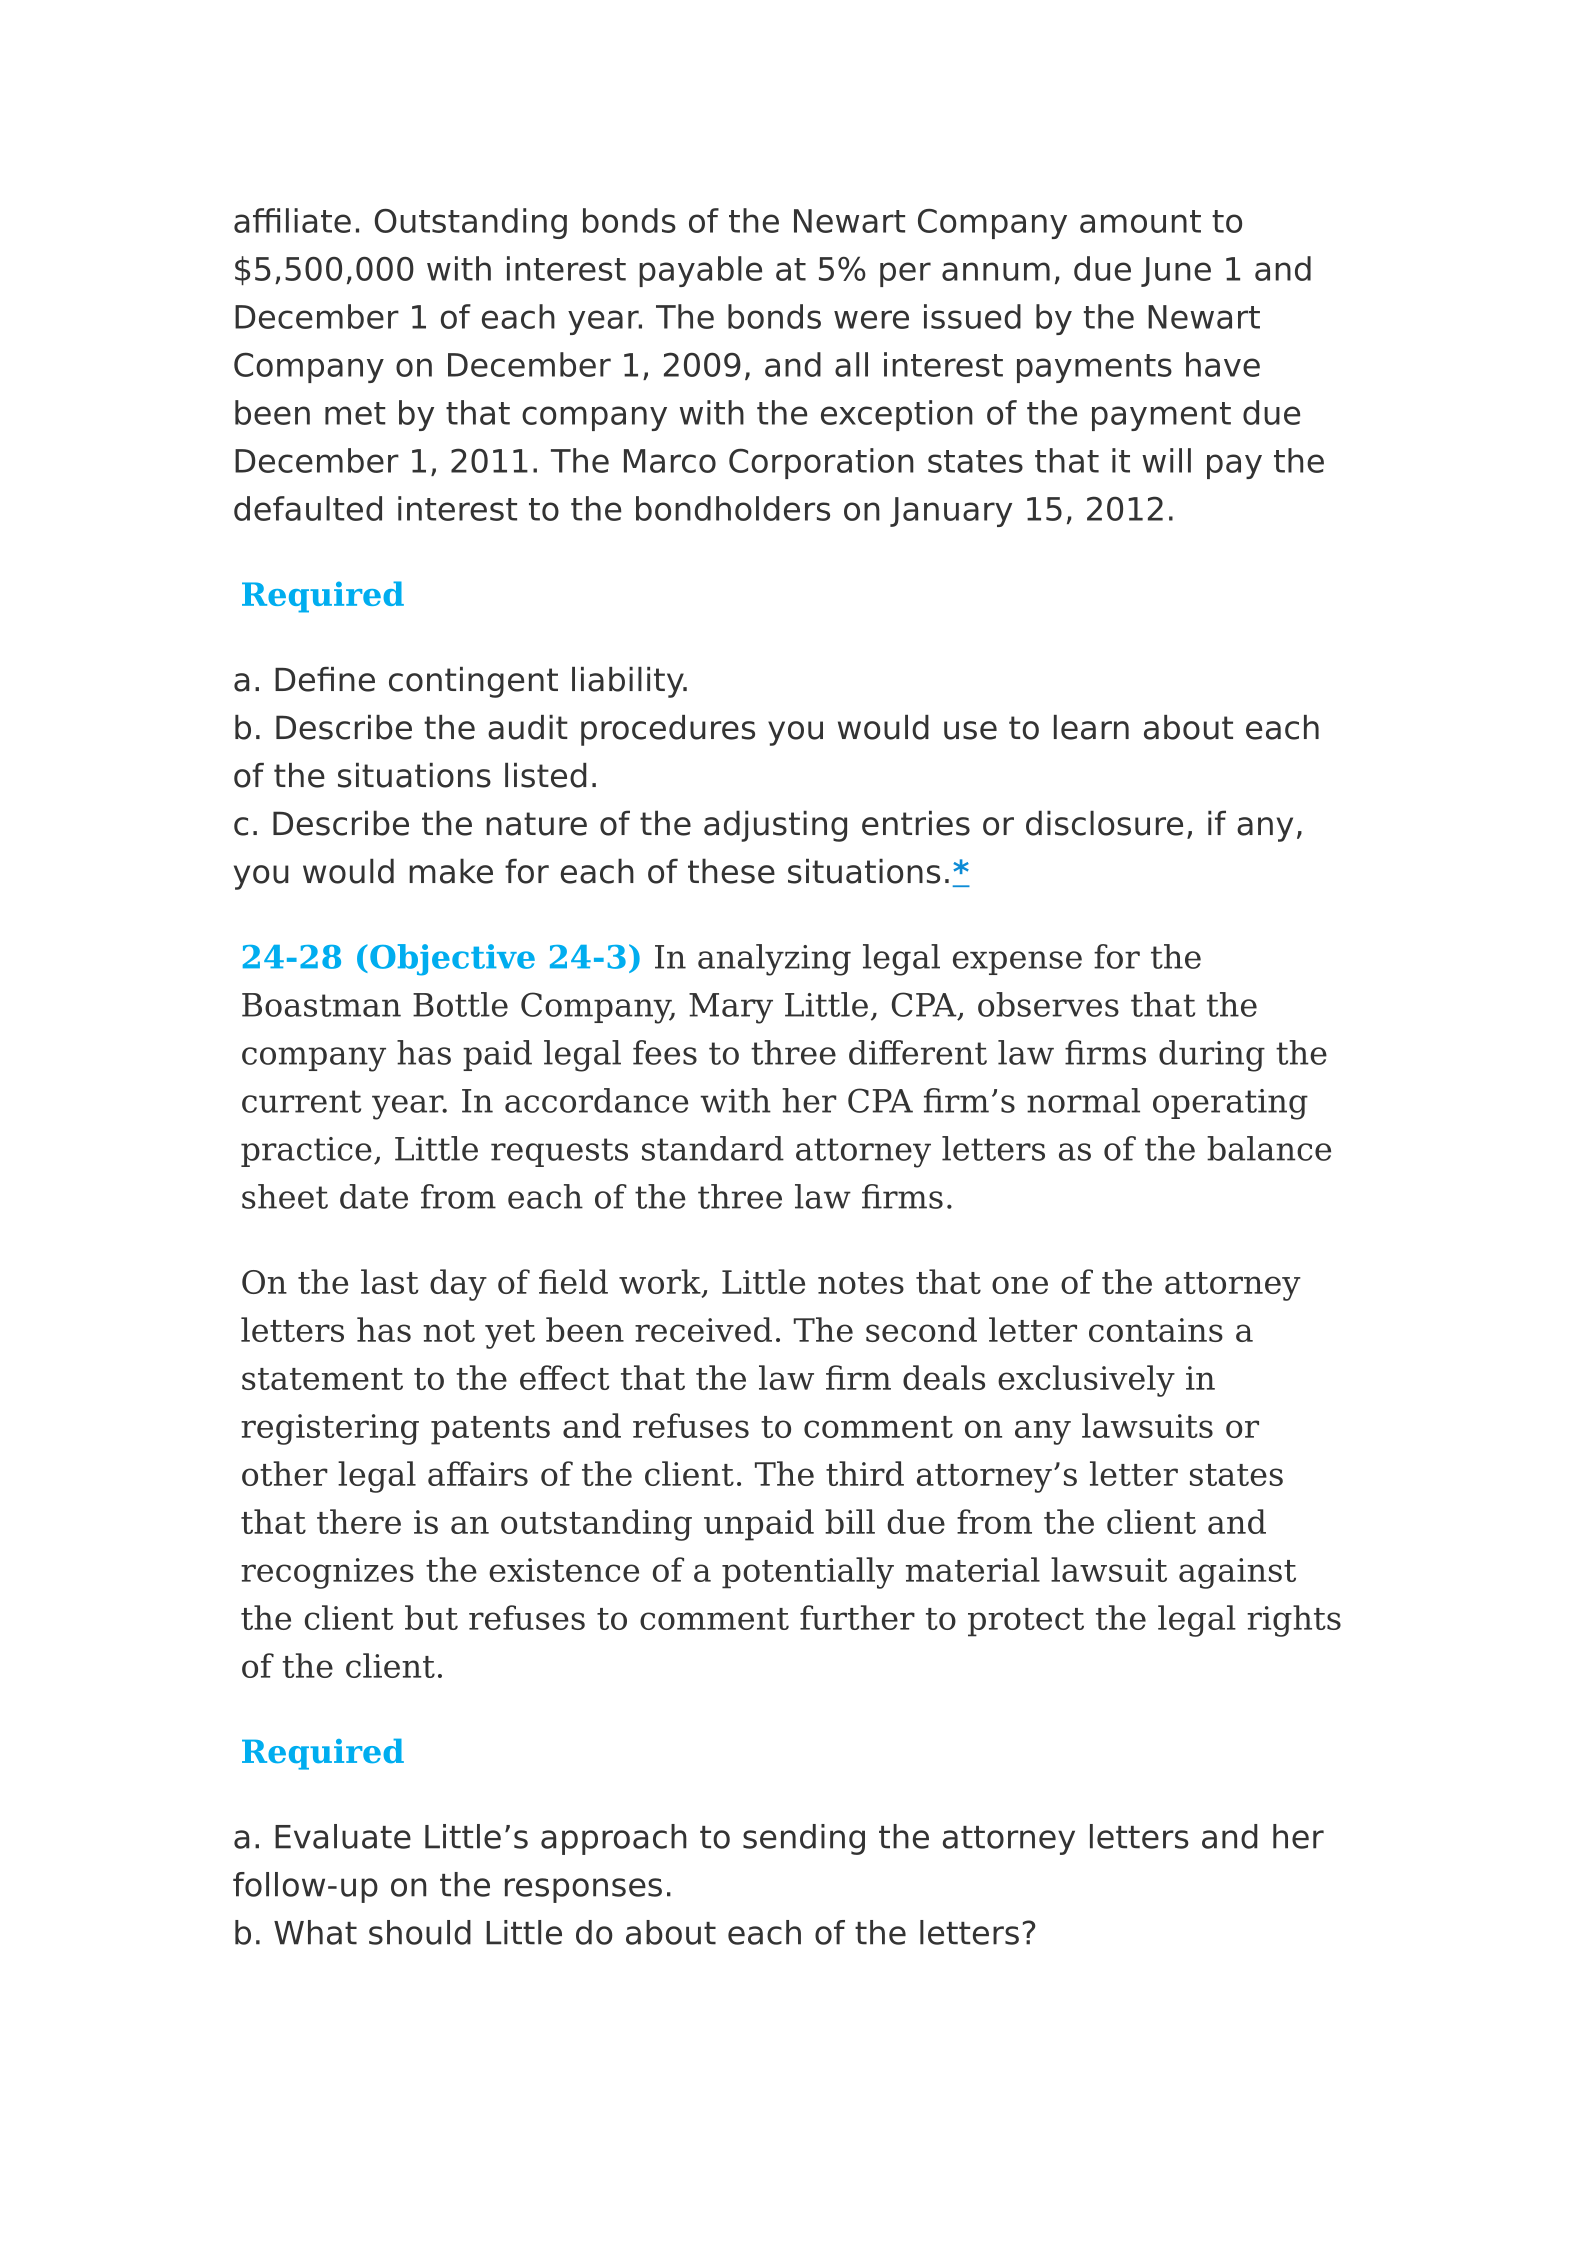
affiliate. Outstanding bonds of the Newart Company amount to
$5,500,000 with interest payable at 5% per annum, due June 1 and
December 1 of each year. The bonds were issued by the Newart
Company on December 1, 2009, and all interest payments have
been met by that company with the exception of the payment due
December 1, 2011. The Marco Corporation states that it will pay the
defaulted interest to the bondholders on January 15, 2012.
Required
a. Define contingent liability.
b. Describe the audit procedures you would use to learn about each
of the situations listed.
c. Describe the nature of the adjusting entries or disclosure, if any,
you would make for each of these situations.*
24-28 (Objective 24-3) In analyzing legal expense for the
Boastman Bottle Company, Mary Little, CPA, observes that the
company has paid legal fees to three different law firms during the
current year. In accordance with her CPA firm’s normal operating
practice, Little requests standard attorney letters as of the balance
sheet date from each of the three law firms.
On the last day of field work, Little notes that one of the attorney
letters has not yet been received. The second letter contains a
statement to the effect that the law firm deals exclusively in
registering patents and refuses to comment on any lawsuits or
other legal affairs of the client. The third attorney’s letter states
that there is an outstanding unpaid bill due from the client and
recognizes the existence of a potentially material lawsuit against
the client but refuses to comment further to protect the legal rights
of the client.
Required
a. Evaluate Little’s approach to sending the attorney letters and her
follow-up on the responses.
b. What should Little do about each of the letters?
Powered by TCPDF (www.tcpdf.org)

