Multiple Choice
Identify the choice that best completes the statement or answers the question.
____ 1. West, Inc. had beginning inventory of $10,000, purchases of $25,000 and ending inventory of $5,000. What is
West's cost of merchandise sold?
a. $10,000
b. $25,000
c. $5,000
d. $30,000
____ 2. If a company purchased $2,000 of merchandise on account and paid for it during the discount period with the
terms of 2/10, n/30, and the company uses the perpetual inventory system, the journal entry would be ____.
a. Accounts Payable 2,000
Cash 2,000
b. Merchandise Inventory 2,000
Accounts Payable 2,000
c. Accounts Payable 1,960
Merchandise Inventory 1,960
d. Accounts Payable 2,000
Merchandise Inventory 40
Cash 1,960
____ 3. If a $10,000 sale is made on January 1st, with terms of 2/10, n/30 how much would the discount be if payment
is made on January 9th?
a. $10,000
b. $200
c. $1,000
d. $0
____ 4. When the LIFO method is used, cost of merchandise sold is assumed to consist of ____.
a. The most recently purchased units
b. The oldest units
c. The units with the highest per unit cost
d. The units with the lowest per unit cost
____ 5. Which of the following entries are required to record the cost of merchandise sold under a perpetual inventory
system?
a. Cost of Merchandise Sold XXX
Merchandise Inventory XXX
b. Cost of Merchandise Sold XXX
Purchases XXX
c. Merchandise Inventory XXX
Cost of Merchandise Sold XXX
d. Purchases XXX
Cost of Merchandise Sold XXX
Exhibit 8-1
Use the following data for the month of April.
ACC 231 Online Exam 2 Test Prep
April 1 Beginning Inventory 100 units @ $4
April 2 Sales 50 units
April 3 Purchases 300 units @ $6
April 10 Sales 350 units
April 21 Purchases 400 units @ $8
April 28 Sales 200
____ 6. Refer to Exhibit 8-1. Assuming a perpetual inventory system is used, what is ending inventory under FIFO?
a. $1,600
b. $1,200
c. $800
d. $1,000
____ 7. Refer to Exhibit 8-1. Assuming a perpetual inventory system is used, what is ending inventory under LIFO?
a. $1,000
b. $1,100
c. $1,600
d. $1,350
____ 8. The difference between gross sales and net sales is
a. Cost of goods sold
b. Selling and administrative expenses
c. Sales discounts and sales returns and allowances
d. Gross margin
____ 9. Amy Company sold $8,000 of merchandise to Tory Turnbull with terms 2/10, n/30. If Tory paid for all of the
merchandise within the discount period, the journal entry that Amy will make to record the collection of cash
would include a
a. Debit to Sales Discounts of $160
b. Credit to Sales Discounts of $160
c. Credit to Cash of $7,840
d. Debit to Cash of $8,000
____ 10. When the allowance method of recognizing bad debt expense is used, the entry to record the write-off of a
specific uncollectible account would decrease
a. Allowance for Bad Debts
b. Net income
c. Net realizable value of accounts receivable
d. Working capital
____ 11. The journal entry
Accounts Receivable xxx
Allowance for Bad Debts xxx
would be made when
a. A customer pays the account balance
b. A customer defaults on the account
c. A previously defaulted customer pays the outstanding balance
d. Estimated uncollectible receivables are too low

____ 12. Following are the account balances from the December 31 trial balance of Hark Company:
Accounts Receivable $ 30,000
Allowance for Bad Debts 1,200 (cr)
Sales Revenue 202,500
Sales Returns and Allowances 7,500
If 10 percent of the Accounts Receivable is estimated to be uncollectible, the entry to record the estimate of
bad debts would include a debit to Bad Debt Expense for
a. $3,000
b. $2,880
c. $3,120
d. $1,800
____ 13. Following are the account balances from the December 31 trial balance of Hark Company:
Accounts Receivable $ 30,000
Allowance for Bad Debts 1,200 (dr)
Sales Revenue 202,500
Sales Returns and Allowances 7,500
If 10 percent of the Accounts Receivable is estimated to be uncollectible, the entry to record the estimate of
bad debts would include a debit to Bad Debt Expense for
a. $3,000
b. $3,120
c. $4,200
d. $1,800
____ 14. Gordie Co. reported an Allowance for Bad Debts of $20,000 (credit) at December 31, 2009, before
performing an aging of accounts receivable. As a result of the aging, Gordie determined that an estimated
$28,000 of the December 31, 2009, accounts receivable would prove uncollectible. The adjusting entry
required at December 31, 2009, would be
a. Bad Debt Expense 28,000
Allowance for Bad Debts 28,000
b. Bad Debt Expense 20,000
Accounts Receivable 20,000
c. Allowance for Bad Debts 8,000
Bad Debt Expense 8,000
d. Bad Debt Expense 8,000
Allowance for Bad Debts 8,000
____ 15. Which of the following demonstrates that a company is managing its receivables well?
a. The company is cash poor.
b. The company has many short term loans with high interest.
c. The company has cash to pay its bills.
d. The company is losing interest that could be earned by investing.
____ 16. In calculating a company's accounts receivable turnover ratio, which of the following sets of factors would be
used?
a. Net income and average accounts receivable
b. Total assets and average accounts receivable
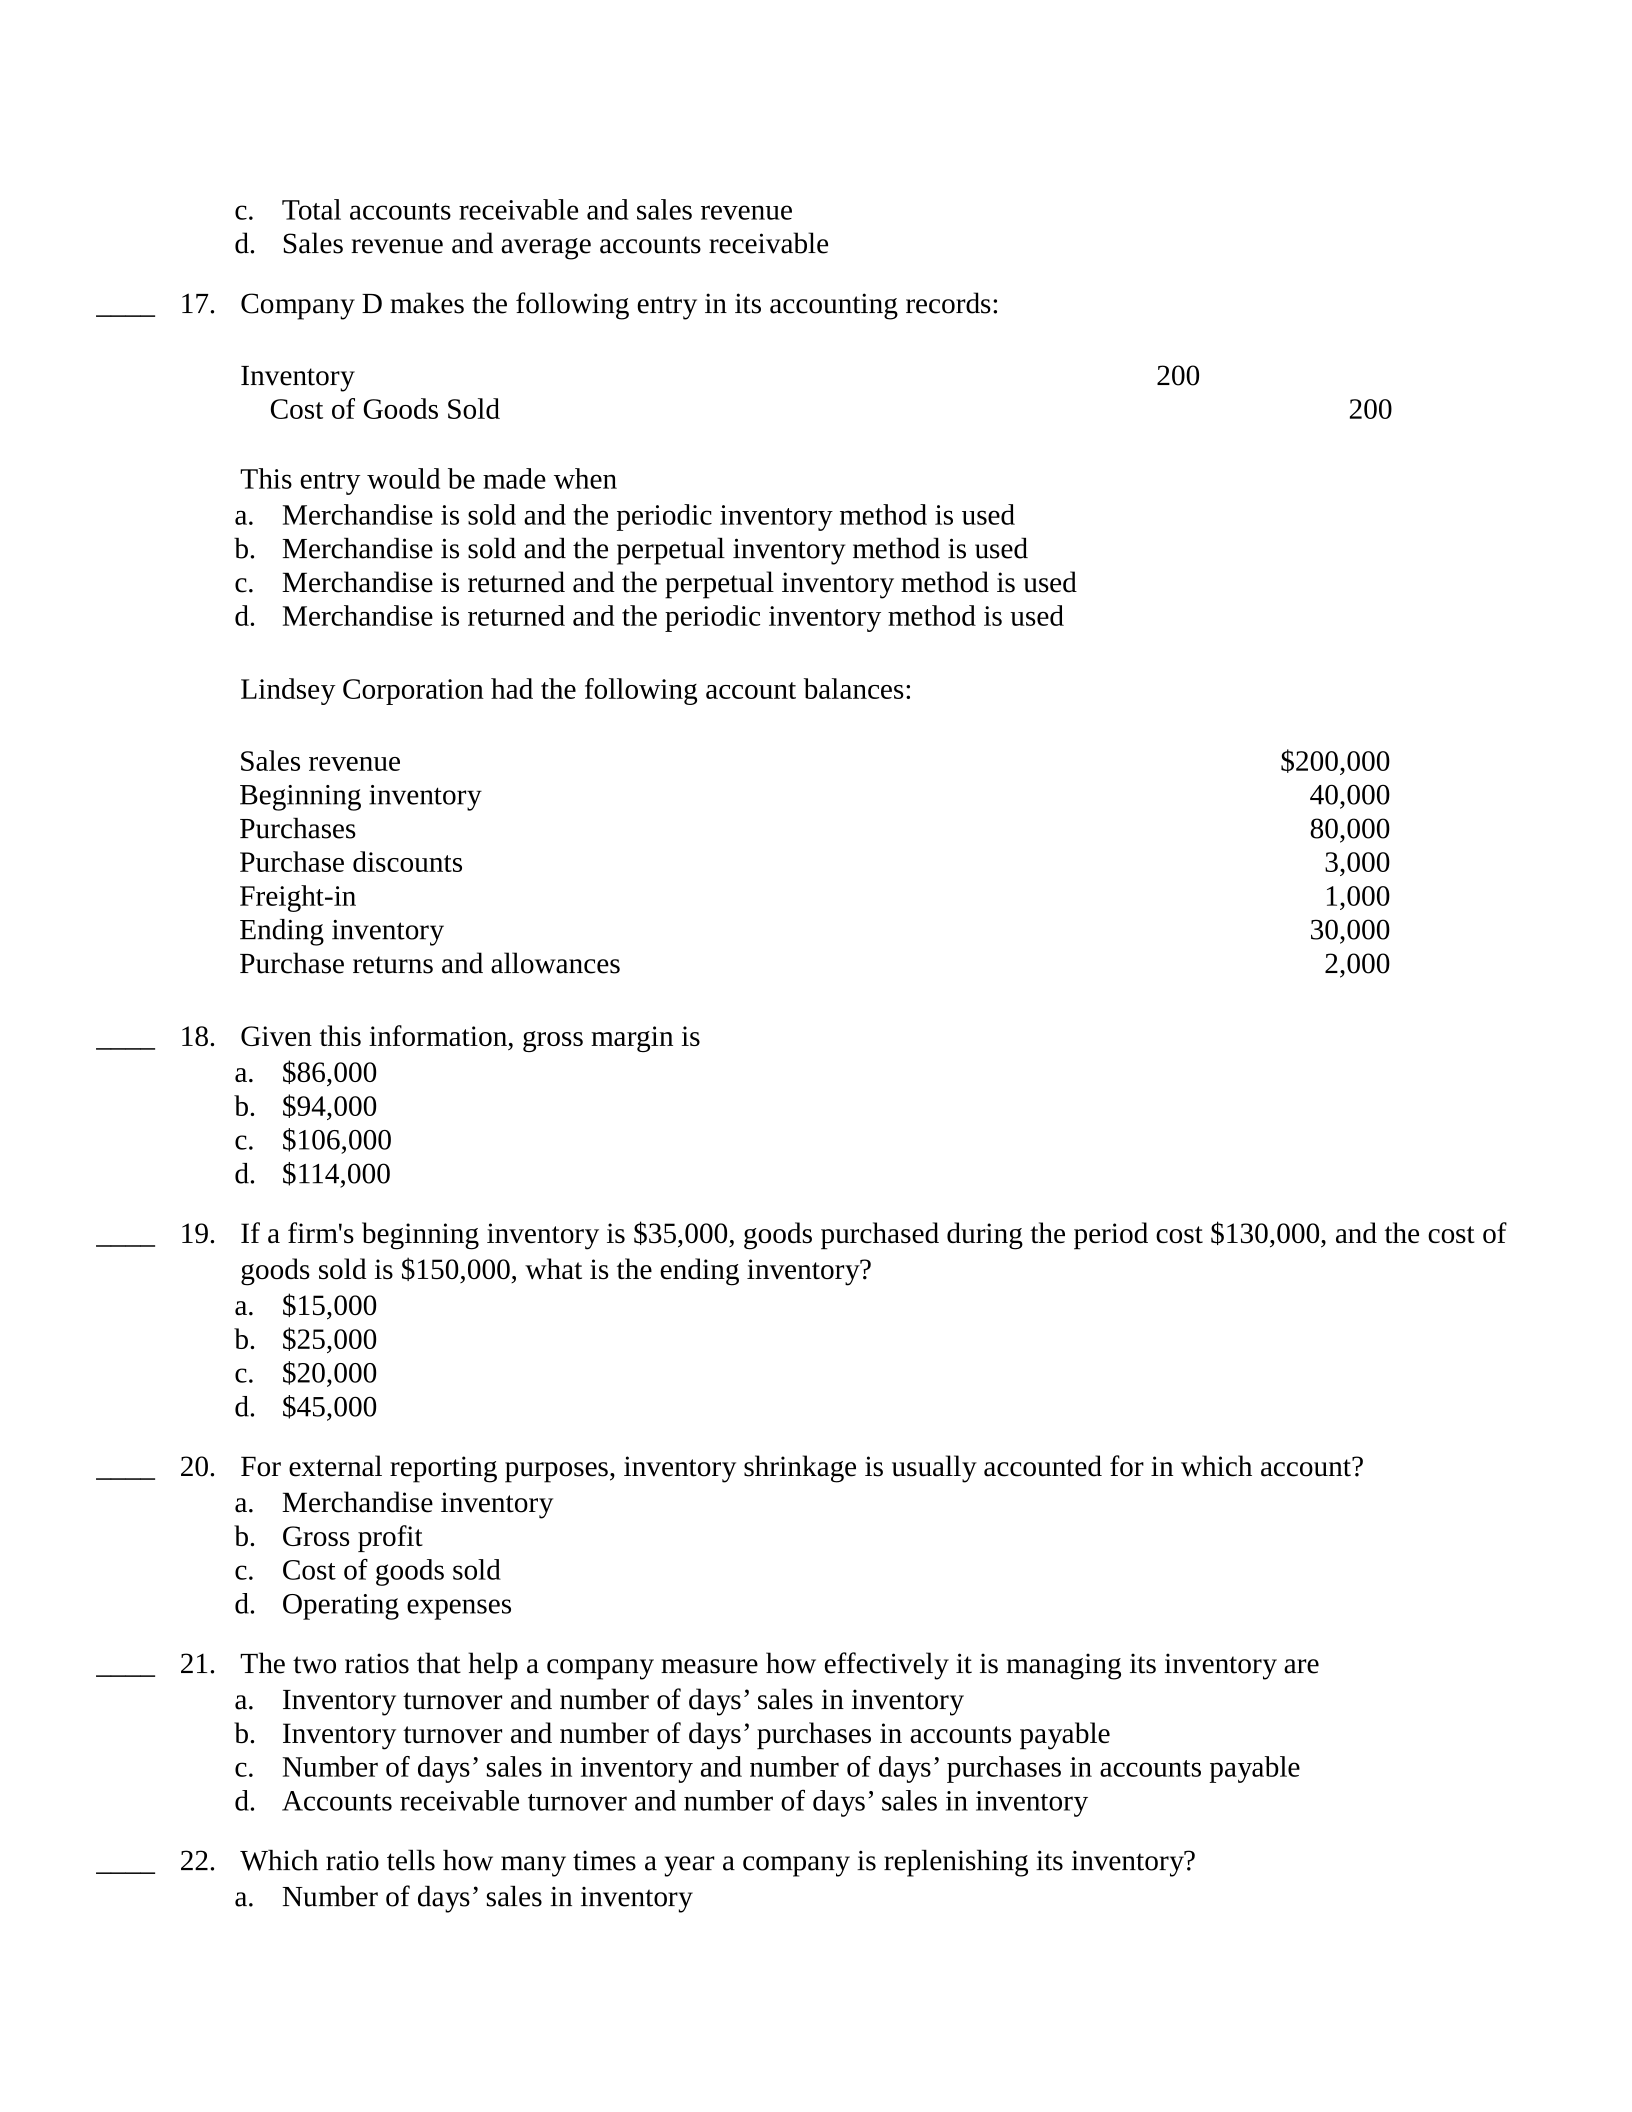
c. Total accounts receivable and sales revenue
d. Sales revenue and average accounts receivable
____ 17. Company D makes the following entry in its accounting records:
Inventory 200
Cost of Goods Sold 200
This entry would be made when
a. Merchandise is sold and the periodic inventory method is used
b. Merchandise is sold and the perpetual inventory method is used
c. Merchandise is returned and the perpetual inventory method is used
d. Merchandise is returned and the periodic inventory method is used
Lindsey Corporation had the following account balances:
Sales revenue $200,000
Beginning inventory 40,000
Purchases 80,000
Purchase discounts 3,000
Freight-in 1,000
Ending inventory 30,000
Purchase returns and allowances 2,000
____ 18. Given this information, gross margin is
a. $86,000
b. $94,000
c. $106,000
d. $114,000
____ 19. If a firm's beginning inventory is $35,000, goods purchased during the period cost $130,000, and the cost of
goods sold is $150,000, what is the ending inventory?
a. $15,000
b. $25,000
c. $20,000
d. $45,000
____ 20. For external reporting purposes, inventory shrinkage is usually accounted for in which account?
a. Merchandise inventory
b. Gross profit
c. Cost of goods sold
d. Operating expenses
____ 21. The two ratios that help a company measure how effectively it is managing its inventory are
a. Inventory turnover and number of days’ sales in inventory
b. Inventory turnover and number of days’ purchases in accounts payable
c. Number of days’ sales in inventory and number of days’ purchases in accounts payable
d. Accounts receivable turnover and number of days’ sales in inventory
____ 22. Which ratio tells how many times a year a company is replenishing its inventory?
a. Number of days’ sales in inventory
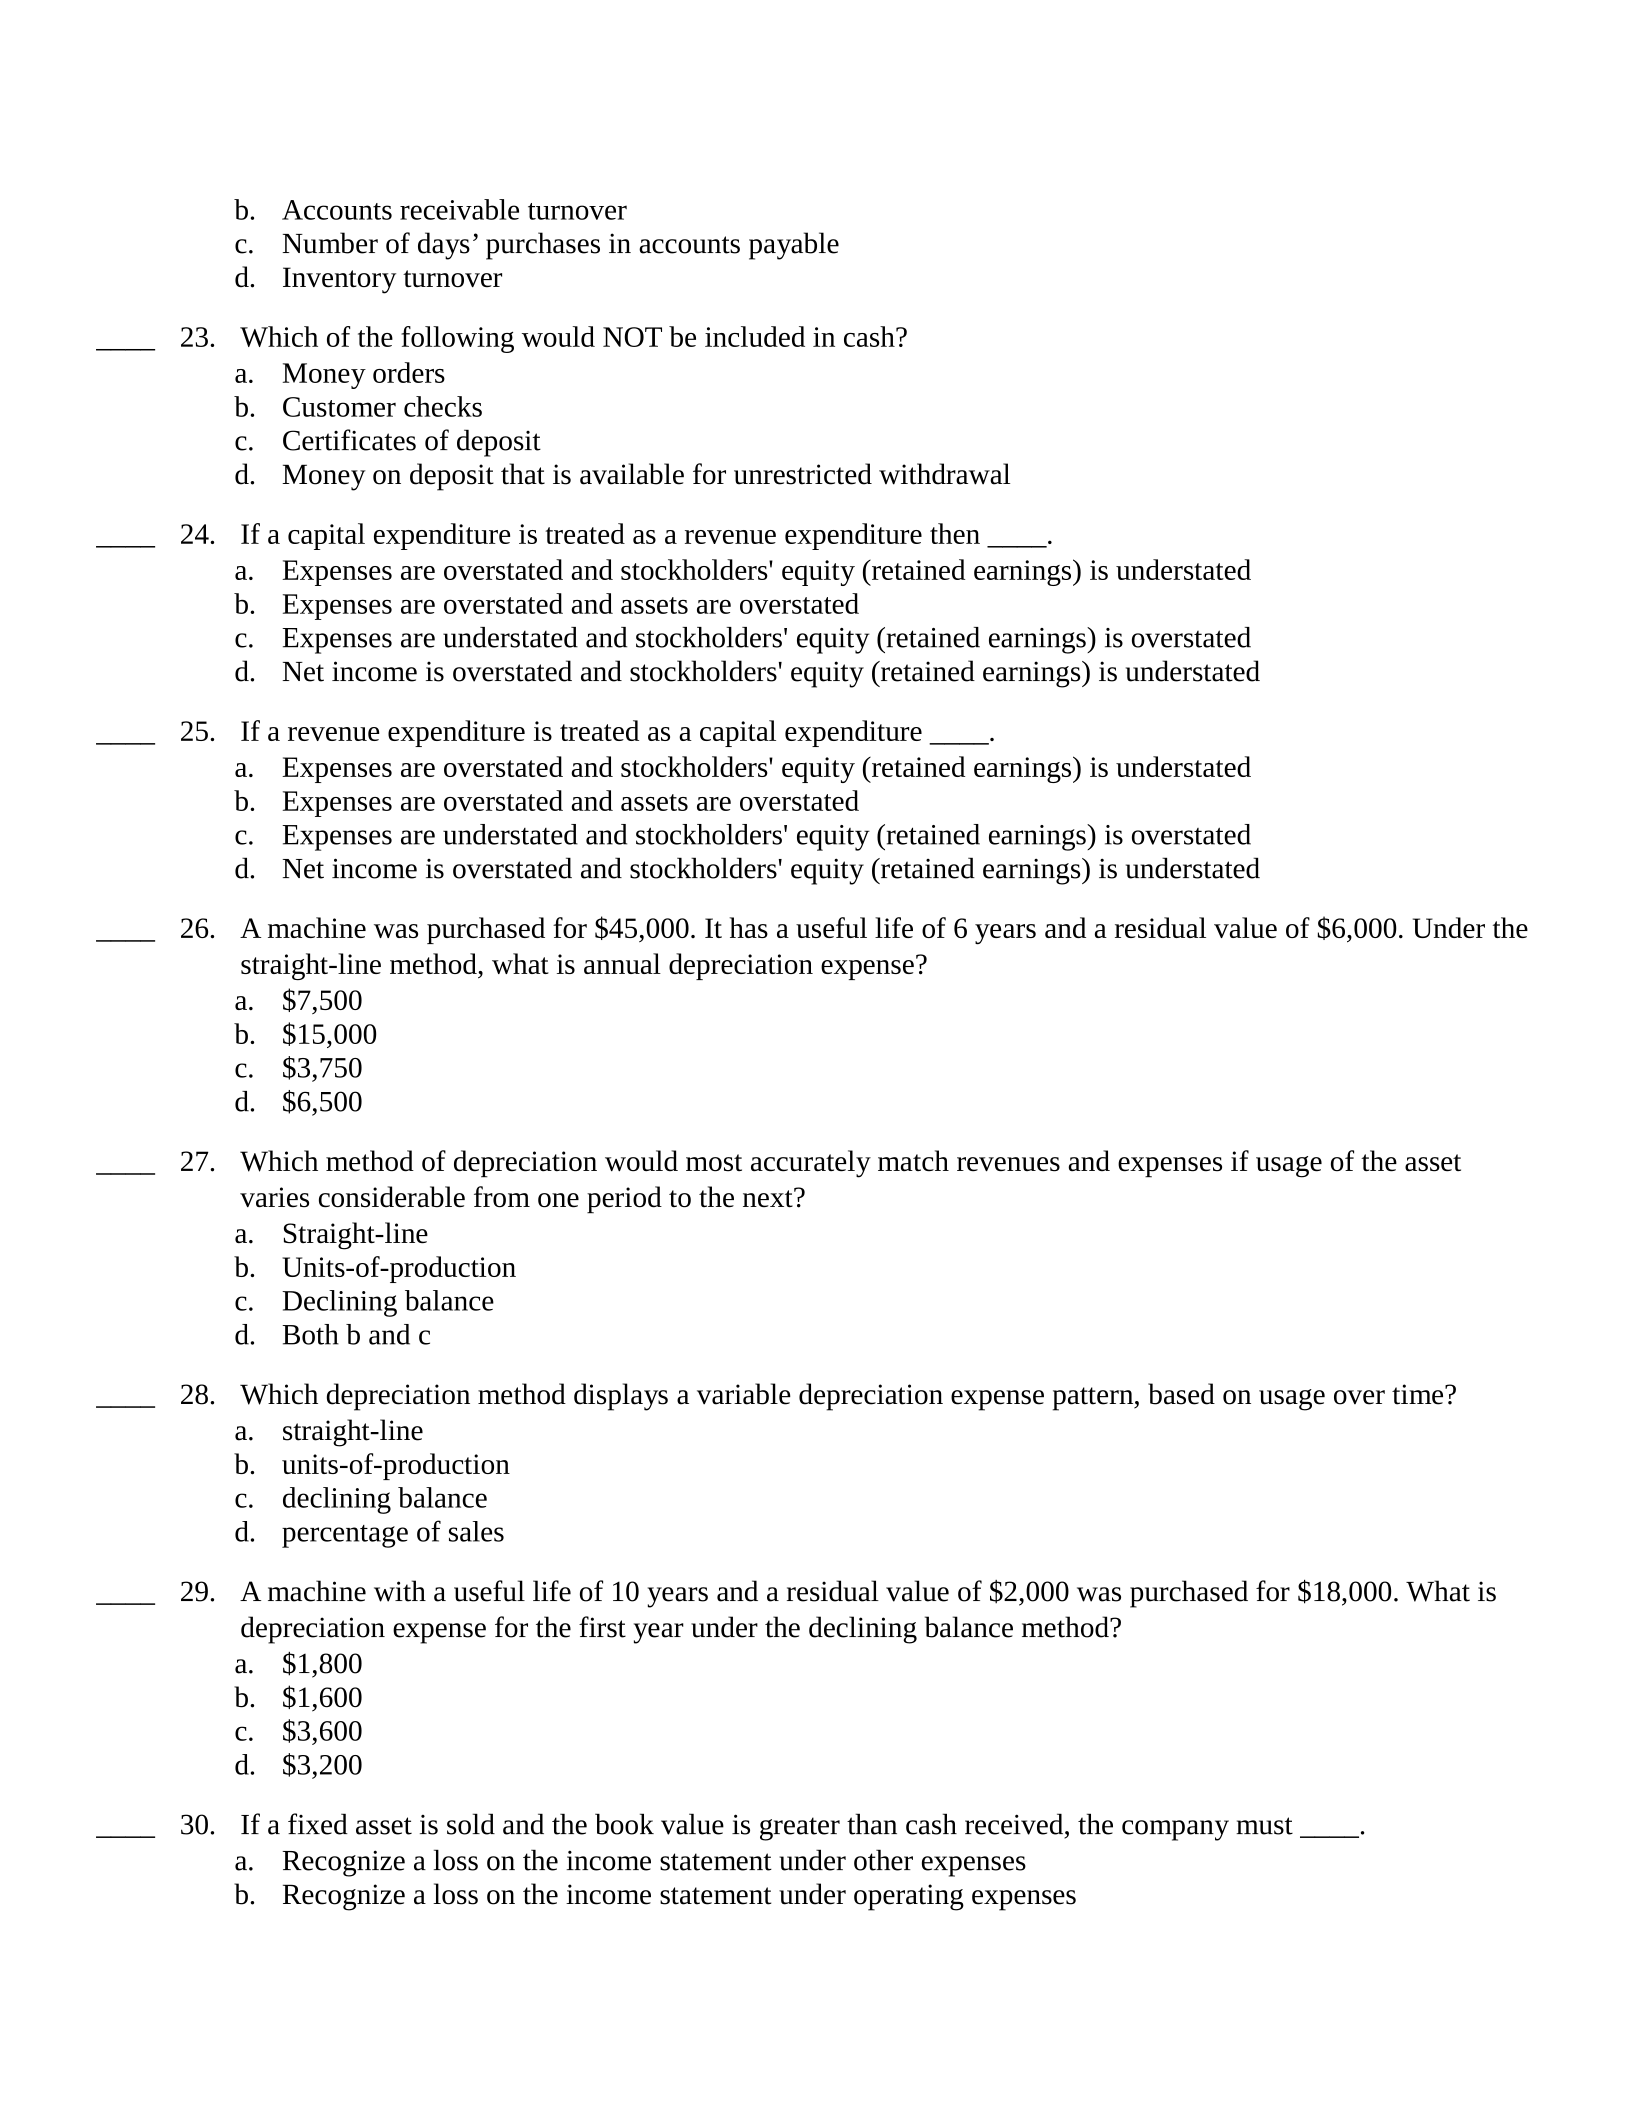
b. Accounts receivable turnover
c. Number of days’ purchases in accounts payable
d. Inventory turnover
____ 23. Which of the following would NOT be included in cash?
a. Money orders
b. Customer checks
c. Certificates of deposit
d. Money on deposit that is available for unrestricted withdrawal
____ 24. If a capital expenditure is treated as a revenue expenditure then ____.
a. Expenses are overstated and stockholders' equity (retained earnings) is understated
b. Expenses are overstated and assets are overstated
c. Expenses are understated and stockholders' equity (retained earnings) is overstated
d. Net income is overstated and stockholders' equity (retained earnings) is understated
____ 25. If a revenue expenditure is treated as a capital expenditure ____.
a. Expenses are overstated and stockholders' equity (retained earnings) is understated
b. Expenses are overstated and assets are overstated
c. Expenses are understated and stockholders' equity (retained earnings) is overstated
d. Net income is overstated and stockholders' equity (retained earnings) is understated
____ 26. A machine was purchased for $45,000. It has a useful life of 6 years and a residual value of $6,000. Under the
straight-line method, what is annual depreciation expense?
a. $7,500
b. $15,000
c. $3,750
d. $6,500
____ 27. Which method of depreciation would most accurately match revenues and expenses if usage of the asset
varies considerable from one period to the next?
a. Straight-line
b. Units-of-production
c. Declining balance
d. Both b and c
____ 28. Which depreciation method displays a variable depreciation expense pattern, based on usage over time?
a. straight-line
b. units-of-production
c. declining balance
d. percentage of sales
____ 29. A machine with a useful life of 10 years and a residual value of $2,000 was purchased for $18,000. What is
depreciation expense for the first year under the declining balance method?
a. $1,800
b. $1,600
c. $3,600
d. $3,200
____ 30. If a fixed asset is sold and the book value is greater than cash received, the company must ____.
a. Recognize a loss on the income statement under other expenses
b. Recognize a loss on the income statement under operating expenses
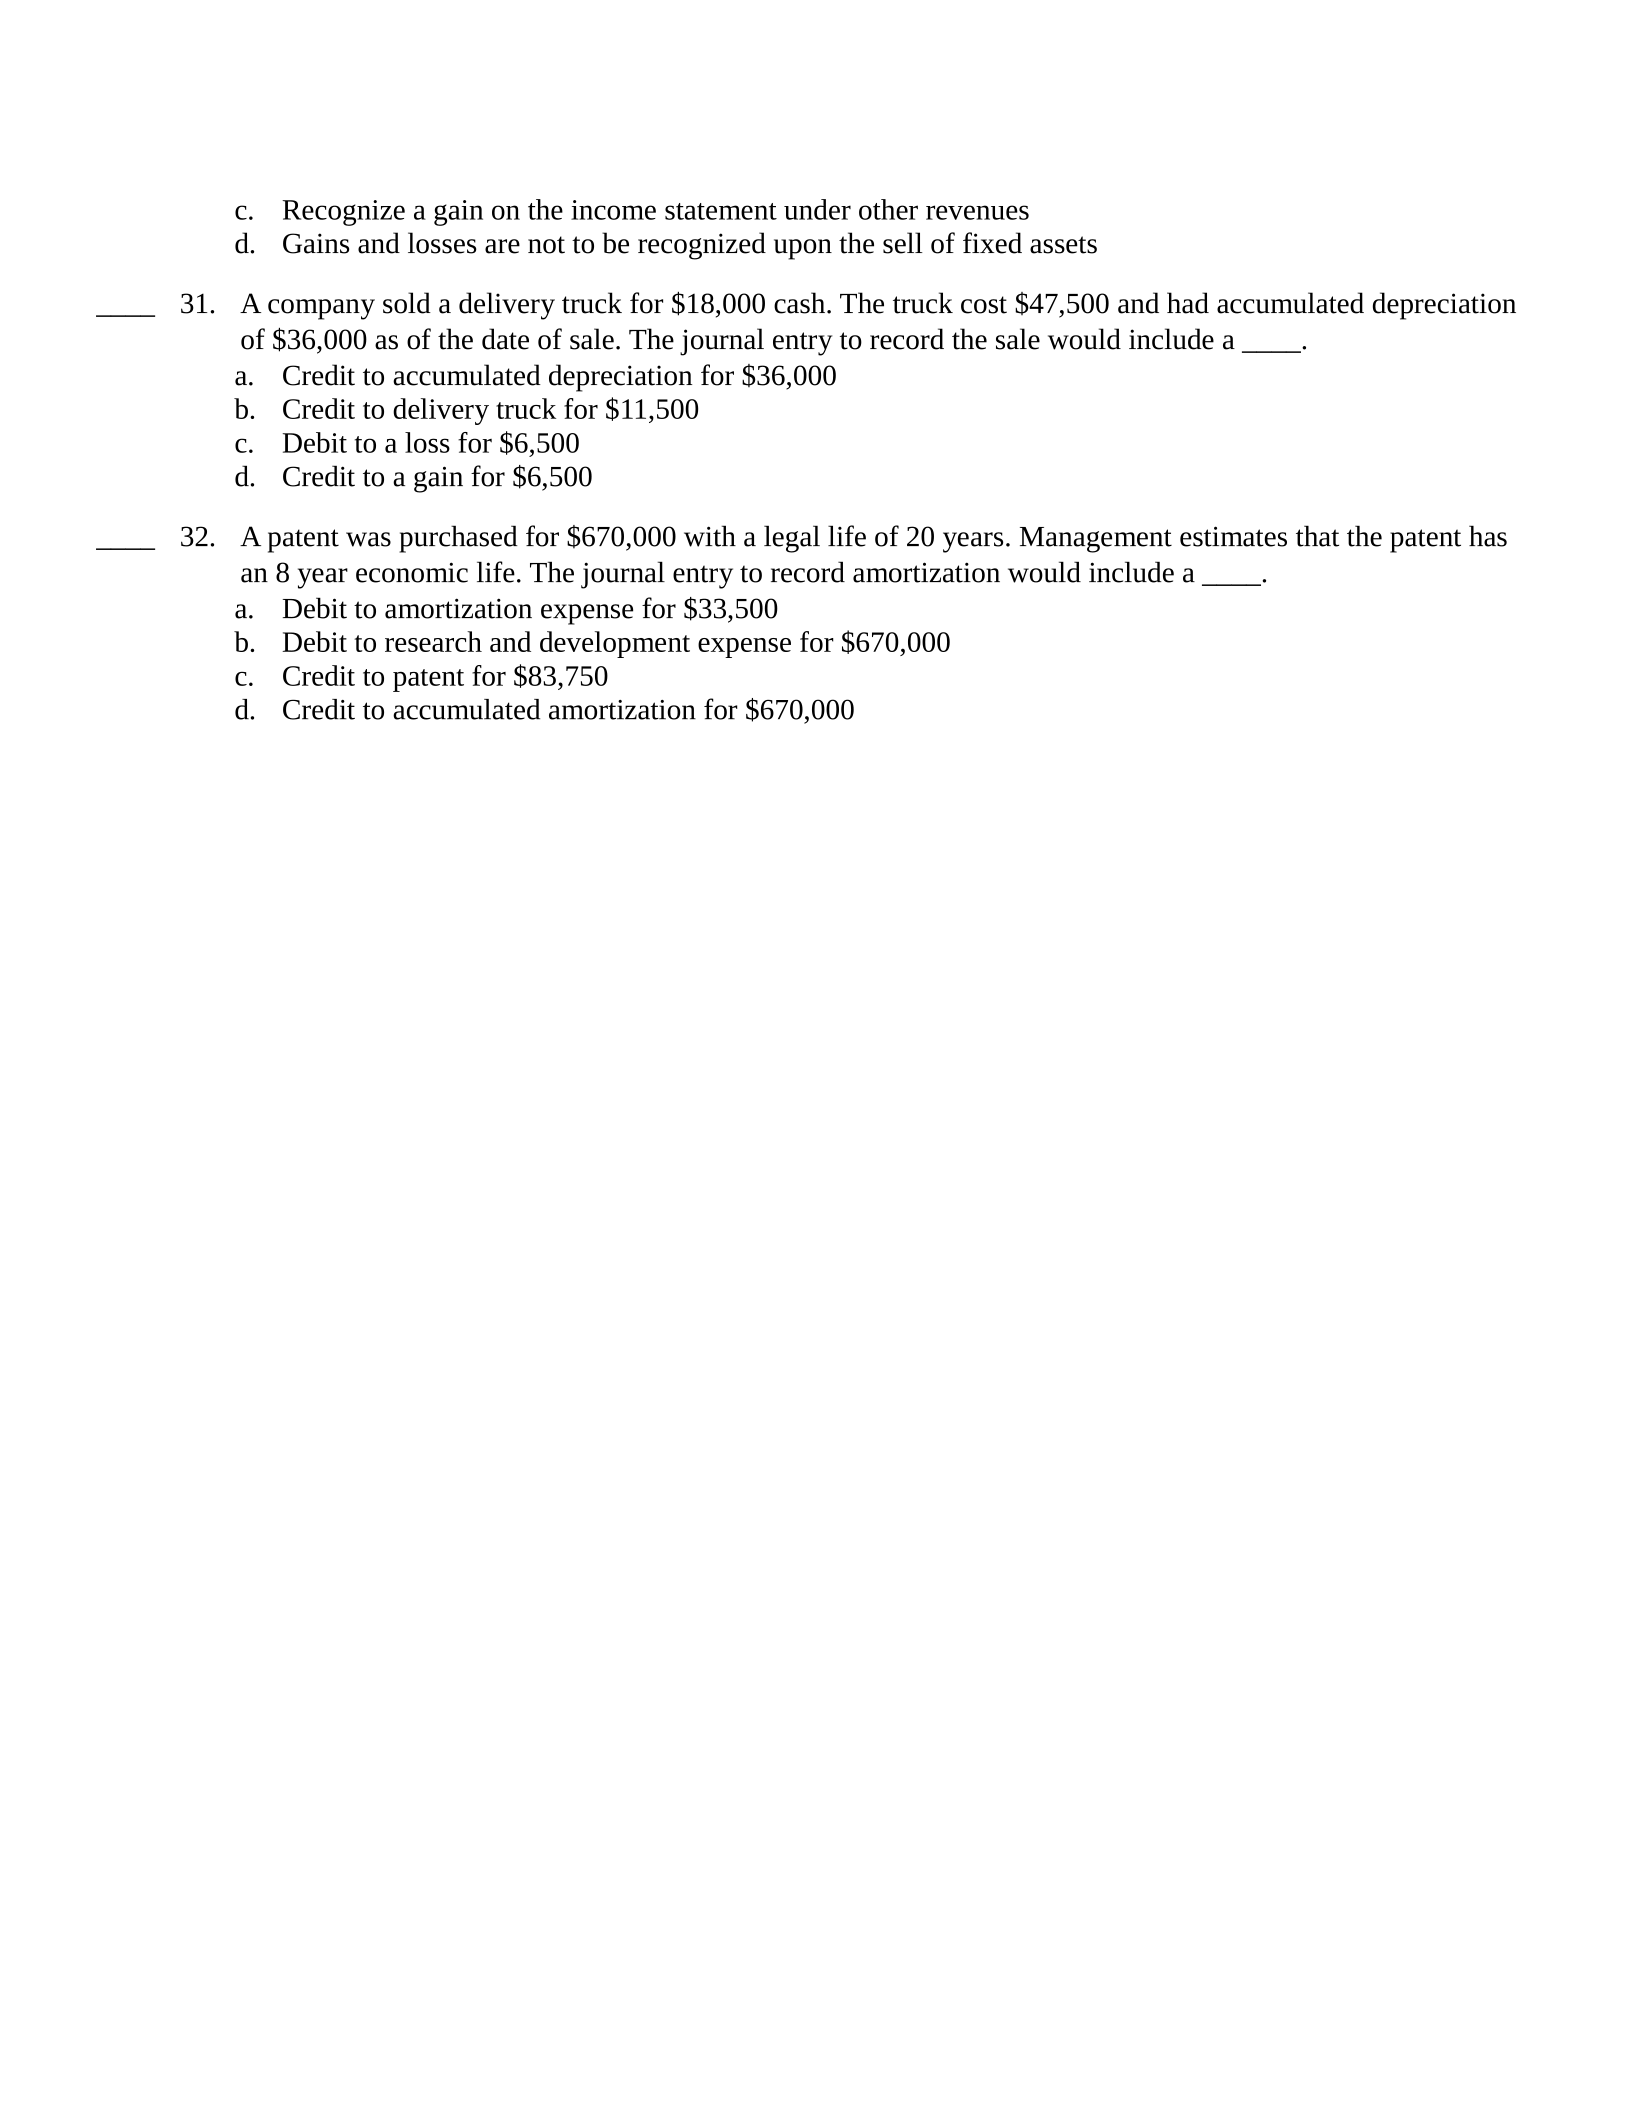
c. Recognize a gain on the income statement under other revenues
d. Gains and losses are not to be recognized upon the sell of fixed assets
____ 31. A company sold a delivery truck for $18,000 cash. The truck cost $47,500 and had accumulated depreciation
of $36,000 as of the date of sale. The journal entry to record the sale would include a ____.
a. Credit to accumulated depreciation for $36,000
b. Credit to delivery truck for $11,500
c. Debit to a loss for $6,500
d. Credit to a gain for $6,500
____ 32. A patent was purchased for $670,000 with a legal life of 20 years. Management estimates that the patent has
an 8 year economic life. The journal entry to record amortization would include a ____.
a. Debit to amortization expense for $33,500
b. Debit to research and development expense for $670,000
c. Credit to patent for $83,750
d. Credit to accumulated amortization for $670,000
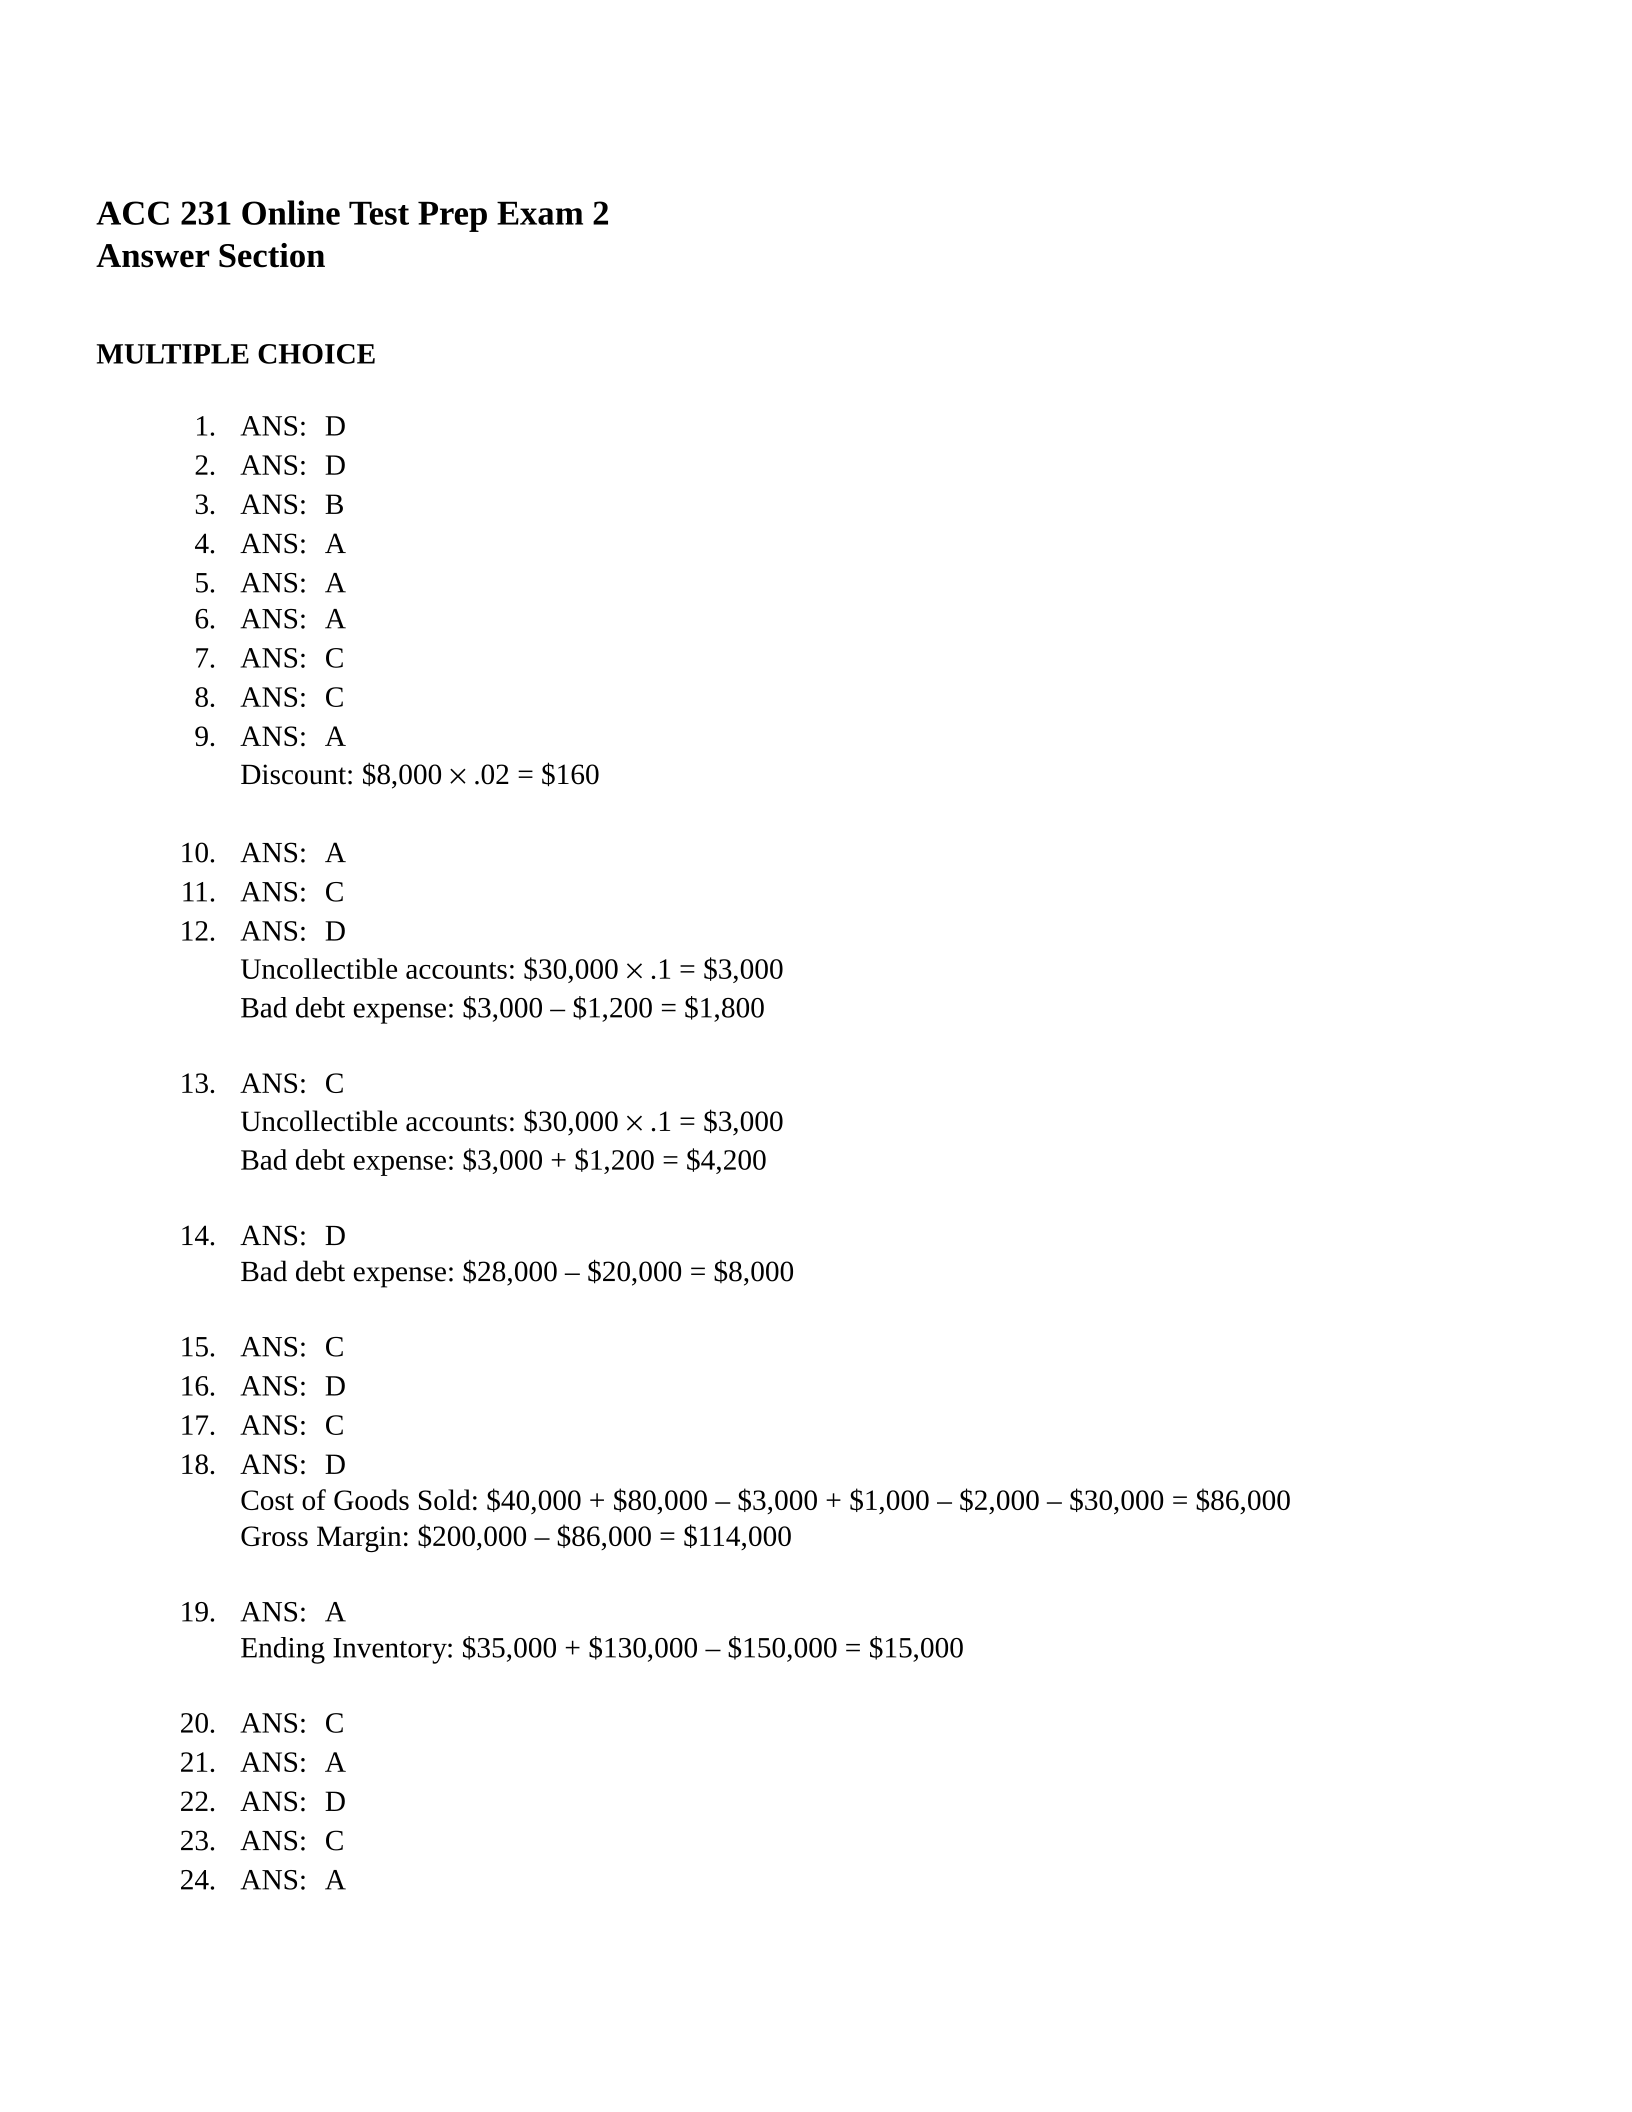
ACC 231 Online Test Prep Exam 2
Answer Section
MULTIPLE CHOICE
1. ANS: D
2. ANS: D
3. ANS: B
4. ANS: A
5. ANS: A
6. ANS: A
7. ANS: C
8. ANS: C
9. ANS: A
Discount: $8,000 .02 = $160
10. ANS: A
11. ANS: C
12. ANS: D
Uncollectible accounts: $30,000 .1 = $3,000
Bad debt expense: $3,000 – $1,200 = $1,800
13. ANS: C
Uncollectible accounts: $30,000 .1 = $3,000
Bad debt expense: $3,000 + $1,200 = $4,200
14. ANS: D
Bad debt expense: $28,000 – $20,000 = $8,000
15. ANS: C
16. ANS: D
17. ANS: C
18. ANS: D
Cost of Goods Sold: $40,000 + $80,000 – $3,000 + $1,000 – $2,000 – $30,000 = $86,000
Gross Margin: $200,000 – $86,000 = $114,000
19. ANS: A
Ending Inventory: $35,000 + $130,000 – $150,000 = $15,000
20. ANS: C
21. ANS: A
22. ANS: D
23. ANS: C
24. ANS: A