


FALL 2020
Professor – Don Frost
CHAPTER 2
ACC 231 – USES OF
ACCOUNTING INFORMATION I
Business, Accounting, and You
H does a busines monitor all its
, , sales (r ),
, a other activities?
T must be a “scor ”
pr that r ,
, r , and r thes
transa in an
, r , and r
.
T must be a way t the
and effe of each transact .
T ’s the of accou in business.
ACC 231 - Fall 2020 2
What is a transaction?
A transaction any ev that has
financia impact on the business
can be mea r .
A pr objec
about the fina
on an of
/services.
T is always a “give” and a “get.”
A r both the give and
sides the transac .
ACC 231 - Fall 2020 3
Business, Accounting, and You
T en acc infor is
, r , and r ,
have rules. In the U.S., GAAP
the rules for r and
business transa .
T rules for r and r
transactions ar based on a set of
techniques that have evolved
. The r is a of standar ,
accepted pr that work.
T k to using these techniques and
is understanding (1)
(2) double en accounting.
ACC 231 - Fall 2020 4
Accounts
Accounts
Accounts
•T ba summary
of
•T r
all the cha
a spe asset,
, or equ
as a r of
period.
Chart of Accounts
Chart of Accounts
•A of all the
o a
and the
assigne
those .
ACC 231 - Fall 2020 5
“Accounts”
T may be multiple R &
C to R
E “R ” or “C to R ”
setup as a “A ”
F Examp :
C in Big Bank
I at S Br
I
D to Bondholder
O ’s Initial Inv
ACC 231 - Fall 2020 6
Organizing Accounts
A have names/descript as
as an account number. U an
number has two or mor digits.
F a large company, may be six or mor
.
T first digit the t of
.
F digi and acco type:
ACC 231 - Fall 2020 7
1
1
•A
2
2
•L
3
3
•O ’/
S ’
E
4
4
•R
5
5
•E
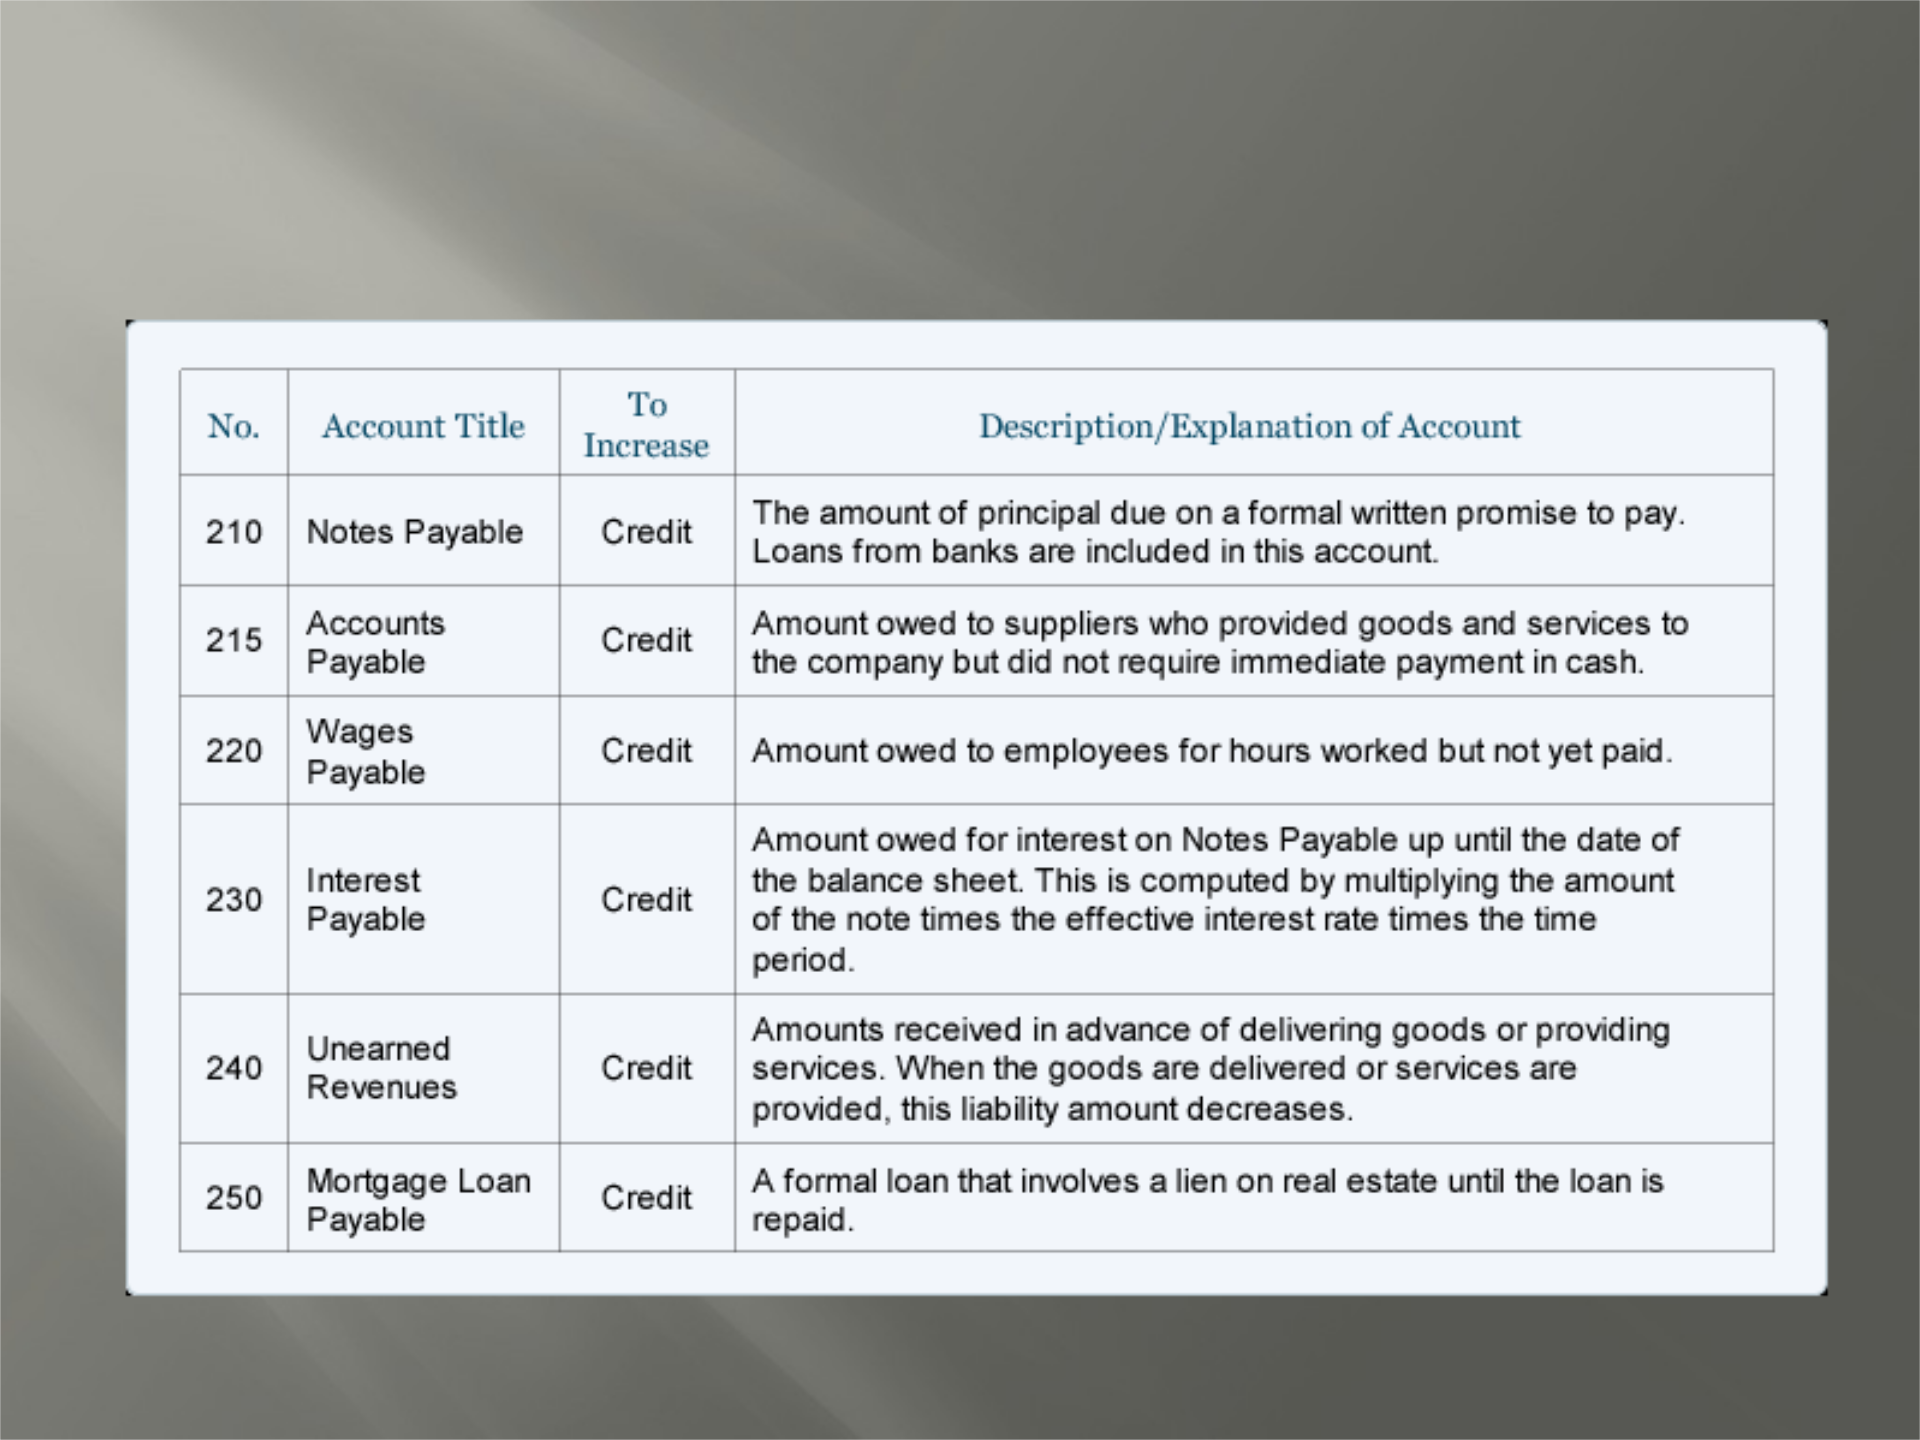
To
No.
Account
Title
I
Description/
Explanation
of
Account
nerease
The
amount
of
principal
due
on
a
formal
written
promise
to
pay.
210
Notes
Payable
Credit
|
ans
from banks
are
included
in
this
account.
915
Accounts
Credit
AMmount
owed
to
suppliers
who
provided
goods
and
services
to
Payable
the
company
but did
not
require
immediate
payment
in
cash.
Wages
|
220
Payable
Credit
Amount
owed
to
employees
for
hours
worked
but not yet
paid.
230
Interest
Payable
Credit
Amount
owed
for
interest
on
Notes
Payable
up
until
the
date
of
the
balance
sheet.
This
is
computed
by
multiplying
the
amount
of
the
note
times
the
effective
interest
rate
times
the
time
period.
240
Unearmed
Revenues
Credit
Amounts
received
in
advance
of
delivering
goods
or
providing
services.
VWhen
the
goods
are
delivered
or
services
are
provided,
this
liability
amount
decreases.
250
Mortgage
Loan
Payable
Credit
A
formal
loan
that
involves
a
lien
on
real
estate
until
the
loan
is
repaid.
Sample Excerpt – Chart of Accounts
(Liabilities)
ACC 231 - Fall 2020 8
Assets – Typical Examples
Cash
C
Accounts
Receivable
A
R
Notes
Receivable
N
R
Inventory
I
Prepaid
Expenses
P
E
Land &
Buildings
L &
B
Furniture,
Fixtures
and
Equipment
F ,
F
E
ACC 231 - Fall 2020 9
Liabilities –Typical Examples
Account
s
Payable
A
P
Notes
Payable
N
P
Accrued
Rent
A
R
Accrued
Utilities
A
U
Wages
Payable
W
P
ACC 231 - Fall 2020 10
Stockholders’ Equity
Common
Stock
C
S
Retained
Earnings
R
E
Revenue
s
R
Expense
s
E
Dividend
s
D
11
N the above incorporates the
Expanded Accounting Equation
ACC 231 - Fall 2020
Double-entry Accounting
R every impacts least two
E account has two side (note “T” format)
T-A - simplified depiction of an account
E T-A r a single account the Chart of
A and the cor account in th General L
( )
O side r increases
O side r decreases
ACC 231 - Fall 2020 12
A Na
D = left
C = righ
D . C .
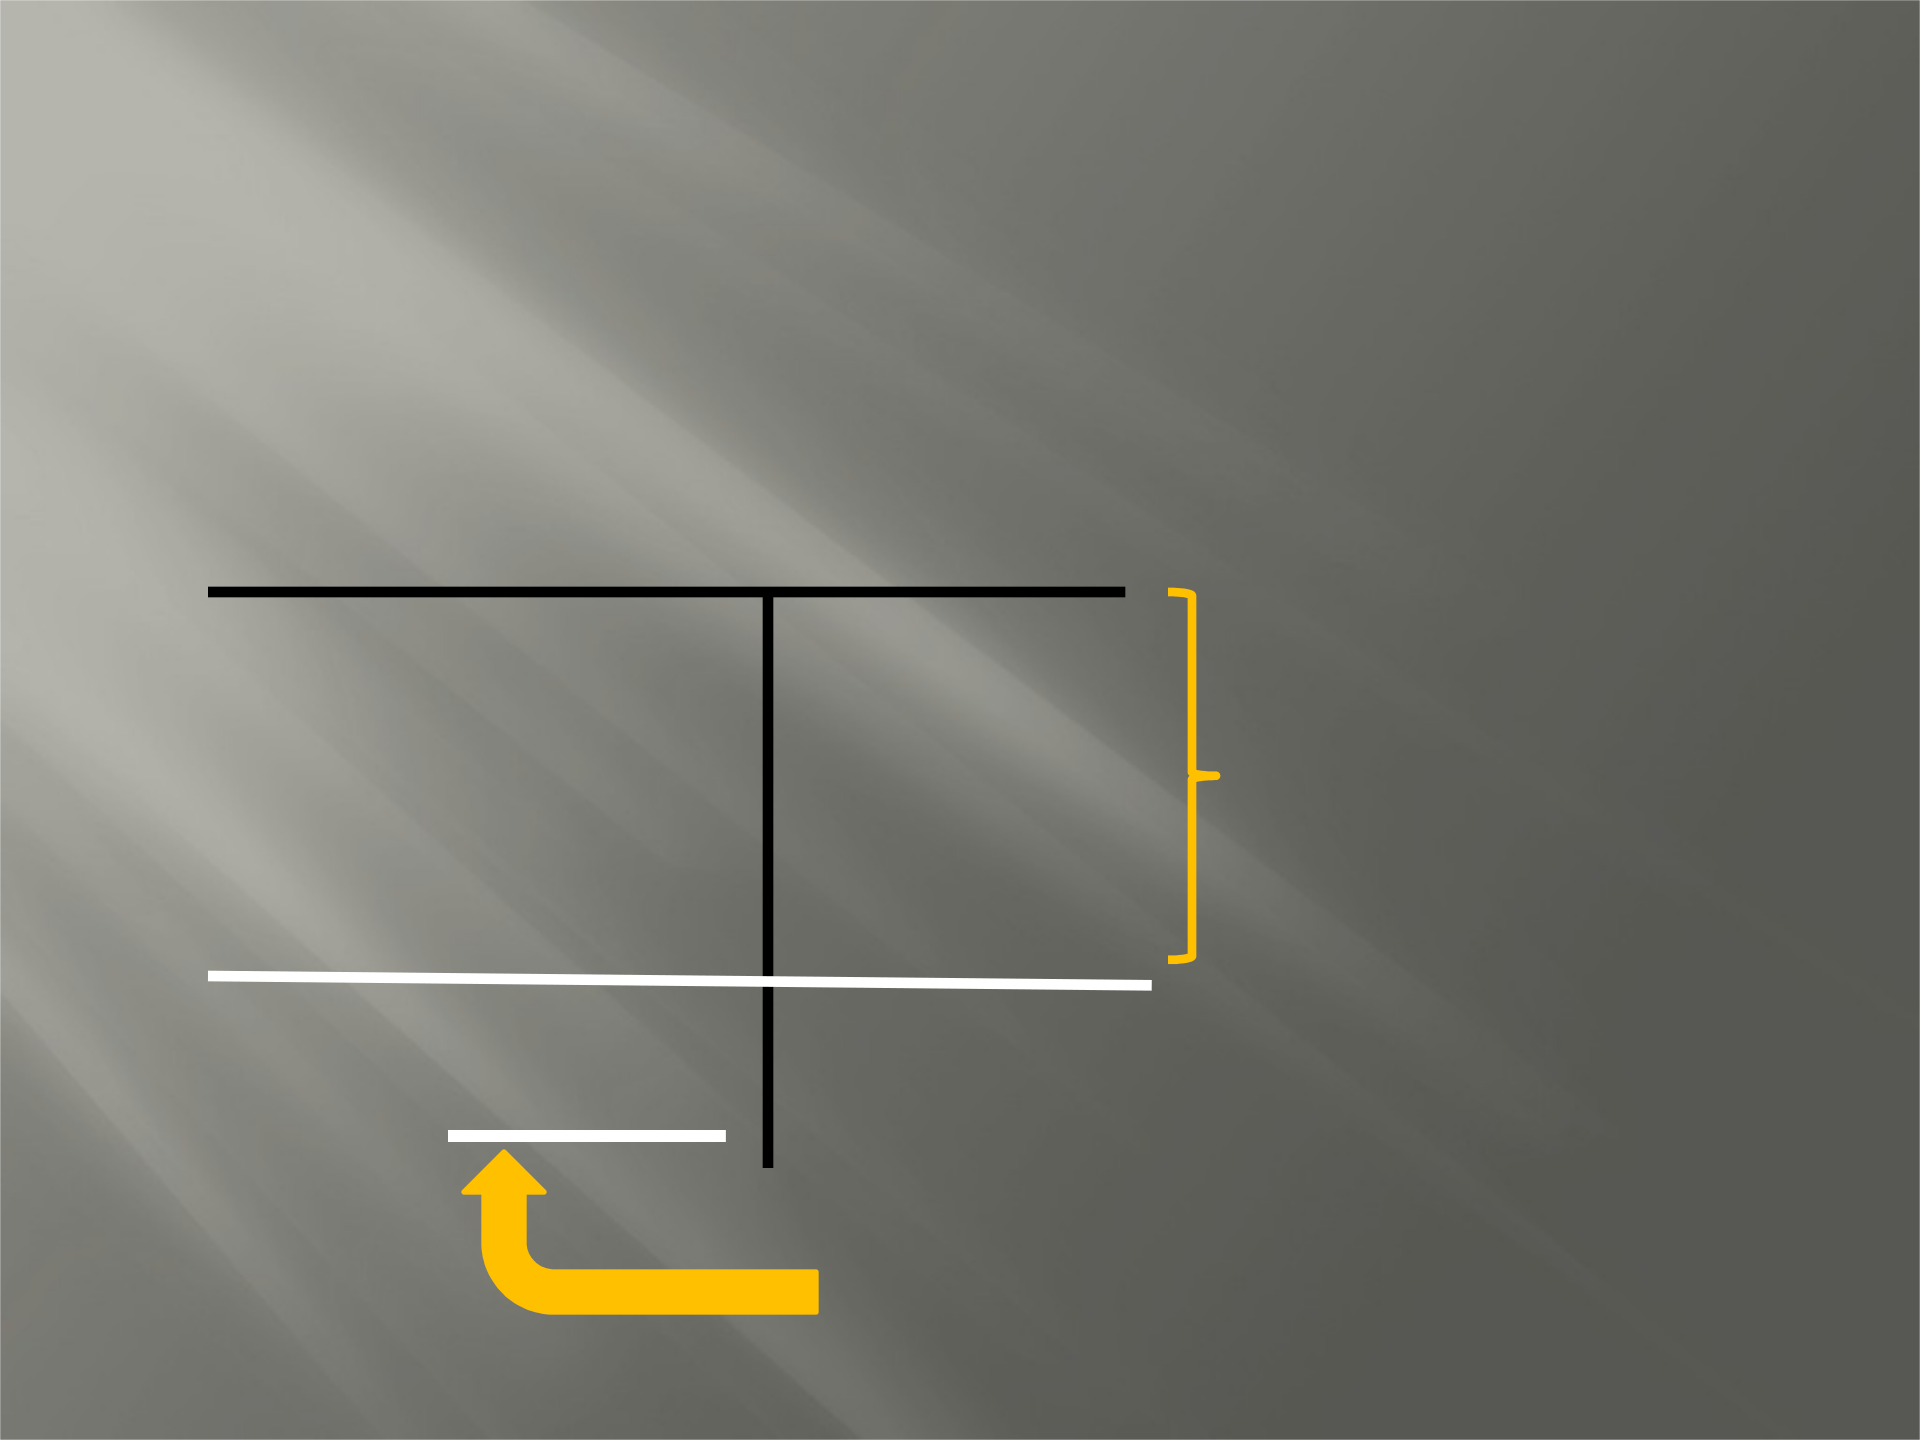
The T-Account
ACC 231 - Fall 2020 13
400 .
A Name
900 .
B . Ba . 0
E . Bal. 500
Debits and credits
are NETTED to obtain
ending balance
Debits and credits
are both entered
as POSITIVE
numbers
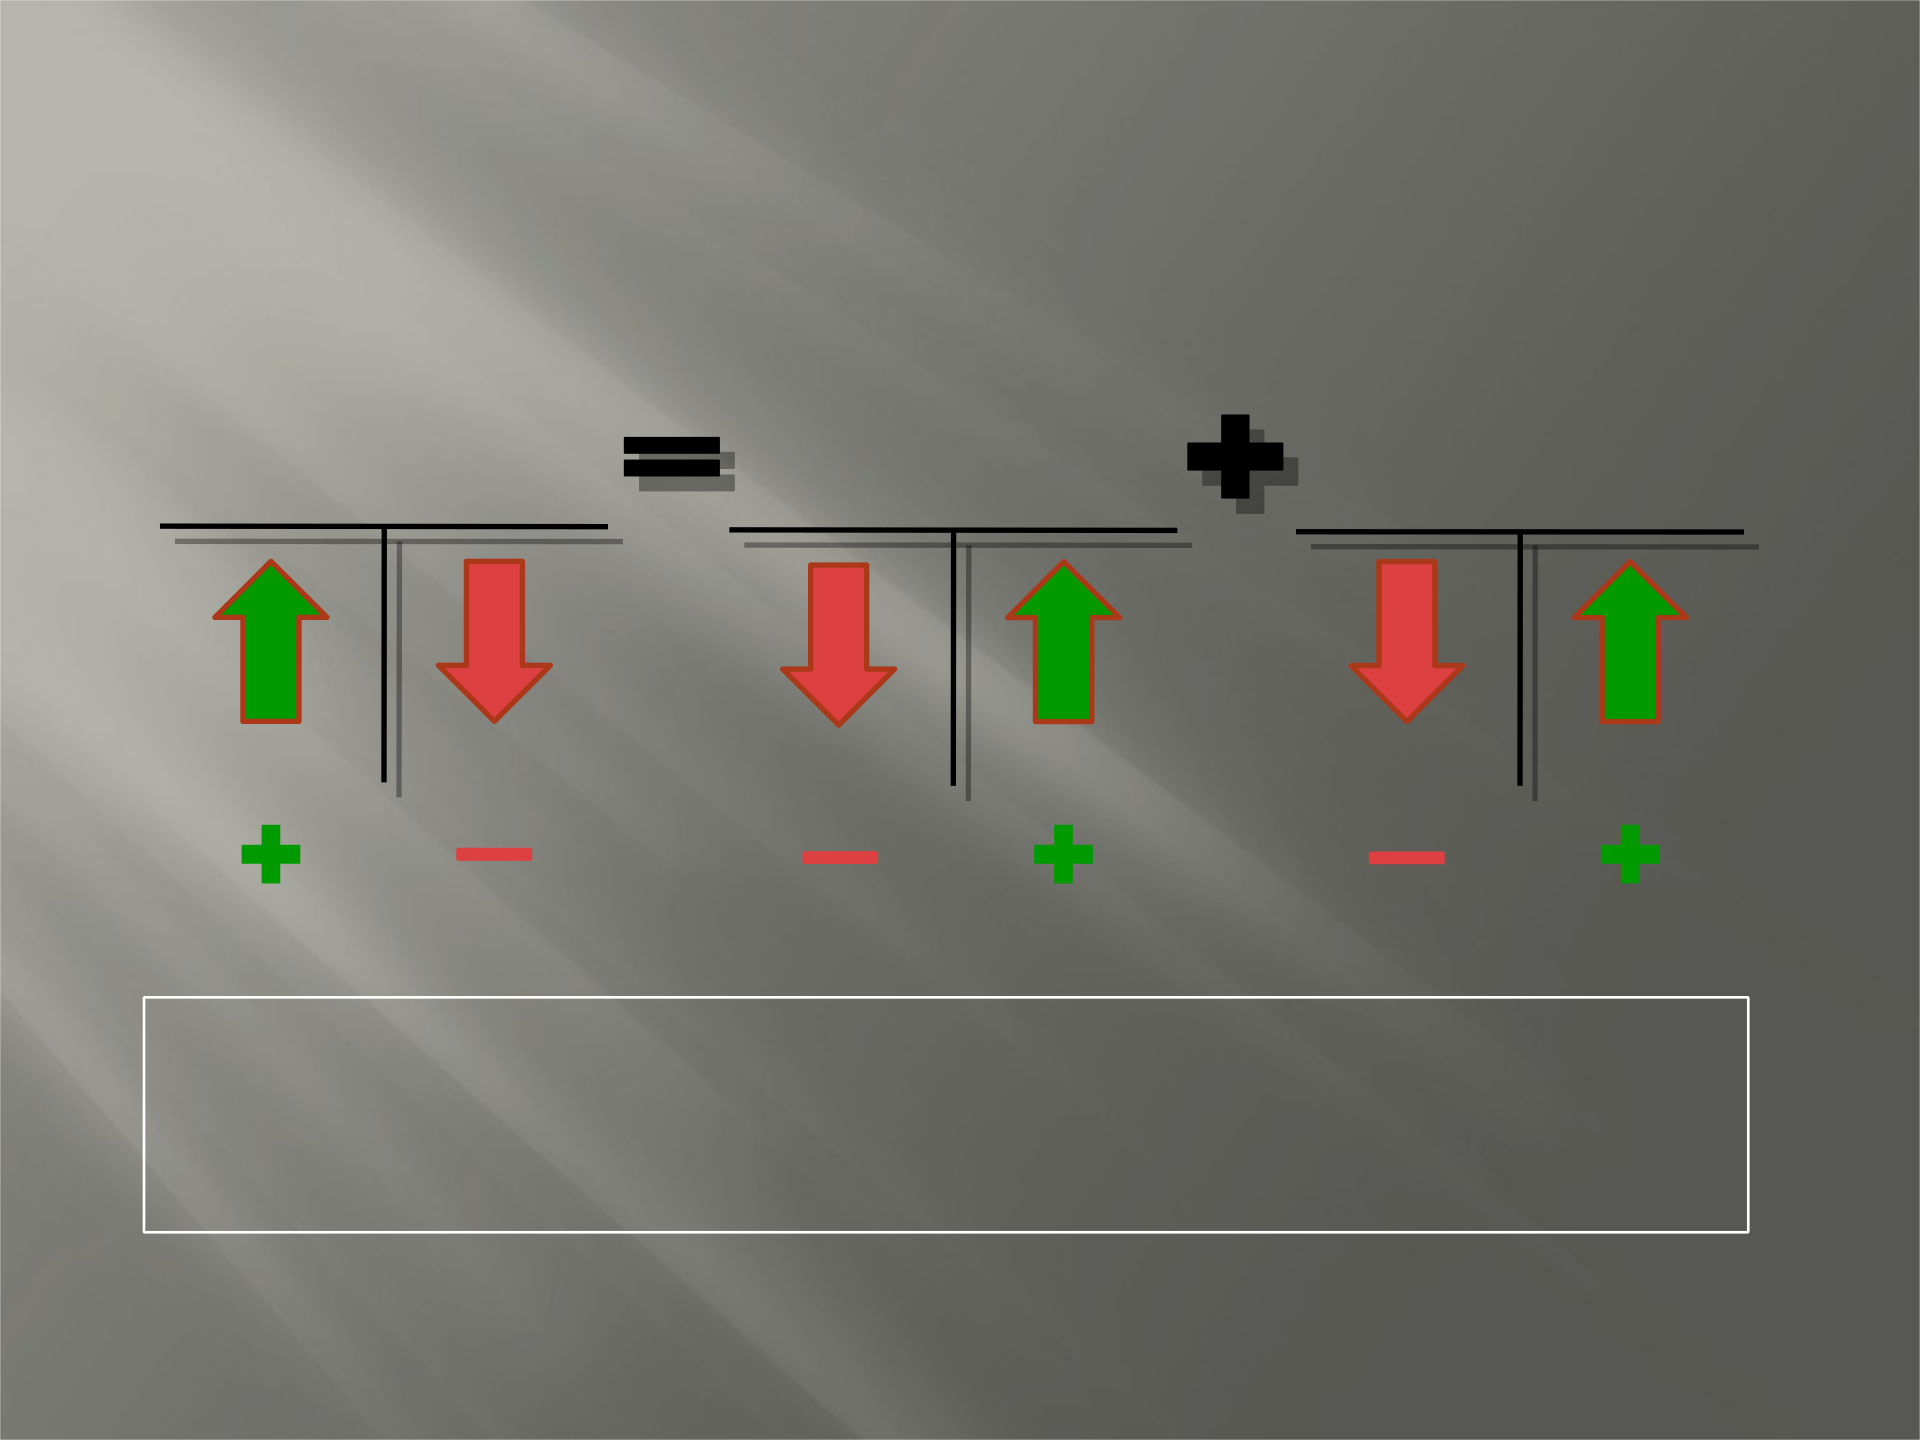
Rules of Debit and Credit
ACC 231 - Fall 2020 14
O ’
E
D
C
L
D
C
A
D
C
T type of account how to
increases decreases.
Debits and Credits
Increases with
a Debit (DR):
Assets
Dividends
Expenses
Increases with
a Credit (CR):
Liabilities
Common
Stock
Revenues
Retained
Earnings
ACC 231 - Fall 2020 15
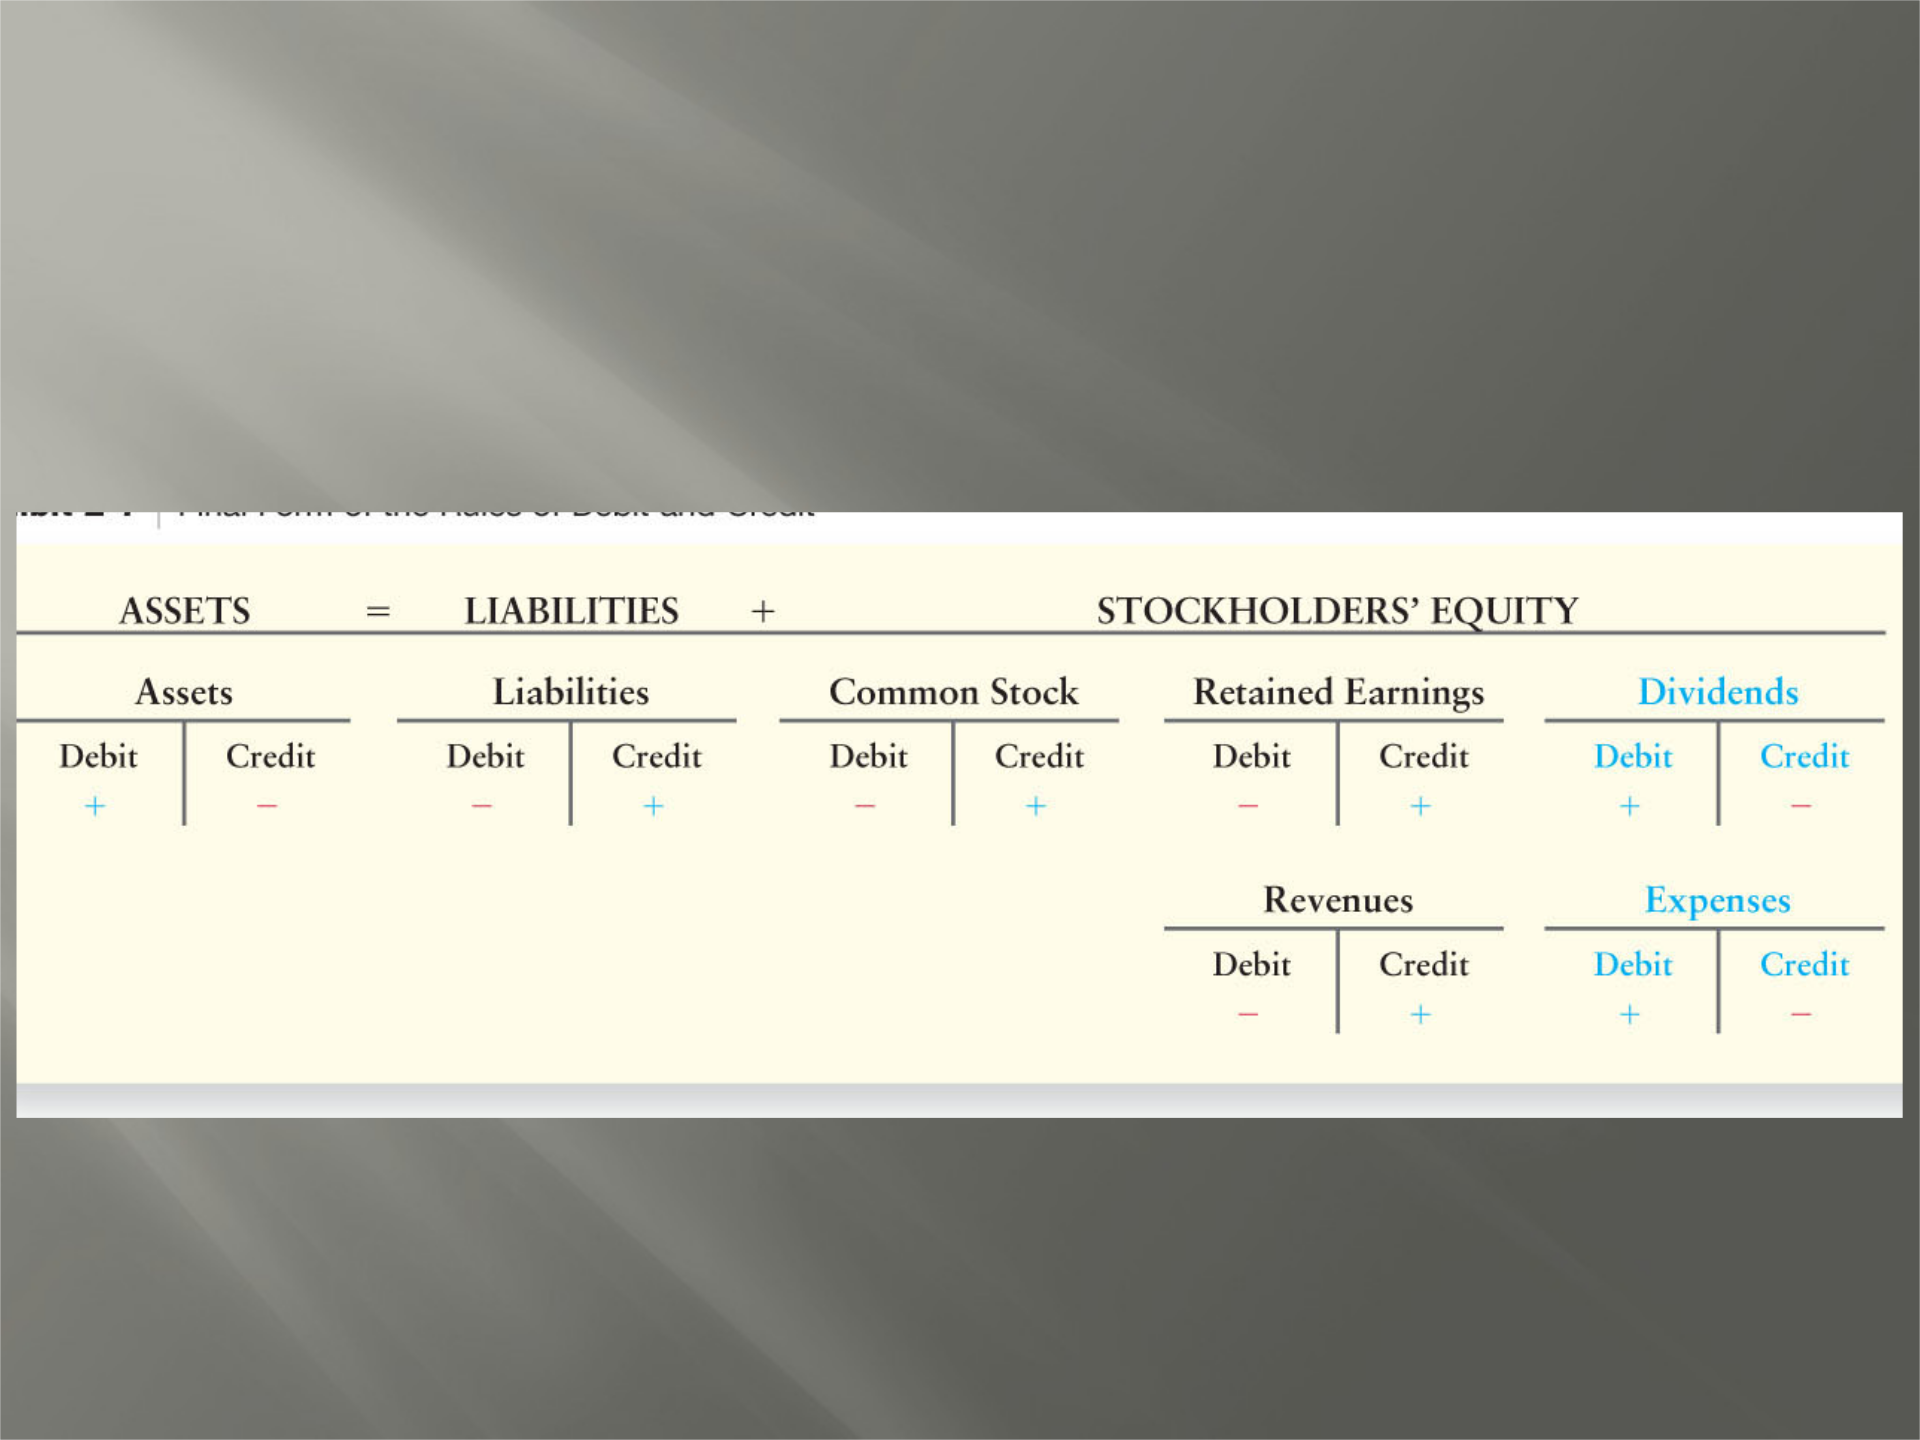
ASSETS
LIABILITIES
T
STOCKHOLDERS’
EQUITY
Assets
Liabilities
Common
Stock
Retained
Earnings
Dividends
Debit
Credit
Debit
Credit
Debit
Credit
Debit
Credit
Debit
Credit
Revenues
Expenses
Debit
Credit
Debit
—
DR/CR Rules – Using the
Expanded Accounting Equation
ACC 231 - Fall 2020 16
T-Account and Normal Balance
T-
N balance is the balance that
on the si of an account wher
increases r and is the
expected balance an account.
ACC 231 - Fall 2020 17
A T
D = left C = righ side
D . C .
Normal Balance - Examples
T normal balance on t
of an account
ACC 231 - Fall 2020 18
A T N B
A D
L C
C Stock C
R Ear C
R C
E D
D D
Normal Balances
Debits & Credits
L ’s r these basic
by looking at the
C 2 handout, A #1
ACC 231 - Fall 2020 19
General Journal
T General jour is the chronological
of the transactions of a business.
R is entering a transaction in a jour ; also
jour .
We will be making “journal entries” (J/Es) throughout
this course.
Recall every journal entry must balance (DR=CR)!
R transaction is an event that has a financial
on a business entity.
T major elements:
1. S each account affected by th transaction and
by type
2. D if each account is in or decr
( or cr )
3. R in the jour
ACC 231 - Fall 2020 20
Making a Journal Entry in “Proper Form”
Record the
date.
Record the
date.
Record the
debit part of the
entry by
entering the
account title
and then
entering the
amount in the
debit column.
Record the
debit part of the
entry by
entering the
account title
and then
entering the
amount in the
debit column.
Record the
credit part of
the entry on the
next line by
indenting the
account title
and then
entering the
amount in the
credit column.
Record the
credit part of
the entry on the
next line by
indenting the
account title
and then
entering the
amount in the
credit column.
Write an
explanation
describing the
entry.
Write an
explanation
describing the
entry.
ACC 231 - Fall 2020 21
J Entries
R the effect of a t on
A
Must be in PROPER (GOOD) FORM
OR
Date Dr - Cash at Wells Fargo $XX
Cr - Owners’ Equity $XX
Brief description of transaction
ACC 231 - Fall 2020 22
Dat
e
Debit - Cash at Wells
Fargo
$XX
Credit - Owners’ Equity $XX
Brief description of transaction
General Ledger & Posting
T general ledger is gr of all the
accounts a bu with their balances.
F e , all Asse accounts will be listed in t same
as the chart of accounts.
O transactions bee enter in the
jour , the infor is then
/copied to general ledger.
T proce of transfe inf
th general to th general
is posting. P simply
cop the amount from t
th .
D in the jour ar posted as de in
ledger, and cr in the jour ar
as in the ledger.
S P C of t subsequent sli .
ACC 231 - Fall 2020 23
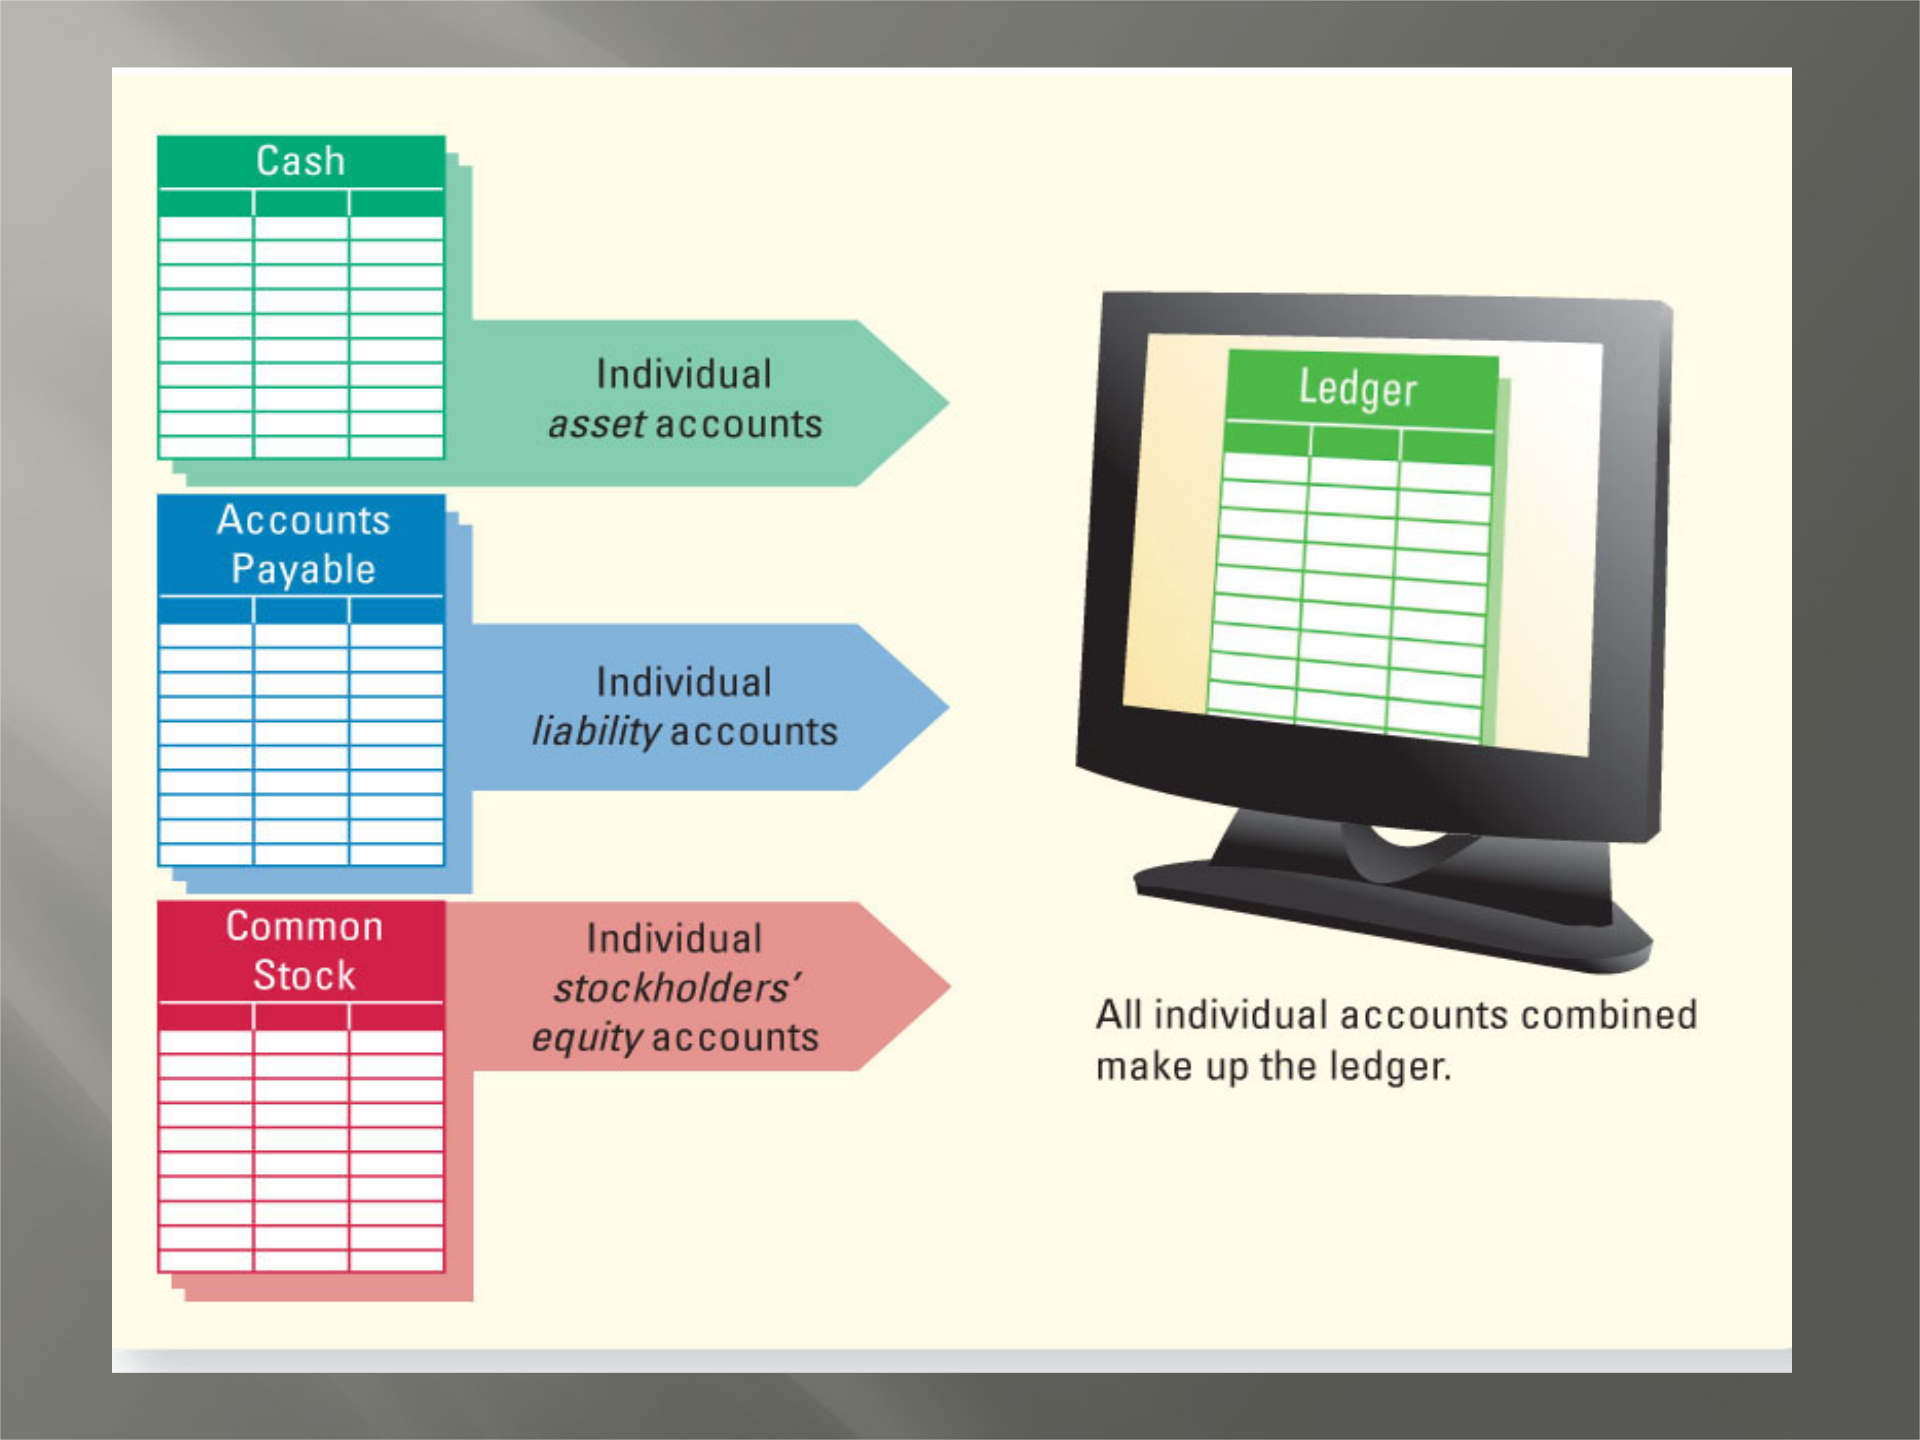
Individual
asset
accounts
Individual
i
eal
liability
accounts
All
individual
accounts
combined
make
up
the
ledger.
ACC 231 - Fall 2020 24
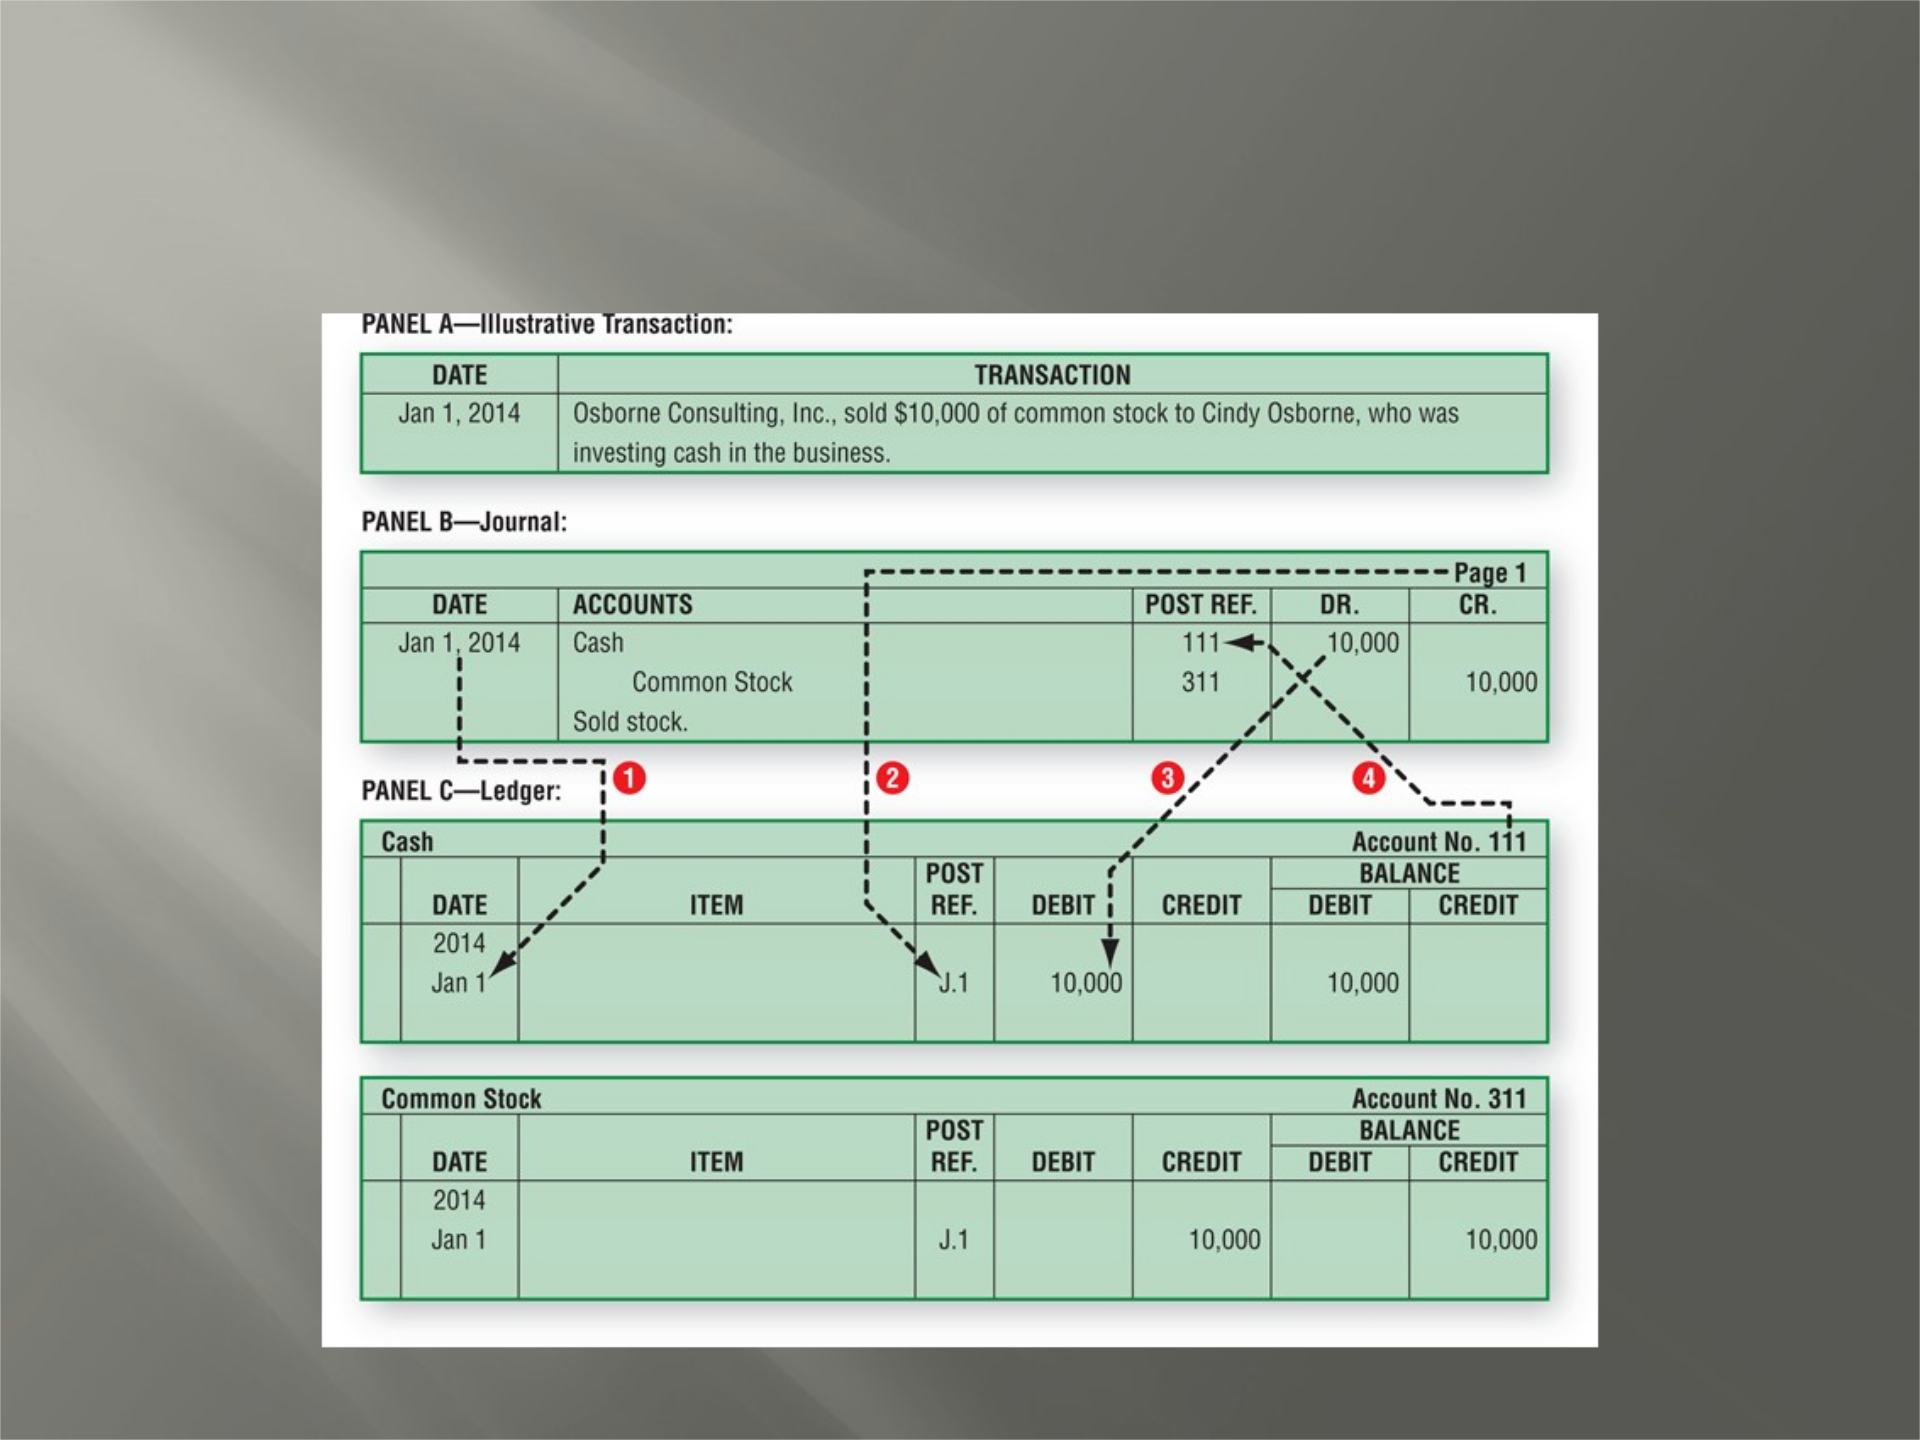
PANEL
A—Illustrative
Transaction:
DATE
TRANSACTION
Jan1,2014
Osborne
Consulting,
Inc.,
sold
$10,000
of
common
stock
to
Cindy
Osborne,
who
was
investing
cash
in
the
business.
PANEL
B—Journal:
givin
a
et
ia
Page
1
DATE
ACCOUNTS
POSTREF.|
DR. CR.
Jan
1.2014
Cash
i
111+
10,000
Common
Stock
311M
10,000
1
Sold
stock.
oa
se
Sooo
aoe
ee
'
“
mS
PANEL
C—Ledger:
|
a
Sone
|
[lash
!
fo
Account
No.
111
ee
1
POST
e
BALANCE
DATE
,¢
ITEM
s.
REF.|
DEBIT;
CREDIT
DEBIT
CREDIT
2014
.¥"
RS
an
INE
10,000 10,000
Account
No.
311
POST
BALANCE
DATE
ITEM
REF.
DEBIT
CREDIT
DEBIT
CREDIT
2014
Jan
1
J.
10,000
10,000
Common
Stock
Linkage of the General Journal and
General Ledger - Posting
ACC 231 - Fall 2020 25
Transaction Analysis – Suggested Process
Step 1:
What
accounts
are
involved?
Step 1:
What
accounts
are
involved?
Step 2:
What type
of account
is it?
Step 2:
What type
of account
is it?
Step 3: Is
the account
balance
increasing
or
decreasing?
Step 3: Is
the account
balance
increasing
or
decreasing?
Step 4:
Should the
account be
debited or
credited?
Step 4:
Should the
account be
debited or
credited?
Step 5:
Record the
entry and
post to the
accounts in
the general
ledger.
Step 5:
Record the
entry and
post to the
accounts in
the general
ledger.
ACC 231 - Fall 2020 26
I the following example , the
proc is show with T-
A .
Example
T 1: The bu sold C Osborne $10,000
common for cash ( inves $10,000)
G journal
P to Gene L
ACC 231 - Fall 2020 27
S 1 S 2 S 3 S 4
Cash
Common Stock
Asset
Stockholders’ equity
Increase
Increase
Dr.
Cr.
D A D C
1 Cash $10,000
Common Stock $10,000
C Stock
10,000
C
10,000

General Ledger
ACC 231 - Fall 2020 28
ASSETS
ASSETS
LIABILITIES
LIABILITIES
STOCKHOLDERS’
EQUITY
STOCKHOLDERS’
EQUITY
C Stock
10,000
C
10,000
Example
T 2: Osborne Consulting pur office
agr to pay $350 w 30 days.
G journal
P to Gene L
ACC 231 - Fall 2020 29
S 1 S 2 S 3 S 4
Supplies
Accounts Payable
Asset
Liability
Increase
Increase
Dr.
Cr.
D A D C
2 Supplies $350
Accounts Payable $350
A P
350
S
350
General Ledger
ACC 231 - Fall 2020 30
ASSETS
ASSETS
LIABILITIES
LIABILITIES
STOCKHOLDERS’
EQUITY
STOCKHOLDERS’
EQUITY
C Stock
10,000
C
10,000
A P
350
S
350
Example
T 3: The bu purchases equipmen , paying
of $4,000.
G journal
P to Gene L
ACC 231 - Fall 2020 31
S 1 S 2 S 3 S 4
Equipment
Cash
Asset
Asset
Increase
Decrease
Dr.
Cr.
D A D C
3 Equipment $4,000
Cash $4,000
C
10,000 4,000
E
4,000
General Ledger
ACC 231 - Fall 2020 32
ASSETS
ASSETS
LIABILITIES
LIABILITIES
STOCKHOLDERS’
EQUITY
STOCKHOLDERS’
EQUITY
C Stock
10,000
C
10,000 4,000
A P
350
S
350
E
4,000
Example
T 4: During th month, Osborne Consulting paid
of $1,700 for expenses incurr includin : salaries
($600), r ($900), and utilities ($200).
G journal (note this is a C Jour Entry)
ACC 231 - Fall 2020 33
S 1 S 2 S 3 S 4
Cash
Salaries Expense
Rent Expense
Utilities Expense
Asset
Expense
Expense
Expense
Decrease
Increase
Increase
Increase
Cr.
Dr.
Dr.
Dr.
D A D C
4 Salaries Expense $600
Rent Expense $900
Utilities Expense $200
Cash $1,700
Example
P to Gene L
ACC 231 - Fall 2020 34
S Expense
600
$600 EB
R E
900
$900 EB
U Expense
200
$200 EB
C
10,000 4,000
1,700
$4,300 EB
S
350
$350 EB
E
4,000
$4,000 EB
C Stock
10,000
$10,000 EB
A P
350
$350 EB
T EB D = $10,350
T EB C = $10,350
O G/L is in balance!
Balancing the T-accounts
N that af the transactions r
posted to the T- , we ea
’s endin balance (EB). H we
D . the Cr. deter the endin
i each a .
ACC 231 - Fall 2020 35
C
B 0
10,000 4,000
1,700
EB 4,300
N the net
Cash
a Dr. (
bal )
Journal Entries & T-Accounts
L ’s get additional practice and go
the Chapte 2 handout, A #2
A #3
(A #2 is sa as Chap 1 A
#1 with and T- )
ACC 231 - Fall 2020 36
The Trial Balance
O tran have been r in the
and po to accoun in the gen
, a trial balance pr at the end of
acc perio (e.g. – end of a mon ).
I Chapter 3, we will discus A Jour Entries
(AJE ). Another trial balance is generally pr af
and all AJEs ar made (the trial balance).
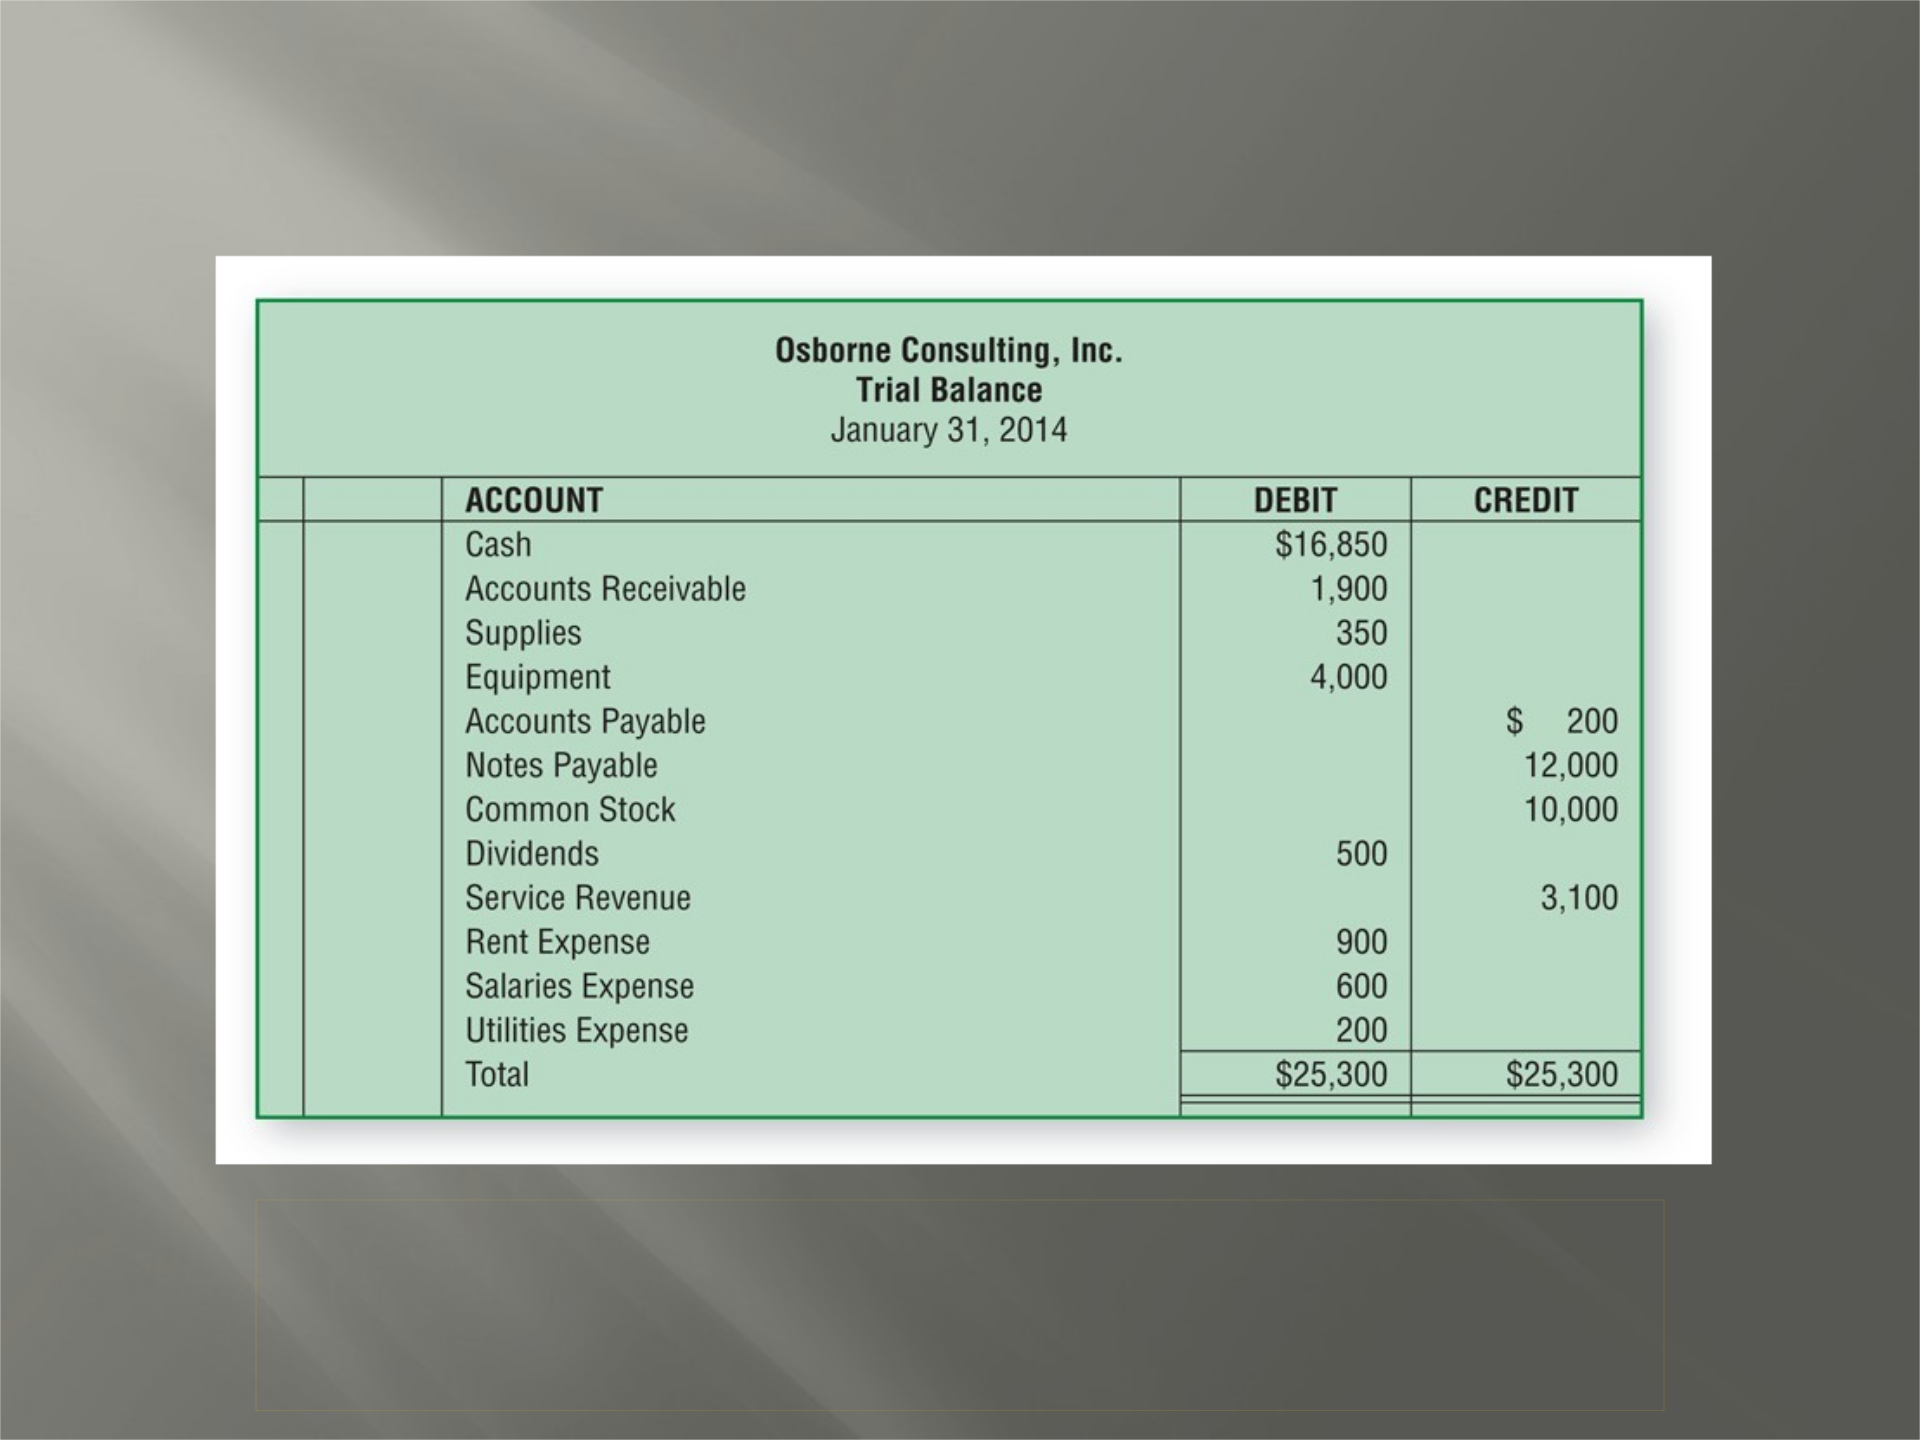
T trial bala is a list of all the accou of a
their ba and its purpose to
that total debits equal total cr .
T trial bala is pr the
’ financia statements.
A th point we ar d a -c trial
. Closing entries be addr in Chapter 3.
ACC 231 - Fall 2020 37
Trial
Balance
January
31,
2014
Osborne
Consulting,
Inc.
ACCOUNT
DEBIT
CREDIT
Cash
$16,850
Accounts
Receivable
1,900
Supplies
350
Equipment
4,000
Accounts
Payable
$
200
Notes
Payable
12,000
Common
Stock
10,000
Dividends
500
service
Revenue
3,100
Rent
Expense
900
salaries
Expense
600
Utilities
Expense
200
Total
$25,300
$25,300
Sample Trial Balance
38
A in trial balance are us listed in
( of accou ) order but can arranged in
ways ( .g. in alphabetical or ac size ord ).
Trial Balance – Example
A W , Inc. accounting r that
the following at 6/30/2020 ( random order):
P a trial balance (in pr or ) using this
.
ACC 231 - Fall 2020 39
I /Account Title A
Sales Revenue $83,000
Prepaid Rent 750
Accounts Payable 1,700
Equipment 41,000
Dividends 12,600
Cost of Goods Sold 38,400
Notes Payable 11,500
Cash 8,300
Rent Expense 10,150
Common Stock 15,000
Suggested Solution
A W , Inc.
T Bala
J 30, 2020
T
ACCOUNT TITLE BALANCE
DEBIT CREDIT
1 C $8,300
1 P R 750
1 E 41,000
2 A P $1,700
2 N P 11,500
3 C Stock 15,000
3 D 12,600
4 S R 83,000
5 C of G Sol 38,400
5 R Expense 10,150
T $111,200 $111,200
ACC 231 - Fall 2020 40
Preparation of Financial Statements
A the T Bal is complet , the
F Stateme can be p in
following or
ACC 231 - Fall 2020 41
Income
Statemen
t
Income
Statemen
t
Statemen
t of
Retained
Earnings
Statemen
t of
Retained
Earnings
Balance
Sheet
Balance
Sheet
Statemen
t of Cash
Flows
(later)
Statemen
t of Cash
Flows
(later)
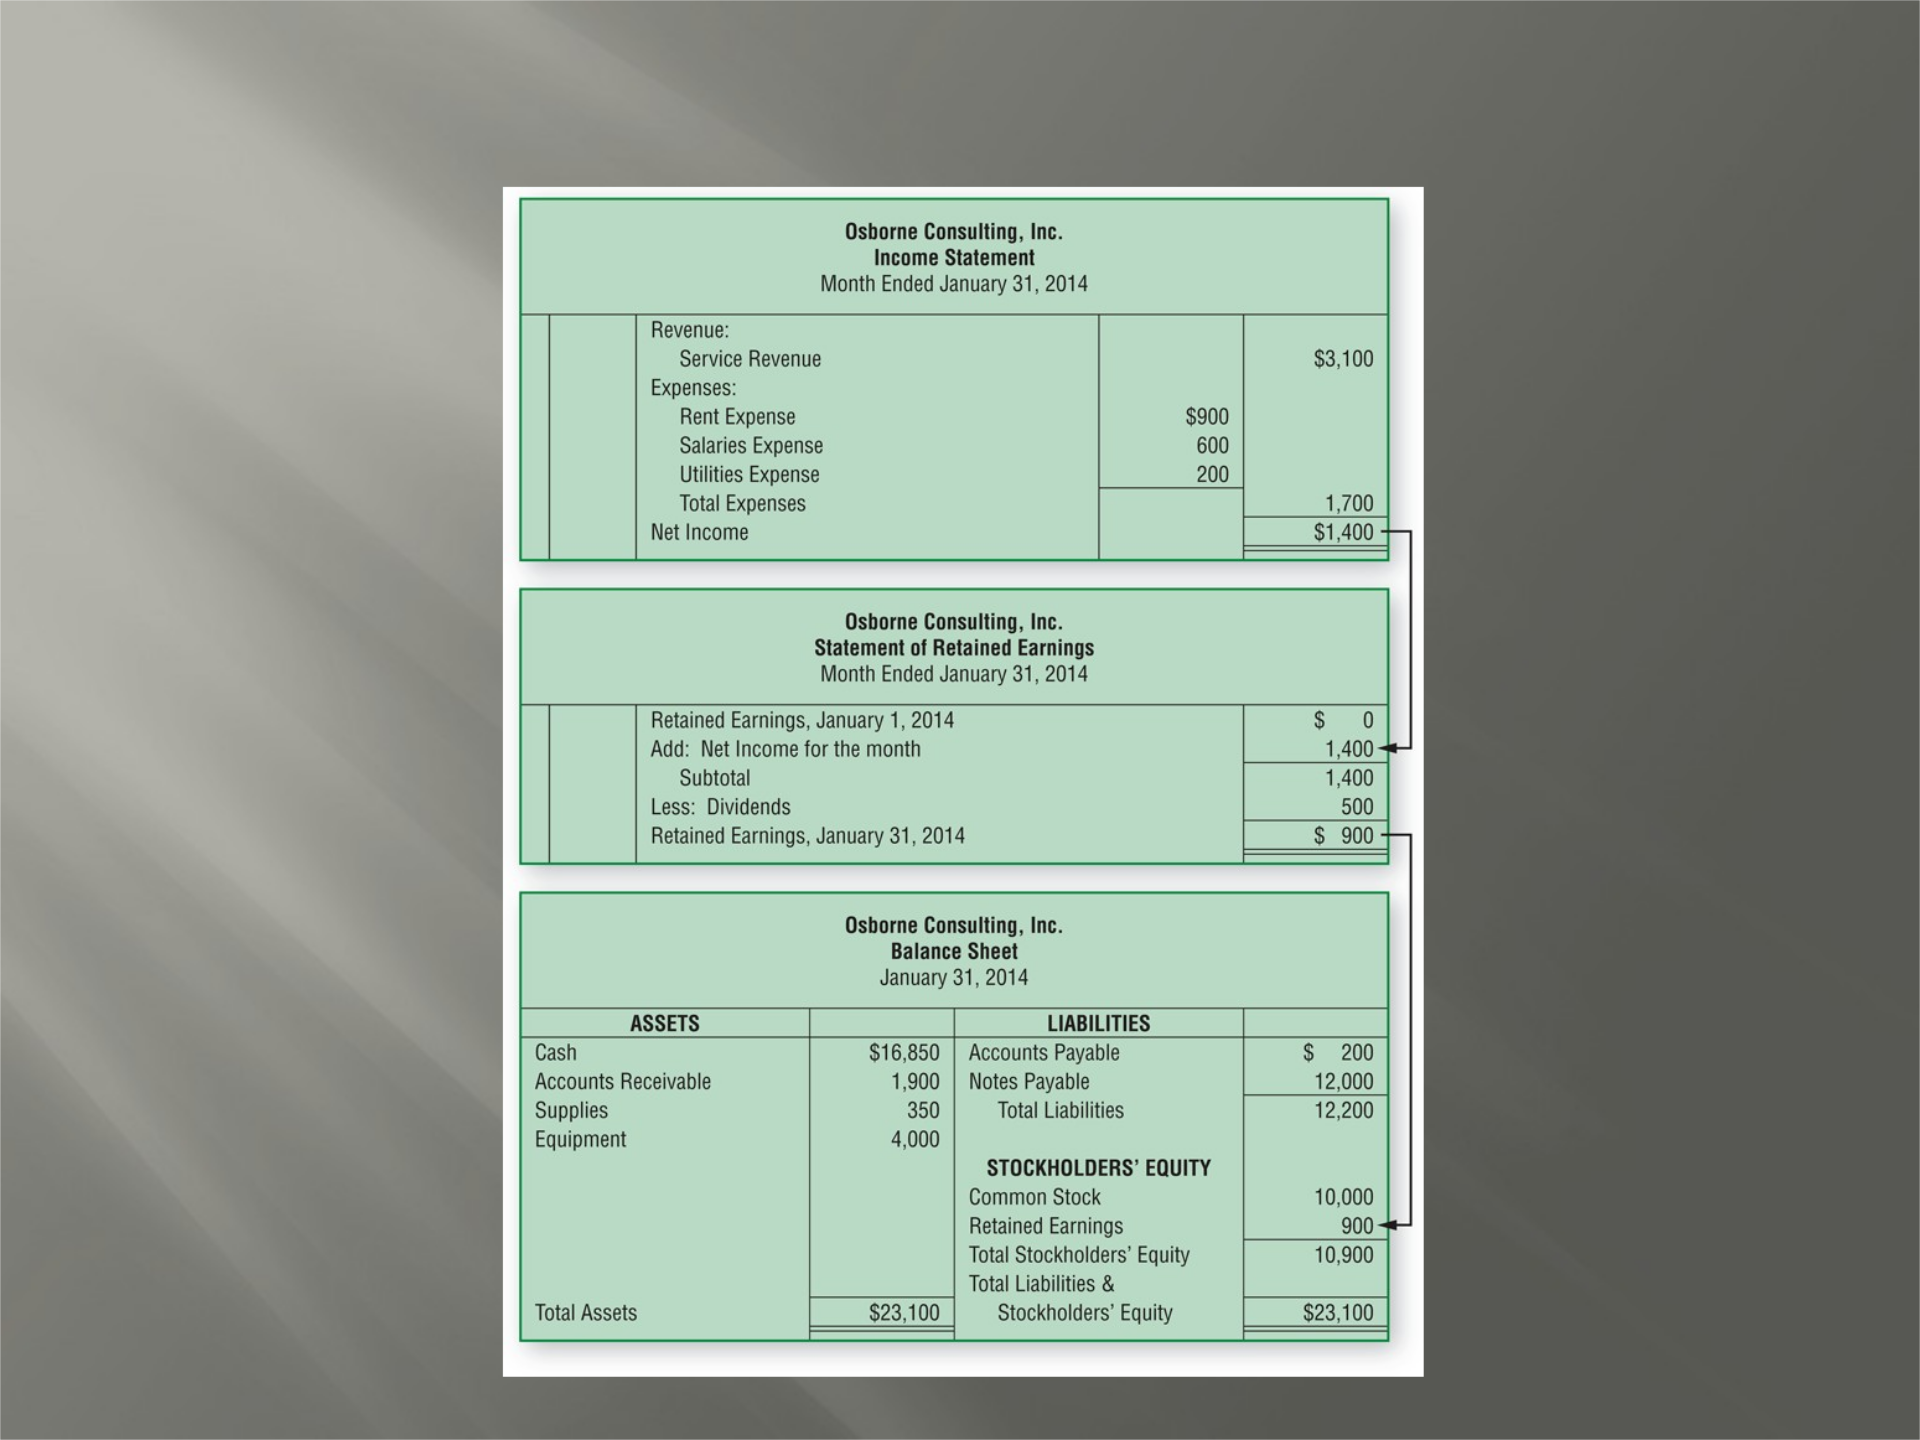
Osborne
Consulting,
Inc.
Income
Statement
Month
Ended
January
31,
2014
Revenue:
Service
Revenue
$3,100
Expenses:
Rent
Expense
$900
Salaries
Expense
600
Utilities
Expense
200
Total
Expenses
1,700
Net
Income
Osborne
Consulting,
Inc.
Statement
of
Retained
Earnings
Month
Ended
January
31,
2014
Retained
Earnings,
January
1,
2014
Add:
Net
Income
for
the
month
1,400
-
Subtotal
1,400
Less:
Dividends
500
Retained
Earnings,
January
31,
2014
Osborne
Consulting,
Inc.
Balance
Sheet
January
31,
2014
ASSETS
LIABILITIES
Gash
$16,850
Accounts
Payable
$
200
Accounts
Receivable
1,900
Notes
Payable
12,000
Supplies
350
Total
Liabilities
12,200
Equipment
4,000
STOCKHOLDERS’
EQUITY
Common
Stock
10,000
Retained Earnings
900
Total
Stockholders’
Equity
10,900
Total
Liabilities
&
Total
Assets
$23,100
Stockholders’
Equity
$23,100
Preparation of Financial Statements
ACC 231 - Fall 2020 42
Financial Statements
T r the concept we have
about F Statements, let’
a look at Chapter 2, A #4.
ACC 231 - Fall 2020 43
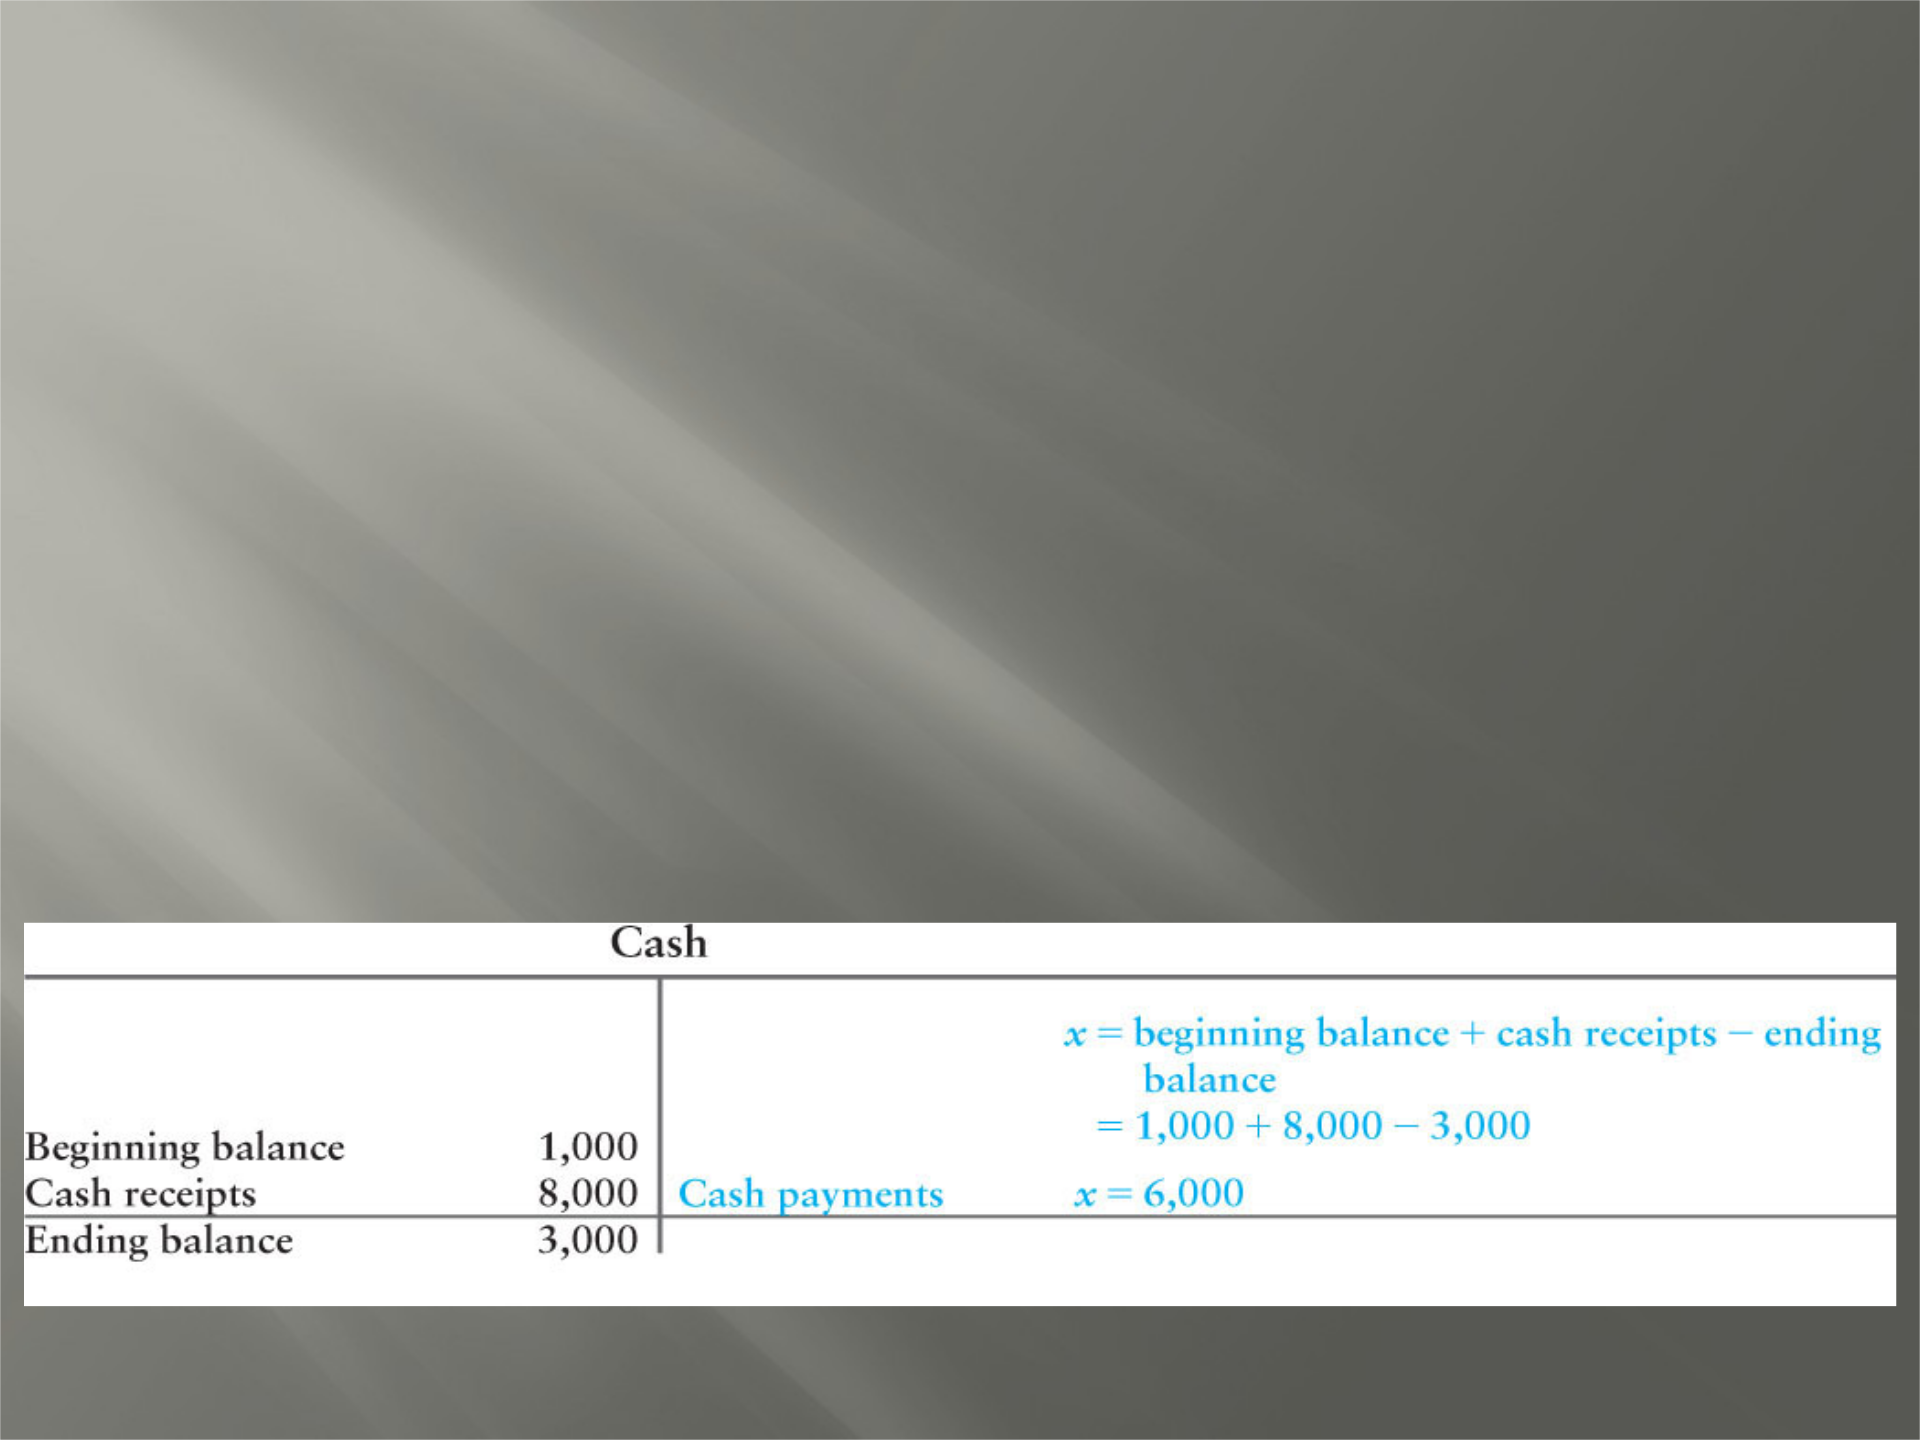
Analyzing Accounts
A Osb bega the month with cas of
$1,000. D the month, O cash
$8,000 end the month wit a cas bala of
$3,000.
Y boss asks for t amount of total ca pa .
Y can compute that amount b anal O ’s
C account:
ACC 231 - Fall 2020 44
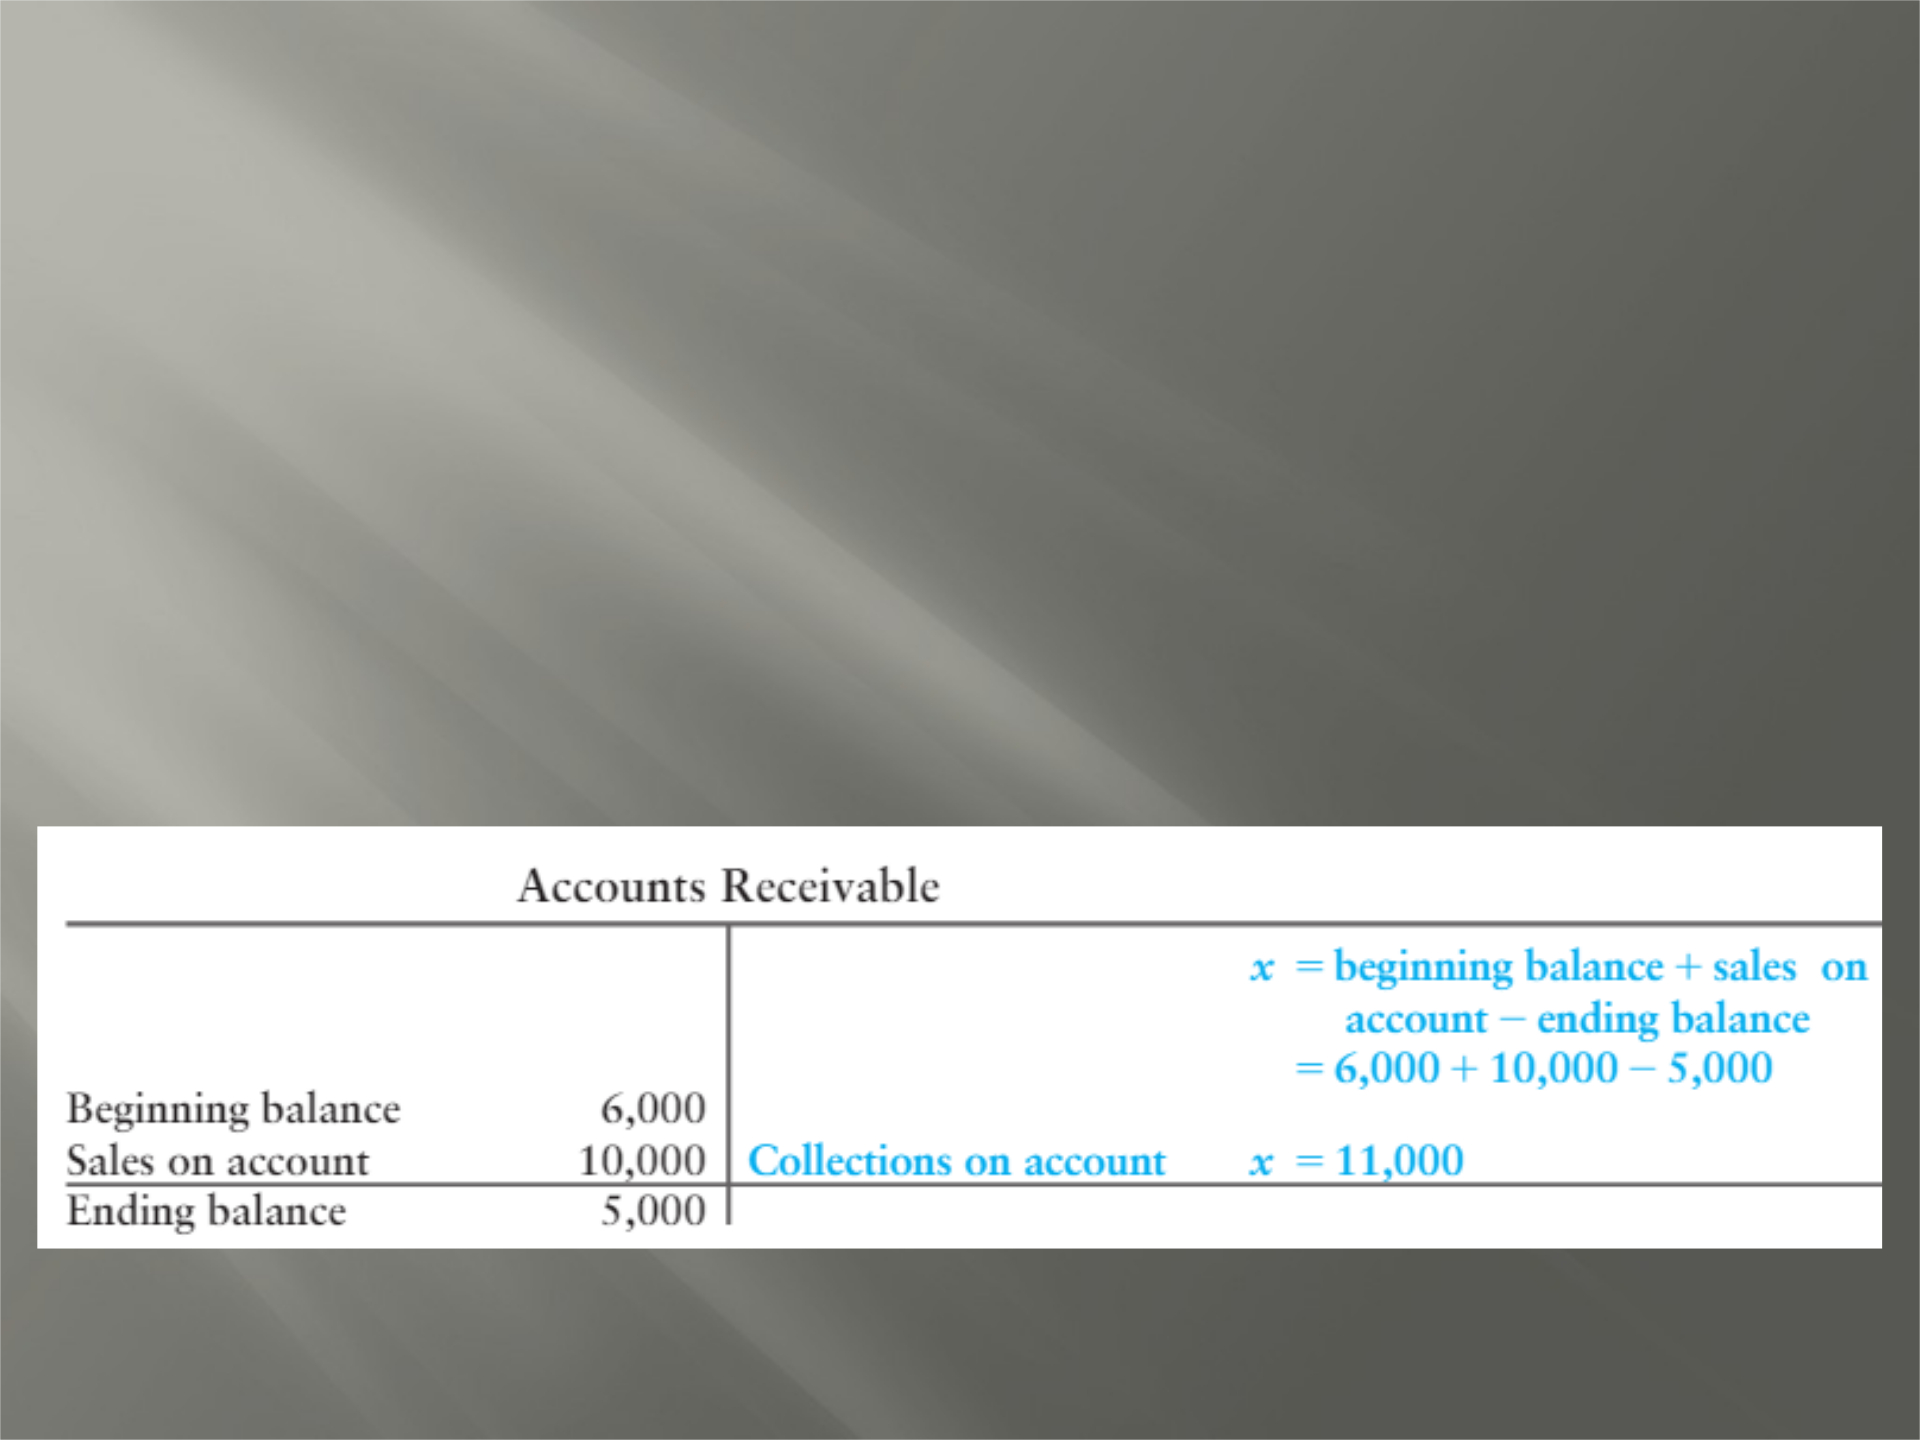
Analyzing Accounts – contd.
Y can c eithe sales on account
cash collections on account b
the A R
(using assumed ):
ACC 231 - Fall 2020 45
Analyzing Accounts – contd.
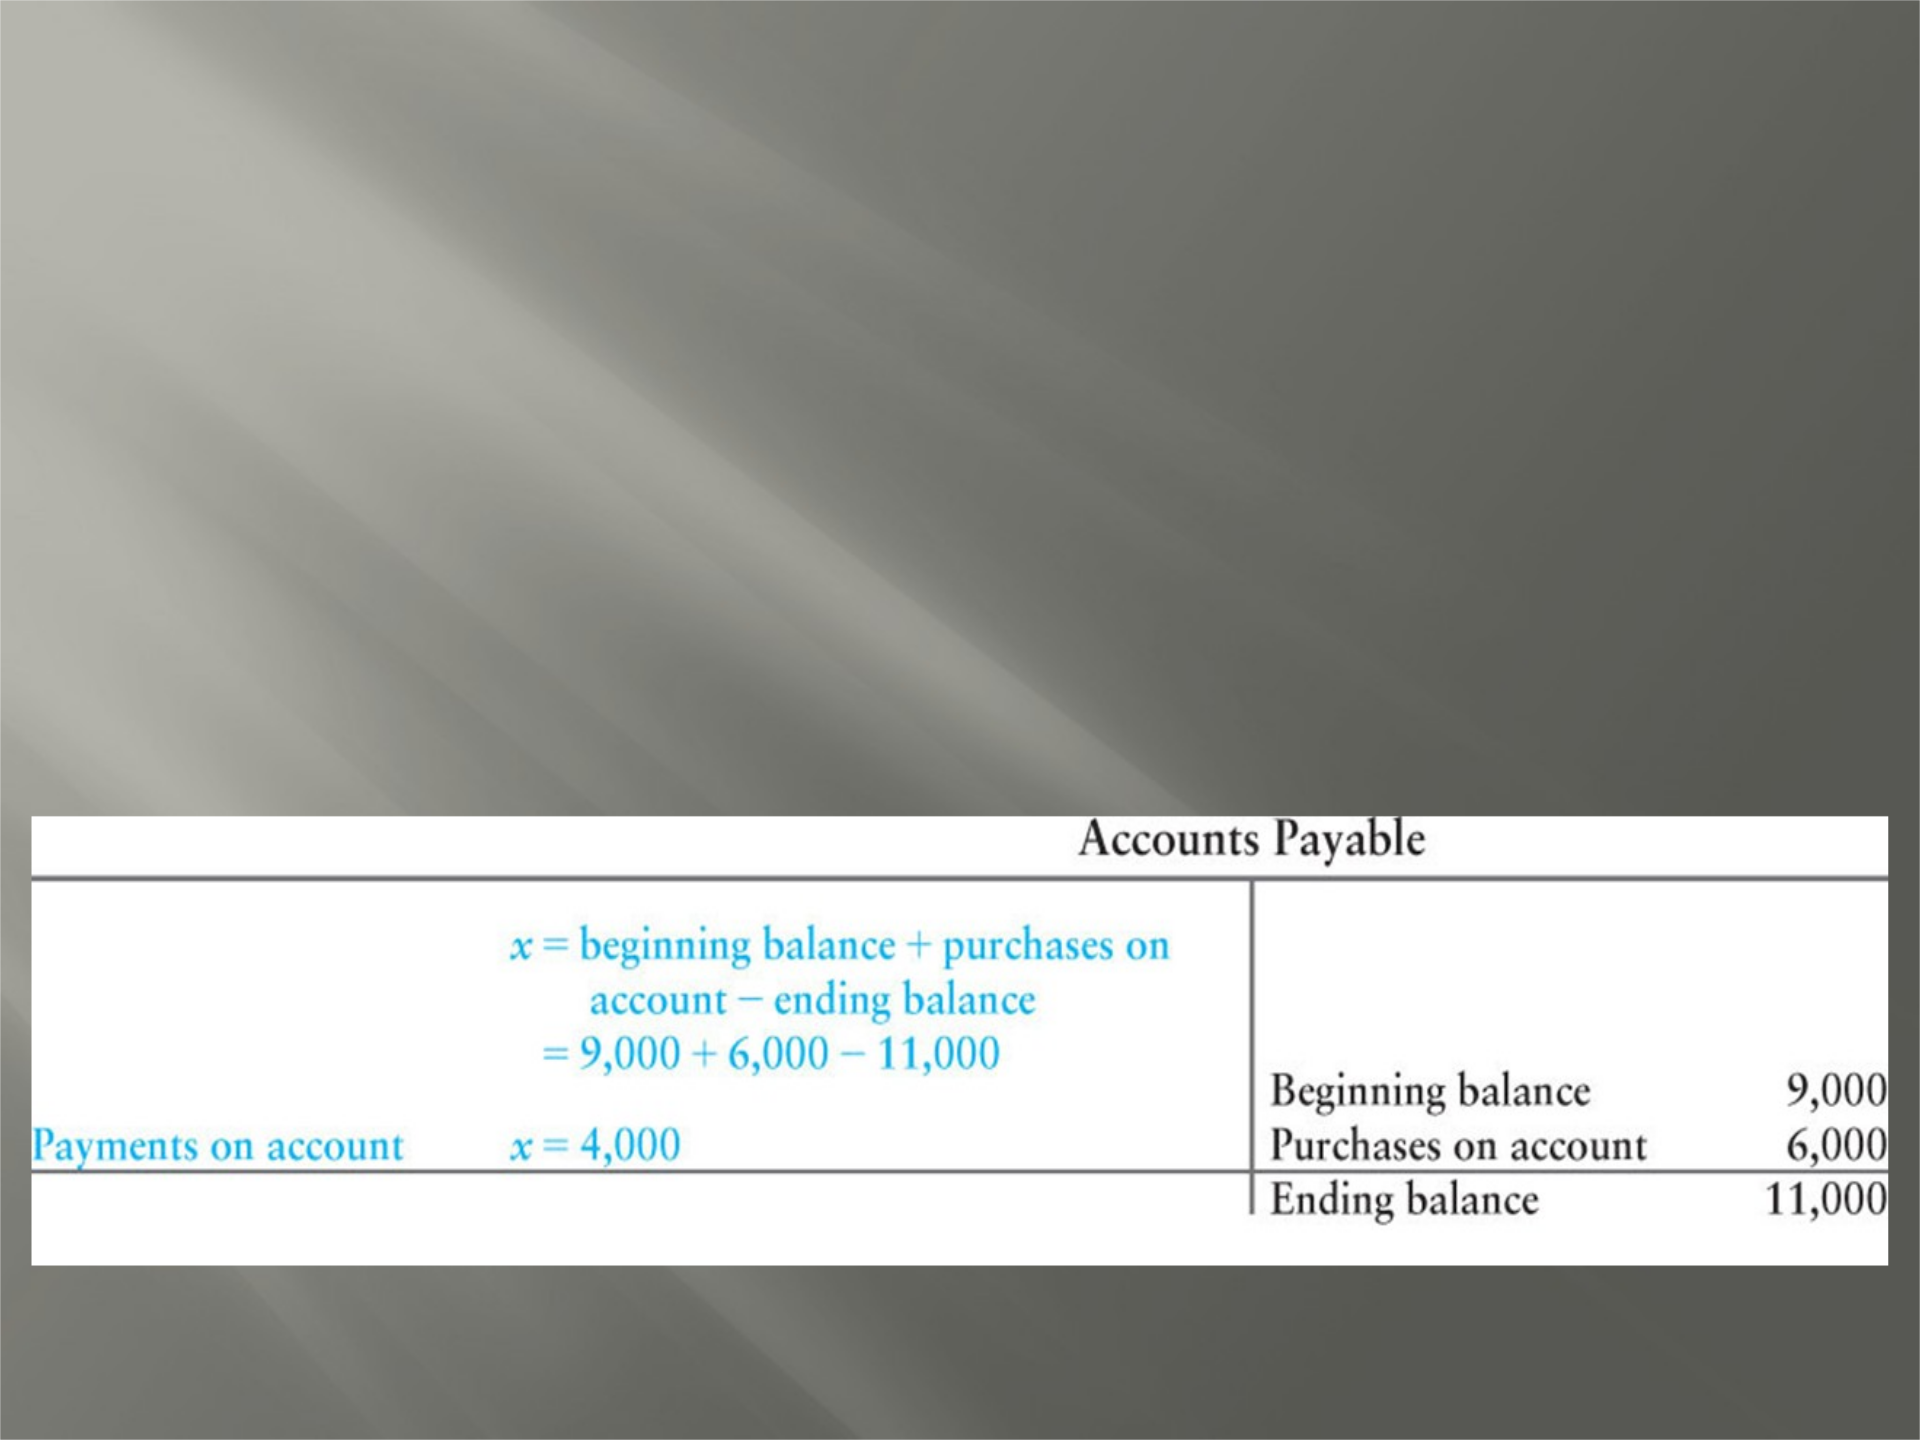
Y can de how much you paid on
by analyzing A P
( assumed amounts):
ACC 231 - Fall 2020 46
Errors – they do happen
A do occur. Y of first
an when have out- -
s .
F compute the d b de and
the tria ba . T should the
out- - a and if i is a DR CR.
D if ther a missi accounts.
I all accounts pr :
D out- - am by 2 (DR/CR )
D out- - am by 9
S ( $400 as $40)
T (r $6,460 as $4,660)
ACC 231 - Fall 2020 47
Error Example - Transposition
A t Osbor Consulting trial
is “ ” (out- - ) by
$1,800.
T accountant this amount is
divisible by 9 ($1,800 ÷ 9 = 200).
T is a str indicator the pr is a
er .
T accountant sear thr
G/L for a lik transposition er .
T accountant di that utility e
debited for $4,660 instead of the cor
$6,460.
$6,460 – 4,660 = $1,800. W have found our
!
ACC 231 - Fall 2020 48
:
Guidelines
—
Decision
Has
a
transaction
occurred?
OS
lf
the
event
affects
the
entity’
S
financial
position
-
:
and
can be
reliably
recorded—Yes
if
either
condition
is
absent—No
Where
should
the
transaction
be
recorded?
In
the
journal,
the
chronological
record
of
transactions
How
should
an
increase
or
decrease
in
the:
The
rules
of
debit
and
credit
state:
following
accounts
be
recorded?
Increase
Decrease
i
ASSOUS
2...
eee
eeeeeeeeeeeeeeeeceeeeeeeeees
Debit
Credit
:
Liabilities
0000
©
Credit
Debit
Stockholders’
equity...............
Credit
Debit
REVENUES
......0..ccceeeeeeeeeeeeneenenes
Credit
Debit
Expenses
..
be
ceenacucesueeeeeneneeees
Debit
Credit
Where
should
all
of
the
information
for
each
In
the
ledger,
the
book
of
accounts
accou
nt
be
stored?
Inthetrialbalance
ss
Where
should
all
ofthe
accounts
and
their.
ro
balances
be
listed’?
Where
should
the
following
be
reported:
Results
of
operations?
3
In
the
income
statement
(Revenues
—
Expenses
=
Net
income
or
net
loss)
Financial
position?
In
the
balance
sheet
(Assets
=
Liabilities
+
stockholders’
equity)
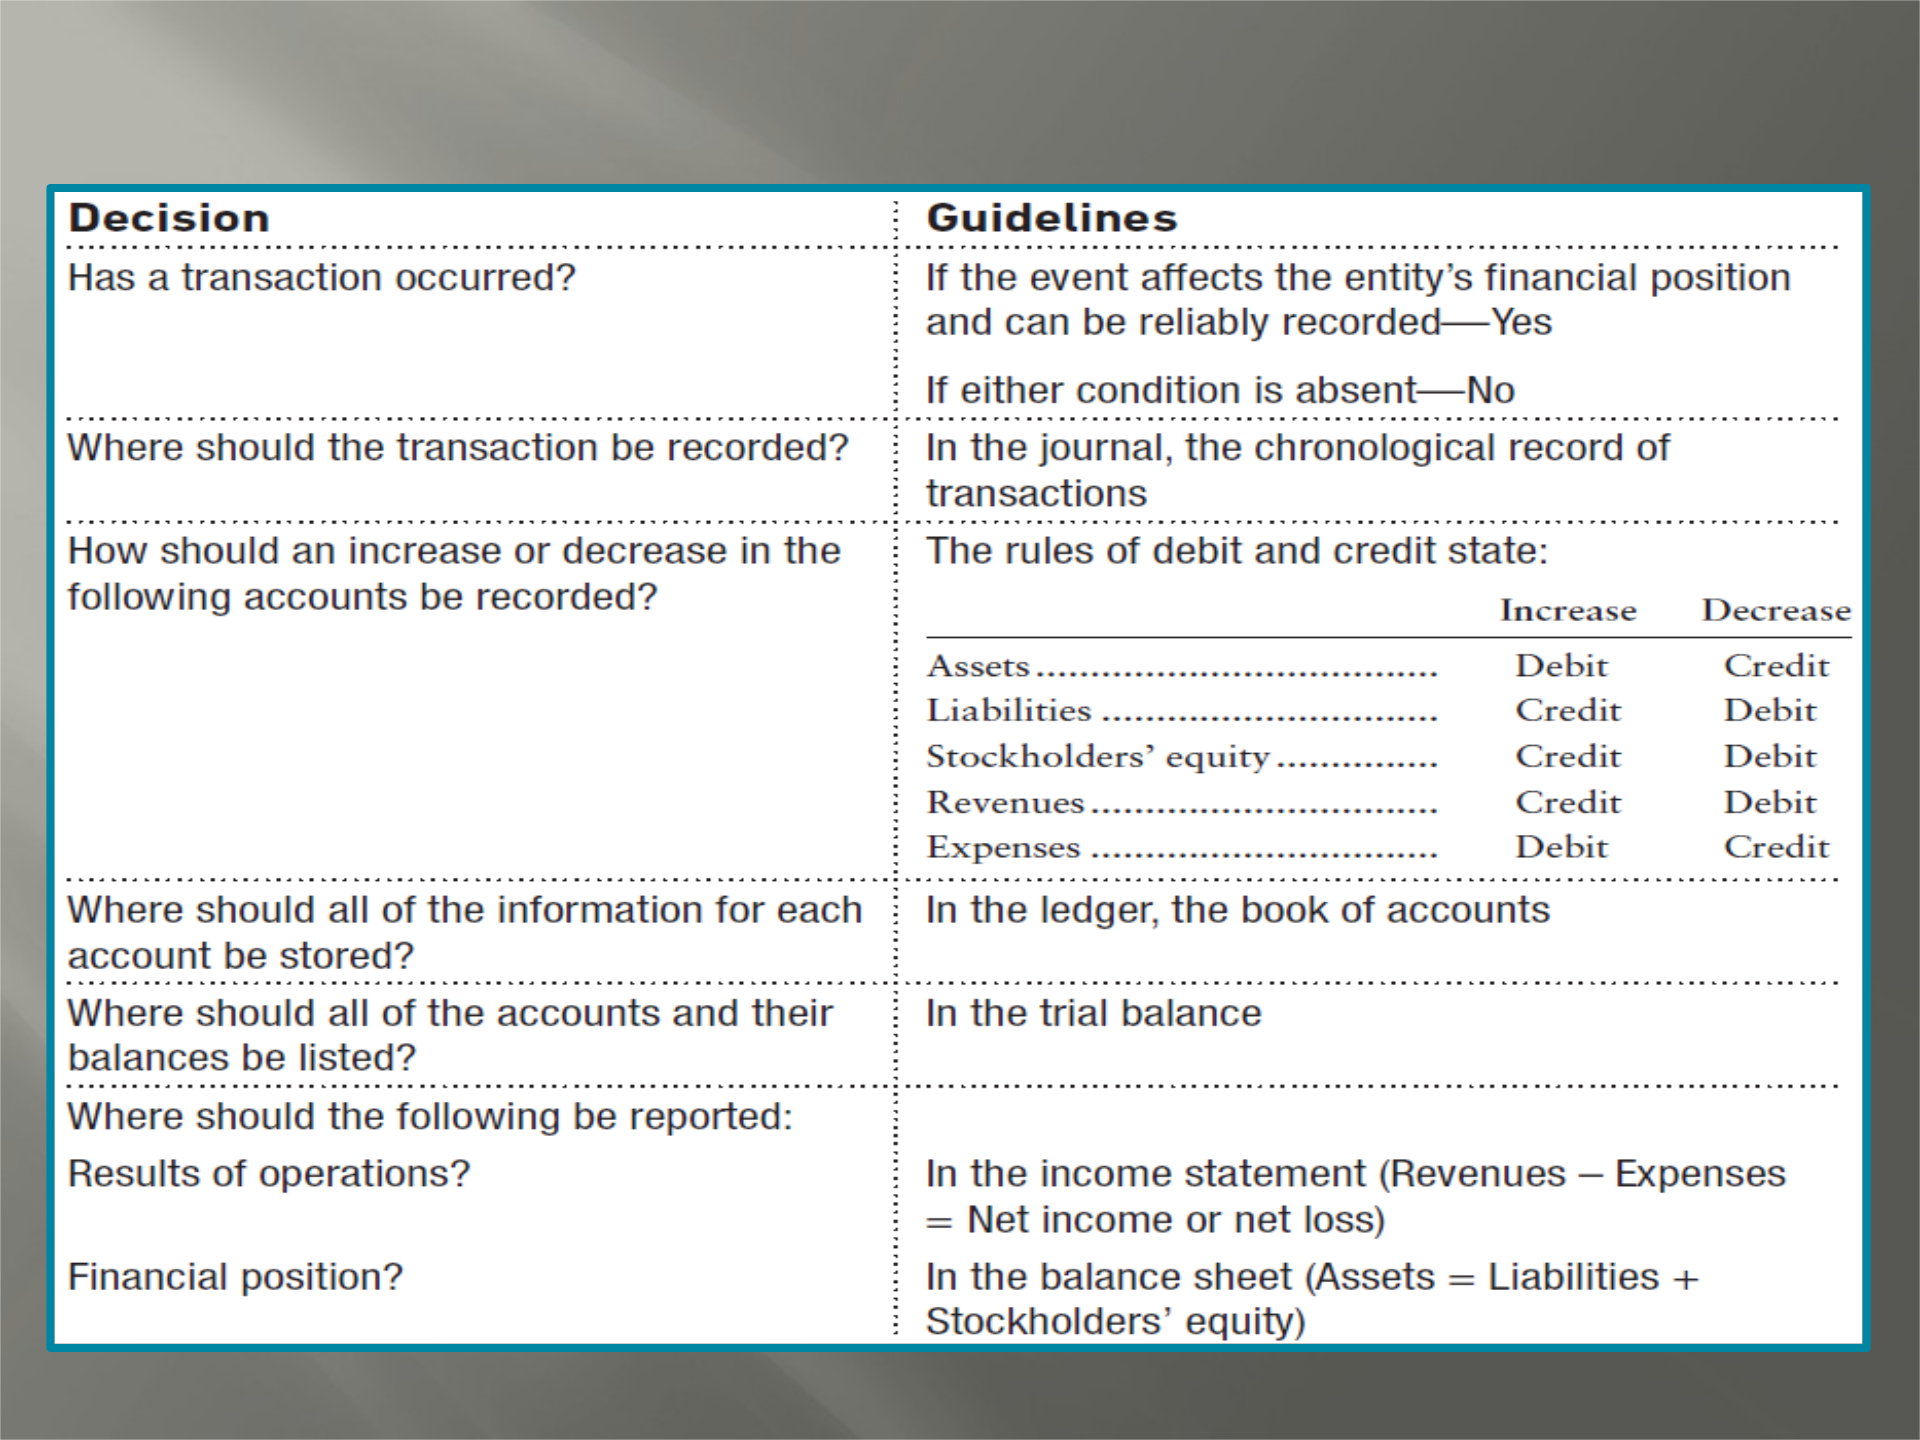
Summary - Decision Guidelines
ACC 231 - Fall 2020 49
Other Elements of Accounting
Information – CONSTRAINTS
• Cost vs. Benefits:
Benefits of info > costs of providing info?
e.g. spend $1,000 to properly classify a $5 item
• Materiality:
Will it make a difference to the decision maker?
Materiality will vary by company/industry
• $100,000 may not be material to Boeing but $50 may be very
material to Bob’s Hardware Store.
ACC 231 - Fall 2020 50
Other Elements - Decision Usefulness
U :
A is: users of fin have
“ ”
R :
C to ma a diff in a
R :
F fr e an bias
ACC 231 - Fall 2020 51
Other Elements - Qualitative Characteristics
C :
B /acr fir with
C :
F one period to the n
Conservatism:
All else equal, use the least optimistic
estimate
o Record expenses earlier rather than later
and revenues later rather than sooner.
ACC 231 - Fall 2020 52

