


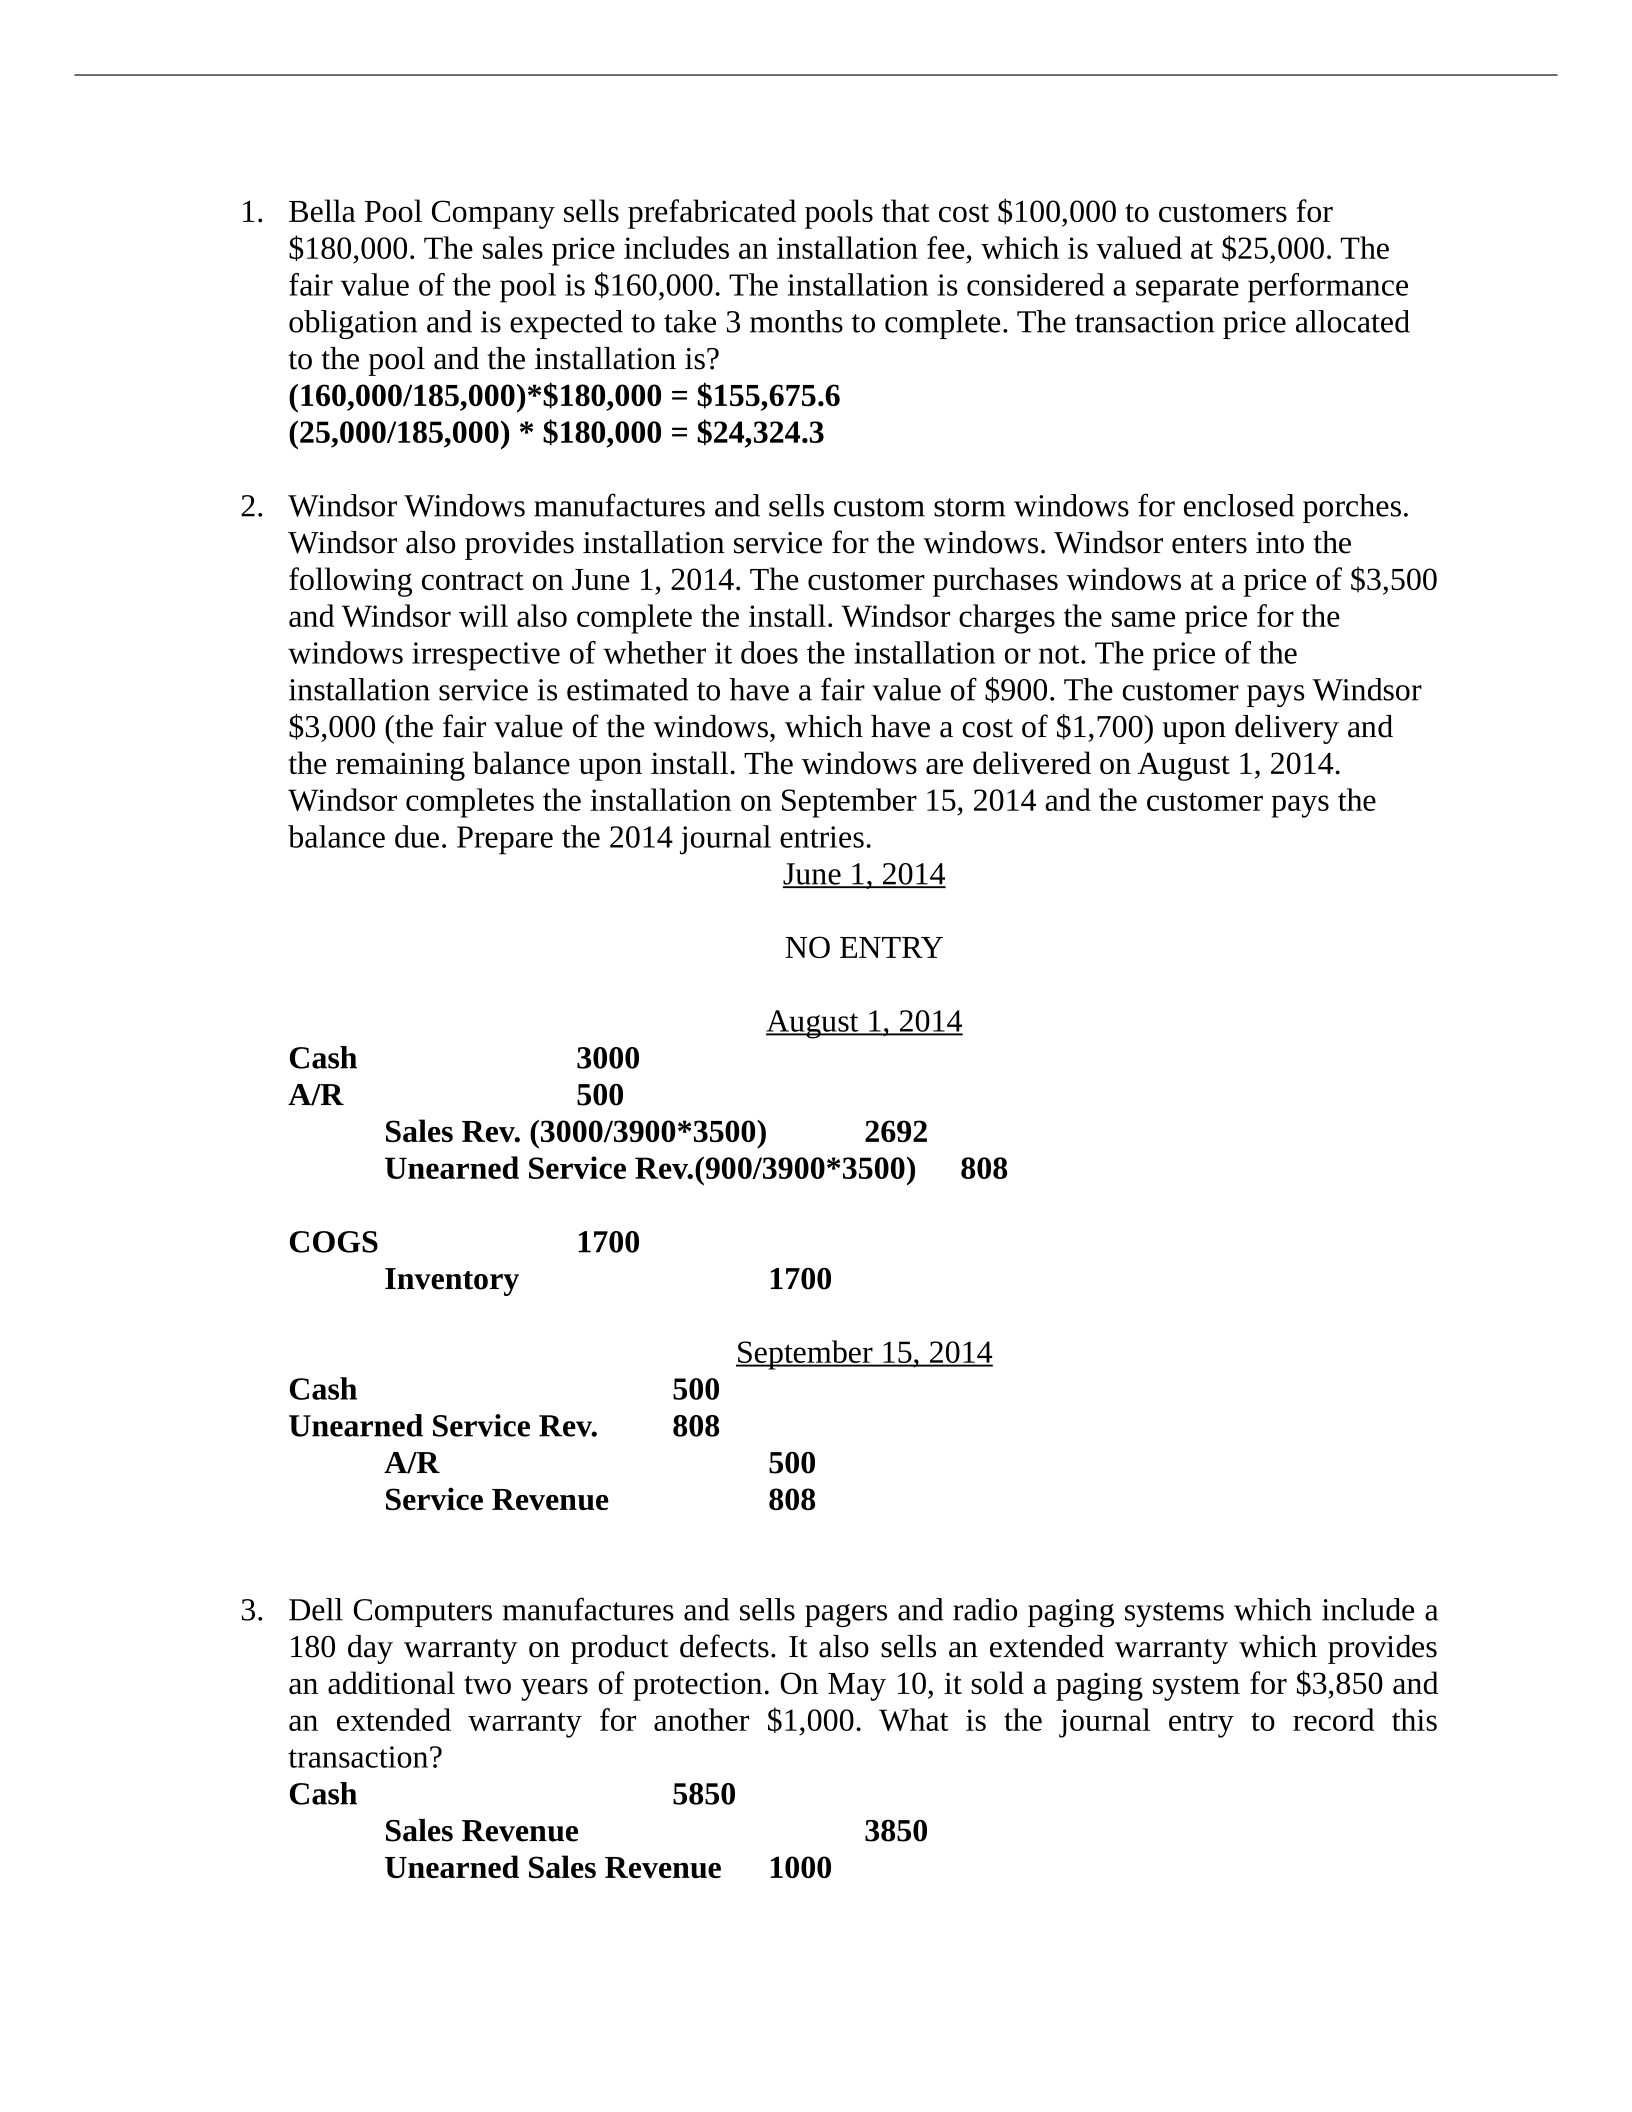
1. Bella Pool Company sells prefabricated pools that cost $100,000 to customers for
$180,000. The sales price includes an installation fee, which is valued at $25,000. The
fair value of the pool is $160,000. The installation is considered a separate performance
obligation and is expected to take 3 months to complete. The transaction price allocated
to the pool and the installation is?
(160,000/185,000)*$180,000 = $155,675.6
(25,000/185,000) * $180,000 = $24,324.3
2. Windsor Windows manufactures and sells custom storm windows for enclosed porches.
Windsor also provides installation service for the windows. Windsor enters into the
following contract on June 1, 2014. The customer purchases windows at a price of $3,500
and Windsor will also complete the install. Windsor charges the same price for the
windows irrespective of whether it does the installation or not. The price of the
installation service is estimated to have a fair value of $900. The customer pays Windsor
$3,000 (the fair value of the windows, which have a cost of $1,700) upon delivery and
the remaining balance upon install. The windows are delivered on August 1, 2014.
Windsor completes the installation on September 15, 2014 and the customer pays the
balance due. Prepare the 2014 journal entries.
June 1, 2014
NO ENTRY
August 1, 2014
Cash 3000
A/R 500
Sales Rev. (3000/3900*3500) 2692
Unearned Service Rev.(900/3900*3500) 808
COGS 1700
Inventory 1700
September 15, 2014
Cash 500
Unearned Service Rev. 808
A/R 500
Service Revenue 808
3. Dell Computers manufactures and sells pagers and radio paging systems which include a
180 day warranty on product defects. It also sells an extended warranty which provides
an additional two years of protection. On May 10, it sold a paging system for $3,850 and
an extended warranty for another $1,000. What is the journal entry to record this
transaction?
Cash 5850
Sales Revenue 3850
Unearned Sales Revenue 1000
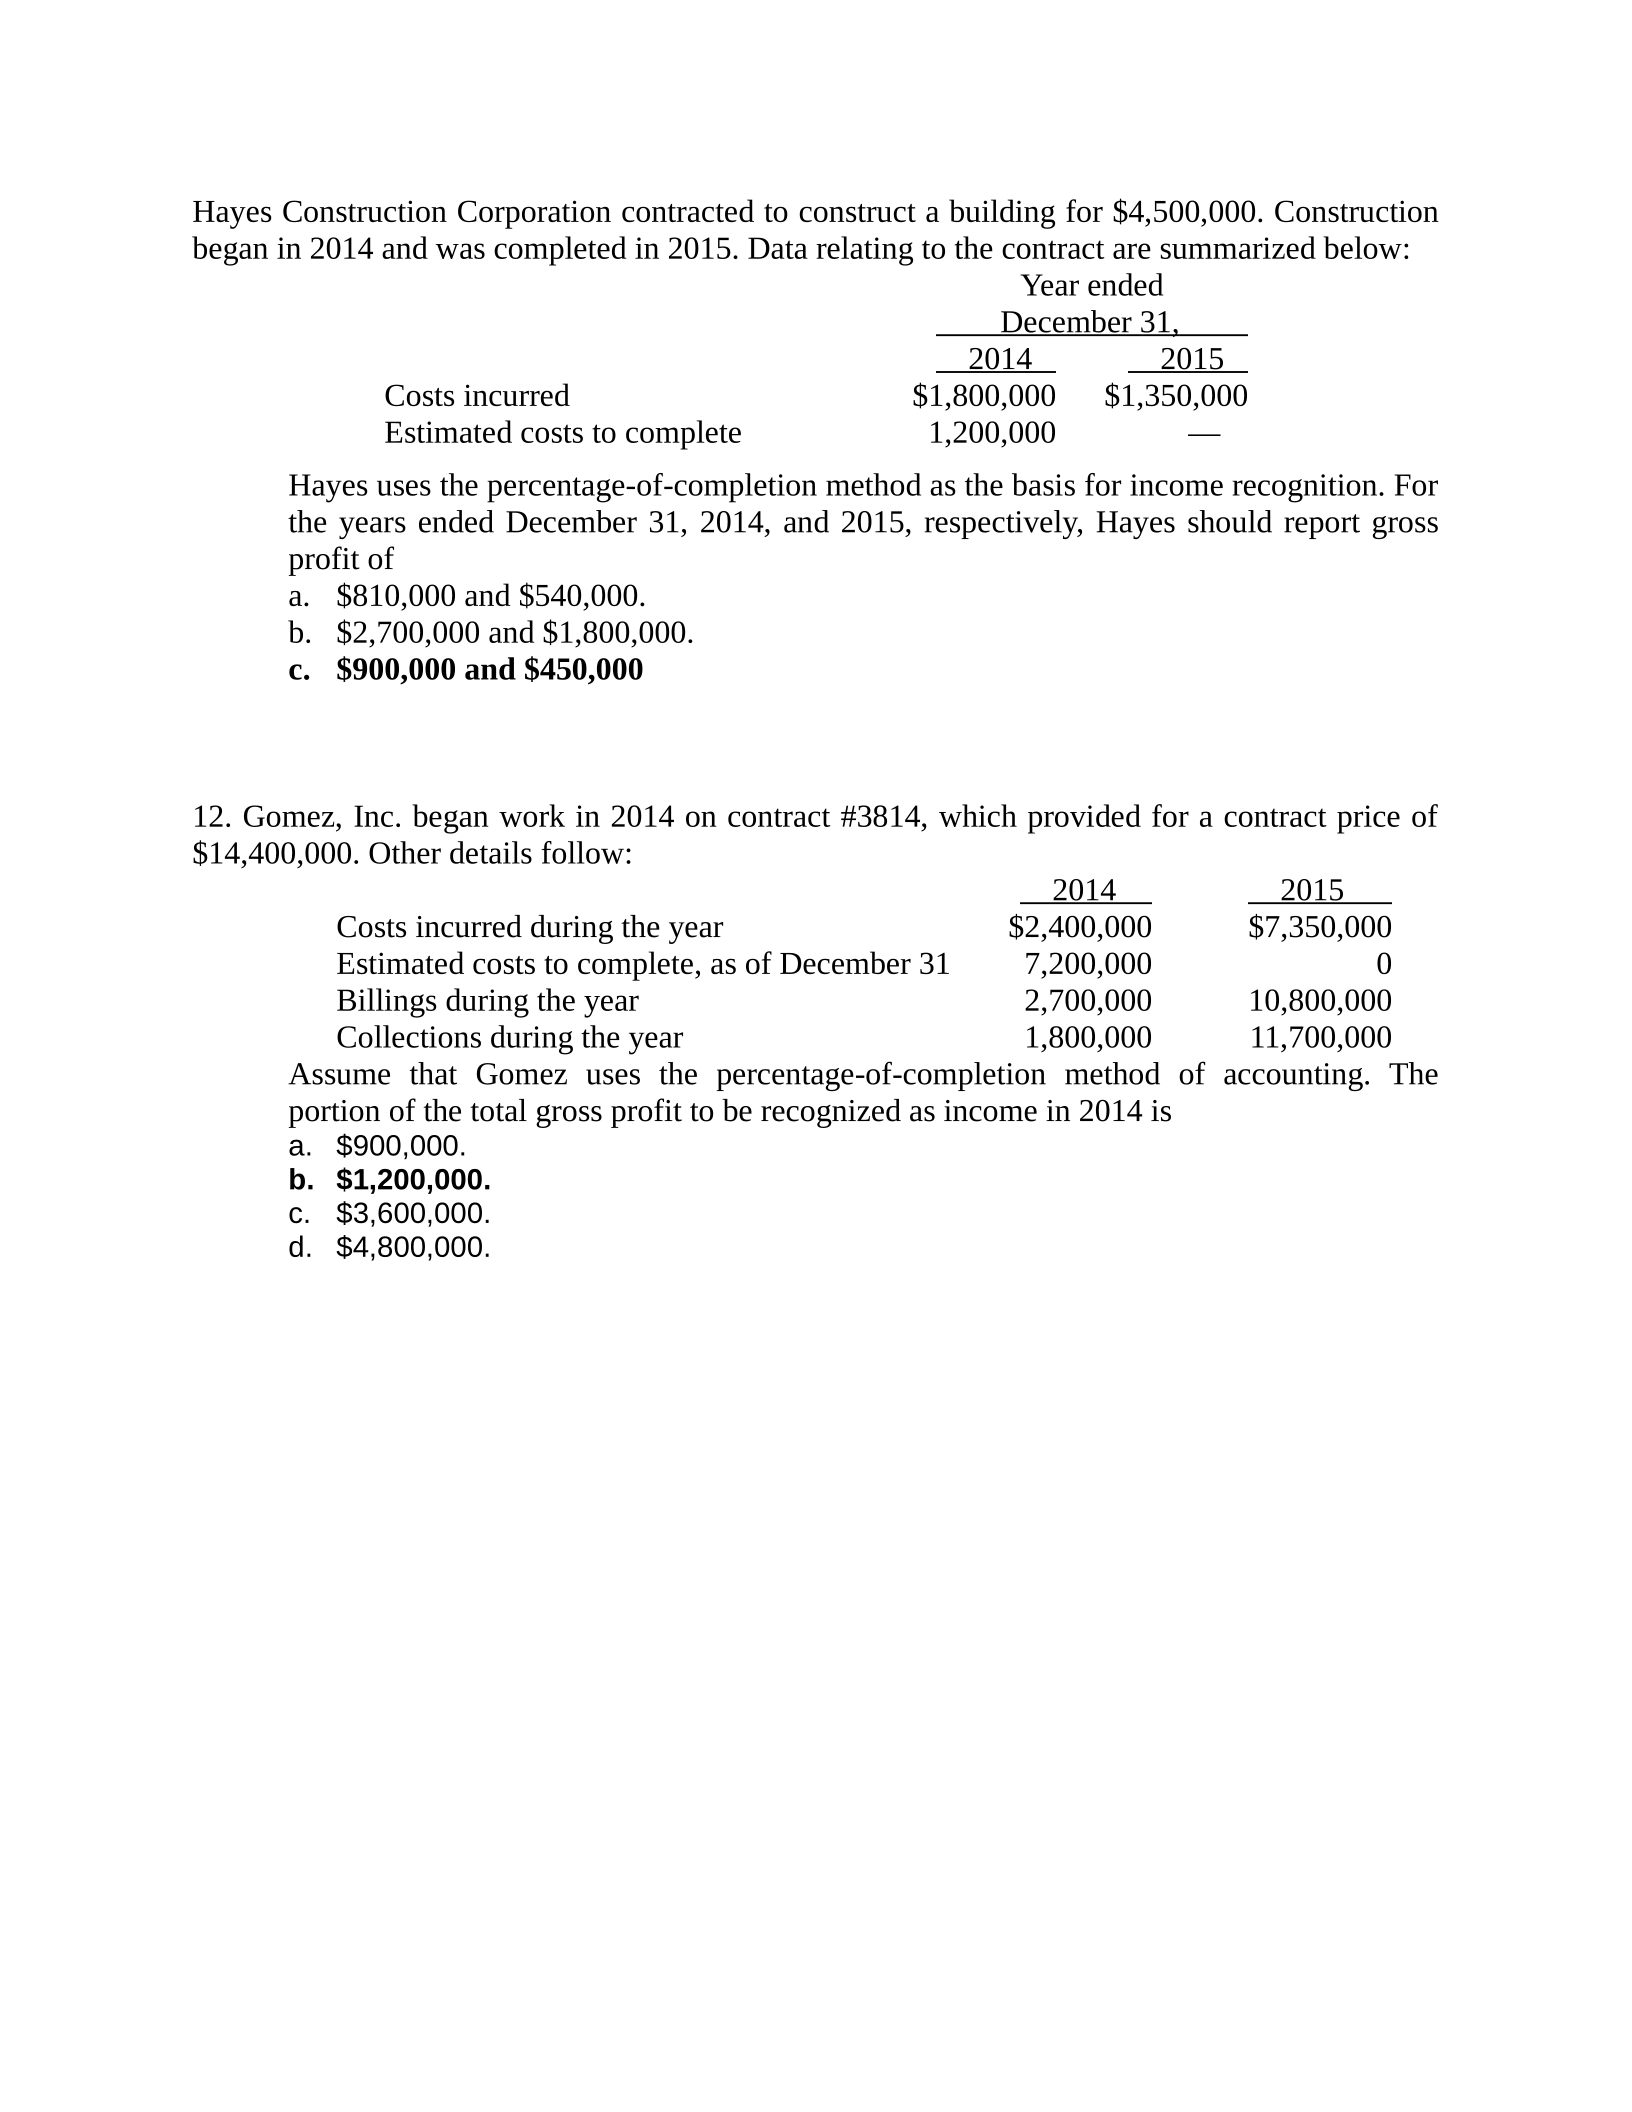
Hayes Construction Corporation contracted to construct a building for $4,500,000. Construction
began in 2014 and was completed in 2015. Data relating to the contract are summarized below:
Year ended
December 31,
2014 2015
Costs incurred $1,800,000 $1,350,000
Estimated costs to complete 1,200,000 —
Hayes uses the percentage-of-completion method as the basis for income recognition. For
the years ended December 31, 2014, and 2015, respectively, Hayes should report gross
profit of
a. $810,000 and $540,000.
b. $2,700,000 and $1,800,000.
c. $900,000 and $450,000
12. Gomez, Inc. began work in 2014 on contract #3814, which provided for a contract price of
$14,400,000. Other details follow:
2014 2015
Costs incurred during the year $2,400,000 $7,350,000
Estimated costs to complete, as of December 31 7,200,000 0
Billings during the year 2,700,000 10,800,000
Collections during the year 1,800,000 11,700,000
Assume that Gomez uses the percentage-of-completion method of accounting. The
portion of the total gross profit to be recognized as income in 2014 is
a. $900,000.
b. $1,200,000.
c. $3,600,000.
d. $4,800,000.
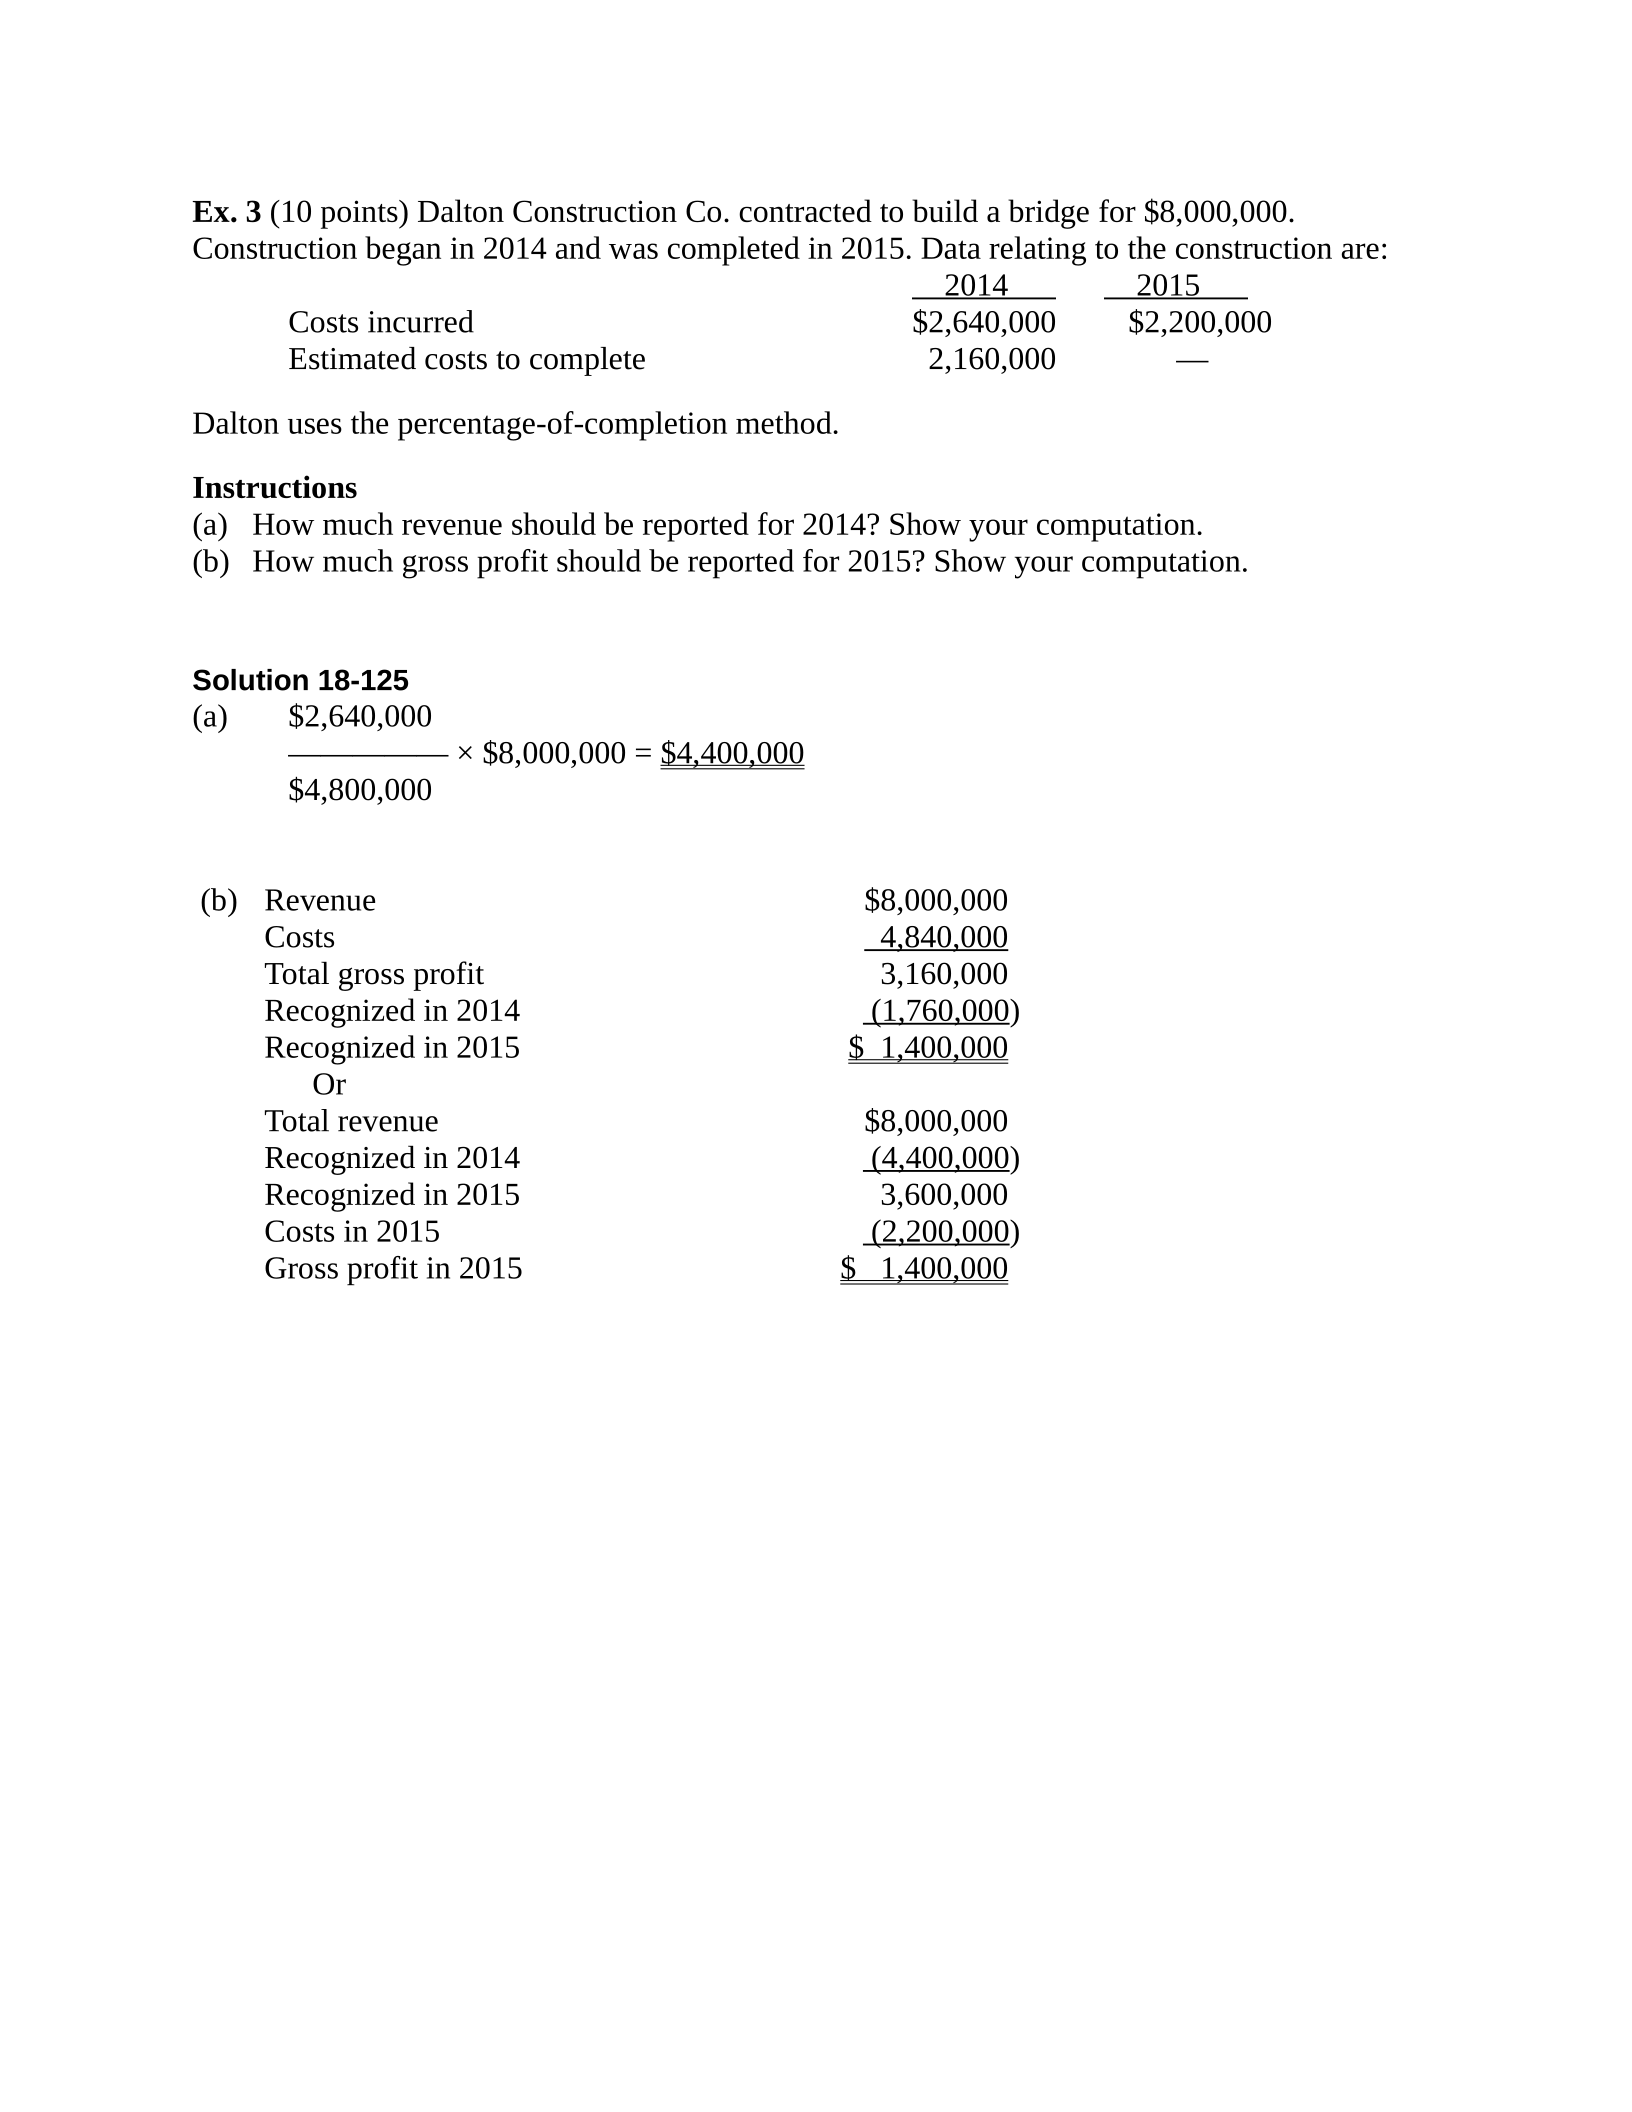
Ex. 3 (10 points) Dalton Construction Co. contracted to build a bridge for $8,000,000.
Construction began in 2014 and was completed in 2015. Data relating to the construction are:
2014 2015
Costs incurred $2,640,000 $2,200,000
Estimated costs to complete 2,160,000 —
Dalton uses the percentage-of-completion method.
Instructions
(a) How much revenue should be reported for 2014? Show your computation.
(b) How much gross profit should be reported for 2015? Show your computation.
Solution 18-125
(a) $2,640,000
————— × $8,000,000 = $4,400,000
$4,800,000
(b) Revenue $8,000,000
Costs 4,840,000
Total gross profit 3,160,000
Recognized in 2014 (1,760,000)
Recognized in 2015 $ 1,400,000
Or
Total revenue $8,000,000
Recognized in 2014 (4,400,000)
Recognized in 2015 3,600,000
Costs in 2015 (2,200,000)
Gross profit in 2015 $ 1,400,000
Powered by TCPDF (www.tcpdf.org)

