


Chapter 3:
Accrual Accounting - Adjusting Journal Entries;
Closing Entries; Financial Statements
Related additional accounting topics
ACC 231 – USES OF ACCOUNTING
INFORMATION I
Chapter 3
FALL 2020
Professor– Don Frost
How Accrual Accounting Differs From
Cash-Basis Accounting
Accrual Accounting Cash-Basis
Accounting
•R impact of
they
•R by U.S.
G A
A P
(GAAP)
•Records revenue when
earned and expenses
when incurred
•R only cash
: cash
and cash
•T to ignor impo
inf
•U r in
financial
•O used by smallest
2
Accrual Accounting
A accounting does r
, such as:
C cash customers
R cash fr inter ear
P sa , r , and other exp
B
P off l
I stock
3
Accrual Accounting – Contd.
A acco also r noncash
, such a :
S on open account ( sales)
P of inventory open acc
A of e incur but not yet
D e
U of pr r , insurance, and supplies
E of r when cash is co in
F accurate fi state ,
mus adjust type of accounts.
W call these A Jour Entries (AJEs)
4
Time Periods & Financial Statements
T P Co
A a bu ge de a “g
” unl li , w must
life an organization into periods
(accounting periods) facil financial .
C for and r their oper on
variety of sc .
T basic acc period is the . About 60%
companies use the calendar year (Jan. 1 thr
D . 31).
Monthly, Q and Semi-annual periods ar also used
interim r .
A we use pe , we r
through or as of a certain point.
5
Accrual Accounting –
Amount & Timing of Revenue Recognition
R P
W r (r r )?
R is r when the bu tran
goods services to customer.
W we r ?
A amount that r the cash ( fair mark
of other cons ) that the e
r e fo those goods services.
T , r is of r (r )
before is r (A r ).
C , can be r after
is r (Def r ).
E of the above follow.
6
Expense Recognition or Matching Principle
E shou be matched t r
help gene , r of when paid.
E .: R in September October’s use of spa .
E .: W paid in March for F ’s wate consumption.
A , the accrua meth general
p of cash wh assign
( ) e in app
.
R expense alo with r
to s expenses fr related r to
net income net loss.
7
Cash ≠ Revenue & Expense
A A & the Matching
P r in Acc and
D
We recognize REVENUE or EXPENSE
BEFORE or AFTER cash is exchanged
T , we must ADJUSTING
JOURNAL ENTRIES (AJE ) to pr
our r and e in t
accounting period.
Each AJE involves at least one income
statement account AND one balance sheet
account
8
Accruals and Deferrals
ACCRUALS DEFERRALS
B has
r
r
fr
…OR…
B has
e
cash is
B r
befor
goods
service to t
…OR…
B has paid
be it
incur
9
Accruals and Deferrals -
Summary
T of Item N L
Accrued revenue Revenue is
recognized
Cash is
received
Accrued expense Expense is
recognized
Cash is paid
Deferred revenue Cash is
received
Revenue is
recognized
Deferred
expense
Cash is paid Expense is
recognized
10
Adjusting Journal Entries
U to ensur that r
principle the
/matching principle followed
T adjustments ar needed :
R unr r (accru r )
R unr ex (a
)
D un r between periods
( r )
D pr e between periods
( e )
I D AJE
11
Adjusting Journal Entries
(AJEs)
AJEs are made at the
end of each accounting
period.
AJEs are made at the
end of each accounting
period.
AJEs are required for
accurate accrual-based
financial statements.
AJEs are required for
accurate accrual-based
financial statements.
An AJE will always affect
at least one Income
Statement account (a
Revenue or an Expense)
and at least one Balance
Sheet account (an Asset
or a Liability)
An AJE will always affect
at least one Income
Statement account (a
Revenue or an Expense)
and at least one Balance
Sheet account (an Asset
or a Liability)
Cash is never included
in AJEs. Why?
Cash is never included
in AJEs. Why?
12
FIVE BASIC TYPES OF AJEs
P , Plant & Equipment (D )
P Expenses (Def Expenses)
A Liabilities (A Expe )
Unearned Revenue Liabilities (Deferred Rev)
Accrued Assets (Accrued Revenues)
13
Property, Plant &
Equipment (PP&E)
E :
B
E
F , Computers, etc.
I ar initially r as long-term ( -
) assets
T cost is alloc (r ) by e
FUTURE periods, generally thr
depreciation deductions.
•A of the Matching P .
N – do not depreciate L .
14
Depreciation Expense
P of system all the
cos of pla and equipm to
o the a ’s usefu li (rata
of an as ).
M of our c will be based upon the
“S Line Meth ” wher depr is
evenly ov an asset’s u life.
W ar NOT trying to m
, j allocating cost over the
l of the PP&E
Depreciation is a NON-CASH expense
R in deter cash flows.
15
PP&E (“Fixed Assets”) – Key
Terms
D Expense: T per- amount
the r our asset cost (e.g. monthly
).
A Depreciation: T sum of our
e amounts claimed to date. It is a
CONTRA Asset (it cost of the asset).
B V or N Book V (NBV): T
(historic) of an asset LESS any accumulated
.
S value: A e to be r when
asset is sold at the end of its useful life.
I ther is a s value, we do not depr below that amount (serves as
). Other ter you may see used are i) scrap or ii) r value.
S value (if any) can also affec the amount of depr e .
16
Depreciation Expense Calculation
S -line depr
C of Asset
U Life (UL)
S valu (SV)
F for Depr Expense (per
):
17
DeprExp=Cost-SV
UL
Depreciation Expense
18
$24,000
$24,000
4 years
4 years
$6,000 annual
depreciation
$6,000 annual
depreciation
$6,000 annual
depreciation
$6,000 annual
depreciation
12
months
12
months
$500 monthly
depreciation
$500 monthly
depreciation
L ’ our c purc a $24,000 of pro
for cash March 1. We have determined the us life of
machine is four and will have no salva value at the end of
life. Determine the annual and deprec expense
us the Straight Line method.
Depreciation AJE for
March
19
GENERAL JOURNAL
D A D C
3-31 D e 500
A depr 500
C -asset
Depreciation AJE
L ’s r Chapter 3 - C
H , A #1
20
Prepaid (Deferred) Expenses
C p BEFORE is i
E :
P r
P insurance
P offi supplies
I r as outfl (CR)
ASSET (DR)
E is r as incur - as the asset
“used up” over period benefitted.
E : Darby, Inc. $9,000 r in advance.
T payment the ne six mont . D ,
I . will an e AJE of $1,500 each mo
the ne six mon (the perio benefitted).
21
Prepaid Asset
L ’s r Chapter 3 - C
H , A #2
22
Accrued Liability
(Accrued Expense )
C paid AFTER incur
E :
W , T , Inter , R , Utilities
I r e incur (DR) and a
LIABILITY amo owed (CR)
W ac payment occur , cash (CR) an the
liability (DR)
E :
D , Inc. $750 of ele durin J .
P to the is not due the end of J . T
must a for the in Jun as follows:
6/30 DR U Expense $750
CR U P $750
T accrue J power usage
23
Accrued Liability
L ’s r Chapter 3 - C
H , A #3
24
Pay Cash BEFORE
expense is recognized
E Rel to
period T
Pay cash AFTER
Expense is Recognized
B S Date
T
E Re to
period
DEFFERAL:
ACCRUAL:
Journal Entry
Journal Entry
Adjusting Journal Entry
Adjusting Journal Entry
Summary - Expense AJEs
25
Unearned Revenue Liability
(Deferred Revenue)
E :
C r BEFORE ear
G Certificates/Gif C , D payments,
S collected in a , Au Club
A D , P for Dance L
W initially r CASH r and
an offsetting LIABILITY for the
UNEARNED REVENUE
W service performed goods
, recognize revenue
the lia acco .
26
Receive Cash BEFORE
revenue is recognized
R Rel to
period
T
B S Date
DEFERRAL
(Deferred Revenue/Unearned Revenue)
27
Recording & Adjusting Deferred Revenues
O 3/21, ABC $750 cash fr a
for services to be perfor over
thr months.
On 3/31, ABC must record an AJE for the
portion of the revenue earned in March
(one-third of total).
28
GENERAL JOURNAL
D
A D C
3-21 C 750
(JE) U r 750
3-31 U 250
(AJE) S r 250
Unearned Revenue
L ’s r and emphasize the
you just with Chapter 3
C Handouts, A #4 (P A)
29
Accrued Assets (Accrued Revenue)
C r AFTER ear
R Income (e.g. an Evil L )
I income (e.g. to a B )
W initially r r ear and
an offset for the
amount we will r
N – this r is an a .
W cash is r , r ( )
and r (cr ) the r
C sim to A R
30
Receive cash AFTER
Revenue is Recognized
B S Date
T
R R to
period
ACCRUAL
(e.g. Accrued Revenue/Accrued Assets)
31
Accruing Revenues
N owes landlor Snid $500
the month of Mar but hasn’t paid
. Snidely r this Mar r as
with an AJE:
32
GENERAL JOURNAL
D
A D C
3/31 R r 500
(AJE) R r 500
Accruing Revenues – Journal
Entry
C w the prior facts, Nel pays
$500 Mar r sh owes to Snidely on
A 15 . S r the of the
M re the followin journal entry:
33
GENERAL JOURNAL
D
A D C
4/15 C 500
(JE) R
R
500
Accrued Revenue
L ’s r and emphasize the
you just with Chapter 3
C Handouts, A #4 (P
B).
34
Receive Cash BEFORE
Revenue is recognized
R Rel to
period T
Receive cash AFTER
Revenue is Recognized
B S Date
T
R to
period
DEFFERAL:
ACCRUAL:
Summary – Revenue AJEs
35
Journal Entry
Journal Entry
Adjusting Journal Entry
Adjusting Journal Entry
How Are Financial Statements Prepared
A all the adjustments (AJEs) have been
, the Adjusted Trial Balance be
C the final balances in the accounts af all
AJE have been jour and posted.
M sur total debits equal total cr af the
entries.
F the adjusted trial balance, one can pr the
basic financial statements. R these should be
in the following or :
T Income Statement
T Statement of R Ear
T Balance Sheet
S of Cash Flows (later in the course)
36
Adjusted Trial Balance
O Consulting, Inc. Ad T Balance Mar 31, 2020
ACCOUNT TITLE BALANCE
DEBIT CREDIT
C $26,300
A R 3,350
S 600
P R 2,000
E 12,600
A De , Equipment $350
A P 13,100
S P 550
U Serv R 300
C Stock 20,000
R Earn 9,500
D 3,200
S R 7,400
S E 1,100
R Expense 1,000
U Exp 400
D Expense, Equipment 350
S Expe 300
T $51,200 $51,200
37
Financial Statements
O t A T Balance is
, is r to pr the
statemen .
H :
N of the entity
T of the statement
I Statement
S of R Ear
B Sheet
D , or period, cover by the
B of the st
38
Income Statement
O Consulting, I .
I Sta
Q ended March 31, 2020
R :
S R $7,400
E :
S Expense $1,100
R Expense 1,000
U Exp 400
D Expense, E 350
S Expe 300
T Expens 3,150
N In $4,250
39
Statement of Retained Earnings
O Consulting, I .
S R Earnings
Q ended Ma 31, 2020
R Ea , Mar 1, 2020 $9,500
A : N Incom 4,250
S 13,750
L : Dividends 3,200
R Ea , Mar 31, 2020 $10,550
40
Balance Sheet
O Consulting, I .
B Sheet
M 31, 2020
ASSETS LIABILITIES
C $26,30
0
A P $13,100
A R 3,350 S P 550
S 600 U Service
R
300
P R 2,000 T Liabi 13,950
E $12,60
0
L : Accumulated
D -
E
(350) 12,250 STOCKHOLDERS’
EQUITY
C Stock 20,000
R E 10,550
T Stockho ’
E
30,550
T Liabi and
T Assets $44,50
0
S ’ Equity $44,500 41
Completing the Accounting Cycle – “Closing the
Books”
To start a new accounting period, all
Nominal (temporary) accounts must
reset to zero
To start a new accounting period, all
Nominal (temporary) accounts must
reset to zero
Revenues, expenses, and dividends
are closed to Retained Earnings
Revenues, expenses, and dividends
are closed to Retained Earnings
Real (Permanent) accounts’ balances are
carried forward to the new accounting
period
Real (Permanent) accounts’ balances are
carried forward to the new accounting
period
42
Real (Permanent) vs. Nominal
(Temporary) Accounts
Real Accounts
Permanent
NOT CLOSED at end of
period
Balance Sheet
accounts:
Assets, Liabilities &
Owner’s Equity (S/E)
- Balances ARE carried
forward to next period
Nominal Accounts
Temporary
ARE CLOSED (brought to
a zero balance) at end of
accounting period
Income Statement
accounts: Revenues and
Expenses (and Dividends from
Statement of Stockholders’ Equity)
Balances are NOT
carried forward to next
period
43
The Closing Process
Record entries that reduce all nominal accounts to a zero
balance at the end of the accounting period
Balances in Nominal (temporary) accounts are CLOSED
(transferred) to RETAINED EARNINGS
44
Revenues
Bal. xxx
xxx
Bal. xxx
Bal. xxx
Beg. Bal. xxx
Retained Earnings
Revenues
Expenses
xxx
Expenses
Dividends
xxx
Dividends Z
accounts
start accumulation
next period’
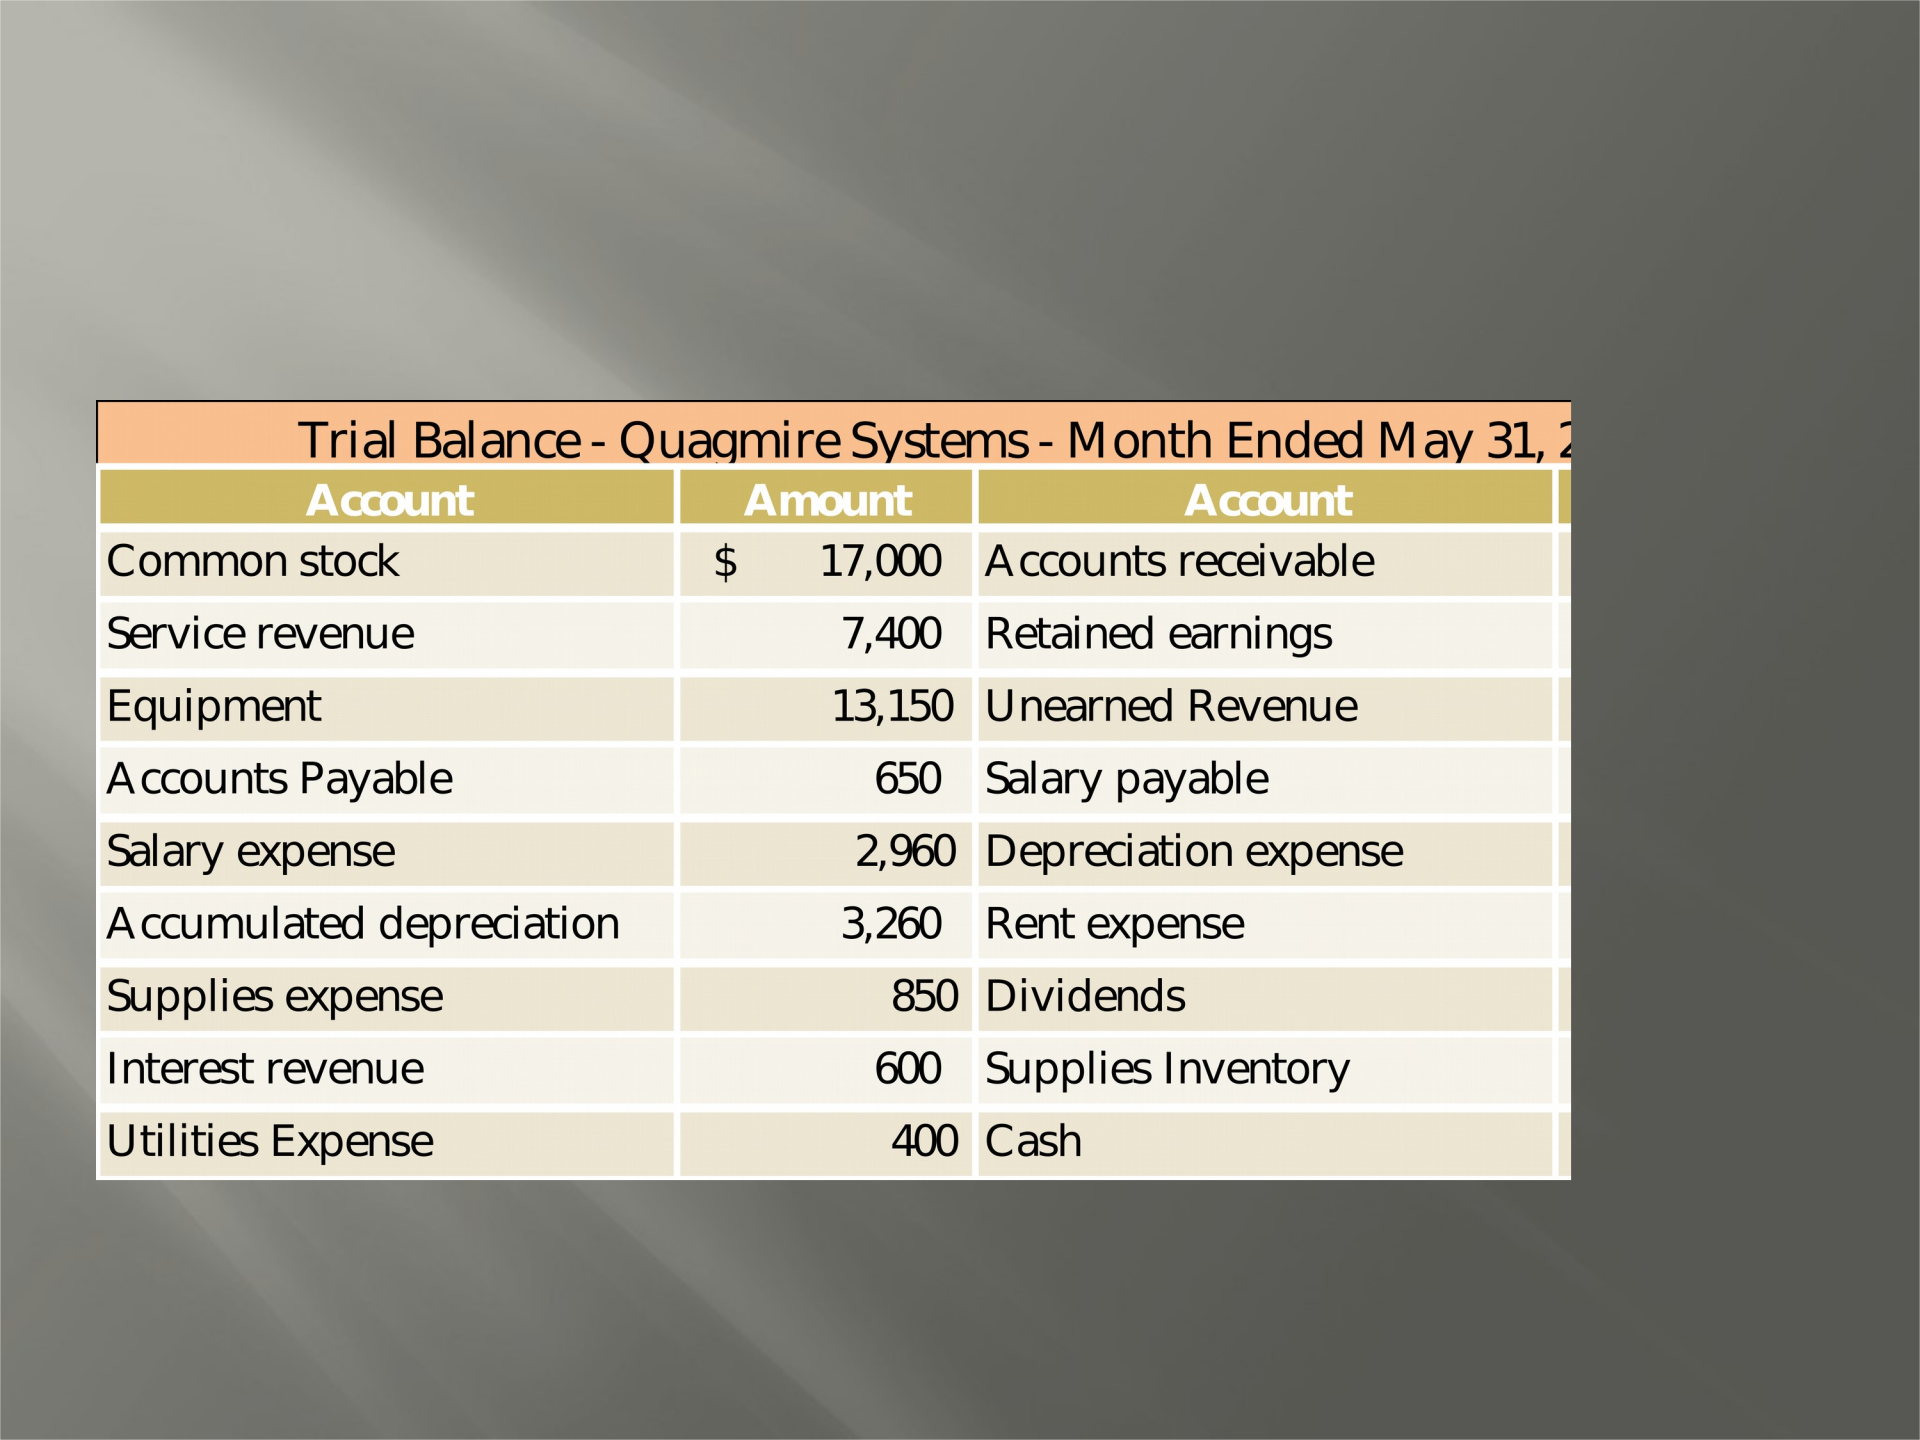
Closing Entries – Example
Q S , I . has the followin adjusted trial
(in random ) for the ended M 31, 2020.
P Closing Entries for Ma .
45
Closing Entries
D A D C
31-May Service Revenue $7,400 T
T Interest Revenue $600 T
T Retained Earnings T $8,000
TTo close Revenue Accounts to R/E T T
31-May Retained Earnings $6,110 T
T Salaries Expense T $2,960
T Rent Expense T $1,000
T Supplies Expense T $850
T Depreciation Expense T $900
T Utilities Expense T $400
T TTo close Expense Accounts to R/E T T
31-May Retained Earnings $3,200 T
T Dividends T $3,200
T TTo close Dividends to R/E T T
46
Retained Earnings
A the c entries, the R
E balance becomes:
47
Q Systems –
S of Retained
E
M Ended Ma 31, 2020
A
Beginning balance 5/1/2020 $6,900
Plus: Revenues $8,000
Minus: Expenses ($6,110)
Minus: Dividends ($3,200)
Ending balance 5/31/2020 $5,590
Post-Closing Trial Balance
F s of the accounting cyc
I only assets, and
’ equity a
N t all have
closed (r to -0-)
Provides a starting point for next
period’s transactions
48
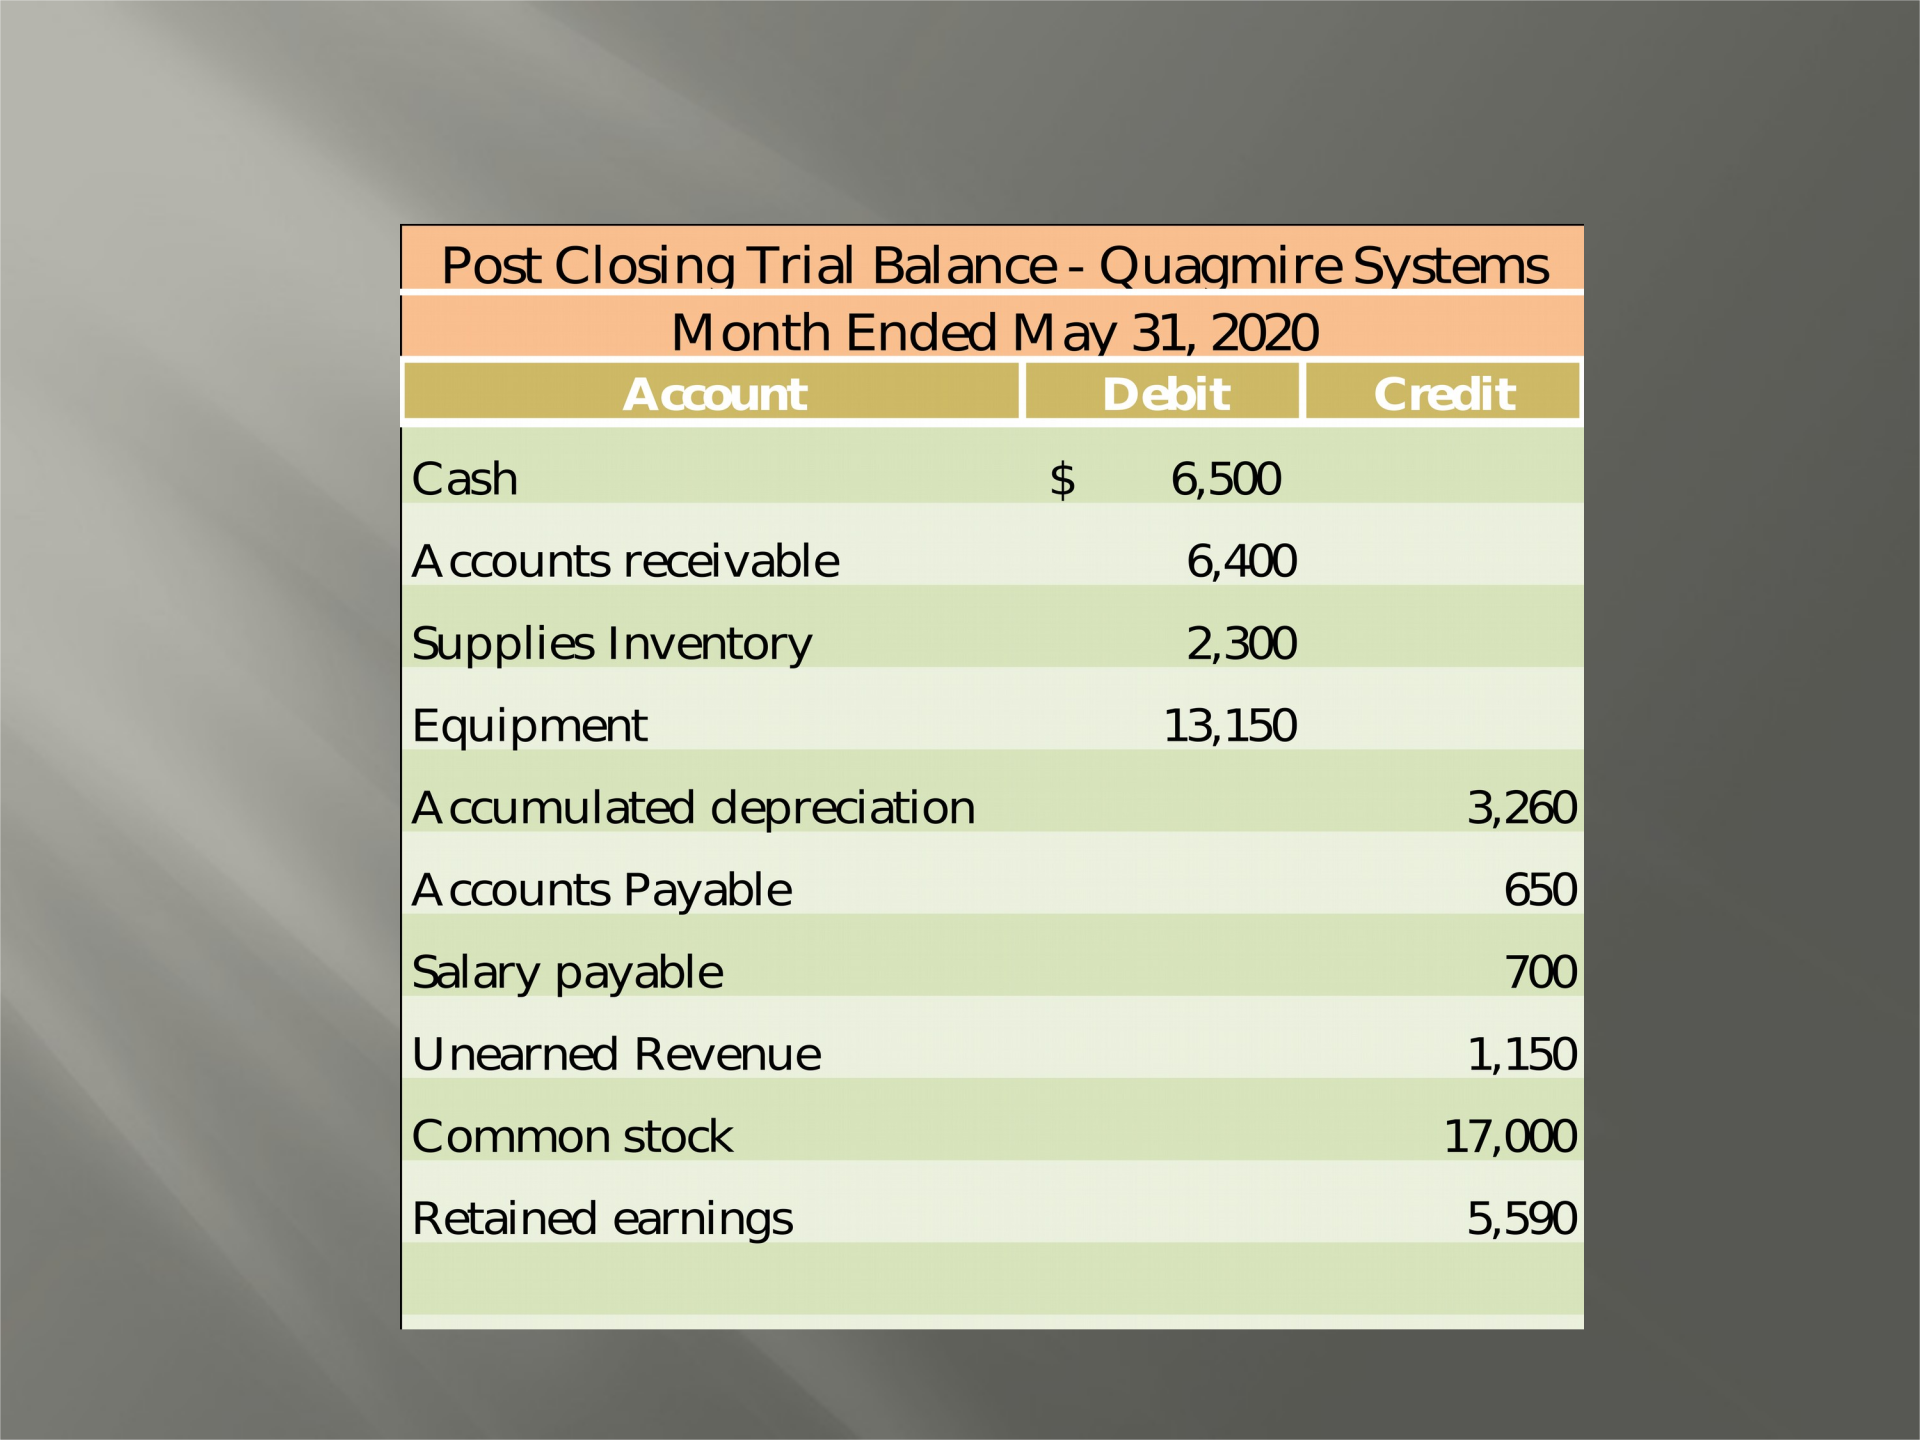
Post
Closing
Trial
Balance
-
QUagmire
Systems
Month
Ended
May
31,
2020
Cash
6,500
Accounts
receivable
6,400
Supplies
Inventory
2,300
Equipment
13,150
Accumulated
depreciation
3,260
Accounts
Payable
650
Salary
payable
700
Unearned
Revenue
1,150
Common
stock
17,000
Retained
earnings
5,590
Totals
28,350
$
28,350
Post Closing Trial Balance
49
Summary of Adjusting and
Closing Process
Adjusting entries
R in
R c
ba
sh
N inclu c
Closing entries
Z o r ,
a
T
a nom
( )
to
R
50
The Classified Balance Sheet - Assets
Current Assets
•Cash
•Accounts Receivable
•Supplies
•Inventory
Current Assets
•Cash
•Accounts Receivable
•Supplies
•Inventory
Long-term assets
Assets
•Land
•Buildings
•Equipment
Long-term assets
Assets
•Land
•Buildings
•Equipment
51
M busi usuall pr a balance
.
A sh lists items in cla in
or of their liquidity. L
r to how qu an a can be
to cash or r lia , how
pa will be .
The Classified Balance Sheet - Liabilities
Current
liabilities
•Accounts Payable
•Salaries Payable
•Unearned
Revenues
Current
liabilities
•Accounts Payable
•Salaries Payable
•Unearned
Revenues
Long-term
liabilities
•Notes Payable
•Mortgage Payable
Long-term
liabilities
•Notes Payable
•Mortgage Payable
52
What is “current” vs. what is “long-term?”
Accountants use a one-year designation. So
anything expected to be converted to or paid in
cash within one year of the balance sheet date
is a current item – otherwise it is long-term.
Basic Structure of a
Classified Balance Sheet
(Report Format)
C asse
+ N ( -term) as
T asse
53
C liabilities
+ N (long-term) liabilities
+ S ’
T lia and stockholders’
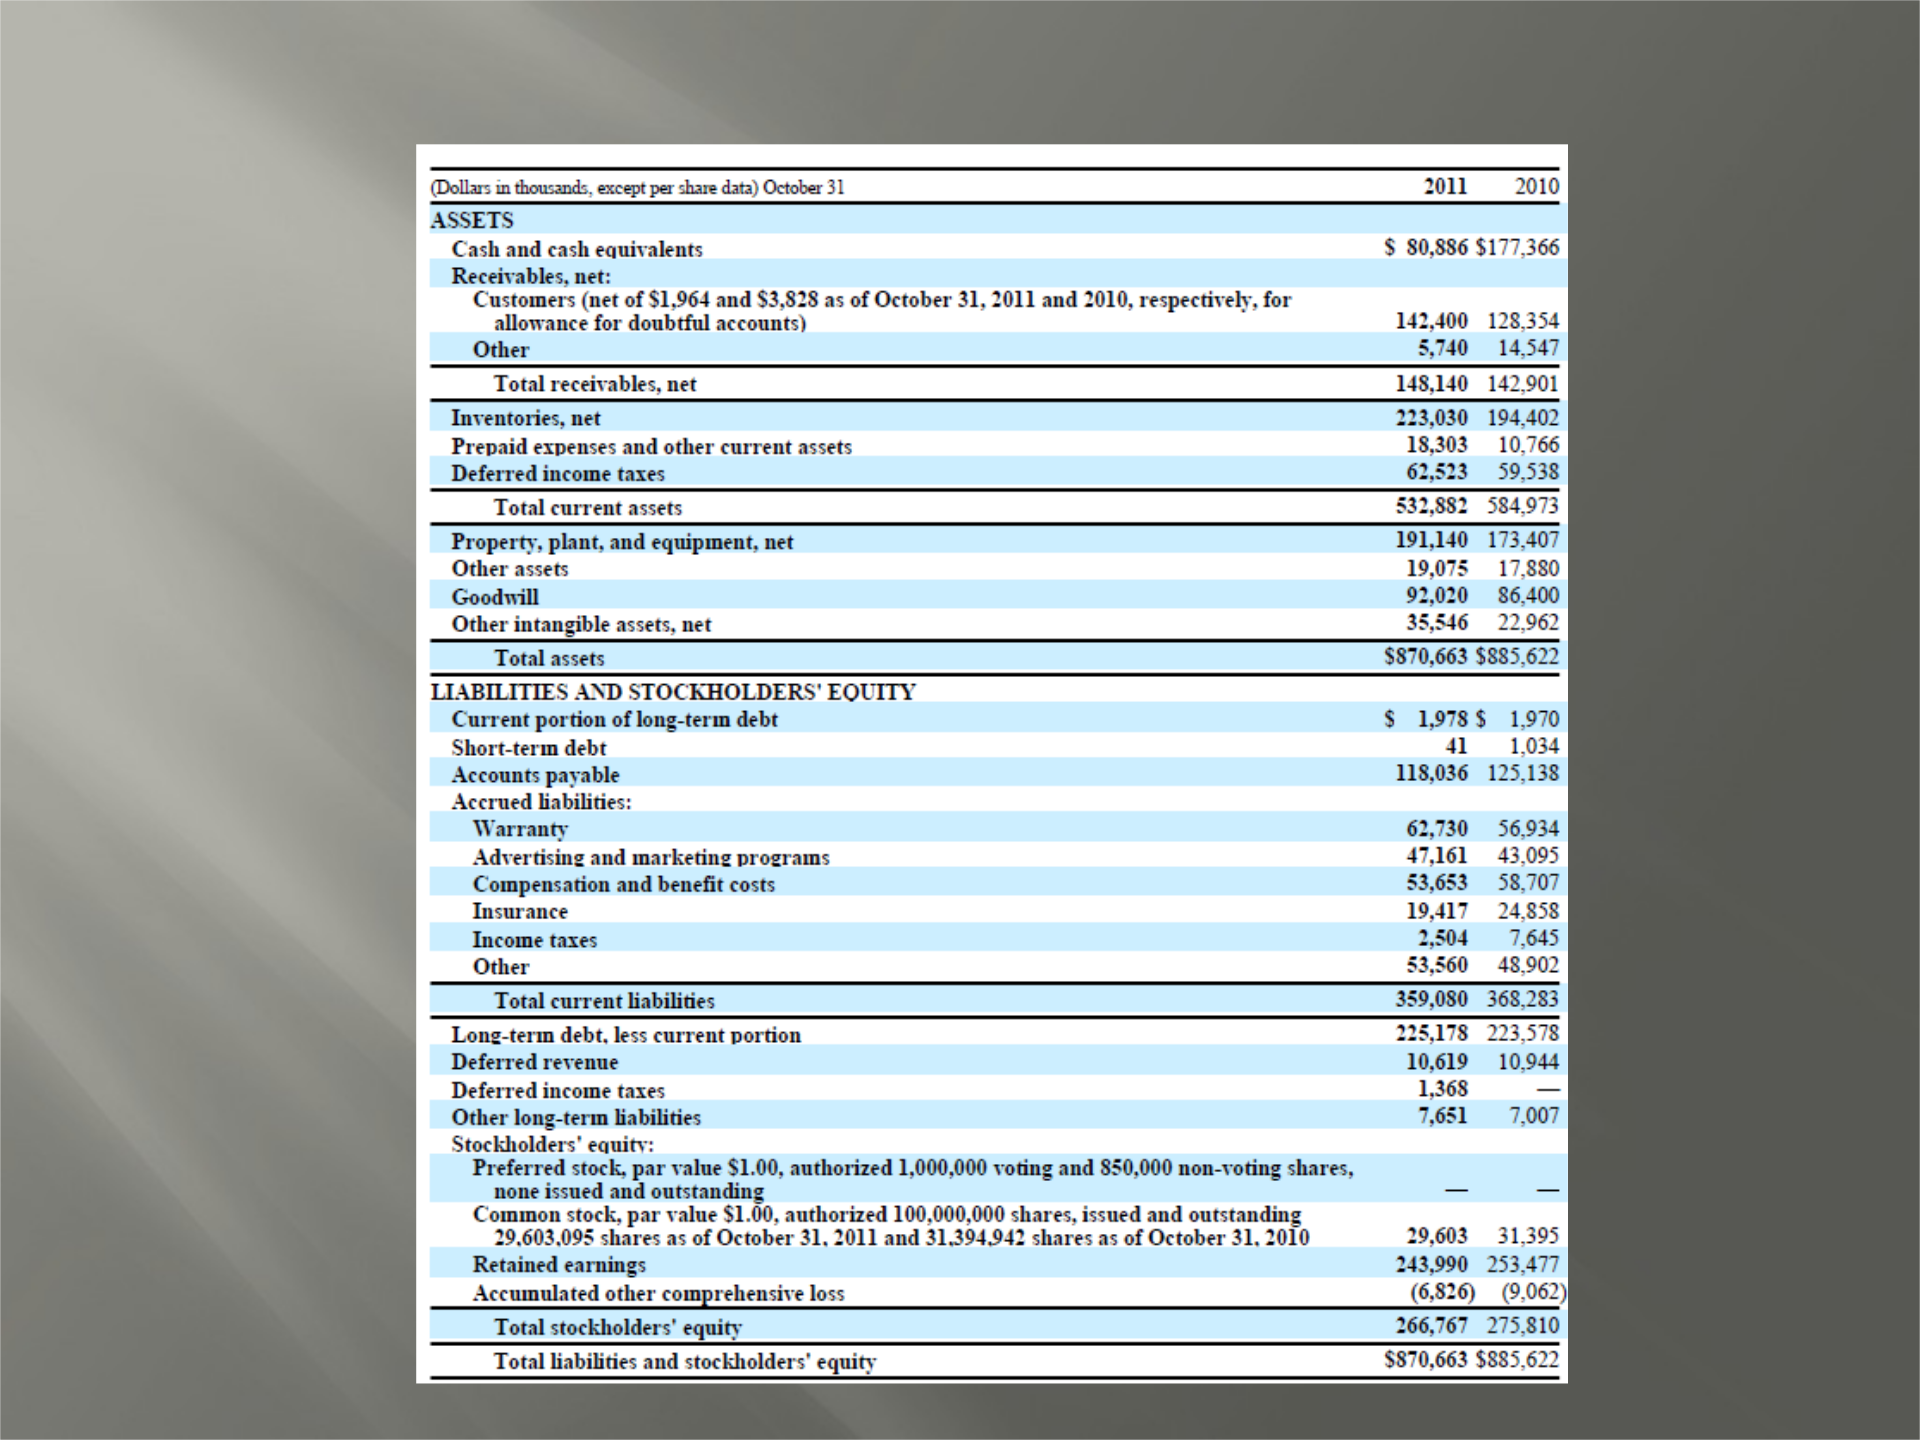
(Dollars
m
thousands,
except per
share
data)
October
31
2011 2010
ASSETS
Cash
and
cash
equivalents
$
80,886
$177,366
Receivables,
net:
Customers
(net
of
$1,964
and
$3,828
as of
October
31,
2011]
and
2010,
respectively,
for
allowance
for
doubtiul
accounts)
142,400
128,354
Other
5,740
14.547
Total
receivables,
net
148,140
142,901
Inventories,
net
223,030
194,402
Prepaid
expenses
and
other
current
assets
18,303
10,766
Deferred
income
taxes
62,523 59,538
Total
current
assets
S32
882
554.975
Property,
plant,
and
equipment,
net
191,140
173,407
Other
assets
19,075
17,880
Goodwill
97.020 86,400
Other
intangible
assets,
net
35,346 22,962
Total
assets
$870,663
$885,622
LIABILITIES
ASD
STOCKHOLDERS’
EQUITY
Current
portion
of
long-term
debt
$
19783
1,970
Short-term
debt 41
1,034
Accounts
payable
118,036
125,138
Accrued
liabilities:
Warranty
62,7320 456,954
Advertising
and
marketing
programs
47,161 43,095
Compensation
and
benefit
costs
53,653 38,707
Insurance
19,417 24,858
Income
taxes
1,504 7,645
Other
53,200 48.902
Total
current
liabilities
359,080 368,283
Long-term
debt,
less
current
portion
T25,178
233,578
Deferred
revenue
10,619
10,944
Deferred
income
taxes
1,368
—
Other
long-term
liabilities
7,651 7,007
Stockholders’
equity:
Preferred
stock,
par
value
$1.00,
authorized
1,000,000 voting
and
850,000
non-voting
shares,
none
issued
and
outstanding
—
_—
Common
stock,
par
value
$1.00,
authorized
100,000,000
shares,
issued
and
outstanding
79,603,095
shares
as of
October
31,
2011
and
31,394,942
shares
as of
October
31,
2010
79,603
31,395
Retained
earnings 243,990 253,477
Accumulated
other
comprehensive
loss
(6,826)
(9,062)
Total
stockholders’
equity
266,767 275,810
Total
liabilities
and
stockholders’
equity
$870,663
$885,622
Classified Balance Sheet - Sample
54
The Income Statement
Income
Stateme
nt
I
S
Single
Step
S
S
Multipl
e Step
Multipl
e Step
55
Single-Step Income Statement
Revenues $$
Less: expenses ($$)
Net income (loss) $$
56
O one t
The Multi-Step Income
Statement
•S R ( – r /allowances).
•C of Goods Sold (COGS).
•G Pr .
•O Expen .
•G and Administrative Expense .
•O Income.
•O R and Ex .
The Multi-Step Income Statement usually includes the
following:
The Multi-Step Income Statement usually includes the
following:
57
Sales/Operating revenues
– Cost of Goods Sold (COGS)
= Gross Profit/Margin
Operating expenses:
– General and
administrative expenses
– Selling expenses
= Operating Profit/Income
+/– Other revenues and expenses
= Income before taxes
– Income tax expense
= Net income/earnings/profit
T
+
N Income
T
Multi-Step Income Statement for a Retailer
Period of Time
58
Debt-Paying Ability & Liquidity
Management
Net Working Capital
R operating liqu
G , companies have e cur assets
cur liabilities
L management is basically how a business
its cash so it can pay its bills
V to various partie , including:
M
L ( .g. banks)
I ( and future)
O simple yet useful liquidity ratio is the
Current ratio.
59
Total current assets – Total current liabilities
Total current assets – Total current liabilities
Current Ratio
R of cur assets t liabilities
A convertible into cash w the next
B due be paid wi the next y
60
C Assets
( , short-term investments, ne accounts
, invento )
C Liabiliti
( payable, accrued liabilities, other debt due
a year)
÷
Current Ratio - Example
61
Cash - Big Bank 45,000
Cash - Little Bank 26,000
Investments in Commercial Paper 12,500
Overnight Sweep Account 32,500
CDs - Medium Bank 47,200
Trade Accounts Receivable 164,000
Allowance of Doubtful Accounts (28,600)
Investments in Treasury Bonds (10 yr) 100,000
Total Cash & Investments 398,600
Accounts Payable 62,300
Current Portion of Long Term Debt 12,600
Rent Payable 4,500
Taxes Payable 16,500
Interest Payable 6,200
Long Term Bonds 145,000
Notes Payable (5 yrs) 36,000
Total Liabilities 283,100
Current Ratio – Example (contd).
62
Cash - Big Bank 45,000
Cash - Little Bank 26,000
Investments in Commercial Paper 12,500
Overnight Sweep Account 32,500
CDs - Medium Bank 47,200 298,600$
Trade Accounts Receivable 164,000
Allowance of Doubtful Accounts (28,600)
Investments in Treasury Bonds (10 yr) 100,000
Total Cash & Investments 398,600
C Ratio: 2.92
Accounts Payable 62,300
Current Portion of Long Term Debt 12,600
Rent Payable 4,500
Taxes Payable 16,500 102,100$
Interest Payable 6,200
Long Term Bonds 145,000
Notes Payable (5 yrs) 36,000
Total Liabilities 283,100
$298,600 ÷ 102,100 =
Debt-Paying Ability & Liquidity Management
T Deb R
M a -paying abi
I is the proportion of a company’s
financed with debt
A debt rati generally consid “safer”
a high debt
63
Total liabilities ÷ Total assets
Total liabilities ÷ Total assets
Debt Paying Ability - Sample Problem
G the above data, compute Sizemor ’s Debt R
64
S Industrial S
Total Current Assets $85,000
Total Long-Term Assets 360,000
Total Current Liabilities 51,000
Total Long-Term Liabilities 237,000
Total Stockholders’ Equity 157,000
Earnings Before Interest and
Taxes
41,700
Interest Expense 12,200
Income Tax Expense 7,300
Net Income 22,200
$420,000
$294,000
Total
Assets
Total
Liabilities
Debt Ratio
65
S Industrial S
Total Current Assets $85,00
0
Total Long-Term Assets 360,00
0
Total Current Liabilities 51,000
Total Long-Term Liabilities 237,00
0
Total Stockholders’ Equity 157,00
0
Earnings Before Interest and
Taxes
41,700
Interest Expense 12,200
Income Tax Expense 7,300
Net Income 22,200
64.7
%
$51,000
+ 237,000
T $85,000
+ 360,000
Debt Ratio

