


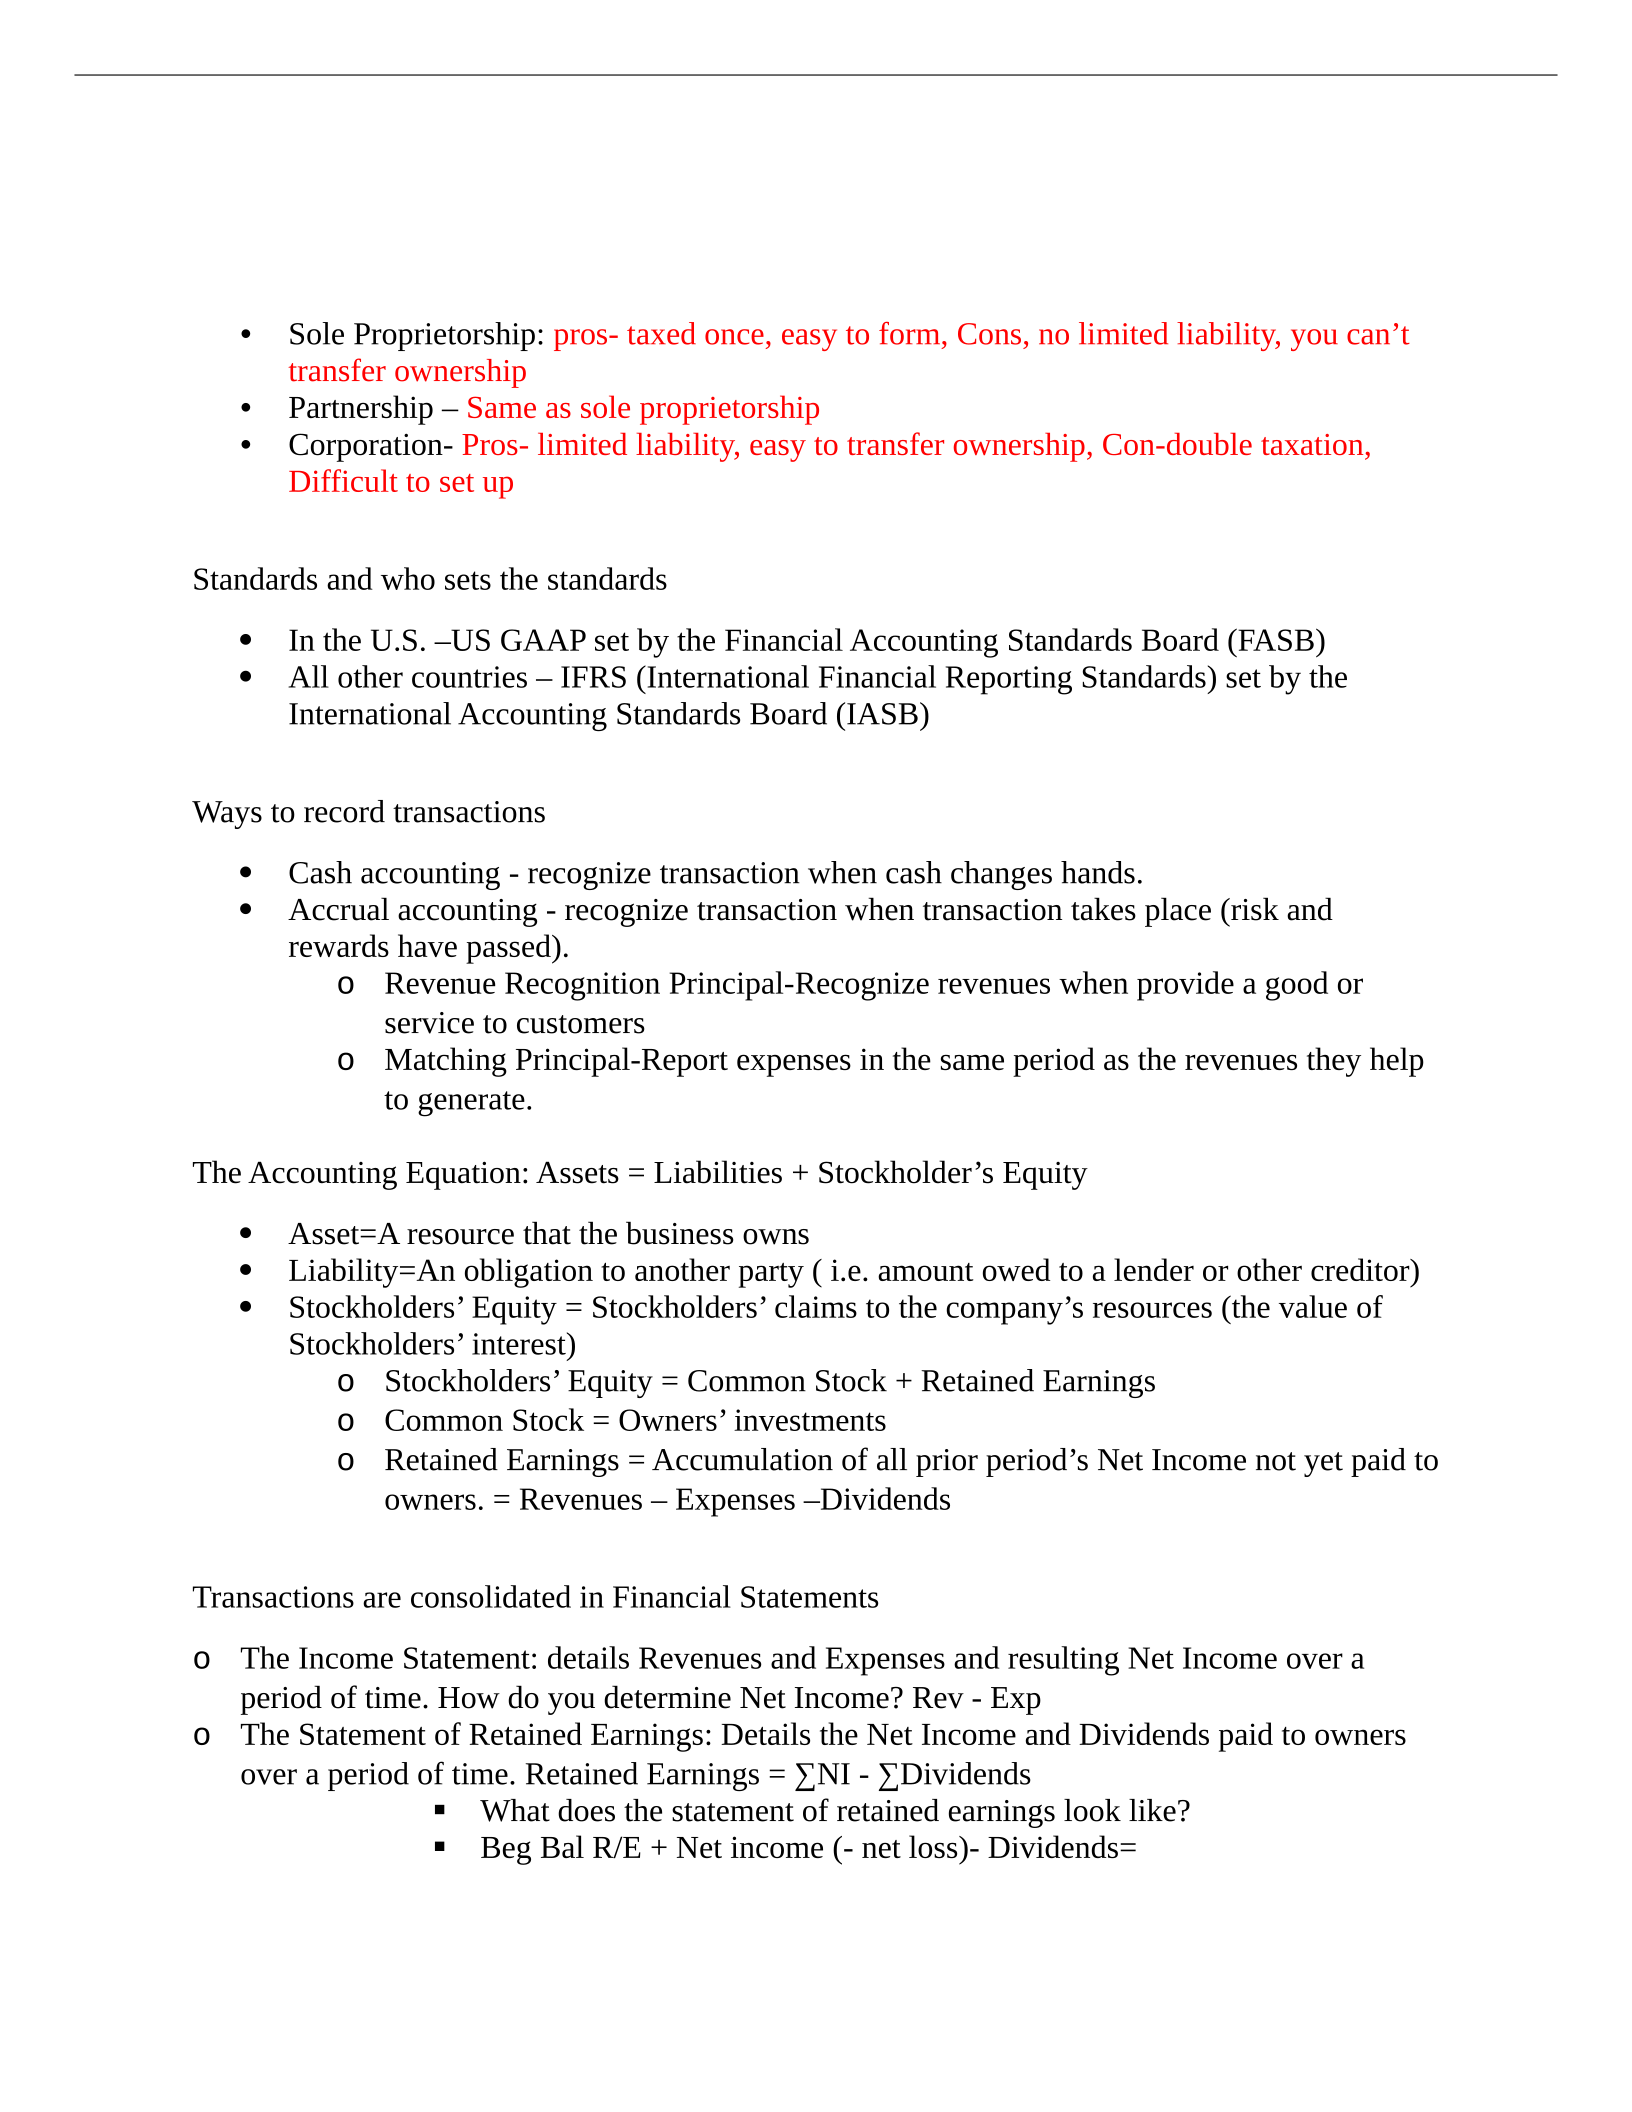
•Sole Proprietorship: pros- taxed once, easy to form, Cons, no limited liability, you can’t
transfer ownership
•Partnership – Same as sole proprietorship
•Corporation- Pros- limited liability, easy to transfer ownership, Con-double taxation,
Difficult to set up
Standards and who sets the standards
In the U.S. –US GAAP set by the Financial Accounting Standards Board (FASB)
All other countries – IFRS (International Financial Reporting Standards) set by the
International Accounting Standards Board (IASB)
Ways to record transactions
Cash accounting - recognize transaction when cash changes hands.
Accrual accounting - recognize transaction when transaction takes place (risk and
rewards have passed).
oRevenue Recognition Principal-Recognize revenues when provide a good or
service to customers
oMatching Principal-Report expenses in the same period as the revenues they help
to generate.
The Accounting Equation: Assets = Liabilities + Stockholder’s Equity
Asset=A resource that the business owns
Liability=An obligation to another party ( i.e. amount owed to a lender or other creditor)
Stockholders’ Equity = Stockholders’ claims to the company’s resources (the value of
Stockholders’ interest)
oStockholders’ Equity = Common Stock + Retained Earnings
oCommon Stock = Owners’ investments
oRetained Earnings = Accumulation of all prior period’s Net Income not yet paid to
owners. = Revenues – Expenses –Dividends
Transactions are consolidated in Financial Statements
oThe Income Statement: details Revenues and Expenses and resulting Net Income over a
period of time. How do you determine Net Income? Rev - Exp
oThe Statement of Retained Earnings: Details the Net Income and Dividends paid to owners
over a period of time. Retained Earnings = ∑NI - ∑Dividends
What does the statement of retained earnings look like?
Beg Bal R/E + Net income (- net loss)- Dividends=
What is financial Accounting?
Legal Forms of Business (what are the pros and cons of each)
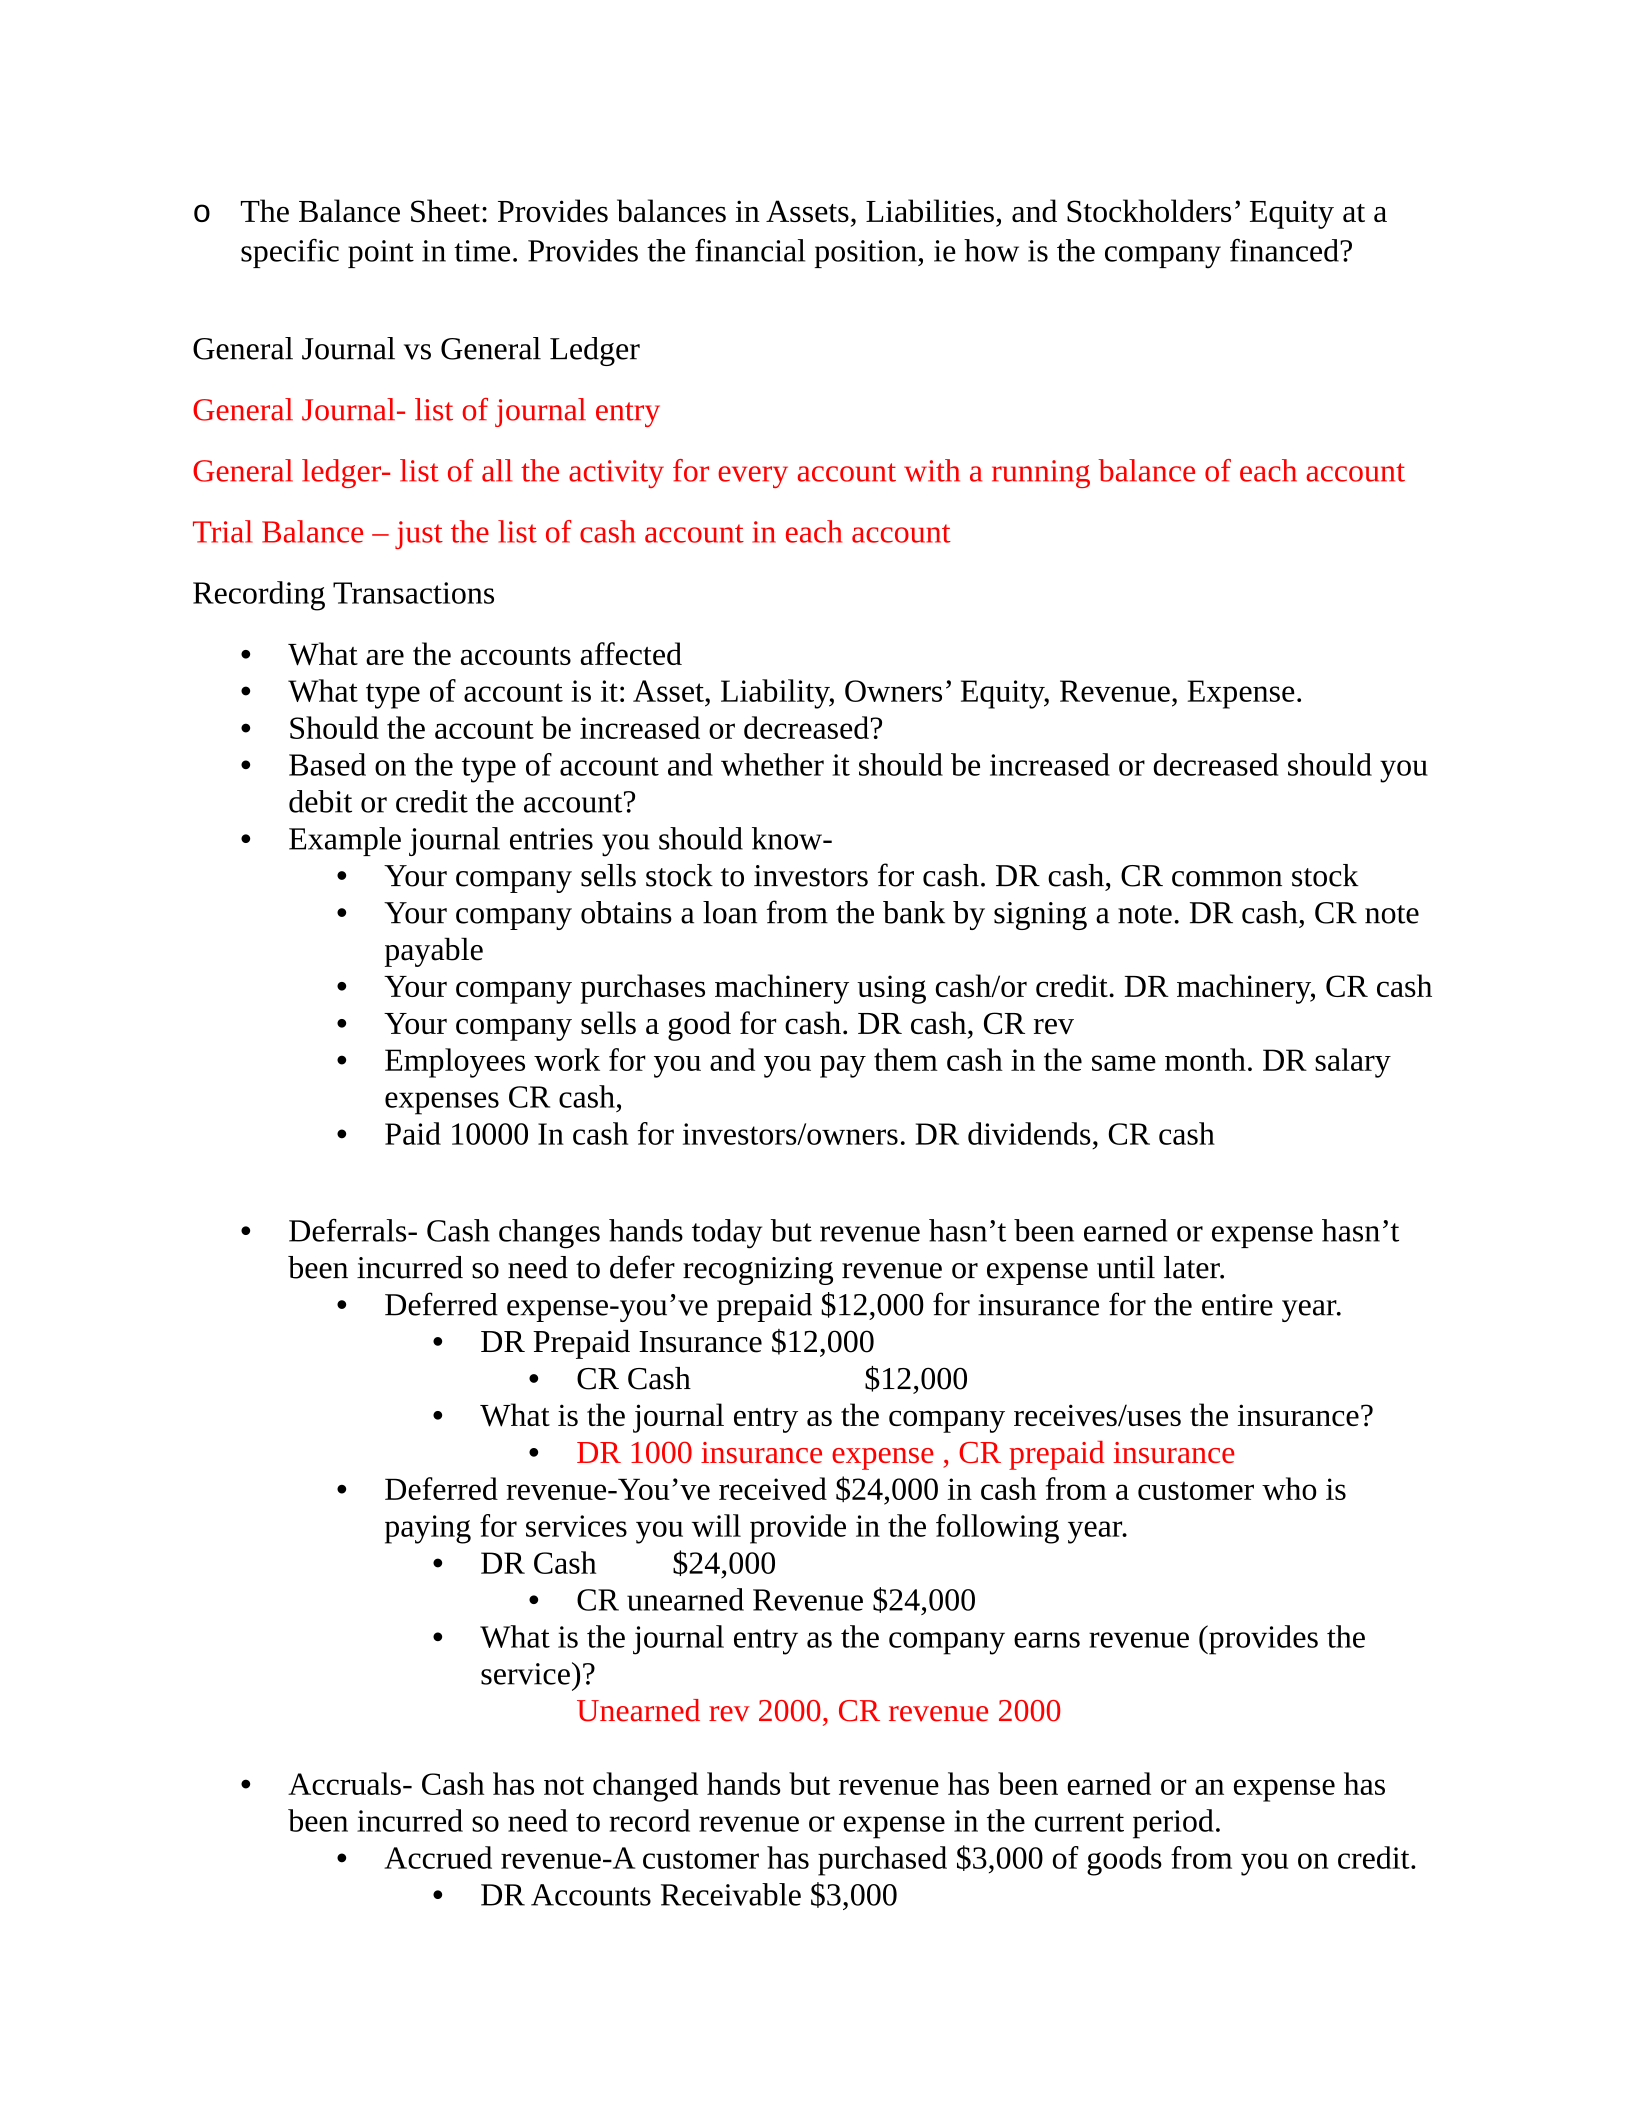
oThe Balance Sheet: Provides balances in Assets, Liabilities, and Stockholders’ Equity at a
specific point in time. Provides the financial position, ie how is the company financed?
General Journal vs General Ledger
General Journal- list of journal entry
General ledger- list of all the activity for every account with a running balance of each account
Trial Balance – just the list of cash account in each account
Recording Transactions
•What are the accounts affected
•What type of account is it: Asset, Liability, Owners’ Equity, Revenue, Expense.
•Should the account be increased or decreased?
•Based on the type of account and whether it should be increased or decreased should you
debit or credit the account?
•Example journal entries you should know-
•Your company sells stock to investors for cash. DR cash, CR common stock
•Your company obtains a loan from the bank by signing a note. DR cash, CR note
payable
•Your company purchases machinery using cash/or credit. DR machinery, CR cash
•Your company sells a good for cash. DR cash, CR rev
•Employees work for you and you pay them cash in the same month. DR salary
expenses CR cash,
•Paid 10000 In cash for investors/owners. DR dividends, CR cash
•Deferrals- Cash changes hands today but revenue hasn’t been earned or expense hasn’t
been incurred so need to defer recognizing revenue or expense until later.
•Deferred expense-you’ve prepaid $12,000 for insurance for the entire year.
•DR Prepaid Insurance $12,000
•CR Cash $12,000
•What is the journal entry as the company receives/uses the insurance?
•DR 1000 insurance expense , CR prepaid insurance
•Deferred revenue-You’ve received $24,000 in cash from a customer who is
paying for services you will provide in the following year.
•DR Cash $24,000
•CR unearned Revenue $24,000
•What is the journal entry as the company earns revenue (provides the
service)?
Unearned rev 2000, CR revenue 2000
•Accruals- Cash has not changed hands but revenue has been earned or an expense has
been incurred so need to record revenue or expense in the current period.
•Accrued revenue-A customer has purchased $3,000 of goods from you on credit.
•DR Accounts Receivable $3,000
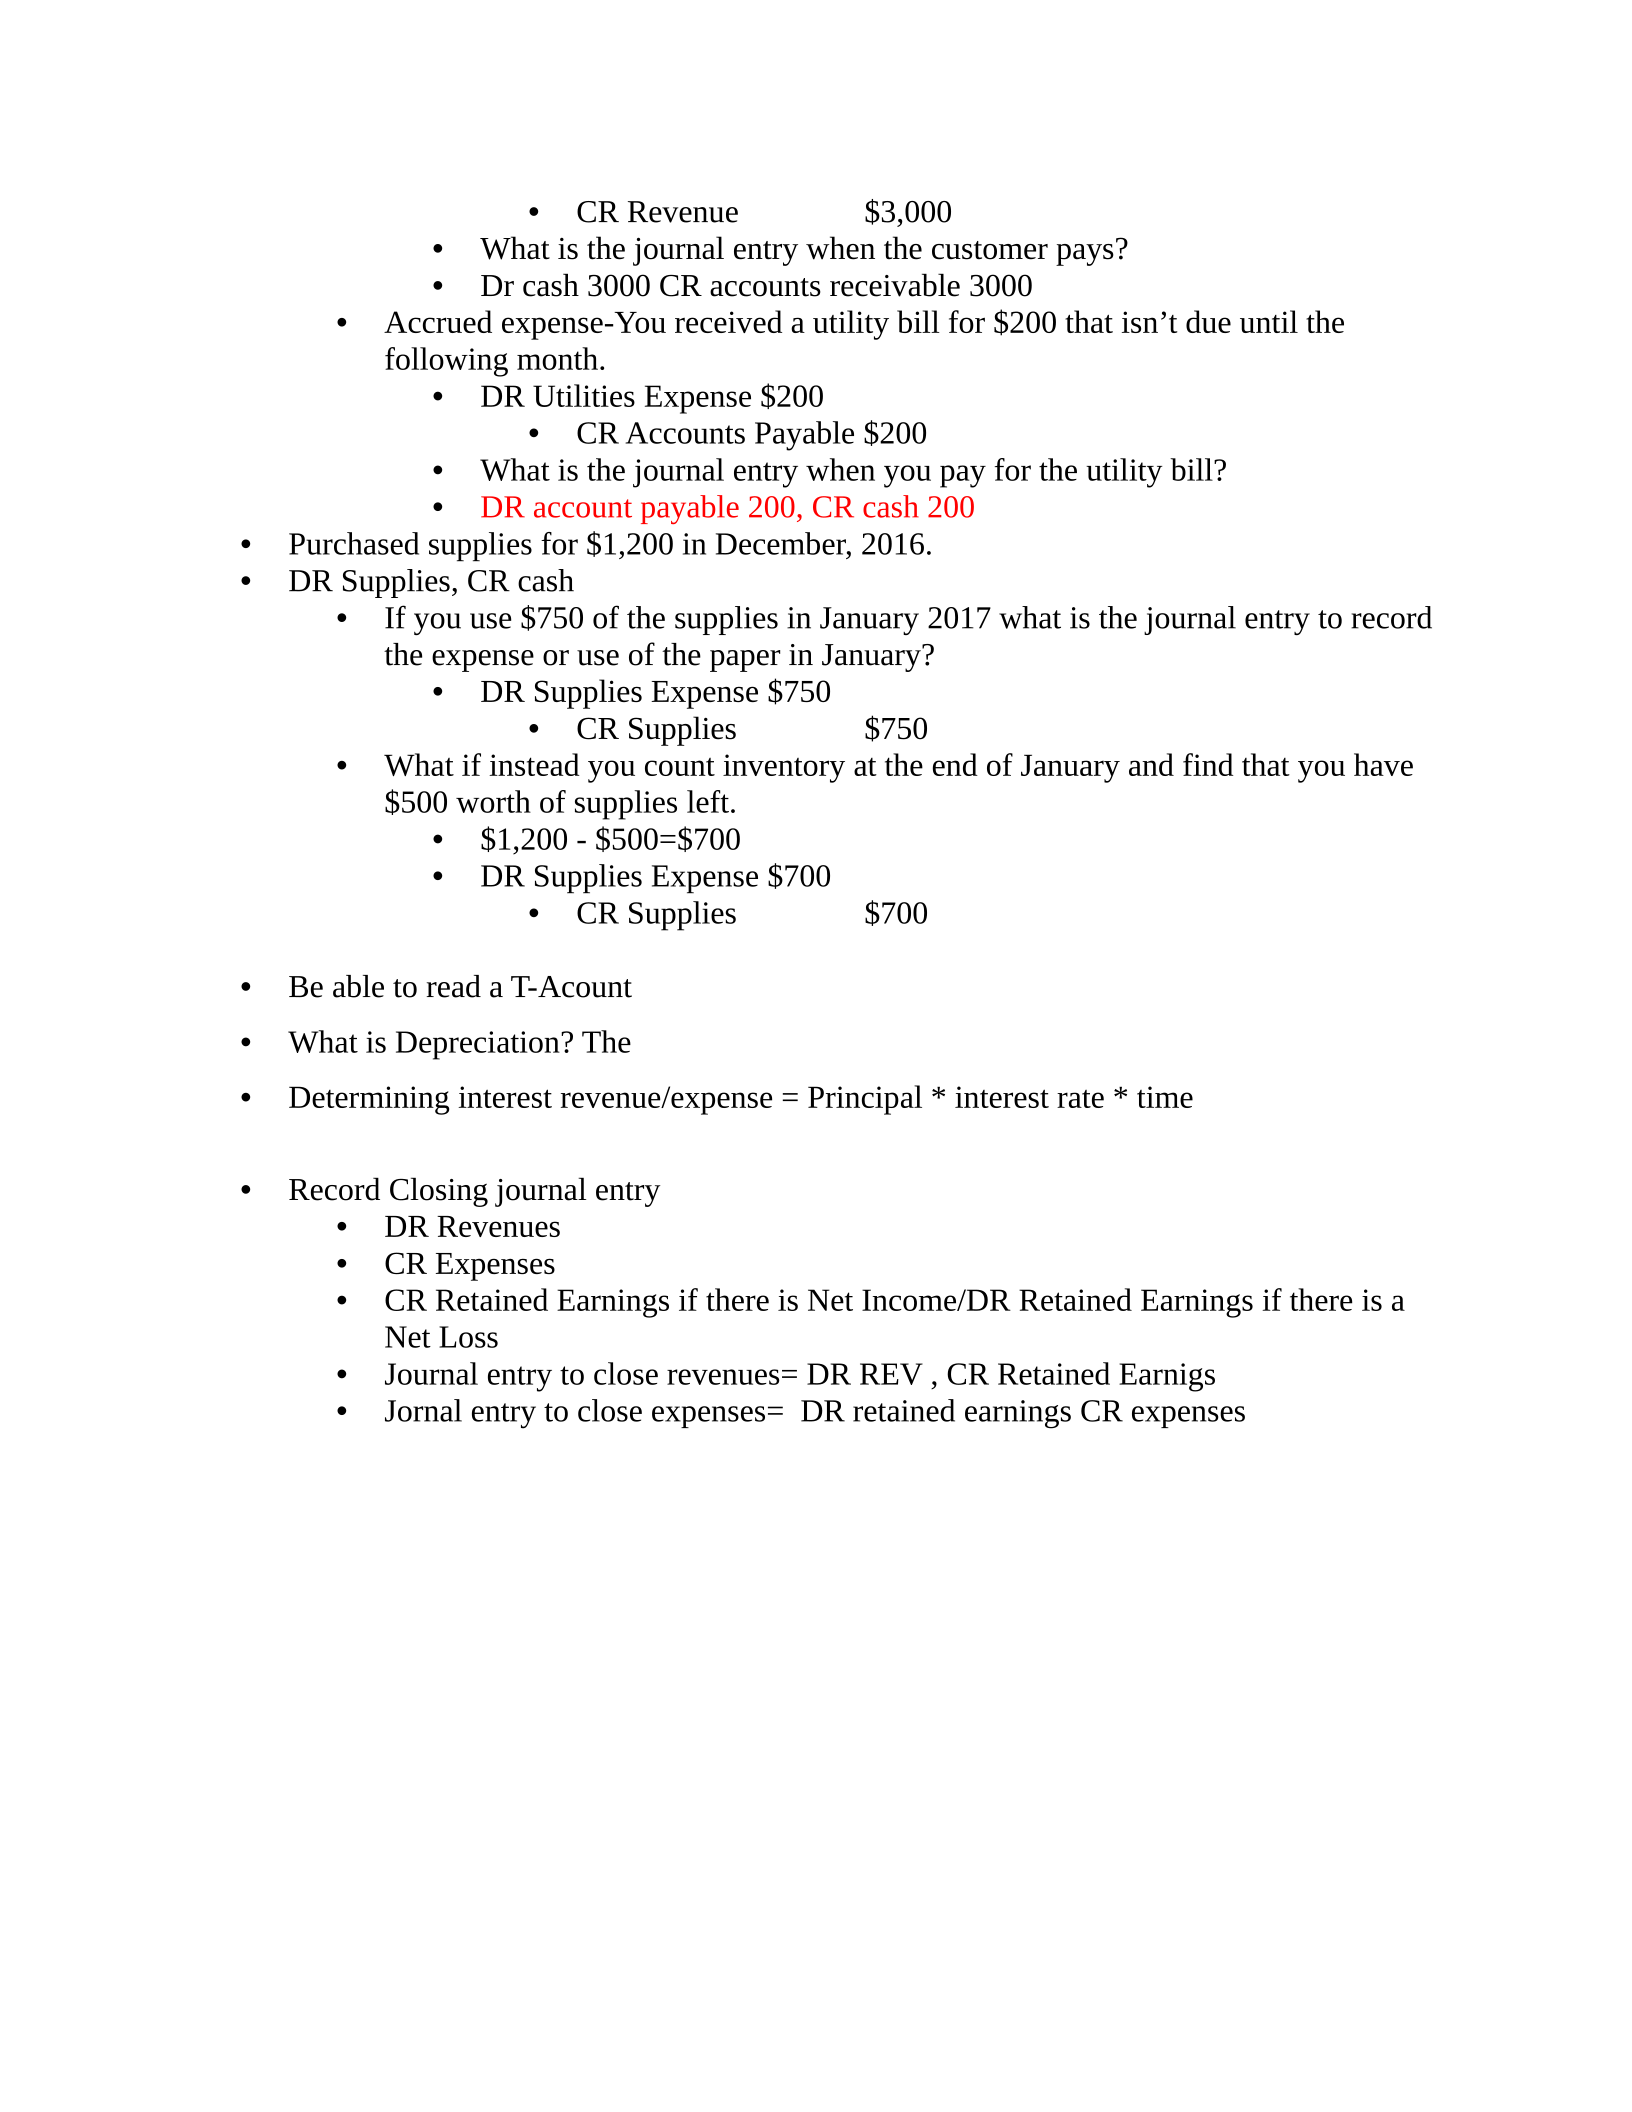
•CR Revenue $3,000
•What is the journal entry when the customer pays?
•Dr cash 3000 CR accounts receivable 3000
•Accrued expense-You received a utility bill for $200 that isn’t due until the
following month.
•DR Utilities Expense $200
•CR Accounts Payable $200
•What is the journal entry when you pay for the utility bill?
•DR account payable 200, CR cash 200
•Purchased supplies for $1,200 in December, 2016.
•DR Supplies, CR cash
•If you use $750 of the supplies in January 2017 what is the journal entry to record
the expense or use of the paper in January?
•DR Supplies Expense $750
•CR Supplies $750
•What if instead you count inventory at the end of January and find that you have
$500 worth of supplies left.
•$1,200 - $500=$700
•DR Supplies Expense $700
•CR Supplies $700
•Be able to read a T-Acount
•What is Depreciation? The
•Determining interest revenue/expense = Principal * interest rate * time
•Record Closing journal entry
•DR Revenues
•CR Expenses
•CR Retained Earnings if there is Net Income/DR Retained Earnings if there is a
Net Loss
•Journal entry to close revenues= DR REV , CR Retained Earnigs
•Jornal entry to close expenses= DR retained earnings CR expenses
Powered by TCPDF (www.tcpdf.org)

