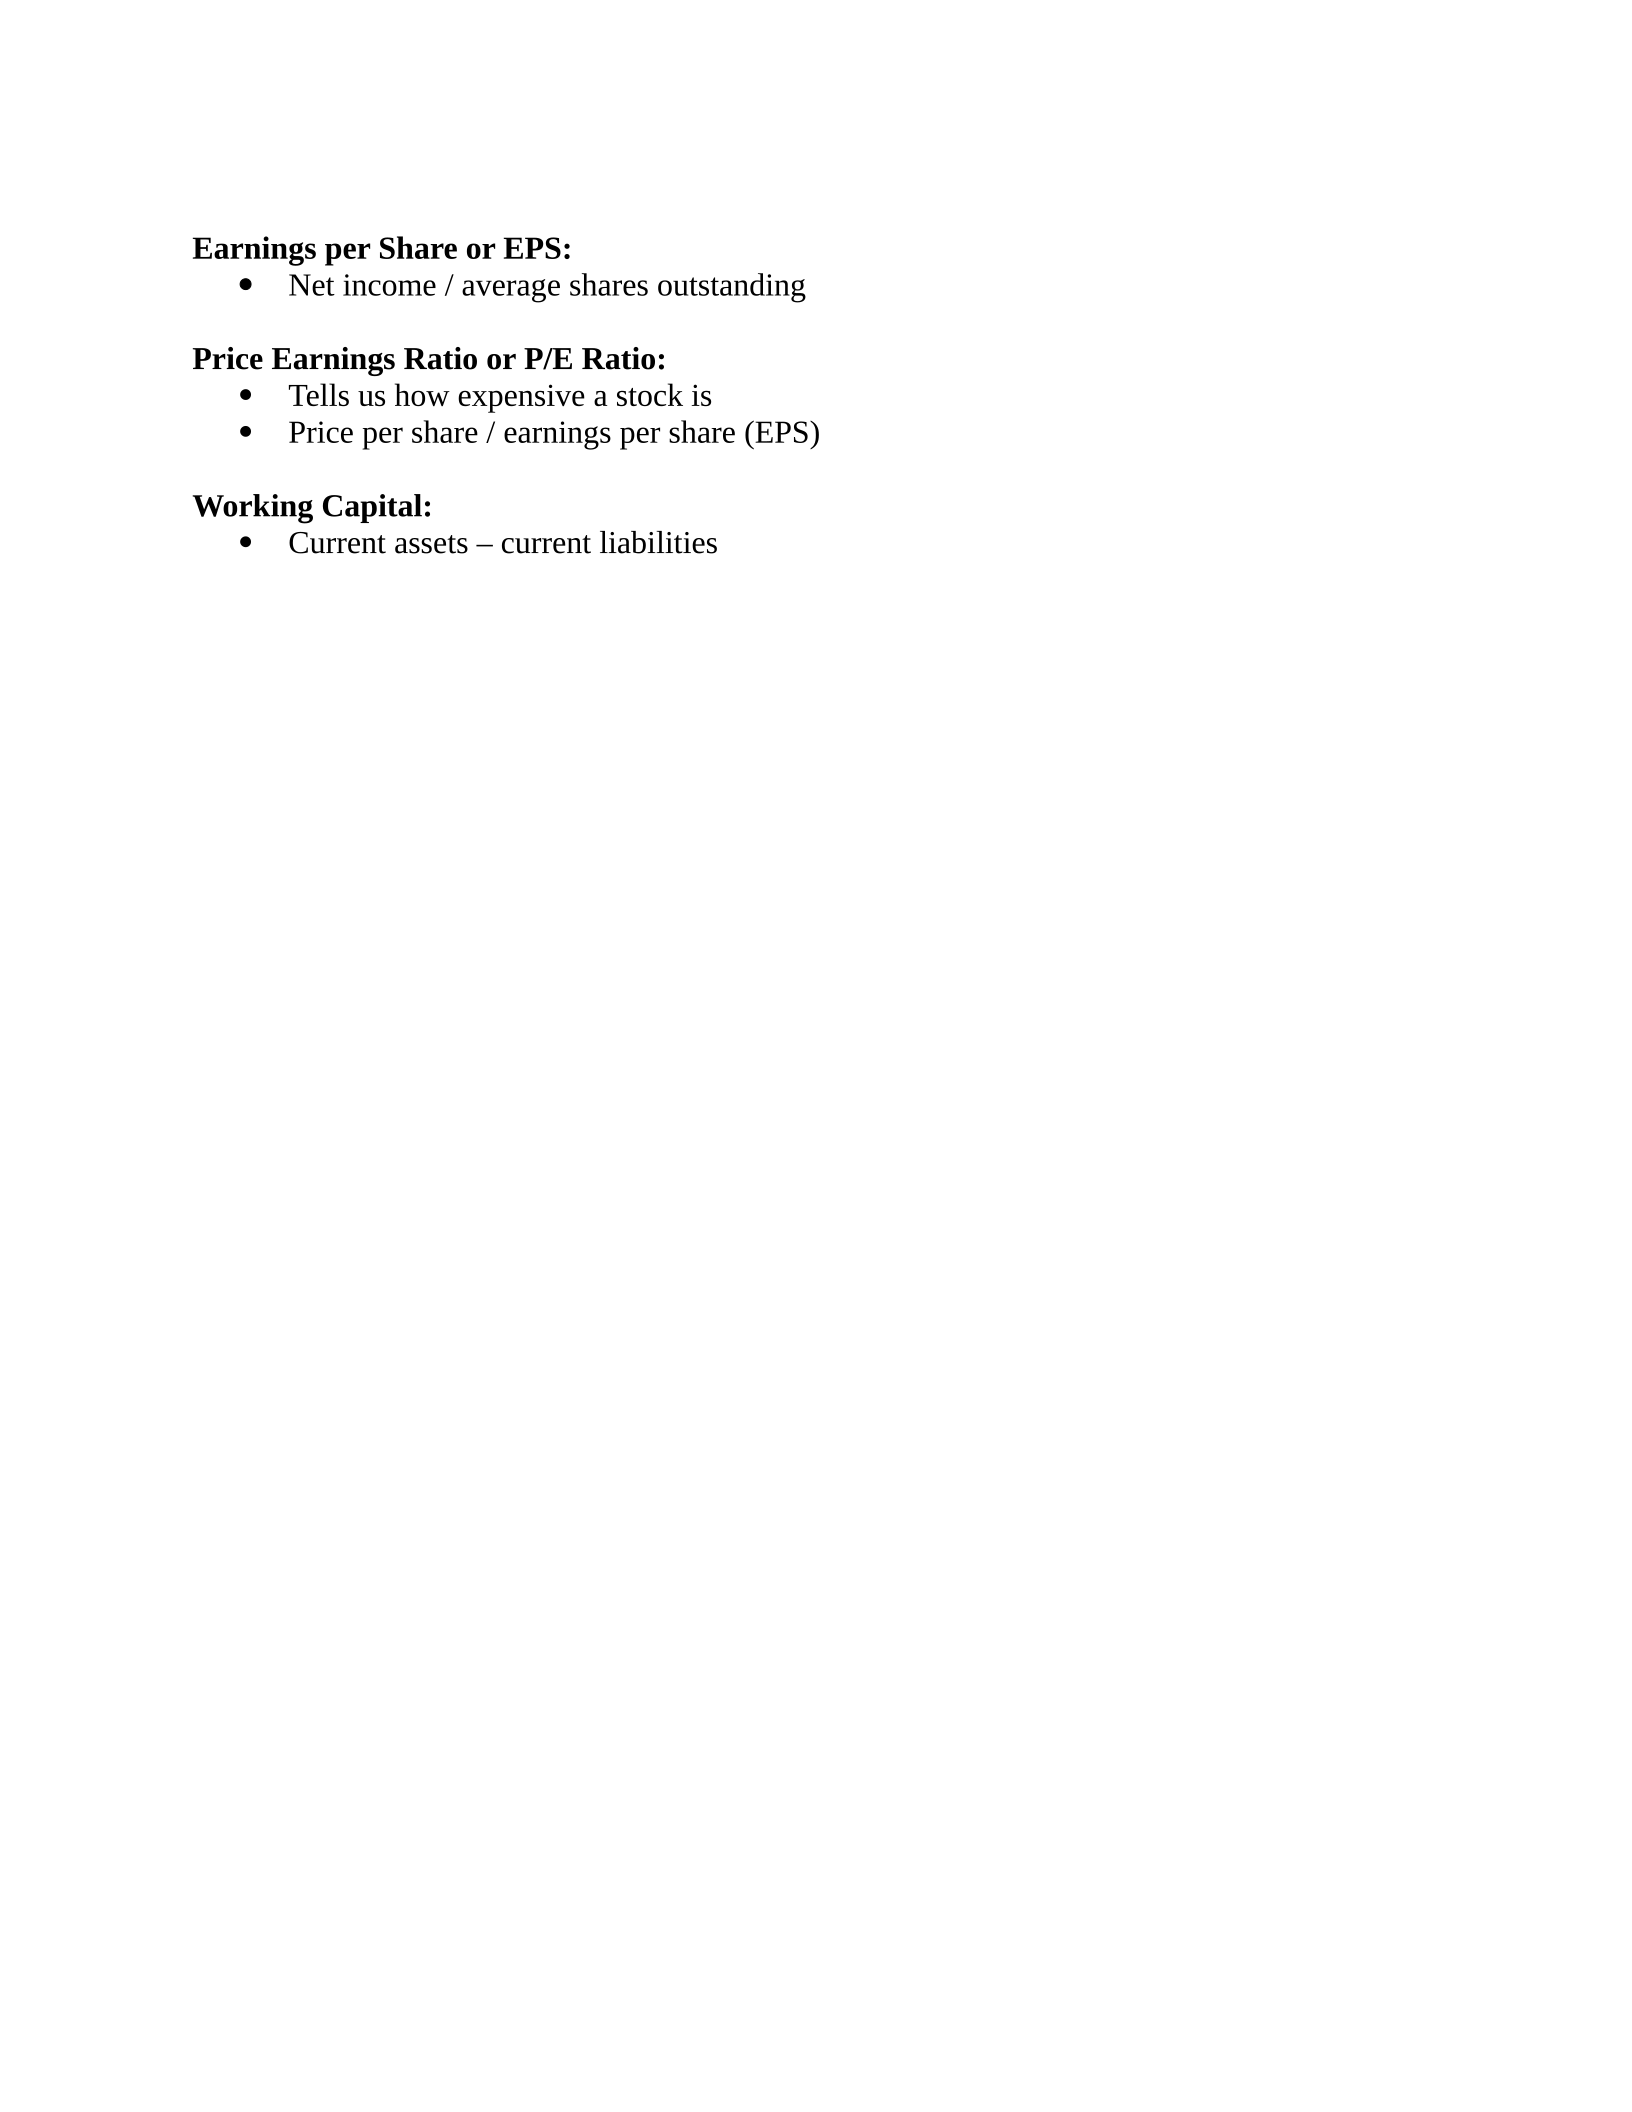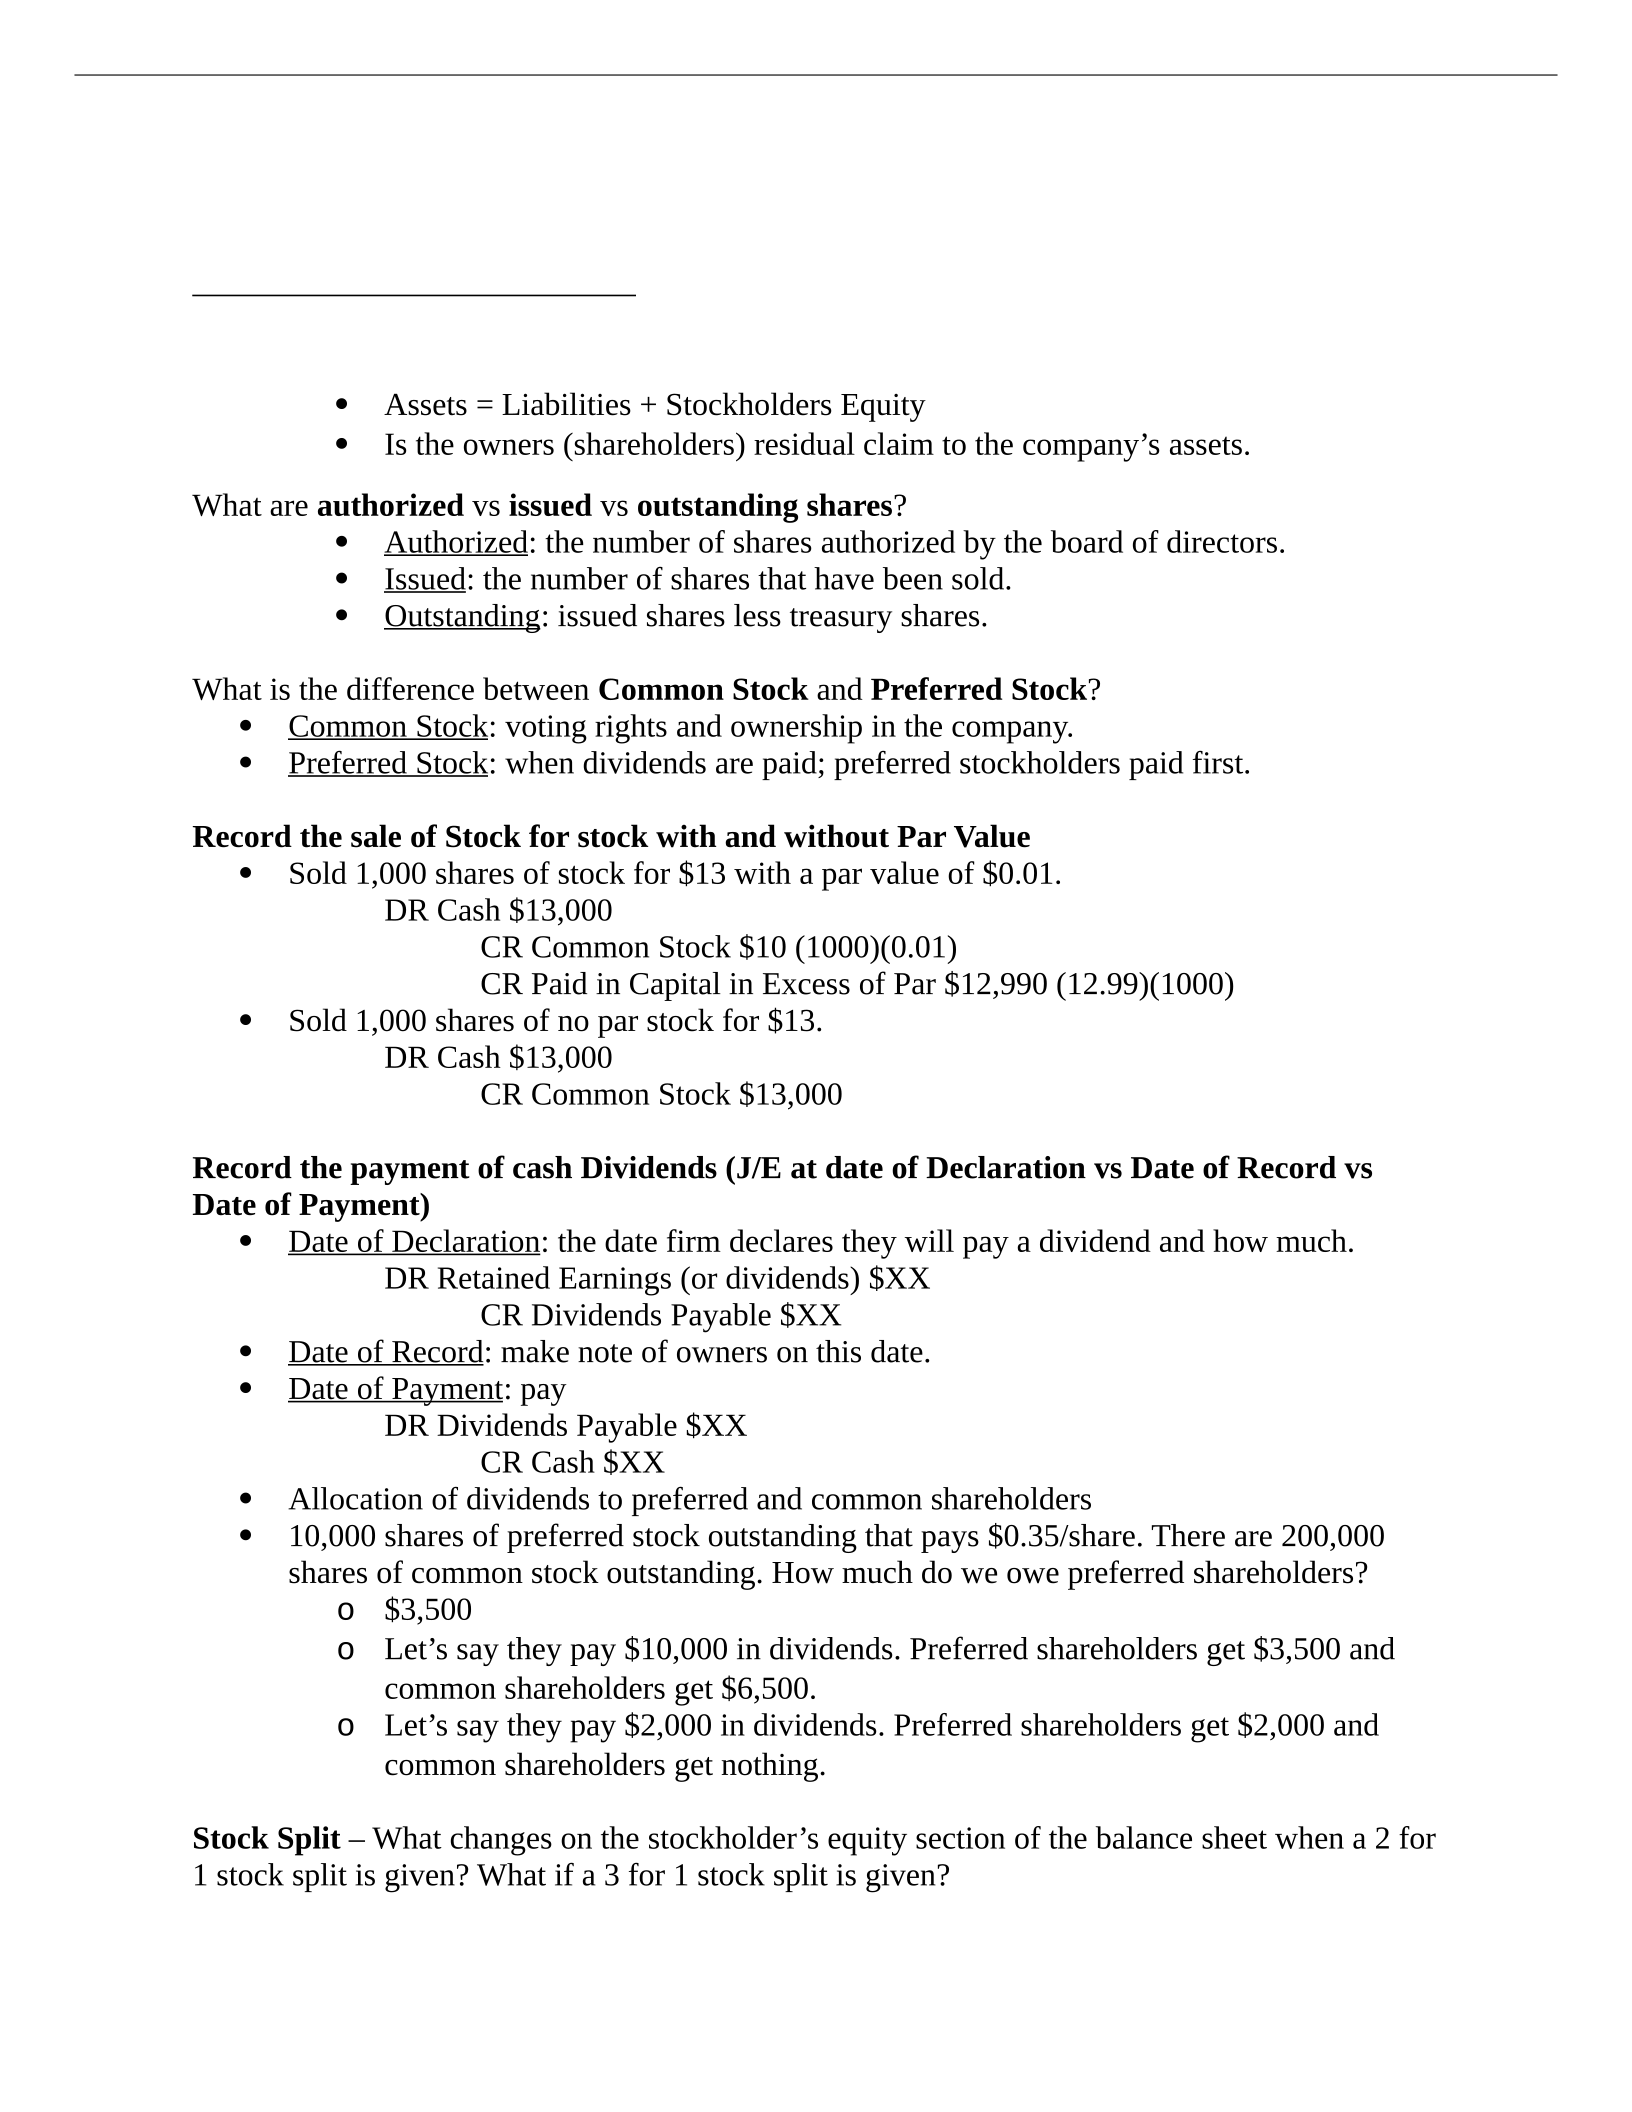
Assets = Liabilities + Stockholders Equity
Is the owners (shareholders) residual claim to the company’s assets.
What are authorized vs issued vs outstanding shares?
Authorized : the number of shares authorized by the board of directors.
Issued : the number of shares that have been sold.
Outstanding : issued shares less treasury shares.
What is the difference between Common Stock and Preferred Stock?
Common Stock : voting rights and ownership in the company.
Preferred Stock : when dividends are paid; preferred stockholders paid first.
Record the sale of Stock for stock with and without Par Value
Sold 1,000 shares of stock for $13 with a par value of $0.01.
DR Cash $13,000
CR Common Stock $10 (1000)(0.01)
CR Paid in Capital in Excess of Par $12,990 (12.99)(1000)
Sold 1,000 shares of no par stock for $13.
DR Cash $13,000
CR Common Stock $13,000
Record the payment of cash Dividends (J/E at date of Declaration vs Date of Record vs
Date of Payment)
Date of Declaration : the date firm declares they will pay a dividend and how much.
DR Retained Earnings (or dividends) $XX
CR Dividends Payable $XX
Date of Record : make note of owners on this date.
Date of Payment : pay
DR Dividends Payable $XX
CR Cash $XX
Allocation of dividends to preferred and common shareholders
10,000 shares of preferred stock outstanding that pays $0.35/share. There are 200,000
shares of common stock outstanding. How much do we owe preferred shareholders?
o$3,500
oLet’s say they pay $10,000 in dividends. Preferred shareholders get $3,500 and
common shareholders get $6,500.
oLet’s say they pay $2,000 in dividends. Preferred shareholders get $2,000 and
common shareholders get nothing.
Stock Split – What changes on the stockholder’s equity section of the balance sheet when a 2 for
1 stock split is given? What if a 3 for 1 stock split is given?
Exam 4 Outline
Chapter 10 – Stockholder’s Equity
What does Stockholder’s Equity represent in the Accounting Equation?
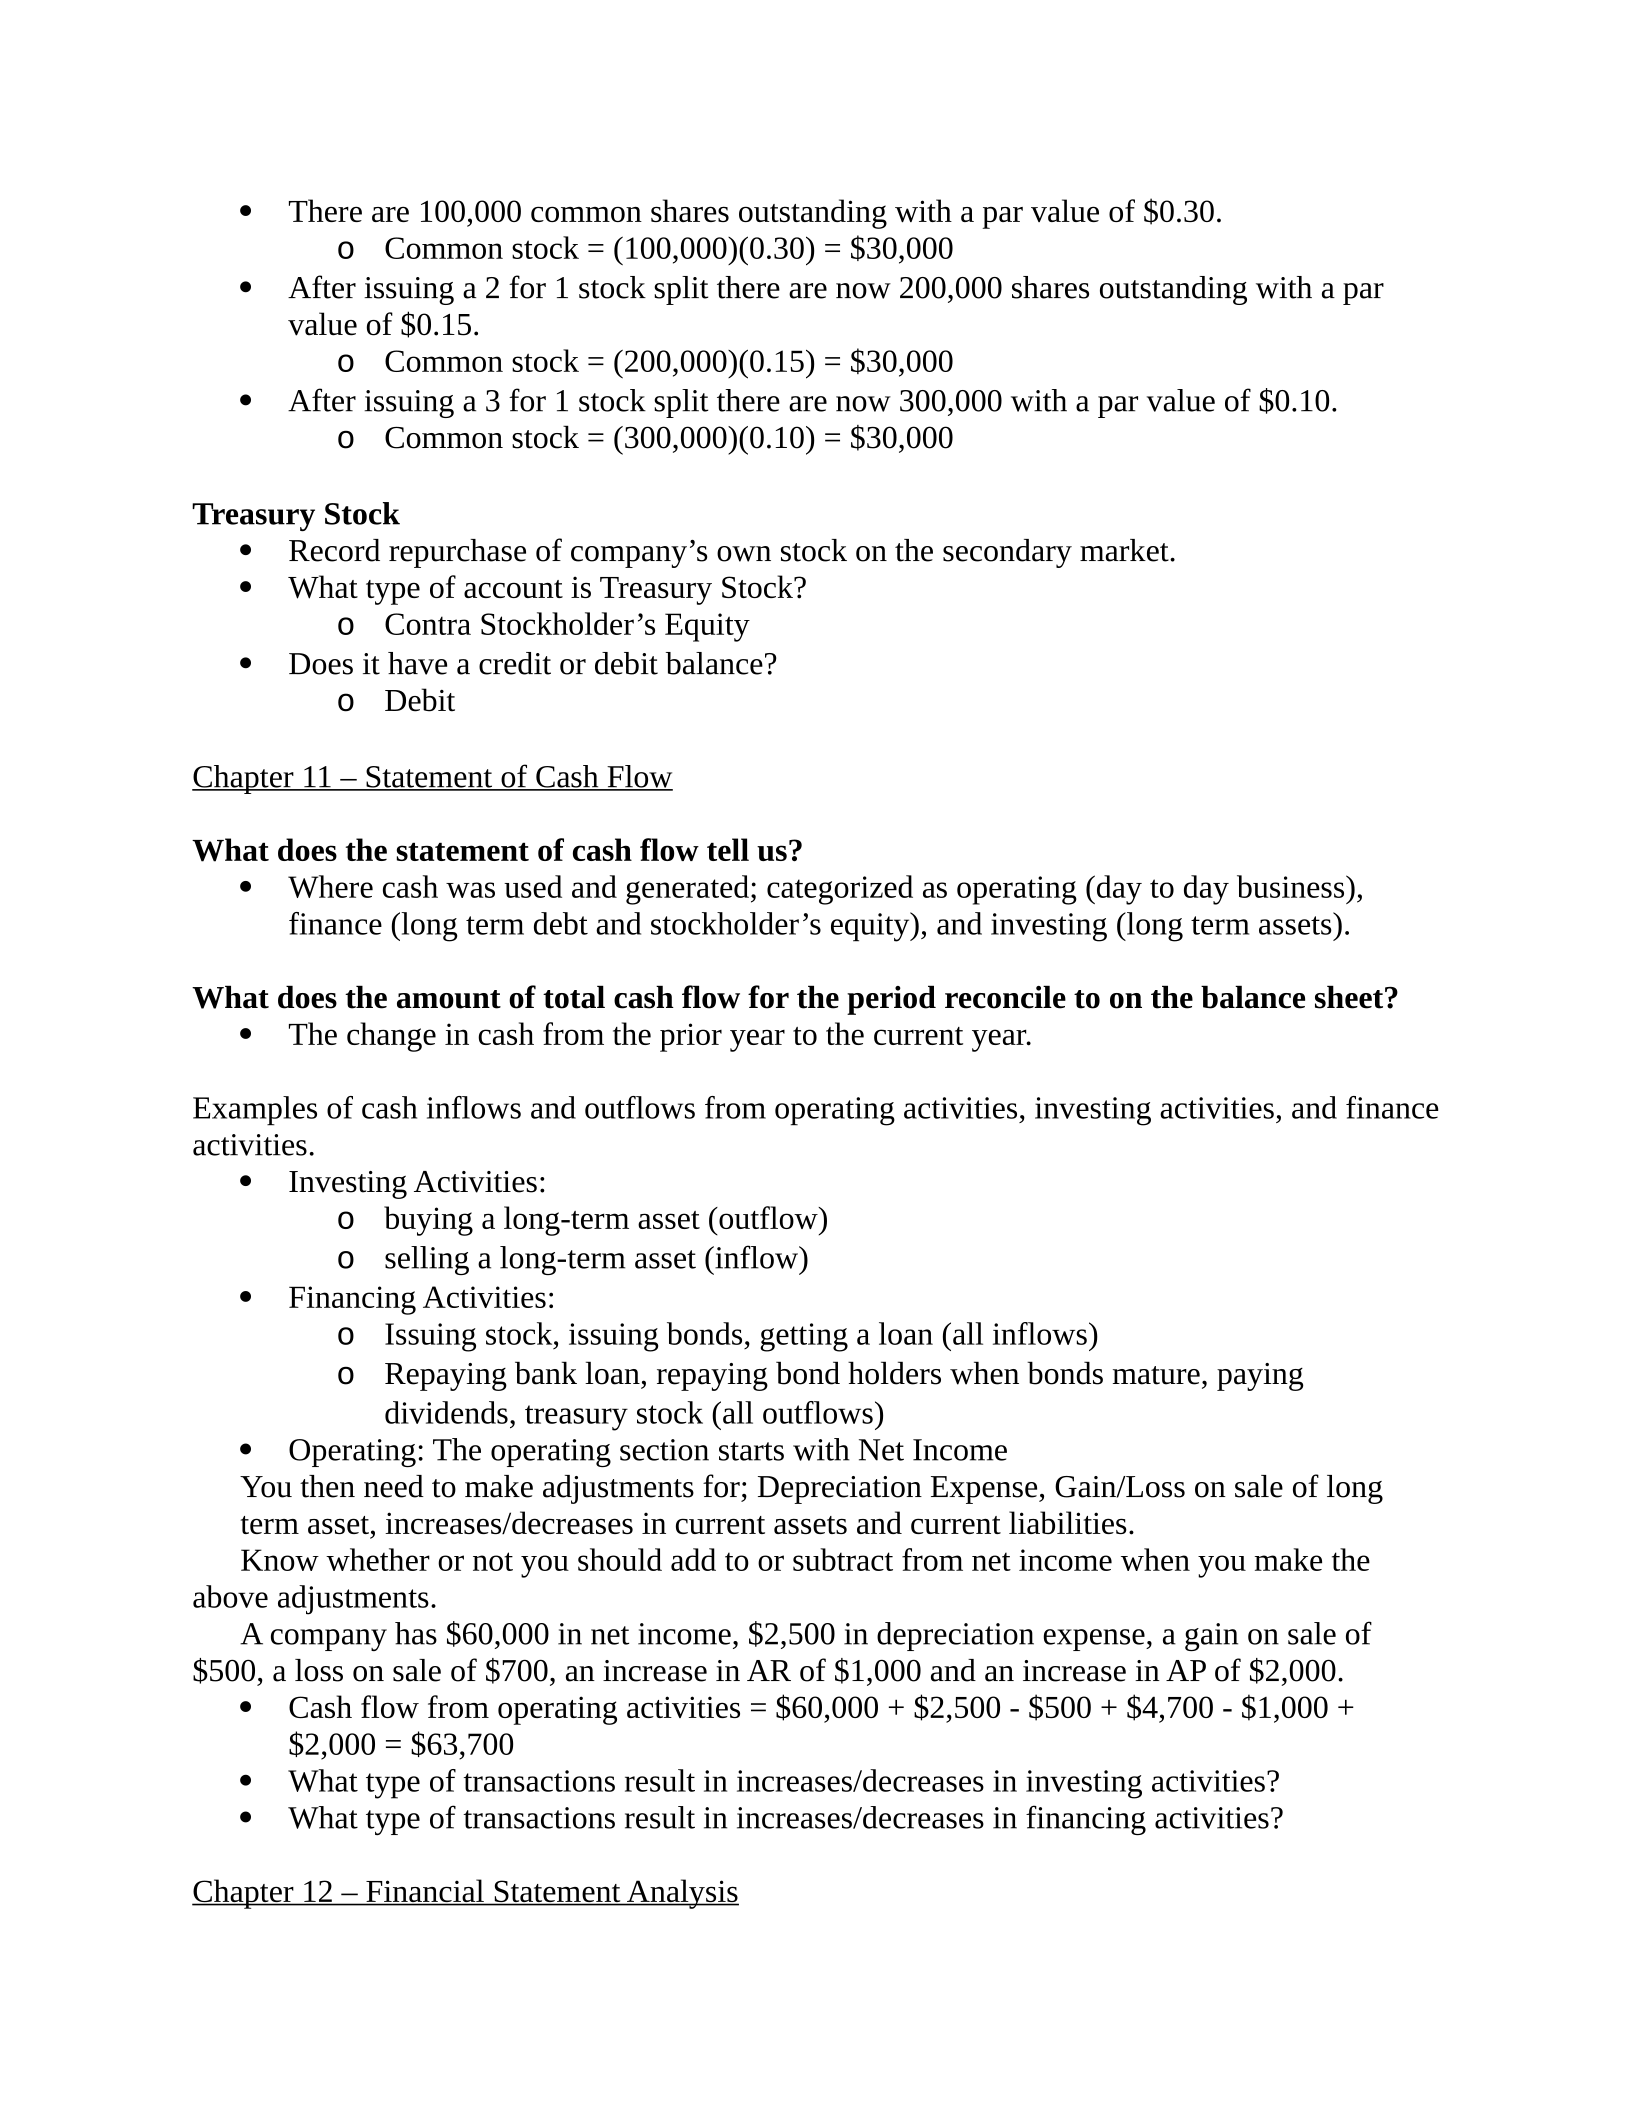
There are 100,000 common shares outstanding with a par value of $0.30.
oCommon stock = (100,000)(0.30) = $30,000
After issuing a 2 for 1 stock split there are now 200,000 shares outstanding with a par
value of $0.15.
oCommon stock = (200,000)(0.15) = $30,000
After issuing a 3 for 1 stock split there are now 300,000 with a par value of $0.10.
oCommon stock = (300,000)(0.10) = $30,000
Treasury Stock
Record repurchase of company’s own stock on the secondary market.
What type of account is Treasury Stock?
oContra Stockholder’s Equity
Does it have a credit or debit balance?
oDebit
Chapter 11 – Statement of Cash Flow
What does the statement of cash flow tell us?
Where cash was used and generated; categorized as operating (day to day business),
finance (long term debt and stockholder’s equity), and investing (long term assets).
What does the amount of total cash flow for the period reconcile to on the balance sheet?
The change in cash from the prior year to the current year.
Examples of cash inflows and outflows from operating activities, investing activities, and finance
activities.
Investing Activities:
obuying a long-term asset (outflow)
oselling a long-term asset (inflow)
Financing Activities:
oIssuing stock, issuing bonds, getting a loan (all inflows)
oRepaying bank loan, repaying bond holders when bonds mature, paying
dividends, treasury stock (all outflows)
Operating: The operating section starts with Net Income
You then need to make adjustments for; Depreciation Expense, Gain/Loss on sale of long
term asset, increases/decreases in current assets and current liabilities.
Know whether or not you should add to or subtract from net income when you make the
above adjustments.
A company has $60,000 in net income, $2,500 in depreciation expense, a gain on sale of
$500, a loss on sale of $700, an increase in AR of $1,000 and an increase in AP of $2,000.
Cash flow from operating activities = $60,000 + $2,500 - $500 + $4,700 - $1,000 +
$2,000 = $63,700
What type of transactions result in increases/decreases in investing activities?
What type of transactions result in increases/decreases in financing activities?
Chapter 12 – Financial Statement Analysis
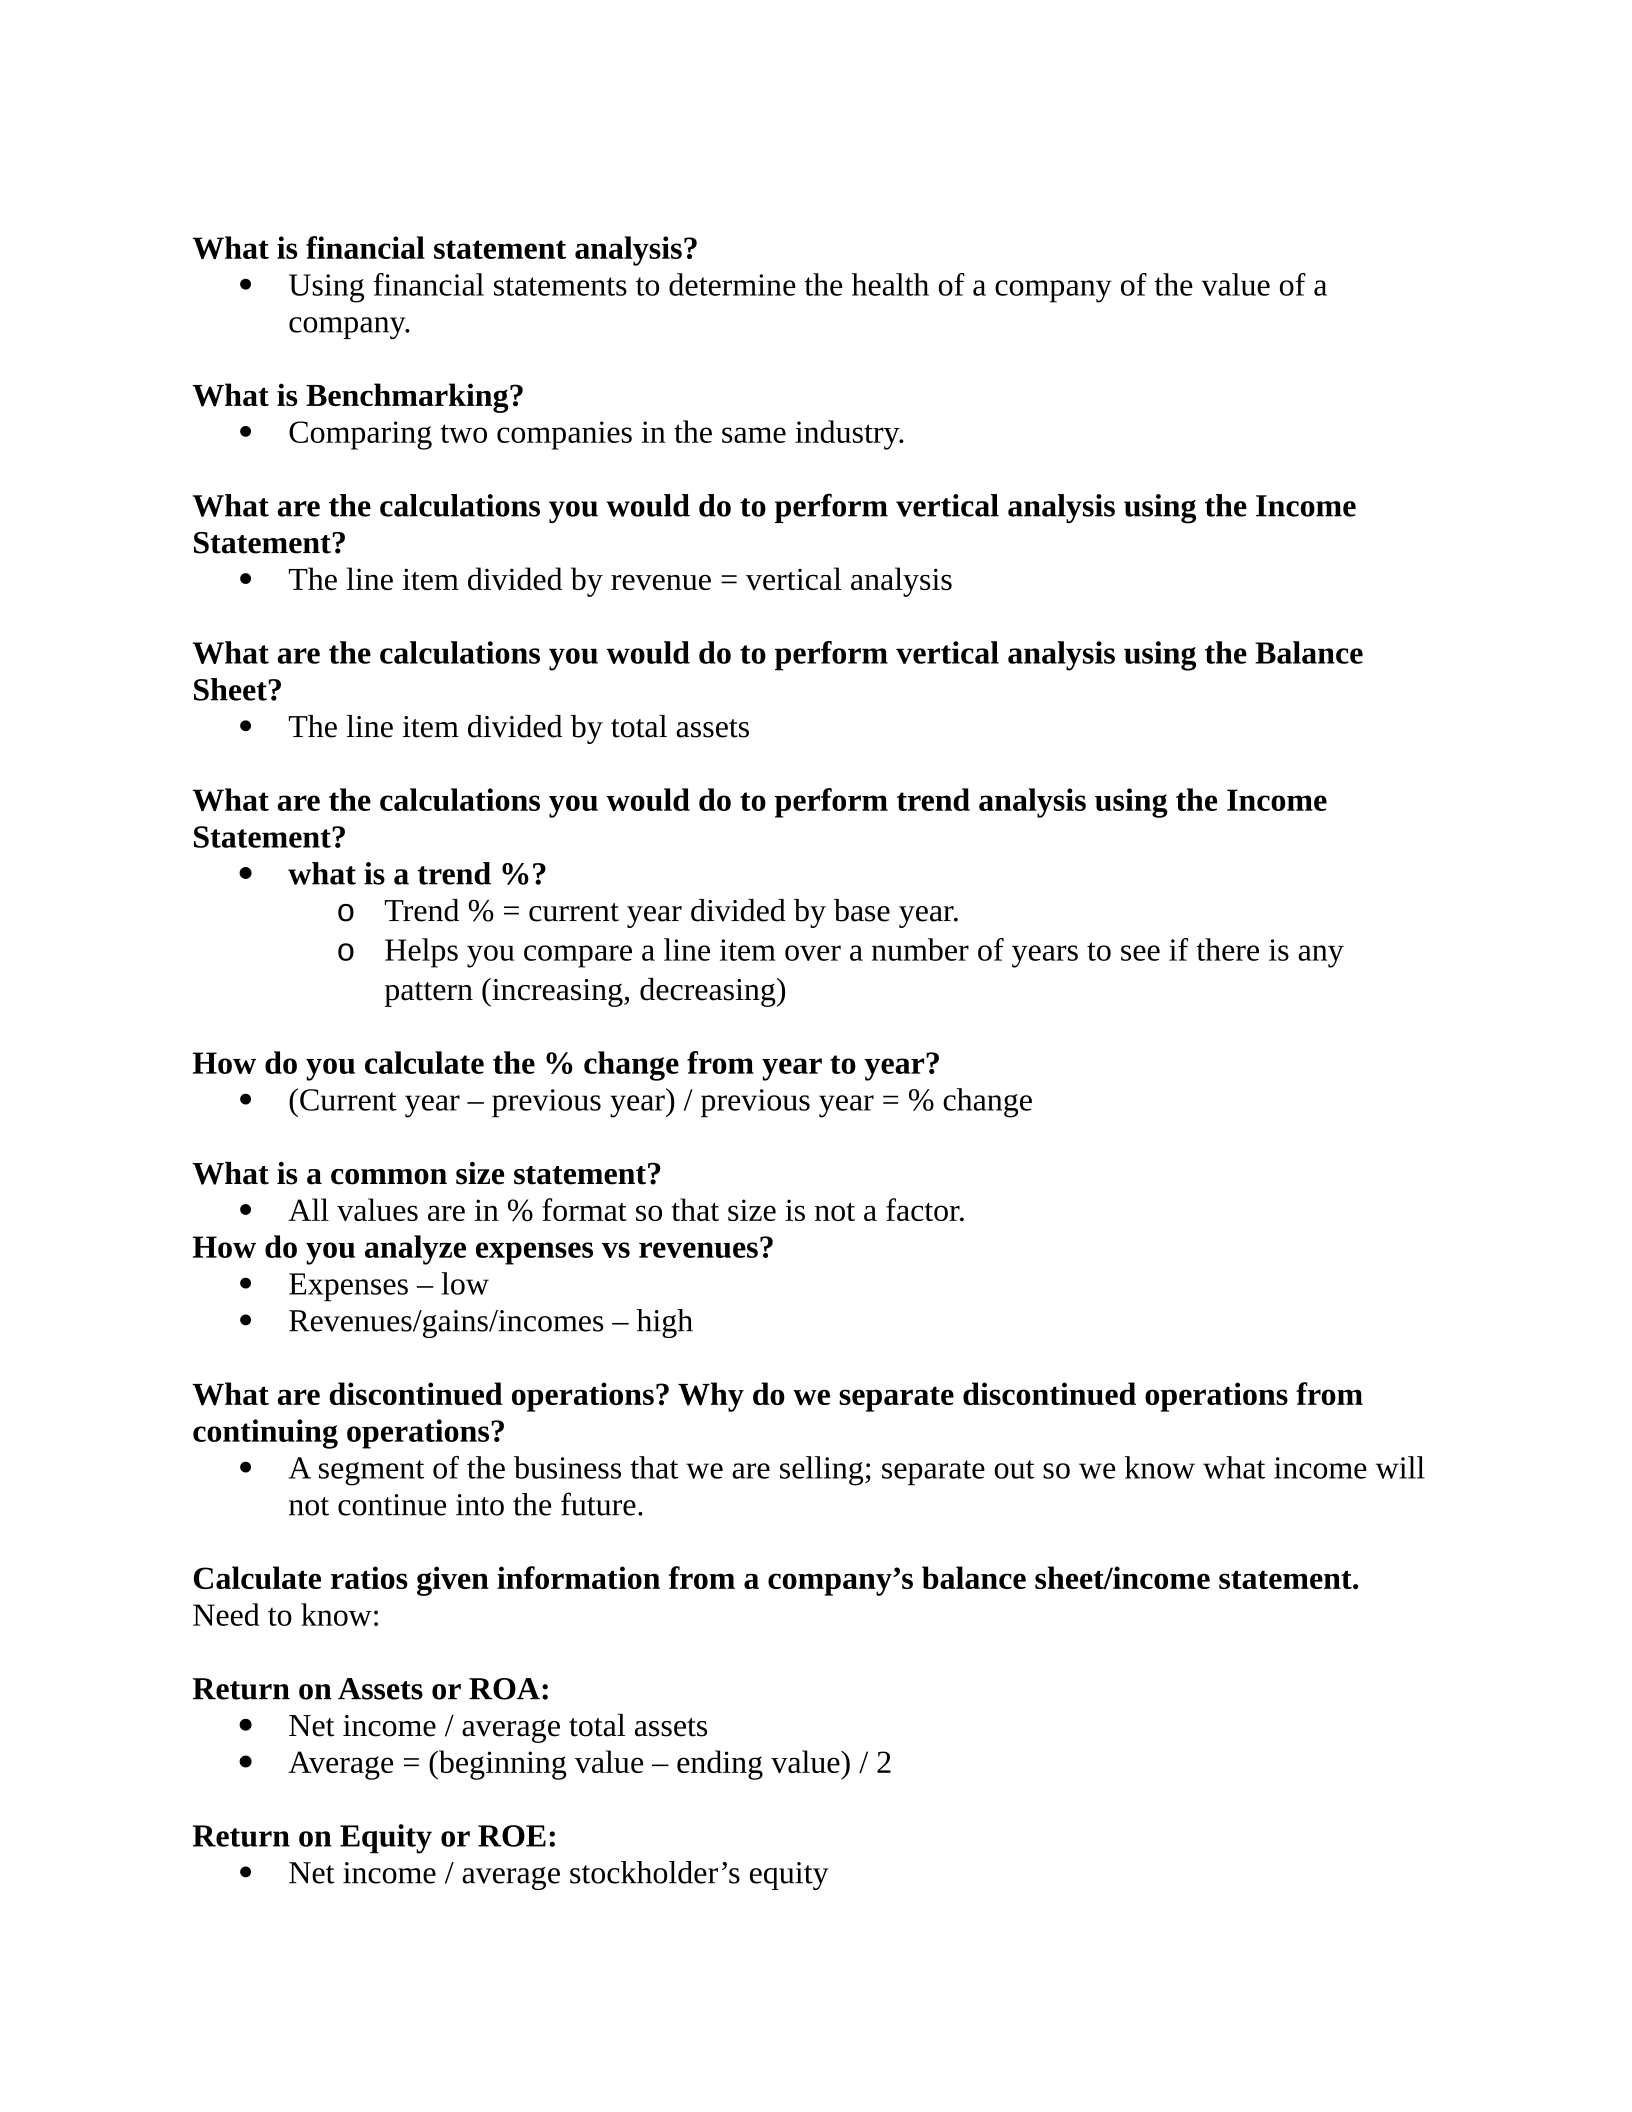
What is financial statement analysis?
Using financial statements to determine the health of a company of the value of a
company.
What is Benchmarking?
Comparing two companies in the same industry.
What are the calculations you would do to perform vertical analysis using the Income
Statement?
The line item divided by revenue = vertical analysis
What are the calculations you would do to perform vertical analysis using the Balance
Sheet?
The line item divided by total assets
What are the calculations you would do to perform trend analysis using the Income
Statement?
what is a trend %?
oTrend % = current year divided by base year.
oHelps you compare a line item over a number of years to see if there is any
pattern (increasing, decreasing)
How do you calculate the % change from year to year?
(Current year – previous year) / previous year = % change
What is a common size statement?
All values are in % format so that size is not a factor.
How do you analyze expenses vs revenues?
Expenses – low
Revenues/gains/incomes – high
What are discontinued operations? Why do we separate discontinued operations from
continuing operations?
A segment of the business that we are selling; separate out so we know what income will
not continue into the future.
Calculate ratios given information from a company’s balance sheet/income statement.
Need to know:
Return on Assets or ROA:
Net income / average total assets
Average = (beginning value – ending value) / 2
Return on Equity or ROE:
Net income / average stockholder’s equity