


Page 1 of 5 ACC 231 – Fall 2020
SuggestedSolutions
ACC231 – Fall 2020 Chapter 2 - ACTIVITY #1
Accounts – Normal Balances, Debits & Credits
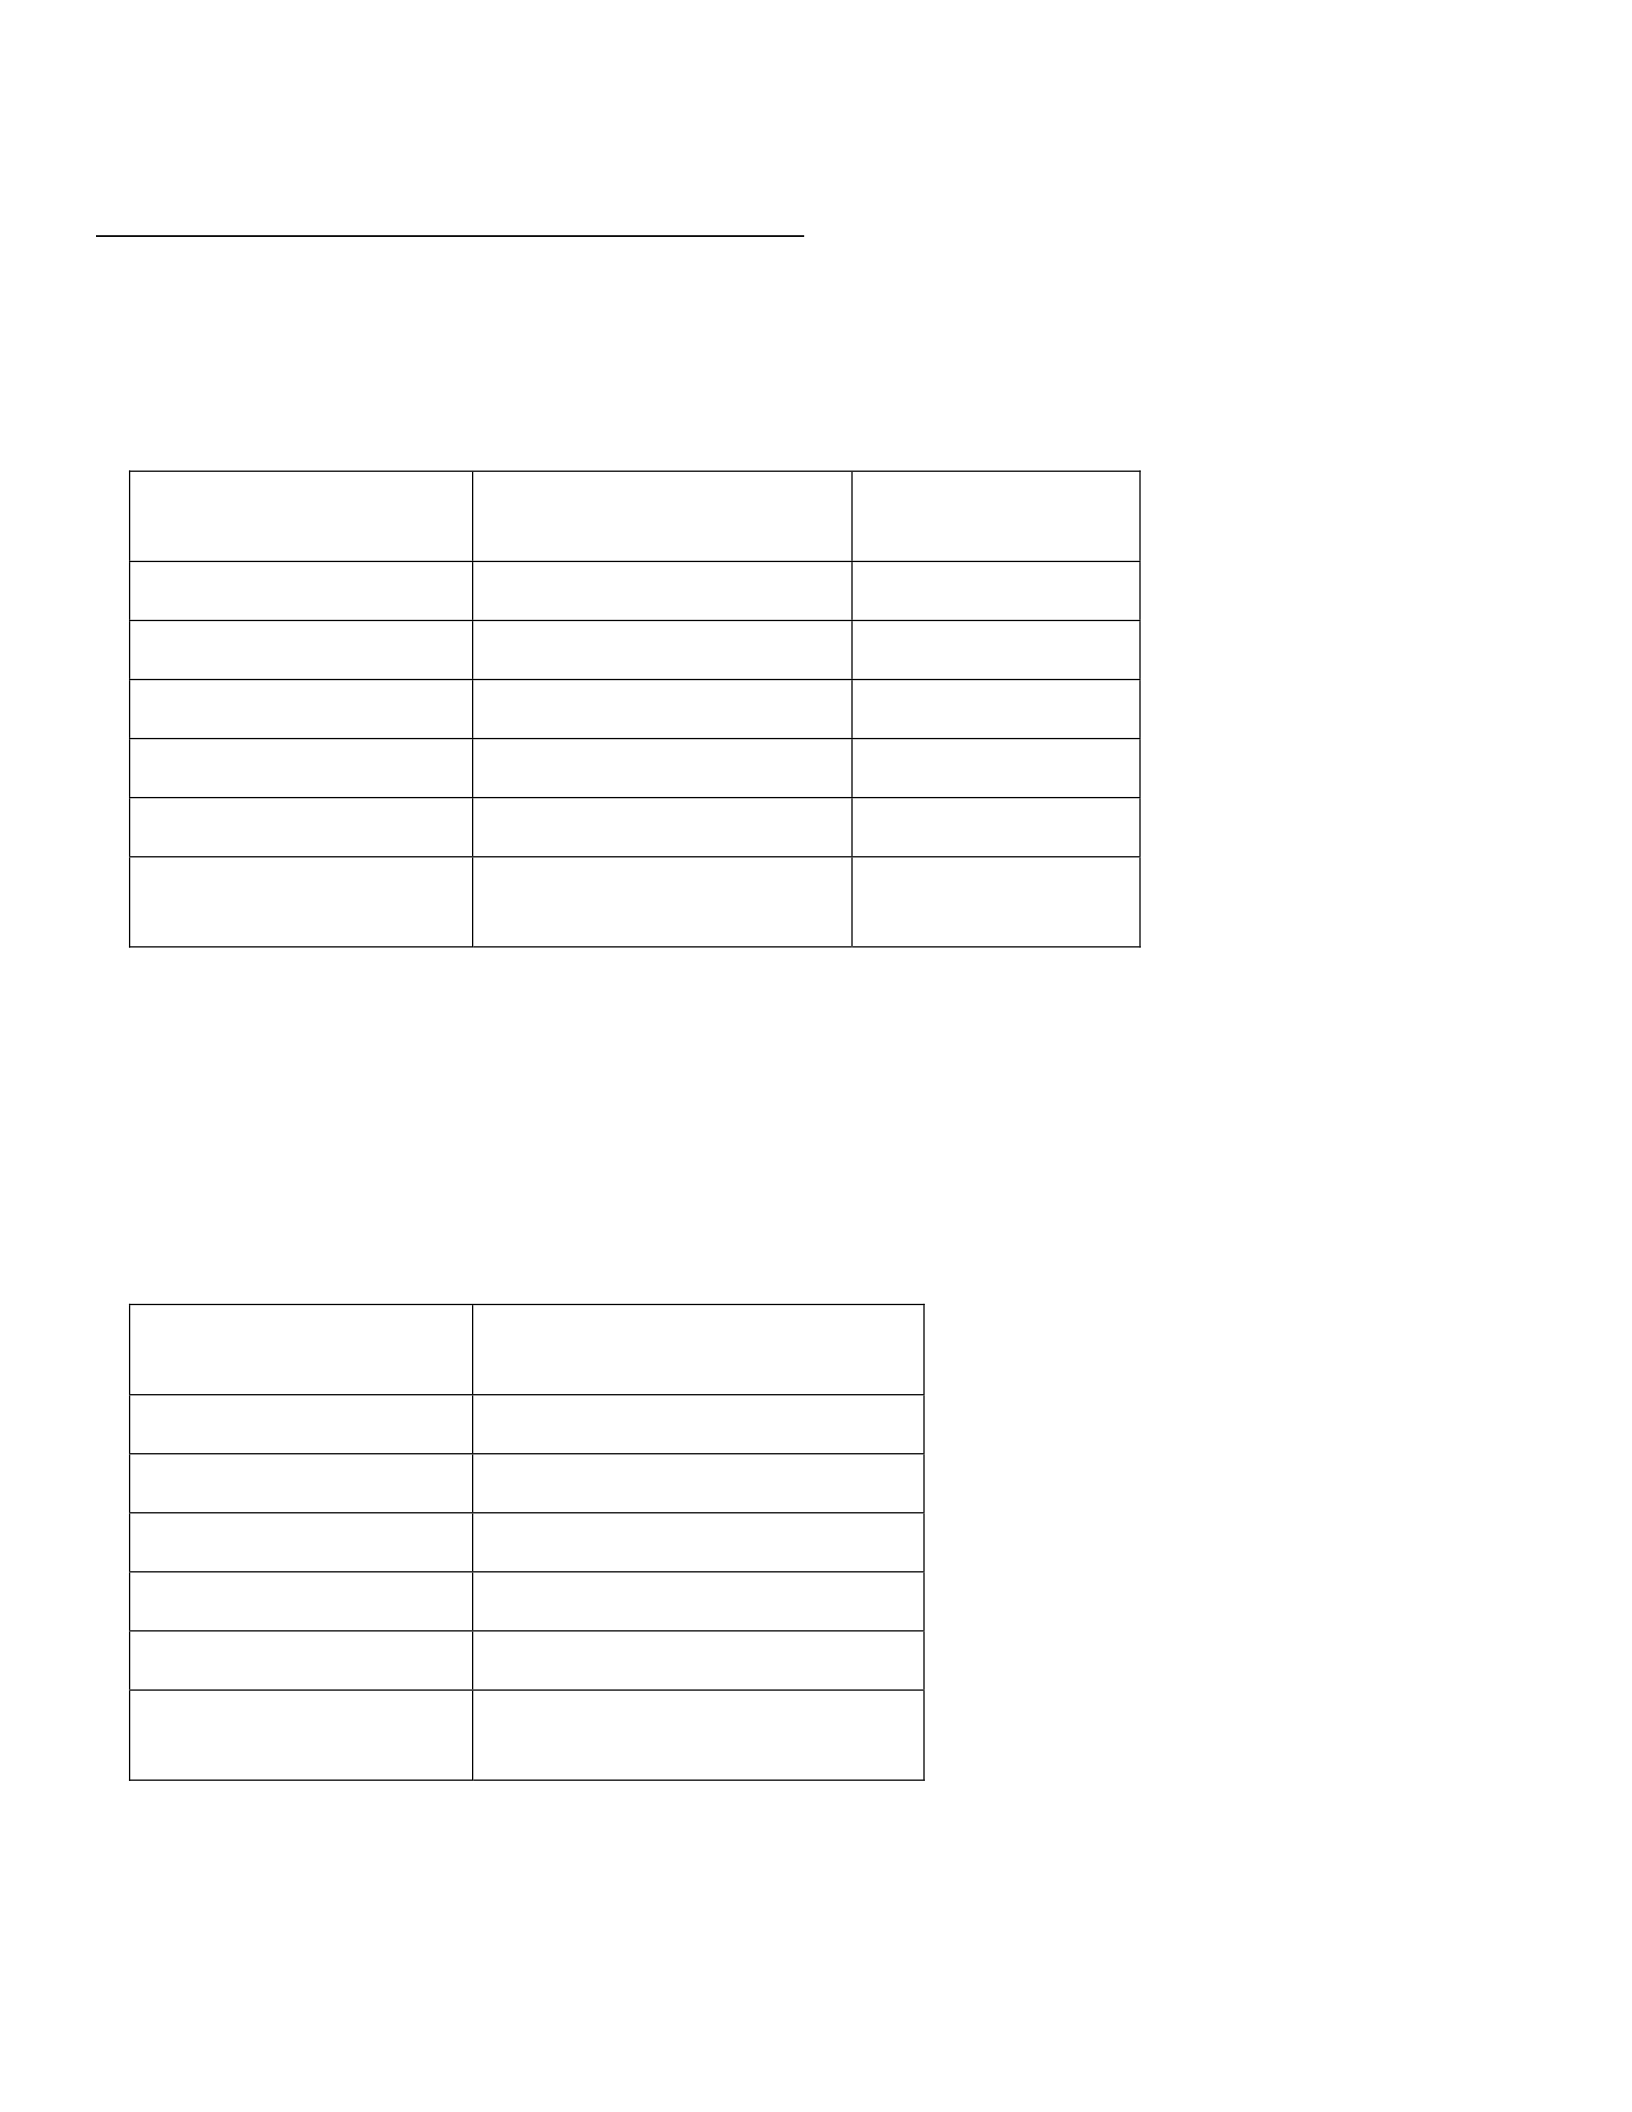
1. For each of the following accounts, indicate whether the account is an ASSET, a LIABILITY or an OWNERS'
EQUITY account and what the NORMAL balance is.
Account Description ASSET, LIABILITY or
OWNERS' EQUITY? NORMAL Balance -
Debit or Credit?
a. Inventory Asset Debit
b. Bank Loan Liability Credit
c. Cash Asset Debit
d. Equipment Asset Debit
e. Accounts Payable Liability Credit
f. Common Stock or
Partner Capital Owners' Equity Credit
2. For each of the following accounts, indicate whether a DEBIT will INCREASE or DECREASE the account.
Account Description DEBIT will INCREASE or
DECREASE account?
a. Inventory Increase
b. Bank Loan Decrease
c. Cash Increase
d. Equipment Increase
e. Accounts Payable Decrease
f. Common Stock or
Partner Capital Decrease
ACC231–Fall2020Chapter2‐ACTIVITY#2
AnalyzeTransactionswithJournalEntriesandT‐Accounts.Remember,thisisanaccrual‐basiscompany
.
Indicatethecorrectjournalentries(transactionsarethesameaswesawinChapter1,Activity#1).
1.August1,borrow$20,000from2ndNationalBank;Put$20,000inyourCashAccount
Date DR/CR AccountTitle Debit Credit
8/1 DR CASH 20,000
CR BANKDEBT 20,000
Borrowmoneyfromban
k
2.August3,Ownerinvests$12,500inthecompany;moneyisdepositedinCashAccoun
t
Date DR/CR AccountTitle Debit Credit
8/3 DR CASH 12,500
CR OWNERS'EQUITY 12,500
RecordOwnerInvestmen
t
3.August5,Companyrepays$10,000onthedebttothe2ndNationalBank(allprincipal‐moneycomesoutoftheCashAccount)
Date DR/CR AccountTitle Debit Credit
8/5 DR BANKDEBT 10,000
CR CASH 10,000
RepayBankDeb
t
4.August12,purchaseComputerequipmentfor$4,500usingmoneyfromourCashAccoun
t
Date DR/CR AccountTitle Debit Credit
8/12 DR EQUIPMENT 4,500
CR CASH 4,500
PurchaseComputerEqp.
5.August18,provide$1,500ofservicestoacustomer–paymentwillbereceivednextmonth
.
Date DR/CR AccountTitle Debit Credit
8/18 DR ACCOUNTSRECEIVABLE 1,500
CR OWNERS'EQUITY(REVENUE) 1,500
Torecordservicesperformed
6.August20,purchase$250ofofficesuppliesonopenaccount.
Date DR/CR AccountTitle Debit Credit
8/20 DR SUPPLIESINVENTORY 450
CR ACCOUNTSPAYABLE 450
Purchaseofficesuppliesonaccoun
t
7.August28,Companypre‐pays$1,400forSeptemberofficerentinAugust.
Date DR/CR AccountTitle Debit Credit
8/28 DR PREPAIDRENT 1,400
CR CASH 1,400
Recordprepaidren
t
8.August30,Companyreceivedandpaida$400invoicefromthephonecompanyforanewinternetconnection
.
Date DR/CR AccountTitle Debit Credit
8/30 DR OWNERS'EQUITY(EXPENSE) 450
CR CASH 450
Recordpaymentofphonebil
l
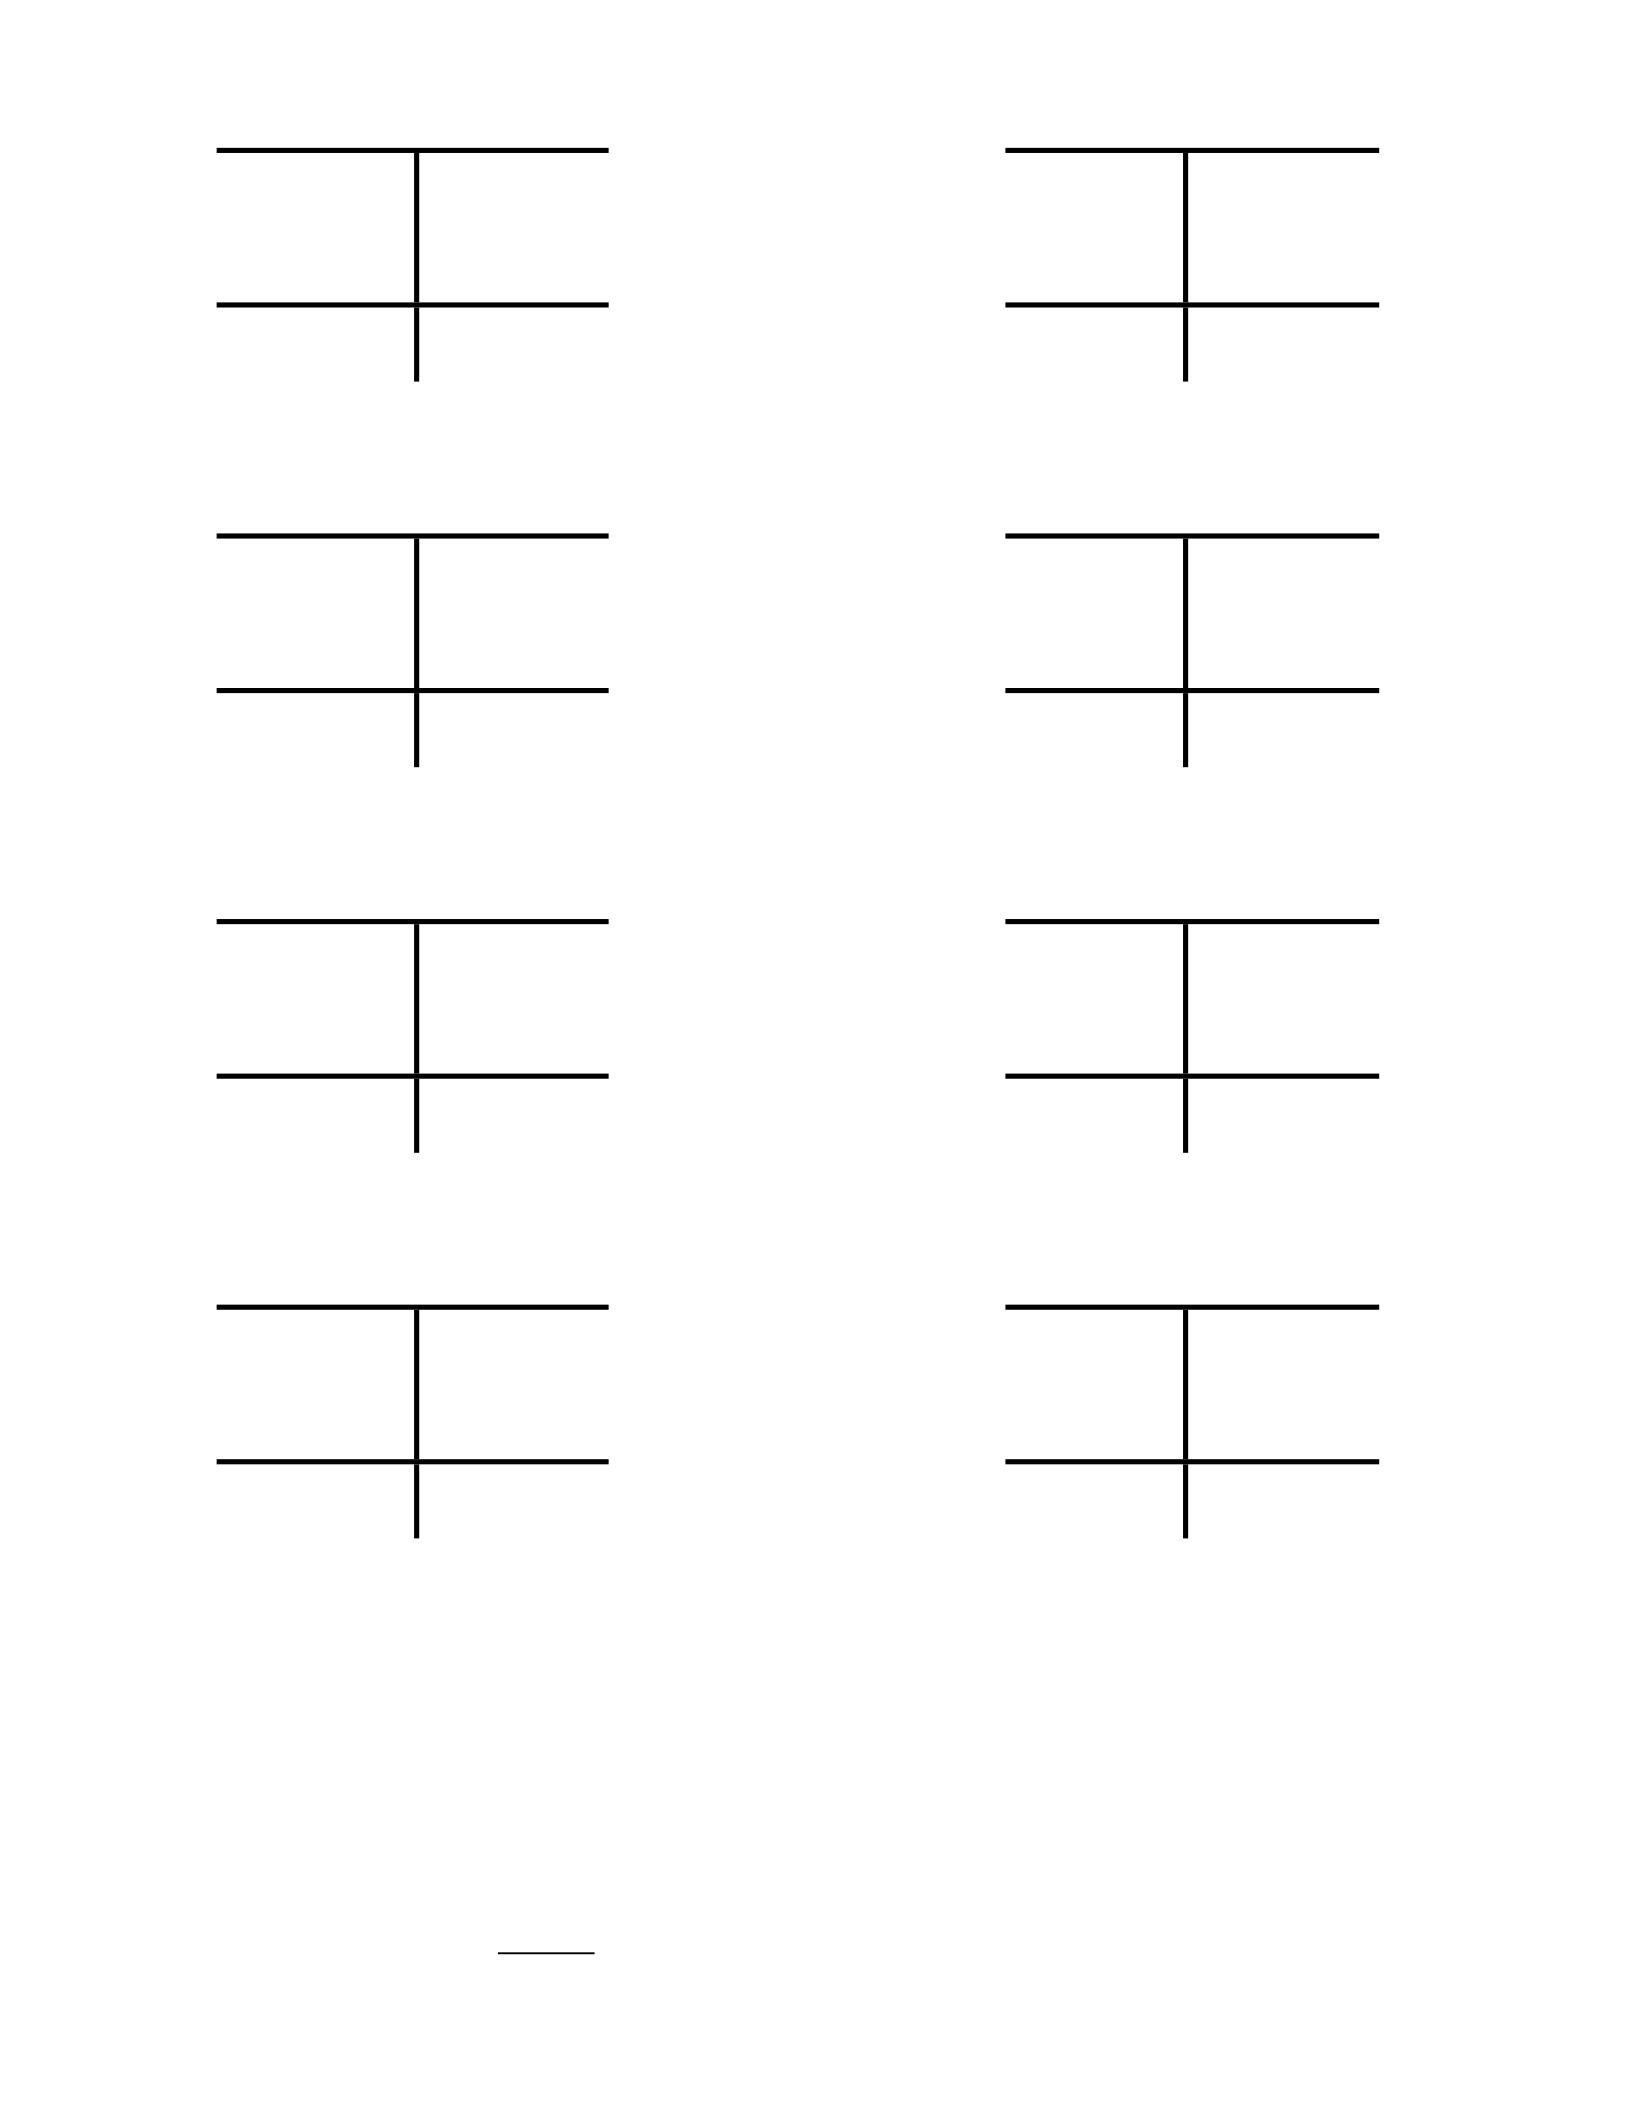
8/1 20,000 10,000 8/5 8/12 4,500
8/3 12,500 4,500 8/12
1,400 8/28
400 8/30
Sub 32,500 $16,300 Sub 4,500
Net $16,200 Net $4,500
8/20 250 8/28 1,400
Sub 250 Sub 1,400
Net $250 Net $1,400
8/18 1,500 250 8/20
Sub 1,500 Sub $250
Net $1,500 Net $250
20,000 8/1 12,500 8/3
8/5 10,000 1,500 8/18
8/30 400
Sub 10,000 $20,000 Sub 400 $14,000
Net $10,000 Net $13,600
TotalNet
Debits $23,850
TotalNet
Credits $23,850
TotalAssets $23,850
TotalLiabilities $10,250
TotalEquity $13,600
$23,850
Supplies Inv. Prepaid Rent
Accounts Receivable Accounts Payable
Debt to Bank Owner’s Equity
Cash Equipment
Page 5 of 5 ACC 231 – Fall 2020 SuggestedSolutions
ACC231 Fall 2020 Chapter 2 - ACTIVITY #3
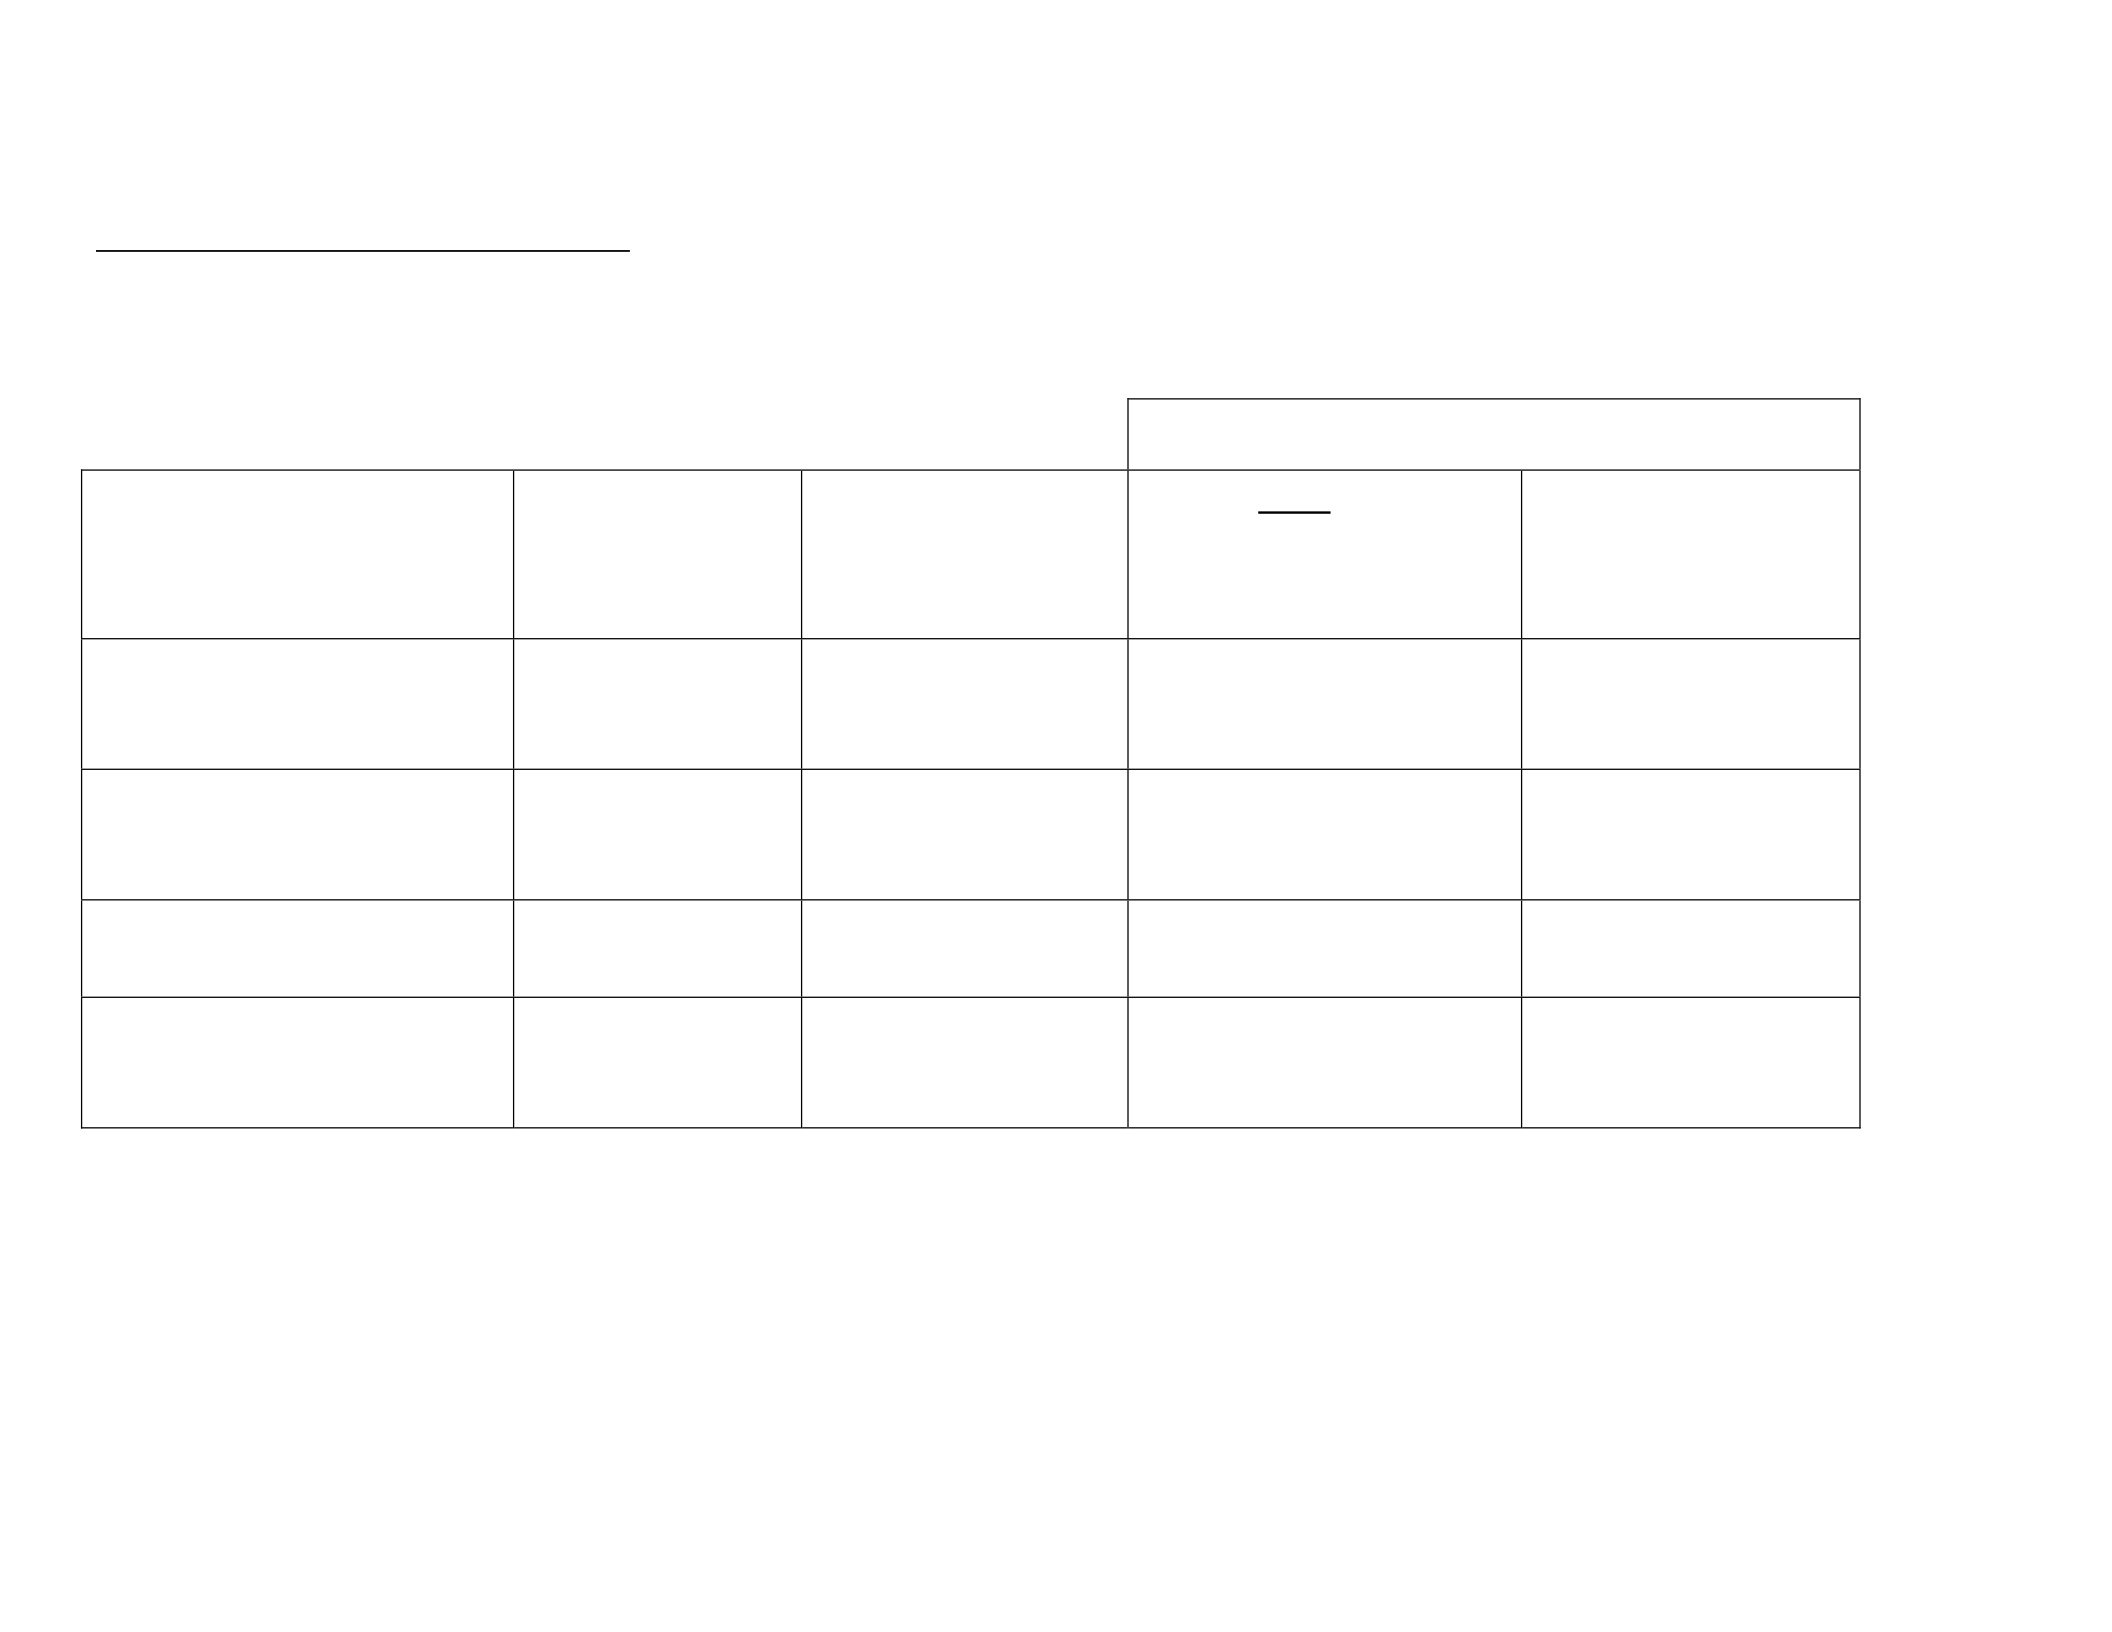
Knowledge of Financial Statements
Articulation with other F/S
Point in Time
or Period of
Time?
Accrual or Cash
Based? What data from this
statement is
articulated?
What statement is
data articulated
TO?
Income statement Period of
Time Accrual Based Net Income Statement of
R/E*
Statement of R/E Period of
Time Accrual Based Ending R/E Balance Sheet
Balance Sheet Point in Time Accrual Based Cash Cash Flows
Statement of Cash
Flows Period of
Time Cash Based Nothing None
Note the financial statements are listed in the correct order of preparation.
* Net Income is also articulated to the Stmt of Cash Flows – on the Stmt of Cash Flows, we convert
Net Income (Accrual based) to CASH from operating Activities. More detailed discussion later in
course.

